UNITED STATES
SECURITIES AND EXCHANGE COMMISSION
Washington, D.C. 20549
FORM 10-K
x
ANNUAL REPORT PURSUANT TO SECTION 13 OR 15(d) OF THE SECURITIES EXCHANGE ACT OF 1934
For the fiscal year ended December 31, 2015
or
¨
TRANSITION REPORT PURSUANT TO SECTION 13 OR 15(d) OF THE SECURITIES EXCHANGE ACT OF 1934
For the transition period from     to
Commission File Number: 1-33409
T-MOBILE US, INC.
DELAWARE
 
20-0836269
(State of incorporation)
 
(I.R.S. Employer Identification No.)


12920 SE 38th Street, Bellevue, Washington
 
98006-1350
(Address of principal executive offices)
 
(Zip Code)


(425) 378-4000
(Registrant’s telephone number, including area code)


Securities registered pursuant to Section 12(b) of the Act:
Title of Each Class
 
Name of Each Exchange on Which Registered
Common Stock, $0.00001 par value per share
 
The NASDAQ Stock Market LLC
5.50% Mandatory Convertible Preferred Stock, Series A, $0.00001 par value per share
 
The NASDAQ Stock Market LLC


 Securities registered pursuant to Section 12(g) of the Act:
None.
Indicate by check mark if the registrant is a well-known seasoned issuer, as defined in Rule 405 of the Securities Act. Yes x No ¨
Indicate by check mark if the registrant is not required to file reports pursuant to Section 13 or Section 15(d) of the Act. Yes ¨ No x
Indicate by check mark whether the registrant (1) has filed all reports required to be filed by Section 13 or 15(d) of the Securities Exchange Act of 1934 during the preceding 12 months (or for such shorter period that the registrant was required to file such reports), and (2) has been subject to such filing requirements for the past 90 days. Yes x No ¨
Indicate by check mark whether the registrant has submitted electronically and posted on its corporate Web site, if any, every Interactive Data File required to be submitted and posted pursuant to Rule 405 of Regulation S-T (§ 232.405 of this chapter) during the preceding 12 months (or for such shorter period that the registrant was required to submit and post such files). Yes x No ¨
Indicate by check mark if disclosure of delinquent filers pursuant to Item 405 of Regulation S-K (§ 229.405 of this chapter) is not contained herein, and will not be contained, to the best of registrant’s knowledge, in definitive proxy or information statements incorporated by reference in Part III of this Form 10-K or any amendment to this Form 10-K. x
Indicate by check mark whether the registrant is a large accelerated filer, an accelerated filer, a non-accelerated filer, or a smaller reporting company. See the definitions of “large accelerated filer,” “accelerated filer” and “smaller reporting company” in Rule 12b-2 of the Exchange Act.
Large accelerated filer    x                        Accelerated filer        ¨
Non-accelerated filer    ¨ (Do not check if a smaller reporting company)    Smaller reporting company    ¨
Indicate by check mark whether the registrant is a shell company (as defined in Rule 12b-2 of the Act). Yes ¨ No x
As of June 30, 2015, the aggregate market value of the registrant’s common stock held by non-affiliates of the registrant was $10.9 billion based on the closing sale price as reported on the New York Stock Exchange. As of February 11, 2016, there were 818,420,728 shares of common stock outstanding.
DOCUMENTS INCORPORATED BY REFERENCE
Part III of this Annual Report on Form 10-K incorporates by reference certain portions of the definitive Proxy Statement for the registrant’s Annual Meeting of Stockholders, which definitive Proxy Statement shall be filed with the Securities and Exchange Commission within 120 days after the end of the fiscal year to which this Report relates.


T-Mobile US, Inc.
Form 10-K
For the Year Ended December 31, 2015

Table of Contents


2


Cautionary Statement Regarding Forward-Looking Statements

This Annual Report on Form 10-K (“Form 10-K”) includes forward-looking statements within the meaning of the Private Securities Litigation Reform Act of 1995. All statements, other than statements of historical fact, including information concerning our future results of operations, are forward-looking statements. These forward-looking statements are generally identified by the words “anticipate,” “believe,” “estimate,” “expect,” “intend,” “may,” “could” or similar expressions. Forward-looking statements are based on current expectations and assumptions, which are subject to risks and uncertainties and may cause actual results to differ materially from the forward-looking statements. The following important factors, along with the Risk Factors included in Part I, Item 1A of this Form 10-K, could affect future results and cause those results to differ materially from those expressed in the forward-looking statements:

•
adverse conditions in the U.S. and international economies or disruptions to the credit and financial markets;
•
competition in the wireless services market;
•
challenges in implementing our business strategies or funding our wireless operations, including payment for additional spectrum, network upgrades and technological advancements;
•
the possibility that we may be unable to renew our spectrum licenses on attractive terms or acquire new spectrum licenses at reasonable costs and terms;
•
difficulties in managing growth in wireless data services, including network quality;
•
material changes in available technology;
•
the timing, scope and financial impact of our deployment of advanced network and business technologies;
•
the impact on our networks and business from major technology equipment failures;
•
breaches of our and/or our third party vendors’ networks, information technology and data security;
•
natural disasters, terrorist attacks or similar incidents;
•
existing or future litigation;
•
any changes in the regulatory environments in which we operate, including any increase in restrictions on the ability to operate our networks;
•
any disruption of our key suppliers’ provisioning of products or services;
•
material adverse changes in labor matters, including labor negotiations or additional organizing activity, and any resulting financial and/or operational impact;
•
the ability to make payments on our debt or to repay our existing indebtedness when due;
•
adverse change in the ratings of our debt securities by nationally accredited rating organizations or adverse conditions in the credit markets affecting the cost, including interest rates, and/or availability of further financing;
•
changes in accounting assumptions that regulatory agencies, including the Securities and Exchange Commission (“SEC”), may require or that result from changes in the accounting rules or their application, which could result in an impact on earnings; and,
•
changes in tax laws, regulations and existing standards and the resolution of disputes with any taxing jurisdictions.

Given these risks and uncertainties, readers are cautioned not to place undue reliance on such forward-looking statements. We undertake no obligation to revise or publicly release the results of any revision to these forward-looking statements, except as required by law. In this Form 10-K, unless the context indicates otherwise, references to “T-Mobile,” “T-Mobile US,” “our Company,” “the Company,” “we,” “our,” and “us” refer to T-Mobile US, Inc., a Delaware corporation, and its wholly-owned subsidiaries.

PART I.

Item 1. Business

Business Overview

We are the Un-carrier™. Un-satisfied with the status quo. Un-afraid to innovate. T-Mobile is the fastest growing wireless company in the U.S. based on customer growth in 2015. T-Mobile provides wireless communications services, including voice, messaging and data, to over 63 million customers in the postpaid, prepaid and wholesale markets. The Un-carrier proposition is an approach that seeks to listen to the customer, address their pain points, bring innovation to the industry and improve the wireless experience for all. In practice, this means offering our customers a great service on a nationwide 4G Long-Term Evolution (“LTE”) network, offering devices when and how our customers want them, and providing plans that are simple, affordable and without unnecessary restrictions. Going forward, we will continue to listen and respond to our customers, refine and improve the Un-carrier proposition and deliver the best value experience in the industry.


3

Table of Contents

History

T-Mobile USA, Inc. (“T-Mobile USA”) was formed in 1994 as VoiceStream Wireless PCS (“VoiceStream”), a subsidiary of Western Wireless Corporation (“Western Wireless”). VoiceStream was spun off from Western Wireless in 1999, acquired by Deutsche Telekom AG (“Deutsche Telekom”) in 2001 and renamed T-Mobile USA, Inc. in 2002.

In 2013, T-Mobile US, Inc. was formed through the business combination between T-Mobile USA and MetroPCS Communications, Inc. (“MetroPCS”). The business combination was accounted for as a reverse acquisition with T-Mobile USA as the accounting acquirer. Accordingly, T-Mobile USA’s historical financial statements became the historical financial statements of the combined company. See Note 2 – Business Combination with MetroPCS of the Notes to the Consolidated Financial Statements included in Part II, Item 8 of this Form 10-K for further information regarding the business combination.

Our common stock traded on the New York Stock Exchange (“NYSE”) under the symbol “TMUS” from May 1, 2013, and our 5.50% mandatory convertible preferred stock, Series A (“preferred stock”) traded on the NYSE under the symbol “TMUSPRA” from December 17, 2014, until October 26, 2015. On October 27, 2015, we transferred the listing of our common stock and preferred stock to the NASDAQ Global Select Market of The NASDAQ Stock Market LLC (“NASDAQ”) under the symbols “TMUS” and “TMUSP,” respectively.  

Business Strategy

We generate revenue by offering affordable wireless communication services to our postpaid, prepaid and wholesale customers, as well as a wide selection of wireless devices and accessories. Our most significant expenses are related to acquiring and retaining high-quality customers, providing a full range of devices, compensating employees, and operating and expanding our network. We provide service, devices and accessories across our flagship brands, T-Mobile and MetroPCS, through our owned and operated retail stores, third party distributors and our websites (www.T-Mobile.com and www.MetroPCS.com). The information on our websites is not part of this Form 10-K.

We continue to aggressively pursue our strategy, which includes the following elements:

Un-carrier Proposition

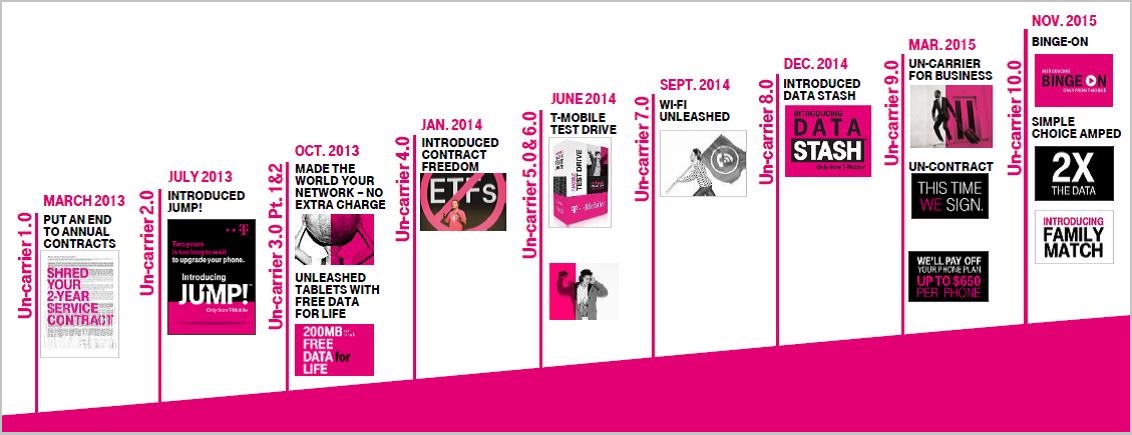
We introduced our Un-carrier proposition in 2013 and continue to aggressively address customer pain points with the launch of different phases of the Un-carrier proposition. Un-carrier initiatives have included, but are not limited to, offering the following to qualifying customers:

•
providing customers with affordable rate plans while eliminating annual service contracts;
•
allowing customers easier options to upgrade their eligible devices when they want;
•
reimbursing customers’ early termination fees or remaining phone payments when they switch from other carriers;
•
allowing customers to stream music without it counting against their high speed data allotment;
•
providing Wi-Fi calling and texting for customers with capable smartphones;
•
giving customers the ability to roll-over up to 20 GB of their unused high-speed data automatically each month;
•
providing reduced United States to international calling rates, and providing messaging and data roaming while traveling abroad at no extra charge;
•
extending coverage and calling, as well as 4G LTE data, across the U.S., Mexico and Canada at no extra charge; and
•
providing select video streaming services without it counting against their high speed data allotment on qualifying plans.


4

Table of Contents

Below is a summary of the phases and updates to our Un-carrier proposition:


Customer Experience

The ongoing success of our Un-carrier proposition and continued modernization of the network has strengthened T-Mobile’s position as a provider of dependable high-speed LTE service. Additionally, we have continued to focus on retaining customers by delivering an improved wireless customer experience.  Branded postpaid phone churn improved to 1.39% in 2015, compared to 1.58% in 2014 and 1.69% in 2013. These results reinforce our position as an organization with a strong focus and commitment to providing an outstanding customer experience.

Aligned Cost Structure

We continue to pursue a low-cost business operating model to drive cost savings, which can then be reinvested in the business. These cost-reduction programs are on-going as we continue to simplify our business and drive operational efficiencies and cost savings in areas, such as network optimization, customer roaming and customer service. A portion of these savings have been, and will continue to be, reinvested into growth of our business.

Customers

T-Mobile provides wireless communication services to three primary categories of customers: branded postpaid, branded prepaid and wholesale. Branded postpaid customers generally include customers that are qualified to pay after using wireless communication services. Branded prepaid customers generally include customers who pay for wireless communication services in advance. Our branded prepaid customers include customers of the T-Mobile, MetroPCS and certain partner brands. Wholesale customers, which include Machine-to-Machine (“M2M”) and Mobile Virtual Network Operators (“MVNO”), operate on the T-Mobile network, but are managed by wholesale partners.

We generate the majority of our service revenues by providing wireless communication services to branded postpaid customers. In 2015, 66% of our service revenues were generated by providing wireless communication services to branded postpaid customers, compared to 30% from branded prepaid customers and 4% from wholesale customers, roaming and other services. Therefore, our ability to acquire and retain branded postpaid customers is important to our business in the generation of service revenues, equipment revenues and other revenues. Our branded postpaid net customer additions remained strong with 4.5 million in 2015, compared to 4.9 million in 2014 and 2.0 million in 2013. Growth in our branded postpaid net customer additions was primarily driven by strong customer response to our Un-carrier initiatives, ongoing improvements to our network and promotions for services and devices.

Services and Products

T-Mobile provides wireless communication services through a variety of service plan options. We also offer a wide selection of wireless devices, including smartphones, tablets and other mobile communication devices, which are manufactured by various suppliers. Services, devices and accessories are offered directly to consumers through our owned and operated retail stores, as

5

Table of Contents

well as through our websites. In addition, we sell devices and accessories to dealers and other third party distributors for resale through independent third-party retail outlets and a variety of third-party websites.

Service plan options include our Simple Choice plans, which allow customers to subscribe for wireless services separately from the purchase of a handset. We introduced our Simple Choice plans as part of phase 1.0 of our Un-carrier proposition in 2013, which eliminated annual service contracts and simplified the lineup of consumer rate plans to one affordable plan for unlimited voice and messaging services with the option to add data services. Depending on their credit profile, customers are qualified either for postpaid or prepaid service. As part of the ongoing movement towards simplifying the business, we continued to drive the penetration of Simple Choice plans within our customer base. The proportion of branded postpaid customers on Simple Choice plans was 94% as of December 31, 2015, up from 89% as of December 31, 2014.

Customers on our Simple Choice plans benefit from reduced monthly service charges and can choose whether to use their own compatible handset on our network, purchase a handset from us or one of our dealers or lease a device through our JUMP On Demand™ program. Depending on their credit profile, qualifying customers who purchase a device from us have the option of financing all or a portion of the purchase price at the time of sale over an installment period using our Equipment Installment Plan (“EIP”). In addition, qualifying customers who finance their initial handset device with an EIP can enroll in JUMP! to later upgrade their device. Upon qualifying JUMP! program upgrades, the customers’ remaining EIP balance is settled provided they trade in their used handset at the time of upgrade in good working condition and purchase a new handset from us on a new EIP.

In 2015, we introduced JUMP! On Demand. With JUMP! On Demand, a low monthly payment covers the cost of leasing a new device and gives customers the freedom to swap it for a new one up to three times in 12 months for no extra fee. Upon device upgrade or at lease end, customers must return or purchase their device.

Network

We provide mobile communication services utilizing mid-band spectrum licenses, such as Advanced Wireless Services (“AWS”) and Personal Communications Service (“PCS”), and low-band spectrum licenses utilizing our 700 MHz A-Block spectrum. We owned an average of 85 MHz of spectrum across the top 25 markets in the U.S. as of December 31, 2015. This is compared to an average of 82 MHz of spectrum across the top 25 markets in the U.S. as of December 31, 2014. Over the last year, we have entered into various agreements for the acquisition of 700 MHz A-Block, AWS and PCS spectrum licenses. In addition, we intend to opportunistically acquire spectrum licenses in private party transactions and future Federal Communications Commission (“FCC”) spectrum license auctions, including the broadcast incentive auction of low-band 600 MHz spectrum licenses scheduled to occur in 2016.

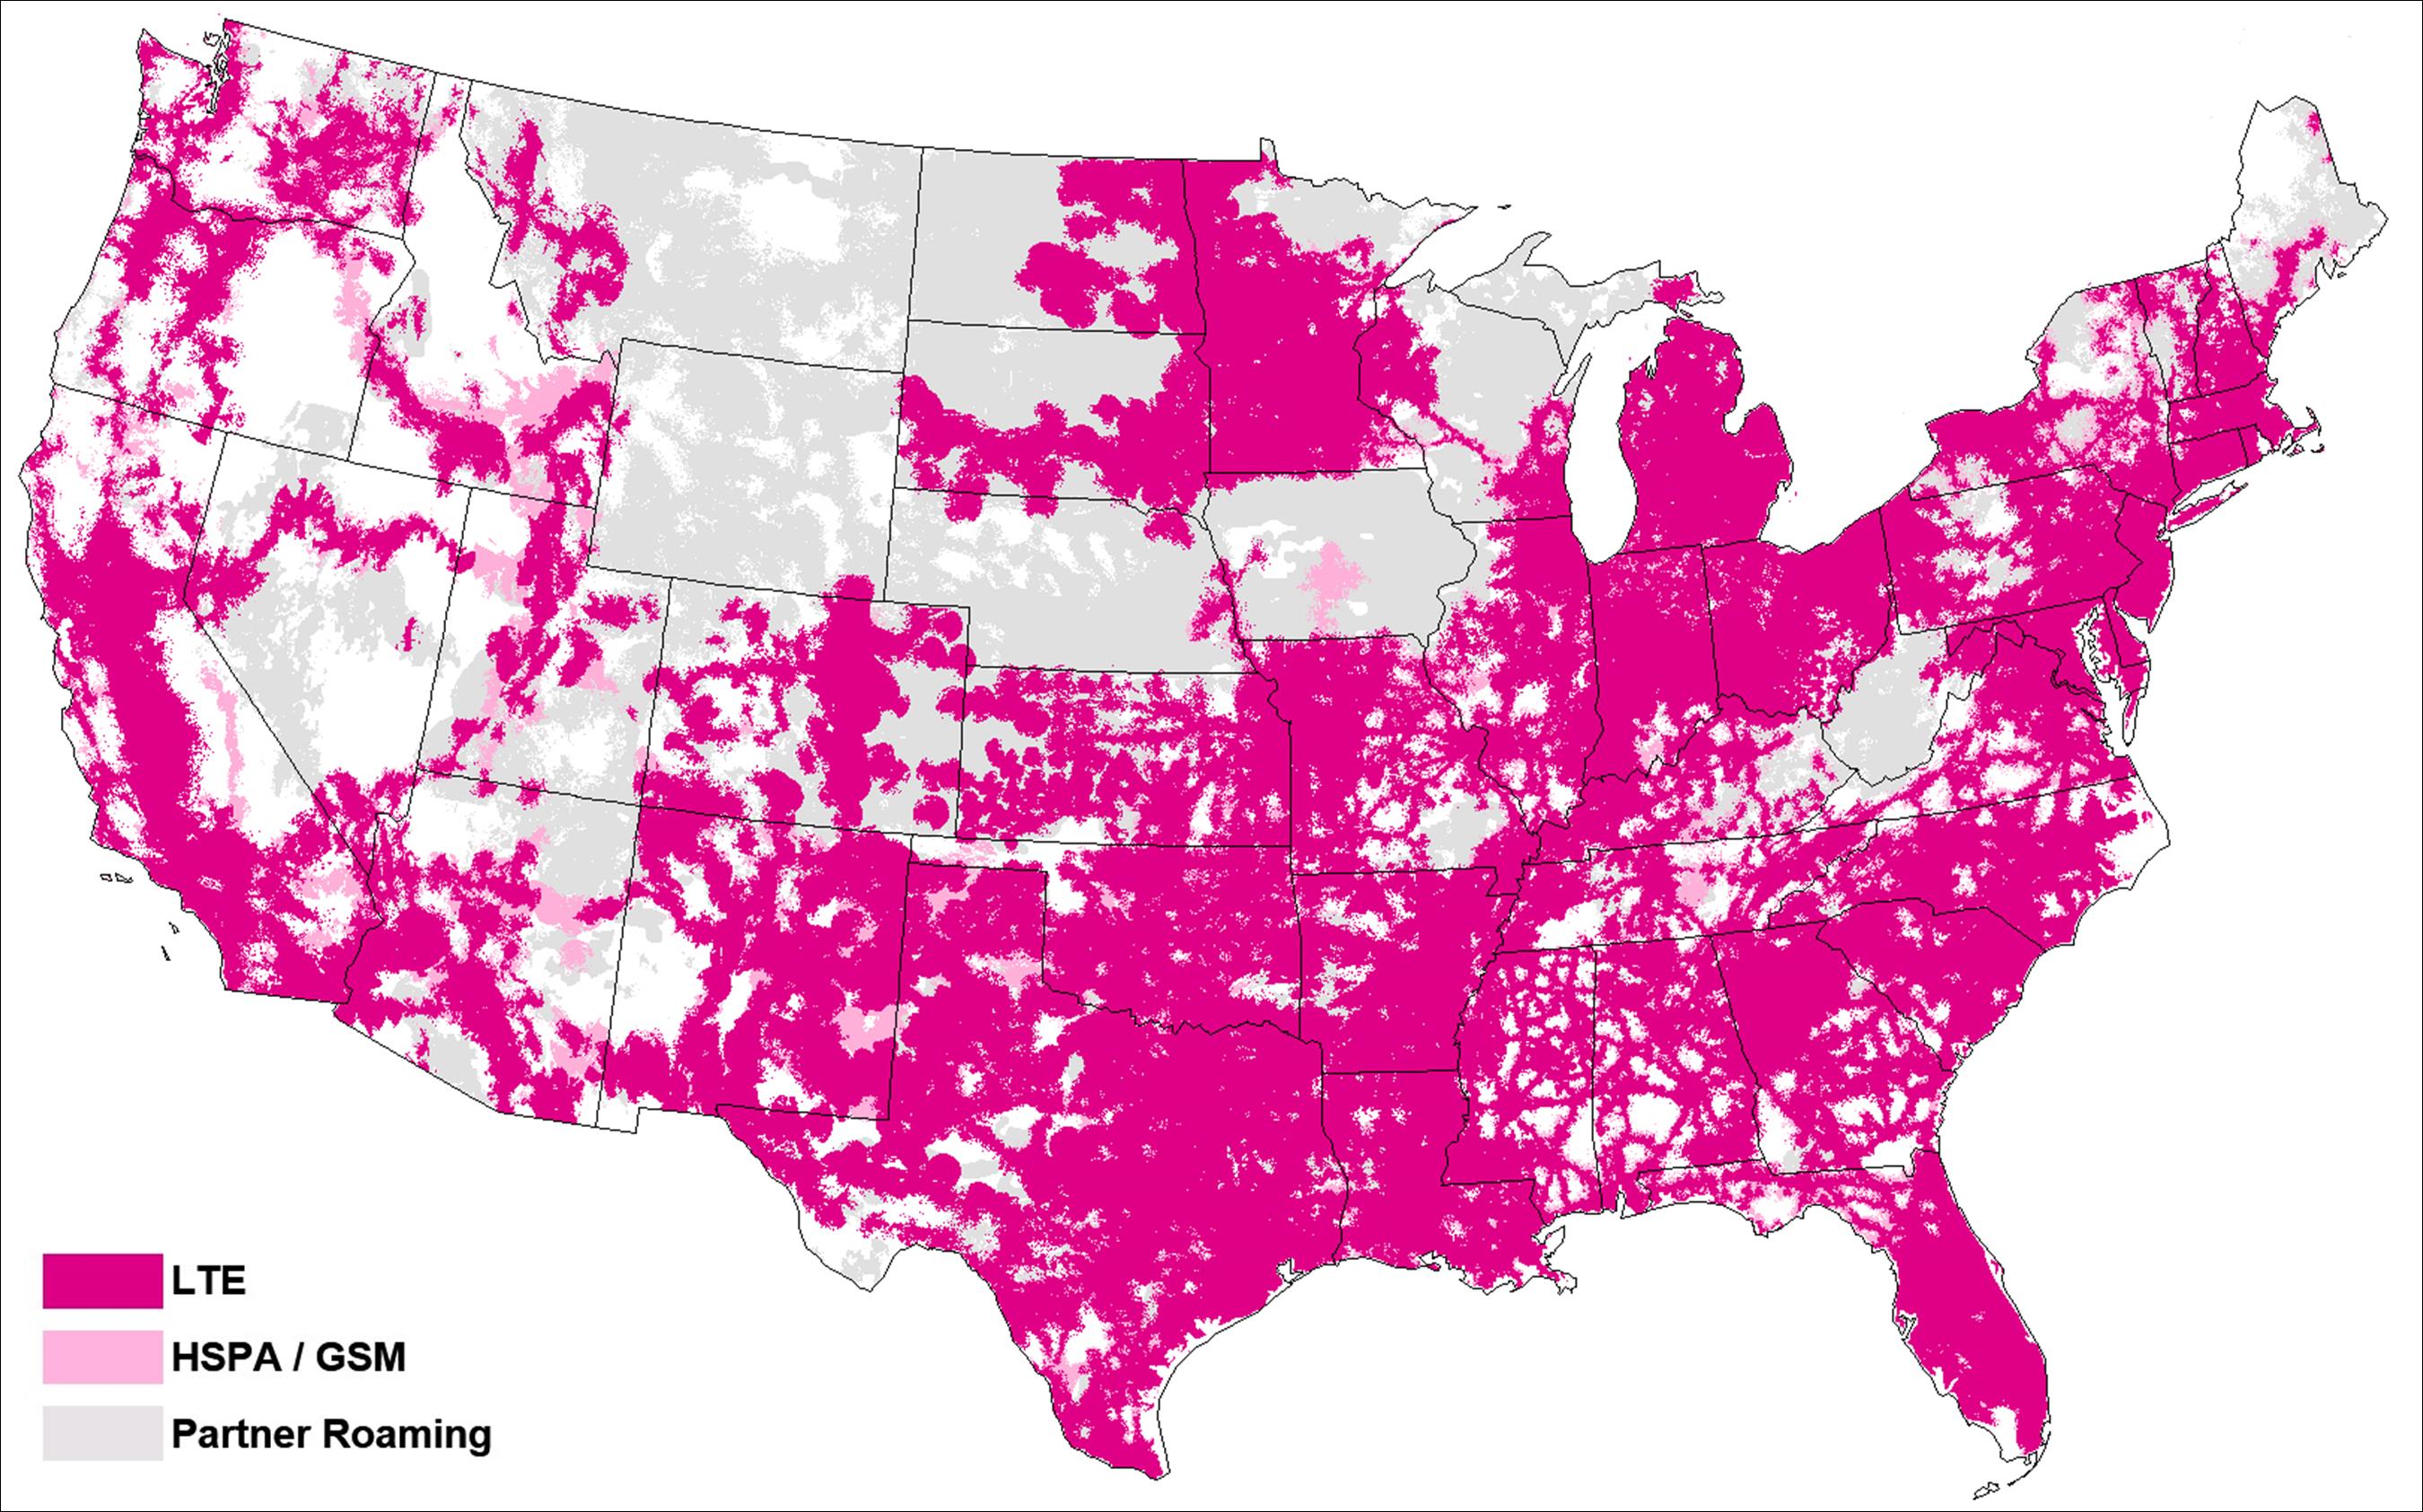
We have substantially completed the process of upgrading our network to LTE, which provides our customers with the fastest nationwide LTE services. Our LTE network now covers 305 million people, compared to 265 million people as of December 31, 2014. In addition, we are currently in the process of building out our network to utilize our low-band 700 MHz A-Block spectrum licenses, which will boost network reach, improve in-building coverage and extend coverage to more areas.

We are rapidly deploying both Wideband LTE to add capacity to our LTE Network and Extended Range LTE to enhance coverage and in-building performance. Extended Range LTE, which operates on our low-band 700 MHz A-Block spectrum, currently covers approximately 190 million people in more than 300 market areas.

Our nationwide network covers all major metropolitan areas and approximately 91% of people in the U.S., excluding roaming coverage. Over the last three years, we have continued to build out our network to concentrate our cell sites where our customers need data most. We had approximately 64,000 cell sites, including macro sites and certain distributed antenna system (“DAS”) network nodes as of December 31, 2015 compared to approximately 61,000 cell sites as of December 31, 2014.

6

Table of Contents

Below is a map showing our coverage, including LTE, in the U.S.:


In addition, we have completed the shutdown of the MetroPCS Code Division Multiple Access (“CDMA”) network. The migration of customers from the MetroPCS CDMA network onto T-Mobile’s LTE and Evolved High Speed Packet Access Plus (“HSPA+”) network provides faster network performance for MetroPCS customers with compatible handsets.

Distribution

We had approximately 80,000 total points of distribution, including approximately 12,000 T-Mobile and MetroPCS branded locations and 68,000 third-party and national retailer locations, as well as distribution through our websites, as of December 31, 2015. Our distribution density in major metropolitan areas provides customers with the convenience of having retail and service locations close to where they live and work.

Competition

The wireless telecommunications industry is highly competitive. We are the third largest provider of postpaid service plans and the largest provider of prepaid service plans in the U.S. as measured by customers. Our competitors include other national carriers, such as AT&T Inc. (“AT&T”), Verizon Communications, Inc. (“Verizon”) and Sprint Corporation (“Sprint”). AT&T and Verizon are significantly larger than us and may enjoy greater resources and scale advantages as compared to us. In addition, our competitors include numerous smaller regional carriers and MVNOs, such as TracFone Wireless, Inc., many of which offer no-contract, prepaid service plans. Competitors also include providers who offer similar communication services, such as voice and messaging, using alternative technologies or services. Competitive factors within the wireless telecommunications industry include pricing, market saturation, service and product offerings, customer experience, network investment and quality, development and deployment of technologies, availability of additional spectrum licenses, and regulatory changes. Some competitors have shown a willingness to use aggressive pricing as a source of differentiation.  Taken together, the competitive factors we face continue to put pressure on margins as companies compete to retain the current customer base and continue to add new customers.


7

Table of Contents

Employees

As of December 31, 2015, we employed approximately 50,000 full-time and part-time employees, including network, retail, administrative and customer support functions, of which approximately 30 employees were covered by a collective bargaining agreement, as of December 31, 2015.

Regulation
 
The FCC regulates many key aspects of our business, including licensing, construction, the operation and use of our network, modifications of our network, control and ownership of our business, the sale of certain business assets, domestic roaming arrangements and interconnection agreements, pursuant to its authority under the Communications Act of 1934, as amended (“Communications Act”). The FCC has a number of complex requirements and proceedings that affect our operations and that could increase our costs or diminish our revenues. For example, the FCC has rules regarding provision of 911 and E-911 services, porting telephone numbers, interconnection, roaming, internet openness or net neutrality, and the universal service and Lifeline programs. Many of these and other issues are being considered in ongoing proceedings, and we cannot predict whether or how such actions will affect our business, financial condition or results of operations. Our ability to provide services and generate revenues could be harmed by adverse regulatory action or changes to existing laws and regulations. In addition, regulation of companies that offer competing services can impact our business indirectly.
 
Wireless communications providers must be licensed by the FCC to provide communications services at specified spectrum frequencies within specified geographic areas and must comply with the rules and policies governing the use of the spectrum as adopted by the FCC. The FCC issues each license for a fixed period of time, typically 10 years in the case of cellular, PCS and point-to-point microwave licenses. AWS licenses have an initial term of 15 years, with successive 10-year terms thereafter. While the FCC has generally renewed licenses given to operating companies like us, the FCC has authority to both revoke a license for cause and to deny a license renewal if a renewal is not in the public interest. Furthermore, we could be subject to fines, forfeitures and other penalties for failure to comply with FCC regulations, even if any such non-compliance was unintentional. In extreme cases, penalties can include revocation of our licenses. The loss of any licenses, or any related fines or forfeitures, could adversely affect our business, results of operations and financial condition.
 
Additionally, Congress’ and the FCC’s allocation of additional spectrum for broadband commercial mobile radio service (“CMRS”), which includes cellular, PCS and specialized mobile radio, could significantly increase competition. We cannot assess the impact that any developments that may occur in the U.S. economy or any future spectrum allocations by the FCC may have on license values. FCC spectrum auctions and other market developments may adversely affect the market value of our licenses in the future. A significant decline in the value of our licenses could adversely affect our financial condition and results of operations. In addition, the FCC periodically reviews its policies on how to evaluate a carrier’s spectrum holdings. A change in these policies could affect spectrum resources and competition among us and other carriers.
 
Congress and the FCC have imposed limitations on foreign ownership of CMRS licensees that exceed 20% direct ownership or 25% indirect ownership. The FCC has ruled that higher levels of indirect foreign ownership, even up to 100%, are presumptively consistent with the public interest albeit subject to review. Consistent with that established policy, the FCC has issued a declaratory ruling authorizing up to 100% ownership of our company by Deutsche Telekom. This declaratory ruling, and our licenses, are conditioned on Deutsche Telekom’s and the Company’s compliance with a network security agreement with the Department of Justice, the Federal Bureau of Investigation and the Department of Homeland Security. Failure to comply with the terms of this agreement could result in fines, injunctions and other penalties, including potential revocation of our spectrum licenses.
 
While the Communications Act generally preempts state and local governments from regulating the entry of, or the rates charged by, wireless communication providers, certain state and local governments regulate other terms and conditions of wireless service, including billing, termination of service arrangements and the imposition of early termination fees, advertising, network outages, the use of handsets while driving, zoning and land use. Further, the FCC and the Federal Aviation Administration regulate the siting, lighting and construction of transmitter towers and antennae. Tower siting and construction are also subject to state and local zoning, as well as federal statutes regarding environmental and historic preservation. The future costs to comply with all relevant regulations are to some extent unknown and regulations could result in higher operating expenses in the future.


8

Table of Contents

Available Information

T-Mobile’s Form 10-K and all other reports and amendments filed with or furnished to the SEC, are publicly available free of charge on the Investor Relations section of our website at investor.t-mobile.com or at www.sec.gov as soon as reasonably practicable after these materials are filed with or furnished to the SEC. Our corporate governance guidelines, code of business conduct, code of ethics for senior financial officers and charters for the audit, compensation, nominating and corporate governance and executive committees of our board of directors are also posted on the Investor Relations section of T-Mobile’s website at investor.t-mobile.com. The information on our websites is not part of this or any other report T-Mobile files with, or furnishes to, the SEC.

Investors and others should note that we announce material financial and operational information to our investors using our investor relations website, press releases, SEC filings and public conference calls and webcasts.  T-Mobile intends to also use the @TMobileIR Twitter account (https://twitter.com/TMobileIR) and the @JohnLegere Twitter (https://twitter.com/JohnLegere) and Periscope accounts, which Mr. Legere also uses as means for personal communications and observations, as means of disclosing information about the Company, its services and other matters and for complying with its disclosure obligations under Regulation FD.  The information we post through these social media channels may be deemed material.  Accordingly, investors should monitor these social media channels in addition to following the Company’s press releases, SEC filings and public conference calls and webcasts.  The social media channels that T-Mobile intends to use as a means of disclosing the information described above may be updated from time to time as listed on the Company’s investor relations website.

Item 1A. Risk Factors

In addition to the other information contained in this Form 10-K, the following risk factors should be considered carefully in evaluating T-Mobile. Our business, financial condition, liquidity, or results of operations, as well as the price of our common stock and other securities, could be materially adversely affected by any of these risks.

Risks Related to Our Business and the Wireless Industry

The scarcity and cost of additional wireless spectrum, and regulations relating to spectrum use, may adversely affect our business strategy and financial planning.

We will need to acquire additional spectrum in order to continue our customer growth, expand into new metropolitan areas, maintain our quality of service, meet increasing customer demands and deploy new technologies. We will be at a competitive disadvantage and possibly experience erosion in the quality of service in certain markets if we fail to gain access to necessary spectrum before reaching capacity, especially low band spectrum.

The continued interest in, and aggregation of, spectrum may reduce our ability to acquire spectrum from other carriers or otherwise negatively impact our ability to gain access to spectrum through other means. As a result, we may need to acquire spectrum through government auctions and/or enter into spectrum sharing arrangements, which are subject to certain risks and uncertainties. Although the FCC has scheduled an auction of low band spectrum to begin in 2016, it is possible the auction may be delayed. Any material delay could adversely impact our ability to implement our plans and efforts to improve our network. Additionally, we may be unable to secure the spectrum we need in the upcoming auction, or in any other government auction we may elect to participate in, on favorable terms or at all. In addition, the FCC has encountered resistance to its plans to make additional spectrum available, which has created uncertainty about the timing and availability of spectrum through government auctions.

The FCC may impose conditions on the use of new wireless broadband mobile spectrum, including new restrictions or rules governing the use or access to current or future spectrum. This could increase pressure on capacity. Additional conditions that may be imposed by the FCC include heightened build-out requirements, limited renewal rights, clearing obligations, or open access or net neutrality requirements that may make it less attractive or less economical to acquire spectrum. In addition, rules may be established for future government spectrum auctions that may negatively impact our ability to obtain spectrum economically or in appropriate configurations or coverage areas.

If we cannot acquire needed spectrum from the government or otherwise, if competitors acquire spectrum that will allow them to provide services competitive with our services, or if we cannot deploy services over acquired spectrum on a timely basis without burdensome conditions, at reasonable cost, and while maintaining network quality levels, then our ability to attract and retain customers and our associated financial performance could be materially adversely affected.


9

Table of Contents

We operate in a very competitive wireless industry, which could limit our ability to attract and retain customers and adversely affect our business, operations and financial results.

We have multiple wireless competitors in each of our service areas, some of which have greater resources than us, and compete for customers based principally on service/device offerings, price, call quality, data use experience, coverage area and customer service. In addition, we are facing growing competition from providers offering services using alternative wireless technologies and IP-based networks, as well as traditional cable, satellite TV and wireline networks. We expect market saturation to continue to cause the wireless industry’s customer growth rate to be moderate in comparison with historical growth rates or possibly negative, leading to increased competition for customers. Customer attrition, also known as churn, may increase as the wireless industry shifts away from service contracts. We also expect that our customers’ growing appetite for data services will place increased demands on our network capacity. This competition and our capacity issues will continue to put pressure on pricing and margins as companies compete for potential customers. Our ability to compete will depend on, among other things, continued absolute and relative improvement in network quality and customer services, effective marketing and selling of products and services, attractive pricing, and cost management, all of which will involve significant expenses.

Joint ventures, mergers, acquisitions and strategic alliances in the wireless industry have resulted in and are expected to result in larger competitors competing for a limited number of customers. The two largest national wireless communication providers currently serve a significant percentage of all wireless customers and hold significant spectrum and other resources. Our largest competitors may be able to enter into exclusive handset, device, or content arrangements, execute pervasive advertising and marketing campaigns, or otherwise improve their cost position relative to ours. In addition, the refusal of our large competitors to provide critical access to resources and inputs, such as roaming services on reasonable terms, may improve their position within the wireless broadband mobile services industry. Furthermore, industries are converging as video, mobile, and broadband companies compete to deliver content as the next generation of offerings. Companies like Comcast and AT&T/DirecTV will have the scale and assets to aggressively compete in a converged wireless industry. These factors, together with the effects of the increasing aggregate penetration of wireless services in all metropolitan areas and the ability of our larger competitors to use resources to build out their networks and to quickly deploy advanced technologies, have made it more difficult for smaller carriers like us to continue to attract and retain customers, and may adversely affect our competitive position and ability to grow, which would have a material adverse effect on our business, financial condition and operating results.

If we are unable to take advantage of technological developments on a timely basis, then we may experience a decline in demand for our services or face challenges in implementing or evolving our business strategy.

In order to grow and remain competitive with new and evolving technologies in our industry, we will need to adapt to future changes in technology, continually invest in our network, enhance our existing offerings, and introduce new offerings to address our current and potential customers’ changing demands. Enhancing our network is subject to risk from equipment changes and migration of customers from existing spectrum bands. Adopting new and sophisticated technologies may result in implementation issues such as scheduling and supplier delays, unexpected or increased costs, technological constraints, regulatory permitting issues, subscriber dissatisfaction, and other issues that could cause delays in launching new technological capabilities, which in turn could result in significant costs or reduce the anticipated benefits of the upgrades. In general, the development of new services in the wireless telecommunications industry will require us to anticipate and respond to the continuously changing demands of our customers, which we may not be able to do accurately or timely. We could experience a material adverse effect on our business, operations, financial position, and operating results if our new services fail to retain or gain acceptance in the marketplace or if costs associated with these services are higher than anticipated.

If our efforts, or those of third party service providers, to maintain the privacy and security of our customer, confidential, or sensitive information are not successful at preventing a significant data breach or cyber-attack, we could incur substantial additional costs, become subject to litigation, enforcement actions or regulatory investigation, and suffer reputational damage.

Our business, like that of most retailers and wireless companies, involves the receipt, storage and transmission of personal information, consumer preferences and payment card information of our customers and other persons who apply to become customers, confidential information about our employees and suppliers, and other sensitive information about our company, such as our business plans, transactions and intellectual property (“confidential information”). The methods used to obtain unauthorized access, disable or degrade service, or sabotage systems are constantly changing and evolving, and may be difficult to anticipate or detect for long periods of time. Cyber-attacks, such as denial of service, advanced persistent threats, other malicious attacks, unauthorized access or distribution of confidential information by third parties or employees, errors or breaches by third party suppliers, or other breaches of security could disrupt our internal systems and applications, impair our

10

Table of Contents

ability to provide services to our customers, and protect the privacy and confidentiality of our sensitive information. Such attacks against companies are occurring with greater frequency and may be perpetrated by a variety of groups or persons, including those in jurisdictions where U.S. law enforcement is or has been unable to effectively address such attacks.

In addition, we provide confidential, proprietary and personal information to third party service providers when it is necessary to pursue business objectives. We and our third party service providers have been subject to cyber-attacks in the past, including a breach at Experian in September 2015 in which a subset of records containing current and potential customer information was compromised.

Although we regularly review our processes and procedures to protect against unauthorized access to or use of sensitive data and to prevent data loss, the ever-evolving threat landscape requires us to continually evaluate and adapt our systems and processes. We cannot assure you that the security measures and preventive actions we take will be adequate to repel a significant attack, prevent information security breaches or the misuses of data, unauthorized access by third parties or employees, or exploits against third party supplier environments. If we are subject to such attacks or compromise, we may incur significant costs, be subject to regulatory investigations, sanctions and private litigation, experience disruptions to our operations or may suffer damage to our reputation that negatively impacts customer confidence. Although the cyber-attacks that we and our third party service providers have been subjected to in the past have not caused significant harm to our company, future cyber-attacks may materially adversely affect our business, results of operations and financial condition.

We are in the process of transferring our customer billing systems from our existing third-party vendor to a new third-party vendor. Any unanticipated difficulties, disruption or significant delays could have adverse operational, financial and reputational effects on our business.

We are currently implementing a new customer billing system, which involves moving to a new third-party billing services vendor and platform through utilization of a phased deployment approach. The first release phase, which is limited to prepaid services, is scheduled for 2016. Post implementation, we plan to operate both the existing and new billing systems in parallel to aid in the transition to the new system until all phases of the conversion are complete.

The implementation may cause major system or business disruptions or we may fail to implement the new billing system in a timely or effective manner. In addition, the third-party billing services vendor may experience errors, cyber-attacks or other operational disruptions that could negatively impact us and over which we may have limited control. Interruptions and/or failure of this new billing services system could disrupt our operations and impact our ability to provide or bill for our services, retain customers, attract new customers or negatively impact overall customer experience. Any occurrence of the foregoing could cause material adverse effects on our operations and financial condition, material weaknesses in our internal control over financial reporting and reputational damage.

Our reputation and financial condition could be materially adversely affected by system failures, business disruptions, and unauthorized use of or interference with our network and other systems.

To be successful, we must provide our customers with reliable, trustworthy service and protect the communications, location, and personal information shared or generated by our customers. We rely upon our systems and networks, and the systems and networks of other providers and suppliers, to provide and support our services and, in some cases, to protect our customers’ and our information. Failure of our or others’ systems, networks and infrastructure may prevent us from providing reliable service, or may allow for the unauthorized use of or interference with our networks and other systems. Examples of these risks include:

•
human error such as responding to deceptive communications or unintentionally executing malicious code;
•
physical damage, power surges or outages, or equipment failure, including those as a result of severe weather, natural disasters, terrorist attacks, and acts of war;
•
theft of customer and/or proprietary information offered for sale for competitive advantage or corporate extortion;
•
unauthorized access to our information technology, billing, customer care and provisioning systems and networks, and those of our suppliers and other providers;
•
supplier failures or delays; and
•
other systems failures or outages.

Such events could cause us to lose customers, lose revenue, incur expenses, suffer reputational and goodwill damages, and subject us to litigation or governmental investigation. Remediation costs could include liability for information loss, repairing infrastructure and systems, and/or costs of incentives offered to customers. Our insurance may not cover, or be adequate to fully reimburse us for, costs and losses associated with such events.


11

Table of Contents

We rely on third-parties to provide specialized products or services for the operation of our business, and a failure or inability by such parties to provide these products or services could adversely affect our business, results of operations and financial condition.

We depend heavily on suppliers and other third parties in order for us to efficiently operate our business. Our business is complex, and it is not unusual for multiple vendors located in multiple locations to help us to develop, maintain and troubleshoot products and services, such as network components, software development services, and billing and customer service support. Our suppliers often provide services outside of the U.S., which carries associated additional regulatory and legal obligations. We generally rely upon the suppliers to provide contractual assurances and accurate information regarding risks associated with their provision of products or services in accordance with our expectations and standards, and they may fail to do so.

Generally, there are multiple sources for the types of products and services we purchase or use. However, we currently rely on a limited number of suppliers for billing services, voice and data communications transport services, network infrastructure, equipment, handsets, and other devices, and payment processing services, among other products and services we rely on. Disruptions with respect to such suppliers, or failure of such suppliers to adequately perform, could have a material adverse on our financial performance.

In the past, our suppliers, contractors and third-party retailers have not always performed at the levels we expect or at the levels required by their contracts. Our business could be severely disrupted if key suppliers, contractors, service providers, or third-party retailers fail to comply with their contracts or become unable to continue the supply due to patent or other intellectual property infringement actions, or other disruptions. Our business could also be disrupted if we experience delays or service degradation during any transition to a new outsourcing provider or other supplier, or we were required to replace the supplied products or services with those from another source, especially if the replacement became necessary on short notice. Any such disruptions could have a material adverse effect on our business, results of operations and financial condition.

Economic and market conditions may adversely affect our business and financial performance, as well as our access to financing on favorable terms or at all.

Our business and financial performance are sensitive to changes in general economic conditions, including interest rates, consumer credit conditions, consumer debt levels, consumer confidence, rates of inflation (or concerns about deflation), unemployment rates, economic growth, energy costs and other macro-economic factors. Difficult, or worsening, general economic conditions could have a material adverse effect on our business, financial condition and results of operations.

Market volatility, economic uncertainty, and weak economic conditions may materially adversely affect our business and financial performance in a number of ways. Our services are available to a broad customer base, a significant segment of which may be more vulnerable to weak economic conditions. We may have greater difficulty in gaining new customers within this segment and existing customers may be more likely to terminate service due to an inability to pay.

Weak economic conditions and credit conditions may also adversely impact our suppliers and dealers, some of which have filed for or may be considering bankruptcy, or may experience cash flow or liquidity problems or are unable to obtain or refinance credit such that they may no longer be able to operate. Any of these could adversely impact our ability to distribute, market, or sell our products and services.

In addition, instability in the global financial markets could lead to periodic volatility in the credit, equity and fixed income markets. This volatility could limit our access to the credit markets, leading to higher borrowing costs or, in some cases, the inability to obtain financing on terms that are acceptable to us, or at all.

The agreements governing our indebtedness include restrictive covenants that limit our operating flexibility.

The agreements governing our indebtedness impose significant operating and financial restrictions on us. These restrictions, subject in certain cases to customary baskets, exceptions and incurrence-based ratio tests, may limit our or our subsidiaries’ ability to engage in some transactions, including the following:

•
incurring additional indebtedness and issuing preferred stock;
•
paying dividends, redeeming capital stock or making other restricted payments or investments;
•
selling or buying assets, properties or licenses including participating in future FCC auctions of spectrum or private sales of spectrum;
•
developing assets, properties or licenses which we have or in the future may procure;

12

Table of Contents

•
creating liens on assets;
•
engaging in mergers, acquisitions, business combinations or other transactions;
•
entering into transactions with affiliates; and
•
placing restrictions on the ability of subsidiaries to pay dividends or make other payments.

These restrictions could limit our ability to react to changes in our operating environment or the economy. Any future indebtedness that we incur may contain similar or more restrictive covenants. Any failure to comply with the restrictions of our debt agreements may result in an event of default under these agreements, which in turn may result in defaults or acceleration of obligations under these agreements and other agreements, giving our lenders the right to terminate any commitments they had made to provide us with further funds and to require us to repay all amounts then outstanding. Any of these events would have a material adverse effect on our financial position and performance.

Our significant indebtedness could adversely affect our business, financial condition and operating results.

Our ability to make payments on our debt, to repay our existing indebtedness when due, to fund our capital intensive business and operations and fund significant planned capital expenditures will depend on our ability to generate cash in the future, which is in turn subject to the operational risks described elsewhere in this section. Our debt service obligations could have material adverse effects on our operations and financial results, including by:

•
limiting our flexibility in planning for, or reacting to, changes in our business or the communications industry or pursuing growth opportunities;
•
reducing the amount of cash available for other operational or strategic needs; and
•
placing us at a competitive disadvantage to competitors who are less leveraged than we are.

In addition, $0.6 billion of the $5.6 billion in principal amount of the senior reset notes we issued to Deutsche Telekom in connection with the business combination between T-Mobile and MetroPCS bears interest at rates which will be reset in April 2016. Some of our debt also has a floating rate of interest linked to various indices. If the resets or the change in indices result in interest rate increases, debt service requirements will increase, which could adversely affect our cash flow. While we have and may enter into agreements limiting our exposure to higher interest rates in the future, any such agreements may not offer complete protection from this risk, and any portion not subject to such agreements would have full exposure to higher interest rates. Any of these risks could have a material adverse effect on our business, financial condition, and operating results.

Our business and stock price may be adversely affected if our internal controls are not effective.

Under Section 404 of the Sarbanes-Oxley Act of 2002, and the related SEC rules, we are required to establish, maintain, and annually evaluate the effectiveness of our internal controls over financial reporting. This process is designed to provide reasonable assurance regarding the reliability of our financial reporting and preparation of financial statements for external purposes in accordance with generally accepted accounting principles. We rely heavily on information technology (“IT”) systems as an important part of our internal controls in order to operate, transact and otherwise manage our business, as well as provide effective and timely reporting of our financial results. Each year, we are required to document and test our internal controls over financial reporting, including these IT systems; our management is required to assess and issue a report concerning our internal control over financial reporting; and our independent registered public accounting firm is required to report on the effectiveness of our internal control over financial reporting.

We cannot assure you that we will not discover material weaknesses within our IT controls or other aspects of our internal control over financial reporting in the future. The existence of one or more material weaknesses could result in errors in our financial statements, and substantial costs and resources may be required to rectify these or other internal control deficiencies. If we are unable to comply with the requirements of Section 404 in a timely manner or determine that our internal control over financial reporting is not effective, investors may lose confidence in the accuracy and completeness of our financial reports. This may negatively impact the trading price of our common stock, and possibly expose us to investigations by the stock exchange on which our securities are listed, the SEC or other regulatory authorities.

Our financial performance will be impaired if we experience high fraud rates related to device financing, credit cards, dealers, or subscriptions.

Our operating costs could increase substantially as a result of fraud, including device financing, customer credit card, subscription or dealer fraud. If our fraud detection strategies and processes are not successful in detecting and controlling fraud, whether directly or by way of the systems, processes, and operations of third parties such as national retailers, dealers and others, the resulting loss of revenue or increased expenses could have a materially adverse impact on our financial

13

Table of Contents

condition and results of operations.

We rely on highly-skilled personnel throughout all levels of our business. Our business could be harmed if we are unable to retain or motivate key personnel, hire qualified personnel or maintain our corporate culture.

In our industry, there is substantial and continuous competition for highly-skilled business, product development, technical, and other personnel. We believe that our future success depends in substantial part on our ability to recruit, hire, motivate, develop, and retain talented and highly-skilled personnel. Doing so may be difficult due to many factors, including fluctuations in economic and industry conditions, competitors’ hiring practices, employee tolerance for the significant amount of change within and demands on our company and our industry, and the effectiveness of our compensation programs. Our continued ability to compete effectively depends on our ability to retain and motivate our existing employees and to attract new employees. If we do not succeed in retaining and motivating our existing key employees and in attracting new key personnel, we may not be able to meet our business plan and, as a result, our revenue growth and profitability may be materially adversely affected.

Risk related to Legal and Regulatory Matters

We operate throughout the U.S., Puerto Rico, and the U.S. Virgin Islands, and as such are subject to regulatory and legislative action by applicable local, state and federal governmental entities, which may increase our costs of providing products or services, or require us to change our business operations, products, or services or subject us to material adverse impacts if we fail to comply with such regulations.

The FCC regulates the licensing, construction, modification, operation, ownership, sale, and interconnection of wireless communications systems, as do some state and local regulatory agencies. Additionally, the Federal Trade Commission (“FTC”) and other federal agencies have asserted that they have jurisdiction over some consumer protection and elimination and prevention of anticompetitive business practices with respect to the provision of non-common carrier services. We cannot assure you that the FCC, FTC, or any other federal, state or local agencies will not adopt regulations or take other enforcement or other actions that would adversely affect our business, impose new costs, or require changes in current or planned operations. We are subject to regulatory oversight by various federal agencies, as well as judicial review and actions, on issues related to the wireless industry that include, but are not limited to: roaming, spectrum allocation and licensing, pole attachments, intercarrier compensation, Universal Service Fund (“USF”), net neutrality, special access, 911 services, consumer protection, consumer privacy, and cybersecurity. We are also subject to regulations in connection with other aspects of our business, including handset financing and insurance activities.

In June 2015, the FCC’s new net neutrality rules became effective, with the exception of enhanced transparency requirements, which are expected to become effective in 2016. The rules include a new Internet Service Provider (ISP) conduct standard, prohibiting actions that harm consumers or edge providers, subject to case-by-case review by the FCC. The new rules potentially subject some of our initiatives and practices, such as Binge On and our network management practices, to heightened scrutiny by federal and state regulators, the public, and edge providers regarding whether such initiatives or practices are compliant.

In addition, states are increasingly focused on the quality of service and support that wireless communication providers provide to their customers and several states have proposed or enacted new and potentially burdensome regulations in this area. A number of state Public Utility Commissions and state legislatures have introduced proposals in recent years seeking to regulate carriers’ business practices. We also face potential investigations by, and inquiries from or actions by state Public Utility Commissions and state Attorneys General. We also cannot assure you that Congress will not amend the Communications Act, from which the FCC obtains its authority and which serves to limit state authority, or enact other legislation in a manner that could be adverse to our business. Enactment of additional state or federal regulations may increase our costs of providing services (including, through universal service programs, requiring us to subsidize wireline competitors) or require us to change our services. Failure to comply with applicable regulations could have a material adverse effect on our business, financial condition and results of operations.

Furthermore, we could be subject to fines, forfeitures, and other penalties (including, in extreme cases, revocation of our spectrum licenses) for failure to comply with FCC or other governmental regulations, even if any such non-compliance was unintentional. The loss of any licenses, or any related fines or forfeitures, could adversely affect our business, results of operations, and financial condition.


14

Table of Contents

Unfavorable outcomes of legal proceedings may adversely affect our business and financial condition.

We are regularly involved in a number of legal proceedings before various state and federal courts, the FCC, the FTC, other federal agencies, and state and local regulatory agencies. Such legal proceedings can be complex, costly, and highly disruptive to business operations by diverting the attention and energies of management and other key personnel. The assessment of the outcome of legal proceedings, including our potential liability, if any, is a highly subjective process that requires judgments about future events that are not within our control. The amounts ultimately received or paid upon settlement or pursuant to final judgment, order or decree may differ materially from amounts accrued in our financial statements. In addition, litigation or similar proceedings could impose restraints on our current or future manner of doing business. Such potential outcomes including judgments, awards, settlements or orders could have a material adverse effect on our business, financial condition, operating results or ability to do business.

We offer products that include highly regulated financial services products. These products expose us to a wide variety of state and federal regulations.

The offering of financial services products to our customers, such as financing of devices, including through our EIP and JUMP! On Demand program, has expanded our regulatory compliance obligations. If we fail to remain compliant with any of these regulations, then we face the risk of:

•
Increased consumer complaints and potential examinations or enforcement actions by federal and state regulatory agencies, including but not limited to the Consumer Financial Protection Board (“CFPB”), Federal Deposit Insurance Corporation (“FDIC”) and the FTC;
•
Violation of financial services and consumer protections regulations may result in regulatory fines, penalties, enforcement actions, civil litigation and/or class action lawsuits.

We may be unable to adequately protect our intellectual property. Additionally, we use equipment, software, technology, and content in the operation of our business, which may subject us to third-party intellectual property claims and we may be adversely affected by litigation involving our suppliers.

We rely on a combination of patent, service mark, trademark, and trade secret laws and contractual restrictions to establish and protect our proprietary rights, all of which offer only limited protection. The steps we have taken to protect our intellectual property may not prevent the misappropriation of our proprietary rights. We may not have the ability in certain jurisdictions to adequately protect intellectual property rights. Moreover, others may independently develop processes and technologies that are competitive to ours. Unauthorized use of our intellectual property rights may increase the cost of protecting these rights or reduce our revenues. We cannot be sure that any legal actions against such infringers will be successful, even when our rights have been infringed. We cannot assure you that our pending or future patent applications will be granted or enforceable, or that the rights granted under any patent that may be issued will provide us with any competitive advantages. In addition, we cannot assure you that any trademark or service mark registrations will be issued with respect to pending or future applications or will provide adequate protection of our brands. We do not have insurance coverage for intellectual property losses, and as such, a charge for an anticipated settlement, or an adverse ruling awarding damages, represents unplanned loss events. Any of these factors could have material adverse effects on our business, results of operations and financial condition.

Third parties may claim we infringe their intellectual property rights. We are a defendant in numerous intellectual property lawsuits, including patent infringement lawsuits, which exposes us to the risk of adverse financial impact either by way of significant settlement amounts or damage awards. As we adopt new technologies and new business systems, and provide customers with new products and/or services, we may face additional infringement claims. These claims could require us to cease certain activities or to cease selling relevant products and services. These claims can be time-consuming and costly to defend, and divert management resources. In addition to litigation directly involving our company, our vendors and suppliers can be threatened with patent litigation and/or subjected to the threat of disruption or blockage of sale, use, or importation of products, posing the risk of supply chain interruption to particular products and associated services exposing us to material adverse operational and financial impacts.

Our business may be impacted by new or changing tax laws or regulations and actions by federal, state or local agencies, or how judicial authorities apply tax laws.

Tax laws are dynamic and subject to change as new laws are passed and new interpretations of the law are issued or applied. In connection with the products and services we provide, we calculate, collect, and remit various taxes and regulatory fees to numerous federal, state and local governmental authorities, including federal USF contributions and common carrier regulatory fees. In addition, many state and local governments levy various taxes and fees on our sales of products and services to

15

Table of Contents

customers and on our purchases of telecommunications equipment and services from vendors and various telecommunications carriers. We impose surcharges on customers to reimburse us for taxes, regulatory assessments and other costs we incur to comply with governmental regulatory mandates. In many cases, the applicability and method of calculating these surcharges, taxes and fees may be uncertain, and our calculation, assessment or remittance of these amounts may be contested by either customers or governmental authorities. In the event that we have incorrectly described, disclosed, calculated, assessed or remitted amounts that were due to governmental authorities, we could be subject to additional taxes, fines, penalties, or other adverse actions, which could materially impact our operations or financial condition. In the event that federal, state and/or local municipalities were to significantly increase taxes and regulatory fees on our services or seek to impose new ones, it could have a material adverse effect on our margins and financial and operational results.

Our wireless licenses are subject to renewal and may be revoked in the event that we violate applicable laws.

Our existing wireless licenses are subject to renewal upon the expiration of the 10-year or 15-year period for which they are granted. Historically, the FCC has approved our license renewal applications. However, the Communications Act provides that licenses may be revoked for cause and license renewal applications denied if the FCC determines that a renewal would not serve the public interest. In addition, our licenses are subject to our compliance with the terms set forth in the agreement pertaining to national security among Deutsche Telekom, the Federal Bureau of Investigation, the Department of Justice, the Department of Homeland Security and the Company. The failure of Deutsche Telekom or the Company to comply with the terms of this agreement could result in fines, injunctions, and other penalties, including potential revocation or non-renewal of our spectrum licenses. If we fail to timely file to renew any wireless license, or fail to meet any regulatory requirements for renewal, including construction and substantial service requirements, we could be denied a license renewal. Many of our wireless licenses are subject to interim or final construction requirements and there is no guarantee that the FCC will find our construction, or the construction of prior licensees, sufficient to meet the build-out or renewal requirements. The FCC has pending a rulemaking proceeding to reevaluate, among other things, its wireless license renewal showings and standards and may in this or other proceedings promulgate changes or additional substantial requirements or conditions to its renewal rules, including revising license build out requirements. Accordingly, we cannot assure you that the FCC will renew our wireless licenses upon their expiration. If any of our wireless licenses were to be revoked or not renewed upon expiration, we would not be permitted to provide services under that license, which could have a material adverse effect on our business, results of operations and financial condition.

Our business could be adversely affected by findings of product liability for health/safety risks from wireless devices and transmission equipment, as well as by changes to regulations/radio frequency emission standards.

We do not manufacture devices or other equipment sold by us, and we depend on our suppliers to provide defect-free and safe equipment. Suppliers are required by applicable law to manufacture their devices to meet certain governmentally imposed safety criteria. However, even if the devices we sell meet the regulatory safety criteria, we could be held liable with the equipment manufacturers and suppliers for any harm caused by products we sell if such products are later found to have design or manufacturing defects. We generally seek to enter into indemnification agreements with the manufacturers who supply us with devices to protect us from losses associated with product liability, but we cannot guarantee that we will be fully protected against all losses associated with a product that is found to be defective.

Allegations have been made that the use of wireless handsets and wireless transmission equipment, such as cell towers, may be linked to various health concerns, including cancer and brain tumors. Lawsuits have been filed against manufacturers and carriers in the industry claiming damages for alleged health problems arising from the use of wireless handsets. In addition, the FCC has from time to time gathered data regarding wireless handset emissions and its assessment of this issue may evolve based on its findings. The media has also reported incidents of handset battery malfunction, including reports of batteries that have overheated. These allegations may lead to changes in regulatory standards. There have also been other allegations regarding wireless technology, including allegations that wireless handset emissions may interfere with various electronic medical devices (including hearing aids and pacemakers), airbags and anti-lock brakes.

Additionally, there are safety risks associated with the use of wireless devices while operating vehicles or equipment. Concerns over any of these risks and the effect of any legislation, rules or regulations that have been and may be adopted in response to these risks could limit our ability to sell our wireless services.

Related to Ownership of our Common Stock

We are controlled by Deutsche Telekom, whose interests may differ from the interests of our other stockholders.

Deutsche Telekom beneficially owns and possesses majority voting power of the fully diluted shares of our common stock.

16

Table of Contents

Through its control of the voting power of our common stock and the rights granted to Deutsche Telekom in our certificate of incorporation and the Stockholder’s Agreement, Deutsche Telekom controls the election of our directors and all other matters requiring the approval of our stockholders. By virtue of Deutsche Telekom’s voting control, we are a “controlled company,” as defined in the NASDAQ listing rules, and are not subject to NASDAQ requirements that would otherwise require us to have a majority of independent directors, a nominating committee composed solely of independent directors or a compensation committee composed solely of independent directors.

In addition, our certificate of incorporation and the Stockholder’s Agreement restrict us from taking certain actions without Deutsche Telekom’s prior written consent as long as Deutsche Telekom beneficially owns 30% or more of the outstanding shares of our common stock, including:

•
the incurrence of debt (excluding certain permitted debt) if our consolidated ratio of debt to cash flow for the most recently ended four full fiscal quarters for which financial statements are available would exceed 5.25 to 1.0 on a pro forma basis;
•
the acquisition of any business, debt or equity interests, operations or assets of any person for consideration in excess of $1 billion;
•
the sale of any of our or our subsidiaries’ divisions, businesses, operations or equity interests for consideration in excess of $1 billion;
•
any change in the size of our board of directors;
•
the issuances of equity securities in excess of 10% of our outstanding shares or to repurchase debt held by Deutsche Telekom;
•
the repurchase or redemption of equity securities or the declaration of extraordinary or in-kind dividends or distributions other than on a pro rata basis;
•
or the termination or hiring of our chief executive officer.

These restrictions could prevent us from taking actions that our board of directors may otherwise determine are in the best interests of the Company and our stockholders or that may be in the best interests of our other stockholders.

Deutsche Telekom effectively has control over all matters submitted to our stockholders for approval, including the election or removal of directors, changes to our certificate of incorporation, a sale or merger of our company and other transactions requiring stockholder approval under Delaware law. Deutsche Telekom’s controlling interest may have the effect of making it more difficult for a third-party to acquire, or discouraging a third-party from seeking to acquire, the Company. Deutsche Telekom may have strategic, financial, or other interests different from our other stockholders, including as the holder of a substantial amount of our indebtedness and as the counter-party in a number of commercial arrangements, and may make decisions adverse to the interests of our other stakeholders.

Future sales or issuances of our common stock, including sales by Deutsche Telekom, could have a negative impact on our stock price.

We cannot predict the effect, if any, that market sales of shares or the availability of shares of our common stock will have on the prevailing trading price of our common stock from time to time. Sales of a substantial number of shares of our common stock could cause our stock price to decline.

We and Deutsche Telekom are parties to the Stockholder’s Agreement pursuant to which Deutsche Telekom is free to transfer its shares in public sales without notice, as long as such transactions would not result in the transferee owning 30% or more of the outstanding shares of our common stock. If a transfer would exceed the 30% threshold, it is prohibited unless the transferee makes a binding offer to purchase all of the other outstanding shares on the same price and terms. The Stockholder’s Agreement does not otherwise impose any other restrictions on the sales of common stock by Deutsche Telekom. Moreover, we have filed a shelf registration statement with respect to the common stock and certain debt securities held by Deutsche Telekom, which would facilitate the resale by Deutsche Telekom of all or any portion of the shares of our common stock it holds. The sale of shares of our common stock by Deutsche Telekom (other than in transactions involving the purchase of all of our outstanding shares) could significantly increase the number of shares available in the market, which could cause a decrease in our stock price. In addition, even if Deutsche Telekom does not sell a large number of its shares into the market, its right to transfer a large number of shares into the market may depress our stock price.

In addition, we have reserved up to 38.684 million shares of common stock for issuance upon conversion of our preferred stock, subject to certain anti-dilution adjustments. The dividends on the preferred stock may also be paid in cash or, subject to certain limitations, shares of common stock or any combination of cash and shares of common stock. The issuance of additional shares of common stock upon conversion of, or in connection with the payment of dividends upon, the mandatory

17

Table of Contents

convertible preferred stock may depress our stock price.

Our stock price may be volatile, and may fluctuate based upon factors that have little or nothing to do with our business, financial condition and operating results.

The trading prices of the securities of communications companies historically have been highly volatile, and the trading price of our common stock may be subject to wide fluctuations. Our stock price may fluctuate in reaction to a number of events and factors that may include, among other things:

•
our or our competitors’ actual or anticipated operating and financial results; introduction of new products and services by us or our competitors or changes in service plans or pricing by us or our competitors;
•
analyst projections, predictions and forecasts, analyst target prices for our securities and changes in, or our failure to meet, securities analysts’ expectations;
•
Deutsche Telekom’s financial performance, results of operation, or actions implied or taken by Deutsche Telekom;
•
entry of new competitors into our markets or perceptions of increased price competition, including a price war;
•
our performance, including subscriber growth, and our financial and operational metric performance;
•
market perceptions relating to our services, network, handsets and deployment of our LTE platform and our access to iconic handsets, services, applications or content;
•
market perceptions of the wireless communications industry and valuation models for us and the industry;
•
changes in our credit rating or future prospects;
•
the availability or perceived availability of additional capital in general and our access to such capital;
•
actual or anticipated consolidation, or other strategic mergers or acquisition activities involving us or our competitors or market speculations regarding such activities;
•
disruptions of our operations or service providers or other vendors necessary to our network operations; the general state of the U.S. and world economies; and
•
availability of additional spectrum, whether by the announcement, commencement, bidding and closing of auctions for new spectrum or the acquisition of companies that own spectrum, and the extent to which we or our competitors succeed in acquiring additional spectrum.

In addition, the stock market has been volatile in the recent past and has experienced significant price and volume fluctuations, which may continue for the foreseeable future. This volatility has had a significant impact on the trading price of securities issued by many companies, including companies in the communications industry. These changes frequently occur irrespective of the operating performance of the affected companies. Hence, the trading price of our common stock could fluctuate based upon factors that have little or nothing to do with our business, financial condition and operating results.

Our stockholder rights plan could prevent a change in control of our Company in instances in which some stockholders may believe a change in control is in their best interests.

We have a stockholder rights plan (“Rights Plan”) in effect. The Rights Plan will cause substantial dilution to a person or group that attempts to acquire our company on terms that our board of directors does not believe are in our and our stockholders’ best interest. The Rights Plan is intended to protect stockholders in the event of an unfair or coercive offer to acquire the Company and to provide our board of directors with adequate time to evaluate unsolicited offers. The Rights Plan may prevent or make takeovers or unsolicited corporate transactions with respect to our company more difficult, even if stockholders may consider such transactions favorable, possibly including transactions in which stockholders might otherwise receive a premium for their shares.

Item 1B. Unresolved Staff Comments

None.

Item 2. Properties

As of December 31, 2015, we leased approximately 60,000 cell sites, 64 switching centers and 8 data centers, totaling approximately 2.0 million square feet. In addition, we had 18 leased call centers, totaling approximately 1.4 million square feet, and 21 leased warehouses, totaling approximately 615,000 square feet. We also leased approximately 2,350 retail locations, including stores and kiosks ranging in size from approximately 100 square feet to 13,000 square feet.

We currently lease office space totaling approximately 1.0 million square feet for our corporate headquarters in Bellevue, Washington. We use these offices for engineering and administrative purposes. We also lease space throughout the U.S.,

18

Table of Contents

totaling approximately 1.3 million square feet as of December 31, 2015, for use by our regional offices primarily for administrative, engineering and sales purposes.

Item 3. Legal Proceedings

See Note 13 – Commitments and Contingencies of the Notes to the Consolidated Financial Statements included in Part II, Item 8 of this Form 10-K for information regarding certain legal proceedings in which we are involved.

Item 4. Mine Safety Disclosures

None.

PART II.

Item 5. Market for Registrant’s Common Equity, Related Stockholder Matters and Issuer Purchases of Equity Securities

Market Information

Since October 27, 2015, our common stock has traded on the NASDAQ Global Select Market of The NASDAQ Stock Market LLC (“NASDAQ”) under the symbol “TMUS.” From May 1, 2013, the first trading day after the closing of the business combination with MetroPCS, until October 26, 2015, our common stock traded on the New York Stock Exchange (“NYSE”) under the symbol “TMUS.” As of December 31, 2015, there were 324 registered stockholders of record of our common stock, but we estimate the total number of stockholders to be much higher as a number of our shares are held by brokers or dealers for their customers in street name.

The high and low common stock sales prices per share were as follows:
 
High
 
Low
Year Ended December 31, 2015


First Quarter
$
33.48

 
$
26.46

Second Quarter
40.77

 
31.19

Third Quarter
43.43

 
36.33

Fourth Quarter
42.06

 
34.24

Year Ended December 31, 2014


First Quarter
$
33.92

 
$
29.06

Second Quarter
35.50

 
27.62

Third Quarter
34.55

 
28.25

Fourth Quarter
29.60

 
24.26


We have never paid or declared any cash dividends on our common stock, and we do not intend to declare or pay any cash dividends on our common stock in the foreseeable future. Our credit facilities and the indentures and supplemental indentures governing our long-term debt to affiliates and third parties, excluding capital leases, contain covenants that, among other things, restrict our ability to declare or pay dividends on our common stock. In addition, no dividend may be declared or paid on our common stock, other than dividends payable solely in shares of our common stock, unless all accrued dividends for all completed dividend periods have been declared and paid on our preferred stock. Other than to pay dividends on our preferred stock, we currently intend to retain future earnings, if any, to invest in our business. Subject to Delaware law, our board of directors will determine the payment of future dividends on our common stock, if any, and the amount of any dividends in light of:

•
any applicable contractual or charter restrictions limiting our ability to pay dividends;  
•
our earnings and cash flows;  
•
our capital requirements;  
•
our future needs for cash;
•
our financial condition; and  
•
other factors our board of directors deems relevant.


19

Table of Contents

Performance Graph

The graph below compares the five-year cumulative total returns of T-Mobile, the NASDAQ Composite index, the NYSE Composite index, the S&P 500 index and the Dow Jones US Mobile Telecommunications TSM index. The graph tracks the performance of a $100 investment, with the reinvestment of all dividends, from December 31, 2010 to December 31, 2015. For periods prior to the closing of the business combination with MetroPCS, our stock price performance represents the stock price of MetroPCS, adjusted to reflect the 1-for-2 reverse stock split effected on April 30, 2013. After 2015, T-Mobile will no longer provide a comparison to the NYSE Composite index since we transferred the listing of our stock to the NASDAQ Stock Market on October 27, 2015.
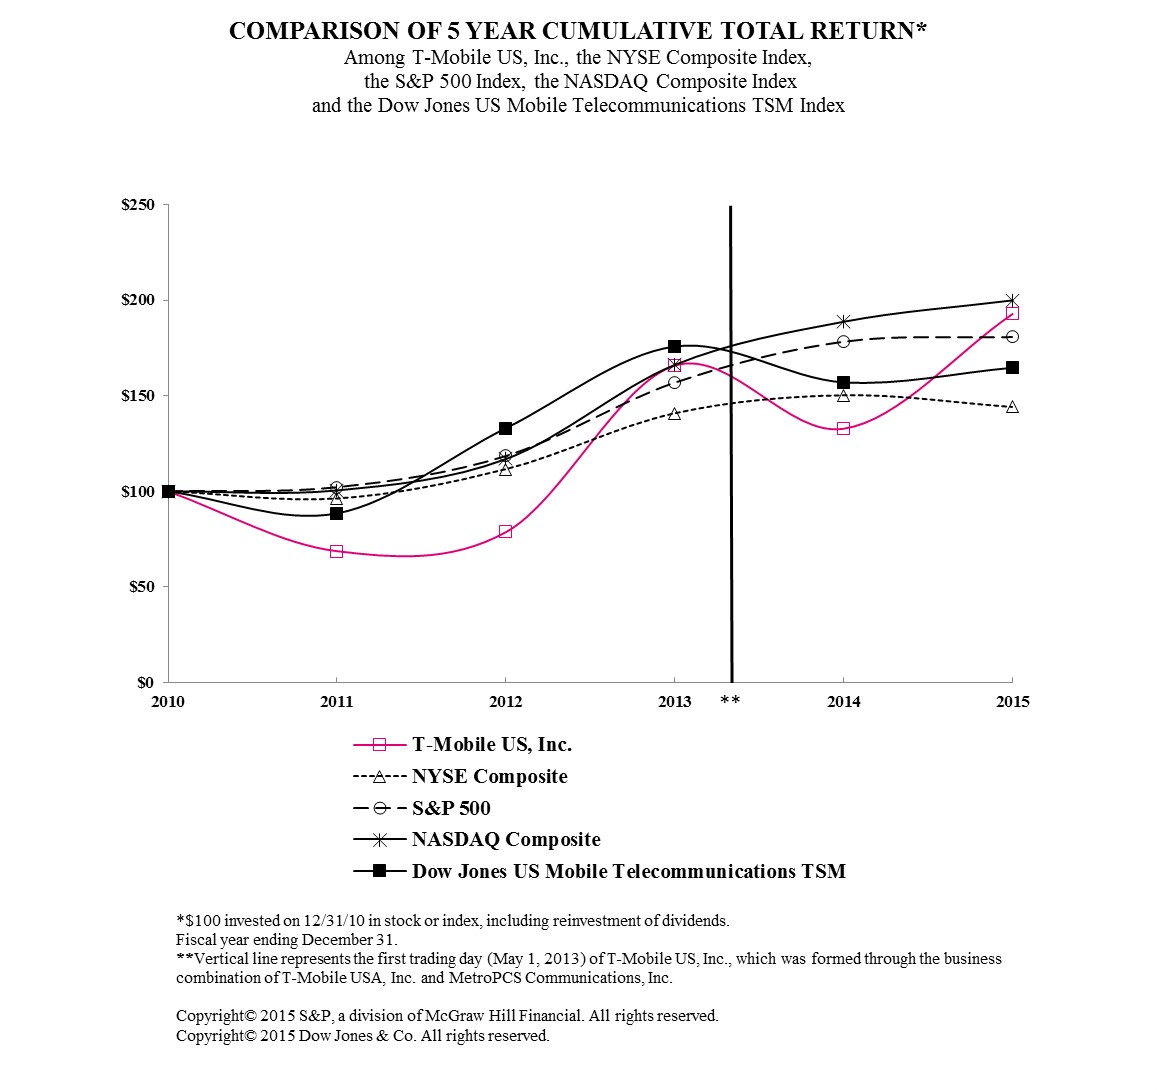
 
At December 31,
 
2010
 
2011
 
2012
 
2013
 
2014
 
2015
T-Mobile US, Inc.
$
100.00

 
$
68.73

 
$
78.70

 
$
165.82

 
$
132.79

 
$
192.83

NYSE Composite
100.00

 
96.16

 
111.53

 
140.85

 
150.35

 
144.21

S&P 500
100.00

 
102.11

 
118.45

 
156.82

 
178.29

 
180.75

NASDAQ Composite
100.00

 
100.53

 
116.92

 
166.19

 
188.78

 
199.95

Dow Jones US Mobile Telecommunications TSM
100.00

 
88.53

 
133.07

 
175.81

 
157.06

 
164.71


The stock price performance included in this graph is not necessarily indicative of future stock price performance.

20

Table of Contents


Item 6. Selected Financial Data

The following selected financial data are derived from our consolidated financial statements. In connection with the business combination with MetroPCS, the selected financial data prior to May 1, 2013 represents T-Mobile USA’s historical financial data. The data below should be read in conjunction with Risk Factors included in Part 1, Item 1A, Management’s Discussion and Analysis of Financial Condition and Results of Operations included in Part II, Item 7 and Financial Statements and Supplementary Data included in Part II, Item 8 of this Form 10-K.

Selected Financial Data
(in millions, except per share and customer amounts)
As of and for the Year Ended December 31,
2015
 
2014
 
2013
 
2012
 
2011
Statement of Operations Data


Total service revenues
$
24,821

 
$
22,375

 
$
19,068

 
$
17,213

 
$
18,481

Total revenues
32,053

 
29,564

 
24,420

 
19,719

 
20,618

Operating income (loss)
2,065

 
1,416

 
996

 
(6,397
)
 
(4,279
)
Total other expense, net
(1,087
)
 
(1,003
)
 
(945
)
 
(589
)
 
(655
)
Income tax expense (benefit)
245

 
166

 
16

 
350

 
(216
)
Net income (loss)
733

 
247

 
35

 
(7,336
)
 
(4,718
)
Net income (loss) attributable to common stockholders
678

 
247

 
35

 
(7,336
)
 
(4,718
)
Earnings (loss) per share:


Basic
0.83

 
0.31

 
0.05

 
(13.70
)
 
(8.81
)
Diluted
0.82

 
0.30

 
0.05

 
(13.70
)
 
(8.81
)
Balance Sheet Data


Cash and cash equivalents
$
4,582

 
$
5,315

 
$
5,891

 
$
394

 
$
390

Property and equipment, net
20,000

 
16,245

 
15,349

 
12,807

 
12,703

Spectrum licenses
23,955

 
21,955

 
18,122

 
14,550

 
12,814

Total assets
62,436

 
56,653

 
49,953

 
33,622

 
40,609

Total debt, excluding tower obligations
26,266

 
21,960

 
20,189

 
14,945

 
15,627

Stockholders’ equity
16,557

 
15,663

 
14,245

 
6,115

 
15,785

Other Financial and Operational Data


Net cash provided by operating activities
$
5,414

 
$
4,146

 
$
3,545

 
$
3,862

 
$
4,980

Purchases of property and equipment
(4,724
)
 
(4,317
)
 
(4,025
)
 
(2,901
)
 
(2,729
)
Purchases of spectrum licenses and other intangible assets, including deposits
(1,935
)
 
(2,900
)
 
(381
)
 
(387
)
 
(23
)
Net cash provided by financing activities
3,413

 
2,524

 
4,044

 
57

 
—

Total customers (in thousands)
63,282

 
55,018

 
46,684

 
33,389

 
33,185


Item 7. Management’s Discussion and Analysis of Financial Condition and Results of Operations

Except as expressly stated, the financial condition and results of operations discussed throughout Management’s Discussion and Analysis of Financial Condition and Results of Operations (“MD&A”) are those of T-Mobile US, Inc. and its consolidated subsidiaries.

Overview

The MD&A is intended to provide a reader of our financial statements with a narrative explanation from the perspective of management of our financial condition, results of operations, liquidity and certain other factors that may affect future results. The MD&A is provided as a supplement to, and should be read in conjunction with, our audited Consolidated Financial Statements for the three years ended December 31, 2015 included in Part II, Item 8 of this Form 10-K.


21

Table of Contents

Operating Highlights

We introduced our Un-carrier proposition in 2013 with the objective of eliminating customer pain points from the unnecessary complexity of the wireless communication industry. We believe the Un-carrier proposition has been successful as evidenced by our strong customer growth momentum since the launch of our Un-carrier proposition. Total net customer additions were 8,264,000 in 2015, broadly consistent compared to 8,334,000 in 2014 and a significant improvement compared to 4,377,000 in 2013. Our ability to acquire and retain branded customers is important to our business in the generation of revenues and we have continued to focus on retaining customers through our Un-carrier initiatives and ongoing network improvements. These initiatives have continued to provide an improved customer experience as evidenced by our strong improvement in branded postpaid phone churn of 1.39% in 2015 compared to 1.58% in 2014 and 1.69% in 2013.

In 2015, we introduced JUMP! On Demand which allows customers to lease a new wireless device and upgrade it for a new one up to three times in 12 months for no extra fee. At lease inception, devices are transferred from inventory to property and equipment. Devices are then depreciated to their estimated residual value over the lease term and revenues associated with the leased wireless devices are recognized over the term of the lease. Upon device upgrade or at lease end, customers must return or purchase their device.  As we do not re-lease handset devices, returned devices are recorded as inventory and are valued at the lower of cost or market with any write down to market recognized as cost of equipment sales.

Financial Highlights

We generate revenues by offering affordable wireless communication services to our postpaid, prepaid and wholesale customers, as well as through sales and leasing of a wide selection of wireless devices and accessories. Total revenues increased to $32.1 billion in 2015 compared to $29.6 billion in 2014 and $24.4 billion in 2013.

Our most significant expenses are related to acquiring and retaining high-quality customers, providing a full range of devices, compensating employees, and operating and expanding our network. Operating expenses were $30.0 billion in 2015, compared to $28.1 billion in 2014 and $23.4 billion in 2013.

Net income increased to $733 million in 2015, compared to $247 million in 2014 and $35 million in 2013. Adjusted EBITDA increased to $7.4 billion in 2015, compared to $5.6 billion in 2014 and $4.9 billion in 2013.

Liquidity and Capital Resources Highlights

The ongoing success of our Un-carrier proposition and continued modernization of our network has further repositioned T-Mobile to provide customers with an exceptional customer experience, which requires substantial investment in our business.

We have substantially completed the process of upgrading our network to LTE, which provides our customers with the fastest nationwide 4G LTE network in the United States. In addition, we are currently in the process of building out our network to utilize our 700 MHz A-Block spectrum licenses. Cash capital expenditures for property and equipment, excluding payments for capitalized interest, were $4.5 billion in 2015, compared to $4.3 billion in 2014 and $4.0 billion in 2013. Payments for capitalized interest costs included in purchases of property and equipment were $246 million in 2015, $65 million in 2014 and were not significant in 2013.

We provide mobile communication services using spectrum licenses, consisting of 700 MHz A-Block, AWS and PCS licenses. We intend to continue to opportunistically acquire spectrum licenses in private party transactions and future FCC spectrum license auctions, including the broadcast incentive auction in 2016, to further enhance our portfolio of U.S. nationwide broadband spectrum and enable the expansion of LTE coverage to new markets.

See “Results of Operations” below for further discussion of changes in revenues and operating expenses and “Performance Measures” for a description of performance measures, such as Adjusted EBITDA and churn. The comparability of results in this Form 10-K to the year ended 2013 is affected by the inclusion of MetroPCS results after the completion of the business combination on April 30, 2013.


22

Table of Contents

Results of Operations

Set forth below is a summary of consolidated results:
 
Year Ended December 31,
 
Percentage
Change 2015
Versus 2014
 
Percentage
Change 2014
Versus 2013
(in millions)
2015
 
2014
 
2013
 
 
Revenues


Branded postpaid revenues
$
16,383

 
$
14,392

 
$
13,166

 
14
 %
 
9
 %
Branded prepaid revenues
7,553

 
6,986

 
4,945

 
8
 %
 
41
 %
Wholesale revenues
692

 
731

 
613

 
(5
)%
 
19
 %
Roaming and other service revenues
193

 
266

 
344

 
(27
)%
 
(23
)%
Total service revenues
24,821

 
22,375

 
19,068

 
11
 %
 
17
 %
Equipment revenues
6,718

 
6,789

 
5,033

 
(1
)%
 
35
 %
Other revenues
514

 
400

 
319

 
29
 %
 
25
 %
Total revenues
32,053

 
29,564

 
24,420

 
8
 %
 
21
 %
Operating expenses


Cost of services, exclusive of depreciation and amortization shown separately below
5,554

 
5,788

 
5,279

 
(4
)%
 
10
 %
Cost of equipment sales
9,344

 
9,621

 
6,976

 
(3
)%
 
38
 %
Selling, general and administrative
10,189

 
8,863

 
7,382

 
15
 %
 
20
 %
Depreciation and amortization
4,688

 
4,412

 
3,627

 
6
 %
 
22
 %
Cost of MetroPCS business combination
376

 
299

 
108

 
26
 %
 
NM

Gains on disposal of spectrum licenses
(163
)
 
(840
)
 
(2
)
 
(81
)%
 
NM

Other, net
—

 
5

 
54

 
NM

 
(91
)%
Total operating expenses
29,988

 
28,148

 
23,424

 
7
 %
 
20
 %
Operating income
2,065

 
1,416

 
996

 
46
 %
 
42
 %
Other income (expense)


Interest expense
(1,085
)
 
(1,073
)
 
(545
)
 
1
 %
 
97
 %
Interest expense to affiliates
(411
)
 
(278
)
 
(678
)
 
48
 %
 
(59
)%
Interest income
420

 
359

 
189

 
17
 %
 
90
 %
Other income (expense), net
(11
)
 
(11
)
 
89

 
NM

 
NM

Total other expense, net
(1,087
)
 
(1,003
)
 
(945
)
 
8
 %
 
6
 %
Income before income taxes
978

 
413

 
51

 
NM

 
NM

Income tax expense
245

 
166

 
16

 
48
 %
 
NM

Net income
$
733

 
$
247

 
$
35

 
NM

 
NM

NM – Not Meaningful

Year Ended December 31, 2015 Compared to Year Ended December 31, 2014

Revenues

Branded postpaid revenues increased $2.0 billion, or 14%, in 2015, compared to 2014. The increase was primarily attributable to growth in the number of average branded postpaid phone and mobile broadband customers driven by strong customer response to our Un-carrier initiatives and promotions for services and devices. Additional increases resulted from customer adoption of upgrade and insurance programs, and an increase in regulatory program revenues. The increase was partially offset by lower branded postpaid phone average revenue per user (“ARPU”). See “Performance Measures” for further information on branded postpaid phone ARPU.

Branded prepaid revenues increased $567 million, or 8%, in 2015, compared to 2014. The increase was primarily attributable to growth in the number of average branded prepaid customers driven by the success of our MetroPCS brand promotional activities and continued growth in expansion markets.

Wholesale revenues decreased $39 million, or 5%, in 2015, compared to 2014. The decrease was primarily attributable to revised agreements with certain MVNO partners in 2015, partially offset by growth in customers of certain MVNO partners.


23

Table of Contents

Roaming and other service revenues decreased $73 million, or 27%, in 2015, compared to 2014. The decrease was primarily attributable to lower international roaming revenues driven by changes in contractual arrangements with certain roaming partners and a reduction in early termination fees.

Equipment revenues decreased $71 million, or 1%, in 2015, compared to 2014. The decrease was primarily attributable to a lower average revenue per device sold, due in part to the impact of customers shifting to leasing higher-end devices with JUMP! On Demand, partially offset by growth in the number of devices and accessories sold. With JUMP! On Demand, revenues associated with leased wireless devices are recognized over the term of the lease rather than when the device is delivered to the customer. If customers continue to shift to leasing devices with JUMP! On Demand, equipment revenues may continue to decrease in 2016. Despite the increase in the number of devices leased in 2015 following the launch of JUMP! On Demand, the unit volume of device sales increased 5% in 2015, compared to 2014.

We financed $5.2 billion of devices through EIP during 2015, a decrease from $5.8 billion in 2014, primarily due to a decline in devices financed through EIP as customers increasingly shifted to leasing devices with JUMP! On Demand.

Other revenues increased $114 million, or 29%, in 2015, compared to 2014. The increase was primarily attributable to higher non-service revenues from revenue share agreements with third parties.

Operating Expenses

•
Cost of services consists primarily of costs directly attributable to providing wireless service through the operation of our network, including direct switch and cell site costs, such as rent, network access and transport costs, utilities, maintenance, associated labor costs, long distance costs, regulatory program costs, roaming fees paid to other carriers and data content costs.

•
Cost of equipment sales consists primarily of costs of devices and accessories sold to customers and dealers, device costs to fulfill insurance and warranty claims, write-downs of inventory related to shrinkage and obsolescence, and shipping and handling costs.

•
Selling, general and administrative consists of costs not directly attributable to providing wireless service for the operation of sales, customer care and corporate activities. These include commissions paid to dealers and retail employees for activations and upgrades, labor and facilities costs associated with retail sales force and administrative space, marketing and promotional costs, customer support and billing, bad debt expense, loss on sale of receivables and administrative support activities.

Cost of services decreased $234 million, or 4%, in 2015, compared to 2014. The decrease was primarily attributable to synergies realized from the decommissioning of the MetroPCS CDMA network and lower lease expense associated with spectrum license lease agreements. Additionally, a reduction in certain regulatory program costs contributed to the decrease. The decrease was partially offset by increases related to our network expansion and build-out of our 700 MHz A-Block spectrum.

Cost of equipment sales decreased $277 million, or 3%, in 2015, compared to 2014. The decrease was primarily attributable to a lower average cost per device sold, mainly due to the impact of customers shifting to leasing higher-end devices with JUMP! On Demand, partially offset by growth in the number of devices and accessories sold. With JUMP! On Demand, the cost of the leased wireless device is capitalized and recognized as depreciation expense over the term of the lease rather than recognized as cost of equipment sales when the device is delivered to the customer. If customers continue to shift to leasing devices with JUMP! On Demand, cost of equipment sales may continue to decrease in 2016. Despite the increase in the number of devices leased in 2015 following the launch of JUMP! On Demand, the unit volume of device sales increased 5% in 2015, compared to 2014.

Selling, general and administrative increased $1.3 billion, or 15%, in 2015, compared to 2014. The increase was primarily to support the growing customer base, which also increased 15% in 2015, and reflects increases in employee-related costs, promotional costs, commissions, bad debt expense and losses from sales of receivables primarily resulting from growth in the customer base and in the EIP program.

Depreciation and amortization increased $276 million, or 6%, in 2015, compared to 2014 primarily driven by $312 million in depreciation expense as a result of the launch of our JUMP! On Demand program. With JUMP! On Demand, the cost of the leased wireless device is depreciated to its estimated residual value over the lease term rather than recognized as cost of

24

Table of Contents

equipment sales when the device is delivered to the customer. If customers continue to shift to leasing devices with JUMP! On Demand, we expect depreciation associated with leased wireless devices to continue to increase in 2016.

Cost of MetroPCS business combination of $376 million in 2015 primarily reflects network decommissioning costs associated with the business combination. In 2014, we began decommissioning the MetroPCS CDMA network and certain other redundant network cell sites. On July 1, 2015, T-Mobile officially completed the shutdown of the MetroPCS CDMA network. Network decommissioning costs, which are excluded from Adjusted EBITDA, primarily relate to the acceleration of lease costs for cell sites that would have otherwise been recognized as cost of services over the remaining lease term had we not decommissioned the cell sites. Although we expect to incur additional network decommissioning costs in 2016 as cell site assets are removed, these costs are not expected to be significant. See Note 2 – Business Combination with MetroPCS of the Notes to the Consolidated Financial Statements included in Part II, Item 8 of this Form 10-K for further information.

Gains on disposal of spectrum licenses of $163 million in 2015 primarily consisted of a non-cash gain of $139 million from spectrum license transactions with Verizon recorded in the fourth quarter of 2015. Gains on disposal of spectrum licenses of $840 million in 2014 primarily consisted of non-cash gains from spectrum license transactions with Verizon, and to a lesser extent, a non-cash gain from a spectrum license transaction with AT&T during the fourth quarter of 2014. See Note 6 – Goodwill, Spectrum Licenses and Other Intangible Assets of the Notes to the Consolidated Financial Statements included in Part II, Item 8 of this Form 10-K for further information.

Other Income (Expense)

Interest expense increased $12 million, or 1%, in 2015, compared to 2014. The increase was primarily attributable to higher debt balances with third parties in 2015 compared to 2014, partially offset by a decrease from interest costs that were capitalized associated with the build out of our network to utilize our 700 MHz A-Block spectrum licenses.

Interest expense to affiliates increased $133 million, or 48%, in 2015, compared to 2014. The increase was primarily attributable to changes in the fair value of embedded derivative instruments associated with the Senior Reset Notes issued to Deutsche Telekom, partially offset by a decrease from interest costs that were capitalized associated with the build out of our network to utilize our 700 MHz A-Block spectrum licenses.

Interest income increased $61 million, or 17%, in 2015, compared to 2014. The increase was primarily attributable to higher interest income from devices financed through EIP. Interest associated with EIP receivables is imputed at the time of sale and then recognized over the financed installment term. See Note 4 – Equipment Installment Plan Receivables of the Notes to the Consolidated Financial Statements included in Part II, Item 8 of this Form 10-K for further information.

Income Taxes

Income tax expense increased $79 million in 2015, compared to 2014 primarily due to an increase in pre-tax income, partially offset by a lower effective tax rate. The effective tax rate was 25.1% in 2015, compared to 40.2% in 2014. The decrease in the effective income tax rate was primarily due to the impact of discrete income tax items recognized in 2015, including recent changes in state and local income tax laws and the recognition of foreign tax credits.

Net Income

Net income increased $486 million in 2015, compared to 2014, as a result of the factors described above.


25

Table of Contents

Guarantor Subsidiaries

Pursuant to the indenture and the supplemental indentures, the long-term debt to affiliates and third parties of T-Mobile USA, Inc. (“Issuer”), excluding Senior Secured Term Loans and capital leases, is fully and unconditionally guaranteed, jointly and severally, on a senior unsecured basis by T-Mobile US, Inc. (“Parent”) and certain of the Issuer’s 100% owned subsidiaries (“Guarantor Subsidiaries”). Additionally, T-Mobile USA incurred $2.0 billion of Senior Secured Term Loans in 2015, which are secured by a first priority lien on substantially all of T-Mobile USA’s assets and the assets of T-Mobile USA’s Guarantor Subsidiaries. In addition, the Senior Secured Term Loans are subject to a first priority pledge of the equity interests held by T-Mobile USA and substantially all of its direct and indirect subsidiaries.

In the fourth quarter of 2015, T-Mobile entered into an arrangement to sell certain EIP accounts receivable on a revolving basis. In connection with the sales arrangement, the Company formed a wholly-owned subsidiary to sell EIP accounts receivables (“EIP BRE”), which is included in the Non-Guarantor Subsidiaries condensed consolidating financial information. See Note 3 – Sales of Certain Receivables of the Notes to the Consolidated Financial Statements included in Part II, Item 8 of this Form 10-K for further information.

The financial condition of the Parent, Issuer and Guarantor Subsidiaries is substantially similar to the Company’s consolidated financial condition. Similarly, the results of operations of the Parent, Issuer and Guarantor Subsidiaries are substantially similar to the Company’s consolidated results of operations. As of December 31, 2015 and December 31, 2014, the most significant components of the financial condition of the Non-Guarantor Subsidiaries were property and equipment of $454 million and $537 million, respectively, tower obligations of $2.2 billion and $2.3 billion, respectively, and stockholders’ deficit of $1.4 billion and $1.5 billion, respectively. The most significant components of the results of operations of our Non-Guarantor Subsidiaries in 2015 were service revenues of $1.7 billion, partially offset by costs of equipment sales of $720 million and selling, general and administrative expenses of $733 million resulting in a net comprehensive income of $60 million. In 2014, service revenues of $1.3 billion were offset by costs of equipment sales of $702 million, selling, general and administrative expenses of $518 million and other items resulting in a net comprehensive loss of $38 million. See Note 15 – Guarantor Financial Information of the Notes to the Consolidated Financial Statements included in Part II, Item 8 of this Form 10-K for further information.

Year Ended December 31, 2014 Compared to the Year Ended December 31, 2013

Revenues

Branded postpaid revenues increased $1.2 billion, or 9%, in 2014, compared to 2013. The increase was primarily attributable to growth in the number of average branded postpaid customers driven by the continued success of our Un-carrier proposition and strong customer response to promotions for services and devices. Additional increases resulted from customer adoption of upgrade and insurance programs and changes in requalification requirements for corporate discount programs. The increase was partially offset by lower branded postpaid average revenue per account (“ARPA”). See “Performance Measures” for further information on ARPA. Branded postpaid ARPA was negatively impacted by continued growth of our Simple Choice plans, which have lower monthly service charges compared to traditional bundled plans. Branded postpaid customers on Simple Choice plans increased over the past twelve months to 89% of the branded postpaid customer base as of December 31, 2014, compared to 69% as of December 31, 2013.

Branded prepaid revenues increased $2.0 billion, or 41%, in 2014, compared to 2013. The increase was primarily driven by growth of the customer base from the expansion of the MetroPCS brand and an increase in promotional activities. In addition, the inclusion of MetroPCS operating results for the full year period following the business combination in April 2013 contributed to the increase.

Wholesale revenues increased $118 million, or 19%, in 2014, compared to 2013. The increase was primarily attributable to growth in customer programs and monthly plans, including data, offered by our MVNO partners and changes to our MVNO contractual arrangements.

Roaming and other service revenues decreased $78 million, or 23%, in 2014, compared to 2013, primarily due to a decline in early termination fees (“ETFs”) following our introduction of the no annual service contract feature of the Simple Choice plan launched in March 2013.

Equipment sales increased $1.8 billion, or 35%, in 2014, compared to 2013. The increase was primarily attributable to significant growth in the number of devices sold due to higher gross customer additions and higher device upgrade volumes, including JUMP! redemptions. The volume of device sales increased 48% in 2014, compared to 2013. Additionally, the

26

Table of Contents

inclusion of MetroPCS operating results for the full year period in 2014 following the business combination in April 2013 contributed to the increase. The increase was partially offset by reimbursements of other carriers’ ETFs and a lower average revenue per device sold.

We financed $5.8 billion of equipment sales revenues through EIP during 2014, an increase from $3.3 billion in 2013, resulting from growth of our Simple Choice plans. Additionally, customers had associated EIP billings of $3.6 billion in 2014, compared to $1.5 billion in 2013.

Other revenues increased $81 million, or 25%, in 2014, compared to 2013. The increase was primarily due to higher co-location rental income from leasing space on wireless communication towers to third parties and higher lease income associated with spectrum license lease agreements resulting from spectrum swap transactions.

Operating Expenses

Cost of services increased $509 million, or 10%, in 2014, compared to 2013. The increase was primarily due to the inclusion of MetroPCS operating results for the full year period in 2014 following the business combination in April 2013. Additionally, higher lease expense primarily relating to spectrum license lease agreements resulting from spectrum swap transactions contributed to the increase.

Cost of equipment sales increased $2.6 billion, or 38%, in 2014, compared to 2013. The increase was primarily attributable to significant growth in the number of devices sold due to higher gross customer additions and higher device upgrade volumes, including JUMP! redemptions. Additionally, the inclusion of MetroPCS operating results for the full year period in 2014 following the business combination in April 2013 contributed to the increase. The volume of device sales increased 48% in 2014, compared to 2013. The increase was partially offset by a lower average cost per device sold.

Selling, general and administrative increased $1.5 billion, or 20%, in 2014, compared to 2013. The increase was primarily due to higher employee-related costs as a result of increases in the number of retail and customer support employees, higher commissions driven by increased gross customer additions and higher promotional costs. Additionally, the inclusion of MetroPCS operating results for the full year period in 2014 following the business combination in April 2013 and higher stock-based compensation contributed to the increase.

Depreciation and amortization increased $785 million, or 22%, in 2014, compared to 2013. The increase was primarily associated with the build-out of the T-Mobile LTE network, which increased the depreciable asset base. Additionally, the inclusion of MetroPCS operating results for the full year period in 2014 following the business combination in April 2013, including accelerated depreciation related to the decommissioning of the MetroPCS CDMA network, contributed to the increase.

Cost of MetroPCS business combination of $299 million in 2014 primarily reflects network decommissioning costs associated with the business combination. In 2014, we began decommissioning the MetroPCS CDMA network and certain other redundant network cell sites. Network decommissioning costs, which are excluded from Adjusted EBITDA, primarily relate to the acceleration of lease costs for cell sites that would have otherwise been recognized as cost of services over the remaining lease term had we not decommissioned the cell sites. See Note 2 – Business Combination with MetroPCS of the Notes to the Consolidated Financial Statements included in Part II, Item 8 of this Form 10-K for further information. Cost of MetroPCS business combination of $108 million in 2013 reflects personnel-related costs and professional services costs associated with the business combination.

Gains on disposal of spectrum licenses of $840 million in 2014 primarily consisted of non-cash gains from spectrum license transactions with Verizon, and to a lesser extent, a non-cash gain from a spectrum license transaction with AT&T during the fourth quarter of 2014. See Note 6 – Goodwill, Spectrum Licenses and Other Intangible Assets of the Notes to the Consolidated Financial Statements included in Part II, Item 8 of this Form 10-K for further information.

Other, net decreased $49 million, or 91%, in 2014, compared to 2013. The decrease was primarily due to our 2013 restructuring program to align our operations to our new strategy and position the company for future growth. Costs associated with the 2013 restructuring program primarily consisted of severance and other personnel-related costs.

Other Income (Expense)

Interest expense increased $528 million, or 97%, in 2014, compared to 2013. The increase was primarily the result of higher debt balances in 2014 compared to 2013, including Senior Notes issued in 2013, the assumption of MetroPCS long-term debt in

27

Table of Contents

connection with the business combination in April 2013, the reclassification of non-reset notes from long-term debt to affiliates to long-term debt following Deutsche Telekom’s sale of the non-reset notes in October 2013, and to a lesser extent, the issuance of new senior unsecured notes in September 2014.

Interest expense to affiliates decreased $400 million, or 59%, in 2014, compared to 2013. The decrease was primarily due to lower debt balances with Deutsche Telekom in 2014, resulting from the recapitalization of T-Mobile prior to the business combination in April 2013 and Deutsche Telekom’s sale of non-reset notes in the aggregate principal amount of $5.6 billion in October 2013. To a lesser extent, additional decreases resulted from fair value adjustments related to embedded derivative instruments associated with the Senior Reset Notes issued to Deutsche Telekom in the recapitalization.

Interest income increased $170 million, or 90%, in 2014, compared to 2013. The increase was the result of significant growth in devices financed through EIP. Interest associated with EIP receivables is imputed at the time of sale and then recognized over the financed installment term.

Other income (expense), net decreased $100 million in 2014, compared to 2013. The decrease was primarily due to the recognition of foreign currency translation gains in 2013 related to the retirement of derivative instruments prior to the business combination in April 2013. This decrease was offset in part by a non-cash gain recognized in 2014 on the extinguishment of $1.0 billion of 7.875% Senior Notes due in 2018.

Income Taxes

Income tax expense increased $150 million in 2014, compared to 2013. The increase was primarily due to higher pre-tax income. The effective tax rate was 40.2% in 2014, compared to 31.4% in 2013. The increase in the effective tax rate for 2014 compared to 2013 was primarily due to an increase in the valuation allowance on certain state income tax attributes, which was partially offset by an increase in federal tax credits and a reduction in the effect of Puerto Rico taxes on the effective tax rate.

Net Income

Net income increased $212 million in 2014, compared to 2013, as a result of the factors described above.

Guarantor Subsidiaries

Pursuant to the indenture and the supplemental indentures, the long-term debt to affiliates and third parties, excluding capital leases, are fully and unconditionally guaranteed, jointly and severally, on a senior unsecured basis by T-Mobile US, Inc. (“Parent”) and certain of T-Mobile USA’s (“Issuer”) 100% owned subsidiaries (“Guarantor Subsidiaries”). In 2014, T-Mobile entered into a two-year arrangement to sell certain service accounts receivable on a revolving basis. In connection with the arrangement, the Company formed the Service BRE, which is included in the Non-Guarantor Subsidiaries condensed consolidating financial information. See Note 3 – Sales of Certain Receivables of the Notes to the Consolidated Financial Statements included in Part II, Item 8 of this Form 10-K for further information.

The financial condition of the Parent, Issuer and Guarantor Subsidiaries is substantially similar to the Company’s consolidated financial condition. Similarly, the results of operations of the Parent, Issuer and Guarantor Subsidiaries are substantially similar to the Company’s consolidated results of operations. As of December 31, 2014, the most significant components of the financial condition of the Non-Guarantor Subsidiaries were property and equipment of $537 million, tower obligations of $2.3 billion, and stockholders’ deficit of $1.5 billion. The most significant components of the results of operations of our Non-Guarantor Subsidiaries in 2013, were service revenues of $823 million offset by costs of equipment sales of $552 million, resulting in a net comprehensive loss of $52 million.


28

Table of Contents

Performance Measures

In managing our business and assessing financial performance, we supplement the information provided by the financial statements with other operating or statistical data and non-GAAP financial measures. These operating and financial measures are utilized by our management to evaluate our operating performance and, in certain cases, our ability to meet liquidity requirements. Although companies in the wireless industry may not define each of these measures in precisely the same way, we believe that these measures facilitate key operating performance comparisons with other companies in the wireless industry.

Total Customers

A customer is generally defined as a SIM card with a unique T-Mobile identity number which is associated with an account that generates revenue. Branded customers generally include customers that are qualified either for postpaid service utilizing phones or mobile broadband devices (including tablets), where they generally pay after incurring service, or prepaid service, where they generally pay in advance. Wholesale customers include M2M and MVNO customers that operate on our network, but are managed by wholesale partners.

The following table sets forth the number of ending customers:
(in thousands)
December 31,
2015
 
December 31,
2014
 
December 31,
2013
Customers, end of period


Branded postpaid phone customers
29,355

 
25,844

 
21,797

Branded postpaid mobile broadband customers
2,340

 
1,341

 
502

Total branded postpaid customers
31,695

 
27,185

 
22,299

Branded prepaid customers
17,631

 
16,316

 
15,072

Total branded customers
49,326

 
43,501

 
37,371

Wholesale customers
13,956

 
11,517

 
9,313

Total customers, end of period
63,282

 
55,018

 
46,684


The following table sets forth the number of net customer additions:
 
Year Ended December 31,
(in thousands)
2015
 
2014
 
2013
Net customer additions


Branded postpaid phone customers
3,511

 
4,047

 
1,938

Branded postpaid mobile broadband customers
999

 
839

 
68

Total branded postpaid customers
4,510

 
4,886

 
2,006

Branded prepaid customers
1,315

 
1,244

 
328

Total branded customers
5,825

 
6,130

 
2,334

Wholesale customers
2,439

 
2,204

 
2,043

Total net customer additions
8,264

 
8,334

 
4,377

Acquired customers
—

 
—

 
8,918


Net customer additions were 8,264,000 in 2015, compared to net customer additions of 8,334,000 in 2014. At December 31, 2015, we had 63.3 million customers, a 15% increase from the customer total as of December 31, 2014, as a result of growth in the customer categories described below.

Net customer additions were 8,334,000 in 2014, compared to 4,377,000 net customer additions, excluding customers acquired as a result of the MetroPCS business combination, in 2013. At December 31, 2014, we had 55.0 million customers, an 18% increase from the customer total as of December 31, 2013, as a result of growth in the customer categories described below.

Branded Customers

Branded postpaid phone net customer additions were 3,511,000 in 2015, compared to 4,047,000 in 2014. Branded postpaid phone net customer additions remained strong in 2015 driven by positive customer response to our Un-carrier initiatives, ongoing network improvements and promotional activities. Branded postpaid phone gross customer additions in 2015 were lower compared to 2014, which included the introduction of Un-carrier 4.0 Contract Freedom and certain attractive family rate

29

Table of Contents

plan promotions. Included in the branded postpaid phone net customer additions were approximately 765,000 qualified branded prepaid customers upgrading to branded postpaid plans in 2015, compared to approximately 420,000 in 2014.

Branded postpaid phone net customer additions were 4,047,000 in 2014, compared to branded postpaid phone net customer additions of 1,938,000 in 2013. The increase in customer development was attributable to increased new customer activations and improved branded postpaid phone churn driven by the continued success of our Un-carrier proposition and strong customer response to promotions for services and devices. Additional increases in customer development resulted from the launch of new popular devices.

Branded postpaid mobile broadband net customer additions were 999,000 in 2015, compared to 839,000 in 2014. The increase was primarily attributable to higher gross customer additions driven by promotions for mobile broadband devices, partially offset by higher deactivations resulting from the discontinuation of certain promotional pricing for mobile broadband services and ongoing competitive activity in the marketplace.

Branded postpaid mobile broadband net customer additions were 839,000 in 2014, compared to branded postpaid mobile broadband net customer additions of 68,000 in 2013. The significant increase was driven by strong customer response to promotions for mobile broadband services and devices.

Branded prepaid net customer additions were 1,315,000 in 2015, compared to 1,244,000 in 2014. The increase was primarily attributable to higher gross customer additions driven by the success of our MetroPCS brand promotional activities and continued growth in expansion markets. Included in the branded prepaid net customer additions were approximately 765,000 qualified branded prepaid customers upgrading to branded postpaid plans in 2015, compared to approximately 420,000 in 2014.

Branded prepaid net customer additions were 1,244,000 in 2014, compared to 328,000 branded prepaid net customer additions, excluding customers of MetroPCS acquired as a result of the business combination, in 2013. The increase in customer development was attributable to higher branded prepaid gross customer additions due to the growth and expansion of the MetroPCS brand, including the launch into additional markets following the MetroPCS business combination in April 2013. This increase was offset, in part, by higher deactivations from the competitive environment in the prepaid market.

Wholesale

Wholesale net customer additions were 2,439,000 in 2015, compared to 2,204,000 in 2014. The increase was primarily attributable to higher MVNO gross customer additions, partially offset by higher MVNO deactivations.

Wholesale net customer additions were 2,204,000 in 2014, compared to wholesale net customer additions of 2,043,000 in 2013. The increase was primarily attributable to higher M2M gross customer additions resulting from strong activation volume, partially offset by a decrease in MVNO net customer additions driven by higher churn. T-Mobile offers its M2M customers innovative products and solutions to assist them in embracing the Internet of Things (“IoT”). MVNO customers continued to grow, although at a slower rate in 2014 than 2013. MVNO partners often have relationships with multiple carriers and through steering their business towards carriers offering promotions, can impact specific carriers’ results.

Customers Per Account

Customers per account is calculated by dividing the number of branded postpaid customers as of the end of the period by the number of branded postpaid accounts as of the end of the period. An account may include branded postpaid phone and mobile broadband customers. We believe branded postpaid customers per account provides management with useful information to evaluate our branded postpaid customer base on a per account basis.
 
Year Ended December 31,
2015
 
2014
 
2013
Branded postpaid customers per account
2.54

 
2.36

 
2.18


Branded postpaid customers per account were 2.54 as of December 31, 2015, compared to 2.36 as of December 31, 2014. The increase was primarily driven by service promotions targeting families and increased penetration of mobile broadband devices.


30

Table of Contents

Branded postpaid customers per account were 2.36 as of December 31, 2014, compared to 2.18 as of December 31, 2013. The increase was primarily due to an increase in the average number of branded postpaid phone customers per account resulting from promotions for services, including the “4 for $100” offer, and increased penetration of mobile broadband devices.

Churn

Churn represents the number of customers whose service was disconnected as a percentage of the average number of customers during the specified period. The number of customers whose service was disconnected is presented net of customers that subsequently have their service restored. We believe that churn provides management with useful information to evaluate customer retention and loyalty.
 
Year Ended December 31,
2015
 
2014
 
2013
Branded postpaid phone churn
1.39
%
 
1.58
%
 
1.69
%
Branded prepaid churn
4.45
%
 
4.76
%
 
5.37
%

Branded postpaid phone churn was 1.39% in 2015, a 19 basis point improvement compared to 1.58% in 2014. The improvement in branded postpaid phone churn reflects ongoing improvements to network quality, customer service and the overall value of our offerings in the marketplace, resulting in increased customer satisfaction and loyalty.

Branded postpaid phone churn was 1.58% in 2014, an 11 basis point improvement compared to 1.69% in 2013. The improvement in branded postpaid phone churn was impacted by the continued success of our Un-carrier initiatives resulting in increased customer loyalty.

Branded prepaid churn was 4.45% in 2015, compared to 4.76% in 2014. Branded prepaid churn for 2015 was impacted by a methodology change during 2015 that had no impact on our reported branded prepaid ending customers or net customer additions, but resulted in computationally lower gross customer additions and deactivations. Revision of prior periods was not practicable because certain historical data was no longer available.

Branded prepaid churn was 4.76% in 2014, a 61 basis point improvement compared to 5.37% in 2013. The improvement was primarily due to the inclusion and growth of MetroPCS customers, which represent the largest portion of the branded prepaid customer base and historically have lower rates of churn than T-Mobile branded prepaid customers.

Average Revenue Per User, Average Billings Per User, Average Revenue Per Account and Average Billings Per Account

Average Revenue Per User (“ARPU”) represents the average monthly service revenue earned from customers. We believe ARPU provides management, investors and analysts with useful information to assess and evaluate our service revenue realization per customer and assist in forecasting our future service revenues generated from our customer base. Branded postpaid phone ARPU excludes mobile broadband customers and related revenues.

Average Billings Per User (“ABPU”) represents the average monthly customer billings, including monthly lease revenues and EIP billings, per customer. We believe branded postpaid ABPU provides management, investors and analysts with useful information to evaluate average branded postpaid customer billings as it is indicative of estimated cash collections, including device financing payments, from our customers each month.

Average Revenue Per Account (“ARPA”) represents the average monthly branded postpaid service revenue earned per account. An account may include branded postpaid phone and mobile broadband customers.

Average Billings Per Account (“ABPA”) represents the average monthly branded postpaid customer billings, including monthly lease revenues and EIP billings, per account.

To streamline the number of key performance metrics T-Mobile discloses, we will discontinue reporting branded postpaid ARPA and ABPA after the fourth quarter of 2015.  Going forward, we will continue reporting branded postpaid customers per account which may be used, along with our branded postpaid service revenues, to assess performance on a per account basis.


31

Table of Contents

The following tables illustrate the calculation of ARPU and ABPU and reconcile these measures to the related service revenues, which we consider to be the most directly comparable GAAP financial measure to ARPU and ABPU:
 
Year Ended December 31,
(in millions, except average number of customers, ARPU and ABPU)
2015
 
2014
 
2013
Calculation of Branded Postpaid Phone ARPU


Branded postpaid service revenues
$
16,383

 
$
14,392

 
$
13,166

Less: Branded postpaid mobile broadband revenues
(588
)
 
(261
)
 
(169
)
Branded postpaid phone service revenues
$
15,795

 
$
14,131

 
$
12,997

Divided by: Average number of branded postpaid phone customers (in thousands) and number of months in period
27,604

 
23,817

 
20,424

Branded postpaid phone ARPU
$
47.68

 
$
49.44

 
$
53.03


Calculation of Branded Postpaid ABPU


Branded postpaid service revenues
$
16,383

 
$
14,392

 
$
13,166

EIP billings
5,494

 
3,596

 
1,471

Lease revenues
224

 
—

 
—

Total billings for branded postpaid customers
$
22,101

 
$
17,988

 
$
14,637

Divided by: Average number of branded postpaid customers (in thousands) and number of months in period
29,341

 
24,683

 
20,858

Branded postpaid ABPU
$
62.77

 
$
60.73

 
$
58.48


Calculation of Branded Prepaid ARPU


Branded prepaid service revenues
$
7,553

 
$
6,986

 
$
4,945

Divided by: Average number of branded prepaid customers (in thousands) and number of months in period
16,704

 
15,691

 
11,913

Branded prepaid ARPU
$
37.68

 
$
37.10

 
$
34.59


The following tables illustrate the calculation of ARPA and ABPA and reconcile these measures to the related service revenues, which we consider to be the most directly comparable GAAP financial measure to ARPA and ABPA:
 
Year Ended December 31,
(in millions, except average number of accounts, ARPA and ABPA)
2015
 
2014
 
2013
Calculation of Branded Postpaid ARPA


Branded postpaid service revenues
$
16,383

 
$
14,392

 
$
13,166

Divided by: Average number of branded postpaid accounts (in thousands) and number of months in period
12,028

 
11,008

 
9,638

Branded postpaid ARPA
$
113.50

 
$
108.95

 
$
113.84


Calculation of Branded Postpaid ABPA


Branded postpaid service revenues
$
16,383

 
$
14,392

 
$
13,166

EIP billings
5,494

 
3,596

 
1,471

Lease revenues
224

 
—

 
—

Total billings for branded postpaid customers
$
22,101

 
$
17,988

 
$
14,637

Divided by: Average number of branded postpaid accounts (in thousands) and number of months in period
12,028

 
11,008

 
9,638

Branded postpaid ABPA
$
153.12

 
$
136.17

 
$
126.55


Branded Postpaid Phone ARPU and Branded Postpaid ABPU:

Branded postpaid phone ARPU decreased $1.76, or 4%, for 2015, compared to 2014. The decrease was primarily attributable to dilution from the continued growth of customers on Simple Choice plans and promotions targeting families. The decrease was partially offset by an increase in regulatory program revenues.

Branded postpaid phone ARPU decreased $3.59, or 7%, for 2014, compared to 2013. The decrease was primarily due to the continued growth of customers on Simple Choice plans, which have lower monthly service charges compared to traditional bundled plans, and promotions for services, including the “4 for $100” offer.
 

32

Table of Contents

Branded postpaid ABPU increased $2.04, or 3%, for 2015, compared to 2014. The increase was primarily attributable to growth in devices financed by customers through the EIP and JUMP! on Demand programs, partially offset by lower branded postpaid phone ARPU, as described above.
 
Branded postpaid ABPU increased $2.25, or 4%, for 2014, compared to 2013. The increase was primarily due to growth in devices financed through EIP, offset in part by lower branded postpaid phone ARPU.

Branded Prepaid ARPU:

Branded prepaid ARPU increased $0.58, or 2%, for 2015, compared to 2014. The increase was primarily attributable to an increase in the mix of branded prepaid customers choosing plans with more data, which generate a higher ARPU, partially offset by dilution from growth of customers on rate plan promotions.

Branded prepaid ARPU increased $2.51, or 7%, for 2014, compared to 2013. The increase was primarily due to the inclusion and growth of the MetroPCS customer base, which generate higher ARPU than the rest of T-Mobile’s branded prepaid customers.

Branded Postpaid ARPA and Branded Postpaid ABPA:

Branded postpaid ARPA increased $4.55, or 4%, for 2015, compared to 2014. The increase was primarily attributable to an increasing number of branded postpaid phone and mobile broadband customers per account and an increase in regulatory program revenues, partially offset by dilution from continued growth of customers on promotions targeting families.

Branded postpaid ARPA decreased $4.89, or 4%, for 2014, compared to 2013. The decrease was primarily due to the continued growth of customers on Simple Choice plans, which have lower monthly service charges compared to traditional bundled plans, and promotions for services, including the “4 for $100” offer.
 
Branded postpaid ABPA increased $16.95, or 12%, for 2015 compared to 2014. The increase was primarily attributable to growth in devices financed by customers through the EIP and JUMP! on Demand programs and an increase in branded postpaid ARPA, as described above.

Branded postpaid ABPA increased $9.62, or 8%, for 2014 compared to 2013. The increase was primarily due to growth in devices financed through EIP, offset in part by lower branded postpaid ARPA, as described above.

Adjusted EBITDA

Adjusted EBITDA represents earnings before interest expense (net of interest income), tax, depreciation, amortization, stock-based compensation and expenses not reflective of T-Mobile’s operating performance. Adjusted EBITDA margin represents Adjusted EBITDA divided by service revenues.

Adjusted EBITDA is a non-GAAP financial measure utilized by our management to monitor the financial performance of our operations. We use Adjusted EBITDA internally as a metric to evaluate and compensate our personnel and management for their performance, and as a benchmark to evaluate our operating performance in comparison to our competitors. Management believes analysts and investors use Adjusted EBITDA as a supplemental measure to evaluate overall operating performance and facilitate comparisons with other wireless communications companies because it is more indicative of our ongoing performance and trends by excluding certain expenses which are either nonrecurring or may not be indicative of our directly controllable operating results. Adjusted EBITDA has limitations as an analytical tool and should not be considered in isolation or as a substitute for income from operations, net income or any other measure of financial performance reported in accordance with GAAP.


33

Table of Contents

The following table illustrates the calculation of Adjusted EBITDA and reconciles Adjusted EBITDA to net income, which we consider to be the most directly comparable GAAP financial measure:
 
Year Ended December 31,
(in millions)
2015
 
2014
 
2013
Net income
$
733

 
$
247

 
$
35

Adjustments:


Interest expense
1,085

 
1,073

 
545

Interest expense to affiliates
411

 
278

 
678

Interest income
(420
)
 
(359
)
 
(189
)
Other expense (income), net
11

 
11

 
(89
)
Income tax expense
245

 
166

 
16

Operating income
2,065

 
1,416

 
996

Depreciation and amortization
4,688

 
4,412

 
3,627

Cost of MetroPCS business combination
376

 
299

 
108

Stock-based compensation (1)
222

 
211

 
100

Gains on disposal of spectrum licenses (1)
—

 
(720
)
 
—

Other, net (1)
42

 
18

 
54

Adjusted EBITDA
$
7,393

 
$
5,636

 
$
4,885

Adjusted EBITDA margin
30
%
 
25
%
 
26
%
(1)
Stock-based compensation includes payroll tax impacts and may not agree to stock-based compensation expense in the consolidated financial statements. Gains on disposal of spectrum licenses and Other, net transactions may not agree to the Consolidated Statements of Comprehensive Income (Loss) primarily due to certain routine operating activities, such as routine spectrum license exchanges that would be expected to reoccur, and are therefore included in Adjusted EBITDA.

Adjusted EBITDA increased 31% for 2015, compared to 2014. Adjusted EBITDA benefited from increased branded postpaid and prepaid revenues driven by strong customer response to our Un-carrier initiatives and the ongoing success of our promotional activities. Additionally, Adjusted EBITDA was positively impacted by focused cost control and synergies realized from the MetroPCS business combination, especially in cost of services. Decreased losses on equipment also contributed to the increase in Adjusted EBITDA primarily due to the impact of customers shifting to leasing devices with JUMP! On Demand as the related costs are capitalized and depreciated over the lease term and are excluded from Adjusted EBITDA. In connection with JUMP! On Demand, we had lease revenues of $224 million and depreciation expense of $312 million related to leased wireless devices in 2015. These increases were partially offset by higher selling, general and administrative expenses.

Adjusted EBITDA increased 15% for 2014, compared to 2013. Adjusted EBITDA was positively impacted by increased branded postpaid revenues resulting from the continued success of our Un-carrier value proposition and strong customer response to promotional activities, as well as the inclusion of MetroPCS operating results since the business combination in 2013, including branded prepaid revenue growth from expansion of the MetroPCS brand. This increase was partially offset by higher selling, general and administrative expenses and losses on equipment sales.

Free Cash Flow

Free Cash Flow represents net cash provided by operating activities less payments for purchases of property and equipment. Free Cash Flow is a non-GAAP financial measure utilized by our management, investors and analysts of T-Mobile’s financial information to evaluate cash available to pay debt and provide further investment in the business.

The following table illustrates the calculation of Free Cash Flow and reconciles Free Cash Flow to net cash provided by operating activities, which we consider to be the most directly comparable GAAP financial measure:
 
Year Ended December 31,
(in millions)
2015
 
2014
 
2013
Net cash provided by operating activities
$
5,414

 
$
4,146

 
$
3,545

Cash purchases of property and equipment
(4,724
)
 
(4,317
)
 
(4,025
)
Free Cash Flow
$
690

 
$
(171
)
 
$
(480
)

Free Cash Flow increased $861 million for 2015, compared to 2014, and $309 million for 2014, compared to 2013. The increases were primarily due to higher net cash provided by operating activities resulting from total revenue growth in excess

34

Table of Contents

of total operating expense growth, partially offset by higher purchases of property and equipment. See Liquidity and Capital Resources for further information.

Liquidity and Capital Resources

Our principal sources of liquidity are our cash and cash equivalents and cash generated from operations, proceeds from issuance of long-term debt, common and preferred stock, the sale of certain receivables and financing arrangements of vendor payables which effectively extend payment terms. In addition, we maintain an unsecured revolving credit facility with Deutsche Telekom that allows for up to $500 million in borrowings.

As of December 31, 2015, our cash and cash equivalents were $4.6 billion and our short-term investments were $3.0 billion. We generated net cash provided by operating activities of $5.4 billion in 2015, compared to $4.1 billion in 2014 and $3.5 billion in 2013. As of December 31, 2015, our total debt was $26.3 billion, excluding our tower obligations as described Note 9 – Tower Obligations of the Notes to the Consolidated Financial Statements included in Part II, Item 8 of this Form 10-K.

The following were the primary changes in sources of liquidity in 2015:

•
We issued new Senior Notes to third parties in aggregate principal amounts of $2.0 billion and incurred $2.0 billion of Senior Secured Term Loans in the fourth quarter of 2015.
•
We entered into master lease agreements with certain partners, which provide us with the ability to enter into capital lease agreements for network equipment up to $750 million. In 2015, we entered into capital lease agreements of $470 million.
•
We introduced JUMP! On Demand, which allows eligible customers the option to lease their devices over a period of up to 18 months. If the mix of devices financed through EIP or leases continue to increase, device financing programs will continue to require a greater use of operating cash flows in the short term since cash collections are received over the EIP or lease term.
•
As an additional source of liquidity, we entered into an $800 million arrangement to sell certain EIP receivables on a revolving basis of which $150 million is scheduled to expire July 2016 and $650 million is scheduled to expire November 2017. See Note 3 – Sales of Certain Receivables of the Notes to the Consolidated Financial Statements included in Part II, Item 8 of this Form 10-K for further information.

We could seek additional sources of liquidity through the issuance of long-term debt in 2016 to continue to opportunistically acquire spectrum licenses in private party transactions and future FCC spectrum license auctions, including the broadcast incentive auction in 2016. In addition to the $4.0 billion in proceeds from the issuance of Senior Notes to third parties and Senior Secured Term Loans in 2015, we believe we have the capacity to raise an additional $6.0 billion in debt to fund such spectrum acquisitions, subject to market and other conditions, without adversely impacting our credit ratings. Excluding any additional liquidity needed to acquire spectrum, we expect our principal sources of funding to be sufficient to meet our anticipated liquidity requirements in the next 12 months and intend to use our principal sources of funding for general corporate purposes, including capital investments other than spectrum licenses, and enhancing our financial flexibility.

We determine future liquidity requirements, for both operations and capital expenditures, based in large part upon projected financial and operating performance, and opportunities to acquire additional spectrum. We regularly review and update these projections for changes in current and projected financial and operating results, general economic conditions, the competitive landscape and other factors. There are a number of risks and uncertainties that could cause our financial and operating results and capital requirements to differ materially from our projections, which could cause future liquidity to differ materially from our assessment.

The indentures and credit facilities governing our long-term debt to affiliates and third parties, excluding capital leases, contain covenants that, among other things, limit our ability to: incur more debt; pay dividends and make distributions on our common stock; make certain investments; repurchase stock; create liens or other encumbrances; enter into transactions with affiliates; enter into transactions that restrict dividends or distributions from subsidiaries; and merge, consolidate, or sell, or otherwise dispose of, substantially all of their assets. Certain provisions of each of the credit facilities, indentures and supplemental indentures relating to the long-term debt to affiliates and third parties restrict the ability of the Issuer to loan funds or make payments to the Parent. However, the Issuer is allowed to make certain permitted payments to the Parent under the terms of each of the credit facilities, indentures and supplemental indentures relating to the long-term debt to affiliates and third parties. We were in compliance with all restrictive debt covenants as of December 31, 2015.


35

Table of Contents

Capital Expenditures

Our liquidity requirements have been driven primarily by capital expenditures for spectrum licenses and the construction, expansion and upgrading of our network infrastructure.

The property and equipment capital expenditures primarily relate to our network modernization, including the build out of LTE 700 MHz A-Block spectrum licenses. We expect cash capital expenditures for property and equipment to be in the range of $4.5 billion to $4.8 billion in 2016. This does not include property and equipment obtained through capital lease agreements, leased wireless devices transferred from inventory or purchases of spectrum licenses.

Cash Flows

The following table summarizes the Consolidated Statements of Cash Flows:
 
Year Ended December 31,
(in millions)
2015
 
2014
 
2013
Net cash provided by operating activities
$
5,414

 
$
4,146

 
$
3,545

Net cash used in investing activities
(9,560
)
 
(7,246
)
 
(2,092
)
Net cash provided by financing activities
3,413

 
2,524

 
4,044


Operating Activities

Cash provided by operating activities was $5.4 billion in 2015, compared to $4.1 billion in 2014. Cash provided by operating activities increased in 2015 primarily as a result of increased operating income from growth of branded postpaid and branded prepaid revenues partially offset by higher selling, general and administrative costs. Additionally, proceeds from the sale of certain EIP receivables contributed to the increase. This increase was partially offset by the timing of working capital payments and device financing through EIP and the introduction of T-Mobile’s JUMP! On Demand wireless device leasing program.

Cash provided by operating activities was $4.1 billion in 2014, compared to $3.5 billion in 2013. The increase in cash flow provided by operating activities was driven by several factors. Our operating income, exclusive of non-cash items such as depreciation and amortization and gains from spectrum license transactions, increased slightly compared to the prior year. This was primarily a result of increases in branded postpaid revenues due to our acceleration of customer growth partially offset by higher selling, general and administrative costs and losses on equipment sales. Net changes in working capital increased slightly. This was primarily a result of increases in accounts payable and accrued liabilities due to the timing of vendor payments and proceeds from the sales of certain service receivables related to the factoring arrangement. The increases in working capital were mostly offset by increases in EIP receivables as a result of significant growth in devices financed through EIP and increases in inventories.

Investing Activities

Cash used in investing activities was $9.6 billion in 2015, compared to $7.2 billion used in 2014. In 2015, cash used in investing activities consisted of purchases of property and equipment of $4.7 billion due primarily to the build out of our LTE network, purchases of short-term investments of $3.0 billion and purchases of intangible assets of $1.9 billion primarily due to $1.4 billion of AWS spectrum licenses acquired through the AWS auction conducted by the FCC.

Cash used in investing activities was $7.2 billion in 2014, compared to $2.1 billion used in 2013. In 2014, cash used in investing activities primarily consisted of purchases of property and equipment of $4.3 billion as a result of our network modernization and purchases of intangible assets of $2.9 billion due primarily to the acquisition of 700 MHz A-Block spectrum licenses. In 2013, cash used in investing activities primarily consisted of purchases of property and equipment of $4.0 billion as a result of our network modernization. This was partially offset by cash and cash equivalents acquired in connection with the business combination with MetroPCS of $2.1 billion and the settlement of a short-term loan receivable, net with Deutsche Telekom of $300 million.


36

Table of Contents

Financing Activities

Cash provided by financing activities was $3.4 billion in 2015, compared to $2.5 billion in 2014. In 2015, cash provided by financing activities consisted of proceeds from issuance of long-term debt of $4.0 billion partially offset by net repayments of short-term debt of $564 million.

Cash provided by financing activities was $2.5 billion in 2014, compared to $4.0 billion in 2013. The decrease was primarily due to higher repayments of long-term debt of $1.0 billion, lower net proceeds from the issuance of stock of $805 million, higher net repayments of short-term debt of $174 million and lower proceeds from the exercise of stock options of $110 million. The decrease was partially offset by higher net proceeds from the issuance of long-term debt of $499 million.

Contractual Obligations

The following table summarizes our contractual obligations and borrowings as of December 31, 2015 and the timing and effect that such commitments are expected to have on our liquidity and capital requirements in future periods:
(in millions)
Less Than 1 Year
 
1 - 3 Years
 
4 - 5 Years
 
More Than 5 Years
 
Total
Long-term debt (1)
$
20

 
$
540

 
$
6,040

 
$
18,600

 
$
25,200

Interest on long-term debt
1,559

 
3,194

 
2,860

 
2,804

 
10,417

Capital lease obligations, including interest
199

 
347

 
184

 
267

 
997

Tower obligations (2)
179

 
360

 
361

 
1,315

 
2,215

Operating leases
2,379

 
4,281

 
3,579

 
5,583

 
15,822

Purchase obligations (3)
2,865

 
3,922

 
1,343

 
1,304

 
9,434

Network decommissioning (4)
129

 
175

 
109

 
82

 
495

Total contractual obligations
$
7,330

 
$
12,819

 
$
14,476

 
$
29,955

 
$
64,580

(1)
Represents principal amounts of long-term debt to affiliates and third parties at maturity, excluding unamortized premium from purchase price allocation fair value adjustment, capital lease obligations and vendor financing arrangements. See Note 8 – Debt of the Notes to the Consolidated Financial Statements included in Part II, Item 8 of this Form 10-K for further information.
(2)
Future minimum payments, including principal and interest payments and imputed lease rental income, related to the tower obligations. See Note 9 – Tower Obligations of the Notes to the Consolidated Financial Statements included in Part II, Item 8 of this Form 10-K for further information.
(3)
T-Mobile calculated the minimum obligation for certain agreements to purchase goods or services based on termination fees that can be paid to exit the contract. Termination penalties are included in the above table as payments due in less than one year, as this is the earliest T-Mobile could exit these contracts. For certain contracts that include fixed volume purchase commitments and fixed prices for various products, the purchase obligations are calculated using fixed volumes and contractually fixed prices for the products that are expected to be purchased. This table does not include open purchase orders as of December 31, 2015 under normal business purposes. See Note 13 – Commitments and Contingencies of the Notes to the Consolidated Financial Statements included in Part II, Item 8 of this Form 10-K for further information.
(4)
Represents future undiscounted cash flows related to decommissioned MetroPCS CDMA network and certain other redundant cell sites as of December 31, 2015. See Note 2 – Business Combination with MetroPCS of the Notes to the Consolidated Financial Statements included in Part II, Item 8 of this Form 10-K for further information.

Certain commitments and obligations are included in the table based on the year of required payment or an estimate of the year of payment. Other long-term liabilities, excluding network decommissioning, have been omitted from the table above due to the uncertainty of the timing of payments, combined with the absence of historical trending to be used as a predictor of such payments. In addition, because dividends on preferred stock are subject to approval by our Board of Directors, amounts are not included in the preceding table unless such authorization has occurred and the dividend has not been paid. See Note 14 – Additional Financial Information of the Notes to the Consolidated Financial Statements included in Part II, Item 8 of this Form 10-K for further information.

The purchase obligations reflected in the table above are primarily commitments to purchase handsets and accessories, equipment, software, programming and network services, and marketing activities, which will be used or sold in the ordinary course of business. These amounts do not represent T-Mobile’s entire anticipated purchases in the future, but represent only those items for which T-Mobile is contractually committed. Where T-Mobile is committed to make a minimum payment to the supplier regardless of whether it takes delivery, T-Mobile has included only that minimum payment as a purchase obligation. Additionally, included within purchase obligations are amounts for the acquisition of spectrum licenses, which are subject to regulatory approval and other customary closing conditions.


37

Table of Contents

Off-Balance Sheet Arrangements

In the fourth quarter of 2015, we entered into an arrangement to sell certain EIP accounts receivable on a revolving basis through November 2017 as an additional source of liquidity. In 2014, we entered into an arrangement, as amended, to sell certain service accounts receivable on a revolving basis through March 2017 as an additional source of liquidity. As of December 31, 2015, T-Mobile derecognized net receivables of $1.9 billion upon sale through these arrangements.  See Note 3 – Sales of Certain Receivables of the Notes to the Consolidated Financial Statements included in Part II, Item 8 of this Form 10-K for further information.

Related Party Transactions

See Note 14 – Additional Financial Information of the Notes to the Consolidated Financial Statements included in Part II, Item 8 of this Form 10-K for information regarding related party transactions.

Disclosure of Iranian Activities under Section 13(r) of the Securities Exchange Act of 1934

Section 219 of the Iran Threat Reduction and Syria Human Rights Act of 2012 added Section 13(r) to the Exchange Act of 1934, as amended (“Exchange Act”).  Section 13(r) requires an issuer to disclose in its annual or quarterly reports, as applicable, whether it or any of its affiliates knowingly engaged in certain activities, transactions or dealings relating to Iran or with designated natural persons or entities involved in terrorism or the proliferation of weapons of mass destruction.  Disclosure is required even where the activities, transactions or dealings are conducted outside the U.S. by non-U.S. affiliates in compliance with applicable law, and whether or not the activities are sanctionable under U.S. law.

As of the date of this report, we are not aware of any activity, transaction or dealing by us or any of our affiliates in 2015 that requires disclosure in this report under Section 13(r) of the Exchange Act, except as set forth below with respect to affiliates that we do not control and that are our affiliates solely due to their common control with Deutsche Telekom. We have relied upon Deutsche Telekom for information regarding their activities, transactions and dealings.

Deutsche Telekom, through certain of its non-U.S. subsidiaries, is party to roaming and interconnect agreements with the following mobile and fixed line telecommunication providers in Iran, some of which are or may be government-controlled entities: Gostaresh Ertebatat Taliya, Irancell Telecommunications Services Company (“MTN Irancell”), Telecommunication Kish Company, Mobile Telecommunication Company of Iran, and Telecommunication Infrastructure Company of Iran. In 2015, gross revenues of all Deutsche Telekom affiliates generated by roaming and interconnection traffic with Iran were less than $1 million and estimated net profits were less than $1 million.

In addition, Deutsche Telekom, through certain of its non-U.S. subsidiaries, operating a fixed line network in their respective European home countries (in particular Germany), provides telecommunications services in the ordinary course of business to the Embassy of Iran in those European countries. Gross revenues and net profits recorded from these activities in 2015 were less than $0.1 million. We understand that Deutsche Telekom intends to continue these activities.

Critical Accounting Policies and Estimates

Our significant accounting policies are fundamental to understanding our financial condition and results as they require the use of estimates and assumptions which affect the financial statements and accompanying notes. See Note 1 – Summary of Significant Accounting Policies of the Notes to the Consolidated Financial Statements included in Part II, Item 8 of this Form 10-K for further information.

These policies are critical because they require management to make difficult, subjective and complex judgments about matters that are inherently uncertain. These estimates are inherently subject to judgment and actual results could differ from those estimates.
Allowances

We maintain an allowance for estimated losses inherent in the accounts receivable portfolio. When determining the allowance, we consider a number of factors, including historical experience and current collection trends, aging of the receivable portfolio, credit quality of the customer base and other qualitative factors such as macro-economic conditions.

Credit collection risks are assessed for each type of receivable, such as EIP receivables, based upon historical and expected write-offs, net of recoveries, and an analysis of the aged accounts receivable balances with reserves generally increasing as the

38

Table of Contents

receivable ages. To the extent that actual loss experience differs significantly from historical trends or assumptions, the required allowance amounts could differ from the estimate. We write off account balances if collection efforts are unsuccessful and the receivable balance is deemed uncollectible, based on customer credit ratings and the length of time from the original billing date.

We offer certain retail customers the option to pay for devices and other accessories in installments using an EIP. At the time of an installment sale, we impute a discount for interest as there is no stated rate of interest on the EIP receivables and record the EIP receivables at their present value, which is determined by discounting future payments at the imputed interest rate. The difference between the present value of the EIP receivables and their face amount results in a discount which is recorded as a direct reduction to the carrying value with a corresponding reduction to equipment revenues. We determine the imputed discount rate based primarily on current market interest rates and the amount of expected credit losses on the EIP receivables. As a result, we do not recognize a separate valuation allowance at the time of issuance as the effects of uncertainty about future cash flows are included in the initial present value measurement of the receivable. The imputed discount on EIP receivables is amortized over the financed installment term using the effective interest method and recognized as interest income in Other income (expense), net.

Subsequent to the initial determination of the imputed discount, we assess the need for and, if necessary, recognize an allowance for credit losses to the extent the amount of estimated probable losses on the gross EIP receivables exceed the remaining unamortized imputed discount balances. 

Total imputed discount and allowances as of December 31, 2015 and 2014 was approximately 8.2% and 7.4%, respectively, of the total amount of gross accounts receivable, including EIP receivables.

Depreciation

Depreciation commences once assets have been placed in service and is generally computed using the straight-line method over the estimated useful life of each asset. Leased wireless devices are depreciated to their estimated residual value over the period expected to provide utility to T-Mobile, which is generally the lease term. Depreciable life studies are performed periodically to confirm the appropriateness of depreciable lives for certain categories of property, plant and equipment. These studies take into account actual usage, physical wear and tear, replacement history, assumptions about technology evolution and expected loss of leased wireless devices. When these factors indicate that an asset’s useful life is different from the previous assessment, the remaining book values are depreciated prospectively over the adjusted remaining estimated useful life. See Note 1 – Summary of Significant Accounting Policies and Note 5 – Property and Equipment of the Notes to the Consolidated Financial Statements included in Part II, Item 8 of this Form 10-K for information regarding depreciation of assets, including management’s underlying estimates of useful lives.

Evaluation of Goodwill and Indefinite-Lived Intangible Assets for Impairment

We assess the carrying value of goodwill and other indefinite-lived intangible assets (spectrum licenses) for potential impairment annually as of December 31 or more frequently if events or changes in circumstances indicate that assets might be impaired.

We may elect to first perform a qualitative assessment to determine whether it is more likely than not the fair value of the single reporting unit is less than its carrying amount as a basis for determining whether it is necessary to perform the two-step goodwill impairment test. If we do not perform a qualitative assessment, or if the qualitative assessment indicates it is more likely than not the fair value of the single reporting unit is less than its carrying amount, goodwill is tested for impairment based on a two-step test. In the first step, we compare the fair value of the reporting unit to its carrying value. The fair value of the reporting unit is determined using a market approach, which is based on market capitalization. We recognize market capitalization is subject to volatility and will monitor changes in market capitalization to determine whether declines, if any, necessitate an interim impairment review. In the event market capitalization does decline below its book value, we will consider the length, severity and reasons for the decline when assessing whether potential impairment exists, including considering whether a control premium should be added to the market capitalization. We believe short-term fluctuations in share price may not necessarily reflect the underlying aggregate fair value. Prior to the business combination, we estimated the fair value of the reporting unit using a discounted cash flow approach due to the absence of comparable observable market data.  The discounted cash flow method utilizes future cash flow assumptions based on estimates of revenues, EBITDA margin and a long-term growth rate taking into consideration expected industry and market conditions. The cash flows are then discounted using a weighted average cost of capital reflecting the risks associated with the business and the projected cash flows. If the carrying amount of the reporting unit exceeds the fair value, the second step of the test is performed.


39

Table of Contents

In the second step, we determine the fair values of all of the assets and liabilities of the reporting unit, including those that currently may not be recorded. The excess of the fair value of the reporting unit over the sum of the fair value of all of those assets and liabilities represents the implied goodwill amount. If the implied fair value of goodwill is lower than the carrying amount of goodwill, then an impairment loss is recognized for the difference.

We test spectrum licenses for impairment on an aggregate basis, consistent with the management of the overall business at a national level. We may elect to first perform a qualitative assessment to determine whether it is more likely than not that the fair value of an intangible asset group is less than its carrying value. If we do not perform the qualitative assessment, or if the qualitative assessment indicates it is more likely than not the fair value of the intangible asset group is less than its carrying amount, we calculate the estimated fair value of the intangible asset group. If the carrying amount of spectrum licenses exceeds the fair value, an impairment loss is recognized.  We estimate the fair value of the spectrum licenses using the Greenfield approach, which is an income approach that estimates the price at which an orderly transaction to sell the asset would take place between market participants at the measurement date under current market conditions. The Greenfield approach values the spectrum licenses by calculating the cash flow generating potential of a hypothetical start-up company that goes into business with no assets except the asset to be valued (in this case, spectrum licenses). The value of the spectrum licenses can be considered as equal to the present value of the cash flows of this hypothetical start-up company. We base the assumptions underlying the Greenfield approach on a combination of market participant data and our historical results, trends and business plans. Future cash flows in the Greenfield approach are based on estimates and assumptions of market participant revenues, EBITDA margin, network build-out period and a long-term growth rate for a market participant. The cash flows are discounted using a weighted average cost of capital.

The valuation approaches utilized to estimate fair value for the purposes of the impairment tests of goodwill and spectrum licenses require the use of assumptions and estimates, which involve a degree of uncertainty. If actual results or future expectations are not consistent with the assumptions, this may result in the recording of significant impairment charges on goodwill or spectrum licenses. The most significant assumptions within the valuation models are the discount rate, revenues, EBITDA margins and the long-term growth rate. See Note 1 – Summary of Significant Accounting Policies and Note 6 – Goodwill, Spectrum Licenses and Other Intangible Assets of the Notes to the Consolidated Financial Statements included in Part II, Item 8 of this Form 10-K for information regarding our annual impairment test and impairment charges.

Guarantee Liabilities

In 2013, we introduced a handset upgrade program, JUMP!, which provides enrolled customers a specified-price trade-in right to upgrade their device. Participating customers must purchase a device from us, have a qualifying monthly wireless service plan with us, and finance their handset using our EIP, which is treated as a single multiple-element arrangement when entered into at or near the same time. Upon qualifying JUMP! program upgrades, the customers’ remaining EIP balance is settled provided they trade in their eligible used device in good working condition and purchase a new handset from us on a new EIP.

For customers who enroll in the trade-in program, we defer a portion of revenue which represents the estimated value of the specified-price trade-in right guarantee. The guarantee liabilities are valued based on various economic and customer behavioral assumptions, which require judgment, including the customer's estimated remaining EIP balance at trade-in, the expected fair value of the used device at trade-in, and probability and timing of trade-in. When the customer upgrades their device, the difference between the trade-in credit to the customer and the fair value of the returned handset is recorded against the guarantee liabilities. All assumptions are reviewed periodically.

Rent Expense

Most of the leases on our tower sites have fixed rent escalations which provide for periodic increases in the amount of rent payable over time. We calculate straight-line rent expense for each of these leases based on the fixed non-cancellable term of the lease plus all periods, if any, for which failure to renew the lease imposes a penalty on us in such amount that a renewal appears, at lease inception or significant modification, to be reasonably assured. We make significant assumptions at lease inception in determining and assessing the factors that constitute a “penalty.” In doing so, we primarily consider costs incurred in acquiring and developing new sites, the useful life of site improvements and equipment costs, future economic conditions and the extent to which improvements in wireless technologies can be incorporated into a current assessment of whether an economic compulsion will exist in the future to renew a lease.

Income Taxes

We recognize deferred tax assets and liabilities based on temporary differences between the financial statement and tax basis of assets and liabilities using enacted tax rates expected to be in effect when these differences are realized. A valuation allowance

40

Table of Contents

is maintained against deferred tax assets when it is more likely than not that some portion or all of the deferred tax assets will not be realized. The ultimate realization of a deferred tax asset depends on the ability to generate sufficient taxable income of the appropriate character and in the appropriate taxing jurisdictions within the carryforward periods available. We consider many factors when determining whether a valuation allowance is needed, including recent cumulative earnings experience by taxing jurisdiction, expectations of future income, the carryforward periods available for tax reporting purposes and other relevant factors.

We account for uncertainty in income taxes recognized in the financial statements in accordance with the accounting guidance on the financial statement recognition and measurement of a tax position taken or expected to be taken in a tax return. We assess whether it is more likely than not that a tax position will be sustained upon examination based on the technical merits of the position and adjust the unrecognized tax benefits in light of changes in facts and circumstances, such as changes in tax law, interactions with taxing authorities and developments in case law.

Recently Issued Accounting Standards

See Note 1 – Summary of Significant Accounting Policies of the Notes to the Consolidated Financial Statements included in Part II, Item 8 of this Form 10-K for information regarding recently issued accounting standards.

Item 7A. Quantitative and Qualitative Disclosures About Market Risk

We are exposed to economic risks in the normal course of business, primarily from changes in interest rates. These risks, along with other business risks, impact our cost of capital. Our policy is to manage exposure related to fluctuations in interest rates in order to manage capital costs, control financial risks and maintain financial flexibility over the long term. We have established interest rate risk limits that are closely monitored by measuring interest rate sensitivities of our debt portfolio. We do not foresee significant changes in the strategies used to manage market risk in the near future.

We are exposed to changes in interest rates on our 5.950% Senior Reset Notes to affiliates due 2023 and Senior Secured Term Loans. See Note 8 – Debt of the Notes to the Consolidated Financial Statements included in Part II, Item 8 of this Form 10-K for further information. Changes in interest rates can lead to significant fluctuations in fair value.

To perform the sensitivity analysis, we assessed the risk of a change in the fair value from the effect of a hypothetical interest rate change of 100 basis points. As of December 31, 2015, the change in the fair value of our 5.950% Senior Reset Notes to affiliates due 2023 and Senior Secured Term Loans, based on this hypothetical change, is shown in the table below:
 
Carrying Amount
 
Fair Value
 
Fair Value Assuming
(in millions)
 
 
+100 Basis Point Shift
 
-100 Basis Point Shift
5.950% Senior Reset Notes to affiliates due 2023 (reset date in April 2016)
$
600

 
$
644

 
$
637

 
$
651

Senior Secured Term Loans
2,000

 
1,990

 
1,882

 
2,105


To manage interest rate risk, the interest rates on the senior reset notes are adjusted at the reset dates to rates defined in the applicable supplemental indenture. We determined certain components of the reset feature are required to be bifurcated from the senior reset notes and separately accounted for as embedded derivative instruments. As of December 31, 2015, we had $143 million in embedded derivatives related to the senior reset notes, of which $44 million related to the 5.950% Senior Reset Notes to affiliates due 2023 that are subject to the reset provisions. The fair value of the embedded derivatives was determined based on the fair value of the senior reset notes with and without the embedded derivatives included. The fair value of the senior reset notes with the embedded derivatives utilizes the contractual term of each senior reset note, reset rates calculated based on the spread between specified yield curves and the yield curve on certain T-Mobile long-term debt and interest rate volatility. Interest rate volatility is derived based on weighted risk-free rate volatility and credit spread volatility. Changes in the spreads between the specified yield curves and the yield curve on certain T-Mobile long-term debt can lead to fluctuations in the fair value of our embedded derivatives.

To perform sensitivity analysis on the embedded derivatives, we assessed the risk of loss in fair values from the effect of a hypothetical spread change between specified yield curves and the yield curve on certain T-Mobile long-term debt of 10 basis points on our portfolio of embedded derivatives. As of December 31, 2015, the change in the fair value of our embedded

41

Table of Contents

derivatives, based on this hypothetical change, is shown in the table below:


Fair Value Assuming
(in millions)
Fair Value
 
+10 Basis Point Shift
 
-10 Basis Point Shift
Embedded derivatives
$
143

 
$
140

 
$
145


42

Table of Contents

Item 8. Financial Statements and Supplementary Data

Financial Statements

Report of Independent Registered Public Accounting Firm


To the Board of Directors and Stockholders of T-Mobile US, Inc.

In our opinion, the accompanying consolidated balance sheets and the related consolidated statements of comprehensive income (loss), of stockholders’ equity and of cash flows present fairly, in all material respects, the financial position of T-Mobile US, Inc. and its subsidiaries at December 31, 2015 and December 31, 2014, and the results of their operations and their cash flows for each of the three years in the period ended December 31, 2015 in conformity with accounting principles generally accepted in the United States of America. Also in our opinion, the Company maintained, in all material respects, effective internal control over financial reporting as of December 31, 2015, based on criteria established in Internal Control - Integrated Framework (2013) issued by the Committee of Sponsoring Organizations of the Treadway Commission (COSO). The Company's management is responsible for these financial statements, for maintaining effective internal control over financial reporting and for its assessment of the effectiveness of internal control over financial reporting, included in Management’s Annual Report on Internal Control over Financial Reporting appearing under Item 9A. Our responsibility is to express opinions on these financial statements and on the Company's internal control over financial reporting based on our integrated audits. We conducted our audits in accordance with the standards of the Public Company Accounting Oversight Board (United States). Those standards require that we plan and perform the audits to obtain reasonable assurance about whether the financial statements are free of material misstatement and whether effective internal control over financial reporting was maintained in all material respects. Our audits of the financial statements included examining, on a test basis, evidence supporting the amounts and disclosures in the financial statements, assessing the accounting principles used and significant estimates made by management, and evaluating the overall financial statement presentation. Our audit of internal control over financial reporting included obtaining an understanding of internal control over financial reporting, assessing the risk that a material weakness exists, and testing and evaluating the design and operating effectiveness of internal control based on the assessed risk. Our audits also included performing such other procedures as we considered necessary in the circumstances. We believe that our audits provide a reasonable basis for our opinions.

As discussed in Note 1 to the consolidated financial statements, the Company changed the manner in which it presents deferred income taxes in 2015.

A company’s internal control over financial reporting is a process designed to provide reasonable assurance regarding the reliability of financial reporting and the preparation of financial statements for external purposes in accordance with generally accepted accounting principles. A company’s internal control over financial reporting includes those policies and procedures that (i) pertain to the maintenance of records that, in reasonable detail, accurately and fairly reflect the transactions and dispositions of the assets of the company; (ii) provide reasonable assurance that transactions are recorded as necessary to permit preparation of financial statements in accordance with generally accepted accounting principles, and that receipts and expenditures of the company are being made only in accordance with authorizations of management and directors of the company; and (iii) provide reasonable assurance regarding prevention or timely detection of unauthorized acquisition, use, or disposition of the company’s assets that could have a material effect on the financial statements.

Because of its inherent limitations, internal control over financial reporting may not prevent or detect misstatements. Also, projections of any evaluation of effectiveness to future periods are subject to the risk that controls may become inadequate because of changes in conditions, or that the degree of compliance with the policies or procedures may deteriorate.

/s/ PricewaterhouseCoopers LLP
Seattle, Washington
February 17, 2016


43

Table of Contents

T-Mobile US, Inc.
Consolidated Balance Sheets

(in millions, except share and per share amounts)
December 31,
2015
 
December 31,
2014
Assets


Current assets


Cash and cash equivalents
$
4,582

 
$
5,315

Short-term investments
2,998

 
—

Accounts receivable, net of allowances of $116 and $83
1,788

 
1,865

Equipment installment plan receivables, net
2,378

 
3,062

Accounts receivable from affiliates
36

 
76

Inventories
1,295

 
1,085

Deferred tax assets, net
—

 
988

Other current assets
1,813

 
1,593

Total current assets
14,890

 
13,984

Property and equipment, net
20,000

 
16,245

Goodwill
1,683

 
1,683

Spectrum licenses
23,955

 
21,955

Other intangible assets, net
594

 
870

Equipment installment plan receivables due after one year, net
847

 
1,628

Other assets
467

 
288

Total assets
$
62,436

 
$
56,653

Liabilities and Stockholders' Equity


Current liabilities


Accounts payable and accrued liabilities
$
8,084

 
$
7,364

Current payables to affiliates
135

 
231

Short-term debt
182

 
87

Deferred revenue
717

 
459

Other current liabilities
410

 
635

Total current liabilities
9,528

 
8,776

Long-term debt
20,484

 
16,273

Long-term debt to affiliates
5,600

 
5,600

Tower obligations
2,658

 
2,521

Deferred tax liabilities
4,061

 
4,873

Deferred rents
2,481

 
2,331

Other long-term liabilities
1,067

 
616

Total long-term liabilities
36,351

 
32,214

Commitments and contingencies (Note 13)


Stockholders' equity


5.50% Mandatory Convertible Preferred Stock Series A, par value $0.00001 per share, 100,000,000 shares authorized; 20,000,000 and 20,000,000 shares issued and outstanding; $1,000 and $1,000 aggregate liquidation value
—

 
—

Common Stock, par value $0.00001 per share, 1,000,000,000 shares authorized; 819,773,724 and 808,851,108 shares issued, 818,391,219 and 807,468,603 shares outstanding
—

 
—

Additional paid-in capital
38,666

 
38,503

Treasury stock, at cost, 1,382,505 and 1,382,505 shares issued
—

 
—

Accumulated other comprehensive income (loss)
(1
)
 
1

Accumulated deficit
(22,108
)
 
(22,841
)
Total stockholders' equity
16,557

 
15,663

Total liabilities and stockholders' equity
$
62,436

 
$
56,653


The accompanying notes are an integral part of these consolidated financial statements.


44

Table of Contents

T-Mobile US, Inc.
Consolidated Statements of Comprehensive Income (Loss)

 
Year Ended December 31,
(in millions, except share and per share amounts)
2015
 
2014
 
2013
Revenues


Branded postpaid revenues
$
16,383

 
$
14,392

 
$
13,166

Branded prepaid revenues
7,553

 
6,986

 
4,945

Wholesale revenues
692

 
731

 
613

Roaming and other service revenues
193

 
266

 
344

Total service revenues
24,821

 
22,375

 
19,068

Equipment revenues
6,718

 
6,789

 
5,033

Other revenues
514

 
400

 
319

Total revenues
32,053

 
29,564

 
24,420

Operating expenses


Cost of services, exclusive of depreciation and amortization shown separately below
5,554

 
5,788

 
5,279

Cost of equipment sales
9,344

 
9,621

 
6,976

Selling, general and administrative
10,189

 
8,863

 
7,382

Depreciation and amortization
4,688

 
4,412

 
3,627

Cost of MetroPCS business combination
376

 
299

 
108

Gains on disposal of spectrum licenses
(163
)
 
(840
)
 
(2
)
Other, net
—

 
5

 
54

Total operating expenses
29,988

 
28,148

 
23,424

Operating income
2,065

 
1,416

 
996

Other income (expense)


Interest expense
(1,085
)
 
(1,073
)
 
(545
)
Interest expense to affiliates
(411
)
 
(278
)
 
(678
)
Interest income
420

 
359

 
189

Other income (expense), net
(11
)
 
(11
)
 
89

Total other expense, net
(1,087
)
 
(1,003
)
 
(945
)
Income before income taxes
978

 
413

 
51

Income tax expense
245

 
166

 
16

Net income
733

 
247

 
35

Dividends on preferred stock
(55
)
 
—

 
—

Net income attributable to common stockholders
$
678

 
$
247

 
$
35

Other comprehensive income (loss), net of tax


Net gain on cross currency interest rate swaps, net of tax effect of $0, $0 and $13
—

 
—

 
23

Net loss on foreign currency translation, net of tax effect of $0, $0 and ($37)
—

 
—

 
(62
)
Unrealized gain (loss) on available-for-sale securities, net of tax effect of ($1), ($1) and $1
(2
)
 
(2
)
 
1

Other comprehensive loss
(2
)
 
(2
)
 
(38
)
Total comprehensive income (loss)
$
731

 
$
245

 
$
(3
)
Earnings per share


Basic
$
0.83

 
$
0.31

 
$
0.05

Diluted
$
0.82

 
$
0.30

 
$
0.05

Weighted average shares outstanding


Basic
812,994,028

 
805,284,712

 
672,955,980

Diluted
822,617,938

 
815,922,258

 
676,885,215


The accompanying notes are an integral part of these consolidated financial statements.

45

Table of Contents

T-Mobile US, Inc.
Consolidated Statements of Cash Flows
 
Year Ended December 31,
(in millions)
2015
 
2014
 
2013
Operating activities


Net income
$
733

 
$
247

 
$
35

Adjustments to reconcile net income to net cash provided by operating activities


Depreciation and amortization
4,688

 
4,412

 
3,627

Stock-based compensation expense
201

 
196

 
100

Deferred income tax expense
256

 
122

 
10

Bad debt expense
547

 
444

 
463

Losses from sales of receivables
204

 
179

 
—

Deferred rent expense
167

 
225

 
229

Gains on disposal of spectrum licenses
(163
)
 
(840
)
 
(2
)
Changes in embedded derivatives
148

 
(18
)
 
13

Changes in operating assets and liabilities


Accounts receivable
(259
)
 
(90
)
 
(158
)
Equipment installment plan receivables
1,089

 
(2,429
)
 
(2,016
)
Inventories
(2,495
)
 
(499
)
 
42

Deferred purchase price from sales of receivables
(185
)
 
(204
)
 
—

Other current and long-term assets
(217
)
 
(328
)
 
314

Accounts payable and accrued liabilities
693

 
2,395

 
611

Other current and long-term liabilities
22

 
312

 
141

Other, net
(15
)
 
22

 
136

Net cash provided by operating activities
5,414

 
4,146

 
3,545


Investing activities


Purchases of property and equipment
(4,724
)
 
(4,317
)
 
(4,025
)
Purchases of spectrum licenses and other intangible assets, including deposits
(1,935
)
 
(2,900
)
 
(381
)
Purchases of short-term investments
(2,997
)
 
—

 
—

Short term affiliate loan receivable, net
—

 
—

 
300

Cash and cash equivalents acquired in MetroPCS business combination
—

 
—

 
2,144

Other, net
96

 
(29
)
 
(130
)
Net cash used in investing activities
(9,560
)
 
(7,246
)
 
(2,092
)


Financing activities


Proceeds from issuance of long-term debt
3,979

 
2,993

 
2,494

Repayments of long-term debt and capital lease obligations
(57
)
 
(1,019
)
 
(9
)
Proceeds from tower obligations
140

 
—

 
—

Repayments of short-term debt for purchases of inventory, property and equipment, net
(564
)
 
(418
)
 
(244
)
Dividends on preferred stock
(55
)
 
—

 
—

Proceeds from exercise of stock options
47

 
27

 
137

Proceeds from issuance of preferred stock
—

 
982

 
—

Proceeds from issuance of common stock
—

 
—

 
1,787

Taxes paid related to net share settlement of stock awards
(156
)
 
(73
)
 
—

Other, net
79

 
32

 
(121
)
Net cash provided by financing activities
3,413

 
2,524

 
4,044

Change in cash and cash equivalents
(733
)
 
(576
)
 
5,497


Cash and cash equivalents


Beginning of year
5,315

 
5,891

 
394

End of year
$
4,582

 
$
5,315

 
$
5,891

The accompanying notes are an integral part of these consolidated financial statements.

46

Table of Contents

T-Mobile US, Inc.
Consolidated Statement of Stockholders’ Equity

(in millions, except shares)
Preferred Stock Outstanding
 
Common Stock Outstanding
 
Par Value and Additional
Paid-in Capital
 
Accumulated Other Comprehensive Income
 
Accumulated Deficit
 
Total Stockholders' Equity
Balance as of December 31, 2012
—

 
535,286,077

 
$
29,197

 
$
41

 
$
(23,123
)
 
$
6,115

Net income
—

 
—

 
—

 
—

 
35

 
35

Other comprehensive loss
—

 
—

 
—

 
(38
)
 
—

 
(38
)
Effects of debt recapitalization
—

 
—

 
3,143

 
—

 
—

 
3,143

MetroPCS shares converted upon reverse merger, net of treasury stock withheld for taxes
—

 
184,487,309

 
2,971

 
—

 
—

 
2,971

Issuance of common stock
—

 
72,765,000

 
1,787

 
—

 
—

 
1,787

Stock-based compensation
—

 
—

 
100

 
—

 
—

 
100

Exercise of stock options
—

 
9,278,599

 
137

 
—

 
—

 
137

Issuance of vested restricted stock units
—

 
62,819

 
—

 
—

 
—

 
—

Tax impact of stock-based compensation
—

 
—

 
(5
)
 
—

 
—

 
(5
)
Balance as of December 31, 2013
—

 
801,879,804

 
37,330

 
3

 
(23,088
)
 
14,245

Net income
—

 
—

 
—

 
—

 
247

 
247

Other comprehensive loss
—

 
—

 
—

 
(2
)
 
—

 
(2
)
Issuance of preferred stock
20,000,000

 
—

 
982

 
—

 
—

 
982

Stock-based compensation
—

 
—

 
196

 
—

 
—

 
196

Exercise of stock options
—

 
1,496,365

 
27

 
—

 
—

 
27

Issuance of vested restricted stock units
—

 
6,296,107

 
—

 
—

 
—

 
—

Shares withheld related to net share settlement of stock awards
—

 
(2,203,673
)
 
(73
)
 
—

 
—

 
(73
)
Excess tax benefit from stock-based compensation
—

 
—

 
34

 
—

 
—

 
34

Other
—

 
—

 
7

 
—

 
—

 
7

Balance as of December 31, 2014
20,000,000

 
807,468,603

 
38,503

 
1

 
(22,841
)
 
15,663

Net income
—

 
—

 
—

 
—

 
733

 
733

Other comprehensive loss
—

 
—

 
—

 
(2
)
 
—

 
(2
)
Stock-based compensation
—

 
—

 
227

 
—

 
—

 
227

Exercise of stock options
—

 
2,381,650

 
47

 
—

 
—

 
47

Stock issued for employee stock purchase plan
—

 
761,085

 
21

 
—

 
—

 
21

Issuance of vested restricted stock units
—

 
11,956,345

 
—

 
—

 
—

 
—

Shares withheld related to net share settlement of stock awards and stock options
—

 
(4,176,464
)
 
(156
)
 
—

 
—

 
(156
)
Excess tax benefit from stock-based compensation
—

 
—

 
79

 
—

 
—

 
79

Dividends on preferred stock
—

 
—

 
(55
)
 
—

 
—

 
(55
)
Balance as of December 31, 2015
20,000,000

 
818,391,219

 
$
38,666

 
$
(1
)
 
$
(22,108
)
 
$
16,557


The accompanying notes are an integral part of these consolidated financial statements.


47

Table of Contents

T-Mobile US, Inc.
Notes to the Consolidated Financial Statements

Note 1 – Summary of Significant Accounting Policies

Description of Business

T-Mobile US, Inc. (“T-Mobile” or the “Company”), together with its consolidated subsidiaries, is a leading provider of mobile communications services, including voice, messaging and data, under its flagship brands, T-Mobile and MetroPCS, in the United States (“U.S.”), Puerto Rico and the U.S. Virgin Islands. T-Mobile provides mobile communications services primarily using 4G Long-Term Evolution (“LTE”) technology. T-Mobile also offers a wide selection of wireless devices, including handsets, tablets and other mobile communication devices, and accessories for sale, as well as financing through equipment installment plans (“EIP”) and leasing through JUMP On Demand™. Additionally, T-Mobile provides reinsurance for handset insurance policies and extended warranty contracts offered to T-Mobile’s mobile communications customers.

Basis of Presentation

The consolidated financial statements include the balances and results of operations of T-Mobile and its consolidated subsidiaries. T-Mobile operates as a single operating segment. T-Mobile consolidates majority-owned subsidiaries over which it exercises control, as well as variable interest entities (“VIEs”) where it is deemed to be the primary beneficiary and VIEs which cannot be deconsolidated. Intercompany transactions and balances have been eliminated in consolidation. Certain prior year amounts have been reclassified to conform to the current presentation.

The preparation of financial statements in conformity with U.S. generally accepted accounting principles (“GAAP”) requires management to make estimates and assumptions which affect the financial statements and accompanying notes. Examples include service revenues earned but not yet billed, service revenues billed but not yet earned, relative selling prices, allowances for uncollectible accounts and sales returns, discounts for imputed interest on EIP receivables, guarantee liabilities, losses incurred but not yet reported, tax liabilities, deferred income taxes including valuation allowances, useful lives of long-lived assets, cost estimates of asset retirement obligations, residual values on leased handsets, reasonably assured renewal terms for operating leases, stock-based compensation forfeiture rates, and fair value measurements related to goodwill, spectrum licenses, intangible assets, and derivative financial instruments. Estimates are based on historical experience, where applicable, and other assumptions which management believes are reasonable under the circumstances. These estimates are inherently subject to judgment and actual results could differ from those estimates.

Cash and Cash Equivalents

Cash equivalents consist of highly liquid money market funds and U.S. Treasury securities with remaining maturities of three months or less at the date of purchase.

Short-Term Investments

The Company's short-term investments consist of U.S. Treasury securities classified as available for sale, which are stated at fair value and have remaining maturities of more than three months at the date of purchase. Unrealized gains and losses, net of related income taxes, for available for sale securities are reported as net increases and decreases to accumulated other comprehensive income (loss), a component of stockholders' equity, until realized. The estimated fair values of investments are based on quoted market prices as of the end of the reporting period. The U.S. Treasury securities reported as of December 31, 2015 have contractual maturities of less than one year.

Available-for-sale securities are reviewed for impairment on a quarterly basis or more often if a potential loss-triggering event occurs. If there has been a decline in the fair value below the amortized cost basis, the Company determines whether such impairment is other-than-temporary. Factors considered in the assessment include the reason for the decline in fair value, the Company’s intent to sell the security, whether it is more likely than not that the Company will be required to sell the security before recovery of its amortized cost basis and whether the Company does not expect to recover the entire amortized cost basis of the security. If an impairment is considered other-than-temporary, the Company records a charge to Other income (expense), net.


48

Table of Contents

Accounts Receivable and Allowances

Accounts receivable consist primarily of amounts billed and currently due from customers, other carriers and third-party retail channels (“dealers”), as well as revenues earned but not yet billed at the end of each period. T-Mobile has an arrangement to sell certain service accounts receivable on a revolving basis, which are treated as sales of financial assets. T-Mobile maintains an allowance for estimated losses inherent in the accounts receivable portfolio based on a number of factors, including historical experience and current collection trends, aging of the receivable portfolio, credit quality of the customer base and other qualitative factors such as macro-economic conditions. The Company writes off account balances if collection efforts are unsuccessful and the receivable balance is deemed uncollectible, based on customer credit ratings and the length of time from the original billing date.

Equipment Installment Plan Receivables

The Company offers certain retail customers the option to pay for devices and other accessories in installments using an EIP. At the time of an installment sale, the Company imputes a discount for interest as there is no stated rate of interest on the EIP receivables and records the EIP receivables at their present value, which is determined by discounting future payments at the imputed interest rate. The difference between the present value of the EIP receivables and their face amount results in a discount which is recorded as a direct reduction to the carrying value with a corresponding reduction to equipment revenues. T-Mobile determines the imputed discount rate based primarily on current market interest rates and the amount of expected credit losses on the EIP receivables. As a result, T-Mobile does not recognize a separate valuation allowance at the time of issuance as the effects of uncertainty about future cash flows are included in the initial present value measurement of the receivable. The imputed discount on EIP receivables is amortized over the financed installment term using the effective interest method and recognized as interest income in Other income (expense), net.

Subsequent to the initial determination of the imputed discount, T-Mobile assesses the need for and, if necessary, recognizes an allowance for credit losses to the extent the amount of estimated probable losses on the gross EIP receivable balances exceed the remaining unamortized imputed discount balances.  The allowance is based on a number of factors, including collection experience, aging of the EIP receivable portfolio, credit quality of the customer base and other qualitative factors such as macro-economic conditions. T-Mobile writes off account balances if collection efforts are unsuccessful and receivable balance is deemed uncollectible, based on customer credit ratings and the length of time from the original billing date. Equipment sales not reasonably assured to be collectible are recorded on a cash basis as payments are received.

The current portion of the EIP receivables is included in Equipment installment plan receivables, net and the long-term portion of the EIP receivables is included in Equipment installment plan receivables due after one year, net. T-Mobile has an arrangement to sell certain EIP receivables on a revolving basis, which are treated as sales of financial assets.

Inventories

Inventories consist primarily of wireless devices and accessories, which are valued at the lower of cost or market. Cost is determined using standard cost which approximates average cost. Shipping and handling costs paid to wireless device and accessories vendors, and costs to refurbish used devices recovered through the Company’s device trade-in and upgrade programs are included in the standard cost of inventory. T-Mobile records inventory write-downs to net realizable value for obsolete and slow-moving items based on inventory turnover trends and historical experience.

Long-Lived Assets

Long-lived assets include assets that do not have indefinite lives, such as property and equipment and other intangible assets. The Company assesses potential impairments to its long-lived assets when events or changes in circumstances indicate the carrying amount of the asset may not be recoverable. If any indicators are present, the Company tests recoverability. The carrying value of a long-lived asset or asset group is not recoverable if it exceeds the sum of the undiscounted cash flows expected to be generated from the use and eventual disposition of the asset or asset group. If the undiscounted cash flows do not exceed the asset or asset group’s carrying amount, then an impairment loss is recorded, measured as the amount by which the carrying amount of a long-lived asset or asset group exceeds its fair value.

Property and Equipment

Property and equipment consists of buildings and equipment, wireless communication systems, leasehold improvements, capitalized software, leased wireless devices and construction in progress. Buildings and equipment include certain network server equipment. Wireless communication systems include assets to operate the Company’s wireless network and IT data

49

Table of Contents

centers, including tower asset leaseholds, assets related to the liability for the retirement of long-lived assets and capital leases. Leasehold improvements include asset improvements other than those related to the wireless network.

Property and equipment are recorded at cost less accumulated depreciation and impairments, if any. T-Mobile generally depreciates property and equipment on a straight-line basis.

In 2015, T-Mobile introduced JUMP! On Demand which allows customers to lease a device and upgrade it for a new one up to three times in a 12 month period. To date, all of T-Mobile’s leased devices were classified as operating leases by considering critical elements of the lease arrangement such as the lease term and the economic life, fair value and residual value of the device. At operating lease inception, leased wireless devices are transferred from inventory to property and equipment. Leased wireless devices are depreciated to their estimated residual value over the period expected to provide utility to T-Mobile, which is generally the lease term.  Revenues associated with the leased wireless devices, net of incentives, are generally recognized over the lease term.  Upon device upgrade or at lease end, customers must return or purchase their device.  Returned devices are recorded as inventory and are valued at the lower of cost or market with any write down to market recognized as cost of equipment sales.

Costs of major replacements and improvements are capitalized. Repair and maintenance expenditures which do not enhance or extend the asset’s useful life are charged to operating expenses as incurred. Construction costs, labor and overhead incurred in the expansion or enhancement of T-Mobile’s wireless network are capitalized. Capitalization commences with pre-construction period administrative and technical activities, which includes obtaining leases, zoning approvals and building permits, and ceases at the point at which the asset is ready for its intended use.

The Company capitalizes interest associated with the acquisition or construction of certain property and equipment. Capitalized interest is reported as a reduction in interest expense and depreciated over the useful life of the related assets. Depreciable life studies are performed periodically to confirm the appropriateness of useful lives for certain categories of property and equipment. These studies take into account actual usage, physical wear and tear, replacement history and assumptions about technology evolution. When these factors indicate the useful life of an asset is different from the previous assessment, the remaining book value is depreciated prospectively over the adjusted remaining estimated useful life. Leasehold improvements are depreciated over the shorter of their estimated useful lives or the related lease term.

Future obligations related to capital leases are included in Short-term debt and Long-term debt. Depreciation of assets held under capital leases is included in Depreciation and amortization expense.

The Company records an asset retirement obligation for the fair value of legal obligations associated with the retirement of tangible long-lived assets and a corresponding increase in the carrying amount of the related asset in the period in which the obligation is incurred. In periods subsequent to initial measurement, the Company recognizes changes in the liability resulting from the passage of time and revisions to either the timing or the amount of the original estimate. Over time, the liability is accreted to its present value and the capitalized cost is depreciated over the estimated useful life of the asset. The Company’s obligations relate primarily to certain legal obligations to remediate leased property on which the Company’s network infrastructure and administrative assets are located.

The Company capitalizes certain costs incurred in connection with developing or acquiring internal use software. Capitalization of software costs commences once the final selection of the specific software solution has been made and management authorizes and commits to funding the software project. Capitalized software costs are included in Property and equipment, net and amortized on a straight-line basis over the estimated useful life of the asset. Costs incurred during the preliminary project stage, as well as maintenance and training costs are expensed as incurred.

Other Intangible Assets

Intangible assets that do not have indefinite useful lives are amortized over their estimated useful lives. Customer lists are amortized using the sum-of-the-years-digits method over the expected period in which the relationship is expected to contribute to future cash flows. The remaining finite-lived intangible assets are amortized using the straight-line method.


50

Table of Contents

Goodwill and Indefinite-Lived Intangible Assets

Goodwill

Goodwill consists of the excess of the purchase price over the fair value of identifiable net assets acquired in a business combination.

Spectrum Licenses

Spectrum licenses are carried at costs incurred to acquire the spectrum licenses and the costs to prepare the spectrum licenses for their intended use, such as costs to clear acquired spectrum licenses. The Federal Communications Commission (“FCC”) issues spectrum licenses which provide T-Mobile with the exclusive right to utilize designated radio frequency spectrum within specific geographic service areas to provide wireless communication services. While spectrum licenses are issued for a fixed period of time, typically for up to fifteen years, the FCC has granted license renewals routinely and at a nominal cost. The spectrum licenses held by the Company expire at various dates. The Company believes it will be able to meet all requirements necessary to secure renewal of its spectrum licenses at nominal costs. Moreover, the Company has determined there are currently no legal, regulatory, contractual, competitive, economic or other factors that limit the useful lives of its spectrum licenses. Therefore, the Company has determined the spectrum licenses should be treated as indefinite-lived intangible assets.

The Company at times enters into agreements to sell or exchange spectrum licenses.  Upon entering into the arrangement, if the transaction has been deemed to have commercial substance, spectrum licenses are reviewed for impairment and transferred at their carrying value, net of any impairment, to assets held for sale included in other current assets until approval and completion of the exchange or sale.  Upon closing of the transaction, spectrum licenses acquired as part of an exchange of nonmonetary assets are valued at fair value. The difference between the fair value of the spectrum licenses obtained, book value of the spectrum licenses transferred and cash paid, if any, is recognized as gains included in Gains on disposal of spectrum licenses. If the transaction lacks commercial substance or the fair value is not measurable, the acquired spectrum licenses are recorded at the book value of the assets tendered.

Impairment

The Company assesses the carrying value of its goodwill and other indefinite-lived intangible assets (spectrum licenses) for potential impairment annually as of December 31 or more frequently if events or changes in circumstances indicate such assets might be impaired. 

The Company may elect to first perform a qualitative assessment to determine whether it is more likely than not the fair value of the single reporting unit is less than its carrying amount as a basis for determining whether it is necessary to perform the two-step goodwill impairment test. If the Company does not perform a qualitative assessment, or if the qualitative assessment indicates it is more likely than not the fair value of the single reporting unit is less than its carrying amount, goodwill is tested for impairment based on a two-step test. In the first step, the Company compares the fair value of the reporting unit to the carrying value. The fair value of the reporting unit is determined using a market approach, which is based on market capitalization. If the fair value is less than the carrying value, the second step is performed. In the second step, the Company determines the fair values of all of the assets and liabilities of the reporting unit, including those that may not be currently recorded. The excess of the fair value of the reporting unit over the sum of the fair value of all of those assets and liabilities represents the implied goodwill amount. If the implied fair value of goodwill is lower than its carrying amount, an impairment loss is recognized for the difference.  

The Company tests its spectrum licenses for impairment on an aggregate basis, consistent with the Company's management of the overall business at a national level.  The Company may elect to first perform a qualitative assessment to determine whether it is more likely than not that the fair value of an intangible asset group is less than its carrying value. If the Company does not perform the qualitative assessment, or if the qualitative assessment indicates it is more likely than not the fair value of the intangible asset group is less than its carrying amount, the Company calculates the estimated fair value of the intangible asset group. If the estimated fair value of the spectrum licenses is lower than their carrying amount, an impairment loss is recognized for the difference.  The Company estimates fair value using the Greenfield approach, which is an income approach, to estimate the price at which an orderly transaction to sell the asset would take place between market participants at the measurement date under current market conditions.


51

Table of Contents

Guarantee Liabilities

The Company offers a device trade-in program, Just Upgrade My Phone (“JUMP!”), which provides eligible customers a specified-price trade-in right to upgrade their device.  Participating customers must purchase a device from T-Mobile, have a qualifying monthly wireless service plan with T-Mobile, and finance their device using an EIP, which is treated as a single multiple-element arrangement when entered into at or near the same time.  Upon qualifying JUMP! program upgrades, the customers’ remaining EIP balance is settled provided they trade in their eligible used device in good working condition and purchase a new device from T-Mobile on a new EIP.

For customers who enroll in the device trade-in program, the Company defers the portion of revenue which represents the estimated value of the specified-price trade-in right guarantee.  The guarantee liabilities are valued based on various economic and customer behavioral assumptions, including the customer's estimated remaining EIP balance at trade-in, the expected fair value of the used handset at trade-in, and probability and timing of trade-in.  T-Mobile assesses guarantee liabilities at each reporting date to determine if facts and circumstances would indicate the incurrence of incremental contingent liabilities is probable and if so, reasonably estimable. The recognition and subsequent adjustments of the contingent guarantee liability as a result of these assessments are recorded as adjustments to revenue. When customers upgrade their devices, the difference between the trade-in credit to the customer and the fair value of the returned devices is recorded against the guarantee liabilities.  Guarantee liabilities included in Other current liabilities were $163 million and $286 million as of December 31, 2015 and 2014, respectively.  The estimated EIP receivable balance if all enrolled handset upgrade program customers were to claim their benefit, not including any trade-in value of the required used handset, was $2.3 billion as of December 31, 2015. This is not an indication of the Company’s expected loss exposure as it does not consider the expected fair value of the used handset, which is required to be in good working condition at trade-in, nor does it consider the probability and timing of trade-in.

Fair Value Measurements

The Company carries certain assets and liabilities at fair value. Fair value is defined as an exit price, representing the amount that would be received to sell an asset or paid to transfer a liability in an orderly transaction between market participants at the measurement date. The three tier hierarchy for inputs used in measuring fair value, which prioritizes the inputs based on the observability as of the measurement date, is as follows:

Level 1
Quoted prices in active markets for identical assets or liabilities;
Level 2
Observable inputs other than the quoted prices in active markets for identical assets and liabilities; and
Level 3
Unobservable inputs for which there is little or no market data, which require T-Mobile to develop assumptions of what market participants would use in pricing the asset or liability.

Assets and liabilities are classified in their entirety based on the lowest level of input that is significant to the fair value measurement. The Company’s assessment of the significance of a particular input to the fair value measurement requires judgment, and may affect the placement of assets and liabilities being measured within the fair value hierarchy.

The carrying values of cash and cash equivalents, short-term investments, accounts receivable, accounts receivable from affiliates and accounts payable approximate fair value due to the short-term maturities of these instruments. The carrying values of EIP receivables approximate fair value as the receivables are recorded at their present value, net of unamortized discount and allowance for credit losses. There were no financial instruments with a carrying value materially different from their fair value, based on quoted market prices or rates for the same or similar instruments, or internal valuation models.

Derivative Financial Instruments

Derivative financial instruments primarily relate to embedded derivatives for certain components of the reset feature of the Senior Reset Notes to affiliates which are required to be bifurcated and are recorded on the balance sheet at fair value. Changes in fair value are recognized in Interest expense to affiliates. T-Mobile does not enter into derivatives for trading or speculative purposes.

Revenue Recognition

T-Mobile offers products and services to customers through bundled arrangements, which may be comprised of multiple contracts entered into with a customer at or near the same time. The Company assesses such agreements as a single bundled arrangement that may involve multiple deliverables, which include wireless devices, wireless services or a combination thereof.

52

Table of Contents

For multiple deliverable arrangements revenue is allocated between the separate units of accounting, based on such components’ relative selling prices on a standalone basis.

Revenues primarily consist of wireless service revenues from providing access to and usage of the Company's wireless communications network, equipment revenues generated from device sales and revenues from leasing a device through JUMP! On Demand. Service revenues also include revenues earned for providing value added services to customers, such as handset insurance services. Service revenues are billed either in advance or arrears or are prepaid and are recognized when the service is rendered and all other revenue recognition criteria have been met. Revenues that are not reasonably assured to be collectible are recorded on a cash basis as payments are received. The recognition of prepaid revenue is deferred until services are rendered or the prepaid balance expires. Incentives given to customers are recorded as a reduction to revenue. T-Mobile recognizes service revenues for Data Stash plans when such services are delivered and the data is consumed, or at time of forfeiture or expiration.  Revenues relating to unused data that is carried over to the following month are deferred and valued based on their relative standalone selling price. Revenue is recorded gross for arrangements involving the resale of third-party services where T-Mobile is considered the primary obligor and is recorded net of associated costs incurred for services whereby T-Mobile is not considered the primary obligor.

Equipment revenues are comprised of revenues from the sale or lease of mobile communication devices and accessories. Device and accessory sales revenues are generally recognized when the products are delivered to and accepted by the customer or dealer. The Company defers a portion of equipment revenues and cost of equipment sales for expected device returns based on historical experience. The Company offers certain customers the option to pay for devices and accessories in installments using an EIP. See Equipment Installment Plan Receivables for further information.

In addition, the Company offers customers a device trade-in program, JUMP!, which provides eligible customers a specified-price trade-in right to upgrade their device.  For customers enrolled in JUMP!, the Company separates the JUMP! trade-in right from the multiple element arrangement at its fair value and defers the portion of revenue which represents the fair value of the trade-in right. See Guarantee Liabilities for further information. In 2015, T-Mobile introduced JUMP! On Demand, which allows customers to lease a device and upgrade their leased wireless device for a new one up to three times in a 12 month period. Leased wireless devices are accounted for as operating leases and equipment revenues are recognized as earned on a straight-line basis over the lease term. Previously leased devices that are purchased by the customer are recorded at their residual value as equipment revenues and cost of equipment sales. See Property and Equipment for further information.

Federal Universal Service Fund (“USF”) and other fees are assessed by various governmental authorities in connection with the services the Company provides to its customers. When the Company separately bills and collects these regulatory fees from customers, they are recorded gross in service revenues and cost of services. For the years ended December 31, 2015, 2014 and 2013, the Company recorded approximately $334 million, $349 million and $362 million, respectively, of USF and other fees on a gross basis.

Rent Expense

The Company has operating leases for cell sites, retail locations, corporate offices and dedicated transportation lines, some of which have escalating rentals during the initial lease term and during subsequent optional renewal periods. The Company recognizes rent expense on a straight-line basis, over the non-cancelable lease term and renewal periods that are considered reasonably assured at the inception of the lease.

Advertising Expense

T-Mobile expenses the cost of advertising and other promotional expenditures to market the T-Mobile’s services and products as incurred. For the years ended December 31, 2015, 2014 and 2013, advertising expenses included in Selling, general and administrative expenses were $1.6 billion, $1.4 billion and $1.0 billion, respectively.

Income Taxes

Deferred tax assets and liabilities are recognized based on temporary differences between the financial statement and tax bases of assets and liabilities using enacted tax rates expected to be in effect when these differences are realized. A valuation allowance is recorded when it is more likely than not that some portion or all of a deferred tax asset will not be realized. The ultimate realization of a deferred tax asset depends on the ability to generate sufficient taxable income of the appropriate character and in the appropriate taxing jurisdictions within the carryforward periods available.


53

Table of Contents

T-Mobile accounts for uncertainty in income taxes recognized in the financial statements in accordance with the accounting guidance on the financial statement recognition and measurement of a tax position taken or expected to be taken in a tax return. The Company assesses whether it is more likely than not that a tax position will be sustained upon examination based on the technical merits of the position and adjusts the unrecognized tax benefits in light of changes in facts and circumstances, such as changes in tax law, interactions with taxing authorities and developments in case law.

In November 2015, the Financial Accounting Standards Board (“FASB”) issued Accounting Standards Update (“ASU”) 2015-17 (Topic 740), “Balance Sheet Classification of Deferred Taxes”, which simplifies the presentation of deferred income taxes. This ASU requires that deferred tax assets and liabilities be classified as non-current in a classified statement of financial position. The Company early adopted ASU 2015-17 for the year ended December 31, 2015 on a prospective basis. Adoption of this ASU resulted in a reclassification of the Company’s current deferred tax assets, net to non-current deferred tax liabilities in the Consolidated Balance Sheets as of December 31, 2015. Prior periods were not retrospectively adjusted.

Other Comprehensive Income (Loss)

Other comprehensive income (loss) consists of adjustments, net of tax, related to unrealized gains (losses) on available-for-sale securities, unrealized gains (losses) on cash flow hedging derivatives and unrealized gains (losses) on foreign currency translation. These are reported in Accumulated other comprehensive income (loss) (“AOCI”) as a separate component of stockholders’ equity until realized in earnings.

Stock-Based Compensation

Stock-based compensation cost for stock awards, which include restricted stock units (“RSU”) and performance stock units (“PSU”), is measured at fair value on the grant date and recognized as expense, net of expected forfeitures, over the related service period. The fair value of stock awards is based on the closing price of T-Mobile common stock on the date of grant. RSUs are recognized as expense using the straight-line method. PSUs are recognized as expense following a graded vesting schedule.

Earnings Per Share

Basic earnings per share is computed by dividing Net income attributable to common stockholders by the weighted-average number of common shares outstanding for the period. Diluted earnings per share is computed by giving effect to all potentially dilutive common shares outstanding during the period. Potentially dilutive common shares consist of outstanding stock options, RSUs and PSUs, calculated using the treasury stock method, and mandatory convertible preferred stock (“preferred stock”), calculated using the if-converted method.

Variable Interest Entities

VIEs are entities which lack sufficient equity to permit the entity to finance its activities without additional subordinated financial support from other parties, have equity investors which do not have the ability to make significant decisions relating to the entity's operations through voting rights, do not have the obligation to absorb the expected losses or do not have the right to receive the residual returns of the entity. The most common type of VIE is a special purpose entity (“SPE”). SPEs are commonly used in securitization transactions in order to isolate certain assets and distribute the cash flows from those assets to investors. SPEs are generally structured to insulate investors from claims on the SPE's assets by creditors of other entities, including the creditors of the seller of the assets.

The primary beneficiary is required to consolidate the assets and liabilities of the VIE. The primary beneficiary is the party which has both the power to direct the activities of an entity that most significantly impact the VIE's economic performance, and through its interests in the VIE, the obligation to absorb losses or the right to receive benefits from the VIE which could potentially be significant to the VIE. T-Mobile consolidates VIEs when it is deemed to be the primary beneficiary or when the VIE cannot be deconsolidated.

In assessing which party is the primary beneficiary, all the facts and circumstances are considered, including each party’s role in establishing the VIE and its ongoing rights and responsibilities. This assessment includes, first, identifying the activities that most significantly impact the VIE’s economic performance; and second, identifying which party, if any, has power over those activities. In general, the parties that make the most significant decisions affecting the VIE (such as asset managers and servicers) or have the right to unilaterally remove those decision-makers are deemed to have the power to direct the activities of a VIE.


54

Table of Contents

Recently-Issued Accounting Standards

In April 2015, the FASB issued ASU 2015-03, “Simplifying the Presentation of Debt Issuance Costs.” The standard requires debt issuance costs related to a recognized debt liability be presented in the balance sheet as a direct deduction from the carrying amount of that debt liability, consistent with debt discounts. The recognition and measurement guidance for debt issuance costs are not affected. The standard will become effective for T-Mobile beginning January 1, 2016 and will be applied retrospectively. The implementation of this standard is not expected to have a significant impact on T-Mobile’s consolidated financial statements.

In May 2014, the FASB issued ASU 2014-09, “Revenue from Contracts with Customers.” The standard requires entities to recognize revenue through the application of a five-step model, which includes identification of the contract, identification of the performance obligations, determination of the transaction price, allocation of the transaction price to the performance obligations and recognition of revenue as the entity satisfies the performance obligations. In August 2015, the FASB issued ASU 2015-14, “Revenue From Contracts With Customers (Topic 606): Deferral of the Effective Date.” The amendments in the ASU 2015-14 defer the effective date of ASU 2014-09 by one year. The standard will become effective for T-Mobile beginning January 1, 2018; however, early adoption with the original effective date for periods beginning January 1, 2017 will be permitted.  The Company is currently evaluating the guidance to determine the potential impact on T-Mobile’s consolidated financial statements. Under ASU 2014-09, two adoption methods are allowed.  Under one method, a company may apply the rules to contracts in all reporting periods presented, subject to certain allowable exceptions.  Under the other method, a company may apply the rules to all contracts existing as of January 1, 2018 (provided early adoption is not elected), recognizing an adjustment to retained earnings for the cumulative effect of the change and providing additional disclosures comparing results to previous rules.  The Company continues to evaluate the impact of the new standard and available adoption methods and believes the standard will require the implementation of new revenue accounting systems, processes and internal controls over revenue recognition.

Note 2 – Business Combination with MetroPCS

Transaction Overview

In 2013, T-Mobile US, Inc. was formed through the business combination, effectuated as a reverse acquisition between T-Mobile USA, Inc. (“T-Mobile USA”) and MetroPCS Communications, Inc. (“MetroPCS”). Accordingly, T-Mobile USA’s historical financial statements became the historical financial statements of the Company. The acquired assets and liabilities of MetroPCS are included in the Company’s Consolidated Balance Sheets as of April 30, 2013 and the results of its operations and cash flows are included in the Company’s Consolidated Statements of Comprehensive Income (Loss) and Cash Flows for periods beginning after May 1, 2013.

Cost of MetroPCS Business Combination

The Company recognized the following expenses included in Cost of MetroPCS business combination:
 
Year Ended December 31,
(in millions)
2015
 
2014
 
2013
Network decommissioning costs, including the write-off of certain items
$
376

 
$
263

 
$
—

Transaction and integration costs
—

 
36

 
108

Cost of MetroPCS business combination
$
376

 
$
299

 
$
108


Network Decommissioning Costs

Prior to the closing of the business combination, T-Mobile developed integration plans which included the decommissioning of the MetroPCS Code Division Multiple Access (“CDMA”) network and certain other redundant network cell sites. In 2014, T-Mobile began decommissioning the MetroPCS CDMA network and redundant network cell sites. In 2015, T-Mobile ceased use of the MetroPCS CDMA network. Network decommissioning costs primarily relate to the acceleration of lease costs for decommissioned cell sites for which T-Mobile will no longer receive any economic benefit as the cell site assets are removed. Accrued liabilities for network decommissioning costs are relieved as cash payments are made over the remaining lease terms through 2028. In addition, network decommissioning costs include the write-off of certain items consisting of prepaid rent expense, construction in progress, favorable and unfavorable leases, and deferred rent expense. T-Mobile recognized network decommissioning costs, including the write-off of certain items, of $376 million for the year ended December 31, 2015. T-

55

Table of Contents

Mobile expects to incur additional network decommissioning costs in 2016 as cell site assets are removed, which are not expected to be significant.

Activities in liabilities for network decommissioning costs were as follows:
(in millions)
December 31, 2015
 
December 31, 2014
Balances, beginning of year
$
239

 
$
—

Network decommissioning costs, excluding the write-off of certain items
349

 
271

Cash payments
(182
)
 
(32
)
Balances, end of year
$
406

 
$
239


Classified on the balance sheet as:


Accounts payable and accrued liabilities
$
117

 
$
78

Other long-term liabilities
289

 
161

Network decommissioning liabilities
$
406

 
$
239


In connection with decommissioning the MetroPCS CDMA network, the Company settled asset retirement obligations of $130 million and $21 million for the years ended December 31, 2015 and 2014, respectively. See Note 5 – Property and Equipment for further information.

Transaction and Integration Costs

Transaction costs generally included costs for personnel associated with the change in control and other acquisition-related charges.  Integration costs generally included costs associated with personnel, professional services and combining information technology infrastructures. Transaction costs were not significant for the years ended December 31, 2015 and 2014, and was $41 million for the year ended December 31, 2013.

Consolidated Statements of Comprehensive Income for MetroPCS Operations

The following supplemental information presents the financial results of MetroPCS operations included in the consolidated statements of comprehensive income since May 1, 2013 for the year ended December 31, 2013:
(in millions)
Year Ended December 31, 2013
Total revenues
$
3,366

Income before income taxes
143


Pro Forma Financial Information (Unaudited)

The following pro forma consolidated results of operations for the year ended December 31, 2013 assumes the business combination was completed as of January 1, 2012:
(in millions, except per share amounts)
Year Ended December 31, 2013
Pro forma revenues
$
26,158

Pro forma net income
52

Pro forma basic earnings per share
$
0.07

Pro forma diluted earnings per share
0.07


The pro forma amounts include the historical operating results of T-Mobile USA and MetroPCS prior to the business combination, with adjustments directly attributable to the business combination relating to purchase accounting adjustments to conform to accounting policies that affect total revenues, total operating expenses, interest expense, other income (expense), income taxes expense and eliminate intercompany activities.


56

Table of Contents

As the pro forma amounts assumed the business combination was completed as of January 1, 2012, pro forma earnings for the year ended December 31, 2013 excluded $213 million of transaction costs and these costs would have been included in the pro forma earnings for the year ended December 31, 2012.

The pro forma results include the following:

•
Increase in tax expenses based on the inclusion of MetroPCS in the combined company of $63 million for the year ended December 31, 2013;
•
Net decrease to amortization and depreciation expense related to the fair value of the intangible assets and fixed assets acquired of $19 million for the year ended December 31, 2013; and
•
The impact of financing agreements entered into whereby an aggregate of $14.7 billion senior unsecured notes were issued and $14.5 billion of senior unsecured notes previously issued by T-Mobile USA to Deutsche Telekom and $2.5 billion of senior unsecured notes previously issued by MetroPCS were retired in connection with the business combination for a net increase to interest and other income (expense) of $91 million for the year ended December 31, 2013.

Note 3 – Sales of Certain Receivables

T-Mobile has entered into transactions to sell certain service and EIP accounts receivables. The transactions, including the Company’s continuing involvement with the sold receivables and the respective impacts to the financial statements, are described below.

Sales of Service Receivables

Overview of Transaction

In 2014, T-Mobile entered into an arrangement to sell certain service accounts receivables on a revolving basis with a current maximum funding commitment of $750 million and scheduled expiration date in March 2017. Sales of receivables occur daily and are settled on a monthly basis. The receivables consist of service charges currently due from customers and are short-term in nature. In connection with the sale arrangement, the Company formed a wholly-owned subsidiary, which qualifies as a bankruptcy remote entity to sell service accounts receivables (“Service BRE”). Pursuant to the arrangement, certain subsidiaries of T-Mobile transfer selected receivables to Service BRE.  Service BRE then sells the receivables to an unaffiliated entity (“Service VIE”), which was established to facilitate the sale of beneficial ownership interest in the receivables to certain third parties.

Variable Interest Entity

The Company determined that Service VIE qualifies as a VIE as it lacks sufficient equity to finance its activities. T-Mobile has a variable interest in Service VIE, but is not the primary beneficiary as it lacks the power to direct the activities that most significantly impact Service VIE’s economic performance. Those activities include committing Service VIE to legal agreements to purchase or sell assets, selecting which receivables are purchased in the arrangement, determining whether Service VIE will sell interests in the purchased service receivables to other parties, funding of the entities and servicing of receivables. T-Mobile does not hold the power to direct the key decisions underlying these activities. For example, while T-Mobile acts as the servicer of the sold receivables, which is considered a significant activity of the VIE, the Company is acting as an agent in its capacity as the servicer and the counterparty to the arrangement has the ability to remove T-Mobile as the servicing agent of the receivables at will with no recourse available to T-Mobile. As the Company has determined it is not the primary beneficiary, the results of Service VIE are not consolidated into the Company’s consolidated financial statements.

The following table summarizes the carrying amounts and classification of assets (primarily the deferred purchase price) and liabilities included in the Consolidated Balance Sheets that relate to T-Mobile’s variable interest in Service VIE:
(in millions)
December 31,
2015
 
December 31,
2014
Other current assets
$
206

 
$
204

Accounts payable and accrued liabilities
—

 
13

Other current liabilities
73

 
55


57

Table of Contents

Sales of EIP Receivables

Overview of Transaction

In the fourth quarter of 2015, T-Mobile entered into an arrangement to sell certain EIP accounts receivables on a revolving basis with a committed securitization facility of $800 million, of which $150 million is scheduled to expire in July 2016 and $650 million is scheduled to expire in November 2017. Sales of EIP receivables occur daily and are settled on a monthly basis. The receivables consist of customer EIP balances, which require monthly customer payments for up to 24 months. In connection with the sale arrangement, the Company formed a wholly-owned subsidiary, which qualifies as a bankruptcy remote entity (“EIP BRE”). Pursuant to the arrangement, a wholly-owned subsidiary of T-Mobile transfers selected receivables to EIP BRE.  EIP BRE then sells the receivables to non-consolidated and unaffiliated third-party entities in which T-Mobile does not have a variable interest.

Variable Interest Entity

The Company determined that EIP BRE is a VIE as its equity investment at risk lacks the obligation to absorb a certain portion of its expected losses. The Company has a variable interest in EIP BRE and determined that it is the primary beneficiary based on its ability to direct the activities which most significantly impact EIP BRE’s economic performance. Those activities include selecting which receivables are transferred into EIP BRE and sold in the arrangement and funding of EIP BRE. Additionally, T-Mobile’s equity interest in EIP BRE obligates it to absorb losses and gives it the right to receive benefits from the EIP BRE that could potentially be significant to EIP BRE. Accordingly, the Company determined that it is the primary beneficiary, and includes the balances and results of operations of EIP BRE into the Company’s consolidated financial statements.

The following table summarizes the carrying amounts and classification of EIP BRE’s assets and liabilities included in the Consolidated Balance Sheets:
(in millions)
December 31,
2015
 
December 31,
2014
Other current assets
$
164

 
$
—

Other assets
44

 
—

Accounts payable and accrued liabilities
14

 
—

Other long-term liabilities
3

 
—


In addition, EIP BRE is a separate legal entity with its own separate creditors who will be entitled, prior to any liquidation of EIP BRE, to be satisfied prior to any value in EIP BRE becoming available to T-Mobile. Accordingly, the assets of EIP BRE may not be used to settle the general obligations of T-Mobile and creditors of EIP BRE have limited recourse to the general credit of T-Mobile.

Sales of Receivables

The transfers of service receivables and EIP receivables to the non-consolidated entities are accounted for as sales of financial assets. Upon sale, T-Mobile derecognizes the receivables, as well as the related allowances and unamortized imputed discount, as applicable, and recognizes the net cash proceeds in Net cash provided by operating activities on the Consolidated Statements of Cash Flows.

The proceeds are net of the deferred purchase price, consisting of a receivable from the purchasers that entitles T-Mobile to certain collections on the receivables. T-Mobile recognizes the collection of the deferred purchase price in net cash provided by operating activities as it is dependent on collection of the customer receivables and is not subject to significant interest rate risk. The deferred purchase price represents a financial asset that is primarily tied to the creditworthiness of the customers and which can be settled in such a way that T-Mobile may not recover substantially all of its recorded investment due to default by the customers on the underlying receivables. T-Mobile elected, at inception, to measure the deferred purchase price at fair value with changes in fair value included in Selling, general and administrative expense. The fair value of the deferred purchase price is determined based on a discounted cash flow model which uses unobservable inputs (Level 3 inputs), including customer default rates. T-Mobile’s deferred purchase price related to the sales of service receivables and EIP receivables was $389 million as of December 31, 2015, of which $345 million was included in Other current assets and $44 million was included in Other assets. As of December 31, 2014, T-Mobile’s deferred purchase price related to the sale of service receivables was $204 million, included in Other current assets.


58

Table of Contents

The following table summarizes the impacts of the sale of certain service receivables and EIP receivables on the Consolidated Balance Sheets:
(in millions)
December 31,
2015
 
December 31,
2014
Derecognized net service receivables and EIP receivables
$
1,850

 
$
768

Other current assets
370

 
204

Other assets
44

 
—

Accounts payable and accrued liabilities
14

 
13

Other current liabilities
73

 
55

Other long-term liabilities
3

 
—

Net cash proceeds since inception
1,494

 
610

Of which:


Net cash proceeds during the period
884

 
610

Net cash proceeds funded by reinvested collections
610

 
—


T-Mobile recognized net expenses of $204 million and $179 million for the years ended December 31, 2015 and 2014, respectively, which were recognized in Selling, general and administrative expense. Net expenses included adjustments to the receivables’ fair value, gains or losses from the sales of receivables and changes in fair value of the deferred purchase price. T-Mobile recognized fair value adjustments for the years ended December 31, 2015 and 2014, rather than bad debt expense, to reduce the service receivables’ carrying value to fair value prior to the sales of receivables.

Continuing Involvement

Pursuant to the arrangements, T-Mobile has continuing involvement with the sold service receivables and EIP receivables as the Company services the receivables and is required to repurchase certain receivables, including ineligible receivables, aged receivables and receivables where write-off is imminent. In certain circumstances, T-Mobile is required to deposit cash or replacement receivables for contracts terminated by customers under the Company’s JUMP! Program. T-Mobile will continue to service the customers and their related receivables, including facilitating customer payment collection, in exchange for a monthly servicing fee. As the receivables are sold on a revolving basis, the customer payment collections on sold receivables may be reinvested in new receivable sales. While servicing the receivables the same policies and procedures are applied to the sold receivables that apply to owned receivables, and T-Mobile continues to maintain normal relationships with its customers.

In addition, T-Mobile has continuing involvement with the sold receivables as it may be responsible for absorbing additional credit losses pursuant to the agreement. The Company’s maximum exposure to loss related to the involvement with the arrangements to sell service receivables and EIP receivables was $767 million as of December 31, 2015. The maximum exposure to loss, which is a required disclosure under GAAP, represents an estimated loss that would be incurred under severe, hypothetical circumstances whereby the Company would not receive the deferred purchase price portion of the contractual proceeds withheld by the purchasers and would also be required to repurchase the maximum amount of receivables pursuant to the agreement without consideration for any recovery.  As T-Mobile believes the probability of these circumstances occurring is remote, the maximum exposure to loss is not an indication of the Company’s expected loss.


59

Table of Contents

Note 4 – Equipment Installment Plan Receivables

T-Mobile offers certain retail customers the option to pay for their devices and other purchases in installments over a period of up to 24 months using an EIP.

The following table summarizes the EIP receivables:
(in millions)
December 31,
2015
 
December 31,
2014
EIP receivables, gross
$
3,558

 
$
5,138

Unamortized imputed discount
(185
)
 
(332
)
EIP receivables, net of unamortized imputed discount
3,373

 
4,806

Allowance for credit losses
(148
)
 
(116
)
EIP receivables, net
$
3,225

 
$
4,690


Classified on the balance sheet as:


Equipment installment plan receivables, net
$
2,378

 
$
3,062

Equipment installment plan receivables due after one year, net
847

 
1,628

EIP receivables, net
$
3,225

 
$
4,690


As of December 31, 2015, EIP receivables decreased compared to 2014 primarily due to the sale of certain EIP receivables. See Note 3 – Sales of Certain Receivables for further information. Additionally, the introduction of T-Mobile’s JUMP! On Demand device leasing program in 2015 impacted the rate of customers financing device purchases through installment plans.
 
T-Mobile uses a proprietary credit scoring model that measures the credit quality of a customer at the time of application for mobile communications service using several factors, such as credit bureau information, consumer credit risk scores and service plan characteristics. Based upon customer credit profiles, T-Mobile classifies EIP receivables into the credit categories of “Prime” and “Subprime”. Prime customer receivables are those with lower delinquency risk and Subprime customer receivables are those with higher delinquency risk. Subprime customers are generally required to make a down payment on their equipment purchases. In addition, certain customers within the Subprime category are required to pay an advance deposit.

EIP receivables for which invoices have not yet been generated for the customer are classified as Unbilled. EIP receivables for which invoices have been generated but which are not past the contractual due date are classified as Billed – Current. EIP receivables for which invoices have been generated and the payment is past the contractual due date are classified as Billed – Past Due.

The balance and aging of the EIP receivables on a gross basis by credit category were as follows:
 
December 31, 2015
 
December 31, 2014
(in millions)
Prime
 
Subprime
 
Total
 
Prime
 
Subprime
 
Total
Unbilled
$
1,593

 
$
1,698

 
$
3,291

 
$
2,639

 
$
2,213

 
$
4,852

Billed – Current
77

 
91

 
168

 
104

 
95

 
199

Billed – Past Due
37

 
62

 
99

 
35

 
52

 
87

EIP receivables, gross
$
1,707

 
$
1,851

 
$
3,558

 
$
2,778

 
$
2,360

 
$
5,138


Activity in the unamortized imputed discount and allowance for credit losses balances for the EIP receivables was as follows:
(in millions)
2015
 
2014
Imputed discount and allowance for credit losses, beginning of year
$
448

 
$
336

Bad debt expense
365

 
285

Write-offs, net of recoveries
(333
)
 
(229
)
Change in imputed discount on short-term and long-term EIP receivables
(84
)
 
56

Impacts from sales of EIP receivables
(63
)
 
—

Imputed discount and allowance for credit losses, end of year
$
333

 
$
448


The EIP receivables had weighted average effective imputed interest rates of 8.8% and 9.7% as of December 31, 2015 and 2014, respectively.


60

Table of Contents

Note 5 – Property and Equipment

The components of property and equipment were as follows:
(in millions)
Useful Lives
 
December 31,
2015
 
December 31,
2014
Buildings and equipment
Up to 40 years
 
$
1,900

 
$
1,948

Wireless communications systems
Up to 20 years
 
27,063

 
25,633

Leasehold improvements
Up to 12 years
 
1,003

 
988

Capitalized software
Up to 7 years
 
8,524

 
7,593

Leased wireless devices
Up to 18 months
 
2,236

 
—

Construction in progress
 
 
2,466

 
1,874

Accumulated depreciation and amortization
 
 
(23,192
)
 
(21,791
)
Property and equipment, net
 
 
$
20,000

 
$
16,245


Wireless communication systems include capital lease agreements for network equipment with varying expiration terms through 2030. As of December 31, 2015, capital lease assets and accumulated amortization were $839 million and $117 million, respectively. As of December 31, 2014, capital lease assets and accumulated amortization were $364 million and $53 million, respectively.

T-Mobile capitalizes interest associated with the acquisition or construction of certain property and equipment. The Company recognized capitalized interest of $230 million, $81 million and $5 million for the years ended December 31, 2015, 2014 and 2013, respectively. For the year ended December 31, 2015, the Company recorded increased capitalized interest in connection with T-Mobile's network modernization, including the build out of the network to utilize the recently acquired 700 MHz A-Block spectrum licenses.

In 2015, T-Mobile began offering eligible customers the option to lease their devices over a period of up to 18 months through JUMP! On Demand. At lease inception, leased wireless devices are transferred from inventory to property and equipment. Upon customer exercise of JUMP! On Demand, returned devices are valued at the lower of cost or market with any write down to market recognized as cost of equipment sales and transferred to inventory.

The components of leased wireless devices were as follows:
(in millions)
December 31,
2015
 
December 31,
2014
Leased wireless devices, gross
$
2,236

 
$
—

Accumulated depreciation
(263
)
 
—

Leased wireless devices, net
$
1,973

 
$
—


Future minimum payments expected to be received over the lease term related to the leased wireless devices, which exclude optional residual buy-out amounts at the end of the lease term, are summarized below:
(in millions)
Total
Year Ending December 31,
 
2016
$
913

2017
347

Total
$
1,260


Depreciation expense relating to property and equipment was $4.4 billion, $4.1 billion and $3.4 billion for the years ended December 31, 2015, 2014 and 2013, respectively. For the years ended December 31, 2015 and 2014, the Company recorded additional depreciation expense of $85 million and $242 million, respectively, as a result of adjustments to useful lives of network equipment expected to be replaced in connection with T-Mobile's network modernization and decommissioning the MetroPCS CDMA network and redundant network cell sites. Additional depreciation expense was not significant for the year ended December 31, 2013. Depreciation expense included $312 million related to leased wireless devices for the year ended December 31, 2015.

Asset retirement obligations are primarily for certain legal obligations to remediate leased property on which the Company’s network infrastructure and administrative assets are located.

61

Table of Contents

 
Activity in the asset retirement obligations was as follows:
(in millions)
December 31,
2015
 
December 31,
2014
Asset retirement obligations, beginning of year
$
390

 
$
388

Liabilities incurred
19

 
3

Liabilities settled
(130
)
 
(21
)
Accretion expense
17

 
20

Changes in estimated cash flows
187

 
—

Asset retirement obligations, end of year
$
483

 
$
390


Classified on the balance sheet as:


Other current liabilities
$
41

 
$
179

Other long-term liabilities
442

 
211

Asset retirement obligations
$
483

 
$
390


For the year ended December 31, 2015, T-Mobile settled asset retirement obligations in connection with the decommissioning of certain cell sites. Due to new information gained throughout 2015, primarily from decommissioning the Company’s MetroPCS CDMA network cell sites, T-Mobile reassessed the expected cash flows related to its asset retirement obligations for all remaining T-Mobile network cell sites.  As a result, T-Mobile recorded asset retirement obligations and corresponding assets in the fourth quarter of 2015 to reflect the change in estimated cash flows.  The corresponding assets, net of accumulated depreciation, related to asset retirement obligations were $241 million and $95 million as of December 31, 2015 and 2014, respectively.

Note 6 – Goodwill, Spectrum Licenses and Other Intangible Assets

Goodwill

There were no changes in carrying values of goodwill for the years ended December 31, 2015 and 2014.

Spectrum Licenses

Changes in carrying values of spectrum licenses were as follows:
(in millions)
December 31,
2013
 
Net Changes
 
December 31,
2014
 
Net Changes
 
December 31,
2015
Spectrum licenses
$
18,122

 
$
3,833

 
$
21,955

 
$
2,000

 
$
23,955


During the year ended December 31, 2015 and 2014, the carrying value increased primarily as a result of acquisition activities of 700 MHz A-Block, Advanced Wireless Service (“AWS”) and Personal Communications Service (“PCS”) spectrum licenses.

In 2014, T-Mobile completed transactions for the acquisition of 700 MHz A-Block, AWS and PCS spectrum licenses, primarily with Verizon, for cash and the exchange of certain AWS and PCS spectrum licenses.  Upon closing of the transactions, T-Mobile received 700 MHz A-Block, AWS and PCS spectrum licenses, paid $2.5 billion in cash and transferred certain AWS and PCS spectrum licenses. T-Mobile recorded the spectrum licenses received at their fair value of $4.8 billion. In addition, T-Mobile recognized a non-cash gain of $0.8 billion included in Gains on disposal of spectrum licenses for the year ended December 31, 2014.

In connection with the AWS-3 spectrum auction, T-Mobile provided the FCC with a deposit of $0.4 billion, which was included in Other current assets as of December 31, 2014. Upon conclusion of the AWS-3 auction, T-Mobile was awarded AWS spectrum licenses covering approximately 97 million people for an aggregate bid price of $1.8 billion. In 2015, T-Mobile paid the FCC the remaining $1.4 billion for the AWS spectrum licenses.

In 2015, T-Mobile entered into an agreement with Verizon Communications Inc. (“Verizon”) for the exchange of AWS and PCS spectrum licenses. Upon closing of the transaction, T-Mobile recorded the spectrum licenses received at their fair value of $0.3 billion. In addition, T-Mobile recognized a non-cash gain of $0.1 billion included in Gains on disposal of spectrum licenses for the year ended December 31, 2015. Also in 2015, T-Mobile entered into an agreement with AT&T Inc. (“AT&T”) for the exchange of AWS and PCS spectrum licenses. Spectrum licenses to be transferred are classified as assets held for sale and

62

Table of Contents

included in Other current assets at their carrying value of $0.5 billion as of December 31, 2015. A non-cash gain is expected to be recognized upon closing of the transaction, which is expected to close in the first quarter of 2016, subject to regulatory approval and other customary closing conditions.

Goodwill and Other Intangible Assets Impairment Assessments

The Company's impairment assessment of goodwill resulted in no impairment as of December 31, 2015 and 2014, respectively. The Company's impairment assessment of indefinite-lived intangible assets (spectrum licenses) resulted in no impairment as of December 31, 2015 and 2014, respectively.

Other Intangible Assets

The components of intangible assets were as follows:
 
Useful Lives
 
December 31, 2015
 
December 31, 2014
(in millions)
 
Gross
Amount
 
Accumulated Amortization
 
Net
Amount
 
Gross
Amount
 
Accumulated Amortization
 
Net
Amount
Customer lists
Up to 6 years
 
$
1,104

 
$
(719
)
 
$
385

 
$
1,313

 
$
(700
)
 
$
613

Trademarks and patents
Up to 12 years
 
300

 
(115
)
 
185

 
295

 
(78
)
 
217

Other
Up to 28 years
 
51

 
(27
)
 
24

 
71

 
(31
)
 
40

Other intangible assets
 
 
$
1,455

 
$
(861
)
 
$
594

 
$
1,679

 
$
(809
)
 
$
870


Amortization expense for intangible assets subject to amortization was $276 million, $333 million and $255 million for the years ended December 31, 2015, 2014 and 2013, respectively. The estimated aggregate future amortization expense for intangible assets subject to amortization as of December 31, 2015 was $221 million for the year ending 2016, $163 million in 2017, $104 million in 2018, $51 million in 2019, $34 million in 2020 and $21 million thereafter.

Note 7 – Fair Value Measurements and Derivative Instruments

Embedded Derivative Instruments

In connection with the business combination with MetroPCS, T-Mobile issued senior reset notes to Deutsche Telekom. The interest rates are adjusted at the reset dates to rates defined in the applicable supplemental indentures to manage interest rate risk related to the senior reset notes. The Company determined certain components of the reset feature are required to be bifurcated from the senior reset notes and separately accounted for as embedded derivative instruments. T-Mobile held five embedded derivatives as of December 31, 2014. As of December 31, 2015, one embedded derivative related to the 5.950% Senior Reset Notes to affiliates due 2023 is subject to interest rate volatility.

The fair value of the embedded derivatives was determined using a lattice-based valuation model by determining the fair value of the senior reset notes with and without the embedded derivatives included. The fair value of the senior reset notes with the embedded derivatives utilizes the contractual term of each senior reset note, reset rates calculated based on the spread between specified yield curves and the yield curve on certain T-Mobile long-term debt adjusted pursuant to the applicable supplemental indentures and interest rate volatility. Interest rate volatility is a significant unobservable input (Level 3) as it is derived based on weighted risk-free rate volatility and credit spread volatility. Significant increases or decreases in the weighting of risk-free volatility and credit spread volatility, in isolation, would result in a higher or lower fair value of the embedded derivatives. The embedded derivatives were classified as Level 3 in the fair value hierarchy.

The fair value of embedded derivative instruments measured on a recurring basis by balance sheet location and level were as follows:
 
December 31, 2015
(in millions)
Level 1
 
Level 2
 
Level 3
 
Total
Other long-term liabilities
$
—

 
$
—

 
$
143

 
$
143


63

Table of Contents

 
December 31, 2014
(in millions)
Level 1
 
Level 2
 
Level 3
 
Total
Other current assets
$
—

 
$
—

 
$
3

 
$
3

Other assets
—

 
—

 
2

 
2


The following table summarizes the gain (loss) activity related to embedded derivatives instruments recognized in Interest expense to affiliates:
 
Year Ended December 31,
(in millions)
2015
 
2014
 
2013
Embedded derivatives
$
(148
)
 
$
18

 
$
(13
)

Deferred Purchase Price Assets

In connection with the sales of certain receivables, T-Mobile has deferred purchase price assets measured at fair value that are based on a discounted cash flow model using unobservable Level 3 inputs, including customer default rates. There were no significant changes in fair value for the year ended December 31, 2015 and 2014. See Note 3 – Sales of Certain Receivables for further information.

Assets and Liabilities Measured at Fair Value on a Recurring Basis

The carrying amounts and fair values of the Company’s short-term investments and long-term debt were as follows:
 
December 31, 2015
 
December 31, 2014
(in millions)
Carrying Amount
 
Fair Value
 
Carrying Amount
 
Fair Value
Assets:


Short-term investments
$
2,998

 
$
2,998

 
$
—

 
$
—

Liabilities:


Senior Notes to third parties
$
17,600

 
$
18,098

 
$
15,600

 
$
16,034

Senior Reset Notes to affiliates
5,600

 
6,072

 
5,600

 
5,780

Senior Secured Term Loans
2,000

 
1,990

 
—

 
—


Short-term Investments

The fair value of the Company’s short-term investments, which consist of U.S. Treasury securities, was determined based on quoted market prices in active markets, and therefore was classified as Level 1 in the fair value hierarchy. Additionally, the Company’s cash equivalents included U.S. Treasury securities with remaining maturities of three months or less at the date of purchase that are classified as Level 1 in the fair value hierarchy. Gross unrealized gains and losses on available-for-sale securities were not significant as of December 31, 2015. Available-for-sale securities held by the Company were not significant as of December 31, 2014.

Long-term Debt

The fair value of the Company’s Senior Notes to third parties was determined based on quoted market prices in active markets, and therefore was classified as Level 1 in the fair value hierarchy. The fair value of the Company’s Senior Secured Term Loans and Senior Reset Notes to affiliates were determined based on a discounted cash flow approach using quoted prices of instruments with similar terms and maturities and an estimate for the stand-alone credit risk of T-Mobile. Accordingly, the Company’s Senior Secured Term Loans and Senior Reset Notes to affiliates were classified as Level 2 in the fair value hierarchy.

Although the Company has determined the estimated fair values using available market information and commonly accepted valuation methodologies, considerable judgment was required in interpreting market data to develop fair value estimates for the Senior Secured Term Loans and Senior Reset Notes to affiliates. The fair value estimates were based on information available as of December 31, 2015 and 2014. As such, the Company’s estimates are not necessarily indicative of the amount the Company could realize in a current market exchange.


64

Table of Contents

Note 8 – Debt

Debt was as follows:
(in millions)
December 31,
2015
 
December 31,
2014
5.250% Senior Notes due 2018
$
500

 
$
500

6.288% Senior Reset Notes to affiliates due 2019
1,250

 
1,250

6.464% Senior Notes due 2019
1,250

 
1,250

6.366% Senior Reset Notes to affiliates due 2020
1,250

 
1,250

6.542% Senior Notes due 2020
1,250

 
1,250

6.625% Senior Notes due 2020
1,000

 
1,000

6.250% Senior Notes due 2021
1,750

 
1,750

6.633% Senior Notes due 2021
1,250

 
1,250

8.097% Senior Reset Notes to affiliates due 2021
1,250

 
1,250

6.125% Senior Notes due 2022
1,000

 
1,000

6.731% Senior Notes due 2022
1,250

 
1,250

8.195% Senior Reset Notes to affiliates due 2022
1,250

 
1,250

5.950% Senior Reset Notes to affiliates due 2023 (reset date in April 2016)
600

 
600

6.000% Senior Notes due 2023
1,300

 
1,300

6.625% Senior Notes due 2023
1,750

 
1,750

6.836% Senior Notes due 2023
600

 
600

6.500% Senior Notes due 2024
1,000

 
1,000

6.375% Senior Notes due 2025
1,700

 
1,700

6.500% Senior Notes due 2026
2,000

 
—

Senior Secured Term Loans
2,000

 
—

Unamortized premium from purchase price allocation fair value adjustment
250

 
286

Unamortized discount on Senior Secured Term Loans
(10
)
 
—

Capital leases
826

 
410

Financing arrangements
—

 
64

Total debt
26,266

 
21,960

Less: Current portion of Senior Secured Term Loans
20

 
—

Less: Current portion of capital leases
162

 
23

Less: Financing arrangements
—

 
64

Total long-term debt
$
26,084

 
$
21,873


Classified on the balance sheet as:


Long-term debt
$
20,484

 
$
16,273

Long-term debt to affiliates
5,600

 
5,600

Total long-term debt
$
26,084

 
$
21,873


Long-term Debt

In 2015, T-Mobile USA issued $2.0 billion of 6.500% Senior Notes due 2026, for which T-Mobile and certain subsidiaries are guarantors. In 2015, T-Mobile USA entered into a Term Loan Credit Agreement, which provides for a seven-year senior secured term loan facility with the right to request incremental term loans, subject to the conditions set forth in the agreement. In connection with this agreement, T-Mobile incurred $2.0 billion of Senior Secured Term Loans pursuant to the Term Loan Credit Agreement, for which certain subsidiaries are guarantors. T-Mobile USA’s obligations under the agreement are secured by a first priority lien on substantially all of T-Mobile USA’s assets and the assets of T-Mobile USA’s subsidiaries that are guarantors, subject to certain exceptions. In addition, the Senior Secured Term Loans are subject to a first priority pledge of the equity interests held by T-Mobile USA and substantially all of its direct and indirect subsidiaries. See Note 15 – Guarantor Financial Information for further information regarding the condensed consolidating financial information of T-Mobile’s guarantor subsidiaries.

Interest on the Senior Notes to third parties is accrued from the date of issuance at stated interest rates and paid semi-annually. Interest on the Senior Secured Term Loans is accrued from the date of issuance equal to London Interbank Offered Rate

65

Table of Contents

(“LIBOR”) plus a margin rate of 2.750% and is paid quarterly. The Senior Secured Term Loans had an effective interest rate of 3.500% as of December 31, 2015. Principal on the Senior Secured Term Loans is paid quarterly equal to 0.250% of the principal amount with the remaining balance of the principal due on the final maturity date in November 2022. The interest rate on the 5.950% Senior Reset Notes to affiliates due 2023 will adjust at the reset date to a rate defined in the applicable supplemental indenture. The long-term debt may be redeemed or prepaid, as applicable, in whole or from time to time in part, at specified redemption prices or prepayment premiums, as applicable.  The long-term debt may also be redeemed by the Company using make-whole call or breakage provisions or in part with equity proceeds.  All redemptions are subject to the conditions set forth in the applicable supplemental indenture or Term Loan Credit Agreement.

In 2015, the interest rate on certain Senior Reset Notes to affiliates were adjusted as follows:
 
December 31, 2015
 
Current Rate
 
Previous Rate
6.288% Senior Reset Notes to affiliates due 2019
6.288
%
 
5.578
%
6.366% Senior Reset Notes to affiliates due 2020
6.366
%
 
5.656
%
8.097% Senior Reset Notes to affiliates due 2021
8.097
%
 
5.747
%
8.195% Senior Reset Notes to affiliates due 2022
8.195
%
 
5.845
%

Capital Leases

Capital lease agreements relate to network equipment with varying expiration terms through 2030. Future minimum payments required under capital leases, including interest, over their remaining terms as of December 31, 2015 are expected to be $199 million for the year ending 2016, $189 million in 2017, $158 million in 2018, $128 million in 2019, $56 million in 2020, and $267 million thereafter, for a total of $997 million, including $171 million in interest.

Financing Arrangements

T-Mobile maintains a handset financing arrangement with Deutsche Bank AG (“Deutsche Bank”), which allows for up to $108 million in borrowings.  Under the handset financing arrangement, the Company can effectively extend payment terms for invoices payable to certain handset vendors.  The interest rate on the handset financing arrangement is determined based on LIBOR plus a specified margin per the arrangement.  Obligations under the handset financing arrangement are included in Short-term debt.  In 2015 and 2014, T-Mobile utilized and repaid $100 million under the financing arrangement. As of December 31, 2015 and 2014, there was no outstanding balance.

The Company maintains vendor financing arrangements with its primary network equipment suppliers. Under the respective agreements, the Company can obtain extended financing terms. The interest rate on the vendor financing arrangements is determined based on the difference between LIBOR and a specified margin per the agreements. Obligations under the vendor financing arrangements are included in Short-term debt. As of December 31, 2015 there was no outstanding balance. As of December 31, 2014 the outstanding balance was $64 million.

Lines and Standby Letters of Credit

T-Mobile has an unsecured revolving credit facility with Deutsche Telekom which allows for up to $500 million in borrowings. As of December 31, 2015 and 2014, T-Mobile had no borrowings outstanding under this facility.

For the purposes of securing T-Mobile’s obligations to provide handset insurance services, T-Mobile maintains an agreement for standby letters of credit with JP Morgan Chase Bank, N.A. (“JP Morgan Chase”). For purposes of securing T-Mobile’s general purpose obligations, T-Mobile maintains a letter of credit reimbursement agreement with Deutsche Bank.

The following table summarizes the outstanding standby letters of credit under each agreement:
(in millions)
December 31,
2015
 
December 31,
2014
JP Morgan Chase
$
36

 
$
36

Deutsche Bank
54

 
50

Total outstanding balance
$
90

 
$
86


66

Table of Contents

Note 9 – Tower Obligations

In 2012, T-Mobile conveyed to Crown Castle International Corp. (“CCI”) the exclusive right to manage and operate approximately 7,100 T-Mobile-owned wireless communication tower sites (“CCI Tower Sites”) in exchange for net proceeds of $2.5 billion (“2012 Tower Transaction”). Rights to approximately 6,200 of the tower sites were transferred to CCI via a Master Prepaid Lease with site lease terms ranging from 23 to 37 years (“CCI Lease Sites”), while the remaining tower sites were sold to CCI (“CCI Sales Sites”). T-Mobile leases back space at certain tower sites for an initial term of ten years, followed by optional renewals at customary terms.

In 2015, T-Mobile conveyed to Phoenix Tower International (“PTI”) the exclusive right to manage and operate approximately 600 T-Mobile-owned wireless communication tower sites (“PTI Tower Sites”) in exchange for net proceeds of approximately $140 million (“2015 Tower Transaction”). Rights to approximately 250 sites were transferred to PTI via a management agreement (“PTI Managed Sites”), while the remaining tower sites were sold to PTI (“PTI Sales Sites”). T-Mobile leases back space at certain tower sites for an initial term of ten years, followed by optional renewals at customary terms.

Assets and liabilities associated with the operation of certain of the tower sites were transferred to SPEs. Assets included ground lease agreements or deeds for the land on which the towers are situated, the towers themselves and existing subleasing agreements with other mobile network operator tenants, who lease space at the tower sites. Liabilities included the obligation to pay ground lease rentals, property taxes and other executory costs. Upon closing of the 2012 Tower Transaction, CCI acquired all of the equity interests in the SPEs containing CCI Sales Sites and an option to acquire the CCI Lease Sites at the end of their respective lease terms and entered into a master lease agreement under which T-Mobile agreed to lease back space at certain of the tower sites. Upon closing of the 2015 Tower Transaction, PTI acquired all of the equity interests in the SPEs containing PTI Sales Sites and entered into a master lease agreement under which T-Mobile agreed to lease back space at certain of the tower sites.

T-Mobile determined the SPEs containing the CCI Lease Sites (“Lease Site SPEs”) are VIEs as the Company's equity investment lacks the power to direct the activities that most significantly impact the economic performance of the VIEs. These activities include managing tenants and underlying ground leases, performing repair and maintenance on the towers, the obligation to absorb expected losses and the right to receive the expected future residual returns from the purchase option to acquire the CCI Lease Sites. As the Company determined it is not the primary beneficiary and does not have a controlling financial interest in the Lease Site SPEs, the results of the Lease Site SPEs are not consolidated into the Company’s consolidated financial statements.
  
Due to its continuing involvement with the tower sites, T-Mobile determined it was precluded from applying sale-leaseback accounting. T-Mobile recorded long-term financial obligations in the amount of the net proceeds received and recognizes interest on the tower obligations at a rate of approximately 8% for the 2012 Tower Transaction and 3% for the 2015 Tower Transaction using the effective interest method. The tower obligations are increased by interest expense and amortized through contractual leaseback payments made by T-Mobile to CCI or PTI and through estimated future net cash flows generated and retained by CCI or PTI from operation of the tower sites. T-Mobile’s historical tower site asset costs continue to be reported in Property and equipment, net and are depreciated.

The following table summarizes the impacts to the Consolidated Balance Sheets:
(in millions)
December 31,
2015
 
December 31,
2014
Property and equipment, net
$
601

 
$
604

Tower obligations
2,658

 
2,521


67

Table of Contents

Future minimum payments related to the tower obligations are summarized below:
(in millions)
Total
Year Ending December 31,
 
2016
$
179

2017
180

2018
180

2019
180

2020
181

Thereafter
1,315

Total
$
2,215


T-Mobile is contingently liable for future ground lease payments through the remaining term of the CCI Lease Sites. These contingent obligations are not included in the above table as any amount due is contractually owed by CCI based on the subleasing arrangement. See Note 13 – Commitments and Contingencies for further information.

Note 10 – Employee Compensation and Benefit Plans

T-Mobile maintains the 2013 Omnibus Incentive Plan, which authorized the issuance of up to 63 million shares of common stock. Under the incentive plan, the Company may grant stock options, stock appreciation rights, restricted stock, restricted stock units, and performance awards to employees, consultants, advisors and non-employee directors. As of December 31, 2015, there were 29 million shares of common stock available for future grants under the incentive plan.

T-Mobile grants restricted stock units (“RSU”) to eligible employees and certain non-employee directors and performance stock units (“PSU”) to eligible key executives of the Company. RSUs entitle the grantee to receive shares of T-Mobile common stock at the end of a vesting period of generally up to 3 years. PSUs entitle the holder to receive shares of T-Mobile common stock at the end of a vesting period of generally up to 3 years if the performance goal is achieved. The number of shares ultimately received is dependent on T-Mobile's business performance against the specified performance goal. The Company also maintains an employee stock purchase plan (“ESPP”).

Stock-based compensation expense and related income tax benefits were as follows:
(in millions)
December 31,
2015
 
December 31,
2014
 
December 31,
2013
Stock-based compensation expense
$
201

 
$
196

 
$
100

Income tax benefit related to stock-based compensation
71

 
73

 
38

Realized excess tax benefit
79

 
34

 
—


Stock Awards

The following activity occurred under the RSU and PSU awards:
(in millions, except shares, per share and contractual life amounts)
Number of Units
 
Weighted Average Grant Date Fair Value
 
Weighted Average Remaining Contractual Term (Years)
 
Aggregate Intrinsic Value
Nonvested, December 31, 2014
19,952,089

 
$
24.15

 
1.1
 
$
538

Granted
9,760,057

 
35.56


Vested
(11,956,345
)
 
25.28


Forfeited
(1,421,530
)
 
27.36


Nonvested, December 31, 2015
16,334,271

 
$
29.95

 
1.2
 
$
639


Vesting of the stock awards triggers a tax obligation for the employee, which is required to be remitted to the relevant tax authorities. The Company has agreed to withhold stock units from the employee to cover the tax obligation. The Company withheld 4,176,464 and 2,203,673 stock units to cover tax obligations associated with vesting of stock awards and remitted cash of $156 million and $73 million to the appropriate tax authorities for the years ended December 31, 2015 and 2014, respectively.  The net shares issued to the employee are accounted for as outstanding common stock.


68

Table of Contents

For the years ended December 31, 2014 and 2013, the weighted average fair value per stock award granted was $28.52 and $22.07, respectively. As of December 31, 2015, total unrecognized stock-based compensation expense related to non-vested stock awards, net of estimated forfeitures, was $327 million, before income taxes, which is expected to be recognized over a weighted-average period of 2.0 years. The total fair value of stock awards vested was $445 million, $209 million and $2 million for the years ended December 31, 2015, 2014 and 2013, respectively.

Stock Options

Prior to the business combination, MetroPCS had established the MetroPCS Communications, Inc. 2010 Equity Incentive Compensation Plan, the Amended and Restated MetroPCS Communications, Inc. 2004 Equity Incentive Compensation Plan and the Second Amended and Restated 1995 Stock Option Plan (“Predecessor Plans”). Following stockholder approval of the Company’s 2013 Omnibus Incentive Plan, no new awards may be granted under the Predecessor Plans.

The following activity occurred under the Predecessor Plans:
 
Shares
 
Weighted Average Exercise Price
 
Weighted Average Remaining Contractual Term (Years)
Outstanding and Exercisable, December 31, 2014
4,348,912

 
$
24.96

 
3.7
Exercised
(2,381,650
)
 
19.91


Expired
(142,908
)
 
38.32


Outstanding and exercisable, December 31, 2015
1,824,354

 
$
30.50

 
2.7

Stock options exercised under the Predecessor Plans generated proceeds of approximately $47 million and $27 million for the years ended December 31, 2015 and 2014, respectively. 

Employee Retirement Savings Plan

The Company sponsors a retirement savings plan for the majority of its employees under section 401(k) of the Internal Revenue Code and similar plans. The plans allow employees to contribute a portion of their pretax income in accordance with specified guidelines. The plans match a percentage of employee contributions up to certain limits. Employer matching contributions were $73 million, $66 million and $58 million for the years ended December 31, 2015, 2014 and 2013, respectively.

Employee Stock Purchase Plan

The Company’s ESPP allows eligible employees to contribute up to 15% of their eligible earnings toward the semi-annual purchase of the Company’s common stock at a discounted price, subject to an annual maximum dollar amount. Employees can purchase stock at a 15% discount applied to the closing stock price on the first or last day of the six month offering period, whichever price is lower. The number of shares issued under the Company’s ESPP was 761,085 for the year ended December 31, 2015.

Legacy Long Term Incentive Plan

Prior to the business combination, the Company maintained a performance-based Long Term Incentive Plan (“LTIP”) which aligned to the Company's long-term business strategy. As of December 31, 2015, there were LTIP awards outstanding for the 2013 LTIP. No new awards are expected to be granted under the LTIP. Compensation expense reported within operating expenses related to the Company's LTIP was $27 million, $44 million and $63 million for the years ended December 31, 2015, 2014 and 2013, respectively. Payments of $57 million, $60 million and $61 million were made to participants related to T-Mobile’s LTIP during the years ended December 31, 2015, 2014 and 2013, respectively.


69

Table of Contents

Note 11 – Income Taxes

The sources of Income before income taxes were as follows:
 
Year Ended December 31,
(in millions)
2015
 
2014
 
2013
U.S.
$
898

 
$
347

 
$
(5
)
Puerto Rico
80

 
66

 
56

Income before income taxes
$
978

 
$
413

 
$
51


Income tax expense is summarized as follows:
 
Year Ended December 31,
(in millions)
2015
 
2014
 
2013
Current tax expense (benefit)


Federal
$
(30
)
 
$
—

 
$
(10
)
State
2

 
6

 
6

Puerto Rico
17

 
38

 
10

Total current tax expense (benefit)
(11
)
 
44

 
6

Deferred tax expense (benefit)


Federal
281

 
79

 
24

State
(37
)
 
40

 
(22
)
Puerto Rico
12

 
3

 
8

Total deferred tax expense
256

 
122

 
10

Total income tax expense
$
245

 
$
166

 
$
16


The reconciliation between the U.S. federal statutory income tax rate and T-Mobile's effective income tax rate is as follows:
 
Year Ended December 31,
 
2015
 
2014
 
2013
Federal statutory income tax rate
35.0
 %
 
35.0
 %
 
35.0
 %
State taxes, net of federal benefit
(1.1
)
 
(8.8
)
 
(31.8
)
Puerto Rico taxes, net of federal benefit
3.3

 
5.0

 
28.2

Change in valuation allowance
(3.2
)
 
18.8

 
(6.1
)
Permanent differences
1.6

 
1.4

 
11.3

Federal tax credits, net of reserves
(9.5
)
 
(10.6
)
 
—

Other, net
(1.0
)
 
(0.6
)
 
(5.2
)
Effective income tax rate
25.1
 %
 
40.2
 %
 
31.4
 %

70

Table of Contents


Significant components of deferred income tax assets and liabilities, tax effected, are as follows:
(in millions)
December 31,
2015
 
December 31,
2014
Deferred tax assets


Loss carryforwards
$
1,997

 
$
2,354

Deferred rents
1,136

 
1,034

Reserves and accruals
928

 
454

Federal and state tax credits
349

 
295

Debt fair market value adjustment
97

 
111

Other
317

 
295

Deferred tax assets, gross
4,824

 
4,543

Valuation allowance
(583
)
 
(614
)
Deferred tax assets, net
4,241

 
3,929

Deferred tax liabilities


Spectrum licenses
6,174

 
5,629

Property and equipment
1,950

 
1,877

Other intangible assets
178

 
297

Other
—

 
11

Total deferred tax liabilities
8,302

 
7,814

Net deferred tax liabilities
$
4,061

 
$
3,885


Classified on the balance sheet as:


Current deferred tax assets, net
$
—

 
$
988

Non-current deferred tax liabilities, net
4,061

 
4,873

Net deferred tax liabilities
$
4,061

 
$
3,885


As of December 31, 2015, Current deferred tax assets, net and Non-current deferred tax liabilities, net decreased compared to 2014 primarily due to the early adoption of ASU 2015-17. See Note 1 – Summary of Significant Accounting Policies - Income Taxes for further information.

As of December 31, 2015, the Company has net operating loss (“NOL”) carryforwards, tax effected, of $1.6 billion for federal income tax purposes and $700 million for state income tax purposes, expiring through 2035.  As of December 31, 2015, the Company’s NOL carryforwards for financial reporting purposes were approximately $383 million, tax effected, less than its NOL carryforwards for federal and state income tax purposes, due to unrecognized tax benefits of $378 million and the Company’s inability to realize excess tax benefits until such benefits reduce income taxes payable.

As of December 31, 2015, the Company has available Alternative Minimum Tax credit carryforwards of $142 million, which may be used to reduce regular federal income taxes and have no expiration. The Company also has research and development and foreign tax credit carryforwards of $186 million for federal income tax purposes, which begin to expire in 2018.

As of December 31, 2015 and 2014, the Company’s valuation allowance was $583 million and $614 million, respectively. The change in the valuation allowance of $31 million is primarily related to recent state tax law changes and to the release of the valuation allowance on state net operating losses that expired in 2015. Furthermore, as of December 31, 2015, a valuation allowance of $33 million relates to stock option deductions included in the NOL carryforwards, which will be reversed as an increase to equity when the related deferred tax assets are ultimately realized.

The Company files income tax returns in the U.S. federal jurisdiction, various state jurisdictions and in Puerto Rico.  The Company is currently under examination by various states.  Management does not believe the resolution of any of the audits will result in a material change to the Company’s financial condition, results of operations or cash flows.  During 2015, the IRS concluded its audit through the 2013 tax year with no significant change to the Company’s tax positions, however, the Company’s NOL carryforwards for periods back to 1998 remain open for examination. The Company is generally closed to U.S federal, state and Puerto Rico examination for years prior to 1998.


71

Table of Contents

A reconciliation of the beginning and ending amount of unrecognized tax benefits were as follows:
 
Year Ended December 31,
(in millions)
2015
 
2014
 
2013
Unrecognized tax benefits, beginning of year
$
388

 
$
178

 
$
89

Gross decreases to tax positions in prior periods
(112
)
 
(52
)
 
(18
)
Gross increases to current period tax positions
135

 
262

 
24

Gross increase due to current year business combination
—

 
—

 
83

Unrecognized tax benefits, end of year
$
411

 
$
388

 
$
178


As of December 31, 2015, the Company had $163 million in unrecognized tax benefits that, if recognized, would affect the Company's annual effective tax rate. Included in the 2013 increase to unrecognized tax benefits is $83 million related to tax positions acquired through the business combination with MetroPCS. Penalties and interest are included in selling, general and administrative expenses and interest expense, respectively. The accrued interest and penalties associated with unrecognized tax benefits are insignificant.

Note 12 – Earnings Per Share

The computation of basic and diluted earnings per share was as follows:
 
Year Ended December 31,
(in millions, except shares and per share amounts)
2015
 
2014
 
2013
Net income
$
733

 
$
247

 
$
35

Dividends on preferred stock
(55
)
 
—

 
—

Net income attributable to common stockholders
$
678

 
$
247

 
$
35


Weighted average shares outstanding - basic
812,994,028

 
805,284,712

 
672,955,980

Dilutive effect of outstanding stock options and awards
9,623,910

 
8,893,887

 
3,929,235

Dilutive effect of preferred stock
—

 
1,743,659

 
—

Weighted average shares outstanding - diluted
822,617,938

 
815,922,258

 
676,885,215


Earnings per share - basic
$
0.83

 
$
0.31

 
$
0.05

Earnings per share - diluted
$
0.82

 
$
0.30

 
$
0.05


Potentially dilutive securities:


Outstanding stock options and unvested stock awards
4,842,370

 
1,426,331

 
4,909,741

Preferred stock common stock equivalents
32,237,266

 
—

 
—


Potentially dilutive securities were not included in the computation of diluted earnings per share for certain periods if to do so would have been antidilutive.  Unvested PSUs were based on the number of shares ultimately expected to vest based on T-Mobile’s business performance against the specified performance goal.


72

Table of Contents

Note 13 – Commitments and Contingencies

Commitments

Future minimum payments for non-cancelable operating leases and purchase commitments are summarized below:
(in millions)
Operating Leases
 
Purchase Commitments
Year Ending December 31,


2016
$
2,379

 
$
2,865

2017
2,235

 
3,150

2018
2,046

 
772

2019
1,900

 
714

2020
1,679

 
629

Thereafter
5,583

 
1,304

Total
$
15,822

 
$
9,434


Operating Leases

T-Mobile has operating leases for cell sites, switch sites, retail stores and office facilities with contractual terms expiring through 2030. The majority of cell site leases have an initial non-cancelable term of five years to ten years with several renewal options. The Company considers renewal options certain on leases as being reasonably assured of exercise, thus included in future minimum lease payments for a total term of approximately 15 years. In addition, T-Mobile has operating leases for dedicated transportation lines with varying expiration terms through 2025.

As of December 31, 2015, T-Mobile was contingently liable for future ground lease payments related to the tower obligations. These contingent obligations are not included in the above table as the amounts due are contractually owed by CCI based on the subleasing arrangement. See Note 9 – Tower Obligations for further information.

Total rent expense under operating leases, including dedicated transportation lines, was $2.8 billion, $3.0 billion and $2.8 billion for the years ended December 31, 2015, 2014 and 2013, respectively.

Purchase Commitments

T-Mobile has commitments for non-dedicated transportation lines with varying expiration terms through 2028. In addition, T-Mobile has commitments to purchase spectrum licenses, handsets, network services, equipment, software, marketing sponsorship agreements and other items in the ordinary course of business, with various terms through 2028. These amounts are not reflective of the Company’s entire anticipated purchases under the related agreements, but are determined based on the non-cancelable quantities or termination amounts to which the Company was contractually obligated.

Contingencies and Litigation

T-Mobile is involved in various lawsuits, claims, investigations and proceedings that arise in the ordinary course of business, which include numerous court actions alleging that T-Mobile is infringing various patents. Virtually all of the patent infringement cases are brought by non-practicing entities and effectively seek only monetary damages, although they occasionally seek injunctive relief as well. The matters described above have progressed to various stages and a small number may go to trial in the coming 12 months if they are not otherwise resolved. T-Mobile has established an accrual with respect to certain of these matters, where appropriate, which is reflected in the consolidated financial statements but that T-Mobile does not consider, individually or in the aggregate, material. An accrual is established when T-Mobile believes it is both probable that a loss has been incurred and an amount can be reasonably estimated. For other matters, where the Company has not determined that a loss is probable or because the amount of loss cannot be reasonably estimated, the Company has not recorded an accrual due to various factors typical in contested proceedings, including but not limited to: uncertainty concerning legal theories and their resolution by courts or regulators; uncertain damage theories and demands; and a less than fully developed factual record. While T-Mobile does not expect that the ultimate resolution of these proceedings, individually or in the aggregate will have a material adverse effect on the Company’s financial position, an unfavorable outcome of some or all of these proceedings could have a material adverse impact on results of operations or cash flows for a particular period. This assessment is based on T-Mobile’s current understanding of relevant facts and circumstances. As such, T-Mobile’s view of these matters is subject to inherent uncertainties and may change in the future.

73

Table of Contents


On April 4, 2012, T-Mobile was sued in a patent infringement case by Prism Technologies LLC (“Prism”) in the U.S. District Court for the District of Nebraska, asserting claims relating to patents that Prism claims are related to authentication and use of the internet by T-Mobile’s network, and sought damages of up to $114.9 million.  On October 30, 2015, the jury reached a verdict in favor of T-Mobile, finding non-infringement on all patents; and judgment was entered for T-Mobile on November 20, 2015. Both Prism and T-Mobile have filed post-trial motions, which are pending.  The Company does not believe that a loss is probable or that the amount of a loss can be reasonably estimated at this time, and does not expect that the ultimate resolution of this case will have a material adverse effect on the Company’s financial position, results of operations or cash flows.

Note 14 – Additional Financial Information

Supplemental Consolidated Balance Sheets Information

Allowances and Imputed Discount

The following table summarizes the changes in allowances and unamortized imputed discount related to its current accounts receivables and EIP receivables:
(in millions)
2015
 
2014
 
2013
Allowances, beginning of year
$
199

 
$
169

 
$
197

Bad debt expense
547

 
444

 
463

Write-offs, net of recoveries
(482
)
 
(414
)
 
(491
)
Allowances, end of year
$
264

 
$
199

 
$
169


Imputed discount, beginning of year
$
271

 
$
212

 
$
92

Additions
310

 
380

 
283

Interest income
(414
)
 
(355
)
 
(185
)
Cancellations and other
(78
)
 
(92
)
 
(42
)
Impacts from sales of EIP receivables
(55
)
 
—

 
—

Transfer from long-term
125

 
126

 
64

Imputed discount, end of year
$
159

 
$
271

 
$
212


The following table summarizes the changes in unamortized imputed discount related to its long-term EIP receivables:
(in millions)
2015
 
2014
 
2013
Imputed discount, beginning of year
$
61

 
$
64

 
$
18

Additions
111

 
141

 
121

Cancellations and other
(13
)
 
(18
)
 
(11
)
Impacts from sales of EIP receivables
(8
)
 
—

 
—

Transfer to current
(125
)
 
(126
)
 
(64
)
Imputed discount, end of year
$
26

 
$
61

 
$
64


See Note 3 – Sales of Certain Receivables on sales of EIP receivables and Note 4 – Equipment Installment Plan Receivables on EIP receivables and related unamortized imputed discount and allowance for credit losses for further information.

74

Table of Contents

Accounts Payable and Accrued Liabilities

Accounts payable and accrued liabilities are summarized as follows:
(in millions)
December 31,
2015
 
December 31,
2014
Accounts payable
$
6,137

 
$
5,322

Property and other taxes, including payroll
494

 
605

Payroll and related benefits
521

 
470

Interest
371

 
349

Commissions
190

 
179

Toll and interconnect
68

 
166

Network decommissioning
117

 
78

Advertising
77

 
53

Other
109

 
142

Accounts payable and accrued liabilities
$
8,084

 
$
7,364


Outstanding checks included in accounts payable and accrued liabilities were $501 million and $409 million as of December 31, 2015 and 2014, respectively.

Supplemental Consolidated Statements of Comprehensive Income (Loss) Information

Related Party Transactions

T-Mobile has related party transactions associated with Deutsche Telekom or its affiliates in the ordinary course of business, which are included in the consolidated financial statements.

The following table summarizes the impact of significant transactions with Deutsche Telekom or its affiliates included in operating expenses in the Consolidated Statements of Comprehensive Income (Loss):
 
Year Ended December 31,
(in millions)
2015
 
2014
 
2013
Discount related to roaming expenses
$
(21
)
 
$
(61
)
 
$
(16
)
Fees incurred for use of the T-Mobile brand
65

 
60

 
53

Expenses for telecommunications and IT services
23

 
24

 
102


Supplemental Consolidated Statements of Cash Flows Information

The following table summarizes T-Mobile’s supplemental cash flows information:
 
Year Ended December 31,
(in millions)
2015
 
2014
 
2013
Interest and income tax payments:


Interest payments, net of amounts capitalized
$
1,298

 
$
1,367

 
$
1,156

Income tax payments
54

 
36

 
20

Noncash investing and financing activities:


Increase in accounts payable for purchases of property and equipment
46

 
402

 
6

Leased wireless devices transferred from inventory to property and equipment, net of returns
2,285

 
—

 
—

Issuance of short-term debt for financing of property and equipment purchases
500

 
256

 
470

Assets acquired under capital lease obligations
470

 
77

 
3

Retirement of long-term debt to affiliates
—

 
—

 
14,450

Elimination of net unamortized discounts and premiums on long-term debt to affiliates
—

 
—

 
434

Issuance of new long-term debt to affiliates
—

 
—

 
11,200

Settlement of accounts receivable from affiliates and other outstanding balances
—

 
—

 
363

Income tax benefit from debt recapitalization
—

 
—

 
178

Net assets acquired in MetroPCS business combination, excluding cash acquired
—

 
—

 
827


75

Table of Contents

Supplemental Consolidated Statement of Stockholders’ Equity Information

Preferred Stock

In 2014, T-Mobile completed a public offering of 20 million shares of mandatory convertible preferred stock for net proceeds of $982 million. Dividends on the preferred stock are payable on a cumulative basis when and if declared by the Company’s board of directors at an annual rate of 5.5%. The dividends may be paid in cash, shares of common stock, subject to certain limitations, or any combination of cash and shares of common stock.

Unless converted earlier, each share of preferred stock will convert automatically on December 15, 2017 into between 1.6119 and 1.9342 shares of common stock, subject to customary anti-dilution adjustments, depending on the applicable market value of the common stock. At any time, the preferred shares may be converted, in whole or in part, at the minimum conversion rate of 1.6119 shares of common stock, except during a fundamental change conversion period. In addition, holders may be entitled to shares based on the amount of accumulated and unpaid dividends. If certain fundamental changes involving the Company occur, the preferred stock may be converted into common shares at the applicable conversion rate, subject to certain anti-dilution adjustments, and holders will also be entitled to a make-whole amount. The preferred stock ranks senior with respect to liquidation preference and dividend rights to common stock. In the event of any voluntary or involuntary liquidation, winding-up or dissolution of the Company, each holder of preferred stock will be entitled to receive a liquidation preference in the amount of $50 per share, plus an amount equal to accumulated and unpaid dividends, after satisfaction of liabilities to the Company’s creditors and before any distribution or payment is made to any holders of common stock. The preferred stock is not redeemable.

Common Stock

In 2013, T-Mobile completed a public offering of 73 million shares of common stock at a price of $25 per share.

Note 15 – Guarantor Financial Information

Pursuant to the applicable indentures and supplemental indentures, the long-term debt to affiliates and third parties, excluding Senior Secured Term Loans and capital leases, issued by T-Mobile USA (“Issuer”) is fully and unconditionally guaranteed, jointly and severally, on a senior unsecured basis by T-Mobile (“Parent”) and certain of the Issuer’s 100% owned subsidiaries (“Guarantor Subsidiaries”).

In 2015, Issuer issued unsecured Senior Notes of $2.0 billion and incurred $2.0 billion of Senior Secured Term Loans, which are secured by a first priority lien on substantially all of T-Mobile USA’s assets and the assets of T-Mobile USA’s Guarantor Subsidiaries. In addition, the Senior Secured Term Loans are subject to a first priority pledge of the equity interests held by T-Mobile USA and substantially all of its direct and indirect subsidiaries. See Note 8 – Debt for further information.

In 2015, T-Mobile entered into an arrangement to sell certain EIP accounts receivable on a revolving basis. In connection with the sale arrangement, the Company formed EIP BRE, a wholly-owned subsidiary, which is included in the Non-Guarantor Subsidiaries condensed consolidating financial information. See Note 3 – Sales of Certain Receivables for further information.

The guarantees of the Guarantor Subsidiaries are subject to release in limited circumstances only upon the occurrence of certain customary conditions. The indentures governing the long-term debt contain covenants that, among other things, limit the ability of the Issuer and the Guarantor Subsidiaries to: incur more debt; pay dividends and make distributions; make certain investments; repurchase stock; create liens or other encumbrances; enter into transactions with affiliates; enter into transactions that restrict dividends or distributions from subsidiaries; and merge, consolidate, or sell, or otherwise dispose of, substantially all of their assets. Certain provisions of each of the indentures and the supplemental indentures relating to the long-term debt restrict the ability of the Issuer to loan funds or make payments to Parent. However, the Issuer and Guarantor Subsidiaries are allowed to make certain permitted payments to the Parent under the terms of the indentures and the supplemental indentures.

Presented below is the condensed consolidating financial information as of December 31, 2015 and 2014 and for the years ended December 31, 2015, 2014 and 2013, respectively. As the business combination was treated as a “reverse acquisition” and the Issuer was treated as the accounting acquirer, the Issuer’s historical financial statements are the historical financial statements of Parent for comparative purposes. As a result the Parent column only reflects activity in the condensed consolidating financial statements presented below for periods subsequent to the consummation of the business combination on April 30, 2013. The equity method of accounting is used to account for ownership interests in subsidiaries, where applicable.

76

Table of Contents

Condensed Consolidating Balance Sheet Information
December 31, 2015
(in millions)
Parent
 
Issuer
 
Guarantor Subsidiaries
 
Non-Guarantor Subsidiaries
 
Consolidating and Eliminating Adjustments
 
Consolidated
Assets


Current assets


Cash and cash equivalents
$
378

 
$
1,767

 
$
2,364

 
$
73

 
$
—

 
$
4,582

Short-term investments
—

 
1,999

 
999

 
—

 
—

 
2,998

Accounts receivable, net
—

 
—

 
1,574

 
214

 
—

 
1,788

Equipment installment plan receivables, net
—

 
—

 
2,378

 
—

 
—

 
2,378

Accounts receivable from affiliates
—

 
—

 
36

 
—

 
—

 
36

Inventories
—

 
—

 
1,295

 
—

 
—

 
1,295

Other current assets
—

 
—

 
1,413

 
400

 
—

 
1,813

Total current assets
378

 
3,766

 
10,059

 
687

 
—

 
14,890

Property and equipment, net (1)
—

 
—

 
19,546

 
454

 
—

 
20,000

Goodwill
—

 
—

 
1,683

 
—

 
—

 
1,683

Spectrum licenses
—

 
—

 
23,955

 
—

 
—

 
23,955

Other intangible assets, net
—

 
—

 
594

 
—

 
—

 
594

Investments in subsidiaries, net
16,184

 
32,280

 
—

 
—

 
(48,464
)
 
—

Intercompany receivables
—

 
6,130

 
—

 
—

 
(6,130
)
 
—

Equipment installment plan receivables due after one year, net
—

 
—

 
847

 
—

 
—

 
847

Other assets
—

 
28

 
387

 
219

 
(167
)
 
467

Total assets
$
16,562

 
$
42,204

 
$
57,071

 
$
1,360

 
$
(54,761
)
 
$
62,436

Liabilities and Stockholders' Equity


Current liabilities


Accounts payable and accrued liabilities
$
—

 
$
368

 
$
7,496

 
$
220

 
$
—

 
$
8,084

Current payables to affiliates
—

 
70

 
65

 
—

 
—

 
135

Short-term debt
—

 
20

 
162

 
—

 
—

 
182

Deferred revenue
—

 
—

 
717

 
—

 
—

 
717

Other current liabilities
—

 
—

 
327

 
83

 
—

 
410

Total current liabilities
—

 
458

 
8,767

 
303

 
—

 
9,528

Long-term debt
—

 
19,820

 
664

 
—

 
—

 
20,484

Long-term debt to affiliates
—

 
5,600

 
—

 
—

 
—

 
5,600

Tower obligations (1)
—

 
—

 
411

 
2,247

 
—

 
2,658

Deferred tax liabilities
—

 
—

 
4,228

 
—

 
(167
)
 
4,061

Deferred rents
—

 
—

 
2,481

 
—

 
—

 
2,481

Negative carrying value of subsidiaries, net
—

 
—

 
628

 
—

 
(628
)
 
—

Intercompany payables
5

 
—

 
5,959

 
166

 
(6,130
)
 
—

Other long-term liabilities
—

 
142

 
922

 
3

 
—

 
1,067

 Total long-term liabilities
5

 
25,562

 
15,293

 
2,416

 
(6,925
)
 
36,351

Total stockholders' equity
16,557

 
16,184

 
33,011

 
(1,359
)
 
(47,836
)
 
16,557

Total liabilities and stockholders' equity
$
16,562

 
$
42,204

 
$
57,071

 
$
1,360

 
$
(54,761
)
 
$
62,436


(1)
Assets and liabilities for Non-Guarantor Subsidiaries are primarily included in VIEs related to the 2012 Tower Transaction. See Note 9 – Tower Obligations for further information.


77

Table of Contents

Condensed Consolidating Balance Sheet Information
December 31, 2014
(in millions)
Parent
 
Issuer
 
Guarantor Subsidiaries
 
Non-Guarantor Subsidiaries
 
Consolidating and Eliminating Adjustments
 
Consolidated
Assets


Current assets


Cash and cash equivalents
$
2,278

 
$
2,246

 
$
697

 
$
94

 
$
—

 
$
5,315

Accounts receivable, net
—

 
—

 
1,817

 
48

 
—

 
1,865

Equipment installment plan receivables, net
—

 
—

 
3,062

 
—

 
—

 
3,062

Accounts receivable from affiliates
—

 
—

 
76

 
—

 
—

 
76

Inventories
—

 
—

 
1,085

 
—

 
—

 
1,085

Deferred tax assets, net
—

 
—

 
988

 
—

 
—

 
988

Other current assets
—

 
3

 
1,341

 
249

 
—

 
1,593

Total current assets
2,278

 
2,249

 
9,066

 
391

 
—

 
13,984

Property and equipment, net (1)
—

 
—

 
15,708

 
537

 
—

 
16,245

Goodwill
—

 
—

 
1,683

 
—

 
—

 
1,683

Spectrum licenses
—

 
—

 
21,955

 
—

 
—

 
21,955

Other intangible assets, net
—

 
—

 
870

 
—

 
—

 
870

Investments in subsidiaries, net
13,470

 
30,385

 
—

 
—

 
(43,855
)
 
—

Intercompany receivables
—

 
2,773

 
—

 
—

 
(2,773
)
 
—

Equipment installment plan receivables due after one year, net
—

 
—

 
1,628

 
—

 
—

 
1,628

Other assets
2

 
17

 
259

 
124

 
(114
)
 
288

Total assets
$
15,750

 
$
35,424

 
$
51,169

 
$
1,052

 
$
(46,742
)
 
$
56,653

Liabilities and Stockholders' Equity


Current liabilities


Accounts payable and accrued liabilities
$
—

 
$
349

 
$
6,914

 
$
101

 
$
—

 
$
7,364

Current payables to affiliates
—

 
56

 
175

 
—

 
—

 
231

Short-term debt
—

 
63

 
24

 
—

 
—

 
87

Deferred revenue
—

 
—

 
459

 
—

 
—

 
459

Other current liabilities
—

 
—

 
580

 
55

 
—

 
635

Total current liabilities
—

 
468

 
8,152

 
156

 
—

 
8,776

Long-term debt
—

 
15,886

 
387

 
—

 
—

 
16,273

Long-term debt to affiliates
—

 
5,600

 
—

 
—

 
—

 
5,600

Tower obligations (1)
—

 
—

 
271

 
2,250

 
—

 
2,521

Deferred tax liabilities
—

 
—

 
4,987

 
—

 
(114
)
 
4,873

Deferred rents
—

 
—

 
2,331

 
—

 
—

 
2,331

Negative carrying value of subsidiaries, net
—

 
—

 
780

 
—

 
(780
)
 
—

Intercompany payables
87

 
—

 
2,589

 
97

 
(2,773
)
 
—

Other long-term liabilities
—

 
—

 
616

 
—

 
—

 
616

 Total long-term liabilities
87

 
21,486

 
11,961

 
2,347

 
(3,667
)
 
32,214

Total stockholders' equity
15,663

 
13,470

 
31,056

 
(1,451
)
 
(43,075
)
 
15,663

Total liabilities and stockholders' equity
$
15,750

 
$
35,424

 
$
51,169

 
$
1,052

 
$
(46,742
)
 
$
56,653


(1)
Assets and liabilities for Non-Guarantor Subsidiaries are primarily included in VIEs related to the 2012 Tower Transaction. See Note 9 – Tower Obligations for further information.

78

Table of Contents

Condensed Consolidating Statement of Comprehensive Income (Loss) Information
Year Ended December 31, 2015
(in millions)
Parent
 
Issuer
 
Guarantor Subsidiaries
 
Non-Guarantor Subsidiaries
 
Consolidating and Eliminating Adjustments
 
Consolidated
Revenues


Service revenues
$
—

 
$
—

 
$
23,748

 
$
1,669

 
$
(596
)
 
$
24,821

Equipment revenues
—

 
—

 
7,148

 
—

 
(430
)
 
6,718

Other revenues
—

 
1

 
356

 
171

 
(14
)
 
514

Total revenues
—

 
1

 
31,252

 
1,840

 
(1,040
)
 
32,053

Operating expenses


Cost of services, exclusive of depreciation and amortization shown separately below
—

 
—

 
5,530

 
24

 
—

 
5,554

Cost of equipment sales
—

 
—

 
9,055

 
720

 
(431
)
 
9,344

Selling, general and administrative
—

 
—

 
10,065

 
733

 
(609
)
 
10,189

Depreciation and amortization
—

 
—

 
4,605

 
83

 
—

 
4,688

Cost of MetroPCS business combination
—

 
—

 
376

 
—

 
—

 
376

Gain on disposal of spectrum licenses
—

 
—

 
(163
)
 
—

 
—

 
(163
)
Total operating expenses
—

 
—

 
29,468

 
1,560

 
(1,040
)
 
29,988

Operating income
—

 
1

 
1,784

 
280

 
—

 
2,065

Other income (expense)


Interest expense
—

 
(847
)
 
(50
)
 
(188
)
 
—

 
(1,085
)
Interest expense to affiliates
—

 
(411
)
 
—

 
—

 
—

 
(411
)
Interest income
—

 
2

 
418

 
—

 
—

 
420

Other income (expense), net
—

 
(10
)
 
—

 
(1
)
 
—

 
(11
)
Total other income (expense), net
—

 
(1,266
)
 
368

 
(189
)
 
—

 
(1,087
)
Income (loss) before income taxes
—

 
(1,265
)
 
2,152

 
91

 
—

 
978

Income tax expense
—

 
—

 
214

 
31

 
—

 
245

Earnings (loss) of subsidiaries
733

 
1,998

 
(48
)
 
—

 
(2,683
)
 
—

Net income
733

 
733

 
1,890

 
60

 
(2,683
)
 
733

Dividends on preferred stock
(55
)
 
—

 
—

 
—

 
—

 
(55
)
Net income attributable to common stockholders
$
678

 
$
733

 
$
1,890

 
$
60

 
$
(2,683
)
 
$
678

Other comprehensive loss, net of tax


Other comprehensive loss, net of tax
(2
)
 
(2
)
 
(2
)
 
—

 
4

 
(2
)
Total comprehensive income (loss)
$
731

 
$
731

 
$
1,888

 
$
60

 
$
(2,679
)
 
$
731

-


79

Table of Contents

Condensed Consolidating Statement of Comprehensive Income (Loss) Information
Year Ended December 31, 2014
(in millions)
Parent
 
Issuer
 
Guarantor Subsidiaries
 
Non-Guarantor Subsidiaries
 
Consolidating and Eliminating Adjustments
 
Consolidated
Revenues


Service revenues
$
—

 
$
—

 
$
21,483

 
$
1,302

 
$
(410
)
 
$
22,375

Equipment revenues
—

 
—

 
7,319

 
—

 
(530
)
 
6,789

Other revenues
—

 
—

 
270

 
140

 
(10
)
 
400

Total revenues
—

 
—

 
29,072

 
1,442

 
(950
)
 
29,564

Operating expenses


Cost of services, exclusive of depreciation and amortization shown separately below
—

 
—

 
5,767

 
21

 
—

 
5,788

Cost of equipment sales
—

 
—

 
9,491

 
702

 
(572
)
 
9,621

Selling, general and administrative
—

 
—

 
8,723

 
518

 
(378
)
 
8,863

Depreciation and amortization
—

 
—

 
4,330

 
82

 
—

 
4,412

Cost of MetroPCS business combination
—

 
—

 
299

 
—

 
—

 
299

Gain on disposal of spectrum licenses
—

 
—

 
(840
)
 
—

 
—

 
(840
)
Other, net
—

 
—

 
5

 
—

 
—

 
5

Total operating expenses
—

 
—

 
27,775

 
1,323

 
(950
)
 
28,148

Operating income
—

 
—

 
1,297

 
119

 
—

 
1,416

Other income (expense)


Interest expense
—

 
(838
)
 
(55
)
 
(180
)
 
—

 
(1,073
)
Interest expense to affiliates
—

 
(278
)
 
—

 
—

 
—

 
(278
)
Interest income
—

 
—

 
359

 
—

 
—

 
359

Other income (expense), net
—

 
(15
)
 
4

 
—

 
—

 
(11
)
Total other income (expense), net
—

 
(1,131
)
 
308

 
(180
)
 
—

 
(1,003
)
Income (loss) before income taxes
—

 
(1,131
)
 
1,605

 
(61
)
 
—

 
413

Income tax expense (benefit)
—

 
—

 
189

 
(23
)
 
—

 
166

Earnings (loss) of subsidiaries
247

 
1,278

 
(54
)
 
—

 
(1,471
)
 
—

Net income (loss)
$
247

 
$
147

 
$
1,362

 
$
(38
)
 
$
(1,471
)
 
$
247

Other comprehensive loss, net of tax


Other comprehensive income (loss), net of tax
(2
)
 
(2
)
 
(2
)
 
—

 
4

 
(2
)
Total comprehensive income (loss)
$
245

 
$
145

 
$
1,360

 
$
(38
)
 
$
(1,467
)
 
$
245


80

Table of Contents

Condensed Consolidating Statement of Comprehensive Income (Loss) Information
Year Ended December 31, 2013
(in millions)
Parent
 
Issuer
 
Guarantor Subsidiaries
 
Non-Guarantor Subsidiaries
 
Consolidating and Eliminating Adjustments
 
Consolidated
Revenues


Service revenues
$
—

 
$
—

 
$
18,396

 
$
823

 
$
(151
)
 
$
19,068

Equipment revenues
—

 
—

 
5,728

 
—

 
(695
)
 
5,033

Other revenues
—

 
—

 
251

 
142

 
(74
)
 
319

Total revenues
—

 
—

 
24,375

 
965

 
(920
)
 
24,420

Operating expenses


Cost of services, exclusive of depreciation and amortization shown separately below
—

 
—

 
5,302

 
50

 
(73
)
 
5,279

Cost of equipment sales
—

 
—

 
7,180

 
552

 
(756
)
 
6,976

Selling, general and administrative
—

 
—

 
7,283

 
190

 
(91
)
 
7,382

Depreciation and amortization
—

 
—

 
3,545

 
82

 
—

 
3,627

Cost of MetroPCS business combination
—

 
—

 
108

 
—

 
—

 
108

Gain on disposal of spectrum licenses
—

 
—

 
(2
)
 
—

 
—

 
(2
)
Other, net
—

 
—

 
54

 
—

 
—

 
54

Total operating expenses
—

 
—

 
23,470

 
874

 
(920
)
 
23,424

Operating income
—

 
—

 
905

 
91

 
—

 
996

Other income (expense)


Interest expense
—

 
(317
)
 
(55
)
 
(173
)
 
—

 
(545
)
Interest expense to affiliates
—

 
(678
)
 
—

 
—

 
—

 
(678
)
Interest income
—

 
—

 
189

 
—

 
—

 
189

Other income (expense), net
—

 
94

 
(6
)
 
1

 
—

 
89

Total other income (expense), net
—

 
(901
)
 
128

 
(172
)
 
—

 
(945
)
Income (loss) before income taxes
—

 
(901
)
 
1,033

 
(81
)
 
—

 
51

Income tax expense (benefit)
—

 
—

 
45

 
(29
)
 
—

 
16

Earnings (loss) of subsidiaries
(104
)
 
936

 
(54
)
 
—

 
(778
)
 
—

Net income (loss)
$
(104
)
 
$
35

 
$
934

 
$
(52
)
 
$
(778
)
 
$
35

Other comprehensive income (loss), net of tax


Other comprehensive income (loss), net of tax
—

 
(38
)
 
24

 
—

 
(24
)
 
(38
)
Total comprehensive income (loss)
$
(104
)
 
$
(3
)
 
$
958

 
$
(52
)
 
$
(802
)
 
$
(3
)


81

Table of Contents

Condensed Consolidating Statement of Cash Flows Information
Year Ended December 31, 2015
(in millions)
Parent
 
Issuer
 
Guarantor Subsidiaries
 
Non-Guarantor Subsidiaries
 
Consolidating and Eliminating Adjustments
 
Consolidated
Operating activities


Net cash provided by (used in) operating activities
$
(1
)
 
$
(4,504
)
 
$
9,940

 
$
154

 
$
(175
)
 
$
5,414


Investing activities


Purchases of property and equipment
—

 
—

 
(4,724
)
 
—

 
—

 
(4,724
)
Purchases of spectrum licenses and other intangible assets, including deposits
—

 
—

 
(1,935
)
 
—

 
—

 
(1,935
)
Purchases of short-term investments
—

 
(1,999
)
 
(998
)
 
—

 
—

 
(2,997
)
Investment in subsidiaries
(1,905
)
 
—

 
—

 
—

 
1,905

 
—

Other, net
—

 
—

 
96

 
—

 
—

 
96

Net cash used in investing activities
(1,905
)
 
(1,999
)
 
(7,561
)
 
—

 
1,905

 
(9,560
)


Financing activities


Proceeds from capital contribution
—

 
1,905

 
—

 
—

 
(1,905
)
 
—

Proceeds from issuance of long-term debt
—

 
3,979

 
—

 
—

 
—

 
3,979

Repayments of long-term debt and capital lease obligations
—

 
—

 
(57
)
 
—

 
—

 
(57
)
Proceeds from tower obligations
—

 
140

 
—

 
—

 
—

 
140

Repayments of short-term debt for purchases of inventory, property and equipment, net
—

 
—

 
(564
)
 
—

 
—

 
(564
)
Intercompany dividend paid
—

 
—

 
—

 
(175
)
 
175

 
—

Dividends on preferred stock
(41
)
 
—

 
(14
)
 
—

 
—

 
(55
)
Proceeds from exercise of stock options
47

 
—

 
—

 
—

 
—

 
47

Taxes paid related to net share settlement of stock awards
—

 
—

 
(156
)
 
—

 
—

 
(156
)
Other, net
—

 
—

 
79

 
—

 
—

 
79

Net cash provided by (used in) financing activities
6

 
6,024

 
(712
)
 
(175
)
 
(1,730
)
 
3,413


Change in cash and cash equivalents
(1,900
)
 
(479
)
 
1,667

 
(21
)
 
—

 
(733
)
Cash and cash equivalents


Beginning of period
2,278

 
2,246

 
697

 
94

 
—

 
5,315

End of period
$
378

 
$
1,767

 
$
2,364

 
$
73

 
$
—

 
$
4,582


82

Table of Contents

Condensed Consolidating Statement of Cash Flows Information
Year Ended December 31, 2014
(in millions)
Parent
 
Issuer
 
Guarantor Subsidiaries
 
Non-Guarantor Subsidiaries
 
Consolidating and Eliminating Adjustments
 
Consolidated
Operating activities


Net cash provided by (used in) operating activities
$
9

 
$
(5,145
)
 
$
9,364

 
$
18

 
$
(100
)
 
$
4,146


Investing activities


Purchases of property and equipment
—

 
—

 
(4,317
)
 
—

 
—

 
(4,317
)
Purchases of spectrum licenses and other intangible assets, including deposits
—

 
—

 
(2,900
)
 
—

 
—

 
(2,900
)
Investment in subsidiaries
(1,700
)
 
—

 
—

 
—

 
1,700

 
—

Other, net
—

 
—

 
(29
)
 
—

 
—

 
(29
)
Net cash used in investing activities
(1,700
)
 
—

 
(7,246
)
 
—

 
1,700

 
(7,246
)


Financing activities


Proceeds from capital contribution
—

 
1,700

 
—

 
—

 
(1,700
)
 
—

Proceeds from issuance of long-term debt
—

 
2,993

 
—

 
—

 
—

 
2,993

Repayments of long-term debt and capital lease obligations
—

 
—

 
(1,019
)
 
—

 
—

 
(1,019
)
Proceeds from issuance of preferred stock
982

 
—

 
—

 
—

 
—

 
982

Repayments of short-term debt for purchases of inventory, property and equipment, net
—

 
—

 
(418
)
 
—

 
—

 
(418
)
Intercompany dividend paid
—

 
—

 
—

 
(100
)
 
100

 
—

Proceeds from exercise of stock options
27

 
—

 
—

 
—

 
—

 
27

Taxes paid related to net share settlement of stock awards
—

 
—

 
(73
)
 
—

 
—

 
(73
)
Other, net
—

 
—

 
32

 
—

 
—

 
32

Net cash provided by (used in) financing activities
1,009

 
4,693

 
(1,478
)
 
(100
)
 
(1,600
)
 
2,524


Change in cash and cash equivalents
(682
)
 
(452
)
 
640

 
(82
)
 
—

 
(576
)
Cash and cash equivalents


Beginning of period
2,960

 
2,698

 
57

 
176

 
—

 
5,891

End of period
$
2,278

 
$
2,246

 
$
697

 
$
94

 
$
—

 
$
5,315


83

Table of Contents

Condensed Consolidating Statement of Cash Flows Information
Year Ended December 31, 2013
(in millions)
Parent
 
Issuer
 
Guarantor Subsidiaries
 
Non-Guarantor Subsidiaries
 
Consolidating and Eliminating Adjustments
 
Consolidated
Operating activities


Net cash provided by (used in) operating activities
$
299

 
$
(1,203
)
 
$
4,380

 
$
69

 
$
—

 
$
3,545


Investing activities


Purchases of property and equipment
—

 
—

 
(4,025
)
 
—

 
—

 
(4,025
)
Purchases of spectrum licenses and other intangible assets
—

 
—

 
(381
)
 
—

 
—

 
(381
)
Short term affiliate loan receivable, net
—

 
—

 
300

 
—

 
—

 
300

Cash and cash equivalents acquired in MetroPCS business combination
737

 
1,407

 
—

 
—

 
—

 
2,144

Other, net
—

 
—

 
(130
)
 
—

 
—

 
(130
)
Net cash provided by (used in) investing activities
737

 
1,407

 
(4,236
)
 
—

 
—

 
(2,092
)


Financing activities


Proceeds from issuance of long-term debt
—

 
2,494

 
—

 
—

 
—

 
2,494

Repayment of capital lease obligations
—

 
—

 
(9
)
 
—

 
—

 
(9
)
Proceeds from issuance of common stock
1,787

 
—

 
—

 
—

 
—

 
1,787

Repayments of short-term debt for purchases of property and equipment
—

 
—

 
(244
)
 
—

 
—

 
(244
)
Proceeds from exercise of stock options
137

 
—

 
—

 
—

 
—

 
137

Other, net
—

 
—

 
(121
)
 
—

 
—

 
(121
)
Net cash provided by (used in) financing activities
1,924

 
2,494

 
(374
)
 
—

 
—

 
4,044


Change in cash and cash equivalents
2,960

 
2,698

 
(230
)
 
69

 
—

 
5,497

Cash and cash equivalents


Beginning of period
—

 
—

 
287

 
107

 
—

 
394

End of period
$
2,960

 
$
2,698

 
$
57

 
$
176

 
$
—

 
$
5,891


Note 16 – Subsequent Events

Spectrum License Transactions
 
In January 2016, T-Mobile acquired spectrum licenses covering nearly 20 million people in seven major metropolitan markets for approximately $0.6 billion in cash.

Additionally, in January and February 2016, T-Mobile entered into agreements with multiple third parties for the exchange of certain spectrum licenses and the acquisition of 700 MHz A-Block spectrum licenses covering approximately 48 million people, for approximately $0.7 billion in cash. In the first quarter of 2016, spectrum licenses to be exchanged of $0.2 billion will be transferred to held for sale and included in Other current assets.  Non-cash gains are expected to be recognized upon closing of the exchange transactions, which are expected to occur in mid-2016, subject to regulatory approval and other customary closing conditions.


84

Table of Contents

Supplementary Data

Quarterly Financial Information (Unaudited)

(in millions, except shares and per share amounts)
First Quarter
 
Second Quarter
 
Third Quarter
 
Fourth Quarter
 
Full Year
2015


Total revenues
$
7,778

 
$
8,179

 
$
7,849

 
$
8,247

 
$
32,053

Operating income
117

 
597

 
513

 
838

 
2,065

Net income (loss)
(63
)
 
361

 
138

 
297

 
733

Dividends on preferred stock
(14
)
 
(14
)
 
(13
)
 
(14
)
 
(55
)
Net income (loss) attributable to common stockholders
(77
)
 
347

 
125

 
283

 
678

Earnings (loss) per share


Basic
$
(0.09
)
 
$
0.43

 
$
0.15

 
$
0.35

 
$
0.83

Diluted
$
(0.09
)
 
$
0.42

 
$
0.15

 
$
0.34

 
$
0.82

Weighted average shares outstanding


Basic
808,605,526

 
811,605,031

 
815,069,272

 
816,585,782

 
812,994,028

Diluted
808,605,526

 
821,122,537

 
822,017,220

 
824,716,119

 
822,617,938

Net income (loss) includes:


Cost of MetroPCS business combination
$
128

 
$
34

 
$
193

 
$
21

 
$
376

Gains on disposal of spectrum licenses
—

 
(23
)
 
(1
)
 
(139
)
 
(163
)
2014


Total revenues
$
6,875

 
$
7,185

 
$
7,350

 
$
8,154

 
$
29,564

Operating income (loss)
(28
)
 
962

 
49

 
433

 
1,416

Net income (loss)
(151
)
 
391

 
(94
)
 
101

 
247

Earnings (loss) per share


Basic
$
(0.19
)
 
$
0.49

 
$
(0.12
)
 
$
0.13

 
$
0.31

Diluted
$
(0.19
)
 
$
0.48

 
$
(0.12
)
 
$
0.12

 
$
0.30

Weighted average shares outstanding


Basic
802,520,723

 
803,923,913

 
807,221,761

 
807,396,425

 
805,284,712

Diluted
802,520,723

 
813,556,137

 
807,221,761

 
821,707,289

 
815,922,258

Net income (loss) includes:


Cost of MetroPCS business combination
$
12

 
$
22

 
$
97

 
$
168

 
$
299

Gains on disposal of spectrum licenses
(10
)
 
(747
)
 
(13
)
 
(70
)
 
(840
)

Earnings (loss) per share is computed independently for each quarter and the sum of the quarters may not equal earnings (loss) per share for the full year.

Item 9. Changes in and Disagreements with Accountants on Accounting and Financial Disclosure

None.

Item 9A. Controls and Procedures

Evaluation of Disclosure Controls and Procedures

We maintain disclosure controls and procedures designed to ensure information required to be disclosed in our periodic reports filed or submitted under the Exchange Act, is recorded, processed, summarized and reported within the time periods specified in the SEC’s rules and forms. Our disclosure controls are also designed to ensure that information required to be disclosed in the reports we file or submit under the Exchange Act is accumulated and communicated to our management, including our Principal Executive Officer and Principal Financial Officer, as appropriate, to allow timely decisions regarding required disclosure.

Under the supervision and with the participation of our management, including our Chief Executive Officer and our Chief Financial Officer, we carried out an evaluation of the effectiveness of the design and operation of our disclosure controls and

85

Table of Contents

procedures, as defined in Rules 13a-15(e) and 15d-15(e) under the Exchange Act. Based upon that evaluation, our Chief Executive Officer and Chief Financial Officer concluded that our disclosure controls and procedures were effective, as of the end of the period covered by this report.

The certifications required by Section 302 of the Sarbanes-Oxley Act of 2002 are filed as exhibits 31.1 and 31.2, respectively, to this Form 10-K.

Changes in Internal Control over Financial Reporting

There were no changes in our internal control over financial reporting, as defined in Rules 13a-15(f) and 15d-15(f) of the Exchange Act, during our most recently completed fiscal quarter that materially affected or are reasonably likely to materially affect internal control over financial reporting.

Management's Annual Report on Internal Control over Financial Reporting

Our management is responsible for establishing and maintaining adequate internal control over financial reporting. Internal control over financial reporting is a process to provide reasonable assurance regarding the reliability of our financial reporting and the preparation of financial statements for external purposes in accordance with generally accepted accounting principles. Internal control over financial reporting includes maintaining records that in reasonable detail accurately and fairly reflect our transactions; providing reasonable assurance that transactions are recorded as necessary for preparation of our financial statements in accordance with generally accepted accounting principles; providing reasonable assurance that receipts and expenditures are made in accordance with management authorization; and providing reasonable assurance that unauthorized acquisition, use or disposition of company assets that could have a material effect on our financial statements would be prevented or detected on a timely basis. Because of its inherent limitations, internal control over financial reporting may not prevent or detect misstatements. Also, projections of any evaluation of effectiveness to future periods are subject to the risk that controls may become inadequate because of changes in conditions, or that the degree of compliance with policies and procedures may deteriorate.

Management conducted an evaluation of the effectiveness of our internal control over financial reporting based on the framework and criteria established in Internal Control – Integrated Framework (2013), issued by the Committee of Sponsoring Organizations of the Treadway Commission. Based on this evaluation, management concluded that our internal control over financial reporting was effective as of December 31, 2015.

The effectiveness of our internal control over financial reporting as of December 31, 2015 has been audited by PricewaterhouseCoopers LLP, an independent registered public accounting firm, as stated in their report herein.

Item 9B. Other Information

None.

PART III.

Item 10. Directors, Executive Officers and Corporate Governance

We maintain a code of ethics applicable to our Chief Executive Officer, Chief Financial Officer, Chief Accounting Officer, Treasurer, and Controller, which is a “Code of Ethics for Senior Financial Officers” as defined by applicable rules of the SEC. This code is publicly available on our website at investor.t-mobile.com. If we make any amendments to this code other than technical, administrative or other non-substantive amendments, or grant any waivers, including implicit waivers, from a provision of this code we will disclose the nature of the amendment or waiver, its effective date and to whom it applies on our website at investor.t-mobile.com or in a periodic report on Form 8-K filed with the SEC.

The remaining information required by this item, including information about our Directors, Executive Officers and Audit Committee, is incorporated by reference to the definitive Proxy Statement for our 2016 Annual Meeting of Stockholders, which will be filed with the SEC, no later than 120 days after December 31, 2015.


86

Table of Contents

Item 11. Executive Compensation

The information required by this item is incorporated by reference to the definitive Proxy Statement for our 2016 Annual Meeting of Stockholders, which will be filed with the SEC no later than 120 days after December 31, 2015.

Item 12. Security Ownership of Certain Beneficial Owners and Management and Related Stockholder Matters

The information required by this item is incorporated by reference to the definitive Proxy Statement for our 2016 Annual Meeting of Stockholders, which will be filed with the SEC no later than 120 days after December 31, 2015.

Item 13. Certain Relationships and Related Transactions, and Director Independence

The information required by this item is incorporated by reference to the definitive Proxy Statement for our 2016 Annual Meeting of Stockholders, which will be filed with the SEC no later than 120 days after December 31, 2015.

Item 14. Principal Accounting Fees and Services

The information required by this item is incorporated by reference to the definitive Proxy Statement for our 2016 Annual Meeting of Stockholders, which will be filed with the SEC no later than 120 days after December 31, 2015.

PART IV.

Item 15. Exhibits, Financial Statement Schedules

(a) Documents filed as a part of this Form 10-K:

1. Financial Statements

The following financial statements are included in Part II, Item 8 of this Form 10-K:

Report of Independent Registered Public Accounting Firm
Consolidated Balance Sheets
Consolidated Statements of Comprehensive Income (Loss)
Consolidated Statements of Cash Flows
Consolidated Statement of Stockholders’ Equity
Notes to the Consolidated Financial Statements

2. Financial Statement Schedules

All other schedules have been omitted because they are not required, not applicable, or the required information is otherwise included.

3. Exhibits

See the Exhibit Index immediately following the signature page of this Form 10-K.


87

Table of Contents

SIGNATURES

Pursuant to the requirements of Section 13 or 15(d) of the Securities Exchange Act of 1934, the registrant has duly caused this report to be signed on its behalf by the undersigned thereunto duly authorized.


T-MOBILE US, INC.


February 17, 2016
 
/s/ John J. Legere
 
 
John J. Legere
President and Chief Executive Officer

Each person whose signature appears below constitutes and appoints John J. Legere and J. Braxton Carter, and each or either of them, his or her true and lawful attorney-in-fact and agent, each acting alone, with full power of substitution and resubstitution, for him or her and in his or her name, place and stead, in any and all capacities, to sign any or all amendments or supplements (including post-effective amendments) to this Report, and to file the same, with all exhibits thereto, and all documents in connection therewith, with the Securities and Exchange Commission, granting unto said attorney-in-fact and agent, full power and authority to do and perform each and every act and thing requisite and necessary to be done in and about the premises, as fully to all intents and purposes as he or she might or could do in person, hereby ratifying and confirming all that said attorney-in-fact and agent, or his or her substitute or substitutes, may lawfully do or cause to be done by virtue hereof.

Pursuant to the requirements of the Securities Exchange Act of 1934, this report has been signed below by the following persons on behalf of the registrant and in the capacities indicated as of February 17, 2016.

Signature
 
Title


/s/ John J. Legere
 
President and Chief Executive Officer and
John J. Legere
 
Director (Principal Executive Officer)


/s/ J. Braxton Carter
 
Executive Vice President and Chief Financial Officer
J. Braxton Carter
 
(Principal Financial Officer)


/s/ Michael J. Morgan
 
Senior Vice President, Finance and Chief Accounting
Michael J. Morgan
 
Officer (Principal Accounting Officer)


/s/ Timotheus Höttges
 
Chairman of the Board
Timotheus Höttges


/s/ W. Michael Barnes
 
Director
W. Michael Barnes


/s/ Thomas Dannenfeldt
 
Director
Thomas Dannenfeldt


88

Table of Contents


/s/ Srikant Datar
 
Director
Srikant Datar


/s/ Lawrence H. Guffey
 
Director
Lawrence H. Guffey


/s/ Bruno Jacobfeuerborn
 
Director
Bruno Jacobfeuerborn


/s/ Raphael Kübler
 
Director
Raphael Kübler


/s/ Thorsten Langheim
 
Director
Thorsten Langheim


/s/ Teresa A. Taylor
 
Director
Teresa A. Taylor


/s/ Kelvin R. Westbrook
 
Director
Kelvin R. Westbrook


89

Table of Contents

INDEX TO EXHIBITS


Incorporated by Reference
 
 
Exhibit No.
 
Exhibit Description
 
Form
 
Date of First Filing
 
Exhibit Number
 
Filed Herein
2.1
 
Business Combination Agreement, dated as of October 3, 2012, by and among MetroPCS Communications, Inc., Deutsche Telekom AG, T-Mobile Zwischenholding GMBH, T-Mobile Global Holding GMBH and T-Mobile USA, Inc.
 
8-K
 
10/3/2012
 
2.1
 

2.2
 
Consent Solicitation Letter Agreement, dated December 5, 2012, by and among MetroPCS Communications, Inc. and Deutsche Telekom AG, amending Exhibit G to the Business Combination Agreement.
 
8-K
 
12/7/2012
 
2.1
 

2.3
 
Amendment No. 1 to the Business Combination Agreement by and among Deutsche Telekom AG, T-Mobile USA, Inc., T-Mobile Global Zwischenholding GmbH, T-Mobile Global Holding GmbH and MetroPCS Communications, Inc., dated April 14, 2013.
 
8-K
 
4/15/2013
 
2.1
 

3.1
 
Fourth Amended and Restated Certificate of Incorporation.
 
8-K
 
5/2/2013
 
3.1
 

3.2
 
Fifth Amended and Restated Bylaws.
 
8-K
 
5/2/2013
 
3.2
 

3.3
 
Certificate of Designation of 5.50% Mandatory Convertible Preferred Stock, Series A, of T-Mobile US, Inc., dated December 12, 2014.
 
8-K
 
12/15/2014
 
3.1
 

4.1
 
Rights Agreement, dated as of March 29, 2007, between MetroPCS Communications, Inc. and American Stock Transfer & Trust Company, as Rights Agent, which includes the form of Certificate of Designation of Series A Junior Participating Preferred Stock of MetroPCS Communications, Inc. as Exhibit A, the form of Rights Certificate as Exhibit B and the Summary of Rights as Exhibit C.
 
8-K
 
3/30/2007
 
4.1
 

4.2
 
Amendment No. 1 to the Rights Agreement, dated as of October 3, 2012 between MetroPCS Communications, Inc. and American Stock Transfer & Trust Company, as Rights Agent.
 
8-K
 
10/3/2012
 
4.1
 

4.3
 
Indenture, dated September 21, 2010, among MetroPCS Wireless, Inc., the Guarantors (as defined therein) and Wells Fargo Bank, N.A., a trustee.
 
8-K
 
9/21/2010
 
4.1
 

4.4
 
First Supplemental Indenture, dated September 21, 2010, among MetroPCS Wireless, Inc., the Guarantors (as defined therein) and Wells Fargo Bank, N.A., as trustee.
 
8-K
 
9/21/2010
 
4.2
 

4.5
 
Second Supplemental Indenture, dated November 17, 2010, among MetroPCS Wireless, Inc., the Guarantors (as defined therein) and Wells Fargo Bank, N.A., as trustee.
 
8-K
 
11/17/2010
 
4.1
 

4.6
 
Third Supplemental Indenture, dated December 23, 2010, among MetroPCS Wireless, Inc., the Guarantors (as defined therein) and Wells Fargo Bank, N.A., as trustee.
 
10-K
 
3/1/2011
 
 10.19(d)
 

4.7
 
Fourth Supplemental Indenture, dated December 23, 2010, among MetroPCS Wireless, Inc., the Guarantors (as defined therein) and Wells Fargo Bank, N.A., as trustee.
 
10-K
 
3/1/2011
 
10.19(e)
 

4.8
 
Fifth Supplemental Indenture, dated as of December 14, 2012, among MetroPCS Wireless, Inc., the Guarantors (as defined therein) and Wells Fargo Bank, N.A., as trustee.
 
8-K
 
12/17/2012
 
4.1
 

4.9
 
Sixth Supplemental Indenture, dated as of December 14, 2012, among MetroPCS Wireless, Inc., the Guarantors (as defined therein) and Wells Fargo Bank, N.A., as trustee.
 
8-K
 
12/17/2012
 
4.2
 

4.10
 
Seventh Supplemental Indenture, dated as of May 1, 2013, among T-Mobile USA, Inc., the guarantors party thereto, and Wells Fargo Bank, N.A., as trustee.
 
8-K
 
5/2/2013
 
4.15


90

Table of Contents


Incorporated by Reference
 
 
Exhibit No.
 
Exhibit Description
 
Form
 
Date of First Filing
 
Exhibit Number
 
Filed Herein
4.11
 
Eighth Supplemental Indenture, dated as of July 15, 2013, among T-Mobile USA, Inc., the guarantors party thereto, and Wells Fargo Bank, N.A., as trustee.
 
10-Q
 
8/8/2013
 
4.19
 

4.12
 
Ninth Supplemental Indenture, dated as of August 11, 2014, by and among T-Mobile USA, Inc., the guarantors party thereto and Wells Fargo Bank, N.A., as trustee.
 
10-Q
 
10/28/2014
 
4.2
 

4.13
 
Tenth Supplemental Indenture, dated as of September 28, 2015, by and among T-Mobile USA, Inc., the guarantors party thereto and Wells Fargo Bank, N.A., as trustee.
 
10-Q
 
10/27/2015
 
4.2
 

4.14
 
Indenture, dated as of March 19, 2013, by and among MetroPCS Wireless, Inc., the Guarantors (as defined therein) and Deutsche Bank Trust Company Americas, as trustee.
 
8-K
 
3/22/2013
 
4.1
 

4.15
 
First Supplemental Indenture, dated as of March 19, 2013, by and among MetroPCS Wireless, Inc., the Guarantors (as defined therein) and Deutsche Bank Trust Company Americas, as trustee.
 
8-K
 
3/22/2013
 
4.2
 

4.16
 
Form of 6.250% Senior Notes due 2021.
 
8-K
 
3/22/2013
 
4.3
 

4.17
 
Second Supplemental Indenture, dated as of March 19, 2013, by and among MetroPCS Wireless, Inc., the Guarantors (as defined therein) and Deutsche Bank Trust Company Americas, as trustee.
 
8-K
 
3/22/2013
 
4.4
 

4.18
 
Form of 6.625% Senior Notes due 2023.
 
8-K
 
3/22/2013
 
4.5
 

4.19
 
Third Supplemental Indenture, dated as of April 29, 2013, among T-Mobile USA, Inc., the guarantors party thereto, and Deutsche Bank Trust Company Americas, as trustee.
 
10-Q
 
8/8/2013
 
4.17
 

4.20
 
Fourth Supplemental Indenture, dated as of May 1, 2013, among T-Mobile USA, Inc., the guarantors party thereto, and Deutsche Bank Trust Company Americas, as trustee.
 
8-K
 
5/2/2013
 
4.16
 

4.21
 
Fifth Supplemental Indenture, dated as of July 15, 2013, among T-Mobile USA, Inc., the guarantors party thereto, and Deutsche Bank Trust Company Americas, as trustee.
 
10-Q
 
8/8/2013
 
4.20
 

4.22
 
Sixth Supplemental Indenture, dated as of August 11, 2014, by and among T-Mobile USA, Inc., the guarantors party thereto and Deutsche Bank Trust Company Americas, as trustee.
 
10-Q
 
10/28/2014
 
4.1
 

4.23
 
Seventh Supplemental Indenture, dated as of September 28, 2015, by and among T-Mobile USA, Inc., the guarantors party thereto and Deutsche Bank Trust Company Americas, as trustee.
 
10-Q
 
10/27/2015
 
4.1
 

4.24
 
Indenture, dated as of April 28, 2013 among T-Mobile USA, Inc., the guarantors party thereto, and Deutsche Bank Trust Company Americas, as trustee.
 
8-K
 
5/2/2013
 
4.1
 

4.25
 
First Supplemental Indenture, dated as of April 28, 2013 among T-Mobile USA, Inc., the guarantors party thereto, and Deutsche Bank Trust Company Americas, as trustee.
 
8-K
 
5/2/2013
 
4.2
 

4.26
 
Second Supplemental Indenture, dated as of April 28, 2013 among T-Mobile USA, Inc., the guarantors party thereto, and Deutsche Bank Trust Company Americas, as trustee.
 
8-K
 
5/2/2013
 
4.3
 

4.27
 
Third Supplemental Indenture, dated as of April 28, 2013 among T-Mobile USA, Inc., the guarantors party thereto, and Deutsche Bank Trust Company Americas, as trustee.
 
8-K
 
5/2/2013
 
4.4
 

4.28
 
Fourth Supplemental Indenture, dated as of April 28, 2013 among T-Mobile USA, Inc., the guarantors party thereto, and Deutsche Bank Trust Company Americas, as trustee.
 
8-K
 
5/2/2013
 
4.5


91

Table of Contents


Incorporated by Reference
 
 
Exhibit No.
 
Exhibit Description
 
Form
 
Date of First Filing
 
Exhibit Number
 
Filed Herein
4.29
 
Fifth Supplemental Indenture, dated as of April 28, 2013 among T-Mobile USA, Inc., the guarantors party thereto, and Deutsche Bank Trust Company Americas, as trustee.
 
8-K
 
5/2/2013
 
4.6
 

4.30
 
Sixth Supplemental Indenture, dated as of April 28, 2013 among T-Mobile USA, Inc., the guarantors party thereto, and Deutsche Bank Trust Company Americas, as trustee.
 
8-K
 
5/2/2013
 
4.7
 

4.31
 
Seventh Supplemental Indenture, dated as of April 28, 2013 among T-Mobile USA, Inc., the guarantors party thereto, and Deutsche Bank Trust Company Americas, as trustee.
 
8-K
 
5/2/2013
 
4.8
 

4.32
 
Eighth Supplemental Indenture, dated as of April 28, 2013 among T-Mobile USA, Inc., the guarantors party thereto, and Deutsche Bank Trust Company Americas, as trustee.
 
8-K
 
5/2/2013
 
4.9
 

4.33
 
Ninth Supplemental Indenture, dated as of April 28, 2013 among T-Mobile USA, Inc., the guarantors party thereto, and Deutsche Bank Trust Company Americas, as trustee.
 
8-K
 
5/2/2013
 
4.10
 

4.34
 
Tenth Supplemental Indenture, dated as of April 28, 2013 among T-Mobile USA, Inc., the guarantors party thereto, and Deutsche Bank Trust Company Americas, as trustee.
 
8-K
 
5/2/2013
 
4.11
 

4.35
 
Eleventh Supplemental Indenture, dated as of May 1, 2013 among T-Mobile USA, Inc., the guarantors party thereto, and Deutsche Bank Trust Company Americas, as trustee.
 
8-K
 
5/2/2013
 
4.12
 

4.36
 
Twelfth Supplemental Indenture, dated as of July 15, 2013, among T-Mobile USA, Inc., the guarantors party thereto, and Deutsche Bank Trust Company Americas, as trustee.
 
10-Q
 
8/8/2013
 
4.18
 

4.37
 
Thirteenth Supplemental Indenture, dated as of August 21, 2013, by and among T-Mobile USA, Inc., the Guarantors (as defined therein) and Deutsche Bank Trust Company Americas, as trustee, including the Form of 5.250% Senior Note due 2018.
 
8-K
 
8/22/2013
 
4.1
 

4.38
 
Fourteenth Supplemental Indenture, dated as of November 21, 2013, by and among T-Mobile USA, Inc., the Guarantors and Deutsche Bank Trust Company Americas, as trustee, including the Form of 6.125% Senior Note due 2022.
 
8-K
 
11/22/2013
 
4.1
 

4.39
 
Fifteenth Supplemental Indenture, dated as of November 21, 2013, by and among T-Mobile USA, Inc., the Guarantors and Deutsche Bank Trust Company Americas, as trustee, including the Form of 6.500% Senior Note due 2024.
 
8-K
 
11/22/2013
 
4.2
 

4.40
 
Sixteenth Supplemental Indenture, dated as of August 11, 2014, by and among T-Mobile USA, Inc., the guarantors party thereto and Deutsche Bank Trust Company Americas, as trustee.
 
10-Q
 
10/28/2014
 
4.3
 

4.41
 
Seventeenth Supplemental Indenture, dated as of September 5, 2014, by and among T-Mobile USA, Inc., the guarantors party thereto and Deutsche Bank Trust Company Americas, as trustee, including the Form of 6.000% Senior Notes due 2023.
 
8-K
 
9/5/2014
 
4.1
 

4.42
 
Eighteenth Supplemental Indenture, dated as of September 5, 2014, by and among T-Mobile USA, Inc., the guarantors party thereto and Deutsche Bank Trust Company Americas, as trustee, including the Form of 6.375% Senior Notes due 2025.
 
8-K
 
9/5/2014
 
4.2
 

4.43
 
Nineteenth Supplemental Indenture, dated as of September 28, 2015, by and among T-Mobile USA, Inc., the guarantors party thereto and Deutsche Bank Trust Company Americas, as trustee.
 
10-Q
 
10/27/2015
 
4.3


92

Table of Contents


Incorporated by Reference
 
 
Exhibit No.
 
Exhibit Description
 
Form
 
Date of First Filing
 
Exhibit Number
 
Filed Herein
4.44
 
Twentieth Supplemental Indenture, dated as of November 5, 2015, by and among T-Mobile USA, Inc., the guarantors party thereto and Deutsche Bank Trust Company Americas, as Trustee, including the Form of 6.500% Senior Notes due 2026.
 
8-K
 
11/5/2015
 
4.1
 

4.45
 
Noteholder Agreement dated as of April 28, 2013, by and between Deutsche Telekom AG and T-Mobile USA, Inc.
 
8-K
 
5/2/2013
 
4.13
 

10.1
 
Master Agreement, dated as of September 28, 2012, among T-Mobile USA, Inc., Crown Castle International Corp., and certain T-Mobile and Crown subsidiaries.
 
10-Q
 
8/8/2013
 
 10.1
 

10.2
 
Amendment No. 1, to Master Agreement, dated as of November 30, 2012, among Crown Castle International Corp., and certain T-Mobile and Crown subsidiaries.
 
10-Q
 
8/8/2013
 
 10.2
 

10.3
 
Master Prepaid Lease, dated as of November 30, 2012, by and among T-Mobile USA Tower LLC, T-Mobile West Tower LLC, T-Mobile USA, Inc. and CCTMO LLC.
 
10-Q
 
8/8/2013
 
 10.3
 

10.4
 
MPL Site Master Lease Agreement, dated as of November 30, 2012, by and among Cook Inlet/VS GSM IV PCS Holdings, LLC, T-Mobile Central LLC, T-Mobile South LLC, Powertel/Memphis, Inc., Voicestream Pittsburgh, L.P., T-Mobile West LLC, T-Mobile Northeast LLC, Wireless Alliance, LLC, Suncom Wireless Operating Company, L.L.C., T-Mobile USA, Inc. and CCTMO LLC.
 
10-Q
 
8/8/2013
 
 10.4
 

10.5
 
First Amendment to MPL Site Master Lease Agreement, dated as of November 30, 2012, by and among Cook Inlet/VS GSM IV PCS Holdings, LLC, T-Mobile Central LLC, T-Mobile South LLC, Powertel/Memphis, Inc., Voicestream Pittsburgh, L.P., T-Mobile West LLC, T-Mobile Northeast LLC, Wireless Alliance, LLC, Suncom Wireless Operating Company, L.L.C., T-Mobile USA, Inc. and CCTMO LLC.
 
10-Q
 
8/8/2013
 
 10.5
 

10.6
 
Sale Site Master Lease Agreement, dated as of November 30, 2012, by and among Cook Inlet/VS GSM IV PCS Holdings, LLC, T-Mobile Central LLC, T-Mobile South LLC, Powertel/Memphis, Inc., Voicestream Pittsburgh, L.P., T-Mobile West LLC, T-Mobile Northeast LLC, Wireless Alliance, LLC, Suncom Wireless Operating Company, L.L.C., T-Mobile USA, Inc., T3 Tower 1 LLC and T3 Tower 2 LLC.
 
10-Q
 
8/8/2013
 
 10.6
 

10.7
 
First Amendment to Sale Site Master Lease Agreement, dated as of November 30, 2012, by and Cook Inlet/VS GSM IV PCS Holdings, LLC, T-Mobile Central LLC, T-Mobile South LLC, Powertel/Memphis, Inc., Voicestream Pittsburgh, L.P., T-Mobile West LLC, T-Mobile Northeast LLC, Wireless Alliance, LLC, Suncom Wireless Operating Company, L.L.C., T-Mobile USA, Inc., T3 Tower 1 LLC and T3 Tower 2 LLC.
 
10-Q
 
8/8/2013
 
10.7
 

10.8
 
Management Agreement, dated as of November 30, 2012, by and among Suncom Wireless Operating Company, L.L.C., Cook Inlet/VS GSM IV PCS Holdings, LLC, T-Mobile Central LLC, T-Mobile South LLC, Powertel/Memphis, Inc., Voicestream Pittsburgh, L.P., T-Mobile West LLC, T-Mobile Northeast LLC, Wireless Alliance, LLC, Suncom Wireless Property Company, L.L.C., T-Mobile USA Tower LLC, T-Mobile West Tower LLC, CCTMO LLC, T3 Tower 1 LLC and T3 Tower 2 LLC.
 
10-Q
 
8/8/2013
 
10.8
 

10.9
 
Stockholder’s Agreement dated as of April 30, 2013 by and between MetroPCS Communications, Inc. and Deutsche Telekom AG.
 
8-K
 
5/2/2013
 
 10.1


93

Table of Contents


Incorporated by Reference
 
 
Exhibit No.
 
Exhibit Description
 
Form
 
Date of First Filing
 
Exhibit Number
 
Filed Herein
10.10
 
Waiver of Required Approval Under Section 3.6(a) of the Stockholder's Agreement, dated August 7, 2013, between T-Mobile US, Inc. and Deutsche Telekom AG.
 
10-Q
 
8/8/2013
 
10.10
 

10.11
 
License Agreement dated as of April 30, 2013 by and between T-Mobile US, Inc. and Deutsche Telekom AG.
 
8-K
 
5/2/2013
 
10.2
 

10.12
 
Credit Agreement, dated as of May 1, 2013, among T-Mobile USA, Inc., as Borrower, Deutsche Telekom AG, as Lender, the other lenders party thereto from time to time, and JPMorgan Chase Bank, N.A., as Administrative Agent.
 
8-K
 
5/2/2013
 
4.14
 

10.13
 
Amendment No. 1, dated as of November 15, 2013, to the Credit Agreement, dated May 1, 2013, among T-Mobile US, Inc., T-Mobile USA, Inc., each of the Subsidiaries signatory thereto, Deutsche Telekom AG and the other lenders party thereto from time to time, and JPMorgan Chase Bank, N.A., as Administrative Agent.
 
8-K
 
11/20/2013
 
10.1
 

10.14
 
Amendment No. 2, dated as of September 3, 2014, to the Credit Agreement, dated as of May 1, 2013, among T-Mobile USA, Inc., Deutsche Telekom AG and the other lenders party thereto from time to time, and JPMorgan Chase Bank, N.A., as Administrative Agent.
 
8-K
 
9/5/2014
 
10.1
 

10.15
 
Amendment No. 3, dated as of November 2, 2015, to the Credit Agreement, dated as of May 1, 2013, among T-Mobile USA, Inc., Deutsche Telekom AG and the other lenders party thereto from time to time, and JPMorgan Chase Bank N.A., as Administrative Agent.
 
8-K
 
11/5/2015
 
10.2
 

10.16
 
Registration Rights Agreement, dated as of March 19, 2013, by and among MetroPCS Wireless, Inc., the Initial Guarantors (as defined therein), and Deutsche Bank Securities, as representative of the Initial Purchasers (as defined therein).
 
8-K
 
3/22/2013
 
10.1
 

10.17
 
Registration Rights Agreement, dated as of August 21, 2013, by and among T-Mobile USA, Inc., the Guarantors (as defined therein), and Deutsche Bank Securities Inc., as Initial Purchaser (as defined therein).
 
8-K
 
8/21/2013
 
10.1
 

10.18
 
License Exchange Agreement, dated January 5, 2014, among T-Mobile USA, Inc., T-Mobile License LLC, Cellco Partnership d/b/a Verizon Wireless, Verizon Wireless (VAW) LLC, Athens Cellular, Inc. and Verizon Wireless of the East LP.
 
8-K
 
1/6/2014
 
10.1
 

10.19
 
License Purchase Agreement, dated January 5, 2014, among T-Mobile USA, Inc., T-Mobile License LLC and Cellco Partnership d/b/a Verizon Wireless.
 
8-K
 
1/6/2014
 
10.2
 

10.20
 
Receivables Sale and Conveyancing Agreement, dated as of February 26, 2014, among T-Mobile West LLC, T-Mobile Central LLC, T-Mobile Northeast LLC and T-Mobile South LLC, as sellers, and T-Mobile PCS Holdings LLC, as purchaser.
 
8-K
 
3/4/2014
 
10.1
 

10.21
 
Receivables Sale and Contribution Agreement, dated as of February 26, 2014, between T-Mobile PCS Holdings LLC, as seller, and T-Mobile Airtime Funding LLC, as purchaser.
 
8-K
 
3/4/2014
 
10.2
 

10.22
 
Master Receivables Purchase Agreement, dated as of February 26, 2014, among T-Mobile Airtime Funding LLC, as funding seller, Billing Gate One LLC, as purchaser, Landesbank Hessen-Thüringen Girozentrale, as bank purchasing agent, T-Mobile PCS Holdings LLC, as servicer, and T-Mobile US, Inc., as performance guarantor.
 
8-K
 
3/4/2014
 
10.3


94

Table of Contents


Incorporated by Reference
 
 
Exhibit No.
 
Exhibit Description
 
Form
 
Date of First Filing
 
Exhibit Number
 
Filed Herein
10.23
 
Guarantee Facility Agreement, dated as of February 26, 2014, among T-Mobile US, Inc., as the company, T-Mobile Airtime Funding LLC, as the funding seller, and KfW IPEX-Bank GmbH, as the bank.
 
8-K
 
3/4/2014
 
10.4
 

10.24
 
Omnibus Amendment to the Master Receivables Purchase Agreement and Fee Letter, dated as of April 11, 2014, by and among T-Mobile Airtime Funding LLC, as funding seller, Billing Gate One LLC, as purchaser, Landesbank Hessen-Thüringen Girozentrale, as bank purchasing agent and a bank purchaser, T-Mobile PCS Holdings LLC, as servicer, T-Mobile US, Inc. as performance guarantor, and the Bank of Tokyo-Mitsubishi UFJ, Ltd., as a bank purchaser.
 
10-Q
 
5/1/2014
 
10.7
 

10.25
 
Second Amendment to the Master Receivables Purchase Agreement dated as of June 12, 2014, by and among T-Mobile Airtime Funding LLC, as funding seller, Billing Gate One LLC, as purchaser, Landesbank Hessen-Thüringen Girozentrale, as bank purchasing agent and a bank purchaser, T-Mobile PCS Holdings LLC, as servicer and T-Mobile US, Inc. as performance guarantor.
 
10-Q
 
7/31/2014
 
10.2
 

10.26
 
Third Amendment to the Master Receivables Purchase Agreement, dated as of September 29, 2014, by and among T-Mobile Airtime Funding LLC, as funding seller, Billing Gate One LLC, as purchaser, Landesbank Hessen-Thüringen Girozentrale, as bank purchasing agent and a bank purchaser, T-Mobile PCS Holdings LLC, as servicer and T-Mobile US, Inc. as performance guarantor.
 
10-Q
 
10/28/2014
 
10.2
 

10.27
 
Fourth Amendment to the Master Receivables Purchase Agreement, dated as of November 28, 2014, by and among T-Mobile Airtime Funding LLC, as funding seller, Billing Gate One LLC, as purchaser, Landesbank Hessen-Thüringen Girozentrale, as bank purchasing agent and a bank purchaser, T-Mobile PCS Holdings LLC, as servicer and T-Mobile US, Inc. as performance guarantor.
 
10-K
 
2/19/2015
 
10.54
 

10.28
 
Joinder and First Amendment to the Receivables Sale and Conveyancing Agreement, dated as of November 28, 2014, among Powertel/Memphis, Inc., Triton PCS Holdings Company L.L.C., T-Mobile West LLC, T-Mobile Central LLC, T-Mobile Northeast LLC and T-Mobile South LLC, as sellers, and T-Mobile PCS Holdings LLC, as purchaser.
 
10-K
 
2/19/2015
 
10.55
 

10.29
 
First Amendment to the Receivables Sale and Contribution Agreement, dated as of November 28, 2014, between T-Mobile PCS Holdings LLC, as seller, and T-Mobile Airtime Funding LLC, as purchaser.
 
10-K
 
2/19/2015
 
10.56
 

10.30
 
First Amended and Restated Guarantee Facility Agreement, dated as of November 28, 2014, among T-Mobile US, Inc., as the company, T-Mobile Airtime Funding LLC, as the funding seller, and KfW IPEX-Bank GmbH, as the bank.
 
10-K
 
2/19/2015
 
10.57
 

10.31
 
Fifth Amendment to the Master Receivables Purchase Agreement, dated as of January 9, 2015, by and among T-Mobile Airtime Funding LLC, as funding seller, Billing Gate One LLC, as purchaser, Landesbank Hessen-Thüringen Girozentrale, as bank purchasing agent and a bank purchaser, T-Mobile PCS Holdings LLC, as servicer and T-Mobile US, Inc. as performance guarantor.
 
10-Q
 
4/28/2015
 
10.4
 

10.32
 
Joinder and Second Amendment to the Receivables Sale and Conveyancing Agreement, dated as of January 9, 2015, among SunCom Wireless Operating Company, LLC, Powertel/Memphis, Inc., Triton PCS Holdings Company L.L.C., T-Mobile West LLC, T-Mobile Central LLC, T-Mobile Northeast LLC and T-Mobile South LLC, as sellers, and T-Mobile PCS Holdings LLC, as purchaser.
 
10-Q
 
4/28/2015
 
10.5


95

Table of Contents


Incorporated by Reference
 
 
Exhibit No.
 
Exhibit Description
 
Form
 
Date of First Filing
 
Exhibit Number
 
Filed Herein
10.33
 
Second Amendment to the Receivables Sale and Contribution Agreement, dated as of January 9, 2015, by and among T-Mobile PCS Holdings LLC, as seller, and T-Mobile Airtime Funding LLC, as purchaser.
 
10-Q
 
4/28/2015
 
10.6
 

10.34
 
October 2015 Amendment to the Master Receivables Purchase Agreement, dated as of October 30, 2015, among T-Mobile Airtime Funding LLC, as funding seller, Billing Gate One LLC, as purchaser, Landesbank Hessen-Thüringen Girozentrale, as bank purchasing agent, T-Mobile PCS Holdings LLC, as servicer, and T-Mobile US, Inc., as performance guarantor.
 
8-K
 
11/5/2015
 
10.1
 

10.35
 
Term Loan Credit Agreement, dated as of November 9, 2015, among T-Mobile USA, Inc., the lenders party thereto and Deutsche Bank AG New York Branch, as administrative agent and collateral agent.
 
8-K
 
11/12/2015
 
10.1
 

10.36
 
Receivables Sale Agreement, dated as of November 18, 2015, by and between T-Mobile Financial LLC, as seller, and T-Mobile Handset Funding LLC, as purchaser.
 
8-K
 
11/20/2015
 
10.1
 

10.37
 
Receivables Purchase and Administration Agreement, dated as of November 18, 2015, by and among T-Mobile Handset Funding LLC, as transferor, T-Mobile Financial LLC, as servicer, T-Mobile US, Inc. as performance guarantor, Royal Bank of Canada, as administrative agent, and certain financial institutions party thereto from time to time.
 
8-K
 
11/20/2015
 
10.2
 

10.38*
 
Second Amended and Restated 1995 Stock Option Plan of MetroPCS, Inc.
 
S-1
 
1/4/2007
 
 10.1(d)
 

10.39*
 
First Amendment to the Second Amended and Restated 1995 Stock Option Plan of MetroPCS, Inc.
 
S-1
 
1/4/2007
 
 10.1(e)
 

10.40*
 
Second Amendment to the Second Amended and Restated 1995 Stock Option Plan of MetroPCS, Inc.
 
S-1
 
1/4/2007
 
 10.1(f)
 

10.41*
 
Amended and Restated MetroPCS Communications, Inc. 2004 Equity Incentive Compensation Plan.
 
S-1/A
 
2/27/2007
 
 10.1(a)
 

10.42*
 
MetroPCS Communications, Inc. 2010 Equity Incentive Compensation Plan.
 
Schedule 14A
 
4/19/2010
 
 Annex A
 

10.43*
 
Form Change in Control Agreement for MetroPCS Communications, Inc.
 
10-Q
 
8/9/2010
 
10.2
 

10.44*
 
Form Change in Control Agreement Amendment for MetroPCS Communications, Inc.
 
10-Q
 
10/30/2012
 
10.1
 

10.45*
 
MetroPCS Communications, Inc. Employee Non-qualified Stock Option Award Agreement relating to the MetroPCS Communications, Inc. Amended and Restated 2004 Equity Incentive Compensation Plan.
 
10-K
 
3/1/2013
 
 10.9(a)
 

10.46*
 
MetroPCS Communications, Inc. Non-Employee Director Non-qualified Stock Option Award Agreement relating to the MetroPCS Communications, Inc. Amended and Restated 2004 Equity Incentive Compensation Plan.
 
10-K
 
3/1/2013
 
 10.9(b)
 

10.47*
 
Form Amendment to the MetroPCS Communications, Inc. Notice of Grant of Stock Option relating to the Second Amended and Restated 1995 Stock Option Plan of MetroPCS, Inc.
 
10-Q
 
8/9/2010
 
10.5
 

10.48*
 
Form MetroPCS Communications, Inc. 2010 Equity Incentive Compensation Plan Employee Non-Qualified Stock Option Award Agreement.
 
10-K
 
2/29/2012
 
10.12
 

10.49*
 
Form MetroPCS Communications, Inc. 2010 Equity Incentive Compensation Plan Non-Employee Director Non-Qualified Stock Option Award Agreement.
 
10-K
 
3/1/2013
 
 10.12(b)


96

Table of Contents


Incorporated by Reference
 
 
Exhibit No.
 
Exhibit Description
 
Form
 
Date of First Filing
 
Exhibit Number
 
Filed Herein
10.50*
 
Employment Agreement of J. Braxton Carter dated as of January 25, 2013.
 
8-K
 
5/2/2013
 
10.3
 

10.51*
 
Employment Agreement of Thomas C. Keys dated as of January 25, 2013.
 
8-K
 
5/2/2013
 
10.4
 

10.52*
 
Employment Agreement of John J. Legere dated as of September 22, 2012.
 
10-Q
 
8/8/2013
 
10.17
 

10.53*
 
Amendment to Employment Agreement of John J. Legere dated as of October 23, 2013.
 
10-K
 
2/25/2014
 
10.35
 

10.54*
 
Amendment No. 2 to Employment Agreement between T-Mobile US, Inc. and John J. Legere, dated as of February 25, 2015.
 
8-K
 
2/26/2015
 
10.1
 

10.55*
 
T-Mobile US, Inc. Compensation Term Sheet for Michael Sievert Effective as of February 13, 2015.
 
10-Q
 
4/28/2015
 
10.3
 

10.56*
 
Form of Indemnification Agreement.
 
8-K
 
5/2/2013
 
10.6
 

10.57*
 
T-Mobile US, Inc. Non-Qualified Deferred Executive Compensation Plan (As Amended and Restated Effective as of January 1, 2014).
 
10-K
 
2/25/2014
 
10.39
 

10.58*
 
T-Mobile US, Inc. Executive Continuity Plan as Amended and Restated Effective as of January 1, 2014.
 
8-K
 
10/25/2013
 
10.1
 

10.59*
 
T-Mobile US, Inc. 2013 Omnibus Incentive Plan (as amended and restated on August 7, 2013).
 
10-Q
 
8/8/2013
 
10.20
 

10.60*
 
T-Mobile USA, Inc. 2011 Long-Term Incentive Plan.
 
10-Q
 
8/8/2013
 
10.21
 

10.61*
 
Annual Incentive Award Notice under the 2013 Omnibus Incentive Plan.
 
10-K
 
2/25/2014
 
10.45
 

10.62*
 
Form of Restricted Stock Unit Award Agreement for Non-Employee Directors under the T-Mobile US, Inc. 2013 Omnibus Incentive Plan.
 
8-K
 
6/4/2013
 
10.2
 

10.63*
 
Form of Restricted Stock Unit Award Agreement (Time-Vesting) for Executive Officers under the T-Mobile US, Inc. 2013 Omnibus Incentive Plan.
 
10-Q
 
8/8/2013
 
10.24
 

10.64*
 
Form of Restricted Stock Unit Award Agreement (Performance-Vesting) for Executive Officers under the T-Mobile US, Inc. 2013 Omnibus Incentive Plan.
 
10-Q
 
8/8/2013
 
10.25
 

10.65*
 
Form of Restricted Stock Unit Award Agreement (Performance-Vesting) with Deferral Option for Executive Officers under the T-Mobile US, Inc. 2013 Omnibus Incentive Plan.
 
10-K
 
2/19/2015
 
10.43
 

10.66*
 
Form of Restricted Stock Unit Award Agreement (Time-Vesting) with Deferral Option for Executive Officers under the T-Mobile US, Inc. 2013 Omnibus Incentive Plan.
 
10-K
 
2/19/2015
 
10.44
 

10.67*
 
T-Mobile US, Inc. 2014 Employee Stock Purchase Plan.
 
S-8
 
2/19/2015
 
99.1
 

10.68*
 
Amended Director Compensation Program effective as of May 1, 2013 (amended June 4, 2014 and further amended on June 1, 2015).
 
10-Q
 
7/30/2015
 
10.1
 

12.1
 
Computation of Ratio of Earnings to Fixed Charges.


X
21.1
 
Subsidiaries of Registrant.


X
23.1
 
Consent of PricewaterhouseCoopers LLP.


X
24.1
 
Power of Attorney, pursuant to which amendments to this Form 10-K may be filed (included on the signature page contained in Part IV of the Form 10-K).


X
31.1
 
Certifications of Chief Executive Officer Pursuant to Section 302 of the Sarbanes-Oxley Act of 2002.


X

97

Table of Contents


Incorporated by Reference
 
 
Exhibit No.
 
Exhibit Description
 
Form
 
Date of First Filing
 
Exhibit Number
 
Filed Herein
31.2
 
Certifications of Chief Financial Officer Pursuant to Section 302 of the Sarbanes-Oxley Act of 2002.


X
32.1**
 
Certification of Chief Executive Officer Pursuant to Section 906 of the Sarbanes-Oxley Act of 2002.


32.2**
 
Certification of Chief Financial Officer Pursuant to Section 906 of the Sarbanes-Oxley Act of 2002.


101.INS
 
XBRL Instance Document.


X
101.SCH
 
XBRL Taxonomy Extension Schema Document.


X
101.CAL
 
XBRL Taxonomy Extension Calculation Linkbase Document.


X
101.DEF
 
XBRL Taxonomy Extension Definition Linkbase Document.


X
101.LAB
 
XBRL Taxonomy Extension Label Linkbase Document.


X
101.PRE
 
XBRL Taxonomy Extension Presentation Linkbase Document.


X

*    Indicates a management contract or compensatory plan or arrangement.
**    Furnished herein.

98

Exhibit


Exhibit 12.1

Computation of Ratio of Earnings to Fixed Charges and Ratio of Earnings to Combined Fixed Charges and Preferred Stock Dividends

 
Year Ended December 31,
(in millions, except ratio)
2015
 
2014
 
2013
 
2012
 
2011
Earnings available for fixed charges:


Income (loss) before income taxes and earnings from unconsolidated affiliates
$
990

 
$
461

 
$
94

 
$
(6,991
)
 
$
(4,919
)
Adjustments:


Fixed charges
2,656

 
2,377

 
2,118

 
1,474

 
1,487

Amortization of capitalized interest
49

 
35

 
34

 
34

 
31

Capitalized interest
(230
)
 
(81
)
 
(5
)
 
(9
)
 
(24
)
Earnings available for fixed charges
$
3,465

 
$
2,792

 
$
2,241

 
$
(5,492
)
 
$
(3,425
)
Fixed charges and combined fixed charges and preferred stock dividends:


Interest expense including capitalized interest
$
1,726

 
$
1,433

 
$
1,229

 
$
686

 
$
694

Portion of rent expense representative of interest (1)
930

 
944

 
889

 
788

 
793

Fixed charges
$
2,656

 
$
2,377

 
$
2,118

 
$
1,474

 
$
1,487

Dividends on preferred stock (pre-tax)
73

 
—

 
—

 
—

 
—

Combined fixed charges and preferred stock dividends
$
2,729

 
$
2,377

 
$
2,118

 
$
1,474

 
$
1,487

Ratio of earnings to fixed charges (2)
1.30

 
1.17

 
1.06

 
—

 
—

Ratio of earnings to combined fixed charges and preferred stock dividends (2)
1.27

 
1.17

 
1.06

 
—

 
—

(1) 
The portion of total rental expense that represents interest factor is estimated to be 33%.
(2) 
Due primarily to T-Mobile USA, Inc.'s non-cash impairment charges in the years ended December 31, 2012 and 2011, the ratio coverage was less than 1:1 in each of these periods. T-Mobile, Inc. would have needed to generate additional earnings of $7.0 billion and $4.9 billion in the year ended December 31, 2012 and 2011, respectively, to achieve a coverage of 1:1 in each of these periods.


Exhibit


Exhibit 21.1

Subsidiaries of Registrant

The following is a list of subsidiaries of T-Mobile US, Inc. as of December 31, 2015, omitting subsidiaries which, considered in the aggregate, would not constitute a significant subsidiary:
Name
 
State of Incorporation
IBSV LLC
  
Delaware
MetroPCS California, LLC
  
Delaware
MetroPCS Florida, LLC
  
Delaware
MetroPCS Georgia, LLC
  
Delaware
MetroPCS Massachusetts, LLC
  
Delaware
MetroPCS Michigan, LLC
  
Delaware
MetroPCS Networks California, LLC
  
Delaware
MetroPCS Networks Florida, LLC
  
Delaware
MetroPCS Nevada, LLC
  
Delaware
MetroPCS New York, LLC
 
Delaware
MetroPCS Pennsylvania, LLC
  
Delaware
MetroPCS Texas, LLC
  
Delaware
Powertel Memphis Licenses, Inc.
  
Delaware
Powertel/Memphis, Inc.
  
Delaware
SunCom Wireless Holdings, Inc.
  
Delaware
SunCom Wireless Investment Company LLC
  
Delaware
SunCom Wireless License Company, LLC
  
Delaware
SunCom Wireless Management Company, Inc.
  
Delaware
SunCom Wireless Operating Company, L.L.C.
  
Delaware
SunCom Wireless Property Company, L.L.C.
 
Delaware
SunCom Wireless, Inc.
 
Delaware
T-Mobile Airtime Funding LLC
 
Delaware
TMUS Assurance Corporation
 
Hawaii
T-Mobile Central LLC
  
Delaware
T-Mobile Financial LLC
 
Delaware
T-Mobile Leasing LLC
 
Delaware
T-Mobile License LLC
 
Delaware
T-Mobile Northeast LLC
  
Delaware
T-Mobile PCS Holdings LLC
  
Delaware
T-Mobile Puerto Rico Holdings LLC
  
Delaware
T-Mobile Puerto Rico LLC
  
Delaware
T-Mobile Resources Corporation
  
Delaware
T-Mobile South LLC
  
Delaware
T-Mobile Subsidiary IV Corporation
  
Delaware
T-Mobile USA Tower LLC
 
Delaware
T-Mobile USA, Inc.
 
Delaware
T-Mobile West LLC
  
Delaware
T-Mobile West Tower LLC
 
Delaware
Triton PCS Finance Company, Inc.
  
Delaware
Triton PCS Holdings Company L.L.C.
  
Delaware
VoiceStream PCS I Iowa Corporation
  
Delaware
VoiceStream Pittsburgh General Partner, Inc.
  
Delaware
VoiceStream Pittsburgh, L.P.
  
Delaware


Exhibit


Exhibit 23.1

CONSENT OF INDEPENDENT REGISTERED PUBLIC ACCOUNTING FIRM

We hereby consent to the incorporation by reference in the Registration Statements on Form S-8 (Nos. 333-142007, 333-168946, 333-189095 and 333-202176) and in the Registration Statements on Form S-3 (Nos. 333-189425 and 333-192178) of T-Mobile US, Inc. of our report dated February 17, 2016 relating to the financial statements and the effectiveness of internal control over financial reporting, which appears in this Form 10-K.  

/s/ PricewaterhouseCoopers LLP
Seattle, Washington
February 17, 2016


Exhibit


Exhibit 31.1

Certifications of Chief Executive Officer Pursuant to Section 302 of the Sarbanes-Oxley Act of 2002

I, John J. Legere, certify that:

1.
I have reviewed this annual report on Form 10-K of T-Mobile US, Inc.;

2.
Based on my knowledge, this report does not contain any untrue statement of a material fact or omit to state a material fact necessary to make the statements made, in light of the circumstances under which such statements were made, not misleading with respect to the period covered by this report;

3.
Based on my knowledge, the financial statements, and other financial information included in this report, fairly present in all material respects the financial condition, results of operations and cash flows of the registrant as of, and for, the periods presented in this report;

4.
The registrant's other certifying officer and I are responsible for establishing and maintaining disclosure controls and procedures (as defined in Exchange Act Rules 13a-15(e) and 15d-15(e)) and internal control over financial reporting (as defined in Exchange Act Rules 13a-15(f) and 15d-15(f)) for the registrant and have:

(a)
Designed such disclosure controls and procedures, or caused such disclosure controls and procedures to be designed under our supervision, to ensure that material information relating to the registrant, including its consolidated subsidiaries, is made known to us by others within those entities, particularly during the period in which this report is being prepared;

(b)
Designed such internal control over financial reporting, or caused such internal control over financial reporting to be designed under our supervision, to provide reasonable assurance regarding the reliability of financial reporting and the preparation of financial statements for external purposes in accordance with generally accepted accounting principles;

(c)
Evaluated the effectiveness of the registrant's disclosure controls and procedures and presented in this report our conclusions about the effectiveness of the disclosure controls and procedures, as of the end of the period covered by this report based on such evaluation; and

(d)
Disclosed in this report any change in the registrant's internal control over financial reporting that occurred during the registrant's most recent fiscal quarter (the registrant's fourth fiscal quarter in the case of an annual report) that has materially affected, or is reasonably likely to materially affect, the registrant's internal control over financial reporting; and

5.
The registrant's other certifying officer and I have disclosed, based on our most recent evaluation of internal control over financial reporting, to the registrant's auditors and the audit committee of the registrant's board of directors (or persons performing the equivalent functions):

(a)
All significant deficiencies and material weaknesses in the design or operation of internal control over financial reporting which are reasonably likely to adversely affect the registrant's ability to record, process, summarize and report financial information; and

(b)
Any fraud, whether or not material, that involves management or other employees who have a significant role in the registrant's internal control over financial reporting.

February 17, 2016

/s/ John J. Legere
John J. Legere
President and Chief Executive Officer


Exhibit


Exhibit 31.2

Certifications of Chief Financial Officer Pursuant to Section 302 of the Sarbanes-Oxley Act of 2002

I, J. Braxton Carter, certify that:

1.
I have reviewed this annual report on Form 10-K of T-Mobile US, Inc.;

2.
Based on my knowledge, this report does not contain any untrue statement of a material fact or omit to state a material fact necessary to make the statements made, in light of the circumstances under which such statements were made, not misleading with respect to the period covered by this report;

3.
Based on my knowledge, the financial statements, and other financial information included in this report, fairly present in all material respects the financial condition, results of operations and cash flows of the registrant as of, and for, the periods presented in this report;

4.
The registrant's other certifying officer and I are responsible for establishing and maintaining disclosure controls and procedures (as defined in Exchange Act Rules 13a-15(e) and 15d-15(e)) and internal control over financial reporting (as defined in Exchange Act Rules 13a-15(f) and 15d-15(f)) for the registrant and have:

(a)
Designed such disclosure controls and procedures, or caused such disclosure controls and procedures to be designed under our supervision, to ensure that material information relating to the registrant, including its consolidated subsidiaries, is made known to us by others within those entities, particularly during the period in which this report is being prepared;

(b)
Designed such internal control over financial reporting, or caused such internal control over financial reporting to be designed under our supervision, to provide reasonable assurance regarding the reliability of financial reporting and the preparation of financial statements for external purposes in accordance with generally accepted accounting principles;

(c)
Evaluated the effectiveness of the registrant's disclosure controls and procedures and presented in this report our conclusions about the effectiveness of the disclosure controls and procedures, as of the end of the period covered by this report based on such evaluation; and

(d)
Disclosed in this report any change in the registrant's internal control over financial reporting that occurred during the registrant's most recent fiscal quarter (the registrant's fourth fiscal quarter in the case of an annual report) that has materially affected, or is reasonably likely to materially affect, the registrant's internal control over financial reporting; and

5.
The registrant's other certifying officer and I have disclosed, based on our most recent evaluation of internal control over financial reporting, to the registrant's auditors and the audit committee of the registrant's board of directors (or persons performing the equivalent functions):

(a)
All significant deficiencies and material weaknesses in the design or operation of internal control over financial reporting which are reasonably likely to adversely affect the registrant's ability to record, process, summarize and report financial information; and

(b)
Any fraud, whether or not material, that involves management or other employees who have a significant role in the registrant's internal control over financial reporting.

February 17, 2016

/s/ J. Braxton Carter
J. Braxton Carter
Executive Vice President and Chief Financial Officer


Exhibit


Exhibit 32.1

Certification of Chief Executive Officer Pursuant to Section 906 of the Sarbanes-Oxley Act of 2002

In connection with the Annual Report of T-Mobile US, Inc. (the “Company”), on Form 10-K for the year ended December 31, 2015, as filed with the Securities and Exchange Commission (the “Report”), John J. Legere, President and Chief Executive Officer of the Company, does hereby certify, pursuant to § 906 of the Sarbanes-Oxley Act of 2002 (18 U.S.C. § 1350), that to his knowledge:

1.
The Report fully complies with the requirements of section 13(a) or 15(d) of the Securities Exchange Act of 1934; and

2.
The information contained in the Report fairly presents, in all material respects, the financial condition and results of operations of the Company.

February 17, 2016

/s/ John J. Legere
John J. Legere
President and Chief Executive Officer


Exhibit


Exhibit 32.2

Certification of Chief Financial Officer Pursuant to Section 906 of the Sarbanes-Oxley Act of 2002

In connection with the Annual Report of T-Mobile US, Inc. (the “Company”), on Form 10-K for the year ended December 31, 2015, as filed with the Securities and Exchange Commission (the “Report”), J. Braxton Carter, Executive Vice President and Chief Financial Officer of the Company, does hereby certify, pursuant to § 906 of the Sarbanes-Oxley Act of 2002 (18 U.S.C. § 1350), that to his knowledge:

1.
The Report fully complies with the requirements of section 13(a) or 15(d) of the Securities Exchange Act of 1934; and

2.
The information contained in the Report fairly presents, in all material respects, the financial condition and results of operations of the Company.

February 17, 2016

/s/ J. Braxton Carter
J. Braxton Carter
Executive Vice President and Chief Financial Officer


tmus-20151231.xml
Attachment: XBRL INSTANCE DOCUMENT


tmus-20151231.xsd
Attachment: XBRL TAXONOMY EXTENSION SCHEMA DOCUMENT


tmus-20151231_cal.xml
Attachment: XBRL TAXONOMY EXTENSION CALCULATION LINKBASE DOCUMENT


tmus-20151231_def.xml
Attachment: XBRL TAXONOMY EXTENSION DEFINITION LINKBASE DOCUMENT


tmus-20151231_lab.xml
Attachment: XBRL TAXONOMY EXTENSION LABEL LINKBASE DOCUMENT


tmus-20151231_pre.xml
Attachment: XBRL TAXONOMY EXTENSION PRESENTATION LINKBASE DOCUMENT


v3.3.1.900
Document and Entity Information - USD ($)
$ in Billions
12 Months Ended
Dec. 31, 2015
Feb. 11, 2016
Jun. 30, 2015
Document and Entity Information [Abstract]      
Entity Registrant Name T-MOBILE US, INC.    
Trading Symbol TMUS    
Entity Central Index Key 0001283699    
Document Type 10-K    
Document Period End Date Dec. 31, 2015    
Amendment Flag false    
Document Fiscal Year Focus 2015    
Document Fiscal Period Focus FY    
Current Fiscal Year End Date --12-31    
Entity Well Known Seasoned Issuer Yes    
Entity Voluntary Filers No    
Entity Current Reporting Status Yes    
Entity Filer Category Large Accelerated Filer    
Entity Common Stock, Shares Outstanding   818,420,728  
Entity Public Float     $ 10.9

v3.3.1.900
Consolidated Balance Sheets - USD ($)
$ in Millions
Dec. 31, 2015
Dec. 31, 2014
Current assets    
Cash and cash equivalents $ 4,582 $ 5,315
Short-term investments 2,998 0
Accounts receivable, net of allowances of $116 and $83 1,788 1,865
Equipment installment plan receivables, net 2,378 3,062
Accounts receivable from affiliates 36 76
Inventories 1,295 1,085
Deferred tax assets, net 0 988
Other current assets 1,813 1,593
Total current assets 14,890 13,984
Property and equipment, net 20,000 16,245
Goodwill 1,683 1,683
Spectrum licenses 23,955 21,955
Other intangible assets, net 594 870
Equipment installment plan receivables due after one year, net 847 1,628
Other assets 467 288
Total assets 62,436 56,653
Current liabilities    
Accounts payable and accrued liabilities 8,084 7,364
Current payables to affiliates 135 231
Short-term debt 182 87
Deferred revenue 717 459
Other current liabilities 410 635
Total current liabilities 9,528 8,776
Long-term debt 20,484 16,273
Long-term debt to affiliates 5,600 5,600
Tower obligations 2,658 2,521
Deferred tax liabilities 4,061 4,873
Deferred rents 2,481 2,331
Other long-term liabilities 1,067 616
Total long-term liabilities $ 36,351 $ 32,214
Commitments and contingencies
Stockholders' equity    
5.50% Mandatory Convertible Preferred Stock Series A, par value $0.00001 per share, 100,000,000 shares authorized; 20,000,000 and 20,000,000 shares issued and outstanding; $1,000 and $1,000 aggregate liquidation value $ 0 $ 0
Common Stock, par value $0.00001 per share, 1,000,000,000 shares authorized; 819,773,724 and 808,851,108 shares issued, 818,391,219 and 807,468,603 shares outstanding 0 0
Additional paid-in capital 38,666 38,503
Treasury stock, at cost, 1,382,505 and 1,382,505 shares issued 0 0
Accumulated other comprehensive income (loss) (1) 1
Accumulated deficit (22,108) (22,841)
Total stockholders' equity 16,557 15,663
Total liabilities and stockholders' equity $ 62,436 $ 56,653

v3.3.1.900
Consolidated Balance Sheets (Parenthetical) - USD ($)
$ in Millions
12 Months Ended
Dec. 31, 2015
Dec. 31, 2014
Allowances $ 116 $ 83
Annual dividend rate 5.50% 5.50%
5.50% Mandatory convertible preferred stock series A, par value $ 0.00001 $ 0.00001
5.50% Mandatory convertible preferred stock series A, shares authorized 100,000,000 100,000,000
5.50% Mandatory convertible preferred stock series A, shares issued 20,000,000 20,000,000
5.50% Mandatory convertible preferred stock series A, shares outstanding 20,000,000 20,000,000
5.50% Mandatory convertible preferred stock series A, aggregate liquidation value $ 1,000 $ 1,000
Common stock, par value $ 0.00001 $ 0.00001
Common stock, shares authorized 1,000,000,000 1,000,000,000
Common stock, shares issued 819,773,724 808,851,108
Common Stock, Shares, Outstanding 818,391,219 807,468,603
Treasury stock, at cost 1,382,505 1,382,505

v3.3.1.900
Consolidated Statements of Comprehensive Income (Loss) - USD ($)
$ in Millions
12 Months Ended
Dec. 31, 2015
Dec. 31, 2014
Dec. 31, 2013
Revenues      
Branded postpaid revenues $ 16,383 $ 14,392 $ 13,166
Branded prepaid revenues 7,553 6,986 4,945
Wholesale revenues 692 731 613
Roaming and other service revenues 193 266 344
Total service revenues 24,821 22,375 19,068
Equipment revenues 6,718 6,789 5,033
Other revenues 514 400 319
Total revenues 32,053 29,564 24,420
Operating expenses      
Cost of services, exclusive of depreciation and amortization shown separately below 5,554 5,788 5,279
Cost of equipment sales 9,344 9,621 6,976
Selling, general and administrative 10,189 8,863 7,382
Depreciation and amortization 4,688 4,412 3,627
Cost of MetroPCS business combination 376 299 108
Gains on disposal of spectrum licenses (163) (840) (2)
Other, net 0 5 54
Total operating expenses 29,988 28,148 23,424
Operating income 2,065 1,416 996
Other income (expense)      
Interest expense (1,085) (1,073) (545)
Interest expense to affiliates (411) (278) (678)
Interest income 420 359 189
Other income (expense), net (11) (11) 89
Total other expense, net (1,087) (1,003) (945)
Income before income taxes 978 413 51
Income tax expense 245 166 16
Net income 733 247 35
Dividends on preferred stock (55) 0 0
Net income attributable to common stockholders 678 247 35
Other comprehensive income (loss), net of tax      
Net gain on cross currency interest rate swaps, net of tax effect of $0, $0 and $13 0 0 23
Net loss on foreign currency translation, net of tax effect of $0, $0 and ($37) 0 0 (62)
Unrealized gain (loss) on available-for-sale securities, net of tax effect of ($1), ($1) and $1 (2) (2) 1
Other comprehensive loss (2) (2) (38)
Total comprehensive income (loss) $ 731 $ 245 $ (3)
Earnings per share      
Basic $ 0.83 $ 0.31 $ 0.05
Diluted $ 0.82 $ 0.30 $ 0.05
Weighted average shares outstanding      
Basic 812,994,028 805,284,712 672,955,980
Diluted 822,617,938 815,922,258 676,885,215

v3.3.1.900
Consolidated Statements of Comprehensive Income (Loss) (Parenthetical) - USD ($)
$ in Millions
12 Months Ended
Dec. 31, 2015
Dec. 31, 2014
Dec. 31, 2013
Net gain on cross currency interest rate swaps, tax $ 0 $ 0 $ 13
Net loss on foreign currency translation, tax 0 0 (37)
Unrealized gain (loss) on available for sale securities, tax $ (1) $ (1) $ 1

v3.3.1.900
Consolidated Statements of Cash Flows - USD ($)
$ in Millions
12 Months Ended
Dec. 31, 2015
Dec. 31, 2014
Dec. 31, 2013
Operating activities      
Net income $ 733 $ 247 $ 35
Adjustments to reconcile net income to net cash provided by operating activities      
Depreciation and amortization 4,688 4,412 3,627
Stock-based compensation expense 201 196 100
Deferred income tax expense 256 122 10
Bad debt expense 547 444 463
Losses from sales of receivables 204 179 0
Deferred rent expense 167 225 229
Gains on disposal of spectrum licenses (163) (840) (2)
Changes in embedded derivatives 148 (18) 13
Changes in operating assets and liabilities      
Accounts receivable (259) (90) (158)
Equipment installment plan receivables 1,089 (2,429) (2,016)
Inventories (2,495) (499) 42
Deferred purchase price from sales of receivables (185) (204) 0
Other current and long-term assets (217) (328) 314
Accounts payable and accrued liabilities 693 2,395 611
Other current and long-term liabilities 22 312 141
Other, net (15) 22 136
Net cash provided by operating activities 5,414 4,146 3,545
Investing activities      
Purchases of property and equipment (4,724) (4,317) (4,025)
Purchases of spectrum licenses and other intangible assets, including deposits (1,935) (2,900) (381)
Purchases of short-term investments 2,997 0 0
Short term affiliate loan receivable, net 0 0 300
Cash and cash equivalents acquired in MetroPCS business combination 0 0 2,144
Other, net 96 (29) (130)
Net cash used in investing activities (9,560) (7,246) (2,092)
Financing activities      
Proceeds from issuance of long-term debt 3,979 2,993 2,494
Repayments of long-term debt and capital lease obligations (57) (1,019) (9)
Proceeds from tower obligations 140 0 0
Repayments of short-term debt for purchases of inventory, property and equipment, net (564) (418) (244)
Dividends on preferred stock (55) 0 0
Proceeds from exercise of stock options 47 27 137
Proceeds from issuance of preferred stock 0 982 0
Proceeds from issuance of common stock 0 0 1,787
Taxes paid related to net share settlement of stock awards (156) (73) 0
Other, net 79 32 (121)
Net cash provided by financing activities 3,413 2,524 4,044
Change in cash and cash equivalents (733) (576) 5,497
Cash and cash equivalents      
Beginning of year 5,315 5,891 394
End of year $ 4,582 $ 5,315 $ 5,891

v3.3.1.900
Consolidated Statements of Stockholders' Equity - USD ($)
$ in Millions
Total
Preferred Stock Outstanding [Member]
Common Stock Outstanding [Member]
Par Value and Additional Paid-in Capital [Member]
Accumulated Other Comprehensive Income [Member]
Accumulated Deficit [Member]
Balance, beginning of period at Dec. 31, 2012 $ 6,115     $ 29,197 $ 41 $ (23,123)
Preferred stock, shares outstanding, beginning at Dec. 31, 2012   0        
Common stock, shares outstanding, beginning at Dec. 31, 2012     535,286,077      
Increase (Decrease) in Stockholders' Equity [Roll Forward]            
Net income 35         35
Other comprehensive loss (38)       (38)  
Effects of debt recapitalization 3,143     3,143    
MetroPCS shares converted upon reverse merger, net of treasury stock withheld for taxes 2,971     2,971    
MetroPCS shares converted upon reverse merger, shares     184,487,309      
Issuance of common stock, value 1,787     1,787    
Issuance of preferred stock 0          
Issuance of stock, shares     72,765,000      
Stock-based compensation 100     100    
Exercise of stock options 137     137    
Exercise of stock options, shares     9,278,599      
Issuance of vested restricted stock units, shares     62,819      
Tax impact of stock-based compensation (5)     (5)    
Preferred stock, shares outstanding, ending at Dec. 31, 2013   0        
Common stock, shares outstanding, ending at Dec. 31, 2013     801,879,804      
Balance, ending of period at Dec. 31, 2013 14,245     37,330 3 (23,088)
Increase (Decrease) in Stockholders' Equity [Roll Forward]            
Net income 247         247
Other comprehensive loss (2)       (2)  
Issuance of preferred stock 982     982    
Issuance of stock, shares   20,000,000        
Stock-based compensation 196     196    
Exercise of stock options 27     27    
Exercise of stock options, shares     1,496,365      
Issuance of vested restricted stock units, shares     6,296,107      
Shares withheld related to net share settlement of stock awards, value (73)     (73)    
Shares withheld related to net share settlement of stock awards, shares     (2,203,673)      
Tax impact of stock-based compensation 34     34    
Other $ 7     7    
Preferred stock, shares outstanding, ending at Dec. 31, 2014 20,000,000 20,000,000        
Common stock, shares outstanding, ending at Dec. 31, 2014 807,468,603   807,468,603      
Balance, ending of period at Dec. 31, 2014 $ 15,663     38,503 1 (22,841)
Increase (Decrease) in Stockholders' Equity [Roll Forward]            
Net income 733         733
Other comprehensive loss (2)       (2)  
Issuance of preferred stock 0          
Stock-based compensation 227     227    
Exercise of stock options 47     47    
Exercise of stock options, shares     2,381,650      
Stock issued for employee stock purchase plan 21     21    
Stock issued for employee stock purchase plan, shares     761,085      
Issuance of vested restricted stock units, shares     11,956,345      
Shares withheld related to net share settlement of stock awards, value (156)     (156)    
Shares withheld related to net share settlement of stock awards, shares     (4,176,464)      
Tax impact of stock-based compensation 79     79    
Dividends on preferred stock $ (55)     (55)    
Preferred stock, shares outstanding, ending at Dec. 31, 2015 20,000,000 20,000,000        
Common stock, shares outstanding, ending at Dec. 31, 2015 818,391,219   818,391,219      
Balance, ending of period at Dec. 31, 2015 $ 16,557     $ 38,666 $ (1) $ (22,108)

v3.3.1.900
Summary of Significant Accounting Policies
12 Months Ended
Dec. 31, 2015
Organization, Consolidation and Presentation of Financial Statements [Abstract]  
Summary of Significant Accounting Policies
Note 1 – Summary of Significant Accounting Policies

Description of Business

T-Mobile US, Inc. (“T-Mobile” or the “Company”), together with its consolidated subsidiaries, is a leading provider of mobile communications services, including voice, messaging and data, under its flagship brands, T-Mobile and MetroPCS, in the United States (“U.S.”), Puerto Rico and the U.S. Virgin Islands. T-Mobile provides mobile communications services primarily using 4G Long-Term Evolution (“LTE”) technology. T-Mobile also offers a wide selection of wireless devices, including handsets, tablets and other mobile communication devices, and accessories for sale, as well as financing through equipment installment plans (“EIP”) and leasing through JUMP On Demand™. Additionally, T-Mobile provides reinsurance for handset insurance policies and extended warranty contracts offered to T-Mobile’s mobile communications customers.

Basis of Presentation

The consolidated financial statements include the balances and results of operations of T-Mobile and its consolidated subsidiaries. T-Mobile operates as a single operating segment. T-Mobile consolidates majority-owned subsidiaries over which it exercises control, as well as variable interest entities (“VIEs”) where it is deemed to be the primary beneficiary and VIEs which cannot be deconsolidated. Intercompany transactions and balances have been eliminated in consolidation. Certain prior year amounts have been reclassified to conform to the current presentation.

The preparation of financial statements in conformity with U.S. generally accepted accounting principles (“GAAP”) requires management to make estimates and assumptions which affect the financial statements and accompanying notes. Examples include service revenues earned but not yet billed, service revenues billed but not yet earned, relative selling prices, allowances for uncollectible accounts and sales returns, discounts for imputed interest on EIP receivables, guarantee liabilities, losses incurred but not yet reported, tax liabilities, deferred income taxes including valuation allowances, useful lives of long-lived assets, cost estimates of asset retirement obligations, residual values on leased handsets, reasonably assured renewal terms for operating leases, stock-based compensation forfeiture rates, and fair value measurements related to goodwill, spectrum licenses, intangible assets, and derivative financial instruments. Estimates are based on historical experience, where applicable, and other assumptions which management believes are reasonable under the circumstances. These estimates are inherently subject to judgment and actual results could differ from those estimates.

Cash and Cash Equivalents

Cash equivalents consist of highly liquid money market funds and U.S. Treasury securities with remaining maturities of three months or less at the date of purchase.

Short-Term Investments

The Company's short-term investments consist of U.S. Treasury securities classified as available for sale, which are stated at fair value and have remaining maturities of more than three months at the date of purchase. Unrealized gains and losses, net of related income taxes, for available for sale securities are reported as net increases and decreases to accumulated other comprehensive income (loss), a component of stockholders' equity, until realized. The estimated fair values of investments are based on quoted market prices as of the end of the reporting period. The U.S. Treasury securities reported as of December 31, 2015 have contractual maturities of less than one year.

Available-for-sale securities are reviewed for impairment on a quarterly basis or more often if a potential loss-triggering event occurs. If there has been a decline in the fair value below the amortized cost basis, the Company determines whether such impairment is other-than-temporary. Factors considered in the assessment include the reason for the decline in fair value, the Company’s intent to sell the security, whether it is more likely than not that the Company will be required to sell the security before recovery of its amortized cost basis and whether the Company does not expect to recover the entire amortized cost basis of the security. If an impairment is considered other-than-temporary, the Company records a charge to Other income (expense), net.

Accounts Receivable and Allowances

Accounts receivable consist primarily of amounts billed and currently due from customers, other carriers and third-party retail channels (“dealers”), as well as revenues earned but not yet billed at the end of each period. T-Mobile has an arrangement to sell certain service accounts receivable on a revolving basis, which are treated as sales of financial assets. T-Mobile maintains an allowance for estimated losses inherent in the accounts receivable portfolio based on a number of factors, including historical experience and current collection trends, aging of the receivable portfolio, credit quality of the customer base and other qualitative factors such as macro-economic conditions. The Company writes off account balances if collection efforts are unsuccessful and the receivable balance is deemed uncollectible, based on customer credit ratings and the length of time from the original billing date.

Equipment Installment Plan Receivables

The Company offers certain retail customers the option to pay for devices and other accessories in installments using an EIP. At the time of an installment sale, the Company imputes a discount for interest as there is no stated rate of interest on the EIP receivables and records the EIP receivables at their present value, which is determined by discounting future payments at the imputed interest rate. The difference between the present value of the EIP receivables and their face amount results in a discount which is recorded as a direct reduction to the carrying value with a corresponding reduction to equipment revenues. T-Mobile determines the imputed discount rate based primarily on current market interest rates and the amount of expected credit losses on the EIP receivables. As a result, T-Mobile does not recognize a separate valuation allowance at the time of issuance as the effects of uncertainty about future cash flows are included in the initial present value measurement of the receivable. The imputed discount on EIP receivables is amortized over the financed installment term using the effective interest method and recognized as interest income in Other income (expense), net.

Subsequent to the initial determination of the imputed discount, T-Mobile assesses the need for and, if necessary, recognizes an allowance for credit losses to the extent the amount of estimated probable losses on the gross EIP receivable balances exceed the remaining unamortized imputed discount balances.  The allowance is based on a number of factors, including collection experience, aging of the EIP receivable portfolio, credit quality of the customer base and other qualitative factors such as macro-economic conditions. T-Mobile writes off account balances if collection efforts are unsuccessful and receivable balance is deemed uncollectible, based on customer credit ratings and the length of time from the original billing date. Equipment sales not reasonably assured to be collectible are recorded on a cash basis as payments are received.

The current portion of the EIP receivables is included in Equipment installment plan receivables, net and the long-term portion of the EIP receivables is included in Equipment installment plan receivables due after one year, net. T-Mobile has an arrangement to sell certain EIP receivables on a revolving basis, which are treated as sales of financial assets.

Inventories

Inventories consist primarily of wireless devices and accessories, which are valued at the lower of cost or market. Cost is determined using standard cost which approximates average cost. Shipping and handling costs paid to wireless device and accessories vendors, and costs to refurbish used devices recovered through the Company’s device trade-in and upgrade programs are included in the standard cost of inventory. T-Mobile records inventory write-downs to net realizable value for obsolete and slow-moving items based on inventory turnover trends and historical experience.

Long-Lived Assets

Long-lived assets include assets that do not have indefinite lives, such as property and equipment and other intangible assets. The Company assesses potential impairments to its long-lived assets when events or changes in circumstances indicate the carrying amount of the asset may not be recoverable. If any indicators are present, the Company tests recoverability. The carrying value of a long-lived asset or asset group is not recoverable if it exceeds the sum of the undiscounted cash flows expected to be generated from the use and eventual disposition of the asset or asset group. If the undiscounted cash flows do not exceed the asset or asset group’s carrying amount, then an impairment loss is recorded, measured as the amount by which the carrying amount of a long-lived asset or asset group exceeds its fair value.

Property and Equipment

Property and equipment consists of buildings and equipment, wireless communication systems, leasehold improvements, capitalized software, leased wireless devices and construction in progress. Buildings and equipment include certain network server equipment. Wireless communication systems include assets to operate the Company’s wireless network and IT data centers, including tower asset leaseholds, assets related to the liability for the retirement of long-lived assets and capital leases. Leasehold improvements include asset improvements other than those related to the wireless network.

Property and equipment are recorded at cost less accumulated depreciation and impairments, if any. T-Mobile generally depreciates property and equipment on a straight-line basis.

In 2015, T-Mobile introduced JUMP! On Demand which allows customers to lease a device and upgrade it for a new one up to three times in a 12 month period. To date, all of T-Mobile’s leased devices were classified as operating leases by considering critical elements of the lease arrangement such as the lease term and the economic life, fair value and residual value of the device. At operating lease inception, leased wireless devices are transferred from inventory to property and equipment. Leased wireless devices are depreciated to their estimated residual value over the period expected to provide utility to T-Mobile, which is generally the lease term.  Revenues associated with the leased wireless devices, net of incentives, are generally recognized over the lease term.  Upon device upgrade or at lease end, customers must return or purchase their device.  Returned devices are recorded as inventory and are valued at the lower of cost or market with any write down to market recognized as cost of equipment sales.

Costs of major replacements and improvements are capitalized. Repair and maintenance expenditures which do not enhance or extend the asset’s useful life are charged to operating expenses as incurred. Construction costs, labor and overhead incurred in the expansion or enhancement of T-Mobile’s wireless network are capitalized. Capitalization commences with pre-construction period administrative and technical activities, which includes obtaining leases, zoning approvals and building permits, and ceases at the point at which the asset is ready for its intended use.

The Company capitalizes interest associated with the acquisition or construction of certain property and equipment. Capitalized interest is reported as a reduction in interest expense and depreciated over the useful life of the related assets. Depreciable life studies are performed periodically to confirm the appropriateness of useful lives for certain categories of property and equipment. These studies take into account actual usage, physical wear and tear, replacement history and assumptions about technology evolution. When these factors indicate the useful life of an asset is different from the previous assessment, the remaining book value is depreciated prospectively over the adjusted remaining estimated useful life. Leasehold improvements are depreciated over the shorter of their estimated useful lives or the related lease term.

Future obligations related to capital leases are included in Short-term debt and Long-term debt. Depreciation of assets held under capital leases is included in Depreciation and amortization expense.

The Company records an asset retirement obligation for the fair value of legal obligations associated with the retirement of tangible long-lived assets and a corresponding increase in the carrying amount of the related asset in the period in which the obligation is incurred. In periods subsequent to initial measurement, the Company recognizes changes in the liability resulting from the passage of time and revisions to either the timing or the amount of the original estimate. Over time, the liability is accreted to its present value and the capitalized cost is depreciated over the estimated useful life of the asset. The Company’s obligations relate primarily to certain legal obligations to remediate leased property on which the Company’s network infrastructure and administrative assets are located.

The Company capitalizes certain costs incurred in connection with developing or acquiring internal use software. Capitalization of software costs commences once the final selection of the specific software solution has been made and management authorizes and commits to funding the software project. Capitalized software costs are included in Property and equipment, net and amortized on a straight-line basis over the estimated useful life of the asset. Costs incurred during the preliminary project stage, as well as maintenance and training costs are expensed as incurred.

Other Intangible Assets

Intangible assets that do not have indefinite useful lives are amortized over their estimated useful lives. Customer lists are amortized using the sum-of-the-years-digits method over the expected period in which the relationship is expected to contribute to future cash flows. The remaining finite-lived intangible assets are amortized using the straight-line method.

Goodwill and Indefinite-Lived Intangible Assets

Goodwill

Goodwill consists of the excess of the purchase price over the fair value of identifiable net assets acquired in a business combination.

Spectrum Licenses

Spectrum licenses are carried at costs incurred to acquire the spectrum licenses and the costs to prepare the spectrum licenses for their intended use, such as costs to clear acquired spectrum licenses. The Federal Communications Commission (“FCC”) issues spectrum licenses which provide T-Mobile with the exclusive right to utilize designated radio frequency spectrum within specific geographic service areas to provide wireless communication services. While spectrum licenses are issued for a fixed period of time, typically for up to fifteen years, the FCC has granted license renewals routinely and at a nominal cost. The spectrum licenses held by the Company expire at various dates. The Company believes it will be able to meet all requirements necessary to secure renewal of its spectrum licenses at nominal costs. Moreover, the Company has determined there are currently no legal, regulatory, contractual, competitive, economic or other factors that limit the useful lives of its spectrum licenses. Therefore, the Company has determined the spectrum licenses should be treated as indefinite-lived intangible assets.

The Company at times enters into agreements to sell or exchange spectrum licenses.  Upon entering into the arrangement, if the transaction has been deemed to have commercial substance, spectrum licenses are reviewed for impairment and transferred at their carrying value, net of any impairment, to assets held for sale included in other current assets until approval and completion of the exchange or sale.  Upon closing of the transaction, spectrum licenses acquired as part of an exchange of nonmonetary assets are valued at fair value. The difference between the fair value of the spectrum licenses obtained, book value of the spectrum licenses transferred and cash paid, if any, is recognized as gains included in Gains on disposal of spectrum licenses. If the transaction lacks commercial substance or the fair value is not measurable, the acquired spectrum licenses are recorded at the book value of the assets tendered.

Impairment

The Company assesses the carrying value of its goodwill and other indefinite-lived intangible assets (spectrum licenses) for potential impairment annually as of December 31 or more frequently if events or changes in circumstances indicate such assets might be impaired. 

The Company may elect to first perform a qualitative assessment to determine whether it is more likely than not the fair value of the single reporting unit is less than its carrying amount as a basis for determining whether it is necessary to perform the two-step goodwill impairment test. If the Company does not perform a qualitative assessment, or if the qualitative assessment indicates it is more likely than not the fair value of the single reporting unit is less than its carrying amount, goodwill is tested for impairment based on a two-step test. In the first step, the Company compares the fair value of the reporting unit to the carrying value. The fair value of the reporting unit is determined using a market approach, which is based on market capitalization. If the fair value is less than the carrying value, the second step is performed. In the second step, the Company determines the fair values of all of the assets and liabilities of the reporting unit, including those that may not be currently recorded. The excess of the fair value of the reporting unit over the sum of the fair value of all of those assets and liabilities represents the implied goodwill amount. If the implied fair value of goodwill is lower than its carrying amount, an impairment loss is recognized for the difference.  

The Company tests its spectrum licenses for impairment on an aggregate basis, consistent with the Company's management of the overall business at a national level.  The Company may elect to first perform a qualitative assessment to determine whether it is more likely than not that the fair value of an intangible asset group is less than its carrying value. If the Company does not perform the qualitative assessment, or if the qualitative assessment indicates it is more likely than not the fair value of the intangible asset group is less than its carrying amount, the Company calculates the estimated fair value of the intangible asset group. If the estimated fair value of the spectrum licenses is lower than their carrying amount, an impairment loss is recognized for the difference.  The Company estimates fair value using the Greenfield approach, which is an income approach, to estimate the price at which an orderly transaction to sell the asset would take place between market participants at the measurement date under current market conditions.

Guarantee Liabilities

The Company offers a device trade-in program, Just Upgrade My Phone (“JUMP!”), which provides eligible customers a specified-price trade-in right to upgrade their device.  Participating customers must purchase a device from T-Mobile, have a qualifying monthly wireless service plan with T-Mobile, and finance their device using an EIP, which is treated as a single multiple-element arrangement when entered into at or near the same time.  Upon qualifying JUMP! program upgrades, the customers’ remaining EIP balance is settled provided they trade in their eligible used device in good working condition and purchase a new device from T-Mobile on a new EIP.

For customers who enroll in the device trade-in program, the Company defers the portion of revenue which represents the estimated value of the specified-price trade-in right guarantee.  The guarantee liabilities are valued based on various economic and customer behavioral assumptions, including the customer's estimated remaining EIP balance at trade-in, the expected fair value of the used handset at trade-in, and probability and timing of trade-in.  T-Mobile assesses guarantee liabilities at each reporting date to determine if facts and circumstances would indicate the incurrence of incremental contingent liabilities is probable and if so, reasonably estimable. The recognition and subsequent adjustments of the contingent guarantee liability as a result of these assessments are recorded as adjustments to revenue. When customers upgrade their devices, the difference between the trade-in credit to the customer and the fair value of the returned devices is recorded against the guarantee liabilities.  Guarantee liabilities included in Other current liabilities were $163 million and $286 million as of December 31, 2015 and 2014, respectively.  The estimated EIP receivable balance if all enrolled handset upgrade program customers were to claim their benefit, not including any trade-in value of the required used handset, was $2.3 billion as of December 31, 2015. This is not an indication of the Company’s expected loss exposure as it does not consider the expected fair value of the used handset, which is required to be in good working condition at trade-in, nor does it consider the probability and timing of trade-in.

Fair Value Measurements

The Company carries certain assets and liabilities at fair value. Fair value is defined as an exit price, representing the amount that would be received to sell an asset or paid to transfer a liability in an orderly transaction between market participants at the measurement date. The three tier hierarchy for inputs used in measuring fair value, which prioritizes the inputs based on the observability as of the measurement date, is as follows:

Level 1
Quoted prices in active markets for identical assets or liabilities;
Level 2
Observable inputs other than the quoted prices in active markets for identical assets and liabilities; and
Level 3
Unobservable inputs for which there is little or no market data, which require T-Mobile to develop assumptions of what market participants would use in pricing the asset or liability.

Assets and liabilities are classified in their entirety based on the lowest level of input that is significant to the fair value measurement. The Company’s assessment of the significance of a particular input to the fair value measurement requires judgment, and may affect the placement of assets and liabilities being measured within the fair value hierarchy.

The carrying values of cash and cash equivalents, short-term investments, accounts receivable, accounts receivable from affiliates and accounts payable approximate fair value due to the short-term maturities of these instruments. The carrying values of EIP receivables approximate fair value as the receivables are recorded at their present value, net of unamortized discount and allowance for credit losses. There were no financial instruments with a carrying value materially different from their fair value, based on quoted market prices or rates for the same or similar instruments, or internal valuation models.

Derivative Financial Instruments

Derivative financial instruments primarily relate to embedded derivatives for certain components of the reset feature of the Senior Reset Notes to affiliates which are required to be bifurcated and are recorded on the balance sheet at fair value. Changes in fair value are recognized in Interest expense to affiliates. T-Mobile does not enter into derivatives for trading or speculative purposes.

Revenue Recognition

T-Mobile offers products and services to customers through bundled arrangements, which may be comprised of multiple contracts entered into with a customer at or near the same time. The Company assesses such agreements as a single bundled arrangement that may involve multiple deliverables, which include wireless devices, wireless services or a combination thereof. For multiple deliverable arrangements revenue is allocated between the separate units of accounting, based on such components’ relative selling prices on a standalone basis.

Revenues primarily consist of wireless service revenues from providing access to and usage of the Company's wireless communications network, equipment revenues generated from device sales and revenues from leasing a device through JUMP! On Demand. Service revenues also include revenues earned for providing value added services to customers, such as handset insurance services. Service revenues are billed either in advance or arrears or are prepaid and are recognized when the service is rendered and all other revenue recognition criteria have been met. Revenues that are not reasonably assured to be collectible are recorded on a cash basis as payments are received. The recognition of prepaid revenue is deferred until services are rendered or the prepaid balance expires. Incentives given to customers are recorded as a reduction to revenue. T-Mobile recognizes service revenues for Data Stash plans when such services are delivered and the data is consumed, or at time of forfeiture or expiration.  Revenues relating to unused data that is carried over to the following month are deferred and valued based on their relative standalone selling price. Revenue is recorded gross for arrangements involving the resale of third-party services where T-Mobile is considered the primary obligor and is recorded net of associated costs incurred for services whereby T-Mobile is not considered the primary obligor.

Equipment revenues are comprised of revenues from the sale or lease of mobile communication devices and accessories. Device and accessory sales revenues are generally recognized when the products are delivered to and accepted by the customer or dealer. The Company defers a portion of equipment revenues and cost of equipment sales for expected device returns based on historical experience. The Company offers certain customers the option to pay for devices and accessories in installments using an EIP. See Equipment Installment Plan Receivables for further information.

In addition, the Company offers customers a device trade-in program, JUMP!, which provides eligible customers a specified-price trade-in right to upgrade their device.  For customers enrolled in JUMP!, the Company separates the JUMP! trade-in right from the multiple element arrangement at its fair value and defers the portion of revenue which represents the fair value of the trade-in right. See Guarantee Liabilities for further information. In 2015, T-Mobile introduced JUMP! On Demand, which allows customers to lease a device and upgrade their leased wireless device for a new one up to three times in a 12 month period. Leased wireless devices are accounted for as operating leases and equipment revenues are recognized as earned on a straight-line basis over the lease term. Previously leased devices that are purchased by the customer are recorded at their residual value as equipment revenues and cost of equipment sales. See Property and Equipment for further information.

Federal Universal Service Fund (“USF”) and other fees are assessed by various governmental authorities in connection with the services the Company provides to its customers. When the Company separately bills and collects these regulatory fees from customers, they are recorded gross in service revenues and cost of services. For the years ended December 31, 2015, 2014 and 2013, the Company recorded approximately $334 million, $349 million and $362 million, respectively, of USF and other fees on a gross basis.

Rent Expense

The Company has operating leases for cell sites, retail locations, corporate offices and dedicated transportation lines, some of which have escalating rentals during the initial lease term and during subsequent optional renewal periods. The Company recognizes rent expense on a straight-line basis, over the non-cancelable lease term and renewal periods that are considered reasonably assured at the inception of the lease.

Advertising Expense

T-Mobile expenses the cost of advertising and other promotional expenditures to market the T-Mobile’s services and products as incurred. For the years ended December 31, 2015, 2014 and 2013, advertising expenses included in Selling, general and administrative expenses were $1.6 billion, $1.4 billion and $1.0 billion, respectively.

Income Taxes

Deferred tax assets and liabilities are recognized based on temporary differences between the financial statement and tax bases of assets and liabilities using enacted tax rates expected to be in effect when these differences are realized. A valuation allowance is recorded when it is more likely than not that some portion or all of a deferred tax asset will not be realized. The ultimate realization of a deferred tax asset depends on the ability to generate sufficient taxable income of the appropriate character and in the appropriate taxing jurisdictions within the carryforward periods available.

T-Mobile accounts for uncertainty in income taxes recognized in the financial statements in accordance with the accounting guidance on the financial statement recognition and measurement of a tax position taken or expected to be taken in a tax return. The Company assesses whether it is more likely than not that a tax position will be sustained upon examination based on the technical merits of the position and adjusts the unrecognized tax benefits in light of changes in facts and circumstances, such as changes in tax law, interactions with taxing authorities and developments in case law.

In November 2015, the Financial Accounting Standards Board (“FASB”) issued Accounting Standards Update (“ASU”) 2015-17 (Topic 740), “Balance Sheet Classification of Deferred Taxes”, which simplifies the presentation of deferred income taxes. This ASU requires that deferred tax assets and liabilities be classified as non-current in a classified statement of financial position. The Company early adopted ASU 2015-17 for the year ended December 31, 2015 on a prospective basis. Adoption of this ASU resulted in a reclassification of the Company’s current deferred tax assets, net to non-current deferred tax liabilities in the Consolidated Balance Sheets as of December 31, 2015. Prior periods were not retrospectively adjusted.

Other Comprehensive Income (Loss)

Other comprehensive income (loss) consists of adjustments, net of tax, related to unrealized gains (losses) on available-for-sale securities, unrealized gains (losses) on cash flow hedging derivatives and unrealized gains (losses) on foreign currency translation. These are reported in Accumulated other comprehensive income (loss) (“AOCI”) as a separate component of stockholders’ equity until realized in earnings.

Stock-Based Compensation

Stock-based compensation cost for stock awards, which include restricted stock units (“RSU”) and performance stock units (“PSU”), is measured at fair value on the grant date and recognized as expense, net of expected forfeitures, over the related service period. The fair value of stock awards is based on the closing price of T-Mobile common stock on the date of grant. RSUs are recognized as expense using the straight-line method. PSUs are recognized as expense following a graded vesting schedule.

Earnings Per Share

Basic earnings per share is computed by dividing Net income attributable to common stockholders by the weighted-average number of common shares outstanding for the period. Diluted earnings per share is computed by giving effect to all potentially dilutive common shares outstanding during the period. Potentially dilutive common shares consist of outstanding stock options, RSUs and PSUs, calculated using the treasury stock method, and mandatory convertible preferred stock (“preferred stock”), calculated using the if-converted method.

Variable Interest Entities

VIEs are entities which lack sufficient equity to permit the entity to finance its activities without additional subordinated financial support from other parties, have equity investors which do not have the ability to make significant decisions relating to the entity's operations through voting rights, do not have the obligation to absorb the expected losses or do not have the right to receive the residual returns of the entity. The most common type of VIE is a special purpose entity (“SPE”). SPEs are commonly used in securitization transactions in order to isolate certain assets and distribute the cash flows from those assets to investors. SPEs are generally structured to insulate investors from claims on the SPE's assets by creditors of other entities, including the creditors of the seller of the assets.

The primary beneficiary is required to consolidate the assets and liabilities of the VIE. The primary beneficiary is the party which has both the power to direct the activities of an entity that most significantly impact the VIE's economic performance, and through its interests in the VIE, the obligation to absorb losses or the right to receive benefits from the VIE which could potentially be significant to the VIE. T-Mobile consolidates VIEs when it is deemed to be the primary beneficiary or when the VIE cannot be deconsolidated.

In assessing which party is the primary beneficiary, all the facts and circumstances are considered, including each party’s role in establishing the VIE and its ongoing rights and responsibilities. This assessment includes, first, identifying the activities that most significantly impact the VIE’s economic performance; and second, identifying which party, if any, has power over those activities. In general, the parties that make the most significant decisions affecting the VIE (such as asset managers and servicers) or have the right to unilaterally remove those decision-makers are deemed to have the power to direct the activities of a VIE.

Recently-Issued Accounting Standards

In April 2015, the FASB issued ASU 2015-03, “Simplifying the Presentation of Debt Issuance Costs.” The standard requires debt issuance costs related to a recognized debt liability be presented in the balance sheet as a direct deduction from the carrying amount of that debt liability, consistent with debt discounts. The recognition and measurement guidance for debt issuance costs are not affected. The standard will become effective for T-Mobile beginning January 1, 2016 and will be applied retrospectively. The implementation of this standard is not expected to have a significant impact on T-Mobile’s consolidated financial statements.

In May 2014, the FASB issued ASU 2014-09, “Revenue from Contracts with Customers.” The standard requires entities to recognize revenue through the application of a five-step model, which includes identification of the contract, identification of the performance obligations, determination of the transaction price, allocation of the transaction price to the performance obligations and recognition of revenue as the entity satisfies the performance obligations. In August 2015, the FASB issued ASU 2015-14, “Revenue From Contracts With Customers (Topic 606): Deferral of the Effective Date.” The amendments in the ASU 2015-14 defer the effective date of ASU 2014-09 by one year. The standard will become effective for T-Mobile beginning January 1, 2018; however, early adoption with the original effective date for periods beginning January 1, 2017 will be permitted.  The Company is currently evaluating the guidance to determine the potential impact on T-Mobile’s consolidated financial statements. Under ASU 2014-09, two adoption methods are allowed.  Under one method, a company may apply the rules to contracts in all reporting periods presented, subject to certain allowable exceptions.  Under the other method, a company may apply the rules to all contracts existing as of January 1, 2018 (provided early adoption is not elected), recognizing an adjustment to retained earnings for the cumulative effect of the change and providing additional disclosures comparing results to previous rules.  The Company continues to evaluate the impact of the new standard and available adoption methods and believes the standard will require the implementation of new revenue accounting systems, processes and internal controls over revenue recognition.

v3.3.1.900
Business Combination with MetroPCS
12 Months Ended
Dec. 31, 2015
Business Combinations [Abstract]  
Business Combination with MetroPCS
Note 2 – Business Combination with MetroPCS

Transaction Overview

In 2013, T-Mobile US, Inc. was formed through the business combination, effectuated as a reverse acquisition between T-Mobile USA, Inc. (“T-Mobile USA”) and MetroPCS Communications, Inc. (“MetroPCS”). Accordingly, T-Mobile USA’s historical financial statements became the historical financial statements of the Company. The acquired assets and liabilities of MetroPCS are included in the Company’s Consolidated Balance Sheets as of April 30, 2013 and the results of its operations and cash flows are included in the Company’s Consolidated Statements of Comprehensive Income (Loss) and Cash Flows for periods beginning after May 1, 2013.

Cost of MetroPCS Business Combination

The Company recognized the following expenses included in Cost of MetroPCS business combination:
 
Year Ended December 31,
(in millions)
2015
 
2014
 
2013
Network decommissioning costs, including the write-off of certain items
$
376

 
$
263

 
$
—

Transaction and integration costs
—

 
36

 
108

Cost of MetroPCS business combination
$
376

 
$
299

 
$
108


Network Decommissioning Costs

Prior to the closing of the business combination, T-Mobile developed integration plans which included the decommissioning of the MetroPCS Code Division Multiple Access (“CDMA”) network and certain other redundant network cell sites. In 2014, T-Mobile began decommissioning the MetroPCS CDMA network and redundant network cell sites. In 2015, T-Mobile ceased use of the MetroPCS CDMA network. Network decommissioning costs primarily relate to the acceleration of lease costs for decommissioned cell sites for which T-Mobile will no longer receive any economic benefit as the cell site assets are removed. Accrued liabilities for network decommissioning costs are relieved as cash payments are made over the remaining lease terms through 2028. In addition, network decommissioning costs include the write-off of certain items consisting of prepaid rent expense, construction in progress, favorable and unfavorable leases, and deferred rent expense. T-Mobile recognized network decommissioning costs, including the write-off of certain items, of $376 million for the year ended December 31, 2015. T-Mobile expects to incur additional network decommissioning costs in 2016 as cell site assets are removed, which are not expected to be significant.

Activities in liabilities for network decommissioning costs were as follows:
(in millions)
December 31, 2015
 
December 31, 2014
Balances, beginning of year
$
239

 
$
—

Network decommissioning costs, excluding the write-off of certain items
349

 
271

Cash payments
(182
)
 
(32
)
Balances, end of year
$
406

 
$
239


Classified on the balance sheet as:


Accounts payable and accrued liabilities
$
117

 
$
78

Other long-term liabilities
289

 
161

Network decommissioning liabilities
$
406

 
$
239


In connection with decommissioning the MetroPCS CDMA network, the Company settled asset retirement obligations of $130 million and $21 million for the years ended December 31, 2015 and 2014, respectively. See Note 5 – Property and Equipment for further information.

Transaction and Integration Costs

Transaction costs generally included costs for personnel associated with the change in control and other acquisition-related charges.  Integration costs generally included costs associated with personnel, professional services and combining information technology infrastructures. Transaction costs were not significant for the years ended December 31, 2015 and 2014, and was $41 million for the year ended December 31, 2013.

Consolidated Statements of Comprehensive Income for MetroPCS Operations

The following supplemental information presents the financial results of MetroPCS operations included in the consolidated statements of comprehensive income since May 1, 2013 for the year ended December 31, 2013:
(in millions)
Year Ended December 31, 2013
Total revenues
$
3,366

Income before income taxes
143


Pro Forma Financial Information (Unaudited)

The following pro forma consolidated results of operations for the year ended December 31, 2013 assumes the business combination was completed as of January 1, 2012:
(in millions, except per share amounts)
Year Ended December 31, 2013
Pro forma revenues
$
26,158

Pro forma net income
52

Pro forma basic earnings per share
$
0.07

Pro forma diluted earnings per share
0.07


The pro forma amounts include the historical operating results of T-Mobile USA and MetroPCS prior to the business combination, with adjustments directly attributable to the business combination relating to purchase accounting adjustments to conform to accounting policies that affect total revenues, total operating expenses, interest expense, other income (expense), income taxes expense and eliminate intercompany activities.

As the pro forma amounts assumed the business combination was completed as of January 1, 2012, pro forma earnings for the year ended December 31, 2013 excluded $213 million of transaction costs and these costs would have been included in the pro forma earnings for the year ended December 31, 2012.

The pro forma results include the following:

•
Increase in tax expenses based on the inclusion of MetroPCS in the combined company of $63 million for the year ended December 31, 2013;
•
Net decrease to amortization and depreciation expense related to the fair value of the intangible assets and fixed assets acquired of $19 million for the year ended December 31, 2013; and
•
The impact of financing agreements entered into whereby an aggregate of $14.7 billion senior unsecured notes were issued and $14.5 billion of senior unsecured notes previously issued by T-Mobile USA to Deutsche Telekom and $2.5 billion of senior unsecured notes previously issued by MetroPCS were retired in connection with the business combination for a net increase to interest and other income (expense) of $91 million for the year ended December 31, 2013.

v3.3.1.900
Sales of Certain Receivables
12 Months Ended
Dec. 31, 2015
Transfers and Servicing [Abstract]  
Transfers and Servicing of Financial Assets [Text Block]
Note 3 – Sales of Certain Receivables

T-Mobile has entered into transactions to sell certain service and EIP accounts receivables. The transactions, including the Company’s continuing involvement with the sold receivables and the respective impacts to the financial statements, are described below.

Sales of Service Receivables

Overview of Transaction

In 2014, T-Mobile entered into an arrangement to sell certain service accounts receivables on a revolving basis with a current maximum funding commitment of $750 million and scheduled expiration date in March 2017. Sales of receivables occur daily and are settled on a monthly basis. The receivables consist of service charges currently due from customers and are short-term in nature. In connection with the sale arrangement, the Company formed a wholly-owned subsidiary, which qualifies as a bankruptcy remote entity to sell service accounts receivables (“Service BRE”). Pursuant to the arrangement, certain subsidiaries of T-Mobile transfer selected receivables to Service BRE.  Service BRE then sells the receivables to an unaffiliated entity (“Service VIE”), which was established to facilitate the sale of beneficial ownership interest in the receivables to certain third parties.

Variable Interest Entity

The Company determined that Service VIE qualifies as a VIE as it lacks sufficient equity to finance its activities. T-Mobile has a variable interest in Service VIE, but is not the primary beneficiary as it lacks the power to direct the activities that most significantly impact Service VIE’s economic performance. Those activities include committing Service VIE to legal agreements to purchase or sell assets, selecting which receivables are purchased in the arrangement, determining whether Service VIE will sell interests in the purchased service receivables to other parties, funding of the entities and servicing of receivables. T-Mobile does not hold the power to direct the key decisions underlying these activities. For example, while T-Mobile acts as the servicer of the sold receivables, which is considered a significant activity of the VIE, the Company is acting as an agent in its capacity as the servicer and the counterparty to the arrangement has the ability to remove T-Mobile as the servicing agent of the receivables at will with no recourse available to T-Mobile. As the Company has determined it is not the primary beneficiary, the results of Service VIE are not consolidated into the Company’s consolidated financial statements.

The following table summarizes the carrying amounts and classification of assets (primarily the deferred purchase price) and liabilities included in the Consolidated Balance Sheets that relate to T-Mobile’s variable interest in Service VIE:
(in millions)
December 31,
2015
 
December 31,
2014
Other current assets
$
206

 
$
204

Accounts payable and accrued liabilities
—

 
13

Other current liabilities
73

 
55


Sales of EIP Receivables

Overview of Transaction

In the fourth quarter of 2015, T-Mobile entered into an arrangement to sell certain EIP accounts receivables on a revolving basis with a committed securitization facility of $800 million, of which $150 million is scheduled to expire in July 2016 and $650 million is scheduled to expire in November 2017. Sales of EIP receivables occur daily and are settled on a monthly basis. The receivables consist of customer EIP balances, which require monthly customer payments for up to 24 months. In connection with the sale arrangement, the Company formed a wholly-owned subsidiary, which qualifies as a bankruptcy remote entity (“EIP BRE”). Pursuant to the arrangement, a wholly-owned subsidiary of T-Mobile transfers selected receivables to EIP BRE.  EIP BRE then sells the receivables to non-consolidated and unaffiliated third-party entities in which T-Mobile does not have a variable interest.

Variable Interest Entity

The Company determined that EIP BRE is a VIE as its equity investment at risk lacks the obligation to absorb a certain portion of its expected losses. The Company has a variable interest in EIP BRE and determined that it is the primary beneficiary based on its ability to direct the activities which most significantly impact EIP BRE’s economic performance. Those activities include selecting which receivables are transferred into EIP BRE and sold in the arrangement and funding of EIP BRE. Additionally, T-Mobile’s equity interest in EIP BRE obligates it to absorb losses and gives it the right to receive benefits from the EIP BRE that could potentially be significant to EIP BRE. Accordingly, the Company determined that it is the primary beneficiary, and includes the balances and results of operations of EIP BRE into the Company’s consolidated financial statements.

The following table summarizes the carrying amounts and classification of EIP BRE’s assets and liabilities included in the Consolidated Balance Sheets:
(in millions)
December 31,
2015
 
December 31,
2014
Other current assets
$
164

 
$
—

Other assets
44

 
—

Accounts payable and accrued liabilities
14

 
—

Other long-term liabilities
3

 
—


In addition, EIP BRE is a separate legal entity with its own separate creditors who will be entitled, prior to any liquidation of EIP BRE, to be satisfied prior to any value in EIP BRE becoming available to T-Mobile. Accordingly, the assets of EIP BRE may not be used to settle the general obligations of T-Mobile and creditors of EIP BRE have limited recourse to the general credit of T-Mobile.

Sales of Receivables

The transfers of service receivables and EIP receivables to the non-consolidated entities are accounted for as sales of financial assets. Upon sale, T-Mobile derecognizes the receivables, as well as the related allowances and unamortized imputed discount, as applicable, and recognizes the net cash proceeds in Net cash provided by operating activities on the Consolidated Statements of Cash Flows.

The proceeds are net of the deferred purchase price, consisting of a receivable from the purchasers that entitles T-Mobile to certain collections on the receivables. T-Mobile recognizes the collection of the deferred purchase price in net cash provided by operating activities as it is dependent on collection of the customer receivables and is not subject to significant interest rate risk. The deferred purchase price represents a financial asset that is primarily tied to the creditworthiness of the customers and which can be settled in such a way that T-Mobile may not recover substantially all of its recorded investment due to default by the customers on the underlying receivables. T-Mobile elected, at inception, to measure the deferred purchase price at fair value with changes in fair value included in Selling, general and administrative expense. The fair value of the deferred purchase price is determined based on a discounted cash flow model which uses unobservable inputs (Level 3 inputs), including customer default rates. T-Mobile’s deferred purchase price related to the sales of service receivables and EIP receivables was $389 million as of December 31, 2015, of which $345 million was included in Other current assets and $44 million was included in Other assets. As of December 31, 2014, T-Mobile’s deferred purchase price related to the sale of service receivables was $204 million, included in Other current assets.

The following table summarizes the impacts of the sale of certain service receivables and EIP receivables on the Consolidated Balance Sheets:
(in millions)
December 31,
2015
 
December 31,
2014
Derecognized net service receivables and EIP receivables
$
1,850

 
$
768

Other current assets
370

 
204

Other assets
44

 
—

Accounts payable and accrued liabilities
14

 
13

Other current liabilities
73

 
55

Other long-term liabilities
3

 
—

Net cash proceeds since inception
1,494

 
610

Of which:


Net cash proceeds during the period
884

 
610

Net cash proceeds funded by reinvested collections
610

 
—


T-Mobile recognized net expenses of $204 million and $179 million for the years ended December 31, 2015 and 2014, respectively, which were recognized in Selling, general and administrative expense. Net expenses included adjustments to the receivables’ fair value, gains or losses from the sales of receivables and changes in fair value of the deferred purchase price. T-Mobile recognized fair value adjustments for the years ended December 31, 2015 and 2014, rather than bad debt expense, to reduce the service receivables’ carrying value to fair value prior to the sales of receivables.

Continuing Involvement

Pursuant to the arrangements, T-Mobile has continuing involvement with the sold service receivables and EIP receivables as the Company services the receivables and is required to repurchase certain receivables, including ineligible receivables, aged receivables and receivables where write-off is imminent. In certain circumstances, T-Mobile is required to deposit cash or replacement receivables for contracts terminated by customers under the Company’s JUMP! Program. T-Mobile will continue to service the customers and their related receivables, including facilitating customer payment collection, in exchange for a monthly servicing fee. As the receivables are sold on a revolving basis, the customer payment collections on sold receivables may be reinvested in new receivable sales. While servicing the receivables the same policies and procedures are applied to the sold receivables that apply to owned receivables, and T-Mobile continues to maintain normal relationships with its customers.

In addition, T-Mobile has continuing involvement with the sold receivables as it may be responsible for absorbing additional credit losses pursuant to the agreement. The Company’s maximum exposure to loss related to the involvement with the arrangements to sell service receivables and EIP receivables was $767 million as of December 31, 2015. The maximum exposure to loss, which is a required disclosure under GAAP, represents an estimated loss that would be incurred under severe, hypothetical circumstances whereby the Company would not receive the deferred purchase price portion of the contractual proceeds withheld by the purchasers and would also be required to repurchase the maximum amount of receivables pursuant to the agreement without consideration for any recovery.  As T-Mobile believes the probability of these circumstances occurring is remote, the maximum exposure to loss is not an indication of the Company’s expected loss.

v3.3.1.900
Equipment Installment Plan Receivables
12 Months Ended
Dec. 31, 2015
Receivables [Abstract]  
Equipment Installment Plan Receivables
Note 4 – Equipment Installment Plan Receivables

T-Mobile offers certain retail customers the option to pay for their devices and other purchases in installments over a period of up to 24 months using an EIP.

The following table summarizes the EIP receivables:
(in millions)
December 31,
2015
 
December 31,
2014
EIP receivables, gross
$
3,558

 
$
5,138

Unamortized imputed discount
(185
)
 
(332
)
EIP receivables, net of unamortized imputed discount
3,373

 
4,806

Allowance for credit losses
(148
)
 
(116
)
EIP receivables, net
$
3,225

 
$
4,690


Classified on the balance sheet as:


Equipment installment plan receivables, net
$
2,378

 
$
3,062

Equipment installment plan receivables due after one year, net
847

 
1,628

EIP receivables, net
$
3,225

 
$
4,690


As of December 31, 2015, EIP receivables decreased compared to 2014 primarily due to the sale of certain EIP receivables. See Note 3 – Sales of Certain Receivables for further information. Additionally, the introduction of T-Mobile’s JUMP! On Demand device leasing program in 2015 impacted the rate of customers financing device purchases through installment plans.
 
T-Mobile uses a proprietary credit scoring model that measures the credit quality of a customer at the time of application for mobile communications service using several factors, such as credit bureau information, consumer credit risk scores and service plan characteristics. Based upon customer credit profiles, T-Mobile classifies EIP receivables into the credit categories of “Prime” and “Subprime”. Prime customer receivables are those with lower delinquency risk and Subprime customer receivables are those with higher delinquency risk. Subprime customers are generally required to make a down payment on their equipment purchases. In addition, certain customers within the Subprime category are required to pay an advance deposit.

EIP receivables for which invoices have not yet been generated for the customer are classified as Unbilled. EIP receivables for which invoices have been generated but which are not past the contractual due date are classified as Billed – Current. EIP receivables for which invoices have been generated and the payment is past the contractual due date are classified as Billed – Past Due.

The balance and aging of the EIP receivables on a gross basis by credit category were as follows:
 
December 31, 2015
 
December 31, 2014
(in millions)
Prime
 
Subprime
 
Total
 
Prime
 
Subprime
 
Total
Unbilled
$
1,593

 
$
1,698

 
$
3,291

 
$
2,639

 
$
2,213

 
$
4,852

Billed – Current
77

 
91

 
168

 
104

 
95

 
199

Billed – Past Due
37

 
62

 
99

 
35

 
52

 
87

EIP receivables, gross
$
1,707

 
$
1,851

 
$
3,558

 
$
2,778

 
$
2,360

 
$
5,138


Activity in the unamortized imputed discount and allowance for credit losses balances for the EIP receivables was as follows:
(in millions)
2015
 
2014
Imputed discount and allowance for credit losses, beginning of year
$
448

 
$
336

Bad debt expense
365

 
285

Write-offs, net of recoveries
(333
)
 
(229
)
Change in imputed discount on short-term and long-term EIP receivables
(84
)
 
56

Impacts from sales of EIP receivables
(63
)
 
—

Imputed discount and allowance for credit losses, end of year
$
333

 
$
448


The EIP receivables had weighted average effective imputed interest rates of 8.8% and 9.7% as of December 31, 2015 and 2014, respectively.

v3.3.1.900
Property and Equipment
12 Months Ended
Dec. 31, 2015
Property, Plant and Equipment [Abstract]  
Property and Equipment
Note 5 – Property and Equipment

The components of property and equipment were as follows:
(in millions)
Useful Lives
 
December 31,
2015
 
December 31,
2014
Buildings and equipment
Up to 40 years
 
$
1,900

 
$
1,948

Wireless communications systems
Up to 20 years
 
27,063

 
25,633

Leasehold improvements
Up to 12 years
 
1,003

 
988

Capitalized software
Up to 7 years
 
8,524

 
7,593

Leased wireless devices
Up to 18 months
 
2,236

 
—

Construction in progress
 
 
2,466

 
1,874

Accumulated depreciation and amortization
 
 
(23,192
)
 
(21,791
)
Property and equipment, net
 
 
$
20,000

 
$
16,245


Wireless communication systems include capital lease agreements for network equipment with varying expiration terms through 2030. As of December 31, 2015, capital lease assets and accumulated amortization were $839 million and $117 million, respectively. As of December 31, 2014, capital lease assets and accumulated amortization were $364 million and $53 million, respectively.

T-Mobile capitalizes interest associated with the acquisition or construction of certain property and equipment. The Company recognized capitalized interest of $230 million, $81 million and $5 million for the years ended December 31, 2015, 2014 and 2013, respectively. For the year ended December 31, 2015, the Company recorded increased capitalized interest in connection with T-Mobile's network modernization, including the build out of the network to utilize the recently acquired 700 MHz A-Block spectrum licenses.

In 2015, T-Mobile began offering eligible customers the option to lease their devices over a period of up to 18 months through JUMP! On Demand. At lease inception, leased wireless devices are transferred from inventory to property and equipment. Upon customer exercise of JUMP! On Demand, returned devices are valued at the lower of cost or market with any write down to market recognized as cost of equipment sales and transferred to inventory.

The components of leased wireless devices were as follows:
(in millions)
December 31,
2015
 
December 31,
2014
Leased wireless devices, gross
$
2,236

 
$
—

Accumulated depreciation
(263
)
 
—

Leased wireless devices, net
$
1,973

 
$
—


Future minimum payments expected to be received over the lease term related to the leased wireless devices, which exclude optional residual buy-out amounts at the end of the lease term, are summarized below:
(in millions)
Total
Year Ending December 31,
 
2016
$
913

2017
347

Total
$
1,260


Depreciation expense relating to property and equipment was $4.4 billion, $4.1 billion and $3.4 billion for the years ended December 31, 2015, 2014 and 2013, respectively. For the years ended December 31, 2015 and 2014, the Company recorded additional depreciation expense of $85 million and $242 million, respectively, as a result of adjustments to useful lives of network equipment expected to be replaced in connection with T-Mobile's network modernization and decommissioning the MetroPCS CDMA network and redundant network cell sites. Additional depreciation expense was not significant for the year ended December 31, 2013. Depreciation expense included $312 million related to leased wireless devices for the year ended December 31, 2015.

Asset retirement obligations are primarily for certain legal obligations to remediate leased property on which the Company’s network infrastructure and administrative assets are located.
 
Activity in the asset retirement obligations was as follows:
(in millions)
December 31,
2015
 
December 31,
2014
Asset retirement obligations, beginning of year
$
390

 
$
388

Liabilities incurred
19

 
3

Liabilities settled
(130
)
 
(21
)
Accretion expense
17

 
20

Changes in estimated cash flows
187

 
—

Asset retirement obligations, end of year
$
483

 
$
390


Classified on the balance sheet as:


Other current liabilities
$
41

 
$
179

Other long-term liabilities
442

 
211

Asset retirement obligations
$
483

 
$
390


For the year ended December 31, 2015, T-Mobile settled asset retirement obligations in connection with the decommissioning of certain cell sites. Due to new information gained throughout 2015, primarily from decommissioning the Company’s MetroPCS CDMA network cell sites, T-Mobile reassessed the expected cash flows related to its asset retirement obligations for all remaining T-Mobile network cell sites.  As a result, T-Mobile recorded asset retirement obligations and corresponding assets in the fourth quarter of 2015 to reflect the change in estimated cash flows.  The corresponding assets, net of accumulated depreciation, related to asset retirement obligations were $241 million and $95 million as of December 31, 2015 and 2014, respectively.

v3.3.1.900
Goodwill, Spectrum Licenses and Intangible Assets
12 Months Ended
Dec. 31, 2015
Goodwill and Intangible Assets Disclosure [Abstract]  
Goodwill, Spectrum Licenses, and Intangible Assets
Note 6 – Goodwill, Spectrum Licenses and Other Intangible Assets

Goodwill

There were no changes in carrying values of goodwill for the years ended December 31, 2015 and 2014.

Spectrum Licenses

Changes in carrying values of spectrum licenses were as follows:
(in millions)
December 31,
2013
 
Net Changes
 
December 31,
2014
 
Net Changes
 
December 31,
2015
Spectrum licenses
$
18,122

 
$
3,833

 
$
21,955

 
$
2,000

 
$
23,955


During the year ended December 31, 2015 and 2014, the carrying value increased primarily as a result of acquisition activities of 700 MHz A-Block, Advanced Wireless Service (“AWS”) and Personal Communications Service (“PCS”) spectrum licenses.

In 2014, T-Mobile completed transactions for the acquisition of 700 MHz A-Block, AWS and PCS spectrum licenses, primarily with Verizon, for cash and the exchange of certain AWS and PCS spectrum licenses.  Upon closing of the transactions, T-Mobile received 700 MHz A-Block, AWS and PCS spectrum licenses, paid $2.5 billion in cash and transferred certain AWS and PCS spectrum licenses. T-Mobile recorded the spectrum licenses received at their fair value of $4.8 billion. In addition, T-Mobile recognized a non-cash gain of $0.8 billion included in Gains on disposal of spectrum licenses for the year ended December 31, 2014.

In connection with the AWS-3 spectrum auction, T-Mobile provided the FCC with a deposit of $0.4 billion, which was included in Other current assets as of December 31, 2014. Upon conclusion of the AWS-3 auction, T-Mobile was awarded AWS spectrum licenses covering approximately 97 million people for an aggregate bid price of $1.8 billion. In 2015, T-Mobile paid the FCC the remaining $1.4 billion for the AWS spectrum licenses.

In 2015, T-Mobile entered into an agreement with Verizon Communications Inc. (“Verizon”) for the exchange of AWS and PCS spectrum licenses. Upon closing of the transaction, T-Mobile recorded the spectrum licenses received at their fair value of $0.3 billion. In addition, T-Mobile recognized a non-cash gain of $0.1 billion included in Gains on disposal of spectrum licenses for the year ended December 31, 2015. Also in 2015, T-Mobile entered into an agreement with AT&T Inc. (“AT&T”) for the exchange of AWS and PCS spectrum licenses. Spectrum licenses to be transferred are classified as assets held for sale and included in Other current assets at their carrying value of $0.5 billion as of December 31, 2015. A non-cash gain is expected to be recognized upon closing of the transaction, which is expected to close in the first quarter of 2016, subject to regulatory approval and other customary closing conditions.

Goodwill and Other Intangible Assets Impairment Assessments

The Company's impairment assessment of goodwill resulted in no impairment as of December 31, 2015 and 2014, respectively. The Company's impairment assessment of indefinite-lived intangible assets (spectrum licenses) resulted in no impairment as of December 31, 2015 and 2014, respectively.

Other Intangible Assets

The components of intangible assets were as follows:
 
Useful Lives
 
December 31, 2015
 
December 31, 2014
(in millions)
 
Gross
Amount
 
Accumulated Amortization
 
Net
Amount
 
Gross
Amount
 
Accumulated Amortization
 
Net
Amount
Customer lists
Up to 6 years
 
$
1,104

 
$
(719
)
 
$
385

 
$
1,313

 
$
(700
)
 
$
613

Trademarks and patents
Up to 12 years
 
300

 
(115
)
 
185

 
295

 
(78
)
 
217

Other
Up to 28 years
 
51

 
(27
)
 
24

 
71

 
(31
)
 
40

Other intangible assets
 
 
$
1,455

 
$
(861
)
 
$
594

 
$
1,679

 
$
(809
)
 
$
870


Amortization expense for intangible assets subject to amortization was $276 million, $333 million and $255 million for the years ended December 31, 2015, 2014 and 2013, respectively. The estimated aggregate future amortization expense for intangible assets subject to amortization as of December 31, 2015 was $221 million for the year ending 2016, $163 million in 2017, $104 million in 2018, $51 million in 2019, $34 million in 2020 and $21 million thereafter.

v3.3.1.900
Fair Value Measurements and Derivative Instruments
12 Months Ended
Dec. 31, 2015
Fair Value Disclosures [Abstract]  
Fair Value Measurements and Derivative Instruments
Note 7 – Fair Value Measurements and Derivative Instruments

Embedded Derivative Instruments

In connection with the business combination with MetroPCS, T-Mobile issued senior reset notes to Deutsche Telekom. The interest rates are adjusted at the reset dates to rates defined in the applicable supplemental indentures to manage interest rate risk related to the senior reset notes. The Company determined certain components of the reset feature are required to be bifurcated from the senior reset notes and separately accounted for as embedded derivative instruments. T-Mobile held five embedded derivatives as of December 31, 2014. As of December 31, 2015, one embedded derivative related to the 5.950% Senior Reset Notes to affiliates due 2023 is subject to interest rate volatility.

The fair value of the embedded derivatives was determined using a lattice-based valuation model by determining the fair value of the senior reset notes with and without the embedded derivatives included. The fair value of the senior reset notes with the embedded derivatives utilizes the contractual term of each senior reset note, reset rates calculated based on the spread between specified yield curves and the yield curve on certain T-Mobile long-term debt adjusted pursuant to the applicable supplemental indentures and interest rate volatility. Interest rate volatility is a significant unobservable input (Level 3) as it is derived based on weighted risk-free rate volatility and credit spread volatility. Significant increases or decreases in the weighting of risk-free volatility and credit spread volatility, in isolation, would result in a higher or lower fair value of the embedded derivatives. The embedded derivatives were classified as Level 3 in the fair value hierarchy.

The fair value of embedded derivative instruments measured on a recurring basis by balance sheet location and level were as follows:
 
December 31, 2015
(in millions)
Level 1
 
Level 2
 
Level 3
 
Total
Other long-term liabilities
$
—

 
$
—

 
$
143

 
$
143


December 31, 2014
(in millions)
Level 1
 
Level 2
 
Level 3
 
Total
Other current assets
$
—

 
$
—

 
$
3

 
$
3

Other assets
—

 
—

 
2

 
2


The following table summarizes the gain (loss) activity related to embedded derivatives instruments recognized in Interest expense to affiliates:
 
Year Ended December 31,
(in millions)
2015
 
2014
 
2013
Embedded derivatives
$
(148
)
 
$
18

 
$
(13
)


Deferred Purchase Price Assets

In connection with the sales of certain receivables, T-Mobile has deferred purchase price assets measured at fair value that are based on a discounted cash flow model using unobservable Level 3 inputs, including customer default rates. There were no significant changes in fair value for the year ended December 31, 2015 and 2014. See Note 3 – Sales of Certain Receivables for further information.

Assets and Liabilities Measured at Fair Value on a Recurring Basis

The carrying amounts and fair values of the Company’s short-term investments and long-term debt were as follows:
 
December 31, 2015
 
December 31, 2014
(in millions)
Carrying Amount
 
Fair Value
 
Carrying Amount
 
Fair Value
Assets:


Short-term investments
$
2,998

 
$
2,998

 
$
—

 
$
—

Liabilities:


Senior Notes to third parties
$
17,600

 
$
18,098

 
$
15,600

 
$
16,034

Senior Reset Notes to affiliates
5,600

 
6,072

 
5,600

 
5,780

Senior Secured Term Loans
2,000

 
1,990

 
—

 
—


Short-term Investments

The fair value of the Company’s short-term investments, which consist of U.S. Treasury securities, was determined based on quoted market prices in active markets, and therefore was classified as Level 1 in the fair value hierarchy. Additionally, the Company’s cash equivalents included U.S. Treasury securities with remaining maturities of three months or less at the date of purchase that are classified as Level 1 in the fair value hierarchy. Gross unrealized gains and losses on available-for-sale securities were not significant as of December 31, 2015. Available-for-sale securities held by the Company were not significant as of December 31, 2014.

Long-term Debt

The fair value of the Company’s Senior Notes to third parties was determined based on quoted market prices in active markets, and therefore was classified as Level 1 in the fair value hierarchy. The fair value of the Company’s Senior Secured Term Loans and Senior Reset Notes to affiliates were determined based on a discounted cash flow approach using quoted prices of instruments with similar terms and maturities and an estimate for the stand-alone credit risk of T-Mobile. Accordingly, the Company’s Senior Secured Term Loans and Senior Reset Notes to affiliates were classified as Level 2 in the fair value hierarchy.

Although the Company has determined the estimated fair values using available market information and commonly accepted valuation methodologies, considerable judgment was required in interpreting market data to develop fair value estimates for the Senior Secured Term Loans and Senior Reset Notes to affiliates. The fair value estimates were based on information available as of December 31, 2015 and 2014. As such, the Company’s estimates are not necessarily indicative of the amount the Company could realize in a current market exchange.

v3.3.1.900
Debt
12 Months Ended
Dec. 31, 2015
Debt Disclosure [Abstract]  
Debt
Note 8 – Debt

Debt was as follows:
(in millions)
December 31,
2015
 
December 31,
2014
5.250% Senior Notes due 2018
$
500

 
$
500

6.288% Senior Reset Notes to affiliates due 2019
1,250

 
1,250

6.464% Senior Notes due 2019
1,250

 
1,250

6.366% Senior Reset Notes to affiliates due 2020
1,250

 
1,250

6.542% Senior Notes due 2020
1,250

 
1,250

6.625% Senior Notes due 2020
1,000

 
1,000

6.250% Senior Notes due 2021
1,750

 
1,750

6.633% Senior Notes due 2021
1,250

 
1,250

8.097% Senior Reset Notes to affiliates due 2021
1,250

 
1,250

6.125% Senior Notes due 2022
1,000

 
1,000

6.731% Senior Notes due 2022
1,250

 
1,250

8.195% Senior Reset Notes to affiliates due 2022
1,250

 
1,250

5.950% Senior Reset Notes to affiliates due 2023 (reset date in April 2016)
600

 
600

6.000% Senior Notes due 2023
1,300

 
1,300

6.625% Senior Notes due 2023
1,750

 
1,750

6.836% Senior Notes due 2023
600

 
600

6.500% Senior Notes due 2024
1,000

 
1,000

6.375% Senior Notes due 2025
1,700

 
1,700

6.500% Senior Notes due 2026
2,000

 
—

Senior Secured Term Loans
2,000

 
—

Unamortized premium from purchase price allocation fair value adjustment
250

 
286

Unamortized discount on Senior Secured Term Loans
(10
)
 
—

Capital leases
826

 
410

Financing arrangements
—

 
64

Total debt
26,266

 
21,960

Less: Current portion of Senior Secured Term Loans
20

 
—

Less: Current portion of capital leases
162

 
23

Less: Financing arrangements
—

 
64

Total long-term debt
$
26,084

 
$
21,873


Classified on the balance sheet as:


Long-term debt
$
20,484

 
$
16,273

Long-term debt to affiliates
5,600

 
5,600

Total long-term debt
$
26,084

 
$
21,873


Long-term Debt

In 2015, T-Mobile USA issued $2.0 billion of 6.500% Senior Notes due 2026, for which T-Mobile and certain subsidiaries are guarantors. In 2015, T-Mobile USA entered into a Term Loan Credit Agreement, which provides for a seven-year senior secured term loan facility with the right to request incremental term loans, subject to the conditions set forth in the agreement. In connection with this agreement, T-Mobile incurred $2.0 billion of Senior Secured Term Loans pursuant to the Term Loan Credit Agreement, for which certain subsidiaries are guarantors. T-Mobile USA’s obligations under the agreement are secured by a first priority lien on substantially all of T-Mobile USA’s assets and the assets of T-Mobile USA’s subsidiaries that are guarantors, subject to certain exceptions. In addition, the Senior Secured Term Loans are subject to a first priority pledge of the equity interests held by T-Mobile USA and substantially all of its direct and indirect subsidiaries. See Note 15 – Guarantor Financial Information for further information regarding the condensed consolidating financial information of T-Mobile’s guarantor subsidiaries.

Interest on the Senior Notes to third parties is accrued from the date of issuance at stated interest rates and paid semi-annually. Interest on the Senior Secured Term Loans is accrued from the date of issuance equal to London Interbank Offered Rate (“LIBOR”) plus a margin rate of 2.750% and is paid quarterly. The Senior Secured Term Loans had an effective interest rate of 3.500% as of December 31, 2015. Principal on the Senior Secured Term Loans is paid quarterly equal to 0.250% of the principal amount with the remaining balance of the principal due on the final maturity date in November 2022. The interest rate on the 5.950% Senior Reset Notes to affiliates due 2023 will adjust at the reset date to a rate defined in the applicable supplemental indenture. The long-term debt may be redeemed or prepaid, as applicable, in whole or from time to time in part, at specified redemption prices or prepayment premiums, as applicable.  The long-term debt may also be redeemed by the Company using make-whole call or breakage provisions or in part with equity proceeds.  All redemptions are subject to the conditions set forth in the applicable supplemental indenture or Term Loan Credit Agreement.

In 2015, the interest rate on certain Senior Reset Notes to affiliates were adjusted as follows:
 
December 31, 2015
 
Current Rate
 
Previous Rate
6.288% Senior Reset Notes to affiliates due 2019
6.288
%
 
5.578
%
6.366% Senior Reset Notes to affiliates due 2020
6.366
%
 
5.656
%
8.097% Senior Reset Notes to affiliates due 2021
8.097
%
 
5.747
%
8.195% Senior Reset Notes to affiliates due 2022
8.195
%
 
5.845
%


Capital Leases

Capital lease agreements relate to network equipment with varying expiration terms through 2030. Future minimum payments required under capital leases, including interest, over their remaining terms as of December 31, 2015 are expected to be $199 million for the year ending 2016, $189 million in 2017, $158 million in 2018, $128 million in 2019, $56 million in 2020, and $267 million thereafter, for a total of $997 million, including $171 million in interest.

Financing Arrangements

T-Mobile maintains a handset financing arrangement with Deutsche Bank AG (“Deutsche Bank”), which allows for up to $108 million in borrowings.  Under the handset financing arrangement, the Company can effectively extend payment terms for invoices payable to certain handset vendors.  The interest rate on the handset financing arrangement is determined based on LIBOR plus a specified margin per the arrangement.  Obligations under the handset financing arrangement are included in Short-term debt.  In 2015 and 2014, T-Mobile utilized and repaid $100 million under the financing arrangement. As of December 31, 2015 and 2014, there was no outstanding balance.

The Company maintains vendor financing arrangements with its primary network equipment suppliers. Under the respective agreements, the Company can obtain extended financing terms. The interest rate on the vendor financing arrangements is determined based on the difference between LIBOR and a specified margin per the agreements. Obligations under the vendor financing arrangements are included in Short-term debt. As of December 31, 2015 there was no outstanding balance. As of December 31, 2014 the outstanding balance was $64 million.

Lines and Standby Letters of Credit

T-Mobile has an unsecured revolving credit facility with Deutsche Telekom which allows for up to $500 million in borrowings. As of December 31, 2015 and 2014, T-Mobile had no borrowings outstanding under this facility.

For the purposes of securing T-Mobile’s obligations to provide handset insurance services, T-Mobile maintains an agreement for standby letters of credit with JP Morgan Chase Bank, N.A. (“JP Morgan Chase”). For purposes of securing T-Mobile’s general purpose obligations, T-Mobile maintains a letter of credit reimbursement agreement with Deutsche Bank.

The following table summarizes the outstanding standby letters of credit under each agreement:
(in millions)
December 31,
2015
 
December 31,
2014
JP Morgan Chase
$
36

 
$
36

Deutsche Bank
54

 
50

Total outstanding balance
$
90

 
$
86


v3.3.1.900
Tower Obligations
12 Months Ended
Dec. 31, 2015
Leases [Abstract]  
Tower Obligations
Note 9 – Tower Obligations

In 2012, T-Mobile conveyed to Crown Castle International Corp. (“CCI”) the exclusive right to manage and operate approximately 7,100 T-Mobile-owned wireless communication tower sites (“CCI Tower Sites”) in exchange for net proceeds of $2.5 billion (“2012 Tower Transaction”). Rights to approximately 6,200 of the tower sites were transferred to CCI via a Master Prepaid Lease with site lease terms ranging from 23 to 37 years (“CCI Lease Sites”), while the remaining tower sites were sold to CCI (“CCI Sales Sites”). T-Mobile leases back space at certain tower sites for an initial term of ten years, followed by optional renewals at customary terms.

In 2015, T-Mobile conveyed to Phoenix Tower International (“PTI”) the exclusive right to manage and operate approximately 600 T-Mobile-owned wireless communication tower sites (“PTI Tower Sites”) in exchange for net proceeds of approximately $140 million (“2015 Tower Transaction”). Rights to approximately 250 sites were transferred to PTI via a management agreement (“PTI Managed Sites”), while the remaining tower sites were sold to PTI (“PTI Sales Sites”). T-Mobile leases back space at certain tower sites for an initial term of ten years, followed by optional renewals at customary terms.

Assets and liabilities associated with the operation of certain of the tower sites were transferred to SPEs. Assets included ground lease agreements or deeds for the land on which the towers are situated, the towers themselves and existing subleasing agreements with other mobile network operator tenants, who lease space at the tower sites. Liabilities included the obligation to pay ground lease rentals, property taxes and other executory costs. Upon closing of the 2012 Tower Transaction, CCI acquired all of the equity interests in the SPEs containing CCI Sales Sites and an option to acquire the CCI Lease Sites at the end of their respective lease terms and entered into a master lease agreement under which T-Mobile agreed to lease back space at certain of the tower sites. Upon closing of the 2015 Tower Transaction, PTI acquired all of the equity interests in the SPEs containing PTI Sales Sites and entered into a master lease agreement under which T-Mobile agreed to lease back space at certain of the tower sites.

T-Mobile determined the SPEs containing the CCI Lease Sites (“Lease Site SPEs”) are VIEs as the Company's equity investment lacks the power to direct the activities that most significantly impact the economic performance of the VIEs. These activities include managing tenants and underlying ground leases, performing repair and maintenance on the towers, the obligation to absorb expected losses and the right to receive the expected future residual returns from the purchase option to acquire the CCI Lease Sites. As the Company determined it is not the primary beneficiary and does not have a controlling financial interest in the Lease Site SPEs, the results of the Lease Site SPEs are not consolidated into the Company’s consolidated financial statements.
  
Due to its continuing involvement with the tower sites, T-Mobile determined it was precluded from applying sale-leaseback accounting. T-Mobile recorded long-term financial obligations in the amount of the net proceeds received and recognizes interest on the tower obligations at a rate of approximately 8% for the 2012 Tower Transaction and 3% for the 2015 Tower Transaction using the effective interest method. The tower obligations are increased by interest expense and amortized through contractual leaseback payments made by T-Mobile to CCI or PTI and through estimated future net cash flows generated and retained by CCI or PTI from operation of the tower sites. T-Mobile’s historical tower site asset costs continue to be reported in Property and equipment, net and are depreciated.

The following table summarizes the impacts to the Consolidated Balance Sheets:
(in millions)
December 31,
2015
 
December 31,
2014
Property and equipment, net
$
601

 
$
604

Tower obligations
2,658

 
2,521


Future minimum payments related to the tower obligations are summarized below:
(in millions)
Total
Year Ending December 31,
 
2016
$
179

2017
180

2018
180

2019
180

2020
181

Thereafter
1,315

Total
$
2,215


T-Mobile is contingently liable for future ground lease payments through the remaining term of the CCI Lease Sites. These contingent obligations are not included in the above table as any amount due is contractually owed by CCI based on the subleasing arrangement. See Note 13 – Commitments and Contingencies for further information.

v3.3.1.900
Employee Compensation and Benefit Plans
12 Months Ended
Dec. 31, 2015
Disclosure of Compensation Related Costs, Share-based Payments [Abstract]  
Employee Compensation and Benefit Plans
Note 10 – Employee Compensation and Benefit Plans

T-Mobile maintains the 2013 Omnibus Incentive Plan, which authorized the issuance of up to 63 million shares of common stock. Under the incentive plan, the Company may grant stock options, stock appreciation rights, restricted stock, restricted stock units, and performance awards to employees, consultants, advisors and non-employee directors. As of December 31, 2015, there were 29 million shares of common stock available for future grants under the incentive plan.

T-Mobile grants restricted stock units (“RSU”) to eligible employees and certain non-employee directors and performance stock units (“PSU”) to eligible key executives of the Company. RSUs entitle the grantee to receive shares of T-Mobile common stock at the end of a vesting period of generally up to 3 years. PSUs entitle the holder to receive shares of T-Mobile common stock at the end of a vesting period of generally up to 3 years if the performance goal is achieved. The number of shares ultimately received is dependent on T-Mobile's business performance against the specified performance goal. The Company also maintains an employee stock purchase plan (“ESPP”).

Stock-based compensation expense and related income tax benefits were as follows:
(in millions)
December 31,
2015
 
December 31,
2014
 
December 31,
2013
Stock-based compensation expense
$
201

 
$
196

 
$
100

Income tax benefit related to stock-based compensation
71

 
73

 
38

Realized excess tax benefit
79

 
34

 
—


Stock Awards

The following activity occurred under the RSU and PSU awards:
(in millions, except shares, per share and contractual life amounts)
Number of Units
 
Weighted Average Grant Date Fair Value
 
Weighted Average Remaining Contractual Term (Years)
 
Aggregate Intrinsic Value
Nonvested, December 31, 2014
19,952,089

 
$
24.15

 
1.1
 
$
538

Granted
9,760,057

 
35.56


Vested
(11,956,345
)
 
25.28


Forfeited
(1,421,530
)
 
27.36


Nonvested, December 31, 2015
16,334,271

 
$
29.95

 
1.2
 
$
639


Vesting of the stock awards triggers a tax obligation for the employee, which is required to be remitted to the relevant tax authorities. The Company has agreed to withhold stock units from the employee to cover the tax obligation. The Company withheld 4,176,464 and 2,203,673 stock units to cover tax obligations associated with vesting of stock awards and remitted cash of $156 million and $73 million to the appropriate tax authorities for the years ended December 31, 2015 and 2014, respectively.  The net shares issued to the employee are accounted for as outstanding common stock.

For the years ended December 31, 2014 and 2013, the weighted average fair value per stock award granted was $28.52 and $22.07, respectively. As of December 31, 2015, total unrecognized stock-based compensation expense related to non-vested stock awards, net of estimated forfeitures, was $327 million, before income taxes, which is expected to be recognized over a weighted-average period of 2.0 years. The total fair value of stock awards vested was $445 million, $209 million and $2 million for the years ended December 31, 2015, 2014 and 2013, respectively.

Stock Options

Prior to the business combination, MetroPCS had established the MetroPCS Communications, Inc. 2010 Equity Incentive Compensation Plan, the Amended and Restated MetroPCS Communications, Inc. 2004 Equity Incentive Compensation Plan and the Second Amended and Restated 1995 Stock Option Plan (“Predecessor Plans”). Following stockholder approval of the Company’s 2013 Omnibus Incentive Plan, no new awards may be granted under the Predecessor Plans.

The following activity occurred under the Predecessor Plans:
 
Shares
 
Weighted Average Exercise Price
 
Weighted Average Remaining Contractual Term (Years)
Outstanding and Exercisable, December 31, 2014
4,348,912

 
$
24.96

 
3.7
Exercised
(2,381,650
)
 
19.91


Expired
(142,908
)
 
38.32


Outstanding and exercisable, December 31, 2015
1,824,354

 
$
30.50

 
2.7


Stock options exercised under the Predecessor Plans generated proceeds of approximately $47 million and $27 million for the years ended December 31, 2015 and 2014, respectively. 

Employee Retirement Savings Plan

The Company sponsors a retirement savings plan for the majority of its employees under section 401(k) of the Internal Revenue Code and similar plans. The plans allow employees to contribute a portion of their pretax income in accordance with specified guidelines. The plans match a percentage of employee contributions up to certain limits. Employer matching contributions were $73 million, $66 million and $58 million for the years ended December 31, 2015, 2014 and 2013, respectively.

Employee Stock Purchase Plan

The Company’s ESPP allows eligible employees to contribute up to 15% of their eligible earnings toward the semi-annual purchase of the Company’s common stock at a discounted price, subject to an annual maximum dollar amount. Employees can purchase stock at a 15% discount applied to the closing stock price on the first or last day of the six month offering period, whichever price is lower. The number of shares issued under the Company’s ESPP was 761,085 for the year ended December 31, 2015.

Legacy Long Term Incentive Plan

Prior to the business combination, the Company maintained a performance-based Long Term Incentive Plan (“LTIP”) which aligned to the Company's long-term business strategy. As of December 31, 2015, there were LTIP awards outstanding for the 2013 LTIP. No new awards are expected to be granted under the LTIP. Compensation expense reported within operating expenses related to the Company's LTIP was $27 million, $44 million and $63 million for the years ended December 31, 2015, 2014 and 2013, respectively. Payments of $57 million, $60 million and $61 million were made to participants related to T-Mobile’s LTIP during the years ended December 31, 2015, 2014 and 2013, respectively.

v3.3.1.900
Income Taxes
12 Months Ended
Dec. 31, 2015
Income Tax Disclosure [Abstract]  
Income Taxes
Note 11 – Income Taxes

The sources of Income before income taxes were as follows:
 
Year Ended December 31,
(in millions)
2015
 
2014
 
2013
U.S.
$
898

 
$
347

 
$
(5
)
Puerto Rico
80

 
66

 
56

Income before income taxes
$
978

 
$
413

 
$
51


Income tax expense is summarized as follows:
 
Year Ended December 31,
(in millions)
2015
 
2014
 
2013
Current tax expense (benefit)


Federal
$
(30
)
 
$
—

 
$
(10
)
State
2

 
6

 
6

Puerto Rico
17

 
38

 
10

Total current tax expense (benefit)
(11
)
 
44

 
6

Deferred tax expense (benefit)


Federal
281

 
79

 
24

State
(37
)
 
40

 
(22
)
Puerto Rico
12

 
3

 
8

Total deferred tax expense
256

 
122

 
10

Total income tax expense
$
245

 
$
166

 
$
16


The reconciliation between the U.S. federal statutory income tax rate and T-Mobile's effective income tax rate is as follows:
 
Year Ended December 31,
 
2015
 
2014
 
2013
Federal statutory income tax rate
35.0
 %
 
35.0
 %
 
35.0
 %
State taxes, net of federal benefit
(1.1
)
 
(8.8
)
 
(31.8
)
Puerto Rico taxes, net of federal benefit
3.3

 
5.0

 
28.2

Change in valuation allowance
(3.2
)
 
18.8

 
(6.1
)
Permanent differences
1.6

 
1.4

 
11.3

Federal tax credits, net of reserves
(9.5
)
 
(10.6
)
 
—

Other, net
(1.0
)
 
(0.6
)
 
(5.2
)
Effective income tax rate
25.1
 %
 
40.2
 %
 
31.4
 %


Significant components of deferred income tax assets and liabilities, tax effected, are as follows:
(in millions)
December 31,
2015
 
December 31,
2014
Deferred tax assets


Loss carryforwards
$
1,997

 
$
2,354

Deferred rents
1,136

 
1,034

Reserves and accruals
928

 
454

Federal and state tax credits
349

 
295

Debt fair market value adjustment
97

 
111

Other
317

 
295

Deferred tax assets, gross
4,824

 
4,543

Valuation allowance
(583
)
 
(614
)
Deferred tax assets, net
4,241

 
3,929

Deferred tax liabilities


Spectrum licenses
6,174

 
5,629

Property and equipment
1,950

 
1,877

Other intangible assets
178

 
297

Other
—

 
11

Total deferred tax liabilities
8,302

 
7,814

Net deferred tax liabilities
$
4,061

 
$
3,885


Classified on the balance sheet as:


Current deferred tax assets, net
$
—

 
$
988

Non-current deferred tax liabilities, net
4,061

 
4,873

Net deferred tax liabilities
$
4,061

 
$
3,885


As of December 31, 2015, Current deferred tax assets, net and Non-current deferred tax liabilities, net decreased compared to 2014 primarily due to the early adoption of ASU 2015-17. See Note 1 – Summary of Significant Accounting Policies - Income Taxes for further information.

As of December 31, 2015, the Company has net operating loss (“NOL”) carryforwards, tax effected, of $1.6 billion for federal income tax purposes and $700 million for state income tax purposes, expiring through 2035.  As of December 31, 2015, the Company’s NOL carryforwards for financial reporting purposes were approximately $383 million, tax effected, less than its NOL carryforwards for federal and state income tax purposes, due to unrecognized tax benefits of $378 million and the Company’s inability to realize excess tax benefits until such benefits reduce income taxes payable.

As of December 31, 2015, the Company has available Alternative Minimum Tax credit carryforwards of $142 million, which may be used to reduce regular federal income taxes and have no expiration. The Company also has research and development and foreign tax credit carryforwards of $186 million for federal income tax purposes, which begin to expire in 2018.

As of December 31, 2015 and 2014, the Company’s valuation allowance was $583 million and $614 million, respectively. The change in the valuation allowance of $31 million is primarily related to recent state tax law changes and to the release of the valuation allowance on state net operating losses that expired in 2015. Furthermore, as of December 31, 2015, a valuation allowance of $33 million relates to stock option deductions included in the NOL carryforwards, which will be reversed as an increase to equity when the related deferred tax assets are ultimately realized.

The Company files income tax returns in the U.S. federal jurisdiction, various state jurisdictions and in Puerto Rico.  The Company is currently under examination by various states.  Management does not believe the resolution of any of the audits will result in a material change to the Company’s financial condition, results of operations or cash flows.  During 2015, the IRS concluded its audit through the 2013 tax year with no significant change to the Company’s tax positions, however, the Company’s NOL carryforwards for periods back to 1998 remain open for examination. The Company is generally closed to U.S federal, state and Puerto Rico examination for years prior to 1998.


A reconciliation of the beginning and ending amount of unrecognized tax benefits were as follows:
 
Year Ended December 31,
(in millions)
2015
 
2014
 
2013
Unrecognized tax benefits, beginning of year
$
388

 
$
178

 
$
89

Gross decreases to tax positions in prior periods
(112
)
 
(52
)
 
(18
)
Gross increases to current period tax positions
135

 
262

 
24

Gross increase due to current year business combination
—

 
—

 
83

Unrecognized tax benefits, end of year
$
411

 
$
388

 
$
178


As of December 31, 2015, the Company had $163 million in unrecognized tax benefits that, if recognized, would affect the Company's annual effective tax rate. Included in the 2013 increase to unrecognized tax benefits is $83 million related to tax positions acquired through the business combination with MetroPCS. Penalties and interest are included in selling, general and administrative expenses and interest expense, respectively. The accrued interest and penalties associated with unrecognized tax benefits are insignificant.

v3.3.1.900
Earnings Per Share
12 Months Ended
Dec. 31, 2015
Earnings Per Share [Abstract]  
Earnings Per Share
Note 12 – Earnings Per Share

The computation of basic and diluted earnings per share was as follows:
 
Year Ended December 31,
(in millions, except shares and per share amounts)
2015
 
2014
 
2013
Net income
$
733

 
$
247

 
$
35

Dividends on preferred stock
(55
)
 
—

 
—

Net income attributable to common stockholders
$
678

 
$
247

 
$
35


Weighted average shares outstanding - basic
812,994,028

 
805,284,712

 
672,955,980

Dilutive effect of outstanding stock options and awards
9,623,910

 
8,893,887

 
3,929,235

Dilutive effect of preferred stock
—

 
1,743,659

 
—

Weighted average shares outstanding - diluted
822,617,938

 
815,922,258

 
676,885,215


Earnings per share - basic
$
0.83

 
$
0.31

 
$
0.05

Earnings per share - diluted
$
0.82

 
$
0.30

 
$
0.05


Potentially dilutive securities:


Outstanding stock options and unvested stock awards
4,842,370

 
1,426,331

 
4,909,741

Preferred stock common stock equivalents
32,237,266

 
—

 
—


Potentially dilutive securities were not included in the computation of diluted earnings per share for certain periods if to do so would have been antidilutive.  Unvested PSUs were based on the number of shares ultimately expected to vest based on T-Mobile’s business performance against the specified performance goal.

v3.3.1.900
Commitments and Contingencies
12 Months Ended
Dec. 31, 2015
Commitments and Contingencies Disclosure [Abstract]  
Commitments and Contingencies
Note 13 – Commitments and Contingencies

Commitments

Future minimum payments for non-cancelable operating leases and purchase commitments are summarized below:
(in millions)
Operating Leases
 
Purchase Commitments
Year Ending December 31,


2016
$
2,379

 
$
2,865

2017
2,235

 
3,150

2018
2,046

 
772

2019
1,900

 
714

2020
1,679

 
629

Thereafter
5,583

 
1,304

Total
$
15,822

 
$
9,434


Operating Leases

T-Mobile has operating leases for cell sites, switch sites, retail stores and office facilities with contractual terms expiring through 2030. The majority of cell site leases have an initial non-cancelable term of five years to ten years with several renewal options. The Company considers renewal options certain on leases as being reasonably assured of exercise, thus included in future minimum lease payments for a total term of approximately 15 years. In addition, T-Mobile has operating leases for dedicated transportation lines with varying expiration terms through 2025.

As of December 31, 2015, T-Mobile was contingently liable for future ground lease payments related to the tower obligations. These contingent obligations are not included in the above table as the amounts due are contractually owed by CCI based on the subleasing arrangement. See Note 9 – Tower Obligations for further information.

Total rent expense under operating leases, including dedicated transportation lines, was $2.8 billion, $3.0 billion and $2.8 billion for the years ended December 31, 2015, 2014 and 2013, respectively.

Purchase Commitments

T-Mobile has commitments for non-dedicated transportation lines with varying expiration terms through 2028. In addition, T-Mobile has commitments to purchase spectrum licenses, handsets, network services, equipment, software, marketing sponsorship agreements and other items in the ordinary course of business, with various terms through 2028. These amounts are not reflective of the Company’s entire anticipated purchases under the related agreements, but are determined based on the non-cancelable quantities or termination amounts to which the Company was contractually obligated.

Contingencies and Litigation

T-Mobile is involved in various lawsuits, claims, investigations and proceedings that arise in the ordinary course of business, which include numerous court actions alleging that T-Mobile is infringing various patents. Virtually all of the patent infringement cases are brought by non-practicing entities and effectively seek only monetary damages, although they occasionally seek injunctive relief as well. The matters described above have progressed to various stages and a small number may go to trial in the coming 12 months if they are not otherwise resolved. T-Mobile has established an accrual with respect to certain of these matters, where appropriate, which is reflected in the consolidated financial statements but that T-Mobile does not consider, individually or in the aggregate, material. An accrual is established when T-Mobile believes it is both probable that a loss has been incurred and an amount can be reasonably estimated. For other matters, where the Company has not determined that a loss is probable or because the amount of loss cannot be reasonably estimated, the Company has not recorded an accrual due to various factors typical in contested proceedings, including but not limited to: uncertainty concerning legal theories and their resolution by courts or regulators; uncertain damage theories and demands; and a less than fully developed factual record. While T-Mobile does not expect that the ultimate resolution of these proceedings, individually or in the aggregate will have a material adverse effect on the Company’s financial position, an unfavorable outcome of some or all of these proceedings could have a material adverse impact on results of operations or cash flows for a particular period. This assessment is based on T-Mobile’s current understanding of relevant facts and circumstances. As such, T-Mobile’s view of these matters is subject to inherent uncertainties and may change in the future.

On April 4, 2012, T-Mobile was sued in a patent infringement case by Prism Technologies LLC (“Prism”) in the U.S. District Court for the District of Nebraska, asserting claims relating to patents that Prism claims are related to authentication and use of the internet by T-Mobile’s network, and sought damages of up to $114.9 million.  On October 30, 2015, the jury reached a verdict in favor of T-Mobile, finding non-infringement on all patents; and judgment was entered for T-Mobile on November 20, 2015. Both Prism and T-Mobile have filed post-trial motions, which are pending.  The Company does not believe that a loss is probable or that the amount of a loss can be reasonably estimated at this time, and does not expect that the ultimate resolution of this case will have a material adverse effect on the Company’s financial position, results of operations or cash flows.

v3.3.1.900
Additional Financial Information
12 Months Ended
Dec. 31, 2015
Supplemental Financial Statement Elements [Abstract]  
Additional Financial Information
Note 14 – Additional Financial Information

Supplemental Consolidated Balance Sheets Information

Allowances and Imputed Discount

The following table summarizes the changes in allowances and unamortized imputed discount related to its current accounts receivables and EIP receivables:
(in millions)
2015
 
2014
 
2013
Allowances, beginning of year
$
199

 
$
169

 
$
197

Bad debt expense
547

 
444

 
463

Write-offs, net of recoveries
(482
)
 
(414
)
 
(491
)
Allowances, end of year
$
264

 
$
199

 
$
169


Imputed discount, beginning of year
$
271

 
$
212

 
$
92

Additions
310

 
380

 
283

Interest income
(414
)
 
(355
)
 
(185
)
Cancellations and other
(78
)
 
(92
)
 
(42
)
Impacts from sales of EIP receivables
(55
)
 
—

 
—

Transfer from long-term
125

 
126

 
64

Imputed discount, end of year
$
159

 
$
271

 
$
212


The following table summarizes the changes in unamortized imputed discount related to its long-term EIP receivables:
(in millions)
2015
 
2014
 
2013
Imputed discount, beginning of year
$
61

 
$
64

 
$
18

Additions
111

 
141

 
121

Cancellations and other
(13
)
 
(18
)
 
(11
)
Impacts from sales of EIP receivables
(8
)
 
—

 
—

Transfer to current
(125
)
 
(126
)
 
(64
)
Imputed discount, end of year
$
26

 
$
61

 
$
64


See Note 3 – Sales of Certain Receivables on sales of EIP receivables and Note 4 – Equipment Installment Plan Receivables on EIP receivables and related unamortized imputed discount and allowance for credit losses for further information.
Accounts Payable and Accrued Liabilities

Accounts payable and accrued liabilities are summarized as follows:
(in millions)
December 31,
2015
 
December 31,
2014
Accounts payable
$
6,137

 
$
5,322

Property and other taxes, including payroll
494

 
605

Payroll and related benefits
521

 
470

Interest
371

 
349

Commissions
190

 
179

Toll and interconnect
68

 
166

Network decommissioning
117

 
78

Advertising
77

 
53

Other
109

 
142

Accounts payable and accrued liabilities
$
8,084

 
$
7,364


Outstanding checks included in accounts payable and accrued liabilities were $501 million and $409 million as of December 31, 2015 and 2014, respectively.

Supplemental Consolidated Statements of Comprehensive Income (Loss) Information

Related Party Transactions

T-Mobile has related party transactions associated with Deutsche Telekom or its affiliates in the ordinary course of business, which are included in the consolidated financial statements.

The following table summarizes the impact of significant transactions with Deutsche Telekom or its affiliates included in operating expenses in the Consolidated Statements of Comprehensive Income (Loss):
 
Year Ended December 31,
(in millions)
2015
 
2014
 
2013
Discount related to roaming expenses
$
(21
)
 
$
(61
)
 
$
(16
)
Fees incurred for use of the T-Mobile brand
65

 
60

 
53

Expenses for telecommunications and IT services
23

 
24

 
102


Supplemental Consolidated Statements of Cash Flows Information

The following table summarizes T-Mobile’s supplemental cash flows information:
 
Year Ended December 31,
(in millions)
2015
 
2014
 
2013
Interest and income tax payments:


Interest payments, net of amounts capitalized
$
1,298

 
$
1,367

 
$
1,156

Income tax payments
54

 
36

 
20

Noncash investing and financing activities:


Increase in accounts payable for purchases of property and equipment
46

 
402

 
6

Leased wireless devices transferred from inventory to property and equipment, net of returns
2,285

 
—

 
—

Issuance of short-term debt for financing of property and equipment purchases
500

 
256

 
470

Assets acquired under capital lease obligations
470

 
77

 
3

Retirement of long-term debt to affiliates
—

 
—

 
14,450

Elimination of net unamortized discounts and premiums on long-term debt to affiliates
—

 
—

 
434

Issuance of new long-term debt to affiliates
—

 
—

 
11,200

Settlement of accounts receivable from affiliates and other outstanding balances
—

 
—

 
363

Income tax benefit from debt recapitalization
—

 
—

 
178

Net assets acquired in MetroPCS business combination, excluding cash acquired
—

 
—

 
827


Supplemental Consolidated Statement of Stockholders’ Equity Information

Preferred Stock

In 2014, T-Mobile completed a public offering of 20 million shares of mandatory convertible preferred stock for net proceeds of $982 million. Dividends on the preferred stock are payable on a cumulative basis when and if declared by the Company’s board of directors at an annual rate of 5.5%. The dividends may be paid in cash, shares of common stock, subject to certain limitations, or any combination of cash and shares of common stock.

Unless converted earlier, each share of preferred stock will convert automatically on December 15, 2017 into between 1.6119 and 1.9342 shares of common stock, subject to customary anti-dilution adjustments, depending on the applicable market value of the common stock. At any time, the preferred shares may be converted, in whole or in part, at the minimum conversion rate of 1.6119 shares of common stock, except during a fundamental change conversion period. In addition, holders may be entitled to shares based on the amount of accumulated and unpaid dividends. If certain fundamental changes involving the Company occur, the preferred stock may be converted into common shares at the applicable conversion rate, subject to certain anti-dilution adjustments, and holders will also be entitled to a make-whole amount. The preferred stock ranks senior with respect to liquidation preference and dividend rights to common stock. In the event of any voluntary or involuntary liquidation, winding-up or dissolution of the Company, each holder of preferred stock will be entitled to receive a liquidation preference in the amount of $50 per share, plus an amount equal to accumulated and unpaid dividends, after satisfaction of liabilities to the Company’s creditors and before any distribution or payment is made to any holders of common stock. The preferred stock is not redeemable.

Common Stock

In 2013, T-Mobile completed a public offering of 73 million shares of common stock at a price of $25 per share.

v3.3.1.900
Guarantor Financial Information
12 Months Ended
Dec. 31, 2015
Condensed Financial Information of Parent Company Only Disclosure [Abstract]  
Guarantor Financial Information
Note 15 – Guarantor Financial Information

Pursuant to the applicable indentures and supplemental indentures, the long-term debt to affiliates and third parties, excluding Senior Secured Term Loans and capital leases, issued by T-Mobile USA (“Issuer”) is fully and unconditionally guaranteed, jointly and severally, on a senior unsecured basis by T-Mobile (“Parent”) and certain of the Issuer’s 100% owned subsidiaries (“Guarantor Subsidiaries”).

In 2015, Issuer issued unsecured Senior Notes of $2.0 billion and incurred $2.0 billion of Senior Secured Term Loans, which are secured by a first priority lien on substantially all of T-Mobile USA’s assets and the assets of T-Mobile USA’s Guarantor Subsidiaries. In addition, the Senior Secured Term Loans are subject to a first priority pledge of the equity interests held by T-Mobile USA and substantially all of its direct and indirect subsidiaries. See Note 8 – Debt for further information.

In 2015, T-Mobile entered into an arrangement to sell certain EIP accounts receivable on a revolving basis. In connection with the sale arrangement, the Company formed EIP BRE, a wholly-owned subsidiary, which is included in the Non-Guarantor Subsidiaries condensed consolidating financial information. See Note 3 – Sales of Certain Receivables for further information.

The guarantees of the Guarantor Subsidiaries are subject to release in limited circumstances only upon the occurrence of certain customary conditions. The indentures governing the long-term debt contain covenants that, among other things, limit the ability of the Issuer and the Guarantor Subsidiaries to: incur more debt; pay dividends and make distributions; make certain investments; repurchase stock; create liens or other encumbrances; enter into transactions with affiliates; enter into transactions that restrict dividends or distributions from subsidiaries; and merge, consolidate, or sell, or otherwise dispose of, substantially all of their assets. Certain provisions of each of the indentures and the supplemental indentures relating to the long-term debt restrict the ability of the Issuer to loan funds or make payments to Parent. However, the Issuer and Guarantor Subsidiaries are allowed to make certain permitted payments to the Parent under the terms of the indentures and the supplemental indentures.

Presented below is the condensed consolidating financial information as of December 31, 2015 and 2014 and for the years ended December 31, 2015, 2014 and 2013, respectively. As the business combination was treated as a “reverse acquisition” and the Issuer was treated as the accounting acquirer, the Issuer’s historical financial statements are the historical financial statements of Parent for comparative purposes. As a result the Parent column only reflects activity in the condensed consolidating financial statements presented below for periods subsequent to the consummation of the business combination on April 30, 2013. The equity method of accounting is used to account for ownership interests in subsidiaries, where applicable.
Condensed Consolidating Balance Sheet Information
December 31, 2015
(in millions)
Parent
 
Issuer
 
Guarantor Subsidiaries
 
Non-Guarantor Subsidiaries
 
Consolidating and Eliminating Adjustments
 
Consolidated
Assets


Current assets


Cash and cash equivalents
$
378

 
$
1,767

 
$
2,364

 
$
73

 
$
—

 
$
4,582

Short-term investments
—

 
1,999

 
999

 
—

 
—

 
2,998

Accounts receivable, net
—

 
—

 
1,574

 
214

 
—

 
1,788

Equipment installment plan receivables, net
—

 
—

 
2,378

 
—

 
—

 
2,378

Accounts receivable from affiliates
—

 
—

 
36

 
—

 
—

 
36

Inventories
—

 
—

 
1,295

 
—

 
—

 
1,295

Other current assets
—

 
—

 
1,413

 
400

 
—

 
1,813

Total current assets
378

 
3,766

 
10,059

 
687

 
—

 
14,890

Property and equipment, net (1)
—

 
—

 
19,546

 
454

 
—

 
20,000

Goodwill
—

 
—

 
1,683

 
—

 
—

 
1,683

Spectrum licenses
—

 
—

 
23,955

 
—

 
—

 
23,955

Other intangible assets, net
—

 
—

 
594

 
—

 
—

 
594

Investments in subsidiaries, net
16,184

 
32,280

 
—

 
—

 
(48,464
)
 
—

Intercompany receivables
—

 
6,130

 
—

 
—

 
(6,130
)
 
—

Equipment installment plan receivables due after one year, net
—

 
—

 
847

 
—

 
—

 
847

Other assets
—

 
28

 
387

 
219

 
(167
)
 
467

Total assets
$
16,562

 
$
42,204

 
$
57,071

 
$
1,360

 
$
(54,761
)
 
$
62,436

Liabilities and Stockholders' Equity


Current liabilities


Accounts payable and accrued liabilities
$
—

 
$
368

 
$
7,496

 
$
220

 
$
—

 
$
8,084

Current payables to affiliates
—

 
70

 
65

 
—

 
—

 
135

Short-term debt
—

 
20

 
162

 
—

 
—

 
182

Deferred revenue
—

 
—

 
717

 
—

 
—

 
717

Other current liabilities
—

 
—

 
327

 
83

 
—

 
410

Total current liabilities
—

 
458

 
8,767

 
303

 
—

 
9,528

Long-term debt
—

 
19,820

 
664

 
—

 
—

 
20,484

Long-term debt to affiliates
—

 
5,600

 
—

 
—

 
—

 
5,600

Tower obligations (1)
—

 
—

 
411

 
2,247

 
—

 
2,658

Deferred tax liabilities
—

 
—

 
4,228

 
—

 
(167
)
 
4,061

Deferred rents
—

 
—

 
2,481

 
—

 
—

 
2,481

Negative carrying value of subsidiaries, net
—

 
—

 
628

 
—

 
(628
)
 
—

Intercompany payables
5

 
—

 
5,959

 
166

 
(6,130
)
 
—

Other long-term liabilities
—

 
142

 
922

 
3

 
—

 
1,067

 Total long-term liabilities
5

 
25,562

 
15,293

 
2,416

 
(6,925
)
 
36,351

Total stockholders' equity
16,557

 
16,184

 
33,011

 
(1,359
)
 
(47,836
)
 
16,557

Total liabilities and stockholders' equity
$
16,562

 
$
42,204

 
$
57,071

 
$
1,360

 
$
(54,761
)
 
$
62,436


(1)
Assets and liabilities for Non-Guarantor Subsidiaries are primarily included in VIEs related to the 2012 Tower Transaction. See Note 9 – Tower Obligations for further information.

Condensed Consolidating Balance Sheet Information
December 31, 2014
(in millions)
Parent
 
Issuer
 
Guarantor Subsidiaries
 
Non-Guarantor Subsidiaries
 
Consolidating and Eliminating Adjustments
 
Consolidated
Assets


Current assets


Cash and cash equivalents
$
2,278

 
$
2,246

 
$
697

 
$
94

 
$
—

 
$
5,315

Accounts receivable, net
—

 
—

 
1,817

 
48

 
—

 
1,865

Equipment installment plan receivables, net
—

 
—

 
3,062

 
—

 
—

 
3,062

Accounts receivable from affiliates
—

 
—

 
76

 
—

 
—

 
76

Inventories
—

 
—

 
1,085

 
—

 
—

 
1,085

Deferred tax assets, net
—

 
—

 
988

 
—

 
—

 
988

Other current assets
—

 
3

 
1,341

 
249

 
—

 
1,593

Total current assets
2,278

 
2,249

 
9,066

 
391

 
—

 
13,984

Property and equipment, net (1)
—

 
—

 
15,708

 
537

 
—

 
16,245

Goodwill
—

 
—

 
1,683

 
—

 
—

 
1,683

Spectrum licenses
—

 
—

 
21,955

 
—

 
—

 
21,955

Other intangible assets, net
—

 
—

 
870

 
—

 
—

 
870

Investments in subsidiaries, net
13,470

 
30,385

 
—

 
—

 
(43,855
)
 
—

Intercompany receivables
—

 
2,773

 
—

 
—

 
(2,773
)
 
—

Equipment installment plan receivables due after one year, net
—

 
—

 
1,628

 
—

 
—

 
1,628

Other assets
2

 
17

 
259

 
124

 
(114
)
 
288

Total assets
$
15,750

 
$
35,424

 
$
51,169

 
$
1,052

 
$
(46,742
)
 
$
56,653

Liabilities and Stockholders' Equity


Current liabilities


Accounts payable and accrued liabilities
$
—

 
$
349

 
$
6,914

 
$
101

 
$
—

 
$
7,364

Current payables to affiliates
—

 
56

 
175

 
—

 
—

 
231

Short-term debt
—

 
63

 
24

 
—

 
—

 
87

Deferred revenue
—

 
—

 
459

 
—

 
—

 
459

Other current liabilities
—

 
—

 
580

 
55

 
—

 
635

Total current liabilities
—

 
468

 
8,152

 
156

 
—

 
8,776

Long-term debt
—

 
15,886

 
387

 
—

 
—

 
16,273

Long-term debt to affiliates
—

 
5,600

 
—

 
—

 
—

 
5,600

Tower obligations (1)
—

 
—

 
271

 
2,250

 
—

 
2,521

Deferred tax liabilities
—

 
—

 
4,987

 
—

 
(114
)
 
4,873

Deferred rents
—

 
—

 
2,331

 
—

 
—

 
2,331

Negative carrying value of subsidiaries, net
—

 
—

 
780

 
—

 
(780
)
 
—

Intercompany payables
87

 
—

 
2,589

 
97

 
(2,773
)
 
—

Other long-term liabilities
—

 
—

 
616

 
—

 
—

 
616

 Total long-term liabilities
87

 
21,486

 
11,961

 
2,347

 
(3,667
)
 
32,214

Total stockholders' equity
15,663

 
13,470

 
31,056

 
(1,451
)
 
(43,075
)
 
15,663

Total liabilities and stockholders' equity
$
15,750

 
$
35,424

 
$
51,169

 
$
1,052

 
$
(46,742
)
 
$
56,653


(1)
Assets and liabilities for Non-Guarantor Subsidiaries are primarily included in VIEs related to the 2012 Tower Transaction. See Note 9 – Tower Obligations for further information.
Condensed Consolidating Statement of Comprehensive Income (Loss) Information
Year Ended December 31, 2015
(in millions)
Parent
 
Issuer
 
Guarantor Subsidiaries
 
Non-Guarantor Subsidiaries
 
Consolidating and Eliminating Adjustments
 
Consolidated
Revenues


Service revenues
$
—

 
$
—

 
$
23,748

 
$
1,669

 
$
(596
)
 
$
24,821

Equipment revenues
—

 
—

 
7,148

 
—

 
(430
)
 
6,718

Other revenues
—

 
1

 
356

 
171

 
(14
)
 
514

Total revenues
—

 
1

 
31,252

 
1,840

 
(1,040
)
 
32,053

Operating expenses


Cost of services, exclusive of depreciation and amortization shown separately below
—

 
—

 
5,530

 
24

 
—

 
5,554

Cost of equipment sales
—

 
—

 
9,055

 
720

 
(431
)
 
9,344

Selling, general and administrative
—

 
—

 
10,065

 
733

 
(609
)
 
10,189

Depreciation and amortization
—

 
—

 
4,605

 
83

 
—

 
4,688

Cost of MetroPCS business combination
—

 
—

 
376

 
—

 
—

 
376

Gain on disposal of spectrum licenses
—

 
—

 
(163
)
 
—

 
—

 
(163
)
Total operating expenses
—

 
—

 
29,468

 
1,560

 
(1,040
)
 
29,988

Operating income
—

 
1

 
1,784

 
280

 
—

 
2,065

Other income (expense)


Interest expense
—

 
(847
)
 
(50
)
 
(188
)
 
—

 
(1,085
)
Interest expense to affiliates
—

 
(411
)
 
—

 
—

 
—

 
(411
)
Interest income
—

 
2

 
418

 
—

 
—

 
420

Other income (expense), net
—

 
(10
)
 
—

 
(1
)
 
—

 
(11
)
Total other income (expense), net
—

 
(1,266
)
 
368

 
(189
)
 
—

 
(1,087
)
Income (loss) before income taxes
—

 
(1,265
)
 
2,152

 
91

 
—

 
978

Income tax expense
—

 
—

 
214

 
31

 
—

 
245

Earnings (loss) of subsidiaries
733

 
1,998

 
(48
)
 
—

 
(2,683
)
 
—

Net income
733

 
733

 
1,890

 
60

 
(2,683
)
 
733

Dividends on preferred stock
(55
)
 
—

 
—

 
—

 
—

 
(55
)
Net income attributable to common stockholders
$
678

 
$
733

 
$
1,890

 
$
60

 
$
(2,683
)
 
$
678

Other comprehensive loss, net of tax


Other comprehensive loss, net of tax
(2
)
 
(2
)
 
(2
)
 
—

 
4

 
(2
)
Total comprehensive income (loss)
$
731

 
$
731

 
$
1,888

 
$
60

 
$
(2,679
)
 
$
731

-

Condensed Consolidating Statement of Comprehensive Income (Loss) Information
Year Ended December 31, 2014
(in millions)
Parent
 
Issuer
 
Guarantor Subsidiaries
 
Non-Guarantor Subsidiaries
 
Consolidating and Eliminating Adjustments
 
Consolidated
Revenues


Service revenues
$
—

 
$
—

 
$
21,483

 
$
1,302

 
$
(410
)
 
$
22,375

Equipment revenues
—

 
—

 
7,319

 
—

 
(530
)
 
6,789

Other revenues
—

 
—

 
270

 
140

 
(10
)
 
400

Total revenues
—

 
—

 
29,072

 
1,442

 
(950
)
 
29,564

Operating expenses


Cost of services, exclusive of depreciation and amortization shown separately below
—

 
—

 
5,767

 
21

 
—

 
5,788

Cost of equipment sales
—

 
—

 
9,491

 
702

 
(572
)
 
9,621

Selling, general and administrative
—

 
—

 
8,723

 
518

 
(378
)
 
8,863

Depreciation and amortization
—

 
—

 
4,330

 
82

 
—

 
4,412

Cost of MetroPCS business combination
—

 
—

 
299

 
—

 
—

 
299

Gain on disposal of spectrum licenses
—

 
—

 
(840
)
 
—

 
—

 
(840
)
Other, net
—

 
—

 
5

 
—

 
—

 
5

Total operating expenses
—

 
—

 
27,775

 
1,323

 
(950
)
 
28,148

Operating income
—

 
—

 
1,297

 
119

 
—

 
1,416

Other income (expense)


Interest expense
—

 
(838
)
 
(55
)
 
(180
)
 
—

 
(1,073
)
Interest expense to affiliates
—

 
(278
)
 
—

 
—

 
—

 
(278
)
Interest income
—

 
—

 
359

 
—

 
—

 
359

Other income (expense), net
—

 
(15
)
 
4

 
—

 
—

 
(11
)
Total other income (expense), net
—

 
(1,131
)
 
308

 
(180
)
 
—

 
(1,003
)
Income (loss) before income taxes
—

 
(1,131
)
 
1,605

 
(61
)
 
—

 
413

Income tax expense (benefit)
—

 
—

 
189

 
(23
)
 
—

 
166

Earnings (loss) of subsidiaries
247

 
1,278

 
(54
)
 
—

 
(1,471
)
 
—

Net income (loss)
$
247

 
$
147

 
$
1,362

 
$
(38
)
 
$
(1,471
)
 
$
247

Other comprehensive loss, net of tax


Other comprehensive income (loss), net of tax
(2
)
 
(2
)
 
(2
)
 
—

 
4

 
(2
)
Total comprehensive income (loss)
$
245

 
$
145

 
$
1,360

 
$
(38
)
 
$
(1,467
)
 
$
245


Condensed Consolidating Statement of Comprehensive Income (Loss) Information
Year Ended December 31, 2013
(in millions)
Parent
 
Issuer
 
Guarantor Subsidiaries
 
Non-Guarantor Subsidiaries
 
Consolidating and Eliminating Adjustments
 
Consolidated
Revenues


Service revenues
$
—

 
$
—

 
$
18,396

 
$
823

 
$
(151
)
 
$
19,068

Equipment revenues
—

 
—

 
5,728

 
—

 
(695
)
 
5,033

Other revenues
—

 
—

 
251

 
142

 
(74
)
 
319

Total revenues
—

 
—

 
24,375

 
965

 
(920
)
 
24,420

Operating expenses


Cost of services, exclusive of depreciation and amortization shown separately below
—

 
—

 
5,302

 
50

 
(73
)
 
5,279

Cost of equipment sales
—

 
—

 
7,180

 
552

 
(756
)
 
6,976

Selling, general and administrative
—

 
—

 
7,283

 
190

 
(91
)
 
7,382

Depreciation and amortization
—

 
—

 
3,545

 
82

 
—

 
3,627

Cost of MetroPCS business combination
—

 
—

 
108

 
—

 
—

 
108

Gain on disposal of spectrum licenses
—

 
—

 
(2
)
 
—

 
—

 
(2
)
Other, net
—

 
—

 
54

 
—

 
—

 
54

Total operating expenses
—

 
—

 
23,470

 
874

 
(920
)
 
23,424

Operating income
—

 
—

 
905

 
91

 
—

 
996

Other income (expense)


Interest expense
—

 
(317
)
 
(55
)
 
(173
)
 
—

 
(545
)
Interest expense to affiliates
—

 
(678
)
 
—

 
—

 
—

 
(678
)
Interest income
—

 
—

 
189

 
—

 
—

 
189

Other income (expense), net
—

 
94

 
(6
)
 
1

 
—

 
89

Total other income (expense), net
—

 
(901
)
 
128

 
(172
)
 
—

 
(945
)
Income (loss) before income taxes
—

 
(901
)
 
1,033

 
(81
)
 
—

 
51

Income tax expense (benefit)
—

 
—

 
45

 
(29
)
 
—

 
16

Earnings (loss) of subsidiaries
(104
)
 
936

 
(54
)
 
—

 
(778
)
 
—

Net income (loss)
$
(104
)
 
$
35

 
$
934

 
$
(52
)
 
$
(778
)
 
$
35

Other comprehensive income (loss), net of tax


Other comprehensive income (loss), net of tax
—

 
(38
)
 
24

 
—

 
(24
)
 
(38
)
Total comprehensive income (loss)
$
(104
)
 
$
(3
)
 
$
958

 
$
(52
)
 
$
(802
)
 
$
(3
)


Condensed Consolidating Statement of Cash Flows Information
Year Ended December 31, 2015
(in millions)
Parent
 
Issuer
 
Guarantor Subsidiaries
 
Non-Guarantor Subsidiaries
 
Consolidating and Eliminating Adjustments
 
Consolidated
Operating activities


Net cash provided by (used in) operating activities
$
(1
)
 
$
(4,504
)
 
$
9,940

 
$
154

 
$
(175
)
 
$
5,414


Investing activities


Purchases of property and equipment
—

 
—

 
(4,724
)
 
—

 
—

 
(4,724
)
Purchases of spectrum licenses and other intangible assets, including deposits
—

 
—

 
(1,935
)
 
—

 
—

 
(1,935
)
Purchases of short-term investments
—

 
(1,999
)
 
(998
)
 
—

 
—

 
(2,997
)
Investment in subsidiaries
(1,905
)
 
—

 
—

 
—

 
1,905

 
—

Other, net
—

 
—

 
96

 
—

 
—

 
96

Net cash used in investing activities
(1,905
)
 
(1,999
)
 
(7,561
)
 
—

 
1,905

 
(9,560
)


Financing activities


Proceeds from capital contribution
—

 
1,905

 
—

 
—

 
(1,905
)
 
—

Proceeds from issuance of long-term debt
—

 
3,979

 
—

 
—

 
—

 
3,979

Repayments of long-term debt and capital lease obligations
—

 
—

 
(57
)
 
—

 
—

 
(57
)
Proceeds from tower obligations
—

 
140

 
—

 
—

 
—

 
140

Repayments of short-term debt for purchases of inventory, property and equipment, net
—

 
—

 
(564
)
 
—

 
—

 
(564
)
Intercompany dividend paid
—

 
—

 
—

 
(175
)
 
175

 
—

Dividends on preferred stock
(41
)
 
—

 
(14
)
 
—

 
—

 
(55
)
Proceeds from exercise of stock options
47

 
—

 
—

 
—

 
—

 
47

Taxes paid related to net share settlement of stock awards
—

 
—

 
(156
)
 
—

 
—

 
(156
)
Other, net
—

 
—

 
79

 
—

 
—

 
79

Net cash provided by (used in) financing activities
6

 
6,024

 
(712
)
 
(175
)
 
(1,730
)
 
3,413


Change in cash and cash equivalents
(1,900
)
 
(479
)
 
1,667

 
(21
)
 
—

 
(733
)
Cash and cash equivalents


Beginning of period
2,278

 
2,246

 
697

 
94

 
—

 
5,315

End of period
$
378

 
$
1,767

 
$
2,364

 
$
73

 
$
—

 
$
4,582


Condensed Consolidating Statement of Cash Flows Information
Year Ended December 31, 2014
(in millions)
Parent
 
Issuer
 
Guarantor Subsidiaries
 
Non-Guarantor Subsidiaries
 
Consolidating and Eliminating Adjustments
 
Consolidated
Operating activities


Net cash provided by (used in) operating activities
$
9

 
$
(5,145
)
 
$
9,364

 
$
18

 
$
(100
)
 
$
4,146


Investing activities


Purchases of property and equipment
—

 
—

 
(4,317
)
 
—

 
—

 
(4,317
)
Purchases of spectrum licenses and other intangible assets, including deposits
—

 
—

 
(2,900
)
 
—

 
—

 
(2,900
)
Investment in subsidiaries
(1,700
)
 
—

 
—

 
—

 
1,700

 
—

Other, net
—

 
—

 
(29
)
 
—

 
—

 
(29
)
Net cash used in investing activities
(1,700
)
 
—

 
(7,246
)
 
—

 
1,700

 
(7,246
)


Financing activities


Proceeds from capital contribution
—

 
1,700

 
—

 
—

 
(1,700
)
 
—

Proceeds from issuance of long-term debt
—

 
2,993

 
—

 
—

 
—

 
2,993

Repayments of long-term debt and capital lease obligations
—

 
—

 
(1,019
)
 
—

 
—

 
(1,019
)
Proceeds from issuance of preferred stock
982

 
—

 
—

 
—

 
—

 
982

Repayments of short-term debt for purchases of inventory, property and equipment, net
—

 
—

 
(418
)
 
—

 
—

 
(418
)
Intercompany dividend paid
—

 
—

 
—

 
(100
)
 
100

 
—

Proceeds from exercise of stock options
27

 
—

 
—

 
—

 
—

 
27

Taxes paid related to net share settlement of stock awards
—

 
—

 
(73
)
 
—

 
—

 
(73
)
Other, net
—

 
—

 
32

 
—

 
—

 
32

Net cash provided by (used in) financing activities
1,009

 
4,693

 
(1,478
)
 
(100
)
 
(1,600
)
 
2,524


Change in cash and cash equivalents
(682
)
 
(452
)
 
640

 
(82
)
 
—

 
(576
)
Cash and cash equivalents


Beginning of period
2,960

 
2,698

 
57

 
176

 
—

 
5,891

End of period
$
2,278

 
$
2,246

 
$
697

 
$
94

 
$
—

 
$
5,315


Condensed Consolidating Statement of Cash Flows Information
Year Ended December 31, 2013
(in millions)
Parent
 
Issuer
 
Guarantor Subsidiaries
 
Non-Guarantor Subsidiaries
 
Consolidating and Eliminating Adjustments
 
Consolidated
Operating activities


Net cash provided by (used in) operating activities
$
299

 
$
(1,203
)
 
$
4,380

 
$
69

 
$
—

 
$
3,545


Investing activities


Purchases of property and equipment
—

 
—

 
(4,025
)
 
—

 
—

 
(4,025
)
Purchases of spectrum licenses and other intangible assets
—

 
—

 
(381
)
 
—

 
—

 
(381
)
Short term affiliate loan receivable, net
—

 
—

 
300

 
—

 
—

 
300

Cash and cash equivalents acquired in MetroPCS business combination
737

 
1,407

 
—

 
—

 
—

 
2,144

Other, net
—

 
—

 
(130
)
 
—

 
—

 
(130
)
Net cash provided by (used in) investing activities
737

 
1,407

 
(4,236
)
 
—

 
—

 
(2,092
)


Financing activities


Proceeds from issuance of long-term debt
—

 
2,494

 
—

 
—

 
—

 
2,494

Repayment of capital lease obligations
—

 
—

 
(9
)
 
—

 
—

 
(9
)
Proceeds from issuance of common stock
1,787

 
—

 
—

 
—

 
—

 
1,787

Repayments of short-term debt for purchases of property and equipment
—

 
—

 
(244
)
 
—

 
—

 
(244
)
Proceeds from exercise of stock options
137

 
—

 
—

 
—

 
—

 
137

Other, net
—

 
—

 
(121
)
 
—

 
—

 
(121
)
Net cash provided by (used in) financing activities
1,924

 
2,494

 
(374
)
 
—

 
—

 
4,044


Change in cash and cash equivalents
2,960

 
2,698

 
(230
)
 
69

 
—

 
5,497

Cash and cash equivalents


Beginning of period
—

 
—

 
287

 
107

 
—

 
394

End of period
$
2,960

 
$
2,698

 
$
57

 
$
176

 
$
—

 
$
5,891


v3.3.1.900
Subsequent Events Subsequent Events
12 Months Ended
Dec. 31, 2015
Subsequent Events [Abstract]  
Subsequent Events
Note 16 – Subsequent Events

Spectrum License Transactions
 
In January 2016, T-Mobile acquired spectrum licenses covering nearly 20 million people in seven major metropolitan markets for approximately $0.6 billion in cash.

Additionally, in January and February 2016, T-Mobile entered into agreements with multiple third parties for the exchange of certain spectrum licenses and the acquisition of 700 MHz A-Block spectrum licenses covering approximately 48 million people, for approximately $0.7 billion in cash. In the first quarter of 2016, spectrum licenses to be exchanged of $0.2 billion will be transferred to held for sale and included in Other current assets.  Non-cash gains are expected to be recognized upon closing of the exchange transactions, which are expected to occur in mid-2016, subject to regulatory approval and other customary closing conditions.

v3.3.1.900
Quarterly Financial Information (Unaudited)
12 Months Ended
Dec. 31, 2015
Quarterly Financial Information (Unaudited) [Abstract]  
Quarterly Financial Information (Unaudited)

(in millions, except shares and per share amounts)
First Quarter
 
Second Quarter
 
Third Quarter
 
Fourth Quarter
 
Full Year
2015


Total revenues
$
7,778

 
$
8,179

 
$
7,849

 
$
8,247

 
$
32,053

Operating income
117

 
597

 
513

 
838

 
2,065

Net income (loss)
(63
)
 
361

 
138

 
297

 
733

Dividends on preferred stock
(14
)
 
(14
)
 
(13
)
 
(14
)
 
(55
)
Net income (loss) attributable to common stockholders
(77
)
 
347

 
125

 
283

 
678

Earnings (loss) per share


Basic
$
(0.09
)
 
$
0.43

 
$
0.15

 
$
0.35

 
$
0.83

Diluted
$
(0.09
)
 
$
0.42

 
$
0.15

 
$
0.34

 
$
0.82

Weighted average shares outstanding


Basic
808,605,526

 
811,605,031

 
815,069,272

 
816,585,782

 
812,994,028

Diluted
808,605,526

 
821,122,537

 
822,017,220

 
824,716,119

 
822,617,938

Net income (loss) includes:


Cost of MetroPCS business combination
$
128

 
$
34

 
$
193

 
$
21

 
$
376

Gains on disposal of spectrum licenses
—

 
(23
)
 
(1
)
 
(139
)
 
(163
)
2014


Total revenues
$
6,875

 
$
7,185

 
$
7,350

 
$
8,154

 
$
29,564

Operating income (loss)
(28
)
 
962

 
49

 
433

 
1,416

Net income (loss)
(151
)
 
391

 
(94
)
 
101

 
247

Earnings (loss) per share


Basic
$
(0.19
)
 
$
0.49

 
$
(0.12
)
 
$
0.13

 
$
0.31

Diluted
$
(0.19
)
 
$
0.48

 
$
(0.12
)
 
$
0.12

 
$
0.30

Weighted average shares outstanding


Basic
802,520,723

 
803,923,913

 
807,221,761

 
807,396,425

 
805,284,712

Diluted
802,520,723

 
813,556,137

 
807,221,761

 
821,707,289

 
815,922,258

Net income (loss) includes:


Cost of MetroPCS business combination
$
12

 
$
22

 
$
97

 
$
168

 
$
299

Gains on disposal of spectrum licenses
(10
)
 
(747
)
 
(13
)
 
(70
)
 
(840
)


Earnings (loss) per share is computed independently for each quarter and the sum of the quarters may not equal earnings (loss) per share for the full year.

v3.3.1.900
Summary of Significant Accounting Policies (Policies)
12 Months Ended
Dec. 31, 2015
Organization, Consolidation and Presentation of Financial Statements [Abstract]  
Description of Business
T-Mobile US, Inc. (“T-Mobile” or the “Company”), together with its consolidated subsidiaries, is a leading provider of mobile communications services, including voice, messaging and data, under its flagship brands, T-Mobile and MetroPCS, in the United States (“U.S.”), Puerto Rico and the U.S. Virgin Islands. T-Mobile provides mobile communications services primarily using 4G Long-Term Evolution (“LTE”) technology. T-Mobile also offers a wide selection of wireless devices, including handsets, tablets and other mobile communication devices, and accessories for sale, as well as financing through equipment installment plans (“EIP”) and leasing through JUMP On Demand™. Additionally, T-Mobile provides reinsurance for handset insurance policies and extended warranty contracts offered to T-Mobile’s mobile communications customers.

Basis of Presentation

The consolidated financial statements include the balances and results of operations of T-Mobile and its consolidated subsidiaries. T-Mobile operates as a single operating segment. T-Mobile consolidates majority-owned subsidiaries over which it exercises control, as well as variable interest entities (“VIEs”) where it is deemed to be the primary beneficiary and VIEs which cannot be deconsolidated. Intercompany transactions and balances have been eliminated in consolidation. Certain prior year amounts have been reclassified to conform to the current presentation.
Use of Estimates
The preparation of financial statements in conformity with U.S. generally accepted accounting principles (“GAAP”) requires management to make estimates and assumptions which affect the financial statements and accompanying notes. Examples include service revenues earned but not yet billed, service revenues billed but not yet earned, relative selling prices, allowances for uncollectible accounts and sales returns, discounts for imputed interest on EIP receivables, guarantee liabilities, losses incurred but not yet reported, tax liabilities, deferred income taxes including valuation allowances, useful lives of long-lived assets, cost estimates of asset retirement obligations, residual values on leased handsets, reasonably assured renewal terms for operating leases, stock-based compensation forfeiture rates, and fair value measurements related to goodwill, spectrum licenses, intangible assets, and derivative financial instruments. Estimates are based on historical experience, where applicable, and other assumptions which management believes are reasonable under the circumstances. These estimates are inherently subject to judgment and actual results could differ from those estimates.
Cash and Cash Equivalents

Cash equivalents consist of highly liquid money market funds and U.S. Treasury securities with remaining maturities of three months or less at the date of purchase.
Short-Term Investment
Short-Term Investments

The Company's short-term investments consist of U.S. Treasury securities classified as available for sale, which are stated at fair value and have remaining maturities of more than three months at the date of purchase. Unrealized gains and losses, net of related income taxes, for available for sale securities are reported as net increases and decreases to accumulated other comprehensive income (loss), a component of stockholders' equity, until realized. The estimated fair values of investments are based on quoted market prices as of the end of the reporting period. The U.S. Treasury securities reported as of December 31, 2015 have contractual maturities of less than one year.

Available-for-sale securities are reviewed for impairment on a quarterly basis or more often if a potential loss-triggering event occurs. If there has been a decline in the fair value below the amortized cost basis, the Company determines whether such impairment is other-than-temporary. Factors considered in the assessment include the reason for the decline in fair value, the Company’s intent to sell the security, whether it is more likely than not that the Company will be required to sell the security before recovery of its amortized cost basis and whether the Company does not expect to recover the entire amortized cost basis of the security. If an impairment is considered other-than-temporary, the Company records a charge to Other income (expense), net.
Accounts Receivable and Allowances

Accounts receivable consist primarily of amounts billed and currently due from customers, other carriers and third-party retail channels (“dealers”), as well as revenues earned but not yet billed at the end of each period. T-Mobile has an arrangement to sell certain service accounts receivable on a revolving basis, which are treated as sales of financial assets. T-Mobile maintains an allowance for estimated losses inherent in the accounts receivable portfolio based on a number of factors, including historical experience and current collection trends, aging of the receivable portfolio, credit quality of the customer base and other qualitative factors such as macro-economic conditions. The Company writes off account balances if collection efforts are unsuccessful and the receivable balance is deemed uncollectible, based on customer credit ratings and the length of time from the original billing date.
Equipment Installment Plan Receivables and Allowances
Equipment Installment Plan Receivables

The Company offers certain retail customers the option to pay for devices and other accessories in installments using an EIP. At the time of an installment sale, the Company imputes a discount for interest as there is no stated rate of interest on the EIP receivables and records the EIP receivables at their present value, which is determined by discounting future payments at the imputed interest rate. The difference between the present value of the EIP receivables and their face amount results in a discount which is recorded as a direct reduction to the carrying value with a corresponding reduction to equipment revenues. T-Mobile determines the imputed discount rate based primarily on current market interest rates and the amount of expected credit losses on the EIP receivables. As a result, T-Mobile does not recognize a separate valuation allowance at the time of issuance as the effects of uncertainty about future cash flows are included in the initial present value measurement of the receivable. The imputed discount on EIP receivables is amortized over the financed installment term using the effective interest method and recognized as interest income in Other income (expense), net.

Subsequent to the initial determination of the imputed discount, T-Mobile assesses the need for and, if necessary, recognizes an allowance for credit losses to the extent the amount of estimated probable losses on the gross EIP receivable balances exceed the remaining unamortized imputed discount balances.  The allowance is based on a number of factors, including collection experience, aging of the EIP receivable portfolio, credit quality of the customer base and other qualitative factors such as macro-economic conditions. T-Mobile writes off account balances if collection efforts are unsuccessful and receivable balance is deemed uncollectible, based on customer credit ratings and the length of time from the original billing date. Equipment sales not reasonably assured to be collectible are recorded on a cash basis as payments are received.

The current portion of the EIP receivables is included in Equipment installment plan receivables, net and the long-term portion of the EIP receivables is included in Equipment installment plan receivables due after one year, net. T-Mobile has an arrangement to sell certain EIP receivables on a revolving basis, which are treated as sales of financial assets.
Inventories
Inventories

Inventories consist primarily of wireless devices and accessories, which are valued at the lower of cost or market. Cost is determined using standard cost which approximates average cost. Shipping and handling costs paid to wireless device and accessories vendors, and costs to refurbish used devices recovered through the Company’s device trade-in and upgrade programs are included in the standard cost of inventory. T-Mobile records inventory write-downs to net realizable value for obsolete and slow-moving items based on inventory turnover trends and historical experience.
Long-Lived Assets
Long-Lived Assets

Long-lived assets include assets that do not have indefinite lives, such as property and equipment and other intangible assets. The Company assesses potential impairments to its long-lived assets when events or changes in circumstances indicate the carrying amount of the asset may not be recoverable. If any indicators are present, the Company tests recoverability. The carrying value of a long-lived asset or asset group is not recoverable if it exceeds the sum of the undiscounted cash flows expected to be generated from the use and eventual disposition of the asset or asset group. If the undiscounted cash flows do not exceed the asset or asset group’s carrying amount, then an impairment loss is recorded, measured as the amount by which the carrying amount of a long-lived asset or asset group exceeds its fair value.

Property and Equipment

Property and equipment consists of buildings and equipment, wireless communication systems, leasehold improvements, capitalized software, leased wireless devices and construction in progress. Buildings and equipment include certain network server equipment. Wireless communication systems include assets to operate the Company’s wireless network and IT data centers, including tower asset leaseholds, assets related to the liability for the retirement of long-lived assets and capital leases. Leasehold improvements include asset improvements other than those related to the wireless network.

Property and equipment are recorded at cost less accumulated depreciation and impairments, if any. T-Mobile generally depreciates property and equipment on a straight-line basis.

In 2015, T-Mobile introduced JUMP! On Demand which allows customers to lease a device and upgrade it for a new one up to three times in a 12 month period. To date, all of T-Mobile’s leased devices were classified as operating leases by considering critical elements of the lease arrangement such as the lease term and the economic life, fair value and residual value of the device. At operating lease inception, leased wireless devices are transferred from inventory to property and equipment. Leased wireless devices are depreciated to their estimated residual value over the period expected to provide utility to T-Mobile, which is generally the lease term.  Revenues associated with the leased wireless devices, net of incentives, are generally recognized over the lease term.  Upon device upgrade or at lease end, customers must return or purchase their device.  Returned devices are recorded as inventory and are valued at the lower of cost or market with any write down to market recognized as cost of equipment sales.

Costs of major replacements and improvements are capitalized. Repair and maintenance expenditures which do not enhance or extend the asset’s useful life are charged to operating expenses as incurred. Construction costs, labor and overhead incurred in the expansion or enhancement of T-Mobile’s wireless network are capitalized. Capitalization commences with pre-construction period administrative and technical activities, which includes obtaining leases, zoning approvals and building permits, and ceases at the point at which the asset is ready for its intended use.

The Company capitalizes interest associated with the acquisition or construction of certain property and equipment. Capitalized interest is reported as a reduction in interest expense and depreciated over the useful life of the related assets. Depreciable life studies are performed periodically to confirm the appropriateness of useful lives for certain categories of property and equipment. These studies take into account actual usage, physical wear and tear, replacement history and assumptions about technology evolution. When these factors indicate the useful life of an asset is different from the previous assessment, the remaining book value is depreciated prospectively over the adjusted remaining estimated useful life. Leasehold improvements are depreciated over the shorter of their estimated useful lives or the related lease term.

Future obligations related to capital leases are included in Short-term debt and Long-term debt. Depreciation of assets held under capital leases is included in Depreciation and amortization expense.

Asset Retirement Obligations
The Company records an asset retirement obligation for the fair value of legal obligations associated with the retirement of tangible long-lived assets and a corresponding increase in the carrying amount of the related asset in the period in which the obligation is incurred. In periods subsequent to initial measurement, the Company recognizes changes in the liability resulting from the passage of time and revisions to either the timing or the amount of the original estimate. Over time, the liability is accreted to its present value and the capitalized cost is depreciated over the estimated useful life of the asset. The Company’s obligations relate primarily to certain legal obligations to remediate leased property on which the Company’s network infrastructure and administrative assets are located.
Software Capitalization
The Company capitalizes certain costs incurred in connection with developing or acquiring internal use software. Capitalization of software costs commences once the final selection of the specific software solution has been made and management authorizes and commits to funding the software project. Capitalized software costs are included in Property and equipment, net and amortized on a straight-line basis over the estimated useful life of the asset. Costs incurred during the preliminary project stage, as well as maintenance and training costs are expensed as incurred.

Other Intangible Assets

Intangible assets that do not have indefinite useful lives are amortized over their estimated useful lives. Customer lists are amortized using the sum-of-the-years-digits method over the expected period in which the relationship is expected to contribute to future cash flows. The remaining finite-lived intangible assets are amortized using the straight-line method.
Goodwill
Goodwill

Goodwill consists of the excess of the purchase price over the fair value of identifiable net assets acquired in a business combination.

Spectrum Licenses
Spectrum Licenses

Spectrum licenses are carried at costs incurred to acquire the spectrum licenses and the costs to prepare the spectrum licenses for their intended use, such as costs to clear acquired spectrum licenses. The Federal Communications Commission (“FCC”) issues spectrum licenses which provide T-Mobile with the exclusive right to utilize designated radio frequency spectrum within specific geographic service areas to provide wireless communication services. While spectrum licenses are issued for a fixed period of time, typically for up to fifteen years, the FCC has granted license renewals routinely and at a nominal cost. The spectrum licenses held by the Company expire at various dates. The Company believes it will be able to meet all requirements necessary to secure renewal of its spectrum licenses at nominal costs. Moreover, the Company has determined there are currently no legal, regulatory, contractual, competitive, economic or other factors that limit the useful lives of its spectrum licenses. Therefore, the Company has determined the spectrum licenses should be treated as indefinite-lived intangible assets.

The Company at times enters into agreements to sell or exchange spectrum licenses.  Upon entering into the arrangement, if the transaction has been deemed to have commercial substance, spectrum licenses are reviewed for impairment and transferred at their carrying value, net of any impairment, to assets held for sale included in other current assets until approval and completion of the exchange or sale.  Upon closing of the transaction, spectrum licenses acquired as part of an exchange of nonmonetary assets are valued at fair value. The difference between the fair value of the spectrum licenses obtained, book value of the spectrum licenses transferred and cash paid, if any, is recognized as gains included in Gains on disposal of spectrum licenses. If the transaction lacks commercial substance or the fair value is not measurable, the acquired spectrum licenses are recorded at the book value of the assets tendered.
Impairment Tests of Goodwill and Indefinite-Lived Intangible Assets
Impairment

The Company assesses the carrying value of its goodwill and other indefinite-lived intangible assets (spectrum licenses) for potential impairment annually as of December 31 or more frequently if events or changes in circumstances indicate such assets might be impaired. 

The Company may elect to first perform a qualitative assessment to determine whether it is more likely than not the fair value of the single reporting unit is less than its carrying amount as a basis for determining whether it is necessary to perform the two-step goodwill impairment test. If the Company does not perform a qualitative assessment, or if the qualitative assessment indicates it is more likely than not the fair value of the single reporting unit is less than its carrying amount, goodwill is tested for impairment based on a two-step test. In the first step, the Company compares the fair value of the reporting unit to the carrying value. The fair value of the reporting unit is determined using a market approach, which is based on market capitalization. If the fair value is less than the carrying value, the second step is performed. In the second step, the Company determines the fair values of all of the assets and liabilities of the reporting unit, including those that may not be currently recorded. The excess of the fair value of the reporting unit over the sum of the fair value of all of those assets and liabilities represents the implied goodwill amount. If the implied fair value of goodwill is lower than its carrying amount, an impairment loss is recognized for the difference.  

The Company tests its spectrum licenses for impairment on an aggregate basis, consistent with the Company's management of the overall business at a national level.  The Company may elect to first perform a qualitative assessment to determine whether it is more likely than not that the fair value of an intangible asset group is less than its carrying value. If the Company does not perform the qualitative assessment, or if the qualitative assessment indicates it is more likely than not the fair value of the intangible asset group is less than its carrying amount, the Company calculates the estimated fair value of the intangible asset group. If the estimated fair value of the spectrum licenses is lower than their carrying amount, an impairment loss is recognized for the difference.  The Company estimates fair value using the Greenfield approach, which is an income approach, to estimate the price at which an orderly transaction to sell the asset would take place between market participants at the measurement date under current market conditions.
Guarantee Liabilities

The Company offers a device trade-in program, Just Upgrade My Phone (“JUMP!”), which provides eligible customers a specified-price trade-in right to upgrade their device.  Participating customers must purchase a device from T-Mobile, have a qualifying monthly wireless service plan with T-Mobile, and finance their device using an EIP, which is treated as a single multiple-element arrangement when entered into at or near the same time.  Upon qualifying JUMP! program upgrades, the customers’ remaining EIP balance is settled provided they trade in their eligible used device in good working condition and purchase a new device from T-Mobile on a new EIP.

For customers who enroll in the device trade-in program, the Company defers the portion of revenue which represents the estimated value of the specified-price trade-in right guarantee.  The guarantee liabilities are valued based on various economic and customer behavioral assumptions, including the customer's estimated remaining EIP balance at trade-in, the expected fair value of the used handset at trade-in, and probability and timing of trade-in.  T-Mobile assesses guarantee liabilities at each reporting date to determine if facts and circumstances would indicate the incurrence of incremental contingent liabilities is probable and if so, reasonably estimable. The recognition and subsequent adjustments of the contingent guarantee liability as a result of these assessments are recorded as adjustments to revenue. When customers upgrade their devices, the difference between the trade-in credit to the customer and the fair value of the returned devices is recorded against the guarantee liabilities.  Guarantee liabilities included in Other current liabilities were $163 million and $286 million as of December 31, 2015 and 2014, respectively.  The estimated EIP receivable balance if all enrolled handset upgrade program customers were to claim their benefit, not including any trade-in value of the required used handset, was $2.3 billion as of December 31, 2015. This is not an indication of the Company’s expected loss exposure as it does not consider the expected fair value of the used handset, which is required to be in good working condition at trade-in, nor does it consider the probability and timing of trade-in.
Fair Value Measurements

The Company carries certain assets and liabilities at fair value. Fair value is defined as an exit price, representing the amount that would be received to sell an asset or paid to transfer a liability in an orderly transaction between market participants at the measurement date. The three tier hierarchy for inputs used in measuring fair value, which prioritizes the inputs based on the observability as of the measurement date, is as follows:

Level 1
Quoted prices in active markets for identical assets or liabilities;
Level 2
Observable inputs other than the quoted prices in active markets for identical assets and liabilities; and
Level 3
Unobservable inputs for which there is little or no market data, which require T-Mobile to develop assumptions of what market participants would use in pricing the asset or liability.

Assets and liabilities are classified in their entirety based on the lowest level of input that is significant to the fair value measurement. The Company’s assessment of the significance of a particular input to the fair value measurement requires judgment, and may affect the placement of assets and liabilities being measured within the fair value hierarchy.

The carrying values of cash and cash equivalents, short-term investments, accounts receivable, accounts receivable from affiliates and accounts payable approximate fair value due to the short-term maturities of these instruments. The carrying values of EIP receivables approximate fair value as the receivables are recorded at their present value, net of unamortized discount and allowance for credit losses. There were no financial instruments with a carrying value materially different from their fair value, based on quoted market prices or rates for the same or similar instruments, or internal valuation models.
Derivative Financial Instruments

Derivative financial instruments primarily relate to embedded derivatives for certain components of the reset feature of the Senior Reset Notes to affiliates which are required to be bifurcated and are recorded on the balance sheet at fair value. Changes in fair value are recognized in Interest expense to affiliates. T-Mobile does not enter into derivatives for trading or speculative purposes.

Revenue Recognition
Revenue Recognition

T-Mobile offers products and services to customers through bundled arrangements, which may be comprised of multiple contracts entered into with a customer at or near the same time. The Company assesses such agreements as a single bundled arrangement that may involve multiple deliverables, which include wireless devices, wireless services or a combination thereof. For multiple deliverable arrangements revenue is allocated between the separate units of accounting, based on such components’ relative selling prices on a standalone basis.

Revenues primarily consist of wireless service revenues from providing access to and usage of the Company's wireless communications network, equipment revenues generated from device sales and revenues from leasing a device through JUMP! On Demand. Service revenues also include revenues earned for providing value added services to customers, such as handset insurance services. Service revenues are billed either in advance or arrears or are prepaid and are recognized when the service is rendered and all other revenue recognition criteria have been met. Revenues that are not reasonably assured to be collectible are recorded on a cash basis as payments are received. The recognition of prepaid revenue is deferred until services are rendered or the prepaid balance expires. Incentives given to customers are recorded as a reduction to revenue. T-Mobile recognizes service revenues for Data Stash plans when such services are delivered and the data is consumed, or at time of forfeiture or expiration.  Revenues relating to unused data that is carried over to the following month are deferred and valued based on their relative standalone selling price. Revenue is recorded gross for arrangements involving the resale of third-party services where T-Mobile is considered the primary obligor and is recorded net of associated costs incurred for services whereby T-Mobile is not considered the primary obligor.

Equipment revenues are comprised of revenues from the sale or lease of mobile communication devices and accessories. Device and accessory sales revenues are generally recognized when the products are delivered to and accepted by the customer or dealer. The Company defers a portion of equipment revenues and cost of equipment sales for expected device returns based on historical experience. The Company offers certain customers the option to pay for devices and accessories in installments using an EIP. See Equipment Installment Plan Receivables for further information.

In addition, the Company offers customers a device trade-in program, JUMP!, which provides eligible customers a specified-price trade-in right to upgrade their device.  For customers enrolled in JUMP!, the Company separates the JUMP! trade-in right from the multiple element arrangement at its fair value and defers the portion of revenue which represents the fair value of the trade-in right. See Guarantee Liabilities for further information. In 2015, T-Mobile introduced JUMP! On Demand, which allows customers to lease a device and upgrade their leased wireless device for a new one up to three times in a 12 month period. Leased wireless devices are accounted for as operating leases and equipment revenues are recognized as earned on a straight-line basis over the lease term. Previously leased devices that are purchased by the customer are recorded at their residual value as equipment revenues and cost of equipment sales. See Property and Equipment for further information.

Federal Universal Service Fund (“USF”) and other fees are assessed by various governmental authorities in connection with the services the Company provides to its customers. When the Company separately bills and collects these regulatory fees from customers, they are recorded gross in service revenues and cost of services. For the years ended December 31, 2015, 2014 and 2013, the Company recorded approximately $334 million, $349 million and $362 million, respectively, of USF and other fees on a gross basis.
Rent Expense
Rent Expense

The Company has operating leases for cell sites, retail locations, corporate offices and dedicated transportation lines, some of which have escalating rentals during the initial lease term and during subsequent optional renewal periods. The Company recognizes rent expense on a straight-line basis, over the non-cancelable lease term and renewal periods that are considered reasonably assured at the inception of the lease.
Advertising Expense
Advertising Expense

T-Mobile expenses the cost of advertising and other promotional expenditures to market the T-Mobile’s services and products as incurred. For the years ended December 31, 2015, 2014 and 2013, advertising expenses included in Selling, general and administrative expenses were $1.6 billion, $1.4 billion and $1.0 billion, respectively.
Income Taxes
Income Taxes

Deferred tax assets and liabilities are recognized based on temporary differences between the financial statement and tax bases of assets and liabilities using enacted tax rates expected to be in effect when these differences are realized. A valuation allowance is recorded when it is more likely than not that some portion or all of a deferred tax asset will not be realized. The ultimate realization of a deferred tax asset depends on the ability to generate sufficient taxable income of the appropriate character and in the appropriate taxing jurisdictions within the carryforward periods available.

T-Mobile accounts for uncertainty in income taxes recognized in the financial statements in accordance with the accounting guidance on the financial statement recognition and measurement of a tax position taken or expected to be taken in a tax return. The Company assesses whether it is more likely than not that a tax position will be sustained upon examination based on the technical merits of the position and adjusts the unrecognized tax benefits in light of changes in facts and circumstances, such as changes in tax law, interactions with taxing authorities and developments in case law.

In November 2015, the Financial Accounting Standards Board (“FASB”) issued Accounting Standards Update (“ASU”) 2015-17 (Topic 740), “Balance Sheet Classification of Deferred Taxes”, which simplifies the presentation of deferred income taxes. This ASU requires that deferred tax assets and liabilities be classified as non-current in a classified statement of financial position. The Company early adopted ASU 2015-17 for the year ended December 31, 2015 on a prospective basis. Adoption of this ASU resulted in a reclassification of the Company’s current deferred tax assets, net to non-current deferred tax liabilities in the Consolidated Balance Sheets as of December 31, 2015. Prior periods were not retrospectively adjusted.

Other Comprehensive Income (Loss)

Other comprehensive income (loss) consists of adjustments, net of tax, related to unrealized gains (losses) on available-for-sale securities, unrealized gains (losses) on cash flow hedging derivatives and unrealized gains (losses) on foreign currency translation. These are reported in Accumulated other comprehensive income (loss) (“AOCI”) as a separate component of stockholders’ equity until realized in earnings.
Stock-Based Compensation

Stock-based compensation cost for stock awards, which include restricted stock units (“RSU”) and performance stock units (“PSU”), is measured at fair value on the grant date and recognized as expense, net of expected forfeitures, over the related service period. The fair value of stock awards is based on the closing price of T-Mobile common stock on the date of grant. RSUs are recognized as expense using the straight-line method. PSUs are recognized as expense following a graded vesting schedule.

Earnings Per Share
Earnings Per Share

Basic earnings per share is computed by dividing Net income attributable to common stockholders by the weighted-average number of common shares outstanding for the period. Diluted earnings per share is computed by giving effect to all potentially dilutive common shares outstanding during the period. Potentially dilutive common shares consist of outstanding stock options, RSUs and PSUs, calculated using the treasury stock method, and mandatory convertible preferred stock (“preferred stock”), calculated using the if-converted method.
Variable Interest Entities

VIEs are entities which lack sufficient equity to permit the entity to finance its activities without additional subordinated financial support from other parties, have equity investors which do not have the ability to make significant decisions relating to the entity's operations through voting rights, do not have the obligation to absorb the expected losses or do not have the right to receive the residual returns of the entity. The most common type of VIE is a special purpose entity (“SPE”). SPEs are commonly used in securitization transactions in order to isolate certain assets and distribute the cash flows from those assets to investors. SPEs are generally structured to insulate investors from claims on the SPE's assets by creditors of other entities, including the creditors of the seller of the assets.

The primary beneficiary is required to consolidate the assets and liabilities of the VIE. The primary beneficiary is the party which has both the power to direct the activities of an entity that most significantly impact the VIE's economic performance, and through its interests in the VIE, the obligation to absorb losses or the right to receive benefits from the VIE which could potentially be significant to the VIE. T-Mobile consolidates VIEs when it is deemed to be the primary beneficiary or when the VIE cannot be deconsolidated.

In assessing which party is the primary beneficiary, all the facts and circumstances are considered, including each party’s role in establishing the VIE and its ongoing rights and responsibilities. This assessment includes, first, identifying the activities that most significantly impact the VIE’s economic performance; and second, identifying which party, if any, has power over those activities. In general, the parties that make the most significant decisions affecting the VIE (such as asset managers and servicers) or have the right to unilaterally remove those decision-makers are deemed to have the power to direct the activities of a VIE.

Recently-Issued Accounting Standards

In April 2015, the FASB issued ASU 2015-03, “Simplifying the Presentation of Debt Issuance Costs.” The standard requires debt issuance costs related to a recognized debt liability be presented in the balance sheet as a direct deduction from the carrying amount of that debt liability, consistent with debt discounts. The recognition and measurement guidance for debt issuance costs are not affected. The standard will become effective for T-Mobile beginning January 1, 2016 and will be applied retrospectively. The implementation of this standard is not expected to have a significant impact on T-Mobile’s consolidated financial statements.

In May 2014, the FASB issued ASU 2014-09, “Revenue from Contracts with Customers.” The standard requires entities to recognize revenue through the application of a five-step model, which includes identification of the contract, identification of the performance obligations, determination of the transaction price, allocation of the transaction price to the performance obligations and recognition of revenue as the entity satisfies the performance obligations. In August 2015, the FASB issued ASU 2015-14, “Revenue From Contracts With Customers (Topic 606): Deferral of the Effective Date.” The amendments in the ASU 2015-14 defer the effective date of ASU 2014-09 by one year. The standard will become effective for T-Mobile beginning January 1, 2018; however, early adoption with the original effective date for periods beginning January 1, 2017 will be permitted.  The Company is currently evaluating the guidance to determine the potential impact on T-Mobile’s consolidated financial statements. Under ASU 2014-09, two adoption methods are allowed.  Under one method, a company may apply the rules to contracts in all reporting periods presented, subject to certain allowable exceptions.  Under the other method, a company may apply the rules to all contracts existing as of January 1, 2018 (provided early adoption is not elected), recognizing an adjustment to retained earnings for the cumulative effect of the change and providing additional disclosures comparing results to previous rules.  The Company continues to evaluate the impact of the new standard and available adoption methods and believes the standard will require the implementation of new revenue accounting systems, processes and internal controls over revenue recognition.

v3.3.1.900
Business Combination with MetroPCS (Tables)
12 Months Ended
Dec. 31, 2015
Business Combinations [Abstract]  
Schedule of Restructuring Charges and Related Activities
The Company recognized the following expenses included in Cost of MetroPCS business combination:
 
Year Ended December 31,
(in millions)
2015
 
2014
 
2013
Network decommissioning costs, including the write-off of certain items
$
376

 
$
263

 
$
—

Transaction and integration costs
—

 
36

 
108

Cost of MetroPCS business combination
$
376

 
$
299

 
$
108

Activities in liabilities for network decommissioning costs were as follows:
(in millions)
December 31, 2015
 
December 31, 2014
Balances, beginning of year
$
239

 
$
—

Network decommissioning costs, excluding the write-off of certain items
349

 
271

Cash payments
(182
)
 
(32
)
Balances, end of year
$
406

 
$
239


Classified on the balance sheet as:


Accounts payable and accrued liabilities
$
117

 
$
78

Other long-term liabilities
289

 
161

Network decommissioning liabilities
$
406

 
$
239

Schedule of Business Combination, Supplemental Information
The following supplemental information presents the financial results of MetroPCS operations included in the consolidated statements of comprehensive income since May 1, 2013 for the year ended December 31, 2013:
(in millions)
Year Ended December 31, 2013
Total revenues
$
3,366

Income before income taxes
143

Schedule of Business Combination, Pro Forma Information
The following pro forma consolidated results of operations for the year ended December 31, 2013 assumes the business combination was completed as of January 1, 2012:
(in millions, except per share amounts)
Year Ended December 31, 2013
Pro forma revenues
$
26,158

Pro forma net income
52

Pro forma basic earnings per share
$
0.07

Pro forma diluted earnings per share
0.07


v3.3.1.900
Sales of Certain Receivables Transfers of Financial Assets (Tables)
12 Months Ended
Dec. 31, 2015
Transfers and Servicing [Abstract]  
Schedule of Variable Interest Entities [Table Text Block]
The following table summarizes the carrying amounts and classification of assets (primarily the deferred purchase price) and liabilities included in the Consolidated Balance Sheets that relate to T-Mobile’s variable interest in Service VIE:
(in millions)
December 31,
2015
 
December 31,
2014
Other current assets
$
206

 
$
204

Accounts payable and accrued liabilities
—

 
13

Other current liabilities
73

 
55

Schedule of variable interest entities - EIP [Table Text Block]
The following table summarizes the carrying amounts and classification of EIP BRE’s assets and liabilities included in the Consolidated Balance Sheets:
(in millions)
December 31,
2015
 
December 31,
2014
Other current assets
$
164

 
$
—

Other assets
44

 
—

Accounts payable and accrued liabilities
14

 
—

Other long-term liabilities
3

 
—

Schedule of Factoring Arrangement
The following table summarizes the impacts of the sale of certain service receivables and EIP receivables on the Consolidated Balance Sheets:
(in millions)
December 31,
2015
 
December 31,
2014
Derecognized net service receivables and EIP receivables
$
1,850

 
$
768

Other current assets
370

 
204

Other assets
44

 
—

Accounts payable and accrued liabilities
14

 
13

Other current liabilities
73

 
55

Other long-term liabilities
3

 
—

Net cash proceeds since inception
1,494

 
610

Of which:


Net cash proceeds during the period
884

 
610

Net cash proceeds funded by reinvested collections
610

 
—


v3.3.1.900
Equipment Installment Plan Receivables (Tables)
12 Months Ended
Dec. 31, 2015
Receivables [Abstract]  
Schedule of Equipment Installment Plan Receivables
The following table summarizes the EIP receivables:
(in millions)
December 31,
2015
 
December 31,
2014
EIP receivables, gross
$
3,558

 
$
5,138

Unamortized imputed discount
(185
)
 
(332
)
EIP receivables, net of unamortized imputed discount
3,373

 
4,806

Allowance for credit losses
(148
)
 
(116
)
EIP receivables, net
$
3,225

 
$
4,690


Classified on the balance sheet as:


Equipment installment plan receivables, net
$
2,378

 
$
3,062

Equipment installment plan receivables due after one year, net
847

 
1,628

EIP receivables, net
$
3,225

 
$
4,690

Schedule of Equipment Installment Plan Receivables by Credit Category
The balance and aging of the EIP receivables on a gross basis by credit category were as follows:
 
December 31, 2015
 
December 31, 2014
(in millions)
Prime
 
Subprime
 
Total
 
Prime
 
Subprime
 
Total
Unbilled
$
1,593

 
$
1,698

 
$
3,291

 
$
2,639

 
$
2,213

 
$
4,852

Billed – Current
77

 
91

 
168

 
104

 
95

 
199

Billed – Past Due
37

 
62

 
99

 
35

 
52

 
87

EIP receivables, gross
$
1,707

 
$
1,851

 
$
3,558

 
$
2,778

 
$
2,360

 
$
5,138

Schedule of Unamortized Imputed Discount and Allowance for Credit Losses for Equipment Installment Plan Receivables
Activity in the unamortized imputed discount and allowance for credit losses balances for the EIP receivables was as follows:
(in millions)
2015
 
2014
Imputed discount and allowance for credit losses, beginning of year
$
448

 
$
336

Bad debt expense
365

 
285

Write-offs, net of recoveries
(333
)
 
(229
)
Change in imputed discount on short-term and long-term EIP receivables
(84
)
 
56

Impacts from sales of EIP receivables
(63
)
 
—

Imputed discount and allowance for credit losses, end of year
$
333

 
$
448


v3.3.1.900
Property and Equipment (Tables)
12 Months Ended
Dec. 31, 2015
Property, Plant and Equipment [Abstract]  
Schedule of Property and Equipment
The components of property and equipment were as follows:
(in millions)
Useful Lives
 
December 31,
2015
 
December 31,
2014
Buildings and equipment
Up to 40 years
 
$
1,900

 
$
1,948

Wireless communications systems
Up to 20 years
 
27,063

 
25,633

Leasehold improvements
Up to 12 years
 
1,003

 
988

Capitalized software
Up to 7 years
 
8,524

 
7,593

Leased wireless devices
Up to 18 months
 
2,236

 
—

Construction in progress
 
 
2,466

 
1,874

Accumulated depreciation and amortization
 
 
(23,192
)
 
(21,791
)
Property and equipment, net
 
 
$
20,000

 
$
16,245

Schedule of Leased Devices
The components of leased wireless devices were as follows:
(in millions)
December 31,
2015
 
December 31,
2014
Leased wireless devices, gross
$
2,236

 
$
—

Accumulated depreciation
(263
)
 
—

Leased wireless devices, net
$
1,973

 
$
—

Schedule of Future Minimum Payments
Future minimum payments expected to be received over the lease term related to the leased wireless devices, which exclude optional residual buy-out amounts at the end of the lease term, are summarized below:
(in millions)
Total
Year Ending December 31,
 
2016
$
913

2017
347

Total
$
1,260

Schedule of Asset Retirement Obligations
Activity in the asset retirement obligations was as follows:
(in millions)
December 31,
2015
 
December 31,
2014
Asset retirement obligations, beginning of year
$
390

 
$
388

Liabilities incurred
19

 
3

Liabilities settled
(130
)
 
(21
)
Accretion expense
17

 
20

Changes in estimated cash flows
187

 
—

Asset retirement obligations, end of year
$
483

 
$
390


Classified on the balance sheet as:


Other current liabilities
$
41

 
$
179

Other long-term liabilities
442

 
211

Asset retirement obligations
$
483

 
$
390


v3.3.1.900
Goodwill, Spectrum Licenses and Intangible Assets (Tables)
12 Months Ended
Dec. 31, 2015
Goodwill and Intangible Assets Disclosure [Abstract]  
Schedule of Spectrum Licenses
Changes in carrying values of spectrum licenses were as follows:
(in millions)
December 31,
2013
 
Net Changes
 
December 31,
2014
 
Net Changes
 
December 31,
2015
Spectrum licenses
$
18,122

 
$
3,833

 
$
21,955

 
$
2,000

 
$
23,955

Schedule of Other Intangible Assets
The components of intangible assets were as follows:
 
Useful Lives
 
December 31, 2015
 
December 31, 2014
(in millions)
 
Gross
Amount
 
Accumulated Amortization
 
Net
Amount
 
Gross
Amount
 
Accumulated Amortization
 
Net
Amount
Customer lists
Up to 6 years
 
$
1,104

 
$
(719
)
 
$
385

 
$
1,313

 
$
(700
)
 
$
613

Trademarks and patents
Up to 12 years
 
300

 
(115
)
 
185

 
295

 
(78
)
 
217

Other
Up to 28 years
 
51

 
(27
)
 
24

 
71

 
(31
)
 
40

Other intangible assets
 
 
$
1,455

 
$
(861
)
 
$
594

 
$
1,679

 
$
(809
)
 
$
870


v3.3.1.900
Fair Value Measurements and Derivative Instruments (Tables)
12 Months Ended
Dec. 31, 2015
Fair Value Disclosures [Abstract]  
Schedule of Fair Value of Derivative Instruments
The fair value of embedded derivative instruments measured on a recurring basis by balance sheet location and level were as follows:
 
December 31, 2015
(in millions)
Level 1
 
Level 2
 
Level 3
 
Total
Other long-term liabilities
$
—

 
$
—

 
$
143

 
$
143


December 31, 2014
(in millions)
Level 1
 
Level 2
 
Level 3
 
Total
Other current assets
$
—

 
$
—

 
$
3

 
$
3

Other assets
—

 
—

 
2

 
2

Schedule of Gains (Losses) on Derivative Instruments
The following table summarizes the gain (loss) activity related to embedded derivatives instruments recognized in Interest expense to affiliates:
 
Year Ended December 31,
(in millions)
2015
 
2014
 
2013
Embedded derivatives
$
(148
)
 
$
18

 
$
(13
)
Schedule of Carrying Values and Fair Values of Long-term Debt
The carrying amounts and fair values of the Company’s short-term investments and long-term debt were as follows:
 
December 31, 2015
 
December 31, 2014
(in millions)
Carrying Amount
 
Fair Value
 
Carrying Amount
 
Fair Value
Assets:


Short-term investments
$
2,998

 
$
2,998

 
$
—

 
$
—

Liabilities:


Senior Notes to third parties
$
17,600

 
$
18,098

 
$
15,600

 
$
16,034

Senior Reset Notes to affiliates
5,600

 
6,072

 
5,600

 
5,780

Senior Secured Term Loans
2,000

 
1,990

 
—

 
—


v3.3.1.900
Debt (Tables)
12 Months Ended
Dec. 31, 2015
Debt Disclosure [Abstract]  
Schedule of Long-term Debt
Debt was as follows:
(in millions)
December 31,
2015
 
December 31,
2014
5.250% Senior Notes due 2018
$
500

 
$
500

6.288% Senior Reset Notes to affiliates due 2019
1,250

 
1,250

6.464% Senior Notes due 2019
1,250

 
1,250

6.366% Senior Reset Notes to affiliates due 2020
1,250

 
1,250

6.542% Senior Notes due 2020
1,250

 
1,250

6.625% Senior Notes due 2020
1,000

 
1,000

6.250% Senior Notes due 2021
1,750

 
1,750

6.633% Senior Notes due 2021
1,250

 
1,250

8.097% Senior Reset Notes to affiliates due 2021
1,250

 
1,250

6.125% Senior Notes due 2022
1,000

 
1,000

6.731% Senior Notes due 2022
1,250

 
1,250

8.195% Senior Reset Notes to affiliates due 2022
1,250

 
1,250

5.950% Senior Reset Notes to affiliates due 2023 (reset date in April 2016)
600

 
600

6.000% Senior Notes due 2023
1,300

 
1,300

6.625% Senior Notes due 2023
1,750

 
1,750

6.836% Senior Notes due 2023
600

 
600

6.500% Senior Notes due 2024
1,000

 
1,000

6.375% Senior Notes due 2025
1,700

 
1,700

6.500% Senior Notes due 2026
2,000

 
—

Senior Secured Term Loans
2,000

 
—

Unamortized premium from purchase price allocation fair value adjustment
250

 
286

Unamortized discount on Senior Secured Term Loans
(10
)
 
—

Capital leases
826

 
410

Financing arrangements
—

 
64

Total debt
26,266

 
21,960

Less: Current portion of Senior Secured Term Loans
20

 
—

Less: Current portion of capital leases
162

 
23

Less: Financing arrangements
—

 
64

Total long-term debt
$
26,084

 
$
21,873


Classified on the balance sheet as:


Long-term debt
$
20,484

 
$
16,273

Long-term debt to affiliates
5,600

 
5,600

Total long-term debt
$
26,084

 
$
21,873

Schedule of Long-Term Debt Instruments - Interest Rate [Table Text Block]

In 2015, the interest rate on certain Senior Reset Notes to affiliates were adjusted as follows:
 
December 31, 2015
 
Current Rate
 
Previous Rate
6.288% Senior Reset Notes to affiliates due 2019
6.288
%
 
5.578
%
6.366% Senior Reset Notes to affiliates due 2020
6.366
%
 
5.656
%
8.097% Senior Reset Notes to affiliates due 2021
8.097
%
 
5.747
%
8.195% Senior Reset Notes to affiliates due 2022
8.195
%
 
5.845
%
Schedule of Letters of Credit
The following table summarizes the outstanding standby letters of credit under each agreement:
(in millions)
December 31,
2015
 
December 31,
2014
JP Morgan Chase
$
36

 
$
36

Deutsche Bank
54

 
50

Total outstanding balance
$
90

 
$
86


v3.3.1.900
Tower Obligations (Tables)
12 Months Ended
Dec. 31, 2015
Leases [Abstract]  
Summary of Impacts to Consolidated Balance Sheets
The following table summarizes the impacts to the Consolidated Balance Sheets:
(in millions)
December 31,
2015
 
December 31,
2014
Property and equipment, net
$
601

 
$
604

Tower obligations
2,658

 
2,521

Schedule of Future Minimum Financial Obligations
Future minimum payments related to the tower obligations are summarized below:
(in millions)
Total
Year Ending December 31,
 
2016
$
179

2017
180

2018
180

2019
180

2020
181

Thereafter
1,315

Total
$
2,215


v3.3.1.900
Employee Compensation and Benefit Plans (Tables)
12 Months Ended
Dec. 31, 2015
Disclosure of Compensation Related Costs, Share-based Payments [Abstract]  
Schedule of Stock-based Compensation and Related Income Tax Benefits
Stock-based compensation expense and related income tax benefits were as follows:
(in millions)
December 31,
2015
 
December 31,
2014
 
December 31,
2013
Stock-based compensation expense
$
201

 
$
196

 
$
100

Income tax benefit related to stock-based compensation
71

 
73

 
38

Realized excess tax benefit
79

 
34

 
—

Schedule of Nonvested Stock Awards Activity
The following activity occurred under the RSU and PSU awards:
(in millions, except shares, per share and contractual life amounts)
Number of Units
 
Weighted Average Grant Date Fair Value
 
Weighted Average Remaining Contractual Term (Years)
 
Aggregate Intrinsic Value
Nonvested, December 31, 2014
19,952,089

 
$
24.15

 
1.1
 
$
538

Granted
9,760,057

 
35.56


Vested
(11,956,345
)
 
25.28


Forfeited
(1,421,530
)
 
27.36


Nonvested, December 31, 2015
16,334,271

 
$
29.95

 
1.2
 
$
639

Schedule of Stock Options Activity
The following activity occurred under the Predecessor Plans:
 
Shares
 
Weighted Average Exercise Price
 
Weighted Average Remaining Contractual Term (Years)
Outstanding and Exercisable, December 31, 2014
4,348,912

 
$
24.96

 
3.7
Exercised
(2,381,650
)
 
19.91


Expired
(142,908
)
 
38.32


Outstanding and exercisable, December 31, 2015
1,824,354

 
$
30.50

 
2.7

v3.3.1.900
Income Taxes (Tables)
12 Months Ended
Dec. 31, 2015
Income Tax Disclosure [Abstract]  
Schedule of Income before Income Tax
The sources of Income before income taxes were as follows:
 
Year Ended December 31,
(in millions)
2015
 
2014
 
2013
U.S.
$
898

 
$
347

 
$
(5
)
Puerto Rico
80

 
66

 
56

Income before income taxes
$
978

 
$
413

 
$
51

Schedule of Components of Income Tax Expense (Benefit)

Income tax expense is summarized as follows:
 
Year Ended December 31,
(in millions)
2015
 
2014
 
2013
Current tax expense (benefit)


Federal
$
(30
)
 
$
—

 
$
(10
)
State
2

 
6

 
6

Puerto Rico
17

 
38

 
10

Total current tax expense (benefit)
(11
)
 
44

 
6

Deferred tax expense (benefit)


Federal
281

 
79

 
24

State
(37
)
 
40

 
(22
)
Puerto Rico
12

 
3

 
8

Total deferred tax expense
256

 
122

 
10

Total income tax expense
$
245

 
$
166

 
$
16

Schedule of Effective Income Tax Rate Reconciliation
The reconciliation between the U.S. federal statutory income tax rate and T-Mobile's effective income tax rate is as follows:
 
Year Ended December 31,
 
2015
 
2014
 
2013
Federal statutory income tax rate
35.0
 %
 
35.0
 %
 
35.0
 %
State taxes, net of federal benefit
(1.1
)
 
(8.8
)
 
(31.8
)
Puerto Rico taxes, net of federal benefit
3.3

 
5.0

 
28.2

Change in valuation allowance
(3.2
)
 
18.8

 
(6.1
)
Permanent differences
1.6

 
1.4

 
11.3

Federal tax credits, net of reserves
(9.5
)
 
(10.6
)
 
—

Other, net
(1.0
)
 
(0.6
)
 
(5.2
)
Effective income tax rate
25.1
 %
 
40.2
 %
 
31.4
 %
Schedule of Deferred Tax Assets and Liabilities
Significant components of deferred income tax assets and liabilities, tax effected, are as follows:
(in millions)
December 31,
2015
 
December 31,
2014
Deferred tax assets


Loss carryforwards
$
1,997

 
$
2,354

Deferred rents
1,136

 
1,034

Reserves and accruals
928

 
454

Federal and state tax credits
349

 
295

Debt fair market value adjustment
97

 
111

Other
317

 
295

Deferred tax assets, gross
4,824

 
4,543

Valuation allowance
(583
)
 
(614
)
Deferred tax assets, net
4,241

 
3,929

Deferred tax liabilities


Spectrum licenses
6,174

 
5,629

Property and equipment
1,950

 
1,877

Other intangible assets
178

 
297

Other
—

 
11

Total deferred tax liabilities
8,302

 
7,814

Net deferred tax liabilities
$
4,061

 
$
3,885


Classified on the balance sheet as:


Current deferred tax assets, net
$
—

 
$
988

Non-current deferred tax liabilities, net
4,061

 
4,873

Net deferred tax liabilities
$
4,061

 
$
3,885


Schedule of Unrecognized Tax Benefits Roll Forward
A reconciliation of the beginning and ending amount of unrecognized tax benefits were as follows:
 
Year Ended December 31,
(in millions)
2015
 
2014
 
2013
Unrecognized tax benefits, beginning of year
$
388

 
$
178

 
$
89

Gross decreases to tax positions in prior periods
(112
)
 
(52
)
 
(18
)
Gross increases to current period tax positions
135

 
262

 
24

Gross increase due to current year business combination
—

 
—

 
83

Unrecognized tax benefits, end of year
$
411

 
$
388

 
$
178


v3.3.1.900
Earnings Per Share (Tables)
12 Months Ended
Dec. 31, 2015
Earnings Per Share [Abstract]  
Schedule of Earnings Per Share
The computation of basic and diluted earnings per share was as follows:
 
Year Ended December 31,
(in millions, except shares and per share amounts)
2015
 
2014
 
2013
Net income
$
733

 
$
247

 
$
35

Dividends on preferred stock
(55
)
 
—

 
—

Net income attributable to common stockholders
$
678

 
$
247

 
$
35


Weighted average shares outstanding - basic
812,994,028

 
805,284,712

 
672,955,980

Dilutive effect of outstanding stock options and awards
9,623,910

 
8,893,887

 
3,929,235

Dilutive effect of preferred stock
—

 
1,743,659

 
—

Weighted average shares outstanding - diluted
822,617,938

 
815,922,258

 
676,885,215


Earnings per share - basic
$
0.83

 
$
0.31

 
$
0.05

Earnings per share - diluted
$
0.82

 
$
0.30

 
$
0.05


Potentially dilutive securities:


Outstanding stock options and unvested stock awards
4,842,370

 
1,426,331

 
4,909,741

Preferred stock common stock equivalents
32,237,266

 
—

 
—


v3.3.1.900
Commitments and Contingencies (Tables)
12 Months Ended
Dec. 31, 2015
Commitments and Contingencies Disclosure [Abstract]  
Schedule of Future Minimum Payments for Commitments
Future minimum payments for non-cancelable operating leases and purchase commitments are summarized below:
(in millions)
Operating Leases
 
Purchase Commitments
Year Ending December 31,


2016
$
2,379

 
$
2,865

2017
2,235

 
3,150

2018
2,046

 
772

2019
1,900

 
714

2020
1,679

 
629

Thereafter
5,583

 
1,304

Total
$
15,822

 
$
9,434


v3.3.1.900
Additional Financial Information (Tables)
12 Months Ended
Dec. 31, 2015
Supplemental Financial Statement Elements [Abstract]  
Schedule of Allowances and Unamortized Imputed Interest
The following table summarizes the changes in allowances and unamortized imputed discount related to its current accounts receivables and EIP receivables:
(in millions)
2015
 
2014
 
2013
Allowances, beginning of year
$
199

 
$
169

 
$
197

Bad debt expense
547

 
444

 
463

Write-offs, net of recoveries
(482
)
 
(414
)
 
(491
)
Allowances, end of year
$
264

 
$
199

 
$
169


Imputed discount, beginning of year
$
271

 
$
212

 
$
92

Additions
310

 
380

 
283

Interest income
(414
)
 
(355
)
 
(185
)
Cancellations and other
(78
)
 
(92
)
 
(42
)
Impacts from sales of EIP receivables
(55
)
 
—

 
—

Transfer from long-term
125

 
126

 
64

Imputed discount, end of year
$
159

 
$
271

 
$
212


The following table summarizes the changes in unamortized imputed discount related to its long-term EIP receivables:
(in millions)
2015
 
2014
 
2013
Imputed discount, beginning of year
$
61

 
$
64

 
$
18

Additions
111

 
141

 
121

Cancellations and other
(13
)
 
(18
)
 
(11
)
Impacts from sales of EIP receivables
(8
)
 
—

 
—

Transfer to current
(125
)
 
(126
)
 
(64
)
Imputed discount, end of year
$
26

 
$
61

 
$
64

Schedule of Accounts Payable and Accrued Liabilities
Accounts payable and accrued liabilities are summarized as follows:
(in millions)
December 31,
2015
 
December 31,
2014
Accounts payable
$
6,137

 
$
5,322

Property and other taxes, including payroll
494

 
605

Payroll and related benefits
521

 
470

Interest
371

 
349

Commissions
190

 
179

Toll and interconnect
68

 
166

Network decommissioning
117

 
78

Advertising
77

 
53

Other
109

 
142

Accounts payable and accrued liabilities
$
8,084

 
$
7,364

Schedule of Related Party Transactions
The following table summarizes the impact of significant transactions with Deutsche Telekom or its affiliates included in operating expenses in the Consolidated Statements of Comprehensive Income (Loss):
 
Year Ended December 31,
(in millions)
2015
 
2014
 
2013
Discount related to roaming expenses
$
(21
)
 
$
(61
)
 
$
(16
)
Fees incurred for use of the T-Mobile brand
65

 
60

 
53

Expenses for telecommunications and IT services
23

 
24

 
102

Schedule of Supplemental Cash Flow Information
The following table summarizes T-Mobile’s supplemental cash flows information:
 
Year Ended December 31,
(in millions)
2015
 
2014
 
2013
Interest and income tax payments:


Interest payments, net of amounts capitalized
$
1,298

 
$
1,367

 
$
1,156

Income tax payments
54

 
36

 
20

Noncash investing and financing activities:


Increase in accounts payable for purchases of property and equipment
46

 
402

 
6

Leased wireless devices transferred from inventory to property and equipment, net of returns
2,285

 
—

 
—

Issuance of short-term debt for financing of property and equipment purchases
500

 
256

 
470

Assets acquired under capital lease obligations
470

 
77

 
3

Retirement of long-term debt to affiliates
—

 
—

 
14,450

Elimination of net unamortized discounts and premiums on long-term debt to affiliates
—

 
—

 
434

Issuance of new long-term debt to affiliates
—

 
—

 
11,200

Settlement of accounts receivable from affiliates and other outstanding balances
—

 
—

 
363

Income tax benefit from debt recapitalization
—

 
—

 
178

Net assets acquired in MetroPCS business combination, excluding cash acquired
—

 
—

 
827


v3.3.1.900
Guarantor Financial Information (Tables)
12 Months Ended
Dec. 31, 2015
Condensed Financial Information of Parent Company Only Disclosure [Abstract]  
Schedule of Condensed Consolidating Balance Sheet Information
Condensed Consolidating Balance Sheet Information
December 31, 2015
(in millions)
Parent
 
Issuer
 
Guarantor Subsidiaries
 
Non-Guarantor Subsidiaries
 
Consolidating and Eliminating Adjustments
 
Consolidated
Assets


Current assets


Cash and cash equivalents
$
378

 
$
1,767

 
$
2,364

 
$
73

 
$
—

 
$
4,582

Short-term investments
—

 
1,999

 
999

 
—

 
—

 
2,998

Accounts receivable, net
—

 
—

 
1,574

 
214

 
—

 
1,788

Equipment installment plan receivables, net
—

 
—

 
2,378

 
—

 
—

 
2,378

Accounts receivable from affiliates
—

 
—

 
36

 
—

 
—

 
36

Inventories
—

 
—

 
1,295

 
—

 
—

 
1,295

Other current assets
—

 
—

 
1,413

 
400

 
—

 
1,813

Total current assets
378

 
3,766

 
10,059

 
687

 
—

 
14,890

Property and equipment, net (1)
—

 
—

 
19,546

 
454

 
—

 
20,000

Goodwill
—

 
—

 
1,683

 
—

 
—

 
1,683

Spectrum licenses
—

 
—

 
23,955

 
—

 
—

 
23,955

Other intangible assets, net
—

 
—

 
594

 
—

 
—

 
594

Investments in subsidiaries, net
16,184

 
32,280

 
—

 
—

 
(48,464
)
 
—

Intercompany receivables
—

 
6,130

 
—

 
—

 
(6,130
)
 
—

Equipment installment plan receivables due after one year, net
—

 
—

 
847

 
—

 
—

 
847

Other assets
—

 
28

 
387

 
219

 
(167
)
 
467

Total assets
$
16,562

 
$
42,204

 
$
57,071

 
$
1,360

 
$
(54,761
)
 
$
62,436

Liabilities and Stockholders' Equity


Current liabilities


Accounts payable and accrued liabilities
$
—

 
$
368

 
$
7,496

 
$
220

 
$
—

 
$
8,084

Current payables to affiliates
—

 
70

 
65

 
—

 
—

 
135

Short-term debt
—

 
20

 
162

 
—

 
—

 
182

Deferred revenue
—

 
—

 
717

 
—

 
—

 
717

Other current liabilities
—

 
—

 
327

 
83

 
—

 
410

Total current liabilities
—

 
458

 
8,767

 
303

 
—

 
9,528

Long-term debt
—

 
19,820

 
664

 
—

 
—

 
20,484

Long-term debt to affiliates
—

 
5,600

 
—

 
—

 
—

 
5,600

Tower obligations (1)
—

 
—

 
411

 
2,247

 
—

 
2,658

Deferred tax liabilities
—

 
—

 
4,228

 
—

 
(167
)
 
4,061

Deferred rents
—

 
—

 
2,481

 
—

 
—

 
2,481

Negative carrying value of subsidiaries, net
—

 
—

 
628

 
—

 
(628
)
 
—

Intercompany payables
5

 
—

 
5,959

 
166

 
(6,130
)
 
—

Other long-term liabilities
—

 
142

 
922

 
3

 
—

 
1,067

 Total long-term liabilities
5

 
25,562

 
15,293

 
2,416

 
(6,925
)
 
36,351

Total stockholders' equity
16,557

 
16,184

 
33,011

 
(1,359
)
 
(47,836
)
 
16,557

Total liabilities and stockholders' equity
$
16,562

 
$
42,204

 
$
57,071

 
$
1,360

 
$
(54,761
)
 
$
62,436


(1)
Assets and liabilities for Non-Guarantor Subsidiaries are primarily included in VIEs related to the 2012 Tower Transaction. See Note 9 – Tower Obligations for further information.

Condensed Consolidating Balance Sheet Information
December 31, 2014
(in millions)
Parent
 
Issuer
 
Guarantor Subsidiaries
 
Non-Guarantor Subsidiaries
 
Consolidating and Eliminating Adjustments
 
Consolidated
Assets


Current assets


Cash and cash equivalents
$
2,278

 
$
2,246

 
$
697

 
$
94

 
$
—

 
$
5,315

Accounts receivable, net
—

 
—

 
1,817

 
48

 
—

 
1,865

Equipment installment plan receivables, net
—

 
—

 
3,062

 
—

 
—

 
3,062

Accounts receivable from affiliates
—

 
—

 
76

 
—

 
—

 
76

Inventories
—

 
—

 
1,085

 
—

 
—

 
1,085

Deferred tax assets, net
—

 
—

 
988

 
—

 
—

 
988

Other current assets
—

 
3

 
1,341

 
249

 
—

 
1,593

Total current assets
2,278

 
2,249

 
9,066

 
391

 
—

 
13,984

Property and equipment, net (1)
—

 
—

 
15,708

 
537

 
—

 
16,245

Goodwill
—

 
—

 
1,683

 
—

 
—

 
1,683

Spectrum licenses
—

 
—

 
21,955

 
—

 
—

 
21,955

Other intangible assets, net
—

 
—

 
870

 
—

 
—

 
870

Investments in subsidiaries, net
13,470

 
30,385

 
—

 
—

 
(43,855
)
 
—

Intercompany receivables
—

 
2,773

 
—

 
—

 
(2,773
)
 
—

Equipment installment plan receivables due after one year, net
—

 
—

 
1,628

 
—

 
—

 
1,628

Other assets
2

 
17

 
259

 
124

 
(114
)
 
288

Total assets
$
15,750

 
$
35,424

 
$
51,169

 
$
1,052

 
$
(46,742
)
 
$
56,653

Liabilities and Stockholders' Equity


Current liabilities


Accounts payable and accrued liabilities
$
—

 
$
349

 
$
6,914

 
$
101

 
$
—

 
$
7,364

Current payables to affiliates
—

 
56

 
175

 
—

 
—

 
231

Short-term debt
—

 
63

 
24

 
—

 
—

 
87

Deferred revenue
—

 
—

 
459

 
—

 
—

 
459

Other current liabilities
—

 
—

 
580

 
55

 
—

 
635

Total current liabilities
—

 
468

 
8,152

 
156

 
—

 
8,776

Long-term debt
—

 
15,886

 
387

 
—

 
—

 
16,273

Long-term debt to affiliates
—

 
5,600

 
—

 
—

 
—

 
5,600

Tower obligations (1)
—

 
—

 
271

 
2,250

 
—

 
2,521

Deferred tax liabilities
—

 
—

 
4,987

 
—

 
(114
)
 
4,873

Deferred rents
—

 
—

 
2,331

 
—

 
—

 
2,331

Negative carrying value of subsidiaries, net
—

 
—

 
780

 
—

 
(780
)
 
—

Intercompany payables
87

 
—

 
2,589

 
97

 
(2,773
)
 
—

Other long-term liabilities
—

 
—

 
616

 
—

 
—

 
616

 Total long-term liabilities
87

 
21,486

 
11,961

 
2,347

 
(3,667
)
 
32,214

Total stockholders' equity
15,663

 
13,470

 
31,056

 
(1,451
)
 
(43,075
)
 
15,663

Total liabilities and stockholders' equity
$
15,750

 
$
35,424

 
$
51,169

 
$
1,052

 
$
(46,742
)
 
$
56,653


(1)
Assets and liabilities for Non-Guarantor Subsidiaries are primarily included in VIEs related to the 2012 Tower Transaction. See Note 9 – Tower Obligations for further information.
Schedule of Condensed Consolidating Statement of Comprehensive Income (Loss) Information
Condensed Consolidating Statement of Comprehensive Income (Loss) Information
Year Ended December 31, 2015
(in millions)
Parent
 
Issuer
 
Guarantor Subsidiaries
 
Non-Guarantor Subsidiaries
 
Consolidating and Eliminating Adjustments
 
Consolidated
Revenues


Service revenues
$
—

 
$
—

 
$
23,748

 
$
1,669

 
$
(596
)
 
$
24,821

Equipment revenues
—

 
—

 
7,148

 
—

 
(430
)
 
6,718

Other revenues
—

 
1

 
356

 
171

 
(14
)
 
514

Total revenues
—

 
1

 
31,252

 
1,840

 
(1,040
)
 
32,053

Operating expenses


Cost of services, exclusive of depreciation and amortization shown separately below
—

 
—

 
5,530

 
24

 
—

 
5,554

Cost of equipment sales
—

 
—

 
9,055

 
720

 
(431
)
 
9,344

Selling, general and administrative
—

 
—

 
10,065

 
733

 
(609
)
 
10,189

Depreciation and amortization
—

 
—

 
4,605

 
83

 
—

 
4,688

Cost of MetroPCS business combination
—

 
—

 
376

 
—

 
—

 
376

Gain on disposal of spectrum licenses
—

 
—

 
(163
)
 
—

 
—

 
(163
)
Total operating expenses
—

 
—

 
29,468

 
1,560

 
(1,040
)
 
29,988

Operating income
—

 
1

 
1,784

 
280

 
—

 
2,065

Other income (expense)


Interest expense
—

 
(847
)
 
(50
)
 
(188
)
 
—

 
(1,085
)
Interest expense to affiliates
—

 
(411
)
 
—

 
—

 
—

 
(411
)
Interest income
—

 
2

 
418

 
—

 
—

 
420

Other income (expense), net
—

 
(10
)
 
—

 
(1
)
 
—

 
(11
)
Total other income (expense), net
—

 
(1,266
)
 
368

 
(189
)
 
—

 
(1,087
)
Income (loss) before income taxes
—

 
(1,265
)
 
2,152

 
91

 
—

 
978

Income tax expense
—

 
—

 
214

 
31

 
—

 
245

Earnings (loss) of subsidiaries
733

 
1,998

 
(48
)
 
—

 
(2,683
)
 
—

Net income
733

 
733

 
1,890

 
60

 
(2,683
)
 
733

Dividends on preferred stock
(55
)
 
—

 
—

 
—

 
—

 
(55
)
Net income attributable to common stockholders
$
678

 
$
733

 
$
1,890

 
$
60

 
$
(2,683
)
 
$
678

Other comprehensive loss, net of tax


Other comprehensive loss, net of tax
(2
)
 
(2
)
 
(2
)
 
—

 
4

 
(2
)
Total comprehensive income (loss)
$
731

 
$
731

 
$
1,888

 
$
60

 
$
(2,679
)
 
$
731

-

Condensed Consolidating Statement of Comprehensive Income (Loss) Information
Year Ended December 31, 2014
(in millions)
Parent
 
Issuer
 
Guarantor Subsidiaries
 
Non-Guarantor Subsidiaries
 
Consolidating and Eliminating Adjustments
 
Consolidated
Revenues


Service revenues
$
—

 
$
—

 
$
21,483

 
$
1,302

 
$
(410
)
 
$
22,375

Equipment revenues
—

 
—

 
7,319

 
—

 
(530
)
 
6,789

Other revenues
—

 
—

 
270

 
140

 
(10
)
 
400

Total revenues
—

 
—

 
29,072

 
1,442

 
(950
)
 
29,564

Operating expenses


Cost of services, exclusive of depreciation and amortization shown separately below
—

 
—

 
5,767

 
21

 
—

 
5,788

Cost of equipment sales
—

 
—

 
9,491

 
702

 
(572
)
 
9,621

Selling, general and administrative
—

 
—

 
8,723

 
518

 
(378
)
 
8,863

Depreciation and amortization
—

 
—

 
4,330

 
82

 
—

 
4,412

Cost of MetroPCS business combination
—

 
—

 
299

 
—

 
—

 
299

Gain on disposal of spectrum licenses
—

 
—

 
(840
)
 
—

 
—

 
(840
)
Other, net
—

 
—

 
5

 
—

 
—

 
5

Total operating expenses
—

 
—

 
27,775

 
1,323

 
(950
)
 
28,148

Operating income
—

 
—

 
1,297

 
119

 
—

 
1,416

Other income (expense)


Interest expense
—

 
(838
)
 
(55
)
 
(180
)
 
—

 
(1,073
)
Interest expense to affiliates
—

 
(278
)
 
—

 
—

 
—

 
(278
)
Interest income
—

 
—

 
359

 
—

 
—

 
359

Other income (expense), net
—

 
(15
)
 
4

 
—

 
—

 
(11
)
Total other income (expense), net
—

 
(1,131
)
 
308

 
(180
)
 
—

 
(1,003
)
Income (loss) before income taxes
—

 
(1,131
)
 
1,605

 
(61
)
 
—

 
413

Income tax expense (benefit)
—

 
—

 
189

 
(23
)
 
—

 
166

Earnings (loss) of subsidiaries
247

 
1,278

 
(54
)
 
—

 
(1,471
)
 
—

Net income (loss)
$
247

 
$
147

 
$
1,362

 
$
(38
)
 
$
(1,471
)
 
$
247

Other comprehensive loss, net of tax


Other comprehensive income (loss), net of tax
(2
)
 
(2
)
 
(2
)
 
—

 
4

 
(2
)
Total comprehensive income (loss)
$
245

 
$
145

 
$
1,360

 
$
(38
)
 
$
(1,467
)
 
$
245


Condensed Consolidating Statement of Comprehensive Income (Loss) Information
Year Ended December 31, 2013
(in millions)
Parent
 
Issuer
 
Guarantor Subsidiaries
 
Non-Guarantor Subsidiaries
 
Consolidating and Eliminating Adjustments
 
Consolidated
Revenues


Service revenues
$
—

 
$
—

 
$
18,396

 
$
823

 
$
(151
)
 
$
19,068

Equipment revenues
—

 
—

 
5,728

 
—

 
(695
)
 
5,033

Other revenues
—

 
—

 
251

 
142

 
(74
)
 
319

Total revenues
—

 
—

 
24,375

 
965

 
(920
)
 
24,420

Operating expenses


Cost of services, exclusive of depreciation and amortization shown separately below
—

 
—

 
5,302

 
50

 
(73
)
 
5,279

Cost of equipment sales
—

 
—

 
7,180

 
552

 
(756
)
 
6,976

Selling, general and administrative
—

 
—

 
7,283

 
190

 
(91
)
 
7,382

Depreciation and amortization
—

 
—

 
3,545

 
82

 
—

 
3,627

Cost of MetroPCS business combination
—

 
—

 
108

 
—

 
—

 
108

Gain on disposal of spectrum licenses
—

 
—

 
(2
)
 
—

 
—

 
(2
)
Other, net
—

 
—

 
54

 
—

 
—

 
54

Total operating expenses
—

 
—

 
23,470

 
874

 
(920
)
 
23,424

Operating income
—

 
—

 
905

 
91

 
—

 
996

Other income (expense)


Interest expense
—

 
(317
)
 
(55
)
 
(173
)
 
—

 
(545
)
Interest expense to affiliates
—

 
(678
)
 
—

 
—

 
—

 
(678
)
Interest income
—

 
—

 
189

 
—

 
—

 
189

Other income (expense), net
—

 
94

 
(6
)
 
1

 
—

 
89

Total other income (expense), net
—

 
(901
)
 
128

 
(172
)
 
—

 
(945
)
Income (loss) before income taxes
—

 
(901
)
 
1,033

 
(81
)
 
—

 
51

Income tax expense (benefit)
—

 
—

 
45

 
(29
)
 
—

 
16

Earnings (loss) of subsidiaries
(104
)
 
936

 
(54
)
 
—

 
(778
)
 
—

Net income (loss)
$
(104
)
 
$
35

 
$
934

 
$
(52
)
 
$
(778
)
 
$
35

Other comprehensive income (loss), net of tax


Other comprehensive income (loss), net of tax
—

 
(38
)
 
24

 
—

 
(24
)
 
(38
)
Total comprehensive income (loss)
$
(104
)
 
$
(3
)
 
$
958

 
$
(52
)
 
$
(802
)
 
$
(3
)
Schedule of Condensed Consolidating Statement of Cash Flows Information
Condensed Consolidating Statement of Cash Flows Information
Year Ended December 31, 2015
(in millions)
Parent
 
Issuer
 
Guarantor Subsidiaries
 
Non-Guarantor Subsidiaries
 
Consolidating and Eliminating Adjustments
 
Consolidated
Operating activities


Net cash provided by (used in) operating activities
$
(1
)
 
$
(4,504
)
 
$
9,940

 
$
154

 
$
(175
)
 
$
5,414


Investing activities


Purchases of property and equipment
—

 
—

 
(4,724
)
 
—

 
—

 
(4,724
)
Purchases of spectrum licenses and other intangible assets, including deposits
—

 
—

 
(1,935
)
 
—

 
—

 
(1,935
)
Purchases of short-term investments
—

 
(1,999
)
 
(998
)
 
—

 
—

 
(2,997
)
Investment in subsidiaries
(1,905
)
 
—

 
—

 
—

 
1,905

 
—

Other, net
—

 
—

 
96

 
—

 
—

 
96

Net cash used in investing activities
(1,905
)
 
(1,999
)
 
(7,561
)
 
—

 
1,905

 
(9,560
)


Financing activities


Proceeds from capital contribution
—

 
1,905

 
—

 
—

 
(1,905
)
 
—

Proceeds from issuance of long-term debt
—

 
3,979

 
—

 
—

 
—

 
3,979

Repayments of long-term debt and capital lease obligations
—

 
—

 
(57
)
 
—

 
—

 
(57
)
Proceeds from tower obligations
—

 
140

 
—

 
—

 
—

 
140

Repayments of short-term debt for purchases of inventory, property and equipment, net
—

 
—

 
(564
)
 
—

 
—

 
(564
)
Intercompany dividend paid
—

 
—

 
—

 
(175
)
 
175

 
—

Dividends on preferred stock
(41
)
 
—

 
(14
)
 
—

 
—

 
(55
)
Proceeds from exercise of stock options
47

 
—

 
—

 
—

 
—

 
47

Taxes paid related to net share settlement of stock awards
—

 
—

 
(156
)
 
—

 
—

 
(156
)
Other, net
—

 
—

 
79

 
—

 
—

 
79

Net cash provided by (used in) financing activities
6

 
6,024

 
(712
)
 
(175
)
 
(1,730
)
 
3,413


Change in cash and cash equivalents
(1,900
)
 
(479
)
 
1,667

 
(21
)
 
—

 
(733
)
Cash and cash equivalents


Beginning of period
2,278

 
2,246

 
697

 
94

 
—

 
5,315

End of period
$
378

 
$
1,767

 
$
2,364

 
$
73

 
$
—

 
$
4,582


Condensed Consolidating Statement of Cash Flows Information
Year Ended December 31, 2014
(in millions)
Parent
 
Issuer
 
Guarantor Subsidiaries
 
Non-Guarantor Subsidiaries
 
Consolidating and Eliminating Adjustments
 
Consolidated
Operating activities


Net cash provided by (used in) operating activities
$
9

 
$
(5,145
)
 
$
9,364

 
$
18

 
$
(100
)
 
$
4,146


Investing activities


Purchases of property and equipment
—

 
—

 
(4,317
)
 
—

 
—

 
(4,317
)
Purchases of spectrum licenses and other intangible assets, including deposits
—

 
—

 
(2,900
)
 
—

 
—

 
(2,900
)
Investment in subsidiaries
(1,700
)
 
—

 
—

 
—

 
1,700

 
—

Other, net
—

 
—

 
(29
)
 
—

 
—

 
(29
)
Net cash used in investing activities
(1,700
)
 
—

 
(7,246
)
 
—

 
1,700

 
(7,246
)


Financing activities


Proceeds from capital contribution
—

 
1,700

 
—

 
—

 
(1,700
)
 
—

Proceeds from issuance of long-term debt
—

 
2,993

 
—

 
—

 
—

 
2,993

Repayments of long-term debt and capital lease obligations
—

 
—

 
(1,019
)
 
—

 
—

 
(1,019
)
Proceeds from issuance of preferred stock
982

 
—

 
—

 
—

 
—

 
982

Repayments of short-term debt for purchases of inventory, property and equipment, net
—

 
—

 
(418
)
 
—

 
—

 
(418
)
Intercompany dividend paid
—

 
—

 
—

 
(100
)
 
100

 
—

Proceeds from exercise of stock options
27

 
—

 
—

 
—

 
—

 
27

Taxes paid related to net share settlement of stock awards
—

 
—

 
(73
)
 
—

 
—

 
(73
)
Other, net
—

 
—

 
32

 
—

 
—

 
32

Net cash provided by (used in) financing activities
1,009

 
4,693

 
(1,478
)
 
(100
)
 
(1,600
)
 
2,524


Change in cash and cash equivalents
(682
)
 
(452
)
 
640

 
(82
)
 
—

 
(576
)
Cash and cash equivalents


Beginning of period
2,960

 
2,698

 
57

 
176

 
—

 
5,891

End of period
$
2,278

 
$
2,246

 
$
697

 
$
94

 
$
—

 
$
5,315


Condensed Consolidating Statement of Cash Flows Information
Year Ended December 31, 2013
(in millions)
Parent
 
Issuer
 
Guarantor Subsidiaries
 
Non-Guarantor Subsidiaries
 
Consolidating and Eliminating Adjustments
 
Consolidated
Operating activities


Net cash provided by (used in) operating activities
$
299

 
$
(1,203
)
 
$
4,380

 
$
69

 
$
—

 
$
3,545


Investing activities


Purchases of property and equipment
—

 
—

 
(4,025
)
 
—

 
—

 
(4,025
)
Purchases of spectrum licenses and other intangible assets
—

 
—

 
(381
)
 
—

 
—

 
(381
)
Short term affiliate loan receivable, net
—

 
—

 
300

 
—

 
—

 
300

Cash and cash equivalents acquired in MetroPCS business combination
737

 
1,407

 
—

 
—

 
—

 
2,144

Other, net
—

 
—

 
(130
)
 
—

 
—

 
(130
)
Net cash provided by (used in) investing activities
737

 
1,407

 
(4,236
)
 
—

 
—

 
(2,092
)


Financing activities


Proceeds from issuance of long-term debt
—

 
2,494

 
—

 
—

 
—

 
2,494

Repayment of capital lease obligations
—

 
—

 
(9
)
 
—

 
—

 
(9
)
Proceeds from issuance of common stock
1,787

 
—

 
—

 
—

 
—

 
1,787

Repayments of short-term debt for purchases of property and equipment
—

 
—

 
(244
)
 
—

 
—

 
(244
)
Proceeds from exercise of stock options
137

 
—

 
—

 
—

 
—

 
137

Other, net
—

 
—

 
(121
)
 
—

 
—

 
(121
)
Net cash provided by (used in) financing activities
1,924

 
2,494

 
(374
)
 
—

 
—

 
4,044


Change in cash and cash equivalents
2,960

 
2,698

 
(230
)
 
69

 
—

 
5,497

Cash and cash equivalents


Beginning of period
—

 
—

 
287

 
107

 
—

 
394

End of period
$
2,960

 
$
2,698

 
$
57

 
$
176

 
$
—

 
$
5,891


v3.3.1.900
Quarterly Financial Information (Unaudited) (Tables)
12 Months Ended
Dec. 31, 2015
Quarterly Financial Information (Unaudited) [Abstract]  
Schedule of Quarterly Financial Information
(in millions, except shares and per share amounts)
First Quarter
 
Second Quarter
 
Third Quarter
 
Fourth Quarter
 
Full Year
2015


Total revenues
$
7,778

 
$
8,179

 
$
7,849

 
$
8,247

 
$
32,053

Operating income
117

 
597

 
513

 
838

 
2,065

Net income (loss)
(63
)
 
361

 
138

 
297

 
733

Dividends on preferred stock
(14
)
 
(14
)
 
(13
)
 
(14
)
 
(55
)
Net income (loss) attributable to common stockholders
(77
)
 
347

 
125

 
283

 
678

Earnings (loss) per share


Basic
$
(0.09
)
 
$
0.43

 
$
0.15

 
$
0.35

 
$
0.83

Diluted
$
(0.09
)
 
$
0.42

 
$
0.15

 
$
0.34

 
$
0.82

Weighted average shares outstanding


Basic
808,605,526

 
811,605,031

 
815,069,272

 
816,585,782

 
812,994,028

Diluted
808,605,526

 
821,122,537

 
822,017,220

 
824,716,119

 
822,617,938

Net income (loss) includes:


Cost of MetroPCS business combination
$
128

 
$
34

 
$
193

 
$
21

 
$
376

Gains on disposal of spectrum licenses
—

 
(23
)
 
(1
)
 
(139
)
 
(163
)
2014


Total revenues
$
6,875

 
$
7,185

 
$
7,350

 
$
8,154

 
$
29,564

Operating income (loss)
(28
)
 
962

 
49

 
433

 
1,416

Net income (loss)
(151
)
 
391

 
(94
)
 
101

 
247

Earnings (loss) per share


Basic
$
(0.19
)
 
$
0.49

 
$
(0.12
)
 
$
0.13

 
$
0.31

Diluted
$
(0.19
)
 
$
0.48

 
$
(0.12
)
 
$
0.12

 
$
0.30

Weighted average shares outstanding


Basic
802,520,723

 
803,923,913

 
807,221,761

 
807,396,425

 
805,284,712

Diluted
802,520,723

 
813,556,137

 
807,221,761

 
821,707,289

 
815,922,258

Net income (loss) includes:


Cost of MetroPCS business combination
$
12

 
$
22

 
$
97

 
$
168

 
$
299

Gains on disposal of spectrum licenses
(10
)
 
(747
)
 
(13
)
 
(70
)
 
(840
)

v3.3.1.900
Summary of Significant Accounting Policies (Details) - USD ($)
$ in Millions
12 Months Ended
Dec. 31, 2015
Dec. 31, 2014
Dec. 31, 2013
Guarantee liabilities $ 163 $ 286  
Maximum potential for losses under guarantor liabilities 2,300    
Federal Universal Service Fund and other fees 334 349 $ 362
Advertising expense $ 1,600 $ 1,400 $ 1,000

v3.3.1.900
Business Combination with MetroPCS (Cost of MetroPCS Business Combination) (Details) - USD ($)
$ in Millions
3 Months Ended 12 Months Ended
Dec. 31, 2015
Sep. 30, 2015
Jun. 30, 2015
Mar. 31, 2015
Dec. 31, 2014
Sep. 30, 2014
Jun. 30, 2014
Mar. 31, 2014
Dec. 31, 2015
Dec. 31, 2014
Dec. 31, 2013
Business Acquisition [Line Items]                      
Cost of MetroPCS business combination $ 21 $ 193 $ 34 $ 128 $ 168 $ 97 $ 22 $ 12 $ 376 $ 299 $ 108
Balance, beginning of period       78         78    
Balance, end of period 117       78       117 78  
Asset retirement obligations settled                 (130) (21)  
MetroPCS Network Decomissioning Costs [Member]                      
Business Acquisition [Line Items]                      
Balance, beginning of period       239       $ 0 239 0  
Network decommissioning costs, excluding the write-off of certain items                 349 271  
Cash Payments                 (182) (32)  
Balance, end of period 406       239       406 239 0
MetroPCS Network Decomissioning Costs [Member]                      
Business Acquisition [Line Items]                      
Network decommissioning costs, including effects of deferred items                 376 263 0
MetroPCS Transaction and Integration Costs [Member]                      
Business Acquisition [Line Items]                      
Cost of MetroPCS business combination                 0 36 108
MetroPCS Transaction Costs [Member]                      
Business Acquisition [Line Items]                      
Cost of MetroPCS business combination                     $ 41
Accounts Payable and Accrued Liabilities [Member] | MetroPCS Network Decomissioning Costs [Member]                      
Business Acquisition [Line Items]                      
Balance, beginning of period       78         78    
Balance, end of period 117       78       117 78  
Other Noncurrent Liabilities [Member] | MetroPCS Network Decomissioning Costs [Member]                      
Business Acquisition [Line Items]                      
Balance, beginning of period       $ 161         161    
Balance, end of period $ 289       $ 161       $ 289 $ 161  

v3.3.1.900
Business Combination with MetroPCS (Consolidated Statements of Comprehensive Income (Loss) for MetroPCS Operations) (Details) - MetroPCS [Member]
$ in Millions
8 Months Ended
Dec. 31, 2013
USD ($)
Business Acquisition [Line Items]  
Total revenues $ 3,366
Income before income taxes $ 143

v3.3.1.900
Business Combination with MetroPCS (Proforma Financial Information) (Details) - USD ($)
$ / shares in Units, $ in Millions
12 Months Ended
Dec. 31, 2013
Dec. 31, 2012
MetroPCS [Member]    
Business Acquisition [Line Items]    
Pro forma revenues $ 26,158  
Pro forma net income (loss) $ 52  
Pro forma basic earnings per share $ 0.07  
Pro forma diluted earnings per share $ 0.07  
Senior unsecured notes issued $ 14,700  
Senior unsecured notes of acquiror retired 14,500  
Senior unsecured notes of acquiree retired 2,500  
Pro Forma Adjustment, Acquisition-related Costs [Member] | MetroPCS [Member]    
Business Acquisition [Line Items]    
Pro forma net income (loss) 213 $ (213)
Pro Forma Adjustment, (Increase) Decrease in Tax Expense [Member]    
Business Acquisition [Line Items]    
Pro forma net income (loss) (63)  
Pro Forma Adjustment, (Increase) in Amortization and Depreciation Expense [Member]    
Business Acquisition [Line Items]    
Pro forma net income (loss) 19  
Pro Forma Adjustment, (Increase) in Interest Expense [Member]    
Business Acquisition [Line Items]    
Pro forma net income (loss) $ (91)  

v3.3.1.900
Sales of Certain Receivables Sales of Service Receivables (Details) - USD ($)
$ in Millions
Dec. 31, 2015
Dec. 31, 2014
Variable Interest Entity [Line Items]    
Other current assets $ 1,813 $ 1,593
Accounts payable and accrued liabilities 8,084 7,364
Other current liabilities 410 635
Factoring Arrangement [Member] | Variable Interest Entity, Not Primary Beneficiary [Member]    
Variable Interest Entity [Line Items]    
Maximum Funding Limit 750  
Other current assets 206 204
Accounts payable and accrued liabilities 0 13
Other current liabilities $ 73 $ 55

v3.3.1.900
Sales of Certain Receivables Sales of EIP Receivables (Details) - USD ($)
$ in Millions
Dec. 31, 2015
Dec. 31, 2014
Variable Interest Entity [Line Items]    
Other current assets $ 1,813 $ 1,593
Other assets 467 288
Accounts payable and accrued liabilities 8,084 7,364
EIP Securitization Arrangement [Member]    
Variable Interest Entity [Line Items]    
Maximum Funding Limit 800  
Maximum Funding Limit - Portion due within one year 150  
Maximum Funding Limit - portion due one year or longer 650  
Other current assets 164 0
Other assets 44 0
Accounts payable and accrued liabilities 14 0
Other long-term liabilities $ 3 $ 0

v3.3.1.900
Sales of Certain Receivables Sales of Receivables (Details) - USD ($)
$ in Millions
12 Months Ended
Dec. 31, 2015
Dec. 31, 2014
Dec. 31, 2013
Qualitative and Quantitative Information, Transferor's Continuing Involvement [Line Items]      
Other current assets $ 1,813 $ 1,593  
Other assets 467 288  
Accounts payable and accrued liabilities 8,084 7,364  
Other current liabilities 410 635  
Other long-term liabilities 1,067 616  
Net expenses 204 179 $ 0
Factoring and EIP Securitization Arrangement [Member]      
Qualitative and Quantitative Information, Transferor's Continuing Involvement [Line Items]      
Trading Securities 389    
Derecognized net service receivables and EIP receivables 1,850 768  
Other current assets 370 204  
Other assets 44 0  
Accounts payable and accrued liabilities 14 13  
Other current liabilities 73 55  
Other long-term liabilities 3 0  
Net cash proceeds since inception 1,494 610  
Net cash proceeds during the period 884 610  
Net cash proceeds funded by reinvested collections 610 0  
Net expenses 204 179  
Maximum exposure to loss, Factoring VIE 767    
Other Current Assets [Member] | Factoring and EIP Securitization Arrangement [Member]      
Qualitative and Quantitative Information, Transferor's Continuing Involvement [Line Items]      
Trading Securities 345 $ 204  
Other Assets [Member] | Factoring and EIP Securitization Arrangement [Member]      
Qualitative and Quantitative Information, Transferor's Continuing Involvement [Line Items]      
Trading Securities $ 44    

v3.3.1.900
Equipment Installment Plan Receivables (EIP Receivables) (Details) - USD ($)
$ in Millions
12 Months Ended
Dec. 31, 2015
Dec. 31, 2014
Receivables [Abstract]    
Equipment installment plan, maximum payment term 24 months  
Accounts, Notes, Loans and Financing Receivable [Line Items]    
Equipment installment plan receivables, gross $ 3,558 $ 5,138
Equipment installment plan receivables, unamortized imputed interest (185) (332)
Equipment installment plan receivables, net of unamortized imputed interest 3,373 4,806
Equipment installment plan receivables, allowances for credit losses (148) (116)
Equipment installment plan receivables, net 3,225 4,690
Equipment Installment Plan Receivables, Net [Member]    
Accounts, Notes, Loans and Financing Receivable [Line Items]    
Equipment installment plan receivables, net 2,378 3,062
Equipment Installment Plan Receivables Due After One Year, Net [Member]    
Accounts, Notes, Loans and Financing Receivable [Line Items]    
Equipment installment plan receivables, net $ 847 $ 1,628

v3.3.1.900
Equipment Installment Plan Receivables (Gross Receivables by Credit Category) (Details) - USD ($)
$ in Millions
Dec. 31, 2015
Dec. 31, 2014
Financing Receivable, Recorded Investment [Line Items]    
Equipment installment plan receivables, gross $ 3,558 $ 5,138
Unbilled Revenues [Member]    
Financing Receivable, Recorded Investment [Line Items]    
Equipment installment plan receivables 3,291 4,852
Billed Revenues [Member]    
Financing Receivable, Recorded Investment [Line Items]    
Equipment installment plan receivables 168 199
Equipment installment plan receivables, past due 99 87
Prime [Member]    
Financing Receivable, Recorded Investment [Line Items]    
Equipment installment plan receivables, gross 1,707 2,778
Prime [Member] | Unbilled Revenues [Member]    
Financing Receivable, Recorded Investment [Line Items]    
Equipment installment plan receivables 1,593 2,639
Prime [Member] | Billed Revenues [Member]    
Financing Receivable, Recorded Investment [Line Items]    
Equipment installment plan receivables 77 104
Equipment installment plan receivables, past due 37 35
Subprime [Member]    
Financing Receivable, Recorded Investment [Line Items]    
Equipment installment plan receivables, gross 1,851 2,360
Subprime [Member] | Unbilled Revenues [Member]    
Financing Receivable, Recorded Investment [Line Items]    
Equipment installment plan receivables 1,698 2,213
Subprime [Member] | Billed Revenues [Member]    
Financing Receivable, Recorded Investment [Line Items]    
Equipment installment plan receivables 91 95
Equipment installment plan receivables, past due $ 62 $ 52

v3.3.1.900
Equipment Installment Plan Receivables (Unamortized Imputed Discount and Allowance for Credit Losses) (Details) - Equipment Installment Plan Receivable [Member] - USD ($)
$ in Millions
12 Months Ended
Dec. 31, 2015
Dec. 31, 2014
Financing Receivable, Allowance for Credit Losses [Line Items]    
Receivable with Imputed Interest, Effective Yield (Interest Rate) 8.80% 9.70%
Financing Receivable, Allowance for Credit Losses [Roll Forward]    
Imputed discount and allowance for credit losses, beginning of year $ 448 $ 336
Bad debt expense 365 285
Write-offs, net of recoveries (333) (229)
Change in imputed discount on short-term and long-term EIP receivables (84) 56
Impacts from sales of EIP receivables (63) 0
Imputed discount and allowance for credit losses, end of year $ 333 $ 448

v3.3.1.900
Property and Equipment (Property, Plant and Equipment) (Details) - USD ($)
$ in Millions
12 Months Ended
Dec. 31, 2015
Dec. 31, 2014
Dec. 31, 2013
Property, Plant and Equipment [Line Items]      
Accumulated depreciation and amortization $ (23,192) $ (21,791)  
Property and equipment, net 20,000 16,245  
Capital leased assets, gross 839 364  
Capital leases assets, accumulated amortization 117 53  
Capitalized interest 230 81 $ 5
Depreciation expense 4,400 4,100 $ 3,400
Additional depreciation expense 85 242  
Buildings and Equipment [Member]      
Property, Plant and Equipment [Line Items]      
Property and equipment 1,900 1,948  
Wireless Communications Systems [Member]      
Property, Plant and Equipment [Line Items]      
Property and equipment 27,063 25,633  
Leasehold Improvements [Member]      
Property, Plant and Equipment [Line Items]      
Property and equipment 1,003 988  
Capitalized Software [Member]      
Property, Plant and Equipment [Line Items]      
Property and equipment 8,524 7,593  
Leased wireless devices [Member]      
Property, Plant and Equipment [Line Items]      
Property and equipment 2,236 0  
Construction in Progress [Member]      
Property, Plant and Equipment [Line Items]      
Property and equipment $ 2,466 $ 1,874  
Maximum [Member] | Buildings and Equipment [Member]      
Property, Plant and Equipment [Line Items]      
Useful lives 40 years    
Maximum [Member] | Wireless Communications Systems [Member]      
Property, Plant and Equipment [Line Items]      
Useful lives 20 years    
Maximum [Member] | Leasehold Improvements [Member]      
Property, Plant and Equipment [Line Items]      
Useful lives 12 years    
Maximum [Member] | Capitalized Software [Member]      
Property, Plant and Equipment [Line Items]      
Useful lives 7 years    
Maximum [Member] | Leased wireless devices [Member]      
Property, Plant and Equipment [Line Items]      
Useful lives 18 months    

v3.3.1.900
Property and Equipment (Leased Devices) (Details) - USD ($)
$ in Millions
12 Months Ended
Dec. 31, 2015
Dec. 31, 2014
Property, Plant and Equipment [Line Items]    
Depreciation Expense for Leased Devices $ 312  
Property Subject to or Available for Operating Lease, Net [Abstract]    
Leased wireless devices, gross 2,236 $ 0
Accumulated depreciation (263) 0
Leased wireless devices, net 1,973 $ 0
Operating Leases, Future Minimum Payments Receivable [Abstract]    
2016 913  
2017 347  
Total $ 1,260  
Maximum [Member]    
Property, Plant and Equipment [Line Items]    
Leased devices, lease term 18 months  

v3.3.1.900
Property and Equipment (Asset Retirement Obligation) (Details) - USD ($)
$ in Millions
12 Months Ended
Dec. 31, 2015
Dec. 31, 2014
Asset retirement obligations, beginning of year $ 390 $ 388
Liabilities incurred 19 3
Liabilities settled (130) (21)
Accretion expense 17 20
Changes in estimated cash flows 187 0
Asset retirement obligations, end of year 483 390
Asset retirement costs capitalized, net 241 95
Other Current Liabilities [Member]    
Asset retirement obligations, beginning of year 179  
Asset retirement obligations, end of year 41 179
Other Long-Term Liabilities [Member]    
Asset retirement obligations, beginning of year 211  
Asset retirement obligations, end of year $ 442 $ 211

v3.3.1.900
Goodwill, Spectrum Licenses and Intangible Assets (Goodwill) (Details) - USD ($)
12 Months Ended
Dec. 31, 2015
Dec. 31, 2014
Goodwill and Intangible Assets Disclosure [Abstract]    
Goodwill, net change $ 0 $ 0

v3.3.1.900
Goodwill, Spectrum Licenses and Intangible Assets (Spectrum Licenses) (Details) - USD ($)
$ in Millions
3 Months Ended 12 Months Ended
Dec. 31, 2015
Sep. 30, 2015
Jun. 30, 2015
Mar. 31, 2015
Dec. 31, 2014
Sep. 30, 2014
Jun. 30, 2014
Mar. 31, 2014
Dec. 31, 2015
Dec. 31, 2014
Dec. 31, 2013
Indefinite-lived Intangible Assets [Line Items]                      
Spectrum licenses $ 23,955       $ 21,955       $ 23,955 $ 21,955 $ 18,122
Spectrum licenses, net changes                 2,000 3,833  
Purchases of spectrum licenses and other intangible assets                 1,935 2,900 381
Gains on disposal of spectrum licenses 139 $ 1 $ 23 $ 0 70 $ 13 $ 747 $ 10 163 840 $ 2
Verizon [Member]                      
Indefinite-lived Intangible Assets [Line Items]                      
Purchases of spectrum licenses and other intangible assets                   2,500  
Fair value of spectrum licenses acquired                   4,800  
Gains on disposal of spectrum licenses                   800  
Verizon [Member] | Licensing Agreements [Member]                      
Indefinite-lived Intangible Assets [Line Items]                      
Fair value of spectrum licenses acquired                 300    
Gains on disposal of spectrum licenses                 100    
FCC Spectrum Auction [Member] | Licensing Agreements [Member]                      
Indefinite-lived Intangible Assets [Line Items]                      
Purchases of spectrum licenses and other intangible assets                 1,400    
Fair value of spectrum licenses acquired                 1,800    
Deposit provided to FCC in connection with auction         $ 400         $ 400  
AT&T [Member] | Licensing Agreements [Member]                      
Indefinite-lived Intangible Assets [Line Items]                      
Assets held-for-sale $ 500               $ 500    

v3.3.1.900
Goodwill, Spectrum Licenses and Intangible Assets (Other Intangibles Assets) (Details) - USD ($)
$ in Millions
12 Months Ended
Dec. 31, 2015
Dec. 31, 2014
Dec. 31, 2013
Finite-Lived Intangible Assets [Line Items]      
Other intangible assets, gross $ 1,455 $ 1,679  
Accumulated amortization (861) (809)  
Other intangible assets, net 594 870  
Amortization expense for intangible assets 276 333 $ 255
Future Amortization Expense:      
2016 221    
2017 163    
2018 104    
2019 51    
2020 34    
Thereafter 21    
Customer lists [Member]      
Finite-Lived Intangible Assets [Line Items]      
Other intangible assets, gross 1,104 1,313  
Accumulated amortization (719) (700)  
Other intangible assets, net $ 385 613  
Customer lists [Member] | Maximum [Member]      
Finite-Lived Intangible Assets [Line Items]      
Intangible assets, useful lives 6 years    
Trademarks and patents [Member]      
Finite-Lived Intangible Assets [Line Items]      
Other intangible assets, gross $ 300 295  
Accumulated amortization (115) (78)  
Other intangible assets, net $ 185 217  
Trademarks and patents [Member] | Maximum [Member]      
Finite-Lived Intangible Assets [Line Items]      
Intangible assets, useful lives 12 years    
Other [Member]      
Finite-Lived Intangible Assets [Line Items]      
Other intangible assets, gross $ 51 71  
Accumulated amortization (27) (31)  
Other intangible assets, net $ 24 $ 40  
Other [Member] | Maximum [Member]      
Finite-Lived Intangible Assets [Line Items]      
Intangible assets, useful lives 28 years    

v3.3.1.900
Fair Value Measurements and Derivative Instruments (Narrative) (Details)
Dec. 31, 2015
Dec. 31, 2014
Embedded Derivative Instruments [Member]    
Derivative    
Number of embedded derivative instruments 1 5

v3.3.1.900
Fair Value Measurements and Derivative Instruments (Fair Value of Financial Instruments by Level) (Details) - Embedded Derivative Instruments [Member] - USD ($)
$ in Millions
Dec. 31, 2015
Dec. 31, 2014
Other Long-Term Liabilities [Member]    
Fair Value, Assets and Liabilities Measured on Recurring and Nonrecurring Basis [Line Items]    
Embedded derivative instruments, liabilities $ 143  
Other Long-Term Liabilities [Member] | Fair Value, Inputs, Level 1 [Member]    
Fair Value, Assets and Liabilities Measured on Recurring and Nonrecurring Basis [Line Items]    
Embedded derivative instruments, liabilities 0  
Other Long-Term Liabilities [Member] | Fair Value, Inputs, Level 2 [Member]    
Fair Value, Assets and Liabilities Measured on Recurring and Nonrecurring Basis [Line Items]    
Embedded derivative instruments, liabilities 0  
Other Long-Term Liabilities [Member] | Fair Value, Inputs, Level 3 [Member]    
Fair Value, Assets and Liabilities Measured on Recurring and Nonrecurring Basis [Line Items]    
Embedded derivative instruments, liabilities $ 143  
Other Current Assets [Member]    
Fair Value, Assets and Liabilities Measured on Recurring and Nonrecurring Basis [Line Items]    
Embedded derivative instruments, Assets   $ 3
Other Current Assets [Member] | Fair Value, Inputs, Level 1 [Member]    
Fair Value, Assets and Liabilities Measured on Recurring and Nonrecurring Basis [Line Items]    
Embedded derivative instruments, Assets   0
Other Current Assets [Member] | Fair Value, Inputs, Level 2 [Member]    
Fair Value, Assets and Liabilities Measured on Recurring and Nonrecurring Basis [Line Items]    
Embedded derivative instruments, Assets   0
Other Current Assets [Member] | Fair Value, Inputs, Level 3 [Member]    
Fair Value, Assets and Liabilities Measured on Recurring and Nonrecurring Basis [Line Items]    
Embedded derivative instruments, Assets   3
Other Assets [Member]    
Fair Value, Assets and Liabilities Measured on Recurring and Nonrecurring Basis [Line Items]    
Embedded derivative instruments, Assets   2
Other Assets [Member] | Fair Value, Inputs, Level 1 [Member]    
Fair Value, Assets and Liabilities Measured on Recurring and Nonrecurring Basis [Line Items]    
Embedded derivative instruments, Assets   0
Other Assets [Member] | Fair Value, Inputs, Level 2 [Member]    
Fair Value, Assets and Liabilities Measured on Recurring and Nonrecurring Basis [Line Items]    
Embedded derivative instruments, Assets   0
Other Assets [Member] | Fair Value, Inputs, Level 3 [Member]    
Fair Value, Assets and Liabilities Measured on Recurring and Nonrecurring Basis [Line Items]    
Embedded derivative instruments, Assets   $ 2

v3.3.1.900
Fair Value Measurements and Derivative Instruments (Gains (Losses) of Derivative Instruments) (Details) - USD ($)
$ in Millions
12 Months Ended
Dec. 31, 2015
Dec. 31, 2014
Dec. 31, 2013
Derivative      
Embedded derivative $ (148) $ 18 $ (13)
Embedded Derivative Instruments [Member] | Interest Expense to Affiliates [Member]      
Derivative      
Embedded derivative $ (148) $ 18 $ (13)

v3.3.1.900
Fair Value Measurements and Derivative Instruments Fair Value of Short-term Investments and Long-term Debt (Details) - USD ($)
$ in Millions
Dec. 31, 2015
Dec. 31, 2014
Fair Value, Inputs, Level 1 [Member] | Carrying Amount [Member]    
Fair Value, Balance Sheet Grouping, Financial Statement Captions [Line Items]    
Short-term investments $ 2,998 $ 0
Long-term debt 17,600 15,600
Fair Value, Inputs, Level 1 [Member] | Fair Value [Member]    
Fair Value, Balance Sheet Grouping, Financial Statement Captions [Line Items]    
Short-term investments 2,998 0
Long-term debt 18,098 16,034
Fair Value, Inputs, Level 2 [Member] | Carrying Amount [Member]    
Fair Value, Balance Sheet Grouping, Financial Statement Captions [Line Items]    
Long-term debt 2,000 0
Fair Value, Inputs, Level 2 [Member] | Fair Value [Member]    
Fair Value, Balance Sheet Grouping, Financial Statement Captions [Line Items]    
Long-term debt 1,990 0
Deutsche Telekom [Member] | Fair Value, Inputs, Level 2 [Member] | Carrying Amount [Member]    
Fair Value, Balance Sheet Grouping, Financial Statement Captions [Line Items]    
Long-term debt 5,600 5,600
Deutsche Telekom [Member] | Fair Value, Inputs, Level 2 [Member] | Fair Value [Member]    
Fair Value, Balance Sheet Grouping, Financial Statement Captions [Line Items]    
Long-term debt $ 6,072 $ 5,780

v3.3.1.900
Debt (Narrative) (Details)
$ in Billions
Dec. 31, 2015
USD ($)
6.500% Senior Notes due 2026 [Member]  
Debt Instrument [Line Items]  
Long-term debt $ 2.0
Interest rate, stated percentage 6.50%
Secured Debt [Member]  
Debt Instrument [Line Items]  
Long-term debt $ 2.0
Debt Instrument, Interest Rate, Basis for Effective Rate 2.75%
Debt Instrument, Interest Rate, Effective Percentage 3.50%
Repayment Percent Of Original Aggregate Principal Amount 0.25%
Deutsche Telekom [Member] | 5.950% Senior Reset Notes due 2023 (reset date in April 2016) [Member]  
Debt Instrument [Line Items]  
Interest rate, stated percentage 5.95%

v3.3.1.900
Debt (Long-term debt) (Details) - USD ($)
$ in Millions
Dec. 31, 2015
Dec. 31, 2014
Debt Instrument [Line Items]    
Unamortized premium from purchase price allocation fair value adjustment $ 250 $ 286
Unamortized discount on Senior Secured Term Loans (10) 0
Capital leases 826 410
Total debt 26,266 21,960
Current portion of Senior Secured Term Loans 20 0
Current portion of capital leases 162 23
Total long-term debt 26,084 21,873
Long-term debt 20,484 16,273
Long-term debt to affiliates 5,600 5,600
5.250% Senior Notes due 2018 [Member]    
Debt Instrument [Line Items]    
Long-term debt $ 500 500
Interest rate, stated percentage 5.25%  
6.464% Senior Notes due 2019 [Member]    
Debt Instrument [Line Items]    
Long-term debt $ 1,250 1,250
Interest rate, stated percentage 6.464%  
6.542% Senior Notes due 2020 [Member]    
Debt Instrument [Line Items]    
Long-term debt $ 1,250 1,250
Interest rate, stated percentage 6.542%  
6.625% Senior Notes due 2020 [Member]    
Debt Instrument [Line Items]    
Long-term debt $ 1,000 1,000
Interest rate, stated percentage 6.625%  
6.250% Senior Notes due 2021 [Member]    
Debt Instrument [Line Items]    
Long-term debt $ 1,750 1,750
Interest rate, stated percentage 6.25%  
6.633% Senior Notes due 2021 [Member]    
Debt Instrument [Line Items]    
Long-term debt $ 1,250 1,250
Interest rate, stated percentage 6.633%  
6.125% Senior Notes due 2022 [Member]    
Debt Instrument [Line Items]    
Long-term debt $ 1,000 1,000
Interest rate, stated percentage 6.125%  
6.731% Senior Notes due 2022 [Member]    
Debt Instrument [Line Items]    
Long-term debt $ 1,250 1,250
Interest rate, stated percentage 6.731%  
6.000% Senior Notes due 2023 [Member]    
Debt Instrument [Line Items]    
Long-term debt $ 1,300 1,300
Interest rate, stated percentage 6.00%  
6.625% Senior Notes due 2023 [Member]    
Debt Instrument [Line Items]    
Long-term debt $ 1,750 1,750
Interest rate, stated percentage 6.625%  
6.836% Senior Notes due 2023 [Member]    
Debt Instrument [Line Items]    
Long-term debt $ 600 600
Interest rate, stated percentage 6.836%  
6.500% Senior Notes due 2024 [Member]    
Debt Instrument [Line Items]    
Long-term debt $ 1,000 1,000
Interest rate, stated percentage 6.50%  
6.375% Senior Notes due 2025 [Member]    
Debt Instrument [Line Items]    
Long-term debt $ 1,700 1,700
Interest rate, stated percentage 6.375%  
6.500% Senior Notes due 2026 [Member]    
Debt Instrument [Line Items]    
Long-term debt $ 2,000 0
Interest rate, stated percentage 6.50%  
Secured Debt [Member]    
Debt Instrument [Line Items]    
Long-term debt $ 2,000 0
Product Financing Arrangement [Member]    
Debt Instrument [Line Items]    
Financing arrangements 0 64
Deutsche Telekom [Member]    
Debt Instrument [Line Items]    
Long-term debt to affiliates 5,600 5,600
Deutsche Telekom [Member] | 6.288% Senior Reset Notes due 2019 [Member]    
Debt Instrument [Line Items]    
Long term-debt to affiliates $ 1,250 1,250
Interest rate, stated percentage 6.288%  
Deutsche Telekom [Member] | 6.366% Senior Reset Notes due 2020 [Member]    
Debt Instrument [Line Items]    
Long term-debt to affiliates $ 1,250 1,250
Interest rate, stated percentage 6.366%  
Deutsche Telekom [Member] | 8.097% Senior Reset Notes due 2021 [Member]    
Debt Instrument [Line Items]    
Long term-debt to affiliates $ 1,250 1,250
Interest rate, stated percentage 8.097%  
Deutsche Telekom [Member] | 8.195% Senior Reset Notes due 2022 [Member]    
Debt Instrument [Line Items]    
Long term-debt to affiliates $ 1,250 1,250
Interest rate, stated percentage 8.195%  
Deutsche Telekom [Member] | 5.950% Senior Reset Notes due 2023 (reset date in April 2016) [Member]    
Debt Instrument [Line Items]    
Long term-debt to affiliates $ 600 $ 600
Interest rate, stated percentage 5.95%  
Scenario, Previously Reported [Member] | Deutsche Telekom [Member] | 6.288% Senior Reset Notes due 2019 [Member]    
Debt Instrument [Line Items]    
Interest rate, stated percentage 5.578%  
Scenario, Previously Reported [Member] | Deutsche Telekom [Member] | 6.366% Senior Reset Notes due 2020 [Member]    
Debt Instrument [Line Items]    
Interest rate, stated percentage 5.656%  
Scenario, Previously Reported [Member] | Deutsche Telekom [Member] | 8.097% Senior Reset Notes due 2021 [Member]    
Debt Instrument [Line Items]    
Interest rate, stated percentage 5.747%  
Scenario, Previously Reported [Member] | Deutsche Telekom [Member] | 8.195% Senior Reset Notes due 2022 [Member]    
Debt Instrument [Line Items]    
Interest rate, stated percentage 5.845%  

v3.3.1.900
Debt (Capital Leases) (Details)
$ in Millions
Dec. 31, 2015
USD ($)
Debt Disclosure [Abstract]  
Capital leases, future minimum payments, next rolling twelve months $ 199
Capital leases, future minimum payments, next rolling year two 189
Capital leases, future minimum payments, next rolling year three 158
Capital leases, future minimum payments, next rolling year four 128
Capital leases, future minimum payments, next rolling year five 56
Capital leases, future minimum payments, due rolling after year five 267
Capital leases, future minimum payments due 997
Capital leases, future minimum payments, interest included in payments $ 171

v3.3.1.900
Debt (Financing Arrangements) (Details) - USD ($)
12 Months Ended
Dec. 31, 2015
Dec. 31, 2014
Dec. 31, 2013
Short-term Debt [Line Items]      
Repayments of short-term debt for purchases of inventory, property and equipment, net $ (564,000,000) $ (418,000,000) $ (244,000,000)
Handset Financing Arrangement [Member]      
Short-term Debt [Line Items]      
Borrowing capacity 108,000,000    
Repayments of short-term debt for purchases of inventory, property and equipment, net (100,000,000) (100,000,000)  
Short-term Debt, outstanding 0 0  
Vendor Financing Arrangement [Member]      
Short-term Debt [Line Items]      
Short-term Debt, outstanding $ 0 $ 64,000,000  

v3.3.1.900
Debt (Lines and Letters of Credit) (Details) - USD ($)
Dec. 31, 2015
Dec. 31, 2014
Line of Credit Facility [Line Items]    
Letters of credit, amount outstanding $ 90,000,000 $ 86,000,000
Deutsche Telekom [Member]    
Line of Credit Facility [Line Items]    
Line of credit facility, current borrowing capacity 500,000,000  
Line of credit facility, amount outstanding 0 0
JP Morgan Chase [Member]    
Line of Credit Facility [Line Items]    
Letters of credit, amount outstanding 36,000,000 36,000,000
Deutsche Bank [Member]    
Line of Credit Facility [Line Items]    
Letters of credit, amount outstanding $ 54,000,000 $ 50,000,000

v3.3.1.900
Tower Obligations (Narrative) (Details)
$ in Millions
1 Months Ended 12 Months Ended
Nov. 30, 2012
USD ($)
Dec. 31, 2015
USD ($)
Tower Transaction [Member]    
Sale Leaseback Transaction [Line Items]    
Property subject to sale, number of units 7,100  
Net proceeds, financial obligation $ 2,500  
Property subject to failed sale leaseback transaction, number of units 6,200  
Lessee leasing arrangements, operating leases, term of contract 10 years 10 years
Imputed interest rate, financial obligation 8.00%  
Tower Transaction [Member] | Minimum [Member]    
Sale Leaseback Transaction [Line Items]    
Lessee leasing arrangements, operating leases, term of contract 23 years  
Tower Transaction [Member] | Maximum [Member]    
Sale Leaseback Transaction [Line Items]    
Lessee leasing arrangements, operating leases, term of contract 37 years  
Tower Transaction PTI [Member]    
Sale Leaseback Transaction [Line Items]    
Property subject to sale, number of units   600
Net proceeds, financial obligation   $ 140
Property subject to failed sale leaseback transaction, number of units   250
Imputed interest rate, financial obligation   3.00%

v3.3.1.900
Tower Obligations (Sale Leaseback Transaction) (Details) - USD ($)
$ in Millions
Dec. 31, 2015
Dec. 31, 2014
Leases [Abstract]    
Property and equipment, net $ 601 $ 604
Tower obligations $ 2,658 $ 2,521

v3.3.1.900
Tower Obligations (Future Minimum Payments) (Details)
$ in Millions
Dec. 31, 2015
USD ($)
Leases [Abstract]  
2016 $ 179
2017 180
2018 180
2019 180
2020 181
Thereafter 1,315
Total $ 2,215

v3.3.1.900
Employee Compensation and Benefit Plans (Stock Awards) (Details) - USD ($)
$ / shares in Units, $ in Millions
12 Months Ended
Dec. 31, 2015
Dec. 31, 2014
Dec. 31, 2013
Share-based Compensation Arrangement by Share-based Payment Award [Line Items]      
Stock-based compensation expense $ 201 $ 196 $ 100
Income tax benefit related to stock-based compensation 71 73 38
Taxes paid related to net share settlement of stock awards 156 73 0
Predecessor Plans [Member]      
Share-based Compensation Arrangement by Share-based Payment Award [Line Items]      
Realized excess tax benefit $ 79 $ 34 0
2013 Omnibus Incentive Plan [Member]      
Share-based Compensation Arrangement by Share-based Payment Award [Line Items]      
Shares authorized for issuance 63,000,000    
Shares available for future grant 29,000,000    
Restricted Stock Units (RSUs) and Performance Stock Units (PSUs) [Member]      
Share-based Compensation Arrangement by Share-based Payment Award [Line Items]      
Shares paid for tax withholding for share based compensation 4,176,464 2,203,673  
Unrecognized stock-based compensation expense $ 327    
Weighted-average period for recognition 2 years    
Total fair value of stock awards vested $ 445 $ 209 $ 2
(RSU and PSU Shares)      
Nonvested, Beginning 19,952,089    
Granted 9,760,057    
Vested (11,956,345)    
Forfeited (1,421,530)    
Nonvested, Ending 16,334,271 19,952,089  
(RSU and PSU Weighted Average Grant-Date Fair Value)      
Nonvested, Beginning $ 24.15    
Granted 35.56 $ 28.52 $ 22.07
Vested 25.28    
Forfeited 27.36    
Nonvested, Ending $ 29.95 $ 24.15  
Outstanding, weighted average remaining contractual term, ending 1 year 2 months 1 year 1 month  
Aggregate intrinsic value $ 639 $ 538  
Maximum [Member] | Restricted Stock Units (RSUs) [Member]      
Share-based Compensation Arrangement by Share-based Payment Award [Line Items]      
Award vesting period 3 years    
Maximum [Member] | Performance Stock Units (PSUs) [Member]      
Share-based Compensation Arrangement by Share-based Payment Award [Line Items]      
Award vesting period 3 years    

v3.3.1.900
Employee Compensation and Benefit Plans (Stock Options) (Details) - Predecessor Plans [Member] - USD ($)
$ / shares in Units, $ in Millions
12 Months Ended
Dec. 31, 2015
Dec. 31, 2014
(Stock Options)    
Outstanding, beginning 4,348,912  
Exercised (2,381,650)  
Expired (142,908)  
Outstanding, ending 1,824,354 4,348,912
(Stock Options Weighted Average Exercise Price)    
Outstanding, beginning $ 24.96  
Exercised 19.91  
Expired 38.32  
Outstanding, ending $ 30.50 $ 24.96
Outstanding, weighted average remaining contractual term, ending 2 years 8 months 3 years 8 months
Cash received from exercise of stock options $ 47 $ 27

v3.3.1.900
Employee Compensation and Benefit Plans (Employee Retirement Savings and Compensation Plans)) (Details) - USD ($)
$ in Millions
12 Months Ended
Dec. 31, 2015
Dec. 31, 2014
Dec. 31, 2013
Deferred Compensation Arrangement with Individual, Excluding Share-based Payments and Postretirement Benefits [Line Items]      
Employer retirement savings plan, matching contributions $ 73 $ 66 $ 58
Long Term Incentive Plan [Member]      
Deferred Compensation Arrangement with Individual, Excluding Share-based Payments and Postretirement Benefits [Line Items]      
Compensation expense 27 44 63
Payments made to participants $ 57 $ 60 $ 61

v3.3.1.900
Employee Compensation and Benefit Plans (Employee Stock Purchase Plan) (Details)
12 Months Ended
Dec. 31, 2015
shares
Employee Stock Purchase Plan (ESPP) Disclosures [Line Items]  
Share-based Compensation Arrangement by Share-based Payment Award, Maximum Employee Subscription Rate 15.00%
Share-based Compensation Arrangement by Share-based Payment Award, Discount from Market Price, Purchase Date 15.00%
Common Stock [Member]  
Employee Stock Purchase Plan (ESPP) Disclosures [Line Items]  
Stock Issued During Period, Shares, Employee Stock Purchase Plans 761,085

v3.3.1.900
Income Taxes (Income Tax Domestic and Foreign) (Details) - USD ($)
$ in Millions
12 Months Ended
Dec. 31, 2015
Dec. 31, 2014
Dec. 31, 2013
Income Tax Disclosure [Abstract]      
Income (loss) from income taxes, U.S. $ 898 $ 347 $ (5)
Income (loss) from income taxes, Puerto Rico 80 66 56
Income before income taxes $ 978 $ 413 $ 51

v3.3.1.900
Income Taxes (Components of Income Tax Expense) (Details) - USD ($)
$ in Millions
12 Months Ended
Dec. 31, 2015
Dec. 31, 2014
Dec. 31, 2013
Income Tax Disclosure [Abstract]      
Federal $ (30) $ 0 $ (10)
State 2 6 6
Puerto Rico 17 38 10
Total current tax expense (benefit) (11) 44 6
Federal 281 79 24
State (37) 40 (22)
Puerto Rico 12 3 8
Total deferred tax expense 256 122 10
Total income tax expense $ 245 $ 166 $ 16

v3.3.1.900
Income Taxes (Effective Income Tax Rate Reconciliation) (Details)
12 Months Ended
Dec. 31, 2015
Dec. 31, 2014
Dec. 31, 2013
Income Tax Disclosure [Abstract]      
Federal statutory income tax rate 35.00% 35.00% 35.00%
State taxes, net of federal benefit (1.10%) (8.80%) (31.80%)
Puerto Rico taxes, net of federal benefit 3.30% 5.00% 28.20%
Change in valuation allowance (3.20%) 18.80% (6.10%)
Permanent differences 1.60% 1.40% 11.30%
Federal tax credits, net of reserves (9.50%) (10.60%) 0.00%
Other, net (1.00%) (0.60%) (5.20%)
Effective income tax rate 25.10% 40.20% 31.40%

v3.3.1.900
Income Taxes (Deferred Tax Assets and Liabilities) (Details) - USD ($)
$ in Millions
Dec. 31, 2015
Dec. 31, 2014
Income Tax Disclosure [Abstract]    
Loss carryforwards $ 1,997 $ 2,354
Deferred rents 1,136 1,034
Reserves and accruals 928 454
Federal and state tax credits 349 295
Debt fair market value adjustment 97 111
Other 317 295
Deferred tax assets, gross 4,824 4,543
Valuation allowance (583) (614)
Deferred tax assets, net 4,241 3,929
Spectrum licenses 6,174 5,629
Property and equipment 1,950 1,877
Other intangible assets 178 297
Other 0 11
Total deferred tax liabilities 8,302 7,814
Net deferred tax liabilities 4,061 3,885
Current deferred tax assets, net 0 988
Non-current deferred tax liabilities, net $ 4,061 $ 4,873

v3.3.1.900
Income Taxes (Operating Loss Carryforwards) (Details) - USD ($)
$ in Millions
12 Months Ended
Dec. 31, 2015
Dec. 31, 2014
Operating Loss Carryforwards [Line Items]    
Unrecognized tax benefits, net operating losses $ 383  
Alternative minimum tax credit carryforward 142  
Foreign tax credits 349 $ 295
Valuation allowance 583 $ 614
Valuation allowance, change in amount (31)  
Valuation allowance, stock compensation 33  
Federal    
Operating Loss Carryforwards [Line Items]    
Operating loss carryforwards 1,600  
Unrecognized tax benefits, net operating losses 378  
Federal | Research Tax Credit Carryforward [Member]    
Operating Loss Carryforwards [Line Items]    
Foreign tax credits 186  
State    
Operating Loss Carryforwards [Line Items]    
Operating loss carryforwards $ 700  

v3.3.1.900
Income Taxes (Unrecognized Tax Benefits) (Details) - USD ($)
$ in Millions
12 Months Ended
Dec. 31, 2015
Dec. 31, 2014
Dec. 31, 2013
Income Tax Disclosure [Abstract]      
Unrecognized Tax Benefits, beginning of year $ 388 $ 178 $ 89
Gross decreases to tax positions in prior periods (112) (52) (18)
Gross increases to current period tax positions 135 262 24
Gross increase due to current year business combination 0 0 83
Unrecognized tax benefits, end of year 411 $ 388 $ 178
Unrecognized tax benefits, would impact effective tax rate $ 163    

v3.3.1.900
Earnings Per Share (Details) - USD ($)
$ / shares in Units, $ in Millions
3 Months Ended 12 Months Ended
Dec. 31, 2015
Sep. 30, 2015
Jun. 30, 2015
Mar. 31, 2015
Dec. 31, 2014
Sep. 30, 2014
Jun. 30, 2014
Mar. 31, 2014
Dec. 31, 2015
Dec. 31, 2014
Dec. 31, 2013
Earnings Per Share [Abstract]                      
Net income (loss) $ 297 $ 138 $ 361 $ (63) $ 101 $ (94) $ 391 $ (151) $ 733 $ 247 $ 35
Dividends on preferred stock (14) (13) (14) (14)         (55) 0 0
Net income attributable to common stockholders (loss) $ 283 $ 125 $ 347 $ (77)         $ 678 $ 247 $ 35
Weighted average shares outstanding - basic 816,585,782 815,069,272 811,605,031 808,605,526 807,396,425 807,221,761 803,923,913 802,520,723 812,994,028 805,284,712 672,955,980
Dilutive effect of outstanding stock options and awards                 9,623,910 8,893,887 3,929,235
Dilutive effect of preferred stock                 0 1,743,659 0
Weighted average shares outstanding - diluted 824,716,119 822,017,220 821,122,537 808,605,526 821,707,289 807,221,761 813,556,137 802,520,723 822,617,938 815,922,258 676,885,215
Earnings per share - basic $ 0.35 $ 0.15 $ 0.43 $ (0.09) $ 0.13 $ (0.12) $ 0.49 $ (0.19) $ 0.83 $ 0.31 $ 0.05
Earnings per share - diluted $ 0.34 $ 0.15 $ 0.42 $ (0.09) $ 0.12 $ (0.12) $ 0.48 $ (0.19) $ 0.82 $ 0.30 $ 0.05
Stock Compensation Plan [Member]                      
Antidilutive Securities Excluded from Computation of Earnings Per Share [Line Items]                      
Potentially dilutive securities                 4,842,370 1,426,331 4,909,741
Preferred Stock [Member]                      
Antidilutive Securities Excluded from Computation of Earnings Per Share [Line Items]                      
Potentially dilutive securities                 32,237,266 0 0

v3.3.1.900
Commitments and Contingencies (Commitments) (Details)
$ in Millions
Dec. 31, 2015
USD ($)
Other Commitments [Line Items]  
Operating Leases - 2016 $ 2,379
Operating Leases - 2017 2,235
Operating Leases - 2018 2,046
Operating Leases - 2019 1,900
Operating Leases - 2020 1,679
Operating Leases - Thereafter 5,583
Operating Leases - Total 15,822
Purchase Obligation - 2016 2,865
Purchase Obligation - 2017 3,150
Purchase Obligation - 2018 772
Purchase Obligation - 2019 714
Purchase Obligation - 2020 629
Purchase Obligation - Thereafter 1,304
Purchase Obligation - Total $ 9,434

v3.3.1.900
Commitments and Contingencies (Operating Leases) (Details) - USD ($)
$ in Billions
12 Months Ended
Dec. 31, 2015
Dec. 31, 2014
Dec. 31, 2013
Operating Leased Assets [Line Items]      
Rent expense $ 2.8 $ 3.0 $ 2.8
Cell Sites [Member]      
Operating Leased Assets [Line Items]      
Lessee leasing arrangements, operating leases, term of contract 15 years    
Minimum [Member] | Cell Sites [Member]      
Operating Leased Assets [Line Items]      
Lessee leasing arrangements, operating leases, initial term of contract 5 years    
Maximum [Member] | Cell Sites [Member]      
Operating Leased Assets [Line Items]      
Lessee leasing arrangements, operating leases, initial term of contract 10 years    

v3.3.1.900
Commitments and Contingencies (Contingencies and Litigation) (Details)
$ in Millions
12 Months Ended
Dec. 31, 2015
USD ($)
Judicial Ruling [Member]  
Loss Contingencies [Line Items]  
Damages sought $ 114.9

v3.3.1.900
Additional Financial Information (Imputed Discount and Allowances) (Details) - USD ($)
$ in Millions
12 Months Ended
Dec. 31, 2015
Dec. 31, 2014
Dec. 31, 2013
Allowance for Doubtful Accounts Receivable [Roll Forward]      
Bad debt expense $ 547 $ 444 $ 463
Unamortized Imputed Discount [Roll Forward]      
Imputed Discount, beginning of year 332    
Interest income (420) (359) (189)
Imputed Discount, end of year 185 332  
Allowances [Member] | Accounts Receivable, Net [Member]      
Allowance for Doubtful Accounts Receivable [Roll Forward]      
Allowances, beginning of year 199 169 197
Bad debt expense 547 444 463
Write-offs, net of recoveries (482) (414) (491)
Allowances, end of year 264 199 169
Imputed Discount [Member] | Equipment Installment Plan Receivables, Net [Member]      
Unamortized Imputed Discount [Roll Forward]      
Imputed Discount, beginning of year 271 212 92
Additions 310 380 283
Interest income (414) (355) (185)
Cancellations and other (78) (92) (42)
Impacts from sales of EIP receivables (55) 0 0
Transfers between current and long-term 125 126 64
Imputed Discount, end of year 159 271 212
Imputed Discount [Member] | Equipment Installment Plan Receivables Due After One Year, Net [Member]      
Unamortized Imputed Discount [Roll Forward]      
Imputed Discount, beginning of year 61 64 18
Additions 111 141 121
Cancellations and other (13) (18) (11)
Impacts from sales of EIP receivables (8) 0 0
Transfers between current and long-term (125) (126) (64)
Imputed Discount, end of year $ 26 $ 61 $ 64

v3.3.1.900
Additional Financial Information (Accounts Payable and Accrued Liabilities) (Details) - USD ($)
$ in Millions
Dec. 31, 2015
Dec. 31, 2014
Accounts payable $ 6,137 $ 5,322
Property and other taxes, including payroll 494 605
Payroll and related benefits 521 470
Interest 371 349
Commissions 190 179
Toll and interconnect 68 166
Network decommissioning 117 78
Advertising 77 53
Other 109 142
Accounts payable and accrued liabilities 8,084 7,364
Accounts Payable and Accrued Liabilities [Member]    
Outstanding checks $ 501 $ 409

v3.3.1.900
Additional Financial Information (Related Party Transactions) (Details) - Deutsche Telekom [Member] - USD ($)
$ in Millions
12 Months Ended
Dec. 31, 2015
Dec. 31, 2014
Dec. 31, 2013
Related Party Transaction [Line Items]      
Discount related to roaming expenses $ (21) $ (61) $ (16)
Fees incurred for use of the T-Mobile brand 65 60 53
Expenses for telecommunications and IT services $ 23 $ 24 $ 102

v3.3.1.900
Additional Financial Information (Supplemental Statements of Cash Flows Information) (Details) - USD ($)
$ in Millions
12 Months Ended
Dec. 31, 2015
Dec. 31, 2014
Dec. 31, 2013
Additional Financial Information [Abstract]      
Interest payments, net of amounts capitalized $ 1,298 $ 1,367 $ 1,156
Income tax payments 54 36 20
Increase in accounts payable for purchases of property and equipment 46 402 6
Leased wireless devices transferred from inventory to property and equipment, net of returns 2,285 0 0
Issuance of short-term debt for financing of property and equipment purchases 500 256 470
Assets acquired under capital lease obligations 470 77 3
Retirement of long-term debt to affiliates 0 0 14,450
Elimination of net unamortized discounts and premiums on long-term debt to affiliates 0 0 434
Issuance of new long-term debt to affiliates 0 0 11,200
Settlement of accounts receivable from affiliates and other outstanding balances 0 0 363
Income tax benefit from debt recapitalization 0 0 178
Net assets acquired in MetroPCS business combination, excluding cash acquired $ 0 $ 0 $ 827

v3.3.1.900
Additional Financial Information (Supplemental Statements of Stockholders' Equity Information) (Details) - USD ($)
$ / shares in Units, $ in Millions
12 Months Ended
Dec. 31, 2015
Dec. 31, 2014
Dec. 31, 2013
Class of Stock [Line Items]      
Issuance of preferred stock, shares 20,000,000 20,000,000  
Proceeds from issuance of preferred stock $ 0 $ 982 $ 0
Annual dividend rate 5.50% 5.50%  
Preferred Stock [Member]      
Class of Stock [Line Items]      
Annual dividend rate   5.50%  
Liquidation preference per share   $ 50  
Issuance of stock, shares   20,000,000  
Preferred Stock [Member] | Minimum [Member]      
Class of Stock [Line Items]      
Shares issued upon conversion   1.6119  
Preferred Stock [Member] | Maximum [Member]      
Class of Stock [Line Items]      
Shares issued upon conversion   1.9342  
Common Stock [Member]      
Class of Stock [Line Items]      
Issuance of stock, shares     72,765,000
Issuance of common stock, price per share     $ 25
Parent Company [Member]      
Class of Stock [Line Items]      
Proceeds from issuance of preferred stock   $ 982  
Parent Company [Member] | Preferred Stock [Member]      
Class of Stock [Line Items]      
Issuance of preferred stock, shares   20,000,000  
Proceeds from issuance of preferred stock   $ 982  

v3.3.1.900
Guarantor Financial Information (Narrative) (Details)
$ in Billions
Dec. 31, 2015
USD ($)
Senior Notes [Member] | Issuer [Member]  
Condensed Financial Statements, Captions [Line Items]  
Long-term debt issued $ 2.0
Secured Debt [Member]  
Condensed Financial Statements, Captions [Line Items]  
Long-term debt issued 2.0
Secured Debt [Member] | Issuer [Member]  
Condensed Financial Statements, Captions [Line Items]  
Long-term debt issued $ 2.0

v3.3.1.900
Guarantor Financial Information (Condensed Consolidating Balance Sheet Information) (Details) - USD ($)
$ in Millions
Dec. 31, 2015
Dec. 31, 2014
Dec. 31, 2013
Dec. 31, 2012
Current assets        
Cash and cash equivalents $ 4,582 $ 5,315 $ 5,891 $ 394
Short-term investments 2,998 0    
Accounts receivable, net 1,788 1,865    
Equipment installment plan receivables, net 2,378 3,062    
Accounts receivable from affiliates 36 76    
Inventories 1,295 1,085    
Deferred tax assets, net 0 988    
Other current assets 1,813 1,593    
Total current assets 14,890 13,984    
Property and equipment, net 20,000 16,245    
Goodwill 1,683 1,683    
Spectrum licenses 23,955 21,955 18,122  
Other intangible assets, net 594 870    
Investments in subsidiaries, net 0 0    
Intercompany receivables 0 0    
Equipment installment plan receivables due after one year, net 847 1,628    
Other assets 467 288    
Total assets 62,436 56,653    
Current liabilities        
Accounts payable and accrued liabilities 8,084 7,364    
Current payables to affiliates 135 231    
Short-term debt 182 87    
Deferred revenue 717 459    
Other current liabilities 410 635    
Total current liabilities 9,528 8,776    
Long-term debt 20,484 16,273    
Long-term debt to affiliates 5,600 5,600    
Tower obligations 2,658 2,521    
Deferred tax liabilities 4,061 4,873    
Deferred rents 2,481 2,331    
Negative carrying value of subsidiaries, net 0 0    
Intercompany payables 0 0    
Other long-term liabilities 1,067 616    
Total long-term liabilities 36,351 32,214    
Total stockholders' equity 16,557 15,663 14,245 6,115
Total liabilities and stockholders' equity 62,436 56,653    
Consolidating and Eliminating Adjustments [Member]        
Current assets        
Cash and cash equivalents 0 0 0 0
Short-term investments 0      
Accounts receivable, net 0 0    
Equipment installment plan receivables, net 0 0    
Accounts receivable from affiliates 0 0    
Inventories 0 0    
Deferred tax assets, net   0    
Other current assets 0 0    
Total current assets 0 0    
Property and equipment, net 0 0    
Goodwill 0 0    
Spectrum licenses 0 0    
Other intangible assets, net 0 0    
Investments in subsidiaries, net (48,464) (43,855)    
Intercompany receivables (6,130) (2,773)    
Equipment installment plan receivables due after one year, net 0 0    
Other assets (167) (114)    
Total assets (54,761) (46,742)    
Current liabilities        
Accounts payable and accrued liabilities 0 0    
Current payables to affiliates 0 0    
Short-term debt 0 0    
Deferred revenue 0 0    
Other current liabilities 0 0    
Total current liabilities 0 0    
Long-term debt 0 0    
Long-term debt to affiliates 0 0    
Tower obligations 0 0    
Deferred tax liabilities (167) (114)    
Deferred rents 0 0    
Negative carrying value of subsidiaries, net (628) (780)    
Intercompany payables (6,130) (2,773)    
Other long-term liabilities 0 0    
Total long-term liabilities (6,925) (3,667)    
Total stockholders' equity (47,836) (43,075)    
Total liabilities and stockholders' equity (54,761) (46,742)    
Parent [Member]        
Current assets        
Cash and cash equivalents 378 2,278 2,960 0
Short-term investments 0      
Accounts receivable, net 0 0    
Equipment installment plan receivables, net 0 0    
Accounts receivable from affiliates 0 0    
Inventories 0 0    
Deferred tax assets, net   0    
Other current assets 0 0    
Total current assets 378 2,278    
Property and equipment, net 0 0    
Goodwill 0 0    
Spectrum licenses 0 0    
Other intangible assets, net 0 0    
Investments in subsidiaries, net 16,184 13,470    
Intercompany receivables 0 0    
Equipment installment plan receivables due after one year, net 0 0    
Other assets 0 2    
Total assets 16,562 15,750    
Current liabilities        
Accounts payable and accrued liabilities 0 0    
Current payables to affiliates 0 0    
Short-term debt 0 0    
Deferred revenue 0 0    
Other current liabilities 0 0    
Total current liabilities 0 0    
Long-term debt 0 0    
Long-term debt to affiliates 0 0    
Tower obligations 0 0    
Deferred tax liabilities 0 0    
Deferred rents 0 0    
Negative carrying value of subsidiaries, net 0 0    
Intercompany payables 5 87    
Other long-term liabilities 0 0    
Total long-term liabilities 5 87    
Total stockholders' equity 16,557 15,663    
Total liabilities and stockholders' equity 16,562 15,750    
Issuer [Member]        
Current assets        
Cash and cash equivalents 1,767 2,246 2,698 0
Short-term investments 1,999      
Accounts receivable, net 0 0    
Equipment installment plan receivables, net 0 0    
Accounts receivable from affiliates 0 0    
Inventories 0 0    
Deferred tax assets, net   0    
Other current assets 0 3    
Total current assets 3,766 2,249    
Property and equipment, net 0 0    
Goodwill 0 0    
Spectrum licenses 0 0    
Other intangible assets, net 0 0    
Investments in subsidiaries, net 32,280 30,385    
Intercompany receivables 6,130 2,773    
Equipment installment plan receivables due after one year, net 0 0    
Other assets 28 17    
Total assets 42,204 35,424    
Current liabilities        
Accounts payable and accrued liabilities 368 349    
Current payables to affiliates 70 56    
Short-term debt 20 63    
Deferred revenue 0 0    
Other current liabilities 0 0    
Total current liabilities 458 468    
Long-term debt 19,820 15,886    
Long-term debt to affiliates 5,600 5,600    
Tower obligations 0 0    
Deferred tax liabilities 0 0    
Deferred rents 0 0    
Negative carrying value of subsidiaries, net 0 0    
Intercompany payables 0 0    
Other long-term liabilities 142 0    
Total long-term liabilities 25,562 21,486    
Total stockholders' equity 16,184 13,470    
Total liabilities and stockholders' equity 42,204 35,424    
Guarantor Subsidiaries [Member]        
Current assets        
Cash and cash equivalents 2,364 697 57 287
Short-term investments 999      
Accounts receivable, net 1,574 1,817    
Equipment installment plan receivables, net 2,378 3,062    
Accounts receivable from affiliates 36 76    
Inventories 1,295 1,085    
Deferred tax assets, net   988    
Other current assets 1,413 1,341    
Total current assets 10,059 9,066    
Property and equipment, net 19,546 15,708    
Goodwill 1,683 1,683    
Spectrum licenses 23,955 21,955    
Other intangible assets, net 594 870    
Investments in subsidiaries, net 0 0    
Intercompany receivables 0 0    
Equipment installment plan receivables due after one year, net 847 1,628    
Other assets 387 259    
Total assets 57,071 51,169    
Current liabilities        
Accounts payable and accrued liabilities 7,496 6,914    
Current payables to affiliates 65 175    
Short-term debt 162 24    
Deferred revenue 717 459    
Other current liabilities 327 580    
Total current liabilities 8,767 8,152    
Long-term debt 664 387    
Long-term debt to affiliates 0 0    
Tower obligations 411 271    
Deferred tax liabilities 4,228 4,987    
Deferred rents 2,481 2,331    
Negative carrying value of subsidiaries, net 628 780    
Intercompany payables 5,959 2,589    
Other long-term liabilities 922 616    
Total long-term liabilities 15,293 11,961    
Total stockholders' equity 33,011 31,056    
Total liabilities and stockholders' equity 57,071 51,169    
Non-Guarantor Subsidiaries [Member]        
Current assets        
Cash and cash equivalents 73 94 $ 176 $ 107
Short-term investments 0      
Accounts receivable, net 214 48    
Equipment installment plan receivables, net 0 0    
Accounts receivable from affiliates 0 0    
Inventories 0 0    
Deferred tax assets, net   0    
Other current assets 400 249    
Total current assets 687 391    
Property and equipment, net 454 537    
Goodwill 0 0    
Spectrum licenses 0 0    
Other intangible assets, net 0 0    
Investments in subsidiaries, net 0 0    
Intercompany receivables 0 0    
Equipment installment plan receivables due after one year, net 0 0    
Other assets 219 124    
Total assets 1,360 1,052    
Current liabilities        
Accounts payable and accrued liabilities 220 101    
Current payables to affiliates 0 0    
Short-term debt 0 0    
Deferred revenue 0 0    
Other current liabilities 83 55    
Total current liabilities 303 156    
Long-term debt 0 0    
Long-term debt to affiliates 0 0    
Tower obligations 2,247 2,250    
Deferred tax liabilities 0 0    
Deferred rents 0 0    
Negative carrying value of subsidiaries, net 0 0    
Intercompany payables 166 97    
Other long-term liabilities 3 0    
Total long-term liabilities 2,416 2,347    
Total stockholders' equity (1,359) (1,451)    
Total liabilities and stockholders' equity $ 1,360 $ 1,052    

v3.3.1.900
Guarantor Financial Information (Condensed Consolidating Statement of Comprehensive Income (Loss) Information) (Details) - USD ($)
$ in Millions
3 Months Ended 12 Months Ended
Dec. 31, 2015
Sep. 30, 2015
Jun. 30, 2015
Mar. 31, 2015
Dec. 31, 2014
Sep. 30, 2014
Jun. 30, 2014
Mar. 31, 2014
Dec. 31, 2015
Dec. 31, 2014
Dec. 31, 2013
Revenues                      
Service revenues                 $ 24,821 $ 22,375 $ 19,068
Equipment revenues                 6,718 6,789 5,033
Other revenues                 514 400 319
Total revenues $ 8,247 $ 7,849 $ 8,179 $ 7,778 $ 8,154 $ 7,350 $ 7,185 $ 6,875 32,053 29,564 24,420
Operating expenses                      
Cost of services, exclusive of depreciation and amortization shown separately below                 5,554 5,788 5,279
Cost of equipment sales                 9,344 9,621 6,976
Selling, general and administrative                 10,189 8,863 7,382
Depreciation and amortization                 4,688 4,412 3,627
Cost of MetroPCS business combination 21 193 34 128 168 97 22 12 376 299 108
Gains on disposal of spectrum licenses (139) (1) (23) 0 (70) (13) (747) (10) (163) (840) (2)
Other, net                 0 5 54
Total operating expenses                 29,988 28,148 23,424
Operating income (loss) 838 513 597 117 433 49 962 (28) 2,065 1,416 996
Other income (expense)                      
Interest expense                 (1,085) (1,073) (545)
Interest expense to affiliates                 (411) (278) (678)
Interest income                 420 359 189
Other income (expense), net                 (11) (11) 89
Total other income (expense), net                 (1,087) (1,003) (945)
Income before income taxes                 978 413 51
Income tax expense                 245 166 16
Earnings (loss) of subsidiaries                 0 0 0
Net income (loss) (297) (138) (361) 63 $ (101) $ 94 $ (391) $ 151 (733) (247) (35)
Dividends on preferred stock (14) (13) (14) (14)         (55) 0 0
Net income attributable to common stockholders (loss) $ 283 $ 125 $ 347 $ (77)         678 247 35
Other comprehensive loss, net of tax                 (2) (2) (38)
Total comprehensive income (loss)                 731 245 (3)
Consolidating and Eliminating Adjustments [Member]                      
Revenues                      
Service revenues                 (596) (410) (151)
Equipment revenues                 (430) (530) (695)
Other revenues                 (14) (10) (74)
Total revenues                 (1,040) (950) (920)
Operating expenses                      
Cost of services, exclusive of depreciation and amortization shown separately below                 0 0 (73)
Cost of equipment sales                 (431) (572) (756)
Selling, general and administrative                 (609) (378) (91)
Depreciation and amortization                 0 0 0
Cost of MetroPCS business combination                 0 0 0
Gains on disposal of spectrum licenses                 0 0 0
Other, net                   0 0
Total operating expenses                 (1,040) (950) (920)
Operating income (loss)                 0 0 0
Other income (expense)                      
Interest expense                 0 0 0
Interest expense to affiliates                 0 0 0
Interest income                 0 0 0
Other income (expense), net                 0 0 0
Total other income (expense), net                 0 0 0
Income before income taxes                 0 0 0
Income tax expense                 0 0 0
Earnings (loss) of subsidiaries                 (2,683) (1,471) (778)
Net income (loss)                 2,683 1,471 778
Dividends on preferred stock                 0    
Net income attributable to common stockholders (loss)                 (2,683)    
Other comprehensive loss, net of tax                 4 4 (24)
Total comprehensive income (loss)                 (2,679) (1,467) (802)
Parent [Member]                      
Revenues                      
Service revenues                 0 0 0
Equipment revenues                 0 0 0
Other revenues                 0 0 0
Total revenues                 0 0 0
Operating expenses                      
Cost of services, exclusive of depreciation and amortization shown separately below                 0 0 0
Cost of equipment sales                 0 0 0
Selling, general and administrative                 0 0 0
Depreciation and amortization                 0 0 0
Cost of MetroPCS business combination                 0 0 0
Gains on disposal of spectrum licenses                 0 0 0
Other, net                   0 0
Total operating expenses                 0 0 0
Operating income (loss)                 0 0 0
Other income (expense)                      
Interest expense                 0 0 0
Interest expense to affiliates                 0 0 0
Interest income                 0 0 0
Other income (expense), net                 0 0 0
Total other income (expense), net                 0 0 0
Income before income taxes                 0 0 0
Income tax expense                 0 0 0
Earnings (loss) of subsidiaries                 733 247 (104)
Net income (loss)                 (733) (247) 104
Dividends on preferred stock                 (55)    
Net income attributable to common stockholders (loss)                 678    
Other comprehensive loss, net of tax                 (2) (2) 0
Total comprehensive income (loss)                 731 245 (104)
Issuer [Member]                      
Revenues                      
Service revenues                 0 0 0
Equipment revenues                 0 0 0
Other revenues                 1 0 0
Total revenues                 1 0 0
Operating expenses                      
Cost of services, exclusive of depreciation and amortization shown separately below                 0 0 0
Cost of equipment sales                 0 0 0
Selling, general and administrative                 0 0 0
Depreciation and amortization                 0 0 0
Cost of MetroPCS business combination                 0 0 0
Gains on disposal of spectrum licenses                 0 0 0
Other, net                   0 0
Total operating expenses                 0 0 0
Operating income (loss)                 1 0 0
Other income (expense)                      
Interest expense                 (847) (838) (317)
Interest expense to affiliates                 (411) (278) (678)
Interest income                 2 0 0
Other income (expense), net                 (10) (15) 94
Total other income (expense), net                 (1,266) (1,131) (901)
Income before income taxes                 (1,265) (1,131) (901)
Income tax expense                 0 0 0
Earnings (loss) of subsidiaries                 1,998 1,278 936
Net income (loss)                 (733) (147) (35)
Dividends on preferred stock                 0    
Net income attributable to common stockholders (loss)                 733    
Other comprehensive loss, net of tax                 (2) (2) (38)
Total comprehensive income (loss)                 731 145 (3)
Guarantor Subsidiaries [Member]                      
Revenues                      
Service revenues                 23,748 21,483 18,396
Equipment revenues                 7,148 7,319 5,728
Other revenues                 356 270 251
Total revenues                 31,252 29,072 24,375
Operating expenses                      
Cost of services, exclusive of depreciation and amortization shown separately below                 5,530 5,767 5,302
Cost of equipment sales                 9,055 9,491 7,180
Selling, general and administrative                 10,065 8,723 7,283
Depreciation and amortization                 4,605 4,330 3,545
Cost of MetroPCS business combination                 376 299 108
Gains on disposal of spectrum licenses                 (163) (840) (2)
Other, net                   5 54
Total operating expenses                 29,468 27,775 23,470
Operating income (loss)                 1,784 1,297 905
Other income (expense)                      
Interest expense                 (50) (55) (55)
Interest expense to affiliates                 0 0 0
Interest income                 418 359 189
Other income (expense), net                 0 4 (6)
Total other income (expense), net                 368 308 128
Income before income taxes                 2,152 1,605 1,033
Income tax expense                 214 189 45
Earnings (loss) of subsidiaries                 (48) (54) (54)
Net income (loss)                 (1,890) (1,362) (934)
Dividends on preferred stock                 0    
Net income attributable to common stockholders (loss)                 1,890    
Other comprehensive loss, net of tax                 (2) (2) 24
Total comprehensive income (loss)                 1,888 1,360 958
Non-Guarantor Subsidiaries [Member]                      
Revenues                      
Service revenues                 1,669 1,302 823
Equipment revenues                 0 0 0
Other revenues                 171 140 142
Total revenues                 1,840 1,442 965
Operating expenses                      
Cost of services, exclusive of depreciation and amortization shown separately below                 24 21 50
Cost of equipment sales                 720 702 552
Selling, general and administrative                 733 518 190
Depreciation and amortization                 83 82 82
Cost of MetroPCS business combination                 0 0 0
Gains on disposal of spectrum licenses                 0 0 0
Other, net                   0 0
Total operating expenses                 1,560 1,323 874
Operating income (loss)                 280 119 91
Other income (expense)                      
Interest expense                 (188) (180) (173)
Interest expense to affiliates                 0 0 0
Interest income                 0 0 0
Other income (expense), net                 (1) 0 1
Total other income (expense), net                 (189) (180) (172)
Income before income taxes                 91 (61) (81)
Income tax expense                 31 (23) (29)
Earnings (loss) of subsidiaries                 0 0 0
Net income (loss)                 (60) 38 52
Dividends on preferred stock                 0    
Net income attributable to common stockholders (loss)                 60    
Other comprehensive loss, net of tax                 0 0 0
Total comprehensive income (loss)                 $ 60 $ (38) $ (52)

v3.3.1.900
Guarantor Financial Information (Condensed Consolidating Statement of Cash Flows Information) (Details) - USD ($)
$ in Millions
12 Months Ended
Dec. 31, 2015
Dec. 31, 2014
Dec. 31, 2013
Operating activities      
Net cash provided by (used in) operating activities $ 5,414 $ 4,146 $ 3,545
Investing activities      
Purchases of property and equipment (4,724) (4,317) (4,025)
Purchases of spectrum licenses and other intangible assets, including deposits (1,935) (2,900) (381)
Purchases of short-term investments (2,997) 0 0
Short term affiliate loan receivable, net 0 0 300
Cash and cash equivalents acquired in MetroPCS business combination 0 0 2,144
Investment in subsidiaries 0 0  
Other, net 96 (29) (130)
Net cash provided by (used in) investing activities (9,560) (7,246) (2,092)
Financing activities      
Proceeds from capital contribution 0 0  
Proceeds from issuance of long-term debt 3,979 2,993 2,494
Repayments of long-term debt and capital lease obligations (57) (1,019) (9)
Proceeds from tower obligations 140 0 0
Repayments of short-term debt for purchases of inventory, property and equipment, net (564) (418) (244)
Intercompany dividend paid 0 0  
Proceeds from issuance of preferred stock 0 982 0
Dividends on preferred stock (55) 0 0
Proceeds from exercise of stock options 47 27 137
Proceeds from issuance of common stock 0 0 1,787
Taxes paid related to net share settlement of stock awards (156) (73) 0
Other, net 79 32 (121)
Net cash provided by (used in) financing activities 3,413 2,524 4,044
Change in cash and cash equivalents (733) (576) 5,497
Beginning of year 5,315 5,891 394
End of year 4,582 5,315 5,891
Consolidating and Eliminating Adjustments [Member]      
Operating activities      
Net cash provided by (used in) operating activities (175) (100) 0
Investing activities      
Purchases of property and equipment 0 0 0
Purchases of spectrum licenses and other intangible assets, including deposits 0 0 0
Purchases of short-term investments 0    
Short term affiliate loan receivable, net     0
Cash and cash equivalents acquired in MetroPCS business combination     0
Investment in subsidiaries 1,905 1,700  
Other, net 0 0 0
Net cash provided by (used in) investing activities 1,905 1,700 0
Financing activities      
Proceeds from capital contribution (1,905) (1,700)  
Proceeds from issuance of long-term debt 0 0 0
Repayments of long-term debt and capital lease obligations 0 0 0
Proceeds from tower obligations 0    
Repayments of short-term debt for purchases of inventory, property and equipment, net 0 0 0
Intercompany dividend paid 175 100  
Proceeds from issuance of preferred stock   0  
Dividends on preferred stock 0    
Proceeds from exercise of stock options 0 0 0
Proceeds from issuance of common stock     0
Taxes paid related to net share settlement of stock awards 0 0  
Other, net 0 0 0
Net cash provided by (used in) financing activities (1,730) (1,600) 0
Change in cash and cash equivalents 0 0 0
Beginning of year 0 0 0
End of year 0 0 0
Parent [Member]      
Operating activities      
Net cash provided by (used in) operating activities (1) 9 299
Investing activities      
Purchases of property and equipment 0 0 0
Purchases of spectrum licenses and other intangible assets, including deposits 0 0 0
Purchases of short-term investments 0    
Short term affiliate loan receivable, net     0
Cash and cash equivalents acquired in MetroPCS business combination     737
Investment in subsidiaries (1,905) (1,700)  
Other, net 0 0 0
Net cash provided by (used in) investing activities (1,905) (1,700) 737
Financing activities      
Proceeds from capital contribution 0 0  
Proceeds from issuance of long-term debt 0 0 0
Repayments of long-term debt and capital lease obligations 0 0 0
Proceeds from tower obligations 0    
Repayments of short-term debt for purchases of inventory, property and equipment, net 0 0 0
Intercompany dividend paid 0 0  
Proceeds from issuance of preferred stock   982  
Dividends on preferred stock (41)    
Proceeds from exercise of stock options 47 27 137
Proceeds from issuance of common stock     1,787
Taxes paid related to net share settlement of stock awards 0 0  
Other, net 0 0 0
Net cash provided by (used in) financing activities 6 1,009 1,924
Change in cash and cash equivalents (1,900) (682) 2,960
Beginning of year 2,278 2,960 0
End of year 378 2,278 2,960
Issuer [Member]      
Operating activities      
Net cash provided by (used in) operating activities (4,504) (5,145) (1,203)
Investing activities      
Purchases of property and equipment 0 0 0
Purchases of spectrum licenses and other intangible assets, including deposits 0 0 0
Purchases of short-term investments (1,999)    
Short term affiliate loan receivable, net     0
Cash and cash equivalents acquired in MetroPCS business combination     1,407
Investment in subsidiaries 0 0  
Other, net 0 0 0
Net cash provided by (used in) investing activities (1,999) 0 1,407
Financing activities      
Proceeds from capital contribution 1,905 1,700  
Proceeds from issuance of long-term debt 3,979 2,993 2,494
Repayments of long-term debt and capital lease obligations 0 0 0
Proceeds from tower obligations 140    
Repayments of short-term debt for purchases of inventory, property and equipment, net 0 0 0
Intercompany dividend paid 0 0  
Proceeds from issuance of preferred stock   0  
Dividends on preferred stock 0    
Proceeds from exercise of stock options 0 0 0
Proceeds from issuance of common stock     0
Taxes paid related to net share settlement of stock awards 0 0  
Other, net 0 0 0
Net cash provided by (used in) financing activities 6,024 4,693 2,494
Change in cash and cash equivalents (479) (452) 2,698
Beginning of year 2,246 2,698 0
End of year 1,767 2,246 2,698
Guarantor Subsidiaries [Member]      
Operating activities      
Net cash provided by (used in) operating activities 9,940 9,364 4,380
Investing activities      
Purchases of property and equipment (4,724) (4,317) (4,025)
Purchases of spectrum licenses and other intangible assets, including deposits (1,935) (2,900) (381)
Purchases of short-term investments (998)    
Short term affiliate loan receivable, net     300
Cash and cash equivalents acquired in MetroPCS business combination     0
Investment in subsidiaries 0 0  
Other, net 96 (29) (130)
Net cash provided by (used in) investing activities (7,561) (7,246) (4,236)
Financing activities      
Proceeds from capital contribution 0 0  
Proceeds from issuance of long-term debt 0 0 0
Repayments of long-term debt and capital lease obligations (57) (1,019) (9)
Proceeds from tower obligations 0    
Repayments of short-term debt for purchases of inventory, property and equipment, net (564) (418) (244)
Intercompany dividend paid 0 0  
Proceeds from issuance of preferred stock   0  
Dividends on preferred stock (14)    
Proceeds from exercise of stock options 0 0 0
Proceeds from issuance of common stock     0
Taxes paid related to net share settlement of stock awards (156) (73)  
Other, net 79 32 (121)
Net cash provided by (used in) financing activities (712) (1,478) (374)
Change in cash and cash equivalents 1,667 640 (230)
Beginning of year 697 57 287
End of year 2,364 697 57
Non-Guarantor Subsidiaries [Member]      
Operating activities      
Net cash provided by (used in) operating activities 154 18 69
Investing activities      
Purchases of property and equipment 0 0 0
Purchases of spectrum licenses and other intangible assets, including deposits 0 0 0
Purchases of short-term investments 0    
Short term affiliate loan receivable, net     0
Cash and cash equivalents acquired in MetroPCS business combination     0
Investment in subsidiaries 0 0  
Other, net 0 0 0
Net cash provided by (used in) investing activities 0 0 0
Financing activities      
Proceeds from capital contribution 0 0  
Proceeds from issuance of long-term debt 0 0 0
Repayments of long-term debt and capital lease obligations 0 0 0
Proceeds from tower obligations 0    
Repayments of short-term debt for purchases of inventory, property and equipment, net 0 0 0
Intercompany dividend paid (175) (100)  
Proceeds from issuance of preferred stock   0  
Dividends on preferred stock 0    
Proceeds from exercise of stock options 0 0 0
Proceeds from issuance of common stock     0
Taxes paid related to net share settlement of stock awards 0 0  
Other, net 0 0 0
Net cash provided by (used in) financing activities (175) (100) 0
Change in cash and cash equivalents (21) (82) 69
Beginning of year 94 176 107
End of year $ 73 $ 94 $ 176

v3.3.1.900
Subsequent Events (Details) - Licensing Agreements [Member] - USD ($)
$ in Billions
1 Months Ended 2 Months Ended
Jan. 31, 2016
Feb. 29, 2016
Mar. 31, 2016
Scenario, Forecast [Member]      
Subsequent Event [Line Items]      
Assets held-for-sale     $ 0.2
Subsequent Event [Member]      
Subsequent Event [Line Items]      
Fair value of spectrum licenses acquired $ 0.6 $ 0.7  

v3.3.1.900
Quarterly Financial Information (Unaudited) (Details) - USD ($)
$ / shares in Units, $ in Millions
3 Months Ended 12 Months Ended
Dec. 31, 2015
Sep. 30, 2015
Jun. 30, 2015
Mar. 31, 2015
Dec. 31, 2014
Sep. 30, 2014
Jun. 30, 2014
Mar. 31, 2014
Dec. 31, 2015
Dec. 31, 2014
Dec. 31, 2013
Quarterly Financial Information (Unaudited) [Abstract]                      
Total revenues $ 8,247 $ 7,849 $ 8,179 $ 7,778 $ 8,154 $ 7,350 $ 7,185 $ 6,875 $ 32,053 $ 29,564 $ 24,420
Operating income 838 513 597 117 433 49 962 (28) 2,065 1,416 996
Net income (loss) (297) (138) (361) 63 $ (101) $ 94 $ (391) $ 151 (733) (247) (35)
Dividends on preferred stock (14) (13) (14) (14)         (55) 0 0
Net income (loss) attributable to common stockholders $ 283 $ 125 $ 347 $ (77)         $ 678 $ 247 $ 35
Earnings per share - basic $ 0.35 $ 0.15 $ 0.43 $ (0.09) $ 0.13 $ (0.12) $ 0.49 $ (0.19) $ 0.83 $ 0.31 $ 0.05
Earnings per share - diluted $ 0.34 $ 0.15 $ 0.42 $ (0.09) $ 0.12 $ (0.12) $ 0.48 $ (0.19) $ 0.82 $ 0.30 $ 0.05
Weighted average shares outstanding - basic 816,585,782 815,069,272 811,605,031 808,605,526 807,396,425 807,221,761 803,923,913 802,520,723 812,994,028 805,284,712 672,955,980
Weighted average shares outstanding - diluted 824,716,119 822,017,220 821,122,537 808,605,526 821,707,289 807,221,761 813,556,137 802,520,723 822,617,938 815,922,258 676,885,215
Cost of MetroPCS business combination $ 21 $ 193 $ 34 $ 128 $ 168 $ 97 $ 22 $ 12 $ 376 $ 299 $ 108
Gains on disposal of spectrum licenses $ (139) $ (1) $ (23) $ 0 $ (70) $ (13) $ (747) $ (10) $ (163) $ (840) $ (2)

IDEA: XBRL DOCUMENT
/**
 * Rivet Software Inc.
 *
 * @copyright Copyright (c) 2006-2011 Rivet Software, Inc. All rights reserved.
 * Version 2.4.0.3
 *
 */

var Show = {};
Show.LastAR = null,

Show.hideAR = function(){	
	Show.LastAR.style.display = 'none';
};

Show.showAR = function ( link, id, win ){
	if( Show.LastAR ){
		Show.hideAR();
	}
		
	var ref = link;
	do {
		ref = ref.nextSibling;
	} while (ref && ref.nodeName != 'TABLE');

	if (!ref || ref.nodeName != 'TABLE') {
		var tmp = win ?
			win.document.getElementById(id) :
			document.getElementById(id);

		if( tmp ){
			ref = tmp.cloneNode(true);
			ref.id = '';
			link.parentNode.appendChild(ref);
		}
	}

	if( ref ){
		ref.style.display = 'block';
		Show.LastAR = ref;
	}
};
	
Show.toggleNext = function( link ){
	var ref = link;
	
	do{
		ref = ref.nextSibling;	
	}while( ref.nodeName != 'DIV' );

	if( ref.style &&
		ref.style.display &&
		ref.style.display == 'none' ){
		ref.style.display = 'block';

		if( link.textContent ){
			link.textContent = link.textContent.replace( '+', '-' );
		}else{
			link.innerText = link.innerText.replace( '+', '-' );
		}
	}else{
		ref.style.display = 'none';
			
		if( link.textContent ){
			link.textContent = link.textContent.replace( '-', '+' );
		}else{
			link.innerText = link.innerText.replace( '-', '+' );
		}
	}
};


IDEA: XBRL DOCUMENT
begin 644 Financial_Report.xlsx
M4$L#!!0    ( &4Q44@6DQ$S:P(  !XV   3    6T-O;G1E;G1?5'EP97-=
M+GAM;,W;W6Z;,!3 \5>I=-Y^=^S#&[N?ZZ-];6E;GZ= R,N5EJ?KRO@U;(A]*FP\A/KNZT]9_T6U((0Z-F +'SS@:X^)]
M"KK!&EVYK3&^;2+G'QOCSM4_1IXKWYJUOF_\FPH_W;O(FF9:X[;U\%3J\R%D
M<>&WU2Q$W:LJG&[\6V=U.PYMZ#9_[!C/__%:3F[BOFUNK7ZH3PKL+S:F\1BU
MNN[.C>JAM[L??;][S\?$C%=5F6H^V+#0^OK,4Q(6WX6H$R'U?]5^?E+*WII7
M%1P77O"EV&IKJF_>AOF>?S=^7W"Y/L:Y3M]?&OH4=&(Z7!")-_4A(7TDD#Y2
M2!\9I \%Z2.']%% ^EA"^H@7E$8HHL844F.*J3$%U9BB:DQA-::X&E-@C2FR
M2HJLDB*KI,@J*;)*BJR2(JNDR"HILDJ*K)(B:T*1-:'(FE!D32BR)A19$XJL
M"476A")K0I$UH[%    *P(   L   !?.0Q(OW[CMB PD.MQ-*O>X^NO ZIK XTHO8<
M4M?'5$Q^#*G*_=ITJK$"2+8CCVG!D4*>-BP>-9?20D0[8$NP+,L5R*V.V:SG
MVL7.U49V[M,41Y26M#;3"&>6X9MY6&3I//B)]!=C;IK>TI;MR5/0!_ZS#0//
M>997'L=V+YRO+0O]C^AY%.!)T:'B1?4C9@,2[2F]@OIZ (4QOCLEFI2"(S>C
M@KN_V/P"4$L#!!0    ( &4Q44A@8-Z:Q0(  &0W   :    >&PO7W)E;',O
M=V]R:V)O;VLN>&UL+G)E;'/%VTN.VD 81>&M(!;0IMYEU/2H)SU-L@$+BH<:
M;&0[2GKW<1A$Y.&K#)#.! 26JLX ?;+*/\_ML%I_*N=F/'7M<#Q=A\7WR[D=
MUM/WF^5Q'*_KJAJVQW)IAJ?N6MKIZK[K+\TX?>P/U;79OC>'4MG5*E;]_3K+
ME^<_UUZ\[3;+_FUGEHLO37\HXV;YK>O?AV,IXU#=WLS3M,%T^>-:_F?[;K\_
M;WXCXKJUP;+:C[(S@=9),C-!SDDR,\'>20HS <%)"C.!T4D*,T'
M)20HSP=E)*B>#ZJ1(+,2,JZ8)(4UH[417!O&:R/ -HS81I!M&+.-0-LP:AO!
MMF'<-@)NP\AM!-V&L=L(O VCMQ5Z6T9O*_2VT+VVNMEF]+9";\OH;87>EM';
M"KTMH[<5>EM&;ROTMHS>5NAM&;VMT-LR>CNAMV/T=D)OQ^CMA-X..BM1AR6,
MWD[H[1B]G=#;,7H[H;=C]'9";\?H[83>CM';";T=H[<7>GM&;R_T]HS>7NCM
M&;V]T-M#9]WJL)O1VPN]/:.W%WI[1F\O]/:,WE[H[1F]O=#;,WH'H7=@] Y"
M[\#H'83>@=$["+T#HW<0>@?H6:5Z6,GH'83>@=$["+T#HW<0>@=&[R#T#HS>
M4>@=&;VCT#LR>D>A=V3TCD+OR.@=A=Z1T3L*O2,T:Z*&31B]H] [,GI'H7=D
M](Y"[\CHG83>B=$[";T3HW<2>B=&[R3T3HS>2>B=&+V3T#LQ>B>A=X)F!=6P
M(*-W$GHG1N\D]$Z,WEGHG1F]L] [,WIGH7=F],Y"[\SHG87>F=$["[TSHW<6
M>F=&[RSTSM"LMQKV9O3.0N_,Z%T+O6M&[UKH73-ZUT+OFM&[%GK7C-[UG=[#
ML>G+[O/8G]K#\.B:WQ:717=X#^/'N3P^Y;:J;+C3>IQV*M7M]>$_Y-NJ/T.J
MO_Y0]_(#4$L#!!0    ( &4Q44CJPJXD;P0  +85   0    9&]C4')O<',O
M87!P+GAM;+U847/:.!#^*QJ>DIFVID!2R%!F""1WF2$7KM#IQB?J;$9-U ,O]:67 LN;8T9\0L?&[72;3GK
MQDEFK.[]I_0/LP"PIAML)]UPUW9W+%J]3M-9X&C?,MCNK+=.V]Z^BYFIL F8
MIWC,M?U#J7![VB2BTZSM['ZS!.,R8G?2(AW9@RQ=8?%V4[(=#90T*A$1DBMB
MMSSA,@0V.4CA*?;L8LS?QTPL_BNB-$S%K!#!&9BKRAAN%E4Q$ZM"$C/)TY3K
ME;,18Y$
M>X1.:2KLVQ:17A9A($-Q9.%^%(DB0)ZP>^0%&N+H3;5T(7*ND7'89R@(+?1)
M/C/P,R\(<;=T\>W-D)A_T8_%DV)5R8]'' U:N%YQ-*XKBX--:6)Y]=%H5] '
MNY@Z3Y?5A=*L5Q=*\_-1H?@C.5",W]PKG6;K7>F\L_J!AOSV7C&QB^IR:M(E
M]LJIV:DNC19=8J\T6G2)O=)H-<[ -,_ T)7W2G!"WP6\F-894F]]J2[U%LT#
M/X;F@1=S1?/@6$M9SU?"C+!7X,VE$J9O#%CVK7KKNJ)YX,?0+=^/H7G@;9%7
M- _\&)H'?@S- R_FFN9!V;[_X5JCW)9PR2Z&@/Q.CK3#TGRDY/PC=IZ41?A\
M&F; ,X'<9(XLYC3,NJW).>MC?-AUW7XNC[3==6Q%"W%;'H'%&$O1XF?IJ6?3
M;BY.Q13=H=S9C&XY!.8^MU@A]BBD2*L?A-='6H$/\X6F@!]#'PE^#'TD[!_2
M;T]LB -#MYQ]3.%,R[YVE39/ CZ%)X,?0)/#>C=KT
MO<"/H<\#/X8^#_P8^CSP8^CSP'O7:Y]Q/VS3S<"+Z= \\&-H'AQ^UOGYZ;VW
M=O8XS.M:QKCLQJVN_3Y^'2>E<(6P'IZ]=>!10;C9Z]J$0KAY
MLD%T!6-!;$#S,(H5)B97UFN.,?1KYKC8\C6P<9;-F ;DDB-G!V#J>F)2E5(4
MP@-'ZSN\%#W>[7Q-,"D8U*#!8&#Y*&=)]6JVQC:F9(.^*J/CF@=<6*E6"N1=
M.Y1=IF)G!*_#40ZR;T]___1 &99TE?N@^JJF:4;-A.KBP#E[7SR]T-FDR@3D
M1D!4!55@ZV">G#J_3>X?EH])-<[R69J-T_QVF88&'W^04"KP=U0KIL6V@;
MZV6HZ'X-T>'EQ)6MK6^/J5_1V:NJO@%02P,$%     @ 93%12)E&UL[5I;<]HX%'[OK]!X9_9M"\8V
M@;:T$W-I=MNTF83M3A^%$5B-;'EDD81_OTV23;J;/ 0LZ?O.14?G
MZ#AY\^XN8NB&B)3R>	+]O6N[!3+UES@6QHO(];JM-O=5H1I;*$81V1@?5XL:$#05%%:;U\@
MM.4?,_@5RU2-9:,!$U=!)KF(M/+Y;,7\VMX^9<_I.ATR@6XP&U@@?\YOI^1.
M6HCA5,+$P&IG/U9KQ]'22(""R7V4!;I)]J/3%0@R#3LZG5C.=GSVQ.V?C,K:
M=#1M&N#C\7@XMLO2BW A(5M>5 TR  6'!VULS2 Y9>*?IUE!K9';O=05SP6.XYB1'^QL4$UFG2
M&98T1G*=D 4. #?$T4Q0?*]!MHK@PI+27)#6SRFU4!H(FLB!]4>"(<7K;YH]5Z%82=J$^!!&&N*<<^9ST6S[!Z5&T?95O-RCEU@5 9<8
MWS2J-2S%UGB5P/&MG#P=$Q+-E L&08:7)"82J3E^34@3_BNEVOZ
MKR2.FJW"$2M"/F(9-AIRM1:!MG&IA&!:$L;1>$[2M!'\6:PUDSY@R.S-D77.
MUI$.$9)>-T(^8LZ+D!&_'H8X2IKMHG%8!/V>7L-)P>B"RV;]N'Z&U3-L+([W
M1]072N0/)J<_Z3(T!Z.:60F]A%9JGZJ'-#ZH'C(*!?&Y'C[E>G@*-Y;&O%"N
M@GL!_]':-\*K^(+ .7\N?<^E[[GT/:'2MSAD6R4)RU3393>*$IY"&V[I4_5*E=?EK[DHN#Q;Y.FOH70^+,_Y/%_GM,T+
M,T.WF)&Y"M-2D&_#^>G%>!KB.=D$N7V85VWGV-'1^^?!4;"C[SR6
M'<>(\J(A[J&&F,_#0X=Y>U^89Y7&4#04;6RL)"Q&MV"XU_$L%.!D8"V@!X.O
M40+R4E5@,5O& RN0HGQ,C$7H<.>77%_CT9+CVZ9EM6ZO*7<9;2)2.<)IF!-G
MJ\K>9;'!51W/55ORL+YJ/;053L_^6:W(GPP13A8+$DACE!>F2J+S&5.^YRM)
MQ%4XOT4SMA*7&+SCYL=Q3E.X$G:V#P(RN;LYJ7IE,6>F\M\M# DL6XA9$N)-
M7>W5YYNTB42%(JP# 4A%W+C[^^3:G>,U_HL@6V$5#)DU1?*0XG!/3-R0]A4)?.N
MVB8+A=OB5,V[&KXF8$O#>FZ=+2?_VU[4/;07/4;SHYG@'K.'YA,L0Z1^P7V*BH 1JV*^NJ]/^26<.[1[\8$@F_S6VZ3V
MW> ,?-2K6J5D*Q$_2P=\'Y(&8XQ;]#1?CQ1BK::QK<;:,0QY@%CS#*%F.-^'
M19H:,]6+K#F-"F]!U4#E/]O4#6CV#30,9FV-J/D3@H\W/[O#;#"Q([A
M[8N_ 5!+ P04    " !E,5%(*$5%"68"  !,#   #0   'AL+W-T>6QE0-NFZS7K1U=6]YQQ].%?Q"[6C^'&#L0(5H[P(X$:I_)/C%/$&,U1,18ZY
MGDF%9$CIH[288AP&/J\9"NF"A"+DJL +EH7L/GW(L$!
M?+K\\+,4ZNX"V'[R<3)QI^[3U=UPYK*9NH+ XGQ) N@M%] Y'?@H[ !T>0[H
MU#7M!<6F#0BNSR1X"7T ?7,$NA.CP7K2!NFW)MUI#B_T4\&[,YQ!ZPC]XAEL
M$=7QG@F/!142*'U)-$_MX8AA&W&/*(DD,-7&,<"%K;LLP
MY)FZ'9/,H@"Z33N=+NK0Z\XLCU!ZN#SM"/T<*84E7^D!:.SU+M>+XX)C*[*.
M>R4ZDVCGS1:]A+K3O)&0"98MLP?WKM"G.%4Z09)L8WHEI-=?IH%KL/.W\3
M+JC2ED!GHSRGN\^49)QA*]:Z5J(9O0;O'8$/?;1'!1LAR;..-QG]=ZU3HZ_@O]Z>_TK>/YOZ,X0#/2<<
MQ4/)(BQ7]>_O^<+FUV-59@KN:*4MQRMMQ =Z,U9I\]NQ*C//I#^3YC3EM%>S
M#RIVZP512:@B?*\!F3?6@]%-#XII5ZTU9E)UA;J>52C23_L#%@V6X!255'TG
M6Z'JR0!V]EL6(H"=_0TGI&3VT=C]?PA_ U!+ P04    " !E,5%(
M1@U45) &   9'0  #P   'AL+W=OP_:3>#T$H(/=)?C>
M'=P9^WUIS'?QLZE;=V /)^NNVQSL[[MRK1KI_C ;U=*YE;&-[&C7WNR;U4J7
MZM24?:/:;C^:3K-]JVK9:=.ZM=ZXR8[F7D-S&ZMDY=9*=4V]A352MY,/[]W!
M2M?JF[*.P$)N-I]EHPXG/^N)J*7KSBK=J>IPDM"NN5.C [;?'/>Z]COI-)WL
M>]A#5Z^L*$VEMK#KM7;_[$Y,1*56LJ^[:VKLPW,/)[,HB:)LR_"7?=/JSB'0
M'Q"R[/2MNI;+P\ET(F3?F7-==\J>RDY]M*;?Z/:&6!.QTM9U"]_=XOA+G]BN(F>X/X[0FWL=#FZL)/+K_Z?.)QD
M4P+>:J>7NM;=_>%DV*Z5[\G^_[HR#/_CEFB'P7GXBX5L*W'6=D01%^WVSZ.A
M\6V@BR^JX<'V0-.&O:AFVZ%"T F)86I=T5A4XEC6LBV5&+KC !(!)'H31.Q=
M20#% (I? "TZ^O&==,*LQ(EI-@!* )2\%90"* 50^C:0=&L 90#*W@1:=*8$
M4 Z@_"EHT3>-M/?#C?JFU33C)8EP5):F)Q$ 5 "H> HZ[IUNE7-^1):Z'<01
M=[I;BT^JLP9 MHDM7#]A7I-! 1-;*:T?K*4CRS-"F&^?' 10(J/6.<_FA,=:?K^C>QV*BR
MLWTC+BFVMHZZ2E!$H=0SQNISJ:WX)NM>T/UJ5J.
M>H'VSAA]KRG\6O%E6>N;;1+ F]'8&:/L6;.IS;U2P]RCGF\-\:T^5JU:(0J=
MG3'27K2E:92XEC_'2J"B,\;1,VE;"L].7%$W%FMI1Q:@ES-&3&IWH[O'P:8Y
MV!%-M:4>-2-",R/&S*.*$AAU7M;BG&8*W4];C_$646AFQ)CYL9>6YJNQ+ DC
M=S2*NHRBBW[IU(_>3Y*SVZ&3HR.(0D4C1M&_J%64$NO[EUN%BD:,HL'X%&'H
MC=#>B+$W&*$H\0,*78X8ET,Q2ESC'(S0Y8AQ.1BFH@)1J'?$Z,V'*;%W/;3K
M':+0]8AQ/1BOXBGF8+0]9FP/QJMXABBT/69L]_&*ZTZ,;L>,VT\"%TL9E1.,
MUL$(%B>(0JUC1FN,8&Q;4.:8D?EI*&,Q*'+,UA&!F";V$(4BQXS(P:@6H\@Q
MBAPS(@>C6CQ'%(H<,R('0U&"(B,[<$4EZ+M*=J>,K:'4:/WP]$+(F-[&(6V
MIVA[RM@>3+PIVIZB[2EC>QB%MJ=H>\K8'D:A[2G:GC*V!U$9VIZA[1EC^[:R
M^"RME7YYYYW8.U44(>I1-LU0].S9^N32M#>_4\YI1$7[SZ!0](P1?8LZD1M-
MTU@,,\4]@T+1,T;T+6J7_MH;<42=I!0_C-6[48[/4/3LF1=&ZJ#/$L,H7ZJ.
M.KH-J5;A:VR&HF>O>9<<#S^B1FLAC.@,RD?Z[:@M,=ED*'K&B,Z@SON.S!*?
M_/H=HE#TC OKH6HQ0]$S%#WCPGH(E:/H.8J>\[8/BZ''_?$*6TX3#8YVIXSMH]1OFFF?5@:HW.(0MOS%XOTL]5*#6N_8G<<
M46A[SM@^1IVJE;(T7X8N^M2%*+0]9VP?H[Y0.I2^9!>7QE=N:'L^6OM[81U%
M[/W=6E4:*FQ_[5J&*+0]?]72"ANL1J'J!:I>L.O:
M(12J7J#J!:-Z\#6IP'J]0-4+1O4P"BN8 E4O&-7#**Q@"E2]8%0/H[""*5#U
M@E$]C,(*ID#5"T;UX"ME@15,,5KH?NO;:8&!O4#;"VZ9)82:H^USM'W.V!Y&
MH>USM'W.V/YT)9";RG,T?$PIZ])_WJ,??_\L2E*_?.OW/YF*GNV_RTW$JJ_K$SKVI;TTTE^W(S]\T/OP
M+U!+ P04    " !E,5%(.4EW.) "  #C"0  &    'AL+W=O*'JE9=7MHL'XV_B2JGT/IJZ%6O_*F6W"@)QO-*&B 7K:*O^
MG!EOB%1-?@E$QRDY&5)3!S@,TZ A5>N7A>E[X67!;K*N6OK"/7%K&L+_;6G-
M'FL?^<^.U^IRE;HC*(M@Y)VJAK:B8JW'Z7GM;]!JCW(-,8@_%7V(2=W3@S\P
M]J8;OTYK/]1CH#4]2AV"J.).=[2N=22E_#X$_=34Q&G]&?V'F:X:_H$(NF/U
MW^HDKVJTH>^=Z)G<:OG*'C_I,(=$!SRR6IBO=[P)R9HGQ?<:\M&756O*1_\G
M20<:3, # 8\$'']+B 9"-!+0]X1X(,06(>BG8A9B3R0I"\X>'N]WKR,Z2= J
M5DM]U)UF9Q=1 P/(0+G&!EZ-*$G,#T&Z;&AQQ-Z:BV1B\A@@0042!QZ;@FXB"4LD(("
MJ4-']B[WD-1 VAZ"\RA=SNADH$[FZB!+!X!@6"(')7*7;V7+%H#,I,L2E%BZ
M_,22 " I+*$/'MIO+3.^ $SS>46L([\ANK7G:3'K']\P&FROV$UX6';G0WX1?JE9X!R;516VN
MTS-CDJK!A NUBU?UXAH;-3U+7&PO=V]R:W-H965T&UL
MA9E=DYLV%(;_BL?W">CH ['C]4SL3J>]Z$PF%^TU:VO7GH!Q@5VG_[Z O1LX
M[Y&3BQCC]Z '(3T(=G6IF^_M(81N\:,J3^WC\M!UYX'4!7MY_H<3OTO
MSW53%5W_M7E)VG,3BOU85)4)I:E+JN)X6JY7X[ZOS7I5OW;E\12^-HOVM:J*
MYK]-*.O+XU(MWW=\.[XO9?>MOOP1;N=@AP/NZK(=_U_L
M7MNNKMY+EHNJ^'']/)[&S\OU%Y_>RN0"NA701X$R=POTK4"S@N1*-I[7;T57
MK%=-?5DTUXMQ+H9KKAYTWW.[8>?84>-O_9FU_=ZWM5:KY&TXSBVRN49H$J%Y
M8HL)_3.2].U_0) (06.]GM9KN5Z+]7JL-]-ZPT[B&O%CY#1&C/7\/#!DM;(R
MB1%)#))81G*-N$DCE.>>D6 HE3&LB&$1PS$,"RVHS',,(>1=I$.<2.*0)&,D
M#CM$9YP$0SIUD4&6B209DK!&-ADVPKIMBY',R11>I/!(D3,*CYU..1M%6R&4
M^LB5R462'$A,RDCR.Z/PBH&)?#*(9A2#324!I<@!!DJ%<:@TMY"0LGE$)"JB
M0X4TQ&D4MF-\SKM&BNG$T
M&/)9Y Z@9/$J-*_AYE5H5<]#6R'4CYO8))?=JU"^ALM7H5J- Q@,450XLH$5
M*MAP!2O4:S]5X&8@Q*QS-C:(90^K'%8_-G*I258HH4(M5RBA''WJ^;@34IEV
M$661K%!"A5JN4)+D$*+)XG3.$EE8HCXMUR<)7H25H1#R601%-B>A.2TW
M)Z$3,\6G@! R-H^PR-XD]"87XH90B$;Q>XH0A,RYU)J,/<$E\B
M"BF?Q59G)%N3T)J66Y.$!6MJ<"Z)WLPBC
M4:]D/*>14CHF/BU+6*.$'9>P%B2Y5 
MWP@Q(A6Y0^G(ZP)4L8/W!4*&WZ#N9^8DLHBU@7N_B_6MK$^-^N27<'/+3#N-
MV^%N9,XABU.C.!T7E48C L>]R)Q#%J9&83JN*"T\YWOG^.I.C-DTI@59F1J5
MF7%):90A],N]R)Q#EJ5&66:@)]3@)YB F(F8R-.C)C)O)H $_];,\A;=D
M8LZ;&)'L2H.NS+B>C.!*9_G28"O%^B>"R) QLBX-ZC+C>C+H0>D!18A)#RC)
MY&WQN7@)?Q7-R_'4+I[JKJNK\?7PT] HWACG$G2
MZ;0/G;FYA_:92TCBG$H.2'+]]@4T1H%]H0\<0.M%5WMHPW1*HIWT7BP"G9&*.FCA  :=20J@W+PJR]
M\+)@1UE7+7WA@3@V#>'_EK1FYWD(P\O":[7;2[T0E44TV&VJAK:B8FW Z78>
M+N#S"B9:8A1_*GH6HW&@X=\8>]>37YMY"#0#K>E::A=$74YT1>M:>U*1/WJG
MUYC:<#R^>/]ATE7X;T30%:O_5ANY5[0@##9T2XZU?&7GG[3/8:8=KEDMS'^P
M/@K)FHM)DL[M6K;F>NSL8]&9^ ]0;H,$ IE\:Q+U!?#4P6Q=U9":O[T22
MLN#L'/#N81R(?N;P.58[M]:+9J/,/9694*NG,IL5T4G[Z27+3H)&$C@H(N5\
MB(!\$9;(,4?3 "M7$2-_A-B;0VSLDW$.J95#)\%&TG8Y0$NS6$*?,R92X3M)@R)Q+R(ST@G!!A+Q%VB:PO9(D?)7I ."'*O42Y
M2Q1;1+G[0;DT=T03$EUL??4)N"R)7:# 0R_T7=F4YT:]A"Z/4S#A[5?5WJ+'
MM%,R;YU=0.22V66PUXRC89AG69RAQ ;S2 '&,PC!C7H$_=49NN49VW6QUTRY
M<)Q#!'.;RR,%69+B%-RHUM!?KJ%;:3&VN1+WZ<08S=QWZ[ZP8XI&!W-#^\[#FP4  (@>   8    >&PO=V]R:W-H965T&ULC9E-
M;^)($(;_"N).Z*INM]L100I8J]W#2J,Y[)Z=Q EH #.VD\S^^[6-0TC5V\E<
M CA/VV]_N!Y_+%ZK^D>S*N1@?AG
M6[XV%]\G??B[JOK1__CKX69J^@SEKKQO^UT4W<=+N2YWNWY/W9%_CCM]/V;?
M\/+[V][_&+K;Q;\KFG)=[?[=/K2;+JV93A[*Q^)YUWZO7O\LQSXD_0[OJUTS
M_)W8L1ENP&,#/C<@_VD#.S:P[PW'ZB"&ATXR!)J]'%(K.\U@)PQ(C" 
M+&61P)&23SJPJOFD#\-&%0> <99X)T,#S#F.5'""'KDE5C6<3&P7V )D5<_)
MD.RZU7.5)&JR )6&(#L.*$YCTX750]H]9*1\1NCR0-EEI1A# \K+,ST'E,_2
MB'P(VX>T?LA(_Y#61C<=\AQ= RP$;V5J8#,;.)(:2XBTA(
ML)-(2XF,M!)IE(!P9%B 1Y3,V$FLC74[1>%FN1=)-
MMEK'" OD9*%#F'42&1(RQZ_\E82@RD) O&BK5(,KE.UP!R
MZG@/(1I:$Q3ZRP$R>F'0 XJ#M=_!^H_
MR_H_0OUCKO?5?:4?HT-,/>K%F(G4*8@:H2;AX%+U9 2@/N4L2;(0ZT/DS0U2
MA)H]7=P#LZ?S>2^>CZT
M_7NOBZWGEZNWW+_O$]M7=)V?7I&^[V:Y.!9/Y=]%_;0]-).[JFVK_?#.[[&J
MVK)+:JXZ7VS*XN'\8U<^MOW7M/M>GUZ4GGZTU?'MO>_YY?/R?U!+ P04    
M" !E,5%(YC1O__EY4R!I3$
M:.2=:@I,UIPY HJ]^^+OLHU!6,"?&CHYV3M&^Y'S#W/X?=J[GI$ !')E/&"]
MG.$ A!A'.O"_P>@G,:YG94SVQ
M^@%S=9/$#2[A%8NR9M(Y<*M$#O42NL]$P=#P0*9;9/>B_Z,=,?
M%&\N0W.&PO=V]R
M:W-H965T&ULC9I;<^(X$(7_"L4[@]4M^9(B5 6[MG8?MFIJ
M'G:?'7 "-8 9VQEF__WZ0HCI/B+S$K YDH\N[J\E97$NJ^_UMBB:R:_#_E@_
M3K=-\^F]5[,OSX]1,WV]\V[UNF^[&?+F87\MM
M=H?B6._*XZ0J7AZG3^8ALU$GZ17_[(IS/?H^Z,TZ#P4^V+=
M=%7D[93@[YK^%S=^P_S\,O<7 I
MA@O0I0!="YCP;@&^%."/ O9N 7LI8$6!^="4OB.RO,F7BZH\3ZIA]$YY-TG,
M@VV[>MW=['NV_ZWMBKJ]^W-IV"WF/[N*+IK5H*&QYJJ8M[5?'T'H$2M2Q>GV
M :E6L)!D6I($V 3#=G)?GF_:&>(*+*S ]A78<04F%ATU:.)><^PU$;-HJ]:0
MC41CM68T)C=>'?3J0&,C7$$(*PAU8P,K&CMHPI%)&\:B1U(@LD:.K19Q2!Z_
M$?0;:;\L!R=23Z' "+M:8Y)0N 6:P#,58V@V!F8383;69ITPDFJ-(=FU0./Q
MFD"OB?9J ^$U4<]P)Q#&/YDR$0&4+IF-1S9B:4@1"I
M8CFY,J0BCV4<^0V#3F9IF74G6QG,@&@F&9"AFGRS&)/&6!V^1R_+;148 ,:!
M-BNL.]"U+I&-!JI$C1(0&1=[/&/F&  =JZ:69H4)8N59JV9D2;V_2!883UI@
M,'J,9H^*YD8SH_63.&D;R&RB7&N5];T1&$ &$$A&[)71Z&@GN[(,5"J:9D#E
M"Y080P9Q2 +>:(#,R*A("51,ZBW6*C:>=Y PC$C#R$D6D29(F,A "43$<
M7+\16! EB0R70*40B]=/)1F0L&_U1IA%!%@DUV8K
MTOQ0;C^59$!"WE20,888K(E4C&0-#[GN38%FIE(J)#+LVZG!&&* (:<<:WK,
M$A?*3D:R-J3(,(ED%"2>M(HQC9A G/3DP.S9I4)\D 1F$-,3N3A-@:I]O5DV
M'*ALXIMAF \,ML;D0*PNHIL>EH.:(I$)C)ID0.99QC+F$0,>A3(Y8TT0M?F1
M I%\B^]*;MUB"C&@4"CIR8 ;+I3P1"JKUK!(1=ZX@QG$@$%R)%<,5CPR\J= 
MI+KXMQ'$&$$,$"1W+%:LX:$VNH"&9&H"--[]6<808@ A.=@K_AQ"0)+$,O&]
M6\_MUCEFD 4,"B7@[;W=M,'MYY(,2$P4>SK78@!9 *!0$MX"9*@\($6J2 9A
M(/+U+R:/_9UUD-7+%P4-H%$G,4 S,^1)4"WFG 6F.]PH3]1=ZHK[J_,0S8H_5X-Q^'#15.>WD_W
MK_]BL/P?4$L#!!0    ( &4Q44A?8^)XL@4  &L?   8    >&PO=V]R:W-H
M965T&ULC9E;4^,X$(7_2BKOF4BMBR4*J%H@L/NP55/S,/ML
MP$!JDIA-S##[[U=V3 9U'SOA@=Q.JX\LZ5/+/G^OMS]V+U753'ZM5YO=Q?2E
M:5[/YO/=PTNU+G=?ZM=JDWYYJK?KLDD?M\_SW>NV*A^[H/5J3DKY^;I<;J:7
MY]UW7[>7Y_5;LUINJJ_;R>YMO2ZW_UU5J_K]8JJG'U]\6SZ_-.T7\\OS^2'N
M<;FN-KMEO9ELJZ>+Z1_Z[,[95M(IOB^K]]VG]Y/6_'U=_V@__/5X,56MAVI5
M/31M$V5Z^5E=5ZM5VU+*_&_?Z.^<;>#G]Q^MWW;=3?;ORUUU7:_^63XV+\FM
MFDX>JZ?R;=5\J]__K/H^N+;!AWJUZ_Y/'MYV3;W^")E.UN6O_>MRT[V^[W\)
MJ@_# =0'T"% CP>8/L < DPQ&F#[ /L[P(X&N#[ '0+;ZMWR?;_81Z+=MYJ\^*-/H/[9?=8'>_I='9I6]_
M7NI"G\]_M@WUFJN]AC(-Y9IKI#&YY@9I;*Y9((W+-;=(XW/-'=(4!\T\79/#
MA2%X8:AKP&8-!'9A]IK0:3:=QFO-W"ZDB**.!>N35%DV#'=2,B.CR>!>&=@K
M WH5V5#N-?Y3'H536)C"RA1!L9E@10IG' 6OAL;(P52N:\9DJ31NP,,&O/2J
M^2![X=6P(;X;E60V"FBCD#:(Y;@J1(Z9859OQS69D0"-!#!V;*5?!=E9;=E2
M7QP1958BM!*!%9;E*HHL%#F]%D=$F95VUT*05,",Y713(E$2V5 8%0>R#2!9
M@VQ\.O2B+%L1"D[3(ZK<#@:A!B0,GMNA4Z&A,9@T(!/OSHV6:"JH\$ZIH608
M41HQBJ][+2&EE>(7>%R4F\$0TPZ8B=R,DWF,&.UQ46X& U$#(D9.;RUY%ZD(
M+@[-8IZ*%,&&L:<"URKFG)K!G?R\8Q!&&P&TB2J#)-K(%KQ+XZ+<#$8? ?2)6H,DU6;$
M1V!4DUO!X",$/KZQD&1:Y"7)XH@H-X/!1P!\?/^Y)@F^=*;O_@:28?(1()_8
M?TB23T?/>SXNRLU@.!(J^OC^0Q)\Q+>?<4UN!<.1$!SY[D,2CMI&;_P B U&
MI$&(Y+N/D8CT%+U6 _TR&) & 9+/= -XQ8_0BR.BW PFF@'U'#^.WAA9S\V(
ME/&#R0;.FX!]8N%"6@D 8DGNS*2@$$5UJ>C.[_;GEA,#0-@*8H+XR$
M9JJJ>)?&1?F]'TQ5"Z@JR@LKJ2K*BW%-;@5#UZ)C-(>NE3P=NMF%:6K1Z9A?
M?2MI2F+[/"+*S6#:6G2(YF2QDJ2\T%R,:W(K W.L'"@>'F>90I7.2-#>&D>@D$DGQ->1D 9IXZ#B@@&PO=V]R:W-H965T&UL?5/;
M;MP@$/T5Q <$+[NY=.6UE$T5)0^5HCRTSZP]ME& <0&OT[\O8*_CI%9?@!GF
MG#DS#/F ]LVU )Z\:V7<@;;>=WO&7-F"%NX*.S#AID:KA0^F;9CK+(@J@;1B
M/,MNF!;2T")/OA=;Y-A[)0V\6.)ZK87]DC@PC;&1Y J4@4
M$O^>.#]21N#R?&%_3-4&]2?AX '5+UGY-HC-**F@%KWRKS@\P53"=20L4;FT
MDK)W'O4%0HD6[^,N3=J'\>8NFV#K #X!^!< &Q,EF=^%%T5N<2!V;&TGX@MN
M]CPTHHS.5'>Z"T)=\)X+GMWF[!R)IICC&,,7,9LY@@7V.05?2W'D_\#Y.GR[
MJG";X-M/"N_6"7:K!+M$L/MOB6LQW[XD88N>:K!-&AU'2NQ-&M2%=Y[.>Y[>
MY".\R#O1P ]A&VD<.:$/+YOZ7R-Z"%*RJVM*VO!_9D-![>/Q-ISM.%*CX;&[
M?)#YEQ9_ 5!+ P04    " !E,5%(9S/?7)X!  "Q P  &    'AL+W=O)MV:=(^3C>[&;8-X%< 7P"?
MLR1\2I1D?A%>E(7%D=BIM;V(+Y@?>&A$%9VI[G07A+K@O90\SPIVB437F-,4
MPU%_\B_WR38)X+]?TO-G4_P;10Y"2W=Q2
MTH7_LQ@*&A^/G\+93B,U&1[[^8,LO[3\#5!+ P04    " !E,5%(L=+V!GO0_J9!H[CSIFFI[0WP.H*4I"Q-;ZGB0B=E
M$7U/IBQP<%)H>#+$#DIQ\^\$$L=CDB57Q[-H.Q<&4AX@8\")@M*LS"=K/B&_!^%T?DS1(  F5"PS<;Q=X!"D#D4_\=^;\3!F 
MZ_.5_6>LUJL_P#8872QI54@W6HKI"$
M*/X^[4+'?9QN]G2I;M"GH)1'/,:8IAJYALB:">?4G!ME*2"@<=!W7E7:;S@<4W^0PO
MBYZW\(>;5FA+SNC\R\;^-X@.O)3T9I^0SO^?Q9#0N'"\\V4'4$L#!!0    ( &4Q44@?(]TPH0$  +$#   9    >&PO=V]R:W-H965T
MA@9<$67"TU&"?1$ O-D3[FA],^1J2 'Q)&MSJ3J/V,^!J-;_61
M9E$"**A\9!!AN\ 3*!6)0N)?,^=[R@AYAAVP ^ _@"N,^2
M\"E1DOE9>%$6%D=BI];V(KY@?N"A$55TIKK371#J@O=2\ORN8)=(-,>ZBTVD-[9A(G00LX!3+9_GV!9+)IF_8"V/@]/QM33FA?
M7 _@R:M6QIUH[_UP9,S5/6CA[G  $VY:M%KX8-J.N<&":!)(*\:S[!W30AI:
ME',^RZWUTL*ID*ZZ1&HR3:(B%]D0?
M\N.YB!$IX)N$R6W.)&J_(+Y$XTMSHEF4  IJ'QE$V*[P"$I%HI#XQ\+YEC("
MM^<;^Z=4;5!_$0X>47V7C>^#V(R2!EHQ*O^,TV=82KB/A#4JEU92C\ZCOD$H
MT>)UWJ5)^S3?%/D"VP?P!&E%'
M9ZH[W06A+GBO%>=9R:Z1:(DYSS%\$Y.O$2RPKRGX7HHS_PO.]^&'786'!#_\
MIO ?^8M=@B(1%/\M<2_F3Y5LTU,-MDNCXTB-HTF#NO&NT_G TYN\A5?E(#KX
M*FPGC2,7].%E4_];1 ]!2G9W3TD?_L]J*&A]/+X/9SN/U&QX'&X?9/VEU2]0
M2P,$%     @ 93%12 /M*4.B 0  L0,  !D   !X;"]W;W)K&UL;5/!;N0@#/T5E \H&9+I5J-,I$Y75?>P4M7#[IE)G 05T-\#J"E*0L36^IXD(G91%]SZ8L<'!2:'@VQ Y*'4QXB8L ? :-=G4G0?D9\#<:O^IBD00)(
MJ%Q@X'Z[P -(&8A\XG\SYT?* %R?K^R/L5JO_LPM/*#\*VK7>;%I0FIH^"#=
M"XY/,)>P#X052AM74@W6H;I"$J+XV[0+'?=QNMEG,VP;P&8 6P!W:10^)8HR
M?W+'R\+@2,S4VIZ'%]P=F&]$%9RQ[GCGA5KOO92,906]!*(YYC3%L%7,;HF@
MGGU)P;92G-@W.-N&9YL*LPC//BG,MPGR38(\$N2?"/9?2MR*N?V2A*YZJL"T
M<70LJ7#0<5!7WF4Z[UE\DX_PLNAY"[^Y:86VY(S.OVSL?X/HP$M);_8)Z?S_
M60P)C0O''_YLII&:#(?]]8,LO[1\!U!+ P04    " !E,5%("O;7/Z$!  "Q
M P  &0   'AL+W=OPUW%;JQ=@AGEOW@Q#,:)]=1V 
M)V]:&7>BG??]D3%7=:"%N\,>3+AIT&KA@VE;YGH+HDX@K1C/L@],"VEH623?
MLRT+'+R2!IXM<8/6POXZ@\+Q1'-Z<[S(MO/1P-T<\AGV#: SP"^ !ZR)'Q*E&1^$EZ4A<61V*FUO8@OF!]Y:$05G:GN
M=!>$NN"]EIS?%^P:B>:8\Q3#5S'Y$L$"^Y*";Z4X\W_@?!N^VU2X2_#='PH?
MM@GVFP3[1+#_;XE;,1__2L)6/=5@VS0ZCE0XF#2H*^\RG8\\O%GTHH5O
MPK;2.')!'UXV];]!]!"D9'<'2KKP?Q9#0>/C\3Z<[312D^&QOWV0Y9>6OP%0
M2P,$%     @ 93%12&9GZRV? 0  L0,  !D   !X;"]W;W)K&UL?5/!;MP@$/T5Q <$+[M)JI774C95U1PJ13FT9]8>VRC .(#7
MZ=\7L-=Q$J<78(9Y;]X,0SZ@?78M@">O6AEWH*WWW9XQ5[:@A;O"#DRXJ=%J
MX8-I&^8Z"Z)*(*T8S[(;IH4TM,B3[]$6.?9>20./EKA>:V'_'D'A<* ;>G$\
MR:;UT<&*G,VX2FHP3J(A%NH#O=OLC[L8D0)^2QCJ@/-H@10
M4/K((,)VAGM0*A*%Q"\3YUO*"%R>+^P_4K5!_4DXN$?U1U:^#6(S2BJH1:_\
M$PX_82KA.A*6J%Q:2=D[C_H"H42+UW&7)NW#>,-O)]@Z@$\ /@.^94GXF"C)
M_"Z\*'*+ [%C:SL17W"SYZ$1972FNM-=$.J"]USP;9:S-G4_QK10Y"275U3TH;_,QL*
M:A^/M^%LQY$:#8_=Y8/,O[3X!U!+ P04    " !E,5%(DB93RI\!  "Q P  
M&0   'AL+W=OPUW%;JQ=@AGEOW@Q#/J)YMRV (Y]:
M=?9(6^?Z V.V;$$+>X,]=/ZF1J.%\Z9IF.T-B"J"M&(\26Z9%K*C11Y]SZ;(
M<7!*=O!LB!VT%N;7"12.1[JC5\>+;%H7'*S(V8*KI(;.2NR(@?I([W>'4Q8B
M8L"KA-&NSB1H/R.^!^.I.M(D2  %I0L,PF\7> "E I%/_#%S?J4,P/7YROX]
M5NO5GX6%!U1OLG*M%YM04D$M!N5>"G)S9Z2UO^?Q5!0NW#\YL]F&JG)<-A?/\CR2XO?4$L#!!0 
M   ( &4Q44@<-0&PO=V]R:W-H965T*D4YM&?6'MLHP+B U^G?%[#7
M<5NK%V"&>6_>#$,QHGUS'8 G[UH9=Z*=]_V1,5=UH(6[PQY,N&G0:N&#:5OF
M>@NB3B"M&,^R!Z:%-+0LDN_%E@4.7DD#+Y:X06MA?YU!X7BB.WISO,JV\]'!
MRH(MN%IJ,$ZB(1::$WW:'<]YC$@!WR6,;G4F4?L%\2T:7^L3S:($4%#YR"#"
M=H5G4"H2A<0_9\Z/E!&X/M_8/Z=J@_J+L?1?$9I34T(A!^5<4=.'_+(:"QL?C
M(9SM-%*3X;&_?9#EEY:_ 5!+ P04    " !E,5%($?&DI* !  "Q P  &0  
M 'AL+W=O2UE
M4U7M0Z4H#^TS:X]M%&!B
MO??#D3%7]Z"%N\,!3+AIT6KA@VD[Y@8+HDD@K1C/L@],"VEH52;?DZU*'+V2
M!IXL<:/6POXY@\+I1 _TYGB67>^C@U4E6W&-U&"<1$,LM"?Z<#B>BQB1 GY*
MF-SF3*+V"^)+-+XW)YI%":"@]I%!A.T*CZ!4) J)?R^<;RDC<'N^L7]-U0;U
M%^'@$=4OV?@^B,TH:: 5H_+/.'V#I83[2%BC@\ZAN$$BU>YUV:M$_S
M39XOL'T 7P!\!7S*DO Y49+Y17A1E18G8N?6#B*^X.'(0R/JZ$QUI[L@U 7O
MM>+YYY)=(]$2-(Q?T
MX653_UM$#T%*=G=/21_^SVHH:'T\?@QG.X_4;'@<;A]D_:757U!+ P04    
M" !E,5%(KP7@K)\!  "Q P  &0   'AL+W=O$^
M$M:H7%I)/3J/^@:A1(O7>9&E%'9ZH[W06A+GBO%2]XR:Z1:(DYSS%\$W-8(UA@7U/PO11G
M_@^<[\/S785Y@N?O%.;[!,4N09$(BO^6N!=3_)6$;7JJP79I=!RI<31I4#?>
M=3H?>'J3M_"J'$0'WX7MI''D@CZ\;.I_B^@A2,GN[BGIP_]9#06MC\>/X6SG
MD9H-C\/M@ZR_M/H#4$L#!!0    ( &4Q44@#X%, H $  +$#   9    >&PO
M=V]R:W-H965T
M*D4YM&?6'MLHP+B U^G?%[#7<5JK%V"&>6_>#$,QHGUU'8 G;UH9=Z*=]_V1
M,5=UH(6[PQY,N&G0:N&#:5OF>@NB3B"M&,^R>Z:%-+0LDN_9E@4.7DD#SY:X
M06MA?Y]!X7BB.WISO,BV\]'!RH(MN%IJ,$ZB(1::$WW<'<]YC$@!/R2,;G4F
M4?L%\34:W^H3S:($4%#YR"#"=H4G4"H2A<2_9L[WE!&X/M_8OZ1J@_J+L?1?$9I34T(A!^1<7XH
MV#42S3'G*8:O8G9+! OL2PJ^E>+,_X'S;?A^4^$^P?1"@>3!G7E7:;S,3TB>P\OBUZT\%W85AI'+NC#RZ;^
M-X@>@I3L[D!)%_[/8BAH?#P^A+.=1FHR//:W#[+\TO(/4$L#!!0    ( &4Q
M44CZ[G-/H0$  +$#   9    >&PO=V]R:W-H965T*D4YM&?6'MLHP+B U^G?%[#7<5JK%V"&
M>6_>#$,QHGUQ'8 GKUH9=Z*=]_V1,5=UH(6[PQY,N&G0:N&#:5OF>@NB3B"M
M&,^R#TP+:6A9)-^3+0L)9MYZ.#E05;<+74
M8)Q$0RPT)_JP.Y[S&)$"?D@8W>I,HO8+XDLTOM4GFD4)H*#RD4&$[0J/H%0D
M"HE_S9QO*2-P?;ZQ?TG5!O47X> 1U4]9^RZ(S2BIH1&#\L\X?H6YA$,DK%"Y
MM))J%$6%D=BI];V
M(K[@[LA#(ZKH3'6GNR#4!>^UY/E]P:Z1:(XY3S%\%;-;(EA@7U+PK11G_@^<
M;\/WFPKW";Y_I_#3-D&^29 G@OR_)6[$'+*_DK!53S78-HV.(Q4.)@WJRKM,
MYP-/;_(67A:]:.&[L*TTCES0AY=-_6\0/00IV=V!DB[\G\50T/AX_!C.=AJI
MR?#8WS[(\DO+/U!+ P04    " !E,5%(@2),0I\!  "Q P  &0   'AL+W=O
MMC#O1UOONR)@K
M6]#"/6 ')MS4:+7PP;0-FA32TR)/OV18Y]EY) \^6N%YK
M87^=0>%PHAMZ<[S(IO71P8J#[3Z_):[%
M;-\E88N>:K!-&AU'2NQ-&M2%=Y[.1Y[>Y!Y>Y)UHX)NPC32.7-"'ETW]KQ$]
M!"G9PYZ2-OR?V5!0^W@\A+,=1VHT/':W#S+_TN(W4$L#!!0    ( &4Q44BL
MN=LOH@$  +$#   9    >&PO=V]R:W-H965T0/* YQTBIR+#5=5>UAI:J'W3.QQS8J,"[@N/OW!>RX;M<78(9Y;]X,
M0SZ@>;,M@",?2FI[3%KGN@.EMFQ!<7N#'6A_4Z-1W'G3--1V!G@504I2EJ9[
MJKC029%'WXLI#+&]4MS\.X'$X9ALDJOC532M"PY:Y'3&54*!M@(U
M,5 ?D_O-X92%B!CP1\!@%V<2M)\1WX+Q7!V3-$@ ":4+#-QO%W@ *0.13_P^
M<7ZE#,#E^;)J2"FO?2O>+P!%,)NT!8HK1Q)65O
M':HK)"&*?XR[T'$?QIOM?H*M ]@$8#/@+HW"QT11YB_N>)$;'(@96]OQ\(*;
M _.-*(,SUAWOO%#KO9>"[;*<7@+1%',:8]@B9C-'4,\^IV!K*4[L/SA;AV]7
M%6XC?/M-X6Z=(%LER")!]HU@_Z/$M9C;'TGHHJ<*3!-'QY(2>QT'=>&=I_.>
MQ3?Y"B_RCC?PFYM&:$O.Z/S+QO[7B Z\E/1FEY#6_Y_9D%"[<+SU9S..U&@X
M[*X?9/ZEQ2=02P,$%     @ 93%12)*Q:^ZA 0  L0,  !D   !X;"]W;W)K
M&UL?5/!;MP@$/T5Q <$+[N;IBNOI6RJ*#U4BG)(
MSZP]ME& <0&OT[\/X+7CME8OP SSWKP9AGQ ^^9: $_>M3+N2%OONP-CKFQ!
M"W>#'9AP4Z/5P@?3-LQU%D250%HQGF6W3 MI:)$GW[,M+7&]UL+^
M/H'"X4@W='*\R*;UT<&*G,VX2FHP3J(A%NHCO=\<3KL8D0)>)0QN<291^QGQ
M+1K?JR/-H@104/K((,)V@0=0*A*%Q+^NG)\I(W!YGM@?4[5!_5DX>$#U4U:^
M#6(S2BJH1:_\"PY/<"UA'PE+5"ZMI.R=1SU!*-'B?=RE2?LPWNPGV#J 7P%\
M!MQE2?B8*,G\)KPH@:
MPP#ZGX&LI3OP?.%^';U<5;A-\^X?"K^L$NU6"72+8_;?$E9C;
M[*\D;-%3#;9)H^-(B;U)@[KPSM-YS].;?(87>2<:^"%L(XTC9_3A95/_:T0/
M04IVLZ>D#?]G-A34/AZ_A+,=1VHT/';3!YE_:?$!4$L#!!0    ( &4Q44A?
M&PO=V]R:W-H965TJ5"?=-KU\'J+QU'7U\'Q3R^#KPT^X.>
M!I*J3&YUVZ:3_=BH/AKD;A4_\H>U8!/$(GXU\CS>W4?3Y%^5>IL>?FQ7,9OF
M(%NYT1-%;2[O\DFV[<1DE/]<2#\UI\+[^RO[-[M<,_W7>I1/JOW=;/7!S);%
MT5;NZE.K7]3YN[RL83$1;E0[VL]HWU/+_)V:4,%]"E
M@)R"9!:RT_Q:Z[HJ!W6.AOF[/=;3%O(',E_$9AJTZ[;OS$1',_I>T9*7R?M$
M=,&L9PS=83X1B6&_21"26)-73KA80(;/[D;.8@!"G?K(2BP]SS@5.Y1B,*5\3&4+0,RT*V/G !%
MYNH@4,"4'-N:"T#AK0> [GP-JYEW (%$@IC@.  W?GPM5!H#2@@S. 
M^P9/O6X#(9"'N@VG  <6S]VL@:! V' <-Q%G!@],)-' @*
M_=;A-"!@],(-'0@*I [A-"#@],+M P@*] 'A."#@],+M P@*] 'A."#@],+M
M P@*] 'A."#?Z8*Y?0!!H3[ <4# Z5Y< Y!@@=@A' ?D6UTP-W8@*! [A/. 
M?*L+MG!U$"CP\T,X#PA8/?7\XX,$"_4;S@/RK2Z8UV\(%.@W@?- ^%87W.TW
M"'+[+;G[2]_)86]/+F.T4:?>'I3N1F^GHT>R1X)/>%4>Z[W\60_[IA^C5Z7-
MP<+^_=\II:69"_MB>O)@SF^WAU;N]'2;F?MA/M',#UH=KP>TVRFQ^@=02P,$
M%     @ 93%12%R%GH:] 0  >P0  !D   !X;"]W;W)K&UL=53=;J0@%'X5X@,4Q=&V$\>DTTVS>[%)TXOVFM&CDH)8P+'[]@5T
MK#O+W@@.753$"OF>R1@N80/23[8^X0'O#*8-*;.7*YGZ1\=XM?]2&*70K H3).
M@=KA#(_ N1.RQA^+YK>E(V[G%_4G7ZW-_D0U/$K^QFK3V63C"-70T)&;%SG]
MA*6$S E6DFO_1=6HC1072H0$_9Q'UOMQFG>R^X46)I"%0%;"7>P3GXU\FC^H
MH66AY(34?+0#=7\PV1-[$)4+^KK]GDU4V^BY3!-2X+,36C#'&4,VF&1%8*N^
M6I"0Q9'\0R=A>AK,,/7T=$M/_N._"PKLO,#NKQ+3JQ)#F%W8) N:9 &![,HD
MA,G#)GG0) \(W%Z9A#!W5R9XU-^
M 5!+ P04    " !E,5%(/;HF,[T!  ![!   &0   'AL+W=O@;KC",W#NA9SQ[U7SP](3]_.;^M=0KO:OX&:PD'+]@H;L(7-9.Q2MPH"1+T?1F9#..\[)2/*RU.("N!;(3'-"2^
M&(4TOU!+ZTJK&>GE:$?J_V!V).X@&A\,=8<]EZAQT6N=9Y\K?/5"*^:\8,@.
MDVT([-0W"Q*S.)-_Z"1.SZ,9YH&>[^E9$1PFV!8?.^NDG-]=+&PO=V]R:W-H
M965T(#%,49VTX[%)DTOVFM&
MCTH*8@''[ML7T+&NR]X('+Z?%=*#$%3].0&7
MXS%*HFO@A36M<0%+
M7]4QBET*P*$T3H':X0*/P+D3LL8?L^:WI2.NYU?U)U^MS?Y,-3Q*_L8JT]ID
MXPA54-.!FQ1 [$&4+NCK]GLV46VCER(E68XO3FC&G"8,
M66&2!8&M^F)!0A8G\@^=A.EI,,/4T],U/;D+"^R" CLOL/NKQ-M-B2',?TSV
M09-]0.!^8Q+ I''8) N:9 &!9&,2PFS/&Z]NAP#5^";0J)1#YUMN%5WZ[('X
MV_4-+_*>-O";JH9U&IVEL7?4WZ1:2@,VE?C&%MS:EV!9<*B-F][:N9J:8UH8
MV5];?7EOBB]02P,$%     @ 93%12 Y;>EO* 0  X 0  !D   !X;"]W;W)K
M&UL=53=;J0@%'X5X@,416?L3AR33INFO=BDZ<7N
M-:/'GQ3$ H[=MU] QUI+;P0.W\\YR"$;A7Q3#8!&'YQUZA@T6O<'C%71 *?J
M1O30F9U*2$ZU6:9K.WB12 V<4_GO
M!$R,QR *KH'7MFZT#> \PPNO;#ETJA4=DE =@[OH<$HMP@'^M#"JU1S9W,]"
MO-G%"_6U+
MW9ADPP"54-&!Z523$B.1UM3^T?C [$'$1A@ZYNMV<2529ZR>,XSO#%
M"LV8TX0A*TRT(+!17RR(S^)$OM&)GQY[,XP=/5[3R0_^B5<@<0+)EQ*338D^
MS,YOLO.:[#P"^XV)#Y/Z3?9>D[U'X'9CXL/\\IND7I/TNT 2;DQ\F.T_P:LK
MR$'6KM,4*L30N;Y>19=FOB/N"G_"\ZRG-?RFLFX[A&UL=53=;ILP%'X5
MBP>HB8%VBPA2TZG:+BI5O=BN'3B 5?]0VX3V[6L;0EGFW<3V\?=WL)UR4OK5
M]  6O0LNS2'IK1WV&)NZ!T'-C1I NIU6:4&M6^H.FT$#;0))<$S2]!8+RF12
ME:'VK*M2C98S"<\:F5$(JC^.P-5T2';)I?#"NM[Z JY*O/(:)D :IB32T!Z2
M^]W^6'A$ /QF,)G-'/GL)Z5>_>)7RJQ1CF/R9%U*2("!17)C',[94)WAR< -V%^VE0K489
M7L.FNCZ!>Q(._@M>E0/MX(GJCDF#3LJZZQ,.N57*@HN2WK@LO7NDZX)#:_WT
MSLWU?&_GA57#Y16N?P75)U!+ P04    " !E,5%(H6%$#K\!  ![!   &0  
M 'AL+W=O=5FHP7(F
MX5DC,PA!]=\3<#4>DTUR#;RPMK,^@,L"+[R:"9"&*8DT-,?D87,XY1X1 +\9
MC&8U1S[WLU*O?O&S/B:I3P$X5-8K4#=6EH56(]+3T?;4_\'-@;B#J'PPU!WV7*+&
M12]EMKTO\,4+S9C3A"$KS&9!8*>^6)"8Q8E\H9,X/8MFF 5ZMJ:3?5Q@&Q78
M!H'MIQ+W-R7&,-_B)KNHR>ZKP"Z],8EA_G.2>=0DCPB0&Y,8)KLQP:O;(4"W
MH0D,JM0@0\NMHDN?/83KB#_@9='3%GY1W3)IT%E9=T?#36J4LN!22>]F_ =02P,$%     @ 93%12)>=G3*^ 0  
M>P0  !D   !X;"]W;W)K&UL=53;;IPP$/T5BP^(
M66Z;KEBD;*HJ>:@4Y2%]]L( 5GRAMEG2OX]M6$*W[@NVQ^=0]@
MT =G0A^CWICA@+&N>^!$W\D!A-UII>+$V*7JL!X4D,:3.,-)'!>8$RJBJO2Q
M%U65TQ>M@=
M3H5#>, ;A4EOYLCE?I;RW2V>FV,4NQ2 06V< K'#!1Z!,2=DC7\OFE^6CKB=
M7]5_^&IM]F>BX5&R7[0QO4TVCE #+1F9>973$RPEY$ZPEDS[+ZI';22_4B+$
MR<<\4N'':=[99PLM3$@60K(2[F.?^&SDT_Q.#*E*)2>DYJ,=B/N#NT-B#Z)V
M05^WW[.):AN]5&F>E?CBA!;,:<8D&\QN16"KOEHD(8M3\@\]"=/38(:IIZ=;
M>OH?_RPHD'F![*\2\YL20Y@B;)('3?* P/[&)(2Y#YL409,B(/#MQB2 *>(;
M$[RY'1Q4YYM HUJ.PK?<)KKVV4/B;]<7O"H'TL%/HCHJ-#I+8^^HOTFME 9L
M*O&=+;BW+\&Z8- :-]W;N9J;8UX8.5Q;?7UOJD]02P,$%     @ 93%12!^"
MYJVL 0  %@0  !D   !X;"]W;W)K&UL;53=;J0@
M%'X5X@,4![6[F3@FG39->]&DZ<7N-:-')>7' H[=MU] QW%GN1G@\/T=@2DG
MI3]-#V#1M^#2')+>VF&/L:E[$-3ZP&330)I $QR1-[[&@
M3"95&6KONBK5:#F3\*Z1&86@^L\1N)H.R2ZY%#Y8UUM?P%6)5U[#!$C#E$0:
MVD/RL-L?"X\(@%\,)K.9(Y_]I-2G7[PVAR3U$8!#;;T"=<,9'H%S+^2,OQ;-
MJZ4G;N<7]>?0K4M_H@8>%?_-&MN[L&F"&FCIR.V'FEY@:2$DK!4WX1?5H[%*
M7"@)$O1['ID,XS3O%.E"BQ/(0B KX6<@X-DHQ'RBEE:E5A/2\Z<=J#_!W9ZX
M#U'[8N@[[+F@QE7/57:_*_'9"RV8XXPA&\P5@9WZ:D%B%D?R'YW$Z5DT81;H
MV9:>Y7&!/"J0!X'\GQ;)38LQ3!8W*:(F140@OS&)88H;$[PY. &Z"_?3H%J-
M,KR&375] @\D'/P57I4#[>"-ZHY)@T[*NNL3#KE5RH*+DMZY++U[I.N"0VO]
M](>;Z_G>S@NKALLK7/\*JK]02P,$%     @ 93%12)_TV9N^ 0  >P0  !D 
M  !X;"]W;W)K&UL;51;;Z0@%/XKQ!]0O,QH=^*8
M=+K9M ^;-'WH/C-Z5%(N+N#8_?<%=*R=Y47@\%W.00[E)-6[[@$,^N!,Z&/4
M&S,<,-9U#YSH.SF L#NM5)P8NU0=UH,"TG@29SB-XQQS0D54E3[VHJI2CH91
M 2\*Z9%SHOZ=@,GI&"71-?!*N]ZX *Y*O/(:RD%H*@52T!ZCA^1PRAW" ]XH
M3'HS1R[WLY3O;O'<'*/8I0 ,:N,4B!TN\ B,.2%K_'?1_+)TQ.W\JO[+5VNS
M/Q,-CY+]H8WI;;)QA!IHR8"EA[P1KR;3_HGK41O(K)4*GFWI61$6V 4%
M=EY@]ZW$XJ;$$.8^;+(/FNP# C]N3 *8(@Z;Y$&3/""0W)B$,+?GC3>W@X/J
M?!-H5,M1^);;1-<^>TC][?J"5^5 .OA-5$>%1F=I[!WU-ZF5TH!-);ZS!??V
M)5@7#%KCIH6=J[DYYH61P[75U_>F^@102P,$%     @ 93%12"T-1?/7 0  
M104  !D   !X;"]W;W)K&UL=53-;IPP$'X5Q ,$
MUL!"5RQ2-E75'BI%.;1G+PP_BHVI;9;T[6N;A1 RO6![_/W, #/Y).2K:@&T
M]\99K\Y^J_5P"@)5ML"I>A #].:F%I)3;8ZR"=0@@5:.Q%E PO 8<-KU?I&[
MV+,L#A=,HMP@%\=3&JS]VSN5R%>[>%'=?9#FP(P*+55H&:YP1,P9H6,\9^[YKNE
M)6[WB_HW5ZW)_DH5/ GVNZMT:Y(-?:^"FHY,OXCI.]Q+2*Q@*9AR3Z\IV_SVO5NG>:;9*'A!'(GD)60A2[QVBMB-(H#VY6Z(ZYS!BRP1Q61-PN"65S()SK!Z1&:8>3H
MT98>A[A C K$3B#^4&*\*Q'#)+A)@IHDB,!Q9X)A4MSDB)H<$8%L9X)AON F
M*6J2?A;(PIT)AOG//Y&A)ADB0'8F&";:F02;_YR#;%P[*Z\48^^&QR:Z3HQ'
MXOKD'5[D VW@)Y5-UROO*K3I-M<3M1 :3"KA@_ETK9EIZX%!K>TV-7LYM_E\
MT&)8AM8Z.8M_4$L#!!0    ( &4Q44A!D.XUHP$  +$#   9    >&PO=V]R
M:W-H965T0/"#;VIM'*:RF;JFH/E:(<
MVC-KCVT48%S Z_3O"]CK.*DOP SSWKP9AG)"\VI[ $?>E-3VE/3.#4=*;=V#
MXO8.!]#^ID6CN/.FZ:@=#/ F@I2D+$WOJ>)")U49?<^F*G%T4FAX-L2.2G'S
M]PP2IU.2)3?'B^AZ%QRT*NF*:X0";05J8J ])8_9\5R$B!CP2\!D-V<2M%\0
M7X/QHSDE:9  $FH7&+C?KO $4@8BG_C/POF>,@"WYQO[MUBM5W_A%IY0_A:-
MZ[W8-"$-M'R4[@6G[["4< B$-4H;5U*/UJ&Z01*B^-N\"QWW:;[)LP6V#V +
M@*V AS0*GQ-%F5^YXU5I<")F;NW PPMF1^8;40=GK#O>>:'6>Z]5_E"4]!J(
MEICS',,V,=D:03W[FH+MI3BS_^!L'Y[O*LPC/-_"BWR?H-@E*")!\:'$PZ<2
M]V+N/R6AFYXJ,%T<'4MJ''4&PO=V]R:W-H965TNF=BCVU48+R X^[?%[#CNEU?@!GF
MO7DS#/F YLVV (Z\*ZGMD;;.=0?&;-F"XO8&.]#^ID:CN/.F:9CM#/ J@I1D
M:9+<,L6%ID4>?<^FR+%W4FAX-L3V2G'S[P02AR/=T*OC132M"PY6Y&S&54*!
MM@(U,5 ?Z?WF<,I"1 QX%3#8Q9D$[6?$MV \54>:! D@H72!@?OM @\@92#R
MB?].G)\I W!YOK+_BM5Z]6=NX0'E'U&YUHM-**F@YKUT+S@\PE3"+A"6*&U<
M2=E;A^H*H43Q]W$7.N[#>+-+)]@Z()T Z0S8)U'XF"C*_,D=+W*# S%C:SL>
M7G!S2'TCRN",=<<[+]1Z[Z78[N]R=@E$4\QIC$D7,9LY@GGV.46ZEN*4_@=/
MU^';587;"-\NX=GM.D&V2I!%@NQ+B?MO):[%_/B6A"UZJL T<70L*;'7<5 7
MWGDZ[^,CLL_P(N]X [^Y:82VY(S.OVSL?XWHP$M);G:4M/[_S(:$VH7CG3^;
M<:1&PV%W_2#S+RT^ %!+ P04    " !E,5%(N&+D2EZK\AM[$44.1\5[7IX$4B.
MC!'Q[P243T
M./W;5:K5R?H>JJ F(U6O?'J&I83$"):<2OM%Y2@59U>*AQCYF,>NM^,T[R3I
M0G,3PH40KH1;WR8^&]DT'XDB12[XA,1\M ,Q?S XA/H@2A.T==L]G:C4T4L1
MW?DYOABA!7.:,>$&$ZP(K-57B]!E<0J_T4,W/7)F&%EZM*7'=VZ!V"D06X'X
M2XG!KD07YHTTB4H^]K:O-]&UF>]#>X4_X44^D 9^$]%TO41GKG0CV.M:[(^:L5_4$L#!!0    ( &4Q44AC
M\?FEN@$  'L$   9    >&PO=V]R:W-H965T(#% =UMITX)ITV3?=BDZ87N]>,'I44Q *.W;)#@F<;S'
M@K(N*G(?>U%%+@?#60]0WC 7P:C7LV1R_TLY9M;_*Z.4>Q2  ZE<0K4#A=X ,Z=D#5^
MGS6_+!UQ/;^J/_EJ;?9GJN%!\G^L,JU--HY0!34=N'F5XS/,)61.L)1<^R\J
M!VVDN%(B).C'-++.C^.T#)R*?Y2 TME!C"_%!D%C3) @)D8Q+")&&3?=!D'Q!(-R8A
M3+8QP:O;(4 UO@DT*N70^99;19<^NR?^=GW!B[RG#?RAJF&=1F=I[!WU-ZF6
MTH!-);ZQ!;?V)5@6'&KCIK_L7$W-,2V,[*^MOKPWQ2=02P,$%     @ 93%1
M2-9S8*2C 0  L0,  !D   !X;"]W;W)K&UL;5/!
M;N,@$/T5Q <4QW':;N18:EI5[6&EJH?=,[''-BHP+N"X^_<+.';=UA=@AGEO
MW@Q#/J!YLRV (Q]*:GN@K7/=GC%;MJ"XO<(.M+^IT2CNO&D:9CL#O(H@)5F:
M)-=,<:%ID4??BRER[)T4&EX,L;U2W/P[@L3A0#=T2_>*PQ-<2M@%PA*EC2LI
M>^M031!*%/\8=Z'C/HPWNPFV#D@O@'0&W"91^)@HRGS@CA>YP8&8L;4=#R^X
MV:>^$65PQKKCG1=JO?=<9,EUSLZ!Z!)S'&/21?4Z1KJ4XIC_@Z3I\
MNZIP&^';)7SW:YT@6R7((D'VI<2;;R6NQ=Q^2\(6/55@FC@ZEI38ZSBH"^\\
MG7=I?)//\"+O> ._N6F$MN2$SK]L['^-Z,!+2:YVE+3^_\R&A-J%XXT_FW&D
M1L-A-WV0^9<6_P%02P,$%     @ 93%12%TMVH 4 @  %P8  !D   !X;"]W
M;W)K&UL?55=DTSLG+AA6>BG.0/:"X*,E,0I2"'/ <-O%96%M;Z(L^$71MB-O
M(I(7QK#X6Q'*AVVWMNE#& L@ 3[]@RTLF6=Y$@IVW\G&SVN4%8P*^6
M#'(VCXSV ^#O-H,9W+,\\\J4M,^IB'A:"@$!00
MDGA"'":?!\G@?])=!:.L E&\DE:K190L0UZZ 0SRKL=^M2A)EJ=AL7E0;!X0
MZ]6]R@-G [T#W 5 R ?M R"X*"Z8O1]&Q-DV(AG5_-(I[2TX*2DS+3M9X+
MU[C<0O'^UH:G?T'Y#U!+ P04    " !E,5%(CG#U8A0$  !*%0  &0   'AL
M+W=O69"YX7N'F2%I/%
MO!W[62[F_"*RM& _2Z>ZY'E2_K=D&;\^3,CD-O K/9Y$,^ NYF[/VZ>A-GSP[))1._^/69
MR1BFC<$=SZKVK[.[5(+G-\K$R9,_W3,MVN>U^R7R) TG@"1 3^CGP0E4$N@[
MP;]+\"7!MR5,)6%J2P@D(; EA)(0VA(B28AL";$DQ+:$IN9=Y;QW2G"?TA>;
M6,]R*S)VC=6VY==$)(MYR:].V:VE<](L63*K6;7Q9K1M]/;'NC.K>O1M
MX1-_[KXUEB1FV6%@A)F.,6L=0WJ$6[O0^P&H'TO0^#">X4E'^"088[XBF#'B
M&V8E'&-6.H8JSGS'S$1CS#.&B<>8%P0#GI+:#U.S^=CAK0Z)/;Q %&\4VAJ@
M(T\-)?9Q"WYKP1^VB*>TT;+#1"VFZ&(E2A_H$!)3I0]T#%4; 3$#2@57""90
M,-]U3*STTS,2E%*>%\P;I0V0F$*E_S?(3+'2$(\GA")1VG;
M=:A-\A>ABF)L$)!IK4:X*Q'BRA2W$.,68GN]:+9*=&_R+!I-@H;! E5E5H*&
M3:^JK(V=#0(RJ"@Q[;<$B2E0?2':--37?-%!$)HRC.^ZCP00;T+5&T!Z+E+W
M( PUV(7&[ACV&$(M5K0$#2?R/26#*P2D57-M8VEC8VF+@$Q]8=@@RF7YBS1DTE6"BJJHAT:5.WXL0$ 1439P.,B7.()H$4\W88,.@=B3Z1.(,
M>D?BCX\W:PG"PY5ITR$T4+.F8XQ[.!C$%1!QI8;<@T',@-CG#0P2!+H$:7G;
M2M!0OWW3/ 9M 41;J,F&89&"_XEX#8L4;$Y/8'%\NH\9^V)8[&!S@@*;(Q0"
MTAVV.43=-S2.RJ (@"B":2<"@R+ )Q0!#(H NB(@E8Z1_S&(FCEDO0<&;ZAA
MO5/L,*76FNKG)(B4S6Z%@'27;2QM/K#4Q>4.[C)R5A[;*[K*V?%+(9H*#4;[
M:\!':.Y"E/$EF;T09'Q-9MONDN_=_&)^3H[L1U(>TZ)R7KD0/&^O20Z<"U;[
M[GVIE]^))?O^(V,'T;R&]7O97?5U'X*?;S>7_?7IXG]02P,$%     @ 93%1
M2!\1AT*[ 0  &@0  !D   !X;"]W;W)K&UL;53+
M;J0P$/P5BP^(P:A^('LJQ7I00&M?Q!DF
M<;S#G/8B*@N?>U%E(4?#>@$O"NF127D@AQ^C&/O?#C-*_-U7QWYXF1P^4EKK^#\@M02P,$%     @ 
M93%12)Q#6+NT @  R@H  !D   !X;"]W;W)K&UL
MI991DYHP$,>_"L/["4D Q4%FU$ZG?>C,S3VTSU&C, >$)E&OW[Y)0$18.M[4
M!R%A=W^[&_^XR96+=YDQIIR/LJCDRLV4JI>>)_<9*ZF<\9I5^LF1BY(JO10G
M3]:"T8-U*@L/^W[DE32OW#2Q>Z\B3?A9%7G%7H4CSV5)Q9\-*_AUY2+WMO&6
MGS)E-KPT\3J_0UZR2N:\<@0[KMPU6FXQ,2;6XF?.KK)W[YCD=YR_F\7WP\KU
M30ZL8'ME0E!]N; M*PH329-_MT'O3./8O[]%_VK+U>GOJ&1;7OS*#RK3V?JN
MB[4&[]^8VT-H0FXYX6TW\[^+!4O;RZN4]*/YII7]GIMGBS\U@UVP*T#
M[AQ0]$\'TCJ0NT-@*VTRLW5]H8JFB>!71S2'45-SYFA)=.?V9M,VRC[3E4F]
M>TD#$B7>Q01J;3:-#>[9H,["T]$[!(80&SQRC_U'PG9L$I YS"!@&<0&"!X"
M+.   1@@L %(/P">J#($ X1 !O&@D8W-PMI4U@9'*)S(,P(QT1@3#+JYB4:8
M$,.,.!H$ZGJ-, "*)D+ LD7D
M>=DA6+@H>$(1K=%#N6APS-O6J'_.+WVKQVS@MP "7@/!Q)L,P0I'T2=Z @L8
M00H>]60^ZLE+-%4M+%D$:7;B=89@_:'X^6HQ+"T,26M8+0:D%4]@8%UA2%=3
M(6#%8/R)8F'%8."?;EPL&?^2XR''ZXT()1,G.SI)9\_/E3+_Q;W=;CQ;8S-B
M#/8W>FQKAJQ[F#2IZ8G]H.*45]+9<:4'&#MF'#E73.?HS[12,CU8=HN"'96Y
MG>M[T8Q:S4+Q^C8Y=N-K^A=02P,$%     @ 93%12+94?,@K @  10<  !D 
M  !X;"]W;W)K&ULC57;CILP$/T5Q >L,<:$1 2I
MR:IJ'RJM]J%]=H@3T!K,VD[8_GUM0[+$.)N^X MGSISQC,=YS\6;K"A5P4?#
M6KD.*Z6Z%0"RK&A#Y!/O:*O_'+AHB-)+<02R$Y3LK5'#0!Q%*6A(W89%;O=>
M1)'SDV)U2U]$($]-0\3?#66\7XSF9!T;\CO,WL_BY7X>1T4 9+96A('HXTRUES#!IS^\CZ:=/
M8SB=7]B_VW"U_!V1=,O9GWJO*JTV"H,]/9 34Z^\_T''&+ A+#F3]AN4)ZEX
M#^&H DR\-T&B ' ,P*+-Q/1-%BESP/A!#
M,CIB<@Y72)]<:3;M0=E_.C*I=\]%@J,W:B ?@+D)4"6()D20">* 9)92&LA,(/("<0#PDOD5Y)XE20S)=A5
M,D#2B9,LRA)'R1RT0&GB5X*]2O!<"7:4X)F3!#K9W\XQ*<)^':E71SK/#;Y3
M'0LOP>+_JR/S$F0>!4[F-]G\O"<7X<;)TNMD^;@$ES,?<90ZQ^W#W$F[Z4^^
M*QT]+L$1,W7CYMT#@7=N KS36^#C"APQV4V=NTKF&.Q6()@TO(X'=YM*XO9_$/4$L#
M!!0    ( &4Q44B"'"P36 (  )L(   9    >&PO=V]R:W-H965T*)];13;TZ,
MMT2J*3\CT7-*CB:H;5 8!"EJ2=WY96'67GA9L(MLZHZ^<$]]RQ;FDG:M9YG)XV_C>\WN%80PSB=TT',1M[VOR>L3<]
M^7G<^('V0!MZD)J"J,>5[FC3:":E_#Z1?FKJP/GXQO[=I*OL[XF@.];\J8^R
M4FX#WSO2$[DT\I4-/^B40Z()#ZP1YM<[7(1D[2W$]UKR,3[KSCR'\4T>3&%P
M0#@%A/> L1*+ =$4$%D!:'1F\GHFDI0%9X/'Q\WHB=YSO(Y4Y0YZT13*O%.9
M";5Z+>,D+M!5$TV8[8@)9YCP$;%S$=$G!"D#=QPD!9VD;D62!";(0(+L__\=.4B0 PZLG=_F
M0#$"6&0%BJP D=0263DB.%D0T=(39B'DCA&7,R2$;C%8+?'
MI*%M)'8ZF=WK (CM \VND9ZI!YF:LS'NW.<2-;?/@7NWR/E/U!+ P04    " !E,5%(NFH"OG4#   M
M$   &0   'AL+W=OM@]T\1)4 %GP6FZ;[\VD)1XQE7V4L#\X_D]-I_CSD^J
M?>OV4NK@HZZ:;C';:WVX#\-NO9=UT=VI@VS,FZUJZT*;QW87=H=6%IL^J*Y"
M%D4BK(NRF2WG?=MSNYRKHZ[*1CZW07>LZZ+]NY*5.BUF,#LWO)2[O;8-X7(>
M7N(V92V;KE1-T,KM8O8 ]T\LMY)>\:N4IVYR'UCSKTJ]V8S*9_XR=?N:T@=/[<^_?^N$:^Z]%)Q]5];O$PE+X03X4NEO-6G8)VF+U#81<)W'-3ZK5M["O;
MOS.EZ$SK^Y(GV3Q\MQV-FM6@81,-7!2AZ?V2@E$I5@R%L^L$CU@1.Y(G+,DC
MVD1,CC/NX^.K<>9T!YSL@/<=\&D'X-1ID&2]I!GJE$'LC)40)7E,.TE()PEV
MXL[8(!&3)%RDCA&L85E&^Q"D#X%\)&Y%!,J111EWC&!1&@M..TE))REVDCA.
M4EP1B!PC6"/BA/:1D3XRY$,XZWB5H1P0H:G!(@&"-I*31G*\1(0SVE6.YS]R
MIP9K(,V=+S-'"]KS85K^4@2*"+,>P( '8G#[UPTDI!Z $2[&ULE59-CYLP$/TKB'L7;/.5B" E
MJ:KV4&FUA_;L$"=!"SBUG63[[VL;0H@9I.T%?_!FYLT;&#N_1:,[JU14PQ5%SB^JKEKV*CQY:1HJ_FY8S6\K'_GWC;?J>%)F(RCR8+#;5PUK9<5;3[##
MRE^CY18E!F(1ORIVDZ.Y9\CO.'\WBQ_[E1\:#JQFI3(NJ!ZN;,OJVGC2D?_T
M3A\QC>%X?O?^S::KZ>^H9%M>_Z[VZJ39AKZW9P=ZJ=4;OWUG?0ZQ<5CR6MJG
M5UZDXLW=Q/<:^M&-56O'6_P@ AU$UD'TI )R5( P,RQC,$@\
M81FE!':0@ X2@$'DL.PPF<6TG91QG#EZ3T$Q(C."I2"5%* 2.U0Z3#**\@5E
M#F@+@,A<\3.02@9021PJV20*(2/M.RI34)2%"4QE 5)9 %12A\H"4"5R"P2!
MT P5TZ6@'SN\"+_$R/["<5QZJ5
MWHXK?3S:0^S N6*:3/BBA3GI:\NPJ-E!F6FJYZ([R+N%XN?[O62X'!7_ %!+
M P04    " !E,5%(CY_V!>T"  #B#0  &0   'AL+W=OS,6/[3*,309>\XTR%DP?WOF:U[5QTD_^,YA^/M,4CL\O[M_L='7\
M5R;Y6M2_JZTZZ+1Q&&SYCIUJ]2+.W_DPA]08;D0M[=]@2,&C81W^L
M6GL\]W>*>"C#"V H@&L!2?Y;0(<".BF(^F1V7E^98JM%)\Y!U_\81V9^<_)(
M=>C=&@^:IU\!( [>*M:N@GY)(![BF #0%V'IZ
MDX+@!A0UH-8@&1ODR60:O::PFK8/F:;%9":N*"6TP*,D:)3$C5)XFI&B!NG\
M9F2H0>8D($DV:4:OR<;-@)),FN&*DB+US"5'H^1(,RAN4* &Q?QFE*A!.:,9
MI3-/DDT7!J(I2SR(^;^!H18CS9@NTD$T?L[H,0-MKJ;(/5$\U!,D2NJQP)$E
M=S!+<&C)'&H'T4WC\SB?ML1509Y[N"4XN 0C-_-8X.B2.]@E.+QD#KW$)9.D
M)9TVQ55!1GV+%@>88 3[%AN.,+F#88)#3.903%Q$=(!C'B>=5A6,,O'=@##C&, =C0# NTND+!U$!S6)/'!QCP##V
M+'K ,88[, 8<8YB#,2 89^7TS8.H (CG+0HXQH!@7/KZBF,,=V ,.,8P!V-P
M$74V)IC&@P[%*:9S*!Y$X]U@-MWZ(AIGBQ2-=N-'MN<_6;>O6AF\"J4W]G;[
MO1-"<>T7/^BU=] ?7->+FN^4.==_@O072APO7U37S[K5/U!+ P04    
M" !E,5%((#$0\E$"  # !P  &0   'AL+W=OW:($] "IK83MG]?VQ!"S- +
MML=OWKRQS4S6,_XA2DJE\]G4K=BYI93=UO-$4=*&B!?6T5;MG!EOB%1+?O%$
MQRDY&:>F]I#OQUY#JM;-,V-[XWG&KK*N6OK&'7%M&L+_[FG-^IT;N'?#>W4I
MI39X>>9-?J>JH:VH6.MP>MZYK\'V$!B(0?RJ:"]F+/S+VH1<_3CO7UQIH
M30NI*8@:;O1 ZUHSJ\Z)WHF
MUUJ^L_X['7.(-&'!:F&^3G$5DC5W%]=IR.<]0X?+J,C^LZ#+58G5VBC.2BSIS(3RGK+PS3(
MO)LF&C'[ 8-FF ?"4^Q3" 2%V*.%.WH.<%@B,((C8# );/SQ4Q(K!"%($!J"
M\(D 6Z< 84(K$0@3P4(B4$@$9!+#!#%($ ,*-E8F R8QF'; A(F5R1*#\8J0
M#2ADLQ 2A+XE9,#$\R!Q9 E98E"R&9-4:?1?U ]>JG8Z+6IZEGJZ47,^-)AA
M(5EW[Y=3T\[_ 5!+ P04    " !E,5%(#)34'UPM+R0QJZ:/\L5:7/CS,Q>VWX4>X/9F@(%_/P&K9T_B82UY@(R(?TMU[F[N@X'\L]8_AX>OV\=9-'!0E=J8(4717U[42E75
MD*GO^=_K/1:=6NOJOW)I#SS::!5NU*TZ5^:'/7]1E
M#/&0<*.K;OP--J?.Z/HU9!;4Q>_I6C;C]3S]DT67,!Q EP"Z!HCDKP%\">"W
M /G7 'D)D%9 . UE%&)=F&(Q;_4Y:*>W=RR&22(>9"_U9F@22 &EBBTSB=)-Q;E%Q,9Q(3"2%1%) )+&(I.YX16H1
M<3&Q9ZYDD$<&>%A]+#/W[;#];EQ,)BQ?9,Y<\KRZ'#+- =/,8IH[+*1TIA$ 
M"1NTSAVR?)OI'=^A6J-Z%0'&N5VP(E;AX:J=PN0C?<&!M?!+T
M\;HD<&43#%@(6Q%VIWWNO$2(DIF'#JZ3 A1*X=,5US81WR$*+DD"U"17%+?@
M4!HE;*L"8''"/D*X- E0FX0O!:XJ(KM#%FQW ?SNRN)ZN;>RHXJ+RC//5"'L
M90)>%IZ"3]B")#ZN"6$+$GU DPOH?44A:_U? 50:YSXZV,Z$[.RIZ80M2/(.
M4; %R=U? %' #H,XL45Q49X:2=C+A+R<>%)@]U%ZAR+8?006=5<1=SDFF3B*
MN"B1I;Z)CYU,R,DI3L'8?AQ]7!3&]F.T MK[!PC*/?U@CS+P*/GV_YX/@#N^
M !C[BM'2YHP6@,BSM6=L/@;F(\\2RM@SG-PQ6NP91BN6,UH (E\_V%@,C$4>
M,S V ^=W?-UA,TBT%MFC12#RU&:)'2.!&
MFBW^!U!+ P04    " !E,5%(46 HW&4"  !)"   &0   'AL+W=OPFV>6_FS0SC2=YQ\28OC"GOO:X:N?$O2K7K()"'"ZNI
M?.(M:_2;$QN'==S;$8!4>>"7MKW>X2L7K.\7W:OK>/\O&
M/KO^31H--)B !P(>"2CY+X$,!/(@6 ]!K\S&]94J6N2"=Y[HB]%24W.T)CIS
M!W-H$V7?ZQ\1X"N(%TS W8^BS]\?".YM
M% ,JG/H!(#Q/:S"YN6LFSG:B2>_ KXT=H)/3<6INL;WY'_ B;^F9_:3B7#;2
M>^5*SP][RY\X5TQK"9^TEHN>Z^.F8B=EEJE>BW[2]1O%V_O@'O\]%/\ 4$L#
M!!0    ( &4Q44ADM;>:D0(  )\)   9    >&PO=V]R:W-H965T&%GVJDW
M!\9;(M64'P-QYI3LC5';!#@,TZ E=>>7A5E[Y67!+K*I._K*/7%I6\+_;FC#
M;BL?^?>%M_IXDGHA*(M@M-O7+>U$S3J/T\/*7Z-EA1(M,8I?-;V)R=C3\%O&
MWO7DQW[EAYJ!-G0GM0NB'E=:T:;1GE3D/X/31TQM.!W?O7\SZ2K\+1&T8LWO
M>B]/BC;TO3T]D$LCW]CM.QUR,(0[U@CSZ^TN0K+V;N)[+?GHGW5GGK?^318.
M9K !'@SP:(#2_QI$@T'T,(A-ICV9R>LKD:0L.+MYO-^,,]%[CI:1JMQ.+YI"
MF7M]8V^BYCS].&F+,[D2'\2?JP[X6V95*>R.3L/
MC$FJ&,,7Q7A2MZ5QTM"#U,.%&O/^_M!/)#O?KT/CG:S\!U!+ P04    " !E
M,5%(T:H,Z<,!   ]!   &0   'AL+W=OM,?T.8UVVP*F^DST(>U-+Q:FQ1]5@W2N@E2=Q
MADD%], Y51\'8'+<1TET,3QW36N< 1NY (0M,,B.P
M59]=D#47!_*-3KXZ.'Y'I&3=0[J:1.KYZ=(#R=8%LE6!S MD7ZJPO:E"P&P]
M1GA,?)/&3X@0!%ZTA8-J_'/5J)2#,*X "^L\$8_$M?7&?K"3$A[V5:;(>]K 
M/ZJ:3FATDL8^&M_:6DH#-L#X;A.AUL[R?&!0&[=]L'L5GG&PO=V]R:W-H965TZ&.+[P[#T_,E88GTF,B,_
M)TF8_9NQF%\F)C*O Z_1X5B( 6LZMEK>+DI8FD<\-3*VGY@/:+3!1$ JQ.^(
M7?+.O2'$OW'^+AZ6NXEI"PTL9MM"F C+RP>;LS@6EDK/?QNC-Y^"V+V_6E]4
MX9;RW\*Y]6OL3WG!4^N%--(
MPL_Z&J75]5*_\>V&!A-P0\ MH?4#$YR&X-P(Y$L":0AD*($V!#J4X#8$=RC!
M:PC>4(+?$/RAA* A!$,)8LWKE;-O%/=K2KO8:+"7ZW(C+%&L.K&JM'P,BW Z
MSOC%R.I:.H6B9-&H9)7&Q6B5Z-7+,C/S7#
M6@4YON/ 6EQ8BPMHD3)FY2IN4.#(TZ>"<" +WJ@@Q]=T!P_6ZREZD2W5_LQ3
M]3I2ND5K5$C CMP]@7ES)
MU5K%^$1>16!FX#7TX37T@9S39&T 6PB&MR"Q^X+;G7T_\]<-J)?5U-9YTFVL
M"/!$9$](\41\K2=XZWQ ^'YUK!M0;XFUCC1; '* D*C&AF830.0;BZCII AJ
MI=+4KA#0)K4!:]HD4OND,K,K!#1*K2--?T-J@Z/4U=C0U!?ROS&SF@I#P8"-
MH0'U B:ZB+&F$#%4B/(:8K40D39KL:80,52(RB.Z"^&DVQ8K58
M*?4U-C1UB+_Q+88U=8C5KS%*Y0]_K'[W4'E65G= M1JK7G
MM!"1=$;;L_P#%@<::7R&1DL$C*_*LW]]4K^9GXY/X8']"K-#E.;&&R_*@U1U
MUMES7K!2N_VC;!)'%N[:AYCM"W'KE?=9?5ZO'PI^NO[]T/X',OT/4$L#!!0 
M   ( &4Q44@8J;P_Q ,  %<2   9    >&PO=V]R:W-H965TMR,MZ/CDH=9RZ;KTYB"*M[^51E,T_.UD5
MJ6H>J[U;'RN1;CNC(G?)\T*W2+-RLIAU8X_58B9/*L]*\5@Y]:DHTNKO4N3R
M/)^PR?O 4[8_J'; 7X,9-J#!@"X&+/S4@ \&_,/ _]3 'PQ\S<#M2^DF8IVJ=#&KY-FI
M^K=W3-LF85._F>I-.]C-;/=?,Q5U,_JZ"$)OYKZVC@;,LL?0",,N"+?Q?@E!
M*,22#'.Z#K R$5R#K$U(XN$D.*R3=_;\JDY+%3YTX'<._"L'6I++'A-WF+*?
M*#\(M&(!*(P2G$H 4PE *EQ+I<>$HRAW\:C@/A4$\BRIA#"5T$C%#[5,0B-(
MD/A:(B8FCBRO-X)Y1&!*M"#+R A"D9;LRL1PKDWM.C)>((U>\E6R,4PV!KUH
M<9! !XE9B0<@LG1\JXQ(&SP4)]+5P42Q43M>![*($$.!8CV0B6*>;PD$
MI>B!$0J4Z(%,5&";.:PVC(,X9.BJB>*V>K H,:1*>B,,H*MD;.5@P6%(<2*+
M"RP4++Q=@!GF.$,DUR68F0QFXR[I:8Y0G-F:%K.8Q3?(\ "ZDMA(;[@51'D6
M 618$UCR?RD>,&/IXK&^/C%3.$+;U! 6#O+ U,06%U@2B-W>+X3)3@2RT+F.
M0+:EAS#9B0,7ME0QC\G_0K68HX0XJK-C %TU@*?)THK,;0$EEO6),-O)W!>8
MW"!SU;]C3&]'A(ILO82%@TSA,*A!YJK.#&H0V$(PBPX25@T"JA&1Q05F.B6W
M-PO'!.6(H#HU$(@L0L QBSD#U=I<8!9S^D*UEKT_(*A!C0$T;H! WR]S<\&V
M$9UCHG.T8.O$X.:"?4>1G@L <5LR6#*X*1D&+[BI&*2OI@#CVS[.L%YPH!>1
M92O$,SD@=J
M/]^U\26;KOL3CP\WB]DQW8N?:;7/RMIYEDK)HON$WTFI1).C=]^\D(-(MY>'
M7.Q4>QLU]U5_[M$_*'E\/\:YG"4M_@%02P,$%     @ 93%12,=8&7VC 0  
M[ ,  !D   !X;"]W;W)K&UL?5/;CML@$/T5Q 6 YM5V
M (Z\*ZGMCG;.]5O&;-V!XO8!>]#^I$6CN/.A.3+;&^!-)"G)LB19,\6%IE49
M<\^F*O'DI-#P;(@]*<7-WT>0..QH2B^)%W'L7$BPJF0SKQ$*M!6HB8%V1[^E
MVWT1$!'P6\!@K_8D>#\@OH;@9[.C2;  $FH7%+A?SK '*8.0O_AMTORX,A"O
M]Q?U[[%:[_[ +>Q1_A&-Z[S9A)(&6GZ2[@6''S"5L J"-4H;OZ0^68?J0J%$
M\?=Q%3JNPWBRR2?:,B&;"-E,2(O_$O*)D-\1V.@LUO7$':]*@P,QXRQZ'D:>
M;G/?N3HD8Z/BF:_,^NRY6FW6)3L'H0GS.&*R*TQVB]A_1N0?$.8-S"ZR11=9
MY!#@ZUT?1LPZ8G3$I'=]^(Q8W9E@5X/I
M^1%^<7,4VI(#.C_C.(D6T8%72QY6E'3^Z
M_0-02P,$%     @ 93%12/\0FU;- @  Z T  !D   !X;"]W;W)K&ULE9?1;ILP%(9?!?$ !=M H$HBK9FF[6)2U8OMVDF5%4VXKD-
MNE-=\_;ODZCD>1&2\#+P4NX/R@Q$RWETS=N6M6BZ4C9!*W:+\ MY7+&9";$1
MOTIQ[F[. U/\6LI7<_%CNPAC4X.HQ$89":X/;V(EJLHHZ9G_#*(?+J\M?\TZL9/6[W*J#KC8.@ZW8\5.E7N3YNQ@84B.XD55G?X/-J5.ROJ2$
M00[:_F4<
MN7GGY)'I)[<08&9!V8?D]U@QGB*'$Z1@RD2+%! @<(?TC@4-77L@3D$>7 2
MAW4(F"5U2."^)W0"*^Y\PGQ8F7_K$FP0@ASB\"C![4_2";38 "0#5H< KA4L"VX F$UBQ#2A:!D:LZ8C5T<,4.X4"IQ2N0K$-Z&P"*[8!
M1:O!B#4?L;IV#]@I%#BE<$@P; ,6^[,R; .&UH-[UB'(HX<9=@H#3BD7B!TU^T)]=UXM*[)0YG>GSMO\0Z2^4
M/%Z^JZX?=\M_4$L#!!0    ( &4Q44@Y+;WI_0$  .@%   9    >&PO=V]R
M:W-H965T
M'3(!M#:FM@G;?U_;$,*"M>\60]X^^B I#.!R6-V+F5E.T6(5%4
M0+%X8BTT:N?".,52+7F)1,L!GPV)$A1X7H(HKALWSTSLE><9ZR2I&WCECN@H
MQ?S?'@CK=Z[OW@)O=5E)'4!YAB;>N:;0B)HU#H?+SGWQM\=4(PS@=PV]F,T=
MG?N)L7>]^'G>N9Y. 0@44BM@-5SA (1H(77PWU'S?J0FSN^F6I7]"0LX
M,/*G/LM*)>NYSADNN"/RC?4_8"PAUH(%(\)\G:(3DM$;Q74H_AC&NC%C/^QL
MO)%F)P0C(9@(?O(E(1P)X9T0?4F(1D*T(*"A%&/$$4N<9YSU#A\NK\7Z'_&W
MD;*ZT$'CK-E35@@5O>;Q;1;%K
MD+^ '&TZH3W9V)IL;$DVM0LD5H'D<;M2JT#Z@%WI(W:M02N[;#I+N]#L05#@
MI>DLPBE8UTC]7\VB4_-Z"?2#6L3WJJD-/>@NDVU(U4JNU."P(7J:>IFO.A$PT+R=I;7YV:>_X?4$L#!!0    ( &4Q
M44AQ/'(T@ (  %H*   9    >&PO=V]R:W-H965TF;L7:+:7L5IXG=B5MB'AB'6W5DP/C#9%JR(^>Z#@E
M>U/4U)Z/4.PUI&K=(C=S+[S(V4G654M?N"-.34/XWV=:LW[M8O.%K]E[$T/?NS7+M(::$UW
M4E,0=3G3#:UKS:3>_&7]B_F>4J^5LBZ(;5OZN]+)5:Y#I[>B"G
M6KZR_CL=UQ!IPAVKA?EU=BZ=
M-=&(>1XP_@3CWR(V-B+X@'A*P%6%#ZKP37UXHR*#"0*0(# $P80@1@@F"$&"
MT%(01#,;!DAJ(.U@0S;W:F.#%F1$H(S(-B*9R1@@\>0-.)DN=M !H*)%2V)0
M2VQIB1&&"1*0('F\*2E(D-YO2FJM$VB*#5J0D8$RLOM-R6R[4V3I % Q"D)8
MB_[W@0*+@+8LA TO9!X_WA@,!Q8#B9U[,F)N>H.L#Q5 +4F!HX\#P)!@@0(.
M/PX_80@<7/Q .>^'#P?'S?DQ$SW4%BE,PW7  5)>E&ULE57;CILP$/T5Q >L;<(M$4%JMJK:ATJK?6B?
M'3 !K<'4=L+V[VL;0A,RJ-L7?.',.3,#Q\X&(=]4S9CVWEO>J;U?:]WO$%)%
MS5JJGD3/.O.F$K*EVBSE":E>,EJZH):C .,8M;3I_#QS>R\RS\19\Z9C+])3
MY[:E\O>!<3'L?>)?-UZ;4ZWM!LHS-,>53Q;\9U/JVF2+?:]D%3US_2J&KVRJ(;*$A>#*/;WBK+1HKR&^U]+W<6PZ
M-P[CFQ1/87! , 4$VH_(=D%IA&%W71UNW1 !0)'$%X1Y#"!!N08.,(-G<$6Y@@
M! G"APRB9%'E"$D=I'.0 %:(0(7HL4:"%Q(0AL B,2@2 P0K628@0?+Q1J8@
M0?KO1J8?;>065-@"-6X6$A FA$6L)Z'_'@,4T?+'AT#QBLZ*OPA L>P8"%HQ
M"($M1@"/D94O2V"3D?]P&8%M1AY]]N@""!3@A0ZZ.F+?J3PUG?*.0INS
MT)U8E1":&4+\9'Q5FRMG7G!6:3M-S%R.A_"XT**_WBGSQ9;_ 5!+ P04    
M" !E,5%( (PKHT\&   Y*P  &0   'AL+W=O8EC^9$[NIJF[V8[\[M+?S3=<=;Q:+]G%3[YBOEN.QK\UJ6;]TN^VA^MK,
MVI?]OFS^NZMV]>EV+N=O![YMGS?=<&"Q6B[>VZVW^^K0;NO#K*F>;N>_RIM[
M*<*@&25_;ZM3>_'_;(C^H:Z_#U_^7-_.Q1!$M:L>NZ&/LO]XK>ZKW6[HJA_Z
MWZG7GX,.#2__?^O]]_%\^_@?RK:ZKW?_;-?=I@]7S&?KZJE\V77?ZM,?U702
M=NCPL=ZUX]_9XTO;U?NW)O/9OOQQ_MP>QL_3^9<@IF:X@9H:J/<&TGS80$\-
M=-1@<8YL/*_?RJY<+9OZ-&O.5^-8#A==WN@^54W*Y
M>!TZFC1W9XVZT*AKQ3U5Z)^211_ >Q0*1J'&]OHR"E'@#C3L0(\=F*O3B(*\
M.VO"J#F<3\.*Z$2 )C@+
MJ9 2ETBITXNLQ,5-TNI&KY$A)=32E-#R9MF,X HG08F+J^@=$FEN'%S )*A@
M6C)=X+(C?4;F<2>4D=3H+2S:F#(GKOO-0994S^FN4"U&G@MK3D:>"U;:Y*\
MUN1XK<$@FQ2O12+#>*UA7AH KS6,UQJ,J,GP6H/I,PE>:X#7:G+?&^"UFKOO
M#0;9I'@M$AGN?0VFW0"O-8S7&HRHR?!:B^FS"5YKD[S6YGBMQ2#;%*]%(FZ>
M8S'M%GBM8>S:8D1MAM=:3)]-\%I+O98^Z%MJM>QSOF7>VZ4X+1(9[IPQZQ8X
M+7N38$!MAM-:S)Y-<%J;Y+0VQVDMQMBF."T4,5,4AUEWP&DMUP4&U&4XKM\[ZK1D^D!F9:9 WM,
MIL\@TV,R/2 S?NOO*7/@K?]GJNMHF/4JP)UEIE@><^=#1DXP=QY8'J6F2'DH
M\W2EB'\H"YCA .R35"PDLDR=#QC0@ !E,A RDH_Y"X@_DGR?E'RZ:/Q!\IF%
M8^2A)/E Y!BC#1CX (!WW-(RAK00Z#2($+JAQCZE(PNR $X,NQ\3+[($0&85(P&QA$T@X&I/+<#R-G&()A]#"+%PZ#*QR:VN-CC>"R?J[_*YGE[:&OW+[OJJ1O^'9X9FO/&SO.7KC[>3AM5WW?+KOX'4$L#
M!!0    ( &4Q44@23_>Z]0$  /\%   9    >&PO=V]R:W-H965T&.?W3G56KLX5A
M<"8-OE+UQLJK5)S=0\* X4\W=KT=1W>215.8/P!- 6@.
M0"YQ![)I?L<*5Z7@8R#ZM2K.X!#=C-&F.
M3H.6&IC-&J#]9PCR0I UB!<&*([\!K'7(+8&NR]9[E99.DUN-;W51$7AA^R\
MD)T'DJP@3I,N(?D#2.*%)!Y(NH(D6TB2^R&I%Y)Z(-D*DFXAZ $D\T(R#R1?
M0;(-)$G]C-S+R#V,8L7(-PR4/GB=A1=2;"$Y7$&*#:0H'D!,$_ 5&O1@HG6E
MP>TCSM:5 A:U/> +^87%I>ME<.)*MPE;S WGBFA#^*3?4JN[\;R@I%%FFNFY
M6OT7*' @.Q
MB#\E:>1@[1GS>\X_S.;78>5#XX%0DBLC@?7E0K:$4J.D(W]VHK>8ACA<7]5_
MV'2U_3V69,OIW_*@"NT6^MZ!'/&9JG?>_"1=#C,CF',J[;^7GZ7B[$KQ/8:_
MVFM9V6O3WDE@1W,3@HX0] 04/R2$'2&\$:*'A*@C1",":%.QA=AAA;-4\,83
M[=.KL7E)T#+2I<[-H:VLO:=+(?7I)8N3( 47(]1A-BTF&&!0CP!:O0\1N$)L
M@@E]%& [180CR&X*64"WB="99VCYX5V>H5L@<@I$5B :%B$>%ZK%)!93606B)T"\?,UG#L%Y@X'LU$-
M6TP\R!;!<5WN0B7.4,D3CRN9A'I!$#H?UU/0.UL+IZV%HP+QR-9B$FOLYA'B
MSH1I>:Z/'CILS+^1^*9OH.=?!N3L"VL4/%&,#I0\J(8#,OGH6C]@T!49$2<[
M7J27\W.E3',9G/8C;&TGV.A\8T:;[;8WF2RM\8G\QN)45M+;)4EIQ99RJ^*50U]%HZ\UC41?P^4\6[O8G><>*DNI3(3*$O1
MQ"NJFC:RXHTCZ'GO?L&[(PX,Q")^5;23L[YCS)\X?S6#'\7>]8P'RFBNC 31
MS8T>*6-&2>_\9Q!]W],0Y_U1_9L-5]L_$4F/G/VN"E5JMY[K%/1,KDR]\.X[
M'6*(C&#.F;3_3GZ5BM"/Q%P^"DA& C!BH!Z
M9S:NKT21+!6\!3ISN9FTB;)K.C*I9V]9G"0INAFA 7/H,?X,
MXR\1QWM$\ Y!VL#DP@==^)8?+%QL88$ % BL0#@7V'JK,'I,8C&-Q6R]_K>*
MYAZ8Q"O@PE((6@KO+441+!"! M'C28E!@1A("EXEI0 2/CHHMEMV)(+_4G$
MI6JD<^)*7ZSV^CMSKJA6]9YTV97ZP9L&C)Z5Z6YT7_1/0#]0O!U?M.E9S?X!
M4$L#!!0    ( &4Q44@S]]9+C@(  "L*   9    >&PO=V]R:W-H965T7@(V9\Z9<7SLB1LN7F3&F')>RZ*2&S=3JG[T/)EFK*3R@=>L
MTE].7)14Z:$X>[(6C!YM4%EXQ/=#KZ1YY2:QG7L222E+*O[M
M6,&;C0ON?>(Y/V?*3'A)['5QQ[QDE-P3"[&(WSEK9._=,N;'%C!4F4HJ'Y
M_,F/*M/9^JYS9"=Z*=0S;WZP6PU+0YCR0MI?)[U(Q "Y!9 N@+P?$-P"@E& UV9FZ_I&%4UBP1M'M']&33[H]5N,:'%5"T&>J"!2HBJ
MA(@*C%1:S*JG0I9S*A&J$B$J9*0236H)R9S*"E59(2K!2 7#+$:;YWW,()$U
MFL@:(1@;!<.$N(@Y6S [^@C%S":'&4?#YW=\"[A? #,#C'76DV,(%C,Z!'<,P1Q#QE>'/ZE''W[FTLFSK9GD4[*+Y5MD7JS75^T)?9N?X,G<4W/[!<5Y[R2SH$KW2'8>_S$
MN6(Z%_]![]A,=V[=H& G95XC_2[:7J8=*%[?6[.N/TS^ U!+ P04    " !E
M,5%(@/;-N;0!   X!   &0   'AL+W=O:_TJVD +'H37)I]U%C;[3 V90."F3O5@70KM=*"63?5)VPZ#:P*
M),$QB>,-%JR549&'W+,N G HK5=@;KC 
M 3CW0F[COZ/F^Y:>.(^OZC]#M<[]D1DX*/ZGK6SCS,81JJ!F9VY?5/\(8PF9
M%RP5-^&+RK.Q2EPI$1+L;1A;&<9^6-G&(VV=0$8"F0A)^B6!C@2Z(.#!6:CK
M![.LR+7JD1YZT3'?\F1'W)AQJZ\-[%^OA9@\3J[KK.YU^%L5_4$L#!!0    ( &4Q44CP
M25/VY@$  )X%   9    >&PO=V]R:W-H965T]SF 
M4$UCF%D2B"4-,HX8-W>;T3W]1G2XV"H,+:?&-JC<^_2#S$E)C
MV' J[3=H;E)Q]D@) X8_7=L/MIW<3%;,:?X$-">@)0&YPAW(EOD=*UQ7@D^!
M<%L[8G."\(#T1C0F:-=MYW2A4D?O=0Z3"MR-T:PY.0U::;(H7S1 ^R\0Y(4@
M:Q"O#%"<^ UBKT%L#3)K,#B#"&:;,IVH6(E@7OHIB9>2^"CYAK(7P2+R4U(O
M)?51B@UE+_J2DGDIF8]2;BA[T9>4W$O)/104;2A[$2R@GU)X*84U2%:_3YIM
M#[_80V*8^BFEEU+N*#!'&TJY^\40VE' ZNZ-^$I^87'M!QF;*S.?!BXNI?M5'K1OO3Y&7]?/LV#2GIR"HMT==I+5O3KILG^Q-5:1->UL=
M@OI4Z737"Q5Y $)$09%FY6RYZ-=^5,N%.3=Y5NH?E5>?BR*M_JYT;B[/,SF[
M+OS,#L>F6PB6B^ FM\L*7=:9*;U*[Y]G+_)I@TD'Z1'_9OI23ZZ]SOE78WYU
M-]]VSS/1^:!SO6TZ%6G[\Z;7.L\[3:WEWZ/2N\U.<'I]U?ZE#[=U_S6M]=KD
M_V6[YMAZ*V;>3N_3<][\-)>O>HPA[!1N35[W_[WMN6Y,<169>47Z9_C-RO[W
M,CR9BU&,%X!1 &X",GI7 $Z>T*Q+YI-I4;[O%/K/]LS85=;OZMHQEN C>.D4C9C5@8(*1-T30:K^9 ,[$
M"H@X/!I84P1:D V%)()W MDXL9?'AS@C7H%B%:A>@9HF >=6H@;,O,>40Z1"
M6K%2C$PB*U@&(QS1AJRS(7$VEK'E[("))D9BVU<&@I:K%#+)RH.G$>MI1-,:
M6>E81<2&#"W,FF*(JQ3BR&G,>AHS.76$.F<5S#]>@@FK(&$\2*Q<):1T8@NR
MIA!45JJ2CZ:JXU2.501U%5PJ',0D/YXNR1+/BP3&"VF3&Y!8(Q3]G\,83S 2
M&6-@&T-B#))WC?%D)"D;Q8 .%3Q%R/ 3^>5[5]+FC4'9(=.V4S*.5&0!UPP0
M0& 4N^+BVU0R?0ID1XMI#T#LL,-WLYPS=FSF8D$N.WS32Z;KP=YX).UII4([
MP10$PB*'#0=R;/9\ZX.@=06)0P7?^B!IR"BLD$?0PZZ0)"&(NA*(T\HP! *K<8!U.U[
M][Y1OG29XCD%&+J@M3B I)R25^B3B>B*>W!I[H=DLN9PX M7:?,T!0Q-T=).
MJ.L0^N 8HY!G&&2&"U+7(^C15.RC8X=#GHF08R*[JD?08P(3/['YE\6Y:P1Y
MOD*.K^Q]AP7%MC\RHPTF
M)Q:%K@[]T4_M;?-V.WY;_
M U!+ P04    " !E,5%(.?+,38$"  "O"   &0   'AL+W=OP.V^8P(4I*J:@^55GMHST[B)&@!9VUG
ML_WWM0UAB9E$N8 ]O)GW/!Y[*"Y!*,[Z]34 0[#)&AHU?IE86TOHBSX6=55RUZ$)\]-0\6_
M%:OY9>$C_VIXK0Y'90Q!602#WZYJ6"LKWGJ"[1?^$LW7*#(0B_A3L8LQ_TB],XCL?7Z#_LN_U4X=M=K0]W9L3\^U>N67GZQ?0VP";GDM[=/;GJ7BS=7%]QKZV;VKUKXO
MW9@4V;7]9TJ6A:"7SS1;<:)FCU'^F![QH$7#8Q<<5TH&Q\$E)7RQ2#4T=*,.H##1,'VQ^EM^7G5ID;=V0=
M>O 2FS[BV%>F-]O^\A6F+$[TP'Y3<:A:Z6VXTEW*]I(]YXIIB7H_?>^H_QZ&
M2R."U 15W8>5JC[L/CO$ 50;L[83NG^_OA!"C%7M"[8/,^,Y!_M0C)1]\A8A
MX7T1W/.=WPHQ; '@=8L(Y$]T0+U\-(E@$ 9!"@CL>K\L
M=.R=E06]"-SUZ)UY_$((9'_W"--QYV_\6^"C:UJA J LP,P[=03UO*.]Q]!Y
MY[]LME6N$!KPJT,C7\P]Y?U(Z:=:_#CM_$!90!C50BE .5S1 6&LA.3&?R;-
M^Y:*N)S?U%]UMM+]$7)TH/AW=Q*M-!OXW@F=X06+#SJ^H2F%1 G6%'/]].H+
M%Y3<*+Y'X)<9NUZ/HWF3!Q/-30@G0C@3-NFWA&@B1'="_"TAG@BQ10 F%5V(
M"@I8%HR.'C,?;X#JC&RVL2QUK8*ZLOJ=+ 67T6N9)7$!KDIHPNP-)EQ@-C,"
M2/5YB]"UQ3Y29N 5BIT"L!>('@=0J
ME,'D&M,;3&2ENH:DEDJUAB2YVVGB=)HXG&9N@=0ID/Y_K3*G0.9PD%NU,IAT
MD6686;5:0V+K:%9K2!JYG>9.I[G#Z;/E-%]_#]OI&I(&EE,'Q+Y%8'%I"6*-
M[G[$V?O,N4Q0 ;]!.RINNY=Z1"MA1]\<^4
M"B0=!D_RX+3RUS O,#H+-/_^ RG]02P,$%     @ 93%1
M2'YDU.S5 0   @4  !D   !X;"]W;W)K&ULC519
MC]L@$/XKR#]@<4A\*'(L;;:JVH=*JWUHGXD]/K0<+N!X^^\+^-ALRDI],3!\
MQPQF*":I7G4'8- ;9T*?HLZ8X8BQKCK@5#_( 83=::3BU-BE:K$>%-#:DSC#
M)(Y3S&DOHK+PL6=5%G(TK!?PK) >.:?JSQF8G$[1+EH#+WW;&1? 98$W7MUS
M$+J7 BEH3M'C[GC.'<(#?O8PZ9LYP21(T20("R9U)"/.)21HT
M20,":5@@"PID_W^6>5 @#V20W94Y8U*/$>L?C_/DS@??7%(.JO6]J%$E1^$[
M_R:ZM?LC\9?\'5X6 VWA!U5M+S2Z2&-;Q5_H1DH#-IOXP9YZ9Q^D;<&@,6Z:
MV;F:>W1>&#FL+\[V[)5_ 5!+ P04    " !E,5%(>Z[>O!0"   .!@  &0  
M 'AL+W=OY*R7
MI&GQ"_=$3RGB_PZ8L&'OA_X]\-I<:ZD#H,C!S*L:BEO1L-;C^++WG\/="6J$
M ?QN\" 6]5^()Z(E_9\ -/1TBU8,F(,+]>V0O)Z)WB>Q2]
MCV/3FG$8=S;!1%LG1!,AF@DA_)(03X3X04B^)"03(;$(8#R**<0)253DG T>
M'_^\#ND[$NX25>I2!TUES9XJA5#16Y'!30YN6FC"'$9,M,"$,P(H]3E%M);B
M$#GTZ&."HXN(+74QJ7V/P>+94,ROIO\(KV1]*_7M6T3G%O<<
MZ6=GQ0^J]8V=ZB%3Y!VZXE^(7YM6>&;OXRH@(  !D*   9
M    >&PO=V]R:W-H965T16O^[&37<&V:W3Y2QT[PK3-JZHC&<1HUO&K#
MLG!]SUU9R).NJU8\=X$Z-0WO_BU%+<^+D(27CI=J?]"V(RJ+Z&JWK1K1JDJV
M02=VB_")/*X)M1*G^%V)LQI]!Q;^5
M3.2_@]-;3&LX_KYX_^Z&:_!?N1(K6?^IMOI@:.,PV(H=/]7Z19Y_B&$,,^MP
M(VOEGL'FI+1L+B9AT/"/_EVU[GWN_^3Q8(8;T,& 7@U(^JE!,A@D-P/VJ0$;
M#!@PB/JAN$2LN>9ET]EEI$B>K>.
M!LVRU]"1YJ:(C/=K"(J%6%+/G-X'6/F*!$C6OF0>XQ ).L[$V2=C"#;A@*$.
MF'/ [A(%()>])G>:UFF^)3$8JZ\!BC7BA4R@SE#4&8*: -1>DXZ"P$GQ%2D 
M_4QQAYFBF"F"R0!FZH4@&>#T)4D.0!$O$PG-4-(,(9T!TLR+\8V C;3R-0P,
M>.U+)G*:HZ3Y%U9I[D]]#DE]338'I(@;AJ/.4=3Y%U;IW$]J N??US"XHQ W
ME.*L]I+ CLGX"XMU$-VM,[BK$ T8]!J1Y!.P$VD,\$8H 9Q"8>N_>+>O6A6\2FVN=W<)[Z34PB#&#^9L
M/9@Z[=JHQ4[;S\Q\=WWETC>T/%X*L6LU6/X'4$L#!!0    ( &4Q44CW\1F-
M&PO=V]R:W-H965TMJI-T?&6R)5E9\_:UX;T^55(W.%GJS+I#
MW=).U*RS.#UN[5=O4W@&,<2OF@YB4;9T^#UC'[KRX["U79V!-K24VH*HQX7N
M:--H)]7SG\GTJT\M7):O[M_,<%7\/1%TQYK?]4%6*JUK6P=Z).=&OK/A.YW&
ML-*&)6N$^;7*LY"LO4ILJR6?X[/NS',8WT31),,%_B3P9X'W7!!,@N!+$#X5
MA),@! )G'(J9B()(DJ6<#18?5Z\G^B/Q-J&:ZE(WFIDU[]14"-5ZR>(X29V+
M-IJ8?&3\!>/-A*/-T; Q8@ _ X19P\\ 8\ *%1CCXV$3-&R"&(#E
MRS$F!&$Q!JQ0@3$1'G:-AETC!F#YZ[O&N;X^[+)TIZI2[&JLS'^\%8D:R_7G?F.U?V#U!+ P04    " !E
M,5%(.W]#1_8"  !S#   &0   'AL+W=OV<1)T ).P=EL_WW-1[*)9V@O
M 9MWQH_'^,59GDW[VAVTML%[737=*CQ8>UQ$4;CGT/;7KI3G9JFST4QMTI[HNVC^/NC+G50CA
MI>.YW!]LWQ&ME]$U;EO6NNE*TP2MWJW"S[#(0?620?&SU.?NYC[HX5^,>>T;
MW[>KD/4,NM(;VZG<5+_*
MK3TX6A8&6[TK3I5]-N=O>II#TB?R&:[G\8ED
M4Q@=P*< ?@V ^)\!8@H07D TD@WS^E+88KULS3EHQ\4X%OV:PT*XRFWZSJ%0
MPS,WL\[UOJTED\OHK4\T:1Y'#;_1\'M%CA7B0Q(Y@"L%)RGX$"]N1X@9G4"0
M"<20(+Z;AO*F,6KDH&DB5>3/!(BZ2F$:)2908H:3@D8R2])8$1.J1$"(F
M9D@2DB3!10'FH21H%,6]]<^Q)IXK24J"I 2(7Y,4#2)B;P5SK.$JH4$R$B0C
M0+QW^3'#%?%?$BR!F_G<<4B20R(.4/ZND[@@X(-@S6Q!% FBB(((#T3AY9<\
M]D@(41(+&J7W5RHJ#);,F0S0M@N4[Z8^
M"395*1CZP&-5)FQ=L/@PK@K1)5;6'2JL]M&>'. E:P*GM;+;_OK8AA."A
MVKV ;6;FO1G[X2DN7+S*(V/*>V^;3J[\HU*GQR"0U9&U5#[P$^OTEST7+55Z
M*@Z!/ E&=]:I;0(LX9>5C_SK
MPDM]."JS$)1%,/KMZI9ULN:=)]A^Y3^AQPW*C8FU^%6SBYR,/4-^R_FKF?S8
MK?S0<& -JY0)0?7KC6U8TYA(&OG/$/2&:1RGXVOT;S9=37]+)=OPYG>]4T?-
M-O2]'=O3^.4[&W)(3,"*-](^O>HL%6^O+K[7TO?^77?V?>F_D&QP@QWP
MX(!'!Y3^UR$:'**;0VPS[9G9O+Y21,+VIKR9E\6)'MA/*@YU)[TM5_J^M;?BGG/%-)?P0>_P4?=!
MXZ1A>V6&1(]%WQGT$\5/UT9G[+;*?U!+ P04    " !E,5%(.-XW$E0"  #,
M!P  &0   'AL+W=O2-?SO=<(,>P@Y'6#">(/=,"]_'*BC" AA^P,^< P.FH3Z6#H^PDDJ.V]
M(M>Q)U;D]"*ZML=/#/ +(8C]*W%'Q[T7>+? +[]@2W/.6]H#A
MT]Y[#'95IA1:\+O%(U^] \7^0NFK&OP\[CU?(> .UT)E0/)QQ0?<=2J1+/QW
MSGDOJ8SK]UOV[WJVDOX%<7R@W9_V*!H)ZWO@B$_HTHEG.O[ \Q0V*F%-.ZY_
M07WA@I*;Q0,$O4W/MM?/B0@(5.:,C8-/F#4B=D6 7RZ6N55"OK/XFEX++Z+5(PRR'5Y5HUI23)EQI
M@D4!9?:E1.@J48:6/7Q?X& K(D-2V9+,=T-$SGE&VA^M(>(/$L3.!+%.$*\7
M*O*-A9HTJ=;TTSS2U)BKK0FVAJ:R-6GF9MTX63<.UL!@G33)JL:W(# WQB':
MF#OC2I2Z:1,G;>*@-8J4B54DB#8&K*T)$Q/6H8G=K%LGZ];!&AFL6ZN&<4X.
M7RHJ6Y%&;L[4R9DZ.&.#,[5JQ(%Q2@[IUR>ZLC7K$_T.-G/"9@Y88W/+S"Z2
MF"L"5Y<>P>RLNP<'-;WT0MT=J^C2H!Y#=6D:\5(VKJG/W-,4^8#.^!=BY[;G
MX(4*>27KB_-$J< 2T7^0_X1&MM9ET.&34*^R5P V=9MI(.APZYU+ R_^ U!+
M P04    " !E,5%(X=N($< $   Y%P  &0   'AL+W=O3O<5M7A)HK*YZW-DO(Z
M/]B]^^"IML&J,LC1@A,LJ2W7XX'C5M/XOQ*'^KTMW>_BP&
MY5N6)<6_$YOFQ]LA'7XT_-J];JNZ(1J/HI/=9I?9?;G+]X/"OMP.[^C-FNH:
M:8B_=O98GOT>U,X_Y?GO^F&QN1V2V@>;VN>JEDC_/]3OF]=U[C\EI9WFZ=^[3;5UWI+A8&-?DK>T^I4?'VWW#J(6?,[3LOD<
M/+^559Y]F P'6?*G_=[MF^]C^X\FG1ENP#H#=C(X]8,;\,Z ?QK$7QK$G4%\
MJ8'H#,2E!K(SD)<:J,Y 76J@.P-]J8'I#,RE!G7.V\R13Q/YM%3DQT'1CJ5#4@]9>N.LG'C=VA1Z\Z>KS-*UOH\UEZ/H
MO5;JF$G+L#,FIJ+/+'V&GHC(N7#R@Z%^3)AGS_H]3'TBIL#3&<+TB3FFHOK,
MO<]PX,P#)J/[S"/&F#ZS0!A&0&B_#X?7/F((GB".%PIO!/BY%S''%6)<
M(6X4XEZI@=!/6D8WS+[MQ0!FZC.4@]C/?(9+"DK!9ZXD!Z6 ]$6 S@.B8T#9
M/2+^&*"S0'2H -#2AQ0'3J^0(,8@B&O$(8%G4^#9%%XV*:SN2+#OE)4A3*;10&JXI&"F(
M-$P!1
M=40 M_(YK0W7&A:QS[D(NQ@'*MG@GAO$B&T6"^ NR.NF@7@C=)$"EMS9,4901ZLH:O.,,12EE3,#]PQQ# Z,/5U6N
M_C7P]0%5Q<,T%+ P4@P>.&8[!3N<8=D6NB8'5@/?*827@PQX![?_(3D#\X_*P1W!*A!A"O..8B24<_S$=D<9DO,8YIRA'L%-(([Y.4:2^OOTV*U87,$E% %IS"3WQPVB:(A1<>"J
M@P8. !0Y 9R525\CL ^FZG^$,;!WHMCFR0LCLMMA+HI,2AA'GX1'IR^1UN?H
M[.HJL\5K'1(
M7NV/I'C=[=;66=Y^3:Y7YKD\WI(;4O5?U3N=]%>[/;/E3Y
MX>.B^G1;/OX/4$L#!!0    ( &4Q44B."9L$70(  'P(   9    >&PO=V]R
M:W-H965TU%I=5>
MM-=.X@2T@*GMA.W;US8D9Y"'-XGWII+K>U$5)71(^_4=+Q7C>@#R<^[\ M^WF-J0US$
MKX:/:M$/;/$'(=[MX,=I%R); V_Y45L)9IH;?^%M:Y4,^<\L^I]I$Y?]N_HW
MMUQ3_H$I_B+:W\U)UZ9:% 8G?F;75K^)\3N?UY!:P:-HE;L&QZO2HKNGA$''
M/J:VZ5T[3G=H/J?!"61.((\$,A4^@5R97YEF52G%&,CIV0[,OD+\3,R#.-I)
MMVYWSQ2JS.RMRI.BC&Y6:([93S%D$4-1]HB)C/X#0D (<0+Q$I(B6" &!6(G
MD'P2P%Z54TSN8GH70^*L@"D)2$D "O$H4PQ=4DB"\92,D 2NI1LC6%;KV7'*3D (5ZE'Q%2=,\ABD%2"D 
M2N91BO5:TIP0&&/= -IQ" #E_I9#ZR\@IQO?&=[8VA@ K?8V7H%BO+4Y,;R]
M,5F#*/)!9 7*LJTG![L !FR ^C8P!WWBX&2# _L !HR ^D: UTY R<9GC6$G
MP( 54-\*\-H+<(RV%@2; 0;<@/IN, C*EU^97X#%H^5G;;F;Z&PO=V]R:W-H965TE;%OE[K_?MB B
M5..^V'9ZSIF9RLPD+65?O$1(6-\$UWQCET(T:P!X7B("^8(VJ)8W)\H(%/+(
M"L ;AN!1DP@&GN.$@,"JMM-$VSY8FM"SP%6-/IC%SX1 ]C=#F+8;V[6OAL^J
M*(4R@#0! ^]8$53SBM860Z>-O777>]=7$(WX5:&6C_:6"OY Z9X-\(P5-"T!.""0%TJ>B'V$,!TX31UF+=O]= ]9&XZT ^=:Z,^F7UG7P*
M+JV7- Z7";@HH1Z3=1AOA'$'!)#J@PO/Y"+S9G3OWL%NCO GD/T:@.$VE,W66ZB">Y=IAXA/$GJ3Y7N0MU:0QU
M:0CU@4!H% A??ZS(*!#-(HB<29K9'!.'*[.3V.@DG@M$#[Z)E5%@]7J:JG>8
MJL5"EKD'"?R!AK,*MZ_U'MN8:8^ &C]D00
M*W2?YU9.S[5053ZR#K-DZZGV-K%G:L;HMG>329,&%N@G9$55<^M A6R>NL6=
M*!5(QN@L9(64<@H.!XQ.0FTCN6?=7.@.@C;7,3?,VO0?4$L#!!0    ( &4Q
M44B)+CP LP$  /8#   9    >&PO=V]R:W-H965T!#4[-8!T.ZW2@EH7Z@Z;00-M DEP
M3-+TB 5E,JG*D'O65:E&RYF$9XW,* 35?R_ U71.LN2>>&%=;WT"5R5>> T3
M( U3$FEHS\EC=KHK4J\^^-&%/_-&ML[LVF"&FCIR.V+FK[#?(3@L%;<
MA!'5H[%*W"D)$O0MSDR&>8H[#^E,VR:0F4 6 HG&8Z%@\RNUM"JUFI".5SM0
M_X+9B;B+J'TRG#OL.:/&96_50Y&7^.:%9LPE8L@*DRT([-27$F2KQ(7\1S^F
MQ;; ?M/C/@CD'SP>M@7R38$\".P_"!RW!0Z; H<-!\6G6XJ8(F!DO*4LWWWY
M5 :O'D: [D+_&52K489N7V67%G\DX6'?X54YT Y^4MTQ:=!56=<>X1%;I2PX
M,^G.N>G=)UP"#JWUR\*M=>S+&%@UW'_9\M6K?U!+ P04    " !E,5%(R?/(
M5OH#  #R$P  &0   'AL+W=OK+*KF97%JV_.S[S>[DRFSYIL]FZK[YV#K,FN[R_KH
M-^?:9/LAJ"Q\&02Q7V9YM5BOAGO?Z_7*7MHBK\SWVFLN99G5_VY,8:\O"['X
MN/$C/Y[:_H:_7OFWN'U>FJK);>75YO"R>!7/VW! !N*OW%R;V6^O%_]F[<_^
MXH_]RR+H-9C"[-J^B:S[>C>I*8J^I:[G?Z9&/_OL ^>_/UK_;1AN)_\M:TQJ
MB[_S?7OJU 8+;V\.V:5H?]CK[V8:0]0WN+-%,WQZNTO3VO(C9.&5V:_Q.Z^&
M[^OXCPZF,!P@IP!Y"Q#QPX!P"@@_ ]3# #4%*!+@CT,9$K'-VFR]JNW5J\>G
M=\[Z22*>59?J77]SR.SP7Y>*IKO[OM9+O?+?^X8F9C,RF&IA(
M+Z8MA S$:KM2"C'9EXIC*A(Z(7,XX$Y= (0D0
MXI@?O>FA91]\?3T(AW,(H$)1ZQ \'PEY,BF"8OKX8$M+AV)H1*]"?F$-3U#\
M<"7J\4E)$A5%$
M-0-J7A#NMT_8JV4 TDQ-8(+N.J(;N11!"=MI 4@Y)H;$I4'RTA %U&@E-_0G
MFK\40'1:/$3NU>*R('E9T#JA:KF9"\G4(BBF>CDT,[Y[P;@J2%X5^$9$[3\'WM:B3U:?F57*_FV-J;^BAA:20$C
MM$,NK@<2U0-JKY*[N!!,+X 4>\P DJX7/5P0)"H(S*FXC3]1#TXAI*EB!+D4
MXX(@>4$ 3@5,G%DK9YA1/4+N7V%Q(0A1(:!&%0+[YDZ%*6I5B')Y58A+08C>
M$JA73=#\A9=J20%#U^46,52N/SL9*4U]'(Z8&F]G+U7;'S#,[MZ.L5YE?[)"
M[F_$\W8\C/IL9KTZ9T?S9U8?\ZKQWFS;VG(X73E8VYI.8O"ML[&3R?:WB\(<
MVO[GLOM=CT=2XT5KSQ\G;+=COO5_4$L#!!0    ( &4Q44C?[OT+<0(  !<)
M   9    >&PO=V]R:W-H965TM-BI5=SH%8IP8/9B@O@M"A)*@I^W@
MEX49>YW*@I]EUP[L=?+$N>_I]+=B';]N?>S?!M[:4R/U0% 6P3WNT/9L$"T?
MO(D=M_X7O*DQT1*C^-6RJWAH>QI^Q_F[[OPX;'VD&5C']E*GH.IQ837K.IU)
M5?ZS)/VLJ0,?V[?LW\QT%?Z."E;S[G=[D(VB1;YW8$=Z[N0;OWYGRQQBG7#/
M.V%^O?U92-[?0GROIQ_SLQW,\SJ_R= 2!@>$2T!X#\#1?P/($D"L@& F,_/Z
M2B4MBXE?O6G>C)'J/<<;HE9NKP?-0IEW:F9"C5[*+,=%<-&)%DTU:\('3?BL
MJ%T%^90$"N!.$8(4H8F/GBBL&M6LR8QF,)H$D]0"<44Q"5=0"(A" !1BHV134@BI#]!08/1]A(3^PGG4[M(+P=E^HT-&?6D7/)5$+THKRE
M4;>4>Z=C1ZF;J6I/\[D]=R0?;]>0^UVH_ =02P,$%     @ 93%12+ @D?P/
M @  #@8  !D   !X;"]W;W)K&UL?55-C]L@$/TK
MEN]=_!6Z&SF6-HFJ]E!IM8?V3)Q);"T8%TB\_??EPW&\F.XEP/#>F\<8)N7 
MQ9ML %3TSF@G-W&C5+]&2-8-,"(?> ^=WCEQP8C22W%&LA= CI;$*,J2!"-&
MVBZN2AM[$57)+XJV';R(2%X8(^+O%B@?-G$:WP*O[;E1)H"J$DV\8\N@DRWO
M(@&G3?R4QKB?'Y3_V9/J]T?B(0=I[_;HVJTV22.CG B%ZI>^? =QB.LC&#-J;2_
M47V1BK,;)8X8>7=CV]EQ<#N/R4@+$[*1D$V$%']*R$="?B<4GQ**D5!X!.2.
M8@NQ)XI4I>!#)-S'ZXFY(^FZT*6N3=!6UN[I4D@=O59/25:BJQ$:,5N'R6:8
M=$(@K3ZER$(IMMF"[B78+1&Y!]DO(4])V$0>/&=N^?D'?AX6*(("A14H/@@4
M7J$60,8[&'V 4R*PV970;.K@-F59]9A\"P)]B"[ "3QK"XA
MJ_^4%0>=XH!3[#G%BW)DN>W*>2=#5;'1S
MGA843LI,O^JY&ULA9?=;ILP%(!?!?$ 
M ]O\5@2I"9JVBTE5+[9K-W$25, 9=IKN[6<;0A/[$&X*F.\/\N
MCHQ)[[-M.K'RCU*>GH) ;(^LI>(;/[%.W=GSOJ527?:'0)QZ1GZ\-1ZH&@+((I;E>W
MK!,U[[R>[5?^,WJJ4*P10_RNV47,J_3A@0C0&1%1 ,CV(*45%)RZ+G%Z\?5N]$]4N"GB)5ZJT>-)4U]U0IA!K]*/,P
M+8(/G6ADU@.#;Q@T$8'*/DV!H2G6V G']Q-L7()82.4B>0A+$/ YB8DG=_$9
MG" "$T0F0727(+<*-3"98;JA4#C/K(<%())8):\ ",4)[!N#OK'KBT++=V"2
MFUGBR+)U$9)8KBZ"9Y8F 4T3P!19IHDS1V1I;  DM-\BEYFI:0J:IH"I-<4Z
M=:N!L]AR=2%K::I'Q)UI!IIF@"FQ3#-W]4-+8^,R.+;7WV6B=$8V!V5S0-9Z
M#]?YPTD&69=)[=^5BQ#85&\6T.4> 
M;V+[HF7?1:0"D(A$,[;@3O&,,&#K[$9XV781J0 $(1S.51?>5! !?#/;ERS[
M+B(5@)!D[MV%=S $;&'(WL)&Z*'M(E(!"$IGMEL$[U\(V,"PO8&-4/;(=A&I
M "3#J64;W'14+>L/IC45WI:?.ZD;DYO1J?U]QKHCL\;7NBTVG=I7FK(XT0/[
M1?M#W0GOC4O5[YFN;,^Y9,HQ_*82GZZ=^?3O
M0?D?4$L#!!0    ( &4Q44C5!C.!  ,   \-   9    >&PO=V]R:W-H965T
M3OO0F4P>VF?%EFTF
M@%PDQ^G?5P)L@[2X=AX"B+-G+]HC+]F)-Q]BSYATOJJR%G-W+^7AV?/$>L\J
M*I[X@=7JS98W%97JL=EYXM PNFF-JM(#WX^\BA:UFV?MVFN39_PHRZ)FKXTC
MCE5%F[\+5O+3W"7N>>&MV.VE7O#RS+O8;8J*U:+@M=.P[=Q](<\K2#2D1?PJ
MV$D,[AT=_#OG'_KAQV;N^CH&5K*UU!1473[9DI6E9E*>__2D5Y_:<'A_9O_6
MIJO"?Z>"+7GYN]C(O8K6=YT-V])C*=_XZ3OK(+@:A#<-PMX@- R\+I6V$"LJ:9XU
M_.0TW>X=J&X2\ARJ4J_U8EO9]ITJA5"KGWD*)/,^-5&/6708&&"N"$^Q7UP 
MYF(!ECF,'2QM1&! 5C8D]?$@ C3/H+4/1GD"3A"B!&%+$(X( J-0'29J,767
MJ=_]&0G? 1R%-$-#FEDAD2@T0NHPR<"3&8N-2!.S^K=81H%&:*"1%6@<&W$B
MD,0(]"9D%$6,1A%;]DDX09"@!,G]/92B!.E_Z[!$(!,QZN,,$[2/-*K1%
M--S0V<2.DHES@]C-EYC)]*#[^YR@)\@+ 22GV00%KG_RP % \!. 8$= 9*;<
M@0@,8VA=<.?" <@!7#F#*
M"/1\"E [9TD-(F=Y36&XR-%6MV[?PMG#4_UE)/7X/5RXS_ GKL--87
M:O;O)O4K39X=Z([]I,VNJ(7SSJ4::MO1<\NY9"I&_TGMW5Y]G5P>2K:5^C96
M]TTWKW$$F7+#\@"
MZA1%NR@09)&L:6ED$>%#)6DK_?OP(2M.R[3>F.3PSKDSHLEJE.I%]P F>>5,
MZ%W:&S-L$=)-#YSH.SF L#N=5)P8NU1'I <%I/5)G"&<927BA(JTKGSL0=65
M/!E&!3RH1)\X)^KW'I@<=VF>7@*/]-@;%T!UA>:\EG(0FDJ1*.AVZ9=\N\\S
M)_&*)PJCOIHGKOB#E"]N\:/=I9FK 1@TQB&('4?B(9[R9YI:WI;;98F+73DQ,RC'+_#U,/2 1O)M/]-FI,VDE]2TH23
MUS!2X<@*<$/"?@4'@P\F5^)8;4E9)CHL*W'8@[PGR+[8=H7-#W
M[?=LH=I&S_6FR"MT=J!)LP\:?*4IL]6L098_F^"H"?: Q0<3' <444#A <4'
M0!$'+** 1:2"Q1]M!LW::X37?%+C,FJQ_,NBS#\!E%% >7N3JRA@=4.305/^
MO\EUU&(=L5C& 9LH8'-[D^XVQ?ZQV0UM3J)_'2:ZNB(#.<)/HHY4Z.0@C;UM
M_DYT4AJPN.S.'FYO'[5YP: S;KJR5@8.5Q>K?GIK-\ 4$L#!!0    (
M &4Q44@7D!2+O1   +=\   9    >&PO=V]R:W-H965T//M7IVD8QM.K\XOK
M5^_>//SNIYMW;PZ_WUU>7.]_NCFY_?WJZOSF/^_WEX=O;U_9J^=?_'SQZY>[
M^U^)/^\V'^[??'WD_OJ
M?SD^?WKX:[HO87^X_WMV_QOGQCS_VN_WEY?U+'=_ZWT^O^K\WO=_P
MY=^?7_VO#Y_W6/\OY[?[W>'R7Q>?[KXG7S:?S[__?+NY\.WO^V?/D2]
M?\&/A\O;A_^??/S]]NYP];S)JY.K\S\?_[RX?OCSV^._S,/39KQ!>MH@?=_ 
M2G>#_+1!WKI!>=J@;-V@/FU0W0:GCY_]8<^=G=^=OWMS<_AVWY]6
M]F,]'IN/][]\.!0/_W;<=[?'W_[QKN7QS>D?]R_TI'G_J$DO-&FIV*DB.\F9
M2MJPE'Q02('\LHS,VV?)3,#Y+K
MQQKK['>'BFJVZG8(B.9F;I>H*+?"'ZG@1RKZD5PA[Q\EXXOW2*W-[B.I:. R
M*I91I8SVXM ^UE'E+6R:?1T@FL?*I8Q8RJA[Q%Y/VD;^*^G3N53"-7,6,5LU;17!6S[O34W&FT ]$P!T>F825-*BG.(MZW
MSFGX6(8JVHN3:%'%_0A"ECAH'>8M<8#ST+*W15#5%EB2!09M6DWRU9B^3YF]
MO^Y(EML<^(FQQUK2>K*O)^D7:#C^Y^M1F8VI!.>,L6>;FG;QIOVD6;[1+$=K
M1;6LANW6U&^+]UL#P\VM^N\3R4QD9R [GHDI,")C>S;UYR)=@%IO;<47K:)Y
M"D8*8W\V->@FOFCJOG)V]23+0MB>3?VYB36:VJ\4TI,L"V&'-K7HXHVM0S5/4UB9VS:2N6;UK
M)C7$-!3]+J%O3I$YL'$F-<[JC3.I)]91^J8UU7*FR]:9U3JKM\ZLGIA&7_..
M5#4%7^[,QIFUR1U]ZY^U>RW#:+X:4,W1D9%V4U6'_6="7+0MB!LSIPDXE1[@4%3X5LSA(R^V]6_QW]L)0A*!BD
M!P'5:('-9#;@K 8\^G$I0U9P-%ZX(]FQ
M*7*O=D:RDORTYP/(1K-@A,GLZ5D]?9*$3LV:&CZ0=1J^S)Z>U=-;":9>A8VX
M#-(S1J%E8?,L:IX26Q:U1?^U7)>A#VU@*=*
M"EC6/;4K6182Q+.0STH=ZY;:E2SK8$LM:JDRYRYJEE)'3[*L@]VT0#KKVY*R
M/O?O2I9UL(L6=5$_YN[*YGE]83I)E'>QB!:;T?CPMZ\EK
M5[*\1L!66&$Z[X>NJMVFKZ,K6=;!AEHAU;X
M5,=FMZSLEA4B5C^OJ^MFV94LZV"SK-" BDM5M<+7QQG=Z.=TJ,MS#1J2&ES7
MH@M;WK"JNN+KT;+L'Y"E*9J[5#;0J@8J66%=-]"N9%D'&V@% Y5#I0;ZVJ1'
M1U74%%=VV@I.*T=);?1U+9/,,$E7QBEJ^RI[;FW2]D51XX[I;
M=B7+.M@M1W5+"0G'=;?L2I9UL%N.$)WZT6-<=\NN9%D'N^4(H:D?/<9UM^Q*
MEG6P6XX0F/K18UQO+;N291ULD2.DI7[T&-=;RZYD60<[XPA)J5SX7W?&KF19
M!SOC""FI=\9Q_:I25[*L@SUQA'S4>^*XWGUV)NNVI4LZV!7G=15-?6;U#-?CQ*FDVJ:HW+87""T[K)=R;(.=ME)75;BOPE:S;$E?Y&,9'D<@VM3$[OM
MI&XK\=\$C6:99EU91+H\3$&+/+'O3NJ[DME-:JK8>Y&NTWM-P;HKN+!?HM./
MS7.:I7V+4KN);6]2VY/4;E)#TW5H($K)J\Y(U;S/?@!5\'68V3YGM4])[^;-
MWCBS-\[@C9*:S>LM9U>R+(1=<8:L4NI8;SF[DF4=;(8S+%SU+<6\;H9=R;(.
M-L,9TDQ92[C>QF,\RT
M_4@XPSI2,1(0+8QD64RPF!0FVG[XF=>;RJYD60>[ZPR1IG?7>3W2[$J6*UK9
M#QM$FMX/VWH[V94LZV#+;!!I^DE86W?,KF19!SMF@SY2K*K1NE"351DDRR5:
M;=C8.AM="?*>U=:]LRM9%L+>V6#EJ!]+VKIW=B7+.M@[&WBG'*#UZ3I(@B:M
ML;TVL%X@P92WYL&Z/?8VK)5AF/T",*>O(AW6+[&M<+<$2
M^P&B3%E%/JPWEGV-JR587C] G"E+PX=U@^QK7"W!XOH!(DU9"#VLFV1?XVH)
M5LP/$&O*.NAAW2C[&E<+6^7C[U>BO&=1OY;-S:@-P:+Y0=M1B?.>1?U:MB^;
M'X)U\X,ZKH1YSZ)^+9L]UX9@V?Q 2X5TQZS[;E_CD*+ > %QTCC/ %\22 4T
MT6IJ"PDG6/VIB-,&Z^UJ7"V!]0+>)'F> ;BD.P96Z8<[)O!>8)LDS#/$EG0Q
M'^H6J_E<38$' ^$D<9X1E 2-&>KBSLPB>@GPI58BK"W"CIYXH2V1GD7$$"!#
M$NH9\$ V*1X#LI3\I.T,9:/'=S^0+-S+@9L"AB39GA%BU%K -%C$& %DI F?
M 4&DEK#=+ /(R( RTEJ 'Y):NAI72V"5"=9Z2M>1-EAE5^-JB4!02#^EZP ,
M26O9WJ4&H)(!J22)GP&%%+Y/X'Y (>FX"821UJ*:R&P""LD 0U(R&!"C/(W^
M2@_)CF83?6T#%LD 1@(V>$,?VM6X6@(K!AA)N6#@C+26[H+@%%.:9:"2#?DZ!8$%J!(!BP2
M8+_ &<&E;I+%E[HMX)$,@"0%@($UTG*V.VU (QG@2,K_ FLDRQ)(9%&''"!)
M!DR2I(0&P%%):1!V'72YEA0UD@&=9$]0T9:DT *HR( JDJS0$"O2W0RJT-D#
MJ,B *I+,T(#PF?045%$-B"L+*" ##$AS0P!\DE8#L%#X[0P<%2 @30[S!D?M
M:MS=)P)'+9"HZOTG-O2J78VK)3!2X)(T.01>J ABBJHQNF]! !89D$6:'@):
M9&W6$X=T=9ZC,SG@D Q )$T1@3("*GA5YBH*'!6(),T2-R!)?8VK)7!2H)(T
M2]R )?4UKI; D8%,TBQQ YK4U[A: C<&.@FRQ"Z?]%S,]N8V@)@,*";($C=P
M3'V-*R;P8D"9-$H$4,G\S&E'JJB:@&* 8YD
MP"-!H@BLT?%WNAM!-H=SEX!),H"2H"+H8G7I%LGBNQ%:P"19A36ITHU46)0J
M>1*(HMNW6, W&0!..@\'? GN38BR\.Z$%I!.!JB3IHP ,L5W( Q8)@.82<=4
M0)6.G;+.]35:0@/7.#60#MI[ @L$]V/<$WF*@H\%K@G#1^!:L)[$I)N<5-"5U/@
MQL! :0@)A!/<P@8X
ME $/I=$CT$YP\T%0=>X^&'!1!F"4YH^ /.59"X)P-KK]F@5@E $9I0DD($]'
M;YD\WH(Z.Q[&J*; JY^HIDT)9, U&8!-FD "LC25)MX*LK%%8)X%9),!VJ09
M)#!+H[@8B"RBFBS F@RX)@TA 5@RG=J!*IRO!$R3 =2D*>0$":WI^ \#*
M@+#2)!+XJ9+TNA?)6GRT G\&UDKS2""IX"Z%* MO4V@!=&5 74$J"=R5(LND
M"I%E"P M T(+DDD L&K3*0O(4ITC5PQ8+0-82_-) +%:DD$#5.&]"RW M0QX
M+4TH@<8ZNEV3^0KIK(WA>10X-;!;FE "F97S -]^T-D07G$,,"X#CDL32J"T
ML,LC7:?+"Y N Z:KE?"#!4;;MC\SQ0*$RH"ATH02 "E_5'B
MV.2&\@^H&B*3#9@L RA+\\GMR)4%S)4!= 7I)#%5)KT J$HTR0K8*P/X"LK9
M<+&KJW&U!);9-CPFY5G4KV7[M:Z X#) N'1FOH'AZFM<+=%]^-F#8@6WV-JR6X83\@6Q(U)J"QDOG9 ZDLBGA20&TE>C"5'"=ZYE3V<]4=
MRH8HPD@!N97L_WC@24!<)2"N])$G]$0I691%*ALB/P^@JP30E3[T!& JK6:[
M?P:P50+82A]Z A"5UK+=/P/(*@%DI4\]@><_:2W;_3-@M1(\(TJ?>@(/@))K
M;"2*KF:E@/I*0'WI##B71HFIRW,]%[/=A*,'3P'SI3%BHF=/"6=%JA8U^-'3
MIX#[D@PQ$?+Z]N37PYW
M=X>KM_'K
MVZ?'A']_5OF[_P)02P,$%     @ 93%12)$4FRQD$   @WT  !D   !X;"]W
M;W)K&ULE9W=5[C=D ")"I)%7C_(O8
MJJFYV+U6$B5QC6UE;64R^_8KR;)C=I\#P#=)['RD6@38W3SD 9__W-S\=?MM
MO=Z>_'-U>7W[XO3;=OO]V=G9[:=OZZO5[6^;[^OKW?]\V=QG+Y\??O?'S91D.
MS 'Y]\7ZY^VC?Y_LH_^XV?RU_^'#YQ>GW3Z(]>7ZTW:_C]7NK[_7K]:7E_M=
M[3[ZO\>]_OK0_8:/_WV_][>'[[N+_^/J=OUJ<_F?B\_;;[MPN].3S^LOJQ^7
MVS\W/]^OCU^BW^_PT^;R]O#GR:P!\W\+\V",4-PG&#T+I!?]R@;]T@'C>(K1NDXP:I=8/A
MN,'0NL%XW&!LW6 _YG1AL:?Z4^^$6IS8YNYM8AVGY>K5=O7Q^
ML_EY;;;:K?S_6\/$_WPG[N9>;O[[=\OQY">G_V]W].1.;]C
MW",F2#]GEI:1!^)L%\)#' [&<>[,]F[^":\L$23.F=> F1-OT%[4]WUK&:^"
M>8=V,\R9]X@9Y\P'P+A.'=KJH9GJ 6>+C!T>((\GBC_LP#_> 1GA@'<0#CL(
MLYFF#MGRCAD.S/7=5PV#$_5U >5\4C,R6TK&+@XXYA['W-N8U619WB'QT 14>)Z79T YX: >3+*0C>QCQ'D8S
M.:13>6 YVJG6C2R1J4D/%@ZC5N7Q^A&8GH!KZ5X"141WHUP#RNAU".W(Z
MXR$H*N@=@'2M?(^^FCK0'V!$>F#!-TM1CROX,%U@,OJTCO0(0AH;L9V-=%&/
M:C ?M! _ZG%%E!Y6P#BOQ]5"G1Y5L)_4Z5&%8>MA17O29?H#W)7N=2&D4\B$
MJ"'H#@4>*#*TI/\3VP!*ISM L8U;IP,&O9V.%B"!1$NZ/['MW^/)?(S6-FZ[
MT\)F18 -HAOVC# ?' N<=(("6D'=P9V+;4P&/^@3R$*]GJ^O$:1SU1L B;E2
M!%#P7I]# !KU*6297<779Y"%%CI9+P'DNMCKX07?SEQ.9Q35R!H,T@H*Z 6%
M]()"FD$!W:#H;E!L$[?++[J?GC"63)<"L#[T.&Y'6D('6D)3S)QMXQ9!?[L)
M44Y?FV1$Q43JF2,MH0,MH3Z'ELYV<4:YF #D>UV" ?2XM9R'3-I!!]I!?56[
M=+:%6]CCW !E -&(22OH;"LXZ@O$I;/=R7Y*)QTSQ'07GQ$VTBE-FAT'FAV=
M-Y;.5MY1S]4)0$%/LPR@G@F+I(8[4,-U(E\Z6WU=T*D#0!)USH00B9C4<0=D
MG%ZG.VUVMG8/7BO(#E4N77)?(4ITB7^-*!_5X7D#*-U&
MOG566UD8E>$=H$:56MZC/?E1[>D#H,2.*_AZ2?<4$SR@NN7.\%"Q$Y[4;S> 
MTT?W9D=H/G)!#R^"=&_6LJOY$9JI
MVH/7A]!"XGI]""WD]=1X Z!%,EG1-D'1YG$+@9EH(381/6FFO&VFQEXW4QZU
M22K@!B8CQI,^RI,^RH,^RNE2Z9$:IIL2 )GJE &T(',*&%]AB=]AF^X6>1M<[ (7M=M1/6:
MRHB*(SNI2*OA&^X8>=LCF&P[01
M>;"D0(2&FR#+8*]53;!5)!>1>;#LH84&;7\9JF+[5$=R$9D'2RI0:%"KIU!5
MJW,1F4="RDIH4:(#+!DF2R/,9FE(L2P=2&T)#3KT,MAZ8$*N(KF(S(,E)24\
M05@-I*2$%F$UU$M*'V* %$DVC2UZ4:PW
M]W4D%Y'YL^ D'Z<6M2C5F_LZDHO(/%B2C5.+2)3JS7T=R45D'BQ)P:E%'$KU
MYKZ.Y"(R#Y;D^M0B#J5Z+$F_8X,4--:S;QW)160>*\F^8X,4--J4:29DO:LO(O-82=8=&Z2@$21*
M'6N]J2\B\UA)LAV?8J9F;NHF.W6]J:\CN8@H(S5U4K=9J>M]?0.3RXR*F+FH
MNR8;=5=O[AN87&94Q,Q W34YJ+MZA]_ Y#*C(F;FZ:Y%&[JGRA'7^_PRHR(F
MI>;N/VH"T3U5CKA>;B>*D?37%!VAX1%TZ(4W5/EXU>O*F5&
M19(.;UB9T1
MUB='9R[+W,AW;P^[3;6^-R4>4$XOKI0AQ6R'P@SX ASX1LP28 7WN^-F$P5:
M)+ S7BO(A<>+<*K@6>9V3U"WA!FL!3BLK;XEP(3<&U_E!+%D'H^$F&?/1PIS
M-0NP-0.M"_B1Q\ZXV2$6]#H$&6%)!G;4F;]9D,'9BE[ E[P;8=M8 FY(>F&S
MC+#DV-._PIS. JS.0/[R: 5!K3E-$//&L(LP3]<4$F:P%M^D@_FV-?+:%LE[
MRBIYS-4MP-8-U##HQ;8KP"$,+ &','J*LHH&G-U % -^;-.I((9=C#++M@#/
M-E#%@-?:C4$OVSA!+B6SFC+D?$@T:;!JA?S;5B$#IFM)@UDG%6%F79F,L+&C
MYQTK55(1I30^LF\
MV0+,V4 #BV"Q8QLV@.S1+D(J:%8_8I/Z%1N> JLSNYU;J 6]P--G#T/@)SC08HVETQ[[D@\SD5NIC[7)#]W I=P#F^NV*R;Z. 
MF)UN"&,+%PKSH@LRHUNMJ\&-WL#D,J,B9B4(.=*MUM5@26]@YOGDX(6BAEU_/D!KH$6>%")G6K<@%+.GV41( F=V0?Q2SM CSM0-5J,+4W,+G,J(A9\4'&=BMI':D!'YS[D"VTL),'46;V
MG#UZ!_+5^N;KX=7>MR>?-C^NM_OFYM%O']X?_KO;OT-9_?Y[X+O?=AGFVWKU
M^>&'R_67[?Z?^]1S<_>*\+L?MIOO+XZO/']X[_K+_P-02P,$%     @ 93%1
M2-;V5""2#0  QF0  !D   !X;"]W;W)K&ULE9U;
M;QLY$H7_BN%WC[M(]H4#Q\!8C<7NPP*#>=A]UB1*8HQM92UE,OOO5Y+EQ%WU
M%/
MZ]U/VR^;I\-?/FZ?']?[PZ_/GZYW7YXWZP^G@QX?KD/7#=>/Z_NGR]N;TVN_
M/M_>;+_N'^Z?-K\^7^R^/CZNG_][MWG8?GMW*9>O+_QV_^GS_OC"]>W-]??C
M/MP_;IYV]]NGB^?-QW>7O\C/LXS]$7."_.M^\VWWYO\71_:_;[=_''_YQX=W
ME]V1Q.9A\WY_?(_UX<>?F]7FX>'X5H=3_^?\KC].>CSP[?]?W_UOI^L]\/]]
MO=NLM@__OO^P_WR@VUU>?-A\7']]V/^V_?;WS?DB3@S?;Q]VIW\OWG_=[;>/
MKX=<7CRN_WKY>?]T^OGMY2]3=SZ,#PCG \+W V0H'A#/!\0?!Z3B >E\0%('
M7+]_'89B=WCUS]O<
MQYOK/X]O=,; +&>E9-Q"6KX5M9E&9;0BRH9J2:@:H:MKM<
M([&J(F:+B)U#]*CHI&D=4!VTJ'55KG7(#) @*3ET'0D6D!8]LF=0D6X)LB2"
M0OV+!#MNW:B)!'.6/&@F%G.8LGKH "318\RJ+A&&SMSI:$]T0)GA ]A!R[0R
M$RQT.3B\.9A( G6>G+=@?9<>+MW\SQY%"(%3H&7$GH.]ZB%<$DD[,; =8=BASJ!"(%8-HRE;D)9E;
M7H\51[4 \) ,F32:V;XT;@N!$@;N@/P%T N==1;@4@/3.+D"5;
MCAG!Q@P9=)88K,HG_7
MXU*P<4D&'9*##3I7)D5;$6K4T0! WGS@^!4@?IFL)]B88Z(78&P9"U6.!*^<
MYM@5;.S*)N &&V]BDJ@I6U3H=?TV RIUKK1R] H4O8RT0JDS1D,:4/VH\S1 
M]2E[]CJ#7IL\3ZW5$'3(7(4NN+-612@T=NJ.56,.U"IF+D"57
M5NE(S2@SF:RR>F=A68W40#*?T.9D/K(.1NK]:,&-I=;.LL'*RI4H^]:)3K)J
M([G3'S]"C5X7*;$F)@
M/,:LM0D:\EX')#D=>6K)FQMD4]HKNFJ"^3.&I321E.IT(=6EM Z9BY E5Y;2
M!%)J&B"I+J5UR%R$++FRE"9JUNC.1VJ6TL12FBA#U8$P55LGJSID+D*67%F0
MDQ5DVZA(5I!MHD(@;]KWK-L]9)RFB=,WMT1ZEN,>Y-@T&?IF(>U92'MH99CF
M0%_M4JSJD+D(67)E">VID:%C?]^<8O:LLCVU'W1HZ>OMAR)D2<1YH GJ:N)Q
M7U?7.F0N0I9<65U[JZZV1.^I%S!&PY=@@XG( /,XL\KVI+):4_J2RI[Y5B%S
M$;+DREK=DU:;\:UK=1TR%R%+KJS5/23/IB#OZT].ZY"Y"%D^\F*!L5I=. ST^5$,&&/U
MFC5O8,T;J-371?A@U6KTGC<,K%<#Y9:Z#!_@:1N450ASRZJ116F$_-($_K'^
M5*X.F8N0)5=6OY'6PFPI#C#WEH\LN"/T3KUB?&01'*EW:FY2
M*1D]7W1SOCJRE(XDI3HU&.M26H?,1A15SHJ:!CO\3]56]9^L3B^Q$%;^.+E-=9(N0)1$6V0E$UH3DJ2ZR=X$TOM1%*KA66BMH!9HKPBV&"6
M  $JY,$;9Y;NB:3;C#,L. CCI$D#*NO . /*8^PLOH:,VE3FDU7G: E;D+VL
MF5#^*+/63Y"=>TLQ,LMX[MHK],P*G2G-U755AOPU]9T.3 3K)6G]))B$SFE.
M9%;J3(FN$YPR:W :E>JYK,S4%S'1KSF0SRV&FIH NU[.5,$F=DQ1D5K%,::@Q9M33
MT")D2<0QB$ ::I*"W& 1:?"(-#@J\ML V8N8Q1AQSG24=O!. DZR&23>RJ6VI?7JS: 
MKB2VKV-3Q/XZ.@QE[%'=.U>C>=X[,M^9VE[ 
M-&='IGEA@7BV.O#5@1,0K'"63#W-+6,484>#A=:"F0DL5CN'SMB5"98&&ST 
M5H@>GHT/?'RVV!=PZ5TE&_<0IJN3F6!AR%X2X?G^R/AG"GXAMYYQ5:X0]I;2
M*_-VA?>^"8M83<6K9[$!MVK"AB%!E'BR-IL7,?,98PB[&U9
M00_Q3/Y!!C*[]P#;S.SF X3S=A]PK&82J0#!W-T#Q+&G"?C3H'G08% K8Q091^O)@ ;CTZ[CC@5-R(-FFP=@0KL2
M=X =[24CFFT?%)UHK]==;S*7,6J;%T=OP=,&[0.PJ[DG AL'P',;\$4MRN"F8N;"=6[M)VP &:ZG+PTTK'*
MR=G UM9$<#QL@B8V4\R104VC5HBR'S,+&KPLR/&Z24\)M".#NWVLUQXKCCA.QQMDO0
M;GX3Q_TF9'^S/8)VYYHXUC5![YKI$13M9J_WNCV)=3QI0J8TFT0TN-(:,',9
MHP@[R@C.-.@.-%C3&C!S&:,(.RK<0S_8[0@XMC$AWYCM" P-C_6*&$7&4=>!
MU-5N2-B@KG7,7,8HPHZZ@M\-.@+@5+.$&]2UB%&$'74=J(5A6@%#N[HZMC@A
M7YQM!308XQHP8XZ " KPWV$&*8VUQV+'!"'CB;@+:;X,1QP0G9
MX&P?H-T')XX13L@)9[L 8(6SLZ)!8XL81=C16+#401< S'+>B1RGG)!5SG8!
M&KQR98PBX^@P>.$@=H-]S9)IT.$B1A%V='BD57%F H_49[ ?7H39YV( D)^?1LT0\6NVRT"T!B]@-$E+OZTC'L
M"3GV;-%_1KW=OE_O6[DBD+ZTF4!O+^V%]/6;+WMXW#Q_.GUKQN[B_?;KT_[X
MG0EO7OW^U1R_A..71:C7[XY?V7'Z$HD?;W-[\V7]:?//]?.G^Z?=Q>_;_7[[
M^.[XA1$?M]O]YD"R^^G \?-F_>'[+P^;C_OC?X_DGU^^9>/EE_WVR[OSMX9\
M_^J2V_\!4$L#!!0    ( &4Q44A84[28^@$  ,\%   9    >&PO=V]R:W-H
M965T"?FN*@#M?7+6J*U?:=UN"%%E!9RJ
MA6BA,3=G(3G5YB@O1+42Z,F1."-A$*2$T[KQB]S97F61BZMF=0.OTE-7SJG\
MMP,FNJV_].^&M_I2:6L@14Y&WJGFT*A:-)Z$\]9_66X.*XMP@#\U=&JR]VSL
M1R'>[>'7:>L'-@1@4&JK0,UR@STP9H6,XX]!\^'2$J?[N_H/EZV)_D@5[ 7[
M6Y]T98(-?.\$9WIE^DUT/V%((;&"I6#*?;WRJK3@=XKO$ R$<":,?G! -A.B[A'@@Q ]"[$K3I^(*<:":%KD4G2?[G]=2^T:6F]B4
MNK1&5UEW9TJAC/56K-,@)SA)(<8$$%4B^1) DZUF:
M/29SF,9A@D6(.TE1)RF29H8+9*A ]OTT5ZC "DDSGCV]%9+F_.EAF'DF9-(/
M'.3%#1;EE>+:N#$VL8ZSZR5T_?2 %WE++_";RDO=*.\HM.E*USMG(3284(*%
M^2V5F:[C@<%9VVUF]K(?./U!B_8^/L<97OP'4$L#!!0    ( &4Q44A]I\;"
M/ 4  *X:   9    >&PO=V]R:W-H965TX(D6[*<(E2%^VVKIN9A]]D)3J &,&L[8?;?KVT< D?'&5X".%^W6GU:
M5W>/2?HK6\=QWOJ]V^ZSQ_8ZSP\/G4[VLHYW47:?'.)]\9_7)-U%>?$S?>MD
MAS2.5I71;MM10IC.+MKLV[UN]>Q'VNLF[_EVLX]_I*WL?;>+TO_Z\38Y/K9E
M^_/!S\W;.B\?='K=SMENM=G%^VR3[%MI_/K8?I(/2^F72$7\O8F/V<7W5AG\
M;DM/1A]7W2W"
M?XZR>)!L_]FL\G41K6BW5O%K]+[-?R;':5SW09<.7Y)M5OUMO;QG>;+[-&FW
M=M'OT^=F7WT>3_^QHC;C!JHV4&>#78J^L6!B[A2W/-# ES38R8E^":&;N,!\%,
MF!M(VY0QX34S(XP2D-H_IF;QYX"7+A(*+I#'"\6K''B74>B0>_"Y![_RX%^&
M .GHGQ!;(?L*L08N%%@?/ V))QD -"*>@@!D'#-/&LIJ0CQY&H2<$DA:
M&$@S%S(VP-'F0IX2VH.R<"D5:@.A+PGE7Q;AE;2:2ZL=::5 ;4^,N
MN(R6T*LA84(HD9'+2&>4NXSO05L3PD"WIBX2&AA\,Y>Y4]#UNF7
M,PDN242AX7(:+J=QY+0>I*]O2)]0AP&!)(H^))!G)"CJ0@;$&ANGD.^D #\3
M%PIA0$R)'R\$/S,7DAJ8.>E8@"6V8'G$*6_)4J2YI &7-'!'*"Y&_8"H!B04MCBB%!WXAY7K#%O$M<([DS"&C#ED>%^L,$98'/J#"MNP1,+L]224J)!
MYA*CQPA!A(;QW*\A# BG&(XY4G/,A[R/&,;$;F@5-_X-[ARY&Z*#03AK"
M=/)49)= DZ,-72UZY-&6QU@[ .*:F%"%2B4GJ'2""VP
MND<,%;9 M3)8 0P-O-#X.$]/.*J4#'#C,J6H%ZIB2^%A,3!4:55X]K >6 94
M&/H"-Y8+ZE4KZP=8M$N"FJ X,^C0-JR9DA_GGZ0B\X'"XE!N9,4:)(VS-1E0
M5 E9Y%Q@<3!42J4T[F%'#&TJ#NHU**2Q(18'\]I0' 25GM9&8JPSZK6A.&BR
M3''^Q;WW@@:@0U5DRV)QN*@)C+5:R::9H^$J07KDN*BQ.#QW?R*Q*EQ&AK@;
M)1 N.2/F" ?2F$%X5S8A$)Z*IJQK>&2D$:'.I&>!085)8WCOLF2M"=N@:L/U
MCG3O=Z0PJ*I[VU"<'YS1SBB4E3 X$D8$$J@J\1,(5)6&C;(R3[BEGE%7>.5'
M(3SP+AAE?3S_T$2!M)V+^^)=G+Y5KT&RUDOROL_+2[^+I^=7+4^JO&^&YWWY
M,)/D^;Q\-5/=3W^Y[W4/T5O\5Y2^;?99ZSG)\V17746_)DD>%Z&+>]UNK>-H
M=?ZQC5_S\FM0?$]/KU-./_+D\/EVZ/R*JO<_4$L#!!0    ( &4Q44BL%BH%
M#ND  "&Z P 4    >&PO?U:E/_T^\>FF;[W1_^4"\>\G56]\IMOH%O[LIJG37P9W7_AWI;
MY=FR?LCS9KWZP[#?G_YAG16;W_WY3W7QYS\U?WY5+G;K?-,DV6:9O-XT1?.<
M7&VXA:+<)&?)IYM7R>G)M\E)4FR2[XO5"CZN__2'YL]_^@,VP&OR_7MS6
M394MFO\>OBD/?\CO"WP"FGB?K?/PJ8]G[W[\_NKM:UB#-+EZ?]EK/5!ERV)S
MG]P\KV_+5>O;=Y]N.CJ^A%%7V0I&N\P_)_^/SMC6N0?_LGSM?N,ZK
MHL3E6":OLJ;UKMF*_^.__;?8DEY &TMJY\TJNP^_OG0V&9Z-!Q^K_G*]6R3]ORJ=-
M_R*GSA7_+6P*2-G\H5',>L>H;QK/*J]=C[LFOK91H?\FU9
M-40]3=:T%T >I]:32YCC?5FUR.1M5MWGR<5BD<-3\,R2G^_JNEROX5C<-.7B
MUS2Y>_OLU6V6>30
M,K";.N0=[SIXAV8.XZY-S^H:FFQ]F]4/=/@7^$O^UUWQF*W@\=:#-P^PUF=-
M7JUA)(]YW:QC3\$Z(H^MDRI?Y-#4[2I/DTW>).5=DJU6Y1/.KL:_3@:#*75\
M,A^U5@V&L24R+S:PLJL5_;Z%I5'MUM3P$0-([JIRG61W=\6J@$5NC?D*IK-I
MRJIH?_4JO\MA]99)DWV6!8SV^F/S "2VV+O2'TN8R8%GKBNX@"H@&%R8W*Q"
MM,L?RG+Y!/30VJ=MOFBJW3H!@LLW=7M./-8"3M[FOL#EV3.OXS8B6>Z@E3N@
MC0080?(,;&7/*NU;G0X:E36#[;N%/6PB&V6W?9L]TY[C F:+1;6#S=OSGFE:
M7JN3IMQ#*>H,+//;UOPLM50Y4-2NQ5)]*MDS*I]4]CSXMMS<=X_'_W;_U#Z6
M3[A]P*;NZ>;??Q3V#$DM0H0_\!*L[, .+L)1CR)7+I@A,2\#00J8<;Y9M!]&
MP>^[>ILM\G_Z'4AV=5X]YK_[<]+::N3P#^5J"1?3[^DH-JVK8]*;]+])WD&/
M&; /O!R D\"%A/1W79EUH);@ED3^DERD0&I5 CP6CLQ)O]>'_PT2./-)C7=)
MF@SZ_;3/__%',*-= W17_"U?_A$8O/T6)SIL/5S@);RD+TMW+?T1V*U]R?QZ
M?U_EL-DYK"Q,;\D"'XTLMK[NUCLP 3.BKBG,!^?I;#9*9\,Q#6?>GZ?SR2 =
M].?^)%)X=)Z.S@?I<' NC\[2\72>3OLC\VC9??=>+)<%S@FH:)L5RS.X0!?9
MM@"J:@NA(,/L8 =KGF'6  G5#4YF-!^FD_Z$NG=_>>.,\*+=>K>B^[SD(U^N
M@=0>@!T7CSFP4O@[3TY795U_N^_E97Y7+(K6L>:#41]!H'*$W,&A:1SSYCZA
MY/0ZP[/]D#<%2)'?'BND7-CKO_7-9K.#<2Z+QV()LG-21<11.FN'#N!"'<"M
M/8 TWZ1N'\"OTUR+Q+]JLW$2^TU-[CDR7];NRSE)'7"2_8\=7.'HX_&5BPGP
MZ3X)OH,W[#TPJ([D?!V!I'OIG?XK.?UO\?1_B8#?DI8_L+31>NE[T,J7,)HM
M#!<9H!%+NA^L\KW/_0Q,(Z]!/>A\XD.9K5$?H^N'6!_>KR"(=KXAS.S 4TX.
M[7J"!8O]O72^NT7-#\>=?]Y&9>9+6$+<2ADG4$S^>;':T8;"Q\L7!;W,;QG=JEZO")DU9:5^[5!N1+4&A--X>^WR](
MVZ=?,J1]JT OR(/1YX2CW.9W966E"Y#28V,SWW7-]7W>-?!7J6F:Q% 282Z_H>R!%'N:A*I%M2HQ;/J/+R
MSN Q3.JG;%OKEI+\[@XHEFP3_13^$V&YQ6^Q"QP'=H%+7MQO7"=H"JU7=$H.
M-WYZ,IJUR/'3!FZ<%5YS/!&>,W:6/6;%"A?R#+H](T9#&"]
M\*=,YYC5QAX[=-+C)=G76;6!HUD[Y:!U[V1UL6C3V6K7M._MGV&9'_!NS4 @
MR>[S(X29+[R2OU"\?2GA==#N<805>?D(LL%&DQ;91-K:MW)H)GP#]]?1QDG'
MI+,%7$]Q\\WREYU8%)%)P'55@NX. ]TX3@*?XU]DI]Q6)7*C97+[K*Z)[O9)
MW#N[S>I\220,&\_780<;M$:,XB#'_#Y;LGFEXWLD*J!3LD'2C8ZKJ(QG>^TG
M78U>/F2;>Y1Q80;KVWRY)&VQ@B91 &B++^YQM5ID:R.N<(QAS0WYRXR$G?/<
M[JK% ^P,;"J*@$Z*[.3[G[F6V=-LMU'S
M[]Y76E*6DKTC-EZ@Y]6.'&X@LY9U$3%!>ZT?9?0GLVC""V_D(EA:;_^CDDNG
M\P$6#/[@ _@R4=1NUJ[FMXLC-N$-- ;\9O]&5>4BSY=RDE&Y))L(+-)JKQ'V
M \C]SY9]^L_*W,DFE:QR/ 1[++#^")I#!EN_X]HW7=-5L-5;78@7Y#GM(,/H
M#OICRC_GU:*H:5782%!NCYB*7LP#DF7WBUJP;,DN* PGHMNR;4UN$Y(BX#IL
MFA7=<6[DV5-6+8_C!7='D ^SX(1LD$=ZW+[/[XL-BE X*'2JM!@OGO3X5WMN
M<-^R_9K,?\?>Y20$MO?$-W4K8TKRK^_P?JI:T0/:#'/4"R"4)3^1T1F73IEV
MK\6T>RG'J*L!;5CEBR J!![S^BNVRW8^*_;2%%0RM8-;=M5G3:*M.W:-41+MAAE;!7@$Q [)*P2+MMN2'#3@7C6N?5O9@42!/R3'?)4]$\/.2K
M)?&^J'[\PF[XJ=8J=3"E-&[JO#J>^>E'O0T]5MQM;<.Q_+KSP6,6 >]?DF?K
M!B2\QAJ0=YNBZ6P 6'92K+?9PK'D(R9TU.')F=,$U-Y2\P^?G",;LNQ GN_D
M!:TW);[$$NX++Z\.BOO-K<9WC)CJ5]R0=B#+%VY(JZ&C-Z3U)M]7XF-%-I*O
MMZOR.<]EA9PN SW\II>[5ODW+&@K4NU+%[35T-$+VGKS9K=>8P08RB7%_:: 
MBQ5#"47KQ+:N08R)N/'__&-UGVWDND@3)^\8(_/9N_(6[1D4!KF!!3G]^[_]
MI_GT[__V/Q*\DAYRZ.\_42S)-L_PX;[C&@:=W1M/#O25
MI<"NL34-].#Y\VER@V2W/Z!'S>2*$U3?Q3[Z;'\[O>
MP?U:)A^*14DOT_/P;?)344'_R56]PBYZK@N95WU@4FA-@%TK5L\);L)],OXA
MH7B8CZ@"O7XL5SO:)1S.VX^O<32@P2X>-N6JO']6_66KNH0UA$.'J_L$74,?
M*Y!>9(^?0$U=X1XO\]9J/N#82>\F^W>CE?/8\%T;$KX$[5)D?S4)6[^P?E/ I-,;SPKZ^N::9D^P#A2+_[ET_OKI,?-T##:_CZ[__O
M_^PI,7OUG$:VH,JAFUU%%SV.4.:;N$^WYF20*OFYR0.Q;_T;7+BQTP+1##@##0B$R"I'?@/S[D_DFYL\>_=L>?=RHGJKME'L8C
MA:9V*Y9/Q="#O<)?'J7O/8Z*A+@);!I)"!?=?H@;4.?W.!SU@FH45B#[!6B@
M>3XKGS9!'TGYB*SAH5@@;[#J=\WK6JX\:GF$5\@*;,W1.0:G%G(F?[IZ71-M
M/ %UYMA<@30-*T6;,@>T9N5;Y)\5:S1SL.6G(7F\;WD$C@'&KIA2$!ZJ 2C
M8Y-LE:X%4"Q665T#S^9I0!L8W(Z_XG2,+7"K:*='Q$.^\,K>'AWD8]I#C8["O6.95'+E_@>J H[)A.A;=@V8'9^N/#]+D.VD^?:
MVIN2RX678$>"E1Y_12'F.(,@[#'%Z*S01V 7DJY2D+U%'+%S3-$L>;?#F*S'
MW!D$\:^EM=%B>(G:<8R\2_D3_ 6V@1Y$1U+HO=1TN_RF\#C=WD!6Y&34TMNK+NL,*&!:U*]
MA?R4AG$O8V3;MKN7VVU'&\!8:4/THO=DES$8V(H1358K=& 7I!
M5\ #\!5]>LE!C]UO&M@*X.6_T+DMDU]VRWN;B -L<4?Q*GP+ 9V#FK8L\(H4
MX^]#J=OM)=:23K^\5I;TR]"TCFRTX""/A^+^ 8;!45MPU6[R9YAN]2L0V]T.
M7?W8(K$T%P5E/8?,\&"+@0DCSWFHX)RM.:,):(M$I(Q9%%X'I".(
MPM-+.+":1+,KYV<@1BSB\._K#F>$GD_G4-4E@'=PRR&:&CZ*FF]#M IC5>2,
M"T&W2M=\UQA[T<"!\V?>.>/ 72M^..)$UGYECHUF,"F->:]+5ZB3&1?.5YRH
M9+&KY429OS"6Y27QJG!6Z&N@%64:"*))45EH"B1@GB)?J89<-9^PK@>SF][Y
M_>NNQ,>%)/G*P D1?>6H;9I?*YL*Q(HG]]A)#WIUH 504)9
M]'>;J)EVVR0\@+"\+SI#]N2QR)]$^4?C5E$Q-X9HL!4H_4#FPDBL17M";P+I :BT$9[CC<
MN[G1R11I4S0:?2AQ8<3KX4#1.%+Z1@XAM(+'#W5:9*(.7YSA
M\L!I!5*I0$KL)6]@)]8M47XO:XB1R9K!LK7W(]0SR#<^I'31+M[2^J^)7C,FCS<1;'WYIO#GC;872K,AGRVC3)OH*
M(Q= )B=C :H'L26E$VA&XJUN">N*8\#+BJ\%:4_('>__>)-R#,QPB 9@0OZ^
MJ)6/;9&_U=ASA5=  AP+4^1@-'N"UY)>8D,%/KC4*W+6.!$OEIUE^+=3V%'B
M$4E>1$IRE[&L#M]CNA%=@U8-3 WC L6R($V=; E%M3P#*;[!V8"NL,*I;#;Y
MBB7O)7 G>)8-$4I1.BS[&K8N#"C/X A8OF.4.#Q\L 6DZCIQGBAG(:J+D:"S
MR+(04X"AE*M'/.%R&-TUA6)39"62;?
M[A[$9:!G.,_ /U=X$.590QHT/"7?\6,B3 I'(A:6H>*UJ,HS5%K+=;% PF3S
M!PMRCB' ":/UOC,KXW37XD[/(K^#]95+;;>!;M"@@^*_,76I&4D32NOV=*'4
MK;.=FLR<9?;:-@IBWCU(9K@0Q3HW B-0%-P7!;I,D8@I! 0VO9>X\)TK93.Z
MQO"=#RK'3Z^ F,,,&9O#94XC]\964"#Y;?9,=";&+2UL*PL7A6K8_FNQVF6D
MQ@%OX0-'$RJ9M:G!L@BGN1?K@\B]C)[(EZY1#[-:KL@".:Z1^2H1T[06B:T&
MFJ28B)@_1K^GT<(=)78%)I:9V]RC%#Y@AXH3O=J14V= -X30M_;:BO<--
M8;V #M-MWCSA=<^6&M6U.16QB?!(X2SDPG6MWE%L]/K9P?/,192&[RN\JX 4
M=PNSXW0 @?$]&STX9V4!14BO%7[$L)'GHY[.!HY_B$J'MD
M8UF+B)#>\KD3(_-&5DXW+]ZM?+:$(\;I ,BR)B:-RZ7LH_8>QY6ZW\!=C68_
MB?^/V07,+AORMG$M3*82SDLL'I@"GSH,S[DM=XVA&(HFN:/ 3-8R29"R,A;H
M+"0Y^F2AM/0VDV7R:BUUV[)"C@
MAI@BQ]_DR,9(@K(CCMRS/DG)B,@FWH14:&_D;57>TO7@$^(]!1C[V^ NH?PS
MQDC);AIU=;=Q6]3:4_,J;[D;-FSLL=>[OO:4K<6[P(,!_R^_Q,UV?J4;_+_6
M[;56T%>+DM+W$041#J=4-5!FF8!1Y:S5'>G+G)\(5-!=Z
M :B#6PP;+OF/Z*L+MR!YF10?CN7K2.X*E<+[/:HNA4[(T'^HNR?.;U68%8>1
MWK$RB48'NBE["26"^:(*LVV*#L@J43^EW2TPJL_&R"D9&O@]FO:*[=9XDM$@
MO6)N43<2D0G+&0R_Y?V$V2^)W7!R?VVR!.YVU6UA8GW-U$5E)@;(GLW01""]
M-%6VS#%T$%O=;>_Q3V2X\,LZ?HGZ4]=!LXIBC&!HOV-V<[8LGS:U";)ARQBQ
M#KZ)R?Y^6Y)9X'#DZCW-?-'4WKC%#H:3XG(C_4BB)
M92$RJ#R;AO#&00H1<_ O<\KLM:RB-
M'@S>4>3NY5!HHLS=VDQCMS'7>K[44J$5;?DN8"SL6FA(R26Q9NAL!GM#"[L)3%F4(Z44D=3(L4LC,,O&@F[%_*EC
MUP\OOEEC"GNQ5L=>X@'UN-LFCM]C>#9Q^MM=L5K:&U]%UULFZ(>$U,\UGOZ4
M?7)H:,>EJ( 6Z&BDB8V" \JYY(A@.\0!&+P8<3E.)YD4>=.!Y\% O^3X^
M.,L8S)4'+.RIK @# +F/?;"7_+QW%BT.4YK@B!:3MB,W?>&(KCY2,!*, W4!
M3_[D? C>.[M4>&5P3\H%2=>>>'*?K7E9>UA+
M?B+TX07C"F?=ZR(I3WP33 )QLGD((D'JMV*JI+K :JNKRP4NV!?S3MY.8@Y&
MSV%BYAF9YDG40=&%G"A*?RHP' 5T?1@2AAG]GR[.R @0*V(4RH142D),IH4"
M4&X6X\5@R(XX9YTM26ZFN ,=ST,D)V?&')4G
MM _YGL/00XX
M@G7%XOIM&I9Y<%JN&V6CL*/7W7[:VK@^2[Y(NL*ET(>0*KI?[^I&@EP2E:(E
M"V=V^ ,]H&C59P=:^"19^EBQ7\QTQLB=H,S*04CTK6^/6<01*UAU8*:!4PTJB3!T
M$@8=:QMR<\=:+_NSEN[RT1 3O'@<"=2CL&)[4Y+B >B0
MZ G0&)PCDIHJ,SQSLW@7%T*V:DT1+.P5GZ\R[S4W8M0<(PDP%
M@UN)-[DD-7MN^,*"/;MMQ%QD(H#^5G)J$"IX0$(2JB=B G:W+DR8SD+B"YC"
MMF6!UU2C)#"Y#_$RSI9\\Q:->&R7I%_FOE;@5D)9_V+'E])%C:!:^0(.$KD-
M%8PSL$LE0CDKHQ\FD"EK-?DJ E 0#JMPS,XR TU^UL:Z$@L :T(&H84,??A<
MW8!0(\<:1HPAAF@,I,W%/5P]FV#&HF+9G39H6V'?%'&.IF(=:D8&2%F&!4.A
M%ON2CDWLDAE)@V&(,.G26LPD,&)7@ZZ?)MN'YYJHZXD",8G@T)RB#K]HIL^M
M&$:V8[OHZR0WX=D@3SZP/Z-VECY/EPM6%TTUALJ,8Z1Q&LX60S#*7:U"#M+ 
M3GI;EK_*;436#[>CL% 4LP;KB587L[\981?076;:;&EZGN!A>D[9E"GAB
M-AW>FWX88>51E;Y]WK!S0,4+:HG3EV=;)H\ [I+V+<"4=+1KSIJ(RY19Q'%Q
M02^!J6XO.I$Y73Y;L*$)9K.CD9%6LE>R$X7NW".JCEJ0&$/QM0%KNHBK!:%;
MR\1:F>N@P][@<0'SK#!P^,OQ336G0M].5X;?UQ05[EP=QLVAW#OMX YQ4RB3
MB:\8L5N+?)+V^&28%I);XS2+HH]%3>N(/KS"!K4T!2&!R1[X,[>V;$/0O>1'
M(GIH- V&49!& _O!)(L7AN_#,A*SUH,7UG@9.5;1T^G9-SQRHXNZ?8"4 19/
MDK#6-G61H1*X-X,BY.*B%)9;ZFW6_1EYH-C<51G?97B.VV!?E@XQE*E<<*!]
MUQUJ+P 2T+34 E?)1EP>= 9 KLQ7Y59VD-$8F+3A[&^([>?6VM"24C L4+Z3
MOIS<4J*H9MR#*S^7AI@>L%A,L7(MU"97QX:SK5&(9@'1QN9:=$!CXT!(6%I^
M#&4U_D;;*&P!AM[Z=W\PZ) ?[D%GUIS+^%,BNO'+B/#2WZ;EKC+3 *KFU BX
M364F:)R^]_.#M/A,IZ22^\E-3_CKTA=[V:UZY4RV8C&^"HVX>TW$WAV5>9%K
M9ADZ[S28O/&3K0HS6/>^/"]Q&!\L^W+
MKJR8\=O[8Y^WOVC+(R_#0J1#(B,?>L=Y[KT;$V'?&CB2))X2K]:2I:B>)$[JR+*'-MX-\7_C%^+4G:['12HH*D_O
M<)X,V\QB19*LF62K)=[Y-_F28!@O_00U0J2N:Y-A^.;RDG)\*/FWCHR*:=&8
M.)RCVL@C#FZR0C+!\9$=Y&\H.M;%_4;BEY8%T&A%DL#BV?6#[6"\H>&M]SEZ
MN;8/R&9-#"**+-K.TF6/E@1+%,UQB)$-H; JF^6R YPS3]O196A
MQ!\RX-T5=PTR>#K*+ G TA'COZ?4G:7IQJ2OP'4,R@-0WDKTB@:M@N6:+A?V
M0'Z,T@$)J+?/GE@$YYXB;!M*ED,]84-2/9-Q(G'%G%QIL&#.)=6>5X1'U1#M=&^6@;SFVI/,TOO(ER4S1F=#J
M510>?6CDD64 '0B37VX]M[F[9+H8;>!=;,0HS&X#T6/OJSRW[D7RZ),%B07B
MV#S(E$=-B"C$-GMEU26;.DF_+KO1B2TNFU+2"T FJCA5#\3WAE/HX^>I*W5 
MKG5KM+61A[ZGT=7@X-A(>3TE[JH4-IM-HL4>":WV"E=(@HLFU@^KJ6^5
M+7ZMH[26M/5C\36SWLBI<=:\%KT$6WXH?+R],$9:Q/N655='PM$P $]M=I((
MM'&O92(36W"('22GK9%_RQ!HD7 #:!GQZ"EZ*L@.LEDY6WN70>JFX8BD#J$5^-%4;]L#&0\X5L#)Q*H($G+4\]+MTE2O:C6CF1)3[5)[53;YUVZSV!>,J
M+(VWDF8.+4V*^R/LN6/QS";5_ZM6+%7SK&E^;1:O C#MZLA*"-?#<6)I89IQ'=$=GB03GI[)3D$1_\RVZQSYC<0K;'
MR1.O47!9TDK@"]9P;E=*/="9U^9WS.G7["M6C"P 38TOBQ>=0,Y^$I]4@)$3
MT0P+E4Q)3TL[N/S.8.RB@/R7[ QP%!USJ'*QJ]D0^Q5J9([?$L7:S3'?^QUI
MWS1XZSBHO/D13+C2I4(4&9HA[C$U;5<@G'RKID
M#)>/Y/5URBZK&YE@$:[0:O:_@X=G,;9$23+^1>A"RCK8DISZ0SRVFX?^8[GL
MB^>CHLB4172UH/B8.K#$'=N?79]]K[9)TC\2@9C^U0Z% QM08W*&IA] Z=G<
M%2CL1Q@SD0SC]MLOT:PO;8KML>",%8G<08_KDA*7M=BIDV1YZ9Y(D2,_(KD$
MK>1MTKM!MB\6!4S"I3WI_!3*H1>/DI_5HV/\?[ 8'V\5;],+9+&.)\
M[G4"\N#4'6]87D:>HAFEEUMPHS5ZCD 9/),X*"_RB6-VR7^^%%6<0E V:&^C
MHY.M.8I+]$4U$XX>DYTRJR>6(KM.?_^W_U 660S/5^D9#&RX= "^\.HS[XSX
MP- H;79319;CMWB])>B882NZD!TMF=H6#$J+;8UDT<"WE-/X!O4%N[=/#W#.
M-A6BIHHKKI,^?U6@QK#[%:\!QF-U$L':UU6QG/
MF-*L58E3?DUF3P[D6I059SZ8D !?=');"Y>RCAV+;3%R#AEYZEO^VSQZIT!R
M_!=I1RGWBKV09&<1C^:=?:X7R1#K6)B&L\2=Y$;LS+OI"\ZK$O^5ISTR[_0"
M'\1 +ABKY'+&TT7F0JE^Z)6.)(G89)-1%!8ZZ3QD(%Y:F_DGEXZE<.5CSE2]
M!I.KY7IM+\&SB:!!E[*\46NAH!W!EH4E(8BB)2#$'9L8 Q5^T&'DL70M"5@6
M"DPHTO@38F)W$'7G)<.2V8:OK2@-Z+O)VQ=EZ.FL$,K!J">#Z2A9,S8WC?-D
M.)^Z#SJP3/!!!#--""K*1K"$H"SQ;$(R4P%/8M:DCDN0,*,Y&0Z5'"A9L9:-
M8;PX])66C3K; @3'^Q&LM9B<]!F%6P3+LC3@+;L^D<79%;0Q:)-1V[WVB6=$&+2DE2\O>
M ([A3V]P;(R;_DXCZ;!$,K-]K8'C3229J8,:9BWH:+#]ETB:!?(%_RF3!AY-#3 _S(
MX&*7:,7-=D?0!'Q:^6WR^BI &B,8%HC:2/$(S*[I57LKDC9YBW*8XI!"/N&H
M&-D5=5J*DO\N>8MZ9C)(_A_&1Q)@)%P)SJ7F&8L23-[;ALD!LTII?U%E#1'SF(C+H<)9\V9:M3;,5ZYAF@ 5YM5F2NWMA0
M9,:D-?(-^X?M94S7*@6P>'&&F"C)%I@V03 E[CAH"Z=HR=50H26YGG&WMTZ(
MGR_@I$D"[FF>_=U'79!R-G MZ K?[N18H)BJD(;EAHJCZ[5CE92J;8V3IK&%
M))WQW$$+KDR_^_I(+#:E@:E+)?SF64-/NDA/%P<8KM%M3@J)R=<2QW30M3UU
ML:PYVL?.(AII!TQ<&D.QB7X8EHLWV:A!?7&7\:I'CAG%LI1J'"$T7DYDIO +
M.V;9@NN(=RI9)-Z3;;=,&XY$?((:&< B M"DN^$+Q*G+=_VFC.,R6M /WY&#
MPZ\*3C-JA>@2%(ECIONAX#"Y@$T=I=(<:1N_SA3;Y!
ME-L/]!UBDP>5ZE5^=R!EW!9WH)FRABZI(#KMG_QU(NK5#SGK0?J>5[7#-,E5
MN39*(5+WWBJ9.J7>P9SA*VP!")<')1@)/D2)=2?HL:!D@V2&Y"?9/ A19)44
MIV>SB6=+.6<&/M8 @Z-DJI"*.$7\=K=9$K"7LU/8[ CD<@2>L(8=)G*\LP8.
MA6#M630,Y5NEHM/"$75_LI/0!2AHVTIDJ,ZQ !RO7#TZ PPL++I$*\%6\-(]
M(ME.H8&(CEBF0[KX5B[OV'P1Z\9;0VN)0 EF)0&JGCIF<7&H' C='!8K69U_
M6A%W6-C$$\44-L&7F*J_*EU6HLW_V3&,6!8XX$UN+2&4A7 *B;DQ(
MM/'0GN<@'CMEPWK3"-A1F) MUA]&B)! :S4@@][NS)@*QEWE5_: =003(D1[
M0P,AV!TYQ>UDY; 3!XL>(!/F03EA\.:L3D76S5RM@D\91^J",&D
M9UG#N0Q.1?&$)DZ66QP_AMH_$.]5@
M11XG\&Y6G\WQ9W@[_F.=
M=[Y;Q]I-X47I7(_=2#^\W'QW!QW9'@S
MXV[6?7MW-"*$Q:IZ&20$;T(\C_\+P2+VX1J(D&IBW"/0$#Y:AL=J_'A/D;P.
MYPSIQ,YKR61%^'X?ML)*+,8CV>9*<>M @,6 (WL12V+*Z$#&Z20-DT#Q:8,L
M%6-;C;3X!A0=+A=U\\96+9)X]-QL VM,-$7C:+S'!=N(,TS2PL33TLIS4Y)C
M[1U,RQLDYU!5'#(IR:U#C-CM(-2:12*1L!9SCXN\Y\&'^-7DA?;VA>4"A1(=
MW0,G9+\1L8]R)Q+.;&G[1;BNG?$)C9(8Z'>^U)8FF-7):#2V;J84_AR?^VZH
MT72HOM=>IA0'"1L8;AY1.T_1ZF= )J_%>*!OJ(?8Z6(;"LCV=4'E1P2#F#1,
M]B##3!#7G!!][^R=!9,K6 DE5P%R198?\,"A.E.R:,D\B+2"O(;[DSNOB*AJ
MG8IG'9M00EM$OS'XPP8_Q@.TP0IA6""UH,O>[IWA\193@_W#3+"9>L/1!%#;
MNI3U\9 ^'/@(-N*!9SCE@9WU(I_I1,8O/1-ZD'867FH\R_6ID1ICF;GV1?'=
M]J;6:YGBGV/GQ,0S-.CUU?>^IU:*$W,=ZU=&%<&21%W..O^6<9J* ?M7WO':
MSX%HUX]B?0PZNS7%PCMZ9:$OWV2)UG7OCD?(Z H%R
M$85,UMH+-7,H0)).MI6"*A,3FSG5SJXGYW59%$!=Q 1E,+*_"X*CA3V(-;/,
MMP3+*'96X^G#,DAB[ $&@]ED<80MA0O22 _8@Y!I<6]'?-JT'H G<
M@5^ ^=3 YZ2,D?.QD"7^CHLR6TY@B\GH<):%*JZE,:<+&R'(]:Y\(W ' 8FW
M$'>+]D[AMEC@\_M=P5^6W7081J0$\-49+;U%+,10PTVBU22I8T>?D\A')$I*
M4XD5Z WK)M.T^&EFD\EX5#@26.LN>4G:79(J,#(%IJ8IO5?*V
MVKU>X-4#39#D_QZ13I#AL@J PW<>%E5%]4;05>OD^Q+IDQ)G+VZ^=YFSR_CC
MG[843(7/7]Q\HL>QJ[/!+#G]6&Z+13(;][]-L;BJ5*I-;LC5<2G.6A<78GDK
ML5IHRF@C-<6[WQ5RF^F"@?A>M!B2T3054OA/>?'54G;JD"GM_WUGN"A:RHJ:3BD>#D)
M:,8# 3+8/P8RX=(KG"6W]NE;+)QE8KNZ2VMYR?HJ_,W5L\\^IQJ^9Q?6$#ME
MY^RWM$?[RE&E^]^U\ ;)0[XD '?MGR.M>]_KF.I;W)OB"PN)REFYZIJUL9(+
MO!9LU<5+BI#Q4?_Q\HK5PEJ75^@L3H8N(RY/%E0G(WD$='#$/04=EDH>?D_<
M^5*7/+SIJH5(DBW91[TJZ;ZO#5VC54&W$#_&[BZGDT$5 -;SY%#2>B_[HS]Z-&FB'7
MP[ 14M\6< !V*!F]%@))KF%=;K!4.E4>7EC*P87A&NIL?I<2"U3>1;QI[W-;
MNR)K&%3$  ?H11!Z-5:;IQQGE"_/#*ZZ*\-@WFI5;K>[5R:;(4LX%P/(_YGMXU4HT,X/IP"\H;JQL3PC"!X4P+0-6XJZE+
MYM%H*HTM^4?O,AV8D"40&L@, ]V1DD>5*"ISB_ ;>-R"S_CH1;LK[LZD,8Q0
M$:+[R91;MH$1KTVY92J63.@[YA/F%9BJK14"X5:<(FLP%^B=9\XFXR0-JC-G
M,1U)3D,\O4DE9"=:[+3)@MD6)'HYQ87C^V?+! ^ PJK(*<#?I
MD4"OH6K%.G9MF2\$'DQ[XMQ$?E_K"MO&B?U8LKD%*1]+[08=*D T)-#;NJQN
M_9A<4RZE:KUKK??B>C7N-39]&@^* 3"@,3*S6R.;%XIMGK?$GV G*;*!G04H
M<7& BMDEI*.;:ZHN#S?+]6OK[X)&J#(]WSYX,?_I#\V?__2'NOCSG_"_YL_?
MFQ3#2Q5\03+X.Q1"KB]OCGFC3O[UXK:F")7_'CZ/843)$*3B?T\.=Y9\5)&U
M"-:&>!1BUQ\IN_ZGFQ3EGAY%:@MNI:[#$(,)2H7;[%P>$=HZJ]H']C16"M77
MA72&ZZP_MO>I';Z/SZ->,T_P'EV0DHJ!-L_>I"Y(-E7NM*B6>YLO*+#G(3_X
MJ"_Y2MT=AW31E65LYQ,K3Z'%Z,-B[P59<])RRRCZ1>B5ZA*$U'
M3:W+P.L?M?BUVH]1\G?)OZ#J]+JM.IUBO#A;]VI63]GH2&O_7M#^@%E:W"B+
MTQ;F0G$U$:Q=I)!MN4+(23*:3>'G<#J"GW__M__/.[5L,VKR^\K)K34]-9HF
M@_[\N"FZ3L[/X2>^9X;_*A@^X]>Q*F6R;'SHES@W4%7?R*R0^^,V021*O)9P
MD:!_Z43Q !#$7Q6,5YF\,^[4"X[H0F9P^>H=\PY==,"LL8DB6NY A("KS3SC
MW!#&T3E6\ZJ[=Y^0HL&L(J5+E\)
M&T@(0A7-._P.QP2XUE YLF-5P?P*THQ,JP2E2LO)MS 9)DR&H!BS3&"S;5"#
M^U3YNJ3 *=B^"DU#J\ 1O=D[5VZ"D+P8S)R!>51H%H%,*C7()!LZOXJ35X;]
MX3P)0A3V]Z\+'>\YT2(3"S6[@##G&4H[RWE@U8#'LK()?[N-^]O >]L@ 7;_
MN&9C\5W+_7,ZGE&14_ $V8AQ&AYE>>KYKJ4%9P:2MT=+NX<6'AN;TI[OH2M=
M,_Z)H+T+XR=C<[K"J[H*$]:6E!#8]
M.I>[X, M0Q"#Q]PRZ/T=S@9\2]LCR0_#\-]./E\#VPU"4@G@U$_2/0<1,]*MU.S,^L3@S1(])^0Z/_2>(U0HKA2
M-S-?^/H))G(76F?O:W=[0.\UKNXJ"L0M(&\G7\0#.K%BF5PS:N](Y0
MR5CH0?LJ5=1F7&/P@E86CEN=D!5W2?;T\,>RH8E(A [(R.EH.C7+=DOHE[[C
M=# >X=G#$(5UYJ4&21"3KY2[;983 !-S+TEXRNE'S;*%LCY_X>6LQK.SFUH,-I.IC,
MU7<;9TV=#-7GMUUFV9.DW^O/U)/+;J,H/?F1XW[E:1F[)[DI+=]%**E-T!8$
MWQZQU5I17 WB'"(%@\"EMM'M%%B/._=,V]P<0(GSH08@"UA0A."=2OW0%LAK
M4=C(0F,8U@2?RM_M>CKB1%:)8:E%;5P$59N]\Z'KJ@C8>2-5HA?&2V_E+JK$
MW42WB^EZ^9OH.E7M6F(YZE2Q4)73!>Z@&SA%/[@,Q !C-2O.2'9Y*2$;_+(A
M#9->0->NVKNC:\MHO@,9X7\B&W,%+;+/SD#BN7BH@5KF9PG=,FU<<7&=<=1V
MV+L!8WM8)'\C/8&2O\EV#/K+D8[[*?RW7(JM^
M>0>6;&C8+"!'"U1T'F<3ZMTDM@P+*8FF>I1"C?7Y#ZWH^4M%J-"H?F,J.E^*
MSJ1R&\)G/PJ>!5,:ASTC'72;[+O>@/Y42 T3Z[]^S#\WR?>K32K^Y?"SC9YH,>4W#"L3R;*7L%?=3&@_\*)""%UHQ^(VI;BN/=#&
M&JLJ>0GPSIQMXE3XR-66 T3,\JFD]]0+N%^1(G-@@SVW1B8T7:^1=8;@?:^X
M>ML4Z&.>[2\J;I5(2 ;Z(IGY1/>6AC'
M72R+#('SV3#$H'04 ,>HQYM?J]VV63R3!:G1CEK:V+T;2GY">>#[#^(OO-Y5
M]4[A?WA#MG1B!B8.(H>!8L!RN,).[A\/:%+UU]-_8%\;&G,;5H+I=K>QB?U+
MS],IC?QT]5IC)** !:P76BCJ![Z![[)%0="@N=L1&#S;?>E,XK)77(_%%N3;
MQ,9C%H+R(HW_NM/]_ARDX:GJ R#;J@F$^XL?,1H4 ZI'W?1QCWS/9Z,9):I(
MI*^;FNH[A9NM,3F5+.IQ(J5='\*Y=X/A4-$GSF!E+4$,]]8PR0@!Z.!1MH;5
MLY%#O*W[#P76IP*2\-@2?K V=TI=:&(N'):IUK"1PA-!K06KB5!.Z6IEP_ND
M&!3!A7-JFH]HXC*:3.RS/A(QN'$]&O(\4']FW6V0H&O8)=MX5!9$1QBFJL,$
M3"QLK6]E_\)K(6!0,<"NW?LU?U;A$X1\NGJ6R]';!LYSP.#BK=3"7>4ZE)M=
MOG30>':FI&#KVE1@92HM)//L4]+OLVF#"%9ST(*)'P7:FF56"5EE9%Z@-X&[
M\D;DROA@6EW%"0^K85L]".$.B.2R >Y5R/7K+/(9ZY
MUW'B_>%C+,KT3D"Z(7-_?WR\VP&=*J #=(,VSD;)9.(D)A2%CY0<60E'^SM>
M1*8*:.#V?8D\V26&[Y[ZOD/YL[=S)0(B8BFED)
M$W&1N-(2)D7O@*38(X>ZX_2HEW1*@99)0\"LKRB7VN19!39;APATICG[L'6/
MN1I7PS$_5O\7$5!1NR97PY(G13QKUD'.[25'*IQ
M,>Q];*O\1:Y>1LEN\94O%!W-- I/6*S]$$J3J5\5]:]*=(N&,V:N:K7+W*<6
M_1C'7BM7MD/ -"-D"YD_>KZYND1-:^4CN=;=NW%)4T"S.D5-2VLO%S,/R8>Z
MVA(Q13UGDG7:TO&#&9@_Q[MW^5 +'I$2\'%
M)7F.^E2Y'0JW)L&(\&3Q>9.^
M'<1?.%4"Z@TTAA626W&X Z>*9M(!1?P>R\,4Z$2!)>S5W"8OY.JYB93VR2,.9#1
M0K)-#-@HM9%MMRLXLK>F!$70Y8;*1-4$VK/(\R7=[>_5AUS,X?99^2#5#5)&
M3G40[^!BCJV'C#LBQ2RW^F.'ZF.+"EG,&]!.&G$](]L(@"P'XA&$970;E. O4,+*H4
MGN$=N
MR\LIAFLT/S]8T$$KV:/QQ#[_E.VK)J$$GY/Q^,!+\C!9O")CP+"S+UV3KB7A
MT@Y]#31T<#)'"8G&[V=LGC*&T--V:'MB5\@7"X:OW)7*X(O'C@*$QW0^Z6.P
MZW0>7Y31K$]VK-\J6QYAVCHL>KYOW=LAZN\B;[52
M2I/YG-]J/XO:'-]C5^V?+WDE@V.\N3;B:
M#7ZFKQC--ON+BME8-]Q!J-.JM'#&(IXITP,\#2
M +DK2*&[)>@X"]O.PD4FV>^JL-3&U-G19@O&JKQF.-%>D-4D6Y>SCED)+' 7
MU8OT35=B*_!&T/(5YR4EXTFK0P(7^3,Y*MTP6W;?!T'*MQ&H@O2V@'-<&>5V
MRW5HS;$,Q\-!J_ 0F2S9:NV3*;2IP"AX"P5X#F,"@.L[T$%IWHZLB:KA-
MH8(V;C<9+C(C8\/J!4[+ -C["/4K.//'ZTC!BZG Q6)NS60RAW\GZ6 T3S[M
ML2QB5N*$LA(I+;'58J0"4JN)43H"96>&>QT*:U 90_:4SF-1\0T=V8V^@X_
MOO 8I-QP$L_D$<"6&ZAQ4YC%U,7D?..)6"$D$45@B=7Y=5D THX[HB;)/-Q#
M;?4C:Q?!\L$" F] ?".F3J#BBDM9H&V,PP#9$%@K6ZC4:G]FR[4N6X3/F'H;
M8J.WW#Y6B,$5 6%.09B)V4
MK[:@J&A[7\"B,'8; 6[:B4A#F,Y9K#PEPJ(HUBTRM8Y+>1MQH^]+$VF+B&Q 
MK$ ,_T,R._[S9G>[E8\(0G#=90PG*RPZN4F,XJKP6%1B@U#1&*&!$Z80?VGQ
MJ'8>BON'2$.]=BOMBA=.1B (IRQ9HN_/"/VE+65H.8JEST#J;1>24/BS;B"\
ME ;RW/6.-U?F:@&)3M=K[8U#ED"IE*XW7$!\5"]B4-)=#V5DK;3!+@3!Y2G
MO9@5'Q\4_&O-@#GJ07=W'0!=^53G=[M5\I8"M;KUD^]WQ6I)>;=^ZY](8QKW
MQ7"-I_F\W^=_80-_[J@-6#_7!*_"KP_-Z\,9B/*C9#@!OC3BDC24-0";6I6/
M8G?A=P9#>6>0]ONCY'P^3RZS;=$(S&U=WC5/R.;YZ9D\/$\GH-W-B!UV5;R1
M]N=&"03F""<3"?NR WP('AE/I\C(9F,/W-=+SJ53H--W3X>C='!.0#)#8(; 
M8+_U=]LNL]5X^C!96MUI.AQ/.I;7KJ[-6.&%,16%7'Z*ANQ1%(/RU6/&O@&5
M(1?"0(WZG3Y35(2"7IU'-E,KY"T(UXZ8CX*"*XAW$R^XLL]E^Z7=CZ:!"VPR
MZNS="=:6]&J5?AN!>-$8CVR:=Q2EE+[X6>ZHGK)4W2O&1_Z\D0Y7/YD/@JF]
MT+?7+A[BK\>;PVG$DZXJ/":#N6,VD;1HL_J_M[5&2?&K-K*A88[M+?(PA-LU
M(IQY"^'%FP([M&9Y"N*U*? S.'3O_N^_)1=GE&),"*A8"CD!#9$\D3&@.@;#
M(UL6':1VW37?CB58:YX5J\-"Y9A39R74BT8:5'$Q\8)A[7!BNNC1I;$A\
M5#KH\9.G>.:?\VI1,#!?J] 9H\WF2Z]7*2XIJC?KA@1M4U,-8:F&PQD::%U&
M*8BU-5Z[BHA2#J"FB/ERY';M&NM7H)AYOW1<=TX>9COF1,3NA"_
M1$Z'5LSJ;)#O"KB 9P89\\V.ZH:B1QVMR391(P!Z$Y/],E:%+?2/=*R/\4X(
M%H@N!"6HP[>[YS.";#91S ;J>6F.I>N44]2MC55RU,,U9W7'H.S@60N9#B[K
M.? KS*!)1N.9O(*+- 0=XU4GAH:!D^D0K0B(2M4V2O'/@5_J:*2^__I<]JA8
M@2B_5LKJO=!F>U#)HK1GXUI.1@.WXNH$=G&G(Z$E+_9!
M\G$1:F.9YMIS+)5PW+Q^EA-209?CL'H:E#TLI4E("IU29HE]U+A8V(_"JI1Z
MZKV6)6 OON!^1;Z;6^];H;@2/SI'P7P$>LA;/]6"O:J#\V3D?6.";$\1_I!4
M /B)^*ZY1PK L$ ]NG3Q1\Z)J_"I!_,9WQM[AQW@4\Y',NQC7#/=T7'0$IIO
M,%)L7XC<&'C'<##83WMZ5$<*DU;>.@IOL@-=)X*F;&V[B@^\8C<-1GAHJ+_[
M3-*+2!;#RXU%076*N,I]FR/I8Q'G3KKPHPHHL\5 Z?(TO%.1A.(615/O7Y4[
M*1'G@']M3U%VZ%A]Z@>Y21WU?=R%X"0K#O)8-@Y+EV+]9XEG4(6%[-H?VIJ(/YT\LK%C'1;HO8,(CUN%&3+FI(MZ]",F'^T1VHG\I&C
MZ!A*5$=E^K&,M/#WYJ47QE;V(H.[W-M32QU\D9: $:VF_>.^N&GU!^QWG@Z&
M0S*CS\E^.@0%8#(AO8)M1L,1??#*!1?OY:R!_!@$BSIMW3&Y4 )4I@Z=G707
MJM,I5E;%ZV;I#%H&[8"*7_U\8VM<7!-<+4@A?HT+[WDI<-&MI6N<*H>&Z*%\
M&9KQ[#6QD?]\P^,"MMWJ3]\ =-7\!'K\WY#)D%2%_,JXKFQ8H[IY]K9M=&^_
MQH /,:99,RMV+QX_(K![&'?%1@U )OJJ"9U]\0.'AV_0@;$ML4IW](P?(6N/.V$/8)G.
M1J[1;+<(QFXSU/#I-Y>7!J;"!/[R!+3JZ0"H#N?%Q*VFAJ9*#6[I1ML>)$G7
M6 ,-^L*-;R\2NZCP_O6*;)\[B^XV+[P5-Q53+$=9R '
MD ):J8QB)GE)A\^LV;C@)N:5=PRZ.ZKX(MBS(F8 -!N\.T1Y-@I9MX$OY%:4
M+ZJZ"23Y:9+JG%@XZRB$4W ,,HC'3&/>LV&9XKMD( N4YNF(]1)/NNV2'-%W
M751$!Q>D,;%%2OE1?E]3N)H\E-F'/!%2EW8%P=-[X65"_K%=%W  [H"!-?G9
MB@YN&[+WM$65WW[-@78M:=M6WAY:2_[M=C,?%?7R ]G(M57\0GON4%(^XI%+
MXZA84>59=O1.E>L:@UM.DM/9 ,,HT)@SH8]'%!QSBL(3?CQ%#'RLG8D.",G3
MR)J8;WH$;YP.!AB5B[&Y0U .3V<8.#L*W_1#?#
M.U0W+O62BB'[?(4#'X>UU
M%48XPMP6<&S-B&@'FCN!Z,[$%\4.4?24%L(W+BMM99M(./TA<.W?@2Q;I
M(ZP4@I@2')B,GLQ-=A_TR7&Q84YY:P:]+J0N!ZRA6;4;]UV>\=$)@E)O4?2^
MVU4+CB6UJ;'MM>/H9 ;,(6]Y@+R2FYUU!;4IKEMV5D/%DCA$>;[M=SK5E;W1
M)QC='QM L*"3WOFD_TURP[/[0+-[;RC#(JYQV@ ERKWW[K--N:<=G>131-?^M+F-74.
MRTBD77/I:KRS08FQ,+@M+BZ7? 7HL\] HFPUF\KO?+Y446*O($.]!8ZXM'53
MJ48M"=W/!1(7"-.FG#OQ;OSP\6;AOHM,KCJ^
M$<0JY4]LPWM8=(]O-5Q-1=*B71L;*HGLY.P.E*)65P[WR:RB'N&-!UO#5C\N
M-IR;/X37<5<&#-AV=V1/E-U;U.7*5(2AQ#XQ)Q887"TA_Y2WCX$BQQTOD1VB
M!R]OZ6<.+R4\4@]%7B$T?/1L'V!UKH2])!^;=#\;*>X[W,C7::2I%0WIB-!Q
M7V3FF0SDWZ&=&8<^[//4<^ 7^-X3_
M'Y%_1WKMZ8J+ZQH_L6+Y'8S.;92/3'$5E//Q+X4O+(#[.C:&$Y-2AY9\^@O#
M?%Z9O-EKD\EZ318QH]QV0ZK6VI#LA=][F=J=T$C<@25;'RJ)T\RK_$B,(K[0
M//[EPQ(=A4KD>7XT8XQC>B3+6K_YU:1B4AT[I]L+S@>^(%
M'[6O12,]NKF%!;7)>>Q5A3! 6W40XD^7V5=(0KDT [S@9&HUJ3U?\>I\E]S$
MAXJ>JO/SN?K7\0:UFM\98J4F&A>G#F^FL;DI
MH.9/O1NLM4CT]6R!JRD,+XNCB?UU5^(9E=A).NUT=#).G^#/Q;5+:B95\Z.Z
M89&+]@738E/3;@,#Y"AE!A3BLT8)1GBT#8KG&:S@&=EY]41B
MU3#WF&[W-J;A$2P0P_$=(/M[:WG$*^01ATET_R'\+T%]1T\B"[<7YQY@6-2%$_A'9 ?2>*VFRQ]MT*^UEQ"B!%;PP" A
M8DC4*7";C%&:8-KE5L_7#-[YNW[;:K?(W'5 ^^#PS/5"V%4ZZ!4@&PNFL;?)
MQ/5DRP$/!I?DT9X\05[1N[L0)8_X*&MYKJ87+:7QR+4,GGPTGW@RP-]7G2':LS'& 2,+4X
MXQ9'H^X'7=?S7O]\=OP$!\&X!UWC'@;CGHT&W0_JX0S.)\UN>,%A!R182M]S#O=PCMM5OKQWYGN_U(Q3;%NEY3O1YJ5,#SM=
MY \]867H&S"^P@]FXJJJ\)62E3N,?1BZE%4VMQC)&RW$2U7LA=!(;9OZW1!>
MRRY^,%9K?Q8>N5_IIEJ$C&YMW;;&[H%,BW%L&JX[TT+(X#"6 EVZZ^(LVVQV
MN+:=8XAL]E']YW\ECU^)S'99BHD=ZW4E/V*F-+S[ 5_!"+VW5]__^('"\[:K
M';K#0"6X1W.VM#GLS5!T$CQ?&KL$FYF(D>ZQ(HH(*L\.-\1SQ$'K(^;GW3:9
MZPH84+'%<,8C5L8?GEN&/DO'<@*VMDU1EAS?M48O'3P7T1:@!VA^A'.8XSMKCDMW]AFI .&EQ+Q
ML0XZZQRJ R>5\0:F.K9<(!39&8]U00RM2FY!,?X5 T/HYN;2J!331*-FVA">
M:>!2T8JR4C-HL>"#=_&A'<$1=%^;*H2ZB1&7N4^.,R*YB)N][@HCP!+GN*[R
MQZ($?D%_O5CCIA>2;^ $3&;X[XN5:7J!&IA.\-\7*ZOT C4P&\^H@1>JE_0"
M-3 ?X[]&VWC+POQE%QJ,JT;Z&S%ANN &K-F,Q2%?R?!1UIEL4HM$0"CBA@.*
M.;3+=%7E85SS"<*5'16_IRJ2Z/B]R3P6OS<8AA]3 -]DV@K@2R6$3Z$_NQB^
M5 3RAK04C.<^/]>(-VY=3@8S+V30U7%T2MF%5LI4N1Z&]\9K] '&0N<^ILCQ
M3MN8N._Q9K[X@>YC[T-=])RPO739SY-!WUN9V[*JR&N/*0U6%-X[#A^U8*'O
M:KP^/S=?WM7Z&..CTDKAA1Q=TF
M(K1LC?SO&NHE/T95A/V]9U50D,CY"NG&224Z.+'+#K2Y(V)=ZPPZ$W=QC:7HANK('1Z1V8N
MD%@QNS9YE;>BZ#0<+>!&0=2UAUKV#[N#6D@X+DCD16'.Q*TQ$9%K9P\-V6ET
MD=#^(1TFH:Y-/KRS78!<.*K("QQ>K2"W>LE;C.MEWP<^#,+2V[QII%:@R!M>
M$$N&5<:5?807Q?O@DC#/;MY& 3=28"#G;$"5#C0S1\];JW"&;#@$;,,!V\
MRW97;4LIS,/.7I67W[(P,$H-VG$7T*N,A
MJA%6>;&^Q?*4S"O])##O CL*SUUO5O>R\#92]*KM\7CO4;B>)PG!0,$/_Q:>
MC).),67&3M))0@@D\VGHZ_I(T9**480/B&!XP%MV3N:25F-RW0R]G.K-8_[,
MTM=EA6A=EUG=F"+3'*M/*=S5EFGF\O**]/R&4_ P^?11F1HE/)X2PZA88QZD
MD\Y2O,),_U*N^RD.CMC0! C)PO0MD[K!SV@<89V9#04K2$$*PM53"7?8""Z 
MM***VS/M?\!IL+#N#7J:#F'0)K5.C8I4GP"K#$?Y6&1 \N]@*>'1:[F\:>],
MM$"CP;- WL;4%S1"H>(+2CJT,S)(F&;J_+Z=.HET*X.#9P7N<'14P46&95KB
MD#G;DK*(BA?A-B/HO(RM4$8JTVU+$C"FO14J+AQN9!EU*@^M045F*X+@$#BR)ON)H51;X (?KIZ'=8W_'WMEL?655[!2*7H% T+0]#8!T9JHP/A
MX=(H")6JPD,Q:(N@WGGQ8;SENEB@UDF>*^5SP/&0_%Q[K1J\:;H*6'.FDTX;
MHHHYZX.*)Y0[X#+/F*\ND8ZX[QON=J,84AHY_EPCSJ]VI=*]E-/:%26S#TL.
ML44H9:3:NEW(_+CC::L/1I(R.4D+0^7$=4,7R"U<*[ %!?Y.T)5ES@]1L8N,
M<^5**I+J.10=-#*V%A!/:HP?NY5+_0R>L8%[SFEICDPK6%L_X091V[KR%AV/
MR@0>J "H3DT:/34%1^,A,!NS?-H,*FU(=P^<]C.B'SJ ;Y6EY<'>-\7RUI+/Y-_92CM\RU-O(>RK"
M/L5]1!3=]F9R2"OKNI'151K)Z]:Q6IOPI$#K1F1!8E3\Q@WF??B_QR+K]@P.E\
MP"EB7-L-,3LF%N49R]M,O%*ZO+_W#/..TKH@4 D1>I*DG;*AV4!G,CE^,'RCI6#G?DJT$M"U!=]%
MP'"N&V)7%2I?[-(,E\K0=B6[M6I)KK>K\CGG6P-XAPNY_YZN-R[XV+(]J6AM
M-._J=S\(B5WBD4SA ,""23;\M=F3 S8KJGW^[\F18XO9&(7QCI(?UYOB=D?0
M7M S,EE\Q[K =L!G*V&2N0MWL9#]"ABDQHFP_9"2$> 2+1>_:I=%8?O84A]:
MFEB3IH,Q;/2:R"08M45_XAUC\:1)[JDI@;X!?H>+24^U/P'QK#")-UK@(W2W
MFE-G>0TE,0*D"E;BLN5C <(7DPX"3)D'1?0D3ULW3D/C\CJ'YP>62.4M>(>5
M9,Q=Q^HIB4">C,^=!/ /-Y_8VE.Z>@UVXE[$9GRFK?4+.[B.=/!K_BS*J$%'
M5_O=2V!,B)O3%(W82V@:>:[E6;=>&MA2+9RG,68):@Q4N-$6EG#U\9A>1V()
MZ2778?]8DH>5BW]\]X4$.:DEO2]1^,58LP 3PN,6FE=I>&@;'8!/I]
M3A=TOX]L,1B,%A'JK@9G@V0V2D9S8/:22XF1IEB<6C4$]_]HS)'^M((7S)1\
MPME?F%3B6X5V2"7EWR5G3(F[Q9U1%6 ]WUNJ
M^T1'_&>#MG$AANR#%2E5)]/(W[7P7EZ/AFF_3G5^1OW@.D.>KAU$UAT&AT,XSR=3?MI?S)+
M1I/>9)K\Q,7L3P>((3Q-1V-$,!M.>L,Y>O+N\H*_3:[AO)
M!(/V1Z-Q.IQ1Y<'S'E81["%B,=8@_$DX@L&68;8AEP]<8_=DHB2J4)J_A6V4
M$Z90"0-((PS9:Y2\BA;X1PH$AQ;E\FZ*$$Z)O,O6&D25R-$@K9FZ-1+84XX1
M)[: BC]@OW5;V7R<#F;3=#P5_+-TV!^E4S@6NA_7JM=BV[[\Z%;26T7F'+(*
MI&$1KJH*5J(0I9F34QS9:I=@P?[5>"JT=0W5#=418MF162+]V0>D8AN!2
MV@/JBU''E$?QD.;PX59%097\0\S +:7,0 L#
MZ%,U1[BPG$;AJ2?75O2_6/.4<.0?<@G?/]0^:/:'V[<6TALT]R[C/0W.@57K
MQ>%729S%2&.\K]$2@RJ4"?]8X8SOO=# >IN=]A!8:S7NC8:OK
M?%_7F(XY'T+W$TR3&_5[F/P(7=]HU=/6?=N[GLJ4M\=C/9X%9WSVPD/>>==8
M&\ '5\_C)GNDF"RB9WTU8]D05FIU^8]:'B?!W0QGG?W"N4R2@>3415Z,6G+9
MQOW!Z:_?&MJ70(,5C.8Q1T/C9;ED8=-@/FP=!=.O'*.FFB>) $7!VQU:+W7Z
M)KL$$90 [FMAZX2R@19Q#KNC@!&KTMSO"JJDGGL]PJ:@:0/Y.1[([%ZPSF0A
M;>\ [6!%\F3U;B;[XS- \B:V(R6*"2!HYRA+<%,@@]$R.195_"ZK5XIDR@)E3^W?0,=* ;Z1C_1^O4FTO$-&NLQMR
M G^\(FN #4TM[C=N[9W[U[FU['BH;EI^OU_J= 8W[,G5@ZG$3W4 \U.
M7\&1%(OV=T'_3MLC1HH*9K@TJ_2\\6C#JWB
M8J;YB#)^]W9T@\1I*X0?$\&293^+^>*M8XG:/K
M@_U?B[U=G X(87Z<3!W:Y/[!#.<#M,@-QS* T]&,,>I/A\-@T4%@'25SBUP1
M:7X(.X)UJ^QHB_:2H\Q+0/Q3,C9.B;Y0#=TL*/<-CYG)G\ #0^1P)Z-%'8:C
MO%3+'*<)1T89@+7SW'^PJ(_:YV!GWQPA?O?#[WQ_U1@GV-ISWAE)A#,5#!X1%X@[)B:>CWI"J%T 7
MIU/J]CK'NPPIRN6OU,F@!QO9&P,_Z+FYXU0Y1MX-!M.""8OY]+R'AQ1H&5YE
M7!2"?N4G88Y4%I._/)W0,%YW[M%P F/[!J@0GH.UQ)%\XT$7^S#HEA95.UDT
M?C-E4J2.T:Z9?;%]75&_=/46800)[!-X$=^L5+?Y?$9.:U2Z[&L5#7V0#D93
M1-$9C2D3U():4^(]1J:>#^?)&%XT6T JA:$ILQG ),^I&@7AG) Y1N"V6G W
M,)8!L @&Y1UA-5)ZK3494\=ZC/HB_)R,1V2>;A'49([(MJ=3."??QAO"[1^G
M6%EQE)X/S_V'=&AMNP3/-!W,Q@CZ J_%XQ]P?0G6:#Z;=5;5&, U,#PWWR-E
MPA)$N)@>S#P=]8?)+)W#Q+#82.>#<+^D_>F 2_6!A'H,%(ZY)I9=ZV5NAO/Y
M'*WP9XO8"QY9\RKC0,8$?O.B,7>+EP='BKMQ_ @-R#B;0S,QZ!.7=;7UEARH
M0T;C#-$5LJ5$ZF$9IYM/-+:SP4R'/C#*+]WDI*-H7G%AP\F2ZQ)H"U?@S!=Q
M]D  [Q&\/<<"\4,K^&+$(HG_[W]\2]*_QQ="+D2F>^",NJR9X?**I=F4*S;M
MJY0VR?-J\MCC*6=XLP!J,[LG1TZ.A%B81<#9[EP^(L58DKD"M4 S1I8%?7/0
M:*XM _X:4 I%\X!Q_$UGARTN&)VN$)!GBO?H]G41F&KFU+A!$1=MN,%?1&/N(M4LTJ-+_:\4!E2Z)P0Z;1MWYJ^S)8J03W3H/J+(V17O<
M2#-M5F5BR',Q,TM!/L1^(*:XALU+.R$:4HP!Z9JB6SB>56T#"$S\]1+IT,3N
M^K%S+39@ZV(B0 VYKQ[SJF;5C5* ^'XA>F!WR=.#Z!%F42-7&8F!7H0)1R_X
M='Y7K#@JWHJJ$EE>1!257T#CKY>%I$0\PKXBB FOO_[.5!31\K[?+48(\N6*
MX32%K",!Y>XNL' TJ0Y7M_&\E,2DBWM+!6.',G/UX4:*EA(EX/;@
MN+R 3=+)< _($$CF[V@=@=A0B8N47 48".JA?$(B.O;28S.GI*6A=1C![3E^
M%"?)?$MM4&LS76P4E5>D$PRD8R@G%2*A !>E ^H]QR[8CK0UADPW,Z& Q)S:2? U2GN1%7\08-_08HD_W;?IN#$4P <3+'P:M&NC!O
MTYBCYVV9L+=HX"3<#(/+X=E>W-M)ID^_H?+Q?62ZWR3K2RT
MNDV%"-$RZIPR<5(+5T#Z]Q(CY,G^3F7,C!G;:TD^C5W_!CC/]4J!I'9 09!/
M]RKQ:!5?:P=J&S_4-:86HT_E\!/=5N#D\WKU'27'_=/OMF+;^9V8AH<()==8YD.5D):L!Q8P%6#@8#F/1>,%P)T'\-;@M@^$Z%KPOM,)%_ @-X3
M?@9=W"?);#0B(R2:9>"4ORH09F.SI#(/,&>1#EA$.9U,Q)B%_ZEFLH:=A!:5
M2+GT.$ "U>PI\3#;U<]A6)*)M%7>FC-9N_D ZZ: GCZ<)_/^)!W.Q^D,]F Z
M@\\GD_1\WH>AKW9,H'QN\9[U("ZT6Y_HFN^Q\W0Z'*7G@WXR3^?G: .8L7$F
M'=*"M%H-EX5L*.EL/$JGDW/ZZ[BI&6*8#X?I=#!+ST"TTOXR'Z6B&1JGQ$(,DT21SWC^'Y1I@'(6WD)XG6!=/&<&"
MC&:$"VVH[\!P78V04(H.SN:>$XF"A?'YF\L48[9+$"03T/+XEB"%\!;M\XC9
M:H:"&0^R(!1C[MAO
MNU*V"#""*H###-E*H)0ZEG*(.YIP@(7N\HATKA]M:X(H8R,K]/ .I7OA6:!@
MY70^G7#BUY#8S"@=3"0!;)CVQ]-D-AN:Z@?G_7XR(^9-U0>P]C':@%5*V"1%
MG1QQ[\W6%X@R ]V7)&827,.FI]ZTL$I0XWLIV;$7&^L .V"';;I*I1I556!U!Z
MLJ@7'!2$NHW#NC ,S-=*3&F4.GS,I<=O+$G!(&>#
MQU! W?D*_9U/R$$ZG@9--#/SS8=P)YC@4P^S^O"VP@ *+H!+Z!MHJV1N2#%2
M1Z-A#B=[:]3:<5"!HR])23R4A?EU,A ;FQW-**-4-NLKY2!VH4IU&MCY[)(F
M91S$;.,(-U(#9^[?3PF*'O;FUJ".=;@5J#S'(JKOOU)(28P_>M2I6;#AWU^+
M..=[SX7N&4-7;(Q8Z'1+#> ".]0>[WU,Z;+%O1R?)9L$45A?A!P%J)GAJ)
MO$,!BM* .'!'B@#34NB<0W,0-<(D"/N2#1Z'?PRX\U^Q,($4L^.27T9/-2/&
M'!0+VV.S2+)60C ?([1&^D)"1G4I&Y,]HQ.B!:5AR7$ O(:K[*G>D8;?X:)-DQMBY6N6,)8*-
M^T.^PTL2OS,CQOTA*(J?BDH60\')\+?F/39W+OB*0L&32*5!+H8;L\7U+ @[
M,S?;0J8PA4);YSD(^%A,#$1RN.XK1%I?@RZ#:;&JF!D%G&>(WTU#HM>*S2^[
MS<*4)"_R.V2T3W"AFVN>00:7>;T M1$IBW@RW?"PYD!FM9@"E3'7F/BSI%[C
MQ$5^II3ADBZ)BI%#C)2/TP,546HF
MSDIE[SR37Y=:ZS77D
M>. 4!$%^$MLJAN.2E\**2C:-AS.;!%K+7\"6:[EL? @B-P!R&\G $&(^7V2[
M.E=7/.[2B@-3-NP'B(XFXL\F7BJ8*XH:Q/QIR!3$7\J4;IZWA,!14,67AO5 
MQ4WT]8W[BLU35#E1_7? >X6L&A)'X8\-W_WW* \^Y&5ECFQC +*,#^.6^1'#
MH[$W$X?T1]>FG&._G66^QHONCW+$G/_Y;D<:-OLOD39%FN?5Z"4_$]1=FR99
MA>7MP=4TVFW@;^$S$RS-?AIFCXS !UEG3+8DWY-V[[+'D
M0HCEKB%[%BKE]&^E>*P_3BGOUS4, 9LB6^Y!MX^(^QQ!2^YG-C<@NRRX_$U=
M&WCNN"G &.#IUK9F&@I)DV30.T)AH93?HEKLUOC00A"=N :BU^!CD3^UF!I'
MB-I0_&*#)Y1Z-?1JZ G9LN_V95F_E_QHZKJ-TQ!;%:_[FBW%M!SQ*PU)_!HN
MXG7R,5\\;*2D9?+V[:6D;<%7!E#2>B)?%8R+ !2!-[ 1<>W',-/W^6V5U;]F
M*2TX!W"P<, 2$(,XFGN8*9O'(4]EE9?#B+FD>+VJ'V@3O2U
MD@:*9*]Q#5(\(D0W*"1XZ\Z>;#-WYA)>U5 #28<+:_>S]*JRI.)%_QXO$%XX
M':;*1PG=RDL\H,T9W^?K4CR3DC%080HFC=+7VB.^WV-U>[.EX8*GS^1E=+<6_<&.DD>;W*
MC\.L&9-*?*C_Q.MP'V24?NG"Q%HP"[I".R^JKB;3QT^8C()5F5B20D5N&/NV
M@PHKI&6;0Z1./2'$"3.6Q&Z#L88=+C%90$RO@\'UIBJ)/1H)^,$/5J/G*EN<3%9(8T
MFG!@]1S_N20-%IPH""?0@<7!\%G)9?
M"\CKN.VC,)C>;/G:L,P>GHP
MAO^&@^Z]&(QLW $G9!RY%_/85JA8@U/ -DJ:ZY&-CCO$SS?1],,B6Q2P3.9SBEGY[T8!9?YPKY*AH?!+,&(
M%;S2FX)LQ+-9,AE)V/V@?YY@4.K1RWR2S*6>ZRP= >UJ9RR(=@B-JPW=V;'M
M7G?.'.& .)5.BGF#CRK7>O&ZR\
MZPQI0,&#!O9DL\U;>J[1SX4Q)JU2*:AGHGKD2HX=;^4+@VB.LN>\ #N3U%$5
MS.?-[/CIN %&4E(+(VQ^T6Y]823_>'Q
M1(U2]QO2ZC4-']AL3P/T:A,J*X'BY%^XX%
MB_&T.RZ\(_X*"LR)9D6-I\FXCZFD;SG;QM:H6.:\R[H* 0DE.+0-Y35RZ:%.
MK%F2GCGN>9@.YQ,KL%PID,PZ*$&ELD58R.H8MYL;%FS";%*\LTPI!A,)&*DW
MZ/E!\1VX>D8:&X3,H'OJBYM9#,;I>-('[:ZP_AIX%2>^BU2(-TX3KB!*7O)C
M.L'H!+UMT;"@
M"W,8_"!7#%9]3^EM_EX!%5MHHSC0 I5AX5L=SXA]TX;/#F?'L"+*^E+1=\!7
M'&*2XTHN (O10KB)#Y_.ALFIYT8CDY@K:('.0L ,454 Y6*/%&Z\HC(ZKV9=![ XS
M8Q>K3$J2AZ:5VQ)Q2R@@S.*=-@ILQ."<3WJ3;R1<96E')[E$5+0(;?ZP=6D'
MSFNT CG9_@W&%=5O>?:">;$-(@H$I%^_BD+9(]"*9
MHN0MM%F62!L+-KYOW-V"]D2*5R($?9.2/NA-!X-S&M>@=SX"B?:86=OJ,N@4
M/N.0.=P]FYF+:6NYF/G,UJOBO5X^K]SX_F)<-+2&;*H+"(<'*%MFE\LOIZR+
M)^/K)DR''Z\I1EL(0I:@:]X2H"N8%QFH97 VS-W.!G+5J+'[>Z$+)H)6ABQP
MM8P]RKUZKG=EU%S(<1!7W&Y#%&KI%OIQ)7K: S.>27Z0*EQS:S:LJP-1AM*67Q/IJ;"I82EA<&0FFZ7-_5
M_*DZPN@/.@EGNRW5/ (MT_>@F9V1HRZ0=%UG/5@8@W.<=4VN54("U$47)9M*
M55CKY;75WP]1'VPM4"=D > ?#FWLC"5
M+:!;U!:CAMRY0BDM!AHCAL*X?K&Z.2>L7O)+^L(#"G!W"2F>(*@&>PG)\
M$[?8+4/^#[L,L8E@MD?9\4%86*+^L^PPNT-_H&3CHIFS_B-&@+P@GG=")K #
MP\+8,)3W;-%VQ0ML+7;>WWB==BD LU=*9.]X4;$]H.#,;R-<2<'Q&RFL:FN^
MBX,T+-[-J%RZZL>GFPOR-J+@FE?L;JS%6<[$;C/_Z"J]YQ7)\:+YI2PH$)+F
MQQ&I*SB[)+\(WW$U7UF*T5V3DY-VB6LH*>!V \ G@X+3,NCWOTFX-!\PU;I8
M%AD;^J$1MTLWZBM&N31UEE-IS"&3F8')$G*U=B+4(*;0ZN;>-RB8=BV^-JC8
M^3_CI4G(:_]_=^_6XT:2I O^E=@#S38%A/(P[A'5V &DE%2CAJI*HY1Z,!CL
M S/)3/$4D\S#BU0Y. _SL/]@]F6!/2_[T^:7K-W4UH8J+*@U%(2+(T*D_J6.AM)+1%.@L$^(UO@R=&=X0EK2&-L8
M(!\RASJPNG;7@9CG=U9IZ10!(\CD-IWQ/@@,%4T\4@.+)UPN=E[OK9F[IKWY
MVAY!0P;B;D%)O]C8VJO7C1H(QFD;^D.#=N@ 1J3MJA<33=.[Q)IJ$]8HK':V
M\DJ)^]$XV-<%>]!>?7R#R=8HTE>/+UI$_JBBK3J)U)OUB_!:4[XN^0Q^AK?#68KU2_XU@O+DL&N=5@DZ 8H]-]E\XOH?Z*:'8C"GA
ML2V[47LF ..CB+5$F(=/K_\SE4ATQS$.0/EUX:D$NS_S=V;0KK0<_+)=^#B1
M?T8U Q5\9#7D39>ZBO#B^VLJ/ U/T=;@C=&UR3I1U'\C!0R8DAUJ *SE*2A1
M=I6I:> 0C/O%]FX1:V,S'1]Q3\:VTQ3D",UQV>G;.,Q+.)",F>.%I5\JN\WN
M$$QG0.W2QJ]X"=".'7\_2:#FO9GQ&85FAU;2%2_:B-IR$?V#
MSE]7!#6PFV92#)4JWBH">< 0PST[%-R+L%W1D5R$-$=DGSPS%VB V2W6>Y-T
MA,Q*O ?CN=!Q!XT@CCQ!4+]4_PMG'&,V!>T:!J  COA_"R(%V[$X8@7T"SLO
MLD"M)_=?%JKJG;&!>6O:+G46C)B=2?3HL?N5,)B8A.2@5>A@<\,"H0B
M@1LXB-VOF6A1A$99P(T+*L/"*C>:>^]B[,Q
M47<2'98Q?Q<%A"OI*?,I%3?<67 <^98Z@W*6#PG*,G1NN7SH+@V]C%?N[P0(3=?+2
MF.?(3J=S5Y]%6<4>DJH4[#L*I*@R"VR6QT6=P@Q8-X&239)=W#1-A/\9.S"F
M0]?.?>QT+?9+6$-T7%1YE":Y25*N:Q6?L%3Q"83[K8(1_'8P;[%N705>WK&T
M.U.Z_OA.W"M+;A
M>%HT45E7QKM1-]/!6H*3Q,6@)$UC.XV8HJGE(0%OHIIX2AFP-)L#^Y3.,^,B@;K4X1TMC1-VRV'";F_3&W8!&74T>A[IMN'5"]
MLQ%G!BA%:(\KA/8"<]J'XC1EEF@(D5 D6Z"FCF7F==*Z^AG3&5#-(%PESO4R
M=6,ZF]<\6IJ7XH? GK4T4\CP&^!X&*GD;5=>7*>(MP>(L4E-FD:9,+&IW63A
M9XHH+6C/)05P[@P'F- K&XK1R\HX*PS*Z,[;5Z*!X)8M*LNBLG@*:S*!W0J]
MQQC.*JXSC/J0^Z0OK1T;;/E<=H $\C((FTMJT(!B04Y)"U^GC0]4Z[R5UQRN
MC_P]6<3?KVKE_UE5+5A@!IF!W4RAG@0WW.26P194/'>$WE0#"\QKNB==4+/&QN0R!=_;E7SR),B1R88]X8=;+IT;)X
MYG'>05&%@991UB0BG.(&]O1H-:N(JVD=%9DH:66,".G?JV8EOIJ5C%>SZFKJ
M?3ZN9F4QQMS 02M32S/)L[BVX>6#:E8:5Y4;VH0OGU3-@NE*Z]:5IVJE"+2?
MHN1(N.H@5K54P)SBG.4^*L22R)"*!J(\^=Y&5<40@^_%B":,W^
M2$4K;RB8N$DH=)W*>O(O'$4[0M%"#/]**^A)4-,J*5#0T4F_GI47C??YN)Y5
M@+8NQ%MFQ3$]JT0]*RE0%#/W *T+F$=(SRKBNBY)G[:D +L-B.UWTK,P#P*A
MK:9"YAB&/4+/:J2#0H<,Z=VK9R'$E']UEIY5R1%I@A^&]*S::(U%W2"BO+=?
MC^E9M*9)Z7T>TK/HZ /*8XG!;TV)TXDU02997)(.BF>[)!]4M&"A@%@-D\)M
M6E*YTX+*+@"7FE;(I>2^TQ2ML]C!__\4+2\,;VR4^V#IC;\)=4S*N>U@QB@\
MVK VQV_Y;YK!$K/)JZ3%GQ1-22N>8@6%1$DQVX+==G$B6A>0(FX\()?$""?O
M[@2H#'DS'A.0+126[MNW)M>DX4J?EZE-0R J">IR44SQ0P3=)C=4GAL;B
M.# FU)B3/FA:M>WT8#2K4WR5'HN??Q00+79*<=',#O2.4X 0R_5Y^Y*7.I#)
M8'E_$Z,L!)6U5,L.WY+&:Y^3*'@F%320YI&QCJ4T:T9)Y'TKKWGN N5-DB7U
M#6U6"+4[Y90W>*HK6BN
MK\2?[(?$S>C1QPF&\3D9L29(1&J(%?62'UT1APN5HK+-4.5MTE7DJ( EJ@)U
MJ9S:GD4[TGI"=?)+;E4CII, 7"L$4[^7[T22,%&-NQ&]/
M0$6U:T;?GHF1RJ"LW)=G$5LH3'_X'M$:/=F"LV#3$G#^1MTTH219^X?(B#^*
MHND]OO16%WN:V+_07X)JMOVMFLC<\^(/$Y9_([:+T<(2U3E>;:RQ@QI2PN70
M4G2S%,/",DL:H38C+.LF)"Q9^YY&"8G *=4TFX;$I7#.:84",P=%;=(4PC>+
M,O_CQ24:C-/$7"C)TR\N,6F]@JF<%%5*XK*$!DX1EW!@2C/0)VHL_X:,HX[K
M,ALM+#-8BCJ5BQQTSM.$9:J]?/#Y1&%9YU/%C>12U1ZS4ZL^'9>E%9QIL%YR
M!A-C**(F52TH24F:QBG5US*6(S0(GR9+,TH9-_G^4R5HZ'PU1I:F5=WBS?)5
M2):2>J).YYD]G0^)0^R>._F?*$H3TNBR:=T>X30[191R,PGI:9PE2=279"%I
MZJH>VJ4"IC%)C51$9\$QT8J^DH0L?I,B=]W.*_-N)?BLK&#D[X3_QAF9Y">T
MR,_+->^<3RCFITLA_C=- ]9U.WWS;'R7HLO]<@BZIXXS\G76:T:05
MO-P)6HOK(3$'C-\ZO1K<;D4\S;)>,5+J=!&2<+G^>%S&L46L
M!K(QY)"1%:M7PC7 ;*N.(,W35)S
M+DV."S-0B)%5-.CT==*LLO,;DF7R#!6R> :/YF3F8KNF/$J_G2:C3KN;":DF
MQB4[@2&2ZI%"S0YBP@?+IJCU,.IIZGX=)]7"X =_^Z9-M\<=^@"M._F8*0IZ
MSLDH$XJ)7*Z?*UZBGGG&5A4\QL6%S&X3-_F4S.-$)0G9U]$5C9!6[QP*@FOE
MPPA4 [OK;GH>6^BQ"O_>Z$D#$\
M1 \+Q!$/PG"XOI7>3N!+SV]GTW0I&=43G[PQC;=WV.:7.]NI_\:B,SFF" 0-
MV*N;HX(=K>RJI @O=4]YL'"8G,._\_ NO'([;BA%Z6U0N@SL#44R\/$(PPM!
MM$0E:)Y3#!*HN,H<3R+0<446J8RB=%T=]IO>X)T)%SJA8*^&3[-E)=@_+) S
MDD.]#;S2N'52QLY%I904"]08SPM& ;UA:#BY=72<]N\D"?]&[)9/* G9]12%B,#,(@J1ZL)4SA]_+)Y&"K%)WOOB]I& JY-KY8EAX5=Y#+ $JB:4(;%"G
MR+JKT2+,O0ND%VZ!Y^J%]JOODUZ5B@/Q7GF2]$+!GWFSPM\\A?2"8T3B3:+Y
MHK^';7;?U*G7.=(EX+O?69KEB:<=\>5H:48KDA\GF8B
M?A!P&"?6!0V2;>LI)-(T+7R)Q%^<+Y%<6UFM@P3DD@(3N5Z8M19QXFQ?G'.F
MN#=^[B?ET1AFH#"A;R"?^IPD!3F?!R66-RCQW(MAJM.L](7SE-"@
M1PB[HZ(J5XE7[ALK"QBMZZA8\D32L#CRX&$P1J7+I/G;$^71,0I.<^]LPY=C
M)4F2!7J956$22#UJYLOSF'\#?)T79))5NONP^_)Q+%]SZ$G*CO5&F'0.#/@T
M?F^I!-8GD4V10?>ZK+XAKQ*_%W-44%>N2L7J04)TD?EM2O";K]2'SC?''^D'
M]3G:&*/^H C[]^Z;74#^>V9N/GCONW7TE]GZ@+@35!Y3@8Y8;M-ECXQ5CT4J
M$.#N42,0/BPV#P0A1+ Z:ZXGBRP.\4"EDQ0XDH:H[0P)KQC@W_QVF
M8\_88SPGW1[L&9I-ADE[ !I.;<,&HTR#LL(SA(R#?6)X&,87LO&^P0R6"])%
M:)-235R*%]:E=:G2ARTU3B IB',E^]=;#0W;H6&*=',$KA*1QC1_(.*W)Y_4,CJW0K>??\>@ 6SBE
ME3/JE;\E6I*7(,H23(6]_$3;QER]Q7(^7]SE 8B'-%KR+;0\OYCV49$^7<<)
MU>&MXII21.I8RI*WHX+%98)P[@6P_@)T8HQ+X=#0KF-H0K&I69F J(.[X(GC
MX8-UAB_ @>S,JH3BF6)
MIUE"%=&G90,'H10^EW%18R!8ZI6$-WWRVDB3.$GAH F'5$80T91?>179%#GG?C'-P]1EGN@;C]@*]>?0EQX
MXI]28%\]S4!+A/]P+T^1*!+*_<7/65/&.6R9&H@HK9%04D5]KS.J$*(I
M4O)B1P!>$7(^H41=J<((+QUXS0?0]Z@N[,1\ZHC"UU1^],'H3J]DUENW1;_=
MKW[8/X7/%V-0P@4!*CH4__\9R1C@6PM>^C^?Q\"P
M[Q8D\$D7I&)1VM3AYZ-A[3\\0G*!$SX%D6YU;Z%&=?$"%YSD[-9?-_!-##KP
M;C>[,U87>-$#3FWM0'?%3O(W!@0F3%V?T&KT:\M(6%GVU7!]"SZ8I!
MD_CUBCF'NN_:D$Q5:)?SMXTF&YO2N%0YQQYI37'G16^^+T_\FWIJ\( !4QNA@9*PAL&[R)$*Z.
M%]8U19H).\O4 ."R0<'*>K?^]ACVOR$\8[')O+3)2.7NS\D@,*]4*SJX),3,5H)&>,&^2"(H!
MO+CB+V(?VP,3HWXOB?URY-7-TIR'*>N2.^(*[&)E)#<[%[[_PB_2@WC.9@&H
M.")5$UZ(C9A/>@I"C5(P+5 A K)2E2]3J,2UL$7<_]T.Q 0/ ]K LXH%43-9
MX(IV.B+G,]NXWD@YR(XA1-"C&3J..4D/M9G78\XL20'BCQ*PB8",-WA$6LPU
M%AL,#UIZ6,DR_?CR)>_[[8+L)$@?ZYD#924<0U.Y4LIF[T DBVE.CJ]<9I(/
M[R'X/&99O%)<%72/%/WFM]D]]<1LG%T[\!=%.YKKI++Q(U8YA1,@8A]W[N4?
MO'OY\5AP([\2?U[)+# S=:49J>X/*%8KXN!D*;]1Q4@X:%9*M,2J4@D^M[0J
MC6R%;DFVV &SZL3DV!1:LQC'NO] !1LN*=#*:<>J!G+V\V(>E;B>K0X2>JN*
M+AYV"]"%H*6O"^<'Q:NY]53?H!+I5AR1_/ 7'+HM^N*LT 3K2"66.16>B[5P
M=1PGXU055*0>2;9??$-X=P*\)#A R\$,6C:=1%]P20*D'M ^>4AP^^UBB PZYO%EU$PUB)_N[>4MO1ED_G\L RI0N%'MJJQ_R)
M*BXOO-Z92LNP%,JD9"OP\E:5NMPLM+@\]7QY:PM8[K]L=+L=#F?-VO3AC3-K
MC[Z1O] &<:I,S\>;+W!66YG"!J &K!>/II 'P[IBB\0*/VV)#AX9 USJU'$A
MAGO@]4AK, +S"YTRMK _H$H^H7KP=;9LM@[5P$"!US='!)9,
M%=V]V>J;)5#RH9MK2\$YA)XGC7?#JF
M2E^F'+VY:A62V!R/D)[1ST!?*AJAA56!AY_]$C<+#U' 4&VI9S>Q-F[#K*;'
M*_[[88.W"QFS>!(X7K(>LXL'/_)P28C9TNZ+?GK0LQ/$]J6U-MHV[GM_M6D'
MT&H; "!0_LV:O( U>1%>$ZSZOI@;Z0BS8*M_FV,\IJ^PLBT W)M;. 1@=:49
M' ZP//B2T$MV.RS@?7?'W@8I>H(&'GR]P^^$Y'ADVT0K6MM>#P:[C#R]P>F"W JEL08&]B-[.
MN.P3[=>Y.'!LR8#=3HYA[K# S-R:*]0(7.^][M$!"+4-!9U/QA)>!H*LYTZS
MXDWSNUK^BLX76DS4,&R1<3-FXS 177 >;-KD6DBMYT=3/B TI;0#34^\V6W7
M.]^8]H3<4=<(-RG;P'2':  &Y*^+FOG0$OE+C6_& *,95BO:WI$M?"BEI5L$
MW2B*#J2?1N[*79_^1!#=S0@ 9\'8N'**HO^2.YG/(? [XG=QX)TY%\>&\\%)
M>[G8JO(F+[C<*2AZL+VI)CPAS8&Q5_0\N,.@0>5]2-7! .1B8^R[AT
MS=4C!2&,NC^V*(26=JJ<0:JWO4&QMQ=)U2J.[!B[5=M9G;(;/- ]
M9,"W<-+<.'8_B]8'8L/8$^86GG4HI#GJE8W,.06K,6RE!M*=&7A^;VLYH
M-570^(8TJ'M*&>7;1/,5ED8\<(:GQ)OMY@4>R#?WRYM.M0?+4;!&/)EP+/*W
M/9*Q$L[Q=&N\7";4N839A^\B5CU"XL>F??CZS//<@*PE;AD2WKJ19#I-DO
M9A>;;<_#8ALUEB*=LUB)3Z%!YDN$KS^@8Z:-B)*6%KGU(]=-04=;TW1,U/@D,U=ZM5F^X4&
MPCV%36>KI9G3V'*MY\]VGD=NZB5(]1Z@^<.-67':Z3YL'5<7@5VXQ=H,&W9S
M>0\M.KG4BD\J%4E/A^T-TZ :69Q)';*6F%4VY&W#Z*2NQ(*,7B1+@/OPKL, N.O-86\H1I5<
M#I7VAM,5Z;@^62C;19>;2S&=]E1W[4WD\K'ZD]6L6.Q1%]Q6I8/F86DSB7V<[=(:J2C:#I49UT:)<0I9D%0TY>"8KV2+5'B71I(;[U
M0@X;T,481D3>B'V;"JWH?]ANKDD.^81XMX7+UC(X
M:8?A*@LCR927W'5[N1NM1VCYJBQ0GJ;0ZO ?KBV8Y7PB5>%O
M0$U0"!2L;C+;Z9A V0WB69SE7$61L]1.2:"M80K&Y&!=#TA/;O\$
MN(+F0J= 4=O)L)',O\>[>A&'3SLNM/OR-$>$M@*H<;3UY^ YK5,LON7)U=TA
M26#/3BM.BKWE8S 5K4+)><$!'[[JPFR<@E:P##4](>VZ$,R=C7/!WX$I?UD^
M/!B?/IKM5\P]=GO)U8'I;76_XX>&T<^)_= QA1ZE4_WM87N]-"EF9NARV">&
MR#[FMG%#WK+?SN:+%TL&$#D\W.$E,F#XL1*6#*3E^)ZM\&BK.P4@I5Y<;\ADH+'[Q5G=BVCQXCE[];6E L>
M\#KG"XI*>$_>&8:U'75VZ#S%T0W:RV.-3W))EJ#YAA@5V0,Q-N<6!?."?46Q
M9>4]D?X#J2;^B=!*;6?BN6)0\5+'VZB8UR[*J[
M\<+"@8V97,^J'Y]\,\<4Q62-KA=^L0$GPL(U" SC)_%Q?5BNYE:-4)F9EI/Z
M$3Z[QQVRD)C=G^AGP*G8 BU(=7))!2)M<;>YW7^CHMGB; U*%^S.?BO'.2["
M> =T#%OR5;ASEC$8.0I\\-MF^RN9W[!JI;GQ(OJGP5%T.,S&A*UT.+WMN7D7
M]NC=)XHM@W[@ <-3:ADB@M?.3A7*'7Y3"ZO;.,T?K75=.[(#'O!N,C!,U_O@
MDOB#]'\RE4K)38;NTE:_VJ.^Z",I3R><[5FLL5]2>;,ZN&&*J=)Y"&9;R3\7
M(V(?7/3R=BXG#9(88V1?D&?"U=UMU?A=8J#0_( G3(P:^U]^5J_W(1P4:BU)-C>1TOW)>I:C3
M]E2T6MYBLHSOB?6C*\Q+N.-D@6MU%$ER\<#UI7LYP];/B>$L0:>O;'H(0;9!
M3XN.D R-+[6]O#T08Y"0K#4MLR2(,#KL>>.JP#]EKG,D[$_LA<,1A 7=2(]L
M3>B>2;&>:)R_]9YU'AR6>XTR?-C>Z]=^?K!AFI9\D72%2Z$')%9T?W_8[26>
M*%+IE#)Q9H4_T@V*5GUVH#584LC'GAW$]F=,]!$JOASO1;_Z1IZ;,(0@GS\X
M)H#RX[8+.,W=J* OCR/.R"!F1=@%Y9@N.=";7"X+,DTQ'-M\R75O>;F-6K'^
MPHFL6PD8=1H&;6L;W73+1VEVY\V=\/'@^F8NZ(H*,#A)2:<7V#^S:S8HT7I_
M6]R+P[K.1U2%_ZIP,V$,BF&MJ^7IKCU%1R5
MY]C'P"Z5"N5,EWZ4Q$R9P,D!TD)0Y*@2Q^PL,]#D9PVW*S$K\$G(8&*2]1#O
MV^U!J9%M#3V6FO2\N+B&JT<39KK]2=HF3,ST9(\1GYQO*F8XB0LY[&98(OSAR^..J.L;A<@2P:&-1FU^.=X^
M=L)%V3CN@NFCA8FV!WWR"SM)=LY\Z)WE6K.+]A]#9<;;LG,0-D<=BKB
M(FX97Z\WFU]%&I$)Q:TH3)0K5>W6=T:P$B3+3!M.OJGN]:J+;3%I6Z9X+V;3
M;;GI1VQN/:K2TNQPT0(#2.'U]MF,W:=>APG5K56ZZ\/%<35CHCM-I.02Q
M]9:6_6\8#U9V5]?&1C8,E(-&:5<%=<9EV(1"/0SU!*-:7=Z04\8H%.H.,Z+4
M#(?4[L<9I@TMK F===NORQW-(WH:ES9(:(]1^G>&
MV/V16XN[V2$7T2^TBZ#1N-6-)1V18#UX#RQ=372E8/,L.ZEP8TVJ@7T:W.Z>
MP<03:R3YNSM2F85Q:PJO[E(7F4]!'##XRD("M=-IPQ7>G4H&<6XN3A_83*+V+
MU>9!J(&A''B; &-:DTQ:6%-(1X7"D$W3?7Z74ZHVJ$<:A^C*S]LBC@S\'Y,!
M70L[DQ=F0PWO4<-G[=7&:,\.<-K?BJ^1HM91;<*EQ-!DXV&UC<)R8@BVKYBT
M.MUFUD/E+Q5;-1ZDP,']-(*^])=I?MB:8?;SHPPB[#%6.T';4'EH=^(EDL4
M9T[)%"&MPAH\08T0"7O8O:1FT[:0_BODJ5DP.3K  %O ,UT0G/8-@>*Q?-C#
M>$MKPE,[BE1MZIEE/6&,%NM5X_2POMM%>UENO0.7<^'89FY6I,+W(N0P>;Q=
MS*D P*6?:(F7R]W.9,J^O;RD/#(,DX$^='O%!&ML.\[M;_0F5P9AB[2$_2,#
MT+^BSKQ;WJTE&FR^!$+>DL9R\^C>@^T(P WQ[;L%^@@?OB +-Z&CJ%II U.?
M(5X2A?%,@ET,+ @%J>T.)N8$-LYO;G>*C@/JR..#G.$HN8PLE[?+VST*#]KO
MK+' U)%0N:/TL+EYC4F1 K4!3DU JBLY4.W1'+JY)\'%_MM/03H@S?SZT5/?
M@#E09/6>\C?Q@$19H?YIW"8:+?YI7^7$N5$>[CWG3VT7*LQYO6']*5;@.+'.:H@Y
M@0P35+_"REBC*WIT25Z8,R?)!)1J>__4*0ESP9'0[&TI+/Y8SP/3 (<_3+"Z
M]H(0G"3JX\8MM^I>K.'L+XG:@%$F/H),9X)$%!@'V3"I"5&SV%FAS-GD3" M
MW27<.I7()?A*6@GH6UM.!X5C!KEH0TA.0RDCHC)8:[6-X_1=K-: *Y&F\GA,
MW%6=5&T6D5:I#'*2!_K$B3T>PA+2T&JA]40'LL7-RA2VP)_47 6';S@PA?AL
M91@>@-=ZL\9$MSTE2#MI[&R]VF?YJ3\"U1>488)DVR!Z6Y6)I/=N;VT,E!T&
MC1BW4VP\N,Z@S'E@>@5&(H]8![2FOM7LYM==D-:B[CE>G.Q\ON7T2VM7#,/$
MM1UP>'MW8HQ*B?(6M==.J)"CZ$\+T6^LTD,>3[?C.7CCF*(;UJCT>T)A%YY5
MP6E,T*$[W1L3RW&,"T63SH0]9WC(0'@'M+P^<&9Z.QG-)H&):$>F#N1S2L"'
MJ#?4JWM2(:X7\G(3)&=F T,_Z,3'$ADQPL3XRNEI-I!1Y6O!G9:5C\NN"NXV
M1FMP27R@=E ;+L^.8"!:=A\R2_/9C:/VN2-XA]\53Q";,=&&^;9YL=LO'MPR
MJW7!.!:[M3HY6L>F)L;U65J(GM#DF47:_5$S%JMQ[FA\7L(X*.U/JAMXT2O_%C"S OGG%/RDW6-5M#TZ+%PU"
MP16DM:F +J<9&LXMB;G>:?+H]#L#O8NZ\A^R(\!>](QANQ"SH\V36.%!T/%;
MHEB[..9W_T6:G-FGVT_Z_4%4(H)MHJE5$GS^R'%M8:T]D-$+_[\#5?-.\CV6
MA")!QWB\PY[P7'Z[,I@9N^Y7\K*[0SF?MB2[/IC/+:?A_Z^7/;D\:BH/67D7=U0/-*N95P<^SX[/T./=DG2WQ*M
MT\&3;0J'HZ'ZY(Q@/\)9:WV[Q#-&@#$3R7#U;OLC>CVD33&G+CGM2"*ET,,]
MISQYK>WJG&R>NF]T?B2_+;E@K<)OT 00&/AF"8-PN6LZR8@@&\2#YZ=FZ42-
MMD+[HX6S>>]XW:B;0FF+LT[ MP1YQ]%?,%#FLP34_/08??B"<6!H!\,/-'@J$5P6,MDG8$Y/-R
M 4MT$!:.=$L428%JJT=G?C(&*LJ%(';I'B=@&T[:\KKEY6(J0E,V!(L-9H"B
M7TBPFA>>QH'5'LXTQ0DA*#;OM]D]A]K)V5:-A$/\9*7,[(E5R\[3?_S;_Z5,
MS)B8H1)SN-['W"&SPZ./O#+B5T0KNUE-E4. OZ),C-#9Y:$<,Q:P6Q:,' PM
MC>1/P:^4S?IVLU5K^^T+;,[U=H,"EU6<7OKTU9U;DVNKDF,D=U(6J:4..%;7
MX7(#Q&K!I)A'!;&EM(7 *H;&[&^ZZ,+F,_*- H_T%:4@0B<
MND<\T%,/EIQ1)WX\[\C)#->+3A%COI19(#<^[BZI= 1O(*&CNK#N[*&+X&8(I&[![[.>SM"[=%SUX.W@CX2\3=)H-,VH#!X7S2,FD!CR)
M69/:+JW4*,W)L*OD[)DM[V5AI-!M3 JAV]N"H\CKT9IK,8_I/0I2!P;Y++W(
M+.1^WZ!Q=,N=,;Z1,C0W[I:-IQ)3#(-E$J2FP=5F1S$,I-A:G=G$8Y_"5V*=
M,N]0;JX'Y8EF16LTOVQ8Q?8Z,((_M;6CM]C5OU)7?U* =:/L?#W/MJ(JMYR.
M* $7/>?3EO7XK6<<( .@\  T22\%G2IVGR2.N
M\)>,CKE$_%0*\6#.3X]: 4NGV6M<)<5LA1+;O6)@9CQ34U;$#]%[/.=&2?2/
M# ."8.ARB)5=#A9;D+DRH2&>'^/DA3C$EG*K]H[_Z>!:E'!V<
M"](&'@ZR+5#C53#C(NS"P)7=4#)UU+?&4=/8C209\MCA%+XU[QUZ1V1A7PT"
M9"P138\:U=5%]KJXS_8<72_H;&/R\\0?WWJUW76A+$E:Q]YB2G$/*F(I+./(Q6X7,P[_YB^O
M%FL$L?Y(OV%A+4:_=)3OD 9:6M#U\A9.SFQ!D'PB#4A!OD]117=?%GQ.T\K#
MI7/3:3K>>O61$+V_G57A]^\B -Q#-@JV4+2G!S4L"1)%C?H@:,\/ARUHCHL 
M#4B*&()IF4/5B%N4Z8"M5@^4ZV@0HDU] 52V%>P6XQM<']9S@L-SIA>;E8/<
MEI! [H$H:%O#@C?,]*8'6C/2;U&FZ ;F)VE+CY$FXL"774.%N"\F]57
M9U."M4#7\%: 0KPTHT"67=OF15M]YM4G(>U@<\L6F=!KO#FTQA74I%82Q^R=
M,"W($[ITV.UDX= 5'Z(98=N:RO$WHZUSV(G
M$H=D QB=P@A4@S8$)L+:L'G/@Q(.7;/1WW$ N:L-!" &+88[D7A\U2%3!,)9
M9E4U")77>P'(U+ U9X"
MCZB@":T9T8W7?^$ALFYDE,(G!2\6Y/(\EHQ= _JF@.8I<@[&)YYTNW[,) B7
M .:,+=38JM'W3=PO^Y)%&:?SGO4%2.=4$%7;:LOZD^-'CO=XK,EVR[.%,3#9
M+5.]8YS,R][KK1^^%VN03?JE&WO(X@2=9?3;'PI(/H5)C-UP5J0^V"1/C.H!(
MC[9>A.I%,)7G2WB4*F+ EO*0>%XK]RD:",%Y?4$OCHB9=D,$1(+!:@ID
M=S/>K;&JB0R0^A=':AQ70.MWQ]>S+#G>&CM1B.16*"UTZ!(>!'"^!%G@I0,
MX6F(DFI2# *0)#Y*B\=J_'!;T;R.IX/IA.(/DD&-E39\N!2KL1@G:Y1J9V^)FD RS,,O")
MB89H?*=W.&%K\>])QI\XCSHIC$ISW'D;T_(&24U5AG -G)+]5M0^2EV).+&HZ^J)V;LE;JXL
M"F'M+^;M@M!9EEO/60R7>>-[UK(R5;]KQUF,G80%;"\>43L/D<]GW0,^EA=G
M\\/0;YXP^Q+:B&RA@6/ ;DG%B 1[FPZC[#^'06/E 4*ROK7B#>9AR>=5\FX@
M V55 _ZCB*TN\"1R&#NVT@CCS,
MI6Y5ACET9K\D-:%GF0.WJ-KK!BB&_>F\&V;J"4=P0,KW&YE1#[[&(>I@(QXB
MC#N9<'"#*'\Z ?;<#:<[:4?AX3WPH2$V*FDH.]P^*+YN5=,^QLO<.7UQ@R87
M4_6[Y]GNHJ92(-PGJECVVAQ[L,)9GX/2EVCN5&3J>:C@@IV?[M(M1\=G/WC9
M->W=?H<&*YB+]8R3:>$)UJ-:\(K+M0!F6U5^M_#Z(]6Z!.;G91!K7)^4J)EC
M0:G$&JS&M35QR#-WC+3SR2E\%NE2URE"?8]\#@)U:J$]0LUPM5X+=VV\FUA5
M30Q+P&&0NRW)8#C[39Q_-\+%Z"$'7D/H3#BW2^>JL TRM\& (F:NA[6:>-J:
M')]",[VB,PIZ!K5K(1B8I5*<%30)5DZ>"M24EA ?ZY)S&#* P@H-?M_$523^0P"HB7O6SVR(>
M"+&0XMDE[",/
MZ,K@6W4$-L?!77JE\D2(3]YCJ;Q1+M.CK9AXN_Z2?!XZA I)M!YOF+98XUX=
MVK4')^SE?DX+/U3&+AY^UF)H1%\6AQ3Q9=WIA3*C80WK6:6
MOG?&S"^X=+#^+T\I7LC\XY?+=WRNW>EB)[U%#='GQ64-6U4-2VE^I 9)KKE HMSJNM_W]^C9I*?E;E.?DP9R$<$,!2U&
MM/O"P!Q$1 >QEL^7XFK\>6&KU,SVC(IC0"WT1,E>,":M;PL<]6+^
MPE1,< 57S%-?*!=T<]B36X:B!HV#3%;T]7)%W3G>V[LE>63D1('&_]7*Y5)3
M8 W"4'U=#+Q=(S1)!SX<;T&YJG5C0CPF$8#I!2@?5SYV&5\:#FAORY#2LTPK
M)JX,M!RR4<'KZ)!*-6>V1NSQ$[@E6]_Q]@R^;GG[0AK#,"(AS#;O^:NI5F\#
M3]Y(M?KQ=W)5>L*K,M\P)T(  GWV$1[*&=@&282>>>1D14[GH:J9%J*55%*$
MQS0^" 8R@%.&E*Q79XC# XH%-O&)!0+#_I"[L)6(.\!1Q 5\W;)K"/8-%RELO5'"$2-K7N\WVVH_>
M-B65MIUGK5-$/-K&:\D69>.8,K R0/2M[*A>[6R,*8>3HWQU/+)#J9\^]B.P;]QNJUZ
MO"\C'%9PL&7B?N3#-M93&-U&3NH/G"VZ,87R^/1N=Z+ K\B&I<@GI"&U/5:,
M,2./0E_^I#*JE*812Z0![PZ#@;SE].JU>3CNWQQN/P3W@#TH6Q\>4C:/F.NV
M:]EQO0A%'_-,.IW!KH(P/&6/ #;
M)AC'@CRFM&1F_;JM,YX_NQ'#R5F^&5F3+->>Q1?0V6R[6;'U;H=ZP'+WQ9 U
M=II,4GC.6-]M'$T,U8PQ[STV #2/=K05'3D8"9JXGY#-V"GS1M?8*>V)FK"0Y\:
MN=-I W0=0#>$'_'B7;^IYIQG<()? EVOM/WHY=4K:Q(R!HQI1B:>*[;46,KY
MT#+5O$9LYG>F-"5!=5Z U&)$.%,)R]IK",G9%K+D !QU6IYI-9[N==DXU]9,
MY(RCK4C@G:L\.K+3,
M++:")\=8S#PKD^W%4I='5S0]\[:=, D5F8O
MI@T1H0DJH[6\M/'(M#R7UFW=3W96798R[UQ^U02)Z IP-&-W1ZO,<7.$, ,:&QNK>=XHWHWFSAY?/9Q8Y10A(>JJ"D ^70[M/YS] 4D
M D%,*LNQ%ZWA(,;]_MTJ&VI?^Y7=_7SRV[>1QY8[A4VT$%>@\';+N;P\=)9B
M&DSMO!W_F0 ^O*V]_[9QX^>3LP2]H-D&N\X/;:S%)^98?0O @_N5[23;PTHB
MMRTI+=<"%&J2[,WL64&"#IOK_R:6#GLX(J_H]8K1FAZ$O+DGM#YT)AG=GQF#
M"IL"?X8QX!P57#&!.:*%S3R5GD50@,X
M\(0(U0EN@= 3=P+CU^PV(R^=,9$'Z 3+PQB@V'UG?YK4S7U0V.&+++=S:I(M
M@0=3<,,^2_8-2W(7K>-F)1%K@7#[CA[WRN!)7:H,$]KJ/Z%8_G!Y!2R.XD+;
M3HR_OQ(+)?;WX\(PC]D-$UT.#8P>8SKKV)ZKK06M_DQO7&TR4DP0P"G(U0C>S1N;B
MR"P3YO686<9XN+1*HDL&5Y7\CDE2I]'S:)+A7]=M)A.0Q[BRJ$GF98!I!VSZ*J%K>=*PNM;TOK)DK*I'!2*@G;*TX*TOCB;TF%&L_*B;)
ML]/7X\-V@_%K][/QBP%,/Z);_7E3M3$$$: B*<@8_DVVQE09_9<=72"
MU)_<6)02Y<'A\^RQ:?]@!Z>F/BWCI*C5;VOGHRI2]?UUG[/K632]F%;JSGF_
MJPGO["RD*79^*?Q&9TI\$E@.ND%%N0CR[PBY.>!,^1=Z//JT^&T?O8+3U*__
M^S!UL+,.UA-3*PWX1LNH(/; 3EB&P2I6A7>^J(PKOZK$\X[)N;VMAZ(PR*;A
M,KH]+?VKF0U7>FYM@]'_^N[-H"3R+GQD(AD>T!/SSVD^GH^CE +R[(]Y_04 '?^1*X_M>?7QCX3("#H135O.[5R0I,U:"CPS.YR-I@T9A<!&S:DI;ZGL7\/@N.[Z^%,3 "/MX0L*"
MY:PSN)CX),Z;/"J3:?2+9 [\$'BJ$R,0U34_U;T7*U=Q=,)VP:[$A@'3RN ;._[(?U05>E=?XJB0I^UZ%74_3 M7P
MN&RFHXX+;EU4;B;CF ;:3Z&S-;UG6J8CGR7@G=GM7LQ0CU1K%)NK\PIHO4SK
M4:/Y?N)"^K_D.;WDLJJ/(7JSP)?(".X, ER7TCKY2<[W;LJV/G9/JF/.ICX%
M?]AB*OO5X?J!/K#V'_SR\UH $Y G%DU&_Y8-+UC:)+2 )1UMTSA-,IK:&M34
M5_S8?_S;OT>7PMJJ*H('$F"I"7#.IH@2.+FK^S[,0$UX#2N;51&0 OR8%:CQ
MUE7_QDKB:EH)PT[41DOCJN)_LW)J-M[0>NL]^4XVU&L-C^1O)%GT][R1\)OS
MN)&8+!Z-WC&XKX^@-!DR<^>@-GE]F^T&;!S.&/3NQ#>'+1YY3F22E2#"Q75H
M8@"S$MX$?.Z?C'7#<3:4V5\7E-T-/#!#_I2F#?S#*$*4GM'N'@6L6?PMTNVL
MN&S/P01$VO.H*'&0I+*0 VMGCCR=VTOL DK9TR?%M[G@8&A2VC30D[LZ1@2&
M'PVQ(!\D*ESU^9@1[#/7O7I/X]!JQ_\KCJ7D\K4!@9%%: /O)^HHK\S-)*L\D\72:14U=ATMK\MV5W%S'
M19I'%7&]OIQL:;_F%.X=\D @=Z06KW:\P0+ 1],X+TOD5U7N16_/!RLA3](L
M3AHR[*7 \X"//A^L^8D'/A@LS6X9I_G@84U&QY 5087)IYYPNOMI-E3OHF=Z
M'9OG>7UFU.OPI$U2NU=[&^2Y 8*KQ#(]>#CBTI@_+=?+^\,]R*?'$!;;B!6XVW]JKQGJ ,6,AAV]K%[@P#8A^^.8$!;!)08KQ?#+;]),FFO)OA
M[TNJ2+WH\OW'TZA)52X
MDJH9/*'F>1JE23+81=VK3K$(*7$3NPJJMJ;J;!THB#9*;AXMX*IF/H#4&2AD
M>@+KP\.T:7_<#]WBL3#Q=9RD*:F\-6D6(!>:HB!FR8P?1$8S;*4;63RY*P&Z
M)=\Z$]"O+(PZHOQ(G%_S^I=:'N)4C;BE57*9Q76I%! \B3R+)E6"&B;NXX*^
MSN@D,ZFF4_JZ1!<)IJI@WKXDY\_V(0TC@R?@/(TG>#S'IW#*F51XR$YA1_-T
MBQY3RQ-P;)FD%=X!R@9\SI A@)+$-WRJJ&OISR8
MNNKLICZ 0E, Z-0#1[5)6!O)M 2NA/O2
MGI1]]F6#L>@\0+C+(X[./A4:Z&V#FFV@K%G"#?$]UE7,WR3/Y.\QNA_SQHY!
M6;^*^*AOE\0?\#_@Q$.KR.4V)^]=1N()*SEL4<-D1Y.$.#."7.D\08Q;O?:G
M ,6>&?SP)M2'9\9(A@R7KD#%')K$2R,M_LK2 HG/;0]BGN\MP6"@;I#9AOP:
MK3)Y^R]^5G$8"+MU&*9#^!,8D.PH7W+T4>FHD\0E'WWJ>$H-)87YIHRG67X<"YGOAYNK5#X7<55/
MS8-75,UZ'GW",;S?(+PD2UV0PI'7]=\=G2AYN4-LOIO*WO,C+//R6]HU968Y^2SIM/5SD
M:? MG1O+M.B_D1=NRH/NF1W0T^'<32U6W&*6]=_H7EU?3)MJ_ "35K^3OGZG
MK7Y76=)_H^Y.TA3CN^,_7%PT:G:./IQ%$P8BGW.^F<:@=%%G>*B8?FASR',?\RQ[^W,))F**44L90;6
MK(;1Y/"C1'Z@C-+XL?A$F8NV0M(F+>.T+.ET4DY!G=D!LS(> 84..3 O4S'I
M]#QYXW3V,;UL24<*P)G6.9^HZBH;=4Y^WVED&N?4")K?H)'6#2%I
MPW_'=>JH]/ADI(>GS+]PJM-'W)3'HS LAB9Y^H :JO*(&3N3 
M]  U4.?P[[ A=[^7R"QV4)VAJOMY_O#A&K$^;;OBXN#*H)0\:0L&C%="_O(A
M^FFSO9NMT=RQPX ULN["G]<+>#V,*'HU6_\:%3FH(K(C=+_,_GL6D?6M+COC
MI P_94WL5[MH] CG:QU"L X# 2C?$1PCQMVGB6X9MOZ7TX3^(I.CS$XU%6E<
M%C7\+=+D!.NW"_4;,-+VF<);YNU]IT]/9XE&@R19HI-ZREJM?&CD ZI\=<(5
M;3B& .T]A;5:HQ^[8S5[<_^PVCPN%CY[]*\ZV)D_O2..C0K;I-&=2!QP>
MHGE#9[)[$7+,J9BSR;@]%[SK\L//]M?XQLECW4!A2*;BAM8'9-R[3FSZ
M&JP2#(G*:I@D<=U)Z7;=$"Q_EA_S[/R\,2%+U/OH):/H&!_#\!ZW!HS-C5CY
M#S8/Z>/59X.$(M \/:'"#+ 2ZY!APM?EG"1TY:R6MRJ.^&>+,/.9$(K^22!H
MHI<"0?,C@1!ASIT^NV@[*P7:XQRIA;L],6
M!RP$21,W!2BQ-06#Y!>PI9(+7/<"5HQZ!]UHXJJL@%AII<
MH*F\'$XB8%KX1>K'?3\Q@.XR7S!8/;.''QBF*+!Z;WY;;&^6.WP&-?MSENT7
M)2 I'(";Y,IGW>7*8;+KN$E27BW8F]E%9?L!DY[&69V J,!)3V 2$T3#)5R.
M29*G<3-%LUA67V1IY]6+H5?CL:E.X?4%JK/9] (/*1>=('0/$'8,6_63%=SC
MH?7;;> DQ7:T@1R'#G\\RZ[X^>+J I44#IK*,5II@E3^X0#B>Q-]7-YL(A!,
MH&46@QD7H.Q02%-.OHEB4'9?>MX:)4L,H/%$A$IG1A5K-OP;4]"=:/[N^3#J
MO7[%1+CWS-L]EZ=W@HR42VMS(!F*9T((@N
MU=FM ;PS^0R(=V,[T[ZQ5=1T("]&$\O;HQT .3*%TY'_#R\3[1L;6&;&8A2%
M"4HGH(;Z@H)@LX3^U6LY_'QVD47XMK0&V>*"TT)(SI/L(B6/(+QB4M)K/RPP
M7Y_@/14L- )J(XIVDERXL>-0^=BEH^0(! \X8W-!X<+)]*(4BPWY?OC."2)P
MPZ_\XZ2@;KSI72,0O G,7CZ%^V NL2>#YTV-):O+I"IK?>=QA53A^Y0# +,]
MV1HQ[Q6!ZHBE),,Y:FP7I!:]7QZ(M 2J-15'DX+0LH]MJ>M)G&#>*OD5/IIE
ML2'_",;?@#:3PX-F00GDQE"H65I.YVP*-MJ0/4]0XCMF/>A+ CR,?7P9AHK0
M8P$T68Z?RE'>PM\BSTB1ZY!G45.<99E@:&2P(20FT*CR),KB)FW\F[3?LQNJ
M4,9)E:-Q"QX+'UIQ?LE\6U=5K]\[ >&7-N9WRE!*0FQ6=Z:.LVD:57$- _MY
M,8"DBU'+TY(#B.NZ&&7RNSP&XVM$%\8;_CP"S]?,,G8D)\OC*7T>#FY6_E-]
MI(P^PIY!31LIO1-QU18/XG5T85"TBJ+V60"??N#N)]*G^MKO"="JR0%(JA,<
M33AH!-3R+9N+]QL/UWPG!:$5K >H"Q1W6=#?!(7$CU(D135B%E<29_PVDPP&
M@';IO/6HJ2!LGJ8^!Y-2C0^_'IR 5JA7DN@)Z-@TNOBIH])N.H_UQ0L='+8#
MYZHRMF%O+FK;ISF&/%H':H/JVT[#[0(=&#'S+*HX?(HT09'-@#<^D+FKD[0*PY;'H1)/2WBM,[C"BBS
MK%(,\XH;.$.\-BBN#D:D%[:5111+N :8,_!UT$CKN&Z0G53,Y^.4)J33:GM:
MB!W'59[!>;&AJW%#,\10IVE<)E7<@!9?)S 8N$Z+&@97(F]#BYRC.[>\9FXP
MX9D""*<764+_3'ON-R^D)U)^8FJ>" +B.O3O'[QS;GHF4"N7LS;6"Z$C01>!/IH3.K0N=1AB'0%;G2>J(++A%#045]7!*^RQTH
MELN1)^B>>&=.>'&MCS7Z$NB&7_(G6*[,>C5O] A&&(1_L:V]Y]8^F);T7!PS
M&./BN?0 ACA7[J4%7P(:]R2D1K.BUVK!<-3
M6@)35U>S,#PL9C_:6%-P*::*;DH_QDFJ&@"JD0&6%R
M+(CX/F0DA%>JD,)<+39@FR"_7P"8%,M8255G TON7%,?B P9H7G
M=;Y'G%(I-/:TADHG/#8;#O!IL5K\BL#V6T;(=W$2&KG#J1<*.JWK<[_R0)>&
MBL^<>41]'6!"VPU6QE(]>R;)/\_0\,+_4A[^VX5.(*+J9#M;*\V!66YQ34%A
M*:>X_F],JY3ZBXB$?A(EIZ=974I!"WSIQ^N_]X>UEKHM%,?W!WF*^LL#<1US"3.-.=E'=
MI%U1[5T[W/Y^N[%AV#%Z1Y"'&FORC=0"8*^J%^OG!9#@,\ *,YU-B*FJ0V%W
M9A1)'N>@Z;]9+37*+P[\$ B<-,4Y*2Z3C 2C7@(*OS==B'8YKG= ?%.,/,?$
M05L(L*LZ\YJJ!IQ8"\1.N?:S,@L%9%!KU"UXA=D,OBT*C6H_+VP>BETKH.)!
MZ$:-<4A[Q#YIK5QIQQ\LM;^!J,X_'($4F".;G"MY@)WP:^8-\+>3&SB:803B
ME# C$(]Y&[E!7AVN=\OY]_SD]X,.3X:,,0?#E4/S1:!LKTL_DXAX
M/,6AX =M?D"P36: 52F>$%)W31HU6:,+.!SUY':P@:B!DQ#^9Q.2*,_C99>6
MF>U8.HN+"EB[X%U!%^KZ)) 9]SH'EG([F=HC^^$^ZYU'LU1E>,?Q7,
MV7*WH#L_E\#O)*XM&&,'<*J.,IA\1$B-IW!L*B7W%YA7#2KE4#C@)'$GA:2)
M"Y04!4^FH 28+%O5K[+.6E==UXZ=2LHT;5_V>'+\-<'<1?WYG2(:! Y3M,X/
M)J#$@\:*]K#:9MK@P3S.Z8A#8HE5:@NO:P]-%/@=8^JU?9 O^;GO1!^RW"NO
MO,^=9+P4UA*6+TT:U/DHEJ T:?,*)2XN2K0!Y#!42E,MJGA*1^5$4&TF10XD
MP<&231L*SIW)!36%^:3NTO?*:P
MH?K<7CN^&6\%F5VJ[9(5FGV0[&$:I:!^>QMP&>6"9;AG\V.55-[G_OQUNY/3
M*A)2SSL!).T'\J*&T2$+S*;\#&PG6,U6=+]LM!KCQTM'WY(3,)@*0/N $@',
M4^Z;;BBOWMGH[0%*$=KC(-]>-ZU]*$Y39HF&$,FGV')Q.Y:9UTGKZF<,%:3*
M<5Z>/&F$G$ $WIE0Y:4K(RSPOB<=]Z^DMIJN&6+RK*H+)["FDQ@
MMQ8-6=JJN,[PB"?W25]:.S;8\KGL  GD93"(@O3S <4"+3 .&E6?LJD 5"NB
M&T%QA3Z5:> "M-8%93=$*/3_/>K&Y=,IX; 546'UIHO3=;7CJ&?_650M6& !
M+TMS,LA1\$F36P9;4,#Z"+VI!A:8U^8">.TY:A,C\_E7IZA-5:D_AM6F:5VT
MKGK#4,QM&%:A/_?J6>2%R8$YYHU1)YL>+8MG'N<=%%48:!EE32+"*6Y@3X]6
MLXJXFM91D8F21AA,WZUF);Z:E8Q7L^IJZGT^KF9E,1ZILVF_2M/U4H)1@6-HD<^SE/B
MK$DL[B)0M9'G3O(RKLA1 C^6(%JS/U+1RANR73<).1@HEX)_(:/M&$4+0TXK
MK: G04VK)*N@HY-^/2LO&N_S<3VK &U=B+?,BF-Z5HEZ5E*@*&;N 5H7,(^0
MGE7$=5V2/FU)843*Y?EZ%GJK4LJ'9C)'J_\(/:N1#@H=?CVF9]&:)J7W>4C/HJ,/*(\EVK::$J<3X^(G
M65R2#HIGNR0?5+1@H8!8#9/";5I2FDA!(;W I:858?#P?:Q@_^TBM8Y
M]C+K0#GF/SG#E'9.V\/1Y'\36N!'4^#ARH*0VXH/S,SY;YH!9;&EK22:FQ1-
M28268AAOHH2G;<'N]C@190]V .YWH-+$R$3O[@2(&T4"GDX(#M5NM_9MB/R 
M*! U9CL _>=3WJ!3=#IVW6VF=(]Q-(FIEY:/8KR'0"YW7S;?$"O^88;1Z%2;
M%OU-CCEC!I@(*+@HVR>62,=_*:YYW\9NH;V@JPSC;*<=#&,/ A,\#
M@:>Z$GV24P2%%NGR53M>AOH8Y8E3(/-TVM-?)U,=+,8DL1\2-Z-''Z< ON=D
M.YL@$:DA5M1+?I21LD)98+892I0D%4E.*)@=%LC>%/!*E H\B-CI2WM52
M(XC>$S+/3W*[$BD=4/A"Q;[BO7P_6J*18LR-^.T)\;1VS>C;,Z-K.9R7^X(I
M\.1HE_[P/:*L>K(%9\$Z.W'^1MTT841>\X?(B#^*?ALJZ"0SCCU-[%_H+\5I
MV_Y6#.*'O[YX4D$\)"S_1DPFHX4E:I&\VICH@8I9PDF#*7IWBF%AF26-4)L1
MEG43$I:L]$^CA$3@E#+_IB%Q*9P3,<.@8Z ?3II"^&8!Y[0_7%RBG3I-S(62
M//WB$B,:*YC*25&E)"Y+:. 4<0GGM#0#?:+&)$ED''5Z,;(TK>H6;Y:O0K*4U!-E%,BL46!(
M'&+WG,'A1%&:D$:73>OV"*?9*:*4FTE(3^-(+**^) M)4Y<;;)<*F,8D-5(1
M?13'1&M*14IP*B=%[KJ=5^;=2O!96<$Y(PG_C3/R!$RR6N+&Y&&^[6SQYKWS
M">6)IEO6*N2,AK-JF0,%% ]HFYG.1K VKHI$F)I0&_1@WZCQ9R*/B!
MITZ(K16PK9JC8@[.R62,Q'$6)8G^!DY6IXBY*L8@?(SEG5 . &@3Y)8>(^6R
MN !*%RF7@82M3I1R6.M6?SY1RJ6*J]-%2,+E^N-Q&<>&.*QI8<@A(^-9KX1K
M@-N:@TMSHG##E&TE8.B#;F\_GQ,M#4P$>3I9:6H&2O5
MFBD)HQ1E6F46:M+(P$9)-&F"MOFD-C(%-O8H<09OFJ3F7)H<%V831% '11%]
MS4Z:579^0[),GJ$4R&?P*$&P%VQ.E4?IM]-DU&EW,R$1,GLN.X'S9^J10LT.
M8L('RX;J3MEAU-/4_OK])E83>[W[?HMJL*G_! 94QTE)8ZIEG;+O!PV) /N79>D A(44\VUU2]N,FU8L5_X+^R/U9QPL"8F
MB36:54Y2@L)XKAS(;?\Q/3MMFW7X._P4D#9-J3_:195UU"'T;@'L6UQ7*SAF
M&W['OTX:LF ^UT"P:@UM,4N,7#"QY83!AL8F(W)=U\W,V-'Y+2Q5>/>JZZG,
M0,MHO$GA;SXN;/9 ]T$.$>F+>K>=*BJ]2'3E]ZT+N4A#RWW_)U[[W0E%]7O9
M"#:)(!Y,(7!]*[V=P)>>4W(N!L/H8;:<>]V3C6EM(CFMA*P$E(RZI]QS5&*6\LQW7JR^EP[NAE*4W@:ER\#>4"0#'X\P
MO%!Z"8)EQ0AK/:D8R((G$>BX(KM71B'(#L#HICJ53)P4IPX7'L1+EU=!#Z[R0)_T:LHT\H"=G!
M&"=Y(6(P,TFLI."P+36'W\LGD8*LN'>^^+VD8"KDVOEB6'A5WD,L 2H)% EL
M4*>9+T0L&?>;/"WSR%](+#2N)-
MHOFBOX=M=M_4J=L]2_?$<@80FVH9*,&=LN^3<=Q8M"85@/:? JGR<6"H%E('.7B5Z:6I[
M="ZJ\@R1A*4*4JISC.'^/G?E(>G7\)"A-Z(/*ISTE2D/-Y4,*YE MU>61Y@Q+/O1BF.LU*7SA/
M"9!DA+ [*JIRE57FOK&RH%,V)"R6/)$T+(X\W":,A.DR:?[V1'ETC(+3W#O;
M\.5829)D@5YF59@$4H^:^?(\YM\ 7^<%F625[C[LOGPI*R^[X1)IT#
M SZ-WULJ@?5)9%-DT+TNJV_(=\7OQ00%%5X]]B4N
M?U[/0(,%-OI\5!+SD?;:CYX!EO=VN=WMS7NP) _(+GOYB8JMF:NW&PPI=9>'
ME51H(,-ARWF$ >L5 S'&"6%N57%-P>UU+)AX[7
M=6W+7*T]*Q.@8X8+/1Z!Q+A)\C=SG]LQ2*9\X8A0I$E%8"<#=&!@^?GL]
MK=$%#EI7&=4)N%S">=KC"5)/3Q"TR>OC33! K4QIL @
MO-\T@=-,BM$=B%M8QAC4:Z)2T:#4FI;
MCO*1L3.?;,1 #V18Y*A)L@!T2+J,ZZH@4DYJ_C>CZ'%,7Z!Z3>W@GQ;%4@)D
M4Z81;(2<@N@PV"- VNSSQ7RD29/3N2$A=_\HLDHLH33R12I?)!8WT:,L]T#=
M?L#")IY"7*C.3RDVJ)XBM"3"3>)G)(J$LA;Q<]:4<0Y;1@-<.N)2;22@ A8,
MY^2U@?_B==UX.))/0UP45X;*/?%]2G\V048C:(M#QR851[DRIZGH*XHS&BA,
MI#&S)7L(I_8#J-^,[?AZL9\M5S"J%]'GJ]?1Y!FN%&J!PO=[L#06"YVGT+[I
MI]EOC.=H4#%).UE1=5B!8[FSAXB!=@SJ]>?U$L@$I\<$.[P]H(OI1=T4EGC4,//3]](K/HI\UZ_V7'I[/.$BX>+C"#
MCH1A=WJW%];%-O1D!Y7K+X=U_X^ZV>Q=:;>HLZ% =>#92=)ZQJV9@T5XCO)5#1(\+FBCSO^5R/U
MH?]4FBH>'HON;0=]KC,O[1N@CQ%WTJA@_7>LVT*__U:&D>Y"DO<_T0]CWN7E
M5.GQL-Y);=,U57M$ZT%(9 1O)L0OM.YLML([3WYRL>A[$@?UE@;E['NQ%A$O
MC$79WU1Z%PZM5[?MB0&\(_Q."WVG"Q2=W2#6&=91=\BQO+B\IWB##1,[UMB5
M@6^]%%GR426XVQ^-0J1_/%D7^>MLNR0>[3H':MO^<5# OP4QL-F2;=<5R-4K
MW-=JC-FF6*V,E%2N)P$S#)][Q8_HDZCU$6;W\KY;H'3A\8\: KSS@U0C1L0"9*H4CLF0!6.;>%!-F&>C#6==+SJMC)NF[YJB?SS,
M0.IRU.N,[3^X\#.I-&7E0FS!AS?;/^T$=?Z 0WNW_KI9?949':!!/)R9B-)^
M^C2XX&0M:Y
M[@/SP]8HHV$-NOO([6$MMM?M8FF*$-QL5JM%&*#7T"!,^F:'T/W[C20(N.G^
MZ[LW8=7,H$U(LKMB%4^R5OR2WZEQ%R?_3@&/8&E&?Z^T^,L9!\-^B),XNC<'
M:W%&H/F__7R:1_>D\O5IY#$7C8ZE2#I.BG.K
M"@2GH!-1I:&G;UJ5-4!-7LI=L]7C/'**R?KTG23Y&L3"2\+"^066\Y\)"^<)
MFIUP.2+]%7 1KAT>78+.=[?9/IY!_B%2C*D>X79.%2AL_,T0?7Y>P\EOI=-D
M>L]S(^\;2P4/,U!T0!1W=;E8S?'H(:HW5O7LG&+KBWK:J=+87%3=+\\8B*X/UQE*NYH$ISQY
MS7G\,U [H]WD8/F5C@G.>HH[U3\X<\SXU@F1IZ\ 2&!4Q\MO?/]4J,(;@1.H
M<_H[FIZ8[V,BZ;W_\QE<>K"]02(&+>1P?V"CP&#^7M=JJJ(NYGZ=RL%[=_;>
MF7KWB%>Q=M"C%7B&@1[_@BK+-!]Q^ZO#;P]L
M=P:RA)'?;?'!8\=M+7M.G-W/N\7M :&_OG;W;#ZEW==[/%*O/7?ZT_&O.'&E
MDG1TRR;BMRM&K/B3;^\AHSA6_V8_=*#^?K8Z^C6P71V3E8MXKEQ;WE_K2J
MU#N@-D'T=,WVB,/L0D?=ON5G3Z$JY^'0[,Z@A2&_XPB]1'NA3&V>H7MZ/)GH
M.EL,28]+5]T,HR?OB01<<9S31C6@8G0>),^DKGH3)B+/!!1RS86?("C.3ZA\
MC7G&P.3&#@OWO0Z]?>>";L50-#&/!"FCOWU4,;F@W!/TH7/C&63Z;CU?W,*&
M!"4895;H/4-Z60<[6 ^QR^C.CG+N^!Y /_]7C"7H6=&W6,[6E6[^7HGJ,[ A5("CA*UR$>O =$B?NBX&&SAUPY'/^SVFWO$SUT.123TW(8^
MUB.2]EUWP@X#6F\95O#01[*XGVU_E:C@V7Z0$(_7X"%>2P7;@*R:^!NWPU#BT\FO!/DY]G6X9[4?3?,6Y!+^:^[:7KJVGV*(ZADL_*P"/MQ-UX^@*GY=M&3JV(&/9ABV
M)[$&4-9Z@HQJCE:=C^CUL7Z@GS?KK?T"0TV'.=^#),_\RR(*/NQS/G>USVCPVS>>T>6Q^
MC\QKO[OTW(EYR@EYFHDXA[]Q3/;$. F QX7O/,>UVR7EH)Y\1G^:K\@ZX%0JS76LI?8T[:Z2K@"-HCLY34,7A)>41=28@GO7ADK^+(7D'9^0[S)G^ "K?S?(!
MOR.:;+ZGS^*B*=S*?UR@?1._/,T9@DC[S:4<,3LM308QEA4!9HEN2'981+?.#C.SP:U#[6J'JDR-
M(3[6)S'Z:-AQUSDZ4@8=CKE[!I9"1A(+29&Q8]_9??9F1#?\[/'NZJ5%F!LD
M]<"2!RBOO,C+/-Q2T]L2/Q3@"'D:9E'3@:;PH>ZW)?3UY*;*X #[IBKMUSC+
M\%25679Z2_A0]]ND;WS]JBL_U/VVRI+3F\*'NM].^V1,OQ*,#YVR?D,MU5EY
MWD,G2,M\H*FLZNET<>2A@.MH?KC9J\C',5&@"F#"W1W0%GIDQ2E"!0B\K@>$
MRL#F1_% _K(7W>IE@7T$KSFM8UE9#DF[H?V/CY[RLOIBVE1#+^O?U_SH:2]+
MFF+H9?W;E1_M*%N@A$<8#! U()/7FWXD0BHNBZB[N
M$_7J;"HH+LJB2P5/TJOO()?BHLJ[Y/)$O3J;KHJ+.N_3 HVNQ$[YSEFF3_?S
M5:PXNF5?Q;WX\@W&#+K_?H.SQH:0S:/]M\4*5/)P&,9Y35*>RO[;YBE;^[)=
M=!WCY[=WNSETO3+?T5S X#.Z.:05TQK7-OW>-D-ARJ.[LU1PY[;LX$-/4C,3
M;%#6ANUHG7WH;$Y\O8PNUGN'X_T(=9@
M%>U[_[I8SV&OG]8%.=QAMBU;TQ;[/6+"8+(618".FBJ:&?L(9K^@U7XXET^]
MB6--8X'T&1JC>9%$I][*BV);FO7ZZ)3V-G'\[7_Y$/VTV=[-UHCZ-)!&:1GS
MJ]GZUWZG9*?HY8"5J(^S)H.YUC]OOEKLA;1G[3K5.?NCZV>K!7/^Z]G-K_XC
M PMM(Z9V+D -(P& 6UD?X@%3L3N]7^QMUEALX+D0K\1.V9A7W<(L(GP2=GYE
M.[]WG3_:C_>+W6[!#[?5\%CA AKV1;N50-;6%(S66;*>*,MWK9P@L;F-&7<=
M.F[U+RPZJ(6Y]CJHLQ['^V"C1[S>64^X9K?1#Y_>];?2/UAO,_63ZQG6JT#[
M/0&)H[?NF_N'U>81" OQ&1;0-QN2SOG)G J" R'DKY<$?_I4N 97>/>+ZQE#
M?*KW:Z%Q_1CI^V2$W),C9F-;NT-*=FB85P(?DS9OU+N[NWDQ7]S Y@.IQE/1
M1Q(?%Q(PC(!QNYU^<8>P$87TE_OU\OJ L*5HLR6[+V;=]#(^P9\[[$$Y0P"B;N]W^^WRAH$[<*EI :/)QZO/B. &!/%AL:4,9G(F
MZ5L^T"U'^DTPN]@)G!8,^,*X;>18^!UC;QU?C,]KE7/NN%@=X2
MD,); HB@9D/O[ D:9UOHK1^DIR&".:>X_1C.)\\F_,M3TQ&&/V\D(3EVT(OM
M>WXD,*I \%_HI6\WV]O%,O"#>M.;H++A===BE[V4":1.O'B-MGWG@^H,YQ>G
MR\31MS;^V79Q/UL*T ^+J@/,*XHO"L8-]"EA_3_M.9/)SPG_W/[5>4.6"/J]
M1@P36K_VC8'H_>$MTAM_2(S* +N&\]-[Y%R@#V=NPA/9_"\/ 0">?D[X74*@
M]F$;45\&1W;D
M=\+*XNPY9/6#J+1GK[:]4:4,7,V^VF0A[WEZYOE9.26"TM4KXSFK^?=C ;G3=EI$="V:C\6YU%/].QFN !O8W7RPWDJ( 764<#S7!V.K]KEN'Z]W-=DE;).BE3XJ0$O\$7;&9
MV+1M?YIM?UWLF4W$;II>!WITR<"X/*&]"A7]2G#U\^@U0Y]\(+$2BT811T-K
M$TB@($69RR%,W%7T&CZ V+IAJ(S-%EC@.<<6OP@?XX"K$GQQ]/GBZN+DASX<
MX)"]B3XN;SJ&5'] N(B;M<&A4\-[8THFGAZNQ?B X?!DN2 4-5&X>0B)8GU#WC3_]-HS.12G<\"Z(+H3V\ ,
M9>%]B)-I%EORVF^EZ9YCU22Y2*9_U^G0A-+]NU]G2?![M6"GO3Z[R+K#"(XM
MK2_2[KX_6T^#:US%IP]?Q]:G0GW7SC&_PR^A;&]T0U&)MXR
M/D7GCH^R(HQ*@*BELU4O/#'>LS/;U"QNT+A/Y^1[%H3'8JE>:^8VF,_TU^/;
MI"=!:@1;'$7S0IQ^5NHQK?JG7_ S"
M&6KN"!Z1LM@HBYCA KG:+[9K#LPVKCA':QXI!XP>J*\,D6: ?F))
M_,3)F 6C)(,/\7%LR'3UBS?2X4UH]A>9'."4>/.%V(#%F'*/#F2X:6KP5@&;
M,J>ELT(H>]H:D1+.T%ESP2_=X2$'EX=R1.F4C:[4+08+L)VDB\).#2S7J@&S
M6<2:Y[4W_#AYEE4+9#<*(=F?0-0#^>,#3WW;'%:$QS:[V0N^-5)\G["QY0L^
M8*T1LIT^C4&^@_D_<,.HHA[!1L;40'C!^,(=V8 0PC@U/$DXU?HIOU8/B;#@
M!@LTTZIQ&X=[U\07O[&F5CW8=$TV_(7*]7\[-P!VNI]A:C)$)
MVSOL9R8@.$!J@VY64_A@]1C9=^UZ,40_V$D?/O+BN7BITFT8,?4.]-6EG/#,
MSZ,=7Y)^IAH>S+-N(8' JF 0^[C;JG&WU>-N:T;=EDY'W-:?@1VZ&56D[EE)
M# O.*=DS-;UW=F:G]\[.!/7>V9FCOCN[TQ2^LW^F>NX/3=81*F[/^8!L[DO7
M:34Q'P,A\!%%7Q^TRF*UBJZ60UEU2='CNVCY]C$EZGAK)T8Y('#"4MQ%0]$.
M?7T, #\=[^-19J0O^&@(,05,"]!7U;
MK69.4R/8G,ZY7'#2=S#B_;?%8FV5=0^?\NF'=3)Z\/'-,[8PS#F[R#3]P$UW
M]2R%%\;X1&+9=&5UX%&,LNT\RE_3DR9\QAQH-%!W"6SAJ]X)&EN4IR-9E9Y_\V5Q\VN@[-8Q O@HT_=AADNA0L%:
M2]X?4C^2''I?-"PQ>U1$+6"H4N!NQ\ /[IQ&+_].+GS8PL8OH
M&GH0\LPSP!(%!<%(;WR<2,)=^F2J"IPQW5>'APM&/
M!FBS?W7@/!U%I:BH1I;K,>^0L:,G]-P47R%+5HL_C"V:VU7/POB5>V'36W.*
MM#7AR8\]4!6>G #[PS;@-52E@D,U?UVEW/Z:OW:(G743B[HI_\RU^7KK&WHJ=NO?AVTK-77M%[2S@.
MQYD7V#6@9(HVAEPS[$2?,UA'95*#U#-XBZ'YH.$-!?"LM73'*G?K]]S#.JMI^)X+)G^_6.;D9Z)
M]K#9NK]$4\]M&*HWTKCUHZT(VD-VI\-V>(G"&CD'9[L?00X.DG.4R?,0. Q0
MYBAX&!^CH;=F6P"-XW@'CTZ5&X$K1<@X9QH$YSME?ITQ,?.9N.'%32D9*6WT=B5[:45KA@8T]E[.[A"@65
MP:/E&T63?QXDCW9=[!9)A6WH-]XT<%$L4>U RO].4_]4"KRN#,8(M=>/T>2P
M(\7BN3(YX@'J:]")H2KSM+;YB2_C.F3#+_M@"YBATF045AVL.KCE*<)V0>BC
MR\$J:8'N.86[OWNX^T#]QKEX\Y5AY=2*#.+VCK5QIX/)AG^9K6W<:L<'\79Q
M?8'%Y8,_ZBK0G1]=.CR&%=Q@J:->Q:8U!<-QKYV;>UK]1]@VL(ZKQ[YM\WD]
M QT7CNU/I6EVZ[^/\/BZ1O[K;K?_^_\74$L! A0#%     @ 93%12!:3$3-K
M @  'C8  !,              ( !     %M#;VYT96YT7U1Y<&5S72YX;6Q0
M2P$"% ,4    " !E,5%(2'4%[L4    K @  "P              @ &< @  
M7W)E;',O+G)E;'-02P$"% ,4    " !E,5%(8&#>FL4"  !D-P  &@      
M        @ &* P  >&PO7W)E;',O=V]R:V)O;VLN>&UL+G)E;'-02P$"% ,4
M    " !E,5%(ZL*N)&\$  "V%0  $               @ &'!@  9&]C4')O
M<',O87!P+GAM;%!+ 0(4 Q0    ( &4Q44C]8#ON/P$  &D#   1        
M      "  20+  !D;V-0&UL4$L! A0#%     @ 93%12"A%10EF @  3 P   T              ( !
MTQ(  'AL+W-T>6QE&PO=V]R:V)O;VLN>&UL4$L! A0#%     @ 
M93%12#E)=SB0 @  XPD  !@              ( !(1P  'AL+W=O+@  >&PO=V]R:W-H965T&UL4$L! A0#%     @ 93%12%]CXGBR!0  :Q\  !@              ( !
ME30  'AL+W=O&PO=V]R:W-H965T&UL4$L! A0#%     @ 
M93%12+'7.H"B 0  L0,  !D              ( !)CX  'AL+W=O&PO=V]R:W-H965T&UL4$L! A0#%     @ 93%12 /M*4.B 0  
ML0,  !D              ( !K$,  'AL+W=O&PO=V]R:W-H965T&UL4$L! A0#%     @ 93%12)(F4\J? 0  L0,  !D         
M     ( !,TD  'AL+W=O&PO=V]R:W-H
M965T%,  !X;"]W;W)K&UL4$L!
M A0#%     @ 93%12*\%X*R? 0  L0,  !D              ( !N$X  'AL
M+W=O&PO=V]R:W-H965T&UL4$L! A0#%     @ 93%1
M2($B3$*? 0  L0,  !D              ( !/50  'AL+W=O&PO=V]R:W-H965TQ7  !X;"]W;W)K
M&UL4$L! A0#%     @ 93%12%]S<:7^ @  ,0X 
M !D              ( !Q%D  'AL+W=OAKT!  ![!   &0              @ 'Y7   
M>&PO=V]R:W-H965TU>  !X;"]W;W)K&UL4$L! A0#%     @ 93%12!P@*LNZ 0  >P0  !D             
M ( !X6   'AL+W=O&PO=V]R:W-H965T
M&UL4$L! A0#
M%     @ 93%12*%A1 Z_ 0  >P0  !D              ( !N&8  'AL+W=O
M&PO=V]R:W-H965T&UL4$L! A0#%     @ 93%12)_T
MV9N^ 0  >P0  !D              ( !AFP  'AL+W=O&PO=V]R:W-H965T&UL4$L! A0#%     @ 93%12"_^-,BD 0  L0,  !D 
M             ( !8W(  'AL+W=O&PO
M=V]R:W-H965T&UL4$L! A0#%     @ 93%12-9S8*2C 0  L0,  !D              ( !
M+W@  'AL+W=O@  >&PO=V]R:W-H965T&UL4$L! A0#%   
M  @ 93%12!\1AT*[ 0  &@0  !D              ( !GX   'AL+W=O&UL4$L! A0#%     @ 93%12((<+!-8
M @  FP@  !D              ( !WH<  'AL+W=O&PO=V]R:W-H965T&UL4$L! A0#%     @ 93%12(^?]@7M @  X@T  !D     
M         ( !UI   'AL+W=O&PO=V]R
M:W-H965T&UL
M4$L! A0#%     @ 93%12%%@*-QE @  20@  !D              ( !AYH 
M 'AL+W=O&PO=V]R:W-H965TN?  !X;"]W;W)K&UL4$L! A0#%     @ 
M93%12 5=\#ZA P  #Q$  !D              ( !Y:$  'AL+W=O&UL4$L! A0#%     @ 93%12/\0FU;- @  
MZ T  !D              ( !DJL  'AL+W=O&PO=V]R:W-H965T&UL4$L! A0#%     @ 93%12.&PO=V]R:W-H
M965TZ]0$  /\%   9
M              "  4"\  !X;"]W;W)K&UL4$L!
M A0#%     @ 93%12+0<1M%1 @  [@<  !D              ( !;+X  'AL
M+W=O&PO=V]R:W-H965T&UL4$L! A0#%     @ 93%1
M2(#VS;FT 0  . 0  !D              ( !$,8  'AL+W=O!0  &0      
M        @ '[QP  >&PO=V]R:W-H965T&UL4$L! A0#%     @ 93%12#GRS$V! @  KP@ 
M !D              ( !7\X  'AL+W=O&PO=V]R:W-H965T&UL4$L! A0#%     @ 93%12'NNWKP4 @  #@8  !D             
M ( !=M4  'AL+W=O&PO=V]R:W-H965T
M&UL4$L! A0#
M%     @ 93%12#M_0T?V @  &UL4$L! A0#%     @ 93%12.';
MB!' !   .1<  !D              ( !O>4  'AL+W=O&PO=V]R:W-H965T&UL4$L! A0#%     @ 93%12(DN/ "S 0  ]@,  !D 
M             ( !N.\  'AL+W=O&PO
M=V]R:W-H965T&UL4$L! A0#%     @ 93%12+ @D?P/ @  #@8  !D              ( !
M>_@  'AL+W=O&PO=V]R:W-H965T&UL4$L! A0#%   
M  @ 93%12/U!1Z7, 0  1@4  !D              ( !#@$! 'AL+W=O&PO=V]R:W-H965T&UL4$L! A0#%     @ 93%12*P6*@4.Z0  (;H# !0     
M         ( !#3H! 'AL+W-H87)E9%-T&UL4$L%!@    !F &8 
*_!L  $TC @    $!
 
end


IDEA: XBRL DOCUMENT
/* Updated 2009-11-04 */
/* v2.2.0.24 */

/* DefRef Styles */
.report table.authRefData{
	background-color: #def;
	border: 2px solid #2F4497;
	font-size: 1em; 
	position: absolute;
}

.report table.authRefData a {
	display: block;
	font-weight: bold;
}

.report table.authRefData p {
	margin-top: 0px;
}

.report table.authRefData .hide {
	background-color: #2F4497;
	padding: 1px 3px 0px 0px;
	text-align: right;
}

.report table.authRefData .hide a:hover {
	background-color: #2F4497;
}

.report table.authRefData .body {
	height: 150px;
	overflow: auto;
	width: 400px;
}

.report table.authRefData table{
	font-size: 1em;
}

/* Report Styles */
.pl a, .pl a:visited {
	color: black;
	text-decoration: none;
}

/* table */
.report {
	background-color: white;
	border: 2px solid #acf;
	clear: both;
	color: black;
	font: normal 8pt Helvetica, Arial, san-serif;
	margin-bottom: 2em;
}

.report hr {
	border: 1px solid #acf;
}

/* Top labels */
.report th {
	background-color: #acf;
	color: black;
	font-weight: bold;
	text-align: center;
}

.report th.void	{
	background-color: transparent;
	color: #000000;
	font: bold 10pt Helvetica, Arial, san-serif;
	text-align: left;
}

.report .pl {
	text-align: left;
	vertical-align: top;
	white-space: normal;
	width: 200px;
	white-space: normal; /* word-wrap: break-word; */
}

.report td.pl a.a {
	cursor: pointer;
	display: block;
	width: 200px;
	overflow: hidden;
}

.report td.pl div.a {
	width: 200px;
}

.report td.pl a:hover {
	background-color: #ffc;
}

/* Header rows... */
.report tr.rh {
	background-color: #acf;
	color: black;
	font-weight: bold;
}

/* Calendars... */
.report .rc {
	background-color: #f0f0f0;
}

/* Even rows... */
.report .re, .report .reu {
	background-color: #def;
}

.report .reu td {
	border-bottom: 1px solid black;
}

/* Odd rows... */
.report .ro, .report .rou {
	background-color: white;
}

.report .rou td {
	border-bottom: 1px solid black;
}

.report .rou table td, .report .reu table td {
	border-bottom: 0px solid black;
}

/* styles for footnote marker */
.report .fn {
	white-space: nowrap;
}

/* styles for numeric types */
.report .num, .report .nump {
	text-align: right;
	white-space: nowrap;
}

.report .nump {
	padding-left: 2em;
}

.report .nump {
	padding: 0px 0.4em 0px 2em;
}

/* styles for text types */
.report .text {
	text-align: left;
	white-space: normal;
}

.report .text .big {
	margin-bottom: 1em;
	width: 17em;
}

.report .text .more {
	display: none;
}

.report .text .note {
	font-style: italic;
	font-weight: bold;
}

.report .text .small {
	width: 10em;
}

.report sup {
	font-style: italic;
}

.report .outerFootnotes {
	font-size: 1em;
}


IDEA: XBRL DOCUMENT


  3.3.1.900
  
  html
  340
  497
  1
  false
  108
  0
  false
  4
  
    
      false
      false
      R1.htm
      0001000 - Document - Document and Entity Information
      Sheet
      http://www.t-mobile.com/role/DocumentAndEntityInformation
      Document and Entity Information
      Cover
      1
    
    
      false
      false
      R2.htm
      1001000 - Statement - Consolidated Balance Sheets
      Sheet
      http://www.t-mobile.com/role/ConsolidatedBalanceSheets
      Consolidated Balance Sheets
      Statements
      2
    
    
      false
      false
      R3.htm
      1001001 - Statement - Consolidated Balance Sheets (Parenthetical)
      Sheet
      http://www.t-mobile.com/role/ConsolidatedBalanceSheetsParenthetical
      Consolidated Balance Sheets (Parenthetical)
      Statements
      3
    
    
      false
      false
      R4.htm
      1002000 - Statement - Consolidated Statements of Comprehensive Income (Loss)
      Sheet
      http://www.t-mobile.com/role/ConsolidatedStatementsOfComprehensiveIncomeLoss
      Consolidated Statements of Comprehensive Income (Loss)
      Statements
      4
    
    
      false
      false
      R5.htm
      1002001 - Statement - Consolidated Statements of Comprehensive Income (Loss) (Parenthetical)
      Sheet
      http://www.t-mobile.com/role/ConsolidatedStatementsOfComprehensiveIncomeLossParenthetical
      Consolidated Statements of Comprehensive Income (Loss) (Parenthetical)
      Statements
      5
    
    
      false
      false
      R6.htm
      1003000 - Statement - Consolidated Statements of Cash Flows
      Sheet
      http://www.t-mobile.com/role/ConsolidatedStatementsOfCashFlows
      Consolidated Statements of Cash Flows
      Statements
      6
    
    
      false
      false
      R7.htm
      1004000 - Statement - Consolidated Statements of Stockholders' Equity
      Sheet
      http://www.t-mobile.com/role/ConsolidatedStatementsOfStockholdersEquity
      Consolidated Statements of Stockholders' Equity
      Statements
      7
    
    
      false
      false
      R8.htm
      2101100 - Disclosure - Summary of Significant Accounting Policies
      Sheet
      http://www.t-mobile.com/role/SummaryOfSignificantAccountingPolicies
      Summary of Significant Accounting Policies
      Notes
      8
    
    
      false
      false
      R9.htm
      2104100 - Disclosure - Business Combination with MetroPCS
      Sheet
      http://www.t-mobile.com/role/BusinessCombinationWithMetropcs
      Business Combination with MetroPCS
      Notes
      9
    
    
      false
      false
      R10.htm
      2105100 - Disclosure - Sales of Certain Receivables
      Sheet
      http://www.t-mobile.com/role/SalesOfCertainReceivables
      Sales of Certain Receivables
      Notes
      10
    
    
      false
      false
      R11.htm
      2106100 - Disclosure - Equipment Installment Plan Receivables
      Sheet
      http://www.t-mobile.com/role/EquipmentInstallmentPlanReceivables
      Equipment Installment Plan Receivables
      Notes
      11
    
    
      false
      false
      R12.htm
      2107100 - Disclosure - Property and Equipment
      Sheet
      http://www.t-mobile.com/role/PropertyAndEquipment
      Property and Equipment
      Notes
      12
    
    
      false
      false
      R13.htm
      2110100 - Disclosure - Goodwill, Spectrum Licenses and Intangible Assets
      Sheet
      http://www.t-mobile.com/role/GoodwillSpectrumLicensesAndIntangibleAssets
      Goodwill, Spectrum Licenses and Intangible Assets
      Notes
      13
    
    
      false
      false
      R14.htm
      2113100 - Disclosure - Fair Value Measurements and Derivative Instruments
      Sheet
      http://www.t-mobile.com/role/FairValueMeasurementsAndDerivativeInstruments
      Fair Value Measurements and Derivative Instruments
      Notes
      14
    
    
      false
      false
      R15.htm
      2116100 - Disclosure - Debt
      Sheet
      http://www.t-mobile.com/role/Debt
      Debt
      Notes
      15
    
    
      false
      false
      R16.htm
      2119100 - Disclosure - Tower Obligations
      Sheet
      http://www.t-mobile.com/role/TowerObligations
      Tower Obligations
      Notes
      16
    
    
      false
      false
      R17.htm
      2125100 - Disclosure - Employee Compensation and Benefit Plans
      Sheet
      http://www.t-mobile.com/role/EmployeeCompensationAndBenefitPlans
      Employee Compensation and Benefit Plans
      Notes
      17
    
    
      false
      false
      R18.htm
      2128100 - Disclosure - Income Taxes
      Sheet
      http://www.t-mobile.com/role/IncomeTaxes
      Income Taxes
      Notes
      18
    
    
      false
      false
      R19.htm
      2131100 - Disclosure - Earnings Per Share
      Sheet
      http://www.t-mobile.com/role/EarningsPerShare
      Earnings Per Share
      Notes
      19
    
    
      false
      false
      R20.htm
      2137100 - Disclosure - Commitments and Contingencies
      Sheet
      http://www.t-mobile.com/role/CommitmentsAndContingencies
      Commitments and Contingencies
      Notes
      20
    
    
      false
      false
      R21.htm
      2140100 - Disclosure - Additional Financial Information
      Sheet
      http://www.t-mobile.com/role/AdditionalFinancialInformation
      Additional Financial Information
      Notes
      21
    
    
      false
      false
      R22.htm
      2143100 - Disclosure - Guarantor Financial Information
      Sheet
      http://www.t-mobile.com/role/GuarantorFinancialInformation
      Guarantor Financial Information
      Notes
      22
    
    
      false
      false
      R23.htm
      2145100 - Disclosure - Subsequent Events Subsequent Events
      Sheet
      http://www.t-mobile.com/role/SubsequentEventsSubsequentEvents
      Subsequent Events Subsequent Events
      Notes
      23
    
    
      false
      false
      R24.htm
      2146100 - Disclosure - Quarterly Financial Information (Unaudited)
      Sheet
      http://www.t-mobile.com/role/QuarterlyFinancialInformationUnaudited
      Quarterly Financial Information (Unaudited)
      Notes
      24
    
    
      false
      false
      R25.htm
      2201201 - Disclosure - Summary of Significant Accounting Policies (Policies)
      Sheet
      http://www.t-mobile.com/role/SummaryOfSignificantAccountingPoliciesPolicies
      Summary of Significant Accounting Policies (Policies)
      Policies
      http://www.t-mobile.com/role/SummaryOfSignificantAccountingPolicies
      25
    
    
      false
      false
      R26.htm
      2304301 - Disclosure - Business Combination with MetroPCS (Tables)
      Sheet
      http://www.t-mobile.com/role/BusinessCombinationWithMetropcsTables
      Business Combination with MetroPCS (Tables)
      Tables
      http://www.t-mobile.com/role/BusinessCombinationWithMetropcs
      26
    
    
      false
      false
      R27.htm
      2305301 - Disclosure - Sales of Certain Receivables Transfers of Financial Assets (Tables)
      Sheet
      http://www.t-mobile.com/role/SalesOfCertainReceivablesTransfersOfFinancialAssetsTables
      Sales of Certain Receivables Transfers of Financial Assets (Tables)
      Tables
      27
    
    
      false
      false
      R28.htm
      2306301 - Disclosure - Equipment Installment Plan Receivables (Tables)
      Sheet
      http://www.t-mobile.com/role/EquipmentInstallmentPlanReceivablesTables
      Equipment Installment Plan Receivables (Tables)
      Tables
      http://www.t-mobile.com/role/EquipmentInstallmentPlanReceivables
      28
    
    
      false
      false
      R29.htm
      2307301 - Disclosure - Property and Equipment (Tables)
      Sheet
      http://www.t-mobile.com/role/PropertyAndEquipmentTables
      Property and Equipment (Tables)
      Tables
      http://www.t-mobile.com/role/PropertyAndEquipment
      29
    
    
      false
      false
      R30.htm
      2310301 - Disclosure - Goodwill, Spectrum Licenses and Intangible Assets (Tables)
      Sheet
      http://www.t-mobile.com/role/GoodwillSpectrumLicensesAndIntangibleAssetsTables
      Goodwill, Spectrum Licenses and Intangible Assets (Tables)
      Tables
      http://www.t-mobile.com/role/GoodwillSpectrumLicensesAndIntangibleAssets
      30
    
    
      false
      false
      R31.htm
      2313301 - Disclosure - Fair Value Measurements and Derivative Instruments (Tables)
      Sheet
      http://www.t-mobile.com/role/FairValueMeasurementsAndDerivativeInstrumentsTables
      Fair Value Measurements and Derivative Instruments (Tables)
      Tables
      http://www.t-mobile.com/role/FairValueMeasurementsAndDerivativeInstruments
      31
    
    
      false
      false
      R32.htm
      2316301 - Disclosure - Debt (Tables)
      Sheet
      http://www.t-mobile.com/role/DebtTables
      Debt (Tables)
      Tables
      http://www.t-mobile.com/role/Debt
      32
    
    
      false
      false
      R33.htm
      2319301 - Disclosure - Tower Obligations (Tables)
      Sheet
      http://www.t-mobile.com/role/TowerObligationsTables
      Tower Obligations (Tables)
      Tables
      http://www.t-mobile.com/role/TowerObligations
      33
    
    
      false
      false
      R34.htm
      2325301 - Disclosure - Employee Compensation and Benefit Plans (Tables)
      Sheet
      http://www.t-mobile.com/role/EmployeeCompensationAndBenefitPlansTables
      Employee Compensation and Benefit Plans (Tables)
      Tables
      http://www.t-mobile.com/role/EmployeeCompensationAndBenefitPlans
      34
    
    
      false
      false
      R35.htm
      2328301 - Disclosure - Income Taxes (Tables)
      Sheet
      http://www.t-mobile.com/role/IncomeTaxesTables
      Income Taxes (Tables)
      Tables
      http://www.t-mobile.com/role/IncomeTaxes
      35
    
    
      false
      false
      R36.htm
      2331301 - Disclosure - Earnings Per Share (Tables)
      Sheet
      http://www.t-mobile.com/role/EarningsPerShareTables
      Earnings Per Share (Tables)
      Tables
      http://www.t-mobile.com/role/EarningsPerShare
      36
    
    
      false
      false
      R37.htm
      2337301 - Disclosure - Commitments and Contingencies (Tables)
      Sheet
      http://www.t-mobile.com/role/CommitmentsAndContingenciesTables
      Commitments and Contingencies (Tables)
      Tables
      http://www.t-mobile.com/role/CommitmentsAndContingencies
      37
    
    
      false
      false
      R38.htm
      2340301 - Disclosure - Additional Financial Information (Tables)
      Sheet
      http://www.t-mobile.com/role/AdditionalFinancialInformationTables
      Additional Financial Information (Tables)
      Tables
      http://www.t-mobile.com/role/AdditionalFinancialInformation
      38
    
    
      false
      false
      R39.htm
      2343301 - Disclosure - Guarantor Financial Information (Tables)
      Sheet
      http://www.t-mobile.com/role/GuarantorFinancialInformationTables
      Guarantor Financial Information (Tables)
      Tables
      http://www.t-mobile.com/role/GuarantorFinancialInformation
      39
    
    
      false
      false
      R40.htm
      2346301 - Disclosure - Quarterly Financial Information (Unaudited) (Tables)
      Sheet
      http://www.t-mobile.com/role/QuarterlyFinancialInformationUnauditedTables
      Quarterly Financial Information (Unaudited) (Tables)
      Tables
      http://www.t-mobile.com/role/QuarterlyFinancialInformationUnaudited
      40
    
    
      false
      false
      R41.htm
      2401402 - Disclosure - Summary of Significant Accounting Policies (Details)
      Sheet
      http://www.t-mobile.com/role/SummaryOfSignificantAccountingPoliciesDetails
      Summary of Significant Accounting Policies (Details)
      Details
      http://www.t-mobile.com/role/SummaryOfSignificantAccountingPoliciesPolicies
      41
    
    
      false
      false
      R42.htm
      2404402 - Disclosure - Business Combination with MetroPCS (Cost of MetroPCS Business Combination) (Details)
      Sheet
      http://www.t-mobile.com/role/BusinessCombinationWithMetropcsCostOfMetropcsBusinessCombinationDetails
      Business Combination with MetroPCS (Cost of MetroPCS Business Combination) (Details)
      Details
      http://www.t-mobile.com/role/BusinessCombinationWithMetropcsTables
      42
    
    
      false
      false
      R43.htm
      2404403 - Disclosure - Business Combination with MetroPCS (Consolidated Statements of Comprehensive Income (Loss) for MetroPCS Operations) (Details)
      Sheet
      http://www.t-mobile.com/role/BusinessCombinationWithMetropcsConsolidatedStatementsOfComprehensiveIncomeLossForMetropcsOperationsDetails
      Business Combination with MetroPCS (Consolidated Statements of Comprehensive Income (Loss) for MetroPCS Operations) (Details)
      Details
      http://www.t-mobile.com/role/BusinessCombinationWithMetropcsTables
      43
    
    
      false
      false
      R44.htm
      2404404 - Disclosure - Business Combination with MetroPCS (Proforma Financial Information) (Details)
      Sheet
      http://www.t-mobile.com/role/BusinessCombinationWithMetropcsProformaFinancialInformationDetails
      Business Combination with MetroPCS (Proforma Financial Information) (Details)
      Details
      http://www.t-mobile.com/role/BusinessCombinationWithMetropcsTables
      44
    
    
      false
      false
      R45.htm
      2405402 - Disclosure - Sales of Certain Receivables Sales of Service Receivables (Details)
      Sheet
      http://www.t-mobile.com/role/SalesOfCertainReceivablesSalesOfServiceReceivablesDetails
      Sales of Certain Receivables Sales of Service Receivables (Details)
      Details
      45
    
    
      false
      false
      R46.htm
      2405403 - Disclosure - Sales of Certain Receivables Sales of EIP Receivables (Details)
      Sheet
      http://www.t-mobile.com/role/SalesOfCertainReceivablesSalesOfEipReceivablesDetails
      Sales of Certain Receivables Sales of EIP Receivables (Details)
      Details
      46
    
    
      false
      false
      R47.htm
      2405404 - Disclosure - Sales of Certain Receivables Sales of Receivables (Details)
      Sheet
      http://www.t-mobile.com/role/SalesOfCertainReceivablesSalesOfReceivablesDetails
      Sales of Certain Receivables Sales of Receivables (Details)
      Details
      47
    
    
      false
      false
      R48.htm
      2406402 - Disclosure - Equipment Installment Plan Receivables (EIP Receivables) (Details)
      Sheet
      http://www.t-mobile.com/role/EquipmentInstallmentPlanReceivablesEipReceivablesDetails
      Equipment Installment Plan Receivables (EIP Receivables) (Details)
      Details
      http://www.t-mobile.com/role/EquipmentInstallmentPlanReceivablesTables
      48
    
    
      false
      false
      R49.htm
      2406403 - Disclosure - Equipment Installment Plan Receivables (Gross Receivables by Credit Category) (Details)
      Sheet
      http://www.t-mobile.com/role/EquipmentInstallmentPlanReceivablesGrossReceivablesByCreditCategoryDetails
      Equipment Installment Plan Receivables (Gross Receivables by Credit Category) (Details)
      Details
      http://www.t-mobile.com/role/EquipmentInstallmentPlanReceivablesTables
      49
    
    
      false
      false
      R50.htm
      2406404 - Disclosure - Equipment Installment Plan Receivables (Unamortized Imputed Discount and Allowance for Credit Losses) (Details)
      Sheet
      http://www.t-mobile.com/role/EquipmentInstallmentPlanReceivablesUnamortizedImputedDiscountAndAllowanceForCreditLossesDetails
      Equipment Installment Plan Receivables (Unamortized Imputed Discount and Allowance for Credit Losses) (Details)
      Details
      http://www.t-mobile.com/role/EquipmentInstallmentPlanReceivablesTables
      50
    
    
      false
      false
      R51.htm
      2407402 - Disclosure - Property and Equipment (Property, Plant and Equipment) (Details)
      Sheet
      http://www.t-mobile.com/role/PropertyAndEquipmentPropertyPlantAndEquipmentDetails
      Property and Equipment (Property, Plant and Equipment) (Details)
      Details
      http://www.t-mobile.com/role/PropertyAndEquipmentTables
      51
    
    
      false
      false
      R52.htm
      2407403 - Disclosure - Property and Equipment (Leased Devices) (Details)
      Sheet
      http://www.t-mobile.com/role/PropertyAndEquipmentLeasedDevicesDetails
      Property and Equipment (Leased Devices) (Details)
      Details
      http://www.t-mobile.com/role/PropertyAndEquipmentTables
      52
    
    
      false
      false
      R53.htm
      2407404 - Disclosure - Property and Equipment (Asset Retirement Obligation) (Details)
      Sheet
      http://www.t-mobile.com/role/PropertyAndEquipmentAssetRetirementObligationDetails
      Property and Equipment (Asset Retirement Obligation) (Details)
      Details
      http://www.t-mobile.com/role/PropertyAndEquipmentTables
      53
    
    
      false
      false
      R54.htm
      2410402 - Disclosure - Goodwill, Spectrum Licenses and Intangible Assets (Goodwill) (Details)
      Sheet
      http://www.t-mobile.com/role/GoodwillSpectrumLicensesAndIntangibleAssetsGoodwillDetails
      Goodwill, Spectrum Licenses and Intangible Assets (Goodwill) (Details)
      Details
      http://www.t-mobile.com/role/GoodwillSpectrumLicensesAndIntangibleAssetsTables
      54
    
    
      false
      false
      R55.htm
      2410403 - Disclosure - Goodwill, Spectrum Licenses and Intangible Assets (Spectrum Licenses) (Details)
      Sheet
      http://www.t-mobile.com/role/GoodwillSpectrumLicensesAndIntangibleAssetsSpectrumLicensesDetails
      Goodwill, Spectrum Licenses and Intangible Assets (Spectrum Licenses) (Details)
      Details
      http://www.t-mobile.com/role/GoodwillSpectrumLicensesAndIntangibleAssetsTables
      55
    
    
      false
      false
      R56.htm
      2410404 - Disclosure - Goodwill, Spectrum Licenses and Intangible Assets (Other Intangibles Assets) (Details)
      Sheet
      http://www.t-mobile.com/role/GoodwillSpectrumLicensesAndIntangibleAssetsOtherIntangiblesAssetsDetails
      Goodwill, Spectrum Licenses and Intangible Assets (Other Intangibles Assets) (Details)
      Details
      http://www.t-mobile.com/role/GoodwillSpectrumLicensesAndIntangibleAssetsTables
      56
    
    
      false
      false
      R57.htm
      2413402 - Disclosure - Fair Value Measurements and Derivative Instruments (Narrative) (Details)
      Sheet
      http://www.t-mobile.com/role/FairValueMeasurementsAndDerivativeInstrumentsNarrativeDetails
      Fair Value Measurements and Derivative Instruments (Narrative) (Details)
      Details
      http://www.t-mobile.com/role/FairValueMeasurementsAndDerivativeInstrumentsTables
      57
    
    
      false
      false
      R58.htm
      2413403 - Disclosure - Fair Value Measurements and Derivative Instruments (Fair Value of Financial Instruments by Level) (Details)
      Sheet
      http://www.t-mobile.com/role/FairValueMeasurementsAndDerivativeInstrumentsFairValueOfFinancialInstrumentsByLevelDetails
      Fair Value Measurements and Derivative Instruments (Fair Value of Financial Instruments by Level) (Details)
      Details
      http://www.t-mobile.com/role/FairValueMeasurementsAndDerivativeInstrumentsTables
      58
    
    
      false
      false
      R59.htm
      2413404 - Disclosure - Fair Value Measurements and Derivative Instruments (Gains (Losses) of Derivative Instruments) (Details)
      Sheet
      http://www.t-mobile.com/role/FairValueMeasurementsAndDerivativeInstrumentsGainsLossesOfDerivativeInstrumentsDetails
      Fair Value Measurements and Derivative Instruments (Gains (Losses) of Derivative Instruments) (Details)
      Details
      http://www.t-mobile.com/role/FairValueMeasurementsAndDerivativeInstrumentsTables
      59
    
    
      false
      false
      R60.htm
      2413405 - Disclosure - Fair Value Measurements and Derivative Instruments Fair Value of Short-term Investments and Long-term Debt (Details)
      Sheet
      http://www.t-mobile.com/role/FairValueMeasurementsAndDerivativeInstrumentsFairValueOfShortTermInvestmentsAndLongTermDebtDetails
      Fair Value Measurements and Derivative Instruments Fair Value of Short-term Investments and Long-term Debt (Details)
      Details
      60
    
    
      false
      false
      R61.htm
      2416402 - Disclosure - Debt (Narrative) (Details)
      Sheet
      http://www.t-mobile.com/role/DebtNarrativeDetails
      Debt (Narrative) (Details)
      Details
      http://www.t-mobile.com/role/DebtTables
      61
    
    
      false
      false
      R62.htm
      2416403 - Disclosure - Debt (Long-term debt) (Details)
      Sheet
      http://www.t-mobile.com/role/DebtLongTermDebtDetails
      Debt (Long-term debt) (Details)
      Details
      http://www.t-mobile.com/role/DebtTables
      62
    
    
      false
      false
      R63.htm
      2416404 - Disclosure - Debt (Capital Leases) (Details)
      Sheet
      http://www.t-mobile.com/role/DebtCapitalLeasesDetails
      Debt (Capital Leases) (Details)
      Details
      http://www.t-mobile.com/role/DebtTables
      63
    
    
      false
      false
      R64.htm
      2416405 - Disclosure - Debt (Financing Arrangements) (Details)
      Sheet
      http://www.t-mobile.com/role/DebtFinancingArrangementsDetails
      Debt (Financing Arrangements) (Details)
      Details
      http://www.t-mobile.com/role/DebtTables
      64
    
    
      false
      false
      R65.htm
      2416406 - Disclosure - Debt (Lines and Letters of Credit) (Details)
      Sheet
      http://www.t-mobile.com/role/DebtLinesAndLettersOfCreditDetails
      Debt (Lines and Letters of Credit) (Details)
      Details
      http://www.t-mobile.com/role/DebtTables
      65
    
    
      false
      false
      R66.htm
      2419402 - Disclosure - Tower Obligations (Narrative) (Details)
      Sheet
      http://www.t-mobile.com/role/TowerObligationsNarrativeDetails
      Tower Obligations (Narrative) (Details)
      Details
      http://www.t-mobile.com/role/TowerObligationsTables
      66
    
    
      false
      false
      R67.htm
      2419403 - Disclosure - Tower Obligations (Sale Leaseback Transaction) (Details)
      Sheet
      http://www.t-mobile.com/role/TowerObligationsSaleLeasebackTransactionDetails
      Tower Obligations (Sale Leaseback Transaction) (Details)
      Details
      http://www.t-mobile.com/role/TowerObligationsTables
      67
    
    
      false
      false
      R68.htm
      2419404 - Disclosure - Tower Obligations (Future Minimum Payments) (Details)
      Sheet
      http://www.t-mobile.com/role/TowerObligationsFutureMinimumPaymentsDetails
      Tower Obligations (Future Minimum Payments) (Details)
      Details
      http://www.t-mobile.com/role/TowerObligationsTables
      68
    
    
      false
      false
      R69.htm
      2425402 - Disclosure - Employee Compensation and Benefit Plans (Stock Awards) (Details)
      Sheet
      http://www.t-mobile.com/role/EmployeeCompensationAndBenefitPlansStockAwardsDetails
      Employee Compensation and Benefit Plans (Stock Awards) (Details)
      Details
      http://www.t-mobile.com/role/EmployeeCompensationAndBenefitPlansTables
      69
    
    
      false
      false
      R70.htm
      2425403 - Disclosure - Employee Compensation and Benefit Plans (Stock Options) (Details)
      Sheet
      http://www.t-mobile.com/role/EmployeeCompensationAndBenefitPlansStockOptionsDetails
      Employee Compensation and Benefit Plans (Stock Options) (Details)
      Details
      http://www.t-mobile.com/role/EmployeeCompensationAndBenefitPlansTables
      70
    
    
      false
      false
      R71.htm
      2425404 - Disclosure - Employee Compensation and Benefit Plans (Employee Retirement Savings and Compensation Plans)) (Details)
      Sheet
      http://www.t-mobile.com/role/EmployeeCompensationAndBenefitPlansEmployeeRetirementSavingsAndCompensationPlansDetails
      Employee Compensation and Benefit Plans (Employee Retirement Savings and Compensation Plans)) (Details)
      Details
      http://www.t-mobile.com/role/EmployeeCompensationAndBenefitPlansTables
      71
    
    
      false
      false
      R72.htm
      2425405 - Disclosure - Employee Compensation and Benefit Plans (Employee Stock Purchase Plan) (Details)
      Sheet
      http://www.t-mobile.com/role/EmployeeCompensationAndBenefitPlansEmployeeStockPurchasePlanDetails
      Employee Compensation and Benefit Plans (Employee Stock Purchase Plan) (Details)
      Details
      http://www.t-mobile.com/role/EmployeeCompensationAndBenefitPlansTables
      72
    
    
      false
      false
      R73.htm
      2428402 - Disclosure - Income Taxes (Income Tax Domestic and Foreign) (Details)
      Sheet
      http://www.t-mobile.com/role/IncomeTaxesIncomeTaxDomesticAndForeignDetails
      Income Taxes (Income Tax Domestic and Foreign) (Details)
      Details
      http://www.t-mobile.com/role/IncomeTaxesTables
      73
    
    
      false
      false
      R74.htm
      2428403 - Disclosure - Income Taxes (Components of Income Tax Expense) (Details)
      Sheet
      http://www.t-mobile.com/role/IncomeTaxesComponentsOfIncomeTaxExpenseDetails
      Income Taxes (Components of Income Tax Expense) (Details)
      Details
      http://www.t-mobile.com/role/IncomeTaxesTables
      74
    
    
      false
      false
      R75.htm
      2428404 - Disclosure - Income Taxes (Effective Income Tax Rate Reconciliation) (Details)
      Sheet
      http://www.t-mobile.com/role/IncomeTaxesEffectiveIncomeTaxRateReconciliationDetails
      Income Taxes (Effective Income Tax Rate Reconciliation) (Details)
      Details
      http://www.t-mobile.com/role/IncomeTaxesTables
      75
    
    
      false
      false
      R76.htm
      2428405 - Disclosure - Income Taxes (Deferred Tax Assets and Liabilities) (Details)
      Sheet
      http://www.t-mobile.com/role/IncomeTaxesDeferredTaxAssetsAndLiabilitiesDetails
      Income Taxes (Deferred Tax Assets and Liabilities) (Details)
      Details
      http://www.t-mobile.com/role/IncomeTaxesTables
      76
    
    
      false
      false
      R77.htm
      2428406 - Disclosure - Income Taxes (Operating Loss Carryforwards) (Details)
      Sheet
      http://www.t-mobile.com/role/IncomeTaxesOperatingLossCarryforwardsDetails
      Income Taxes (Operating Loss Carryforwards) (Details)
      Details
      http://www.t-mobile.com/role/IncomeTaxesTables
      77
    
    
      false
      false
      R78.htm
      2428407 - Disclosure - Income Taxes (Unrecognized Tax Benefits) (Details)
      Sheet
      http://www.t-mobile.com/role/IncomeTaxesUnrecognizedTaxBenefitsDetails
      Income Taxes (Unrecognized Tax Benefits) (Details)
      Details
      http://www.t-mobile.com/role/IncomeTaxesTables
      78
    
    
      false
      false
      R79.htm
      2431402 - Disclosure - Earnings Per Share (Details)
      Sheet
      http://www.t-mobile.com/role/EarningsPerShareDetails
      Earnings Per Share (Details)
      Details
      http://www.t-mobile.com/role/EarningsPerShareTables
      79
    
    
      false
      false
      R80.htm
      2437402 - Disclosure - Commitments and Contingencies (Commitments) (Details)
      Sheet
      http://www.t-mobile.com/role/CommitmentsAndContingenciesCommitmentsDetails
      Commitments and Contingencies (Commitments) (Details)
      Details
      http://www.t-mobile.com/role/CommitmentsAndContingenciesTables
      80
    
    
      false
      false
      R81.htm
      2437403 - Disclosure - Commitments and Contingencies (Operating Leases) (Details)
      Sheet
      http://www.t-mobile.com/role/CommitmentsAndContingenciesOperatingLeasesDetails
      Commitments and Contingencies (Operating Leases) (Details)
      Details
      http://www.t-mobile.com/role/CommitmentsAndContingenciesTables
      81
    
    
      false
      false
      R82.htm
      2437404 - Disclosure - Commitments and Contingencies (Contingencies and Litigation) (Details)
      Sheet
      http://www.t-mobile.com/role/CommitmentsAndContingenciesContingenciesAndLitigationDetails
      Commitments and Contingencies (Contingencies and Litigation) (Details)
      Details
      http://www.t-mobile.com/role/CommitmentsAndContingenciesTables
      82
    
    
      false
      false
      R83.htm
      2440402 - Disclosure - Additional Financial Information (Imputed Discount and Allowances) (Details)
      Sheet
      http://www.t-mobile.com/role/AdditionalFinancialInformationImputedDiscountAndAllowancesDetails
      Additional Financial Information (Imputed Discount and Allowances) (Details)
      Details
      http://www.t-mobile.com/role/AdditionalFinancialInformationTables
      83
    
    
      false
      false
      R84.htm
      2440403 - Disclosure - Additional Financial Information (Accounts Payable and Accrued Liabilities) (Details)
      Sheet
      http://www.t-mobile.com/role/AdditionalFinancialInformationAccountsPayableAndAccruedLiabilitiesDetails
      Additional Financial Information (Accounts Payable and Accrued Liabilities) (Details)
      Details
      http://www.t-mobile.com/role/AdditionalFinancialInformationTables
      84
    
    
      false
      false
      R85.htm
      2440404 - Disclosure - Additional Financial Information (Related Party Transactions) (Details)
      Sheet
      http://www.t-mobile.com/role/AdditionalFinancialInformationRelatedPartyTransactionsDetails
      Additional Financial Information (Related Party Transactions) (Details)
      Details
      http://www.t-mobile.com/role/AdditionalFinancialInformationTables
      85
    
    
      false
      false
      R86.htm
      2440405 - Disclosure - Additional Financial Information (Supplemental Statements of Cash Flows Information) (Details)
      Sheet
      http://www.t-mobile.com/role/AdditionalFinancialInformationSupplementalStatementsOfCashFlowsInformationDetails
      Additional Financial Information (Supplemental Statements of Cash Flows Information) (Details)
      Details
      http://www.t-mobile.com/role/AdditionalFinancialInformationTables
      86
    
    
      false
      false
      R87.htm
      2440406 - Disclosure - Additional Financial Information (Supplemental Statements of Stockholders' Equity Information) (Details)
      Sheet
      http://www.t-mobile.com/role/AdditionalFinancialInformationSupplementalStatementsOfStockholdersEquityInformationDetails
      Additional Financial Information (Supplemental Statements of Stockholders' Equity Information) (Details)
      Details
      http://www.t-mobile.com/role/AdditionalFinancialInformationTables
      87
    
    
      false
      false
      R88.htm
      2443402 - Disclosure - Guarantor Financial Information (Narrative) (Details)
      Sheet
      http://www.t-mobile.com/role/GuarantorFinancialInformationNarrativeDetails
      Guarantor Financial Information (Narrative) (Details)
      Details
      http://www.t-mobile.com/role/GuarantorFinancialInformationTables
      88
    
    
      false
      false
      R89.htm
      2443403 - Disclosure - Guarantor Financial Information (Condensed Consolidating Balance Sheet Information) (Details)
      Sheet
      http://www.t-mobile.com/role/GuarantorFinancialInformationCondensedConsolidatingBalanceSheetInformationDetails
      Guarantor Financial Information (Condensed Consolidating Balance Sheet Information) (Details)
      Details
      http://www.t-mobile.com/role/GuarantorFinancialInformationTables
      89
    
    
      false
      false
      R90.htm
      2443404 - Disclosure - Guarantor Financial Information (Condensed Consolidating Statement of Comprehensive Income (Loss) Information) (Details)
      Sheet
      http://www.t-mobile.com/role/GuarantorFinancialInformationCondensedConsolidatingStatementOfComprehensiveIncomeLossInformationDetails
      Guarantor Financial Information (Condensed Consolidating Statement of Comprehensive Income (Loss) Information) (Details)
      Details
      http://www.t-mobile.com/role/GuarantorFinancialInformationTables
      90
    
    
      false
      false
      R91.htm
      2443405 - Disclosure - Guarantor Financial Information (Condensed Consolidating Statement of Cash Flows Information) (Details)
      Sheet
      http://www.t-mobile.com/role/GuarantorFinancialInformationCondensedConsolidatingStatementOfCashFlowsInformationDetails
      Guarantor Financial Information (Condensed Consolidating Statement of Cash Flows Information) (Details)
      Details
      http://www.t-mobile.com/role/GuarantorFinancialInformationTables
      91
    
    
      false
      false
      R92.htm
      2445401 - Disclosure - Subsequent Events (Details)
      Sheet
      http://www.t-mobile.com/role/SubsequentEventsDetails
      Subsequent Events (Details)
      Details
      http://www.t-mobile.com/role/SubsequentEventsSubsequentEvents
      92
    
    
      false
      false
      R93.htm
      2446402 - Disclosure - Quarterly Financial Information (Unaudited) (Details)
      Sheet
      http://www.t-mobile.com/role/QuarterlyFinancialInformationUnauditedDetails
      Quarterly Financial Information (Unaudited) (Details)
      Details
      http://www.t-mobile.com/role/QuarterlyFinancialInformationUnauditedTables
      93
    
    
      false
      false
      All Reports
      Book
      All Reports


    tmus-20151231.xml
    tmus-20151231.xsd
    tmus-20151231_cal.xml
    tmus-20151231_def.xml
    tmus-20151231_lab.xml
    tmus-20151231_pre.xml


  true
  true


IDEA: XBRL DOCUMENT
begin 644 0001283699-16-000073-xbrl.zip
M4$L#!!0    ( &4Q44C?$:K"/'P# +2U4@ 1    =&UUJI%PH\)"H)B'9 
MJ:BOO]L(< 9SQ@ ""*]5*R4Q^9XGV[;WO_WO'W?=G[X7Y:#3[_W[*_PS>O53
MT;OIMSN]K__^ZJ^?7IM/[LV;5__[M__U;__OZ]?_UWY\^Y/OWXSNBM[P)U<6
MK6'1_NG/SO#;3W]O%X,_?KHM^W<__;U?_M'YWGK]^O%+][^V;BE&;?V%WB#*
M;H1N\:(EOS#:DIJ1&\+_OQ^_%@I_$805[=O;+^SV5GSY4MQBV;[YTL;B"\9X
M_&,_OI3=SJ_IOS\!U+W!KS?]46]8/OS[JV_#X?VOO_R2WOIY4-S\_+7__9?)
MF[\0A.EKA%]3_&KZM5%9 I*KOC=Y-WV1+7ZQ773JOP-OU'R\^''SK?[SZ9WT
M!;[XA4[O>S$8UG_E\;T:;#J#/B-85M_Z\\\_?QY_LU]^A8\C^LOD$],O=#N]
M/]9\.KW]I34HIA_OM3HW@WJ8QF\ED/ B2+U^KS>ZJW]&>UC^,GRX+WZ!#[V&
M3Q5EYZ;ZWN8O+7ZA+&Y78B)^@7>G'QQT;NI1@#=J$!@,[\L5GX=W:KXPO!L-
M%B 9OK[K?^ETBY]O^G=C3F,R^_1H\/IKJW5??>&V-?@R!GOR1HUHP#MEOUL,
M:K\S?J?^2XEJ]5\:OU/WI6%9?%U)5?T+O#_]:'JCO:02%?4?WUSXZ+#VH_SQ
MH\/YCW;6B7-O,&SU;BH!_9$)])]T_&FLM?YE_&[UT4&[[H/PL_B7__O[VT\W
MWXJ[UNS#G3P7A9P#D
MU>3MQ(=_?S7HW-UW :5?TL\\&KJ;?F]8_!C^U &8HT]?_0O[QV>?'C3]")CA
MSO AO3!]I=-.K]UVBO*G,1S% @I3*79O_NO5;P@0(8H*K?_ME^4OCY_QR_)#
M)L^X!Q7LM^>?"B0HAQZ\P6]3>4)X^O79>W-?*'KMV<IY
MTQP(?3LT:;'0!NX_=^3X/N_/PU!>E*&&_YG!'"Y
M_MU]OP?_')@?G4'UJ0\0U160*;8_#?LW?_Q>W'TIRI-1KM*:XFL"=/S2XVMM
M>/*/^V[GIC-\A.FG=@<^\IC>3V#_=2V&KWZ;?JP.Q7_[I?8ICT#]DD%U)I(]
MLWT[7F9G0W
MZJ:"V/OAMZ),'RN+;XD5WXLWO9O^77&=0K,MWB<2H'.(LGAC:<[?TCQSE>()
MEJ81E!=G4?:*7>#ENW[O>L/3#+\F1FE2EI.F+&=E)_9+8QLC<3$)[%YA9D5[= J>YW>U\%5BD0]DI>I]Y-CG:88<2G%B&,>=DWJ\XTP
M7* P'/S48N^(H/$!+R$VV-U.-'+Q4BQ XQ'.XZSBN>W$WI7%QE2\A!KC?@?F
MC6TY"]ORW (T:<-LSK;.[6SKF$VH>Y],-%7*ZSV3V-T*--)P$=J^7YK9'$)>
M6(JYET%O,H278-IW/X!JTH-S*$:?RS%5$^U?^G'4'A:@8?JE:_KN$7T3#EQ@
M;+^[06\2MXLQW+LSM]'A"V3S[J:ZR<\OS$SO465ODK S2,+.Q&%L=7(S]A^E[8G^A@Y;D[9PXD3)];/\*/
M>^#,A<7R>\G.,K(O5U0V^X\/[M/GLM4;M&[2FZX_&%Z?/UF)XPL2#+Z'8+PK
MAG_VRS]\ ;EP9Y#(#EIXM2*R"=L3"N^MQWXRK$99G$)9S"$?VR<+F4M=6KYU\\]>R]5*2
M]948-]E8(S3G*C3G8&GVB6$:H7E&H7GN6&:Y7\2VNFF1T:=O13%\V[]I52(S
M_<"X:0;RR\<-:<.WG=:73A<(72R7@CY"*EF.;H:C\GZ*D2,O4CPO11;.*@.J*= UPG,IPO/<
MA;IE3]M(SAE+SBDO835UE*:.?/B4B-N97DTR)7SM
MZ_BRXF5)9@VZ$ZG<#=_+#&1JZD0-_\^,_V=5&UH^.&JDYK ;OER8T&-!KPC!IP=$>_W8F>>SR.,H-!,5PN?[ZP
M[&'+,[P:BAU(S,\_?3FKIM>E$]5&A/M^+QY.[22CV_K;FTW,UAO\9=>[3Q]\D0+O=
M]-+]H?RR^%[U1<6$MDT\EPRR=K:?#=;BU@PF+;40EU4:>
M2U".7B9K!.4Z!.7H]]2.*BC5F^.CPEZKZ\JBW1D7&0>#K/4_'1]>6-CS?!*V
M Y#KB#^_'ZMS79O/FL#J>@*KR_&7]41J#.$1I:PQA1?DY#^-OMR_9/%^=C^_
MR(#+E>\3NOI&PB_,@#^#C!^]?:NQX6S"_>IH^^C2_:U
MRMP+9>=9!9L7*#97%6E>G71?<0#XLF*KLZUN7J;P7)75NI8:$&L,5\/42XR!
MSC.X>+XKM%OV1 [\J#"W0+KWO>(?1:M\5US-9:PM.Q]74N Z I5&0"Y;0,[?
M@KQ B6AL1","EVT%ZE9TI,O!"V'@[ZT?G;O1W66QMD)C%O4MX'$\?IW5Y=3]
M9E5D,_\OA>M;WLG?::?!%1CPNA$.U\[C56A>IJ%^TLRDAM77K]77SN,KU>,/
M91]^8?B0PLJT^*0*.>U#=D;PMF@-BF_];OO-W7W9_SZ>X')AS-X"W1G?U^![
M'9J]#?/'N9<==0#9WM=!:^Y#5\CY<=:U!MG+U?E=V3[]K.O?W8^&1?FI?SO\
MLU6FT9"0V'32O>XT4.H*96#ZX:TP?SD",;8#?^^41;<8#( V=Z/>9);HX-/#
M8%C<7:,G&-N#+9"^7#'8-Q9X'"+.N;0M!I"T%G$?DW">!S)X!G$?0UWO^YO/\IUB >)@"XMEZ.$P0*36?)
MB:5WC4]_T>*[9ZS3R.^)Y'?;,.Q%"O$APK5&DD]LB;>JJKY(<3Y8W;F1Z5-:
MYS55XA2>P#)?=-K%[>=7F=8O.U\3W/[%\S'P#[\WOIGOQR/\%^,
MD3LWB>7*M;\!T/_J]RY+FG>DTUS0O(I0!Q+MU9O6%NC<2/@)
M)3PZ]^F^N!F6HSOS6!5JA/W(PKZ*Y"]$[O,[](W0-T)_62=/-!YW<(H910>6AVL[
M%3REW#0'A,\DSS4>OY'CW2.A1GY/++\;@K07+<-/".8:.3[I]+3:\,$# -_A
M>]^+-^.["HE"'SN#/Q9^)@N+11W$9QEX3A)2GNY6GL=;K:1E4;
M'WNM/A9?I<8V/G8OQ<4O3W$O3V.O,RIN5+4)AZ].5:_3N3:JVGC5LU#51J_.
M2Z_.5XK3:31=/(T^GN-XT[OIWQ5I__3X>D>^)&^\?K88#,./>V!8\;'HPD?;
M'UKE\.&R!/MLS?8:%DS.SS?RX$3GVW2W\VUZ@CZ-1C,:S3@#S7CNSH^:2["-
M9C2:<0::<6[WA??]$:C,IQ"FY;@\[2
M=<9663YT>E\_%O?]$G)O<]PF96Z-3*R*-FVN4O%'R1LE?AB??-Y8-@V'G#JCZ_K;Z1A/(/E\@
MNPL[+M?!G8GL-WG9QUQSB-=;_K**QL[/^QY^@?!FRW^0V+UB;FL3F
M!90H&WUL@KLKTX#&P5VY0C4.[AIRMZ9R=Q6EBY>1NUV@:WM)LG_ACNA%V?TF
ML;D6\3_'Q.;HUM\77X:S9L?9%4'#?]8N2\[7?A-\=(3D)R0TTV)^U&RB?2/8O%?[*6%"[TU< (#V C$)0G$
MT4M];SL]B(!=6;0[X/QOTO6$AYE?_,\/O_?+KZV>^]8:7%AHM@JQB9^JP>PE
M,-07$'8"8VRK]\=5\3-'['+9R1IV/A,[C]XZT)C;TYK;Y\LHU<](R_H\:+EX
MWF2/5?:XF6I-IGC]H<2ZKG"([_*UZ]RM78#:RN/5=R,RM1U]65X^0RM;/$R4I?+QFV-;W,F\=+S
MY//V-!ODN#%'E\'&;0,&1C*/BBZ?H57 L!J]J_M8NP:]R]7:
M+5E+)<]PY]?#VC7H73UKFPSN\EB[Y>W)FL($5M?"VK7H7;VOE11G8GUA2\+6
M:>T:]*Y<:\7/0/%K#J/6H'?U6EOGC,3UL'8->E>OM0UK+T]KMV2M('EV<$4E
MBS7H73UK<0WN5Q1&K4'OUC[!UUX1:]>@=[FLWO]VLQO:JKIE?A?9A@6=E17XO K47O#F:LJ9R_%\K/7I6[\;5HSCB\$<^KCZN:KL_+UN.F-?"Y6@.?3VN;Z?N'
M:U5KIN^??VC=]$M>+6N;HNT5L[8Y,KQLUKZX0*'QR-OK-J77/#EB#7J7R]IM
MQ\ U0T&N,V]L;C!NU!<;UZ/&;S1B2/QVG@9CGTD(T]\AIA^'_UB]5[NW9QQ=$8_K.
MX;2^D8MGDXM3MC&N8?/?0*CZY75S>1..E\ODS>%:P^2+#].V9')CL"^7S?Z1
MS4W(=A:<7@C9V&XA&SMPR)8D@_R%O>M_Q\,^_)>BF82TNL7;HC4HOK1N_I@[
M'/#%X*;LW*>_SF3F<__/HIS[T(4)RG:H3D2G'M<3R0MYC7>1E_''*3IIV[T=U2\]8+,D,526;EP06:
MK).9QMH=P=KM)KZM'XWX+HOO/$T:\;UT9WU9\GA!@G(.A=OY.L"';JOWKG4W
MEQ2^[?>^IE3J3>\F(?>]2!^Y+'F81VK"]#5876ZF3Q0$!>SUR^+QPO(3IB\.[8GTGJZF];3
M0VM]C7MHA.56Y742-96F\Q$NR%*RQ%)=A*9ZYI#P.)FD33)X\F*0G.#;*
M>?FA+-K%33$8],OTYH4I=@T;ZQ%Z0;K+U^JN29+V_J[7^3(:7)?^;L#LNP/=.+TE(.M*ZL \<:C/(]'.4/FUQNBNOCJXZ>_OBASM)8&C5$Z
MN5%J:A37Q/+-P6W#[S,.:3?W&C3L.^,.@V7V-06E\RPHG:*UI%'=ZS[V7?:T
MD/[T[XK/K1]F-/S6+SM+L[ \O#D8=FYY_CLK.H-VYP+;D30S>@.9ELKJN@0@@:G>ZHU1.^U3< *+#3C$(
M/VZZHW;1CF7_SO7O[D= #<#]_6UHE;U.[^L XJIQB=<^U/_ DLA Y)5^!I@P
M_IW+JT8>D4SS,K>23B_DQ*RN<;H1T$9 SR86KRO -P+:".C9E&6?R8)"@GY;
ME.6D^M)(9B:9=01J;&8CDB]3),_!2CY#(M2(Y/F*Y#FD/LM'Z&4??F3XD(*8
MH>FUP_^,.O<)3_NP>-3CBF[W4V=XK>UF6]!A/($OH6=/CK6.-3
MO6RT:.W^<]0&8K2Z'T==L 27)7)UB,VX7X?9RQ6"8YBI^8$[ER(SYVBFMAU<
MU$AHG82^:,F[,I&8A/OMHO/?;XNOK6X8X[ 8GD.PBOEJ&B_[;2^=+KC?.LR9'+*_54HS^U!VQKG
MRSRRS9;C;3NP\6KMU2'"G4NW4Z=H+6T\9>,IGU<"MRQCO0#).T0EJI&X[26N
M";7./]0ZR=3&" +"NMA5\+&Z*SO=$B[2I=_KWQ8K"FW0F4K1]
M9S#^I26+M5+.QM^MTOBTU:S5[::_IA1_]JS!N^+"MD$\A:*3&D8M20]D^59K
MP?C1NW#D!9WN+Q^E-EK3:,UY:\TYU'86[N\U*M.HS-FIS+&CK>6NL$8)&B4X
M.R4XJY.LY:FN3U*9ZD>ZW?Z?B1&Q7_K^Z,OP=M2=_O"V*K0,T.QQ+TECJE_9
M2-&C:] R0LL,.8G7./@PW&R09N,RSDH!&I=QZ@/!Q@.8!&
M_AOYOS#[?^B\N5&!1@6:K+G)&IJLX8RRAJ/DS:31@$8#+D4#R+EW=S1Q4Q,W
M-;T=C.G,.G1T'B[0:A6D4Y@+CK*7ZU,>B"SK5_@":^/"Y!(:UQI,T
M!XE#LW<6A?3VMM/MI/?"&)W+$M'M$9Z3@EJ,7TB!IB;0:(3FW(7FN3UM34;7
M",VY"\USIS07UT#B1X6Y'1;E^U[QCZ)5-G6QJ,?C7Z<
MN/WDHHX2&_UH]..$!XV7>*VC49%&12ZL.M+H5*-3%ZU39U@\:G2JT:F+UJES
MJ*U=5)-9HU"-0CU/"]JZX7K_,6J5\*!^^6GT9=!I=UKEQ0R36CLA;PU>+\1 
M;BD -:,$+YKQ.XY&?'D,?]?O7:O2KT?MY8G!E.6NWQOTNYWVV"F^&19WBT,J
M%]X.WYEB,24^_58SJ1C YHO3SS668E*?1[># :CHKP,45AK'>I1
M>D%LYPW;3\WV)3,W+1]NF'E!QG83
M,QMC>W4L;;+2"V9>DY6>/0M)P\)+O@6R#0L;KWAU++U6?EXM,YMJT+E5@YY%
M;YMH]HR9QQL]/4,]/54G'OP,AD;6:N3M9M16;33
M)QI9>XJL+9'Q(F4M]<"*O^!/?D&PBO\9 5CA._PGVY.S]/Z2W,T-R,^^^;9S
MDPC<^VJ^ED61Z' AQFY>UFI(LRB,&6T.)(LUE)T]>"5ICR>4"YV\8K=.WO''
M#]C).Y'B1H8;&3ZE#)/71!],AL=>?T&(A_![":E/0!?(7_N+(CQY,?;+XJ8U
M>%DR7$>9.0FN)
MQ[M$]!)(!722.]VZ0?K@I.)_P9= JIWOJR\HX,$&%%P&J3 Z@ZO]ET JMANI
MCG3O\2(4<.<;@D=00'89'I#MY@'9,3P@OPP/R'?S@/P 'G#4ZSS2:31H?RC*
M3]]:93%/IW;G.^ V#T#ZQKO175&VAOWY*+7SZUW1&HS*XK?.H,\(EK_^]9.?
M/G?ZUGQN/SZ]7/&-"H03N8--#EGYK^E:%VOQG:RCS^)!YHFP'
MQ(:?[8V64YO%G[V'O^[\H\#%NE]/2H8)!T@M#9XS9ET7D@9M5"142\P)I%'0N.KWVY;W0'@D_WX](EN5*83
MF=@9W+2Z:>!W>!3GK1[NA0^6*6:-4()RP^SXX90PS:)Y]=OKJ:M:]Z0I)+Y_
M,RZK/G[@PUB%(KPVV (4%U#D1@;E-#61(8X">:1#X%Q:_.JW^(]'*%8^I1Z,
M!.>V0'AAHW TH( 9CD@I82H@%(GDU=AXU(%1/649B$?XMF=)"$%9(H-40DO'
MN" $/;*$4DM$?+40:ZU\TC(8*;/=XNG,,\LUB3YH#X^V@JCX^'3,M$;HU6\0
MZ/S7XG/33T\?]UC/=_!JV>J^Z;6+'_]5/&SQ7(HL8=1H[D0D 8L@@YEBS1'6
MBYYCY9.6P.C?W?5[GX;]FS_&UGGP?C1,"70;TOD%F":G,]F'7OW4+FXZ=Z!_
M\)EW<0Y>*X4W+"J@#F;$:FF9F"J.Y-&]^BG9A/&/3XV@PHH1)(E:@'\-B$O(
M/.K>Q^*^7P[AW50QV4ZQ8B2< 6A(("JX $D.4Y8*2=BKW_Z1;/"F)RU"$SO=
MHG0@9U_[Y3;\52X8)[C!(DK#!5=23^B%N/&,O_KM;:O\6OQD;FZ*;O)K1?NG
M\3/F 5MXZ"(\'T9?NIV;V.VWAHO0/+*6S'/RM9H##&NL%7.<,"*T4X9K[:> 
M41+9'"/''@(CT(+'_\V#-O?\1< ^%E\[@V%J7'G7NMO*)%ON%-'(&^^B14%I
MRZ?^0$8%)OGSZ]_?VS=OPT]__?3__?3FG?MY'I#%YRW"\K=^=]2#R.B1D-O(
MCN#2&0[V&%F BPH6D)G*CB<$[.&[_OS3EYZP^/B_%]WN?_7Z?_8^@0/M]XKV
MX_'>%F!( B99$".I5U)IYC!R4VV+X"8R$5[QJ"D\G\M64K!/#W=?^MUMI%>"
MFW1:"(51B-Z"WO.I6\"(6.#)[W_]] C PF^G!XZW=H!"4D?!QB-N":62*F^F@ >",G43:E^XV^U.JNBVNKZX+P&8Q];.'_=%
M;U!T>I-OP4M_=H;?WA7#/_OE'[_WVT79Z_QK_-%<+-A$+%;QQ 2-E"')2?/D
M'Z04("8A2A($YG89-; XB[@]%>)CXL[7XXZBX8[S$(0 .\IQ"MFF=B*R()=Q
M5_S(J ^&_:4=/3E.5[/(;!57M*08<@H!'#'2>$#:XBE7@C4TLQ($U[(E)^:+
MH/=F G,B!0I,6-6"E(BCSD DY(
MAXW@578BLC5B(S23XA^(2,W"\3F"IT3 )?
MS4KD5?2.8#8T(<%SS\%"(R99Y3?!B89,H/%1!?K2Z+V%Q4#*.N8,XS9H$7$D
MGDTM--(ZL] 4[RS0%I*M=M'^T!\,[UN=]L?B>]$;%379%=T00UD1+ &[YIE0
MP44B)R4%2#(0O)3) EV.ZE= LCND&R)=%B&.B(@2XKR6T4A$JN)'"%3D9IAJ
MJXM%6BS8Q;!I1IQFOA7(1C9S W<)X[H ZW&,L@J!'>:U?)J+,JDU&A5;V(
M/A',#6QG7D, YCPEQCF,(&10=@HFZ%46)TC.Z[F^"LS1H-,K!@-S S9J,#80
M'\K4G'37>M.[37^,35EZMRR*L?G\6 SA[^T\6YZ?EECSNS-[^'LQ+/OW-X,:
MBS=?T(+T&G)0(5(V*IP)*EA6N11)\S24HT63MS]R>]%GTMQ_,OH(QYD"T46&
M!I1J:I">3^E#C*TQ7D\AT")V.Q)H_-5QY>H4=.&0J'L=30R0R$B<\)[211&<
MEY28W(LNF_<_18#ANN/OR#ILP$YZTT0B$X[_?2[R[T
MC:YXQ(:@2B%%J3(@%8IQ;4&7@J].%$C(3,R1".A2\-CM/GX=['5_^*VNFGQI
M98<]LF*J(,2-4@H*-M]28? L=I H3R(6F%%+QFLG\F:J>F.05H8+B3CG#G./
MS31SB/"O+"(CAZ?JI148=L]_D3 H**NP\MA*3*VM+$GT(B_HJ(;(FZDJ<5!*
M:RDIN#G+B72D2GJU#MDABSZ"Z%Y:*6'WXCKCS&,=(K$!$B(:%"%3T47&DCQ=
M;XB\F:I!.>XY%XPJ[R.)"+LX+4 JCK/00NYF$ ;?8K?_Y\ 6PS^+HC>^^'%;
M0) .'YW^ UXOAC?PR?NR?U,4[4%[5 +UX(<>6P(W&I"Z>SIC B4$^^FWX&GA
MS8?Q;5.(?SPU=]UV )[B;>=[
MD;V]6^>$XTHB*S131G,6HO&23!O-L!%9L,P%T:MP/PCX)Z3+.HD@&%$&*;& 
M9-C'P$4(O&H[-#&O[&')3D67K"7@ME^^+5J#=%7_>^=FCP*AXJG^Z$VF#_&L&;:CT](G$(:65+5?HPV
M-67R16ILP/ )I&"G)@4*1(> ?8C.&BHC4K$ZD5/!U>C!J4C!3TT*32A!+EI'
MP19$%Y'752796Y^=29 ]2;$J'[,"IOOL$K'\JD
M_K=E_ZX*3N8"D9VKE=9&4$:./?96&P)1,1>S]MV8<6%*_J<">D2,-QTOZF"#
MB(8:E+H:%9:BLD:$HJP23="B)SICS#>X)4*B=L$) D&]U@;^*BOC8WC(:_!+
M?70'Q'S<63D>\05:,$[>=HNS&+,!V:"L(8LW1\=HPRW,E:DAJ&XWDD/Z$
MP S#+%2'I91FSE_+4R-6-T%OI0H%AP(U@0>22E\13Z_/ #96Q+P3]>38K!CI
MN)(]D(^I5"25UEO%A$-:5>SQ*#NM.C F!YH3O/HLSCOG9("H2T#Q>$["(A^;8^H9U!YKAK?7(@"F+#%*!ZNH!IK7/.#V[$GSB1>J2@@.90Y([4)8,^JZB3U&8MKH2.FMPEMRL#5J>C-B131OGC @B
MG=%,:1D)1-:5V;!2Y:;M>-BN"]1X#%%ZY:74RG+*L*=Q:H&1=5DK_3& .T*X
M%D!;D 0G@A5+$0ZJW(HE=*LL^JA([6G=F&1>(.9X1("&5MCI*K@))&]W/CE>
MNU@W#);-2Z0CP>"+:/06N#-A$@&'].S([&C=:,!8>XJTA10!@DW+776K#4N1
M"=W:4.;)B!W;N@7OB(<06T?/)=/*F#!E'K5Y6+H^<*O#]FTQ&!1%.AM:++8-
MWM^G00?PXOC<:/ &GM-I=5.U^?TMH#,L ;Z-QP ?RC[\S/ AE:V'IM>N2MKV
M8?&DW!7=[J=.-49]=HZ0X%D@Y:3Z/27@@L0[""UI=8/*"9[DU$6BIX6-7-"8Z%4?CR2YOP3S5#T[8W/'R
MA"X7&T+ C%L6(3)B2EK'6"HS"*\H4R0+D::7.Z=(UR!Q! 3K#B:6].YO$&,D
M(SLVO<5@./9Y$'78!]=M#0:=V\YC<]K[VQIO6/OEAW?]X8<2B%8^V*)7P \D
M=[DI#6 !HC'P_DJB8 2U#J)D(XC32H& YOU>
M\5"TRM/+D>)$:AY$D(+I-! &'"?(D5,:4T9KV@4VX[T"MW7DN*^^,OEPO^R"
M&B[W29Z"()X*Y#U/HWNT(I:EXDHBB$%.( @(LXAI,T%68E>1Y!U$>\/.]\*U
MRO(!OI9ZL(KWM_-1^+MBQ[DRSDR9B\,,!,GH18Q ._* 1$^Q3
MT9R;B_?B;-7A>HRB TF*&H
MG%.24\EUJ,ZT#$CP,W/Q&"4OZYS&P K(LXU6@@D>JOF7.-:TMQ/U3%P[ACV.
M@D-:(E$TD)A0 LE3J,81IGSES!F^BSU6V%MEP?& H@IK()"<= @!HP56*QL;
MS@35'>UQ1(\-&Y 9I(N$7%>3=BE5EF29\S-@>V1[+)0!3"-6#*+,,!ZEB*H2
MB,AKOJ^?JMG]7KIL$6YO"T@H;U-J_K&X>;Q(/(GP/[=^[#ZFA2!$.9+>"8*C
MA100L2D:BIO\MNW2%:7MP'HR%AMZ+(F"H("Y: 1F-B(7HZHJ($RKU7'?::#?
MT"?IX'\0JT9!I/)&:"%B58;B&&4Q^Q.AG\EX_W9\MVZ^Q//77NLNY6K_FEV;
M^U 6=YW17:9HV\R!L=88[T&RB, @4&EB[Q0SZV1F%!EEM=*U/\A'Q7[3",W@
MN"42+"/&D0N(86GE^Z6UJT/T\\9Z@S13Z;PA6DOM,1;$>J:KRUB(D=4^_^!8
MS\WF6%U 5 >\.]0?Z0B30*
M@PS RK!$5-)9>5OFW8A'AG93M[A102.D%8Z!8J<8FNOEDWZ3%=P%VOD/U$[J
MV4(H)'?2*NE$=)1XAWPTE6DS7F;54LP87RT4-1#M#_D&L=!"6N+2[$F.4G4,
M">ZFXNQJ;MP>'=X-@F&D\+[J1@.N^/R:/]V
M>O5\=@":[AC,?J+5:[]/=['G#DB'W\K^Z.NWR8]-[MKL;FN402H5HU6 6"""
M%0VFLC68\6S(+6ATG5 =!9EGHM@&Y*CNA(;-(RW/4=J3#;&'(S;?BYH\-38(K9W@L#Q&9]" #_I.A
M^W.WNC=UXG-ET\TUYJ/E$GNE)[VKZ'.D:4[
M%HB]8T%9:B! EXX3#0EXHP5?&AD>&]^#6%%EJTXJ+J VEQA#N4;41
MSD%R>8YX[FE-G:<6\1C 3<@H%?9A,BT<6,JDR%002WY*43R8-=7!,26"LRE!
M5BC(X*HR%X[L](' %OCMVOX0E.(-[;V;]/3%XF3:$/^PM[UO^-A'_Y+T8SE\&-OIS\VU[;GB\%-V;E?
MG#[XN?]G4A+M/GQ^DY,/S4?8XVHS]3PP< D]\_1:):5$
M2%.L$14T(B/E;+87.,B\&6/QG'DO.K]T+FUF"T&*14(%)RI:CXWVB$S]-PLV
MR^?/D2N7-D][9]WA%!R>#>E($(RX12P=$TR'E@N5ZPXFHF'3"2;V"PQ?GVA8""U9(;2#QQH"QH++T+
M)H#M#C:RFJ0+_8P0X15-=L5J1I#'6;]FTM7PJ2C34.S)(KV=>WP@CY8,XBQ-
MC39-8]%CC$!0E/J/*=(D4JKG(MM\-YZF>\ \7@WPV'CHQQL0/HS7'WSZ
MUBI3K]GWHAR MI=?BW)ND]SF,>G;;3R#E^_ZO3$(F]1'<6&Y5X($P5$0.-I8
MQ9,"\_D>^<$8]C20%V(D":2;$&0_5#=1:GSQ86="K3:=E"JN:6K2<%)%1ZE4
MU9TC9K.0@6BYV,*P%YC'0?(D^^^(DZF[B8)=34,O(-,058,/T?G,F ,3;*ZE
M>RFL:?7:U0*.VW[IP$]TAJF+J&Y QOP"R7/RY)P+K3'C0K)HHA?$S.X\,FNR
M=GA*%PWG7N0Y-''9F1+76!EYQ$P$JJ.(")R3JH[^>,R("^;L_(C+SY2X#,P_
MT4$[C[11F#A%XE1R2;3Y5I&EM3I/)6X)B'_MI:]_;OUX'&.2UJP\QJH?B\&H
MF[H*4]^I&Y7E8UP'9J=F&^?N-SY$A"#-0RSF-4%"Z&I+ :4\Z"R]4I(%%+!S(5).CM]VP.X0^)T\*8_"G&?DE9X0I2GD4@B9[-3
MC,G/(2%@OP1:[#LE25EM.'.*"LJM9 'SJA) ',NZR?"LQ_^KF
MN5&^SXS3X6=9/4N:,V:,Y 686&
M0%I!CC6)WAP(Z[FE$KM1_VEAFX"LF](HTTJC$#BD6@A58^$PR^I_QY)/P+-=
M[%5=$U&J-)_'@R]&(0)3!9I5,&56:>64D TXS .S-\SK0DOJE> VN, DEU88
MAGEU)1O!&S758?E$F&=GC>^*X5Z$IL82Q;#R!JP7P&.PMA70M$94E."K@*Z#
MYDE0'SSB=<8*2;01UG@.B 83J^5DTKB:C=EX)8M.B^V>,:T"3P6!/43V5I*0
MEMW'JC)+A,NJU&QE1'-:='<*6E--C4)T"LY8I5U48"VJ=C^4GZ<].W*[7D[V
M07N:BA1"<$*5$*Q:Z0RR7+>J[OCX'3G@!.MON$Z;7Q&.6 ?C5%4_9CQO$#@Z
MSFN7/EL]OJ/HL7 >E,=I+Z? >BMR&PK8G4;-CE$U$#H-JA(<"P/Q!,+$3N=(
M4BHIS8-?+E>&%Z?%=D\;2@R.$N(H8;W51H$=15691%B9G6Z1U>'4:?'=Q8A&
MKV/ BFCKG9*&V33P;[HZDN9SJ9X=N5T'J@L=7!IW8+$%.\JH"E77JA3/A-^1
MC:B/WH)K% Y+;#TCUN/9?7++#F1$RU&K&_OEY]:/8C#NX_[\K=6KVD7V/%VG
MV#AB' 0L"D=#<:SNOQ &.5^^(@G51:5;@G8HA-;6G0GAR$.BJG$,1%IO9)70
M1,DS^6.ZSHCLBU#1-NWO13GLI!V!>S$$0=;%,14 >[1$CY<35-.#BD#VA7;L(A7#M$%5(4XCAPDUGE05-A3RK;!8UAT9KX;F"6"O(S2Q2D;M&*06@G@6>6"S
MX7E(YJ&/KJN9;PWVZ&[4;:5&U^*^!(!:CQ,G[KO%N#[2:YO'AMCQZRO7=>[&
M&,.DAD0=,@P;I#,@H)^&'.L8KB#XH\P'[#5/X^:1
MF R]HI@9%/.5GA3KNLK,,/)K(U!.8>@1OLR42&YN]
M(/ZCP'[*T[I:/5NE([3GH&HRW@>Z@B*UC)XJ0MRACD4$27(ZW5E=;SKP.
M63#_^J"8U5^GF;MSM1N7P*OBZ#WG22*U5(22JI9E(9C(&VLYRMW41J">BL(Z
M?AB"/<-*,^T4AC1?R-FJV>CR]8*I&I"?R>Z(PC]'C_<>/O=7?+.*,!['"<>R
M?S>^DV9;@Z*=& [<'FOJ/CM,E(>P%#.(S=->&>=MNGPZO>IL?)9>O> %#1(.(26,YB35(>U<%
M,H;+C#@T#\\OGC@GD4+'220*,@:5EFD3D08-5DTG+N]-ORY";]Q4)1FX+6MH
M*C9A&VDZW^1ICV.Z+I+G+7D2^R7];^TN]TC2C) 78-2:LYP$--"2]I9
M4;.4O"9@VAO:(R-]&J^J$,;"VK3D)^6(W-I0W5<3.@LZ+X. FW9)092J.01K
MVD%N' /S*HS5A[N AOWJ\3[EQ\>K>>D#XPD%.R<$)#B0+!=T.G$Q
MPCJI5-5LAF6^&0;E-:4CXW0.]#N)F/*TFL9(!6&(HDXHRW5UDU!)OZKP\7)X
ML<&]6HY\L"#' 419&>7=9$%G*DD(F05TN*;#^@70[S0QGXU"8*8B9H%!],=H
MK/J[ ZK9?O+2>+'!Z0LC4WBH*(I>:<2CPBJY+# 0B@2:'0$1DI^JO #ZG2:+
M5H8:*Z6$R($0K*S0X_P%HDL"V6,6@#T[+ZICM/ C_JP6]-A%10/#G!G.,>.85"O(G-9Y\"YV!G(Z? 8"4-\??1G>CKIY
M1T%>&2=S/1%/&N)9_<@:0+8=ZKD,T-;S?; 2C%(>94P]ZHY*;]'4WZ@H\D8I
MG>OH5H0\!.GI59$^S:>C'LQB()KXU(LPF::8YE81DX]/%7E]YV2D9U=%>H\@
M; (+HQFSD-\:))VI2$]Y34? ,Y*>7Q7IN4..,,(]EQB,J49R>OZ)./$VO\!8
M,Y'D2*3?JR?&2)3N(#KE@\*:>Q%F/5,2J353PO8"[H!8K3OB90%[:14G(GAB
ME<%(5 TE'!QRONT^3T..B];?2XCMWM_>;AZ;>?DZXPSC5A"(FQ7!P@09IMNM
M$6TI]J'^!Q;O;Y3%;0$^O+UB_CA:.-!FRG%ED0[IFE\P5'+LB0]!
MZ:AJIX_/4_<0-+M.)HQI/U_]2EVHZWD!T;:1G%K%7&007N@@'GGAP.3XA5[Y
M*2^81L!!?'D<60Y SDPML'3682/! D7(2Y4CA"96>"V!-YQ=AUH\ Q/V4 OJ
M():@0FHLTEX1PH(+8UY([SE:F(I7+4A@1%!Z@6JQ' >>F5H(H+OPRG!CTG(Z
MD];3)59H:IWE3M:P@H+F2")$PXOC:(C5T&R)[CKZDY84XR2NR8Z^D"BI;/1OH;F!R2TYE+3X<'=/LE[
MO(?Q6/V9F]>RJ1*2-NYB+-+UEN@9M=K-UMGSD!\+U?1$/CO6VZ-+F76*K*88>'MQC
MRR077@.>5EHN3"H%,5>=XU"?WXIDI^#1T4028VG!VC,I(LB^(E))5]D=B?+:
M%\MK+4]"-UW%'%_ V^7\>\'00^)#,(K(I4NL)CFSBE\2Y\VP-1,4MX7M0 AM
MJ%Q0&CDGF*;5#"05[CVJ6!(@K\Z-XG$1FA.F-[V;I$[MW2M)R&CAI0-C3P-Q
M'M-8S:ER+M_YN;TAJ8'N<%AMX!07!,DT,,"D/?$:4G!MIJT70=&:972G1.M3
M,1QV]^ 5!X/@L7,.$EF,/(W25_V7H6[9VO8&,(?N8$AM8)61@>/((/:S#%!1
M:25X-R\+%*8(E%<#$$3S5VD"4%
M.ALBA?/N2H[KFE8.AL*>LY*X1"H*)J1(I4Y.5.J^F<[MHJRF2X_7QS '06*7
M 4A@9B-&@G)NE2&8:(!V"KEF-?V%7/)ZLW00T'<<;R03YJDA\!+(2%U-+HPHY+>50>A6Q,-;
MH;1VZ$5T7N%@; #C+E@P3%2#H9'"F6X*PFA^@K4+*(-$4O5"W\$ Z1F,_OG++A*$CL
M8EZL$X9Y8XE7S!'C99!5;Y9"/(=<",=.0
M+EN(OB .UE[.PC15,Q^-$%E?D3\"'CN:)BF#@0C!1ZHEV-@HO*YZ>EC ^7PN
M4K-LZPFH'-E.Z6A!W!P541G( D)DOM(AR,W6SG#<$ZNU96@C.8M:$*&%H,$I
MQJI(* :741LSM>)P9#_ #FZC6#0!$PL1$7*2&*=UK-:'2U?3KH[ 69\*H3V-
ME%01DAE*M-1>3A'>()8*O@03*1.@E?D
MGE@?9SVB*J!,WK;'ZOVM[PSN^X-6]S_*_NC^32^=9'=Z7\>+SH$MO5'1GJS\
M73_ F@(IBP_J(V35Z,_;*X:0V6]\W4$78C6U;26@49(>$B4C-A
MC(B4[XX?!TP9I0B)=CX,)J,&M1ANK*+(V>'YPN$]PV4&8P_?J[8C@;M9D3
MA.Q-D/E0I$P=1>/54-7-\:6[!=7/3>;1N/Z@5A\7XW>G F48U#%R)(-0OFJV
MJ>L->DWR)9-;D^9 ]#R,@"V>_1,2"%/1.H(5U9ZQJ"HRV'PQ;EXVOQPB'%^H
M:&#>X#38-CH)%$2$B"DUKPW\Q[9 58&\BZH[,^^.DN71 /FP^4) +S+%W= IDZW"&=_C))U5:8RP.0
MX(/[-!>(;V.$$;=IE*XF"O1#\ "FA5;Y.Z0YFYOWMD=P UF2JG\M6]N29367
MN1/.*PJV0*2U#$&3JMB(?3YA'*.5/-X,W6%Q.GCES!.A(=/W$ MS84#\N:P,
M(E,TGW5S(;38=].>%08'G\:+I7EBW/(8JKD7+-\2=>YDV&D#G_$\0-R.<* $
M+"!*.C+5=!VS(NJYX[YC><\22&$@8D_+HX4+5NG)M!D0!,YX5A0_!_3W-?P0
M5\X]:BLW8)##R@3)("B0PD!F4YW9\XAK1DB>CYTX6?-&=B7#;W$H$6!R4@@9-;!
M03[%)L,.@4U2^]EQ#$U;K'9S16O
M\@M2YX[[CG&F,<13JUG:BADQ=E3/3F+SO&;S!#D#;\_7QYEIP"$%;9;4:1F0UL'0J;?'*M\%D:]$>@Z4
MUL:9@G%/(!WP2D/T8JP-TXE/D0M9A%9
MU2I&O*K9 WX6**W=-R644(9Z+B5A 0"Z>#QYF8\(A=
M#(AY([3@V$Q7-6"&#,V"BTNAQ;Y-A)H[J2&FC$+KM!:>!CL[[\K+N^=.AEWB
MS"@-!%H.QQA5FJ@?O8M5NX<5F5J<.^X[QIE$!Z'!TEEIF6),(2VJ(D%:%W:.
MZ)\NSO11ISGNCJ;#/H%",-/+8."T8]X"?4[4.5:3NO!".H:Q%HSAM#=8S2X+
M\_Q^W#%(,CTG?=.[37^,,9@T5;TOTZGQ^]NQ3)1%\:G3NRGF!,3#,\S-<-3J
M+A!P4@?^O?6 AWU?W%!\T!-CP9)]U>!U ^9&$LU]G(83@N3A!)B>+?S-0'YP \]2=[%D9]UBT.\-1
M.1LQ84?#=_WA/XIAVLBR^TDUI!-8I3O*S@#^Z6;LK&-1Q,R%96AO"]EAL-DT
M6X$3&RA2PA BL?:0R+II.D%\S60UP].:
M)OPGP^>0['E;M ;%;!K#CJ,6%"@2=2&"9"EC.7;<5*RP/N0#H:>+>#+8E^'8
M"]1UEY4D0]&!SE,2F4HW]2*>[8.G^6UA15:1>0]0][H""O;*(9IZ027S2 1E
M>'60CK#)4\S,):R'YBEPKZ.T9>E>.0B&L#:M/T*25G.?%%:94.#\;O.3 5\]
M.6B#J111*<8)Y#=$!1&8,;P2DT#R\MBV-*^;%;0S[)O6]SKB.8F.L70O4*EH
M5-6$XW@^)4%FYWG'!'[36'#*L>>"IL[X\W[&R"I#]@%VGEL0H9AB6
MW.@ 0IUNQE9-B9RHK/5"T>SH;%=@!W&4G-'OG5[G;G3WH?4POI/CE[LP-T$>
M:5 R@E5!%O.4BE>#'C #^F<9A":FE+LAUP]K/NCO!^V-HV[ ']&%/:8B72]
MH6H,H13Z<2M:O4A^?WBFD[G/>%\(JI_]G<47<2P
M\23%-M1#:!!C(%7%/Y(<4;76?FX-Y6YH3N\Q/-Y 3'=:I^_L*, F=6\)S[%P
MR9NDE4"*RB#!
M%D/,P9U55>,FS:B^+<#+%O.S96NN)M_.IXN)+%],2C"KR1]6PO-$L ]^I@JR%B*@2J.2H%20
M\&FEC&?"($()77>2]$Q8[GE:BK2AD(*+D#(KRYP--DP011;2E_-#=*=Q40I!
MED+3HG<7 Y-8*#?&3D?!:K"3M,9 /@N6.P]J,=0001T-$04"B94/H"("UWW&%N91JV
MC'FHBAM.B\QK'QG:3>/)N8'TUUBA&,8L0*PM*F@-67NFO@NTO7;Z(\ 'OK>Z
M*?HT0]T>S"B0N;XY<387QD!XB]IX%*92!I,,)QI&97%87*#\V?@0KKUFQ)1@GV
MZ2XA.!BE= 2K-H0+&3Q
M"W\V8[4)^WU[-H6-TF+@/=AJ$R)V(E:M:: ,J[F(G.IX*?"]X[VFT' 8KRX^WURF-AN*35X!YP5'D]0>B:
M6OSI4#^R >?,>4C%5>#8$!K_-#W*1_GUUF>@PKH"7=2. /C">\AKHO1$
MAZJ-PJET
MX)0$:JDQ$A%-%35*FNI"1I0JBSR?+^$ZY#AR<-426T*\LQ(IKYSGLY9JD:_O
MJ1M'?BYX[[Q9(;"(J;,L>*>I%4)6_20$YQVJA-3U IX.]2,;<.10?YE)^J;YJ#E74T<573"'H\\-_W)"""#9,!M)A!-(I #E EP1"5
M9F5)67.L>AX$V.G&%/"1,>8HX4%9#/D6K3*/P&/6:58SJ_U8!9]&P5-!@]$X4JNTBMC,1AKI[ 3E\%3X
M4)2=?OM-[Z9,A_&^>/QSYY-:@KQ3$1'O@\;I-@42U4FMP2R/Q=FVP6@]@(=&
M[."V'?0X0(#"'340E(*>DUD?'V*YH+\F^=K.LR7(GL8^"$4\I)J(@,6/P2!J
MJXMOW+%\,5Q-_]"94F07ZZ_)>$D 7#K,.:]$0T)0OW\!Y@P(L>N0%B'Y
M^/HL#>.C\JAG!WU4YTTVVU=D3D2+(SL(9@S$B#A >A^C($QI6YTIC(31
M4!VB4)_7X*89P"708T\WX14VB L7.5,L$*=3P\*TOB%#5M]XO6U6> 8DV6FC
M4TB%'A(<2I<>&0M*H3G1R&*JU^*""+&CG_":@1Q CHB=UA G>T]8M8#2YV,+
M7[-\Y<.STN+8S4@T*0L"8\(D<2)B:V9S[B#%/#L_L:$!*%V7\(ICJ6B4*DU!
M8M4)NU'Y>++7DFY9&3@-8H>?MV-UZM[%5.*T^HH8,]E2EV[_&9$%2EALFSB?
M 4'V=!1105C$H^32,6L@XXRDND/$:CK17^O(FQ)!49[6UUTR>29IYFNDS
M.&*BP5@Z+K2P'FLJJ@@]V(P3+>?/A;?^]WOG=[7QX=.O[MY5N3*
M=8.))OVTXZ75:XC42J0AMXF60!8+$LAT
M%&DZ 0H^;ZI8HNIQJ?/4$,-Y[DQ6PW0WG"OI3SC EL2HU \,@X\()-U:D!Y00P_,MSCN'Q7
M6JN0UB"9$"*C7** C,-5[U84H09FA93B&".U!N1'6/8"=RV)@;;!T(@DQ591
M)+4PU:$-)..UX&(M)96$/0W<]Z/A8 @N!>S=^C;_:FUT"LZ'#REW[/?&!G,Q
M;ZA^/W=$BSA[%T)J.:%*2_!(W*;>V8DGTL33&IPY39-RD)1K<)Y#:'_$Z3$1
M1QY$D$A@L]-<8I/FN$X1IW%A:MM,-K&26J%US#X(XFN5*JT48L@&I(*$M YD
M%2$OE#-@D$5$=89 (0FF&C*5$P!^/(Y);P-ES@CE*4I;:X6O)GMQP]1S(K[6
MKB#JM.<@.XB2]!EJ-R>!D')==K_TX-V 6ML]29%%
MGFO0)VE-%5T[O;[DOP$H^.+CA(T4:\^-;?UR
M@XTV;:6(%)QFU7426-Z!DY\M[4.<^[+X5O0&G>_%XW;F=\7P_>WGUH^=N^V<
M]4I#FN@B<#FM/0/?7@T^Y3X_(:^#?Q4T3P3ZX"=?:6@&!:-&- 2B3AB*>54/
M81CEPPUKYJ<]#[9['FM9CYS ),W,-]@0BP2N%J0ZR;("T.N:H^[G07B70RNK
MQK=/(5#S7F@/67>L]L.D+8OYH16J,U'/@>:NEU:T@F#<>$,AF>)4!*QGI9 L9E<<7JM:+WUP[#>TJ7$CC81$-C"=
MYG03T$0RC:V(SFNPA.4W"X\&]<$MK*),"8@C%8V*@SX2P:KYZE&2?!8GK6E(
M?1YT]S2Q3C&($;U%$"!)QWV@N)KF)U%-YP ]B4\Y< .9LVD;D0=/(H*67$5%
MJ^N1G)$\S#D;*=[1PB()DNLHYVE>$+>.&EO5;:F769M:V*"!.H
M<.!3($[GVO-8%5AMP,^LK4E,/.EV[QH2QNB[28(3LP^NM]VKZ6/CA8-L<*[R),FXJ\5D+R2HCPP3$",35%JKJ^HB/Q-45>_+.FC,R3;6=ZG)J*HUCX#Q8(X5'D\O4D*5*
M[3/G(W3-9:I%&/8 [^"A$M'  \D@5@J6*A,5&(IJCP CN4_]_]E[V^;&CMQL
M^+_DN[<:_8K^AWW*[RFL[:R=WY=-3\H@S9J*1)I3D7>?7/VA*;$KJHT,>
MBH?B>)U4[$P$6=N!E#*&M4W9]X'$Z%%.;BQ0H0U@LAXVF]IV@:A/?
M:W?1O$!F]EVLD\F0)\\71PA\9PBOM\D=WZ@W)%IDT:GK"V+!P;!
M0.7_;KIG)Z'+[MN!)HXWBW?\1XO:R9P8$<=Z0H*SN,U()-5KW>L!",&AXM:&Y>Z1@P.<@:>LMXIW?'HJ"E;Q
M]<[AAL_$SIC8>BM9ND[K7IB!M.JLL YM'(2@98X*$E62"2+C6LTU8^LNGI_9O&*]9D(UB>,"M>7PD6.O
M;)S6_%]6;:"D!+MMUTP8IF;'(5OI^9I(C$&6S">[41%G'W9;KC? F-EN*0>!
M(B]+#*8@Q*RA-9=[&&#L&:!H/!CBKGG.0862,U;:E,\1)$X)ZA#DU\00_$BZI( 30)R
MIETQ0JLN<'PMSI\)U12K)15[(T[PVB OB7!2;TF;>"/N3AC-A&&BU<+H<\1 
MX+1/@F__(+:7?NB/]C%AS.UMQ0*FCL&.@=@^I'KN&S1PH\.Y#H:V:ZB5JD__
M8(1A[TH:Q/Q8L,[6RE/JW1%VO(YW!&8*$I5(F"[G!'6@M9+1*BL@N0*4778JE>WKT,#5,E0_/R.J*=8*O3:5:B\4A47RMDO;
MUL4ZQ7C&LW!,:V6]TN!DBA*5\"D7LYT[:T*_(L>$,;.UDH(7J$3O4XHKP%:J="?D?7Q;7MP?$A,E(XLM!J3J+3TB@L!D4 W529Q=F2*6'3\%3
M*0Z1\.A&*Y=0^Z)%5B&E8!0$VVB7H^GS/XS,#5JM69$=.H7.:XTRJPX)IHPHPP'43)9
MIS+92O!A6A\A?WF7W_AF*#.;L6)E5)IB$"4+8=E^H-Q4=-K41\'?^.&\ZN$X
M=['/*F\5!XU2:Y8I.DBF>6 8L2_K1]"# >-;)3RZ11/9&V<@%U1HLG-NS8OY
MV$VC^IH)R1\93-;/BNS0R)$O'A?9[CG-'4*F! UK/#DQP'%UZ$=WC:M$J^
M:)RKK&FF)L2B<&U>!JC> H 9*H^?&=ND=DZE0GW;\E%GGSAJB5LNUIQ#E]T[
M)8ZI)HW#G6)RTL%D5"9F]*W47?H^I7%L*#.;M*2CS+8( (\ V5F++=BTQ?;M
MJ*WQ=E^@]ZNZ;\KB+#PA<_L?GE_XRM
MAU1:T;N5 _2"XR*]2?I=K:391BDS7_8D/8/7L:GF\&826&=CY!^"[/-=":.J/PN]P1R[=T
MB?7"YDM:%\I2;Y,/V+>Y]4]7DX5_Z*5Y^ZZ)0FD!?$*MK;3SI#-M=XT7G>Q]
MF>RH/&^1?%<1K05?*WREC-&Q!XJ6&N=RP -1/\L.%7V=3<)7U[?W7PXQOV$)I%SE>4@I124X].*K0Z>=-^&
M\0J <;&.@&/'+O(Z67*UH4W[7$+VDEI57!:I\TG?#<F<8U)X]C=
M009A4?+UE:UHS__U0NN?R0?&@XT+]!;1QQC)7&7>3UG5O'-BH9639J-X809$
MM])VFVB:Z(]+-5'%@DV\S\I99#>_/L?J;>>Y<%VL@MTE]>1/3Y'HZ#$R63:<
MBLVG]HEU'SDL;L2O EU7]=V_S\R!Y%!2#JW1@T(=0DCU&::81KH2P(YEQ>9 
M,2FA%V*A KSKBR*?.+YZ?%!BT8W.8UFP.42?.I05,ZO=%Y^=E\EG,-O"A$RJ
M2XO;+KMZ*(B90UV;#4I 1=D \2'7NL1V/$Q_H[T1T9AMS+)R\:4DI&:_TJ;*
M)KPQZQ%MY]5#/\OK0)&.W]NDM/0QQ%QJ:.*R!MOFLQF/740+]B10#IU 34$3
M4N1CR[L>$2'9]KB@>QZRF5%,*OQ'@%2R"!)EX,,K=&A%3HQJANU]3*OC>_V0=9[&XK)\8P(]/\W6"7==8IYHC
M8>#E])&DP^!4SN2IR[YL%O;ET@XA/C^M7"]O5M_?W W:F:=:2>AC0;#!*&41
M/)94M4)9QSHRY=7M/J]61B"N9YJ0_8L1X@G*R_N%Y/7= 5:&2DS :RYEC8<1
M. ZK6Z!$5P3[W6<']H!='MFUPT2\>*#9S4A%9(:8:NY1B-C=&\>!^"W#6BUN
M[_[&H6G^^+$.'/JM#L7XP-^[^+1CB/VAN,VSZB)8]Y)#-0M?WZU]4YWLH\SKL'9#VT\7#B) W*.)AMYN_2-/M=L!=5")6E$H\IT,I
MFH1@U\ZU+N(7\P*>*,5(LX].7D([L4+\1B%_6]PN[I[8 +6J7^#;<;&\IB^K
MY17_3OO"89V]\FT=C-/97K5S
M;(@!1?=L8#\Q"([Q;YZ[,H]?
M_'&U^&UY4J,>YK
M6"]E[? ]+DY_,!)?3B+G$I6IX_@B\(W5$A?"NE<.!D/X4]'O<3 L\0WJI HE
M6"#C1(J6#X92TB:^55^Y0HTU7\5ZN=ZI,#N="G8HV$"P?Y9BY(#(N])\K,S!
MT6L[V'T-=ZBVNHN!_,X]DIRD#%*&@I'J19?;F8[^66W]4XWPW_H*-#*4 ]&[
M- (Y*EUGD6?$2@F@@F^43$:_%BK;/4/E,]3(0%;HQ; SGYW144:=5+%1@J8$
M,2E6E,C:O79JOH8S8[3L]"%VQJXJHB\:R%N*TG*$HMJC4$HAO*:/I_RX9ZL1
M.Q"L[=1(4K7XJE)+(WCV$IPMC:TP&?>:9_!UQ"9#&MD9S:M:'54I$FMSCU/!
M)MNLB$,!7[=&E)H>OB+?N3Y&X4P@@RA,[??9]&2PP7U-(TI]!1IQ"J:G.*) 
M0*$">QY>238BU:AN_&F;7TMQ\-_Z"C2"RDX_-3E')P0(Z9Q7F:)5T;?'153Y
M%8WPWSI[C>!?A'?#$0:DE<+"G$HIPMI+;)YY3HQ3G\-ZP7>#*^7//W!J"RY5DI%5EDL
M,F1CMW6<"5YYEV"OY_SO[?=0].P'8\UQX57)I#U9CE RU!R'5R12L.:5I+A!
M?>3U^O?KB\\L\/)_%Y=I>?MA^#5[K+I5F,A'64GD,$&7"*E&&0Q ><=?-KO*
M3T8E>:/88P5R'E/40?G:_E@X"DH&X%'L2OBR3Y?7<<3GK?-Y>?]YFM)# )OK
M,%:5D\W"2RW;"[!$ZMMP<;#P>4R@MPD_.DD:4R57KD.IP*=B4\SMG<)*W\^)
MZWN"_!W
MTEO\>'5Q_?W%Y\769'UW<_WIY\7J\[?7]?S5^@+^R"YJRMKV6'A'2EF<+VBE
M:+1)49>^K6.@*O9M0.=5FIY#:9760&3VOK6W&+.);=I '7/65\7TG4CGK30S
MA])$)2)BEYAJC1#O.$B^]4X['&A8&>A'>">EL66]6RU_N5]?ZC]>+"][RZ.>
MN!3'T1=E9Q%BY6XAC::6OVY;:G7H:JEMUS+V-HQS:DL?75LU[B5O=2C*:0LJ
M&VR3!^L+QNXY?.>K+7-T;2$!U)GP07LM?"'GMV<1,78UU>9M9W$O;3VV4!^K
MSU7:P#8&R1=E F")2C%^P84':T+%HHB>J(VU"I&D-V^?$9
MKG:<^9[:L"F=,'S5JAV Y:';^E@[
MK-1A-UA;,"%1C!%$:ESW4F%GH+L.]OWD.@:270S3+FD%$**1T7(\[TMN5PWE
M?B3!JS[@_$AV=<66(-;)3W"&HZS*$Q0W^ZO8?H8E##3M' KE6/LJ&:M,EDEG
M3TJ7'$IZ2C;;-U&]>I7-(?Q.\CDRM1(QKR=>)54'AS;76-B>&D&^N@)S2+]C
M^Q2965J.R$E)JDD%Z\Q6]7U60?93Q-XB_7?+BU^65\N[Y4O>G%V!N0LH2^';
MP6N,@@0KU6^:<3!2/TP0X=7K;DB:PZ4>38;4QG5V0X@H6PTR;U@1Z@G.JC>@
M Y,KIDK]-W9.(O_W\N[[F^L/A_15)Y<\Z8) P4;)KKC0;1*Y%/T\2JGZ$2=C
MTKQ)ZJ.W08:$&6TNF*P)J0B$Q]$5E74 ?-_F=#9H#Z5AE,"72 C&&8[P4ZG5
M7VW:0BKC3<[O@7-2+V4AH[.MK%@F(@4LIG72RQ+H[,!-[+8424$D0[:R,GC4
M)JO06J%!O@^^#9:Y^&CS [T>8C B1S2VM/FX18QRTLV#>"H2I=@,&5.JN-Z9>Q/F
MWQ;7]XN#N'R\]JJ>*4]"2[8CSJ56^F22Z\Z5-J^F@)Z+<:"@QV?;X%5P3J"1
M&;,.WB=J!+^UE?RL !XZT$[4\R1=6#\7U6G0?CO'2]!^]F-N;-/&VE63J"D7
M[R5!0.5A PAR/SKC70!-G9(N(QL!IU7('.H(ZZ4US8.T9IPHY9B89C9\B>.<
M.F1"1,'Q'>4,OH4Y?/[&)BD?#^>8IVAML(IDR> 46V7G2VX6 >) TKLGV3RJ
MH,>/K L%CBTC6_*L:XF\$(U3'K3M0Q,,YL\Y5/-Z$#DDT;&Q"PI;@Z<=+I+91V$\QF=YK%>!++V+@:L ^$Y
MH+18.)#<2&YLGU3_YO6D^C[R'0_7+A+H$(N2DAA)H(>3U%X#A8/N-;!G:'\?
M6#M>$7*V),#ZX*SR.A1I16X4R])V1N(;]:IE/Q07?XAN;Q=WM_^ZNKF=^IC 
M'@_*J+*Q#K.W7H0VMR6J?A"--OK5!\'GX9H?'U5_X)DCYY8OA^<1@YJZV#)&(2@H.>HNKKTB.[8$W:Y7X\P< XD_W$
M.A*0HWL_.FOT]9V0@:4DV!9CR]2"Z<>$GK4"#B5E-#[(6MGA767N5))#PHT.
M%(S.TSX?[).>'T*!B"3JW'!VZ>NUUIX?$HI];N#W!SS1N\I!4&4M-NQCQ4ID
M2;HM,KC<;?1WPSQWIBU89+B(R@LV?$II&9\<^'$:SU/I8>RR@<"KA\ZA,2KP
MB3":8WS/UXO<5L+PW=@/V/#RU93:4RFF2SGZ
M'J38XW,N&2*5(>=&G7P>%\.Y=DP#N0ZL&4
M/0B+L7]IV^?.VG_Y#]JT19)+,6<.525?N<&IC7XYZ)A-2"TR8-O8Y7R 78/9,-W]NEA-6Q+#GJK3/@<=)04A
MZ[3:C?A@J:_>]-WTS6$Q#A%T3,]*2>=1!C3L3B>2F$1[RJJ=BIWQ>SVW-D%0
M_L?#0] ;=CTX:7W-RY:8)<<(X*,W):9$VW=_]>K-ZZ0(F_N;MW?)#K.UVJY>]FX-_
M\-G/UW[2B]6'7W?EZ(.-(CARJO8S)TP)M^D1$;OL*0RUV\VE0+JZ6ZRJZ_?;
MXJ_+Z^7G^\_\N>D;A-TH*U%34,9"VH0#Q:3<;Q#0KZ:U#A%V%^C-UQZS+771
M5K\MZCQ ^O!A=<]XIAWMS$:HL.D7MQRLTVK-]QFTSNEN^  ^A%O;Q-W3N"C5=S"9_(8ZP (1[;6J;2A
M[)CZ0',/C_9XN/_CXNK^H3?MZNKF[Q?7'P;8($9#OA@%WZH)5 Z6()EDJ#GL
M(#N/U[Y>5S\BTYLAC*V/<'6ZKT8,#G0P0 E:S&%%[%XCZBS%HT$XN*/!4%9U
M1%Q 8==4YZS_YCQB,)WSB#CF"._H"GA+%X.U?-F%(*+Q,0MMR88MS6L>&$LI
M7N_4G2KIO][<7/Y]>77%Q^+;Z[N+ZT_+7ZX6#TOT\G]/5+^I8_ED=DY #/7-
M$1O30X"^"EZ.GNK#))X9_NB9224[$B1<(B G@]>Q&7-9NF,/;LR#F0O^H1TL
M44A?I 1<#T+C@P:R51-69Z5_-G-C)F%0HC=+?_07)R%TS1TB;VPJSFKCMP5%
M*N0N]Z+]T$3$]T1]X#.3RYY-ORSLG$($(.3K>0/U%Z&?QG W(J47:Y(/P(C@E2W*ZOH"W(A:5Y#XUE_/AG/D)B?]*
M"7S/ER@%1253I1!Y7&-'U 48W\"H-S:#$D;#(\(D+#O*(1@O50"[)=/VMN]-
MVM]/.*+T,[SS5[8Q=H1L208M+YAI#SS&R9/84HHCA"X4^ ;L#'[3
M :]53FF%"HR#DE6Q[!"$]I1"HN?G&$W(O!3E8(E'0\DZBH5R5 6R=FARB4^&
M..U5H7J0J#^N;KXL5G>_5^:@.I8\_\_]\LOGR7&%S]4VB
M[TH\. #9\*N!1L8VR!R:?:H$J\M&W?'V+9\0UHB<6\4/T@6_!MKRN;$O7
MC4BI?CY__G)U\_MB5:D?5XOZ5;9H3S\T-"AR'PJ28GR*?,+9T](N)&^V%"0A
MABZ#;X;N[#<(/"?T'37)E1,+HL\4O?:\MKPM6O5KD**#;H=RV&<*?1:R_KGUW>+;Y;_K;H\BKA
M][]>_-?-*EY=W#Z_$+];?EAJ6O%?
M75_F>YWT9P-[R>5@+'OI(:4LK$NY#9:LW9C](_V@9$V _04;.(=/!2,M"EG"
M$#ADRM$H+UV;-HI]<>RF+NSM@@VQ1YVR[C9'<3Z ,U
MQO^^6I^5^N;Q0#2[_Q(_.];1%LL^FZD>A4LQA=!RN>!2%W@J.T2]N5NP8P$Y
M?G-Q--*ACDE@8C-WK@+>%,%'!@."IS8FL=4?!%;BG)9'QK
M(4K0SZ''@5*+,]' E  UQ6R)4L9L;=; A@[:8X[FDZMA%RX#$\'Y.A6FWWMRAC-IBHJL!"(-=*LMH:>\T*I
MT7OV715P*!D9YB^KO8<&IECM6O,JE:_)$.] 
M&'*;TF^I*;CQX0YG@G>BU0;I;8D^9F\"H3/>;9NP;]7;RH
ME)!1:KRB7VJGTR#@*BM!:;
M#I3KXHVA@JLST< 4JVUK!59V5M8J2+ZHO,O;I&'HT[_GB'>BU98I.8B2!)$*
MN?#:FL:C7]_$S@7RS%9;.!$R($?7"*P.)?@VVZBA$M8?50W\\9M/UW7JSD,J
M[*?%A_O5&O/]3TWG8LP<-/U%]__?OZ;>3Q0Q=7
M#]_YZ\7UQ:?%Y<\WGQ;UNS^NEOS-+_S==7[RA_N[V[N+ZTO^G>,9R=?SAOS%
M&_ZEG_BWY&]_;**_')^P*ZHELBZ)0$E#=)1*XF@G";2U$?7Y9/F'1*T=N&3.
M0H]?Q=*:$RZMXW"]2 VH%.:@K0,PFWDL%/EB;9>_K?MO]LGH
MAXNK6E/\TZ^+Q5UE/EFK\*FA6LOU*,[SE/WV#VT'=?UM>?O?SWX\\X]<7BXN
MMQ]N&+<_M9/;BA!47,\J-J2)G57!BV%R88.7K>B;(0>6Z9E._ACZ:C]4+I:K
M6B>^"+^W?_[?Y6)5&]]^_V[QV^+JV=]HG_GV^@OOH?4'!H8DORB&*QEUM+%$
M8(\KV +Z<0E*<3OHGO]4_KCR!^8QOZ!R=E*4B.@5.@PV8!8/RH\NI3SN^_RI
M_''E#XQ^?EZ.$&+(&#G2J/.;H$A']E'Y'G-?"OGNQN>1.>"=;;8"99+5V9FH
M8P:R]/@4QK>KPWZ^QT!@]@=6VRE--R0MLR[:!;Y%95#>&;<)&?A?YV2ZO]HU
MV&7!54J4T%.$J*14L8!M+T6U\>?/-9C?D!=BLQT46*L5+X'D*-HUFA[ONM>Z
M RW2OUXLKRL]R _7VZ]U9#W[S#Q3MG+MN6S!^QA"D<;ZXE!YG2#E@1+\$8%?
M$>HH"$ZP.QY((MJD[F>;=QT2;D9CMQ[6[2SP70&^,C)HW@H1$PJ^JD)(C1E!
MIX&:VY.K>!\ 7_<^(:HNG_0)C%'&
M:J#M9,B I4N\G5[+NTH.V>\2!=G6U0GTY)%CN<=M8H3% 7NBWPG"U[U1LE-\
M#DLDR39%H4\B-ZH5$+%+5AQ1S[L:JR=Z D]^W;N%$5;EDC06]IAJ0.Z.>/IL!3!A1.AJ"EC!P+RZS 8';4Z!G!CM<,_+D6QPTL @$Z
M!)>5($TZ6=G:YV.Q^P46?Z[%40(,OE:S-9E43&RU/.BR&3.AZI#TGG+P3;;J
M^_LJS \?GT#^OXNK'1/@9S7"?UJ?<;V&
M\B__QPPIXA6<;U2*>1^E@"H^9JV+!(GDC5*AM:H*#69 *7"H4NI$^,7UY>V/
MJ\9P?_/AOZ=3[+.<$+4&#)5(7'/\S+XM9BT-\&W<67O3%YD,2_(&8;=%!!L/
MKK9RW?U>JR=NKJLVGJT=75XNJR6ZN/KQ8GGY[76\^+*\N[C:^3Y8> ^'0E1)
MTWU(.?@Z?"X'IP/9+C(\#/C]HJQN/M/'CWS8&8H!N2F1!=SZ%Y WA?AH26H'*T7
MOK-M$1&5L+68O+&'E+Z!_YW032E4*I@4(E)0,N=8J2.P#5^(J9^\]$Z0IM;]
M:UX:&5PBDB$&3U:UW1AC&G6 CXQJ@V"F%Q)CV[\JB-5 &5A:T HG"M*
M;1 RUJX&Z7T1'FC\:D]!D2J2".",Q@RZ>48>8/2-^X3H)LW@B*K6EF=99"EH
M1)+08K-:O'DFD"8:/XS14HJND)"!,:DD6\> ]GU&9D94,QL_LHQ(>$CU\5\D
M+[)KC0(&]2@!U%Y(?[YYF]\G'3M%GF)0,2)[#T#;GI4B^IX5J7K>C2$I#A/S
MZ'8OV:**-B;S_HJ)%Z ]S?!71.Q)+ESO@9\(WH%&S_"=I13521SLO]?Z]<>B
M9D9(.-Z#<2)DDPP>.2_1%,F;T6FIBHUM\ S)\2FU)X(S=:00*/!\^<944$4?
M2?DV.\M3[OP?,W3U'@W8S/9.QIR0PWT JXL.F+W'YM8&/]K'>224HP-L^ ZM
M[ITF(S(4+,XVSAL.S?NG #6;.9C#RS->%9, ,L=_(1;)GM!VYKTOG9=GWPW=
M@<8N:2DT$6^Q:,$7Q4Y=\_"D''\V.!&R*<9.!-Z(&DEKK2@F$]SCZ,DZSQYV
M1>LG@3.UQ4;R+2M%G0M?27E2DM00.='/>'1].?P1@LK\9)5U?[DOJF1:_W&TSN]M':3)_\4;\M+A>WJPJ)_O=]S=WB]O+
M^P4OFEK5+[ :%LMK^K):7O'OM"_>0)Z^8C_IKK@-OS_]SO/4Z0;%YJDHK3%NH2-!5"%?A[W&>L5
M_R*\&]8KG%RO)NI40N;8#>N0ENK4M!P!AP1]:]4YZQ6\&=:K/+E>4])>81#9
M@->UAM5LI\()2_WDFW?1J_E#7&5\-2F;/%7J;U,RN>2;;9"^'YO\+E?97JH^
MJZM,HJBY#07D(%.0A57;V#=T/!.3NZ=>S^@J8U7FP&8ADK."5#36M^IVF_IG
M^C/6ZUE=9:2=]U(5F;2VR@5OMFRT?*OU=;_GK-T4T(7IZWSB.S:
M;DC#4C^.^-AZ/72BB[Y0CL;ZYLC-
MG)]RAHQ#'=BP)! E(6%;3#Z,^S\-'1/K_-="9%=?)@['.31G2RML9LQ\ZV:+
M*B;?/6G.O]:C0\8I%I5CD91J<5/21;2A''ZH-O(4TAZ_^ ZEPP#( 9#PC$](
MV\J="MG]WX7F!G?HPP0'U%YYDTCIK(HO5K=5M ;VS^3/C6_2\P1EG+U?7R
M^M/MCXO53[_R&0L7M\L/^S1LRZ<;TY.!I# E 5('="":L!R4O^BOW/PI7JN_
MB"=]#X.B'""K_C?XM]=EM3H678)4Q+IU)5(&N^G@JOS_K\GZC> 0<@YAY8BP
M,CKV?_B.5=9;JD, H'5H8WS9"/]4L7H66=6(K+J2$[)7ZBN#JK4LGVX\#Y23
M&5.LG$-8/2(L$7HMA8_6AN"UX1/5%,M787I=L:!FD77D=)$#:_QZT+=D50(&
MVUX47-+R=5D5'%]6,WJZ9!V]E]EG!6MCEB;:HMN&U2^M];--(&;8L6;T=&'-
M&$J^3Z0Q+A=V&(3;^ D:7\X?>G:Z9M@$9O1TD<;D/%F35&%MFJA".UT&\=73
MQ1MV!A-K1@]7SD)6'@939X#(C#IO\T0VO9S\^VS#SB/KR.$2+E,4I=;V4RV+
M""6W*C?1,2$^E17?L@?2\NJ>78')%VW.'A2E%*%H$Q2B:_-GP;^'2)S; Q)=M"6P7[:."PB_AM\HY>QLFC0NLR&PAC
MI!32M62(Q3QRX)2>3=Z1 R=-\4ZCIN($ K!/)MN!8T?=C5S($_?#QX^+#P^=
M[Y40Y^>+?_RMOJ2QM,OK>_[9'[XL5@\9BGUN:?745U.>34.=@95"G5JL43Y)
MC>+3_-.FT[WZZD_5O;=LQT+46\&GB*+C.QR-#!&,9U^>)#1/F1W2/(A("_F>
MB/IM]A21+T5X,NNY?RKXF-"V>I,56VF.!'4;_26C&2(D
MJ5Z2W6D##D9P4N6,'QCEE8BE@',.HS1:Q8+-XOMG'2O;S0*(?PS=C!^D"(X]
MJ61+"2();42BUHW%!F;H(-6-HW9>AR=33KE9+9:?KI]](BWY!^OSP/+B:K+'
M8VVMJ$QV_=3&5H9\:].WX(?] XD3%;)+ZOFU,'YF0N0(491L4%JJ35%.-0-K
M\[.AWELMB*D&]OVUL.-T(.B4,_*I4)0JS;:"%N'C*Y9#*/6^6OC^YOIR<5FG
M;/]RM7ADOIQZ"C1:]B5*T0H-YB)D<&43&O*=.[S^ !.1#TDZ#]KQW>Z!KT]%
MBHV^2$J);$.C>'#X;);@DW7>'>6\%]KQ72UTJD4Y3M22.3[@VFU[YNKTS%?0
MVM.C?9A%3U]?Y(\Y-]1E6:XE$)3N?BH-6
M"Q/E4"ZBPH2)E]);8:[)[.CZLA)G7K7/O:3Z:GJ
M9,S\C'3K"5RV8=/@OB;N?+#'-[-$(WTBC94'RKD
M]H[-C4%[HRU&%#E%$TUHY'_T?#[-L\T],8([%FS^8F0_?CG=)N*E3GX,C%&K,]W=:)>
M#F8[\%G+KBG7R(XMZB#Q?UJL?EM63NB'FH#%92U@9:?N(;Z_N/V5EW+!RWM9
M&;/R/Q:K#\O;Q0\?UU2I/WP93=5O*V.O+JZ_O_C\9$CDC[P=^/?>WMZLZC=W
M55BB(^?YHC0N9LGA>J'4)NH*E?L1@^XUW1P![LFT:(ZLQ2*$3!P#A<@'(D>7
M5##-1*MG_N2S$W(>6N3 X[?%+>]K^OO%ZO+VYYN[BZMG?_;FMO;,_>?B[F]M
MZ.=XB>SZ%ST?7OHW_@NKY8>[1R[@?V=]W%Y\CS>KSVOR]/;U7>14I$O(
MQ4?(14=V?Z(6K;!$B:Y70AVX:0_1RTF4STI;WER6VLZX_E+]'.SCBEWCB Q87T"2% E*AJ!D*T%/V77&R[WJC!Q1
M%?^H5]WS'QG^M=MISM4S'1B,,3 >[Z
MS9[JZBW(9E31L=TX@S8:+25DH]E#US%;+YT,@,5Z*+VMT=VN.E--'=M5,U8D
MWCI"0&:;' *P@]8*(O* *?)S:HJ=-[J^_.GB:G&[=\KK!5%G\"X7I('?FGU5U>7B\MOUSYO39V'W^/5Q>WM
M#Q^'1&@6K\Y\^5(_7ME.+JZNZC^KZ=M^=A<+1(DI%1,X5N(M#MG39AH/Z.)$
MQP(A97<<#]'1\75LSE?'@)K8T4]6D(9"]1[>-D-!&# FG<\[@XY[=>Q%O$P?
M/MS<7]_=KIESOKOA6Y9-W,"OOPV_A^75%7]M70!VVZ+-S2^JWUU<_FWQV^+Z
M?G=_.M9!6JPK&4-M>41E:)-5,:7TU$Y^GVWZJ@J^0M4]F>MYMUA=Q\+VG3Y?8VF\X'_\-H[OJ5(L;B8(\E$VD#*/B?7NN54[D).:=4?V3P?
M0^U[&@L7K 1;)+L4E1@978FMGCU8[%P+*?O9[>^C>?/N/H67)A:+-M>GYPS$
M5YK;5OY@%XF"W2>J^".I[OB60O$%5B?%%;**@VHAV*-K<;4U_9C&[KGF3Y5/
MMQ*Q4.UQ\H5$2*66(6RX3FJ/Z$NN$W8IND3S'TCK$UT*+Y,P65BO2H*4A'78
M"E.L$-2_,/X3:N_XAL(([6P,,J)Q-B0MM6P7&Z78IWR,_R-?;"=T*41B2YPR
MI( ^1H$"5.OX@1!ZS5M_VGOQQXO;NW2_.,J58S3:%W
MA/&PZ^U1 U^AYF;(4GCG2PHZ\,GC_R?I7&LS26[@N>NP7[)BF2DC)G
MQSZTQ00F"M_&+K)#T?/1'A9F'UWK[Q]UJ%A')T27,DL3*JVK:DV#TN7. SXP
MD?GU:N[X)@*=J?T.F+)6QD8L13:2-R<'GAS/Q"J?JGV.7B^M?H(VK]I^6GZ^7'Y8>+Z[OU<^S.2I5]]5V9/C?_?EY0]^WG
M+Y5J)"UOU[_IA:;#Q=6ZIN[7Q>*N]A.LVW@G/#G=,F;ZR*OUP_7B/Q<7J^\7
M=[O6P^2(0J.H(T; :1=0>W95HO4Y6QR;]K:'0O_I]+];X24&9(>0O6.* 4R"
M8)$5K@MJPZYT5X]Q8H7KKTSADS>\2M'JG&MI79$JE3H\>;WA#3F7U'MO^*]-
M_[L5[B+9;'TH42'[A2(6E'7#9PR)LAV;7_\."C^G"@'*L7*YJD111T_*ZDJ8
MF$OT7D;9SXP\L>9>5H^?^U:=;"J@3N0+6K&S8K,JV47KUJ9"(UN-GEQ\GX3'
M/_TJ[%9[3J9D2%J2S]H*S6ZBK08C&1+:Z6[J@-DG=I];[^=D-QRI2NIG99+K
MV2B.G'JT&[5XHXML[#XYTAT*7-XMOJM=1QPK7%Q_J@0%:S::?[]=?+R_^F[Y
M\=4Z^*<:?.67W=S>?%ZOOEK=O4 ]9I5Q!PS&!\+J82E78RD>C,*P>^S5J9\U,\/+3!VLI
M&N>$\ZB2CD7DK,ELI^8F&VO#$\ZBIENV^_>?[]?-I_3Y9G6W_-^U:9Y6))R"
M4FA YX 3VI]3$"I,QL<0QPELKH,-9-M4N@*$0"&O.6O5&F'F!\^1!:0
M#Q)"2;$H7^DK-YVFK,J^O?(,[[BW*NP0\T-:>D/H(J*3E )'%F7S7J*TZ,*R
MOJ=^/KT]^9''[M5UI%_#_,(_,,T.8>(;W*1*+IY()SXP3T:\QM1Y03T;R!M$
M/1SQ]PSPY[\OKGY;_)71_CJQF=^U:^PZ1\(\Z;^]4TG"ZA9(\
MEJU+3OB!N:%O7->-E&_#^?.OJ\7$!8U.F9S8Y78ZH-;%06K'%LU ,]!@8\HA
M*K>,/!!95@5;&E'=487@Y)J:580_F=Z5+N"?-?5S>W$YM3
M)0?.6GNR4AD(P5G^0J-&33T[#MB^Z7J71&^6_J1NG>>H2&EE9/1.&"@B/O(%
M\64K+7:UN7*PW^<,%7*0RX8 B74!9.O00)&SS)O AVU8%S'RMIFRX\] &X?X
M8Y:MF_8.M3$*,9 H,;6*3!N[$K>>)V1>G8RV;O,B"L&KZ*-S',>*ZD,^;N^@
M^T*QRBU[N!5%B!JPBVEB+DDWNNX;:OL6R#4I*S(.RKDD /O(T>N,1F)
M?+>EDM#KUCE62NJ:'6':77X&VCCDP.O U[[$E$4H@J*J)$F;6[*._7R3)S=%
M)]\O)O)#EF38 <.LK-+LK"2MHV_S5$U_OV//#SDNSAL%/_I@^"*C"IECJCHW
M2 4O2-@VB=&YSA<]*\ '#HO71OH,+@HM 1T2Z=Q&8?ZT1H\UC@^/?#^#$(?).A0(F>>=KKR-#)=,PDL?.QIP,
M8[M&YIDC#R+:'.I4"LR!PXNX83EEW)*MU+OC/H4/DD-11#48(P<%.;#<-&R#
M5C! ]0I34GSOI(Q#_ ^;R07"( (9]BR"-WF;5(^V4X2=%&^\LR(.<3U<\*""
M*T[$R@&L"E C6N&@O4N:ZQ->9Z.IDA"KK ZM5Q[9C0[8QCADY;K7$>.G^)%O
M%_SXCH$^ #'8_,U[%@XZV%*Z)R?&C(K8\Y
MV"YU?198IS@>*A)8=JZDY[@YH2L2MJ/Y7%_/=18 )SH>$0MXH[W-.3/&[(-K
M&]>R2_EN&&=V/+)&87RQ(5D#I'U]_][FML2.)T7B,B:U9P21 LCNZ.06>PXZ>$?HK4L1!2/+GYK,
MP*HD>R!6U4'/POF"E.V6W4129[Z[CK<]!3LBEJ/[)38*FW1,+OF4="83H67T
M+-JNZ^G<=7"@JV*C&"$V.G@!5L\KJ^8SKAR?$?BS-:=&H,32TMBK)9J&(8PEO#,2-
MKR"]Z1\5NZ3-:<'H,3"5:=RPO13**U+.RXS0QBXYW>VS_@'AQ&!&>=,9AB"I
M3'!\;J+)%$JK0[Y:^'0
MA U9-IU1%Q^]"&@H0&LF0M4KXGP5,,4+*E8Z(VTEZ^7KSY,/LJ$N$+H@]WQ1
M3_2"*-?A$]'P@DLE5%'!MJD)2KHN>?R^P.?V@@" G7\*-F41D_\QF_9?'KW*!GS<+_L5@M__?F>@ T/JVH]OP[,=<26W:=!!L[;#M 
M2-F!QKZXY93@S;@+2,4)J:,L:$P(F1ZBIC3HMEU//C^]"Q
MR EL*A*2CU; QED*Z+L<(/2LV2=&,^;ZD2M%@$1&)!.FS"%&HX2S!O8I5CX]
MFJ.[?M)F4%9XBMX$2O5QKHVWDT;WM>EGKX4#7;\80Z"BJMV4A(B0J)48<$QP
M+J[?'@J8XOIY"(Y**$E4BUMG.XHVC[24\-KS
MW?+#XOJVCK;[M%HL/@^0<[S1J60+&71"H[$DY[,SE"2'43;(G(MU?9'P<9S*
MFYO+OR^OKB8VN!25Z;'6>3?](E8F(=
MY4%):,N1(SM2N=44%]N(=@!1ME):2B\7[D((7K;329SJNW#.;<.N*
M0E^L4GR/\QH$6UJ/80(8O<@G81GM7%71E""LU%H4J=BSS,VE+KKO#7O[,9RC
M4LVQ1R %FV\ G]@_2EA:(D3;.! 8S(WB0&/B/.HJ=^%+B/=%MG;CW"E5"(YG
M3(Y94B8P@@1!IE@9:VU)>9R=J2JSDQXK*3NNT%-SB2!)4]&U33V)ZC[YINPL
M^@*9-\D]LS$AKW)*4&I:+ 0.!)UKKV_@^M!X3RP/T^Z_O?ZP6ES<+M+BX;_W
M>;/Y]OOR-%]MG$'+%XORM5)!LVLEHI2%X_C@4W] !\0;%N4M0O?9AN=")R/0
M%K+ \EIRI*5MEAK1_'5L2+U>IW=GK_X^+J
M%7K_UXL%DE3603%Y3>Q#O#-:DY1P/9.+Q&Y"[[Z"'0?,*(=&?566$(7.1EDO
MO2.U 9-]WBOMGF&=B5W,
M)@?Z,O<0ZBD&WGDWGQ7^;($02K!N1G)6AVJ#VY,X>3^?FF,ZD'B[L7)!W[&ZG1/:(
M05!]FXH6C6HM+Z!"EVJP7P'D'5O;QR!]B,(I@S$JD,F7-A7,N@':RK.!_-?E
M])OZX@-/BET??G\MU0RX#OVYN]^O7E")#R]"#DH:RIQM??LQF7M(9O6
MG>MLZ'(W??/X"=&=F5*/'OM&;S-'+J"])0H*4B+?TH%:#3Q7]K/?_UR.8P;Q
MD )(%3GT]0(B6I.":&6=MB!DL!9UXFNLU21 *&.5
M%7]J_QCI%15K[8&(E1.O2.-2C'*[ *Y;@&_XM/QY#DY50<]'(J@L!3GKHM0I
M4!!/$K]C!!3_C(NRPU'.H1#FE(Q!2$59*4L+ X'#A:ZGO:\7_^?5ZM%=(M*J
MTKJQNQY]X,LU:-E\^-I&TR>,Q#%R$?\,RW'HNT94%A+'4J$.H'3\#].ZMJRP
M73[RFYZ.^\\%>;-+9"+D$#&EV@NLC';T2$9A>%+ZIN>$_#\*IZNFERB0Y0..H@8"CZLK-U:R4EG_Z1),R
M:<(J82-1"KF2G6FM0NM1"4GT8XC[82;_O%H]?IJ(#U&HLSW8U$?R1E0ZHTU5
M.[J^:1[Z@=I_+L4$%GA/[5&*3],U@[69VY
MT[96U27G+ FOH].J71M*Y[$6P[-8E*?V^/O%W0\?^>],?N\J :FPN=8^VIC0
M!#30**2EV-](#$ES'-F/[B] 42*X^MQ=V"UCGPV\V7AOB;_55W-T;$EG@?W 
MR]EP@*Q5AI0JU8S.,6[Z*P1_:Y2[]BQ@3RH&#V#J*$[A=$Y>*Y%CXP+'U(^&
M_F: (?TL0$^\>G3)VB,'?=:Z;&0I+1JO\'4?H*@=Y0TSPI[9S /RJ:XC?:PX&$VKG!GF*F
M=>UQD3&86IKDDDR(OKTQR;XR2>XJ-7PGS%-;?OBVSOK.=GBG]1DD7;\%Z)QR"]])L.I1XB3#T[K1^ATT\8ZN^CL4G
MF2DZD8WB:RK[!A]H_\SZ.\&>Y$Y;*42E)RLUYVHQ1='ZU(/Q/1'>KGJ\=\(\
ME70;.%#T03D3".)ZA["5F*B3
MY W"'I\]+QAC" I)KX6#%,&VY :(WI72KV0<3P;R0+,KV"TV(:F0U@26E$5T
MF[#.EWX2S3>RH_\Y,= IAC8998G#UEQBX3,F,="6_@S=;N?_9*BFFM*Z'W5)
MQ(X1Y5(T;)-/RO4C8^8%-K.MS%(YRM$(LNS[I5P)ZUO]>J"QEN=C@MV16U"V
MV.PD^>0*>4J\(JUTQD774_6^U@IS3&F/;A=#)@,6BQ*HI<$BHM]F$^1 'SW.
M:B_FRQNDPCLKEDA\RI*E6BF^K1#,/6G'-SUCW8F!3N)(5UKJ;"FSE\UKJ)Q6
MK8X%<93=X\2HICX6%F>*\Q+1UMF/[%;I=@J3%[O#B*,"F]DP$LDZL82O9+ZT
M2V+#[Z!5Z^6X^^GM.&!W!/.(4D)(6+D3HE(H$K3T#-D^L)7S^E)SA>]".M:Y
MRBK;:!+_AVU4<]'$OI\>7DFSG@SEH4,E4E"YN(RF)F8D>UBR!:])#@R->26]
M=#*5)DH.7MAKY&4$Y"L\;\?X4+''N@06MS]>+"^[X47[A- 8/8)C+\HD
M34ZQO]A&K&GMNG?%QSJ[(3F;$%-%W-6O(JP.,K'[IB,XH]#9LLW'];RPK[U\
MOD7$78W8E%0)3A;)%R'%&(.)F]@U*-_1/;[VL#4BXC-2EF^OZ<.'F_OK._[P
M[Q>5K^_ZDK^RNE]\^&5YM;QC\SEY,R 'J!P?1%VG7I+A>UMN"F;*:P?"B%FP_JWQ8?%\K?Z2R9OV4H$A[* LR(E%V6)KC',
M)F%Z:D8SE,C=*=?;<>RJ!\  %.J<;90B&K[]13-RWJF.L,,/V>$3P-BQT9R/
M*1&'WR0]IF*I0/,]4Q+]NZ\9"LK?B"/=+VH6FCY^Y%UX<;?8L"=-WEPQ<+3M
M@3B@EN S:;>=WT78F_5O!DB0]A?ON*!F:%3T2;+#C5!"]-JBTBU03VQ"OUIE
M'!A]L!:*CM984Y.>T5O [>Q.T[^;G+L:)@WFM8Z=, H1Z]%PI#5N"RXM[7@5
M/S_L4\?;%6_J0YG(UGK)T)5H'=1IH [\'.#/7>VA5/%U3KITB+Z25*:V(Y2(
M8X3GIU?)CKN8+R6V< ZE\UJGDF7>9.Y 9QEV1*@GQK*KL4WD@NL$#U;*-P7^
M"1$]]7[%#%@*;Z'K#XOM[7U 8.),P%IZ(TKVR6E4MG6^\-$;B%('GWIW"O9V
M(+M(RMAM4%X954 )11%%:(4'7LCN$I5Z\)7S!$!V112D5>6?!\PA!W(8L'&X
M9B^[2K=O0 R^O[P12>VKJ/?V(=%NG<69;^$!D+Q!\$3+R#13D9KQJG6J)79RN_1ZJ/X[D.[9-XO!+US2?DXIR
M+MZF%A_PONEI1?4^4??>HJ\G<:?%QP6;K1:F_G[(SJEM1J'8&DR'H -MS1'V
M;.ARGT,\+-MQ\.S*A5P%M@\_:1=3CV6-1YL2S8Y?Q9R IIZQ&
M@85#3(]MZI"!T/EG8(>JCX^%Y[&'[/K3@6/441G+DLOL@A V&TFR[3;'<6D?
M> T^Z.PAVC' [#)=WD1,?(!*K@TM8/1V5JT*N7O,5G*/?,U<6';5!@2>@]\C_
MOBK>T5#MV'(&HI&0205,*D?'J]"6*:G2;SG8XYZ?']4N6N/@(.8@DL7B7-;2
MQ):_E@7ZF_2HH&HGZ\55O/G\^>;ZIU\O5HM;NKM;+7^YOZM.V\\W'$;^MEC=
MKJ<*_;AZ-)H_W=U\^.]]-J5X^OJCLP4^.=[D.CF-$5C:/*U(4D_K0V[7@O0Q
MS.'"SHJ[W[9/<4.QM1/,96-S$=FE;'"#N\AG.88-;G":XR+_=:#OM_=3]-)&
M59!$4K%$7G@K'V<&UU77@.>UZNNO!3Y"ES]>_%X_3*O5Q?6GQ=Z,Q4^A$[O!
MVF:MR04PA"FG!KUD1P/0%?ML4IF)"AB5>FX=C&]^$L9(@PF==,CF./$&:"V>
MZ5F L]%!;3!#=%^3#L:/ *I 5B9I9.!EETYHM-M)$F7(\'G6DH>I!V&"#D8G
MXAT^?^6Y$U*RA\Q185(XU)-R@*0S0-WU6J:4]D%;"!BC
M9;=+4N,3X?_N>8XV+RHS0GT87[C8#B_LYX:HL1E=.D00E&LOAC;&2DI;(EVA
MNCIWX.,]X)F,B_0V\<=FT2BC O"=ZW@3JLB!HXS-^,8!-L[*-#$0"\\L_O$)
M-%+1IB1'I.LP*09>VH!#(7.W:F<(^\!7/ UL91A.!*DX&HB2_U<;[!1:Y9"$UE@ 
MO!1;8F_O^PM0G=SNS#$"$C*[MA:S,B[Z9"-$TUKC4^E; \X0]J$\@B&ATA*$
MSIFLK8U'9E-NJE+/(W@V>*?U^B')RIC(9["NK7);.JK(7SI;D!/-K66'M5@G
M@&R,QL<8/&U\/>/D>$_CW#AG-K=:"Y$R*F]+E,+(" HWV*/%XV._&O+NZCQ++3KR'H$CE<)NCC0V9!(Q
M)BN"$I9=@(ZWX=VT.-2$-J2+N\_WM__??W"T^K\WUSO $]^?CEWVM&ZBR";(
MK#>NCHVEVT(;>I+W0O^BU61'Q!Y^_^O%?]VLXM7%[>U^NV2W7DN,/WU9?+A;
MW7^F^_7W=ZC8YQP=U6UE%(?R06?V(5F-Q2DC2^RG4OS3JWB_K2N<0C*57IQ0
M9A4, KL*5M<^*"U\Y_D-UM >H-8'BM)X"T#DMRF+0[,HE$4J/#Z"5%%<&PP&7C;-;YW]UX
MQ('7S&.*NR,;&*4Q-G.<7EPLIG(\ND;Q2#IUT6L;N7N8O(]M99/W@*]92A&L
MB8;W+JG"SNV#]4W6A'X8DQEJHGTFP@'2';^Z7:'E&U09*#IX)2)JK.1MQ1KA
M^<1VJ$X-ZM J=;8KQJLB- 4V/N!43 ^X5)1EH#_णP4V*;*J1)'"I0S6
M2K0NAQ(>T4@G1;=*IT,Q,70*0BLK4B@F4BDB%Q/$ Q#(!*E+?*BATI$W YHY
M1D)32@9%R+XJJ9"=E.H!I,2$?7;G2.!VO2\%YU JD_BH$\8016E)PNQ#%YV#
M..Z1F(M:3WZC
MT3 F]C5)0T..9P4VR8!%7AF7E$^*#3!%--3FS/#9&&=+FA7%1 /F%28?2ZC3
MAGRMY\NR\5F9*+H26%0#=7QO!C2S 7-LC1,%%_FJJ4UNB+[U^62/]
M 3OJ.9^/I80WBE"\2KDBC;D
ME+&>SY#D,++M/2'Z!N:#P/UM<75Q5XN'5@>T4H ,')AS.*XU*>]3]"5MO#$.
M,[OXQ X19K\JSANE/CZ7ITF":ET?H1;.\G]2:_]2),9?#=X%Y:%<]Z$DE(F2
MS\;SUF.O#39U-(:CM_,#.LD(NN#8R8949&#'QQ"*5I[(EW%W5;T_NHG&,?.!
MC%D[:65@^Y@R0BN#LL7T?"$G/94S&TVCP6"2DKT^<#&RT=PTFPJ#N(.SZ?B@
M=X2SX$U@ER'%6C>94\@I-0.J2L^.-#AQ8"ZICVY A5<6!%AG,X-C;]=N*R>R
M[<..]T=Y:-Z.-$509AM*(RSQ?DXT!IVTE,YLP&M--X<+V@GIT5PYY9
M9.,) AT'NU)H!]H)]=]G]/[TJUV'MC%E$%(Y.-F93.<
MVO=<#H,$[)T8!TIY=$/)D8Z(;!%).RR%(.;H""
MB,+(QN!"H>QC0F8&-HE&GB-Q$;W+#HF48?NH6V&QA[U"\IG13/4@<]80H4"@
MC"*+:%P+ $20^[P]' '01O@-!>/W-W>+V^]N+JYOZ?KR@:QG>?UI2]<3?M_^
M^WE]U+>?O]RS)4K+V_5O>E%6%2ZN*N_/3[\N%G??W7Q86\GMS]9)RE]J-=:W
MU[=W%U=7]9\_\@\\H0GZ?G&WZ\H$12%JP5%Q%M)%*B*WL%[T33#P^JO)$14[
MVPT24BQ%2UE;R!5$E.V=T=J^].G(('?D+(*7?&UHR
M;CFN&TD7?9=S[PD@ 220-SL"B9\SGNANN]L^O6.N3K"ELL49F?0F*7=KGGXG
M2BH492Q6<177*I;L[G#(8I'$EP#R#YE?5F.0\OY9=((FY/S YEB.@%ASB6QB
MDEM2(G9&&KDJR1WNUC@+FKFU1523#\D&P]QX:[TUG;665#CW?0Q%0K^"/HC=9K:N
M,Q):YL%%L?K)K.'*Z$YM_VMCGI2-(+Y5*<0FJ#Y9MJ;5O?2%DS#.)&4T&CEW
MT7GKTN-:" P7@&9N0U]& .\P9#EW@5U49L__%<8I3A/$#8O!^@/9CU;(8#V7
MF F3&!"#B7:OJ7)J1KK.*?Z^Q06[DOV [>@"U+ED)^&K-[OFK-:LE>$Y3SM'
M0)XZZD9B#B"5BX3/7%K<85VOD!4U-*2^M783),)?K&'6\HX$12J&7 ,GA=:C
M(P7RSAEH0=I#\26%^=,
MC;%62,[KQQ%B&>-?_V1R^]!"/Y'B?AQV^Y@<)4@P+(%=2A5+D*L,G^>_BY.E
MX_A^-UU@NO_MLU:UPMP*!)^]*5@(T11/W(DQDN7!J)T/S:F)6TK.0&:H["4$
MA]9-W?/NK Z_#JR!8X[/5'+*D"7,9H" -3G]>2":+-['(W4-:RQ^[KN40B!O
M8E' #MI@LMB9DBH5<#8=S?VO@F*-\6!%[M9W#2*5H;RB%GADK*US>
MA0E7'+ODE3BQE3$K.40ZE-W=R"8=GCMSZOI75C[6N%I3MJE2$FN0T;@^QEMV
MY]0]N7_8=N_7J^N[OU^]_[!IT=_[V_L/=YO#*K9_ W_L?_SWZ\W=U=V;=Q__
MM/EM\_X+U/TSW]Y(D'F__8#^783YZ$?^>7/5EM"6QE?WU[^3X-7=W<=M3/OK
M[9T$K/&7%JY.(#@Z>%K.N6(YWD9IBL&)K0T29HJ )1S#8_[!TY+[ \BXW#^(
MR!XVW_W4OV.^@*L&"VQ#%JU14V%67<#9ZK%3Z2P"=I7&-(A19CHK=:FR6CEJ8)%H0:QHP\7S[=0IJKE5S55E,I?'ABF8JV=2T.TI%
M7,QQN!M,L?5@RAJ3#[E $A'&DQ@25Z.1*3ECJQ!/\%\2R
M.5055(BZ#9IARRGWT3/&\I#8Z>R<*RQUXCG^\5)S]1F2N7!3L_WOYS<_?H0[L;]XC^+=2(6FY6\LFHD'WH.HKENOT__^M[X__SL9!.
MD<&K2O'Z9G4IAO:&;L1;4+:USK8W]LY5FD!ED2*8KTB*RTHG XO"-LXVCT%<
MT ($&:D82.C$:1?I:'5ITIFJ$?O^[E:^_^%C*WE[$$W1R^'XXY_-NPU1N&9P\Z\XZY-8XI%E$NG,7"
M5A>IQ419[4"'/-;9N"%JNA30\!SFDHG)<8F5C1$*PK'9M'C[JP=]KS#RC55E[^S)>%_:I W!19X4NM[&P7E>JU?=>%"AJ9!/?;??%
M )_5LAG;G4PN9L?H2&,MO;I<;/)P/34Z//_M7%(M6Y5=$A
MYF%_K00-9U;+9WA9<18;HZL$N<'%=6S5DT;$*(5NQCBG6_31J
M^6OEA-38\C!
M"CNPA@/)5+T7*U.A\6UM^:UH9V",&GMF@Q^[M]='=JJ/R&(CLP1XQ68+ADW9
M]?0;0]D/08%1AS(U*V&;Y09F%45#0W+&M>'K&IEV@-3AIJ/U@C]P_:SHZ,OM:M=*565FHI)Y\S1")$:W3Q)<3]>,QTJ$[MV?CD?KPY
MR5DSM8@A!U.5PX2A)MW3SU5-E/,"C!P?D^LX;:'+#V=*MM4%%E**K+':F=+3
M&JV98N3.H(/N\ZH 3]1R*'HMFH2MP-9PJ\(JO:8XT]@( 68<"70NB+.XH@LG
M)\$$2.S'4"T;*ON]&[M&PZNAFJGY-!E; D=3O0F2DD/89]&@'M^X;@P>=C!?A/>3F59T+!E^-;_$"IB*N
M7>< ,A/\)BAF>,6%+C_'J41O)8PMZ!0;B8^*[0Y1EO^/41[0(9=H58"GLGR6
MS+J0]K+V6HFH..B)HPF2&O'@5[M<2_I^Q=96=%*B3KZ]%B-S+UTC& D.AZZ1
MCH_UZ>I7^9/LUF]7U^\;^U*];;5>;S???[A[TY[MCU2/
M__#N]NZA52WES3\>OJRC^_>KF[?WFX?.;_>H[.F8,;2N%A9UKX&]!1]Y3U(:
MY"\F:(Y&89R"]:BT/@F5;^_N;O\ID'8_\;",'@\N>%1'=]]H_O9?^>(@]5+W
MMY\NT['[TG2U+;HZ2YC16>]ZC4]F?+*RZ9C GH![3$R];_J[GSZ57CRJQ3CL
M;:PBJF__4A_K3$ZV$4H00O$)*SKJU>8^U$/$(W.Q+BNGU8_4EW**XF)3J!+Z
MM!Z"!-%3)S]4)AYBMWJ1G!HMYDN8\U3(N4U9:069Q8.1/XFK[% "!C)U;-QY
MO.[Q=\]>VB%?LMU+IQ,Y1%8NE6J8/B\M82XC/<%X2Y^_PM>@,H%79MJP$O02
MJY2I)&CCRFQQP;6! 6)))-!XYMX?X7WX6J6\",4&:0G/@OAD6G2 A*J<)#IM
M(O;&2IATB#1K31$OS&+RV@?9^=90QC9Q+4&+!PC!-RGK;"$:-08L:L*B__'%
MO&
M?N]81_=OXOW_L+FYOKW;4DF__;"1;PW'\I[;LE,?C,VFH)A"^LP9+)$C2(SU
M'"?QT=H7QH3_)K_I]YC '$ND*Z0LP:^L5="@Q/BF3U\I>@R_A5!39P^T,=2,,D$.67%I(0QB5>FZIX;
MSX\SZO54#>F:H(P?=\H=R[]4I5*53:J.HXKB()?>$";'<:P#]F?>*8MVT!-T
ME/7<<(@@&Q582R!NS>(ALV7AVLC5@5BX4!BSKZ
M "(^NHV,LB%5''9J]6*?3UV .FKR/NU%4S
M89[.?>JF0!VSN;46;UWVB9 2V52P]IE,CM!X& QZ]$4]BARFR'G)6B[GFS\)T
MFFM.[195K;SS*IHB@93M-ZJ4.$&A=V90)[GFF9Q*&B2VT"118H;=-&.Q4IE'
M-;&80G\FJ--<<[ 0Q =O'9B%)> (W3>".)Z^Y13Z,T&=XII38B"L%DWB:F6;
MU(ZMOCH=I^*-,^_4*:ZYK-N*V(_]<6KT8A=3Z,\$=8IK+M&?
M:+P@ 9/.Q5/REL-NIY(?^QG.?J=.<G
M$WAK@CK!1V<,15 HS^*I^Q90E3XWJ5@U5)6=_?B=XJ,3!&N#SX%5"!9J:6'4
MYSL5863G/OOQ.\5'S^PQ:93(,+;QMDYY[(JB0IU(3)Q[IT[PT15E.6D%@RT9
MD*QOZF^W4]F-=NK\S09WBHQNOD@0;
M02EG-8L5ACVQ:[%E.'XG^NBGECBSSJ&5'9I:,Z0DK@':WMCLS>@;(/BQY&UR
M(2S9 )XZ/,PF$V.H&A"2];JU
M>^^GH1WN?#@;MCGE?%#8^)Q0-HX<*:L=]")@8\*A><7G S2WL-D3I5"SMF#$
MF@;1WWUR@75E?,QP8:*P>5%T_;%VG6*^8+6OJ7KE0HI>2ZCXZ.H5.$2MOQS.
M0V4H6#EK;:XD[V#2\!RJ%A%^?#-JNY(S>7M36J
M,"F?)!STO3W7:G.(Y_Q\@.;.6/2$)B&*.U2,YI8R[P_4M=HQ9*(P5?6U)+J5
MU1\5"_(/>A:T3.Q"_FS$Y%_E<'WE+)S?;^[>R)>O?M[P1N[+S<]_EW^W HS=
M/-F_73T<*5V9<'O[/F_DUV_>MD\X@H<3ZI=AJQ
MV;[YL/U1_TO]FP+OII$_"]>70KF_;Y21\M'-S9N/^>H7^=[['VX__/SN85N(
MKAP]?'H3_^/#V^LWUU?N_?7@OOV%B]]T7=SBTP6&(
MM#F4GR?V"F"N- 9^86CE>LEB7PKZ]L/=":"I1+!L,]<*8GV\D\NY
M UW$-Q]!#P;H)8M](>CO;K:RFP=9'&[M;-3@ U (U1#TR:[6C\,')$A9 /+G
MI;X0\(_O[C:GG&TO9@B-$:>^B)T-;-R.W5:UL'ALFEEDF_>K?2GL?]Z> +J5
M]K,&*[>:-.9@"G8_WZ>1HFXAT)_7^ACR7S8/Z>K^W?=WM[]=O]V\Y8__W_WF
M[;A^I,3902<%%AQ+JYLYY
M1WS(W;Y(,XC0X!74"U?H1@N!-ZAYS&2D4:63HO4@@S@\PV\$KV&BUF
M[\2BDW7]#<&[L;*[5===C!S6#D?% :A1A]-=+%D0WS544R,=/G
MBUQJM"9 %$N07".X#-6'?MY% 8QMT9=PWNTZAL :<6F=\BR^#M5B,.?0#8$+
M8\^T;I[?UR"-$RV!>$*MYU_%F!0H$Q7I_N8+$0<'\)O^DGWA\IAC$L09L(8S
M%?$%L+$K6=7'7B6<>$Y5:G#]+U((4X%B^V,%\6-_"H61U*/
M5Y/#RB;!4L92HCA-8AE2=JAJIPEV <>!JWKB??K\PIF8HO8EVW5)9%*)FHI1
MC-5]'J  U7$82SZ,U1>PXVX=XP"8BP>5LV,P5 GA,^/LITJE@4#D&Z\'_I"+
M%,:IMH%*=:TWQ.569N=TW3/P!N/'J*D7!%VX/&;1OXHB=*Z")D/%1PX:.LN*
MUW'D@_\J)##3,'A2B>42> C!4V4?;:^+552'!#VJ2_ AW5D,@XK6IY)5,26O;&U.OE#=X@-C'1KVJK+D08XWX$7=&'>FS/
M+Y(C^2.Q:3G7@C8JV4")=+3>/R04-WJ!'NP%Z+Z5$DA!XB4',5N)! '%]\FI
MST]!I\?Q1E^--$XM*,N9BS,DUC$"I*SUOFK;QG!9EF#AO%&)M3+$$I+2R9<<
M<3Z,G9 T.$"3#)*U2?G2W0$31_*12X"_M@EHA8A>
MQ1PRI=Q*2'8=0L84H\=GIHLX&D?212756"C(:;$O4AJGV@(.B:)F+MD7\,F6
MTCUC$J?YHM3 PGDB"U!#%:U'.S9:\KA9FVH+AB
MY0@X@QX+N )@^TS>@CB,XQ!!T'-?4]87Q,I6H2262$ \)'&8N"CCO7M$#$]C
MW^C:AZ2/DG]!KHB"1:,4AAB*#N@#[VH%M=4 @PMHG'TNJ(GE+0MJ^521(=9L
M-&AN'#!4*_1)*$6/4WZM&:O++E(8I\Z#J^BKRHC:N- 2Z89[^)BA#.I@'/9\
MD=*88QI$#>JJ"WN)"LBWRM+2LP$)QW8.>+8^?%T9S&WJ<\I8B$%9X&!B"ISZ
MLN56/SM%LCJHY8=]JM*HQ<$4J-89T*7VT%B+CSQ,_#-C
M5^%%"N/D47I)Y(%4"L5$-3'MQRV',FH!_=SRJ]>5QJR.;1>=H1!K5;:ESZ)R
MO=Q(;.7@+UV -5@^9<0Y9["@,5OO3%1>N4[M*O[DF%9V^A*\QO,DCX*+&+6V
M+);1$187?4^J,KF75.6M*)LCR2.6 Y\"YEBB8LM9:>SV/VLSSAVRXXC UP*U
MN%G06]X6A1E\A4:,Y'+9$Q*.+(NT*[Z^=&&<:!:*MZ1#<25'!2:KG%2GDQ/'
M<6*@V-=Q-F:ULFN?!"RT^K, RF=#O=1(3.9$QY3XHDLX[-+\H[+YMN;-[>_
M;%JG]>P442Z,XN]2XW'1FE',VYZE08W$BF9JU?O?/WMAB^OOXL0VEQ@HJ0@:
ML*@]4:E8[^$EA,S4&5T+T:E5/:;6Z#4P8L(82ZZF4_5%;\<"6#=5\K46J%D5
M_2:7XA%SB21G+1JU(T5JT\[*E"H]Y_[,3:E#B<;XZ@DM.SEOA;MA*([&Z].Z
M>[\ ^K?-P]7US>9MN;J[$8UY#)]SXM!H7\2Q\Z@RBR;,.WQBYE?.'U.*;V]*7!H:7):AP5;6/-OJ*I['6?4*_%
M! XRHP579@ZMC(A#ZR!SN?J@*[4T9J?JFA@T^47-.&QV14@G>@!. C"FY%"\S.!D=RQUJG(S5=)@
M%E/$2R?92JO5#IX@8ZQB-[WMXV#E D^T-Y_SQ,UT !P;4='1ZF*J 2*-IE]L
MK>I(3;(XF)4]@&WO0-02[['$,\ 2\NWKR?/(XM;ZNZ .)9>R4V+$N8
M)MZHW+'0.4=R\'CZ [[ $[7UO!) :TKK%A,2.HKPXDKCU./N[* +
M8%.U,>0 B32+;7,J[9D:_,C:82:KJTYU3L%L
M1L*RY=2D.^(">(FF#1O+"BM#0*5[A9YQXW QH 7/V4$7(";.Z&H645"IY* &
MMW,!O!I7)D[5LBM;W 7P62.@<>!L% 7-+7K>R5I6/R@M'<89D"M".K5@(XG5
MU"9KQ1;;:V&:XP&DS$Z6G"-*<&E=%072RY) -,7K'KC9
MC,BF]>)E976%Z$RU?O]XXLRP*\N#6=D#D/BD.@E\*2L%/@2KPEYQE5&E?@,8
MUH*XB@> J#%R442-&ADY)''EP#DQ;E;4%F\3$6VT0(V<@CQJK7/$F:2A HT:+HC"8SC
M*UP4W)'8M-KVS$ Y5% !8@Q4=N!L%N4WUS4[,[HC[AU@INS(-$I54>D5D!-5
M"5DI5<=VHF'IPM ==!%)@77>RM42EP>M[*-&0>="[K"KBHJ<(XJJE4BQN(>:M^A\# #C$PH<
MT??G1W?0W0V9HBC'ZET +UI33-MGK=+H%P=T>"2E_2KH%G>9D]Q)EZQ5;9! 
M)!V858C1. N(/,YA/.HR7YY83JV+LSK$=OH#A>QBBA(H;26#+#==3U!L?&5R
MF=58B>*LBU7VN;D>82L!1&8TPJ@3QEKY7ELCT=
MH%,A-[QG'G,>7T<@*X<023R G(S+&(L54](F-FV%%!K!+PXME\=#B)EBNKUY
MH/G_\COI$0XOZZ+;_1]$?9[%\V;_5\.E^Q(+JV/M*$%6.CG.A\
MW%8\UZ&FVH_ZX?G+6PS5,6X!0ZJY-NPM6P]%A]P;!G. \5G(C87BKX#JB.FG
ME(P6UT9<;)6BQJJL[;,I[<@1,#&8=QU4]?I?F[?R?1N)9-O?WIUR$DWT.EC'
MNF*.'+RX:TIGAY;$Y49]L,ES_O(61W?D1+8Y6HPQDE=!>R7*-H>&#FH*UH^1
M[H6A.W(RJQRUE+1L8!LQ6BB"YX9.^^JR;.4XG2*,$<6J,+>S.K[[Z:6'%"EZ
MY9  53(E%.-#3]!''EM0Q$6?B7-ZH2L@/7)@556^&@5522R,)EG83S:'.*:5
M+A#AD4.;)>Z-G@S)D755H8E[5E)3ZJ&)?4L@O-W517YR"\J_?MW=E)#3.->ZY6;Q50HR1%4
MJ"1@0L.[KI]F%$V8V-@)LH3SHYV5RJJ)G&>5,?A4G3AGC\9L8![V\W61S52>
MC2Z<7$9*(4IHWIJ4^L7T)DR0HDMD?Z8-7%E[HE,<4HY9FP**MWH4U2]?@RQ3O#KB_-SI@U<
M.U7O32H9/0:3;$G5)ML'+*7("VC/A\U]O'G[I]NKF_N_;=YLKG]K:?S6^GA@
MR/O3KK*G8+!D%V-B+#YSZHP-BL?:1:,FBOV/+>GEZU^^PM%D96T))E*0HTF\
MXWL4T\$2!GX-N$\M@]18DPDH5VX[^L5;URB*YL;'2I8PM=)HZBW(A<9>MS,C75GA5B15BW6D
M&;PWWL9] S;H\4WJC.@/C6J-&IRSLG)==4;;&/1Z@&BC&VN$S$0EP/KK7USQ
MFD(J5!UB$4OC@%S(.X3%2]E3^!0!TV<$%I-3.K0C3O()?W*
MB&=UJ#M=$'2)+H@UL4A5P2[O&*&\IGTY!G-NDL#;PL%6ENC#>C&G1>%N0U/2
MAWWX]9&N[>E6!$,8.37>2_+*H-[?Y+'^=GGT[=WK%*>WFJH(5?$:D[4NDM$]
MEL9 (X,Y3KWC'%_5(BB6[^\MSN=80FEM/6WX40+WR& .&OART9^HAZL77]^H
M9"PGZRV!3]UC(#6R$5T<[CG:6'M5H=7[IY3ENA;#J5.Y!QX+#B\.[-S40P+E
M*MM@5&:KHN$2=YL;)PI!7@7ORIHY4&+C'1B-Z.2H6RRA8D&"KO()E722IRKW#TJ#8>+U"X!]ZP4<"%N%>!18B&7@U,,W7VL
MRAPN<+H$L'-GZ:!.Z#6 E9/L312W(O6,3!Z)45\%[]J/:V!<4;5EI"06])IL
MZDZSQW&PTDME\/W5Q_:A>G5]MZT)R]?W;][?WG^XVQRV3/T;^&/_X[]?;^ZN
M[MZ\^_BGS6^;]U^(HW_FVYM?/SS<;S^@/XEBZD?^>7/5EM :45NM^>]$>W5W
M]_'ZYN>_;7Z]O7O8O(V_W'ZX>9A <"PM5AJ]>(T!J TOK:5\?H1H5 8Z3A!O
M3LVU/BS$/X*\R_V#B.]A\]U/_3OF"YM2J+[:UI]0?:F6V/:2FV+#2-"$:H(W
M\.L1-ISG<#]JR7XO6_2V57M^_%',ZKT(O:D;_OCX*U_\JOC33]?OK]O7/JGN
MHQ4KS(%=
MB]@6E3&V!O_0\ABZ]>903V%0SA-L-(JF,U9?A[#_>+8E$'F&]N8!V?I**=9]
ME4&AD2#_Z[XM?S#;TIKA)"!'-C%FA3:S[TD)H\8I3ZBF&@'F[=X^OOE_[P9B
MFV/Y_=0&T,2"QK 6CZ9JAMZFJ*B,KLP4B]G$*DY:99?ZM_*UNYNK]^EN\_:Z
M-3EN[N_;.?@R?W!W_,>O'AQ>8(A5^'7@_?/C'
MK\]!J&)KYD-@T12N D6_ITS28PX0S 1IP"((#S[A>\\!HH-@='::.8?>^%1K
M&+1:HT!8;97+'[-2"\14.1*;X&U0*7220O)J-+OR=Q<"[YG'3!L.!8RA""5%
M'1Q"G]BD2QKTA'QBHL9[%L*_;&:^56+%Y IE,9^>3;+*?G[/:(>,1Q)+BQ.\
M(L,:3EAA%RY?O;^Z>;/YX=UF\_"GVS?;M-=6^@^_?+C__QNQV*]M0[Z]N7^X
M>O^^_?%[^8;]+[C/'S;Q)]G%[VXV_[FYNI-?>,P $25=R"8RT;"H/O-YK%2K
M6 MC1<&3+Y:7(X-G@!9/*3E+SD."%%J%HM\9,3FH R_>DQ6*+P)]2/^U-D@3
MN9('F[%:T89]J(*X>.,*88+%:8D5ON+1#,6ZX(V5F!N,IIRTZM?3.'[V@\WE
MB. X9J0*2>G"7'2)@&"Y9XK$Q1][[9\JX7H2]'=?ED&?-)BEN!R3,TI^>= Z
MM2?%?9D#3LPQH:$"?6(9)ZYR\8="SF Q*A*A8VPLDA4[#8 F'FH^)Z8MGPG=
MB2^!;59HZ_M7FD!)\%$M]=;<1JF][C[@ZV.VP(*"5W^Q45 :+4D595JE4
ME6-OI&[%UBN#/#+I!.4V%-0ND.BZQ@T9TMX*\T2GXN@;+;/*@W26JK4$R94V
M/D*UVF4;]\.R%0TU5S0Z,\NL\B M94Y5DT=5VV.(5J)C7<\T*H^#TK%#U]DR
MBSS(+FD+>F\D+N9H Z*I/M;=(M&-$\?LR)BVT"H/F=]@2L[&1F6585VSA=C;
M+XP:NTRTU:O8WY6:V8%TYN91F)K:I6O=W5TGF#*^=T[0T9\)WJD#4]#8-JY;
M@P*'GIG"GI>-U#C.6*]U&19M6A=?-2LOB@AJ]K$D^:]>G)YX;0N\?*-ZFRZ,
MHOJM!W+(U2;7&]5K'!O9U@&TM@5N# /:I@*--,)*\+$?->[R.%=Z89#'B*BM
MLL[Z-MN9Y0]98N+>RNNIC(^!>A55<(106E$*!-77$JNNXB)(6+9;9>%1(;MU
M%-818FAOT36;RYFQ2)3I6M9QIW44#'K5Z56,VQ&"9Q SIA4BDM,:D\]VWY].
M&(;,1QC?%Q9:Y2$3K)UF$@M5J)(OB@K47@8,:AQ+#0I7"1)78D3(5>E8-#+(
MB"=VJC0"!NK]XE3JG(/%+M^9;6=V,"QIN-, .>8
M8),HMK+N*'YAXS)L)2L]%(BC_WI^-#--:^?GAH3]W7-]>_?/CE^ZN/
M+5'9LK/S,M36U!B+Q"!9MT[_8AU"&RX=&218YI&4W05X.NX\O+(3P'Q[\[?;
M]^_;8.J6C&1SZ <0#1
MB0N=B_4O#=2GG_#C/S?O?]O\68"^FUDR8H9V!@*R5I\/\]D;.?#OZ,T]L"9DE
MRI!]#$:?NGZZM_7+^_
M?I  XC3.I]9I%BQ!D%W485L4UTE'87P[U';TB0XNYR4+/VCXF<0TA&JUZ(S 
MXMQA3P-E$\=Z'34JCYD+WQ)HGR1E18#%A1869/3:6MCWL288Z4YU&V4VN=K'
M:SAAAL9]WB[G,9^P&KY'Y>0_
M?OQU\ZB,Z-OO?]B\^7 GNO-_/E48W/7=3Q-G?O*;/_[E]J$5YP7>).N2*.1JQ,D,;(E=
M:J,_A_2&Q$KK7HCC,KVZ>?N"PU.2*5!(L?* $$CT,^BL @9PWH^5&*L /IAP
M"@JCJ5DB=J5U$@7ENM'W<>RI
MT/8UD)UH]*$E;!/$]JZ3733%V=2+S2R.)143*9;5L!*2^)JD_-NVKDQOO"Z#LP9*"%B2V#6T-)Z
M[=VJ2F#YB2\/,M9TD+YS67QKF/NL:ZVV",!H=1O%%;3>FOLD09'W$V1CZVCL
M/Y+9-[:VDCF7*R5;Y%YX53^;_6+%-9YXUWUMF;[,[+/QE%51;>:E(/599>A,
M'FHL_S#CB,AG SZ54]"UPRUV4'8C*4\6G>9>AY/TF-D,8TG U"I.6^;RYA]M
M;07+T0-HF]M+A.^15W)#P@_XD&V+U3?&2E$F1N"55N-8MB%M5"4C
M'V*\6PKNH8"6:TD()4NT5QC%D\NUAWUIHO??XFKW;(VHMA2Q9\6AAZ!]2!XY
MT.YBU0##83/C_*!SP3N5=#P1*J<(V2(&B6NQ]#>3H$:V7Y@HXSX3PED!KG9:
M] *(4HB(R:$HQ5[;6 ^.^#L7G+G$M84#0RTE 9"KR0?E=QO%A2<BKJIB[O-N\W-_?5OFWUI
M8?SMZOK]EFQ&M.75^\T.QN8^OOVO#_:1Q;+"\BJIJ%/-23&TUA\EUZD=?>71.IT.,
MKT8<1ZKN69S7'(*7^-Y5*EJ4N.W3>+29Z,>\7'&<*?<++HN..!C;24<5836
MP^EUUC48B51Z_?[$W(]7 )PW=]>_B<'Z;7/_UP]7[Z]_:K1X\?[?-V]_WA)<
MG*;V8_&4,)0D[HII=1]N/Q@UBQ,S%B_. ?ZL-:\L@*-'G1E4 >_1:6R!0N#]
M&R .U:I?$?)CDV;1HUQM$XL.X$TCE,-.;QS&*ON+0WZ2FZ.*RUBB4Z5RK!JJ
M[3W[M4S5>2UVWE>%?>24DTXU2E02D[,H,*,IO;G/TUBX=_%XCYQML&T.&Q!K
MIMS*<9"[ ;/YX(28<^ 5.["Y_OGFTZO-F\<4E_'F[?:_WG\*35[NUP-$)=AC
MZWR-VSRY5KW-6"*VP;)-D%2L@N0U9'7DEM1BE"$0?:A9&Z-R]?W4B-][M([K
M#R&C(S>KE8H[Q:)"52:5'&K7LQR:#PZ\N#P9_?YGGG+!2JK&YNS$84:?5! 7
MRG66=FR5Y?"D:NC&JU?M9R82&6T+=/'HCUR*
M4HFP%ML:@WC)5ER&/:>HG0@')Z@!
MGK&NI7 L_J)"P<5*V8)G77*I.IE.L,)IY%1]XA7]$N"?^.+22*>K256U$6;)
MMNE[G9 +4CGZHG<)T.<\Q1 X#5'74JMH,E^5AY[_"_K@.,6+P3OSK284)YYQ
MM4J,%I;6F;KCEJPNQ;'P^K4O^G6Z&0(0R>(![3#8]PWKWSI
M^ZX_7#ULWS(:+>K#Q_;C;F_D/[^42GSSYL,O'[94^D_]UJ.C=6(.VJ#-SB6H
MBQD*JO3"3/_2,!8W;VID*K&$;*OC'QE Q<,
MEYPL:]3MP$=O50_DQ<,=8I97,F_V=:BX'MNQJ>QM_:"
MX9_:!59LML0Q*"/.;(048R>4@SH^;%XB]'F!6R(5$R#D6'W$6$W/Q$0],N1?
M\([/96PC=!A$F1=Q9*QB9: _88N']!)MMQN I.$()-K^/4I2[N:23%A;(-
M24M4!6T*.G<6CTACIY6;H#4](\13O8G*%A1@9#EJXC_ZUN:[(\!//&RD>]5]
MG.,W1)9+HS36V+S%HMFGWGI5[,BJ^4J09OH$-8AB4\&50L8KJ*6Y!9\?+MJ8
MWS.B6MG>,Y:Z]?!KRT*HLF@O[Q$YQ? ?-M>,M6V^IRS=J!V[=FQZK(N(68&
MJ-#-4//USJ2<%VYNTS[Y5'3 ;(++413E+I&NG"UXM.1E050K&]?4.'P%8^$@
M_KOA#*6W?XBK>\[]^P,95Q#7+$=$5ZWBE*E H$_&532A% 3[2U%F-RU*9DVU K&%!V
MC[6&H_Q49\4XJX?<^V2RQ+ A)!U,BDEW3AL[037_JL#F&EP@$TR(Y$,L*K27
MR\YFPT'/B=&7P;:RV46)/:J+K6L^&YM;/E_UEEP[#@,Z&]ZU[8.8@RRPD6JI
MXF.U$=1)]I?10]4T#J!>%?C!P0YB#ER1(^DD#)$8!=GWJF=2;IS%HIYH^5]Z
MQ2L8!Y"=P))<+5:WB:*[!B)CJH,AOTD3,V?.#O34,"J*ELG2H6S%GLO2K1W/'H]1M.O"FPN@Y:UT>4V^T\'
ME6!;AM^9SL7E?.X8@,4QKFPJ0/1-P)24C\4J4PKOR%[%Q\DP)_VY+-ZU3855
MKD;0!I4%":%OO3E>RA,".)9A\@468=L'?8Q\8 3
MC!K3P<5K03[UP"_2L'%]&(X>8G3AO
MI08/$6KO)J=TU%E]+8PS#8R8D9 34)#H6.>B*U#<'V,_#@F:+BQ9$^W*IJ8B
MD8F1;$Y1-CQD2'V>O,ECFOHLT(\-;B\<5&D%K[94AP'LY^D3+8>#>>2OT6>\
MB"M5]I<:$]CD=*Q)*4'N]B1YVMO!)3CC05UQP+OE8(DT1"^.K?.M^G5W/5,Y
M[@>]%MQ9LV:5<<5:8TK@+!L))?<'/VM''_=2,,ZER"\L<682KYVXVB ;FGH4
MIF'D7/I&3S_!K@EW956;L6IE)/ NG) S*8\]]5P8AD?HLT _1A5&69S;J$H 
M"-Y4BM2;+#2/TQ_/JFI7*C,/#29'C(U1UE>;=N\96]X(.-K^_5I83U2RR:@8
MO2DV,8IA\8ERKZVM.$$I[L3%T;
MY;)R2_%5+Z%SRLKL1JMHN;1A;.9\HH9D3;@KZUH'K2+.H>,HO],W!M=>/B^N
MU# C[W3H?71F?/-P_=NGY\NK^W?U_>T_>_WW?!ZWQ,5AK#$HMN(@Z-U\M=;I
M$B=&&9GI^/HYBUL(T1&?/59R%H&CW$!E0D5;]P$ECH,QGT@XGQ'0$ANB+L_F7S?R3IG4JI%2LSLG:'9!$%KW2THY,
M+^*3'X;Q^Q6]?.V+&WB34Y8P4=SMQ%YNF0[[6*IR'K?NPC"?:.C;[!&4Z>S,"4?=5'7A+FR96^NJAQ=3P"1@_=R-^MNAZ-U1QM_5H%^
MC)744T8P-=;6(>.;*>^1GP4"!?HP:05-N;\=B_"+H!*D1/NSZI:U=<+L:Y??]WS:_;6X^G.1Q6ZH.
M&4U-CJJ6.$?77@>FZ\2$\"?&W?QN':>N]$-8_$C48LY(@LWF;! +TNQ7@8RC*?JDLY!\19;Q$@SK($ZC&I
M)/J]FE(Z:9P/- 3IKX%G+@^>N/U,X-J(0;'.2%'W60_B+QY-!"T%:>VW!=L"
M.FI3>C4HKD;[?4A;Q^Z#;_QT2/MBN,?20+&*[YXB@560F$,;R=+Y^?V@II\:
M8[W0.A=7?MI!-(2LY>[D@EGBLGV,K<>Y._#$'-ASX#O5QU79!)5MFTANBT6H
MI9?^6#_&GKLYCZ\!<8[RLX8+!#"^*IUCU+7N)ZP#X]'GN7/@F:G\6$Y<,,'+
M=HE!HN[A2,Y'W\^7@K2R\M.-"Z2H3 F"-48;RCTB2326P#[UWO%BN$=\
MU.R"]J46+UZ""XX]U[Y.8W!(3KDG1J0NM,X5/#\Q0$9S*1%!.]<&5W:6GI*&
MU(QQTZ\6Y\!WHO*+$1 ETF@WRUBY73YVGE11^N-<-;^2<[OPRZBI"E4;R2L^
MDB$#&O>/P,:JHUFU<^"9SZ!E8T)VK0L3M7A&M7=S.#6. EIWH];.BL8WOVR_[=N;WS;W
M7SYBS8^+P4$B6\2/CLC[DKEVX0&8Y
MK3F2CFV@ [69)2%%PULI!%\=CR\+7X\4YM:\)/9MX!U;*PX6!*ZM\5<$0<'Y
M6@^U05V (-9VD%'DXK/X)P3!:'!&NZUP4D9.\5)/R;%7-0#(8N#%LD??N$B,
M*I\-!HO!&%0C#'G4UP>WN+WP7 )X"/'!-G7(Y YYL*SBK'H;!.@Q_9$J[:G0R5O
MC!O[Z[X>*OC;4!([AV
M5,3QW)X2MA(<^H/5$PV&KZ&TB<%LQ*0J4&)"
M82L8CR8J?:C$ZL(%,L=@@$+?^(/(DU=@@C,!MU+0T/B)+]5S7#Z;Y*Q$E@9,
M*<8T&GJ%5FT%T8IDN1Q*I5^ (%8V&(4I!9?:NZ.2,$R!S;P5#B%E@$-E3\L(
MYV_RN;L/;QX^- J"HV;SBT^GV_N'>/-6_FYS]]LC1H,_;Q[N;K]//_QE\_#/
MV[O_SILWM[]/$Q,/BALMH,-0)/
M 3Q-".XUA"#*HYKH!+6R5+V.UNZI$5(718%.6C'D5]WN44NSW4AAL\ET7'&
MA^(9M$_-1'*
MP.9X+$DYK9/VMD)J=<>@Q&<1-"7%6B8TCAW>?L3D10D''4-CZ):C&$QN,PI>#O)OF^VDE1]O
M?[SZU_^^?GCW[O;]6S$F8EQ^>">GC*_N-V_;0=ODVB:N\9UO1BYSL[@&H@N&5(U)
M428)N6@K&D[<)GU_;:)9V;HZ7XPI18FFADSD [I/-ZPX%,_O.4GORQ#7D6@$
M'*8L'GL1]]PD&SGO>T%"';F2]%B'=HEXEY\674SQV/P4)K'ER=9]T5=K?/HC
MRNE$XT2I)L3DD1_H:Y;+3..$[:?Z9J6A1-MX]=CN1%,J/R=@NRC1K&R^T:)ZJAPY.9B"<7M0B"Y6,>@^RJMS$JD,C'UUQZ,:J:\.0O$_FI
M[3&H4\&,DX4MC+8E?4SR1Z3B\::0'*TL4;;SW4]
MS%ZXM@".9*H4BQ+&QG!3V%8K<:(S?>M,&<[IKB3NG/IHK>P3"5QE;8I9E9C$
MJ)9.4B7:Z6N!?FJS#A<+*>28G3@4Z,78KFS+MME49_YQ2[Y7!KEUN0>PR
M>9U<"5:'9/2^CS"&9]7GG4D 3\Z+^/OF[OI_;F\F@(;'FINL*Z[J-OJAO>)!
MJ[[Y7#V0).(AIQB&JJ +A7YJQJAHI/:BSB5CL267U/TE[482ULL"/#;F[>;GZYE,9L_7?^V>?O[[^>/
M?[[ZK]N[[9#8+R3SI^LWFYO[5G;X\]UFR[]Z_[N1LT^/04KIAU\W;Q[N/OP2
M/VR_?L3".3+: 2@,U3($G1N!BZ^%&FU2=$^3:2PIUNWDVV]O'BNW>/,V_O33
M]?OKJX<3.K/D;J04K6:GO%=94D[5\)SUK85O>8OH5+464Q#[UXC(
M'2;?21'1SB
M1+*RI<8:/-KBO3!4!>*;_EF8&_%*2UR3510I4WA_78"["+EOFB.&2'^$*_&M',8O4MQEE P!1]C9G$2XF[*V23&XF-2#TK6+](P3(T&^?'MSGLB0L@B).$<*&7.T/OA.#.AKX F85'(?W
MY/*6!;5\[1@Z[X,+:%!N!S=GO1..6OG+KU88I[8+IX0I!<4FZ4*4-.S3?26-
MM727+H8YM@,E2E%>)?&\G,I$.N=.ZJJS/L2Q>Y'8YQ+-U2B8?8+<"-B2MR7W
MT@!6XR/K)IWM;LXNC7A_4\J.3J&8Y[\VTEVKESC=EWV=8TLC?_+4(XT2UKVJ;
M)J9JR')_N^SPUJ>6_?&!*OEI/%&+C4D*#7LCMQ
M=K]:89RH]K,((F5&G[4S/K(3Y;>31R,AO,"#ON 07:T2Y1JJTJT>I[C8+T;&
M\M5AGZOV0Z"LP%M35(%8.>\"/>6*YFJSA;Y1(ZC-XX;:LRM7Q"8%L'QJQ(="4$1\=X86NMLUB+*5;.
M423_>0] 91QJ.R7,/!Y?K IE<5L;B[<>503V60Y@4>UR1;E7,>LFGM^+@.20
M7JX$3C2P-GGQ'+.O240@^E7\RKH5 AM089Z1>3WPLTJX"]9&8YQM4<;JP('2
MIVVOP8ON^CH0SRWE1I:#'KEJ_O16S8V8NH%FA#22I6BB)_F*SX1^95NJ-!=6
M5HX!RW5G4>:V?)*(1%3F651ZSQ?$W>:GS=W=YNT/#[=O_GM'F_.WJX?-]YN[
M-_+IJY\WS[%!W_ZE/O8&P!2M6LV73F(U*24E?F&2H]W>3KY($=U\V,KB?ZE_
M4\X] O*,=2V%8W]R=\/6F\?Q\+%=VMN;)K$O;_07OVKN//A:,]^VV9
M(>/;__IPJIO7V$*,>*P2MLHEPZ I6.US=HT80TSOH1OV[%4MA>6(P]?( )5"
M)KE=U5>,IA'4-BRB4 -?%A;W5_W70WGV7(Q"[^2$*:M9-L,JJL9&2SMU2.?U2M LH<@58Y>%.<)EF
M*@2L"3!+T& PX&>] !3-D*^;X.-\)4B+AU/B/Y/H^!RCP?9"02HTWD33$M)D
MXD&_^A)E<&) Q7)34['.M9FK&4V;0+@5 ['SVGQU8I@36E57):X2,XF)K%>A
M]7TW[**^=)$HZRN]#;/+% H5:P-G%JT@WH(VGTZ 1D!4!\G27@O^VHG+:*.5
MFQ&!O]A6AA/$Y)@L>0R
M0'003(H,V(=S1AY5_6X,[-,W_>F5+8/&'4+#1BPW)M QAY1"*'O"#37E::V"
M1O3L=W?;4_=V^\G=]A_=F2_/F#@>5H?8LADVR::H$CI_&B"'I\Z8A)'RCWX*
MT5.K6P*/.X0GV^PX2- E48O3?CM;N7>X>1//AF?[Y?OXX>'=[=WU_VS>SMP7
M'0*5 D7.5IOQHW7$7M.JDW]\R.ZWO^G1.7L*Q.^7])+%']R$%E-E3QZM]]E5
M:L^2N\7CETGBU1:_-;USI=XZA2-X*DJ6'-HM\&;WAJB_K!C<+1R>M>Y/JWG!
MFN?Z7 L;IB_=MN1,,$Z!%M_5)0MM9M>N[)Z4>B4I'3R2*5>(51&*$@AB2HNB
M7O@H,;)=>3L, &D+AY7]"'&A8O+*LOB3XF6*HK>=;B<8X@GL
M1T _@O,BY&9EY.)KA%A<5(X)R6BM8MK=YYS,E"(Z$_*#:HAJ G2DR1? 8A0$
MK3.&VIC*O3C%)Q_6!5>_ZKX!!&@D.J23C#;GVKR9+M0U>L1+F7L/IU Y?LD%/VJJ)FVF'H@W16J':;%.U%(TG<:EZ
M(;.WAZ,]<22PVN
MC5_+NNJ]TQP&W3/)4W ^Y"LG)='JD%$"'(\Y,-9JL1?1.^6&[9^F;3B#.(Z\
M03$IULH4DA@N8]0I4:=_,_KP/)>SK7YQ'5U)0A\KEM17:L]+9-0^F8KC6*3+
M0WVJCB9+07OM'533'A2*[[ZTQ_K:.GKA)R4!FYJOV5@-V;!<4-M9T'RJ!TN>
M+P/MW$J]-AZ^HO$8B
MNC0LE\&1GZ8Z.%T<;
MY,F>.R)4'$4$5Q&T!(=9HF-PGP]UY6J?&Q^N"'9EM6Q,5&R1"JO(XH=E=)\/
M>/!,AWDG5Q; D82&5:D@8H3F5+A "76/^=KXPU=<^;%2L]#0L4DFII)= :J]
MQEETS.&BZ.?W?@71,Q[X
M E7MLR_=8P-G]2V@EW)7>0Q_>J#(5(G3%"ESJ<6__L5)DDE*F>*F3(J4TFUT
MBQ*9C(@3^XD%2(^,EBB0E%M:#\#"QUB$1T"K%:L=?)4F<&.A/3BK@1 5O!(%
M5LB8DD3HBOWKSXY=[=8?##S8!6)$]!([KXT-;I4^Y++LOET.-8[T#)QW"C$2
M-?,AQ>F!*KLBB-A5'7C6!#G$:PC*JK02!G2P37L4/#5%#CR$6&H^O#QA.?$-
MO@T12)AZ78RVS$M-=1%@2%4NO+P\@AY:@TF8(Q9\4"J1PY9XQ=5*SJ2P6P=R
M/C\A&O;>./5<1(>CC^G2"0G+3:&5#=M>H'HVQ-E/C$R_/T@TZ0[?=P?]=R/7
MO1O,NL.=\H25(IX; YZB8!B!U[C*.GDA2S[*F;@5.S&N
M!QIMJ8VQFH!?C(4BUBDN3(ZNQE(H43K:9Q7GIFVT1480#0Z=]%@ST'&4YK2(
MGDF\HYNJ:1+LB(6]"R95UZ:N3(^DX<"_17L "&W%;)&*YL73(%'_X$9ID97$
M&^:L33V $A>#&SD_(L([,C(? S2I9WCD3JJ9=&3@.F.;J8SP/5 M1PALK3!I=FLX!\JO-C'M3A:JUG%
M;M-G%.>F:T8L(R)R1+&( @R5"4JO: $2<'CZN$X2['#[TY03K(7"T3$DM))^
MW<5!F2[O2=>R/ /F1$C4OZ'#I$662#O'?"I;=2:*U46RPMLG9IX#SD>J91Y8
M6LIKC!
MZ1(/OP61WG:H>\#8 'KU[_,SRG$M T2'&M@]0'0(07]T\%_!C"A%%!=(EF.K
M 07GBGL)ND^A@%,>2"PI0Q/_[,GY9TB0@T;E:F.U$S:-D%82$>S)@@J4BVCC
MODFA,Z3"H48!"97VE'LO0%J$%Y&2)3MH[464/"8$!<#-:M>)_!S2[Q/MUY5/ ]R]0\C
M$L9*$EV0TAMMP1.T5J6Z&60DV-:R.DPR%1P7GEF*1;9W^>-Q4.3>TXSKA% E,B
M*;8N7Y"="!%)B"+LZS<_$R$:-A>$@ 95"#D)I-!8X^!SXG@JK4)FW]CYU,39
MD062+(U(1((%KP(-$1%AB^$!OMS1N3UH?![D:C<7S!D?9.1 !DXH-^P"W2!M-3"AGV5VS,A?=#]@.51.L. O3%+:_28\PM,-4GS
MB"^#L0]4V8A3*06RA*:U@1P,%SBOB^/%B&S?[W$:9!M6RU9'!\X[V&[IP)-!
MW&"V($"(0977RYV0 +M:2J0"!>P-!78E-#AKUF4T5)45,3DYNS:4O&&8>B*!
M.9$"=U,1S4T1HC J]TUB/A/&Q_:,(LF(0FFGI5=44X+9>C:'W+MB_9F0/LB=
M9IZ(B)$T A%P)\'0%',WB"H/ZS]+OCZTM-%@*9R2FC$U/@@FK4!HW
M;(@K3EM9_9QJN.:LAG": &_'R$D:[N8-6N],0@:7*J+.DJ\/5,,.1!><8,NI
M\LA[ZU!8EU>$\)S.X&F2%)JE3=I((2N98$ISLAK$B;@4OLX0MWJ[Z%\GX^F#
M%,W# :2/?M9^^_CM+LOI,+N=3_\_.Q\,T^C(:7?C3;M26%B N=&$8F' R7(0
M[!?#WC4+Y2 0 O\*OM^"W,G)\(_!)!MFTVGJYP?@>PM&^/!MFKAFUV(&G);(
M2(857^I)Z7KHOQVFD\]F3(A>,F_&P_^[V;C+^G'?1[NR[
M(R#YX/L1RCVP R*^
MK(KI;.C,R? T\T&]8HR8\8D-UQ#Q$:@4W:(5D6NUT
M3)33*'(')G@H,52QB!E8&*;2HH7EBCW SWBTX[JS(?R:SND@K+D =K4(PC0X
M7H1H40"._(ZJG 9PWK;^ CEPH7EDF$HG.5.6+LL/ 5CARGV8JSTB)Y SWH :
M]502SJP1Q)DT\BV:0%?]P@XT:SE>X&Q_P]\HNL?.9U%IJILDH&4@0G*&.E78
MR6!%*8'.^/X^7Z/X'I0[#T8+GNHIO!)6>&]Q,0$ 5.OIU54
MTD@&>C0:ILPJK@MDQ_ZJ-XV&\0S=UWZ7_N?AW&8\C* 0 68JP9QZ!TF>.AM5U:> ^:@\4
M(A= H=TYD"-H \H#>X*10XKDPR)-I@\
MG3A@*/\WZ\V XR?F][8E]7T"# _._"'C
MC-;<"BE$06NRHW3L(L'J1VAJ',T(I,TX9['#:HNS@N%P:FB"T
MH:B$%-;R:1)8QN[S8 HB"&_TX_G5#'0R".EX#C;BX):5=+<0TN6L)MP0#2'G
M:F=2JIQ&I0P(J]0FC\+S5+C7/M7RC;^,9]GTIW%W- 7#5#3X_);ULL'G1#S[
M;?USV3$;#L=?TI2:"@@>6%?;':8W?KC)LME/XX6?>_]9R\^MOVYGP["4DBF+
M:4S%D."N4+D>M%->0G$R2N^HI3<0VMG (3BWVLOHL8D%W+(B+\A855:B,;A?
M$(> HI18>YW&]*;[3^EI,3H[TO*$O)-1>D>9+S5I/Q5%@5#)#/:(F*(PS*%R
M81BOK(=L#.X7Q"'$>BP$3J5W..#@@Q;K&HI8;N^HB=*)5@M?<-3/P]F?P(O8
M8[I !6WAI_&DG_7?C3YGT]DB_''#[G3ZZW7%N]>)AR(&>3>:SKK#8?HQQ2=[
MDPY\Y"#2!F8=$-#0<*9HD9=3Y?)-\%.VD>X1DCR9@OQ\*:@=)LZ"SE=.(>NU
MH[38_Q1(N:"+BJ=2< W:/P:SFW=YY@#PGF43P-P/ICG7EITWLI'Q?)+,YW1;
M?NWJZ_:5\3UI/O7SS%P#1K^.LG]FWTY'"4 VCAK')*1*T\5BMJZH@,"\8II
MUOC9)&!;4D(';DQ 8. #24,P07Q=T4^'6"F@H>4)9R=$XW(8Z&!!IC1*E'A)
MI*ZX0)G3A25CQ)8%N328M#V'HP19@&JB$N)Y'D5(:_4VJTM1N4N!R&>C_+9$
M'-<*J5=;2HAY3E :ZX[-*?$(W+8:"#!9D+&:C%$5%KI X1^W77
MB_2D7,%=2F*WYW"4('LC&BD?KJ^S-&PI
M^^<@&Q:__:T[J[@?/:]D =TLQ*(6G!P"@:[64CKNB2D6T:19P!MD'1*=I1"%-/C0?%'A]
MY7XZ?";:KZ'I<0YTOG'.@+.">0@AJO6 :QK*=V0719 CS0%#E#M/>:*&\]PX
MBHIL841;MY^=+2D.,0>IVC"U(:>Q-^ :< K!^ZH-!X&_=(GX'SJ!#C$CN0XZ
M>AVQC<*BHF7%:KFM_/!92="P.7 L]>=[[PC&EC&F1"S:E:+:VA#Y/&394<82
M'$?$>*FD-X&0 +'INA1.T)(GS$NU%<^)5OW]=X"R-,H;[4/ R'FMQ(H<0N"2
M,;@@(A(Q4E4"/M :3'>
MG#&[K77O;/$_=(R_E=XBH( /SJG@%"+%MHM(MVYU>%82-&P*M 1+2, Q"IPZ
MC81!I"B-X';K_M ZR/+A9CR9[5H[OZ4PEQEKB?-(!!X=AO"WF,1CN"L!3\IE
MEX\"\R2(:U?IR"MMO9=!>,P]UYA 9&NB46F>GR@/]#X/3(]=[\@C8X(ZSW"(
MJ66>YBL) %DE;<7.YN=%\B"7W%MO@Z!IV)Y0 A%GY!(S)+G=-SUQ(LP.G;JO
M,7;.&FQ4,,3;:.T*.2HXV5?#UHAC@&Y4R@ZRJ]+ )B.M?FNN"!V61IDT%RY!0
M6.)5T OVOL2$YX'IL6M,M,0N6)"M:#7#3H;5Q )*<0S[)GQ/A.0ABE)1*]/8
M31$8": 8M?B\A2"MM,CU["BA .S
M 3QOE*9H"N^^7B/S?[J@_S6;K55232>K;7@^4V!9_
MFU16#X&WC5BD&8!I3J*R04HXZ7*;(4)-ZZ ="10"\; B1!#/0.; BL=8E &A
M2$H'Q*LJ<826DL+G@>FQT]V")AY"!4&8
MY('HE/@HVM*"*54+/B^2!ZU3H=: ); *U&C:I6*+W#;BCHM3NE[UIRH\=M@#
MHW+)O?*1^[CN%5/ KJ='KF'[X#E/UWE!07CDC0PZFC6?BI,:1'X"^P!1;0Q*
MDK21C6DP_506V3AJ27F>\M'V83&S=3Y)X(WZOV7Y+ @WGL[>C7KSR63Q\TXC
M>>\YZ1/YLZ;9Y/,&.7[.9I/Q>_?AEVSV93SYW6>]\>U@FCK&EA_:Q021^+QH
M+V@&VCFMP%).840E$X&84+$AJ:*T>2^$:Z$1?PX:!2,1LV"]P),@+*2BZ6+M
M/9;ENGO**FYYGT8C=].=?-JCDL'.IX-1-IV:WK_F@^G@?@GMDPGA- %>@3!6
M"6Z#0(;9=4>C==LM6QF;P[%EI\0V^*BE!S-'HU-(2X%_Y970HS[\9C+/^C\-NE>#87Y)\7!,UTF.6FJ&H](T"!<1PTAR
MX_.CA@./*):&0IT%-?.N;PA**&$P8U(YC UB1EBW\@*C5"4O
M\#S(>68Z@U@?;1I4K2T/S#GM33&3FV-7RB 0U9S@G#J*8 1""-"!%$4#H197
M8CT[/;A2P'[J3!-7TWBC"ZT%O<.@B"L<]"N!R*&:<89PY
M7JR2=%S-IH?T6IC(,8(QDD'=#2"!VE\,=@W*%,>6<_8:FK])JR+;S\$HMHSOI$)
ML#VI+IQ(YBS\Y(LI:)&5IZX01F5%MW'-F!R9T<61"B(P1RI81*@(RJEB7G6AH?M-T$UPWU@5E:QH*CQ 2RO
M=3Y=:&%1;#4@.UI+C@"]X9PKD!XS@PDWB'!AC$6JF,4"GG0I[GBKGRK?[&_X
M;UM73@=KM/>!@\?NB;6"%FMJ#:*EL%*HIXHI^QO9!A#" B"A LP?ME8' ,.O
MLM)!J)+7*BNG%!P&$-T&D-<4&>9%JN^-RC&I25'%X6+Y7E%2_N0C8]L TH@I
M[7B29)]RDIKCHG@065I*V2I5]WN'0U1_#;=D.@HND5%",F5 :Q9)%DO+(1/12%8,NZD9DR.MEM LS0\V
M=.'K2!=%D;\,HGR]C MGHD%<#C);CH'/9HUC\ /FE%!3M!(9D,G:='_]Q29"
MB(@U&"T:0]KU!:%@6('.@MS>^G<$Z V;K1! &3.4)D$&<.MHY+PH)8E(EB3\
MK7ZJ#N3;S9;0,H+>3PK'6:,,MLL=(:"4L0DE1UG*J@S>80!M-5O2I[YX[1'1
M'DY=\TB*6@ZC4$ES*"PK(MO# -INMHR41%HLA9&@I@16K&C6)+B\9%JJJENK
MPP#::K:4$XD6P$J>2*XC#JN(@%(%H4*)0J0\C/5@@+:9+1T"=L#'T6)D(LGW
M8:UO.LK#Y"E!O.*&YW"(:C=;X$9R@:2W"OQ):0R$*\75-M9E34_! 7VBJF^N
M?"9(D6^KL%@K192B&RZR @3+4ZK8DW5-K68+/$1%?)K?3Y  30D26#2"P<%L
M6Y)7.]R'FBUFG),V[1I "@>7R@8+VHMR 6A%KN<(!!HV7M)J$82#@(N:J*G4
MV!5M:!"/E?SEMQCMR5'C;]WA[%OX>I>-IA6#A.C#8H4\7P2L-/OV$<1BVLT7
M^T[3O*SU7^XGPZ^O!\-!^MOB;'?=SU-B) 6?CUD(]UTPH&37H4KY^"K4V3V4
M#D&V5+W2-+*"6XHCD6#\P6TW7&'#UKQJ2F78HGRF1R-;*D-I&ED4O/..Q4!0
M]((H0+7HM94"ETZV(@'U*+(?NL,L'RQ]U>W]O@'^8LR0GV=_'_6S257%U6'9
M9,(-$Q(1SR+X'TI'"+96]M:C\H)*L%$E_7(\K UBW( ]Y\#5/!A/B:6!2[ZL
M/($XSI'RZHN*HJS+(]2QW1B&25!MB 2(< .AVI-BS3!WJ,Q5I!R:7!ZQ#O%'
MK.21QD@<#R$5+A'$"FYB=&O5UN41YN#^Y(BP%4XC%S33#*QF<3MDL=A6]'N>
MM&G8ET(!6QREI&!].7;(\UCPDHA^V^;2\Z/7MFM#$RUU$>RL]P)C],^5^3(8OP%@UM+$Z:A+3
M4 P/,:*%^#!P7^31/&;E7805.9#+(]8AQDI*SAQS$/I;CR%N2QU;1IV%CQ%")Z1A%U1-D(Z@@5O 3Q
MT_/1*]\J^7XR[F59?[I^2)J]>]R(5BH(T9B&5)^//&,V+@?4IQ2'W=J8=2R,
MS>"YXZ;1&^0XN!Q12>&]!U]VU:",F;/ZF!-]'CQWI:9YVM6*/3.:POL-W4C>
MVQC+O4KEA-4YXEO_,%Y,5<0.?/<8++BFX+TC':.7R%JE_;8)2Q='GV-KEX(/
M7AN-O7'.>VV#B3F)(A@02EX4B0ZZ7!:(8V&D I91QD>3%O0 79@+3A*Z;=;!
MQ='ET)HK(;P146D#N?N?9
MQ_&7;++QIC*UR*9:$A([S#75:466I5$P@:5QVBGEY#W?;'.5P6Z25:!;!Y4J
MVY2?0I[W']]MIQ"RQBA*@C#"2B 68JP?8!Z.A+;$D+@3Q@N
M<+ *-*/#"EG$  D6!+ R*M?0"K1WFN,()/95?Z<3[K=JDUC&T;0&!L(MC D8
M#T>QRKO,A>2&5%SUH+U-R';L:Z;?:<3^0;=Y$$)9*BA!0#>>:@B T2S7.'EQ
M3[&^AY'NU^L/LW'O]_>302][GTT^W(!WM;U-]\,,=$D*@M.BF]FWY(B-1VE<
MP@/[>GL['N7/+I/BW2_QWAUO<,8[CP,QJ?(VR'5N@$S\=)\85:@\
M1'>ZO.+_ZWC<3ZND#M^3XCT!9QN9**6*5&L9"V"%X.6UWHB6[M^K #D6T-JC
M+1(= X_9H"!\8,8&Y' Q(<7H$F=R22ISXB=!\,APR1!NB>0!XPBN;R1.^EBL
MLN+EW>S/@=IAQ4BI&"S&M&_>1$:(1T7&!(*=71=<)\'GT/'R6B;_1W*I//&I
M1T 7PZ2"VCJHM%:4FBY;@L#!"_"8K @&22K@"%=H&J3*-;="EXH^ZL%W1U).
M&N(A4B1<$!U9I! B%N-1+/RVY!G)2\P ^G5&!1%74H2-2
M'J0G:7G-Q\D0/+:,(E!/X+ D1/S2"R(,*PK6R2F$JN;> MH;D9/@,](!=@F]0 #=
M&"4KEAQ*6[ZU>;NJ8JP=WQU)>L45=9389(>P)B0M%BWF:])RM:60Y:FW=0):
MN]ZS@04M#3A!P>J8EDY37=Q".%;N?,/L^1 \4N]I!Z&JMAA1AAS"4L&7%3=*
M%5-#GP.U0_0>B=*EQIA4#P>1MO1(R")B)3]-^CB-D@,_#^G4(6]"I $731Q&EB\DWK*GZ;T/V>0SA,-'A;I&
MF^A3OTSJ;@N4!;OT%I++YWEYM(Q&8JMJV #F"?#6K@&9#TZZ@$5JA0:' @MF
MB\9_\'?+O2A4EZ9VG!C/8TN3)/..,\LU=^ %*O">BKEOPO!2"8$B6Y,7)T#T
MH!4005KLJ/(Q #II8-4JK$<\9:;WU"$GP.K@J>966!KA,!1H>Z9QQ(5R)-'L
MJQQK0JQA%:F"-DKD[3D,LV#":M\B>+\0=)6,VUO,*Y/P=6&](S"V@O&('!,\
M:O!H61!BO:Y;\O(T%U(Q Z5^>.N/CYUVCD'(Z,!(*R32EI45GMA4X E^8J/*
MH\$PF2L"L0DA.L3@P 0*4O34LRA*M?2@7TJ-EB?&]! UF5I.G-,L#0H($8/)
M"P5Z,J)M'?KUF4"7TJ-7F:"#H:+XDR$9"3&"LG
MF2MR'URPE#M6(2 QRF0,B.-""0X5 Q[J!H%^7Q8':@F0Q#<61(=
MIA#6(;!PJSU.F E5OL)L%K&&U:0#@0P6#'2D*M((]HX7I\B#+ 6Q;_EQL5U:
MQYC&!#Y4Y*IP9$]$!K/!OW/N
M6!9 =(=FFO9)C"?_N!GT;O)BB>ML\FZZG$.;]G5P
MPB1J(G/?./G(@%2:G5^D&37=6J!?']@GH\:.P$@)FB:5$="A!'D#ZE,4Y>U!
MRA(UWE8,R[EX6\Z8#]+=:K/99Q98H0M9BEH62[Q>$LJZA$O
MEBPGXS[GF8O@\:8;LJ""H'@U+SORX&(Y67-*,@^'@-]?LU$V@:>-^J8/3L, 
M3!=\S^=LQT"7+5EQZAV3X P*YI5P@OLBWP._+#&6I*J<'-@+M/J0J3W* 9F*
MCB@L7"J3I5*)X%:95NUI>7XGJ<@%G1,1C@R!+!4!+7:E>5FF
MPZIDY%S)<-C$" 3%-+36
MD'6=T([U>"='N^'8BG"$T_!!$Q!S-'+@@F**+P^\8LYQ.:-S,I+L\%;3S@=*
M A,47%-&J?2K2T "CE5YNIY2Y450IT:F_BD/EH'YME8GCHX&.;_F;0SZK40$
M67$_>$Y$.%*MJRBC3X,BM74BZB#D.I&-HA=4YH-ZS6P:5!*/4[
M<>LC!N]>Z6*E$$.AE*I_2\MC=T]'DQUQ($2[+G"J70Q*&($EC>N%+(!;>=@E
MKBA)G!KMIB]#C$&"$>-!GR-/';.ZJ(,%%BCG
M"@6J0Q>F1CS;G:;MM[?IKSFL!R=>K-3,^^@C(HR *^*\+708JE@O7[':N1J2
M8V#=%4W@8*@TRDJ(@SC C.Y]-AF,^WBG].2?
M*=*=A:K,)M?CR>UBDQY\56DW7@+EWB=^[GX=W,YO5T*UON<108)S["PS$OSC
MM/ZD<) (Q?J[O[RG_]Q%G>-P/S.:YKOJ!KU9UL];;_\.C#+][#;S7;QDX
M\7A_M _&HC3S*VJ*TD)[&Z@RW&*6*WY<-*;J7)\%I
MH"Q8(P[1$>)$^\*E /_2;YS(-%3BJDI#S-X>;?.ST/Z9/*4A2H85@(!W9!V; 1Q]PKL5M)GT[[Z[D\
MQ=G=I]1SG,X1TD=/*'W*,9-*0X) PH/J!"MF351,I;X:1QX?]T&^1\]P@F3
MXA4Q8B2YP$QSHPH72!K_V!%3_CT_B0T]RR/^93SZ#$>0]7_)'?7MI:*-&E&:
M]EY2KBD/W,4HN9)%K:)W]YH>"Q=6:TZ0TJ$.I/3X::AJQ0&74H#!1%)%BJHJ\>3 /I_5MG*K^7K_*
M4_UU/IO.@-:#T:<'$/V6W78'(_B]@].< ''GW>'';'*[>^MM32>\;H.$X,.;
MM-$DF!@\_Q/_?(KC.X)<%W2.S;BE&]>:BB(BC5#I
M=C\0ZWV*)[6)E&C'='Z.Y'6?X__DRN%,TC<,.0@--7-(2S@VK-:;.@FY-ZN^
M\&VPYH*RDZC2^Z1ZCN/Y.)YUA\^8K+E_98QMC#8XQX3S0FIAD#'1*.(,TQ#V
M/=*J=?J3ND^UB+Y4ST8J;OK;
MDSN1>GRPT(B%:"P6)@H<)*:"J71R$@=-X>Q*J]98N5+KU9SIXD>EI?_X?9N./Z69:F<:S52O;R1H6)B
M__W;<:LBDMBEVGWB/?A\J=/;I-8$#0)SKPFAYMOQ'7C40JM%@N77ZT7%BIG/
M;L:3P;^S_O9@^/VP._JE>[O!TB;Y#;_>C@97\^D[8.!1JM5*;]O571HPQTZF
M5<[>!<1,B(6S%G1D%S7,XGB2\_VI*!R,40QA"#H]
M(2X =7EQ&>W]O0+E%85)?:9Z!Q%J(73Y4MN,^N'KW6"R*%K<.RPI$_W]) .R
M9M/I>)+^N"/RL)9+:Q%+0R8]HS'(50$L8/0&27U/Z[@DK(-(=9[6
M1O)@G]NAIPJ#=%J)@*-$Q"%@?V)-T>.D)*FZ8@"716E<(^U+*)^8GMLU^H'T
M9*DEU":E LJ%8T'66W\Y$;9*N2C"*&>71\_]]48=7'OO?L59%-(./^I49$%R
M;M:SZ\S#!4WW[E=T'=?.A]'B+,C_5":_MZ[,B^@\A*:.64$T-W15UPXZ6S].
M?HJ^YW6X*PV2?[KC.U=//@_C&2E6D4BB,%+!$"MU+.2 (N8>.PBLO]>'7!'7
M2I72>5SM9H&K@T-:\^G3)/L$ =B[$43QH^F@EX>NQ179B6^'[SO["G-+3-1,
M2H' !",*KU2:$N@CEOYA;H?384' >R$L3
M79J!FMI%U,.KO]/B?79D/]H2KJ>0.Q( @+BB8(!J+61G6V$1V4 FNO(V-,
M$5]U1PJZB0I)'Q#]0*P;IUKMRR,E96 Y4:2*6BN=A0"L\$A5L%4YG3.EU"GO
MX$G R&*A@P2'GEGGF-NHWJ55#4SP>\'$PV#UW*A6.W]AJKT/"H(>)4TJ__*!
M$\+3%I>(B:EJ-FF 4N/)+&DU.YY,QE_@8]/M3FSQ@30=]3X/_5]@F#17K]@,
MNVW4WWU21*8Y]Y/24,FD+P?[)1?SS9#[_[/=L$
M4\NH-\(+HPF'_Q3]Y&>C/OSWIXG^6 (!E?6H>@(0XQI
MA1Q?CWGRY1&&S6#*&V=8Y3@'_QPD%DGBTG1ALYY R^/60=>G0_ 0AKV/7UH)
M""$(\IQR UHI4%UH<4&V#_0X"7Y/9U5P>X2W BGFK0G>(8N*5GM.Y=:5/GNB
M^"Z/C_*0ZK"-]\ZJ@%(8;ZU"$F$959"!2V\5 5U2"N:K8-OX\L.!V[K)/@IG
M/==<*@M>))6&D 5P,O%)N?Y'ZXI40TU0UK^T4(#[0C$G0D6-/4X[N951D3/D
M(T$EMM"Z(A _!7)'CBGB7HB\KYR [@)KA"&D7>"'B8W;9VN>!*^#UG+!J7 5
MA AIJ)HG3%BV1$:CX+<.X#D),@<.%&(@6\I@JP6.2J;=8H0OF4];7EZ%C!OE
MOK5/V\R,3Q1!NX64G)0LF@@^T0I9#BKF29R8_.^'">
M1DIX366P:>>#]L84/B?A5=?JLEPP=3)J')6>>3_)KK/)9)F&V,4?R+)@C $5
M2 VRSA%JBYD^C-^;OU9D:,J3N^JER(-,RJ(4*IO]>KU1#7)Z29*6(Z*QH40$
M,"1!LN5<*:"4Q\I4%=L1A?6>9-H'Z88IV'0VT 04L)66&1\LE9Q$N8SA*07&
MJ\K6" )J_=Y@B3.G8=/6SC-'DA,-K,>EEBA-RR&$<\4"#O>WZ&WISSD9$?,_
M/KB-KB@E;%IVHQ,N]9QQ< <=!"4A+2M=BOQK)M*3(9&9KBSNI!/[D(5;X';1<6^K'42*M5,XTRHGP;6/$MQ%G^X?4K#A-).1:VE+B9OR-,YCX&P,T0,YPO3[@W0$
MW6&Z+WDW'(XP5#A @6
MD?#>6QV F]/.PM7UIB^W7V*IY"&H'>(Z[X?*2<[;\IBR25IQ8Z)CR,GE"LNT
M>438TO+;QLERD!?R^&E3XPQ*_K\*B&N*)2\6J@"2Y?W,&5)KQQAIX/)T3R$4NX\M;V\R/6#L\@$AD5PQ"M II4,Z32
MO 0NK>!2(5[B!G:F")Z&&\!Y"M@P"0ZTY4$[R7%.+&:$(V55V@2Q4HU'-IDN
ML"MG[\F6Z[L@K:=(:1!\Y;DR5*PG##NJ2G>+:6!V)0+W8#@"PD,/J]>;W\Z'
M\-9^7I^:WC;);K+1=/ Y>S?JC6^S7;N!381XV:7Z=BF"DP(ORS! OETT92ZO
M=N5.C?=13(J\Y9R) '9?.^J05;K8M:20+.]!3KOGS@'=W[)9=S#*^J$[2<67
MNRZ19+!,8,N1Q"IOWT$;R]4D*>'YEE! -6>A=VA]2H #H6XH40DA8,2,FPO+8%E+BOB"6?AQP7QCYU*3B% Z(!R8IJ!TBJLGBRUF@?93YQIYCY3ARWAMO782@
MKNCV .>YE/>CBJ.&Q+11\PW8<2(@M*&4(()2PY5;A7\Z^)+@0KBKF@B$ME68
M&@G.$_@87F+!F16&KBI=P#28;F L7'L#C'?0A.C
MF/ 4_!%#9)"*J4(%:E7>;_H\O'B@^:;*. G6"P)G&HGAH,V*C*:TE)>QPJK<
MJE$+5@V;;V=!JP41% 2B#-.@N/,%2Z)R:]%;)A5MP&'FSV"^$40]Q$;DH@B:
M4R.P9X1PI3S5Q/ERP_H@:N"L%(YK@Y+;4PI+*5*B+,X
MY@/MM[88[")$WH!PE"#$G"_/U/N(;)7]QNC)X7?.@ =?,H'/K 63 0($(B@.
MR*BB_,0K4X)U#[V9 _($6$]S?6@%M5AKP2$4" $3A>E*YPAF2NF'8_#^..FF
M+L\/66\^ 1 ?WIH_]"5M=[A83YIELY_&O467_":F"Q4SGR3+:*;3;-7G6[P!
MOG T!>S@@_>[S!+*XW2+T1WUP[OW*XC^_; 3?Y< I_(MD-\HB)'@)+$ T8=3
MEH>(+2HS"T$E@U2BR8$$XQ=%,(A29)H9PB5)W7K10W#J0"'$@'@(Y9$AM)Q4
M/CW!P+'L/2>3\30935CK:/ &(V(U=>D"SX 6U:IB G*3)&L:6Q? %17>I51M
MWC^$C4L!1"@;!-+SO@.=+/N=#[YEJNK1:G;SCSM_=([ D2WZ5K=1\_!
MLF$DS;H,@596!$,DP1'?!+$$Q<% ;IT#[#G3&F/.4XVRX^!-8+8R8\A*6C>0
MCV\:>OQ.VDION$/:*\MBX,E97T7UAI7+.= CD)5&,>\#V+90GDBNK94L*)J*
M*$+:H%%4H 914E)[ _;WT23KC3^-TM#>C]VO-AMEUX.J3K9M=^&&NK1"W:"\
MAI^F,KBB:-A&5\KME>7C$3".@G3;':*A05I+N+<$_%F09+%:# XN!0!?49;6
M)*C;>#$J,$H!;!(F 8'L  ?&%:B$EQ.FM'P[5">HV[@S1"2<)N >(F&\% 08
M8 4JV-92&,S*N9CC0?59+W%XWK0P'Z9]X6D9]OO)8#Q9SL#O?GT_GN;^YQ'E
MG50(QKE!*M6F20C^=,$P$ Z53@'O>P@'@=T\&7:$((9K9(PBR#I$C &S9XM1
MP);0DL'GI2TCET&&705>'NL /H['7A,1>:0K^P#< ,:VQ WXN>CP;E3UO*6?
M78-<.)IF=3 ED&$*Z$; X2A4OF3E,*/D =8#^"E(L4,VO(_@*S@G7'#&.\L"
M#6M%3.PRQI^<04-E"0#S$HN7[S%(P=3):?+SI
MSOXQG@_[[V[O /9P?9WUTDH >,M>6R[NWWMQHN'455IB[I70+"F'9=F*JI '
M7+Z4UD$2B0"/!SL12[:9F]!'Y/PK8HW#V\^S=Z)>$XG@X!/;Y^"4;?LY^
M!K1O#G1WJ.6I]-/!@:M@@,$-$"-A#WX-Q+^E'"E1XA$N?R+8Q]-A^3!S/#X&AHT>'L1HCF%B2'66)H3P2MJB2M??=!RHNGI,#^9 L8U1!,D
ML6Z!MK91BO*EM\3U'/D*VEK0_G@SR0[E]0@'*YD(PLFDX:1@"[REY]2:4E&#
ME(]8^&/!K0?Q+^/#T&8112.Q<"XJ)A6VC+L<;1Y#E.62*[JJ<*\%[R_C3:Q3
MXF*1MAL.QU^2/?#+$1=@!_,*X 0V21*:K:
M15F?O:6E&/90&._C-QFDO3[O .I)-ITM[J87_UZNL?II/)V&KW?CZ7R2;3':
M)TN+!B,(!']^J7RS6C$#L'X@3(A(?\@!A
MV>0@0]4T$864 .5#Q+G@MTV_6.6BH-%CQ<#%UU$Y5V3!O*Z:9&V2J_.CTE7=:^H"#P55 PZ%_RVZ1/9.
MIJ&E8F4?N!*5]H\P<(DQ/A/]4O9J[]D_RS CB@;%.$4B@&?K5_8A&E&U'!3.
M3V"I::/ZI?09VYT.>H=Z9T$Z;3QA)@4DTF$F5]8A;U2JG,8F"3AQ6NWFSFH0
M:\1MNV=F*,Y; R(G/#IJTE[7XJ)2XDK-LK=G=@+*27 IJ_.
MC1!:Z8F!#Z/ &)#GQVV[%\8#P0X<9A2, U<3W!5;I#:0=-6X[>N%G0"W;;H$
M7,J8&J,)1RY&FVKXBN7,J92OTH/&@!NB9R!OV[TO'A3XE 'G649@2FT86]DW
MQW&E]<8<"4WD6?#D-EV2MF@;X2@RR 1%66I]+&;!V,K,2LHI*2[5>>"V+6LD
M:0"O2V@F*$M-CWB]-YEC4>DU8P@?&"*[O:['<4NYO1_L?#H89=.IZ?UK/EC<
MA7Z8W]T-\X1>=_ANE"\BRG."*?'V$="RPW'O]\=Q7!=]&JF"H/FJ>?"8O2N_^\M_#6<_]@>?.]/9MV'VY^^NX9%OK[NW@^&W'SX.;K-IYY?L2^>W
M\6UW]&/^M^G@W]D/&-W-?OSNOS[-?GSP\2$@\O8FI\(/F* __)C@>]L=#CZ-
M?AAFU[-'GY%^7P7#8'2330;5G_MXDW6NQREOF]SLZ0;).H,US3IW0/M\TOLL
MO7^Q+0/>,LGOI*>=\77GYVPV&;]W'SKCNVRYIQJ>T!O.^UD??L@_V"N:<.!W
MTU4%??[QWF9W2OK@^#;KP)'VLL[/W6\=_*:3W&( =9(_*:'[IX3/4W#_EG4G
MG6P$ -;RN'J \EDO3S__5_?V[L?_ (W](UTB7\OC?R@]Y4_ >G5RX<8S[KK]
M)*EOT_M_0'=?%\\8 ,5'B]>;7S)*S#;\GK7[:U>'RZ#7P;]V0W\"#A>I1N;R=L>"$3W;IK]L/JAA/P:J$GQ4QHK
ME4 9_?D[,%&3\9?%S[AX[Y]F_?6/D\HGY+#\^3LE_W#O">LG5SYM_4%\[.>.
M_N!!GWL,[>6A@<:?#7K=X9+25^/9;'S[XSTN(L 1FRRR^7KQ_GN_FN2LE7ZS
M$\P-OGV%8C&>Y
M@_ Y&\VSZ0&<7;LN>)3<2]'(+4U)+LZ#BO]9%^%V\MPV C9 IYQ=:R04?4.%
M:)Q8)^"8I[OTZ7-7DTYO"/KMS]^-QJ/LNS\51&A*I[TDU;5HCN]<91!M%+'(
MK/OU(#56 $]V&.AC*'> 5:U;T##;VSCNXID7*#!_RH.4RO=7_/S??WI2[J)(
M?OPT'GU:K;A\-YK.)O,\KEY5%Z5RZ8.S'L$SPQ1S+@U]B!*[Z"@A(BCE'1/2
M-9[U>/83/A5P[T;)Y>1O\L3&8'EFG4DJQ4][I4%TNA D?,A&@_&D\ULVS6:=
M7\8SH.]LW.E>7P^&@VYZ]04^U^GV_W<^3=F5[G29UIFV$?\I(G[QQ(A?TF,#
M<'+J5,%Y WHAWLL8 +D&\?SA9M 'X:A7VQ6IPV/\%7Y."84S3A\\S!GP%^9?
MGR^'[O*HVY378SR[;!OL)(_P.5,R+6>VG'F?,]]/LL^#\7QZ$&M>>O:UOJA<
M?$^4^L/N(*$_SY*MTB=+*QZ4J+V /&-.Z)-1;\U6ST2^FC-K?SA+OGMAUJ@5
MV,V/\>^Y; 6V<8&]D*"F3D- A=C;XA+TG.[VF8AB3K*ZZ7"0Q%V84)V?_%R6
ML;M@6>'?"][*2M,&Z(S[PP^;P@4;PL
M(_<2Q8Y_+UDK=FU<=I3&QIKO;_U(ZVLN2-;ZFFUU@FQ5I9.7!M8U$5^:%WD_7GPVQ\73EN;9!-P[OW!]=%(J8#1Y$)Y%$^3U^G24U<"<*5
M#=Z\H&[01?G=='Y["_3[=[9H_NQU)Y-OZ:_=?"C=M-,=]3N]87__'*O
M-'%1-+'9M;HZV6O,4U9KJV:HUS[L_\QD_US:@UAT.;>JS
MMN'T#&JJGS'UAMKL%+D9#S$X:SL^4O51@:L#8O12HN/:2OCTE,K[>X*;OK
M?LNO2-(%6+?7F\RS>Q=A3BER=&Q^U\5$;'^UO18ZJBSRBNG%S$8CIKU82
MQ]4VAXTYDWXP[0WSU;.'E$9BH[A1:2LN-MX[&Z@K=@EIQL*EED8NW9C%$M_R
MW7C^K?VT[3FGW0^)%Q;?E?H..IAU"C' /W;6A.\4E.]LD+[$/P<"6P(OAZ1<
M5%EW6>')9&@;L#4!5TW#S9FL9U&DNC'7ZT0EJH\PUS;V?9%\UA"PBY?I[3\,
M@,D&O4<(7NQ97Q13O[N]2PLI.TEKITS3N:%U46>P=QU\OM(^5:]WNO>/8S[J
MWH[!=?EW*FE?'DU_>32=23;,A70V[@QFTW5ASRI'.,EZV>!S^L+%PU(=_<;O
MVO+P4Y2'8_+$^G"N7V;Y](NO#W_Q"+[FY%6U,6T+XI^MH+C.$O==5&ZS3"W'
MUL*Q]=U$MAS;>\W9ZOQCMMOO]+.K62?[>I>-IH)#K_+2JDQ@&C.XCR4N+X
M\U,U9^<"$IS_K0V62?07
M\WW;=2[;9N1CU'@ZY*6(V@5)U=F9X-IM+7D.U^?E)R^6:H$L3%M$+7MM#74U_:[O)^+8S[:8=?^/KARO^VKCN
MQS^V&9 V ])F0-H%ZVV%8BL5K50\^]WL&45#S9G;CY/N:'J=31;>V7"S7]XTO%:MO3BU
M5N-@C5:MM6JM56NM6CL+M5;?O)!6K=T/1?\T2T42E>_?^'D#K^%@E+U=S50C
MZ _/C]@VX)H\A8\W6>=ZG+8X@$AU1,*=23;LIE_,QIW!;+J^+'E8R_)#XX38>,8]Y8M 5>3/
M&(S K"Q>;W[):#RY[0[O*1R$&?5!2^?,^?OT/?Y:]!B'JKUQ5'\'%P
M"Q3\)?O2^6U\VRU9M"^#_NP&?@0&J5'ED JQ_<>A[H@1RHGOC" D61-DWT[J7I;ZK.LA]A*5)8[5
MI"<(UW??W49B+<>>@F.;7[34?[DUS,KM-IH?';6NE5KK5H[0JTU7T'6
MJK56K;5JK55KIU1KN/EA+J]"K;WFA'7^,=-OCE"U\Z$;86N%;H3"UWS-ZVO0>@N)'57'V7:<91["EAM1NTUB-'Y2!^,?.AU71C0-QZPY&G=^V
M%=X\%9?.>/1HF4]>5'Z6%&/W*!;^-1_CZ:P['.8_OQ]V3T"[*I*M
M)J%N'9>:WMA-@U=3&7_G>@QB,\GZ@UEG.)Y.X4'I-]?S22KI[PQ&UXD"J=+_
M^^>6I<7+]/8?!D#K0>_>2:V'-IE>CN>T\[[[+1^;FA"&7T[F0(6?!MVKP7 P
M&^RH)3N5;CAKQ550\FZ#DMTE)8=K2G:ZDXWAO?"6Z7*T;SMR]R0C=]43)^Y*
M^C+GM;8#:<\CCFT'TKZ&88D>G)';JVRRSBQ0_*;SF(&KL-Y@CDY99/Q<'A,
M&/+"NJ:8KNW6\J5(T/D)R]E9^92[U&2O!3INR!!NUPC]5($BTG4"E8;)NW'+._2'40V;:3=
M_<+DALIV1FP; [4QT%(:F&ZEX67%0/4QAQO?W@ZFTZ863[P43PSKUA-K0YPS
MLD$O1K!D;<;IQ0O6JP]Q/JZR)+$;P+
MDK'+M4\O1;!D\SM@7HI]3&TNU R)/0K\+'Q"IWB#5SHALX]:3N@JMXFH5UY,39F]H.]RV*1_MS(?;
M/CO5M@'7Y!'_.I]-9^ X@KQV>C=9[_?ILH$\C1X=)7=ROQ&27[))5L_(U__D
M"*]FP-7RP,.FT>X8_[@,II:"NOAC>LAJ(&7^F_O39_/C2W?IDWP0ZP^)(Y:H
M,J1K1C4?QUO+LZKG:57.?6O^5+8]J7*4US$/>M.99-.[K#<;?,Z&WYY]8.Y9
M:[I-/E_/8/LPO[L;9FF*!N9B7/;Z]FV0W
MV6@*!]]Y-^J-;[/.'W\:3ZM&4#X!H6K X N+(?+S:!WDX^CWG1"TL=ZF^)[#4\8P=O?AWF3+P=[)VUL,R"[&?D]S,@]N[^"(TZ%,P=T<7$-@ ]]S[^CW/^_U":99
M1:#@X%NSKW>@9]?L< Y&8G-+P!F8B1R.6B:OET:P7OCL=>#43X/1 LCN?#9>
M_6*1Q,I_T\!X=DR>.)^=ZY2,G@V:6;U^#BQ>_/B&"Q*]R[5:+T:NZFO+;>6JE:M6KHI!7NV\
MH2,R["O>8@
M_KZ97=G5-YU1ED_)Z]XNQB/WNG?Y3,I_9X<4IC=;#RI*Z;IC(MG7
M4JO*VQKP-D/4UH#7+E>T^;D.K5RU>7\U>E>]U?QJ.\
MXW<\+[&2X[SX[>SHT_+/RW_M/QS3I>L
M9^1Q-IHHF63=:5:YCS8-K;B;3WHWW33"8GS=N9ND96.S;[G%S/XU']REU$KK
MJ3Y.7]9&@&T$V$: ]S?)-I_/NJ)=/^Y_>C">S
MM[-L<@L.W-4L3_*M+[\>3?*M$X%M]+2ED JU-]-M6N*,K-M+$2Q27_5O*UBM
M8+6"523296NQ7EC&KSD_TDRGV6S:Z?; *TS9/CCJ;++JS^T,\XOD\15\\V*]
M01NNU2E>+T6*SD]@+M<*79@TR+:)LQ6&5AB6S2&M++RL_%U]K/%;-@/_*D^[
MC:\[PW&"NDC8S<:=[O7U8#CHSMIDW(E3Y2\^Q+D@<;M<0]4*6"M@K8"U K9[
MZ@5[PWB;GWMA^;GZ^",,![>#49YL2XYB*JF;C[JW8\#SWUF_TQ],EQT=Z2KW
M#CS*P?QVVH$WG]JEO#"Y:XLLVH1%F[!HI:*5BE8J=M[PT-J&)[T4:6@3>56%
M=Z/L2YO*.Q_3\^*CH0L2N,LU5JV M0+6"E@K8+M3>?@-:8O#VU3>8_SQ(9O-
MAL65;S&*99+ULL'GQ326U%J[=A?SG-YX!@_LC.>SZ0Q>I@:.J^XP.9QM%J_-
M5[3YBC9?T4I%*Q6M5.PSJ;DMQVNS>+NW"5QEH^QZ,%LX8WD.#SRTU7ZR_"*V
M#8+:+$.;9;@P:]4*6"M@K8"U K8[C2=KVT3YX@7KU>7P?LEFG>Z#%MG!J/-S
M-IN,W[L/G:OY=#!*D_/ G;Q:UNV]Z61?>\-YGKO+UQ*L/MD&96VJHDU5M*F*
M5BI:J6BE8J=4*-+VEC_N?_UIEJX0J]Y_,L VB#8$+^CMS6(O$R;H#S^>'16?
M =C\96E9U8?YW=WB6K@[[)1 /I8>M8#FQJ/I>#CH=V?@YGZ8P7]6M]
M[S?PQFPR+:R5_+$3P+.=?2L3_@DH58/6>3>Z'D]N=^=C6Z;<@[SYVW_(4]R]
M1PC^?I(M!X#G9W]N:%P4S9=7#O5(.T&X7)Y^S(/>=#Z^_7E\-1AF*7H%G92D
MOMNYFU\!5X#0P_$/%O-#:X*[ ^\95LGO,8_K3&^ZD\4.H]ON"%16&D[?&X]R
M!R 5U]P5##Q-#)Q/14WM='>3<2_+^M/:$/M/K4BMJ'W?Z?C!YP$XE_V\M6]V
M4\8&<"^6.L%;NIW>_'8^!/7X.>M<=:>#:>?+33;**XH&UYU^UAMVTX>OON5/
MW=&W#4T^[5R-NY-^(DI_,,EZ0,YIISN#!\#_1W,P51,P![71C'_/_U 7
MK3X"0OV"7K?=;YVK1)M!GJE)"9@W&[P"G'X+],J)"+^?7_TOX)JJ]GO -UWX
M0.J_G"V&G;WI ,L F3:3._DS\J0.4+;ZL=^?I?JY*%WY]]%PD53+Q1GX%H >
M#K+)&_BA=[.@^V*P\7VI^ )2N/I4ISL'U[^;1P/#;TE(?-;+;J^R20?S-QU0
MHQ(8!$[^*IM]R;*:M#/^7F"LZ]%PB<5J DI35MZN]$2U^[@HS:>)\I,T;WHV
M>-L?#.>YZ'3[_PM_22XEB%8_N\L6]8U+#=<%MQC.*BDT^.SOH*D_=X?S_)C3
MG^])6*=C9KEDS@:WV9N'"G(!X5(1%#ST)JF#+^##9DFLX>>[[F3V)NFX]/';
MP6AP.[]=OGV:P*U5X=7)%X\=0?:UE]W-.OUY;K>[G>LYV,5EH-&[Z8X^99OH
MW<$7C/M RG?I9/J#1>IZZ>.OJ ?DZ@;YBHSAB>.RD=<2[M#T]X(O5UPVX)&2T/U$(=)
M=_3[M#/-1@-@RB^#V4T'H+Y;@C,<0'C57]B=Q0>SU'F60%C1M9-G7::=#<27
M$O)N<4+9YU4!,A 3" R@),G,16#]YQ=[EHM(+B+TE;2KVWM0@>;P("F30J\]O^D]27J#V
M-+V]77^M?O[O/\VG;S]UNW<_F*5OU!W&Q4Z5[G C%^D'T]YP/)U/LH_ OW8(
M9/C+__O__/?ZPWD^8@J'Z<;3V?3]&,[W6_'6Y(PDOO\MN_[S=]$#>_&_L7]^
M]-]U!GWX!9B&M]Q&BB0+T42%HU0,!4,].),D\, L^^XO#P1KDR(?P3V>=G[)
MOG1^ X?\\;NJ;7)9I^(KJ;D-^G3"5X@(IMG1"N2LM5N=P!6J(UM0;+H,D*8+
M/V^#I.N&LKO)^':\8./%QX"IYY.%H[$,M])#5H^^YW!,L\EB+>1BYM2X/^^E
M>ICDL8-O#IX!N X1_(WT@&] L"DX?/VLIMAU%;2OKT8ISJ/W>O3"FS-+RM87
M]-=HJS99JN Y./SAO+^HAZKE>SYD8*%&G]YT/F6C; )\FDC1[:?('/S:/+59
M#XD+%+Y R%&3F8+XOG-5HXFMB2\!+E8K7/7Q)X"&:B;9,G0&1AE^.]S,;[74
M]XSZ<#C^DEIR0>FY/!C[:3P%?OIU%%=;UWXKFGRG']._#['X8.A50);)P(EV
M..AH46[Q*6%:1W,I%G]AX--Q#&;?5F']YC##P>W=?+8QU' A\"OBYA\4UZ.[KXAD#,(2C
MQ>O-+QDE]W%XK_X&I_<4#YXM4E6@$9?O^?-WZ+O\]?2NVUN]/OS\OPSZLQOX
M$7"\&D_ZV205*@^[=]/LA]4/)>370&V6_!9%-*JR1&B/HN$2#%X([N3JJ.9/X*26\;9T_^SW?Y45_#173T7
M"YE=T@;??>WD]3J=_[C._U?1@) 1!-%C$V3?3NH>J+UL4@^QEZ@L<:PF?65 
M<&P;QPXJMS6G+V_:
MW#B.['N_OO=3('JYXXY@U8C4WG7F1+A=5?WX1D]5W;;GG)B7% 79Z*9(-1%\JJP/>P3K$T=6NQ:Z[,QN6^6L\\-QPP#M!)@!7)27NVF6WTW[1KT
MY?RFJ\VS6GG8+^XT*X-##UB/:\=.M.Y V=RR*9CH1X1VCKRI-#@CT(#Y^8'*
M\M_\]_1=.)OQF;?8?$]Q%MZNL?N%>F:RTIKKYN&+%.B:^
M;@J&YKJPQE#G.)N;-$#=\=2U?AIUE6VX8<%FFH/7XLAV9
M!VR@' ['@T^]3X/!+YW/P[']BVT/!]D&2KO7[WRV*]] 6>6KOBW5QA(KZ=$T
MJT$DQ,9_4!'3BG_;OYVPX?\
MUHJK3DD:TUGJ\XO-EA7WY.O(JT)MJT-55IWL%8K:+W,WXBJ\5E%S0]%D&; Y
MMQ'B&)_*@G*+*.2O,)&%&E=O?-MU YH\AM&?_#W-(C=.HM03E2RV5 M8JF8D
M%-83S_E^<^_Z'K.VQQR53=3.82]'O)99%8[Y%X6>QU[=4,>:8K>#.9_O*
MZ??ZSN"7C]W>U>"7J\^Y)>MV1P-[;+PERW9J"SSX^R=21D(LJRKD&7LR6"WT
M(U>@6:G:2"W%1M14TA *F<[S>BW;6@?)#>RE@E#RN?^O&Z2B1E]V)PYVM=>Q
MJ[WWQEWMHR$V?3UF#=5EM+/?WV Y>[^;:?PO'\$DZAF75YYVF
M'('L[;/L;TN7'(DJLNE1"\35)E:8'ZDQ9^.K,[#LOK)X2P-#)D:FEM1A-@(Y
MG1>=UD_Q?FW).>YO5N;'OG*XY#ULB28OGNB+(4I9Q*L!)UQT"UUTYWT'O1+A
MH(\V(K+%1=9>YW0STCJ'K9*V-KGL4Y<6CXRK;PO)7ZUBK%LJMA\0B>_V.IW^
MQ\NQ\_G2&8P^VI>_#$?%FN*@,[PR-1*?*UV^GKT13)%7G8IE1BF[G\7[SZ[U
M)4PH<IF0VF.O-OMP9[7UW3.M;QQ$CAG
MN-GM,KV-W"#.6].(!5D.=G*4^Q+EXDPJSJ7&;=QO[I%DO(7;3P4N\PK_+V*TL[LFTT
MI-NC&"7WK>EO,GUV@:QNU]8IR>7P$J>OA^$TR7>I-%;>D)#X=H&BE45:V>8ZW\O$?S4_:Q8LFCFTH9G#$,TM
M!F_@@)O]%C%1MSO,:M3[82QDF^_7WU[G8%DP8$H?J!\NZ/H:VL)W@SBO%K_<
MZBG.]C+!,[](J9K!E)*/+*O73_XIJOLO^%4N/4_<0KFLP=7'?ZY712BJS\N=
M['E6:"AK_4=TRJVAR^52?$=LQB0Q2VB<]2@0>>2EAYK0.S?8N-?U&^677[OD
M01?IER[B9>7UTYAN2J%T:W__#VZ7&9^OK\_:RLA&CYDQXCM
MZ.6SB78$R[N5?\W>W?)F'QG_:Q#*]A)2HJ)AB"CM_TSX:8)PSCPNM8#.6"(J
M$$@]*DY8KO8?T3D?$4ZS^A-12M>K/8@+!Z\^;'8.G]&LP456LF#A/F>[_,5?
MYR[7H&4?!7X]K@?B^.SQ12OO>%G'8P/&4^!Q.LZF;S_E1)F6B/%-QMCKDLBQ
MVI,1+6OVLSC)65M$=.$RH:S\]O+-V);\CNS6(/MW!*+B_UW$>;/(S'T(([F=
M6:AX&JP^2W'R;XC?3^F,BGX?:Z<5!3X*[2GM!W_UH0[/]+;$;Y1(_8?N<%!L
M*%-RPOI[(&QNRCI1_98O3+Q#T918-FKQTFBIE:Z_5RW%'0TDFZ\8 "LW,.)7
M09CD%\S:ITPH/XJKRXR/?8,$)3'>?+.7G.R'S,**KB]'&=Q'*DKEQWD-AQ@]
M+NHHRS!Z8U6&8;>9>_I1M$"/! ML]U:VE='4N@9'#$;.FC>D+)]7NT V-/Q,
M&G[PCG/L[RT.RZL>\FG;JOB=XK[JV#V"W2/;5Z6[ZE:E6[UKY,R6J[F>''8-
M=NUX06%7G ZIVR:/RO947:%/RJNN-'4C1+>G;(S1%)KT T<[O]]4&IRA#1J:
M%0JH<%=0>06_"GC>G'IH"'47]DA=O\JWRFRE9<<*[6R*>,SJ@CX*UU:7V!JJ
MNX"Z#JA;-_E;A>1I,%4=C*]B'X4>"E7;CHCJ)*+:1/4ZM>V(;;GJ=@QNG"?E]L;W>+T$.$6N1I:3(#M>UAY=)HRM33(/NC
MES6'C6FUC1FJ*R#4=!/3YDF;/.RK+'LB:G6\$P4O3AS1-#8];81D3 WW75L&*I@SHQ;GF59^FUZ+L\9\E7;7XM0\45;9.]!NK *[
M"KO:Z#R<=MM5U#@V[F:O15_)(*!9CK('ZC^_)^2&4C6W^"5,*.F39>T#^P/Y%H4+[D2>I1P^_96R
MA737JO2P7&4?A=R[VC 8U<
MWW]>U6U?E0SGG,7"B_G"^X0>S>XHZ+$+'=UW(_Y\JUE)=A=
MCX,9RQ+"[[(RY5/Q_>B.QN]7=G'M%>^YGY=WL+PW2]2OGE'I5UV?^\OH@7DT
MSNK"RQKVPMN6:"8)]>X#/HR\$Q>916Y6##N-9.'V31')DKBB:'&I2C&\ATKO
M(>[IT8T5#11Z%0X4:GG3726GA].JPVE=\>&WF'1*PW23\/]DK0GXB%R,X"-Z
M3X-8M$ZX#K@QHE*9EJ/^KXN\7P-S\D4L2X'VRF\]7GOKWMI;9]E;CYE(
MF/ZG^TQRPI=&10GJ*\NDQN*98-Y0F;Z.RO2]-U:F'PU1N+UI*4?;'6'3"[=K
M7+GZW\+\?Y(#T\+HDIVV%GL'CESFN T3.4!XH$&JZ0X!E'EM3IG7KM4=J,M7
M0('7ECKI?!5*SCXFE,\VEG.1Q'U"6C _S.X=[!Q;F B)A6;M;_;0$-6W*"2?
MQ9R4?%[&.ZY+(9&+?P5N.F4)G;X^;L?[.#H,M>"BEX)>CQB5HDVE().A<6:Q
M,I.*N,2N[L$RM"_"8CY-LBZN_+G_KQND;E3$PQQ$=H1YVF(JB]'0YE+UB&DHX=,E 5GS-E>[0PLNZ]LBW4#
M)X"( N\P&P%-\E!*%4&4IM0Q[ZLK8X[R!:UQR1,W9A[A_%JP D7W4(7
MW7G?459FJ=6VHF4.>LK\5 2:WF1&6N>P5=+6)I>-A1(S;E8$YE?A^#R 521V
MRMCU/8N3,!+:7$3E@[MRJ/[VW3_#"?,I^=?-I4Q97V:*+B(F8O?ASA"XE>U9
M<*=_I'&2I8I.642]Q'\F;I)$;))F8>17SD'D/@JY-D^)75K[?(U];OLA__9.UMMIG^OURND!)[W:?+N[,SAX1O+:DQXU[:JY3(8743&,%<["?5H.-$4@<-5P
M0D(IMO>N;<]:;L420QFY33@;2"JKA3%0[$Y;[/;4#)BVW.6Q\W/8/]@_C>S?
M%YJ(ND"9#103]7G(;_Y_W&4-C"E=1%24/1"_*&;114&%/%@P-82XU,Y?\K<-BPF(VR6**
M:1OC STO$98KW\ O@I]W$24VWDO%4\1A G-:]"P.!;]BM255..WWU=[^URR.YZ ^[$'
M%J:QJ.R3/0=_*VLA=?ZV/M(TB3W^BF^I3_\,YRK+QYWY49?S%ODJLSI^T[QX
MTEJ=P)V!6N$0E^E'RR'#,B*_*K[T,ABO3M_'%976@8\_-1+X9O]>?/\__I[&
M[^Y<=_'S+[GR7:UT[R.+/3^,N8[?7&]Y?!5/Q'
M%.3C8U%AB+^)I:;GY0&R2AC_\#N=_>.[SQ]%1:O_U_OW[7'WOC3[W^9_'?RWZOV_TXL.UNMSO^/!Q]]Y\O7,]KXXU=7J>&%1GY<;-4
M$!>/I%3^4!+4R>%%E8[UI'!B730%O_\JKS>32V1Y_&H\^_#'I#I_,YH\WI#?OV+Y735G5T7 FUL@*I
MW5TK05IZ%1G0Y9>QJ0?GID=7M'>8R95PSWV#6DM/'OB_&)\\$I%KX.3
M'Q<;- _?H#EZXP;-8;>9&S3/>!QVH)Y_!VH3]YD>7H'G]?=0]R;4KTLW\IMT
M(V\.-Z+EH&FJJ[%V?BO&,X>.(K&WXH"] <7&HV1-L [:"*NY
M9A4:AQ'IJD) QU96AQ'[3@W:=^I8W2$ZAF/XKM1!PP(890%&@\UV.RVW )@>
MO3)2.&;K=.NVECN6TU6&4^/WEAN$E'8NN'5H=2V[WP%:F-,>[*F.J7G7U-+O
MCM7I*9O;-P4._3@PU[T8QL-PJ*Q:7U-HP&SG%1]R3'2L=4,RVQIW,"3#;$<3G=S[>.4$[TG1%1>1
M?7D"^BC[\8A2;''^2J[RR$A;W1/'+[_$7%7&U#$05]:+B2TPFE,FN1FX<
M!OSU/,O^,'D=8/I$(X^)IC[)?1JO=?*8K=>9D>=;KS;CYEV#BM?M+A91^,3F
M;D+Y592(Q>XKE#$7XW5 Q%@E:]"TGW\N"CX,D(6715>41>*\78V\^E/$X(6ME=KQW 9J[!>>< K'QS* =^4>F&F(S^+
M1\ZNMK->I)H77M+SK.]37K@LD17TI+T6JI[CG@7K7M+^HOQX$C[2B(03/GQU
M2P9*UI0JSE[^LRPO%83)1J<@=\+GCB2KUN1F[:R*)E;3E,K#2OZ3WS"_L"RM
M>G5UO=XP(DXGXIX%B&[$6;V3E8'Y?=U01;5&3QVZ/:[5K)*GD@7FQFOUY6ZE
M2+^N9+8)PIM=3/::H[Q@K.R"(R[U>AE#%76^M# 0E9:HSKOI!813)!AY
MX56L' 'QF]>=BR5I5?+B?W#>CY060K84W5?W?4=M@6:5M:/5BFQ9]U@.9[*:
MQ35%65UG,:>,%Z(L^ ,?/K>F(V9%-YM]W!\U.;IZ% 1_
M;&2E7&>T*%*JU<1JN!_YK\1]; 7XBP6B<-9\L@'R%9>^5I(BLLQB,,HOF>+,4IN A,[C
M8O =1GP8(EJ^>F$:Q;*R==&$P%J^ ='40'>Q9U./9??;?*X1T9F?6=.B1U(>
M/UD.NX[G+.5YD#9)(%.3Q^X:VV8*IA\
ME4M-E^IV2S)^X^\DFW-I:4K-M/M,6)F'T'_(YOJ%(?'=QSAE A[/=]E<3H<>
M:)RL @6B0'44>I2**5+1LCQB>;_(O59+XE-T= W2.8W$9<57$Y+U-.;7\'UZ
ME\7?^_LD-"/])M#5(Q(-.W;E[)ZR_
MZR?WT@+S*W,SX/$+\0>2MR0/8\$?:9!9/&ZO&)V)F,HC]?UE2#])1-1X2F,O
M8A-ASF3\14;SN=2Y;8OC+,I3/'Z+"*ZQ"4"*8+E9QI7G/
MFTNY8F&'_R)SG\+.KZO*-.0R$0]31.*%'G/FV#2WT-$RP%4TH!)NFM\=/S5_
MW,O54['UY^6W'JRN,Q%OD?/!_;;XXH3+3KRG2;;((M$@?AC'4FQ%*^XTBO*.
M46[A6KA*!OSOY34  =U<.A%"/O/[S<8'+T18]D/B$N*12]ZN? FX:TU)$3[PG^4U^+^(\.V['VGK12$P&I^OZ( *$)4V=<;;XT(F:22E'8,2;%:?W&1^<2<7_F?O\7+$2N=#"/P19^.9.K'3])$]K(2
MS;;D?Z.2P5V_7R'NHA/]EMLIFL8%RU[?_"1Y1$XX K' *[K,B-RE8D5KX8K,
M#_[F(L*_R$)IG>Y9+)MHQK$T\*S4K+@0_MI32@;Y%^7XD=.=E='E%^=FF3[P
M8:!\E=G;]UCDI7/Q)3["%[:!&]W4N[>VG_F!T<<-BR=N*$XG?^2&43KH[/*%
M*A>J)HPV']MR3U6\V2SLWY(0L,J;^QJ02^Y=?-*3D33GQ3*+[ ''9>SN'"((
M<_&-CVSFY)9Z]T'HAW?B-?WVVQ6Y*-ZYT_D@O[+\;'_XJ7ASLK_11Q9S]\O?
M^Y4UECPPSL9'^0A'G"-=*%N@_\&V
M>^_5=JA]OXJ@$JX 7[G+$6.A;B>+IF;.ZP_1;XK[-D\.8 BW15/Q*L22NC!R
MXBD+R5C"($KC(,:':RHB1,O-7OY:,N?P1SJ]DW\4&E;TO!3O?*EZ_*@O?$@G
M1VA.?E?CC]F3<,Z?:=_Y9C:-&Q]T6$C7+![%2+K#]996[\MA$S*PI=Z
MFHN=2+FWP\_6$F(0_?O$X"9+&Q#+,.3K/& 3/A>X#D03"C$/%D)?VC'NN,*L
MOY7T5'&M4G'!LN4W_US(XR9:/NY"/6YY!
MR6EZY,H+"]SS3#$K_R@FROCUN'%T9="4FUDF0M3R4.'TBB^2*>-W(N9+V2!85?I@
MY6N?B9PJRQ:_:B+C:HS?\1;*L6]UU6K)=.$6LQ7+NKM9*W-
M 'Z_^=?:^%_0Q6^.B7>WQ"R;2^91ANU<;="ZZX+?7KG@G_19)(UZJ5"*^,7*
M"B>7WVRVJ)+X6?1'/B>5H1I^'U2HTDHCE])85\UL'$=E4K4<0<=REI)-R,7O
M^#A(Y,GR$:)"R]U5FVKZ[:4D[OFH0F#5*D'D\=\UO;L+L\ GGR&)R<(T#T_G
M@641]\GD4@SD_>="8E-QV)2*V4@^1RH$][=XU4%]S2/=B2%")D<1.F8S1J<;
M=_,BP=KUX[ TON#3DB5-V8M9KM\*J[C&SJ>;;]_*\+PAW18V,S_N1LC\719R
M\\K#ZR+73ABV(D+!/9:(&B;N$Y]+RI%WG#EG5X3X?#$3VVQL6GJRM>U_;6I$
M:CMO[$3:'S>S46?C.Y$V_@%;7QBOZ9U5-6Y/6CV/\OCD-7
MU;.J[7K8Y!7]5;;+'OH+_3V#_AY-,O;-T\YI(7:^@,.;LC>@KLL^
M+7Q-@!7(27F3EXY=N:AJT)?S5X QR)QIY[QANF"ZCA>4/5;6G0JF"Z8+I@NF
MJS;354/OHU:8KM:'J:\WUN[*BW6Z\3OESRC2X>F3)S>=KL9=59#3E 8JZGKK
M-;X[BD%8F>N1FL*5PD+]X I<@:LU*8TOYH"F#DM,+23XKF*/6ZD ,ET
M%'(IMR3J=L=&B5<>)_;'9/LG9(UM469*=H?P\H)#JSV#O]_\2^[(^";^*Z6_
MN>%"]1-A PDEMNU0;+BVQ+S+[.=M.'*Y:%_ELMBRQ>M(.DI/;[[8^E?G+$P%D6?_=N7\;_D+/OZ[%)VK[BCY518;^2CJ+WUV643^R_73+94QH+2G*JTQ
MBGJXSSN[TOY.Q6Y_,;&Y*OF\6]'7[.+?HA;",2X/"@RK6[$"7R[KL5YS=65!
MS+S,T)X0WS)R$;2Z'+0OH:Q(+BH1[RP=5?U"Q9M#S.?,9+?&?SKH=]TB(M71-3X_3>JZN; "L#*Z.EX(S8 _*^^IVW4$,XNQ8[N[ZZ
M5-[&N[HV+_O(PV04ED[/:5HTP69L#0<=J],?JI)%4QC1#P?MW&UC-X7TW_>5
ME1L #ZWA03/Y5)DS"V6"<=53=9IB;[$$M4N#_DNN/VD93]'$/%_8MC7N#ZQN
MK_KP[Z:65"8UO]KKKRB0<*J\U3&?@U!7NR5,%7
M\\1E^+ZKKLKR'MDTQ:6!)_T<6&MG*U"VUAKORN]2M
MB:LV]L#J=GN6HZY:]MW7NV)MGZK;9-?U/FC-^/S^\+8,5@
MQ?0996@[*[7?.]!$S341_K35_G3055U)S:M6>76ETW)S(Z.7BBAINH
MD"H[6>6U44G"6;JC44Q4?YRS)VV2)(R+JTP=1ATNT)$'=>K<,Y5^YG<
MN_RJ=Q'-#GQDR?U]Z$_SVTM%L3DRB\+YVDV(;WK"]\C?KM_QB]/+$U)^PHUW
M<(H,>Y8]'%B]P6;QE5/.)@L<*CF38SF=KC78TG7HI/LJ"W\EZC4Q\Y<6QZ''
M9&,T(63RL-*O-=T2#[G4#<^-[_DW7O'MI]SP#W9_4!24U.S-_##LJKVSG"YW
ML8C"123D_Q*P);//HFH8H<&4*GJ8(T*29^9A6WVD4TYD<=6-%U14FJ;^\_O5
M@TLC$]"B;"FWAW&ZLGU+0R7+F'J>*%G*_RI>##=W89K$"7]608L7SN?K)
M7;;AFSQR'5=C/)W1^_[FO/G,%MUQWG_>5PK0B_9G%(OC*27_UG@7HOMY]H6)J[/!QT1O_I=P$1/L%W=
M5@E]$C_3&')8TT%ZH8G$EI^+T4FQRNN4MTWQ7HF*GC545ONMF#B/7Q
MLXYC1E,&N&5W_;+#T->%G)3K=LM&R5<>]XV[R*B8QDW2F%\[CL7@8\(".?:P
MR#]I$H7?KF[(O3L5PPIWXK/X7CAB?LCRCU=\8I<&S,NB)1:Y#KSWPO1TR*>_
M4M&UB/^"!H(+&:M:#FV^^6Z0#;TOYYDI%%3_+JXC_-Z^\W=Z!YQ?GE)C3F\P&O;5]>$:O[$-5W^,
M-ESM:L-ER+9![3(.T%SJU97U0SI)W,@0^A$RATX>J)/H;J*L/<^G)QIY+!8#
M&^8=W.,$ROHV^:!7U%9E5-V->@KJTR%RE.(-S2XYKL]?C]65M2@+2,;\ #Y
M(#QVVEAE(39_:3E2UF4(8_<<:]RIODXY1C9:0:>7"6MC$>GNZ'T706:@U>SP
MC[F"4S.L:M1XZN5R(SUHN;&V^D\GK9=L#4^^K9:E\EFS-7)Z5K>O;MUV7^F/
M"H1BG$=IN_UK"HW:KF >*#_#C5>W\UY=>!R&"X9+2\-UZ+JG7FPZ)ZU[:EXL
M2SMTSW6SV;ZX,-MU68S57]__1.YH0".YM6X1A1ZE4UGL0>Z&>Y*E"?QG55O:
MU58B4+ES7/&=O6GK>(/*9QA5.DE+HI6;'T4W5]:R54;XIZ+ U.\T81&=4W[.
M&_>!N\E86IMSW[76(I7'E8L$Q@MNQ4-9_C!:R3/.Y;D0VYX+0S-W_Q!EUIZ%
MZ1;E\8I*7W%N^F.A\-RZ+;6]U[$O_ORIV.M\+38.!*[/W]L##5)Q"U,JX8T9
MOV4WDEZ01U;/&GJH*+@-MBQ+V1QJY
M851P:4,%ES8XECV^.ILT?$LC[]Z-*?STL7YZK4+(IYMOWS+7R T.'Q(R4:)A
MEY/,7)02'NS^CVI07[KKU=V[42!''$DHZRG*,LUTSMZY02#V]RT*S7FE<$JY
MGBAQ$^[#IRPNZH\NQ-95B\3IY \.M!")K 4C3SYW^20TG9.IJ#@1$70NE"^@EUN)QQ<3:9ZN2K)X?QJRH1)-)@G!!B3_-6!0GA+LPW^7_
MG;K/RQK9[(EP:2:B9/&,7Y(?GM70R\OP45%H+SL5BPE711KEPZ@@%5Y+%J];
MJP^[B@_LU&EEE>V& ]OJC!3-+\L>WB '#W]UO+_ZC=ZYWC/Y+>3J+K<4K]=?
M.O=-:RU1>=P!-<1*%H"(K=QBZB0*< G[,A.Q)"[RO/#IKO>P5HGKM]OK;^7B
M6WF94!DK6=G _(I_$[9*Q-S%29?W%R6'[DU?9"M&(6GI?"Y[/@<"%"O>+B
M^3?B9A2M6N1FWU,F:!;]]]\]PPGRZ-GR7AGR:RGD"
M#(!.2G*6:%CQ\W_\/8W?W;GNXN?RT.$RF!93ZU]H0&LE[_J_?/X\'/:=SJ7SJ>N,!L/1<-S].+#MKMT;.)_L[_[SQ4BY
M+)D]"Z;;,BSJG;I\%:-!LB8NDLF+7/P6QO%/IZ\]MF;VDLG06Y-AOI1TX4L9
M&GWG!\>26-J_-QT/UL5V]<*TJ0V)()4S:]N[->OH1<$^P^
M6;YS^P/Y-77%U)I/DI;2YC9:!CT2!8.X[8ZA)3DGE5;&3Z,XE?T7:2ZE4XO\$;(@R;\7BW4 
M\0U+.C3^6=YH&L3YK4Y<[B_7;F6MBCYW,?Q5KYE2\4!Y0D61.;)VLW*^H6;A
MI=-1M:#U*$*-<3J)V92YD>A$6'[,%?^32VVD=BY9A8B"[-$C<<.7+G@NQ
M6"$&83ZC@;!? N"$@\JDS>/_)\Y>MJ%K-LCEH^DD7C84R3^^=L1V.\ '>EQU
M1:;_:H'D%8,OGJ6TBOWR6;C[F=XMU\GS4283N7=4S%MD0^"7GB'S7%N>7:3Y
M35DDKI7I0OXA7K_]&ZHHG4T.FD9K8Z:/W%6J"T[/TDC.'=AJU(76*"HLKS":
MUDJK9)5H.9_),RTBKOAW67(I_TU,N7X57OZ36+K*&L6*0*-'^316#*WD@"*B
M#Z$ODE&SD43&"A^;!%FR:9;4*1,6Q/2Y=)GUA4;QMOGMB$O]\OLG2[0(Y',R
M__G="\_]7.HRR"T?'WYEDS)QKB]A\&X[P>*&LEF4#!"(/3G9"MAL.!0!46T!%7LYR"!\7SF&',K_P
M,**9O4A[*A*4_\&G9,_>%#XS?;=[:?>[^
M2472U2JS^T/VN^*I62!:=LI8R@<125O+(/M O(B*<)$8?<0B!RM[!BZZ=#Z)
MI&P_9(8T,Z,R1.=Z>0JYL'NKZ>/N+PHAB<@]OTG^/E>
MC?_F-+JC5LFN\0]A)"VXM;SI1]$=@I]N$

2:(G& M8GD/(M/>]>Z+M_5BI0!VZP0_T _%=H^U7JK4*T#)=,TL)KRF(@M^BRR1&8JE*\E==/)JI20, M\33Q\:)IB?E4&N_A8J,R!69"18B=Q5D>Y3%>7G:[-R.32,,==/*6D$W2EL5D MF7>W*V50)H@ETE=.LY664F@M$H98K%5Y?*8;L]4&-!E76]K&W$B_.)-T!MG, M0]8>$N>(UNWZVOS]GCM,/LOV1)ON)?/QAXF*Y2"P< MB54L/D00/C3.)"*F/W'J)V5_X(5^.@^R05=$9SZ78;SJ1IE/5?9;JM+=+%Y8 M.W%/6:YW+/TX_2NEJ]BW.&$ZSVU<[HRVOC7^O\M%Q'S2[4BVNOEX+P])S&ER MGW5D+[T!;FC3./.2^6_EW8A)6A3?LT4ID,&"M<&*F+>)[)55:%Y-2'6CWU$% M2_?+-3C1TJCTMGYQ?;EQ\>:>TN35A:*S/]C)RV35F>+MLJX^SEXZAV&M6 >= M<5=E)U:G]\96K,[)K5A//*[NZ]5]')Y/C_O$\^'YJKM>FYO);/?Z%WRTF&=* M']X?$MUD]PG[D :>>8K'X3+73$NU*T('G7RS3N93>^@D=%(;G=R1(P8=A8YJ MHZ.[,R"@I]!3??1T/8PJ.YB+C( @^WRYVK<#M87:ZJBVAS<70Y>V@X, ES+Q MI!*5UJ77L0F&PA3-U$YP4$>HHT:"@SI"'342'-01ZJB1X*".4$>-! =U5"[5 M-J^R9^$*N<\GR3=T5*&,]41\]%(K_31(._E ?Z _T!_H#_1'3_E ?Z _T!_H MCSG3L@-GO1W#)VRB9FA6,([_(/;A/;C^N=,@=HI>#YFIZ\N^3\5>D9$F?9V[ MPU'ETFA+-W4$*V%C8&,V#[.MX>#@[O&P,K RL#*P,D?+PK&Z@\W:*K RL#*P M,K RJF0QW*R5!!,#$P,3 Q.C2A;+\F1.]:C!UL#6P-:TU];TK/[(@94Y4 * MT@,-7VZZN0^C)*O!7"J$?80"+6_\&I6!B7%DT MT3"ZL%R%Y2HL5X$*4 $J#MBBK:[<#'@ #X;S "\!*D %J 5H )C)R3 59P M1V91."?N;,9\YB9'-?AM7= 8JS)8E='2;0$P ; -C^RLX#< 6NP!4<%P # M8 ,@ $P (:1(;+ACE*6Z^"!!DD8L6KBA8:A@[4IK$UA;0I4@ I0L7_?@3/N M@P?P ![@)4 %J 5H )48.R$;#?E4:JO"?\3\=(H$GLUW3BFU70E:$H(&&LL M6&/1TD\!, &P #8 2/$GHU>G$ +:*EO"M?I "R !; P* 1@ ,P@P&QKA$%A MM?'$-8WH#LP.&]Z&B>O7$38,HRF-"HG8BR<2ASZ;DN\[\M])F.7G%-_8/.$Y MLTO5;5/?)[;#16 PI5@% X.$3M6:.QNE4_H%AMMF8=X*I3KF]1N.!/ M^TS<8$IHT5U#-M @&](\Q9GPP^)TL4.R7$ ??!;0=_=4RL%V.C^6SM)?)/(D M%_9/\E[XB8XTN*U;9<$R)I8Q]?38 R 3 MG>X.[;Z/53! 5M@2WWV:!^- M@@$6P,*H$( !,), X"5 !:@ %: "5&#LU,),N^HB5#<+ZB51 M.B<^\V@0H^4OUE>POF*#"WR#2EQ)TE-")< M]N29OP8DU"&ZC'53$]T: -@ R [05LU!L"+( %L."Y !@ V #( !, P- MD3)WE+)DA>2RZG%50&48.XC38_4*JUD;'@%&D"#X30X M]A@T@ ;0D.7$V0-ES@$9<4"EP:CTU)'2%,=1829<=V!VF.HV3%S_^##5ZY(+ MHRF-BJ>W%T\D#GTV)=]WY+^3@-KY-O*+B4,WKZ2'C'^H2[![5?8U 5<@QPK* M]?4'SMFE68/*G=]F8F7L]*$%K".LXQD&?H[E=-15U(%UA'6$=81U;(AU[ ^M MSM ^NS1A'6$=81UA'36SCK;5':BKU0WC".,(XPCCV!#C>-'O6.)RU< M&J"H*'0+TZF71L)T*A+DP+%ZW<'9I=F*@66;MUS(3X]4WM D]*?9>7YC[H3Y M+&$T)FXP)3=)Z/UYS_],H_AO1%2!29Z/T,WE&PU2/.T$ M!XV#QD'CC!"<-L*"QD'CH''0.&BJEYW%=2&*R<)]% M(PFY].AZ7I32Z8F36.71$CTDI2S-HKHG1AT\;1)CX9)@!QIC![H#E/X#_^"_ MK?P/K=Y865XD+ L "R 81; <91MN /_X!_\&\8_(@&P [ #L ,CJS-25K6I M*1:@RFPXPY<7BG2X?'4A)DE(W-F,^LJ6GHH M ; !@ VY\J:@\!%L "6/!< R 3 !L &(:&R&D[3EN^)OQ/Q%/3(Z)A M 7@L2V%9"LM2H )4@(J]!4D=9:,NT :#*=AU 4,@ $P8, $*D#%UL-Z-G;) MJ(A&'1:V[ [,#E/=AHGKUQ6FFH31E$:%6.S%$XE#GTW)]QWY3VVD.+^8^,;F ME9KEM4Z6Z^$R,IA^+/+4L<@#M+GK[2MKG@*D@320/C_2(VLX4+?L"Z@!-: ^ M.]3=CK(P*I &TD#Z_$AC5@VT@78CT1Y;?0?S:GT#Y?4#75TX_+=0W#<*$6*- M%6NL6&/=74%D;(U0C!! (C\L,$ K>) VC H E4@ I0 2I Q6%4.!VKASZ[ M2@)1&H6HJ2D\(.-N;P/@Q'VJO$)B0\+1 M6._!>H^6K@J 3 !L#V!]8L1V'5$: %M( 6?!< V#5 W9A*ZQ9NT\F*R4Y M5BAGF]'_!.I 704CQLY V6)LXQV:(2EX-8051><5= 6N9%C8%%CTX\)<=P,J M0 6H,)P*Q^J-D/@&'L #O 2H !6@ E2 "HR=D/ZF/$[UA8HMHP^4>&X4/?,[ M) ^NGU(2SDB<3F(V96[$:&R1@%;2,*$IX6&L>F+54TOW!< & #8/N;/" A M#F !+'@N ; C +LH@[7A80X4 ?JX-:0%O<6I;D.$AIYX9Q?^YDLW&=WXE>S MU=8PF/JJ$&H**?I!8:[',8P%K.N""E"QX2&L<7\,'L #>)"'V8,!: -H"$/ M@5EV5UF%>,2Z $N#8<$$ XER1RO-UX3_B?C+_JPH%8+$I:+T]U:T[,#MB MN*+J-DQE3]; +W(K@:G6F'8'5K>OKLD&/"82.G41O57Y#%19F06UQ>3:%"$"L2#V0&)[0VO45;?, M F2!+)!%F,B0H2_2;//DVE5*+7&#Z5OCNAHOR9Q-T#_4+;^:Q56%F4-2)/(_ MZAUJP'+!<7G+7=RR^8T)E_H(_D]G+O!![+KEK8M\#ZR:7+_L],[Q&2OZ^OA7SYNC9GK M\#$*N_%BUUER_/&. G+/\[WE<2[CF";981-1W M$_XY"4ER3XG3L1UR&S[2B-SRL\6NE[ P>$_(#:5D0YBGPG;^I=[6:?>_? E2W+,TDNT!6# 3]R-% M]&:K>)@2GC7X/EB9AHKQEV98[TQ9UGKG(\?C_H MC+O#_H_%H(L+WW<7,?VY^&%#!-L]\"JIK[X #RIOB9]@_..1SCL_T#[Q MN+JO5_=Q>#X][A//A^>K[GIM[J:^?2ATP4?Q_"!?C'2/F>HL'Z![:C62F?RW M)1F;.IW.L%>%V%\7]<8 [0W"SA\E?\;MHO_&YU5KL<[Q3K )Y_-69!]OIS^D<;) MG-\3U!9JJZ7:TNFADD<=PX.# -FR8"4J7:,\3; %V@BKN484&@>-@\9!XZ!Q MT#AH'#0.&J>3X*!QIPBNS>O660 @C<1B*7$KFZFV4:WTTR#MY /]@?Y ?Z _ MT!\]Y0/]@?Y ?Z _YDS+#IS8=@R?L+GQOG 6">@QU566M[ZOX^HIIN>,O5,K M<-M-X0;K_Z "5( *4)$?9ELC6UFL&CR !\-YZ"E+00$,@,%P&#!D A6@8LN0 M:: L4M44'I 8O5-?/OV5LH4HL498$">N[\N?%[X;E&)7<67!*Z4+#LUR1HT/ M$V,QJ@;W!< & #8'L!ZUJ=@0.T@!;0@N\"8 ,@ $P ; ,#A$_IN"_#2&)WK&[1 !R"0W"H3R@4/()'\'ABY+1KC4<]H'CN\*I& MRQGJE.M;%"[XTSX3-Y@26O3DE;N(R88T3W$F_+ X7>R0+!?0!Y\%]-T]E7*P MG "E !*D %J,#(">EN:B-6U\$#C1-17"XF+"!Q.HG9E+D1 MH]5%K9H2';:[5D\=:XV/#AO$F[F^JBEL=3M6=X25%[ %MDR8-@$P ; !@ M V U ';1ZUJC&A)S-O7D6+F<;6+_$\ #>/!L&GBVUF?%70<)C;QPSJ_]3"+J M4?;@3OQJ=M:"IZ9@HQ\AYKH?PZAPK.$0)1O WB EP 5H )4@ I0<6!H3.G@ M"0$PP-)@6.!"D#)WM-)\*MJQ$A;$B>O[\N>%[P;EX!:9II2XLX1&A,N>///7 M@(0Z1)>Q;FJB6P-@ R ;!#B@T[:)(*M( 6?!< V #( !, "&P2'2YDXK M)I=5D*L"*\/H<521TQ1 ]&/!7!=C& OV$# !L"0.8;^ !M"0N0:G!QI M VC(LN%L6QD.R(4#*@U&Q1DIBTTUQ7%4F /7'9@=G+H-$]<_/CCUNN3":$JC MXNGMQ1.)0Y]-R?<=^>\DH':^C?QBXM#-*^DAXQ_J$NQ>E7U-P!7(4?F8N&\- M^^H*]9TJS1I4[OPV$RMBIP\M8!UA'<]0:K%O]=0%#6 =81UA'6$=FV(=^[9E M#Y0M,, ZPCK".L(Z-L4ZVE:GKRPQ!\81QA'&$<:Q*<;QHC>PAKWSF\>3%BX- M4%24N(7IU$LC83I5S;H'UJ"OK(H1!I:O2:_-&RWDIT8DILD]/Z\YW^F4?PW(NJ_),]'Z.;RN;H59(SL$:KQ+@8N&/H#_8'^ M0'^@/YK*!_H#_8'^0'_.(A_4Z=P50[A*HTA4YO17L[DJE*Y.66JOC08IGG:" M@\9!XZ!Q1@A.&V%!XZ!QT#AH'#1.'\%!XVJ;QZX+JF/V?/72\[@N)#%9N,^B MA81<>G0]+TKI],1)K/)HB1Z24I9F4=T3&U"RAV!O[! M?UOY'UAC=16M8 %@ 6 !#+, =L<&_^ ?_+>4?T0"8 =@!V 'AE9W@)G B^>L M,AO.\.6%(ATN7UV(21(2=S9C/G.3TS+CVM*WJ0*/V_CN35A 5K" W!; ^@-P M!:[ E?HV47V !; %D:$ R 3 !L F#C,Z2I;16P\6$A-OKD/H^1=0J,Y MF=))4@58AO5BLPM7@;@RC8J"L9!]@ R&PX!&O( !,&"\!"I !:@ %:#B M0"I&0\"@( +5CK2VCW1&HXA.240?:)#2*OAI2M 7JRI85='200$P ; -A> MP'I]=:U8 1; ECP7 ,@ $P ; C 8,0\.*XXF-"AM^3?B?B*>F143#XN]8 ME<*J%%:E0 6H !5[MVZ/.J !-("&C 9E^ZT! V P' 8,F$ %J-C<(@,?H2(: M=5C8LCLP.TQU&R:N7U>8:A)&4QH58K$73R0.?38EWW?D/[61XOQBXAN;5VJ6 MUSI9KH?+R&#ZL VL\1ONKI@#6MP8=95LU@1;0 EKP70 ,@ $P ; !@ V #+.O MP0&Q?+!Y\%]-T]E4]O M.YT?2V?I+Q)YD@O[)WDO_$1'6L>F+@E@H0P+95@H Q6@ E3L[0$\M$$#: - M&0V6TT>Y4/ 'C!F A6@8I>7Z#L8-:D(B6D4@JZA 7#B/E5>(;$AX6BL]V"] M1TM7!< & #8/MK>5IC=7M:@1;0 EKP70 ,@-4 V(5M]VI3K)62'"N4L\WH M?P)UH*Z"$>-(W4;>QCLT0U+P:@@KBLXKZ I E0 2I !:@ %1@[(?U->9SJ"Q5;1A\H\=PH>N9W2!Y2!SZ;$J^[\A_B")7(+JF M0&P0K^;Z/ *0 $H #T[H -[ # !)L#4#4QX3@ *0 $H 6@ !1#6P,CNVOZ MTAV8'<%=,7D;)JY?7RS7,.J0BWCL<\)W-18&Q[9Z(V5>"$ ",.!L&UK/$"! M&0 !((J\W&X/(R;P ![R5,2N-1@H P*IB("EP;!T'LX)39_[J^H[NQS^^ :# M:Q"CYKJX=E#9M7K#ZJNZ@$I0"2H/'Z[:5J>O;DT65()*4*F@(:C5ZRL+R:NM M@%8#RMK$:4 LB#V0V%[7Z@S[0!;( EDSD$68"+F(JN.XI;Q#X@;3M\9UWY0 M6RVK9Q/T#W7+KV9Q56#FAGUU<;=]6==ML'98WH7E@N6J/C;9MWJ.LJ5T6"Y8 M+E@N6*XZ+%??MNR!LM*NL%RP7+!"MMQ#R\_/68B#<)H[OK9F;Z$"25CLBQT9W_([_SKA+\Z M5]SXEHI'I]W_\B5(<<_22!;,9\%,W(\4T9M-[H'6SZ.BRZ0J^U>6[23TI]F) MKL* CQICKA;\)^GY^#,&=^0FX;HRYS= PAG_TWP1T7O^/?9 R77@A7-*+GX+ MX_@G_FDI&!46OXYG_C#UY"WQ$XQ_/-+AY@?:)QY7]_7J/@[/I\=]XOGP M?-5=K\T]P;=[_0L^\N8'^6)T>LST9/D W5/KY\[DORW9V=3I=(:]*L3^NJ@W MAG5O$';^*/DS;A?]-SX7XJ)6%$!"5!BD/CJY/9($'86. MZJ.CNR.>T%/HJ3YZNAY %;'[3SZ;LR#[?#G](XT3$5&%VD)MM51;.CU4\BAL M>' 0X'?Z0(/TM(8<>Y6Z6HENSXO(E6F?1FMG*DS13>T$!W6$.FHD.*@CU%$C MP4$=H8X:"0[J"'742'!01^52;?,ZNSSLAD8/S*,D.GYFK5Q&>DA$V?:2ZI[8 M@)[73=GIH9\MT,N P@[ #L .P [ #C3(#CA=:]@;P03 !, $M-0$V-9 7?4Q M6 !8 %@ PRS 17^LK*G3II(;\^91S0;& <9A8X;0LT:.LNY231D?F)[)ITX_ M/OV5LH6L>'#"PL)J]WF=ZUQG;"-30=QMIVB:PII!6&GGAP$8 -@ $P=8$/+ M5APAC9&C)5&%IN4 MI_Q5%HZM,IAH&#_(U<-*7 WNQC JL"0%%L!"=EBWKRQ_ S2 !L-IL(?P#: ! M-.0Q+UM94W1$MD!*@TGIJR.E*7ZCRC2WCMEAJMLPVU=& ZI,BRC68 FW"S2 >Q"L:G#M6I]\]._&M\.-MSN&4 MGS;:N7Q=T"AKZ$2?%C2(JVGL4H$(33"$FJF5=O*!_D!_H#_0'^B/GO*!_D!_ MH#_0'W/Z@F@4EJDNB'45Q@D)9R3.&H?$%I^[>7X:LP1_UG\F$\E=>272G(=MD4?T!"R9ZAD\!& # M8 !L;P*]U:^AO@K0 EJM0\M1MC4%7($K<(4Q(0 #8/6,"?OP794&(YL8JBG4Z >(N7X'5( *4&$X%6.KT^^#!_ 'N1A0T=96!HT@ ;# M:;CH=9657MA\Y<<^N_E[M(!*8U$96]T>BH*I"%)I%!2NSJ3<4-_G]V61.QK0 MR/6SM+CIG 4L3L3^IP=:!51-B15C,0:+,5IZ+0 &P 8 -M?*Z=C=0;*(F]@ M"VR!K640KZNN>@7 E@ JX@'#CKCVA2KS8%"4 ?JRD-%>U0]=TWQ:*W/C/OX MVG;;*D SC"=D F$!"PM8H )4@(I]5/2L00?Y<> !/&2'C91%U@ #8# J&3-*8!32.^1W-)RRH+&K5E/ P M4G6PZJFEWP)@ R ;#]#6>& X %L 6/!< V #( !, "&H2$2WXY2EE]= M%I P(%,6+\+8]65+B@7UDBB=$Y]Y)W<3;%B$'NM66+?"NA6H !6@8G_[]X&R ME!_L[ $J#48%#@14@ I0 2I !895:H=55>;/=MV&B0AU+:@H&Q?<$?JT MJ"S0-0FC*8T*J=B+)Q*'/IN2[SORG]JP724]B $B=7F*1L;=)6?'JF\H4GH3_,H;,*_6T1@+_*LY9].BL5VZZR& ML4? )AA#;81EK!>!QD'CH'$Z"TX;84'CH''0.&@<-$X?P4'C3A%4=@$I[4>DK6YL' M*2"ER:38ZK9( !6@TF!4,"L!%:!BV[[:D;)\CS:X$*1S'!H*(TE(W-F,^J@,XPMK#BA14OK'AM;' &"V !+,C# M>K:R["'0 !H,IP'C)5 !*D %J 5>T=.CK(M"DVA 8EQ.XO+;RUK9)& )E6@ M5&O[B&9YII-%UQ2(#>+57%_7%D O;$,[-NGA-I"4!VCA5>%5 2@ 7?.J9^<2 M3A7,@EDX53A5 -H,0"\4IB'"JRH.$J_KDN&=1F_#Q/5)J%=(^!1:=>U@<0Y? MVX8^%ECM!(^GN5;+&0SJ0O$D)UH#O]K,6X$I,-UV6'>@+!<4[A(<@L.3W>5H M#&<)9PE(-884243W(&[PXM.6'9?6>$)N#2@ M!;2*P\;5UP\#5^"J=5QA+@; %B5CFNH;L&]Z6 94MU2>1@Q<9_06!JE:+!P MAE(TH )4@(K#(VYV#S2 !M"0)?:P:JZ?:PN8 MMC4>U[=%$F@"3:!Y()H7O?.#B9Q70 MHSYQ@!*\*0 &H*J_J6(/1^2>C<*S@ M%MS"L9H7"E[7&\,W-G^A16MM4@6G.1_9 ^/< M3F,2!F01T1F-(BH$$7I_5D%=4T+O%WT45\-ZF"&NKBG0H5(-$D4 & #8 , M@ $P ; !@ ,P*PEN0DJ@R,()%8<0BSJ7F*;I)$;)(F[L2G) GY+]#GVO1,3O5WZ24U2XKG$W8/]0MOYK%I3Q_0&'-5_2+.P^6FX9/F:BU&\? MYL'FZ;<*#9L'FP>;!YNGK\VK(N,:5@]6#U8/5D]?JZ<\.QXF#R8/)@\F3U^3 M5V^-%.QT@$F$281)U-HD8HT#NU*4[TJ1GQZIO(%)Z$^S\WQ-^'?%LNXBHO@J=-44J4)7H:NF2!6ZJERJ"G*]C9G_5SK=?^LF#=/V8CA:KU?H$?5% M\24-=T,!-( &T :0 -H *TA^^CW2*@IR[B@"E3MH*H'EL 26,)04+NA8)6Y M1X;7F;@-$]=_$8S,ZTY M3:._TCKOWV6Y_*W?+_U<>BZ?!?3=?5::P78Z/RI]L'>O/D%==W&2>%^[N9(N M>#1(:*3J=N7'C3H95V' O4A,IX3_)#783;@Y(#>)F] YOP&Q>>9J;2G[.E_* M_DTL9?-/LS":\X/"P)1G_C=_5^03?^XI^4@].I_0B'1MBS@=>S/?2LD5B0K1 MO&H:2N=8\ZDBE4*>@XGWG'TN7R00+\]?\PJV^,[RQ%F+#(_Z?OZ=?WS7^4Y^ MY@;-*SYO$= MF].8?*&/Y/=P[FX,5![9-+G_>3Q^/^B,N\/^CX4UY9;2=Q#X\7W77,V3/<25SN^U>_X(%A!_D\Z'143E_AV^(WS5SF&=6\0=OXH^3-N%_TW-^)75#5#1)0'.OEVG;R.XY1&T$GHI#XZ M^6OJ1FZ0A!&Y2204^AI[KKZ7H U0VFY)// MYBS(/E]._TCC1$14H;906RW5EDX/E;SIA<=K# +\3A]HD![EJ_0NB)T$!W6$.FHD.*@CU%$CP4$=H8X:"0[J"'742'!0Q[;6]JXNA_J&1@_, MHR0Z?F:M7$9Z2$195KDYFV,J*#?9E(QM_6R!7@84=@!V '8 =@!VH$%VP+&M MGKINZS !, $P 8:9 -OJ=I25^(4%@ 6 !3#, EST;&4U@3:5W)@WCW8N, XP M#ALS!,?J#OL8'ZP_I^F9?.KTX]-?*5O(B@^J*WZ.PK^@#M0=TG# M&HXP8JPTLMBD/.6O"?]3I<%$P_A!KAY6XFIP-Z "5( *PZEPALHF.* !-!A. M@]T##: !-.31+V3YJ8QQ@93&DM+KP&^H"$L=&,'LF!VPN@T3UZ\V^^VM77'?E6@1X563:@@SU2*\&[9KSSH7E_L-FY&UY-!B]?%S3*6CS1IP4-XFI:O50@0A,,H69JI9U\H#_0'^@/] ?ZHZ=\H#_0 M'^@/],><3B$:A66J"V)=A7%"PAF)LU8BL<7G;IZ?QNR!BE]/Z2*B'N.SNC"0 MC7S=>O+AA0+ MZB51.B<^\T[N)=BP"#W6K;!NA74K4 $J0,7>'3^CGK+\-VSL 2H-1@4.!%2 M"E !*D %AE5JAU7(G]LEPJ\)_Y-% II4@553XLA8J,%"C99^"X !, &P/;7 MM )6P I8P6\!, &P 8 -@&!@>@Y6"!+F.V<'"VS 1:7$+*AI,!'>$/BTJ M2XJ;A-&41H54[,43B4.?3 FI #:@;!+6MKL87D ;20/KL2&,( M#K2!=B/1MJV>/0#4V@;*ZP>ZDG"X_/1(Y0U-0G]:*G90Q,8O\NSE8]8 ET_2 MK:">R!XQFF +-5,M[>0#_8'^0'^@/] ?/>4#_8'^0'^@/V>1#XK4[0H:7 <) MC6B<%!M.*XG.-&0_-PHF(/RI9_BS(8!=C+KJ$GKWR:3)15E!':@[G+I^]85* M !V@ W1EZ.R1NBUFH [4@3K,X#"# V#G=FM69ZBNB$&;'5N;H+(C8!C\#5%J+"AP(J 5H )4@ I0 2I M!28;&@:U-(HPUQ#MRO905<%64X+,6,7!*HZ6S@N 3 !L#V M;MJRNL [ M%L""YP)@ R 3 9C1@&!H>#I8A*7+JE&-[E26+!#2IA*D*VHDTS'?MD5!3 M2-,/*H,]5;.HNK!K:Q_9AA4RD ;2=NA0#UX+7@LL82P(JD 5J )5H*H55%W8 M-F989N0@&M[E]#9,7)^$>D496]&\X0R>L]TM'+ HIX$C;@7:%[9E=VOSX&IK M9M1@"K2)K()X$*]H#;^CKHPIG#B0!M)G1UIIO4:X<+AP\*XU[YB/PY4#[4:B M+6I4=M35J(0SKS,.WZAP^W4>8O?#./Z)3.@LC&@1=T_<)Q2YK,81M\5EPC,V ME@JU,>4VK/H"EM;"8EN#CK(<=3@/\& X#Q<#> YX#I""R0?\!Z@XGHJ>K2QZ MUA0:4-=R3XPK<9^6?5PN)C2@,Y8S 6%6&&YL45?SD1@&_K[C(G0MG M)$XG,9LR-V+5Y,TUK*B$TQLJPPTE6K#DU6Z:;$MA(SCP!)Y:SM-%O[9BEXAT M@+06DX:2??!?H*J"_1F](:KVP84!-K@PC5T8:F'NU*HO-%G6P)1!QKJM^5%[ M[<]8.^*M@OZA+L'NU=N:-]X;'-)%K1*L:YXV2(%IA&D\0WP>IA&F$:81IA&F M<7/ILCMPSBY,&$<81QA'&$?-C.-%]_R5O$^*[AN@I,C3A]G42R-A-HU<_H3E MA.6$Y83E;(+EQ!J.SBO?]9M%)9HE/SU2>0.3T)]FY_DJVSQZX7P1T7L:Q.R! M$K'0+1L]BATUB?MTA"XNGZ-;0;6K32&^J;J\6= \:!XT#YJG M@2!-$)Y6 H/F0?.@>="\*H5G>GE:=?&5;9/>M2SOM\Y^M6K!=M8B96>/8V%; ME%80ZV42P2R8!;-@%LR"63 +9NMD]@P;EAM?$A& E!E@-96? I8 DM@B;&N M5F-=!:E1AM?^N T3UW\M2ER7'KX9T.9GA%8G$?6YGE/I%^"9G:C1+J MSU-'.OHQQL>$K'.[/LO4BN1RF"W]S!8LDZ;#(E& HH.!$2R,Z18& Z/QJ MK/]P4F3) )5#A6>#39H>*J23U=+%,-E6;U#;5N$V1+UA?O0S/P:X-YULDPDC MJAJ#X*T(-946Z_Z>N!.?;OU^Z>?2<_DLH._NL[H MM/Y\8-V#WK@S7HT2&C4 MTMN5'S>J.UR% ?<9,9T2_I-4?3?AYH+<)&Y"Y_P&Q!Z7J[45SNM\A?,WV5+U M.IB%T9P?% :F//._^;LBG_AS3\E'ZM'YA$:D:UO$Z=C=C6=06QH)XU/?S[_SCN\YW\C.WA%[Q M>8N ;MFG) XH*\)7Z"\8][K?ZZ^\D/M$\\KN[KU7T)M]_H7+"#\()\/C8Y*!3MX _O.FT, MTDWM! =UA#IJ)#BH(]11(\%!':&.&@D.Z@AUU$AP4$<]BG0W9(HM#[NAT0/S M*(F.GUDKEY$>$E&67&[.QI8*:B,V)=5;/UN@EP&%'8 =@!V '8 =:) =L$=6 M=SR "8 )@ EHJ0D8.9N[M\ _^ ?_[>#_PN[;JI\:E2Q@'& <&F <[+'5&2@K MTM64\8'I>7SJ]./37RE;R'H')RPKK/:>U[G*U;#.1&AQH@U6VOEA ; !@ M4P=8WQHZZFJV BV@!;3@NP 8 *LAT#D8JRN.V>8.=J .U!TQ8NQTE2TP-MZA MM3Y+^6O"_U1I,-$P?I"IAY6X&MP-J 5H,)P*AQUF1R@ 3083H/=4];0'C2 M!L-IN!CV5&M)FV-<(*6QI'3M,?R&@K#4@1',CMD!J]LP)2&2D^ MO*N7\1/^D^7:BLYG6.2I8Y$': -MH VT&XJVT[.ZP_HZDH)J4 VJ*Z=Z/ #2 M0!I(-PCIB['3.3O3)\65#6ABC\1*\*X9[WQ@WM. ^%9X\3;G=,I/&\U=OBYH ME+5WHD\+&L35M'FI0(0F&$+-U$H[^4!_H#_0'^@/]$=/^4!_H#_0'^B/.5U" M- K+5!?$N@KCA(0S$F=M1&*+S]T\/XW9 Q6_GM)%1#W&9W5A()OXNO.0R^I_ MLE_$]^$C_W^Z7!20, MR)3%BS!V?=F[8D&])$KGQ&?>R6T'&Q:YQWH6UK.PG@4J0 6HV+L12%DB$+;[ M )0&@P+W 2I !:@ %: "@RJ5@RKDU.T2X=>$_\DB 4VJ@*HI,60LTF"11DNO M!< & #8/M+U?? %;@"5W!< R 3 !L &$:&=:?'=AN)HJ&["" [!(3@\C<.+L5.; M0SPI1ZP&>I&5#TBUAE2,6QWXR[,'80\,UAL>G?VZC,NRP OGU30%WJ>#*I=% M=,7Z'.&A77)M!?18T=3 ,0-MH VT@;:I:(\[ROJS &D@#:0U0%I=CUD0#:)! M]-F)QO@;: /M1J(]'@^ M+8A\OIQKB00+C\]4GE#D]"?ELHLH'^@/]@?Y ?\XB']2GVQ4S MN X2&M$X*7::5A*<:]A,'FVCAI-#DR2)"3N;,9\ MYB9H$5N-+VN+RX)G:BP5%X.ALG;D;? S0*6UJ,"!@ I0 2I !:@ %: "5&"R MH6%02Z/X<@W1K@H+BS4DQ(PU'*SA:.F\ !@ V ;"]@]F@,L 6P(+G F M#( !, &P# T1!6FHY1E>]$EBP0TJ82Q"OJ*-,R7[9%04\C3#S*#/5>SJ!K7 MUHP', &FAL-T45L]SS:L/@,T@+9KV@6G!:<%EC"O E6@2DNJ%,8%6P(3^ICN M5*;;,'%]$NH5/FQ%BX8S.,=VMVK ZIL&OK85:%^,.^=OEG92'*<&0Z!-D >\ M@W=%,2-'V=X?N' @#:3/C_2%/73.SC1<.'@'[YB-PY4#;:!]^FQ<82%*N/(Z M-_PW*M1^G8?7_3".?R(3.@LC6L3<$_<)E2RK<<-M<9CPBXVE0F4\&>E]0*7! MJ-A6IZNLFP9+$3P'/ =(P=0#_@-4'$]%7YG[: H,IE>N5![02MRG M96>6BPD-Z(PEQSCEOS9GN38[TH98#%3_4C&-A-V,WZ[6;W_ 5@4-0)EA&6$991,\LX M[IY_0 G3"-,(TPC3J)EIO.BC C#FVC";,)LPFYHNB\)NPF[";L)N-L%N(D:I M\8*XH5MLY*='*F]@$OK3[#Q?9;='+YPO(GI/@Y@]T/5U<-GX46S%2=RG(Y1R M^4#="FI@;4KS3?7FS7(Z=0O,-(\-S8/F0?.@>= \#01I@O"T$A@T#YH'S8/F M52D\TZO65A? JGPVK%63MG9MXFA\O1B#"-;+'@+0+2MW74,7[O1P)%B; [3U M0^NQ(6C_&,IF0FW[1U=IH&:!Q ML&@&6S0]5$@GHZ6)71KW:YL.MB6&"ON"$9/FQL>($5-]Q2,P9())T\ZDZ:%" M.EDM70S3J*.W9=)#,I1*#.L/;W]\2=^'3;]VN;NI9D MX[. OKO/JAG83N?'#]K-LU^[6:UOKB1)CP8)C5IZN_+C1L&,JS#@CC2F4\)_ MDFR["3< Y"9Q$SKG-_#_L_>VS6WCR-KPYSV_ D_.3-V9*L4CZM5*=K;*L9.] M<]=L)IMXSJG]"%&0Q1V*U!"D'>^O?QH@J1=+MB49I$#R2IVS8]DB"33[NKK1 M:'2KTT&77,[81[*[DGT*IF$TI^^$056F^"]Z->P#37/"KH0KYF,1L:[38IVV MLUV79FW<&^99;?GK<7M*7NGG]8D%2BK^!I\ZZCO+J6BZ8:[P_>P[O[QJO]*? MB3+=_/..N5Y[K$(=_MXU_[06,+O+)+3DH?6WO M4_>/+JVF^M^.E$K1:;>'O2+$_K2HMURJ%P@[FTHVQ]VB_\(C>B)B2L9B2M#) M%^OD)RD3$4$GH9/VZ.3?$Q[Q( XC]BT92V_B\<@3$CH*';5'1S^'P1OH*?34 M=CW=C%7R8,(^^-[<"]+/%Y-_)S)6P4NH+=362K45DWTEC^IF^Q?_7H@H8P0W M]FZ]^#"[M;^"ERC=*C"#-<*J+Z5"XZ!QT#AH'#0.&@>-@\9!XVP2'#3N&,&A M$,MG$3-7Y=8MHO#64PEJXWOV.E'9>%[P$PM?MIY%;OKV9T7JMON6%JBJ@=6 UL!I8S1Y6&[5&O799,FM$+V40%X@+Q%4X M<3G]\DJ5@[9 6Z MT):1N-AP^^PPUI!80X+3K-$O<-IA\NJW>@Z<,9/.6-5S M=Q_27%[$8TCW.3GE5773W2HA6B,X:"(TT0[!01.AB78(#IH(3;1#<-!$:*(= M@H,F-ED34?AJJ])-<"MD"6=>FYB@;I]B62US$3?R;>8GY80=WE+#IEQA4. MJ+-E.E,A5<7SCM,I/H95EUR$"N'.+A8#P P P ,WT*==@QEVSWG%2:W*42 MN /N8-A@V P P \ J#C!XCD5T VY<-LEV&%(NA!M'R9SYGJLZPDH=CPQC MNIIY0NGZA9L8E8A-([J-?"WJBM&#@+L'Y-,7*P94 % M4 %4- 85KYW6J&NLB$ 3_#6 I;%@@0D!*H *H *H "K@6%D1"+,H*EU41&P6 M1O&;6$1SYNEC5H>V%&U<'1DP:<:!OW;"/HCFP([9-@WQKXQ4 %4 !5 !5 !5 5!;2M-+G: !Z AXKC M 58"R77/*LEOZBQIBP6BF.)VSW6,5@B.U35I "@ "H " MH"<'Z&@ 7 *7P*5MN(3A!$ !4 4 5 5!XMM4+VVZJ2[O:^8:?1*P#.R(' MM@T'UN8SY1;OR,R$OHTSI/O8 _#G>J.7*="J"=$:P4$3H8EV" Z:"$VT0W#0 M1&BB'8*#)D(3[1 <-+')FMCD(FWZTUWZ*L:A/TGO\]$+>."^/&GJ.94\C>:= M'+*6*99U\H'^0'^@/] ?Z(^=\H'^0'^@/]"?ZJS6+ HF%+>#_"4*72$FDDVC M<,Y!876,&@ %@ !@ ]GP:0G]8FEXA!P&@ ^A@U6#5 # # # MP"H+,+B-)RQM7*>XY&9F71S>B:CHX&/%H(;M+VQ_8?MKZVQMSUC]?: !:*@X M&F C@ J@ J@ *H *H *H "JPGG@Q&I!,MU\RG9R%4;R633<-([9((G?&I=!? M\();^FX8W;?8(@H7)+=[G7(G_DR\A;I-BP6BD+.C=0DW8S\'^SE66CD # # MP "P/39,![W2%*O..Z9 '5 'LP:S!H !8 8 %9S@,%O1*:=&4E]"F(1N>&< MGGW/Z(D> 7K"%MR;%(&_BL$,FV+8%,.F&% !5 50 50 50<7L]^:*R:?1/6 M(X!*8Z%B$"DP'$!#Q=$ =PH9> 1Z4K>'U0%)%BY0S"Z]K&>L;&13+!8,4VW!@)TO MH *H "J "J "J J@ J@ J@ *K#(1B)=6:&K:_Y=2'T*E$7"Y[&8L#A4Y>B8 MG/%(,"GBV!>J2-TJG,7O>#1!7UALW6#KIFJ6# #P P &R/E+K^H#3%JO/F M*% 'U,&LP:P!8 8 : U1Q@\!N15&=&4K_%]*?B.F.$T41$N1RWPX&<1,Y?+F6JIJVH!3MCXGKU.)/W@!3^QJ1?PP*6!,^[& MWJT7>Z*8C,5G--%H7#][F/K&,SI?+K#-1?R/E>;^DJDP&V CS@*;VPQ M]H= M&G;; M0#P0#\0W _'=5L_IGASPC5BF5R0=]R&@9T+?QAG2?>P!=[> >AO/R*UJLH)> M0:^@5]"KJL@*>@6]@EXU2J]>M"JR6I!0.FN5KKIZA5RN1^,8ES,>W CF!6E& M%P\FZ0_BS\2[Y;X(8E2;>SKP.VJ;"_PV^=0U8K=EQ&[K@KN>P8QFH ZH ^KV MT"JG-1@8*W",XCV %J"U-&@=!_8,]@R@*Q-T*$D'JP: %9KWWC67)--DLU:1 M')A")*4_W:7!Y''H3[+ I57 )K;T.R=OD(7H EH IH/ZVR-S&6R )@ )H!I")BCTU>_ RZ!2^"R MA&09 !0 !4 - ;3?ZCJGKSI7%V@V.>-&7_8AF!P5GWV16KT8:1C/]%K]\](ZG-6%8=:VF'Z. M^=@7.[^_]O/:O'PO$&_R"IN=]H_OUB;JBB 6T>FG>I+AZH_;I\7#@!A3=2BF MG[0V\5@=0/@6\UC,:0!JJTL?*?](!"O9IV :1G/Z3AA498K_HE?#/@2J'?.5 M<,5\+"+6=5JLTW:V0QAKX][@857-5(_;4_)*/Z]/+%!2\3>(R5'?64Y%ZS%S MA>]GW_GE5?N5_DP@=?//.^9Z[CT=F@/>H.^S_F/$($X?.%%&_S']X])(75Z-=W>E<)!KV=N_I[ M;!;K(=$-1C\^RUF;_)A=Z!QY7=G/*_LZS,^.<6)^F%]QSVMR"LYN&__:"QA= MY)-;(@\IB;?W0=U'7>^I_K-@\9!XZ!QT#AH M'#0.&F>3X*!QQPC.P"YVQ7M,?Q9QVJ5E$86WGDI0&]^SUXG*QO."GUCXLO5L MZ4G(V3UU[EM!N:EURE N0ES&:\Z5):\2=.?T>:X(Q5/3OW(CV*99U\H'^0'^@/] ?Z(^=\H'^0'^@/]"?ZJS6+ HF%)>:\"6)W!F7 M0NI6X9$ZRAG?ZTIEXL_$6\P/*YF[G$6GS+C" 96TJM">Z3'1U"47H4*XLXO% M # # #P,SF#_=:7<=<$_;GI')0ZK =+I*Q[&#@#KB#88-A \ , , *LX MP. Y&O,<*Y)-4E#842Z$&T?)G/F>JWJ\2AU_#&.ZFGE!S(,;3_4DY5**6+;H M5ZZ?J%FPB5B$TCNH>\+>**T8& NP=DTQ:K!=0 50 50T!A6O.ZV1N:(!3?#/ M );&@@4F!*@ *H *H *H@&-E1>#+HBBT.9&EQZ=4OAWS B:/:VG;O!BTTQH: MK'_6Y!ATA5!778-6%]QA7/M5@@BCG 6T E]YHAZAD)U058]F&HP@8*J *J@"J@ZNE= MYM*Z76/?"TAK,-)@OV"_@"J@"J@"JFQ'%;S"RB0FMLL 9G$R_"QBYG(Y8XD4 M$Y6LZ!FJ_/Y2Q!H-[^_?%K!DG)O=5WNI2-$*%AMVI[/1C4#\"?SE1^7:B&:I M@#:@79(Q'[8Z)78ZAC$'XH%X&',85456T"OH%=J\EK'.UI_NTGI^/7L #]^4Y6\^I9)G2K4+TS1IA539L"8V#QD'C;!:<-<*"QD'CH''0 M.&B@(>*XP%6 J@ *H *H *H*+?:P/9+/W3V]B. *%DZ9'ZH9B6C.)F)<3!%OU,-O;#W\"H&ON@:L M+@#KM$:C+J %: %:L%T & &@ %@ !@ !H !8 85E\60:OQJ7)?Q8+?ST40 MR^TH(N/!9)D]1Q*6@H5C&@17&72%%.VN&-80P\?.%G:V@ J@ JC8(SFB[1CK MNH+D"("EQF"!"0$J@ J@ J@ *N!8F7:LD%]W>'[=(A)3$45"22ET_R@"=W6) M0(_..Z;06/OX\4 / # # #P P P \ , ,P0T; M@87DNHWD.CD+HW@MNVX:1FR11.Z,2Z&_X 6W]-TPNF^Q110N2#SW.@5/_)EX M"W6;%@M$(6=[*P9";(1A(PP;84 %4 %4/+L]W'/.3:M)G3>' 97&0@4&!*@ M*H *H *H@%N%G+MR1/@IB$7DAG-Z]CVC)WJ$VPE;<&]2!,SJ$H?&1@\V>JRT M8P 8 : 6 & &@)WV8)2Y8OS/RJ3.:S>@#JC;OX%8":"#.0.P&@'B0E?7_+N0.@^.1<+GL9BP.%0'0)F< M\4@P*>+8%^I8Z"J]X-"DDFH4HQ/VWVW]KVJH*\*L/2.AIE@W&#&@"J@"JH J0ZCJFJML## !3,T&$TP4 M4 54 55 %5!E.ZK@^-F4M=BN=GCPLXB9R^5,M;!0M?PF;'S/7B>2?O""G]C4 M"WC@TL 9=V/OUHL]44R^XC.::#2LGSU,?>,9G2\7V$ZKW3;6&?MHB>XOG0HS M O;B++"[C0!UKS48F=O* Z@!:H#ZY*!^[;1Z0V,%M5\LTH,V\$N@ B2% O&U M0[S!0G' ._ .O%N.]]8 B ?B@?BF(+[3ZG=Z)P=\(Q;J%4G*?0CHF="W<89T M'WO W2V@YL8S+?=%$*.HW%.QW<&YN13*)A^N1G"VC.!L75#7 MZP-U0!U05RKJ!CWTMP.P "SSY@P^)*P90%'YROK),NZR3#_0'^@/]@?Y ?^R4#_0'^@/] M@?[4+N&DLFLY?=E[<>,% 8U,M2Y,&+H%+X-(4+AV#.X8 )H )8%J<+ . J MJ"F/MG4^<@#-9A65*2Y*^R&8'!6??9%:O1AR)Q/7#V6+R+Q$S$>_.N55M:T+ M[]A',=99?C ,&&;),+W2P@5@&# ,&*9A##,8E;9/ 'X!OX!?&L8OH])J!(-> M0"^@EX;1RPDV;< SX!GP3,-XIM_J.GTPS-%;3#_'?.R+G=]?^WEM7KX7B#=Y M=*P.('R+>2SF- "U MU:6/E'\D@I7L4S -HSE])PRJ,L5_T:MA'P+5<_E*N&(^%A'K.BW6:3O;#4/7 MQKW!PZJ2J1ZWI^25?EZ?6*"DXF\0DZ.^LYR*UF/F"M_/OO/+J_8K_9E ZN:? M=\SUVIL+R3Z+._8UG/,MXS;GT8T7I(/D21SFOT@MJ?[-G3>)9V]'H[/S=F]P M/NS_F!,),83/%U*\S7]X]Y 55L-?W^I=91CT=F[K[[%;K,?TRZMN^\=G26N3 M(+,+G2.O&Y7\O+*O.Z_(./'^,#^;QVGW_)J<@[/;R+_V D87^>27R$-JXNU] M4O=1WWNJ_^W(^Q*==GO8,R3VW?W*LF.2)0XJ]08&AP*=4 MX,]A\ 9*#"6NM!)O1D]5^3?B8SG!U;AA$Y#I^W0:;'W.1<4 M=]H[9/';0D097;BQ=^O%AUF\_;6_1.E6@3:L$59]^18:!XV#QD'CH''0.&@< M- X:9Y/@H'''",[ GGO%VV%_%G':5&81A;>>RJ<;W[/7B4H>](*?6/BR]6SI M.=.[PS)&4VGKE%!=A+B,'WL?C;V*99U\H'^0'^@/] ?Z(^=\H'^0'^@/]"?ZJS6+ HF%)>:\"6)W!F7 M0NHVYI$ZMQG?ZYIEXL_$6\P/*]B[G$6GS+C" 66SJI!H]9AHZI*+4"'J_K12AV/#&.ZFGE!S(,;3_5/Y5**@WHH M[(W0B@&Q $O7%(,&NP54 !5 16-0\;I[[IA6DSI[9H!*8Z$" P)4 !5 !5 ! M5,"MLB#@95'TN3@1?IN%4:LZ@SO+?=%$$O&7?H0Z?ZL[!\BCL(OE]_8.)%>(*2D M\8H_T?^;:2KY M4F0? ^#LGNH;VS>L1W+CL^#>6P0U-KVPL,!AX6F50"*0""0>Z^_V6IWNH"PH M'N78EH!?:Z*]@"E@:DO<"&83> 0>@4?@$7BT'8^O.ZWVJ ,WUN;@K<7[,#.A M;^,,Z3[V /RY=N9E"K1J0K1&<-!$:*(=@H,F0A/M$!PT$9IHA^"@B=!$.P0' M36RR)E:D6%LAH0?]Z2Y]%>/0GZ3W^>@%/'!?GO[TG$J>1O-.#EG+%,LZ^4!_ MH#_0'^@/],=.^4!_H#_0'^A/=59K%@43BMM!_A*%KA 3R:91.&>>E DMX@0+ MI\P/U8Q4;[^)&*.#'[I(X RH#5361(!U6KV1L1)\@!:@!6C!=@%@ !@ !H ! M8 8 : 6!8?1F 5I,30_1E7\6"W\\%71=.FJ#NVU=( M89R*X:H PU47$-F'E^J:(: "J J*HZ*UR/32E+G4H4 2F.! O,!5 50 50 M 53 J4()D=/FT+GA?!X&=+O0_:,(P-4EQ.RTAN?FRLO6/<1<(=!5UY;5!5K8 M'@7 # # #P P P \ , , $-XPTYH(8,NSZ"3*H8H9V$4KP[BLFD8 ML442N3,NA?["(@H7))-[QH,)$W\FWD)=6P0>*P8[['IAUPN[7D %4 %4/-^/ MHF?LC$,3=H,!E<9"!08$J J@ J@ JB 6X4DNU,DV8GO(G(]J9/L='8="Q>% MG2NM31BZBR!TX0* ,6L>L+"!"H !8 8 : 6 & &@ %@ !@ AN"&CQ/VWVW]KVK(*L)T/2.AN@#-/DQ5 MV% !54 54 54/;G?['2M$T@]>\!.;>@$/7!HXXV[LW7JQ)XK)67Q& M2XV&_;.'J6\\8U[*A;W3&G7,=:XY5J+[2Z?&QA=[=0"U&5";;4<%4 /4 /7) M0?VZ.SP]IH_RW$L@ FNBO< [\%[9,!=,.: -: /:@#:@#6@?!>U>JVWN.#] M;3S"?GI SX2^C3.D^]@#[FX!136>D5O59 6]@EY!KZ!759$5] IZ!;V"7E5% M5M KZ)5Q62$-Z]%0Q>6,!S>">4&:C*5:(^@?5'^$6^ZKY@J%A(EJL_YTE\9]QZ$_R6*,)B.+=L:Z M3TY*EFF7=?*!_D!_H#_0'^B/G?*!_D!_H#_0G]KEAU1V+:R]NO""@D:D& M@@OZ5C@I)%)2YJFAFH4JCQ5=7>(M%<*I7:P'@ *@ "@ 6BF =L[-[40 F F M@&D(F$X;P 0P 4SK@ F7%@ %0"T&:->",JUU 6:3DV_T91^"R5&AVA>IU3$" MK$ ]T!_*EE_)XK+[,.1S5-:$ZE;V,9=U[@2("\1EUU%3$!>("\0%XBKC9$9Y M,5>P%E@+K 76,K%5-!R MD!;H"W05I5HZQ0;:: OT!?H"_1EY!3_^:BTYLZ- M(*ZUS<:?8S[VQ<[O[_CYKS\G\LT-YXNWEV% !"/%Y&/:[YC[WV(>B[DZ'7]- M4W_OA^X??_NOO_QU[0(M3!Y[8?"%?G+OE]\C409*7E_%])=7'Z\Z;:?_S]Z_ MKJ]>,6]"O^!N_.9][\-%_Z+_?GCY_GV[VW$&3J?7O1HX3M?IM3^\'[SZVP/Y MK\ORVIL+R3Z+._8UG//':7'M.[@MZG_KA5>. ]EYY4VZ%? M(B%)I%IH3[[=IX9^GZS3_"L><+_2V/OK'Q$)F,I3?Q>.0)><96 M7T[OH>Y-_\_RE^I30H\KCD*_I1YY)WQ?_?>6+E$8IWG'@J9(WP]BW9:[L:3[=Q8F/4MRC5/@_V>OYE+V=#^KEW*=7[\&+ M']\3+P[:[<'PP]5%>_B^W;_LI+S8Z5V>7Q3/BX7R8"XIO=U(MG81(SY5LJ?59%(S223\E&5!O/P@>&8S+Z^1-V,CV48C=-[?E\(5TW2 M#Z6B7V*?A]?J>ZK+B'^$E_]2$)4G)))(Q$F4VIC5&)5%H _SD-2=2'*N'GN_ M$.I+]$X5'9,UH0)3)E5"F( M_^CU_2>;Y3HETY^U3ZPFX1%OT5ME;L:X1*@B3EE[XLDX\L9)G$Y15TQ22U&9 MOF]2$AIF]GUUI_PEKX_KAJQ)Q'T:&-TK<4DV*5=[ 1EF]=R5:NB;$J-[ MH!])M_D_,G_$F,B3KO;TEY5!U_J60Z&5.0%:/]1HU[^J?B')>-+WLT_I/9\V M!^"W-W8$V^6HU\+X6W]G)2Z9/29Y!XY-;:(2$FN<\( M8T9>#RWP9ND?PKM4=R?T=#A"+&EAY_3BF>=C13HZ4QE%W<>IQ15B2RDSC22<=+/.G;Y;Y6 MF/@3FFJL)J(!--[DQ8P$,U'N]#3RF? M2K52R-YKJM6YBF_+GW2.G'SUQRDI:(H@UXO<9$[KG71=$Z6OV2,&%Y-UWA,\ M?\ R/CQ\1S@-]5*!D=Z2Y^7)6H65&:WEJ/32);=2K27OK,:KW)$XM]V[_1(^G1(-K0OUM4QH)#PS M7723@-^(2&8CCVX]LK;R)P6U;:\B"3QE&%.C&8EYJ+^@1IT_\8T:5)0JP@K2 MRSOM08^:-:Q R'%QKZ?7:4^MOQXLVL@M(I^$^[\MV?NC)UWN_XN&\P\>*P_J M_IL[$Y/$%]?JGH<$N)P/[9'3/[_J?^Q<7@ZOWH]ZO4&ZD.MV/[:OSJNRD-/7 M?4R4[\9HS>[-DSF!Y#X-O6BG/-5 I6AQ"K6E.%,ME(YN."&J4YL9Q]N. M?8-V:_?8V'10/9+T/3P5[4P_KS\D4#3C;P3:'?6=Y8UU=)7<9=_/OO/+J_8K M_5D2C^6?#W^C=]XDGKT=CH*C[1C+ M*7SQ\>'JIT04-V/SN:3&NNK4,"T!ANHA2QQR8*)QC3Z<<_0RAF U3T%RVFUSN4?G+\P]&G;K MF7MTPNN07(7DJH8E5^W,!&*/62SEX9CR8U$P!/I[ OW=NXH_PI./UB@YZ_3; M/[)O(E!'T)5#+]DD$>S O6;C[/"H\'?7.!!Q?(>9F_^5B"OIP^OG)B*C,F8^NL.G@-O 9>LR%N;//RVISF#,XZY^=+=^RK4.=J M4Z=,';>?3CW?XVLN6B&I397;&B8/UA3LBBRGBCQT MU&X_DB7>A>NH>IHAG(ZE%)92P .64L=8ET>/M'9Q!@D'); \JHZE K2:""TL MD,[.NP,LD$H(-M0%,O:AH[I&!VBH.AJP.'JB8MUCH;>]FZ8UTX$SF.):>P>N M0E"KKID"M)H(+:R-SKK#1\)[A[2MK:LWZ+2&\ >Q.L+J"'BH[_JHE/70 $[; MXW+KP&G#>L@NPU07:*52.N\XG>+UJRX J\BJR)R29 ;KFW"32$S8M8CF[->0 M!Q(NGUG;5!>$V >&ZEJ:BN&A (-2%U14?2%47)CM]X#/0YK]?\BZ+"(Q]Y(Y MFT;AG"V2R)UQ*>BWGBL8]_W0Y;$7!FS*O8C=XX8* M.4%80MEDV&H#K/-#@C?-!E;CED[KEFWB29?>;C%_# I9$Q'D4\N!$JLH=U$;P]K(&P M!MJ^;'#(49)&@*'(I4^[VK;E.E0KH8D8V[]5- ZCB8CT-YS%=R9#WYNP_V[K M?R<-=P]:G4'QZZ3]IU]AI&(15;5%E+6H=%JC0?&+K$:@LB(K,'/*\ZN0\BUC METD4T5*++=2&51BP<(IMJJ<@A[0_K,*P"D-LXH3+L;K8&1=[5'O*T!DE<5GMO76L@H]W)4!CH+&C:&9=5U?<""_$L]*>[]!V-0W^2'5OS MN93>U!,3=5XZG@DVYCX/7,'D3(B8-*XT@:\*# MZ=92(1&W%T>RJ[_BK-#"L=WJF8M_U67]9Q\)V,6WG-; X9'PZ]7R/Q\BF?$IN_9;!AG:U#\%6"&K6V69 "] J=MV+A)-R=VJ+ M/PIIC>.\K_Q*%E?%$T^:<)86JW8P%YBK;KDF36"N-8_LYYB/?;'K^Z4-;$UH MOA>(-_F6=J?]X^FE5L+@],>M/>)5V./J.6_QJ3%:IX9EO>U/ =L:QS'WZ;2= M[7:XQ]RHQ:[?_",<>[Y@OW^[8)Z4B9B8&>,/G;,VHSO[7A@8N:$ZMVSD1FE; M2#-CVME;LL6F]+N[F>?.5O+EP82Y1/_<"YA,QM*;>#SRZ"H>"7:3\(@'<1C) M,\9LUQ(1$ 60FGB!BGNNBI2P2_JM%[.+FTCHHWFM3 :+*+SU)C15)1;.I+@5 MP9M[ BC]J,4GLWHGFEI\=:LI=SW?B^_9G1?/=#:*-N$JTAJ)/Q,A8WJ\&^G' MT#)V>:%L*>'^6[CZJ^HZ-PQH4*2$DAX3JR'0#;TTPX7G(TVE3E\-Z$IU1CY[ MK"=7WUF3 CU:G:FW&2F/5I)1/7YD0LJ6"^BI][?2X_U4=UU/EH<.A^\D"\=$ M]SQ]#4E WLRF_/6=/Q@CAOJE-5]2.W5+SV-/DGSF E?"VL#G&JN.X7DT143+U+/ M4M_Q@NS#^HQI^-^$,*/5BA*9TV=+\3KOV-]S.>9'>0FZGP)2LKE6#3/*KW1V MFA#*2V?NV:RFRHRU(Q-L5H MA;-AN2>4:G&>:[AA1S4Q>=&$+3@ME^@7BH9=-U*^B6Y3IJZ@]Z6AH7P6G:;( MU2#HEY,E1%BD]N.TNB\X+9FDF'MO>! D"A<:JCL'L0.I>PV *I,44C7!!.Z MI;[]F =_L-^F4VTQOZI+7N<:U&F_^_73^]^^+C\[[WXBS"?T+#;GT0TQ2Y0] MPXP_<#;LF_)[-(7(5*PT[8AFJD5Z_:089WQ"5S)!XB S>RLVWY2QB78-.GA< M&AO6E7#%?"RB5=2JZ[28,2^-I/\E(L_$6Y 6[J/1FR]OI;Y&1M,^ZQA3MLP M+I:SXW/=UVGE&XHYV6%%WWG.\M8ERC?/A*(HWB>$Q8FVLAK'GB&?^W-XJ]^Q M6@=L%PXZ\K4J4#U 2CH3(P_HGXV,O:E,W[X*Y6HOR7R5&Y$OD;KT[L@M23M) M*N9.WZ*Z2K\.[0WIF4X$O2[-Z:D+MUCXGJO"0V1QZ>=\ > I:TXO5&3BVMS7 MHI=]S\;J"1/E;TX8C7$1"06 ED+XZJXM]:"[64CW5VZ$YGIOK@>D_TM_54:I MI:W-0KAIPKRZ[UQ[@&GC3+E\P+WV;K,>F_+!P\Y63/#8H+DOPXV1D[^GY' 9 MSA<\N&>)5%H_YW^(-^FH7>WN16P<"?X'OQ'IXDMJQSN,\O>,D\2OJ&*\2$ MO+_5>"[H+JM9;;FJSRZLGGM-:BR/+SSH)5KAI5CN0FG;D2XRMN@A7YL\B\@[ MNBX#(JD75XMTWP_OGCGM82*\MW:/C6T5M;&N[Y%JB_Z\_I! N>7^QE:"H[ZS MO+$.'Y,$?#_[SB^OVJ_T9[G@;OYYA[BO">*2?19W[&LXYUM[57?>))[1CS3' M+"3ODJSX0HJW^0];DU\-:CW-8!FF'^S,&-DC44&/Y9=7P^Z/SVX ;.Y$9!S5T*/+4Q6AH8C2I'=0 M^^TBQ&-R4> M1S9O.[OF&N =A;B*@1&FA/9^5E[--S?,CE6 MNI:6P%#+TD[OL6+XK! 4JV7DZ@B[_MFP!]AA77848SNC_O[6SUA3N JC38L, MOB;695B7[6&9SGO RG$&",>!CQ]<04=M]AO> MU6DXR2+A9VG0@8COPN@/G:N[T,G$.G7WED?W*O-7?%]X47I&224.JS-KY++> MS$R=(.UN!Z"/N=$98Q\3G?<[]P)OGLQ9EAHM]7%.3QU.2(\%;G8F5NG8KI_H M4UMYBFN+*:NELEZ]:"WS/YU^=8YKZ)1J>GW"57FWL<[R-G+C'YS1B,1L\#BI M.E&GDHSUD5T1Z+=A2+^<[6#E,3=JF1+=N6'1F3I70I+:7MB>5%+]U))=>R5U'9"SRDEU1_8*J@=^[#'"4J=FS0CK,Y@:%9:ZL"TX%.RHZVL4$.L M2P2:LJ<_C$9F1[SN'!B"ZM QKH&YVX)#X8?LZ#J,HO",9R/4SFK\O"Y<\*:O6Q@E-=_W NSIF_3T6 MNB!!>C0T7;9,]=',VU"?':4_Z0-L:Q5&\N?=TJ6JTLJ#@Z,[#P<__3X]R29" M/5R?KAUSF?9]T@4)\B($JP.N63F"15ZW976C]:'\MK/(R]/C4*N@E,;30[Y& M7N&W61C%3Y2U/>:>ZQ.UKD*3.;^"AK1=D?4XZ[QDF23V?/KC1(\R/79M#/MM ML]A?J>U.=3UC[*)"$08+E4)[F>R.[P@/'G/#(#0CJI!L5\S3T$960P(.V_-^ MQ)J=6[D2J9':#2"9.A*J&-4B\LBLW.^(<.J2 9[0%<56-I<,W"(K&[.*E&[; MVG"129E;5ZUD.0YO:I\II/#WP1RRF+@7DZ0(_JO#(F&8C1&Y(%0*?LJ/+ M>="P=EO/I\=4'>M9*>*L$$F5(UL_:KB(EMM!JGE6"L,&YV6][F8D;D/_5J'+ M3:OJ;)927:[2KX4O_@CGQ:[-^Z;]\\VU>:6,BHW>^)H:&1J<*5NW>LL;%B-W MC,@9R_7Z#(D&SP[N8[:#NTBB1:AR,P@TFC"43'=6-ETOV$MTD)5P7@9SR,]/ MHK0[N(AN5=AJ39G6HHK!6HU?12XRHWQ_1?D936EV^G]?V#_"Z$:5!)NIE @5 M2FRQSV<79QNAQ@=?6P\VJDP#57QM[XG>B$!$W,^O6)_X[BEE8U\;>B2\^3B) M9!;16DYX.V9:TS5EH;%J%8O1)GE11]3VZYE(\K6$H=@BMKE[^B M[2)G*$KVRZOSDQ4E._:ZTHN2U7."%W3 M16F?%Q9*V_3''[-=AU12LT^CKM\?E?:X-O?'%_,OD:)KF1L9H[FA) MEJ!NIR?/"D4JK7,QP(Q@QA-4^C(720 S[N=6/E[T:-?/?_TYD6]N.%^\O1+C M^,J3KA_*)!+7--GW?NC^\;?_^LM?5U^)O%NN#E+(+R1&]W[Y+=734-T MG5Z__]%Y];<'\EZ7W3.I++M>5[D'CE>BV>A0+N,H>=G1XY-K65F#6Y/@>BOU MI02S8S]TF[4B1VJ?=**.L$Q6JJG3!?/SKVXX7] \U?599]^T6>Q4\+2;Z'2] MW?$3S2[39.=(K,H.I95WQMXTB5S=/5R?V='?K^D&!%)NS-/((=4XJ3WZ< MA#2Q(*3'J>>JLU/AUIN*(ZX7>RK'[W.Q<6H-_IPWGW5'7%#A+=@U-E M!V?C4$+)^7_HVG3^"D=1\T._L^6Y!!"F*RA[YZ M/70K19"//WZ2)JUOC.#+\[<@4I$>F0::VF9>M&*<<)$EMG_]]GMZ!NL+_=!2 M7<,U9:LR?#)_:AP)3D[D?7;M7,2S<)*6,"(ZF? XI+_1X[2GK][J(A)3$2FC MFEZQGK+_X&^;]4%V/MZ;OLENK@[.ZH<_<]1CFZ>?8>"GR/H0FGY_WAN]OQB> M]]K=H?/QXJH_//^PI.D/%Y6A:;/TKAPPYG38\KB%\X[M0_DO /WN@538]2CS M)']*8&DQ46*/L;8T"NV3QWE/G=Q%S_AGCV>,1F>#]J@[[)L[I.%T7GA*HS^J MYR&&VI_2J/T$*Y*-8]WFP&JXCDU9^_MG5SX=KBT[@?]?JMSQ!UU$)L_E9UVG M=40PUV8M/M%AJA83WUVQB/-EB_(S5FX%GY/NQ;4\<555-)@\8/7<*T!6-W3] MQ+IN+/\3N@Y=MUS7NX6Z-!:E\Q@1ZH/ MBF>P!E#G#'<>=FPNS<^<*Y/7NN8B88VFM2:'R--L696E)8*)5$FF M#U-DCHB1/'?PM(@3(B<\F/JZ7WQ(^H%D*MAS^9!=%,N09YV_T%2D+7.X.N9\ MUF=0E$==8"?;RAZ6L>D C@''@&.:RS$E; #4A6(J$N-_2"_YX;0AW>?D M5+-W#F0!A2S.&_S?[.*'2ROV+&C0L:;](SZ,8KY M[$:#21F?<(?AW.FT1J->J]TI/BI7%X^U0OBS;E':\U=#H & & M@)G?3R(+UN^W1N?FRG/7'6 5B;D4F5>9U4;+*K ]50PM+?AYQZ/)(9OC>^.P M8G ;M0:=;FODH.5'Y4( U;%-%>M\U&V=GQO;5P0F@(F*8X)L1&?4ZIC; M"*L+)A#2.\ IL^#(2UW622?():[].JI"L*VNX6L*0)W6L-=M#?HCP+,L>):I M68!OO>$+^VJ)KUPGEWB_7>ZL_CI6G>_..YW6P!FV1EUCV]EUP9)]L*FN3:L: M*IQ^:T3(Z/2!"J "J,@WC@>M\_-^JV.N;G5=4%'U&*6]"9T'%2PN4:!5$Z(U M@H,F0A/M$!PTLK?Q2WN!F;]N;;9^?&RJ#7 MQ8VW#_[6+6Y! /4A@*X# @ !@ :2P!M!/)J%L@K>+EP^,:I<;I 49\*$/L%UQ%%J?F0A>_/5FF+0ENA8SSX0I=LJMSBRAYUKA@FGU>L,6EVDC@$3P,323HS:H]:P M!TP@V/&(BGS9K,NVT4B6B3\3[Y;[(H@+*9A;EX(QW4ZKTQVV.H-!XLG$_)YO8#%,Z&$Y7TF^]<"*9-V5QR"8ADR&["Q-_PF:<'CP6(F"O_E' M./9(%7,\#]])-DXD"5WJ6=#PYSQP!>,W- .Z5#U+TNV\J4>W6/_&3" MK=G/?_TYD6]N.%^\S<]F?!'1-S7N:P+P>Y^6$G_[K[_\-?_21^Y%_\/]1%Q( M*6)Y$4Q^]3@-6[^D?P@N$UJ._!9\52\NHKO1%SZ'091_?,^E)Z\5XI9WIQ<8 M**[X*J:_O/IXU6D[_7_V_G5]]8IY$_H%=^,WSD7W_<=^N]ON?.R?=RXO>^WS MJ^[5P'&Z3N^RW[]\];==2ZQ,Z:Z].;V"S^*.?0U).H\J;5F*?DUO;4I29+=* MC$I+!*G+1>A"ZZY5KSU0N.DKE:O;%Y)E:E)9PM9:F/V9.*W-,/OG[M^G!+$OJ:_=8\.?U MAP1*@_T-B^NH[RQOK-F:4.S[V7=^>=5^I3^3*7+SSX>KP9TWB6?T(\TQJ_=) MULWG"RG>YC]L37XUJ/4PQ,HJ#G9Z!7M$,O1@?GG5Z__XK,'=M.K9AT?+O)50L)/QVCO ML\DO92KOX'Y5]!@@=;MM"@QTBM>+@ M>!%RJO)^8 EZ<_K-P@HQFG4F&10&"@.%@<) 8:"P1E&8TS.VL@=U@;I 7: N M4%?%J&NO+%/3F5>E311I8D@3LSU9"!/$!)$F9I]CBC0Q8VEBO2.\$9MU%6EB MQO:9]W>R[=)U*W/(C*U8["5CJ'.!ZFQ9]AG4&>I :< VX!EQ3:&5), P8 M!@P#A@'#G)QAFKSYN1:?.3@NLQQNS8JK%[ .J M4[$.%=387J J@(JFH,+8 MSCVP "P "_7"PL%G/+;K+ILOJ;RS8/.5)UT_5#>3A]1>'O7:_?;@PZ@_^' ^ M;/=&%Z/+H:Z]W/G0=P:7P\)K+Q?]]@^\3G_;5??-O(@ M]3J9?I\L4XVT1K2J]7RU*A_]:54^>EN3'U/KI]["R3%7PN!V2_Q#7IU[7_%" MHIO7?0H4S03"U47)[[QXIBO7+TO;N^%\[ 5\]==_B#@*OUQ^:RUKXC-/RD2U MN1*!%T:,*$S$JAD D4L,J2+KGDHD4B7V(ZZ^J#H M\,F_$UVYGZ?5\],;37AVH_2+$S&E@2W["_#%PB?[I$^/5R6C] CR9@6JQ0&] M4X7S<+HV\*G@:@!Z:I'J]Q6ESQF3=+UI$KGZP=,HG#_R:$T;4BQXE'8GX*X; M)H&^*%31HN=*TZNAYZ]H)OS)BTE/*\R4GF+D1KN&+]6T2(I&'G# J8QC;D_B MO2AAL-N5AH^Y?([]&?3W>^;@=S*PMH:)G]4.8 MQ(\/*V^(D]F1_>_^Z!T3I3W_4V?=M6]G-J M1FG)YR8IW#:ZX\A%)#C]3L1WJLG.JH'-O:!#G4-_#BJM'/@HD1C[?[C\I*'(F:7U"TW#5(Y,@'$L1 MW>JG><&"7M[K+&O^)V5]O%A=HP6^+IS4\Z2?E=OP9AH)L?4H-427C#S=(1/C MQA"_K0V"M(*^(&E>](XF(O^0.37ILY1"TMM,;J]:(*DBF'?TPWX(RS1X-_A4"QO7YU*FVD)RS&2:SVGM&3-/1#QR M9R! ]"-Z> \4FD"A"6NNJ\Q ,4$4FJCR/@P*3;RTT 3Z$:'0Q#YBMTN=K:PE M40]*A5+6JB($E!)*:5U=!RAELY42U1D,9O^C'Y%!D5IQ#JD*Y:31S .G):TQ MR: P4!@H#!0&"@.%-8K"T-0#U 7J G6!NII+7>A'A#0QI(DAR :] M! P#A@'#@&'J MS3!-WOQZUYP2-U MX%4D0O_6)#LPXYHP2EQCHR.RF1TO'9Z MYZ6)8X6;X@1D6%<.\9FK0D36&5(04',)R"F>?NJR]0.* <6 8H[Q<8K/6VV" MBX.MYT(&:VAPZ4?U];=>3'-W'UER7XFIB%1SWR])Y,ZX%.Q+Y+F"73R?JEL; MD1Y\IEO09V]HD;^A MA7Y#:3+UJCLSC]?[.LHWSMG$DRZ1E4HJ<+F<,662L[;U:7/[C4[F MJW;;BR26K:SOO/J:FTCB+*'ZC$^YZ@&N.\"GW;PCD79[#L*-'NDT\. F[4>^ M-LAI&*5=W]4^C]#[/%LO\1BA']#4\IC;Z\[61NZT,P1[S(U4-W@AS SJ6+:Y MV\CBT+?Z',:"5&B9V.N\8]]RS;_,-/_K2O.W$?SB5Z54;)I$^OB!%TS5V!02 MCV\47REF,SVX%ZC%RN2DID6#Z-=58RKVCS4B^Z@XXG_2!O6*N;XNF\Z_5TWG MC>K)[D%N0^E4,K=6(51BF\NCZ%Z]%SY7EB5]JRN&UT!7#'\9SLF9O5\2P?"= M9'(61G':H,P+;H6,TUPV=8=5Z[*)&,>I12%3F*;1(8/ML0RVT>BLXYP/^Z@. M785L+4P0$T2>GGW!P>5PAS9MY%N\;7_ <@OI)=#*4VLE2I8C?[1ZN5&7^4KK M0J^TP*SFF17*>:QRKN(UT$OHI3UZ"=*$39M5SG@OT3---A:NMXH2JJ:)W@H(Y01XL$9XLZ0N.@<="X0F.4['7(SE?%U(4"BMP0JD@ M J@ *HY?;EC>S^WD4BMS< =>EWY47W^Z[]M:U91/3U5-6?]PS%#06.>XQCIK M7=(.;J'38G]GW\[8=:1;+-TSJ1;4^I ;?56WF%.WH"E- M5NWB_DQ"U2ANSJ,_1)RVG-/MV[BK&LIGOZ?K5;L>U5U+3$/5^XWNYOI<2F_J MJ59.,FLCYZA+X\UYS3P1\@&NE=0 MVI..'O38_-*.>Y&8B7 M7?>6'?6.F=_?HY!NG00T0I]>]H3=T(#R7D=2JN&0:&^YYROF?4.R?*-:!&[, M)&VK%V_TU>-J'D]8^&/4K^#N>>IM/SG1F?!)#^_7M>")R1?<,=!0>SXK>,5J MTBO0UOVZ["9V)<8[BD##QMELXYX\S6.)^3IX-MLA;3V2Y[*-4A[<-=]'NKOR MQ2(*.?D":8/73"J9.&B89(3B*$D;[VE3*3UZ=3QBZ@GIF-9,IOK( T9^AC=7 MYC'OWRIC^@NM:TC%F$O3\F(6>?(/]8"\E:UB?=<-([46?,K$FY#/KC?8>>8- M6@$*JQ%[X<>S,+F9;=CEV2;\U)]R[=CL YGJW]+#R8&YUI)5OV WG),[YM\3 M3EVQ4#=1UZ=_GPL:P"3TPQOMN&KO=D)O4-WNW\GD1FFQ1G"D7$2E/?3*/573 M?1&)./7^]$/)M>-*;R9*,\+%NDKD@Y=+W7Z90FYSP^H)6E>7 -Z0Q%),9ER< M;'^TK?^E+2 G@L"HG_96Z5DIGI^1OLG[SL5D:^4+6FDE[NQQUEJ]5)[YJ0&) M4DH>T=WIU4[(8=5V)[,,:;?4#201=Y/;FZT/M*5BJN>MTNE,;<7WM(OVT\YD M_O-??T[DFQO.%V]5GP'=9N"*+ 2M-DB/Y37)[;T?NG_\[;_^\M>M+V:M>!6@ MOH3D5]VG_[N\2&%/2?ZKF/[RZN.54I!_]OYU??6*>1/Z!=G8-X/!QX_#T66_ M>SFZN.@/KP;=]L?NU1Y'R*MRL$3A?]87VU_I";_2U)S!^7'&IIXS/5%L>+K5G M\MW+G+T608EH7])K42Z'LLXCLA@J7SJ5Q5UZ,YQ\OHPGRE M-3K2D-F)-"!!TXY6SHFV1%ZP2&)E15.KEEZN)K8231[UH>F'RE_[C[)%,Y%? MNC0TZG?A6(KH-I\)7[9I?CBLEA*QB<;+)U=P8XV7V6-#VI6CD[9E'NZU';2Y MY5!4F]]5F7$TH9T<5I5R1X\LW=X"+ZN'BY8G_5N/BM\PX^4O;%:H(C3+< MJ?7Z\QC@/' K]&($Z&D@>KKU1L_O0;B%'P6(U#G4H4[EU!$*8OH"_2$(U^,B MN1>9Q5"6\;OU> DA*IDOE*NK'<<[Y5#O\G53)YM\5H51A=:E)YX[V$MO^KD( MW#Y@M-K_+"U*]\@B:C,LFL9":>6@2#(2M ;86!Z0KR]DS'P=.=518E*C=.%$ MJK.^!:?C\1OQK;4E1+:HV14P41H@I5YG9$N/U5U='2;AF2XE*AJ=#>"IA^4: M*Y>QP%86OKY7\3CAI@NOA<]=D3_WD17G6.A@87KOB8Z+/Q4\MN*]6ZV42@O< MO!5K%A F\>MM"AWU?;"OWWHTL8&[>H]#9NMV!?^=OV33*)RO;PSHK8O\>PM^ MGT97U>[(]VPO8_5J)XG(=6UM' ]3!X3FM>7V2:;L.Z;YX=.7M9')QY[*T^7Z MQCN$C;H>00P':K48D^'N1Z9>'I; MCH85;<3<)9]KTY1O1JT-IL5T-(0>'= HUS8'PHGPY;-FY/'@Z',QSXU J1:3 MT-L %\'D5[I4R*_+%Y=>N4>0M'M^_J$];%^]'XZNVA^''S]:>C_1^R3%T3]_\HPU5,!< MA5C)U'//9VXBXW"N_J"#@=J54XQ'O*@Q2(Z>!J:BCW3MI;;CI QUO%;OJBU? MX')K+U!$IS9+4D,;>_/4CF]\FZEDGXU]%.;-R;:KAZUH:YIC7'DA*2^F7BM1 M%-U*,4B4I6L+>97'"_'*(.O29D$(026BJ' M++2;SF>R&EFTBN_F1$EDG >)M5.R_NS<(=HUDYQ9W64TFZY,_#A=!:\$N!S] MRGJD HZ4'T0F(''S=QYO&:TEWX<1W7T1!FHMMGF16$(Y(A\Q2%)3DB\5EB*3 M&P)9CDZ_N]0DD 68IYMD=.,'^UT; ES./Y\X24E\7]!T5+[#NE%[1!/2;3R> M":RU-MI02+UEIV1%/NA_Z!%,"O(^U3!7%F9E1_FFAGNT'$I_G\Y7:&]3ID8Y M0YZ*LH]#\F$SI5EF:*1&?IG'F/F97D".!MFW3<58]W8S)5E-,-.P+6&'P98F MJ9C^TE=01P]2WS8U:I,-N&K/)P7X:FHJUK)\.>FN_!)G6H!:W9;?H,D1V:BI M&=F/_4T34G;3UTH' BE^TGZ0J?U>*VG=:@__6S*61 IBM23,53@G@Q1$F=H^ MU-(U.*8KPXPZ J'22,@:D'JUF#==;JO?MU;:IG?^GO!R\Q'1NQ'9IOL:ARRS M5<@I'^M5P2:-W.C,W4T($7GYZEE2[==H0M:&13 M+% MB2+<[#9Z9;B4XW)2>7H:5R9\951HV7E#1D^)0+%ZOHRAQ89'LB0UIAGX2JC9 M9NW*EU4.36X_N P#&MB]CI!%Z:;R6+"U(6TNZ?0+UJ: !IKNM*Z\B6BU.7U\ MB*%2A%2T4YS[%PH":V2TPSRNVV,C1F6E+^O6=:'6/FN/-F?$5HJ]S'VV=M8Z MWL*GL6*Y0+![4B>CUGQ)0+,T282<795&-<^,E<[ZR!=(#Z6B$4H^;NC?*O1K MF.:+ X70F$ ?I_Y.2@2*IY=!E#2^>'9P3&*?\,)V/((&N/K2I>:Y?Z;4_BE- M0"/&OE9_.R2/ZW+@C#K]P?#\ROEXT7U_-1RUK](01:=WT6NWJY+'M22!W&;H MT-CC=C)[]:GU3]F9EG^9]2!9BILPRHZEK.7'E. ZKMUC:YM,W\,+U-:G_KS^ MD$!EE_H;QW.=C:TU8WN9#T:>[E:.1F>#]J@[[/_X;JQSIE31'I\OI'B;_[ E M@MV;H*NCR;V=!XGWV,340Z(;C'X\/$_#"_XIYG MH"Y9LVMJ.,YS]?Y2"YF)PEE\9Y)\O@G[[ZG^MZ/TG>BTV\->T=4X7*%B>FL2 M>4$YCFS@V8QV[Q@=:Q*?DO&"V@EM-(NK;P.8^Y#):&2 M]J@D;#=4TC*5A.V&5MJGE0?9[B+[X55VW9Z=+E.),&+ODY-%@+O@QA_6=-5\ M5J$JT&ZSU1^]_+QE4QJ^5(AAK#.18)DFL\Q@= Z6 _USA);UHESWK'+],3N 3I4U\:5PZ$I(-4%+_9!PSKC6UQ*$^P7>W8[(-*_:VT2G]9"O9BY-4@-WE/$=F?HNRTANW2J*DN#(0] M5# ,&&9OACGOFSLV#H8!PX!AP#";A2GZ?7/E;\ P8!@P#!AF\[CX< B& <. M8< P13%,=] &PX!AP#!@F&)VAEM.%S[,\7M-/^O^P#N_O^/GA\VLO8-[4S_3 MWUH>TL2Z-WK?'0Y&@V'[_?#]^T'GZJ+OY$VLNX->O_ FUD6_XP.OTQ^W2N1_ M#F/!>AM''E8-W#^M-7#_HAJXK[V*;6UZ3+6>DM')];ZLP2W[T8?3J8CDLO=\ M).@_/G,32:2B_J"ZDH>+V L#U:=^P>_9-(S4;[V(3<2MYPJIVYB']*N(+9+( MG:E.\8SNY:U>EV3**C/.%C2B<*+:G2<+=<,M81PSF<[V<=MC;L/F],N99(DD ME-.D5#?VLQ=T4V^.,I&.I-WGE>#2'NXRF<]Y1-^3NQK;O]T:]]I8-UP>RUO* M.^VVN6;RYR_L)3_LEMTCNBI-J2V?8)/+;NWV ^K>BC5[O*:KK6=;W,)H=]OA MQZR3R2[9S[TP!!J@_+8I?[&]N"U*?JYJGN4QDGI4[/NK=0UB=N&;I>5"\;5S7MH1[FT5JLQ&\B'Q'\N@9YW/T%BH=;NEGUNJSM$GZB*K+8;8AQK JU>Z[P] +2PW-M/ M72Y4B@[W2C\#+ 86.SX&,1B5=NJV]BS6 M^!B% 3.P=QIMD0E*NPYQ5DV0EBF==683BG8RRK/(FROQ5,VESZ7TIIZ8,'6> M?<"U&MZP@L'8DG2U4 M!8&B0GU\UN*UY_3TQK6]" N$%?-4EJ:0%Q[ MU8 N;6!K0JM6T=_?M[2,O2".PDGBZB+8-,*\=O9R^,-WDOV_W__QY?]COP7L M2LQ5/>RT-C8CZ.IJTHLHO(GX7)7%5GJL#H!S5YT 5P^(>)R^Q&75[6E>;#Z_ MSZJP=CRCA??-;"OR*,^LI(4]G;!3#6]9!SU1LN7J/1'.1,RC^_R HW3#2+V) M>3@1/HF?QVQ.;S6)LM+6V=?^3%L)J/?(EV^2T9?5=V)OKM\P7RQ\U6E :9)2 MP7GZ<&*=>1)D?Y!,BDB_]+00N13D&'"?34EAPHA6XC)Q9XS+_,%C&@E/UK6X MI=H1R$0]/_M.Y,D_]$2R:NWY$W3(FA0K4LI(7R+_0W'&>\V%R8)&N9Q)=B<2 MT-33 8&EZ-P\JTAN$2M!)UP7$LU0W) X4ZCG .JTWWTA'4K [+YXQ6F((5;">E.O/1 3N?2H2]93\UGO= M9T9JN>-&BF \8R:6DNZ7SU+C;T/='&'&;P4+PIC="\*J$$&F$HK\LU8*:W01 MK<%IHD#^>T 8\\6$-&#?ASUXR#B)LZ^INZN1++A,:4EU+5'0)^K23L5$&:+M M,;S7(]@PUY=)%)&&'C\JA3PUA%S[/6EB6%_4+:X28:DMM'FQ<;V6#:I>#K]1 MQH=8>D?[!L55/*W$2]=(>G?C^P<4?\^(<(5Z36EG"/GV!9TT]GTI:_?8",58 MWD1B-#H;M$?=8=]<*XE.[X6])#JCDELME/V\LJ_#_.P8)^:'^17WO(KD6ENW M[;(:KF-3[XK*-:,PV7$%:@FU-*>6Q?9"J4EVZ6Z9UKT9EL7JG,8E0:C&"14J M>:Q*+D/AT$IHI35:>1W&W(=*0B7M44G8;JBD92H)VPVMM$\K#[+=.!7Z>#>L M=*O^E.!N3&'$ZA<^=%K]$?J:E*80#3:18)DFL\Q@A'._8!FP#%BFT*.Z(PA[" !J"AYF@8&3LH"S #!4'@S,RMK%6%S0@T?F 8%1>>*L( M*+VX"7I%,-@UU_JFZ6W0*P33ZIJXIN#27&#,Y8(!E\ E<&G* MCRVO:1-P"5P"EWOBTF"^$7 )7 *7AG!YCKB/17F"=>O;JJOTEZ5@+T9>#7*3 M7][CT)(49:>8%N6YT$?!Z2COY'3)@W7R2J\?C$ MDVZ8T+UUDVO5FEJWO%9MR[,.UGXHI9!Y,VRY[-+^L GV'9?K_:V/ED#-NUL[ M[;:YOM;G+VQK/>R6W:ZV*OUQ+9]@DRL Z4_H"OFXJ,MNF&*RR^YS4L9"!1IK M1&.+;$-!<6#AE]^0SGS)^@?*0E5F1]WIHVE&: M.C38M);',9EMUJO/+<,, EH)L Y&<^JZ X*%U4)^G)ZZFKRJE9?]IZ3-R7& M,1/?%R*0A=0/J=AQD.X A:E*,%0U,^1U14/G'&C ^GQ/9?E?^KUX$TZGM/(. M1*S6W)%P%58]<<@9J/V/*-;D".+K;K?XEB?;6E.9G(%#XNM5@6%U35AM4-?I M%-_.K FH:_PRZG+&@QNATAZVTAS"@,E9&,5O8A'-=<#:#]4DU:<'&0UP-]^] M/C=6(KL)P+,/8]6U:A5#2M]8"!#K,CL<0G.Z\6F^X&XLV30*YTQRE2Q'2[$2 MK$U32L:\'IA;KKU49$VV;Q:AM[J&KRF@7=9+[Q@+?*/@4]-7?H>G) GZ@N%D MI"(."^W>_S5ZAL2>?(&7GR0J0ESFTP;*\UJ*UY[3DY]]/&>=$P+: FW9E(L) MVMKPV2P_.&F=%,LZ2'F]X[CCC$]8>JZ W$U.^LUO!!/3J5"'+L5RX\%3!QN$ MC%G$XS3NLS6C8T9T?G;^HY$;:0?9R)U&9T-30S(GIRMZ8_.QB%;6LNNTV,X# M2Z>5WLX3*I%OKW9T^S4/;S7W].Y)L;SA=O/WH!+93(*GU=J?HU MP?Z]'[I__.V__O+7_(M_#\/)G>?[%\'D4Q#SX,:CKU[0DBJ65[3VHM55$HGE ME43/@6*/KV+ZRZN/5TK^_^S]Z_KJ%?,F] ONQF^N^H[3;7\<]8>=WD7GHM-^ M3Y^O!H[3^= ?.9?GK_ZV*SZ[W\G;72:A='8[\#K]<>O@TNO\5T?[9Z22Q]2]N*47N34-!@=[^I_+78-MI*B3:W MOI$@6TO_8X0A@] ,][LZRT"J- .71]&].M9VR_TD-?,WV?M?UDM0$2:IPDW" MD,EHGFU[VIH!3,?PU);1L&W8E9+Q6OK18\0@663NFT7U@[ MI5O3TB*UKYV""6*"ED^PR?NXN]T4E/N,QSPR3"Q&C^, ?V%_H)8H9@U4\R#B77OH@I5/]127!K5MX=A MS5-2 DK[%7;VQ'C3P_.6TS'7BKWN&?XGYAIC95G':8WZYJKH@X/ 0> @<-!A'-1JM\UU5@0%@8) 0:"@PRBH"S?H M ["V<'*#?8JB50^<'XB <"7G*CEI;C9I(U\P(W$ER25!>1-^<1W41E5W-U M,"[Q=1ED[OZ9>-*+O3"@GW673"_-SAZVV^P?__<_[.*-/KC68A>36U4Z9,+^ MUXN$+Z1DWT1TZ[F"O MM_OZ+Y>;UV\EB>/HPXL'^RE06.BUV/6;?X1C3R6JA_.%+]0QW3CB@52:H%Y0 M?F)G74MVJL;_?DM?].6W[1?66M.^.R^>L?^A@?TG#%II$1HN9_I:]1SQ/3U* MI![BDB'C7O#TO<]6"&>_+VATZKREEW;54C=YU.DKV3ZDL10>C]4WO(A-.?U/ M2CFFCBO_T#L[-RH>FB"IO7+WE#)LZD)X$WBJ%3!G!-PW6H@W2F+&)M,V/!G% M['XRT:?JS0SQ[S1?J6H"3SRY""5Q]:X#.F8&OWX.,+/ZCQKLWMGV_&R@T*KQ MO1L&@= \F'*PDC\1PIONZB7SQ'T C444WGHY$7R\O$POY6PB2$6\V"0^>D;Q MT6)W,\^=Z4[G.Y#?<4WBBO:W23QM?D&&DB_H+7\G^QP+LL]&YC$:Y@<4S(AE(4)R3C1M M<*+PFYM(W-!P26.T8^L:M#I.(59'+3S68:6$L^Y"/UQ0?0KWG?,-G?.N69K9#U5J8RI_AE>I(V#^HV4ZL?C MZ]18+>V""VDIUWG!@_O_(U6%RERJ?"G5CK$MV+M0I0546A5) M+WE?;772*,ENIE3RD#E0@^P4-<@&+ZQ!YO2/+4?4K4C!I5%%QHGY87XVCQ/S M.^7\*E+/S;I4\.70CVZ:5U8MC+USB,NNA?&[%-/$9[_2,@556LQIYFJXCDVJ M6;FB+(<47X%:0BW+4\N]BZU5Q+A7H%BK91*S%]V6EP;;_VRB75SP]RB4\K'0 MWL5<-92U2YOK>P@4JEZLJE^X;C)7&]\J5W8>DF3_H[/IH-_0[SKH]V<15XG( MH@HS)L.;\ M5(2<3)/7ZZ$S*DU6*QB>2'J&M MK.%ZLFNN,3/6DZ @VRD(KE5]7*O7PQ(:4V ]"=(#Z8'T;"&]00G^6B/6DTT^ MH*$ONX[X1,QY](?4A506/'ZV@)+5&9#%[X [';-;X,@27:MZ\4QJT3&R.B#E MQWC8SYQK6A?"!1H:BX;7COGSO %+PH(.5YN^$,83<,Q#OM/.!BF%!TB6%3ZF*GQ H*B';.*W4F MJ!E4;52()^3POE.X6M6%VX$KX&K_543'F&]D-FO&#F^@*HDQ %V50-?!J4W@ M"K@RCJLAG$3@"K@R[R1VBP<6G$2 #J!;NZQ7_'&&NA@S ]F[[1I$K;=[MIG2 M(/ /Y/,B!GJL%&!;_SM*?KO/)60WM .5YLZQ["F_DL5E_@!RKV^N0,(S,BM! M?TYO&4%<("X05_$+Y/.!N17RGB(S< ;9*IU#)A"*@;9 M6Z"M4M:0@Z&YPJ(@+A 7B O$5[CF4C/RC$13(2AH5X)5\S'(EI9^Z[38IWVCFH[)WS7-)[MN.)IWS$- M:;N,XG$BBH1<$(2]6^'?GS%V3>]9R-B;ZVZ5_.8F$C?T(YLF<1*)390?QPU$ M#>&T$OICDL8Z3G&85) D5\N8:@UL0M\/SL PTWJ!,4EMGT0[J:3:/6LEM5WY MXY22ZAM&HRE!O4# .R(QMDB[:ZE:'B_MSHY%HCW>P0^FC8U*U15\&HOH[.EU M7_;S7W].Y)L;SA=O_QZ&DSL:RD4P^;3T$"ZT@W#E2=>^'[A]_ M^Z^__'6/*_,_?:$5LWM/B^- +8>^BNDOKSY>*>O_S]Z_KJ]>,6]"O^!N_&;4 MZ8ZZHW[WP^7@JC-T>N\O>Z/NUK_/APZN_/5AOK4OFVIL+R3Z+._8U MG//'PUQ/+=<,:5_Z47W]K1?3ZL]-?[/5D#D7T-'+2Y-H,;[V-3FX7%)*B:1J MK:Q\4^57B>^ND,M/BR1R9YQQNR?@ MMS]/Q-0+O%C\2NN6R=X\T+X:#@87W8^CKG/U_F/':5^=?TQY@#CAW.G6C0>^ MJ95=E,S9KZ2UM%)[^G2%U4I6UN"6(O,SD3%.RUZ71Y&GUL,Q:9EB"2]PDTA! M6JUN4WC__^R]:7/CR+$N_/G<7X'3U[[NB8#:)$5M/1Y':)VW';/T&74?AS^" M0)'$# C06*2F?_V;2U6A0((218$42-;<&SXM"4LA*_?*?)(40K9X.UAU_ O? M!Y=/4S'UEEXNX[J0(FI.M129<"&:]L<8.NO'$/E*U;+P)!G+WXE I%[D7">3 M21&'/JF;C'X,LPSC\?<IWO[ZZO]4_=[[]SX)("%K6XS,=Q".N9ILD# M*#WGR]'/R2 $I?<8YF.E/B/0I"=?#;%)'\THZL*0I : MAN 5B9A38RY].M#0 5OAP()C_$CY&B<5L7CTHLQ)$R!%+. YR!O 4IX3)Q.P M!!'MKMRXQ66.110X@QF]!/9OZL4S3,$@Z\%#'CQ8;9$Y 5!6;;ZZ:B"B4#S M(\+<(6LW@%O02,$73 0:*O@=[@(\:X)3%,!ZH?GSTAE>D@D? MGJ0SEU1\"IJ\P#_ /D]%'F+JRG4$_ G>[3NP-0FUE@WANB0%%AG#NJ)P M^. M:P!I&A81_ +IL>Q3F'ZI@(T6SRV]AA#9."EPKX# P*642$.5H8S6$;X\6$R9 M[;07L*W%F7P-&YN3529X."0QJN-1*B07$^\":P-/@$(: [5K=NM#F3UTODXQ MK8D/PWP:/0YW&+0_WHL/=9V074+@PS@#%D,=@TPQ0#40X)O)*(R]!T&:2*1^ M" *1%8,,MMM'55ZK@%+Q$(I'J8)"^+XPQ?>Q_V M"H"N1 MJ-DBR1_D1\%S&DQ>K!21F-'-)RV2OZ8W'JW)[U.YW+? IZ2RJ]E[?KG M6_O\,OL,S)N19AR+.7NE7*^12L"@PDPD)L!SCI+S?D$C?$>6;9K@$#!4-Q4+ M&A?DMO/)8]VA(>JD"?AZ*A9!#Q14-OC,Z$; ']G^H*)V_##UBPGK,O+J,-(0 M*D"CY4THY@'WCU>!FJ04$FW8P,K-G:FR0%>4^8X_.RD&-YM1"\HKJ42HBEOHG,Z&,"NDY,2]DP MF!F"N[RTN(I*02+8A#Y'&Q>967JP2ZBG.#K;%LEW-8"0T+\GL]!T<48HB- MCK3GCUV9.X&+]4?)2WQO2M;M/RHG+'>YZBF5M%Q<*7]ZAL%P0+3 &R1/@!;2 MQ#*NJ%)+KW^>7J0Z,4U0=:U0:T>A-PB!DT*1U1/&E?XM_IR/DTQP3(ZBC;PT M,.-^Y=2I4I1*&O[9'=")^0Q,0^U-^A-P&4L^ AX*#,,1Y)B4>(3)O])4$=N6 M^Z,NJ+[)9.HH>:2%+1, _'W)[! R97.1@BKW*&,9PZ18X[*F<4$-DBU)9LTI M(%0]L5$/11K>5<=&>(7.?%7IUR1_Z<<\(:/J'I\SE0M-T6;-58O_B EK!7KXD4^9B>E MOBPKYU9]7TF@I^Y=9,^J4IG+"#6C5BK,IU:7F:MC$X:8R!9QH8,'$?#D8C\!(@"ES#"8RI..2YQ*SBZF##83[E6P" M4?.+]ZVFB&*%M,#UZ=G=[?'97;][=]8]OKNXN>EV.2UP=W+:O=O\.>B&RMFM 3H8I&\_HF7B=_T"<:/3[3KJ\*O;_=YA&CM Y'T]-]UD$P$= M825%ZHOFRGW7O4_NY(".KWY^ MN8X !3L*8UZD5^2)^@7W(=)O'L,@'\/50 C9)P7"'7G33'Q4_UC@WW+=)J1F MV3O5J\5&70&5DQ;SP[N3BS\_VY95[0^3-W;7O6_M&W?EOIU9:+L_L $XV8/L M&"Z7VWT.HWE9,^>0_JM!+!:]3N>LOVD,YR8GH\F%RR^J/P'Y%U8=W5)=DDJD M.\===U6:[PBC;J0?NYZ@[\-8%6MG+P$#T!]PW";.?8;L[>+EVD8Q"[_P:F5J M.?(5'-D8A)WE2,N1C7#D8J>Q'='[0E21KQ_NGRD^VJQ<;WB>1GM :IYCIN8G M\S0.0'.QV"IKIZALB!T.V#9:'7.X.N:XO_D1NE;'6!UC=0! MC(><,*7;/A?PB8GS6^@GZT3^S\Y>W LZ!N.8#S?&GKEH=AW:\8/5IA.%X'0 MK#!98;+"M(XPG5AAVL:,X-7"T>Z..X4OJ>AK$5S\H42OSP&?[WYT>W'67)9^ M76KMBYZS&;8-9=BL#K,Z[ E:]5<_V;-X3M M_0?NR+EXZYQMV_'VT@IXV_%F.][VJ)O#=KQM0)E:CK0=;Y8C]X8C;N'=4M&>HZ;6ZN!@],#[KO41-MW!?1AM//2JQLEMGB^KR$6MWF /L.!#W!IF2L,"V# MO]Q:[[X5)BM,>RY,S24##T68-EDTV-EMI_!+DGN1GL/96.W@:T5R7^*S]]VW M;Y<^A)2_39JTP([NB]#V&^N/.'B( RN75BY;F.P\=+$\Y!99NNU&# 6XO,'V MNF4V0+U=4&(MXZC6T<'-S9>N^\N=S-OCN4-LZS M12LK"];9A94K*U=6KAHW6,WE+?==KFPUV.8Z 79,:MX?-U;I94_:;$R^QY+2 M;ZSP9%_,B!6&@Q6&][W&.L4.P6S85%Q;Z_+W)?KI-M>Y>>C'PS;K8*LV&I-+ M._+*BJ45R]:)I9VFV9YJY-@ MAV75)FS:+8=O&C]N+8"TTF2E:=^ER3:IVB;59OW+<(49FYMAL;4\2COR>%]& M'O?ZC8WP.OA@V>:PUO*?S9?$23KQHHJ2 MZN(U^L'$O8XOHDA>\\.[SCOZ&4335S_7[,67<"(RYQ?QZ/R63+P%T_@8!OD8 M_@G?*+4%2'OD33/Q4?UCX>/+19D)'*TE+FKS<2ND@&@M/[P[N?CSL_JGJ@3E MC=W>NC=N^SZ[T*:/E@_2R]3+/6_34.86CV#^%UA$YQ94<.#<"%],!B)UCKON M&NZ$Y=-U^'3MTR$[/+S3;2P[:SG28FLV"SH"FA%VW'F-@>X M\(;!UX?F4%'VO51QAZ1NM^S9/@K6-I(:5K"L8!V<8/7./S0'C[#ODG7PN;[K ML1>/L.;<>?"B@HO9/:PT]V+_1:#C^QN0-2=.AQ"/M4]X=LLD[;"H=!M,\^V+ M@;'B<+#B\/[4'A#93%XCF3R13KQ8P'U!.!R*5(!OEMD8Z E+]*&Y!N1]#X%V M2,)VRW3MIV#9R66MY \K6#LN6%U[T&2S=B]M<,%^%C\509B7A[NIR$3ZT)Q_ MN,-"]?[B0^,=I_L<@;5/A';+,.VRJ'0[S<5,5E:LK.RQK# QSGO=7F/4.&C/ MK$6!T.84RZ\Y_(F;?_2F31=;@ZMOME>J'5S8F'EKDT4FNEUDKM5J3VI,%"0BNUFTQG[OI@[=MEX+?;XK\=%M/>27-E)JN2:0>E M<0,0'M9H'JS0]3O;LXU6Z*S06:&#VXZ;K#ZQ0K>30R9:E_Q^J\7>PU/#(3 V MW HN\S3!^M ,"P#T=&_#E_:R3,!?<>9$%'J#, KS$!O":40C.=\BOK#U:0_[^8&'7/!$/RT );\/8P=NBL(DSEZ2'M4?<&PQJM?$J%9C)TH_ MX[CK.LN,IT7]WPS&NN7?K?'ORD&'K7Y8%I/<*)^T=$8WPO2;I>7J>*>[H$IV MA2M;1SC+CHU3U1Z!_91DF>-[:3H;)NFCEP:[6,#?UI&[NY/C[+H7%V=-??:^ M5)7:N,!J@(/1 #WW^*2Q8XY]T0 ;C*QVW7'0H56*!P#KN+'/CFO;6'';MFUK M]]CB0M@(<8L1XN&(5N?8(D/8:'=5?OE--JG3B;3G^VGA11NQ73LF1Q<]BZ!G M@[^-F9L=DX:^#81L(/1B4!0T*9D:8:;@4:SS]D1=9?_"NFXV*FJ/F=H7P>I= M-%;ZLO>"96.B&S'(G:$7IL[$2_\0.2'R"\<+?B^R?"+BEP!'[*M':,_&;'AD MPR.5=.LVUOBY+])@PZ.G 8BLM_94>UECQF7OO34;!MDPR(9!;3%@57[H[+:= MJBD5=QW8\ZPUYT/U=;>R:_I!ND5/G*'I[IZ&ZV5 MVE=(K0T@:P/(E^&N-R:^.R:E?;?7WQJ8Y+ZXOC:(M/*T[$C!O>@U5UMU(/)D M4316LFP&CMLZDOC&V 6[!4^P0]S7.L)9CEN'<+8<[GXJ_#PM)J#H?!%GZVFY M/:OX.76[9[8EPOK?K3K$>4-Y.'%/F_.O]T4>; W<4G[YG"93^/P9]0B)?Q?A M=%-UU?N2M^VZ%R?-3=S;]^H=&R?8LK@7B-;YF:TXM0'1BPJXG3#.O7@4(KK] M^CBJ>^8&=L\L:H(-BFQ0I,JM;9.<#8G>OBWH0"I;6/><][J]YL*$=4FW+_)J MXZ@6G+7OBX VUR5[\')IB\N^)+D7E2/6&CB(/["2F'/WN+.UT:G[(GSMSS[556[XL\V6ZEI?STB\B;,&];%\$-^UZM&63P:J^]_1,0^F[GU/KL M-I9^>Z?":C&KQ=:EU;%[?MX<[LFA:[$=F8 \K\'45/0S>,Z;:[.5*['?IN"Z M5;2R?&7YJAU%_2WRS[8XW_TZ\K(L'(80A":QDX^%,_ BA,YPLK& $-7+/FZ" M0VT/BHT<;-?3;BG(/=&#K/:*%,?X53-PZV$8;+:D:?=#T-V))#=08;(O86'[ M=$.[%*K5 WND!R[.;9FSC:A6/<=+XB._SILPSO/>#!9I7TK+[$F5/:EJAY6W MHKD@FN=G;X\3NB^B:0L_=[4NIAW4V]K!\>YX\UOU'?9%#]EXWVH8JV%6),E6 M*U#V1<,8GLY?-QUG5ZGN\CJZSS>;6:5+S[(6>Y ^*GP M,H%QZV3JT-]$Y@R3U!D6J40A@9\F--7D0RL5CM6. M&]*.* 37*+3QS!E[&>H$!T'5/&+ *,DRY[UBVE[G^U]^_4G_U/W^.\?WTG0& MO//HI0%H%%0Q8C@4?BX"MS$B_*G[X=0!M14!>S8C"L3[ AP@+P+>)Z' I4^+ M=)ID(!N-*>(_G74ZSJ3II6>Y!]JD9N&N([Y-PQ2W+A^G23$: Z\;4BO/L^\P!+JQR'F]H&'NQ'\*6IF*:I,3 >D%*!(@@OG8BYTP7_KEDI61;9_@#6GWBC@5?@(&YS_2*1B(6 SQ MZ8T)[/'9>;-''@1\2P;T@!SX1SOP\M*J1DQ7^N/P=^"J% M;](+>&7JS3!2L);PH"VA]^"%$?*!(,SG MY+$YH]?O-:Q8'L07";D;N3 MAAVB!IWQTVZ_894*N@[G&H!EB&92'_K@JXU([)'^=;1NSLWJ-DOI,#.R)*F( MP).4-L(7]#AT+2F-Y#W*[V3C(+,I< NF@? #EWY[+!^S&&@*\G-SJ3<#J3A/ M@*QWG*:8@.UP'6]GE *L=8'UD=_]6)-'VX80KAI.C>IR(N4MIUVZ.N'^P_:!_J]2,,L"(DQ M7&#T-$R*3$JW^3=6$?"$SX5(8=M_"_W$S$B8"P -)//6L,E%#"\"=0#?$+,, M#6;5]V3F-G;PE+FR M_IN"$C>H?MAV?_KM'A^G! ZE %>J4SMX#5Q]3#LU UZ#3\C'Z*1G1C[Y^<63 M%YMDM&J0WW'RB#+[TO0+?&&8P+^Q> K?UKVX. <23#R@)7Q^3!<9FSD7/L#. MCR H!\:"G??!'K#I 8Y3#.=*WD)N,EBIPB#X#J0$&3+XMUP'O*N5LK=3BL(N M=F-I$O2P0-##*/24?J(>60PE8U0*-. D#NB?$SP>PDN6)_(XVXERB4Y'36^M M\:65&A&LZJ,O#4'WQORS28H8CXFB2M%$%Z_1GT]G[(XOHDA>\\.[SCOZ.9MZ MOOJYACY?P@GH[%_$H_-;,O$6"F\>PR ?PS]A)V3I@@_?YDTS\5']8V&+RD69 M-8YE+4.OMIYUA3))6LP/[TXN_OQLF42U)$/>V%WWOK5OW)7[=F:A[?[ '6F\ M;5VQ7;G<[KIU]T/ZKZ:$7/0ZG;/^INON,5 7J4&15U2=R87++Z*_+0 [_ O= MSML8'50533L01*]*\QUAU"TB9;P'=UD&]=EWZ[#NLP@%V^3-F^L@>05XZ2;HU'A?27,X%&_)+V_?:[)#JJUUIMFJ+JNZ M7DZH!B>%6M5E59=5759U;6UPUH757$UHKD/.(--M/Z;8I*5:,*EXJU+0@;4L M7 PA*S3629CLV4SE]]UN8T/K%OEB9T 67G*^T#)Y:IT7L+>B@A2(H]'7C:HU.5\N31*3 /=N&J#MXF1&]?8".[Q\TA)NT[*.0.R=[N MVK1]$:S>:7-3OZU@6<&R@J4$J[GIW_LN5S;U5W$4%;Z+\A6I(VQ09&&,2"A^ M,AG(+JF-B-^FD4BW*X7_K_D9/8>"N-D^ =QAHV:ERDJ5E2HK54^>)&]M+L:^ M")--/:Y1F"SBH.F2Y$T(X@NK(1KE[/84S[QV*M"+BVM>1\?&AW%TWWZ,UQ;X M[>TUZ0XIS=;Y*U8U6M6XV]T>5C5:U6A5HU6->Z(:F^PFL:IQM?A[^5"FK2WL M*=2O-Z?:FT&2[1#*:A6YO2FPX.YIP^BJ8?P$8ALBW[I..'3*"USG,2FBP/%H M%H3YE7]!2,VX\"(Y)P*!Z0FMT\O%!P?'_%0P6@DCT@1>7;Z,L"D4Z*9!H TT MXFIW@^?_NR"X8!,5L^[4D\$Q?Q9YFGR^O@_F.\7(-P,^G(7'5O__VUR([&GG>]",/A?KB?;L),\3=+%+Q!13+ M593X?_S]__S7WQ:NHZE4,WT-0I2B)OI-#']X=W>#0S_W5S?G%YU+HYO3KO=WMW)R<7)^;N_SZDZDRV> 0:LLWV; M4N/TXP(DACE5:S\-39.+NZD#=P;>-R;3$4\;_#Z@T7(@P;F83),49Z8%(2B^ M5,0^7#T0^:.0$-(E#B]AQ>JQ$R0R5$R+T+_U;T6=,7) !/U<+B\E-&P48U_J MG@$!N[/6U<#56'IAK(=7+_&I'>>R%@,\S.@+4U0R])PPQ]\AQ#DLZ@_$N*:A M/PAB3*CH&?(8C35"?- 4'T7?4H.6S4C&#']LK@3UCL+0EK_7<*.USPD$:"2< MR<'$-<;LL"Z$QV3%<(@SZH#.[=" MN,^*# D'[RZF\.L*7KG67/#>7/CC&$-%^*94CMO"W^L'LF/Q.SPNHS\\X:;% ML$+@#GR$FL, OQN"<+%>\\/4+R:P+M1(+L^\\C+S6CG&P64/Q#-D34FA5^3C M) VUAV2,\J$G^.A-PB/6Q^ _&)G[%#N_) ^,CEGBN]]I]C=F?M[#G@4$JGZ5 MH)8SIR_>7=Y?_3]S_&*89>A$UM[^=1J@2C7OO[S_6KE=#3IUWG])IJ'OG/4[ MW[F.<<.5%Y&\WH\%F(/K"$2&O$QE-;0Q9^>G?+:: I&%DVD$MPCFZ"G.AHIS M?;^V.::^(3$%0<1)K*D@[UY.!JD=##%GQ4$@?;E.'CH1&[-P22$8?R[5#BRF MU$9*(N<4AC$L%HE>#HHE#8K?1R678@$-E:Y#-> !!1(5"Z!V"/%K+XWQLWGY MY3@\@%6NAUIQ@?C+X/EK!_\:LXI11<8K# A6RKZ1 .Z5WK;$':='78.BPK08 M14<5#JUQOU\=>.[.N!D,:LJ;:^XGXMBY^+0: MPX)Z'(7@*UZ2/( &#G/Q$U EX+M6"&9/^KWSDYNKVZNS_LE=_^+X]N3TE()9 MC&W[UQ<[%( M4Q:&Q(,XCW%81*!_'V0(Z4TPV$/7#X_G4!.'8%LR#M^"RO4@^=<@T,#^*?PB MR^6Q,+@H_OHC_ Q*ALU1;.EWY*F' MNW:$.RA7__+$US/*8$YSX S0Z&LF[I-A#@&H6%ECG/5NSNXZYY>W)V<7W=NS MD]NKNTO6&+W^Q=7M\<8UQK;&1_G>E%3)?V#%,IP$\F04+I"W08P$!(N%7Z9D M95R!6XMY#4H+/5T] M%)R^W^'%YMK1^:RN>C[OW(A/\#G%R5,0T], &: LA6_D!C;D'F',6FHJ]%6K MLDE.KJ%8%A78L,P5H1PBE:H\$Q2I(BD$$%&(X74Z4U1%)W[$0B)L>0LG^IU#8EI65NGB($]:)7C&A]:]_>7-W=7QSZ2Z474)(QNXYRS">DX&2 IL&T M&(@ZVA-XZ!]:J:"W$@B0BPGGZ\B?R&3*A&^1#\:D]#?25)A@%BFH&/H[/.@> MW!ZR5CP6.PZB4K5,O9#M'PR)FS9:J1T!D'$!D8!^F$*%?4W4!(T_,O=OGJ5-Z\6LQQ-Y1J'G9=G MG=[5Z5WO\O;Z^KIW?'S7Z9UWKOK]BW[_ZN[N;K_TXCWX0?G1%Y HIR2:59%- MNM5_R9R,J(QZBR1$4EGK3I!7FLSZ):7#DADXNN#1UW(,9M(%:5(^'5].!"9V4@'H2$(W!YXPSI9 I"0U738O4 M!Y\:'7AL,I(^\ B>*'.X- &:$Y3)4-=[F(EAEQ:]^ GFY_+A*YZ3RNROR TD M)3[&,'"50"<7DX)?E5"B UX'3N88G,/P09]EOL?5?8?SG/'/P#F<,:8AR6.0 M!9%F?Y'CC%T',_'1_+EKZ?>6I,V4HE7[B8O7JO#?18*7L_U"\TAV4)\:R78L MCL?I7!@VAJ-U^)%M+/ B;0VEX.QGZ]36 M2M*.0-*.ZB7M(12/R-0@BB%HJS#ETQ2, _]=>,!E>&0B8\"4504$(W@VBV>Y M4V!QD!;83A2PHSP-1R-!P9YXH.> >*:8-/I$G XWZ[ <"Q9\BC#5F72IL@8" M/ R.*'5H2HX-+:1:,*C=P?(,?CI#!CG01"@ZF!V8$-XX5<2#2 MTJ'BPV6^G7TM*:I>)L<4DW(L/Z%<_O+!RQ35TOD-%J6QX\8;,G-7/L4V/[X< MTJZ*Z&H>#1<,$UF1 PX9.>A4>59#6]*P:B45,JN)W)PL9&_7+],"P 5I_7;I M7(U<#G,#CI*O[)"Q!76;5=UTY[D]H#M=( '2/[R[ N;VZ/#\YOST_/3N]ZZB#D-/.U8Y7]?V&?'7+&[B[ M::&M%1552K S->\>%'G$OA9J/)P"[600\658$IN#<0&US^?9\!N02!15\A:' M.NB'&!6/O 4E\>(,'1=.^^+G8&6++#5C)Y:\!)%!@,@OQ_-M+\K,#"(F^G8G,#=5,U4I&4>!%20F)JI;GKZ2]5'G68P M-6Q^>SA M1I6')HCS4UE/T4H?;V>T2H(%MAFY?=46KJ0&-&BKD M6_F0EE?XH0R%G,\>-HF%4]9*Y;,GN&05&9??-DR3BA-:DR=-? 2L'Y1KI JK,Y'G$9Y=\ZYBVE3,>->D>XXG MZ6JGC50K_G64).#!)ND?G-2-@[(VT]@H4,VUF\5J'_\*:]KA\IIM+>X.W0(M M#H_C!/@H33JALSH/'ECS A0-L%8R"7T^ %#%&P,!LAXFU&4$ M]GPRE;X1AY#*A5&7_R4SOJ->&M ;D-_@5@L[C'!9?CP) IYG8.E_Y49B_C09 MJ 8 .E/%8U@:4JJNJQ!%%YFK(NLE) *'R>/MD2DLRA>""M%Q.68*EA0VRP:Y M,&8?43D^5-?H"\ZN^5P[#A1%IP3>@!JK4N68R6^+.-<98CV!:[I63&1N,.#J ME6J)NN$T89S>U ,U![U&MGL!MO>S73HC.0>%QC'%F9[2T>)7G9 M+:WE I-Q?JQED\;K(CA.5Q6PT1-.VEK92JJ\;.11S;>AXBXVL[3>^6G#2]N= M?'1C5*P=\;[.@^;:3.]IN&U%+&YM_11R"#Y7X6_W5",$=>1)B7#7'DARGY\F( M#Q4HN WEX;=N T$7+ Q"CXN#\!P"$UZD>V04F/)1-2T.ZS6+6$J"#IXK?O9# M K]Q':!VYHU4L0^\R\/SW8".63)G&'DC*H(>I,C?KN'VPM4*:L!5P[_ABFLQ_F41?A*LSI')S&>_DJC MTHH3 /T?G9^2>,1%'+4D&@@XIF27K[?"1?]SWE,^9+J\K"!J,B5/9V40#%)52Z&!;1$R \ MB.C?F#^I;@V8R\JG4ZT"Q ;FLS!UX?P:.S<0@\6!O+Q_WON>FKM8C\$;9F[- M9J4"WE^D9(-QZSQ?: MH']X1?=TZU*4B_I\45E75+EX++LH/Z<0G&-'-$59K/=??CYVUKN^N[R]O#X^ M.^D>WU[U;N].;Q3JQ6WOM+/;*>[?P'>)\VAV]&EY#VHK4DRMSG]]BIU+T,>1 MV15\>7^E&WM5CVGGN-*7>\]MM3.5$?H\UU=[(P:Y@QM#"H3*Z4W[PFD,7?.I MFVP#O"U4MW%9J@&\XYE( '1MF<88Z.;>L@9"A189=0]3HB. ]_C8ZJA':.\,W>/P-^#,&,L@R49&A-$0(,0H+:M^V)/ M=DTR[I*NX-+DDD43=,1?XB_AT[1V'PBPT92,^X<7%]BLP'[]*=='R*H+;PJ; M2*F[2GNF?!]N,:>N*KW!>AFA64_!&R0/"@PP("J2\*D@I]8D5)RH.E0'F\-> M189_]F:XO?VE$MP_ZEQ4)/@WF9TF_K_6)IQ8^EI;Y!5D%BMG*$1UBMS9E M8 ?@$J@#?I71K5Q-I_J,/L$UCBZ!Y/A/7Z12DTO>)<_/2QU@' =XF2XX K65 MP0U9"4]0_SB"5',NBQ&>UCVCJ)$':K;YKKK-_ZQLLX)?..V;8$E/)#30(-RX!W&8OALA+]8/T>5Y!J\Z0QF9>5D<_KN_'MGG#P" M#5+71$_0K7^X+O#:1]2=-[? H=')ONSY9UJ73I&UF='NB M^UU5.3)^W004$,KWC)-J123'QFJ."PE\:J%4."NM-J+$#'Z7M7FJ>Y,!JS!/ M*+[)@I)L<4VTC1RJK;HR7$RY.O$-3#H9?TJNS3&1\UZ?Y,XQD;*!$9G [URM M >7!=GE6PNI1XO3 4Y"9,EV'*8O "O;9+,-^'1>)X?.YGD8\C.41 M6YI$LM]3/<#0Q"]-PKTT+#-#NE_3D1?++N$2,P1^N(P#TV'^=:B!>.ZUN)9@ MB'#U?>E0&:N18?E+0D)@YE[WI'?=NS[I].^N3F\N;J]42-BYO-S9GDF)82QA MBA<"1GIK@.>!1/"/Z,#QNWX!_>ITM<7L@E&[+R83CZN,#;J;\:6B_/YD*UK3 MSG4C,C\-=>'@E<11;=OB=XK2-C%N$^,V,6X3XP>K .M-S95J[C%]L58D=%J= M;?K"*9BG@\U*SYE,PZJL"(D/+6&GRH:^DDS8FHV?@8WINIBX;+Y(Q,C M7(]YA_%8!&KY'1%&9T?)8SSW%@XA9$8*TYPB]<., 2,PQJAH,:RJE-C#"GM= MI<5,E?6_GVZSBLYZI)["4.)" .TT?BR5%(3DB')-"U XY=("?(I<&'BF$F89 MO=N27I0Q@I6H(-A(8,G 3.T)I6RIH5$"V^0:)*D,6!"]0@;D4T+X(YQ)3I2; MCRA1(C48%^:SRD(^+G2X)A9)'>,'!,Y-P#S M%C[F4$1@AM2PH?"D:33'JC]>7E;-JT[X&C!4L*\3[X^RN$OBI)25PZJWOYP@ M4;MRZ2DPL^*B@*E)SF^_>1-:FM(GJL] AO89I5*POKG(*1,S P.-U5:43IJ_ MEO]0N99O=R6DW(-0TQ9DO[M;(J9KF&HL3P-)&I@(UE2%ZT7D-6 E*F:;U9&0 MZDTN+BK @.( MC>WH@#(ZGH)PI=;8JB LLV\.WQO&&#+O (=B+D9+#!\RYI&,M5_ MANE0)N)\4Y_+ A'7-R.["/BC#\)+A^*D,#_R#[(+I2R.,PXD:N<,6(1&.:G M7*K%S]-B K3P:;B&NX@/Z,H>P13VD+/2FKW1>86[9>KUMI00$V.A%E#&E69! MGI<,5 \-^]R+TF4(I,ZWR1D 3%,A(R/2P6;].F?:LXH $S@/OI\2U49*]O"9P=A?#G #O9Q$R!G"!X(BOSI=@E9%:7(=%4\&= 85%,O0R' MIFU1TAZ$=!8,RH)!63 H"P9EP:#V3P=9,"@+!F7!H'8(#,IJM75*0H1)4#5^@JF?U.9VKO#8O34,Z M:Z7SX3 -CJ8>@N!+T"DLZHI%5$VX!N"B&0 C?-AL'#$\G_%43JYTQ@C7H/3! MU/D'VBRL3#/P4Y2>545W*G'JU= IX6E0#TE$\,G2AI5>NP'>P@G12K::LV;F M<@@J7_K=QGA*M$FEEZHSH)R7TF:M9GWH3 Z3*$Q*W]5SXH(F824,Y$"XU\8! M=UT.SMQK1Z5\<8X>@4'#QHQ4=R=7^R^\WE4@!H0PD\]T09^&VB @%YW6X\MD M$E$:@Z?T MF/=5%0UU#=KZB*J2!'=+0NMODY_.R=I,/S02\2@?$R7"B2A;+W0%+O5)2PP. M:UR:-RZWNK3BDU%:\1DQFTIS8PW,)G##E&Y5)D#7WI, <,$;ENMZ,]D75,X= MD'E_HY*&!J3J#_4V&[.LY@.*!].<7L4'UIQ"*5'@VH'FOI7H@TR.K_GDOL!GDLK.(.W:EO#$P8S/02:7@3 MCW<"HLF41:[*B:N';7(N_9?ET#.5=^O.AYHOX:6"AA:J44R=@="<1$U V? M@,Y1_6>I[C]31^.J^XP70%EFS.^DB*F1\$B?RDUEE91R#$RK:L21)D'TZFCO M6&\;#D^L+9[,\U0(6.KQLD-.-W])C2\-=3TG(&>68$-&R94.Q\K^(0^<$#KP M%K73J[TJA^L&.M5<0^?-Y'N8H_^HN4+R"AD"-@M>M,&X M\E#JW9I2YU:R#3N.-#)M2 O5ST(F.!=HB2& ;T[(+S M7E4(+1;.[7SI^W-,X-DIJEY;HX885Q]52@[NKP M9UH[9]J(G19*M^?.3G306T7S!QX8<#N5> WA,$?S_:F!%4UHPLZ.L_*VPFZ2G[P7*:1 M@'CF/XOFH-,_(/8NI@KFPE@.AHO4%87!MX1W*"8:Q!$K9'F=56.,%#)2+G'@YDTI$L8X/E=4,2F!F==H&.5_:N5/5W^,83P*/27 MJ/_*''L=5+7M:W:*](MT+?6V=($IF!L4813H5)&^QBT]RFK_N<:(H28A+(A% M>4U!?4WJ)?BTCY](90$QZ=!.=69'A0A ML*K11$-/G-]H=$=1/*$Q%U7AH-GX5=,QQB1DHLO.+?CJGVIWI_JUU3\ELHZ/ M:KNQNVAN8?.??3#'"&\@H-6A(#D'2=SN8A2Q!SCTQ@\]C8-IN%1TF "<:T93 M9:>JOE,L]>V6#;BS!K$)1$F&&=0[$V+/>U#@X23/R=*@&BH]$)&79=0U)'*@ MH&=&_"KT#KG$@$=58VTD$I(E,J74\I)' MED*I=&Z85B9 53]%'6OSUE6I"4<_5@L)5 I, M5,_M630>2P5 M9034 *_:Q%4 '(\97S:5D$5E+%Q1H1H(8,A'IMR;$)3^)S7&<.U'QHS(^ 24 M6#;\9W8;\#_KLJ.+<2UWE!9,P#M&YH,-V4N6(K$46 7%4'B3(PAQB<3+( M906"0BCX3T(_4O;\ 4LNVP%PBOX8QC<$KLP;2)T:/W O8 M_0YSV8@34/)>6)%LN'RSY":CGJK.UG@^*$>5J$JK(2-J7XV?L\3P7AM1:5FX M5>V/](P:0*H!56!#"@M MCD2FQB(=DA 4A&BF,'["E+-WQ.73%%^.J(U4?V?BB? 0;B8$)D-'?/2##;G+ MR,+X%&HI.:+-\(176;\B&S"+S!N!ZS =SS*2T4<"*"*QQ;-L0ZO*(Y/9 E0- M5P>6 'J.4(A[:K9A3FM1E3>5C.X<@?&,6PFKJCC-RRRG!N4M&_/\RZ>?C0U?+,3,>_S5>%BT@IG MF?Y2&\5\IW32'5>MFB#S1OJCFEU9.,]LI([COFS[QZD5S17)-/*DGW2536.+ M,W2BGEG ":VQB *)J3-'^4W4\-S,9U%D;6,]8.%:VR -B*V3:=9YT)V]RAS4 M0F3I/&IU=F$D1CB$P9PJ4>-V5'.O^HRS/@D[WU&@L"B4 [[D7++B*JAKI:<, M/Y4.JO%-824@^!1KO/^L4J>L:I2-POK%YFA98VRPHP(B?T3H>X*5Z,:T[G"Y$KUJ3)Y\#&_DEV$I[ISZP@I^PD[PDH9 M??-J^X!*"9DG$+XNPJFQO+46O'(.6CW&KD1'B[;"*"DR9BPL,AH5WH"SAZM1 M213MH27FCM>]5P5C83Q,/7:":7QGO!A72=9$= ME'$P@V_PX6-9^"UG6H%OF4RE5%!DD[*^D',6\)A>'9TM!MD(1B/_*%]6AMT) MC3F1S2Y1%8::?$UP;1%ROWQ"IG"O-=K&!'-LG/'0R'=>D8-_(GL1" P0 VOD M9 3U4MTS^J' S8AK-Q=WS:UZ(VY4_8%*PW7'1G/1DE.2%^J8ZRK/!$6J2 I: MBX%C(:225,7:N5$5YMO,39$63&6,4E):^B!!-9>TMH2U6ORW7+W #5N?RA*H M5Y:P'0)MY4'87-78DS5IE6#8JR#(*&E;&CRCC*D.F2A4,E$^H.P S(K)43(\ M@G\>8:%^=A2 BP+7RS; 4J[5>4N=I\9XMV#K<4A"6*W,(F"K<%#D@M7G7+ND M'G&HT@S\]=+;7*BS6_X=%:7$J[1'J')3'*Y8MT9606 U\I!QU3#-=6<7X$C&,:@8& M(R*8\] MF%42;N )$OAA3D--\)"*1J7,M4MHH/DP+\=)HU;&$A*:MEV.>.33)8T;P!V? M/D'S2XA_B>%80\>\\B&XBI^35"0TT-5<-9+':&/+&4 _%09>6YQPI@M/ T=8 MH)BD/,Y;H;BZ/$( Y[8\P.;HNBULUJ( 2IW\40R 06]>/?N3(Q-J/X7IEQ)X MY7-+KR%$-B:$_4&EW[4,/98YW];LO3!?AL475'W(5=+RK'F4"J'[@*A;F:IG MY'#6Q;V>+P^CA\D$&M6ACRK3.=953@23H\&2"@X@P=58,N+FH M9E3%DWBX,O^BJP,U %.U-4A7R4F(*'F[2P;*. ?3P-=FJDP"(B&N :!M5J":',&2$[I/*#C+<,03'$. 4@I_E* M98*(>P3,D[XEUY=V:98]C-A1ZVJGG95[U%9K,6'%3!Z^?%D4B\OP_LEH!EKX$%.03MNFI0\4DKE]>R3_WSK0U\F0TT\9\6VT71 MO1F9.2?58/N<,^*\7Y"Z[\AZU+76D5-5!^FO0=REOX]>'JC%EW3C MRB"(EC>AN&(@Y"I0NDO3TXI=VAD6PAYF.MGCB"9%- NN(&0H?@UC92#3PY7: M#5X-/[[6XO((R'(*!<1M](QR* ,-EYRK=*#B2CX88_A-7@A>45U*)8Q1WT2F MZC$!72>FI6P8S(S]V*556X"A?XXV+C*S]!*74$]Q=+8MDKG&AV;T@8N>I@&B MILFC2"%=)N(-_$,U**)9@*G408M+GEMK+8BF]-6>O;D. ,53?1#DK'K^V.A* MT1\E+_$KA]_E+E>]D9*6BROE3\\PX R(%GB#KK@MB65((RME:.DYHO4\GM/KL#9:%I"2%0O4E_ BYC MR4>D0A;;:,S3"!-LI:DBMBWW1UU0?9/)U-PZLUP EB,!2&]<3];0\8)A4JQQ M6=.X,+A%?<*H9O0+_/\1!/ C"7D;T@1+.HO *W1^L9QO9525J"JP!VH+*T\6 M.,7F\?APD.T'$_$$& M=H=1%17YU** MAIC%J3%TQ#Z$\5O^$2LGY3-E]4_(<,RR"QA[7P(:LV2&[N8@'Z;B(Z4SJ9V# M.C-T'D5-&// /O@A?$0)ZVV"+],@-UF!7<6LKB"?MD)WM56Q+CG:UD.(?RJ- MZ]I+W:FBS$T9+#D"P%L HY, =*[S#^P*_BJ[AW^>.9_'V!-OGJ-1UWUU.$SE MQ"S#^>VLI\IF8T^==XG@B"55O[H\1)-OS9KJGC-P(E)7-BFLF M6!L^C<21[.2O].XS?!?UT04RV4]-TC$>A9(.]R8,2+"0AS:^B2$1Y&XJBLK# M.TTQHT;:*)Y"N%,#1!ET8QYQM37N*AT'S7C79-T[5I"IG38P$?&OZ+LZ6'K- MA952#Q(1C8U"Q(6ZS9)@U_!7G"+1"B%JM83?88))B\/C&"QCG"88.7"TME38 MJY';4 T!,="!Y4@'R==S@4WI<2PX&T](NIXM/^\JU Z=-P] =+RKSH/UP2C/ M2%)8Y0)D/4Q2!MU57975(+*4!G"S3>"(.FE JR^_P:T6-"YZ6H4Q3;YZ(S$_ MX<16&M/< M+M'E549(<:>JF:G+1@))VV= MIS-63B./^E/W]-B9(&I_4VV*C76+_JEW?MKPTG9G>G%C5(0E]1MY$*JLLJ=] MWD*5AJ)^!@@=A8/=9?-K&((YG&?36B.34\F;%TZDFAF(6 PQ[8G)A])J4<9) M:9'!Z3DKD*,W6.3ZF(0!7@)97<5*7W4/L( ME#:!GY*,>@\ITZ236 KHZR5NA6N.]"H'% ^>]+Q-3R3&M( KA56/X'P_B:@G%%$\+FL7(OA[?3OU1QC!UE;.!0"G,J5N5'7^Z M54=:=.8PP,2(X6I+G32_+*H \_#D@Q 8/[:"A]9B\)P',<,.3[T ;>\/[SKO MZ.=LZOGJYYJ5?*&*S5_$H_-;,O'B[YUE2\I3_:] />@Q#/+QQ[/>]-OW[YP4 M* A,\,.[[CN<&:7^K5>;!\8#5K_XK\:+:Y;P(%+"FI2)TCR9/KN2%VRD).81 MYE\_=O S7[.S/^%95VGTNT_N:)5>2[_V><*_58KY?XJ$(9CMMUS\*HU3I&U7!9P;#W[7$)PY MMX(B52L]!R@]Q_LM/5_C9$%^4"!T>SZ/V@8IR",J;H\U+B]"^+OZ7("[!'7" MFE+/A-Q2 3;$Z6%>.TU<1QE;[G]M:W.62 M(*J*45Z>]L6(\ 4Q0"4\P#(2@MR'_>;3@FDA R<\1@2^Q39'+]:I<".[8800 M3\!'&?4ZNE!4/=67@X.8EXK(2]4"GGJ9XMC,^;T(1EPKQ# ^$.#07&O.AVBH MSA)Q;YY8 T%GR6K4CNSNG'NUCL]L_F2UZ:R5(C!2'-1PI#N/7E\W]69\K%6.'32W%@>62EXSU@%7 M%:E9TDIZ#2'(:&VU$[#HTOFAHTO>*D'^*U!+7HAL!:)OUX,%P JJ#!\/*=M)TD@(EN5M58V\P8N?> ZRCO- )]* MFK_UJEM-TGD*UHM0B8THP1*QUG$R$$% A\/J[CD4:S"<\)W&F3E*/@B9\!BO MEW]Y+^(0[OJ-_O9+0H6GB:G[RN&MK4$7H6+J6^R1(7P2RXK%EKV3H$KF(2/915F2"OV"Y*/=KS\S1J!O?, M5XV29^*92$\8AJWGII,+7 M&FX34:0T!]5J3ZET\/2*QGY(IXJQ.7'.=)2\?GS9P@P@#7+L&C.1]'OFYMK*0E :F:2 MJ(T%(;XR]QRJBE$I\W.#UG#.^OP7>5&6:&G1OX4]BV6;2/FUTNZ3-U.K:TI$ M*%4_ ]Y1D;)K44(>+:XA%52E L^5H-J8[@T>%#(#2!M"&?$_!8-5A55O1GHA MCV,M7N,TY11=ZB:8N:,X'_CJ@59J,$T9LA4:C K,^TEY/JB M",%J;G",Z'U.4"2P%CD#FYBG\@52Y7RKP4'9+K-@2Y3 -@ M9;[FF>/D4H&7RKJBRTLFJY2/CE*L0AJR$)0FAVV@RK3")GJ1U#QA&AQA3FU6 M4O*1HO]R$&.FBX%>JB'3FK&*V:C18Z0-8#CUY M4_U^)@U1916U@P^U.B[]U(I42\.)#YZ2TS2KUEP3C@*\*YUS(F7/@V=V/-18 M48:'JAT\2"RKZ_:DV>1";J.*A@<]\1#/;PB]1YV2U;5(3UR'\X;C#>2>*BT) M:E[B0M02FH=Q@7*((I9PLSV);*8HAX93VD9>Z7S&IJ??C'PBO@4B?FE'L=56 MP@JT@HE;+6&?T.W@RLMJDXW:9*,O;GDG'CI=V^JMJ[80Z?IE>(1NYPW-8U[I".:Y<2_N1%HLF*VN1W)^;4?I7]B(E+KFC,@^C5)++V:,5NJ;5BE A]'Z- MT5(C5)\*VNX*(++95OSU_JX"SUOB>0V%XEW.^1!;J!; $7)9+)O3Y.@5V>VT M,$S&".BRBD+3VE7.2M+":\Q;7-!^P, 8;"K.HD@MDT=]):XKKY[4H1'?4B]M MA9G900_CQ4#'9%PC^KV3T1BA\SJ,IMQ(6GO#_11NRSI^&FU"6BP76H]$)K^5 M^JX\"@;>:^1-?SH^[C?:?=;0[O[IN'_1UH:]X]->PR0S6\Y<%'/0A?/ZCZPL M*PF;G%W[K @>/)Y80."CPU7092$?;E ?#/KXG#S S\'D;\(Y./:G*84J,HB=^>4IF?K, M'/RE1C>6?B:_AZ\P&LLYC/8B#?)&VI'J5-01\C)/URU=7=C#(ZI* MBWAZ=75%;N/Q-33!94!5NI0;L0IA586@ M@F I#Q*65[JFGD'2TG:!QS))I-#1;0$EU>\$F2VF>:WZ:.!^?N"KU7#,>MAD2ZT]H$MCBPVFCC?E-^>_=#_V& M 0,:\]^['SH-DZP*&=$&5=U6.U)OC3\QMN,7[YN=XK6*99*GQ+GW;6D;?#59 M6QXBBPDZY.G,0"_*JI-#=$5J!EZY*,>TP,L&Y/8O;X7@LR81>SR_$^[@4P)S MI">C5 CNL5#G>IFHK(=7SY.0P<9?&I7;97VZ>;!,SWD.E9;""GV@D"HD9Z\\ M=M<$Y4%2$EO:6 D&"7B>0=7X_'N- U+[G$"@RY.I^EC50P]T4)4Y$)Y@:!12 M:9KW339B^3($HILP[3--:0*Z/_:PA$["2,D^$_,"> 3NP>\0^F0097&%D-&3 M0F7Y$+@]>FF@PQ#O >(V"3GC(J0_Y@LE]9Y8#6S[8GX%-ESFF1\!0+?QHYYB,U"RK^G M R829#K27E:#N2HP]-R[U;BVK,AX%)%3T(RJ;]Y$E5!6.LURX8]C.D6?X.:4 M(SO5 ]ES0V0WCDV*V* \:3!&5B)21W10B9U%9EUZ+42>,:*PO!:?%WF/+C>8 M>(:L*2DTCR,X\4$MD7JS?4P.P".LS[#*B?HOR0-%9/)(%O>W;$"Y+&7DGBJC M4M!K5PEJN^@N\PJ#1_>AGGM"3('RD$X\^EVL&B.;T=2B+G% 9P%J:U M@H2J='!YBGY#(XZ78;R*P!T5>'/^#6R=\K9E)AP\A" Q$F/ZRQ$.4LA1O* ( M%HB_#+I+?6P-M;B#+D\J1*E<5T5"WTR!= M&0&^_RG)LN^L"[HJ\FJ%AM("O(^(AN:0

:5UR51M/,9V#>8%U[T/?(EB4C!AD^?V:0/ZMN*O_'K]J5I5 M0^6"JH](-PE1;4F>^'^,04SG$.+1@8"8AAL#]$YA$.^E")5M&Q?74H/W2.ZC M*XIO4!D"=Q!3O_5J6TU*@W(<&?H&Y?@HBGH(\ K'PR3'0BIVM)B+=!ZH;(GYE!%'R2_41BP0\\0:V7_FW=+9"DWLYX( MCCSL@1Y!>%50D(]Y.+F.,8W;3(J<>MP(MU9U'BJ5=A-&1-[GJ3\*J;U-'CA@ MHU 4E6-^"8X&'A4^B"=>;Y0:Z15\?OX11B>P^32I/M54$E:8H/Q1\[GE0+C MT)4X3 BLR$S>R\I2(5;% 1<:P^OHN!QW%=Q-F9+@.TPK-?>WJL6J?7TX/)(/ M1S0>J:E;(8-M51#U6O9_O30DH=/@)+? 0J^::G8(Q&3:?;IEOT!(DK%;5V:" M(@_XW#A,DV$+ST:>A%QG1#?/>/XES_)"'XX00>5#0^#N(M?M6WBR4@R2-, # M"1&8!R[%% -.+NV7Q4Z(08<^&=\Y=,O0(,&6.QX<5H3XC?E"@LC+8R+^6FERAB&ZL!-6T!^6H5T*J] MG$\.@4OAWW.#-_PRG6[0=]EH:V!Z*1)+'DUN!G7>JP)HV/]$G@5/>69K @R: M*I1*0WWQJ%VEY0CI!N7.T"G C3C25=X*B_F+,4;-"')="97 *H6/3-EHZ6,- MN-E=KE%*)5*K./1)K.X416W 7^P3%*SII U$'9"H)&49GNI]R!RR%T9=2(#X M0/IP>PGU"?E6Z*\#L8]E$4@@C*=;[V?%'FBJ#T"M))N8B:L5BR_2WR7GG/MY MZT?556OE3;U' _#H!96CO#2)N. HPW GS,9*1^+V4@T-ILCC45):3)F)R:;X M'CU=31ZI5D9'4T()M"_-TG8EBCC/X9R3R]5$L;+R.J'\7N)SX5R?ZOL, KLT MA2J>N:0Y6&'()!$9+;TJ;G"65LK5>J=<+[HCN;+=]7X)@^6:1'VO2B6X HI' MF*<59+$44_MIC5=1Q"$:1H7_,$GH ERU>N,1+BI5^ ]*I/635E"/I#5:(2%M M%=_ZX 6A(9!GCSXM+YEXZY6WFJQ**UZ"YHO,(I;+^RM=AZ)*(CK'E3*2>ZX" MT:KE\UP9R(T8Y YN#,4TUXBJ\\%PE]G?R.0VE34A =X6JML8C,LEHI9='+D/!'9IV>G&EMJF9I M4> !M3TUIA=36X1H5>,J,ORS-\/M[2^5X/Y1YZ(BP0J4B_C_.E%0F,32UQIN M8 69U?D/=J99/#4ZBG+895UP9%0[>;#?#^((1&G* -AS)V.9[ MY._FR5@9"6#B00X?KEQMCCZ3L];P8B90N8R(\*:!FF^^JV_S/RC:K:L'3SNEW'V4)H!>IC[_5*N8& M9[TML(0'&8,+!MZF M:Q;[51 X$G#W0NH'K"YP:!1>+7O^F=:EG-3C6$SG ,U:PU#7\>'P:=E!(,VG M-@F5$=GL0,J@\_6*U'&^(FYB52/DCTE)$DZE2VP3/-?$@K(2DXEO3_3IJ,OP MLO1U-*@"Y)L/5=(BDA":FN-"ZI4P1H(KTFJKC47-@]_EJ8A.@5%_Q8":/&6W M<;:X)MI&2D&MO#)]!&0)YIE(V<"(3.!WKM: $N2L MK'1B]2C+RO4QD3I(DA4ZR'OR9$@I.ZKO5AVG"IZU3 :CXQ'1)%<^9O)2[DG' M4E/ZSJF$-^(OGQ\@K*=9)N@Y%TP:R9QR\KID.UX.0C]IN:3J=E6)5<-%,:(% M@X/Q(+5;5:#5C)Z\UM7 %VF-67KVV0S,Q01T.1##YUI_;CR1(Q5H1Y-(8CW5 M0*$^[4ZH?__MKT5V-/*\Z<=?TY$7R\1M6:8*/US&@>GT_CK4M=_W6N1N].; MU?>E4U2&*I_A>3YH_R_B6WX%5N>/O_^?__J;?C=R-.P0Z!5ZW!>DL[Z2OA5^ M^$T,?WAW=X/Z]G_Z__IR\P[,(OP"-NWH\N[F^J)[=G?6N3F^[9]WSN]Z)[VS MSO7-2?_L\NKRYMW?Y]P4T^.8'_*US&/9&G130>BGV 8[*28EO.R0ID!54 YJ M(<04B!>EYR5%2=-EQ02ADJDO38"V67].Z*J3L8QG+ P+HV>$,7HV]+/Y$EDS MK>[)DRD^V!@PUMA$M[F5\\RV;@>^<4"G%4>(+^5-,_%1_6/AX\M%F1/8]*RQ M\\H,,DWIYV>XT5I^>'=V_.<7CH^3-W;7O6_M&W?EONV\\&6S^09)#CYJ=:8> MC@XT9<#\F:^O_(JR>1]7FC=H".9R63Y?3Y.=+\UDO<>9R-P 7E> :]JG"OGU M!QR_>YIZ4F8E;;K3;P[9,>?_#NF_[P>>_\<(XK0X0+E.TH__5_0ZG;-^0V27 MKR=UM?#N6C50OP\^S6EH9B?D=\I%U._+K]J,$(#ET]G$548OOADSHS>$I\4? MQV$ EJ79U(CV*/>0=5O,G9^5/V-XB*ONP%HZ>)'4P0#_W[XH9[KM7]CO=\N% M<;7=71MA\BU2=A>T0VN(M;]JU7*<]4CU;7@P]);.33NH\*>F2=#\%Q/C-+GQ M[O'915.?W-OW1 M%P3MS8M3[[@Q<5I*E'V1LQT2J=:9X(,3K6.W>]*QHF5CVI4MU?DFQ&G'I*;G M=OJ-Q?;[(ASMDX/=-2\[)@]G9STK#3;:6=F&O"0[=G N6=>]Z%B7S$8[+3)' M^R):9S5S5*Q@V5AGB9WJO40-[ZMOUW5/[6F6C75LK"-O.^U9:;"QSHK,\@7^ M(KQA+M*-N&7+RC@[]-_>N&TG[LGYXK2Y=1VW=8FV+]*Z0X*YNT;M4$2SZQYW MFHNI#ETT&XBY.CMN,)/!*RP01W^)PB2D$^^QPA($0< MW/Z["&D28PD:\1*HAY/SV]/^]<7=6>^L?WYR>75\>W%]?'/:[1YW^Y>=?G?C M4 \;VECI/4M.HS^:G9#T5L1"9\G MN6-G\<4V*6=?QL:D)L++F9J4%8JR/*[.R^20E,P":VP#6*/;>26RQLG%NC@0 M6X?D:#?2Q=Y_X"$?O"Z8(GK.NE >+TQS;@[C8'52;AOOX&LFAD7D_(1C&FW, MV'R>V")QK,N9]5. E[ETM=.!+?]:_MT=_ETYLV"/VY-/BE@."LD4C/SN MAN&;]YM[#?O-UG#M;9]![\SMG#96];PORM<*Q.$*Q(E[>FP%PB8#5^07@IS;=USKUO3\M))U.<]U=^QY]6M&RHK5ZP?*Y M3>O8M,Z*S'+M3<,78R'4E?CEW3WJ-]8WL MB[ZU\G"P\G#FGES81,Z>)7(:3MQ@\;P\9@K$0^@W5Y[<(IIM(7-S[DS@;^-] MI-[NZNM]B2]Q,$-C.-A['V%:T;*BM;)HZ1;;WN;Y:U\$S*9PDCC+T\+'>APG MC+&#>)2""V5CLL84D:7/8<:L/;=_:D=^6'FP\J!.;<_/;$YSSW(XF_-,+GV_ MF!21EXO "<0T%7Y(5QNNXG081%9XSFYMG MH+=/>EC-U3[-99530Q1I/&UZZO;ZC2'560QQX_JM+YN'H0"(4! MX82Q'Q6!<'QN*G BK.ESO%$JN W3&28IA@^/2?J'B6T=YF/GP4MG(+V.^#8- M&8'H3!6B3,=1[OSF]>EHF#-+ZW;/ M&EV:ZZ0BFPH_#Q]$-&N,259E[Z5\M'B^MX-\='S:;RL?G1QOEHW6-A2M\P7> M:K%?CGY.!F&D[1C\%6T;F".1Y^,O=ZI MK<[G5%,:D#+R4^[7J551H.I !<:"%2!I2:53_Y+I &"20!@;2^/ORN !0P!\ MY0!!G9VD('V'OU!WY8E3Y"&^D'X-2P(5&LU8!:>PBK-.Q_GY__N/U6,N7 +I%>(?PN3%6KEX,9/,=SP$2&28#[7E W4R.,O+PE:BV-HX+2?WS] M^?-_.[_&SHV 4#- +SZ7WP;\+*;,VE%];YOC@;^;IUZ< =60=8=I,H'['H"C MDW2&W[[48_@Z!3HJXD+0+%(_A)<"T>:6A)HH+]*82K#*USYX48'^=T[[$B7@ M>Y.GDJ"'D3H3+_U#R,@<)?\1*"&<('FDS9-_-3P5+Y.W#HVX/O,BP2Z_^9%P MO_Y$ZZYN9(;8,GZS0\3>8(C8^2MGB)UM?138SHSF:O<''G)C$OW4V$BO?1E, M\\1#U'MV:7:-G;W4W&&Q9?%MLKACIS)MN@Q@"9Z'Z\"7OVUOZE+R;V(44VN+ M*UXQP&(3=-I-D(HM<,S;UV'LD#IKG5FWRLLJKY<3:ILP( >AP@XY%*?;EG7B MKA.A[%E/^_M>>2-CQ/L2EF80& M&Q$WTDCV,I?K,#O,FG?EV]5ZUG4OSIJ;<[(N,6U+FLU36.5HE6/+E.,;^(N' MK2)WIZ6N=51\J\7>%7F1"F<2QN&DF#A3;\:M=.(;UK5R/=V ZV##!_B1BBBI MIH\K+$4Z@3]RY@Q+3G[X5W_E25GYV>V(FO? MTL#TDZW(6J(BVEFN\B7)O:@-&:2=Y7JZ[5_8Z<6?-*FL5M!Q6TAQ=V8XSXP5QUG@O/0 MA/"PK+/=>?2RAL!:^A_ZSJ"%\#;]#]U&U]4@OLUQPR2S"#<'BG"S2WO=*&V; M L^K1=U!]T<>R05UZK4Q9+#SAH&NFM-0O7YO@^AY+H)C>/BK(B(L$R_XO!BPME8A#)=.)6=1IY/T$@O1D0BJB%TXV029AG\0D$C_2SR M-/E\?>]_%JU,10/#JP3K4;_%XTLG"7&0(3?,,_Z#MC1.@(;@KX1!\ M3WC0<-NX55*_#,1EZSO2C)I='W7K8'SF2\1( M1;@FV'+2)LD (@=B8 9MFJ8A5E-$,V("A2H9B1%(M'DM< \^(4"42L5'VM]& M_4-U'H:-T8589]^7VBB,AZG'.)98@4+0K0'6H<#O/%28&M0U100I'QFW);N\ MVF'4UO85S4L(I(?-(K30I_89E;"%:+(034_?MS-02^W^P$,^@Z:?;$'0,*6^0#"E>?$N%89%+#@"YY/BBN9/. M@T8L>6/MUAB-6V?HK5ZS>FT-O79^;O5:$WKMD"-NNNVGT!N$49B'-%/(+Q 3 M?YTX9<]0F+H731YMQIKL2[? ^V[- M4-=-^;R'C +8(N';7;.U-U+7ZUJA:T#H#CYXNO1]S'67!5W66?S^1>V!!^$M MMD\B=M<$[9@P]!KS[O9%&&SHM(Q7KL=>/*(LG".R/)Q0X:WO96,'1?4E(VH: MPWO>%X>O>]Y<4_:Z)-L7 =XA6=U=,W\?@BP"^W3::US.*S:LFJK33645FWM?@9D7LFI+K\S>,Z; M*[RV *.^%/NT541L#>$L)VZJ=+I.I^X4A0\YRJ6?%OJ=KB,OR\)AB$,7N+%[ MX$5>[ LG&PL(B+UGNK?79-^WT9=O+MXMX[/6TP+:5W3-M"18[6^^LFM?XM =TC?MTMY6Q1RTBNF>-=8; MM/MW&G-=] MD08;**]3Y-*8>V(';;_-R?&^#]K>9B7,00_8WB%5V3HWPZI&JQKWN]KFH%6C M'=JTK:$@,9Z&7*\9SH%?/3][(QEJR/W*6(V;0B#B?BP>$3(? M8='I.2.X$"O ;^!)^$:]1OJADS4NZI7+< M08QYAQ2GLR0\N5L.&Y 8^L.D2&&?_EUX:2Y2W!ND+D\^&$;PO7253RU^RSK\ MS+5^P:MKWN?B-](H&-\O)@53S9R>XIJT?!K97Z2BL3$XW;9.Z+EH>G90UMA< MHT,<)%49TO6TJ9;__MM?B^QHY'G3CY_ER)#/D1?GEW%PJ\8.6$ MO_#\_.CLLM\_.3Z[ZIS=W-UU>\?=[LW5\0N?A5_"_\"8:.J$/'S, M6(X3#H$@X+_X0@09O3LK)NI#((P"-82?5G5MYD:PC40,3\.?R=VB.S.>9D04 M+7 :6@A6/Z/9:%4R59?(Y'GJW9*/>,5+GU/QZ^:VB4B,L]\,S@#291G21[E. MKC,!%P_4+Y*27\-[/)@9LYUJ&.#Y75#$1D8AN\CRQ$%0:",2C""+W^K'J-6X[?PRBMB%$I MHI;(9EDN)F ;:+K:&+80Y34%S46JW 7AF])>_P<$+4N&^2.H47?I3#^.=F(> MMH;/!]4.3QN!VD4;[C^^_OSYOYU?8^=&3'!'V*OQ:":B MXQ=9GDQ O^@QJ;!)K$II^XKI*/5 O$,>7^M1:@Z( 7]@,4X%Z#4*#D/<7QSB M"@L<.\ !81(@LR2HQT!A8]X+U(U:8D4#2F6N=#BE=_RR)P@3%Z1#4?NQ1D+_ MC*Q. "^"W_I &SQ&<$"E2/7#_J7\J#1%1Y\84<4@Y5^IO T_EW)\\-AD$OJ@ M.(>P[-)SDW.!X97HZ&IWG/.;N'"<"YS/KQ0UI)AR>FNIS8+/!<&(LZ% #'MV MK\,8?>HDG2&AZV5*J>4ECRR%4NE<^)0R>S?_*0^"S0-O7<7Y1ZT.E':*G"T) M_$KMHRL9"GSJ4AU426LF!W_#2*$0E"=-Y-ITFG@)?73B$$D9YQQ)X@>6+T3= M-HK)1=#?4;^ KU-01)+#%7 M#I+'&+=!_M7X?B^3MPX-Y9MY$5GQ5JJOG=*UUXGT[[ [J#P6_=NRE(Y;>4B-)J->,&9$G9L"BKDU_&9D'O7%OD/ Z4:#&P@OT'>K@ M )X&.HLB_52M4WF5M6I^T=%=H,^U^LF3BYG $\DF(/^#/CNJ./=25\T/4T8J M"7\&9PB%I#ZBIV6F$;![D\AV&KXCK_X:,C;XJ[Z$6\IRJDP==-0J0. MN32PWOM1&5ZA?17D^3-&<]C$=V01F&ZLND&-(S32.M M39R!LQNT<79CF$A]+BP)KQ^!2'E9.$H"!$9+?A0X?@TC,- MD,NG*;X\1K&$5^DW@Y&MC$;'9.@H2?$%<-E2LL!>9.521,EH MYHB')"KP;QBC8^8OI[4,X968?*UD=.<(#"&J%M8@'((;AF_664X@]$.8%)G, M.D]T_K8\QQTDR1_2D<)G&)L*I"K/C9^OLKTZ'<"<9?I+;13SG=))=P7:\LJAM9'^J&97:">E32+CVLB! MY3UR 7?N!&*PF/M\VW/9GW1;46.+,W2BTN(RH346(#L%V-QTGO)AUCSA;^:S M*-X$=D)Z-,UL@S0@'_;(>7C!F?G[I\>GIZ=G= M2?^V3R?EQ[W^V?7)[:Z>E&MG";QJB()5EF1)OHZ2,!XZ 90J>AJ I8FO,9Y1 M*4'N3+_Q,_ X.>:?S9?$6"<658IHNWB-?C"52%)AE;SFAW>==_1S-O5\]?/+ M]_(Q#/(Q_!.^49:=^D K;YJ)C^H?"Q]?+LKL"2I+43NU35PKM!718GYX=W+Q MYV>K7*MUN/+&[O&Z-V[[OJV_<#\_\)#[F^L/C=^#!R +[K(-3N\2O4[GK/^V MI.13Q6:(*3]+3M>M)^U7CCNP(.M-X7#VK,]G=:"^9?T4VR:7MXLSZ2M9E M+FQMA:OE7\N_N\._B^70MH']A8UN2XJ(-N M7-A$SIXEQAA+2%S,TYX[[L(_5V5U_O2WS9^")A-X2S!U[0Q66.*R-+G,&/6GML_;%:^7A8.6AZYZ? MV9SFGN5P-CA:]BDTXR=Q>&PPM>4IE)9P-@I5M[WO';O=B][6>*ODD\UUSS2L MV38(2&(%[^6"]]I1KSLCF%WW[*+;&.^]EFS[++@-I)4ZN^V]U0^O(/AW&RK: MU%(;Z+.1X>EV1OH"_79\%'JOXW8:1%1XSFP>PM!SJ[G:I[FLP70ZEJXZO\I@!(Y#2V!:^&G.)<_?HIQ M?@.E*K_(R5!)FEW#-X1Q 3SW*7Y((NXU_((K?0F^=;=[V[L]OKHZN^J?=V]N M.I=7%U?=FT[WHGMS=MD_/]MY?&N&K YQ5")!/V?%9.*E($ MX6PD<^0'CGS$Z5"I\$7X@ ]@G+?;3Y\KOTMX"LX"ZW5"-+-V(3D,JM39*\ HAR$W3:0,79R>:Q<+? ,6^?3]DAQ=8Z&V^5EU5> M+R?4V>GFD5@.0G4=4N1-M_V:CW$\)@[XCG,Y.'.=D&3/ZL^/SQKS!?9%--HG M!:TSWOLJ#;V.[<6P$?V3%F1SEF-?:FK[CYLE &-LQ9 MI4$0MC//G*DWHP( :@ST_;00@1.%WB",PCQ\49IY7YV]U4\U#L77:Y]@[*[5 MV35AL$""-O!9*76V82.R+][:F<7BMU%0B^S1OLC527-5__LN5P<7_+"ABA)< MK4@G-MZI'O58#\^&.S;! MAIL-4&875$S+N*5U]+'\\T8.]8X#HBUZV$&1AHAK,!;.%.Y* NL(/#$0[]QZ MV-;#MAZV];!WV\/>.RLVA.T6@3.8.:D(XP>1(58-HJ,(FBEC3R,:%;%]D20; M:!RL--CSB%7LR[J@=1N H9M#N4MSD4:SNS#V8C_T(O.Q+P"NN[R[.S_K=ZYN M>U=G%YVSD\N3T][QS6FW>]SK7U\?GV\YY7(<,=["IRV]\AP M]@/M![;\ P_I:*G>HIO@A:XCOF%9A).-O51"6TU%RC_B:#+L2MI'A,,6X[S= MA6F6.]+OLE'H]H^[+&LN8\U[ >%08'G3\F;[>//+.$PM:UK6;"%KWB5%FH\M M;UK>;"%O%E'D_$MX*[.EK31?&EF]$%!\=>[=(O5V0>S_?_;>M+EM),G_?[S[ M*NKO'L>H(V W -[V]$38.B;\CQG;T]+N1C\$@:)9VR# QB%9^^I_507P$BGS M4 &L KZ.Z Y1(JY$?C*SLK*RM!%6<^TE- X:!XV#QD'CH''0.&B<)@7V]6M; M=06(=W'FA22A]S3*S[N#B![R4-9.O[HG5MYNR!H,E+7&;TKIF'XV0"_#"0O0 M( LPM)S!"!8 %@ 6H*468& -N[ L "P &VU $/+[0Y@ 6 !8 %::@$ZKF7W MT.E11890HT1U=8A\F=/$R_B=B:YV\8P>H3FMZPK@.,I\:^.[ A@$EW;>N'5@ M]48 "V !+/5@J=O6!6 !+("U3+1TJM^''& !K-:!Y5IV'SN\5)K7:%+Z0K1> M*Q(7Y"*,T],6F#>LE]1%7UG0M_W:CJW\\"(7BL(S75@@ [0 3I =R)TU=$J"]Q V@PG 9WB/E?T :BL/Z M:+6H9'RN4::LNJ'7M9=$_+[2Q;!]N2G>*2"A+S Z4==KNJ%QT#AHG,Z"TT98 MT#AH'#0.&J?A_@ZVV6.(CU[*_',F)O000PO[.5[8;VUE/9TQ@8FT'*Q#@ZR# M_;:+O#P, Q >PW 4?L$PP# , -,L =& 8 !@ -IK %":HR1A>&#*U?!, MXA4+\XP&YS05%7?EU,:&[%4H_8V+TNQCJ]LGMO'V!8)M/H,>6L K/[+< ;*S R 50!8W^H->]8 TQ\ #(!5 9AKC49= MRW:5M;YL/&#H6W/\:I.FMHRM((?1%$R06FXO%:YC.:YK]3K8>@)4@(H%%:YE M.P/+=6U0 2I 14E%UQKP8;[C*%N1"BI A?%4N%:?^XI1!UM2J!A^:Y3TJG,O M2?XIS .:OCL%*30S1OMLO2JLH''0.&@<- X:!XV#QD'C="EH;M3DWF6<9B2> MD'_1+(F_7MZ2<9ZRB*:IV(E^S"(O8W%TSA2&'F)J84]*1UV10%.2$4C1@?_6 M\*^NT0GP!_[ WS#\G1$Z4H-_\-]6_EUEJ\B /_ '_H;AWQF@Q%E%LK =W0_^ MX;$H)7%$ I;.X]0+14HQG5,_2_(9"9E/HY2FY B-:MW:G,+>#EW'569P&[\V M!Q-&-=32-06P"U?9@!:;H Z0'<0=-7W(@%S8 [,;3#7P79?H [4U4Q='_&E M"NH,:>BN1#+RTX-LX,Z?) S*U+OM'#/WCI:E-2>EFVJJH3_0'^@/] ?ZHY5\ MH#_0GWI7.&@TL*UN0'(79UY($GI/HYRFY^016[,94Q;1MX8#[#*+!)J!7A]6 MQA@K,["<(:P,K RL#*Q,E5:FTU/6FQ!6!E8&5@969NNPH>7TE*TDA96!E8&5 M@979.LP=6;T^S$RE6>$F)7^_S&GB9?S.-EMH'J% 3>U%>Z&N[4L;JI7T@T8[ MO]Q44D9]9=N4-<6O@(;6TM!%0W_ !A*&#IHG@,:0$-QF&-U'7234#$$URC] M5^/&%E4@U)QE1STLL<5B/T,<5U.HZXRJAZXIC@Y@ :S#W=FH^DD<>#- !^C6 MQVM;$.; L$"P0(=&>8XU7?41Y@# M(P,CTV8CTT'Q4Z49Y$8EBJ]8F& #K .O0(.N@TC@@/( !@ $PS@!TE#7;;XH! M0 ^P#0@'A>"]XT6*\%2$N=9FGF1N.-,T)PV@@+&@>-@\9!X[18]]:HJH5CE["['4UGCE]+T+H&JA4,V!N_2 <)UAH<5&, W MG XZ%0,P &9"&@& 3 M@1,P"4@&Z(G%@ #8!6$B#UKY+J6VU.VOK'Q@+5^ M,XNM/3S%IS /:/KN%-;0SOEXR&"KH3_0'^@/] ?ZHZE\H#_0GWK+>MLQLW@9 MIQF))^1?-$OBKY>W9)RG+*)IRN]H-F:1E[$X.B>G:)!XY)#_?.N6:V@"W911 M/])J&H4",#'&F!@7)@8F!B8&)J8Z$S-">0M,#$P,3$R% Z4^YD=A8V!C8&,J M'"F-4.14:7ZX46G@?W@L2DD0,NP"E2-064L"_))YXY#N^GYMV8DUV80LHF^FLLO[.\>U7[_7+I7RHYM5 M>7/77A)Q)4L7"T7F-"FZW1,FZ]7FHDD&85% YY3_+\K"1S*)$T(]?TK^S+TD MXP=X44"R*25I/A-)#O%C^:>4S+Q'$L49H?PW(3_LN_-V_BRN&CS>&GB)]T)LOM[OC[_1C&_A]__\__ M^-OBB-^H3]F]T,OT+O$"^B$*OO!;2#[X?IQ'6;KZ^X>0FU=^4GH3)U=Q/L[X M72Z^]34.F?_(914))?J-3GY]=7/EVD[OW]W?[ZY>$1;P7WA^]J8_M+NC#S>7 M';=O#WI._Z;ST>U<]1VGXW:O+X?7K_[^Y,6OO\,[-J,I^4P?R&_QS'O>QI]! MR>7'A^(ZXS@,BA,MQ$-64I1ZLA1EV@Y8J[S9I8R3E8RY'J8LS<@\83,OX6<0 M1'JSXGMC%H9B6PO^'OP\20J<@YQ3E\0S_JN4.QH.K45BP0'QO21A N("<)8$ M;^8 MTRCGRBQL ;^9<9Y) _%(L^7]9=(4<(,C;EZ:&FXH6!R\)>3NS;]B_C5*IIZX M+\)OT8N^T1E_%I+%)!57\;G']5C$/R3WS.=ZMT-.,3]4W$LEYI% M'J:,7TS8HRRAGMP")"4I?Z!4W,ED85GX;U.:I>NW,^,7S&3*5]S40LD+6YEF M_%V(DPFCQT\EWZFX87Z/XD%WW=\\3K()-RVQN#5^J+S?*)^-^7L1M\(M2BS> M5+&R3SS"E+_V.!&1!J'?A;RHN(&U=RT"AI#ZPAZ*QXL"?KCW31Q:&NU=E[>( MG]" 9<*BARQ[7'QWH2SR]N15"ITIOL:-[CU=W"3W"T*HPA?X2?R&\,<13FMQTI!&W[*I ME 0WRP4\XO=<^ER<7/Y"CX5< _[6C_5C*KW2IK>3W/'#XV^1%'OQG:5K/,"% MC6X^?K0[W;YK?[CZT'-'[I5]*5V8>]/[R'^JW(55ZK)*"9$U$?UX>J:N($WK M"')I 3FNPE?,DSC(_:R@I;3 J3#-2_?"64GB_-N4F_XHD/9^9<.7-EC$C6,J M0]"$22XG9):'&9L73BY+/'$1?@@WI2)"Y5=X8)Q*;X4O]R/<_$9<:D5XZG%8 M!;%/S(TPYM(N%W;J6T*+6Q$FRR,I!UE8C^U[Y2?E5Q WRB+A1^CJ!@,:,K%W ME*!X\43E&FQ^EPD-Q7*0@$K96*O?+,7%;]M;7RXB[C^A\>0MX:SOO,R&$!=. M5M@ZX8M\Z7W&-'N@M' Y*>6>G/^6VT"62>=66EK^M&N64$I$O .N<_R\"Z?N M#-[S2X2%E1=(&"-\%?GHKMRTJ77>K[7]/5V?BKG7$-\*62I1R5["%. M_K#$:(W-I8XOK_.-1C21>B2O6"AO&1N)2VW>$!=Q*F]G\<4%\___?_WKZ_]' MOD3DBG(G("*ZVZ=/Y(5IO*3E:;@H JK5T]Y[(==R+PCH,[;&6@8?/%8-4MD8 M(43E)06H_*OSA//$BLA:?$X* M%_)__/"'Z1*YXAI,X,G'TDD9B7- R]AI06VRYH!\$0LES./WSUD;"WYG-..W MO-07:87$1444S>\JC2-N$*19R\4UN#BD(5U&.LL[3()%8.E[Z;0@58AJ[CV6 M!C!91% T*(WF^KUQO5H\^)K!"2CW XD,KS(^2%B^EN)DY8.7H_W%X8O8C >N M7#7%&_G$/T;"OG#-X_^/-CW(QA-(,\U/FI>A;;RXF_7X?/E&=B'$[^;*RSQR MFPDYS/F]I,5[D\JS\02ER2W?G7B&0!PILR5Y<(,R_/+ERPN(H=D7'[\'L1W9,HD%H&@ M.&C&[L-6[Y2LD)G2W%_2_@H1LILP^44 M/E#>NE0381D*R[,:-RXE^2#KEE-)CA6X4BB&,(!]MC/G0.2Y23.LWP2V5 M=%II&O,!F;!*?IS*NY"#G<).;%YN_+AQ04'+CR\*I[4_?;CM)X3V;41MFXZA M",1"R8)P$E)'9L5;V?!&B_"HL)'2J_'QE; -5X5'6?_]8^F(-NZB\%AA^+C3 M'*_BU VJ2\N#-Q3U?6$ENYN4UGQ&T M\'C<669<@@7A>>'1(W+]Z:OTF92LWO^GU3?)5VY U_)^Q9--\J3TH\NL[%L, MK_;>W"<1=A1I$FL]BEN^Y)5/7(9:(FWPAK\]KN+?$F]F%4'78AQ21$\BHN)6 M3L8#Z^<0%8ILPEW,&^D#5B>3$U72+SAL:O4L_6QF'"/7$O$W]"-%YWP0 MD5&QUGP0'\,*$\1E\R0H7N8AA5]??\5<^H7-7+YK&>1OO!#YA>#I*+/PU]QM M/A#AY_-Y$3SPH:Z,4R3L'G'<,H18IEO_N?-LA=$L1XREL^516#RG1:JLN(G" MHNPR@IL1LK<,[LNQ8^()0;\17)5!:1'NR-2;>'P>$<_XS7WE9V1QGG(+7S[U MXO:6,?$\3_RI_--30[X90F;+H(@'!&*FJM2A]$@C7FK'UT3(@D<\XJLK(_F\ M>FAA:[0VA#*49ESEEFFM0%=NF'0EM:5\R4, MTA)>_I+_9Q%[/+5^7('%8'.A67*D)D^;"AW]EO- 7<0X\NZ?3M7P;SUN*G,1 MH*_-?^Q4W+71[TTY&GN40UHQ1 NV%?*4=W;%8P Q8['R#AW'DG90R>DM-7?) M[Z>KY$12OJIN:;M\\301K>O;RM[-N9Y^E[-27/>47.DOG4Z7S,3$QX[N-F=\ MNW_I=$=*[TO=6_Y+I^\J%AGW7V( P4UD^&@)S+DM?&K_I)40818\G3'0Z;4DV;TBJ5^&(L,U3$34)>]JU'GPX?A1[LS'+A7 M_=[P>E344'0ZHYN!;6H-A=J)K,]Q1LF(++/USGMR%S_PU_]%)#:*7._V.]>M MND'K:*0(Y]VU<)XK[SU]+#((ETG\$)%++\WX'SZ)*:IB&H?'%9=Q,G^[$:U< M7G[:B%9DZ<-W/^3#[7NZ&G9QC16Y?,FRC+-I%59\8#GV=HWC269R(9DW7!;K M0XC-+$\F%3.5$_Y/I%(J[:WXVX:$>&C#!3058S\94HMD()>$3VD@I[+4&&?W M;:^8R%?E-]8?3RA/^7QK1G']*47V5;S[8BY'_9ON6ZZJ-[T8)Z^]R@G#!6RW6)(IAA"6N;J1?%2,>GPY VFW*3"021;N3A!#>2XM4K SGC@RXI&T4A M5C'=4@P=BV0JO^.$1O3!$R.XK!R\:9?IS&-V/?27&ZZ MTW6E_'JGD2/MZ^%&N4Q.=J-5#!*=KJUV,/;$J?;.ZU3=GJ*W_KP7%6^T\**% M(A?9[T71TM;+_Y?\4O!B#R#.]?3<\ #P *I*V65!M33*X=I\RMK\_C+M6LXR M%%,Y"U4Z, 2]_7HM$I[EU%-5RL3@FEUXC*^9GE M%8N<,K]L+F[56O\#_W&6TO!^,1ORG:5RAB3-Q\L:J=4%Y4,6J9IR3KPLR2J? M6MP&C;RR3G(Q&[0$ZXD(Q/S-FC"7CRNEN$P%+*:"-X20R"PXO\I\,9.1>=_+ M9RCNCWZG?B[3TK+R@E_KO^:B7BF,T[62\MWC'$L&E)[_9\YDC4H8+KXOIE,R M45 IRCJ+@@[Y>_'B9'ZHM%-/ M!B[CI:F]PN3UZD/S?CX"?K"Y83/V7B;&/X M(=_9>HVI,+MR\/)$64@N*IM*Q5B:/_GG8#5OM]L.;BOO\]+ L:9Q?(LTG MQOR,3ZV%,=+:4BZE'%"AHBPJ@7[Z3G'KHY8<;!^>]/U[(8<+-R M=*E1W*!E4@-"_G(7,^P/15%:P/70S\JE+1RIPOP4U=)B]BEEWR(VX:&K7'_$ M^+G+;R^7AG"3(V='9;5EH2?B?HHZEW3CM(M"41D-R0N,T3L:KDIUR=<]RZ%/LMJA\7,]6$V33JUC;F>-?5@V:+@;;W*;E8%/GG MXJV6RQ8DQLOP:LT>KXW'-[7I010)<[4NP@FILGPP57 FRB#>A(L9G[5E!4^K M<>5$9!B+%>\BV%^]U15E2X=5+&!*NL[QQKE%B0B1 MX_]J!KO#UVK&@HO@.[ZE/O^\;ZH*E[BVCDVNMZ(+J?R'$RVUY"?UR]2 MBF2].8PCOK,\A4 M&WKSE+Y;_+#U\*N;6N_YNNQ3,]S9N^> KK'R7GY]->B\WML!9[,%3WF@<^IQ M)Q]HRG'U7+#-.S*OV[=5B/,OQ-I3#>FPJ<3A*MSN'2>JD)/J;I1]VZE< M5#7HRYD&YM@/1XGOANF"Z3K%=!T<:\!T*8_$3 ZX[IY."9PRSFA86VK7ZO>4 M[7[7%#+T@T [W]U<'GJNLM"X*3R@%WLE-ZORYFZ*">49B]@LGZUFIV6CKJ*> M[IE"AF1M116YO12NH9/:8U&;[M.U^Z[/74S6]T7SFP-!YCXP<1/$Y+D M&N?![^+,"RL=66F4*:HNR_&[Z*=\'FHECMDM]^!TB%+AG3%/X@R5[6:' M_>Q;X'*/R3$W-;>HD)E6H]$6!W1,N ('! <$!_0\3.XQVM)NFQMB&4WG,/,1+]0GIS8-% MI'_ZT[7<^BQ1 PV.YI4O9Y=:[3V,V*)AP;=B+W+1^RVDY3XILAIFHRO9LB1F MT8WA2?/"LFG@[OXX1>>@U>6V2FA$2YIEC[1%XY%Q+#KW%#NLBMX^CXM>)$&^ MO/VRLX38:_UAU>MA?;N]C79OJUV+RMUBMM[)J2_\R./DQQU+[V7_>*>ST4#^ M,I[-6%9N"\E?R.5"CCZC%2S(?W:KG!]3'SS=J^"([01 [P=LM71)V/?"L)H#RJ^;\K>FG4)U*: G@:-5[%JFRJA@>3*6)^\\K&/U MU"VH;/<"Y3.;,64RUL[=P[+!LATOJ)[E= =)G'-#LX^Z]HU6>9S>:Y6*(: ML%2F2T\9M[RTW,"PJH(+9UC;5-ZV"ADS"WQ,_D(A-^$0I3E^0@.6E5N>(00]8+3759=W00BJ(7D&.[2FH::N.0A0 MPVCOR-%>W:JG9(Y'#W'6MN+C)=,\FLSD="S7Q:(T#)S/'V? BL&*G9Z#Z(_4 M]8!HNQ5K?8Y"@1LXN(RVR@*E72LP31.D9DJGG=N$HIW-Y&D4S=6XJN8R]-*4 M3=AJ4>JXW%4Y%;LJ$V_'PCQT[JTY7-9',[43'#3N%,&U/B:\7NS*25B49EX8 MRI_GW/)5EKI[<<+<_+&K.4-0U^H,L'L6XO>S+\" !3A;*MWN*ZL/;8H%P,#J M90&%[ \D6R_RT18EC_PU'!MCM*XB;=@]IE]_N^O1#$)1.]?=.K ]K GM[/]<=M8;]ZC^+;_!S\-TE.@W\R;\Q"EC&:WAW;%[8_Z+F7'X9NO_NQ M=WUU,[3MT671%];I#BZ[CE%]81<2$DV;B_;)44"\0DBRSW,II:>[EWMIV4YV MSW3TCYZCX3N8H^^L&?UC]7[ -L\,RT^MZSO;I.Z:RL:&&/9 ?]$=UC#[O3/" M/*=%0/?$%G1/[%M.I_H9RE9T3S3(@&GGKF&\8+R.%U3/ZKCJNN"UVGBU>>0L M#_N:Q'/^D(\RIQ?+/;HR[[N8*"[V3^/W+(*R) Z/V>?RX+(,PZHONJ.#@_VV M5!?J!XMV7KZI-/1M9:F;IM" (?ZSCJ9P(M+/)#3T1-O4,8WHA&75=)UK2,%? MSW4J#_6:0I]!H)GKI)H"5G>@KK:CZ6"U?ICT2TY4OHIH:,=D/!CLVTM,8 M[&CDC!H#5K?ZY4%- 0LM(@]M[Z-,I=!]K1;Y&=Y];6C90V6KK=!]#>-6&"X8 MKEH29E:G#\.E?=O(P_L]/M,W,DUI]AO-6$+%MA%?QEQV7B9J/8_N%CFR+P>7 MCNM\N.KB323:1.XYSIAVCWH_8)LG]N0GM(E\7M3:M]E#F\@*,J+07[2)-,)^%Z'E M#T))BXSI-Q:) D,23^0N;>5414/)/$EH<,HXI6%EA Z:1F#0CIK:TMN !20 MCG*K"D &\2JN6ZN M+6 64ARZCJM._]H.*$9E/RQ"HF(;-;7E1UAV5(_\#%]VU!TJFTC!HB,M;9IV M 0?,%LR63C64,%OF9T">&KG%*K\!/\_9#=[AZR9J%*AI0M1&<-#$JDJG=]E4 MHR3#0SODVE0;741:\ M-H4&#)1/*7)1%IY4,4%\7+N!=LX4IAW.C?7HX%1/!]2M)IG&1%2H9%]S3- MI$SE&5;)FH!+G#S0A*(#^OX.Z*/16]<9#GKJVJ [_1?V0>_VFMDFO/%]T/& MIC^@(8E_[08=R]L=Z-3WV[@NW^A&#ZW44BNK[3'?D 3W;IEB*Y"SJ?-B@$H^ MR)$6+*MZRPKE/%4Y18Z$R"0)]!)ZJ8]>PFA".;55SN.-INFE&!5&IC+[7\WJ M*FWV53'!+IBBBMH)#NH(==1(<+JH(S0.&@>-JS1':1N;I)2'W>XL(SCG4$\/ MN2@K!S-G69AKC4;*-F5K2I$5DAFP + L "P + +; %;2SAAV '8 =@!UH MBAW --*STTAK>V>:.)=D5N[*()733G#0.&@<-,X(P6DC+&A<&S0.,T*W-&)Q M0C['&4U)%I-LRI* S+WDW$U,]1!/"P>#SL#JV]@'%/D@Y(-::P*&EHVI(9@ MF(#VFH >H@"8 )B -IN OF5W#EX WA834.6$4#-R";]1T>IUF5'P)A,6,B^K MIH-X4W865^IN&]^G'YEB!9GBMJ#%W=A 6=]^H 6T@!:\%M "6A6C-1@"K4I' M94TAW.C%"Z]8ZH=QRL<( MQ^_(XEX[SH=AS_XP<#Y>70WZ]E7?*79D<;I75_T;XW9D*?9(X:(GQ5XC:3Z; M>0G_7DKNWOPK'C/^8C=V85D3)/&Y=(DP1"EAT41L9B(VT,%^*\_LM^+8ML*M M5MP7;K72&S5S'XO&;]31^ (DTSN<X]R)=(D3L@\3_PI_T(J9F3G23SGLGJ4'I/^F;.Y2*T@4GU>OEV, #$"Q A0 M/5G?,N"SR2VB6)^B1)I*:ECM4MH2N*9#IQY.Y+LHP'M#] M!E2 "E"!+-_+LWQIFGN13T7 E4[C)'N3B>ZT 1UG,LFWFOQZ-LFW2@1B]/2# M0BHT8T=:0B?OUA2P7'75OP +8 &L92)] (_5L(Q?=7'DAS2E64H\GT>%(MO' M7S5-%NMS22@GDN,QO[+LQ(FDGE*\FD*1?L"8ZX4,HV& 19R 3"4BT/ 0K/R M=^I4XS>:\?A*IMWB"0EC<=?+A!UV]#U?JKSQ0QR#<#/740$P ; -C^KA== MJ]M#?JYA^3EU^G$=LAF+9+)-!(JBI"Z/O%G,G_/_:$ "EI8K.L14[IQ'E"R? MI81_N>Z0TC#N4&2!A 42%J "5("*O3,\'67-DYI" Q)YNPKO(OJ 5)X^KJ?Q MHR&#@#/760$P ; -C^5)YCN2@.1RKO.?VXI5D6+J=\EZU8$NI3=E]T8Q%+ M:U?AHLSIQ1D_(8GS+,WX1[& 8^R%(N!$%@_Y"N0KD*\ %: "5!S2J1GE>,CB M[=]-8$PC.F%9$8S)'!Z/T!;[D\F)6 R"D&5 EL$P;P7 !@ V#[TW@#93M1 M-AZLUN7P/M.,>$^6R+*(_(MF2?SU\I:,\Y1%HG,>#R?'9=V>1>AW/\QE[DYN M2[ X$H,RI"J0JD"J E2 "E"QEXJAB[7ES\=?OV1B"G'G]W?\_+=?\O3--\^; MO[OUIS3(0_IE#;G#Q%EZ9=)D5*[\[Y??Y_3**4?B[S:YFFX[",AX-_HY-=7-U>N M[?3^W?W][NH580'_A>=G;T8?[0^=WN"R>^W:-S?=FX_VQV'GJN\X[DW/&8RN M7_U]5[17"O^.S6A*/M,'\EL\\YZ'<^WPD =P;Z;%EE*.:[\^_PNO\^9..6XM M>4J+=[W]..L?3KD&82E)\]G,2^2Z%R\EDSCDRKIG!Z\?B6X-;)^K+$T.T8X- MFVES@RC/PB)N^8O/ZY>)XF3FA1MFU1'?69Y8,DM\&H;E=WY]9;^2G[E!\A>? MC]=K+J9O+"INTLNS>/&+PL/)WSRP()OR;W-!C.,DH(D8HH;>/*7O%C^\?VKZ M5O>]/MA;F4]WIW=/*EPK]@(8D M.O2-11UG7_JP,$*E*)SY=Y+&(0O(3Q/Y;TA6'<5NN887A+'EC9=/ M)/^VM7?E[SPR(-?L$BP@\*1;NZGT]1W7W; M[=6JN7O$KI WOUQA0:^0*-5+:6#QH)C52BD0?7I9E>KU5=V]K+/$E$ M8?U:#H)>,RK70Q!_42T"]4^L>DKWHJ-LO>RV>AOSXH\)4#$BA6UHAVU M$13L .P [,"%@QCAB!BAPARAZ2.-V\S+*#EEO-N6M2]NY5F4MKA@I)& U?(P M;&P*K( 5L#H;5L@R?\WY,\;D-^;'E2#U7'V#+?^91I:C;*7-/L$TA3"D9 #3 M"$=-,H[23#_0'^@/]T6EE23L*P8Y?F&G#F+S!I'25%9XTQ8T MAM;"<.$J6RG6!K>!5)RN=?E-&?TXZE9NMGUZ&%D'5&THXU+9EM/ $E@"2U58 MUK8BI_%8*BBF:L0B@F!'3=4Y"#T%Q-WM-'A(V##8,-LQD&W9V837%A*T--G_)O'%( M=WY_Q\]_^R5/WWSSO/F[6W]*@SRD7R:7\6S.[R#*TB^33W*0=N=]ORZ&:!^+ M)=5WXAIW7" ?P]C_X^__^1]_VW6:*!"'!!^]T(M\>CNE],F!7.*1$.MO=/+K MJYLKL;GNO[N_WUV](BS@O_#\[(W3^=BY.8];R[7#@]91-],BRTM'==^_?Y'&VF^ MZ,7+CUN;9RZE1OA/4HN]C.-+2B$2*47R*9K$R8S_)8Y^J")G>; 2L9*]K<>4 MUPVH'R?R_M\);5^LXB]V!U]YHHYCD9U;+BN1]8_+Y0^4W0]MP=HY-IR=2.#( M)Q-L--VRY([ZS/+&$G/@T#,OO_/K*?B4_=0:]UPO3RM]IZ,U3^F[QPY8(5K>VGNU:Y4N[.[.7!R3,Y"WQ$XQ> M[[76FRZC/- Y\;BZKU?W<7@^/>X3SX?GJ^YZ;6X-M-OK7["(\(-"'GNDU6RD MC9WAGQ']5T^T)54UZD/Z!3KYE% KD,V8U'Q^4/POWF:S42R&VH+ MM=51;6EPJ.2K+#EL6!+@0YK2HY _7*6KE>?N91VE*IG5SM,@S=1.<%!'J*-& M@H,Z0ATU$AS4$>JHD>"@CE!'C00'==1C9X*&#+"+=$6YXZ17V;BZGHR/7FJE MGP9I)Q_H#_0'^@/]@?[H*1_H#_0'^@/],6=8UHX>+)=>.I75$+[X@?Z9LWLO M/'<91&L6]YJ_>+L+E6W3'V?V X7@<&48A8,')[$H37HJROT!HD@$22> M&)7:EMU3MO$K4 2*0/%$%/O# 3@$A^#PS!Q6D0D%C^ 1/)X8HG:MX4C=K!]0 MK+9:LPYPU2G7UR2>\Z=])%X4$+K874-NH$&VI'F*,^&'I?G\&O0?<1P\ ML#"L@BG#T$$7$TS)U>!I0 6H !6&4^%8_:&R13K@ 3P8S@.\!*@ %: "5( * MQ$XMK+2K+D-U.Z=^EN0S$C*?1BFV_,7\"N97C/-1 R 3 MG\"LV.->LK: M9H,ML 6VX+P & #8 ,@)D-&*)#E+<=HR_%GBHLRKSH&QN'M.R/*-?M5L&9 M83AA@@H35)B@ A6@ E3LHZ(W4K8F#C2 !L-I@(\ %: "5( *4('(">5NRI3E M4W1/TTPTETL)BTB:CU,6,"]AM+JL55.RPT[?O)L7(YV\#^9X '\.#9-/!L MK:^*^Q1E-/'C&;_V(TFH3]F]-PZK65D+GIJ"C7Z$F.M^#*.B;SD=9;D_\ > M#.>2O 05UR"YCWM1$MP; !@ V![ 1MV!P +8 $L M>"X !L & #8 ,H2%*YHY2EJ*17-$]K@JH#&,'>7K,7F'VZNEA[A P ; M( _K#)6%5Z !-!A.@^N,0 -H U%39S35^8<4!$'5!J,2E<=*4UQ'!56PG7Z M9J>I[N+,"X]/4_U83%QZ/:5])#Q M7^H2[%Z5_9& *Y!C!>WZ>GWW[-*L0>7.;S,Q,W9Z: 'K".MXAL#/M5Q;74<= M6$=81UA'6,>&6,?>P+('SMFE">L(ZPCK".NHF75TK$Y?7:]N&$<81QA'&,>& M&,>+7M<:],\?.YXT<6F HJ+1+4RG7AH)TZE(D'W7ZG;Z9Y=F*P++-B^YD)\> MJ+RA<1P&Q7G^R;PQ"UG&:$J\*""W6>S_,>5_IDGZ5R*ZP&2/1^CF\KDZ%52, M[!&J\2X&+ACZ _V!_D!_H#^:R@?Z _V!_D!_SB(?=.M\+H=PF2>)Z,\9KD9S M52A=G;+47AL-4CSM! >-@\9!XXP0G#;"@L9!XZ!QT#AHG#Z"@\;5-H[=%)1M M]GCU@^]S7Q482*NO:U!0+4&4UG.'3"XMRN')V(2593+S)A(7,RTZKC&O+_DT5 M>-S&[^.$"60%$\AM 6R@KH4,N )7X&JQBKX'KL 5N$) ", & #8 ,@(G# MG Y"PTISBHU*'=Y.XR1[D]%D1@(ZSJH RS!^, F'2;@:W(UA5* R!3 AD6( MI6[',= &@RG 0$3J 5H )4@(J]D=,0D9.*'%0[ZMJNZ(0F"0U(0N]IE-,J M &I*VA?S*IA7T=)# 3 !L V/Y246< L 6P(+G F #( !, &P! :HJ;M M.&WYDO$_$5_-'A$-2\!C6@K34IB6 A6@ E3L;4CJ*HNZ0 -H,)R&80

PB"_>]_OGW;LOM=MOYO3,*?8B$XR]G[^8DD$SY>V6'7P7 736EEZLD7A M0G%)_ 3]=QM9_Z7YF1WH['E'^ZON]S29E%5)B+?:ZA^' M,>$'1=PUVJD4;.L&]K61S:CXMZ(\D;FVW6U5(?;71;WDUKU!V+-;F=WC:M%_ MH2G_1>1TI.5TH)-OULF/639E*702.JF.3OXRI2F-\R0EU]-A%@8A34.604>A MH^KHZ*0D]5U].7"50:!^0R"L=A7+X_"_XSS7*1487:0FV55%L6;"MY MW0>%U9@$^,KN63S=R59MK]352G3UPNA,F?2:;*>1;BHG.*@CU%$AP4$=H8X* M"0[J"'542'!01ZBC0H*#.JHQI-N0$+LX[)JE]Z'/2+I[9"U=1FI(1%IQN3Z- M+17,1C2EU%L]+E"+0,$#X 'P '@ /& 0#S@]R^MW0 &@ %! 0RF@YRYW;P'_ MP#_PWPS\'SMM1_9=8Y(%R 'D8 Y.'W+[D@;TF6*?Z!['9\\_;C\[S2<%/,. M]EA6>.X]KW.5R["=B;#%B3*P4LX. V & &@,D#6-OJNO)FM@):@!:@!=L% M@ %@-20Z.WUYPS&;O(,=4 ?4[> QVIZT!4;C#5KCJY0_Y_Q/E283-<,/*O6P M$E>#N0$J@ J@0G-4N/(J.8 &H$%S-#@M:1O: PU @^9H..ZV9&M)DW-<0(JQ M2/&%<,[=\Q;"B"^$5:\R36=Q;NES5T^3UA:;N_$ODU8G%6SS4L% M(M2!"!53*^7D _V!_D!_H#_0'S7E _V!_D!_H#_Z[!*B4%JFNB3619+E)!F1 MK-Q&)+-X[.9'TRR\9^+C@$U2YH<\JDOB8A-?.DZXK/Y7?I#=)0_\OVQ">=S' MHDMD,"M M^?/^^RB+ [ MK J&0TG;5@9E<0 =0+>=H^CUT#Y1:<;1I,3BX+7^VRIPIAF<4 :$U2NL7@$5 M0 50L7$#**O=DC;A&G@ 'C3'@[PX!& �' UPFH *H6':9.FX7>)"0E%(H M"5Q]$^=O+$^3+Q?79#C-PIAE&;^B\3",G[)6;Z2CQF6-4;^#M5 E[1D !H ! M8 #8YBH>NP=@ 5@ %BP7 : 6 & &@,$U1$'<3LKR"PUCDL0D"+-)DM&H MV+MBPOP\G8Y)%/I[;SMH6.8>ZUE8S\)Z%E !5 5&QN!I!4"H=T'0#$8*# ? M0 50 50 %4 %G"J93A5JZM:)\'/._V21F.55@,J4'#(6:;!(HZ35 L , , M -L\JKX%7 %7P!4,%P &@ %@ !@ !H#!,ZR[/,[6.UUXD^2B*&["Q*X3\2UA MWR:5E<0-DS1@Z5PJSN0;R9(H#,C?[.+?7CB;G5-\8_F$AEFY#>+;7A0:(Q8K M9, C\ @\ H]ZX]'UK%97WJ!^0!%0!!3W@V*O*R]@! Z!0^!P/QP>]]W:#.)> M-6(UH!=5^0"ITB 5?JL+>WGP).R6R7K-L[.?G_*R8>PGXVHV!=ZD@S*7152% M]2'20^ODV@C08T53 <,,: /:@#:@K2NT^[:T_5D :4 :D%8 TO+VF 6B@6@@ M^N"(AO\-: /:1D*[W^\ TLJFR.N'7D _V!_D!_H#_0'S7E _V!_D!_H#\'D0_FTZW+ M&7R,C M, IICBUBJ[%E33%9L$S&HN*XTY6V'7D3[ R@TEBHP( %4 %4 %4 !5 !5 ! M5"#84#"II5!^N89L5X6#Q0Q),6,-!VLX2AHO P \ L(T DFR6E$$K72AXW8HN$ QK'96S5@]4T!6]L(:!_W[<-OEK97'J<& M(E FR0.\ ^^2CGNP'+ <0 I"#]@/H&)W5+2EF0]3P*#[ MY$KI":V5XR&(V"O-=#&[C)CM@= J6BY2T30 8 : 6 ; 5;#SG[ M%7#5.%P=N]7/_$(:#Z #Z. MPJH!8#6MR_5-H7/%(,&- %-ZPQ7 M&W8+=@M(TS/# ?L%5#4;5<==>5O^PH !:H :#)@B&<5FS+[\Q/*GF9=%]K%N M-M^IN_Z TR+>*NB_UR78C7I;<[.]SKE>C#+ XJ=\#P:\"=ZLGS>]PP^ P5 G M,".8$MS$!&+$V:!.T"=I4=%D4O G>!&^" M-TW@3>0H%5X0U[3%IGCWP(H+&"914)[G<[';HY^,)RF[8W$6WK.7Z^#%QH^B M%2>GWW90RJ<;\BJ8@;4LS3?-F]?+Z-0M,-TL-C0/F@?-@^9!\Q00I ["4TI@ MT#QH'C0/FE>E\'2?6EM= JOR:%BI3=J:U<1A_+P8C1"L%A\"H"M6[CQ-%^[4 M,"18FP-HZP>M>_CZ31A3X!*XA+<+@ *@^@#T6 '+"6\7H 5H$:(J!UH)15*: M#P>Y27(:O986KDL/WXQ0\TM#JY.(S@,\FL!3ZM5M*N=#U%_-CJ+U79A)A]KT M8T]ITM) X\!H&C.:&BJD$FDIPDO]=FWA8%-RJ. 7>$R*DX\6'E-]PR/@,H'2 ME*,T-51()=92A9AZMMK,I(;F@'PT)A\-C)M*S*2%/X4,U '6_G[(Z3!B*[^_ MXO5//TRSDUM*)^^O_3L63"/V>721Q)R#,A9\+-;.KG.:LS&+\QMQXAM^L^=1 MXO_Y\U__\M/RL0,VS#_&69Y.Q1'9T[>Y"&,AIZ]L].'H:N#:3OOWUA\W@R,2 M!OP#ZN?#D7U4 MO.>P\.?O=W\L#V&0W_&7_!YG:.1(B^@D8^_G+Y9N_OFB%A>YGQ#:6UGIL,4R M>7$M'XZZWKN-V'_)7+,#G7V/V_M 78ZKYPN.S;5F>53\6U&.PUS;[K:J$/OKHO8Y[;%4CK!GMS*[Q]6B'S"?C8W+'OK*,Y3.G+$\('8W"**0++EI_ MGP!E4XN09IT^CL4]6%EP,P4XZF%$.=,./#0(#T@ K+#(-=&1TPAJ^AHJ0*N)T-(D1JK2@G7<]AH+1N 0@#1U^X #_KC0?< 2:8Y65WKT&HQ,*8X[@AE8V82"EC!6@U M$5H-C(F<=:M"NXS^,]<'1!(<,1%B(N !,=%6UJ3K.35:$SAI3732-(*6OH8) MT&HBM!H7__1.G7Y[^RP>8B+DQ1$3(28"'@R/B:HTV5 M^"Z;M)CK.GI(IR.40B@%/""4VL>ZK&UI]="#A$8)A$?Z6"I JXG00H!TVO,Z M")!J2#:8 AGUT*&OT0$:=$<#@J-7)M:M2[UMO6E:,QTXB26NQCMP&D%-7S,% M:#416HB-3KWNFO3>+MO6FNH-.E87_B"B(T1'P(.Y\5$M\5 '3MMZN;EPVA / MJ6683(%6*:6>Z[C5ZYJ!05]+HQD>*C HIJ!"]T"HNC3;/V,Z3OC=_X];ETG*QN%T3$9I,B:3:>K? MT8SQ3T.?$1I%B4_S,(G)B(8IN:<1#Y]H\)]IEH\9?P#P]-8;*M0$(812R; 9 M ZS>+LF;9@.K<:'3HF4+PLSGSS8GW'PAI%HOLV-'FJ5:5H-=;_U@/M$NK=6* MP4=?FZ094A!L&1MLR5.2"SH)CLMPS7;D],(2OJ:(U. MU9+GT1D/+$U"I.H:!$C5I1%GAJR^E:I9W#T3S7+HK1G6JN@ZW" A4["G'LPT-EUFH4K> M2EA3P(25L@TK95$BKEYD_79<,ZL==Q4[76\5Y]_KDMU&[91?^%[!"J/=JXW+ MC/?6$07O[TJ QD!C>].88_6Z\I(*3:0Y.9T^7[E6P M^K1!;KK)"GH%O9(N*]W7 BOQ+(IW#^4S&B91,&M;BVB6A:.0!:)?.K]C9$@C M&ON,9'>,Y81F[ZO0T#J%K;\'K(YF*BF4 "BI^V\!I(GA(Y&8132'-64 MK\FM;4GN??IAF)[>43MY?^W__+3JVR.6IBRXH=_.LHSEV5D<_!K2(0_H M\Y!E-^)JGD[!11P+.7YEHP]'5P/7=MJ_M_ZX&1R1,. ?4#\_N3BWS[J=JY9W M;GO.^\;Y]?%4NWD=X+2A=.?7&6 M,.;&JGR_^#-QDHYI](+&'/&=IQ,7JDM\%D6S[WPXLH^*]QR7_OS][L]]3-/; M,"XODD[S9/Y!:92+3Q["(+][W^^?]NQ6I]=MOYL3!R>%B$XR]G[^8DE!GB]_ M,1AZ(I/>RKAVBW"JN*0/1UWOW4::>LF7LP.=?8_;^T!=CJOG!YN\/%R\6RJ3 M.0YCP@^*PB3.=AD9OWUYPCIG8%3\6Y&:8:YM=ULUE2^\1K%O$/;L5F;WN%KT M ^:S\9"ESUZ_YUADG=\A##.B)OGY5.AO;?J[=6H$"W7K K6Y:[_@C%:B]-7* M"1 64,150 M5K_?E77;IN0D$1> 1K# *[EM5$%75]DI;OC\!1:I95-X3*D-,NQ' \[G2%" M1-5C!="R/7D51*9#"]'N5Y:Q])Z5*]+4]],IC3!(3P:)YT'1EMKR.>=_@K?V2ACD2#,NQGMK"(,0!B$,4L6 O=0'S0=BK"@5MPA_YIDR MZT.J;H;>LGJN[#$.9C<[(W@"DE8CJ=V2/5; ;"1A2[&URO0O&DUIL>,S%7WU M8I9[)=[B6[>6T<2;/&[W#K^[S+*N:5-2O4NW-&*\RF.\IJ"VLWT;+5#[!M0B M@%P90,:LDN4SP[;2;5EN2]J:0E-VTT40"3RM6U*P^JZ\VJJ&X E3-+:R; MS MW/9!(K9GPK2,>KD?&H>!&#N0W?6$^6)P*"(<=K,->?ZU*7A #=Q:??F2)A-^^X]%CQ#[[S2<5%57;4K>UK'Z;6QG@SA! M(1ME#K1Z752<(B#:J8";A'%.X]M03+???XZJ86Z@T\74! 1%"(KFY=9HDD-( M=/BVH(94MI35VO8'$A?B& ME<3T+,]VZP*D*;A#- <\K<%3U^K55UEM"I[0K;16GSZQ7(9YJQV"%?M>RFQD M\&:O7?T=$%J6W8'/CECZ\$X%6 PLMJ^L/*O7DS?WI.DLILD.R-\SV'Q7]"X_ MS\'9;.M*[,,47"LE*^@5]$J-HGZ%_+,:]W>_B&B6A:.0!Z%)3/([1H8T$J,S M2';'>(A*L_=5:"AZ4! YH.M)+X(TA =+VINF8AN_EQFX_6885%O2I'\(JD\D M64&%B2EAH7KQL)YWL+%(II268:4* M*U5J6'E [AYX2: DT4?NI:%Z.&]&I;.-;'FZ_5=S"%AQ#O@V' ,%N* MI-8*%%,89L'3^2&GPXBM_/["ZX7[BL*8GCL]4\_3+.36THG M[Z_].Q9,(_9Y-)\N>4._G14K#F=Q\.NSDW,CA''#;^@\2OP_?_[K7WY:=8HT MO*=Y>,\^QID8WL;B//N%AO&O299]C*_%KMSBL\^CJS"FL1_2Z NGSR0=BZ7= MIY-S]8F%Z+ZRT8>CJX%K.^W?6W_<#(Y(&/ /J)^?]+RKRUZG?=6^] ;]]MF5 M:U]XWJ#C.)[3U1ROS4=[<,3)* MQ.80G$A(H74DFX['-.7?RXK5[ULN1'(<<3'^@_#[#^_#_)&D+.("Y>YH0MAX MR+C]";B/.G\$&0F?'P+_KI_P['X[L MH^(]YR-__GYWG7@(@_R.O^3W.&-"3G$1G63L_?S%TLT_7]1BR/1,C>[*\'B+ MJ*NXF ]'[?Z[C:S[DN%G!SK['K?W@;H[/U^NLV\:;U3\ M6Y&18J[-[6+5:3R?"HNAD=!(*1JY]:H>BD/6908O5V0+#HGSQK0]ZM_6>.RTI%6A-7JC/HV(2#E# M"@)J+@$YU=./*6M9H!A0#"AF'Q]'7N5@DUVEK*VO'KA^I*F,9=U MQH^XOJ,I.Z=9Z)_%P2",IKE8$E]<^]YB>;K3'G2O+B_Z5^[ N^KVSESGZJQ< MGG9;;>>BK=WRM)^,)U,NXC")23(B0R&?8A>=H)0083,)D@E+229D2!YH1OC_ ME2O;6%1>MZC<[Y]V[+[7;6-I68<55-P@EI8U]&<575J>_5C!N4N_I' >&NO. M%:X[6X1]\]DD+_V(K/ SGMT*.N:ZEQNY.*TK&F2N7&]Z!'5+6ENBAZY7I>O5 MS]N&KD/7U=#UQJRVR\N/B5;1,/:3,5,RWRR-#@Q/1EELA4%=H*[=!>6VJM_\&M15/769&UV U\!KNPO*DY<):S2M-3E%7APV".]# MSH-!)B:@3]+Y[*$L3_P_]\F1-&QCO.-V;;,OFE#+HQ[RE/,7FHJT ^R ;HJ1 M ZJ *J!*"==1H0Q?%4L1A.9Y&@ZG92UCGHB*SC%W+ MW\BZ)N&*HV0*X.MB1 MJK$&Q\9ODY-L3NMTJV_>J4%?#L]P&I&9<@X%.GN:V]E3QZ(#. 8< XYI+L?4 ML !@"L5HDN-7=T=9[+Z+79VA5P>7%?0*>J7&9K@*.>75>9O_+IX1"PCE0J"W M;-XGEDSS+*>QN&9R4O:H[Z.8&Q<:#-DBJ^>X5K_?LFP7(W40%*NTDF<*P.RV MY?9:5M=Q 3 # "3OY[$+5B[;?5[-@!F5LZERKK*:"K&2!$V&C$_%^.,%AW' M8D&<)!,QZJ@U7>D@&VP8J@ J@8KYPW+%ZO;;ERIM;;0HJ M=,]1JEO0N=/ XAH%JIL0E1$<-!&:J(;@H(E-UD1-4B7RW+?+YH9#S):+*R MHN[2% 9^89 <].K@LH)>0:_4*#M0R"V7XE,5[Q[*9S),HJ \SYTBAZ M+!.-HK4Y8_Z4GR!DV?LJU%&Q\IB#XU@98>D6'4+CH''0./4%ITEP*B]U\?G5 M,6W3^)YE^7Q6E:OY5I>%Z/;M N.U&%GPS#A6"VW8WDH M'0,F@(DG.]&W^U:W!4P@V;%&1;Z\G,OV8B-9POX[#>]IQ.*\DH&YI@R,\5S+ M];J6V^E4'EZ: D"-L*:OM3(%7U4,9 + # # "3X4+^D--AQ%9^?\7KGWZ8 M9B>WE$[>7_MW+)A&[/-H7M/^A:77HJ+]7'2_GL7!H"QKOQ'GO^'".(^X6_;S M7__RTXI3%*-VPWOV,>8^'+NAW[[2G'UE?A+[8112D5I[>1XN_%A(^"L;?3BZ M&KBVT_Z]]N>W;>/>NT.[VS*Z?C#3J.XUZUSR_= MBZ.?5SFF,^G?A&.6D4_L@7Q-QG0]KA<.C\*8G[/_R$,\CO^DM_C;#PB M)X.(3C+V?OYBZ>:?+RI=Q=?]E1RZ1=Q77,N'HW;_W49Z>LF!LP,==]\#ZSX. M%ZKCJHNZ+E)OWZ&QH^+?"C^!N;;=;57M0OF<"UDJQX>:7?CLCHJ_+=60_,'= M#'+)*3@@ ^:S\9"EQ'.L2A-6T%,)PXVKT-/=UZH/J+G"+Y05%4 CH9%2-+(% MC81&*J616\\LTGWMJ;K&KJM-P;>2R<\9*HK >0D2BK2)>>W3ZGM1E]7J0-*3 MK);/I/I.204TS!P!N4 ND OD KE [B[(U21%5IW,KG.Q[,1]9999)&;%MIOS M]:PAB]DHS \9-2L"RV/G5%HYY%[H4T-9_H$$2CUV3V>H]$ZE;3,$J J)D/% M$? W]I!YGKKHJQ@,&7Z?2]A POI)1(]3I9<],!%8= M20T "\!J'+#XU$K43?$J@%:H':6E#;EEA("-16F.+]<-OZU+_S2&J=N65V:RK9@T M1&,%(SQ@-!L+NI9=GVT$Z Z@(X?YLFL/@'H*MN#8N<-)-9L1#&>1,DC8]]"[M3^2X55:;VK\5.;"=#(4"Q.=N3! G[ M)EZ7&U*D+*)BL]P%-WS6))Z1!Y:R5W>B6+BS%RS3I)TC'/=@6T?L>USM.S+@ M!K6\P<9771V',>'?B<3>XKND9)^N=^,^]IB+7?YM:2[VXE8715?JJD5J;#!0 MS3AWJ.U;U?99_AOT%]L10']UUE]L7B!A^NKK<=HA&6+M ]!@$O#?I:6.-FFA MYO.F.8PK%U4-^G+X8DB-Z$PYXPWJ G7M+BBG7WW?-Z@+U 7J G7)IBZ[^GF8 MC:"NQJ>I/RZMW3TMZ^4)/]?J\'*?Q,JF?1[?7&M0+P2[TN(>4["D'FR4L_;& M@D':. J 6#0' P>YEK*\+(4BAKEZ<97QN_Q?]R;8M]\EF6+?E<5R*FNTZAF M^]*O/-PQ!6L:P4I?BV0*KCP,Z .N@"L=AKX8#S"Y;05RVP%6]QQQ9\C',:WX;\JL^RC/$C7[0L;---,/#Z9UW'.S]OMSJ]=ON\U^T4W03N9?NJ MY;6T[B:XN6-%^C 18ZDS,7"!@3.QYTW-B X[7VK MR3U-ZN5K[[# _>'^<'^XOR:VXR@7N3Q=^L;(Y=!EX5L[_G67A?\S8Z-I1(2; M?- QTX9IYO/E.BJIIG;]">@#@UJJJ99;YV8U,>Z5%#&MENF^S;>*24Q=="O> M);=][:):7/!+FF2%D[0JD7HVYO*2-A"Z;D%#U:'JBZI^YOO3\;2L-.6:S27[ MOUU+2Z'?T&]E]?M3.;M?%R*'+D.7X99 U9NNZG!+H-\FZ[ER8ZF>I;KA9-1-]AASQRY=1%=N:RL7135G$5HQ$-Z*KT MF%N.C?)P4%!C* @#,LP9D''<=:IO&5N&X8&DU] =Y$!Z(#V0WF+CN;1*IF9/ M!0*O:<]KH"[UXDEO^XG/B"=!0;I3$%PK++)#1K%837TL6\JO9G');T!NM>4-2-@@LQKTY_"6$<0%X@)Q51\@ M]SKR(N0M12:A!UDIG4,E%S@-G*8.I[7[\E:IX(J!MD!;H*U:8LA.5]Y@41 7 MB O$!>*J)8:T:^,MQ)#@-' :.*UJ3NMUY2UBPQ5[L=#]0TZ'$5OY_16O?_IA MFIW<4CIY?^W?L6 :L<^CJS .<_9K>,^"CT\+QV?%NO&-./<-%\1YE/A__OS7 MO_RTXO!I/DW9;_PDX^GX*^-GB+[0Q[$8&W65I)\G+*4Y5]E?&UW_U8 MI1J4HB/C4G9D,A,;8=\FS!?[VN4)&3*2,I^)IT.$;2#Y'2.1$";)63KF?RRW MP.-???I+0!Y"_CG+,A*P^]!GF44>[D+_CI_9CZ8!(\E$;)5'(WYX%@93_F(X M?3Q)ICFAQ=YB&:%Y<3X6\Y\=??>C%J'\LK/I>$Q3?DSU\LW?SS12V6L#QQ56ME*=(613#%M7PX MZG7?;63!EW0\.]#9][B]#]SIN"9/[BO>+6T@>!S&G%JBB ,]V\4A?KH!Q3=V MW%23]\I)YK]SP.T=;Q)N*/>P]VC3?G'8']R#(I>QN#8RX'9R/.0FTG.L2O1= ME:'&RH>-32;CXC#NRG8.F8-00PK2PN3J[EAVI-N7-XG9P& 5QNM[EMBEZ[IQ MK0]>J_JF]$:CS*C>AYT\:B2VD=B64F7@=I#:5C>UO7]N>G6R^V/L)V-VSD9) MRLK7-_3;@/]/QI_G61SPL_) /]XYS7T^Z/;.+^V>YYU?>4Z[U^D..MZ@XSB> MV^HY]KG6:>Z;.\:5=9KZ_"J3$5G2A'W5;)_CRH=&AL43)&'Y+J??V(H>N;=> M(WE@J>C (Z,DXJ%Y)B5!OI2GTCQ%/J;I;1B7%TFG>3+_H/0NBD\JR*([[AO3 MZ.V^F6GT QZGS86J?8.:Y-[42EB^X 9'I76/'<+ONIM=$4;%B M5]N*W0%U63CELN(XD"DT4HI&2FN\@D9"(Z5HY-:+6UCT63LD_?3Z])"XKG@E M1)T,]!OV_%4DN]SK2]O:Q?CU+XVX13G;"(YI+L=@C1T< XX!QU3:TBIOF%N3 MQP8W.6%:'/9ERF\Q(5]#/]DG\M]8-E=!S<\!J^=ZM16F-,6^PXPW%DP=:>7\ M !/ U' PM0$F=7HH',V=PETJ^A2J!6]*]+JIIEG_Z+8O;P/VO:5E"L\APU91 MA@T6VKX#!P&#@,'%9_5%G;U@O&4YC4)KR]>N;6M=\%;+3MN+HM MVNXZ/<^]]%J#P95ST;KJ7[J]2>1M.R"R\3(^;2Z9A$H<_BC']81;<:QKD]7]3*1C37?F,CFF=H&Y/Q?5JX M0=R@XC?8Y(*#XATZM-:+NN[N@WF+X7-?I[M*KH)Y&*Q>70W_?K+^? M6$YF+CD4$XJICF+N3*QH2X3^*J2_(%8HII**N3.Q;ETFC^[:=8L U]^G-0]) M"8U97-)_\U?/DE>& @D!!H"!0 MT$ZRI"P(\ROJAU&8ARS;:=OIP?F@[9X-+B[:CGUVZ0T[@" +ZJW"E&@HJUH5"__>%_):DMS06-5894S* EI:$,#RZKD). MTA=!Y4%SF*LYY&0*_S0Y\)TYJ],\\^\8.:?QG_O$"9N& M0NXCK$,.?936-F(*1-1#@W+&UE@P2%O@-@4,54;@MMZ6Y";):?1B269((QK[ MTH+Q6@=KK8X,I,[K5Z\KV MO,M+[ZS?_Y-P)YA\ M$?_[0-, INQ6<.Q'KJYAG(5^2;1[Y%Q03/OBL*=?U/8!FPC)*"TZ$EQ#F5M[,;U!#& M#L9NN1[5D[>'M>FFKLG+/L5A11:6!8>D%D5@T[>Z'=NRVUU9LC %(^K!03ES M:VIK@]<^;4LK;@,>&H,'Q>13(4*@3"!7157'%+[%$M0Z#?I7L?ZD9#Y%$7H^ M=L00]([EM:I/_RYK275RDJQ(TJH6%(*=OG:L.B#6"SZW?>HB%05HF;WJHHBE M@_J!V9-2D^6 M+/#5'+AT3R5.!]P@&U-,&O"DG@%K;+0"96LL>5<>FS2$S['L\I;.'WG+#6\= MKJ1AP.-T+,]K66Y77JWPOE(T!-MJ>=CQYTP*:;DVESE/=9C3JZJ&J7])DPA_0 MX_5T^!_FYS?)Y_3LGH:1./0J23_S/]*<:^.OC&8[C5D]]USGK#]HG]F7K<&E MY_8N+J^<\XLKQ^GT!^?G ^W'K/K)>,*?>IP7&SE'0CYB_&'*(I9E)&#WH<_O MX8&),7W9;"@K9JQBDVB])Y>J?8--KNPHWF&3Z#4["-=P1H= M5+P&%2?88;KJ4/;7U3ZH1?B=9P>=2(P-IQNPX;1KN=AS&JGV0YMUD!?(:W=! ME:K6I V@L*:'(H7AYWY_G0\C:B88!ZP2:U>"J8T=8$W>$=:Q^5YI[ M@4UAD:HR?*!%,=L=>',*UN %_M^+^P" M_H8-OS6O?3I@8=-5F&8YF7E1LGQIQ,50S;>KYC7C#GL W81NJJ>;-W=A"M6$ M:BJHFE?)-,WOH)O0305U#K!71ECF M\B4T#AH'C8/&0>.@<= X:)Q\P6FR$%-=Z=%-DM.(I.R>Q5-VT"Y:->0AK12K MNCN67335M;I=:7NIF5+8I!X'J$6<8 "#&*!G.5UIL^_ & ,(!F#-"U>BTP M !@ #-!4!NA9;JL+!@ #@ $:R@">:]EM::VEIE" [I4&U4'DJ1^+A+&?C-D. MFK/]/ M#=K5V'&FVU?C9\1J!2SEKW#A@M?L %H %8,D'EB-OR@B !6 !6/-$ MBR=ML17 K K/EAKF5WY.V':3JT&E_Y](GEL\0%.8Z2;+\&<]-&UV)R[2TF MUQ[$"FF&%*\C;0-Y4RP*T-!8-#CR8AJ@ 6C0' VNO)PTT T:(Z&KH>: AFQ MMT*YKNI"KT%X'W(T!AE)8C))V8BE*1."2?P_D?MZ)7#??H?)-^M9DR-ZA4"H MKP$#Z Z@ Z@VQ-TU=']5^@ 6@H#^M@U**4^%RA3%EUH=-4W!_!UOO&.*<9J%_ MR,2$&F)HX#S'8_O4EC;3&0N82,N!'0QB!_NTA;P\" $T%P"V&F?8! " $ M8!8!>" $ (H+D$@-(<*0G#+5.NFF<2!V$TS5EP2*JH>"JG,ARR4:'4)Q>I MV<=&]R]AU4PA9P4,I T#V:U;';EMMMX/8%@FT^HB\,0!SG )@MB=M/TP # #P)X!QL'5Z5MN%]E9 P MJP!@':O=:UM=+'\ 8 !8%0!SK7Z_9=FNM-&7Q@,,$ZEN.Z5MO#UA- !5 Q1X5KV4[7G(*Q(P)1F!%!WPWQC\RQMT O@#_H"_9O!W^IA(#?P#_TW% MORNMBPSP!_P!?\W@[W51XBPC6=B,Z0>_T##.2!*3(,PF248CD5+,)LS/T^F8 M1*'/XHQE9 >-:EQO3LFW/==QI1&N\;TY6#"JH9;.%( =N]("6FR" M !=%N! MKOI9), <, ?,O<"!?RD"=)@/=I4BF>/=0#'#G=Q(%L]2[ M[>RR]HZ1I34GI4VE:N@/] ?Z _V!_B@E'^@/]*?>#@>% MOJ I*;)*<12=D] MBZL36;-F41':O7Q2ZS2*!I:/7!,MJP3-=R>F 9L Q8!BQ3)Y;2E=9*"9< R8!FPS-)A;M]J=T SE6:%34K^?IZPE.;\ MREZ.T-Q!@4R=17LL;^Q+$ZJ5U .-?7 MG],L] ^)0[0::--J<&R?.IBOBB2U89X &$@;!K)/Y17;&I]7!,F 9$ R^[DY MTOI;X.: @0 ]P $ +0C@ \:.T$)PRPH+&0>.@<= X)?K>C*I:V+6] MS=1!M#W;M=JN;75=C&=&+@[CF>>H\*R^R_]?7KDM4 %4:(^*KN6ZCM7M2*L/ M!2J "@-0X?4[5LN5MC\Y4 %4:(^*MN7V6E87:_Q2@N]F#)W9O9>@<0-4*PC8 MC6_208*U!@-E#, 8(W?S&)I#T_Q+IH&+'N_#]8PSGEWD(&KH3_0'^@/ M] ?ZHZA\H#_0GWK+>INQLGB19#E)1N0WEJ?)EXMK,IQF8!C&- ^3 M^) XQ8#$'4/^P_4MUS $VI2H'VDUA5P!4(PV%.."8D QH!A03'44TT=Y"R@& M% .*J3!0ZF!]%!P#C@''5!@I]5'D5&E^V*@T\"\TC#.2Q"0(LTF2T4CDA+,) M\_-T.B91Z+,X8QG90:-,;> Z=J3-9EQ6ANKH!9.;E;72QB*EVY(62@,J@(K) M4)$W3P5( 5),1DH7[A>0 J1L@91>"U#9 2H+28 ?R'-/H8CY)T7)13W8BSW_ [/H\2_\^? M__J7GY9/\)5%-&?!%WZ:QYN4QAGUQ:'9RV.Y5&,ANJ]L].'H:N#:3OOWUA\W M@R,2!OP#?LR)/1B<]7MG':][V;_J7W4&W0O7&W07[M'/WSV*1;G> MA&,>]7]B#^1K,J;KP;IP>!3&[.2NF$G_WG'M=U(!?G/'R"B).'UP72/%4R+9 M=#RF*?]>1G+^YW \X;==I"^X-H4CKLS\=_(%$9*',+\C S;-,RYNO?.:QBR0@<\OG:7;Z-T+=A;9N.(L8JU+4%=86ZZJ.N6Z_U8-/#]0-1,Y_?8D[2,D]&\H1?%S]L(4%S2%)8 M^Q"V5]MF5]%5(2?I&7:W^D%]>V7>-5 R:2M8"M&=#R-N33*>D_N:Y&/-R1CZ7WH[[0NL#6Z3)G@C\W3I!DGA:"G MK]4R!E?22A2 *^ *N'J:I&1C(.0>#N3;&YRVZT]:U]N4Y>G4SZIX%Q=.]\J]N'(N6FZG=>FVSN>M379WX%7>VE3ETQ:M3J)?A\:/ M).4>[6W,_QX4:<3G#JB%7J3G5J6M1GKOWYVSA:#TZ,5!HPWZ4%2Z4+5O4).5 M'75=,K4:;70MGT47#KIPI.Y4@T8;XY@6&HE>&FBD,1K9F'89>6FQ3RQ_2-(_ M25 LA859QJV[R!?X(L5BS;(%X@.13GC@)V$GR6@DD@8^%Q+E+@'_:(P.FCW% MCYK,+07E=:NOR:Q!7PZ?V]6(Y92STJ N4-<>*[J=ZDLE0%V@+E 7J$LR=96J MUG,=MWJ0-H+"FIQ5+A>KGRL BFK+,,[9;5HL-)[>FP>_NQF_[ M,&]6>_:Q/<6M8$=<=.3][LV+?*;*<-H]101'E;W=6I<$TUB8U!M0=0UP'JQ@5_ MSREY%@>RD_%5U,FIH5"U5;Q5)Q'9%-6R:^MX,"4<. 1^#/,4P#_@'_D+? WA M']W3$=^ST;S0M,O/,Y81NZ!'84T,/HX@'1[!B>J:BC41::)8<^:[ M=E"L66/K-'O6DN*%LM*>@7*^"G@5O&IT'4ZS M>77O&78__3#-3FXIG;R_]N]8,(W8Y]%7EN7IU,^G*5>YLSCXRB*:LT ,8\]N MN!#.H\3_\^>__N6GY4.O:<1^931CXG$L;)GS?!P7[\/J#OMWK.Y=>[[)U=N%VNUZW<^7USL[[1S]_]V06 MI:SZY+V;.S:;G">,+%P%\GQ=LE'=A7P78\KGC[ M\&*47KGH:Q_JVMK7 '5)]\1T=KAND@?NR"9# M?C_%KIPH*^.NN]5I8[M;Q-TH+)OCH>VBM&R]I7C[TMWF];KP1E[C+:MZ9.[BX.C_K];N7K;[C]CM7G:XW MZ#B.>]5V6V>.0:MY="8CDOC^-$U90+CWPZVB6,7[PM\RGV59DI(O$7\P6-E: ML[+5[Y_V[%:GUVW+6^#JOW&!J]W?=SG&U67!2>V%*@G'[;9&J8D#KZ_O.2H[>,7'YCJ1]FPK$)?09EK2=Q M6Z<";A]3'5P9O[(Q#8NNDPM^0,K]\"F-R(UH=#S^@\=EVU=RZ+Z"6F$'Z33/ M44T9MCU_)Z MCM5IV[*%8?(>'NJA13G"-G6QV>F?]K'8##PRT7*MO5S^U$)Z-4J!3B\)V6J,V9,M KWF[+\MKRUFTWS6UJPG@FA)7-0*.R*YAOW]E1!_+R M[%-YZ7$0%XA+2>+:=MU3+6RZ>ZU[2NB(VK.S:76?U#_CE/G);Q?=\ZONX+S7NIKW1[5MQ]6Z/^J, M"'G%?AB%A=S%KO+%!H'L-HSC)]]^YN:/Q0Y1TE+,T$AHI!2-]"HU[@JM?E:7 MLO[GNLC=6HCY>83_R+VK0^(?TPP;,,W0ZU5?:]:(:88:49MRIAG4!>K:HPZC MALV]05V@+E 7J$LR=4DR<)B MX9Z$,9FD89*2"3]%$F#DM.BQD3=-!FTTR"V:#)4VD *D "G;&!5IP6@3D(+5 M@=<]NC!>\.B*0>G\1*4+]]+!JP)ZIK1T.IZ\7B,HDF#*%GU%43Q"AM,LC!G_EI^,AV%I*\M8%N0 34H][%R:S.)!=DES) MP)+=JB&:.7\%5 CJ%'O;@]0(Z@1U AJ M-(0:97:3@!JWB[_?/KILUV%CJT>6_8M&TV)QY"P.?I]RN8T>N0:?^;X8MI4- MPLR/DFR:[C2S[-)K=5W'Z5]>#EH]]ZQ_U7,'Q MY7+L5S8=CVG*OY<5X\O\.QK?LJ( G8HOTMCG[\0HLVE,QPG'C<@RA./)5.Q2 M&W 9%Y/-4A91\4&>$#'+;+Z<16?/0LQ*8^&]^,'R9)*V_]49'X#7I :E)<>HF1&4$!TV$)JHA.&AB MDS51DY2G/+?NXW?36A3K]3,L'-#'W7>[TM983''GU:,!O=(%P+].^)>WH3+P M#_P#_YKAOP_X&Y;-J[!,@E\6=J[=-*?;L2M/AY@"-8U0I9P);AZP>@ 6@ 5@ MR0\!)6Y$9CJP-,D;5^<#?A0C_EB6B]UKDS&:]N4VES2AVEP]M.AK@G2#BM>6 M-A094 %43(:*TP-4JNYA4B@,JDZ$%Z*Q*8J*37+*C5>2G'\9$=$KX).XH523 M&PLUPI^^ALT8T,E;B@+H #J ;KOD!4"'%GHY]:74SS,R2I,QR:C8XR\9?;_% M'^*Z'X^1 4$&!!F0+72D%$;/==Q=I-&($B6@ J@ *I "W%9I;E(:9R.6EMY9 ME(B[8.D8@=$K;?"NO.T[32^*T AC^MHI*2[A"T:QLX58/V')[[?M/P0&O&T9K$ MP1J@-= :: VTI@2MR9L7 EI[&8K^D(LBB97?7WB]<%]1&+.3^4PUUWYW^!M[ M[>*J? HW=XR,$K&+ X<4*>1(LNEX3%/^O8SD_,_^'8UO^>LP)M.8CA.ND?_C M$7#X721,4A91\4&>D##/GA=+OJ]E>5^Y(!;.\8)\;4X5Q3G"F)N5\OWBC\1) M.J;1"\)QQ'>>3ES*1Q2%S[[SX<@^*MYS$/GS]RL>P4TXYA+\Q![(UV1,ERS: M0QCD=_PEO\<9=CDN(SK)V/OYBZ6;?[ZHQ43,,Y[=E1FU+7(YQ<5\.&KWWVVD MBI><-3O0V?>XO0_4Y3AM+E3M&VQR$K)X]U#2U3")@EEM'.=F?E D&E5VJ1#; M?ASJAAAA.?'-7-ONMJH0^^NB]IGHLY8C[-FMS.YQM>A=VY&WWHU(#!I;A\96 MO]$2-!8:*U-CMQZT@EHV30=9KWT&J[,9,X510[3R M:O^ ZG+XY->!"4V:C)6SUJ UT-H>M%9]!1EH#;0&6@.MU4EK3O7#7!I!:TU. M6!>'G045SC_7K-K<<;!O4 T&RM0LHFEH: $-0 /0,&_Q QID^$Z-R.=C/.4> MLV&K']B_K"Z[RD3_X4(*X4]?VV4.Z# 3%J #Z&H&7?4KK4T G2:I.WF2P3C* M+0$FS:@U 4;J(49?$Z494#!W#Z@ *H *9/SD3:/,$^)/TY1Q62(&>B4&JF$4 M);PWI<"GKP$S"'75SZD$ZH ZH&X1=364(#__N6G5:=)0W$I'\6T%I;EEW$>YB'+G@[C\HZ%4+^RT8>CJX$89?5[ZX^; MP1$) _X!]?.3UL#U!OW+7G?0Z3A>O^=TVY>]R[;K="[MSJ#=/?IY562ZW=3# M5<^XTLF%SQ]N'%\,NRM#R)"Y@6\SS/:20JS/WO R(MUXWEP"=3P\5*ULW)[\E M7%+L:8FT^V-&[F>ZS"56*K,0W35+[[E\R;\^7F*H:!U#17MOG"G:]/?!LQGXR%+GV,ES['(.H]-YD!.Q)K0WP/H[]:A M&4JEUH6WGT4KY+Q(:N:N'Y(5,"^G ?-R7+OZRI=&#,S1B,*4,]B@+E#7/M2% M$8:'JUXWR?.:IZG)A#X6F2V1_*2^GT[9BR3H/C$(FD":T@2B'F*4,_2FHD+> MC!93P( P?[LPOV+K8DJM>+?Z(4BF($\CD.EKGTS!5;OZ;D-3<"6Y7&9#G_U6 M_\SM#&ZKWW8\7%T,BBU%Y]VG45 M]>REBG5=7"FY82$Y?T%R_$V6DU&2\A.*0BSZ0-,@L\C#7>C?S-KOWCU^M_/KUS?BPKC2;<$(BB$U&TL^ZX+R^/LTB8D3&C MHJJ,1^O\TFB8DGL:31E)RAJEVY3R^QUPX)88_YE\JC9]\NKIU_J;@3_F-<=AGA;+#Z7LBT M.+4XD#\%*O3C1.@*%U-^5USLE]>/?ZXTH^(G1;G7/7^@XH-LQEVG2BCI?F2^ M3,B[,^L+8IX.,_;?*?_.Y3W_STY5BK9S/KCHVD[7.;^T!UW'.;?/>N?.N>LX MG7[_HE,Y_59D:U?3\:>$Z['3(4_I(^='\BP]4HIO;\U2SFU01N[7@M/2Z9C\ MRME&(+R8Q\'U;^/.!@>3]W9^^Z$N[V-\L,K7XKC_H_&4IH^$4\J*A=NW7I7U M;(VH_]]I*"QK-E>AJ%2AC),;-XK")L0<$]&C'(&X]KQ63K2$7.>X$G[B%1NF3R!;@$11@U54P.<)H;6ID79O- MX8^Q;_X=C6\+9\[G 305BKF$ M+/'KXML%^+)P7KK?M6WRV__W/W)V4GH7KT"R CUN]:I IE4A[+K5P(Z0CZ57 M/@I3'@K]E^L(5PCQ@$I%67XL7$^&S\^^F%$@ZQY=N??XP$\FKC6?S>L2>LZO M_HY%01GST=FRZ&(?B)2?WJKL;9\3GSZ[$N13$I^(9TAN.?#*".@IWBL?TD) M-)V(:'<6I_%']@*_^8(#-0]^OS]=XO/;(47U=7 RTXWI\#_\[^*O*;N=\E@R M$6PCU)_'C<];(7!!\ !P+-AG?@4\EIAM1?4Z\:\(;];%)XM!S'Q"6\8#GK([ MA?_HY]%5&/-H/*316?%$=@EMVLYYO]-V+]OV5?^R>V7;GNL4F27WJNWT^MJ& M-AN/VW#ML[SHK(VP_*,XR;S?9LF%+^XCX(J9%G'I>V%4%^(I[V4X-1]\?#$S M+U]?&WZLFD'6RGMX\@CN1.YDT2M89 >!]8QQ6GVR][/4D0"[F$Y-YV4G"V.J M9PFEERQ3;Y\+5L0JJ"UCFI^&0W_.01.\BYIEP>!W%-;\P0^WPO);C!??31- Y* M[VH\#O/BMZ1YY]VVY&2&8.MY CX0KF98>@3E^@ 7RV\TY7XHEVN7&Y G\G@A MF\(G#:AH_"[*&SF1<\#&^6?A8_&I-9/ JIO[U\<7-S<7ZH-P>C*Q!!YF=V7 ,Z*^*&(JNN'G#X_? MUI#%;!06/H1X0FEV%TY>=,.ON+ZYB%ZD4>!BU&'RYD4)9%Z50(JRA$?5[DJ-(7LXOHKS!L:@;R+AYITDJ0EZY(L)=&] MB)>X!9L?^#0#Y06WSY]K>3PKDCF+5U-DV(K?FS^ ;'Z>YQ//#=!WI%BFAF9D M:#WY+O/:'/A64H[R^=7_KW<>E3.5G MJ1#VXPHC7J"I^*RHVWTL,WKCY'[QCA=/75S'[^ZI%7!=&"_#!7V6O;A5<3$+A!)N K U#_JG4?XBOBRHANNX.-9?'*53 MIC76IQV>O[DJ8<"O6$E"EFX]9%L+S'S"S"?,?,+,)]5F-ZE]@YITLCXC #.? M&CPS!S.?WE(!"/T]M/YBYA-F/F%PBHZ#4S#S":VV!S;8H"Y0US[4A9E/LKN9 M58Z4,?-)@2$!F/F$R%Q"9&X8*C#S"6$^9CYAYI,*R-,(9/K:)U-PA9E/^UBT M]3.?:KLP8XIE#M-*(UJN7NV)@ZC11:.![.==-$637C)-\[OO6M';>_;6K.M) M?+VOIJR]+6I7N8/+O=K_E>5GLYZ 1WEM-3U;;EN-)2ZMK#>5:EE2>A@56U+\YZDXD>& M9;G@4\5QRHIY-T_G>_KRA#Z6I>-B#,)T(N[#;95?RU3I7UKLWA$WMV-;TMKK M6-F;E*UM3IK]]&)CTNRC#4U)L1C/L%C,*1[UBS:EHAWHI"S*?JIWYXI4RFE% M93N]9ZN:'M!)A$XB387__[=W;Y%$EE= M2VK8(6VQ0DF.M1S)\V,BT >.8#YLN/&0&&@I1J@=S>A02&5S2FG$6VQ MDU1J[8H6^*"$%7@C.T74[^;T&;RP"GGDBF@2SJG"7BP''K%96(T\:AC))Z&. M[H,+^:5T*/SR7YZ +XLP(OK.@_=8B]JK%ZQ:FGONMGEQN@#$=N+32J['B%@I(2W*< A@9;C#+&@C@_9\7Q# MKX>_O"E\P71>]XJ/$HB^7XV(6UF7;HJ].HR+A V-N"1'M:0!V/+RDVT/Z+), MGPWX)8!:[IAWP*,$/$K HP0\2@N_+2P_"00\2G?R^0,>90V_*@;Y#7B4KB:J M!#Q*2.I^CDRZLY#4'=* 7MAA!],53-?C%VH-J?&[;<(Z=P3VZ,AK6[/L M3UL+#;9%0S9/&3;.EV^K,@0@UM8>Z=L3DI<$-FY+BOS#KY)V/D6^0SK673^U M+7KUG,>E;5&P<"*B$U$JI1@87"_TS1*2^%G$P_$4&:4D[FJ M2'TSP]>D8GK9MUDT)YP&/+;4C YB6 ^U'XM<*&2-<5GI=9H<2@)U+^X-2["/ M-,D2@T[A8OHFT=>.RCW] 0,J9(VXVX"Y;7&RCAR2@%@>%U>3W+$)I#,ZL("T MJLA#E..]$LSY&VF"L=%CJAQXUF70\F](DXL-/+@I\G48'MT%H%:9D9C1$61@J<>X),YU;_VR%Q,B*\9 MK)@<"A$33NR3]^$TP?3OP=P" ]"25? .V8&T\"\.AT"$K_A>'V -UY @'G . M+2FM$T9B61&.#68%&4?? E<-$"CR-*E"X=@^RE M&;>O/=!FQ:B&V>O"4-/* M!>XUGQ^HH5!5QWLF3<1^#U8TYI)*D,"F$ 0"P&DM/LPA<9LFSE#=>-3:/N;( MX: H3$*XFX&IK9J\$@6T)Z6*FO;. ))TSV-223ALH2E21#$#JW4#0HV#(@9F(#1 [QWBR:\V/BE><0&C+7 MPHB7]TKW:4N-N\D!'"/G[>!O4B6\/.AE,A:ID:$287ME+@?H_0W($ARE[OWX MJYA"JQ/S]T\^=[33(RL2J!C^3M?04ZNUA)VVD7P7(#PT#D'VR%:6_2\G%V]: M9EG5K=6J6)Z[O#3'_BG#MUZYXN3T=;MKB=O'[#U^H<[/+H+I:L-T[=+)^^%WVKN76'URWEHLL"VJL7E:L''.>UNU MH442VFW1AG"B?Z[Z'=L"!6VOL,?6(T [I$?=]4';HE M*9!MT9;-4XSN>IVN*4.H-A ./H'CO,6;ZL!Q'DY!&^2/MD6O L=Y./R$>E)/ M^JDG1'CAN!...^NZ2]L6K0CG'MOMTT*Y$8TH^0HJ'^*TN](,3]^$'X+"$6B# M?-2VJ-;9T?KS=[=%L7;O#&3*1US>7=WIB8";-:Q,%TS,ADG+QJU/D)\7"J@/ MGT/Y'J8RK!A1M%[%?I##>P;:K8MFA2.&CLK#:$WR,>XE\VG-]BXU;QI2:[6&Z: M2V"8VO:8IU0 M)72!P=A4(),)%]R="543V0Z7J_[D:YNK#QK%OY=<0]RQ1OB59ZJ2J5ZI:YAU ME&!=>4RLT3B=JL<,NCK;:#C'EHE/(&28AUT/;_ MITE>XJY\S*;D/I=*E\@_82081!W-'!DDCR@'3!HR?-@E M3ZHE9XX$$G[8G ?7X36<.K_(K$#2+M-M@83'$F9**YJK80SLK;Z;XVV MIZ(0@(6#+4T&:9/89\QT6[6GU ICWZ#7G,&BB5=R-,(9)!GR'N034.>/>452 MDJAAF2'+Q5#XZ]68G! 1J6"C.3:1L[RY[#BFVTF[ MB13P9""')(MDDR)(VFX)GG MTC?P702;$; KS\^G3C#$P5R<3AZYEG&.)3S*_3"!DGDCTMB21GDT8\1C10^,4BU9 MPY9&$A-O/:,,T>;-,^!*/:/GRW+"%&@Q48?!C$E]\[EEPYKO5\* ;LX9C0'$ M*+"2[$C@G08,[YB;5\8HI[:FP2_Z" M+K,.>$H:6AFXF]W"_O_;@U*_&D=1Y?$7ZS1_&WVP!&575&KF*]CF MOZ5R^/W=#W]Z:[M^T^*WT;610+:DT.S?8O37O0_O47G^=?K?K^_W>DD,'X 0 MO+HZ.[T^A7^NK]_ O\=GKZ^/+T[>GQT='7]X?7YQ=+'WKN$C? 6[AQ%@V8WR M6B-Q9MUCGERS016KFZX8%(D:+P?IRAS+[K?]+_OV'@:9UH:8RBUBRX^)L@+: M!",5*,@_VLT^/OP9;8#[\^CGGZQZH(O((S;R'&1\%\XXL%I%6I=9P3$6VYMH M-")B.R3S6#9S4[6!)0XG!5))(=;U+4PAK2YU/&\R%13G0$Q I&.@92C*\L6*"J=^PC(]NH3&&D*=]7$+P,_XI-+2@D=(3Y5UN.I(Y$ M+0BO#@)"@N'Q'=/E8Q*C7:9[$8J[(91#DC@(_&,>4\$'$,(,4$@UVB@,A2#N MAEYXV.%%K-@7J3]T@\AU^/T5,\ZA^(A<.QL[$LD$C1VQPW&<[-W.&,H_EC\O MN!E+&>-Y",9&6Z=*Q-4-Z681CRM@:OG8:!<#AP7+#GM(XE.)=Y)K[(WCHR!7 M&@)3(9@CQIG(">*WMC*OUQ M'^LLZA8??0%HY??+D903M V_PA^]6_I(2;2E-Y-)<7EP,)O-]F\'*MV7:GQP M?'AXGY_?L[Y'YLB%[VWB M'8T&PY/A:#SL65Q-[']R$?Z^1?TRI^Y[0I><8%OKH5@AS1J(.PS@.U$C9>"VL]C23T\.SL[ MDF\34M]1$7*VPZ-_?KZ;201[O_YD61)1Y*T)918N(+$ _ER6#/S^$H"UU*$_ M&/:%%J$=W!$;,&EU41FIA++@$729'S_IIZS>22O7042 M!K$O@22O)@+IK*A$G&(1\:L?E^N+1_WA:#Y:C1 M+'&)G>M7NV03,;(EOX0%]RA-,TF:BY$%Y$3^<@SAR!00%9_4J]*']OLE>3JR M28 9W0C/-#9Q::IR\8]^RJ2A, &E/*.17(]K29,MF/SJIVR:R>- 5%N4N(SX M8VO1FI(UI SQ3"J3Q4L&*PH7YSV18O?C3/I?-G#?\XPW M)BE4L)U1R C%B]B!*Y6X2X6,.0B??=[S>6.[,-+\+U?*@8NZ2O$B"*,6Z^2" M>5V=>!'HME2=-85UU>%%?#X6;F1X@L$C)[ 0']9=.(Y$&K@W"/,,'0'WEO<_ MZDG6/4L0?WVX+1^'2G$JN,3UQQ*D!O;K:'@\& X&5M^Z0K[M$C^@D/](&5H) M1RO#\I>C/*-<%8$/G7O\J_P[WUA1X8A$4S#7NXW+;7<@9;'H88Q%8X0N;)D3 M^5.P 7,77F"'/Z$!=.X0X!@A8817D 'D^OL!LTZ%.MR/CP?'@W%=W*UWH"N&.=/ 66;1PJP#VSQ>+_V4%5)I2T% MJ$Y+5FIE:SV801&A6;!>A_/KP)UQ%>6?_OUB OS5#>\_?H9VKZ;1I.)*WT>1\^W)5B)>.M3'/$<=#.NC'K+N$FR7@8\P]/T)\>:\ M3037;XBM/D/&!\.V,6)5;+1#R<&Q8B@9<[0R+,/E:%SO%<0^>H*WF*,%[XCOWQ :E[Q?0PJ:)(Y_H41:]SXX5@Q'JVW' M>I>5,)\X9(6T0BFM=T+.GRWN+%(FJ:S=]/F51N"S^T7\2T&\;YLSK*[2H I# M6#.#\IFPGN2)JM#!3A3 32F1,5@5[/=K(B8U55I'85!K8AUQS>K,XV 6"K#J MY8QFS+1)X^!8D32:@-N]M)$WAH>8C)@7V.&QE"&\A-RNS0'3L="FB^,/BG0Q MPTW.'F[Q.P C6B'SJJ97K<=4ZT#''Q3A50N>B*S)ZVXZ2FW[9W[PEW>\SF63 MR+E3'960%V)F)>39GX(@K?1@ SE\HF$(7MY!X-=>$JK/N!+MPH"L NVD'BNL MZ(!P#HAZJ5 U(VT:-/Z@2(,J$.QB!I3.'UP"5RQ4SE80LAHHE3'0H,,S'_Z? MR'Z2*0L)3F8N(^)EA;6R560W.L^"@QR[NKO4FY MG-@$-C4C/6+CBMY5ML1XP*IL;G=GY$K8ZG$(]K]6C5(GV'<+R"V8>]RET$&L 5P6G2L *>\)"P"3; M<,(Q9"QS!2.H%,4K\2G,(4;X<%Y]CHMG.?QW=R'Y JB8 M,GV"#? HE*T$H[!B$X*1,.HN#O5F9C,EM%.PPU/%%&S8YMV;:8T/J>'._AJS M[2W Q@VOXZ&!8I#,MR9'Y63^%&$B9-?1C]RN <4\N?&GD,Y6?,QL"D>AG'[! M?Z@8?L0L+,[#DDPZW.XU@T!9[%BVMO[9(-A&*&#V(__/P5.Y<0\UK8U 78'!D#5EK7-3I1N:Z(JY5E*X-) MQ-B2G ^09=LY)GF #%$YC)Z!)V'LZT]')XJI'4/3L-XE MA*E 5B11M#Z?*2_+_-S-)+T&MG+.>!I0>P5\*-Z\GAF55E5I,H6)IOHF(RNW MXMKEZX-ME FV^KB&5#G%9R*@GDE_L44S!3_$/:PN@/>.DCNU^+-:P&>XUZ) M>&$FK";B47T'R$M J9FL&S/4YN^C$U7^;@IL!Y/Z/P*T%EG.K3B2U'7%GZ(Q M'J -T5,]! U8:9/Z@6HY-.%J9=A*O*P,XP-BV6:^1NO,K[KNMBE_K<,=J&:[ MS;#E&=;M-/N@HQZW&I??*/']S._+3;C"-@$,+@G=[-\23&NLM(UB,#:T#2G! MUJ/Y)EI8M&(I#@93 E_-$&W,4!NB!ZI%&%.X#Q%:T>I?,? (9>A/Z&B.&KLA M-.P78C/>:X2%G<2H]!#%.1U#D\F(9>E/1).G$$2^(Y2NFY[C!B#Z.W #^!D" MT=CQ)R]7D/)697(GJ<^H7*PS-J!Z3+6)XG"L2!0%?TM68&5KD BG=5B92@Z( MJAL_(;Y?9#[H3UY?;N[@$W1K^H]7E$"_S6*L2"[JVXKU+E.&++:.&TB)>.HA M)3NXC3H0SU;R;L):O]%QK!AC-\&\>^/MWPAQ MGI'KSM;0%NUPAVR(?;DG_I8KA9=(G//./:7YT*<.2_W 1W4Y0,S];U;,WXHK MD-"F55AA'0FE??<;ZI$]U.'<#V#N8\P6 LP(O5$<8&J,II:)-J\[5DUH)_PZ?^>3MF4G M!#O"G)WTU *$E]FCA9H?>[O_BK5^^U@U5UUA!O),OU .:TN0[4.0#J?B-L R M.?IB+Q>_O)X E495F(MN;%3I,2&'FV#V:5[J8WK>S-B,Q:DTO>(X93^FISEF MZ&"+.O";SE#78UII%\6YC2J[Z/CTL[;]:XX[#%AI1QK'JNGE2@"[-ZX(_=(C M>#'')EM$.V88?52,&2)'*(MWLYU%8" 8RK/0DL?7+V+;?UV/5Y.KUN6-/BI2 M^RQ:\CCVJ X1X-)W5E1/-]U>!H0KN("40H?_"*_UK<^X$N!"FKT- M<%R-!#6:; F/8._X-;T9**X7"VBS).ODSQYXUO< ;<(#BHN:I,(-N5>B7=Q36\YX*.R"4_>-SP7;/+%;RV>E:@6#JC;1C5S9X+XL&2KCLY#6F^8 M42RH'52,/BH&%=O@='H$\153'CB66'S(P!]$GZ[NT)DJ&%;VI ]ZL++LI9>, M*^AF-YI2PET+VXBCTN(O5TQ!4Y;5C@X'JLN\8C;A 6LQHXYC(!/Q]+27^[G; M[**G1KRU?6R@NN!)C:'U3E:5/;4FK>S0W^)FDF1="6]AV% &;_S\;_*C1;;]^H!VW!+U MDDX-!VWV.5#=SE6&7/?RT'\$@#)(W8UJR> K!H&#&'1,03+DIM\SHSHM)&%< MM@:1,#^ EV_NFLZS'E/]>J#J<) :4';259JU?SWG68NG?H50=UDV +DP.F %] %D/Q0Q2,>!^/:S+*ZB$O) FF4$> MU7B O@R91PJPOY 7'B6Y29-/.II7H!^=JHZUU$*?U+=]6DEWO_&8!7,?_A%P M!:Z?&ASP4%9?P3.$Z)8O,>G&7/&2^^6X"QAOE,Z_ "[PIV#0Y"ZP63ZU_ M')XI!OD%N*QW80U65(45U]'-B?%\\S?]X*F23R5TA="F@*[C7S7E&UF,:>6V MASFPO\LQ++ ;;,:IR[82RL*!0]P)B$TLMGXA%TPZUB8.XSRBWUO,=H 'L2 M/.8%_K\N>"(WOO]ZK)D.N*)H\K\/EX MFB$6"&E^HR18G_=>YM1%GQ"#7L]B7)?S'B88!]XGAW@ X5O^0JC8LT+"-:2( M.(^2T FHU*MG'=50[>3]Z&0P@Q@1^H4PZ#L!Y&I\S&E61=5*Q510 M3$_52L44_6TT+"BFIVJG8A\_*KO5\*RH735I*U4@H*(!:3M5_%#L M42=%[;14K53L^/2X$.>*EJFG:J5B)PKG?EQ03$_UPRB6C^955.U4['A4$+GH M0?14K53L5!&.BXKIJ7X8Q8IIEIZJG8J-QP;9B)ZJE8I]& \-\D<]52L5^S@^ M-3!%/54+%?OX?G#V09TQY>W1B+25*@[/3M1RYRW3B+2%*CX^YA3)/'@S<5/Q M;)M7[3P2+HD\@A92FU< ;38)*)7?JT9B&Q V42=\XA$,&:";O#[S\$#+\YXM MKVA3J8G$37"B>IV6CB-GU8![!=<4VN$Q'-$A.PA'BO!'SXBMOD#V3.CWS\2! M%*,_HS:,6F$/C%ZQE1PX5S=2,]--E%5]&W 1%2LV305U<_TY"X27N]M\)*G/ M2.[2PKPN2HHWL7(CQ2XI[YK0F1*?K0%R'N 3Q(&8?@^U*G_=?I4HU&E4>-LZ MA4H[V66 7(=;M0\R7R]N1PP]R=O'D,O 1QCZ_H7-A?-EQYE2-_++8ZV?\ [] 05-\\5VFE??%O-SE1EBD.%73M2XLEZ-$ M;'EKICAY!G,9-YKY$4/:MYH=*=7Q^G8Z@S8/GRR:PKJ@/,@N87&<:D3Y]I:: M#*'%K:? =>414&+G&GC)[-86EW\GBM4IT1S 6/K]0U@B?_KQ: Y(<_KV3;A7 M"^]?!?!BP2"]Q_#_(*!?8-Z0=V+Q0S9)DS9HM](WDTE\_=U%(.?DMQ74O&^A M,OPA$>Z]U/EJ*5JLD)C3-(XPM4NU3_'_X:+SM#M:(]$ :D+8/O5RRR7;*I6] M?/NCK MK0'>\)PG^K0C5ESYKK4CRZR\6\=N%=79?MVR:?7RCB@T@#Z+QE71<&L**-OD M.J4!8?O\S/]./Q/*P\!$]*EMA=2OWM['W$'?A_*3M.T^G[GA0+@,_U9\ 01< M,9P0U_+AK5'DKDS>;G22M@/!2R'7%9S+Y)+*8;$?VZ&X+T6]YM&DX%LN=I0: M;ZR(YOLJ/4D+C)G+QR(L>**2_6LC1C38OPFP6(N_0QY* M.J7Z5 8M\2XJ8"-WQ4J]&OO,0/I/8Z42(2GU"76R;4*:XK MTS+52_W/9\@HF4YFT08UGJP2#_D^%Y-K.2$^RRTUU:!O7Z80"Y_Y-ENC8BG5 M#Z%8M#-S&7(S4U-7IJ5*KVV56MFG;Q\@O\"E/.-!WB;%NXE8S83W"W&L&'(0 MH$C.G\4*&%.W-CQ^(5BLMX=7X)&%B.Q\X!3NMX@F:![!2Z*O*77;%NP*^KH\ M*(1;3\A"[CW*YC-?N;8B7OR93GI,*?10X&6QWP>GMK=39EN6*C^LI&KOK$A6 M]*S0N;U\U61MAW &&0M?D45TAI>?SHV(&:U4*QY4[L6NI,S<"5MQ)9:KB%E\ M7E&N>5ZKCO::3_GUAN*Z8>D?4R,R)6Y9(IHJ&S!!)))I>P7M[PG\JA>M#76Q M73&2G2:\0D_(@=A)=*HF:YU5EJ9=/-8XO)OY/J%B(B*7?I6^;5_^&.\83K>) M31B>2L72756-VFA5L7@#/- ML0[3ARG/'/@_]XM[BI8<3/=BN:1BMD"L)'-DU_R)E_UVL5')1MZ,N[)U6(<. M_283E ]06)5(9N66[Z^B=_+@RC621AQO!9?/M[UWHY)O[\NC3; 7T9 FN2U$ M?M"8Z%9!U%YKGO&DW@E<2!:_ XJ$D$GN(+;"(NA?WT[5BW[-BK;B&R=I:>%L MQI7\_&0J.3]6GK+.,>Z7Q;/K\)6?C^BU2[5N([D\E#6S\+#MN$O?MF\TD1=U^GBK MUR5+T$)U*'"@!^AW&2BY0>%\4-52M$^AS%QY;L?A W'=FW#&+-;-E/C-$^1R M03DHR2=R/,N92'H#"WYVE@ MX(J)4C%E'!U0$P82Q3?#:2/ME6?K(E)5XWV!;&N"N:)=%.1M,Y=2%_$[Q ZA MU9NP#>C:Y_]^YPS^S,?7_,.W'_-\6Q$7BDD8]6BG_'7K.E8I$M\0Y332,7@! M1G;XR?YLX_/ZOEY,EU;.;U;/KW7\A?\"]/XM3/0CV]^/LO?WQ$ MSSZ^>//FEW__MW_YV_]"Z+^>?WC[Y.7,+R_C=/'D11/M(H8G7^K%YR?_"''^ MYY/4S"Z?_&/6_%E?6X16E9ZT?TSJZ9_.SN.3K_/ZKW/_.5[:MS-O%VVSGQ>+ MJ[\^??KERY>_?'7-Y"^SYN(IQ9@]O:OU:(G\"=T60_DK1"ABY"]?Y^&7)]"Y MZ;P#_77)OW[-7WQ3_@MK2Q-CS-/VU[NB\WI;02!+GO[7;V\_MEU$]72^L%,? M?_FW?WGRY&_-;!(_Q/0D___'AS??U%^@RYFK)_$O?G;Y-!=X^BR$.N-C)Z_K M*1"I[>3--,V:RQ8UX".S\]?/34Q__V5QN9Q#[XD@=-7W?^U6>W%S%?_^R[R^ MO)H "$\'Y_*9][/E=#%_;V^LF\1GTP#?-,L8WM86Z$#-.'\9%[:>S(_K4(^& MQN[[F\NK)"][;9G'SJ;'3N?7Y MZV'ZV9'XV'W\N+P"RGGILY./"^ H_SE_EU[8^>?7@/M\H^P@_3ZBP5-A\7$Q M\W]^GDT"["BO_GM9+VY*@7)(RV.C\RDO04?V\UL:QW/\?#FOIW$^?S&[=-!< M;N(?L''_%A?-[,KO9;9C]='Y? 'S?C:I0UX0OID3L\NK)GZ.TWE]'=^ !G,9 MW\[F\]>SYK;FNZO8V$,6I?*<%$!OOGB7;C]M*3P4-(S=F)MFVC# M=/F %D;O;;?EYR BQ_,,S5S6BW:.@*("DV,#_/@6MIZ+0^1_"-JC]G"]JDXOWD:PZ 88J=T$1^U+MQGP"OW2@, MQ.UL>O$I-I?Y[T-8?+S:,'S];INL<5S' YAZK,XP''531+XO.4#KZV,&$(E7 MH-A\X\[9RT^'NL=S^,HV4YA;\_>Q^?@9EO-]7#U6?GA..HK/GFK#\]5-FG;7 M&H KJ#J[B3'OS+ MKXX/IN%YG,94+]Z#ZK>?Q>XDBO![6^0#Z!--N\Q_M-<9 MP]8NN*_6%NXJ'>,V6Q275FEYOVS\9]BK\R_#8["OB2+];9EX]L4V83/*?N:$/T^UBUMP,U]<#6RK2^XYSZ%!" M17C_8VHO9\VB_I\8=ASCOYXU*YBSRV!(T1VB^>-Q>FWKYC_M9!E_ QMZN=(@ MLN[P,C; YZ)UF,P73:O+[^UU+V*%^W!7^%W:."BZ^_GYS=MX'2<=AWG\ED^' MSL?/()W9UGXSO8[S.Q]W#\.]' >%T?K5UM/Y:F*^2UM+C('0P:T61N50%\H@ MQ OWL=N^=P3)X_OSZVP6OM23R<>KZ',;;VL/^FOKX'LS7=CI19V#]$"*]J_K M/4@5Y?^V:$>!.YYRT=Z]6WR.S?V7\]6WP_>U4SM%>_ZPR/!]WM-"T=YV6U-Z M$QR@+TO;V.EBUO0)ANY4>60>7\RF(8,5[D_6ZNG%YE'SX4%)HS5X$BSNCAF/ MBJD=O>&38[/]1+DX4H>R,3)NAVI^O8B-W(>.JW!W$L?SNQK93_;K?KZV%!VT M_2QQL^DJ#.'NZU=?LV>TZZ#WHS9H+U[&%)LF!OBPVBG;B+E#;\/T)CAH7UZE M!(K W?R'[S[ ^O A^AF(Y:0^9#$ZCNJ@O;K[\R7\-U_4'@!]/6MB?=&C,]V) M#=J'^^!%6)-?P&IV RO$(0=#?6@-VH-N:^&C%0;EY8]I ])W,M<%@ MX66\KKM?\CN4SCBO8B5ZD,W2>E#Z_@>?+23[&I_ 3)JZT-.X?=6 M')&W]0^]#MZ/(CI^GX;OT"E[\S$V>8L9OE-["8_8M_:.>&J#B.^FZB%>SJ,) M#]"WI9O'_U["7O3J^H"CO#W5AN?KX>=#&7RL_A"<7E[:Y@8D$2RM.M4^JR"K M)!%@R;R?3>HN5P\/HU**Z\[2T(-8J3X,.P+#C\2GV9?8W%L/>_E\K/SPG+Q> M+I9-_*V>UI?+R_?VYI"S_CZTAN_!H:[:KO6'YS1O!:TMYJS_W$+R=MZ;=09ETRLS!(LU3FWHJV;EK$T4!]A?67CW- _ T3A;SVV_:(4&8K)-8_>OZZZH+ M>R^63;/AM9E8%R=__P7XJ7I0J8S&GA(B$5:$("*-0YISB[0+U/"0I,;R6R0F M.:77K%D/5"DH8"*%>'#7-VM54BGOG/*($J$09Y(@24E$.B7.(C$!6[6GJQM2 M^:SQ3V9-B,W??R&_//D2ZXO/B_;/%0';^.^$]=N\9.L23^=Y\\L4$9B6E[?U M(@6$*O[BT]M9K*#5N"]=:L8/./8*20\ MS"3,@D(JP$RR0:;H-*5,LEY"Q'XJ(1H#R *R\V:ZB$V<+];P[!>8[14JYW64 M45D4!6-(&6R1D8D@(Z1F%G/K5>PE)?RGDI+!T"NU6\70^I]>Y.0N\YR6M>,& M]5B]BF,;#=$:)9LXTD$%^ ^5O;GGX M-)M,;!M2&1L_FTZC7SPN!-TJ5HJPX'DP(/"2(Q$U129)@5B0A#HNE%#[E/GM M4B!_"BD8#<4"R\:'F./X_6+9U-,+^!";Z[ACM=A6O+)<"VNEAZT2="U)8)>D M$3!S4@INM=-<\%[BH7X*\1@8NW)[R;-P'9M%/0=V.^\CW]>IG##&&DI0PC8A MF9Q!SEF"-%%$4^9%C+B7>.B?2CR&!+" C+1V5Q\OTNZ*%>8:=DF8"XK %NF= MU BVN>P/,%X&HC'G_183\U-)R^ HWHO,WYX^<)*.Z3@]. ]Y(8?N07G#"_%T M=$[O$_-Y>)KM0@QO.ZL8K.F#LE^7:G6T!-3E.M G370I[@[.Z%R*L5$E_477 M7,LE6GRQ)U=RF8.W!WF MQ^9+W=97!TI5))J,!P\1@Z[@(S7'+G$&=)"68^I M,SKYDQRX=>G [S :'\!RAE*?OL3)=?P-AO+S_$A8'J%:29NAX@*)?,8$UKA" MC#, S6J1'(O1DGX&29D#NU$DXJ%Z613>$N9*-]#>3-<]^K_1-I^^S(Z?F \I M5HGC9(56R!&!$>CX&(%%)Y!DGA.KC0!3[XR/^'M&0.F>B#P))9R_09GSN>J_3UQ/9>031EV2EHX+-0#@D M2"*(!BL1QU0BI5G2$MM@1;\XK3)GF6Y86L1E! K^A6WD2I.$R M(.QH0$E%BC0,%8+)"S/51&N\/>/#U',4PV,!+B"+J\O;,%#ACZF?36^]D;=) MG^\#IS=S[#R[S#[Q'9)X!-7*)M@41+0P41VH*$1$A#W3B"JJDC4L!;UO+SXQ M5*T('.XZ&(1^Y1WQ.,>'11,"4MP2L'>51(0[3!AEDBIQQDZ$8I(S.P_PSVF* M'^9G.(9LY<$DQI3! "5J4*2>(TE90MB*;!0SETR_<- RSH8?0TJ/QORLA7./ M*^(XPA6W!DM0$I$A!G;LP#P22GL4.97.6F?I6?LC?CP![8GZ.8OH'F_%472K MJ"@'.SH@2K1!,%P>,:5!KY2:)L(U9HGT$M R+HL?3D![@G[6\KG;G#R*;F49 MI=0;B027%EEL*2)"^&QY!PPB(Z+O=YA5QJOQX\EG/]#/53Z[^CR.)UXIKZ66 MCH%*!*!I3 5R3$K$C&?"@?ZN>;^#KS*.CQ]*4H]%?K1HP)T1&P<]!5TBB*3+ M,\XE^!@Y;*?3,\ME F8V8ED!A,,Y MWT,?=OAFXR!68!OO$$6W121VU*H$"YP0D9!G@2 9#6C3B3*4 N'<484EZ7?; MLXP3:%3!&!:W N)QT)*X!:R $^/&6D1T9$@RZ(^6-B I1=)*,8]EO_L591PN MHPK#(' 5D('WS3IM=\MP^U#/#B'84KIBPCAL/0=ET$=DJ2$H*>:03XE@YC2) MMM^24&:O.':@9F,@5&AOF$T[C?K#HI6/'%L&-(V3#IGD&7+)2122# :6B5$ *R EGYKVE;:;3NO"]X4K[*AEA@;D1!#9 M,8$1MSAKQ= =+8,FLI\+<7R_::8GL;])&[6[_'Q;OT MR7[=M5(<1JD*03I%L42>F(1X $P8,PX1)HT7RJ>(TQG[G(=>-D9'KT@>B)RO M.(97MIF"!33?Z-3+F&I?[_)'[*]9;>?'RR5Z)H[-7@.[.X_FP,@5$*"7R_AI]BRE]CFN#CGLMI:O+%/. M,2803"F,<#0!*0(K)>CG.= 73+EXSN;LP$(Q%$8EAC^Z'1G)MI2J(C4XB>R" M]2FA2(-#@2J-C,H]T-X'U6_7*.ZR'&2HCT*FR "OG&D?XG6<+KM,\*T50'J9 M)#F'#<5<(1JP0H$'CWPPRE'0O/K.\.+*PC##/A!(I7)#'9X4:EL>HZ Q-I8@ MDY@%ZYM&)&WR;3Y6QQQL83VW_C*6YL R,!Q*)?3$]G&;#IK@9KF*F6BCDQ2I M"%:5$)@AKA/0UYZ&E+ ]$YR1I^3+.430O@O*_O7=M*>&2[:-RW!AMOKC^]2 MO_*!\1"]0X(YB2(&$:$ZNYRL49QX[G#JM]45RB7??RP?^N='@JO$">WG6;/X M%)O+-]/K.%^=+>\ZH]U2O%)*,6R"158$@T*^S!LDHX"?U]9(J8P_YR01P\G! M0.@4M(OOW_SZ/790='=5JW@ -5W(!!T%().GI4BV4H7TP M21@.H +CGW>S*0S"#0CJCD'?+%8!-,IP#^"PV!IX!,7D&#+&TI1(HMSW.W4K ME(5]L)$^$I6"+I!/]NNJVYOQIUUV@&X$*L*U <,?-KUD-:+&@0XD8/LCADFB MC2,A]3./"V5>'V[RCX57*6])5VOY^\(58U3IR!,*BGAD*+^C*O_#_:L;"=3I22"(SHBY6"G$&! HIBU02RHP%6*>C!^V9V70/RSV_^F$=@?V7VYAM=?E%?M^O9+L.A,Y%*:"MEX5IC^W$ T Y"EDYT"/>:?ZE7-&>\P4,F %(J&"09Y1BRP3C/+VIWZ) M.]C/+4,#@5G$B?+M/O]F^M 'U,&@ZDZDHH$;+65 S":&P%+Q2 2EAF] )T3Q( [3/VT1:2FV$1++B/O9XU@(V/,9HS!%G$7A)18B:#[Z4UE0@].[1@8!M(BE\CO9\2;^7R9'9+O MTMO9]"(K?SG*=->"M;=R%5P4G&N%$F<):4HH&"%.@-DJ)$U6$M\SW7H9!]-8 MP_O=U?,1@"QR7^QJO;A^RVT[]=IKLQ^C7S;[UJ5#R%2&2(]MT(AS@I'UDB M M\ENY/B;J4V1I[Q-7Y^@5&%JD1L:T1 0=+-IMQBUG_9\;KV_^VLSF\[L9<] & MV)=D97VD2?"$2(XKBE)HE)]615%IT$H"<[JGT5WUJT2<5JD?,=#^8"$\AX)ENU@!W:J43*ZGF99F>BO M$ZC30^%X,EOLQ6QZ'9M%/L[Y-D/5P8;9HY0JKD+B)#\/[[!'A!.&N,0.@4J( M>4J$JIYY&4E?DA4%C)U2"B4&TPJP22C1A)%3,*N<\\*1?KYO\U.J307P+;QV M;7CU6T_^88Z RE5F#E,' 5]@3&&A+,*!6=!U=0*4T\IZ!(],V7BGW5A&P?6 MTQVUW&6!/^:H90N1['R+)#J%*$DV'W!A9'.^8>RPB$$RIE0_"[",;^G41RW# M0%I&KN[SP.T6G?MR59341^VR:Q9(4DDITL)HQ*+D7'$1C3CG'+UC#=KWLG$4 M9D5N UTUT=?KIRRN)K$=CVEX=CD#Z^%_]FE*7:I72C-GN!=(2IY7;)_32L#^ M#0NZT-X;QET_)V.94]M"PC(2E$62"ARH7S^BW07NC7'"()_S@'F>7];")J,7 M0@K0;]XS%.FDQQE#R\E@X!6\:[A:!4'+?_4U9"C0@ MZ7+2L*0(LHP3) .SGCHF%>YG:96Y9%YL31D:Q3+VU'4]!PQ!1W\Y6[I%6DYN MK08J/4[",ZYF@J)R\ 0EMAZUM$" MJ^UQ;^<(\>#-?]R6&9_-\*/RKK:=9,WLWS9]V[5?# MM5))PQD,2$ 8YB9*B3DDDF8 J.",2\P$.?JLY 0NHL%WN9-"?I(+ JT_XG;% MOKTCONL%G:XD*D8H84)*I$/.,()SV&C"676DU&N"?;+]%/"3'J0,+7(CPEE MGNYE_F4]OYJM8M/?I0.NOG6D4%D,* K%0&DP.3U\I,CE\/<8@S'*:E W^ZGI M^J=:P<:#LXCBWM37@,;UQEIZ_]WNQ#![ZU9.J6@4V*Z,@18A'(-^AZQ*I @? MDLTIZG_ 8Y+AM??A@3S)SO9]AK2#=K7OJP.L 31.D=\VD!HI#HNQ)01V> IJ M:F L1-$OW';SY.,G$*&1P#R)%*V4P'C/^*[-K$OU2F+LE:< )?,2$1HBXAQF M$R&>6I4PABM0 <$ SENV(1&9 M"!\!QYA2=$Z;?N]4DM-&^X\O-\>AN%-@%I?0;!8#0M="D+_YCH=Z>JO0W[Y2 M_KZI?9QGD%Y;GWF#_C=@6E[$1S*/#$*WPEPZ"1LURH?7B&J2\P,3"1NX)-0R MKTWLYP@@ITT",)00G0KET]G^]\CM,]6Z$:BDHM*"$8&<5AQ9F20*RJ2SI-JV[L>X>FE?^\B6 F)I3")(X>C08E:D5\K-4A) M'+PGEDC?.F 0:H]5L'A MU,]Q0$YZTZ#T>G8X?*;4K(NS21.^2J,XV*)*EB $9R,G:$HW5( M4.^1LI1+IA*3?=]P^ZG\XV,">B]3(V8V_2:YZ/:'4+_EJE"JT>]9Z? N[HY: ME>18".4-,AI+)%U,R&#-D?%>&6JX3FK?><\_@PV'"T4=:J1^O.C"(]]^[O1D M<51$6@\=-T'E/)025',J%?*8&Q( M!HRP\199J2-*^<41I5*BSDIB8S\SO5+Q+0K[B67ZV;6M)]D?D2_CV4F\ M3\LSF!0?TD2E.3=),HTB-AQ%G3S*[CADX+,5B1(O^LEMF=CPD\KMR$"7\33= MSD& %FPZL$"7L'>LK5&P\9['-&OB79QSG/]63V?0R9LWTT5LXCQGF/J62KX6 MMKCY+2X^YQMA77([%^2B2F U$Y=/XDW*V=4H#(/6%''O;;Y_F.#GDYAP=PZ M3H;GXEL5J9P5ADIL461<(U@F-1),B?Q@'B'.)F5\ST/3,MO L6/R75ZJWKB4 M",Z'O6:^9O%C;*[S0>WNT,%':E2!QF#V2@X'3.H33QD3+\M71D32:)2(X9!:W0I)B12#'>L M)FG.^3GHT8;T:)CZC.@_/D/?YZV.WW9EW?QC0_I(\4IH)G14%C$.BQ58KM#O MR.2:6<*-[!DX4L;:&GQ,A\.ISZ!^F-G+["B;AM;*ZS:T.RM5BG8AC22H_-^_D@#/#1:A;6K7V>S<(!J=5N\\E9R::$G@@B#E(*]1F.; M4%(X1N=QHCT3")=9NP?7JXX II2_;I/=W2.^K7A%,+<*ZYB[0U&*'A0+9CG" M+KFH>(C:]].DRZSL@XSX0, 4&/$7H!?F%^37U_9WF<@/BU:::L*E=$A+KQ#T MQR.ODD=,4::P !IOZB60C'J0]O* P!4:,3?I=L];<]XWQ>L0-'0B3O PVD! M1'$^_J>@DX"V:2T5R?2\5EXJ1N*8P=DRTD=!4VR<1(2S &J6A)S(P%(G@"38FF"'G?((WPD@?@TV1N[0_<(JM0MGZAA2*'S>1 MUO/EO)[&^?S%[-+5TY;1?&1PL3I76&=+;;':(2_=B508S$P6A4>6Y/50NI#S MU5-$/!/8,D/!9#IC*W!0J1D5MG_F?SBCMR$&%9L?.LO#MQ'=*SU[C4H'T_+1 MBI4R(>( G74N2I0<]T@X8A 3--\E5S[VS+95*,?1H!(R.%8E?$MQ C0O?HU3 M8'N2]\YP64_K^:)IH_?6[._R-G4B4.7DC059 7GZ?36=;)7R'B#Q:IS)$2$V3@A72>T0C*/ 2+#9$E XA M>4]OLR9'V:*TJFI0D(1%%Q\!D5%$C MJ0Q,JN T$X%IWC/%>:GL'\,,X'>7!X=$K+Q@=!>&2@=F+;<9I8'09^HW25HDS!4H9\@.T35#"*8H"^ M>>J49]XRZ<_YC'O_NF<_;2)'[&Q2[ MB0C)%3]A03GU%A/9>4!*!Y MP^^?XZ*&%K]E\2X_P9K/P5G:'*Z5"3H2 YL/6(] >OVV?/L*^/QE7(!4/I;J M88CF[A\5N\]$5J#9M_D X3_;5R %I+UON39LWE-^?! S?YRC93$,O\#EK[C$RA9L8= MJ(>MC3IHKRZO)K.;&#??WH$!7#^H\GYBIR=L^;;(!]@LFG;5^6BO,S3Y);R- M:FWAD0>E.[?M)G.7SA%^.3EG+4?/OM@FG!ZES9?"3\[,N%,+%(RK++1OIG/8 MK"?YS]SJEH3/Y5M^55]M?!IY(/:S\VL#FN'&Y^AN%[/FYN0,GEI2 M_IC:5;A/#&\NKY:@U[ZLYVVBQ7RR-IG,ON3\U:]GS0JWK&B//:RO;=W\IYTL MXV^@ABY7ZW->F>^SHN3N-,MOC,E3\G!7^%VZ>X!GX^?G-V_C=9R<$6@;#'_\ M#*.?==*-T[*L&A?35 ]B/$>1S%7?JDGDX]7 MT><&W]:^/>YO3VFWAU>=CH/;HN,.S@$,M:Z8^R_GJV_/AKV'1FD; MFQ/Q;RSL8QN?.]M\,8,VINVCIK>N*#!/<8C>H.WAM% MN8[WBREYPD-"J3TOBUZC&*)!DD>,%7&&N'T/U(S9@54.JUTA?M^4JYB)-CI) MD8J1(2$P0UPGH*\]#2EA$<4YW]OO,RBS8?$H$J'@ZTUF5ZSWNDCE M"-9!8HY(OD?)HQ2(::(0-9P[Q;B7PIYQ%,0 XWL$%$7B7$),]110> L:;UCK M"\\NFACWIRO;7;52 @H00I 71")/<]0QT1$ISJW71@=GS_GZQP!C/P)$!63B M]3W'#Y7&W2O][HI5R'G;*KKX3R@.-O7N MY>,(NE72Q@ F"FDM.4P7)A%+#B,;+. $0 K<+XRAS$,=@ZPM9?'KDUFF#?<# M ^W*3F]VOZNXJWCEA,,Q>8%@.<1(2NE1\C'=I<'A+O0+V"]SC>.(P1X8EB)7 M-5;B]G9FIQLG"+"\_3Z;^KUF89?J5;:,-,<1!>-8OJ/"D(\J@'Z,3< F"A#B M7O*@SUT>1H:I5&#M>LOK(A!;RU?&&1VE-BC*X!"+PJ$HR RB23&DJTC9CGD_8R]8L.+P6 X%4J< MUT:".NO_W'S$X3*'!X! _S&%L=@6P[E#4/H3K1(WUNOV69\DD-'"(!LQ10D[ M;["QT?MS=L$-+TQ%L2R2 &@5I?[)?CUTJ]U7M0K,8.P4F!?61J2]X4A86'"Y MQ3)IXD60_;+OEO'AC; A#8]801'Y !RN(I(.$H]MU2K-5$JD=519T%DIE8AJ MZ9"W*A+ML"<]WUDHX\X;3S0&0JN/P^7W>-&&KKRP39,?O[J-5MIP"FUWX1Y0 MNPHQ,LPB!N&.#!%&(DHDD#N_ ]&AWRNY97QOPPW\N* =ZW!;/_C!E'&Q#;^X#XK5:'?_>L1 W=W'>Y=N7UJ> M=XZ%.D',UB:_VV\TGD(A[K&/"?3Z0=_$3:V=RS/TRNOCMI/&?0BQR! MKSNVSDBQOK*T5TZ_JU$Y'7PB!M0^G1,(4QV0SD8=08_XWE?OP6LJHWFZZR1CQ<.DZHY)W5SC!.%]$2VA>::2M2SDN,ABPY(5B_1+H%7IR9,#! MW"XG R)73E!:\[V-7/*]Q&5W_8I:3W/62*2$5LAZK%&0$OY*1KB 27+NG%^+ M'%]H!L>OX!H#-F9],>VSQCQ2LR(N*LLL0=YYAG1*V2LO5$Y *8@/5/9]*[S0 MNR;CKS'#(5?PF/-P965/S4H[GC.C!R0=+*0D*8(LXP3)P/*,85+A?F=>)7.& M#ZNM# ]900E9[YW]!64W@0I;;$S"'F:&)( I5R@YF5 P(7EOG;2TW]VG,LK+ MH&/[B-P,CF!!\?EF%^TO1%W(5)BXT,[,E"A@346^/.@=DC8%18B2V!V=1?P' M%Z61<"RY'JWVV2/6HYT$JA Y$=A*:-]9)/+KPH0&CICPCBGEC;?]].(RBDZ1 M]6AH!$?S.V[XQ3;"T5:7 ?(LN#^E/J%K;'N@W,&QB%52!L<$=HB)DB-LM$$T M2@K:IL78.RJ#/(UC[#OHVZ1IW3JX4:&R44F'\U/ D8)T!9U6ZY+71,L0-*;A MZ-P78YX)#3%NCP=9'H=4V>C;=4*BVRSV^1BCC0I+LZ9-]GB(;#Q.I:),:Y=4 M0"XGQ9Z^EM4MCQGR- WZ*(JD@0#T(A[!BH[%X(!LI6DO2L25,_DY,Q@?#".D?$I$]+.ORUR&.9OEZ@A M3Z+K[WD8;GN%*E!MN ;;"-9@B027.=%/ %P3K,]!<\YEO\VMS V:(AI\3Z!. M<W2;TL]_GU'V0[^VQ[,T/;V(-W4[%D[?8Y0S\[+Y1/=AG\T22C!_MC'Z5411YI[G:V,1R*8+WFE&(*:>:5 M$S:2I/H=>9[HG.I8H2N'X\G$ZG;R;$DOWF'M&XQVQ10)@$I VA""@I<$1H9KE'62U!(@/IB=@H++5_'7PW*[:,\AYAKW]>N../4Y+-EL$\U[/54P\J, M<4[:1E*,22?;[[BNN&-RM-.Z05 [A;#L3F^\K7CE#<$,3%M8%HE'F,,J28/5 MB%(LO8[2.]O/E#_18=S!?2IR='O22X_C8S3PA!DOW.152M$O[F[;PWN=_.WK8;RSNF>76P)3-]\4/ABA@ZA7UB<1" M(DJ"0T!XC!8HFLL+CI+Q3 M6/:+:BRS;HXE)+-S0+K UMNE8]NC.G?Z6(\A6W''7.0\(2&U0E&U6BWCR OF MA6>)X-A/LROCP#@CD1P0XC.1Q8?!H;G$RQHJYDLRM=WU%LX0Y"MEG*#<,!0# M=SD0GB(1;$*1&$VI$E'V=*Z5L3K.2#9'@/I,9/3%YYRG],WT.!MXX)9 \V=" MD@AS/'*&! ,=62L2D,"P"W%B:=^4UF5<*V.B?B9"_'M.^A664,Q-XCI. MX$AIW4:R$AP+GGQ"V"6+C(7YSJ-52$DLN9*6J)Y)+,L$;)R16 X$[YG(WUTP MU+%JYCVARJG@A"^@TZ#Q?BG!\K.B-9.PK4,Y&PU[ZT.N4K#&,Q5X3J$F40C>(4691LY%'6T(BIE^9DR9%*YG)&T#0%O" M*7?WYTOX;[ZH/5A>:RWWY*F1_IDP\J"$D6B-"RTMU2KJ+UA*<#,,8+! MI+4>$2;A8[!$*V$3YOWR;I1,_G2&4G5\YLXCAJAX(L9.'5JOA,,*\IIH)2WL M08IC9$QP2#L&2D@.E$C$D:BT%A'W2Y=>,BW(3RG'_4>HQ);]^/W$<;-%;K!0 M*C?D'],&E*J+:?T_K<=B?9U^Y'[>1M=M"W4LT%3KEOD0%W6SRE3N)O5%A[/1 M,5AI'SH*+^-U[?>E QBC^4?#',NS,JK _\?2-K @3FZVI6']8VJ78+/&<-+& MQT6\&P^CCD%^UVO^+KV @;?U=,M[PZ7:6__PJK[:^')<^/?Q_+W/S^N!SO-^-JE]/2+"71H?&_NL-]QMK^T^L_NI@J9*$G@6*4;R2J"56#);\1,6Z( $/ED LA,)#+__;__>3?_Z7M9K6;+Q=_^ M O\*_O)3N9@NKV:+F[_]Y??//ZO/YMV[O_SW__9?_OW_^_GG_ZT_O?_)+J>; MNW*Q_LE4Y61=7OWTQVQ]^],_KLK5/W^ZKI9W/_UC6?US]GWR\\\/G7[:_C"? M+?[Y=;(J?_IS-?NWU?2VO)N\7TXGZ^W7WJ[7W_[MEU_^^../O_[YM9K_=5G= M_(( P+\TO0ZVB+_]7#?[.7[T,T0_8_C7/U=7?_DI$+=8=1A_U_+?XE^OUDV' MIXWI+P]_;)K&OL^&_@-OVT(IY2_;OS9-5[-]#<.@\)?__>O[SULT?IXM5NO) M8EK^Y;_]EY]^^O=J.2\_E=<_Q7]___3N6?_USW?+K[-Y^=?I\NZ7V. 7=74U MBU!.YGZV"(/,)O-WB^ME=;<%.,PC3N??;JOR^F]_6=]M5@$H2"%Z@.F_=NN] MOO]6_NTOJ]G=MWG ZY?>9ZFFT^5FL5Y]G-Q/OLY+M;@*GU2;\NK];!+&"3W+ ME2W7D]E\=1Y!"5\T-.WO[KYMPE*RL]5V:G%*\_GRCR@._=!\PA<,3>NG"HO/Z^7TG[?+^54X?-R_-K/U?2Y03OGFH='Y$K>@,^E\/L;Y M,]:;U6Q1KE9F>?SJ[@A/%L3 MR[MO57E;+E:S[^6[H.S^7JY5?5G7/#]_*:G+*II1_)AG06ZT_7->_[6G< M%S2G?X=I=]9[U7N3YGPT0$&G.M^52=YYL>'RTY'LORDCCT/X M7IXPJ4-]^IE1-T7D=OGUW(Q%$P@7%YID[IW4^'?J>/T,WJ19A;:T^EM7G MV["=M\WJ4/O^9])1?%JZ]3^O;M)TO%,=S:!8_=MHV[2L>P7YL5EZW2\G%3 M36_#61W_TC\&;5^1A=[M)-0?D^JJ1RX?'C0?31^^G>*Y/6_4+%1UW I/':B' MN0>=_EM.FX6ROU?! ME'SRN[Y_T)I-L-=NEM5]?[2>^$U9J.^XADX=*,OO:?Y=61:WR_ MK!Y@CBZ#/D6WCZ\_'R<_F57_,9EORE^##;UYT""B[F#+*LQSO768K-;55I=O MI3IIL,PT-(T_7#^Y*&K^K._?E]_+>4-CSO! M<,\W@\QH_7TR6ZP>%N:'Z[TMAD#HY&_-C,JI+I1>!L],8[=S[XPASZ?G[\OE MU1^S^?SSMW(:O^/];!KTUZV#[]UB/5GOBT?UH[?4]6RE\VZ9_FEF_(2FVW/25YP!YHV4RJR6*]K%*" MH3MU'GB.9KFXBF!=/=ZLS18W3Z^:3P]*&NP++X)%<\UX5DSMX%]\<6SVWRAG M1^K4:0R,VZF:7])@ ]/0<1?N/L3Y\WW@[)?)G^WSVM.TU^^/$K=]\&"'7N?R^Z(*TG>SB/[2\,'N_B4!RFX#G3_WC]4R M,&U]'R,@:F]PVS2/]1EF1MOMZO'R^,/7^6DQR>>,.0Q%VV"P*UM^GW5_Y'?J M.,/,O/XL7A2LG_[A#"JZCCD,1=TVD/:>Y\_N?P6%;5U6\_M]"MOOB\GF:K8N MK]IF>MHHN6;=43R2!LM%0S=)21GK? H^3^;1U6Z"C$YFI]S"MW8<<&Z[/R1= MO)\UZ/ T]4_0):GY7%;QB.F?J-:!!Z1M^T;\>AM$W"S54[R<9P_< VV;KZOR M7YMP%KGO)USEM73K?UXO?S]U@H?Z]S'3N[M)=1\D,5A:L^O9-*H@#TDB@B7S M<3F?=7EZ>-HHN6;=61H2!LM%0[\?,E;_%)SJJNW:O_^9QJ-@:XM]G4S_^23W2.+$.P[7/QW= M#K[CO?;-:E)-ZXGM?GPZMR;5TFRQ_N5J=O?+KLTOD_F+]W0'DCG5^9EB#BBZ MG>*3GCW.)_P<[S&6BY^ORNO)9KY.G-W!<8:9Z_(NZ"?G3_79,'W.=#OPSW?E MW=>R2IWFOC%ZG.-M&*J:;KZ6/S> ),[TR$C[YAL$).RZ<9F]#TUV#>.4>LD* M]O"-Y9_KG%R87KSY70?]%O8KR>KKUOLPYYU,YE\^R5N M7+^4\_6J_F2[E?T,X"Y/W'_=?5PT5Y:!YO)=^+&9Q7SRM9S_[2_A:XO#C0ME MO;>*2Z8!%@1Y#I561A$KF34,J>"M@T+Z!'@!C&L M.6;662H1WA%CK,6RA9A' 5+5]*=E=556?_L+K#OMUM1)VW],+M@?"Y8]$A\F M&S[8+O)_F\Z7J_(J')E!K!\_7"[6083=0S:JL+[+FP>7^;"L?QK 46=;5'_. MCDGUH2Z% PCC) $@#M#O7?4U< BZ&@><3BRW?79D M=^3X0Z?"<14PP\Y[@K%6EG!B&@*59,5>U64HWA_4F%YS_GR6=9"!LT#Z :4A MNQ0\HV7<0I"=^5TTK5^?:5+]7DJC2;JGIRJ=\N'$][%0X#CI#ES"M.#88!1563J*@' MHY*&'K7(_C#)P_9J$^RT9?40NA/#ZK_<3A9/ ]^Z2$''00HE#>264:HD$E0X MQPRI 2",\!2A0&]#*(:!*(.,/*9MV.95?K*9M8M&:]\BT 4083#\ET*"J7.V M0503C5,D K\!B>@;F0R"\"X8L%6Y6N]VMG;N[^]02&@ Q4)P8 03D'(IFL-/ M!1A36$[> ,M[@2/7H5!>;>^U34P:N8JZ=L=SX%"_@A-KA5"0&.<<91P$NFLR MI68^A>OT#7"]3U2.,O_U!4W\I/[^+\MY4'BOMC(X72X6Y71]F*/=.A8>, (D M]0)9@;7E1'!?3QXCIU-8RD;,TD%@R;"@/Y7QY>YTO:EFBYOP2UE]/^8$WM>\ ML( H$M01BH#3'C.! 'DTF#5,X34?,:][!"/?EJVNOI?5>K8*4^V\7;_N4S M)$+4<,< "KN)9\ V BQ1T@$MW@"O^T(D \.W%L1K]T([UX]W+!3#R@EHL : M0\ZUI(UD6R1M"NOE&V!]K[",Q+=WLO_FV"@%A]8#P()!ZKE0"GM(V..IIER2 M/P>\ =$8#J04=>[#9AUKA,7B;-/;L'AD4G__LOSB(@!@R1.KM65)SBB7@J_+=7D\63-&_O M.X1,=!VB0!) QDA@,''*(15,9&,#RX#%3BG?9EP,%$@11.AJ,R\_7#^C8TM$ M?*E99]!^)*@UXB)MQ((2&K870F207!3PP+*!1Q!'D\SIGD,S^F?URX"-+-B- M-;*C*\WZ_@G]@:*6Z(]SABT@=5 *AYF1V @:$C1(86H@/J M1 9\L[@6GLZQ-;1@7_,"$,^=A]!0+27CD"%1$R6#8:U'&V*2AY6O'!*]0?B# MR,?8@D[>CECD-UN?Y(JUR\W7]?5F7L/5'HK2VKD@%"EK/)$>&J."#28(JS6) MZ(4=5=#!>2Q[>:ST#4Z*M2Z8D_8O<% MTQB,;7WX+BNWCAFA#6DDGR$Y6IWP?)9UCSA- ^D'E(:Q:8!C$H*+74T\;H*= M@XQ?=BD@I !H$B.R.968& T:E050^69"BCLSZ8"SX$Q@4G2Y#F4A?BM;5+Q3 MQBA00()R0+$2GC*LX].AE$)N/U?+[+&KR>^9]1%B.=2ND M"HO/ 0^0XTP[P*E_)))C,BKU)9^(](C9:/:3?U2S=?GA^OKH->II(Q402Q0 M@!@0S2!!0,D:7X\91Z-2<<:VPZ3"F*(:'ZZ%%^GU![66[IT+ ZCV"#@?W_Y8 M)*GCNB;"*V_&M94,I:8,!EC6:\]_S-:WNYG7[W]J"CK=@Q[I7V!J1%A/A!K) M" $(A555DQU0SI2/HT5.AF#CP;O/_M!*>FJSB^E;K95'5OB>UH7& #M&*9),2 (Q M%N%DK"4T\8E<[SI AO5\/C8IJ]=$-6,^?\AE.%E<+0]P\'#C0CI *;-0""ZY MD-!!5[OW@Y#ZI VY]Y>M0Z_9/J#)L%SW7-8^R1F[?:YY9/EVZ%T0!24E&" O MA/,&*<9D33+E)"D#1N\O7C,LY_ZQ2EG>G92$L.-4,>&J+1_^/;3\DP8KK!98 M$\BY<@8 S"'RI"$2FB0;K_?WLD-O#SF@N\B;C5TFAX^3:GW_)%GO)=]K')C2 M^P[O--JZ%IIP#,#V/8[B2DI.&=R]HI$*V;;=;1B"'P-T#G$C!ET^^4OGUQDG MC%<$0UUP[1!#?I,;X 2(^@&$8]7CH&!L,SB0GJ<88>X^9>-"VX5 M!=)(&/1M'0@S@O!Z 6LG^&@CZ(9@VA&Y. NN'T .QA8[-T[VY[^)NK[>%B\M MK]QB/5O?M\?0[>U0&.(]-!P"88#W2%J@ZNQ2DBJ>]FQ_J+N$-W5ROXX'O]MGX%UD)H"*TG6"L$I?6Z?K8N#1:Y@F!/ MYV0O^N40&.78O9?WD_GZ?C?!8SOWLX:%0<8:"01 QCM+';:\SD\L(4!)RW; M9S #&1-G@9*!NS&?VV8Q>XCQBY>?3RNKE]/;Q7*^O+D_PO5N Q1&6\8,<(9: MYZ'6.NQ>#7X&C^-B8'!I& 2LB[B*/F^^?7NP32?S)L])K"$X6=WZ^?*/U9.V MQ]U'@Y9J.33-S^OE])^WRWF0HU6,3EW?=Y[OL,MQ/EG5T^OBX]K;OF B2 PS MVA#@.2;::4J#,"$1E 4$V*43CVQGJ^^W<^_NOGK5J_ R[*0&2N@MQ(H(#(1Z M(-,H1%L+U>1P4IW)GX.>J7/!&-;_M"JG?[U9?@^[T2S*!XD_1+$@3\0B?%2\ M+V\F\P?E]H!+:4^KPL0D=@)X*2PRDA*I(:\I!0:..T/'&8Q;]@5)9[6B*Q\? M9G+0M'_9I.!$48X(Y5YSPH&'@M-ZNN&0\Z-S[)R%^;)7%$;/O+%X8R["L^SZ M>]!1P[8<],IODT6[AV5/ZT)(8H*]*9RGWCE@+#%V1Y+'S"2E2NW=*$]GQ,M@ M[K,1R,#41E-]4$WC;)>+J+BV7+P<[5= %$0<&8VYY49#9YEC-9F2J4RO$R]V M;@X!4@99>#'+5O_YWO9%@"@8DB[(N8[!A5!JY&NRG,%X="=NS]QZ6;JB1Y!^ M&!D8R\$]1M;G/]?#6&55E5?;C:_]8-_3O&!DF^V;41>17T(.(HD+[V(A"<%FL]F(.]7_:> M"T:.:Y/)XJ8M46G3IA!.-1\B(I+#KT]WC%]?-4@')Q<_6 M5?JD5>$4(0A+)P+%#@-##) U"!;^R_[(S\'%R9_=N/BT M78&IT$']=Y8C;I677N/FO,<4)J6S&"ZZH \NGD%^=GOE\^VD*E?O5JM->2S] MS>%.A5"0*T6=^ %(S71-"R= M404<#;F!]()/%F?( ?E]N@/^_FVY>&CXU#C=ZRXY>;3"<^E5?.1+/(30:R@> MUPF$'ARKZMO)_]:S.[V@9T/?RA#-MDYUUE;^]"QB>D#8%0#M&8-*[+C]5L&H_& M[9R/"<.!+H65VF!$M$(,$\Z99[#!SDF85/%AL,K"/;._'TPN$L.\]54/%):L M-ZN [2K62_\:OCH.$),%_%JNJ^6WZ66^-)S=J^4\;MMQ%W\2L[V\^U:5M]&I M^+U\R%CS?KE:^655]_SPK:PFETX%4%.GIN'L6=7PM(9('^M6&&&E$]IQB[G6 MBG*QJ\<9[&IB0)N5,'2D])ZYK_3]D]^ZAT]W&ZK 4G 5-@".&41(8J(\J@&1 M&(_AX7\_##T86CT(4&-][[^'V+9B./M[%-A0#AP&87N71C+@A+$U'@SY3*\T M$V\P^^;YR]H7O6"602G:-]'X8U6V%[YK[5M0 RE6CD!AC:(*.*9Q3:X*MN-H M+T3/YE\'>>@#JA]>0L9VP3H^P3A!( Z\_JYUON.U,)ZW*@B(+]D=UA@"Y360 M4#;'KJ=^7-%$&%4Q)[;S65FL=J"=A"'?BBC0I'Z84]*9_*5;"W M@_A$%[5:7.U2/$0NG? &O764PG-',6-.0AL,114+9>D:!DY5IF,JW7_2F8U' MDB;VB]%H72<]%A(V4 AE$4)&.!X++WMJ:T2"N3!NYTF/#.]://@TO'(H+GV7 MBY54A?.6.\D\%DPK&"]3'PC$04T;KZOD;):=4#CCY#YN?F%##)^$\^KJ_6P2-,C A_*P;^7T00ICA*2,Z+"]6BT@!LRR&@!F MV+C2(_;!R ,%AGN'*H.L; N#_+9<3#=53$MPBH2T=2V,)DI:PJ3&QGO"@2&^ M.70]3LJ.=)%BQ(ERT3- %_*MIUW& >BED9(Y%91Y91EQLB'-,)+DCLV6ZF% M?;(7N-[\+8L$0$JL$(58"@HAT:!94<0Q-5[E\ES^G7S=D@;5#R\AHU,X1R<8 M/=W#?32??RO7?RRK?]IRNKR;K2(<85O<;H8=;N@Z]"\"(M8((8P7VG@6 QD: MK0A)/:Z2XCURYM7=7?]@G:&;AQB\$WC?98P".ZK#))R#W@J@ ME :&UR1!B,95]GE@_@\ 6$\RD,;UI],FQ$LAM:(>:2TUEX VFR%&*.G)[& O MHO+Q.1VB'#D*GNK"<:9;?7A55M];@%(JP)XL$\,6E%<2(ZTPDIJ20-M-7E",SM:TZ W MOBV'A>J'DXBQF0+C$X0W9 I@BB#@-A!!$!=6<^2;\X\%G$9E"O3 D203X#20 MLBL)MY/JYNB;QGW-"T4D)XHQ8+0$!E@JO=H192WTX\H5.$@$0P^P7"9"[HF5 M\E0/.BWF[< @A;6>8JZ8IPH1Z&00<%,#0$5:RJO+1+&ERL5@8.7>&7:G8->= M8=>\<,AB[)1SR$@O$",>U]:NC>G$QFXV]KPSI,&2F]?/;:)W#Y=@VY^[LO_P M" 6!5&""&<&$,>N#Z6UH37H,#TV1B,'R9 PO$;TAE2-%QN1^^^C7+ZMG-!R1 MBD-="JQN-RO#5 M_]VLUO%;6^ZG#G_#B#X8UTD6S@+J!Y6*L5U2C4T8 M\MNC^S7;#N\BCO0KC(8RWNE9:P0&G =R_KMR R*\J@N,?IAV*O'$/WADW)3 M6;_O?B1HO?PR^=/]^2VLC,/%-CKW+;S%2GOB8FE&98"@V.D="0@:F'1/-=A] M1*\L'@JCOMBL[I;5>O:?DUWLG"V_!=IGVU]/YWOK8(5#$D@< WP= 9@*YJ2K MB:0R+6IQL&N)/(+0-VA]24:\+JO*U3IY%]@[0&&0L$%I=C@0@"$$&,':2D-< M@"0S8;!KB#P2T =0;^JADY7244,(LPI C803HD8. 4:2HABS/70:V%3L![,W M_Y9%: <(!TH2"IU!.JC5C?2+H B-UF(\FW\G/VI)@^J'EY"Q68_C$XR>0AQ/ MS3JHD=$4(Q<3C4M,&8+!LEEENZJ5EUVN>I.6[PO M>Q?"2"0U,,0%YY=^@?I0L+QF_E^C$/?:)X/!NC &X; M? .!"_#2&,$+7 .MM$F56RX3QSB$D)R#U65$I9YYG3VPKCNA)ZO9]#2).3I4 M 3AR-NRIU&HFJ [6,T$[, BW>%Q^AER"TR=DXY(?.YMOUD>#H$X?K!#4"&RM M!\!8[:UCTM<6''$$)=V'7R9@,H,,I8&6HG,>F=238)7?ENLCI4S3!BJ,"P1A MJ GWVCD%'?3-$D$P+:S^,K&3ITI$%L"&DX8'E7U9;>?V$-QWIECL&[' *AIS MC#!$%?*&8P[K(Y@(EY;4:[""8I>2CQZ0&UI0RK)O07D^8D&"L6@- <@+I;2+ M\<:\(5>GO=NZ3)CMX()R%G*7":(8*465V:Y6(=3N%Q,9Q?X MPB=_NF!LZ#9CW).I-+)Y1!L\V*>0W'/.F$ :".DTM4IK30A63 Y5"7 @&B=%A$DD$(-?9>.%@3)\,I/MH+MG.9U#?;>[J!XV_A3/HTW(>OOOFRQ_E_'OY:SB7 M;H_J0>FC!MN>4L(!]5Q8QA$(9H"O(>( CZNTTP"*13;H1B)==E.^6^RH^3_E MI/KRQ_),R=HS8D'"@H786N$L)I!#X6-U^@=HL 'CREQQ&:DZ'[:Q2E28P%&S M)G7,PGC",:;AE&#<\>TM>[W@(&1D7$D41R)5"<"-5*[\\\"JEF3+B%.RO0QV(W5Q>3F M1)@R2,CO\0%+Q/OJ]\5TN;C:\F R_[BIIK>!DL?T-ENI/]V#T,OXA;(HIEX) M"J743BG@C9,U;,3S) _T8'ED^I>N2X X.MGK[%HX9]BP0(/F"8RFC@@DMA5% M0 T2@&E%^>2/*FEG83=J 6OQ-)PW<*$ 1&$A"NX@X\ 3Z'2S$J4226'+CP^ M?V0I2X!OS'+6XGDX:]P"*:\IEV%KAUX[ZY'WC<7CD4N3LC?D@<^)WJB%[+B] M>-:XA<%$8:,LY5HKJB0/:[/QU8"TS WP#3GD2,:"PE9-.>#K\ASWT^[ 8*P#T:E/KDE_#']V'XFTOG+XT/])Y-['V'(-7# MG0J/N WFOK 2$,.MCO]N4\DJ:2"2;=MD)B+;PE3W=RBH!")N8=8;)#2(=T0U M<3KL:)GR@1V-4^V#-8,X5 M<19YY:%U(GR3\#515.EQE3 [ES'+W@')L:2?G6+W=G(WN2E7GY>;F]OU?TSF M1Z^76_L6DCCN@'9.&!/6":8,@H9X7MR-7_(IX+.9 M7&U+N71[#WBT8Q%TLN@[$9AB2XWBF(J'*$ANH=/BTJ4B]LZ^>WF(P]T+AJRG MD! IJ -,J_##@X.!&P]E6KGIOI\,]L2Z@T4A>H-GK,;9ITE8R6UUR>LVA1(" M<<&E]QIC)$#X3>X !4@!E4OS>Q;5+CT?2Q2 MWZ(1=>A=& &#(0\P%) PI+V GM8DMD;*BGL>E^& M ZV,9UN,H*JJJ.]LW9LOW)GO(KJ3^9>RNOMP'?V>U62Z+R[I_$$+[2"AG%H' M'.78&VPTJ(FVR"?E/A@NGK=?OUMV^')&XA)8C;(R4 M,7TF=[@A"PN85()CN"C;H23B?&3R7[8-FUNTSH957CV-_+S(75Z\8-^NT"[W M=Z\;%PP@YS6S4%.K!0580KZ]-;4 ",&.9KHD/WH/=PX+7MZ]G4/\6&_9&J(^3\O%I)HM6_Q+>]L74AFED/)< M,^"$"O#N8@$"%C;U9>' 'J5$;AX2BC/PR' ^U[/[?;'Z5DYGU[/RJM7>/]BG M8+'V#X206!J,(4*I\PUYX0_CK9M^)K=>7<;W"] /)P=C\_:,A?W9V?Z@G*JO MJS93[GG#@C&,D/?6!U/52DT1Y;HY*B7+%-S>42'O\:@_"X9L_#2;J@KD=F;K MB_:%4_'-E$<46A9]6L"&7W=D,9LMRVXW[J:R9"]GST,B X/-9'4;;:SP3W1F M?I_,MU;7VDRJZCY876T!KIWZ%\!0@YSQA"DF.$>(2MGL?-#GVK]/$8!DSKU, ML3P 0#G.[]MEM8[.H'>+[^5#H>ZCVOJ>Y@7!2#@'.-& *DXDA++>%*& /LG+ M,IC?K5^N]X!'CMU].HUO6E>?RFD9)#.8)[^5ZQT$QS;Y(]T*YAV2A'GNH%:8 M66 (J8DT"B0%7 WF6NN7Z3WBDH'YV[)"\8'P M;8"""N\ %AAX(:6C6 K9G%\8NR1E;K $J#TO["$0RB :V\0ISZ X(@:O&Q<6 M,X!CF".D0)%@]\9S:T>0)2 I['JPK*3]LOQL-'+[9KKZ9 HH;/0UDF!O,H M@6WKL[F92'P6-7H':/E^]KV\>C^;Q@@:=5.599N[K*UK(;AV,.@0-&!%A33. MN>:PT2ZM"L; YO/9G.X9E P2X!]G^VZQGBQN9L'.?T#C^)Y]O&,!J6=6*"B< M)90IB;A2-:'4FJ3D+P,;T6=SOU=(+NH^^VVYF)[A07OL7C!KD)#(ATV/2@+Z9]MA MN3@/J(S7X!\G]U'5"("$3ZI--$%>$M'A5KS#*(7"5L='@8Y31B$)OWE;0V"I MR13&?+JL)+/RP$UY_UCEN2S]LCSMJO1U^VC04"=\6$2,8.,(PE#49/F Z*@. MC %$H ]4LERO?>UTA_;UR>6^<]P'.46,L_CB%XOZ- _FI!N"L;+HMW;X>"82NYL%P&D@PP(K[)K@G#UB3#_W"!,[@&67';Y M2-9T\K?M[U X9Q#"V@=K M5X?SR0CCF_W*T+3+\!Q*V$ V6Q\@95? ._'_4)?"6<& ,QJCF);-0_7H24;. MF"2_30YM;1@)Z FF'.\3)O-M-HORZV3ZSR_59+$*=$J( !SI56@9SCSM/7 <0:4EI+*^6<=,L20U8;"8 M[<'%H#^D+ M=5F5JRXWT_U^44$AM$@JA 7D,&REPHOZ(@;'RO%)-Y3@S2@M &; #"Z78>>KEPKGXICI.(OU_CK( MQ-"P>!5=AX[@@2&'G-.&^V2I"VNPSF^UX&U)9W9:P:^ENY_G#]9?+G\9B\4T8J=-AC ZI*JV!0 M2N7C=6<-A9,L*2YO,'_L2"1J6(PSB-NG6+!U45ZY2;4(P*R>$&0#0Z>S8V97 M>^<"6H$$\Y8RKP1R M4@F,H6[V8>]0DN-_,&?O2.3D;!A'\ REFU=X;]>"A@W4&1 T.26%XMQ144?F M8"%<4K 2_"%>'?2!UZ-P]%S>X$"=@8^3Z-&^+=>SZ63^?"IOH^B U-I11"0S M6@!O6&"AL0(J3JW&D+8==0,3=6+1 66<#3J*-#'5$[1J&XM>$X-(IJ2EIQ8= MZ,R"XT4'3B-^\D,7'0 ,0FVE0%1X2J0'GLL:"YX8[)VWZ$!G;G8J.G :'CDT MKUZ3S7L@/3>4&ZPH5II)ZAKRM"#C+4=Y)K;K^OKS?QU+MX.+SA/&:< 5D@0U$>$C'#AT!4&- =ML#[& M=N'5FZ(P)$K9;SKM[/OL*BC6GP(\'\/Q&J8\N>E^];F_>^'#6@/&$8@(]#BL M.B1L3;2U:%QO.WL4C0' R2X1P0;[4&TQN=JZQ\/,/]\&NZRS3!P:H/"80*6X MU! ##'T@UZ"&< J3SI,!K[4&DHJ>X,DN%]M)KM1F?;NL9O\9BPUVE(>7'0L1 MD_UCC0&@R@5R>?BW)E2JM$B) :^M!I*#,V&Y$/_?K5:;DWG_T*D(FI)CRFG. M.# !*(I L_$)"I.NM0>\7!J4[TF07(CG'S;KU7JRB*[M$QG_I&I"!A"5= PX6\]^C3/2/35YQ.$%!/-*K<&$'5)Y(Z(U6V!$-":U) MY%8GY7X=+-9_&/:?B ZL-\ MNT:H/K0N%#/6>*V4,M(B2;W#ICFP5)K6#]^"*_!\,#($7S3TKCYA=V@GC') W% ME"A;$R,TR50M^-2XB\XL.!YW<1KQ/W;]"_J^(8993EV-!58T4U'P M<^(N.G.S4]S%:7B\N?MVH("R"DCE!:>Q/H_WM"8O* 3PC<5==.96YXOW-(!^ M.#EX&W$7^=F?G>VQ]F'0FCY6RWC1>Z7O?U_%XBT?PGXYB6_RU70]^_X0C-O^ M?OWTP0J+K668,44$HY8ARCVJ ;$J[4(UIQ&5JC(,#E4>V7E\&W1<+![;%<98 M*!AS&L4@) U@;)95*!5S\W+\2'9]%HBDE'*\F#X_VY6#QD[OBP_E4$IG)_UEV=]6,L37%11:;PG0$5GO"*+!&-Z!ZC''XRKPD5'T1@!V!@FVY;[B8Z?_W'Y^1"*[="\XA1!X$]^F:"05<9"YAFCMDIXS M#[:Y79;MKY+$]0YO#JTY>L7T)* 2G\P&9;--BO9W*%#0'QB*SC5*-4 *(PF*.< M>PVY5361Q)&DI^W#E:D=D_CT"&N.HZJ<;JI9?93N\C9/YMO"?X& ?]S.IK?; M-,]A3;Q;[>@HK]0J)H+^>V!.!/?#(OYV['SK[UL*JA$T*NSCRC$1& %Y8P-Y M(G72QC9<"=TQ2>;EN)!!D .@\6*RM.7#OP'"F+.DWLSK]^/'WN1W':+@1!L? MYD$(@A IP:1KB!>0C2OOQZA$<""(,\C7H_S;V>K;$S2-0S"6YARL@=EE#NS@9^T^2*$Q4HY# M)+%Q/J +"&P L$%%&)6=F=%[.AB$%Y&AU\^ 3Y*>U]T+$6C$FB%"O7=*:D5T MLR2!P./RB0[!S%9Y.1NTBTC*@UE1/D[ZF$K4I7OA"90.2(&5Q M49 B*8-Y02\B*6>#=A%)>;?X'D[Y976\>L+1?@4#B@03P4O+"8E5(0!^/-BU M'M?IGT?%KLTX M[S9 :!4@#").+.,,&H"$C7AG,FD6('!G(\7V6]Z@.VB&N['R7T\0>,=\W1: M;1Y]4J<>4UT&+*#688)**0>0$3&4V,,:& 9@TK8TF"?QHEIPCS".8#]*%:J# MHQ26&DR"RL<#T%Q1BH&F#>**)#TW',QK.(*=*1V[#.+S8A-MO!+U4Z8FY/2( M\'0>HS!(\?A\RTKCN.*Q!O#.5G! L+2ZE(/I1AE=.$,A.*H [EX"MPM#"14H MIG1&5J"P:J@U-0!&VW%EP,D;OCL,A)>3H6A0KOIZ!'!DL'"H"X6\APXQ XQ0 M+LRS!@0:,:[HM^$? ?0'58Z0I,G][@I'3?^UF57!H%P&F5_??YQ/%NN@Q,6L M[=]:3K#N@Q0.6Z_)MGR6\,YZP &I : TK9QN[N<#O3#X93#24!!>0H9.N&MO M[5N 6*5&0,ZQL0P(+ 2A-;G*NS<1]9]%8LY$[A*"\OEV6:V_E-7= T#;/YXB M+/OZ%]XYI(%G1!E@'278ZD;'\P:,*Z#VD@+3 WH7L=#MIO0!2'5]'>S"<)JO MVO-*=Q\D;*^&8 (P!@(J++A R-4 .&23'KCE-K*&$)_!(,R10"A@M!/ZJ^V4 MX\\/44='A.9(K\*I6!_68TXD SI8DY(]HLA(4G[IW';4$%+2'V89SR._K (V MT[*\6L4Y;]T)>\#I<#)U'*G #E--I-8\GL\"@(!(#85E+NF,&LR=?($S:A@< M1V6+]V*#%T0Z2P$EQ#HD#'8*ZV:KQ48GV5.#>9,S"M)@$%Y.AG;O /KQYQP9 MK##0,^F5-]A0@B03D-I'%= G1Z#++R MJ?RV.VZ?SU0MKG:7>_5#I*.GU2G#%%*)6(+&(Z"DC=2SJOD*G7(0J&(-#= M6D %L(0(W7 JZ0=*K?[9P@)RP1HYGVK\6&U'&T'^Q1AR;"P*0N#!-":(&TD M:[RD1B1E^\[M[QEZ1SH'L8QV_(?KNN!5%UO]2>L"2J X0HI)1&(&9.QM8V80 M[9+"NW*[%.5D2^G@2(4C6&&' M(7926, !DZX^0R%W:8_O%X09%J53.8]Y[[\LOTS^_,=L?7N[G,?*"WY9G9R, M+'7( BNG 8^>54*MLP1+K6IPJ$FK>358@9L+:#L# YIY6WIRI[*]1SG-#C]Q MI )9)WPL<:TQ49AZP4VM'4)B9-*6-5PUG0OM6?T#.:IKB5ZN(PJ$B2?,*6PX MUE18XJUL%A6G28;Y\YJOZGW60."=#%)Z7#C>;QC(8A$ MAAOFL;)"ZUCDN@X9@#[\."I7S^#2D C+Y?@?MKZJN@^[7%L%V$[]"\RTHR! M)YUAS@J/ZI?V#@HMTZJ##24-?;&PFV25"OI>OJQJ\ MJ4)B3E'L! 8V (L4=9Y1912Q6B,0L&^1R(&).K&0F,#".,(DL(RSH'UX%939 M'3&!LDSU04XN)-:5!<<+B9U&_.2'+B0&' RJJ.182@VI M(C7V/!7%I0?MY" M8IVYV:F0V&EXY+C"[[6 E)-!E;3&.^R(8<12"61-GE3*O;%"8IVYU;F25!I M/YP<9.=_4B&Q_.R_0$S%]W*QZ111^K)IP0550@B)HZM30J.1=S4QR([L36>/ MQ_V90!SEZH&T7;J:1 WVXW*U_C:97=4SV,.M8\T+8N/C>*H\-@XKH@5QHIZH MHS;-23L4Q])A7O8.Q3D\J\I36/:\]8/VX9@1$ BEA0+(-]/4+JTB[V!QD_UR M["PD4ACVC]M ZRI8P9_+ZOLLIFOU4<"/#J6RH0(QS*KEFCM63 M)HHFV:Z#N8W[X5^?@&0*.U[M9K>;Z^IX#O8#/0KLI142"(<H,AH M77:P*@NH.6&:A[D+*@B(Z8^;R1,*DO@X6,Q;;WQ,)#_'/5RPF%8Q =%#<;U. M-[ 'NA1(6 " Q\'&LHIA22AIW!Z&BZ3<&EDSA25Z"GH")!.W/US7RD +CQ\; M%MXZ9ID07B""'),*T-H[CA6PXZH2<3X[]O W&8QL7-V>_Y^7\V/O(5ZT+ CT M7D*&(>/& ZFHQ34B6(0#9E0K=B"^IJ*10S$NYV',F[^7B[*:S&/.Y:M@P,TB MV;'PT0Z(8ZIRIP$*S FB-$;>AS/(.ZZ"]5T33A*+P SFR^A=# 8!*8-T9"F9 M[KA50%.B9;S*B&6]84TTDVF)T0?SDO0N&0- E$$N]&855)K5RBSOOLX6VTF^ M6ZS+FVK[XR[Z?8O5$>GH/DA!!7(D!IPZ #D'T7E7^Q.P9&F[QV#>E=YE9#"@ M,DA*OF*:&H- JZ"$28D\P)PU]S#8HC09&L7[F69_>)+*^;V0R"$+42:MRM6[W&;QH60@;4[D*HH/:ZCD@,B@G M-2G8D%Q!?AW?Z?7'F5<)DL^!)3^'=Y;'QTFUON_.[:>]"F14H"58+<8)P;!@ MS#4D*J)8"N>'R^:6B_-G0)11"AX@V&J:';C_I'6!@!#04^FL9HYR::ENK%02 MM)11G>?#47R9_EJM?9XME-5O?U]M=,%:?CQ+?C*[O M?RW7M_%9>9!CRT%8O;U*&(>'T'#HM6*",L'1U]7\W':J$=1ZDB'DH)0FD(Z6T<@PZ56]<1%J>%-TRF.^Y1S$8#*+<"UY] MG\SF\7GVE^63['\Q7UM9K?1D-9MVW1+:1RHH\@XS!"$DVBCNO6F>@1*(>9(J M,5C:O*$VC=YQRF4$'T@1$HC[M_D=Y=5,V!"?* M6J>Q"ZF"ADXPE@02I8".2;YJN+C621*A M@./T_DEYB* 3;'^;;XW&1\W@3&E-_\)"4@P%0QQ!@001S$,/FN-%@7&5&Q^I M"&>#_\)RW6@K,7?O]EUR742G-TD^Y2L*1"@3SGM+#<86"&MUHTUSP9*N2@>[ M.AFI[ X(^$ATT3.US0(P1!A4E%JGKA646,B]$%!%#Q BT+)F2\=*T!1Y&0"K+:S^69]M,K5@1X%9-@9(RA! MU!!)K0\V:TV:XZVY9O.:4H.S.PV5# S_1[#5;L/,U/>RFMR4OVTB4+$J7YCT MZL-FO5I/%K% R59>.^SS2>,51A(3CCA'&-6>,@HQ:-8!4S))2X!OX?5^#KC& M)D5]24]!.'4&"*F8(L9#[TF3$(-P!L<5'#PPI\^1JQ.!O)P\[7;15U2<+E&' M1BJ$LPHX8KA""#!(H'AT07DHD@)0!]N(1B%3/4'Y*%67S.K_,1"Q"%;@>C:= MS)]/\&VD^+>", Z05TA[A 'TV._R;RG)2*LY-3!1)Z;X!U!+P"FA2#/J@== M@X88FA8A-7R*_\XL.)[B_S3B)S]TBG_"(772$FP8$T92@C&KL>">)176R9OB MOS,W.Z7X/PV/',EB>DWM+CE37"@7K"_C&&;2VD?R&--O+,5_9VYUSO&>!M / M)P?9^9^4XC\_^T=U\W0TI&&@F)3H-8=>.(*"42YQ?!CM.=6N!@G#M-)\.?W* MJ6I$1M!&&%GR,K:@WS"2/:,7C'E)E 6.AR/>8N1Y[2)4*BS/)-TDI^MJ"#D; M!KO1!GP,$>$1X8DF.K,&4N*I,H8YPVP-CR0B:0O+F=UB"-'J$[',/H>GX

HH=!$ZBU9 XZ(3B!<C,@N,>AM.('[V'X6%)Q6UCN=A6&>WH:=C7KV >020X=H1S3(0P MT/@:&^MEIF#F9#\X)H#X74 M$H- B:9,!*AJHF+,W:@\!&?RY>@KS20\\H2CUJ\ 6SG\JFUA&)<, ^V"'1"6 M@!(&JYH< =-"3X>+0.J5O>>"D8&WZNIJ"^YD_G$RNWJW,)-OL_5DWLKGH_T* MH*2SC&#J%,,&!/J<:0!3,LEC/)C%W"_/^P0F!_^GT\W=9IO-[)"YWRX+7<+?0L%P.!E$%&/I7K0'EY54=3M@K$_@Y% M,))1O'GQX3S#AGI+ *X),T@GQ1$,]@BA7^[W@DB>M#K/'E2\6[SVEGU:SN=^ M6?TQJ8X%))\X4B&<)] "A0R/*4L,-:)QIL1BE*/2 GMT!@V+4XZ[YH/NU+W> MGI>-"V&5,@I08)4ATA$?DRON"'(!PU$Q?C!NO?+^G(E3=MOOE&C0EIX%]!([ MS$S0EL*J(C:L*_U(ZLCN\G*)1+^@Y34;3Q&.8]T*I($GS!GEA12**$=1?6 & MBTJ/*S%M+LGH$;$,8I&6SLTQ;T&,72; 6R\XUY#59 CQE6$*A?CSX'H!WD( M;Q 1P"N@H9;0,F28$371@@&?(A>#V12YY&( Y(Z*2ZPLOQ4"B'8BL*TUOZMQ3M4B[#QTL"6E6ATC/T&7QD2RG97FUS:T>YSA93,OX MZG$19'X=JSX^M^J/^DQ.&JG '$B$48!;8.H$)$PWUH"A.LVM-EC&T7Q.E"%1 MO-P6]+"5GK$'O1B@D,I1#H W!A $L2,.DYIP)T2:^/P8;MF^P"/Y73Y2Q M"JB=<,'^!4HQ$$QAQVGC36$BK0PF?/.>Z:%QO/2!VY-<'1FLX#$\P# /$3# M*":E;300&"RD),%Z\Y[OP8&\\(;E[K[-E_?EPR+YN*FFMP',C_/)T0?<*>,5 MD!J'04R1Z6(]:B&HJ:^5C=6)I5W?O <]!Y:7WKP.TI%L/AP>L6#6DF Q>64% MI8I"3.3CONYHTOT=?+.>][QH7EK0/I6K=36;KG=&M8J0;:^A GS7Y6R]J=(M MUBYC%TP 3J2+]8P8,11H(!X=B4%]31*^-^O!OQ2N>>W<78GF+\LODS__,5O? M1O@"C?&Y\B[QZW.SIYL)>^JH!4.0$0&E%)8*9BPCI(&(JT0_RIN]#U@YZ< MQUJ>U]?E=!V]V_NI"UMXIXVNEV\JK!".$XBU!]%!)*EJEFI$&TB:M4AD4N0%^C%N(,F&O-._G[0&BC]CBV_ODA!T"36 MV7W;.2/O-LKW$=Z5C:^KYJOAOLW/%I/%-"9IJZK)XN8AD]#Q;QU8Y5Q6ZR]E M=12XC[[3C!T)HM>I:WL#8[1IAQZ1EB8 M:ENJH7WM"VLEA2[LC<1!"6-R8(=J+!!PF1)4GI9BJ!?>OC*6SD>SJN9$)GY]"=$1<#O8IL#4:*L,H(V%A&"^, M;98*AVGWP'EVD?,EHB]4EE5RS]BOIPNRMUCZP(B!S7WRD)AA6,>2PQK MDACBXRK"WK?A?S8> SH$(WDKM;AZ7Z[79;6JMZ@+NM+V[91=/&I'^Q5.:\XU MP8;+<-([BR!^2("N A^ :E-#\Y':YE4[V*= &FMBD9,3B_/]-__SXZ\!E,G"1'/PN,MF3]/"0\@)L5@*Z!0!F)J@ MJ>XF"#R2F5C83>WN#^YEK["D\,V6F_5J>EOJR>)PBNX#+0O M%"*.&6,Q$KD0M 8@:,M)+S9.%XL+JVZ#X9598%J/Y]>-"R,QH3S6R83. M"*0]H\VV90*AHU78AF#:$;DX"ZX?0 [&IIB-D_W9V:ZNK\,&&*?I%NNP$;:G M\=_;H5"Q8C:0UAMJG9=8,]D01L*OHU+JSF',RS#M/N"XU'7;MN+GNO$ UU<_ MIUZR'1BF, ![(IW5+"BU2 1,96/B$#8RFP)KPL)C9_,JNT#YP_7ZFZY M6:R[Y6L^=:B":.(E9-0Y2()V[1C3M69ME,=)L9AY[8U!A*='S'((T/,+G"=S M?9C\,8%IZ5HXQ90#P8 #BGKBPE8K64VL$3@I+&NPV[N!!*1?C(:\T5LN;NK+ MRPM>X\6O?[=8K:M-UYJZ!WH4ED%O':58*B2 !S'QI#.(&4L5]JC-[LU!7MNE MW9[6A3,:2:4I4,PQ0(GVV.W(8AJ1M#?P_5[7GJK![!B@YHF%V ML_M]L?I63F?7L_*J/>#Y4)\"*:&0MAA3@RRFD*!@]N[(XQB:T3IUSN36J]3C,N-[X-D!*>@)GQ_P#@AS[@1 #&KHL3""4,J:HY6HM/?W;T=# M& RI-^#U=T '95MBYA4@SAL-XSWH3O8Q!:-5%(9@6KO[/PVN'T .QJ8HC)/] M;_;V1U-#J!)8>D098U2H6"5J2Q@/_\MU^9=\^].9,=UN?TZ#XQ*/89/>P&OH MH"'><&4)9(K2^$Q@1Y8B)"EPZW2/Z^4\ 3V \J8>/ANEA'> <$$44\(@SFO% MED,LU6@/]S,YU?$%=!H\/Y0$C.U8'P?CLS/\8[6\VDQ/>RG?N6_!&3#2VA@? MB9BUF$%4.]8YXG1<\;IG\^QU*:!>XGPW.#R8!8SOEQ\#X$QA^X#6&HG]%%'PN%[-E]=MR7:ZN-F5H M)8Z_S#C>JR#<*H8@ .$D$E(B1YI-3S N,F6PZWA6GP_^)C MIW)5KI_,0K9PM;UK82VQ&B -)3?QVDH%(&H">+:7%I=A;>_P)/*7,/)*P-I9 M>Z17H;%GSBE%E=M:($'B M.R)M&4?8$R:L0C4!QJ=E%AJL)%?OK.T9GD3^4H)>"E@'UA[I52CL)%42<8\8 M,UYC]CAM;$G29>=@A;!ZYVI_R"0RE"&:P- CO0J'.3:$&,@9ET;Y<%;4OG]! M)4PZ5PJVS(=BN+1WN55@IM)"82 K#A2_RNT-V22 M&"K^"B3??Y*W<;6]:R&ELPP(+I4C+"AY .-:(J4W)BD1ZV %B7IF;>_P)"Y8 MN.<(0*T+]DBO E*BO%/ M]"J$8]9[23$50!#G29AT/6TI<=H=T%MQ+/4)3>(>#"7=OU.TL;6]:^%ML+^T M J?G U69>SA?I6S>:A.VOU M$:<,5^"8/Q0"0R73B G$,:TCI"7 *BV([ZTXH[)@EKB? _!:I\>M^_F17D70 M_7W A6D#L*9ASR((U]-V1J4]ZGH[SJG^H.G1C='.T2.]"HB@,(19XRBRR H6 M,=E-VX T-\9P%=JS^#'2H$GDJ, L@:-'>A6.8>L)A5H*2!V"4H(Z\#BZVI(\ MC<,50^^=H_U!D^H[WK-)D';?\>%>!8,4"($)<,@0[*%@O!9$I7WB>[KJG^ MH$F][>&O-PG:?M%SN%=!*'7,Q1*:1,292P7KXU\I1M)")]Z.;ZH_:'I!62>(J$%UYX[2HECX?^[:;.@Z"5Q]*VXI/J$)D>@O+ MMH43#&@;LZX(PP$-:I]J$D:$'2@;'8R+DG2GI[)6=7#PNX7G4N*@IVMIBUI_UK[1H^KM4Y( M(*$@!DLJ=:.%2HJ3BL5D\G,-* R)\&20!C/Y-EM/YN_+R:K\\'4^NYEL7]H? MD8$#/0I+#-<$ 6%=V.)X4&E<_89+0P23RGMF\H>=S_E^0,GY^C2Y+A_#4+)@ M9Q)"81!:RW"34$=CEI9-().7K(=#_FQ ,NWP0;<\?6D?[UAXR8!WG&-L@I8* M#!"@MF4U)6EO'#)YT_K9VWO#)HMU/EFL/D[NXVM+TVJ_[6E=6 ^M($Y[(HDB M6 0KQ#8D29NTH6=RM?5AJY\+R.4.[W9V'^]8A&-*(@2)8,(AK:% 36";=LJG M%6#/Y'L;["Q/ R?%Z$,TC9FPP/2.FNA M5(W#6#N/TWQQHW?�A19I]K)\?<_@X%D3:(+8(6>&009]S*^KVE)B#Q]OK- M>.-Z 26[2S;!$?N$.*:VQZ1&H1TGIO5K#;Y.J"BK)]_*'*-6 M0*!8.="C5LKFTY#*<'R?FZK7 M*Q<6GQ3>&"1XK&R(34V0EPZ--M_3$$QKS]F;!M=J M/H=179/YI8'S@TG V,[S,3#^_)N4D3S=]=A@R0P&D@7<$.1$\MJBEMR-JP## M^>SJX^7N:9"-YGT*( 0(@QT2GF(#/$*@7B-,@-;"HR-) YG&Z3Z1&?WS%,4( MX41K(X#BG"DF+:K)49PFNN)HG1 M7*55S[P8277FG@](=@7-3Z9E:^'R0UT*1ABGB)LHKX1BRS5O!-C2M)=)V2_$ M^W'=)Z.2.0#B\7).EY,JB.A_A/]&N_3I/5['V(A.8Q7868VUP<1 ^/_8>]/M M-G)D7?2-[L(\_,18QV>Y;1_;W;WV+RR6E+*Y6R+='%RE?OH+4,R4+(ED$DR M257W4"7+B4S$%P$@)D1XR[GR5G=P<)^EQ5>/H><*26FXSAI<=S/-Q,?TVG4UNU;=OB^9;G-BG*-!7TQ_Q-[M.D\PW!:(D8TC":-8@C+V/YS!?=9#%+>G]$ M^LOWR:*I\Y4S)C6IB.OU]':=SJ2-A1O):9;NSZO;=?RVCR)OYG<_UJL-YA]O MGL_\?8\LJ*$^$806(NKEG"BA,4&*,FR=H7%?9%)Y>NAR1B&;^^I[<[V^;3[> MG$CGH8RK83\4/-7"&\@=8EA32]0F"70+)LR[Z3)PLE9]P7GN$#@GY&--##L1 M"GW_^@L.Q),+?C48A[0DC.%X:G/%D ,0MWR)BE>E BU'!:;/)9G/4Q=&PY4: M>2ZOSK57B/30T. 4] #9N"L!XZ&3./ZB)982-]Z6AZ.0@%Y2>3+:;US$QA:- M?Y.253\DM)I?_2L!%5'?(/7I=C(['/O;/2I0KD2Z$LB-5/%G9KSMS@J*,R_* MEK+0AV/8<]5P,(0J",&G^*YFL6BN-[/NT8#[Y>/!HN25Y!QI:"-5$!C'6J(P MAUG!WV*QHF)L'P":LQTCO;?.@P'%0=X?N#:>>&\H40XSKJPF'0\\]WFUA^M* M5$5;]!R8%W(;OFJ#%'(ANKL?M_/[IGFZ5:O9M6YF\86KM&F?[\/M(Y^;U72Q M,>*_3'XF8%+-E6='R_*L%Q\?]KQ?2%DL)K-OFTG_<[KZ_FYV/?TYO5Y/;A\D M,E+QH(5-EBE)?A,%261]FB]7BX[<+1C+/E[$>I,(DE,H>+2&H04H;N!,::R, M(E8J*<3!HNBE_8S%D=#W7Z>K]*7'UR3)O?\:Z7W]\_U]EV.=?$!< \Z]P (H MD7KJ8"!:IDM$*YU&!RZOCF\)[/28OA%&C]4+F\Z$I,\><)L^?2Q8@8W7""G# M 3 Z_I^;EG)O_+C]G)G@3&!7-W;#[$Z1DL7T^NT-# N8* MVMN$B M55%.9]5\-EG+=:N!K7;>P+T(RKLJ.. MW/:'_.E#[L_TX_YTP=->'5+NY*:C'E54,8(QM+X%"PJ559"]X+V&2Y#=F@P9 MF_3&M=DMQ^6GR?1Z*-E]\>(@&2(H^8=5/-VD)R2>3BU0S/(LR2UXV>)M2>ZI M["CE+N_O2=Y$I3ZM%U??([[I;\[H-?YE3A__F#6+Y??IC\V9]^7CIW3>WV70A''M M'>30>>2\S/.A! M>O7YX!2UTDC HQ'C@:*"6=2N4J@]':V;<"!NSJ/R>+Z;Y,_IW?KN^Z@7/^^O%I,?Z31!\H0E/ID*MZ M.18:T4( ME)$QLEV&&D3S<5R25E&]'0?@8Y;FMF%ARJ7[VV3QKV;U:3&]:EISVA:2Z!Z? M#4Y+(@%5AG#IG%+:(M:"["S/JJ90S*%Y"5(]/.BU4+C;!;3?>LMZ8\ TM724@DJEC!"*N?:^6(1&PZQ2KL7Y_,S M;J:^64#GS$?-7O5]/(VGOSQP@)'C %K'I1%,.PZ)%= )W44J$-9$J4]CPQ.B\_)VH/ MM2)IGPG<:FL X$ *KQQ4V@/9THRPJ&2,9CHEJS'\>2."3/@JJ$6;J1UT2CQY M*C G("58^GCNQ@-=,&%$2P*4Q(S6^YC!A=?X>!(,%\G1L?D2ZS*R.@.W3H.# M+/SEN6!@ M/A<@!5!X##'#'D&*J*>V)<-14*D<^(4=KZ= . :?VDY8'@F;7??..B_QN%PK7%_JUEL"J'.KIH'W_+AFBZOCPC$$8($9TPJCC1AVGK?NJ",0)6:LEVB MR R#:,[]L->$=3*[?CJA[O?[KXT=_Z;@(>*22[^)AP"G.58=>1&N+/6^6.AG M% )3!^F*MT:/N7..O3 .&J*8%1I313UIMTX-)F5M:HJA&&G7C5:<7\C5\-[LV'^+. ^,"^;NV*R50FD9U+PUM&HG0%R5&9"+L3SH7'(89>*O\(? M[V;3W]?+(V[S'Q@6G,.64>$0DA1#P)&4'0B4VZSH>#&E?0@&#@O(&/Q/NQ2' M#^M$T%;U6*KUZOM\,?U/L^_*Z>#?"@H@IJ!SR )&O= 1R#8FI:,:@T>U09PS M#^/,R%^0(/^<3&^33NSGB]_BV'V%*TI],CC!//,82XF0!PX2[T4'KE)9N>'G M\W6,7ZQ/9,"8I7OSCW]$F[[+\80E)/J5SP1E((CZJF90Q],.."05Z/Q+'&=) M\?D<,".4XM-!/YOD'BV#01-O66ID[(AW8A.S40^$*4 AS:H)6*Q/X^BDZ4CX M:ES-;)/,F\7/Z=8S_6+:7R=_;K.ZV[K1_8OS#/.!8 #A4%/MO+92&BZL,2UP M\==9Y:6*=84\H]R=!>X:\- MT&,!-$D.=D"B%JX=V]J1*8^+97FKBW6?/*=45D2YUF&ZJ?@35=5(52H+]'U^ MFZH5Q5_D';5'OBZPN"BQE53&-O\].E+O>502'.B("(1-T6$:Y5/!Q:<#A'6748Q!N4O$H CT5)_#"? M_8Q&4/-@#RV_SE>_UO8S\^7JPWSU/\WJ?KK8W'%_ZZ%.GP9L^/SH3C.8Y/ZY.-UN\WE^>QLWD#3H+ OFM8D$K(3PD/O4. %+S(5&KF4$!31OH?PW>%:9 M+V]C@3R$&<^[-A[F$ BVS%AJK360(B(58J*%WTKV1C(E"HMF_164Q;V+7CR; M /RR/67/LG9^G4(PG'JSR0-@/G+! F18)QY0CBN)[2^_=$YBWD6OG%_UTQ&8 M,(%PY1P1TGI'%+'(Z4=_(K0'*]M?2 ;(6UDY)S'OHE=.Y,E-,SWWXGDQBR@C M"@$>MS"#$35(2R<[&;&$9=UY'%_.RUM9/Z?R[Z*74,>C?S;3;]^3*_)GLYA\ M:S;'<:I2VKE*1N,U.&:F01C,F2?1H';:2T\89K0+C2&=5^-@?&?91;@5"C+N M+[(&1[[P@J34,1LW=D* YQ!28KLT"$EQK3MZHSGXRDC\"%?ND9R_Z.7ZJZ4Z MSC5[Y!P#8Q 8)0R%G"!(%=:\E3W$">0/=7\]=<^.HMR_Z+7KU;6STU4QCGTCUF@L$9 M3!GF4#&CB6:(,MTF'R!">%8VU27[B2Y\W1;D_44OVH_KU7(UF:4X?&Z2 MZ,7?;QK23ZY6Z\GMUV91IG]&B7F&31W[P8'CTNHK,TE=H2]=^N4CLE$!*!)#4<6:*M MC+MB-/PMU$XI*Q0#_^TJ=? ;@0@H!%>.)[>)3'=-,6XA1 Q6ZA)2NJM4;T$I MUE7J.)PG(^TJE5/NU%/OD?$NDLP55=P89EK*M:M5@?M,Y4Y[LWU?N=/C$!QQ M04P=5QWWR#-B(99(4\9D2PBC;+PM[O/8L;\R9AX8%\S=ZEP]IMQI):8>PNE9*)S]M/>#@0N+ MXB*RR DI,>*"](Q&*#V&4FD@ MJ<"HVW*\SZLO.#YI'DBDRDEX%C=J"/>^%N=/73GNSVB#3)?[/9A'ORQXQ*&5 MD+-H4DB.<02D.\4H=%DV_/A280J)9VFX+V!S?1(%5+-K]^>/Z6+SAJ)WX_I^ M.U#!'40>(>M@5- 1Y;1;[ECR+.D>7ZK(.#??H;ES 8MA=VRNW0$^+:97F[C^ M34WMNN=D B", @XA<, Z);&)9E*W.Q&9=AC5O9ZVZ8 Z:5YA(TF&$.DM M$% H[9QJV20\S*KC>0FVS]E7VXBX.N94ONQ\1G1HR=6=34!:2"X@%4YSR"&& MEOA6D BW65;3^!;:0%;3J'DSEE*Z9K+\_KFY:J8_F^O4"Z#= C[>//4J[ED& M WXE&,.UUD9(8Q#24BAANNBV@7GB/>:4[USQ/A_FY\LUW20J[4HOW4XI^_/_ M7D]_)/ZDI-W)[6WZ,7WT ;[S?MA-?SSYTQFS;-75U7P=%?P/\]5&G7@_CUQY MG%J?7-J^KP@6*T6E,%(:3[T@UGH3150B8#B7_%"K^M(9L[_0L2$B$M/U2WDD MJ']^[%%O#,!B9Q4TQ$"MF><*(;J%AP&*\FJO#)L-.SRK=^:\EL1NK!FNKY"7 MRI9'5EZ_V]PB>#B S.UDN?QX\\K3!U)C!WE_\$"X>)I$J\%1[K33QO(6:RWR MKD]7RZDM)%;S\P-=0??L1=9NH@[F= [R_L"],DH3C21TEJ0NOX^@B(\V MT;>RU.3(;"'P_RN[/>$;6QKS7T%D3T^;/FP0[$^D[CL^&,^2/UU(99AW$&"N M.E(($N,J*%:9>_/R@%;8QO0D3C,Y!YIF]3[Q+S%KO]:W:T@ A$('+#*"0RN\ M@)K"ECC#:J7NC5J1&PB[,PG&P4-K]Z# A6*$1G0PUI0A[N+6W!((O(*CU:). M9UD/&3@)I#2*ZJE'#,&:XY2#;*0*,=^N&W6S:A8?9\W_-)/%$+*PZY7!0TM9:M!"G-+< M:LL=Z?0M@[-N[Q7+P3F#: P$7(4S8J,Y/<[\M\5\N4^-?.WQH!B&48'BTD.E M%3 2 ] 2!9G+:AI3;*,H[KT> *(*?'^<8.J6_.[NQWI3/C'*;+2Y['2Y 6F/ M(/0:'RRB6E(4861$,^>0,*PE&T.759&HV#Y17#)*8'9N48E;F[H[15:Z%P0C M+?<>I.81%@J*+>)/-F.2E2%=+ /FO,*2"]IY7*SJ]G;^1SJ"_7QA%LWU-![# MRV5S9)!JUUL"U)OBZ=X:Y30TF#LL.^U+@ZQR@L522XK+33GDZFLC4 (X )$=5PIC+S#6@#?J5? 9.FEQ0K@U=9$C@>H5$K0805ZHS4]^;.^?Q!< M,UDUW^:+^S,FR_3R6/=)F3GN1=%T,%2:9&H2 U/!D6BY**.(U9A@20Y%W$LG MSO1SY&^8^/_6D]M-&<7KZ6:2_7-I3OU(<$H@SR3D#FK"L(%>RBV(V&1FV0Z< M7E-*+'8FV50&=:QY-QO=:C:Y?:!4I0-RN4GLW!]8V3]#3OG]@T$(A:!'P(![34:TGEOIV85/@ MP&AC+\.PKZ=,G 36&Y:.L<5BQB@4U87ATR+BM=,K_\I3 4%#0%3:/4),:LB- ME; E06$[KC)Y0['C>8'#;#QJ7%Q;__ZC%U=_?3!@R+S$C!O-TS4\C:GM"('. MCZO1>B'&G@1)!=[VS2Z)UJF>WL;/?_NRFJS6RZ]Q@@>TQE-?'9AAP'I$/%$2 M<:2D@+@%"\&\'AK5TG;.IEE6AKVJ[ZS_L' M!(*H]X"E%"R#C(%*/JH-&(BL_JG%=-NAF#0O $V-5,+C./[:X\'CB X#B!IH MG:7:Q8.Z)0H@EY5/5DSE+<3O 8 9S369]6+1[(W['_.:8"70!D*I>53A&(W( M=BH= 9S6&OA=!]]00#'(D6?)LN5W=MW])C7!.6L0@1"BX%2S"'BH.C6 M93R>1[7'C$F*\@"\D 1%;1%#WF *A8#(Q]5@5.N&/+WV>1NOEA-_Q-9\I"8U6;O19-A5[;-N%(6=LTR,W'AX.N"1!)XYH7Q M"%+NK+'(I,:'$(B4Z7AH#9XA?6$732>E*^Q]:: ^=27GV%B5[J88K3UM03)2 M5ZJJ<&QZPH#,/R9)84@HQYJ4 >X"A(L12YVR+M92F4FWCX9S1 M TE6D7H@QV$]%C7_[#45()=0,Q1-(<"(H9X JUK8O$!BM/[LRE)3I+A"'OC_ ME=V>\(W-D_Y7$-DC1/7<]4 04\8+%RT[I+T74G/6*5^*X0OTK W'O:QZ(,NX;6N[FIKE:37\V_S-M;KO??IZL]MDPF6\,@C#F+-=,&L^%I0";3C=BN)8F MF"]KY4R9.HB.ZX)7OP:@>2\,W,7Y.0211(ISK04$_/%\\.-J,U15U*H FG/D M[?:;39[XS6X.WA+,?UF@T$'$D8S'@G)Q'X?*LVXY&3_ZPW!01LXKPUDEQ7;^ M>Q*U> @9;A551)+/2 M@6M&J$H*505 +AV9M\=2US2). M.YF5R:.Q6&]^7R9H?M04NH<[%\[D]LE?Z_OWS<_F]ISQ\G:"Z:K+AH[WTTDD M. *3DO8V%%Y_3(ZA]2)U[(X/?)C/%NT?]60Y[1=('_([@1%$L>'4(!5M11%/ M/2.,<$P"HP4VY^FL,02)AP+N@WTCH%2?RWG!J&#I&I(CQK802GZPQD*5^/MY M9.;YWG@FR,<:IW]MG_L\7?[K0/A]W["@J7<,2\BC5H*-=90SW"*#I1UCBXTS MB,6\&*(5%+S'V;8]Y])MDH-AQ7W# F..<.JMC@9V*BV(/$*/1#(\VDCW,*S; M*0^#0?5&Y6)L4>3QB4-U,7#1'KJ.VN[CK%_3EP_>QCGF-0%#*KF5'B,OJ>!, M<\1:$!QCXW*0#\/.%RT8B\%5XZ;6@+TA$+#*&<08E(0C30%POB-.U0JQ79@& M,A":9Q*54_H#8)0ZXP*HB2',T&A80-,2"("^P&X1O5G6OU% 'DAO4!K&IF^, M20BJ,_\A0/=TISR@4[P^($!@B<'&">FP8PX#)KHS%Q@SKCO=0S!H7@"66OS> MWAQ]."G[//B3/QA40+\7STX&IQ?5CV/T+.0P3 M"0237!M@XH\V*M<3$*D1,&RU7WW?_?A_ILTB?OK[0U3E MT'V@7B\(6B-/C!)(:6P!TXRISNHA F>=[<>+PH49!D6PK2E43V-[+RDX?!GB MF/<$J3"/6R8G5AE,#:%>J&[S=%R/UI@8FLV[I*@@BG]9H1J;37)1LG0^&7HW M^[%>+3=XP(.*S9Y1@5JEO8+)T".">!E5MTXU0![22O+1,QVF#/=VRQD4P*C/H?!*1!U>5V.KOJ\]XS/&!/!(O*%[>2IV+YRDNW)9P@;RN% M8?NE-!=G[FZ/[% CC5!^7-SN]&<)HO5_=?%9+:<7&U U/=/_^9 =*#_2P+% M3B$?40):60Z=L)RWJ$%'S9B3EP>1AA?E'PI!5T%E>3K#'ET!GC\7A(EF+9'+DZ"ZPW(P=B\[^-D?W6VJYN;J+6G:;K9:KJZ M/^@]>WU L$(XZ:R%6 CK!<92V0XCJFJ5,>M;_S^?,<^;#@T!QQM*'H#1A(MG M*/8.(RB(I,#25EM#4F3=:ZJ555Q"-2@"VQL.X1*,!<'6 N"EX,H*U.GZ7EY\ M7D!O-I\8R\U!\2\K5&/33"Y*ED81\SLM+X ;"1T'4<<3\S1Y <-)1!Y<=97= M)Z!L@@[]M=S71@:B $+<""H]=U11HT@G_)J[2J6\1JG>#H!73=%(A:)NYVG& MR4#(_:7T1D M1JRCCD]2JDN(F2P6]YM:8C_FBU5S_3#=5V@YJ)4<^::(LY54("VAP4+'_PK9 M&0%8C#7_:!#FSFLB5T&(W'(UO9ND"I?=I',DZ)C7!&*L-1AJ[3T'$ACE5>O9 MIIS02HWFQR ^!6&K(#M/,D9>F?4>:=D_,,3M6W/JH--1!U2:4?.X2!"C6>FP MY;>7VID&@X)805HVW2$_3>Z3YG^\\@3DP,A"')4#,<\R2H0DDQ]U.JJ+..,ZDQ]H",RR*8TA[ M_"WBO7RHYOOQYM4GSICJ^#39^'#VXBM/!R,A0-C9J%\Z9AFR1# C"",>: ?I MH4XYI! MXZD!!_#*<=B" ( XU#-^1+5(>[/SE%JDQ\%5Q><45?^FLW;>]RM'NF=4$ )X MXJEV#A#"9*H!C%I]#7(\QMS!H;2)X6 Y'^,.9QRK^1T#9 MDAE_'N]%@D%XUT\>3H+JS4K&V!2*\0G$$8*PHR%:U\SVSQ\1A>9I!OW^3M8' M!P;/L6680N6DQP!( SAH)T^P&E<,M M'QP;'&?40R6,T8(QB@D#I",7^*R^914TPR$=3\- ,P9/[X?)8K'YW44[=#4Q M7D60%=-840(L!< B0242$CMWR ,Z-HA^[30CH'W;C/'P[("4VUQF 2,S88: ^/_$FY8Q*02 AG.#<22&0@\;$%P+*\864%E^U16GN*" M/0ZJ"O)2N^X+PQQJ(#!EJ0"^ \[K#@ )79;+OK*#-E=C*(9293')*>U!O/;0 M>"XC.3 UR(DTM6HW$IJ,5GLHP;3#-3[RX'H#*JK4C3 *"9$0-ZI9( M)W56Z*7P?=?A? 2#X7*AB3P:2D))*L#J/18&,8)52Z2/\C[:,3A[^$9P$8+!BQF #&A0+>,HD[$$2UGN0#)'CU9NX4G!#D/3T8 M-0PTU1W1Y;MJ& \D ])9*!'FF"(C.FB50..ZECRL;!3": R9 !MU?%?\?SNY MW(G\-I]?_S&]O?WRH[E*WWL_O4JY-&DN$<7)[-LT?OO7G@QGFT#[Z/Z$B'KS MV;0^??SE\N&WYVPUD"B.J^EG\V*N??(W^@P/4;,S-I[=%E#DF "Q-T6:J<, M%(J"0\Z,,H1_N?K>7*]O4Q&"W30+I/5_2S#$P7@T04D-5Y@P#@!K M<0."CC')I(14/"]S5 S!"MK@GLD_3KU7ML*1;PJ":B,=YXPH;["UG(L6"@24 M,*-U2!7A=W^9&A#,O[1\C+7\WIK)P.56!$(((P[R%4VE$)O;9*J>UT.29H9-6*"O-U6+ JK.MG9NL6BD/K>\^H M@(7Q"EB*+3:2$\T0="V)VIN1=6"LM,Z' ZQ&ADN<97,HWZU])F@..51, JR( MK8)ODXE.+O0>7^).G L/0(A-%WFMD#:>*0-V2$&D2 MH[48,KCP&A]/@N$B.3HV';TN(ZLS\&^3/Z=WZ[N#+/SEN:"9<49H0Y5BR">O M':0M&92BD:62Y> _'X[\\YK')GI9RI5[/YGCM&L/>@7%[-)3&[9%C[I'P'EE*.D()SBI32"]2 M+@8%ZKSGB%^OUHOF*4';JCIFO5BDB\2S:Q_'?5E?737-]:9L]_)J0?1$%\.7M.H_WG (%.80:2LZZ!VE&1=MV 7*9/C0OK,JO9+4C\T M?ZZ^_M'<_FS^-I^MOF<::#U>'(2*JQ\Z@"5C"CC%K&\M7@&HRW**G\-\JRLU M1VCO@_-@=,*:,/SZQWPP&=V^+P"&+7%*"@>5@%HD6^=15:&5KJ/_I40S#_IQ M2F3\?)YQL?>- 4'!(#<1#J:=X))AX3NS&]N1M31Y.U*9 ?XHY=+/UWO[%F>] M,$#C)>"0<2I]M.<$ Z8-_PI-=-:5BG-8P1C_WHA%+=K)K%X)+YRUN# H!R@HSRSEK@ MC7"Z4W(D4%F1JW-8XQ3@]^W^-.5<[K MHLA8QY701@CI'44*L:WO)VX\BASRL):^8W6 IO[WK/J\*%#&701!I<:T%@'& MN.=;, 2EMI(?9>]=J[),WGGWJ@!\8[U_]:0*52HO<"!3\96G@\0>4$;B/ZU, M*=9*,MWBP$W>U>AJ]ZF&Y?1\:+0J*#E/)GGP]LJ+9X-@#&IAK6$>$8"B+. M)67L44)]I,VD/(IV4AA6JX34ST(X =/Y0 CDL,4;T^K5:KV9_7X.[7H^.*,I MX5)SCRGV(M7H ^U4!3+C"A<,Q*R!P,CAF_KZ=3^CN@>"%8@3IQ5!GA)%*:2/ MD]&9M8"*NF=9295*-MYQE,=X?)V,#@OI? M>8O0C$U_OV0QJRY>#R[>Z>R;^K9HFG[5,W>."9!X!'P\[D$\&R*D@*K63'(2 MZW$UX2C*OWD9R.IO.-L8P..\^^\N+X8&Q;R1DA-&)6;*,,M5JS4XHNW86F16 M=",/#-WY#Z9/T;R>Q]]>+9K)LK'-P[_SCZ;7WQ>T 5JD*![7A$@:L1"TA05 M/ZX2F^>4J")X5A"S3Y/[AZJ;-J:?+S4R/O9;7\PT!*<(IYEPA1)#WU!C?;9.IW=^HLJ^JBD@9 M!&M M'1&;_@<;Q=I,?FRZ^+WOD;9XU'L"XLXQ*Y17GDIMO#2:&)E4BE=?OC[,9&=,Z_DC 6/)+7 F=1K2%&D? ME<5VNIZ*\?7W/0GS^: HC)YY8XDRGH5G9_"Z)AW8S.]^3&:'&^V^\G3P2B(* M@912^/@?J3GL,,% C*/8>#XC7GA+3T6@ E._K']?3J^GD\7]N^5RW2P.\O7U M ?%HD4XC"!6%(II#40_QMM-#",FJ4S9XS&4PU@X"0@V/5FLP=1.>-H=C^7M& M!>N(-TA; K5$Q*2R'; E$3&8%:NO#PC>&1%ATA$= MX0"ACJ-.G VKU3!B-*;/H&B=10P.YOWM&A*8U01:"" SE"L,*/&\)8X3P4=G M,PW%K(.\/PF@-R8%8S&^QL;\\S+=W4[OXAZX\1(>;@BU?V1P!AB+I?1$@KAI M"DX>#SL'9%8DNUAJWND,VR#IXY%X2668DHDUM9&C%IO!,7CJG^9 MRY)7.7L:$C4V]WF_;C*S-9+.ZGLV^;SN3[MO8^XX.T M1NEX. *$HKEDF)9:MF1K*<[Z[%P"HAK_N^WRQ^MHL[M[-?C;+U:'L M^]<>#Q9A)C#T3D%'M&3"X4XEPL)E92H6RX\>ENL#X%%C=[^ZFJ_CS#XW5TV4 MS&B_?FA6/;*%]@P+W-)HZ'*-$-* 28\B@IT>K.DX''=EF#X@+E7<>*M-+L_[ M^61VK 0<'!N0Y08SJ#75!!"G*(&='\1+DA52*Y:E/*P8# U.C03D=>,C*NKF M9GH[C5KN80G8,2(@H9'42FJLL8]*L6>D5B^#P-)E;L*/YOD M=K[?WS'HZ6/!$Z>A)8Y;SI7B@CAC.B)+)-X6+Z>@$.5NP,W3:3S^NOD MS[9OQ.3W*("K:;/LM9?W>T%@*@4X/%2$ZTBJY5AW$>6(:M9-[&)YO@,O[!(( M51"-3=OA7Z#8(P8O'PZ0<:TYT !*I)G2"NHNS PYS[+:Q&6P_&0T:OMF^OID M I80"$PH5D9)(C5WJ(/*Y157*VR"G^QY&Q"0&JDSVUL6^_)D MMH\$@"P1FGEK-;4:(.F9ZDX8![,VY,*V].W7>SSN9?/DWEBK.?7VU^&T^A_SN/^/XC/KY>-/NWAA/> M&U@$A'(!D<.(&HJ,49V740N9=1NSL)D^P+Y1#[&]@K6CB&<4YV9Q]9">_>@. M?$T&]CT>E(-,QPEJ UE\/S,:D4=]-:^O96$#/)NU P)Q5D_ZA_GLZ@1G^N/P M(%+K<O[_#9BNDSN@=5]C]RFOJ\(SB"+%9%8"B'B M406D>O0L,9]5=:68TZ5.GELA[.H*3O\TN-V#@N"2<*09)L*E/F 6T2X)))YD M;E2I4,.S;;=RM(9***68D X(#%1' MEF$NZRISL;.D@ @,@4J5*/SOO4+MW5-! HT UY1Q0Y"F!&N#6Q) /%I'Y'P>4L>OU1^GRP M"E+DE"#<**8D]E(\WO;")LM!4\S37H#1)T-2@\?SV;>4A)_.FEZ^N-<'!&NL MD:FOE#(>(\>]Y)UU(Q@=1]&1>C;;$"!55\![\7_7D* HT]!Q:CPBR%D.I.D4 M3H1\5M94#6VMC 0,!%.-:TR3V^9]:B[P^^3J7T^ZSJF[9%A&.OX^B[AL75^S M;VH1'_G6W.V7DOR7QF,0"28EXPBFUC^>"M'MMH2S+.]/#86PC!Q5 [)N'O;3 M].!>N\Z!H8$:9A0A+%I(" .#-%>/7E>=)S4UE,I"N\^P<%4U)V- M[!L6J*-02HPIDLA!90U6H%L 0&7I)#7TS[(R,0!4.2D>'YIOD]7T9_/+I=Z/ M-T]34%Y/"#MB=(A39URPJ)\S1YT%"#[>$4:.RAR.%TL *<;Q#5,.N?$'Y/GOQQ<,! BD0)002B[Q0?-/ZO/6 *YR7!7"Y M:0 G(S2"#*(3,H<"$T KRIRQ2'L('<>XTU!3<]8L<;A@#^.P>#T*Q[#]<8[O M$M.E5GV\206!_.W\C^5?N5N,UI:KN)@1IA)0Y:GSR IH@,&&(WPH"%YH;Z_> M+4:@2"MQ#"(5EPS'RC*ZA4$SD]=(]JS=8GKS]81N,<>!-KG@;C'2&."-8-&8 MI7$7123J/"VE ,A*=1.+E4SNS<@]W6*.@ZBWME"JX0A1PD* G -26N@!)9"U MTZ7&N=%5/CX)\UV=1_)0&#WSJC/MB&XQQ7E672T_O5L,,= 392$'G#OF#6#$ MM(>5=&X+ MR67M("!4X.[PW6($!=8RC SG.EJ!GBK:";#0>37DRW>+R>7S<$A4N1Q;IEN, MUL1*R'VT+X"F@"(O8$LH,B/)I!B,Y8."48'K0W6+ 80:##7%GFH/))(^4KHE M+)Y3E4H(C\;T&12MLXA!?I\03KD$VCCL)$,*,BH ;HDC3,G1V4Q#,:MOPY \ M@-Z8%(S%^!H;\\_+]$&[Q4BN#8#, O%S&F!*0<,I[LGO 4$.CBN"]=UW.S%41R56 TB3D%@(RUA#G/'"=58 ]=A MS82N%*/I*48E&9PM2T=">#X9>B@H-M#6M.=E04%*680]:OM:,!?W9^(ZS T= M5X.4LVY-PZ%8Q25]_V#CS=75O]?31;.S(NU>3W7?EP2KF'2,*N!Y5"*3+DE; M9=*F,@B7L#4-PN 7KNY"$)Y#AIX7Q3Q&=)Z/#=HB@YP"R!-E #>,=WX'*P#( M.LR*;3SGE)@3D3N'H!S9N:O7^$"@(@HX0XSG+E5B14RT9$=XQW7_\9P",P!Z M%83FW>QJD>[=V>;AW^]FSYO7]+@4W_\E@4N'HU4*C+?"IX+KEH ' BRFH_# M67\&\2D&80T'3VIL^"#TUYLIIY^7&R[M<^[L'A4\(! Q(.-*@=()8@'N2(2: M9C4K*';-L:*4#(?9F1279A$Q>3?[I2+S[/I1QH_490Z]+D#FM0?6.6PML5!I M1V@+BI6]01A! MP)B&.OX@.H*QS J^U_8W7F4;]/^[!TU7*0 MWG/,:P)541E FC),*"4IO5R2%@1L45:LHK8CL83\% 2Q1K[^CD)>ORWFRV6W M-%["MD>J2 ^^T$]*(%D^<#O5+\#J6WI%.06RO0.PHJ]0Z%%;SIT6![#01 M/;O>66'IP+!@;!1E"P'U'&DH@+38=?MF9IF%VG[!(5E= +2SJ;A10__9+%8I M5/MIL:T&MZD<<;2^N_--00L M9/!Z0'H]">DLTR>8A7>SK1K#('<&8^> MN[OY+/>PZ<8&A;FD''ML)5): 01\IU?!J&=E.>**E8(;P?F2"UW%$^5SZEA%7[9-'HR:9$U-V/)IIC!U(GKO.R;YW_D]9=O_G-RF=?"I64SGU\^S'P^E#?9\33! *TTC @)9$55( MSO V7$R(]28K3:>8![A.)+P@?F<3(K7ZI?S[T=+S;'R@SFE&(KP,."(CS5*T MU@:)5FG6_E/,$7Q.L3D-N$=Y&5,UUJC=+9KOZ5+_SR8NB/E=\WZ^_$O79@4. M:(2)YA!Q&6E MZIVU-FMOOIY0F_4XT"877)L5<>2MTEQCAS%$FCGL6TH)S;NS,*+:K+T9N:.9'5V?H),QWU?G,0V'TS*O.M"-J MLQ;GV1F*B(U%).HY["8/Q>3@D:GAX"]5F1=X@ZXTRV%+-L?<4TI902WR64ER^-FLN MRP<%HX8WK5AE/D.]@YP1H9$4B%ODN'UR5F5MZ8-[T ;C^[!HU&;\"45Y!:1$ M09@(T@IZ1#7DK0LL8I!?CM4BY3T3A@O)H[X"@07MYF:1 M(6!TQO)0S.I;ES4/H#>.=8X (S%!+JB1Y1W_] MHKR]&79L4=ZCT*ERA>9G,UOWNHK^_-$@-(. 2^TAT2 JM4)+W1)#-!Q'OYRZ ML9$3,:IT0V^YG>:79O%S>K6K)?V!$4$I3HF/L&!(+$50>-5AY$!>Q_)B[,]G MS"NWYTY'HS*C?YO/KX_@ASE [(4;CFBK(X$XH* M_-WD#SZ=ZG[^OO9X(,@2KKR *MJE6C&%*&V)XDJ.ZQ+V8/P= (J*)W./$SDH M0ZPSAAN:KF12(J+JNIT\ID!E92P52W0;C(^9Y%=1KY>K5#W-_9E2Q7MI5[N& M!!@/$V2L]H8ZXBR&BF_[.'#"<%[;@I'4!L_5L@;"JI(@?+QI]80#[']\,+AX MR!#*G4)Q.Q+IVJUN3QOB#1Z;:GTJ.U[A;S88U;BZ40V^S&_W70I\]F005, H M\T")N+,92I,GL24E6IGCZ$-9F*^Y:-30F9O;^,YOOS6S9C&Y3>4OKZ,%/TUD MKZ8_FRT0^[3H7B\(2$/&)1>:8^.BT9!.KI9PXO+JDA8LT3:P&!0!J8)TV.;' MHHEGVD,6\(_;9L.!./V[^6(U_<^A:WM]A@F:1"KY=1I5DNS?SN]ZV_+U70^+;8_+B]4[C!:H]T]'])4!1K)S%D M46.27D+E">O0520KD:+@_82!9:084#62:B)BZ3K!QYF=+G_,'TIW?[PYHJ5' MSS>$:+(*1 @3($+ID$$,XF[S!'FW,8M5N!E<1LJ@5,NIT[7,>KA_LD6EAWMG MY\ @)3>":.>QD1PJ*@D7+:'4N:PMHUC!FL'%85!PSN ^.,)M$*R(ZK27VF@C M#;!2 M>)=-2NLUQ!Q>K/%+$P3H"CQ@K_50S3+K5O6;]\.D"#@>8.6",%(4HA MK3JKR?N\.G7%RL@,OY9/1J1./N7\U>VF3\7O0V,#$)PA12 QV"MB*$*BW:^H M S!+ $92X#O7(S@T:!5DI&VY<=BI\.S)X**D4TGC@>5TTE@$,NV>1J76XTJQ M&) S+WHFG0)+?0YO39-/D\7JOC^WGXX*$$,#,=),>Z9$ZIR!?$MB5%NR;C65 M*[%2B_,G0%11"AX@V*BB/;C_Y.G@XL9G)#)*&@7BMNCC\=@)MH)9677ERJ$4 MYWH^-+4,N)T8'#+@=@X,R$0;Q1AAC;(46QEEF7:@,3*R8M;%9&!0E,ZI".8H M@,%Q@8E30!B G+6 ,-CM;009F2,$Y2I4%Q."H0"JLOFW1DK;/&0Z6\=I;ZV8 MJ/OJYF:^V%8:^3KYLUG^;3J;+Z:K^W:[B\;3KV])!5A6]W]K5M]3R9X^K5TK MSB((2HASQG%-+7?($*5ERP(!^;A24>H8)^.%O]H*B$1MUZAN9I'%!]K)OC8B M1&T.2@SCCJX$E 3S5&QQ2QH6>?='1U*6Z33).A6JZOO@T\N1'YK5QYM(0>_M MZ[7! 6#%T>:B-)82 B2T)RW!W-"LBKD%PQWU=YT!4*NA+C6K7F[17YZ+"#D+ M(< 8*:\]M(C8S@B@5F^7!,\LU@9BCS@PT)ETF^=Q/S19$E(P*%)#0HJA5WN;4#\GT]MT7_?K_$DA M\%2YN5DL]60YO>J[D1Q^4R!2&<0E!1I[PB'?-+IY@$(A0L=5PO\,6\W@$-9R MV>RH^]A#.^DS/'"#L99 :JP9M9X"9UJ%3#-/\_)YBU7TKR,X!8"K$IM_,>$> M0K)G5% : ,<(1)!H)U(O==>>SCI5'LB2C0N_1SD<7H\B4:_*[(?)XB&5]2]7 M*]89AZ-%(352!&C('67(&!+-# TL@8*]8I1N-11I1U&%/CJ(V: MTP8&Y:'(NS=YUEJQO?EZ0JW8XT";%*T5>TJ2^.]1'UK&J:2O':BK\_+A(#U' MCAO'@01 ""%!--&-=:\1U9'MS>07F>$G(E7E?L#3.7Z8W#4'*ZGL M&A*\X:G!H@>4.$N=YSP:7@_$<4"9'FT]G5,8M9?G)X/SQB2@.NJ_6BN4ZD]V#OLV>#=5)I[8'VJ<=I7 <.P59IPMQ6*H]W/O:> MAD=O]I:MZZ^PCAHOEI@QKJ&E@%/3*BP.VRS7\8AJ'!ZKCYT.T>!\/;8TO+-> M(ZH40YYJIKQB'+;315;3T:E6)V&^JT9\'@JC9]Y8M**S\*S^^3A0"7@ '*3" M8N8 TP)Q)+1K"=/&935J*U_=OS<[^I6 /PZ$ZM:,GUPUZFZ^GNW+W=DU)'B1 M:IT#+3U"SD$EE,&= TF-[,Y"'=_80%B=P\&]T1UVN;6WD\G]\),LN.(?2&&& M^>RA+?WS7*K]OOOAYF"W0_-U?SR/S;MB1#G;ET/\:-MEFNIE<1$C]?---OU:;073-,T*.IM,OD,14()::4[=+6P-MF'8C8' M1@9D$1,:1#JQ2VFR%!*P)5JU7KU?9-5 M?2 J\_J P"WG7'N@L'<.4")M2H9Z0-EHDY5_7#@R,QB#=^4=GX)0S>3S;IX' M_?&[A@252I0ADE(//(LJF0.HQ4IB0&F@Z\^'QA3G.!($*.*&JJL@J@[6?W(:IR?SISG%NH F-3P0B7C M/%E-$?[;_[M>3)?7TZL$^F%WU/Z1@2K$)"=:&:TI2R7=00=<5+2RO(W%(CB# MLW]8="H(0J3=1$MZNGJJZAQ0]G:."7%?Y,!Z9Z2 F!#G@34M>=R"K#M%A2,_ MI?2]H4 ZEPSTRL0X,#) $P])32W34&H",5>:=:1J,UX%< #N]9&'DZ%ZT](Q M-L5P?$)171@^-\LF?N;[037AUP<#)!QK#>*4@?8($\VM: G1/J_^5C&E<#"N MO&B^< (F>YF[NHO?2"R#:,NP])N]9]N?#][KYK52[/T'!^\036$\)RB(9%"% M@=\2$7_%:@67^S&VA&.P&%8Y#/_[;-%V=]LW5X.>SG 7RWL. M#T0+&/5728C0B@/ ,)$M(<3F]2PLIN,78WH9M*H$J9^%SU[=\);J=M4L9IM+ M.7^+_+I;W^V_L'7*:P.*."=$4D%>J M5,<(0861X=H);I2PM#V4':4JJ]!3L2(Z(Q"@(P$[AZS\8W*[W@31U>WM_(_) M[&I?W++'Z, 0!"*E(&G!D!$N;L>J)=E(FW51J%@YG*HR3CY1R?DV&^ M3V;?FG>S@SE7Q[XJ8*@@)=831Y%V4?V7TFW!\)SS+,DI5BRGI.041BY'Z>TA MS)N2"BES*5KZNWK.9+\K($^L4A!@I;Q@#BBMVIW4:P>R;*!BQ72*J<,5H"N4 MM_7_O9[^>,@CJ?6EC4A\;E;3Q2:3Y>/O MM]-O/1+DR@?!TFS>]T@%>_EP<)@1(@TQAE.ME3#>06-05+\U]N)@=DMAH@Y> MSO_EP1"W::*4Y5(1(;FC,.J'+3'(^4H>NKUY7:>PX+4X72[Q8\W:TI/;S2[[ MO6E6*0"YX<;^4-ZN(4%)805W,-H$ %@.66H5L45$2UW)-W_<':Y,GCYOEC4, M)!44XM=F>C HLWM0H)I"2@&C E!E,<7(@Y9 1R@:;;3N=);UD(&30'J#TC"V MZ-R8A* Z\Q\*@ZVC_IU.Q^XFQ,$PW=YQP>IXNEH+4VUX9"'S4LN63&EXI?3= MGH;-$.QZM=S:,.C4$H*CN?^2, P$PT90!:UP1&$.TNVL!\*LXUF5]XJ%=TJQ M_518*O![ITVUA^4[QP2=<'(*>HH8IQ 1)75+'H1@7"'Z 4V!H1 Y)\.?".N[ MV57:L/9U6#_F-4%1*AF!#"D%D<"4<&,A^ZUOQ*S^=T>^>@S//#4\M80:EBTKCRPE.A._58>9^T>Q:)L PI& 7 * MQ=%>B_N\;R;+5-'LY_3J4&&&PNTS'N;V*5J+JU\FV"/V<:5; %)2 M_ CB1T.R<6?1YD%A&FND:2>1^OYKG/B!H%./T2'JQ]9Q)+UT4"(#/<:TQ8E) MF763K%I-YZ%DX$7_F:%QJZ :[,8BSN!@?*+'Z& 1!Q8B;73JAP(T4(*T)%-B MP&C#5H/RLZ^LG S<7T)FQA;<&KNHG,%9(R: M2"84V$BH6@*MU^,HIUB$8Z_9H4-@5.,V8LHT/:!L=,\$SA3CTK@X:4 @LMX# MV4[?0)CE6:A6EKB02I&+3BWF'KYG^OA4L)Q$&YAP(HRAUB&.H6A)(%+:T2H" M&5QXC8\GP7"1'!W;,5V7D=49^+?)G^FFV4$6_O)Z#:2<#-?_.)Y>X59?8<&)3TS2#)CN65 M13H(; G GHZKH%,!'T\AH"JLU_?-GLFUHLDFQO*C(_7@))!"R_-HN[ M3>>#U6)RM>_>5-X+@\,>6$D)))3'Y> HD*@%!CJ4E5I2+(>@H)>P"GP5G?L[ MH7K#CGZN.660*2,2"(B<5P8X*4Q+ L<67H"%W9L+>PRS/!@NDJ/C MM;!K,/)"+&S@J=7)R"3&IZD3)7!WF'$QKGL:6?COM;"/(_^<\:O!PN.&44HP M8-0Q"J7DT +=D@P!'W>+O4(G[?"XO8U0I[* $F$$Y8[RN,0,[-:8X'9\O?N* M\#,GYID%W%]"9L:F%8Q=5$[W\>KU]/9Z.ONVG#R9P4XUX="0P*1%3BC.&)8$ M(*>@A!T8T-4JO3M@N+LO!^9%$,IAZ3^GB^:V6::.:G?KV?3AZN+RR_TR.2CV ML[;'T*"QI-A[*:#'C@M"N;?=,4IM5D9#?:?KJ2P>'JDJ?OO)LOD^O[U^=_=C M,?_YX",^:!/L&16TQ)1#RK470D#"W!-I)@YEY3L5NYU50AB&!ZG&M8KYW8_U MJEE\F=^L_I@LFG>S532>IE%)WF3I')2(7N.#]-XAAZW PGO,C>"@(QN8O.A, ML6M9)66C!%P7F H'K8H4:L,I%\I$-!L.HRE:Q:8N[ MZ37S;A91^;:(IUZ/'6+WL! UGZ0A2V.E !!+K*5ZW ]MEB 4*WI9=F,8#*5S MFH>_+5ZO_=YO8-#6$NFTP@(I)355ACZJ22#OAOKE*GRF,42?[[=7#Z.)*B[^6(U_<_F]SO)VW>:#/2)(#1'4&E(/$8,:P>A M[ERYP.E*?LWSR]B9 #WG[O2AV2=A^X8%*CR#GA#$C8[JN_9$MJ$@Z S/JOU> MW[HIN#,=#](Y)>'OR^9F??M^>K,O7Z7'Z "(!UX1QQ0#,I[2C)".9$JMN0S+ MIJ!<9&-5KZ; @_K]H(H?4F!V#0F".TTAXTII2CPWB'#9$B<0RO)GUS=I3A>$ M@0"JS/UERIMLFJ>5WA[FKN__-OG?^<+<3I;+%R?FH4IH WTA"")AZ@=,O4%8 M.HHV9@ M)\*.^*R;AN("N7P"*#D!-75]O4%M=_.+ I5)"$:F19UX:"H!IS3"(@<@Z).0%2<198*QX$Z)D MWY#_MYXLXFYY>^^GLWB<3B>W[V8W\\7=!I*_SR;KB.KC:72.;Q?M6])O"B49 M\&427_WQQD2FQ^7SN;EJIC_/\;GM7[CICR>_/.-5FW],%M,TA_8P=[/5='7_ MOL<]FP,C ^71Y"1("X(D%5+1=)4VM06*_XS+_%#UG]*7;%Z=_G3;/6@/V3W? M$%5@0QD1TL*H E-$O!:@)3]::%E^BX&OV S&P9WW:X:$:*S7:[XN)K/E9'/F M]4@,?N7I8"F,Y'+@/&900 4YI"T.5.$LUV>U*S<#L?AY4_638:I@5CR9Y,&, MS1?/!N>UMM)@ 1&#Q/-H)+..G(C2:'-Z3^+-;CZ?!,O%3-OPVI.KVOOS,@^/#!)$NT50R#&(NQL0VF'43I_;O.R:8E'T$]"? MEX0EAZO;.T-^/4LIO^^G=]/7XHV['@V)4 . P)(K("!EG.%V@E[G^72*\6UH M[6P@5 9BVZ<4^)[/KM=-9[33FB]MYW$J.X?[.=P2&G-.4(F\Q!DQYHJ'K M=B&ILT[:8HD$M?@_%%P5]*Q-CN9#I&G;MFN/HO7RX:"<1))Y(Z)^0E#42PBA MC]N9R+*FBB4,E#+!3\:E+J,_S!^Z\/3E]>/S 1*NK>9,4<4(C2@!T"D=1MFL M>A7%T@(JL#L;FCI9C*F?_/+3Y#ZAD!+@KJX6Z^;Z29^=PVO^B+<$R "VE#&M MN% ZRC]'000XRPO7+' ?BGI* =8K5WBR40/;1!/'@V4.:FQ5UAK0W1<#518 M9QBR@% +=-914"Q27W1OR$>E4 #N4(!D'-&1_[>>1-"BN?LSK9KXI\23S1^? MQ*\V!O9-$U6J92KW-IVMH];U;O9S?ONS=V?Z83\4H%>:0:\I80)381B'[J': M'(?(X$,U5T<,YJ'PS' ?"<+:Y.KR"'$3MT2(A&,MB)[P2NTK]D9PSB4V\Y& M/M:8T*X^UGL$=W?K:V:TT\ PHT0\@"6'5+>(0)+7,ZMP=.@<\M"C\7<&G!44 MG*%[OD>LB-542D8L-=X[AU&WB!&1HXTKGC%85/(DW M![-/\F"Y>&Z/3=4[+Y-/CVS[^+WY(FY)J?)<=KK1<6\)6BEOC&,*0415JJW* M'UTT7H^K3/ )7)G7@JC.LDZ!^';>>V,8+YX-!@CC)74V=8&3%E$(5 >9YK7Z M9_7C^$@B6.5.XJ*YFG^;I1N3#PIJ)]?-]<>'8.[ODZM_-=?;.S._=)MY M&)$B>;/[C;;;7:S9*KN3V>1;JGCUK4E_^RFNGJOIC_BW=RD2^'&]6JXFF^R0 M/:(XDAD&H#VABG$%L$31=G.2=0H>,WI(\T MPH ]NJ%XGJU5++ML),)X,HP7DXR$HLZ:? O216U5"P^A(BU9@J(L[:Q8[MGX MI",;R;>9NT2U\T RBJ2(ID>$0'9[IZ%^7#4\1R),Y? ]0ZI3SP/J%=*TD" > MO= !"*TEC'C;;:\,PRSG?[&TMY&(SC!8GD%,^I]7KPX*@'-N,958*^&U8 I' ME!X(1/&W61FTQ;+D1BHLV7!6D!D\MBI7S.+'AG@WV<6Z.9W]X^5#A:?FZFLY_-SO]=\NME95%SD? RK(\.L7:![^N;T2FZ;O_OPQ7ZX7S8.S>H^T M9KTO8"NL2G=K-/**&4H%:R/8"'&8US_[K87S:Y:#QX)Q[PF0&"DTHI)0J!/G70N"1(J-5C*/TZ'<%@XR!D@+'> HI M4\2UZ%P&45L6@GUT"H7$!B.S?1Q$/:&L"4XU':!=SNGX80XK-R<M;%^"Q"%ESO>-R.',<#@< M8.\JLUAIQQP' $D&M)).._HL&J*MIHFS5=?M-$UT!B=U0'*7?G)YNW>>:]"+ MMS;7J^SK)L+C'N./;1L#&4,>IX9X7A1D4\A)7> C9[MK;H>.6G7BM49)VN*3(Y7L]T%I_ MTM$^ 6(B/? 0>FD$,%Q@S"KQ9-SWC-8YV9FO>OX[0?33:<+8W(CC48!S$U_K M^CO8/IA"&F[BWD5+("3C@/)*+(7%N&K-],#.:;Y;@9(V4Z%E1I) &'-O3)$^ MJ0C#AE%8B62C137&8&:?*WMW3$:?D**Y D@YK33V&%H-HC3/XO#W50FN,3>U MF2GM8'GW;(]MI3XORB$:UZ6&'=A9# -("FML/5F7(_PS#GFRS!=U._!#[8, GB*L**::::4H M% !8))V2"A&,6IWE>[L7_HS[[QY024'V=G1_S5&D5 M4TQ@X[T12 .AM^))HX09[;K=D:U79PSZ!>BGTX.QK>ACH?]LM/O%,IM.5@VV MW@<[A#@K2D^+HW0**.@-)+AP9?.X_>3:M"O*,MS>NSL_1QCOA$H"NB_F6Z2S M6?Y8'/E>3^9W>1$??BJA./VZR9?9H6H6;WQ"M&H(=\ 81Q$J[NNTB+N=UPKK M5#- *V=,]PC-,"BER-8HQW=Y:_/5PV(UF7U8+C8/%_/I;%/D$L5/IT\G:K.; MRVA8E:EI#9(W6C\T8(E>C9, -%=O?"Z;O M_SU4"/^^R%V\O/TSOYN7&93S]38=IJAML9CETWRX]($FWWW.I(+*TFF43O"J M<="6@;B6&<>+UQ:H? M]_!;81AD8[@RL0L%QW:D;80?:\* 6_$I\:;\7A#D&:XB 1YM8Y MRQ#"&&!6H>&%2Y1'\C9W14L^]T\4] %(BJ,HK\99?^SD2)<07Q]BB9'1U$=6 M,PN VPE'G$*C]5-T):N6^TX _61:,#8OQ5C(3T[ZA\UD&0VI++N\GN5WY7BK M)%8S62Z_1]/J[\EL"Q0#N1G 6MUH7!#I#T2'=W M+%)XJ&X>L^4Z+T*I40?CRGGJY7[=."#&O(\K&F9.:L>)@83LS&0F6L6?!SL1 MTB.YG:$8S$?4Q&,RK-?F:O%OMGPQQZ7Y%K]9QPGTC_BL.)]^GGR_KS]OTO,( M/L6%O:R>>$Z'5)QK/F:355;<[_0BWZ*1?ZJN;Q <104G B C(-(&"B!TXIDPY,IYH70W3"9R* MV8:;JAYA7_2-31\4?KZZ>!N+NPZ!4TZU11@CZ3G@)/Z*G@4GXRJKDHK(MO D MF+*_%-4O:ZR^79M@L&.>48>C!% ;Z8S:J2+2;I0GIP:QZ]I"DHK1VC3,%ZT" MT-P2KPD$1E"CA6-<52)0Q>QH;;$6+!SBL1,,[Y+1L1E*:8E,3N#615=+X0_M M0ERD >988J8@D%([7Q0@?G)E*"L3;:(;+J6M\%_T)WX*%I\"5_4LOFP7H+;$ M,J)1D:C+M4&>5& 09'FK"]0',XAZ8;&#^&V,U\_+130'UM]7F^M_LNEZ7>2Y M9O--\>V+VTW$[I!IT[!G4!1CSY4AF!BG-8C3DZ^&SXELQ5[R?4E[[^@P,)W3 M$Y&M=_?8/=4$F]^I^)_'LJY9&^_$R0<&S!RPA'BJ@:.FO*VI6LZ(MWADZ>?) MO>N]HM?+Y'$[R6=Q-'&\LVJ\Z^?QMIM6WO#,(CH+@3+<"2\UQA1#5VU("!-@ M7+4G4TTXPP&8XO1[MEIE)4P_7C>QVAZYF-^5$*ZNLN7]Y6UQX=PRRG5B*FKW MP,"A$S*NOIXCY;%G"+MB)99,Q3TP5JWJ&@^7MS#85)0$O3.N$#3PG2:X:98)9J3Q6"!!!2(0X-:97$1M^? @T'V4 ),OM)&\>C M$@DS1VI+L/[V:_&?ZSC,WW_Y#U!+ P04 " !E,5%(COKJ%M]! 0"J(!$ M%0 '1M=7,M,C Q-3$R,S%?;&%B+GAM;-R]:Y/;.I8E^GU^!6]-W!M5$>DJ MD@#XZ-L]$P (5'O"=>P^=G7/1,4-!5-BVJRC%+-(RH_^]1>D2$GY$!-/BN[J MT^=DIM/::Z]-+&P\N/<__\_O]UOO:U$W9;7[E]\%?_1_YQ6[=;4I=Y__Y7=_ M_?@&?Z1OW_[N?_Z/__;/_]>;-_^;_/K.RZKU_K[8M1ZMB[PM-MZWLOWB_<>F M:'[S[NKJWON/JOZM_)J_>7/X2U[_Q;;<_?9/W;]N\Z;POC?E/S7K+\5]_JY: MYVUO^TO;/OS3G_[T[=NW/WZ_K;=_K.K/?PI]'_SI^+9WGO!PU_2V)8R,O_[]V>]_ _UO!VF:_JG_T^.O-N5+OR@^-OC3 M__[+NX^]GV_*7=/FNW7QN__QWSSO0$==;8M?BSNO^^]??WU[$5WZI^XW_K0K M/G=\?RCJLMI\;/.Z?9??%EL!H_^T+W5Q]_)';.OZT2=T#*4=0T'4,?3?7_G@ M]L=#\2^_:\K[AZV@YT\&^#4 M\_!ND+7D_"+#L@I5I]^H&6\G\30+>PB?OZ1 MEC$?'C2VV[AX?I]^K&7L=B$[?3*J-M]:?C*>?>1%S-ONM]Z)KX9?[#Y]0GY[ MXX.HGGUP\;TM=IMBTXOFHX_VRLV__$Y\M=HW;S[G^<,J*V[;K&S6VZK9UP6^ M;=HZ7[Q"GA$-"$)9Q&@,($K?I/6Q6[-W_].-KN?V3ETW^G MXOUS7NNBJ?;U^C I"5C=G'Q ^C\Z0-X)D?>W$=/_]\]_.CGQB+9J_=)ST".Y MRYO;'L[@KX 5H#\5V[89?_*F^\D;/QAFU?\^3OU*!(;?^-.Z$E/T0_OF43"ZK,:N$Y75I^O B7#A M)3Z>#90N']GLM\7[NX]?JKH5:G_?V?^4WVZ+59B@ $4A2T" 28QA&,)D, D9 MHV#5'B>'5\>,D2&5D=->F+ FAL^(S:ONO![=&_$A]UX_JO[6([P\CARP*B=" MLQ&J)D4F7#K1I"F>)I3)"KW+T"<[KE0.'C]%K7ID2/Q5_+UL5EF6HH"%2099 MD 9^C" +1UNASV(ED=*RX%J='H^B&Z\#)J9X 4U5EO0(E-0CY]PI"I$.;6X4 MZ"5FIJ3'B,F%:(Z9#T_%Q@(CVBJ35?=YN5NE.$JC $<$18CZ612D(!VM<42Y MDU=1IB91NAK.C M_LAG2=0^ F:)XOY<+"OV;7?2Y9%\]YN'_RP[*W0<]%H?A(/2R['R@N!;IO.Z MNF_;F!AB!HXVN8^1]"1@;,GQ''# M9T^OS)F5F %F)55M E@>GPKR/RNO>NH_R6\O_@]U>9_7/[Q=T7ZKZM^\XA_[ M\J'_XV;_\+ MQ1@QG ]>H^G2=&"-W@7,!O9\J5P\@ 9[$>_*7?&V+>Z;%4V2 M+ Q)&B0L\TDQ+P[$=[?.F1>#\UD'T*!0HUM"#?L&>U" MR!'G?@_B2(WL%H0ZEPO<@=!P8FH#0I<36;7I/O_]':V+3=GR?%UNR_8'S1_$ M5^T/_#4OM]W9#J_J3W6^*3Z(!_!+WA3-*H0IB](X]!,HE(]E08K\XS8LI*&* M&CF"X%BM2%77U;=NTE\/6-4TRA7Q;+KOI M1O?#&([N%\K=5_&[52W$X*&N'HI:B$&^VYS66C?=\DM-G0WB(2? CF.@I;&/ M>7^25N10SL00;K44A5UH7Z=IPO57^PGC5>I=!FT.U M3- E?9I)H )S3O._)]1(I'ZZ9"Y#I8R]N)#PF;%BHCG=EW4Q7FI&-$ ,RA6 M;10C[+.(@-$NILQ8?=2L74&';KP1H^8[#Q8XUE>Z2%8UH1P!?]?/[&>-1)V MIQZ6U[ON^LK[^EW5-%)P20Q( (*4^S@-0@3$7,E&N'X8Q*NO17U;V9V#',!4 M$;ESCZ2U[NUN7=T7WFTAO"B\\O!=FW]W,S&Y"*3-^>G*$70X38V>"1'T.M]^ M\OE*/5#&TY;#9^-GFKUI@>3VNLU+'U[L&.<72A Y8(7<98]F. M*Y6#AT]M3&5%77X5P_QK<;CT(T9M L,(<3]+6!HE",71: 7P1*GLL>IG.]X6 M.,'1NYVH3)6>MOZ80L(8AD(,H )#@.A!:AT5! F=);[QH?[UPG;EOO!$GKAIX.:;)R MX90O5<50HLI9WX7'A$P*AS9[2]$.?0=>Z+5@Q(6>@OR2WX\W8F(*4 :Z]Z08 M@JQK[P#94;#20*E\N;:1>=7DQNN@:=ZQTR=21UL<<6BD,++TS: T)WJD]4:# MT26JCHX;D]JCS8NL K'[VV*S*3:GC&DH9Y9O3RC&NRIAE.(D"6DKP>DM6*T2;&<2EZ)736-5"+640D>69HF M-- !U\M00!>./:O:XX@['?4;TE3("0\HCU-A)O"%'6%K,"3^(=HJ)_GQ\ZJ9 MUEI5AS1UW7+ EY$^765=^IP022529&]YBJ/JP(2R:'$AJR#X[J[0K.&0P#AD20P8#&CW=41'8W',4A45T33A?/=K:/KQJ=@6OU7WFHM(7?[D M!&4&ZM1$Y03(.R"ZT@+P96(FQ,60R64(C*D3E=6G2_":>JEP !E@J0DRH#7I4F4B2L7 M)G=\,Y1 RG'7SJBKVH&@GR'?'RT!QJB>,LE__FR"I*L\"E2I"HX; MEK1UYGJOA+] B92RJ!.X-$'1\."BCNBRH2X?O^R[M=[[N[-SNG\MMIN56/'Q M"+$P#+-.MD 8QB"=UU^:?BQ7E?AKY:=<;* 0Q0"%-CNJ*DU#Q71)K9N>^\#F"]7[M MW_D\X/5.@$WN@)KQ+ZM_5Z%>50AML3[#U=$I#J4ODUH)Q%)4TKYCDQ=.+7*G MIYN'%W88)6&*"1+Y)XM\! GODL[N( !%)(2*::#ZYSM6PO-:]>^JW>>SUJR/ M+C?JO8RG0:>.WMEG4DW8+)$X@ZJ]_M*>/J]+U"E%#R8%28<-Z4XGG6F4\A+9$RHB!EYR] 10Q^>-O:PP(A\UZ2#B;_NFH=B7=Z5Q6;8B0]Q M@D.2 8!HF $4P!#RT5X, J5<1M_*3)IRXYU!TSRS,Z!24F9F85%/:A0)=-2C MZ (_4^ICS.E"%,CPPHZI$'^KB:UGMF^V/7XN'JA9+N>&"59:"($[2 M,(:81!E+ >/Q:!8&,=$1)&UCL^G2":$W0M2\I4M2[1 M)2%>QDPO2\/,W;D@999XDE6T#W6UV:_;X>6^W6=[<1@CI?OBYM8<:]H T#LB],X@:FJ:!8KE1&U>=M54S9!8)ZKV M*E\3LF:/ZV7HFD5_*E=/I4*/(HS^&"+_8[$KJ_J7JBV:S;X03T$R=@:),QR% M@>\+][R2*)8K.&?#CF,UZ\']W]X!GM?C\P1 KT.HT[_'E-5I&9N; M4#4!6QJ7"KV19N14KU>2&;=R_9.F27A!Z6U2MX#^2K8\J>P_6"JZ'OTQ3)*# MQ5^+IFC/S*9CHIS!C/@A"=*8=KN.F ;):#9FF50I'6O&'"M\C_ X,88QPIR$08PS2K/1(J%8:OO"AAWG$X$ ]W(*I2M31JS* MJ?]"Z!!&4)R:(X!!Q&28;#T2SE5+[WM UCSA5>()Q(D4)?4YO,6983^UD) M5E7\Q7*K)OZS#;L.)\(!+@74RAMF3)B54[]YR)45?B7Q:6: MVL_%J:[0FW KK?43)$S(O WJEJ'P5CRI[#]8:KH>A>BB109B0"&D01S%*<6< M93X>+:(T4-K0-['C7-<%.+M:9,2JG*[/1:BJKB^+2S5=GXM375TWX59:UR=( MF-!U&]0M0]>M>%+9?[ 43VN?GP^'P?%&8T*2%,"4!0%($AIT+>0&BVD E;;F M3>RX/Z.]<+LA#'1/$$U8E3R8G8E0Y3/917&I>! [$Z?:9[ &W,H?PUXF8>H$ MU@)UR]!U*YX\/7>UQHYTO@[ 18LD)A$&$4FBB.,,1GX4IJ/%(*!8*5\WL.,^ M7P? KA89L2J9K\]$J'*^OB@N%?/UF3C5SM<-N)7/UR^3,)6O6Z!N&;INQ9.G M^;HU=N1T/?FCG\8O;^N/9M.499&?Q"EF, IB[ ,P3B0\\#H?%R<#BU0N84:PZ4[E MZ)%3R_F#%W:/PL%B@"#F'*?B7UD24PIQ1(X6&>-\#[?8_>Z^![ MY<[K'>A>;HS^H%DDQDV@9*:M>(^5P^3;M4?I^&2+@ND0]_% MB<]Q-)8P&;IVL9KQZ5;;*//]Y]>LP+B$HP'/LC BU <$B14<#,%HD5&L]"JR MB1WG&V4"W,L;$$!S<\>(5;F-LKD(5=TH6Q:7:AME* M18!FXE2[") !M_)%@"Z3,*'K-JA;AJY;\>1I$2!K[$C7^XR?KQ#08!$BQ"(6 MTP#"I#.:XF#;P@W1J4)JS*Z?I+4>!+]7*V8>=ZB7MD,=F49E4_<7=!J+7$_2I2"3N>NQ(]\4NUONZV&3%[=C3D2613S((:)S0V$4!5SZI;1 MP]4 _]-FU(9,R.I&9^#MKFGK?H)Z5^Z*MVUQWZRR*."9D">0XC#QN0\R=+0& M>"BUB6MJP[&&]&/BA,O[6X?,ZZ$I2HDVB7*",@=_:K*B19T3=;G S83&F+*Y M#*4Q]J*R^XRIJBC- $@X1%(698(-4N."UT<1"I2H_3! MCO6EP_)&_+U[;R/0J"F*&D%R,N*,&S7M.-&23='B1"W.*9B0""VFEJ$+>M K M"T^*8MZQ+SY5^.ZNW)9Y6]!]70O9P;O-+\+-PS>K$(4^@RA+* 9Q' 8X0.-K M=YCR(%9*0F0P2(\)4YQ"I?6,L3''"G&&R'LX0/*ZP'H/ MXB]\R9M"_+1<%UZ^[1^NLMIY=WE9>U_SK9B>\\W?]TW;>6:RWZ(3 IV-%\?L M&^W W'CGD1C@77,GYCE9TELR!CPO0\?LN3.Y26/,D['B966SKO8BPP(DSC*6 MI'X:))""%*7D>*:5(I!9D3QI:S-JWF; Y EA&PYJQ_R@6T![[ZI\I[I\,V?; M4-V<$&U1WD9\"]&W$8Z.P"E3O7"%4_='5N(TF9+5.)H_E&V^?5>(G.7][;;\ MW"C; \K8=+D6QTJ9-3J+F M8$Q-F$:R>DC>&:9YQ>@",1,29$KE,H3'V(O*[@.FN&7T18A9EQ>0JJZK;^7N M<[.*0)!&"4D@1($0L"P"_&@)1'&R^EK4MY7TYI&&!97!<@Y&>LSPU^(.BD_:9!\P+Q$SMH1C0N(R!8N3!TST58S945AIXM[DT*GD:^9S%,0 T M2ZA/_<0?&RX1!#/E2RD&IAS/R9^J;I)1WW4U)5!^Y3 3=QK+AGRW\18R34\3 M]9139=Z--X Y\8; ,U] M]^49(Y-78/3Y6X;J&'GP[$*,*1N&^Q"C4;$02<,P@$F4L)"0( F/;<4(PURJ M]Z,E4_.KSMK^1H4TKT;[%2XHM;1M<24QFB9*?1M#E>%E2)0M9^0V-?0XDGJQ MM+LHT@X7!D7Z??YM>[JR-5 MDI<7I@@GM"[@'57K+E4.'T/]]T#.+FS"-!-S4AAD/@]I&$=QEK+1&/3E*D,: MFECPS4I=TF07SL[Y,I']&X]]7V_WF^XT85PB_"5O]W79EO+:8_]M$JE[W8;< M+B-I-75BXET3;4[TWCHY,Q=A1K*8L(0!"C#*: #&8BO$YURJR:JQD5DUQ]X; M)BHT2IXOS,&@XLG"D[=);KP3K&N^6:+Q/HD&G\M0'G,W)M\=T>9%[Q[EVYT8 MBT73_BI,?Q0I>;'Y4(AG3V3GGXL5\5$4^RE(($;B7PC'<&Q'2GC(F-JM (N& MG5\6&-%Y=3_*FAZ@]W!$>,U+?U/,2=_^LT+_0@:D \UL!-TW1-EBLD[7[BBL%EGIX=6S>OR6Y$W9?.K. M#3X5WULBV/MME:4 QT)0,@HHC"A* Q9@BF&&&<(9EBJD>45XCM.4C^LOQ6:_ M+;H=_\X[KW>O^RXKZO)KWI9?B[.KP8JIRS7"*9?T+#R2:NG26> &Z'VL;KPC M_'X?Z=P![V\]>J^#[_7X9RXE8C\ $W/"%:.]C+GCF@14BQEYBO='!VE\?W>2 MPC,E_'->[MY53?-VU\^-W<_>WPV7+_.MF"GOJOI>?'.&,TJB,($123,(0Q ! MR'@XXDSC2&G=.S^Z&6>B#GWC_;YSH&C^T+WN8V,VND) Y2:C9<=2<>G^8J!N M^I >(OJ'J\\]UOF>NMQ\M=@N8^:YHO]/+U9?.1+J\P[-Z_J'F//ZZ;*;*5G3 MEO?=0NPXB3:=-^>+MJ=S8YP0XHLE6LQ3CL6TR+(L&S'Z-%6JZS,OLAGGF]&= M0Q+=]-GR*:ENNE^1+*2UA(BJ3CI+"Z;:A/-:'(_./(WHD[=>FP5-2Q8B(C4E MS1GYI4U'L_I^<2J:/P+2MP7Z>Y_X5EC-U^T*LX2E+(F2,*4)AS$(:9H%A&$2 M)" .L>R!M]JG.CSH[H%X?QNAS#S6'_,P=8JM1]@R1ILN^*>GUB8<2*==^;;H M#=WFZ]\^U?FN$;;*:O=+T9*J^JT?BJN 0$JC) ,HBI,4!4D$V& ZC6* E;(I M&P8=)TD?ZNJAJ-L?_4Q:_&-?/AP*1.P*U13("KN2F=\3GG0&\ M\01$K\-X2%-F3C\D:)O**FRRO@SYLNO2TQS /E^F4H?ONYH?V;[XZTXP>WR1 M')_>(U_A*, IAC&+&:*1GR4\HB,@EJ2A#0&T ,/Y3?-O1>U5$B^ZSLZ_F43. M3+T]X3P ][J+0_L.NG9KS]8#>%< MMQY^UJL.<]QPD [H,F:)*_CMZCZ#(O.R#\P;D7E_Z[ I:K@^CW*2/ N% M:@JKQYX3#;W$SH0D&A.Z#(4S=Z.R_*"9ZT]6W>?E;@5"$&30[S8YNFM;"-" MC@9]GRC5US PER'^RR'4F(GB)K-?77IE!.D&7A4$Z.!0!7:G.C0R\1,:) AD\O0'U,G*JM/ MEX;NC%VS^N7B8 YBF"0^3<3:#X0T@HS[R6@NX9'22TK:1ASG08=A,Y81." S M$1PM'A4DQS6%.J*CRIX[W7F!G=>4QX30!6F/D1LOJ8\Y+TKZ\\A.!&#J)U$: M$^I3\646H^.:#W*D5.19_=-G41QSI5%C3$%BG)&EHRW7UQ05,=&B;D$JHH?_ M)?DP8$+Y')+\.'[YKV51B[__Y<>[XJL@KMM (B3DD.(DQ 1D?D2B"$='XPE0 MVL^Q9'*V$\0;[XA.:WO9%L6*YW_SL:M[N*= K-O3NTFJ9([F['"]# VS[=2E M0S6;G"FKW?FQ\G,8PPY5BD$L\K,89I@"1"'B"3YF:BPF6J)GQ?)\MR?.1JC6 MKK9EQA4U<':RM>\Y*/#L5@ME*).11*O4+TP9[?IV22 =,*BLDV]W#_NVZ64Y M&/)0E&'"<="=),($\E0L9(_[]B%7Z^1G8F?&_.^ [L;K\7F!YH+3B%1%X7/, MIW[&ITRE6[5[SI.,MAFPNS E,_'DDFX9LV.B4N%@,4V3*/%1Q+KZ,5D,8H#1 M:!& 4.D*E(F=JZE4:%&EI$G55RD7?-I2*0DJ9U.I4$NE5-E=KDHI>R*A4GKL MF*@4&"QRD;L%,6:0!I#XD$9"#D>+&50KEVQBYVHJ!2RJE#2I^BKE@D];*B5! MY6PJ!;142I7=Y:J4LB<2*J7'SISO([TK=\7;MKAO5A$,$: QHB%F&4U0S.CI MC!-0I;/'>9'-J(3#J5S?!^;LQM'H4E<;;^)]E]XO[V^=9U[OVA5>7%((N*+F M+B[6^BH]6Y@7^X;3,2(R\\&LD5_8##*O[P[>=M*-@'SE_[&\WQFV%=JBTF.YEJ HSGJ L[T50Z#7 MD=9J*.3:TJIQ](*!Z?[M::7%E1B=21'?1648.Z="_:J[G7$UEW^[6U7UQ MU/:CIFJO(D)R<.*5))B1#D[!E*(4N^*>E74TX4-:%TPE7 MEL H]D..0\)#X <<#"VB>@'*E-X.TOCX^?3AG>X5 QW2%(7"#5_:8B%#E5O% M>"=QUF[ WL*40\.!2^JARX5:@9CJ_J$NOA2[IN]0UV4V76.ZTY9T\V_[?%O> M=7V#9ST7S*OZ\"GC 8 I:D(/8SG\>(L!$2"(!2JS>G0!RK4M=$XW/7 M;E*LOL43TS3>NJ^PL?[AE>?][KWF6_[0W'AM_EVG_(RK*,F)VV("I":#0QF; M<]S>L!H[- >].6OUVG@G^%[>> <';KQ/$P%S6/%&C^P)B9TEALL0XWE0ISY+!99; 9"'M-@ M0(8994H7#.; ,X/<;SN5%W)_=X!\$OSV!-JRT%N+EKG>7R-0UF5_<,(;O?#. MW/!.?BQ,_26IUYP$; =V^7.!=8\5I@0W;-N8&?#7O-QV&Q<"8M>DYF-WG[:_ MU-;A83!"448#!#G"E$:,1MF()X6)M;S?#(7C6>"ON[H0T_A_%IM#[O_[;=]J M7FA'/L+N9@>OZ9I(-4?DEB<%PT"93P7SQ"L-MD5E;.Q\ZI'\0P:+N^SF/SU./9%!1F$@H9$Y88#4,> M(7BP&V8!AK)J8&[(W:@?L=UX/;I#/_81W]4.75]E;&( VV-[&0/5HC^5J^?2 MTL [W:+ 73E=ZM,D)'X01R1&"1T-B\6]4A=G"^9<'](,S>:]ZLY[U,_Y"%4M M_[%!L*&TN>'6JK;UYXS>U2Y\O4Z=CLBI\[YPE=-P2%;F=+F2/FP>AO7[NQ'" MQ_WMWXMU^ZEZ7Y]G/._%'XI5[.YSW]KT!"M-8C^$+(PCD#$:^Q2A8(05\D3I MA4CG8&;4R![9QLN*K^5:]4U)]T&1//I>4CP4#\I?FJX&]%Y;";$XK13[%?W1 MA4/DKBZ]IMQ/GH#MU%3]@"3+(,AR1.49B(_#OA(!RQ0>Q#/=UWB6A&\3^XX0U^>*,+ MNK. TSBI3@5+"9'^?/ D.@B+0_%H=_?;LO/_6'64R"A6)L0P##+$")^%"8# M:^9G%/\>LW<"[9VAUIT![(5!5>ZO$@%];9\B?T$B+LNJE&);#]'2Y-F^@Q>U MV!&7LL+[YZK:?"NW6[S;O!7SP.YS*8P>:D><7N0[O9<$PP"@C&>"7MS]$XB% M0M!=, N3"!'92T%VC;H;YR/.?I/TA'2L>G?^BNR5SH24F)P8VVXBLHQA[+>KO;%'.@GT-9"('C]$F&3*G4R6I4EJ&OKIR[ MF#(YX%!68?O+E4+ 17[V2?S%OIM;"KB/(BC^G:64=F=C$1DMQ30$*C*J\_F. MM?(,DM=ATFH3J<6;G.*YIDQ-UE39'GFEQ<,R,FBK,1XI"25!WY.A5_)0F2:Z:YR/W7M! M PX64(M3$WAE''\%N>.4?GPHUEV9;KSOI76PQ2A!,$Y)S $"/(ECEOJCK22D M4G=!S"PX%D&!RQN!>0,RG<&OSZ"$.,Y"GII.7I\W!?VUXS ?ZJCNO M&2G=ENMBUTQ<+Y63UDN>7U)98Z86(+CF/E0VGQT%&<:?/@T?GB5A#!G!,.0( M8H0"=/IP E.I.Q>*'^E8:/&G_R>_?_A_/^F(A (O$FKJAA(U^9R)#06-=,.* MGBC*LR.G@D??+LF>NO,+T#D-T)51P%6+!D\>'I ??\G_7M5TFS=-O_>7$9A! M@F,:0X@!"@/*\8C")[[2-3/;MAUKX]FQW/;2L9S&68#U",AM\EV3?#45-N?= M4=%G)0(G=@U=A6(9>XK.O'M6/-HEBY;T](3AE_R^&'9&8<8S$D.,?4H3*A2> M,SH@85&*I38N7=J_NJ[>>#UNKP?N=<@UCTR<1,>*WCH/C&W-U8G)-73X)6+U MM=@H3#^%'IMYJ*;)%MB4U>5W_4Y-5QSR74 >>ASD4/[G"$Q'_@( MCZ?9+ 5$Z05J?2N.-?8(S#LA4US56F!23BGG(5%-#_7XA M71;\J&P_;,[6V^^.5_C7@ [8VH MO=^/N/^PJ/SQ96[U$TC#6"U27VW[J)9"6F%4NC[M4"#F4X77_]B7=?$4S2J( M00)C/PC]%"8T XBDR7$&B"A=?2WJVTJZ0*VQ/951?@Y->K!_$#__TA=K>NF* M7%\TH.KKQY3E74]9CM:RV\@9TS\5UYF*UK]$U(9;V MJ%Z&,%KTYVFE6LM,J:>>VY?$=P"S624T!2DCD4]BB$"0,7*\IL1\B(F:[-FR MZES\>%[6WM=\NR\NJ-^ 5#?9-"1=-;VUNO=UORMWGKE)@M6O+W;[8#&68JZ&Q9[L*&(Z1SQ-*8A\'.(BBZ B( MHDSI5,,A#,?".2QZOA3;S;'AHII,N@R!G'(NA'W%M&Z> S8YY57?8XG%'>&P"U#A.=PM)I]4*A)-:WN[\N^>W*#=QO:6_]<[-9E M\5)%UQ2&*411XK,0$@R3E,917YXY34#F1XFD--@UZDX-SG#V!QV/D"ZA,K(2 MD1-#WDU EC'*'?E6S?%(ZW4I'X$\J:WNHXB$22S^#PN;:<9! D>CF'"EEWP- M3;F^&?)ZTZ"^'\V9 WIMQG69EI/)&4E6T\5CP_"C.EZ[!\0T51/*9XGC94B= M+6QY.E[\]SFZ]_.ZY7VA8]!PH,L\<-$"&B0@3 @"H<*96P78S6N6$:SY&U73+@$PWI=>G>)H0+3O\ M+D.S+/GRM(ZZ189,%2LKFG5=/G1?]B4*".#='36"DS3$01(3$/F#=8 !4]KB MLF7S:BIVXYU!U:JT8HUV,VUSR;@ME5,B>U;%>\*>AO;I\K]L%=3V2E(/S5@S M5<:S^@!1FF9QE&*.0DJS,*0X1:-AF,F5>;9H[HIZ:% (Q0;/9BKHB&)[ GC% MDB:OQJ$+UOQ=!R2%#MMKJ0*B'ZJOA7UF;6AX$"8808XRA+$ 8I#RB$A MHR66 /GZ]9J?[UC)>E2/5U+J535UJ9O6JKE84Q.GJQ*F4)-T!N+T"I1J$"A7 MJ?1ECU_09!O\+*"&J:D'E;VGQ4!F/WQZ.QB+48Q(%@(0ICSV8RB^#$^:#IFV MTLJ;F%UL!30;^J% HH;FNN'/5';GI\Y ?=U0:$N I:C4$^&CX[(ZK,[4 J58 MPXDI-=;E1'9]_VOWQGV_?T !BWB$&! F D)31O%1\$/"4I5EO/RG.I;='HC6 MWJ0",7+K;C>+2 <*1T_JKRN?.,=*W--R5Z%$:[ V:TQOM5]LS.&'AMS"ORM*!1 MKXK\I7&OY;WLR!\N3PTV1,;F@QAT%9 "/TT)XX0--B#.4J7S2[5/=CSZQSMB M>A5T%4F24P!W_*AI@#0U3E3@$0L3.J#'UC*40!-[9>-Y452#_/N9C8!D,(L@ M"6',_)C0D,-1<6"8Q4I5%=4^V;4:',#HJH$:29)JX(P?1360I<:-&IRS,*4& M6FPM1 WTL#]5 P,&3,_VWQW+O2:Q8(#!Q ]I$H2$!@E+1KN)3Y4**)A;N]K) MOD$Q:PLZ;^3J$5MC^QE:)9%?R0/]'69DCIH^E!7#T7= M_FCVMW\OUFW;O:Y7[/:=E%9W^UW9E8-% / 84P@@983X%# ^6HUA*I7[V++E M6-=&A-X L2L6TX&\\0XPNU=M>J *1RDV&)8XCIJ97#556RJO"F=5,_.K=VAE MSK/<^=7K9%PZR+)(XP).M&QZ4[EYV"S=82U:@6E=%)N&E[M\M^ZZSH@_^5JV M9=&L0,3\#$*.B,\0[=L=SL8?[2]4%'@57H)XR)62US< M./%S4/>CNDNVS\:T2,*K$?EAU(N? M" OWG52L!_B*?7T=14ENM;2 *G-LT-L!L0>?A2;(^C#>DK\Y-,0&_I:;-ST M#-9B=V*YY#A_^P;_LZ^X48'.VO>5NL4DXB$"51 MA@A'. R@#^$X:P04QC9VKG3L.E;G 5+7SJC'Y(D@%2[WK;2X-]NL2>T[F[,DJ)\OKG=#JKAW=QR_Y62E' MG_L41(2GF/DA"A- $L"H^ )'@/-,MLZ\]N>[&Y#NEJ=TTOL3 PX M8T*7,;K,W:@L/VAJX^:7HGV[6U?W15>-7F0U:8I]1B*8 4 )" D,1QM=8S.U M-F)JGZTR4+2:A76G*66/Q_O]MFO'H)8?*#(E)RON*%+3DHZ;MP,WAU85N&WK M\G;?]G5#V\K[D,]?/OT1.Q-:HL?B,@1$$WMEXSE2;+XJ(EO4=;'YV%;KW[*R M:TJUVW3EE/L"I'CS]WUS*$"ZBDF6AIP",<73&/A^G)!@!$##"*UVA4C1B\TG M^26*1>M2PR@]#*-G0*6'U!%BU_7E843O-1U\Q=:K%HF7DZ6YR=8\D6@'Z, \H3%)*%!%M( 'D4[(B:YEP7K!(]PN#@? WCGB&Z_'?,6T\'5"91-'BZ%9ALHZ M\VXJ^;3.HJS>_D=1?OXB4C4LY"?_7/S2'[&^O^L7T(P9R M^GH]\M74]I_)E 4FZ%SS_D1ZHHGF=#W+ ,LHS!.PSC 9 "6H"R6 MNL0Y(QS'1Y=9N=VWY=?"*^[NNJMD8N"?*VZ?WWI57^S[L(;-O^7U1K'UT1Q1 MD]/EA05,3:S/P!_SWH-(/]T8/4:5':/:_^:;V\ZKL:'5HZLJ\ZJZ>1PFI'[& M("]#_^=TN+K:@'(P4]!J)R:SIN]S_'AS9H4Y3^,0,YX$E" 4$TRS$16G5*E& MB6LL\\\11GO'SD-C<2Z8*2HS3@0GC[KOGFQ8+W 6N!P!TRG 0FQ_(OVWX:V. M^%MCV7#3I1\*PO+3Y$*"((-I* M]#MOZR_%9K\MWM_A75MNADV4C\5Z7_>52=CW]7:_*39<^"U6O@_[PQO^[^^> MPCSTCN:(B/5L$+,P @1E$ =@/ M+<9 AI=?BYH7F>&MQ]*9;\9S[XYT<\D:/ MO.XI\\Y\ZO[22R^<:/6XGSGB,@>Q<90B-_'CY PY-@5A(4AA% /M^C*.NS??X?E=*DR12F;BNB=/Q M+'9)T73:?UTUG'*STL\22;4I2C.(3F89APQ/3#E+B.LRYI]%,%$M;]39F)G. M.JHS'' _S#)&?/,"381?$?<6E%M M65IG5.\37QQ7L8L,+_;=K<1=7F?:;;!]]5^UZYB0CGDG"*( M&>C:V1-X7/WSF"N]XSL/(M=9:) V1WDX1BP?9,HQNR=?H9?3%8.@U[W)@'=EUQY M5KE_4G5O+D_"Z2^D?2J^MV3;O8B;LA"'"61Q(')YG*4H#N&()0LBM;X=3A#, M> _YE0&L>Z_8:CPDC[ZN'@K%0S'Y* RW?[T.MM?COMI%8 5NI>[[NHC5,E); MQSY>O+WKCE&IU!5OA/(+2_GV)?NG9@I!5_PF(2%(@RQ)PA2$_& YHB")@$S* M:LF4P^7N$>"E<:V3G]IB6"$OO0+3>OFH#<;EDE Y2BXEGY8)74#2:=NCRMWC MI[A)NUYWR_SF0_ZC$T^\VXB?U/MB\Z[,;\MMOV4PG$D&C @[,&$)ABP#1) 8 M#@ RE/EJ5SSMF75]K#<@]0:H?>7$ :QWAE;SMH)-_B5W6:]#O>+<8HUU-YNE MTAQ.[8C:#\0R%;%R0C@OIVKZ-V)[,W)YANY*DO%K>RS)1\C?Q##_0AYQR-I0'U$4B2V*=)E 0H3I/CXA<37TG# M-$TX%JX1E6K=>CVZY)1I!J;4Y&@$=%IS7D6"7N9E0G<,B5R&V)@Z\:Q2NP5. ME!:6Q>9COA4"5MW?ETU7_7VT&<,L2Q(<0,H80U'L"Q"CS91$7'DMJ6W)LKS;C3V%%. MU&HO [N7$#IAW0G;--=\EFEY;YAG3NPPMLN3+2XLY2PS) M7<,X&/PD5BQBP=(KHB!@5ZS;T2CW(^BGB"=AE@"2Q3")Q]/2#(1,JN>/)5.. MM>G3N&PKS["I7+@PYW):IJY HYY.'9D\A_>Z6#FA5.7ZRJS4ZMUII"A:;R/63'W?PMMM^3D_="HL=^M]_XY[ M^Z6N]I^_='N(PV]VL7H8#XCKLND,]._8M'6^:_+UX0/&)7A;B7]>&"M>_KDN M#@W,_FAZ;>:U4%R\,6,MADNX+&//F%;YI6B_5?5OWJ98'R=T@4XM^]5C M3B[I=4Z:VASR"(XWX)DWOWV)D8FTUHC 962S9BY4%A\HK54UWGPMZK:?MD8% MBWP_#4-$8Q;YH9A;>.1G1P5+0Z7].GTKKB^.G!!IK:9U>%-:23NF3"\[/0-U MW07T7SP;,+H,J;'@Q\N+9F-F9$6G/V)]?DON>,H: G)CRFW,FISXRTJ4G0X>[&"]=OKR1$TT1-J)$EAI0M!C3^H0Y*PS[/I+L?ZM6?$@\],LBI+N@,5'/ E.JU4?$JF[O9H?[3IG M.^M@?4"DL!VO093$B89;CA03M)GI43B=<$N3WFF$ EUR^_[/G+RTSZ_/Q@+V M]0W 5U:>".W.CX-0_U*U1?.NRG>-T.KA9=MNKV]=E%_[-S7ZWEX((J'/$*8" M0H@Q!VE",P'-ST "&5*ZU>(*@V.Y?=3C;P!^X_70;[P>?)\.'>%[)_S&/1OM MQDHN)5U"F-04WV6$7'=;5*%X(GEU';1E)++.O;S<*-$AJZK[ J]A(#_.\ @+ M?2NL +$@31B(: IX"+@/6#!"HB"6N@,T"Q#':GXV]#M(>KT,G09";>/@ZC%0 M/1I6HM_I=H$.=1+[!TXCL@P=GL?5"SL,,_ K?QOFW-#0HLN'/&8\""@B:1K% M010FHZDT%!F\VFT8#0/S*:A>>S\]UN1DT3EAVG)WG9Y]+_$Q>0_&@+YE:).9 M"\_NP1CS(9W=;;?5M^[Z)Z_JK-K?MG?[[2AY0_46B$*<40Y3'E"*>9PD,!H, ML^YVGU(.9V[.]+#Z6M2WE=2IC)X!E5%VCD5ZL VPO!&7HG29<"=Q3..>-#5INB);"J#7NU93M MIZ)=(0N]&OUZR>DI#.59&!ZZ,-3G8=C)A$$N;U5AZ%(ZZX3E!62Y;ORJ7#^? M=B>D;%_@.Z'D[W?%_RGR^@2'>!22O4C9F="FR58+N:WGR9.=F? 6>)E.B&ZB9NU.?(2AP93 MIG%8?HX9U-Q-Q0G5$J]:%]#P;M-?PCC!>7?LH1ZF?A!%D& *&68A1N!X_XUA MS/4OFYD8G6E/2OKB:8?MS7?^X<&WA?#1WL#U^P&WQDHAF5,SOC+@/B-TK).JQF/U.R8N4:EXQ M,0O/0M36G7\*%U!L,&E7?U3S%J7+J[\6Z+S^6N*W37O5?U0ZPO7"CKZWS;E%.K)+O2T"6* MIK%22C/_,\FCO%-:FJC(F:P0?JBKKV57P_(%XZL4BY27^=P/61P1YL>(GTS& M *KDG$:&'*>7)-]XF^*V]8KO#\6N46S8:$:AG*+-QIZ:CAUAO:QC\XK7%$<3 MDF6%VF4(E1U7*@>/GHOL[#_JLBW>W]TUJP"DH; = !^2*("AC],Q1^0@BL/5 MKOC<5;K^9'N)+ ]!:@RFAS'X#*WT>.SQO*D$H,-ANLC5ZF)=?149H'+]*]LQ ML)FZ6>;=<0YWXYWBLL1\[LBF<6*G'I=E"*QNO1]S:SZTG=$J+7P+;J^N*\L>7_JM9@LWS_32)5W M2F\MIL:9U)6EO^[R^ZINR_\L-D]>'>AVPX8]U!7U$>&ASWC7)3$+4\1B,AKF MF%/IRTEVS#E>EYV!])Z_X**QT6^3:8E+1?.3K);"+)I?AW7' MZ;"U[96-E_?Y^6Y=;LO^H[JI)O<&+1Q:]G3-@,YW7W/O,*WU?7O$'PXSU/AC MTU8]4F1>NO]C-Q(+N.ECV:'*V5.K6ZSD/\KVRV!^;* YPE@!1!,D9CA$TPA" M/PQAQ$;;F$*D?OQAQ^XLIQ]/!='X#,02YW+KZ/F)5IMZSDZ)OPF Q^EGA'AS MY/U:-5(F>)M(NNWROHRM($-UU=J1F0J[1L-&)-(EV3D/AYKY[SF7Y<#E9EQP=-NH=\<+FF[?9UM]M#]^1\MZEZ0RGS$8JR($GB-$[2@ 4L&PVQB",%/3&P,H^]/92!F=&S0*2-T,' M*FN/B5K*]D(-YH_EYUUY5Z[S7?LQ%^G\"N(@11#X(4\2QFF(HR@=+:,8^AHI MG VS,Z5T]P_YNFT.>_M-!ZS;361O/YRO>-02/2N 9/WMQ'5W%T=+Y S,;J,^5S&@#)WXVGC13N\ MZ Z;3\7WE@@'?UOY,8<^)9P1#"$A*49).MICA""E_K?:5AS?"WDVA!3[U>JS MIZRKY"8F7)[A=Z@\ 2IOCFSRQA(5CQY=LIOBQW9P?1>K-CRMMQ]?E%Z'SWL$4*\QO3&YH6K">6RQ?(RU,N:-Y6;9U$S)<#[]DM5E^V/OHEQG,5Q3+B/ 6?, M1S#-Z"B9*254JHV*H0G'FG66$AQQ:;5HUV50,9]R1YYV*B7-F]LLZA$S,@F4 M'I7+4!]3)RZE32:PBG 8I7%7X)\0%"4<8_^H9!0CM5,=0UNNSW8Z>(KG.:;L29[JS$B5;KP.HN;FD#&]!AKEB%DK2B5+ZGR*=6)+5;%ZP>NEX M(Z-AVBS)7TUO"O&[7X;$+8 Q(,07'^<3'@)(XBP9C1 >A"K"I?C1CG5J1.-= MS *46OWJ\B>G3 ZI4Q,B<]8<7=,_YV=">C2)7(;2Z()_=L/>@ /SFT3OCHTB MDRP(D]3/0A1QL0KD&56\4O=/M9VN%:3D9FIMD-6TRYW?F M.T;O)+K5VJ1\&2IFU2/I^T:Z;$F]S3YUS>D[N[LKUFVQ67$6(LQQQ!+D"ZE% M&/A\,"Q^%$EMFULT-YO:;;O1N#Z'J? JM"5JI_7M2JS:D[>;/A\;077Y2;[Q6L%[,:"^\?*O>;GM*P2TE2>RXWW7ZVC?=A?SQ2_V?W"H M2^CM=T)FO6*7=W^Q_Y1M_LVX;J<4N2_,-@XBLX"WRRT[5#E[BI6:GG3M#S[O MNN(%PA0I=L5=V3:_%.TC2"M(DH 0E$*8$!S[?@1@.IJ&&?05VI[8,>AXNCF' MV0^GVP'HT-;MT1B6+1=EEW&).>@:9*O-0H]X[B8=3U+78%FI"^^_[7WJHFD,=XANO>2C6?76G[?;'BT.C MF]-^*W;>\%?K0DQ?.^.929+K2W.3[5 M8':R[E+E\-%6O)18W!5UW5O&XI%J MFQ?WLAN\%4*_$V"^%G\1#^[]_E[\WBH4J[#.?HP@1PA%!+#QGC;C),1*=Q== M G$\HYV!\NX/J/H!N3[LNIZGH8K7()U&1VXG:3&!49O]1MB'2Y4]\)M+6^'B M3\Y#..#O?GOFNY<&5$]=T9PC@LO8L9K'U:<7/N?CU[*LKUB6O&O8QDLI9 M-SZ_Y-UXZQYBMVN6W\LWNG/'OYPB7I5Z-7E\00EOO.>:^6+M;;$4GPZ*$^E4 M)7="1YW%:1FBZLZ]:J;G7>$(3T+E/[;5^C=:W3\4N^9PD-'5G<8X\ '&/(F8 MCPD>\UE.F"]_><2)]6L(;M.A]-9G,!6.F]S$0.*$[^KTN\E);[P>M4>7% Z% MH\"KA\7T7' S!JK;?M_*[;;_L]M"6,BWW1&3Z>F@#OV7C@J=AG(! MYX9N_:OF&A2*)0G67XK-?EN\O_NU:-IZOV[W=;G[C'>;7P\/.:V:\UJS< /9':U)^+0WO! ;J' MUVWYM6Q+U0YJU@,BMUZY9BS49L['U)]3WD,_,#X4D MV5UX)-8MBXB,F@(? W&&^7(@5 1YSM@H+&(6$2.]A8R[6,DM0'2IN[0(<1Z* M!2Q$W/M8S?EPJRU(7H#SH:YXA^$+,NVJ> MIURY-,E+ZZ+3#L:Q.8H/4I9&810%@$/NPY22K.\T1 EAJ2^[V6#/X#6V&4XP MK]842)K B1%L/PC+&+L._'I>Y\,)0'\UR MH/2VG+$QQVK9X_-. +TSA)KEVLSYE1/%6:E54T(S5MV43'J%K0G!LT;T,E3. MGCM/*R79Y4GJ?.DO15M7'^C'7XKV6U7_EA7KZKYL&K%T%*+:2^E@6QC*:)(D ME">$\B@%((M&VV%*,NGS)&L6'2O;B-,;@'J/D8YYB)+$6:9-R>53G>^:O&\^(59R;W=M\;GN']5S^X A(AZ7[E0H M2WR,B4_CT7X0A%+]L>Q;G6N2.0/;KW;/X)H+H!W^%6:;V:G7G'%^ M8UII[9 MV=>;?HY1:)]$H3R+PKJ#;&O6D2'FM9G'*KD+FGWL^O72#.2 .=U9Z-PBA#Q- M4H(1#PE)29QVK:\'BR!4N"AG:.<:,XU-C5/B5&\N<46GA=GC:DR:S0^N&+4X M([B: ?0T7X>P9:J\EB>OZ+H^.UH7#CIS_<9_4]1?B[Z75,9#C &(>!#Z61R% M 4_8:#7#C"@V1S&RY5C1'Q^1?1*_KM5FSIA1C8L;CLDTN:XAPZ/[BQG/"9*] MCF% [3*VUZUY,W7UPI@EZ2YTXK>?'%4.O:*@3W"%M7$29- -]WE+O$SH4WFG"Y#E2SX\;27 MG"5F]#*GPVNG*PS3&.(H\BE)?>IG*.5X,)5E ??5RD)JF5 9.UHU(,=CI:<' M&_W"XJ9K_K#=;[H?''I&-(]>W2^[_C0F"94LT3I9E .&35*G <\UTZ8# NE< M29' 94B1F0N369$6'ZJOYYR]9G*V"7A^>VN591R!&$<&4%5'P?5T#ME\+[5HLUSYOJ[NYP\^O0L,AT&602#XV5T4RA,%DL M/7VEI:^1VL/LOUW$2X%/R9,5/@OT+U +;7@E]SJ@(6NRBODA_]&=T3:\JA\! M60',0A 1,,HC((HPXC#T9SX(EWMBL\=SD_R2JEM2VH\IH?Q^ R6_-(K;[YX M(T8UG=-G44[8W#*GI60CI+Y>Y2-0\\K6)6HF=,J8S64(D[D;E>6GS,(*AR1I M M,,!@%G'*9^EISEA8B@887#=AN#]]=5-(7* GWA=(TOE,H:, MF0LRZQHU/F2'2E_F]=>B+>N^K-+[VVWYN=^(.'L_[&/1MMMBLV(0!C$C8> 3 MF%(_!KY_/#EB70>"88:4&S\V+6M,XVJ#J@?;=48=T'K5$6[C-0>4:A.[5>+E MYOK9&=>:_@]4GV!Z)YPWC]Y4_?@*[4Z438'#"<%S$8EEZ* 3SRKWS['Q8=-9 MI:1'>[@IYIQ32A*8^#&-0;>5.\IV2J+4\+!)U^Q_B<,F;$H(2X(P!A@# M'D11D U[3LAG+)"]]ZO[\>[&XP'1C7?$=+5:;!>XF1AIIFPN8U@9>U'9?<9T M:ZA]J"MAL_WQ03Q?W75B)L;M0Y?P',H/)3SF76,JF"'.8^: M*GBC_ZZ6%:HECYUF9MFB ,H1[.9$ZG76I@ZG+'*^#.VSZM'3(ROK;!DK7F=W M>(DC"V,_"T)"NPH&V"<^3N!H&4'J6U$\!7M+4#RMU[ZLD&VH>8YX=J!Y5WDQ M3((W'=738'WAJJ?CD:SJ:;.E=!#9]&OMS:>J+U8YONM/,D:2-(H0%6:#!- T MP*/!C!.EUHX&9AQKW &3]ZVLBVVWG[LIOI9K[3*W)G0JG":Z9U+C\+#Q!B[; MRCO@NE)5V\L4O78V:,;K,G3*AB,OG?S9X,8X%WM7[HJWW;7E520D,,(H2!!@ M. +0CW$T&B8A5+KQ;<'<=7?@.IQ>#]16'J9 M&$:YH9CJUMO,O3.FX,=2=-) MP=097X:RV71(-@'3Y4JJB%U6/-1%5Z:WK';L>]?:N[BKZH/.9H<\9(53'M$P MC6@69Y&/0?=*VF@6<"1?0=6&,<.F>G&C:0Z6NC/O MNA:/5W_;[G00?C@7_U34]^_O:+4['(HSP/TL13" *(Y#SI"?AB.8@(6A2C;L M",(\Z_AA^7[C;;OO/?%!]VH9L:L R&7)"^!>;6HY /8&Q-XYY//+../UG YW M=T%Q1#[WU1P==B=O[C@-US+2;M=./KOW,P.GJAL1'_>W?R_6[:?J?8V_YN6V M.WGG5?T8TB]%>[RE!*,PCM,LQAG/0!8E&0K8<7:@1*G/HC,0,VU:> /P;F-0 M:,41>Y\:/=&(FZYAC,S=O9G#I;;)<=5(Z6U]. F2TTT159(EMDJ MS0O;*HYY=:+F?ZZKIEFE,(C3((@B/\(L9#Z Y#BMP)A&SG1OSGR7A<7X9[?+8$6"U$/Z'T*CIH(KHZ7#J16[Q>[^_W M_8LQY[LOJPB&//8!08C$:/U=?P"];:4W32R/Z'6&[MLHOYV^':UF;+BP(<4 MX!AD29C$D'#DCZN &&N=S78EV47SM@QVT6 MAA@.J9\21%.8\#1#*![!1#'@*@+K"()CF7U^1'4 [@W(C_4#O1-V[>UI5U&2 MT^,%!$A-E5W%QHDVZ[$[H=".P[4,G7;M9#7K$'"IV;0K'+MK5WX0 ,$T(IA3 M'P%"*!I?]PU23*@[R99%X%BQQ?B+7,JN--$N5-<%Q^Y%]\8;<"]9<@>(UA17 M-50_H^ J^VBDMWJ,NI';M[M/WZK_4^1ULZ)!"A!F@!$>Q32 @(\];U$ (56Z MRN$,A'O1C5V*K@K=+G37$=-S2&^Y\P1VKP>_9/T]46Q-@C6B]C.JL(Z;1D*L MS:L;+5[Y) XP\WT>A"1!24!C,KYZ$^ X5MH'MFS:L>Y^JMI\ZU)X7^?6A=Q: MI=6]R"Y95JV)J71,?D8)E7?.2#@5.32N%I^5S7I;-0+2<:\B(0CQ!!!.>1!Q MF(:4II2&.(D)2#(J.YYMFG0WF">*EGLGH%?;$U0@<6(8NPC%,L:P$\]DJY8; MLR>=['3U$H:U[5FI]*& 0D8B"+,LR"C.PDR83$/BA>K]:?5LJH^LI+,4,X^4.-$\ZV?X0"V9+S6A> MY]DPB[-*KK6<;2'9F4XN)DWH,K3*@A^R>98B,S8[:(WM-E<8H32"011B'(0) M0%'LQR,$E'*F7,K.EF'7EPC/$H-RP&2_7Y8\S8:JY9IA:T+VN&/6V]>8OUK+ MK!&9CN*9!&/A(FCDFD;7+$W^7#0;Y &*0B3D&F0\83C+<()&!#R-B$:78)OF MI4:S<>/@\\'[6I?!_R+M[F2)_WE&KK)G!NWNU-@S'K=XO>Y6),?:1"L6(8"! M'_HD%HK!!)KLF&*1A!(K^8VR53/FK,.XZA&&. M,P:RP$\X)\%S[^Y/V0 MWGE68T9V;-'\H6SS;?F?0PO?)_8/;7UCR#) (:(12"GW,P3)T33F0&E%9L6@ MZ\78TY&V[E")[.,(7>/-=3M,RR4?LY.LEG6)R!4ZC[\C][8:5B^JRVY>:P_MMM/H@'MQB*I;^_X^4N MWZW+?/M1_.10NO5XPXJ$*$38ATE$F8\X3Z(@PA3#C*1!3"/IE^IF >/P^LX9 M_AOOD0=][Y%S'[H4Y>B%=W+C>F\ZVR!_ZD[0K,%=AFK,[//3.T978'P6W3F[ MX[G;?"P_[\J[%FOJ_VNN];]07S>NNRJ27]OB8C(;RLB%F%1G$&$.,3B M?S&(^>@&B(#:ZWY+ ^\X"_RXO[_/ZQ^=9)T!]DZ(O1&RXEW/I?$XQSQU[?A? M84H[N[/?_9U7GB'O;YWC7N_YSS0':@36U73I\AG[+S"S.J7'YB3L/HZR\_7; MW;JZ+S[EWT^0SDSZ(?89]WV,8,!CCC*<]293#"#WE>I-&1ER/ \>L'D"G.I, M9T:?W*PT&W-J,\B)M$?O;EU-XZ=HFM!C*^PN0SOMN%(Y>/K4-.GT@N9IM4*C MB/LH"&.?13A)XS1)T$']0!KC0'8G0N>CW0VA,S17VQYX@9&)T6+"WS(&B9$' ME;VG26U(?%Q_*3;[;?'^;D@1FE^JMFC>5?FN$2G$D&+L/I\0G0:I'P4XA#!, MXH0S3&!,:#@B"@!)5&9QESA<+W8'Z/U9_[%9\-M=T^;;;?]UUTWVK(R 8BK@ M-$1RZK:4Z*BIX'E@1MPW7H_\QNNQ]ZO+(_I'Y2,_]?^Y6M)AP/B$RLX1QV6H M\2R>5O./$C5U?\$DK8M-V?[;/M^6[8^WNTW9QZGY] 0.$JD6B+*8!XAB/_.# M=%@3 O$=\%6DW1F(Q>FZ=_O#.[CF4;$B_US5/]2DWEV\Y'1^$:%2$_D7U7L( MPH#:.\&^NJ[K,CPAZLZ#M@Q%=^]F-?-@4+S*M]U6WP2@KIS\ <>[JFF*YOW_ MS]Z[-<>-HVNZ?X4W$[L[0K4V08"GN0-!H,(SKK+&=G?'BKK(H#(IF:M32369 MZ;+7K]\ DV2F3BD<2:IG3\2L=OF@[_U>D \^' CL7A#Z3!*)2!2&XIIJ#'U, MDP@.@P=, 49*.Z%="IF0Z7_;%?=UL^^VTGRX?SATU^]4;==S=X7AF&AW[4// ME&.NW>^X*/;=MK)<+["8!E;K"2XU5[U[L6K< TXOS_M++^^O$VTHO MFW5I1ZDEFY?!.&O9/-U':M4E15)UJ]9XM_G(S7TAM@_%40=QEC,:)7F4I2A& M0VP48*#!*\.(KFO3_:6/Q%PZJ42N"4W4XU[%Z)&?ACF-*()8GZ:^)!",D1-TS#7J<1T8SEFVO6A M;/:U][E:UWK5F+:':M78%/9I5F-':0NBV&MF251CIC8OBESFV;Q2C=EQ29%6 MXW:7$V@!"O=4$JL&E5)OW'='0O>NG_O M]OQ]*X?W[>:M]\V)LTH(F\)4/8*=[>=;!L!>L>IM?IEZO"A\&2?S,KWL>"0+ MK[R\+<6)>?T(]K7@"0H0#Q1&22;V$1*&P%CG 1Q"E8K+4L@E3H'9 X([8WA2:75_5R#>YI9K\>SJCMCP.RC@I04.K#;(L)MI-[14R M.O!/N1(\CIY?"\Y8!C,^;$Y@3F#&0! &> B>Y'&@50F:A5SJ%)PM1Q6KP>G, MU*T&^QFYY5'PLGJ:%I.412)Y&IF\L@D'$6KWW];^2*+'%HT8C;^=KKLOGRK3@_:""@/O"Q M#_,,4) &>Q?.N4D 2&#>8AIC-*(,13XX?&D1)Q" M0#.EZPAU8SA&CY"E.@[3-$MV_.7>)]5QU\U^&2<=O>+-Q6&6F9O+((QQ%L^& M539<43_"A56[:E]^K+Z+$=V>/V/5S;;LSH8^?H*T"BG!"20TBQ +,&4)ROP. M;P0 !G1.['%.*SK5<&SCSZ/6G_IQ'HGM<=#U(?/ 15OH+?9 '(0F\E[-:Y9 MM-WQ$2MOF7@!@ Y:8AE,=)'8J^>E6/9.X7B4U\)F/W\K_JMNR+9H6_RC:E<$ M41"0!*0AB3%$4>S[T:# 3T*E@:+-N*[WD5U^<6]^>IU>KQ/L_2$D*]+3:B/( MX7,N_]7X:=5Z5X>9R/IX :$N6F,9#'62V?-32ARY9X&BI_B_%_=E7M\7U6Z5 MA!E):1Q'"#,"\SR.DT%%X.-$J0BU'7M6FEX]>J&%:N^/HVY[2-5K$6.L.F\, MFVC5:8>I^?J2H7J,-6J:Q7/6+#MYUEIP4?Z#K79?WY?-QZKE<7H6ZMGEES@DXF!RV"040;//J4R=>,MENSO#^WJ:U-LRONB^6=;[#;7 MQ5Y<(-%'0PF*& , 9S1, YMZ?;@?+D19A(N/%#EW\PFY1:(=CT'0T_B-U%\@LBVS MYJ6RM2QJNX^0XIUW^V]E\ZS2/$:$"6'8ST.80Y+&*(L"0(>(&2-*AXB8Q'%, MZ4Z:9L%G9)]57A%ESQ\(L MW\=J5W[8E_?M*LTBDC,4YWX8T"CQ$S\(^M )#OW4TM2>?,!Y5T?^$$*]3JF] M&3P%MXVG[=P8;7491,KCJ6?G1M_TIN34;5\&Z>RF)#_YINN7!?;]VM1MNXIP MFH<) 5D: Y"!-,N"87">H)PIW15L'&R2BJPZO8A%/VE^)]19PYRDL<:(L^^I MW:6(7R^Z.C78.C5Z4%,S>O% 4TQ''F8Z/ED &5ZO#_>'+1_5;O#Q6H3CI$KJ M0P@H S#QL^[ .1(D@Q"21V2U*^_$/_IJA7"Z*J3>S_3X?CX3+/VNGJGSBC-Y MUJ"GW0C&&'1JO!,PGC<&EFF,J5GYBJ5Z]#1MG\7SU#A!><+:\=("L!3L7CQ<%-*1AYDZAZ90^MO;7E[V'ZL;LL5B:,@3Y(H"!(_2A&O4-,Q M-(R!THTR5@(Z!MB'Y^@Z=.*\+==M;>BKXK IR1R9:Y%G5]Y1HR=$+@5K)]NT MX*;A^M(1IY.2-.BT_9*^6_&L#/QT^Q2SO# D8<@+PQC&+$@8"_(0C4$15+J* MQC"48\2=JQN//Q?7Z3TKVQ2O-30T6(YS$WJK1KA'MM:WSXNVB2\=O.C3!:19 M,G@9,+.5S-.K 6UZ9&&0R0[[0U.>J^J/7.D/;.]N)O]>?CFLUV6YJ79WK&K7 MQ?8_RZ)I\4V[;XKU?L6R,$P(\R,081B! .=T5$U#I'2@\-Q:7:\)=SD\FI(: M#BWZG]:&N=,TJO$X>7'M:7D*\H4V%A^/\*3%M>/C!]!_#+DL9X7:1LOH#>PG M?2:6T=,LQ@WYJ8496LG&(M9SO;^7/_9?_RRWW\O?ZMW^6[M*,.^ ?5A&D78 MISC*63:(\D.JM''2L13'/16G1F1OZ;+6!.[/D5_(A+PCAEXQQ06TXM( MV*VYW&6Q'1??!UA-5F$9S+K';@@N^I2O?]8K/X(YHCA-*, )R!*Q4G>:^@F1 M.W#+*G#/Z]@EKZ6-=H%I%QY/06>AF]/Y];L5%L#DWEMK*%9MJ_=(8.4.&")C;.JG#2(-[YB;.F2MGMC/J6O=Y M.NX*Z8LGKQ!IE[U*+?9NZ:N6I3E_-5QU1V#&7Y<5("SU8Q#%84D<2W/,W=ZRY/15RA?.GR%1JOL56JN]XI>M22-R:OA MJ4/P\K^[R@ C 24! 2F @, 4DG00DP/D&KPR$IR#-_"=@U?*:F?@M>WR=.#E M_V;QX.5_URYX59KKW8)7*4ES\*I[Z@:\^)8C:E2$?3^,44#$);&YSTA"LW$6 M)/6QK<]IC74X1O#7;V53%D*12Q K6N^"QNY:Z^"F..#OM M\Z",D2R%"8!AAA.0(A;'W;TF:>XCAF77]1VK<,>-L\M[ZEOO7+K7:_\1^Z?1[0P*S;0\S\_L"/B9JR&409*IDG]XQ-*7'ZE<1T?N';?VS++^4S?=J M779*,J'D7"O>=HW7;93^7*[KNUWUWUQKV53U,8'3U4F 8X]AYD/&\Z9FQPN3[E M?;2U6G=SWLQ#5EZ?UJ,>YCPS7KV.N8E_>,K..Z9W[*+ZJYB\V>Z@<]9@%_JK M^1^2971E"_#AU2NBYFT9]0[P]WKWO6PY9#NE>+VOOE?[G]W+=1(1Y4$0IXD? M)"A%24I1GH-!!$.IU#';CD)/V%6->H^=EH?_+)I-ZPW"=7LD.RV@VLU,;KY^ MWW'F>W>]\2!V07V C)M28+?:+$NCM=WD7D6P P_5N?HR^#MP?'H0OVQ?$98G M*(^@G^<1QG%.L _3R3]J ML*LEBF6.V_7I?'=?<*O,G\BKV7[@>.$Q<>Z;1GWB]2[?;4[5+N[3P]E MTREKL_*V;LKCW_M:_"C;G/^BW5?K%6,@SRE,0$ASF($@2-+C[=MIRF <*'WX MYU*'8_+W_39N\:9S! MW$6K3,GR7O_B4=[KM$MRU<9[MR!73M2.L3X;]6N%L?C?-AQZO$N!N\V MCW\*_=>!__%OY?Y;S?]$S#AU2]_9 A@S"/H]6^WA=; M9]QWIENIHQA35.523YWS/L)YM^"NJ9WU(XMH9;<=SS$#[YB"=Y;#U9,^B?[8 M-P7':+4KFI_'*Y:NQ*(!Y^.>Z]R*'S_XM/B.2[=A[?9TSA^O=]LUNG?&O"^= MJ/6D+X(_7_G>;885\GXGSS6'Q-EZ=Q+X880B/P8XCDD:AXP,Z]TQ"Z#24K/5 MP(['2>,&F6>;H'JY7J=7\2IYJ\[+=6:SF:[6&SVS>6R 1WY[?\RV2J%BY 7Z M.VF/9>#;36I/+[EWYY\F0#^7^ZHI!;%/FVO'#;,YB7G8)( I#D+$8)S1'N$X M#2&3G:>V&7+"E_BDTSO;[#[7QG4%$^5?8"M-LGT8_C?Y;_+!;\7]RF[Q3@F*XVSOU\E;:;3[!?Z-WKD'>].6NJ#)+7[::GB MI=^"9=1(_TZ&OKI[Z_VGIE01BD'C[\5]B7]4[2I/(&%9$& 2^S[)^/^/QZ*3 M$:;TQ:#2#W9]R[D)%SBNY=4R MB*DGO;;PK.A1(*_OBVJWBI(@3!$$((AH!@#V242'(!!BI0MV%7_T="0X"M)D M@:Q1:C1PX)$V#]ZRQRD1CL$EF*#HV+*HH"K^%2YH>? 6&?;WAW;UL=[=?2V; M^P\\K=V^^EZ*D+^5]S=ELX(Q!G$2D"#P4S^(<>JC: @7X"20881Q$,>T$-(\ MH,P"'H*OY7]"SRV9MB\9+:71FWY05(\E,KUX/5CM2N[74VK- Y!$H.8@MP/ M8 PBG,$A@20!2O/T"Y+MN$>9=,+1^T/D?=R%IECG+JA%9$]"6XYB=]WI A\? M-\>L3=:8%\88"WRBEC%^6:(Q3X]Z6Z!$U9Z<1]B(/99-=7,0^D7UT&_Y:<2. M 2&J%ON,S_\2OJ\/N_TJ2YG/H)]BQE)&48@PCL=IHAC'BKVS2RG3;&9LO#/" MM<5WWMJM]\#_YI5W7^S7WP0@UV?B%7._>=0_>1=EX/7E;F>*1EQ,5S))LL^[A^D\=C)X._]+_:G'JS2 D&: MDA"'.$(0@IP-LD""E4YK<"[&,?8?%?#E4=_D[[1 M;O.//5[PV]:(PJ0I%P/WB=(UJ?[-?78">-X'G8K1ZZ+:K-(H0$$2Q 1#R/L9 MA%"$!U%1'KO#N[H4UZNXP^S%?;$IO7WM/13-OEI7#\5.]31FUVWB@/%NF\,Y MX1_)]X3^!?/]F=>VZ*[?B.^0[0;)FI#=U&-9KO]MUXP')W\M?@Q31*LX#3%# M(0F#),64()3GE*1A M,()[R+63UTIRQ_V7-ZR6%;-Y(* )Z*DF;!N;A'Y^-? M>3?E7;7;B3F6^M;[61:*MS-I&RQ'WRE<5OZ[;J:+D*D(\)I0#Z M+(@SG.1^F)(41820T(\I6.W*.W$?QE?YFG,275+O9'I\)Y^E(/U^_MK4;>MM M!N6B!-WSM_1AD.E5.^]!9. =::I8E$[3@D9PG*'5[)*4%Z)]"MZ8PO$DF"Z) MX88/\4_&/!9!7R7GU5'MIF$7S75'*DD8.O #?[5\0AQ(: M1I#Y, YQ@*(L3*)X$!?D2.GSD8DD.9ZH./83U>ZLGU@?M?8=P^-NPTHO8;W5 MC/J).1O,6D\Q)/&TI^C36&Y?H>B^>F_AJGD7W5\X2UJNQW#KN=2' 6\H&X7= M/A66'=IJ5[8MJ>]OJMUQ,S9B.(JI'V592&&: TC1J(_X6/Y+@DE53=IS>)M# M>=YYB"D4[Z97[:U/LA6VTT_;AI<[D64WW]3]R)"/1]Y!PRI\6+'8!M;[$N.X M&43,:(ZO*1_V'\Z;7U1W-\-VVN9QHS^>,-A_*_:>N%%L4_%_O]_^Y'_]>.$H M?^V+%]_UUV^;)NY[[9;.S;I)F,88PQWE$(0'( M)S",AFA1SH)^W83N-F:K)F_%45\U&23I=1;GM+CRRMWFS=62A<_ZRQJ\Z&I? M/@O)67\U5PQ?IJ^\7_E'?=AN/MP_%.L]O;TMQ>53XG#>S[Q[6:4H"?( AP1D M*$LQRPD@@Q@:9DHW@SB2X+C2OO *_BE4>U4GVRL'W=U?:KAR*],UQ@UD-#TS M9=M8*J./I5(GVCNJ]D;9W5_\?*EIIB3F&^:J ]56:RV:M]:2E,.Q74^E#^+D M8XUNQ\JG6U*TW]BV_K,=S_Z,,I"G-/59PNLL'CIVRVDW$OV73A%;7B[C)>1#NI/#U1S9X_LB_5[^5>A+INZN_5 MIMQD/__6EIL/N_YV@MU=?^UF59Z$Y##/(QA%&"51F$=!&+-@$))CD*F4/P[" M.RY]1FE>,6I3*VI<6"Y'MYG=5F,>%WM$W2!7G/?Y%Z'8JW9_]4[M<%(]&P_5 MC;U 28>MM QVNDRPGNR)5^;LZ0Z7%2$Y2**(9@'S4^;S,@FD0PSHIZDB0A5^ MLF,ZBI?V>/?7Y"_@R83+[Y:&68MY;72T/W\CM!V0?=CQYK\._9U$7^O/IW& M=U+\OOBOM>A6'\ZZU=JXJ)FGR>7*GL6WMEIA]*2AQX0\ =_'M_3Q/WXO)92+ M1KK0$&HAH./>YUQC=T!6<29.]?-2&_[*=0V36ZN& M^G-Y8O-]+[ S&,L8[.AKT+=-NX!>JYXO Z5V4WKV_:9UOZ2GW,?#O+HB8<,3U;,^QJN0^Z-%^F7'%?<# M@ 2%F 5YFA!>U>5HB.I'R@?T&<5R7D[U9T0, _?BQYOH<7KRPRL^7>SF[3B\ MC/?*6C:O',Y@QR7I?KU<'YIJ*!Y8M2OX<*O8XK8M]ZQN_O&M6G_[VA2[EHO[ MT.+U6NS:+3>X_5)LRU^+:B?&8Y]VXK]6818 @CD/,(T2/JH"\3B%R%":Q1I? M/4\I3^I%-O[X60@JV^,FYI;+:L5"/J_JRNJ[N*A*<;)MTN:3+$*6UF1ZE6.VQ[_MW?)_]Z=(V!LR]JK6&W/VBM83 M>5YY(N]AJHZ'$[\Y<8UDK]4N%58S/!O+Z#5FR?QI"3>;^[*]T;"_?OBL^\/N MT_Y;V0Q=X\>JN*FVU?[G*D898?Q11B@ (,!)E-(Q? (BI=/N+YC%6C70CU^5_640^5?Q(5*G\W29[*AT6BK+^GOI]N'MEH+2DY\GH"D@Q?>6MMML(R7 MUGI6M=LG5W72JN%C.+'[_4S'^'N_EWL>EQ=,/#3.(ICG:4IS2,:XF9]HO*SF M0:=Y3/Y'7.34 M\X1O>'9QIM"6W\L GL5\GLT6VG7*8(0V;+L@Q4.UY\/)8<]%!@-,8Q"DD% 6 M1"612@D#&* MTPRC;-RAYB<0:=2&5N).4QX.PLY60DSIJ..Q+A==^6J3B*/%G]^V>"(0/K=- M"8$&KB\5?B8IO8D]8[_T@7=<;"A/D=L50R"E?II G,,HAV$0DG'G"*.A;P5X M&G&G 1[]UZ%ZZ+[CKG8M[X*VW:_%E8KZB\%V;-=EH"NK;3*PUWB&P(EG!F5L M4V*@@>M+9:!)2F\RT-@O?09^V'WG[WC=\)'?*O(Q0BA@:1XCY <@\>'I>X0L MPU;@IQ)P&NJ=*3)%FY*;NDRS[J!-F,F8.1'$SJ0HT4O'WZ5B2RN7-WFE[Y#4 M4<1/ U:[88'SFC^,W_CO7#?5NFR% 8R/D+F0W=W9EJ<5B%B2ABR-,$A3@N(T MB<9=B23)5*JX:01- [IQX\!#KUI<:,(+#\-M?Q.UV65<+JB=;.)T;+(A >^8 MP;'-QAS.-_PMJM$4CA)>5./I'1_\]5MY.CCX+YNQ(3>'KI'V_(_[.R*.QP7S M_]Y<>B?%7[@=V[@XY6IZ3K"IUR_TI].VX0+. YXNUWJ.M\3*'LG3U\_'/0X^ M2+&/HC2(HSQ"44BXFB%X'*6AE1&&5N1I>N#C!K[AR/]NY:W>W?VR+YO[?CG. MRM9)9=NUE]Z<66U_V^39<1*7G9YRT^03[]2W3.J:O]0!BUE2-X?3ODTQG@)9QI\@C#'U Y*$<4H8&,1$/O#--BA8D>!XL\*X M)O1P%'D\K^$HT^9.!3O-8;HZ-UE+V%VONSYKFUZX]U&B;29>Q+ODKM:RGI7F M6BI\[28IO?1GT5-;]>JY@CPD$*74CP')8QR&T,_" -RJ=%H?2!EZ H?U&6 8*'>15NWY\7=U*L"(A"I, L00$ M>1)P]H8Y&020+ >K?;TOMG(F=(3+&1I'WE=%R0)3A@#- @(CY),.4/UR $ MD$3I%$<'X1V7DJ,TV[ TLMP(FE.Y;16>IW98P"'DZL:J\]1&*RV:JU82E..K M/2]E.7M=_.P/*C3K,R:ZC6\/O=ANKK, ZJ EE@%2%XG5SI]B0W ^.Y_%SW &$Q#' MD.21G\ D0>$0%S.JLW?)/.@,F'QVC%'WXM;=;%TUZN^W,UV)_9#;PT844)NR M._UFXK'GFQZKO-':[;/0%UD_G[?>7T.GM%_;+]_J9L\?\?MC[=7]X8I1&F0^ MBQ F?DY#!/-LG 5DQ%CQ\M3A(-ZQH]GS5+&N<6FU1K4O>2;"NZ,?%\H\LQR>@M[%AS3W\*2'TK&#<"WM]6VXEU]2XZ; M-WC)1!!$/H1^ C!,XB0(Z"" !GEJ9=NU=O1I:IBN9;SC3NM!HK>M'WW:KK%T M:[,5=/>SN'7>ZN=,A_[+EI/6*Z]7._=^EM=<5-K.8MP4RZ"FB\3>W,QBR3M9 M?HH)NY[:FRZN^/7Q=,X5Q2$/QV",TLC/4D+3Z#0Y%Z% I6 TB>.X3.SFO<7H MK5NK%5->WXMM5]D4O6#QTOY6[IOZFGSQ;@YMM2O;5EPY=5/M-.[.,_)<#H]3 MV:W&P\[I05:/P).P:=%WP:$+K+/AZS+@9B63VOY3IS?R975SW=3KLMRT(G"W M->:%=8<5I##,4)IEL1B$)[RBBL8B-(^HSIG*"F;\,8CO8_;7?R/S2:NH\8V1).R5&R[8;9AF0=);=*R-H-R[:WYZR0BG- M0S]$**=!0B#%,!N+44@R&QOZ=,).M:'O<-P8T<\D3K,_Y6W/;>]+L6JW\_TH M2]V$8F7SB713+(.;+A+3WFRBZ)TA+5&T)S*;:OP/+L@<;&;^2X8J\Y3&ZVT:*Y:25". MK_:\E![BGQ7$']KV(,X(_73[L=[=B16FO+S9K_(81 3C&*$,D)S &)!Q53V M:IND+81SO:Q]/J;TJEZC6.,^?9J\X3H5!_86;)8<_'J[+^'ZWT^=BWQZ=02QUW.PQ^? MZ:;3%"K7>_-G7;CEW" M\\IWA0-1V<;$3W,_3/P(>V8=F.#*[W=?K M?^HMXBM9J;90;]T^L\5X7J>.>N99:C\S1&(Y7<>^96#**(-7EL7UW="99/PB M7JA/#UWU0G^4S;IJR\TJ(03$((A#@AG-_22)V%!Y\O^;(=TY1KUHD]9T92^K M^XQ&R/7J!XW:SH+'ZA.,[NTUF5_LU'F]/&_4-]_DXHMV2_%EXO50272J5A1!#"D$D*9)[L=^E-*A> ,Q5;L:W';L MV196S*HMVRU@LLPRC?FVUES.U'JCW",UE[ \ZJ9RJLQYLVR/'Y:S4YJG<:6 MBZ9LO;^O=\>X.&,8)4&:!23,"*4LR=@0E\!0Z1X#\VBS\7/=B;0)3P6+S7#I MQEU[@.R,71 11[\T&*CN];*IIY&/).=TG5*=;/M<;KO9JOIK\>,?U?[;MWHK M3C%A=?/E6]&46<$+5Z[FH=RUQ\OM(*:9'XM3O5"8TQS!-,.#G)"D.K?G.M,R MS;0=5UN*6URJC=<<,Q G)NS*O=<*V5Y;[O?;[IS>T_BZ^+-H+DQ43=QD:C-_ M\S23V?3@YU/#<-7>F>SN,YY.^"\W0KEW+GV>F415@R6F&YVUV4+X[#S-5R8N M'?NJ4Z>>?6K4?5[TT@).D-.$,9_%&408ABR)R3#'"A!)M:M6&[$=U[#:WT7: MMEB]:IW:79,:]B_GGTD.WT7.OSJM:*=DB6NS818"5%?972A_[;MH_TN?50 1 M0Q'%D,0P"Y,YN?7]ZY-&*981A &.: M^X2)97U(QQF,,(6Q"C.M!G9,3?)-7$RA7,,IHZ).'\2Z@+@=:;>O]C\_[&[KYKY;3AV+GCS-6> CBB*&_(0A MFD* "4:\^(FCZ,W)#GN!W'6)@[SC!6*=0.],H4RM[\K<3?]3CDO6GAEY M1GQM"K%C[,O/^YMZNR(L)R /4DAPDJ,X20#(AY_/PE3J"C?UG^J8"KT8[ZA& MG@:*UKR- 7>NJ+W_DH98>.\?9?S*"Z_GROQONJ;NVO1Y4.W_"2\\FF+[8; MI*D?Q1G-R/CC^0A%ZCMMY1_JF [CL%J(D4>"FB]OD\"9)9HS.A?=L/#6G^?[ MRLNN9[-KP45!_HZ^'^?6\V/,XF# 01#"EXGKH)&<(D)$<* "JK[;: M3Y_J'>_W78DU J%+_757-$W^O7?GER8 9*VRR()''KP!!3V_ED,'3?TO8,+$ M"1E>8!YD(P*Q;7&W\F."0!R&(()Q$/IA& =X^/E!AJ0V@JG_5,=\&,5X0HT\ M%12M>9L&[EQ1HX"D(1;>_4<9O_+.Z[DR_[NNJ;LV?1[4:P%6M>MB^Y]ET3#^ M.^V*!7Z4P@S#C($D]3&),.PC)5$0*Q?ZJC]_JGK@J,L3PKQ.F7I%H&R=?$W@ MTC7-JD#>,(MUP1,?WJ@,=%V;GQ?&&;Q0'9BYH2!%%Q[NE,44K MAU>IHN^(#%?(H6D> 6P8XB"2\-(G]V&*8I(E?*2#TS%4D$E=@& 4P#%5>EV/ M^EKU&0M]^]Z&RB3.J3%%RS0+3'G-BE>08NS<_$0Q3Z&V^"2IKGS^H]QN__>N M_G/WI2S:>E=NQ EG9;."& -*2QW_(QYE&E60H4ZKY/G M#?J\HT#5)5%M-V671J;P^[?='\9-66O\(KBE&$8Y P%$80)3%*\+#"D\0)E3KD7_^G3T.< M495WE*7*&67/9/GBTBXMKD@[98TF3RRX2!%=NY9"#VW]SZAAYH3"3JUC@?2Y M?*@;<<7\EWVQY\,M")@XK _QH G'4^:+8'VX !'IJ16C(!/MV^HK^U&==Y2G MO'U+TTE9E$Q@HA91E/VSMZ?K14K%QO&+H5+=I)Y7LG8\TB>6M>'FVVU9MNZV*\@09BP("(8 MXP!G<1[3D8QY'$GO8%/_R=,PZ:C(ZR2I\D?))UGGWFW*75MN^B-IQ6VC*\7-\$"81(1Q,7%_D!Q3Z*EN7&J_%C?;<D9U$.-VVUJ8KFYW$G;A^,!4&4 MY12Q( %A$)(@"@9@D2S"4F>4&89P3)*C%DV2Z+HF.;*VN9G" M>-&82[,59DXN RRF23R=@[#AB2Q>?CT4XNS4NAFC5F7;1TQ"/\\C&) XSE!$ M6(C#$6A)EB@QQB2.8]",TKQS;9K@,?)3CCY36:F&(%T7G7#H@D478&3#V&40 MR4HFM?W'3O'6YWIW*6B6H3P%,4O]T,]"/PQ8 H:@ 8FDIDHLA7),**[N%ZN4 M,G56#E03FJK&*A,_W=S7?-&I"\BR9/$RJ&4KF:=W,=OT2&%_35MOJTVW"O]A M7]ZWW>RQCT("019"%F;,3X.4\>A],#YBS)1N#M4+X9A5CU1YG2RE-1Y3 ^70 M-(%WR@O2JK:YVA;T@C&7M_J8.+D,\I@F\7Q+CKDG^J3IY[1C<15&1BBD:11@ M$(6)#X=P*,)2]]@8!YF#-DKK3.8VZA+'@8,6F&.P*&63.J\N65GS[N M>"_=H)'_-][\UZ'=]]O+M 9MQE9K@,JQRP:\NO+.M7=A#^V5-PCV_A"2C_6%.O)LMH0T &=J!&4<6O1_HH],+EAYF98.FF0Q M['21VYM?B=AS4'H^O]R+VZFOF_I[M2DWV<^_<3T?=I\>RJ:KD?!Z7WVO]E79 MKA)(TAQ%%,8T1F$&,Y^. J(D4_H>Q&)8U_/\Y=Y;0Z_5N_GI_>4@7O%J M]U>O'A1[Q2AYXGEJ:2LOS5G;;X]EO,DN$GLZE^W*._DMC3^/GT#4>/VO0]64 M7[[5S?YKV=Q_V'TO^P'."@&,L$\)(BRF.,N"($KZV#DED*UVY1VGS^:KREY' M&X&E7N#T^ (_TRB_O8___K>B+5OQ75?T;(.@?<>TW]$/._[X\: ?=N?K7WBWP;>WU;;B3WF[ A'+F)]3"O,< MY0!G%/5?,Z& I6%LXY6UH6.:-_C42/RE]=HSM:H[FETTA=PX9C[[-?=$'^5Z M^]KK!7N#8M$(CY;IQ>S:2?7,,)7P586M-IMIH:BUFN);Y+7OI^& YPB7Q]5: M!"+(<)+$$8UB .,0G01@!I7V6EH,.^^ IQH4+VW \X*5Z@,>D_98QGOM(C&Y M 8^Y=]+%5%.ORW+3,IX]J7?[IKHY=+,EXC>.GX&L0N(#%"/BTRR/ \!.2VL( M!C15VM5C(Y[CMW:0Z(DG@K^_#]6^V'KK,[&*19(-BR5KHHG=52R!'AG[2-_Q MMXX*)RYWWK;L4G5CT?!E0,]J1D]K%^MNR6+N<_G0UTV?;C_6NSLQ4LW+FSTO MD\CQ!?]2K@_-D;0A)A &F3C;/0R1^+HM18,$F =88ZQH-?XT8\239#'-L^6B MC[,\&RZ[&Z ,9-R615MZ]^%-=M)"RWBEW:163_"$R[WD M^_M#.XZ+]G4W(%H?OUW-*U%7[3;MBN0^C7/@ARP.,I#X:0[I&-)G5.&EMA)O MJHF>DS9OTXOS'HIJ(U?#V+'V/[!S%36GEIK^4L2/M-(?7Q6$1&H1]:F&[2"3OO=-/MH'AITTTO6*D^W632'LLHTUPD)C?=9.Z= M[#O\M2EV[2U_M'E9^*5LOE==U.&@UA#1(/&#&&4HB3& * W[&V[BB$1I(#D+ M8A;$724QZNJ&3Z.RV.DLY5*[> )USR/^>]%4X@C/866H M.PJ,O]-?RQ_[C"?_SU46T3P+<.RG#/A)%*2!'PP*DBA5VM1K,Z[C#O+\/.)! M[&D1=I#;'X_K"=E>IUO[6&(++2&'O+D:00V ]OUW?%+QFV9>H*2+)ED&,YUD M]NI)Q;;=DYI-&L+7KX:G'ZZ[Q_0D Z1'^?)B/642JUQ.PL^ M(5F_#V]V-;S9Y?!F_^)QY=I\==]F:_6T?LB M-RVFX=EK4V4N[5_ ])G3].J)'F.U<<3_.13;2CS.WTL^>N'_)>)W_WEV\*$59%J0@30' ,: 0AS[_5:\TSM1.!9Y# MWX2])^,CQ+KI/JEN>!)WG5RU\<!VUS87@TYY.PC&'4K [4RWDO%89E]%^'ZD&$^K!K]\5V M*WYYS5_)WXH?U?WAOE^7$EL/5EF6881!EM$,\\%A3E),29+RL2&)(C^5NL?< M=DS'W2HU3O@?^=*^_^J-;K-VEX8BN/0I5OTWB)P=9,GJO1_V3WF4KO MNK.[%^KU2KVO\]FM,)::R7:](90U^^7&3/+>O#94 AC'E"DD> M#]JR!"B=YCN-(L>=5:>N&_",VQ). GG!S/^]UL&:$S67W'!G>2VEUL59:"0G M0Q4KOEX8G$S;;LL8CDR<.#GPR),1'-49I"&.6]MC@) M Z5/(*=1M(0>0.NPTXD:S&(?,&E;.>@#9CE6U8JSIKV M99[1[V O9QU>@'+ MCAM-/)UB]T#L//,*%X)*QE MRPTFG)RZ;6NZ:3%&6YAJ/-IIF>^J(ZR:3MZX*GF/1SDIE@,G1, M_A:H?=F>8OW:U&V[PA$$D1_&*0,XPSY)H>\/H4!$F=K=3QH!9ENI\)I1:7OE MW0FQJG<_Z?@I5\H[MU*M1WBY(/_UHF>.[G=Z[LN%NMK(QF64R68I/+O!R=@/ M^7,0ABC_J/;?/MP_'/:BM#[N-,JK=ET?=OM5'H19&@9AFD0HBR@-$A(-L2&@ MF=8!"#8"2[U+QA]-R]+IL"ONZV9?_;?XP.Z8T;B';^HS$"3LO,2_EWM\WP4G:1XSYH3&AIO;].6T2N#)FA,=0*D[-AT9]@7WGB4^6CS 6!]'J=['R[Y/M?[RFHEJJRS&3;$,K#K)[.T5$TON:4Y@<9ZO*/+CQ(\RB#$, M&(59XK-Q <8GN<'TE6DUL25;1-M4.WW"VY-,6G%X\M/6:D8 MN P6F21P>;I*W0N#TNWLJ^^ 9+'/(1;F <8H"43,/$C"-"!!&F+3'94*D9:P MPFI>DS^$9+IX; MMZ@4V^NZK<2:\W@$D)^R" )QH2Z8:\$HIM+'OMB(Y>Y%&^6= M;1\KMMZ@<+:#KV1LN_#>675]&:^?W92>GN5BWR_9E_%\+)37AYO][6&+U]WD M_%D)0PY-=_:XGR>I'R9!$)"$9AE-"*]=CAJRB&&E8R/M1G9<8HQB%9E#J#5(?C7YZM=-B4,G("SQTTR#+ *.CW.HI'FG5FV#*VY(' MV'S9\^)H.,SW,T?W==!H'85C(6 MKL&XVQUXQ3*>G-YP=:JWO]BP58Z,DSNJ!L11GM?INQJ/^?:$Q"OO)'+J*V#> MMNT"_JRZO@SJV4WIV2TPUOW28]QUT7QJNN)T\_=B>Q#AOWPK&AX<(H!QG&8 M^A P'I($8_ 0*%YX926D8\Z%_Q'Z_\/[K=AMQ'/W4]QV];UL]I58PG\87]M6 MI."U97=');[R'HK&^R[2,$&B?BOH0'&2!C#$(M?(7W'OJ-+K9 HV>IW0.='X MFGG2<#1V?XEX-$_J(B M>::'R"Y2BP_[;W4C]DFM$I!P'F?0]T-,>>B8_^\0 M-,6!TA#9,-0BD=AV67C%F(8)&M7=UT&B4^,-47C4YN&W[9P ?T^-DL:>ML-+ MQ)U^,A7B2S41"71I>6."K4^'?;OG[W&U MNULE:0@@@9#Z?APA<0Y^F/112828T@>#IK&6#+#ZE(E&P2L_#DC( M&1NG*:-9 A-$XR$\25*EKYNL!5TD^HJ[NZ;[&L#;GC(SG['6?QY@3DZ_9)D])""RP1F3;2NLA.:[[)0I34]_?U[O+L89#X,/69 MV%R3)""%>0J'V4,"4*1T!9R->([1>91X9*/VPH457^78-[6E:MCKW5S>>H6$ M;1=P9]/T99#.:D:UNT=4FV_/I@TI+T0Q0RE@),.0H@R@81\AB?-,Z;, DSB3 M\LQPU<'(3V6>.;72A&,S+S91A&(N9EDJ>,4;%0 INKE0 M^*AF\19XM%S1AL[Y1%V6IHE/(@"R*(W\%"5Y-H8D4: [TE,/- U^GKQ$,O/3 M#CS5))$K.VW@:+:9_DLNJ8!)Q]R%TDDKE;<0I>^/+*>^-F71'IJ?9T%7."(Y M81G&F*1YD(:,0C(.$;':TJ7.SW=,I4'24!85>V]=JYXOIN6;'()<6Z9&GM&M M1^R9%C;/ZOM]KILJGKS8;<6D AN*,FR@#+$QP"JB?!SX,_32AQ%>BBF$HQX 9U!V/-5Q_$W<&J]'%U$HY MT$SHHAIS3@8>I7F#-N\O@[J_3DN@RU9=@)$ECY?!)5O)U$Z>0\5#(?H;OC_= M=E#,>*0-K[\>REW;K0N>W?7=9C]/?Z>_WA#_632;[GK=%4I DL28QGPAE]Q QY/SW<9";GI:ZM MNF[*3;DNV[9NQ'EA;7^3"00)R_(P1#C#40QIDM%HB!2'3.I\1I.?[[@W.%/5 M'9/6ZMR*I&O=939/Y9H:96N@7L[XA8[ AC\+N.K) M-(/:WM.B6."_!?_7V/^QVI4?]N5]NP(H"=*0Q$&.LCPE&4(H&(3AR)>Z.G!" M.:Y+>HEJ[XUB3^3B=Y' MD_0B9A(=]RQ_Z18GO%[CZU.[BVHUQ]W%= TV<1=R-;3SH_T+WA\B/:_/[[UT M+1<;R45W8^>I>.==D"43;'5+-MMDAJ[J]T,W"$M9%'*-#((49WX:)C!(!YV, M_^[JH5N=^;(OFOWD?96D1A7J/4U'&H!GLJZ\F_*NVNV4=[+-T'R3=U<.VFP1 M/=65=\SLW7911_G3]$Z*#\&_7<>DFK^[/DFK)>1O6.#U^W$_=7YH>+3C4OYQ MNU'WA[T@^J-LUE4KMET',M6NWY(T]?48JLY?PKN[9EP(OQTF^.PB M#<=>3C4@X,.5V[+:'\0'>;L-_?%0-=U/:#_LCBFMPB2F(&!!D%- & W".!Q[ M#IC&1.,JUOE%:T!>YP)7H4R9\[.;,]&88:)6G+T7.O$]SU7(MN"_Q[4,LC?^5R)6DO,0*5_E-7=-UZ2XN]E M4]R5PQCCNJG6I5B#N.W7('P4A7X,@$_]G.(4$I2#<;N0A":*$9'RHU*M/"M77_UH\\E2VSB]>#$)"@,0 M093Z. IC!F)&TWA((L>)TAU3"Y/N>%RLNW]A62;9ZE.7V[3VN];+W_1?WCCQ MWOI8J^UJTM7.\X"]DQYW)G-4.]XYVW Q.TDNYM2-TPE"*#7U M!AF++;RTZ>TXC6$8(A@'A,$DHQ"$:%!/61C-N*7&2/?_O]'FWVF"4K:U_STH M:MV5F28HU5I-B8PW;ZN_45;_N;PO*K$\1>I=M^A_*+9?R^8^6 59DL8)"!.: MQ2 &$.2(C5N1XEQ]!\_"]#L>##TBY9]#T5KT16LSR!;7MPZZ/1[F_DVLOI\' M1&'LM##I[V/$='D9<.TO?$_G/T&-/V[YO]=X+?=H6U),OU:&7>O6E:E7J MX>G]P[;^699?RN8[KR->+E=(T7[[7*[+ZGNY8;SAAM+CT^WY=W\K0N(LRTB2 M$A($69K@A)!!(0%J/?>4NASWR$(E[WB/,CWQX'OE,'=4W_8WIM='K6J][Z2- M)]>K+K7=U'K+(0NO3^/5X[^OO*YU/S]J77K6NH\V5$_; 5ILB@L=VQP-OHP. M:Y;,Z_E?-[4.YF.UXX%(4VZJ/2O6U;;:_SP>.1YD,$-YP-(LS),T#(.$QR08 MY1AD.(^4CIS5C^(8_D*8X,!1FC=HT[OEPCUKEABO32\GJY%--+1X)F!CY)7>?TOZY_XSX4._*-CR_[ MZTP8 #%".4P30#'R84@0&<+X+)#:PJC]PQU3ZW]=>T=-7B=*YU8B+/DKFUZ(=D7D&OLRP(N;#*27UMZ/A00FI>'?;O^ M5F;%[I]]%#_*$HP1Q81@2L2N-@S'\C,FL31!-7ZV8X .BCPA28<*.G9)T-.Q M4VKPG,4D!7(Z-DL/G(JFR6'S>::O4=/ DP5 TT1];>?)L#"6'N]'HED6QQF" M)$Z)G],\ # ?8L8^5OJHU2S27"L)'W5OFC,TUF#X[,132\L*,G9.-VZ6N-#- MCL,+'C&KYR(S7-9TR(1:Y- T8G-0W33UGV*/3_' _V3_3F$\6G=ER C+YURZ"*@?ZG']\9.B'+C;R\V7_8M?NF M6Z'B!5G98XHEB,:QGZ4L"'CIA1-,("$(QT'& V>YVNA2.XS[462]N_M%?!ON M;;A&K^KN_E,CB;Z'MRUE*FM?,N4 98S^7 1OS-&K+ MSYD:>CZ7W\O=H6R'&S%6218!/TXSSK3,AWF89&F6)X#X),I1!I16.95_N.." M9="C1A9UB^2(XM0=-9(,4F:[&>6I%Q? H6W;,H"A+[^V]/@HCFF*;=GVL?IO M/]O?R_T*XSA$3%PE"% >BNI'?+UYC$;]""F-;#1C.!_?'#_);K2PH6V; M+A3)(C^(2$193 !((Y %_C%4'& E+Z7U K@F#'T7X?JH3O[R)PR\J:I(\:) M7T9\Z13-#)?!%4FR*)NX/*RHIW"!*9I^R +ET_Y;V9S'$Z%0D*,8LX0/H((X MPQ$.PG (%>,4JP!%*X!CH'2:-&&B9Y@<3)Q[I0:3HTTC3":GR$MV7*"(D7O+ MH(A9"K7%ITEOAF2%"DA[C#H0@"JE(E: =Q72D\E.)$_-V=5_;* MU-Y_??/D>#");VI\Z"0-=W=THF:;,7W-G0L0,39T&5 Q3Z.V_*"I0^?3[3"? MLJ)\R(/"F.* ERT)%9=-#6,?Q A46G!1_-&. 2/4=.>.CC.!Y8_U]M!6W[M] MJ9ORH2G7U?%P:/%.%?=ULZ_^^_@;[;?Z3_Y_RX>"0ZK<_O1XY/I/=4*I."W/ M)4K/G@@MY3A]VHK!H X>%/Q2X8,;J_0 T6GQA)@Y M$#$Z\28CU#U;$B0TU+]("5T7Y'>I;OF?WOU:[GC]O^5U#][<5[M*U#Q[WC7W M5= JR$ 4IW&2Q9!0AG,Q]!J"(QHJ;EVU$M+Y>F^G\LJ[.^H\%B6/E*KN;K7C MM.1RS?0F*R[@#/[^>N;O8Y'#N&KJW;$RSEU:Y+%K_3*H9CNI9YMK'7BFM#0T M3H!\V*WK^R&BF$E.TY@D**,,DC0&.$Q1G Q!0TJCU:Z\XZ.2S5?%M2+]B%)O M97I\*Y^)4UL5N?)V%U9#G-BIL(3DV$*#Q:33?-I1FO>77MQ?YUI?>M6KMU:: MS$U>!L)L)?/2ZI,MCW3GJE=YP@M#EF8D(^(XD33U*1S"\#I1:3U*^8=/LBY5 M6YZA?MLRO9EIJVZ9SDC/.PVM,/TL[=HR6*(O_XWI9D4?I$N218Q MCDU3K%R>U2P?+[KEIE9Y;LFE L7 P&60Q"B#IZ6(L1NR//F]WM4OECSC$U >!RHR1>;1)]MD-C.GK$T7,6+!4#CK3NJF&H'-M MST9.LRVOO^G8!4+99[5$-,,\$SJ!H&5&J\4K9-CDY.K-)BT6C/+-/03WRX0!A= MQY;!$VWUM9WGQH@5G\NM>/>NBV;_UMM:WX#U26>\TM7@:A M;"7STG*O+8^,IUM7-$X@HMA/B!_0//=1!,;J 05$ZBI$\RB.>_9^ =@6KPS< M-)QAM6JDQ9G5A4RGZDRC2ENZ#"I9R$-VVE31&?F1A8CQM?C1A\G*77E;[5=\ M[ )2"#CN< )2!&.$QV@P"2.UT85>#.-&6BP,-,R.7 M\=(89_%LP&'#%;471BS&,I[9E\--6VVJHJFZXY,^W7(9*Q_B." A?TMAF@)? MW&""AL Q4;N6W4(XQZ\1+9H=AU7;[\;HO@H\DZDZ:6CNKNS8;&51#Y_:AJ 736/=3WI(K726Y/F9L2^MR22V6SEG7+ M>%-/F?!V^ MC'-OS4':,GX9(+.;TDOSD7;]DO\(Y5G4,2+.?)]&" 0 931! 4OI -HL YGB M]RCZ<90@I_MIRF/(&6PU-W)4#FQ3F:G&,TF277EXOV^JF\.^N-EV>TVN"W$C MZ-2?N;QJX06PV3!^&3RSDLFS[V!LN:.PIM*4XL)G<1'8YK\.[5X<'8)_5.V* M!33E96*4^F$0$!8C0"(>,(LCWV=AK+IW73>,XP+M7)EWDN;](<0I7MUE8J;T MFLH4/BHOJNA8Z&I5Y16#+B^KF+JZ#";92.3YPHH=;\R(E-?W1;7C(5$(>:E& M4)@@!-,LB,,^)$"IV@DL1H'FHM)1GA4NR5IJ0B8';EIBTUM&3DBGHQ1E/BEZ MNV1"J:8BQ2@M?V0IA=?_.E1M)Q=M\P]W1P%>4X2Z,?(SP 8 M8\9$"5-FD1QSZKJI/58W]\79N\6')R?)OS3]'N[C5_EZ5Z(:FBT'L.E\5B.8 M@9E.&';1IPL0L^/O,BAF*9?:Q1,HQ[']_:%=\;>W>WE/[^Z^/NT'Z..R'.*, M(9H2!C'QDQ#2K(\; "*W7]Y>M%EX]A<^%&_*0GQ\FY?'7WG53DS%#-^J*(+- MHON7X3:/\6J >\ES,:FU"'LW];J[=;0[@7EA-C_2)M^?/#*Y>K:9RRO:]G O MRN7]-_X?)R9Y&XXDKUZ+0HOW0<6^^PLWY5VU$QM9NL4L_AL/O#EON^9\*)M* MG++ZP-7PM$ MBW0]& CZ_DNZC5[HP^RW[[S]F(-\:E=O@F%_AL].4"]VF_SLA/5>" U2/X4^ M8"E%/@R3B*9T$!*F@=2UG0[#S]WC\8[N/(GN8*WS-&PSVD*#:?:)T[:5G4[R M#WUL=?]0K/=#_WE;5(WWO=@> MNALAGO6_VWIW]PM_S^]%/UWR4:!H]Z)[[4^J/ED OHBY^> MDF"+\9IMH-G5NK??3O>Z,+<->U'WKML9DCXY3(4_]:YZTTUY(W8PM_NFD]VZ MZ/]>=%VESS-KMH7V[/B:ZEVD:L52N76?J=U4ZY@&=>=K:E?> MJ;OJ%4Z[!"1AV86%()N&+V,YR&I&M;O'TQ[6GGY/ @ B(? IA#@, ^#[PS ! M)FD.;<%-+>IDB-M)?P7EVF=SXKFSV"[WQ&[H&<_GEK90DX-ZS;!\&FKFI*V0:X]+0?&UJ3N>[77B.1P]PP5ZG^,KK-,\.T8N.JK'4 M3N,L%JF6TGN;K#9]= #8O-H>]J6X&)0D,,^9[XO;R7,:I0P.0B@*B"/$RH:? M#+*;HZ I,2O=!-9!Z\)]]ZCM52\6MKT^.[A5;:)W!USE!/61J^>EU++&((,Q2RC% ,*V$C^ "3RVV;LAW8,VR_EKJH;[[!K MQ4<'G+4[HI('UWJOU?UI4S>=F,_EON+,7D&DUBK7=SWAH.N[E!>T_6 MSXMJ(>L]G_.6FJ +5&PQFYWA2_:9]8I&#?)NND>S+-7[20NN6N\PR_*1&I2B M,"?(#UB"<4:#*(CB44W&Y+\#=*AAY@ZS+!UWF*I-8KG#=-@:SCM,WC93=)BJ M+>2HPW384I-UF-(M9K_#?&R?C0Y3LT'>68>IFZ5NAVGDJNQBU*^'HBEV^[+\ M=+.M[KKH+1'?P.[VI&B:G]7N[N]B@_$J)7D81! G!,1^%L1^SF40C/(L29,\ M5[K[P5I0QUWBJ-/;5L5-M>7MI;K7TYZ_H-, MK],Y[3J2K'L75H^L-\ RUHSLIU4[?G#-.?A;\:.Z/]S3'P]URROB5C2\^M8'%HA4'AE?>WW:9JU_5A-_DRNX2!BF34M7^Y4-3.2(*' M9F[)HI#^6%=MB7>;+\6V;+\6/\IV)0Z])#[S$691DO@,)L$8B>9RGZN:_'S' MJ&,E?U(XX/ZVJ[[S?\U_]:5LOE?KTF,<=-U7Y\>K"6]+5;YIN2G',]=&JO'K MJ*;SJM/C=8*F!=0+CEP DHE_RP"040:UO:=)\7C)#7_)]GSXN[L;[U2-(L9\ MG\*(IAF-$0$(#8&B*,%*9TJJ_WC'>#E3].:M@M8JL%&VT:'=RB^ MZ-$%!-EP=ADLLI+)B]M<6J68_XO^J3.*D5_%TTKU5SD>*7ED-2&F2?GR/3G M=/V_?R5][!B",E/NU.O_=[N5_1. H9P DA M61)%(421C\:X/HM7?-1_4\O6K.;Q5%ZG].A" MA67/WV5461;SJ5T]B6IOW)?UMW)SV):?;DF]VXB7?9,5_ %7^J[CR M]&OY8Y]Q&_ZY0@E.0I3 ',8AR-(H(0'M9M#2D,1!&*J,%^U&=ER+#6+%YN-1 MKOA56V^K3=&=AMFK]SKYYSLLU8:6EEM$;J@Y7V.HU6\G[Q^[_4>GT!,2O4[C MQ$-0)?\N ---.RP#GHYRJZ=XDHVA^F0D_40&(R$?0+,L">( ^#2/88@'&7Z6 M2 UJG05? %I/4TW=7WKUVFZKU#5L,FWP3M=:NNQ]-@&X0/Q>=%&-P'8:9+$0 MMI3>VQRVZ:,!BDG1?F/;^L_7A* ,4A* $&4IYGT#P3X8A6 _53H[VD'XQ>&8 MY^.)A%JK]#5N)6W^3ME N@0>35\VA-^P4@W#MMIEL2"VEN#;*+;KI2R,/XD= MJ[Q\NZ^Z:P/:+NB*AF%":8 !#4D4L21+TCA#".(H\P,_4-K)JQ?!,5([4=Z9 MJOY555QSUG1/CH/NC5-#G;IG3ICVHBT7L&5FXS+(9)A#;?/!,N/+QVI7?N!\ M:U=IS.(XBI(@\Y.49F&.LVR(AV*2FC!&/LKTG!':O$Z<(6P4K-0#CAL7C:$C M8^ DY!G]4:"/NJ?+))!&'F]02-<9:1(]E$TW5OHH;I)KV6%_:,K?JIWX6.JZ M^-EI^)U76Y_K+?\I=U__++??R]_JW?Y;NR(10'/@MS-BB*?:BT MR.)2AVN:#=*]HW;O%X^_*I$BQERV@R3H%M($BBA\XOZ5=Q3N]E3+D_FKDURYX?RPZZ7])]ET7S]L^8C M9I\!F.<)S2$",4A8 @:N.L4R?VS+%6$HAC!,,S^*:4Q@@-*A MFP @0HES,$NIF 7-R01HEFL#AW"V;O^T>!;RWP&@A4S;B%9JN7<,:;4\;6!: MPUF7H&;\Y5D1Y%,"&?1IFD1<6)S$>) 3!K'2M]+.1,R"Z=0]IN5:P!VEK9L_ M*:2%^N4S6JBTC&BE9GN_A%9+TP*@-7QURN?J>[FB ,$X#+,LC5+"PC"*,!CD M!%'HO(Z6$C$'GP-_ CY+M8!#/MLV?UH^3_[1E*['MOFLTFSOF,]*:=K@L[JO MKOB,;SG'1DTX"% 6=)\Q1#C/<$[@L*\"Q#ET"FDU)=.3^NNWLBD+(=(MKQ5; MQ VTW37&5.3N6NJ]\/N1W18AKM>,[Y/DFKD:XMS$8M]L;5*[S=C*G%ZE&?$:?%3G"#Z;8.MPMBJMXZP*ZB[2+2: M0U3:_G>%2_FL],"HZ)HL O^V:\JU\'#SMQTW9--=-%-LK_GS^XW+.1TIWK'Y MM2T?. \@8WF$DC2C&/N,T'30AE@L=2G:M(H]2=M%9,?\"O*=MW&6@?>*$[Y[E: MKK9PKN&P>YJ+=5$"$88$YV&<93C$:=TOSQ5A<_ 'F>8)2'8>BCG$1! M. I+D*]TYO $VVD:_7IN^8^YH)VX"_ MB=?6>X#ST^_Q?7W8[5;_ M'(IM=?M3=!3KM8C>YE6[WM;MH3D[@IF&-(H1Y:(@'S^@) G\Z'@$%^?EY]'B[K?\4+==ZQ4X@H[BOFWWUW^)*BON'P[Z[FN)X9C5=Q46]X)E>V3T_5!R% *0J'LM M17>'3;@TO+M,]56^._=7'?#GMQ]_;8I=6ZQ%!_14AI\& 0,1#2,^8,!!RO^' M##(@]",]J%L*/B'(']_V?:Y9%]VV&D 5US-XKX_HUVU?$)3E')4"L>7&61I\ M;:?W*G"=^*AQ.]]P(=7AX6';W4A5;$_5_%,U$4L3/T,A)2D U/>#G.%!3<#+ M>LTK^JQJF!"YYX+/KH:S<1V?W691)?!\+:(/XM'_J\?MNS^U.?7EVO717;: -5'D]L MOSZ$A5!O5+K4^:W8'YIJ_W-0^A3R?ACY"$8913%.2$8A" =-(4R4;IQQJV3"4OC),4>L MVG'45KS\.J6E2%S'C22'X.6TCQJ3SW0_VJMWE'[(]\9VG)O01FY?0/8T MK;@,AD^4:SW'>Z)8-A]NVO)?!UZRT^_#3=LKR$@8193E<99"C/P,HS /DC % M:19DL5IYK!/ >1D\:/(Z47I77NM9)UG5NG9-L7I5-UI3F?NA2A?]C_*,2YS0Q<3$BB5F<(YCC@*5PB):D2&T92C/&U&P1PKP_ MA#1#ODB;J(<8%_X94D;&NDE(TWNC !M5-Y?)&^4LWD".GBL&U,GK^Z+:K0!$ M*?,9 "PEB4_B!,)HB)=BHO2%L'Z4>GCP$4K_'G+P*D(=-2A MQB!%3Q=+(=4\WN:0EC.:)/JMO+\IFQ41(6*2H3Q+_22-8C^,AU@8)B;5CV2$ MR<=51UUF\)%U3PL\#HPS'5J]Y=D4O#EJD&>-HHV+Y(QJ#I<9H^6(_&)GN2N: MJF9U4ZZ+=@C&!V\I"P'+0NQCP A T.?!8BXBSHC:F;.:(9S/IA]577F#+EW& M:#HHNRCIW#S5Y4=UWQRM+[[DS,651",K%T(:PR2>K0Y:\$2SEOE8[FJ&]&=^1+''5#%\(>XS0N%SJZOJAO[*)%LZMV=^UUV7SY5C1E5K35&N\V M>;45G]<^62\C- S"!/HA"#D!&>=@FARWF24XX668WAXONQHFW'LP"/>X :LEUR?PKK]/=?:O6*Y]]9X&FQU+;P-RTVD((ZSK+5S>' MN715?I_8_7VU[V[HXI'%'@>NJ-RMJ_+%+YY]W___V/O6YL9Q+,N_P@\3,=41 MK@X^P-='@ 1[O9&5ZRYP[@5P 2 (PQB9L05)C$@"$/8@@$DB!E]AF-2F%:OQ =IVV+_ MRUOV)9=S-@U>D&X^Z3W+M!X7/?!Q>;9L2XE3]%!65<:]*,,33L1$I.L*0W.EJT9AV-/K 1- M#L.<&C87N:+Y&1^O:O7L#%.I\@)>DBD,NM>K^0I99%5.''=Y ]IDWVY M'5L^ R&*X\BQ$$H2WPS-"";0'R#XP.5ZBU)JP_,EBV)J*9=E-JE%]%+'O[.B*42-^BAE&I,*V?HQJ++?4?6&<>;,;XU!"7MKU'ZV%Z/ M\6FL-L((N9%K0>3[%D'F00S- 5: ()=N*@4_QXJ88ZTRKGXH=JH?NSV?NR?7367AFC0^7Q5-6=WOR M1T+3R@T3Y+O8PBB)2=.>&^T3=]MS0Q[UG]B4ZB+.>S*3^97\PPU3Q/U!E-E,2P'HHGRYA222_D4ZO/99,-SP(< M:]6#481-A_Q/%-H(^+%E)N,F5&AR74 PM2W%>O6I+.XZN=ID-YQ/74VFD4VH MYF203ZE:9,-#)EIHU3M'$$0\>C6U+8WU:C*-;'HU)X-\>M4BTTJOWN'JC%[)8ED/O9)F M3:FF+_+J55V_J,ON*A'=T SH^]5Q$I$&S##P?-#>B0E#Y)J Z\(#P2:4JU-= MOSJ_(%3M+$H@JT IYXY7E[AI4Z1&QX@Y*T*3F-1%>Z89\49R)'#"K#1YT]_, M2Y>\=ET-8>)$L16&=A"%81@GOI^$=M]49,<1UVJ34 .J56;$9'2@A J.Q:AC M5!C5K''J"R]A:M3E""GGM&4*AYHHRR037NO*=#Y$5:6OVXN "7#B.#ZTXL3! MCANZ<&@L#D.N*U0$FYA?682J@44)%%,7!=Q-UI=%BGV/$\.A,9Q,ZJDRO$:\ MHS-"G+ JS?_=;7*Z8?=U1SYTUY=P.+X/ 8[M!"96C /B[" 9FG(AXEI^%FI ML$F3(FZ'"/EC+9,XE /99EF0BFQ3TU.B3#D/=6:42Y$=.DYSA]2.^R^ENYN[MOVE7I50BPCTV$ M<1!%9#[GN)YECEJ(?:[SE]-;4ZQ0/2*C;B%-$20A*D5T236+D^3I^<(8*.WP M770[6TO*U!'"F-5J"MDZBM8D>\YJUW2F!!XM;LKUG^@YVJ9UO[R=A*$91%9H MD?3-@2!PS "V&VEA!&W7AH)O%'.WH[J\\?!A7 J.WD#3PA-\E6T*I6PB-A>; M?/(U@4C5+PF_9NF,9LG@5@^UDF+)Z6>!)[+#JE!7:46+OLN'Q[1X[J>800@B MRXH#G+@)QF84@RCN6TH<+W)63UEU4[)JDT@+/*/H$ SS8.I &3VJA99'CC!S M9N1,X5&/$3/)@E)>K^*,X_)G4DN(XWF$R]J#$WCR<1B9C_)Z-1[X(SDVAFKA]CIUSD5L* MJWHHD21;7D=OB0PQ7T7PLJE^ZXED" F9O! Y1+%#\H40VFT:B'WDRTX?7I?@F,\-S^3O>UR6QD MV("*'0LCG, $ M<'V#7#OIV8/E^?\,T.^+]?^=R@@]3/L04O>N)GC4U3U-+% MIR=\/"F[9?T%'6=T1)PZ/31D OXCUZ%/88)9.^CB1;^4L=\L\@(41%Z$(F F MO@,01JX[M&6;'M\M:"+"F1E..$7-. M5R81J8FV3+/AM;Y(8(1Y_9)X/JNJ;-.VUCZ24U_6]2[;K )H^1"Z&&. /-/! MH8_\H4'/AS;G,J9X0\HS%HJCO56&#)_' :=14Z 71MU"G7EE\R19YQ8XIS.L MQVB28VKWNELD1EY"\W8$6S&>@3'.W]0P#[K#&-9XGGG("-:8X3; MI1 71N^0RP.'1.\[1-%$A9O5LU,9=3[20T*56OAF.J2:3;%DYE/^SUV^:<\5 M=+_("'6K,' 0".(XB5$0AJ9GQU8PM(S-B$MD9;2G6%0/0/6I#45E/&95E]CP MZ:H4@MET=&YN^73SC58>\KQ'R/"8[ SYXU'RF!/):=3K(8=2+3J;6LI@BWUG MG338R6N\J_+BCO2VO-QTLOLY^][^JEY9B>E%<>R:;@#=,#)],I$<&G> :_+- MXR0U.NNGDX0=I?+VG?B.3Z6"6T!>KKDL@<(P6#V=5DQA+Y[5).4&<^PCS M9^8E.*]?)D+O))M*!K*K5L MZ=Z,K/*)["1"E61XYZDZD]M)XEB/K$Z6,:62?LB1R7W*2!L9;8ZT"JN*=+[V M/$[]$DI]6>1-GFZOL^KARRV]%Z!*U\T*80NXOAMC$[N^DT1.A,P!4&PG@#GO M4PM#]89K"][8=NB-] #^A5&.(WC;6G!AY)T-1GO!?KN2UYG!D3TI]AI#'JJ/ MP_@$M?=5#]R +WSU2FW)3WKXQG7OJT@[7W'DQ?KX3"R+5NT[MLQ[$HNG\O1Y M7*-!5C^3H>7LW9[SHB[:(BPV7^D@V.(?CUE19ROLAU;LVTX4A:$?!Y:/G7AH MRPDLKI/Q8BTHCI04C)%U6#BOXQ(CC"W]5\_5I*R?:%E+''Z'.#6W;1WCYDR: M/XU+/;+[B3:\ODE+ B/\.U*7Q;I\R%!V6U99]^?K]$=,_E,W^9J@2?,*4>0EGF-Y@94$ MD8E]%$?8&1#!,.2Z %\ECAEE_N":H;W"$/Q#YF7\TIOP%U'A5^ F7M%?UD/B M@L_N'(W$GIML)J%7YT+=1%ZAI2<%7C6[_.*.;V^S=9,_[>/-U[3)OF:4SGR; MMZMHKR E00A]RPR@8_I)$H< (6N E,184-T5 )E1WD?TA^I!#3!>6B J[BK< MQ*ON"WM(7-Y9G:.1N/-SS:3N"EVHF[RK-/6DOBOGEU_@X_X\&<'2[?F2><2G M/+TA<)KA<<\]&C] "'M!$"6V9?NQ#5S7'-#88<)W@:HB##/*^@"\58R^/H). M_0_ BRJZ9+_PBOER+A'7<09O:"3A7 PSJ;<:G^DFW(JL/*G9*EGEE^N_%Q6) M%G=%_J\643\IJ+^6VVU25M_3:O,*D NQ;T.8H 0&?N+'P$G< 5!LQY&88DN' M,:-H'V)OI6) ;U#X1H]?5+?E.XA7NA?UC;AZL[E%(P'GY9E)PY4Y3S<95V?H M2257S*U([GW37!9U4[452?6^8=OV$8)V9(=!X",_MN6)%*UX\BQ*+'^>/ .GXJ+ZDD[C *E&0GJ*0\:D=Z(#=!/& MZ0:=266E<,56W4UZ'JUG>]7F94%Z8U8W=-WCM=K&GA-C:,/0M-S"^#UT1'[JS&8T*U.EEAO=QM:"IEOR&?RVWS=PKQHCT^0#]QF:;-K+R%:DQ22_*,JW1I5]L]= M7O7?2E>?RN8^J\B7$80/W39"D:VSNDZK9Z,IC=2X3?.*WI97#SS\U;B^)W\C M #.C!?X":7.?-@1^?I<7Z7;[/#2X(7]X3)_I9XP'6I=$/E<8S?=L^Y21'Q3- M/8%SVU HXU4NE7%7911W_^'[S"@HRNW!T9'U\[H3)OI;2D/S3*CI:,VJO_*> M]3]5V<[;"T]6LROKSCI4L*LSKIQ%$D0G2I_R@NZ.DUZ>-TFZ'I;>]B5./H@! M1%X0A;$76GY@VD/['NEK@O.EJ:W.F35D#?V&MEBEQ2LZV41!9KNTBRXY)E[(C9(86\CFOY935+,_H%;J8\W 0 M#U@OC!9MFYV->)>^M.@\D4R#5Y(O=!N[LLPZ.72E\L:T.()V^9;.+.KTH+7^ MGA OC&T<0-_SG!"8-H96: W-619FNK)C\;X4S-9&7QI,&>58D8IN1]Q2/4_\BK;9G5- MG^';%?T24/WMN:;7HO3-(B=TG20) RMQL!\ UT_B,4*X,=/T4UICBJ5[@&B\ MQ&CT($442 K%#%(^-[M\DJXKL1P2/S?!8E(_F6@VR6<@XY3TR^11@Q @U9Q2 M47\3N$3COMQN+A\>J_*I6YH?6@P=U[=<'R5!$%C PP=!"&";Z_S+E'84!X(1 MFG&(3? )YDE\LBTYSD4EYR:C((OJ+MPX3M&9!0@9Q.JQYB#%DF-7<$AAA^,1 M^,<=&=#?RMOF>TI/BC>DQ]$'T]KZY;[M,$FPC9TX<((D?#1"[8QC+O3?_ M/G-GA$TN\WI(G&2;WKY5+YTQCC=PZ5;UFN: E\555=Z13CLHK>>$B#011G$8 MF)83.BB$>Z6-.=5N0D.J1>X &ZUI&= )"]T43EGU;28Z>65-E$E53]*>9.FL MA$D@5Q?EDF'*V]=D9?'#_FSLB=VFOU5E7:]0'(,0(^@$-H0AKIL?U M9L_$IA1KU8"N77'/!FB\3\1.(Y--HF;DD4^DSNYH7Q@MO+G?@CU'U1FEDL2Q M'EHERY@WC[]*Y(A5K^!ZO7O8T?+639P]5MFZNZ: _'F;T3\0'/"AK)K\7_T[ MM"TE6MV@9L-&],0#KLA_,8,YN%\ M8(ZQ.;"G'=?I@2%\(CF?!]GD5"^O"0GOH:<.;;@P1BM:IQW:%8"@.U'R/412D#H]DU:./)# M*>DO2T.+)+\71I')RH"9V)R8_\HF4FKV^_D,E?/FO@2)2.;+PZX>TB?'%-:L MEY^?R1+U]SJ[W6T_Y;?9R@2)F4" />B988AB#X"Q9=>-([Z*:ADM\HPTH6+J M#HNQS9]X[[620NA$L5+$I%3-ZAFF(#71KCUK(A(FP+GF2B9B$:N@";/%O$?2 M[8$>/O'6+1T$/D:NY?D0(A#G-LA/7DOWH)<9(7Q%#GG=D&F\JF')DTWX_7NAQQ>1-2G M[I[&0NF6'D7_=I]E30< /?^6_D]915LR/M],9+L:U "$%C9=X":1[838M3&] M::]#!WQ36*Q48II3V^I1V]*#92KQ]X 1&T9[#S?II_"Q6GPD)\['.&D&&*RBBLF[J M@X*^%4V0XR2*+-/U, R]R$/)T%R, =>]U,*-S%C .-Q5PR?DXO2Q*?,LS/%) M[7A/4XO). UKUZ>HN:, $YF4P]%FVY&*;F7\6G.88PEB7$) M%UFCK&&00!Z=X?IBQ=IRB$7LE50^FMCT1!E#?!JR7)9UV/(9I1#B20]U$(-> M2N@G'&> X6:3T^].MX\RY04QM7/_.6N^E]6?OY6$N:*?;ZW\ M$,( @A#9B9>$D6N:T;"3:CEFP#1EG0F*8J79&_"RQ(5+=.;RRGF9TM AG%4L M>U^\" ##LW9Y8>SQ&]0 H[? >&&"7D[C.+"LE_/$CC._,Z",@UOUT]I(R=_K MW;:A]R&EF__9U4U_JV1I[ YV]^BOB][58W5"^Y5KNNY /GU#O_EQFZ[;VO^?AD+B_3CQ=/=ES1\+IS%U"@Y/9,QI;+C+L^%+]ZRHM MZEL2TV"Q^9953_DZ+^Z^W"9YD18$Y+9;_=C?Z8:"*(!A[,&(9!:.F5B1W[T/ M@'S?M?D6HF6WK3B,CW#;'>P1,-6-$?*P@OD'][W(RAS"-N]8TA=\$5RZ&Y1, M8SCY/#/34>49/29#RJPKY^G?$[8#DQV]2ONWO,@?=@]7W3W6]6>"@+[.0M!= MMQ=9_];>8[U*/,?S$L_S'<^W?2?!%HA:/-#Q0^ &PAN 4E',NN5W8=RVV(V' M#KS1WP5>TY)2,NRKSH"7%X)/V :4ZR^!C;_%7#5MJZ^#;?2XC:O12Q2ZT6,W M.O#&;^>]I'YCCX=DUJT\)8[30[]GL//<=IU"9N5I>KS++HL>T']G:77]O5Q! MFZ3L04B2=]_!#H(.A,Z Q0IC\8(.:0BTU/)G IX(>BE;QH5<)$O"57M'D7P3 MV'099!!PBIRH^&G7+*3=1]B=I-M3O/51-'N2C=QZ/9U1A5I-.FNVBDG80 ZT M3,]V?+-YB55VBW=03-*=W+..YHH-\4H5;BY'/91=9O/R,FR+<"I0M7. MG[)59-M!X+A>$D(KB"W?"P :P"2NPU7@K B"QJI-X"M7;28O*5-MV0Z:4[7/ M>4<7U288Y:HVC\,^K&IS&3E=M?DY5:/:D+ZS.R(B67\0>[;C.#!R$MN/8XC' M[#\)8G72S8=#%_W>$(T8Y+M[L7@6$>=TF@HE5^>O>>2\\]:'$/475$M3=C$' M?D1Y%[1TDL9/85>JT*\2'X=V'":Q;SL(!N3_>6.0\>(82Y?T=UO40[RI=BO0 MZ/?YEJC&4JE6HKM4=C74UJDJRDS\!])+=IM$E)&3,7D:.!S!O"S6V]TFVUP6 MPV]6KNE@+_##,(A,V\0P#F,X0"(BS75_N5(@>BCFQ7B4F_RALX%F5,.O98OI M%,?)TMB9?*8HY1T/E%\>N.OJ/7&6&5S;\> M&BK=JE)MK^4X]Y^D:\(L77FH*M)-V[<;^[>!;. $3A3Y(4+(=+W0Q;'?MX9C M@H'Y0/^$-A0KWXC,.( F\@SU%!K/*]N<#/(IF1;D<9R$GXE$L2/N1\F<>(#\ MM,%'%%P611H<^99A12FWX_#EJJ>B 'IN[Z/+;_MWP+_F5"B.B# MDP!ZEI_$)K1#U$-)@@@X/(FK$@"*M?Q<,D7Q<2:N:GS EL4N3C]?(!!G7DD6 M*\+>F916J3/TR&_5FEC.V+DY5X%?-7@4VG-B%P+6S9". $ M#Q!"&_*5I\EL>!E=?;XP7EIA_-'AY7U_5ZH/&!=PEZ)?BJX*,*]F;9:#Q7-K ML2JNJC'M]5JK.OXFY:O/G\OFJLH?TNH9945& .;DCWW>'-E19(6NB3T? MAZ;MVCX*!AQ$V[D*QN2WOIBB$M!&C]HX@"WXM+D"MTS(7V?SB"R1%7;&?%GM M.4YY4UHI_M%#=Q7:QY+,2F1RF@)_RHOLLLD>2/[LX=CU;-_W C>R462[P!I; M=2*NZX2FMK60NAI_4(A&BU&*D'*P.T4VU1 K1R39.)U1#T>RN-6/GV:=M4[ M&B9E$V6):2_JM_0'+1%(=L4F+^X^Y0]YLW(2'YB!Y<=FC)($1J83Q5TSD6M" MMIL8A+]D]&"XM@W$>*+8;=)-55\VK,(2QS;2JK9$MM/XF.-;3_I MB*6G-I*FD*+!#M(D^*6DSL&7 7YI[K.JN]4RVE45Z3 K/W)BTT9Q9'H0^V2B M'UC]HFD$ $BX2O@%OEZQ>K:(C'4'IG\.CB^M$Z&,+9-3S!:?@'9$#<]9]GCF M3=;>\G$F/YM GAXIV10#2FD=B4\^X'I=[HJFODJ?:=8'BPWY2;7+-I](%IAO MVQV: 4&0N-"S FP[( @LVPM\! 8!==FB- M[1[NO$.+@\ S8TZ%&_08C$HL*]5W8H'H?Z0UB+"'?=.T0\]$,,0(N_O6;)<_ M!1!H8]8\@&4_X=M(=X;2#.;-LW',)]"'9![ M@&S!1S[.$G5&L.00K(=L2;*E5-$%>5\]OA7X<8=.) X(A=)T$(J>[WC(DJNKR'?F5V:YB>:. C/4A M(MX74R52S"9F2['+)VT#2H/ ')=F1J1&RWO$Q+NB1UF923PC>RIICRIMMZ^,17FGR"P$M"WT6^XT8>F?/: M,;0&8%8 N>J\9H"C6$['45_Q9X)S.$-089?U@P3AI7\>?]&;<&$,1K3)_&#& MQ?Z#7V>?*D]GGD>MU;E54Q%7:/![VJZ::[62OPIM+P0AAL#&=NS P/4A'../ M94;J9?Y="(JE_858I#VH.13^?>Y5JKI4VN=5\H\@W=+EFME?'UFBV8V4(LN< MG$Z1XHC\/6]>YOX>1"#P,4[B,#*!CX&;@*%UUW&G+4T(MJEZU34C_2[=ML.Y M;M(F,QHR[MVN7^=/,_N[HY>P7&(GY1 MF4HI<JK.M50++3"#F!E2#@!Y;K^?8X?8P#TUTU);U+56RT ML#7!)2HC&OXA0Z=I:3]D[BBRB4K#2*"@TLCG3H+2_.TL;?,H38N!1VGXF-14 M:3B->$]I1#@15AI:6],>((/;;?D])02LD(4"$P(A[:R* M["YMR'=,2&D$FF4:3F$WG-X@9!Y:(S C'9 M/*;>4L4SP"80K>EHFV+1>T-O M,EO"X_!SUJQ"'"'+#1/;#WP_":($QN.,Q8NA-2G>LS2P1+0OLJE+.4S4"49Z MV:Q)B/,$4G=%^"!44!.A(L!XE(F'6DVEB,N$][2'GP^FNQ,.VCDX _"WLMQ\ MS[>DMVTNBX;TN9P>3VIQ7!:;[#8O\B;[E#]E;WZ] G8<>*%OH.B^(^CMH@I(>&&,,UK3+ MU7O O=H:>XN,UJ2W']':R1RW56CM;+&K+N #/7Q)@^7F,/,83@(^&VG35/G- MKFD/[38E_6WWQ^SAL:SHE6Z;_);\RXR$A]J@ <'(]QUBVW:(?-\ANI3&*-OS M<\U]6AAW/7U_G7C!AFSG'(G3RW8"#:[V6,[V4H=A*#Q_.8!Y596/6=4\7Q&@ M#2PV^)^[_/&A/=P,78A6Y";#\<34CM(%H':"4MA6G!0.P-L)D RKA M.8\^7Q@#6O(GBK?U G[7"ZIG3"QTLDVFI#I&NWF67.M.3\$4 ML#A-2@?%A\<4_Y7$6P0,##S?,ST, 49N' JW69D,O97J MDRD*O)0[9&DR^R1J1AWF()5;F54X3&>M5F(ODWJK8WJ:GG?E ZY)0DAD)P$T MDP C .SQ;(X?H#B9KM1L[6A=*\3/VA0ME4^8+)5C?V_! DV"4M(HB&)A,_L$4V&84:4KS9>$W_ MR?&%/^XKP*81RJ=.RKF4)4\+UAL=XXA!GR91JY= 33/EA$))X&=:DK3R0S*[ M]CPSH646.$%1"(9B"Q^[0218 <'3A&)9HKOWYX5.B !(!JGCV85.^?R[)[6!-T0]>XC@$5R%G@GH[/UT":JN0MHEB MV].G1FM?FOV>U J2I)'2BEIP3&@GL<&DL_^X)_;5Z3;KG=^WM3*!#T,3>SB( M$$"V:0PV+2E-*\:]*,P M-,/(#6S/]]W01Q[VA@8!9+O[5$(SBB6W!]>>:>A.G;W2$QX)GD@H@Q#/QR6? M'+]+XWPLR$86XN]A.L*%-$V%%< =86)S$*M9%_E!#5G MME.FDJG'+LID*TJY78SS+=_AG:>N4(^^]K3R?3,VD>DX49*0^6I,DZR^)2=Q M(ZX!(_+]B@?+_N6SO,4T\PNT;PDY,T2FT*?'\)ADP>M79R>SP?7$]>>R*%^V MV%\1O$*V[0';"A .3.389A"/8]'!IF=QOW0MWI3BZ[EYI,TG1M"R^-:4ZS_ORRVAJT9IG:]7KIU@Q[,MRP(H@GZ21/8P MY(#E^$!X.$AH>[8!\^8^LG6+V*@/("\XJ-ZGDG78272*A@-3IG7GAJYT%KDF M7*3)QRJ[)P$S?\KVH C"+[?7Z8^KK,I+>J*PRM(ZB[/NO_"F;JITW:Q\@("/ M_9CDJJ85^8EGQ]$ #'HFU]MT,\"99>*V/C1AG,9MB17='(X>,6G2'WRU[7/X MZOS6CZ9NXMLBZCST KUQV7OH4^>A_A 0+:#_8T#\_Q:8=T^B^+VY^3S^TT/4 MYS3XV!Q_3JYE2'], #V1Z=135O_7+MWFM\]T5ZG^/]GF+AM1KT+H@P0X3@@L M *&)TR!L., M \M:+Q_89NR-TS,LB3M),%;-T"OT#V!SD, 1U6;SB8Q0-R[7$=3?VA)IHL7M M8>LC\&S@>@%.DMB-'"V.TCUD\?A",4DIF1G93O[O:4L3$U<>6(F=F#'-G:$IW(CB!&W 93S2(U04V;S# M[!0O9X;69"KU&$[3S2@E=[%IPZ:K7B"1$5G(<\CL+ Y"G" 0#>7BP+9MII=& MI[6@>,"T()8=(^_5[4SC3<_1P6G#.T-#A!'1<1'GVUV3;5:6Y^ H"EQ@NQ$( MW3B!/AA:PS[F>DY/M W%8Z.'L>SHZ$%PC ]>]O0<(=Q6O#-&Q%AA'27_R/*[ M>_+U\"FKTKOL\^[A)JN^W+8MUU]V3=VDQ8; :4?J&,FB$$26GV#@N2AQ/==R MS''$>C!T><:0&@2*1]@ VD@[U%W*5AOE'B_?FI@B/[ M@"WO K[5KI']'K#1 M(::+5AUFXP#TA='"7JRP3(C<,ZJIUEEZ:*IB&\LYN[]"/5X!W\61&830@R!* MK"0!R8C!]RRNK0ZY+?]\V3\7/[+&+S//'W#)W,MM8C=KIU;&-6$HNL MH_:R+PJ^2O,-O6O$ CZ(71*,= M$[E@E8^H"[?M11F;O-F1#G79/12S0;OF<]G\=]8*V I[5F23E,?%=N1 'T,' MP:%Y)X9<6W?2&E4O->T1/",OC'2][A(4(CKM:?[;LC(>R3^\)Q^H:0;S6-'; M1YKGMOHP^^P*=8BGN#3L1ZB<8C1&$ :-[O&(#"-YZS+B^;5 M-U;ZSJB>= _HH87RS2H5]USNZ[/6:7W_I;I*JZ;_"UR305_GM#X]R7^0667[ MJ&#[4X+*6EF1AZ$?N#:GU+1OF(U_42E=&-\)V"V65T; MFZR]7;,[M]0_5D<[$E';)R*<9?5,;TPYKJKCM+'*B.L+S@Q0B?/8!'=IO_%I M;P^0R(5!\1K#WP\07Q@MYO[E5&- /?L]:KRLGI%DE3[20YV56OCV5C;%;$K2 M[#B[:0B0W0-%X/LP-F-D ].)[-@T(TP:'K+MT.*:0\ML5W7&2W#05XZIM-;W M9=7\2K[D@4CU3=,FO+=Y07Y-#[F?3'CW2;%44>;SCA0Q5N88!2),L1H]6*VT M]Y!$<4? 5@$ <^"!(/Q:[C M1430_5'1+;X]C:EM*=;0/A-*^VAF[(H-/;'23V.W[8)"N8PV7D5R^5::)3#/3BC1S:O$Q^R>H>C([% M*K4:/&8ES9120=?C#P%XFS^0&2_M2N7MF_;_7J0/9(I,2U7BO&ZWAZZ(7N:[ M![I?%[LP!MCQ/"\D\)(L(\_ M$.KBQ6FQ,GOIS>8^8QR9Q^+I[I'\8A]/*2I)$74"V>\$W3G[NOO^RJ[[@>(5\S_-MU[8""X8.?4_,'/%ZML,=(I9!J3C M[(UJ#W@,!935B+LK]SG((/?OM1\<63=NTBV-4P+:N9#SV4.8_GX7"X O73]8 M9GQ]Y7KXTO7#H_*C?49OX+CG?<55\;\\TP)!6/\N,2V$UR^Z!ET+.A"$8:@; MW_/F_D 9),TCE7#[3D*PK#_U22<6YN%(,J*#9[A6H]NKCLM;6LY!< P')=MA M2"] Q&1RC&/H.S8M[D!)'*!@3*)"CW_%>6)[ZD]G# ?!;K(BN\V;+JBTL]?J M%5Z!]<:I;'.L",](M."J[WC+=EMH]AKDQ=EKF=51++!L.R/5T^)D_K9[IR1- M(CV[WFV;8;66QL_]%>CT)T>[OZQUV//LO;?6*HE[?6*:-(N.K9E*94M2C?3O MZ7:7?;E]7:\-0 0MTXN=Q/82)XY-US4'+&&$N*K[U"!0'(OHY?3IJ[J_O#!^ MRYJJO(J^&3>[.B_HH118B*;>2KNI;"**MN?UO?9YO=EK1W66Q( MLE#D3?8I?\HVER3_*.YR,F'I@%RW[TMG/QI$B/MS%;GT,AMH(A/$<8!],D4) MHP !U_8MVW2Y;C%7A4'U,F4/N[VH\9'$W&KW8'S*UUG!?89%F1?8U%@'!_#I M\2'W>\R_MJ"-/>I!B?]H@1L4N=%"G_G63$&"SZBR:I?IHA0,01X%KQH$#L15[P8 D#&RN.S15M#^C)G>[ F_$0%29)?J 5Y67H5]< MD9./HL;,Q#(IL7PWZ:;""BP\J<"JV&1:.<>75\/#7=W*":PJ J%=]/\MH[<] MKD(SC-S M7S'=#U@!@@[-HY<.XAPY,<1TQVHLMI278=]>66\A&@<8#3^Z%"> M'L5J^&58)Y^96C[%U)-5CJ7QF=D56Q:?RC+;.O?[5)Q:XY9(H@;KVS*M*=5T M-8XH\%OZ(W_8/22[MI[H4_Z0-U>TX+@L-KN,5AKD15EDSUE:K7P3!6X,,32Q M'=J^&?LX'%I/')_ICB;9;2J."CU2HX=JM%B-7XT>KD'P&AU@@R V*&0.+9/) M/4.D6(AVOHCQ<1CGB"(+,2\6361Z@"VRL--S*L(H(%B#2*/"JE)MMYP6>1[' MUOMVRXJ>O""1S[,Q1JYK)['CF!Y, ++P&/E"Q%Y4++75A:+/X\%('(8@W;;K M4$^3PPDN$ M!\[ O)PAI2ORT2#2/ ^3&(D%'"(>CDQQQ!*3I/.L9DB38]4Y0 MDL4;0>Q%A2'FVXS M(17801 DC&V/0#U7?,&AHZD#=&'L(MOR<@(J1II!U"\(_)AC@/K(H!OZ?5YIK\ M$_@CKU>6:UI!XEB.YR2VY=INXL9Q8$4F#B$F$L4C%WS?K%@K6C &16/\0?$P M;@4)LL0F#^H(XM,&=FZ4:,,+&LX(@QA=>JB"(/921H?A+)2B#RXB^DI$5#X\ M9D7]>HNH1L_[S_0G[EI@>W3%YHITL,_I0Q:7#VE>K#S']KPX01X$L>,1L0*F M/T"-@XCKX:)% ,ZH3ATB3GU:QFML,J>]PSA+#?ZYRYMGHW/9N]Y24W2E@-%S M55E+.E /_5Z6@M=U7EQEXI,7( M25P(0@!C&+D 6D.;5FAS'5F;UI)B?=^#,UIT1@O/^(4 K/_"69TDB5HV[9Z/ M53X1GDBH$E4^R]49>97#L1XZ*A-*]P9YWQK -B! M[WDA]&T$/!0G2=\:B@*;*Y45;4.Q6AW >CFZKB;(E3"?;$(U!Y5\$O6"Q1;2 M0KIT@IHSBC253#VT:+(5I=PNQE&RDF@HF1 M[\ 1!Z71PCI0D[9Q#-/$$1Z'+PAX1*W=1 MX1FVFA=^NDY5OB@D7H/Z%Y76E?-T7XYX!TE'<;X\%/G-CKXJ1?IS_I31!8J^ M28R=V',#;-NAZUBF;X?AL#B!7#]F>@E42D.*(QE%9_3PC!&?00&*2.-D6ADB MTIR,\H4?W'+"]>38./]>;U&U% M7AB=5>T-2IWW]X9IMCW)ZYY/*^H >BUP+VL^[*ZG8$W-'HJZ:7949=Q3@ M,J&)WY?S1BBE;M0@4+WH#G\[VP^TCEBO_31#X!+N&C]7_!*G05$8F^@7Y=&L M_3^_9S5]*?(JJ_)R8ZU@9)D.";2>A>B!%&R'T!QWLGQGG@@F FR6\LRG#I/Q MV(*:*5 )N4EQ<%+MH=D#4N??WB+CZKQ_]0I 1WRA(NA,:9("D.(D>>RJFR;=IT#V?6=)>M5Z?U 7B^,#.7\]@" MC(9^XPLM@P%&;X%Q*M:T;^\8Z/ %I!>AJ#=EWI@BA_XST61F_^H11^8VNEQT M3''&CA_KK*Y?MGX<89(7:;$FP0RNF_RI.]]J)4Y@(D"K"$R L8VPUV\\02L$ M'MMS2C^+#S41^'EL?:WK,S+,M;947Z7Y)BDK NT?>7-_7V[I=4GD!\?1 MK3P23)PX=$,26SS@D&CBP &*$WK)ZBFK;DJN5239$'@TXQ M[R['(X'=KFA3 M ?^^1][^K*:?,:8F_&I5G_30;+4F'EO$49KMA6#D)QFDU@#B)]L!!#'W/MM/GE(^GM HV1TG6XF9,Z47[/2()R ME^DA"^K-?'U$;!Y>I:[E?BX+NK.5=6O,]779I-O#WT=EW7PNF__.Z NXY5W1 MEN9$";*B$+LPB:&?A'[BV,F UPX]KFOEED.I6&#^7E0CEI,+O&22?WYM4#?/ M2ES[7=RIRI:#1\NZO<7ZXN5Z,#6,?*8QGK/V(??>-@W7AT5<-'7)6&FWT",R M:<"#R,+R#)Y9/+9UVZLD5/<_HI^S5HX7!HF'8M\$/HX=)P"6.1B!,>?BM%[0 M%4?!?V3YW3VQX]?T*:O2NZROGVGGV]4>IR;Q3]#["P=%]8[7+%)>]%4Z;2_Z MRM"+/E8$/>K/)<+JM([UD\?:B>3,%8!E^%!Y.6IWJ^)E4=.7W^D4NKW^^/H^ M+;X\TJ^H?V_-OBPZ:UK#DS2O?D^WNVP5!29P$P?';N)A-T">FZ#!F,C'\Q2N MJC5!]6(816/<$CC&$\7S>LG+Z+K=3%6OBGN#XOI8?3K"[)6T_>6H![;W3X3G*RB1'>>7J='2->=)%EEOW/Z=/D0 M/R8W7\OMEN0K]!^M'!@$B>4G9H1,)W3\ -EX,,(U74U"NQ!TQ2&=WG_67>E$ M_MMM6OY%E_@MYNJEX[9R+^L:KT?#CQS>_(.28?1LZ'81NE17+Q*U)_6YGSU: M3R-GMB@MP8<:1>=. 5; B;TH=N,XCBS7!B&TO6# 'X>>L^K6>;\U:=5H$YX9 ML?-H]FLSF>7[0%11=I<715[<:1>?69VM36A6X.$/$Y5_NN#;F;5LW.7L4/\V M(9>7E_FCK9#GE@^T[741]3"G7T6^FT3ME1%>0NR(33ORQCS!"IGN/M4.M.*I M;XM&G]5J7H\N'4P5.E/76-J9O%^1_EE"Z4M7+A))!7O3SQY(16F9+8Y.\MOR M8?3ETO@*^!!C$(1Q@@$$L8W1OL+:BF-K561W;= +\QDUF, M?]=X!_A]]RX=4U6X5/.8^GJ7]V>)J2]=J<%>+G-O^MECJB@M"^W7EXZLB MWVH>8D>K?[XH^\:ABP1:\6[UL\?:"F_YB/MZ,=NSS CX5H@M",(P M!M#UX[%L&^*DWW7%Q6;I8,N+G'_/=3!29,>5_-MSVZT?3"MUW#!C]??/KI/" MO"RV8<;G.8TTD W.B1=ULMOU+L!U7_^E6FRNU,2T^/EN]'NDZA#I*"XUW5 M>-55C3_@#?G*=-W\?-6N/+UCV2Q#23_^M\E%U+ W?\:BL!=\I+QF%;HN]F)D M.@"8B6]9+HC'Z^5"UPFT+,:=;M;_UNE*["(?)T61VB]^FKSDWR\9T3P#8>ZF M_YMV\%.F8:[!Z>_E$XR7%5[OV^?1E2$81*[E ]MRH8/\(8&R?0!L/99,9%OU M[URK+*%/+)U6+-D==,TM7E<[_[NE&)Q]0H.R:7G]]F=/-I3QME#AM6S/+Y]V MO"R"8TBK4)AXR/8]"+PDBI$7)\-5978"+*Q'VB';*L5IA\[5W!*ZQ-)9QY*] M0=>LX^VM7_]>60=GG]"@L%Q>O_W9LPYEO"U4FB[;\\MG'7TMX(Y(X?O&XWH!7L6_[)JZ25OQ>&77O+MU>9]5#O0I@C$S@^;;M)R16A1"[XRS8=T-'CXFB"LL4SQ3SI$; MXX T!'(0/0GD23CTM.!GR"[V_6QDH5NX/C@LL$ BL8C#W\L:].Z%&J4(FA-U M+!_0'#)7\/^-9!H/NX=/&0'ZXDR? M"3 SN$^/ #&'H>7L0T.Y0%]_+RF@>I4 #X8H!%Z $I=$#YC@8$"4.-!7K-#, M.-1+M*]0:2_M^B)3)=&BU][B1Z(EJO1W.[[L"+-;^ETE19D M5Z5,DUZ<]9A,%UH>\!!*@.6$+D30'3"%/E*=2G,@42_5@7JIYB!>G5BKX7Q& MN:8&?!3!'LF6+-G\3ORXHBU@JP39%F58H7 G9#CUD%S@F]#QG)#$$-OTL ?@ M (G,!$S%NLT.1+ULA\IEFX-V9:JMAO'Y1)OB_R":/5(M5[+Y/?AA%5O U.F" M+FU M$L9GU&N"_Z/H]4"U9+WF]N#'U6M^4R7HM2"_2O3Z^CZKLO26*-HJBFWL)*$- M_00&86@Y 1Y7T[$#7&52S8%!L4KOD2C4:A[*%OAR//"R")I>PRQ&Z!PQ. D,%0FON^VK%IRRR;= M*E3;]YE5H+%2256NK!JKJ2P-97;(!U1.=MNFZ"4G@ZPJ">LZ:^KA>8V596+2 M K8L/P[#Q')L+P11"+PH\A/L6QZ/#')^M>J2\18-G]#QDL.F9 IYX9.J#LAB MCZN\Y.&,T@@2IH>4B((OI70:$3&(=E5%BWB'MA(7>R T04PFRB!T4!R':&C+ M<9V87Q-X6U L#3T<(Q66"&[*>)1")5LB@G%A#(0MJQRO>'E70$1YU$E'A&TX M*B?3&&%5E2BM[V&QH?^A9P*>2(9#$AW81&E5/>?%77^Y71Q!9"-DVK83^I&' M0I+?]&VC,.12&3DMJE8=@JY]LF]-_Y#M<K;UL#]FT4XY5;#M>X%@)?6P4H- +L&.-PS[ G&=2!1I0/-):3+_2 MJRJ,?(^*]ZBH"'%L85XY9WQ1_H"N2P:Z%!US?$O)&1&:Q* >FC/-A#>']B;S MP3QG6*_+'?GZK]DZ(UIVL\T^9TV?6*S\V$V Y2/;MI'IA8E-$HRAR0BYYNHI MJVY*YLG#E*9XQLLA*O;DN$=G5".\"Z/(&L[YQ"0Z&:<5<_'(.;L8"/QZ0"!! M-LXW9IYDG&'IW%Q#!KEZ2)(<4U[//.3QPRI1G\LFJTG&]:E,B^/MVK$?.9Z% MD(N "3!T@>4.[28AX'J9?'IKBM,AFG0^MIH.:-,4\G40X\F6U'*[6)\VD,G MFP6A[YFHW"H!&%DQP'[L^Q#Z F2W&9&7S77ZH]M>^I2G-T1W M&C)4#O(>#SJVAQ(+ A^1YF+?07AH'(0FUY/&DII4+!D#2J-)?_2;S *S*UGT M,B8G\S/+F:L,I!*$QK QO=RLBHVO$B*(_5R]"R<#K(+PM[+)!T>]P197*0OSERK.80861UET_L&SLV&[DVE$$QPTM%/ ]5J,6R0S+)CUX^AQU?0!:8"ZDV"GL MBR]Z^(-_M>; %72/"FZ>4C):C:;<+_W2,TLOO+0WYJ+]1ZT]QF#0_*L^PMR_ MLTRDWJ=Z*.],MAY9B)J+X?UN'&/YL23Z/NO,#.QAJO;AX0]G5>PC;ENKU$ MO[U\?WGB7L!11^"KT$'-:P."9??AX)S!1U1>"C_+BK<<$TJ)_456+=9G8G@_ M/P^B.+)]'S@>3&R2QP,_&;,[22FJ1 M%H\#V#+DV;GG$W2>4JT]8%VJM?:(A JV!#R@1]HJUR3FLBUAOOCV$U:>&R.0 MV*%C.= S8S,QS7$5PPT2DW\CX=VOG&4'07SGX'U*>+8,I+(ALE>PQ!;!NWL# MS*SHH0&\H(_N!G#:S#J.#_8@B9!\:\KUG_?EEA!2=R]BC:=M<63'#@2A$P9! M0%(M,X3[70@OX;KO35JCBC.= YQMQ#U$^I_]JWQ\&B&/;C85681I/IUY37+_ MV.%2I_59&3LC4M))UT/&Y)M5*NZLPE+X^JJ!P ^!;R// 0'V+ _&MCL>1B39 M%184/]YF%,O=<%'&=H]06-VX&>36,Y7D"2O8\K>-G&:(3;%$:=5.HX0-.:U* MT[CA.!1S7;XI@L$&(S<$PXIG^1AR'GD1B!%F92G\?TN5M :LHI M9V%$*&33(/7L\'O^93(C[.7O-V/% M:6@BV_21Z_D1L)$+'!0Y0PMFB"*^&G?V[U4L* 2;/1>' MKF>-9>>NEW ]O2+8A&(]&,]@5!TLL0,MO+2Q:H-RQGAEHB>K1[3P0967O)Q5 MCTE$ZB(DTXPX,;.3#L=C'0Q[7V(BUTK#!W'M4,;6S".'&B.AU1,&(A-"@0: MFF]JP'W7ZC0">:<'BKD3GB20U*<#MESQV3F2F&8,$[C52YNFF7)R]C"9'Z83 M#I^SN[3)G[(7%TQ_N3T\7[@V:[E81?'IFWM;YRVL*TRAO14^G227[O(PMQ3.?FHT4#PB-WP>*7QXM.W=KD#J*.0Y5 M+$"UV!D+*92SG;M@X^1(G%#!J :G,F1;5*KK?X+'XZ[ZC>25[3@8)0YP0\]" M.+%08.]O5/$]IMLDQ;]=<6!X<4QIV#L7/.3%SAB#WBLGBT_=7_!T-1=/@B?A ME/ EX1C M+/8OM2QPFI\SBP(22-5C24"&(:7T#B>\I7C05N2;ENE@$Y$&4>S$$0"C\J'V M%02A746.%F;96)2@08+\<>\N*J)NP@;C4IK#*S?32-1#:2;:<'JS49@1YF?F MWIPT65EF&-@N !:([22 /@KB>*R-@ [F$1>!KY]%6>H7I]DR@=-L(L2QJ8IB MSO@DY=BQ/P,V397?[)KVX8:F)%.C^67F+4MG-&8"I7H(S!0#7K\X-Y4+6<=K M5UY@(NAZ.(IME%@6]AUGW$!!9L(E-),;FR>A>77><[H,32>9.]51SZ]PUG-P MB%:OD[-L^<\T9O50*GGF<)Z0Y>2)]ZY@TN9ET9!^EY.@UUU+$.?U>EO6NRJ[ MSGXTB+#PY\ITH]B,@\3S8\LF<&R?"&H$08RL./!\KJH1R4TK7C8:T%X8WQZS M=5/M'HQ/^3HKZN$6RKT-QCOW:\SB"#;=6] '?"HX #U.M;$':_Q!X1HMWIG/ MY_*1>48S%7E%#P559=R)VYB5<,BJKO^U2RNB-=OG_D*O='M9W);50[M/LV\< MN#ZP$7 !#F. 7. EH1/;@1M:88"!S:6JDII4K*8C2F.$:1S@-'[Y>Y'N-GF3 M;?[")Z.R&&>3SP7(YI/-]WA>3BS9J#LCDI*YUT,<91M5*NVOG&MQZ3;[E*5U M=I.N_[RNTJ).U[3=8W+L.)%KAC&TL.LZ*(I1:$6QA3!$3H CG^OB39GM*I;% MZ_)[5AE?;K;Y7>L2SAQ2*L.,JWD+DN%0V7LL0HDVM5YD=5U5#[<$'T^U;B+ N@@X(4VC&'@$BB6WZ6J@8]A MR/6JCZ0F%LJ"C'P4)Q@^GBT&UD 1ZX= MQ($+;.8K-.4TIG)WLL?75LT?VZI> =X^G,.)M$JQ[#:IH)I<1NQC=H M2/A\*(O#=B+/#SW'1#@B?W( #"('#NT$5L!USS;_MRO.T3M VHR3-_R<&23B M7.HQ0B;@+V7U*LXG)C:;G.:5Z?8JS3>7190^YDVZ[=LT88AC#S@NAIX3F:0Q M' UM A+5>,;)M)84CYFKM.I/179O'PY0#8KUU[PP>K3OCR$5++/ET/,1S)<[ M3V%3S0,8YX@ZHTYR"-9#J239\OH5#8D,,2O8>KU[V&U)3KYI#TT0Y7RLLONL MJ/.G[+)8EP_9D%T VS=M/PSLQ \Q@@$.T:B@'M\CW/):5:QL!T"-[L#0"ZA& MAU54U^1QSZAQB]#.J7=?HLL3EBZ(BYE@%\FO6 MI'F1;7!:%60:4/>-!3ZP@RATV_?)(C>)@>D,C44VXBIU$6QB1NF+L]M\G3,, M0*D4LHG:#.SQ*=@ R!@0+:1;QXDY(U(3F=1#D:8:44KM77Q:0^2LHCNW<=;] M][)XNT3ZM=QND[+ZGE:;58 38,4FM",RI44P'3SY7&\001M!TS1A&(,0@2=QP: A;+EX]9E5>;KXU:=6P2:M (SSC]34> M]GJ)E/QUG5T8-]E=7M#P1O=GNZ_[6*=$6>G48XA-,>#]4Z)\7(AMG7Z[)Q/R M^F!W9&4EH8,=+S)A""P$8A1Z:-\JCOE'S=069QE"^XW5]HSHA5&W.(UR#_1@ M>"VYQ?J&0.;=5G'J]1ANTJPYNP<[E26![=BW3=K(3("'(Y@$80 !Q*X]3$NB MR$,V_RB'%-.[^U.Y8?IOLXC980UW/S/ MKFYH%5-]79[8MFFO$E@%!$F$2$@V@8EMS_)B,(A Y%@6TP&0&6 HGJWCV]ML MW=0TO:3OW!E5MN[0Y?]J+>&XY%*Q.\Y/SS7S!-],_5AY='UA'$!OW^A\N=]L M[/>;+XS6 GU\Q7%SJ3X^$[OB=!Q A9'N'?38.Z@?3$9:&RD96_5NVU;:-O?9 M\>'VUXF7HTYB\TCHF]%%&ERW.I.AY>S=GR.HMN'[LJYWV2;>521R7[7I7UM$ M1-^ (Q'FMZRZRRJX)K/:NL56KSR$7-L+K00XB46BO$\FMP,0UX_9;\E6T[SB M(#J<$1IR7-+7"%*Z/;=[)+I0=;B-AQ9X^\I"*P)T=6U7/7<)/I+Y*OU%^FK\30VQ0J2> M"JUJ/:1!2%5L8#E;;Y\>0KLY\6DD-ID(XR1&R'--SXE=TW3C 8F)(J:B9)7M MZQ5$NT]-E^/)7A&/D7,Z1%Z0[%"KCI*3W3(]3,[I'K$X^>U4S)LEXKW##V?( MD\6VOC%/FH4,04\NFUQ[]B_L;,N6-L>G'%L2D;7H1FF_O)ZTHB"VN MFW>DM*BZ(HJ@H-OY=&2N7^R)M-FKP+79TSEF*W::GU[IDSD"L_O S(\>,U'W M7BV%-.KUV'62;-.QB@O)C+$7893K+-O4";%Y&.Y?;J,NA:7W0K[=L-%&G-78G Q=[8R0XT/ M]!BYRJQ[4[FADD7VP\/O+\"W&=9-6F<;>NXE*^HV=?^:=4E6]BVKGO)UUDG0 MUVQ=WA7MM[1JM#)]SP0Q"!,;6%'L0Y0XHPCYV+3YSA\O#%9Q]M0Z^M<6/,V> M1O2\)Y67=BE;QK4X3G7)&L=V=FMA[_-#&^FJ0V^ET9O9YWO&@:%SG[I6Z[$S M,4>;SJ)'D-*'CC?'QW4!)FTZW_[NRV.[FH!_9-4Z)\A7%L(!]BS/A- S36QC MWPT&'%[@0UE3>['659=2]4#:W:AV8EH^BERQ*Y_UZ9-]]81+G_CW]P1UF(T1 MM#ZK $1;H7T<*P4RF)PHL-WB[7$@/CW:&GF)99N1&4$O#.-Q MPF/9021!8:),_,3# 4GI@L"-AH-B48P EI5&B2.88\X_[&O2 M4I^L1]J/^L<>J_%(_IF\]&J"1Z:G6/,X0WJ:-<#N\ZT!N'%USC.SYUHGR17, MMZ8[2VM-EF4C1]XEBU$IN==),/7*BV,016X"X\!UH6LY(-QG@M@UI25@$S#H MI,Y\E5K*O3-)IV=UC/R*K7-2K5/F?)I@T?19@LNTUFMY5O(DTM)8E:+97[.Z MJ?)UTV\-0GHWR>>L^7*;E-5MEC<[\AGZQ*T/0HP0"#T0N28R@WW=$[#D39^E MH)FQ+NF)X"7*48VP>RW?%7GS_NQZ*6])4//9'25?U_&D%+G]IBT -# M-!)Y%MY%Y5ZJ3S^ \,NUER<$*&!:H$CC:]9>AGE=7J<__D&/T95;>N< P="B M1*]WU5:>;7D@L,(PB-W BV(/@!&1#P.\*K*[]AN%RC"DPV&2E["3ES?(>:O) MQW.(56<&W:NG)Q;;$.=-LQQ>#NAB14J_70M6L2IW(77&QC.,F%U-\W3N* M #<.D+>SLU/%%(N52?#2S%8!H@2 62P]7;>@F%WF&4"K4;1P@K3,"B6P M$>F3=NP'"4*N![T$#!<4Q@[$L8#:*\'Q061^D9TV ;[/98\JW:>'7J@U\76. MJ)Y/_K3P9*E5=S<]@=G=W4)KC8]#))GL*@X"[ /+08E)ZZI"%XXZ1H6-ZSKY MN;$I7C^@R4;^\)BN]R(AL4YW)O?Q)HGZ>4XT<7RO"+=_085ZN3/)H"ISIC:7 M&+943BG%*TQYYKS^UR.6+&;]R7QT"2^(WUS=/H^RBF'@X""DP2T B0G\_+$\]'PC&9L.5AD M25.TJ7GFL2,Z>O4BZR%2N92R29!2&H4D:$1T8;QZ?WI>!3K!S!D%FLJE'@HT MV8I2;@^3^^" B9%/5 _$*+ WQC*.7T)@' M%--C UG[WY_EI0%6UO48<=*LX7QI@(\E*2\-@#"A.0<& -C #,F4QAZ7U0(< M(][A-ZFQ&<;>^Z\,+#'P5#PQP$JV'D-.CBD\3PSP\3/A(2K7A&X (APD 7 = M*TI,+]BO7-L![Q 3:&*&@34^0M6-GX_Z A4KDWJ,FBD&O/\"%1\7K".D6VH; M'_V]3G]\)7,Z>DB]6.?;O%UN@TV2$2#I]EN3-CO"\/.+#Z\LC ,;DE0ULFP3 M!ZYE8PPC,H3#$ 9F'/(LCLV!1_%"6@^.1+4>G9%WJ_%-^L.H"$"^&>XL'F*; M#>OF'+Z9\XC^<'>$8C)>6G!AI(TQ.'&TXO4_NJ"EG.NLF'G;1((+SDCPG [6 M0[-GM;A<;CC)CPH44 9)8D(\N-^ZR>J5Y?H^\LP@(#D!%E?W&L3X;L1M+RLW69'=YJ>U8P&OR L!LSA$E?9W7B.S$J.%?_!Y MZD9M-?\4YQ/%?K(K/X[*3S=50-XE\2M3UY.RRO*[XL4GXIS\PXIT_#S=KBS3 M]P&(4 1L+W& ;T,G&J!9(>(ZAS4+(,4Z?[7+JJ8TON;K:H_JYM4 MJ7]OQ)O/'1JB<11XSP<3HX$T%W^.#BHM MW7P:L!GI $Y^O)#J-7FA8RF'J8HB>Z\.%K6?[6PR1J.,T2J-0PJ';R9&%Q6] MX.,$&B76"\0<=5Z0&7X^E\4FV^S6[;WR^ >M#,Y6?N#:2>(BQPIQ8":NYX-D M@ --C^OJ-64@5$]&LNHA+>@)@4V?**QY[WY0Q[^\B*&<>E6AX05PHT>NL?P? M(WJBSD_RW<<1]&EF"BBW!%YE2C3Y843B1][4*R>TD>G: +H@<%WRGR0:0?C( ME;YBQ-'T3'O!=.MWW4$:5X?(/\NJ)Q7JS$.]/$U6Q+HJ)::_Z/!J++][3B>* MKH!S/H[4BA@G(+#"',J4U?9\RL'E#BMLF2 )80BLV'41B$*2AP]00,!WJ[@2 M (HEML73BJI\(>4G6YZ<*N59E:BVH(T#U!IKZVN")RJLL+\^CLZ*FRB@MA/Y MG*:Y45DT>;'+B[LOCR2!:^^;7X6VCV$0F@A#$\>VA[&/1M$/Z?7!99-NIRBM M4+-<^CHB%!C\"LH8Q7B>(K+**58EK1KIZ#$.N=5SDB-TULQIAC$II03N6/61 MOD->T,=W+1!&;F#A,(E @GS+"4,_#JR(M =PZ',]_) V0^B ^;U<_0LB97C^%/CT&P"0+2GF=B6]8?,Z:?1OP M** IRX-G0]A)-D0!'ZV.$9,K+;5CR< MZ.WSK4^.-G:(Y]WS'$R>F8\JO*-'F-5F77E M/#V<;XS_UR[=YDU*$TI8;,C?2![9_?6RN"VKAVZ=LTJ+^C:KRJK>)YJ7Q5.Y M?6JO%;VFR%=!')LX<1+;]J/8]2P[P%YLD>0S\JT$^%R7*\X(2[$R'%C2'B(X MM,4X,.;"V)OSG[6Q-\@XL,CXH[7I__'-M.?T,=M,7%/W\LW4Y_6LDI@@SP]G MPL4"SM8CDBQA>+GX0..<>M%%W<^$SUU%:YB[RK+?LH>;K%J9+IGK@<"*,0Z0 MA3PRYW.'%MT0\$W!)K0SQW[54 OZ1X>)4^$GL<@FV7,1R*?!'7=[6,PTJIG6 MGN;HW/16 K-Z")X42UY/=Z6Q\YXD-0^[>I6D:\(@T3\2T?'EU;>,M)LW^;^Z M0M>JHK6P5!-[! C")(JP!VW+=F$06:Z/!P1V@CP6B5+1KNHJI@%MF_@0O,9+ MP,8!8DY)4^*%\Q*WM /X).^C<;\IUSOZ^?;?:^N#%R@7\L6KF$0I:2.-9?=Q M1H"D(W%')=7+QB&EEI7J.^H"2S>?\B*[;+*'>F4E$'E6@ES@!8X;1)YO[4%& M3CS[\@T[M(^UA$/M,EK#EEC'X7#XC&LY:GR]Z'H.BYOU7=09':)Z88??\WK, M=98R7L4"CZ@/6",5:9]>.CF$R:Q>1680):&+8]<,K#"V7\KF"#?^W MJRXBZ0 9>T1\.B] %YM4JV6*3VTY2%*BDF^X."-TXKSIH543\)>R>A#GPQA9 ME:W+NR+_5[;IEGS&'#O;?*G:']VDZS^S39(7:;$FF [2[NY?$#V$1?=\1_^A M=-LO'Z5%>D??O[S+Z&^O2":_SA_);Q_*7=&\N/(;)<"%G@]-)[1#V\:A-RYZ M>Q'B6H+^*#8I5L=#&KI'*K/J*5]G!OEQEC_1O89ZG$X?_(SS&9 /0C;KLR,? MQ!QU\>)$FDU?/C5>=*DAV:&7;(QV]OL"%T9GDG%@T\ROI.CAR#/!3A.$S%U- MCQ#[X5A[_>K,1\//]\9&6M\GV_)[C;+F>Y:-$Z*,3IKVLZ.KJEQGV::F#PU^ MSKX/OZA7,;0#')JV"3W;B@(( M?I4=EQ%'!=)*(:RPR5CFMB@O'8 S1JXLSV M+! 9)CGO$['*/<,67W5R"F=NW6V9EF6GK_A2DDOQWL\='IAQ4OP;YVNSH/@Z) M2MUS*"LWP4Z"'#L)$@_$3AA@Z _ @!OXS#OZ\\"97>T[@ 9!^-X#,HMYB&&W M7S_GJ%3]XB-ZD:-N0#]OBI43''CUIO=J:C0O_;K_09:]=>.;8R=%]GW[//X3 M.B=.NPJY*MO2MUKI9[*\K:)+C?K%/O9%]]%?N[3?N!WR?B/=)_X7),*1!/ A MWZ;5V J]Y_+[?;Z^;X$=X+]/:V.]G\?GK^?QAQ^O]DV2Z7L/>E>0<+I]'FQN M/YNNVTJ+7T@"NMUU;\01^XVB;(PM =;9>-&O,K6_IC.=745O6:.$$G\0RMHO M:5^?W>/]SYI )*))/D#_]"Z\O_QU8FF'E'Y\JN)CWD&B02'(S :7BPF2\KEP M5&ZW63="OF9DU)(!D6TNBZ\9';\$\E6+=Y_<.;[KQYBD=FYLA2!PD). 3BR M^4X":0!W]ASKENK'*9N%+^GJ^B?J!E<;>3!J3 M1D.-SM(/-)_G=)W<*;^J?O-A5P64$3)]X4"MKYB?CGV1'+]&@$5S3,NKMJ9Y8PB32>T:HEG*6'*"UB^>MG=!=C MGU5F?D^KG$[>+_N9)Z8%?<_=__TM_9$_[!XH!OSCL:QW5=;MH*V<.(@A=!!" M=@*]R'4#SQZPV+[%M&JI%H'B)+H'1J6C1477->A%'!?&_HS&[Y>8+W-6Y NV M9'AY-_#EMP->8P!L=%@O2([Z6%;M74/=3PX+."Z,P7/4&&.P9BC4F#<""%%^ M1NO5NE /55=L8SGGH."]"*]=0;U*J^;Y>K\26<.;NJG(GU>Q%?@@=$/2JH?, M_U_=U?4VCB/;]_T5?-C%G07< Y'Z)!980"+%10,]D]SNS"XN^L%0;"41UK%R M+3D]V5^_I#YL.4X44B)ES0 SG4G!.??OB(K9['51O1\W@R];ESUHU/*T_2"[#50[K>;]*K MN_< 1"\G/ZG:5F +!B%S(RKN2_60AYESP&)1I'32P P"PYE1"UK<,/'^\[H0 MNXVG/Q[4:\A0D.24\O+Q49-/8Z$QLSX>PF[?2MAHM.:AP89]?+VZG8#1D=G1 ME\-1L\CQ;BK$TQ M>U5D4#)7-4>>8F9: VDU>^(4](2%OH1S&%TS22\'@G^=3([A0+KF,G]\W&^S M57TQ3[A==YNSI*N';;[)[U^6)**>1ZR8N#1F,(JB@%B'O)783*EN4H])P_H2 M'R9=+BUENDE7)["KLKC/-VV+ -7"1TVLRVG/!0A7TR3R!K5'B."(<>+*02G> M^JK_]!(_#W73[=3K*CP3G,FKX78MGOKUH?[F&\_CJW* XB;]O8PX$?]>>C:. M/-?Q_(B%KNLQQ!Q_T?&Q[S),?-=U8X*\R/)]Y""EDS(#?KUA1:-IL=IE55<( ML6:,]D6V30O%+&X(:W*R99@P-8VJP0B:CG NJ$SGW/3(T @BYZ$Y8QQX?:W7 M6"X4LJ@BWV3KRL@U_VKU8!1:CT&8!H:PUB3U'ZEX"+88,*XRX M&JT0#\TU_U"[':R<*8W@43I!FH9"Y;SH"&L!:F#@>_/G);.B=]GJ3X;&DSP/ M/=+CRGGJHXL?68WZK>!*&!=EQIJQ6AD>>YONUA!T<^LIC/G-8VLQ73&RT6#>M+=7A< M[-A67W1PJK<"T,"N9-(S.;&*V<][G,Y'GZ0H[$N)M(9@'FJFV:Q&,($*^:*R.?-N*K)AYK3V;Q$K;1,.M&-:X;P_YKOQTD^X> MP1&CFKZ-8%!.TZ8A3TW'CICF(USO\M0C5N.YG8= :? CUSWJ5&OW#UWW;W;) M6G3FJ+HZ-^?AB^//P\TF_Y%P6EB^H_G^MKS;;]I/U5B7-K)%?D@B2) 5,=]& M?@LQ""*L5-0P*3##B 4?0539R0*Z8VTT;-#FYG&V\U!2VXT9U^=>ZCE1S MT\%E7#\[,G$Q_F4GG?J%;/HE M3ZJ"E"]I4J0=7(UM88V$#K1M!C$F#G4]W-H.'0I59A,]%DU7R/%5R%/5(O7S MMBB3S:;Z^II_IB,XQ:B90Q/SJ,Q#\'5[%-NC7?CC>T #;S(JL[U M+G]*=^6+R#E*+GF'C.2U^1 %;NS!P/8@=OD?#"&_-4\\2VF74IM1PZKT)=_> M?_J2/:?KYHHY-6W2QZV<5EV$5C7M:B$NJB2WK*^";&'.1\]DF>S1-^W!F(?> MZ7LZ_IF6VJ\J&KVXWV7U=Z= MQBHZ.-J8Z5U,@0\< 8(.0C4I'$^KG 1.RJB:]/61.1_E^XC 'L73QOT\E$Z? M.[FA,:JZON0*L$TVOQ7IM_RN_)'LVO6LBRDFL<5\UX_\D% G#*V#DMI4J;_P M<"NF7T W: !)GK(RV31=HE57FX,YE%UN3D&?ZGJSQ@1$J5^+:CZ*]2YEO8O/ ML33/0Z,T^'&V_-3#C((J\;&6B7<3U0J+9=NL3*LU5V,W]&.740='-O)"%'D4 MV\%AM\TB1%&=1EHSK%+U6\Z_#G7-:U,R>K;/_)\_2/;;*I3^*<0VA\U]D6Q3V#%D>]9L059 MZ-'8/KQXC;&KHG/ZK!K6NQ:-FL!I)%5.Z"[#IYK@M4":WA]GZM?^?#[*)\UJ MCP+JC\P\E-" 7[GI,:U-&<__?YW>G0EV$"(60A2ZD*+8C5$0AE$#*W:L0.G MF7$PIE>W3^FJW(F+5K*50A_)Z6(Q6F>G#X->^7WS6ZT+<\M)Q\9AF&#K#?'L M=5RSN_+R;H)GZ?7^XU.2[:I]SQW-BJ>\2#97=^)%:V6[!=3<]OT::0WM]9L@ M[/@,V\SUH$>=WX)5:G>K0Z/V' M2\1852Z(V:;QZJVI:"X3CX'X]&V?7' TS&-Z MNB@#K[=H+AX-V4GL%RZ6C_O'IJ=?FK8O[GP" S>V Q)#;%&$L<7:+?*8+YV4 MMJJ'VC"]8=/BX2N-Y#;;9*5RR>9@]N0D?@KBU&2Z002.D.8CN.^PU2.:8_F= MA_"-]B+7.^H4C]-PH?QGLMFGOZ2)N KS6!]U5B5EX=!S/=]R:1QXB+F8V0?[ M1*W1JCZKAD5* 454M"!JGIP1A_';9XUM0#VGZ$4,2X$#/$PCBV8-#18:7-XA%F# O? M$=E)F^E"; VK*^ 8.N4D;R(FU32N VH^PO8^4SU*IH'>>4B7#D=R[4-/M>_& M<[K=IU_357Z_S=YJTTBLV*8>)8%+;==W?0?C@RB*&E"U9AICK1F6J@8@Z"!4 M;8DQFD\YD9J62C6M>H/%^6C6A\3U2)<^TN>A8!K].>O^H)_-L5B MZM\AR'==UH;AUF)LBW&CLHU#IK/(@ \95:UM^>.^71KKD%,HX4VJB5,&9 MCPR]Q4Z/\HPB@S MER\@PU;(F!\PM;-W(VT9%IH.O&%Z,YI+.>F9DD8U%>HR6$&;CR)]0%J/..FB M>QXZI8SI1MD M!QLQ7612X0(TYKVV]ONCO8=MS0=I$3.A'_!SJ0M.8)04K[2]J,&M:E M^D#="5K0/'X_?F=,>@WG(GGZW MSJ^A-<&;K"Q^>TAV:<37KFL!A*.HSOM?51<65D71JW0KMO]%HYE#YX7(\8(( M0FSYMH-=U_;]IK-?8-' 5JHD-F'?L%A^*WDX/E6801>TFD8:(5Y.+B_-N9IR M5F@_W9[1O0 UXJ8XN\%<=IH M*N4D=$H6U>3RG,#YI)D?L-:C?+KXGH?*:?,F-S,J1]S"^\]DEXDFT%6'G+0H M8RZA99/++I$71FY(/1(%7N#0T(IMU-J'L5J3&GU6#2M:BPVTX$"%3OE @$:: M95?5EV!8=5E]T-*F]2VW=@9F'+!KPJ^_^7XW,R4KEK^F/YB(1 M+M/7NWS+OUS59?=O+_ICZ+@L\+ 5,^I!WT56'+4P8A@H+;6U&S=>12(2\,W+ MI\]%L1='- _@P;>2+_J2W5I10O73+Z>D%V5>35 YU"[1IV#G(Z.JC/:HJ;'@ MS$-4S;F73S3(-;7JIUFQVN3BP$6GAIF$-/ 8PSY#%G%"+T1V2$)'M)+%H5JI MC%;#AJ6UQ7K:65Y3W_Y!1,L)Z<4X5A/1WO[]X(@5?)]?[_XWF.P13R,!F8=P MFG%-MH__>/[DCX/=EL?#3RQ9I>&C4/&EYWA5WN:DYW$;3>,\'JWQ;IP=4]+"BW11/Q\U MXI)N8?8ZW8EE2G*?1BE?4&[O7R\KOR9ENK1C&MD1L1T"(:.^'S(:'7#X+%2J M^-=NW?!#)H!VSE'= ?%+FDY++Q M4,M,CGHGT"[ $2]H )_OH9U\JCM.0(;TDL&SFAZ^+8=8* NF[,2(LAC%VE%Q!Z+5]8@H_">\2L>@Q>:R#D MI/=R,5"37:WT3Y",?L"D=(:J*R+S4%=#OO7FLGH9_$A5R\=]L?R:/B4O55.2 MVLS5W=4NN\^VR2:\O]^E]QS)-5?Y5?;$OU.GV4Z(/0]A:%L8V39C+D18H"!! M8*,@9#*Z:LJV\;<4#>+VT057=Z %#0ZHP0$VJ''+J:NQ@/3KZQQBH::P?] P MK/-5]9A7+R1G'8X3I /"DM\!ZV?D_D5\43ZD7*V;V"2'V#P=8I-4^'^6G0(% M/]7$!E$SK0UD[(V)S33WEYW:C'N73S."%4]0U^^I.G?6_YJ69+_;I6++B,4( M.Q[S8QB%MDN%AO8'< MP#:MGM1DL\E_)'SD M5&VP_PRA5[W#^'-@3WP$N(>_GB14"^WSR#GUN/+ZY*\^?A2.WSUF9?4V.-RN M25Z])4[YLYX6RPA'7A0Q9L4^@F&$H8OMQJ+MA9[2YN@8.X8?N ZTZFE:=<$I M'[ ;SJ;X^@WMJ]\;3.0YFT>')^&$X3.]+GW\1A MKH=\P\DJQ,O7\N70._TZWU5'0_ ](*W\43\Q-'"HY MG9QQE-2D]31 M2O=^S :;T#7'5#FX-2AX\[F]]:GJ8_<:0U(CY1?*/+S4/]+ M.?_Z#-\E8R!?DIC>I3RY7E=HJ];/R\C&@6NYEFT'S X1L1@]SF8(*4T40WZ_ M8;5W?W:MOX!?1)4V'Z4O(D^KF@T)S3C !15>\"W=\?D=A OPE.S <]4V_<_6 MSQ;_!X*G= >*^A0;M*R%5?];?XNG@/OR(=]E_TG7?P/H^%.1&:*S#V=U&;GX M8;XO"U%"SL? W_CR]O"7VB\/6U*;C ^J^KA C4RU1G) Y.7F'=-!5YL\7L5T M47>_Y]-'Q?G4I8UGS/16, [G<1Y2/,J#LWK$L6RH; CDVXZ9,*9V'%@>(H$5 M.S2.?(>U9E#D.:J[ $J_?(*E/U>0YMGX0.9:W7I/Z *(%[YO+WSD5*(56,$B M<.$"6L&IU"WX1X.%C>$"0=Q\U%\X7K#P++O]:$<*U?<@U (HO_%@+';JNPW' ML%U0TEYS\L$&PR#ZYB%FP^&_L94P@@?Y9JSKJIMTLKE.LO7G+4F>LC+9=*PO M8S^FB&>5,,0,>Y;E6#S+; S[OJ/V0F&\.=.O%0X(NK: MS:ZZG.BE(Z QM&AH$^;'#@ILQ"+/]P]YH,7G]VVU9EK?R,O9 "M2CQJN'[4S M0-*/70L,%/7@X_[)V[ +_6534<\^3E,RJ$]E?4& G-/)32F'?G M=3<&692_8JU,LFVZ;KN%=5#1]"Y;9>424>H[F'AQB @+J1\YX7'+S_&5[H'4 M8&Y")5W7D%0O61O/J)Q$3DRFFBJVX,"A!^%/76H;@._/18:N5_N(L1[9TTCW M/)1.IT-G-ZQIYDJZA&?UD*[WF_3JKKG-=7M_+&P4%[YQ4OG2^3DMJLHBLDOY MFOI_]\FF>EN\SJJ(W(@/+^,P0,S#4-0^.IY-(,.X[K!@V\2G2BT/)H1ENG2G M\43D, =?P-=.V7#K#CCZLP"U1Z!Q"1Q\ M\KK]XO"[EXE"4K?^898,6JGXEC M:Z;D1ULD^LI]I@_W/.:,2SC^NLSG4MS+WVK%=76;;&K+85&D12&0A+]GQ1+Y MF#C,#?F_S(5V%/HL;DWZ4:@TJXPR9'B>:+&UZG!$![X+?(J*/XY3.0V?C$XU M51[.I*%;K]YGJ4N34QA0S:M(B28JA6N(# [TUQ.H\S4,?!B$_JQD>ZKWT#M_^ M]JECQ(8>P[;GD\AW',PBVZ4'(S!F4MUF!OYJTSMM#9J!$J#*D^0^ESF*%/>J MI-DQL\MTPD/?3M$PPN:A"$/!O]ZQ&<.!:A^/7_,R+;[DR5:<&GYCAZB(7J*L M.O'UK4S*?7'#K52++(]X%F7(84Z(D8]"'$"[A84@5BT?,0O&L/8TH$"-:@$$ MKD'[-N:C(EU.,I^ J"G=D%@8;< RE,/^DI)IPC,/79W.W7>:O4S$LWP5RM%P MUVRSA/0IA01:3AQ#/V+4"X+H8!0&CM*>^4A3AG6W@PZA1H))/S4)ZQ3N1:1Y>:TD1OF6(VES//0BZ!-*9N%/O4:TU9*%8Z M*3_(P 0KT?$:,XPZ.84QSIKZ2C+.!=RC6-*356DBJB^ M9-OTGJQY;/[P_9TS4?FO&WJVN:%:M-7NSYN*U/)4:. MYTW<'A:I5;2:@J$Z>+7SE'D%GG3(OR:_Y6'I$B!P Y^BK]= M7_\5=/"//5*N.UIRJCF+0*FI:4^,#K /0;I2#)+AL^%J)/?5]YJ.VSS$V;R; M[Y[R-LJKK)A+@SAN)F(WLGTKL!AR@H@@V_<"V@")@H@JM?HU8-[TBE15M >_ M,S$1&CG-OG!4U-1:7:$O]@I%G=<>@388I'E(LTD'\\D&O&)N+3KL1EQ/UMWD M/MSM^(A/Q5(Z>CE^Y+J^:#;\D>S6OR2_9X_[QX,C^]MBMJJ4!7Q@L/<=# M$?;M* H=!^*(N=AIX5I^K"3:%P-I.C<7H#_="M3@9$7=<0W=M+&CH] .*F8O5]L/$AF]W^$H:"8_5]T%)A9'AB*4M_RX=(#8QYSV.5I M>+W\N#B@:>9#,6>+$T&,A^279/?OM+S>9:NT3=>I@!Q'V,&6&Q+'QW$/D#SYK:J5"U\RI/SY*]W[75[G1_4Y<%YONLGQ=P2Q.UKPM M&+'D+9:V&_LQP8&+PY $0>C%-CN@B:"S?$YWM[G2%=\&4*AH6Q>PO,15&THU MZ M;U=-'>"#NWS7]@ZL/3#0)GQDS%3?ZEXT7,/?Z^J/U/1-OWMYEGJU:RQX,U'V M"1Q5:>*MD]L19<;OP>B\W$#88AX+"$/0]6-**"(ME,!SE [?&@%@6-,'J,/@ MU[QF B0GXQ>/C9J &PK+5/7)'U*K5J>L+U+S4&NS+GY0P7W@V M"8=UC]*+P;!.'V&#'QPW:("#%B-?G[?8004>_-3^J'H-IWAEI+%(R:GU'(*D M)MCFXF.XB942P3VR;3ID\U!NXUZ^VP_+)*L&,NRO^6;#OR5VA9=^S =AC"#" M*/3]* J@Y;=@,%\)&,JQ52#,+\L6Z$$#WUR>K10F[9FVJ0@9S[7E@G/I;+M# MKYY\>TB\YJ';IIT_'6O'JQ/O? G( =%"#^E0@+?Q[*AQ1DKQ^I? ON#G/P M2;.#'P_9Z@%D!5BGZ_U*_*6J@$;\EKN$A_;T%Q__*I]0^/.8;!?54'A.-ONZ M8N?TP7W3*/]-"1]!NQ2DOS^EEZ1:M'9Q=]Z6;+ MP#[2OW99F5[=W8D;5&,:4$(898[KQ]CR8-A "5V$V7*;WHO&$#=&-I/D<4@] MM;A^:L\@2S_!%9Y/.0>T -NT2H%X$I,_\W6.AAY[&J*A?;-(1"4\R+9OKF6+![Z ^,1_[6.5 M3&WR[7W]?_'G:ZE.J')+R$',O;>$-!N&&2PA#3N83S:DC>_]4HR]P"+(W\?@1!?>>W16MPWS?E'_AHQ_ M_/7GOW_Y17TQ'S[\_#__QW_[]__OEU_^C_[\\2=;#)=W^73QDYGE@T4^^NG[ M>''[TS]&^?R/GZYGQ=U/_RAF?XP?!K_\LF[TT^H?D_'TCV^#>?[3C_GXW^;# MV_QN\+$8#A:KU]XN%O?_]NNOW[]__\N/;[/)7XK9S:\( /QKU6KG$_&G7\K' M?HF_^@6B7S#\RX_YZ.>?@G#3>8W^-T_^VX_XBQ?/?\>KIZ&4\M?57ZM'Y^-M M#X9NX:__Y[>/7U8B_C*>SA>#Z3#_^7_\MY]^^O=9,AD[&@\F'Z74QNUNA%L81A_-OM[/\ M^J\_+^Z6\R ]I!"M9?_O]5HO'N_SO_X\']_=3P((OS8^2C4<%LOI8GXU>!Q\ MF^1J.@J_F2WST.7Y7WH.4Y] M@\F711A1_.?\T[49S&]]P'W^[-E&Y#[AA>?"XLNB&/YQ6TQ&845Q_UR.%X]= M@7+,F]M&YVN<@DZ4\V4?IX]8+^?C:3Z?F^+N6WA=?,4_PL+]6[Z8%??#@X.M MV;SU<9KPW1>3\2A.""^^B>+N?I;?YM/Y^"'_$"R8N_QC,9_[8E:V_'2?SP;' M3$K=CZ0#].:+3]?E3UL>;@J:XU[3NMQ7LV+U86W[T)H1^8@WM"YMO>GGJ$Y. M'W-XS=UXL?I&@J$2/IY%V&*$K<;X\$AK-&UU?,_^5),L29VU+,.S'\(?/X:E MY^88_C?1=ZL2;F;5Z%UR[@R;&^K38Z<$D;C&^W.;Y MHL88#S1L<6QAPQ"PN= MRY',G]2^VY/P[>XH59[=/9T^>IM_6QP:U_-GFGFC&=R/PV;RJ&7C4+MF1K8Q M)JS9L;U^V 6+8Z'_(A![6K3S(CJ&2)OGVS@[9MCAD )%PR;%^Z< M@^.IT?;T$;K!;!J^K?E5/OMR&Z;S0Z/:]7SS(ZE)GP/-FA]7/3;M;]7 J$+3 MXC'/X\H7 73[_ 0ZW?1R7C+1SX'>V*VFN:_#!XBAJM] MP5.SU<-UV='N:SO%966T7"UGP]NP5L>_-(_!H5=T(N]J$.K[8#9J4,N[.^U. MID_WQWAN3^NU$ZEJ3H7'=M3 V(--?Q\_Y0_QZ'HRB?^,+_J<#_/Q0[U1U^^B MD_&Z\?VSG^IRZ,1^.Y'L;[.PE7SVLWY<6\TF[-=NBMEC<[(>^:9.I*_Y#1W; M42=C__MT<%?,%N-_Y:,]Q_B^F*UACBZ#)JG;Q.M/Q\D/QK/_'$R6^6]A#[U< M6Q#1=K#Y+(QSL7*8S!>SE2U_4.JDSCJ6H7KXT_6S@Z+JS_KQ8_Z03VJJN?TW MGP^=+[>!G7&O_6'ZD,\K'W?"QKV[$72,UM\&X^E\_6%^NM[Z1!L('?W6CE$Y MUH722.<=RUAOW3NAR]/E^5M1C+Z/)Y,O]_DPON/C>!CLUY6#[\-T,9C>C&.0 M7F#1X7D]H:M.QU\^6I-PI_?UUGLZE?SU(\W+?. - MG4I;;TY)[K !69:#V6"Z*&8IP="U&K<\1E-,1Q<=/)VGAZ\_RH^?B@I-9> M>!8LJF/&DV)J6W_QV;'9?J+<.5+'#J-EW(ZU_)(Z:UF&FK-P_2Y.'^]:LU\' M/PZ/:\NCC;X_,JZ8KL,0JE^[']$S6E?I:;TU*H7-K_/9+!^%']8KY2IB[MC; M,,D=-BJ+N[X.AD#U_8???0[SP^=\6 1:3L;'3$:G]=JH5-4_;?C/?#$>!D!] M,@A?#G&S";/889HAC#H92^FI4@GISX_8?MH9>?F[>%"P>/Z'$Z2HVV<[$M6;0 ZW/'UT M_Q$,MD4^FSQN,]C^/ATL1^-%/CHTTN-ZZ6K4->F1U%E7,M1C2DI?ITOP93") MKG83.#H8'W,*?[!ABV/;_"'IX/VD3MN7J7F!SBG-EWP6EYCFA3K8<8NRK>Z( M7Z^"B*M/]1@OY\D=-R#;\ML\_^"N]DV,].YN M,'L,3 P[K?'U>!A-D'62B+"3N2HFXSI7#X_KI:M1UV9#0F==R="L!IK7Q-?B M>SY[VCT<'.>NYYL?B5\NEK/\M_%T?+>\NQH\'G/6G])7\Q(";+5<+?UUMP@?\\7S8[S=8?-#?4JGXV+D9LV#.SV;IL> M]I=%V%:U,?"W'3XZAZ M277TZB:;6*YO\\4LK!_E*R=1YK_^'-Z1)?2282HM(Q 0:Z4$S@MJI3**6,F9 M9\Z]E&P2D_<5LPV<6T3;8+A2V/5@_FVEM2#MS6!P_VL4^==\LIB7OUF!\ N MF\Q]_WWSZVP_V#%F>5+$X+:O 6D=AO#'%C"2^\H @$Q[JZ!UGFL)L6!N PGG M7K$#D#SGF)H-?RIFHWSVUY_ASS^%OZS/[#ZNA[DS0>&*<8LW,\-@-GS#U)<- M-T_\>K^Z9_[+\'8\J5R#,4MC!SPINH4_2%Q^W+^^_KI;_>234P\FS@X'1G-@ M5JC7.@.02\2%1EA"*P22&/DU]LP$/>"SS 85*5>&Z9Y/_>6#&?0(<(,8UAPS MZRR5")?"6(OE97S'36NV:!#3IX^S-7(\#VPK4\NJ'^/Y'IKL:I()P##""$D MN#/4>T;Q_.E/7!7N:2:8 %09Y# MI4N!#$,JC3>H?[QI:-TZ&<+NYYZOL\$H-\O9[%ETUN')YGFKS&' $;)ANZ8X M-1B&+TN5(BKJP<7,+J>H=_^L<@*>W5!FM@S;@&*VCM^,=ZN^W@ZFSZ.?ZS"H M9B>9D@9RRRA5$@DJG&.&E 01OCE33N-$*H=>#O@UU/>GU5B_F<+ZV%:'6R; M!;D (@R&_T\AP=0Y6R&JB3[D>MC!)GS1;&H:U0Y(]&$:$,[GB\V,>I@YVQMD M$AI L1 <&,$$I%R*RHA3 <8TNI"+IDLC4':UD.6C54"6B=F.Y[%.4[ MC!-KA5"0&.<<91P$N4LQI68^C3'THAG3)*)[B;/+Z;U^_]=B$C:,HQ5_A\5T MF@\7N]E0KV'F 2- 4B^0%5A;3@0O':(6(Z?3Z, ND@ZM0-K!1/(YCZDNAHOE M;#R]"3_DLX=]YP?;'L\L((H$\XLBX+3'3"! GAQ=&J;QA%\D3QH$LKME1HT> M\MEB/ ]#K;W$O&V3,0 D0M1PQP *LYAGP%;DERC1(!$7S9.FT.R +*N=VEN7 MXF'&[&^8*8:5$]!@#0"'G&M)JZ_"(FG3:",OFC:-0MJ3LDXM!X M)ISS7"B%/23L:256AZ)Z=OGZP-&T>A,NUF-:M0=PBNG[:;F(141C2=;A;3[\ M8]N9P/8',P\MD):%O5PPQT&PQ^#32@N(3G3,P :(Y\Y#:*B6DG'(D"B%DB@LT!=#M6Y4_\:!I^_5< MU32P*;NG5W;Q3C;L?CCC !D,'<.2 *< )6'+5PX2:I_H^#TZO.$AGWTKWH/^ M&X/RG46-.^8]\M9+A[W %#EO2DO4A1WG!47?=6ST-(3X.PPOC\&+UH=W6;GR M. AM2/6],/3^;ZXTI^+ZX>7'@=KA#N[I>ZD=3/ZZ20;C%EB3&'G/J<3$:%"M MJ(#*/T7H>&T%[]A1T MXL65'BY6#?*D;91;(HY=YNHZ /UIFO]7/I@UP:-=76;&>^H<10)8K[4)8P7E M$N^"V9AXWM3#X,TST*HAT+MV2:ZJ)@7+\$F2CS5NM]3M(D,20,:(5H8XY9"B MN#(J7; Q$_T_/63<65V-S6G@S.Z@)P$^%Y/))I%UHG=H:U\9)YH+&KY"2BWC MBA/F4 D'Q30QD*.'%ECS!#G"@=0$]KVAXLG\R[0E&L;+1Q8: 3''%O&-X)Y[ MVY79?[\C\U+CU&N/&4DQC%&>\NX]]!M7[-,JO#Y.N !SV3]FXT6P4J[WFG?']91!+%$ &) -(,$ 25+ M?#UF'+5MY1U*__9^&=BN)GI#RM.76" ,$XXY0*@E0#"M;?4U&@,3W?M'7S2[ MWYJ5\=+Y=R3Z*9Z4W36QHYA^YTZA?N/, *H] L[':Y@62>JX+H7PRIO+64#; MVAJT!G:GT2[_&"]N-R,OKV*6$M0*?]G3/L/4B/ )$FHD(P0@%#[$4NR Y MJ]K>";1!A)VQ+\WAG73W<1,(.5\4KZ0\%&;[MD5F'>60.<&P=PQQ)KFIAFL] M?/^Y&EHD1K/8=GC'?IU48G5;9L_\LN7I3&. ':,4228D@1B+L)27[$Z^*]T_ MN[N#Z>1T>%,F#Q--J\EDG=!],!T5.TBP^^%,.D ILU (+KF0T$%7'L$'GOO$ M%:6^X7L!'&@,W0XFC2T'"<]J;ZPR .R91&JTSHB"DA(,D!?">8,48[(4F7*2 MF("J?@*&"R!4>W"G3#*U+*4P[\UB[0N;K_^[:Q)*ZBRS6F!-(.?*F: A#I$G ME9#0)#J(CL[BT&:09MOS4Q? 7\PV2VF*K'3$>B8)@(8I44W;UI!$7_C1V2#: M]0;U9I-U'-IGNX2Y2;]U%3:]C\_*^Z1=P&SJ:]@^I#TW->LVS8+1PHFD4B// M-!"0:UR&M49_($K!_4[R: FGH7YD5GC('%:.TPK *!_ M_W>#.^+'FV6J)0UT3,$:=RQ?/YQQJRB01L*P0=5!,",(WP@DM1.I623Z1ZDV ME+R'1TGP=G&@>GT]GHSC,-UT,5X\'KZ,L+5!9HCWT' (A '>(VF!*M-)2JIX M:NZ9?O/F6*6^/@UM LKS+6L?:T3V'FJ::<(Q *O<+8HK*3EEL!16(9OH'NK1 M$46OEK!4W%/\1-7&<3V41?&Y&-R-IS?NQWT^G6_U*]9JEV$MA(;0>H*U0E!: MK\LD/=)@T?H]N:[#@YK39=$>S%U,0\7C8+)XW QPWZ3SXL',(&.-! (@XYVE M#EM>%JV1$*#$I:F'4TSC1&D$T Z8$9,4+Z?C]<6<&(+RS$WS-1_>3HM)4*P&%K,1A^/T[Z5K1[+WXO%?^4KEN\S&FIVD3D*04(<,#AMX%0SJ4GAL5>+Q88_,ABY(U1+: M'5#M]V(Z# ;!IUDTIS8_J.$_E^/Y"B\__I&/U'R>+^:KWP:!X![6)?260<.< MXH82Z@DAV$A!6 D)30X3[E'9G"X(V#[PY^>BS;\M@@S+NY,X^+R7C'-E@=6( M &S"Q@ 8%R0O9WX)WW\!GAYP[P3 NUMJ/\8(HD_?)N.;]>:OG+T/K["[6F9$ M"2LX$9YI2S$SX>OBU><%4VWZ'E7SZ7!A;0CD%$_QAM"K^T.+HCH5F7_.%^/M M!*G3+%-A3P(]YLY1XCR"@-AJ\K5*)-9FZ5$-GS;9T0+")U##3<9W0;HH47'] M9CC/@M9*K_;5++\;+^^V[_\:ZCFS5%GB,&-,A@\$. Y]*;[ UB7>\.M1\9^N M"-:=$DZ=GCZ$538>ECR-KL[L]+95YB4*VY( &@JSJ& (25%NB(4R/O%0HD<5 M@#J=G$X&^ 1>?,D7B[43N+A^>Y=70T> M5S[D ZQJY9V9YHQQ1!$44$EL># >*\@8PMW5#WKWI.R#?DY9;J^O\V$8>MQ7 MA&&M#<3QO]:G-(,?AY;4_:TS%R9I9Q7'*.Y1M+="B^K+E"QQV>Q3H:+.ULU& MD3Z_^^$_!Y-E3'G7E#-L>W\9(49!P"SVB'EL+: 4E+!(HU./@OYD7OXNL._= MR>Z713'\X[:8!(W/8Q;/Q>-[/N+5SL449AJ%;9O'D#-!F3,4!4TH!=6A8-^V M[W2LP-:/9C*8S^O?W'C3*IB"$@@#)?068A6V!4"H4LRPG+[_BAZMZ'SG%8U3 M :Z]SLSSX5]NBH=?1_DXTH?$?T36D&>L";_*/N8W@\DZA';'W8HM3V4FUID5 MP$MAD9&42 UY.6A@X.74$FI$/U(QHFB'!'*O>:$ P\% MI^5PB97O_]+,23HJ&D&M U/R:H6!*>[N!]/#MQ:V/)T)20R$5CA/O7/ 6&+L M1B2/F4GT#Q]-A#9OD:>K\77JRI/QZX 2E:&VMLSB:(MIM-L.W+C;VRZ#*'P@ MR&C,+3<:.LM:A=^#ITO+(. MXW784BQG<%<32X>%F$_3;M$\J%TL0*4R5E_+X15HR^,9(V%99H!1%[XH2BS& MO(((()QX^ZF'3#E1IV\2*9^,94>W$HII/7:\>3;#%D.GG5=>A>4Z%C>6&VPL M(#@U&5LO"Q$V2XY3H>SB)M-@>G.H)'/U3":XBM=((6*,*>"Q X#0PR0I0C*B\1 XAXN%PE:VZ;W M)-@ZT/QOX^GX;GEW4/O9+V?K6@C##@!NBZLP[BV M;5:ZCS4R*6Q]/F/Q1)<9;0CP'!/M-*75] A8HA.[1Y'];=H&34#:^4;SR^U@ M5@8\U=YN/F^4"06Y4M0Y1S0#V$FNJ\F0<968/;-7?L^&-+QWVWD"IIV0IACF M^6CN R9QC#$=\:=K4TP#[(MQ^&I>"K.724?UE&&"G-;&*N8(=T"&?;DKH7 : MO_^D\VV1JTV8.Y^F[/AA/,JGH\^#17Z5SX91I3?[#O#K-,^ X812)I5&U&D/ MO&"D%)J"U C%'FZ%VYRX&L&V$__9#NX_GWG_?E],UP_&PFI[/6Q']Y9Y+KV* M*=N)AQ!Z#<73-P:A3'3D]]"Z:I9N[4/=^73VJM%L& 9LE!4,SA(/7_NT1^5=C3)K-0&(Z(58IAPSCR#%79.0IA&GAY=F&R).LW@ M>;98YY43I9FHY>=AT]6KGJ($UG_:EXX^H9=,6"E$0-9BB2WR2GFWR9?*J>/@ MD ^L[2CF& B__B:FH_]8#B;CZ\GRW&:2>!)40'.9-!\*FU,7KG&N0B%")CNT>>9'. MP];6-=$I77=E4DZ@:+VN,B 1\I Y&JMA*R3#?TP)!L8@,1BT1PZH\]"R%?0[ MI6*9\O,Y=$^3?PHCC^HQ8UX*H$FP+X-AZ0! UJL2&A36E7?OJCH/,=M40HL& MOU[.P[9F/C?%W;=-8HU8<>NW?#$K[H=GJ4VU94AUZE+M:Y;QL!+)6&^>>ZZ1 ML0[H=19B+3A5]-!%WLX$/<[(K]=!1K506!,FD;)*4&PHY*7P3LGWG]"V60H4 M'8!\OB_:!$R*272$1K_HLTS4Q5UXYVT^G8\?\G5>UH_%?.Z+6=GRTWT^6V-Z MQL)U;4P.4(;ME5 4:Q#+"5(CZ7KRU]QYK<]=L*X<^[,K\W/]^.RG^C>>ZW65 M82FXXIAPS"!"$A/E*T "5G^2":,V+7;:!*W W8&QNF754/F=2>TG32>J*&B*3C/,U]4)V['315/!W4F[.N=T(Y;S+56E M5"4D,N)R" M3N=%*=YRZAD41D#MD2:8LPV<7FEY.==XFB'5X7U[I_KH#;W=8#8=3V_F MGV9Q0]\)RX]_9:8YUA!#Z8&2$(7EC6Y*Q05P 8)=!8-W$8]T1KJWKIAS.K;F MBT_7Y4_;O';G\UI]SN>+V3+@&>/%U'2T.<4*"(\?5B>I-5Q8M?O( )9.,L08 MQ)YX0&*V1 MUT)K63H)#X:+MG\5N%23J[XCD?0=[R3QW%#/F)+3!T%%A6%9O M8##1XWLQRV<+S-AS_MHL[%VLDH-)O"+SY3;/%Q^+=4')0^ZL'4TR X50%B%D MA.,>0N-I": )F^[+<3NTHO'72U8S*)^)0H>=6#L;9592%5;XL-5B'@NF%8R! MYVL!,4F]^=9#&IVNXAJ<20*U ];4":$Z>*^_?B>9,4)21G3X$JT6$ -F60D M,^QR)J$ T-\-;=[ MG)@1N8<>M!8XU3"X[^K@#T OC93,*:>DLHPX68EF&$GTUO>0-YT82HV _.[/ M_"0 4F*%*,124 A)/)C?B$L<>__9V1O3]]%G?L=!FWSF=V6^_)XOOA>S/VP^ M+.[&\WBC-WPMJV^DQFE@C?990,0:(83Q0AO/XF%&M3PCF5RSXWVP)%&K;\X) MFP?Z%,X\"_0>3$>QM/S-.A+M"-[4Z2/#CNHP".>@MP(HI8'AI4@0HL2T>3U< MM5KF3@M@-\2?-,8\'S8A7@JI%?5(:ZFY!+2:A#%"B:G5>G2QHWN.I,/;@4WS MPJR+(UV9=O-\]G P,>O^EIGU2"F,F8<(6,X0],*5HEKE$F]B])!)7=C(S8+= M :^^AA>] N2@C;RS30SG45S(&.2.E=22!ME*\81FEV/U-*;GHAUH7S#G_<#: M@/CG-B+[&X8FJ @;-NR]U30L:9QHCDLAE7*)9F6/KMR=V1F2BG3GUL/M8':S M-WG/MLVA,;>7N-0V20#U/,->SC=/S M[^>X\*P=G636>HJY8IXJ1*"33#A3 D!%:HKX]['7/9U3K0'=]9RTL9WJSDF; MQS.'+,9..8>,] (QXG&Y>;Y?[=>ZMQ6"V>'\<:@#8KMGR(R$OQDQJGTV-H=P!PG^\:@_K\VSGGH&3OIW;T4DFE??>&"V( -QP'#<;Y?CSW8>YFA6K:S_;$KE>6@(7C2%RVEAN&3):.D>9%5!S!H#5!X/-VK[PTGT" M%T\=\=Y!98@"%G#--"X!49J8BSD-:H86IR9P.0[N#A:?WXOI+(][OK@5'/W? MY7P1%] #Q]6[&V4>.6DA9!)0A(SG!)H*24_YY>1>:$_U14M@GXU-!P^K]S4+ M0A**/86&4$$(EAIQNA$2$IGJZ^DAHYI0="WN) ';R2V8K794C8LO>]IE1D,9 MC_>M-0(#3H"&L!(SF&47SI]CE?WFMDMSV*8$YI4WTY\$6A1?!S_A\S]4,TN_^&IW0#A .E"04.H-TV'Q4WXP( M)M_%F,XGZ_OH:W3'09M\I>78U)D:&4TQ2A$$P%702IM8-KF'%G3G!#L%Y_/0K!QYF0"S++VJ!_/Q\#BV M[>TJ QPY&^P#:C435$L,"-J 0;C%E^,TZHIT3<+=+^[9\62YV!MM=GQGF:!& M8&L] ,9J;QV3OK1.B",H\>B_AVZG<_,O#?"4/=^>03V+Z?F]6.3S=5WR7=O" MHSO*C L"8:@)]]HY!1WTU>>%8.HEH?KQU.^339V W1Z3UEOF8K8:VSK^\D1* M;>LQPRHZ8AAAB"KD#<<'1@=>7RZT&4&^;9'G>-,E>]I@12:@U M!" O5"Q(S!#CE;@Z]>YL_1CL/PG)3D+]?#&R*X?.Q83! L3CA1Q!F1*2 *H! MV90.$!2I@XMUVV&P>U,"'%F"NT9/&>?>$A)K?$I'C :,JPH.P%*W_SWV+YU& MBK24[XEH-[2N/"^V_&Q..EA#^Z3^,FT4US%M&1"8*V.YXVHC*M,^-0-8C_U* MC1"K2\S/N\]_+L4159QK]I0AP14#QIFPJ'ME%=2@+&3,*$T-G>VQAZG1>:U= MM%LT90(*=^/%NFS]-,R^TT68CO/I<'P> V;/<)[*8]>P:([J)^,8QNK=5AE* M"7%$:[:N?"@%,9P=.I4\(Q1U9H+C.LH %HI:36P4 5#W@LB2S" ,(E'M#TT M<%KB2-$A^N>9&)[]Z8Q7_LXS54#$$0KJID[&:Q:$N;!($((54QYHQ6M+XMCH-)X+<@<49 MQ)\7D_%HG6PJ^G4.1)9N;Y!)J8&0A@C!(<'<8"MU*9AGN*MT M&D#S+#0Y&#.ZJTF& F[>*TE@Q!J[+UPL!1.&G4Y]XA/5>Y!KB0!V@%;7G\C ME<_XB$7IR<\LN>><,8$B;$Y3&T0MQ2/<)":AZ*%GI-FII2E N^#+?1Y3'$YO M/N:#>3[WRT58@7\;3\=WR[LR;]3OP:S\7$S"NV^^?L\G#_EO8>&^WSK]^)$ M5F[I,2-A<8#86N$L)I##L#7$)338@,O)K'H>1IX.>5_9& :P=S.8VF=F/.$8 M4QF/91Q?W5LH/U8(&;F^M')G:9&0*Z_)>< ;=%K'F0(0A8]8< <9!YY IZNO6"J1&AT-_A]#&X:^ MSQP]X!TZJ=\,*:\IEV%)@5X[ZY'WU>[0(Y?*T#_%R4Z7R/>:H/OWY2?UFQE, M%#;*4JZUHDKR\%U7_C20FF04_BD.>KI$OJ\$K>L].KWS#"!HK5#$4DH!L88A M6@$F"$A,)@C_%"= G9?;O-\H>Z*Y71?@.X)O6:>$8 M$L%Z M5] @AYP1U:X2V=2LA,>?"+U#CU-WN)\KC/W9#^&/'X. -^J'8KG8!2 M*NJ!4Y R"/6Z;+&2&D)QR*_0#A0Q"]2+@1\*:]_>(*,2B#A16F^0T"">4I)2 MN#!O7DY2_Y9T7K2 <@>+T=/G_"4H;WDHK'W;XYG'Q@:,D#!22ANF42_11BB# M;&KD:0^IW;&\0(".(\QEQ!Z['#5-+R2S(Q+SS#G"OB+/+*0^M$>)/PI5!4ZQB'GD]>7ZL<=UA=Z/,(VY5,)ZM!,1PJ^-_2P$ADI>3H[_I5:]ET>GHGF=S^RI,2(]!DQ3:!D6:',ECALG,#ATQ[ =*)ZR M'[U4SVA5D_K@_K9.\XPAZRDD1 KJ@O J_$-O!/=0NE2?;/\^_9;XL#-A56.8 M=["Z?!X$* YL>*MG,B4$XH)+[S7&2(#PT_KDF%N %% 70YEFE5DT@V=7=#BX MJ_+K>2@=[+K1VY=DT^F7P9+_(#=09? M/991)QCB!FKK%8:48,E-.3!A+FA_TJB6BL80[?P*VF8ZK>-&W]\P X3'6"B! M*;;4*(ZI\*6@3HM+K#?8PLK4*,@I$\?'/+PRCV^/07"S633:5IZ?5V[.#]/Q M8CR8?,UG=Y^NHTMHAT_Q]$XS[2"AG%H''.78&VPT*(6VR">F8^GAI-24\HLS M0=_%84Y-<0[R\K0.,ZJ\TIXRZ9F0$&@L?;GYA B@"TJ4UBPG.X6]$SZ&4:YJ M*L3T]YO:]GOIMN7YS'$)+4?8&"ECG17N<"46%C"QOG,/U\[6V'0ZJN0P.6ZVLGZ[] M>!K&$HR\JV)=-Z/&UUVG>299G&"1$UYHA2V$&*_C/RP(_X,/+5\M"W[PK/_% M@YEWRA%GJ'-62!66(ZIA*0QW]'(">II5[>O#_%- [_QUPY4IV[6'$"BEV08S.ZOT_G]_EP M?#W.1P?]ZSO;9$QJ8""$Q%)NPG::.E^)%_YP.9=B3M3NFW"@9@#MJ.K>RXC04.R"'&0CX,)JMM],(,9K/'L(T^=$6A M5OL,&&J0,YXPQ03G"%$IJU48^LLQ0D[4^NLZ,"V VX5!YIES#LD"?/<0:TPL\"0TE4 C0*)@BQ[#K;-!.462,=$6/,) =(@4.[LH),LL2YB#XL*-$NA MIH'M@$=VF?N BKJ^'D_&82-PF#T[6F0BGAT% UJD,B9'N;] M;Y8SS<#9 5/B.CH-*GL,=-Y#C^>/91!!+A0@E@/ K5?68E<*H6'J/-+#A/O- M1?C?%YK_:G704:%=P +#+R0TE$LA:S67(Q= MHN%[?.;\=T:>5M#M(AXVGBJ_@.+0@?^+AS.+&< QTA-2H CE.JZU&X$L 8DW MN'J8SKY9NIR,9-=^N[K^N@P*&\\U"#6(.0PH=:9B>(T0E\8RQ[>>!['A?= ) M()[S]LU^LV1?LXQ21A /^W\@@8&42**?EEA)+B>(M"&/;H-@=L"8OQ7%Z/MX M,MG#CO*1C!CN, KC#\NC#+.>AM"4@YZ:T/Y62N-(%B9QOB@SOA M##GEN?.> FR$MP2B:@^(C&2)-S:/]XETM 5N*%3E2-BZN-WVY,(+$]F713'\ MX[:8!&7,X]9K\5@CEJEN%YF26E!OO",DYEI CE7^9@0QHA>S&6XP\*TE<+ME M5OVXN-V-,L*!97OYM1I('<8QG(U>(RF M50 D_&:VC%N]UT+4B&JIT4NFL-4Q"8CCE%%(PD_>EA!8:B[GQD<3--@1Z=(\ MSMT$+'PMC@M7>/M\W#A2)WSX !G!QA&$H2C%\@'1BUGD6J!/$XAVLU!WNN6?+DSX[[B>];6O6>80%))9)8%4 M0%@JB(.5B4!2+_[W,/"B,SXU /,97 +UXS&V?RS<6N.X MFL0 GAX&9;3.H\9 [M934&\CN%4L9RBB&C,,D$1$48(\J9 2J:'J/8SHZ/)\ M-1G?+M*2[$[IN8<\>UIE6H9U6GL/'$=0:0FI+*-;,%,LT2PZ_E[,^Y]^FD.Y MB_W@&_D_3(>3Y2@,^:J8K;2Y6,S&WY:+53K7(GX4,=UW,0E#N?DP#?K*YW6B M0YI]448AM$@JA 7D,$SAPHOR8!$KKQ-]%Q#\"?EZ5LUT#\>C#U SNQ\&8 M?C;P?2%R!QMG8=-C48 .*NDE X 6&Z?<2RB=3&^_IXPKG&5=,#!K[-\,%_. M'FO-:6\?SAP$5F'CN2-(8.0UX[R:HD'JK%;?ER_7')OF-S&W_]<_"]5.UD0W MH<#+N^4DZJ6L$Q&4>IM/Y^.'/*!6W.4?BWF\O??I^NO@Q_YPX&-ZRG28X@.J M2JNP?Y?*QPB $@HG66)(< _=_3UA8[OZZ8"JG_/%8#S-1VXPFP9@YL\$LOGU M>#C>M\L]W#A#UG(B#7/!B/7*&)&FAZ>%_2$D(VKY"Q>F:,\*QD2 MS%O*O!+(224PAKJ:_[U#B6=2QY\EM.X/[@G'3E9!#VX+UCMTV-HTHV'B=@8$ M U9)H3AW5)0!=E@(EQBO"(_WD%S4 4036#\1J[M"6EN'*G. M6E6UCD.Q"W(T6E7+AV^(&\H-5A0KS21UE7A:D,2:27TF29IV:U?5.@[0+B>3 MCVE5M:36CB(BF=$">,."J62JSPG2Q&UP+X] FIU&4B'LPLLWF13?HQWHBYDM MEM\6U\O)VP(*-:[\']-/!JR0(!C!"!GA B3"@ J&L/^ZI-/9= J\]M*UB'#G M1_IV_# >A6W%YP#/53X;1FW>U#_CW]X\\V'N!L81B CT.,SB2-A2:&O1Y20# M:)!6+0#;.9O"[O73;(7):'68$D;^Y38 69M/NSK(/"90*2XUQ !#'\0UJ!*< MPD2CJ)=GL"TQJB%H.^?4:I!SM5S<%K/QO_)1;2Z];IB)6)$*:PP 52Z(R\-_ M2T&E2@U%ZN%]J=8X="*D9^+.A_E\>31OUHVRL%MP3#G-&0=8R$Y)";#!V8:_"PCX6!BMP(ZIA MQ/LTYO3RK+)5YJ1CVCE]/H[_N8P^_:"R]1_RL$LX+FAV=Q<9X/':/ =<2N^T MP((X7@IOA$QT'O;PDE-KA&H,W&Y#9!.LZAJM,R0 EL!'O[P04&(K<6GW&4A8 MXD%W#\O[-,BGYG'MEDI'&--[6F4NS+S*$PF]T0H[HB$I3WD,MSHQZ7X/+SRU M0YT3\3P'90[:T#M:9!XHQ)D&EE)&O842N>IKP,BEIA7MX66C-KF2!.8Y>%+/ M=M[7+--2"F#B*5 LTBF)L+H2TK#4 *R$@)AWS9AT1+N.EE^/MVZX_/KI3#%C MC==**2,MDM0[;*I%5J7NKN!ENYA/![*CD*A*YOFG:S.8W_I)\7W^A^.ZBGH "RBH@E1>R $[%\>EA-KV9%#'<8Z<>_ MSV-=PD_W^6P04[^HX6+\L [H/VQU'=]99K&U##.FB,D2Y1R4@5J6&%?1Y MUDD@P^OJ?VW#W WOGNY3[J?4TW.9,18*QIQ&,:040$V@K"9ID#H#]9 M;:KX M+9N2$>XDM\3_7<[7":F^%I_S83$=CE>5+I\&_;5H;@IKXW49A=9; G1$UCN" MJ#=L ZK''%]._;D.:=L#177 ?IL'%0_'*]6'?T_R%0>F(W47+XC^:_7[/6RN MTSSC%$+@3;R3IY%4Q$'F*J&U2\Q\T<-)];R4>9,OMG'5=+&%B#Y+/0BHQ-0( M^71^B(';&V0HV#P,1=%>UA%'.O>->L5CJ) M*@N@S(.2M]PPV1M)MKM91H&STB .&9"<>PVY5:60Q)'$.V,]#'[N%?4:5$D7 MRVL^7,[&Y?)?7?)>U? . OSC=CR\757'" K_,-_(D8_4/-;/^-M@/(W@?IK& MG_:MR.Y_>;%!R?KC\$#DQOQK$ =?P$]YD*-7O()#)((>L-Q<0#31BS M^LDVYXGS:_V8\S_U_-J.DCK90,W&#P&-AV>S_-/O II[MU 'V@9QPS(1)%:: M86NE=!:;2EP-$C?O]>/6_]2<;%H]YUG)2V VF85K..;K=Y)IC)3C$$ELG _H M @(K &PP>0*E U)@93&SF")J*H>M=Q2T M[3W_4Y#M9-S/0K8/TX< :#';7TMK;[N, 47"5LM+RPF)-<( ?C)-M&Y]_?Q3 MT"L=\+V\6MR%5T:V0+3A2OS-F_>/I^4N^VHY&]Z&WUS-QL-\'L'Q0= PKD/U MDQOI-X/,"TF]9 I*:0B7@E6N?R-TXE36W[(++7+M' HYGQ_PR<@]Y&JIUT$& MH%2 ,(DXLXPP:@(2I>"#QV@*Q#B-X7"V?')2 M'KO>UNDP@UJ' 2JE'$!&Q.!C#TM@&(")DV,/W=)GW4TTJ((>3(>IA-S92V:I MP238O3P S16E&&A:(:Y(X@7R'J8]Z<&,F(Y[!]1[-7E7SJ7R.EX5XKZ'>+7[ MR Q2/%Z,M=(XKKB'2FTV6PX(EEJ:OH?Q$AUZ\=I"OU<751JYH)(92JA L?P% ML@*%+XY:4P)@M.TL[USK14&ZO6K0#OSGXU_KR6"Z"$9K MK*QS?V#5K=])YK#UFJPJR@KOK <=?Z!:D_$^E.!/\<7/MR6\P602MW:X!6?SR& M;]O:9]XYI(%G1!E@'278ZLK"]093/XE.QR]P'(-7U==B-ASEA M?KCN1_U.PNQN""8 8R"@PH(+A%P)@$,V\1IS?P\].F1@:UKH(I=?P&CSW8Q6 M0X[_7@<=[N'=GE:94S3(YS$GD@$=MO*2/:'(2&(9D!XF3^^08%2ZHM9 MP&:8YZ-Y'//*#[0%G!J+:LV>,NPPU41JS:-I(<*DPZI)WK*#2=9./KNXX#FN M757TRI?2B \E(])9"B@AUB%AL%-85S,]-CIQ3]O#BM(=DK U^,_'O\T%JF9\ M>7LZRPST3'KE#3:4(,D$I/;) /:)UXUZN/5HWY?7',S=7"NN9NN84#K&%WZZ M_EA,;^(6R>;?]OKP#C;.+(?,*,4)T=!8@SDTU4X>X50?<0\S>;1)AK<7B)N% MO0.>?<[O-R;"RY&JZ6ASD%W>'-V[PA[332:5B,45/0)*VGALB$R%+W$B<8U- M=>%="OM:5$$7U]D'D_QCW(5_&PS_6%U$#E@$!?]M5LSGU8?U%K8]G$SM,E,H M(LT-D!90 2PA0E<:P"IQ;NSAFMLA.SM21L5 &"2 MU@1I(UGE43:%]*:[!J3=G>UARL0>42T6]0]/L/3"$VJ=)5AJ58)#36I5V?JE'/\$1E[+.NEX5GQV_+8*$R]X*8TBB$Q,G'&[&/YR#--FC[NA"EW-GL, ML^NJ9OWQ%'K9/L-,.PH"=-(9YJSPJ$P=XZ#0,K4,[[%,NE]]T$';LT6K?&J* M!/6X=1+6%T,Q%@U/@BT2,GJ*2)"75AY+*Q+]Q$??/%Q3S$W;/=L_*\&.0_J) M8-V5@@Z;Y%E^&_;)XX?\;?VV+@M#K]]>#:Y>!M%M+3(A.1+,08X0ED03B %1 M1A&K-;(8'HI<:2ET(K$Q5KJC%@J@2S%DTJE.EMZ3)(T[=:N!'TSPC-F;] MH(J^9_DQZG[Y]'K.<\P("(320@'D MJV'JL)Y=S%S?K+9/0C%%V?^X#:+.!Y/\2SY[&,?$Y:M7[]+VCLUHD6$OK9! M..0P#/@P22K1+/.7DQOQ9)XTBV3')/E;48R.8$CY>.8Q0H8"IQP$G @;;Z*5 M0G'-$RV&'@:6MT*/1!@[X,9ZEGLVU/WD,JY0@'K M+!7#^^%& S!VZ#VHX37(H.:$:1[&+J@@(%8\J09/*$CDP/%!V.]G^4B$KHLC MZ+"KGN*[K5B8W8TR9"P "/PS[8*H8EH:1RDQHN$M.B]7"GV: 7J2$P M.V+*I^O2^#G CZ<',V\=LTP(+Q!!CDD%:.ESQ0K8UBOK=<:*TU6YA1O)0';& MB)6]\Z5X0F8G):HG,P*]EY!AR+CQ0"IJ<8D(%F%1O)B9HB5.I"+9Q08DGX0^ M;_Z63_/98!*+LHS")GL5#-<+Q26?CW)%_I+@S_KI@MQO\Z=,&K3O.,.VX5T)1H M&8]ZD50$ED(SF5JQJ8<>M,99U0*\'7!*+^?!A)O/37'W;3Q=#?+#=)'?S%;_ MW-P[6V&UAUGU.\FH0([$*Q<.0,Y!= J7_B(L6>JLU;_71]1 K^FCUD&H,@JZ"$28D\P)Q59Y+8HE1^]3=K:^,T:P?HKIQ[ M526>=73E!I4:;KZ=#3.#8IPTU\ +(R"&4@538".H(R+Q3*F^P^_=,ZI1?,_@ M$3K"$Y19CA&UJZ(G88\:JQ]+70J#O.DL/4/KGL%6]G4G0-G%!/.2PL_O#6R; M5=X^G86UV (-,#;>!_//QN/U4B2?7)KH^"W;6>Y?)OH'3\>QB]ODQ;38.L'5 M2;]\J&V&*6;1O4ZE-LX@R92SI;C!P$M,L-'#/5F#M&D:U0Y(%*WYH*K%80_1 MJRKQ[YQE8FE/NF^HKIR#;/4DVV[ZKP6SQ M6)\PSUMER*@@2]@R&B<$PX(Q5XFHB&)MNZ(OECPGH-PAD=80K&ST&@1Z]G2& M@!#04^FL9HYR::FNO PDV&@7XX!NGS'IL':UL=Z)P:&-]@8=LF1-#TT:]KC3Z,(G]-.3K&/LR ((LXI(0EGRAMN01E+$M9FF.B9 MZ6$49WL$:@K<3A:L M%D82BTWT, *Z<>J=BF47JW"^J.7"?/%&/56_W2D:U=#@TQJ#>6NYQOU,!A/8BZ"K\6S#-LQH7%0AQ[,Q\.Z,]+A MGC**O,,,00B)-HI[;ZI,& 1BGFA!U4]-_>[GK,8Q[LI?L2/15Q#NTW58HK?G M[ZQQ6G-ZYQDGFL0XL+ W!]!PSY U)6"*@=0,5SU,2-WD,6#7N)^9J#;(\K * M1YW_QW(P&5_')'MJ_K_RT4U>"9S(TUI]9U*%30W!6!)(E (Z9K(MX>):)YXZ M'GUMX2&??2M:YFF7Y#J"UVWHZCWE?8O*ZHGU?:)] MG0&&"(.*4NNT==@:7YUK$2'AY=0QZ"E#$Q712>SNFP'7(-V>5ADE%G(O!%31 M78<(M*Q:2K 2]&(.8<[(M>;P[X!B;C";!CL\E@!9%=^JX338U23SSGGJD4 6 MN6#!4\!,9;LK:%-= 3V\&]Z@*Z A-,] E4/NS:W/9V%1UU#'F#%OA71>$U-& M.Q.$T.7D#SA=L0>8DH+G&6ABQY/E8F]MY!TM,LBP,T90@J@ADEJO>)DA@3A^ M06F-6Z=*&J(=D.4?84]\&T:F'O+9X";_?7GW+9_%4O)AT/-/R\5\,9C&VI K MKM=8FY+ZRXPD)BS+CC"J/6448E!]0TS)1*L(]I!I#2Y<74#=-P8VQ;R,<.H, M$%(Q18R'WI,J\Q3A#%Y.3O^667(*)X]4POFXN)F]WTAQ/!MW]90)9Q5PQ'"% M$&"00/'D8O10)$:_]W "[ 4?&U+#$R//77'J:H7];;X8#P>3EX-\;^6GK+'< M2$^A<0)Q)"GVFUV_DHP.P[&+M%R-E)\B'%(G+<&&,6$D)1BS4BSN66+=TQ[2(U6=M3R<>T\E-6$,8! M\@IICS" 'GOT-,FF^GU[:#PV/8VD0MCG:*Z6 KGBX0GTPA&$G9 XILSPG&I7 M@H1A:L'W/L]$"01I*B+K>,![&(SU.J2FV*:DQ-9 X0Y&P M\1S,'SK>,D M5$SCIUO7S;.M7<8\@DAP[ CGF AAH/&EF-;+KNY =+Y/JZW>72QI ,TN B]> MCO*@RV?K\YG%A@@CD90..R/#*H9+L30Q//4LO,V\_)Z'93?!Q>4/V M(#_>/)L9QB7#0+M@_H8/2 F#52F.@*F!QCW#R4&.[&V7 26=9013IQ@V(,@7=NTE8,&TNY@-:K-\:1+4+K@S M'"[OEJM$DKMVUX=Y5+>/C! 4]OU<"N2Y=%H))W7UZ3"8N%GJ84J^ACG5$L = M\.MSO@B2YZ,R_O4@F;8WR 0G*![V^; &8T.])0"7@AFD$^,F>EC7I5GF-(+F M.SCPU 1J+9F#3@398/0UTU(@@-7E!*8WO9%.A;";;',OKH%]F+[U.WTN)A-? MS+X/9ONN,QS94R:<)] "A0R/&;4,-:*"(M:JO[P==P(-WF:G:Q'C3J:@71[X MK5/0ZX.OM_,5"QC C2J$% [ZK'7[KB3"ZXE0+J.^E MVN(NO#D2"*(-?>)OMM65?99H:/ZUV.$Q_1H5L854IW>:B3#]&AVL2$" 0PPR M2\KEW6 (<1K5>IA]O&VJ=:Z+% *N1/XPGR_SD5W.PBJ\SC+SGX/),O^8!^G,A0,2>>MUHP"ABT%@-K*=M F\=CN^ JQ%TVU9I70E7-K MQR?S>_Y]]9?]+O<:[3-M'> 6*A?$1EI1CI[F;ZI/P_>RB#7>7_I?]OK'CNHIPQQ(A%& 6V#J!"1,5SLG M0W6J$_;HW.==A$!UYRQK4P?GF_S6D_@)L]^K#C*I'.4 >&, 01 [XG 9^QRK M> 4^#OI.8K,,;H)40WP)XH[A+#UOTE>H_YVM#(O^2SQ[&PWPM M\.=\6-Q,5[VL9O^]85WMOCH#G %BB?2(0&.YTAY7ZPUW(-%QW,?D7%VQO&U^Y+/A>+XW6^'1?650.^$89$ I!H!#CM/*Z\5$:L5[V,/@ MQCY8JDWHX-QF0D.(F" 44Q*6]E-,.PH$TGY)SY5:5T)9YXH MW=W]I'C,UQ_8U7(VO U@7DT&>]/*I/2706H*K3 MK2;.3=+/^7PQ&P\7&_>%BI"MCD<#?-?Y>+&'(6!W,]D;A_PM.A<^FD6W_"YWQU$^1K\77PXQ_CQ6V$+\@8\UYLDM"_W"+6 MU3<7'1EAT*<3 M-J6[3" =!HZ5*9VH(U.I]:=OK=UX%20T%U? MY\-%/ G9+EU82&I-MXV\*;-".$X@UAY$EYZDJOK:X^>?6D&RAY5^NY][SZ&A ML]QR684)'G759=4BLTK$/(3QHQ7$ \*?,OW88/$GQC2A'MZ2.M]5EQ2D.R"1 M'3^,1_ET-*]]CK^C16:"<KTQ7KEQK,9")W$J\X.*FHXL@5K.HO].K4T3Z.!T[0@@B M0(9%'54VK'#)^;6//JJY+&HU"/D[N"],@:*"&">\(!1#XP$33_L@E&J\'WVD M!BZY-C1 M_NUG3E7O:U.S$3Q;_NXVF_>/<>Z9VY@59S)_S]\B<$HIRK"CTF*!$0)2KL'% M'"!]Z I;2Z;6CN^6=U>#QY5#^_> )=V/X'1;'+8(IL M9/FO?##[^KTXB8Q;^LL4 H(*B8SFV&&ML K_MX$%2GLYF3<[)^+I:/>3A.'U M^R*\$WO,;/@X-580,$0YQLPZ3TMH+(2)][-Z&/5Z?B(FX-U+*OIBN3?-<%*' M&6":4^B8%U(IB!0VDI7 :,DO)W_(V8F8 '<_>3A^:'9&C!UF!B$A,&5>*B@L MY$Q$7\,:&$\Q2^-A#Z-:S\_#X^'N'0_5=5!4XV1\T6OX5%%,Z(EQL%FP1]Q: MY:HEPXO$6)4>!K&>E9&G8-X76IY*P,QS)Y&5WG(4S&01_H=57R.S-M'?U<.P MTW-0[4AT>T&J#].@BWP>,Y%-EJ-\]&%:_N4DKNWN-J, .R:XE,( %/1AY2JU MYPJD\!U>3K*2SBG8&.@M^V7]>#J8#N.4/)L-IC?KJ<3>\S4?+2?[I^LMM,5M\S6=W:*($3$1E#BG$G,I?9^O*RU%?VF&GECH'82QOU\C.&MA\K>;7L^LU:&;6@P MMHB#$L9"W0Z58H69Z(+*13>BW#?1UJ=C>@ZJ'"Q[MZ-%)A63#"JF*:,&6 8E MEJ5HGIK$C*!]I,MIFCW$DR0X4Q+@_:_!=#3/MZ[I.^N^U&N8"4(!P@8P2[4S M4' B7#EX[&E7I>W.P(5CM5>TB&L**?XS6&W%['A.'&J720DA$=)[:@7T"*E8 M&J=$!*C+.59KE!(-P]KU@O*Q3GV@K0TR(X1%2$LHG 6:,\AU!9=1/C5HLX=\ M:=WZ2 6U [;$H7VZ-D$;XX4?#,>36$UKZAVLXV M&;9&0V48921,P<8+8ZM)F2@YEY9&"/CF<<2PU(DAGBB7[^'41X-D^1T+%OVE481YVHZ^I@O(KCE+'D! MWE* E:*:!ZWQJ*^5J;EV24.MW)F\I=M6HD.NTIUM,J2Q)A9YJ8-=+2E%L0!0 M*:)-O:O=0WO@5!77L =2$#V3Z7G 3[JK24SD(13&$@C)78"*"*I+X21)C0/H M(5T:T&\-QB1@>B;"?(S3]NR@S_10T\QRP2 ED"LKP@Z/$\%X*2Q2%Q3]?KJZ M:_#G!&A3?&;_^^JW@,9@:N+F9K^;;,NCF8>0$V*Q%- I C U91P^U,"CQ)O/ M[T3W::HJ&H4T1>-(F_ _>A;GPT<<9_-N)L[;R(!N9HM MUE&K*G/7ZN\O_TV#OM&^DX"$,%)J@;D!EGBGA* 5 #9:5I.FU'D:R& H9Z99 MHQ;R\\?!2$PHIP1CZ(Q VC-:;Y0F3G0R9\\00C[!HR1XG2=;A"4EH #:;VAUGF)-9/UQ$C\QTGRIJM07VK:52":> D9=0Z2:'PX5CXA?0+#*(\3 VH[Z]TYBHCEHUZ/B.>@WX\7/"_& M^C3X4W1K:!J<8LJ!:!T#13UQ44FHWH)"8P1.#*J\DE.S!W+UB^_0-X;+Q>?J M@G0"UX2""F>=\@HQ2J1QQ!+L#&+&TOAO6%/*V>$F]V811[C=I0UNN" \\'5P M1B.I- 6*.08HT1Z[_;281B2U ,3XEN2Y8CV0>.H\++.D"8SV63F^#[?%8K:: M+YM>3ASZ/F#OD&7,2,ZAV;TPX;J:%K7))1?'29%DF?Z4"_!\*',P9#^ZORW6 M7XO;^?V\N&M^,G&L34!***0MQM0@BRDDB/AJ>APG5Y,9'U/.E.Y/S['Z 30C M7]ZOBF_SY7;]\/V/XNMRM2GN&GUO34V#E1AR(1$G2C/K)':>5Y,ED$_'ZNU! MWD<8U!.V$[Q1PIP[ 1"#&GHLC""4LGH?)RJU8L#XR-7G(388OE=PE^2 1@)( MS+P"Q'FC87D7NU\Q.+FDW_@(,X20F^^2NL%[17=)FAI"E<#2(\H8HT(9L9\8 MC_^;YAUD5Z&VNTOJ!N75O$37T$%#O.'*$LA4M#-M/2U%2&*$U B]8+W:4SU M>54/T(U2PCM N""**6$0YY7&QB&6J67BQ\>2,R7;\@%Z-S@S,.7]:GFWO>WV M7KUUV\ 9,-+:,OH,,6LQ@PA4TT6<3B<*\VQY_U1BIE]H,S#IQVVVX4CZ^>. M&':",( =A66R3H:XK2;D&4R\]!MI0M2^SJ.S<SQ^;3Z%B3 !C3Y9MM M%S=F;SVP%LG]Y 0T<#IJ[3F"/D!(Y4J\5P;B85KJM\P2W' K5)#*P_T%"/ W@CRB# MS8M1R 9&-#<-MBRX!I"&DIO2SZTB$-4$^)2"M7NF1>_0)G*#,/(3.9MI<:)5 MT-@SYY2BRFM4OH8PIMHPA39JJA9N#XSH#]5$,F#&#E(2@49&-#4-2) R5E1; MQA'VA FK4#6!,I'A1!7-'FC1,[2)W* $O29G"UJ<:!44=I(JB;A'C!FO,7L> M-K8D\59FI#GP>V5$?Z@FDH$AFD"&$ZV"PQP;0@SDC$NC?#S?*N^QH!(FZA$C M33_?*QGZ0S55O?Q9OT6P6;,\WBI8*;20F$@'(1;"0%#[_X2$J4[RD2:([U>I M[ W5U)T!XP0RG&@5--=,8:8%8U[9:(FS%U! D^@+'VFJ]GYWAMY032*#^!\@ M^6'-I8D1S4V#E,XR(+A4CK"H$ .,*S9+;TSB(RPY>5KT#FWB1@$/'%NH<:,X MT2I 2I3W2L:_6,&-(8KI>MC.IV9M!I.G1)^P)K*!8YC AA.M@G#,>B\II@(( MXCR)@ZZ&+25.O02;OL.R3U@3SPTHZ>$=JHD2S4V#M]%&ULI)1"&-.'" :3T! ME+Q+3-]CV3NVB5<;LE)Q7X\"EZ+9W,TVQ7RAOJ[F#[$Y:[SS2.DNX#*[(P2& M2J81$XAC6H7J2H!5:GS@])V<6?!./(, ^-EVPHUGT(E6(=I8/N+"M %8T[A7 M$E2]+XI8J=3',[^"T[,_6'MT<36SX42K !$4AC!K'$466<%*3/;#-B#5Q05_ M!8=G?[ FLD%@EL"&$ZV"8]AZ0J&6 E*'H)2@"J?8':^JM*?]YT&2%G&P5(/,4"2VX]MQ1 M2AR+_]\/FT6E.)$-TW=U]@EKCN<#Q>TVRJ($H?D][>MO@Q,,:%OF%1&& QI5 M9%5%)JNXTZ5F[YFR][,O,+-'\[YMD<+N2(M@632>(M^Q5$@ #["E]=2P1XF: MQNB-D#X#OE/!S,"3EWEW3I#CY6>!(4"EP%AXAJ6S(C)B*BV*I/-E[(Q( MD.+KE$SI*.;8,K;%QV7]N'*? D\M[MXM%[=/_W!J]VAL'!!%P!%JA5&8RKBG @8PU!Z89W0XEHGGS.@]Y.?3 M(QW$['K(WQ:SQ^5J,_]O6D&<]D021;"(]IZMIR1MXC$T>F=_ M']Z8<\&\G+K23)73#4,\7"5"D @F'-(:"E2';&NG?&(T_/ACGP?37M* 3;DS M++V(F[T7<;:X>_F/FV3 M8\IIR[43#ANLJ#405R$6&GB?^NKB%W#[]@1I=N?=FT7$NEAO_HBCWF5&OWM? MK&Y+(7YN7X[B5"=! \HXD%@01>-?J.*D>G*B/7(N5Q3U-5K=@\'\S+-!ZL>\ MFZU6L>FW8@+%8X"#PB@!(HQ<(N"E(2)J"!@B1I%F3;IYCD6<4CQ&"(Z4]%!( MAHTDE&-$JFE)P%(?4HUSIS]'K"V*QW3#,L,>GSM#/V!6(%,^)D2$0$,8I:P" M0.G4XF C)5.R]-,S]'?#-S/!4C+T>^5 7'/"&X,$+ZL<8U--R$LWG;I$0PBY M.4-_-W@S\*6O#/V<>TLL ,HI@IV'4:E6-4:>)T8MC9PW787:+D-_-RBS&R;= MTS+ M<$]6X\3DA%+SGR/8MKF0NX%YQ0D#/#98,H.!9!$W!#F1?#]1)KF;:@;M%%'W MD2^@&]RC>>D%" '"8(>$I]@ CQ"HUA<3(/5MQN@/H+-9TB>JHW_HI1@AG&AM M!%"<,\6D1=5T%*>)[M#1>]C/($E?6%[5.R^L553V0=3+J?,80<\1J*9FXY0G M2I,^E=E4,*\BE%%ZKQ'7UC%''.'&>NZJ*3$ZV<+."3)M$*SF?*3TAFCE8Y/E*4!>S5:3W MW^-?RUWUY>UARSB25GT%[*S&VF!B(/26<^6MKN'@/M&D'OU1=3[!AH;ZHL$$ M[OZ^N"VO@,^,)SC03S @*@2*4NDH$<+2"+NI]3Y'$U-J7-%3LWZVM'YA3C'# M_RB^SKZ70]G_UIO[F]7\\WPQ>U"?/Z^*SW%@[^-BN)U_C3\Y=@(F]A2(DHPA M"3&0"&/OX]AD.3TC!$9")5Y:7M$[LZXLR@/T!$.@/,8Z6K:>,QI-&X\MYI4] MP\H H#2F=7Z;=LD(J/YWK#-1'C@":F?(7G79($YAR.OYGUYU-W>DKF#_,-_.BX[;4T$=@ M\4 C2C-AI&42<@%0-7T6QY>X.XW4TAYD=^H7X2%UB.7MT\7]8A^U\V9QOUP] M[GKJIE4@IQ0E>O#0P@S66OF+;>PMM2XN-J=C=??/[P_?'3\N$(%W[X)AAO M#;1(8J.$)5P("&TU8$_E]1_MPY+@'#![E_[3U$R)L"I2V3#B([@'%O">:#VSHIJMA]C]T?(\/*3 MX*)&H$J_A2C3TT=;1IMZN!&+Q N/$;F?A^7 &5@.)OKWQ6J^C/.\LX=OQXY^ M&UR9T1&524.%B%JH]02:FKL$):9N&)$7.0\9S@&U=U:H.**[W:7OP^SS$3;\ M\$T W!#(*85QFH@"2CE2U8"1)HDYZT:4?6Q8%IP#YF![@H\&Z.SAG\5LY>-/ M#@7HG/@Z1 R8Q%IA7<8Q 668POM)"(9XXB$QHHH@>?:%\V =F!M/FU9[=KSX M/D@D')3 .*2A- 11IGPU$:=8XAWVB'**Y>1'.K"],V2?>>B9MZ>5BF.?!V)$ MW/@LP))PHT4\"96LIX%TXI.#$242&Y8?/>$ZD 7ZC^+AX?\LEO]9?"AFZ^6B MN'NS7F\/!I(WM@E8*>B<]1( IJ(&O?-@[B=D>6JF[C'E#LMADO:#[D!T^?OR M81M%M/KNYP\1Y9,T>?5M5*4)4QQ&,"C#1' B5&5@"2Y<:@*H7\R)>1ZJ0_FQ MGO:X/XJO99[GQ>SGPXB)K5&U2_CY.P1 MW(&XLN.MB0?@Y^7JM,?SAR\#9AAS"(U%2#,K%4065(/'$$^@5'(.9IR#Z5"; MQ_+Q<;GXL%G>_NO#EPC0^F:[69;S\]S&_]PW)VZ)+XX'<2,4@HIS2UWX%F5 M8HD^LC$54,[!C71$!XQ6<+/5HGQ)%>WP'6$O$??X>@PM(A^/-0F&,&>E9 81 M;"%SW%MOH79*:8@XN$SLX^O1MHDM.MHF( <@4 !;#1V4R')/8#5%[_!T'A"> M+^3E,)AF7(\73,/8Y[($'AC,M)?* 421P%I@9^(?%,/>-R;7'V:"[XK-FT5$ MOGB[7)]ZQ?O#=X%#*15PFA&+L=$8:8*JJ:#TO,QC?!)POCB7_2&9(2;T?26! MG0)GY]_F=W&=K:,^<+/Y4JS4W?_=KC>[2-<3;&G?2>#:2N0-IMH;C@'@(FX_ M>P ,8HDE)]K;[O*)2HO=VY^[CY?;T%/Y-!C6&PJ: $XA\<)Q+Z83MS!.CL&KG\'ZQWK#+3[ M1S'__"6N=A7AGWTNWFW+?"PW]S]9JTVDZ]1/B(:OA(X[ 6C\8_P/UKY>?<8D M[G2CS"3>.^6&1#H#X>)R617E'CQ[V"^2W<#59K.:?]INGI;/[F=Q F7>S-T; M5;5:S1:?BZ;#]OS.@Q=E8*NUV%E#N$0<*KT'3%#+IU.7O7=B9@=_+&PURT5< MB^LH\9O['U60@O)<<*><%-)I2KI6Q%53>F,2\4B,*5+LL3WM#_G)G MN)T_;.-/VUP*)/84M.-6EH51"+50$LXIEQ44EM%$U7&4=3ASG>,]89V!=J\1 M:5(1#WX?'*;02DDA]=$$@Y9(\;SEP]2L5IW#YZZ20GT@>@&B["G>@2K[%D$I M0AQ32M#R+2?5T507U=2BHIN8<[-S+-TDR)*&:=:GV&JQF=^5PYQ_*W9)0W>/ M?-V?MP_;N^+.1\SB ?YU^R30F_N?_/D-U73Z_47!4QW/?\@=8EA32]2N0-@. M2*E@:L78,<7O#<;-BTHB Z7/G)7^?KB#AM(* _[64$9E2\(85@!PQ,/JLE2,J$* M *-@3"L6)TLGAS)2FOPE4,5BO4/J_<-LT9PM_GBK0+D295%B;J2*?V;&VWH' MH#BY1/BU$#!%V*^UA=[0S7Z)W,B<0Y\'B\I\G9PC#6V<%03&L6I2F,-$LV=$ M0=V#4Z8'6,>O)KYM4::@KU\1A!8"<<.)$AH3I&B9T*M29#P=/%CAMP*817#C M9WUC0OU>^@]<&T^\-Y0HAQE75I-ZY_'[V3L_&[*%G]A@-)(JH MP(!"&C51CP2/N.SA$S6YQ/D*.NP"$1'W*]/WY]6'XOBI<&2ARU+A;% M_7Q3FBJ7R29=9^&\N7\YM'U]6K-<;]8[F#^]",Y8M\DZ?5;'07,O:%2&J!5: M"LLIL7NY6>XT:W(D#@/6*]E5(GTIPS:[1Y=N@D" ,L( AXI'!G/J30V$1\D/ M-,>W9>0BS#*;,"Z[FU2?_%%LYD^!+1]FW\J-,W[WVDNRON #DE=3>!YNIR3W M'7H)UO H.H&P5(@2C[EV3P^VI2J=04T/%8=64NQ^7?XPI>=PN'_,-U_>+.[* M*/;M[.%)_RT?H[^.H"OE_#XNFE4-Q9X=:_W]XWQ3_J;G;DKN?"\3]AW^]>VO M3,(Z0,!\#H^']>R\<;/\7KU.LGU&L?<[I ,[*R\0;UQP\#$XA*@B%$ MS&D(%3#,51/!6$WGOC1-?$218TE$IYLRBK)Y5EWT[=3S8U"9@KR 4R M" $)$%<2$%8-&"DQGB@O,;[JI:R-^#WQOZJU/'+^2P7L]7W MEQ^UJ"]]3L=!2P\\!K)\!>,=H40I7I^,7"7631CA"3%&\OV\/O*)C? \N0[>YQ3FV)AORS), M^Z6\?C^;GWI)GJ)5& AXM*@\4 M%[KQ\H]@)J!*R_2?#6^[/CIVP"5H PZ!1#R!)MH?%M5 M3:<,G,O$D2ROV<^3Y\^A/&=!F6,7:;NWMG&;=^\L2*HQ!P)X1(0VT,!M'(GLQ).R3Q7JMLXQ#6F%=" MB7?I12_?H_QUMOI7L7F_FM\6E;/B2*6X'+\V."V)+(O3$"Y=F;/<(E:!["Q/ M+ (TPKW_&E9$_P++]>I]5SCMSFY7\\7GI[J,3TG)CCKG3AO?23T&3%T\E:6@ M4BDCA&*N>BX9H=%P4LF),[(YBS0NZT/>#7^W!"\9]#[69S>"8" !M-XBCN)! M3""55D #G(R:L+M,!89G7;YQNUT?VV_;NZ#/_!U!"REA7'P 6T2EQ%PY4D'H MO9Z.3SH7U8YZK/-**L/Y^D)O:\KX^/*[ "F PF.(&?8(4D0]M?7!2\$40Z O=6Z< _P8O%Q'87F>V.*N M]1.B(7Y=* OD,.LU4\1B9D%92J=>E,+D*K26(0%/&I>Z.JR&ET$.I:@HP]QN M-_O$;G];S#?K/S[\K5E-.M4NL#A)@SU51!)E59E#"#Z?(BBUP.WXJ'99DKS6 MP7J428X'E<5J5PYX<5L\^;A&((P0)SIA4'&G"M/5^/[5=9?GIG--C MHEL_TDAYLWF(Z+,XKQ<#JG]^^BEG]YZ"AXA++OW.3PR.5M=[J^"=2K3:M.)]H[H'6XCN=>Z ;>"GGV/L(8'%;K-?+U>[&[?19=?CK M@+2'IK1JF)= >B8%KWPMVAD@)R?CKN)9]HUABJA5_!&^>5S,/VW7'5)--#0+ MSF'+J' (28HAX$C*&@3*;>(5V@@UWSZ$WR^88_ Z'3L+W[:(B3V_\\ !1HX# M:!V71C#M.*P.6XV(2#Q>.E+)G+LYJ=<7ZWN2VA4M@F^S^4.YP_CEZB^Q[:G( MIZ%^97"">>8QEA(A#QPDWHL:7*4F]&;B^I?$F<(;\\K8_>7OQ7I3QV7"(5;# M@5\3E($@FI^:01V52."05*#V?7*,NB640< M\4[L[D#5T\14F>(_,2'J&'7SL3&Q(_0YWU(6JV_S_6W-3\/^./MS'_U=58AI MGQRJGU\0#" <:JJ=UU9*PX4UI@(N_C@Q-1K]S=E+BRH'Q_\LW7H_#OSPY/Q\ M,5O1YB=O$_D?E M=Z?\31PG,58$ @J03B7JK&724E_KZ/KD.F87=M/:<#>+-:; MU79W"M]LOA2KCU]FBYM=CICUWW>(O5D\ ;'#S,_FJ[_/'K:#I%,Y:T#!"$"H MQ\Y2SQP5FE&O*\&8]-1#OR]1KTZV5[WHZIWJC^7#0]Q\RD8766R'!A*P$L)# M[LLR3%AB+C1RE2 HH*F+[/>U[-7(=!J+Z^D"^[+KZFD,@6#+C*766@,I(E(A M)BKXK62Y8G^^/B4=VLQ6FW&NJX')G7\-)LG_JI??+CAD79WQ%UE]/PXAF+*8 M]"Y&A?DH!0N0834]H)Q.S/,OO^S.$OQ5K[H?->L1&&Z!<.4<$=)Z1Q2QR.EG M[RVTJ?F0VTR M[SRWN?B^_\4I_&HOO'\7\\Y?R#N9;L9I]+G8:>9ERN_;SCL;E MV66D01C,F2>("*>]](1A1NM8!*13[28ISI;"8D*MUF#4SPK7?D3M7O>!_=)6-<]5W'&-@I<*EA*&0$P2I MPII7W$.<$/3;T?O++/IAJ7/5*_]'/]TX5W[',0:II6<:<:8(\\9J9GT5L(4\ M@>[W,]I?9N4/2YVK7OE[]V!9T6B+/\R:WY WESU@I^.5>^0=)B5*:]$>;&H,.95 V2%B8&4/VZCO0K7_"# M,>>JE_O-=K/>S!;EJ[I7N/Q1E%D0X\_-E6*H#30J4R,HIW3;6+DG@3,9@O MUO/;W>95;W--R_0B@PH &0T!1<"0LI(N!\16;Q"10:D:./R=?^4JY?N\ "]6 M?'8_L=_59W\J"4%>D1EF6N%_P,(8/3*>Z8BVJ#59_M)JF1UO+PU'MDO(NCYXHJ;@PSU22TFU)) MK/QR/U7+HQON(Z[EH0FRW"//2+1R)=*4,5E-A%&6F-MFA 1*$]_I6A[=P+M8 M+0\,A=>64J*T8AR[.$56#9-3/YU-(E4\+6IY=,-PS ZBMWFJ.$ BD*2&(TNT ME=$R)U$:>\ 4 XD15F,,L[CXR91=6F.F]\^NI(%CB4_^PL"%1?%\L<@)*3'B MG-@:6&A!8L+D$>Z].4G8%__[%-UUK8GA7K\<^UU!>D8CE!Y#J3205&!4G\;> MIR:QGU[(;4^D'&Z-),DSQ_(HG7MOUNMM<6>WJSH;_VY:/WC^W)_%ZG:^/NTP M[]Q9\(A#*R%G\;"6'.,(2*TB4N@273_M-9X?'U+^4N0>6EA7L+F_B&Y1BSOW MY]?Y:M?#H$DVVO[N0 5W$'F$K(/1[D:4TWJSP)(GKHT)OO,?Y^[?MX"O8#U= M5EG2RD%@*2=1"?8:0T@ J. DUB6ZY3K',8P\DFF-A]3LN[Y6 "((P"#B%PP#HEL2$6UJ<_P8E6^1B=4Y.PRH<1ZW36V>47 M5R#,($WC7F:I04P8'=6!/?32.*U^6_?9R'V9==B1 6-8?$?=\:^LQ6,O!'M; M@[T.)#B,(,-$ L4H+W.?.,DK05@E?M=+'>,BO"0%QK 6SS5 +W0\GC6NL&.2 M(41Z"P042CNG*C$)#Q.+JTSI0>H(5^J(&'$%"_=Z-%@N.::1&1P9CX5VN$SL ML8?>^6RE;:_.Y3+V!3F,_,?\D"3Y-0UJ6H9Y1Q.0%I(+2(73''*(H26^]IMQ MF[@DIW0^]N2F&;56^TQ )B MJJ/Y+(GG7!E%HC4-B%=-$=1#/XQJ153UL!M7_-/-_>O2=KOY?XPRUO&;?[5Z M*-7S[PP04.Z5!]A'T\57 [%N9YJ_4IU-\E] M??;ON_VM&]O;=!2818A+ 9 @D@CIB+6P L(3"2;C>+TXA0<01U9>'EYS+Q6& M,[B:VGDH@Q$8!M8RI;@U"F!)*\ HAXEYZ$=H;EV_M_&L)2YDZ M8/;P4/ZQ5!Z?5.&+*9 O?GT+K?# UT$A:@3!6',GH1#,&JTL$E0B@Z2E34DB MAYF6GR]FB]LRONEYQ&TVA9/M C*: X,YM4BI:"-I 7P]5:H2\V&.4.4Z2\[+ MX2"][/IT\Z\O_NF"Z3#.7[11A%33^!^G&'34.L1DM+4E H9I"IJB3UH^QCV& MZ5]G?\X?MX_[[O<1FWCW7)3K-\N9XOR&O' IM,^I4FG'@.PV%D%#3$1'N:Y0N5& M^00-H"BQALD(C9@^>)<7[ P\/##2TOJ/0KQ[LS.YGCRNYF&V7M_<'_BZ(7E) M+_T'#X0SQBH;9<1=7,3&\EI,(C61]PCWQL%YU:S<#"Z>L;#Z^*0:L[!24K\T:_"GD\&T;1^,9V6( MH)#*,.\@P%S54R%(Y*J%-!+>]2?Y-KKIF<+(L'?J61QF>4M0%)NW^RN!AD/^ M6), "(4.6&0$AU9X 36%U>0,&_Z%]&3/[9X0OQ"=&L_7XXT"%XH1&M'!6%.& MN(N'035!X%6NK!+#4^I\$;?@3!*HPQQNZW?%YMP#[KF/P#3&%$) HQTGG.#2 MR&IE<<5,:FG.Z^!)5[%V.[F241Z(.'9;J/L(],VB^&2YYHE]XA)>TN76H@220@7Z[$3^/]"^KY?H4U0Y]'A3# M,,+#I8=**V D!J":%&2I->A'>#[V+^9E[_!FX,SS /\QWWQY\_AUNZN'%_&/ M=G 9'U&"U.H6[D3[8!'5DJ(((R.:.8>$8=6T,72)M1]24V(-G_9G<'(- ?NE MV18/=O5X#MWJ#H*1EGL/J$':0D&Q1?R%*D(2LQ",\'"\+-%2 ;^,J[\,9?U/ MJ;SZY%QVOJ8[U$J#>%0'WUBBGH<'<85G;/!HDUIQJ_Q)C-CIK MIS>^^&?]_8GX)J[RS\O5]ZN.UT)..*XA%] #! G50OA=&*O&V /3I!<.'8/3 M[J)H)X[_?SM[V!70NIOO!MD^+.?<7Q*<$L@S";F#FC!LH)>R M$DOXX=H0YZ^KCO5+" N#?%4Q?]["K%6W+MJ MDERKZ9#L$L18#B:("[*M\3;O=,.@A4+0(N!!/*"C/4$LK58VHR'+@JX"@(2!J(L.'/?L)VX M HIFDIX_Q%__^4.4YG;],0ZP0?TYM^O # /6(^*)DH@C)07$%5@(IA8='R'W M1J B91965M?X^H<1-ZI1IQL&;BTT$!#G(-?>,B%T/5$HR'04]WR4..HB[T$ M&9CVM\6G.,SB[H_B6['8%L=K29YN$ BBW@-61IL99 Q4\OF,P4"@R3"K+P$O M!X U1ZAF-[8<^CQX'-%A %$#K;-4N[BW5Y,"R$WR-5F?7.D!U+&\KWG;(@JJ M6T?!0T.E*8,.B8%E;5=&:+UD)$E\!S;"Z]X1:%Z#BF8L'#7;52F.L64TKOX::P(XG8XK:RAR)#W=2@)_+ Q\/UMO[/;4#5*7;H)R5B$" MH<5 *>80<5#4YTY4>R=S_HZ)@6G@7TF@J+:((6\PA4) Y.-*,JIV&5J=J-&- M\,S-Q*@>0+YLH,+ELH6>'X=@&/. 0L2!8TI(+H6HA":Y@DT/$H>.0V@=^-XI M/USG7@-@,&YD! DNO%.:<&U0!1/$>CHOA,_BR/DY01(!OXSN39K-/-F9".\=5T)%8T)O%P=1L;>EX3KTXP7$E%.:BFHQ3U2("&A%Z0$5$NH+)=$\Z40[)H:SXCE/=AJHEYYI MCHU5Y=M]H[6G%4A&ZNEDL3J+(5WB-_O$>RP.H8LG6S/E2T4#N ]2?YI'QKW80QK@>L MB3?JC=T%B23PS OC$:3<66-1#8I@9#I1&^,X\OL6R*4?]+O[^Z(L7U'\D'HZ+'&Z//_O31KCVD[_6#X\ M^*=BM?ULJ"\Z#-S%\3D$D42*_*)X;@CW%*STC2+,%*4R>,NO]D+ ME]]]8T**],X"A0XBCF14FI2+6@Y4GM5+T?A<:N93/>L/F]EJ,Q;>)5%AF5D@ M6=[>+;_-UU&^$8SR6O)M,5L7:G%WL_E2K!ISI+1H'22!U!*(*3)&(VJ,XK7- MR+%,-+&O>]<[AWW#83^NH_@?J_DF*N7W/5DV=7-+*\:-^# MHBB2@Y>XRYVL)S,O,\@DY30^J;Q>VJ7$:V>/K[L=,XJ;- 0!F)JH%F M%C)&H!/ 59,D,K6XPPCK=><\AW.(XC(;XX?YY\7\?GX[6VP^S!ZZYBI[W3JJ M'D:I,DVN1@YI:+VW%;J*>Y/(OO99I7Z];>],$5RIS6&E9 (8Q&B,YX!OSX^>L1V+(NX_KB^ M6ID]O/C7^OO;XEOQ<,$@MR%6O&=<&,*9]&79)F8X0MH(QR0PD(C&VID#3[1, M%K,3V-OY+$IVOIF7+XIWHKR[*6]&MZM5/,WB!^^6BU7UCWJVGC=&P?7V.P(J M,Z0[+Q@5K,P^XXBQ>PBUY*E/>J]M)VE-I&,[268Y9#"2#NTR?\S7_VJ(@3O5 M+&CJ'<,2\F@08F,=Y0Q7D\323I!L^7BQ'$P.6BS2B4!I62#&H(RF MAJ8 .%]/3DTI4N'BAV)/,K@0PQM7B7 X":BRW[[#U/6W([OAQH$H@B0@ CXI:,D6'$>2"JR0G/IA-X,A1? MS@K.*O_O+D?6YZ/MFJ@Z U\L0H@93&%C#-F*J- 2)PHBHS0AI=7E\> M1"(YJ?CRYN3G&32_>^S23Y *\[A)P5+PX4(XF54".I# WE(IT>L?B5_C%]G0WTA M-J$D-NU;!2D%$X!&"T1Q;#GF6-':8X?1!/U-V=F4!O6%V(23V(2KW-@1-,A5 MU"@@T8"8J%_45JV-"VAZVEAV-J5!G9--9RBH;]N\J>[S]P1&4#2[.#5(N:@% M4^[,LU6-3:(9.L;(\/'8#Q<07)9;ZT^;Y\NJE^]RRUH$Q=W[8G5;4N7SJ5"> M]IT$(K%#DL9#1$JGA8[_J&L J,UE8.1PRUZ(.3]=@@\DFZPA%2^0:Q5+\>+[ MJ ]SI:$TG"L "+*2 M>0,D<_+9 \IE8H;\,2N,(V%4$OXC#&_^\&6YVGPL5H_/.8V>ZMDO/I<_+??L MB84Y*PN=01A1(HCDP&'H@#,4B:CV8]A85&)P=__+^XZ_K);;KY&^K2.83S0/ MV!/!HKG#K>1E]1SEI:LFCKR=3M1"/^(_[KWO"^(LF8X>=JK5;+7Y_G$U6ZPC M!%%^:_W]Y;]IN$IJWTF@V"GDXX2!5I9#)RSG%0#0T::2!%?(L5[H\%/^HH$ MS\RX%E5 7W\/G+Q3FTIL69<0Y=4+_*. =N)'31P%%(Q,/ :P:5J::H[!2)U:_D.\0Y=(/Z M*N,<'$#""@B\%M0+CE TH*LI,I#ZV'3,1V-V-J5!G5?]>@'*SJ7:7N\ZU#(0 M!1#B1E#IN:.*&D7JA:.Y&SRAW>04KAY0SDFH9P==Z9=7C[M"@^T5K!/- Z,B M6BU> .7C@C($6HRK26.C$ZDUYN/O7.DWYW4Y%^4,U#*SU>K[+JO5U^4J&K9/ MPSTPE\;3L&-/$6 PF,\JKR#U).:&)RAC$K9T-0;T#(LRII!_2+ M.AO +M)F5[AF]G7G;>X4,9C8=7!:4T.ATIS#B!=33H%:2]8JD9]C#A(<5LW+ M(H8,G'T13X4$*.)8=1C/HH'I\1R0 %D M8-JN>/G[V?=R 7:C6D/+P)0Q#N#X/R.1)MQ&P[U6KR688$Q?;J[U*X$,9"MK M&J21K:%E( Y+@)CGF)5G!9 \/ M?C&Q(#\ #8C'#Y,:.>:QD[1,I$48\0 Z3)M2Q@\=Z-L4S_?JRVCE8@TDI 19 MB3&.E@VUU72F&59UEE"/1NVFH)DU KR_[*!( ^T(YP(;C#1FFCE>31)C/L6$ M>AVEVR7'9SM'U%UR?':#-H>; M\@(Y/I77ACL*'"]+U0"O'(<5" "(Q/H:H^;7.50X)\=G-ZBSN'JBYEK4"OO; M=FD^3[0*0@!//-7. 4*8+//R5MJ AAQ/)R*AKP.N/S OQY?& ^YDNT 0X((; M;WC4'U7\CX"RFF;\\W2"RWN1=3O^)$%[DD%'*D35!9S__%HLUL7+..BCYU2[ MAB&:\Y9A"I63'@,@#>"@&CS!:CIWMSW)<#D@NIE?N4D',RHO285;ZRVX6SS][5YQR1S6V#8XSZJ$2 MQFC!&,6$ 5(O ^ 3RQB.,N'$6=(^RIQ^@!V+3_;=;+7:_6QBKE>'#-",EMD[ MD$,6"4YL_"N52 COY&7*2*6[7B&&@I0U"($53C)!*6?5=+ 7TRE\TH]0&URO MW=#,GG6HT>'Z^N. G-!46\PL)EIQ&)&AU82@<;F2N^=7!%I+\F06H 0,LY/B MW>RQC6/U<)/ #:861XR8H\1AA0%Q-4X2YCKU%B!X%AJ%JG1,RJ%!N>X4+O!/,%<'@QSJ(' E)49\!UP7M< 2.@2 MW?57X&!-/=H&P_8*TG80KSTTGLLX'5A6 XISVD\H_D]/YVYG""$WI^WH!N\5 MI>U09<1>U!,X=@2:\L_,5!/CW$TG5/<(-SA4X7M/MK=[0O-*P%@TEH:1,Z^@]%@8Q@E4U21]7R62VF'Y$ MW26LI1NT/_#G&F$]!X%)F2+G7Z!I8KPB'BBFL:($6 I A1MV+C&B=81/POK? MQU-!S,J+=]N2N3?W+\C\OXMGG$ZRY$C;$+4:SZA#"-ERK6'$>+V%(2*G$P5] MEJR/\J8?6+.[7X>O!& \D Q(9Z%$F&.*C*BA50)-Y_ETO[P:"-^QW,_NMNO) MW,H:K30RDOIH;EH?#4('K#**6.6HC;*_R*UL;S55/D;!Z#C&?[6!I[=?%JPL M2U%Y9PW>%2"5T,$*5&4GE'.T'VH-4,_F+(%D.,H^W'XI[K8/Q9%7=U5$RYM% M'9)W53!*3E+=,Z-\& < MA-^7ED=6>E=Y>W8HEFNYRJ9R5V.[>WKZ4FEHOW?W^GL"%UH#13'WTJNX03AK M:X$"(Q.OY$?H0QR8UOEE,:!N^)?E\NX_\X>'#U^+VW*L;^>W93AS.:VHW,X6 MG^=QW#\6Z,FI$U;#.S"<9^&V4!([]1,$$!XZY 6,0D%,$&/83CH:6D=Y4YCS M!:%HLZMTZR@ :BRPPC-N(=**(EZ6H7P"0S ^'6UO((XL,Z(_CHVB^O2"$;Z7 MV3>@D4I#!!.J/B_)UF)!IOS@NB004"Q'XZEQ@#<>.H-=(S\AFLYQ,CUM__.ON_RY5Y MF*T; 51 0:<3"C$$+5Z[+P?#_;+4>QYZJX>,*&^PM9R+"@H$E)C._C<(/]ISL ?P,_#0;->;Y6.Q>CM?MW@F M<>#KX+S#3B/JO ?&( N9J X.I+A*?(E]77PZ3]:O,["?#7)*/J]E=\3A; M_6L]6]R]GVU./IMI:!&((,Q[")5V-!H)VBJE]L/EF* )Y60=F!/] IUA/WEE M:>VA:-I73K0*6!BO@*788B,YT0Q!5TU1>S.A"NN9]I?^P,[Q+":.LFAZ4E5] M$S2''"HF 59$.:QH7!S5\"5-#5 ;X;Z30;U.1347*1HWE1=?!8:A128N%*^1 M-9PJ G4UA3BGZ;@($Z1V2.Y)L&60_%]G?\X?MX^-LO_ANZ"9<49H0Y5BR .* M'*35-"A%$WKCE"*[97_07=9P?MNFE$J+YD'&65M/N"WGRP00 *']I(6B()$O M(U0Y+NNE207\LBS[RVJY3F38KFE@2EHJ#-220ZBAU'%]5I,EUM/)[$;]BKX] MKU)@OBRGU.WM]G&[>Y^J'I>KS?R_._&FL>Q(9R%J A@Z#[$ &CMLK$&B L18 M-KAR+)]XMR@^ET/[.%GZ]8/_90EY.M7>Z88!.X&E40IK9#PK<\'AZJ@0GMA$ M97N$Q^>E&-8=Y(NRZ6_KXG[[\'9^?^H&MTWS8#A#5@B&D !,DKBCRWK2F*?F M4;NL,AH8<27YQL&+=E0VG)$ M"4XLND!_,4[U"O)ESSZ_W92!$2\FM,^L;+:K$F>UN/.QW8?M[6U1W.W*8:UO M9P__+&:K5J_$AOW-P6L:U5X/&&0*,XB4=374CI+$!!WL%^/SN*1T8>ODYZF^ M*_[HGAQ_\L>^/WOK\ &+;$*2D<5 )J4=J%S^H5G4YNOVG0.DUL MXV1S_/5IAMC)'@."@D%N(AQ,.\$EP\+7[@UL)U0:=3J,3A#<*#GME]M3MX%I M'09HO 0<,DZEC[:O8,!4 19"$YV8EN2ZO U7QN@$N8V3T/';?@D=OPT:>H.< M009*B*'!$AM9 6,A223T=;DZKHW0W>4V.D*K^RCQWEG]0Z]! 4 Y049Y9RWP M1CA=*V82J,1+U>OR>EP1M<\1WCB>%+[^Y)=[3&@)@IA:;R.)5?D_R/9"0X)1 MW>28&?HQX9N(^WT?#PK;=!0HX\X[JD!)8008XYY78%!JI^.E&H@C1Q\5#H!^ MAO/Q15[Z,E5M0_SR@:^#Q!Y01N)?K2P??"C)=#4E;E)3(HZ04$.)>MDWQGEI MT_CL[Z=O@V ,:F&M81X1ARTAQ%73T5Y.IX;J6;(\SHLD&%.>6OV]6,W_NUR< M?EWUPT=!Q+&4\;:44!_G9LH@CVI0&$XHA?H9\ECVA%Z*2+TQE4*HMKO1GY;N ML>^#,YH2+C7WF&(ORK(1H!JJ0&8Z]P(]";HG(%-DKCY^/"WD^H-@!>+$:460 MIT11"NGS8'1RXNP1^L9[DFHJB(X]!:N)+:OX&4Z(PA1!XU4% M!=!@BH_;!E4)A\7_\E3LF$F3TDCDDU';5D,*YT MXV0/0LC RR>76)DP^O.J*-H5X#S:)D#B$?!QMP=QD4=( 5659N\DUM.IMCFH M[)?#P'WY7>[ETGO;X@%@2G?!:^NX$MH((2,L2"&&*E",(HDQPB/4W\9W]*8* M(3\S]S1?(-2&21BP$K6 !T$^G0,\EV3B(+#)0]/WL^U-B^:6Z_?=V MOBHZO,UI;!L@QX)P !&01!B+J9:B7I',Y'*=?"M6GY93(E_?R&?="Q\.O[O= MS>-4B;N6/01A))9.,Q!U:XJA=;KV.CE 5.+IVSGR;W*D&P;_#-2SQ=?E>KYI MW,]^^"Y@X;".LY"462 (P%"Q:AH8-&9AOYYXNZPD.@?C#%2IR@K=+.Q\O1MI MUP>K+7L(2!%.,><*(8*\I\;X>H/F!D\GYBTKO89!/\<#Z:=4]_=/PYX]_&6U MW'Z-ZN/#MHSU*Z-SEHO-?+$M[FZ^%JN=V/>!@2>XF-YI@$YQ"KPPF@,%%62, MU0 9:A.-!OZ+TS.;0,819GFY(J 7*OB$/5,0,*\,!DPIJW&DB"84<8@XPN$02>(-8("*[!RT#)102(%:EJXU^,BR\W,H40PY/FVG:UFBRC?NIKHF\6N MF.C+I&XYSS*SC+\CGK!WAP9T<_]^)WBS?/PZ6WR_63Q\[W3 G=]YH$9K%Q4A MQ"#1%F,BV)-/4W&CB6VR9'*!5M>)7;?915JU#PQ+S2AA7'M%*?/($UE/G:KI M7&_GI,GKB@H#2.)2VT<]E_B']?)A?A=_6M;B?B@K%7_X4A2;%Q]?\%'2V+<< M@K40T7+'AAFF-<.&,R-+OS;WWB)_847[)&5;OUUJ["4XQJB*A[16HJP,%FWN61VO->EW<_L_GY;?_=5?,2S:2\@\E":-$+@#DN.RM3I1[P MO&@.]C[1*EA'O$':$J@E(J;,&PBK*4:[+]$>'E&H;6\5T MP[A7*D(P$@Q:QASP."Z$^O25J=5,1Y2CJS>Z] ID!L:\\&\L%[L[TX;W=(<; M!.^,B##IB(YP@%#'4;T4#)M0+,;X(>1K?OQUK$IC5!%H((#.4*PPH M\;R:'"=B.M;MN<)MY$H2H+G9XA[FCW'9E']L41#Y=,O@## 62^F)!'&="4Z> M=U4'9&($X%5PIZNP3['G;&3SD.CHIFMF7W=C?]OB@5JG?@+BSC$KE%>>2EU: M!)K4%@$BB9O3B-3ES*?;8-!G"P!L<7WRXX(;C::5#DAV[+EU??!4\?BUDLLQ91(K*V-&%5.*HJGD_$N M59P'67$>BCE.L=GZBUKRL6A-F:V6GV?+S[_??:P/77WV*I] MD-8H'55*@%"T9@W34LMJVEK*J9$G6>JOSZ[=P-OE;-&5/XUM [+<8 :UIIH XA0EL#8DO"2)%]HC\BX/0Z&^@27GP5/G(:6.&XY5XH+XHRI)^%2#Z,1OM3LEQ-G8)CE3?@3 M]!]G?U95)V>?(GDW\V+=ZOQIUT%@JKSI\U 1KN-4+<>Z#@>)J"8FV1OA.\J> M-Y0AT,U JYO-EV+U Q0G*/3SQP$RKC4'&D")-%-:05W'B$#.$VUK,76ZG(UD M;L]=6X]=P!)B#@V#E,EX@,9Y&%%-0WG6%.E^A!"R,R&6F]G#%1'B'!!S!&FN MEE^+U>;[^X?9KK)/Z1#Z6MKWI]624\T"*(NU"DPH5D9)(C5WJ(;*I6:9'ZV3 MY6R?;H]@YHC5VS_ 5ULCHN _*,KD71;(VYB3BB6&;HW62G,V<7N',Y"397S>\6=0^G?7+N-,X M^N7M[J?QY/S_EO/%YN_Q\^VJ.+TEG=%O8!$0R@5$#B-J*#)&U=YK+61B1J+1 MNF%ZV*_RH7V2E$N1:4>?@]T$#@[ T4H-X5$MJO&1U6(;W+-&DZNZ&N1:N](%B M-I]5[ 6-UP/07,=<0M@\!?7"/$G>S# M9GG[KR_+ARB-=>G^V7QO$5'9MHO@#+)8$8FE$"(>KT"J9Z\C\XD97D?HD,L3 MF3L0[GE)USYP]WBC(+@D'&F&B7!EI7>+:!T"%D_?Q&QU(PS [%_DQSEU'L@9 MX^S>S[Z7:E<$)/YDM2T]4:\GT2+LKD4OP44,@!4R[OS>:0P1>'9H>2^GD]VL M#QH<"<3K'^<\\50?E]VBJ7[^/DY+:ZB$4HH)Z8# 0-73,LPEYA$9X?DW 'WZ M0#1+%,VG5J$R]5=! HT UY1Q0Y"F!&N#JRF J Y,YFYJ"%(DXY@QH.J/XENQ MV+;9- XV"!Q2"Y36$I0)'9VD[#E_#F4^\4WD"*^E!B%(#Y#F\LET4EN.M B^ MK%H8J2\C_SU0G-GG4.2H 2:R981740.PI1],+V(_=;*;@E60(J<$X48Q);&7 MXOD5.S:)SKON-T>#.V\&(,G9<.;@QW+QN7PF59Z/K7R\AQL$:ZR19:%Z93Q& MCGO):RM2,'K]&<[RV=5] )S=T&G%G6--@J),0\>I\8@@9SF0IE;.$?*)D9KC MUFR'84]/$.=X'#M[*-Z6A3T_S6[_]7$U6ZSCO$L!/I;&?YS'WQ81E[U;=/%9 MK>(GGW>.T1,,2^\T'MU(,"D91[ L8N^I$/4N3YH+T%RE\CP,![,)(>];EY?/ M*%KM=@U- S7,*$)8M$01!@9IKIZ]^3J5<>-6P ?:]?J%.JO)O]B8^/=Y.^WK M5+- '8528DR11 XJ:[ "]>(!*E$'&V&45S8^]0!S2GC7N^)SE,*WXH?T%C?W M+\//#@>A=F@=XM!96;^*0N:HLP#!YVP9R%$YF>"OP=@R'-KGQ@3N;TY:!016 MWP:$L=,>$RH9U,Y#+9![B.(/+PC(C#P 30BC)G+-(>0L^"@VVJQT$JHH0]!409!I##0#HKH $&,R=%TUN1@4Z@ M[ 4'!4+8$,<@4G&!<:PLHWL8-#,^\31^I0;MN"@- 9X M(YABG,:=&9&HOU6#!D!.)V/U()(\47"P&["]L\%U+#A(E+ P+@P'I+30 TH@ MJX9+C;O^,/:S9'2LX& WU'+DLCF[X" QT!-E(0><.^8-8,3LIV2D<]=?9R-= MB"T*#G9#+X=AW%/!08\0TV4M-"0@1=0@ABJ0C&8J,;9O1.$XO=&B%P S,*/_ M@H." FL91H9S'6VP:-K3FOQ"IY9W&E'036\53$&J9>(U\"=KL+N6'"P&[)Y2'2!@H-:6ZX4=@C3 M>'(K3YU'%0P\[O%7KRYG/MT&@SZ'CEULRDN@]ZOEM_E=<:>__VU=YB>\^5JL M=I=%ZG8S__9T$=9\Q=*]LP"C88&9TP)3#A@N'YKQ"A#HX/6[_P;FR6N%?6@) MC(J2O5 Q"&RD)/%HP%S43XFK,#9V.\7G1+;$_"62Y7?G^I*HLU>V_M_-5<31M_./+3YKT2Z,\&_!- =_KOTK<:X' 63@W9O%[:I\\6N+I[^_6;PN M:]@B_4C[3@*7#AL @?%6^+*\C"7@"0""K.:#7T9-F(&'9["L$_ZT;NYV M0R[_O)Z78C[E!SS>*GA (&) QL4&I1/$ EQ/$6J:6!EJA&^T,S*L/[POI+T5 M4:J;-XL?RD$L[I[71T>%KJF[ )G7'ECGL+7$0J4=H14H7M+$2(WV#[LGO-ME MD$=&DOKE*H)V6Q1WZW)A[9X2'D"M!3];]A0H=H1P;1B(@ M%N'6^/@)<:B&( M]J_(?P%J#B.*4;D$>W$%!@89]DH(SASC$'-*GI>E\CAQFQSA _:,)!P,_LOQ M[SGQ4 \NZ1.=!6DI)E$[9A);@HR6B-E:ES$H\;'&"&^,+^J2[D\".0[J%QMY M1&VSFG_:[N I?_ 4H7[J<&YN'6@TR @G!K@(,X+^.0J$8.1DXCW(]=S+]4*' MG\O=]HQ[9JJ5H>T1E>+F_F5VR99,.]PX,*.\-P@C"!C34,<_B'K"6"8&7(WP MPNU"1.L%]@P\^Z/XNE=4?QQI-)GBWC_?Q,.@N-VNFO2\+MT$JJ("@S1EF%!* MRK&=E/_(AOB.:"?Y-21G'Z5"VBS?)E5SL[+22_NCJ;W:V@6C(VK MP4) /4<:"B M=O6VG9SSYNK\R7VR90#<+V8C1!/G6[':E'$.[RN![K+Y=#88 MCO84M !0>TGCK(U'4I?!DA44E)G$PW&$V4VN!-?!X:T M=,QX 30&6!GM-:VM(YZJ<[5W 4]P9^L/[LP;VH[D-T_>1_=GW([G$9N66]C! MML%S@!33@'$1C9YX]'L :B42Z42S$4=W_]W+O'RSDQBKJF'<6(T<=4+4]Q2B@B2PSSA-T,B#V%R.@VOQ0K*8S\UZU#]0YS4B$EP%'9)RS%)6!1C@UB?M> MYQCYKSNA1!*L-I,EWGG03X9QUFM,.=4&&NNT8)S2:JR)<6YQ M]\OPK1OPSWP;6P;_:$>MBB_QF_FW(F[CR\?B[7+].Y]_J^3LQ!@DI+-,(X4I M%M K_<0!5B9&;'K].5#@1_9\_AHHYCPW4$,=EP30S+,*!D1<8K3Y" ,M31^B@<-I\_XLA;I;G&#F.(-'/85X,F-/5YX0A)-(@D3^3S[P9L[VQP M'?/Y R:8-%(: 1G6?');XHGY$/#A+1L?R^7=#+8O/_MQ\_IA(758_ MP<)YJ;'G4M3<-XI??QK+="&VR.??#;T<\:@]Y?.'#D@GA#51B\>*J,,ME1S[#V%M)JH)3Y1]1Q1>'IO=.D5R!P^N,&2;!OJ'>2,"(VD M0-PBQ^V+\S7Q&!I1-I3>.-,ODKE)D0UW.<^919 ":Y> M4\EAT?:*\47(DUX$PB+E/1.&"\FC9@:!!=5V:I$AB00:D074EW#;%H'H!N@/ M;+EF,+O.?@(;^ 6J(@ '-,)$.8VM4X1$$ZM2EZW79O"7N%/;[@>#/LN3QF_% M8MLJF\KK3X/0# (NM8=$@ZA("RVK&P)+-+S^.I8#R_BG1XMGX9OII?9Z/\P/ MQ>K;_+98ORM.<>9(BZ 4I\1'6# DEB(HO*HQ>$5]/I*92?*7 MY?*N T.JSX/1#"!FGC9D*!G4:!\BPU&I9TW&(!F$'HDP9N#&+@[YY5!/<^/0 MYX$@2[CR JJHPFG%%**TFA17$R!2HQ>'&' ;&\<2(0NBPVTWI2Y6MV?Y3.95IKHL28!Q@,0&:N]H8XX MBZ'B^[)WG#"<6F-KA.=&'HVT)YPSD>CFOM*+&JCS_&%P\6 DE#N%XC8HRD0/ MNCHAB3=X2B;,N:(\P(UD(+,Q8J<*?5@^(W.4$O6705 !XWH!2L0=U5!:.@"J MJ;BX^4YH$QF$$ZE(YK!-BH?8Y^>_%(MB-7LH$X3?/HH_9.H4$ SL L6T31Q'/X*0[]ZT.Q MDUT<_N-RM9G_M^F5=YOFP0A*@)">&2>YI\ ZSNL]-D[[ZF__!V/5 /!FX)3> MKJ,*MUZ;Y>.G_4U&F:/J\VKWQ_W;\QU6)YC5OI.@*-9.8LBBABC]_VOO37?< MR+%UT?_G92[G ;@X ,>&+URVK\N]&_L7(6=&VNI22MX:[/9Y^D-*"F4Z4U*$ MJ @JI'(!Y9R"5*QO?207R35(J#QA.W05R71&&I"G0&_\Z@WD$DYMH_$T!=*\ MG]KQXMML4]/E_<,)!>]:]A"XD@(1P@2(4#ID$(-X-VF#W(C_X::PZYQF_0!= MZMQO5Q)W$[RU1:7%">#!AD%*;@31SF,C.514$BYJ0:ESF3/6<"N9=,ZH3O&] MP&'1"8=$P8JX$?%2&VVD 59*X':C(NY+,@\-3R\U4B#*OH=]W1E0EIA@?J5P MFB2/S2JOGP[08*"Y ]9(08A22*O=7M7[W&R\)^>)^U[-/\^N;A8Y&\\R/MFS MO1-=FT(R36T#$)PA12 QV"MB*$*BGBFI S"3/H/<\9>X:\ +\JHO0-1\B MO7@RN#A*J*1QF74ZF6H"F7HVI5+KS-ON 2=JZTZYK^J@GH-L>9)L=X8?1O/E MS_:$>=XJ0 P-Q$@S[9D2J98<\K6(T5[+C$(=<"WQ4N0Y ^6"1-I L#;C6Q#H MV=/!Q>G72&24- K$R=G'!7XW-A3,]-D>X(K5/V/R82VU]SZ(0=/>^V##@$S< M&QHCK%&68BOC.* [T!@I52JEA,'<'X,ZQ?B21G2.\1P<%Y@X!80!R%D+"(.[ M694@DYD2:H 'SOT1J"MPBRQ9]>:PKLDWGJ[B:V]WCW'?H*N'V7R;V^G3Z#_5 MXH_Q=#8?+W_6$VW4.&:*TK%4@(+\=-[4RF\+AJJ[8Z(E";<>WKJ;5P_C8H<6!%B':KU!B&%<2 M): DF*YK' !6'*T3 MU(+S W-+()PBP@Y"R' &"FO/;2( MV-V6B5J=&0R4?8MW(ZOE.1@7H,JO=:UVY8GB KW>$ZG[?Z^:C;GVG03/+-8& M8H\X,-"9%%+\-!V;3)(-M\I4&9+UIH#2DY7Z/AI/4B#PI]FS"C.IGD?4E!XM MQG=MI[/FG@*1RB N*=#8$P[YNO;D!@J%""U5DZK,76/QN:YS!90ZI#N0X;B% M==:F>> &8RV!U%@S:CT%SM0&J6:>YL8Z#+!(51G2]0!Z$0^:5R_<@F!'6@6E M 7",0 2)=H(@+UUM6NB43"&35Z<'T=R(X=8=UD]T*IO+_=UHOG'7_YV1_6!Z M;2D4]MP2):4"SDI%A#&&Q V=DLC*IMFXI_B8XAG9G6(T+KA$68#]!PY;AP'$@ A MA 0<&>. $F>I M\YS'C>M&. XHRZU1.#SRG*/8HQS)!K-(-.AT/)N_FRU;).9]]6Q@$.*X<80L MN3BV1\Q7Z*L;S/"R+4.,NKKSW2?06U'CQ;+!.*JT] MT%Y[2>,8<@ANIE<-,+>WDT^U!VJ6GE!EF%DY/410RH/2_<9KP?:Q8T0 HX#T D$/3<4ZML M+2CQX/JK1'>J[4.Q->C;],V3 F"' M=T!*26]G!]'G#-4-N.5X='I0^/&& 4".B$[_0JB%$M+#G:#QG\P8W@%F+.B1 M1=U@6^3J:*.2[<)\.IG:=1 $020*29G0:NW71>!N%H:*9EY7#C#A0!^DZ@7C M@N3Z987.IUB;;@*2<5 I[RR%0B&>REOM0, "9&:V&& &@CZ)U@/2)>>RS1)^ MQEQVM(/@O<8Z+OX"6X.UAX@B50LN;&Z:X/:Y"FZ"8IUB7)!<^:PZ)"I5!A"- M ;< >:4)97PG*M"YA8(&F).\3SIU ^Y5Y7#B$&FJ)1+,<8 4P\SNYE]G2(;"37?VKSB>]^E?!,$2!9%HCBK5W M$2"X PI($"T@91SM3P J0&0)R^J'X14^C.B-+ M#J:7(,M_C2:KCMPX::@$4<48R;#DG(.YQ:I&%1)GWQ,-- MT5N$36?C? EJ'2\*O._Q()W1D$J/N.#<"^.5W:W$S.9ZTUW9B7AGK#D=T:,T M63[&3TK*AVBK^O2;YQ_[[$S['[/9_8_Q9#)*M3I^K6S]9GI?/8RGXV7U=OR] M>O7G/9SIY7,"058PR:$V6,6]"-8([:#Q(C>_RQ!3Z7;)MB'HHNQL]DS"#_-4 MIVGY\T.4,96A285GOCVV/K)MTU,0BBI-E4/:*M@H4Q"%ID!<*>.$T22[^6Q&YT#8WUN[O=P]P)K*7<,EZ]LJG^&,] M:Q8,C9]%+>.2^.30B+32M9">BTS?/GAEWN_GTJ<#:"\V^9P\[P0NHP' &/!I M%YW"V.0.+>ZHR#6Y3C]]OVK.G 7JA0XHMM$>)YY3;%L%RX2+$ZH"&#H-"1;> M[R949W%F"2#X=SU@ST;V8E/-N]GT[A0&[6T:%()&4NJ990Q*3#PA9K?/1>(F5;N0DH&^ R/J'NX:&Z6^Z*P\3??1PMJX_577SM*,&Z\YMR#)4. M($4EA80[QU)"%E /:26L;+H8Z$?,-EI0==!["JI9Q9?Z^?%.(NVQ.%'0 \ M @D1PP374')(,G>A5^;(VB>9^U/&0'C]+J52O%_%QSY/JJW#Y)D$WM=EX((B M[ZG&4#H!/&5QQU>#HP#++.-V94ZN?3*U ]0'0LF=/_FY)NM31P%+I %%)&4! MI31^\68'!-RW/V9U'O977 0D&B=2P(MI9H8&=>' M&A0BGDV]=)D(@[)230+E6; M1 M 4YQ*DD%MMA[Z5!3Y$*?8J9X=1^YNH\SNGJ(RGB>)F*KID88LGH-WD-K'1:0 M.HLU1$C(>B[TF#=F^[V-D^367-F;;J0$\,52V)PDS';>Z)::VTZ#D8A*)B! M4D!I!32[,TRO1.X)QI6='A=D9A[NPR3F'^/I;#Y>_GPSC>J+XVWM1?F\E^3K MN_SY1[7\.HM_^5XUV_8%WR( $??@!%.-C >0P#@CU.>@GEJ>&:)Y^DGT1>VS M@M0OI*@R!M[AM#@W9=\1:P61AFEM%=(4D>059"@22@AN?%.@3C]B'L9^77[F MB*@-+0.*VP>A ?46NS0IQVT+J,5EUOT]4D>UUOFL3W!+IA-4JSCES ^7*#_> M('#+.=<>*.R= Y1(:VK I-&Y"20&R)K.-'PHH> YN%Z$, =+F3TFU*2*M?.?C47/]SX?&%.I8;*GL-/#E5L2]]4SO LP!-?G$O^O]6\_'B?GR7U-5(F(:6 M@2K$)"=:&:TI$SY:T3O@C,JM+#ODO7U7U.D6V0(D^K0O!UB#-7.P38CS,0?6 M.R,%Q(0X#ZRIQ>,69%8Q&2!Q^C)HNH+V4LQY-WJL&DV;AI8!FKBD:VJ9AE(3 MB+G2;">J-K=CX72@[3;\R8:V (M20K?X,5\;UZQ?'PR0<*PUB*\,M$>8:&Y% M+4BJ7'#;',G1Z*Q#/ L0X_ ,^W8\K=XLJ\=C2U2+UD%8B(0$%E'FX]KKK;-T M9]!)ETFA 3H4][58=0]R3BZC8]+]9^,-4-WOH4K[QL$[1)57S D*XO"@"@._ M%2+^BF7:PP.<;#K5Z*QGG'/(\L_IO+J;?9F._\_:)7A;@")%L?[RAH?HTK)Y M(%K :.!+0H16' "&B:P%(99D>O!M[%_"%FD3E3$?)4>F/ M\73\N'J,SQT[XSFCVX BS@D1GLJV4,HT=O61F?,:9=[57]5*ET_'"VA@.#0] MGY'!<8&@PLAP[00W2EA:&ZB.4I49#'MRJ$N)0/D!T.]$N"_!M,[3US($@7#6 M:RT8,L+%A4#5(AMI;R=$I2B_S@:Z +=>O^-+,>HX,/68#O./$.W4K@*&"E)B M/7$4:1O@#RQ2D& E?*".:"TJF=PKUVYI.Y72:Q2L)=Q%EN?S]R(1QB2."X72D+E M'-0<*5X7?8LCFJ(F.["G.]2[K]7]:E*]?]B\^@O?P]=!&&N-?(HZT/&%_CIV MQWI>SZD*#Y(,:LPUL)8[AU)Y\0U<6,',J[0!GCEUPIF7U[!%P2]QU[\3*,U9 MLVER;ZV%^_2RGFH&1T_N-1CF&89,0"\,<%Q;XW -D9+R=HZX^N5GW\ 7Y6:[ M>..3R7EZM\&+E+H!"(4!]]Y*HC6L08HV1"8[!WCBU2\[>T>^*#T;2CIG,/.D M'@,76CLFA/$((FX1H77(A()(^DQWWRM+^G(^*?L$O2@?#]QQ?)Q-)GZS$">VX)]CN%6&0S$QP,\/2L7U;VC'N9_>8!(6XJ,HEB!B!& MRD%&C/> &<*,C/\;0[W0_"+[T / 'Q'Q0(O )56>T'1P(94SA%CKC*0"2Z;R M:[F=O&_\5LW'L_L_EZ/Y\F*#NK6F9WU 6V I.3A<[^;5:%&E:JFK23I@2T&2 M'Z)"YA_6:HG/?I@MQDTI2[KH/B "4B)6B(%'/)7>!%362@#<99:':[]/'%)M MP8X)V:". >J;9)YKO@[XD?$(APE&$/,*<*$::I8+P&#EE2+-S[EJC; MKPXZ] RK7W3WG@\OWU.O%N-IM5B8V>/G\?3H=5"7GQ&(5XP[P+2F#DL+L2,[ M2 Q0F>ZK5[:;/)66EU;#Y:;5#%-2:JXPMLHRAPTDP&"Z Y=9G\FPDW>&&U/2 M3>^OAF7= GLYSGSZ.EK^:[::W+]Y_!9QV)T&?FJLHI#789!$((L4-5 3+96W M!IH:&$=UIJ/B 'TJ"K*M6\Q[/(>H"W[NJ]%:\LCA8.'1%@2^Y1\ 0Q13"-1"1AK=3 M)*5#3LR*X5UXG*\/\C]6R_&\2C^^_SP9?QE=N)S2X74K:FZH'1HJ+6ACD M:!"6%%=Q!RAP MEL/XQ=;"::EO)_P[5ZFS7H"\$$L:LP4<;A2HII!2P*@ 5%E,,?*@%M 1>CM3 MS/DJ;L&9+%!+1(*G!/';&) YYZNF14N<#/!"6_5DMEY.S2;;M M)?BXUT T#C5LO7#*6B7H#F?),C-=M_>&*.W/4YAJ>3!?DFGJ[FY>I6^:BU"V M[B,X1K'" '-.5CO;^UN.M?"9+)L@,X-)>AU)KJ7)-?'ZOMXD8K$/;C%KKWQWA M3IOF@1-GL2'4,"R-!Y82O1-:>9RYS TPU4.'%.H!V,*7W6^3E^&]C9/F777) MV)KU>SP5)&IQF7V@1?!2I^D><:P4]I Q:*F%VBD335@'+^/4\A2;==!/HO%* MNV4707CN4QX:8JGW!'G%E:X!2!F<;^8VX6P&' R@ZQ3A NO#P??5/S_%=VBX M_6[1.L2-GW48JUI%@AQ:VQ5#V)H0#- M=*<9JO9/U=VL.^@N::NV<:)I;AQ87$:9HE!0[!3#!'#%:H$U(DV>\=<3@WVY MK5 NV#G!UK:*N-]M\H=M+Z4>9O-?SL7V\*5MTZ"D9P9)9BRW#*@X2@BL!<"> MWLYI3)?*G/4*,AU,S>=IUEW7@7_*,[P^O/I4S1]3XL5I\VEG M3H?!80^LI 02RN-$[2B0J 8&.I1Y-S1 8[<']A6%ON"Z^.?J\[^KNV7 8JT-K<_3H%0Z,PWV $W3OFES%DOSM#$X MDKZ9?OHQ^^]J-&]7H_RT+H.!$E/EL-.><0-3XG!?@T.(N9V-_*"IFJV0P;&U M,XX&H#E4#@ /D1940,-U?=P'%>>W8V\.FIDGJJ&P]_/AI&67\X3N-^6?1@Q@ MYYU2AD&&HFJ\L?%-D%%*"=#D_7+]WM$P;GR8(A1%.AI($=40;0#00,+&D@M= MV58E$F=TR(9<3^G3T!Z@K M=AJF@_05,P12QR6(&V7GE0%."E.+P+&],6^AT[1VQ%?L--@&ZRL&/+4ZN3P1 MX].K$R5P+8;GXG8NCK)T=]17[#3H;B)PQC!*"0:,.D:AE!Q:H&N1(>"9_C\# MW"#WOH1TC_9M!,XH"R@11E#N*(\#T\#=R!3<9I[ #' ZZE3_.8$S)P&=XXJH M5Q& N+->C)Z]P<'5J:E)8-(B)Q1G#$L"D%-0PAT8T-U.\MI.M3?K!=T<.OQK M/*\FFQ(OCZOI>)/Y" $)<\]& G'H M=@I<]T&D[@$ND8]D]OAM%?'^<_:P_!&A>Q/5-_TR3L?+*6ZPD4VMV@?IO4,. M6X&%]Y@;P<%.;&!RG9<'F'BK3U[U ?45!@5#JZ*$VG#*A3+1+#1^)R##IE3] ML.OF4F?X%IFBIHOE?'67-/9F&E'Y$E783*%CS4*T]-)N0AHK!8!88BW5TSQL M2V7:NFX2=8CP#003Y$##66X+H>V^ERQT.Y8%^276WC M'?8W#-I:(IU66""EI*;*T*=-!\A-C'M-._\,I;?E4P[$)2RF_4[H\?O).N%J M%$$]SN;+\?]9__Z@>,?LJXX^(@C-$50:$H\1P]I!J'?W ,#IW@_%2R=N[I&F M%]+))2?'=H$)^YH%*CR#GA#$C8[[:>V)K*\QH3,\L]#C )?;2TR,IP-\21;] M. 5<4PQ(*/YR@C9B4RIS?36/OF8XJ(>13VR*AOI M$IO,3?[7S8YXLSMNLMP.-0F".YT\+Y72E'AN$.&R%DX@E'F/=TTG%.>3J"-P M"S-GD3(,5-7S.E>;=]<__QC]>S8WD]%B\6J=;PHQ[>@3@B 2NKC3I]X@+!U% M#O$:.L)!)B^OZ="C6UZ6TT4!&K^91KU4BTVFZV?9L(_P\E"3D.9SZXV!@#*G M)#-,U^!"ZTBF7]4 $Y#W2+2.P"W G):!\K_$4PMNA5!&80HLA#X>S.PY<*B44D1IYYJ6A )AZPPLQ$)D+F_Q;L.DB*B@<'+0^CK[! M$"#"K!*&.$>L=@9%Z"F).:3L1/UW]K'\E,E M8&:]OG5HER6A#NG.[#E)P@$BT MX!FVSG!@*(4U6,B+3+>I:_*_.YN2A750E+"_!-9^3)J>U.&UKP1:K->JTUA[ M1O\!*FVM0II+BD14G/ 8U; 1!3+O;Z[I&+U#ZI931%'^'BROED/6MIT%%)3-]&$V M?UQW]<_I:!5W+$^G4^UL^@,[VW8?=<1BS^@E2&N@IXI1I)223 KEJ$6"2B@% M-;0II*.?,7]4AC;CO%T'@5!.D":4.&F)IB1N&7$MO"/H^FM0] ?J^_5=+4W#_[+1P(D MTE !G?2&>,TAEI)O!8@A6C*KTYMI'*+5V^.7WGN>#D;& M/1>GC'@$E=)(,F)JD:!OK-,Y_.UO2:*<#W !SKRKEJW8\LMS0>-4G4;S:,$" MA(P#2.M:# :-ZWNO^<)7<);N<:^=+N<@7,1G:ZN9/Y?1!K'C[^/[N( OXBYG M'7.B[O^]6BS7&^2CA\)M.PG4 6>HIBYNGA7T'E"H=B.%D,RIJ/VFL90[:DF* M]09_Z8EJ=XSX:9;B?&?3M4 I4C/J28\6X[NV4UES3P$(@4$F?6I)578!\ >[8\62U/.J8=:!%P(0BSCB4D$#D M:=QMJ-WTC#'+C'H\V2_K5OF3!W,!!OVK&G_YFB2.R(^^5.]6*4+S_[.-U*VSK$_S+ M<7 [9EY)<3H+#_44((Q[(1 M4HP\1\H2B^06"J4-REPU3_8.NW$>=@1_ 2;J MU6(\W>3Z^1R1VD2O+ZLO\_6W'ZNUK_;:[?8("=MW$KBE6G D/=?01%L"*XEJ M "A7F?,@!'_/K4!OP!=@WC]&XVG:P;R?VO'BVVRQ]KE\__ BDMXK7PYZT_2G@AXG@S]'<92_?S#5?!GGL:>Z'A?QB_\T'TT7D4'I%/G/:OY] M?/>L=MF187"T76 6<:T8QQ!X;^,4#_'6>8ESS82]R$RP]Y7?/^RHLUDTVLP! M)_84M#!Q%;),&>@(!AX:3FLX*,J-]QS0Z.^8%;.2<%]BI&__X,;?GOWR@@5R M^ID%$$HEB3!&!'O- 0(,Q"F>(F&;KJ,AN36 M'[B5!7"TAR"(H8P(::%!F"+BM0"U^.J62@YVQ(*#JWR7,!?87*[A&*VC]%H4 M/-CS=+ T>9=PX'P$2$ %.:2U2%3AS)0Z V1.YSK>MW* M:RL-%A Q2'Q:C^N\86H^3]5@ MF@L2-+<,$B1G1@HY!G&@ *$=1O7K X# DBL@(&6:0S3S:?6S&AU<8-KW$#C0@EKE%'!((@XL=W(G#N:W4YRZ%$&Z ;HCWGS; MOYT!76)X):U MA_+ZH,ZLY@G$(_;*ZX>#X \W;VQ:S^P"XU.SU[T::)Z=FC@3(G-?8*:VV(CB.)"NL,0Q80:H'.7+X& MF(BSUSDI']$+7O+=\@V?3;5DXOY6<$>=-XH#P"S43AD.G)47RYT1.1(U^3U- M,/&G1,'UC\^=0[9RS>8+,XL/3%?K2-_OL\FF3F#3)6!W'Q*$M>D VR/$39SP M(!*N!A%ZPJ\_!T?'7'J==>,RFBCA(?TLH_7;V29C=<-]XJ$F03&CG0:&&27B M\BDYI+H6#A)\.P6,+D&(E[[1W2CA0@QKO(4\W"A$K(C55$I&+#7>.X=1+2!" MY':NKL]7<0O.9(%:RA3>&NJ;C6)C%;I-.$4TNQO%0 U5! !K7-"0\V\B8;_5D0J=(+K5?A3*0$DPHX8) 2S!%OH=C#%[>+M4&4 IL_Y^ _>Y8IZH$@<&TAS M@"FC#EA8B\.DSTS5.\ 5ZRQ=-KIY7I_42M%+> M&,<4@HBJ5&^7[Y9>Y'5FS9UAL^-4CP*%Y4=676T^244(_=HW_%*EOWZ(J\_=^%O\ MZV.ZG6R7_&0@;QB ]H0JQA7 $L5-OY-L-R4QHW_O;3H>/->I]ROP\ +">T>! ML8IXCS3"@#V=F_+<3?JMVB/G$_EL%5R-0QB*^]1TH"5=W*%JX2%4I!9+4)2Y M(QN@[^#PF)6MA=OT'Z/:>2 915+0N%N%4.[F;$-]9I36 #T3!T+$_G1S 7>S MEHOJ'M&TD"":"] !"*TEC'B[F]89AIDW; -T6QP([;K1PP4HUGZ-W=LH ,ZY MQ51BK837@BD<4=H(B.)O,SVO!^CE.%"B9:NB -?,:/'53V8_%KI:_JBJ'3I5 M0O )J@_SV5U5W2]\Q/Q=]6/G,G:$D&?V'*Q"PDF @&((&J&(H#NHK!&984D# M+($^$-:6U5?.O=&A-YS%K_=/KSNMEG?QR6_;%[U?I5N,."2_5?/Q;%]:\.XZ M#]0[[#5&7GA&+);"*5Z#0*C(G&H'6&G]PJ2]F,J&.26;V62R*4"_^%B-I]^K MQ;*Z?S/]6"6HH[0?UJ+V-&N?^.$!<\JMB],$M5 2@37V]8X3:93M6#V@?+\# M&22#U6F!0?3K??6OQ[E^-O_7U_'=U_KUWRRV.])T=)S"0YX2V::?CHR6#C\E M<.VM44)))2DQ2$*Q<[1'PKJFH(VN4Q+_'0;&Y=1WL;PTFW^W0>OI]=U_OLT6 MJWFUN1K,5^%/;HPCG@LA(%2,80L@DK5(F-U0R$KG.F[A+'X: MN(-W%G?2.,BT$L[&5188YJC>BN, EC>6^SM7E\WY.4^"\2QG\=,=PU][*2." M!38IU9+6@++D6L?KU[5QF-RBUD_5U%XG\'.AO-1^)TZ%^J>9C!:+\<-X$Z/U M_F%C##V%(Y@HTP,U.WRM0 ?1+G.2^>-?] M>[/&U>N4;@($1BJMF"04.H@T<=[5($BD;B?.I5^*O#Q"[4\%%SL*>C=;?IB/ M'T?SG[J:5E&VCX]L.,F8#YBQEB',FJ$':($K@3E1L,J^6!NBL?)'U-QOH'+O_S(S9V'," M!.066.V],@ ;NWE!0X%*MR(W,NETIJFFC-FG(7H%D0WAI@>$ROT]/9P%[BKG-W,_2ZFN*- M522EQ"$!$">:"*X@)I*:;4U(9IAL"KVYV%WG216)&WL).E)3?I29A:S:9"77.SJ5^F]G!MW%O/C06ML[M*BAI)+2&$<0<590! M;L4.1.DR/6X&:-9VRZ5">%]+YIO6A==[^+1 M$822@FAXM!A14'\;@LIURYS M\SY $[J?Z?#R*NG3:%I]7E3_LXJ-W??XSR7=OUZ^2@MKZ%"3P#W0-AJ@%BEM M*!-81B,7"1HQCS"#IIOI(@(V>GCM>3Q@'\5ASENN)58D6MR$;@732.=6)AN@ M:7.^:E]:->?#6<+1_L5;-KMN'6@1E/7&46JXYRF!H4)>XEHT(I]@& MEN2A>1FB--Y\'VP3TFKH@8?02R. X0)C5HL7A]7M>(F>K=]FOF1!6IXQC5?3 M>Y\/)DG#C8ZFB@1",@XHK\526-SNM)*AV>-V-2U(,B#!M& MZR5:6V4S_0('N&?N=.DY'\G!NPEKK@!23BN-/896@RC-DSC\MG-*M]9EHYOP M:3 68,7;\5TU7:3-]I=YM=[O-E<].-@F,*4$\@H!ASGSTF-!32T>ANAVRG.? MH=E9/V"6,$.B9M9O^&=\Y=%\/&O:W^Q[/@C@*<**8JJ95HI" 8!%TBFI$,'H MAER3.MW==(!E"8ILW^Z?T\6WZF[\,*[NF_8,M9B);?!+]MX25[J$G -%IM'!G%%6048&$\V"VM#-Z. M2TF?)VRY5K68ZF7\;)AVJ3W_KN?U;CJ*0CU&G9 M0S32"'? &$<12D7I+>)N=_J$=:DEZGLU_SPKRZ4,]<]*8%S"EW+]?N\?['CQ M;;883?XQGZV^O9G>35;)2SC^]FYSD5C=O_]6S=?*;>%:F=UIP YK(A@@5%@@ M"9+>Z1H@$*?M6SVU.9^"Q4 O>!'\\N=KOQ$VB'$DO(EF,(026)O2TZ64+(I8 MIO"%7.->O&TK1[A#;0+@G@"C(X,4(5I+186L171:_PWNAELK^;A-DHUIK^/S M,<6CO7_X<_QENHZ*FRZWKMTI@=QL,KX;7\:5]?W\RVBZ3?IE9M-%?)7[#8FF M]Q^>R?O,^W:W4VTSI#OI/VA$4=R$Q+G6.$"]%PRRC<>-A-RP)A-K@-"E=66R MR3HUO3_*BC;32NE7"3KYBW)+*/5$Q?\XYKY6"&;X=F:KPOQ]Z;8_;+U>?,:\ MH,/;M4R<0C+DF% IV;IW6/BM0ZZ01HLF[]&>+Q$:G>A^>7!-3BLI$RAN_WPZ MY=*V%B8.J-QDN;<[Z;34_:%[AAS42V02>8[(>N_7< FUOT&0)D6$8VZ=LPPA MC %FM6!>N-M9PW(5^C+O1Q1*%J E;[1;W2:\>CAHRT 4RKAU+)6A#M6!"7&6!>YV(N<[FD7. MAK )_ZQ&LVCO5E5[S]/QE_6NJDC9LUH/O\9+=#_&DU6QTR7MEW$$68I8CB5 M">= (PZL4+7PPMH;B%G;!"-U%NH32?6B=;">>&XMD$YCRU*5 M>[,3F5!].R&//?/I/%P+4,G]YVZ\6&_M4^C\I]%_CI8TW_-TB&!Y SP@*L[? M G@LT$XD9T&F<3-$-ZSNJ'(^CB4N)^^_5_/E.+D41OY6T\6Q2>7UPP$QYGVT MS#!S4CM.#"1DM[;'_>3M^$9T1XRS8;SX8=KO:XBF$Q6,#>,< 6:UY=X19)5U M!C$-.%227.8:\MUH&=>G]P^[V^ECR\#KAX/"Q'!-%>&24R\-IY1NA>*(Y#KC M#M +&.MK(27+C60=H#UZ M67IUJ(,"1/OG(HX$MUB.'R, Q^:K7Q\,R'C#G35"Q0V=DIYKJVI!C.697DX# MM%@O2Z:S4"\Q3XT67R,0Z8O[G]7X>S3%4XZ\]A-6F_;!6,T8Y9A)(G5$T7-/ M:K$]SIVY!F@%7WCFZD$91?R+4R'(!$%[WAUL$S34$"&N+-2(8Z"!\ZP6#QN7 M:831WUSK1P$%^/5K"L3[=.2PR3&[S0CZ]'KS\F$UV>4- M78MYA))=?DS "*<%PFAH$-">8\1K$(70,K-L)_O-XL'HK #Q-XA5;V>C:4H% M]K8:+:IG(C4RNE7[D 0UBD",/932$$N9K,56Q&:F5>._J=J_,@HM[M.H\)^G MK>W[F@3#!#(:$(.)P (@842]^1(6FDRFB=],ZP7_ N3Z,)]]J^;+GQ\FZ1AV M>I^LWF^G&9)MNP@*">H8%)A!2>,7'VV<6GC#0*9=*7^3KX@^2L6Q?:R6X_D: MBF<7H(T+;5/3("#Q$EFH!#7*6RBL1K6PD,G<"H/@-_MZ5421]37J9#J:_'-1 M_3E[6/Z((#?2[6";0*65Q@'/*==<&4N4 KM!A6UNY/_O*XQ72VPW&BA#L%\" MB?TZQOAMBC%N0[3C;8/BCGI+I,:(*:29E5CL[%5@ U MF]W_&$\F$9^7;U__J9& K?L(Z=!* *+=Y=]F5FW]?B+QT$.M) M(Y[4_?O*YZ4-<7'=%1@.?\01^[AZW/DQ-V_>#[0(W$!!'1;& MI10,2$K@:TO>Q14MU[3]?8Y!2/A[WN9E_-P,4:;JP>.Y\+F%0GY?NQR.+.M #T4N7^YFC]6GT7].\9[9WR2D3)Z2&<.M ME3KNC60J6+T5SD<4,TGV^ZKEU55+)PHH$J3T&%7W-57,2$4\TVN?NA]MVT4< M6IA0A2DBBNCX'R30U,(;@S(M-?3[?N55]%(O"BF1/N9KA%='0^ ^R1 %V*#T M;0M=E"4"%(5*GD'-IW(9O06A"1/KC*D\5<6EF/.M\Z0 5N2F8D2_+U%>)J[I M734=^WV>\ M3$#1J1Y*!Q7O+27_LW%>;-U'0$QIJBPS6C!!K(H;?%2+#UVN:P[Z?7]Q+-ZX M0XT4(.2[ZL>SY!?SV31^>[>!Y51#\M2N@H.$>L$D<-XRR"D"3M=@."AR%^O? M]QLOLRWTJY@><[5\FOVHYL]<>'_]X#+96#9A.BW2JOSZ8. 80200Y6F44XV- ME7"=;U]'P\WX>W?WUO&CC+CUVJ\(-[7M)I*5 6@5=M/BT M2;FSS18&X0S'F>?[PQOCN>I_:5GWAFW!<>I7*;_+]EK_P^CG)@7[Y?*3YXYA M+3$"'FA@#%13MU;]E<^*^Q?80:Q;_&B^_CJ?OI]5_5Z-C M=03S.PT48>&UD%9:Z*Q"F#.S TFSS"N6X8_PUN38[^W2/]3E?*U.D>73CUF2 MY5BBFS-Z#9XP);5,1PV>&@V5=Z*&R&-U.RD_+\?&3*P'2L?X^54?A-SU&SR@ M"C+"M/8$8DF55K2&27*=.4$.\-S\@I3,17N8I/2SU;P'3NZZ#9X2#A1F6,81 M&W>4CA%5@Q37ETS7P@$>DU^.DKE@#Y21X^]]S)*[;H/F2"E <0H$!Q 09P2I M0<(P-VYU@"?F%V1D)MA#8^2GK]6\&CTLCQ9&S^PQ&(L<]A(I[I60$J:== V- MPR3S4'* 1^:7X&$VSD.C8%?$"Y0YPY@T,!WK*D>%ECL8L%>9?F,#/ *_!-U. M1+?@ =F[T7R^=O^^PD,Q$?6C*# ,4LZ<4A!@9YD42D $V:7*Z!W@0&-5O6/M M A8>VI0FR2$"+4;17#.UJ(SDIM@=_M%6:Q6W/+S.0;.$O]*AL_9J<36W4Y*O>#B@:.MA3*ZC'E"/CB=;U:SJ!;Y\2.2J;=8UK%^K_ M\.G-:0S8-0B<#@A+'GJ0 TM\1K H$1U&CA M&%>U"%2QV]G>9&AMG]ZS8"MW=-6H^U^>"W'U 9ACB5G/Q>@ML0RHA'A#G!MD"B$ 6= M=\&=YMLVE;R;V@;!(^J.Q 73Q 4RA3XZ48LK0&[>]@&Z,)0]O\@%.&=W4:?E M7JP^_[NZ6RY3[J]JNDILGCVLIN/E/H:T;!D4Q=AS90@FQFD-XC+KZ]?G1&;. M) -<2SK4Y*Q/B"]YME4MHSAW576_V$8S3+^H^)?OX^7X:'V[O X#9@Y80CS5 MP%&#TOU.;=(1;W&F%3O 5:Q[[A5%OI-)ZV$TGL2WB>\[J=]W^?2^>=/9"7VF MBL@0*,.=\%)C3#%T]0I F "9CE-7M!!V/='U!WZ1#$6+1;6&*0V,^3R9F>LK MZ6UAV^F7S<7:IVK^^/[!S*;-5ZTY'08.G9#1 O4<*8\]0]@E:U0R%0T6G)OE M:(#N?/U-@460O^"J_.;QVVI9W==1J1]'RYQK\3V]!.DUPTPP2[6G"D$""*D1 MAX;^?7W?+@+^K0I(ILIO MQ[K.H2ZX>JP/V*YJD6!6$^Y7D^K] MPV$G[#81_B=T$ZRDQ&AN'<.$1+O'N3J^!0,(46[UAL$/W]8$>#E\^P.W3 JC MM?BKT>1I^/KQXFXT2<$E?XR6J_EX^;,6%*&.TP MI#5,% MRJTM(+@=+HGU\%?E__Y_TZ.&UL4$L! A0#% @ 93%12!$M9BJN%P $1L! !$ ( ! M:WP# '1M=7,M,C Q-3$R,S$N>'-D4$L! A0#% @ 93%12%->KK8" 5 " :_! P!T M;75S+3(P,34Q,C,Q7V1E9BYX;6Q02P$"% ,4 " !E,5%(COKJ%M]! 0"J M(!$ %0 @ 'H<00 =&UU&UL4$L! M A0#% @ 93%12/48WP%TX L&$+ !4 ( !^K,% '1M I=7,M,C Q-3$R,S%?<')E+GAM;%!+!08 !@ & (H! "AE 8 ! end

F;G::ZBS,OK"M--8Z3@"8+L3CS[R2-0Q:0 MGVSY3VVFN+R8^,;VE9KEM4Z6Z^$R,IA^3/+4,1D35$,T( 2#*P_I];!4'&D #@B90 2I M!:@ %8=1X=I6%_OL*DE$:91RKBM#A4UVT1X#/),GN7!^EO?"3W2D=6SJE FRC!1 MAHDR4 $J0,7^;C\.: -H*$HIK#<+MJ%@@?P@)@)5("*Y[Q$7UVCIJ;P@(J[ MO1L 9][WRCLD-B0=C?D>S/=HZ:H & #8 !L?V+-M?MDLE*28X5RMA']SZ .U%40,=I]99.QC7=HAI3@U9!6%#NO8%?@ M2L+"IL"B'Q?FNAM0 2I A>%4N%9WB,(W\ >X"5 !:@ %: "5"!V0OF;\CS5 M9RJ6C-Y3XGM)\LCOD-Q[84Y)/"%I/DY9P+R$T=0B$:UDPX2FI(&LKB7*,VG**.) M'\_XM1_)W'OTQF$U2VT-@ZFG"J&FD*(?%.9Z',-8P+PNJ 56Q["&O5&X $\ M@ =YF-/O@P;0 !K*%)CE=)1UB$>N"[ T&!8,,% H=[32?,GXGTBXW)\5K>*0 M)<;DI[D^JRF .5T78 $L@*4:K)$+L 6P%(.5@=8 2M@A9$6 -@!@'F6'8- MC1>;@M;+2]TZ?;,SABNJ[N+,"VO,'<9)0).%B)SY=Y+&(0O(3[;\=Q)WY3G% M-[9/V(3"N7U".UP !D.+23%0> J%;L_J]=6E2X B4 2*)T:I/NDTV MX#%1T/F\LA5)V32+_3^F<<@U(?TKH7_F+'NL!&.5(M657Z=O]7K53Y&T ER# MNN;:$2F?8!96@$E3J0V6G8]E.]1O*@4I0"2J/V%N5CT"5M5E0VTRN31DB M$ MB#R2V.["&'773+$ 6R )9I(D,"7U19EL6UZY*:HD7!2_-ZVH\)7,V0?^E M;OG5+*XJS!R*(E'_46^H 75=R[75S1C 3B8-9@UF+6J MS5K?M;H*RPH0D&W,5?Z2B9W?=GY_[>>UYPI91-],J;1/CFN_?J_=@\HG(CX- MPU+C?WUEOY*?^>OR%Y]WW,D=F]&4?*8/Y+=XYD7OR7.WM&N"]X$%V?2=VSW$ M9&_JZ^%?/FZ.F>OP,0J[]6(W6=RPQK9XRI>$*L[+O2Q_O*. W/-\+WF<#VE* MLV*Z>WWZ>Q(GY',E/%/M_DX90'S$CD[GE R3]B,?PH?"8O\, ]H MP'\@__WI.B4)#;V,?\YBDDTI<6W')7?Q TW('3];ZOD9BZ.WA-Q22K:$>2IL MQSV\_/10B#2*DYD7%F?Z'&>4C,BR$:+SOKSS+V/^ZCQQXSOZ;9UV_\N7(,4] MR1.Y/0"+)N)^I(A>;!4/4Z(S6;L#3;-/Q8:?JFYW_<6/XS H3G091SSJ3+G. M\I^DY^0O(/I&/GJA%_F4W$XISS,4U687+'L02T/YZ]4^%8U\ZQ9:3E.9AX+<7G]8N4Q*Z'B>$J1Z.W?7O4&?1>+X(N+OS0FZ?TW>*'+1'L]L"KHK[NSF*Z SRHO"5^ M@M'K(YUW>:!SXG%U7Z_NX_!\>MPGG@_/5]WUVKR;^NY0Z()'\?R@4$2ZQPQU ME@_0.;4;R43^VU&,35W;'G2K$/N/1;T5H+U V.6CE,^X6_1?^;B*BUI1O@A) M7.CDRW7R4YKF?&P G81.:J.3N[-2T%'HJ#XZ^GSV%'H*/=5'3S?SG6(>X#ID M,Q85GS\$_YNGV8S?$]06:JNEVM+@4,FCC^'!28!B6K 2E:Y1GB;8 FV$U5PC M"HV#QD'CH''0.&@<- X:!XW327#0N%,$U^9YZR(!D"=BLI1XE8U4VZA6^FF0 M=O*!_D!_H#_0'^B/GO*!_D!_H#_0'W.&90<.;&W#!VQ>.I7U!;[X0733O??" MVU-3VKX_1@90X4@(+R0,.GFS[X/G^_F6A&Z5-V+_K!622BQW176=[Z MOAU73S$]9]P[M0*WW11N,/\/*D %J 5Y6&.-724Y:K! W@PG(>NLA(4P 8 M#(6$H?YZ'7K26NTHK M2UXIG7!HEC-J?)H8DU$UN"\ !L & #;"UC'LOLNT ):0 N^"X !, &P 8 M $-PB/HW!?5O9)+$,^)-)BQD7G;41B1-S=5C!@LS6)C! A6@ E3LHV*@K"\$ M8 ,AL, %P$J0 6H !6@ H$3JN&4*E@S+=@OD5+WP3 M !@ V '+).PAVCH ;2 %GP7 -@ R 3 AN 0U6Y'Z\L5G= DH0')O._E MEK#H]H8YJ1<^)SP/J 5H*(U5(R&:&\%&D #? 2H !6@ E2 "D1.*')3G:[Z MDO$_$3]/$M'JKCTS4X6WL69%]:1+(R3@"8+ MB3CS[R2-0Q:0GVSY[R3,RG.*;VR?\)S1H^4.E"7L]PGN<"$8S"GFOD#BB20J M',F!1) ($D\C<639?66=6D B2 2))Y+8&:F;- "'X! F#GM M6*-A%RB>.[VJT72&.N7ZFL1S_K2/Q(L"0A=[\LI5Q&1+FJNTLO7DF3W+A_"SOA9_H2(/;NFD6S&-B'E-/CPW !@ M V![P]V>-;#5S5*"+; %MLK#>IT!P )8 M1(0 #8 8!YO0MMXO>B)4F..OG MJKKRT7_$52 MPB*2YN.4!#96E\5]RG* M:.+',W[M1Y)0G[)[;QQ6L[(6/#4%&_T(,=?]&$:%:PT&:-D 'L #O 2H !6@ M E2 B@-38TJ#)R3 $N#88$+05,3W1H V #( =TFS8Q2:I0 MHP7F7\G:1RR@/QDRW\G ?7LVR@O)@[=OI(>,OY+78+=J[(_ M$G %$_>L04]=H[Y3I5F#RIW?9F)&[/30 M81UO$,K19[5E==T@#6$=81 MUA'6L2G6L>=83E_9! .L(ZPCK".L8U.LHV/9/66%.3".,(XPCC".33&.%]V^ M->B>WSR>-'%I@**BQ2U,IUX:"=.I:M3=M_H]95V,$%C^2'IM7F@A/SU0>4/C M. R*\_R3>6,6LHS1E'A10&ZSV/]CRO],D_2O1/1_R1Z/T,WE:J4+HZ M9:F]-AJD>-H)#AH'C8/&&2$X;80%C8/&0>.@<= X?00'C:MM'+LI*-OL\>H' MW^>ZD*5D[CV*+23DU*/G^TE.@Q,'L#NS&,BKZREGV 3 8#@,VX@4,@ 'Q M$J@ %: "5("* ZD8#@"#@@Q4.\K:KNB$)@D-2$+O:933*OAI2M(7LRJ85='2 M00$P ; -A>P+H]=5NQ BR !;#@N0 8 -@ R &0T80L.*\XF-2AM^R?B? MB*]FBXB&Y=\Q*X59*VJ !-("&@@9EZZT! V P' 8$3* " M5&POD8&/4)&-.BQMV>F;G::ZBS,OK"M--8Z3@"8+L3CS[R2-0Q:0GVSY3VVF MN+R8^,;VE9KEM4Z6Z^$R,IA^3/+4,6TW,!-: & MU,V!VE'8#Q9( VD@?7:D,:H&VD"[D6@/K<$ _EK?1'G]0%>7#O]G+.X;;0@Q MQXHY5LRQ_F :0V'RGP2@ 0A@/104L=T :$#2!"E !*D %J#AT*-&WW &Z MFJM(1&F4 W,\1ONKI@#6L_JVLJ6:0 MH 2WX+@ &P 8 -@ M R 3 AM'7N=*+]6.E3CWNX@>:D'C,G\?+6!RE9$M4IUAU?EB:SY\1&Q?+ M^Y!%],V4RJ=W7/OUVEEZ\TR>Y,+Y6=X+/]&1UK&I4P*8*,-$&2;*0 6H !5[ M]P >.* !-("&@@;+[:%=*'@ #XB90 6H>,Y+]%Q$32I28AJEH&O8 #CSOE?> M(;$AZ6C,]V"^1TM7!< & #8/M[>5HC=6M:@1;0 EKP70 ,@-4 V(7C=&M3 MK)62'"N4LXWH?P9UH*Z"B'&H;B%OXQV:(25X-:05Q E0 2I !:@ %8B=4/ZF/$_UF8HEH_>4^%Z2 M//([)/=>F%,23TB:CU,6,"]A-+5(1"O9,*$IZ6',>F+64TOW!< & #8'L! M&PS1801@ 2QX+@ &P$P"[*(.UX6".% 'ZN#64!;W$J7Y%&4T\>,9O_8CF7N/ MWCBL9JFM83!A@[UCGQ,NI[$P8&(75("*'7U-AB/P ![ @SQLA) ), "&,@7F M6@-UR].0ZP(L#88%XPL4RAVM-%\R_B<2+O=GK;I57)P$-%D(QIE_)VD&[&@N#ZUC=H3(O!" MA.% .(XUZJ/!#( $(NZW$X7$1-X ]E*6+'ZO>5 8%21,#28%@ZKN6JV\VE M*=X#58C/Z4N1N4JSV/]C&H> IL?] M5?4[NQS^^ :#:Q"CYKJX=E#9L;J#ZKNZ@$I0"2H/#U<=R^ZIFY,%E: 25"K8 M$-3J]I2EY-5V0*L!96WR-" 6Q!Y(;+=CV8,>D 6R0-8,9)$F0BVBZCSN6MTA M\:+@I7G=%Q7 5LOJV03]E[KE5[.X*C!S@YZZO-N^JNLV6#M,[\)RP7)5GYOL M65U7V50Z+!_+<+>V:/7Y@039]YW8/\0>;,!S^Y>,FL#D@Q]"P]6(W0=\P];9X MRI?$0<[+73A_O*-HW_-\+WF<#VE*LV(N?7UN?1(GY',E/%/M_DX M90'S$CGUGE R3]B,?PH?"8O\, ]HP'\@__WI.B4)#;V,?\YBDDTI<6W')7?Q M TW('3];ZOD9BZ.WA-Q22K:$>2ILQSV\_/10B#2*DYD7%F?Z'&>4C,BRT9WS MOKSS+V/^ZCQQXSLZ'IUV_\N7(,4]R1/9,)]%$W$_4D3*3.[??LG3-]\\;_[N MUI_2( _IE\EE'/$P+J7!1R_T(I_>3BG-[L31=]PN?@QC_X^__^=__.T'!UYZ MZ?2&1X2W&7_=,QH].9IK=21,[&]T\NNKFRNN!KU_=W^_NWI%6,!_P=7@C7MM M?[CN=[H?/HZ]T;NI>]5W]_@L*/C-YSFG&@"_"IV&I3 ME1-85[!Q' ;%B9:B(_PGZ?[YBXZ^D:4$23PA0JQ$R#4EGU;*H,++U?&(OW.' M1ZXC80^NJ$]G8Z[3'<<25F"[?'/MOK>LM+QO)N15?%Y_L!+9]2#4V;#LRCSI MDV?F)N\;BXJ;]/(L7ORB&%+)WQ3N=#1ZV[='G4'O]2+JXS8^].8I?;?X82O^ MV.VE5U6%W9W5? =X67E+_ 2CUTW#&2O@M-@\;I)#AH MW"F"4S"+;1L[@BW2K30COJBMFR?Q/1,%:N-' G^?L)L_427>MA*B-X*")T$0]! =-A";J(3AH(C11#\%!$Z&) M>@@.FMAF343CJZU.-]$]36M8\]K& G7]%$L[^4!_H#_0'^@/]$=/^4!_H#_0 M'^B/.:,UC9()U94F?,T3?^JE-!6[*\P3L= S>Y1]S.B?.9O/CFNHNWP*M\Z\ MPA%]ME17*BPW0W&KSV$UI1;!(.[TLF( #( !, "F>A7JP%57;+=/*D>5#NL1 M(BFK#@9WX Z.#8X-@ $P ; # <,D:.RR+'-U23;:G)_9JO<8UD4G@1T'J?LJ+T6#J;6,#@K\'YM<7+P9: " M5("*UE!QX5BCCK(F FV(UP!+:V&!"P$5H )4@ I0@E 5 "D !Z-D!'?7! M);@$E[IQ"<<)0 $H 6@ !2 (K(U+VV[J2ZVV?6&GVE&?"^=DCRE@2@Y9(KV MFGPIK:= 69Y3?&/[A(VI6SQ48 E-@JC&FY\@C58_=^<>LX!$\GKV:%22"1)!X:@ [X@&LC0!6YS7E&L_( M3*D\C3/@Y]$'\'U[H]U3R?-HWMF1U4RQM),/] ?Z M _V!_D!_])0/] ?Z _V!_I@S6M,HF5#=#/+7)/8I#5(R2>(9\;TYR[R0WTV4 M)6R<9RR.3M'!MG2]KZ*^K^GKS0S"3B\CUD; U!;L 2V@!;3@NP 8 -@ R M&0V8XI8";=YS#-R!.S@VO;OL-"G1R-(T]R*?DGA"PE@\$4UF)*#C2CJF@Z^F M8*0?,>:Z(\.HZ%BC@;+&-. !/!C. [P$J 5H )4@ I0 2I !484YTI4:90> MKBZ#]1N=>X\S&F7I=M:*>%&PK)[CHD\IB_[=.'FTR#R)YUQNC[+D MCOZ9L[DXC44B6LG:T::DFS&?@_D<+;T< -@ R '3!AVN_6IEA-GC$%=: . M;@UN#8 !, &P!H.&.)&5-JID=2G**.)'\_XM1\)OR+C0 =D[K&@"OX,PPR3 M8I@4PZ08J 5H )4@ I0<7P_^X&R;O9M&(\ E=:BHI 4. [08#@-"*=0@7>T MTER5^:N4Q!&9)W1"DX0*P<3^'U4PU9ATO!J\&P 8 -@ .R VCKLOXS2.@62VFQB1[_3Q&>IW!Y6 M)B1)/$BJ$Z- MI+YD_$_5[8P1)P%-%G)PYM])&H.A5;ZHI>@ $9 M/Y*+/.4_L.AG,F&1%_G\QHGG9^R>98Q64[&X1Q.5YO7+BXEO[-'Y>L%6E_$_ M59J'2\9@:X"). U\;CN MFQ774LU0 VH ?79H;X8..[9F3YIZKX&0X!Z4/#> M--X5[C,!WL$[>->==VO0L4$\B ?Q[2"^8W6=SMF!;\4PW9!RW*= 3ZD\C3/@ MY]$'[DX%_3;VR,TT64&OH%?0*^B5*;*"7D&OH%>MTJL7C8JT%B243ENE,U>O M4,OU;![CX 6T%HZ-->!/X,_ W1U0H>6=/!J M *S2NO>.NB*9-KLU0VI@*I&4_/10))/'<1B4B4N5Z4H]$^AGMU>::9=V\H'^ M0'^@/] ?Z(^>\H'^0'^@/]"?QA6=&#N6DX=]I-]8%/$[$_L:SOFWXJ"2)$J= MZY3.F&1Q+7(U$M$>8^L^M+23;$Z^AD8[?P^[ OLRV(YVD#A8M(&=@9V!G6F9G>E: MO6%M.YPUQ<*L33']DGGCD.[\_MK/:\\5LHB^6738=.W7[]<>U*=11I/S/^I9 M;E=^W%XM'D?<8HH=BOE/4IN\3"Q N,V\C,[X#8BI+KFD_(8;V)1\BB9Q,N/? MB2-3'O%W_FK(=22V8[ZB/IV-:4(ZCD5%)Y6_>6!!-GTW&KWMVZ/.H/=Z84>X@0B]>4K?+7YX M_]0HK.Y^?:9W56#0W3FK?\!DL;PE?H+1Z[TV:],^E@DQ+O(,7ZCX;>D_DOQUE7]2U[4&WIA6^ M/PJI7B#L\E'*9]PM^J]>PJ^(Y(&RY %T\L4Z^2E-ZJZGF[E*T>SR.F0S%A6?/P3_ MFZ?9[,B>EU!;J&UM:DL/7CB";DD')P&^S&E26@0_8_.@<3H)#AIWBN 4S&(;OL?T9YH5N[3,D_B> MB0*U\2.YR$4U'HM^)O'+QK.U%R&7YY2U;Q75IC:I0KD*<2GO.5>7O&K0G?/7 M-2/+#*,%HU6YT;KH64ZWMH9?VP V0^N4[2P+JP:K!JOV\E"LSI8;",=@N&"X M8+B4=".K;P\>6"U8+5@M6"T5@TC'MC&$Q! 2-DU?_8)-.TY>7U-@1C MIE?G/C5SBS8= WZ>LYL\4Z?5M1*B-H*#)D(3]1 <-!&:J(?@H(G01#T$!TV$ M)NHA.&ABFS41K:VV>ME$]S2M855K&TO0]5,L[>0#_8'^0'^@/] ?/>4#_8'^ M0'^@/^:,UC1*)E17FO U3_RIE])4;A6>B*67%0-@ R 3"U]<-=J^.HVX1]GU2.*AW6(T12 M5AT,[L ='!L<&P #8 ,@!D.&")'99&C(=4D%:4=TSGULR2?D9#Y8H_75.8? MXXP?35B4>=$W)O8D]=*49JG%?^6'N7@*$M!YG+*C=D\XF%+#8*S V[7%J<%W M@0I0 2I:0\6%:XW4-0UH0WP&6%H+"UP(J 5H )4@ H$5EHDOC3*0JL36;%\ M2M3;$1:1]+0M;=N7@W:L@<+^9VW.01M$G;D.K2G<87(5DZL #( !, &P 8 M -@3PZK9V0&M(!6Z]""[ZJI [+)"<4OHG[.(A&M9@%O!9W<&T;4'@DU!2S] M&#+808$J4 6J0-6/9YEKV^T:\UX@K<6DP7_!?X$J4 6J0)7N5"$J-*8PT:X# MS.ID^)EFQ/?2*! /9PYG#K2!MMX%KX :4 /J MLT.-"%V/"-V0\EU]-ZS5?XLHK60%O8)>0:^@5Z;("GH%O8)>0:],D17T"GJ% M;5[K&&?+3P_%.QK'85".@=C7)/8I#5(R2>(9\;TYR[R0WTV4 M)6R<9RR.3M'!ANT_4$%Q85LJAF"9&TN%TKH\\ >#.&%BBZ5I[D4^)?&$A+%X(IK,2$#'U33Q1C_\ MUO;#-P@^KKCJ^OFR=T0I.$"BG% M_A]5<->4#/1HZ*JBL?'Y9X.H,]>A-04LS)T", &P 8 -@ R 3 !L M&)(;.H*%XKJ-XKIT&B?96G7=)$[(/$_\J9=2^046W?/OQLFC1>9)/.?B>90E M>/3/G,W%:2P2T4K6]AH&(2;",!&&B3!0 2I Q=[IX:XS5*TF39XZNO.^TU36P9&$AEY& Y+%8@$H2:=> M0DE*LRRD8EGH*IWE/7A)4$DV"UGD]F:1#<+17$\&P 8 -@^\MZ!M5O[X6J M'D 'Z.#5X-4 & #8 #,>, 0-IYQ(6^3\I)?,OZGRCK1C>,DH,E"#L[\.TGC MD 7D)UO^,XVZ*MS:'@FUQ;O!B8$J4 6J0)4BJCKJ.AL#)L#4;IC@HD 5J )5 MH I4Z4X5 C^=JA9ML].#GVE&?"^=BBTL1"^_@(P?R46>\A]8]#.9L,B+?'[C MQ/,S=L\R1JNI5]RCB4K3^N7%Q#?VZ'R]8#N6;2O;&?MDB1XN'8,M N;B-/"[ MK8"Z:_5'ZJ;R #6@!M1GA_K"L;H#90VU7RS2HR;P:S %* H%\8TC7F&C./ . MWL&[YKQ;?1 /XD%\6XAWK9[;/3OPK1BH&U*4^Q3H*96G<0;\//K W:F@Y\8> MN9DF*^@5] IZ!;TR15;0*^@5] IZ98JLH%?0*^6R0M'6LZF*RZD7?:.$147I MEA<%Q0_TSYS=>R&-,C25^U%NMS]45T+9YL752,[6D9QM"G7='J@#=:"N5NKZ M7>QO![ EGIWAA@2W@S0U0L=VL[!JP&P*KU:;]"'6T/?N1=)2GYZ*!+)XS@, MRJ2ERE2EGLGSL]LKS;1+._E ?Z _T!_H#_1'3_E ?Z _T!_H3^,*3HP=R\G# M/M)O+(KXG8FM"^?\6W%021*ESF5(9UUI-.J??VDA\IOP!T!S"\W^Z/Q]/8 F MT 2:3P[K*=N,&UR"2W"IBDM'X8PAP 28 %/C8AD "D !J*J(UAJ.'*#9KJ8R MU65IKZ/@I/SLB]3JQ8%Y:9E[.,&D# M.P,[ SO3,CO3LSI.#Q;FY"FF7S)O'-*=WU_[>>VY0A;1-XONFJ[]^OW:@_HT MRFAR_D<]R^W*C]NKQ>.(6TRQ#3'_26J3EXD%"+>9E]$9OP$QU267E-]P YN2 M3]$D3F;\.W%DRB/^SE\-N8[$GLM7U*>S,4U(Q[&(:SO;&X:NW?>&'1:=3.5] M,R&OXO/Z@T5"*N&&87+$=Y:/(O68^#0,R^_\^LI^)3]S2/W%YQW/>L=F-"6? MZ0/Y+9YY6\YMYB7?6%3(7A2>5OWE@039]-QJ]'=K=_G#0>[TP)-Q" MA-X\I>\6/[Q_:A56M[\^U;NJ,.CNG-8_8+98WM.OKSKVZ[U&:]- E@OY8=Y_$.U_X:I6N"V=!&6,VUM] X:!PT#AH'C8/&0>.@<= XG00' MC3M%< KFW W?#OLSS8I-9>9)?,]$/=WXD5SDHGB013^3^&7CV=IKIG>G9926 MTC:IH+H*<2E?]CX:U26Q&K3G_(782$+#;,%L56ZV+AS+M;=KT2L6VE'; AJ@ M=LYL\4^?0M1*B-H*# M)D(3]1 <-!&:J(?@H(G01#T$!TV$)NHA.&ABFS417;>VFN5$]S2M80EK&^O- M]5,L[>0#_8'^0'^@/] ?/>4#_8'^0'^@/^:,UC1*)E17FO U3_RIE])4;F.> MB'6;V:/L64;_S-E\=ES#WN53N'7F%8YHFV5"H=5SHFE*+8)!W.EEQ0 8 -@ M $SM>M.N9;OJBNWV2>6HA:9ZA$C*UI*".W 'QP;'!L & #8(8#ALA16>38 MYFJ2[31D.J=^EN0S$C)?[$>;RGQDG/&C"8LR+_K&Q/ZI7IK2H_90.)A0PT"L MP-.UQ:'!;X$*4 $J6D/%16?HJ%:3)D=F0*6UJ,"!@ I0 2I !:A 6*5!PDNC M['-U(KR=QDE&,IK,B#>9L)!Y&25A[$4DH3YE]]XXI!:)*,KR,/>#N1_3W!H M V #(#M;X%GJVN7#K %L""YP)@ R 3 9C1@" T/!\N0PCIURG$I]F05 MY7)R"VF4I<3S^8=$[L]*_D6S)/YZ>4O&>B+#:'"LK@T>P -X0 D$J 5H )4@ I0 2I Q6E4 MN);3[8('!;DJC3+#ZM3CBUCJ65V1V[X-X1J2)ZYB(N94T36%48-P-->9 5 M"D !Z-D!O7 ZZJ9:7RJS)B\' ;6@%FX5;A6 E "D !*.+>-L2]"LH3[3J0 MK4Y4GVE6E"K.D_B>!30@XT=RD:>R3O%G_I^:325?2O8I )?G%-_8/F$SBAOW MPGVP"!KL>N%AP6'E994@$22"Q%/CW:[E=OIUH7A28%L#O]ID>X$I,-4E;P2W M"1[!(W@$C^!1=QXO7,L>N0AC=4[>:CP/,Z7R-,Z GT_K1/)<^C>6='5C/%TDX^T!_H#_0'^@/]T5,^T!_H#_0'^F/. M:$VC9$)U,\A?D]BG-$C))(EGA*5IS@=QE,03$L;BB<3>?@$=8P<_["*!-: Z MF+(V N9:W9&R%GQ "V@!+?@N ; !@ V #( !, "&T9<"M-I<&"(/^XW. MO<<9Y'23"F)Q_R"8C8(.G-]65/0PO0H -@ R 3 !L & #8 ,@"&] MH2=:J*!;5-"E(H>83N,D6RW$)9,X(?,\\:=>2N47YDD\YS)Y)%X4$/IGSN;B MV"IX- P[S'IAU@NS7J "5("*_?M1=)6M<6C#;#!0:2TJ<""@ E2 "E !*A!6 MH67K2AN3ANX@"5VY .#,V@<6)E !& #8 , M@ $P ; !@ V #,D-'<%J?87=EXS_R2(1K69?BS@):+*0@S/_3M(X9 'Y MR9;_3".K"M>U1T)- 4T_I@QV5* *5($J4/7#^6;'=>K"J0WST4 -J,&!P8&! M*E %JD"5H50A+#2G3-$V.[7XF6;$]]*I6)9[SP(:D/$CN'[&[EG&:#4UBWNT5&G:O[R8^,8>]U(O]HXUN9DF*^@5] IZ!;TR M15;0*^@5] IZ98JLH%?0*^6R0AG6LZF*RZD7?:.$144QEM@:0?X@]D>X]T*Q MN4(E::*&K*9VK5'?KCP!V91D#3*P=61@&X-6?S0$6D +:*GO-MRIWFFUH;X? MU(&Z@[6J/X(W U?@RH1"&@ &P !8>5C/ZH[0-*[29&/]6%42/=QR' M09EC5)E9U#/7?7:CI)EV:2"8+Y@OF"^9+ MR2K^X:BVS9U;8;C6)AM_R;QQ2'=^?\?/?_LE3]]\\[SYNUM_2H,\I%\FEW'$ M34U* [%:_H8;G]O,R^B,1MF=./4=E\/',/;_^/M__L???G#TI\B/9_298[FL M(R'0W^CDUU[TPF=P\6/VR)8'5KZQ4. MJ[*:[LY:E@.*).0M\1.,7N^UT)NNHCS0.?&XNJ]7]W%X/CWN$\^'YZON>FTN M/=OM]2]81/A!(0^-TF-:JAZ\5OW94/6UO#GY%>@G'0]3A7MX477GNFILBU[WCXUT]W3=I*:CQ )VV^\0=BS6YG=XVK1?Z$I_T5D8*1E M8*"3;];)CUDV92ET$CJICD[^,J4IC?,D)=?3818&(4U#MLM<0N@H=+1B'?V4 MQ"?04^BIZGKZ,H$JYKU>1N$XC,OW9\%_IED^WG'L*]06:EN;VK*M&Z8P,&SK M),!7=L_BZ4ZV:GNEKE:BJQH MHT*"@SI"'142'-11C6'=AH38Q6'7++T/?4;2W2-KZ3)20R+22L&KNV,-FE%, M* \8Q .N9W5;TF88@0) : S2C L3J=/A@ # & M:"@#'+?[TB;K+"NY-D]^EUX3D /(H1GDX+:LGBMM (0I_H'NE7SR]./RO]-P M4DP\V&-AX;G[O,YU+L-V53%]J>I;I*<1M76O&W:+$MF?GC[G;>T3W[M+==& M[$Z&I9TZEG8 ;8D9/ :@ :@#P]HS['2U[5%$ -4 /4 M!P?UL6/9"J!ZKXRR!IO,HY 2B%<,\9YKV6WOX(AOA!UO<@UG\6YI.Y?/$Y:6 M&SJQ;Q,69]5L[%*!"'4@0L742CGY0'^@/] ?Z _T1TWY0'^@/] ?Z(\^^X(H ME):I+HEUD60Y248D*S<.R2P>N_G1- OOF?@X8).4^2&/ZI*XV+:7CA,NJ_^5 M'V1WR0/_+YM0'O>QZ)$,&7_DE61W#&F3Q?0'+)BHF3X%P P P VUA ;[5K MF*\": %:C8.6*ZTU!;@"KH K^(0 & !6CT_8ANVJ-!EI8LZ1/>TJD-$(4\"J ML52FH$8]@.AK=X *H *HT!P5?'J*.6:11&_+HO M2MHM P \ L,T;SG0[ !: !6#!<@%@ !@ !H !8 87$,4ONVD++_0,"9) M3((PFR09C8HM*2;,S]/IF$2AO_=N@H9EZ+%NA74KK%L!%4 %4+%Y^_>.M)(? M=/8 *@9#!08$J J@ J@ JB 6R77K:JR?L[6.^MUD^0BU35A8FQ_9CXQO(OF671]I;K]C(RV$YBQ0C0 M!K0!;4 ;T%Z_+V;?:G6D]:4 U4 U4'UX5#M6NR-O(VF &J &J \.ZF/'LEN' M1_5>>;4:J$"9M4P@'HB7YISWY36-PXY+3Z4;E3'__)0K#V,_&3-R"%R;!-]# MI,V: %4L$ ./>T7%0"%0"!0>&H56MR=M2T @$4@$$O<-+WOU99. 0^ 0.$2< M"#P"CZKCT96Z!R&06&V=LK9)U^+= RLN:)A$P2P+F_/OSC.PQ[.JY7_LE8OU MZIR&L4' .I"A,L+2UHI XZ!QT#B5!:>,L*!QT#AH'#0.&J>.X*!Q^PBN\0/F M/L8Y2UF6SWMLJ\@_[2,OLU*ZIN2"U$.&6G1B,"J.>ZVN;#4Q>;P#H-)]+J/9I@0E#.L6TJC.0)H:-1 M&(4TKVCVG"%;FE11!&GZUB8:04Y?:V8*P(Y;CKP&.*G#(=2@;LQ_ .I@UF#6 M # # #P P P \ 0F.D2F*$0;YY]+-O'J@"=9MC"BA=6O+#BM=3@#"P M"\!"<5C+D58]!#0 #9JC ?X24 %4 !5 !5"QT7-RI;4HF((&%,:M'2Z_/,,LR[2TZ4T"L$5[UM75- >BQH^F.36J8#13E ;2PJK"J "@ M^L*J'AR7,*K +# +HPJC"H": =!CB66(L*J2D\0O=4GSG49ODIQ&)%$K);P/ M6E7=P>(0MK8)^UA@M1-XW,^T6FZG4Q<4]S*B->!7F;@5, 5,5QWF=:35@L)< M H? X=[FLM>'L82Q!$@5!BEB3!A-X%$=/!9C+*6-UX?9K"*+N^52@>;IW8^S ME&Z49-D_R)"-DI3-\[PY_88YF!BW@F50_6RI(0 K 5J ]L %1K"J "@ M*LNJNE:G=_A@%(85N 5N85CU2P6_U!O-&YL_L?G6VJ0*<.Z#,56G$IHFI M,P5TF%2#0A$ # #P P P \ , , -,"8 VI2929&$$AL>04IJEUBC3/ MTW XS>DP8B1/^"6-QTE<9C'ODHAKT2Z=ZF]2RFJ7%0XF[+_7+;^:Q26]?D#B MS%?L%W<86"X3GS11*^?'@// >>JM0H/SP'G@/'">NIQ71<4U6 ^L!]8#ZZG+ M>M*KXT%YH#Q0'BA/706B5DNAI+G]-L.NOAT'UZ=95%OL2_ZVQ15 M)*F;I8:N0E=UD2IT%;JJBU2AJ]!57:0*786NZB)5Z*ITJ4JH]=8F_J\TW']K MDX9NO1BNTNL5:F1],7Q)P6XH U ] - -0 /0#.FCWR A4Y9Q@2J@:@VJ M6L 2L 0LP154SA6LLO9(\SD3-TE.H^^2D;.Y$\AIEP.P>E0;*X"^S6B"AW4: (U@OUT<^\< MJ]>KKY\&#AY83'T6@X/7' >OQID2\._ C)HS(\A/-_].#)#H]I41F,F+&: X M$R@.SE]SG#]D]VKR_A;6>7\HQN6O_/["ZX7[BL*8G=R5HQDIK,LMWB[-R;A(8FY%,A80_JK08)IS.B#7.+&4_7&VE/VK6,KF[T9).N8');$N]_P'?U;DDM]W0 ;,9^,A2XGG6,2U MG>5Z*RF_2&2(YE5J6#C'"YLJ2BF*F$5'/&=IQ.76V3X M+(IFW_EP9!\5[SFA^?/W*P1T$XY91CZQ!_(U&=,E1^4A#/*[]_W^:]WV MNSF;XTIBN]56_SB,"3\HXJ[13C5_VS?$KXM< M1L6_%9$+LFM>X.P9[,U)@&^LGL63W>R M56H/Q)LIDUX#\3323>4$!W6$.BHD.*@CU%$AP4$=H8X*"0[J"'542'!0QZ;. M]JZNAOJ:I?>ASTBZ>V0M749J2$1:5;D^S3$5C)LTI6);/2Y0BT#! ^ !\ !X M #Q@$ ^XCM62M]LZ* 4 K0C (0 3IQ^5_I^&DF'BPQ\+"<_=YG>MU8[5:@'4 #5 ;1"HC_MM>=61;Q7H3IEE#7:P1VDE\*X8WKEKWNXL M[]P-*ZY*^MR0JL[BW=(&+Y\G+"VW>&+?)BS.JMGJI0(1ZD"$BJF5X8TCB+ M>1!8+E$S?0J 6 & "V"6!MJ]OI EJ %J E?^<6X JX J[@$P)@ )A& .,^ M8:\':%69C#0QY\B>]AG(:(2Y8-58*E-0HQY ]+4[0 50 51HCHJ^U>I+2Q@ M#\"#YGCH8LM3H %HF'=^M>6U:"\_\EWO7?\>+4#%6*CTK8Z\E1=33 ,P#K-<]#_=LRI 94JN&(LQ6(Q1TFH!8 8 : M;018S^JZ'J %: %:T@L)')01 %@ EOQTH->M'EG($P)U0-T+3['7@:=8:$Y2LL7P$50 50L7&_)\OSL.,3\ \S$(1%,><_\DB,60LU&"A1DF[!8 !8 8 +9YIA5@!5@!5K!; !@ !H !8 8 ;'[^+<7S&;G M%-]8/J%A1FZ#^+87A<:(Q0H9\ @\ H_ H]YX=+M6MRO/4044 45 <3\H.I8G M<=L9(!%(!!+W0^)QORVM!FQ;N>U4(U8#>E&7#Y J#5*W9SDM>7O>P%Y66\NI M>7[V\U-F-HS]9,S((> K=6%$55P?(D.T3JZ-0#W6-!6PS( VH UH ]JZ0MNQ MW'X7H :H 6J#0.W(F_$%2 /2@/3!(0T7'- &M(V$MF.UG Y K6RBO'Y 5Y(. M+]X]L.*"ADD4+ P[F.?&CV?5R[NL 3[=B5?!/)$-8M2!"Q53+>7D _V!_D!_ MH#_0'S7E _V!_D!_H#\'D0^&U*U+&GR,O(+>33(Q>2@K4 ?4;8^Z=O6#2@ Z@ Z@6P2=TY/78@;4 75 '2(X M1' V*'-FF5WY0TQ:+)A:W*-RC, IICMUBJ[%F33%:L$W&HN+8 M[4I+(C;!S@ JC84*# A0 50 %4 %4 %4 !5 !8(-!9-:"F68:\AVE3U456#+ ME"0S5G&PBJ.D\0+ # # #;"#"O+6^P#H %8 %8L%P & &@ %@ )C6 (-K MN#VP-"F1DZ<268JF [$<-LUP8)F8(T]4"EL:4R"U7'3FW;1S9A MA0Q( ]+6Z% +5@M6"UB"+PA4 55 %5 %5#4"5<>.@PA+CQI$S7+59<+DS,VJ@ F4RJT \$"]I#=^6 M-\841AR0!J0/#FFI\QIAPF'"@7>E\8YX'*89UY>*/2 M[1]G*?8HR;)_D"$;)2F;Y]US^@U#+JLQQ$TQF;",QJ)";DZY":N^ $MCP>)8 M'5M:C3J,!_"@.1Z..[ " )^"IX7@Z;MNT/.#OBK8+^>UV" MW:BW-3?>:YS2Q:P2K&ONYZ2 &D&-!\C/@QI!C:!&4".H<7GITNNX!QX2=Y[Y7=UT!)4:E\'0?3RLOO[(JZ'U1Y?W6Z%>I+=@..J3LX'DLM$4I!6*U*!&8!6:!66 6 MF 5F@5E@MD[,'J!AV?B1B H "H-H+4-GP(L 4O $KZN4KZNA-(HS6=_W"0Y MC5[+$M>EAV\&J/D5H=5)1'YMI[1=J)LRGTB]@DSEO(3ZZ]11CKX+^>A0=>[4 MQTR-*"X';:E'6V F1=TB,8#"AF,$AM&=8> 8&><8U3C_8:_,D@8JAPG/&E.: M&BJD$FNI0DR.U>K4UBK+'"^7&VPOEKL:7JQWB4I&-^4!+KLI1XCD5&%!Q0I[<8Y0/.?R_>*/ MQ.+A12^LAB.^\W3B@BR(SZ)H]IT/1_91\9XSH3]_OT) -^&89>03>R!?DS%= M