UNITED STATES
SECURITIES AND EXCHANGE COMMISSION
Washington, D.C. 20549
 
FORM 10-K
 
x
ANNUAL REPORT PURSUANT TO SECTION 13 OR 15(d) OF THE SECURITIES EXCHANGE ACT OF 1934
 For the fiscal year ended December 31, 2015
 
OR 
o
TRANSITION REPORT PURSUANT TO SECTION 13 OR 15(d) OF THE SECURITIES EXCHANGE ACT OF 1934
 
For the transition period from      to
 
Commission file number 001-33493
 
Greenlight Capital Re, Ltd.
(Exact Name of Registrant as Specified in Its Charter)
 
Cayman Islands
N/A
(State or Other Jurisdiction of
Incorporation or Organization)
(I.R.S. Employer
Identification No.)

65 Market Street, Suite 1207, Camana Bay
P.O. Box 31110
Grand Cayman, KY1-1205
Cayman Islands
(Address of Principal Executive Offices)
 
Registrant’s telephone number, including area code: 345-943-4573
 
Securities registered pursuant to Section 12(b) of the Act:
 
Title of Class
Name of Exchange on Which Registered
Class A ordinary shares,
$0.10 par value per share
The Nasdaq Stock Market LLC
 

Securities registered pursuant to Section 12(g) of the Act:  None
 
Indicate by check mark if the registrant is a well-known seasoned issuer, as defined in Rule 405 of the Securities Act.  Yes x No o
 
Indicate by check mark if the registrant is not required to file reports pursuant to Section 13 or Section 15(d) of the Act. Yes o    No x
 
Indicate by check mark whether the registrant (1) has filed all reports required to be filed by Section 13 or 15(d) of the Securities Exchange Act of 1934 during the preceding 12 months (or for such shorter period that the registrant was required to file such reports), and (2) has been subject to such filing requirements for the past 90 days. Yes x No o
 
Indicate by check mark whether the registrant has submitted electronically and posted on its corporate web site, if any, every Interactive Data File required to be submitted and posted pursuant to Rule 405 of Regulations S-T during the preceding 12 months (or for such shorter period that the registrant was required to submit and post such files). Yes x No o
 
Indicate by check mark if disclosure of delinquent filers pursuant to Item 405 of Regulation S-K is not contained herein, and will not be contained, to the best of registrant’s knowledge, in definitive proxy or information statements incorporated by reference in Part III of this Form 10-K or any amendment to this Form 10-K. x
 
Indicate by check mark whether the registrant is a large accelerated filer, an accelerated filer, a non-accelerated filer, or a smaller reporting company. See the definitions of ‘‘large accelerated filer,’’ ‘‘accelerated filer,’’ and ‘‘smaller reporting company’’ in Rule 12b-2 of the Exchange Act. (Check one):
Large accelerated filer x Accelerated filer  o Non-accelerated filer o Smaller reporting company o
 
Indicate by check mark whether the registrant is a shell company (as defined in Rule 12b-2 of the Act). Yes o No x
 
The aggregate market value of voting and non-voting Class A ordinary shares held by non-affiliates of the registrant as of June 30, 2015 was $869,305,700 based on the closing price of the registrant’s Class A ordinary shares reported on the Nasdaq Global Select Market on June 30, 2015, the last business day of the registrant’s most recently completed second fiscal quarter. Solely for the purpose of this calculation and for no other purpose, the non-affiliates of the registrant are assumed to be all shareholders of the registrant other than (i) directors of the registrant, (ii) executive officers of the registrant who are identified as ‘‘named executives’’ pursuant to Item 11 of this Form 10-K, (iii) any shareholder that beneficially owns 10% or more of the registrant’s common shares and (iv) any shareholder that has one or more of its affiliates on the registrant’s board of directors. Such exclusion is not intended, nor shall it be deemed, to be an admission that such persons are affiliates of the registrant.
Class A Ordinary Shares, $0.10 par value
30,829,333
Class B Ordinary Shares, $0.10 par value
6,254,895
(Class)                      
Outstanding as of February 19, 2016

DOCUMENTS INCORPORATED BY REFERENCE 
 
Portions of the proxy statement for the registrant’s 2016 annual meeting of shareholders, to be filed subsequently with the Securities and Exchange Commission, or the SEC, pursuant to Regulation 14A, under the Securities Exchange Act of 1934, as amended, or the Exchange Act, relating to the registrant’s annual general meeting of shareholders scheduled to be held on April 27, 2016 are incorporated by reference in Part III of this annual report on Form 10-K.

1


GREENLIGHT CAPITAL RE, LTD.

TABLE OF CONTENTS


Page
ITEM 1.
ITEM 1A.
RISK FACTORS                                                                                                    
ITEM 1B.
UNRESOLVED STAFF COMMENTS                                                                           
ITEM 2.
PROPERTIES                                                                                                       
ITEM 3.
LEGAL PROCEEDINGS                                                                                                
ITEM 4.
ITEM 5.
ITEM 6.
SELECTED FINANCIAL DATA                                                                               
ITEM 7.
ITEM 7A.
ITEM 8.
ITEM 9.
ITEM 9A.
CONTROLS AND PROCEDURES                                                                             
ITEM 9B.
OTHER INFORMATION                                                                                             
ITEM 10.
ITEM 11.
EXECUTIVE COMPENSATION                                                                               
ITEM 12.
ITEM 13.
ITEM 14.
PRINCIPAL ACCOUNTING FEES AND SERVICES                                             
ITEM 15.


2

Link to Table of Contents

PART I
Special Note About Forward-Looking Statements
 
Certain statements in Management’s Discussion and Analysis, other than purely historical information, including estimates, projections, statements relating to our business plans, objectives and expected operating results, and the assumptions upon which those statements are based, are "forward-looking statements" within the meaning of the Private Securities Litigation Reform Act of 1995, Section 27A of the Securities Act of 1933 and Section 21E of the Securities Exchange Act of 1934, as amended (the "Exchange Act"). These forward-looking statements generally are identified by the words "believe," "project," "predict," "expect," "anticipate," "estimate," "intend," "plan," "may," "should," "will," "would," "will be," "will continue," "will likely result," and similar expressions. Forward-looking statements are based on current expectations and assumptions that are subject to risks and uncertainties which may cause actual results to differ materially from the forward-looking statements. A detailed discussion of risks and uncertainties that could cause actual results and events to differ materially from such forward-looking statements is included in the section entitled "Risk Factors" (refer to Part I, Item 1A) and include but are not limited to:
 
 
●
Our results will likely fluctuate from period to period and may not be indicative of our long-term prospects; 


●
If our losses and loss adjustment expenses greatly exceed our loss reserves, our financial condition may be significantly and negatively affected;


●
Our investment portfolio may be concentrated in a few large positions which could result in large losses;


●
The property and casualty reinsurance market may be affected by cyclical trends; 


●
The effect of emerging claim and coverage issues on our business is uncertain;


●
Rating agencies may downgrade or withdraw either of our ratings; 


●
We depend on DME Advisors, LP ("DME Advisors"), to implement our investment strategy;


●
Loss of key executives could adversely impact our ability to implement our business strategy; and 


●
Currency fluctuations could result in exchange rate losses and negatively impact our business.   

We caution that the foregoing list of important factors is not intended to be and is not exhaustive. We undertake no obligation to publicly update or revise any forward-looking statements, whether as a result of new information, future events, or otherwise and all subsequent written and oral forward-looking statements attributable to us or individuals acting on our behalf are expressly qualified in their entirety by this paragraph. If one or more risks or uncertainties materialize, or if our underlying assumptions prove to be incorrect, actual results may vary materially from what we projected. Any forward-looking statements in this Form 10-K reflect our current view with respect to future events and are subject to these and other risks, uncertainties and assumptions relating to our operations, results of operations, growth, strategy and liquidity. Readers are cautioned not to place undue reliance on the forward-looking statements which speak only to the dates on which they were made.
 
We intend to communicate certain events that we believe may have a material adverse impact on our operations or financial position, including property and casualty catastrophic events and material losses in our investment portfolio, in a timely manner through a public announcement. Other than as required by the Exchange Act, we do not intend to make public announcements regarding reinsurance or investments events that we do not believe, based on management's estimates and current information, will have a material adverse impact on our operations or financial position.


3

Link to Table of Contents

Item 1. BUSINESS 

Unless otherwise indicated or unless the context otherwise requires, all references in this annual report on Form 10-K to "the Company," "we," "us," "our" and similar expressions are references to Greenlight Capital Re, Ltd. and its consolidated subsidiaries. Unless otherwise indicated or unless the context otherwise requires, all references in this annual report to entity names are as set forth in the following table:
 
Reference
Entity’s legal name
Greenlight Capital Re
Greenlight Capital Re, Ltd.
Greenlight Re
Greenlight Reinsurance, Ltd.
GRIL 
Greenlight Reinsurance Ireland, Designated Activity Company (1)
Verdant
Verdant Holding Company, Ltd.
                                                              
(1) During the year ended December 31, 2015, GRIL was re-registered and the entity's legal name was amended from Greenlight Reinsurance Ireland, Limited, to Greenlight Reinsurance Ireland, Designated Activity Company, in accordance with the requirements of the Companies Act 2014 of Ireland and as stipulated by the Central Bank of Ireland for all regulated insurance and reinsurance entities in Ireland.


Company Overview
 
Greenlight Capital Re is a holding company that was incorporated in July 2004 under the laws of the Cayman Islands. In August 2004, we raised gross proceeds of $212.2 million from private placements of Greenlight Capital Re’s Class A ordinary shares and Class B ordinary shares, or, collectively, the ordinary shares. On May 24, 2007, Greenlight Capital Re raised proceeds of $208.3 million, net of underwriting fees, in an initial public offering of Class A ordinary shares, as well as an additional $50.0 million from a private placement of Class B ordinary shares.
 
We are a Cayman Islands headquartered global specialist property and casualty reinsurer with a reinsurance and investment strategy that we believe differentiates us from most of our competitors. We conduct our reinsurance operations through two licensed and regulated reinsurance entities: Greenlight Re, based in the Cayman Islands, and GRIL, based in Dublin, Ireland. Greenlight Re provides multi-line property and casualty reinsurance globally, while GRIL focuses mainly on the European market and primarily serves clients located in Europe. Our goal is to build long-term shareholder value by selectively offering customized reinsurance solutions, in markets where capacity and alternatives are limited, which we believe will yield favorable long-term returns on equity.
 
We aim to complement our underwriting results with a non-traditional investment approach in order to achieve higher rates of return over the long term than reinsurance companies that employ more traditional, fixed-income investment strategies. We manage our investment portfolio according to a value-oriented philosophy, in which we take long positions in perceived undervalued securities and short positions in perceived overvalued securities.
  
In addition, from time to time, we may seek to form long-term strategic alliances with insurance companies and general agents to complement our property and casualty reinsurance business and our non-traditional investment approach. To facilitate such strategic alliances, we formed Verdant, which, among other activities, has made and may make strategic investments in a select group of property and casualty insurers and general agents in the United States.
 
Because we employ an opportunistic underwriting philosophy, period-to-period comparisons of our underwriting results may not be meaningful. In addition, our historical investment results may not necessarily be indicative of future performance. Due to the nature of our reinsurance and investment strategies, our operating results will likely fluctuate from period to period.

Description of Business
 
Greenlight Re is licensed and regulated by the Cayman Islands Monetary Authority ("CIMA") to write property and casualty reinsurance business as well as long term business (e.g., life insurance, long term disability, long term care, etc.); however, to date we have not written any long term business. GRIL is licensed and regulated by the Central Bank of Ireland ("CBI") to write property and casualty reinsurance business. Currently, we manage our business on the basis of one operating segment: property and casualty reinsurance. We currently offer excess of loss and quota share products in the property and casualty market. Our underwriting operations are designed to capitalize on inefficiencies that we perceive exist in the traditional

4

Link to Table of Contents

approach to underwriting. We believe that we conduct our business differently from traditional reinsurers in multiple ways, including:
 
 
●
we focus on offering customized reinsurance solutions to select customers at times and in markets where capacity and alternatives are limited rather than primarily pursuing and participating in broadly available traditional property and casualty opportunities;


●
we aim to build a reinsurance portfolio comprised principally of high frequency and low severity contracts with favorable ultimate economic results measured after all loss payments have been made rather than focusing on interim reported results when losses may be incurred but not yet reported or paid;


●
we generally seek to act as the lead underwriter on a majority of the contracts we underwrite in an effort to obtain greater influence in negotiating pricing, terms and conditions. We may from time to time participate in contracts that have been negotiated and priced by another party. For example, on some longer duration casualty business that is comprised of larger, syndicated reinsurance placements, we may follow the market on these transactions;


●
we maintain a small group of experienced generalist underwriters that are capable of underwriting many lines of property and casualty business rather than a large staff of underwriters, each with an individual, specific focus on certain lines of business; 


●
we implement a "cradle to grave" service philosophy where the same deal team underwrites and services each reinsurance contract rather than separating underwriting and servicing duties among many employees; and 


●
we compensate our management with a cash bonus structure largely dependent on our underwriting results over a multi-year period rather than on premium volume or preliminary underwriting results in any given financial accounting period.
  
Our investment strategy, like our reinsurance strategy, is designed to maximize returns over the long term while minimizing the risk of capital loss. Unlike the investment strategies of many of our traditional competitors, which invest primarily in fixed-income securities either directly or through fixed-fee arrangements with one or more investment managers, our investment strategy is to invest in long and short positions primarily in publicly-traded equity and corporate debt instruments exclusively through a joint venture with DME Advisors LLC ("DME"). Our investment advisor, DME Advisors, is compensated with a fixed annual fee based on assets under management and the joint venture participant, DME, is compensated on the positive performance of our portfolio, subject to a loss carry forward. DME Advisors, which makes investments on our behalf, is a value-oriented investment advisor that analyzes companies' available financial data, business strategies and prospects in an effort to identify undervalued and overvalued securities. DME Advisors and DME are both controlled by David Einhorn, the Chairman of our Board of Directors and the President of Greenlight Capital, Inc. DME Advisors has the contractual right to manage substantially all of our investable assets until December 31, 2016, and is required to follow our investment guidelines and to act in a manner that is fair and equitable in allocating investment opportunities to us. However, DME Advisors is not otherwise restricted with respect to the nature or timing of making investments for our account.
 
We measure our success by long-term growth in book value per share, which we believe is the most comprehensive gauge of the performance of our business. Accordingly, our incentive compensation plans are designed to align employee and shareholder interests. Compensation under our cash bonus plan is largely dependent on the ultimate underwriting returns of our business measured over a multi-year period, rather than premium targets or estimated underwriting profitability for the year in which we initially underwrote the business.
 
We characterize the reinsurance risks we assume as frequency or severity and aim to balance the risks and opportunities of our underwriting activities by creating a diversified portfolio of both types of businesses, although over the long term we generally have a preference for frequency business.
 
Frequency business is characterized as contracts containing a potentially large number of smaller losses emanating from multiple events. Clients generally buy this protection to increase their own underwriting capacity and typically select a reinsurer based upon the reinsurer's financial strength, service and expertise. We expect the results of frequency business to be less volatile than those of severity business from period to period due to its greater predictability. We also expect that over time the profit margins and return on equity of our frequency business will be lower than those of our severity business.
 
Severity business is typically characterized as contracts with the potential for significant losses emanating from one event or multiple events. Clients generally buy this protection to reduce volatility from their balance sheets, and accordingly, we

5

Link to Table of Contents

expect the results of severity business to be volatile from period to period. However, over the long term, we also expect that our severity business will generate higher profit margins and return on equity than our frequency business.
 
While we intend to continue to add to, and diversify, our portfolio, our allocation of risk will vary based on our perception of the opportunities available in each line of business. Moreover, our focus on certain lines will fluctuate based upon market conditions and we may only offer or underwrite a limited number of lines in any given period. We intend to continue to:  
 
 
●
target markets where capacity and alternatives are underserved or constrained;


●
seek clients with appropriate expertise in their line of business;


●
employ strict underwriting discipline;


●
select reinsurance opportunities with favorable returns on capital over the life of the contract; and


●
strengthen and expand relationships with existing clients.


The following table sets forth our gross premiums written by line of business:
 
 
Year ended December 31
 
 
2015
 
2014
 
2013
 
 
($ in thousands)
Property


Aviation
 
$
691

 
0.1
%
 
$
391

 
0.1
%
 
$
168

 
0.0
 %
Commercial
 
16,667

 
3.3

 
11,529

 
3.6

 
9,999

 
1.9

Energy
 
2,009

 
0.4

 
2,131

 
0.6

 
659

 
0.1

Motor physical damage
 
34,529

 
6.9

 
24,008

 
7.4

 
57,952

 
10.8

Personal
 
57,495

 
11.5

 
64,479

 
19.9

 
145,807

 
27.2

Total Property
 
111,391

 
22.2

 
102,538

 
31.6

 
214,585

 
40.0

Casualty


General liability (1)
 
28,355

 
5.6

 
11,639

 
3.6

 
(815
)
 
(0.2
)
Marine liability
 
9,283

 
1.8

 
5,120

 
1.6

 
1,956

 
0.4

Motor liability
 
203,624

 
40.6

 
127,858

 
39.5

 
253,698

 
47.4

Professional liability
 
72,217

 
14.4

 
27,009

 
8.4

 
29,901

 
5.6

Total Casualty
 
313,479

 
62.4

 
171,626

 
53.1

 
284,740

 
53.2

Specialty


Financial
 
7,824

 
1.6

 
5,292

 
1.6

 
3,498

 
0.7

Health
 
56,784

 
11.3

 
43,837

 
13.5

 
37,094

 
6.9

Workers’ compensation (1) 
 
12,646

 
2.5

 
730

 
0.2

 
(4,215
)
 
(0.8
)
Total Specialty
 
77,254

 
15.4

 
49,859

 
15.3

 
36,377

 
6.8


$
502,124

 
100.0
%
 
$
324,023

 
100.0
%
 
$
535,702

 
100.0
 %
 
(1) 
The negative balance represents reversal of premiums due to premium adjustments, termination of contracts or premiums returned upon novation or commutation of contracts.


6

Link to Table of Contents

The following table sets forth our gross premiums written by the geographic area of the risk insured:


Year ended December 31
 
 
2015
 
2014
 
2013
 
 
($ in thousands)
U.S. and Caribbean
 
$
383,236

 
76.3
%
 
$
275,402

 
85.0
%
 
$
496,949

 
92.8
%
Worldwide (1)
 
104,336

 
20.8

 
31,106

 
9.6

 
9,821

 
1.8

Europe
 
14,085

 
2.8

 
17,432

 
5.4

 
28,932

 
5.4

Asia
 
467

 
0.1

 
83

 
—

 
—

 
—


$
502,124

 
100.0
%
 
$
324,023

 
100.0
%
 
$
535,702

 
100.0
%
  
(1) 
"Worldwide" is comprised of contracts that reinsure risks in more than one geographic area and do not specifically exclude the U.S.
 
Additional information about our business is set forth in "Item 7 — Management’s Discussion and Analysis of Financial Condition and Results of Operations" and Note 15 to our consolidated financial statements included herein.


Marketing and Distribution
 
A majority of our business is sourced through reinsurance brokers. Brokerage distribution channels provide us with access to an efficient, variable cost and global distribution system without the significant time and expense that would be incurred in creating a wholly-owned distribution network. We believe that our financial strength rating, unencumbered balance sheet and superior client service are essential for creating long-term relationships with clients and brokers.
 
We aim to build and strengthen long-term relationships with global reinsurance brokers. Our management team has significant relationships with most of the primary and specialty broker intermediaries in the reinsurance marketplace. We believe that by maintaining close relationships with brokers we will be able to continue to obtain access to a broad range of reinsurance clients and opportunities. We focus on the quality and financial strength of any brokerage firm with which we do business. Brokers do not have the authority to bind us to any reinsurance contract. 
 
Reinsurance brokers receive a brokerage commission that is usually a percentage of gross premiums written. We seek to become the first choice of brokers and clients by providing:
 
 
●
customized solutions that address the specific business needs of our clients;  
 
●
rapid and substantive responses to proposal and pricing quote requests; 
 
●
timely payment of claims;  
 
●
financial security; and 
 
●
clear indication of risks we will and will not underwrite.

The following table sets forth the premiums sourced from brokers who each accounted for more than 10% of our gross written premiums:


Year ended December 31
 
 
2015
 
2014
 
2013
 
 
 ($ in thousands)
Largest broker
 
$
278,003

 
55.4
%
 
$
161,405

 
49.8
%
 
$
282,337

 
52.7
%
2nd largest broker
 
110,246

 
22.0

 
61,809

 
19.1

 
119,117

 
22.2

3rd largest broker
 
—

 
—

 
40,773

 
12.6

 
—

 
—


$
388,249

 
77.4
%
 
$
263,987

 
81.5
%
 
$
401,454

 
74.9
%

We believe that by maintaining close relationships with brokers, we are able to obtain access to a range of potential clients that meet our criteria. We meet frequently in the Cayman Islands, Ireland and elsewhere with brokers and senior

7

Link to Table of Contents

representatives of clients and prospective clients. All contract submissions are received, reviewed and approved in our executive offices in the Cayman Islands or Ireland. Due to our dependence on brokers, the inability to obtain business from them could adversely affect our business strategy. See "Item 1A. Risk Factors — Risks Related to Our Business — The inability to obtain business provided from brokers could adversely affect our business strategy and results of operations." In addition, we may assume a degree of credit risk of our reinsurance brokers. See "Item 1A. Risk Factors — Risks Related to Our Business — We may be subject to the credit risk of our brokers, cedents and agents." 

We believe that diversity in our sources of business helps reduce any potential adverse effects arising out of the termination of any one of our business relationships.

Underwriting and Risk Management
 
We have established a small team of generalist underwriters and actuaries to operate our reinsurance business. We believe that our underwriters' experience, coupled with our approach to underwriting, allows us to deploy our capital in a variety of lines of business and to capitalize on opportunities that we believe offer favorable returns on equity over the long term. Our underwriters and actuaries have expertise in a number of lines of business and we also look to outside consultants on a fee-for-service basis to help us with niche areas of expertise when we deem it appropriate. We generally apply the following underwriting and risk management principles:
 
Economics of Results
 
Our primary goal is to build a reinsurance portfolio that has attractive economic results. We may underwrite a reinsurance contract that may not demonstrate immediate short-term accounting benefits if we believe it will provide a favorable return on capital over the life of the contract. In pricing our products, we assume investment returns that approximate the risk-free rate, which we review and adjust, if necessary, on an annual basis.
 
Actuarially Based Pricing
 
We have developed and use proprietary actuarial models and also use several commercially available tools to price our business. Our models not only consider conventional underwriting metrics, but also incorporate a component for risk aversion that places greater weight on scenarios that result in greater losses. We price each transaction based on our view of the merits and structure of the transaction.
 
Team Approach
 
Each transaction typically is assigned to a deal team comprised of at least an underwriter and an actuary to evaluate underwriting, structuring and pricing. Prior to committing capital to any transaction, the deal team creates a deal analysis memorandum that highlights the key components of the proposed transaction and presents the proposed transaction to a senior group of staff, including underwriting, actuarial, risk management and finance. This group is provided an opportunity to critically evaluate the proposed transaction. Additionally, our Chief Executive Officer or Chief Underwriting Officer must agree that the transaction meets our underwriting guidelines before we submit a firm proposal. Our Chief Executive Officer and Chief Underwriting Officer maintain the exclusive ultimate authority to bind contracts.

Act as Lead Underwriter
 
Typically, one reinsurer acts as the lead underwriter in negotiating principal policy terms and pricing of reinsurance contracts. We aim to act as the lead underwriter for the majority of the aggregate premiums that we underwrite. We believe that lead underwriting is an important factor in achieving long-term success, as lead underwriters typically have greater influence in negotiating pricing, terms and conditions. In addition, we believe that reinsurers that lead policies are generally solicited for a broader range of business and have greater access to attractive opportunities. However, we may from time to time participate in contracts that have been negotiated and priced by another party. For example, on some longer duration casualty business that is comprised of larger, syndicated reinsurance placements, we may follow the market on these transactions.
 
Alignment of Company and Client’s Interests
 
We seek to ensure that each contract we underwrite aligns our interests with our client’s interests. Specifically, depending upon the opportunity we may seek to:
 

8

Link to Table of Contents

 
●
pay our clients a commission based upon a predetermined percentage of the profit we realize on the business, which we refer to as a profit commission; 
 
●
provide that the client pays a predetermined amount of all losses before our reinsurance policy incurs a loss payment, which we refer to as self-insured retentions; 
 
●
provide that the client pays a predetermined proportion of all losses above a predetermined amount, which we refer to as co-participation; and/or 
 
●
charge the client a premium for reinstatement of reinsurance coverage to the full amount, which we refer to as reinstatement premium, if coverage has been reduced as a result of a reinsurance loss payment.

We believe that through profit commissions, self-insured retentions, co-participation, reinstatement premiums and other terms within the contract, our clients are provided with an incentive to manage our interests. We believe that aligning our interests with our clients' interests promotes accurate reporting of information, timely settling and management of claims and limits the potential for disputes.
  
Integrated Underwriting Operations
 
We implement a "cradle to grave" service philosophy where the same deal team underwrites and oversees each reinsurance contract. We believe this method enables us to best understand the risks and likelihood of loss for any particular contract and to provide superior client service.

Detailed Contract Diligence
 
We are highly selective in the contracts we choose to underwrite and spend a significant amount of time with our clients and brokers to understand the risks and appropriately structure the contracts. Where necessary, we conduct or contract for on-site audits or reviews of the clients' underwriting files, systems and operations. We usually obtain significant amounts of data from our clients to conduct a thorough actuarial modeling analysis. As part of our pricing and underwriting process, we assess, among other factors:
 
 
●
the client’s and industry's historical loss data; 
 
●
the expected duration for claims to fully develop; 
 
●
the client’s pricing and underwriting strategies; 
 
●
the geographic areas in which the client is doing business and its market share; 
 
●
the reputation and financial strength of the client; 
 
●
the reputation and expertise of the broker; 
 
●
the likelihood of establishing a long-term relationship with the client and the broker; and 
 
●
reports provided by independent industry specialists.
 
Underwriting Authorities
 
We use actuarial models that we produce and apply our underwriting guidelines to analyze each reinsurance opportunity before we commit capital. The Underwriting Committee of our Board of Directors, which we refer to as the Underwriting Committee, sets parameters for zonal and aggregate property catastrophic caps and limits for maximum loss potential under any individual contract. The Underwriting Committee must approve any exceptions to the established limits. Our approach to risk control imposes an absolute loss limit on our natural catastrophic exposures as well as an estimate of probable maximum losses, and we have also established zonal and aggregate limits. We manage all non-catastrophic exposures and other risks by analyzing our maximum loss potential on a contract-by-contract basis. The maximum underwriting authorities, as set by our Underwriting Committee, may be amended from time to time, including as and when our capital base changes.
 
Retrocessional Coverage
 
We may from time to time purchase retrocessional coverage for one or more of the following reasons: to manage our overall exposure, to reduce our net liability on individual risks, to obtain additional underwriting capacity and to balance our underwriting portfolio. Additionally, retrocession can be used as a mechanism to share the risks and rewards of business written and, therefore, can be used as a tool to align our interests with those of our counterparties.
 

9

Link to Table of Contents

The amount of retrocessional coverage that we purchase varies based on numerous factors, some of which include the inherent riskiness of the portfolio of business we write and the level of our capital base. Given our opportunistic approach to underwriting, which may change the composition and inherent riskiness of our underwriting portfolio on an annual basis, it is not possible to predict the level of retrocessional coverage that we will purchase in any given year. To date, our retrocessional coverage has been primarily used as a tool to align our interests with those of our counterparties.
 
We intend to only purchase uncollateralized retrocessional coverage from a reinsurer with a minimum financial strength rating of "A- (Excellent)" from A.M. Best Company, Inc. ("A.M. Best") or an equivalent rating from a recognized rating service. For non-rated reinsurers, we monitor and obtain collateral in the form of cash, funds withheld, letters of credit, regulatory trusts or other collateral in the form of guarantees. As of December 31, 2015, the aggregate amount due from reinsurers from retrocessional coverages represents 1.1% (2014: 4.4%) of our gross outstanding loss reserves. For further details please see Note 8 to the consolidated financial statements. We regularly evaluate the financial condition of our reinsurers to assess their ability to honor their obligations. At December 31, 2015 and 2014, no provision for uncollectible losses recoverable was considered necessary.

Capital Allocation
 
We allocate capital to each contract that we bind. Our capital allocation methodology uses the probability and magnitude of potential for economic loss. We allocate capital for the period from each contract’s inception until the risk is resolved. We have developed a proprietary return on equity capital allocation model to evaluate and price each reinsurance contract that we underwrite. We use different return on equity thresholds depending on the type and risk characteristics of the business we underwrite. 

Claims Management
 
Our claims management process begins upon receipt of claims submissions from our clients, which the underwriter reviews for authorization prior to entry and settlement. Additionally, our in-house claims manager is responsible for overseeing the review of claims and providing approval for complex or large claim settlements. We believe this ensures that we pay claims consistently within the terms and conditions of each contract. Depending on the size of the claim payment, additional approvals for payment must be obtained from our executive officers.
 
Where necessary, we conduct or contract for on-site claims and underwriting audits at cedents and third party claims handlers, particularly for large accounts and for those whose performance differs from our expectations. Through these audits, we evaluate and monitor ceding companies’ claims-handling practices, including the organization of their claims departments, their fact-finding and investigation techniques, their loss notifications, the adequacy of their reserves, their negotiation and settlement practices and their adherence to claims-handling guidelines.
 
We recognize that fair interpretation of our reinsurance agreements with our clients and timely payment of covered claims are valuable services to our clients.

Reserves
 
Our reserving philosophy is to set reserves to our best estimate of the actual results that stem from the risks underwritten. Our actuaries provide reserving estimates on a quarterly basis calculated to meet our estimated future obligations. We reserve on a transaction by transaction basis. We engage independent external actuaries who review and provide an opinion on these estimates at least once a year. Due to the use of different assumptions, accounting treatment and loss experience, the amount we establish as reserves with respect to individual risks, transactions or classes of business may be greater or less than those established by clients or ceding companies. Reserves may also include unearned premiums, premium deposits, profit sharing earned but not yet paid, claims reported but not yet paid, claims incurred but not reported and claims in the process of settlement.
 
Reserves do not represent an exact calculation of liability. Rather, reserves represent our best estimate of the expected cost of the ultimate settlement and administration of the claim. Although the methods for establishing reserves are well-tested, some of the major assumptions about anticipated loss emergence patterns are subject to unanticipated fluctuation. We base these estimates on our assessment of facts and circumstances then known, as well as estimates of future trends in claim severity and frequency, judicial theories of liability and other factors, including the actions of third parties, which are beyond our control.


10

Link to Table of Contents

Collateral Arrangements and Letter of Credit Facilities
 
We are licensed and admitted as an insurer only in the Cayman Islands and the European Economic Area. Many jurisdictions, such as the United States, do not permit clients to take credit for reinsurance on their statutory financial statements if such reinsurance is obtained from unlicensed or non-admitted insurers without appropriate collateral. As a result, we anticipate that all of our U.S. clients and a portion of our non-U.S. clients will require us to provide collateral for the contracts we bind with them. We expect this collateral to take the form of funds withheld, trust arrangements or letters of credit. As of December 31, 2015, we had letter of credit facilities with an aggregate capacity of $720.0 million (2014: $760.0 million). As of December 31, 2015, we had issued letters of credit totaling $245.6 million (2014: $273.7 million) to clients. Additionally, as of December 31, 2015, we had pledged $78.6 million (2014: nil) as collateral through trust arrangements. The failure to maintain, replace or increase our letter of credit facilities and trust arrangements on commercially acceptable terms may significantly and negatively affect our ability to implement our business strategy. See "Item 1A. Risk Factors — Risks Relating to Our Business — Our failure to maintain sufficient collateral arrangements or to increase our collateral capacity on commercially acceptable terms as we grow could significantly and negatively affect our ability to implement our business strategy."

Competition
 
The reinsurance industry is highly competitive. We compete with major reinsurers, most of which are well established, have significant operating histories and strong financial strength ratings, and have developed long-standing client relationships.
 
Our competitors include ACE Limited, Everest Re, General Re Corporation, Hannover Re Group, Munich Reinsurance Company, PartnerRe Ltd., Swiss Reinsurance Company, Third Point Reinsurance Ltd. and Transatlantic Reinsurance Company, as well as smaller companies and other niche reinsurers. Although we seek to provide coverage where capacity and alternatives are limited, we directly compete with these larger companies due to the breadth of their coverage across the property and casualty market in substantially all lines of business.
 
While most of our competitors have had a longer operating history than us, we believe that our approach to underwriting allows us to be successful in underwriting transactions against more established competitors.

Ratings
 
Currently, our reinsurance subsidiaries, Greenlight Re and GRIL are both rated "A (Excellent)" by A.M. Best. On October 23, 2015, A.M. Best affirmed Greenlight Re's rating of "A (Excellent)" but revised the outlook from stable to negative. The "A (Excellent)" rating from A.M. Best is the third highest of 15 ratings. We believe that a strong rating is an important factor in the marketing of reinsurance products to clients and brokers. These ratings reflect the rating agency’s opinion of our reinsurance subsidiaries' financial strength, operating performance and ability to meet obligations. It is not an evaluation directed toward the protection of investors or a recommendation to buy, sell or hold our Class A ordinary shares.
 
The failure to maintain a strong rating may significantly and negatively affect our ability to implement our business strategy. See "Item 1A. Risk Factors — Risks Relating to Our Business — A downgrade or withdrawal of either of our A.M. Best ratings may significantly and negatively affect our ability to implement our business strategy successfully."

Regulations
 
Cayman Islands Insurance Regulation
 
The legislative framework for the carrying on of insurance and reinsurance business in and from within the Cayman Islands is comprised of The Insurance Law, 2010 and underlying regulations thereto (the "Law") which was brought into force in the Cayman Islands effective as of November 1, 2012.

Greenlight Re holds a Class D insurer license issued in accordance with the terms of the Law and is subject to regulation by CIMA.

As the holder of a Class D insurer license, Greenlight Re is permitted to carry on reinsurance business from the Cayman Islands, but, except with the prior written approval of CIMA, may not carry on any insurance or reinsurance business where the underlying risk originates and resides in the Cayman Islands.
 
Greenlight Re is required to comply with the following principal requirements under the Law: 


11

Link to Table of Contents

 
●
to maintain capital and a margin of solvency in accordance with the capital and solvency requirements prescribed by the Law;


●
to carry on its business in accordance with the terms of the license application submitted to CIMA and to seek the prior approval of CIMA for any proposed change thereto;


●
to maintain adequate arrangements for the management of risks and a system of governance as approved by CIMA;


●
to maintain a minimum of at least two directors and to seek the prior approval of CIMA in respect of the appointment of directors and officers and to provide CIMA with information in connection therewith and notification of any changes thereto;


●
to have a place of business in the Cayman Islands and to maintain such resources, including staff and facilities, books and records as CIMA considers appropriate having regard for the nature and scale of the business of Greenlight Re;


●
to submit to CIMA an annual return in the prescribed form together with:
 
 
1. financial statements prepared in accordance with any internationally recognized accounting standards, audited by an independent auditor approved by CIMA;
 
 
2. an actuarial valuation of Greenlight Re's assets and liabilities, certified by an actuary approved by CIMA;
 
 
3. certification of solvency prepared by a person approved by CIMA in accordance with the prescribed requirements;
 
 
4. confirmation that the information contained in Greenlight Re's license application, as modified by any subsequent changes, remains correct; and
 
 
5. such other information as may be prescribed by CIMA; and


●
to pay an annual license fee. 

It is the duty of CIMA: 
 
●
to maintain a general review of insurance practices in the Cayman Islands;


●
to examine the affairs or business of any licensee or other person carrying on, or who has carried on, insurance business in order to ensure that the Law has been complied with and that the licensee is in a sound financial position and is carrying on its business in a fit and proper manner;


●
to examine and report on the annual returns delivered to CIMA in terms of the Law; and


●
to examine and make recommendations with respect to, among other things, proposals for the revocation of licenses and cases of suspected insolvency of licensed entities.
 
Where CIMA believes that a licensee is committing, or is about to commit or pursue, an act that is an unsafe or unsound business practice, CIMA may direct the licensee to cease or refrain from committing the act or pursuing the offending course of conduct. Failure to comply with such a CIMA direction may be punishable on summary conviction by a fine of up to 100,000 Cayman Islands dollars (which is approximately US$120,000) or to imprisonment for a term of five years or to both, and on conviction on indictment to a fine of 500,000 Cayman Islands dollars (which is approximately US$600,000) or to imprisonment for a term of ten years or to both and to an additional 10,000 Cayman Islands dollars (which is approximately US$12,000) for every day after conviction that the breach continues.
 
Whenever CIMA believes that a licensee is or may become unable to meet its obligations as they fall due, is carrying on business in a manner likely to be detrimental to the public interest or to the interest of its creditors or policyholders, has contravened the terms of the Law or has otherwise behaved in such a manner so as to cause CIMA to call into question the licensee’s fitness, CIMA may take one of a number of steps, including requiring the licensee to take steps to rectify the matter, suspending the license of the licensee, revoking the license, imposing conditions upon the license and amending or revoking

12

Link to Table of Contents

any such condition, requiring the substitution of any director, manager or officer of the licensee, at the expense of the licensee, appointing a person to advise the licensee on the proper conduct of its affairs and to report to CIMA thereon, at the expense of the licensee, appointing a person to assume control of the licensee’s affairs or otherwise requiring such action to be taken by the licensee as CIMA considers necessary. To date, we have not been subject to any such actions from CIMA. 

Other Regulations in the Cayman Islands
 
As Cayman Islands exempted companies, Greenlight Capital Re and Greenlight Re may not carry on business or trade locally in the Cayman Islands except in furtherance of their business outside the Cayman Islands, and are prohibited from soliciting the public of the Cayman Islands to subscribe for any of their securities or debt. We are further required to file a return with the Registrar of Companies in January of each year and to pay an annual registration fee at that time.
 
The Cayman Islands has no exchange controls restricting dealings in currencies or securities.

Ireland Insurance Regulations

Our Irish subsidiary, GRIL, is authorized as a non-life reinsurance undertaking by the CBI. The Solvency II Directive 2009/138/EC (known as "Solvency II") introduced a new European regulatory regime for insurers and reinsurers and has been transposed into Irish law by the European Union (Insurance and Reinsurance) Regulations 2015 (the "Irish Regulations"). GRIL is now authorized to conduct reinsurance business under provisions of the Irish Regulations which became effective on January 1, 2016. GRIL is required to comply at all times with the Irish Regulations, the Irish Insurance Acts 1909 to 2015, regulations relating to insurance business or reinsurance business promulgated under the European Communities Act 1972, the Irish Central Bank Acts 1942 to 2015 as amended, regulations promulgated thereunder and directions, guidelines and codes of conduct issued by CBI (collectively the "Irish Insurance Acts and Regulations"). In addition, GRIL is required to meet risk-based solvency requirements imposed under Solvency II on insurers and reinsurers across all member states, including Ireland. Solvency II, together with European Commission "delegated acts" and guidance issued by the European Insurance and Occupational Pensions Authority, sets out classification and eligibility requirements, including the characteristics required for any capital contribution to qualify as regulatory capital.
  
Overview of Investments
 
Our investment portfolio is managed by DME Advisors, a value-oriented investment advisor that analyzes companies' available financial data, business strategies and prospects in an effort to identify undervalued and overvalued securities. DME Advisors is controlled by David Einhorn, the Chairman of our Board of Directors and the President of Greenlight Capital, Inc. Effective January 1, 2014 we entered into a second amended and restated agreement (the "venture agreement"), wherein the Company, Greenlight Re, GRIL, and DME have agreed to create a joint venture for the purposes of managing certain jointly held assets. The venture agreement, which replaces the previous agreement dated August 31, 2010, expires on December 31, 2016 and will renew automatically for successive three-year periods unless at least 90 days prior to the end of the then current term, DME notifies the other participants of its desire to terminate the venture agreement or any other participant notifies DME of its desire to withdraw from the venture agreement. Simultaneously with the venture agreement, we entered into an investment advisory agreement (the "advisory agreement") with DME Advisors to provide discretionary advisory services relating to the assets and liabilities of the venture. The advisory agreement term period mirrors that of the venture agreement.
 
Pursuant to the venture agreement and the advisory agreement, DME Advisors has the exclusive right to manage substantially all of our investable assets, subject to the investment guidelines adopted by the respective Boards of Directors of Greenlight Re and GRIL, for so long as the venture agreement is in effect. DME Advisors receives a monthly management fee based on an annual rate of 1.5% of the capital account balance of each participant. In addition, DME receives a performance allocation based on the positive performance change in such participant’s capital account equal to 20% of net profits calculated per annum, subject to a loss carry forward provision.

The loss carry forward provision allows DME to earn a reduced performance allocation of 10% on profits in any year subsequent to the year in which a participant's capital account (other than DME) incurs a loss, until all the losses are recouped and an additional amount equal to 150% of the loss is earned. DME is not entitled to a performance allocation in a year in which such participant's capital account incurs a loss.
 
DME Advisors is required to follow our investment guidelines and act in a manner that it considers fair and equitable in allocating investment opportunities to us, but the advisory agreement does not otherwise impose any specific obligations or requirements concerning the allocation of time, effort or investment opportunities to us or any restrictions on the nature or timing of investments for our account, or other accounts that DME Advisors or its affiliates may manage. In addition, DME

13

Link to Table of Contents

Advisors can outsource to sub-advisors without our consent or approval. In the event that DME Advisors and any of its affiliates attempt to simultaneously invest in the same opportunity, the opportunity will be allocated pro-rata as reasonably determined by DME Advisors and its affiliates. Affiliates of DME Advisors presently serve as general partner or investment advisor of Greenlight Capital, L.P., Greenlight Capital Qualified, L.P., Greenlight Capital Offshore, Ltd., Greenlight Capital Offshore Qualified, Ltd., Greenlight Capital Offshore Partners, Greenlight Capital (Gold), L.P., Greenlight Capital Offshore (Gold), Ltd., Greenlight Capital Offshore Master (Gold), Ltd., Greenlight Masters, L.P., Greenlight Masters Qualified, L.P., Greenlight Masters Offshore, Ltd., Greenlight Masters Offshore I, Ltd., Greenlight Masters Offshore Partners and Greenlight Masters Partners (collectively the "Greenlight Funds"). 
 
We have agreed to use commercially reasonable efforts to cause all of our current and future subsidiaries to enter into substantially similar venture agreements, provided that any such agreement shall be terminable on the same date that the venture agreement is terminable.
  
We have agreed to release DME and DME Advisors and their affiliates from, and to indemnify and hold them harmless against, any liability arising out of the venture agreement and the advisory agreement, subject to certain exceptions. Furthermore, DME and DME Advisors and their affiliates have agreed to indemnify us against any liability incurred in connection with certain actions. 
 
Greenlight Re or GRIL may also withdraw as a participant under the venture agreement prior to the expiration of its term at any time only ‘‘for cause,’’ which the venture agreement defines as:
 
 
●
a material violation of applicable law relating to DME's or DME Advisors’ advisory business;


●
DME's or DME Advisors' gross negligence, willful misconduct or reckless disregard of any of DME's obligations under the venture agreement or DME Advisors' obligations under the advisory agreement;


●
a material breach by DME or DME Advisors of Greenlight Re’s or GRIL’s investment guidelines that is not cured within a 15-day period; or


●
a material breach by DME or DME Advisors of its obligations to return and deliver assets as we may request.

In addition, GRIL may withdraw as a participant under the venture agreement prior to the expiration of its term due to unsatisfactory long term performance of DME Advisors, as determined solely by the Board of Directors of GRIL on each anniversary date of the venture agreement.

Investment Strategy
 
DME Advisors implements a value-oriented investment strategy by taking long positions in perceived undervalued securities and short positions in perceived overvalued securities. DME Advisors aims to achieve high absolute rates of return while minimizing the risk of capital loss. DME Advisors attempts to determine the risk/return characteristics of potential investments by analyzing factors such as the risk that expected cash flows will not be obtained, the volatility of the cash flows, the leverage of the underlying business and the security's liquidity, among others.
 
Our Board of Directors conducts reviews of our investment portfolio activities and oversees our investment guidelines to meet our investment objectives. We believe our investment approach, while less predictable than traditional fixed-income portfolios, complements our reinsurance business and will achieve higher rates of return over the long term than reinsurance companies that invest predominantly in fixed-income securities. Our investment guidelines are designed to maintain adequate liquidity to fund our reinsurance operations and to protect against unexpected events.
 
DME Advisors, which is contractually obligated to adhere to our investment guidelines, makes investment decisions on our behalf, which may include buying publicly listed equity securities and corporate debt, selling securities short and investing in private placements, futures, currencies, commodities, credit default swaps, interest rate swaps, sovereign debt, derivatives and other instruments. As of December 31, 2015, DME Advisors was in compliance with our investment guidelines.
 

14

Link to Table of Contents

Investment Guidelines
 
The investment guidelines adopted by the respective Boards of Directors of Greenlight Re and GRIL, which may be amended or modified from time to time, take into account restrictions imposed on us by regulators, our liability mix, requirements to maintain an appropriate claims paying rating by ratings agencies and requirements of lenders.

As of the date hereof, the investment guidelines for Greenlight Re currently state:
 
 
●
Composition of Investments: At least 80% of the assets in the investment portfolio will be held in debt or equity securities (including swaps) of publicly-traded companies (or their subsidiaries) and governments of the Organization of Economic Co-operation and Development, (the "OECD"), high income countries, cash, cash equivalents and gold. No more than 10% of the assets in the investment portfolio will be held in private equity securities.


●
Concentration of Investments: Other than cash, cash equivalents, United States government obligations and gold, no single investment in the investment portfolio will constitute more than 20% of the portfolio.


●
Liquidity: Assets will be invested in such fashion that Greenlight Re has a reasonable expectation that it can meet any of its liabilities as they become due. Greenlight Re will review with the investment advisor the liquidity of the portfolio on a periodic basis.


●
Monitoring: Greenlight Re will require the investment advisor to re-evaluate each position in the investment portfolio and to monitor changes in intrinsic value and trading value and provide monthly reports on the investment portfolio to Greenlight Re as Greenlight Re may reasonably determine.


●
Leverage: The investment portfolio may not employ greater than 15% indebtedness for borrowed money, including net margin balances, for extended time periods. The investment advisor may employ, in the normal course of business, up to 30% indebtedness for periods of less than 30 days.

The investment guidelines for GRIL are identical to Greenlight Re's except for concentration of investments and leverage, which for GRIL are as follows:
 
 
●
Concentration of Investments: Other than cash, cash equivalents and United States government obligations, (1) no single investment in the investment portfolio will constitute more than 10% of the portfolio, (2) the 10 largest investments shall not constitute greater than 50% of the total investment portfolio, and (3) the investment portfolio shall at all times be comprised of a minimum of 50 debt or equity securities of publicly traded companies (or their subsidiaries).


●
Leverage: The investment portfolio may not employ greater than 5% indebtedness for borrowed money, including net margin balances, for extended time periods. The investment advisor may use, in the normal course of business, an aggregate of up to 20% net margin leverage for periods of less than 30 days.
   

15

Link to Table of Contents

Investment Results
 
Composition
 
The following table represents the fair value of the total long positions in our investment portfolio as reported in the consolidated financial statements: 
 
 
December 31
 
 
2015
 
2014
 
 
($ in thousands)
Debt instruments
 
$
39,087

 
3.3
 %
 
$
49,212

 
3.2
%
Equities – listed
 
890,653

 
76.2

 
1,246,427

 
82.4

Exchange traded funds
 
15,341

 
1.3

 
19,748

 
1.3

Commodities
 
98,046

 
8.4

 
96,872

 
6.4

Private and unlisted equity securities
 
21,037

 
1.8

 
18,719

 
1.2


1,064,164

 
91.0

 
1,430,978

 
94.5

Funds and cash held with brokers and swap counterparties
 
120,276

 
10.3

 
79,806

 
5.3

Financial contracts, net
 
(15,030
)
 
(1.3
)
 
2,579

 
0.2

Total long investments
 
$
1,169,410

 
100.0
 %
 
$
1,513,363

 
100.0
%
 
The following table represents the fair value of our total short positions as reported in the consolidated financial statements: 
 
 
December 31
 
 
2015
 
2014
 
 
($ in thousands)
Equities – listed
 
$
796,054

 
90.2
%
 
$
823,390

 
75.5
%
Exchange traded funds
 
12,427

 
1.4

 
10,838

 
1.0

Corporate debt – U.S.
 
—

 
—

 
6,064

 
0.6

Sovereign debt – Non U.S.
 
74,425

 
8.4

 
250,439

 
22.9

Total short investments
 
$
882,906

 
100.0
%
 
$
1,090,731

 
100.0
%
 
    DME Advisors also reports the composition of our managed portfolio on a delta adjusted and notional exposure basis, which it believes is the appropriate manner in which to assess the exposure and profile of investments and is the way in which it manages the portfolio. This exposure analysis does not include cash (U.S. dollar and foreign currencies), gold and other commodities, credit default swaps, sovereign debt, foreign currency derivatives, interest rate options and other macro positions. In addition, under this methodology, the exposure for total return swaps is reported at full notional amount. The notional amount of a derivative contract is the underlying value upon which payment obligations are computed. For an equity total return swap, for example, the notional amount is the number of shares underlying the swap multiplied by the market price of those shares. Options are reported at their delta adjusted basis. The delta of an option is the sensitivity of the option price to the underlying stock (or commodity) price. The delta adjusted basis is the number of shares underlying the option multiplied by the delta and the underlying stock (or commodity) price.
  
The following table represents the composition of our investment portfolio based on the percentage of assets in our investment account managed by DME Advisors:


December 31
 
 
2015
 
2014
 
 
Long %
 
Short %
 
Long %
 
Short %
Debt instruments
 
1.9
%
 
—
 %
 
1.0
%
 
(2.8
)%
Equities & related derivatives
 
86.0

 
(74.0
)
 
102.1

 
(64.1
)
Private and unlisted equity securities
 
1.6

 
—

 
2.7

 
—

Total
 
89.5
%
 
(74.0
)%
 
105.8
%
 
(66.9
)%
 

16

Link to Table of Contents

As of December 31, 2015, our exposure to gold on a delta adjusted basis was 10.7% (2014: 6.8%).

The following table represents the composition of our investment portfolio, by industry sector, based on the percentage of assets in our investment account managed by DME Advisors as of December 31, 2015: 

Sector
 
Long %
 
Short %
 
Net %
Basic Materials
 
7.7
%
 
(4.6
)%
 
3.1
 %
Consumer Cyclical
 
26.9

 
(9.9
)
 
17.0

Consumer Non-Cyclical
 
0.7

 
(8.3
)
 
(7.6
)
Energy
 
8.2

 
(5.9
)
 
2.3

Financial
 
11.8

 
(8.8
)
 
3.0

Healthcare
 
5.0

 
(13.2
)
 
(8.2
)
Industrial
 
10.8

 
(9.8
)
 
1.0

Technology
 
11.2

 
(13.5
)
 
(2.3
)
Utilities
 
7.2

 
—

 
7.2

Total
 
89.5
%
 
(74.0
)%
 
15.5
 %
 
The following table represents the composition of our investment portfolio, by the market capitalization of the underlying security, based on the percentage of assets in our investment account managed by DME Advisors as of December 31, 2015: 

Capitalization
 
Long %
 
Short %
 
Net %
Mega Cap Equity (≥$25 billion)
 
25.5
%
 
(24.8
)%
 
0.7
 %
Large Cap Equity (≥$5 billion and <$25 billion)
 
29.1

 
(37.0
)
 
(7.9
)
Mid Cap Equity (≥$1 billion and <$5 billion)
 
26.8

 
(12.1
)
 
14.7

Small Cap Equity (<$1 billion)
 
4.6

 
(0.1
)
 
4.5

Debt Instruments
 
1.9

 
—

 
1.9

Other Investments
 
1.6

 
—

 
1.6

Total
 
89.5
%
 
(74.0
)%
 
15.5
 %

Investment Returns
 
A summary of our consolidated net investment income is as follows:


Year ended December 31
 
 
2015
 
2014
 
2013
 
 
($ in thousands)
Realized gains (losses)
 
$
22,227

 
$
352,133

 
$
122,568

Change in unrealized gains and losses
 
(265,401
)
 
(187,753
)
 
149,012

Investment related foreign exchange gains (losses)
 
(3,725
)
 
14,797

 
44,492

Interest and dividend income, net of withholding taxes
 
15,313

 
31,423

 
22,265

Interest, dividend and other expenses
 
(31,092
)
 
(38,892
)
 
(47,665
)
Investment advisor compensation
 
(19,246
)
 
(49,133
)
 
(72,532
)
Net investment income (loss)
 
$
(281,924
)
 
$
122,575

 
$
218,140


17

Link to Table of Contents

Our investment return is based on the total assets in our investment account, which includes the majority of our equity capital and collected premiums. Investment returns, net of all fees and expenses, by quarter and for the last five years are as follows: (1) 
 
Quarter
 
2015
 
2014
 
2013
 
2012
 
2011
1st
 
(1.8
)%
 
(0.7
)%
 
5.8
%
 
6.5
 %
 
(3.4
)%
2nd
 
(1.5
)
 
8.1

 
2.0

 
(3.3
)
 
(1.9
)
3rd
 
(14.2
)
 
(3.7
)
 
4.0

 
8.8

 
0.1

4th
 
(4.0
)
 
5.3

 
6.6

 
(4.4
)
 
7.6

Full Year
 
(20.2
)%
 
8.7
 %
 
19.6
%
 
7.1
 %
 
2.1
 %
 
    (1)    Investment returns are calculated monthly and compounded to calculate the quarterly and annual returns. Actual investment income may vary depending on cash flows into and out of the investment account. Past performance is not necessarily indicative of future results.

  
DME Advisors and its affiliates manage and expect to manage other client accounts besides ours, some of which have, or may have, objectives similar to ours. Because of the similarity or potential similarity of our investment portfolio to these other client accounts, and because, as a matter of ordinary course, DME Advisors and its affiliates provide their clients, including us, with results of their respective investment portfolios on the last day of each month, those other clients indirectly may have material non-public information regarding our investment portfolio. To address this issue, and to comply with Regulation FD, we present, prior to the start of trading on the first business day of each month, our largest disclosed long positions, a summary of our consolidated net investment returns, information on our long and short exposures and from time to time certain other material information relating to our investment portfolio, on our website, www.greenlightre.ky. DME Advisors may choose not to disclose certain positions to its clients in order to protect its investment strategy. Therefore, we present on our website the largest positions held by us that are disclosed by DME Advisors or its affiliates to their other clients.

Internal Risk Management
 
Our risk manager is responsible for the construct and review of our internal risk management function. We review our investment portfolio together with our reinsurance operations on a periodic basis to ensure that we have sufficient capital to withstand losses on either or both of our investment and reinsurance portfolios under stressed scenarios. With the assistance of DME Advisors, we periodically analyze both our assets and liabilities including the numerous components of risk in our portfolio, such as concentration risk and liquidity risk.

Information Technology

Our information technology infrastructure is currently housed in our corporate offices in Grand Cayman, Cayman Islands. We have implemented backup procedures to ensure that data is backed up on a daily basis and can be restored in an appropriate time frame as needed.
 
We have a disaster recovery plan with respect to our information technology infrastructure that includes data and systems replication between our Cayman Islands office and Dublin office and other off-site locations. We believe we can access our core systems with insignificant outages and restore operation of our secondary systems in the event that our primary systems are unavailable due to a disaster or otherwise.

Employees
 
As of December 31, 2015, we had 30 full-time employees, 25 of whom were based in Grand Cayman, Cayman Islands and 5 were based in Dublin, Ireland. We believe that our employee relations are good. None of our employees are subject to collective bargaining agreements, and we are not aware of any current efforts to implement such agreements.


18

Link to Table of Contents

Additional Information
 
Our website address is www.greenlightre.ky and we make available, free of charge, on or through our website, links to our annual reports on Form 10-K and quarterly reports on Form 10-Q including XBRL instance documents, current reports on Form 8-K and other documents we file with or furnish to the SEC, as soon as reasonably practicable after such material is electronically filed with or furnished to the SEC. In order to comply with Regulation FD, our investment returns are posted on our website on a monthly basis. Additionally, our Code of Business Conduct and Ethics is available on our website. 


ITEM 1A. RISK FACTORS

Any of these factors could result in a significant or material adverse effect on our results of operations or financial condition. Additional risk factors not presently known to us or that we currently deem immaterial may also impair our business or results of operations.
 
Risks Relating to Our Business
 
Our results of operations will likely fluctuate from period to period and may not be indicative of our long-term prospects.
 
The performance of our reinsurance operations and our investment portfolio will likely fluctuate from period to period. Fluctuations will result from a variety of factors, including: 
 
●
reinsurance contract pricing;
 
●
our assessment of the quality of available reinsurance opportunities;
 
●
the volume and mix of reinsurance products we underwrite;
 
●
loss experience on our reinsurance liabilities;
 
●
the performance of our investment portfolio; and
 
●
our ability to assess and integrate our risk management strategy properly.
 
In particular, we seek attractive opportunities to underwrite products and make investments to achieve favorable returns on equity over the long term. Our investment strategy to invest primarily in long and short positions in publicly-traded equity and debt instruments is subject to market volatility and is likely to be more volatile than traditional fixed-income portfolios that are comprised primarily of investment grade bonds. In addition, our differentiated strategy and focus on long-term growth in book value will result in fluctuations in total premiums written from period to period as we concentrate on underwriting contracts that we believe will generate better long-term, rather than short-term, results. Accordingly, our short-term results of operations may not be indicative of our long-term prospects. 
 
Established competitors with greater resources may make it difficult for us to effectively market our products or offer our products at a profit.
 
The reinsurance industry is highly competitive. We compete with major reinsurers, many of which have substantially greater financial, marketing and management resources than we do. Competition in the types of business that we underwrite is based on many factors, including: 
 
●
premium charges;
 
●
ability to obtain terms and conditions appropriate with the risk being assumed and in accordance with our underwriting guidelines;
 
●
the general reputation and perceived financial strength of the reinsurer;
 
●
relationships with reinsurance brokers;
 
●
ratings assigned by independent rating agencies;
 
●
speed of claims payment and reputation; and
 
●
the experience and reputation of the members of our underwriting team in the particular lines of reinsurance we seek to underwrite.
 
Additionally, although the members of our underwriting team have general experience across many property and casualty lines, they may not have the requisite experience or expertise to compete for all transactions that fall within our strategy of offering customized frequency and severity contracts at times and in markets where capacity and alternatives may be limited.

19

Link to Table of Contents

 
Our competitors include ACE Limited, Everest Re, General Re Corporation, Hannover Re Group, Munich Reinsurance Company, PartnerRe Ltd., Swiss Reinsurance Company and Transatlantic Reinsurance Company. Although we seek to provide coverage where capacity and alternatives are limited, we directly compete with these larger companies due to the breadth of their coverage across the property and casualty market in substantially all lines of business. We also compete with other reinsurers, such as Third Point Reinsurance Ltd., which may have similar investment strategies and may seek similar underwriting opportunities.
 
Further, our ability to compete may be harmed if insurance industry participants continue to consolidate. Consolidated entities may try to use their enhanced market power to negotiate price reductions for our products and services. If competitive pressures reduce our prices, we would expect to write less business. If and when the insurance industry further consolidates, competition for customers may become more intense, and the importance of acquiring and properly servicing each customer may become greater. We could incur greater expenses relating to customer acquisition and retention, further reducing our operating margins. In addition, insurance companies that merge may be able to spread their risks across a consolidated, larger capital base so that they require less reinsurance. The number of companies offering retrocessional reinsurance may decline. Reinsurance intermediaries could also consolidate, potentially adversely impacting our ability to access business and distribute our products. We could also experience more robust competition from larger, better capitalized competitors. Any of the foregoing could significantly, and negatively, affect our business or our results of operations.
 
We cannot assure you that we will be able to compete successfully in the reinsurance market. Our failure to compete effectively could significantly and negatively affect our financial condition and results of operations and may increase the likelihood that we may be deemed to be a passive foreign investment company or an investment company. See "Item 1A. Risk Factors - Risks Relating to Insurance and Other Regulations — We are subject to the risk of possibly becoming an investment company under U.S. federal securities law."
 
If our losses and loss adjustment expenses greatly exceed our loss reserves, our financial condition may be significantly and negatively affected.
 
Our results of operations and financial condition depend upon our ability to assess accurately the potential losses and loss adjustment expenses associated with the risks we reinsure. Reserves are estimates at a given time of claims an insurer ultimately expects to pay, based upon facts and circumstances then known, predictions of future events, estimates of future trends in claim severity and other variable factors. The inherent uncertainties of estimating loss reserves generally are greater for reinsurance companies as compared to primary insurers, primarily due to:
 
 
●
the lapse of time from the occurrence of an event to the reporting of the claim and the ultimate resolution or settlement of the claim;
 
●
the diversity of development patterns among different types of reinsurance treaties; and
 
●
the necessary reliance on the client for information regarding claims.
 
On the majority of premiums we underwrite, our estimation of reserves may be less reliable than the reserve estimations of a reinsurer with a greater volume of business and an established loss history. Actual losses and loss adjustment expenses paid may deviate substantially from the estimates of our loss reserves contained in our financial statements and could negatively affect our results of operations. If we determine our loss reserves to be inadequate, we will increase our loss reserves with a corresponding reduction in our net income and capital in the period in which we identify the deficiency, and such a reduction would also negatively affect our results of operations. If our losses and loss adjustment expenses greatly exceed our loss reserves, our financial condition may be significantly and negatively affected. For a summary of the effects of reserve re-estimation on prior year reserves and net income, see "Part II. Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations - Critical Accounting Policies, Loss and Loss Adjustment Expense Reserves."
 
The effect of emerging claim and coverage issues on our business is uncertain.
 
As industry practices and legal, judicial and regulatory conditions change, unexpected issues related to claims and coverage may emerge. Various provisions of our contracts, such as limitations or exclusions from coverage or choice of forum, may be difficult to enforce in the manner we intend, due to, among other things, disputes relating to coverage and choice of legal forum. These issues may adversely affect our business by either extending coverage beyond the period that we intended or by increasing the number or size of claims. In some instances, these changes may not manifest themselves until many years after we have issued insurance or reinsurance contracts that are affected by these changes. As a result, we may not be able to ascertain the full extent

20

Link to Table of Contents

of our liabilities under our insurance or reinsurance contracts for many years following the issuance of our contracts. The effects of unforeseen development or substantial government intervention could adversely impact our ability to adhere to our goals. 

A downgrade or withdrawal of either of our A.M. Best ratings may significantly and negatively affect our ability to implement our business strategy successfully.
 
Companies, insurers and reinsurance brokers use ratings from independent rating agencies as an important means of assessing the financial strength and quality of reinsurers. In October 2015, A.M. Best reaffirmed our financial strength rating of "A (Excellent)" for each of Greenlight Re and GRIL, but amended the outlook from stable to negative. A (Excellent) is the third highest of 15 ratings that A.M. Best issues. These ratings reflect the rating agency’s opinion of our reinsurance subsidiaries' financial strength, operating performance and ability to meet obligations. It is not an evaluation directed toward the protection of investors or a recommendation to buy, sell or hold our Class A ordinary shares. A.M. Best periodically reviews our ratings and may revise one or more of our ratings downward or revoke them at its sole discretion based primarily on its analysis of our balance sheet strength, operating performance and business profile. Factors that may affect such an analysis include:
 
 
●
if we change our business practices from our organizational business plan in a manner that no longer supports our A.M. Best ratings;


●
if unfavorable financial or market trends impact us;


●
if our actual losses significantly exceed our loss reserves;


●
if A.M. Best alters its capital adequacy assessment methodology in a manner that would adversely affect the rating of either reinsurer;


●
if we are unable to retain our senior management and other key personnel; or


●
if our investment portfolio incurs significant losses.
  
If A.M. Best downgrades or withdraws either of our ratings, we could be severely limited or prevented from writing any new reinsurance contracts, which would significantly and negatively affect our ability to implement our business strategy.
 
Some of our reinsurance contracts provide the client with the right to terminate the agreement if our A.M. Best ratings are downgraded below certain rating thresholds. We expect that similar provisions will also be included in some contracts in the future. See - "A downgrade in our ratings below specified levels or a significant decrease in our capital or surplus could enable certain clients to terminate reinsurance agreements or to require additional collateral."
 
The property and casualty reinsurance market may be affected by cyclical trends.
 
We write reinsurance in the property and casualty markets. The property and casualty reinsurance industry is cyclical. Primary insurers’ underwriting results, prevailing general economic and market conditions, liability retention decisions of companies and primary insurers and reinsurance premium rates influence the demand for property and casualty reinsurance. Prevailing prices and available surplus to support assumed business influence reinsurance supply. Supply may fluctuate in response to changes in return on capital realized in the reinsurance industry, the frequency and severity of losses and prevailing general economic and market conditions.
 
As a result, the reinsurance business historically has been a cyclical industry characterized by periods of intense price competition due to high levels of available underwriting capacity as well as periods when shortages of capacity have permitted favorable premium levels and changes in terms and conditions. The supply of available reinsurance capital has increased over the past several years and may increase further, either as a result of capital provided by new entrants or by the commitment of additional capital by existing insurers or reinsurers.

Continued increases in the supply of reinsurance may have consequences for the reinsurance industry generally and for us, including fewer contracts written, lower premium rates, increased expenses for customer acquisition and retention, less favorable policy terms and conditions and/or lower premium volume.

21

Link to Table of Contents

 
Unpredictable developments, including courts granting increasingly larger awards for certain damages, natural disasters (such as catastrophic hurricanes, windstorms, tornadoes, earthquakes, wildfires and floods), fluctuations in interest rates, changes in the investment environment that affect market prices of investments and inflationary pressures, affect the industry’s profitability. The effects of cyclicality could significantly and negatively affect our financial condition and results of operations.
 
The global economic downturns and any significant weakness in the U.S. economy could harm our business, our liquidity and financial condition and our stock price.
 
Weak economic conditions may adversely affect (among other aspects of our business) the demand for and claims made under our products, the ability of customers, counterparties and others to establish or maintain their relationships with us, our ability to access and efficiently use internal and external capital resources and our investment performance. Volatility in the U.S. and other securities markets may adversely affect our investment portfolio and our stock price.
 
A downgrade in our ratings below specified levels or a significant decrease in our capital or surplus could enable certain clients to terminate reinsurance agreements or to require additional collateral.
 
Certain of our assumed reinsurance contracts contain provisions that permit our clients to cancel the contract or require additional collateral in the event of a downgrade in our ratings below specified levels or a reduction of our capital or surplus below specified levels over the course of the agreement. Whether a client would exercise such cancellation rights would likely depend, among other things, on the reason the provision is triggered, the prevailing market conditions, the degree of unexpired coverage and the pricing and availability of replacement reinsurance coverage.
 
If any such provisions were to become exercisable, we cannot predict whether or how many of our clients would actually exercise such rights or the extent to which they would have a significant and negative effect on our financial condition, results of operations or future prospects but they could have a significant adverse effect on the operations of our Company.
 
If we lose or are unable to retain our senior management and other key personnel and are unable to attract qualified personnel, our ability to implement our business strategy could be delayed or hindered, which, in turn, could significantly and negatively affect our business.
 
Our future success depends, to a significant extent, on the efforts of our senior management and other key personnel to implement our business strategy. We believe there are only a limited number of available, qualified executives with substantial experience in our industry. We could face challenges attracting and retaining personnel in the Cayman Islands and/or in Dublin, Ireland. Accordingly, the loss of the services of one or more of the members of our senior management or other key personnel, or our inability to hire and retain other key personnel, could prevent us from continuing to implement our business strategy and, consequently, significantly and negatively affect our business.
 
We do not currently maintain key man life insurance with respect to any of our senior management, including our Chief Executive Officer, Chief Financial Officer, Chief Underwriting Officer or Chief Actuarial Officer. If any member of senior management dies or becomes incapacitated, or leaves the Company to pursue employment opportunities elsewhere, we would be solely responsible for locating an adequate replacement for such senior management and for bearing any related cost. To the extent that we are unable to locate an adequate replacement or are unable to do so within a reasonable period of time, our business may be significantly and negatively affected.
 
Our ability to implement our business strategy could be adversely affected by Cayman Islands employment restrictions.
 
Under Cayman Islands law, persons who are not Caymanian, do not possess Caymanian status, or are not otherwise entitled to reside and work in the Cayman Islands pursuant to provisions of the Immigration Law (2015 Revision) of the Cayman Islands, which we refer to as the Immigration Law, may not engage in any gainful occupation in the Cayman Islands without an appropriate governmental work permit. Such a work permit may be granted or extended on a continuous basis for a maximum period of nine years (after having been legally and ordinarily resident in the Cayman Islands for a period of eight years a person may apply for permanent residence in accordance with the provisions of the Immigration Law) upon showing that, after proper public advertisement, no Caymanian or person of Caymanian status, or other person legally and ordinarily resident in the Cayman Islands who meets the minimum standards for the advertised position is available. The failure of these work permits to be granted or extended could prevent us from continuing to implement our business strategy.
 

22

Link to Table of Contents

Operational risks, including human or systems failures, are inherent in our business.
 
Operational risks and losses can result from, among other things, fraud, errors, failure to document transactions properly or to obtain proper internal authorization, failure to comply with regulatory requirements, information technology failures or external events.
 
We believe that our modeling, underwriting and information technology and application systems are critical to our business. We utilize modeling tools to facilitate our pricing, reserving, and risk management tools to manage risks in our reinsurance portfolio. These models help us to control risk accumulation, inform management and other stakeholders of capital requirements and to improve the risk/return profile or minimize the amount of capital required to cover the risks in each reinsurance contract. However, given the inherent uncertainty of modeling techniques and the application of such techniques, these models and databases may not accurately address the emergence of a variety of matters which might be deemed to impact certain of our coverages. These models have been developed internally and in some cases they make use of third party software. The construction of these models and the selection of assumptions requires significant actuarial judgment. Furthermore, these models typically rely on either cedent or industry data, both of which may be incomplete or may be subject to errors. Accordingly, these models may understate the exposures we are assuming and our financial results may be adversely impacted, perhaps significantly.

Moreover, our information technology and application systems have been an important part of our underwriting process and our ability to compete successfully. We have also licensed certain systems and data from third parties. We cannot be certain that we will have access to these, or comparable, service providers, or that our information technology or application systems will continue to operate as intended. Like all companies, our information technology and application systems may be vulnerable to data breaches, interruptions or failures due to events that may be beyond our control, including, but not limited to, natural disasters, theft, terrorist attacks, malicious cyber-attacks, computer viruses, hackers and general technology failures. A major defect or failure in our internal controls or information technology and application systems could result in management distraction, result in a violation of applicable privacy or other laws, harm our reputation, cause a loss of customers or give rise to monetary fines or penalties or otherwise increase expenses. We believe appropriate controls and mitigation procedures are in place to prevent significant risk of data breaches, interruptions or failures in, information technology and application systems, but internal controls provide only a reasonable, not absolute, assurance as to the absence of errors or irregularities and any ineffectiveness of such controls and procedures could have a material adverse effect on our business.
  
Our failure to maintain sufficient collateral arrangements or to increase our collateral capacity on commercially acceptable terms as we grow could significantly and negatively affect our ability to implement our business strategy.
 
We are not licensed or admitted as a reinsurer in any jurisdiction other than the Cayman Islands and the European Economic Area. Certain jurisdictions, including the United States, do not permit insurance companies to take credit for reinsurance obtained from unlicensed or non-admitted insurers on their statutory financial statements unless appropriate security measures are implemented. Consequently, certain clients will require us to provide collateral often in the form of a letter of credit, a trust agreement or funds withheld. When we provide collateral, we are customarily required to provide collateral to the letter of credit provider or beneficiary of the trust agreement. Our ability to provide collateral, and the costs at which we provide collateral, are primarily dependent on the composition of our investment portfolio.
 
Typically, letters of credit are collateralized and trust agreements are funded with fixed-income securities or cash. Banks may be willing to accept our investment portfolio as collateral, but on terms that may be less favorable to us than reinsurance companies that invest solely or predominantly in fixed-income securities. The inability to renew, maintain or obtain letters of credit collateralized by our investment portfolio or fund trust agreements may significantly limit the amount of reinsurance we can write or require us to modify our investment strategy. 
 
Our investment portfolio is used to provide collateral so that letters of credit and trust agreements can be issued. In the event of a decline in the market value of our investment portfolio that results in a collateral shortfall, we have the right, at our option, to reduce the outstanding obligations under the applicable letter of credit facility or trust agreement, to deposit additional collateral or to change the collateral composition in order to cure the shortfall. If the shortfall is not cured within the prescribed time period, an event of default will immediately occur. We will be prohibited from issuing additional collateral until any shortfall is cured.
 
Our access to funds under our existing credit facilities is dependent on the ability of the banks that are parties to the facilities to meet their funding commitments. Those banks may not be able to meet their funding commitments if they experience shortages of capital and liquidity or if they experience excessive volumes of borrowing requests within a short period of time, and we might be forced to replace credit sources in a difficult market.

23

Link to Table of Contents

 
Any significant consolidation in the financial industry could lead to increased reliance on and exposure to particular institutions. If we cannot obtain adequate capital or sources of credit on favorable terms, or at all, our business, operating results and financial condition could be adversely affected. It is possible that, in the future, rating agencies may reduce our existing ratings. If one or more of our ratings were downgraded, we could incur higher borrowing costs and our ability to access the capital markets could be impacted. Our inability to obtain adequate capital could have a significant and negative effect on our business, financial condition and results of operations.
 
We may need additional collateral capacity as we grow, and if we are unable to renew, maintain or increase our collateral facilities or are unable to do so on commercially acceptable terms we may need to liquidate all or a portion of our investment portfolio and invest in a fixed-income portfolio or other forms of investment acceptable to our clients and banks as collateral, which could significantly and negatively affect our ability to implement our business strategy.
 
Our failure to comply with restrictive covenants contained in our current or future credit facilities could trigger prepayment obligations, which could adversely affect our business, financial condition and results of operations.

Each of our credit facilities requires us and/or certain of our subsidiaries to comply with certain covenants, including restrictions on our ability to place a lien or charge on pledged assets, issue debt and in certain circumstances on the payment of dividends. Our failure to comply with these or other covenants could result in an event of default under one or more credit facilities or any credit facility we may enter into in the future, which, if not cured or waived, could result in us being required to repay the amounts outstanding under these facilities prior to maturity. As a result, our business, financial condition and results of operations could be significantly and negatively affected.

The inability to obtain business provided from brokers could adversely affect our business strategy and results of operations.
 
Since we began underwriting operations in April 2006, substantially all of our business has been placed through brokered transactions, which involve a limited number of reinsurance brokers which exposes us to concentration risk. In 2015, we had two brokers (2014: three brokers) who each accounted for more than 10% of our gross written premiums, and in the aggregate they accounted for approximately 77.4% (2014: 81.5%) of our gross premiums written. Because broker-produced business is concentrated with a small number of brokers, we are exposed to concentration risk. To lose or fail to expand all or a substantial portion of the business provided through brokers, many of whom may not be familiar with our Cayman Islands jurisdiction, could significantly and negatively affect our business and results of operations.
 
We may need additional capital in the future in order to operate our business, and such capital may not be available to us or may not be available to us on favorable terms.
 
We may need to raise additional capital in the future through public or private equity or debt offerings or otherwise in order to: 
 
●
fund liquidity needs caused by underwriting or investment losses;
 
●
replace capital lost in the event of significant reinsurance losses or adverse reserve developments or significant investment losses;
 
●
satisfy collateral requirements that may be imposed by our clients or by regulators;
 
●
meet applicable statutory jurisdiction requirements;
 
●
meet rating agency capital requirements; or
 
●
respond to competitive pressures. 
 
Additional capital may not be available on terms favorable to us, or at all. Further, any additional capital raised through the sale of equity could dilute existing ownership interest in our company and may cause the market price of our Class A ordinary shares to decline. Additional capital raised through the issuance of debt may result in creditors having rights, preferences and privileges senior or otherwise superior to those of our Class A ordinary shares.
 

24

Link to Table of Contents

Our property and property catastrophe reinsurance operations may make us vulnerable to losses from catastrophes and may cause our results of operations to vary significantly from period to period.
 
Certain of our reinsurance operations expose us to claims arising out of unpredictable catastrophic events, such as hurricanes, hailstorms, tornadoes, windstorms, severe winter weather, earthquakes, floods, droughts, fires, explosions, volcanic eruptions and other natural or man-made disasters such as acts of war or terrorism, cyber attacks, major aircraft crashes, riots or political unrest. The incidence and severity of catastrophes are inherently unpredictable but the loss experience of property catastrophe reinsurers has been generally characterized as low frequency and high severity. Claims from catastrophic events could reduce our earnings and cause substantial volatility in our results of operations for any fiscal quarter or year and adversely affect our financial condition. Corresponding reductions in our surplus levels could impact our ability to write new reinsurance policies.
  
Catastrophic losses are a function of the insured exposure in the affected area and the severity of the event. Because accounting regulations do not permit reinsurers to reserve for catastrophic events until they occur, claims from catastrophic events could cause substantial volatility in our financial results for any fiscal quarter or year and could significantly and negatively affect our financial condition and results of operations.
 
We depend on our clients' evaluations of the risks associated with their insurance underwriting, which may subject us to reinsurance losses.
 
In some of our proportional reinsurance business, in which we assume an agreed percentage of each underlying insurance contract being reinsured, or quota share contracts, we do not expect to separately evaluate each of the original individual risks assumed under these reinsurance contracts. Therefore, we will be largely dependent on the original underwriting decisions made by ceding companies. We will be subject to the risk that the clients may not have adequately evaluated the insured risks and that the premiums ceded may not adequately compensate us for the risks we assume. We also do not expect to separately evaluate each of the individual claims made on the underlying insurance contracts under quota share contracts. Therefore, we will be dependent on the original claims decisions made by our clients.
 
We could face unanticipated losses from political instability which could have a material adverse effect on our financial condition and results of operations.
 
We could be exposed to unexpected losses on our reinsurance contracts resulting from political instability and other politically driven events globally. These risks are inherently unpredictable and recent events may indicate an increased frequency and severity of losses. It is difficult to predict the timing of these events or to estimate the amount of loss that any given occurrence will generate. To the extent that losses from these risks occur, our financial condition and results of operations could be significantly and negatively affected.
 
Changing climate conditions may adversely affect our financial condition, profitability or cash flows.
 
   Climate change, to the extent it produces extreme changes in temperatures and changes in weather patterns, could impact the frequency or severity of weather events and wildfires. Further, it could impact the affordability and availability of homeowners insurance, which could have an impact on pricing. Changes in weather patterns could also affect the frequency and severity of other natural catastrophe events to which we may be exposed.
 
We may be subject to the credit risk of our brokers, cedents and agents.
 
In accordance with industry practice, we frequently pay amounts owed on claims under our policies to reinsurance brokers, and these brokers, in turn, remit these amounts to the ceding companies that have reinsured a portion of their liabilities with us. In some jurisdictions, if a broker fails to make such a payment, we might remain liable to the client for the deficiency notwithstanding the broker’s obligation to make such payment. Conversely, in certain jurisdictions, when the client pays premiums for policies to reinsurance brokers for payment to us, these premiums are considered to have been paid and the client will no longer be liable to us for these premiums, whether or not we have actually received them. Consequently, we assume a degree of credit risk associated with brokers around the world.

In addition, we are also exposed to the credit risk of our cedents and agents, who, pursuant to their contracts with us, may be required to pay us profit commission, additional premiums, reinstatement premiums, and adjustments to ceding commissions over a period of time, which in some cases may extend beyond the initial period of risk coverage. Insolvency, liquidity problems, distressed financial condition or the general effects of an economic recession may increase the risk that our cedents or agents may not pay a part of or the full amount of their obligations to us. To the extent our cedents or agents become

25

Link to Table of Contents

unable to pay us, we would be required to recognize a downward adjustment to our premiums receivable or reinsurance recoverables, as applicable, in our financial statements. While we generally seek to mitigate this risk through, among other things, collateral agreements, funds withheld, corporate guarantees and right of offset of receivables against any losses payable, an increased inability of customers to fulfill their obligations to us could have an adverse effect on our financial condition and results of operations.

Our reinsurance balances receivable at December 31, 2015 totaled $187.9 million, which included premiums and ceding commissions receivable, a majority of which are not collateralized. We cannot assure you that such receivables will be collected or that valuation allowances or write downs for uncollectible recoverable amounts will not be required in future periods.
 
We may be unable to purchase reinsurance for the liabilities we reinsure, and if we successfully purchase such reinsurance, we may be unable to collect, which could adversely affect our business, financial condition and results of operations.
 
We purchase reinsurance for certain liabilities we reinsure, which we refer to as retrocessional coverage, in order to mitigate the effect of a potential concentration of losses upon our financial condition. The insolvency or inability or refusal of a retrocessionaire to make payments under the terms of its agreement with us could have an adverse effect on us because we remain liable to our client. From time to time, market conditions have limited, and in some cases have prevented, reinsurers from obtaining the types and amounts of retrocessional coverage that they consider necessary for their business needs. Accordingly, we may not be able to obtain our desired amounts of retrocessional coverage or negotiate terms that we deem appropriate or acceptable or obtain retrocessional coverage from entities with satisfactory creditworthiness. Our failure to establish adequate retrocessional arrangements or the failure of our retrocessional arrangements to protect us from overly concentrated risk exposure could significantly and negatively affect our business, financial condition and results of operations.

The failure of any risk management and loss limitation methods we employ, as well as an unexpected accumulation of attritional losses, could have a material adverse effect on our financial condition and results of operations.
We seek to limit our loss exposure in a variety of ways, including by writing many of our reinsurance contracts on an excess of loss basis, adhering to maximum limitations on policies written in defined geographical zones, limiting program size for each client, establishing per risk and per occurrence limitations for each event, employing coverage restrictions and following prudent underwriting guidelines for each program written. In the case of proportional treaties, we generally seek per occurrence limitations or loss ratio caps to limit the impact of losses from any one event. We also seek to limit our loss exposure through geographic diversification. Notwithstanding these loss limitation techniques, one or more future catastrophic or other events could result in claims that substantially exceed our expectations in ways limiting the applicability of these techniques, which could have a material adverse effect on our financial condition and results of operations.  
Currency fluctuations could result in exchange rate losses and negatively impact our business.
 
Our functional currency is the U.S. dollar. However, we expect that we will write a portion of our business and receive premiums and pay claims in currencies other than the U.S. dollar. We may incur foreign currency exchange gains or losses as we ultimately receive premiums and settle claims in foreign currencies. In addition, DME Advisors may invest a portion of our portfolio in securities or cash denominated in currencies other than the U.S. dollar. Consequently, we may experience exchange rate losses to the extent any of our foreign currency exposure is not hedged, which could significantly and negatively affect our business. If we do seek to hedge our foreign currency exposure through the use of forward foreign currency exchange contracts or currency swaps, we will be subject to the risk that our counterparties to the arrangements fail to perform.
 
There are differences under Cayman Islands corporate law and Delaware corporate law with respect to interested party transactions which may benefit certain of our shareholders at the expense of other shareholders.
 
Under Cayman Islands corporate law, a director may vote on a contract or transaction where the director has an interest as a shareholder, director, officer or employee provided such interest is disclosed. None of our contracts will be deemed to be void because any director is an interested party in such transaction and interested parties will not be held liable for monies owed to the Company.
 
Under Delaware law, interested party transactions are voidable.


26

Link to Table of Contents

Risks Relating to Insurance and Other Regulations
 
Any suspension or revocation of our reinsurance license would materially impact our ability to do business and implement our business strategy.
 
We are presently licensed as a reinsurer only in the Cayman Islands and the European Economic Area. The suspension or revocation of our licenses to do business as a reinsurance company in either of these jurisdictions for any reason would mean that we would not be able to enter into any new reinsurance contracts in that jurisdiction until the suspension ended or we became licensed in another jurisdiction. Any such suspension or revocation of our license would negatively impact our reputation in the reinsurance marketplace and could have a material adverse effect on our results of operations.
 
CIMA may take a number of actions, including suspending or revoking a reinsurance license whenever CIMA believes that a licensee is or may become unable to meet its obligations, is carrying on business in a manner likely to be detrimental to the public interest or to the interest of its creditors or policyholders, has contravened the terms of the Law or has otherwise behaved in such a manner so as to cause CIMA to call into question the licensee's fitness.
 
Further CIMA may suspend or revoke our license if:
 
●
we cease to carry on reinsurance business;
 
●
the direction and management of our reinsurance business has not been conducted in a fit and proper manner;
 
●
a person holding a position as a director, manager or officer is not a fit and proper person to hold the respective position; or
 
●
we become bankrupt or go into liquidation or we are wound up or otherwise dissolved.
  
Similarly, if CIMA suspended or revoked our license, we could lose our exemption under the Investment Company Act of 1940, as amended (the "Investment Company Act") (See "— We are subject to the risk of possibly becoming an investment company under U.S. federal securities law.")

Our reinsurance subsidiaries are subject to minimum capital and surplus requirements, and our failure to meet these requirements could subject us to regulatory action.
 
The Insurance (Capital and Solvency) (Classes B, C, and D Insurers) Regulations, 2012 (the "Capital and Solvency Regulations") impose on Greenlight Re a minimum capital requirement of US$50 million, a prescribed capital requirement of US$466.5 million and a requirement to maintain solvency equal to or in excess of the total prescribed capital requirement (the "Capital Requirements"). As of December 31, 2015, Greenlight Re was in compliance with the Capital Requirements.
 
Under the prudential regime applying prior to the introduction of Solvency II, GRIL, our Irish subsidiary, was required to maintain statutory reserves, particularly in respect of underwriting liabilities, and a solvency margin of US$18.1 million as of December 31, 2015 as provided for in the Irish Insurance Acts and Regulations. As of December 31, 2015, GRIL has been in compliance with the capital requirements required under the Irish Insurance Acts and Regulations.  Solvency II has introduced risk-based solvency requirements which GRIL is required to comply with as of January 1, 2016, including calculating and maintaining a minimum capital requirement and solvency capital requirement.
 
Any failure to meet applicable requirements or minimum statutory capital requirements could subject us to further examination or action by regulators, including restrictions on dividend payments, limitations on our writing of additional business or engaging in financial or other activities, enhanced supervision, financial or other penalties or liquidation. Further, any changes in existing risk based capital requirements or minimum statutory capital requirements may require us to increase our statutory capital levels, which we might be unable to do.
 
We are a holding company that depends on the ability of our subsidiaries to pay dividends.
 
We are a holding company and do not have any significant operations or assets other than our ownership of the shares of our subsidiaries. Dividends and other permitted distributions from our subsidiaries are our primary source of funds to meet ongoing cash requirements, including future debt service payments, if any, and other expenses, and to pay dividends to our shareholders if we choose to do so. Some of our subsidiaries are subject to significant regulatory restrictions limiting their ability to declare and pay dividends.  The inability of our subsidiaries to pay dividends in an amount sufficient to enable us to meet our cash requirements at the holding company level could have an adverse effect on our operations and our ability to pay dividends to our shareholders if we choose to do so and/or meet our debt service obligations, if any.
 

27

Link to Table of Contents

To the extent any of our subsidiaries located in jurisdictions other than the Cayman Islands consider declaring dividends, such subsidiaries are required to comply with restrictions set forth under applicable law and regulations in such other jurisdictions. These restrictions could adversely impact the Company.
  
We are subject to the risk of possibly becoming an investment company under U.S. federal securities law.
 
In the United States, the Investment Company Act regulates certain companies that invest in or trade securities. We rely on an exemption under the Investment Company Act for an entity organized and regulated as a foreign insurance company which is engaged primarily and predominantly in the reinsurance of risks on insurance agreements. The law in this area is subjective and there is a lack of guidance as to the meaning of "primarily and predominantly" under the relevant exemption to the Investment Company Act. For example, there is no standard for the amount of premiums that need to be written relative to the level of an entity’s capital in order to qualify for the exemption. If this exemption were deemed inapplicable, we would have to register under the Investment Company Act as an investment company. Registered investment companies are subject to extensive, restrictive and potentially adverse regulation relating to, among other things, operating methods, management, capital structure, leverage, dividends and transactions with affiliates. Registered investment companies are not permitted to operate their business in the manner in which we operate our business, nor are registered investment companies permitted to have many of the relationships that we have with our affiliated companies. Accordingly, we likely would not be permitted to engage DME Advisors as our investment advisor, unless we obtained board and shareholder approvals under the Investment Company Act. If DME Advisors were not our investment advisor, we would seek to identify and retain another investment advisor with a value-oriented investment philosophy. If we could not identify or retain such an advisor, we would be required to make substantial modifications to our investment strategy. Any such changes to our investment strategy could significantly and negatively impact our investment results, financial condition and our ability to implement our business strategy.
 
If at any time it were established that we had been operating as an investment company in violation of the registration requirements of the Investment Company Act, there would be a risk, among other material adverse consequences, that we could become subject to monetary penalties or injunctive relief, or both, or that we would be unable to enforce contracts with third parties or that third parties could seek to obtain rescission of transactions with us undertaken during the period in which it was established that we were an unregistered investment company.
 
To the extent that the laws and regulations change in the future so that contracts we write are deemed not to be reinsurance contracts, we will be at greater risk of not qualifying for the Investment Company Act exception. Additionally, it is possible that our classification as an investment company would result in the suspension or revocation of our reinsurance license.
 
Insurance regulations to which we are, or may become, subject, and potential changes thereto, could have a significant and negative effect on our business.
 
We currently are admitted to do business in the Cayman Islands and the European Economic Area.  Our operations in each of these jurisdictions are subject to varying degrees of regulation and supervision. The laws and regulations of the jurisdictions in which our subsidiaries are domiciled require that, among other things, these subsidiaries maintain minimum levels of statutory or regulatory capital, surplus and liquidity, meet solvency standards, submit to periodic examinations of their financial condition and restrict payments of dividends and reductions of capital. Statutes, regulations and policies that our subsidiaries are subject to may also restrict the ability of these subsidiaries to write insurance and reinsurance policies, make certain investments and distribute funds.
 
More specifically with respect to our Irish subsidiary, European legislation known as "Solvency II", was introduced with effect from January 1, 2016 and governs the prudential regulation of insurers and reinsurers, and requires insurers and reinsurers in Europe to meet risk-based solvency requirements. It also imposes group solvency and governance requirements on groups with insurers and/or reinsurers operating in the European Economic Area. A number of European Commission delegated acts and technical standards have been adopted, which set out more detailed requirements based on the overarching provisions of the Solvency II Directive. However, further delegated acts, technical standards and guidance are likely to be published on an ongoing basis.
 
   Although we do not presently expect that we will be admitted to do business in any other jurisdiction other than the Cayman Islands and the European Economic Area, we cannot assure you that insurance regulators in the United States or elsewhere will not review our activities and claim that we are subject to such jurisdiction’s licensing requirements. In addition, we are subject to indirect regulatory requirements imposed by jurisdictions that may limit our ability to provide reinsurance. For example, our ability to write reinsurance may be subject, in certain cases, to arrangements satisfactory to applicable regulatory bodies, and proposed legislation and regulations may have the effect of imposing additional requirements upon, or restricting

28

Link to Table of Contents

the market for, non-U.S. reinsurers such as Greenlight Re and GRIL, with whom domestic companies may place business. We do not know of any such proposed legislation pending at this time.
 
We may not be able to comply fully with, or obtain desired exemptions from, revised statutes, regulations and policies that currently, or may in the future, govern the conduct of our business. Failure to comply with, or to obtain desired authorizations and/or exemptions under, any applicable laws could result in restrictions on our ability to do business or undertake activities that are regulated in one or more of the jurisdictions in which we operate and could subject us to fines and other sanctions.

In addition, governmental authorities worldwide have become increasingly interested in potential risks posed by the insurance industry as a whole, and to the commercial and financial systems in general. While we cannot predict the exact nature, timing or scope of possible governmental initiatives, there may be increased regulatory intervention in our industry in the future. Changes in the laws or regulations to which our subsidiaries are subject or may become subject, or in the interpretations thereof by enforcement or regulatory agencies, could have a material adverse effect on our business. 

Risks Relating to Our Investment Strategy and Our Investment Advisor
 
We have limited control as to how our investment portfolio is allocated and its performance depends on the ability of DME Advisors to select and manage appropriate investments.
 
DME Advisors acts as our exclusive investment advisor for our investment portfolio and recommends appropriate investment opportunities. Although DME Advisors is contractually obligated to follow our investment guidelines, we cannot assure shareholders as to how assets will be allocated to different investment opportunities, including long and short positions and derivatives trading, which could increase the level of risk to which our investment portfolio will be exposed. In addition, DME Advisors can outsource to sub-advisors without our consent or approval.
 
The performance of our investment portfolio depends to a great extent on the ability of DME Advisors to select and manage appropriate investments. Our advisory agreement with DME Advisors terminates on December 31, 2016, unless extended, and we have limited ability to terminate the advisory agreement earlier. We cannot assure you that DME Advisors will be successful in meeting our investment objectives or that the advisory agreement with DME Advisors will be renewed. The failure of DME Advisors to perform adequately could significantly and negatively affect our business, results of operations and financial condition.
 
We depend upon DME Advisors to implement our investment strategy.
 
We depend upon DME Advisors to implement our investment strategy. Accordingly, the diminution or loss of the services of DME Advisors could significantly affect our business. DME Advisors, in turn, is dependent on the talents, efforts and leadership of DME Advisors’ principals. The diminution or loss of the services of DME Advisors’ principals, or diminution or loss of their reputation and integrity or any negative market or industry perception arising from that diminution or loss, could have a material adverse effect on our business. In addition, the loss of DME Advisors' key personnel, or DME Advisors' inability to hire and retain other key personnel, over which we have no control, could delay or prevent DME Advisors from fully implementing our investment strategy on our behalf, and consequently, could significantly and negatively affect our business.
 
Our advisory agreement with DME Advisors does not allow us to terminate the agreement in the event that DME Advisors loses any or all of its principals or key personnel. The advisory agreement expires on the date on which the venture agreement expires or terminates for any reason. The venture agreement requires that we utilize the advisory services of DME Advisors or its affiliates exclusively until December 31, 2016, subject to limited termination provisions. See "— The venture agreement has limited termination provisions."
 
Our investment performance may suffer as a result of adverse capital market developments or other factors that impact our liquidity, which could in turn adversely affect our financial condition and results of operations.
 
We may derive a significant portion of our income from our investment portfolio. As a result, our operating results depend in part on the performance of our investment portfolio. We strive to structure our investments in a manner that recognizes our liquidity needs for future liabilities. We cannot assure you that DME Advisors will successfully structure our investments in relation to our anticipated liabilities. Failure to do so could force us to liquidate investments at a significant loss or at prices that are not optimal, which could significantly and adversely affect our financial results.
 

29

Link to Table of Contents

The risks associated with DME Advisors’ value-oriented investment strategy may be substantially greater than the risks associated with traditional fixed-income investment strategies. In addition, making long equity investments in an up or rising market may increase the risk of not generating profits on these investments and we may incur losses if the market declines. Similarly, making short equity investments in a down or falling market may increase the risk of not generating profits on these investments and we may incur losses if the market rises. The success of our investment strategy may also be affected by general economic conditions. Unexpected market volatility and illiquidity associated with our investments could significantly and negatively affect our investment portfolio results. 
 
Potential conflicts of interest with DME Advisors may exist that could adversely affect us.
 
None of DME Advisors or its principals, including David Einhorn, Chairman of our Board of Directors and the President of Greenlight Capital, Inc., are obligated to devote any specific amount of time to the affairs of our Company. Affiliates of DME Advisors, including Greenlight Capital, Inc., manage and expect to continue to manage other client accounts, some of which have objectives similar to ours, including collective investment vehicles managed by DME Advisors' affiliates and in which DME Advisors or its affiliates may have an equity interest. Pursuant to our advisory agreement with DME Advisors, DME Advisors has the exclusive right to manage our investment portfolio and is required to follow our investment guidelines and act in a manner that is fair and equitable in allocating investment opportunities to us, but the agreement does not otherwise impose any specific obligations or requirements concerning allocation of time, effort or investment opportunities to us or any restriction on the nature or timing of investments for our account or other accounts that DME Advisors or its affiliates may manage. If we compete for any investment opportunity with another entity that DME Advisors or its affiliates manage, DME Advisors is not required to afford us any exclusivity or priority. DME Advisors' interest and the interests of its affiliates, including Greenlight Capital, Inc., may at times conflict, possibly to DME Advisors' detriment, which may potentially adversely affect our investment opportunities and returns.
 
Although Mr. Einhorn, Chairman of our Board of Directors, recused himself from the vote by the Board of Directors of Greenlight Re approving and adopting Greenlight Re's investment guidelines, he is not, under Cayman Islands law, legally restricted from participating in making decisions with respect to Greenlight Re's investment guidelines. Accordingly, his involvement as a member of the Boards of Directors of Greenlight Capital Re, Ltd. and Greenlight Re may lead to a conflict of interest.
 
DME Advisors and its affiliates may also manage accounts whose advisory fee schedules, investment objectives and policies differ from ours, which may cause DME Advisors and its affiliates to effect trading in one account that may have an adverse effect on another account, including ours. We are not entitled to inspect the trading records of DME Advisors, or its principals, that are not related to our Company.
 
Our investment portfolio may be concentrated in a few large positions which could result in large losses.
 
Our investment guidelines provide that DME Advisors may commit up to 20% of Greenlight Re’s assets under management (10% for GRIL) to any one investment. In addition, GRIL's investment guidelines require that the 10 largest investments shall not constitute more than 50% of the total investment portfolio and GRIL's investment portfolio shall at all times be comprised of a minimum of 50 debt or equity securities of publicly traded companies. Accordingly, from time to time we may hold a few, relatively large security positions in relation to our capital. As of December 31, 2015, we were invested in approximately 101 equity and debt securities and the largest five long and short positions comprised an aggregate of 24% and 21%, respectively, of our investment portfolio. Since our investment portfolio may not be widely diversified, it may be subject to more rapid changes in value than would be the case if the investment portfolio were required to maintain a wide diversification among companies, securities and types of securities.
 
We are exposed to credit risk primarily from the possibility that counterparties may default on their obligations to us.
 
We are exposed to credit risk primarily from the possibility that counterparties may default on their obligations to us. The amount of the maximum exposure to credit risk is indicated by the carrying value of our financial assets. In addition, we hold the securities of our investment portfolio with several prime brokers and have credit risk from the possibility that one or more of them may default on their obligations to us. Other than our investment in derivative contracts and corporate debt, if any, and the fact that our investments are held by prime brokers and custodians on our behalf, we have no other significant concentrations of credit risk.
 
Issuers or borrowers whose securities or debt we hold, customers, reinsurers, clearing agents, exchanges, clearing houses and other financial intermediaries and guarantors may default on their obligations to us due to bankruptcy, insolvency, lack of liquidity, adverse economic conditions, operational failure, fraud or other reasons. Such defaults could have a significant and

30

Link to Table of Contents

negative effect on our results of operations, financial condition and cash flows. Additionally, the underlying assets supporting our financial contracts may deteriorate causing these securities to incur losses.
 
DME Advisors may trade on margin and use other forms of financial leverage, which could potentially adversely affect our revenues.
 
Our investment guidelines provide DME Advisors with the ability to trade on margin and use other forms of financial leverage. Fluctuations in the market value of our investment portfolio could have a disproportionately large effect in relation to our capital. Any event which may adversely affect the value of positions we hold could significantly and negatively affect the net asset value of our investment portfolio and thus our results of operations.
 
DME Advisors may effectuate short sales that subject us to unlimited loss potential.

DME Advisors may enter into transactions in which it sells a security it does not own, which we refer to as a short sale, in anticipation of a decline in the market value of the security. Short sales for our account theoretically will involve unlimited loss potential since the market price of securities sold short may continuously increase. DME Advisors might have difficulty purchasing securities to meet short sale delivery obligations and may have to cover short sales at suboptimal prices.
 
DME Advisors may transact in derivative instruments, which may increase the risk of our investment portfolio.
 
Derivative instruments, or derivatives, include futures, options, swaps, structured securities and other instruments and contracts that derive their value from one or more underlying securities, financial benchmarks, currencies, commodities or indices. There are a number of risks associated with derivatives trading. Because many derivatives are leveraged, and thus provide significantly more market exposure than the money paid or deposited when the transaction is entered into, a relatively small adverse market movement may result in a substantial loss, and may potentially expose us to a loss exceeding the original amount invested. Derivatives may also expose us to liquidity and counterparty risk. There may not be a liquid market within which to close or dispose of outstanding derivatives contracts. In the event of the counterparty’s default, we will generally only rank as an unsecured creditor and risk the loss of all or a portion of the amounts we are contractually entitled to receive.
 
The compensation arrangements of DME and DME Advisors may create an incentive to effect transactions that are risky or speculative.
 
Pursuant to the venture agreement and the advisory agreement, we are obligated to pay the following:
 
●
a 1.5% annual management fee to DME Advisors, regardless of the performance of our investment account, payable monthly based on the capital account balance of each participant; and


●
a performance allocation to DME based on the positive performance change in such participant's capital account equal to 20% of net profits calculated per annum, subject to a loss carry forward provision.
  
The loss carry forward provision allows DME to earn reduced performance allocation of 10% of profits in any year subsequent to the year in which our investment account managed by DME Advisors incurs a loss, until all losses are recouped and an additional amount equal to 150% of the loss is earned.

While the performance compensation arrangement provides that losses will be carried forward as an offset against net profits in subsequent periods, DME and DME Advisors generally will not otherwise be penalized for losses or decreases in the value of our portfolio. These performance compensation arrangements may create an incentive for DME Advisors to engage in transactions that focus on the potential for short-term gains rather than long-term growth or that are particularly risky or speculative.
 
 DME Advisors' representatives' service on boards and committees may place trading restrictions on our investments and may subject us to indemnification liability.
 
DME Advisors may from time to time place its or its affiliates’ representatives on creditors’ committees and/or boards of certain companies in which we have invested. While such representation may enable DME Advisors to enhance the sale value of our investments, it may also place trading restrictions on our investments and may subject us to indemnification liability. The advisory agreement provides for the indemnification of DME Advisors or any other person designated by DME Advisors for claims arising from such board representation.  
 
As of December 31, 2015, representatives of DME Advisors (including Mr. Einhorn) sat on the board of Green Brick Partners Inc., whose securities are publicly traded and were included in our portfolio as of December 31, 2015.

31

Link to Table of Contents

 
The ability to use "soft dollars" may provide DME Advisors with an incentive to select certain brokers that may take into account benefits to be received by DME Advisors.
 
DME Advisors is entitled to use so-called "soft dollars" generated by commissions paid in connection with transactions for our investment portfolio to pay for certain of DME Advisors' operating and overhead costs, including the payment of all or a portion of its costs and expenses of operation. "Soft dollars" are a means of paying brokerage firms for their services through commission revenue, rather than through direct payments. DME Advisors' right to use soft dollars may give DME Advisors an incentive to select brokers or dealers for our transactions, or to negotiate commission rates or other execution terms, in a manner that takes into account the soft dollar benefits received by DME Advisors rather than giving exclusive consideration to the interests of our investment portfolio and, accordingly, may create a conflict.
 
The venture agreement has limited termination provisions.
 
The venture agreement has limited termination provisions which restrict our ability to manage our investment portfolio outside of DME Advisors. Because the venture agreement contains exclusivity and limited termination provisions, we are unable to use investment managers other than DME Advisors for so long as the agreement is in effect. The current venture agreement term ends on December 31, 2016 and will automatically renew for successive three-year terms unless at least 90 days prior to the end of the then current term, DME notifies us of its desire to terminate the venture agreement, or Greenlight Re or GRIL notifies DME of their desire to withdraw from the venture agreement. Greenlight Re or GRIL may also withdraw as participants under the venture agreement prior to the expiration of the venture agreement's term at any time only "for cause", which is defined as: 
 
●
a material violation of applicable law relating to DME's or DME Advisors' advisory business;
 
●
DME's or DME Advisors' gross negligence, willful misconduct or reckless disregard of DME's obligations under the venture agreement or DME Advisors' obligations under the advisory agreement;
 
●
a material breach by DME or DME Advisors of Greenlight Re’s or GRIL’s investment guidelines that is not cured within a 15-day period; or
 
●
a material breach by DME or DME Advisors of its obligations to return and deliver assets as we may request.
  
In addition, GRIL may withdraw as a participant under the venture agreement prior to the expiration of its term due to unsatisfactory long term performance of DME or DME Advisors, as determined solely by the Board of Directors of GRIL on each anniversary date of the venture agreement. 

Greenlight Re may not withdraw or terminate the venture agreement on the basis of performance. If Greenlight Re becomes dissatisfied with the results of the investment performance of DME or DME Advisors, we will be unable to hire new investment managers until the venture agreement expires by its terms or is terminated for cause. 

Certain of our investments may have limited liquidity and lack valuation data, which could create a conflict of interest.
 
Our investment guidelines provide DME Advisors with the flexibility to invest in certain securities with limited liquidity or no public market. This lack of liquidity may adversely affect the ability of DME Advisors to execute trade orders at desired prices and may impact our ability to fulfill our payment obligations. To the extent that DME Advisors invests in securities or instruments for which market quotations are not readily available, under the terms of the advisory agreement the valuation of such securities and instruments for purposes of compensation to DME Advisors will be determined by DME Advisors, whose determination, subject to audit verification, will be conclusive and binding in the absence of bad faith or manifest error. Because the advisory agreement gives DME Advisors the power to determine the value of securities with no readily discernible market value, and because the calculation of DME Advisors' fee is based on the value of the investment account, a conflict may exist or arise.
  
Increased regulation or scrutiny of alternative investment advisors may affect DME Advisors’ ability to manage our investment portfolio or affect our business reputation.
 
The regulatory environment for investment managers is evolving, and changes in the regulation of managers may adversely affect the ability of DME Advisors to obtain the leverage it might otherwise obtain or to pursue its trading strategies. In addition, the securities and futures markets are subject to comprehensive statutes, regulations and margin requirements. The SEC, other regulators and self-regulatory organizations and exchanges are authorized to take extraordinary actions in the event of market emergencies. The regulation of derivatives transactions and funds that engage in such transactions is an evolving area of law and is subject to modification by government and judicial action. Any future regulatory change could have a significant negative impact on our financial condition and results of operations.

32

Link to Table of Contents


Short sale transactions have been subject to increased regulatory scrutiny, including the imposition of restrictions on short selling certain securities and reporting requirements. Our ability to execute a short selling strategy may be materially and adversely impacted by temporary and/or new permanent rules, interpretations, prohibitions, and restrictions adopted in response to these adverse market events. Temporary restrictions and/or prohibitions on short selling activity may be imposed by regulatory authorities with little or no advance notice and may impact prior and future trading activities of our investment portfolio. Additionally, the SEC, its non-U.S. counterparts, other governmental authorities and/or self-regulatory organizations may at any time promulgate permanent rules or interpretations consistent with such temporary restrictions or that impose additional or different permanent or temporary limitations or prohibitions. The SEC might impose different limitations and/or prohibitions on short selling from those imposed by various non-U.S. regulatory authorities. These different regulations, rules or interpretations might have different effective periods.
 
Regulatory authorities may, from time-to-time, impose restrictions that adversely affect our ability to borrow certain securities in connection with short sale transactions. In addition, traditional lenders of securities might be less likely to lend securities under certain market conditions. As a result, we may not be able to effectively pursue a short selling strategy due to a limited supply of securities available for borrowing. We may also incur additional costs in connection with short sale transactions, including, in the event that DME Advisors is required to enter into a borrowing arrangement in advance of any short sales. Moreover, the ability to continue to borrow a security is not guaranteed and we are subject to strict delivery requirements. The inability to deliver securities within the required time frame may subject us to mandatory close out by the executing broker-dealer. A mandatory close out may subject us to unintended costs and losses. Certain action or inaction by third parties, such as executing broker-dealers or clearing broker-dealers, may materially impact our ability to effect short sale transactions.
   
We may invest in securities based outside the United States which may be riskier than securities of United States issuers.
 
Under our investment guidelines, DME Advisors may invest in securities of issuers organized or based outside the United States. These investments may be subject to a variety of risks and other special considerations not affecting securities of U.S. issuers. Particularly within the Euro-zone, there is increasing market concern as to the potential default of government issuers. Should governments default on their obligations, there could be a negative impact on both the Company’s direct holdings as well as non-government issues held within the country of default. Many foreign securities markets are not as developed or efficient as those in the United States. Securities of some foreign issuers are less liquid and more volatile than securities of comparable U.S. issuers. Similarly, volume and liquidity in many foreign securities markets are less than in the United States and, at times, price volatility can be greater than in the United States. Non-U.S. issuers may be subject to less stringent financial reporting and informational disclosure standards, regulatory oversight, practices and requirements than those applicable to U.S. issuers. 

Risks Relating to our Class A Ordinary Shares
 
A shareholder may be required to sell its Class A ordinary shares.
 
Our Third Amended and Restated Memorandum and Articles of Association, or Articles, provide that we have the option, but not the obligation, to require a shareholder to sell its Class A ordinary shares for their fair market value to us, to other shareholders or to third parties if our Board of Directors determines that ownership of our Class A ordinary shares by such shareholder may result in adverse tax, regulatory or legal consequences to us, any of our subsidiaries or any of our shareholders and that such sale is necessary to avoid or cure such adverse consequences.
  
Provisions of our Articles, the Companies Law of the Cayman Islands and our corporate structure may each impede a takeover, which could adversely affect the value of our Class A ordinary shares.
 
Our Articles contain certain provisions that could make it more difficult for a third party to acquire us, even if doing so would be beneficial to our shareholders. Our Articles provide that a director may only be removed for "cause" as defined in the Articles, upon the affirmative vote of not less than 50% of the votes cast at a meeting at which more than 50% of our issued and outstanding Class A ordinary shares are represented. Further, under our Articles, a director may only be removed without cause upon the affirmative vote of not less than 80% of the votes cast at a meeting at which more than 50% of our issued and outstanding Class A ordinary shares are represented.
 
Our Articles permit our Board of Directors to issue preferred shares from time to time, with such rights and preferences as they consider appropriate. Our Board of Directors may authorize the issuance of preferred shares with terms and conditions and under circumstances that could have an effect of discouraging a takeover or other transaction, deny shareholders the receipt

33

Link to Table of Contents

of a premium on their Class A ordinary shares in the event of a tender or other offer for Class A ordinary shares and have a depressive effect on the market price of the Class A ordinary shares.
 
As compared to mergers under corporate law in the United States, it may be more difficult to consummate a merger of two or more companies in the Cayman Islands or the merger of one or more Cayman Islands companies with one or more overseas companies, even if such transaction would be beneficial to our shareholders. Cayman Islands law has statutory provisions that provide for the reconstruction and amalgamation of companies, which are commonly referred to, in the Cayman Islands, as "schemes of arrangement". The Companies Law (as amended) of the Cayman Islands (the "Companies Law") provides for the merger or consolidation of two or more companies that are Cayman Islands entities or the merger of one or more Cayman Islands companies with one or more overseas companies, where the surviving entity is either a Cayman Islands company or an overseas company.  Prior to the adoption of certain amendments to the Companies Law, the "scheme of arrangement" was the only vehicle available to consolidate companies and Cayman Islands law did not provide for mergers as that term is understood under corporate law in the United States. Although the current merger provisions have made it faster and easier for companies to merge or consolidate than the "schemes of arrangement" statutory provision, these provisions do not replace the "schemes of arrangement" provision which continues to apply. The procedural and legal requirements necessary to consummate these transactions under the merger provisions of the Companies Law or the "schemes of arrangement" provision may be more rigorous and take longer to complete than the procedures typically required to consummate a merger in the United States.
 
Under Cayman Islands law and practice, a "scheme of arrangement" must be approved at a shareholders' meeting by each class of shareholders, in each case, by a majority of the number of holders of each class of an entity's shares that are present and voting, either in person or by proxy, at such a meeting, which holders must also represent 75% in value of such class issued that are present and voting, either in person or by proxy, at such meeting, excluding the shares owned by the parties to the scheme of arrangement. A merger requires approval by special resolution of the shareholders of each company (which normally requires, as a minimum, a two thirds majority of shareholders voting together as one class) and such other authorization, if any, as may be specified in such constituent company's articles of association.
 
Although a merger under the Companies Law does not require court approval, the convening of these meetings and the terms of an amalgamation under the "schemes of arrangement" provision must be sanctioned by the Grand Court of the Cayman Islands. Although there is no requirement to seek the consent of the creditors of the parties involved in the scheme of arrangement, the Grand Court typically seeks to ensure that the creditors have consented to the transfer of their liabilities to the surviving entity or that the scheme of arrangement does not otherwise materially adversely affect the creditors' interests. Furthermore, the Grand Court will only approve a scheme of arrangement if it is satisfied that:
 
●
the statutory provisions as to majority vote have been complied with;


●
the shareholders have been fairly represented at the meeting in question;


●
the scheme of arrangement is such as a businessman would reasonably approve; and


●
the scheme of arrangement is not one that would more properly be sanctioned under some other provision of the Companies Law.
 
In addition, David Einhorn, Chairman of our Board of Directors, owns all of the outstanding Class B ordinary shares. As a result, we will not be able to enter into a scheme of arrangement without the approval of Mr. Einhorn as the holder of our Class B ordinary shares.

Holders of Class A ordinary shares may have difficulty obtaining or enforcing a judgment against us, and they may face difficulties in protecting their interests because we are incorporated under Cayman Islands law.
 
Because we are a Cayman Islands company, there is uncertainty as to whether the Grand Court of the Cayman Islands would recognize or enforce judgments of United States courts obtained against us predicated upon the civil liability provisions of the securities laws of the United States or any state thereof, or be competent to hear original actions brought in the Cayman Islands against us predicated upon the securities laws of the United States or any state thereof.
 
We are incorporated as an exempted company limited by shares under the Companies Law. A significant amount of our assets are located outside of the United States. As a result, it may be difficult for persons purchasing Class A ordinary shares to effect service of process within the United States upon us or to enforce judgments against us or judgments obtained in U.S. courts predicated upon the civil liability provisions of the federal securities laws of the United States or any state of the United States.
 

34

Link to Table of Contents

Although there is no statutory enforcement in the Cayman Islands of judgments obtained in the United States, the courts of the Cayman Islands will, based on the principle that a judgment by a competent foreign court will impose upon the judgment debtor an obligation to pay the sum for which judgment has been given, recognize and enforce a foreign judgment of a court of competent jurisdiction if such judgment is final, for a liquidated sum, not in respect of taxes or a fine or penalty if not inconsistent with a Cayman Islands judgment in respect of the same matters, and was not obtained in a manner, and is not of a kind, the enforcement of which is contrary to the public policy of the Cayman Islands. There is doubt, however, as to whether the courts of the Cayman Islands will, in an original action in the Cayman Islands, recognize or enforce judgments of U.S. courts predicated upon the civil liability provisions of the securities laws of the United States or any state of the United States on the grounds that such provisions are penal in nature.
  
A Cayman Islands court may stay proceedings if concurrent proceedings are being brought elsewhere.
 
Unlike many jurisdictions in the United States, Cayman Islands law does not specifically provide for shareholder appraisal rights on a merger or consolidation of an entity. This may make it more difficult for shareholders to assess the value of any consideration they may receive in a merger or consolidation or to require that the offeror give a shareholder additional consideration if he believes the consideration offered is insufficient.
 
Shareholders of Cayman Islands exempted companies such as ours have no general rights under Cayman Islands law to inspect corporate records and accounts. Our directors have discretion under our Articles to determine whether or not, and under what conditions, the corporate records may be inspected by shareholders, but are not obligated to make them available to shareholders. This fact may make it more difficult for shareholders to obtain the information needed to establish any facts necessary for a shareholder motion or to solicit proxies from other shareholders in connection with a proxy contest.
 
Subject to limited exceptions, under Cayman Islands law, a minority shareholder may not bring a derivative action against our Board of Directors.
 
Provisions of our Articles may reallocate the voting power of our Class A ordinary shares and subject holders of Class A ordinary shares to SEC compliance.
 
In certain circumstances, the total voting power of our Class A ordinary shares held by any one person will be reduced to less than 9.9% of the total issued and outstanding ordinary shares, and the total voting power of the Class B ordinary shares will be reduced to 9.5% of the total voting power of the total issued and outstanding ordinary shares. In the event a holder of our Class A ordinary shares acquires shares representing 9.9% or more of the total voting power of our total ordinary shares or the Class B ordinary shares represent more than 9.5% of the total voting power of our total outstanding shares, there will be an effective reallocation of the voting power of the Class A ordinary shares or Class B ordinary shares which may cause a shareholder to acquire 5% or more of the voting power of the total ordinary shares.
  
Such a shareholder may become subject to the reporting and disclosure requirements of Sections 13(d) and (g) of the Exchange Act. Such a reallocation also may result in an obligation to amend previous filings made under Section 13(d) or (g) of the Exchange Act. Under our Articles, we have no obligation to notify shareholders of any adjustments to their voting power. Shareholders should consult their own legal counsel regarding the possible reporting requirements under Section 13 of the Exchange Act.
 
As of December 31, 2015, David Einhorn owned 16.9% of the issued and outstanding ordinary shares, which given that each Class B share is entitled to ten votes, causes him to exceed the 9.5% limitation imposed on the total voting power of the Class B ordinary shares. Thus, the voting power held by the Class B ordinary shares that is in excess of the 9.5% limitation will be reallocated pro-rata to holders of Class A ordinary shares according to their percentage interest in the Company. However, no shareholder will be allocated voting rights that would cause it to have 9.9% or more of the total voting power of our ordinary shares. The allocation of the voting power of the Class B ordinary shares to a holder of Class A ordinary shares will depend upon the total voting power of the Class B ordinary shares outstanding, as well as the percentage of Class A ordinary shares held by a shareholder and the other holders of Class A ordinary shares. Accordingly, we cannot estimate with precision what multiple of a vote per share a holder of Class A ordinary shares will be allocated as a result of the anticipated reallocation of voting power of the Class B ordinary shares. 


35

Link to Table of Contents

Risks Relating to Taxation
 
We may become subject to taxation in the Cayman Islands, which would negatively affect our results.
 
Under current Cayman Islands law, we are not obligated to pay any taxes in the Cayman Islands on either income or capital gains. The Governor-in-Cabinet of Cayman Islands has granted us an exemption from the imposition of any such tax on us until February 1, 2025. We cannot be assured that after such date we would not be subject to any such tax. If we were to become subject to taxation in the Cayman Islands, our financial condition and results of operations could be significantly and negatively affected.
 
Greenlight Capital Re, Greenlight Re and/or GRIL may be subject to United States federal income taxation.
 
Greenlight Capital Re and Greenlight Re are incorporated under the laws of the Cayman Islands, and GRIL is incorporated under the laws of Ireland. These entities intend to operate in a manner that will not cause us to be treated as engaging in a trade or business within the United States and will not cause us to be subject to current United States federal income taxation on Greenlight Capital Re's, Greenlight Re's and/or GRIL’s net income. However, because there are no definitive standards provided by the Internal Revenue Code, regulations or court decisions as to the specific activities that constitute being engaged in the conduct of a trade or business within the United States, and as any such determination is essentially factual in nature, we cannot assure you that the United States Internal Revenue Service (the "IRS"), will not successfully assert that Greenlight Capital Re, Greenlight Re and/or GRIL are engaged in a trade or business within the United States.  If the IRS were to successfully assert that Greenlight Capital Re, Greenlight Re, and/or GRIL have been engaged in a trade or business within the United States in any taxable year, various adverse tax consequences could result, including the following: Greenlight Capital Re, Greenlight Re and/or GRIL may become subject to current United States federal income taxation on its net income from sources within the United States; Greenlight Capital Re, Greenlight Re and/or GRIL may be subject to United States federal income tax on a portion of its net investment income, regardless of its source; Greenlight Capital Re, Greenlight Re, and/or GRIL may not be entitled to deduct certain expenses that would otherwise be deductible from the income subject to United States taxation; and Greenlight Capital Re, Greenlight Re and/or GRIL may be subject to United States branch profits tax on profits deemed to have been distributed out of the United States.  
 
United States persons who own Class A ordinary shares may be subject to United States federal income taxation on our undistributed earnings and may recognize ordinary income upon disposition of Class A ordinary shares.
 
Passive Foreign Investment Company. Significant potential adverse United States federal income tax consequences, including certain reporting requirements, generally apply to any United States person who owns shares in a passive foreign investment company, or a PFIC. We believe that each of Greenlight Capital Re and Greenlight Re was a PFIC in 2006, 2005 and 2004. We do not believe, although we cannot assure you, that none of Greenlight Capital Re, Greenlight Re or GRIL has been a PFIC from 2007 onwards. We cannot provide assurance that none of Greenlight Capital Re, Greenlight Re or GRIL will be a PFIC in any future taxable year.
 
In general, any of Greenlight Capital Re, Greenlight Re or GRIL would be a PFIC for a taxable year if either (i) 75% or more of its income constitutes "passive income" or (ii) 50% or more of its assets produce "passive income", or are held for the production of passive income. Passive income generally includes interest, dividends and other investment income but does not include income derived in the active conduct of an insurance business by a corporation predominantly engaged in an insurance business. This exception for insurance companies is intended to ensure that a bona fide insurance entity’s income is not treated as passive income, except to the extent such income is attributable to financial reserves in excess of the reasonable needs of the insurance business. We believe that we are currently operating and intend to continue operating our business with financial reserves at a level that should not cause us to be deemed PFICs, although we cannot assure you the IRS will not successfully challenge this conclusion. If we are unable to underwrite sufficient amount of risks, any of Greenlight Capital Re, Greenlight Re or GRIL may become a PFIC.
  
In addition, sufficient risk must be transferred under an insurance entity’s contracts with its insureds in order to qualify for the insurance exception. Whether our insurance contracts possess adequate risk transfer for purposes of determining whether income under our contracts is insurance income, and whether we are predominantly engaged in an insurance business, are subjective in nature and there is very little authority on these issues. We cannot assure you that the IRS will not successfully challenge our interpretation of the scope of the active insurance company exception and our qualification for the exception. Further, the IRS may issue regulatory or other guidance that causes us to fail to qualify for the active insurance company exception on a prospective or retroactive basis. Therefore, we cannot assure you that we will satisfy the exception for insurance companies and will not be treated as PFICs currently or in the future.
 

36

Link to Table of Contents

Controlled Foreign Corporation. United States persons who, directly or indirectly or through attribution rules, own 10% or more of the total combined voting power of our shares, which we refer to as United States 10% shareholders, may be subject to the controlled foreign corporation, or CFC, rules. Under the CFC rules, each United States 10% shareholder must annually include his pro-rata share of the CFC’s "subpart F income", even if no distributions are made. In general, a foreign insurance company will be treated as a CFC only if United States 10% shareholders collectively own more than 25% of the total combined voting power or total value of the entity’s shares for an uninterrupted period of 30 days or more during any year. We believe that the dispersion of our Class A ordinary shares among holders and the restrictions placed on transfer, issuance or repurchase of our Class A ordinary shares (including the ownership limitations described below), will generally prevent shareholders who acquire Class A ordinary shares from being United States 10% shareholders. In addition, because our Articles prevent any person from holding 9.9% or more of the total combined voting power of our shares (whether held directly, indirectly or constructively), unless such provision is waived by the unanimous consent of our Board of Directors, we believe no persons holding Class A ordinary shares should be viewed as United States 10% shareholders of a CFC for purposes of the CFC rules. We cannot assure you, however, that these rules will not apply to you. If you are a United States person, we strongly urge you to consult your own tax advisor concerning the CFC rules.
 
Related Person Insurance Income. If: 
 
●
our gross income attributable to insurance or reinsurance policies where the direct or indirect insureds are our direct or indirect United States shareholders or persons related to such United States shareholders equals or exceeds 20% of our gross insurance income in any taxable year; and
 
●
direct or indirect insureds and persons related to such insureds owned directly or indirectly 20% or more of the voting power or value of our stock,
 
a United States person who owns Class A ordinary shares directly or indirectly on the last day of the taxable year would most likely be required to include their pro-rata share of our related person insurance income for the taxable year in their income. This amount would be determined as if such related person insurance income were distributed proportionally to United States persons at that date. We do not expect that we will knowingly enter into reinsurance agreements in which, in the aggregate, the direct or indirect insureds are, or are related to, owners of 20% or more of the Class A ordinary shares. We do not believe that the 20% gross insurance income threshold will be met. However, we cannot assure you that this is or will continue to be the case. Consequently, we cannot assure you that a person who is a direct or indirect United States shareholder will not be required to include amounts in its income in respect of related person insurance income in any taxable year.
 
    If a United States shareholder is treated as disposing of shares in a foreign insurance corporation that has related person insurance income and in which United States persons own 25% or more of the voting power or value of the entity’s shares, any gain from the disposition will generally be treated as a dividend to the extent of the United States shareholder’s portion of the corporation’s undistributed earnings and profits that were accumulated during the period that the United States shareholder owned the shares. In addition, the shareholder will be required to comply with certain reporting requirements, regardless of the amount of shares owned by the direct or indirect United States shareholder. Although not free from doubt, we believe these rules should not apply to dispositions of Class A ordinary shares because Greenlight Capital Re is not directly engaged in the insurance business and because proposed United States Treasury regulations applicable to this situation appear to apply only in the case of shares of corporations that are directly engaged in the insurance business. We cannot assure you, however, that the IRS will interpret the proposed regulations in this manner or that the proposed regulations will not be promulgated in final form in a manner that would cause these rules to apply to dispositions of Class A ordinary shares.  

United States tax-exempt organizations who own Class A ordinary shares may recognize unrelated business taxable income.
 
If you are a United States tax-exempt organization you may recognize unrelated business taxable income if a portion of our subpart F insurance income is allocated to you. In general, subpart F insurance income will be allocated to you if we are a CFC as discussed above and you are a United States 10% shareholder or there is related person insurance income and certain exceptions do not apply. Although we do not believe that any United States persons will be allocated subpart F insurance income, we cannot assure you that this will be the case. If you are a United States tax-exempt organization, we advise you to consult your own tax advisor regarding the risk of recognizing unrelated business taxable income.
 
Proposed changes in United States tax regulations and laws could subject United States persons who own Class A ordinary shares to United States income taxation on our undistributed earnings and may cause us to undertake changes to the manner in which we conduct our business. 

In April 2015, the IRS issued proposed regulations that would provide guidance regarding the exclusion of the investment income of a foreign insurance company from the definition of "passive income" for the purposes of the PFIC rules.

37

Link to Table of Contents

Furthermore, in June 2015, U.S. Senator Ron Wyden, a member of the U.S. Senate Finance Committee, introduced a bill that provides a "bright line" annual test that a foreign company must satisfy in order to qualify as an insurance company for purposes of the insurance company exception to the PFIC rules.

We are monitoring developments with respect to both the IRS proposed regulations and the Wyden bill. At this time, we cannot predict whether or what, if any, regulations will be adopted or legislation will be enacted. If regulations are adopted or legislation enacted that cause us to fail to meet the requirements of the insurance company exception, such failure could have a material adverse effect on the taxation of our shareholders who are U.S. persons. In that event we may undertake changes to the manner in which we conduct our business, which could have a material effect on our results of operations.

The tax laws and interpretations regarding whether an entity is engaged in a United States trade or business, is a CFC, has related party insurance income or is a PFIC are subject to change, possibly on a retroactive basis. New regulations or pronouncements interpreting or clarifying such rules may be forthcoming from the IRS. We are not able to predict if, when or in what form such guidance will be provided and whether such guidance will have a retroactive effect.
  
If investments held by GRIL are determined not to be integral to the insurance and reinsurance business carried on by GRIL, additional Irish tax could be imposed and our business and financial results could be materially adversely affected.

Based on administrative practice, taxable income derived from investments made by GRIL is generally taxed in Ireland at the rate of 12.5% on the grounds that such investments either form part of the permanent capital required by regulatory authorities, or are otherwise integral to the insurance and reinsurance business carried on by GRIL.  GRIL intends to operate in such a manner so that the level of investments held by GRIL does not exceed the amount that is integral to the insurance and reinsurance businesses carried on by GRIL.  If, however, investment income earned by GRIL exceeds these thresholds or if the administrative practice of the Irish Revenue Commissioners changes, Irish corporation tax could apply to such investment income at a higher rate (currently 25%) instead of the general 12.5% rate, and our results of operations could be materially adversely affected.
 
The impact of the initiative of the OECD to eliminate harmful tax practices is uncertain and could adversely affect our tax status in the Cayman Islands.
 
The OECD has published reports and launched a global dialogue among member and non-member countries on measures to limit harmful tax competition. These measures are largely directed at counteracting the effects of tax havens and preferential tax regimes in countries around the world. While the Cayman Islands is currently on the list of jurisdictions that have substantially implemented the internationally agreed tax standard, we are not able to predict if additional requirements will be imposed and if so whether changes arising from such additional requirements will subject us to additional taxes. 

ITEM 1B. UNRESOLVED STAFF COMMENTS

None.

ITEM 2. PROPERTIES

We currently occupy our office space in Grand Cayman, Cayman Islands under operating lease agreements which will expire on June 30, 2018, unless we renew the leases for an additional five year term. Additionally, we have an operating lease agreement for office space in Dublin, Ireland which expires in 2031 but provides us an option to terminate the lease in 2021 without any penalty. We believe that for the foreseeable future the office spaces in the Cayman Islands and Ireland will be sufficient for conducting our operations. 

ITEM 3. LEGAL PROCEEDINGS
 
From time to time, in the normal course of business, we may be involved in formal and informal dispute resolution procedures, which may include arbitration or litigation, the outcomes of which determine our rights and obligations under our reinsurance contracts and other contractual agreements. In some disputes, we may seek to enforce our rights under an agreement or to collect funds owing to us. In other matters, we may resist attempts by others to collect funds or enforce alleged rights. While the final outcome of legal disputes cannot be predicted with certainty, we do not believe that any of our existing contractual disputes, when finally resolved, will have a material adverse effect on our business, financial condition or operating results.
 

38

Link to Table of Contents

ITEM 4. MINE SAFETY DISCLOSURES

Not applicable.

 
PART II
 
ITEM 5. MARKET FOR REGISTRANT’S COMMON EQUITY, RELATED STOCKHOLDER MATTERS AND ISSUER PURCHASES OF EQUITY SECURITIES

Market Information
 
Our Class A ordinary shares began publicly trading on the Nasdaq Global Select Market on May 24, 2007 under the symbol "GLRE". The following table sets forth, for the periods indicated, the high and low reported sale price per share of our Class A ordinary shares on the Nasdaq Global Select Market. 
 
 
2015
 
2014
 
 
High
 
Low
 
High
 
Low
First Quarter
 
$
33.23

 
$
30.42

 
$
34.24

 
$
29.97

Second Quarter
 
$
31.91

 
$
29.14

 
$
34.70

 
$
30.83

Third Quarter
 
$
30.05

 
$
22.13

 
$
35.18

 
$
31.55

Fourth Quarter
 
$
25.20

 
$
17.86

 
$
33.87

 
$
30.18

 
Holders
 
As of January 31, 2016, the number of holders of record of our Class A ordinary shares was approximately 45, not including beneficial owners of shares registered in nominee or street name who represent approximately 96.9% of the Class A ordinary shares issued and outstanding.

Dividends
 
Since inception, we have not paid any cash dividends on our Class A ordinary shares or Class B ordinary shares, or collectively, our ordinary shares.
 
Holders of ordinary shares are entitled to receive dividends when, as and if declared by the Board of Directors in accordance with the provisions of our Articles and the Companies Law. In the event of a liquidation, dissolution or winding-up of the Company, the holders of ordinary shares are entitled to share equally and ratably in our assets, if any remain after the payment of all of our debts and liabilities and the liquidation preference of any outstanding preferred shares.

We currently do not intend to declare and pay dividends on our ordinary shares in the foreseeable future. However, if we decide to pay dividends, we cannot assure you that sufficient cash will be available to pay such dividends. In addition, a letter of credit facility prohibits us from paying dividends during an event of default as defined in the letter of credit agreement. Our future dividend policy will also depend on the requirements of any future financing agreements to which we may be a party and other factors considered relevant by our Board of Directors, such as our results of operations and cash flows, our financial position and capital requirements, general business conditions, rating agency guidelines, legal, tax, regulatory and any contractual restrictions on the payment of dividends. Further, any future declaration and payment of dividends is discretionary and our Board of Directors may at any time modify or revoke our dividend policy on our ordinary shares. Finally, our ability to pay dividends also depends on the ability of our subsidiaries to pay dividends to us. Although Greenlight Capital Re is not subject to any significant legal prohibitions on the payment of dividends, Greenlight Re and GRIL are subject to regulatory constraints that affect their ability to pay dividends and include minimum net worth requirements. As of December 31, 2015, Greenlight Re and GRIL both exceeded the minimum statutory capital requirements. Any dividends we pay will be declared and paid in U.S. dollars.


39

Link to Table of Contents

Performance Graph

Presented below is a line graph comparing the yearly percentage change in the cumulative total shareholder return on our Class A ordinary shares from May 24, 2007 (the date on which our Class A ordinary shares were first listed on the Nasdaq Global Select Market) through December 31, 2015 against the total return index for the Russell 2000 Index, or RUT, and the S&P 500 Property & Casualty Insurance Index, or S&P Insurance Index, for the same period. The performance graph assumes $100 invested on May 24, 2007 in the ordinary shares of Greenlight Capital Re, the RUT and the S&P Insurance Index. The performance graph also assumes that all dividends are reinvested.


The performance reflected in the graph above is not necessarily indicative of future performance.

This graph is not "soliciting material," is not deemed filed with the SEC and is not to be incorporated by reference in any filing by us under the Securities Act or the Exchange Act, whether made before or after the date hereof and irrespective of any general incorporation language in any such filing.


40

Link to Table of Contents

Purchases of Equity Securities by the Issuer and Affiliated Purchasers
 
The table below details the repurchases that were made under our share repurchase plan during the year ended December 31, 2015.
Issuer Purchases of Equity Securities
Period
 
Total Number of Shares Purchased (1)
 
Average Price Paid per Share
 
Total Number of Shares Purchased as Part of Publicly Announced Plans or Programs (1)
 
Maximum Number of Shares that May Yet Be Purchased Under the Plans or Programs (1)
January 1 - 31, 2015
 
—

 
$
—

 
—

 
2,000,000

February 1 - 28, 2015
 
—

 
$
—

 
—

 
2,000,000

March 1 - 31, 2015
 
—

 
$
—

 
—

 
2,000,000

April 1 - 30, 2015
 
—

 
$
—

 
—

 
2,000,000

May 1 - 31, 2015
 
—

 
$
—

 
—

 
2,000,000

June 1 - 30, 2015
 
140,000

 
$
30.28

 
140,000

 
1,860,000

July 1 - 31, 2015
 
360,000

 
$
28.95

 
360,000

 
1,500,000

August 1 - 31, 2015
 
113,540

 
$
26.68

 
113,540

 
1,386,460

September 1 - 30, 2015
 
—

 
$
—

 
—

 
1,386,460

October 1 - 31, 2015
 
—

 
$
—

 
—

 
1,386,460

November 1 - 30, 2015
 
—

 
$
—

 
—

 
1,386,460

December 1 - 31, 2015
 
—

 
$
—

 
—

 
1,386,460

Total
 
613,540


613,540

 
1,386,460

(1) Class A ordinary shares.

On August 5, 2008, our board of directors adopted a share repurchase plan authorizing the Company to repurchase Class A ordinary shares in the open market, through privately negotiated transactions or Rule 10b5-1 stock trading plans. From time to time, the repurchase plan has been re-approved or modified at the election of our Board of Directors. On April 29, 2015, our Board of Directors amended the share repurchase plan to extend the duration of the repurchase plan to June 30, 2016 and reinstated the authorization for the Company to purchase up to 2.0 million Class A ordinary shares or securities convertible into Class A ordinary shares. As of December 31, 2015, 1,386,460 Class A ordinary shares remained authorized for repurchase under the share repurchase plan. The Company is not required to repurchase any Class A ordinary shares and the repurchase plan may be modified, suspended or terminated at any time without prior notice.


ITEM 6. SELECTED FINANCIAL DATA

The following table sets forth our selected historical consolidated statement of income data for the fiscal years ended December 31, 2015, 2014, 2013, 2012 and 2011, as well as our selected historical consolidated balance sheet data as of December 31, 2015, 2014, 2013, 2012 and 2011, which are derived from our audited consolidated financial statements. The audited consolidated financial statements are prepared in conformity with accounting principles generally accepted in the United States of America ("U.S. GAAP") and have been audited by BDO USA, LLP, an independent registered public accounting firm.
 
These historic results are not necessarily indicative of results for any future period. You should read the following selected financial data in conjunction with our consolidated financial statements and related notes thereto contained in "Item 8. Financial Statements and Supplementary Data" and "Item 7. Management’s Discussion and Analysis of Financial Condition and Results of Operations" included in this filing and all other information appearing elsewhere or incorporated into this filing by reference.

41

Link to Table of Contents


Year ended December 31
 
 
2015
 
2014
 
2013
 
2012
 
2011
 
 
  ($ in thousands, except per share and share amounts)
Selected Consolidated Statement of Income Data
 
 
Gross premiums written
 
$
502,124

 
$
324,023

 
$
535,702

 
$
427,844

 
$
397,659

Net premiums earned
 
408,387

 
354,240

 
547,899

 
466,714

 
379,775

Net investment income (loss)
 
(281,924
)
 
122,575

 
218,140

 
78,941

 
23,118

Loss and loss adjustment expenses incurred, net
 
317,097

 
234,986

 
338,493

 
366,601

 
241,690

Acquisition costs, net
 
116,207

 
107,665

 
171,872

 
142,721

 
138,751

General and administrative expenses
 
23,434

 
24,500

 
20,958

 
16,755

 
13,892

Net income (loss)
 
$
(326,425
)
 
$
109,592

 
$
225,699

 
$
14,598

 
$
6,769

Earnings (Loss) Per Share Data (1)


Basic
 
$
(8.90
)
 
$
2.94

 
$
6.13

 
$
0.40

 
$
0.19

Diluted
 
(8.90
)
 
2.89

 
6.01

 
0.39

 
0.18

Weighted average number of ordinary shares used in the determination of earnings and loss per share


Basic
 
36,670,466

 
37,242,687

 
36,838,128

 
36,702,128

 
36,548,466

Diluted
 
36,670,466

 
37,874,387

 
37,585,167

 
37,361,338

 
37,286,454

Selected Ratios (based on U.S. GAAP Consolidated Statement of Income data)


Loss ratio (2)
 
77.6
%
 
66.3
%
 
61.8
%
 
78.5
%
 
63.6
%
Acquisition cost ratio (3)
 
28.5
%
 
30.4
%
 
31.4
%
 
30.6
%
 
36.5
%
Internal expense ratio (4)
 
4.5
%
 
6.0
%
 
3.2
%
 
2.8
%
 
2.8
%
Corporate expense ratio (5)
 
1.2
%
 
0.9
%
 
0.6
%
 
0.8
%
 
0.9
%
Combined ratio (6)
 
111.8
%
 
103.6
%
 
97.0
%
 
112.7
%
 
103.8
%

Prior to January 1, 2015, non-investment related foreign exchange gains and losses were recorded under general and administrative expenses. Effective January 1, 2015, the presentation has been modified and any non-investment related foreign exchange gains or losses are now recorded under "other income (expense), net" in the consolidated statements of income. Therefore, the general and administrative expenses, corporate expense ratios and combined ratios for prior periods have been reclassified in the above table to conform to the current year presentation.

42

Link to Table of Contents


December 31
 
 
2015
 
2014
 
2013
 
2012
 
2011
 
 
   ($ in thousands, except per share and share amounts)
Selected Consolidated Balance Sheet Data


Total investments
 
$
1,064,164

 
$
1,430,978

 
$
1,393,679

 
$
1,177,928

 
$
1,030,146

Cash and cash equivalents
 
112,162

 
12,030

 
3,722

 
21,890

 
42,284

Restricted cash and cash equivalents
 
1,236,589

 
1,296,914

 
1,334,074

 
1,206,837

 
957,462

Total assets
 
2,712,522

 
2,995,292

 
3,095,276

 
2,722,753

 
2,343,488

Securities sold, not yet purchased, at fair value
 
882,906

 
1,090,731

 
1,111,690

 
908,368

 
683,816

Due to prime brokers
 
396,453

 
211,070

 
314,702

 
326,488

 
260,359

Loss and loss adjustment expense reserves ^
 
305,997

 
264,243

 
329,894

 
356,470

 
241,279

Unearned premium reserves
 
211,954

 
128,736

 
173,057

 
188,185

 
225,735

Total liabilities
 
1,863,749

 
1,801,251

 
2,008,972

 
1,862,343

 
1,497,790

Total equity
 
848,773

 
1,194,041

 
1,086,304

 
860,410

 
845,698

Adjusted book value* (7)
 
825,391

 
1,165,151

 
1,051,595

 
821,708

 
803,103

Diluted adjusted book value* (8)
 
836,944

 
1,184,779

 
1,067,623

 
840,683

 
821,318

Ordinary shares outstanding


Basic
 
37,027,467

 
37,384,543

 
37,046,814

 
36,702,128

 
36,538,149

Diluted (9)
 
37,744,807

 
38,516,460

 
38,257,545

 
38,193,418

 
38,007,149

Per Share Data


Basic adjusted book value per share* (10)
 
$
22.29

 
$
31.17

 
$
28.39

 
$
22.39

 
$
21.98

Fully diluted adjusted book value per share* (11)
 
22.17

 
30.76

 
27.91

 
22.01

 
21.61


(1) 
Basic earnings per share is calculated by dividing net income by the weighted average number of common shares and participating securities outstanding for the period. Diluted earnings per share is calculated by taking into account the effects of exercising all dilutive stock options. In the event of a net loss, any stock options outstanding are excluded from the calculation of diluted loss per share. Unvested stock awards which contain non-forfeitable rights to dividends or dividend equivalents, whether paid or unpaid (referred to as "participating securities") are included in the number of shares outstanding for both basic and diluted earnings per share calculations. In the event of a net loss, the participating securities are excluded from both basic and diluted loss per share.
(2) 
The loss ratio is calculated by dividing net loss and loss adjustment expenses incurred by net premiums earned.
(3) 
The acquisition cost ratio is calculated by dividing net acquisition costs by net premiums earned.
(4) 
The internal expense ratio is the ratio of general and administrative expenses, excluding any corporate expenses, to net premiums earned.
(5) 
The corporate expense ratio is the ratio of corporate expenses to net premiums earned. Corporate expenses include expenses relating to Greenlight Capital Re being a publicly listed entity and certain non-core operating expenses.
(6) 
The combined ratio is the sum of the loss ratio, acquisition cost ratio, the internal expense ratio and corporate expense ratio.
(7) 
Adjusted book value equals total equity minus non-controlling interest in joint venture.
(8) 
Diluted adjusted book value is the adjusted book value plus the proceeds from the exercise of in-the-money options issued and outstanding at year end.
(9) 
Diluted number of shares outstanding is the sum of basic shares outstanding and the in-the-money options and restricted stock units issued and outstanding at year end.
(10) 
Basic adjusted book value per share is calculated by dividing adjusted book value by the number of shares and share equivalents issued and outstanding at year end.
(11) 
Fully diluted adjusted book value per share is calculated by dividing the diluted adjusted book value by the diluted number of shares outstanding at year end.
* 
Adjusted book value, diluted adjusted book value, basic adjusted book value per share, and fully diluted adjusted book value per share are non-GAAP measures. For a reconciliation of the non-GAAP measures to the most comparable GAAP measures, refer to "Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations — Results of Operations".
^ 
For detailed discussion of change in loss and loss adjustment expenses, refer to "Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations — Financial Condition" and Note 7 to the consolidated financial statements.

43

Link to Table of Contents

ITEM 7. MANAGEMENT’S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS
 
References to "we," "us," "our," "our company,"  or "the Company" refer to Greenlight Capital Re, Ltd. ("GLRE") and its wholly-owned subsidiaries, Greenlight Reinsurance, Ltd, ("Greenlight Re"), Greenlight Reinsurance Ireland, Ltd. ("GRIL") and Verdant Holding Company, Ltd. ("Verdant"), unless the context dictates otherwise. References to our "Ordinary Shares" refers collectively to our Class A Ordinary Shares and Class B Ordinary Shares.

 
The following is a discussion and analysis of our results of operations for the years ended December 31, 2015, 2014 and 2013 and financial condition as of December 31, 2015 and 2014. The following discussion should be read in conjunction with the audited consolidated financial statements and accompanying notes, which appear elsewhere in this filing.
 
General
 
We are a Cayman Islands headquartered global specialty property and casualty reinsurer with a reinsurance and investment strategy that we believe differentiates us from most of our competitors. Our goal is to build long-term shareholder value by selectively offering customized reinsurance solutions, in markets where capacity and alternatives are limited, which we believe will yield favorable long-term returns on equity.
 
We aim to complement our underwriting results with a non-traditional investment approach in order to achieve higher rates of return over the long term than reinsurance companies that employ more traditional, fixed-income investment strategies. We manage our investment portfolio according to a value-oriented philosophy, in which we take long positions in perceived undervalued securities and short positions in perceived overvalued securities.
 
Because we employ an opportunistic underwriting philosophy, period-to-period comparisons of our underwriting results may not be meaningful. In addition, our historical investment results may not necessarily be indicative of future performance. Due to the nature of our reinsurance and investment strategies, our operating results will likely fluctuate from period to period.

Outlook and Trends

The reinsurance industry has experienced significant consolidation in the last several years, fueled by many traditional participants with excess capital looking to strengthen their positions in their core markets and boost their investment returns in a low interest rate environment. We believe further consolidation will likely continue but do not believe that consolidation will result in a significant reduction in total capital within the industry. Rather, we expect the industry consolidation to create concentrations of capital in fewer, larger participants, and that with a reduction in the number of competitors in the industry, pricing may partially stabilize. Further, while some opportunities may become available on an attractive basis to only the largest reinsurance companies in the industry, we believe that the consolidation trend may create new opportunities for us if more capacity becomes available as a result of the industry consolidating.

We do not believe that the over-capitalization of the market is uniform across all industry participants and there are many insurers and reinsurers with lower financial security profiles than ours that have and will continue to suffer disproportionately. We believe the value proposition of our reinsurance offering and our differentiated underwriting strategy positions us well to compete for new, targeted business in niche areas that we know and service well.

A key part of our underwriting strategy is to identify and partner with companies that have suffered dislocation. Accordingly, given declining or flat investment earnings for fixed income investors, resulting from a prolonged low interest rate environment, we believe underwriting opportunities may increase, which we intend to pursue where we believe pricing is economically rational. Conversely, if attractive opportunities are not available on economically rational terms, we anticipate that we will seek to maintain or even reduce premium writings rather than accept mispriced risk in order to conserve our capital for a more opportune environment. We believe that significant price increases could occur if financial and credit markets experience adverse shocks that result in the loss of capital of insurers and reinsurers, or if there are major catastrophic events, especially in North America.
    
During 2015, we experienced more success in closing targeted new business opportunities, especially new transactions with existing partners, than we have experienced in the prior two fiscal years. For specific information regarding our gross written premium by area of business as at December 31, 2015, 2014 and 2013, please refer to the table in Note 15 of the consolidated financial statements. Additionally, several of our renewal clients experienced growth in their portfolios, which, in turn, resulted in growth of the premium ceded under our transactions with these clients in 2015. In particular:

44

Link to Table of Contents

•
We observed stability and favorable trends in our underlying rates and profitability for our non-standard automobile business. We continue to believe we are achieving acceptable risk adjusted returns on this business and expect to have a high concentration of premium in this line for the foreseeable future.
•
We observed an increase in the size of the U.S. health stop loss market as employers seek to control their health care costs by moving from first dollar health care plans subject to the Affordable Care Act. We believe that the majority of this growth has been absorbed by large carriers that elect to not purchase reinsurance. However, we have seen growth in the portion of the market controlled by managing general underwriters that rely heavily on quota share reinsurance and we expect to modestly increase our market share in this line for the foreseeable future.
•
We note that pricing for property catastrophe retro and other property catastrophe business is under severe competitive pressure and we believe much of the business in the market is being priced below the expected losses. As such, in 2015 we have decreased, and expect to continue to decrease, our focus in this line of business unless there is a market changing event that improves expected profitability.
•
Our specialty casualty business is comprised of larger, syndicated reinsurance placements for general casualty and professional liability. For most of this business, we are not a lead underwriter and, instead are following the market on these transactions. This business has a longer duration of claim payments than business we have historically written, which leads to a build-up of reserves and exposure over a longer period of time. We expect this portion of our business to grow modestly in 2016.
•
We also observed a decrease in the underlying rates and profitability for Florida Homeowners business. If rates and expected profitability continue to decline, we would expect to further decrease the premiums written in this line.
 
On October 23, 2015 A.M. Best affirmed Greenlight Re's rating of "A (Excellent)" but revised the outlook from stable to negative. We do not expect any of our current business to be affected due to strong client relationships and our capital position; however, there is the potential for new business generation in the rating sensitive areas of the market to be adversely impacted.

While competitive market conditions have made finding and successfully underwriting new business that meets our targeted return hurdles challenging, we believe that we have a strong pipeline of attractive opportunities with counterparties that seek highly customized structures, terms and conditions, which aligns well with our underwriting strategy. We intend to continue to monitor market conditions and pursue opportunities to best position ourselves to participate in future under-served or capacity-constrained markets as they arise, and intend to offer products that we believe will generate favorable returns on equity over the long term. Accordingly, our underlying results and product line concentrations in any given period may vary, perhaps significantly, and are not necessarily indicative of our future results of operations.

Our investment portfolio had a net long exposure of 15.5% as of December 31, 2015. Our goal for 2016 is to protect capital in an uncertain environment and to find investment opportunities on both our long and short portfolios that we believe will generate positive returns. Despite a Federal Reserve interest rate increase in December, monetary policy remains very accommodative globally.  Additionally, there are many global economic and political risks that are coming to the forefront. Global equity markets have had a difficult start in 2016 with many global market indices falling, and volatility rising.  Given the current investment environment, we judge it appropriate to maintain comparatively lower gross and net equity exposures and to hold a significant position in gold and other macro positions.

Segments
 
We manage our business on the basis of one operating segment, property and casualty reinsurance, in accordance with the qualitative and quantitative criteria established by U.S. GAAP. Within the property and casualty reinsurance segment, we analyze our underwriting operations using two categories:

●    frequency business; and 
●    severity business.

Frequency business is generally characterized as contracts containing a potentially large number of small losses emanating from multiple events. Clients generally buy this protection to increase their own underwriting capacity and typically select a reinsurer based upon the reinsurer’s financial strength, service and expertise. We expect the results of frequency business to be less volatile than those of severity business from period to period due to greater predictability. We also expect that over time the profit margins and return on equity of our frequency business will be lower than those of our severity business.
 

45

Link to Table of Contents

Severity business is generally characterized as contracts with the potential for significant losses emanating from one event or multiple events. Clients generally buy this protection to remove volatility from their balance sheets, and accordingly, we expect the results of severity business to be volatile from period to period. However, over the long term, we also expect that our severity business will generate higher profit margins and return on equity than those of our frequency business.

Revenues
 
We derive our revenues from two principal sources: 
 
●
premiums from reinsurance on property and casualty business assumed; and
 
●
income from investments.
  
Premiums from reinsurance on property and casualty business assumed are directly related to the number, type and pricing of contracts we write. For financial reporting purposes, we earn premiums over the contract period in proportion to the period of risk covered.
 
Income from our investments is primarily comprised of interest income, dividends, net realized gains and losses, and changes in unrealized gains and losses on investment securities. We also derive interest income from money market funds and notes receivable.
 
 In addition, we may from time to time derive other income from gains on deposit accounted contracts, fees generated from advisory services provided by Verdant and fees relating to overrides, profit commissions and early termination of contracts.

Expenses
 
Our expenses consist primarily of the following: 
 
●
underwriting losses and loss adjustment expenses;
 
●
acquisition costs;
 
●
investment-related expenses; and
 
●
general and administrative expenses.
 
Loss and loss adjustment expenses are a function of the amount and type of reinsurance contracts we write and of the loss experience of the underlying coverage. As described below, loss and loss adjustment expenses include an actuarial analysis of the estimated losses, including losses incurred during the period and changes in estimates from prior periods. Depending on the nature of the contract, loss and loss adjustment expenses may be paid over a period of years.
 
Acquisition costs primarily consist of brokerage fees, ceding commissions, premium taxes, profit commissions, letters of credit fees, federal excise tax, and other direct expenses we incur that are directly related to underwriting reinsurance contracts. We amortize deferred acquisition costs over the related contract term.
 
Investment-related expenses primarily consist of interest expense on borrowings, dividend expense on short sales, management fees and performance compensation that we pay to our investment advisor. We net these expenses against investment income in our consolidated financial statements.
 
General and administrative expenses consist primarily of salaries and benefits and related costs, including costs associated with our incentive compensation plan, bonuses and stock compensation expenses. General and administrative expenses also include professional fees, travel and entertainment, information technology, rent and other general operating expenses.
 
For stock option expenses, we calculate compensation cost using the Black-Scholes option pricing model and expense stock options over their vesting period, which is typically three years. For restricted stock awards and restricted stock units, we calculate compensation cost using the grant date fair value of each award and expense the stock awards over their vesting period, which is typically three years for employees and one year for directors.


46

Link to Table of Contents

Critical Accounting Policies
 
Our consolidated financial statements contain certain amounts that are inherently subjective in nature and have required management to make assumptions and best estimates to determine reported values. If certain factors, including those described in "Part I. Item IA. — Risk Factors", cause actual events or results to differ materially from our underlying assumptions or estimates, there could be a material adverse effect on our results of operations, financial condition or liquidity. We believe that the following accounting policies affect the more significant estimates used in the preparation of our consolidated financial statements. The descriptions below are summarized and have been simplified for clarity. A more detailed description of our significant accounting policies as well as recently issued accounting standards is included in Note 2 to the consolidated financial statements. 

Premium Revenues and Risk Transfer. Our property and casualty reinsurance premiums are recorded as premiums written based upon contract terms and information received from ceding companies and their brokers. For excess of loss reinsurance contracts, premiums are typically stated as a percentage of the subject premiums written by the client, subject to a minimum and deposit premium. The minimum and deposit premium is typically based on an estimate of subject premiums expected to be written by the client during the contract term. The minimum and deposit premium is reported initially as premiums written and adjusted, if necessary, in subsequent periods once the actual subject premium is known. For catastrophe contracts that contractually require the payment of a reinstatement premium equal to or greater than the original premium upon the occurrence of a full limit loss, the reinstatement premiums are earned over the original contract period. Reinstatement premiums that are contractually calculated on a pro-rata basis of the original premiums are earned over the remaining coverage period.
 
For each quota share or proportional property and casualty reinsurance contract we underwrite, our client estimates gross premiums written at inception of the contract. We generally account for such premiums using our best estimates and then adjust our estimates based on actual reports provided by our client and based on our expectations of industry developments. As the contract progresses, we monitor actual premiums received in conjunction with correspondence from the client in order to refine our estimate. Variances from initial gross premiums written estimates can be greater for quota share contracts than for excess of loss contracts. All premiums on quota share contracts are earned over the risk coverage period. Unearned premiums consist of the unexpired portion of reinsurance provided.

At the inception of each of our reinsurance contracts, we receive premium estimates from the client, which, together with historical and industry data, are used to estimate what we believe will be the ultimate premium payable pursuant to each contract. We receive actual premiums written by each client as the client reports the actual results of the underlying insurance writings to us on a monthly or quarterly basis (depending on the terms of the contract). We book the actual premiums written when we receive them from our client. Each reporting period we estimate the amount of premiums that are written for stub periods that have not yet been reported to us by the client. For example, for December year-end we may have to estimate December premiums ceded under certain contracts since the client may not be required to report the actual results to us until after we have finalized our audited financial statements. Typically, premium estimates are only used for unreported stub periods, which accounts for a small percentage of our reported premiums written. We believe that estimating premiums written for these stub periods is standard reinsurance industry practice.
 
We are able to confirm the accuracy and completeness of premiums reported by our clients by either reviewing the client’s statutory filings and/or performing an audit of the client, as per the terms of the contract. Discrepancies between premiums being ceded and reported under a contract are, in our experience, rare. To date, we have not had any material discrepancy in premiums being reported by a client that required a dispute resolution process. 
 
We account for reinsurance contracts in accordance with U.S. GAAP. Assessing whether or not a reinsurance contract meets the conditions for risk transfer requires judgment. The determination of risk transfer is critical to reporting premiums written and is based, in part, on the use of actuarial and pricing models and assumptions. If we determine that a reinsurance contract does not transfer sufficient risk, or if a contract provides retroactive reinsurance coverage, we use deposit accounting. Any losses on such contracts are charged to earnings immediately and recorded in the consolidated statements of income as other expense. Any gains relating to such contracts are deferred and amortized over the estimated remaining settlement period. All such deferred gains are included in reinsurance balances payable in the consolidated balance sheets. Amortized gains are recorded in the consolidated statements of income as other income.
 
Investments. Our investments in debt and equity securities that are classified as "trading securities" are carried at fair value in accordance with U.S. GAAP. The fair values of the listed equities are derived based on the last reported price on the balance sheet date as reported by a recognized exchange. The fair values of listed equities that have restrictions on sale or transfer which expire within one year, are determined by adjusting the observed market price of the equity using a liquidity discount based on observable market inputs. The fair values of debt instruments are generally derived based on the average of

47

Link to Table of Contents

multiple market maker or broker quotes which are considered to be binding. Where quotes are not available, debt instruments are valued using cash flow models using assumptions and estimates that may be subjective and non-observable.
 
The fair values of our investments in commodities are based on the commodity’s last reported price on the balance sheet date as reported by a recognized commodities exchange. Our investments in private and unlisted equity securities and limited partnerships are all carried at fair value, based on broker or market maker quotes, or based on management’s assumptions developed from available information, using the services of our investment advisor including the most recent net asset values obtained from the managers of those underlying investments. Investments in private equity funds are valued based on unadjusted net asset values reported by the funds’ managers.

For securities classified as "trading securities" and "other investments", any realized and unrealized gains or losses are determined on the basis of specific identification method (by reference to cost or amortized cost, as appropriate) and included in net investment income in the consolidated statements of income.
 
Financial contracts which include total return swaps, credit default swaps, options, futures and other derivative instruments are recorded at their fair value with any unrealized gains and losses included in net investment income in the consolidated statements of income. Fair values on total return swaps are based on the underlying security’s fair value which is obtained from closing prices on a recognized exchange (for equity or commodity swaps), or from market makers or broker quotes. Fair values for credit default swaps trading in an active market are based on market maker or broker quotes taking into account credit spreads on identical contracts. Our exchange traded option contracts are recorded at fair value based on quoted prices in active markets. For over the counter ("OTC") options and exchange traded options where a quoted price in an active market is not available, we obtain multiple market maker quotes to determine the fair values. Fair values for other derivative instruments are determined based on multiple broker or market maker quotes taking into account the liquidity and the availability of an active market for the derivative.
 
Loss and Loss Adjustment Expense Reserves. Our loss and loss adjustment expense reserves are comprised of: 
 
●
case reserves resulting from claims notified to us by our clients;
 
●
incurred but not reported ("IBNR") losses; and
 
●
estimated loss adjustment expenses.
Case reserves are provided by our clients, and IBNR losses are estimated each reporting period based on a contract by contract review of all data available to us for each individual contract. Each of our reinsurance contracts is unique and the methods and estimates we use vary depending on the facts and circumstances of each contract. The resulting total loss reserves, including IBNR loss reserves, are the sum of each loss reserve estimated on a contract by contract basis.

We establish reserves for contracts based on estimates of the ultimate cost of all losses including IBNR. These estimated ultimate reserves are based on our own actuarial estimates derived from reports received from ceding companies, industry data and historical experience. These estimates are periodically reviewed by the Company on a contract by contract basis and adjusted when necessary. Since reserves are estimates, the setting of appropriate reserves is an inherently uncertain process. Our estimates are based upon actuarial and statistical projections and on our assessment of currently available data, predictions of future developments and estimates of future trends and other factors. The final settlement of losses may vary, perhaps materially, from the reserves initially established and periodically adjusted. All adjustments to the estimates are recorded in the period in which they are determined. Under U.S. GAAP, we are not permitted to establish loss reserves, which include case reserves and IBNR loss reserves, until the occurrence of an event which may give rise to a claim. As a result, only loss reserves applicable to losses incurred up to the reporting date are established, with no allowance for the establishment of loss reserves to account for expected future loss events.
 
For natural peril exposed business, we generally establish loss reserves based on loss payments and case reserves reported by our clients when, and if, received. We then add our estimates for IBNR losses to the case reserves. To establish our IBNR loss estimates, in addition to the loss information and estimates communicated by ceding companies, we use industry information, knowledge of the business written and management’s judgment.
 
For most of the contracts we write, our risk exposure is limited by defined limits of liability. Once the loss limit for a contract has been reached, we have no further exposure to additional losses from that contract. However, certain contracts, particularly quota share contracts that relate to first dollar exposure, may not contain aggregate limits.

For all non-natural peril business, we initially reserve every individual contract to the expected loss and loss expense ratio that we calculated when we originally priced the business. In our pricing analysis, we typically utilize a significant amount of information both from the individual client and from industry data. Where practical, we compare historic reserving data that

48

Link to Table of Contents

we receive from our client, if any, to publicly available financial statements of the client in an effort to identify, confirm and monitor the accuracy and completeness of the data. We require each of our clients to provide loss information for each reporting period, which, depending on the contract, could be monthly or quarterly. The loss information required depends on the terms and conditions of each contract and may include many years of history. Depending on the type of business underwritten, we are entitled to receive client and industry information on historical paid losses, incurred losses, number of open claims, number of closed claims, number of total claims, listings of individual large losses, earned premiums, policy count, policy limits underwritten, exposure information and rate change information. We may also receive information by class or subclass of business. If the reserving data is not available from a client, we rely on industry data, as well as the judgment and experience of our underwriters and actuaries.
 
We rely more on client and industry data than our own data to identify unusual trends requiring changes in reserve estimates. Each reinsurance contract is different and the degree to which we rely on client data versus our own data varies greatly from contract to contract. The extent to which we rely on client data for reserve setting purposes depends upon the availability of historical loss data from the client and our judgment as to how reliable we believe the client’s historic loss performance is compared to its current book of business. We may from time to time supplement client data with industry and competitor information where we deem appropriate. Where available, we also receive relevant actuarial reports from the client. We supplement this information with subjective information on each client, which may include management experience, competitor information, meetings with the client and supplementary industry research and data. 
  
Generally, we obtain regular updates of premium and loss related information for the current period and historical periods, which we utilize to update our initial expected loss and loss expense ratio. There may be a time lag from when claims are reported to our client and when our client reports the claims to us. This time lag may impact our loss reserve estimates from period to period. Client reports, whether due monthly or quarterly, have set reporting dates of when they are due to us (for example, fifteen days after month end). As such, the time lag in the client’s reporting depends upon the terms of the specific contract. The timing of the reporting requirements is designed so that we receive premium and loss information as soon as practicable once the client has closed its books. Accordingly, there should be a short lag in such reporting. Additionally, most of our contracts that have the potential for large single event losses have provisions that such loss notification needs to be received immediately upon the occurrence of an event. Once we receive this updated information, we use a variety of standard actuarial methods in our analysis each quarter. Such methods may include: 
 
●
Paid Loss Development Method. We estimate ultimate losses by calculating past paid loss development factors and applying them to exposure periods with further expected paid loss development. The paid loss development method assumes that losses are paid in a consistent pattern. It provides an objective test of reported loss projections because paid losses contain no reserve estimates. For many coverages, claim payments are made very slowly and it may take years for claims to be fully reported and settled.
 
●
Reported Loss Development Method. We estimate ultimate losses by calculating past reported loss development factors and applying them to exposure periods with further expected reported loss development. Since reported losses include payments and case reserves, changes in both of these amounts are incorporated in this method. This approach provides a larger volume of data to estimate ultimate losses than paid loss methods. Thus, reported loss patterns may be less varied than paid loss patterns, especially for coverage that have historically been paid out over a long period of time but for which claims are reported relatively early and case loss reserve estimates have been established.
 
●
Expected Loss Ratio Method. We estimate ultimate losses under the expected loss ratio method, by multiplying earned premiums by an expected loss ratio. We select the expected loss ratio using industry data, historical company data and our professional judgment. We use this method for lines of business and contracts where there are no historical losses or where past loss experience is not credible.
 
●
Bornhuetter-Ferguson Paid Loss Method. We estimate ultimate losses by modifying expected loss ratios to the extent paid losses experienced to date differ from what would have been expected to have been paid based upon the selected paid loss development pattern. This method avoids some of the distortions that could result from a large development factor being applied to a small base of paid losses to calculate ultimate losses. We generally use this method for lines of business and contracts where there are limited historical paid losses.
 
●
Bornhuetter-Ferguson Reported Loss Method. We estimate ultimate losses by modifying expected loss ratios to the extent reported losses experienced to date differ from what would have been expected to have been reported based upon the selected reported loss development pattern. This method avoids some of the distortions that could result from a large development factor being applied to a small base of reported losses to calculate ultimate losses. We generally use this method for lines of business and contracts where there are limited historical reported losses.
 
●
Frequency / Severity Method. We estimate ultimate losses under this method by multiplying the ultimate number of claims (i.e. the frequency), by the estimated ultimate average cost per claim (i.e. the severity). By analyzing claims experience by its frequency and severity components, we are able to examine trends and patterns in the rates of claims emergence (i.e. reporting) and settlement (i.e. closure) as well as in the average cost of claims. The approach is valuable because sometimes there is more inherent stability in the frequency and severity data when viewed separately rather than in the total losses.
 

49

Link to Table of Contents

In addition, we supplement our analysis with other reserving methodologies that we deem to be relevant to specific contracts.
 
For each contract, we utilize such reserving methodology that our actuaries deem appropriate in order to calculate a best estimate, or point estimate, of reserves. We use various actuarial methods to provide data point estimates to aid us in our estimation of reasonable and adequate loss reserves. In setting our reserves, we do not select a range of estimates that may be subject to adjustment. We analyze reserves on a contract by contract basis and do not reserve based on aggregated product lines. Whether we use one methodology, a combination of methodologies or all methodologies depends upon the contract and the judgment of the actuaries responsible for the contract. We do not have a set weighting of the various methods we use. Certain of the methods we consider are more appropriate depending on the type and structure of the contract, how mature is the contract, and the duration of the expected paid losses on the contract. For example, the data estimation for contracts that are relatively new and therefore have little paid loss development is more appropriately considered using the Bornhuetter-Ferguson Reported Loss Method than a paid loss development method. 
 
Our aggregate reserves are the sum of the point estimate of all contracts. We perform a quarterly loss reserve analysis on each contract regardless of the line of business. This analysis may incorporate some or all of the information described above, using some or all of the methodologies described above. We generally calculate IBNR loss reserves for each contract by estimating the ultimate incurred losses at any point in time and subtracting cumulative paid claims and case reserves, which incorporate specific exposures, loss payment and reporting patterns and other relevant factors. Each quarter, our reserving committee, which is comprised of our Chief Executive Officer, Chief Financial Officer, Chief Actuarial Officer, Assistant Controller and Reserving Actuary, meets to assess the adequacy of our loss reserves based on the reserve analysis and recommendations prepared by the Company’s actuaries. The reserving committee discusses each contract individually and approves or revises the stated reserves.
 
Additionally, we contract with a third-party actuarial firm to perform a quarterly reserve review and to annually opine on the reasonableness and adequacy of our aggregate loss reserves. We provide our external actuary with our pricing models, reserving analysis and any other data they may request. Additionally, the actuarial firm may inquire as to the various assumptions and estimates that we may use in our reserving analysis. The external actuarial firm independently creates its own reserving models based on industry loss information, augmented by specific client loss information that we may be asked to provide as well as its own independent assumptions and estimates. Based on various reserving methodologies that the actuarial firm considers appropriate, it creates a reserve estimate for each contract in our portfolio and provides us with an aggregate recommended loss reserve, including IBNR. If there are material differences between our aggregate booked reserves and the actuarial firm’s recommended reserves, we review the differences and make any necessary adjustments to the booked reserves. To date there have been no material differences resulting from the external actuary's reviews requiring adjustments to our booked reserves.

Because of the uncertainties that surround our estimates of loss and loss adjustment expense reserves, we cannot be certain that ultimate loss and loss adjustment expense payments will not exceed our estimates, or be less than our estimates. If our estimated reserves are deficient, we would be required to increase loss reserves in the period in which such deficiencies are identified, which would cause a charge to our earnings and a reduction of our capital. Similarly, if our estimated reserves are excessive, we would decrease loss reserves in such period in which the excess is identified. By way of illustration, since we started underwriting operations in 2006, the reserve re-estimation process has resulted in the following effect on the prior year reserves and the corresponding inverse effect on net income (excluding any adjustments for additional premiums, reinstatement premiums, profit commissions or ceding commissions) during each of the years ended December 31:
Calendar Year
 
Effect on prior year reserves
 
 
Effect on net income
 
 
 ($ in thousands)
2015
$
50,301 increase
 
$
50,301 decrease
2014
 
18,229 increase
 
 
18,229 decrease
2013
 
6,120 decrease
 
 
6,120 increase
2012
 
56,898 increase
 
 
56,898 decrease
2011
 
26,015 increase
 
 
26,015 decrease
2010
 
8,678 increase
 
 
8,678 decrease
2009
 
7,597 decrease
 
 
7,597 increase
2008
 
11,988 decrease
 
 
11,988 increase
2007
 
1,077 decrease
 
 
1,077 increase


50

Link to Table of Contents

Given the uncertainties involved in estimating ultimate reserves and since we reserve to a point estimate on an individual contract basis, our estimated reserves may be deficient or excessive. Historical development of estimated reserves is not an accurate reflection of future loss development. Additionally, external factors can influence prior year loss development. For example, changes in specific tort law which may cause ultimate loss awards to increase or decrease could have a material effect on our loss reserve development. We are unable to predict with accuracy the magnitude or direction that such external factors may have on our estimated loss reserves.
 
Acquisition Costs. We capitalize brokerage fees, ceding commissions, premium taxes and other direct expenses that relate directly to and vary with the writing of reinsurance contracts. Acquisition costs are deferred subject to ultimate recoverability and amortized over the related period of risk covered. Acquisition costs also include profit commissions. Certain contracts include provisions for profit commissions to be paid to the ceding insurer based upon the ultimate experience of the contracts. The methodology for calculating profit commissions is specific to the individual contracts and varies from contract to contract. Typically profit commissions are calculated and accrued based on the expected ultimate loss experience for such contracts and recorded when the expected loss experience indicates that a profit commission is probable under the contract terms. Profit commission reserves, if any, are included in reinsurance balances payable on the consolidated balance sheets.
 
Bonus Accruals. Under the Company's bonus program, each employee’s target bonus consists of two components: a discretionary component based on a qualitative assessment of each employee’s performance and a quantitative component based on the return on deployed equity ("RODE") for each underwriting year relating to reinsurance operations. The qualitative portion of an employee’s annual bonus is accrued at each employee's target amount, which may differ significantly from the actual amount awarded. The quantitative portion of each employee’s annual bonus is accrued based on the expected RODE for each underwriting year and adjusted for changes in the expected RODE and actual investment return each quarter until all losses are settled and the underwriting year is declared closed. The quantitative bonus is calculated and paid in annual installments between two to five years from the end of the fiscal year in which the business was underwritten. Any subsequent changes to the quantitative bonus are incorporated into the following open underwriting year. The Compensation Committee of our Board of Directors approves all quantitative bonuses prior to being paid. The expected RODE calculation utilizes proprietary models which require significant estimation and judgment. Actual RODE may vary significantly from the expected RODE and any adjustments to the quantitative bonus estimates, which may be material, are recorded in the period in which they are determined. 
 
Share-Based Payments. We have established a stock incentive plan for directors, employees and consultants. U.S. GAAP requires us to recognize share-based compensation transactions using the fair value at the grant date of the award. We calculate the compensation for restricted stock awards and restricted stock units based on the price of the Company’s common shares at the grant date and recognize the expense over the vesting period. Share purchase options are expensed over the vesting period on a graded vesting basis. Determining the fair value of share option awards at the grant date requires significant estimation and judgment. We use an option-pricing model (Black-Scholes pricing model) to assist in the calculation of fair value. Effective from August 2014, the estimate of expected volatility was based on the daily historical trading data of our Class A ordinary shares from the date that these shares commenced trading (May 24, 2007) to the grant date.

Prior to 2014, our shares had not been publicly traded for a sufficient length of time to reasonably estimate the expected volatility. Therefore, for share purchase options granted prior to 2014, we determined the expected volatility based primarily on the historical volatility of a peer group of companies in the reinsurance industry while also considering our own historical volatility in determining the expected volatility. We typically considered factors such as an entity's industry, stage of life cycle, size and financial leverage when selecting the peer group. Additionally, we used the full life of the option, ten years, as the estimated term of the option, and we have assumed that dividends will not be paid.

If actual results differ significantly from these estimates and assumptions, particularly in relation to our estimation of volatility which requires significant judgment, share-based compensation expense, primarily with respect to future share-based awards, could be materially impacted.

Results of Operations
 
Years ended December 31, 2015, 2014 and 2013
 
For the year ended December 31, 2015, we reported net loss of $326.4 million, compared to net income of $109.6 million reported for the year ended December 31, 2014. Our investment portfolio reported net loss of $281.9 million, or a return of (20.2)%, for the year ended December 31, 2015, compared to net investment income of $122.6 million, or a return of 8.7%, for the same period in 2014. The underwriting loss before general and administrative expenses for the year ended December 31, 2015 was $24.9 million, compared to underwriting income of $11.6 million reported for the year ended December 31, 2014. The underwriting loss for the 2015 fiscal year was driven by adverse loss development relating to construction defect losses on legacy

51

Link to Table of Contents

general liability contracts written during the 2008 to 2011 underwriting years. For the year ended December 31, 2015, our overall composite ratio was 106.1% compared to 96.7% for the year ended December 31, 2014. General and administrative expenses decreased for the year ended December 31, 2015 to $23.4 million from $24.5 million for the year ended December 31, 2014, primarily as a result of lower quantitative bonuses accrued relating to prior underwriting years, partially offset by non-recurring professional fees incurred during the year.

The poor investment performance during 2015 was primarily the result of losses experienced on three equity securities (CONSOL Energy, Micron Technology, and SunEdison) which were among our largest long positions. This coupled with very few securities that reported gains during the year, combined to result in the large investment loss reported during 2015.

The poor underwriting performance of certain contracts that were written between 2008 and 2011, and are currently in run-off, have had a negative impact on our recent reported financial results. The below graph presents our underwriting results reported during each of the fiscal accounting years from 2007 to 2015 compared to the underwriting results for each of those underwriting years. This graph shows that while accounting results have been negatively impacted in recent periods, particularly from adverse loss development on contracts written during the 2009 and 2010 underwriting years, the underlying business written in the more recent years has been profitable and the contracts written since 2012 are performing well.
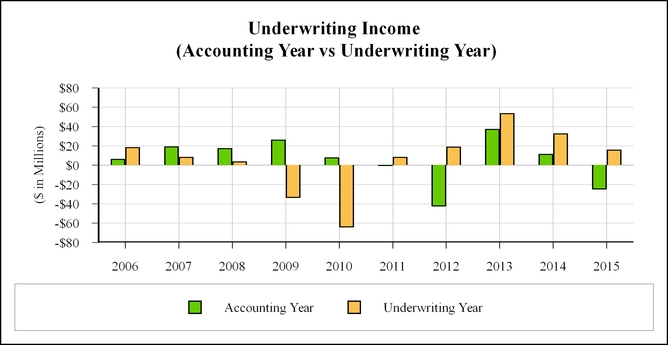

For the year ended December 31, 2014, we reported net income of $109.6 million, compared to net income of $225.7 million reported for the year ended December 31, 2013. Our investment portfolio reported net income of $122.6 million, or a return of 8.7%, for the year ended December 31, 2014, compared to net investment income of $218.1 million, or a return of 19.6%, for the same period in 2013. The underwriting income before general and administrative expenses for the year ended December 31, 2014 was $11.6 million, compared to underwriting income of $37.5 million reported for the year ended December 31, 2013. The decrease in underwriting income was driven by adverse loss development on prior year contracts and to a lesser extent by lower volume of premiums earned during 2014 compared to 2013. By comparison, the 2013 underwriting income included a reversal of $12.4 million of loss reserves (net of reinstatement premiums) relating to super-storm Sandy due to revised loss estimates recorded during 2013. For the year ended December 31, 2014, our overall composite ratio was 96.7% compared to 93.2% for the year ended December 31, 2013. General and administrative expenses increased for the year ended December 31, 2014 to $24.5 million from $21.0 million for the year ended December 31, 2013, primarily as a result of higher quantitative bonuses accrued relating to the 2012, 2013 and 2014 underwriting years.
   
Our primary financial goal is to increase the long-term value in fully diluted adjusted book value per share. For the year ended December 31, 2015, the fully diluted adjusted book value per share decreased by $8.59 per share, or 27.9%, to $22.17 per share from $30.76 per share at December 31, 2014. For the year ended December 31, 2015, the basic adjusted book value per share decreased by $8.88 per share, or 28.5%, to $22.29 per share from $31.17 per share at December 31, 2014.


52

Link to Table of Contents

For the year ended December 31, 2014, the fully diluted adjusted book value per share increased by $2.85 per share, or 10.2%, to $30.76 per share from $27.91 per share at December 31, 2013. For the year ended December 31, 2014, the basic adjusted book value per share increased by $2.78 per share, or 9.8%, to $31.17 per share from $28.39 per share at December 31, 2013.

Basic adjusted book value per share is a non-GAAP measure as it excludes the non-controlling interest in a joint venture from total equity. In addition, fully diluted adjusted book value per share is also a non-GAAP measure and represents basic adjusted book value per share combined with the impact from dilution of all in-the-money stock options and RSUs issued and outstanding as of any period end. We believe that long-term growth in fully diluted adjusted book value per share is the most relevant measure of our financial performance. In addition, fully diluted adjusted book value per share may be of benefit to our investors, shareholders and other interested parties to form a basis of comparison with other companies within the property and casualty reinsurance industry.
 
The following table presents a reconciliation of the non-GAAP basic adjusted and fully diluted adjusted book value per share to the most comparable GAAP measure.
 
December 31, 2015
 
December 31, 2014
 
December 31, 2013
 
  ($ in thousands, except per share and share amounts)
Basic adjusted and fully diluted adjusted book value per share numerator:


Total equity (U.S. GAAP)
$
848,773

 
$
1,194,041

 
$
1,086,304

Less: Non-controlling interest in joint venture
(23,382
)
 
(28,890
)
 
(34,709
)
Basic adjusted book value per share numerator
825,391

 
1,165,151

 
1,051,595

Add: Proceeds from in-the-money stock options issued and outstanding
11,553

 
19,628

 
16,028

Fully diluted adjusted book value per share numerator
$
836,944

 
$
1,184,779

 
$
1,067,623

Basic adjusted and fully diluted adjusted book value per share denominator:


Ordinary shares issued and outstanding for basic adjusted book value per share denominator
37,027,467

 
37,384,543

 
37,046,814

Add: In-the-money stock options and RSUs issued and outstanding
717,340

 
1,131,917

 
1,210,731

Fully diluted adjusted book value per share denominator
37,744,807

 
38,516,460

 
38,257,545

Basic adjusted book value per share
$
22.29

 
$
31.17

 
$
28.39

Fully diluted adjusted book value per share
$
22.17

 
$
30.76

 
$
27.91

 
Gross Premiums Written
 
Details of gross premiums written are provided in the following table: 
 
 
Year ended December 31
 
 
2015
 
2014
 
2013
 
 
($ in thousands)
Frequency
 
$
464,376

 
92.5
%
 
$
295,861

 
91.3
%
 
$
512,096

 
95.6
%
Severity
 
37,748

 
7.5

 
28,162

 
8.7

 
23,606

 
4.4

Total
 
$
502,124

 
100.0
%
 
$
324,023

 
100.0
%
 
$
535,702

 
100.0
%

As a result of our opportunistic underwriting philosophy, our reported quarterly premiums written may be volatile. Additionally, the composition of premiums written between frequency and severity business may vary from period to period depending on the specific market opportunities that we pursue.

Year ended December 31, 2015

53

Link to Table of Contents

During 2015, our gross premiums written increased by $178.1 million, or 55.0%, compared to the year ended December 31, 2014. For the year ended December 31, 2015, our frequency gross premiums written increased by $168.5 million, or 57.0%, compared to the same period in 2014. The increase was primarily driven by new contracts bound during 2015 and premium growth on existing contracts renewed during 2015.

The gross premiums written for motor liability (including motor physical damage) increased by $86.3 million during the year ended December 31, 2015 compared to the same period in 2014. The increase was partially a result of higher premiums on an existing private passenger motor contract which was renewed during 2015. New motor contracts written during 2015 also contributed partially to the increase in motor liability gross premiums written. The frequency gross premiums written for professional liability increased by $41.3 million during the year ended December 31, 2015, compared to the same period in 2014, as a result of new quota share casualty contracts bound during 2015 and during the second half of 2014. The frequency gross premiums written for specialty health, general liability, workers' compensation, and commercial property lines increased by $12.9 million, $13.5 million, $11.9 million, and $7.5 million, respectively, as a result of new quota share contracts written during 2015 and the latter half of 2014. Other lines of business also reported increases in gross written premiums with financial, marine, aviation and energy, in the aggregate, accounting for $5.5 million of the increase in gross written premiums during the year ended December 31, 2015 compared to the same period in 2014. The increase in gross premiums written were partially offset by a $11.6 million decrease in the personal property line for the year ended December 31, 2015. The decrease was primarily a result of a Florida homeowners' contract which expired during 2015 and was not renewed.

For the year ended December 31, 2015, severity premiums written increased by $9.6 million, or 34.0%, compared to the same period in 2014, primarily due to new severity contracts written during 2015 which accounted for a $14.7 million increase in severity gross premiums written. Additionally, a multi-year severity quota share contract written during the second half of 2014 contributed $7.6 million of the increase in severity premiums written for the year ended December 31, 2015. The increases were partially offset by a net decrease of $10.1 million relating to property catastrophe contracts that expired and were not renewed or were renewed at a lower premium volume during 2015. For the year ended December 31, 2015, the severity premiums reported were net of return premiums of $2.5 million relating to an excess of loss catastrophe contract. This contract was previously expected to incur a loss and we had recorded a loss reserve which had triggered an additional premium. During the year ended December 31, 2015, we were informed that losses incurred by the cedent on this contract would not breach into our layer and as a result the additional premium was reversed along with the loss reserve, and a corresponding profit commission expense was recorded during 2015.

Year ended December 31, 2014
During 2014, our gross premiums written decreased by $211.7 million, or 39.5%, primarily due to a private passenger motor contract that we terminated at the end of 2013 and due to some of our personal property contracts renewed during 2014 at a smaller share ceded to us. However, during the second half of 2014, we entered into several new relationships which offset some of the decrease in gross premiums written during 2014.
For the year ended December 31, 2014, the frequency gross premiums written decreased by $216.2 million, or 42.2%, primarily relating to the motor line (physical damage and liability) and personal property line. The motor line gross premiums written decreased by $137.0 million relating to a private passenger motor contract that we terminated at the end of 2013 on a run-off basis. Additionally, our remaining private passenger motor contracts reported a decrease of $24.3 million in gross premiums written during 2014, compared to the same period in 2013, due to competitive pricing pressure on the underlying premiums written by the insurers. The personal property line frequency gross premiums written decreased by $78.3 million, primarily relating to a decrease in our share of the Florida homeowners' contracts which renewed during 2014, with the cedents choosing to retain a larger share on the renewed contracts compared to the expiring contracts. The decrease in frequency gross premiums written was partially offset by a number of new contracts entered into relating to the general liability, specialty health and workers' compensation lines of business.
For the year ended December 31, 2014, the increase in severity gross premiums written of $4.6 million, or 19.3%, compared to the same period in 2013 was primarily due to new and renewed severity contracts written during 2014, including excess of loss and multi-line property and casualty retrocession contracts.

Premiums Ceded
 
For the years ended December 31, 2015, 2014 and 2013, retrocessional premiums ceded were $9.0 million, $13.5 million and $2.8 million, respectively. For the year ended December 31, 2015, the decrease in ceded premiums compared to the same period in 2014 was partially due to a retroceded contract for catastrophic risk protection that expired at the end of 2014 and was not renewed. However, in the first quarter of 2015, we purchased an industry loss warranty derivative contract ("ILW") to reduce our net exposure to natural peril catastrophe events. In accordance with U.S. GAAP, the ILW is recorded as a weather derivative

54

Link to Table of Contents

swap and the cost of the ILW is amortized over the risk period and recorded in the consolidated statements of income as "other income (expense), net" and not as part of premiums ceded. For the year ended December 31, 2015, the ILW amortization expense was $2.3 million.

For the year ended December 31, 2014, our ceded premiums increased by $10.7 million partially relating to a retrocession contract purchased during 2014 in order to reduce our net exposure to natural peril catastrophe events, and partially relating to higher premiums on the inward contracts which were proportionally retroceded to entities affiliated with the ceding insurers.

Net Premiums Written

Details of net premiums written are provided in the following table: 
 
 
Year ended December 31
 
 
2015
 
2014
 
2013
 
 
($ in thousands)
Frequency
 
$
455,375

 
92.3
%
 
$
286,121

 
92.1
%
 
$
509,316

 
95.6
%
Severity
 
37,748

 
7.7

 
24,409

 
7.9

 
23,606

 
4.4

Total
 
$
493,123

 
100.0
%
 
$
310,530

 
100.0
%
 
$
532,922

 
100.0
%

The movement in net premiums written is the net result of the increases or decreases in gross premiums written and premiums ceded as explained in the preceding paragraphs.

Net Premiums Earned
 
Net premiums earned reflect the pro-rata inclusion into income of net premiums written over the risk period of the reinsurance contracts. Details of net premiums earned are provided in the following table: 
 
 
Year ended December 31
 
 
2015
 
2014
 
2013
 
 
($ in thousands)
Frequency
 
$
380,565

 
93.2
%
 
$
330,617

 
93.3
%
 
$
529,779

 
96.7
%
Severity
 
27,822

 
6.8

 
23,623

 
6.7

 
18,120

 
3.3

Total
 
$
408,387

 
100.0
%
 
$
354,240

 
100.0
%
 
$
547,899

 
100.0
%

Premiums relating to quota share contracts and excess of loss contracts are earned over the contract period in proportion to the period of protection. Similarly, incoming unearned premiums are earned in proportion to the remaining period of protection.

Year ended December 31, 2015
For the year ended December 31, 2015, the frequency net premiums earned increased by $49.9 million, or 15.1%, compared to the same period in 2014. The increase was primarily as a result of the motor liability and physical damage business which increased by $41.0 million during the year ended December 31, 2015, compared to the same period in 2014, primarily due to an increase in volume of underlying premiums earned on private passenger motor contracts in effect during the current period. Our professional lines premiums earned increased primarily due to new contracts entered into during 2015 and the second half of 2014 which contributed $29.7 million of the increase. The increase in professional liability premiums earned was partially offset by a decrease of $11.3 million relating to solicitors' professional indemnity business due to a lower volume of underlying business written by the cedents. Additionally, the general liability, specialty health and workers' compensation premiums earned increased by $11.1 million, $7.9 million and $4.5 million respectively, during the year ended December 31, 2015 as a result of new contracts entered into during 2015 and the second half of 2014. New contracts entered in other lines of business also contributed to increases in premiums earned with marine, financial and commercial property, in the aggregate, accounting for $6.6 million of the increase in net premiums earned during the year ended December 31, 2015. The increases in premiums earned were partially offset by a $40.7 million decrease in personal property premiums partly due to a Florida homeowners' contract not renewed upon

55

Link to Table of Contents

expiration during 2015, and partly due to a lower share on other Florida homeowners' contracts in effect during the current period compared to the same period in 2014.

For the year ended December 31, 2015, the severity net premiums earned increased by $4.2 million, or 17.8%, compared to the same period in 2014. The increase was a net impact of new and renewed severity quota share contracts entered into during 2015 and the latter half of 2014, partially offset by severity contracts that expired and were not renewed or renewed with a smaller share during 2015. For the year ended December 31, 2015, the reported severity premiums earned were net of $2.5 million of return premiums relating to an excess of loss catastrophe contract. This contract was previously expected to incur a loss into our layer, resulting in an additional premium being recorded. During the year ended December 31, 2015, we were informed by the client that the loss will not breach into our layer. As a result, we reversed the additional premium along with the loss reserve and recorded a profit commission expense. Additionally, the severity premiums earned for the year ended December 31, 2015 appear higher than the comparable period in 2014 because the 2014 earned premiums were net of $3.8 million expense relating to a retroceded contract for catastrophic risk protection which was not renewed in 2015. Instead during 2015, we purchased an ILW contract which, in accordance with U.S. GAAP, was recorded as a weather derivative swap and the cost of the ILW was recorded in the consolidated statements of income as "other income (expense), net". For the year ended December 31, 2015, the ILW amortization expense was $2.3 million.

Year ended December 31, 2014
For the year ended December 31, 2014, the frequency net premiums earned decreased by $199.2 million, or 37.6%, compared to the same period in 2013. The decrease was primarily attributed to a private passenger motor contract terminated at the end of 2013 which accounted for $159.5 million of the decrease. Additionally, the volume of premiums earned on other private passenger motor contracts decreased by $13.9 million, compared to the same period in 2013. This decrease was due to a reduction in earned premiums reported during 2014 resulting from competitive pricing pressure on the underlying premiums written by the insurers. The personal line premiums earned decreased by $40.1 million during 2014, compared to the same period in 2013 primarily due to the explanation provided above for gross premiums written. Other decreases in net premiums earned related to the workers' compensation line and the general liability line which decreased by $11.1 million and $2.4 million, respectively, primarily as a result of certain multi-line contracts terminated during 2013. The decreases in frequency net premiums earned were partially offset by net premiums earned on new contracts and increases in the volume of underlying business in other lines including $10.3 million relating to professional liability contracts and $3.0 million relating to specialty health contracts.
Premiums written relating to severity contracts are earned over the contract period in proportion to the period of protection. For the year ended December 31, 2014, severity net premiums earned increased $5.5 million, or 30.4%, compared to the same period in 2013. The increase is partially a function of the reversal of reinstatement premiums reflected in the comparative period and partially due to the new and renewed severity contracts entered into during 2014. The increases were partially offset by decreases due to catastrophe contracts expired but not renewed during 2014 due to inadequate pricing.
    
Loss and Loss Adjustment Expenses Incurred, Net
 
Net losses incurred include losses paid and changes in loss reserves, including reserves for IBNR, net of actual and estimated loss recoverables. Details of net losses incurred are provided in the following table:


Year ended December 31
 
 
2015
 
2014
 
2013
 
 
($ in thousands)
Frequency
 
$
314,459

 
99.2
%
 
$
231,185

 
98.4
%
 
$
347,217

 
102.6
 %
Severity
 
2,638

 
0.8

 
3,801

 
1.6

 
(8,724
)
 
(2.6
)
Total
 
$
317,097

 
100.0
%
 
$
234,986

 
100.0
%
 
$
338,493

 
100.0
 %

We establish reserves for each contract based on estimates of the ultimate cost of all losses, including losses incurred but not reported. These estimated ultimate reserves are based on reports received from ceding companies, industry data and historical experience as well as our own actuarial estimates. Quarterly, we review these estimates on a contract by contract basis and adjust them as we deem appropriate to reflect our best estimates based on updated information and our internal actuarial estimates. We expect losses incurred on our severity business to be volatile depending on the frequency and magnitude of catastrophic events from year to year.


56

Link to Table of Contents

Year ended December 31 2015
For the year ended December 31, 2015, the total net losses incurred on frequency contracts increased by $83.3 million, or 36.0%, compared to the same period in 2014. The increase was driven primarily by $51.6 million of additional loss reserves recorded during the year ended December 31, 2015 on two legacy general liability contracts that are currently in run-off. One of the general liability contracts, which was in effect from 2008 to 2011, included general contractors' liability with the majority of exposure relating to single-family homes. During 2015, we completed an in-depth analysis, with the assistance of a third party expert, of the construction defect claims reported and the potential for claims not yet reported on this contract. Based on this assessment, we revised the actuarial methodology used for reserving these claims, which resulted in an increase in IBNR reserves of $36.9 million recorded in the third quarter of 2015. The other general liability contract, which was written in 2010, included general contractors' liability with the majority of exposure relating to construction defect claims in the western United States. During the second quarter of 2015, we experienced adverse development on known claims, which caused us to re-evaluate the expected value of known claims as well as the value of claims still to be filed. Additionally, we re-evaluated the claims handling costs associated with this contract and increased our provision for case reserves, IBNR reserves and the cost of claims handling by $14.7 million during the second quarter of 2015. We have reviewed all other contracts and do not believe that any other contract has similar exposure. Some of our prior years' Florida homeowners' contracts also contributed to the increase in losses incurred due to unfavorable loss development of $9.3 million (see Note 7 of the consolidated financial statements for details). The remainder of the increase in incurred losses related primarily to the higher earned premiums recorded for the year ended December 31, 2015 compared to the same period in 2014.

For the year ended December 31, 2015, the losses incurred on severity contracts decreased by $1.2 million, primarily due to the elimination of $5.1 million of loss reserves resulting from favorable loss development on an excess of loss contract. The decrease in severity losses incurred was partially offset by an increase related to the mix of severity business.

Losses incurred as a percentage of premiums earned (referred to as the loss ratio) fluctuates based on the mix of business, and any favorable or adverse loss development on our larger contracts. The loss ratios for the years ended December 31, 2015, 2014 and 2013, were as follows:


Year ended December 31
 
 
2015
 
2014
 
2013
Frequency
 
82.6
%
 
69.9
%
 
65.5
 %
Severity
 
9.5
%
 
16.1
%
 
(48.1
)%
Total
 
77.6
%
 
66.3
%
 
61.8
 %

The higher frequency loss ratio for the year ended December 31, 2015 primarily related to the adverse loss development on the general liability contracts discussed above. Excluding the affected general liability contracts, the loss ratio for frequency business for the year ended December 31, 2015 was 69.1%. The loss ratio for the Florida homeowners' insurance contracts also increased during the year ended December 31, 2015 due to unfavorable loss development primarily as a result of sinkhole claims, higher than anticipated water damage claims from rainstorms and an increase in the practice of "assignment of benefits" whereby homeowners assign their rights for filing and settling claims to attorneys and public adjusters which led to increases in the frequency of claims reported as well as the severity of loss adjustment expenses. The increase in the loss ratio for the year ended December 31, 2015 was partially offset by a lower loss ratio on specialty health contracts due to no adverse losses developing on the employers' medical stop-loss contracts in the current period compared to adverse losses recorded during the comparable period in 2014. The loss ratio for professional liability line was also lower for the year ended December 31, 2015 compared to the same period in 2014 due to a shift in the mix of business from predominantly solicitors' indemnity contracts to a more diversified professional liability book of business.

The severity loss ratio for the year ended December 31, 2015 reflects the elimination of $5.1 million of loss reserves on an excess of loss contract entered into in 2008. Excluding this contract, the severity loss ratio for the year ended December 31, 2015 was 25.4% compared to 16.1% for the same period in 2014. This increase in severity loss ratio was due to the change in mix of severity business with a higher proportion of quota share severity contracts in effect during the year ended December 31, 2015 compared to the same period in 2014.

We expect our severity loss ratio to vary, sometimes significantly, based on the change in mix of business between catastrophe and non-catastrophe business and quota share and excess of loss contracts.


57

Link to Table of Contents

Year ended December 31 2014
For the year ended December 31, 2014, the net losses incurred on frequency contracts decreased by $116.0 million, or 33.4%. This decrease was primarily the net result of the 37.6% decrease in net premiums earned relating to a private passenger motor contract terminated at the end of 2013 and Florida homeowners' personal property contracts renewed at a lower assigned share. Additionally, the multi-line contracts terminated and commuted during 2013 also contributed to the decrease in incurred losses for the year ended December 31, 2014. The decreases were partially offset by an increase in losses incurred relating to adverse loss development on general liability, commercial motor, solicitors' professional liability and employers' medical stop-loss contracts (see Note 7 of the consolidated financial statements for details).

For the years ended December 31, 2014 and 2013, the loss ratios for our frequency business were 69.9% and 65.5%, respectively. The higher loss ratio for the year ended December 31, 2014 was due to adverse loss development relating to prior period general liability, commercial motor, solicitors' professional liability and employers' medical stop-loss contracts. Additionally, the loss ratio on the motor line was also higher primarily due to current year private passenger motor contracts reporting higher expected loss ratios compared to the prior year contracts. The increase in the loss ratio for the year ended December 31, 2014 was partially offset by a lower loss ratio for the general liability line due to a decrease in the amount of adverse loss development during 2014, compared to the adverse loss development during 2013.

For the years ended December 31, 2014 and 2013, the loss ratios for our severity business were 16.1% and (48.1)%, respectively. During the year ended December 31, 2014 our severity business was not impacted by any major catastrophe events. The net losses incurred on severity contracts was $3.8 million for the year ended December 31, 2014, and primarily related to attritional loss reserves on certain excess of loss contracts. The negative loss ratio of (48.1)% for the comparable year ended December 31, 2013 was due to the reversal of loss reserves relating to super-storm Sandy. Excluding the effect of that loss reserve reversal (and the corresponding reversal of reinstatement premiums), the severity loss ratio for the year ended December 31, 2013 was 29.9%, which included a $4.0 million increase in loss reserves on a casualty clash contract.

Losses incurred can be further broken down into losses paid and changes in loss and loss adjustment expense reserves as follows:
 
Year ended December 31


2015


2014


2013


Gross
 
Ceded
 
Net
 
Gross
 
Ceded
 
Net
 
Gross
 
Ceded
 
Net
 
($ in thousands)
Losses paid (recovered)
$
274,713

 
$
(9,851
)
 
$
264,862

 
$
303,272

 
$
(9,695
)
 
$
293,577

 
$
355,275

 
$
(7,386
)
 
$
347,889

Change in loss and loss adjustment expense reserves
44,080

 
8,155

 
52,235

 
(63,897
)
 
5,306

 
(58,591
)
 
(27,019
)
 
17,623

 
(9,396
)
Total
$
318,793

 
$
(1,696
)
 
$
317,097

 
$
239,375

 
$
(4,389
)
 
$
234,986

 
$
328,256

 
$
10,237

 
$
338,493


For the year ended December 31, 2015, our net loss reserves on prior period contracts increased by $50.3 million primarily related to adverse loss development on general liability contracts relating to construction defect claims. For the year ended December 31, 2014, our net loss reserves on prior period contracts increased by $18.2 million, which primarily related to adverse loss development on general liability, commercial motor, solicitors' professional liability and employers' medical stop-loss businesses, partially offset by favorable loss development on private passenger automobile business. For the year ended December 31, 2013, our net loss reserves relating to prior period contracts decreased by $6.1 million, which was partially due to the elimination of reserves relating to super-storm Sandy, and partially due to the favorable loss development on the private passenger automobile, commercial motor and personal property businesses. The decrease was partially offset by adverse loss development on the general liability and casualty clash businesses.
For further details on prior period loss developments, please refer to Note 7 "Loss and loss adjustment expense reserves" of the consolidated financial statements.


58

Link to Table of Contents


Acquisition Costs, Net
 
Acquisition costs represent the amortization of commission and brokerage expenses incurred on contracts written as well as profit commissions and other underwriting expenses which are expensed when incurred. Deferred acquisition costs are limited to the amount of commission and brokerage expenses that are expected to be recovered from future earned premiums and anticipated investment income. Details of acquisition costs are provided in the following table:


Year ended December 31
 
 
2015
 
2014
 
2013
 
 
($ in thousands)
Frequency
 
$
106,411

 
91.6
%
 
$
103,008

 
95.7
%
 
$
168,109

 
97.8
%
Severity
 
9,796

 
8.4

 
4,657

 
4.3

 
3,763

 
2.2

Total
 
$
116,207

 
100.0
%
 
$
107,665

 
100.0
%
 
$
171,872

 
100.0
%

We expect acquisition costs to be higher for frequency business than for severity business. Acquisition cost as a percentage of net premiums earned (referred to as acquisition cost ratio) are generally higher for our frequency business than for our severity business, but fluctuate based on the mix of business. The acquisition cost ratios for the years ended December 31, 2015, 2014 and 2013, were as follows:
 
 
Year ended December 31
 
 
2015
 
2014
 
2013
Frequency
 
28.0
%
 
31.2
%
 
31.7
%
Severity
 
35.2
%
 
19.7
%
 
20.8
%
Total
 
28.5
%
 
30.4
%
 
31.4
%


Year ended December 31 2015
The decrease in the frequency acquisition cost ratio for the year ended December 31, 2015, compared to the same period in 2014, was primarily due to Florida homeowners' insurance contracts that contain sliding scale ceding commissions which decreased during the year ended December 31, 2015 as a result of adverse loss development on those contracts. Additionally, the private passenger motor contracts in force during 2015 reported lower ceding commissions than the prior year which also contributed to a lower frequency acquisition cost ratio for the year ended December 31, 2015. The decrease in acquisition cost ratio was partially offset by the change in mix of professional liability contracts which carry higher ceding commission rates than the predominantly solicitors' professional indemnity contracts in force during the year ended 2014.

The higher severity acquisition cost ratio for the year ended December 31, 2015, compared to the same period in 2014, was primarily due to profit commissions of $3.4 million recorded on an excess of loss contract during 2015. These profit commissions were triggered by the elimination of loss reserves on this contract based on updated information received from the insurer. There were no other significant changes in acquisition costs during the year ended December 31, 2015.

Year ended December 31 2014
For the year ended December 31, 2014, the slightly lower frequency acquisition cost ratio compared to the same period in 2013 was related to a combination of decreases in specialty health, professional liability and workers' compensation lines, partially offset by increases in general liability and personal property lines. Acquisition cost ratio for the motor line remained unchanged due to the lower ceding commissions on the in-force private passenger contracts being entirely offset by an increase in sliding scale commission adjustments from the favorable loss development on prior period private passenger contracts.

For the year ended December 31, 2014, the acquisition cost ratios for severity business was slightly lower than the same period in 2013 due to the impact of reinstatement premiums reversed during 2013 relating to super-storm Sandy with no corresponding reversal of commissions. Excluding the impact of this reversal, the 2013 severity acquisition cost ratio was 18.0%. The acquisition cost ratio on the new severity contracts written during 2014 was higher due to a change in mix of business. During the year ended 2014, we wrote several new severity quota share contracts which had higher ceding commissions than the catastrophe excess of loss contracts written during 2013.

59

Link to Table of Contents

 
General and Administrative Expenses

Our total general and administrative expenses for the years ended December 31, 2015, 2014 and 2013, were $23.4 million, $24.5 million, and $21.0 million, respectively. General and administrative expenses for the years ended December 31, 2015, 2014 and 2013 included $4.3 million, $4.0 million and $3.8 million, respectively, for the expensing of the fair value of stock options, RSUs and restricted stock granted to employees and directors.

Details of general and administrative expenses are provided in the following table:
 
 
Year ended December 31
 
2015
 
2014
 
2013
 
($ in thousands)
Internal expenses
$
18,476

 
$
21,341

 
$
17,683

Corporate expenses
4,958

 
3,159

 
3,275

General and administrative expenses
$
23,434

 
$
24,500

 
$
20,958


Internal expenses include all general and administrative expenses except for corporate expenses. Corporate expenses included those expenses directly related to being a publicly listed entity and certain non-core operating expenses. Prior to 2015, corporate expenses also included non-investment related foreign exchange gains and losses. Effective from January 1, 2015, the presentation was modified and any non-investment related foreign exchange gains and losses are now presented on the consolidated statements of income under the caption "other income (expenses), net". As a result, foreign exchange gain of $2.6 million and loss of $0.8 million that were previously included in corporate expenses for the years ended December 31, 2014 and 2013, respectively, have been reclassified to "other income (expense), net", to conform to the current period presentation. For the year ended December 31, 2015, a foreign exchange gain of $0.03 million was included in "other income (expense), net".

For the year ended December 31, 2015, internal expenses decreased primarily due to a decrease in bonuses relating to prior underwriting years. The increase in corporate expenses for the year ended December 31, 2015, compared to the same period in 2014, was mainly due to non-recurring professional fees incurred during 2015.

For the year ended December 31, 2014, the increase in internal expenses was primarily related to higher underwriting quantitative bonuses estimated relating to the 2012, 2013 and 2014 underwriting years, and to a lesser extent, related to information technology system upgrades and an increase in head-count from the comparative period in 2013.
 
Net Investment Income (Loss)  

A summary of our net investment income (loss) is as follows:
 
 
Year ended December 31
 
 
2015
 
2014
 
2013
 
 
($ in thousands)
Realized gains (losses)
 
$
22,227

 
$
352,133

 
$
122,568

Change in unrealized gains and losses
 
(265,401
)
 
(187,753
)
 
149,012

Investment related foreign exchange gains (losses)
 
(3,725
)
 
14,797

 
44,492

Interest and dividend income, net of withholding taxes
 
15,313

 
31,423

 
22,265

Interest, dividend and other expenses
 
(31,092
)
 
(38,892
)
 
(47,665
)
Investment advisor compensation
 
(19,246
)
 
(49,133
)
 
(72,532
)
Net investment income (loss)
 
$
(281,924
)
 
$
122,575

 
$
218,140


Investment returns relating to our investment portfolio managed by DME Advisors are calculated monthly and compounded to calculate the quarterly and annual returns. The resulting actual investment income (loss) may vary depending on cash flows into and out of the investment account.


60

Link to Table of Contents

For the year ended December 31, 2015, investment loss, net of fees and expenses, resulted in a loss of 20.2% on our investments managed by DME Advisors, compared to gains of 8.7% and 19.6% for the years ended December 31, 2014 and 2013, respectively. The investment loss for the year ended December 31, 2015 was primarily driven by our long portfolio, which reported an investment loss of 17.2%. Our three large long investments (CONSOL Energy, Micron Technology and SunEdison) combined, resulted in a 14.9% investment loss. Additionally, the macro positions and other expenses accounted for 1.9% and 1.5%, respectively, of the investment loss. The short portfolio reported a gain of 0.4% for the year ended December 31, 2015.

We expect our investment income, including realized and unrealized gains (or losses), to fluctuate from period to period. Fluctuations in realized and unrealized gains (or losses) are a function of both the market performance of the securities held in our investment portfolio, and the timing of additions to and dispositions of securities in our investment portfolio. Our investment advisor uses its discretion over when to realize a gain (or loss) on a particular investment. We believe that net investment income, which includes both realized and unrealized gains (or losses), is the best way to assess our investment performance, rather than analyzing the realized gains (or losses) and unrealized gains (or losses) separately.

For the years ended December 31, 2015, 2014 and 2013, the gross investment returns on our investment portfolio managed by DME Advisors (excluding investment performance compensation) were (20.2)%, 10.8% and 24.6%, respectively, and were comprised of the following:
 
Year ended December 31
 
2015
 
2014
 
2013
Long portfolio gains (losses)
(17.2
)%
 
17.8
 %
 
41.2
 %
Short portfolio gains (losses)
0.4
 %
 
(4.2
)%
 
(17.0
)%
Macro gains (losses)
(1.9
)%
 
(1.1
)%
 
2.2
 %
Other income and expenses
(1.5
)%
 
(1.7
)%
 
(1.8
)%
Gross investment return
(20.2
)%
 
10.8
 %
 
24.6
 %

For the year ended December 31, 2015, included in "other income and expenses" was $19.2 million (2014: $20.6 million, 2013: $18.3 million) relating to management fees paid to DME Advisors. For the year ended December 31, 2015, no performance compensation was recorded due to the negative investment returns for this period (2014: $28.5 million, 2013: $54.2 million). Due to the investment loss for the year ended December 31, 2015, based on the advisory agreement, the performance compensation for the subsequent years will be reduced to 10% of investment income until all the investment losses have been recouped and an additional amount equal to 150% of the investment loss is earned.

DME Advisors and its affiliates manage and expect to manage other client accounts besides ours, some of which have investment objectives similar to ours. To comply with Regulation FD, our investment returns are posted on our website on a monthly basis. Additionally, our website (www.greenlightre.ky) provides the names of the largest disclosed long positions in our investment portfolio as of the last business day of the month of the relevant posting, as well as information on our long and short exposures. Although DME Advisors discloses all investment positions to us, it may choose not to disclose certain positions to its other clients in order to protect its investment strategy. Therefore, we present on our website the relevant largest long positions and exposure information as disclosed by DME Advisors or its affiliates to their other clients.  
      
Income Taxes
 
We are not obligated to pay taxes in the Cayman Islands on either income or capital gains. We have been granted an exemption by the Governor-In-Cabinet from any income taxes that may be imposed in the Cayman Islands for a period of 20 years, expiring on February 1, 2025.
 
GRIL is incorporated in Ireland and, therefore, is subject to the Irish corporation tax. GRIL is expected to be taxed at a rate of 12.5% on its taxable trading income, and 25% on its non-trading income, if any.
 
Verdant is incorporated in Delaware and, therefore, is subject to taxes in accordance with the U.S. federal rates and regulations prescribed by the Internal Revenue Service. Verdant’s taxable income is expected to be taxed at a rate of 35%.

As of December 31, 2015, a deferred tax asset of $1.8 million (2014: $33.4 thousand) was included in other assets on the consolidated balance sheets. The increase in deferred tax asset during the year ended December 31, 2015, primarily resulted from the operating losses carried forward relating to GRIL and to a lesser extent from the temporary differences in recognition of expenses for tax purposes. As of December 31, 2015, an accrual for current taxes recoverable of $0.5 million (2014: $0.8 million)

61

Link to Table of Contents

was recorded on the consolidated balance sheets relating to a refund for taxes paid by GRIL in prior years. Based on the timing of the reversal of the temporary differences and likelihood of generating sufficient taxable income to realize the future tax benefit, management believes it is more likely than not that the deferred tax asset will be fully realized in the future and therefore no valuation allowance has been recorded. The Company has not taken any other tax positions that management believes are subject to uncertainty or that are reasonably likely to have a material impact to the Company, GRIL or Verdant.
 
Ratio Analysis
 
Due to the opportunistic and customized nature of our underwriting operations, we expect to report different loss and expense ratios in both our frequency and severity businesses from period to period.

The following table provides the ratios: 
 
Year ended December 31


2015


2014


2013


Frequency
 
Severity
 
Total
 
Frequency
 
Severity
 
Total
 
Frequency
 
Severity
 
Total


Loss ratio
82.6
%
 
9.5
%
 
77.6
%
 
69.9
%
 
16.1
%
 
66.3
%
 
65.5
%
 
(48.1
)%
 
61.8
%
Acquisition cost ratio
28.0

 
35.2

 
28.5

 
31.2

 
19.7

 
30.4

 
31.7

 
20.8

 
31.4

Composite ratio
110.6
%
 
44.7
%
 
106.1
%
 
101.1
%
 
35.8
%
 
96.7
%
 
97.2
%
 
(27.3
)%
 
93.2
%
Internal expense ratio


4.5


6.0


3.2

Corporate expense ratio


1.2


0.9


0.6

Combined ratio


111.8
%


103.6
%


97.0
%
                
The loss ratio is calculated by dividing loss and loss adjustment expenses incurred by net premiums earned. We expect that the loss ratio will be volatile for our severity business and may exceed that of our frequency business in certain periods. Given that we opportunistically underwrite a concentrated portfolio across several lines of business that have varying expected loss ratios, we can expect there to be significant annual variations in the loss ratios reported from our frequency business. In addition, the loss ratios for both frequency and severity business can vary depending on the mix of the lines of business written. 

The acquisition cost ratio is calculated by dividing acquisition costs by net premiums earned. We expect that this ratio will generally be higher for our frequency business than for our severity business.
 
The composite ratio is the ratio of underwriting losses incurred, loss adjustment expenses and acquisition costs, excluding general and administrative expenses, to net premiums earned. Similar to the loss ratio, we expect that this ratio will be more volatile for our severity business depending on loss activity in any particular period.
  
The internal expense ratio is the ratio of general and administrative expenses, excluding any corporate expenses, to net premiums earned.

The corporate expense ratio is the ratio of corporate expenses to net premiums earned. Corporate expenses include expenses relating to GLRE being a publicly listed entity and certain non-core operating expenses.
 
Prior to January 1, 2015, non-investment related foreign exchange gains and losses were recorded under corporate expenses. Effective from January 1, 2015, the presentation has been modified and any non-investment related foreign exchange gains or losses are now recorded under "other income (expense), net" in the consolidated statements of income. Therefore, the corporate expense ratios and combined ratios for prior periods have been reclassified in the above table to conform to the current year presentation.

The combined ratio is the sum of the composite ratio, the internal expense ratio and the corporate expense ratio. The combined ratio measures the total profitability of our underwriting operations and does not take net investment income or loss into account. Given the nature of our opportunistic underwriting strategy, we expect that our combined ratio may also be volatile from period to period.


62

Link to Table of Contents

Financial Condition
 
Investments, Financial Contracts Receivable, Financial Contracts Payable and Due to Prime Brokers
 
Our long investments and financial contracts receivable reported in the consolidated balance sheets as of December 31, 2015 were $1,077.4 million, compared to $1,478.1 million as of December 31, 2014, a decrease of $400.7 million, or 27.1%, primarily due to the loss on long investments. As of December 31, 2015, our exposure to long investments decreased to 89.5%, compared to 105.8% as of December 31, 2014. This exposure analysis is conducted on a delta-adjusted basis and excludes macro positions which consist of CDS, interest rate swaps, sovereign debt, currencies, commodities, volatility indexes and derivatives on any of these instruments.
 
Financial contracts receivable as of December 31, 2015 decreased by $34.0 million, or 72.0%, compared to December 31, 2014, partially due to a decrease in the fair value of equity based total return swaps and partially due to put options exited during 2015. As of December 31, 2015, financial contracts payable decreased by $16.3 million, or 36.7%, compared to December 31, 2014, primarily due to a decrease in total return swaps that were in payable position and to a lesser extent due to the expiration of certain credit default swaps during the period.

From time to time, we incur indebtedness to our prime brokers to implement our investment strategy in accordance with our investment guidelines. As of December 31, 2015, we had borrowed $95.0 million (2014: $76.1 million) from our prime brokers for investing activities and to provide collateral for unrealized losses on short positions. In accordance with Greenlight Re's investment guidelines, DME Advisors is allowed to use up to 15% (GRIL: 5%) net margin leverage for extended periods of time and up to 30% (GRIL: 20%) net margin leverage for periods of less than 30 days.

Additionally, as of December 31, 2015, we had borrowed $301.4 million (2014: $135.0 million) under term margin agreements from prime brokers to provide collateral for trust accounts and for some of our letters of credit outstanding, whereby we pledge certain investment securities to borrow cash from the prime brokers.
 
Our investment portfolio, including any derivatives, is valued at fair value and any unrealized gains or losses are reflected in net investment income (loss) in the consolidated statements of income. As of December 31, 2015, 90.9% (2014: 83.9%) of our investment portfolio (excluding restricted and unrestricted cash and cash equivalents) was comprised of investments valued based on quoted prices in actively traded markets (Level 1), 8.0% (2014: 14.5%) was comprised of securities valued based on observable inputs other than quoted prices (Level 2) and 1.1%  (2014: 1.6%) was comprised of securities valued based on non-observable inputs (Level 3). (Refer to Note 3 "Financial Instruments" in the consolidated financial statements for details of transfers into and out of Level 3 during the year ended December 31, 2015).
 
In determining whether a market for a financial instrument is active or inactive, we obtain information from DME Advisors, based on feedback it receives from executing brokers, market makers, analysts and traders, to assess the level of market activity and available liquidity for any given financial instrument. Where a financial instrument is valued based on broker quotes, DME Advisors requests multiple quotes. The ultimate value is based on an average of the quotes obtained. Broker quoted prices are generally not adjusted in determining the ultimate values and are obtained with the expectation of the quotes being binding. As of December 31, 2015, $129.8 million (2014: $316.4 million) of our investments (longs, shorts and derivatives) were valued based on broker quotes, of which $128.0 million (2014: $315.7 million) were based on broker quotes that utilized observable market information and classified as Level 2 fair value measurements, and $1.8 million (2014: $0.7 million) were based on broker quotes that utilized non-observable inputs and classified as Level 3 fair value measurements.
 
Non-observable inputs used by our investment advisor include the use of investment manager statements and management estimates based on third party appraisals of underlying assets for valuing private equity investments. 

Restricted Cash and Cash Equivalents; Securities Sold, Not Yet Purchased
 
As of December 31, 2015, our securities sold, not yet purchased were $882.9 million compared to $1,090.7 million at December 31, 2014, a decrease of 19.1%, primarily due to disposal of certain non-U.S. sovereign debt short positions and, to a lesser extent, due to an increase in unrealized gains on the short equity securities. However, since macro positions such as sovereign debt are not included in the exposure analysis, our short exposure was 74.0% as of December 31, 2015, compared to 66.9% at December 31, 2014.

Unlike long investments, short sales theoretically involve unlimited loss potential since there is no limit as to how high the market price of a security may rise. While it is not possible to list all of the reasons why a loss on a short sale may occur, a loss on a short sale may be caused by one or more of the following factors:


63

Link to Table of Contents

•
Fluctuations in the share price due to an overall positive investment market;
•
Sudden unexpected changes in the underlying business model of the issuer;
•
Changes in laws and regulations relating to short sales;
•
Press releases and earnings guidance issued by the issuer;
•
A merger or acquisition of the issuer at a price in excess of the current share price;
•
The shares of the issuer becoming difficult to borrow; or
•
A short squeeze.

Given the various scenarios under which a loss may occur on a short sale, it is not possible to quantify the risk and uncertainty of loss relating to short sales. However, DME Advisors typically performs a detailed analysis prior to entering into a short sale. Thereafter, the investment is routinely monitored by DME Advisors. As of December 31, 2015, Greenlight Re's investment guidelines limit any single investment from constituting more than 20% of the portfolio (10% for GRIL's portfolio) at any given time, which limits the potential adverse impact on our results of operations and financial position from any one position.

As of December 31, 2015, the restricted cash included $882.9 million relating to collateral for securities sold, not yet purchased, compared to $1,090.7 million as of December 31, 2014.

Overall, our restricted cash decreased by $60.3 million, or 4.7%, from $1,296.9 million to $1,236.6 million, primarily due to the decrease in securities sold, not yet purchased. The cash collateral held by derivative counterparties decreased by $19.0 million to $52.2 million during the year ended December 31, 2015 due to a decrease in derivatives. Additionally, as of December 31, 2015, included in restricted cash and cash equivalents was $301.4 million (2014: $135.0 million) of cash and cash equivalents pledged as collateral (for letters of credit and trust accounts) to our cedents to satisfy our reinsurance collateral obligations.

Reinsurance Balances Receivable; Deferred Acquisition Costs, Net; Unearned Premium Reserves
 
At December 31, 2015, reinsurance balances receivable were $187.9 million compared to $151.2 million as of December 31, 2014, an increase of $36.7 million, or 24.3%. The increase in reinsurance balances receivable was primarily attributable to the increase in premiums written during the year ended December 31, 2015 compared to the same period in 2014.

At December 31, 2015, deferred acquisition costs (net of retrocession) increased by $25.4 million, or 73.8%, compared to December 31, 2014. The increase was closely related to the corresponding increase in unearned premium reserves which increased by $83.2 million, or 64.6%, during the same period. We evaluate the recoverability of deferred acquisition costs by determining if the sum of future earned premiums and anticipated investment income is greater than the expected future claims and expenses. If a loss is probable on the unexpired portion of policies in force, a premium deficiency loss is recognized. As of December 31, 2015, we believe that the deferred acquisition costs were fully recoverable and no premium deficiency loss was recorded.

Notes Receivable

As of December 31, 2015, notes receivable increased by $23.6 million to $25.1 million from $1.6 million as of December 31, 2014. The increase was primarily related to a settlement agreement entered into with a ceding insurer during 2015 whereby certain amounts, previously classified under reinsurance balances receivable, were converted into a ten-year note receivable. For further details on notes receivable, refer to Note 2 "Significant Accounting Policies" in the consolidated financial statements.

Loss and Loss Adjustment Expense Reserves; Loss and Loss Adjustment Expenses Recoverable
 
Reserves for loss and loss adjustment expenses were comprised of the following table: 
 
December 31, 2015
 
December 31, 2014
 
Case
Reserves
 
IBNR
 
Total
 
Case
Reserves
 
IBNR
 
Total
 
($ in thousands)
Frequency
$
103,347

 
$
165,740

 
$
269,087

 
$
103,357

 
$
124,173

 
$
227,530

Severity
8,188

 
28,722

 
36,910

 
13,692

 
23,021

 
36,713

Total
$
111,535

 
$
194,462

 
$
305,997

 
$
117,049

 
$
147,194

 
$
264,243


64

Link to Table of Contents

 
During the year ended December 31, 2015, the frequency loss reserves increased by $41.6 million, or 18.3%, to $269.1 million from $227.5 million as of December 31, 2014. The increase in the frequency IBNR was driven primarily by an increase in booked reserves on prior period contracts as a result of unfavorable loss development, partially offset by a net decrease in claims reported on active contracts during the period.

The severity loss reserves decreased by $0.2 million, or 0.5%. The increase in the severity IBNR was due to new severity quota share contracts written during 2015 and in the latter half of 2014. The decrease in the severity case reserves related to the elimination of $5.1 million case reserves on an excess of loss contract based on updated loss information received from the insurer indicating that the losses would not breach into our layer of coverage.

For most of our contracts written as of December 31, 2015, our risk exposure is limited by defined limits of liability. Once the loss limit for a contract has been reached, we have no further exposure to additional losses from that contract. However, certain contracts, particularly quota share contracts that relate to first dollar exposure, may not contain aggregate limits. Our severity and frequency business both have certain contracts that contain natural peril loss exposure. As of January 1, 2016, our maximum aggregate loss exposure to any series of natural peril events was $236.3 million. For purposes of the preceding sentence, aggregate loss exposure is net of any retrocession (including any ILWs) and is equal to the difference between the aggregate limits available in the contracts that contain natural peril exposure minus reinstatement premiums, if any, for the same contracts.

We categorize peak zones as: United States, Canada and the Caribbean; Europe; Japan; and the rest of the world. The following table provides the theoretical maximum single event loss exposure and aggregate loss exposure to natural peril losses for each of the peak zones as of January 1, 2016: 
 
 
January 1, 2016
Zone
 
Maximum Single Event Loss
 
Maximum Aggregate Loss
 
 
($ in thousands)
United States, Canada and the Caribbean
 
$
165,357

 
$
236,263

Europe
 
114,440

 
144,383

Japan
 
114,440

 
144,383

Rest of the world
 
114,440

 
144,383

Maximum Aggregate
 
165,357

 
236,263


Since our maximum loss exposures are theoretical maximums based on contract limits, these limits may be significantly higher than modeled loss estimates which are commonly used in the insurance industry. Therefore as of January 1, 2016, we also estimate catastrophe losses in terms of the probable maximum loss ("PML"). We define PML as the anticipated loss, taking into account contract terms and limits, caused by a catastrophe affecting a broad geographic area, such as that caused by an earthquake or hurricane. We anticipate that the PML will vary depending upon the modeled simulated losses and the composition of the in-force book of business. The projected severity levels are described in terms of a 1-in-250 year return period. The 1-in-250 year return period PML means that there is a 0.4% chance in any given year that an occurrence of a natural catastrophe will lead to losses exceeding the stated estimate. In other words, it corresponds to a 99.6% probability that the loss from an event will fall below the indicated PML.
It is important to note that PMLs are estimates. As a result, we cannot provide any assurance that any actual event will align with the modeled event or that actual losses from events similar to the modeled events will not vary materially from the modeled event PML.
The PML estimate includes all significant exposure from our reinsurance operations. This includes coverage for property, motor, marine, energy, aviation and workers’ compensation.

65

Link to Table of Contents

As of January 1, 2016, our estimated net PML exposure (net of retrocession and reinstatement premiums) at a 1-in-250 year return period for a single event and in aggregate, was $113.0 million and $143.9 million, respectively. The following table provides the PML for single event loss exposure and aggregate loss exposure to natural peril losses for each of the peak zones as of January 1, 2016:
 
 
January 1, 2016
 
 
1-in-250 year return
Zone
 
Single Event Loss
 
Aggregate Loss
 
 
($ in thousands)
United States, Canada and the Caribbean
 
113,004

 
142,196

Europe
 
50,602

 
64,809

Japan
 
33,010

 
41,555

Rest of the world
 
34,600

 
49,087

Maximum
 
113,004

 
143,851

Shareholders’ Equity
 
Total equity reported on the consolidated balance sheet, which includes non-controlling interest, decreased by $345.3 million to $848.8 million as of December 31, 2015, compared to $1,194.0 million as of December 31, 2014. Retained earnings decreased primarily due to net loss of $326.4 million reported for the year ended December 31, 2015 and $9.2 million related to repurchase of Class A ordinary shares. The non-controlling interest decreased by $5.5 million due to investment losses attributable to DME's interest in the joint venture during the year ended December 31, 2015. The decrease in additional paid-in capital for the year ended December 31, 2015 of $4.2 million primarily related to common shares repurchased during the period, partially offset by stock based compensation for the year ended December 31, 2015.

Liquidity and Capital Resources
 
General

Greenlight Capital Re is organized as a holding company with no operations of its own. As a holding company, Greenlight Capital Re has minimal continuing cash needs, most of which are related to the payment of administrative expenses. All of our underwriting operations are conducted through our wholly-owned reinsurance subsidiaries, Greenlight Re and GRIL, which underwrite risks associated with our property and casualty reinsurance programs. There are restrictions on Greenlight Re’s and GRIL’s ability to pay dividends which are described in more detail below. It is our current policy to retain earnings to support the growth of our business. We currently do not expect to pay dividends on our ordinary shares.

As of December 31, 2015, Greenlight Re and GRIL were each rated "A (Excellent)" by A.M. Best. On October 23, 2015, A.M. Best affirmed the "A (Excellent)" ratings but revised the ratings' outlook from stable to negative. The ratings reflect A.M. Best’s opinion of our reinsurance subsidiaries’ financial strength, operating performance and ability to meet obligations and it is not an evaluation directed toward the protection of investors or a recommendation to buy, sell or hold our Class A ordinary shares. If A.M. Best downgrades our ratings below "A- (Excellent)" or withdraws our rating, we could be severely limited or prevented from writing any new reinsurance contracts, which would significantly and negatively affect our business. Insurer financial strength ratings are based upon factors relevant to policyholders and are not directed toward the protection of investors. Our A.M. Best ratings may be revised or revoked at the sole discretion of the rating agency. 

66

Link to Table of Contents

Sources and Uses of Funds
 
Our sources of funds consist primarily of premium receipts (net of brokerage and ceding commissions), investment income (net of advisory compensation and investment expenses), including realized gains, and other income. We use cash from our operations to pay losses and loss adjustment expenses, profit commissions and general and administrative expenses. Substantially all of our funds, including shareholders’ capital, net of funds required for business operations, are invested by DME Advisors in accordance with our investment guidelines. As of December 31, 2015, approximately 96% (December 31, 2014: 96%) of our long investments were comprised of publicly-traded equity securities and other holdings which can be readily liquidated to meet current and future liabilities. Given our value-oriented long and short investment strategy, if markets are distressed we would expect the liability of the short portfolio to decline. Any reduction in the liability would cause our need for restricted cash to decrease and thereby free up cash to be used for any purpose. Additionally, since the majority of our invested assets can be readily liquidated, even in distressed markets, we believe sufficient securities can be readily sold or covered in a timely manner to generate cash to pay claims. Since we classify our investments as "trading," we book all gains and losses (including unrealized gains and losses) on all our investments (including derivatives) as net investment income or loss in our consolidated statements of income for each reporting period.   
   
For the years ended December 31, 2015, 2014 and 2013, the net cash used in operating activities was $59.9 million, $133.7 million and $92.7 million, respectively. Included in the net cash used in operating activities were investment related expenses, such as investment advisor compensation, and net interest and dividend expenses of $35.0 million, $56.6 million and $97.9 million for the years ended December 31, 2015, 2014 and 2013, respectively. Excluding the investment related expenses from the net cash used in operating activities results in net cash primarily provided by (used in) our underwriting activities, which was $(24.9) million, $(77.1) million and $5.2 million for the years ended December 31, 2015, 2014 and 2013, respectively. During the year ended December 31, 2015 and 2014 , the use of cash for underwriting activities was primarily a result of losses paid in excess of the premiums collected (net of acquisition costs). Generally, in a given period if the premiums collected are sufficient to cover claim payments, we would generate cash from our underwriting activities. Due to the inherent nature of our underwriting portfolio, claims are often paid several months or even years after the premiums are collected. The cash generated from underwriting activities, however, may be volatile from period to period depending on the underwriting opportunities available.

For the year ended December 31, 2015, our investing activities provided cash of $177.7 million (2014: $142.0 million, 2013: $74.0 million), primarily as a result of borrowings from prime brokers under term margin agreements to provide collateral for trust accounts and letters of credit issued. The cash provided from investing activities for the years ended December 31, 2014 and 2013 was driven primarily by the trading of long and short securities in the investment portfolio. Cash provided by investing activities is net of withdrawals from the joint venture by DME during the year ended December 31, 2015 of nil (2014: $9.5 million, 2013: $10.8 million). We used $17.7 million in financing activities relating to the repurchase of Class A ordinary shares during the year ended December 31, 2015 (2014: nil, 2013: nil).
   
As of December 31, 2015, we believe we have sufficient cash flow from operating and investing activities to meet our foreseeable liquidity requirements. We expect that our operational needs for liquidity will be met by cash, funds generated from underwriting activities and investment income, including realized gains and the disposition of investment securities. As of December 31, 2015, we had no plans to issue debt and expect to fund our operations for the next twelve months from operating cash flow. However, we cannot provide assurances that in the future we will not incur indebtedness to implement our business strategy, pay claims or make acquisitions.
 
Although GLRE is not subject to any significant legal prohibitions on the payment of dividends, Greenlight Re and GRIL are each subject to regulatory minimum capital requirements and regulatory constraints that affect their ability to pay dividends to us. In addition, any dividend payment would have to be approved by the relevant regulatory authorities prior to payment. As of December 31, 2015, Greenlight Re and GRIL both exceeded the regulatory minimum capital requirements. See Note 9 of the consolidated financial statements for details of statutory surplus and regulatory capital of Greenlight Re and GRIL.

Letters of Credit and Trust Arrangements
 
As of December 31, 2015, neither Greenlight Re nor GRIL was licensed or admitted as a reinsurer in any jurisdiction other than the Cayman Islands and the European Economic Area, respectively. Because many jurisdictions do not permit domestic insurance companies to take credit on their statutory financial statements for loss recoveries or ceded unearned premiums unless appropriate measures are in place for reinsurance obtained from unlicensed or non-admitted insurers, we anticipate that all of our U.S. clients and some of our non-U.S. clients will require us to provide collateral through funds withheld, trust arrangements, letters of credit or a combination thereof.


67

Link to Table of Contents

As of December 31, 2015, we had four letter of credit facilities with an aggregate capacity of $720.0 million (2014: $760.0 million) with various financial institutions. See Note 14 of the accompanying consolidated financial statements for details on each of these facilities. As of December 31, 2015, an aggregate amount of $245.6 million (2014: $273.7 million) in letters of credit was issued under these facilities. Under these facilities, we provide collateral that may consist of equity securities or cash and cash equivalents. At December 31, 2015, total equity securities and cash and cash equivalents with a fair value in the aggregate of $324.3 million (2014: $302.6 million) were pledged as security against the letters of credit issued. The decrease in letters of credit issued as of December 31, 2015 compared to 2014 was a result of canceling some of the issued letters of credit for certain cedents and establishing regulatory trust arrangements in the amount of $78.6 million as of December 31, 2015.

Each of the facilities contain customary events of default and restrictive covenants, including but not limited to, limitations on liens on collateral, transactions with affiliates, mergers and sales of assets, as well as solvency and maintenance of certain minimum pledged equity requirements, and restricts issuance of any debt without the consent of the letter of credit provider. Additionally, if an event of default exists, as defined in the letter of credit facilities, Greenlight Re would be prohibited from paying dividends to its parent company. The Company was in compliance with all the covenants of each of these facilities as of December 31, 2015.

Capital
 
Our capital structure currently consists entirely of equity issued in two separate classes of ordinary shares. We expect that the existing capital base and internally generated funds will be sufficient to implement our business strategy for the foreseeable future. Consequently, we do not presently anticipate that we will incur any material indebtedness in the ordinary course of our business other than temporary borrowing directly related to the management of our investment portfolio. However, in order to provide us with flexibility and timely access to public capital markets should we require additional capital for working capital, capital expenditures, acquisitions or other general corporate purposes, we have filed a Form S-3 registration statement, which expires in June 2018 unless renewed. We did not make any significant commitments for capital expenditures during the year ended December 31, 2015.

Our Board of Directors has adopted a share repurchase plan authorizing the Company to repurchase up to 2.0 million Class A ordinary shares or securities convertible into Class A ordinary shares in the open market, through privately negotiated transactions or Rule 10b5-1 stock trading plans. The current share repurchase plan was renewed on April 29, 2015 by the Board of Directors and expires on June 30, 2016. The Company is not required to repurchase any of the Class A ordinary shares and the repurchase plan may be modified, suspended or terminated at the election of our Board of Directors at any time without prior notice. During the year ended December 31, 2015, 613,540 Class A ordinary shares were repurchased by the Company.

On April 28, 2010, our shareholders approved an amendment to our stock incentive plan to increase the number of Class A ordinary shares available for issuance from 2.0 million to 3.5 million. As of December 31, 2015, there were 658,775 Class A ordinary shares available for future issuance. 

Contractual Obligations and Commitments
 
The following table shows our aggregate contractual obligations as of December 31, 2015 by time period remaining: 
 
Less than
 1 year
 
1-3 years
 
3-5 years
 
More than
 5 years
 
Total
 
  ($ in thousands)
Operating lease obligations (1)
$
548

 
$
863

 
$
164

 
$
31

 
$
1,606

Private equity and limited partnerships (2)
6,107

 
—

 
—

 
—

 
6,107

Loss and loss adjustment expense reserves (3)
132,742

 
86,421

 
44,036

 
42,798

 
305,997

 
$
139,397

 
$
87,284

 
$
44,200

 
$
42,829

 
$
313,710

(1)    Reflects our contractual obligations pursuant to the lease agreements as described below. 
(2)    As of December 31, 2015, we had made total commitments of $20.1 million in private investments of which we had invested $14.0 million, and our remaining commitments to these investments total $6.1 million. Given the nature of the private equity investments, we are unable to determine with any degree of accuracy as to when the commitments will be called. As such, for the purposes of the above table, we have assumed that all commitments with no fixed payment schedule will be made within one year. Under our investment guidelines, in effect as of the date hereof, no more than 10% of the assets in the investment portfolio may be held in private equity securities without specific approval from the Board of Directors. 

68

Link to Table of Contents

(3)    Due to the nature of our reinsurance operations, the amount and timing of the cash flows associated with our reinsurance contractual liabilities will fluctuate, perhaps materially, and, therefore, are highly uncertain.

As of December 31, 2015, $882.9 million of securities sold, not yet purchased, were secured by $882.9 million of restricted cash held by prime brokers to cover obligations relating to securities sold, not yet purchased. These amounts are not included in the contractual obligations table above because there is no maturity date for securities sold, not yet purchased, and their maturities are not set by any contract and as such their due dates cannot be estimated.
 
Greenlight Re has entered into lease agreements for office space in the Cayman Islands. The leases expire on June 30, 2018 and Greenlight Re has the option to renew the leases for a further five year term. Under the terms of the lease agreements, Greenlight Re is committed to annual rent payments ranging from $0.3 million at inception to $0.5 million at expiry. The minimum lease payment obligations are included in the above table under operating lease obligations and in Note 14 to the accompanying consolidated financial statements.
 
GRIL has entered into a lease agreement for office space in Dublin, Ireland. Under the terms of this lease agreement, GRIL is committed to minimum annual rent payments denominated in Euros approximating €0.1 million until May 2021, and adjusted to the prevailing market rates for each of the two subsequent five-year terms. GRIL has the option to terminate the lease agreement in 2021. The minimum lease payment obligations are included in the above table under operating lease obligations and in Note 14 to the accompanying consolidated financial statements.

The Company and its reinsurance subsidiaries have entered into a joint venture agreement with DME Advisors under which the Company, its reinsurance subsidiaries and DME are participants of a joint venture for the purpose of managing certain jointly held assets (the "venture agreement"). In addition, the Company, its reinsurance subsidiaries and DME have entered into a separate investment advisory agreement with DME Advisors (the "advisory agreement"). The term of each of the venture agreement and the advisory agreement is January 1, 2014 through December 31, 2016, with automatic three-year renewals, unless 90 days prior to the end of the then current term, either DME notifies the other participants of its desire to terminate the venture agreement or any other participant notifies DME of its desire to withdraw from the venture agreement.

Pursuant to the venture agreement, we pay DME Advisors a monthly management fee of 0.125% on our share of the assets managed by DME Advisors and we provide DME a performance allocation equal to 20% of the net profit, calculated per annum, of the Company’s share of the capital account managed by DME Advisors, subject to a loss carry forward provision. The loss carry forward provision allows DME to earn a reduced performance allocation of 10% of profits in any year subsequent to the year in which the investment account incurs a loss, until all the losses are recouped and an additional amount equal to 150% of the aggregate investment loss is earned. DME is not entitled to earn a performance allocation in a year in which the investment portfolio incurs a loss. For the year ended December 31, 2015, no performance allocation was recorded due to the net investment loss for the year. For the year ended December 31, 2015, management fees of $19.2 million was included in the net investment loss.
 
In February 2007, we entered into a service agreement with DME Advisors pursuant to which DME Advisors will provide investor relations services to us for compensation of five thousand dollars per month plus expenses. The service agreement had an initial term of one year, and continues for sequential one-year periods until terminated by us or DME Advisors. Either party may terminate the service agreement for any reason with 30 days prior written notice to the other party.

Our related party transactions are presented in Note 13 to the accompanying consolidated financial statements.

Off-Balance Sheet Financing Arrangements
 
We have no obligations, assets or liabilities, other than those derivatives in our investment portfolio that are disclosed in the consolidated financial statements, which would be considered off-balance sheet arrangements. We do not participate in transactions that create relationships with unconsolidated entities or financial partnerships, often referred to as variable interest entities, which would have been established for the purpose of facilitating off-balance sheet arrangements. 

Effects of Inflation
 
We consider the effects of inflation in our pricing and when estimating loss and loss adjustment expense reserves. The actual effects of inflation on our results of operations cannot be accurately known until claims are ultimately settled. For the years ended December 31, 2015, 2014 and 2013, inflation had no significant impact on our revenues or net income. We do not believe that inflation has had or will have a material effect on our combined results of operations, except insofar as inflation may affect interest rates and the asset values in our investment portfolio.


69

Link to Table of Contents

ITEM 7A. QUANTITATIVE AND QUALITATIVE DISCLOSURES ABOUT MARKET RISK
 
We believe we are principally exposed to the following types of market risk: 
•
 
equity price risk;


•
 
commodity price risk;


•
 
foreign currency risk;


•
 
interest rate risk;


•
 
credit risk; and


•
 
political risk.
 
Equity Price Risk
As of December 31, 2015, our investment portfolio consisted of long and short equity securities, along with certain equity-based derivative instruments, the carrying values of which are primarily based on quoted market prices. Generally, market prices of common equity securities are subject to fluctuation, which could cause the amount to be realized upon the closing of the position to differ significantly from their current reported value. This risk is partly mitigated by the presence of both long and short equity securities within our investment portfolio. As of December 31, 2015, a 10% decline in the price of each of these listed equity securities and equity-based derivative instruments would result in a $13.4 million, or 1.2%, decline in the fair value of our total investment portfolio.
 
Computations of the prospective effects of hypothetical equity price changes are based on numerous assumptions, including the maintenance of the existing level and composition of investment securities and should not be relied on as indicative of future results.

Commodity Price Risk
Generally, market prices of commodities are subject to fluctuation. Our investment portfolio periodically includes long or short investments in commodities or in derivatives directly impacted by fluctuations in the prices of commodities. As of December 31, 2015, our investment portfolio included unhedged exposure to changes in gold prices, through ownership of physical gold and derivative instruments with underlying exposure to changes in gold prices. Additionally, as of December 31, 2015, our investment portfolio included derivative instruments with underlying exposure to changes in oil prices.
The following table summarizes the net impact that a 10% increase and decrease in commodity prices would have on the value of our investment portfolio as of December 31, 2015: 
 
10% increase in commodity prices
 
10% decrease in commodity prices
Commodity
Change in
fair value
 
Change in fair value as % of investment portfolio
 
Change in
fair value
 
Change in fair value as % of investment portfolio
 
  ($ in thousands)


  ($ in thousands)
 
 
Gold
$
11,926

 
1.1
%
 
$
(11,926
)
 
(1.1
)%
Oil
4,216

 
0.4

 
(4,216
)
 
(0.4
)
Total
$
16,142

 
1.5
%
 
$
(16,142
)
 
(1.5
)%
We, along with our investment advisor, periodically monitor our exposure to any other commodity price fluctuations and generally do not expect changes in other commodity prices to have a materially adverse impact on our operations.
 
Foreign Currency Risk
Certain of our reinsurance contracts provide that ultimate losses may be payable or calculated in foreign currencies depending on the country of original loss. Foreign currency exchange rate risk exists to the extent that our foreign currency loss

70

Link to Table of Contents

reserves (case reserves and IBNR) are in excess of the corresponding foreign currency cash balances and there is an increase in the exchange rate of that foreign currency. As of December 31, 2015, we had a net unhedged foreign currency exposure on GBP denominated loss reserves of £3.1 million. As of December 31, 2015, a 10% decrease in the U.S. dollar against the GBP (all else being constant) would result in additional estimated loss reserves of $0.5 million and a corresponding foreign exchange loss. Alternatively, a 10% increase in the U.S dollar against the GBP, would result in a reduction of $0.5 million in our recorded loss reserves and a corresponding foreign exchange gain.
 
While we do not seek to specifically match our liabilities under reinsurance policies that are payable in foreign currencies with investments denominated in such currencies, we continually monitor our exposure to potential foreign currency losses and may use foreign currency cash and cash equivalents or forward foreign currency exchange contracts in an effort to mitigate against adverse foreign currency movements.
 
We are also exposed to foreign currency risk through cash, forwards, options and investments in securities denominated in foreign currencies. Foreign currency exchange rate risk is the potential for adverse changes in the U.S. dollar value of investments (long and short), speculative foreign currency options and cash positions due to a change in the exchange rate of the foreign currency in which cash and financial instruments are denominated. As of December 31, 2015, some of our currency exposure resulting from foreign denominated securities (longs and shorts) was reduced by offsetting cash balances denominated in the corresponding foreign currencies. 

The following table summarizes the net impact that a 10% increase and decrease in the value of the U.S. dollar against select foreign currencies would have on the value of our investment portfolio as of December 31, 2015: 
 
  10% increase in U.S. dollar
 
10% decrease in U.S. dollar
Foreign Currency
Change in
fair value
 
Change in fair value as % of investment portfolio
 
Change in
fair value
 
Change in fair value as % of investment portfolio
 
  ($ in thousands)
Argentine Peso
$
(1,846
)
 
(0.2
)%
 
$
1,846

 
0.2
 %
British Pound
(1,993
)
 
(0.2
)
 
1,993

 
0.2

Chinese Yuan
13,989

 
1.3

 
(6,694
)
 
(0.6
)
Japanese Yen
1,189

 
0.1

 
(662
)
 
(0.1
)
Other
180

 
—

 
(180
)
 
—

Total 
$
11,519

 
1.0
 %
 
$
(3,697
)
 
(0.3
)%
 
Computations of the prospective effects of hypothetical currency price changes are based on numerous assumptions, including the maintenance of the existing level and composition of investment securities denominated in foreign currencies and related foreign currency instruments, and should not be relied on as indicative of future results.
 
Interest Rate Risk
Our investment portfolio includes interest rate sensitive securities, such as corporate and sovereign debt instruments and interest rate options. The primary market risk exposure for any debt instrument is interest rate risk. As interest rates rise, the market value of our long fixed-income portfolio falls, and the opposite is also true as interest rates fall. Additionally, some of our derivative investments may also be sensitive to interest rates and their value may indirectly fluctuate with changes in interest rates. 


71

Link to Table of Contents

The following table summarizes the impact that a 100 basis point increase or decrease in interest rates would have on the value of our investment portfolio as of December 31, 2015:
 
100 basis point increase
in interest rates
 
100 basis point decrease
in interest rates
 
Change in
fair value
 
Change in fair value as % of investment portfolio
 
Change in
fair value
 
Change in fair value as % of investment portfolio
 
  ($ in thousands)
Debt instruments
$
12,401

 
1.1
%
 
$
(16,280
)
 
(1.5
)%
Interest rate options
3,089

 
0.3

 
(541
)
 
(0.1
)
Net exposure to interest rate risk
$
15,490

 
1.4
%
 
$
(16,821
)
 
(1.6
)%
 
For the purposes of the above table, the hypothetical impact of changes in interest rates on debt instruments, CDS and interest rate swaps was determined based on the interest rates applicable to each instrument individually. We periodically monitor our net exposure to interest rate risk and generally do not expect changes in interest rates to have a materially adverse impact on our operations.
 
Credit Risk

We are exposed to credit risk primarily from the possibility that counterparties may default on their obligations to us. The amount of the maximum exposure to credit risk is indicated by the carrying value of our financial assets including notes receivable. We evaluate the financial condition of our notes receivable counterparties and monitor our exposure to them on a regular basis. We are also exposed to credit risk from our business partners and clients relating to balances receivable under the reinsurance contracts, including premiums receivable, losses recoverable and commission adjustments recoverable. We monitor the collectability of these balances on a regular basis.

In addition, the securities, commodities, and cash in our investment portfolio are held with several prime brokers, subjecting us to the related credit risk from the possibility that one or more of them may default on their obligations to us. We closely and regularly monitor our concentration of credit risk with each prime broker and if necessary, transfer cash or securities between prime brokers to diversify and mitigate our credit risk. Other than our investment in derivative contracts and corporate debt, if any, and the fact that our investments and majority of cash balances are held by prime brokers on our behalf, we have no other significant concentrations of credit risk. 

Political Risk

We are exposed to political risk to the extent that we underwrite business from entities located in foreign markets and to the extent that DME Advisors, on our behalf and subject to our investment guidelines, trades securities that are listed on various U.S. and foreign exchanges and markets. The governments in any of these jurisdictions could impose restrictions, regulations or other measures, which may have a material adverse impact on our underwriting operations and investment strategy. We currently do not write political risk coverage on our insurance contracts; however, changes in government laws and regulations may impact our underwriting operations (see "Item 1A. Risk Factors").

ITEM 8. FINANCIAL STATEMENTS AND SUPPLEMENTARY DATA

Information with respect to this Item is set forth under Part IV Item 15.
 
ITEM 9. CHANGES IN AND DISAGREEMENTS WITH ACCOUNTANTS ON ACCOUNTING AND FINANCIAL DISCLOSURE

There have been no disagreements with any accountants regarding accounting and financial disclosure for the period since the Company’s incorporation on July 13, 2004 through the date of this filing.


72

Link to Table of Contents

ITEM 9A. CONTROLS AND PROCEDURES
 
Disclosure Controls and Procedures
 
As required by Rules 13a-15 and 15d-15 of the Exchange Act, the Company has evaluated, with the participation of management, including the Chief Executive Officer and the Chief Financial Officer, the effectiveness of its disclosure controls and procedures (as defined in such rules) as of the end of the period covered by this report. Based on such evaluation, the Chief Executive Officer and Chief Financial Officer concluded that the Company’s disclosure controls and procedures are effective to ensure that information required to be disclosed by the Company in reports prepared in accordance with the rules and regulations of the SEC is recorded, processed, summarized and reported within the time periods specified by the SEC’s rules and forms. Disclosure controls and procedures include, without limitation, controls and procedures designed to ensure that information required to be disclosed by an issuer in the reports that it files or submits under the Exchange Act is accumulated and communicated to the issuer’s management, including its principal executive officer and principal financial officer, or persons performing similar functions, as appropriate to allow timely decisions regarding required disclosure.
 
Our management, including our Chief Executive Officer and Chief Financial Officer, does not expect that the Company’s disclosure controls and procedures will prevent all errors and all frauds. A control system, no matter how well conceived and operated, can provide only reasonable, not absolute, assurance that the objectives of the control system are met. Further, the design of a control system must reflect the fact that there are resource constraints, and the benefits of controls must be considered relative to their costs. Because of the inherent limitations in all control systems, no evaluation of controls can provide absolute assurance that all control issues and instances of fraud, if any, within the Company have been detected. These inherent limitations include the realities that judgments in decision-making can be faulty and that breakdowns can occur because of a simple error or mistake.
 
Additionally, controls can be circumvented by the individual acts of some persons, by collusion of two or more people, or by management override of the controls. The design of any system of controls also is based, in part, upon certain assumptions about the likelihood of future events, and there can be no assurance that any design will succeed in achieving its stated goals under all potential future conditions; over time, controls may become inadequate because of changes in conditions, or the degree of compliance with the policies or procedures may deteriorate. Because of the inherent limitations in a cost-effective control system, misstatements due to error or fraud may occur and not be detected.  
  

Changes in Internal Control Over Financial Reporting
 
There have been no changes in the Company’s internal control over financial reporting during the fiscal quarter ended December 31, 2015 that have materially affected, or are reasonably likely to materially affect, the Company’s internal control over financial reporting. The Company continues to review its disclosure controls and procedures, including its internal controls over financial reporting, and may from time to time make changes aimed at enhancing their effectiveness and to ensure that the Company’s systems evolve with its business.


Management Report on Internal Control Over Financial Reporting
 
Our management is responsible for establishing and maintaining adequate internal control over financial reporting. Our internal control system is designed to provide reasonable assurance regarding the reliability of financial reporting and the preparation of financial statements for external purposes in accordance with generally accepted accounting principles in the United States of America ("U.S. GAAP") and includes those policies and procedures that:
 
●
pertain to the maintenance of records that in reasonable detail accurately and fairly reflect the transactions and dispositions of the assets of the Company;


●
provide reasonable assurance that transactions are recorded as necessary to permit preparation of financial statements in accordance with U.S. GAAP, and that receipts and expenditures of the Company are being made only in accordance with authorizations of management and directors of the Company; and


●
provide reasonable assurance regarding prevention or timely detection of unauthorized acquisition, use or disposition of the Company’s assets that could have a material effect on its financial statements.
Because of its inherent limitations, a system of internal control over financial reporting can provide only reasonable assurance and may not prevent or detect misstatements. Further, because of changes in conditions, effectiveness of internal control over financial reporting may vary over time. Our system contains self-monitoring mechanisms, and actions are taken to correct deficiencies as they are identified.

73

Link to Table of Contents

 
Our management conducted an evaluation of the effectiveness of the system of internal control over financial reporting based on the framework in the Internal Control — Integrated Framework issued by the Committee of Sponsoring Organizations of the Treadway Commission (the 2013 framework). Based on this evaluation, our management concluded that our system of internal control over financial reporting was effective as of December 31, 2015. The effectiveness of our internal control over financial reporting has been audited by BDO USA, LLP, an independent registered public accounting firm, as stated in their report, which is included herein.
  
ITEM 9B. OTHER INFORMATION
 
None

PART III

ITEM 10. DIRECTORS, EXECUTIVE OFFICERS AND CORPORATE GOVERNANCE

This item is omitted because a definitive proxy statement that involves the election of directors will be filed with the SEC not later than 120 days after the close of the fiscal year pursuant to Regulation 14A, which information required by this item set forth in the proxy statement is incorporated by reference.

ITEM 11. EXECUTIVE COMPENSATION

This item is omitted because a definitive proxy statement that involves the election of directors will be filed with the SEC not later than 120 days after the close of the fiscal year pursuant to Regulation 14A, which information required by this item set forth in the proxy statement is incorporated by reference.

ITEM 12. SECURITY OWNERSHIP OF CERTAIN BENEFICIAL OWNERS AND MANAGEMENT AND RELATED STOCKHOLDER MATTERS

This item is omitted because a definitive proxy statement that involves the election of directors will be filed with the SEC not later than 120 days after the close of the fiscal year pursuant to Regulation 14A, which information required by this item set forth in the proxy statement is incorporated by reference.

ITEM 13. CERTAIN RELATIONSHIPS AND RELATED TRANSACTIONS, AND DIRECTOR INDEPENDENCE

This item is omitted because a definitive proxy statement that involves the election of directors will be filed with the SEC not later than 120 days after the close of the fiscal year pursuant to Regulation 14A, which information required by this item set forth in the proxy statement is incorporated by reference.

ITEM 14. PRINCIPAL ACCOUNTING FEES AND SERVICES

This item is omitted because a definitive proxy statement that involves the election of directors will be filed with the SEC not later than 120 days after the close of the fiscal year pursuant to Regulation 14A, which information required by this item set forth in the proxy statement is incorporated by reference.

74

Link to Table of Contents


PART IV

ITEM 15. EXHIBITS AND FINANCIAL STATEMENT SCHEDULES


Page
 
(a)(1)
Financial Statements


Consolidated Balance Sheets as of December 31, 2015 and 2014


Consolidated Statements of Income for the years ended December 31, 2015, 2014 and 2013


Consolidated Statements of Shareholders' Equity for the years ended December 31, 2015, 2014 and 2013


Consolidated Statements of Cash Flows for the years ended December 31, 2015, 2014 and 2013


Notes to the Consolidated Financial Statements
 
 
(a)(2)
Financial Statement Schedules


Schedule II – Condensed Financial Information of Registrant                                                         


Schedule III – Supplementary Insurance Information                                                                      


Schedule IV – Supplementary Reinsurance Information                                                                   
 
 
(a)(3)
The exhibits required to be filed by this Item 15. are set forth in the Exhibit Index accompanying this report.


75

Link to Table of Contents


SIGNATURES
 
 
Pursuant to the requirements of Section 13 or 15(d) of the Securities Exchange Act of 1934, the registrant has duly caused this report to be signed on its behalf by the undersigned, thereunto duly authorized.
 
 
GREENLIGHT CAPITAL RE, LTD.
By:
/s/ Barton Hedges                 
 
Barton Hedges
Chief Executive Officer
 
February 22, 2016


Pursuant to the requirements of the Securities Exchange Act of 1934, this report has been signed below by the following persons on behalf of the Registrant and in the capacities and on the dates indicated.
 
 
/s/ DAVID M. EINHORN               
 
/s/ LEONARD GOLDBERG          
 
David M. Einhorn
Director
 
Leonard Goldberg
Director
 
February 22, 2016
 
February 22, 2016


/s/ FRANK D. LACKNER              
 
/s/ ALAN BROOKS                      
 
Frank D. Lackner
Director
 
Alan Brooks
Director
 
February 22, 2016
 
February 22, 2016


/s/ IAN ISAACS                              
 
/s/ JOSEPH P. PLATT                  
 
Ian Isaacs
Director
 
Joseph P. Platt
Director
 
February 22, 2016
 
February 22, 2016


/s/ TIM COURTIS                           
 
/s/ BRYAN MURPHY                  
 
Tim Courtis
Chief Financial Officer
(principal financial and accounting officer)
 
Bryan Murphy
Director
 
February 22, 2016
 
February 22, 2016


/s/ BARTON HEDGES                    


Barton Hedges
Director & Chief Executive Officer
(principal executive officer)


February 22, 2016


76

Link to Table of Contents

Report of Independent Registered Public Accounting Firm

The Board of Directors and Shareholders
Greenlight Capital Re, Ltd.
Grand Cayman, Cayman Islands
 
We have audited Greenlight Capital Re, Ltd.’s internal control over financial reporting as of December 31, 2015, based on criteria established in Internal Control - Integrated Framework (2013) issued by the Committee of Sponsoring Organizations of the Treadway Commission (the COSO criteria). Greenlight Capital Re, Ltd.’s management is responsible for maintaining effective internal control over financial reporting and for its assessment of the effectiveness of internal control over financial reporting, included in the accompanying “Item 9A, Management’s Report on Internal Control Over Financial Reporting”. Our responsibility is to express an opinion on the company’s internal control over financial reporting based on our audit.
We conducted our audit in accordance with the standards of the Public Company Accounting Oversight Board (United States). Those standards require that we plan and perform the audit to obtain reasonable assurance about whether effective internal control over financial reporting was maintained in all material respects. Our audit included obtaining an understanding of internal control over financial reporting, assessing the risk that a material weakness exists, and testing and evaluating the design and operating effectiveness of internal control based on the assessed risk. Our audit also included performing such other procedures as we considered necessary in the circumstances. We believe that our audit provides a reasonable basis for our opinion.
A company’s internal control over financial reporting is a process designed to provide reasonable assurance regarding the reliability of financial reporting and the preparation of financial statements for external purposes in accordance with generally accepted accounting principles. A company’s internal control over financial reporting includes those policies and procedures that (1) pertain to the maintenance of records that, in reasonable detail, accurately and fairly reflect the transactions and dispositions of the assets of the company; (2) provide reasonable assurance that transactions are recorded as necessary to permit preparation of financial statements in accordance with generally accepted accounting principles, and that receipts and expenditures of the company are being made only in accordance with authorizations of management and directors of the company; and (3) provide reasonable assurance regarding prevention or timely detection of unauthorized acquisition, use, or disposition of the company’s assets that could have a material effect on the financial statements.
Because of its inherent limitations, internal control over financial reporting may not prevent or detect misstatements. Also, projections of any evaluation of effectiveness to future periods are subject to the risk that controls may become inadequate because of changes in conditions, or that the degree of compliance with the policies or procedures may deteriorate.
In our opinion, Greenlight Capital Re, Ltd. maintained, in all material respects, effective internal control over financial reporting as of December 31, 2015, based on the COSO criteria.
We also have audited, in accordance with the standards of the Public Company Accounting Oversight Board (United States), the consolidated balance sheets of Greenlight Capital Re, Ltd. as of December 31, 2015 and 2014, and the related consolidated statements of income, shareholders’ equity, and cash flows for each of the three years in the period ended December 31, 2015, and our report dated February 22, 2016 expressed an unqualified opinion thereon.
/s/ BDO USA, LLP
Grand Rapids, Michigan, USA

February 22, 2016


F-1

Link to Table of Contents

Report of Independent Registered Public Accounting Firm
 

The Board of Directors and Shareholders
Greenlight Capital Re, Ltd.
Grand Cayman, Cayman Islands
 
We have audited the accompanying consolidated balance sheets of Greenlight Capital Re, Ltd. as of December 31, 2015 and 2014 and the related consolidated statements of income, shareholders’ equity, and cash flows for each of the three years in the period ended December 31, 2015. In connection with our audits of the financial statements, we have also audited the financial statement schedules listed in the accompanying index. These financial statements and schedules are the responsibility of the Company’s management. Our responsibility is to express an opinion on these financial statements and schedules based on our audits.
We conducted our audits in accordance with the standards of the Public Company Accounting Oversight Board (United States). Those standards require that we plan and perform the audit to obtain reasonable assurance about whether the financial statements are free of material misstatement. An audit includes examining, on a test basis, evidence supporting the amounts and disclosures in the financial statements, assessing the accounting principles used and significant estimates made by management, as well as evaluating the overall presentation of the financial statements and schedules. We believe that our audits provide a reasonable basis for our opinion.
In our opinion, the consolidated financial statements referred to above present fairly, in all material respects, the financial position of Greenlight Capital Re, Ltd. at December 31, 2015 and 2014, and the results of its operations and its cash flows for each of the three years in the period ended December 31, 2015, in conformity with accounting principles generally accepted in the United States of America.
Also, in our opinion, the financial statement schedules, when considered in relation to the basic consolidated financial statements taken as a whole, present fairly, in all material respects, the information set forth therein.
We also have audited, in accordance with the standards of the Public Company Accounting Oversight Board (United States), Greenlight Capital Re, Ltd.’s internal control over financial reporting as of December 31, 2015, based on criteria established in Internal Control - Integrated Framework (2013) issued by the Committee of Sponsoring Organizations of the Treadway Commission (COSO) and our report dated February 22, 2016 expressed an unqualified opinion thereon.
/s/ BDO USA, LLP
Grand Rapids, Michigan, USA
February 22, 2016


F-2

Link to Table of Contents

GREENLIGHT CAPITAL RE, LTD.
CONSOLIDATED BALANCE SHEETS
 
December 31, 2015 and 2014
(expressed in thousands of U.S. dollars, except per share and share amounts)
 
2015
 
2014
Assets


Investments


Debt instruments, trading, at fair value
$
39,087

 
$
49,212

Equity securities, trading, at fair value
905,994

 
1,266,175

Other investments, at fair value
119,083

 
115,591

Total investments
1,064,164

 
1,430,978

Cash and cash equivalents
112,162

 
12,030

Restricted cash and cash equivalents
1,236,589

 
1,296,914

Financial contracts receivable, at fair value
13,215

 
47,171

Reinsurance balances receivable
187,940

 
151,185

Loss and loss adjustment expenses recoverable
3,368

 
11,523

Deferred acquisition costs, net
59,823

 
34,420

Unearned premiums ceded
3,251

 
4,027

Notes receivable
25,146

 
1,566

Other assets
6,864

 
5,478

Total assets
$
2,712,522

 
$
2,995,292

Liabilities and equity


Liabilities


Securities sold, not yet purchased, at fair value
$
882,906

 
$
1,090,731

Financial contracts payable, at fair value
28,245

 
44,592

Due to prime brokers
396,453

 
211,070

Loss and loss adjustment expense reserves
305,997

 
264,243

Unearned premium reserves
211,954

 
128,736

Reinsurance balances payable
18,326

 
40,372

Funds withheld
7,143

 
6,558

Other liabilities
12,725

 
14,949

Total liabilities
1,863,749

 
1,801,251

Equity


Preferred share capital (par value $0.10; authorized, 50,000,000; none issued)
—

 
—

Ordinary share capital (Class A: par value $0.10; authorized, 100,000,000; issued and outstanding, 30,772,572 (2014: 31,129,648): Class B: par value $0.10; authorized, 25,000,000; issued and outstanding, 6,254,895 (2014: 6,254,895))
3,703

 
3,738

Additional paid-in capital
496,401

 
500,553

Retained earnings
325,287

 
660,860

Shareholders’ equity attributable to shareholders
825,391

 
1,165,151

Non-controlling interest in joint venture
23,382

 
28,890

Total equity
848,773

 
1,194,041

Total liabilities and equity
$
2,712,522

 
$
2,995,292

 
  The accompanying Notes to the Consolidated Financial Statements are an
integral part of the Consolidated Financial Statements.

F-3

Link to Table of Contents


GREENLIGHT CAPITAL RE, LTD.
CONSOLIDATED STATEMENTS OF INCOME
 
Years ended December 31, 2015, 2014 and 2013
(expressed in thousands of U.S. dollars, except per share and share amounts)
 
2015
 
2014
 
2013
Revenues


Gross premiums written
$
502,124

 
$
324,023

 
$
535,702

Gross premiums ceded
(9,001
)
 
(13,493
)
 
(2,780
)
Net premiums written
493,123

 
310,530

 
532,922

Change in net unearned premium reserves
(84,736
)
 
43,710

 
14,977

Net premiums earned
408,387

 
354,240

 
547,899

Net investment income (loss)
(281,924
)
 
122,575

 
218,140

Other income (expense), net
(3,413
)
 
2,987

 
(1,710
)
Total revenues
123,050

 
479,802

 
764,329

Expenses


Loss and loss adjustment expenses incurred, net
317,097

 
234,986

 
338,493

Acquisition costs, net
116,207

 
107,665

 
171,872

General and administrative expenses
23,434

 
24,500

 
20,958

Total expenses
456,738

 
367,151

 
531,323

Income (loss) before income tax expense
(333,688
)
 
112,651

 
233,006

Income tax (expense) benefit
1,755

 
624

 
(538
)
Net income (loss) including non-controlling interest
(331,933
)
 
113,275

 
232,468

Loss (income) attributable to non-controlling interest in joint venture
5,508

 
(3,683
)
 
(6,769
)
Net income (loss)
$
(326,425
)
 
$
109,592

 
$
225,699

Earnings (loss) per share


Basic
$
(8.90
)
 
$
2.94

 
$
6.13

Diluted
$
(8.90
)
 
$
2.89

 
$
6.01

Weighted average number of ordinary shares used in the determination of earnings and loss per share


Basic
36,670,466

 
37,242,687

 
36,838,128

Diluted
36,670,466

 
37,874,387

 
37,585,167

 
The accompanying Notes to the Consolidated Financial Statements are an
integral part of the Consolidated Financial Statements. 


F-4

Link to Table of Contents

GREENLIGHT CAPITAL RE, LTD.
CONSOLIDATED STATEMENTS OF SHAREHOLDERS’ EQUITY
 
Years ended December 31, 2015, 2014 and 2013
(expressed in thousands of U.S. dollars)

 
Ordinary share capital
 
Additional paid-in capital
 
Retained earnings
 
Shareholders' equity attributable to shareholders
 
Non-controlling
interest in joint venture
 
Total equity
Balance at December 31, 2012
$
3,670

 
$
492,469

 
$
325,569

 
$
821,708

 
$
38,702

 
$
860,410

Issue of Class A ordinary shares, net of forfeitures
35

 
492

 
—

 
527

 
—

 
527

Share-based compensation expense, net of forfeitures
—

 
3,661

 
—

 
3,661

 
—

 
3,661

Non-controlling interest withdrawal from joint venture, net
—

 
—

 
—

 
—

 
(10,762
)
 
(10,762
)
Income attributable to non-controlling interest in joint venture
—

 
—

 
—

 
—

 
6,769

 
6,769

Net income
—

 
—

 
225,699

 
225,699

 
—

 
225,699

Balance at December 31, 2013
$
3,705

 
$
496,622

 
$
551,268

 
$
1,051,595

 
$
34,709

 
$
1,086,304


Issue of Class A ordinary shares, net of forfeitures
33

 
—

 
—

 
33

 
—

 
33

Share-based compensation expense, net of forfeitures
—

 
3,931

 
—

 
3,931

 
—

 
3,931

Non-controlling interest withdrawal from joint venture, net
—

 
—

 
—

 
—

 
(9,502
)
 
(9,502
)
Income attributable to non-controlling interest in joint venture
—

 
—

 
—

 
—

 
3,683

 
3,683

Net income
—

 
—

 
109,592

 
109,592

 
—

 
109,592

Balance at December 31, 2014
$
3,738

 
$
500,553

 
$
660,860

 
$
1,165,151

 
$
28,890

 
$
1,194,041


Issue of Class A ordinary shares, net of forfeitures
26

 
—

 
—

 
26

 
—

 
26

Repurchase of Class A ordinary shares
(61
)
 
(8,483
)
 
(9,148
)
 
(17,692
)
 
—

 
(17,692
)
Share-based compensation expense, net of forfeitures
—

 
4,248

 
—

 
4,248

 
—

 
4,248

Short-swing sale profit from shareholder
—

 
83

 
—

 
83

 
—

 
83

Non-controlling interest contribution into (withdrawal from) joint venture, net
—

 
—

 
—

 
—

 
—

 
—

Income (loss) attributable to non-controlling interest in joint venture
—

 
—

 
—

 
—

 
(5,508
)
 
(5,508
)
Net income (loss)
—

 
—

 
(326,425
)
 
(326,425
)
 
—

 
(326,425
)
Balance at December 31, 2015
$
3,703

 
$
496,401

 
$
325,287

 
$
825,391

 
$
23,382

 
$
848,773


The accompanying Notes to the Consolidated Financial Statements are an
integral part of the Consolidated Financial Statements. 


F-5

Link to Table of Contents

GREENLIGHT CAPITAL RE, LTD.
CONSOLIDATED STATEMENTS OF CASH FLOWS

Years ended December 31, 2015, 2014 and 2013
(expressed in thousands of U.S. dollars)
 
2015
 
2014
 
2013
Cash provided by (used in) operating activities


Net income (loss)
$
(326,425
)
 
$
109,592

 
$
225,699

Adjustments to reconcile net income to net cash provided by (used in) operating activities


Net change in unrealized gains and losses on investments and financial contracts
265,401

 
187,753

 
(149,013
)
Net realized gains on investments and financial contracts
(22,227
)
 
(352,133
)
 
(122,568
)
Foreign exchange (gains) losses on investments
3,725

 
(14,797
)
 
(44,492
)
Income (loss) attributable to non-controlling interest in joint venture
(5,508
)
 
3,683

 
6,769

Share-based compensation expense, net of forfeitures
4,274

 
3,964

 
3,675

Depreciation expense
405

 
436

 
325

Net change in


Reinsurance balances receivable
(83,113
)
 
16,155

 
5,881

Loss and loss adjustment expenses recoverable
(916
)
 
5,306

 
17,622

Deferred acquisition costs, net
(25,403
)
 
17,377

 
7,380

Unearned premiums ceded
776

 
(854
)
 
443

Other assets
(1,791
)
 
(1,349
)
 
(291
)
Loss and loss adjustment expense reserves
41,754

 
(65,651
)
 
(26,576
)
Unearned premium reserves
83,218

 
(44,321
)
 
(15,128
)
Reinsurance balances payable
7,524

 
1,583

 
3,497

Funds withheld
585

 
(3,568
)
 
(7,289
)
Other liabilities
(2,224
)
 
3,092

 
1,369

Net cash (used in) provided by operating activities
(59,945
)
 
(133,732
)
 
(92,697
)
Investing activities


Purchases of investments, trading
(1,252,969
)
 
(1,603,856
)
 
(931,036
)
Sales of investments, trading
1,388,162

 
1,722,936

 
933,356

Purchases of financial contracts
(25,765
)
 
(13,302
)
 
(64,153
)
Dispositions of financial contracts
7,002

 
113,011

 
90,282

Securities sold, not yet purchased
892,085

 
934,769

 
940,486

Dispositions of securities sold, not yet purchased
(1,068,891
)
 
(952,843
)
 
(766,680
)
Change in due to prime brokers
185,383

 
(103,632
)
 
(11,786
)
Change in restricted cash and cash equivalents, net
50,400

 
35,476

 
(107,932
)
Change in notes receivable, net
2,279

 
18,983

 
3,281

Non-controlling interest withdrawal from joint venture, net
—

 
(9,502
)
 
(10,762
)
Fixed assets additions
—

 
—

 
(1,040
)
Net cash (used in) provided by investing activities
177,686

 
142,040

 
74,016

Financing activities


Net proceeds from exercise of stock options
—

 
—

 
513

Short-swing sale profit from shareholder
83

 
—

 
—

Repurchase of Class A ordinary shares
(17,692
)
 
—

 
—

Net cash (used in) provided by financing activities
(17,609
)
 
—

 
513

Net increase (decrease) in cash and cash equivalents
100,132

 
8,308

 
(18,168
)
Cash and cash equivalents at beginning of the period
12,030

 
3,722

 
21,890

Cash and cash equivalents at end of the period
$
112,162

 
$
12,030

 
$
3,722

Supplementary information


Interest paid in cash
$
21,959

 
$
21,482

 
$
23,741

Income tax paid in cash
—

 
—

 
531

Non-cash transfer to notes receivable
25,859

 
—

 
—


The accompanying Notes to the Consolidated Financial Statements are an
integral part of the Consolidated Financial Statements. 

F-6

Link to Table of Contents

GREENLIGHT CAPITAL RE, LTD.
NOTES TO THE CONSOLIDATED FINANCIAL STATEMENTS
 
Years ended December 31, 2015, 2014 and 2013  
 
1.   ORGANIZATION AND BASIS OF PRESENTATION
 
Greenlight Capital Re, Ltd. ("GLRE") was incorporated as an exempted company under the Companies Law of the Cayman Islands on July 13, 2004. GLRE’s principal wholly-owned subsidiary, Greenlight Reinsurance, Ltd. ("Greenlight Re"), provides global specialty property and casualty reinsurance. Greenlight Re has a Class D insurer license issued in accordance with the terms of The Insurance Law, 2010 and underlying regulations thereto (the "Law") and is subject to regulation by the Cayman Islands Monetary Authority ("CIMA"), in terms of the Law. Greenlight Re commenced underwriting in April 2006. Effective May 30, 2007, GLRE completed an initial public offering of 11,787,500 Class A ordinary shares at $19.00 per share. Concurrently, 2,631,579 Class B ordinary shares of GLRE were sold at $19.00 per share in a private placement offering. During 2008, Verdant Holding Company, Ltd. ("Verdant"), a wholly-owned subsidiary of GLRE, was incorporated in the state of Delaware. During 2010, GLRE established Greenlight Reinsurance Ireland, Designated Activity Company ("GRIL"), a wholly-owned reinsurance subsidiary based in Dublin, Ireland. GRIL is authorized as a non-life reinsurance undertaking in accordance with the provisions of the European Union (Insurance and Reinsurance) Regulations 2015 ("Irish Regulations"). GRIL provides multi-line property and casualty reinsurance capacity to the European broker market and provides GLRE with an additional platform to serve clients located in Europe and North America.  As used herein, the "Company" refers collectively to GLRE and its consolidated subsidiaries.
 
The Class A ordinary shares of GLRE are listed on Nasdaq Global Select Market under the symbol "GLRE".

These consolidated financial statements are prepared in conformity with accounting principles generally accepted in the United States of America ("U.S. GAAP"). The consolidated financial statements include the accounts of GLRE and the consolidated financial statements of its wholly owned subsidiaries, Greenlight Re, GRIL and Verdant. All significant intercompany transactions and balances have been eliminated on consolidation.

Reclassifications
Certain prior period balances have been reclassified to conform to the current period presentation. Prior to January 1, 2015, non-investment related foreign exchange gains and losses were recorded under general and administrative expenses in the condensed consolidated statements of income. Effective from January 1, 2015, the presentation has been modified and any non-investment related foreign exchange gains or losses are now recorded under “other income (expense), net” in the consolidated statements of income. As a result, foreign exchange gains (losses) of $2.6 million and $(0.8) million that were previously reported in general and administrative expenses for the years ended December 31, 2014 and 2013, respectively, were reclassified as “other income (expense), net” to conform to the current year presentation. The reclassifications resulted in no changes to net income or retained earnings for any of the periods presented.


2.   SIGNIFICANT ACCOUNTING POLICIES
 
Use of Estimates
 
The preparation of consolidated financial statements in conformity with U.S. GAAP requires management to make estimates and assumptions that affect the reported amounts of assets and liabilities and disclosure of contingent assets and liabilities at the date of the consolidated financial statements and the reported amounts of income and expenses during the period. Actual results could differ from these estimates. 

Cash and Cash Equivalents
 
Cash and cash equivalents consist of cash and certain short-term, highly liquid investments with original maturity dates of three months or less.

Restricted Cash and Cash Equivalents
 
The Company is required to maintain certain cash in segregated accounts with prime brokers and derivative counterparties. The amount of restricted cash held by prime brokers is primarily used to support the liability created from securities sold, not yet purchased and derivatives. Additionally, restricted cash and cash equivalent balances are held to

F-7

Link to Table of Contents

collateralize regulatory trusts and letters of credit issued to cedents (see Notes 4 and 6). The amount of cash encumbered varies depending on the market value of the securities sold, not yet purchased, and the collateral required by the cedents in the form of trust accounts and letters of credit. In addition, derivative counterparties require cash collateral to support the current value of any amounts that may be due to the counterparty based on the value of the underlying financial instrument. 

Premium Revenue Recognition
 
The Company accounts for reinsurance contracts in accordance with U.S. GAAP. In the event that a reinsurance contract does not transfer sufficient risk, deposit accounting is used and the contract is reported as a deposit liability.
 
The Company writes excess of loss contracts as well as quota share contracts. The Company estimates the ultimate premiums for the entire contract period. These estimates are based on information received from the ceding companies and estimates from actuarial pricing models used by the Company. For excess of loss contracts, the total ultimate estimated premiums are recorded as premiums written at the inception of the contract. For quota share contracts, the premiums are recorded as written based on cession statements from cedents which typically are received monthly or quarterly depending on terms specified in each contract. For any reporting lag, premiums written are estimated based on the portion of the ultimate estimated premiums relating to the risks underwritten during the lag period.
 
Premium estimates are reviewed by management at least quarterly. Such review includes a comparison of actual reported premiums to expected ultimate premiums along with a review of the aging and collection of premium estimates. Based on management’s review, the appropriateness of the premium estimates is evaluated, and any adjustments to these estimates are recorded in the period in which they are determined. Changes in premium estimates, including premium receivable on both excess of loss and quota share contracts, are expected and may result in significant adjustments in any period. A significant portion of amounts included in reinsurance balances receivable represent estimated premiums written, net of commissions and brokerage, and are not currently due based on the terms of the underlying contracts.

Certain contracts allow for reinstatement premiums in the event of a full limit loss prior to the expiry of a contract. A reinstatement premium is not due until there is a full limit loss event and therefore, in accordance with U.S. GAAP, the Company records a reinstatement premium as written only in the event that a client incurs a full limit loss on the contract and the contract allows for a reinstatement of coverage upon payment of an additional premium. For catastrophe contracts which contractually require the payment of a reinstatement premium equal to or greater than the original premium upon the occurrence of a full limit loss, the reinstatement premiums are earned over the original contract period. Reinstatement premiums that are contractually calculated on a pro-rata basis of the original premiums, are earned over the remaining coverage period.
 
Certain contracts may provide for a penalty to be paid if the contract is terminated and canceled prior to its expiration term. Cancellation penalties are recognized in the period the notice of cancellation is received and are recorded in the consolidated statements of income under "other income (expense), net".

Premiums written are generally recognized as earned over the contract period in proportion to the period of risk covered. Unearned premiums consist of the unexpired portion of reinsurance provided.
 
Reinsurance Premiums Ceded
 
The Company reduces the risk of future losses on business assumed by reinsuring certain risks and exposures with other reinsurers (retrocessionaires). The Company remains liable to the extent that any retrocessionaire fails to meet its obligations and to the extent the Company does not hold sufficient security for their unpaid obligations.
 
Ceded premiums are written during the period in which the risks incept and are expensed over the contract period in proportion to the period of protection. Unearned premiums ceded consist of the unexpired portion of reinsurance obtained.

Deferred Acquisition Costs
 
Policy acquisition costs, such as commission and brokerage costs, relate directly to, and vary with, the writing of reinsurance contracts. Acquisition costs relating solely to bound contracts are deferred subject to ultimate recoverability and are amortized over the related contract term. The Company evaluates the recoverability of deferred acquisition costs by determining if the sum of future earned premiums and anticipated investment income is greater than the expected future claims and expenses. If a loss is probable on the unexpired portion of policies in force, a premium deficiency loss is recognized. At December 31, 2015 and 2014, the deferred acquisition costs were considered fully recoverable and no premium deficiency loss was recorded. 

F-8

Link to Table of Contents


Acquisition costs also include profit commissions which are expensed when incurred. Profit commissions are calculated and accrued based on the expected loss experience for contracts and recorded when the current loss estimate indicates that a profit commission is probable under the contract terms. As of December 31, 2015, $12.2 million (2014: $11.0 million) of profit commission reserves were included in reinsurance balances payable on the consolidated balance sheets. For the year ended December 31, 2015, $7.5 million (2014: $2.7 million and 2013: $3.7 million, respectively) of net profit commission expense was included in acquisition costs on the consolidated statements of income.

Funds Withheld
 
Funds withheld include reinsurance balances retained from retrocessionaires as security for a period of time in accordance with the contract terms. Any interest expense that the Company incurs during the period these funds are withheld, are included under net investment income in the consolidated statements of income.
  
Loss and Loss Adjustment Expense Reserves and Recoverable
 
The Company establishes reserves for contracts based on estimates of the ultimate cost of all losses including losses incurred but not reported ("IBNR"). These estimated ultimate reserves are based on the Company’s own actuarial estimates derived from reports received from ceding companies, industry data and historical experience. These estimates are reviewed by the Company periodically on a contract by contract basis and adjusted as necessary. Since reserves are estimates, the final settlement of losses may vary from the reserves established and any adjustments to the estimates, which may be material, are recorded in the period they are determined.
 
Loss and loss adjustment expenses recoverable include the amounts due from retrocessionaires for unpaid loss and loss adjustment expenses on retrocession agreements. Ceded losses incurred but not reported are estimated based on the Company’s actuarial estimates. These estimates are reviewed periodically and adjusted when deemed necessary. The Company may not be able to ultimately recover the loss and loss adjustment expense recoverable amounts due to the retrocessionaires’ inability to pay. The Company regularly evaluates the financial condition of its retrocessionaires and records provisions for uncollectible reinsurance expenses recoverable when recovery is no longer probable.
 
Notes Receivable
 
Notes receivable include promissory notes receivable from third party entities. These notes are recorded at cost along with accrued interest, if any, which approximates the fair value. Interest income and realized gains or losses on sale of notes receivable are included under net investment income (loss) in the consolidated statements of income.

The Company regularly reviews all notes receivable individually for impairment and records valuation allowance provisions for uncollectible and non-performing notes. The Company places notes on non-accrual status when the recorded value of the note is not considered impaired but there is uncertainty as to the collection of interest based on the terms of the note. The Company resumes accrual of interest on a note when none of the principal or interest remains past due, and the Company expects to collect the remaining contractual principal and interest. Interest collected on notes that are placed on non-accrual status is treated on a cash-basis and recorded as interest income when collected, provided that the recorded value of the note is deemed to be fully collectible. Where doubt exists as to the collectability of the remaining recorded value of the notes placed on non-accrual status, any payments received are applied to reduce the recorded value of the notes.

At December 31, 2015, $23.0 million of notes receivable (net of any valuation allowance) were on non-accrual status
(2014: $0.0 million) and any payments received were applied to reduce the recorded value of the notes. The increase in notes receivable during the year ended December 31, 2015, related to a settlement agreement entered into with a ceding insurer during 2015 whereby certain amounts, previously classified under reinsurance balances receivable, were converted into a ten-year note receivable.
 
At December 31, 2015 and 2014, there was no accrued interest included in the notes receivable balance. Based on management’s assessment, the recorded values of the notes receivable, net of valuation allowance, at December 31, 2015 and 2014, were expected to be fully collectible.


F-9

Link to Table of Contents

Deposit Assets and Liabilities
 
In accordance with U.S. GAAP, deposit accounting is used in the event that a reinsurance contract does not transfer sufficient insurance risk, or a contract provides retroactive reinsurance. Any losses on such contracts are charged to earnings immediately. Any gains relating to such contracts are deferred and amortized over the estimated remaining settlement period. All such deferred gains are included in reinsurance balances payable in the consolidated balance sheets. Amortized gains are recorded in the consolidated statements of income as other income. At December 31, 2015 and 2014, there were no material deposit assets or deposit liabilities and no material gains or losses on deposit accounted contracts.
 
Fixed Assets
 
Fixed assets are included in other assets on the consolidated balance sheets and are recorded at cost when acquired. Fixed assets are comprised of computer software, furniture and fixtures and leasehold improvements and are depreciated, using the straight-line method, over their estimated useful lives, which are five years for both computer software, and furniture and fixtures.  Leasehold improvements are amortized over the lesser of the estimated useful lives of the assets or remaining lease term. The Company periodically reviews fixed assets that have finite lives, and that are not held for sale, for impairment by comparing the carrying value of the assets to their estimated future undiscounted cash flows. For the years ended December 31, 2015, 2014 and 2013, there were no impairments in fixed assets.

At December 31, 2015, the cost, accumulated depreciation and net book values of the fixed assets were as follows:
 
Cost
 
Accumulated depreciation
 
 
Net book value
 
($ in thousands)
Computer software
$
556

 
$
(348
)
 
$
208

Furniture and fixtures
620

 
(513
)
 
107

Leasehold improvements
2,002

 
(1,229
)
 
773

Total
$
3,178

 
$
(2,090
)
 
$
1,088

 
At December 31, 2014, the cost, accumulated depreciation and net book values of the fixed assets were as follows:
 
Cost
 
Accumulated depreciation
 
 
Net book value
 
($ in thousands)
Computer software
$
556

 
$
(277
)
 
$
279

Furniture and fixtures
620

 
(442
)
 
178

Leasehold improvements
2,002

 
(966
)
 
1,036

Total
$
3,178

 
$
(1,685
)
 
$
1,493

 
Financial Instruments
 
Investments in Securities and Investments in Securities Sold, Not Yet Purchased
 
The Company’s investments in debt instruments and equity securities that are classified as "trading securities" are carried at fair value. The fair values of the listed equity investments are derived based on quoted prices (unadjusted) in active markets for identical assets (Level 1 inputs). The fair values of listed equities that have restrictions on sale or transfer which expire within one year, are determined by adjusting the observed market price of the equity using a liquidity discount based on observable market inputs. The fair values of debt instruments are derived based on inputs that are observable, either directly or indirectly, such as market maker or broker quotes reflecting recent transactions (Level 2 inputs), and are generally derived based on the average of multiple market maker or broker quotes which are considered to be binding. Where quotes are not available, debt instruments are valued using cash flow models using assumptions and estimates that may be subjective and non-observable (Level 3 inputs).

The Company’s "other investments" may include investments in private and unlisted equity securities, limited partnerships, and commodities, which are all carried at fair value. The fair values of commodities are determined based on quoted prices in active markets for identical assets (Level 1). The Company maximizes the use of observable direct or indirect inputs (Level 2 inputs) when deriving the fair values for "other investments". For limited partnerships and private and unlisted equity securities, where observable inputs are not available, the fair values are derived based on unobservable inputs (Level 3

F-10

Link to Table of Contents

inputs) such as management’s assumptions developed from available information using the services of the investment advisor, including the most recent net asset values obtained from the managers of those underlying investments.

For securities classified as "trading securities", and "other investments", any realized and unrealized gains or losses are determined on the basis of the specific identification method (by reference to cost or amortized cost, as appropriate) and included in net investment income (loss) in the consolidated statements of income.

Dividend income and expense are recorded on the ex-dividend date. The ex-dividend date is the date as of when the underlying security must have been traded to be eligible for the dividend declared. Interest income and interest expense are recorded on an accrual basis.
 
Derivative Financial Instruments
 
U.S. GAAP requires that an entity recognize all derivatives in the balance sheet at fair value. It also requires that unrealized gains and losses resulting from changes in fair value be included in income or comprehensive income, depending on whether the instrument qualifies as a hedge transaction, and if so, the type of hedge transaction. The Company’s derivative financial instrument assets are included in financial contracts receivable. Derivative financial instrument liabilities are generally included in financial contracts payable. The Company's derivatives do not qualify as hedges for financial reporting purposes and are recorded in the consolidated balance sheets on a gross basis and not offset against any collateral pledged or received. Pursuant to the International Swaps and Derivatives Association ("ISDA") master agreements, securities lending agreements and other agreements, the Company and its counterparties typically have the ability to net certain payments owed to each other in specified circumstances. In addition, in the event a party to one of the ISDA master agreements, securities lending agreements or other agreements defaults, or a transaction is otherwise subject to termination, the non-defaulting party generally has the right to set off against payments owed to the defaulting party or collateral held by the non-defaulting party. The Company may from time to time enter into underwriting contracts such as industry loss warranty contracts ("ILW") that are treated as derivatives for U.S GAAP purposes.
 
Financial Contracts

The Company enters into financial contracts with counterparties as part of its investment strategy. Financial contracts, which include total return swaps, credit default swaps ("CDS"), futures, options, currency forwards and other derivative instruments, are recorded at their fair value with any unrealized gains and losses included in net investment income (loss) in the consolidated statements of income. Financial contracts receivable represents derivative contracts whereby, based upon the contract's current fair value, the Company will be entitled to receive payments upon settlement of the contract. Financial contracts payable represents derivative contracts whereby, based upon each contract's current fair value, the Company will be obligated to make payments upon settlement of the contract.
 
Total return swap agreements, included on the consolidated balance sheets as financial contracts receivable and financial contracts payable, are derivative financial instruments whereby the Company is either entitled to receive or obligated to pay the product of a notional amount multiplied by the movement in an underlying security, which the Company may not own, over a specified time frame. In addition, the Company may also be obligated to pay or receive other payments based on interest rates, dividend payments and receipts, or foreign exchange movements during a specified period. The Company measures its rights or obligations to the counterparty based on the fair value movements of the underlying security together with any other payments due. These contracts are carried at fair value, based on observable inputs (Level 2 inputs) with the resultant unrealized gains and losses reflected in net investment income (loss) in the consolidated statements of income. Additionally, any changes in the value of amounts received or paid on swap contracts are reported as a gain or loss in net investment income (loss) in the consolidated statements of income.
 
Financial contracts may also include exchange traded futures or options contracts that are based on the movement of a particular index, equity security, commodity, currency or interest rate. Where such contracts are traded in an active market, the Company’s obligations or rights on these contracts are recorded at fair value based on the observable quoted prices of the same or similar financial contracts in an active market (Level 1) or on broker quotes which reflect market information based on actual transactions (Level 2). Amounts invested in exchange traded options and over the counter ("OTC") options are recorded either as an asset or liability at inception. Subsequent to initial recognition, unexpired exchange traded option contracts are recorded at fair value based on quoted prices in active markets (Level 1). For OTC options or exchange traded options where a quoted price in an active market is not available, fair values are derived based upon observable inputs (Level 2) such as multiple quotes from brokers and market makers, which are considered to be binding.
 
The Company may purchase and sell CDS for strategic investment purposes. A CDS is a derivative instrument that provides protection against an investment loss due to specified credit or default events of a reference entity. The seller of a CDS

F-11

Link to Table of Contents

guarantees to pay the buyer a specified amount if the reference entity defaults on its obligations or fails to perform. The buyer of a CDS pays a premium over time to the seller in exchange for obtaining this protection. A CDS trading in an active market is valued at fair value based on broker or market maker quotes for identical instruments in an active market (Level 2) or based on the current credit spreads on identical contracts (Level 2).

Share-Based Compensation
 
The Company has established a stock incentive plan for directors, employees and consultants.
 
U.S. GAAP requires the Company to recognize share-based compensation transactions using the fair value at the grant date of the award. The Company measures compensation for restricted shares and restricted stock units ("RSUs") based on the price of the Company’s common shares at the grant date and the expense is recognized on a straight line basis over the vesting period.

Determining the fair value of share purchase options at the grant date requires significant estimation and judgment. The Company uses an option-pricing model (Black-Scholes option pricing model) to assist in the calculation of fair value for share purchase options. The model requires estimation of various inputs such as estimated term, forfeiture and dividend rates and expected volatility. The Company uses the full life of the options, ten years, as the estimated term of the options, and has assumed no forfeitures and no dividends paid during the life of the options. Effective from 2014, the estimate of expected volatility is based on the daily historical trading data of the Company's Class A ordinary shares from the date that these shares commenced trading (May 24, 2007) to the grant date. Prior to 2014, the Company's share had not been publicly traded for a sufficient length of time to reasonably estimate the expected volatility. Therefore, for share purchase options granted prior to 2014, the Company determined the expected volatility based primarily on the historical volatility of similar entities. The Company considered factors such as an entity's industry, stage of life cycle, size and financial leverage when selecting similar entities. The Company used a sample peer group of companies in the reinsurance industry as well as the Company’s own historical volatility in determining the expected volatility. 
 
For share purchase options issued under the employee stock incentive plan, compensation cost is calculated and expensed over the vesting periods on a graded vesting basis (see Note 10). 

If actual results differ significantly from these estimates and assumptions, particularly in relation to the Company’s estimation of volatility which requires the most judgment, share-based compensation expense, primarily with respect to future share-based awards, could be materially impacted.
 
Foreign Exchange
 
The reporting and functional currency of the Company and all its subsidiaries is the U.S. dollar. Transactions in foreign currencies are recorded in U.S. dollars at the exchange rates in effect on the transaction date. Monetary assets and liabilities in foreign currencies at the balance sheet date are translated at the exchange rate in effect at the balance sheet date and translation exchange gains and losses, if any, are included in "other income (expense), net" in the consolidated statements of income. 

Other Assets
 
Other assets consist primarily of investment income receivable, prepaid expenses, fixed assets and deferred tax assets.
 
Other Liabilities
 
Other liabilities consist primarily of dividends payable on securities sold, not yet purchased, and employee bonus accruals. At December 31, 2015, other liabilities included accrued bonus of $8.2 million (2014: $7.6 million). Under the Company's bonus program, each employee’s target bonus consists of two components: a discretionary component based on a qualitative assessment of each employee’s performance and a quantitative component based on the return on deployed equity (‘‘RODE”) for each underwriting year relating to reinsurance operations. The qualitative portion of an employee’s annual bonus is accrued at each employee's target amount, which may differ significantly from the actual amount approved and awarded annually by the Compensation Committee. The quantitative portion of each employee’s annual bonus is accrued based on the expected RODE for each underwriting year and adjusted for changes in the expected RODE and actual investment return each quarter until all losses are settled and the underwriting year is declared closed. The quantitative bonus is calculated and paid, with the approval of the Compensation Committee, in annual installments between two to five years from the end of the fiscal year in which the business was underwritten. Any further changes are incorporated into the following open underwriting year. The expected RODE calculation utilizes proprietary models which require significant estimation and judgment. Actual

F-12

Link to Table of Contents

RODE may vary significantly from the expected RODE and any adjustments to the quantitative bonus estimates, which may be material, are recorded in the period in which they are determined. 
 
Also included in other liabilities are accruals for income taxes payable, professional fees and other general expenses.
 
Non-controlling Interest
 
Non-controlling interest in joint venture on the consolidated balance sheets represents DME Advisors, LLC’s (‘‘DME”) share of assets in the joint venture whereby DME is a participant in the joint venture as disclosed in Note 13. DME’s share of investment income or loss is included in the consolidated statements of income as income attributable to non-controlling interest in joint venture.

Comprehensive Income (Loss)

The Company has no other comprehensive income or loss, other than the net income or loss disclosed in the consolidated statements of income.

Earnings (Loss) Per Share
 
Basic earnings per share are based on the weighted average number of common shares and participating securities outstanding during the period. Diluted earnings per share includes the dilutive effect of restricted stock units ("RSU") and additional potential common shares issuable when stock options are exercised and are determined using the treasury stock method. The Company treats its unvested restricted stock as participating securities in accordance with U.S. GAAP, which requires that unvested stock awards which contain non-forfeitable rights to dividends or dividend equivalents, whether paid or unpaid (referred to as "participating securities"), be included in the number of shares outstanding for both basic and diluted earnings per share calculations. In the event of a net loss, all RSUs, stock options outstanding and participating securities are excluded from the calculation of both basic and diluted loss per share since their inclusion would be anti-dilutive.
 
Year ended December 31
 
2015
 
2014
 
2013
Weighted average shares outstanding - basic
36,670,466

 
37,242,687

 
36,838,128

Effect of dilutive service provider share-based awards
—

 
8,498

 
144,726

Effect of dilutive employee and director share-based awards
—

 
623,202

 
602,313

Weighted average shares outstanding - diluted
36,670,466

 
37,874,387

 
37,585,167

Anti-dilutive stock options outstanding
211,821

 
—

 
218,197

Participating securities excluded from calculation of loss per share 
307,013

 
—

 
—


Taxation
 
Under current Cayman Islands law, no corporate entity, including GLRE and Greenlight Re, is obligated to pay taxes in the Cayman Islands on either income or capital gains. The Company has an undertaking from the Governor-in-Cabinet of the Cayman Islands, pursuant to the provisions of the Tax Concessions Law, as amended, that, in the event that the Cayman Islands enacts any legislation that imposes tax on profits, income, gains or appreciations, or any tax in the nature of estate duty or inheritance tax, such tax will not be applicable to GLRE, Greenlight Re nor their respective operations, or to the Class A or Class B ordinary shares or related obligations, until February 1, 2025.
 
Verdant is incorporated in Delaware and therefore is subject to taxes in accordance with the U.S. federal rates and regulations prescribed by the U.S. Internal Revenue Service ("IRS"). Verdant’s taxable income is generally expected to be taxed at a rate of 35%.

GRIL is incorporated in Ireland and therefore is subject to the Irish corporation tax rate of 12.5% on its trading income, and 25% on its non-trading income, if any.

Any deferred tax asset is evaluated for recovery and a valuation allowance is recorded when it is more likely than not that the deferred tax asset will not be realized in the future. The Company has not taken any income tax positions that are subject to significant uncertainty or that are reasonably likely to have a material impact on the Company.


F-13

Link to Table of Contents

Segment Information
 
Under U.S. GAAP, operating segments are based on the internal information that management uses for allocating resources and assessing performance as the source of the Company's reportable segments.
 
The Company manages its business on the basis of one operating segment, Property and Casualty Reinsurance, in accordance with the qualitative and quantitative criteria established by U.S. GAAP. 
 
Recent Accounting Pronouncements
        
In May 2015, the FASB issued Accounting Standards Update 2015-07, "Fair Value Measurement (Topic 820): Disclosures for Investments in Certain Entities That Calculate Net Asset Value per Share or Its Equivalent" ("ASU 2015-07"). The amendments apply to reporting entities that elect to measure the fair value of an investment using the net asset value ("NAV") per share (or its equivalent) as a practical expedient. The amendments remove the requirement to categorize within the fair value hierarchy all investments for which fair value is measured using the NAV per share as a practical expedient. The amendments also remove the requirement to make certain disclosures for all investments that are eligible to be measured at fair value using the NAV per share as a practical expedient. Rather, those disclosures are limited to investments for which the entity has elected to measure the fair value using that practical expedient. The amendments in ASU 2015-07 are effective for reporting periods beginning after December 15, 2015, with early adoption permitted. Entities are required to apply the amendments in this update retrospectively to all periods presented. The Company will adopt ASU 2015-07 during the first quarter of 2016. As the Company measures certain investments in private equity funds using the NAV as a practicable expedient, upon adoption of ASU 2015-07, the fair value of these investments will be removed from the fair value hierarchy for all periods presented in the Company’s consolidated financial statements. The Company will continue to disclose information on these investments for which fair value is measured at NAV as a practical expedient.

In May 2015, the FASB issued ASU 2015-09, "Financial Services - Insurance (Topic 944): Disclosures about Short-Duration Contracts" ("ASU 2015-09"). ASU 2015-09 requires additional disclosures for short-duration contracts including incurred and paid claims development information, claims duration information, quantitative claims frequency information (unless impracticable), and an explanation of significant changes in methodologies and assumptions used to calculate the loss and loss adjustment expense reserves. ASU 2015-09 is effective for public entities for annual reporting periods beginning after December 15, 2015, and interim reporting periods within annual reporting periods beginning after December 15, 2016 with early adoption permitted. The Company is evaluating the impact of the disclosure requirements of ASU 2015-09 and is preparing to disclose the additional information in its consolidated financial statements for the fiscal year ending December 31, 2016 and thereafter.


3.         FINANCIAL INSTRUMENTS
 
In the normal course of its business, the Company purchases and sells various financial instruments, which include listed and unlisted equities, corporate and sovereign debt, commodities, futures, put and call options, currency forwards, other derivatives and similar instruments sold, not yet purchased.

The Company is exposed to credit risk in relation to counterparties that may default on their obligations to the Company. The amount of counterparty credit risk predominantly relates to the value of financial contracts receivable and assets held at counterparties. The Company mitigates its counterparty credit risk by using several counterparties which decreases the likelihood of any significant concentration of credit risk with any one counterparty.  In addition, the Company is exposed to credit risk on corporate and sovereign debt instruments to the extent that the debtors may default on their debt obligations.    
 
The Company is exposed to market risk including interest rate and foreign exchange fluctuations on financial instruments that are valued at market prices. Market movements can be volatile and difficult to predict. This may affect the ultimate gains or losses realized upon the sale of its holdings as well as the amount of net investment income reported in the consolidated statements of income. Management utilizes the services of the Company's investment advisor to monitor the Company's positions to reduce the risk of potential loss due to changes in market values.
 
Purchases and sales of investments are disclosed in the consolidated statements of cash flows. Net realized gains on the sale of investments, financial contracts, and investments sold, not yet purchased during 2015 were $22.2 million (2014: $352.1 million gains, 2013: $122.6 million gains). Gross realized gains were $350.5 million (2014: $596.6 million, 2013: $312.3 million) and gross realized losses were $328.3 million (2014: $244.5 million, 2013: $189.7 million). For the year ended December 31, 2015, included in net investment income in the consolidated statements of income were $265.4 million of net

F-14

Link to Table of Contents

losses (2014: $187.8 million of net losses, 2013: $149.0 million of net gains) relating to change in unrealized gains and losses on trading securities still held at the balance sheet date.
  
As of December 31, 2015, cash and investments with a fair value of $324.3 million (2014: $302.6 million) have been pledged as security against letters of credit issued, and $78.6 million (2014: nil) have been pledged as security relating to regulatory trusts.
 
As of December 31, 2015, the Company’s investments in gold and gold derivatives was the only investment in excess of 10% of the Company’s shareholders’ equity, with a fair value of $98.0 million, or 11.6% of shareholders' equity. As of December 31, 2014, the Company’s investment in Micron Technology Inc., was the only investment in excess of 10% of the Company’s shareholders’ equity, with fair values of $151.1 million, or 12.7%, of shareholders' equity.

   Fair Value Hierarchy

The Company’s financial instruments are carried at fair value, and the net unrealized gains or losses are included in net investment income (loss) in the consolidated statements of income.
 
The following table presents the Company’s investments, categorized by the level of the fair value hierarchy as of December 31, 2015:
 
 
Fair value measurements as of December 31, 2015
 
 
Description
 
Quoted prices in
active markets
(Level 1)
 
Significant other
observable
inputs
(Level 2)
 
Significant
unobservable
inputs
(Level 3)
 
Total
Assets: 
 
($ in thousands)
Debt instruments
 
$
—

 
$
38,582

 
$
505

 
$
39,087

Listed equity securities
 
900,369

 
5,625

 
—

 
905,994

Commodities
 
98,046

 
—

 
—

 
98,046

Private and unlisted equity securities
 
—

 
—

 
21,037

 
21,037

Financial contracts receivable
 
20

 
13,195

 
—

 
13,215


$
998,435

 
$
57,402

 
$
21,542

 
$
1,077,379

Liabilities:


Listed equity securities, sold not yet purchased
 
$
(808,481
)
 
$
—

 
$
—

 
$
(808,481
)
Debt instruments, sold not yet purchased
 
—

 
(74,425
)
 
—

 
(74,425
)
Financial contracts payable
 
(488
)
 
(27,757
)
 
—

 
(28,245
)
 
 
$
(808,969
)
 
$
(102,182
)
 
$
—

 
$
(911,151
)
 

F-15

Link to Table of Contents

The following table presents the Company’s investments, categorized by the level of the fair value hierarchy as of December 31, 2014:
 
 
Fair value measurements as of December 31, 2014
 
 
Description
 
Quoted prices in
active markets
(Level 1)
 
Significant other
observable
inputs
(Level 2)
 
Significant
unobservable
inputs
(Level 3)
 
Total
Assets: 
 
($ in thousands)
Debt instruments
 
$
—

 
$
26,953

 
$
22,259

 
$
49,212

Listed equity securities
 
1,259,298

 
6,877

 
—

 
1,266,175

Commodities
 
96,872

 
—

 
—

 
96,872

Private and unlisted equity securities
 
—

 
—

 
18,719

 
18,719

Financial contracts receivable
 
2,463

 
44,708

 
—

 
47,171


$
1,358,633

 
$
78,538

 
$
40,978

 
$
1,478,149

Liabilities:


Listed equity securities, sold not yet purchased
 
$
(834,228
)
 
$
—

 
$
—

 
$
(834,228
)
Debt instruments, sold not yet purchased
 
—

 
(256,503
)
 
—

 
(256,503
)
Financial contracts payable
 
—

 
(44,592
)
 
—

 
(44,592
)
 
 
$
(834,228
)
 
$
(301,095
)
 
$
—

 
$
(1,135,323
)
 
The following table presents the reconciliation of the balances for all investments measured at fair value using significant unobservable inputs (Level 3) for the year ended December 31, 2015: 
 
 
Fair Value Measurements Using Significant Unobservable Inputs (Level 3)
 
 
Year ended December 31, 2015
 
 
Assets
 
Liabilities
 
 
Debt instruments
 
 Private and unlisted equity securities
 
Financial contracts receivable
 
Listed equity securities
 
 Total
 
Financial contracts payable
 
 
 ($ in thousands)
Beginning balance
 
$
22,259

 
$
18,719

 
$
—

 
$
—

 
$
40,978

 
$
—

Purchases
 
—

 
5,009

 
2,340

 
—

 
7,349

 
—

Sales
 
(21,561
)
 
(3,290
)
 
—

 
—

 
(24,851
)
 
—

Total realized and unrealized gains (losses) and amortization included in earnings, net
 
(193
)
 
599

 
(3,027
)
 
(692
)
 
(3,313
)
 
314

Transfers into Level 3
 
—

 
—

 
2,536

 
5,189

 
7,725

 
8,835

Transfers out of Level 3
 
—

 
—

 
(1,849
)
 
(4,497
)
 
(6,346
)
 
(9,149
)
Ending balance
 
$
505

 
$
21,037

 
$
—

 
$
—

 
$
21,542

 
$
—


During the year ended December 31, 2015, $5.2 million of equity securities, listed on the Athens Stock Exchange (the "ASE"), were transferred from Level 1 to Level 3 securities due to trading being halted from June 26, 2015 to August 3, 2015 for all equity securities listed on the ASE. Since there was no active market with observable trading prices to determine the fair value of these securities, during this period these securities were valued based on the last trading price of these securities on the ASE and adjusted for the estimated decline in the fair value of American depository receipts of other comparable securities. When the ASE resumed trading on August 3, 2015, the fair values of the ASE listed equity securities were once again based on observable prices in an active market. Therefore, $4.5 million of listed equity securities trading on the ASE were transferred from Level 3 to Level 1 securities during the year ended December 31, 2015.

The fair values for derivatives for which the underlying securities traded on the ASE were also transferred to Level 3 securities during 2015 when the ASE halted trading, and were subsequently transferred out of Level 3 securities when the ASE

F-16

Link to Table of Contents

resumed trading. Therefore, for the year ended December 31, 2015, $2.5 million and $8.8 million of financial contracts receivable and financial contracts payable, respectively, were transfered from Level 2 to Level 3 due to the fair values being based on unobservable inputs during the period that the ASE had halted trading. During the year ended December 31, 2015, $1.8 million of financial contracts receivable and $9.1 million of financial contracts payable, respectively, were transfered from Level 3 to Level 2 as fair values were based on observable inputs once the ASE resumed trading.

There were no other transfers between Level 1, Level 2 or Level 3 during the year ended December 31, 2015.

The following table presents the reconciliation of the balances for all investments measured at fair value using significant unobservable inputs (Level 3) for the year ended December 31, 2014:


  Fair Value Measurements Using Significant Unobservable Inputs (Level 3)
 
 
Year ended December 31, 2014
 
 
Debt instruments
 
 Private and unlisted equity securities
 
Total
 
 
 ($ in thousands)
Beginning balance
 
$
527

 
$
46,323

 
$
46,850

Purchases
 
21,561

 
3,958

 
25,519

Sales
 
—

 
(37,252
)
 
(37,252
)
Total realized and unrealized gains included in earnings, net
 
171

 
9,734

 
9,905

Transfers into Level 3
 
—

 
—

 
—

Transfers out of Level 3
 
—

 
(4,044
)
 
(4,044
)
Ending balance
 
$
22,259

 
$
18,719

 
$
40,978


During the year ended December 31, 2014, $4.0 million of securities at fair value, based on the date of transfer, were transferred from Level 3 to Level 2 as these securities began actively trading on a listed exchange during the third quarter of 2014. However, due to lock-up period restrictions on those securities, they were classified as Level 2 upon transfer until the lock-up period expired.

Additionally. during the year ended December 31, 2014, $14.4 million of securities at fair value, based on the date of transfer, were transferred from Level 2 to Level 1 as the lock up period restrictions on those securities expired. There were no other transfers between Level 1, Level 2 or Level 3 during the year ended December 31, 2014.

As of December 31, 2015, included in private and unlisted equity securities are investments in private equity funds with a fair value of $12.6 million (December 31, 2014: $12.3 million) determined based on unadjusted net asset values reported by the managers of these securities. Some of these values were reported from periods prior to December 31, 2015. The private equity funds have varying lock-up periods and, as of December 31, 2015, all of the funds had redemption restrictions, and therefore have been categorized within Level 3 of the fair value hierarchy. The redemption restrictions have been in place since inception of the investments and are not expected to lapse in the near future. As of December 31, 2015, the Company had $6.1 million (December 31, 2014: $8.9 million) of unfunded commitments relating to private equity funds whose fair values are determined based on unadjusted net asset values reported by the managers of these securities. These commitments are included in the amounts presented in the schedule of commitments and contingencies in Note 14 of these consolidated financial statements.  

For the year ended December 31, 2015, included in net investment loss in the consolidated statements of income were net realized losses relating to Level 3 securities of $1.4 million (2014: net realized gains of $13.5 million). In addition, for the year ended December 31, 2015, amortization expense of $2.3 million (2014: nil) relating to financial contracts receivable, valued using unobservable inputs, was included in the consolidated statements of income as "other income (expense), net".

For Level 3 securities still held as of the reporting date, the change in net unrealized gain for the year ended December 31, 2015 of $0.6 million (2014: net unrealized gains $1.4 million), were included in net investment income (loss) in the consolidated statements of income.


F-17

Link to Table of Contents

Investments
 
Debt instruments, trading

At December 31, 2015, the following investments were included in debt instruments:
 
 
Cost/
 amortized
 cost
 
Unrealized
 gains
 
Unrealized
 losses
 
Fair
 value
 
 
($ in thousands)
Corporate debt – U.S.
 
$
25,674

 
$
155

 
$
(5,519
)
 
$
20,310

Corporate debt – Non U.S.
 
2,109

 
—

 
(1,795
)
 
314

Sovereign debt – Non U.S.
 
17,688

 
1,225

 
(450
)
 
18,463

Total debt instruments
 
$
45,471

 
$
1,380

 
$
(7,764
)
 
$
39,087

 
At December 31, 2014, the following investments were included in debt instruments:
 
 
Cost/
 amortized
 cost
 
Unrealized
 gains
 
Unrealized
 losses
 
Fair
 value
 
 
($ in thousands)
Corporate debt – U.S.
 
$
23,677

 
$
5

 
$
(1,423
)
 
$
22,259

Corporate debt – Non U.S.
 
5,870

 
49

 
(1,405
)
 
4,514

Municipal debt – U.S.
 
1,759

 
—

 
(6
)
 
1,753

Sovereign debt – Non U.S.
 
21,769

 
—

 
(1,083
)
 
20,686

Total debt instruments
 
$
53,075

 
$
54

 
$
(3,917
)
 
$
49,212


The maturity distribution for debt instruments held at December 31, 2015 and 2014, was as follows:
 
 
2015
 
2014
 
 
Cost/
 amortized
 cost
 
Fair
 value
 
Cost/
 amortized
 cost
 
Fair
 value
 
 
($ in thousands)
Within one year
 
$
—

 
$
—

 
$
—

 
$
—

From one to five years
 
4,202

 
4,129

 
21,922

 
21,923

From five to ten years
 
18,840

 
14,780

 
2,401

 
1,282

More than ten years
 
22,429

 
20,178

 
28,752

 
26,007


$
45,471

 
$
39,087

 
$
53,075

 
$
49,212

 
Equity securities, trading

At December 31, 2015, the following long positions were included in equity securities, trading: 
 
 
Cost
 
Unrealized
gains
 
Unrealized
losses
 
Fair
value
 
 
($ in thousands)
Equities – listed
 
$
1,011,424

 
$
67,114

 
$
(187,885
)
 
$
890,653

Exchange traded funds
 
31,570

 
—

 
(16,229
)
 
15,341

Total equity securities
 
$
1,042,994

 
$
67,114

 
$
(204,114
)
 
$
905,994


F-18

Link to Table of Contents

At December 31, 2014, the following long positions were included in equity securities, trading:
 
 
Cost
 
Unrealized
gains
 
Unrealized
losses
 
Fair
value
 
 
($ in thousands)
Equities – listed
 
$
1,079,955

 
$
247,109

 
$
(80,637
)
 
$
1,246,427

Exchange traded funds
 
42,126

 
—

 
(22,378
)
 
19,748

Total equity securities
 
$
1,122,081

 
$
247,109

 
$
(103,015
)
 
$
1,266,175


Other Investments
 
"Other investments" include commodities and private and unlisted equity securities. As of December 31, 2015 and 2014, commodities were comprised of gold bullion. 

At December 31, 2015, the following securities were included in other investments:
 
 
Cost
 
Unrealized
gains
 
Unrealized
losses
 
Fair
value
 
 
($ in thousands)
Commodities
 
$
102,092

 
$
—

 
$
(4,046
)
 
$
98,046

Private and unlisted equity securities
 
18,720

 
3,491

 
(1,174
)
 
21,037


$
120,812

 
$
3,491

 
$
(5,220
)
 
$
119,083


At December 31, 2014, the following securities were included in other investments: 
 
 
Cost
 
Unrealized
gains
 
Unrealized
losses
 
Fair
value
 
 
($ in thousands)
Commodities
 
$
95,815

 
$
1,057

 
$
—

 
$
96,872

Private and unlisted equity securities
 
17,238

 
3,451

 
(1,970
)
 
18,719


$
113,053

 
$
4,508

 
$
(1,970
)
 
$
115,591

 
Investments in Securities Sold, Not Yet Purchased 

Securities sold, not yet purchased are securities that the Company has sold, but does not own, in anticipation of a decline in the market value of the security. The Company’s risk is that the value of the security will increase rather than decline. Consequently, the settlement amount of the liability for securities sold, not yet purchased may exceed the amount recorded in the consolidated balance sheet as the Company is obligated to purchase the securities sold, not yet purchased in the market at prevailing prices to settle its obligations. To establish a position in security sold, not yet purchased, the Company needs to borrow the security for delivery to the buyer. On each day the transaction is open, the liability for the obligation to replace the borrowed security is marked-to-market and an unrealized gain or loss is recorded. At the time the transaction is closed, the Company realizes a gain or loss equal to the difference between the price at which the security was sold and the cost of replacing the borrowed security. While the transaction is open, the Company will also incur an expense for any dividends or interest which will be paid to the lender of the securities.

At December 31, 2015, the following securities were included in investments in securities sold, not yet purchased:
 
 
Proceeds
 
Unrealized gains
 
Unrealized losses
 
 Fair value
 
 
($ in thousands)
Equities – listed
 
$
(803,842
)
 
$
102,469

 
$
(94,681
)
 
$
(796,054
)
Exchange traded funds
 
(9,572
)
 
—

 
(2,855
)
 
(12,427
)
Sovereign debt – Non U.S.
 
(77,443
)
 
3,018

 
—

 
(74,425
)
 
 
$
(890,857
)
 
$
105,487

 
$
(97,536
)
 
$
(882,906
)


F-19

Link to Table of Contents

At December 31, 2014, the following securities were included in investments in securities sold, not yet purchased: 
 
 
Proceeds
 
Unrealized gains
 
Unrealized losses
 
 Fair value
 
 
($ in thousands)
Corporate debt – U.S.
 
$
(7,066
)
 
$
1,007

 
$
(5
)
 
$
(6,064
)
Equities – listed
 
(813,365
)
 
91,690

 
(101,715
)
 
(823,390
)
Exchange traded funds
 
(9,180
)
 
—

 
(1,658
)
 
(10,838
)
Sovereign debt – Non U.S.
 
(246,589
)
 
6,635

 
(10,485
)
 
(250,439
)
 
 
$
(1,076,200
)
 
$
99,332

 
$
(113,863
)
 
$
(1,090,731
)
 
Financial Contracts
 
As of December 31, 2015 and 2014, the Company had entered into total return equity swaps, interest rate swaps, commodity swaps, CDS, options, warrants, rights, futures and forward contracts with various financial institutions to meet certain investment objectives. Under the terms of each of these financial contracts, the Company is either entitled to receive or is obligated to make payments, which are based on the product of a formula contained within each contract that includes the change in the fair value of the underlying or reference security.

In addition, during the year ended December 31, 2015, the Company had entered into an ILW with certain third-parties in order to purchase protection against worldwide wind and earthquake exposures from January 2015 to December 2015. In return for a fixed payment, the Company is entitled to receive a variable payment in the event of losses incurred by the insurance industry, as a whole, exceeding a specified threshold. Through December 31, 2015, the Company was not aware of any industry loss event occurring that would have triggered a recovery under the ILW.
 
At December 31, 2015, the fair values of financial contracts outstanding were as follows: 
Financial Contracts
 
Listing
currency
(1)
 
Notional amount of
underlying instruments
 
Fair value of net assets
(obligations)
on financial
contracts


($ in thousands)
Financial contracts receivable


Call options (2)
 
USD
 
47,259

 
$
657

Put options (3)
 
USD
 
147,326

 
8,790

Total return swaps – equities
 
EUR/GBP/USD
 
50,205

 
3,748

Warrants and rights on listed equities
 
EUR
 
59

 
20

Total financial contracts receivable, at fair value


$
13,215

Financial contracts payable


Call options
 
USD
 
2,601

 
$
(64
)
Commodity Swaps
 
USD
 
42,160

 
(12,784
)
Forwards
 
KRW
 
2,908

 
(22
)
Futures
 
USD
 
21,195

 
(488
)
Total return swaps – equities
 
EUR/GBP/HKD/RON/MXN/USD
 
71,874

 
(14,887
)
Total financial contracts payable, at fair value


$
(28,245
)
(1) USD = US Dollar; EUR = Euro; GBP = British Pound; HKD = Hong Kong Dollar; KRW = Korean Won; MXN = Mexican Peso; RON = Romanian New Leu.
(2) Includes options on interest rate futures relating to U.S. dollar LIBOR interest rates.
(3) Includes options on the Japanese Yen and the Chinese Yuan, denominated in U.S. dollars.
 

F-20

Link to Table of Contents

At December 31, 2014, the fair values of financial contracts outstanding were as follows: 
Financial Contracts
 
Listing
currency (1)
 
Notional amount of
underlying instruments
 
Fair value of net assets
(obligations)
on financial
contracts


($ in thousands)
Financial contracts receivable


Futures
 
USD
 
13,204

 
$
3,461

Put options (2)
 
USD
 
299,907

 
22,349

Total return swaps – equities
 
EUR/GBP/HKD/USD
 
43,355

 
18,898

Warrants and rights on listed equities
 
EUR
 
8,054

 
2,463

Total financial contracts receivable, at fair value


$
47,171

Financial contracts payable


Credit default swaps, purchased – corporate debt
 
USD
 
221,198

 
$
(1,305
)
Credit default swaps, purchased – sovereign debt
 
USD
 
251,467

 
(1,714
)
Forwards
 
KRW
 
20,563

 
(512
)
Futures
 
USD
 
33,625

 
(867
)
Total return swaps – equities
 
EUR/GBP/HKD/INR/RON/USD
 
122,667

 
(40,194
)
Total financial contracts payable, at fair value


$
(44,592
)
(1) USD = US Dollar; EUR = Euro; GBP = British Pound; HKD = Hong Kong Dollar; KRW = Korean Won; RON = Romanian New Leu; INR = Indian Rupee.
(2) Includes options on the Japanese Yen and the Chinese Yuan, denominated in U.S. dollars.

Options are derivative financial instruments that give the buyer, in exchange for a premium payment, the right, but not the obligation, to either purchase from (call option) or sell to (put option) the writer, a specified underlying security at a specified price on or before a specified date. The Company enters into option contracts to meet certain investment objectives. For exchange traded option contracts, the exchange acts as the counterparty to specific transactions and therefore bears the risk of delivery to and from counterparties of specific positions.

As of December 31, 2015, the Company held $8.7 million OTC put options (long) (December 31, 2014: $22.4 million).


F-21

Link to Table of Contents

During the years ended December 31, 2015, 2014 and 2013, the Company reported gains and losses on derivatives as follows:
Derivatives not designated as hedging instruments
 
Location of gains and losses on derivatives recognized in income
 
Gain (loss) on derivatives recognized in income


Year ended December 31


2015
 
2014
 
2013


($ in thousands)
Commodity swaps
 
Net investment income (loss)
 
$
(12,061
)
 
$
—

 
$
—

Credit default swaps, purchased – corporate debt
 
Net investment income (loss)
 
(156
)
 
(345
)
 
(3,552
)
Credit default swaps, purchased – sovereign debt
 
Net investment income (loss)
 
(90
)
 
(298
)
 
(1,087
)
Forwards
 
Net investment income (loss)
 
1,009

 
(490
)
 
11,209

Futures
 
Net investment income (loss)
 
(952
)
 
16,721

 
12,504

Interest rate options
 
Net investment income (loss)
 
—

 
(26
)
 
(82
)
Interest rate swaps
 
Net investment income (loss)
 
(706
)
 
—

 
—

Options, warrants, and rights
 
Net investment income (loss)
 
(13,955
)
 
1,020

 
21,446

Total return swaps – equities
 
Net investment income (loss)
 
(12,590
)
 
13,142

 
85,638

Weather derivative swap
 
Other income (expense), net
 
(2,340
)
 
—

 
—

Total


$
(41,841
)
 
$
29,724

 
$
126,076


The Company generally does not enter into derivatives for risk management or hedging purposes. The volume of derivative activities varies from period to period depending on potential investment opportunities.

For the year ended December 31, 2015, the Company’s volume of derivative activities (based on notional amounts) was as follows:
2015
 
Year ended December 31
Derivatives not designated as hedging instruments (notional amounts)
 
  Entered
 
Exited
 
 
($ in thousands)
Commodity swaps
 
$
103,358

 
$
43,261

Credit default swaps (1)
 
—

 
—

Forwards
 
—

 
13,377

Futures
 
311,536

 
294,441

Interest rate swaps
 
9,139,000

 
7,213,000

Options, warrants and rights (1)
 
661,103

 
341,702

Total return swaps
 
67,844

 
185,128

Weather derivative swap
 
12,000

 
12,000

Total
 
$
10,294,841

 
$
8,102,909

(1) Exited amount excludes derivatives which expired or were exercised during the period.

F-22

Link to Table of Contents


For the year ended December 31, 2014, the Company’s volume of derivative activities (based on notional amounts) was as follows:
2014
 
Year ended December 31
Derivatives not designated as hedging instruments (notional amounts)
 
  Entered
 
Exited
 
 
($ in thousands)
Forwards
 
$
—

 
$
82,688

Futures
 
308,178

 
356,216

Options, warrants and rights (1)
 
1,044,241

 
314,876

Total return swaps
 
121,125

 
160,065

Total
 
$
1,473,544

 
$
913,845

(1) Exited amount excludes derivatives which expired or were exercised during the period.

The Company does not offset its derivative instruments and presents all amounts in the consolidated balance sheets on a gross basis. The Company has pledged cash collateral to derivative counterparties to support the current value of amounts due to the counterparties based on the value of the underlying security.

As of December 31, 2015, the gross and net amounts of derivative instruments and the cash collateral applicable to derivative instruments were as follows:
December 31, 2015
 
(i)
 
(ii)
 
(iii) = (i) - (ii)
 
(iv) Gross amounts not offset in the balance sheet
 
(v) = (iii) + (iv)
Description
 
Gross amounts of recognized assets (liabilities)
 
Gross amounts offset in the balance sheet
 
Net amounts of assets (liabilities) presented in the balance sheet
 
Financial instruments available for offset
 
Cash collateral (received) pledged
 
Net amount of asset (liability)
 
 
($ in thousands)
Financial contracts receivable
 
$
13,215

 
$
—

 
$
13,215

 
$
(8,937
)
 
$
(2,036
)
 
$
2,242

Financial contracts payable
 
(28,245
)
 
—

 
(28,245
)
 
8,937

 
19,308

 
—


As of December 31, 2014, the gross and net amounts of derivative instruments and the cash collateral applicable to derivative instruments were as follows:
December 31, 2014
 
(i)
 
(ii)
 
(iii) = (i) - (ii)
 
(iv) Gross amounts not offset in the balance sheet
 
(v) = (iii) + (iv)
Description
 
Gross amounts of recognized assets (liabilities)
 
Gross amounts offset in the balance sheet
 
Net amounts of assets (liabilities) presented in the balance sheet
 
Financial instruments available for offset
 
Cash collateral (received) pledged
 
Net amount of asset (liability)
 
 
($ in thousands)
Financial contracts receivable
 
$
47,171

 
$
—

 
$
47,171

 
$
(24,265
)
 
$
(9,452
)
 
$
13,454

Financial contracts payable
 
(44,592
)
 
—

 
(44,592
)
 
24,265

 
20,327

 
—


F-23

Link to Table of Contents

4.        DUE TO PRIME BROKERS
 
As of December 31, 2015, the amount due to prime brokers is comprised of margin-borrowing from prime brokers relating to investments purchased on margin as well as the margin-borrowing for providing collateral to support some of the Company’s outstanding letters of credit (see Notes 6 and 14) and trust accounts. Under term margin agreements and certain letter of credit facility agreements, the Company pledges certain investment securities to borrow cash from the prime brokers. The borrowed cash is placed in a custodial account in the name of the Company and this custodial account provides collateral for any letters of credit issued. Since there is no legal right of offset, the Company’s liability for the cash borrowed from the prime brokers is included on the consolidated balance sheets as due to prime brokers while the cash held in the custodial account is included on the consolidated balance sheets as restricted cash and cash equivalents. At December 31, 2015, the amounts due to prime brokers included $301.4 million (2014: $135.0 million) of cash borrowed under the term margin agreements to provide collateral in the form of letters of credit and trust accounts, and $95.0 million (2014: $76.1 million) of borrowing relating to investing activities.

Greenlight Re's investment guidelines, among other stipulations in the guidelines, allow for up to 15% (GRIL: 5%) net margin leverage for extended periods of time and up to 30% (GRIL: 20%) net margin leverage relating to investing activities for periods of less than 30 days.


5.        CASH AND CASH EQUIVALENTS
 
 
December 31, 2015
 
December 31, 2014
 
 
($ in thousands)
Cash at banks
 
$
44,133

 
$
3,426

Cash held with brokers
 
68,029

 
8,604

Total cash and cash equivalents
 
$
112,162

 
$
12,030

 
Due to the short term nature of cash and cash equivalents, management believes the above noted carrying values approximate their fair value. Cash at banks include cash held at non-U.S. financial institutions which are not insured by the FDIC or any other deposit insurance programs.


6.        RESTRICTED CASH AND CASH EQUIVALENTS
 
The Company is required to maintain certain cash in segregated accounts with prime brokers and swap counterparties. The amount of restricted cash held by prime brokers is primarily used to support the liability created from securities sold, not yet purchased and the amount of cash encumbered varies depending on the market value of the securities sold, not yet purchased. Swap counterparties also require cash collateral to support the current value of any amounts that may be due to the counterparty based on the value of the underlying security.

Restricted cash and cash equivalents also include amounts held by the Company to provide collateral required by the cedents in the form of trust accounts and letters of credit (see Notes 4 and 14). As of December 31, 2015 and 2014, the restricted cash and cash equivalents were comprised of the following:
 
 
December 31, 2015
 
December 31, 2014
 
 
($ in thousands)
Cash held by prime brokers relating to securities sold, not yet purchased
 
$
882,906

 
$
1,090,731

Cash collateral relating to letters of credit issued
 
222,852

 
134,981

Cash held as collateral in trust accounts
 
78,584

 
—

Cash and cash equivalents held by swap counterparties
 
52,247

 
71,202

Total restricted cash and cash equivalents
 
$
1,236,589

 
$
1,296,914


7.        LOSS AND LOSS ADJUSTMENT EXPENSE RESERVES
 
At December 31, 2015 and 2014, loss and loss adjustment expense reserves were comprised of the following:

F-24

Link to Table of Contents


2015
 
2014
 
 
($ in thousands)
Case reserves
 
$
111,535

 
$
117,049

IBNR
 
194,462

 
147,194

Total
 
$
305,997

 
$
264,243


A summary of changes in outstanding loss and loss adjustment expense reserves is as follows: 
 
 
2015
 
2014
 
2013
 
 
($ in thousands)
Gross balance at January 1
 
$
264,243

 
$
329,894

 
$
356,470

Less: Losses recoverable
 
(11,523
)
 
(16,829
)
 
(34,451
)
Net balance at January 1
 
252,720

 
313,065

 
322,019

Incurred losses related to:


Current year
 
266,796

 
216,757

 
344,613

Prior years
 
50,301

 
18,229

 
(6,120
)
Total incurred
 
317,097

 
234,986

 
338,493

Paid losses related to:


Current year
 
(132,017
)
 
(163,139
)
 
(177,871
)
Prior years
 
(132,846
)
 
(130,438
)
 
(170,018
)
Total paid
 
(264,863
)
 
(293,577
)
 
(347,889
)
Foreign currency revaluation
 
(2,325
)
 
(1,754
)
 
442

Net balance at December 31
 
302,629

 
252,720

 
313,065

Add: Losses recoverable
 
3,368

 
11,523

 
16,829

Gross balance at December 31
 
$
305,997

 
$
264,243

 
$
329,894


For the year ended December 31, 2015, the net losses incurred included $50.3 million related to net adverse loss development on reserves relating to prior years. During the year ended December 31, 2015, the loss development on prior year contracts primarily related to the following:

●
$36.9 million of adverse loss development relating to a general liability contract originally written from 2008 to 2011. This contract contains underlying construction defect liability coverage predominantly on single family homes. During the third quarter of 2015, we completed an in-depth analysis, with the assistance of a third party expert, of the construction defect claims reported and the potential for claims not yet reported on this contract. Based on this assessment, we revised the actuarial methodology used for reserving the construction defect claims on this contract, which resulted in an increase in incurred but not reported losses;

●
$14.7 million of adverse loss development relating to a general liability contract originally written in 2010. This contract contains underlying construction defect liability coverage. Based on updated data received from the insured, we conducted additional actuarial analysis and updated our actuarial input parameters based on consultation with external industry experts. As a result, the average estimated cost per claim was increased;

●
$9.3 million of adverse loss development relating to our Florida homeowners' insurance contracts as a result of deterioration of sinkhole claims, higher than anticipated water damage claims from rainstorms and an increase in the practice of "assignment of benefits" whereby homeowners assign their rights for filing and settling claims to attorneys and public adjusters which led to increases in the frequency of claims reported as well as the severity of loss adjustment expenses. However, because some of these contracts included sliding scale ceding commission rates, the increase in loss reserves was partially offset by a $5.1 million decrease in ceding commissions and profit commissions recorded as acquisition costs;

●
$2.4 million of net adverse loss development relating to our solicitors' professional indemnity contracts as a result of multiple large claims reported during the period and an increase in incurred losses;

●
$5.1 million of favorable loss development relating to an excess of loss property contract resulting in elimination of loss reserve based on updated loss information received from the insured during the period

F-25

Link to Table of Contents

indicating that no losses will breach into our layer of coverage. The decrease in loss reserve was more than offset by a reversal of $2.5 million of earned premiums and an accrual of $3.4 million of profit commission recorded as acquisition costs;

●
$4.5 million of favorable loss development relating to private passenger motor contracts during the period. The decrease in loss reserve was partially offset by $3.3 million of additional ceding commissions recorded as acquisition costs;

●
$2.3 million of favorable loss development relating to the employer medical stop-loss business as a result of better than expected claims frequency reported by the cedent; and

●
$1.3 million of loss reserves released upon commutation of a private passenger motor contract during the period. The decrease in loss reserve was partially offset by $1.1 million of additional ceding commissions incurred as part of the commutation agreement.

There were no other significant developments of prior period loss reserves during the year ended December 31, 2015.
 
For the year ended December 31, 2014, the net losses incurred included $18.2 million related to net adverse loss development on reserves relating to prior years. During the year ended December 31, 2014, the loss development on prior year contracts primarily related to the following:

●
$7.8 million of adverse loss development, relating to a general liability contract currently in run-off. Loss reserves were increased on this contract after a detailed actuarial review of existing claims data received from the client, which reported an increase in the number of open claims. The loss reserves were also increased to take into account the corresponding claims handling fees expected to be incurred to settle the open claims;

●
$7.1 million of adverse loss development, net of retrocession recoveries, relating to commercial motor claims on a multi-line quota share contract currently in run-off. Loss reserves were increased on this contract after a detailed actuarial review of existing claims data received from the client, which reported significant increases in incurred losses on some claims as well as an increase in the number of open claims;

●
$4.0 million of adverse loss development relating to a solicitors' professional indemnity contract as a result of a combination of large claims reported and increases in case reserves on several smaller claims. Loss reserves were increased on this contract after a detailed review of existing claims data received from the client, audits of claim files at the third party claims administrator and actuarial analysis based on all available information. The contract terms included sliding scale ceding commission rates and profit commissions. As a result, the increase in loss reserves was offset by a $0.6 million decrease in ceding commissions and profit commissions which were recorded as decreases to acquisition costs;

●
$3.0 million of adverse loss development relating to the employer medical stop-loss business. Loss reserves were increased on these contracts after a detailed review of existing claims data received from the clients, audits of claim files at the third party claims administrators and actuarial analysis based on all available information; and

●
$3.8 million of favorable loss development relating to private passenger automobile business, primarily as a result of better than expected loss development noted on our private passenger automobile contracts after a detailed review of existing claims data received from the clients, audits of claim files and actuarial analysis based on all available information. Since these contracts included sliding scale ceding commission rates, the decrease in loss reserves was offset by a $2.2 million increase in ceding commissions recorded as acquisition costs.

There were no other significant developments of prior period loss reserves during the year ended December 31, 2014.

For the year ended December 31, 2013, the net losses incurred included $6.1 million related to net favorable loss development on reserves relating to prior years. During the year ended December 31, 2013, the loss development on prior year contracts primarily related to the following:
 
●
Elimination of $15.0 million of reserves relating to super-storm Sandy based on additional information received from the client which indicated that the losses would not exceed the threshold of coverage provided

F-26

Link to Table of Contents

under the contract. As a result of the reversal of loss reserves, the Company also reversed reinstatement premiums earned of $2.6 million;

●
$4.0 million of favorable loss development relating to commercial automobile business due to better than expected loss development on open claims and settling of claims at lower amounts than expected. Loss reserves were decreased on these contracts after a detailed review of existing claims data received from the clients, audits of claim files at the third party claims administrators and actuarial analysis based on all available information;

●
$3.0 million favorable loss development relating to a private passenger automobile contract as a result of final settlement of losses upon commutation of the contract at an amount lower than originally reserved. However, because this contract included a sliding scale ceding commission rate, the decrease in loss reserves was offset by a $2.3 million increase in ceding commissions recorded as acquisition costs;

●
$2.4 million favorable loss development relating to Florida homeowners' insurance business due to better than expected development on sinkhole claims, primarily as a result of legislative changes implemented in the State of Florida during 2012;

●
$17.7 million of adverse loss development, net of retrocession recoveries, relating to general liability business. Loss reserves were increased on these contracts after a detailed review of existing claims data received from the clients, audits of claim files at the third party claims administrators and actuarial analysis based on all available information; and

●
$4.0 million of adverse loss development on a 2007 casualty clash contract based on updated claims and loss information received from the client. The new information indicated that ground up losses under the contract estimated by the client had increased resulting in additional losses attaching to the Company's layer. As a result of this increase in loss reserves, the Company recorded reinstatement premiums of $1.2 million.

There were no other significant developments of prior period loss reserves during the year ended December 31, 2013.
 

8.        RETROCESSION
 
The Company, from time to time, purchases retrocessional coverage for one or more of the following reasons: to manage its overall exposure, to reduce its net liability on individual risks, to obtain additional underwriting capacity and to balance its underwriting portfolio. Additionally, retrocession can be used as a mechanism to share the risks and rewards of business written and therefore can be used as a tool to align the Company's interests with those of its counterparties. The Company currently has coverages that provide for recovery of a portion of loss and loss expenses incurred on certain contracts. Loss and loss adjustment expense recoverable from the retrocessionaires are recorded as assets.

For the year ended December 31, 2015, loss and loss adjustment expenses incurred of $317.1 million (2014: $235.0 million and 2013: $338.5 million) reported on the consolidated statements of income are net of loss and loss expenses recovered and recoverable of $1.7 million (2014: $4.4 million and 2013: $(10.2) million). The negative loss and loss adjustment expenses recovered for the year ended December 31, 2013, were due to reversal of loss reserves on retrocession contracts that were novated during 2013.

Retrocession contracts do not relieve the Company from its obligations to the insureds. Failure of retrocessionaires to honor their obligations could result in losses to the Company. At December 31, 2015, the Company had losses receivable and loss reserves recoverable of $3.1 million (December 31, 2014: $18.3 million) from unrated retrocessionaires and $0.3 million (December 31, 2014: nil) from a retrocessionaire rated A- by A.M. Best. During 2015, the Company reached a settlement to commute a retrocession contract with one of the unrated retrocessionaires, which commutation resulted in a decrease in the losses recoverable from unrated retrocessionaires. At December 31, 2015 and 2014, $3.1 million and $2.8 million, respectively, of losses recoverable from unrated retrocessionaires were secured by cash collateral held by the Company.

The Company regularly evaluates the financial condition of its retrocessionaires to assess the ability of the retrocessionaires to honor their respective obligations. At December 31, 2015 and 2014, no provision for uncollectible losses recoverable was considered necessary.


F-27

Link to Table of Contents

9.        SHARE CAPITAL 
 
The holders of all ordinary shares are entitled to share equally in dividends declared by the Board of Directors. In the event of a winding-up or dissolution of the Company, the ordinary shareholders share equally and ratably in the assets of the Company, after payment of all debts and liabilities of the Company and after liquidation of any issued and outstanding preferred shares. At December 31, 2015, no preferred shares were issued or outstanding. The Board of Directors is authorized to establish the rights and restrictions for preferred shares as they deem appropriate.
 
The Third Amended and Restated Memorandum and Articles of Association as revised by special resolution on July 10, 2008 (the "Articles"), provide that the holders of Class A ordinary shares generally are entitled to one vote per share. However, except upon unanimous consent of the Board of Directors, no Class A shareholder is permitted to vote an amount of shares which would cause any United States person to own (directly, indirectly or constructively under applicable United States tax attribution and constructive ownership rules) 9.9% or more of the total voting power of all issued and outstanding ordinary shares. The Articles further provide that the holders of Class B ordinary shares generally are entitled to ten votes per share. However, holders of Class B ordinary shares, together with their affiliates, are limited to voting that number of Class B ordinary shares equal to 9.5% of the total voting power of the total issued and outstanding ordinary shares. 
 
Pursuant to the Shareholders' Agreement, dated August 11, 2004, by and among the Company and certain of its shareholders (the “Shareholders’ Agreement”), the holders of at least 50% of the outstanding Registrable Securities (as defined in the Shareholders' Agreement), may, subject to certain conditions, request to have all or part of their Registrable Securities to become registered. The Shareholders' Agreement requires, among other things, that the Company use its commercially reasonable best efforts to have a registration statement covering such Registrable Securities to be declared effective. The registration rights granted pursuant to the Shareholders' Agreement are not deemed to be liabilities; therefore, there has been no recognition in the consolidated financial statements of the registration rights granted pursuant to the Shareholders' Agreement.
 
As of December 31, 2015, the Company has an effective Form S-3 registration statement, on file with the SEC, for an aggregate principal amount of $200.0 million in securities.

Shares authorized for issuance are comprised of 300,000 (2014: 300,000) Class A ordinary shares in relation to share purchase options granted to a service provider and 3,500,000 (2014: 3,500,000) Class A ordinary shares authorized for the Company’s stock incentive plan for eligible employees, directors and consultants. As of December 31, 2015 and 2014, there were no remaining Class A ordinary shares available for future issuance relating to share purchase options granted to the service provider, and 658,775 (2014: 803,558) Class A ordinary shares remained available for future issuance under the Company's stock incentive plan. The stock incentive plan is administered by the Compensation Committee of the Board of Directors. 

The Board has adopted a share repurchase plan. Under the share repurchase plan, the Board authorized the Company to purchase up to 2.0 million of its Class A ordinary shares from time to time. Class A ordinary shares or securities convertible into Class A ordinary shares, may be purchased in the open market, through privately negotiated transactions or Rule 10b5-1 stock trading plans. The timing of such repurchases and actual number of shares repurchased will depend on a variety of factors including price, market conditions and applicable regulatory and corporate requirements. The share repurchase plan, which expires on June 30, 2016, does not require the Company to repurchase any specific number of shares and may be modified, suspended or terminated at any time without prior notice. During the year ended December 31, 2015, 613,540 Class A ordinary shares were repurchased by the Company. As of December 31, 2015, 1,386,460 shares remained available for repurchase under the share repurchase plan. Under the Companies Law of the Cayman Islands, the Company cannot hold treasury shares; therefore, all ordinary shares repurchased are canceled immediately upon repurchase.

The following table is a summary of voting ordinary shares issued and outstanding:
 
 
2015
 
2014
 
2013
 
 
Class A
 
Class B
 
Class A
 
Class B
 
Class A
 
Class B
Balance – beginning of year
 
31,129,648

 
6,254,895

 
30,791,865

 
6,254,949

 
30,447,179

 
6,254,949

Issue of ordinary shares, net of forfeitures
 
256,464

 
—

 
337,729

 
—

 
344,686

 
—

Repurchase of ordinary shares
 
(613,540
)
 
—

 
—

 
—

 
—

 
—

Class B shares converted to Class A shares
 
—

 
—

 
54

 
(54
)
 
—

 
—

Balance – end of year
 
30,772,572

 
6,254,895

 
31,129,648

 
6,254,895

 
30,791,865

 
6,254,949


F-28

Link to Table of Contents

Greenlight Re is subject to the Cayman Islands' Insurance (Capital and Solvency) (Classes B, C, and D Insurers) Regulations, 2012 (the "Insurance Regulations"). The Insurance Regulations impose a Minimum Capital Requirement of US$50.0 million and a Prescribed Capital Requirement of $466.5 million on Greenlight Re as of December 31, 2015 (2014: $443.5 million). As of December 31, 2015, Greenlight Re's statutory capital and surplus of $788.9 million exceeded the Minimum Capital Requirement as well as the Prescribed Capital Requirement. For the years ended December 31, 2015, 2014 and 2013, Greenlight Re's net income (loss) was $(309.5) million, $113.3 million, and $229.8 million, respectively.

Greenlight Re is not required to prepare separate statutory financial statements for filing with CIMA and there were no material differences between Greenlight Re's GAAP capital, surplus and net income, and its statutory capital, surplus and net income as of December 31, 2015 and 2014.

As of December 31, 2015, $325.3 million of the Company's retained earnings were restricted from payment of dividends to the Company's shareholders. However, since most of the Company's capital and retained earnings are invested in its subsidiaries, a dividend from one or more of the Company's subsidiaries would likely be required in order to fund a dividend to the Company's shareholders. Any dividends declared and paid from Greenlight Re to the Company would require approval of CIMA. During the year ended December 31, 2015, $5.0 million (2014: nil, 2013: nil) of dividends were declared and paid by Greenlight Re to the Company. As of December 31, 2015 and 2014, $322.4 million and $658.8 million, respectively, of Greenlight Re's capital and surplus was available for distribution as dividends. The amount of dividends that GRIL is permitted to distribute is limited to its retained earnings and the Central Bank of Ireland has powers to intervene if a dividend payment were to lead to a breach of regulatory capital requirements. As of December 31, 2015 and 2014, none and $2.7 million, respectively, of GRIL's capital and surplus was available for distribution as dividends.

GRIL is obligated to maintain a minimum level of capital (the "Required Minimum Margin"). As of December 31, 2015 and 2014, GRIL met such requirements. As of December 31, 2015 and 2014, GRIL's statutory capital and surplus was the same as its U.S. GAAP capital and surplus of $50.3 million and $42.9 million, respectively. The required solvency margin for GRIL as of December 31, 2015 and 2014 was $18.1 million and $13.6 million, respectively. GRIL's statutory net income (loss) was $(12.8) million, $(3.3) million and $3.6 million for the years ended December 31, 2015, 2014 and 2013, respectively.
 
Additional paid-in capital includes the premium per share paid by the subscribing shareholders for Class A and B ordinary shares which have a par value of $0.10 each. It also includes share-based awards earned not yet issued.


10.      SHARE-BASED COMPENSATION
 
The Company has a stock incentive plan for directors, employees and consultants as detailed in Note 9 above.

Service Provider Share Purchase Options
 
On September 20, 2004, the Company had granted share purchase options to a service provider to purchase 400,000 Class A ordinary shares at an exercise price of $10.00 per share. During 2014, the remaining 20,000 share purchase options outstanding were exercised, resulting in the net issuance of 13,861 Class A ordinary shares (net of shares surrendered as a result of the cashless exercise of stock options). There were no service provider share purchase options outstanding as of December 31, 2015 and 2014.

 Employee and Director Restricted Shares
 
As part of its stock incentive plan, the Company issues restricted shares for which the fair value is equal to the price of the Company’s Class A ordinary shares on the grant date. Compensation based on the grant date fair market value of the shares is expensed on a straight line basis over the applicable vesting period.
 
For the year ended December 31, 2015, 78,685 (2014: 127,186, 2013: 111,231) restricted Class A ordinary shares were issued to employees pursuant to the Company’s stock incentive plan. These shares contain certain restrictions relating to, among other things, vesting, forfeiture in the event of termination of employment and transferability. Each of these restricted shares cliff vest after three years from the date of issuance, subject to the grantee’s continued service with the Company. During the vesting period, the holder of the restricted shares retains voting rights and is entitled to any dividends declared by the Company.
  
For the year ended December 31, 2015, the Company issued an aggregate of 28,215 (2014: 28,060, 2013: 36,374) restricted Class A ordinary shares to non-employee directors as part of their remuneration for services to the Company. Each of these restricted shares issued to non-employee directors contains similar restrictions to those issued to employees and will vest

F-29

Link to Table of Contents

on the earlier of the first anniversary of the share issuance or the Company’s next annual general meeting, subject to the grantee’s continued service with the Company.

For the year ended December 31, 2015, 9,621 (2014: 38,706, 2013: 16,826) restricted shares were forfeited by employees who left the Company prior to the expiration of the applicable vesting periods. For the year ended December 31, 2015, in accordance with U.S. GAAP, $0.1 million of stock compensation expense (2014: $0.4 million, 2013: $0.2 million) relating to the forfeited restricted shares was reversed.

The Company recorded $3.6 million of share-based compensation expense, net of forfeitures, relating to restricted shares for the year ended December 31, 2015 (2014: $3.3 million, 2013: $3.2 million). As of December 31, 2015, there were $3.7 million (2014: $4.2 million, 2013: $3.5 million) of unrecognized compensation costs related to non-vested restricted shares which are expected to be recognized over a weighted average period of 1.6 years (2014: 1.8 years, 2013: 1.7 years). For the year ended December 31, 2015, the total fair value of restricted shares vested was $3.2 million (2014: $2.9 million, 2013: $2.8 million).

The restricted share award activity during the years ended December 31, 2015 and 2014 was as follows:
 
 
Number of
non-vested
restricted
 shares
 
Weighted
 average
grant date
fair value
Balance at December 31, 2013
 
328,991

 
$
24.74

Granted
 
155,246

 
32.58

Vested
 
(115,444
)
 
25.35

Forfeited
 
(38,706
)
 
27.43

Balance at December 31, 2014
 
330,087

 
27.90

Granted
 
106,900

 
31.56

Vested
 
(120,353
)
 
26.26

Forfeited
 
(9,621
)
 
30.49

Balance at December 31, 2015
 
307,013

 
$
29.74

 
Employee and Director Stock Options

For the year ended December 31, 2015, 40,683 Class A ordinary share purchase options were granted to the Company's Chief Executive Officer, pursuant to his employment contract (2014: 31,821). These options vest 25% on the date of the grant, and 25% each on the anniversary thereof in 2016, 2017 and 2018, and expire 10 years after the grant date. The grant date fair value of these options was $12.29 per share (2014: $15.71 per share, 2013: $13.09), based on the Black-Scholes option pricing model. The estimate of expected volatility for options granted during 2015 and 2014 was based on the daily historical trading data of the Company's Class A ordinary shares from the date that these shares commenced trading on May 24, 2007 to August 5, 2015. For options granted prior to 2014, the Company had determined the expected volatility based primarily on the historical volatility of a peer group of companies in the reinsurance industry while also considering the Company’s own historical volatility.

The Company uses the Black-Scholes option pricing model to determine the valuation of its options and has applied the assumptions set forth in the following table.
 
 
2015
 
2014
 
2013
Risk free rate
 
2.15
%
 
2.47
%
 
2.85
%
Estimated volatility
 
32.8
%
 
34.3
%
 
35.0
%
Expected term (in years)
 
10

 
10

 
10

Dividend yield
 
0
%
 
0
%
 
0
%
Forfeiture rate
 
0
%
 
0
%
 
0
%
    
At the present time, the Board of Directors does not anticipate that any dividends will be declared during the expected term of the options. The Company uses graded vesting for expensing employee stock options. The total compensation cost expensed for the year ended December 31, 2015 related to employee and director stock options was $0.5 million (2014: $0.5

F-30

Link to Table of Contents

million, 2013: $0.6 million). At December 31, 2015, the total compensation cost related to non-vested options not yet recognized was $0.4 million (2014: $0.4 million, 2013: $0.4 million) to be recognized over a weighted average period of 1.5 years (2014: 1.5 years, 2013: 1.5 years) assuming the employees complete their service period for vesting of the options.

For the year ended December 31, 2015, 250,000 (2014: 318,500) stock options were exercised by directors and employees resulting in 158,925 Class A ordinary shares issued, net of shares surrendered as a result of the cashless exercise of stock options (2014: 207,328). When stock options are granted, the Company reduces the corresponding number from the shares authorized for issuance as part of the Company’s stock incentive plan. The intrinsic value of options exercised during the year ended December 31, 2015 was $4.8 million (2014: $6.7 million, 2013: $0.8 million).

Employee and director stock option activity during the years ended December 31, 2015 and 2014 was as follows: 
 
Number of
 options
 
Weighted
 average
 exercise
 price
 
Weighted
 average
 grant date
 fair value
Balance at December 31, 2013
1,402,987

 
$
15.82

 
$
7.08

Granted
31,821

 
32.37

 
15.71

Exercised
(318,500
)
 
11.29

 
5.67

Forfeited
—

 
—

 
—

Expired
—

 
—

 
—

Balance at December 31, 2014
1,116,308

 
17.58

 
7.73

Granted
40,683

 
26.67

 
12.29

Exercised
(250,000
)
 
11.10

 
5.57

Forfeited
—

 
—

 
—

Expired
—

 
—

 
—

Balance at December 31, 2015
906,991

 
$
19.78

 
$
8.53

 
At December 31, 2015, the weighted-average remaining contractual term for options outstanding was 2.9 years (2014: 3.0 years).
  
At December 31, 2015, 851,020 (2014: 1,062,022) stock options were exercisable. These options had a weighted-average exercise price of $19.22 (2014: $17.02) and a weighted-average remaining contractual term of 2.6 years (2014: 2.7 years).
 
The weighted average grant date fair value of options granted during the year ended December 31, 2015 was $12.29 (2014: $15.71, 2013: $13.09). The aggregate intrinsic value of options outstanding and options exercisable at December 31, 2015 was $2.6 million and $2.6 million, respectively (2014: $16.8 million and $16.6 million, respectively). During the year ended December 31, 2015, 38,998 (2014: 53,828, 2013: 45,871) options vested which had a weighted average grant date fair value of $12.82 (2014: $11.76, 2013: $11.08).

Employee Restricted Stock Units

The Company issues restricted stock units ("RSUs") to certain employees as part of the stock incentive plan. The grant date fair value of the RSUs is equal to the price of the Company’s Class A ordinary shares on the grant date. Compensation cost based on the grant date fair market value of the RSUs is expensed on a straight line basis over the vesting period.
 
For the year ended December 31, 2015, 6,821 (2014: 9,668, 2013: 5,941) RSUs were issued to employees pursuant to the Company’s stock incentive plan. These shares contain certain restrictions relating to, among other things, vesting, forfeiture in the event of termination of employment and transferability. Each of these RSUs cliff vest after three years from the date of issuance, subject to the grantee’s continued service with the Company. On the vesting date, the Company converts each RSU into one Class A ordinary share and issues new Class A ordinary shares from the shares authorized for issuance as part of the Company’s stock incentive plan.

The Company recorded $0.2 million of share-based compensation expense, net of forfeitures, relating to RSUs for the year ended December 31, 2015 (2014: $0.1 million, 2013: $0.03 million).


F-31

Link to Table of Contents

Employee RSU activity during the years ended December 31, 2015 and 2014 was as follows:
 
 
Number of
non-vested
RSUs
 
Weighted
 average
grant date
fair value
Balance at December 31, 2013
 
5,941

 
$
24.41

Granted
 
9,668

 
32.60

Vested
 
—

 
—

Forfeited
 
—

 
—

Balance at December 31, 2014
 
15,609

 
29.72

Granted
 
6,821

 
32.21

Vested
 
(260
)
 
24.30

Forfeited
 
—

 
—

Balance at December 31, 2015
 
22,170

 
$
30.55


For the years ended December 31, 2015, 2014 and 2013, the general and administrative expenses included stock compensation expense (net of forfeitures) of $4.3 million, $4.0 million and $3.8 million, respectively, for the expensing of the fair value of stock options, restricted stocks and RSUs granted to employees and directors.


11.      NET INVESTMENT INCOME

A summary of net investment income for the years ended December 31, 2015, 2014 and 2013 is as follows:
 
 
2015
 
2014
 
2013
 
 
($ in thousands)
Realized gains (losses)
 
$
22,227

 
$
352,133

 
$
122,568

Change in unrealized gains and losses
 
(265,401
)
 
(187,753
)
 
149,012

Investment related foreign exchange gains (losses)
 
(3,725
)
 
14,797

 
44,492

Interest and dividend income, net of withholding taxes
 
15,313

 
31,423

 
22,265

Interest, dividend and other expenses
 
(31,092
)
 
(38,892
)
 
(47,665
)
Investment advisor compensation
 
(19,246
)
 
(49,133
)
 
(72,532
)
Net investment income (loss)
 
$
(281,924
)
 
$
122,575

 
$
218,140


Interest and dividend income in the above table are net of any withholding taxes. Investment returns are calculated monthly and compounded to calculate the annual returns. The resulting actual investment income may vary depending on cash flows into or out of the investment account. For the year ended December 31, 2015, investment income, net of all fees and expenses, resulted in a loss of 20.2% on the investment portfolio. This compares to a gain of 8.7% and a gain of 19.6% reported for the years ended December 31, 2014 and 2013, respectively.

The comparative 2014 and 2013 amounts presented for realized gains (losses), change in unrealized gain and losses and investment related foreign exchange gains (losses) have been reclassified to conform to the current period presentation. The reclassifications resulted in no changes to net investment income (loss), net income or retained earnings for any of the periods presented.


12.      TAXATION
 
The Company and Greenlight Re are each domiciled in the Cayman Islands and under current Cayman Islands law, no corporate entity, including the Company and Greenlight Re, is obligated to pay taxes in the Cayman Islands on either income or capital gains. The Company and Greenlight Re each intend to conduct all of its operations in a manner that will not cause it to be treated as engaging in a trade or business within the United States and will not cause it to be subject to current U.S. federal income taxation on its net income. However, because there are no definitive standards provided by the Internal Revenue Code, regulations or court decisions as to the specific activities that constitute being engaged in the conduct of a trade or business within the United States, and as any such determination is essentially factual in nature, there can be no assurance that the IRS will not successfully assert that the Company or Greenlight Re is engaged in a trade or business within the U.S.

F-32

Link to Table of Contents

 
Verdant is incorporated in Delaware, and therefore is subject to taxes in accordance with the U.S. federal rates and regulations prescribed by the IRS. Verdant’s taxable income is taxed at an effective tax rate of 35%. GRIL is incorporated in Ireland and, therefore, is subject to the Irish corporation tax. GRIL is taxed at a rate of 12.5% on its trading income.
 
At December 31, 2015, included in the consolidated balance sheet under other assets were taxes recoverable of $0.5 million relating to GRIL (2014: $0.8 million relating to Verdant and GRIL), and a deferred tax asset of $1.76 million primarily relating to GRIL's net operating losses carried forward (2014: $0.03 million). At December 31, 2015, GRIL had a net operating loss carryforward of $14.1 million which can be carried forward indefinitely. Based on the likelihood of GRIL generating sufficient taxable income to realize the future tax benefit, management believes it is more likely than not that the deferred tax asset and taxes recoverable will be fully realized in the future and therefore no valuation allowance has been recorded.

At December 31, 2015, Verdant had a net operating loss carryforward of $1.7 million which can be carried forward for a period of 20 years from the year the loss occurred and therefore will expire in 2033.

The following table sets forth our current and deferred income tax benefit (expense) on a consolidated basis for the years ended December 31, 2015, 2014 and 2013:
 
 
2015
 
2014
 
2013
 
 
($ in thousands)
Current tax (expense) benefit
 
$
15

 
$
638

 
$
(534
)
Deferred tax (expense) benefit
 
1,740

 
(14
)
 
(4
)
Income tax (expense) benefit 
 
$
1,755

 
$
624

 
$
(538
)

The Company has not taken any tax positions that are subject to uncertainty or that are reasonably likely to have a material impact to the Company, Greenlight Re, GRIL or Verdant.

Federal Excise Taxes

The United States also imposes an excise tax on reinsurance premiums paid to non-U.S. insurers or reinsurers with respect to risks located in the United States. The rate of tax, unless exempted or reduced by an applicable U.S. tax treaty, is 1.0% for all reinsurance premiums. The Company incurs federal excise taxes on certain of its reinsurance transactions, including amounts ceded through intercompany transactions. For the years ended 2015, 2014, and 2013, the Company incurred approximately $3.3 million, $2.2 million and $3.5 million, respectively, of federal excise taxes. These amounts are reflected as acquisition costs in the Company’s consolidated statements of income.


13.      RELATED PARTY TRANSACTIONS
 
Investment Advisory Agreement
 
Effective January 1, 2014, the Company and its reinsurance subsidiaries were party to a joint venture agreement with DME Advisors, LP ("DME Advisors") under which the Company, its reinsurance subsidiaries and DME Advisors LLC ("DME") are participants of a joint venture for the purpose of managing certain jointly held assets, as may be amended from time to time (the "venture agreement"). In addition, the Company, its reinsurance subsidiaries and DME have entered into a separate investment advisory agreement with DME Advisors, as may be amended from time to time (the "advisory agreement"). DME and DME Advisors are related to the Company and each is an affiliate of David Einhorn, Chairman of the Company’s Board of Directors.
 
Pursuant to the venture agreement, performance allocation equal to 20% of the net investment income of the Company’s share of the account managed by DME Advisors is allocated, subject to a loss carry forward provision, to DME’s account. The loss carry forward provision requires DME to earn a reduced performance allocation of 10% on net investment income in any year subsequent to the year in which the investment account incurs a loss, until all the losses are recouped and an additional amount equal to 150% of the aggregate investment loss is earned. DME is not entitled to earn a performance allocation in a year in which the investment portfolio incurs a loss. For the year ended December 31, 2015, no performance allocation (2014: $28.5 million, 2013: $54.2 million) was netted against gross investment income due to a net investment loss reported for the year ended December 31, 2015.  


F-33

Link to Table of Contents

Pursuant to the advisory agreement, a monthly management fee, equal to 0.125% (1.5% on an annual basis) of the Company’s investment account managed by DME Advisors, is paid to DME Advisors. Included in the net investment income (loss) for the year ended December 31, 2015 were management fees of $19.2 million (2014: $20.6 million, 2013: $18.3 million). The management fees have been fully paid as of December 31, 2015.
 
Pursuant to the venture and advisory agreements, the Company has agreed to indemnify DME and DME Advisors for any expense, loss, liability, or damage arising out of any claim asserted or threatened in connection with DME Advisors serving as the Company’s investment advisor. The Company will reimburse DME and DME Advisors for reasonable costs and expenses of investigating and/or defending such claims, provided such claims were not caused due to gross negligence, breach of contract or misrepresentation by DME or DME Advisors. For the year ended December 31, 2015, there were no indemnification payments payable or paid by the Company.

Green Brick Partners, Inc

David Einhorn also serves as the Chairman of the Board of Directors of Green Brick Partners, Inc ("GRBK"), a publicly traded company. During the year ended December 31, 2014, the Company, along with certain affiliates of DME Advisors, provided debt financing to GRBK and acquired equity shares of GRBK. During the year ended December 31, 2015, the Company's investment income included $1.0 million (2014: $0.4 million) of interest relating to this debt. During the third quarter of 2015, GRBK repaid the debt (2014: $21.6 million) in full along with all accrued interest and prepayment fees, and the Company purchased additional equity shares of GRBK. As of December 31, 2015, $25.0 million (2014: $18.4 million) of GRBK listed equities were included on the balance sheet as "equity securities, trading, at fair value". The Company along with certain affiliates of DME Advisors, collectively own 49% of the issued and outstanding common shares of GRBK. Under applicable securities laws, DME Advisors may be limited at times in its ability to trade GRBK shares on behalf of the Company.

Service Agreement
 
The Company has entered into a service agreement with DME Advisors, pursuant to which DME Advisors provides certain investor relations services to the Company for compensation of five thousand dollars per month (plus expenses). The agreement is automatically renewed annually until terminated by either the Company or DME Advisors for any reason with 30 days prior written notice to the other party. 


14.      COMMITMENTS AND CONTINGENCIES
 
Letters of Credit
 
At December 31, 2015, the Company had the following letter of credit facilities, which automatically renew each year unless terminated by either party in accordance with the required notice period:
 
 
Facility
 
Termination Date
 
Notice period required for termination
 
 
($ in thousands)


Bank of America, N.A.
 
$
120,000

 
July 11, 2016
 
90 days prior to termination date
Butterfield Bank (Cayman) Limited
 
100,000

 
June 30, 2016
 
90 days prior to termination date
Citibank Europe plc
 
400,000

 
October 11, 2016
 
120 days prior to termination date
JP Morgan Chase Bank N.A.
 
100,000

 
January 27, 2017
 
120 days prior to termination date
 
 
$
720,000


As of December 31, 2015, an aggregate amount of $245.6 million (2014: $273.7 million) in letters of credit were issued under the above facilities. Under the facilities, the Company provides collateral that may consist of equity securities, restricted cash and cash and cash equivalents. As of December 31, 2015, total equity securities, restricted cash, and cash and cash equivalents with a fair value in the aggregate of $324.3 million (2014: $302.6 million) were pledged as collateral against the letters of credit issued (also see Note 4). Each of the facilities contain customary events of default and restrictive covenants, including but not limited to, limitations on liens on collateral, transactions with affiliates, mergers and sales of assets, as well as solvency and maintenance of certain minimum pledged equity requirements, and restricts issuance of any debt without the consent of the letter of credit provider. Additionally, if an event of default exists, as defined in the letter of credit facilities, Greenlight Re will be prohibited from paying dividends to its parent company. The Company was in compliance with all the covenants of each of these facilities as of December 31, 2015 and 2014.

F-34

Link to Table of Contents

  
Operating Lease Obligations
 
Greenlight Re has entered into lease agreements for office space in the Cayman Islands. Under the terms of the lease agreements, Greenlight Re is committed to annual rent payments ranging from $0.3 million at inception to $0.5 million at lease termination. The leases expire on June 30, 2018 and Greenlight Re has the option to renew the leases for a further five year term. Included in the schedule below are the minimum lease payment obligations relating to these leases as of December 31, 2015.

GRIL has entered into a lease agreement for office space in Dublin, Ireland. Under the terms of this lease agreement, GRIL is committed to minimum annual rent payments denominated in Euros approximating €0.1 million until May 2021, and adjusted to the prevailing market rates for each of the two subsequent five-year terms. GRIL has the option to terminate the lease agreement in 2021. Included in the schedule below are the net minimum lease payment obligations relating to this lease as of December 31, 2015.

The total rent expense related to leased office space for the year ended December 31, 2015 was $0.5 million, (2014: $0.5 million, 2013: $0.5 million). 
 
Private Equity and Limited Partnerships
 
From time to time, the Company makes investments in private equity vehicles. As part of the Company's participation in such private equity investments, the Company may make funding commitments. As of December 31, 2015, the Company had commitments to invest an additional $6.1 million (2014: $8.9 million) in private equity investments. Included in the schedule below are the minimum payment obligations relating to these investments as of December 31, 2015.
 
Schedule of Commitments and Contingencies
 
The following is a schedule of future minimum payments required under the above commitments: 
 
2016
 
2017
 
2018
 
2019
 
2020
 
Thereafter
 
Total
 
($ in thousands)
Operating lease obligations
$
548

 
$
548

 
$
315

 
$
82

 
$
82

 
$
31

 
$
1,606

Private equity and limited partnerships (1)
6,107

 
—

 
—

 
—

 
—

 
—

 
6,107

 
$
6,655

 
$
548

 
$
315

 
$
82

 
$
82

 
$
31

 
$
7,713


(1) Given the nature of these investments, the Company is unable to determine with any degree of accuracy when these commitments will be called. Therefore, for purposes of the above table, the Company has assumed that all commitments with no fixed payment schedules will be called during the year ending December 31, 2016.
 
Litigation
 
From time to time in the normal course of business, the Company may be involved in formal and informal dispute resolution procedures, which may include arbitration or litigation, the outcomes of which determine the rights and obligations under the Company's reinsurance contracts and other contractual agreements. In some disputes, the Company may seek to enforce its rights under an agreement or to collect funds owing to it. In other matters, the Company may resist attempts by others to collect funds or enforce alleged rights. While the final outcome of legal disputes cannot be predicted with certainty, the Company does not believe that any existing dispute, when finally resolved, will have a material adverse effect on the Company's business, financial condition or operating results.


F-35

Link to Table of Contents

15.      SEGMENT REPORTING
 
The Company manages its business on the basis of one operating segment, Property & Casualty Reinsurance.

Substantially all of the business is sourced through reinsurance brokers. The following table sets forth the premiums sourced from brokers who each accounted for more than 10% of the Company's gross written premiums:  
 
 
Year ended December 31
 
 
2015
 
2014
 
2013
 
 
 ($ in thousands)
Largest broker
 
$
278,003

 
55.4
%
 
$
161,405

 
49.8
%
 
$
282,337

 
52.7
%
2nd largest broker
 
110,246

 
22.0

 
61,809

 
19.1

 
119,117

 
22.2

3rd largest broker
 
—

 
—

 
40,773

 
12.6

 
—

 
—


$
388,249

 
77.4
%
 
$
263,987

 
81.5
%
 
$
401,454

 
74.9
%
 
The following tables provide a breakdown of the Company's gross premiums written by line of business and by geographic area of risks insured for the periods indicated:
 
Gross Premiums Written by Line of Business 
 
 
Year ended December 31
 
 
2015
 
2014
 
2013
 
 
($ in thousands)
Property


Aviation
 
$
691

 
0.1
%
 
$
391

 
0.1
%
 
$
168

 
—
 %
Commercial
 
16,667

 
3.3

 
11,529

 
3.6

 
9,999

 
1.9

Energy
 
2,009

 
0.4

 
2,131

 
0.6

 
659

 
0.1

Motor physical damage
 
34,529

 
6.9

 
24,008

 
7.4

 
57,952

 
10.8

Personal
 
57,495

 
11.5

 
64,479

 
19.9

 
145,807

 
27.2

Total Property
 
111,391

 
22.2

 
102,538

 
31.6

 
214,585

 
40.0

Casualty


General liability (1)
 
28,355

 
5.6

 
11,639

 
3.6

 
(815
)
 
(0.2
)
Marine liability
 
9,283

 
1.8

 
5,120

 
1.6

 
1,956

 
0.4

Motor liability
 
203,624

 
40.6

 
127,858

 
39.5

 
253,698

 
47.4

Professional liability
 
72,217

 
14.4

 
27,009

 
8.4

 
29,901

 
5.6

Total Casualty
 
313,479

 
62.4

 
171,626

 
53.1

 
284,740

 
53.2

Specialty


Financial
 
7,824

 
1.6

 
5,292

 
1.6

 
3,498

 
0.7

Health
 
56,784

 
11.3

 
43,837

 
13.5

 
37,094

 
6.9

Workers’ compensation (1) 
 
12,646

 
2.5

 
730

 
0.2

 
(4,215
)
 
(0.8
)
Total Specialty
 
77,254

 
15.4

 
49,859

 
15.3

 
36,377

 
6.8


$
502,124

 
100.0
%
 
$
324,023

 
100.0
%
 
$
535,702

 
100.0
 %
(1)  The negative balance represents reversal of premiums due to premium adjustments, termination of contracts or premiums returned upon novation or commutation of contracts.


F-36

Link to Table of Contents

Gross Premiums Written by Geographic Area of Risks Insured
 
 
Year ended December 31
 
 
2015
 
2014
 
2013
 
 
($ in thousands)
U.S. and Caribbean
 
$
383,236

 
76.3
%
 
$
275,402

 
85.0
%
 
$
496,949

 
92.8
%
Worldwide (1)
 
104,336

 
20.8

 
31,106

 
9.6

 
9,821

 
1.8

Europe
 
14,085

 
2.8

 
17,432

 
5.4

 
28,932

 
5.4

Asia
 
467

 
0.1

 
83

 
—

 
—

 
—


$
502,124

 
100.0
%
 
$
324,023

 
100.0
%
 
$
535,702

 
100.0
%
(1) "Worldwide" is comprised of contracts that reinsure risks in more than one geographic area and do not specifically exclude the U.S. 

 
16.      QUARTERLY FINANCIAL RESULTS (UNAUDITED)

The following table presents the quarterly financial results for each of the quarters ended during 2015:
 
 
2015
 
 
 Quarter ended


March 31
 
 
June 30
 
 
September 30
 
 
December 31
 
 
 ($ in thousands, except per share amounts)
Revenues


Gross premiums written
 
$
129,682

 
$
92,990

 
$
134,568

 
$
144,884

Gross premiums ceded
 
(1,626
)
 
(1,868
)
 
(2,288
)
 
(3,219
)
Net premiums written
 
128,056

 
91,122

 
132,280

 
141,665

Change in net unearned premium reserves
 
(33,263
)
 
563

 
(30,286
)
 
(21,750
)
Net premiums earned
 
94,793

 
91,685

 
101,994

 
119,915

Net investment income (loss)
 
(24,829
)
 
(20,305
)
 
(191,322
)
 
(45,468
)
Other income (expense), net
 
1,588

 
(3,760
)
 
(542
)
 
(699
)
Total revenues
 
71,552

 
67,620

 
(89,870
)
 
73,748

Expenses


Loss and loss adjustment expenses incurred, net
 
63,207

 
76,653

 
97,421

 
79,816

Acquisition costs, net
 
26,841

 
23,939

 
32,146

 
33,281

General and administrative expenses
 
6,160

 
6,894

 
5,382

 
4,998

Total expenses
 
96,208

 
107,486

 
134,949

 
118,095

Income (loss) before income tax expense
 
(24,656
)
 
(39,866
)
 
(224,819
)
 
(44,347
)
Income tax (expense) benefit
 
215

 
(54
)
 
1,233

 
361

Net income (loss) including non-controlling interest
 
(24,441
)
 
(39,920
)
 
(223,586
)
 
(43,986
)
Loss (income) attributable to non-controlling interest in joint venture
 
394

 
324

 
3,909

 
881

Net income (loss)
 
$
(24,047
)
 
$
(39,596
)
 
$
(219,677
)
 
$
(43,105
)
Earnings (loss) per share


Basic
 
$
(0.65
)
 
$
(1.06
)
 
$
(5.98
)
 
$
(1.17
)
Diluted
 
$
(0.65
)
 
$
(1.06
)
 
$
(5.98
)
 
$
(1.17
)
Weighted average number of ordinary shares used in the determination of earnings and loss per share


Basic
 
37,173,008

 
37,303,265

 
36,710,216

 
36,720,454

Diluted
 
37,173,008

 
37,303,265

 
36,710,216

 
36,720,454


F-37

Link to Table of Contents

The following table presents the quarterly financial results for each of the quarters ended during 2014:
 
 
2014
 
 
 Quarter ended


March 31
 
 
June 30
 
 
September 30
 
 
December 31
 
 
 ($ in thousands)
Revenues


Gross premiums written
 
$
118,901

 
$
33,654

 
$
97,200

 
$
74,268

Gross premiums ceded
 
(5,940
)
 
(2,759
)
 
(2,706
)
 
(2,088
)
Net premiums written
 
112,961

 
30,895

 
94,494

 
72,180

Change in net unearned premium reserves
 
(1,272
)
 
56,960

 
(15,003
)
 
3,025

Net premiums earned
 
111,689

 
87,855

 
79,491

 
75,205

Net investment income (loss)
 
(10,150
)
 
113,932

 
(54,027
)
 
72,820

Other income (expense), net
 
182

 
(1,400
)
 
2,663

 
1,542

Total revenues
 
101,721

 
200,387

 
28,127

 
149,567

Expenses


Loss and loss adjustment expenses incurred, net
 
67,363

 
56,644

 
53,028

 
57,951

Acquisition costs, net
 
37,796

 
25,570

 
22,478

 
21,821

General and administrative expenses
 
6,200

 
5,559

 
6,012

 
6,729

Total expenses
 
111,359

 
87,773

 
81,518

 
86,501

Income (loss) before income tax expense
 
(9,638
)
 
112,614

 
(53,391
)
 
63,066

Income tax (expense) benefit
 
560

 
14

 
254

 
(204
)
Net income (loss) including non-controlling interest
 
(9,078
)
 
112,628

 
(53,137
)
 
62,862

Loss (income) attributable to non-controlling interest in joint venture
 
197

 
(3,075
)
 
1,369

 
(2,174
)
Net income (loss)
 
$
(8,881
)
 
$
109,553

 
$
(51,768
)
 
$
60,688

Earnings (loss) per share


Basic
 
$
(0.24
)
 
$
2.94

 
$
(1.40
)
 
$
1.62

Diluted
 
$
(0.24
)
 
$
2.89

 
$
(1.40
)
 
$
1.60

Weighted average number of ordinary shares used in the determination of earnings and loss per share


Basic
 
36,808,386

 
37,246,922

 
36,984,650

 
37,356,187

Diluted
 
36,808,386

 
37,902,106

 
36,984,650

 
37,905,836


F-38

Link to Table of Contents

SCHEDULE I
 
 
GREENLIGHT CAPITAL RE, LTD.
SUMMARY OF INVESTMENTS — OTHER THAN INVESTMENTS IN RELATED PARTIES
AS OF DECEMBER 31, 2015
 
(expressed in thousands of U.S. dollars) 
Type of Investment
 
Cost
 
Fair Value
 
Balance
Sheet Value
 
 
($ in thousands)
Debt instruments, trading, at fair value
 
$
45,471

 
$
39,087

 
$
39,087

Equity securities, trading, at fair value


Equities – listed
 
1,011,424

 
890,653

 
890,653

Exchange traded funds
 
31,570

 
15,341

 
15,341

Total equity securities, trading, at fair value
 
1,042,994

 
905,994

 
905,994

Total investments, trading
 
$
1,088,465

 
$
945,081

 
$
945,081

Other investments, at fair value


Commodities
 
$
102,092

 
$
98,046

 
$
98,046

Private and unlisted equity securities
 
18,720

 
21,037

 
21,037

Total other investments, at fair value
 
120,812

 
119,083

 
119,083

Total investments
 
$
1,209,277

 
$
1,064,164

 
$
1,064,164


F-39

Link to Table of Contents


SCHEDULE II
 
 
GREENLIGHT CAPITAL RE, LTD.
CONDENSED FINANCIAL INFORMATION OF REGISTRANT
CONDENSED BALANCE SHEETS — PARENT COMPANY ONLY
 
(expressed in thousands of U.S. dollars) 
 
 
December 31, 2015
 
December 31, 2014
 
 
($ in thousands)
Cash and cash equivalents
 
$
6

 
$
1

Investment in subsidiaries
 
840,196

 
1,148,308

Note receivable
 
2,175

 
1,566

Due from subsidiaries
 
—

 
15,276

Total assets
 
$
842,377

 
$
1,165,151

Liabilities and shareholders’ equity


Liabilities


Due to subsidiaries
 
$
16,986

 
$
—

Total liabilities
 
16,986

 
—

Shareholders’ equity


Share capital
 
3,703

 
3,738

Additional paid-in capital
 
496,401

 
500,553

Retained earnings
 
325,287

 
660,860

Total shareholders’ equity
 
825,391

 
1,165,151

Total liabilities and shareholders’ equity
 
$
842,377

 
$
1,165,151


GREENLIGHT CAPITAL RE, LTD.
CONDENSED FINANCIAL INFORMATION OF REGISTRANT
CONDENSED STATEMENTS OF INCOME — PARENT COMPANY ONLY
 
(expressed in thousands of U.S. dollars)


Year ended December 31
 
 
2015
 
2014
 
2013
 
 
 ($ in thousands)
Revenue


Investment income
 
$
5,962

 
$
671

 
$
1,100

Total revenues
 
5,962

 
671

 
1,100

Expenses


General and administrative expenses
 
4,048

 
3,806

 
3,735

Net income (loss) before equity in earnings of consolidated subsidiaries
 
1,914

 
(3,135
)
 
(2,635
)
Equity in earnings of consolidated subsidiaries
 
(328,339
)
 
112,727

 
228,334

Consolidated net income (loss)
 
$
(326,425
)
 
$
109,592

 
$
225,699


F-40

Link to Table of Contents


SCHEDULE II (continued)
 
 
GREENLIGHT CAPITAL RE, LTD.
CONDENSED FINANCIAL INFORMATION OF REGISTRANT
CONDENSED STATEMENTS OF CASH FLOWS — PARENT COMPANY ONLY
 
(expressed in thousands of U.S. dollars) 
 
 
  Year Ended December 31
 
 
2015
 
2014
 
2013
 
 
 ($ in thousands)
Cash provided by (used in) operating activities


Net income (loss)
 
$
(326,425
)
 
$
109,592

 
$
225,699

Adjustments to reconcile net income (loss) to cash provided by operating activities


Equity in earnings of consolidated subsidiaries
 
328,339

 
(112,727
)
 
(228,334
)
Share-based compensation expense
 
4,274

 
3,964

 
3,675

Change in


Due from subsidiaries
 
15,276

 
971

 
(2,006
)
Due to subsidiaries
 
16,986

 
(3,808
)
 
2,438

Net cash (used in) provided by operating activities
 
38,450

 
(2,008
)
 
1,472

Investing activities


Change in note receivable
 
(609
)
 
2,162

 
(2,053
)
Contributed surplus to subsidiaries, net
 
(20,227
)
 
(158
)
 
59

Net cash (used in) provided by investing activities
 
(20,836
)
 
2,004

 
(1,994
)
Financing activities


Net proceeds from exercise of stock options
 
—

 
—

 
513

Short-swing sale profit from shareholder
 
83

 
—

 
—

Repurchase of Class A ordinary shares
 
(17,692
)
 
—

 
—

Net cash (used in) provided by financing activities
 
(17,609
)
 
—

 
513

Net increase (decrease) in cash and cash equivalents
 
5

 
(4
)
 
(9
)
Cash and cash equivalents at beginning of the year
 
1

 
5

 
14

Cash and cash equivalents at end of the year
 
$
6

 
$
1

 
$
5


F-41

Link to Table of Contents

SCHEDULE III
 
 
GREENLIGHT CAPITAL RE, LTD.
SUPPLEMENTARY INSURANCE INFORMATION
AS OF AND FOR THE YEARS ENDED DECEMBER 31, 2015, 2014 AND 2013
 
(expressed in thousands of U.S. dollars) 
Year
Segment
Deferred
acquisition
costs, net
Reserves
for losses
and loss
adjustment
expenses
– gross
Unearned
premiums
– gross
Net
premiums
earned
Net
investment
income (loss)
Net losses,
and loss
adjustment
expenses
Amortization
of deferred
acquisition
costs
Other
operating
expenses
Gross
premiums
written
2015
Property & Casualty
$
59,823

$
305,997

$
211,954

$
408,387

$
(281,924
)
$
317,097

$
116,207

$
23,434

$
502,124

2014
Property & Casualty
$
34,420

$
264,243

$
128,736

$
354,240

$
122,575

$
234,986

$
107,665

$
24,500

$
324,023

2013
Property & Casualty
$
51,797

$
329,894

$
173,057

$
547,899

$
218,140

$
338,493

$
171,872

$
20,958

$
535,702


SCHEDULE IV
 
 
GREENLIGHT CAPITAL RE, LTD.
SUPPLEMENTARY REINSURANCE INFORMATION
AS OF AND FOR THE YEARS ENDED DECEMBER 31, 2015, 2014 AND 2013
 
(expressed in thousands of U.S. dollars) 
Year
Segment
 
Direct gross
 premiums
 
Premiums
 ceded to
 other companies
 
Premiums
assumed from
other companies
 
Net written premiums
 
Percentage of
 amount
assumed to net
2015
Property & Casualty
 
$
—

 
$
9,001

 
$
502,124

 
$
493,123

 
102
%
2014
Property & Casualty
 
$
—

 
$
13,493

 
$
324,023

 
$
310,530

 
104
%
2013
Property & Casualty
 
$
—

 
$
2,780

 
$
535,702

 
$
532,922

 
101
%


F-42

Link to Table of Contents

EXHIBIT INDEX
Exhibit Number
Description of Exhibit
 
3.1
Third Amended and Restated Memorandum and Articles of Association as revised by special resolution on July 10, 2008 (incorporated by reference to Exhibit 3.1 of the Company’s Form 10-Q filed on August 7, 2008)
4.1
Form of Specimen Certificate of Class A ordinary shares (incorporated by reference to Exhibit 4.1 of the Company’s Registration Statement No. 333-139993)
4.2
Share Purchase Option, dated August 11, 2004, by and between the Registrant and First International Capital Holdings, Ltd. (incorporated by reference to Exhibit 4.2 of the Company’s Registration Statement No. 333-139993)
10.1
Form of Securities Purchase Agreement for Class A ordinary shares by and between the Registrant and each of the subscribers thereto (incorporated by reference to Exhibit 10.2 of the Company’s Registration Statement No. 333-139993)
10.2 (1)
Greenlight Capital Re, Ltd. Third Amended and Restated 2004 Stock Incentive Plan (incorporated by reference to Exhibit 10.19 of the Company’s Registration Statement No. 333-139993)
10.3 (1)
Form of Restricted Stock Award Agreement by and between the Registrant and the Grantee (incorporated by reference to Exhibit 10.6 of the Company’s Registration Statement No. 333-139993)
10.4 (1)
Form of Stock Option Agreement (incorporated by reference to Exhibit 10.7 of the Company’s Registration Statement No. 333-139993)
10.5 (1)
Greenlight Capital Re, Ltd. Form of Directors’ Restricted Stock Award (incorporated by reference to Exhibit 10.20 of the Company’s Registration Statement No. 333-139993)
10.6 (1)
Greenlight Capital Re, Ltd. Form of Employees’ Restricted Stock Award (incorporated by reference to Exhibit 10.21 of the Company’s Registration Statement No. 333-139993)
10.7
Form of Shareholders’ Agreement, dated August 11, 2004, by and among the Registrant and each of the subscribers (incorporated by reference to Exhibit 10.8 of the Company’s Registration Statement No. 333-139993)
10.8
Form of Deed of Indemnity between the Registrant and each of its directors and certain of its officers (incorporated by reference to Exhibit 10.11 of the Company’s Registration Statement No. 333-139993)
10.9 (1)
Amended and Restated Employment Agreement, dated as of December 30, 2008, by and among Greenlight Capital Re, Ltd., Greenlight Reinsurance, Ltd. and Tim Courtis (incorporated by reference to Exhibit 10.2 of the Company’s Current Report on Form 8-K filed on January 2, 2009)
10.10 (1)
Concurrent Private Placement Stock Purchase Agreement for Class B Ordinary Shares, dated January 11, 2007, by and between the Company and David Einhorn (incorporated by reference to Exhibit 10.16 of the Company’s Registration Statement No. 333-139993)
10.11
Service Agreement, dated as of February 21, 2007, between DME Advisors, LP and Greenlight Capital Re, Ltd. (incorporated by reference to Exhibit 10.17 of the Company’s Registration Statement No. 333-139993)
10.12 (1)
Amendment No. 1, dated February 18, 2009, to the Amended and Restated Employment Agreement, dated as of December 30, 2008, by and among Greenlight Capital Re, Ltd., Greenlight Reinsurance, Ltd. and Tim Courtis (incorporated by reference to Exhibit 10.26 of the Company’s Form 10-K filed on February 23, 2009)
10.13 
Letter of Credit Agreement, executed July 21, 2009, between Greenlight Reinsurance, Ltd. and Bank of America, N.A. (incorporated by reference to Exhibit 10.1 of the Company’s Form 10-Q filed on November 2, 2009)
10.14 (1)
Greenlight Capital Re, Ltd. Amended and Restated 2004 Stock Incentive Plan (incorporated by reference to Exhibit 10.1 of the Company’s Form 8-K filed on May 4, 2010)
10.15
Amended and Restated Letter of Credit Agreement, executed June 17, 2010, between Greenlight Reinsurance, Ltd. and Butterfield Bank (Cayman) Limited (incorporated by reference to Exhibit 10.3 of the Company’s Form 10-Q filed on August 2, 2010)
10.16
Amended Letter of Credit Agreement, executed June 14, 2010, between Greenlight Reinsurance, Ltd. and Bank of America, N.A (incorporated by reference to Exhibit 10.2 of the Company’s Form 10-Q filed August 2, 2010)
10.17
Letter of Understanding, dated June 10, 2010, between Greenlight Reinsurance, Ltd. and Citibank, N.A (incorporated by reference to Exhibit 10.1 of the Company’s Form 10-Q filed on August 2, 2010)
10.18
Letter of Credit Agreement, dated August 20, 2010, between Greenlight Reinsurance, Ltd. and Citibank Europe plc. (incorporated by reference to Exhibit 10.1 of the Company’s Form 10-Q filed on November 2, 2010)
10.19
Master Reimbursement Agreement, dated August 20, 2010, between Greenlight Reinsurance, Ltd. and Citibank Europe plc (incorporated by reference to Exhibit 10.2 of the Company’s Form 10-Q filed on November 2, 2010)
10.20
Reinsurance Deposit Agreement, dated August 20, 2010, between Greenlight Reinsurance, Ltd. and Citibank Europe plc. (incorporated by reference to Exhibit 10.3 of the Company’s Form 10-Q filed on November 2, 2010)


Link to Table of Contents

10.21
Amended and Restated Agreement, effective as of August 31, 2010, between Greenlight Capital Re, Ltd., Greenlight Reinsurance, Ltd., Greenlight Reinsurance Ireland, Ltd., and DME Advisors, LP (incorporated by reference to Exhibit 10.4 of the Company’s Form 10-Q filed on November 2, 2010)
10.22
Letter of Credit Agreement, effective as of February 3, 2011, between Greenlight Reinsurance, Ltd. and JPMorgan Chase Bank N.A. (incorporated by reference to Exhibit 10.38 of the Company’s Form 10-K filed on February 22, 2011)
10.23 (1)
Amended and Restated Employment Agreement, dated July 26, 2012, by and among Greenlight Capital Re, Ltd., Greenlight Reinsurance, Ltd. and Barton Hedges (incorporated by reference to Exhibit 10.1 of the Company's Form 10-Q filed on July 30, 2012)
10.24 (1)
Employment Agreement, dated August 15, 2006, by and among Greenlight Capital Re, Ltd., Greenlight Reinsurance, Ltd. and Brendan Barry (incorporated by reference to Exhibit 10.24 of the Company’s Form 10-K filed on February 21, 2012)
10.25 (1)
Employment Agreement, dated September 28, 2006, by and among Greenlight Capital Re, Ltd., Greenlight Reinsurance, Ltd. and Claude Wagner (incorporated by reference to Exhibit 10.25 of the Company’s Form 10-K filed on February 21, 2012)
10.26
Amendment to amended letter of credit agreement, executed on December 16, 2011, between Greenlight Reinsurance, Ltd. and Bank of America, N.A. (incorporated by reference to Exhibit 10.26 of the Company’s Form 10-K filed on February 21, 2012)
10.27
Amended letter of credit agreement, effective as of December 16, 2011, between Greenlight Reinsurance, Ltd. and JPMorgan Chase Bank N.A. (incorporated by reference to Exhibit 10.27 of the Company’s Form 10-K filed on February 21, 2012)
10.28
Second Amended and Restated Agreement by and among Greenlight Reinsurance, Ltd., Greenlight Reinsurance Ireland, Ltd., Greenlight Capital Re, Ltd. (for limited purposes) and DME Advisors, LLC, Amended and Restated as of January 1, 2014 (incorporated by reference to Exhibit 10.1 of the Company's Form 8-K filed on January 7, 2014)
10.29
Investment Advisory Agreement among DME Advisors, LP, The Venture Among Greenlight Reinsurance, Ltd., Greenlight Reinsurance Ireland, Ltd. and DME Advisors, LLC, Greenlight Reinsurance, Ltd., Greenlight Reinsurance Ireland, Ltd. and DME Advisors, LLC, effective January 1, 2014 (incorporated by reference to Exhibit 10.2 of the Company's Form 8-K filed on January 7, 2014)
10.30 (1)
Employment Agreement, dated July 31, 2014, by and among Greenlight Reinsurance, Ltd. and James McNichols (incorporated by reference to Exhibit 10.1 of the Company's Form 10-Q filed on November 3, 2014)
10.31
Amendment Letter Agreement between Greenlight Reinsurance, Ltd. and Butterfield Bank (Cayman) Limited, effective June 1, 2015, amending the Amended and Restated Letter of Credit Agreement dated June 17, 2010 (incorporated by reference to Exhibit 10.1 of the Company's Form 10-Q filed on August 3, 2015)
10.32
Amended and Restated Letter of Credit Facility Agreement, dated May 7, 2015 between Greenlight Reinsurance, Ltd. and Bank of America, N.A., amending the Amended Letter of Credit Facility Agreement dated December 16, 2011 (incorporated by reference to Exhibit 10.2 of the Company's Form 10-Q filed on August 3, 2015)
10.33
Letter Agreement between Greenlight Capital Re, Ltd., Greenlight Reinsurance, Ltd., Greenlight Reinsurance Ireland, Ltd., DME Advisors, LLC and DME Advisors, LP., dated June 17, 2015 (incorporated by reference to Exhibit 10.3 of the Company's Form 10-Q filed on August 3, 2015)
12.1 
Ratio of earnings to fixed charges and preferred share dividends.
21.1
Subsidiaries of the registrant (incorporated by reference to Exhibit 21.1 of the Company's Form 10-K filed on February 22, 2011)
23.1
Consent of BDO USA, LLP
31.1
Certification of the Chief Executive Officer of Greenlight Capital Re, Ltd. filed herewith pursuant to Section 302 of the Sarbanes-Oxley Act of 2002
31.2
Certification of the Chief Financial Officer of Greenlight Capital Re, Ltd. filed herewith pursuant to Section 302 of the Sarbanes-Oxley Act of 2002
32.1
Certification of the Chief Executive Officer of Greenlight Capital Re, Ltd. furnished herewith pursuant to Section 906 of the Sarbanes-Oxley Act of 2002
32.2
Certification of the Chief Financial Officer of Greenlight Capital Re, Ltd. furnished herewith pursuant to Section 906 of the Sarbanes-Oxley Act of 2002
101
The following materials from the Company’s Annual Report on Form 10-K for the year ended December 31, 2015, formatted in XBRL (eXtensible Business Reporting Language): (i) the Consolidated Balance Sheets; (ii) the Consolidated Statements of Income; (iii) the Consolidated Statements of Shareholders’ Equity; (iv) the Consolidated Statements of Cash Flows; and (v) the Notes to Consolidated Financial Statements.
 
 
(1
)
Management contract or compensatory plan or arrangement.


Exhibit


Exhibit 12.1

RATIO OF EARNINGS TO FIXED CHARGES AND PREFERRED SHARE DIVIDENDS
 
 
The following table sets forth our consolidated ratios:
 
 
Year ended December 31, 2015
 
Year ended December 31, 2014
 
(2)
 
(2)
Ratio of Earnings to Fixed Charges (1)
—
 
5.94
Deficiency of Earnings to Fixed Charges ($000) (3)
333,688
 
—

(1) The ratio of earnings to fixed charges was determined by dividing consolidated earnings by total fixed charges. For purposes of the ratios of earnings to fixed charges (i) earnings consist of consolidated net income before considering income taxes, minority interest and fixed charges and (ii) fixed charges consist of interest on indebtedness, interest expense on funds withheld from reinsurers and that portion of rent expense that is deemed by our management to be an appropriate interest factor. We have estimated that one-third of rent expense represents a reasonable approximation of the interest factor.
 
(2) No preferred shares were outstanding during the years ended December 31, 2015 and 2014, and no preferred share dividends were paid during those periods.

(3) For the year ended December 31, 2015, earnings were insufficient to cover fixed charges by $333.7 million. This was primarily due to a net loss reported for the year ended December 31, 2015.


Exhibit


EXHIBIT 23.1

Consent of Independent Registered Public Accounting Firm

Greenlight Capital Re, Ltd.
Grand Cayman, Cayman Islands

We hereby consent to the incorporation by reference in the Registration Statements on Form S-3 (No. 333-158970) and Form S-8 (No. 333-139993) of Greenlight Capital Re, Ltd. of our reports dated February 22, 2016, relating to the consolidated financial statements and financial statement schedules, and the effectiveness of Greenlight Capital Re, Ltd.’s internal control over financial reporting, which appear in this Form 10-K.

/s/ BDO USA, LLP

Grand Rapids, Michigan, USA
February 22, 2016


Exhibit
EXHIBIT 31.1  

CERTIFICATION OF
CHIEF EXECUTIVE OFFICER OF
GREENLIGHT CAPITAL RE, LTD.

I, Barton Hedges, certify that:
1.
I have reviewed this annual report on Form 10-K of Greenlight Capital Re, Ltd.;
 
2.
Based on my knowledge, this report does not contain any untrue statement of a material fact or omit to state a material fact necessary to make the statements made, in light of the circumstances under which such statements were made, not misleading with respect to the periods covered by this report;
 
3.
Based on my knowledge, the financial statements, and other financial information included in this report, fairly present in all material respects the financial condition, results of operations and cash flows of the registrant as of, and for, the periods presented in this report;
4.
The registrant’s other certifying officers and I are responsible for establishing and maintaining disclosure controls and procedures (as defined in Exchange Act Rules 13a-15(e) and 15d-15(e)) and internal control over financial reporting (as defined in Exchange Act Rules 13a-15(f) and 15d-15(f)) for the registrant and have:

a) Designed such disclosure controls and procedures, or caused such disclosure controls and procedures to be designed under our supervision, to ensure that material information relating to the registrant, including its consolidated subsidiaries, is made known to us by others within those entities, particularly during the period in which this report is being prepared; 

b) Designed such internal control over financial reporting, or caused such internal control over financial reporting to be designed under our supervision, to provide reasonable assurance regarding the reliability of financial reporting and the preparation of financial statements for external purposes in accordance with generally accepted accounting principles; 

c) Evaluated the effectiveness of the registrant’s disclosure controls and procedures and presented in this report our conclusions about the effectiveness of the disclosure controls and procedures, as of the end of the period covered by this report based on such evaluation; and 

d) Disclosed in this report any change in the registrant’s internal control over financial reporting that occurred during the registrant’s most recent fiscal quarter (the registrant’s fourth fiscal quarter in the case of an annual report) that has materially affected, or is reasonably likely to materially affect, the registrant’s internal control over financial reporting; and 
5.
The registrant’s other certifying officer and I have disclosed, based on our most recent evaluation of internal control over financial reporting, to the registrant’s auditors and the audit committee of the registrant’s board of directors (or persons performing the equivalent functions):

a) All significant deficiencies and material weaknesses in the design or operation of internal control over financial reporting which are reasonably likely to adversely affect the registrant’s ability to record, process, summarize and report financial information; and 

b) Any fraud, whether or not material, that involves management or other employees who have a significant role in the registrant’s internal control over financial reporting.   

Dated:
February 22, 2016
/s/ Barton Hedges         
 
 
Barton Hedges
 
 
Chief Executive Officer


Exhibit
 EXHIBIT 31.2 

CERTIFICATION OF
CHIEF FINANCIAL OFFICER OF
GREENLIGHT CAPITAL RE, LTD.

I, Tim Courtis, certify that:
1.
I have reviewed this annual report on Form 10-K of Greenlight Capital Re, Ltd.;
2.
Based on my knowledge, this report does not contain any untrue statement of a material fact or omit to state a material fact necessary to make the statements made, in light of the circumstances under which such statements were made, not misleading with respect to the periods covered by this report;
3.
Based on my knowledge, the financial statements, and other financial information included in this report, fairly present in all material respects the financial condition, results of operations and cash flows of the registrant as of, and for, the periods presented in this report;
4.
The registrant’s other certifying officers and I are responsible for establishing and maintaining disclosure controls and procedures (as defined in Exchange Act Rules 13a-15(e) and 15d-15(e)) and internal control over financial reporting (as defined in Exchange Act Rules 13a-15(f) and 15d-15(f)) for the registrant and have:

a) Designed such disclosure controls and procedures, or caused such disclosure controls and procedures to be designed under our supervision, to ensure that material information relating to the registrant, including its consolidated subsidiaries, is made known to us by others within those entities, particularly during the period in which this report is being prepared; 

b) Designed such internal control over financial reporting, or caused such internal control over financial reporting to be designed under our supervision, to provide reasonable assurance regarding the reliability of financial reporting and the preparation of financial statements for external purposes in accordance with generally accepted accounting principles; 

c) Evaluated the effectiveness of the registrant’s disclosure controls and procedures and presented in this report our conclusions about the effectiveness of the disclosure controls and procedures, as of the end of the period covered by this report based on such evaluation; and 

d) Disclosed in this report any change in the registrant’s internal control over financial reporting that occurred during the registrant’s most recent fiscal quarter (the registrant’s fourth fiscal quarter in the case of an annual report) that has materially affected, or is reasonably likely to materially affect, the registrant’s internal control over financial reporting; and 
5.
The registrant’s other certifying officer and I have disclosed, based on our most recent evaluation of internal control over financial reporting, to the registrant’s auditors and the audit committee of the registrant’s board of directors (or persons performing the equivalent functions):

a) All significant deficiencies and material weaknesses in the design or operation of internal control over financial reporting which are reasonably likely to adversely affect the registrant’s ability to record, process, summarize and report financial information; and 

b) Any fraud, whether or not material, that involves management or other employees who have a significant role in the registrant’s internal control over financial reporting.   


Dated:
February 22, 2016
/s/ Tim Courtis              
 
 
Tim Courtis
 
 
Chief Financial Officer


Exhibit
EXHIBIT 32.1   
CERTIFICATION OF
CHIEF EXECUTIVE OFFICER OF
GREENLIGHT CAPITAL RE, LTD.  


This certification is provided pursuant to Section 906 of the Sarbanes-Oxley Act of 2002 and accompanies the annual report on Form 10-K (the ‘‘Form 10-K’’) for the year ended December 31, 2015 of Greenlight Capital Re, Ltd. (the ‘‘Issuer’’). 

I, Barton Hedges, the Principal Executive Officer of the Issuer, certify that to the best of my knowledge: 

1. The Form 10-K fully complies with the requirements of Section 13(a) or Section 15(d) of the Securities Exchange Act of 1934 (15 U.S.C. 78m(a) or 78o(d)), as amended; and 

2. The information contained in the Form 10-K fairly presents, in all material respects, the financial condition and results of operations of the Issuer. 


Dated:
February 22, 2016
/s/ Barton Hedges                
 
 
Barton Hedges


Exhibit
EXHIBIT 32.2  
CERTIFICATION OF
CHIEF FINANCIAL OFFICER OF
GREENLIGHT CAPITAL RE, LTD.  


This certification is provided pursuant to Section 906 of the Sarbanes-Oxley Act of 2002 and accompanies the annual report on Form 10-K (the ‘‘Form 10-K’’) for the year ended December 31, 2015 of Greenlight Capital Re, Ltd. (the ‘‘Issuer’’). 

I, Tim Courtis, the Principal Financial Officer of the Issuer, certify that to the best of my knowledge: 

1. The Form 10-K fully complies with the requirements of Section 13(a) or Section 15(d) of the Securities Exchange Act of 1934 (15 U.S.C. 78m(a) or 78o(d)), as amended; and 

2. The information contained in the Form 10-K fairly presents, in all material respects, the financial condition and results of operations of the Issuer.  


Dated:
February 22, 2016
/s/ Tim Courtis                      
 
 
Tim Courtis


glre-20151231.xml
Attachment: XBRL INSTANCE DOCUMENT


glre-20151231.xsd
Attachment: XBRL TAXONOMY EXTENSION SCHEMA DOCUMENT


glre-20151231_cal.xml
Attachment: XBRL TAXONOMY EXTENSION CALCULATION LINKBASE DOCUMENT


glre-20151231_def.xml
Attachment: XBRL TAXONOMY EXTENSION DEFINITION LINKBASE DOCUMENT


glre-20151231_lab.xml
Attachment: XBRL TAXONOMY EXTENSION LABEL LINKBASE DOCUMENT


glre-20151231_pre.xml
Attachment: XBRL TAXONOMY EXTENSION PRESENTATION LINKBASE DOCUMENT


v3.3.1.900
Document And Entity Information - USD ($)
12 Months Ended
Dec. 31, 2015
Feb. 19, 2016
Jun. 30, 2015
Document and Entity Information [Line Items]      
Entity Registrant Name GREENLIGHT CAPITAL RE, LTD.    
Entity Central Index Key 0001385613    
Current Fiscal Year End Date --12-31    
Entity Filer Category Large Accelerated Filer    
Document Type 10-K    
Document Period End Date Dec. 31, 2015    
Document Fiscal Year Focus 2015    
Document Fiscal Period Focus FY    
Amendment Flag false    
Entity Well-known Seasoned Issuer Yes    
Entity Voluntary Filers No    
Entity Current Reporting Status Yes    
Entity Public Float     $ 869,305,700
Common Class A      
Document and Entity Information [Line Items]      
Entity Common Stock, Shares Outstanding   30,829,333  
Common Class B      
Document and Entity Information [Line Items]      
Entity Common Stock, Shares Outstanding   6,254,895  

v3.3.1.900
CONSOLIDATED BALANCE SHEETS - USD ($)
$ in Thousands
Dec. 31, 2015
Dec. 31, 2014
Investments    
Debt instruments, trading, at fair value $ 39,087 $ 49,212
Equity securities, trading, at fair value 905,994 1,266,175
Other investments, at fair value 119,083 115,591
Total investments 1,064,164 1,430,978
Cash and cash equivalents 112,162 12,030
Restricted cash and cash equivalents 1,236,589 1,296,914
Financial contracts receivable, at fair value 13,215 47,171
Reinsurance balances receivable 187,940 151,185
Loss and loss adjustment expenses recoverable 3,368 11,523
Deferred acquisition costs, net 59,823 34,420
Unearned premiums ceded 3,251 4,027
Notes receivable 25,146 1,566
Other assets 6,864 5,478
Total assets 2,712,522 2,995,292
Liabilities    
Securities sold, not yet purchased, at fair value 882,906 1,090,731
Financial contracts payable, at fair value 28,245 44,592
Due to prime brokers 396,453 211,070
Loss and loss adjustment expense reserves 305,997 264,243
Unearned premium reserves 211,954 128,736
Reinsurance balances payable 18,326 40,372
Funds withheld 7,143 6,558
Other liabilities 12,725 14,949
Total liabilities 1,863,749 1,801,251
Equity    
Preferred share capital (par value $0.10; authorized, 50,000,000; none issued) 0 0
Ordinary share capital (Class A: par value $0.10; authorized, 100,000,000; issued and outstanding, 30,772,572 (2014: 31,129,648): Class B: par value $0.10; authorized, 25,000,000; issued and outstanding, 6,254,895 (2014: 6,254,895)) 3,703 3,738
Additional paid-in capital 496,401 500,553
Retained earnings 325,287 660,860
Shareholders’ equity attributable to shareholders 825,391 1,165,151
Non-controlling interest in joint venture 23,382 28,890
Total equity 848,773 1,194,041
Total liabilities and equity $ 2,712,522 $ 2,995,292

v3.3.1.900
CONSOLIDATED BALANCE SHEETS (Parenthetical) - $ / shares
Dec. 31, 2015
Dec. 31, 2014
Shareholders' equity    
Preferred share capital, par value (in dollars per share) $ 0.10 $ 0.10
Preferred share capital, authorized (in shares) 50,000,000 50,000,000
Preferred share capital, issued (in shares) 0 0
Common Class A    
Shareholders' equity    
Common Stock, Par or Stated Value Per Share $ 0.10 $ 0.10
Ordinary share capital, authorized (in shares) 100,000,000 100,000,000
Ordinary share capital, issued (in shares) 30,772,572 31,129,648
Ordinary share capital, outstanding (in shares) 30,772,572 31,129,648
Common Class B    
Shareholders' equity    
Common Stock, Par or Stated Value Per Share $ 0.10 $ 0.10
Ordinary share capital, authorized (in shares) 25,000,000 25,000,000
Ordinary share capital, issued (in shares) 6,254,895 6,254,895
Ordinary share capital, outstanding (in shares) 6,254,895 6,254,895

v3.3.1.900
CONSOLIDATED STATEMENTS OF INCOME - USD ($)
$ in Thousands
3 Months Ended 12 Months Ended
Dec. 31, 2015
Sep. 30, 2015
Jun. 30, 2015
Mar. 31, 2015
Dec. 31, 2014
Sep. 30, 2014
Jun. 30, 2014
Mar. 31, 2014
Dec. 31, 2015
Dec. 31, 2014
Dec. 31, 2013
Revenues                      
Gross premiums written $ 144,884 $ 134,568 $ 92,990 $ 129,682 $ 74,268 $ 97,200 $ 33,654 $ 118,901 $ 502,124 $ 324,023 $ 535,702
Gross premiums ceded (3,219) (2,288) (1,868) (1,626) (2,088) (2,706) (2,759) (5,940) (9,001) (13,493) (2,780)
Net premiums written 141,665 132,280 91,122 128,056 72,180 94,494 30,895 112,961 493,123 310,530 532,922
Change in net unearned premium reserves (21,750) (30,286) 563 (33,263) 3,025 (15,003) 56,960 (1,272) (84,736) 43,710 14,977
Net premiums earned 119,915 101,994 91,685 94,793 75,205 79,491 87,855 111,689 408,387 354,240 547,899
Net investment income (loss) (45,468) (191,322) (20,305) (24,829) 72,820 (54,027) 113,932 (10,150) (281,924) 122,575 218,140
Other income (expense), net (699) (542) (3,760) 1,588 1,542 2,663 (1,400) 182 (3,413) 2,987 (1,710)
Total revenues 73,748 (89,870) 67,620 71,552 149,567 28,127 200,387 101,721 123,050 479,802 764,329
Expenses                      
Loss and loss adjustment expenses incurred, net 79,816 97,421 76,653 63,207 57,951 53,028 56,644 67,363 317,097 234,986 338,493
Acquisition costs, net 33,281 32,146 23,939 26,841 21,821 22,478 25,570 37,796 116,207 107,665 171,872
General and administrative expenses 4,998 5,382 6,894 6,160 6,729 6,012 5,559 6,200 23,434 24,500 20,958
Total expenses 118,095 134,949 107,486 96,208 86,501 81,518 87,773 111,359 456,738 367,151 531,323
Income (loss) before income tax expense (44,347) (224,819) (39,866) (24,656) 63,066 (53,391) 112,614 (9,638) (333,688) 112,651 233,006
Income tax (expense) benefit 361 1,233 (54) 215 (204) 254 14 560 1,755 624 (538)
Net income (loss) including non-controlling interest (43,986) (223,586) (39,920) (24,441) 62,862 (53,137) 112,628 (9,078) (331,933) 113,275 232,468
Loss (income) attributable to non-controlling interest in joint venture 881 3,909 324 394 (2,174) 1,369 (3,075) 197 5,508 (3,683) (6,769)
Net income (loss) $ (43,105) $ (219,677) $ (39,596) $ (24,047) $ 60,688 $ (51,768) $ 109,553 $ (8,881) $ (326,425) $ 109,592 $ 225,699
Earnings (loss) per share                      
Basic $ (1.17) $ (5.98) $ (1.06) $ (0.65) $ 1.62 $ (1.40) $ 2.94 $ (0.24) $ (8.90) $ 2.94 $ 6.13
Diluted $ (1.17) $ (5.98) $ (1.06) $ (0.65) $ 1.60 $ (1.40) $ 2.89 $ (0.24) $ (8.90) $ 2.89 $ 6.01
Weighted average number of ordinary shares used in the determination of earnings and loss per share                      
Basic 36,720,454 36,710,216 37,303,265 37,173,008 37,356,187 36,984,650 37,246,922 36,808,386 36,670,466 37,242,687 36,838,128
Diluted 36,720,454 36,710,216 37,303,265 37,173,008 37,905,836 36,984,650 37,902,106 36,808,386 36,670,466 37,874,387 37,585,167

v3.3.1.900
CONSOLIDATED STATEMENTS OF SHAREHOLDERS' EQUITY - USD ($)
$ in Thousands
Total
Ordinary share capital
Additional paid-in capital
Retained earnings
Shareholders' equity attributable to shareholders
Non-controlling interest in joint venture
Beginning balance at Dec. 31, 2012 $ 860,410 $ 3,670 $ 492,469 $ 325,569 $ 821,708 $ 38,702
Increase (Decrease) in Stockholders' Equity [Roll Forward]            
Issue of Class A ordinary shares, net of forfeitures 527 35 492 0 527 0
Non-controlling interest contribution into (withdrawal from) joint venture, net (10,762) 0 0 0 0 (10,762)
Income (loss) attributable to non-controlling interest in joint venture 6,769 0 0 0 0 6,769
Net income (loss) 225,699 0 0 225,699 225,699 0
Share-based compensation expense, net of forfeitures 3,661 0 3,661 0 3,661 0
Ending balance at Dec. 31, 2013 1,086,304 3,705 496,622 551,268 1,051,595 34,709
Increase (Decrease) in Stockholders' Equity [Roll Forward]            
Issue of Class A ordinary shares, net of forfeitures 33 33 0 0 33 0
Non-controlling interest contribution into (withdrawal from) joint venture, net (9,502) 0 0 0 0 (9,502)
Income (loss) attributable to non-controlling interest in joint venture 3,683 0 0 0 0 3,683
Net income (loss) 109,592 0 0 109,592 109,592 0
Share-based compensation expense, net of forfeitures 3,931 0 3,931 0 3,931 0
Ending balance at Dec. 31, 2014 1,194,041 3,738 500,553 660,860 1,165,151 28,890
Increase (Decrease) in Stockholders' Equity [Roll Forward]            
Issue of Class A ordinary shares, net of forfeitures 26 26 0 0 26 0
Repurchase of Class A ordinary shares (17,692) (61) (8,483) (9,148) (17,692) 0
Short-swing sale profit from shareholder 83 0 83 0 83 0
Non-controlling interest contribution into (withdrawal from) joint venture, net 0 0 0 0 0 0
Income (loss) attributable to non-controlling interest in joint venture (5,508) 0 0 0 0 (5,508)
Net income (loss) (326,425) 0 0 (326,425) (326,425) 0
Share-based compensation expense, net of forfeitures 4,248 0 4,248 0 4,248 0
Ending balance at Dec. 31, 2015 $ 848,773 $ 3,703 $ 496,401 $ 325,287 $ 825,391 $ 23,382

v3.3.1.900
CONSOLIDATED STATEMENTS OF CASH FLOWS - USD ($)
$ in Thousands
12 Months Ended
Dec. 31, 2015
Dec. 31, 2014
Dec. 31, 2013
Cash provided by (used in) operating activities      
Net income (loss) $ (326,425) $ 109,592 $ 225,699
Adjustments to reconcile net income to net cash provided by (used in) operating activities      
Net change in unrealized gains and losses on investments and financial contracts 265,401 187,753 (149,013)
Net realized gains on investments and financial contracts (22,227) (352,133) (122,568)
Foreign exchange (gains) losses on investments 3,725 (14,797) (44,492)
Income (loss) attributable to non-controlling interest in joint venture (5,508) 3,683 6,769
Share-based compensation expense, net of forfeitures 4,274 3,964 3,675
Depreciation expense 405 436 325
Net change in      
Reinsurance balances receivable (83,113) 16,155 5,881
Loss and loss adjustment expenses recoverable (916) 5,306 17,622
Deferred acquisition costs, net (25,403) 17,377 7,380
Unearned premiums ceded 776 (854) 443
Other assets (1,791) (1,349) (291)
Loss and loss adjustment expense reserves 41,754 (65,651) (26,576)
Unearned premium reserves 83,218 (44,321) (15,128)
Reinsurance balances payable 7,524 1,583 3,497
Funds withheld 585 (3,568) (7,289)
Other liabilities (2,224) 3,092 1,369
Net cash (used in) provided by operating activities (59,945) (133,732) (92,697)
Investing activities      
Purchases of investments, trading (1,252,969) (1,603,856) (931,036)
Sales of investments, trading 1,388,162 1,722,936 933,356
Purchases of financial contracts (25,765) (13,302) (64,153)
Dispositions of financial contracts 7,002 113,011 90,282
Securities sold, not yet purchased 892,085 934,769 940,486
Dispositions of securities sold, not yet purchased (1,068,891) (952,843) (766,680)
Change in due to prime brokers 185,383 (103,632) (11,786)
Change in restricted cash and cash equivalents, net 50,400 35,476 (107,932)
Change in notes receivable, net 2,279 18,983 3,281
Non-controlling interest withdrawal from joint venture, net 0 (9,502) (10,762)
Fixed assets additions 0 0 (1,040)
Net cash (used in) provided by investing activities 177,686 142,040 74,016
Financing activities      
Net proceeds from exercise of stock options 0 0 513
Short-swing sale profit from shareholder 83 0 0
Repurchase of Class A ordinary shares (17,692) 0 0
Net cash (used in) provided by financing activities (17,609) 0 513
Net increase (decrease) in cash and cash equivalents 100,132 8,308 (18,168)
Cash and cash equivalents at beginning of the period 12,030 3,722 21,890
Cash and cash equivalents at end of the period 112,162 12,030 3,722
Supplementary information      
Interest paid in cash 21,959 21,482 23,741
Income tax paid in cash 0 0 531
Noncash Investing and Financing Activities - Transfer to Notes Receivable $ 25,859 $ 0 $ 0

v3.3.1.900
ORGANIZATION AND BASIS OF PRESENTATION
12 Months Ended
Dec. 31, 2015
Organization, Consolidation and Presentation of Financial Statements [Abstract]  
ORGANIZATION AND BASIS OF PRESENTATION
 
Greenlight Capital Re, Ltd. ("GLRE") was incorporated as an exempted company under the Companies Law of the Cayman Islands on July 13, 2004. GLRE’s principal wholly-owned subsidiary, Greenlight Reinsurance, Ltd. ("Greenlight Re"), provides global specialty property and casualty reinsurance. Greenlight Re has a Class D insurer license issued in accordance with the terms of The Insurance Law, 2010 and underlying regulations thereto (the "Law") and is subject to regulation by the Cayman Islands Monetary Authority ("CIMA"), in terms of the Law. Greenlight Re commenced underwriting in April 2006. Effective May 30, 2007, GLRE completed an initial public offering of 11,787,500 Class A ordinary shares at $19.00 per share. Concurrently, 2,631,579 Class B ordinary shares of GLRE were sold at $19.00 per share in a private placement offering. During 2008, Verdant Holding Company, Ltd. ("Verdant"), a wholly-owned subsidiary of GLRE, was incorporated in the state of Delaware. During 2010, GLRE established Greenlight Reinsurance Ireland, Designated Activity Company ("GRIL"), a wholly-owned reinsurance subsidiary based in Dublin, Ireland. GRIL is authorized as a non-life reinsurance undertaking in accordance with the provisions of the European Union (Insurance and Reinsurance) Regulations 2015 ("Irish Regulations"). GRIL provides multi-line property and casualty reinsurance capacity to the European broker market and provides GLRE with an additional platform to serve clients located in Europe and North America.  As used herein, the "Company" refers collectively to GLRE and its consolidated subsidiaries.
 
The Class A ordinary shares of GLRE are listed on Nasdaq Global Select Market under the symbol "GLRE".

These consolidated financial statements are prepared in conformity with accounting principles generally accepted in the United States of America ("U.S. GAAP"). The consolidated financial statements include the accounts of GLRE and the consolidated financial statements of its wholly owned subsidiaries, Greenlight Re, GRIL and Verdant. All significant intercompany transactions and balances have been eliminated on consolidation.

Reclassifications
Certain prior period balances have been reclassified to conform to the current period presentation. Prior to January 1, 2015, non-investment related foreign exchange gains and losses were recorded under general and administrative expenses in the condensed consolidated statements of income. Effective from January 1, 2015, the presentation has been modified and any non-investment related foreign exchange gains or losses are now recorded under “other income (expense), net” in the consolidated statements of income. As a result, foreign exchange gains (losses) of $2.6 million and $(0.8) million that were previously reported in general and administrative expenses for the years ended December 31, 2014 and 2013, respectively, were reclassified as “other income (expense), net” to conform to the current year presentation. The reclassifications resulted in no changes to net income or retained earnings for any of the periods presented.

v3.3.1.900
SIGNIFICANT ACCOUNTING POLICIES
12 Months Ended
Dec. 31, 2015
Accounting Policies [Abstract]  
SIGNIFICANT ACCOUNTING POLICIES
 
Use of Estimates
 
The preparation of consolidated financial statements in conformity with U.S. GAAP requires management to make estimates and assumptions that affect the reported amounts of assets and liabilities and disclosure of contingent assets and liabilities at the date of the consolidated financial statements and the reported amounts of income and expenses during the period. Actual results could differ from these estimates. 

Cash and Cash Equivalents
 
Cash and cash equivalents consist of cash and certain short-term, highly liquid investments with original maturity dates of three months or less.

Restricted Cash and Cash Equivalents
 
The Company is required to maintain certain cash in segregated accounts with prime brokers and derivative counterparties. The amount of restricted cash held by prime brokers is primarily used to support the liability created from securities sold, not yet purchased and derivatives. Additionally, restricted cash and cash equivalent balances are held to collateralize regulatory trusts and letters of credit issued to cedents (see Notes 4 and 6). The amount of cash encumbered varies depending on the market value of the securities sold, not yet purchased, and the collateral required by the cedents in the form of trust accounts and letters of credit. In addition, derivative counterparties require cash collateral to support the current value of any amounts that may be due to the counterparty based on the value of the underlying financial instrument. 

Premium Revenue Recognition
 
The Company accounts for reinsurance contracts in accordance with U.S. GAAP. In the event that a reinsurance contract does not transfer sufficient risk, deposit accounting is used and the contract is reported as a deposit liability.
 
The Company writes excess of loss contracts as well as quota share contracts. The Company estimates the ultimate premiums for the entire contract period. These estimates are based on information received from the ceding companies and estimates from actuarial pricing models used by the Company. For excess of loss contracts, the total ultimate estimated premiums are recorded as premiums written at the inception of the contract. For quota share contracts, the premiums are recorded as written based on cession statements from cedents which typically are received monthly or quarterly depending on terms specified in each contract. For any reporting lag, premiums written are estimated based on the portion of the ultimate estimated premiums relating to the risks underwritten during the lag period.
 
Premium estimates are reviewed by management at least quarterly. Such review includes a comparison of actual reported premiums to expected ultimate premiums along with a review of the aging and collection of premium estimates. Based on management’s review, the appropriateness of the premium estimates is evaluated, and any adjustments to these estimates are recorded in the period in which they are determined. Changes in premium estimates, including premium receivable on both excess of loss and quota share contracts, are expected and may result in significant adjustments in any period. A significant portion of amounts included in reinsurance balances receivable represent estimated premiums written, net of commissions and brokerage, and are not currently due based on the terms of the underlying contracts.

Certain contracts allow for reinstatement premiums in the event of a full limit loss prior to the expiry of a contract. A reinstatement premium is not due until there is a full limit loss event and therefore, in accordance with U.S. GAAP, the Company records a reinstatement premium as written only in the event that a client incurs a full limit loss on the contract and the contract allows for a reinstatement of coverage upon payment of an additional premium. For catastrophe contracts which contractually require the payment of a reinstatement premium equal to or greater than the original premium upon the occurrence of a full limit loss, the reinstatement premiums are earned over the original contract period. Reinstatement premiums that are contractually calculated on a pro-rata basis of the original premiums, are earned over the remaining coverage period.
 
Certain contracts may provide for a penalty to be paid if the contract is terminated and canceled prior to its expiration term. Cancellation penalties are recognized in the period the notice of cancellation is received and are recorded in the consolidated statements of income under "other income (expense), net".

Premiums written are generally recognized as earned over the contract period in proportion to the period of risk covered. Unearned premiums consist of the unexpired portion of reinsurance provided.
 
Reinsurance Premiums Ceded
 
The Company reduces the risk of future losses on business assumed by reinsuring certain risks and exposures with other reinsurers (retrocessionaires). The Company remains liable to the extent that any retrocessionaire fails to meet its obligations and to the extent the Company does not hold sufficient security for their unpaid obligations.
 
Ceded premiums are written during the period in which the risks incept and are expensed over the contract period in proportion to the period of protection. Unearned premiums ceded consist of the unexpired portion of reinsurance obtained.

Deferred Acquisition Costs
 
Policy acquisition costs, such as commission and brokerage costs, relate directly to, and vary with, the writing of reinsurance contracts. Acquisition costs relating solely to bound contracts are deferred subject to ultimate recoverability and are amortized over the related contract term. The Company evaluates the recoverability of deferred acquisition costs by determining if the sum of future earned premiums and anticipated investment income is greater than the expected future claims and expenses. If a loss is probable on the unexpired portion of policies in force, a premium deficiency loss is recognized. At December 31, 2015 and 2014, the deferred acquisition costs were considered fully recoverable and no premium deficiency loss was recorded. 

Acquisition costs also include profit commissions which are expensed when incurred. Profit commissions are calculated and accrued based on the expected loss experience for contracts and recorded when the current loss estimate indicates that a profit commission is probable under the contract terms. As of December 31, 2015, $12.2 million (2014: $11.0 million) of profit commission reserves were included in reinsurance balances payable on the consolidated balance sheets. For the year ended December 31, 2015, $7.5 million (2014: $2.7 million and 2013: $3.7 million, respectively) of net profit commission expense was included in acquisition costs on the consolidated statements of income.

Funds Withheld
 
Funds withheld include reinsurance balances retained from retrocessionaires as security for a period of time in accordance with the contract terms. Any interest expense that the Company incurs during the period these funds are withheld, are included under net investment income in the consolidated statements of income.
  
Loss and Loss Adjustment Expense Reserves and Recoverable
 
The Company establishes reserves for contracts based on estimates of the ultimate cost of all losses including losses incurred but not reported ("IBNR"). These estimated ultimate reserves are based on the Company’s own actuarial estimates derived from reports received from ceding companies, industry data and historical experience. These estimates are reviewed by the Company periodically on a contract by contract basis and adjusted as necessary. Since reserves are estimates, the final settlement of losses may vary from the reserves established and any adjustments to the estimates, which may be material, are recorded in the period they are determined.
 
Loss and loss adjustment expenses recoverable include the amounts due from retrocessionaires for unpaid loss and loss adjustment expenses on retrocession agreements. Ceded losses incurred but not reported are estimated based on the Company’s actuarial estimates. These estimates are reviewed periodically and adjusted when deemed necessary. The Company may not be able to ultimately recover the loss and loss adjustment expense recoverable amounts due to the retrocessionaires’ inability to pay. The Company regularly evaluates the financial condition of its retrocessionaires and records provisions for uncollectible reinsurance expenses recoverable when recovery is no longer probable.
 
Notes Receivable
 
Notes receivable include promissory notes receivable from third party entities. These notes are recorded at cost along with accrued interest, if any, which approximates the fair value. Interest income and realized gains or losses on sale of notes receivable are included under net investment income (loss) in the consolidated statements of income.

The Company regularly reviews all notes receivable individually for impairment and records valuation allowance provisions for uncollectible and non-performing notes. The Company places notes on non-accrual status when the recorded value of the note is not considered impaired but there is uncertainty as to the collection of interest based on the terms of the note. The Company resumes accrual of interest on a note when none of the principal or interest remains past due, and the Company expects to collect the remaining contractual principal and interest. Interest collected on notes that are placed on non-accrual status is treated on a cash-basis and recorded as interest income when collected, provided that the recorded value of the note is deemed to be fully collectible. Where doubt exists as to the collectability of the remaining recorded value of the notes placed on non-accrual status, any payments received are applied to reduce the recorded value of the notes.

At December 31, 2015, $23.0 million of notes receivable (net of any valuation allowance) were on non-accrual status
(2014: $0.0 million) and any payments received were applied to reduce the recorded value of the notes. The increase in notes receivable during the year ended December 31, 2015, related to a settlement agreement entered into with a ceding insurer during 2015 whereby certain amounts, previously classified under reinsurance balances receivable, were converted into a ten-year note receivable.
 
At December 31, 2015 and 2014, there was no accrued interest included in the notes receivable balance. Based on management’s assessment, the recorded values of the notes receivable, net of valuation allowance, at December 31, 2015 and 2014, were expected to be fully collectible.


Deposit Assets and Liabilities
 
In accordance with U.S. GAAP, deposit accounting is used in the event that a reinsurance contract does not transfer sufficient insurance risk, or a contract provides retroactive reinsurance. Any losses on such contracts are charged to earnings immediately. Any gains relating to such contracts are deferred and amortized over the estimated remaining settlement period. All such deferred gains are included in reinsurance balances payable in the consolidated balance sheets. Amortized gains are recorded in the consolidated statements of income as other income. At December 31, 2015 and 2014, there were no material deposit assets or deposit liabilities and no material gains or losses on deposit accounted contracts.
 
Fixed Assets
 
Fixed assets are included in other assets on the consolidated balance sheets and are recorded at cost when acquired. Fixed assets are comprised of computer software, furniture and fixtures and leasehold improvements and are depreciated, using the straight-line method, over their estimated useful lives, which are five years for both computer software, and furniture and fixtures.  Leasehold improvements are amortized over the lesser of the estimated useful lives of the assets or remaining lease term. The Company periodically reviews fixed assets that have finite lives, and that are not held for sale, for impairment by comparing the carrying value of the assets to their estimated future undiscounted cash flows. For the years ended December 31, 2015, 2014 and 2013, there were no impairments in fixed assets.

At December 31, 2015, the cost, accumulated depreciation and net book values of the fixed assets were as follows:
 
Cost
 
Accumulated depreciation
 
 
Net book value
 
($ in thousands)
Computer software
$
556

 
$
(348
)
 
$
208

Furniture and fixtures
620

 
(513
)
 
107

Leasehold improvements
2,002

 
(1,229
)
 
773

Total
$
3,178

 
$
(2,090
)
 
$
1,088


At December 31, 2014, the cost, accumulated depreciation and net book values of the fixed assets were as follows:
 
Cost
 
Accumulated depreciation
 
 
Net book value
 
($ in thousands)
Computer software
$
556

 
$
(277
)
 
$
279

Furniture and fixtures
620

 
(442
)
 
178

Leasehold improvements
2,002

 
(966
)
 
1,036

Total
$
3,178

 
$
(1,685
)
 
$
1,493


Financial Instruments
 
Investments in Securities and Investments in Securities Sold, Not Yet Purchased
 
The Company’s investments in debt instruments and equity securities that are classified as "trading securities" are carried at fair value. The fair values of the listed equity investments are derived based on quoted prices (unadjusted) in active markets for identical assets (Level 1 inputs). The fair values of listed equities that have restrictions on sale or transfer which expire within one year, are determined by adjusting the observed market price of the equity using a liquidity discount based on observable market inputs. The fair values of debt instruments are derived based on inputs that are observable, either directly or indirectly, such as market maker or broker quotes reflecting recent transactions (Level 2 inputs), and are generally derived based on the average of multiple market maker or broker quotes which are considered to be binding. Where quotes are not available, debt instruments are valued using cash flow models using assumptions and estimates that may be subjective and non-observable (Level 3 inputs).

The Company’s "other investments" may include investments in private and unlisted equity securities, limited partnerships, and commodities, which are all carried at fair value. The fair values of commodities are determined based on quoted prices in active markets for identical assets (Level 1). The Company maximizes the use of observable direct or indirect inputs (Level 2 inputs) when deriving the fair values for "other investments". For limited partnerships and private and unlisted equity securities, where observable inputs are not available, the fair values are derived based on unobservable inputs (Level 3 inputs) such as management’s assumptions developed from available information using the services of the investment advisor, including the most recent net asset values obtained from the managers of those underlying investments.

For securities classified as "trading securities", and "other investments", any realized and unrealized gains or losses are determined on the basis of the specific identification method (by reference to cost or amortized cost, as appropriate) and included in net investment income (loss) in the consolidated statements of income.

Dividend income and expense are recorded on the ex-dividend date. The ex-dividend date is the date as of when the underlying security must have been traded to be eligible for the dividend declared. Interest income and interest expense are recorded on an accrual basis.
 
Derivative Financial Instruments
 
U.S. GAAP requires that an entity recognize all derivatives in the balance sheet at fair value. It also requires that unrealized gains and losses resulting from changes in fair value be included in income or comprehensive income, depending on whether the instrument qualifies as a hedge transaction, and if so, the type of hedge transaction. The Company’s derivative financial instrument assets are included in financial contracts receivable. Derivative financial instrument liabilities are generally included in financial contracts payable. The Company's derivatives do not qualify as hedges for financial reporting purposes and are recorded in the consolidated balance sheets on a gross basis and not offset against any collateral pledged or received. Pursuant to the International Swaps and Derivatives Association ("ISDA") master agreements, securities lending agreements and other agreements, the Company and its counterparties typically have the ability to net certain payments owed to each other in specified circumstances. In addition, in the event a party to one of the ISDA master agreements, securities lending agreements or other agreements defaults, or a transaction is otherwise subject to termination, the non-defaulting party generally has the right to set off against payments owed to the defaulting party or collateral held by the non-defaulting party. The Company may from time to time enter into underwriting contracts such as industry loss warranty contracts ("ILW") that are treated as derivatives for U.S GAAP purposes.
 
Financial Contracts

The Company enters into financial contracts with counterparties as part of its investment strategy. Financial contracts, which include total return swaps, credit default swaps ("CDS"), futures, options, currency forwards and other derivative instruments, are recorded at their fair value with any unrealized gains and losses included in net investment income (loss) in the consolidated statements of income. Financial contracts receivable represents derivative contracts whereby, based upon the contract's current fair value, the Company will be entitled to receive payments upon settlement of the contract. Financial contracts payable represents derivative contracts whereby, based upon each contract's current fair value, the Company will be obligated to make payments upon settlement of the contract.
 
Total return swap agreements, included on the consolidated balance sheets as financial contracts receivable and financial contracts payable, are derivative financial instruments whereby the Company is either entitled to receive or obligated to pay the product of a notional amount multiplied by the movement in an underlying security, which the Company may not own, over a specified time frame. In addition, the Company may also be obligated to pay or receive other payments based on interest rates, dividend payments and receipts, or foreign exchange movements during a specified period. The Company measures its rights or obligations to the counterparty based on the fair value movements of the underlying security together with any other payments due. These contracts are carried at fair value, based on observable inputs (Level 2 inputs) with the resultant unrealized gains and losses reflected in net investment income (loss) in the consolidated statements of income. Additionally, any changes in the value of amounts received or paid on swap contracts are reported as a gain or loss in net investment income (loss) in the consolidated statements of income.
 
Financial contracts may also include exchange traded futures or options contracts that are based on the movement of a particular index, equity security, commodity, currency or interest rate. Where such contracts are traded in an active market, the Company’s obligations or rights on these contracts are recorded at fair value based on the observable quoted prices of the same or similar financial contracts in an active market (Level 1) or on broker quotes which reflect market information based on actual transactions (Level 2). Amounts invested in exchange traded options and over the counter ("OTC") options are recorded either as an asset or liability at inception. Subsequent to initial recognition, unexpired exchange traded option contracts are recorded at fair value based on quoted prices in active markets (Level 1). For OTC options or exchange traded options where a quoted price in an active market is not available, fair values are derived based upon observable inputs (Level 2) such as multiple quotes from brokers and market makers, which are considered to be binding.
 
The Company may purchase and sell CDS for strategic investment purposes. A CDS is a derivative instrument that provides protection against an investment loss due to specified credit or default events of a reference entity. The seller of a CDS guarantees to pay the buyer a specified amount if the reference entity defaults on its obligations or fails to perform. The buyer of a CDS pays a premium over time to the seller in exchange for obtaining this protection. A CDS trading in an active market is valued at fair value based on broker or market maker quotes for identical instruments in an active market (Level 2) or based on the current credit spreads on identical contracts (Level 2).

Share-Based Compensation
 
The Company has established a stock incentive plan for directors, employees and consultants.
 
U.S. GAAP requires the Company to recognize share-based compensation transactions using the fair value at the grant date of the award. The Company measures compensation for restricted shares and restricted stock units ("RSUs") based on the price of the Company’s common shares at the grant date and the expense is recognized on a straight line basis over the vesting period.

Determining the fair value of share purchase options at the grant date requires significant estimation and judgment. The Company uses an option-pricing model (Black-Scholes option pricing model) to assist in the calculation of fair value for share purchase options. The model requires estimation of various inputs such as estimated term, forfeiture and dividend rates and expected volatility. The Company uses the full life of the options, ten years, as the estimated term of the options, and has assumed no forfeitures and no dividends paid during the life of the options. Effective from 2014, the estimate of expected volatility is based on the daily historical trading data of the Company's Class A ordinary shares from the date that these shares commenced trading (May 24, 2007) to the grant date. Prior to 2014, the Company's share had not been publicly traded for a sufficient length of time to reasonably estimate the expected volatility. Therefore, for share purchase options granted prior to 2014, the Company determined the expected volatility based primarily on the historical volatility of similar entities. The Company considered factors such as an entity's industry, stage of life cycle, size and financial leverage when selecting similar entities. The Company used a sample peer group of companies in the reinsurance industry as well as the Company’s own historical volatility in determining the expected volatility. 
 
For share purchase options issued under the employee stock incentive plan, compensation cost is calculated and expensed over the vesting periods on a graded vesting basis (see Note 10). 

If actual results differ significantly from these estimates and assumptions, particularly in relation to the Company’s estimation of volatility which requires the most judgment, share-based compensation expense, primarily with respect to future share-based awards, could be materially impacted.
 
Foreign Exchange
 
The reporting and functional currency of the Company and all its subsidiaries is the U.S. dollar. Transactions in foreign currencies are recorded in U.S. dollars at the exchange rates in effect on the transaction date. Monetary assets and liabilities in foreign currencies at the balance sheet date are translated at the exchange rate in effect at the balance sheet date and translation exchange gains and losses, if any, are included in "other income (expense), net" in the consolidated statements of income. 

Other Assets
 
Other assets consist primarily of investment income receivable, prepaid expenses, fixed assets and deferred tax assets.
 
Other Liabilities
 
Other liabilities consist primarily of dividends payable on securities sold, not yet purchased, and employee bonus accruals. At December 31, 2015, other liabilities included accrued bonus of $8.2 million (2014: $7.6 million). Under the Company's bonus program, each employee’s target bonus consists of two components: a discretionary component based on a qualitative assessment of each employee’s performance and a quantitative component based on the return on deployed equity (‘‘RODE”) for each underwriting year relating to reinsurance operations. The qualitative portion of an employee’s annual bonus is accrued at each employee's target amount, which may differ significantly from the actual amount approved and awarded annually by the Compensation Committee. The quantitative portion of each employee’s annual bonus is accrued based on the expected RODE for each underwriting year and adjusted for changes in the expected RODE and actual investment return each quarter until all losses are settled and the underwriting year is declared closed. The quantitative bonus is calculated and paid, with the approval of the Compensation Committee, in annual installments between two to five years from the end of the fiscal year in which the business was underwritten. Any further changes are incorporated into the following open underwriting year. The expected RODE calculation utilizes proprietary models which require significant estimation and judgment. Actual RODE may vary significantly from the expected RODE and any adjustments to the quantitative bonus estimates, which may be material, are recorded in the period in which they are determined. 
 
Also included in other liabilities are accruals for income taxes payable, professional fees and other general expenses.
 
Non-controlling Interest
 
Non-controlling interest in joint venture on the consolidated balance sheets represents DME Advisors, LLC’s (‘‘DME”) share of assets in the joint venture whereby DME is a participant in the joint venture as disclosed in Note 13. DME’s share of investment income or loss is included in the consolidated statements of income as income attributable to non-controlling interest in joint venture.

Comprehensive Income (Loss)

The Company has no other comprehensive income or loss, other than the net income or loss disclosed in the consolidated statements of income.

Earnings (Loss) Per Share
 
Basic earnings per share are based on the weighted average number of common shares and participating securities outstanding during the period. Diluted earnings per share includes the dilutive effect of restricted stock units ("RSU") and additional potential common shares issuable when stock options are exercised and are determined using the treasury stock method. The Company treats its unvested restricted stock as participating securities in accordance with U.S. GAAP, which requires that unvested stock awards which contain non-forfeitable rights to dividends or dividend equivalents, whether paid or unpaid (referred to as "participating securities"), be included in the number of shares outstanding for both basic and diluted earnings per share calculations. In the event of a net loss, all RSUs, stock options outstanding and participating securities are excluded from the calculation of both basic and diluted loss per share since their inclusion would be anti-dilutive.
 
Year ended December 31
 
2015
 
2014
 
2013
Weighted average shares outstanding - basic
36,670,466

 
37,242,687

 
36,838,128

Effect of dilutive service provider share-based awards
—

 
8,498

 
144,726

Effect of dilutive employee and director share-based awards
—

 
623,202

 
602,313

Weighted average shares outstanding - diluted
36,670,466

 
37,874,387

 
37,585,167

Anti-dilutive stock options outstanding
211,821

 
—

 
218,197

Participating securities excluded from calculation of loss per share 
307,013

 
—

 
—


Taxation
 
Under current Cayman Islands law, no corporate entity, including GLRE and Greenlight Re, is obligated to pay taxes in the Cayman Islands on either income or capital gains. The Company has an undertaking from the Governor-in-Cabinet of the Cayman Islands, pursuant to the provisions of the Tax Concessions Law, as amended, that, in the event that the Cayman Islands enacts any legislation that imposes tax on profits, income, gains or appreciations, or any tax in the nature of estate duty or inheritance tax, such tax will not be applicable to GLRE, Greenlight Re nor their respective operations, or to the Class A or Class B ordinary shares or related obligations, until February 1, 2025.
 
Verdant is incorporated in Delaware and therefore is subject to taxes in accordance with the U.S. federal rates and regulations prescribed by the U.S. Internal Revenue Service ("IRS"). Verdant’s taxable income is generally expected to be taxed at a rate of 35%.

GRIL is incorporated in Ireland and therefore is subject to the Irish corporation tax rate of 12.5% on its trading income, and 25% on its non-trading income, if any.

Any deferred tax asset is evaluated for recovery and a valuation allowance is recorded when it is more likely than not that the deferred tax asset will not be realized in the future. The Company has not taken any income tax positions that are subject to significant uncertainty or that are reasonably likely to have a material impact on the Company.

Segment Information
 
Under U.S. GAAP, operating segments are based on the internal information that management uses for allocating resources and assessing performance as the source of the Company's reportable segments.
 
The Company manages its business on the basis of one operating segment, Property and Casualty Reinsurance, in accordance with the qualitative and quantitative criteria established by U.S. GAAP. 
 
Recent Accounting Pronouncements
        
In May 2015, the FASB issued Accounting Standards Update 2015-07, "Fair Value Measurement (Topic 820): Disclosures for Investments in Certain Entities That Calculate Net Asset Value per Share or Its Equivalent" ("ASU 2015-07"). The amendments apply to reporting entities that elect to measure the fair value of an investment using the net asset value ("NAV") per share (or its equivalent) as a practical expedient. The amendments remove the requirement to categorize within the fair value hierarchy all investments for which fair value is measured using the NAV per share as a practical expedient. The amendments also remove the requirement to make certain disclosures for all investments that are eligible to be measured at fair value using the NAV per share as a practical expedient. Rather, those disclosures are limited to investments for which the entity has elected to measure the fair value using that practical expedient. The amendments in ASU 2015-07 are effective for reporting periods beginning after December 15, 2015, with early adoption permitted. Entities are required to apply the amendments in this update retrospectively to all periods presented. The Company will adopt ASU 2015-07 during the first quarter of 2016. As the Company measures certain investments in private equity funds using the NAV as a practicable expedient, upon adoption of ASU 2015-07, the fair value of these investments will be removed from the fair value hierarchy for all periods presented in the Company’s consolidated financial statements. The Company will continue to disclose information on these investments for which fair value is measured at NAV as a practical expedient.

In May 2015, the FASB issued ASU 2015-09, "Financial Services - Insurance (Topic 944): Disclosures about Short-Duration Contracts" ("ASU 2015-09"). ASU 2015-09 requires additional disclosures for short-duration contracts including incurred and paid claims development information, claims duration information, quantitative claims frequency information (unless impracticable), and an explanation of significant changes in methodologies and assumptions used to calculate the loss and loss adjustment expense reserves. ASU 2015-09 is effective for public entities for annual reporting periods beginning after December 15, 2015, and interim reporting periods within annual reporting periods beginning after December 15, 2016 with early adoption permitted. The Company is evaluating the impact of the disclosure requirements of ASU 2015-09 and is preparing to disclose the additional information in its consolidated financial statements for the fiscal year ending December 31, 2016 and thereafter.

v3.3.1.900
FINANCIAL INSTRUMENTS
12 Months Ended
Dec. 31, 2015
Financial Instruments [Abstract]  
FINANCIAL INSTRUMENTS
 
In the normal course of its business, the Company purchases and sells various financial instruments, which include listed and unlisted equities, corporate and sovereign debt, commodities, futures, put and call options, currency forwards, other derivatives and similar instruments sold, not yet purchased.

The Company is exposed to credit risk in relation to counterparties that may default on their obligations to the Company. The amount of counterparty credit risk predominantly relates to the value of financial contracts receivable and assets held at counterparties. The Company mitigates its counterparty credit risk by using several counterparties which decreases the likelihood of any significant concentration of credit risk with any one counterparty.  In addition, the Company is exposed to credit risk on corporate and sovereign debt instruments to the extent that the debtors may default on their debt obligations.    
 
The Company is exposed to market risk including interest rate and foreign exchange fluctuations on financial instruments that are valued at market prices. Market movements can be volatile and difficult to predict. This may affect the ultimate gains or losses realized upon the sale of its holdings as well as the amount of net investment income reported in the consolidated statements of income. Management utilizes the services of the Company's investment advisor to monitor the Company's positions to reduce the risk of potential loss due to changes in market values.
 
Purchases and sales of investments are disclosed in the consolidated statements of cash flows. Net realized gains on the sale of investments, financial contracts, and investments sold, not yet purchased during 2015 were $22.2 million (2014: $352.1 million gains, 2013: $122.6 million gains). Gross realized gains were $350.5 million (2014: $596.6 million, 2013: $312.3 million) and gross realized losses were $328.3 million (2014: $244.5 million, 2013: $189.7 million). For the year ended December 31, 2015, included in net investment income in the consolidated statements of income were $265.4 million of net losses (2014: $187.8 million of net losses, 2013: $149.0 million of net gains) relating to change in unrealized gains and losses on trading securities still held at the balance sheet date.
  
As of December 31, 2015, cash and investments with a fair value of $324.3 million (2014: $302.6 million) have been pledged as security against letters of credit issued, and $78.6 million (2014: nil) have been pledged as security relating to regulatory trusts.
 
As of December 31, 2015, the Company’s investments in gold and gold derivatives was the only investment in excess of 10% of the Company’s shareholders’ equity, with a fair value of $98.0 million, or 11.6% of shareholders' equity. As of December 31, 2014, the Company’s investment in Micron Technology Inc., was the only investment in excess of 10% of the Company’s shareholders’ equity, with fair values of $151.1 million, or 12.7%, of shareholders' equity.

   Fair Value Hierarchy

The Company’s financial instruments are carried at fair value, and the net unrealized gains or losses are included in net investment income (loss) in the consolidated statements of income.
 
The following table presents the Company’s investments, categorized by the level of the fair value hierarchy as of December 31, 2015:
 
 
Fair value measurements as of December 31, 2015
 
 
Description
 
Quoted prices in
active markets
(Level 1)
 
Significant other
observable
inputs
(Level 2)
 
Significant
unobservable
inputs
(Level 3)
 
Total
Assets: 
 
($ in thousands)
Debt instruments
 
$
—

 
$
38,582

 
$
505

 
$
39,087

Listed equity securities
 
900,369

 
5,625

 
—

 
905,994

Commodities
 
98,046

 
—

 
—

 
98,046

Private and unlisted equity securities
 
—

 
—

 
21,037

 
21,037

Financial contracts receivable
 
20

 
13,195

 
—

 
13,215


$
998,435

 
$
57,402

 
$
21,542

 
$
1,077,379

Liabilities:


Listed equity securities, sold not yet purchased
 
$
(808,481
)
 
$
—

 
$
—

 
$
(808,481
)
Debt instruments, sold not yet purchased
 
—

 
(74,425
)
 
—

 
(74,425
)
Financial contracts payable
 
(488
)
 
(27,757
)
 
—

 
(28,245
)
 
 
$
(808,969
)
 
$
(102,182
)
 
$
—

 
$
(911,151
)

 
The following table presents the Company’s investments, categorized by the level of the fair value hierarchy as of December 31, 2014:
 
 
Fair value measurements as of December 31, 2014
 
 
Description
 
Quoted prices in
active markets
(Level 1)
 
Significant other
observable
inputs
(Level 2)
 
Significant
unobservable
inputs
(Level 3)
 
Total
Assets: 
 
($ in thousands)
Debt instruments
 
$
—

 
$
26,953

 
$
22,259

 
$
49,212

Listed equity securities
 
1,259,298

 
6,877

 
—

 
1,266,175

Commodities
 
96,872

 
—

 
—

 
96,872

Private and unlisted equity securities
 
—

 
—

 
18,719

 
18,719

Financial contracts receivable
 
2,463

 
44,708

 
—

 
47,171


$
1,358,633

 
$
78,538

 
$
40,978

 
$
1,478,149

Liabilities:


Listed equity securities, sold not yet purchased
 
$
(834,228
)
 
$
—

 
$
—

 
$
(834,228
)
Debt instruments, sold not yet purchased
 
—

 
(256,503
)
 
—

 
(256,503
)
Financial contracts payable
 
—

 
(44,592
)
 
—

 
(44,592
)
 
 
$
(834,228
)
 
$
(301,095
)
 
$
—

 
$
(1,135,323
)

 
The following table presents the reconciliation of the balances for all investments measured at fair value using significant unobservable inputs (Level 3) for the year ended December 31, 2015: 
 
 
Fair Value Measurements Using Significant Unobservable Inputs (Level 3)
 
 
Year ended December 31, 2015
 
 
Assets
 
Liabilities
 
 
Debt instruments
 
 Private and unlisted equity securities
 
Financial contracts receivable
 
Listed equity securities
 
 Total
 
Financial contracts payable
 
 
 ($ in thousands)
Beginning balance
 
$
22,259

 
$
18,719

 
$
—

 
$
—

 
$
40,978

 
$
—

Purchases
 
—

 
5,009

 
2,340

 
—

 
7,349

 
—

Sales
 
(21,561
)
 
(3,290
)
 
—

 
—

 
(24,851
)
 
—

Total realized and unrealized gains (losses) and amortization included in earnings, net
 
(193
)
 
599

 
(3,027
)
 
(692
)
 
(3,313
)
 
314

Transfers into Level 3
 
—

 
—

 
2,536

 
5,189

 
7,725

 
8,835

Transfers out of Level 3
 
—

 
—

 
(1,849
)
 
(4,497
)
 
(6,346
)
 
(9,149
)
Ending balance
 
$
505

 
$
21,037

 
$
—

 
$
—

 
$
21,542

 
$
—


During the year ended December 31, 2015, $5.2 million of equity securities, listed on the Athens Stock Exchange (the "ASE"), were transferred from Level 1 to Level 3 securities due to trading being halted from June 26, 2015 to August 3, 2015 for all equity securities listed on the ASE. Since there was no active market with observable trading prices to determine the fair value of these securities, during this period these securities were valued based on the last trading price of these securities on the ASE and adjusted for the estimated decline in the fair value of American depository receipts of other comparable securities. When the ASE resumed trading on August 3, 2015, the fair values of the ASE listed equity securities were once again based on observable prices in an active market. Therefore, $4.5 million of listed equity securities trading on the ASE were transferred from Level 3 to Level 1 securities during the year ended December 31, 2015.

The fair values for derivatives for which the underlying securities traded on the ASE were also transferred to Level 3 securities during 2015 when the ASE halted trading, and were subsequently transferred out of Level 3 securities when the ASE resumed trading. Therefore, for the year ended December 31, 2015, $2.5 million and $8.8 million of financial contracts receivable and financial contracts payable, respectively, were transfered from Level 2 to Level 3 due to the fair values being based on unobservable inputs during the period that the ASE had halted trading. During the year ended December 31, 2015, $1.8 million of financial contracts receivable and $9.1 million of financial contracts payable, respectively, were transfered from Level 3 to Level 2 as fair values were based on observable inputs once the ASE resumed trading.

There were no other transfers between Level 1, Level 2 or Level 3 during the year ended December 31, 2015.

The following table presents the reconciliation of the balances for all investments measured at fair value using significant unobservable inputs (Level 3) for the year ended December 31, 2014:


  Fair Value Measurements Using Significant Unobservable Inputs (Level 3)
 
 
Year ended December 31, 2014
 
 
Debt instruments
 
 Private and unlisted equity securities
 
Total
 
 
 ($ in thousands)
Beginning balance
 
$
527

 
$
46,323

 
$
46,850

Purchases
 
21,561

 
3,958

 
25,519

Sales
 
—

 
(37,252
)
 
(37,252
)
Total realized and unrealized gains included in earnings, net
 
171

 
9,734

 
9,905

Transfers into Level 3
 
—

 
—

 
—

Transfers out of Level 3
 
—

 
(4,044
)
 
(4,044
)
Ending balance
 
$
22,259

 
$
18,719

 
$
40,978


During the year ended December 31, 2014, $4.0 million of securities at fair value, based on the date of transfer, were transferred from Level 3 to Level 2 as these securities began actively trading on a listed exchange during the third quarter of 2014. However, due to lock-up period restrictions on those securities, they were classified as Level 2 upon transfer until the lock-up period expired.

Additionally. during the year ended December 31, 2014, $14.4 million of securities at fair value, based on the date of transfer, were transferred from Level 2 to Level 1 as the lock up period restrictions on those securities expired. There were no other transfers between Level 1, Level 2 or Level 3 during the year ended December 31, 2014.

As of December 31, 2015, included in private and unlisted equity securities are investments in private equity funds with a fair value of $12.6 million (December 31, 2014: $12.3 million) determined based on unadjusted net asset values reported by the managers of these securities. Some of these values were reported from periods prior to December 31, 2015. The private equity funds have varying lock-up periods and, as of December 31, 2015, all of the funds had redemption restrictions, and therefore have been categorized within Level 3 of the fair value hierarchy. The redemption restrictions have been in place since inception of the investments and are not expected to lapse in the near future. As of December 31, 2015, the Company had $6.1 million (December 31, 2014: $8.9 million) of unfunded commitments relating to private equity funds whose fair values are determined based on unadjusted net asset values reported by the managers of these securities. These commitments are included in the amounts presented in the schedule of commitments and contingencies in Note 14 of these consolidated financial statements.  

For the year ended December 31, 2015, included in net investment loss in the consolidated statements of income were net realized losses relating to Level 3 securities of $1.4 million (2014: net realized gains of $13.5 million). In addition, for the year ended December 31, 2015, amortization expense of $2.3 million (2014: nil) relating to financial contracts receivable, valued using unobservable inputs, was included in the consolidated statements of income as "other income (expense), net".

For Level 3 securities still held as of the reporting date, the change in net unrealized gain for the year ended December 31, 2015 of $0.6 million (2014: net unrealized gains $1.4 million), were included in net investment income (loss) in the consolidated statements of income.

 
Investments
 
Debt instruments, trading

At December 31, 2015, the following investments were included in debt instruments:
 
 
Cost/
 amortized
 cost
 
Unrealized
 gains
 
Unrealized
 losses
 
Fair
 value
 
 
($ in thousands)
Corporate debt – U.S.
 
$
25,674

 
$
155

 
$
(5,519
)
 
$
20,310

Corporate debt – Non U.S.
 
2,109

 
—

 
(1,795
)
 
314

Sovereign debt – Non U.S.
 
17,688

 
1,225

 
(450
)
 
18,463

Total debt instruments
 
$
45,471

 
$
1,380

 
$
(7,764
)
 
$
39,087

 
At December 31, 2014, the following investments were included in debt instruments:
 
 
Cost/
 amortized
 cost
 
Unrealized
 gains
 
Unrealized
 losses
 
Fair
 value
 
 
($ in thousands)
Corporate debt – U.S.
 
$
23,677

 
$
5

 
$
(1,423
)
 
$
22,259

Corporate debt – Non U.S.
 
5,870

 
49

 
(1,405
)
 
4,514

Municipal debt – U.S.
 
1,759

 
—

 
(6
)
 
1,753

Sovereign debt – Non U.S.
 
21,769

 
—

 
(1,083
)
 
20,686

Total debt instruments
 
$
53,075

 
$
54

 
$
(3,917
)
 
$
49,212


The maturity distribution for debt instruments held at December 31, 2015 and 2014, was as follows:
 
 
2015
 
2014
 
 
Cost/
 amortized
 cost
 
Fair
 value
 
Cost/
 amortized
 cost
 
Fair
 value
 
 
($ in thousands)
Within one year
 
$
—

 
$
—

 
$
—

 
$
—

From one to five years
 
4,202

 
4,129

 
21,922

 
21,923

From five to ten years
 
18,840

 
14,780

 
2,401

 
1,282

More than ten years
 
22,429

 
20,178

 
28,752

 
26,007


$
45,471

 
$
39,087

 
$
53,075

 
$
49,212


Equity securities, trading

At December 31, 2015, the following long positions were included in equity securities, trading: 
 
 
Cost
 
Unrealized
gains
 
Unrealized
losses
 
Fair
value
 
 
($ in thousands)
Equities – listed
 
$
1,011,424

 
$
67,114

 
$
(187,885
)
 
$
890,653

Exchange traded funds
 
31,570

 
—

 
(16,229
)
 
15,341

Total equity securities
 
$
1,042,994

 
$
67,114

 
$
(204,114
)
 
$
905,994


At December 31, 2014, the following long positions were included in equity securities, trading:
 
 
Cost
 
Unrealized
gains
 
Unrealized
losses
 
Fair
value
 
 
($ in thousands)
Equities – listed
 
$
1,079,955

 
$
247,109

 
$
(80,637
)
 
$
1,246,427

Exchange traded funds
 
42,126

 
—

 
(22,378
)
 
19,748

Total equity securities
 
$
1,122,081

 
$
247,109

 
$
(103,015
)
 
$
1,266,175


Other Investments
 
"Other investments" include commodities and private and unlisted equity securities. As of December 31, 2015 and 2014, commodities were comprised of gold bullion. 

At December 31, 2015, the following securities were included in other investments:
 
 
Cost
 
Unrealized
gains
 
Unrealized
losses
 
Fair
value
 
 
($ in thousands)
Commodities
 
$
102,092

 
$
—

 
$
(4,046
)
 
$
98,046

Private and unlisted equity securities
 
18,720

 
3,491

 
(1,174
)
 
21,037


$
120,812

 
$
3,491

 
$
(5,220
)
 
$
119,083


At December 31, 2014, the following securities were included in other investments: 
 
 
Cost
 
Unrealized
gains
 
Unrealized
losses
 
Fair
value
 
 
($ in thousands)
Commodities
 
$
95,815

 
$
1,057

 
$
—

 
$
96,872

Private and unlisted equity securities
 
17,238

 
3,451

 
(1,970
)
 
18,719


$
113,053

 
$
4,508

 
$
(1,970
)
 
$
115,591


Investments in Securities Sold, Not Yet Purchased 

Securities sold, not yet purchased are securities that the Company has sold, but does not own, in anticipation of a decline in the market value of the security. The Company’s risk is that the value of the security will increase rather than decline. Consequently, the settlement amount of the liability for securities sold, not yet purchased may exceed the amount recorded in the consolidated balance sheet as the Company is obligated to purchase the securities sold, not yet purchased in the market at prevailing prices to settle its obligations. To establish a position in security sold, not yet purchased, the Company needs to borrow the security for delivery to the buyer. On each day the transaction is open, the liability for the obligation to replace the borrowed security is marked-to-market and an unrealized gain or loss is recorded. At the time the transaction is closed, the Company realizes a gain or loss equal to the difference between the price at which the security was sold and the cost of replacing the borrowed security. While the transaction is open, the Company will also incur an expense for any dividends or interest which will be paid to the lender of the securities.

At December 31, 2015, the following securities were included in investments in securities sold, not yet purchased:
 
 
Proceeds
 
Unrealized gains
 
Unrealized losses
 
 Fair value
 
 
($ in thousands)
Equities – listed
 
$
(803,842
)
 
$
102,469

 
$
(94,681
)
 
$
(796,054
)
Exchange traded funds
 
(9,572
)
 
—

 
(2,855
)
 
(12,427
)
Sovereign debt – Non U.S.
 
(77,443
)
 
3,018

 
—

 
(74,425
)
 
 
$
(890,857
)
 
$
105,487

 
$
(97,536
)
 
$
(882,906
)


At December 31, 2014, the following securities were included in investments in securities sold, not yet purchased: 
 
 
Proceeds
 
Unrealized gains
 
Unrealized losses
 
 Fair value
 
 
($ in thousands)
Corporate debt – U.S.
 
$
(7,066
)
 
$
1,007

 
$
(5
)
 
$
(6,064
)
Equities – listed
 
(813,365
)
 
91,690

 
(101,715
)
 
(823,390
)
Exchange traded funds
 
(9,180
)
 
—

 
(1,658
)
 
(10,838
)
Sovereign debt – Non U.S.
 
(246,589
)
 
6,635

 
(10,485
)
 
(250,439
)
 
 
$
(1,076,200
)
 
$
99,332

 
$
(113,863
)
 
$
(1,090,731
)

 
Financial Contracts
 
As of December 31, 2015 and 2014, the Company had entered into total return equity swaps, interest rate swaps, commodity swaps, CDS, options, warrants, rights, futures and forward contracts with various financial institutions to meet certain investment objectives. Under the terms of each of these financial contracts, the Company is either entitled to receive or is obligated to make payments, which are based on the product of a formula contained within each contract that includes the change in the fair value of the underlying or reference security.

In addition, during the year ended December 31, 2015, the Company had entered into an ILW with certain third-parties in order to purchase protection against worldwide wind and earthquake exposures from January 2015 to December 2015. In return for a fixed payment, the Company is entitled to receive a variable payment in the event of losses incurred by the insurance industry, as a whole, exceeding a specified threshold. Through December 31, 2015, the Company was not aware of any industry loss event occurring that would have triggered a recovery under the ILW.
 
At December 31, 2015, the fair values of financial contracts outstanding were as follows: 
Financial Contracts
 
Listing
currency
(1)
 
Notional amount of
underlying instruments
 
Fair value of net assets
(obligations)
on financial
contracts


($ in thousands)
Financial contracts receivable


Call options (2)
 
USD
 
47,259

 
$
657

Put options (3)
 
USD
 
147,326

 
8,790

Total return swaps – equities
 
EUR/GBP/USD
 
50,205

 
3,748

Warrants and rights on listed equities
 
EUR
 
59

 
20

Total financial contracts receivable, at fair value


$
13,215

Financial contracts payable


Call options
 
USD
 
2,601

 
$
(64
)
Commodity Swaps
 
USD
 
42,160

 
(12,784
)
Forwards
 
KRW
 
2,908

 
(22
)
Futures
 
USD
 
21,195

 
(488
)
Total return swaps – equities
 
EUR/GBP/HKD/RON/MXN/USD
 
71,874

 
(14,887
)
Total financial contracts payable, at fair value


$
(28,245
)

(1) USD = US Dollar; EUR = Euro; GBP = British Pound; HKD = Hong Kong Dollar; KRW = Korean Won; MXN = Mexican Peso; RON = Romanian New Leu.
(2) Includes options on interest rate futures relating to U.S. dollar LIBOR interest rates.
(3) Includes options on the Japanese Yen and the Chinese Yuan, denominated in U.S. dollars.
 
At December 31, 2014, the fair values of financial contracts outstanding were as follows: 
Financial Contracts
 
Listing
currency (1)
 
Notional amount of
underlying instruments
 
Fair value of net assets
(obligations)
on financial
contracts


($ in thousands)
Financial contracts receivable


Futures
 
USD
 
13,204

 
$
3,461

Put options (2)
 
USD
 
299,907

 
22,349

Total return swaps – equities
 
EUR/GBP/HKD/USD
 
43,355

 
18,898

Warrants and rights on listed equities
 
EUR
 
8,054

 
2,463

Total financial contracts receivable, at fair value


$
47,171

Financial contracts payable


Credit default swaps, purchased – corporate debt
 
USD
 
221,198

 
$
(1,305
)
Credit default swaps, purchased – sovereign debt
 
USD
 
251,467

 
(1,714
)
Forwards
 
KRW
 
20,563

 
(512
)
Futures
 
USD
 
33,625

 
(867
)
Total return swaps – equities
 
EUR/GBP/HKD/INR/RON/USD
 
122,667

 
(40,194
)
Total financial contracts payable, at fair value


$
(44,592
)

(1) USD = US Dollar; EUR = Euro; GBP = British Pound; HKD = Hong Kong Dollar; KRW = Korean Won; RON = Romanian New Leu; INR = Indian Rupee.
(2) Includes options on the Japanese Yen and the Chinese Yuan, denominated in U.S. dollars.

Options are derivative financial instruments that give the buyer, in exchange for a premium payment, the right, but not the obligation, to either purchase from (call option) or sell to (put option) the writer, a specified underlying security at a specified price on or before a specified date. The Company enters into option contracts to meet certain investment objectives. For exchange traded option contracts, the exchange acts as the counterparty to specific transactions and therefore bears the risk of delivery to and from counterparties of specific positions.

As of December 31, 2015, the Company held $8.7 million OTC put options (long) (December 31, 2014: $22.4 million).

During the years ended December 31, 2015, 2014 and 2013, the Company reported gains and losses on derivatives as follows:
Derivatives not designated as hedging instruments
 
Location of gains and losses on derivatives recognized in income
 
Gain (loss) on derivatives recognized in income


Year ended December 31


2015
 
2014
 
2013


($ in thousands)
Commodity swaps
 
Net investment income (loss)
 
$
(12,061
)
 
$
—

 
$
—

Credit default swaps, purchased – corporate debt
 
Net investment income (loss)
 
(156
)
 
(345
)
 
(3,552
)
Credit default swaps, purchased – sovereign debt
 
Net investment income (loss)
 
(90
)
 
(298
)
 
(1,087
)
Forwards
 
Net investment income (loss)
 
1,009

 
(490
)
 
11,209

Futures
 
Net investment income (loss)
 
(952
)
 
16,721

 
12,504

Interest rate options
 
Net investment income (loss)
 
—

 
(26
)
 
(82
)
Interest rate swaps
 
Net investment income (loss)
 
(706
)
 
—

 
—

Options, warrants, and rights
 
Net investment income (loss)
 
(13,955
)
 
1,020

 
21,446

Total return swaps – equities
 
Net investment income (loss)
 
(12,590
)
 
13,142

 
85,638

Weather derivative swap
 
Other income (expense), net
 
(2,340
)
 
—

 
—

Total


$
(41,841
)
 
$
29,724

 
$
126,076


The Company generally does not enter into derivatives for risk management or hedging purposes. The volume of derivative activities varies from period to period depending on potential investment opportunities.

For the year ended December 31, 2015, the Company’s volume of derivative activities (based on notional amounts) was as follows:
2015
 
Year ended December 31
Derivatives not designated as hedging instruments (notional amounts)
 
  Entered
 
Exited
 
 
($ in thousands)
Commodity swaps
 
$
103,358

 
$
43,261

Credit default swaps (1)
 
—

 
—

Forwards
 
—

 
13,377

Futures
 
311,536

 
294,441

Interest rate swaps
 
9,139,000

 
7,213,000

Options, warrants and rights (1)
 
661,103

 
341,702

Total return swaps
 
67,844

 
185,128

Weather derivative swap
 
12,000

 
12,000

Total
 
$
10,294,841

 
$
8,102,909


(1) Exited amount excludes derivatives which expired or were exercised during the period.

For the year ended December 31, 2014, the Company’s volume of derivative activities (based on notional amounts) was as follows:
2014
 
Year ended December 31
Derivatives not designated as hedging instruments (notional amounts)
 
  Entered
 
Exited
 
 
($ in thousands)
Forwards
 
$
—

 
$
82,688

Futures
 
308,178

 
356,216

Options, warrants and rights (1)
 
1,044,241

 
314,876

Total return swaps
 
121,125

 
160,065

Total
 
$
1,473,544

 
$
913,845


(1) Exited amount excludes derivatives which expired or were exercised during the period.

The Company does not offset its derivative instruments and presents all amounts in the consolidated balance sheets on a gross basis. The Company has pledged cash collateral to derivative counterparties to support the current value of amounts due to the counterparties based on the value of the underlying security.

As of December 31, 2015, the gross and net amounts of derivative instruments and the cash collateral applicable to derivative instruments were as follows:
December 31, 2015
 
(i)
 
(ii)
 
(iii) = (i) - (ii)
 
(iv) Gross amounts not offset in the balance sheet
 
(v) = (iii) + (iv)
Description
 
Gross amounts of recognized assets (liabilities)
 
Gross amounts offset in the balance sheet
 
Net amounts of assets (liabilities) presented in the balance sheet
 
Financial instruments available for offset
 
Cash collateral (received) pledged
 
Net amount of asset (liability)
 
 
($ in thousands)
Financial contracts receivable
 
$
13,215

 
$
—

 
$
13,215

 
$
(8,937
)
 
$
(2,036
)
 
$
2,242

Financial contracts payable
 
(28,245
)
 
—

 
(28,245
)
 
8,937

 
19,308

 
—


As of December 31, 2014, the gross and net amounts of derivative instruments and the cash collateral applicable to derivative instruments were as follows:
December 31, 2014
 
(i)
 
(ii)
 
(iii) = (i) - (ii)
 
(iv) Gross amounts not offset in the balance sheet
 
(v) = (iii) + (iv)
Description
 
Gross amounts of recognized assets (liabilities)
 
Gross amounts offset in the balance sheet
 
Net amounts of assets (liabilities) presented in the balance sheet
 
Financial instruments available for offset
 
Cash collateral (received) pledged
 
Net amount of asset (liability)
 
 
($ in thousands)
Financial contracts receivable
 
$
47,171

 
$
—

 
$
47,171

 
$
(24,265
)
 
$
(9,452
)
 
$
13,454

Financial contracts payable
 
(44,592
)
 
—

 
(44,592
)
 
24,265

 
20,327

 
—


v3.3.1.900
DUE TO PRIME BROKERS
12 Months Ended
Dec. 31, 2015
Due to and from Broker-Dealers and Clearing Organizations [Abstract]  
DUE TO PRIME BROKERS
 
As of December 31, 2015, the amount due to prime brokers is comprised of margin-borrowing from prime brokers relating to investments purchased on margin as well as the margin-borrowing for providing collateral to support some of the Company’s outstanding letters of credit (see Notes 6 and 14) and trust accounts. Under term margin agreements and certain letter of credit facility agreements, the Company pledges certain investment securities to borrow cash from the prime brokers. The borrowed cash is placed in a custodial account in the name of the Company and this custodial account provides collateral for any letters of credit issued. Since there is no legal right of offset, the Company’s liability for the cash borrowed from the prime brokers is included on the consolidated balance sheets as due to prime brokers while the cash held in the custodial account is included on the consolidated balance sheets as restricted cash and cash equivalents. At December 31, 2015, the amounts due to prime brokers included $301.4 million (2014: $135.0 million) of cash borrowed under the term margin agreements to provide collateral in the form of letters of credit and trust accounts, and $95.0 million (2014: $76.1 million) of borrowing relating to investing activities.

Greenlight Re's investment guidelines, among other stipulations in the guidelines, allow for up to 15% (GRIL: 5%) net margin leverage for extended periods of time and up to 30% (GRIL: 20%) net margin leverage relating to investing activities for periods of less than 30 days.

v3.3.1.900
CASH AND CASH EQUIVALENTS
12 Months Ended
Dec. 31, 2015
Cash and Cash Equivalents  
Cash and Cash Equivalents [Line Items]  
CASH AND CASH EQUIVALENTS
 
 
December 31, 2015
 
December 31, 2014
 
 
($ in thousands)
Cash at banks
 
$
44,133

 
$
3,426

Cash held with brokers
 
68,029

 
8,604

Total cash and cash equivalents
 
$
112,162

 
$
12,030


Due to the short term nature of cash and cash equivalents, management believes the above noted carrying values approximate their fair value. Cash at banks include cash held at non-U.S. financial institutions which are not insured by the FDIC or any other deposit insurance programs.

v3.3.1.900
RESTRICTED CASH AND CASH EQUIVALENTS
12 Months Ended
Dec. 31, 2015
Restricted Cash and Cash Equivalents  
Restricted Cash and Cash Equivalents Items [Line Items]  
RESTRICTED CASH AND CASH EQUIVALENTS
 
The Company is required to maintain certain cash in segregated accounts with prime brokers and swap counterparties. The amount of restricted cash held by prime brokers is primarily used to support the liability created from securities sold, not yet purchased and the amount of cash encumbered varies depending on the market value of the securities sold, not yet purchased. Swap counterparties also require cash collateral to support the current value of any amounts that may be due to the counterparty based on the value of the underlying security.

Restricted cash and cash equivalents also include amounts held by the Company to provide collateral required by the cedents in the form of trust accounts and letters of credit (see Notes 4 and 14). As of December 31, 2015 and 2014, the restricted cash and cash equivalents were comprised of the following:
 
 
December 31, 2015
 
December 31, 2014
 
 
($ in thousands)
Cash held by prime brokers relating to securities sold, not yet purchased
 
$
882,906

 
$
1,090,731

Cash collateral relating to letters of credit issued
 
222,852

 
134,981

Cash held as collateral in trust accounts
 
78,584

 
—

Cash and cash equivalents held by swap counterparties
 
52,247

 
71,202

Total restricted cash and cash equivalents
 
$
1,236,589

 
$
1,296,914


v3.3.1.900
LOSS AND LOSS ADJUSTMENT EXPENSE RESERVES
12 Months Ended
Dec. 31, 2015
Insurance Loss Reserves [Abstract]  
LOSS AND LOSS ADJUSTMENT EXPENSE RESERVES
 LOSS AND LOSS ADJUSTMENT EXPENSE RESERVES
 
At December 31, 2015 and 2014, loss and loss adjustment expense reserves were comprised of the following:
 
 
2015
 
2014
 
 
($ in thousands)
Case reserves
 
$
111,535

 
$
117,049

IBNR
 
194,462

 
147,194

Total
 
$
305,997

 
$
264,243


A summary of changes in outstanding loss and loss adjustment expense reserves is as follows: 
 
 
2015
 
2014
 
2013
 
 
($ in thousands)
Gross balance at January 1
 
$
264,243

 
$
329,894

 
$
356,470

Less: Losses recoverable
 
(11,523
)
 
(16,829
)
 
(34,451
)
Net balance at January 1
 
252,720

 
313,065

 
322,019

Incurred losses related to:


Current year
 
266,796

 
216,757

 
344,613

Prior years
 
50,301

 
18,229

 
(6,120
)
Total incurred
 
317,097

 
234,986

 
338,493

Paid losses related to:


Current year
 
(132,017
)
 
(163,139
)
 
(177,871
)
Prior years
 
(132,846
)
 
(130,438
)
 
(170,018
)
Total paid
 
(264,863
)
 
(293,577
)
 
(347,889
)
Foreign currency revaluation
 
(2,325
)
 
(1,754
)
 
442

Net balance at December 31
 
302,629

 
252,720

 
313,065

Add: Losses recoverable
 
3,368

 
11,523

 
16,829

Gross balance at December 31
 
$
305,997

 
$
264,243

 
$
329,894


For the year ended December 31, 2015, the net losses incurred included $50.3 million related to net adverse loss development on reserves relating to prior years. During the year ended December 31, 2015, the loss development on prior year contracts primarily related to the following:

●
$36.9 million of adverse loss development relating to a general liability contract originally written from 2008 to 2011. This contract contains underlying construction defect liability coverage predominantly on single family homes. During the third quarter of 2015, we completed an in-depth analysis, with the assistance of a third party expert, of the construction defect claims reported and the potential for claims not yet reported on this contract. Based on this assessment, we revised the actuarial methodology used for reserving the construction defect claims on this contract, which resulted in an increase in incurred but not reported losses;

●
$14.7 million of adverse loss development relating to a general liability contract originally written in 2010. This contract contains underlying construction defect liability coverage. Based on updated data received from the insured, we conducted additional actuarial analysis and updated our actuarial input parameters based on consultation with external industry experts. As a result, the average estimated cost per claim was increased;

●
$9.3 million of adverse loss development relating to our Florida homeowners' insurance contracts as a result of deterioration of sinkhole claims, higher than anticipated water damage claims from rainstorms and an increase in the practice of "assignment of benefits" whereby homeowners assign their rights for filing and settling claims to attorneys and public adjusters which led to increases in the frequency of claims reported as well as the severity of loss adjustment expenses. However, because some of these contracts included sliding scale ceding commission rates, the increase in loss reserves was partially offset by a $5.1 million decrease in ceding commissions and profit commissions recorded as acquisition costs;

●
$2.4 million of net adverse loss development relating to our solicitors' professional indemnity contracts as a result of multiple large claims reported during the period and an increase in incurred losses;

●
$5.1 million of favorable loss development relating to an excess of loss property contract resulting in elimination of loss reserve based on updated loss information received from the insured during the period indicating that no losses will breach into our layer of coverage. The decrease in loss reserve was more than offset by a reversal of $2.5 million of earned premiums and an accrual of $3.4 million of profit commission recorded as acquisition costs;

●
$4.5 million of favorable loss development relating to private passenger motor contracts during the period. The decrease in loss reserve was partially offset by $3.3 million of additional ceding commissions recorded as acquisition costs;

●
$2.3 million of favorable loss development relating to the employer medical stop-loss business as a result of better than expected claims frequency reported by the cedent; and

●
$1.3 million of loss reserves released upon commutation of a private passenger motor contract during the period. The decrease in loss reserve was partially offset by $1.1 million of additional ceding commissions incurred as part of the commutation agreement.

There were no other significant developments of prior period loss reserves during the year ended December 31, 2015.
 
For the year ended December 31, 2014, the net losses incurred included $18.2 million related to net adverse loss development on reserves relating to prior years. During the year ended December 31, 2014, the loss development on prior year contracts primarily related to the following:

●
$7.8 million of adverse loss development, relating to a general liability contract currently in run-off. Loss reserves were increased on this contract after a detailed actuarial review of existing claims data received from the client, which reported an increase in the number of open claims. The loss reserves were also increased to take into account the corresponding claims handling fees expected to be incurred to settle the open claims;

●
$7.1 million of adverse loss development, net of retrocession recoveries, relating to commercial motor claims on a multi-line quota share contract currently in run-off. Loss reserves were increased on this contract after a detailed actuarial review of existing claims data received from the client, which reported significant increases in incurred losses on some claims as well as an increase in the number of open claims;

●
$4.0 million of adverse loss development relating to a solicitors' professional indemnity contract as a result of a combination of large claims reported and increases in case reserves on several smaller claims. Loss reserves were increased on this contract after a detailed review of existing claims data received from the client, audits of claim files at the third party claims administrator and actuarial analysis based on all available information. The contract terms included sliding scale ceding commission rates and profit commissions. As a result, the increase in loss reserves was offset by a $0.6 million decrease in ceding commissions and profit commissions which were recorded as decreases to acquisition costs;

●
$3.0 million of adverse loss development relating to the employer medical stop-loss business. Loss reserves were increased on these contracts after a detailed review of existing claims data received from the clients, audits of claim files at the third party claims administrators and actuarial analysis based on all available information; and

●
$3.8 million of favorable loss development relating to private passenger automobile business, primarily as a result of better than expected loss development noted on our private passenger automobile contracts after a detailed review of existing claims data received from the clients, audits of claim files and actuarial analysis based on all available information. Since these contracts included sliding scale ceding commission rates, the decrease in loss reserves was offset by a $2.2 million increase in ceding commissions recorded as acquisition costs.

There were no other significant developments of prior period loss reserves during the year ended December 31, 2014.

For the year ended December 31, 2013, the net losses incurred included $6.1 million related to net favorable loss development on reserves relating to prior years. During the year ended December 31, 2013, the loss development on prior year contracts primarily related to the following:
 
●
Elimination of $15.0 million of reserves relating to super-storm Sandy based on additional information received from the client which indicated that the losses would not exceed the threshold of coverage provided under the contract. As a result of the reversal of loss reserves, the Company also reversed reinstatement premiums earned of $2.6 million;

●
$4.0 million of favorable loss development relating to commercial automobile business due to better than expected loss development on open claims and settling of claims at lower amounts than expected. Loss reserves were decreased on these contracts after a detailed review of existing claims data received from the clients, audits of claim files at the third party claims administrators and actuarial analysis based on all available information;

●
$3.0 million favorable loss development relating to a private passenger automobile contract as a result of final settlement of losses upon commutation of the contract at an amount lower than originally reserved. However, because this contract included a sliding scale ceding commission rate, the decrease in loss reserves was offset by a $2.3 million increase in ceding commissions recorded as acquisition costs;

●
$2.4 million favorable loss development relating to Florida homeowners' insurance business due to better than expected development on sinkhole claims, primarily as a result of legislative changes implemented in the State of Florida during 2012;

●
$17.7 million of adverse loss development, net of retrocession recoveries, relating to general liability business. Loss reserves were increased on these contracts after a detailed review of existing claims data received from the clients, audits of claim files at the third party claims administrators and actuarial analysis based on all available information; and

●
$4.0 million of adverse loss development on a 2007 casualty clash contract based on updated claims and loss information received from the client. The new information indicated that ground up losses under the contract estimated by the client had increased resulting in additional losses attaching to the Company's layer. As a result of this increase in loss reserves, the Company recorded reinstatement premiums of $1.2 million.

There were no other significant developments of prior period loss reserves during the year ended December 31, 2013.

v3.3.1.900
RETROCESSION
12 Months Ended
Dec. 31, 2015
Reinsurance Disclosures [Abstract]  
RETROCESSION
RETROCESSION
 
The Company, from time to time, purchases retrocessional coverage for one or more of the following reasons: to manage its overall exposure, to reduce its net liability on individual risks, to obtain additional underwriting capacity and to balance its underwriting portfolio. Additionally, retrocession can be used as a mechanism to share the risks and rewards of business written and therefore can be used as a tool to align the Company's interests with those of its counterparties. The Company currently has coverages that provide for recovery of a portion of loss and loss expenses incurred on certain contracts. Loss and loss adjustment expense recoverable from the retrocessionaires are recorded as assets.

For the year ended December 31, 2015, loss and loss adjustment expenses incurred of $317.1 million (2014: $235.0 million and 2013: $338.5 million) reported on the consolidated statements of income are net of loss and loss expenses recovered and recoverable of $1.7 million (2014: $4.4 million and 2013: $(10.2) million). The negative loss and loss adjustment expenses recovered for the year ended December 31, 2013, were due to reversal of loss reserves on retrocession contracts that were novated during 2013.

Retrocession contracts do not relieve the Company from its obligations to the insureds. Failure of retrocessionaires to honor their obligations could result in losses to the Company. At December 31, 2015, the Company had losses receivable and loss reserves recoverable of $3.1 million (December 31, 2014: $18.3 million) from unrated retrocessionaires and $0.3 million (December 31, 2014: nil) from a retrocessionaire rated A- by A.M. Best. During 2015, the Company reached a settlement to commute a retrocession contract with one of the unrated retrocessionaires, which commutation resulted in a decrease in the losses recoverable from unrated retrocessionaires. At December 31, 2015 and 2014, $3.1 million and $2.8 million, respectively, of losses recoverable from unrated retrocessionaires were secured by cash collateral held by the Company.

The Company regularly evaluates the financial condition of its retrocessionaires to assess the ability of the retrocessionaires to honor their respective obligations. At December 31, 2015 and 2014, no provision for uncollectible losses recoverable was considered necessary.

v3.3.1.900
SHARE CAPITAL
12 Months Ended
Dec. 31, 2015
Equity [Abstract]  
SHARE CAPITAL
SHARE CAPITAL 
 
The holders of all ordinary shares are entitled to share equally in dividends declared by the Board of Directors. In the event of a winding-up or dissolution of the Company, the ordinary shareholders share equally and ratably in the assets of the Company, after payment of all debts and liabilities of the Company and after liquidation of any issued and outstanding preferred shares. At December 31, 2015, no preferred shares were issued or outstanding. The Board of Directors is authorized to establish the rights and restrictions for preferred shares as they deem appropriate.
 
The Third Amended and Restated Memorandum and Articles of Association as revised by special resolution on July 10, 2008 (the "Articles"), provide that the holders of Class A ordinary shares generally are entitled to one vote per share. However, except upon unanimous consent of the Board of Directors, no Class A shareholder is permitted to vote an amount of shares which would cause any United States person to own (directly, indirectly or constructively under applicable United States tax attribution and constructive ownership rules) 9.9% or more of the total voting power of all issued and outstanding ordinary shares. The Articles further provide that the holders of Class B ordinary shares generally are entitled to ten votes per share. However, holders of Class B ordinary shares, together with their affiliates, are limited to voting that number of Class B ordinary shares equal to 9.5% of the total voting power of the total issued and outstanding ordinary shares. 
 
Pursuant to the Shareholders' Agreement, dated August 11, 2004, by and among the Company and certain of its shareholders (the “Shareholders’ Agreement”), the holders of at least 50% of the outstanding Registrable Securities (as defined in the Shareholders' Agreement), may, subject to certain conditions, request to have all or part of their Registrable Securities to become registered. The Shareholders' Agreement requires, among other things, that the Company use its commercially reasonable best efforts to have a registration statement covering such Registrable Securities to be declared effective. The registration rights granted pursuant to the Shareholders' Agreement are not deemed to be liabilities; therefore, there has been no recognition in the consolidated financial statements of the registration rights granted pursuant to the Shareholders' Agreement.
 
As of December 31, 2015, the Company has an effective Form S-3 registration statement, on file with the SEC, for an aggregate principal amount of $200.0 million in securities.

Shares authorized for issuance are comprised of 300,000 (2014: 300,000) Class A ordinary shares in relation to share purchase options granted to a service provider and 3,500,000 (2014: 3,500,000) Class A ordinary shares authorized for the Company’s stock incentive plan for eligible employees, directors and consultants. As of December 31, 2015 and 2014, there were no remaining Class A ordinary shares available for future issuance relating to share purchase options granted to the service provider, and 658,775 (2014: 803,558) Class A ordinary shares remained available for future issuance under the Company's stock incentive plan. The stock incentive plan is administered by the Compensation Committee of the Board of Directors. 

The Board has adopted a share repurchase plan. Under the share repurchase plan, the Board authorized the Company to purchase up to 2.0 million of its Class A ordinary shares from time to time. Class A ordinary shares or securities convertible into Class A ordinary shares, may be purchased in the open market, through privately negotiated transactions or Rule 10b5-1 stock trading plans. The timing of such repurchases and actual number of shares repurchased will depend on a variety of factors including price, market conditions and applicable regulatory and corporate requirements. The share repurchase plan, which expires on June 30, 2016, does not require the Company to repurchase any specific number of shares and may be modified, suspended or terminated at any time without prior notice. During the year ended December 31, 2015, 613,540 Class A ordinary shares were repurchased by the Company. As of December 31, 2015, 1,386,460 shares remained available for repurchase under the share repurchase plan. Under the Companies Law of the Cayman Islands, the Company cannot hold treasury shares; therefore, all ordinary shares repurchased are canceled immediately upon repurchase.

The following table is a summary of voting ordinary shares issued and outstanding:
 
 
2015
 
2014
 
2013
 
 
Class A
 
Class B
 
Class A
 
Class B
 
Class A
 
Class B
Balance – beginning of year
 
31,129,648

 
6,254,895

 
30,791,865

 
6,254,949

 
30,447,179

 
6,254,949

Issue of ordinary shares, net of forfeitures
 
256,464

 
—

 
337,729

 
—

 
344,686

 
—

Repurchase of ordinary shares
 
(613,540
)
 
—

 
—

 
—

 
—

 
—

Class B shares converted to Class A shares
 
—

 
—

 
54

 
(54
)
 
—

 
—

Balance – end of year
 
30,772,572

 
6,254,895

 
31,129,648

 
6,254,895

 
30,791,865

 
6,254,949


Greenlight Re is subject to the Cayman Islands' Insurance (Capital and Solvency) (Classes B, C, and D Insurers) Regulations, 2012 (the "Insurance Regulations"). The Insurance Regulations impose a Minimum Capital Requirement of US$50.0 million and a Prescribed Capital Requirement of $466.5 million on Greenlight Re as of December 31, 2015 (2014: $443.5 million). As of December 31, 2015, Greenlight Re's statutory capital and surplus of $788.9 million exceeded the Minimum Capital Requirement as well as the Prescribed Capital Requirement. For the years ended December 31, 2015, 2014 and 2013, Greenlight Re's net income (loss) was $(309.5) million, $113.3 million, and $229.8 million, respectively.

Greenlight Re is not required to prepare separate statutory financial statements for filing with CIMA and there were no material differences between Greenlight Re's GAAP capital, surplus and net income, and its statutory capital, surplus and net income as of December 31, 2015 and 2014.

As of December 31, 2015, $325.3 million of the Company's retained earnings were restricted from payment of dividends to the Company's shareholders. However, since most of the Company's capital and retained earnings are invested in its subsidiaries, a dividend from one or more of the Company's subsidiaries would likely be required in order to fund a dividend to the Company's shareholders. Any dividends declared and paid from Greenlight Re to the Company would require approval of CIMA. During the year ended December 31, 2015, $5.0 million (2014: nil, 2013: nil) of dividends were declared and paid by Greenlight Re to the Company. As of December 31, 2015 and 2014, $322.4 million and $658.8 million, respectively, of Greenlight Re's capital and surplus was available for distribution as dividends. The amount of dividends that GRIL is permitted to distribute is limited to its retained earnings and the Central Bank of Ireland has powers to intervene if a dividend payment were to lead to a breach of regulatory capital requirements. As of December 31, 2015 and 2014, none and $2.7 million, respectively, of GRIL's capital and surplus was available for distribution as dividends.

GRIL is obligated to maintain a minimum level of capital (the "Required Minimum Margin"). As of December 31, 2015 and 2014, GRIL met such requirements. As of December 31, 2015 and 2014, GRIL's statutory capital and surplus was the same as its U.S. GAAP capital and surplus of $50.3 million and $42.9 million, respectively. The required solvency margin for GRIL as of December 31, 2015 and 2014 was $18.1 million and $13.6 million, respectively. GRIL's statutory net income (loss) was $(12.8) million, $(3.3) million and $3.6 million for the years ended December 31, 2015, 2014 and 2013, respectively.
 
Additional paid-in capital includes the premium per share paid by the subscribing shareholders for Class A and B ordinary shares which have a par value of $0.10 each. It also includes share-based awards earned not yet issued.

v3.3.1.900
SHARE-BASED COMPENSATION
12 Months Ended
Dec. 31, 2015
Disclosure of Compensation Related Costs, Share-based Payments [Abstract]  
SHARE-BASED COMPENSATION
 
The Company has a stock incentive plan for directors, employees and consultants as detailed in Note 9 above.

Service Provider Share Purchase Options
 
On September 20, 2004, the Company had granted share purchase options to a service provider to purchase 400,000 Class A ordinary shares at an exercise price of $10.00 per share. During 2014, the remaining 20,000 share purchase options outstanding were exercised, resulting in the net issuance of 13,861 Class A ordinary shares (net of shares surrendered as a result of the cashless exercise of stock options). There were no service provider share purchase options outstanding as of December 31, 2015 and 2014.

 Employee and Director Restricted Shares
 
As part of its stock incentive plan, the Company issues restricted shares for which the fair value is equal to the price of the Company’s Class A ordinary shares on the grant date. Compensation based on the grant date fair market value of the shares is expensed on a straight line basis over the applicable vesting period.
 
For the year ended December 31, 2015, 78,685 (2014: 127,186, 2013: 111,231) restricted Class A ordinary shares were issued to employees pursuant to the Company’s stock incentive plan. These shares contain certain restrictions relating to, among other things, vesting, forfeiture in the event of termination of employment and transferability. Each of these restricted shares cliff vest after three years from the date of issuance, subject to the grantee’s continued service with the Company. During the vesting period, the holder of the restricted shares retains voting rights and is entitled to any dividends declared by the Company.
  
For the year ended December 31, 2015, the Company issued an aggregate of 28,215 (2014: 28,060, 2013: 36,374) restricted Class A ordinary shares to non-employee directors as part of their remuneration for services to the Company. Each of these restricted shares issued to non-employee directors contains similar restrictions to those issued to employees and will vest on the earlier of the first anniversary of the share issuance or the Company’s next annual general meeting, subject to the grantee’s continued service with the Company.

For the year ended December 31, 2015, 9,621 (2014: 38,706, 2013: 16,826) restricted shares were forfeited by employees who left the Company prior to the expiration of the applicable vesting periods. For the year ended December 31, 2015, in accordance with U.S. GAAP, $0.1 million of stock compensation expense (2014: $0.4 million, 2013: $0.2 million) relating to the forfeited restricted shares was reversed.

The Company recorded $3.6 million of share-based compensation expense, net of forfeitures, relating to restricted shares for the year ended December 31, 2015 (2014: $3.3 million, 2013: $3.2 million). As of December 31, 2015, there were $3.7 million (2014: $4.2 million, 2013: $3.5 million) of unrecognized compensation costs related to non-vested restricted shares which are expected to be recognized over a weighted average period of 1.6 years (2014: 1.8 years, 2013: 1.7 years). For the year ended December 31, 2015, the total fair value of restricted shares vested was $3.2 million (2014: $2.9 million, 2013: $2.8 million).

The restricted share award activity during the years ended December 31, 2015 and 2014 was as follows:
 
 
Number of
non-vested
restricted
 shares
 
Weighted
 average
grant date
fair value
Balance at December 31, 2013
 
328,991

 
$
24.74

Granted
 
155,246

 
32.58

Vested
 
(115,444
)
 
25.35

Forfeited
 
(38,706
)
 
27.43

Balance at December 31, 2014
 
330,087

 
27.90

Granted
 
106,900

 
31.56

Vested
 
(120,353
)
 
26.26

Forfeited
 
(9,621
)
 
30.49

Balance at December 31, 2015
 
307,013

 
$
29.74


Employee and Director Stock Options

For the year ended December 31, 2015, 40,683 Class A ordinary share purchase options were granted to the Company's Chief Executive Officer, pursuant to his employment contract (2014: 31,821). These options vest 25% on the date of the grant, and 25% each on the anniversary thereof in 2016, 2017 and 2018, and expire 10 years after the grant date. The grant date fair value of these options was $12.29 per share (2014: $15.71 per share, 2013: $13.09), based on the Black-Scholes option pricing model. The estimate of expected volatility for options granted during 2015 and 2014 was based on the daily historical trading data of the Company's Class A ordinary shares from the date that these shares commenced trading on May 24, 2007 to August 5, 2015. For options granted prior to 2014, the Company had determined the expected volatility based primarily on the historical volatility of a peer group of companies in the reinsurance industry while also considering the Company’s own historical volatility.

The Company uses the Black-Scholes option pricing model to determine the valuation of its options and has applied the assumptions set forth in the following table.
 
 
2015
 
2014
 
2013
Risk free rate
 
2.15
%
 
2.47
%
 
2.85
%
Estimated volatility
 
32.8
%
 
34.3
%
 
35.0
%
Expected term (in years)
 
10

 
10

 
10

Dividend yield
 
0
%
 
0
%
 
0
%
Forfeiture rate
 
0
%
 
0
%
 
0
%

    
At the present time, the Board of Directors does not anticipate that any dividends will be declared during the expected term of the options. The Company uses graded vesting for expensing employee stock options. The total compensation cost expensed for the year ended December 31, 2015 related to employee and director stock options was $0.5 million (2014: $0.5 million, 2013: $0.6 million). At December 31, 2015, the total compensation cost related to non-vested options not yet recognized was $0.4 million (2014: $0.4 million, 2013: $0.4 million) to be recognized over a weighted average period of 1.5 years (2014: 1.5 years, 2013: 1.5 years) assuming the employees complete their service period for vesting of the options.

For the year ended December 31, 2015, 250,000 (2014: 318,500) stock options were exercised by directors and employees resulting in 158,925 Class A ordinary shares issued, net of shares surrendered as a result of the cashless exercise of stock options (2014: 207,328). When stock options are granted, the Company reduces the corresponding number from the shares authorized for issuance as part of the Company’s stock incentive plan. The intrinsic value of options exercised during the year ended December 31, 2015 was $4.8 million (2014: $6.7 million, 2013: $0.8 million).

Employee and director stock option activity during the years ended December 31, 2015 and 2014 was as follows: 
 
Number of
 options
 
Weighted
 average
 exercise
 price
 
Weighted
 average
 grant date
 fair value
Balance at December 31, 2013
1,402,987

 
$
15.82

 
$
7.08

Granted
31,821

 
32.37

 
15.71

Exercised
(318,500
)
 
11.29

 
5.67

Forfeited
—

 
—

 
—

Expired
—

 
—

 
—

Balance at December 31, 2014
1,116,308

 
17.58

 
7.73

Granted
40,683

 
26.67

 
12.29

Exercised
(250,000
)
 
11.10

 
5.57

Forfeited
—

 
—

 
—

Expired
—

 
—

 
—

Balance at December 31, 2015
906,991

 
$
19.78

 
$
8.53


At December 31, 2015, the weighted-average remaining contractual term for options outstanding was 2.9 years (2014: 3.0 years).
  
At December 31, 2015, 851,020 (2014: 1,062,022) stock options were exercisable. These options had a weighted-average exercise price of $19.22 (2014: $17.02) and a weighted-average remaining contractual term of 2.6 years (2014: 2.7 years).
 
The weighted average grant date fair value of options granted during the year ended December 31, 2015 was $12.29 (2014: $15.71, 2013: $13.09). The aggregate intrinsic value of options outstanding and options exercisable at December 31, 2015 was $2.6 million and $2.6 million, respectively (2014: $16.8 million and $16.6 million, respectively). During the year ended December 31, 2015, 38,998 (2014: 53,828, 2013: 45,871) options vested which had a weighted average grant date fair value of $12.82 (2014: $11.76, 2013: $11.08).

Employee Restricted Stock Units

The Company issues restricted stock units ("RSUs") to certain employees as part of the stock incentive plan. The grant date fair value of the RSUs is equal to the price of the Company’s Class A ordinary shares on the grant date. Compensation cost based on the grant date fair market value of the RSUs is expensed on a straight line basis over the vesting period.
 
For the year ended December 31, 2015, 6,821 (2014: 9,668, 2013: 5,941) RSUs were issued to employees pursuant to the Company’s stock incentive plan. These shares contain certain restrictions relating to, among other things, vesting, forfeiture in the event of termination of employment and transferability. Each of these RSUs cliff vest after three years from the date of issuance, subject to the grantee’s continued service with the Company. On the vesting date, the Company converts each RSU into one Class A ordinary share and issues new Class A ordinary shares from the shares authorized for issuance as part of the Company’s stock incentive plan.

The Company recorded $0.2 million of share-based compensation expense, net of forfeitures, relating to RSUs for the year ended December 31, 2015 (2014: $0.1 million, 2013: $0.03 million).

Employee RSU activity during the years ended December 31, 2015 and 2014 was as follows:
 
 
Number of
non-vested
RSUs
 
Weighted
 average
grant date
fair value
Balance at December 31, 2013
 
5,941

 
$
24.41

Granted
 
9,668

 
32.60

Vested
 
—

 
—

Forfeited
 
—

 
—

Balance at December 31, 2014
 
15,609

 
29.72

Granted
 
6,821

 
32.21

Vested
 
(260
)
 
24.30

Forfeited
 
—

 
—

Balance at December 31, 2015
 
22,170

 
$
30.55


For the years ended December 31, 2015, 2014 and 2013, the general and administrative expenses included stock compensation expense (net of forfeitures) of $4.3 million, $4.0 million and $3.8 million, respectively, for the expensing of the fair value of stock options, restricted stocks and RSUs granted to employees and directors.

v3.3.1.900
NET INVESTMENT INCOME
12 Months Ended
Dec. 31, 2015
Net Investment Income [Abstract]  
NET INVESTMENT INCOME

A summary of net investment income for the years ended December 31, 2015, 2014 and 2013 is as follows:
 
 
2015
 
2014
 
2013
 
 
($ in thousands)
Realized gains (losses)
 
$
22,227

 
$
352,133

 
$
122,568

Change in unrealized gains and losses
 
(265,401
)
 
(187,753
)
 
149,012

Investment related foreign exchange gains (losses)
 
(3,725
)
 
14,797

 
44,492

Interest and dividend income, net of withholding taxes
 
15,313

 
31,423

 
22,265

Interest, dividend and other expenses
 
(31,092
)
 
(38,892
)
 
(47,665
)
Investment advisor compensation
 
(19,246
)
 
(49,133
)
 
(72,532
)
Net investment income (loss)
 
$
(281,924
)
 
$
122,575

 
$
218,140


Interest and dividend income in the above table are net of any withholding taxes. Investment returns are calculated monthly and compounded to calculate the annual returns. The resulting actual investment income may vary depending on cash flows into or out of the investment account. For the year ended December 31, 2015, investment income, net of all fees and expenses, resulted in a loss of 20.2% on the investment portfolio. This compares to a gain of 8.7% and a gain of 19.6% reported for the years ended December 31, 2014 and 2013, respectively.

The comparative 2014 and 2013 amounts presented for realized gains (losses), change in unrealized gain and losses and investment related foreign exchange gains (losses) have been reclassified to conform to the current period presentation. The reclassifications resulted in no changes to net investment income (loss), net income or retained earnings for any of the periods presented.

v3.3.1.900
TAXATION
12 Months Ended
Dec. 31, 2015
Income Tax Disclosure [Abstract]  
TAXATION
TAXATION
 
The Company and Greenlight Re are each domiciled in the Cayman Islands and under current Cayman Islands law, no corporate entity, including the Company and Greenlight Re, is obligated to pay taxes in the Cayman Islands on either income or capital gains. The Company and Greenlight Re each intend to conduct all of its operations in a manner that will not cause it to be treated as engaging in a trade or business within the United States and will not cause it to be subject to current U.S. federal income taxation on its net income. However, because there are no definitive standards provided by the Internal Revenue Code, regulations or court decisions as to the specific activities that constitute being engaged in the conduct of a trade or business within the United States, and as any such determination is essentially factual in nature, there can be no assurance that the IRS will not successfully assert that the Company or Greenlight Re is engaged in a trade or business within the U.S.
 
Verdant is incorporated in Delaware, and therefore is subject to taxes in accordance with the U.S. federal rates and regulations prescribed by the IRS. Verdant’s taxable income is taxed at an effective tax rate of 35%. GRIL is incorporated in Ireland and, therefore, is subject to the Irish corporation tax. GRIL is taxed at a rate of 12.5% on its trading income.
 
At December 31, 2015, included in the consolidated balance sheet under other assets were taxes recoverable of $0.5 million relating to GRIL (2014: $0.8 million relating to Verdant and GRIL), and a deferred tax asset of $1.76 million primarily relating to GRIL's net operating losses carried forward (2014: $0.03 million). At December 31, 2015, GRIL had a net operating loss carryforward of $14.1 million which can be carried forward indefinitely. Based on the likelihood of GRIL generating sufficient taxable income to realize the future tax benefit, management believes it is more likely than not that the deferred tax asset and taxes recoverable will be fully realized in the future and therefore no valuation allowance has been recorded.

At December 31, 2015, Verdant had a net operating loss carryforward of $1.7 million which can be carried forward for a period of 20 years from the year the loss occurred and therefore will expire in 2033.

The following table sets forth our current and deferred income tax benefit (expense) on a consolidated basis for the years ended December 31, 2015, 2014 and 2013:
 
 
2015
 
2014
 
2013
 
 
($ in thousands)
Current tax (expense) benefit
 
$
15

 
$
638

 
$
(534
)
Deferred tax (expense) benefit
 
1,740

 
(14
)
 
(4
)
Income tax (expense) benefit 
 
$
1,755

 
$
624

 
$
(538
)


The Company has not taken any tax positions that are subject to uncertainty or that are reasonably likely to have a material impact to the Company, Greenlight Re, GRIL or Verdant.

Federal Excise Taxes

The United States also imposes an excise tax on reinsurance premiums paid to non-U.S. insurers or reinsurers with respect to risks located in the United States. The rate of tax, unless exempted or reduced by an applicable U.S. tax treaty, is 1.0% for all reinsurance premiums. The Company incurs federal excise taxes on certain of its reinsurance transactions, including amounts ceded through intercompany transactions. For the years ended 2015, 2014, and 2013, the Company incurred approximately $3.3 million, $2.2 million and $3.5 million, respectively, of federal excise taxes. These amounts are reflected as acquisition costs in the Company’s consolidated statements of income.

v3.3.1.900
RELATED PARTY TRANSACTIONS
12 Months Ended
Dec. 31, 2015
Related Party Transactions [Abstract]  
RELATED PARTY TRANSACTIONS
 
Investment Advisory Agreement
 
Effective January 1, 2014, the Company and its reinsurance subsidiaries were party to a joint venture agreement with DME Advisors, LP ("DME Advisors") under which the Company, its reinsurance subsidiaries and DME Advisors LLC ("DME") are participants of a joint venture for the purpose of managing certain jointly held assets, as may be amended from time to time (the "venture agreement"). In addition, the Company, its reinsurance subsidiaries and DME have entered into a separate investment advisory agreement with DME Advisors, as may be amended from time to time (the "advisory agreement"). DME and DME Advisors are related to the Company and each is an affiliate of David Einhorn, Chairman of the Company’s Board of Directors.
 
Pursuant to the venture agreement, performance allocation equal to 20% of the net investment income of the Company’s share of the account managed by DME Advisors is allocated, subject to a loss carry forward provision, to DME’s account. The loss carry forward provision requires DME to earn a reduced performance allocation of 10% on net investment income in any year subsequent to the year in which the investment account incurs a loss, until all the losses are recouped and an additional amount equal to 150% of the aggregate investment loss is earned. DME is not entitled to earn a performance allocation in a year in which the investment portfolio incurs a loss. For the year ended December 31, 2015, no performance allocation (2014: $28.5 million, 2013: $54.2 million) was netted against gross investment income due to a net investment loss reported for the year ended December 31, 2015.  

Pursuant to the advisory agreement, a monthly management fee, equal to 0.125% (1.5% on an annual basis) of the Company’s investment account managed by DME Advisors, is paid to DME Advisors. Included in the net investment income (loss) for the year ended December 31, 2015 were management fees of $19.2 million (2014: $20.6 million, 2013: $18.3 million). The management fees have been fully paid as of December 31, 2015.
 
Pursuant to the venture and advisory agreements, the Company has agreed to indemnify DME and DME Advisors for any expense, loss, liability, or damage arising out of any claim asserted or threatened in connection with DME Advisors serving as the Company’s investment advisor. The Company will reimburse DME and DME Advisors for reasonable costs and expenses of investigating and/or defending such claims, provided such claims were not caused due to gross negligence, breach of contract or misrepresentation by DME or DME Advisors. For the year ended December 31, 2015, there were no indemnification payments payable or paid by the Company.

Green Brick Partners, Inc

David Einhorn also serves as the Chairman of the Board of Directors of Green Brick Partners, Inc ("GRBK"), a publicly traded company. During the year ended December 31, 2014, the Company, along with certain affiliates of DME Advisors, provided debt financing to GRBK and acquired equity shares of GRBK. During the year ended December 31, 2015, the Company's investment income included $1.0 million (2014: $0.4 million) of interest relating to this debt. During the third quarter of 2015, GRBK repaid the debt (2014: $21.6 million) in full along with all accrued interest and prepayment fees, and the Company purchased additional equity shares of GRBK. As of December 31, 2015, $25.0 million (2014: $18.4 million) of GRBK listed equities were included on the balance sheet as "equity securities, trading, at fair value". The Company along with certain affiliates of DME Advisors, collectively own 49% of the issued and outstanding common shares of GRBK. Under applicable securities laws, DME Advisors may be limited at times in its ability to trade GRBK shares on behalf of the Company.

Service Agreement
 
The Company has entered into a service agreement with DME Advisors, pursuant to which DME Advisors provides certain investor relations services to the Company for compensation of five thousand dollars per month (plus expenses). The agreement is automatically renewed annually until terminated by either the Company or DME Advisors for any reason with 30 days prior written notice to the other party.

v3.3.1.900
COMMITMENTS AND CONTINGENCIES
12 Months Ended
Dec. 31, 2015
Commitments and Contingencies Disclosure [Abstract]  
COMMITMENTS AND CONTINGENCIES
 
Letters of Credit
 
At December 31, 2015, the Company had the following letter of credit facilities, which automatically renew each year unless terminated by either party in accordance with the required notice period:
 
 
Facility
 
Termination Date
 
Notice period required for termination
 
 
($ in thousands)


Bank of America, N.A.
 
$
120,000

 
July 11, 2016
 
90 days prior to termination date
Butterfield Bank (Cayman) Limited
 
100,000

 
June 30, 2016
 
90 days prior to termination date
Citibank Europe plc
 
400,000

 
October 11, 2016
 
120 days prior to termination date
JP Morgan Chase Bank N.A.
 
100,000

 
January 27, 2017
 
120 days prior to termination date
 
 
$
720,000


As of December 31, 2015, an aggregate amount of $245.6 million (2014: $273.7 million) in letters of credit were issued under the above facilities. Under the facilities, the Company provides collateral that may consist of equity securities, restricted cash and cash and cash equivalents. As of December 31, 2015, total equity securities, restricted cash, and cash and cash equivalents with a fair value in the aggregate of $324.3 million (2014: $302.6 million) were pledged as collateral against the letters of credit issued (also see Note 4). Each of the facilities contain customary events of default and restrictive covenants, including but not limited to, limitations on liens on collateral, transactions with affiliates, mergers and sales of assets, as well as solvency and maintenance of certain minimum pledged equity requirements, and restricts issuance of any debt without the consent of the letter of credit provider. Additionally, if an event of default exists, as defined in the letter of credit facilities, Greenlight Re will be prohibited from paying dividends to its parent company. The Company was in compliance with all the covenants of each of these facilities as of December 31, 2015 and 2014.
  
Operating Lease Obligations
 
Greenlight Re has entered into lease agreements for office space in the Cayman Islands. Under the terms of the lease agreements, Greenlight Re is committed to annual rent payments ranging from $0.3 million at inception to $0.5 million at lease termination. The leases expire on June 30, 2018 and Greenlight Re has the option to renew the leases for a further five year term. Included in the schedule below are the minimum lease payment obligations relating to these leases as of December 31, 2015.

GRIL has entered into a lease agreement for office space in Dublin, Ireland. Under the terms of this lease agreement, GRIL is committed to minimum annual rent payments denominated in Euros approximating €0.1 million until May 2021, and adjusted to the prevailing market rates for each of the two subsequent five-year terms. GRIL has the option to terminate the lease agreement in 2021. Included in the schedule below are the net minimum lease payment obligations relating to this lease as of December 31, 2015.

The total rent expense related to leased office space for the year ended December 31, 2015 was $0.5 million, (2014: $0.5 million, 2013: $0.5 million). 
 
Private Equity and Limited Partnerships
 
From time to time, the Company makes investments in private equity vehicles. As part of the Company's participation in such private equity investments, the Company may make funding commitments. As of December 31, 2015, the Company had commitments to invest an additional $6.1 million (2014: $8.9 million) in private equity investments. Included in the schedule below are the minimum payment obligations relating to these investments as of December 31, 2015.
 
Schedule of Commitments and Contingencies
 
The following is a schedule of future minimum payments required under the above commitments: 
 
2016
 
2017
 
2018
 
2019
 
2020
 
Thereafter
 
Total
 
($ in thousands)
Operating lease obligations
$
548

 
$
548

 
$
315

 
$
82

 
$
82

 
$
31

 
$
1,606

Private equity and limited partnerships (1)
6,107

 
—

 
—

 
—

 
—

 
—

 
6,107

 
$
6,655

 
$
548

 
$
315

 
$
82

 
$
82

 
$
31

 
$
7,713


(1) Given the nature of these investments, the Company is unable to determine with any degree of accuracy when these commitments will be called. Therefore, for purposes of the above table, the Company has assumed that all commitments with no fixed payment schedules will be called during the year ending December 31, 2016.
 
Litigation
 
From time to time in the normal course of business, the Company may be involved in formal and informal dispute resolution procedures, which may include arbitration or litigation, the outcomes of which determine the rights and obligations under the Company's reinsurance contracts and other contractual agreements. In some disputes, the Company may seek to enforce its rights under an agreement or to collect funds owing to it. In other matters, the Company may resist attempts by others to collect funds or enforce alleged rights. While the final outcome of legal disputes cannot be predicted with certainty, the Company does not believe that any existing dispute, when finally resolved, will have a material adverse effect on the Company's business, financial condition or operating results.

v3.3.1.900
SEGMENT REPORTING
12 Months Ended
Dec. 31, 2015
Segment Reporting [Abstract]  
SEGMENT REPORTING
SEGMENT REPORTING
 
The Company manages its business on the basis of one operating segment, Property & Casualty Reinsurance.

Substantially all of the business is sourced through reinsurance brokers. The following table sets forth the premiums sourced from brokers who each accounted for more than 10% of the Company's gross written premiums:  
 
 
Year ended December 31
 
 
2015
 
2014
 
2013
 
 
 ($ in thousands)
Largest broker
 
$
278,003

 
55.4
%
 
$
161,405

 
49.8
%
 
$
282,337

 
52.7
%
2nd largest broker
 
110,246

 
22.0

 
61,809

 
19.1

 
119,117

 
22.2

3rd largest broker
 
—

 
—

 
40,773

 
12.6

 
—

 
—


$
388,249

 
77.4
%
 
$
263,987

 
81.5
%
 
$
401,454

 
74.9
%

 
The following tables provide a breakdown of the Company's gross premiums written by line of business and by geographic area of risks insured for the periods indicated:
 
Gross Premiums Written by Line of Business 
 
 
Year ended December 31
 
 
2015
 
2014
 
2013
 
 
($ in thousands)
Property


Aviation
 
$
691

 
0.1
%
 
$
391

 
0.1
%
 
$
168

 
—
 %
Commercial
 
16,667

 
3.3

 
11,529

 
3.6

 
9,999

 
1.9

Energy
 
2,009

 
0.4

 
2,131

 
0.6

 
659

 
0.1

Motor physical damage
 
34,529

 
6.9

 
24,008

 
7.4

 
57,952

 
10.8

Personal
 
57,495

 
11.5

 
64,479

 
19.9

 
145,807

 
27.2

Total Property
 
111,391

 
22.2

 
102,538

 
31.6

 
214,585

 
40.0

Casualty


General liability (1)
 
28,355

 
5.6

 
11,639

 
3.6

 
(815
)
 
(0.2
)
Marine liability
 
9,283

 
1.8

 
5,120

 
1.6

 
1,956

 
0.4

Motor liability
 
203,624

 
40.6

 
127,858

 
39.5

 
253,698

 
47.4

Professional liability
 
72,217

 
14.4

 
27,009

 
8.4

 
29,901

 
5.6

Total Casualty
 
313,479

 
62.4

 
171,626

 
53.1

 
284,740

 
53.2

Specialty


Financial
 
7,824

 
1.6

 
5,292

 
1.6

 
3,498

 
0.7

Health
 
56,784

 
11.3

 
43,837

 
13.5

 
37,094

 
6.9

Workers’ compensation (1) 
 
12,646

 
2.5

 
730

 
0.2

 
(4,215
)
 
(0.8
)
Total Specialty
 
77,254

 
15.4

 
49,859

 
15.3

 
36,377

 
6.8


$
502,124

 
100.0
%
 
$
324,023

 
100.0
%
 
$
535,702

 
100.0
 %

(1)  The negative balance represents reversal of premiums due to premium adjustments, termination of contracts or premiums returned upon novation or commutation of contracts.

Gross Premiums Written by Geographic Area of Risks Insured
 
 
Year ended December 31
 
 
2015
 
2014
 
2013
 
 
($ in thousands)
U.S. and Caribbean
 
$
383,236

 
76.3
%
 
$
275,402

 
85.0
%
 
$
496,949

 
92.8
%
Worldwide (1)
 
104,336

 
20.8

 
31,106

 
9.6

 
9,821

 
1.8

Europe
 
14,085

 
2.8

 
17,432

 
5.4

 
28,932

 
5.4

Asia
 
467

 
0.1

 
83

 
—

 
—

 
—


$
502,124

 
100.0
%
 
$
324,023

 
100.0
%
 
$
535,702

 
100.0
%

(1) "Worldwide" is comprised of contracts that reinsure risks in more than one geographic area and do not specifically exclude the U.S.

v3.3.1.900
QUARTERLY FINANCIAL RESULTS (UNAUDITED)
12 Months Ended
Dec. 31, 2015
Quarterly Financial Information Disclosure [Abstract]  
QUARTERLY FINANCIAL RESULTS (UNAUDITED)

The following table presents the quarterly financial results for each of the quarters ended during 2015:
 
 
2015
 
 
 Quarter ended


March 31
 
 
June 30
 
 
September 30
 
 
December 31
 
 
 ($ in thousands, except per share amounts)
Revenues


Gross premiums written
 
$
129,682

 
$
92,990

 
$
134,568

 
$
144,884

Gross premiums ceded
 
(1,626
)
 
(1,868
)
 
(2,288
)
 
(3,219
)
Net premiums written
 
128,056

 
91,122

 
132,280

 
141,665

Change in net unearned premium reserves
 
(33,263
)
 
563

 
(30,286
)
 
(21,750
)
Net premiums earned
 
94,793

 
91,685

 
101,994

 
119,915

Net investment income (loss)
 
(24,829
)
 
(20,305
)
 
(191,322
)
 
(45,468
)
Other income (expense), net
 
1,588

 
(3,760
)
 
(542
)
 
(699
)
Total revenues
 
71,552

 
67,620

 
(89,870
)
 
73,748

Expenses


Loss and loss adjustment expenses incurred, net
 
63,207

 
76,653

 
97,421

 
79,816

Acquisition costs, net
 
26,841

 
23,939

 
32,146

 
33,281

General and administrative expenses
 
6,160

 
6,894

 
5,382

 
4,998

Total expenses
 
96,208

 
107,486

 
134,949

 
118,095

Income (loss) before income tax expense
 
(24,656
)
 
(39,866
)
 
(224,819
)
 
(44,347
)
Income tax (expense) benefit
 
215

 
(54
)
 
1,233

 
361

Net income (loss) including non-controlling interest
 
(24,441
)
 
(39,920
)
 
(223,586
)
 
(43,986
)
Loss (income) attributable to non-controlling interest in joint venture
 
394

 
324

 
3,909

 
881

Net income (loss)
 
$
(24,047
)
 
$
(39,596
)
 
$
(219,677
)
 
$
(43,105
)
Earnings (loss) per share


Basic
 
$
(0.65
)
 
$
(1.06
)
 
$
(5.98
)
 
$
(1.17
)
Diluted
 
$
(0.65
)
 
$
(1.06
)
 
$
(5.98
)
 
$
(1.17
)
Weighted average number of ordinary shares used in the determination of earnings and loss per share


Basic
 
37,173,008

 
37,303,265

 
36,710,216

 
36,720,454

Diluted
 
37,173,008

 
37,303,265

 
36,710,216

 
36,720,454


The following table presents the quarterly financial results for each of the quarters ended during 2014:
 
 
2014
 
 
 Quarter ended


March 31
 
 
June 30
 
 
September 30
 
 
December 31
 
 
 ($ in thousands)
Revenues


Gross premiums written
 
$
118,901

 
$
33,654

 
$
97,200

 
$
74,268

Gross premiums ceded
 
(5,940
)
 
(2,759
)
 
(2,706
)
 
(2,088
)
Net premiums written
 
112,961

 
30,895

 
94,494

 
72,180

Change in net unearned premium reserves
 
(1,272
)
 
56,960

 
(15,003
)
 
3,025

Net premiums earned
 
111,689

 
87,855

 
79,491

 
75,205

Net investment income (loss)
 
(10,150
)
 
113,932

 
(54,027
)
 
72,820

Other income (expense), net
 
182

 
(1,400
)
 
2,663

 
1,542

Total revenues
 
101,721

 
200,387

 
28,127

 
149,567

Expenses


Loss and loss adjustment expenses incurred, net
 
67,363

 
56,644

 
53,028

 
57,951

Acquisition costs, net
 
37,796

 
25,570

 
22,478

 
21,821

General and administrative expenses
 
6,200

 
5,559

 
6,012

 
6,729

Total expenses
 
111,359

 
87,773

 
81,518

 
86,501

Income (loss) before income tax expense
 
(9,638
)
 
112,614

 
(53,391
)
 
63,066

Income tax (expense) benefit
 
560

 
14

 
254

 
(204
)
Net income (loss) including non-controlling interest
 
(9,078
)
 
112,628

 
(53,137
)
 
62,862

Loss (income) attributable to non-controlling interest in joint venture
 
197

 
(3,075
)
 
1,369

 
(2,174
)
Net income (loss)
 
$
(8,881
)
 
$
109,553

 
$
(51,768
)
 
$
60,688

Earnings (loss) per share


Basic
 
$
(0.24
)
 
$
2.94

 
$
(1.40
)
 
$
1.62

Diluted
 
$
(0.24
)
 
$
2.89

 
$
(1.40
)
 
$
1.60

Weighted average number of ordinary shares used in the determination of earnings and loss per share


Basic
 
36,808,386

 
37,246,922

 
36,984,650

 
37,356,187

Diluted
 
36,808,386

 
37,902,106

 
36,984,650

 
37,905,836


v3.3.1.900
SCHEDULE I
12 Months Ended
Dec. 31, 2015
Summary of Investments, Other than Investments in Related Parties [Abstract]  
SUMMARY OF INVESTMENTS - OTHER THAN INVESTMENTS IN RELATED PARTIES
SCHEDULE I
 
 
GREENLIGHT CAPITAL RE, LTD.
SUMMARY OF INVESTMENTS — OTHER THAN INVESTMENTS IN RELATED PARTIES
AS OF DECEMBER 31, 2015
 
(expressed in thousands of U.S. dollars) 
Type of Investment
 
Cost
 
Fair Value
 
Balance
Sheet Value
 
 
($ in thousands)
Debt instruments, trading, at fair value
 
$
45,471

 
$
39,087

 
$
39,087

Equity securities, trading, at fair value


Equities – listed
 
1,011,424

 
890,653

 
890,653

Exchange traded funds
 
31,570

 
15,341

 
15,341

Total equity securities, trading, at fair value
 
1,042,994

 
905,994

 
905,994

Total investments, trading
 
$
1,088,465

 
$
945,081

 
$
945,081

Other investments, at fair value


Commodities
 
$
102,092

 
$
98,046

 
$
98,046

Private and unlisted equity securities
 
18,720

 
21,037

 
21,037

Total other investments, at fair value
 
120,812

 
119,083

 
119,083

Total investments
 
$
1,209,277

 
$
1,064,164

 
$
1,064,164


v3.3.1.900
SCHEDULE II
12 Months Ended
Dec. 31, 2015
Condensed Financial Information of Parent Company Only Disclosure [Abstract]  
CONDENSED FINANCIAL INFORMATION OF REGISTRANT
SCHEDULE II
 
 
GREENLIGHT CAPITAL RE, LTD.
CONDENSED FINANCIAL INFORMATION OF REGISTRANT
CONDENSED BALANCE SHEETS — PARENT COMPANY ONLY
 
(expressed in thousands of U.S. dollars) 
 
 
December 31, 2015
 
December 31, 2014
 
 
($ in thousands)
Cash and cash equivalents
 
$
6

 
$
1

Investment in subsidiaries
 
840,196

 
1,148,308

Note receivable
 
2,175

 
1,566

Due from subsidiaries
 
—

 
15,276

Total assets
 
$
842,377

 
$
1,165,151

Liabilities and shareholders’ equity


Liabilities


Due to subsidiaries
 
$
16,986

 
$
—

Total liabilities
 
16,986

 
—

Shareholders’ equity


Share capital
 
3,703

 
3,738

Additional paid-in capital
 
496,401

 
500,553

Retained earnings
 
325,287

 
660,860

Total shareholders’ equity
 
825,391

 
1,165,151

Total liabilities and shareholders’ equity
 
$
842,377

 
$
1,165,151


GREENLIGHT CAPITAL RE, LTD.
CONDENSED FINANCIAL INFORMATION OF REGISTRANT
CONDENSED STATEMENTS OF INCOME — PARENT COMPANY ONLY
 
(expressed in thousands of U.S. dollars)


Year ended December 31
 
 
2015
 
2014
 
2013
 
 
 ($ in thousands)
Revenue


Investment income
 
$
5,962

 
$
671

 
$
1,100

Total revenues
 
5,962

 
671

 
1,100

Expenses


General and administrative expenses
 
4,048

 
3,806

 
3,735

Net income (loss) before equity in earnings of consolidated subsidiaries
 
1,914

 
(3,135
)
 
(2,635
)
Equity in earnings of consolidated subsidiaries
 
(328,339
)
 
112,727

 
228,334

Consolidated net income (loss)
 
$
(326,425
)
 
$
109,592

 
$
225,699


SCHEDULE II (continued)
 
 
GREENLIGHT CAPITAL RE, LTD.
CONDENSED FINANCIAL INFORMATION OF REGISTRANT
CONDENSED STATEMENTS OF CASH FLOWS — PARENT COMPANY ONLY
 
(expressed in thousands of U.S. dollars) 
 
 
  Year Ended December 31
 
 
2015
 
2014
 
2013
 
 
 ($ in thousands)
Cash provided by (used in) operating activities


Net income (loss)
 
$
(326,425
)
 
$
109,592

 
$
225,699

Adjustments to reconcile net income (loss) to cash provided by operating activities


Equity in earnings of consolidated subsidiaries
 
328,339

 
(112,727
)
 
(228,334
)
Share-based compensation expense
 
4,274

 
3,964

 
3,675

Change in


Due from subsidiaries
 
15,276

 
971

 
(2,006
)
Due to subsidiaries
 
16,986

 
(3,808
)
 
2,438

Net cash (used in) provided by operating activities
 
38,450

 
(2,008
)
 
1,472

Investing activities


Change in note receivable
 
(609
)
 
2,162

 
(2,053
)
Contributed surplus to subsidiaries, net
 
(20,227
)
 
(158
)
 
59

Net cash (used in) provided by investing activities
 
(20,836
)
 
2,004

 
(1,994
)
Financing activities


Net proceeds from exercise of stock options
 
—

 
—

 
513

Short-swing sale profit from shareholder
 
83

 
—

 
—

Repurchase of Class A ordinary shares
 
(17,692
)
 
—

 
—

Net cash (used in) provided by financing activities
 
(17,609
)
 
—

 
513

Net increase (decrease) in cash and cash equivalents
 
5

 
(4
)
 
(9
)
Cash and cash equivalents at beginning of the year
 
1

 
5

 
14

Cash and cash equivalents at end of the year
 
$
6

 
$
1

 
$
5


v3.3.1.900
SCHEDULE III
12 Months Ended
Dec. 31, 2015
Supplementary Insurance Information [Abstract]  
SUPPLEMENTARY INSURANCE INFORMATION
SCHEDULE III
 
 
GREENLIGHT CAPITAL RE, LTD.
SUPPLEMENTARY INSURANCE INFORMATION
AS OF AND FOR THE YEARS ENDED DECEMBER 31, 2015, 2014 AND 2013
 
(expressed in thousands of U.S. dollars) 
Year
Segment
Deferred
acquisition
costs, net
Reserves
for losses
and loss
adjustment
expenses
– gross
Unearned
premiums
– gross
Net
premiums
earned
Net
investment
income (loss)
Net losses,
and loss
adjustment
expenses
Amortization
of deferred
acquisition
costs
Other
operating
expenses
Gross
premiums
written
2015
Property & Casualty
$
59,823

$
305,997

$
211,954

$
408,387

$
(281,924
)
$
317,097

$
116,207

$
23,434

$
502,124

2014
Property & Casualty
$
34,420

$
264,243

$
128,736

$
354,240

$
122,575

$
234,986

$
107,665

$
24,500

$
324,023

2013
Property & Casualty
$
51,797

$
329,894

$
173,057

$
547,899

$
218,140

$
338,493

$
171,872

$
20,958

$
535,702


v3.3.1.900
SCHEDULE IV
12 Months Ended
Dec. 31, 2015
Supplemental Schedule of Reinsurance Premiums for Insurance Companies [Abstract]  
SUPPLEMENTARY REINSURANCE INFORMATION
SCHEDULE IV
 
 
GREENLIGHT CAPITAL RE, LTD.
SUPPLEMENTARY REINSURANCE INFORMATION
AS OF AND FOR THE YEARS ENDED DECEMBER 31, 2015, 2014 AND 2013
 
(expressed in thousands of U.S. dollars) 
Year
Segment
 
Direct gross
 premiums
 
Premiums
 ceded to
 other companies
 
Premiums
assumed from
other companies
 
Net written premiums
 
Percentage of
 amount
assumed to net
2015
Property & Casualty
 
$
—

 
$
9,001

 
$
502,124

 
$
493,123

 
102
%
2014
Property & Casualty
 
$
—

 
$
13,493

 
$
324,023

 
$
310,530

 
104
%
2013
Property & Casualty
 
$
—

 
$
2,780

 
$
535,702

 
$
532,922

 
101
%

v3.3.1.900
SIGNIFICANT ACCOUNTING POLICIES (Policies)
12 Months Ended
Dec. 31, 2015
Accounting Policies [Abstract]  
Reclassifications
Reclassifications
Certain prior period balances have been reclassified to conform to the current period presentation. Prior to January 1, 2015, non-investment related foreign exchange gains and losses were recorded under general and administrative expenses in the condensed consolidated statements of income. Effective from January 1, 2015, the presentation has been modified and any non-investment related foreign exchange gains or losses are now recorded under “other income (expense), net” in the consolidated statements of income. As a result, foreign exchange gains (losses) of $2.6 million and $(0.8) million that were previously reported in general and administrative expenses for the years ended December 31, 2014 and 2013, respectively, were reclassified as “other income (expense), net” to conform to the current year presentation. The reclassifications resulted in no changes to net income or retained earnings for any of the periods presented.
Use of Estimates
Use of Estimates
 
The preparation of consolidated financial statements in conformity with U.S. GAAP requires management to make estimates and assumptions that affect the reported amounts of assets and liabilities and disclosure of contingent assets and liabilities at the date of the consolidated financial statements and the reported amounts of income and expenses during the period. Actual results could differ from these estimates. 
Cash and Cash Equivalents
 
Cash and cash equivalents consist of cash and certain short-term, highly liquid investments with original maturity dates of three months or less.
Restricted Cash and Cash Equivalents
 
The Company is required to maintain certain cash in segregated accounts with prime brokers and derivative counterparties. The amount of restricted cash held by prime brokers is primarily used to support the liability created from securities sold, not yet purchased and derivatives. Additionally, restricted cash and cash equivalent balances are held to collateralize regulatory trusts and letters of credit issued to cedents (see Notes 4 and 6). The amount of cash encumbered varies depending on the market value of the securities sold, not yet purchased, and the collateral required by the cedents in the form of trust accounts and letters of credit. In addition, derivative counterparties require cash collateral to support the current value of any amounts that may be due to the counterparty based on the value of the underlying financial instrument. 
Premium Revenue Recognition
 
The Company accounts for reinsurance contracts in accordance with U.S. GAAP. In the event that a reinsurance contract does not transfer sufficient risk, deposit accounting is used and the contract is reported as a deposit liability.
 
The Company writes excess of loss contracts as well as quota share contracts. The Company estimates the ultimate premiums for the entire contract period. These estimates are based on information received from the ceding companies and estimates from actuarial pricing models used by the Company. For excess of loss contracts, the total ultimate estimated premiums are recorded as premiums written at the inception of the contract. For quota share contracts, the premiums are recorded as written based on cession statements from cedents which typically are received monthly or quarterly depending on terms specified in each contract. For any reporting lag, premiums written are estimated based on the portion of the ultimate estimated premiums relating to the risks underwritten during the lag period.
 
Premium estimates are reviewed by management at least quarterly. Such review includes a comparison of actual reported premiums to expected ultimate premiums along with a review of the aging and collection of premium estimates. Based on management’s review, the appropriateness of the premium estimates is evaluated, and any adjustments to these estimates are recorded in the period in which they are determined. Changes in premium estimates, including premium receivable on both excess of loss and quota share contracts, are expected and may result in significant adjustments in any period. A significant portion of amounts included in reinsurance balances receivable represent estimated premiums written, net of commissions and brokerage, and are not currently due based on the terms of the underlying contracts.

Certain contracts allow for reinstatement premiums in the event of a full limit loss prior to the expiry of a contract. A reinstatement premium is not due until there is a full limit loss event and therefore, in accordance with U.S. GAAP, the Company records a reinstatement premium as written only in the event that a client incurs a full limit loss on the contract and the contract allows for a reinstatement of coverage upon payment of an additional premium. For catastrophe contracts which contractually require the payment of a reinstatement premium equal to or greater than the original premium upon the occurrence of a full limit loss, the reinstatement premiums are earned over the original contract period. Reinstatement premiums that are contractually calculated on a pro-rata basis of the original premiums, are earned over the remaining coverage period.
 
Certain contracts may provide for a penalty to be paid if the contract is terminated and canceled prior to its expiration term. Cancellation penalties are recognized in the period the notice of cancellation is received and are recorded in the consolidated statements of income under "other income (expense), net".

Premiums written are generally recognized as earned over the contract period in proportion to the period of risk covered. Unearned premiums consist of the unexpired portion of reinsurance provided.
Reinsurance Premiums Ceded
 
The Company reduces the risk of future losses on business assumed by reinsuring certain risks and exposures with other reinsurers (retrocessionaires). The Company remains liable to the extent that any retrocessionaire fails to meet its obligations and to the extent the Company does not hold sufficient security for their unpaid obligations.
 
Ceded premiums are written during the period in which the risks incept and are expensed over the contract period in proportion to the period of protection. Unearned premiums ceded consist of the unexpired portion of reinsurance obtained.
Deferred Acquisition Costs
 
Policy acquisition costs, such as commission and brokerage costs, relate directly to, and vary with, the writing of reinsurance contracts. Acquisition costs relating solely to bound contracts are deferred subject to ultimate recoverability and are amortized over the related contract term. The Company evaluates the recoverability of deferred acquisition costs by determining if the sum of future earned premiums and anticipated investment income is greater than the expected future claims and expenses. If a loss is probable on the unexpired portion of policies in force, a premium deficiency loss is recognized. At December 31, 2015 and 2014, the deferred acquisition costs were considered fully recoverable and no premium deficiency loss was recorded. 

Acquisition costs also include profit commissions which are expensed when incurred. Profit commissions are calculated and accrued based on the expected loss experience for contracts and recorded when the current loss estimate indicates that a profit commission is probable under the contract terms. As of December 31, 2015, $12.2 million (2014: $11.0 million) of profit commission reserves were included in reinsurance balances payable on the consolidated balance sheets. For the year ended December 31, 2015, $7.5 million (2014: $2.7 million and 2013: $3.7 million, respectively) of net profit commission expense was included in acquisition costs on the consolidated statements of income.

Funds Withheld
Funds Withheld
 
Funds withheld include reinsurance balances retained from retrocessionaires as security for a period of time in accordance with the contract terms. Any interest expense that the Company incurs during the period these funds are withheld, are included under net investment income in the consolidated statements of income.
Loss and Loss Adjustment Expense Reserves and Recoverable
 
The Company establishes reserves for contracts based on estimates of the ultimate cost of all losses including losses incurred but not reported ("IBNR"). These estimated ultimate reserves are based on the Company’s own actuarial estimates derived from reports received from ceding companies, industry data and historical experience. These estimates are reviewed by the Company periodically on a contract by contract basis and adjusted as necessary. Since reserves are estimates, the final settlement of losses may vary from the reserves established and any adjustments to the estimates, which may be material, are recorded in the period they are determined.
 
Loss and loss adjustment expenses recoverable include the amounts due from retrocessionaires for unpaid loss and loss adjustment expenses on retrocession agreements. Ceded losses incurred but not reported are estimated based on the Company’s actuarial estimates. These estimates are reviewed periodically and adjusted when deemed necessary. The Company may not be able to ultimately recover the loss and loss adjustment expense recoverable amounts due to the retrocessionaires’ inability to pay. The Company regularly evaluates the financial condition of its retrocessionaires and records provisions for uncollectible reinsurance expenses recoverable when recovery is no longer probable.
Notes Receivable
Notes Receivable
 
Notes receivable include promissory notes receivable from third party entities. These notes are recorded at cost along with accrued interest, if any, which approximates the fair value. Interest income and realized gains or losses on sale of notes receivable are included under net investment income (loss) in the consolidated statements of income.

The Company regularly reviews all notes receivable individually for impairment and records valuation allowance provisions for uncollectible and non-performing notes. The Company places notes on non-accrual status when the recorded value of the note is not considered impaired but there is uncertainty as to the collection of interest based on the terms of the note. The Company resumes accrual of interest on a note when none of the principal or interest remains past due, and the Company expects to collect the remaining contractual principal and interest. Interest collected on notes that are placed on non-accrual status is treated on a cash-basis and recorded as interest income when collected, provided that the recorded value of the note is deemed to be fully collectible. Where doubt exists as to the collectability of the remaining recorded value of the notes placed on non-accrual status, any payments received are applied to reduce the recorded value of the notes.

At December 31, 2015, $23.0 million of notes receivable (net of any valuation allowance) were on non-accrual status
(2014: $0.0 million) and any payments received were applied to reduce the recorded value of the notes. The increase in notes receivable during the year ended December 31, 2015, related to a settlement agreement entered into with a ceding insurer during 2015 whereby certain amounts, previously classified under reinsurance balances receivable, were converted into a ten-year note receivable.
 
At December 31, 2015 and 2014, there was no accrued interest included in the notes receivable balance. Based on management’s assessment, the recorded values of the notes receivable, net of valuation allowance, at December 31, 2015 and 2014, were expected to be fully collectible.

Deposit Assets and Liabilities
 
In accordance with U.S. GAAP, deposit accounting is used in the event that a reinsurance contract does not transfer sufficient insurance risk, or a contract provides retroactive reinsurance. Any losses on such contracts are charged to earnings immediately. Any gains relating to such contracts are deferred and amortized over the estimated remaining settlement period. All such deferred gains are included in reinsurance balances payable in the consolidated balance sheets. Amortized gains are recorded in the consolidated statements of income as other income. At December 31, 2015 and 2014, there were no material deposit assets or deposit liabilities and no material gains or losses on deposit accounted contracts.
Fixed Assets
Fixed Assets
 
Fixed assets are included in other assets on the consolidated balance sheets and are recorded at cost when acquired. Fixed assets are comprised of computer software, furniture and fixtures and leasehold improvements and are depreciated, using the straight-line method, over their estimated useful lives, which are five years for both computer software, and furniture and fixtures.  Leasehold improvements are amortized over the lesser of the estimated useful lives of the assets or remaining lease term. The Company periodically reviews fixed assets that have finite lives, and that are not held for sale, for impairment by comparing the carrying value of the assets to their estimated future undiscounted cash flows. For the years ended December 31, 2015, 2014 and 2013, there were no impairments in fixed assets.
Financial Instruments
 
Investments in Securities and Investments in Securities Sold, Not Yet Purchased
 
The Company’s investments in debt instruments and equity securities that are classified as "trading securities" are carried at fair value. The fair values of the listed equity investments are derived based on quoted prices (unadjusted) in active markets for identical assets (Level 1 inputs). The fair values of listed equities that have restrictions on sale or transfer which expire within one year, are determined by adjusting the observed market price of the equity using a liquidity discount based on observable market inputs. The fair values of debt instruments are derived based on inputs that are observable, either directly or indirectly, such as market maker or broker quotes reflecting recent transactions (Level 2 inputs), and are generally derived based on the average of multiple market maker or broker quotes which are considered to be binding. Where quotes are not available, debt instruments are valued using cash flow models using assumptions and estimates that may be subjective and non-observable (Level 3 inputs).

The Company’s "other investments" may include investments in private and unlisted equity securities, limited partnerships, and commodities, which are all carried at fair value. The fair values of commodities are determined based on quoted prices in active markets for identical assets (Level 1). The Company maximizes the use of observable direct or indirect inputs (Level 2 inputs) when deriving the fair values for "other investments". For limited partnerships and private and unlisted equity securities, where observable inputs are not available, the fair values are derived based on unobservable inputs (Level 3 inputs) such as management’s assumptions developed from available information using the services of the investment advisor, including the most recent net asset values obtained from the managers of those underlying investments.

For securities classified as "trading securities", and "other investments", any realized and unrealized gains or losses are determined on the basis of the specific identification method (by reference to cost or amortized cost, as appropriate) and included in net investment income (loss) in the consolidated statements of income.

Dividend income and expense are recorded on the ex-dividend date. The ex-dividend date is the date as of when the underlying security must have been traded to be eligible for the dividend declared. Interest income and interest expense are recorded on an accrual basis.
Derivative Financial Instruments
 
U.S. GAAP requires that an entity recognize all derivatives in the balance sheet at fair value. It also requires that unrealized gains and losses resulting from changes in fair value be included in income or comprehensive income, depending on whether the instrument qualifies as a hedge transaction, and if so, the type of hedge transaction. The Company’s derivative financial instrument assets are included in financial contracts receivable. Derivative financial instrument liabilities are generally included in financial contracts payable. The Company's derivatives do not qualify as hedges for financial reporting purposes and are recorded in the consolidated balance sheets on a gross basis and not offset against any collateral pledged or received. Pursuant to the International Swaps and Derivatives Association ("ISDA") master agreements, securities lending agreements and other agreements, the Company and its counterparties typically have the ability to net certain payments owed to each other in specified circumstances. In addition, in the event a party to one of the ISDA master agreements, securities lending agreements or other agreements defaults, or a transaction is otherwise subject to termination, the non-defaulting party generally has the right to set off against payments owed to the defaulting party or collateral held by the non-defaulting party. The Company may from time to time enter into underwriting contracts such as industry loss warranty contracts ("ILW") that are treated as derivatives for U.S GAAP purposes.
 
Financial Contracts

The Company enters into financial contracts with counterparties as part of its investment strategy. Financial contracts, which include total return swaps, credit default swaps ("CDS"), futures, options, currency forwards and other derivative instruments, are recorded at their fair value with any unrealized gains and losses included in net investment income (loss) in the consolidated statements of income. Financial contracts receivable represents derivative contracts whereby, based upon the contract's current fair value, the Company will be entitled to receive payments upon settlement of the contract. Financial contracts payable represents derivative contracts whereby, based upon each contract's current fair value, the Company will be obligated to make payments upon settlement of the contract.
 
Total return swap agreements, included on the consolidated balance sheets as financial contracts receivable and financial contracts payable, are derivative financial instruments whereby the Company is either entitled to receive or obligated to pay the product of a notional amount multiplied by the movement in an underlying security, which the Company may not own, over a specified time frame. In addition, the Company may also be obligated to pay or receive other payments based on interest rates, dividend payments and receipts, or foreign exchange movements during a specified period. The Company measures its rights or obligations to the counterparty based on the fair value movements of the underlying security together with any other payments due. These contracts are carried at fair value, based on observable inputs (Level 2 inputs) with the resultant unrealized gains and losses reflected in net investment income (loss) in the consolidated statements of income. Additionally, any changes in the value of amounts received or paid on swap contracts are reported as a gain or loss in net investment income (loss) in the consolidated statements of income.
 
Financial contracts may also include exchange traded futures or options contracts that are based on the movement of a particular index, equity security, commodity, currency or interest rate. Where such contracts are traded in an active market, the Company’s obligations or rights on these contracts are recorded at fair value based on the observable quoted prices of the same or similar financial contracts in an active market (Level 1) or on broker quotes which reflect market information based on actual transactions (Level 2). Amounts invested in exchange traded options and over the counter ("OTC") options are recorded either as an asset or liability at inception. Subsequent to initial recognition, unexpired exchange traded option contracts are recorded at fair value based on quoted prices in active markets (Level 1). For OTC options or exchange traded options where a quoted price in an active market is not available, fair values are derived based upon observable inputs (Level 2) such as multiple quotes from brokers and market makers, which are considered to be binding.
 
The Company may purchase and sell CDS for strategic investment purposes. A CDS is a derivative instrument that provides protection against an investment loss due to specified credit or default events of a reference entity. The seller of a CDS guarantees to pay the buyer a specified amount if the reference entity defaults on its obligations or fails to perform. The buyer of a CDS pays a premium over time to the seller in exchange for obtaining this protection. A CDS trading in an active market is valued at fair value based on broker or market maker quotes for identical instruments in an active market (Level 2) or based on the current credit spreads on identical contracts (Level 2).
Share-Based Compensation
 
The Company has established a stock incentive plan for directors, employees and consultants.
 
U.S. GAAP requires the Company to recognize share-based compensation transactions using the fair value at the grant date of the award. The Company measures compensation for restricted shares and restricted stock units ("RSUs") based on the price of the Company’s common shares at the grant date and the expense is recognized on a straight line basis over the vesting period.

Determining the fair value of share purchase options at the grant date requires significant estimation and judgment. The Company uses an option-pricing model (Black-Scholes option pricing model) to assist in the calculation of fair value for share purchase options. The model requires estimation of various inputs such as estimated term, forfeiture and dividend rates and expected volatility. The Company uses the full life of the options, ten years, as the estimated term of the options, and has assumed no forfeitures and no dividends paid during the life of the options. Effective from 2014, the estimate of expected volatility is based on the daily historical trading data of the Company's Class A ordinary shares from the date that these shares commenced trading (May 24, 2007) to the grant date. Prior to 2014, the Company's share had not been publicly traded for a sufficient length of time to reasonably estimate the expected volatility. Therefore, for share purchase options granted prior to 2014, the Company determined the expected volatility based primarily on the historical volatility of similar entities. The Company considered factors such as an entity's industry, stage of life cycle, size and financial leverage when selecting similar entities. The Company used a sample peer group of companies in the reinsurance industry as well as the Company’s own historical volatility in determining the expected volatility. 
 
For share purchase options issued under the employee stock incentive plan, compensation cost is calculated and expensed over the vesting periods on a graded vesting basis (see Note 10). 

If actual results differ significantly from these estimates and assumptions, particularly in relation to the Company’s estimation of volatility which requires the most judgment, share-based compensation expense, primarily with respect to future share-based awards, could be materially impacted.
Foreign Exchange
Foreign Exchange
 
The reporting and functional currency of the Company and all its subsidiaries is the U.S. dollar. Transactions in foreign currencies are recorded in U.S. dollars at the exchange rates in effect on the transaction date. Monetary assets and liabilities in foreign currencies at the balance sheet date are translated at the exchange rate in effect at the balance sheet date and translation exchange gains and losses, if any, are included in "other income (expense), net" in the consolidated statements of income.
Other Assets
Other Assets
 
Other assets consist primarily of investment income receivable, prepaid expenses, fixed assets and deferred tax assets.
Other Liabilities
Other Liabilities
 
Other liabilities consist primarily of dividends payable on securities sold, not yet purchased, and employee bonus accruals. At December 31, 2015, other liabilities included accrued bonus of $8.2 million (2014: $7.6 million). Under the Company's bonus program, each employee’s target bonus consists of two components: a discretionary component based on a qualitative assessment of each employee’s performance and a quantitative component based on the return on deployed equity (‘‘RODE”) for each underwriting year relating to reinsurance operations. The qualitative portion of an employee’s annual bonus is accrued at each employee's target amount, which may differ significantly from the actual amount approved and awarded annually by the Compensation Committee. The quantitative portion of each employee’s annual bonus is accrued based on the expected RODE for each underwriting year and adjusted for changes in the expected RODE and actual investment return each quarter until all losses are settled and the underwriting year is declared closed. The quantitative bonus is calculated and paid, with the approval of the Compensation Committee, in annual installments between two to five years from the end of the fiscal year in which the business was underwritten. Any further changes are incorporated into the following open underwriting year. The expected RODE calculation utilizes proprietary models which require significant estimation and judgment. Actual RODE may vary significantly from the expected RODE and any adjustments to the quantitative bonus estimates, which may be material, are recorded in the period in which they are determined. 
 
Also included in other liabilities are accruals for income taxes payable, professional fees and other general expenses.
Non-controlling Interest
 
Non-controlling interest in joint venture on the consolidated balance sheets represents DME Advisors, LLC’s (‘‘DME”) share of assets in the joint venture whereby DME is a participant in the joint venture as disclosed in Note 13. DME’s share of investment income or loss is included in the consolidated statements of income as income attributable to non-controlling interest in joint venture.
Comprehensive Income (Loss)

The Company has no other comprehensive income or loss, other than the net income or loss disclosed in the consolidated statements of income.
Earnings (Loss) Per Share
 
Basic earnings per share are based on the weighted average number of common shares and participating securities outstanding during the period. Diluted earnings per share includes the dilutive effect of restricted stock units ("RSU") and additional potential common shares issuable when stock options are exercised and are determined using the treasury stock method. The Company treats its unvested restricted stock as participating securities in accordance with U.S. GAAP, which requires that unvested stock awards which contain non-forfeitable rights to dividends or dividend equivalents, whether paid or unpaid (referred to as "participating securities"), be included in the number of shares outstanding for both basic and diluted earnings per share calculations. In the event of a net loss, all RSUs, stock options outstanding and participating securities are excluded from the calculation of both basic and diluted loss per share since their inclusion would be anti-dilutive.
Taxation
Taxation
 
Under current Cayman Islands law, no corporate entity, including GLRE and Greenlight Re, is obligated to pay taxes in the Cayman Islands on either income or capital gains. The Company has an undertaking from the Governor-in-Cabinet of the Cayman Islands, pursuant to the provisions of the Tax Concessions Law, as amended, that, in the event that the Cayman Islands enacts any legislation that imposes tax on profits, income, gains or appreciations, or any tax in the nature of estate duty or inheritance tax, such tax will not be applicable to GLRE, Greenlight Re nor their respective operations, or to the Class A or Class B ordinary shares or related obligations, until February 1, 2025.
 
Verdant is incorporated in Delaware and therefore is subject to taxes in accordance with the U.S. federal rates and regulations prescribed by the U.S. Internal Revenue Service ("IRS"). Verdant’s taxable income is generally expected to be taxed at a rate of 35%.

GRIL is incorporated in Ireland and therefore is subject to the Irish corporation tax rate of 12.5% on its trading income, and 25% on its non-trading income, if any.

Any deferred tax asset is evaluated for recovery and a valuation allowance is recorded when it is more likely than not that the deferred tax asset will not be realized in the future. The Company has not taken any income tax positions that are subject to significant uncertainty or that are reasonably likely to have a material impact on the Company.

Segment Information
Segment Information
 
Under U.S. GAAP, operating segments are based on the internal information that management uses for allocating resources and assessing performance as the source of the Company's reportable segments.
 
The Company manages its business on the basis of one operating segment, Property and Casualty Reinsurance, in accordance with the qualitative and quantitative criteria established by U.S. GAAP. 
Recent Accounting Pronouncements
        
In May 2015, the FASB issued Accounting Standards Update 2015-07, "Fair Value Measurement (Topic 820): Disclosures for Investments in Certain Entities That Calculate Net Asset Value per Share or Its Equivalent" ("ASU 2015-07"). The amendments apply to reporting entities that elect to measure the fair value of an investment using the net asset value ("NAV") per share (or its equivalent) as a practical expedient. The amendments remove the requirement to categorize within the fair value hierarchy all investments for which fair value is measured using the NAV per share as a practical expedient. The amendments also remove the requirement to make certain disclosures for all investments that are eligible to be measured at fair value using the NAV per share as a practical expedient. Rather, those disclosures are limited to investments for which the entity has elected to measure the fair value using that practical expedient. The amendments in ASU 2015-07 are effective for reporting periods beginning after December 15, 2015, with early adoption permitted. Entities are required to apply the amendments in this update retrospectively to all periods presented. The Company will adopt ASU 2015-07 during the first quarter of 2016. As the Company measures certain investments in private equity funds using the NAV as a practicable expedient, upon adoption of ASU 2015-07, the fair value of these investments will be removed from the fair value hierarchy for all periods presented in the Company’s consolidated financial statements. The Company will continue to disclose information on these investments for which fair value is measured at NAV as a practical expedient.

In May 2015, the FASB issued ASU 2015-09, "Financial Services - Insurance (Topic 944): Disclosures about Short-Duration Contracts" ("ASU 2015-09"). ASU 2015-09 requires additional disclosures for short-duration contracts including incurred and paid claims development information, claims duration information, quantitative claims frequency information (unless impracticable), and an explanation of significant changes in methodologies and assumptions used to calculate the loss and loss adjustment expense reserves. ASU 2015-09 is effective for public entities for annual reporting periods beginning after December 15, 2015, and interim reporting periods within annual reporting periods beginning after December 15, 2016 with early adoption permitted. The Company is evaluating the impact of the disclosure requirements of ASU 2015-09 and is preparing to disclose the additional information in its consolidated financial statements for the fiscal year ending December 31, 2016 and thereafter.


v3.3.1.900
SIGNIFICANT ACCOUNTING POLICIES (Tables)
12 Months Ended
Dec. 31, 2015
Accounting Policies [Abstract]  
Fixed Assets Table
At December 31, 2015, the cost, accumulated depreciation and net book values of the fixed assets were as follows:
 
Cost
 
Accumulated depreciation
 
 
Net book value
 
($ in thousands)
Computer software
$
556

 
$
(348
)
 
$
208

Furniture and fixtures
620

 
(513
)
 
107

Leasehold improvements
2,002

 
(1,229
)
 
773

Total
$
3,178

 
$
(2,090
)
 
$
1,088


At December 31, 2014, the cost, accumulated depreciation and net book values of the fixed assets were as follows:
 
Cost
 
Accumulated depreciation
 
 
Net book value
 
($ in thousands)
Computer software
$
556

 
$
(277
)
 
$
279

Furniture and fixtures
620

 
(442
)
 
178

Leasehold improvements
2,002

 
(966
)
 
1,036

Total
$
3,178

 
$
(1,685
)
 
$
1,493

Schedule of Weighted Average Number of Shares
 
Year ended December 31
 
2015
 
2014
 
2013
Weighted average shares outstanding - basic
36,670,466

 
37,242,687

 
36,838,128

Effect of dilutive service provider share-based awards
—

 
8,498

 
144,726

Effect of dilutive employee and director share-based awards
—

 
623,202

 
602,313

Weighted average shares outstanding - diluted
36,670,466

 
37,874,387

 
37,585,167

Anti-dilutive stock options outstanding
211,821

 
—

 
218,197

Participating securities excluded from calculation of loss per share 
307,013

 
—

 
—


v3.3.1.900
FINANCIAL INSTRUMENTS (Tables)
12 Months Ended
Dec. 31, 2015
Dec. 31, 2014
Schedule of Trading Securities and Other Trading Assets [Line Items]    
Fair Value Measurements, Recurring and Nonrecurring
The following table presents the Company’s investments, categorized by the level of the fair value hierarchy as of December 31, 2015:
 
 
Fair value measurements as of December 31, 2015
 
 
Description
 
Quoted prices in
active markets
(Level 1)
 
Significant other
observable
inputs
(Level 2)
 
Significant
unobservable
inputs
(Level 3)
 
Total
Assets: 
 
($ in thousands)
Debt instruments
 
$
—

 
$
38,582

 
$
505

 
$
39,087

Listed equity securities
 
900,369

 
5,625

 
—

 
905,994

Commodities
 
98,046

 
—

 
—

 
98,046

Private and unlisted equity securities
 
—

 
—

 
21,037

 
21,037

Financial contracts receivable
 
20

 
13,195

 
—

 
13,215


$
998,435

 
$
57,402

 
$
21,542

 
$
1,077,379

Liabilities:


Listed equity securities, sold not yet purchased
 
$
(808,481
)
 
$
—

 
$
—

 
$
(808,481
)
Debt instruments, sold not yet purchased
 
—

 
(74,425
)
 
—

 
(74,425
)
Financial contracts payable
 
(488
)
 
(27,757
)
 
—

 
(28,245
)
 
 
$
(808,969
)
 
$
(102,182
)
 
$
—

 
$
(911,151
)

 
The following table presents the Company’s investments, categorized by the level of the fair value hierarchy as of December 31, 2014:
 
 
Fair value measurements as of December 31, 2014
 
 
Description
 
Quoted prices in
active markets
(Level 1)
 
Significant other
observable
inputs
(Level 2)
 
Significant
unobservable
inputs
(Level 3)
 
Total
Assets: 
 
($ in thousands)
Debt instruments
 
$
—

 
$
26,953

 
$
22,259

 
$
49,212

Listed equity securities
 
1,259,298

 
6,877

 
—

 
1,266,175

Commodities
 
96,872

 
—

 
—

 
96,872

Private and unlisted equity securities
 
—

 
—

 
18,719

 
18,719

Financial contracts receivable
 
2,463

 
44,708

 
—

 
47,171


$
1,358,633

 
$
78,538

 
$
40,978

 
$
1,478,149

Liabilities:


Listed equity securities, sold not yet purchased
 
$
(834,228
)
 
$
—

 
$
—

 
$
(834,228
)
Debt instruments, sold not yet purchased
 
—

 
(256,503
)
 
—

 
(256,503
)
Financial contracts payable
 
—

 
(44,592
)
 
—

 
(44,592
)
 
 
$
(834,228
)
 
$
(301,095
)
 
$
—

 
$
(1,135,323
)
 
Fair Value, Assets Measured on Recurring Basis, Unobservable Input Reconciliation
The following table presents the reconciliation of the balances for all investments measured at fair value using significant unobservable inputs (Level 3) for the year ended December 31, 2015: 
 
 
Fair Value Measurements Using Significant Unobservable Inputs (Level 3)
 
 
Year ended December 31, 2015
 
 
Assets
 
Liabilities
 
 
Debt instruments
 
 Private and unlisted equity securities
 
Financial contracts receivable
 
Listed equity securities
 
 Total
 
Financial contracts payable
 
 
 ($ in thousands)
Beginning balance
 
$
22,259

 
$
18,719

 
$
—

 
$
—

 
$
40,978

 
$
—

Purchases
 
—

 
5,009

 
2,340

 
—

 
7,349

 
—

Sales
 
(21,561
)
 
(3,290
)
 
—

 
—

 
(24,851
)
 
—

Total realized and unrealized gains (losses) and amortization included in earnings, net
 
(193
)
 
599

 
(3,027
)
 
(692
)
 
(3,313
)
 
314

Transfers into Level 3
 
—

 
—

 
2,536

 
5,189

 
7,725

 
8,835

Transfers out of Level 3
 
—

 
—

 
(1,849
)
 
(4,497
)
 
(6,346
)
 
(9,149
)
Ending balance
 
$
505

 
$
21,037

 
$
—

 
$
—

 
$
21,542

 
$
—

The following table presents the reconciliation of the balances for all investments measured at fair value using significant unobservable inputs (Level 3) for the year ended December 31, 2014:


  Fair Value Measurements Using Significant Unobservable Inputs (Level 3)
 
 
Year ended December 31, 2014
 
 
Debt instruments
 
 Private and unlisted equity securities
 
Total
 
 
 ($ in thousands)
Beginning balance
 
$
527

 
$
46,323

 
$
46,850

Purchases
 
21,561

 
3,958

 
25,519

Sales
 
—

 
(37,252
)
 
(37,252
)
Total realized and unrealized gains included in earnings, net
 
171

 
9,734

 
9,905

Transfers into Level 3
 
—

 
—

 
—

Transfers out of Level 3
 
—

 
(4,044
)
 
(4,044
)
Ending balance
 
$
22,259

 
$
18,719

 
$
40,978

Investments Classified by Contractual Maturity Date
The maturity distribution for debt instruments held at December 31, 2015 and 2014, was as follows:
 
 
2015
 
2014
 
 
Cost/
 amortized
 cost
 
Fair
 value
 
Cost/
 amortized
 cost
 
Fair
 value
 
 
($ in thousands)
Within one year
 
$
—

 
$
—

 
$
—

 
$
—

From one to five years
 
4,202

 
4,129

 
21,922

 
21,923

From five to ten years
 
18,840

 
14,780

 
2,401

 
1,282

More than ten years
 
22,429

 
20,178

 
28,752

 
26,007


$
45,471

 
$
39,087

 
$
53,075

 
$
49,212

 
Investment Holdings, Other than Securities
At December 31, 2015, the following securities were included in other investments:
 
 
Cost
 
Unrealized
gains
 
Unrealized
losses
 
Fair
value
 
 
($ in thousands)
Commodities
 
$
102,092

 
$
—

 
$
(4,046
)
 
$
98,046

Private and unlisted equity securities
 
18,720

 
3,491

 
(1,174
)
 
21,037


$
120,812

 
$
3,491

 
$
(5,220
)
 
$
119,083


At December 31, 2014, the following securities were included in other investments: 
 
 
Cost
 
Unrealized
gains
 
Unrealized
losses
 
Fair
value
 
 
($ in thousands)
Commodities
 
$
95,815

 
$
1,057

 
$
—

 
$
96,872

Private and unlisted equity securities
 
17,238

 
3,451

 
(1,970
)
 
18,719


$
113,053

 
$
4,508

 
$
(1,970
)
 
$
115,591

 
Investments Sold, Not yet Purchased
At December 31, 2015, the following securities were included in investments in securities sold, not yet purchased:
 
 
Proceeds
 
Unrealized gains
 
Unrealized losses
 
 Fair value
 
 
($ in thousands)
Equities – listed
 
$
(803,842
)
 
$
102,469

 
$
(94,681
)
 
$
(796,054
)
Exchange traded funds
 
(9,572
)
 
—

 
(2,855
)
 
(12,427
)
Sovereign debt – Non U.S.
 
(77,443
)
 
3,018

 
—

 
(74,425
)
 
 
$
(890,857
)
 
$
105,487

 
$
(97,536
)
 
$
(882,906
)


At December 31, 2014, the following securities were included in investments in securities sold, not yet purchased: 
 
 
Proceeds
 
Unrealized gains
 
Unrealized losses
 
 Fair value
 
 
($ in thousands)
Corporate debt – U.S.
 
$
(7,066
)
 
$
1,007

 
$
(5
)
 
$
(6,064
)
Equities – listed
 
(813,365
)
 
91,690

 
(101,715
)
 
(823,390
)
Exchange traded funds
 
(9,180
)
 
—

 
(1,658
)
 
(10,838
)
Sovereign debt – Non U.S.
 
(246,589
)
 
6,635

 
(10,485
)
 
(250,439
)
 
 
$
(1,076,200
)
 
$
99,332

 
$
(113,863
)
 
$
(1,090,731
)
 
Fair Values of Financial Contracts Outstanding
At December 31, 2015, the fair values of financial contracts outstanding were as follows: 
Financial Contracts
 
Listing
currency
(1)
 
Notional amount of
underlying instruments
 
Fair value of net assets
(obligations)
on financial
contracts


($ in thousands)
Financial contracts receivable


Call options (2)
 
USD
 
47,259

 
$
657

Put options (3)
 
USD
 
147,326

 
8,790

Total return swaps – equities
 
EUR/GBP/USD
 
50,205

 
3,748

Warrants and rights on listed equities
 
EUR
 
59

 
20

Total financial contracts receivable, at fair value


$
13,215

Financial contracts payable


Call options
 
USD
 
2,601

 
$
(64
)
Commodity Swaps
 
USD
 
42,160

 
(12,784
)
Forwards
 
KRW
 
2,908

 
(22
)
Futures
 
USD
 
21,195

 
(488
)
Total return swaps – equities
 
EUR/GBP/HKD/RON/MXN/USD
 
71,874

 
(14,887
)
Total financial contracts payable, at fair value


$
(28,245
)
At December 31, 2014, the fair values of financial contracts outstanding were as follows: 
Financial Contracts
 
Listing
currency (1)
 
Notional amount of
underlying instruments
 
Fair value of net assets
(obligations)
on financial
contracts


($ in thousands)
Financial contracts receivable


Futures
 
USD
 
13,204

 
$
3,461

Put options (2)
 
USD
 
299,907

 
22,349

Total return swaps – equities
 
EUR/GBP/HKD/USD
 
43,355

 
18,898

Warrants and rights on listed equities
 
EUR
 
8,054

 
2,463

Total financial contracts receivable, at fair value


$
47,171

Financial contracts payable


Credit default swaps, purchased – corporate debt
 
USD
 
221,198

 
$
(1,305
)
Credit default swaps, purchased – sovereign debt
 
USD
 
251,467

 
(1,714
)
Forwards
 
KRW
 
20,563

 
(512
)
Futures
 
USD
 
33,625

 
(867
)
Total return swaps – equities
 
EUR/GBP/HKD/INR/RON/USD
 
122,667

 
(40,194
)
Total financial contracts payable, at fair value


$
(44,592
)
Gains and losses on derivatives recognized in income
During the years ended December 31, 2015, 2014 and 2013, the Company reported gains and losses on derivatives as follows:
Derivatives not designated as hedging instruments
 
Location of gains and losses on derivatives recognized in income
 
Gain (loss) on derivatives recognized in income


Year ended December 31


2015
 
2014
 
2013


($ in thousands)
Commodity swaps
 
Net investment income (loss)
 
$
(12,061
)
 
$
—

 
$
—

Credit default swaps, purchased – corporate debt
 
Net investment income (loss)
 
(156
)
 
(345
)
 
(3,552
)
Credit default swaps, purchased – sovereign debt
 
Net investment income (loss)
 
(90
)
 
(298
)
 
(1,087
)
Forwards
 
Net investment income (loss)
 
1,009

 
(490
)
 
11,209

Futures
 
Net investment income (loss)
 
(952
)
 
16,721

 
12,504

Interest rate options
 
Net investment income (loss)
 
—

 
(26
)
 
(82
)
Interest rate swaps
 
Net investment income (loss)
 
(706
)
 
—

 
—

Options, warrants, and rights
 
Net investment income (loss)
 
(13,955
)
 
1,020

 
21,446

Total return swaps – equities
 
Net investment income (loss)
 
(12,590
)
 
13,142

 
85,638

Weather derivative swap
 
Other income (expense), net
 
(2,340
)
 
—

 
—

Total


$
(41,841
)
 
$
29,724

 
$
126,076

 
Derivatives volume of activities based on notional amounts
For the year ended December 31, 2015, the Company’s volume of derivative activities (based on notional amounts) was as follows:
2015
 
Year ended December 31
Derivatives not designated as hedging instruments (notional amounts)
 
  Entered
 
Exited
 
 
($ in thousands)
Commodity swaps
 
$
103,358

 
$
43,261

Credit default swaps (1)
 
—

 
—

Forwards
 
—

 
13,377

Futures
 
311,536

 
294,441

Interest rate swaps
 
9,139,000

 
7,213,000

Options, warrants and rights (1)
 
661,103

 
341,702

Total return swaps
 
67,844

 
185,128

Weather derivative swap
 
12,000

 
12,000

Total
 
$
10,294,841

 
$
8,102,909

For the year ended December 31, 2014, the Company’s volume of derivative activities (based on notional amounts) was as follows:
2014
 
Year ended December 31
Derivatives not designated as hedging instruments (notional amounts)
 
  Entered
 
Exited
 
 
($ in thousands)
Forwards
 
$
—

 
$
82,688

Futures
 
308,178

 
356,216

Options, warrants and rights (1)
 
1,044,241

 
314,876

Total return swaps
 
121,125

 
160,065

Total
 
$
1,473,544

 
$
913,845

Offsetting derivative assets and liabilities
As of December 31, 2015, the gross and net amounts of derivative instruments and the cash collateral applicable to derivative instruments were as follows:
December 31, 2015
 
(i)
 
(ii)
 
(iii) = (i) - (ii)
 
(iv) Gross amounts not offset in the balance sheet
 
(v) = (iii) + (iv)
Description
 
Gross amounts of recognized assets (liabilities)
 
Gross amounts offset in the balance sheet
 
Net amounts of assets (liabilities) presented in the balance sheet
 
Financial instruments available for offset
 
Cash collateral (received) pledged
 
Net amount of asset (liability)
 
 
($ in thousands)
Financial contracts receivable
 
$
13,215

 
$
—

 
$
13,215

 
$
(8,937
)
 
$
(2,036
)
 
$
2,242

Financial contracts payable
 
(28,245
)
 
—

 
(28,245
)
 
8,937

 
19,308

 
—


As of December 31, 2014, the gross and net amounts of derivative instruments and the cash collateral applicable to derivative instruments were as follows:
December 31, 2014
 
(i)
 
(ii)
 
(iii) = (i) - (ii)
 
(iv) Gross amounts not offset in the balance sheet
 
(v) = (iii) + (iv)
Description
 
Gross amounts of recognized assets (liabilities)
 
Gross amounts offset in the balance sheet
 
Net amounts of assets (liabilities) presented in the balance sheet
 
Financial instruments available for offset
 
Cash collateral (received) pledged
 
Net amount of asset (liability)
 
 
($ in thousands)
Financial contracts receivable
 
$
47,171

 
$
—

 
$
47,171

 
$
(24,265
)
 
$
(9,452
)
 
$
13,454

Financial contracts payable
 
(44,592
)
 
—

 
(44,592
)
 
24,265

 
20,327

 
—

 
Equities – listed    
Schedule of Trading Securities and Other Trading Assets [Line Items]    
Trading Securities (and Certain Trading Assets)
At December 31, 2015, the following long positions were included in equity securities, trading: 
 
 
Cost
 
Unrealized
gains
 
Unrealized
losses
 
Fair
value
 
 
($ in thousands)
Equities – listed
 
$
1,011,424

 
$
67,114

 
$
(187,885
)
 
$
890,653

Exchange traded funds
 
31,570

 
—

 
(16,229
)
 
15,341

Total equity securities
 
$
1,042,994

 
$
67,114

 
$
(204,114
)
 
$
905,994


At December 31, 2014, the following long positions were included in equity securities, trading:
 
 
Cost
 
Unrealized
gains
 
Unrealized
losses
 
Fair
value
 
 
($ in thousands)
Equities – listed
 
$
1,079,955

 
$
247,109

 
$
(80,637
)
 
$
1,246,427

Exchange traded funds
 
42,126

 
—

 
(22,378
)
 
19,748

Total equity securities
 
$
1,122,081

 
$
247,109

 
$
(103,015
)
 
$
1,266,175

 
Debt instruments    
Schedule of Trading Securities and Other Trading Assets [Line Items]    
Trading Securities (and Certain Trading Assets)
At December 31, 2015, the following investments were included in debt instruments:
 
 
Cost/
 amortized
 cost
 
Unrealized
 gains
 
Unrealized
 losses
 
Fair
 value
 
 
($ in thousands)
Corporate debt – U.S.
 
$
25,674

 
$
155

 
$
(5,519
)
 
$
20,310

Corporate debt – Non U.S.
 
2,109

 
—

 
(1,795
)
 
314

Sovereign debt – Non U.S.
 
17,688

 
1,225

 
(450
)
 
18,463

Total debt instruments
 
$
45,471

 
$
1,380

 
$
(7,764
)
 
$
39,087

 
At December 31, 2014, the following investments were included in debt instruments:
 
 
Cost/
 amortized
 cost
 
Unrealized
 gains
 
Unrealized
 losses
 
Fair
 value
 
 
($ in thousands)
Corporate debt – U.S.
 
$
23,677

 
$
5

 
$
(1,423
)
 
$
22,259

Corporate debt – Non U.S.
 
5,870

 
49

 
(1,405
)
 
4,514

Municipal debt – U.S.
 
1,759

 
—

 
(6
)
 
1,753

Sovereign debt – Non U.S.
 
21,769

 
—

 
(1,083
)
 
20,686

Total debt instruments
 
$
53,075

 
$
54

 
$
(3,917
)
 
$
49,212


v3.3.1.900
CASH AND CASH EQUIVALENTS (Tables)
12 Months Ended
Dec. 31, 2015
Cash and Cash Equivalents [Abstract]  
Schedule of Cash and Cash Equivalents
 
 
December 31, 2015
 
December 31, 2014
 
 
($ in thousands)
Cash at banks
 
$
44,133

 
$
3,426

Cash held with brokers
 
68,029

 
8,604

Total cash and cash equivalents
 
$
112,162

 
$
12,030


v3.3.1.900
RESTRICTED CASH AND CASH EQUIVALENTS (Tables)
12 Months Ended
Dec. 31, 2015
Cash and Cash Equivalents [Abstract]  
Schedule of Restricted Cash and Cash Equivalents
 
 
December 31, 2015
 
December 31, 2014
 
 
($ in thousands)
Cash held by prime brokers relating to securities sold, not yet purchased
 
$
882,906

 
$
1,090,731

Cash collateral relating to letters of credit issued
 
222,852

 
134,981

Cash held as collateral in trust accounts
 
78,584

 
—

Cash and cash equivalents held by swap counterparties
 
52,247

 
71,202

Total restricted cash and cash equivalents
 
$
1,236,589

 
$
1,296,914


v3.3.1.900
LOSS AND LOSS ADJUSTMENT EXPENSE RESERVES (Tables)
12 Months Ended
Dec. 31, 2015
Insurance Loss Reserves [Abstract]  
Schedule of Causes of Increase (Decrease) in Liability for Unpaid Claims and Claims Adjustment Expense [Table Text Block]
For the year ended December 31, 2015, the net losses incurred included $50.3 million related to net adverse loss development on reserves relating to prior years. During the year ended December 31, 2015, the loss development on prior year contracts primarily related to the following:

●
$36.9 million of adverse loss development relating to a general liability contract originally written from 2008 to 2011. This contract contains underlying construction defect liability coverage predominantly on single family homes. During the third quarter of 2015, we completed an in-depth analysis, with the assistance of a third party expert, of the construction defect claims reported and the potential for claims not yet reported on this contract. Based on this assessment, we revised the actuarial methodology used for reserving the construction defect claims on this contract, which resulted in an increase in incurred but not reported losses;

●
$14.7 million of adverse loss development relating to a general liability contract originally written in 2010. This contract contains underlying construction defect liability coverage. Based on updated data received from the insured, we conducted additional actuarial analysis and updated our actuarial input parameters based on consultation with external industry experts. As a result, the average estimated cost per claim was increased;

●
$9.3 million of adverse loss development relating to our Florida homeowners' insurance contracts as a result of deterioration of sinkhole claims, higher than anticipated water damage claims from rainstorms and an increase in the practice of "assignment of benefits" whereby homeowners assign their rights for filing and settling claims to attorneys and public adjusters which led to increases in the frequency of claims reported as well as the severity of loss adjustment expenses. However, because some of these contracts included sliding scale ceding commission rates, the increase in loss reserves was partially offset by a $5.1 million decrease in ceding commissions and profit commissions recorded as acquisition costs;

●
$2.4 million of net adverse loss development relating to our solicitors' professional indemnity contracts as a result of multiple large claims reported during the period and an increase in incurred losses;

●
$5.1 million of favorable loss development relating to an excess of loss property contract resulting in elimination of loss reserve based on updated loss information received from the insured during the period indicating that no losses will breach into our layer of coverage. The decrease in loss reserve was more than offset by a reversal of $2.5 million of earned premiums and an accrual of $3.4 million of profit commission recorded as acquisition costs;

●
$4.5 million of favorable loss development relating to private passenger motor contracts during the period. The decrease in loss reserve was partially offset by $3.3 million of additional ceding commissions recorded as acquisition costs;

●
$2.3 million of favorable loss development relating to the employer medical stop-loss business as a result of better than expected claims frequency reported by the cedent; and

●
$1.3 million of loss reserves released upon commutation of a private passenger motor contract during the period. The decrease in loss reserve was partially offset by $1.1 million of additional ceding commissions incurred as part of the commutation agreement.

There were no other significant developments of prior period loss reserves during the year ended December 31, 2015.
 
For the year ended December 31, 2014, the net losses incurred included $18.2 million related to net adverse loss development on reserves relating to prior years. During the year ended December 31, 2014, the loss development on prior year contracts primarily related to the following:

●
$7.8 million of adverse loss development, relating to a general liability contract currently in run-off. Loss reserves were increased on this contract after a detailed actuarial review of existing claims data received from the client, which reported an increase in the number of open claims. The loss reserves were also increased to take into account the corresponding claims handling fees expected to be incurred to settle the open claims;

●
$7.1 million of adverse loss development, net of retrocession recoveries, relating to commercial motor claims on a multi-line quota share contract currently in run-off. Loss reserves were increased on this contract after a detailed actuarial review of existing claims data received from the client, which reported significant increases in incurred losses on some claims as well as an increase in the number of open claims;

●
$4.0 million of adverse loss development relating to a solicitors' professional indemnity contract as a result of a combination of large claims reported and increases in case reserves on several smaller claims. Loss reserves were increased on this contract after a detailed review of existing claims data received from the client, audits of claim files at the third party claims administrator and actuarial analysis based on all available information. The contract terms included sliding scale ceding commission rates and profit commissions. As a result, the increase in loss reserves was offset by a $0.6 million decrease in ceding commissions and profit commissions which were recorded as decreases to acquisition costs;

●
$3.0 million of adverse loss development relating to the employer medical stop-loss business. Loss reserves were increased on these contracts after a detailed review of existing claims data received from the clients, audits of claim files at the third party claims administrators and actuarial analysis based on all available information; and

●
$3.8 million of favorable loss development relating to private passenger automobile business, primarily as a result of better than expected loss development noted on our private passenger automobile contracts after a detailed review of existing claims data received from the clients, audits of claim files and actuarial analysis based on all available information. Since these contracts included sliding scale ceding commission rates, the decrease in loss reserves was offset by a $2.2 million increase in ceding commissions recorded as acquisition costs.

There were no other significant developments of prior period loss reserves during the year ended December 31, 2014.

For the year ended December 31, 2013, the net losses incurred included $6.1 million related to net favorable loss development on reserves relating to prior years. During the year ended December 31, 2013, the loss development on prior year contracts primarily related to the following:
 
●
Elimination of $15.0 million of reserves relating to super-storm Sandy based on additional information received from the client which indicated that the losses would not exceed the threshold of coverage provided under the contract. As a result of the reversal of loss reserves, the Company also reversed reinstatement premiums earned of $2.6 million;

●
$4.0 million of favorable loss development relating to commercial automobile business due to better than expected loss development on open claims and settling of claims at lower amounts than expected. Loss reserves were decreased on these contracts after a detailed review of existing claims data received from the clients, audits of claim files at the third party claims administrators and actuarial analysis based on all available information;

●
$3.0 million favorable loss development relating to a private passenger automobile contract as a result of final settlement of losses upon commutation of the contract at an amount lower than originally reserved. However, because this contract included a sliding scale ceding commission rate, the decrease in loss reserves was offset by a $2.3 million increase in ceding commissions recorded as acquisition costs;

●
$2.4 million favorable loss development relating to Florida homeowners' insurance business due to better than expected development on sinkhole claims, primarily as a result of legislative changes implemented in the State of Florida during 2012;

●
$17.7 million of adverse loss development, net of retrocession recoveries, relating to general liability business. Loss reserves were increased on these contracts after a detailed review of existing claims data received from the clients, audits of claim files at the third party claims administrators and actuarial analysis based on all available information; and

●
$4.0 million of adverse loss development on a 2007 casualty clash contract based on updated claims and loss information received from the client. The new information indicated that ground up losses under the contract estimated by the client had increased resulting in additional losses attaching to the Company's layer. As a result of this increase in loss reserves, the Company recorded reinstatement premiums of $1.2 million.

There were no other significant developments of prior period loss reserves during the year ended December 31, 2013.

v3.3.1.900
SHARE CAPITAL (Tables)
12 Months Ended
Dec. 31, 2015
Equity [Abstract]  
Schedule of Common Stock Outstanding Roll Forward
The following table is a summary of voting ordinary shares issued and outstanding:
 
 
2015
 
2014
 
2013
 
 
Class A
 
Class B
 
Class A
 
Class B
 
Class A
 
Class B
Balance – beginning of year
 
31,129,648

 
6,254,895

 
30,791,865

 
6,254,949

 
30,447,179

 
6,254,949

Issue of ordinary shares, net of forfeitures
 
256,464

 
—

 
337,729

 
—

 
344,686

 
—

Repurchase of ordinary shares
 
(613,540
)
 
—

 
—

 
—

 
—

 
—

Class B shares converted to Class A shares
 
—

 
—

 
54

 
(54
)
 
—

 
—

Balance – end of year
 
30,772,572

 
6,254,895

 
31,129,648

 
6,254,895

 
30,791,865

 
6,254,949


v3.3.1.900
SHARE-BASED COMPENSATION (Tables)
12 Months Ended
Dec. 31, 2015
Share-based Compensation Arrangement by Share-based Payment Award [Line Items]  
Schedule of Share-based Payment Award, Stock Options, Valuation Assumptions
The Company uses the Black-Scholes option pricing model to determine the valuation of its options and has applied the assumptions set forth in the following table.
 
 
2015
 
2014
 
2013
Risk free rate
 
2.15
%
 
2.47
%
 
2.85
%
Estimated volatility
 
32.8
%
 
34.3
%
 
35.0
%
Expected term (in years)
 
10

 
10

 
10

Dividend yield
 
0
%
 
0
%
 
0
%
Forfeiture rate
 
0
%
 
0
%
 
0
%
Schedule of Share-based Compensation, Stock Options, Activity
Employee and director stock option activity during the years ended December 31, 2015 and 2014 was as follows: 
 
Number of
 options
 
Weighted
 average
 exercise
 price
 
Weighted
 average
 grant date
 fair value
Balance at December 31, 2013
1,402,987

 
$
15.82

 
$
7.08

Granted
31,821

 
32.37

 
15.71

Exercised
(318,500
)
 
11.29

 
5.67

Forfeited
—

 
—

 
—

Expired
—

 
—

 
—

Balance at December 31, 2014
1,116,308

 
17.58

 
7.73

Granted
40,683

 
26.67

 
12.29

Exercised
(250,000
)
 
11.10

 
5.57

Forfeited
—

 
—

 
—

Expired
—

 
—

 
—

Balance at December 31, 2015
906,991

 
$
19.78

 
$
8.53

Restricted Stock  
Share-based Compensation Arrangement by Share-based Payment Award [Line Items]  
Schedule of Share-based Compensation, Restricted Stock and Restricted Stock Units Activity
The restricted share award activity during the years ended December 31, 2015 and 2014 was as follows:
 
 
Number of
non-vested
restricted
 shares
 
Weighted
 average
grant date
fair value
Balance at December 31, 2013
 
328,991

 
$
24.74

Granted
 
155,246

 
32.58

Vested
 
(115,444
)
 
25.35

Forfeited
 
(38,706
)
 
27.43

Balance at December 31, 2014
 
330,087

 
27.90

Granted
 
106,900

 
31.56

Vested
 
(120,353
)
 
26.26

Forfeited
 
(9,621
)
 
30.49

Balance at December 31, 2015
 
307,013

 
$
29.74

RSUs  
Share-based Compensation Arrangement by Share-based Payment Award [Line Items]  
Schedule of Share-based Compensation, Restricted Stock and Restricted Stock Units Activity
 
 
Number of
non-vested
RSUs
 
Weighted
 average
grant date
fair value
Balance at December 31, 2013
 
5,941

 
$
24.41

Granted
 
9,668

 
32.60

Vested
 
—

 
—

Forfeited
 
—

 
—

Balance at December 31, 2014
 
15,609

 
29.72

Granted
 
6,821

 
32.21

Vested
 
(260
)
 
24.30

Forfeited
 
—

 
—

Balance at December 31, 2015
 
22,170

 
$
30.55


v3.3.1.900
NET INVESTMENT INCOME (Tables)
12 Months Ended
Dec. 31, 2015
Net Investment Income [Abstract]  
Net Investment Income (Loss)
A summary of net investment income for the years ended December 31, 2015, 2014 and 2013 is as follows:
 
 
2015
 
2014
 
2013
 
 
($ in thousands)
Realized gains (losses)
 
$
22,227

 
$
352,133

 
$
122,568

Change in unrealized gains and losses
 
(265,401
)
 
(187,753
)
 
149,012

Investment related foreign exchange gains (losses)
 
(3,725
)
 
14,797

 
44,492

Interest and dividend income, net of withholding taxes
 
15,313

 
31,423

 
22,265

Interest, dividend and other expenses
 
(31,092
)
 
(38,892
)
 
(47,665
)
Investment advisor compensation
 
(19,246
)
 
(49,133
)
 
(72,532
)
Net investment income (loss)
 
$
(281,924
)
 
$
122,575

 
$
218,140


v3.3.1.900
TAXATION (Tables) - USD ($)
$ in Thousands
3 Months Ended 12 Months Ended
Dec. 31, 2015
Sep. 30, 2015
Jun. 30, 2015
Mar. 31, 2015
Dec. 31, 2014
Sep. 30, 2014
Jun. 30, 2014
Mar. 31, 2014
Dec. 31, 2015
Dec. 31, 2014
Dec. 31, 2013
Income Tax Disclosure [Abstract]                      
Schedule of Components of Income Tax Benefit (Expense)                
The following table sets forth our current and deferred income tax benefit (expense) on a consolidated basis for the years ended December 31, 2015, 2014 and 2013:
 
 
2015
 
2014
 
2013
 
 
($ in thousands)
Current tax (expense) benefit
 
$
15

 
$
638

 
$
(534
)
Deferred tax (expense) benefit
 
1,740

 
(14
)
 
(4
)
Income tax (expense) benefit 
 
$
1,755

 
$
624

 
$
(538
)


Current tax (expense) benefit                 $ 15 $ 638 $ (534)
Deferred tax (expense) benefit                 1,740 (14) (4)
Income tax (expense) benefit $ 361 $ 1,233 $ (54) $ 215 $ (204) $ 254 $ 14 $ 560 $ 1,755 $ 624 $ (538)

v3.3.1.900
COMMITMENTS AND CONTINGENCIES (Tables)
12 Months Ended
Dec. 31, 2015
Commitments and Contingencies Disclosure [Abstract]  
Schedule of Line of Credit Facilities
At December 31, 2015, the Company had the following letter of credit facilities, which automatically renew each year unless terminated by either party in accordance with the required notice period:
 
 
Facility
 
Termination Date
 
Notice period required for termination
 
 
($ in thousands)


Bank of America, N.A.
 
$
120,000

 
July 11, 2016
 
90 days prior to termination date
Butterfield Bank (Cayman) Limited
 
100,000

 
June 30, 2016
 
90 days prior to termination date
Citibank Europe plc
 
400,000

 
October 11, 2016
 
120 days prior to termination date
JP Morgan Chase Bank N.A.
 
100,000

 
January 27, 2017
 
120 days prior to termination date
 
 
$
720,000


Contractual Obligation, Fiscal Year Maturity Schedule
The following is a schedule of future minimum payments required under the above commitments: 
 
2016
 
2017
 
2018
 
2019
 
2020
 
Thereafter
 
Total
 
($ in thousands)
Operating lease obligations
$
548

 
$
548

 
$
315

 
$
82

 
$
82

 
$
31

 
$
1,606

Private equity and limited partnerships (1)
6,107

 
—

 
—

 
—

 
—

 
—

 
6,107

 
$
6,655

 
$
548

 
$
315

 
$
82

 
$
82

 
$
31

 
$
7,713


(1) Given the nature of these investments, the Company is unable to determine with any degree of accuracy when these commitments will be called. Therefore, for purposes of the above table, the Company has assumed that all commitments with no fixed payment schedules will be called during the year ending December 31, 2016.

v3.3.1.900
SEGMENT REPORTING (Tables)
12 Months Ended
Dec. 31, 2015
Segment Reporting [Abstract]  
Gross premiums written by brokers greater than 10% of premiums
The following table sets forth the premiums sourced from brokers who each accounted for more than 10% of the Company's gross written premiums:  
 
 
Year ended December 31
 
 
2015
 
2014
 
2013
 
 
 ($ in thousands)
Largest broker
 
$
278,003

 
55.4
%
 
$
161,405

 
49.8
%
 
$
282,337

 
52.7
%
2nd largest broker
 
110,246

 
22.0

 
61,809

 
19.1

 
119,117

 
22.2

3rd largest broker
 
—

 
—

 
40,773

 
12.6

 
—

 
—


$
388,249

 
77.4
%
 
$
263,987

 
81.5
%
 
$
401,454

 
74.9
%
Gross Premiums Written by Line of Business
The following tables provide a breakdown of the Company's gross premiums written by line of business and by geographic area of risks insured for the periods indicated:
 
Gross Premiums Written by Line of Business 
 
 
Year ended December 31
 
 
2015
 
2014
 
2013
 
 
($ in thousands)
Property


Aviation
 
$
691

 
0.1
%
 
$
391

 
0.1
%
 
$
168

 
—
 %
Commercial
 
16,667

 
3.3

 
11,529

 
3.6

 
9,999

 
1.9

Energy
 
2,009

 
0.4

 
2,131

 
0.6

 
659

 
0.1

Motor physical damage
 
34,529

 
6.9

 
24,008

 
7.4

 
57,952

 
10.8

Personal
 
57,495

 
11.5

 
64,479

 
19.9

 
145,807

 
27.2

Total Property
 
111,391

 
22.2

 
102,538

 
31.6

 
214,585

 
40.0

Casualty


General liability (1)
 
28,355

 
5.6

 
11,639

 
3.6

 
(815
)
 
(0.2
)
Marine liability
 
9,283

 
1.8

 
5,120

 
1.6

 
1,956

 
0.4

Motor liability
 
203,624

 
40.6

 
127,858

 
39.5

 
253,698

 
47.4

Professional liability
 
72,217

 
14.4

 
27,009

 
8.4

 
29,901

 
5.6

Total Casualty
 
313,479

 
62.4

 
171,626

 
53.1

 
284,740

 
53.2

Specialty


Financial
 
7,824

 
1.6

 
5,292

 
1.6

 
3,498

 
0.7

Health
 
56,784

 
11.3

 
43,837

 
13.5

 
37,094

 
6.9

Workers’ compensation (1) 
 
12,646

 
2.5

 
730

 
0.2

 
(4,215
)
 
(0.8
)
Total Specialty
 
77,254

 
15.4

 
49,859

 
15.3

 
36,377

 
6.8


$
502,124

 
100.0
%
 
$
324,023

 
100.0
%
 
$
535,702

 
100.0
 %

(1)  The negative balance represents reversal of premiums due to premium adjustments, termination of contracts or premiums returned upon novation or commutation of contracts.
Gross Premiums Written by Geographic Area of Risks Insured
 
 
Year ended December 31
 
 
2015
 
2014
 
2013
 
 
($ in thousands)
U.S. and Caribbean
 
$
383,236

 
76.3
%
 
$
275,402

 
85.0
%
 
$
496,949

 
92.8
%
Worldwide (1)
 
104,336

 
20.8

 
31,106

 
9.6

 
9,821

 
1.8

Europe
 
14,085

 
2.8

 
17,432

 
5.4

 
28,932

 
5.4

Asia
 
467

 
0.1

 
83

 
—

 
—

 
—


$
502,124

 
100.0
%
 
$
324,023

 
100.0
%
 
$
535,702

 
100.0
%

(1) "Worldwide" is comprised of contracts that reinsure risks in more than one geographic area and do not specifically exclude the U.S. 


v3.3.1.900
QUARTERLY FINANCIAL RESULTS (UNAUDITED) (Tables)
12 Months Ended
Dec. 31, 2015
Quarterly Financial Information Disclosure [Abstract]  
Schedule of Quarterly Financial Information
The following table presents the quarterly financial results for each of the quarters ended during 2015:
 
 
2015
 
 
 Quarter ended


March 31
 
 
June 30
 
 
September 30
 
 
December 31
 
 
 ($ in thousands, except per share amounts)
Revenues


Gross premiums written
 
$
129,682

 
$
92,990

 
$
134,568

 
$
144,884

Gross premiums ceded
 
(1,626
)
 
(1,868
)
 
(2,288
)
 
(3,219
)
Net premiums written
 
128,056

 
91,122

 
132,280

 
141,665

Change in net unearned premium reserves
 
(33,263
)
 
563

 
(30,286
)
 
(21,750
)
Net premiums earned
 
94,793

 
91,685

 
101,994

 
119,915

Net investment income (loss)
 
(24,829
)
 
(20,305
)
 
(191,322
)
 
(45,468
)
Other income (expense), net
 
1,588

 
(3,760
)
 
(542
)
 
(699
)
Total revenues
 
71,552

 
67,620

 
(89,870
)
 
73,748

Expenses


Loss and loss adjustment expenses incurred, net
 
63,207

 
76,653

 
97,421

 
79,816

Acquisition costs, net
 
26,841

 
23,939

 
32,146

 
33,281

General and administrative expenses
 
6,160

 
6,894

 
5,382

 
4,998

Total expenses
 
96,208

 
107,486

 
134,949

 
118,095

Income (loss) before income tax expense
 
(24,656
)
 
(39,866
)
 
(224,819
)
 
(44,347
)
Income tax (expense) benefit
 
215

 
(54
)
 
1,233

 
361

Net income (loss) including non-controlling interest
 
(24,441
)
 
(39,920
)
 
(223,586
)
 
(43,986
)
Loss (income) attributable to non-controlling interest in joint venture
 
394

 
324

 
3,909

 
881

Net income (loss)
 
$
(24,047
)
 
$
(39,596
)
 
$
(219,677
)
 
$
(43,105
)
Earnings (loss) per share


Basic
 
$
(0.65
)
 
$
(1.06
)
 
$
(5.98
)
 
$
(1.17
)
Diluted
 
$
(0.65
)
 
$
(1.06
)
 
$
(5.98
)
 
$
(1.17
)
Weighted average number of ordinary shares used in the determination of earnings and loss per share


Basic
 
37,173,008

 
37,303,265

 
36,710,216

 
36,720,454

Diluted
 
37,173,008

 
37,303,265

 
36,710,216

 
36,720,454


The following table presents the quarterly financial results for each of the quarters ended during 2014:
 
 
2014
 
 
 Quarter ended


March 31
 
 
June 30
 
 
September 30
 
 
December 31
 
 
 ($ in thousands)
Revenues


Gross premiums written
 
$
118,901

 
$
33,654

 
$
97,200

 
$
74,268

Gross premiums ceded
 
(5,940
)
 
(2,759
)
 
(2,706
)
 
(2,088
)
Net premiums written
 
112,961

 
30,895

 
94,494

 
72,180

Change in net unearned premium reserves
 
(1,272
)
 
56,960

 
(15,003
)
 
3,025

Net premiums earned
 
111,689

 
87,855

 
79,491

 
75,205

Net investment income (loss)
 
(10,150
)
 
113,932

 
(54,027
)
 
72,820

Other income (expense), net
 
182

 
(1,400
)
 
2,663

 
1,542

Total revenues
 
101,721

 
200,387

 
28,127

 
149,567

Expenses


Loss and loss adjustment expenses incurred, net
 
67,363

 
56,644

 
53,028

 
57,951

Acquisition costs, net
 
37,796

 
25,570

 
22,478

 
21,821

General and administrative expenses
 
6,200

 
5,559

 
6,012

 
6,729

Total expenses
 
111,359

 
87,773

 
81,518

 
86,501

Income (loss) before income tax expense
 
(9,638
)
 
112,614

 
(53,391
)
 
63,066

Income tax (expense) benefit
 
560

 
14

 
254

 
(204
)
Net income (loss) including non-controlling interest
 
(9,078
)
 
112,628

 
(53,137
)
 
62,862

Loss (income) attributable to non-controlling interest in joint venture
 
197

 
(3,075
)
 
1,369

 
(2,174
)
Net income (loss)
 
$
(8,881
)
 
$
109,553

 
$
(51,768
)
 
$
60,688

Earnings (loss) per share


Basic
 
$
(0.24
)
 
$
2.94

 
$
(1.40
)
 
$
1.62

Diluted
 
$
(0.24
)
 
$
2.89

 
$
(1.40
)
 
$
1.60

Weighted average number of ordinary shares used in the determination of earnings and loss per share


Basic
 
36,808,386

 
37,246,922

 
36,984,650

 
37,356,187

Diluted
 
36,808,386

 
37,902,106

 
36,984,650

 
37,905,836


v3.3.1.900
SCHEDULE II (Tables) - Parent Company
12 Months Ended
Dec. 31, 2015
Condensed Financial Statements, Captions [Line Items]  
Schedule of Condensed Balance Sheet
GREENLIGHT CAPITAL RE, LTD.
CONDENSED FINANCIAL INFORMATION OF REGISTRANT
CONDENSED BALANCE SHEETS — PARENT COMPANY ONLY
 
(expressed in thousands of U.S. dollars) 
 
 
December 31, 2015
 
December 31, 2014
 
 
($ in thousands)
Cash and cash equivalents
 
$
6

 
$
1

Investment in subsidiaries
 
840,196

 
1,148,308

Note receivable
 
2,175

 
1,566

Due from subsidiaries
 
—

 
15,276

Total assets
 
$
842,377

 
$
1,165,151

Liabilities and shareholders’ equity


Liabilities


Due to subsidiaries
 
$
16,986

 
$
—

Total liabilities
 
16,986

 
—

Shareholders’ equity


Share capital
 
3,703

 
3,738

Additional paid-in capital
 
496,401

 
500,553

Retained earnings
 
325,287

 
660,860

Total shareholders’ equity
 
825,391

 
1,165,151

Total liabilities and shareholders’ equity
 
$
842,377

 
$
1,165,151

Schedule of Condensed Income Statement
GREENLIGHT CAPITAL RE, LTD.
CONDENSED FINANCIAL INFORMATION OF REGISTRANT
CONDENSED STATEMENTS OF INCOME — PARENT COMPANY ONLY
 
(expressed in thousands of U.S. dollars)


Year ended December 31
 
 
2015
 
2014
 
2013
 
 
 ($ in thousands)
Revenue


Investment income
 
$
5,962

 
$
671

 
$
1,100

Total revenues
 
5,962

 
671

 
1,100

Expenses


General and administrative expenses
 
4,048

 
3,806

 
3,735

Net income (loss) before equity in earnings of consolidated subsidiaries
 
1,914

 
(3,135
)
 
(2,635
)
Equity in earnings of consolidated subsidiaries
 
(328,339
)
 
112,727

 
228,334

Consolidated net income (loss)
 
$
(326,425
)
 
$
109,592

 
$
225,699

Schedule of Condensed Cash Flow Statement
GREENLIGHT CAPITAL RE, LTD.
CONDENSED FINANCIAL INFORMATION OF REGISTRANT
CONDENSED STATEMENTS OF CASH FLOWS — PARENT COMPANY ONLY
 
(expressed in thousands of U.S. dollars) 
 
 
  Year Ended December 31
 
 
2015
 
2014
 
2013
 
 
 ($ in thousands)
Cash provided by (used in) operating activities


Net income (loss)
 
$
(326,425
)
 
$
109,592

 
$
225,699

Adjustments to reconcile net income (loss) to cash provided by operating activities


Equity in earnings of consolidated subsidiaries
 
328,339

 
(112,727
)
 
(228,334
)
Share-based compensation expense
 
4,274

 
3,964

 
3,675

Change in


Due from subsidiaries
 
15,276

 
971

 
(2,006
)
Due to subsidiaries
 
16,986

 
(3,808
)
 
2,438

Net cash (used in) provided by operating activities
 
38,450

 
(2,008
)
 
1,472

Investing activities


Change in note receivable
 
(609
)
 
2,162

 
(2,053
)
Contributed surplus to subsidiaries, net
 
(20,227
)
 
(158
)
 
59

Net cash (used in) provided by investing activities
 
(20,836
)
 
2,004

 
(1,994
)
Financing activities


Net proceeds from exercise of stock options
 
—

 
—

 
513

Short-swing sale profit from shareholder
 
83

 
—

 
—

Repurchase of Class A ordinary shares
 
(17,692
)
 
—

 
—

Net cash (used in) provided by financing activities
 
(17,609
)
 
—

 
513

Net increase (decrease) in cash and cash equivalents
 
5

 
(4
)
 
(9
)
Cash and cash equivalents at beginning of the year
 
1

 
5

 
14

Cash and cash equivalents at end of the year
 
$
6

 
$
1

 
$
5


v3.3.1.900
ORGANIZATION AND BASIS OF PRESENTATION (Details)
May. 30, 2007
$ / shares
shares
Common Class A [Member]  
Class of Stock [Line Items]  
Shares issued from initial public offering | shares 11,787,500
Price per share of shares issued from initial public offering | $ / shares $ 19.00
Common Class B  
Class of Stock [Line Items]  
Shares issued from initial public offering | shares 2,631,579
Price per share of shares issued from initial public offering | $ / shares $ 19.00

v3.3.1.900
SIGNIFICANT ACCOUNTING POLICIES (Details) - USD ($)
12 Months Ended
Dec. 31, 2015
Dec. 31, 2014
Dec. 31, 2013
Accounting Policies [Line Items]      
Prior Period Reclassification Adjustment   $ (2,600,000) $ 800,000
Premium deficiency loss $ 0 0  
Profit commission reserves 12,200,000 11,000,000  
Profit commission expense, net 7,500,000 2,700,000 3,700,000
Amount of notes receivable placed on non-accrual status 23,000,000 0  
Impairment charge relating to accrued interest and principal on the note placed on non-accrual status     0
Accrued interest 0 0  
Provision for uncollectible notes 0 0  
Gain on deposit accounted contracts   0 $ 0
Other Liabilities      
Accounting Policies [Line Items]      
Accrued bonuses $ 8,200,000 $ 7,600,000  
Minimum      
Accounting Policies [Line Items]      
Annual installment period to pay quantitative bonus 2 years    
Maximum      
Accounting Policies [Line Items]      
Annual installment period to pay quantitative bonus 5 years    

v3.3.1.900
SIGNIFICANT ACCOUNTING POLICIES Fixed Assets (Details) - USD ($)
12 Months Ended
Dec. 31, 2015
Dec. 31, 2014
Property, Plant and Equipment [Line Items]    
Cost $ 3,178,000 $ 3,178,000
Accumulated depreciation (2,090,000) (1,685,000)
Net book value 1,088,000 1,493,000
Impairment of fixed assets 0 0
Computer software    
Property, Plant and Equipment [Line Items]    
Cost 556,000 556,000
Accumulated depreciation (348,000) (277,000)
Net book value $ 208,000 279,000
Fixed asset estimated useful lives 5 years  
Furniture and fixtures    
Property, Plant and Equipment [Line Items]    
Cost $ 620,000 620,000
Accumulated depreciation (513,000) (442,000)
Net book value $ 107,000 178,000
Fixed asset estimated useful lives 5 years  
Leasehold improvements    
Property, Plant and Equipment [Line Items]    
Cost $ 2,002,000 2,002,000
Accumulated depreciation (1,229,000) (966,000)
Net book value $ 773,000 $ 1,036,000

v3.3.1.900
SIGNIFICANT ACCOUNTING POLICIES Earnings Per Share Reconciliation (Details) - shares
3 Months Ended 12 Months Ended
Dec. 31, 2015
Sep. 30, 2015
Jun. 30, 2015
Mar. 31, 2015
Dec. 31, 2014
Sep. 30, 2014
Jun. 30, 2014
Mar. 31, 2014
Dec. 31, 2015
Dec. 31, 2014
Dec. 31, 2013
Earnings Per Share, Diluted, by Common Class, Including Two Class Method [Line Items]                      
Weighted average shares outstanding - basic 36,720,454 36,710,216 37,303,265 37,173,008 37,356,187 36,984,650 37,246,922 36,808,386 36,670,466 37,242,687 36,838,128
Effect of dilutive service provider share-based awards                 0 8,498 144,726
Effect of dilutive employee and director share-based awards                 0 623,202 602,313
Weighted average shares outstanding - diluted 36,720,454 36,710,216 37,303,265 37,173,008 37,905,836 36,984,650 37,902,106 36,808,386 36,670,466 37,874,387 37,585,167
Stock Options                      
Earnings Per Share, Diluted, by Common Class, Including Two Class Method [Line Items]                      
Anti-dilutive outstanding                 211,821 0 218,197
Restricted Stock                      
Earnings Per Share, Diluted, by Common Class, Including Two Class Method [Line Items]                      
Anti-dilutive outstanding                 307,013 0 0

v3.3.1.900
SIGNIFICANT ACCOUNTING POLICIES Income taxes (Details)
12 Months Ended
Dec. 31, 2015
Verdant  
Income Taxes [Line Items]  
Tax rate for taxable income 35.00%
Ireland | GRIL  
Income Taxes [Line Items]  
Tax rate for trading income 12.50%
Tax rate for non-trading income 25.00%

v3.3.1.900
FINANCIAL INSTRUMENTS Financial Instruments Additional Information (Details) - USD ($)
$ in Millions
12 Months Ended
Dec. 31, 2015
Dec. 31, 2014
Dec. 31, 2013
Fair Value, Concentration of Risk, Financial Statement Captions [Line Items]      
Realized gains $ 22.2 $ 352.1 $ 122.6
Gross realized gains 350.5 596.6 312.3
Gross realized losses 328.3 244.5 189.7
Fair value of cash and investments that have been pledged as security against letters of credit issued 324.3 302.6  
Restricted cash pledged as security relating to regulatory trusts 78.6 0.0  
Net investment income (loss)      
Fair Value, Concentration of Risk, Financial Statement Captions [Line Items]      
Change in unrealized gains and losses on trading securities (265.4) (187.8) $ 149.0
Micron Technology Inc.      
Fair Value, Concentration of Risk, Financial Statement Captions [Line Items]      
Fair value of investments in excess of 10% of stockholders' equity   $ 151.1  
Commodities      
Fair Value, Concentration of Risk, Financial Statement Captions [Line Items]      
Fair value of investments in excess of 10% of stockholders' equity $ 98.0    
Percent of Stockholders' Equity, Total | Percent Investment Concentration Risk | Micron Technology Inc.      
Fair Value, Concentration of Risk, Financial Statement Captions [Line Items]      
Concentration risk, percentage   12.70%  
Percent of Stockholders' Equity, Total | Percent Investment Concentration Risk | Commodities      
Fair Value, Concentration of Risk, Financial Statement Captions [Line Items]      
Concentration risk, percentage 11.60%    

v3.3.1.900
FINANCIAL INSTRUMENTS Schedule of Investments Categorized by the Level of Fair Value Hierarchy (Details) - USD ($)
$ in Thousands
Dec. 31, 2015
Dec. 31, 2014
Fair Value, Assets and Liabilities Measured on Recurring and Nonrecurring Basis [Line Items]    
Debt instruments $ 39,087 $ 49,212
Listed equity securities 905,994 1,266,175
Commodities 98,046 96,872
Private and unlisted equity securities 21,037 18,719
Financial contracts receivable, at fair value 13,215 47,171
Total investment assets 1,077,379 1,478,149
Listed equity securities, sold not yet purchased (808,481) (834,228)
Debt instruments, sold not yet purchased 74,425 256,503
Financial contracts payable (28,245) (44,592)
Total investment liabilities (911,151) (1,135,323)
Quoted prices in active markets (Level 1)    
Fair Value, Assets and Liabilities Measured on Recurring and Nonrecurring Basis [Line Items]    
Debt instruments 0 0
Listed equity securities 900,369 1,259,298
Commodities 98,046 96,872
Private and unlisted equity securities 0 0
Financial contracts receivable, at fair value 20 2,463
Total investment assets 998,435 1,358,633
Listed equity securities, sold not yet purchased (808,481) (834,228)
Debt instruments, sold not yet purchased 0 0
Financial contracts payable (488) 0
Total investment liabilities (808,969) (834,228)
Significant other observable inputs (Level 2)    
Fair Value, Assets and Liabilities Measured on Recurring and Nonrecurring Basis [Line Items]    
Debt instruments 38,582 26,953
Listed equity securities 5,625 6,877
Commodities 0 0
Private and unlisted equity securities 0 0
Financial contracts receivable, at fair value 13,195 44,708
Total investment assets 57,402 78,538
Listed equity securities, sold not yet purchased 0 0
Debt instruments, sold not yet purchased 74,425 256,503
Financial contracts payable (27,757) (44,592)
Total investment liabilities (102,182) (301,095)
Significant unobservable inputs (Level 3)    
Fair Value, Assets and Liabilities Measured on Recurring and Nonrecurring Basis [Line Items]    
Debt instruments 505 22,259
Listed equity securities 0 0
Commodities 0 0
Private and unlisted equity securities 21,037 18,719
Financial contracts receivable, at fair value 0 0
Total investment assets 21,542 40,978
Listed equity securities, sold not yet purchased 0 0
Debt instruments, sold not yet purchased 0 0
Financial contracts payable 0 0
Total investment liabilities $ 0 $ 0

v3.3.1.900
FINANCIAL INSTRUMENTS Fair Value Hierarchy Additional Information (Details) - USD ($)
$ in Thousands
12 Months Ended
Dec. 31, 2015
Dec. 31, 2014
Fair Value, Assets and Liabilities Measured on Recurring and Nonrecurring Basis [Line Items]    
Transfers into Level 3 $ 7,725 $ 0
Transfers out of Level 3 6,346 4,044
Amount transferred from Level 2 to Level 1 due to lock-up period restriction expiration   14,400
Total realized and unrealized gains (losses)included in earnings, net 3,313 9,905
Net investment income (loss)    
Fair Value, Assets and Liabilities Measured on Recurring and Nonrecurring Basis [Line Items]    
Total realized and unrealized gains (losses)included in earnings, net (1,400) 13,500
Change in unrealized (losses) gains 600 1,400
Other income (expense), net    
Fair Value, Assets and Liabilities Measured on Recurring and Nonrecurring Basis [Line Items]    
Total realized and unrealized gains (losses) and amortization included in earnings, net 2,300 0
Listed equity securities    
Fair Value, Assets and Liabilities Measured on Recurring and Nonrecurring Basis [Line Items]    
Transfers into Level 3 5,189  
Transfers out of Level 3 4,497  
Total realized and unrealized gains (losses)included in earnings, net (692)  
Listed equity securities | Significant other observable inputs (Level 2)    
Fair Value, Assets and Liabilities Measured on Recurring and Nonrecurring Basis [Line Items]    
Transfers out of Level 3   $ 4,000
Listed equity securities | Quoted prices in active markets (Level 1)    
Fair Value, Assets and Liabilities Measured on Recurring and Nonrecurring Basis [Line Items]    
Transfers into Level 3 5,200  
Transfers out of Level 3 4,500  
Financial contracts receivable    
Fair Value, Assets and Liabilities Measured on Recurring and Nonrecurring Basis [Line Items]    
Transfers into Level 3 2,536  
Transfers out of Level 3 1,849  
Total realized and unrealized gains (losses) and amortization included in earnings, net 3,027  
Financial contracts receivable | Significant other observable inputs (Level 2)    
Fair Value, Assets and Liabilities Measured on Recurring and Nonrecurring Basis [Line Items]    
Transfers into Level 3 2,500  
Transfers out of Level 3 1,800  
Financial contracts payable    
Fair Value, Assets and Liabilities Measured on Recurring and Nonrecurring Basis [Line Items]    
Financial contracts payable, Transfers Into Level 3 8,835  
Fair Value, Measurement with Unobservable Inputs Reconciliation, Liability, Transfers out of Level 3 9,149  
Financial contracts payable | Significant other observable inputs (Level 2)    
Fair Value, Assets and Liabilities Measured on Recurring and Nonrecurring Basis [Line Items]    
Financial contracts payable, Transfers Into Level 3 8,800  
Fair Value, Measurement with Unobservable Inputs Reconciliation, Liability, Transfers out of Level 3 $ 9,100  

v3.3.1.900
FINANCIAL INSTRUMENTS Level 3 reconciliation (Details) - USD ($)
$ in Thousands
12 Months Ended
Dec. 31, 2015
Dec. 31, 2014
Dec. 31, 2015
Fair Value, Assets Measured on Recurring Basis, Unobservable Input Reconciliation, Calculation [Roll Forward]      
Beginning balance $ 40,978 $ 46,850  
Purchases 7,349 25,519  
Sales (24,851) (37,252)  
Total realized and unrealized gains (losses) and amortization included in earnings, net 3,313 9,905  
Transfers into Level 3 7,725 0  
Transfers out of Level 3 (6,346) (4,044)  
Ending balance 21,542 40,978  
Debt instruments      
Fair Value, Assets Measured on Recurring Basis, Unobservable Input Reconciliation, Calculation [Roll Forward]      
Beginning balance 22,259 527  
Purchases 0 21,561  
Sales (21,561) 0  
Total realized and unrealized gains (losses) and amortization included in earnings, net 193 171  
Transfers into Level 3 0 0  
Transfers out of Level 3 0 0  
Ending balance 505 22,259  
Private and unlisted equity securities      
Fair Value, Assets Measured on Recurring Basis, Unobservable Input Reconciliation, Calculation [Roll Forward]      
Beginning balance 18,719 46,323  
Purchases 5,009 3,958  
Sales (3,290) (37,252)  
Total realized and unrealized gains (losses) and amortization included in earnings, net 599 9,734  
Transfers into Level 3 0 0  
Transfers out of Level 3 0 (4,044)  
Ending balance 21,037 18,719  
Financial contracts receivable      
Fair Value, Assets Measured on Recurring Basis, Unobservable Input Reconciliation, Calculation [Roll Forward]      
Beginning balance 0    
Purchases 2,340    
Sales 0    
Total realized and unrealized gains (losses) and amortization included in earnings, net 3,027    
Transfers into Level 3 2,536    
Transfers out of Level 3 (1,849)    
Ending balance 0 0  
Equities – listed      
Fair Value, Assets Measured on Recurring Basis, Unobservable Input Reconciliation, Calculation [Roll Forward]      
Beginning balance 0    
Purchases 0    
Sales 0    
Total realized and unrealized gains (losses) and amortization included in earnings, net (692)    
Transfers into Level 3 5,189    
Transfers out of Level 3 (4,497)    
Ending balance 0 0  
Financial contracts payable      
Fair Value, Assets Measured on Recurring Basis, Unobservable Input Reconciliation, Calculation [Roll Forward]      
Beginning balance, Liabilities 0    
Purchases, Liability 0    
Sales, Liability 0    
Total realized and unrealized gains (losses) Included in earnings, Liabilities 314    
Transfers Into Level 3, Liabilities 8,835    
Transfers out of Level 3, Liabilities (9,149)    
Ending balance, Liabilities $ 0 $ 0 $ 0

v3.3.1.900
FINANCIAL INSTRUMENTS Schedule of Investments Included in Debt Instruments (Details) - USD ($)
$ in Thousands
12 Months Ended
Dec. 31, 2015
Dec. 31, 2014
Schedule of Trading Securities and Other Trading Assets [Line Items]    
Cost/ amortized cost $ 45,471 $ 53,075
Debt instruments, trading, at fair value 39,087 49,212
Corporate debt – U.S.    
Schedule of Trading Securities and Other Trading Assets [Line Items]    
Cost/ amortized cost 25,674 23,677
Unrealized gains 155 5
Unrealized losses (5,519) (1,423)
Debt instruments, trading, at fair value 20,310 22,259
Corporate debt – Non U.S.    
Schedule of Trading Securities and Other Trading Assets [Line Items]    
Cost/ amortized cost 2,109 5,870
Unrealized gains 0 49
Unrealized losses (1,795) (1,405)
Debt instruments, trading, at fair value 314 4,514
Municipal debt – U.S.    
Schedule of Trading Securities and Other Trading Assets [Line Items]    
Cost/ amortized cost   1,759
Unrealized gains   0
Unrealized losses   (6)
Debt instruments, trading, at fair value   1,753
Sovereign debt – Non U.S.    
Schedule of Trading Securities and Other Trading Assets [Line Items]    
Cost/ amortized cost 17,688 21,769
Unrealized gains 1,225 0
Unrealized losses (450) (1,083)
Debt instruments, trading, at fair value 18,463 20,686
Debt instruments    
Schedule of Trading Securities and Other Trading Assets [Line Items]    
Cost/ amortized cost 45,471 53,075
Unrealized gains 1,380 54
Unrealized losses $ (7,764) $ (3,917)

v3.3.1.900
FINANCIAL INSTRUMENTS Schedule of Maturity Distribution of Debt Instruments (Details) - USD ($)
$ in Thousands
Dec. 31, 2015
Dec. 31, 2014
Financial Instruments [Abstract]    
Trading, debt maturities, within one year, cost $ 0 $ 0
Trading, debt maturities, within one year, fair value 0 0
Trading, debt maturities, 1 to 5 years, Cost 4,202 21,922
Trading, debt maturities, 1 to 5 years, fair value 4,129 21,923
Trading, debt maturities, 5 to 10 years, Cost 18,840 2,401
Trading, debt maturities, 5 to 10 years, fair value 14,780 1,282
Trading, debt maturities, after 10 years, Cost 22,429 28,752
Trading, debt maturities, after 10 years, fair value 20,178 26,007
Cost/ amortized cost 45,471 53,075
Debt instruments, trading, at fair value $ 39,087 $ 49,212

v3.3.1.900
FINANCIAL INSTRUMENTS Schedule of Investments in Equity Securities, Trading (Details) - USD ($)
$ in Thousands
12 Months Ended
Dec. 31, 2015
Dec. 31, 2014
Schedule of Trading Securities and Other Trading Assets [Line Items]    
Cost/ amortized cost $ 45,471 $ 53,075
Equity securities, trading, at fair value 905,994 1,266,175
Equities – listed    
Schedule of Trading Securities and Other Trading Assets [Line Items]    
Cost/ amortized cost 1,011,424 1,079,955
Unrealized gains 67,114 247,109
Unrealized losses (187,885) (80,637)
Equity securities, trading, at fair value 890,653 1,246,427
Exchange traded funds    
Schedule of Trading Securities and Other Trading Assets [Line Items]    
Cost/ amortized cost 31,570 42,126
Unrealized gains 0 0
Unrealized losses (16,229) (22,378)
Equity securities, trading, at fair value 15,341 19,748
Equities – listed    
Schedule of Trading Securities and Other Trading Assets [Line Items]    
Cost/ amortized cost 1,042,994 1,122,081
Unrealized gains 67,114 247,109
Unrealized losses $ (204,114) $ (103,015)

v3.3.1.900
FINANCIAL INSTRUMENTS Schedule of Other Investments (Details) - USD ($)
$ in Thousands
Dec. 31, 2015
Dec. 31, 2014
Schedule of Trading Securities and Other Trading Assets [Line Items]    
Cost $ 120,812 $ 113,053
Unrealized gains 3,491 4,508
Unrealized losses (5,220) (1,970)
Fair value 119,083 115,591
Commodities    
Schedule of Trading Securities and Other Trading Assets [Line Items]    
Cost 102,092 95,815
Unrealized gains 0 1,057
Unrealized losses (4,046) 0
Fair value 98,046 96,872
Private and unlisted equity securities    
Schedule of Trading Securities and Other Trading Assets [Line Items]    
Cost 18,720 17,238
Unrealized gains 3,491 3,451
Unrealized losses (1,174) (1,970)
Fair value $ 21,037 $ 18,719

v3.3.1.900
FINANCIAL INSTRUMENTS NAV Instruments (Details) - Private and unlisted equity securities - USD ($)
$ in Millions
Dec. 31, 2015
Dec. 31, 2014
Fair Value, Investments, Entities that Calculate Net Asset Value Per Share [Line Items]    
Amount of unfunded commitments relating to private equity funds $ 6.1 $ 8.9
Significant unobservable inputs (Level 3)    
Fair Value, Investments, Entities that Calculate Net Asset Value Per Share [Line Items]    
Fair Value of investments in private equity funds $ 12.6 $ 12.3
Percentage of funds that have redemption restrictions 100.00%  

v3.3.1.900
FINANCIAL INSTRUMENTS Schedule of Investments in Securities Sold, Not Yet Purchased (Details) - USD ($)
$ in Thousands
12 Months Ended
Dec. 31, 2015
Dec. 31, 2014
Equities – listed    
Investments Sold, Not yet Purchased [Line Items]    
Unrealized gains $ 67,114 $ 247,109
Unrealized losses (204,114) (103,015)
Exchange traded funds    
Investments Sold, Not yet Purchased [Line Items]    
Unrealized gains 0 0
Unrealized losses (16,229) (22,378)
Corporate debt – U.S.    
Investments Sold, Not yet Purchased [Line Items]    
Unrealized gains 155 5
Unrealized losses (5,519) (1,423)
Sovereign debt – Non U.S.    
Investments Sold, Not yet Purchased [Line Items]    
Unrealized gains 1,225 0
Unrealized losses (450) (1,083)
Securities Sold, Not yet Purchased    
Investments Sold, Not yet Purchased [Line Items]    
Proceeds (890,857) (1,076,200)
Unrealized gains 105,487 99,332
Unrealized losses (97,536) (113,863)
Fair value (882,906) (1,090,731)
Securities Sold, Not yet Purchased | Equities – listed    
Investments Sold, Not yet Purchased [Line Items]    
Proceeds (803,842) (813,365)
Unrealized gains 102,469 91,690
Unrealized losses (94,681) (101,715)
Fair value (796,054) (823,390)
Securities Sold, Not yet Purchased | Exchange traded funds    
Investments Sold, Not yet Purchased [Line Items]    
Proceeds (9,572) (9,180)
Unrealized gains 0 0
Unrealized losses (2,855) (1,658)
Fair value (12,427) (10,838)
Securities Sold, Not yet Purchased | Corporate debt – U.S.    
Investments Sold, Not yet Purchased [Line Items]    
Proceeds   (7,066)
Unrealized gains   1,007
Unrealized losses   (5)
Fair value   (6,064)
Securities Sold, Not yet Purchased | Sovereign debt – Non U.S.    
Investments Sold, Not yet Purchased [Line Items]    
Proceeds (77,443) (246,589)
Unrealized gains 3,018 6,635
Unrealized losses 0 (10,485)
Fair value $ (74,425) $ (250,439)

v3.3.1.900
FINANCIAL INSTRUMENTS Financial Contracts Additional Information (Details) - USD ($)
$ in Thousands
Dec. 31, 2015
Dec. 31, 2014
Derivative [Line Items]    
Financial contracts receivable, Gross amounts of recognized assets (liabilities) $ 13,215 $ 47,171
OTC options | Financial contracts receivable | Put options (3)    
Derivative [Line Items]    
Financial contracts receivable, Gross amounts of recognized assets (liabilities) $ 8,700 $ 22,400

v3.3.1.900
FINANCIAL INSTRUMENTS Schedule of Fair Values of Financial Contracts Outstanding (Details) - USD ($)
$ in Thousands
12 Months Ended
Dec. 31, 2015
Dec. 31, 2014
Derivative [Line Items]    
Schedule of Derivative Instruments
At December 31, 2015, the fair values of financial contracts outstanding were as follows: 
Financial Contracts
 
Listing
currency
(1)
 
Notional amount of
underlying instruments
 
Fair value of net assets
(obligations)
on financial
contracts


($ in thousands)
Financial contracts receivable


Call options (2)
 
USD
 
47,259

 
$
657

Put options (3)
 
USD
 
147,326

 
8,790

Total return swaps – equities
 
EUR/GBP/USD
 
50,205

 
3,748

Warrants and rights on listed equities
 
EUR
 
59

 
20

Total financial contracts receivable, at fair value


$
13,215

Financial contracts payable


Call options
 
USD
 
2,601

 
$
(64
)
Commodity Swaps
 
USD
 
42,160

 
(12,784
)
Forwards
 
KRW
 
2,908

 
(22
)
Futures
 
USD
 
21,195

 
(488
)
Total return swaps – equities
 
EUR/GBP/HKD/RON/MXN/USD
 
71,874

 
(14,887
)
Total financial contracts payable, at fair value


$
(28,245
)
At December 31, 2014, the fair values of financial contracts outstanding were as follows: 
Financial Contracts
 
Listing
currency (1)
 
Notional amount of
underlying instruments
 
Fair value of net assets
(obligations)
on financial
contracts


($ in thousands)
Financial contracts receivable


Futures
 
USD
 
13,204

 
$
3,461

Put options (2)
 
USD
 
299,907

 
22,349

Total return swaps – equities
 
EUR/GBP/HKD/USD
 
43,355

 
18,898

Warrants and rights on listed equities
 
EUR
 
8,054

 
2,463

Total financial contracts receivable, at fair value


$
47,171

Financial contracts payable


Credit default swaps, purchased – corporate debt
 
USD
 
221,198

 
$
(1,305
)
Credit default swaps, purchased – sovereign debt
 
USD
 
251,467

 
(1,714
)
Forwards
 
KRW
 
20,563

 
(512
)
Futures
 
USD
 
33,625

 
(867
)
Total return swaps – equities
 
EUR/GBP/HKD/INR/RON/USD
 
122,667

 
(40,194
)
Total financial contracts payable, at fair value


$
(44,592
)
Financial contracts receivable, Fair value of net assets (obligations) on financial contracts $ 13,215 $ 47,171
Financial contracts payable, Fair value of net assets (obligations) on financial contracts (28,245) (44,592)
Financial contracts receivable    
Derivative [Line Items]    
Financial contracts receivable, Fair value of net assets (obligations) on financial contracts 13,215 47,171
Financial contracts receivable | Call options    
Derivative [Line Items]    
Financial contracts receivable, Notional amount of underlying instruments [1] 47,259  
Financial contracts receivable, Fair value of net assets (obligations) on financial contracts [1] 657  
Financial contracts receivable | Futures    
Derivative [Line Items]    
Financial contracts receivable, Notional amount of underlying instruments   13,204
Financial contracts receivable, Fair value of net assets (obligations) on financial contracts   3,461
Financial contracts receivable | Put options (3)    
Derivative [Line Items]    
Financial contracts receivable, Notional amount of underlying instruments [2] 147,326 299,907
Financial contracts receivable, Fair value of net assets (obligations) on financial contracts [2] 8,790 22,349
Financial contracts receivable | Total return swaps – equities    
Derivative [Line Items]    
Financial contracts receivable, Notional amount of underlying instruments 50,205 43,355
Financial contracts receivable, Fair value of net assets (obligations) on financial contracts 3,748 18,898
Financial contracts receivable | Warrants and rights on listed equities    
Derivative [Line Items]    
Financial contracts receivable, Notional amount of underlying instruments 59 8,054
Financial contracts receivable, Fair value of net assets (obligations) on financial contracts 20 2,463
Financial contracts payable    
Derivative [Line Items]    
Financial contracts payable, Fair value of net assets (obligations) on financial contracts (28,245) (44,592)
Financial contracts payable | Call options    
Derivative [Line Items]    
Financial contracts payable, Notional amount of underlying instruments 2,601  
Financial contracts payable, Fair value of net assets (obligations) on financial contracts (64)  
Financial contracts payable | Commodity Contract [Member]    
Derivative [Line Items]    
Financial contracts payable, Notional amount of underlying instruments 42,160  
Financial contracts payable, Fair value of net assets (obligations) on financial contracts (12,784)  
Financial contracts payable | Forwards    
Derivative [Line Items]    
Financial contracts payable, Notional amount of underlying instruments 2,908 20,563
Financial contracts payable, Fair value of net assets (obligations) on financial contracts (22) (512)
Financial contracts payable | Futures    
Derivative [Line Items]    
Financial contracts payable, Notional amount of underlying instruments 21,195 33,625
Financial contracts payable, Fair value of net assets (obligations) on financial contracts (488) (867)
Financial contracts payable | Total return swaps – equities    
Derivative [Line Items]    
Financial contracts payable, Notional amount of underlying instruments 71,874 122,667
Financial contracts payable, Fair value of net assets (obligations) on financial contracts $ (14,887) (40,194)
Financial contracts payable | Credit default swaps, purchased | Corporate Debt    
Derivative [Line Items]    
Financial contracts payable, Notional amount of underlying instruments   221,198
Financial contracts payable, Fair value of net assets (obligations) on financial contracts   (1,305)
Financial contracts payable | Credit default swaps, purchased | Sovereign debt – Non U.S.    
Derivative [Line Items]    
Financial contracts payable, Notional amount of underlying instruments   251,467
Financial contracts payable, Fair value of net assets (obligations) on financial contracts   $ (1,714)
[1] (2) Includes options on interest rate futures relating to U.S. dollar LIBOR interest rates.
[2] (3) Includes options on the Japanese Yen and the Chinese Yuan, denominated in U.S. dollars.

v3.3.1.900
FINANCIAL INSTRUMENTS Schedule of Reported Gains and Losses on Derivatives (Details) - USD ($)
$ in Thousands
12 Months Ended
Dec. 31, 2015
Dec. 31, 2014
Dec. 31, 2013
Derivative Instruments, Gain (Loss) [Line Items]      
Gain (loss) on derivatives recognized in income $ (41,841) $ 29,724 $ 126,076
Commodity Contract [Member] | Net investment income (loss)      
Derivative Instruments, Gain (Loss) [Line Items]      
Gain (loss) on derivatives recognized in income (12,061) 0 0
Credit default swaps, purchased | Corporate Debt | Net investment income (loss)      
Derivative Instruments, Gain (Loss) [Line Items]      
Gain (loss) on derivatives recognized in income (156) (345) (3,552)
Credit default swaps, purchased | Sovereign debt – Non U.S. | Net investment income (loss)      
Derivative Instruments, Gain (Loss) [Line Items]      
Gain (loss) on derivatives recognized in income (90) (298) (1,087)
Forwards | Net investment income (loss)      
Derivative Instruments, Gain (Loss) [Line Items]      
Gain (loss) on derivatives recognized in income 1,009 (490) 11,209
Futures | Net investment income (loss)      
Derivative Instruments, Gain (Loss) [Line Items]      
Gain (loss) on derivatives recognized in income (952) 16,721 12,504
Interest rate options | Net investment income (loss)      
Derivative Instruments, Gain (Loss) [Line Items]      
Gain (loss) on derivatives recognized in income 0 (26) (82)
Interest rate swaps | Net investment income (loss)      
Derivative Instruments, Gain (Loss) [Line Items]      
Gain (loss) on derivatives recognized in income (706) 0 0
Options, warrants, and rights | Net investment income (loss)      
Derivative Instruments, Gain (Loss) [Line Items]      
Gain (loss) on derivatives recognized in income (13,955) 1,020 21,446
Total return swaps – equities | Net investment income (loss)      
Derivative Instruments, Gain (Loss) [Line Items]      
Gain (loss) on derivatives recognized in income (12,590) 13,142 85,638
Weather derivative swap | Other income (expense), net      
Derivative Instruments, Gain (Loss) [Line Items]      
Gain (loss) on derivatives recognized in income (2,340) 0 $ 0
Derivatives not designated as hedging instruments (notional amounts)      
Derivative Instruments, Gain (Loss) [Line Items]      
Entered 10,294,841 1,473,544  
Exited 8,102,909 913,845  
Derivatives not designated as hedging instruments (notional amounts) | Commodity Contract [Member]      
Derivative Instruments, Gain (Loss) [Line Items]      
Entered 103,358    
Exited 43,261    
Derivatives not designated as hedging instruments (notional amounts) | Credit default swaps, purchased      
Derivative Instruments, Gain (Loss) [Line Items]      
Entered 0    
Exited [1] 0    
Derivatives not designated as hedging instruments (notional amounts) | Forwards      
Derivative Instruments, Gain (Loss) [Line Items]      
Entered 0 0  
Exited 13,377 82,688  
Derivatives not designated as hedging instruments (notional amounts) | Futures      
Derivative Instruments, Gain (Loss) [Line Items]      
Entered 311,536 308,178  
Exited 294,441 356,216  
Derivatives not designated as hedging instruments (notional amounts) | Interest rate swaps      
Derivative Instruments, Gain (Loss) [Line Items]      
Entered 9,139,000    
Exited 7,213,000    
Derivatives not designated as hedging instruments (notional amounts) | Total return swaps – equities      
Derivative Instruments, Gain (Loss) [Line Items]      
Entered 67,844 121,125  
Exited 185,128 $ 160,065  
Derivatives not designated as hedging instruments (notional amounts) | Weather derivative swap      
Derivative Instruments, Gain (Loss) [Line Items]      
Entered 12,000    
Exited $ 12,000    
[1] (1) Exited amount excludes derivatives which expired or were exercised during the period.

v3.3.1.900
FINANCIAL INSTRUMENTS Schedule of Volume of Derivative Activities (Details) - Derivatives not designated as hedging instruments (notional amounts) - USD ($)
$ in Thousands
12 Months Ended
Dec. 31, 2015
Dec. 31, 2014
Derivative [Line Items]    
Entered $ 10,294,841 $ 1,473,544
Exited 8,102,909 913,845
Credit default swaps (1)    
Derivative [Line Items]    
Entered 0  
Exited [1] 0  
Forwards    
Derivative [Line Items]    
Entered 0 0
Exited 13,377 82,688
Futures    
Derivative [Line Items]    
Entered 311,536 308,178
Exited 294,441 356,216
Options, warrants, and rights    
Derivative [Line Items]    
Entered 661,103 1,044,241
Exited 341,702 [1] 314,876 [2]
Total return swaps    
Derivative [Line Items]    
Entered 67,844 121,125
Exited 185,128 $ 160,065
Weather derivative swap    
Derivative [Line Items]    
Entered 12,000  
Exited $ 12,000  
[1] (1) Exited amount excludes derivatives which expired or were exercised during the period.
[2] Exited amount excludes derivatives which expired or were exercised during the period.

v3.3.1.900
FINANCIAL INSTRUMENTS Schedule of Gross and Net Amounts of Derivative Instruments and Cash Collateral (Details) - USD ($)
$ in Thousands
Dec. 31, 2015
Dec. 31, 2014
Financial Instruments [Abstract]    
Financial contracts receivable, Gross amounts of recognized assets (liabilities) $ 13,215 $ 47,171
Financial contracts receivable, Gross amounts offset in the balance sheet 0 0
Financial contracts receivable, Net amounts of assets (liabilities) presented in the balance sheet 13,215 47,171
Financial contracts receivable, financial instruments available for offset 8,937 24,265
Financial contracts receivable, Cash collateral (received) pledged 2,036 9,452
Financial contracts receivable, Net amount of asset (liability) 2,242 13,454
Financial contracts payable, Gross amounts of recognized assets (liabilities) (28,245) (44,592)
Financial contracts payable, Gross amounts offset in the balance sheet 0 0
Financial contracts payable, Net amounts of assets (liabilities) presented in the balance sheet (28,245) (44,592)
Financial contracts payable, financial instruments available for offset 8,937 24,265
Financial contracts payable, Cash collateral (received) pledged 19,308 20,327
Financial contracts payable, Net amount of asset (liability) $ 0 $ 0

v3.3.1.900
DUE TO PRIME BROKERS (Details) - USD ($)
$ in Thousands
12 Months Ended
Dec. 31, 2015
Dec. 31, 2014
Due to Prime Broker [Line Items]    
Amounts due to prime brokers $ 396,453 $ 211,070
Collateral for LOCs issued    
Due to Prime Broker [Line Items]    
Amounts due to prime brokers 301,400 135,000
Bank Overdrafts    
Due to Prime Broker [Line Items]    
Amounts due to prime brokers $ 95,000 $ 76,100
GLRE    
Due to Prime Broker [Line Items]    
Maximum temporary leverage 30.00%  
Maximum long-term leverage 15.00%  
Greenlight Reinsurance Ireland, Ltd. [Member]    
Due to Prime Broker [Line Items]    
Maximum temporary leverage 20.00%  
Maximum long-term leverage 5.00%  

v3.3.1.900
CASH AND CASH EQUIVALENTS (Details) - USD ($)
$ in Thousands
Dec. 31, 2015
Dec. 31, 2014
Dec. 31, 2013
Dec. 31, 2012
Cash and Cash Equivalents [Line Items]        
Total cash and cash equivalents $ 112,162 $ 12,030 $ 3,722 $ 21,890
Cash at banks        
Cash and Cash Equivalents [Line Items]        
Total cash and cash equivalents 44,133 3,426    
Cash held with brokers        
Cash and Cash Equivalents [Line Items]        
Total cash and cash equivalents $ 68,029 $ 8,604    

v3.3.1.900
RESTRICTED CASH AND CASH EQUIVALENTS (Details) - USD ($)
$ in Thousands
Dec. 31, 2015
Dec. 31, 2014
Cash and Cash Equivalents [Line Items]    
Total restricted cash and cash equivalents $ 1,236,589 $ 1,296,914
Cash held by prime brokers relating to securities sold, not yet purchased    
Cash and Cash Equivalents [Line Items]    
Total restricted cash and cash equivalents 882,906 1,090,731
Cash collateral relating to letters of credit issued    
Cash and Cash Equivalents [Line Items]    
Total restricted cash and cash equivalents 222,852 134,981
Trust Accounts [Member]    
Cash and Cash Equivalents [Line Items]    
Total restricted cash and cash equivalents 78,584 0
Cash and cash equivalents held by swap counterparties    
Cash and Cash Equivalents [Line Items]    
Total restricted cash and cash equivalents $ 52,247 $ 71,202

v3.3.1.900
LOSS AND LOSS ADJUSTMENT EXPENSE RESERVES Liabilities for loss reserves (Details) - USD ($)
$ in Thousands
Dec. 31, 2015
Dec. 31, 2014
Dec. 31, 2013
Dec. 31, 2012
Liability for Claims and Claims Adjustment Expense [Line Items]        
Case reserves $ 111,535 $ 117,049    
IBNR 194,462 147,194    
Total $ 305,997 $ 264,243 $ 329,894 $ 356,470

v3.3.1.900
LOSS AND LOSS ADJUSTMENT EXPENSE RESERVES (Details) - USD ($)
$ in Thousands
12 Months Ended
Dec. 31, 2015
Dec. 31, 2014
Dec. 31, 2013
Dec. 31, 2015
Causes of Increase (Decrease) in Liability for Unpaid Claims and Claims Adjustment Expense [Line Items]        
Liability for Unpaid Claims and Claims Adjustment Expense, Period Increase (Decrease) $ 50,300 $ 18,200 $ (6,100)  
Profit commission expense $ 7,500 2,700 3,700  
Liability for Unpaid Claims and Claims Adjustment Expense, Activity in Liability [Abstract]        
Schedule of Liability for Unpaid Claims and Claims Adjustment Expense
At December 31, 2015 and 2014, loss and loss adjustment expense reserves were comprised of the following:
 
 
2015
 
2014
 
 
($ in thousands)
Case reserves
 
$
111,535

 
$
117,049

IBNR
 
194,462

 
147,194

Total
 
$
305,997

 
$
264,243


A summary of changes in outstanding loss and loss adjustment expense reserves is as follows: 
 
 
2015
 
2014
 
2013
 
 
($ in thousands)
Gross balance at January 1
 
$
264,243

 
$
329,894

 
$
356,470

Less: Losses recoverable
 
(11,523
)
 
(16,829
)
 
(34,451
)
Net balance at January 1
 
252,720

 
313,065

 
322,019

Incurred losses related to:


Current year
 
266,796

 
216,757

 
344,613

Prior years
 
50,301

 
18,229

 
(6,120
)
Total incurred
 
317,097

 
234,986

 
338,493

Paid losses related to:


Current year
 
(132,017
)
 
(163,139
)
 
(177,871
)
Prior years
 
(132,846
)
 
(130,438
)
 
(170,018
)
Total paid
 
(264,863
)
 
(293,577
)
 
(347,889
)
Foreign currency revaluation
 
(2,325
)
 
(1,754
)
 
442

Net balance at December 31
 
302,629

 
252,720

 
313,065

Add: Losses recoverable
 
3,368

 
11,523

 
16,829

Gross balance at December 31
 
$
305,997

 
$
264,243

 
$
329,894

     
Liability for Unpaid Claims and Claims Adjustment Expense [Roll Forward]        
Gross balance at January 1 $ 264,243 329,894 356,470  
Less: Losses recoverable (11,523) (16,829) (34,451)  
Net balance at January 1 252,720 313,065 322,019  
Incurred losses related to Current year 266,796 216,757 344,613  
Incurred losses related to Prior years 50,301 18,229 (6,120)  
Incurred losses related to Total incurred 317,097 234,986 338,493  
Paid losses related to Current year (132,017) (163,139) (177,871)  
Paid losses related to Prior years (132,846) (130,438) (170,018)  
Paid losses related to Total paid (264,863) (293,577) (347,889)  
Foreign currency revaluation (2,325) (1,754) 442  
Net balance at December 31 252,720 313,065 322,019 $ 302,629
Add: Losses recoverable (3,368) (11,523) (16,829)  
Gross balance at December 31 305,997 264,243 329,894  
Hurricane        
Causes of Increase (Decrease) in Liability for Unpaid Claims and Claims Adjustment Expense [Line Items]        
Liability for Unpaid Claims and Claims Adjustment Expense, Period Increase (Decrease)     (15,000)  
Reinstatement (reversal) of premiums earned     (2,600)  
General liability (1)        
Causes of Increase (Decrease) in Liability for Unpaid Claims and Claims Adjustment Expense [Line Items]        
Liability for Unpaid Claims and Claims Adjustment Expense, Period Increase (Decrease)   7,800 17,700  
General liability (1) | Construction Defects - Single Family Homes [Member]        
Causes of Increase (Decrease) in Liability for Unpaid Claims and Claims Adjustment Expense [Line Items]        
Liability for Unpaid Claims and Claims Adjustment Expense, Period Increase (Decrease) 36,900      
General liability (1) | Construction Defects - Other [Member]        
Causes of Increase (Decrease) in Liability for Unpaid Claims and Claims Adjustment Expense [Line Items]        
Liability for Unpaid Claims and Claims Adjustment Expense, Period Increase (Decrease) 14,700      
Commercial Automobile Business        
Causes of Increase (Decrease) in Liability for Unpaid Claims and Claims Adjustment Expense [Line Items]        
Liability for Unpaid Claims and Claims Adjustment Expense, Period Increase (Decrease)     (4,000)  
Private Passenger Automobile Business        
Causes of Increase (Decrease) in Liability for Unpaid Claims and Claims Adjustment Expense [Line Items]        
Liability for Unpaid Claims and Claims Adjustment Expense, Period Increase (Decrease) (4,500) (3,800) (3,000)  
Ceding commissions 3,300 2,200 2,300  
Private Passenger Automobile Business | Commutation of contract [Member]        
Causes of Increase (Decrease) in Liability for Unpaid Claims and Claims Adjustment Expense [Line Items]        
Liability for Unpaid Claims and Claims Adjustment Expense, Period Increase (Decrease) (1,300)      
Ceding commissions 1,100      
Casualty Clash Contract        
Causes of Increase (Decrease) in Liability for Unpaid Claims and Claims Adjustment Expense [Line Items]        
Liability for Unpaid Claims and Claims Adjustment Expense, Period Increase (Decrease)     4,000  
Reinstatement (reversal) of premiums earned     1,200  
Commercial motor related to multi-line contracts        
Causes of Increase (Decrease) in Liability for Unpaid Claims and Claims Adjustment Expense [Line Items]        
Liability for Unpaid Claims and Claims Adjustment Expense, Period Increase (Decrease)   7,100    
Professional liability        
Causes of Increase (Decrease) in Liability for Unpaid Claims and Claims Adjustment Expense [Line Items]        
Liability for Unpaid Claims and Claims Adjustment Expense, Period Increase (Decrease) 2,400 4,000    
Ceding commissions   (600)    
Total Property        
Causes of Increase (Decrease) in Liability for Unpaid Claims and Claims Adjustment Expense [Line Items]        
Liability for Unpaid Claims and Claims Adjustment Expense, Period Increase (Decrease) (5,100)      
Reinstatement (reversal) of premiums earned (2,500)      
Profit commission expense 3,400      
Homeowners' property contracts        
Causes of Increase (Decrease) in Liability for Unpaid Claims and Claims Adjustment Expense [Line Items]        
Liability for Unpaid Claims and Claims Adjustment Expense, Period Increase (Decrease) 9,300   $ (2,400)  
Ceding commissions (5,100)      
Health        
Causes of Increase (Decrease) in Liability for Unpaid Claims and Claims Adjustment Expense [Line Items]        
Liability for Unpaid Claims and Claims Adjustment Expense, Period Increase (Decrease) $ (2,300) $ 3,000    

v3.3.1.900
RETROCESSION (Details) - USD ($)
3 Months Ended 12 Months Ended
Dec. 31, 2015
Sep. 30, 2015
Jun. 30, 2015
Mar. 31, 2015
Dec. 31, 2014
Sep. 30, 2014
Jun. 30, 2014
Mar. 31, 2014
Dec. 31, 2015
Dec. 31, 2014
Dec. 31, 2013
Dec. 31, 2012
Ceded Credit Risk [Line Items]                        
Loss and loss adjustment expenses incurred, net $ 79,816,000 $ 97,421,000 $ 76,653,000 $ 63,207,000 $ 57,951,000 $ 53,028,000 $ 56,644,000 $ 67,363,000 $ 317,097,000 $ 234,986,000 $ 338,493,000  
Loss and loss expenses recovered and recoverable                 1,700,000 4,400,000 (10,200,000)  
Loss and loss adjustment expenses recoverable 3,368,000       11,523,000       3,368,000 11,523,000 $ 16,829,000 $ 34,451,000
Funds withheld from unrated retrocessionaires 7,143,000       6,558,000       7,143,000 6,558,000    
Provision for uncollectible losses recoverable 0       0       0 0    
Ceded Credit Risk, Secured                        
Ceded Credit Risk [Line Items]                        
Funds withheld from unrated retrocessionaires 3,100,000       2,800,000       3,100,000 2,800,000    
AM Best, A- Rating [Member]                        
Ceded Credit Risk [Line Items]                        
Loss and loss adjustment expenses recoverable 300,000       0       300,000 0    
Unrated [Member]                        
Ceded Credit Risk [Line Items]                        
Loss and loss adjustment expenses recoverable $ 3,100,000       $ 18,300,000       $ 3,100,000 $ 18,300,000    

v3.3.1.900
SHARE CAPITAL (Details) - USD ($)
12 Months Ended
Sep. 21, 2004
Dec. 31, 2015
Dec. 31, 2014
Dec. 31, 2013
Class of Stock [Line Items]        
Preferred shares issued   0 0  
Preferred shares outstanding   0    
Registration rights   50.00%    
Aggregate principal amount of securities   $ 200,000,000    
Stock Repurchase Program Expiration Date   Jun. 30, 2016    
Increase (Decrease) in Common Stock [Roll Forward]        
Amount of retained earnings restricted from payment of dividends   $ 325,287,000    
Common Class A        
Class of Stock [Line Items]        
Number of entitled votes per share   $ 1    
Percentage of total voting power of all issued and outstanding ordinary shares   9.90%    
Shares authorized to purchase under the share repurchase plan   2,000,000    
Number of shares available under share repurchase plan   1,386,460    
Increase (Decrease) in Common Stock [Roll Forward]        
Balance – beginning of year   31,129,648 30,791,865 30,447,179
Issue of ordinary shares, net of forfeitures   256,464 337,729 344,686
Repurchase of ordinary shares   (613,540) 0 0
Class B shares converted to Class A shares   0 54 0
Balance – end of year   30,772,572 31,129,648 30,791,865
Par value per share   $ 0.10 $ 0.10  
Common Class B        
Class of Stock [Line Items]        
Number of entitled votes per share   $ 10    
Percentage of total voting power of all issued and outstanding ordinary shares   9.50%    
Increase (Decrease) in Common Stock [Roll Forward]        
Balance – beginning of year   6,254,895 6,254,949 6,254,949
Issue of ordinary shares, net of forfeitures   0 0 0
Repurchase of ordinary shares   0 0 0
Class B shares converted to Class A shares   0 54 0
Balance – end of year   6,254,895 6,254,895 6,254,949
Par value per share   $ 0.10 $ 0.10  
Service Provider | Common Class A        
Class of Stock [Line Items]        
Shares authorized for issuance in relation to share purchase options granted to service provider 400,000 300,000 300,000  
Shares available for future issuance   0 0  
Stock Compensation Plan | Common Class A        
Class of Stock [Line Items]        
Shares authorized for the company's stock incentive plan   3,500,000 3,500,000  
Shares available for future issuance   658,775 803,558  
GLRE        
Increase (Decrease) in Common Stock [Roll Forward]        
Cash Dividends Paid to Parent Company by Consolidated Subsidiaries   $ 5,000,000 $ 0 $ 0
GLRE | Cayman Islands        
Increase (Decrease) in Common Stock [Roll Forward]        
Minimum net worth requirement   466,529,000 443,500,000  
Insurance Regulations Minimum Capital Requirement   50,000,000    
Statutory capital and surplus   788,900,000    
Net income   (309,500,000) 113,300,000 229,800,000
Amount of capital and surplus available for distribution as dividends   322,400,000 658,800,000  
GRIL | Ireland        
Increase (Decrease) in Common Stock [Roll Forward]        
Minimum net worth requirement   18,100,000 13,600,000  
Statutory capital and surplus   50,300,000 42,900,000  
Net income   (12,800,000) (3,300,000) $ 3,600,000
Amount of capital and surplus available for distribution as dividends   $ 0 $ 2,700,000  

v3.3.1.900
SHARE-BASED COMPENSATION Narrative (Details) - USD ($)
$ / shares in Units, $ in Thousands
12 Months Ended
Sep. 21, 2004
Dec. 31, 2015
Dec. 31, 2014
Dec. 31, 2013
Sep. 20, 2004
Share-based Compensation Arrangement by Share-based Payment Award [Line Items]          
Share-based Compensation Arrangement by Share-based Payment Award, Options, Outstanding, Weighted Average Exercise Price   $ 19.78 $ 17.58 $ 15.82 $ 10.00
Share-based Compensation Arrangement by Share-based Payment Award, Options, Outstanding, Number   906,991 1,116,308 1,402,987  
Share purchase options granted   40,683 31,821    
Expiration period after the grant date   10 years 10 years 10 years  
Grant date fair value of the options   $ 12.290 $ 15.71 $ 13.09  
Total compensation cost related to non-vested options not yet recognized   $ 400 $ 400 $ 400  
Number of stock options exercised   250,000 318,500    
Intrinsic value of options exercised   $ 4,800 $ 6,700 $ 800  
Weighted average remaining contractual term for options outstanding   2 years 11 months 3 years    
Number of stock options exercisable   851,020 1,062,022    
Weighted-average exercise price   $ 19.22 $ 17.02    
Weighted-average remaining contractual term   2 years 7 months 2 years 8 months    
Aggregate intrinsic value of options outstanding   $ 2,600 $ 16,800    
Aggregate intrinsic value of options exercisable   $ 2,600 $ 16,600    
Number of options vested   38,998 53,828 45,871  
Weighted average grant date fair value of options vested   $ 12.82 $ 11.76 $ 11.08  
General and Administrative Expense          
Share-based Compensation Arrangement by Share-based Payment Award [Line Items]          
Share-based compensation expense   $ 4,300 $ 4,000 $ 3,800  
Stock Options          
Share-based Compensation Arrangement by Share-based Payment Award [Line Items]          
Share-based compensation expense   $ 500 $ 500 $ 600  
Weighted average period for recognition   1 year 6 months 1 year 6 months 1 year 6 months  
Restricted Stock          
Share-based Compensation Arrangement by Share-based Payment Award [Line Items]          
Cliff vesting period after date of issuance   3 years      
Stock compensation expense relating to forfeited restricted shares reversed   $ 100 $ 400 $ 200  
Share-based compensation expense   3,600 3,300 3,200  
Unrecognized compensation costs related to non-vested restricted shares   $ 3,700 $ 4,200 $ 3,500  
Weighted average period for recognition   1 year 7 months 1 year 9 months 1 year 8 months  
Total fair value of restricted shares vested   $ 3,200 $ 2,900 $ 2,800  
RSUs          
Share-based Compensation Arrangement by Share-based Payment Award [Line Items]          
Cliff vesting period after date of issuance   3 years      
Share-based compensation expense   $ 200 $ 100 $ 30  
Vesting on Grant Date          
Share-based Compensation Arrangement by Share-based Payment Award [Line Items]          
Vesting percentage   25.00% 25.00%    
Vesting In Year 1          
Share-based Compensation Arrangement by Share-based Payment Award [Line Items]          
Vesting percentage   25.00% 25.00%    
Vesting In Year 2          
Share-based Compensation Arrangement by Share-based Payment Award [Line Items]          
Vesting percentage   25.00% 25.00%    
Vesting In Year 3          
Share-based Compensation Arrangement by Share-based Payment Award [Line Items]          
Vesting percentage   25.00% 25.00%    
Director          
Share-based Compensation Arrangement by Share-based Payment Award [Line Items]          
Cliff vesting period after date of issuance   1 year      
Common Class A [Member]          
Share-based Compensation Arrangement by Share-based Payment Award [Line Items]          
Share purchase options granted   40,683 31,821    
Issuance of shares as a result of stock options exercised   158,925 207,328    
Common Class A [Member] | Restricted Stock          
Share-based Compensation Arrangement by Share-based Payment Award [Line Items]          
Restricted shares issued pursuant to stock incentive plan   78,685 127,186 111,231  
Restricted shares forfeited by employees who left the Company prior to the vesting period   9,621 38,706 16,826  
Common Class A [Member] | Director | Restricted Stock          
Share-based Compensation Arrangement by Share-based Payment Award [Line Items]          
Restricted shares issued pursuant to stock incentive plan   28,215 28,060 36,374  
Service Provider          
Share-based Compensation Arrangement by Share-based Payment Award [Line Items]          
Share-based Compensation Arrangement by Share-based Payment Award, Options, Outstanding, Number   0 0    
Number of stock options exercised     20,000    
Service Provider | Common Class A [Member]          
Share-based Compensation Arrangement by Share-based Payment Award [Line Items]          
Number of share purchase options granted to service provider (shares) 400,000 300,000 300,000    
Share-based Goods and Nonemployee Services Transaction, Quantity of Securities Issued     13,861    

v3.3.1.900
SHARE-BASED COMPENSATION Restricted Shares (Details) - Restricted Stock - $ / shares
12 Months Ended
Dec. 31, 2015
Dec. 31, 2014
Share-based Compensation Arrangement by Share-based Payment Award, Equity Instruments Other than Options, Nonvested, Number of Shares [Roll Forward]    
Number of non-vested shares, Balance at beginning 330,087 328,991
Number of non-vested restricted shares, Granted 106,900 155,246
Number of non-vested restricted shares, Vested (120,353) (115,444)
Number of non-vested restricted shares, Forfeited (9,621) (38,706)
Number of non-vested shares, Balance at end 307,013 330,087
Share-based Compensation Arrangement by Share-based Payment Award, Equity Instruments Other than Options, Nonvested, Weighted Average Grant Date Fair Value [Abstract]    
Weighted average grant date fair value, Balance at beginning $ 27.90 $ 24.74
Weighted average grant date fair value, Granted 31.56 32.58
Weighted average grant date fair value, Vested 26.26 25.35
Weighted average grant date fair value, Forfeited 30.49 27.43
Weighted average grant date fair value, Balance at end $ 29.74 $ 27.90

v3.3.1.900
SHARE-BASED COMPENSATION Black Scholes option pricing model assumptions (Details)
12 Months Ended
Dec. 31, 2015
Dec. 31, 2014
Dec. 31, 2013
Disclosure of Compensation Related Costs, Share-based Payments [Abstract]      
Risk free rate 2.15% 2.47% 2.85%
Estimated volatility 32.80% 34.30% 35.00%
Expected term (in years) 10 years 10 years 10 years
Dividend yield 0.00% 0.00% 0.00%
Forfeiture rate 0.00% 0.00% 0.00%

v3.3.1.900
SHARE-BASED COMPENSATION Share Based Compensation Options Rollfoward (Details) - $ / shares
12 Months Ended
Dec. 31, 2015
Dec. 31, 2014
Dec. 31, 2013
Share-based Compensation Arrangement by Share-based Payment Award, Options, Outstanding [Roll Forward]      
Number of options, Balance at beginning of period 1,116,308 1,402,987  
Number of options, Granted 40,683 31,821  
Number of options, Exercised (250,000) (318,500)  
Number of options, Forfeited 0 0  
Number of options, Expired 0 0  
Number of options, Balance at end of period 906,991 1,116,308 1,402,987
Share-based Compensation Arrangement by Share-based Payment Award, Options, Outstanding, Weighted Average Exercise Price [Roll Forward]      
Weighted average exercise price, Balance at beginning of period $ 17.58 $ 15.82  
Weighted average exercise price, Granted 26.67 32.37  
Weighted average exercise price, Exercised 11.10 11.29  
Weighted average exercise price, Forfeited 0.00 0.00  
Weighted average exercise price, Expired 0.00 0.00  
Weighted average exercise price, Balance at end of period 19.78 17.58 $ 15.82
Share-based compensation arrangement by share-based payment award, Options, Weighted Average Grant Date Fair Value [Roll Forward]      
Weighted average grant date fair value, Balance at beginning of period 7.73 7.08  
Weighted average grant date fair value, Granted 12.290 15.71 13.09
Weighted average grant date fair value, Exercised 5.57 5.67  
Weighted average grant date fair value, Forfeited 0.00 0.00  
Weighted average grant date fair value, Expired 0.00 0.00  
Weighted average grant date fair value, Balance at end of period $ 8.53 $ 7.73 $ 7.08

v3.3.1.900
SHARE-BASED COMPENSATION Restricted Units (Details) - RSUs - USD ($)
$ / shares in Units, $ in Thousands
12 Months Ended
Dec. 31, 2015
Dec. 31, 2014
Dec. 31, 2013
Share-based Compensation Arrangement by Share-based Payment Award [Line Items]      
Share-based compensation expense $ 200 $ 100 $ 30
Share-based Compensation Arrangement by Share-based Payment Award, Equity Instruments Other than Options, Nonvested, Number of Shares [Roll Forward]      
Number of non-vested shares, Balance at beginning 15,609 5,941  
Number of non-vested restricted shares, Granted 6,821 9,668 5,941
Number of non-vested restricted shares, Vested (260) 0  
Number of non-vested restricted shares, Forfeited 0 0  
Number of non-vested shares, Balance at end 22,170 15,609 5,941
Share-based Compensation Arrangement by Share-based Payment Award, Equity Instruments Other than Options, Nonvested, Weighted Average Grant Date Fair Value [Abstract]      
Weighted average grant date fair value, Balance at beginning $ 29.72 $ 24.41  
Weighted average grant date fair value, Granted 32.21 32.60  
Weighted average grant date fair value, Vested (24.30) (0.00)  
Weighted average grant date fair value, Forfeited (0.00) (0.00)  
Weighted average grant date fair value, Balance at end $ 30.55 $ 29.72 $ 24.41

v3.3.1.900
NET INVESTMENT INCOME (Details) - USD ($)
$ in Thousands
3 Months Ended 12 Months Ended
Dec. 31, 2015
Sep. 30, 2015
Jun. 30, 2015
Mar. 31, 2015
Dec. 31, 2014
Sep. 30, 2014
Jun. 30, 2014
Mar. 31, 2014
Dec. 31, 2015
Dec. 31, 2014
Dec. 31, 2013
Net Investment Income [Abstract]                      
Realized gains (losses)                 $ 22,227 $ 352,133 $ 122,568
Change in unrealized gains and losses                 (265,401) (187,753) 149,012
Investment related foreign exchange gains (losses)                 (3,725) 14,797 44,492
Interest and dividend income, net of withholding taxes                 15,313 31,423 22,265
Interest, dividend and other expenses                 (31,092) (38,892) (47,665)
Investment advisor compensation                 (19,246) (49,133) (72,532)
Net investment income (loss) $ (45,468) $ (191,322) $ (20,305) $ (24,829) $ 72,820 $ (54,027) $ 113,932 $ (10,150) $ (281,924) $ 122,575 $ 218,140
Net investment return (loss) (percentage)                 (20.20%) 8.70% 19.60%

v3.3.1.900
TAXATION (Details) - USD ($)
3 Months Ended 12 Months Ended
Dec. 31, 2015
Sep. 30, 2015
Jun. 30, 2015
Mar. 31, 2015
Dec. 31, 2014
Sep. 30, 2014
Jun. 30, 2014
Mar. 31, 2014
Dec. 31, 2015
Dec. 31, 2014
Dec. 31, 2013
Income Taxes [Line Items]                      
Deferred tax (expense) benefit                 $ (1,740,000) $ 14,000 $ 4,000
Current tax (expense) benefit                 (15,000) (638,000) 534,000
Income tax (expense) benefit $ (361,000) $ (1,233,000) $ 54,000 $ (215,000) $ 204,000 $ (254,000) $ (14,000) $ (560,000) (1,755,000) (624,000) 538,000
Valuation allowance 0       0       $ 0 0  
Federal Excise Tax rate                 1.00%    
Federal Excise Taxes Incurred                 $ 3,300,000 2,200,000 $ 3,500,000
Other Assets                      
Income Taxes [Line Items]                      
Income Taxes Receivable 500,000       800,000       500,000 800,000  
Deferred tax asset 1,760,000       $ 30,000       $ 1,760,000 $ 30,000  
Verdant                      
Income Taxes [Line Items]                      
Tax rate for taxable income                 35.00%    
Operating Loss Carryforwards 1,700,000               $ 1,700,000    
Operating Loss Carryforwards, Expiration Date                 Dec. 31, 2033    
GRIL                      
Income Taxes [Line Items]                      
Operating Loss Carryforwards $ 14,100,000               $ 14,100,000    
GRIL | Ireland                      
Income Taxes [Line Items]                      
Tax rate for trading income                 12.50%    

v3.3.1.900
RELATED PARTY TRANSACTIONS (Details) - USD ($)
12 Months Ended
Dec. 31, 2015
Dec. 31, 2014
Dec. 31, 2013
Related Party Transaction [Line Items]      
Debt instruments, trading, at fair value $ 39,087,000 $ 49,212,000  
Listed equity securities $ 905,994,000 1,266,175,000  
Board of Directors Chairman | Investment Advisory Agreement      
Related Party Transaction [Line Items]      
Performance compensation full rate 20.00%    
Performance compensation reduced rate 10.00%    
Loss carry forward recoupment required 150.00%    
Performance compensation expense $ 0 28,500,000 $ 54,200,000
Investment management fee rate - monthly 0.125%    
Investment management fee rate - annual 1.50%    
Investment management fee expense $ 19,200,000 20,600,000 $ 18,300,000
Board of Directors Chairman | Debt instruments      
Related Party Transaction [Line Items]      
Debt instruments, trading, at fair value   21,600,000  
Listed equity securities 25,000,000 18,400,000  
Interest Income, Related Party 1,000,000 $ 400,000  
Board of Directors Chairman | Service Agreement      
Related Party Transaction [Line Items]      
Investor relations fee monthly $ 5,000    

v3.3.1.900
COMMITMENTS AND CONTINGENCIES Letters of Credit (Details) - USD ($)
$ in Thousands
12 Months Ended
Dec. 31, 2015
Dec. 31, 2014
Line of Credit Facility [Line Items]    
Aggregate amount of letters of credit issued $ 245,600 $ 273,700
Total equity securities, restricted cash, and cash and cash equivalents fair value pledged as security against the letters of credit 324,300 $ 302,600
Financial Standby Letter of Credit    
Line of Credit Facility [Line Items]    
Facility 720,000  
Financial Standby Letter of Credit | Bank of America, N.A.    
Line of Credit Facility [Line Items]    
Facility $ 120,000  
Notice period required for termination 90 days  
Financial Standby Letter of Credit | Butterfield Bank (Cayman) Limited    
Line of Credit Facility [Line Items]    
Facility $ 100,000  
Notice period required for termination 90 days  
Financial Standby Letter of Credit | Citibank Europe plc    
Line of Credit Facility [Line Items]    
Facility $ 400,000  
Notice period required for termination 120 days  
Financial Standby Letter of Credit | JP Morgan Chase Bank N.A.    
Line of Credit Facility [Line Items]    
Facility $ 100,000  
Notice period required for termination 120 days  

v3.3.1.900
COMMITMENTS AND CONTINGENCIES Lease and commitments (Details)
$ in Thousands, € in Millions
12 Months Ended
Dec. 31, 2015
USD ($)
Dec. 31, 2015
EUR (€)
Dec. 31, 2014
USD ($)
Dec. 31, 2013
USD ($)
Future commitments [Line Items]        
Operating Leases, Rent Expense $ 500   $ 500 $ 500
Operating lease renewal option 5 years 5 years    
Operating Lease obligations, 2016 $ 548      
Operating lease obligations, 2017 548      
Operating lease obligations, 2018 315      
Operating lease obligations, 2019 82      
Operating lease obligations, 2020 82      
Operating lease obligations, Thereafter 31      
Operating lease obligations, Total 1,606      
2016 6,655      
2017 548      
2018 315      
2019 82      
2020 82      
Thereafter 31      
Total 7,713      
Private and unlisted equity securities        
Future commitments [Line Items]        
Private equity and limited partnerships, 2016 [1] 6,107   $ 8,900  
Private equity and limited partnerships, 2017 [1] 0      
Private equity and limited partnerships, 2018 [1] 0      
Private equity and limited partnerships, 2019 [1] 0      
Private equity and limited partnerships, 2020 [1] 0      
Private equity and limited partnerships, Thereafter [1] 0      
Private equity and limited partnerships, Total [1] 6,107      
GLRE | Minimum        
Future commitments [Line Items]        
Annual rent payments 300      
GLRE | Maximum        
Future commitments [Line Items]        
Annual rent payments $ 500      
GRIL        
Future commitments [Line Items]        
Annual rent payments | €   € 0.1    
[1] Given the nature of these investments, the Company is unable to determine with any degree of accuracy when these commitments will be called. Therefore, for purposes of the above table, the Company has assumed that all commitments with no fixed payment schedules will be called during the year ending December 31, 2016.

v3.3.1.900
SEGMENT REPORTING Schedule of Revenue by Major Customers (Details)
$ in Thousands
3 Months Ended 12 Months Ended
Dec. 31, 2015
USD ($)
Sep. 30, 2015
USD ($)
Jun. 30, 2015
USD ($)
Mar. 31, 2015
USD ($)
Dec. 31, 2014
USD ($)
Sep. 30, 2014
USD ($)
Jun. 30, 2014
USD ($)
Mar. 31, 2014
USD ($)
Dec. 31, 2015
USD ($)
Segment
Dec. 31, 2014
USD ($)
Dec. 31, 2013
USD ($)
Revenue, Major Customer [Line Items]                      
Number of operating segments | Segment                 1    
Largest broker $ 73,748 $ (89,870) $ 67,620 $ 71,552 $ 149,567 $ 28,127 $ 200,387 $ 101,721 $ 123,050 $ 479,802 $ 764,329
Broker Concentration Risk | Gross Premiums Written                      
Revenue, Major Customer [Line Items]                      
Largest broker                 $ 388,249 $ 263,987 $ 401,454
Concentration risk, percentage                 77.40% 81.50% 74.90%
Broker Concentration Risk | Gross Premiums Written | Largest broker                      
Revenue, Major Customer [Line Items]                      
Largest broker                 $ 278,003 $ 161,405 $ 282,337
Concentration risk, percentage                 55.40% 49.80% 52.70%
Broker Concentration Risk | Gross Premiums Written | 2nd largest broker                      
Revenue, Major Customer [Line Items]                      
Largest broker                 $ 110,246 $ 61,809 $ 119,117
Concentration risk, percentage                 22.00% 19.10% 22.20%
Broker Concentration Risk | Gross Premiums Written | 3rd largest broker                      
Revenue, Major Customer [Line Items]                      
Largest broker                 $ 0 $ 40,773 $ 0
Concentration risk, percentage                 0.00% 12.60% 0.00%

v3.3.1.900
SEGMENT REPORTING Schedule of Gross Premiums Written by Line of Business (Details) - USD ($)
$ in Thousands
3 Months Ended 12 Months Ended
Dec. 31, 2015
Sep. 30, 2015
Jun. 30, 2015
Mar. 31, 2015
Dec. 31, 2014
Sep. 30, 2014
Jun. 30, 2014
Mar. 31, 2014
Dec. 31, 2015
Dec. 31, 2014
Dec. 31, 2013
Segment Reporting Information [Line Items]                      
Gross premiums written $ 144,884 $ 134,568 $ 92,990 $ 129,682 $ 74,268 $ 97,200 $ 33,654 $ 118,901 $ 502,124 $ 324,023 $ 535,702
Gross premiums by line of business as a percentage of total gross premiums                 100.00% 100.00% 100.00%
Total Property                      
Segment Reporting Information [Line Items]                      
Gross premiums written                 $ 111,391 $ 102,538 $ 214,585
Gross premiums by line of business as a percentage of total gross premiums                 22.20% 31.60% 40.00%
Aviation                      
Segment Reporting Information [Line Items]                      
Gross premiums written                 $ 691 $ 391 $ 168
Gross premiums by line of business as a percentage of total gross premiums                 0.10% 0.10% 0.00%
Commercial                      
Segment Reporting Information [Line Items]                      
Gross premiums written                 $ 16,667 $ 11,529 $ 9,999
Gross premiums by line of business as a percentage of total gross premiums                 3.30% 3.60% 1.90%
Energy                      
Segment Reporting Information [Line Items]                      
Gross premiums written                 $ 2,009 $ 2,131 $ 659
Gross premiums by line of business as a percentage of total gross premiums                 0.40% 0.60% 0.10%
Motor physical damage                      
Segment Reporting Information [Line Items]                      
Gross premiums written                 $ 34,529 $ 24,008 $ 57,952
Gross premiums by line of business as a percentage of total gross premiums                 6.90% 7.40% 10.80%
Personal                      
Segment Reporting Information [Line Items]                      
Gross premiums written                 $ 57,495 $ 64,479 $ 145,807
Gross premiums by line of business as a percentage of total gross premiums                 11.50% 19.90% 27.20%
Total Casualty                      
Segment Reporting Information [Line Items]                      
Gross premiums written                 $ 313,479 $ 171,626 $ 284,740
Gross premiums by line of business as a percentage of total gross premiums                 62.40% 53.10% 53.20%
General liability (1)                      
Segment Reporting Information [Line Items]                      
Gross premiums written                 $ 28,355 $ 11,639 $ (815) [1]
Gross premiums by line of business as a percentage of total gross premiums                 5.60% 3.60% (0.20%) [1]
Marine liability                      
Segment Reporting Information [Line Items]                      
Gross premiums written                 $ 9,283 $ 5,120 $ 1,956
Gross premiums by line of business as a percentage of total gross premiums                 1.80% 1.60% 0.40%
Motor liability                      
Segment Reporting Information [Line Items]                      
Gross premiums written                 $ 203,624 $ 127,858 $ 253,698
Gross premiums by line of business as a percentage of total gross premiums                 40.60% 39.50% 47.40%
Professional liability                      
Segment Reporting Information [Line Items]                      
Gross premiums written                 $ 72,217 $ 27,009 $ 29,901
Gross premiums by line of business as a percentage of total gross premiums                 14.40% 8.40% 5.60%
Total Specialty                      
Segment Reporting Information [Line Items]                      
Gross premiums written                 $ 77,254 $ 49,859 $ 36,377
Gross premiums by line of business as a percentage of total gross premiums                 15.40% 15.30% 6.80%
Financial                      
Segment Reporting Information [Line Items]                      
Gross premiums written                 $ 7,824 $ 5,292 $ 3,498
Gross premiums by line of business as a percentage of total gross premiums                 1.60% 1.60% 0.70%
Health                      
Segment Reporting Information [Line Items]                      
Gross premiums written                 $ 56,784 $ 43,837 $ 37,094
Gross premiums by line of business as a percentage of total gross premiums                 11.30% 13.50% 6.90%
Workers’ compensation (1)                      
Segment Reporting Information [Line Items]                      
Gross premiums written                 $ 12,646 $ 730 $ (4,215) [1]
Gross premiums by line of business as a percentage of total gross premiums                 2.50% 0.20% (0.80%) [1]
[1] The negative balance represents reversal of premiums due to premium adjustments, termination of contracts or premiums returned upon novation or commutation of contracts.

v3.3.1.900
SEGMENT REPORTING Geographic information (Details) - USD ($)
$ in Thousands
3 Months Ended 12 Months Ended
Dec. 31, 2015
Sep. 30, 2015
Jun. 30, 2015
Mar. 31, 2015
Dec. 31, 2014
Sep. 30, 2014
Jun. 30, 2014
Mar. 31, 2014
Dec. 31, 2015
Dec. 31, 2014
Dec. 31, 2013
Revenue from External Customer [Line Items]                      
Gross premiums written $ 144,884 $ 134,568 $ 92,990 $ 129,682 $ 74,268 $ 97,200 $ 33,654 $ 118,901 $ 502,124 $ 324,023 $ 535,702
Gross premiums by geographical area as a percentage of total gross premiums                 100.00% 100.00% 100.00%
U.S. and Caribbean                      
Revenue from External Customer [Line Items]                      
Gross premiums written                 $ 383,236 $ 275,402 $ 496,949
Gross premiums by geographical area as a percentage of total gross premiums                 76.30% 85.00% 92.80%
Worldwide (1)                      
Revenue from External Customer [Line Items]                      
Gross premiums written [1]                 $ 104,336 $ 31,106 $ 9,821
Gross premiums by geographical area as a percentage of total gross premiums [1]                 20.80% 9.60% 1.80%
Europe                      
Revenue from External Customer [Line Items]                      
Gross premiums written                 $ 14,085 $ 17,432 $ 28,932
Gross premiums by geographical area as a percentage of total gross premiums                 2.80% 5.40% 5.40%
Asia                      
Revenue from External Customer [Line Items]                      
Gross premiums written                 $ 467 $ 83 $ 0
Gross premiums by geographical area as a percentage of total gross premiums                 0.10% 0.00% 0.00%
[1] "Worldwide" is comprised of contracts that reinsure risks in more than one geographic area and do not specifically exclude the U.S.

v3.3.1.900
QUARTERLY FINANCIAL RESULTS (UNAUDITED) (Details) - USD ($)
$ / shares in Units, $ in Thousands
3 Months Ended 12 Months Ended
Dec. 31, 2015
Sep. 30, 2015
Jun. 30, 2015
Mar. 31, 2015
Dec. 31, 2014
Sep. 30, 2014
Jun. 30, 2014
Mar. 31, 2014
Dec. 31, 2015
Dec. 31, 2014
Dec. 31, 2013
Revenues                      
Gross premiums written $ 144,884 $ 134,568 $ 92,990 $ 129,682 $ 74,268 $ 97,200 $ 33,654 $ 118,901 $ 502,124 $ 324,023 $ 535,702
Gross premiums ceded (3,219) (2,288) (1,868) (1,626) (2,088) (2,706) (2,759) (5,940) (9,001) (13,493) (2,780)
Net premiums written 141,665 132,280 91,122 128,056 72,180 94,494 30,895 112,961 493,123 310,530 532,922
Change in net unearned premium reserves (21,750) (30,286) 563 (33,263) 3,025 (15,003) 56,960 (1,272) (84,736) 43,710 14,977
Net premiums earned 119,915 101,994 91,685 94,793 75,205 79,491 87,855 111,689 408,387 354,240 547,899
Net investment income (loss) (45,468) (191,322) (20,305) (24,829) 72,820 (54,027) 113,932 (10,150) (281,924) 122,575 218,140
Other income (expense), net (699) (542) (3,760) 1,588 1,542 2,663 (1,400) 182 (3,413) 2,987 (1,710)
Total revenues 73,748 (89,870) 67,620 71,552 149,567 28,127 200,387 101,721 123,050 479,802 764,329
Expenses                      
Loss and loss adjustment expenses incurred, net 79,816 97,421 76,653 63,207 57,951 53,028 56,644 67,363 317,097 234,986 338,493
Acquisition costs, net 33,281 32,146 23,939 26,841 21,821 22,478 25,570 37,796 116,207 107,665 171,872
General and administrative expenses 4,998 5,382 6,894 6,160 6,729 6,012 5,559 6,200 23,434 24,500 20,958
Total expenses 118,095 134,949 107,486 96,208 86,501 81,518 87,773 111,359 456,738 367,151 531,323
Income (loss) before income tax expense (44,347) (224,819) (39,866) (24,656) 63,066 (53,391) 112,614 (9,638) (333,688) 112,651 233,006
Income tax (expense) benefit 361 1,233 (54) 215 (204) 254 14 560 1,755 624 (538)
Net income (loss) including non-controlling interest (43,986) (223,586) (39,920) (24,441) 62,862 (53,137) 112,628 (9,078) (331,933) 113,275 232,468
Loss (income) attributable to non-controlling interest in joint venture 881 3,909 324 394 (2,174) 1,369 (3,075) 197 5,508 (3,683) (6,769)
Net income (loss) $ (43,105) $ (219,677) $ (39,596) $ (24,047) $ 60,688 $ (51,768) $ 109,553 $ (8,881) $ (326,425) $ 109,592 $ 225,699
Earnings (loss) per share                      
Basic $ (1.17) $ (5.98) $ (1.06) $ (0.65) $ 1.62 $ (1.40) $ 2.94 $ (0.24) $ (8.90) $ 2.94 $ 6.13
Diluted $ (1.17) $ (5.98) $ (1.06) $ (0.65) $ 1.60 $ (1.40) $ 2.89 $ (0.24) $ (8.90) $ 2.89 $ 6.01
Weighted average number of ordinary shares used in the determination of earnings and loss per share                      
Weighted average shares outstanding - basic 36,720,454 36,710,216 37,303,265 37,173,008 37,356,187 36,984,650 37,246,922 36,808,386 36,670,466 37,242,687 36,838,128
Weighted Average Number of Shares Outstanding, Diluted 36,720,454 36,710,216 37,303,265 37,173,008 37,905,836 36,984,650 37,902,106 36,808,386 36,670,466 37,874,387 37,585,167

v3.3.1.900
SCHEDULE I (Details)
$ in Thousands
Dec. 31, 2015
USD ($)
Summary of Investments, Other than Investments in Related Parties, Reportable Data [Line Items]  
Cost $ 1,209,277
Fair Value 1,064,164
Balance Sheet Value 1,064,164
Debt instruments, trading, at fair value  
Summary of Investments, Other than Investments in Related Parties, Reportable Data [Line Items]  
Cost 45,471
Fair Value 39,087
Balance Sheet Value 39,087
Equities – listed  
Summary of Investments, Other than Investments in Related Parties, Reportable Data [Line Items]  
Cost 1,011,424
Fair Value 890,653
Balance Sheet Value 890,653
Exchange traded funds  
Summary of Investments, Other than Investments in Related Parties, Reportable Data [Line Items]  
Cost 31,570
Fair Value 15,341
Balance Sheet Value 15,341
Listed equity securities  
Summary of Investments, Other than Investments in Related Parties, Reportable Data [Line Items]  
Cost 1,042,994
Fair Value 905,994
Balance Sheet Value 905,994
Total investments, trading  
Summary of Investments, Other than Investments in Related Parties, Reportable Data [Line Items]  
Cost 1,088,465
Fair Value 945,081
Balance Sheet Value 945,081
Commodities  
Summary of Investments, Other than Investments in Related Parties, Reportable Data [Line Items]  
Cost 102,092
Fair Value 98,046
Balance Sheet Value 98,046
Private and unlisted equity securities  
Summary of Investments, Other than Investments in Related Parties, Reportable Data [Line Items]  
Cost 18,720
Fair Value 21,037
Balance Sheet Value 21,037
Total other investments, at fair value  
Summary of Investments, Other than Investments in Related Parties, Reportable Data [Line Items]  
Cost 120,812
Fair Value 119,083
Balance Sheet Value $ 119,083

v3.3.1.900
SCHEDULE II Condensed Balance Sheets (Details) - USD ($)
$ in Thousands
Dec. 31, 2015
Dec. 31, 2014
Dec. 31, 2013
Dec. 31, 2012
Assets        
Cash and cash equivalents $ 112,162 $ 12,030 $ 3,722 $ 21,890
Notes receivable 25,146 1,566    
Total assets 2,712,522 2,995,292    
Liabilities        
Total liabilities 1,863,749 1,801,251    
Equity        
Share capital 3,703 3,738    
Additional paid-in capital 496,401 500,553    
Retained earnings 325,287 660,860    
Shareholders’ equity attributable to shareholders 825,391 1,165,151    
Total liabilities and equity 2,712,522 2,995,292    
Parent Company        
Assets        
Cash and cash equivalents 6 1 $ 5 $ 14
Investment in subsidiaries 840,196 1,148,308    
Notes receivable 2,175 1,566    
Due from subsidiaries 0 15,276    
Total assets 842,377 1,165,151    
Liabilities        
Due to subsidiaries 16,986 0    
Total liabilities 16,986 0    
Equity        
Share capital 3,703 3,738    
Additional paid-in capital 496,401 500,553    
Retained earnings 325,287 660,860    
Shareholders’ equity attributable to shareholders 825,391 1,165,151    
Total liabilities and equity $ 842,377 $ 1,165,151    

v3.3.1.900
SCHEDULE II Condensed Statements of Income (Details) - USD ($)
$ in Thousands
3 Months Ended 12 Months Ended
Dec. 31, 2015
Sep. 30, 2015
Jun. 30, 2015
Mar. 31, 2015
Dec. 31, 2014
Sep. 30, 2014
Jun. 30, 2014
Mar. 31, 2014
Dec. 31, 2015
Dec. 31, 2014
Dec. 31, 2013
Revenues                      
Total revenues $ 73,748 $ (89,870) $ 67,620 $ 71,552 $ 149,567 $ 28,127 $ 200,387 $ 101,721 $ 123,050 $ 479,802 $ 764,329
Expenses                      
General and administrative expenses 4,998 5,382 6,894 6,160 6,729 6,012 5,559 6,200 23,434 24,500 20,958
Net income (loss) before equity in earnings of consolidated subsidiaries (44,347) (224,819) (39,866) (24,656) 63,066 (53,391) 112,614 (9,638) (333,688) 112,651 233,006
Net income (loss) $ (43,105) $ (219,677) $ (39,596) $ (24,047) $ 60,688 $ (51,768) $ 109,553 $ (8,881) (326,425) 109,592 225,699
Parent Company                      
Revenues                      
Investment income                 5,962 671 1,100
Total revenues                 5,962 671 1,100
Expenses                      
General and administrative expenses                 4,048 3,806 3,735
Net income (loss) before equity in earnings of consolidated subsidiaries                 1,914 (3,135) (2,635)
Equity in earnings of consolidated subsidiaries                 (328,339) 112,727 228,334
Net income (loss)                 $ (326,425) $ 109,592 $ 225,699

v3.3.1.900
SCHEDULE II Condensed Statements of Cash Flows (Details) - USD ($)
$ in Thousands
3 Months Ended 12 Months Ended
Dec. 31, 2015
Sep. 30, 2015
Jun. 30, 2015
Mar. 31, 2015
Dec. 31, 2014
Sep. 30, 2014
Jun. 30, 2014
Mar. 31, 2014
Dec. 31, 2015
Dec. 31, 2014
Dec. 31, 2013
Cash provided by (used in) operating activities                      
Net income (loss) $ (43,105) $ (219,677) $ (39,596) $ (24,047) $ 60,688 $ (51,768) $ 109,553 $ (8,881) $ (326,425) $ 109,592 $ 225,699
Adjustments to reconcile net income to net cash provided by (used in) operating activities                      
Share-based compensation expense, net of forfeitures                 4,274 3,964 3,675
Net change in                      
Net cash (used in) provided by operating activities                 (59,945) (133,732) (92,697)
Investing activities                      
Change in notes receivable, net                 2,279 18,983 3,281
Net cash (used in) provided by investing activities                 177,686 142,040 74,016
Financing activities                      
Net proceeds from exercise of stock options                 0 0 513
Short-swing sale profit from shareholder                 83 0 0
Repurchase of Class A ordinary shares                 (17,692) 0 0
Net cash (used in) provided by financing activities                 (17,609) 0 513
Net increase (decrease) in cash and cash equivalents                 100,132 8,308 (18,168)
Cash and cash equivalents at beginning of the period       12,030       3,722 12,030 3,722 21,890
Cash and cash equivalents at end of the period 112,162       12,030       112,162 12,030 3,722
Parent Company                      
Cash provided by (used in) operating activities                      
Net income (loss)                 (326,425) 109,592 225,699
Adjustments to reconcile net income to net cash provided by (used in) operating activities                      
Equity in earnings of consolidated subsidiaries                 328,339 (112,727) (228,334)
Share-based compensation expense, net of forfeitures                 4,274 3,964 3,675
Net change in                      
Due from subsidiaries                 15,276 971 (2,006)
Due to subsidiaries                 16,986 (3,808) 2,438
Net cash (used in) provided by operating activities                 38,450 (2,008) 1,472
Investing activities                      
Change in notes receivable, net                 (609) 2,162 (2,053)
Contributed surplus to subsidiaries, net                 20,227 158 (59)
Net cash (used in) provided by investing activities                 (20,836) 2,004 (1,994)
Financing activities                      
Net proceeds from exercise of stock options                 0 0 513
Short-swing sale profit from shareholder                 83 0 0
Net cash (used in) provided by financing activities                 (17,609) 0 513
Net increase (decrease) in cash and cash equivalents                 5 (4) (9)
Cash and cash equivalents at beginning of the period       $ 1       $ 5 1 5 14
Cash and cash equivalents at end of the period $ 6       $ 1       6 1 5
Common Class A [Member] | Parent Company                      
Financing activities                      
Repurchase of Class A ordinary shares                 $ (17,692) $ 0 $ 0

v3.3.1.900
SCHEDULE III (Details) - USD ($)
$ in Thousands
12 Months Ended
Dec. 31, 2015
Dec. 31, 2014
Dec. 31, 2013
Supplementary Insurance Information [Abstract]      
Deferred acquisition costs, net $ 59,823 $ 34,420 $ 51,797
Reserves for losses and loss adjustment expenses – gross 305,997 264,243 329,894
Unearned premiums – gross 211,954 128,736 173,057
Net premiums earned 408,387 354,240 547,899
Net investment income (loss) (281,924) (122,575) (218,140)
Net losses, and loss adjustment expenses 317,097 234,986 338,493
Amortization of deferred acquisition costs 116,207 107,665 171,872
Other operating expenses 23,434 24,500 20,958
Gross premiums written $ 502,124 $ 324,023 $ 535,702

v3.3.1.900
SCHEDULE IV (Details) - USD ($)
$ in Thousands
3 Months Ended 12 Months Ended
Dec. 31, 2015
Sep. 30, 2015
Jun. 30, 2015
Mar. 31, 2015
Dec. 31, 2014
Sep. 30, 2014
Jun. 30, 2014
Mar. 31, 2014
Dec. 31, 2015
Dec. 31, 2014
Dec. 31, 2013
Reinsurance Premiums for Insurance Companies, by Product Segment [Line Items]                      
Net premiums earned $ 119,915 $ 101,994 $ 91,685 $ 94,793 $ 75,205 $ 79,491 $ 87,855 $ 111,689 $ 408,387 $ 354,240 $ 547,899
Property & Casualty                      
Reinsurance Premiums for Insurance Companies, by Product Segment [Line Items]                      
Direct gross premiums                 0 0 0
Premiums ceded to other companies                 9,001 13,493 2,780
Premiums assumed from other companies                 502,124 324,023 535,702
Net premiums earned                 $ 493,123 $ 310,530 $ 532,922
Percentage of amount assumed to net                 102.00% 104.00% 101.00%

IDEA: XBRL DOCUMENT
begin 644 Financial_Report.xlsx
M4$L#!!0    ( .""5D@=SB.R60(  .@R   3    6T-O;G1E;G1?5'EP97-=
M+GAM;,W;W6Z;,!3 \5>)MV%+Y$-I\R'$Y[,[;?T7W884XM"(*7#\C*,Q+MZG
MH!NLT97;&N/;)G+^L3'N7/UCY+GRK5GK^\:_JO#3O8NL::8U;EL/3Z4^'T(6
M%WY;S4/4O:C"Z<9_=5:WX]"&;O/'CO'\/Z_EY";NV^;6ZH?ZI,#^8F,:CU&K
MZ^[%65J1:##0NMK\\\)6'Q78@Z$5*_J?;SDU+VUKRH
MX+CP@B_%5EM3??,VS/?\N_'[@LOU,[%    *P( 
M  L   !?.0Q(OW[CMB PD.MQ-*O>X^NO ZIK XTHO8<4M?'5$Q^#*G*_=ITJK$"2+8C
MCVG!D4*>-BP>-9?20D0[8$NP+,L5R*V.V:SGVL7.U49V[M,41Y26M#;3"&>6
MX9MY6&3I//B)]!=C;IK>TI;MR5/0!_ZS#0//>997'L=V+YRO+0O]C^AY%.!)
MT:'B1?4C9@,2[2F]@OIZ (4QOCLEFI2"(S>C@KN_V/P"4$L#!!0    ( .""
M5D@(76=8I (  /(S   :    >&PO7W)E;',O=V]R:V)O;VLN>&UL+G)E;'/%
MV\MNVD 8AN%;0;Z F#E/4,@JFVR;WH %PT$!&]FNVMQ]7!85/?A3%TCO!H0M
MS;RK1];XYZD=EJLOY=2,QZX=#L?+L/AQ/K7#:KJ^K@[C>%G5]; YE',S/'27
MTDYW=UU_;L;I9[^O+\WFO=F7VBZ7L>YOUZF>G_Y<>_&Z75?]Z]94BZ]-OR_C
MNOK>]>_#H91QJ*]?YF':8+K]<2G_LWVWVQTWY:7;?#N7=OQ'1?UK@ZJ>#[+S
M018)"0KS00$)BO-!$0E*\T$)"IP/>D2"S%+(N&22
M%-:,UD9P;1BOC0#;,&(;0;9AS#8";<.H;03;AG';"+@-([<1=!O&;B/P-HS>
M5NAM&;VMT-M"S]KJ89O1VPJ]+:.W%7I;1F\K]+:,WE;H;1F]K=#;,GI;H;=E
M]+9";\OH[83>CM';";T=H[<3>COHK$0=EC!Z.Z&W8_1V0F_'Z.V$WH[1VPF]
M':.W$WH[1F\G]':,WE[H[1F]O=#;,WI[H;=G]/9";P^==:O#;D9O+_3VC-Y>
MZ.T9O;W0VS-Z>Z&W9_3V0F_/Z!V$WH'1.PB] Z-W$'H'1N\@] Z,WD'H':!W
ME>IE):-W$'H'1N\@] Z,WD'H'1B]@] [,'I'H7=D](Y"[\CH'87>D=$["KTC
MHW<4>D=&[RCTCM"LB1HV8?2.0N_(Z!V%WI'1.PJ](Z-W$GHG1N\D]$Z,WDGH
MG1B]D] [,7HGH7=B]$Y"[\3HG83>"9H55,."C-Y)Z)T8O9/0.S%Z9Z%W9O3.
M0N_,Z)V%WIG1.PN],Z-W%GIG1N\L],Z,WEGHG1F]L] [0[/>-WH/AZ8OV[>Q
M/[;[X=XUORTNBV[P'L:/4[E_RG55.7!^H_4X[53JZ^?=4;RN^C.D_NOO/<^?
M4$L#!!0    ( .""5D@+<\$+'P0  -,3   0    9&]C4')O<',O87!P+GAM
M;+U8WW.B.A3^5S(^]3[LXFIKO1W7&8JI!)<'=O6]9B)4I@D-2I[U__0VA
M6FQ#*#ZL+X;D^W)R?N4>[&\-@T89N
M"?LL()E87>?%EG#Q6-P;^7J=1'261X];FG%CT.^/#/K$:1;3^-/NN&EO.BFE
MF+M=FD2$)WDV7291D;-\S0%\BF@Z,=X")$/LC&CT6"3\>=JO,/4IB4$12:DE
M9$W7)&6T0KU.2HR5;WS:J)R?)'EBXP_F,<%IGG2Y4NV](06,A]&3WXZ3$
M+)Z%GFG)M38DNZ=Q'?M^\6"+%2U8J>F7P>>^^!U-<)BO]J8D3K)[GR0%FT[V
M_&9/(YX7+V[:\W.]%.=1Z72VPN)\K =^$T;+X=?>GA0)R7@/L.0_\3CH56*K
M63E.=XP7TQ]Y\< VE'(V,8Z3
M4N:M?5+P/V0*J=/!$./K7DW[PQ; S&( ,R["$=A9)4HXKVZ2X\CR7.0Y]LS$
M< 9N3<=T+0C0 D*,NN+!A4_:.0B+OR5T!=Z[ [9K>5TY:&$&73F6B19*CA?,
M3=?^U\2VYP+3+75"MJ3X 410R4'VW+7O;,MT,3 MRPM=;+MSX O9E@W5=KNS
M76$JVW2$R@@'H3R9$CD+(<">$&\O(;@-O&\P:'"%T$D>60[@]]!>F4[CMD(;
M'-A6:1H54LM2E/2/$NQ"+$RZ@B\G*P-JJ78;-G\V;Q- 1X:-;P;X%\"!*61:
M);HI#99+&U?A)2WIR1B ;F, (#B7!PR@[P4E5HGZ'@KY,'!^@=> $9X+G3*]
MP@:#6@LX"QT([);EUO4VP*I[.@RNS^",/YY"X *3W^(._JM;BE2T[HDR_-(]
M48:#]CS0J]&4$"^LC^>%7LPA05ILJ@M]+T&;!\.^V,-9OKKWQ+]7^
MU8;K98-_M9SA&9S+,SA7'5+I+LE(%B5$G1=J#A)]3?R84M!%CFB@P(JDCQTX
M#MW3% Q!T?UL5_TS..HXT'/4<:#GJ.- S7'-E>CGQ/H9
MT^6Z/W#4EX"6,U+'@:K? AZ'==RKAOZNW<%_U@H\C50O[[I.>I^^3UG3O/[@NPV2002
M]2NOMKL8-S0 Q^ZB+>9K;8B59S'-&(W!+4G%C4I!PZN!DH,XX;1\G>_.&:O3
MO-[I?UB-E1KY[N/(FT\AQNDGO.G_4$L#!!0    ( .""5DA-5]9=/@$  &D#
M   1    9&]C4')O<',O8V]R92YX;6S-DTU/PS ,AO\*ZKU+FXD=HJX'0)R8
MA,00B%M(O"VL^5#BJ>N_)\NZEL$NNW&K:[^/7\=))1P3UL.SMPX\*@@W>]V8
MP(2;9QM$QP@)8@.:ATFL,#&YLEYSC*%?$\?%EJ^!T**8$0W()4=.#L#<#<2L
MKJ1@P@-'ZWN\% />[7R38%(0:$"#P4#*24FR^M5LC6U-149]747'#0^XL%*M
M%,B[;BS[FXJ=$;P.1SG(H7WZ>]%#RI"LK]P'-52U;3MIIZDN#ER2]\732SJ;
M7)F W B(JJ 8=@[FV:GSV_3^8?F8U;0H9WE!7$U>VMKX[IGY%9Z^J_@902P,$%     @ X()62)E&UL[5I;<]HX%'[OK]!X9_9M
M"\8V@;:T$W-I=MNTF83M3A^%$5B-;'EDD81_OTV23;J;/ 0LZ?O.
M14?GZ#AY\^XN8NB&B)3R>	+]O6N[!3+UES@6QHO(];JM-O=5H1I;*$81V1@?5XL:$#05%%:
M;U\@M.4?,_@5RU2-9:,!$U=!)KF(M/+Y;,7\VMX^9<_I.ATR@6XP&U@@?\YO
MI^1.6HCA5,+$P&IG/U9KQ]'22(""R7V4!;I)]J/3%0@R#3LZG5C.=GSVQ.V?
MC,K:=#1M&N#C\7@XMLO2BW A(5M>5 TR  6'!VULS2 Y9>*?IUE!K9';O=05SP6.XYB1'^QL4$
MUFG2&98T1G*=D 4. #?$T4Q0?*]!MHK@PI+27)#6SRFU4!H(FLB!]4>"(<7<
MK_WUE[O)I#-ZG7TZSFN4?VFK :?MNYO/D_QSZ.2?IY/734+.<+PL"?'[(UMA
MAR=N.Q-R.AQG0GS/]O:1I24RS^_Y"NM./&K;YH]5Z%82=J$^!!&&N*<<^9ST6S[!Z5&T?95O-RCEU@5
M 9<8WS2J-2S%UGB5P/&MG#P=$Q+-E L&08:7)"82J3E^34@3_BNEVOZKR2.FJW"$2M"/F(9-AIRM1:!MG&IA&!:$L;1>$[2M!'\6:PUDSY@R.S-
MD77.UI$.$9)>-T(^8LZ+D!&_'H8X2IKMHG%8!/V>7L-)P>B"RV;]N'Z&U3-L
M+([W1]072N0/)J<_Z3(T!Z.:60F]A%9JGZJ'-#ZH'C(*!?&Y'C[E>G@*-Y;&
MO%"N@GL!_]':-\*K^(+ .7\N?<^E[[GT/:'2MSAD6R4)RU3393>*$IY"&V[I4_5*E=?EK[DHN#Q;Y.FOH70^+,_Y/%_G
MM,T+,T.WF)&Y"M-2D&_#^>G%>!KB.=D$N7V85VWGV-'1^^?!4;"C
M[SR6'<>(\J(A[J&&F,_#0X=Y>U^89Y7&4#04;6RL)"Q&MV"XU_$L%.!D8"V@
M!X.O40+R4E5@,5O& RN0HGQ,C$7H<.>77%_CT9+CVZ9EM6ZO*7<9;2)2.<)I
MF!-GJ\K>9;'!51W/55ORL+YJ/;053L_^6:W(GPP13A8+$DACE!>F2J+S&5.^
MYRM)Q%4XOT4SMA*7&+SCYL=Q3E.X$G:V#P(RN;LYJ7IE,6>F\M\M# DL6XA9
M$N)-7>W5YYNTB42%(JP# 4A%W+C[^^3:G>,U_HL@6V$5#)DU1?*0XG!/3-R0]A4
M)?.NVB8+A=OB5,V[&KXF8$O#>FZ=+2?_VU[4/;07/4;SHYG@'K.'YA,L0Z1^P7V*BH 1JV*^NJ]/^26<.[1[\8$@F_S6
MVZ3VW> ,?-2K6J5D*Q$_2P=\'Y(&8XQ;]#1?CQ1BK::QK<;:,0QY@%CS#*%F
M.-^'19H:,]6+K#F-"F]!U4#E/]O4#6CV#30,9FV-J/D3@H\W/[O#;#"
MQ([A[8N_ 5!+ P04    " #@@E9(%>Y),Y<"   2#P  #0   'AL+W-T>6QE
M9+D[LF#J7[F;_T?&Y?.<[TI$Y#G*UIOA^@;$"*T9Y'L*%4ME[S\MG
M"\Q0WA,9YMJ2"LF0TJ]R[N69Q"C)31"CWL#WAQY#A,,HX 6;,)6#F2BX"N%X
MJP(N_E8D.(0/YV^_%T+=O %N/7MW=N8_7-PT]>?6< &!P_B8A+ _O(+>\: ]
MOQU7VQK0P].@]R W@$UO
M.P\;A$EL21&F2)&Z-JI;1I[F4H_1KB0-K?+T,S3\ZM,
M9+HX+CAU)ZW? >R[1
MNC^XJ@781>>-A4RPW&;NPXTJ"BA.E0Z09+XPJQ*9H2Z4$DP+"4%SP1$UD)N(
M4M"P,TSIO?ET?4MWL%B%*LVL)OJU=$<=AUV^"I=+^IA%F6H$E!$LL%9G5
M-8\295.\4F4'>ZNTC>%K2_Z;G/[\KE5L= O^Z^WYK\GK9V.O(6SP.>(H[@H6
M8SFQ7^G3B5V.NLK,3!J=I3;L+K4.'^BXN]2NNTKMLK/,S S:66K][E(;_"8U
MKYR/:D/8S@BVU8*X(%01ON& S-!\9WC3G>FH&K\T9K*J)B]K52C6/Z@[6318
M@E-44/6%+(6RQA!6\B=#7X]M&Z_I%B*$E?P9)Z1@]B?(J_Z"HU]02P,$%   
M  @ X()62+1B.+$N!@  K!H   \   !X;"]W;W)K8F]O:RYX;6R5F5USFS@4
MAO^*AJOLQ6[,-\TTG2$V2=AUP 6<;?=.L>5:4PP>P$VWOWX%CI.7Y)B-KPR8
M\R")A\.1^%A?/);5]X>R_,Y^;O*BOJ@NM773;"_.S^O%6FQX_4>Y%87Z;U56
M&]ZHW>K;>;E:R868E(O=1A3-N3$:.>>5R'DCRZ)>RVVM/='J]]#J;27XLEX+
MT6SR/6S#9:%]^EA?K&0N[D55*S#CVVW$-^)2^YEK+.=U$RQE(Y:7FJ5VRT?1
M.U#MME<[F;<[]LC6SEO8H:NSBBW*I=C#LK6L_W[Z0V-+L>*[O,E48P_7O=1T
MPS(,9\]H3[N7XK%&8'N \44C?XB,/UQJ(XWQ75->R[P1U80WXJ8J=UM9?%,L
MC:UD53=IV]WNS(TLY$;^:MNM]NIU^7A;5O)7630\3Q=5F>==5/M'%Z2N4#\?
M46ULY*)W8L,?DO9.7&K.2 %_R%H^R%PV_UYJW78NVIZPNZ#B-UHT)_JL8VS9)Y
MUS$(_P#A']Z&3^8!RV+5^O N8%=)_%>08+0^0O%&Q,BJX>L&HML(/L_#>W_Z
MJ@EZSUY"7S5T61*.VYM#\1"%#NN$Q-,X3;OX_<;DSWF:M4/"@B^S(.JU"BW6
M"8V3($OB<9"FZEYC'$JK$]:V:@:J_;,P\Z<8B)+JA*5=X._*J'8&%IG4-:]A/7B4#J#DNXY[A[#T#.#\&PP?QDNHM XX]14:'B(0A&-]R9#
M=J;>Z;FH?T,2RFA0,A[+:WL:O@Q11Y/0<3"[F3JB4$Z3D',PNYD&HE!.DY(3
MLQ0U1&;O+4^)>B1=/<$0A?*:A+QDUB(;A3J;A,Z']$4&H]0F(?5@!F)GB$*I
M34KJUSF(;!#Z;!(^#R8C\P.B4&B3$!KR ]44"RVV"(L'*Q\++;;08HNP>/"!
MM]!B"RVV*(L'42:B4&>+TGD092&J5[92N7@092,*?;8(G^F,=BT+7BPDQSQD
MH=T683>-2M7,<;G+!4,4VFT1=A]I%9<5N^?Y#E&HN/7NE#T5/T3.3%8A"A6W
M",4'.VB/<+J MMN$[<,HM-U&VVW"]F$4VFZC[39A^S *;;?1=INPG49%_KV:
M@-8-#KN-MMN$[<.M0MOMWC3M5-MM!U%HNWVJ[386*#;:;K_;]@,*"Q0;;;??
M;?L!A0G=1MOM4VUWT'8';7<(VZE)(#N;B(;+O/>6<%!VAUJ(.%XVM3A$H>P.
M(?M@V>2@[ [*[A"R#Y9-#J9V!V5W"-F'42B[@[([A.PXOZ1'N[<8017A_1J.
M0J#;#E6G'"OB(EY5O$$4NNT0;A]%)4)E%(DH=-NABI5CJ*N<+[[CJ\I%MUUJ
M,G@,E:YYU7OKN2BW2]4M0QUT,9.[*+=+R'VDX"7NH(MRNX3<+Q4O%8T^NX3/
MQZ?N'0]1Z+-++K(-5<^X$N*BV.ZIA;B+R=OMK;.]JQ!_KGC*%<,U1!<%=RG!
M!U&XRN"BX"XE^!O4C2B_57R[E@LF<>770\$]0O#!.8*'I8J'@GN4X,]S!%(F
M#ZWV!A<\0C8NBZ4H:K%D5SQ7KV_!>HN::+4WO H"J+3AC6A7S!&%BGO#*R-O
M41ZF; \5]P872\(C0X1F>U3*?EENH0'HL^<^?4OH_NX^'RS%2A9BV7Y+]HN+^FGC=<.RVY6V=O^N7*HKMI]*-+;:Y?E8'8N+:&PO=V]R:W-H965T&ULC5;;;J,P$/T5Q <4>[A7!*E)M-I]6*GJP^ZSFS@)*N#4=IKN
MWZ]OT*9R@1>PS3ES9HR/-=65\1=QHE0&[UW;BU5XDO)\'T5B=Z(=$7?L3'OU
MY%I^9XDGHAJJMHY.V;CO:B87W Z6$5/N#[+8"&&,2?AE[%IW&@DW]F
M[$5/?NU7(=(YT);NI Y!U.N-;FC;ZDA*^=4%_=#4Q,_C(?H/4ZY*_YD(NF'M
MWV8O3RI;% 9[>B"75CZQZT_J:DAUP!UKA7D&NXN0K!LH8="1=_MN>O.^VB_)
M0/,3P!%@)$ Q28@=(1X).)DD)(Z0?"%$MA2S$5LB25UQ=@W$F>CC@>\5G.L@
M*G*@JA=J8TU,;K:VKMYJ5$5O.LP- @QB;1%X1$0JME< 0A\=#!V^%]A81/P]
M8FL1R7P*\6T*L:TQ-O1TGI[$+"06!>HO!*%&XG)B0<9,%Q
M*;T2I>6G$Q(.DLU+8.35,,LJ0C[QTQT&$%YP=#'VZSCW%A/%#)AR@0KX59S)
MO=?(H.(P"RX2'/M5K(_!>Y<,*@ZSP"38[W9LS0S)E(K#+/DO?LMCZVB8NE4&
MS)):_(['UM#@/66YO5L=ILC*&*4Y6N!][#<_MM:&8D&$+]YV]S0NEE[4V.]<
M;'T)Y?>NVCA,C HHXWC!WH+?P8!E%\,RDZEM,>W%@
M3%*5 [I+P^"D&M!QTM*#U,-Q$LO/088YM;OT?4$L#!!0    ( .""
M5DBBRRFQ6P0  !H5   8    >&PO=V]R:W-H965T&ULC9C=
M;N,V$$9?Q? #K#G#_\ QL%91M!<%%GO17BNQ$ALK6ZZDQ-NWKZ0999-=>LR;
M6%(.J8\4>41Q?6G:;]V^JOK%]V-]ZNZ7^[X_WZU6W>.^.I;=I^9R'T_9YU9W;JMQ-A8[U"I5RJV-Y."TWZ^G:EW:S;E[Z^G"JOK2+[N5X+-O_
MME7=7.Z7L)PO?#T\[_OQPFJS7KV5VQV.U:D[-*=%6SW=+S_#7:'MB$S$WX?J
MTKT[7HSA'YKFVWCRY^Y^J<8,55T]]F,5Y?#S6A5578\U#7?^ERO]<<^QX/OC
MN?;?I^8.\1_*KBJ:^I_#KM\/:=5RL:N>RI>Z_]I<_JBX#5/"QZ;NIK^+QY>N
M;XYSD>7B6'ZGW\-I^KW0?X+B8ND"R 7PK0 8L8#F OJG BM*-K7KM[(O-^NV
MN2RZFJS?MUH6*]>QWH^(#@A6T+P.E%P
M)3^0U7#_9 C\&((N?D8JKV^7UQ_+&RJOJ;SY&/$T(9X:P4A4P5^G"J),1,AH
MBTEF,70CF[J+HRR$1&5C3$8FK" ,T#GP]G88H$";P7;2S0>"*F8LN@KF=)R;S1)H,2LA#"&@$8;P77)$'GS%P0"7#
M3)>'2D!(PPP$'Z74Q::%/J,-&DK \G42%IF
M9@AC!%T6C(%U+B-.VLI ,I7NLV7&!5%F3(T%(6QD<3U I#3'H 2U*(IS!
M&"W&C+24BM(D9:B?V"
M7,^1-BJ2!IUD5&:T5^+8FRF=T2LZ[5--#G223YDQ@T^5M.IASBIE;FT3S4YT$D^92:@U5'L(_8I. LYTT%?
MV3X@"TKKK"TSJ'605C\S%D+,Z:*T4/6L02D/,<$$[Z5AS=SP9C+*Y'11VJJ:
M%Z-)J\Y;+/;6$G'>9;'"$G'U;A?K7#Y7?Y7M\^'4+1Z:OF^.T[[54]/TU5"1
M^F27BWU5[MY.ZNJI'P_]<-S2UAV=],UYWHE\VP[=_ ]02P,$%     @ X()6
M2+2_)C%X @  60H  !@   !X;"]W;W)KD*1[^P&?DR8M.&XN8B#G
M?/S 1X3BQ/BKJ"F5WEO7]F+EUU(.#T$@-C7MB%BP@?;JEQWC'9&JR_>!&#@E
M6V/JV@"'81ITI.G]LC!CS[PLV$&V34^?N2<.74?XOR?:LM/*1_YYX*79UU(/
M!&417'S;IJ.]:%CO<;I;^8_HH4*9EAC%[X:>Q%7;T_!KQEYUY^=VY8>:@;9T
M(W4)HAY'6M&VU974S'_'HN]S:N-U^US]NUFNPE\302O6_FFVLE:TH>]MZ8X<
M6OG"3C_HN(9$%]RP5IAO;W,0DG5GB^]UY V>36^>)_@ER4>;W8!' [X84#QI
MB$9#],$0 )E9USYD6 C>0()=BLJ4$3ODD#-;X7 MQ P^(@!(K_OCV[],?@C\"]O$7LCR6$1
M( D7R*VI/FN<'+&5(S8%LM V1PH<($E"^+B%E4/H)$JL1 D065<]$H%D"N6C
MPLF06AE2R,^,MYM9TY'-3D=NG3^'/< 3Z!<@0>']
M>+B43B846J',L***)ZA&311F&4[L^SA2G94(X64:SWAC"-FIX$3)DBDJ-)L*
M?94*VZGP...,"I$URBB:G65D/V)0?#_-HV8ZSA:1F\5^N*#D?J)'#4[N)MJE
M=%/9CQN4SD@T:%*
M>&LFU7W"_.WO&)-4%0H7B>_5ZIYWZ;1T)W4S4VT.-Q_H2#:<+W*7VV3Y'U!+
M P04    " #@@E9(]>)E(2()  " ,   &    'AL+W=O_C2U6=.O]L-[OCC^[+Z?1VV^\?'UZJ
M[?K8V[]5N_27I_UANSZECX?G_O'M4*T?SXVVF[X2PO6WZ]==]_[N_-V?A_N[
M_:_3YG57_7GH'']MM^O#_P;59O_^HRN[_,5?K\\OI_J+_OU=OVGW^+JM=L?7
M_:YSJ)Y^=/^0MROE:^1,_/NU>C]>_-ZI._]SO_^[_C!__-$5=1^J3?5PJDVL
MTX_?U;#:;&I+R?-_R>B'S[KAY>]L?7(>;NK^S_6Q&NXW_WE]/+VDWHINY[%Z
M6O_:G/[:O\\J&H.M#3[L-\?SOYV'7\?3?LM-NIWM^I_\\W5W_OF>_Q($-2LW
M4-1 -0T:/^4&FAKHCP8&-C#4P+1M8*F!;=O 40/7MH&G!KYM@T -0ML&D1K$
MM@UJS;-RXJ.)PTT:L65K+RRW5%^:]'-@G<-RM#ZM[^\.^_?.\6U=+U9Y6_.'
MVDXRWDG!>$QQ?C9[.$?Z_=WO>^_N^K]K0Y^0W&Y B+^.+#(B&Z*?.E#NA>J6
M7*AS>W7=PS 3/EQ'1ADQUXDQ&8G7D4E&-.C*-"-!7$=FA,CKR)P0X&CQ[:PL
MO^_MBOSH%MKHS]KH'"$Z&S M#)C/!DPV8+(!^[F3NS/BL_X9D<:$8*YC0\*T
ML2YJ9&1,E0EB938Z:< OV:L$>!/$Z9\@+8FC64!6.<$V6C*89,IA9$15&.
MA4PM>8S:Q*+(&5LU';O8O*YK[(H:NZRQ!QH[6LW2N>*B)Y$)TTEE, .CC$4I
M57&9DLID+)FR2.:,>261RRFY-"865Q;)G"DM0@2CG%/'ZGT&*+C(6))/EIEP7H8> HHZ2WHSI P+13:&T89LPY,P)A-
M:86PB2=M%)!F2K:D%0+8FG&WH@-CG+,QY4&8+H@*QFLP$\N,&>TE4MG3.HL7
MN=EUD4-1Y)!%!AO5(% $QRC1S*"0')3)3Q:#^;9,I;)9#,
M1$43P0*B8
M9Q3X&63DQEB##M0A83+66S=0.O*1JI$\8\9,4&!*)Y%V[J#0SDW&;,IVP,3/
M(LFHX]?<^9/:/%(AT?:VX!$$&H(5-V$U(_489&7'.
M.[06Q^Q56@LZ-R$L'6/6@>F:$I=6&5S:C*4S'#I86$CL@142D_!LMHS)1$R<*$
M*8\RPRE30H)^S;CW%A9EV-:5.AY+;7G5:I3O,68LLK9B3$0;VNA 4:PDUVC2+:K5CEXNTLA-@58XXIP4R-V5S5FMXE2=.2N4D/,O)
M7G1(T44S6JT=NK4L+_QBZ3UM'UIH'>C6C(UI@29]SL90YK,@
MR%J4@"P;CRZ@QVB,.>_:W.!5N7"CN  !GCX/"$HK7):+J/1DG#DEH_OZIL8E
M.&)01UN^$M#3\<:@$>6<@1Z/$^?$E:.1GH^S.2L]>HX^:R8EVG*)@)Z1L[UP
M)?[I&7DS6N5,^5$0/26_\%NNI-%CG@)%3=.Q\E87*&H("[WB]A0H9-JX7!'E>K*5U.6RC>*2 9C.
M 4'?2FW:26W:26W:26U8:J2T::4T%6UZY0=PK+1II[1II70;ERNB7$^T>@_.
MEC<&2TJWN1>H,>FU2!LN>N;7D#*Q
ML";P8=,ZB0KZTZ:?,:3K)LA>9XW-E*9%] ASWM@,]:-<5/UK2.>%0;?8Y85W
MY> #H@_O.DC5*J$L%PF41_L'1X1O'1&^=43XUA'A6T<$DU'8@-ZBF#;]_#XB
M/FPJB=[MFC -Y6A^?SB^W'SL/^
MU^Z4W^YLOFU>GO]#U6\0?_E^(&_GLO#]0MZN\JOQ'^;O[][6S]6_UH?GU]VQ
M\W-_.NVWY[>+G_;[4Y4Z+7JVVWFIUH_-ATWU=*I_]>GW0WY!/G\X[=_X??_F
M/QW<_Q]02P,$%     @ X()62$5QB[/A!   AQP  !@   !X;"]W;W)KP:,%X@\>R_7T MQ[&EEO8EON3KH_;!J(]A?6Z[G_V^JH;%KZ8^]D_+_3"<
M'E>K_F5?-67_K3U5Q_$_KVW7E,/XLGM;]:>N*G=S45.O:!"(55,>CLO->G[O
M>[=9M^]#?3A6W[M%_]XT9??OMJK;\].2+/4;/PYO^V%Z8[59KRYUNT-3'?M#
M>UQTU>O3\C?R*"F?D)GXZU"=^ZOGBZGYY[;].;WX8_>T#*8>JKIZ&2:)E<>5_0/1SS:GP^KE6+^:/.[;_7/95VM9_'W;#?NPV6"YVU6OY7@\_
MVO/O%7R&N<.7MN[GOXN7]WYH&UVR7#3E+_5X.,Z/9_6?.( R\FT1&Y<5X0/KQ6,^:W7RT-^N/#0FB]>IC$OK"T)G9
M:B:V,ZEF$CN3*480.Y(#0NU( 2N1P,Y(D DOR&HTQ.@*_>I*J%RAL,9-J\>9
M485;Q<0B"&];N<92A3$1(5"FH#"AH4CL6 Y:E',,*Z S2J+;0W:-25"+HX"Z
M?6)??6+*)P8^>0B$1J-#$&"F/H4R6C&<1G8F50SC=B0+M<=V)E>,\4@IHO!H
M1MZJ6#WA1D\X>!(BGBCF83QO;\^5+[9PU^?)G$3N) HG(8WM6FT11EL$V((<
MXZUB1&0^/< 4X33%2>1.HG 2TM"LU9+(:$D$FR[R%=@JAM)QR\!,B9RF.(G<
M;ZG"#Y.WZUF]B8W>Q/!U$8@W,>S-MR/IBS.QTQD?F=PI4_C(R%L9JRN)T94$
M7$&VKVVBQ[U@ ;('I8IC48#MN@GLND)0;.-5&.>$"N/( HMT:YSP!%E50FMA
M%'B<6R0PSK;Y;<_A1HC1;:*S"C;> &((DWHP&3#8">I&"H^5Y)V,W1=SO"(Z
M7V$C#J"'A&/[6PH8=GZZD=R-%&Y$&ENVF\/,YNA0A0TZ@)B(T:\-K8;HTY+9+08^!=H(1C62\ESK"7N9'<<[7"DY-W2]H],J='HN,C-O@ 
M8@G#)A]QQT'XXPXS2, (9(APF8^HQ&/V/,6B.8D1G,70,*H@B
M7]O4@\F(,VCE;J3P6$G>R=A],88?83;%2^RY7^(+R;E&[3>:@2?5U22Q$
M 112;)-,J3MF>@GE;J'"2TC>"=G=,4=,"A&3HI?'%31.FB@R;H+Z^CC7EQ$0
M*@,J3$08(*OF6HUR&ANO<>A+Y- =Y2Q!]"1PE+'X-O^LKFZWG,JWZL^R>SL<
M^\5S.PQM,]]@>6W;H1IE@F]\N=A7Y>[RHJY>A^EI-#[OU'TR]6)H3_JVW^7>
MX^8_4$L#!!0    ( .""5DC3+9#_2@8  -4A   8    >&PO=V]R:W-H965T
M&ULC9I-;^,V$(;_BN&[U^0,/P/'P%I"T1X*+/;0GI5$28RU
MK=12-MM_7TH<.HE+C[F'M:T\I%Y2PWF'DE9OW?%'_]RVP^S7?G?H;^?/P_!R
MLUSV]\_MONF_="_M(?SEL3ONFR'\/#XM^Y=CVSQ,C?:[)0AAEOMF>YBO5].Q
M;\?UJGL==MM#^^TXZU_W^^;X[Z;==6^WVCUL]^VA
MWW:'V;%]O)U_E3>U YJQ7SVT#XV
MK[OA>_?V>TMCT&.']]VNG_Z?W;_V0[=/3>:S??,K?FX/T^=;_(L3U"S? *@!
MG!I(PS9 :H#O#13;0%$#==9@&8S>9OU+,X:'O GX<>PD]#P+
MH^_#Q$Y]'J>I7:]^KB7 :OES[.@3 Q.S(>9$+$/OV5/ /-<X@'ORJ8@?B3.1A8FP<:606"$:!OLQ5J2^O/=-=
M'3$ ;;R_+EMGQZUIW.IZ!R8[;D,=9,=CXK@C T8K(2]C%77EK-5X&:LCMI#*
M"UEPN6Q6MB79AI$=F06$?Y:131AJD,CI)DZ.%\Q=U^VRNAWI9@1M(H.6NR:5
M2[-H/=-739A2ZD,H7M3LLYI]U"RY$(G,0FOA&-&10N.X>8Z0L:9@44B153P=
M'B5SX4&0 JL8R42A-PQ5)\I872!:YD6G7,W,X(8@);C82! RPZ\)0BA1#-GD
M(X$4EUPIS \Z)F[%Y)4-,0N'4C*!4Q$GC=3,[-2$:><*+$_FW4(JBAU.-MF%
MYZ*P(DJC8"\668HU4+",IG:NR7@L6B[]$&;1B0+9>8>2
MT3 4L_XVQ%C+3C4YC]/L4DZG*_ FF3>,%2>$YV\SI?$
M=-Z:9/0*S<:TH^5JN3FL"%L8;30SNCIQH;3X<.4N"\_[D_2TA#CAG@I,D)Q!
M$1;\,H"<<.*D_IBN+Q?.>9N"Z!K<5&Z(L1JX"2=*:M99B0JA9 LTYUT*HFUP
M&7:3&,>9%$&A[C+,%:D39L$5N Q 7G0T*LTM2&+&8+^1M#&B+
MA6R&BI 5G* J=166H.3<@#@OP!549Y!W,? I97"ZR<8\"#ZY>HH"9;E542=.
M">4*H@7S/H;D/LCM:@E:2&&<8VN>1'H-CBM6ZP1:8TQ)@8EY2T.9%B$GGR"G
MD?/8BKC%F#O81'L"I2V:^KRS83(:YBIO"-)""<9+*L)0*ZZ,K@D+([0>"^(=
M\_:&9&^*LS>" "R7VU-7SK/E#V$()1L_S&_\D(R-W; 2Q,YUVAQJ-B4F+,RU
M*9GJO)4B62F[726(%7T5J3'9K% E"S)OG4AFQ^Y4$Q3V?([;]9TZ \&%6DV<
M54*6+,\D*'D2
M++@L21PK6)8'A,H;DB)#4EPMD" AV/*^4NFQ$'=7N5;)D$(-7; 95WD_4LF/
MN"H@02"X75E%&-KSYVZ?=9.Y!=\J"9$+SZV2(;$Q39 $?I>1.'YX-6&?AG=9
M=_[!E2)/TB5#S]N$HLS.W6+:$ 32:W9Q)$PY]I(1AE85U! JO[E29!+LG3:"
MV"B[BM2$Z))]N,K[D2(_RM]>2T]&(P3:Y6WE3X"N/#\[/C&WE3Q_<-WKM9KUZ:I_;/YOBT/?2S
MNVX8NOWT!/VQZX8VJ!)?]'SVW#8/IQ^[]G$8O]KP_1C?.H@_ANXEO41Q>I-C
M_1]02P,$%     @ X()62-)X"!&A 0  L0,  !@   !X;"]W;W)KP)%7);4]T-ZY8<^8K7M0W-[A -K_
M:=$H[GQJ.F8' [R))"59GF7W3'&A:57&VI.I2AR=%!J>#+&C4MS\.X+$Z4 W
M="D\BZYWH<"JDJV\1BC05J F!MH#?=CLCT5 1,!O 9.]B$GP?D)\"%4:G(@=>#B[S=[#31#QRL1[LW[LJ&GBX%5YKC:[HF3G('2%2<3CC%D1
MS*O?;)'36_0\TO//Z=MK^C8YW,X.=Y\+%-<"11(H/AHQ88X+YOY=$W:QIPI,
M%Z^.)36.VJ4M7:OK[7S(XYF\P:MRX!W\XJ83VI(3.G^R\0!:1 >^?7:WHZ3W
M[V=-)+0NA%]\;-*52HG#87D@ZRNM_@-02P,$%     @ X()62+:$=R^D 0  
ML0,  !@   !X;"]W;W)K8K3I0W-Y@#]K_:= H[GQJ6F9[ [R.)"59GF7?F.)"T[*(
MM6=3%C@X*30\&V('I;CY>P")XYZNZ%QX$6WG0H&5!5MXM5"@K4!-##1[>K_:
M'38!$0&O D9[%I/@_8CX%I*G>D^S8 $D5"XH<+^;(.*5B?=F
M_=A1T\3!R^)4KK:W!3L%H0M,(AXFS()@7OUJBYQ>H^>1GG]-7U_2U\GA>G)X
M][7 YE)@DP0V_QLQ80XSYOL_3=C9GBHP;;PZEE0X:)>V=*DNM_,^'B+[A)=%
MSUOXQ4TKM"5'=/YDXP$TB Y\^^QF2TGGW\^22&A<"&]];-*52HG#?GX@RRLM
M/P!02P,$%     @ X()62#L)N!NB 0  L0,  !@   !X;"]W;W)KQ-W5S.PL'^6$YMWV (Y\**GMGO;.#3O&;-V#XO8&!]#^
M3XM&<>=3TS$[&.!-)"G)\BR[8XH+3:LRUEY-5>+HI-#P:H@=E>+FUP$D3GNZ
MH4OA372]"P56E6SE-4*!M@(U,=#NZ?UF=]@&1 1\%S#9LY@$[T?$]Y \-WN:
M!0L@H79!@?OE! \@91#RC7_.FI\M _$\7M0?X[3>_9%;>$#Y0S2N]V8S2AIH
M^2C=&TY/,(]P&P1KE#9^23U:AVJA4*+X1UJ%CNN4_A3%3+M.R&="OA*^9M%X
M:A1M?N..5Z7!B=B!A[/;[#S.FB8.7I6G:G.7E>P4A"XPB7B8
M,2N">?6K+7)ZC9Y'>OYO>G%)+Y+#8G;X'_VWEP+;)+#]VX@)R2>\*@?>P0LWG="6'-'YDXT'T"(Z\.VSFUM*
M>O]^UD1"ZT+XQ<KHP$ 
M +$#   9    >&PO=V]R:W-H965TW#2E4?=I\=&,"JS5#;A.[?KR] DRIJ7_#,<,Z9,[[D(^I7
MTP)8\JYD9_:TM;;?,6;*%A0W-]A#Y_[4J!6W+M4-,[T&7@62DBQ-DBU37'2T
MR$/M61 D@HK5?@;CG!'4CIA5SCMTGSHZ4G
MGL>S^D.8UKD_<@-W*/^*RK;.;$))!34?I'W!\1&F$39>L$1IPI>4@[&H9@HE
MBK_'571A'>.?[:^)=IV03H1T(?Q,@O'8*-B\YY87N<:1F)[[LUOM'%Q[$:=,
MG#?CQ@Z:.@Q>Y*=BM5WG[.2%+C"1>)@P"X(Y]:LM4GJ-G@9Z^CU]?4E?1X?K
MR6'VO4!V*9!%@>RK$2/F,&,VGYJPLSU5H)MP=0PI<>ALW-*ENMS.VS2\
MR'O>P&^N&]$9&PO=V]R:W-H965T
MK#[K,# UBU
M&6J;T/Y]?0&:K*+-"_:,SSESAK&S ?6[:0 L^52R-3O:6-MM&3-% XJ;&^R@
M=2<5:L6M"W7-3*>!EX&D)$N39,,4%RW-LY![U7F&O96BA5=-3*\4UU][D#CL
MZ().B3=1-]8G6)ZQF5<*!:T1V!(-U8X^++;[M4<$P!\!@SG9$^_]@/CN@U_E
MCB;> D@HK%?@;CG"(TCIA5SACU'SIZ0GGNXG]>?0K7-_X 8>4?X5I6V2_N&PPN,+02'!4H3OJ3HC44U42A1_#.NH@WK$$^6]R/M,B$=">E,N$N"
M\5@HV'SBEN>9QH&8COO9+;8.KKV(4R;.FW%M!TT=&L^S8[[8;#)V]$)GF$C<
MCY@9P9SZQ1(IO41/ SV]3E^>TU?1X7)T>'M=8'4NL(P"JU'@[KK ^J*#]?_^
M4<3L)\S]/T78R5 4Z#KNKV.=S(&%KOIA&PO=V]R:W-H965TF8W8P
MP)M(4I+E67;/%!>:5F7,/9NJQ-%)H>'9$#LJQ3XBO(?C6'&@6+("$V@4%[I-Z;S:CI(&6C]*]X/05YA:B
MPQJEC5]2C]:A6BB4*/Z65J'C.J63XGZFW2;D,R%?"9^R:#P5BC8_<\>KTN!$
M[,##[#9[#S=!Q"L3[\WZMJ.FB8U7Y;G:/&0E.P>A*TPB'F?,BF!>_6:)G-ZB
MYY&>_Y^^O:;ODL/M[/ #]7?7 MLDL)L%/N"@N.F@^-<_2ICC@MG^581=#$6!
MZ>+=LZ3&4;LTDS6[7N_'/ [U'5Z5 ^_@.S>=T):
M/\ UD-"ZL'WP>Y/N9 H<#LL+6Y]Y]0=02P,$%     @ X()62)=J8?.C 0  
ML0,  !D   !X;"]W;W)K&ULA5/+;MLP$/P5@A\0
MRK*<%(8L($Y1M(<"00[MF996$A&2JY*4E?Y]^9 4.S":B[B[FIF=Y:.N6'/F*U[4-S>X0#:_VG1*.Y\:CIF!P.\B20E69YE]TQQH6E5
MQMJSJ4H
MQHOZMSBM=W_B%IY0_A:-Z[W9C)(&6CY*]X+3=YA'V 7!&J6-7U*/UJ%:*)0H
M_I96H>,ZI3]%/M-N$_*9D*^$+UDTGAI%FU^YXU5I<")VX.'L-GL/-T'$*Q/O
MS?JQHZ:)@U?EN=H\%"4[!Z$K3"(>9\R*8%[]9HNT[?)X79V
MN/MZK =/'J6%+CJ%W:TK6ZWL['>(CL'5Z5
M ^_@)S>=T):&ULA5/+;MLP$/P5@A\0RK)3IX8L($Y1)(<"00[IF996$A&2
MJY*4E?Y]^) 4NS":B[B[FIF=Y:,8T;S9#L"1=R6UW=/.N7['F*TZ4-S>8 _:
M_VG0*.Y\:EIF>P.\CB0E69YEWYCB0M.RB+5G4Q8X."DT/!MB!Z6X^7L B>.>
MKNA<>!%MYT*!E05;>+50H*U 30PT>WJ_VATV 1$!KP)&>Q:3X/V(^!:2IWI/
MLV !)%0N*'"_G. !I Q"OO&?2?.S92">Q[/ZSSBM=W_D%AY0_A:UZ[S9C)(:
M&CY(]X+C(TPCW ;!"J6-7U(-UJ&:*90H_IY6H>,ZIC_KF7:=D$^$?"'<9=%X
M:A1M_N".EX7!D=B>A[-;[3S.FB8.7A:G?6K+7)ZC9Y'>OXU?7U)7R>'Z\GAW=<"FTN!31+8_&_$A#G,F.__-&%G
M>ZK M/'J6%+AH%W:TJ6ZW,[[/)[))[PL>M["+VY:H2TYHO,G&P^@073@VVX^.B
M 0  L0,  !D   !X;"]W;W)K&ULC5/+;MLP$/P5
M@A\0RK+3&H8L($X0I(<"00[MF996$A&2JY"4E?Y]^9 4NS":7,3=U+V!GO0_D^#1G'G4],RVQO@=20IR?(L^\84
M%YJ61:P]F[+ P4FAX=D0.RC%S9\#2!SW=$7GPHMH.Q<*K"S8PJN% FT%:F*@
MV=.[U>ZP"8@(^"5@M&3RK/\9IO?LCMW"/\K>H7>?-9I34T/!!NA<T"AW7K!\[:IHX>%FVI M/&JV-)A8-V:4N7ZG([[_)X)A_P
MLNAY"S^Y:86VY(C.GVP\@ ;1@6^?W=Q2TOGWLR02&A?"[SXVZ4JEQ&$_/Y#E
ME99_ 5!+ P04    " #@@E9()B,HV*,!  "Q P  &0   'AL+W=OP)$W);4]T-ZY8<^8K7M0W-[A
M -K_:=$H[GQJ.F8' [R))"59GF5?F.)"TZJ,M6=3E3@Z*30\&V)'I;CY>P2)
MTX%NZ%)X$5WO0H%5)5MYC5"@K4!-#+0'^KC9'XN B(!? B9[$9/@_83X&I(?
MS8%FP0)(J%U0X'XYPQ-(&81\XS^SYGO+0+R,%_5O<5KO_L0M/*'\+1K7>[,9
M)0VT?)3N!:?O,(^P"X(U2AN_I!ZM0[50*%'\+:U"QW5*?^Z+F7:;D,^$?"4\
M9-%X:A1M?N6.5Z7!B=B!A[/;[#W.FB8.7I7G:O.P+=DY"%UA
M$O$X8U8$\^HW6^3T%CV/]/QS^O::ODT.M[/#XG.!XEJ@2 +%_T9,F.."V7UH
MPB[V5('IXM6QI,91N[2E:W6]G8]Y/)-W>%4.O(.?W'1"6W)"YT\V'D"+Z,"W
MS^YVE/3^_:R)A-:%\-[')EVIE#@ROM+J'U!+ P04    " #@@E9(X@ZN
MYZ,!  "Q P  &0   'AL+W=OP)%W);4]T-ZY8<^8K7M0W-[A -K_:=$H[GQJ.F8' [R))"59GF4/
M3'&A:57&VHNI2AR=%!I>#+&C4MS\.8+$Z4 W="F\BJYWH<"JDJV\1BC05J F
M!MH#?=KLC]N B("? B9[$9/@_83X%I+OS8%FP0)(J%U0X'XYPS-(&81\X]^S
MYD?+0+R,%_6O<5KO_L0M/*/\)1K7>[,9)0VT?)3N%:=O,(]P'P1KE#9^23U:
MAVJA4*+X>UJ%CNN4_A3%3+M-R&="OA)V632>&D6;7[CC56EP(G;@X>PV>P\W
M0<0K$^_-^K&CIHF#5^6YVNP>2G8.0E>81#S.F!7!O/K-%CF]1<\C/?^<7ES3
MB^2PF!T^?BZPO1;8)H'M_T9,F.."V?W3A%WLJ0+3Q:MC28VC=FE+U^IZ.Y_R
M>"8?\*H<> <_N.F$MN2$SI]L/( 6T8%OG]W=4]+[][,F$EH7PDP)$W);7=T=ZY8K_:[M_8%;>$#Y1S2N
M]V8S2AIH^2C="TZ/,(]P&P1KE#9^23U:A^I$H43QM[0*'=.FB8.7I7':G6W*=DQ
M"%U@$G$_8Q8$\^I76^3T&CV/]/QK>G%)+Y+#(G7?9%\+K"\%UDE@_;\1$V8_
M8S;_#LG.]E2!Z>+5L:3&4;NTI4MUN9WW>3R33WA5#KR#7]QT0EMR0.=/-AY 
MB^C M\]N;BGI_?M9$@FM"^%W'YMTI5+B<#@]D.655A]02P,$%     @ X()6
M2)F&ULA5/;
M;J,P$/T5RQ]0$Z#=;D20FE95]V&EJ@^[SPX,8-5FJ&U"]^_7%Z!)%;4O>&8X
MY\P97XH)]:OI "QY5[(W.]I9.VP9,U4'BILK'*!W?QK4BEN7ZI:900.O TE)
MEB;)#5-<]+0L0NU9EP6.5HH>GC4QHU)<_]N#Q&E'-W0IO(BVL[[ RH*MO%HH
MZ(W GFAH=O1NL]WG'A$ ?P1,YB0FWOL!\=4GO^H=3;P%D%!9K\#=&P4;#YPR\M"XT3,P/W9
M;;8.KKV(4R;.FW%C!TT=!B^+8[GYF1;LZ(7.,)&XGS$K@CGUBRU2>HF>!GKZ
M/3T[IV?1838[S+X7R,\%\BB0?S5BQ.P73/ZI"3O94P6Z#5?'D K'WL8M7:OK
M[;Q+PYE\P,MBX"W\YKH5O2$'M.YDPP$TB!9<^^3JFI+.O9\UD=!8'_YPL8Y7
M*B86A^6!K*^T_ ]02P,$%     @ X()62.""V<:D 0  L0,  !D   !X;"]W
M;W)K&ULA5/+;MLP$/P5@A\0RK*=-(8L($Y1M(<"
M00[-F996$A&2JY*4E?Q]^) 4NS":B[B[FIF=Y:,8T;S:#L"1-R6UW=/.N7['
MF*TZ4-S>8 _:_VG0*.Y\:EIF>P.\CB0E69YEMTQQH6E9Q-J3*0LQ[/ZCSBM=W_D%AY1
MOHC:==YL1DD-#1^D>\;Q)TPC;(-@A=+&+ZD&ZU#-%$H4?TNKT'$=TY]M/M&N
M$_*)D"^$;UDTGAI%F]^YXV5A<"2VY^'L5CL/-T'$*Q/OS?JQHZ:)@Y?%J5S=
M;PMV"D(7F$0\3)@%P;SZU18YO4;/(SW_FKZ^I*^3P_7D\/9K@&PO=V]R:W-H965TI#^^S  %9M#[5-Z/[]^D)HLHJV
M+WAF..?,&5^*$+.IZ9EMC? 
MZTA2DN59=L,4%YJ61:R]F++ P4FAX<40.RC%S9\=2!RW=$&/A5?1=BX46%FP
MF5<+!=H*U,1 LZ7WB\UN%1 1\"9@M"O=[;N$!Y;NH7>?-9I34T/!!NE<Q[.;K'Q";?\++H>0O/W+1"6[)'YT\V'D"#Z,"WSZZN*>G\^YD3"8T+
MX:V/3;I2*7'8'Q_(_$K+OU!+ P04    " #@@E9(]^D8?Z(!  "Q P  &0  
M 'AL+W=OVAM@G;OZ\O0))5U/8%SPSGG#GC2SFA>;4]@"-O2FI[
MH+USPYXQ6_>@N'W  ;3_TZ)1W/G4=,P.!G@324JR/,L^,,6%IE49:\^F*G%T
M4FAX-L2.2G'S^P@2IP/=T*7P(KK>A0*K2K;R&J% 6X&:&&@/]'&S/Q8!$0$_
M!$SV*B;!^PGQ-23?F@/-@@604+N@P/URAB>0,@CYQK]FS4O+0+R.%_4O<5KO
M_L0M/*'\*1K7>[,9)0VT?)3N!:>O,(^P"X(U2AN_I!ZM0[50*%'\+:U"QW5*
M?W;%3+M/R&="OA(^9=%X:A1M?N:.5Z7!B=B!A[/;[#W.FB8.
M7I7G*L\V)3L'H1M,(AX3YH)@7OUNBYS>H^>IQ;_IVUOZ-CGE:76_G8Q[/Y *ORH%W\)V;3FA+
M3NC\R<8#:!$=^/;9PXZ2WK^?-9'0NA!^]+%)5RHE#H?E@:ROM/H#4$L#!!0 
M   ( .""5D@'I_TSI@$  +$#   9    >&PO=V]R:W-H965T&+"!.4;2' D$.[9F65A(1DJN2E)7^??F0
M%+LPD(NXNYJ9G>6CG-"\V1[ D7U#98],<:%I5<;:BZE*')T4&EX,L:-2W/P]@<3I2#=T*;R*KG>A
MP*J2K;Q&*-!6H"8&VB-]VAQ.14!$P"\!D[V*2?!^1GP+R8_F2+-@ 234+BAP
MOUS@&:0,0K[QGUGSHV4@7L>+^K4?X6C>N]V8R2!EH^2O>*TW>8
M1]@%P1JEC5]2C]:A6BB4*/Z>5J'C.J4_^_U,NT_(9T*^$KYDT7AJ%&U^Y8Y7
MI<&)V(&'L]LE9+PW8L*<%LS^OR;L:D\5F"Y>
M'4MJ'+5+6[I6U]OYE,&PO=V]R:W-H965T&+"!.4;2' D$.[9F65A(1DJN2E)7^??F0%#LPD(NXNYJ9G>6CG-"\VA[ 
MD3U#EN/EW!(G3@>9T*;R(KG>AP*J2K;Q&*-!6H"8&V@-]S/?'
M;4!$P&\!D[V(2?!^0GP-R<_F0+-@ 234+BAPOYSA":0,0K[QWUGSO64@7L:+
M^O4/X1C>N]V8R2!EH^2O>"TP^81[@/@C5*&[^D'JU#M5 H4?PM
MK4+'=4I_=KN9=IM0S(1B)3QDT7AJ%&U^XXY7I<&)V(&'L\OW'FZ"B%ORG-59 \E.P>A*TPB'A,F7Q',J]]L4=!;]"*U^)R^N:9ODL/-[/#K
MYP+;:X%M$M@F@3R[-6+"'!?,QR'9Q9XJ,%V\.I;4.&J7MG2MKK?SL8AG\@ZO
MRH%W\(N;3FA+3NC\R<8#:!$=^/;9W3TEO7\_:R*A=2'<^=BD*Y42A\/R0-97
M6OT'4$L#!!0    ( .""5D@V'?^\I0$  +$#   9    >&PO=V]R:W-H965T
M+F!@?H
MW9\&M>+6I;IE9M# ZT!2DF5)\HLI+GI:%J'VK,L"1RM%#\^:F%$IKO\?0.*T
MIRE="B^B[:POL+)@*Z\6"GHCL"<:FCV]3W>'W","X%7 9,YBXKT?$=]]\J?>
MT\1;  F5]0K<+2=X "F]D&O\;];\:NF)Y_&B_ABF=>Z/W, #RC=1V\Z932BI
MH>&CM"\X/<$\PM8+5BA-^))J-!;50J%$\8^XBCZL4_R3W\ZTZX1L)F0KX2X)
MQF.C8/,WM[PL-$[$#-R?7;IS<.U%G#)QWHP;.VCJ,'A9G,HLS0IV\D(7F$@\
M1$RZ(IA3O]HBH]?H66SQ,WUS2=]$AYO9X>9G@?Q2((\"^2R07QLQ8@X+9ONM
M"3O;4P6Z#5?'D K'WL8M7:OK[;S/PIE\P&ULA5/+;MLP
M$/P5@A\02K+SJ"$+B!,4[:% D$-[IJ651(3DJB1EI7]?/B3%#@SD(NZN9F9G
M^2@G-&^V!W#D74EM][1W;M@Q9NL>%+QI%BR A-H%!>Z7$SR!E$'(-_X[
M:WZT#,3S>%'_'J?U[H_;4=) RT?I7G'Z ?,(MT&P1FGCE]2C
M=:@6"B6*OZ=5Z+A.Z<]#-M.N$XJ94'PBL-0HVGSFCE>EP8G8@8>SRW<>;H*(
M5R;>F_5C1TT3!Z_*4U7D=R4[!:$+3"(>$B9?$VEP#8);&>!AVLC)LQAP7S[U(2=[:D"T\6K8TF-HW9I2]?J>CL?
MBW@F'_"J''@'O[CIA+;DB,Z?;#R %M&!;Y_=W%+2^_>S)A):%\)['YMTI5+B
M<%@>R/I*J_]02P,$%     @ X()62,J+O"3< @  ^PP  !D   !X;"]W;W)K
M&ULC5?;;J,P$/T5Q <4;#"D%4%JNEKM/JQ4]6'W
MF29.@@HX:SM-]^_7E[%[D>7X)6!SYIPQ.3,:N@OC+^)(JYFD1Z_PHY>FN
M*,3V2.=!W+ 37=23/>/S(-62'PIQXG38F:!Y*G!9-L4\C$O>=V;OD?<=.\MI
M7.@CS\1YG@?^;T,G=EGG*'<;3^/A*/5&T7>%C]N-,UW$R):,T_TZOT=W&]QJ
MB$'\'NE%?+C/=/+/C+WHQ<_=.B]U#G2B6ZDI!G5YI0]TFC234OX+I.^:.O#C
MO6/_;HZKTG\>!'U@TY]Q)X\JVS+/=G0_G"?YQ"X_*)R!:,(MFX3YS;9G(=GL
M0O)L'M[L=5S,]6*?D!6$A0,P!& ?L"I-XE;(I/EMD$/?<7;)Q&G0?QZZ4W"N
M211SIG(3ZMB&DYN#]]UKCW'9%:^:Z!/&!FXL!GE$H=B#$C@/A6,K<3V\^AQ>
MV0PKJTY6UPGJSP2U):CAB"AT1(O9.$Q"EB0H0H"@BH@X3'U=I F*-/95-&U$
MI $1*Q'0<*,$!J KK5$ 1\X '
M)9@ A==0'#I3B@W 30%#A==0'#I3B@W ?0%#D
M==0'#I3B@W K0%#G==0'#I3B@W W0%#J==0' "()/L#A?H"AU$G,!QZ4X ,<
M[@<82IW$?.!!"3[ X7Z H=1)S <>E. #'.X'&$J=Q'S@00D^P.%^@*'42A/U@0.E^"#<#S"4>A/U@0.E^"#<#S"4>A/U@0-]]4'Q83B=
M*3^8&5QD6W9>I)U-_:Z?\^^Q&6[?X7UW&@[TU\ /XR*R9R;5B&PFV3UCDBK]
M\H;DV5%]B?C%1/=2W[;JGMO9W"XD.[E/#?^]T_\'4$L#!!0    ( .""5DA"
M$E:OL@$  !8$   9    >&PO=V]R:W-H965T?#T"3"BTW^,!W^OEM
M\D'I-],"6/0AN#1'W%K;'0@Q90N"F@?5@71O:J4%M6ZI&V(Z#;0*),%)FB1;
M(BB3N,C#WHLNP*NAB->X6GCE36M]1NDR,G,JY@ :9B2
M2$-]Q(^KPRGSB #XS6 P5W/DLY^5>O.+G]41)SX"<"BM5Z!NN, 3<.Z%G/'[
MJ/EIZ8G7\TG].53KTI^I@2?%_[#*MBYL@E$%->VY?57##QA+" E+Q4UXHK(W
M5HF)@I&@'W%D,HQ#?+/9CK1E0CH2TIFP3T+P:!1B?J>6%KE6 S(=];U;'1Q<
M>Q&GC%PVX\H.FCH47N27(MWN82#Q%S&I&$*>^:)'B)7H:+>[3U[?T
M=4RXCN[9_K[ YE9@$P4V8XG[I1(CYC1AOMTWR19-LBBP2_YC,F&^?DERU3@!
MN@GGTZ!2]=+&OLV[\Q5X3$/C/^%%WM$&?E'=,&G065EW?$*7:Z4L./OD(<.H
M=9=T7G"HK9_NW%S'&PO=V]R:W-H965TV$[=_75S:)O,"^!'LX<\X,$X\G'PA]
M8Q7&'+RW3<.'0;#V
M6U1W7I$KVPLM*.
MU:0#%)\VWA8^ES"5$(7X7>.!W:R!#'Y/R)O<_#QNO$#&@!M\X)("B<<5E[AI
M))-0_FM(/S2EX^W:LG]7Z8KP]XCADC1_ZB.O1+2!!X[XA"X-?R7##VQRB"7A
M@31,_8+#A7'26A37(DS"W+]*HCM,J# [C8$CPA?L
M3HG0<[F'6N)S@5(CHG!>(;I7T,9M9)*(Y@E6]P0K3; R!"M7D!JSLYAX7B1V
MBL2&8#TA8C')YYC28M+Y0-;.0-:&()L(Q%XD<8HDA@!.B%C,@L*G3I'4
M$$03(A:SFA?)G"*9(8@G1"QFHK:EQ23S@<# &8DR2XIT(I01E"W0@6X=TQ6R
M8$K'@B8J7(Z@!26&H3L8TS^RJ2*/H 55AI%;QW21;,$!AP]MQ/0A:'O$@D8$
MW4T"FM.=376)$;3DK^3N = <\&Q!%X&).]OD"]FZSR],EV1K08]_:/_FPFLQ
M/:M!@($#N71<7T:C=1PVMJ&\,!_L.SF$J(OT@Z;(>W3&OQ ]UQT#>\+%=:QN
MS1,A'(NX@J?8 Y48D\9-@T]<+A.QIGIPT!M.>CL'C<-8\1]02P,$%     @ 
MX()62&/SLB2F 0  L0,  !D   !X;"]W;W)K&UL
MC5/+;MLP$/P5@A\0RI*3!H8L($Y1-(<"00[MF996$A&2JY*4E?Y]^9 4.S"0
M7,3=U357BZ*30\&R('97BYM\!)$Y[NJ%+X45TO0L%5I5L
MY35"@;8"-3'0[NG#9G?8!D0$_!8PV;.8!.]'Q->0/#5[F@4+(*%V08'[Y02/
M(&40\HW_SIKO+0/Q/%[4?\1IO?LCM_"(\H]H7._-9I0TT/)1NA>&7BO5D_=M0T_6J+G%ZC
MYY&>?TXO+NE%X54Y\ Y^<=,);  MH@/?/KNYI:3W[V=-)+0N
MA-]\;-*52HG#87D@ZRNM_@-02P,$%     @ X()62(L1COZF 0  L0,  !D 
M  !X;"]W;W)K&ULC5/+;MLP$/P5@A\0RK**"TVK,M:>357B
MZ*30\&R('97BYO<1)$X'NJ%+X45TO0L%5I5LY35"@;8"-3'0'NC#9G\L B("
M?@J8[$5,@O<3XFM(OC<'F@4+(*%V08'[Y0R/(&40\HW?9LV/EH%X&2_J3W%:
M[_[$+3RB_"4:UWNS&24-M'R4[@6G;S"/L N"-4H;OZ0>K4.U4"A1_#VM0L=U
M2G^*+S/M-B&?"?E*^)Q%XZE1M/F5.UZ5!B=B!Q[.;K/W_6:+G-ZBYY&>_YN^O:9OD\/M[/ _^A?7
M D42*&:!W:T1$^:X8.[_:L(N]E2!Z>+5L:3&4;NTI6MUO9T/>3R3#WA5#KR#
M']QT0EMR0N=/-AY B^C M\_N=I3T_OVLB836A?"3CTVZ4BEQ."P/9'VEU1]0
M2P,$%     @ X()62'/O&_VE 0  L0,  !D   !X;"]W;W)K&ULA5/;;MLP#/T501]0.4[2=(%CH.E0; \#BCYLSXI-VT(ET9/D
MN/O[Z6*[21&@+Q))G7-(BE(QHGFS'8 C[TIJ>Z"=<_V>,5MUH+B]PQZT/VG0
M*.Z\:UIF>P.\CB0E69YE]TQQH6E9Q-B+*0LV&34/L)\2TX/^L#S4()
M(*%R08'[[0Q/(&40\HG_3IH?*0/QTI[5GV.WOOH3M_"$\H^H7>>+S2BIH>&#
M=*\X_H"IA6T0K%#:N))JL [53*%$\?>T"QWW,9T\9!/M-B&?"/DG DN)8IG?
MN>-E87 DMN=A=JN]AYL@XI6)K\WZMJ.FB8V7Q;E<9[N"G8/0%281CPFS6A#,
MJ]],D=-;]#S2\Z_IZVOZ.E6X3MEWVZ\%-M<"FR2PF5I\N-5BPAQGS+=/2=C%
MG2HP;7PZEE0X:)>N=(DNK_,QCS/Y@)=%SUOXQ4TKM"4G='ZR<0 -H@.?/KO;
M4M+Y_[,X$AH7S)VW37I2R7'8SQ]D^:7E?U!+ P04    " #@@E9(01!%;J8!
M  "Q P  &0   'AL+W=OQ-W5S.PL'^6$
MYM7V (Z\*ZGM@?;.#7O&;-V#XO8.!]#^3XM&<>=3TS$[&.!-)"G)BBS[PA07
MFE9EK#V;JL312:'AV1 [*L7-GR-(G XTITOA172]"P56E6SE-4*!M@(U,= >
MZ$.^/VX#(@)^"9CL14R"]Q/B:TA^- >:!0L@H79!@?OE#(\@91#RC=]FS8^6
M@7@9+^K?XK3>_8E;>$3Y6S2N]V8S2AIH^2C="T[?81YA%P1KE#9^23U:AVJA
M4*+X>UJ%CNN4_NRRF7:;4,R$8B7<1P)+C:+-)^YX51JHA>17OR;OKFF;Y+#
M3>I^_Q_]M]<"VR2PG4?,;XV8,,<%\]DEN]A3!::+5\>2&D?MTI:NU?5V/A3Q
M3#[@53GP#GYRTPEMR0F=/]EX "VB ]\^N]M1TOOWLR826A?"KSXVZ4JEQ.&P
M/)#UE59_ 5!+ P04    " #@@E9(3]RJ.^L!  #J!0  &0   'AL+W=OXP5D4%G*H'
MT4)CGI1"X9%WJCDTJA8-DE#NHT>R.Q '<8C?-73J9H]L^*,0
M[_;P\[2/8IL!&!3:2E"S7.$)&+-*QOEO+_KI:8FW^T']V;5KXA^I@B?!_M0G
M79FT<81.4-(+TV^B>X&^AZ45+ 13[A<5%Z4%'R@1XO3#KW7CULX_V<0]+4Q(
M>D+RA8"]D8OY@VJ:9U)T2+74_GED9^#2BAAE9+(IT[;3E*[Q/+OF*4DS?+5"
M=QA//'@,&1'8J ;8(*-%TCB;]H<,#,^
MF&W09-L+S/AD2!SLTY5G-DI(, 0A,UH=0>D7'WQS%SG(LQLY"A7BTFA_%$W>7/^%YUM(S_*+R7#<*'84V$\%=W%((#<8_?EA&J#*#=SPP*+7=KLU>
M^E'D#UJTPV0=QWO^'U!+ P04    " #@@E9(RT&3(J8!  "Q P  &0   'AL
M+W=O&=M8.
M.\9,U8'BY@8'Z-V?!K7BUJ6Z96;0P.M 4I*E27++%!<]+8M0>]%E@:.5HH<7
M3)MP 2*NL5N%M.\ A2>B'7^.^L^=72$\_C1?TI3.O<'[F!
M1Y3OHK:=,YM04D/#1VE?<7J&>82M%ZQ0FO EU6@LJH5"B>*?<15]6*?X)\MF
MVG5".A/2E7"?!..Q4;#YBUM>%AHG8@;NSVZS M_N&Y%
M;\@1K3O9<  -H@77/KG94M*Y][,F$AKKPSL7ZWBE8F)Q6![(^DK+_U!+ P04
M    " #@@E9(FW+#,< "  " "@  &0   'AL+W=O"GV!ZD7O#SS6MVVJ&@M"E8[G.YF[@V:KA--&.!W0<_BXM[1N;\R]J8?
MEMN9Z^L4:$DW4CL0=7FG"UJ6VD@%_FL]/T-JX>5]XWYO=JNR?R6"+ECYI]C*
M@TK6=YTMW9%3*5_8^9':+43:<,-*87Z=S4E(5C42UZG(!UR+VES/\$_4R+H%
MV IP*T##@L *@D]!."@(K2 <*XBL(!HKB*T@'BM(K" 9*YA8P62L(+6"=*Q 
MUQPJY[>2B3\L:8N-1D=IRHWP-XD'C67:\I9(DF>/^" L@
MDDD_<@M(V$_<69.T'[G']D#ZD0= )GX_\F@1U(\L+3(0:/7CJ3S]G.W:Q@E&
MU";X6IL 6B2 VJ;^"(?PJT,(#J'-LK-XP*P:)AT1)>J,$H%#\*TNM6$2B (,
MBOJ1)T#B8-+/K(&YBH)P1+9Q9[:QS19UA8DA6V!0$G9N": G@*Y0V,^L+3,F
MVZ0SV\08I&G_F+.#0&S  ;A(.B';A-[N)T; N8.&#Q4R'OK@_T!HP=K
M-!3LT68]@"P!B>*AWK,V2334?0#%>"#8NCF@BQ:%>GH7GX"*\KV9;(2S8:=:
MPMO=KK;#TPW6GY!OZW,T7:*.]94:MF V^K3/LR/9TU^$[XM:.*],JD^7^;SL
M&)-4Y>M?JVG@H,;!]J&D.ZEO$W7/84*"!\F.S;S7#IWY?U!+ P04    " #@
M@E9(#$%.^K$!   6!   &0   'AL+W=OPXH789DC_OEZ S$2H\X*W
MLUU=FW)2^M7T !:]"R[- ??6#GM"3-V#H.9.#2#=2:NTH-8M=4?,H($V@20X
M29/DG@C*)*[*L/>LJU*-EC,)SQJ940BJ_QZ!J^F =WC9>&%=;_T&J4JR\AHF
M0!JF)-+0'O##;G\L/"( ?C.8S,4<^>PGI5[]XF=SP(F/ !QJZQ6H&\[P")Q[
M(6?\-FM^6'KBY7Q1?PK5NO0G:N!1\3^LL;T+FV#40$M';E_4] /F$D+"6G$3
MOJ@>C55BH6 DZ'LA839M']V_UM@?Q:((\"^5QBME5BQ!P73'[;I-@T*6:!XC\F"^9S)>2B
M<0)T%^ZG0;4:I8U]6W?7)_"0AL9_P*MRH!W\HKICTJ"3LN[ZA"ZW2EEP]LE=
M@5'O'NFZX-!:/_WBYCK>V[BP:EA>X?HKJ/X!4$L#!!0    ( .""5DB!Y.A7
MPP$  'L$   9    >&PO=V]R:W-H965T&,"*+]0V2_KW]07(;H22O."Q.9<9F'$Q
M*OUB.@"+7@67YH [:_L](:;J0%!SHWJ0[DVCM*#6;75+3*^!UH$D.$F3)">"
M,HG+(IP]Z;)0@^5,PI-&9A""ZG]'X&H\X V>#YY9VUE_0,J"++R:"9"&*8DT
M- ?\L-D? 3.O9 S_CMI
MOEEZXF4\JW\/U;KL3]3 H^)_6&T[EVR"40T-';A]5N,/F$K8><%*<1.>J!J,
M56*F8"3H:UR9#.L8W^391%LGI!,A70AW24@\&H4TOU%+RT*K$9F>^G^WV3NX
M]B).&;G%F?T[-K
M>A8SS*+[_?WG MMK@6T4V$XEWJV5&#''&?,%D]VJR2X*;),/3&;,%[YDOFJ2
M3P+I!R8S)GMG0BZZ0X!NPQ 85*E!VM@%GTM(5?5+=,&G12
MUO5H:*5&*0O./KG98=2YFV#9<&BL#V]=K.-PQ(U5_3SJRWU3_@=02P,$%   
M  @ X()62,I9-N.F 0  L0,  !D   !X;"]W;W)K&ULC5/+;MLP$/P5@A\0RK*<%H8L($Y0M(<"00[MF996$A&2JY"4E?Y]^9 4
M.S#07L3=U*"TVK,M:>357BZ*30\&R('97BYL\1)$X'NJ%+X45TO0L%
M5I5LY35"@;8"-3'0'NC#9G\L B("?@F8[$5,@O<3XFM(?C0'F@4+(*%V08'[
MY0R/(&40\HW?9LV/EH%X&2_JW^*TWOV)6WA$^5LTKO=F,TH::/DHW0M.WV$>
M81<$:Y0V?DD]6H=JH5"B^'M:A8[KE/[LBIEVFY#/A'PE?,VB\=0HVGSBCE>E
MP8G8@8>SV^P]W 01KTR\-^O'CIHF#EZ5YVI;%"4[!Z$K3"(>$V:S(IA7O]DB
MI[?H>:3G_Z9OK^G;Y'";Z-E_"!37 D42*.81=[=&3)CC@KG_U(1=[*D"T\6K
M8TF-HW9I2]?J>CL?\G@F'_"J''@'/[GIA+;DA,Z?;#R %M&!;Y_=[2CI_?M9
M$PFM"^$7'YMTI5+B<%@>R/I*J[]02P,$%     @ X()62 GVD@C  0  >P0 
M !D   !X;"]W;W)K&ULC539;IPP%/T5RQ\0LT[2
M$8.4256U#Y6B/+3/'K@LBHVI;8;T[^L-,A.A3%_PPMDN7+N8A7Q5'8!&;YP-
MZH [K<<](:KJ@%-U)T88S)M&2$ZU6LRP+
M,6G6#_ LD9HXI_+O$9B8#SC&R\9+WW;:;I"R("NO[CD,JA<#DM <\&.\/^XL
MP@%^]3"KBSFRV4]"O-K%C_J (QL!&%3:*E SG.$)&+-"QOA/T'RWM,3+^:+^
MS55KTI^H@B?!?O>U[DS8"*,:&CHQ_2+F[Q!*R*U@)9AR3U1-2@N^4##B],V/
M_>#&V;_)LT#;)B2!D*R$A\@%]T8NYE>J:5E(,2,U4OOOXKV!2RMBE)')IDS9
M3E.ZPLOB7*;9?4'.5N@*XXE'CXE7!#'JFQ8)WJ(GCI[Q%5R2^*=CV\""0OC!'Q_P"4C_L@"N:+U^[<*G.!JQ(OO+ICT,N.
M]TA LP]^1+M#81 6\-;!*&_VR&0_+N?U7_9:G7Z(Y'PS.E[5ZM6APT#5$-#+E2]\O$W3"6D1O#$J;2_
MZ'21BK.9$B!&/MW:]78=W9=\IOD)\42(%T(2VN#.R,;\212I2L%') =B_KMH
MI^'"B&AEI+-)7;;5%+;PJKQ629J6^&J$[C".>)@QV8+!6M]K$M^;;)Q)/ GD
MCP62>X'$"223P/:QP,:;8#,)%/=E]A:3N3(=)HKR;9Z&X6.GU.N4.J!G.$O$>>NE^C(E9XL.P -YPJT1/B4!JC5[]=RH- HL]4#B80;:7=0?)@?
MJ.65K+X 4$L#!!0    ( .""5DA7!D)7V@(  / +   9    >&PO=V]R:W-H
M965TM-?>
MQ$G0 DYM9[-]^_HP(8?F6],^#7%B8LWN6=,!1]-WQ&!/#8-%7^7K.:G18C"\\;/:K=79B,JBZB+VU0-:V7%VT"P[2)\0H\K;"56
M\:MB)WFU#@S\*^=OYN;[9A'&AH'5;*U,"JHO[^R9U;7)I"O_@:27FB;P>GW.
M_M6VJ_%?J63/O/Y=;=1>T\9AL&%;>JS53W[ZQJ"'U"1<\UK:[V!]E(HWYY P
M:.B'NU:MO9[<+WD,8?X # &X"T#98$ " G2 8D*R?)DW&(Y!8B<7TFT"<>3S"[3> VGV:0(+F%;*V&
MN#Z [@9 #<:7 2
MCY'G4Y_KW,LR!Y9\H.GYU!(H]M:PVZ;(?*!A$ VU^DG2#X+\(.C\^(9 T#C(
MO:0?!/M!P @)&JJ"^T' 7CY)^D$2/XBS2YQ.\%MTYY=@N.ALF!,<%_D=#H'%
M$3Q@<2#*^]T%S!F$))OXDB*_XR&P/#+E:(C_:,A_'(W?*Q"8!;ES_VO1LA.E
M$^KX?0"!$9!L/ 6.O=WB>'JWV/^"8C2AVTY$[NI$5W-1P\3.#I@R6/-CJ]S,
MTNUV0^P3-G/5W?Y2#[=N%+VD*8L#W;$?5.RJ5@:O7.FIS0Y76\X5TUSQ0QH&
M>SU^=S&ULE9==;YLP%(;_
M"N(^Q3Y\5P2IS31M%Y.J76S7-'$25, 9=IKNW\_8)FVJ W@W 9OW'#\V+R=V
M<>']BS@R)KVWMNG$VC]*>;H/ K$]LK82=_S$.O5DS_NVDJK9'P)QZEFUTT%M
M$P A2=!6=>>7A>Y[ZLN"GV53=^RI]\2Y;:O^[R-K^&7M4W_L^%D?CG+H",HB
MN,;MZI9UHN:=U[/]VG^@]QN(!HE6_*K917RX]P;X9\Y?AL;WW=HG P-KV%8.
M*2IU>64;UC1#)C7R'YOT?"/WK;<]"\G8,\;VV>C/7NM/7BWF2C&%X -@ N ;09#8@
MM 'A>X!>NL"0Z7E]J615%CV_>.)4#6^;WBMY/R11F3TU&:'62>?L]4J5Q6L9
MIED1O Z);C2@-8]&0Z^*0&5'AP ?"P<=#M,#;(PBA.41PML13.=#:">1+R>(
M;A-$)D%D$F3D%K+3FM1,PVIHFA$RH]O@NDF@& 6*+1#%!DH,D-&L@.1D@L@(
M-U9(DRQV0DI0I,0BP0R2T5"23:V1);*Z* ^=@%(4*+5 X0R0TK=W-V[E* (NGO2O78AK"B.D_DW@^NFD2B.1!W\:T6K,%IPRRB$
M-'6# AP*YAQLOW(K K+$9'5I[H84XDBVD"D]4Y_AW1'$?*78R:NQL5\%H&8RUS24%1HP)U-RK@E0+ P:@P
M5@H"\V]@0C@-A=<*"!VL:D4K"I O4%EEGKA5>L K"T0.7K6B-)WZ?NS6R>HH
M"1&FX,/VMF7]06_[A;?EYTZ:K>>U]WJT>(!A>_RI_U$=.Z$]XSEVKSK??(>\XE4VSD+O:]HSH471L-V\OA-E7WO3DFF(;DI_'4&PO=V]R:W-H965T
M[US1Q$E3 
M62!-]^T78T/:"%SW)H#S_3,_]@RRXY,LWZJ]$+7WD6=%=>WOZ_HP"8)JO1=Y
M4EW)@RB:?[:RS).Z>2QW074H1;)I17D6( !HD"=IX4_C=NRYG,;R6&=I(9Y+
MKSKF>5+^NQ69/%W[T.\&7M+=OE8#P30.>MTFS451I;+P2K&]]F_@9 6Q0EKB
M=RI.U:=[3YE_E?)-/A+F'4(5<"VSJOWUUL>JEGDG
M\;T\^=#7M&BO)_T/!T8V+$!&@'I!GV=8@(T GP7$*B!&0%P%H1&$K@)J!-15
MP(R N0JX$7!7060$D:M K;E>.7"64+ND7VSHG*5;;H@N)($NK+8L[Y(ZF<:E
M/'G5(5'-"B>*+U6<)KC7%&/5U'D;MFPK?1J_3S'GC2>8:8)9O%YIQ$R3MR;(-$X\J 1;+'RJ!$.QI$G@\!Q
M9&X02Z+%M[.R_-[MRN3!#FN#OZX-UB6"38E$#A'(UPA$1R Z0G0Q8T7+4%T!
MAJ$, 1*2<7#6@Q @2,?!.P,R##"BX3AXWX&P00$?!Q_ZB"&%G(V#CYW'B!,:
M6M[ZJ8N("(T0&@?G740...:6MUYT(&6 4 NX/*=&U/8RJSXUYA!QAR((!XL@
M-$4 +>8U8YFPI28XB2SKM-(0)(0AZN"7#OJEQJ]E51;T6[^:H @C8 FT,AA 
M&+HT*AMTS(QC;&DSYMIFS+7-F&N;,='0W.'D0_F3X\[ .[3)^!  /0
MTO%+PUFG[Q+1CH-/.\II6REHT;L%5<[C8-\?+_B$3VUK=
MLN:^U &ULC539;IPP%/T5RQ\0=F81@Y1)
M5;4/E:(\M,\>N"R*C:EMAO3OZP7(3(1"7O#"V:[A.ANY>)4-@$)OC';RA!NE
M^J/GR:(!1N0#[Z'3;RHN&%%Z*6I/]@)(:4F,>J'OIQXC;8?SS.X]BSSC@Z)M
M!\\"R8$Q(OZ=@?+QA ,\;[RT=:/,AI=GWL(K6P:=;'F'!%0G_!@#L(#?
M+8SR9HY,]@OGKV;QLSQAWT0 "H4R"D0/5W@"2HV0-OX[:;Y;&N+M?%;_;JO5
MZ2]$PA.G?]I2-3JLCU$)%1FH>N'C#YA*2(Q@P:FT3U0,4G$V4S!BY,V-;6?'
MT;U)9MHZ(9P(X4((4AO<&=F8WX@B>2;XB&1/S+<+CAHNC(A61CJ;U&5;36$+
MS[-K'AW2S+L:H3N,(YX=)E@0GE9?M0CQ&CVT]'";'MW38YX'(
M"<23P'Y;(%E-D$P"A[4SL!ZVSIKCHUXIF=?U ;0ZP$-ZSA^K^S.7'!VH'B.FWU
M;JYUIZ]G\TD66!I.()9 1@(DDX30$L(/0C1)B"PANB'X)A3](M:5J,JB9V>'
M'RN5'O @X;T2D_UJR^*MC(*D\-^4T!6&:,S28&!$^%(=W8*X
M&)UH.OE\@Y5!A!.0M8%DX7T3X;6)T,09VCC3^P+1M8!9?(RL0'9MLM.8W$1J
M,(1XY'/0RH#"F'CP.6IM4""UDON.8]1Q;!WGV#:J,)3EV+H)O'@"MC*P.$^\
M9 *VMFI O!D'E:"N$^,:@BG7B4V8[&(?Q+6!D2B:#&YM8)#EWHSL2%'7J76-
M'NG@.K6NHVG7%A;,.OH,M9-9.V@>#G8,*,V\.+_\PRB)<688P7U7.>HJU_1\
M!A\"M(CU\LPJ!D ]@&UX,'4$2XOZ1I+8BZ;.:@!"EGIH9TA-BED<1/D,YP1W
M3JSS:(8$W@3A"UT0\#8(M@\"6E&VQ5D0Q.#-^-8 O'V![5\PHPH@P>--OA O
M7MB03L6;VG0QH#R;L0U>L#!4[!RG.1YL/C]8$J NB*TON$GE2]!J!,U(98(7
M(;%%2&:T D+0: GY0K0A[B*\'^UR )';1/8OIJV6]GL]MG)GPTZ=,)/0N#J.
MQH]$36LWZTLY,IL!]T.F+([5GOZJ^GW=<>>%"3D+ZI%MQYB@TI?\NG:=@QSJ
MQX>&[H2Z3>5];\9<\R#8<9C:QY\.Y7]02P,$%     @ X()62,+)T3C(!   
M]!H  !D   !X;"]W;W)K&ULC9E!R>28QCUX#Q HEG__T":GD2NVETB0WYU'Y(Z#T)
M-I>F_=$=RK*/?M;5J7M<'?K^_!#'W>NKXZG\UD;=6UT7[7]/9=5<'E>P\B>^
M'U\/_7@BWF[B:[O=L2Y/W;$Y16VY?UQ]A8=<9R,R$7\?RTOWX7LTBG]NFA_C
MP9^[QY48-915^=*/)8KAX[W,RZH:*PV__"\6_?6;8\./WWWUWZ?+'>0_%UV9
M-]4_QUU_&-2*5;0K]\5;U7]O+G^4> W)6/"EJ;KI;_3RUO5-[9NLHKKXZ3Z/
MI^GSXOZ3"6Q&-Y#80%X;@&8;*&R@;AK$3MET7;\5?;'=M,TEZL[%.-KP,.#M
M6&2H' T7TPW]--5LIY[:;MZW6LI-_#X6^L3(B7ER#$/DCE"_D'@00*J0GU6X
MDU\EJE#+!=3G MH54$ZBS3Z+/$V,<9?A&&5%9N:IW%':2@BX&DV*T7@UFOJ9
MU(EQC!6)M0R6.PQDFH))EO4DI)[$Z8&4T>,8FPG-4#E2:68".B'+,.A.9SH 1Y#DU.$VV+ @$J6@Z/4HBISE*
M0LAH]A[+$9-)FH@ VP&@%7G_9$;C":&US*1F)2&G=6(#YA=(6A*:J>+N:H36
M%@ 2;N \"* 2%>+/0!LTH*^J@/D!-[:*(0'>5T-4T$X("9<3OF\I"M%$
MNZ#T+LA%!4++67$% \-"TCXH_:*2F^L(<8-VA\P+H:U/JH",0&BM,T9NCE2(
M%GII*G5 ." TCI1EC><*AHX4[V/RPB$DI1=[" UN+$)D$.;H+0!\8 0.Y]ND?FM'NV 
MRCL@%PL(<4+ND'DAM.TI6(X%9$"!Y0;(E])&!,PC13N>\H['C1!"B=&"NX,1
M,UFB0@3-[,J]\W&YH&X]C1 3;'N*MCWEEX[. 6.C&0=&>IY* 4$!H
M+8U)N)VPYP(W#HI>DZHT(!L06H.0P%J@!Y4 80,>72C:E14N2D-6)^K&1S$;
ME/?1D!*T]RD;D T()8*]>["2'!;K <^7: ?4W@'9)TS+#GB'S NA'5!#0"8@
MQ JY1>:%T-:GO?5QF8#0TG,EQ (?+&G:^K1:S@:]['QWR+R.F6>1WOG8$4)+
M@T1S4]K7$M8$9(*FC4][X^,R02]OP>^0>2&TW6F_9.3F-$*LD%MD7@AM<=H$
M1 %"K)!;9%X(O>#4&1< ^!1=,_MM?(1^AS@A\8?W$^?BM?RK:%^/IRYZ;OJ^
MJ:RN!U6Y[\>O9OC>NIZ+MJ_
M2UFIT\)G_KCP6.[V>E@(\GEPMMN4M6RZ4C5>*[<+_Y[-5@(&B$'\*N6INSCW
MAN2?E'H>+GYL%GXXY" KN=:#BZ(_O,B5K*K!4Q_YCW/Z%G,PO#P?O7\SY?;I
M/Q6=7*GJ=[G1^S[;T/#LXZ3U[?3%=SY/QV1JF\OE++D#,@Y?!T3L,-YBEQ; S(NB]HR&XCYES8\X_
M#["R".#7(\#["';Q'FP1'*X[$.\=".M .!:B]TDV!I/8,BPF2?@$:&5!X?4\
M(C2/R.418R%BFX?%Q" F0"OG*!3B>BHQFDKL4DDFHE@,$R(D5)R@81(7)IVH
MV&( &$SD8D%9%D;74TG15%+K@5!*AN["C+X+68AF8):OL>% 7]@EZQ_Y<# &
M$>7F,(8G-+:';"HA"XJGTW%-A+15&,>SL7TB(W0BAC<*=D.G8'BK8*Y7B(EJ
MEP[$89H3+M@3N:
M1Y#($D*@# ^4471H05_BC#"W."YX[@0O*,.5H3>0,_H-Y+BN.)_BU4VV$112
M!,P!#^3D)RB,";Q<<4.YN&IX1-BO#A1Q4KGX".4Q8;^.(%*;YK@"N5.@H)"2
MXKRF-_"*JX9G%%XMB$<7I'S^M(>K!D("KP[$4D%H.("//V"$7N] $')"PP%<
M@>#$17E<@T^>@6\8;8"/-IA\#![+=:.-M%\!5R!0GG,=B*6D0+@"89QNE#V0
MX+PF-_"*SRT81](DKQ:4ID!X@ 5<@> 4./5JL'2@C%&$(7 %BG%N$;:\P.>6
MN&%N"5PU@A-X=:"4M(T$/K<$3/$ZOA^"X_5#H.#BQ;R6[V@\<]D*KP_B]YOS1*/\'4$L#!!0    ( .""5DB2
MCWV^P@0  $P;   9    >&PO=V]R:W-H965T>MJLN\
M[3[6[V%SJ&V^&1J510A1%(=EOMO/EHOAVO=ZN:@^VF*WM]_KH/DHR[S^=V6+
MZO@X4[/QPH_=^[;M+X3+17AJM]F5=M_LJGU0V[?'V9-Z>#:F1P;BKYT]-F?O
M@U[\2U7][#_\L7F<1;T&6]C7MB^1=R^?=FV+HJ_4]?P/%?WJLV]X_GZL_MLP
MW$[^2][8=57\O=NTVTYM- LV]BW_*-H?U?%W2V,8%+Y613/\#5X_FK8JQR:S
MH,Q_N=?=?G@]NO^D$37C&P U@%,#%7L;(#7 KP;:VT!3 WW5('1#&2;B.6_S
MY:*NCD%SR/OEH1XZO.Z+=)6#;O1--[%#S7J8VN7BY/FZR*0&O-2 ;IA(P\SN%]"7!=S%)^T*F.A2
MXWY@$C=08J(L2:>I-5%Q>E9K4HQAQ1@2H[AN8B?&,0F>#?D&6CL(C%&"B8E9
M+3%I 8\6Q\Q!IS[):\(P 2/XHA-63D)?-/L]D1S'("KTB'%0ED7FOI24E9(Z
M*6@\4AR3="/V2'&08+5DK(Z,=,0>'8Z9QZ@]U)HH'6E]7XR*6#7#Y7[!>"9_
M11 HHSWK:CW6NG#+PIY%>@+F'%:' 0 QN=JP@PD
M CE\W"DMB!B"/(K7A'1?9"RX?R@^[I019 Q!\\NN&$5&ZB;%!YZ*!1%#D,I\
M$3-"B61J^+A3B2!D"/)^3]?(M! ^[%0J2!EUG62,$''8*3[M5";)%P>9R!>[
M!%VZ;7KOP\<=4$2!X#8"BDT74/)T >!5@"!="%)IHGSI,M:*$5 @B(\[0$&^
M$&2BR*O'49@908 #'W>@!0E#T!PA\ZW@$R;;Q@"?>6 $*4.0R;SSXZ"LVPH*
MU/"9![$@9@CRSLTU,BV$SSM(!#$#]_..$.%6!OC,@U00-02!BC#Q"4H9\TT+
MXK,/*/NTP)@8L6&#D3QLD-]0H1*$#4&"E8!\I"$($H0@0"WIB(\J1$$V$"3I
MA4\@U *_$X219&>'?+"@$5@9QQ^&9SZ;[HC/#(P%5B5HKE+1@N-# 1.!#_%^
M*-P@TT+X0$#R>B:XV6/&^R^3^T_S6PX="?Q'D&"LFG>Y5@+_:;'+->]R#0+S
M$23IA;>X1H'Y")K'F>"NKB>>(FF!^0@R*I6L =[EV@C,1]"\6VR"/-&\S74L
M,)^^OS6X0::%\"F@*05 ,FLI:SZ=_@_S\;=@/?[\T+[IR*1C-;S%S6AQWSHR
M8HL;WN)FM+AO$1FQQ0UO<3-:W+,]6A&$2K!;,[S)S7@?9Q_.COTX*$U1$.&&
M-[D9?TQX=N4K@N:9DBPV,_$^YY*F^L''K>/I.\CSS>(TQJ>G3F4MGX?
M#F^:X+7ZV+?N/.!T]71 ] 3]F<75]95Z6+MCGJ\RR\4A?[=_YO7[;M\$+U7;
M5N5PZ#WW75=$_AL>]/CU'4;8^Z+KI/
MYJ2;X9^]:>NB'R[;0]2=6EWLIJ"ZBCAC250791.N5]/8MW:],N>^*AO]K0VZ
MA*;_LQ13$<7G6NJVK,-%3^#Y.^U1P#;\_G
M[)^GVQWHOQ2=SDWUL]SUQX$M"X.=WA?GJO]N+E\TWH,<$VY-U4V_P?;<]::>
M0\*@+G[;8]E,QXO])V481@=P#.#7 $B< 0(#Q%O U+K(,IONZY^B+]:KUER"
M[E2,LPV/ [P=DPR9@^%FNJ%/4\YVZM1Z];J.$UA%KV.B=Q@^8386\X:(ANQD
M"1Y2X7P*Y_<+Y!8A^'(%\;Z"'7P6MH(2RPGB]PEBFR#&+GP@V4P896\#,3)6
M
MB3B*;!#T("5D#BXS#&+N,4D -"%8%BUB.!/ 7'P0QKG,//APF@_'!B4>*6A3
M@;]P%:!M!9R^,K?%@C@PYRRAL:2*>="AC06DAWP1Y)RAV5@\F-"V HF/?A,4
MILI<:^D*BYG/@E(T(>6A7\2 RV00%,L;U'TRM.7!['D>/@49+=[,7[R<]AC.
MEL6;(PB4SUKEM'=P6)9ECB /\7/:$3A?EER.H QUQY6!R"8'C"
MN/@H;\71RYBGRXK;(.@AEB['G5' 4I_)HE]>>+;L<8B!]/:5C^"#]L*2U&.I
M"-I@A/4.GGE(6  I80'^$A:T+PCN(>$9=._E']N",,^W?T$[B! >$D80B-0E
M&T1)CT>1H&U&Q"X-X\X(00]*T9QQ:S3#1 8?'VS1S=:UUNUAVM)WP=:U_]\;T>F#&
M/LDP..IB=[VH]+X?3]5PWMI/ /:B-Z?YB\;UL\KZ#U!+ P04    " #@@E9(
M'D29/V("  "@"   &0   'AL+W=O>4N("#Z&?N3KL!5B6D41W[9DP/R)3F245_:4#5C(+CM$?&($[W30
MT$<(@"P:<#>&=:7'7EE=T:/HNY&\LH ?AP&S?R^DI_,ZA.$R\-8=6J$&HKJ*
MSG&[;B C[^@8,+)?A\]PU4"D$$W\[LC,+]J!DM]0^JXZ/W?K$"@'TI.M4"FP
M/)U(0_I>99)W_FN3?MY3!5ZVE^S?]72E_@9STM#^3[<3K;0%8; C>WSLQ1N=
M?Q [AU0EW-*>ZV.P/7)!AR4D# ;\8<[=J,^SN5( &^8.0#8 G0-@X@V(;4!\
M$Q 9,SVO;UC@NF)T#OB$5;7A2N),)9&9 SD9+I^3SLGTDZJK4YUD916=5*(K
M!FGFQ3#H/M$8(OY$(BG@M$#7%F;P&>EXF,&O$\37"1*3(#;3R,&UY*B9W$S#
M,!ZBN27N2B1.B<1*0-"UPL U'I<>'Q6; ,@/P!(>@66A9(W_>T0*GWVV\LEL;@HO+WA9!;R*R5L?,]MBO=PI2@
M<#Y'N]Q9+"D1O*U8=+&73/A ?F%VZ$8>;*B0VY+>/?:4"B+3@*&PO=V]R:W-H965T)E5]V)YIXB2H@#/L--U_/V.;-*TASEB0\O
M8L^8#-ZZMA>+<"_EX3Z*Q'K/NEK<\0/KU2];/G2U5(_#+A*'@=4;;=2U$1*2
M15W=]&%5ZK7'H2KY4;9-SQZ'0!R[KA[^+EG+3XL0PFGAJ=GMY;@0565TMMLT
M'>M%P_M@8-M%^ #W*\01T<2OAIW$Q7TPBG_F_&5\^+%9A&34P%JVEJ.+6EU>
MV8JU[>A)1?YCG;['' TO[R?OW_1VE?SG6K 5;W\W&[E7:DD8;-BV/K;RB9^^
M,[N'='2XYJW0?X/U44C>329AT-5OYMKT^GHRO^3$FKD-T!K@V0"R68/8&L3O
M!HG>J5&F]_6UEG55#OP4B$,]GC;<*WP8G2C/@=J,4'G2/@>=J:I\K1*:E]'K
MZ.@#@YI9&@;.1*2\.T-@Z#)';8[7 ZP,$>/M"/''"&;Q(381:'S;0?+106(<
M)"8+V2>1O6:HV89ETH3"=6IEJ#0F-+TM)G6*24TV4E>4S&@Q2$'2HDBN8RN#
M 689^,C)G'(RD]S"PP%UG@[U/YW4&R-)Y39!L0JHRCCR1T2T+;ZWPR[6XT\!^=!MRM!F9[S909 \60
M4C*7&.L+U;^XAR!WNX'4HYHM-"OF,W)=B+O10.93QIDMXPRQF%-C.<3XXMUV
M71)U2Z(>56P82./$^6*8!%FLH(F/'G)2PA8 D
M./^2FD! )+G/D.%N. @>96RA6UW98KYM&=W]!G&NGNU48:$O2)(KFNQ@,8% 
M8@*?CS^Z&/TZ-NST2"R"-3_VTHQEY]7SV/V@I^Y/ZTLUCIOA^=U-51[J'?M9
M#[NF%\$SEVHPU?/CEG/)E#9REX;!7GTPG!]:MI7C+57W@QFAS8/DA^F+X/Q9
M4OT#4$L#!!0    ( .""5DA&PO=V]R:W-H965T
M=L].XB2H
M@+/8:;K_?FWLI&GD@"_!-N^,GS&O)BY/?'@3>\9D\-&UO5B$>RD/3U$DUGO6
M4?'(#ZQ7;[9\Z*A4TV$7BA*OE1MDW/7H9 
M'+N.#O^6K.6G10CA>>&UV>VE7HBJ,KK$;9J.]:+A?3"P[2)\AJ<:?NGVFSE*S_]8+8&HA.N>2O&WV!]%))WYY PZ.B'
M>3;]^#R9-SFR8>X ; /P)0"2R8#8!L0W 9$A&^OZ1B6MRH&? G&@^FO#DY(/
M.HG*'*ABA#JG,>#C7BAX2E*13/'"#?!\&
MNV&PAW.MJ,AG8*PLS3./A@GNA@>F3278YV,G3O-"XN]><#<7(![^M2)0Y4YZ
MQLHR''LT.W W&$A]#)SZM-Z+BGCT%W W&,A\/)S9Q@K9!'5]D7GU7\C=0/F4
MC^T?I15A0'%V7U9;F?JN4-P 15=7D0/=L5]TV#6]"%9/G8
M21CLU6WS,FG95NIAIL:#N7^9B>2'\W7RM_@-02P,$%     @ X()62"A:
MH\K4 0  (04  !D   !X;"]W;W)K&ULC53;;J,P
M$/T5BP_ W$DC@M2PJKH/*U5]V'UVPA!0;),M@$+OC/9RX[5*#6N,Y;X%1J3/!^CU2L,%(TJ'XH#E((#4EL0HCH(@
MPXQTO5<6-OUZ>!%('ADCXM\6*!\W7NC-B=?NT"J3P&6!S[RZ8]#+
MCO=(0+/Q'L-UE1N$!?SN8)07N,%Q@)0V"NC0/1P@@HH-4)Z
MX[^3YL>6AG@YG]6?;+7:_8Y(J#C]T]6JU68##]70D"-5KWQ\AJF$U CN.97V
MB_9'J3B;*1YBY-V-76_'T:VL@HFV3(@F0G0FA,E-0CP1XD\$[)S9NGX01)K@<0)Q)- SY;3A7H#4"/_50J]^K&PO
M=V]R:W-H965TT==D/K^U^V9U;6VXGH[I: F-J69?'
MTV*]FL:^M^M5\]Q7QY/]WB;=6Z]7R:K<]
MUO;4'9M3TMK=_>*!WQ72C) )\??17KHWS\E(_K%I?HXO?V[O%VSD8"O[U(\N
MRN'GQ1:VJD9/P\S_>J>O3]/OQ?W',&^&&X W@*L!
M5U$#X0W$JX&<5NJ83>OZH^S+]:IM+DEW+L=L\[L!WHY.!L_)L)ANB-/DLYTB
MM5Z]K*4QJ^7+Z.@=!B;,QF'X%;$1P;D82HH<*)59;$<'%&>&DB%<7+A7EYRP)&!HAH#1
M,P3X3@:_DW,>B8H'I29G)M.1P 0@9UH-!T "*\!9 :%N/(BS3)HH*8?+-!::XSH6*,/(YS82@2"KCH0#B!1'/GU<08R%F45) =EC,M* 4!3ZEK[V#!A),1B$X!<"$7X2@ N06 H96U\68-4
ML<^$Q^5OB:1O+>,'&-N>'\8W_*YPC=]7-^O5N=S;O\IV?SQUR6/3]TT]]3YW
M3=/;@1O[DBV2@RVWUY?*[OKQ40_/K6O_NI>^.8=N]K6EOOX?4$L#!!0    (
M .""5D@Q0_0FR0$  ,$$   9    >&PO=V]R:W-H965TZ)'
M!:SQ),$)C:*<"-8/N"I][4E5I3P8W@_PI) ^",'4OT?@4TO8-"]')""=H,?XG6=.X0'_.YATASP9&S !QVQBDP
MNQRA!LZ=D-WX[ZSYMJ4C7L8G]>^^6^M^RS34DO_I&]-9LQ%&#;3LP,VSG'[ 
MW$+F!'>2:_]$NX,V4IPH& GV&M9^\.L4WJRBF;9,H#.!G@EQ^BDAF0G).P()
MSGQ?WYAA5:GDA/3(W,>.UQ:NG(A51K89;>?D-96?5%4>J_0^+\G1"5UAJ,<\
M!@S]&%$'1/(&(=; H@MZ[2(4'^CLHK@MD%P+I$$@F056UR8'CRE"&P$3)S3.
M/D;5LU(1%_%M,^FBF70V2+#O(OC"-@5D44?3*- *(TO4 %
M+^3BM(UL#[^8VO>#1EMI[,'UYZN5TH!5B>XRC#I[GYP3#JUQ86%C%7ZQD!@Y
MGBZ,\ZU5_0=02P,$%     @ X()62( [ ^GA!   FAL  !D   !X;"]W;W)K
M&ULE5E+;Z-($/XKR/<,=/4#B!Q+$Z/5[F&ET1QV
MSR1N/S0\/$#BV7^_0!=,')7;Q<4VS5?5'_4VO;[4S8_V:&T7_"J+JGU:';ON
M_!B&[>O1EGG[I3[;JK^SKYLR[_K+YA"VY\;FNU&H+$*((A.6^:E:;=;CVK=F
MLZ[?NN)4V6]-T+Z59=[\]VR+^O*T$JMIX?OI<.R&A7"S#F>YW:FT57NJJZ"Q
M^Z?55_&8&3E 1L0_)WMI/_P.!O(O=?UCN/AK][2*!@ZVL*_=H"+OO][MUA;%
MH*G?^2_HO>6NW=?'O:=<=>[;1*MC9??Y6=-_KRY\6
MGT$/"E_KHAT_@]>WMJO+2605E/DO]WVJQN^+NY-$*$8+  H 5T"B@.0**!10
MGP1"]RBC(;*\RS?KIKX$[3D?PD,\]O!F4-)K#OJG;WO#CCJ;T;2;]?M&1]$Z
M?!\476%@Q&P=1LR(L-=.;@$K2AQ&<;B]0>80$N[O(*]WD.XAY"BOTOB^ G6M
MP"U^56@%09%TF*W#0&)N8[()PR"B22(:B7RR5C5B8D?$880$H6^C,H=2L8@9
MCC,D&8-D)+6-<60R(E[RM(R#!)^&&2D@Q2
MGW?0(*G?.VB/=(EW1$2R&9<'.HJA0I 6$8)O$@$T"T 6^G9>/,\@X[$<@E0,
M.F70D30=2?OHFH[DT'$@HSFVH(A.8V%H#UT%)(+ZN&6%
M$YVA(KZ?(!F"I#*F  [\0P$7(@&:O$QP<'BR1)&6D%=+$!+#:"
M,R[&M)OB!6ZBZP,D'#00^&$?R2'@DDC@2"HX(>V^6"N5W2*2A3CEEQ
M(@!A&#U&T?FE(H9=$?0@($X8=E%T&U?8H06C>R@@3:M@P3]G.F^49)@609!&
MO@8TH2+-*7#JQE]YQ7& PM+B&U0G$*LD*#J?U93/AJ'"T#XR"WQ$)Z&*.3YR
M(! B]55;A$EI@!-W=']6"<=)"=;UQ!LTB$H,QSYT>5!3>>"\MXE(+^F([R5-
MY[,6#"\A*!9)K#Q609@ ,!R[:+I-:V^;GEY'8?L5O9]B'Z6I34,U':--9PB"(:,X;.E&K1F-.D/0@Y 1(RDU727T5"48
MHZ&F6[5>T*HUG8N:T:HS!$$_5G#"V]"]VGA[-;Y'-5.OCCDCC)E3N\(]A@6_
M")U[YL8KLZL_Z1,(& .+H1/*3._"4M\^"(+/ V?XXK<
M.^YY=3X@>H;AS.+3^E8\9H)8[PWXN#74G?[A^SN4KIYN?V<\A0I_D]JLS_G!
M_ITWAU/5!B]UU]7E> RRK^O.]D\9?=&KX&CSW7Q1V'TW_(S[WXT[.G(777V>
M3L+FX[C-_U!+ P04    " #@@E9(M8+H[#4%   K'@  &0   'AL+W=O15']M,V+K/Y6'O-#^\]S6159TQY6+U%]K/)LTP<5^\@HY:(BVQVFBWE_
M[GNUF)>OS7YWR+]7D_JU*++JOX=\7Y[NIWHZG/BQ>]DVW8EH,8_.<9M=D1_J
M77F85/GS_?0W?;=V20?I$7_O\E/]X?>D*_ZQ+']V!W]N[J>JJR'?YT]-ER)K
MO][R9;[?=YG:*_]+2=^OV05^_#UD_[T?;EO^8U;GRW+_SV[3;-MJU72RR9^S
MUWWSHSS]D=,8;)?PJ=S7_>?DZ;5NRF((F4Z*[)?_WAWZ[Y/_)U$4Q@<8"C#2
M *  . =H%PQ "L#W  P&6 JPGP(B/_:>N5769(MY59XF]3'KGB=]U\*K+DF;
M>=+25;=WHL]9]?=B,7];6&/FT5N7Z )C>LS28_09$;79V4N8*1=N^O# !58>
M 0'(VD,2N%T$7!8!?IQ XQ0DP,L$Z!,@)<#+(@\])O8C]9@9Z@3U==C*PTP:
MAY*M/4H;IV)WNVC+%FVI:'L[@6-IHZ
M8OT9<;76A*TUH5H%=*LC5]GPJJ)K7%CV(BR1%PG.7C. NY:M(
M)=RE]-A9$^+.H[2+34 (UP/,6(6WRS:\TAA2&A#(I=$L>4;+R3.&K\((R"-0
MJ&,),C,!15P/H$2@=(;7&$,: Y+9$/*LX0C6>%LW5L*:!\UB%7()0H5Z]0OD
M>KF\NAA2%Y#P'O.DQ2-(X]W=)!+2$M)T2&W -E>$T\H$F?,HHQ$%Q[(&2LP>\Q8,6L$>@=B9G@_Y*. T: W*X)EAB'0C<$7B% 5(8$$@E
M7%D[C%@\ &_S$%P^#/31^L$ !MG#ZRU+:XJ.LAH&!+ K6MF.*5=== '"$Q!HN2QX$7$B A@3A4E0Q^I]U&2@I_<
MXXC)/?)]A:F$]O3F_/0+Y/J+''ZZ;I7@>2>0!H@#L!7!$N,200-:OM:T(+@_! *M@[C5@%.)CB7$\%9O47*GAG> B$'+(AQ89[3D
M+>"5UX D'BB8@%O>S>T(-[=\1UN)FQ.HM<-4*4F[\!YM)1Y-H':Q#;)K\1IA
M22-00(WCO=>-\%[']Z.3>"^!7)Q@8"*Z(I@V6HM>'?,6[20632"=6&W8EVWT
MSGS .:6+AS)A63VYW@O=R.\W/'MZ"1>3B!M1(^FX_W<7?'SBUT+ DFO
M=&[N UVC.Q$.X7O4)?P\XF*R,8"^S(VC#[M=15Z]]/N,]>2I?#TT?@_G?/:\
ME_E@NMVR3^>7^FZMF?/MP.Y6[>"^_M,6U?[3;XM&[Y=>S(_92_Y75KWL#O7D
ML6R:LNBWV9[+LLG;L:AO+1W;/-N<#_;Y<]/]C#N>_%ZF/VC*X[ U>]X?7OP/
M4$L#!!0    ( .""5D@9+\/EGP,  *$0   9    >&PO=V]R:W-H965T.9>#)F<5;-K_8@91?\JLUR%)NNIXBUY=7N9)EV3-IS[\=Z9O/WO#R
M?F!_-LO5\E_R5JY4^;/8=@>MELV"K=SEI[+[KLY?I%M#U!-N5-F:WV!S:CM5
M#2:SH,K_V&M1F^O9SJ3,F=$&Z S0UX [ SX:0#QI()R!& W$)#YR^.C-P;1!
M[ SB:P>A#94)]%/>Y\S[UP_F&MWT')HXT-%M=>(,96-2MUR\+B,1
M+\+7GN@*@P:SLA@8$:%F)UW@C#)'8XZW':PM@N-]#_S: [>+X,9>9,E] G%-
M("R!L%'@[Z)0&TQBEV$QP# 3J8#;P+4#BH1'0MQ7%)&*(JF-03N_?$(\0)F:/$/TVP&
M!P+.DPG8VL%2C%.?X-+E ER]$)D'143G)_I ?N@M";%/?BR( TSBU@..I9#X
M!":A)24^F;(@74<%74<'21;'HQ@A]I!$EPUP=2/R>?\R.E>9?ZZ0WM'(/'+E
M0'$,P/A$8!P.F! H?#[+0&L"CV0Y$!>0,/(3;LF>!K*INK@>R$"D"=EP6++G
MD"--N.JVW0@3T]\K#JUZXC[@6D3NBCP&_OXJ@<:0#[M)*?W)\=_
MMCCA9]C$_)V?\.*H4\EF;\ZD;;!1I[JS#>@X.IY['\VQ]]WX2I^'@1K'^1.%
M7^/\F1K7 9^O.2-F=+#T#.5#+T_/&+;P;1'+Q3'?RZ]YLR_J-GA1G3X%FM/:
M3JE.ZJBP3_JX>)#Y=GPHY:[K;Q-]W]@3M'WHU''X0V#\5V+Y%U!+ P04    
M" #@@E9(;EF$,HL"  "^"0  &0   'AL+W=O)JVBTE5+[9KDI#8JFTR($WW[\=7TJ3%
MQ+N)@;SG]<,Q'*A.E+WPEA 1O W]R)=A*\1A$45\TY(!\P=Z(*/\9T?9@(7L
MLGW$#XS@K0X:^@C&<18-N!O#NM)C3ZRNZ%'TW4B>6,"/PX#9WQ7IZ6D9@O \
M\-SM6Z$&HKJ*+G';;B C[^@8,+);AH]@T0"D)%KQJR,G?M4.%/R:TA?5^;%=
MAK%B(#W9"&6!Y>.5-*3OE9-\\Q]K^OY.%7C=/KM_T].5^&O,24/[W]U6M)(V
M#H,MV>%C+Y[IZ3NQ9=$$L!) 6\IS. CU/$@ _<-DEL#9 P2
M;8#*XA9RU)K<3,-H0 )!.JUJK%,.\ADPR F#;$Z=K\D,C-'$TXKFHV(2(G5"
MI!8B\T"D_HQ8D/1_,I(Y83(+DWM@C*8H$X^H,2*(8);>9\F=++EE<2X5RV(T
M,$X\V6N,J$3IC&5?.%$*BU)Z4(P&RBE[4 K[(='5/IYD*9TLI6')/$MR931?
M8 &1;\%8&4)I.2,U(';RZ&$%!#Q 5N3;1I\DTR# #6)+9.;Y "LKNIN:LVYN
M;J ;"5JDQ(<$YVPHJYJYHX"[^H+$\B ?CZV_91)[MEYC97+OP7P&D+L" UN"
M,T^E7P%/#;:'P2>) 8FN3MH#WI.?F.V[D0=K*N2AK<_6':6"2(OX(0V#5EZF
M+IV>[(1JYK+-S/7"= 0]G&]+ERM;_0]02P,$%     @ X()62(=F/$IL @  
M  D  !D   !X;"]W;W)K&ULE5;;CILP$/T5Q N[?DZK(485E'$=S7I,'^B ^GEFP-E'19RRXX1'QC!>QW4M1$"((LZ
MW/1A6>BS%U86]"3:IBT#1@[K< -7%5PHB$;\;,C(+]:!$K^E]$UMON_7(5 :2$MV0E%@^3B3BK2M
M8I*9?UO2CYPJ\'(]L7_5Y4KY6\Q)1=M?S5[44BT(@STYX%,K7NGXC=@:4D6X
MHRW7O\'NQ 7MII PZ/"[>3:]?H[F39K9,'< L@%H#H#W V(;$'\$)+I2HTS7
M]04+7!:,C@$?L/JWX4K"F2*1S($LADN?-"?33I7%N4RSK(C.BN@*@S3FV6#@
MC(@DNS,%"EWA2(>CVPDJ@XC1XPSQ=09SN(EM$?EC@N2:(#$$B2587(OL-28W
M91A,O,R2-+X-JPP,00AR\%A.ZI236CG+QP29TY#,WY#=Q]!1<^KDZ@Q3]YHHN!TQ%VU(.8
M!SMZZH69-_/I/.PW2 ^L#WA9#/A(?F!V;'H>;*F08T]/IP.E@LC\X"D-@UI>
M1^9-2PY"+7.Y9F9 FXV@PW3?F"\]Y5]02P,$%     @ X()62&S4OAD8 @  
MQ 8  !D   !X;"]W;W)K&ULC97-;J,P%(5?!?$ 
M-;;YC0C2-$G568Q4=3&S=A(GH!K,V$[HO/WX+VE2D80-V/"=P[D7RRX'+CYD
M3:D*/EO6R7E8*]7/ )";FK9$/O&>=OK-CHN6*#T5>R![06A;(OX]4\:'>0C#TX/W9E\K\P!4)3CKMDU+.]GP
M+A!T-P]_P-FJ,(0%?C=TD!?CP&1?<_YA)C^W\S R$2BC&V4Y-9^^#>Y-"+QL7("] 9P&,[PJP%^"I@M@+XJF"Q N2
M;P+@:K>=6Q)%JE+P(9 ], URD[RV2N&XZ!$,$4W<86'D,1CFY32T?A#-VQ6CD(P;R8T)EXM+#8%X8>
M&R2CK4VFMS8=39#>:VWJ6NN8.(88WZ86CL(Q2A]GR4:S9#X+?FR0CW8CG]Z-
M8C1!,6&A.2;-(U3<66>.RM,H_I8%7&P'/=G37T3LFTX&:Z[TSF(W@!WGBFJ3
MZ$EGK?61&ULE57;CILP
M%/P5BP]87[BO"-(N5=4^5%KM0_OL)$Y "YC:3MC^?7V!;+)U$OH2VX>98(92;FG54/O"!]?K)CHN.*GT4>R@'P>C6DKH6
M$H02V-&F#\K"UEY$6?"#:IN>O0@@#UU'Q9]GUO)Q%>!@+KPV^UJ9 BP+>.)M
MFX[ULN$]$&RW"I[P8X5C [&(GPT;Y=D>&/-KSM_,X?MV%2#C@;5LHXP$US90 =/3=K4UOU]$]2:.)YB>0B4!.!'R;$$Z$\!,!.F>V
MKR]4T;(0? 1RH.;?QH\:+HR(5@:Z&:ESLIK")E46QS+.H@(>C= %AEC,L\.0
MZXC*(<(/"-0&O"[(I0M7?"*6CY/LOD!X*1 Y@7!J([XTV5M,ZMIP&$S"),[R
MZ[AJQN5)CJ/[AB*OH6@RE-P7B+V1Q,LC2;P.DEN1)"X2A\DRDJ/D.JQR,(QR
ME(;XOI_4ZR>=_*3W!3)O(MGR1'*O@WQ!(@Y#",EB6
MC:$%'6'LS03CY:%@XG=!%L0R@=+LGTEQ$[9#RKV32_!FBL]^^V(WG&NF)9!
M#W$ :GTGGPXMVRFS3?5>N%O*'10?YDOW=/.7?P%02P,$%     @ X()62+#_
M!04# @  R@4  !D   !X;"]W;W)K&ULC939$!(A:Q>3 S#7:GO>A,)A?MM6R$82(A*LDF??MJLV,[V,X-6OC.T?D%
M4CDQ_B8ZC*7W3LD@EGXGY;@ 0&P[3)%X8B,>U)N6<8JD&O(=$"/'J#$B2D 4
M!"F@J!_\JC1S+[PJV5Z2?L OW!-[2A'_]XP)FY9^Z!\G7OM=)_4$J$IPTC4]
MQ8/HV>!QW"[];^%BG6C" +][/(FSOJ>S;QA[TX.?S=(/= 1,\%9J!Z2: ZXQ
M(=I(+?S7>7XLJ87G_:/[=U.M2K]! M>,_.D;V:FP@>\UN$5[(E_9] .[$DS"
M+2/"/+WM7DA&CQ+?H^C=MOU@VLF^R0,GFQ=$3A"=!"&\*XB=(/ZJ #H!_*H@
M<8+D2@!L[6;G5DBBJN1L\L2(].\4+A3.M8ER]M1V"?4EC"0W]D=R\1!4A39G=VQ6)3"",X69[&5&ULE5I-<^(X$/TK%'<&JUL?=HI0-89L
M[1ZV:FH.NV6NI\^6+Q7]8]F6Y;M
MY.=A?VSNI]NV/=W-Y\W3MCP4S9?J5!Z[_SQ7]:%HN\?Z9=ZXX72Z&=]_JY:)Z;?>[8_FMGC2OAT-1_YN7^^K]?JJFX<7WW;-I#!L1?N_*]^?!]TI-_K*H?_<,?F_MI
MTG,H]^53V[LHNH^W;
M=MNQ3::33?ECG
MD[KKX'7OI/,\Z<+5=",Q^*R'L5@NWI8FTXOY6^_H @,#)O<8=4;,.^]L$S#E
MS&$PA_$&5AZ!$4)E[21!\)I$B8ZP[TI0/M'6AR8"\Y'@>,
M\[$@3()),HY:>91*(89:>]3,J@^H4"[6,_8@<#'0VH/0
M2?A:=HPL\4VO.W!LAQTYR+AYY#&YQU@)RY1EF9(#0<9D+,N,'$!D6#P&K :-
MD8')*+6R]'.*7PP-P8S53M!ME;"TA]<][PBAG$ SI0S$B)]Q-H4LPCS@4&LC
M"+A2/'5%U"-!R@D$!AS$DH%PJ#"Q)D:=< ")R@34@:<.1#W25$X@L-;Q]2E0
M)YRRSK!%(5"GDJVU52B@CCQU).H12CF!^IJI8LPQ%,WX=,%0-4$RT?E*KS3Q
MCH0H)Q JE_#U-1#W.$"=I9$XK(,_3'4F"3E?\94AZFF,NJ'S3L >A=8%45\54ET"8=*NV6"TBW+45T3KXNUP2C5/G
M51=(=95@NP#\A@-NV'$ +T00W7.$#M-&075+>('F 2\<0,*AHDV94+Q$+?%%
M'JC(?U"><1>.#ZV[(;1\N8/T>FA7!')I=-]#J$[[1%'A"QF$0B;0'TS8J& B
MCPKR&8OJ>E1R J'-)/U%/L$P))B@O.#(COZ&!$,^P5"08#F!E!:-+_+YA91?
MDF4I\KMCM#?TEU^BH!,4% +-M*B>()]?2,L)$*P&,>/[F]UP9,-KITX$XTN@
MF8Z?@008QJO!&2:*GN;S4)-R0FQ90R <.6P*M$DW1PZ; FM"H8@TG]*:4AH$
MVQ?-I[2^Y91NY)A.DM(Z:*:LOWQ*:R,9) ]2HE,\S2NF)L4$P7I&\XJI;U!,
MS6>T%BCFFD"RTJ%Y*=1!"J,->9 "T>DH7QT,K:Q!$!2CV+@:)8^KX=/&@& E
M0B G.PSFCV,,'<> %;C0?'?U#=T=.9,V@OPD$.CXJ;2Y8;(9/K>,O9[$*P+-
M1,M>PTNOH=,!$"Q[#7_P;-(;HL_GELDDT?>@F1'--LLGETVN9W%.H!D844N\
M6-J0@['C.@*A%C7$9ZH- B=8HUM>X.P- F=Y@;,2@2-0%KV(6A-J!K*H\ EM
M)3)((.F4XG/5AEP5[!DLKX/V!AVTO [:J [2]8T]'Y1%;P()QJP5YQ]N>P]E
M_3+3I^KUV/J;V//;\UW^5^AOBS^]S]7=VM_(_W*S7)R*E_+/HG[9'9O)
M8]6VU6&X,GZNJK;LB"5?NA!LRV)S?MB7SVW_U?6Q\??R_J&M3N%G!N??.BS_
M U!+ P04    " #@@E9(,;&BT:0#   J$0  &0   'AL+W=O-W_LA5-E7?]:;,+VD/#\XT4566 PY &55[4_F(NQYZ;Q5PJRIL_-[P4IRL?^>>!;\5NWPT#P6(>C+I-4?&Z+43M-7Q[Y5^CV1-B R*)
M[P4_M>^.O2'X%R%^#B?[WR6UZ6@U,_\R\P?9MS$+X_
M/KLO9;I]^"]YRV]%^:/8=/L^VM#W-GR;'\ONFSC=<\@A'@S7HFSEI[<^MIVH
MSA+?J_+?ZKNHY?=)_4)2D.D%& 1X%(SSZ 41"*(W ;$*" B(JR &0>PJH""@
MK@(& N8J2$"0N I2$*2N@J'GJG/AFX3:)6.SD?,LYW8C["PY-QQ]['B@UJ)<
MR7=YER_FC3AY[2$?KF\T&_AF\.G-O7[]MOVE(6T;>7$LYJ\+&H7SX'5PNF"P
M9&X4PY@962D$C4301Z / _NZ*;#48_,,MXI@B1FY4P@Q$U_ )#4C2X5$EE"^
M*B2QE.P>$&1&'@"Q3+2:K$HV'>TCS!.9D2>%Q.\R,O@2.E<60%OQ#(#X?,"BX5
M&+,TMD_]%< HQ(D5O >04D*LX /$R")J3V:EP BQ,+5GDRD21R1-["5_!,\H
M(>G%[.9E$&N707PNM&XNJN)7#!IBU\>DN$QQLFPV[E%QGU"(+TES[%0;.U7S
M64*_H5 F:FJZXI:*0RC&IEY"+1P-LVE#:"2 -,&I%7R"F0FY7.GFHC%MT1@T
M/+)433$,$7LQEN 5Q_9BK!S],KV?.<-$FV$"&6IO;9"A8FRY31*K22+[2)@S
M2;69I)!)[." 0NV#0@Z[/BD0TH:!D,.: 2A"$U?_$D!Y&[:N&E?'S.!HR1/K
M\\20)W7QT#^8T?\\F9'^T8S(](T-F&BRVF1R'3M:9?]861+3/VS0^6G#7#RH
MOL#T?PJLOP;3PJWNSD%KSU
MUN)8=^I]<1P=M_G7>-BX?!B_0;,'I!E?H=FCVL2_V2_FAWS'G_)F5]2M]R*Z
M?L,D-S5;(3K>!QU^[K>M>YYOQI.2;[OAD/7'C=K*JY-.',[_3(Q_CRS^ E!+
M P04    " #@@E9(JDJQCRH%  #A'0  &0   'AL+W=O \0")
M9[_] FHY?K0:)8?X]5,_)/5?#2R.=?.SW1K3S7Y7Y;Y]G&^[[O 01>W+UE1%
M>U\?S+[_Y;5NJJ+K/S9O47MH3+$9!U5EQ.,XB:IBMY\O%^-WWYOEHG[ORMW>
M?&]F[7M5%D)'X9V>.[=G[V1#\OW?6OXWI]N$_%ZU9U>6_NTVW[:.-Y[.->2W>R^Y'??S30 YJ,/A2
ME^WX?_;RWG9UY8;,9U7QV[[N]N/KT?Z2QC ,'\!A #\-8)(<(&" ^!R0D ,D
M#)"A'A0,4%<#(IO[.'/KHBN6BZ8^SMI#,>PG]M#CS6"DMSSKIZOM5V*TV8QK
ML5Q\+!.1+J*/P= %PT?FR3&9GUE9AON)M24$@>062<4)B?H\T&3X93+")L.M
M"Y5.&Q"7!J0U(&RF,KX,I"H2X4N$ 7
MPS(KQP2L1H(Z2<" Q/+0UHEE>@FS?].N-.I*@RM%Y..89-I)BNZN% SH:0,9
M&F4&!E)B0C*H$L53'30A+$9]C5_W,QM0"HRAZ3(67DV,XT%PR#@C,@:(!7C!
MBY9!U:J86/T3%.('KTL&A:DX49@ \=#]S/ "95!]2E"^+,1$VN_J$%\)OM!)
M^,9F>/TQ*"Z%UKH+UT*",9YYB@ $U)&QSEB:*#^9GT@I-=-90 (IG@ 4MR*<
MK0#BJI]N(M$U<$)HS=&=[X('3LHD#5 EAJL* UE1"16ZA>X2)A1UNJT!))#\
M!O&?TK@V\1@BUD3$ %&Q D)MNOS&C#]8A@<+W8\B-NP*H'[#:JXTH0]K1TX6
M0?YI\[((_ G@(LQ!A!6Z%5-(P$+Q/=ITI!#[+>0/!M=J+B"I  M7*NQZ/!E^
M+'%<7+EK;:AC"2 6$BG>__ DX%QR4(A^OTC1E_L+C,"2=SE$X[:'(+AX+Y&1BTA87GPM.U
MIY1( T2+- +Y@\$;70&-;A)BXDIB09.$^L*E."Z?PBDC<9P^ 20ONVUDX1,X
M=VANC7/^T/%V6( B)U3W#A 9S37B#P37=0$">]:N^DUD^$IFX2LI<L[53=(?H/X(\;[.0G]7!*2-'X-++]P
M#2SQHI>NZ*D#""#9UP+/)O8YH#)\I^,B()T($*W8"B 5?"-.XKV8A%Y,4VH,
MD$[3+-";PI5%@;)HZEXI0'9:&)H$KD0*1H:X;5\K=
M/N=39]U:G40K.#!  I>7!%X%V32D(JPD)WC*>3<0%*U /(.)#A\XK+J-)4-<#Q
MHXC>"0X>0+C&PHG.'I4=BC?S=]&\[?;M[+GNNKH:'XZ]UG5G>D/Q?1_NUA2;
MTX?2O';#6SWD89] V@]=?7 /5$]/=9?_ U!+ P04    " #@@E9(I0B,NB$&
M  #2)   &0   'AL+W=O L=I+9MU_CKG9"*!?%33CDJ_;?U5T'
MMUF\U8=?S5-5M9/?N^V^N9D^M>WSE_F\N7NJ=F4SJY^K??>?A_JP*]ONX^%Q
MWCP?JO*^-]IMYTH(-]^5F_UTN>B_^WY8+NJ7=KO95]\/D^9EMRL/_WVKMO7;
MS51.\Q<_-H]/[?&+^7(Q'^SN-[MJWVSJ_>10/=Q,O\HOM[Y'>N+O3?76?'@_
M.8K_6=>_CA_^O+^9BJ.&:EO=M<#3^^SZ/?
M]M/MY/\LFZJHM_]L[MNG3JV83NZKA_)EV_ZHW_ZH8 [V..!=O6WZOY.[EZ:M
M=]ED.MF5O]/K9M^_OJ7_! %FN($" S482$,::##0[P:!-#!@8-X-/&E@P<"^
M&SC2P(&!^S2'>7)6[^I5V9;+Q:%^FS3/Y7$#RB\=?C@.THT\Z?S;=$O7CWGH
M%V^Y>%TZ;Q;SU^- )XSJF6_ Z#C.%(E1X\0J$9I U@D)>ARYS7KMP,R[N:(3
M5J<3UFG"*LF0YO( ^G0 DP;0H,"=JMSW3$C>2(R,,Q_&J150?F8):@V4G06%
M43[Y!2AQ>58&G96!67GL&LFP2$P4+D8YCJT2)J5T6J 32]P:."-4#/ZR;HOJ
MMJ";N%"1&"/B@1)-5.1V,@^;U&/#@8;&2@]$_&RYH!J#J"9B(0BP&J+<6;%8-;G
MS*C8B(J-();8=$5BE!4"UP)[,^:]:3ERI$#U]%\?!1G">P"90/HO#^5)#P(5
M6)HEKAGR?;!$2 V0(V)J@!BI1BIC224
MHT#$9R&'>J30R($PED-!$AQ!>"&14$DBD;R* 9+4BF6((P:O#A+*0T1C,&_Y
M!"E';_E$2F9EPW7A(DU(3(
M2$+J4Q;/_:O@-[ *3ZH*4B&^G+ + 3*:W(69&BE?4 B TJS047CR5="X1\Z\
M->XZ?87K\.RF#,=U";*TYQC0.E^.Y3<\!:J< JFF%*"S-)
M4CE8)D:;J#R^TOZ*E<93C HP$:)$%2HWI)QXQE."BG =JJ<%2-([*C*Z6H 4
M9WTTWD=J0<4 % V ]$@1@YJ1J9$D R4C4SS1>,[3$MQ,=0( :;*M70%E%.GH
M/!:K8]=XSM.*$;L >8$>X4#L#A#11Z\'R#$4CQR.:!@"/4?(;M;GZXFX.5$J
MTFX&BE5:-)[4M0$]C$936S3A:,M/.!I/>]HQ$HYV_(2C\9Y/>RI\\Q+YLS2!
MK)"_G)76 &G.\N"96.=,S.B[=,27)_*7Q^!9SPA00<4B0(8*LQ4"C8O!LYF!
M;,8Z[\//0<0^-B1@XP#;B$<5=A\" V5P2QP8/8.(Y+
M',7,/*:";A+PA4NP1L<$SDNB1R7G$/CI\5X%%N(8JD90TC4
M)5;R76+QNFYSH:52?898U\$#U$*AM9SC=8//UEPQVY$C>M89/?.0_JI3>HL'
MJ84@E=2I!T#2AJ@(;@6<$EXK1H&R>*C:'*J,ULOBH6JO"%6+AZJ%4)744Z ,
MA;-#V5._P"V+\O+SN>Q)KQ%5 Z?.R#SW4#
M)EU0C#5S>!UWN8XS;G4=7L?=%77@JA[X3-D7 B>0UQ^HD0\QCS_32*;??&ZVZ2=L!7#Z K?"N7'I>-Q[
MB'M%+15 4@?WV<_S#S_U>"X?J[_*P^-FWTQ^UFU;[_H?=SS4=5MUPXB9G4Z>
MJO)^^+"M'MKC6]^]/Z2?W*0/;?V&ULC9;+&7\3!TIE\-%W@UB%!RF/CW$L-@?:-R)B1SJH?W:,]XU43;Z/Q9'39FN"
M^BY& *1QW[1#6)6F[YE7)3O)KAWH,P_$J>\;_F=-.W9>A3 <.U[:_4'JCK@J
MXRENV_9T$"T; DYWJ_ )/M:0:(E1_&SI65R]!QK^E;$WW?B^785 ,]".;J2V
M:-3CG=:TZ[23&OFW,[V,J0.OWT?WKR9=A?_:"%JS[E>[E0=%"\)@2W?-J9,O
M[/R-NAP2;;AAG3"_P>8D).O'D##HFP_[; ?S/-M_( $[P#,^H@PDAY#Y0Y@7*'% Q V0U#T6*X R.4^$\
M PNF)_?2Y)8&SRS#VFHPR "K1QV*DGP!$O(C
M(8=$9I%CJ*O9F/VXD*T+%]1;Q["3R_WZS//'5N==3OC?W 1%LV&F0]DR:>J<[QQ/2
MY^8__6M]%S'GZ<6F*H_-GOYH^+X=1/#*I#J5S>&Y8TQ2!0:B) P.ZK8T-3JZ
MD_HU4^_!V:[F357U!+ P04    " #@@E9(OO11TS$"  !M!P  
M&0   'AL+W=OYQU2ID6LJV56;O?OL'ZHCHB;3E>=^^_8+]LH[Q3U%A+,$7
M)8U8>I64[0)"L:TP1>*%M;A1;_:,4R35E!^@:#E&.R.B! :^GT"*ZL;+,[/V
MSO.,'26I&_S.@3A2BOB_-2:L6WHSKU_XJ ^5U LPS^"@V]44-Z)F#>!XO_16
MLT69:L( OVO"2?"]DPT$=8RD>\_#IN,ADW<
M)O%$6,LDZ435BB>8\I:Y&W8^&G;NPB8387MF]#_EPC[!E+?,W;#I:-C4&4Q]
ML^D389]@REO&AH47MQ+%_&"N=P&V[-A(>V,,JT,'607Z5ONVOE:=Q3:"LTV>
MM>B ?R%^J!L!-DRJ.]-<;7O&)%:Q_)?8 Y7J?<.$X+W4P[D:<]L.[$2RMF]N
M0X?-_P-02P,$%     @ X()62%5W\*MS P  -P\  !D   !X;"]W;W)K&ULE9=-CYLP$(;_"N)>P#886"5(&Z*J/51:]=">V<1)
MT ).@6RV_[X&#VP^!H?F$,!Y9_SXZR6S.,OZK3D(T5H?95$U2_O0ML'MFMPDX4[QFWS4E1-+BNK%KNE_4R>UI1U
MDE[Q*Q?GYN+>ZN!?I7SK'KYOE[;7,8A";-HN1:8N[R(51=%E4CW_@:2??7:!
ME_=#]J_];6W%+CL5[4]Y_B9@#$&7<".+IO^V-J>F
ME>408EME]J&O>=5?S_J7R(,P/(!" !T#"#<&, A@GP&^,<"' /\FP-5#Z2=B
MG;59LJCEV6J.6;<]R).2UUT2E=E2HV_4Q/8YZWYJD\5[$OKQPGWO$EUI:*]9
M:0T9%:[*CG9!;2R<]N%TNH-4*YA!LM:2B#V&8-<03(^3Z7$&WN,$_G4"W?CL
M0P)R#5GU&JY'JC6$$,Z\:%J7@L[W:!R%CX$"%"@ (&H TAK?XQ<3=X^C58Q$
M=,8:]U_'_[FWCHD>V;._(Y*0@Z
M=@+V%J"T$=@;^%OHF&3I( N&G0I&8S387/F
MB.%(8(TC;8)A+4 5.8+2?4<9GN _%'9J"0S/3.Q)$IB-V)YD&
MP9V9@C/CCCN T,<@MY)I$-R/Z>#'IG<6B"(GH/'EQ_#^&O).'! X]*/J[GRX
M%^5%*>I]7ZJE;_]1];QUKPF7;ER4W[2M6(NJ+[3),LCME>_,CJ?5XU
MUJML5?'3UR@[*5NAP#PGL*V#JF+'AT+LVNXV5/>UKNOT0RN/0YDZULK)/U!+
M P04    " #@@E9(3."X_^("   O"P  &0   'AL+W=OTJ%]]XV'5_Z>R$.#T' UWO:$KY@!]K)
M?[:L;XF0RWX7\$-/R48;M4T PQ '+:D[O\CUWE-?Y.PHFKJC3[W'CVU+^G\K
MVK#3T@?^L/%<[_9";01%'HQVF[JE':]9Y_5TN_0?P4,%L))HQ>^:GOB'>T_!
MOS#VJA8_-TL_5 RTH6NA7!!Y>:,E;1KE24;^:YV>8RK#C_>#]^\Z78G_0C@M
M6?.GWHB]I U];T.WY-B(9W;Z06T.L7*X9@W7O][ZR 5K!Q/?:\F[N=:=OI[,
M/VEHS=P&T!K T< \B9L&R!J@LT$T:1!9@^C*(#"IZ =1$4&*O&S)[+A^L]MGK1UOD;T6"LSQX4XXN-%!K5D8#1D4@O3M#0-]E#K4Y
MO!V@- HT(:F,)$7W(= E!#)Y(A,"1/<=1)<.S.9CI!W@++V$[+0F,9D:C3Q?
MMS6ET8 I364T*+S/&CN3CK*LP[/('+W5!!9HFB2*+*G)5HXR8?JB&:7:NRFL6T3Q5.E&M\],I\D
MMT'H'&P_$HO8R3M4#IY38-4@SH+]+OZHY[+TS(H4?/)EO&!)5D,CW?
MV\OI=5PT="O4;2+O>S//F85@AV$\'6?DXC]02P,$%     @ X()62!"&H:9N
M P  XPT  !D   !X;"]W;W)K&ULC9?;;J,P$(9?
M!7'?@HW!)DJ1>FX.*U6]V+VFB9.@ LX"2;IOOS8>2!L9EUXTX'S_S&_/0.SI
M250?]8[SQODL\K*^<7=-LY]X7KW:\2*MK\6>E_*;C:B*M)&WU=:K]Q5/UZVH
MR#WL^Y%7I%GI)M-V[+5*IN+0Y%G)7RNG/A1%6OV[X[DXW;C([0;>LNVN40->
M,O5ZW3HK>%EGHG0JOKEQ;]%DB5JD)7YG_%1_N7:4^7=4PJ_77?2G=KK2_GM:\WN1_\G6S4ZZ]5UGS3?I
M(6_>Q.F%PQQ"%7 E\KK][ZP.=2.*3N(Z1?JI/[.R_3SI;T(*,K, @P#W@CZ/
M61" (#@+B%5 0$#&"D(0A&,%$0BBL0(* CI6P$# Q@IB$,1C!:KFNG+^61+9
M)7VQT>@L7;D1OI!XNK':MGQ(FS295N+DU/M4/:QHHOA*Q9'!'=F,M>SS-FS5
M=GHR/2:4^E/OJ")]8[3PKF.&D;E&4$]XTH'9!G9-*7"KQ\,9[C5!V3#RH!$R
M3#Q"D'@8>=)(8+'RK!%F6;(70- P,@/$DFC^XZHL?G:[A#S!B-H$WVL3Z!8)
M=&T9'1&!?(] = 0"#72Q'&7+4#U7S6#Y1X>IA::"$*,@&,:6&D,8AQ$;X3HT
MN@[!-38EBK1KS5SA*"2^<7::6P G%Y&&1N.:6VH.D=A'>(3QR&@\ N.61'/-
M7 44AQ;;$=BAL;$H8%I3A)!XC&=J]$S!,[%XU@P* V29V4)3 2+8MM"T:[AR_ (13$ES\"7[E9/U\?A9:\
M\WX:3)7>\B+N$LM7K+G_X4T,'$8,$7],[9&Y]MT>Q+@)(6"^@XR;! +&.\BX
M"2#@&B!V:=G[LLDJ>+5MSPZULQ*'LM&_G_UH?SZYQ6J3=C%^AR8S9!B?J_-,
MNZD[AT^F^W3+?Z75-BMKYUTTDZL]UR7]02P,$%     @ X()62+%O2-;4 P  CA(  !D   !X
M;"]W;W)K&ULE5A-[VM5*,#V+\JTZ<%Y;?_.L
MJ.[L0UT?)XY3;0X\3ZJOXLB+YI>=*/.D;A[+O5,=2YYL.U*>.=1U R=/TL*>
M3;NQEW(V%:*/G5D2#8QMM*G
MF] ;B@.%U97E8U(GLVDISE9U3-K%2B8MOFQU&G&K*<:JJ?-.MNPJ?39]GX41
MF3KOK=(5!HASQ(1JR!(@%Q&G\4#N!K5E)FC'IVH+#Q0=54,> >*K$=]0)%9#
M%@#Q-*Y\!TCDJB%/"-',ZC-"-(:6H[.R&O=VC78\@]QXU[GQH$0\L!%'!@K^
MM8(/"CXH>#?34728$&(%S!<2^F[SIP:N $A\+6H-J"N0VFLF]9JAUU(S 7C-
MT&NF\ 9@*X0%7J3%K0''/$._ ZG?02<2Q^K9F0/DBQ<0[2P^(([09A9TP$< 
M,GU2OJ$<54X7X!: HZY>[GLO-V+VJ8]"#WM&& M4!8@Y[^5"-I)U! 9491BS
MCI-W71SJK(?2K(?8'ZG:T!PP&E<6&@2NTU&-U2U"'4DDC23"2#Q94P/,LL?X
M!E9BJ948%9@FUKCO /J*6 &.4B4.FQ+JL6NJMY'J:&#UYC![&&.IB!! )E:T#
M&QL"/3UL::JWDNII8I1OSP3WYS@TT6#R>F*?J2?YQD4"U)">SW#E(\@W"UC>
M*TG?+"-=4D-,PLBJ7BJ &J_D?8_T34T;/H)B(T/RUD>P]\5&YW57FF_J?B+?
ME$C]H$27!CRJ((CX9"P/*J3&+WE?H] Z@M#DS$SEAV;ZF5,SE:]+VA]BI<=[
M+(@!=.NL\^%],.?EOOO,45D;<2IJ..H/H\.GE'O:OD_>C,_)Y)E(QI=DLH8/
M)1?YV?28[/F/I-RG166]BKIYC^W>-7="U+SQU_W*;.O D^WPD/%=W=Z&S7T)
MGTO@H1;'_NO/\ EJ]A]02P,$%     @ X()62/;P[%'U @  0 P  !D   !X
M;"]W;W)K&ULC5?;;J,P$/T5Q <4VX"!BB UB5:[
M#RM5?=A]IHF3H ).;:?I_OWZ!DTJQ_%+P.;,F3.>89C49\K>^($0$7T._<@7
M\4&(XV.2\,V!#"U_H$UWGMF
M34U/HN]&\LPB?AJ&EOU;DIZ>%S&,IXV7;G\0:B-IZF2VVW8#&7E'QXB1W2)^
M@H]KA!1$(_YTY,PO[B,E_I72-[7XM5W$0&D@/=D(1='*RP=9D;Y73-+SNR7]
M\JD,+^\G]A\Z7"G_M>5D1?N_W58*'GG\3&D"O"#>VY_HTV
M)R[H,)G$T=!^FFLWZNO9/,' FKD-D#5 LP'$7H/4&J1?!IG7(+,&V3>#Q(2B
M#V+=BK:I&3U'_-BJ\H"/$LX4B62.9/1<'JSF9/IHF_JC*2I4)Q^*Z J#-&9I
M,'!&))+=Z0+%+G.DS3T.5@:1>B!K RG3^R+2:Q&IB3.U<0809-<$9O,I,QJS
M:XVCAA0F4 NI0%D  &X#5P:850BB2^!-1;E346Y8D$^2P50@KZKLAB9L-!DD
M1!C#(@]2A9VJL#WH[#Y!X5'<=U(YG536"?8X
MF3 !3B!P>M';BJ+TN)E!58 ?Z/9C7O'25[5+"_(5D86@4E60CVQMD7F&KI&W
ME2.W$F*0
M"."[";&<91J:$'=7@KD-  =08&<'@#B\!<#"K:+PM.OI; P&01P:L;O?P-+7
MB+%-F0$A\V)X4U;:1&2ALMP="E8V$85/E@'!VZKL)\L"0S4A=S]#P&HJ RB@
MLS@0#"\.Y.X9:&H'E><=LR#'IS"YF+,&PO9Z8.71AIY&86:@>7<>BI_T3/QM
M?RF'93/:?M$T];'=D]\MVWOSGX;F/U!+ P04    " #@@E9((Z6K-* "   +"P  &0  
M 'AL+W=OGY:ICB=#AZ[W5Z9@ZQMLCENTPULE!T?$\&V
MR_0.WZZ &(A%_.[829ZM$R/^B?-GL_FY6:;(:& ]6RM#0?7EA:U8WQLFG?FO
M)WW+:0+/UQ/[=UNNEO]$)5OQ_D^W47NM%J7)AFWIL5>/_/2#^1H*0[CFO;2_
MR?HH%1^FD#09Z*N[=J.]GMR=&OFP< #X )@#<'DU(/T;RJW(\#$$9(Z<,RBF]'/(Y015\
M/E7\\ZF#"FI/4%PQQ&$J_6<54^DBF&?A\Y2?$V 4+-4>1]:*<5 $QM>J]6^C
M!^'(,#;<5+F*,=2",(HT-
MMPPN8XPMOV!L%<[C6PMBI-9A8^LO&!MN&[R(,=:!2*2Q@(*I $48.X$@YIL5
M;D+P30@1'R6 H+$ \<9"N&\@CS#6@V+?6 A_ H'$&$LN&)N=S1X#$SL[D\ED
MS8^C-LO)
M=-[T;*O,LM)KX68UMU'\,(V>\_S;_@=02P,$%     @ X()62 N08 CB P  
MC!,  !D   !X;"]W;W)K&ULE5C;XXNNUII<=;U
M2W-0J@W>RJ)J[L-#VQ[G4=1L#JK,FCM]5%7W9:?K,FN[UWH?-<=:9=O!J"PB
M&L+H>U'O5SH4UODE?I1!\VI++/Z[X,J]/D^)*%M^)GO#VW?$"T7
MT6BWS4M5-;FN@EKM[L,O9+YFLQXR('[EZMR\>PYZ\<]:O_0OW[;W8=QK4(7:
MM+V+K/M[52M5%+VGCOD/./W/V1N^?[;>UT-W._G/6:-6NOB=;]M#IS8.@ZW:
M9:>B_:G/7Q7T0?0.-[IHAM]@-T[
MZ3P'W?@VW=0-/NMA\I:+UV5*V2)Z[1U=8.B 61D,&1%1YQVEH"%F3H&"3U,\
M6HR8QCQ9C)S&K"TFN2V678IE9CP8.$AO.^"7#KAQP,'![%)E-6 2,R(&(^)X
M&O/D@5E_Q$R*%:A88<2R&!M2@UD9#$N2:IN#Q"C)T-RS" >+
M!?G0$)P&4A"3+AH"0^9!0W$:2 TL<=$8$)&Q]" :,\A['U^(22$T)LX.&924
MPF,1$(XS<1+@H6AZ
MM3R)/P^>#(C-!LYQ2_W7-IX.B(EU$CMI#"A)"+M-1/&40$VT<^HQQ?0JW&&#
MI;;B\%B.% ]E:D-Y-KTE/0!(Q*XH!) D,1I!L!5;OIG/1DL9KAD*"^[8:A\ 
M=$.S ?E(P2L4"B4*)RXIW$<*]Y:"UQ\4"A!.75*$CQ3A+06O0"@D%8Y6PE:*
M])$BO:7@=0J%O,/1BME*27RD)-Y2\ 1&(8%QM#"W4E(?*>G'4)M6@^.NWD)ISCYQ$F%X*F F@).9QS;()-Y;^8G>XJ'';.BA]0>!XPZ@XCL?K6-@
M54#1-[A-\-7/9GB87<0B@%)Q/1/1N]N!4M7[X2*G"3;Z5+7F+#NVCI=%#[2_
M7;AJ7Y'YFB#M7==OJX$K%3
MH2H;&^3O'%TX\C7R[*CJEV8G91O\+HNJN0QW;;N_B*)FM9-EUGQ6>UEUGVQ4
M769M=UIOHV9?RVP]B,HB(@BQJ,SR*IS/AK&G>CY3A[;(*_E4!\VA++/ZS[4L
MU/$RQ*$9^)YO=VT_$,UGT:A;YZ6LFEQ502TWE^$5OEB2 1F('[D\-B?'05_\
MLU(O_L
MD3>J^)FOVUU7+0J#M=QDAZ+]KH[W4E]#TANN5-$,K\'JT+2J-)(P*+/?\)Y7
MP_L1/A%(R^P"H@5D%,"=F!10+:"^@E@+8E]!H@6)KX!I ?,5<"W@O@*A!<)7
MD&I!ZBOH,X?DT)M$N"5CV-A[%A,W?I]W! MK6):W69O-9[4Z!LT^Z[^L^*+G
MZ]ZG,P^ZQ=ATZWRPK8>5/I^]SD6"9]%K[W3&@/ :&,ZGD04@;R915X&]#!+:
MIB!0!HFGY[C13$*FF5O#T&GFBV$<<]V9>M@T\]7X)-/,O6$Z^GQ#I'HN? 
MMCDXK#E@..6QF*9N@/HD4L&M!0-V"QCCC#BH+WI*G+Q?Q*?4'5 X3A/&I[&O
M@!&!B8.ZUQ1"5#BP!STGPIPX[ME"8X2BQ'&=CX#%/!7(<:%+?3M83(G/I+LW948!X-8^VHP"P-DWA4BY&UW&&X]V ^'MB:-<8?"!L3
M>QW$(VX-$2ZZKYXC;\UAAF.4. (W?H)0ZM.],;773CTRUY!XWW[.0A\AA]-R
MA+QNM_WW NL?C)/^Z_!([+$G'XG=WF@P\XD=((P1B9DK=N 8%LC1#9:C78JQ
M5^K<7CKW25WW06Y]%C2I&\CZ%&92-Q#U*=G>4K'NJ=RGO>'4GGKZ@=2)O>D0
MY)&ZAEP_B1J)$>>.=K#\Q\E1,+87C#VRUA"/7=]P#0EN?<+565NS]7A2R$W;'_+NN(;M.IRT:F_^?1C_
M IG_!5!+ P04    " #@@E9(!B)JQI\&  !;*   &0   'AL+W=OO9\TQ?_,\U_-A]O[JVG4U)#MLKNJ29'6
M+[^SFVRW:S+5(_\+2=_&; */WX?L7]K3K]T>VM?7[B]Q!&%X@(0 
MR0U0$*#Z *')  T!FAM@(,!P RP$6&Z @P#'#8@A(.8&> CPW(!&\TZYZ"W$
MTB&]V((]2I!;2'9($%R\*=Y&S+I+L;V0/Z55NEP4^>ND?$Z;VUO,&[QHTM2Y
M)_7E6]9W1INU:.^-Y>+W,G9V,?O=9#IA9,M<=XQSP\BJ0T1/S.H*\#+D%!M"
MMO%R>(2;CG#Q,/*I0_0P\1F2^&'D2X2
M7*YV#>,HAC;J5)ONX$<%EXAC9-"G&72707<9S&F5AQ9QW070(4+K.-;#V U@
M2AL;#V.?.LQ+[Z-AZC,DD]Z>JW",?>DPIR4UY%<8TM73XS#UK:.4LH8XRULH
M3,0^$L/8JL-,)(4DLB4PIM215,/8&K(IXR+)4-J@2ANX5M#;M&-6':-CM)]T
M3,)@UN^9X6HM6JUM,UC)R>#0>\.-N#=BM(;XXKVQBN%R$,H3ET,"6"2-(B[4
M=8=)H[1JS] Y,(K0.3!H1P:=@3GJM\/5B@@MMSW(,LI&>^A IHH:RH0'E?0]Q/(;$NZB$+NHY,X+$3:T[2(FKL!,\X;UO>'FS3)<6D!.I]A3B4/$-73>XC3CR7>2R7T4J\Y
M.7"O)L>8-8EW&LFP:\ 8ISV!)8!9K<_=SZGD8.MJNQ:Q"L<-F^0XM@"=UWVJ
M>8#0+8.@>8 X)2N\FRKHIIYC7Q1NVM08TZ;P=J,8I@T85:],*343X(035EI"
M=>!DK)WF=#F%NS?%<6\!\D3?3@#RYZO;$]5[B&.S%=Y45=?BK& IAKLW-<:]
M*;SC*(9[ T;&RE!WN@KNS2KJ3@?LKU@0M]\&*!-Q_)+"+9[B6#R ?$29>L6Q
M>'TF8B6X 8AY7GAW5C$,Q)DE%.X#U1@?J/'.I1D^$!@O8V)3)@'*"$GL*JV!
M$MYPOCR-&T'-,8( ^8B:(7J(FB'T>TM)E(QW9BUA()96N!'4H[8W!_8W&480
M&!DI2^_6A5U)%QO*"H9\1EG6!*EQ+Z@Y7A @?^Y-3U4/$&7_ R0XDYK&.[,.
MVW:LBQWW@GJ,%]1XM]$,+PB,DU)0ZWO I"-7A>N >=X,JW$KJ#E6$" O*/O?
M0Y3]#Q!O5QEOJ ::I> L(0QN!HB:\'N(3
MG1TH(\]7RZ>"6]@P8'5U@QL\PS%X)M@R8II..- Z0()5,MY-#2R')6
MS8SQ;A9O-9;AW8 QUE$_5B: :14KHOFO 5,N8NUN6-R^68Y] \@+:JD7H'/+
M>2)Y&,YS)B*+=U,+]DVR4FM]'J(6,2M>XB80C8 ,<^K[\H'.*/FP(48O"G:
M]RO,=] U0%Z>_S8Z.WJ\9I\5C^US9N7D+G\Y5-WOR_W1_EFVC[)Y/.?L^+68
MWPKD^$K,-]CQM9QOL#SU-S'?6(N-8%UXC&[V5NIR\9P^9INT>-P>RLG/O*KR
M??L8T$.>5UE][M$',YT\9>E]_V&7/53-6U>_+[IGW[H/5?X<'N7KGR=<_@]0
M2P,$%     @ X()62 #B!M[Q P  C1(  !D   !X;"]W;W)K&ULE9C;&^12<0>!S/U$G3)+9G,KW8^YK8LLV4@S?@
MN/OM*Z$%L5TA*S?&B.]?6N)?DH#IJ:I_-7LA6N]WD9?-G;]OV\,D")KU7A1I
M\[4ZB%)>V59UD;;RM-X%S:$6Z:83%7E $(J"(LU*?S;MVE[KV;0ZMGE6BM?:
M:XY%D=;_ST5>G>Y\[/<-/[/=OE4-P6P:#+I-5HBRR:K2J\7VSO^&)RM"%=(1
M_V3BU)S]]U3R;U7U2YT\;^Y\I'(0N5BW*D0J#^_B7N2YBB1[_@^"?O2IA.?_
M^^B/W7!E^F]I(^ZK_-]LT^YEMLCW-F*;'O/V9W5Z$C"&4 5<5WG3_7KK8]-6
M12_QO2+]K8]9V1U/^@J/0&86$!"001 CJX""@ Z"(3&S@(& ?0B851""('05
M1""(7 4C/?PH D>CR/?-<+&B4<(DHPC/S1"
M+:D\:21&X\@S('@<>0'$TM'BYEU9WLYV!?U0!V_HI3>Z\1N%$N$.$=AE!*8C
M,)U">)EEV2%<%X!&,&-QS,:Q!\ H"Z-X'/O.(.4D0>/4(P0C273MPCGV0V.<
M$5N73] EE_OC./6L*4JCT#+*%T@,QPG"X]A"8R$BF%BB+:%/PA"AX]@*HM&0
M(^+@=&AT.H0;;YRFFEEHAL7&]40S2P=F]3LD^-PSQH42
M?.X9EZK$R+\8LWPDTML-LP,;I]SLR!"9'%ZP5 
M&#%JK0G@*,:V<"O DI@XW2!J'AR]711S@/X:W47E])$HM93. !DW?*B='D*A
MR[C,NQ>&I9TZQ0C-Q1-^IGC,JQ6.;B\5P&"&;-BRQSB[?G2X+ N-D=AQ\G%S
MWMQAL>BAZVJ^M+R';-N" ;*D;%Z4<0PQ8I<8B=GRY!.6$V3,@Z#;E@/#(FXQ
MO ]D>P  !KFDB\WI8@>G 8K-3[[@-$":$C#FO8
MG/3+T_4F&YR]IQ6BWG5?+!IO71W+5C]6#:W#5Y$Y4>]Y5^WW>/*"#>T+/%F9
MVN6()TMBBB23E5>Z#R_!1TJSZ2'=B55:[[*R\=ZJ5KZ3=N^-VZIJA1PC^BIW
MU[U(-\-)+K:M^LO5MJN_ENB3MCKT'W^&+U"S/U!+ P04    " #@@E9(/ +^
MM20)  "!,   &0   'AL+W=OMXF8F(LSUVXHEA@;,[9IYKS]45F9A>'(/W738/,I4]*?
MDE)9U3?ON_W?AZ>J.G;^W6Y>#C^Z3\?CZW6_?[A[JK;K0V_W6KVDOSSL]MOU
M,7W4O_GQ^?#K67_1O;_I-N_OG;?5R>-Z]=/;5PX_N;_)ZI7R-
MG(C_/%?OA[/?.W7G?^YV?],
M?OBL&Y[_SM8GI^&F[O]<'ZKA;O/7\_WQ*?56=#OWU?SR^GG>_Y+$-2LW$!1 ]4T:/R4&VAJH#\:
M&-C 4 /3MH&E!K9M T<-7-L&GAKXM@T"-0AM&T1J$-LVJ#7/RHF/)@XW:<26
MK;VPW%)]:=+/@74*R]'ZN+Z]V>_>.X?7=;U8Y77-[VL[R7@G!>,AQ?G)[/X4
MZ;1149D0_13#\K=4-V2"W5JKRY[&&;"A\O(
M*"/F,C$F(_$R,LF(!EV99B2 *9L1(B\C$R-LI85#&*R]28
MC*GHOHIPCDTRYHU"+J?DTJ>S[C(URY36SH)1SJEC,D0A+V.+C%FAI +6EN13
M&:'T96Q%UK3U0K50VA:5MEEI5_+CLM(9N=)*QLO4D"BE0G'2,S4B2H:R-)D:
M,^44Z->$/0KD<,,J8=6 "QFQ**X1-/&FC@#13LB6M
M$,#6C+L5'1CCG(TI#\)T050P7H.96&;,:"^1RI[663S+S2Z+'(HBARPRV*@&
M@2(X1HF6,V$B<6#5C (M9U=."$AFHHQ'^]DD4]XJ@60F*IH(%N",)L('BU8S
MST7J/IBR1<:,"!IME,N,:6L4.@-6&;/&AQA;"!V+0L<\H\#/("-7QAITH X)
MD['>NH'2D8]4C>09,V:" E,ZB;1S!X5V;C)F4[8#)GX6248=O^;.G]3FD0J)
MMK<%CR#(6$[%2&[RJI3U8$)6&4M'E#1MCFDIBGJ?OJX7&A":"S+.M,5WC0[0$Q7GN#%C9A5R'U&V5DQ#GOT%HC[U4I5  I."+,^6N!TREB=?:*X(L)4.FG!&3-FS 4#G$X8
M2[LTE)PP9;X6##]+3IBU:+N;\TB]CV"D"\EU&P?#=LF<\/!ZO&+.R^#;7.)D
MN28C\Z4?=7U C(D1'@^6%A(Z(D=$I?P8+*,Q4Q(E"Q.F/,H,ITP)"?HUX]Y;
M6)1A6Q?J>"RUY56K4;['F+'(VHHQ$6UHHW.Y+B.I:($*,Y*+$4&@+6#(7-J5
M#)BM$7,BY14@OL;KE((W,1 "W< 3%7)H4K"(\A*<%LC%5GC@IE9/P+"=[T2%%%\UHM7;HUK(\
M\XNE][1]:'%61P;2ETLWDHHDJ'9#C$:UQR%!*<4%"V5$U%7YV04K'NB !MO+
MA"TI 4Q-V13R-^.N0YFI?H*.F@4;\JC\LR3*H6O^JIDHW6H[+Y=K)!4+T,DQ
MD%RQT3!['#*GE+:P LN@CA%?[9JBC<'Y6J3Y"@Y>Y+ELDS9#>+>+S0)#N?R<
M[46!\K]%,UHM(PK]9>-7*UBY(4YI=5Y! P_#RZ4;)?AJ"K0G*, DG2 =!=K.
MF4)1/6Y, 6A"4/U  "UM'J!VH%LS-J8%FO0Y&T.9SX(@:U$"LFP\NH >HS'F
MO&MS@U?EPHWB @1X^CP@**UP62ZBTI-QYI2,[NN;&N?@B$$=;?E*0$_'&X-&
ME',&>CQ.G!,7CD9Z/L[FK/3H.?JLF91HRR4">D;.]L*%^*=GY,UHE3/E1T'T
ME/S,;[F21H_)B5/*NE:U>%6NWBA%[MID?JI2@8*GL59^_ATH=@@3O?(%-U#HT !ZY;,A4.0T/L$X9T2I7GE["A0U
M3-R193KR592E\LVBDL&8#H'!'TKM6DGM6DGM6DG
MM6&ID=*FE=)4M.F5'\"QTJ:=TJ:5TFULD*NA/FW[&
MD*Z;8.RSQF9*TR)ZA#EO;(;Z42ZJ_C6D\\*@6^SRS+MR\ '1AW<=I&J54):+
M!(J*!"A7'Q#4)B)\ZXCPK2/"MXX()J.P ;U%,6WZ^7U$?-A4$KW;-6]L?A\1
MOG5$L/?@#7QHM6I(&ZQT7]_ZZ)^] KRM]H^G-]L/G;O=V\LQO]W9?-N\/?^;
MJE\A_O+]0%[/9>'[A;Q>Y7?C/\S?WKRN'ZO?U_O'YY=#Y^?N>-QM3Z\7/^QV
MQRIU6O1LM_-4K>^;#YOJX5C_ZM/O^_R&?/YPW+WR"__-_SJX_1]02P,$%   
M  @ X()62-NR1!]# P  -1(  !D   !X;"]W;W)K&ULE9C=;IM $(5?!?$ 86=V^8ML2TVJJKVH%.6BO2;VVD8!UH5UG+Y]@5W<
M6)K8PXWY\9ES9KU\AF5Q,NUKM]?:!N]UU73+<&_MX3Z*NO5>UT5W9PZZZ;_9
MFK8N;'_8[J+NT.IB,Q;5581")%%=E$VX6HSGGMK5PAQM53;ZJ0VZ8UT7[=\'
M79G3,H1P.O%<[O9V.!&M%M&Y;E/6NNE*TP2MWB[#+W#_H.)!,BI^E?K4?=@/
MAN9?C'D=#GYLEJ$8>M"57MO!HN@W;_I15]7@U"?_\:;_,X?"C_N3^[=QN'W[
M+T6G'TWUN]S8?=^M"(.-WA;'RCZ;TW?MQS!VN#95-WX&ZV-G33V5A$%=O+MM
MV8S;D_LF$[Z,+D!?@.<"=(V[H+'-KX4M5HO6G(+N4 R3!_>]O!U,>N>@[ZWK
MASUZMN/ 5XNW5:YP$;T-1A<:5_C@-!FJLR;J_#"#/*#1@ZOL3>/U\ D Q?F; )H^X.#G15DN
MDI@S+)H_X #H1>PHFD!P"*HT9UC0$,(,"H'&$#@<3B*(4\%(HDD$#HI>!+%4
M#.219A$Y+'H1-XEF$1V+K(L;/[D)SF 1:1:1PR).+"K,*9A$3'Y4P+&@6<0:+2+.('!:]"$26J81Q"T":1N30>!;%(F- 
M(FD<)0?'_R)>%,VC]#P"8QXES:.<\U3ZR6,IATQ$VB0533 I)C08.H9H"H:! 5!T1U7B%FP !1?;)"9"T1_1H1
M^@4 9U0TB>HJB7[9ZT5D5/3AC<"AV.F?1;LKFRYX,=::>GP'L#7&ZMY'W,5A
ML-?%YGQ0Z:T==M-^OW5O-=R!-8?I).2$Y+I)T^'I:-IJ^&!/IIO^.=B^K<;IL'].
MAU-OJOT2U#8I9)E*VZKN-KOMFL>?;#=NL
M)[[4S\=Q/I'NMNDE;E^WIAMJVR6].=QN_F$W#U#,R$)\K/,[F<4_6OM]
M/OBXO]UDLP;3F*=Q3E%-7Z^F-$TS9YJN_#\F_7W-.?#M[S7[OXO=2?YC-9C2
M-M_J_7BIJ]SHG<,+,R=8^ Z43J">Y![
MAVA^'7EPB-39A4DG'Z09>&^&.S. 9HIP OX^@7 )N//QQV!T"Y*[P7 (8\ 4
M7,=*Q"#CV77J'J^7@R?5@X. Z2)B8 3I2RPIA*2NHIPOAX!D0EVG2D,1NTOK\.(1IQ?,W
M4_-O/RN73<996(\F_6A<1.'X@O13N#4DR6F+A@J>$=(\#BIB2+F8&,KJ*,HS&?)!ZYR%2MQ9$"$K/NXK:Q8188>N?2S'0?4N!P?I
M:7D67E-8_IC0/(NI&9K6I,-['3+ <@]5(A6WV3&ZFK*UG'J7IX,\%;=$A$G(
M(\0 74XA"^^]R&@!//<5+^2B2P4P 3+ ;0"Y^B=,E$ I/-X /5;3C]"B]//$>K!W-E"C[,$D^FFI_.6C,
M89Q_YK,7]UK!'8SVM+XEN;RJV?T"4$L#!!0    ( .""5DCD?AT"9 0  .H3
M   9    >&PO=V]R:W-H965T/;;+Z#&5PE9^Q(#^77K+W6KU3 \Y<7O
MRKZO@M49J$
M.(IXF,:';# :ML]^%J-A_EDEATS_+(+R,TWCXM]7G>2GEP$:= ]^'7;[JGD0
MCH;AV6YS2'56'O(L*/3V9? =/:^0:)"6^.N@3^75=="(_\CSW\W-?/,RB!H-
M.M'KJG$1US]?>JR3I/%4C_P/.+V,V1A>7W?>I^UT:_D?<:G'>?+W85/M:[71
M(-CH;?R95+_RTTS#'%CC<)TG9?LW6'^659YV)H,@C?^8WT/6_I[,?X0$,[L!
M!@-\-CB/8S<@8$ N!M1I0,& ^AHP,&"^!AP,N*^!  /A:R#!0/H:*#!0O@9-
MS$WDHHL)=YN<@XV\1^G"C?"=26@2JTW+25S%HV&1GX+R&#>;%3TW?-'XJ9T'
M=3*6=9ZW;HLVTT?#KY%B;!A^-9YN&&/X:A@A^I&%0="9"&L%=AEX8!L"M_:X
M?X2Q(83L1R8&H?W$&SA1_ 8J00],,A#/F\#0'3W4B]4,+
M V%"B6-Z2Z H<_E: 14I)CU"*ZRA%7#2N&)KF"=::[9N$(@N8!A3B1SK- &.
M*,D=H[YU[BAWB9L:C)/(Y>P=G#%"E'7S0IP-AA#FR!&>.7A3G#BR?='-DQ N
M'=SR,BAS:%L)R!Q2]^T>X9;6<$LH8JZJ+R'_9%#Y)6S7GB6%P@_.&!+<@=PTVXNWEB
M3K%UW2#$!'_DQ[9
MNT)$'Y[U"V#JG>HJ:T 1&3E\K3I*$.8CFME%L\>GV (@I%RE?0G4$T'$L8E7
M'8:YGVY[7X6@L6*N8P2@NK#(^O1R2>?=02+L_6ZG'?J&QI_7KK9W#D@\/DL6
MJ#L$>ZLB],-G;WUE$1IBX*QU,;QZUTYUL6L_(97!.O_,*O,:=7YZ_DSU'3?O
MZG?/7]'S'%F>+YK/6NV[_<7]:'B,=_I'7.P.61E\Y%65I^U[_#;/*UU+CKZQ
M0;#7\>9\D^AMU5R*^KHPGZ+,394?NR]KY\][H_\ 4$L#!!0    ( .""5D@6
M".GQU@4  $,@   9    >&PO=V]R:W-H965TC/=K.K+L>O=?UV,9U63Z_Y-JN^%&_YKOG+LRJ^+S=_K5?W:6"O&HU7^G+UOZI_%QWV./D2MPJ=B4W7_CI[>
MJ[K8>I'Q:)O]<9_K7??YX?X2"Q2C!0 %H!?HQZ$%% JH3P'-"F@4T*$"$0I$
MH0(&!4RH@$4!&RH0HT <*I"@0!(JT*ZY6SGQ*6)XD7ZQ9? H?KDE'(E,76!U
M87F3U=E\5A8?H^HM:S>KO&CYLM73*!\UP5@U<=ZI+;M(G\]^SY,HF4U_MYH.
M&"=XY1AK3R,+A\B>F#86T&; F!H".GDX/<*U(VQ\&KEQB#Y-W*(2QMD[ARC&
ME&\.B<5IY!X1>1IY0(09:#$X*\MA:U,<1P6LC3I<&^5"1+FUA1 -^E"#=AJT
MTR".S-QUC'41X)B)5E)$I[%KQ$ FYC@@][D;Y%03V>8T=NO5::$9;7<.,\+$
M\6GJ&RJ+I#4,=N]G(XDB=1I[0&UQ?!Q%^]3"^PE& S-OR\]!$V854H' ;^02,(D-L#LA/4_0[I#<+P7I
M>O>XT:$YWQ$".,[>!ZY[57$2DWL+/4=,01QDMJ3-QJ*GF9$6'K)-3F"B>=DK
M \%-0XJT^U@4N%!<(,1XMAY$4D4B&E"!)UR")
M&1#8(-/'Q9*P5P_;>XPPUD:TM9A#)1/L"X0F3;VAD[JW.!JV^!AA+*93ML2<
MK;FOT6@NF68NA2Q@^EB>B>Z?H+ )BZH_SHJ9E@10)YQR@>@[0#N
MG(\3B!!S8L49[+6=.K+B%"(7?&8%NLL!W^:$E$2@:PQH7 AF5RX0:LX>2G$Y
M$+E)$VH6F 25>A!:C4'6TS4'?,WA,CA" \=NI ;.W9X*.WB#H=?-G''T!KH.
M@,5UXTYR",D(+'>0\[HLV;5YS[$*M#>C(6;310!B-)N9Y 5"TB3L^1.QB8K9
M\H48:!52O(#.V^![!B[1(J1B'7'U!K%V)EF[?:FP(7E6"3+4E#BCUU%TTZ#\
M.9_S':$)?TA"BB]$J=<%(@JZ J)3NW))-C&LV9B)!7#Y:HF8Y+)DBM D"MG6
MBNY0E.]0N&V-4#,_L>(V"')-G'$IS6N338L>8KBF TV?T9XI.INK** ]4X.=
MP7(821$).XHKNGU0/HVS 6:&VS,UW#K\#V&LI0N&\HT#5RJ5/^H/-#O(L1;;
MJMAYAK5$387F#O/87862X^(MR!S&WVG=>#^,SIP5]'M:2(A)R?--T/=3X LJ$
MU%1-WV;I+OM3,E9:_:#]&G,73O9=XV[Q\Z=Y-
M5Z.GXGU7N_I>[O]J7X^>\M>\N]9^;+>
M5:/'HJZ+;?>"\+DHZKRQ5GR)QJ/7/%OU/S;Y<]U^M@"  !["@  &0   'AL+W=OFNU.CQ-956:GN'73B5XULD\&L9FE#_!^"=&(6.)W
M(X[J[#T9S3]+^3(.?JYG*1@]B%:L]"A1F\>K6(BV'97,RG^]Z/N:8^#Y^Z3^
MW6[7V'^NE5C(]D^SUCOC%J3)6FSJ0ZN?Y/&'\'N@H^!*MLK^)JN#TK*;0M*D
MJ]_ F'X@5(/C28V\1YC;J
M$,H+%*$6CL*$(/ UM?1:D'%VW3$-.J;^KPV:R9UEQV! ^=DZG["%PU!.4#@!
M#EMZ-<0+3JZ[SH.N<^^:1%SG_L^$G$:PA<,@*AC.(ZX]QDP6;L@U"[IFKCQY
MQ+1#""AP$4NUPS UJ0[6AS?M,$I8P?EUTT70=.%2'5EF[I!OJ( ]*#!3S;WI>^>= W]R4266CN& P9B!:VPQ FO(B5B%?#!>$W'" 0!&W;
MZ=%W9*6YAR#,$8@9GSC \E@>EA/'8,'0#=9AV/IT340LS3UDDHECI3)AA()8
M@4\8X+2XP3<*^_;71C!#_M3V# 4(ADO[KK?A5#]NF5\FSU*:!
ML/?\1DHMC#5P1]-D9SK!TZ 5&SV^,O,^N-[(#;3<3ZW>J=^L_@-02P,$%   
M  @ X()62.3E9K(I P  VPP  !D   !X;"]W;W)K&ULE9?M$"EB0$ @XRT]HO/W:FTQ^[OZE&90K$A5B[=[\)><76
M"93](Q"?;5I167@$H= KL[QRTZ0=>Z[31!QED5?\N7::8UEF]=];7HC3
MU,7N>> EW^VE'O#2Q.MTF[SD59.+RJGY=NK>X,D*MTA+_,KYJ?ET[NCPKT*\
MZ8OY9NHBG8$7?"VU1:8.[WS&BT([J9G_@.EE3BW\?'YV?VA_KHK_FC5\)HK?
M^4;N55KD.AN^S8Z%?!&G)PZ_(="&:U$T[:>S/C92E&>)ZY39ASGF57L\F6]8
M!#*[@(" =()N'KO !X%_$=!! 04!'2L(0!",%80@",<*& C86$$$@FBL( 9!
M/%:@]]SL'+I(PF%)M]EX]"SG[<;D2N*9PFK+\BZ369K4XN0TATS?K'BB^5K[
M*'-'%6.CZKRUK=M*3Y/W- ZCQ'O73E\8([PU#&/]R,(@N",\E< >@[BV*4BK
M)_TSS S!!G+>&83V$_=@$O\_-:J/@#2[8P
M&$61'[%^;&DP/Z"$HGYL9;" LB@>L]&!=:,#LZ(,C7 (K<46_D>Q,6L&!AFL
M^Q":I3.,=3D,L?R66%T3_3DC:\X(F61@F0 03ZPT*F6/XWZ*(#(4&-S]@B(R(C9$U=SL\_/^S $:M(;8G
M@KL).!^CP!^ZG8 +?!*34=&Q/3H\GYGUJ48A^QD*^J%E!X7]T*J#V%5D[U-S
M4?)ZU_;,C;,6QTJ:YT8WVO7E-T0W)U?CMW@RQY;QA>[CVV;F8I\FAVS'?V;U
M+J\:YU5(U12UCUZ;W-A12'\ZM$]SZ3
M_@-02P,$%     @ X()62$&I'!,G[P  /*$# !0   !X;"]S:&%R9613=')I
M;F=S+GAM;.R]V7+C2)8H^'SG*V!AD5:4#8))@'O68J:0%)FJBJTE9677M-T'
MB(0D=)($"P!#H7K*/YB'.V8S;7;[Y_)+YFSN?AP+245E=G7/7+.J#(H$?#E^
M_.S+[\JR"G:;[*^[]"S?;:K?OYA/9R^"S^O5IOS]BX>JVG[S]=?EXB%=)V4_
MWZ8;^.4N+]9)!7\6]U^7VR)-EN5#FE;KU=?Q8##Y>IUDFQ=_^%V9_>%WU1_.
M\\5NG6ZJX'2S#"XV558]!9<;'B'+-\&KX/OK\Z#W\N1W7U=_^-W7^!*_&,7!
MNWQ3/93PUC)=UG\^3Q?]8!B%03R(QO4?WZ2W_2":TX^3^H]_W&W@S4'[FW:Y
M2?MR_^5MMDF#RRI=E_^]_JX\?I7>9V55)##(^V2=UI_Z]NKBXOW;RV^_NPG.
M3C]>WIR^#:XNPN#MS7F_8\ S6$^1K& =R_1S\*?TJ?[5(WI7[V*XE?#J&.J-]DJ+8(S>.\^+QKSO$V*^S0X72Q2> J>6?+S
MG3"\>=HVYH\&K_[4^<+'M,CR9>?:S9G_;__MO^T].PV'-_!E>>A)F;?UV3=_
MJ7]S"J\N^?55K5S]N\L=-<)TF9;X!$%Z6Y:X)P[^D
MC87(&'_.5W!-DT(.J_'8^[P+C01+KM)M7E39YCZXKI*JN6%Y_./N=I4M8(MY
M4C40+E^OX3*N'
M]]G]YO3]^>OC^["*Z_N[BXN78T)'@99)O@YB'?E3!'\]@5S1C5
M?[SB \_?Y!5@<=:]@[.D?""2ML /*:P+QFE[\ I&*+(%
MWNW%L>^\R3;)9I'!"A8Y4JI%509%NDCA^=M5>F#I5RD =@?4%/)[^:?@#RUO'R>WJ5P!Y9!LH#=E!E1]$5>
M(GPW:0/+O]\  <$K"BQNG>W69;!(6SC1^[S:NV0^3$#JM DZ/KCVW]YFR6VV
M(KRI_W1M,2HH\]425I]7P5-:!=M=L7A(RG1Y .IM1[9-GHXXK_-=&E0Y@"1;
MPX$5^8\M).C0(0&PRK3XU-Q7'>*=#[9BC6R@L=<=D(+@,:L>'M)5X_3X=%;=
ML.8CVO, W_+ZMQ\+@VPE4CZX1-L,!^IM$X%L\'+0CP:_#9)=]9 7V=_PT,:#
M<#"@__\6SA0DC0RYP[(A''TH@(H@#Z@-+A3YFV#O+-% 3<,ST''ECCB'*"%-
MIW$XGL9!#^GE-T@YHW@>3D:SDV\,F3XP4SP^/-$DC,>C<#8?FWGL%R>-?9\N
MEW1K8:_;)%N^ FHO>V]B2 5B*,R'& 7S-.\00NX!;@\@\,\__1L1."#6207T
M[W97(28AHI?JL>;-W[RB^Y.O5LA/LTV5 L8BKPC^-8>_@D^ ];NB@UZGK8C3
MP#>"6/NS^YAB[V."[/XAK3(0<4Z 2;X,ON;M[(7%;SKFZD#H4"% #_:]!%@D
M!5Q&N%7T8.,,.P=RB$,C\5*/?UWP:\^KOD0"\ GR@H0@>.W/M ,0!%E2.>["
M';OFKK'-\'E^[,/[RZ.EIV&>[6QZW3;
MK5.]2XIN54V_V9#)M*K6^%$/V_A1BWK#)FV >[EK7H-O"^17EML_ HNMTLV!
MI]IE N3%!\8Y>T@VH$X!T$'V !7\2-;G#0&S<13$1-
M?D08]$FK/,24J>@ WH4(8,^7V&!R5$V6K9.>'B6J?9MN4E21<9YDNI'=98\U\2GH:^&NU
MHRN]Z> LK<#M\2@G#=[5--AS?
M85WG\O;0Q^OO3J\NOOOP]OSBZOHWP<4_?7]Y\Y>CJ24AUW&T_!A>_"RIY'5Z
MGVT0 $8R1H%>T\.X!6N+%+2&H >/T2?$1>:3=B6BS/[+%2!3\"8O'I-BV3"!
MD3$#ST $T?K!T>7%W^$^W:49XM[Q4A5]B5# I48[
MW'- S6WE1?6J?,2)2E#_@?7D0,L(VAH+G[>VAA2PYQZ>G5Y_%[QY^^&'X^T\
M9.V A7[*@#4'MT]!3^C%29!OT7*)2P.=-_O4JM"=6AY5(DJ@00%T9=C[QI%%
M1!7X:_'WS81T=F'%@-T&[MZ*9,E[T%T<_0*"1QAOS3OTRUU3AV\;OS;FEPT$
M]QV(,R*S++='HYVT+Z\IC('  A/H^[ 7%*T_(J@=>#70CP$UF_?V/_-1[D>)
M%\2SOHG9KG$[X$8<_; W^A$P/\_*;0/HY+189D_<2>3=%HNW&G41K9Q:V5
M8F W*.9MR4?SK#%2-#7M>_MZM]VN4KRVR $SY^=K4@]!&K0ZF4WN$?[W/08(
M28M5%&F#GC0#]%,+=&!X-T6R*>] ?(6+Q8;FJVY#\]6WI^\O_X_3F\L/[X/3
M]V@1NKXD'OKQZN(:^"G]TI1*[Y--]C?:=AB< ;KDJVS)M!H7]A$540"0D:Z=
MZ9@L)\Q&_N7TMB22U) (CUM4\&V1IIL5RO_!F1@SK^ 2OJV6_:#WXMNW5Q8)&.D2(0;'?D;?("C?)H\&%\Z2IS6\
M=EFN4'A WO7'W>HIB(8HFPQ&_0"G^_FG?T,E'Z;+MK"81Q!S5D^O\D=4TK'*2CH-PB9UR!9 V_ ):BL,_HO*-O
M"S=HWY\L>,#MBR!W'M!C9,I>D(U=;$N A,D"0+8D.0QI'L$ 528B^#?PQZ6U
MI0.42$ ;T"((CJLG1,HBO=^M$F83:#%(4?K&@5[ *W T^'A6(F3^-5U4+#:9
M-Y"FM,#]70XD%N_=*=O08+.]%V>7[TX13*C;F27BNS!+??MPVH!\BU36B586
MIN_!*9S;"L]RT@\N[N[2!1D"WB5/8DL:3$,Z8T*854J8A (,#("&979\YO!B
M(?0GBL+I;!J.!X,NN1G)SM*%YF9A8?,*BA)>(BW Q\[3%;!4W+Q=1300< .Y [J5E0_P
M7ON]"2Z+%+$CA'%*$#AI"B&(3V;I>*VN+M^VK%A=%KUZULI@I>=XM$#E9!; 
M*!@'\5:9<>E2H1JXRNY2;T1"LRKY4;"L[5K1[2Z-,(7?7.SP6@-Z?;_!J]!S
M=PVOC-KZ"0:.V#N&2A+L\[( :.D?7IS(HBT=6>]650:+W:2'*0C:')(%@A(N
MJ+"=5+\F'+PBYV ,1)W",\ER@$#2T*&2?8(-%4&BU5&W&"5+PQN\ 0T
MX'O0)!^"TS4@Z2+I!Z=BQ4%B@F="Q$1.^$5 1OX2+NAJQ==W16NFM1"MJ?!'
MPZLTL@*Q[Q-5Z[JIYI+A50)DQ)?A8-XGY3+Y:_ M4^7K%*<%DD'@(SC"PD"G%C!B'#MLSO8#%FN@0D8KHXA525*
MI+FHQM;Q^Y  \MW"V$&ZRL@2R&>ZT,),'R4G1 D:G$O:
M#6, L0;?SXN>?_EWM]] N3Y'HPRZ 
MEH9="^KQ* 1BUBF-S4QFALT5=1\];1E1Q=/:2C-INFR$2%Y?
M?OO^\LWEV>G[F^#T[.S#]^]O+M]_&WS\\/;R[/+BNNE-LH3V(Z#$ C6#3MT%
M@V"_*8%AIK]_L15WW(L_! >F#+YG#?P"=+LUT>>;!T/]K1)U#%%N< E+V@%P
MH.@B+P-Y.KEG\0^@NTY^3%'(DGD)MT +6&^-W Y(F=!])NA:?$S6EN8;XP82
MFUH(PC(K%W %0,F0'2 8*52VXQV>92F"X7%,Q+";MK4)XE XA+DC2Q8R';+T
M45SJ4S!:'S/D-I"I:R(QUH:7AZ]0#L$J@H>=V1
M&J9EB4S,FLVZEWUC5=\GE&X%79:,(\!4<9%FL;1Z7'1Z#RH;J]5&"* E>O8\
MQH24E \D5O1@6@!N5U;PXB/#+=1M?!B A=J@/V1&BC:(GAD BF1"E"AW6\0 
M.EF#54\!FID(=\C]<-!665LMK,\%$"&)/,(&Z<0!9$.T :*0*V1>!9G6C:J;
M%RBD[$IS%]*JPNTAA@#PL\JHY/A^NJ2#ZI5PQ&S784H^"4[J0.0%@2*)=!]>
M_T32%&P+K@!I=#FS.9'=.11'+MQA$(5*PC-[<@@CFKM9KC!48@XX V[684OK
MIOO!I=,:PF[4,7/R=M5::KA@F)'=)N*X(1)$X=:@Y]^FQAK-.[,S&6508.8!
M2YD['&UR8;\HRG%HAL2/H$"9WV\X-D%?.0N1.V)R2OVRP98M^J,E[P0R7!!.
M4PG9;ATG6.8 .3S3RM@)R]W='?(U%+"R\D>$.!GXM8Z1B>JE9'L>CFB%(;PH
M$IF7[0WL>QM%FPLL  0EH$T(1O*VNUTF**NN,, U^.LNKQ+C^38/^*,YSD6G
ML>*_7+"+D8=@;YD:Q1+^&Y^NTX6UIZV,N^(Q,&1$$!P!L[#F0F(R=B1Z+D&^
M4I"%"&@&/@X2;KH26!H;%^^ECQ[R3KBPU%Q1 (K=IIE-A1LG6LQ/FI%)AL4"
M8TRW1K30!\K+: 6]E=S;IS(S6/CA3G &Q:L)*H8T/#YDBX>@>MIBM"&JK#P@
MPYF8&"J%N!BXA7C-:@2,C'UD#"51%>Y'FBP>:CM!+"EL^L(JN0];8%)H6'JW
MG5YT4-H'>E).2+)@$H)WJ72&1IQ(B1ZP$HN%ADCX>(A:0/K(>**$-CC 59H 
M$;5@Z0?7.]@W/V]4<[R*A)NP#%Y_8H0%(Z(IS6O4++*8^.*,$87GFE;WT\_>&V ZG9"YG(>D#$KV:(U"JX+@$HN@4(X!1V@.2F2
M881_:'7%Q/?!5RU7VZ*K<"71ON$OP<6'E-'0! B!^A",;;@ON]!=VI?JMQQ1TWC%#1' 8^AZR)Y5*2N)2E0^\7>0. P,JSWH,*APW7
M$R19LE=U;SH%(@SK4FU(+YAM0U70PIZ5I3.XD, &)R[G1'IY%5@3-_%<[\9Y
M-GS%7Q4',#88Q356*]#V+>\T!,>M,]/L$0$1W.U6&#.]1E;%T9EB=*'G/F\S
MMF$GBIZ 7"1@L*$@SWLO90,PG!X-(P]\92
M%!W.-ZLG?]\B%K#-E6,HVY:8;WP6W^#Y!&W1O&OK(!206+S=%D;:)D_FAYHM
MF%?,5'J15$#2X/8_:(F'+Z7Y>T=,PLA\='W5V!WP@*=9((1)[DD30($@X1U:
M3X17RWY,C,JIHW#.F0V/?EX($5D[, 
M@'N;BOO:ER7P!IA 2R%G"\3P%5$0N6YH *;KQH(6/H_J-3XFOD">*%,T'&C;
MWQI4'#_"-<-#D)S;$%WN,82\L+_>%"V>65ZM/RL:)
MU+"#64YNZ+?0)OD-=660,/CLD$^UY)XY@P,34X(S/N$X@J;^)J*C[_G7[([.
M,&S=$[]AK-U"A&]:#,8<[3 81D5YW>[*C/@Y&998GI%9"?<$U5A<$DL-V8R,
MO8/@+6^@HM@KT@JC6(C-)&C4.NG7EK4F\RNJ(*O4T?3*$4%ZRA\%,]A6)#JL
M4[0YXMG?KK+[Q+D/ZB.Y*:U6A;&-6J,2=?K)J")9 >= ET4-WA?8>C2D16AL
MD5<$;BS/6^06K/QRU(+?*A;H6A&+5OM<],IOV7;;#VQ6I0[5/\-0?;:Q/K6E
M6Y8HY":E$C%\"<,\QTZ"8 E+653D V39XQ,Z(1"CF'H;YW]MD4K,:.01.!$?
M*(6X%V]!H%IJ282D1Y-NY&(;K&!MDTW9/&5.#"0S -K??/K,E-X>'=-&3_\5
M,5BNH#\T[&S9F;Z*M]!(N:3@B_5GMU:7N'[N+&H#B=1DQC;?+.Y6!,A&% 
M;8B6K,K<.EDE?EJ+UGS]O9O^^)!N;%X,\J'&2YQ!8 4(.LS%HMC5=5Y[7BRP
M?D:J0*(0DC"%Z9NE8Z(TNS:V\;NB,,"ZENCJ28U@T]R3=^S.>^[A?DE>-XH8
MJ9]=&+R,XGYLO6D]/LEOX.NH/[!?GPAMJ\UM$J?X8 \J1Y(UK 1E)SF8\'4J
M;U*R=&L\4,Z5_D$SIP$^CJ3>8YZ)8D\5.@,Z FH:
M*(,>#1.,:6! :*@9N&A#36;+=H0[VABQ9=D7+Y^?R41):4VF"E.:/92U&P LA&R$&'E$V='=>SQ75@$V*2(]B";]X!J%.!\JRM!$7A32ZLJTJE96W9:30/V,
M)!QKH+8#Z1BZ;F.9GHO9BWA%\#N$?;C/A-9J.7M6Y0T_IDCL5&A2Z2 /B,\B
M2:\.SD,TWHT0)""D\.TSHO=!A-YC)-;HVH*J![#)0Q\//8BI+G&A2XTG^JKC
M&>$RX9R,KF/NEY-(V.!\N,*&$E\4_(TYNWX"6 $!\%&$3A@Z.=%P
M[\NI7EH*&X1,*%@+&[!B1JEC)?GXC=V9[92.R;0B&(%3OGABHUV QNVTL))'
MOQ$Q']1KM6BQ##DKNG#K627F$F;%,F 7(CJ@K+N[3.4-WX52,3KEZ*#S4-W,TG[,YR<>R
MNW9DX9M!1MWF8E"2_)0MV1R&2)#!ZUEA"[ 95&&$H[N.UDIGW^A"'Y;8-Z_@
M.E((#:545VG-X4BQTZ4L*]_0&W1*$I.R*YTH;$_600UQ=(YI[6WQ'^@2O%WH=>]]3E7H"$[#5B,[JVD1;DC5M)["J;^0YL
MLNS0JD&WB8=*!6NC,#WQ'N%J6B[N">ME[6?JE*6!I^@92:>Y.QKL"[9WPWYS
M3F!KR274RL,!=<^8=F#V1,MS5BY!AL%T 9/6Q?LJ\JQ)VUG:;(DQHF>1HK0I
MUE1AX*$.)E5AG4S%#WC^0FOG (99F;4D0%HVKVA_A-ON^:/,*@7KG\!ZZ\S-
MTTD=_BKXRAJ[O\'.)
MBSEUH8^J7!N%/'6[ /=$Y+1Y^)X?^..>YQ @TK>=S=@D=I!XEG!PMY=FADJV
M$B5VRF\GAJ<'K 1*\+&AN]D:2&)&HBJ/P%*)#J1H&=$9N)09,I
MB^R?C4G1"@"XG2XE3&&[0R-UF=]5F'L6PI4%K"3[-!@-.79 
M2H.KH */&2&E5@'*!>CL8A: $>*8N,*)5NNT>LCA=X.F(*['#!@F,OG^#=)+]!&_U@,,
M(-7BI_!T7"/?W^DC(LI%Z3-WF%69&F"P)"G"'3G8T+"(T$!]):RK &1PH:@G
M.85%4A04/^)Q=#-IWC@*\5$ @\Q*B]@87WJ',0^^/;[S?,?:RS/@S4+0(A3%,CQ#;G>L$AS
M^[#OO2&#WDNF6E))Y80.VM%^P23P(>F, 
MTDD0#:9=^!J'@T$<]*(PCN?PY'0Z#+@:U\M@&$;3&4X&S\P'-%T4#F:S-D".
M_JL",IY.&9#3^5Y CD8Q A( LA^0\\D$GPL'PTD3D%$XF8T%D*/Y4.7O7[J*
MQH&J?HS[4(5$<%G=OUY35/E[N,I_ 7A\M('WBEZ0,)?Y(RQK%955C4L=L^X"
M9[PDIA=2844]^D(<8D61,1O1QI,;SYAB3U^2/V5:KRH.,0(V25M%'(/\R'^:
MH=#0VVV,:>^$G14 -$^A06YE>E84!
MT5*3K<#IQ<;&4S@1D'D->U=)ZD26O&'R%M8,NDA<>0.&N.:W9&)>FD0"VJCE
M'@PD9HB)I+-0NHI05@!W#HX*8(@S0CH<-&") M
MP_SE @UD*9@B164_)>&9#A6EU#L2[EG])N%;9YO*P<7FX%S\HPL&:BR:6).$
M8L%.*4][ZX#2L1(G+RA[$NLAMQF%2QOS@KQ@6&GR*Z3?.E/.8 C";)XRF&&J1QE=I)Q#.IPDG=
M&? 9-O0WDPW!284*SHSB&MW--:ECJW$] !S-7==[PT6U' E+1VU E?( QYT*
MV3+TNF61+6A;7U@K*=AMFF/544Y=^KI%P:+W$E_)M\:[:)?A)8HH^1^FI$,5
M>JCLYQR?6.1E3B9B@^$&G;?'I5KO+Z7%::B$3Y*47+JW.A8]%
M\;&JDK^Q$"0W&<&B+P4]"A8$3D4!
M*&0^+@F#G?(BLERI\P>DNHS2,W\AC\4Y.A]2'KN66>JKI3:6YM72O(+C\H6M
M?TN&Z0=)?$UH0NM%4&=JPR'6F$3G:@W@ 5J2GZZR>W)HF-PG-Q-F79-RW.8:
M:H1(U+>3;*RW@$X035HV,Z]=1&Q)/Y;P2W:(J7A8(JTJ[]*M1A(#+[7#C(A0UZKCL<[(AI' R)>Z9OP_]K"0X-[HT?.,-
M*#!99X4WKN0DN8=T"2Q>"0Q\X;([$/TEU>MI2^2[\623.:H$R;8DQ"[+2TMQ
M0,^8>WY@6,]>Y,DUAV81ZYFWD]^4WNDO%IMPE
MG%V/\])=XTK#6"7F,1%N>*YV>UJ6N5$2>R\NK\]/7YP >2]1%W2A"J&FX2M!
M.?'JU+P2.:0E*H<^M3T5)3]<0X4_)'8\M=/%C#I$K&
M6V0%*,%8;WY!T9TZH=>S6"?B(,<4#>=G1! \'P!P#O7]HW4WP:1^,6FKBX1$
MEQY_Q *(*E17U88.Q5^P>27C$*K1@AVZ8_D2\C90F1HJ;4288]&F ;6*PTO]
M 8F^6-PR>>]=\S?#0%@NR+C2+/U+/B3VVGCUSMQ--%*/C8N2Z-0">Y$]J0XO7$Z@^$WUS)_N*/9S9(;V(M0VE@--2VR@&^4-J6(O9
MK?#11(XHYDYU4=+[)SVORK%C<=Z&&TF)^FI7  +C]0Q-\KW G+_%2G/GUUA!
MC$V$B%$L&(82]+J@@ 0L]_.Q7$''V]V9R
MZ8 >X]%)6^2)#$7^MBE5Y@D@]"9&V&W6)U./&<@"MYRU7:V,DY8(K+M+-+ ?
M"J>G:=^'\=M\R2:\Y.)G[$+R/-*EK;=R_!YNZLCI44-[^,?X396-+V6H@6>YLY&W->=QF<@E;[8>=!@T3
M'LX:  IH^_6$.PDQ^N4(JU](AF1)IW[@&*Y B81?VI 5+#5'.6-"!7SP^ 4X
M<"]&!_^5V8)%?<-,+4**2BJLDE!+K"CN;2M+>%AE[S'=>V+VF+%"-JOTT\ ;2:N:N
ME4N]686XOB'06$<25CS+;)TA#-KH<\O*G8&0(+]I-1@+BCN+NS-BV35*1%ZK
M9?N$0ANDG "B%T.QC@*Y,@ZK;$0B*B!3?;@Y>W'B'M)P$Y[!%9O9%I87JK)3
M0LC,94RP!@; \J^[E#4O4YFWQ2X%)B]5XC_JN#Y"D_+"=V\9I//\'EK"W$/O8J)W'H4U4KJ<
MJ/0>)V#:T96:ZV@;=^?A2,,SW9U'HS*J_EYZC7110+JTH05N00JGS;##)<<+
MDZZWJ_PI%6,57AJ62 "]6RVF;C[I+<,6T[*K?Y!'KIU#0AV"A"S?4\MQ76X1
M"W%WB8K>'%QKQ=;",R7-25)UWQ(P=IN,+ A7U]^70.O]^DK:8ZQ9[8(;+[I2
MZ;7UF@AS8ZWV$GS9H&<"L (*P!*O@^% II&"$8[/52YT#5BP.J[3XYHA&7;5
M6)8]-5V 1WRB)K+D7W?+>ZX.I\&\8^.EC/W**Q@6]%ZODL6/KZX7#SFUCV%V
MY3US0L'$)67D&ZE.DGTE[%IMB0AMZYYX43RKW8S: $7)%AA1;!B(81LNAHK+
M6+JN55Q3T:@UA:TT:H-F/^6XRF:Q.(()G0;77[FSJ&)-+U@A@6*QR 7D1ZWA
M.AHO4-)?XJI1;'+=7\M$/IK5EBQWZ\)=S54T2AYCI%'H+0;?:-DNHJUW'Y8)
M5K1428F&Q%+"HG]/?E-V%BRW/D)"2I.B4*;F=]<(P8S?PUX'\8A['9P8QN P
M6U6E=KMS"V%D>DB6DHT&I\)-$59/5A<@ ZR*.5ZEFWNL[W%G>5%!'>Z!FKK*
M?O:2MR&*J9_4CB+SNI7W9"77E
M@(1X@KU$UC/V&V>4#5$CXX@00K[%TP*EO9*\9I[19I5*\ AY#\O4!*CL7PX7
M=D1= X6^;8JEP8M\MS6!LES>,#-)32XO5A*A63K%9Q766T1(;7YC[F)KLP;1 *NR
M7JJJ>UQ:6(H**^ZP>FHM,1S42C&'2A7FNEX<)N^*MVBHUPBV [I1_91L05$'
MAB>%W5*%[4KHK@$95:3Z "Y#@F?U$"10H(F<:BJK=&+->)^&*NTWWN4V2$9*XA @M
M00;7Y::,&U&];WF_%9B9K:$(S>6R31Z>LI6IQA[,D5,@L
M@L,MZU++VC/.9FG'X?/N:";@LE#K+N6]M;&>86OB#L.2/O"A4AD"IN:0(L6Z
ME9Z96N?V4!WUS-6:"?T87J[W+"D@V(C+Q&'SO#I'A[_19]6Z'"T[V$(AQY95
MMA3L-M_L;'YF=UAXWEB3/1!;W(5&@H6]G+562)FJQ@0G6.[);X6%K(B'  40
MR!Z(=N0*,2LE@E-A=D\ESPE4V(KUF!,9 :2'0_X&U?:L!&6,KG+QY'Y31B=V
M^U>LVKN<+I*A&C.+WFO[X]#;R.>,3ZC__]/_ _ZX^
MG%_\_-._GY!L0;-Z+E3*?].)2EZA*VXN::5IO1U=C'/C[R39;"BXAF"8E?;\
ML"V=WO9O++C9=*#K->SE+X89B<6!XJ5L23RDT_1YP[G5RH=C6< 9%I.IJC2U
M^W* 5AMK'E+7UMKK#B'L]\'=*Y) =4U\.[H_$-4LR7[,%535S#F-+V[
M74%4QX!=V(#N\"4R"2=&4&@4;*,).Q,.I\]+:ZT[%%O^QG8\H+',-R7^V!-E
MCM.WI<\#36,+IG3K]T2U(82=S5+K[:^/\5(KO_SYNXO@E.-D
M 8QOWYX1(1'J##\2<6:](+=-2 22_KS&)8TCDN&8)>ELR_VB6M[ H!9N7<(P
M9I%^&/0#FOC?2C=Q4_:PKC<_.N,HT2>07GGXZ4O;C/>):+@P1=.]_"TY_.K6
MRTTN1]X6VVCV8L0,6]+/;\K#-G0-L"/EO N3"2R+^PASD-T5,[RSA_*5'_ K784K=Y<
MD*VW3N86?(XZ,HD2<+?7'"I=,'55Y!Q+B[*#3R\>-5U7Q,9KU2ME +F1KZMO
MJZP:S@2,45L@I3S)"!QD[5L#*+"+XP)VQJW7V(/$7K6"!2'D]D4OYT-9V$4S\0N
MRTJ9W$Q)RS NPJ+%6A'\_-/_%U>^1=/@
M)B]>99M79R!W2?60YJ0A:O=>-'BSVRM BIK^IE*EE?HIX^1KNBHAD9\:20X]G:XZ/1Q,'^8ZP/"@'$5(6@\W=017$I"Q+V/2&
M0&O)7E))1[>4>_@N=Y6$W !X,XKYQNF_2V<.TIXW'?=C_.FFV+3:=B
MHPRR_Z'6Q=HB85MQ4N*$=^F2>V990Z_NE8T2\ )$/Q?:2"])'@$V.>=64M="
MR'HO+J^NL="F+%SL,9]-L3I3EMG&J]=JU>!ZRU%/YC(U%;?;C,%666KH-5>72R.;I \KKQJ9A@P)NE*II.K2=SCWJ4/>V)Z9M!7QYE)BK#M;;0S
M/4SQ3!:))%>7^:Y8.(\($DKVQCB['TO?_ \J.!+H/9H'UB"1< @N]UO91
MSU:D])3Z3D,LM.TZ:)^9#MJJ@4)K>Y>J9A;$EWV[)?9)@Y/QPDN 'JB6;U><
M*:H;E!;Y)DN43P@4>7[+;D"\(U7V/+^Q1N,
M&?@SQ0R\XS@0.JC>3;X%^6L6#TZ^ >7(=/GDPZN5?C"]1"[$^0B03U 2$#,8
M5<4@4[_,L[5*((X%8[@VE2^ V)U>?V_6]\(V/@16*7@'S$7"9(SSR#@]&=NX
M2S:#MM 1[^ %B3GFJI>3"6MZ?_AE4."<%]9 )PBJ<\G'",;E;#"^R18:7
MF8W^4$L'T.:?3!DZ4H],DU:LG'Y/O>9-B8;:HA\R0,MB\?#$[B\%?SP/5J34
MXTC3>/=:-X3-:#W[V&5+ F;7VBGAP:2/+6N84E^M)5DVB959E%VM'TKV_+5?
M)3D(TGC/7*7ZT#89L/Z6P/(K\6ED^VH%-9H44DG@8E@ BA=X,
M"1=90DS,YCN*,_H6Y+P-.="3.[1A6\U*JA"-Q;B2
M>87K^RIWJ;%$"@;<;27>J2IR5WV>7H-#;79A]IM (H.DM7C[58:7NZQP+>[P
M4L(S$RK_KQV^+C1-$*RC#H2X=KB(NX\U'JX@QMG3"3EBUH(,%J$66Z\](%RG
M]&M1F!P@OA]*W6Z]O.9*-*!G51HO0.Y 8^06D','9@YV-?8ZCR';4/9GT1# 
M[@8H/33?SX@L4.?(<.Q.KDW]A%>84RZN-6$\\]&HQGB26]!S@6]@&^7S76$<
M)A+8Z3...3(.]:.'=/J1"I'B)78@CNT
MOYM1O1]]>8"?O"LHQGWQY!U;;[?!RFU4Z(&+)C1.T[,1G;'NF*=98^N9GSCDII"B\^9WN%
MB48[U-6HD6TDX_M0&W53+D([!27%NAYW,'&J'P&H_[NOJS_\[NLR^\/O\/_5
M']Y-AUI+1OS+Z6U)%^N_'S6H,95N<,-(
MX'8%E[W1HKP?[F<"+DJ;>U#:D-;6G,9ZQK!4KFF6L:'J-85Z:D#Q98X)^.2/9=.-'"A)P(O<[)1NX^4F%8W;GK8T](RCVT=MQ2M
MVGKT-(C7U*X;U21M0U#-\4^5LL=!?_5$U[O5#GWXMJ!=>Q*RU2-RH5D*SY
MQ^;!FS8+B&A8GI$<0;4 6G=+VI,W;<+G\:[6=\K*8H(J:#FU*E7.:M*L5T4G
MEV^R*J_'ARDCE5]/79I".K>FSK?2P@>?!R>O]6U52*%OR2HM?6>[)+@]P^>L
MB[BBR:%>M*IV.FZFL(W6&!'#K:>#X/I5VC&U[V75Q7:CE\1
MO#6I_0I2[+=4M*:V%YYF.!ZT]A0;SR=J)#?#,(K[PUH!_7M_>$%J&3^>J>=5
MS[+12,VK=C";JZYE)T>W1CMAO 4W(Z7GR@T*]LLS?MG).W:M788"^HO!D^5K6&[^YKC4>H7\=7Z2G@
M:[!PJ*/60QT.-/J=J.)CI@B2;M=F4BU7:55)@3KA1*SS\>UY.9VI,>UWM$EC7HFL&@WNLETN(CQ^TG/4HI%FZ:BL45-W=H\%7
M;;EL9)5"6@^PP*Y);(X(.XY@/E,81;ZN*.I/OK)A!C+0;V28KMV.]NX6U_TN
M6Q28SY@N'C:H]CUAJ% ?.QK\6GNMU<=\&8TC1?)XKW%_^A5^[-JMLDA_9RTG
M-[55M(L%>TI)F.A.O+X'"AK^"B5W;KQ02?94V$"X/2@;*M.P]1:N*(75A'BV
M&HD[KL',_67G&^?DJF3]]Y_JZ?#72LYEQ45_PZ5M.,;_FV8M[/.Z
M2/J2X@I>!L-9.)[%6!E[,,8_Y^%@-@W>=E03#>:#03BI1T/\-)Z&HP'N$\8;CV*N:CZ=AL/I7"'DUA51%=E^%X%DZ&N-4I$(TAUK8?#<(Y%;F/PA%\
M">+;+W"9AJ,PCFVNO;TN/#^*H;M:\XFU4N[5
M&;X)VMW69? ]3:=OT?=ZNLOZ=.TABS*-Y*?I#+'&I3L2]0\@>>?-9!JPE\K6
MZ<)K:]PV2H2B!'+G?#RV=P;_=)HY_C4.!X,YW,'A:$!_ WN"&X6?KDEG[R'S
MFB"%[@&'H^XD>"V$2,\WUGXV1VXED)KB6FWKU
MHCEB]'@^QQ4,8N0SO0E="OA[2&U'AD"';Z0A@M2@--7!+6L'\C&!W8(."WN<
M F^;A3-@T^XU]#[!/:B_"/=J-D(.U@.6..?9 4;8?*,W)_)S$ERPE=T=!TLV
M(D?X9V&% ?SS_.A^&KZ2?V/NTV*'(H7#H^>[NZQ
MV/50OC&DI7D5:NN_OC -E2N_Z9PN&T-*B;K_9EW"@M'%8J+H.]V]&H;6@9V5
M?OMPM4X"F]@EO0BI%7;/]%;0-HG:8#,/CFRVMOP%)J7ARIOQ(NA;6J>8D6_[
M>*'Z;&H,4K1399)"DD(BI\P2J)B:6P6W$G65)&"!_J$UR_0+P\"W.TFBM'S$
MZ"ZJ:-=6[$^5WJI5!/+*0[S4!JE:OQ2_>8S;@EG?/BP?.BR/?"P_[EXVFT90
MH:!:.5T7>M(LJF@6[2&^M"7"N!R]\*X;Z361=(/(K120L(;\R#7T3*$UKNUA
M)ZB10'V6>_"E4#9R7
MN9#R/2ADVZM)LIKES28K5JYJ:-< V.;.[EEW]K^L=#SZCY&.1U\L"K,D>)38
M.HY1/!I-2&VA#[/Q0$FH(GP.0=^=!?$X'(-HRW(IB6:8,C1F2=!\.D8,[18V
M4>^NA#0Y)7(,:^VFT-<:VW1>-P4"W)59A[S>V/O68Y9@OLSC5=U#B5
MA .BO(FDWJA?^[=_)+&APX'=C'[UTXFU("/&_Q7EJAX-,K?5_RA:/ KV.7KT
M+3VN\908]P\'D+:[;2+M(.NUD=V7-0=K6SLPUR*PV0'*>OU-Q7.O_Y-_GT#Y
MH1PW\XOFLG8L/U?(!>/N-@C6E)O9
M997),G">TW;LIHO=+"7\:^+JC93/=LNL.]I<5$Q+6'2Y>$B7.P[<\ ;AZJJX
M7:FB96LYC-Q"C@BD_OLC%4PQ]F?$*6QTD(H-)W*GUZ)G$1U2_,+YU%L"7O#9
MH=*C3FI194?J8IXASH3]XN!Q6R !._?U-O9K(Z'?A+)%_&5W]1=5VMA;KHQ/
MO07(.AK#FC)<$#%.*4V&;M01)M?FKO[(V%[E=P5^L$KZ9G
MPXAN>_I8._7)BTBI+[<>ELC]E;^N]?X#):4&!_6%W!OEEFOINFR"(FF^GW_Z
M'YQD]Q)5ALETA,+U& VR/=8@N)]U.(P&;:^^SZ5.8!Q&@[FQ 4_)V8*&YFL_
MZ-)[)9J&D]D,76OQ&&3^,9K+0:Y'!Q5U7[V'<,XG$T'P6A.KPWP%$9PBJ/@W6Y#
M10]6MSH>[CTT4#*G$WO0@QFN#-!C,IMT']IX& ZFY.0?D3LN
MG$?$=FHP$P]7 *5R"&\+,Y8#51W(.FPD6SCF**QM&SQH,1?<193;3.443L/RUHI_-P3CPDQO"$P9RC6\+)
MD*\](.MH L"?=@ 78!3%$W&;QN%PBG[\:!Y.1[.]P(W@X<$L\N>-!H#0T=A,
M+%$<7-M4<_87'ZI&SVV3 N-UMCZZM7.WPJ/HE!Z:#3!8F(Q*6\&K%)=YNR,1
MI[,FJH\4=9]2LWB>VF(3#]1'.OH6MN46#! = ,CGL:5S9+J;,"H_*ZH,#7KQ
M(!B&HWE$X1E3O!#6*1P!_9I%. \_0>))' _X6*,Y<:*C+LU_+'SFP) IT@TV
M,G;>[>=%"H&@% ]GN/,QP68^%5&)3:!1!!A.(4[ ZP"H
M3%.)22K$UGVX.DW"J!XF*+K9&)C3:]0R6M_CU& X=4I:PMP;6^I/9L>*@AOK
M\POE;=NUT&6KD-W0]F>Z\[N.=\$,4VDPK#A=ZMR7X]OWUJK.-PM#F:KQ:M/[
MUN.#FC+W4^RQY <&\/[K'7FP8Z.KV('IT,*,<%0+\,X"T'H;&P (S72;%T7^
MZ!\9BX&KC K:B,N1>O[T@P]2U'8I#8?J'6]!QPU;#HKBO>U&I((&6;YH;%H#
M*H1F!90#!1!:OJKR5P96G&Y=(?_!J6)[
MH>R7/)#BK;M"TK+)6'(G);:\0H8V%XX7; H)4%:Y;!4[(+/3P\?L7X OULS@
MAV_--UA[9D$H^ZO(4" M#4'(YV!&Y+&C"0DS\Q%H6AS'W)L"$QF,R4W6*D7U
MYB"BVN#(.)R-40CJ13%)7B=[M;S>=!J.1A0M!L+3K!;FC.L#Z7@V%G$.9-81
MZ0Z]^90BQ_B1&8BZ _SC[^;+_\#SZ=;2>]-P,)F(7,G:5$^@ P=#-HFVP^W-
M@%T/)_CD/ HG\P&*J*!4DXC:FX'N/Z3 P71 &M 'CI4
ME+K',]14)B"+C^FU$:D[O7@,'X-!I!BQ!S.?A+L_%KUK)8F
MW_")2ZG:='23>(LIY_46W.UY\EFUL\F?ZU2UBU>VQIQ*EF54"L)U&$"G0FE+
MQEN3?&O"98W'[^\H7!<"O+[+NF5AK1N9:CF,-11VJ\14H'7N):\1- M77A%@
M9_=MC1G485Q4TL?P*\=7/#O\L9$I!] 'RT2^_4$ZJ)Y9*)Z.$
MII8&BH]YL5H^ JN"P:0,(*RK>@ V_&/*6=X[VX3JC\F&RBN:>$Z[;OR"=BH8
MS>VAN#6''%3SS%L..R&DY"@7M(M_=/QP\BT>I[\>U(Z4*@&V>Q#(,KW6!*[0EH[B0+CDC
M*[BD]W28B:MDZ/H>P4 0F4L;*-G&)2.#_>B$U26,MV>
M&^9XX^&]=1"638YR(/C]3!7% +I\$GQ_?8Y9'ASW,@&>^Q%#9\P#0WX@@B>&
M\20 G1"X1Z./.G,@4[4CN/C^ZNMO7W_\&M\$PA\/QL#GT;KR@U!)KM)I^_W6
MJG[@^\$8;8HRTR&GEA_F]=+D?^T+Y/? @.N,P\F ]'[BK&>6VE_3]@A(<1A-
M!B3A3&?XT!LI)!+\Z>J' (61&=J3\ &GIOBRS7^KA;9JI=
MG:I_5/#V\O6'*_\=X(R(O6UCXQW^8P+$!+GC7]*-557.'C+^;H?]S4![H,HI
MXAO7_:I:R.*H3KN&0;>4Y_G/I.*H62X(ONG
MUWW:]:OVQ$&Z(6P_Y3K,VFX5(ID5S<"*L"2']E1M+>H234W'X>G>UE[P$QKM
MD2KOAI[0U\R\>.**V>X1R=@AL]0M!ZGIG[E&A[+0LG0NH<&-_O-':E)O.AO)
MUS4G^Q17B!=-11>Z<@W0%WX':3_R[I:M-=P="^Z,=)A3+3:Z[%*I9 11T(=!
MW1PI(6YM55R\$FV*4YZK[Q%]X28"[>-N8.C(7][7&>%;*H3-_H!#,ZD.V(0S
M%-[S+>*/Q/@<\_QQ;3HZW3QB;J :2YVQ1B])*!U,ZA4(OH#W[)VG%XTIU7+(
M4N0P'%.8_Q72$T+-]=@[#EM#)VQL"TYJ0QQQF+TI&35-2L.'IH5)238'
MCFM(?G*""BA3(%*,1I.#K/S F  9!NXPC$9Q,!N'DR&(72D[NA2SPJ$#X_5N
MB0E$HS%F.KN]\LJ0WV.>+V-S/(<#H:@Q#"J93CRB[[HP6.'PZKB"6Y(P\MLF=M<1M?38!3;(U>ZJ!4SZ>QO>:$%V([
MN_A,)<$/DCNT^J-83T4F0(, TM9&94@>--AC"824@!E.I_;J#X$4H.<@GH_@
M#D2MMW(>1ABE-!@$TS!&GS=\:MP^??EP\LD$Y/3!,!@"RDX'<=OEFDP!F4>@
MGXRIB5+734$*#C/*/^8J1(,0UXRWX24H+.BKF2.!BTX,+$7WD_9"I5]FBPRS
MDDN"^$ZZINMNUM*;[0AL;*N%]0MCX^@?BHT6DPPSG<442FJQ:3"C:+?A> *8
M,CF,)1B8-0IC.,0A6G"FK40X0I4/-*YH,@!>/G8H$(ZFP&I'2 3GZ"(9C7_%
M\]?DU454W-U1%YA*#^]!F<.6)&T3=0.37G PX,!V@$?#+;4':;9S,47KJ/3>
M I6DB@K&>D2^4587)/ =D5I>@33-PV7MPM0A2FNJ[=EO^-3QF:\^G4@Q3+-0
MC0:FE8L.&^E]XC'P]?^=!]#5F/S!*!K "LO&%*6ZKM9GWS?S>Q^;A:"Q!*AB=.#I0 :^]7)<,B$DF,55;JY?"/__^(KCY
M$'R\NGQW$;R^^O"GBZM&>?US9A+6(/.ZR'],BU?G:;)"LQ-UJUJEW$O@0W&?
M;"2':U\)_K9Y#S 1.0-A6=L"X[UN:2G<#5T']ZZ3 H2A5QQH93LN^N]H?XJ.
M@G'*>[Z1@>I5M9O#8^<):@-*C@J/2QM&7+HT6D]\U/Z09IG;7IFFE&D(PC2!
MFNS81$VP1"VU ]M1:J'$0J3%VJ[ZODA31WZ,!9 G47/<)0L.WW,OU!H=T%5H
M:X[CQ:C:"$.ND&TZU'A@9P''1L#1DUCC" ,$Z3HG(*V4%2A$2!QY<^:6;Y(&
M!(6NXODWWI*^K*4^#Q,AUU5/V"_UE%&EIU5ZC_(J]93$>D9$.9IJ0#,*DC9G
MM]H.#Z^Y=WY88$S*]AOP: ,(:58R=!KYLPG/9\^I^C;;&M#T075'WALW4),X
M:S PBWDY'+1FG;Z,AF-56^+$EF&WT-UYD4 M-X F)830^&!":W)X!^,[&FC1
MO&E2[E_J5\^]W&9K'-YAJ L!$&POI
MTC#(UG;\E.UXSZ+(0"BYV^+$T?BKH(<-.;\)X-,)B2\"K54J+83OR!E0L0IJ
MV'*&9\.,#0X[+1$^;L]/J[X/3]
M>4 ?+O[I^\L_G[YMZPMS9C"5/KCF?^71#P;_\A9CYB^K=%W6>5CP>;WZIMP"
MW?K]BZUT)WKQAZ!S=:U%CQMB7,,Z1$NKX$IN?J0LS5$842%2$ KB"?],EYW"
ML @^DGB65+;K&OWR9G$E)PG0=3%V +5_,S][VHJ 6(\X'V:R"PB4-VYTE%
M;5VY(6Y[.*&+TD/!E\*U7/36F_/+,].N@X*;O.;NB% Z$JYKVRS=IATVGZ?G6GRNCI (;)H"W5BS&'.86HQKY\X6\^1I$!%-H+KF
MVCY_9J_F/D%Z9 7IH_((R4-]S&Z;289>''Z;)>I8#M!^ 31O/0*I7P8F<8#B
MZB7&O*X"ZT&[Q.0@CC'K(0;==!3.9Y%:9%+6Y2O_=+" ]FS$/MI.2)KMMI"*
M8(PVGBF&!<;*Z7#$\5"2ZI#C].GS?!+.HU&=1+[]<'U-=)$_G/_Q^^L;[! 7
M7/SSQXOWUQFM95[6"]NB#;\48SQH0D$T3=QZI%<*J
MXWDXHVQS](2,IH/@+0BNW]#12SP$"L!DG$%X4)T)S&>?43Y[#^[-B&I6HWFI
M=;88$)WR=M$?-QG#C"";17.,N^+@CWT\(RK6D=#3)SA0(CI@)*E
MS,HH>:V'I\%),[UX/@S'TRE#%BL-S#EL@L(N;.!H8?IGHLH6A\.8(X(!.FA4
M&8WB^FEH]]MP$(<3+/=0.Y?3Y;+UV#$5:1;(VDD5"I*5%%1IVT+8+Z29L0]B,X.RB/U"_EZ>,2&*?SJ4'N %>/WCMI% B
MW(#$)8=L/B)-_T3LB=:-W1L+G,"U&Q8M@/N;4S]"@=.>E=>78%*ZL#+P2EP,
M!$+):N?P-DG_D=!1NQ^^=;]E=(Q&*L[PUT)'6 Z<^>"70T)U!-R9G2).$Y,E
MI>R8HD8+NFTPWPT1P'4/=D=D\$Z,1SQLCLG+]A&JP89XEZQ3DCFM/H+KAJ-@
MLLW]DC_#$]R?6%*?&%,Y#C21LQ/#H]PM5\V>DK*WJ6"E*?I&I[N4HYLK$GGL
MR>%VWJS@B)8)W=3\<4/MQIP1P9&TQ*V2?8;88#IWO5OAWO^(J6."I&'PD-W;
M6@JVM@,F$J*<#0>TQBW:SMYP0 5EV.68%"G)]!J#V0Q-#;[IVK] *G"_64N:
MVRV@X%V&95H>T0Y^^Z0V%/"C8J>10 ^\<7=@$A$KQ<2;4&Z& _6*^UX:.1LC.E"1
MH4LL3DB ;X*--9SAV#3^#U[;2!:+7 C0?J1B!"&^(4MQL
M6'DT=J.#8($-'@"K:33SD+8/OIK.Y 2$_"CI"&*'++J^>@JB!=992R8#H_J&-5A4R%
MM$F13M<\O9-ZMNPB#)92=%-K],%UB>GW 1*I+!$!=3Z8B=O#'W4:B#H4?A9
M:[!QY&F:JE%;%!A 72Q@A]A;V*%C1[C77BBU753898TU6';78NV]U^2X?.
MHHV_9I_&P3*)EW)IMWZK3NQO3:Y
M;J^@SJWDVY!9/U<-7L"2
M#Q(XP!>BP#XM.=OA9*U 3Y8D\=VE7,'?UBR_31T"NFI7E&SG%O5;'
M>$INH@IKT3CN@J(?"F%>OVRXP!CTBYHB$QJK^"4LEKRBPFA_W>4 ;VH5_%_N
M\#7E\:3GFLA$-@44=&46)3L?BS^63P^^0+=]A@19YUQ8/F5]JR6P5D&2FY,K
M""P\ZS3NGR(3@%FN@5\8+;#\NP_UBX\RV2TSYA&LCX(>E9:F/;NVQI@S6X(<
MBI5\L5,YRV%-/=M*I!2/;B,?E4C*=, 5GZ'Z.<]3=CKTD!8E?+]"Y*E!NDCY
MEZE!4N>,&U0X^R3796O\UL,=S.@#95\<(S VYB1PU)P8;MB_Y3_D:?SY5?;!C'^W::,
M+JF[Y>;&2J;4%_ZY>M$_0+@>'2=<#X\2KG4$8$VVWH/TOZ!T/?RUI.L+WP;R
M,AK[Y+)U ^4.#N85V2*#:\!I%6FB-++]QA*^*4+9Q3Z2JM:&QCY"9:ZX:XXM
M VO+;&D;B8DVT8&CS@EQZM,0#@!QMA$/P_Q(:8G8(:Z!% &-L-+XPME.Q);"
M5A;'[=HEJR/II))R6PBD"?HYCAKBQ$[@\RVZS@";X!UX1!+H@HSI^5*TGT
M-.$PZ-Y=>TE0UY6TZC-K=1UY8^.2G![GDGR>AMTTGOPOF?=Y6C+9(F*L= OJ
MZBY9\:)*51RTX6)0Q/D(;P,#A76^#8!3/UWCI_<%5H["$']#21H<4CE3C868
M&336"G7'Z_E/%*^7<9.J2A8/2HD2)OJ;DGT:+7PX*[M5R7I-'2$#'3R8Q!SB^OKRP_MF!+BC-^=9B77-*2._.\E.CZ:#ND/!"ZJ8
MGM._KF9-Z=UYRC9462'88R*8!L!5[LK+U7$,N
MNKK<+?AWDJ8MZ1"$!.%L1UE7Y8\EO9#?4KRY0B/"2XR#()J0;),%Y;!MV.PH
M,58X@?<@VHE@R5GNMU(-?5*'Q1MO4PXG(6J\3I'R9N6:1%HR$I)8B.OCD@]:HQ=Y3F%H/_SG#Y
M0!&Y?(82"6Y"K3E01FK LG,&6S,IIXXE+]9U;A6>7"4!&/(M]'Y_7*8+D;/D
MR4.YC$I'UZPWG =\=,680^&A>A_HNHRTZ=EE<\5>VIDMWP6_#("8>DU;5JR;_.KU]J)!/S[1M
M_/05"@JG_7?]X#40,VO(X'!%GV\GV(,5%0FGU8A^N\-^/NWXPM21N)/)6>G8
MEO&=:-7(B_7S]!)E7&@0KLXI.HY9!>9[AT5PCI5U%'D1UCCD#N:A4NJ.7P-?
M'4H*82FMGC[4DH7CV"YC!]N(C;;
MQDY H$7GJYVV%UB9D5RVWO+,VOU%$:]*L''1D[E!4L2C/B+K>J;6OD  :R0*
M*W(E/]JR_OGM508P7[KP$DI9I!0E?$9GC&RI/P("B&';28P)>_QG17'E@5$,
M=N/RI6D"F_).=B"O<4/Q2G=S8LF1(B>9LZN.X5Q*HC8]QS8^ 7#2-6?+@O9A
MZ\#>D"Y[NF9>C"-BV &F5K;"6"]S=U[<.:1T)':Y:B,)@2
M2;$I>26F;YK8&<Y4_ L]> PYTD&AN)O"C9JAJ0/VB5?$9]V79O3;@AN1TA8)O40[8-BMT*:^3,
M^_.OZJH:-WZ!W;$B],C.?;QU'7>F=EZ,;A:)[G8%:%:9/N4"R
MNA9N>X3-^^.O]@/6
M_7(L>#_NBG*7L,1#)CU%9G\3G)KPLS!@O>)T=X^YE1'1KL$H)&OI9BGU(>H$
MTVAKPJP]$D[7^>>?_J>>\.>?_LU-^?-/_WX2U@\770 @*57!>&!!H?=WA8;+
MBCFLZGG8(V_\'77",;;+]HV>8#T!N#KECDI5DR#H=$X6/L@8^=<=5K1$\0%[
MG# GU6%\@ $=BR%K+2ED!3V _)_QO&--@60EU^IP8$.?>S)"U3HU(I5@;=UX
M:,BRCJ826LLMKCR] [K/54IX![(:20EP!BRVP*)]?0>4:-^>G$  @[,4Q?OR
M1A8V=(^U&S&^]S@$M*44D"'9."_%L'_K[!TA?R0[Q"UVT=M0RQTL%V;Z&384
M9B=C^JIS]&'UH=U10'G2I%==7YR%4G4H2.ZE
M1@+:#C?<,]RQF)=PA96QP6O&UN>=>!+%'36GPNTNV)C@I>\.!P,JIFHM ^:+
MDTYFG(F[.F/NQ5*=K7UO*D ;4',\%^98+:PWE<.1AN&X,;G]JGOZVM;4.5!Y
MI;+*%S^B[01Y!1S%=I6P; ^J_CV)]1*#@Q=S::4PPR@Q@6A3'=
M.C*>O2MT!GYG=VP#-Y./UH/(G/LD53H(CI=N2L8I+'2,(E;:+:%I89HNWQ) 
MQ-: ![8(NG9BM"#7 *[U@5#-HX7Q![_RA'F%RQK%OM,&:7<7@!MV]'[GHWX+
M6T!)H..LCE*$;<=KH:G:T>@J2QYZ+C:"N^3^8>)$7F'3UWN01MBKHULPP#*N
M0$ $0?YV_"J2PS1=YQ%D<@851GJ0NY\8C8.K)*$GD.&;U#% ^-.53''?GZ9Q%F$&EO#7]CRFDN1W72CA*X,
M7+)F \K&D#2;: +WW];^-:57:OBB1L1O;#N*!C1P@7)^6.(;VW>@+%-N65/+
MN5R?-$(A?_P38Q.RCQS3(3<#09'" R"DB[_9=4WV)> -Z0M\FCU?J3IS4V'2Q76*+!9]&+9(,G1?$]
M%4I5.[M+3P9I,ZYH "3LF%FDJ(5D:PSCY(M$2J9[DC'+^;PJ]OZB&T<5K1!-
MH,%A6]6 1DT*([=-Y%,XF8_ER/IKCER,J1CI77U[BFBD&O$Z9Q'D!\+U+,ZX.'F,MC E7
M=QD.I^$TGO-G+#TQF]#G*W?ZS5&#GD%=5]Q>_]]L69X6,LJLT]/L2_O*>!3T
MJ+Z#^4*#BVB3 13 9!I39U\%J*.AY]7N0XQ02DL3BW\3N'(QO;-DFU449+#$
MGO&?, GK!+Y>D>TT>!T&9RP#G/-;(,V>H.QOZO[1Y8S%)N/&54^\$(=/ZX\8
M3()NQ21X!QQ\O5L'9D%7CJ8BF+Z_QNH1OD,L"3X65!GX-EUVO?=R-)GHO+Y-
M#5A)![51;JW14+O;]A&H>@U%E,YWQ"\6"LP ANUJQW$ T]E,%8[@T$&1$O8!
MI)9XO!\,ON?R&8V"ZMO9I/6^)&B[?MD;#N;]\8GR(;R,(IVK*&4KXWC>Z6GH
M-W%8<4%N] &4,"'' F;J8_\("]U6G4TEAI-*=';Y[M2YPZV,C;$D%&;CFJZ7
MMNMZ'0+?GIY^-&<9VH,TI;@9-KQ;,G/4C[_KE4XLM)K!/JQ[.8S'?E*D+T\7
MJ;3^Q>!/M!08'FP+5W&)8F<,=Y;]1GB,-MTHVUA)4=]KZ3GOOZ)QO[F6A,*R
ML#@G"Y@$N-UMF0$7Y'BOQ*Z'%]H2"*+6IUX5:^DJ^Q&YZ6WJT$EW"<86W'J.
M UL^]9K<6T,')81@:2!:HH_,_HBR*B/@D4G]$SNH$46?(VN];"T$BU[1T'C?
MV47JG:F)AZTM'.2P?.(0]G@A1%/
M[W3O00!H?@GX&Q#7FI=+^Z.[+
M!!%_=2YVC@C7*\JT9)![+>QMYTWCR[%TCLX.& 7*3&30UOX(7*.1YW$-33\,
M:_%B+ =AQ)4L?3GH1X, +V\_N*R\&J3"1UYQ-&W"$7N2CF&*4TDA^%;7_:O7
MI]=8.O?#.ZS$>'K3$J;I0C.)F6@#V)4DUYQA*'K()EU9RD=*2O0U'"O63 WF7+^Y'UR+;?*CL?C2+M!QQ2J=Z=[Z
M80./;BM&JGA@'%3U0"=C^>PPC+8;F;7);B1VY4[;;,6E7KCMD^FMBN%SH,@,
MM(O1A22-3,U78_B->8Z.138:6MLF4Z$? EU)ZI@UO,(ZL*D5=GCK6'Y/E&SY
MLZ2H3HY1J24)D \E*1^H?KK=+[Y*R""+/:G'.3> >\0F#Y&[?G AR,5*JR"=
M+ADL[HQ35VN#9?4FWOHX0Y?3:T=@++'8X8M( L4HN1;*F7+9,D$2#*@[&#H-
MMU)3OZ @< JZ\&ZU5S?9/<5K:*T&;8Q!)KA2S*-X[TD HW($U Z,8JTK4,Y=3H+)S.E4T?Q-(QF$R>E8MW6>!A1,*LK-K[/@BCV+(QML=2D
M[H([Y,,AA"Q39='QZHM[L3'*E=+N?!70A,HH92Z>C7DR)E=1TWCEK-!OQ%A^
MAU%A%*H&J"Q"8$6K;"+>8@4J*TTL$4F8;VB8JPUP7DIJCKGZ8=TZQ(0P)3 A
M#+(-0M;<3NM.M'J TD]\?-!.>NG2&"I5,!*BI8K&2-HUK;J]^/F-
M/)TQ5/E%8;W8D$N;?N#OP63@L'0X"8?3T7%(BEFW^>:504[M%BQKT0% ['<8
MD5(9"4E WPSA/800[E)TS&UK,Y:@X@ X?1RGZ= :UW:Y\(#(K4+X)C0'0+[*
MW&'?907BXF:34=!U\>31'<5\FC[63?J9WD1R:9*ZL'DX7:F_$V&/Q)!Y.(DC
MY3B>A=@3V-$HK*,[\4]?4R2Y]XRA#FZ/#ZC9W?F!&>Q<,044
M%JAQZ!_E*]?C?R7[PE,>C"PBQ*;DJOVO9AVR0
M]%)]&BJCQE.V#6!U]/N)T;K]P5E;,XV#GNHY=IV*K*^$ZTKP[ZV[=N_9_% '
M>%W&8WB\;BWJ+5L< A>;SZF"_*@/W.M;47NB\3B,1Q/XO3^>!7_F)?0B4+]'
M(^1Q:%,>XS')_>T)/81?IOW1<-^DHV X'%#_>'AT/G!3#B;A?(#ER_OCB9L2
M6P2.L91Z/.D#@553,D4^"89 >N;[9D2_V#3$[6+KOJMRT*"5:&]$P(R-5W(_GREJC6K"-^]/(_>(N;S3L#^;!
M2>AK0J]7R>+'5]<+3'$O90Y2OO#6KO-ENN+%F51BSO 6XOGLK6"94-#W#TB-4D\F$N5#B>,-IL3_&QYRC">_4&LMZC0ZKI1T?YG^7
M/&'S3<[I!F222-VQ5\JQOBTKD#@;A+:54)7H-1G!16)I (OW[PH)""04#-3#
MG/"9PH%BRO>6;, V_$*TID(E'=MBV]QKD.QJ)F?&D&*OL>7CIGUF7\[8E6(J
M/(PQY"4P4&#=Q_9S$!."@:GQ ) 4)Q"#\]VMY7>L+8$AMP^VQK0?TM&O!V5<
M9>6/6"*54]J"N ^_?@7_C*;TSPS_NK!I\0K,0V1N7P7#$<@L\ ]ZB^!)R^:Q
ML5H/UL \&:\S_^_<>"B>,LS4PI?,_]\XY9;6HG\[K8S9E7(A.+>[/=C.Q3FY
MBN*,W[[2QU6'E;=*L=[4VX<) =]*GE;CF '3D< ;>9K[#*+0A']95PJTM8SH)RE "IQ+%4LR:CF_DS,T$<*)E/B^'C5C%\X@F@W7?MI%QC-
M@ES_!"L5RAK;>F9VJ0HC)<-^D90Y;DJ9XX:4.3883;?.XHM5R4R#"M&_K1V2
MY\'C-%A2QZHC)89X7 ]"!LXYIA#DVC%[-EM4'/WP8;=FSYH;C4&FB\?=X=2D
MOUMEZ)>RX"K+"$A;(%@BIOWPD&YJCR5. *IGV&+EA5*"[G4M5XE?M RO/3#;
MQ9S[A9*/,O2A'Q:(1YDMG!1B5NR.X-B*R(3\(Z4[..2?>%Y6A_R>GG%QD C\
M.OJ&V7%#M:CY*7X)U2,*1X,XG,^PJQ"(<#/L\CGM#V96(1 Q%MC4'U2C/=3<4,M7YIR<
MZ\BH#>2!0!ZIY5G/L8#:.PD&L"!W\.8GAJW@OJ6,I
MQU==4,Q,FMMI1\!9KM]Y#U3S'V699IW9-(@TGG>R?/"78:HAUCYJ8:#X%XS!R 1F-IZJ:58113Q%N_;),M.H\2CV/F
M85G4GT[T<41(R30EUSY&0GW,HRUK+6T;/D1Z3B8*D\;A?(2(1.OY
M_ZFWD?;^#W(P?MAX9[NT91MMY@7'WI=LQ(*E2DL:P(\.*QV[%^GR80VZ@P:7
M7T/^;'HWM._D%_%NT*D]TZ&A74%:7!T,6^55A/:O(IE:B7.O3,EWDXS9\*^1
MV/@"@QPY&1B[LI&WFI+9?L%P'$Z S:(1.;;#3XR8"O\U9NMX@B(@+&,X>-X<
MXR".PV@ZH*:;_?'X2Z/SZ6:)IY1$'U=#$O%.5QN3TMM[G'Q-Q#KA[ G/V^45
ME93@ON[07H.'SLQBW,0>5_+$Q+#!&UD1)L161G7?+VV5YD;HW/N+F^#R_9\O
MI(WQY?NS#^\N&@_!YB\I!)VHXR4'.CZW=W+K5'Y#80ZCM!-)1.47!44^L[7P
M59JLB(S=D_N_QW6(3O BQ6$<3ZF9,*#E$#TH$7PWAOMT1@5?<21T-GH#F)I@
M&"<63\:@Z$74SW8V#:?DRXE&\Q 3@Q14RQJW4,*G$T&NR%A:U\A%&3
MDB28N()_E(%0AU+?/R<@ &+&622KQ8Z/#:20ZF%E4E_76RS5RI?1/F2<250^
MDT>Q'E6Q7HGZU=PZ)JM^PGO":;OBS*#287>(X\+BJ0"2(21J%&D3](SXB-H"
M+ IANN:=H2P&%TPX92J%VJ@>'JJ/P,*MMTV-J4I]2G?4]=;$!26$\/CVK#_]
M2M16\Q4HMY.O EO2\1C:L"=4^N8AE:F9*?A/F^KI8K%/3?O:5E(12OWG%G*@
MJ0$)6L^_\Q1,324Z"C3UER5E+'/U/:H7;&1)*2YJC+6R=-56QKV_2(PP[4YN
MD]LRUM(7H>L2ACKHG'<))]5==UG
M\Q\SNB=KXG'4$A[1#(-B,[9[7IA(:Y)BO2Q1>I73IPW,:P^LDD/%DU"\DF\Z3+_A>NH5NZ/0$\(%N+)*G!B8_5VQ53W=W"?WINXTN65ID:XN
M;X8J'.W-+[-EX^M:QM  R7&!QGD4FG9)L
M&*,M5B#J0V9J E,U,9 Z*R0!Y(Y#(#K$-*=$7N/C0I+BD+:EEBZOKMVQP218O/%N1\7%8.RB
M"AI%F3!SIY[KJC9\:(=X[G].,:X/H_GI?.7ZT>OG0' ?*4;"IKI2Y>=:4KBY
M8_4803N%02W7;4N?\]8E'!ODN'+K(CT8D9%+C+!00M^D2Y,58>L:87FY0BP(
MP_%7@4L?JV_-9-?!_T.WL[ EW_VRR*CB*+]-1862SVY@MQ [WAU=H]K5\K[K/6
MQPQV$/6#5T[D(E#C=6Z&B"7]_,JV =>F*"YQA5!:U%:BA,460DNC#FBR7,T)X2N/R4,K/DT!QR[6@
M,4$0\8XREB4;F?IS(,VP]*'E=.@*-U#$!$4PF;&2F DFX27YMQ]HEPM725!G
M).2T==&,2:KSC Q./>.8E!=T[RF1&*6<_/&@;F D49Y.C:3NA>F6ZVV1H"*!
M:12[!@I7>\44NGX<@(,]UPQ')57*G('CJ.9@@Y[H B=LEJ[==K1*?Y$B?UAW
M/Y,%XF+<(LRRT+4*_YD,T5O8&P]193S7J-1\)0JGH$/VHA'IIJ3*VMVV3@ Z
M/$2XG/Q(+0=(B ,=J)0Z2AS94WB"S&XCEN_JB?,!Y!%;
MGO#)7A5;F-#6:LA@WD7=\A[6I4NZUC"V("_HAL+4+CZ32_&&KM9-4Q2CM$TJ
M3,)%^/AQW!.16A>79GMZ4&:I1,X0_\RD6 JK#O8O8K*BHQ$QH28.JWQAF%Q#
MBA&MQ@1R)I]# )V)TUA3B3*: B,KEER%TZOEBHO!E9.,^D3<,NH/ON)KMUJU
M;L>7HJE=06DE @<-=@35:GOJ\73Y+ZT5&,5S(<5.N((8Y@B_USQ0C)KC3J,F&DE; &&<.V9GC,EW*XY0
M:^L'934G9Z@%7C=[N+ F_I'Z
M#MWHPFS[VKAT#:\-1J=L_GI213HOK'SWQV2S0[-.9,ZJKA+6D<:OX)%2VC8N
MF2PG_YH#E@3HX2(F9^>C>W6.]E9>"Z#;VX]![X7^ZL6)R&$N6=-2CKV+H!!R
M-5#P]NT9CPU#)K) BF*4PZJOTS"&[:[82A,5DA(H*$&N#[V!0<,81R_
ME^9XN!D\@) <_:09 7:&5K\
M>6V5(NNUDAO #U&>H397Y 1:$8$GAXMQN\>N;'&[%:K-M4BN3),C)GW16=PD
MRN]!!G>]$L;B>603);!9( U([6J'0<;"!,E_B*%8:]E!G;[.-NHZ-^W!AGGQII%U5MF*^)Z1
M)U/7\&>W%:DR\9H]22D9>W31_\O>N^ZVD67I@K_//$7 <$Y1F+"*<8_(QOR@
M)=JI:EE227)FYQ3F!R52$ML4J>;%3C7J1^&\P/SH H2.[O L=B OV\K9ZKT1AMGJ9/UAY>Z\PF!Z8S(#4>EW*@R7'U+
MI2S/J+[C4F#&X_9NFT'S&#;Y!H)'J7L+RRZ[FX!VJ/>S?QAA0DP/(X>)&''[
M^1*#]/H#WUGTD%K+22252^F']@_(GUT/0I<_>K=K?9*7[DQ7.FC.EQ/7=X*S
M='"34ZV'SW^]5>.R9T.4IMB&S]#!,^GJNKYQJWH.RHI_8U FF/SC?'KW[)<)
MRB^OHR;XZ.LZ;R&5&QD]8OP7"#R^F=[HRS&NV,C>.U:N,>H%CKA@QH.2-I^0
MYM24<+YB$?*M&GE!3^%-\O-:W"J!#W-!C=6;Y2,\G]V!A32C.Q^!4Z10U!&:;
MKN @6Q'%9%U&+Q=3F\_
MD1:,52M"/(.N.L#FGU2Z4OM84Q \&2T*R,S;0>_5^\NW_XBE2H#?;V[ .)L]
MLY]W+(E/S[N&0J8U36XT6RB$0Z5*FH(3-$2'%^D-QV(W"CA1.?G>_B,?QUM!
MG9IP42$5]'='C^P3LVF-] \^:6 JET<^)+M:Q@C1MEQ\NXGFTQ7-QQD:EUD%
M)K]<ZWFH@
M^E=J6!HW/%1N\1 ]YR:$YU7MRFT_K"I@52A 2*$[6"_@VZ
MEA'_8S#&NFU+KHA#JE30(T0[)7%T0+J: !>?6F"%WULI.#*??*&-G'.9+E;"
M+?QQ!,R82GRKLL 'FADCY(\N>5Y*^JHJ>,6J[FRM%"8I' [5<.\5#])],V136_W>":W5$:++7=XX"$@^!4&$?4
M5RW;0/[;6SZ"A;_!%H>;Y>()PX1O-:#<.6@4N+5ZH##\;>W]Z2+XL%C>@XIR
M1&@$-%J:O1ZA..+B0G+Z=VCU=5#(RK7+(P=%R:XIDV:6*+4D;&'CGI"(G1D*
M%]JTH^X-AC^'M!FZM>'[;6IVA*[FCJ8 )5TVH 2@''+&+/8(/"L4E>+0*/+-
M^8 O@13L1A<-)>5V>P]A=Q>B?S@0<_.:&P)7/HE3IW2JAJ[IQXYRP\[5V61\
MSSYJ:X64&4]>DL;NR,;T1%.>,%!C2G'B)HO VA*3[;!9(8M9/G.: C4*ILD(
M\U YR$"R(#Y/J-[4?$2VH+DZN %##4T3@]$;\F<5@0+4-)WP!S.?T*U$PNMH
ME64#=G$_D9S;U4BJ%%I.6 6VKF%81U1>@P*)%)RBDKX*W58MK&R[C40;.G-=
M.:B,E "/.JDJQ*%""ZSZ@@U6KB 4ZX7%$7!X;C)"U$I/?IFN9&:U8FB=0L(-
M6U'7T-#WP_1F:N.(4]:&C2$^)?-LR6 FGH*OZ$ BT_H1U#L$X*#B;DM!; I+H_I UFT4A>UV9
M/73;JR\O!XT:B&H=5HN>/V7R E'3)0(MO%,P>40VUN1)E=1R@DJD>-[$9OCB
MY)U0G1VY1U^X!6I*3T#=@UC("]T3JPUKTQA?\*N*C:1=\HT^=-[T@:VP!O.&
MBM.!XD*^6?S:8$93[1:%56_M7PUZ;*7[;_=)2>1)0RNO[8UWJX_1C)^'*BJI
M99\13=QM+-1A2,[VJOEYMQG.T4+I7- UJ@PKZU(3)_WK?_U_[40>5K$)"J8?
M1Q( 1*75S44)**"(Z$T0)YR-Q\%>!(UAL?'UEX7M?<<-?*,W<&6MHDL'6D_T
MD3N':("QO>O^HVMT7QHPB]]* 4CS+)UIQ54^C'6E1"V,W>W?S15;A_ (=P#Q
M< J-7'!)K4!J.^,>*K53N9<>ID^KX%W]'LW5@!Y'GR:V\X58K93K4M+I\^2!
M"JL>VKBXKO=&7W*JZPER&=;:L7JI#X('0N46E!DOQM3N-1'']FOL"N;L1.?"
MYG7NU*-7:VY76CGPK($U]KW9TFX,R=Z#=IJ\4ETM[H)ND].-;N)*4-;+$@I6
M&^/*V%-US=I:W._9\B!#@5@__%/AD>TSBC/G@U[3T6F884;,\OFS5^5UD*6E
M_C>AX"5"AJ!_$L(^"/-^KJE_8JA?*7U/-O7WHH,@#Z-^X:W:Q+^\AO_F%,/4
MT6T1%AA^! 8IB-894.F1]I.!A_-KH%K&L
MN).5L_!:KT(C7( Q5:0K%>CF& *M1UAI/IX[$P3 H1";$0>YNQW!V.8+8.B_
M3$PU"D5 ]8'XP SP[SH%YT#!I].U['>3-^F[+KQWG%&X.$=$J&CG)M^XH75'
MU9N.XQV_R9DF\L=XNGK:4"4^73<EF-BJ%40&-%-Z8\-<^Z
M@.7UB2Z2<15NN=2O#$QJ>L\MBH>P
MEF@MX\^/3]#+S3._L?*TO-3#0O)!0XB'AHA!B.%&!N(4V;6L-2XU/&@V$@A5F2 +X%)
M_Z^CQZ=_  L(S-D9_'EI2!_$&JB06.6!LRTDXX9:5[UA(#^P@ULK)M ^/#?+
MQ:>)*M3:$=0KNBT'9JH&R4*2%@B3F31D]'RWO477A0F-Q9E&&_GP19=I@&WZ$RA&:KH"AD:'&>$+!3B6AK^$7:A[%F:5"DH&5]Y]LB?5$A
M!8X^C?&^IV65]?ZIY;YY9OP/2U 0#X7O[R>+^^7HZ0$SBZ!=?(3#:CGJUD23
MJ R]*9Q,BHOZ'HQ9[.U"]?:3Z>U4>GNK>GOA-NNS,?@\97$#RD@58=0)+5QB
M?8[RDA;\.]+[N&([XH[G>1%@T&H4A5E@>[#R@G2K 
M"U-,X\8V\R#/*FK[PP)O@YX>GE<$ARFQ#TE*K>701IS"VXB"E099$599#"< 
M:.X"#@MIU/!E6F4(>)4%>1JF!5$5_(.@.WW"^8U%&=3SQ9H..#FBN*B/B<\E
M0O\"<4;0K,*X3 B .@O1RXV=1C"MG-:'5\,\'?>3$$/;4UPR+$U19C#0"J8:
M9_!+508I+@Q,[ [H@$T,\W81AS$ZTU-<^8(V 2]B8]B@?D3CYG71\TRBA!8P
MQTII40&3BO,@2V";XC*ER/P,\:NO,%N.7GBG90H,#<:)L\G"N(KI$S0&(^P#
M0_AA H\_!%D>%F6*>Y4$:1*6"*V&$*-(^@&N<"^EN@BTWA3Z3Q,R RP*K$2* &ZPB!4L7X6?$ZZ74 2(" 6*
M-U! A*.G4O-$^4AU<6)]DR596/1C_0V.YYJ,_WO.7U;WU#J^1"'(<_T\S34D
M8D55@&+/A]+:75@^^*PU1=2@-^OFZX<=O.2]X5 #
MX5"7Q*%.A$.]D+=0<#^9A7 ";FXFHSGQZB2,DSPH[BMQHH$9SQX::R])\5-Y
M%UH<6!(>-9FZX.#K;L[DE%Q5TE4FO[#-@#($E[RNFOWYX^#R>GAY^G/P[N1L
M<'9T,C@%)>OJX^GU5=#[>#;X>'QR/3P^:+S&H2DS^X2?L$'#-Z$[7"COVK=7
M9])G""?V+WHT1H<59;7A$91G52:&C8DMZ4PR-WF@1K@A%;I]6EM8WY(W<:!R
MBU=RFAIZ -[E5F%.5GL5@Q!$')T(15F.7"9*T[ LT_K;G&C28UZ+."5AF2,G
MZP'S+ND#G)FH$ER.1J<15H(!Z5%A168@QP1? [&21H0%8G!2YI3K*57=%/<1
M#1SQ1*"7''% ,OBWEX"J5M)P8LRPZM=[EV8J1$%)L&^LH12!GE55*>ES%2QT
M)XY(#TY4&5?413],^L3#(V@IB1G+!!@#KBDH#,!LL
M=@#ME)%6-;I@D_(P@OE"([#869@ P:6$/\@SUH\!*XT11;0/8X+-1$I$UAI%
M0#%5IC+K9#]N)!?;I-MI ";8J3PC8DA@6CF3!6X?464/R#I)BVVI>E2]B J.
M8SDM%,"1$(@]"G.9BMEJQ#.!,7#"LX2SX7!2PL##X51QGX>3 "DPH UJ__B)
M-K+'[1^@8X!*@BH_6&O[*M]%1P$GL,K _T&;J5"!*GWC?DW#ZM,RO*:!957.
MG^'LAGDA/\#@(B+UH4+JD 8,NWD[0L#,UZC0$)8/?(H.^])8=EB5ZKL(VSR>
MSC9H(^[Z? ,[=V[@=VN K-T4NHS )TN@K.%NCM\3/H)
MH1N!WE6@'0B' S_"T4?+3,UBGW?^/E*#$:7A/YU28R?9 ,<.U>[7>-+S#--5
M@5G$?102!6BQ>=DB&1!6CHD<.'$E'_I\"D'-*5LE ZC+%9PRX.4E'/<*H:I2
MM DBD \[RP4XK45,8@$:P\S4E'!4T5S+DA2G86J#I
MQ?UM0@&V.&"9: 3OEP4 ,U"G[!4>9HB"&P_+MEHC=I$ 9!Y 9PB
MSL(,I%$<@_E5 J\DA78W48 4!&\#9>2$:H8GI*J+ C)X,]H2=*&4L"Q1&91Y
MF %%[BP(@)%1?C525@YGH@=31#/Z (5@'P1#IP3(H6_8( WV!K*SQQ4>$?.O#8,D3I0+!H
M?2"E+"$6#+26,Q/.$;R[W(WW"[Y:?%BES+Z)![Q&NSIVN;Y^$HY<['HQ'!@=/\WGFG0K.KG]?>J?I96"9Y
MP^=\],/P^./I,#AI_&) #4_L*[%SB>+% !CWPMG./\:[RXYJPQ\_?!A<_AR<
MO[/P%*^"-\'Y]0_#R^#ZA\&9\\/)66#G*7L"=\T\@O>7P^'9ZGU\&+1TC/;JSET'@RM\_WAX-/SP%EXQ@*MP5I>(-S1VI!JN()GQ
M$F<-*O7ST\1=5ZK:'+S#J+\?'=3]AH0\QL Q#-Q;;I2WPQNTCTX T/T+DI05
ME>K2'X:[1O[SD[B7O_[MWU2>003\$:$6TZ"L^J2MJ_\.%?2;Y+WP/1&L#S)E
M1&D$?5/^<]T6+]DR$.@TCV@NZ#]\P@V<$"PKO@"M:C7T;6
M)R4$K5?=7M%'NQCS"KPF#R>"14(#H/J#K:$_J(ML!E2S\S'LR8%@1;4+Y5(?
M&*W\A\>_V#84C&\N02ZA5=A'UZ?\MS%]FG4,C#,N"EZ!/ 5#)[4_MY^>!ALX
M6H"F1E#=?A<&D/$%A_VI:Z;S.>B*.WDVCL[/CH=G6'+<>#9.SMZ=7WY@F#LX
M99?#]R=7B$IPW3'FSB._5R?6TV\'I_#T,+CZ83@4%@$,8$C/?+@8G $3.3O]
M>?=#WXP#::(\-H%A6@.%00SBCMH\A )VK"3_,@4UL$*_>)265 F#@GB7T"TT
M@W(,5<& "
MFGZ"_X+>9<)G*8?P#0:ERF/H-468VPP46E0[+AN D EHF#%PT!QTD!+T AY:
MRS1+>!CU.K,^S9ETK))_B7\+4K^Z!OG&XHX$(\$:?S7!O]#CK: '3QK6S6N$
M!L^1_^8%!Q%%_7[=*.%'\ '^65LANY@!Z'L FQFTJ9RH)?,HJ*+8ZX@R0QSL
MGK;@76R:CL(*#SCJV!G;G#E]&.[93@^K?29))9I[$>.%+WZ38N28>6GNTZR3
M& @\SHQN3=(L!CI%7Y_-47L:Q?_@[T!R1X.K'X)WI^<_?0,^2V0WW)OLB-/:
M>)@]4>0/K' ("];2:[ETK^_ W%%Q%#6L,<*S>O:*()=K _(.8U_R4=334\1#
M7C^FGP/FFAWE">" Q 6Y\'+\-R]LS[A?@(CPJ.! HI^%'"X^GB\LO8>'KR2_
M0PK,&E>9%L+LQM8E24#A YN'>B,#%[1@A5)>>]1RW]0D8P]+!. H(N FV!1!
MGF-L)EG!M*Q+RI*L383]$>B,CWEUHPP'D57;YC+U#1#; :N-1M('8[_'5P,'
M2AEKTB3%Q$W&@JW77NA-7=-E0 Q-P8;05<#[Z:13O85W^7$
ME,6]:ZVVT8L*('UT?*GWMJS"G6]>U KMAQJQG+XEQ9[VQA/^1"&_[;E5&4/A
M];"A=L5JA+%E]]/YW"IG0-&0H!>@XZ7S300=MM]16AJ(K@[]U6-[/SW-**8/
MU_)$QT?9BG>7=7UQ<4K,%4W=D[.KCY>DR5I\N6LP6PSHK6V+?8Q9KO =6-3#
MX.?AX/(J& +S/V[:S:+[XO/,FO?B]"IH3@,B7BJ?ZT?EC45B4?]G/* P&#QB
MB-V_\E*R'UKMCLA%59\#G*[HE@\;P7B$K*,RZ@.\JJV0!NN2!
M]U8TN"(*RX*D7Q]6IS17_>VD]V/',9@Y,?-6U*&)QL#+"'-4CG2QX5T/RN5P
MSZ/RXQXGI:7QW^FL$*2)Q.'I]=,?\)S48R Q4 SK':'O4X V.@B'XS\J$%F1
M1>(8E@+Z+\5_Q!CWSR_NSDWBON* !98"#
M>3P%WD!Q\ + !N/:9;N^JCQ)J*G$4.YHM<.BM9,WJ57?HB;(-ZSZ\9&58%6@
MO7[F_<'Z]9=H&@0PM+1##PW1F.MWBWP8K0P7"LU RIP@QO]^,+@PD(T6L!LF
MHF*2WD3WRR443/%ZSJC@/ C&]A"*4,K9<;];8>'XE7H^RV=:M[P@V
MNH(_KI\5[[05[I)O;+*U#F::E=FDZD@..!]'A3+<+C8S'#S,VQ2I7EGK=!@T
MW-?*$J /0\L2:+<1+#@*8ZB( %B1&88WAF'P,+U_('QL>-XWJ]"GT)2[@2#@^S+] /:A3K)\BK>JF[5.S$TJF5J(AT=74+7A),\2)
M302[8JS2,60:6(I 9WT(/#M=I3 X!.9M+)_X-E$PB#3X2!VY@T!U;YYK34Y7
M5KD#,CC)7']"JN&D91WE?2L57MCH-9=DR2GJI :Y?;P$AMW"RJ': &)708>^CXD!R-B2/7DQ9DFFZ)7J.TDHIA1%+/!/2PV(\
MF2'0#3F+$.O7$P_ NO5;E
M_5WI5#&U?K>M&L4M?2U_ &).N!F(OJR-)T8"2:"A63
M<.D0S0("[KMQP),%/&9ME@5S.V\?Y'F58;VB&BE8>G"ZXO&/E$XEIU4/'%.8
M?WGB4@G-(V1#;ZH^-/JV*FVO<"2YIZ?Z?*SJ/V8FA,K+#3)E$:(*'!3"^EWI
M#/M&:X3MS?5TE!PC%NK>X*P]1UN3JP@T,<=MA&\F0YUM#KMS),;)=-X)*]44%(E6",54_U3CBEA-&I*@V@U&NGD4-)F4-K$XRHPC%V,Q7D-JU^NP\
M:-&P$IAV[2PGQU+L(\:5)40+B?73*'P/$P9@
M>N8'#3\9^%M7X/(X%<'6?&#\/$\W/ *G=E+8*=K=%'NFX)42[HVA6'QX@:$^
M4X]:<#N;3FQH_OH0%W-7Q#=D/JVV I9RQT$D(&&8E+NGD5GN:B@Q,F+FTK>C
M-; T./T/ML8C=:L,0,-,X[CQ\;7:;ED/C3(/G=R3$2'AD80RH0PU]32-F'[A
M(E<*$ZZ^1*'8MUY2XPJ?=+F!*^'VU-! +OV-Z'I,[NRM>L!4!0L8YILEK)V!
M"/#-2_&5VJ#@1SA%?+9DR]2HFB<,^9!*(%.IA8/!][VKPTNSJ@F!%Q*UI/5
MPG1E% O%ANJR8*L/4)R*KSJ\8Z\.C:/>5B[$ES=[MD<_6C5VI$8=+'(6BG\K
MW#!=J@TU#-Z["0&@N0D.CC^#F2GCRHUMB>#6G^*[WF:9(]^5SA&F;NS^I*.W
MFBZ-1  P*C<_.LAFM7[F$]2SQ*Y-M2?AC:**OZ5V\Y6>,-
M/&>1H_/MX+ VK$=RY*+M,IL88; VW).>"W\PV8"C3$J@#=),;X;
MK/QNZSY+JWBE7>%/J?*Z>"7[TM16C_B6W94(+%OTGC,W=BQN4;SE[+I-,\8I
MCZ19<>WF6>O5Y%(05]7FT3K]=8)AY5Z [R9.;7-3V;8AV+4&+:U*80W;ZWP8
MG-RI6DSDB%S<*)6]E2:?Y&)14+"P!,=(ZPZ(Y(HG%TA)-6J8?4MA3PV-&DI&
M2NO:T54-G9LQ.0-5\5%3EA3;FB]:AX-PB%:9T48'7'11T+DDQ,A6Y@6AW&81
M!.&DLL,.":"C]A*'^6J5A8M;<.D&1^?7^\4J\B_(3DCY8GQ\&[1+BVT%WZ8]
M@_RNF"@:9$:I4LTY.=MND,,' +'-PJDOK:!@UW[Q%IAG..;JO-4D4F,KZPF6.3
MOGT3VZD"XSM*8_D)F"SZZ+M_#?C/+^I/1>XM%K!M&9OEO+O+UL[77N
M*'TP$;0JKMN$>^%#EX99?;.&ZLY@^&X*YV!ESI?+0337,7ZANFW7R]NSRU4'=M3RVQ;&:R[+F^K#+52$XEW$?F^'2
M18JA2NS6,FZ4?]7Q3*-_80PKNJ2+2,99>9ABA1*"HS+LUN\/M_V0-DDR 8KO
M=C&W/"7XI/E,EJD#@$SEZO P@7YT&%Q-&5+(6A7+O[;6.(6KR7H]TUX&V0DT
M2TG-TGYYW9 A!Q-@TO01VGT9F,J;B48?#+L\AUZ'X?:4:EMN*R:TUI=_C)_4
MPG:0GL4.F&WMAP2-:<'!MV3#82M!=_C&;7+UD.H6:G+(QR$/DNQC'.C8IA/[
MJ.,>"32ELM34^3)J$?O9MRR2JT-9ZZ^\^/4=P"0@H$=3H AD<]V*Q&MAO*]P
ME64O.*6JVMP0+UK769DZGVK[E;N=W;-&>'D)C)93OGAF7V6 /GTL&R/J3X.S
M\]7TI78";_M=[K(MK[&E2J(V@'?D\_HS(UG8XG6$WD#?>B:/,\#)KQ%&NC4KY$+^Z
M9?;P-(1/:2^[7>Q<>L++.^ PS0)U; 8Y:+YU/ZW!*C:=,!(S]V(1M#3!
MD^6MT%YEVJ!QR]:@UU;B;5BLCU8/;XP8M^]\I[730TNA.[;*'6J%MGN[A>NS
M2YEM7(OZ$+L8MWR\V-RH*BK-#;><$>[JM7>]ZER0D._6#'R[\B0O)USPCD?,
M/LTMDURU> *PKF!BF8T^#M.3.S8?@2D$A_Y[:I0]LXU0I1LW946,OF-XU
M1Q=P]L]TWIR&!\B\Q42URD",;/7/@&I/[,(A
MM+B^OC+&]CMWC/5=H.>--MR\%$
M Q.>:N6G[Q0XV=T$1:FU7[UV1$+Y;E;W#[@RSW/H%3D2C,M=%4\C_7#$4?9+
M&]4;O0>6
M&RO!L%SKT.K8!-!7J'7=GF0O[.,'\RE/=3_80 _1=+#_I1_6";$N_'8^O5(M
M66/8:TIB,J22T&Z@G(HAL]_R** UDK2\]9XHZ'=46X))O^NW@/]04>"UK> %
M4"/?NO3-*U:EM)-ZH,H;'S8[K:')/F*I #@NB[OUEQ$5X-@ !>NRY7?37]8;
M92M1I1.Z0P,=$8Z-%8O.Q LEZHA:#]5A1+>DN$[VK
MN!IH+85U X2\0Q29)KMP.UHN*<;'T2=4IXO&5LBM#E8R6NE#@.'#=QB7XGK 
MV])BLF9RC'MRS8#YOL=:B*83VD+?T>!/.SU4A^FZ,H';.++V7Z\HK!O,[N!G
MD,H7.O+=VM%:V7MJ85Q#J.([L088D@D_<7*#7BGP)O/H*[GD62ZG?-!MX_K:
M,;9-[3T'@\FIRD1'E3VA9$\#R<2W7K7QM9O5*WH79=%5,J7+(/8&D$.G,#J=J'.L24$:Z1
M ,.:?Q#)GR>@R']Q0ZK*6$7RTT3U^>9%8I8UDIP3RBD1VC?KQ.V0?)26>+K>
MV38)P;?TW( A!]-%J$H/ZUMOLG757^;R7(:">4U+?$8*7M"FHLYQ1\H?FV>D
M2MF50F7C8K5Q)HK0A-0T!DW,0P*:8*:/Z!E\,HO2,A+#T2U_ ^NI-U,*.E;F
MI[R@F-T(J_CQDG@7E=9\+#NHV92)!*>-M5*\W#AR.[5!+O>1W)4?QMIS6:O$
M)7*;%[QJ )F]P-#3H
MDC95^*'E3QUQ97H[!AN?>%R0LXV8"5JLM-N:GF[L6UUZG(:ZE X6*R?HV*E)
MB-MBR+0XDC$S\4?6,
M*9>2#VS]6W)4WUK_XA9;":%7W QF>5/9M-[H&<+G8#S&73AY%N38&%A:MZX-JC)"2AFQH$V[Y^$'/)B&/,F)GA@5UQIMH#%@BW]0T^K],[,-LDWTJP8!M/-F6K
ME>#H2R)L,ZV=.T%QMMB^PN,MS3K. TR^%&/A9:.K%5H(
MEEPVX+Q*K]+%,7<*LJYY#>BN@6%/S&4#]K^XNT,./B(ZXA!<*T]4U7DG&Y=]
MUX=H#V%)][6Z&J"CRDC/B%;S923"]-B:[6"U6MQ*C;#>JY.KX\&K Y .*[3C
M[3KAE@B8";1ZSZ=SM9U1)R'??E2.Y?,4_"7&/A$NR_ %ANL39_
M5?A^)?Y-ZR ASZ;'OR 0FA6]:F%SA^*.GK^1=HC4:,"&W%4!;*IR21Y,P
M3.MGZT&@RM.?@"BU.::NZ4;NN<7C"5R?F;XZDX>6>#C233KQ4W-*X::A^C@&
ME_YTJ79DRE5/U[:W@5QKZ\G]L]VOE>C&UH .?A&<4*SZ%:SP>(8J>5[6G+^%
M)3@ZOGIU$(H/""F*]A4V:R;KLBE5?IATA)FZ R0&:\X2
M->P&9MG=^.>AG/@OF823X;O'+"1G8C+6&"N[S^&Z3IP.-]2;OXMC?+5%X(MC
MN'7-0F.;M2L%>N7<"-*5\MCX=A2YMKU$T)^$,BS&FUM)LDPD^]VG=H96!4H_F6GR9B_-]9$DQXJ)WR]'CI";"ZDV0%EK?:YR(
M40V$'>B]MQQ=*DJ#0P&UNJ\?E="'R?1)Y%@#!.I1>^[ESMF>A84X8 8]&7&Z
MDE4YVFP$X_UL0[*P>)7IOYD]JXV>]>*>=6/-V6I+,M[H.-#:3:+/8Q-ZW8^M
M_A 5!,T6 "IHW7;"G42P?#O&Z@+!D"YIS ]LPP",2#"@CHA  #C*OQ(NX"Z/
MBX*!Z<8\Z1T=;QP),MYV8NH?#U
M73'"W38N[]\8'I
M,4K E]5'5K(>3B%%!G8 ASF^%XU]NO
M+^K&B@:)ID('B+H#RC7?V[+RC@Y%P[2,)3&@!Z<,]^/1K)FKZ.@5DQ-J&?%V
MR\0E)>C:,E_9 *!0";8!R%I=J7Q_Y<]D+Q9/#V?!E^,C&N/]9H16U&2RLK6:
MF\US3N](&UC+Q?WZ8;IR\FMY&Y3CN84\Y?JIY?@(3X)^G-LQ173.M8FM87;PNYCX
MG<-AE98N.[J"-1B->3%UZY:9JWE; _J5(/ YKNW(@L#?]3GG!*#'P,D1$1!V
M9&=SFM<3*.^T!GS-L\!S-GE\FBV>)^+CPK/&B@R<"J^CU?0G5078T;IJ _-W
MN+RY!K'V3@)I[Y&N'63&$5J]+1JFTP?CI&@(/(	P77?$N+L9E/R?%P>?5Q
M!2+"Q4:R[ZEM"4W*P%RWVQBOBGM6/G(G59;]@"HP)Z# '+GK4()+8?$KG?K8
MRBJN+19"ZQ/&C@'$5U*N,2R]:S9XCMS$JG3(?]Z,[QD4SE[F#?L\I>TW#MA7
MT'L[&]U^>G-U^["8H5+!4LYYAFI*X&T2E^CCF!A.FY5@8&M*Q)^]<^)!<:]Z
M,M8$*'9SB7&N2NXH:6-B:QCA$OJXFYA0)6T-+34HJ0[E_+S 43:!WFA-:#<8
M.^5.DXKVV"!( <7HT,63&\V$XVB\0)EK(P,(,5]8(]71]1K#-HNN+$9+MZ!8!R63PG:M0A8FM(X!^6(DCQ^'
M(4&5=A.D4*!GG>"7K9Q8G 0,^-:'M_U.W&*JWN2VWP4A7%TA3O/.XV.Y>%P-RG
M!@\F=$.=&4!:$A2PUG-+Y"\/HSTGI?F C-PF ^_P;2U&@W_LBNNL>>G-8K[1
M^8OMR6>+QICT7FO %FH)!O:Z]**>%%:]@P/$?E)\W2@:W 18L," 0KG9]V'#'W1*.B46Q65"\6(:6 \E!GV><^ZQ=0FEA1$6[D6$LHF>EUEH
M:V+-36J;FA]+"->^:]T=S &""7$O MR&&+N()NY4*"$"H!X$CU<@0"WX$&2=
M?+]H\+.;PZ'L5PXM"[!&PV3L61X]]9KB@ZPL--*O
M':5J-\M?BE-0-QI_I.6L>(C(#T/BV>:O0B;IQC0>6/=%5HI7/9I,R0UV!+(0
M!6$XL>ZC$?1)<"MFP9WRBW%SJH2-QEQKPDC,WY#?#S88-U-%5.[Z7%#_P^ZSHTM/G*B-4]$742(G$9YKHY'&X[;^4)HS!<-JE9!
MZ34:%] M+L2W#O92OTQG':J\6AGK!71)'NB='\14[>FM2=!]FBBSN7$S^V6"
M;E%D^^(NF%-]$)TH,;?=N9K6UFYD>K#8K#$LD+U3S?([Q],9E5'U#$C#RY.'
M"I^CBE1B"-UU>I!?"=Z !0*]0$!4ODJU!X_. 0->XQ9'90Q"+IUJX'PM1Y#Q
MFF-\'*A3S]("1\.[#A0*H>,(C(VZ0&W,0:+);[K7MW:2+"7',6F6,0AW^S-$*&B^JM]0&S8)2%MKFA/%U
MM?!K.CV:TF27;"K2N:\W1,KL-6ZE(DLZKVJU2SC2:** ME&/PLN'L$8%=M^=
MI,[D(C,QU3M<]WK+R!D87H]Z14AE:XH1I,4A4*TORCN" OR-.A(-+G$]^L5[
M5Z6^%XM)794=C9[!&@E.P$3'O9Z-OH14*4VI1^)JM)-?WI]>LHKQ?@G:VXRN
M3RY1RUMY8KM(BLO&UOI"A\#4MNX)H/UINE8)Z8<-=JQBO=:C3SJL'UM^CXZX
M^6+Y9CI_/E.(;TNFJ
M138;($5WCI.Y((H^![/)_50Y0NCQZ2,'L:/93S?GS2CO%61.C#R20F>C<98N(/Z24)]@>^(467KCB'#..G+Z\0FU$&+CZ'7Q1@F8(3UD'E-;P2
M'"\9TB-VM<&^)MEWH)B]OSPY]:W""2[G?-R]"##LD^64BE_QNT2(0 JJCR@^
MA%XD\L#<]C,Q4OZZ^1GE1OT1=N&QT=7T:3G55.1J6+#BV!'BPPB;&C!A@0&F
M=AYQ>K/I)T*J1J6+8$_4$?3T;5.[C@-4U<;((=WD-=3FZ-.$2YX8JR0@7(RI
MJ9*X=!(*;-/.!@RC$R2/6W=8:A8+3L<8&4P.]GS70!";H0I2SM>J"KX37(WG
M/9$,EE8A)YP$W;W)-'84Q:DZ!79,F603ZV)"&U5%%+?V=B1YV*O%9GEKKC&0
MW_(5BG&1L?['#S:O-MF=3\=*#; >?81#8+5+NPGJB8V4BE*?:6C*">/P=#%A
MJ_" MY[*NN9!PY==%Q\6)H,-=F)"@*U8-=8\Y8)Q$0<&' C&-E\@=7E3];8]
MCXH07>7JNKGO!E=OU4V9]=H5:CZD-7Y\(H<^OO&F7X3!JW<8*/ C!0I\X. /
MVNC>]>()E)LR[A]\#^J]J@*J"G,[>=^J^,=0;AQAYT:HD(C'B4I0DQ=>^GG2
M9@RV!6V8DI2O@.<.KCZJ\;W210Y!8@O=@HR3V!AU!:1N.IE:)S,YP!++XHGP
M<(/)C/I?R_Z%L9P-?@0CQ&AT/93%, JC/A]P_.X3AB)I>-SQ5(=\6$.'I5U\
M5HAHI. _2N C H_?+Y9XR2MH$+5!/TR!K)>W#\]\B66M/^X'FP+6X\A:>?:V
M=0.3L2W%78),AIO5P8\'9Z#3:U64?9K=J(F)AT>2G@F
M)_1\^]K6Q*,)@;5 3L@M"L.:NU3CT I2G-Z=D*-K]9+!(*S!UF$.1&JM7-@+
ME2_$Y\,R&+V'5QV)QNIIR\J)BMM2.-FSY%RAF0-CE:?*$>@Z['TO'@+4W5A*
MA\R[!9%>U H%CI[)E8)J>(/YYW*+)8*G2M.:X!G=@ D/<@/+*A]OENIN0H) 
M7<%1H>"P_C0.%%K'"!F1#6799^; I-[LCR-G3!]
M]#0@0O3%'>3;6*I]\(P]I-B.TOCOQ.FI:ZA;HG/ELIN*9[22HO%RO:N/,/%H
M0[HV:4SGDAV^K!Q?GIR=')\,K.,5(H$V7O8,A>.U#"F\).&!/.T&.W-YN'N4J4Z/T
MJ4NW.44#+#[5 ,2<4 T&JEW)+>'J>RKKA-JRO]DSI\F@]YIY]6*S0L?0 9&!
M@]T7O ZR+(=_>TE:!@?P(>Z7P3L_%&$>]X->%B7P7 0"L@79+P[[_3CH16$<
M5_!D42229/HZ2,*H*+$S>*;J4W=1V"]+7^1&^I]U(>.BX(4LJLZ%3-,8%Q(6
MI'LAJSS'Y\)^DC<7,@KS,I.%3*ND0?JW8.AM&-3])W6Y,I#+E3/M\B8#9S?$
MV>!G+ZPQDSYM&P$._E2_R?%XU=^(4SK)P[SHARG,,RG".(UA3@5^6R9E&,6E
M!#%SW)#YK2 <3L6N<4R':6LOC
M)(QA3_)^'"8[SU(YW-UYED4:)CC/(LS*+(SR(AC8/O:.*X$XBL(RCFA(<01K
M5!7!1=L5@7L]4+L:J-T!)*!)XNYAP_#_!D,\.1N<'9T,3H.3LZOKRX\?AF?7
M[>S3IKUK\=K5$" Y6DS]*)SV+Z>8%7$"DF#U?S9&X'4 K$*LU@#*CKHO.5O,
ME^J+QI6$$W/!?AQ]-5Y7:RW%,[0,7^V2G5$RC^(W7A.XI<+6]\$[*[G9FDOK
M&\?D#V;I_N=Z8N"5I47QO;#]#;,-7M_OF\SLN([L]YHH -A,";09(VOK9_AG
M!-@&-6/";X&$5GY7^N'^@:T-H=O]H!QI#$R??>O+C2*
M7EJB= ?9%!99H5Z-2^"V+#UH,%5>\1\1\+>HC*TA]RK@.5&&@_T/<8#2O0]0
M^GL(0SC!^.EJA+F>/126.4J$'DA4,N<4
M5^G%:5B2L,"_%,10%R!HC\.))8:*@3N5R\ $ZJA@&Z[6T8LJ/*A95>$(^C'*
MM5Y.AQ#^3LA.38#O7PN2M:!_*5A7K4H N\IAME%9P1P+D*4E6!Z9]1KZ\N <
MU%^$/Y >.(<#^.8:-\=/^H'AA/5QRYJ_+\&Y#DA&FXM5K/:.5X
M@HSK GU"?ZSA!MMJYK;?&P3TDPN77SOPYM]W:)OC4VY&0DK>AC2,X@KIJHIC
M_D_"+]"3!":X(26PZPA4M+*/^EH_0NT15/D/"[H/Q%AA_33L8XHM]\F;
M!-9  ?0(*FN_3R2>@=H6&;,/2!^X;)%I);9]NX,?0.-B$CTW0_;W6I\I@V!E;RIF1
M9/M9(1&P0# 58.89K4U5X+PU5XG 5.^3^03*=5_\G?P,_@B\M8JZ>(XI(_)L
MEQ'YYM17N^?=GL?X/<;&W$XF&.-2Y_36%Y)BU<5@AJJ@QZ]_^S=5Y(.L^008
M 9LC2,EI7I$1GX:Y>")Z!6Q5/R/^WH!4PXMI4&&R0ILW,4@YM&%Z$?(,U'6N
M,(R.LGN)"V/_9PO)+>X519BFI'^%_:BL.2IP?!50?5;(^(#1$'_I507I8OQ(
M&8,\PS^^FOI_Q_TYTB'->I5HA7 #PGZ>JSL0XK@]61W8F)PVQK.YO1(.19+C
MDU44YJ!V]R*P,(N(=J>,X4=2Q5LW-2J5IHZ7!QFYA:(^^MJW;6H,NDY6HE:;
M@ZF?T6LIW3Z V0P?$^4] BF1@^3BS=(&ZG'H@X0"*)<[!H"J"*!M8K4Y8N
M"C3\>/G']V\O_HAOPH;&H$TF89&6P4\,URQ!RAJ3L%Y4"-X':PS=K=Q3-QQL
M6+,[7BO/;)?)ZRP#CC,.\SY)33HQ2D8]"PPZ+5(<1GF?.%=1XD/O%(3R/U[^
M%""3*6%!D=.]$RQ):CTBD6$]SS0-]C#
M9:$;Z@;!K:V*=M/N0.GIWX'2-6I%"\D[%4:,:MY^$JQP_ ,D*]]H]STN]E8B
M6?53UK# ,G/.B1RDN$+CJ4"-&)T<^VPWD1AP71"/J'U7>YV6DD0P^U5?=F;$
M!=MY9CQ8XZ'C!_TW*_6&&#^M"1T!T;J2/O+Y75I:N2*$6LHBF&&![111\P3V
MP6!.,+"@?@:3A"Z2>F5>['D&3\XNZ1S2]L.FYM@[&*E1E;[P$"K_;OT0OJ_C
M^B[F#ER]A?VF"WTTJIRX18/WJ^IGU?,6C-X&U'!M2/9!MVM$H!HTGJ#C1^'N
M8T6,^CD^7=QJ%].VGGR3#W#%%#CP+L_O%G#0:JX\"ZV<=8$4OR;QT,_KMW0O
M.#J=_?2BC-R#"5V[]9(P(P_0"\Y5=S>D O;P%NF 5"V2/?K4=;X;D=NWEU(3
M402LL]*'!F'WX!: QPQ3?.MG&A+F[ RO+A)&(&-5F:@
M38/4F% TN(TY2T#XVE
M%0)R;1XY[0##(7DZ.O.F!I'?+ *ZRP5.$_/:=&K-W>J_USJ  [\OKX5C[,_K
M>LT.AU*4??@+!>=O93MHWZ)V0!>BH(@ B_&==E*FU"[J@RKA"DE1Z".8P)%$
M&SD&6SZ%'?:=#C#RT&<'!AC8!^A#@4^-4V ? NP\ST'<]Y,@ =(I^K&/R/,"
MB"H%-2>CL*PVBD5."CW*?Q1)@K&(8T:J? UZ#WHEJG[U A)*?WL22G]7$M+;
MKR11B1%QI2&!?DD.VR0#*SO*MV]MA(Y\L"$BO X#@\3+P2)4]T#; EL)!&%F
M]BU,"Y!3*7*0"BWX-&O @%$-*S(.[.7WPL(UC)B6:"?>8ZZ8I6(\5=$"=YOK
M!7\Y YY23G6M(S?9N.7EAA74'%5O"@Q\RO_ O_\[??%&??7Y('C/ Y:!6@6^
MO,7F>I^Y#7S]?^,&[" 5MS'"G]#ZD3*>K*6M]][5\YF[G-[6&@D?;A/OO-59
M3,E+PO?F(1S5MJ.GRDX)+E71+8* _BDD:!-L\B0M?0(+'-]VXNVT&_?8HK5G2X]RX
MWUW<6\UKF=D",V5T;GS#]>\)+A,$@>8-V+>[?P&!"VI:2EHW*$U1E)*%68+^
M)-'Z> &29TF+FQZFFQ5]<=+GDD@!]C_H9B*7FW=IU&L:4[BMW6O<3^DC^>(E
M''>G&Y7_L$M;5&24 <_& ]"O^,(+C"BY3PKQH@(OJ?R+B_[@.!J,Q
MKN$ R2,O\_9-TR$G&3&S)*PB/N7^$)2CP=4/P>#L.* /PS]_//EQ<-J9I4)R
M7, V'BQPAU7PE\'-BJ1E(PO%SFQI?7^W;"I?FD=#0VML/_6)<+WS3T39P.$I
M]!KD/7 V^IDBH2@Q5-55RLNP#X*D#/-^*@M^JP9/'RR8-8JOP'LSRH5 +;G?
MP/L87EU?GAQ=#V6Q]UIU>P4O#2#=[[:8JA8N@E1/](K9X,7;@P90JDO, HDI
MN=ZN*XIVHS.PFBD,[TY5#Y(L]#C&@(L8-+@TK,K(&N1H93>&4UEBI?<1XZ>L
M*/J^3-EYW;J[:KI2Z<\I>INA)53@S65L>8'T%G623!@G'") GZL<3FM:W_K3
M\ZLK(A;^*J+N5'A8 8+/.+T=:(T_C@PR>)#21;_"W4?7$]^60=O9XO;3\UL
MM-W]G0KSC\''.2]?RXW76?\PT?CB"J5,"F./QL!15Y+<;J?NTZ.+Y?1^2A4N T%<5J5MP/SF,BH1YKQ/32%(!3RYLN^F,0<=SHY4
M-)A08JC=G61T GL9+[!8-T$?(X@GO(RFX.B1"N(L'B?N,J\?ILMQ#2L$84\8
M9QU./(7XPN:_&4^>J$KI:/9,N1P&X9J*)3%..@)&+XKY$-ULUG3G/1\^-3]
M Y-CE!X6OSDYPG!@S_O?C@BM+6"@FS%77=+%6S60"\&$(5HDD=LIR0G-)>=%4:CL;-\!._:$0VJ;W#E+HBF)R1
M[!VS&94M;0IBD5*,>225[L[EJVK+!:YZ\[A=-[-8(O&(SJIBR^PCZL_
M!*8.@56/TXR2O7&(UZ$0"PFG9/X)BYP)D8;!P_1>AS8C- HE7\-$&2!"1.E]IT&TSH8 ?
M#00LDQW_>.+NIC.5$DT8_41R/"*DZS4,9CYY%CAE!CV1H@%+A=DKI;352#6L
MJH%^0>6ESG'K20C.H8-]#/
M:C8E#Q)BA""NUYC/U./CE%!45;UK/AEFJ6D,6G9^40#(=(C%O0?K.P*Y?!AI
MFAM/3 .-GF0)"4S5^=I4>,6*#J ML3N%"%XQI?@PM2F[4^C7J1MA5&ZG6*GK
M#RY:/=8R?IS;K*I!XKH*ZPQ+930VL0&=[:-:S7<=-FNO&]7W^PP'"96I;CY+
MM7H(+%$A$R@T1,U$>?1LAB,N&TIF!\Q MM6P*L7:I%BUP:)IY9Z>F6.1V5N%
MF3-"":.T.<;46E*1#$JXP5V9C9X5:KGBX->$$>JG02+!1YV@89/@$D_$BHM=
M *%D]K)B'M!DK&JN:J8B=0WHC<0EK0:![D2?J=OMCKNIT,Z>4&&8W\-Z/"X0
M6L.0HP>;?>LJ^0XJS+(F&K2X\QS4W4YD\H(9$QX?PXG 9"=CPAT#AO_TAE[3
M4*"U8WA#1B!OO<;D;0!LZ6,IB?,P,^C_'VC36;5QQ^SR.!CFQ)1HQN78K/6Y
M&6W=JV^W59'+&;JWRB"8<6M&Z37C']TO)Q-=M!1K4N _NH*"G<9H[=N*3P-:
M-G+"W?4:[V@V<1' '0,6NFW R*X\]3O8@.EO9@,6A^4NFENXN](M./)2;G S
M?P,4=AB8)^3Q"<@F*OP+;I;LC>
M7*KRNJ0K26$TVO ;L5KRADHC8Z7ND:JJ\)]L\VW.XVC/-96)? JHZ$HOENZ\
M*_UH.=U_@6V[AP99EUPCW,@;6P/S*I(,?VBMP.W(PF+DRG^?Z:BO'D=4)EX=
MBZ_V/4GHVQ5BS>%JP72U--S;6S3?$^W%T=
M4V"II,P']'RPYLN^QDZ+'>(QPKL-(L<,ZEO5#U]F!O'9H VT]2_5&)NC+;]>)Q 5+:U,6SJ_'N
MHO V>IPOQ!N)!E5GEW_/W7GYT;Y2]76^VI71IG5[3FYLZ93V@=_7+OH=E.MT
M-^4ZV4FYSBTMIJ9;=Q#]-]2ND]]*NQZZ/I#74>:R2^\$5AO8F#?DBPRN@*:?
M+0KV _>VG13A[.(?H7L X6#*/T(%I- CC[X=N2A8/\"P"/#4\I$H+$^[;+JY
MA!BX/(0A;XQOQ*$P-R]*2@*0U$".0-5 &6?8^$[$E\)>%B/M_)K5CGS2TG(]
M#!*.@104V(4;8L=&X7,]NL8!.\(S\ 59H,1!.JUZI9UB)O__E78-)6)7=^1N
M4JRUGP.5]L*J?J2W,5,\H[R1Y!<\DDNS?VN,M=;=C4N-Y)
MMKQ M"3?1+1XG. [;E#WSKW2^UG83>?)_]1Y][.2R1<1(S#'K2K#!(-:/9@3UKAB
ML)CS#K<-O"AL\\UA.5V>WB^!(Z#S5G.2AH2T+E.5AY@%],-H;&VO.3Q=M9N2]01E80,M,IC4%TMA_1V4SB1H5@_X
M87 Y#(X&%R?7@]/=8I*XVNL5X7=;2"7!):AN*KMK%X _*JF\VCP^8F%":/CS
M@G:N7ME08L:H-+7IS<8UHYFI&HFJ0.*VO]]*:@3&<)H:%# ,6K\$ Z*K,$\1
MJ#;.TK"LLB#IAT45A66>R9=56N&7*64J5-:7)SAFU)0EB-'(4:9*F%#V*GR\G*A#/TVK0RR/,8;-39>W_JRG+TW"F@"F(SJV6
M17Y3KV1IT"/T)/6%O5Q20)X7"M:DB E+R5JH75?/2XUOW@ZN,.SR_ -&S VN
M3\[/V@G30K+'@SB9KYC%##!74"KE <>PG[L8/=/7 R343CQVF^Q;6PC545!Y
MBC_JHHL#4]/%=R 4YZ 8/SRZ;V>CVT]OH-<%R@U5ZF0YO472I*+WG PEY9+I
M'5/B$09)TD?56H9=HOJNF$FE0IBL(C.HZP 9KA]TS(-[/@_K)^QRNOJ$5W83
M3L:-#^'7[^ _:4'_*?&OH6;3GQE-!["S6;[ONH4TMC2T<<&[M8UO0=L+E&6!7,3$P.RPBV$Q5T[N71&68
M]1E=X1 X67:8%VJ_)F.'+P$)4/DS^[N.H:68I1+EE(@(:F56PK"*1 \KQ5C[
M)(AS[#"*L6]K6 CAU5?# N+*#K-O-*PLJ/IY6!&X850=$MQP>9@UBI58@>!$
M;2\CU'HK1#V-+S]2X?8V*KXF[X*ID\YU_(@;_B;4BX5M/>796>)\"Y)-XE(V
M($X/BU231)1EF"V%I K4\B,/H8?0BBE!O\;989)95-!+RI#1->+B,$VZB3$!
M@899-?!HU3==(BT G27189:;+C%/**.,D/PPSNTN04S&B&21] ]!<>BD,U6_
M!$$O8)H- KOZN&,F@=D:O?J=ZYN!K);5A?^JJ<+(\Q+7-N^KB5H0#[6#U7VN
MLS!',&Z85:R;SQ67@7_5.L9YG[(W#Y/^?GUDF"(4%9@7!0N=-7+8SH;7P:MJ'\^O&"
M+EL R3EWBD"?DRR61!O,!I140
M:VRODW+U8B5M#.B&4'Q#0;U5@ E!:Q08+A(6O* >J4K8HUABM
M^\#PO%*C'!-+D4=PMAC.%C10U59H&B(#@VPP';0)PHQ0<@^(,Y3\"93]G)*1
MK9F!F3U=4421I8+VHHJX#[Y3T _BL6,[VP";XA*AD#E_C_:C8&1UK#31
MR%:Z'OR3JR<';PABK/<:7\=D9$4)6RR[I\5<69M"U=>C7X*W')T;]"1YI$'D
M/O..\M-9P<0[+HEKX,U3U<2M"N WJ@^% <0N"J>6'I>7?M%QV7Y"CF2 .!@S
M"#4LU(4P\9A*?_2R)*52'%91].8K45BD",S(:.-$,'JVW@[@Y% ?E%C=PRHC
MS7R^KD$V$W.[QM=H^OS#AY-K+GI%V6[G5$AP>-991="F'[*DD(XXV>O=Z-:/
MBN*72AUIPJ:$_+B>Q49E4;%$I
M_Q*(%>0#[*MK*4BNB_AY)W8T/X -Y)K,45^U/,>J:3NW? 0+CUF;P7"#HR$XNZY#<$]PTJO& (,/H1$PV>%KRE>)@*WE<>8AE-GT.*?WF-
M0,M9UMTMJ!/(K*&Y]]//$XD2&]$2+CQ%H%U^@:6SYP9#1KE-Z SC[^,)AM>2
MG_P6Y-/H]AG33\P5@5YX75L:F8@4G5U.4(\)I:3N\FDAF9IFY]8,MNERL!4[
M893O>T25HNV.8&SSA53W%.K0!%0?B,_O._46D6TZ?H?O2=6]'%Z<7U+%V#86
MSQ@UVH^M\L" 3ZI,8EC%D;Y]BOK?L;.:G]]35> \(>EJ!8K#K;I44)U]>5@P
M_Y8046&A)L% !N#Z]QF72(U=]?#]2^$W3S$4$%11'A0J9D4)+ 5,I>PP#;[#
M\Y(SSD!:D?,+GBCC,$F*((L/R6&&1\=M)4(0.5 8X_BP'\#K)=A$47484:&$
M",\\!KPDR\:+ZEREZ(Q-T/EA"A!BF4/$[U2<1# %C&OY--X\67>MET^FIM)GR;?
M8$XR^WZRN%^.GAXPR0O:I:O$Z>K32J>]*+51%9[6EU#?![O/\*7T4%+XDI=8PD3E.0\PR
M1C+)BA#Q3J,^$.\%G#JZ1<,ZDE6&#K0LR,$F*X@\X9\T UHE3XA*J=?SC6"T
M.#DB741%1+4VB6!8,5AW60D'I _4?J0N(=\W;G:1]\'5,$_'?81C3G$XJ)L4
M89G!0"N8:IS!+U49I+@P%W8,L7D;S+H8M8\45[Z@32CQ(^)N1S1N7A<]SP31
MJ_#."",#H@(F%>=!EL VQ65*A@/\$0=73UBS&5\P,%"-XJD'^ *]U)"F*/U-J#Q9H %HO6C+PA-'W^_3+0!0/E(=&.;FFRS)"*)3?8/CX5OD>XY(4*AFRXFN$68'2VFN
M(:$1\K>5EHEJ@J454I26!HY?F@8807(B>47SQ6=Y?ED/<]&O-\1L.VMY;QC6
M0!C6)3&L$V98W[)>=8,?$6(-0Y$LIS:Z:<@X% ]/2SI"A#TQ8J8%#KR\!R*60 'OP\'
M']N(@*4D<8 T@SY<^3A834KBO @HE>@0;8349N_M/
M6AE=X=/MDH@0.W\1F$Q=V)!38T%Q@"L\$'=B;4IU:I([M.1U\OCSQ\'E]?#R
M].? 5)^^'%Y]/$5TF8]G@X_')]?#XX.=S.\_,RC#S.85)R;J8N^:>_^BVS-8
M\AP:P3X84L)$0+'76-3J,8:QOD6*0FBA'(!E_#RF01.0>-XQ3=DF!%.[FL)FRCER!F,I5Y
MQ!H!8&K')0T'P:0(]LOI79JIT"V:4($<.$98'P=1[U!)K&"AN^&YL70EX>WU
M\$JBST6/H*4D9N559=0QDTT"R(0A\
M7L!"][$R$L%P'8!4(42ZH7*UGBK8T-8,>A7WS&/(L>I% :R*< 8K8"/ 8PIH
M'6R=03T(CU^)#4$[9:35#@K!,E%9*&WT '(JM *-P&)G
M85)BZ;JJTJAZZK$*BP,!9^O#F& S">,(6&84E50H]\39CQLR(FT_J+1#.Y4+
MG#Y,*V>RP.V+N"@G,-NTV.951(G-@1R(7H3".!("L4?!P91X8O&JCG@A, 8.
MHQ*?.PXG32,93A4S C^L9<8$FZ))@9]H(WO<_@%&7%%)0V6$M[8/1^6?%_!7
M '1#UGT"JPQ\'2M-HC)5^L;-T*#]5.!N86!9)?6UX.P25!S] 8.+B-2'4EM2
M-6#8#18KYQR6DENM5B>0A/
M1B(RE,M"ZQFJ-J8Y*?49)!B*E) >#Q^3?D+7':"#%6A]!G,7)EJV2 :\\V0B)R! 
M_M#G4PCJ2]DJ&4!UKK!":I^BGA#''BBYB*DRV1>H
MXER<>:4"6EIY"4>EH&)VP NQX")H<%CH:DO-AGX8,<@D5H0 )0Q8AE0( J!9
MZ!.6*D]3@E2,2S9@HS91@%%VP"FP?BU((RP4BA5".:YE-U& % 1O9QCUA]><
M.87MU40!&;\9;0GZ94I8EJ@,2JS!'NTN""HJH'% E)4CQE^6D$E]@$(0B^QU
M2H L1[4D0-,,P7+US>.^_+\*^X4>!2PPCB(B3-H<2"2/OQGCCZJ""EX77)@D
MR2L\<5Q7U"L"RK"4JH]1'TB)*FKV,D3C9":<]PE-=2?>+Q>N\6'%F,:'J93C
M/(09.EQ?/UE6]2?[?T]^#_I(OX3SE"-1(S0PEM&%;ZL2]8<^<70X&A$<.,WO
MG7>T=Q%(NDT8UE:NC'X;''T^'P:Y5QDB48\LP
MN5(!TG BCT82WK9K+*9I4(5\7"' >(QWAL&5XG9^_.+S_P1?KY.WCV_7@[-IZ^NW@%)X>!E<_#(=@HU%=
M^<'ED)[Y<#$X^SDX/P-K#L\A[*[>6Y%8.'BR \<( 9-&U-@2._C6T'I.[AR"E\PSD2J1!*J>28DKTBT$:XGV2RR3[L6-VW3B=
MHF>4E,S75C$@"_]>_8P_7OF[N&*LA='3%-\%$P0KPH0%L->!219 #,TWE,?/
MCZ'3 \-;,I!;R%TN,5$$):X^G0D(DA@.6 ZLILQ549B6:9;P,+)OLS[-F72L
MDG>)=SLL(B?TT?M[G)>KZ\'UD(,*X!&)J_KJ4_-"KY>HB^[IH#5YC3%N! ><
M"XAVU._7%1A^!!_@G[7&LHO*@'8*UH(ND=4"R64>829*@.PT0H I"F,7E8F$
M<0Y&A$"T*#.CA,O54OU:@9C?HYT>QE$F5.<6I7P1XXT3?H.EXZV7YCXIG,2Y
M+H!,'M:2;)H4) 2N,BV$V8VM2Y*4(:+W4V^D/(.AH4(B:X]:IF%-'/U0ONA1BRG3]"YQS8Z=SN:
M>,81@3ULJ%V;0Q!\.S5-AWF ,H)&7>>;DJ6EWU&J(8BZ1H6SR_>#LY/_@]DD
MQOZ]'5R=$#>\0+CRLVL)+CVF%-GF+<2'T?.AQ(GUB]?!'V7)^=^F-4#Y@VJ;
M_O*!^&)#W^??,1>":*73-' 2!8E20 03%+3 OB[N[B;D6_IKX!_4Q5)"\\2X
M0AK=IU4SZ<;@3MZ?G;P[.4*9,S@Z.O](497!Q?GI"0=6JD4U(;N-$'(.=,&>
M+@C.:M)M*EU0Z-L%QQE>3C"O=T574IR4IEE_\SUV0XTG=]@)XC*B"&@^UH39
M9+_5]B>%>1-G:DQ3%Y-"#NC4AGJ:C6XG4N!P_D9!@&*2[:;1Z0G8H-,E*7? 
M$Q"QRX$]P'?IL%O!Y$^PBUP#9"$19LB"]^ET4&O6LQ*?I[0"Z /=S+'(P02X
M"DZ.9NLKO,SU@ZE&D17LI*\JV\9PLYAC1F'CD'+$8>.M^7PC%<%&LQFG+#/E
MX-7YZ!F=M$![:[EZQ[;K3<0-9V\[CA](4QAAW<3KV7JB@,;A:+3YRUU$&:!*6!
M,V++V<,DGS;H^%XM[M9?@*\TBC.8EZW<>-CWNPV:DI[#^&X#2AEYV' IH'/*
M/F[4KT#A1=@UTT<4AA-O2:=MFZ5];<"$Q.B^%!53PI_L'?0SSF8;H?)@A2B>
M;3D2HFTK+LSK+RJK^0/!]'?N=<-1)US?RC2' 6+>P6UC?'>$9P\;.<9147U8
M+ !PJZ%^1)B($DL)=LU9-EN9^)-,MS:UVUS&O(2-';438)L\8CU]H\=GM;3U!B
MP.+_-7A_>7+:W;Q4^?,W'\6'6;-YIP&4+=V-Q-XQVC8NF+0?V8"U(S],H2G+
MN64%A/BX*&<+?6"(BB8+P7Q,3&^'HPCVQ^UDOC85!#!X*?1Y>'?S[[H):OXP
MJN4^SW VF7<*G%**QJE2H.VJ9Q0!]#!":3?!6&&I=SE:J2I)S\&(!K!NK7#4
MD?O+MK2G35M+64[N4=@LP'JA DA-^;!39AYJ,T):IL!34R^X7<*#UY/;ASF7
M-(&#UHAC<]?-7JZIC6LOL==DWXGO\@_BS_+: 6/OD(#CWXJ0O'):8A=#*(ZY
MOP;J0->W(&&R/
MVXFU>T=P2.\72Z(?0=8Y1=@90G72QSWX80HB!6SLYW:FT9IB:'.-@:F:;;O[
M/X#604':.&^DU*4J['&V /I67[RE_+\N+G+*A30;)2X])A+EL5!UF/ELQ[=X
M[ZQ[=+_RUC:(D&JK-4NK-?/VW$*!N[[740EWZTPZ:IC_>4-8I80PL>)T.-(#
M'D?+3Z2,,\%$S>!$"\N(,VL7-Z@BB3P&!5>_''>^O)FWOI@T7FP1C#Y:WE1M9U*X+%?1:@=[;[XY'27RM[OZ:^=7P=7"0-#TB<=A&]+ &'UQ'0H
MV>VC?;A/>#"NL1B:,H=VC]V'J*LL^->NB)?#R#CT78K'T'VQO/3+1Q*'H64[OC=;_AUU(9N6$3^DM -6FLO!KW_+NBT\F.,''=KC=0/8M'LC$2HPXA0. Y_S===W
M7])[ABU$_9=U7WOY)?USROY+!U!_NWT$^_$!V%2YS;^RK!<9QPLH<*B0?M =
M@>KLQB?WM@Z1HY#M@;Y0NNZQ1&>#'UN/WVY6Y$N\:R:X#QQ?H0$(?*4P9$K^73.&5=,QM$L#%]K#PO 8
M&$EC7'"@]$P8L=*V:IJN$,SS^UI?" S8D'MP1770S\#H_AE6^$+70=^?Y.P^
M3*O/3JN=]]N^03FO>RZ_*/)B_Y9 -Z:3SU&>_Q8P4;^LG5T._4XM[:@C[-36
M5TMM8U@<:[,6F.+L>^[
MQ*Y#G,H8RL):P#H$8G;7;&DO&_LW[\G9RR-$I%GX[P&WK0DB7'$=;DO&Z&K@
MT_;%_DNT)XDC56Z\%]A?2ZQ_B?\](W
MV&=K ?C"<#RY&V&U 6HN-,Y]1^RA$?BM6]]#$/9B[0PQ^.+D>Y4@*K[-YB5U
M-$@K'CHX/7E[?NF^T\3+@!/I[0HOIOXT>AK-$9GKY\FWZR>ZIM5(T9>8H;XA5!(/0F2;*<&P,]QA#:%
MB9G!6+*>ZW%Z8@HZ3A^01E>V:*.E/"1KS_(B(GM&7.?FUMX8Y[MO;39$36OJ%L:A-:ZL,D&OXR]1A*WV( ^PG+;]5C][G[
MC7IMD^7?JGF_T/]&K7M.XV_4TYYZR#?JM>5$-B1X=!#P85 :HZ @K1PIQ>"\
M$ZFUL%AR':2)KMA@(5ORK?8+Y/>/BQE,J&;S#:QD#DML?Y-%VOEBQ'.Z$*.J
M32*UB)R]N/EV=KTC"_9SOM]]L\7G@3%#Z!F*HQ*"D^RL7VKK8U^ #-)GU=' ;,8@(&OZM%X%^Q38 K2830K
M3W#?EH^X\)S9!E5.[D!%2KY\=?3BF+5YWB_&X6N=:7LU_E7T86SVOPMQZ.Z^
M+67H9K\-67@692>:./XX#*[/@XO+DP_#X.WE^3\.+[W96ML,/8[0NEA.01*]
M9;S>[=3'P>G)%U>8M7?'BKQ#N?\D__'!T3PIQBJ%OJX'(*H/#FZ'LKDOM$LE>;@QK3O/"<:
M]LVS2]IN 6]SD;.BBYRMH:]U5F&WMFN0_C5&V@>2;+EJ3TQM3;I5$R,[E=/U
MEHB*[U')3\^ON,H&?SC^TT>I/#3\)RQZ.$00T.'EC\,K)TP:#[E;]W/_S=.A
M4=3:D:GI*A]->JC"M^A.EL.LY[;\SY.W9YO/I?V&HU$%X]RE^LO@9D6RM!.3Z<7=-@2@
MKPZ,KC(7"BI<.SQI[5G]B[7,&U,?
M3=5-B:P1(HYR1>BF6 LL#].B'YQ.5M"\.+VE&C>#4A */96TBG(%*9O 8F21
MX+1Y>XLSA/KH$_QY'T$FXSC$&B8G@NBG,I=4J;#UXGM=F(E0#.(\9^@^Z+7(
M"BZ2"U/FG'K@;)4$"]^(J"3/",(65A89+[..=%$_C>EJWF#=F2L#VXC")&=,75@<1
M)M(TKN^Ǐ]!'-KVKLRV \]FY[$B9Y&R\8WB,ONP'<4-*%],]:U):BY
MG?P;(VBA]_IS;03>]-"WT;5#3WN\9A'6'F^YM-^0+5Z2[QQARRL=HVMYP]"^
MQ_G52NE;]L.BP(9X\5/V5I+I:/('C,>_'![JDC!@5.E@.%;&_W[
MZF#L]!!=%Y 9S@E 6 4.[> WP17(&#C#[T:/T]ES\,/B<=*NY>[9--_)M*K,
MIH[) *NQ+6X0:JJM:HR*JKQ $QW$Y'*7EXXF)$&->O2R9N6NQ5/:HX)(>
M"#KPH"]H.M;@D4J/6&?@<3-;3]]099O6P!U_X1&_:::P+QJ$"EN^^#*G?-0G
M5:&EM4>N)-*T*:\OSX^&5U<.(E [#L<1P2F+PYMR6CM5:4<#TN!Y;+$=<>7F-8)*_AU L"U [2,MO*,1H3#3F:M'FV!Q^"
MMU1[=/ FN&0SM8VX/LK8VWZ_^F%P.=10>#MLQ]7DZ1"1CA&JJ2%_+Y:J8J0#
M?K3UL0Y$B,O)O8 A4DJU[R(B\_IJ!O?W2RSX,K'0>8SWKCU'EX$L+$@PV-7[
MY>B1RWJ;HQ8\U;-
M#)@RL!FEAPE4FO]->SZ"^>97V%00:2M]5#ZPDBO!M+E0F#9_=9!W@L'V+4=N
MBC1%PYS.Q3F'05T+V3*S4!(',1D(;HYHX$G#DR_8&$ !F
M0Q@F"DF98(T9J]*GP/M#U0S?]#13V_:QG3PW6K4S3\3UP9 -ODSP2M4W;P>(
M#HO(K\.S*T9 /,-[==I5OW/RCUIPSL%\G>(%_):X=!+'?;\XMB%0'5H=X.W^
M/5L5-\\.5.J%2(X!RJ PT!$!5OA\:.#I!X(4-538G(2#^'<;!S-T;W>M+*$9
M?:#%NJ ?<%(<'DIZA8K^-JZ<^GXC];U^P\JE4Y[#ENAIN=>Q%P;3*&T%'T&>
M,.P-O9 R'76E82Z3.\2= Y>JPR::)Q:(?XY5 ?2PM[[3  V#LPS*"=M2IAHR
MW=_1-:X*R6U7^00.,(@BL'3FZX?&@B7^M=\R7Y_.K4;_1HU>@\P^^0BY\7C[
M9-LF5;3,2?U>MOQNU-EI^RYU+.I.[W>LE%E<]3#3XU9ZN&\[$=WMV)#H Q<2
MO<7OOPWP>>M(Y?C?D6U-A\KG*8K8@9NW[-/1;'IW%RCX8X>CT!I@CF.G4N'%
MJK:O(T5CG(QMK5_$!GN(FJN)V>TZYJ3!:58MK*;1?LM:M-&T_%QU_]Q&\\-S5'VCNZ::QF.'[!9:K%C T#0XJ UXQ(,[HEH%>_LQ@O73):*7#GGC]
M.*UJKKV8 IYNJ;OUI8:O.N"OOUYW%"0".W:3W+.3,3I5?2&O#P
MNSTSYG&+>2H[_ZVY M#>@IT::/"ZD'E9EZ+7_?J/7EZYZ]OOU.E\Z?0G'D/I
M]]C=AO5B1(0-\]8>MK";CK/;UN_:5LO6[_JZ?^MW?;MUZU^P$CXJ:.,C;VDN/'A ?1EG#;14?
MIH7GR[+YY%"C9W]>H);FNU9)X,VF:RQ)#Y/FMZC>TL$CFZD'UC]9!LWX4O%-
M!,_3R:RQIGXX"^UL]"Y$ZSYO\TI?1..A?WD0R-E?6[:L?D3NB4RM:)EZ5
M=.:VNS-#$BO_QYT,&6(J]9!_VKY9!$:]%@0HS3T
M$/ATBEJL"F'P$!_/GN8I-V+-8TD_CQC?BZ@]5;]9>T"L3SQH-0];S>^LWT^I
MY.7A&950?-S]O5#_R1U><).%(L80FDJYR3ZP&7H&HQ>48ZH8@D4+J0!9?5F:
MQ8[:2VS4BQ@YL^?V5# #U$]&5%"QQ556V@W#4\ZYR-S=.9"9OK:-LA@$!1_!
M&(2VY6NBBE&,HD$7\!W#[FC\.8#2AM?=<]BM2I6E1O+<#&.(!#(\"=X@G9\3
M4!0!62G]+UB];KY9X@NJP=E=P=F[H'O/E7>RY!3;8+HLD(6Y:^ENR^\.BB^<
M/?@6;J%>$\E,I#J-.S2%'0KD%J'C>+N69PQ?-BVV"NEX%2==#O>UL4R\4RQO
MX#MIX_ M0Z_JPC)%FH=ARS9B2D>+L>N
M19HEU,V2,:L95T+%RNIUL7K(9:H_$N<1A$+R'[I+!E&[C>#RL&O!S2'IU93I
M?/I"%(AH#UVBO=CKK,DUO9T'(^XC:PL_W8$O0)!X(&(YW@>#^9(R*2J->LZW
M%P"$0;2%>$^^658=*P!'[$WUK\/@(MG<\\-WCCYOI)Q:T+*C!)V1TXQ4I/HX
MY0]1(_CVUS^^3*HF#//(UH(Q(VY+[.=\0-+8*)
MC.=897LK&3LPD@CB)UBAC\7ABQU.ZG8XK=O!JA]=TJ'5
MK-5AS!5UAF^\];J!++4$K'.L83X7+MHUXF0' !*%J.R'^=JQ!W4Z6_M1I[.U
M-W4Z6_M4H[.]9Y4[O\&:DWLI8^K\A3,Q8D]Z2EQ1>8Y*F-0(O#670]8X\R/I
M+GA^$).D>4'US*5L<,M_XR8=FQV*Y09+NX'WX7J[62<2=@L$Q+?)$Y3XPYP+
M)D4/\-0-[GZPM2#!,\0:YR?BM*T261A3>9]2"3)-OW[)4V)FC<%(!"9\R JI
M\_6+%,K'=J;@Z"/Z-4;1\&J$)0KS:?_X:G/-AE]Y%_$?@)+>%-ZDYESN>XH=HN>:W5.JMES%1F$-
MO?>>Z?-6DC<5PV.='GJF 53YY=JF2"5@60PBYP997$V@O(8*BO6)*Z^/S+HQ
M3TX..[:9=$H:3R<=*@R^/@W\'_[/.CJBB.J<40]51V2INKV(:H$(]1+6:E'F
M<7AV&-J_\K:M-R*LO2DC+&Q1WBV_*'!,!\JPM-PRY-@>2:D%.\LTHR+,2"U9K4HB$)):F=4(=%F'1*Q"B17>+HO&H3>T0_Y48_XA:LP/:JI@XITZD?Q0I?KZ'F-['$(2F(^:\$
M5Q]3"Y 9VC:[4C[ZD!HX;%.?_BG90&Z=;W_^G7=)$E!BLE!QDV*( V1P._LK
M**?@EL(R\?)Y:\-DEC$5VAHO7),\=@IF3[KC R-:9%2D'Q>
M$IXIFQ\I/88Z:=UT'A=_>\Y
MR14Q,H+Z"C5W3'__7/BZ0!]"V[47/\;^2BA9O(&E14H9= WI#.DFQ2JX('5$
MC2NZ92(S3QOM.0>YBV[IY>N#-CL#Y]TLR!&VC][8):L.BR OB9&S](\?=>6M1)85?:$ZFP+SB+D:WLFL0VD6)0;<
MO@HKB*><*]*Y1NL4>PK)J!T>KAGT:M[LM9@ZAV9FS\+":IROV$5D JYO##?)
M;#M]5$X7KQ16"4>"[^/E^D>G-2+>;$O4DXRX*2;4X/PIQ.Y44>?LH)R+**#*
M.N74)OF0FGDG$^H4A$W:L]'LT#\7(EA^2-/'G_X%4$L! A0#%     @ X()6
M2!W.([)9 @  Z#(  !,              ( !     %M#;VYT96YT7U1Y<&5S
M72YX;6Q02P$"% ,4    " #@@E9(2'4%[L4    K @  "P              
M@ &* @  7W)E;',O+G)E;'-02P$"% ,4    " #@@E9("%UG6*0"  #R,P  
M&@              @ %X P  >&PO7W)E;',O=V]R:V)O;VLN>&UL+G)E;'-0
M2P$"% ,4    " #@@E9("W/!"Q\$  #3$P  $               @ %4!@  
M9&]C4')O<',O87!P+GAM;%!+ 0(4 Q0    ( .""5DA-5]9=/@$  &D#   1
M              "  :$*  !D;V-0&UL4$L! A0#%     @ X()62!7N23.7 @  $@\   T         
M     ( !3Q(  'AL+W-T>6QE&PO=V]R:V)O;VLN>&UL4$L! A0#
M%     @ X()62.E2#?^[ @  \@H  !@              ( !;!L  'AL+W=O
M  !X;"]W;W)K&PO=V]R:W-H965T&UL4$L! A0#%     @ X()62/7B92$B
M"0  @#   !@              ( !G"4  'AL+W=O&PO=V]R:W-H965T&UL4$L! A0#%     @ X()62-)X"!&A 0  L0,  !@         
M     ( !BSH  'AL+W=O&PO=V]R:W-H965T&UL4$L! A0#
M%     @ X()62"\ QZNC 0  L0,  !D              ( !%$   'AL+W=O
M&PO=V]R:W-H965T&UL4$L! A0#%     @ X()62)=J
M8?.C 0  L0,  !D              ( !LT4  'AL+W=O&PO=V]R:W-H965T&UL4$L! A0#%     @ X()62"8C*-BC 0  L0,  !D 
M             ( !0$L  'AL+W=O&PO
M=V]R:W-H965T&UL4$L! A0#%     @ X()62)F&PO=V]R:W-H965T&UL4$L! A0#%   
M  @ X()62/?I&'^B 0  L0,  !D              ( !7U8  'AL+W=O&PO=V]R:W-H965T&UL4$L! A0#%     @ X()62$(25J^R 0  %@0  !D     
M         ( !NV(  'AL+W=O&PO=V]R
M:W-H965T&UL
M4$L! A0#%     @ X()62(L1COZF 0  L0,  !D              ( !+VD 
M 'AL+W=O&PO=V]R:W-H965TAL  !X;"]W;W)K&UL4$L! A0#%     @ 
MX()62$_&PO=V]R:W-H965T&UL4$L! A0#%     @ X()62 Q!3OJQ 0  
M%@0  !D              ( !NW4  'AL+W=O3H5\,!  ![!   &0              @ &C
M=P  >&PO=V]R:W-H965T&UL4$L! A0#%     @ X()62 GVD@C  0  >P0  !D         
M     ( !>GL  'AL+W=O&PO=V]R:W-H
M965T&UL4$L!
M A0#%     @ X()62-G/5N4) P  A@T  !D              ( !B((  'AL
M+W=O&PO=V]R:W-H965T&UL4$L! A0#%     @ X()6
M2(SX.RH& P  1@P  !D              ( !:8L  'AL+W=O&PO=V]R:W-H965T&UL4$L! A0#%     @ X()62)*/?;["!   3!L 
M !D              ( !=Y<  'AL+W=O&PO=V]R:W-H965T1)D_
M8@(  * (   9              "  4*@  !X;"]W;W)K&UL4$L! A0#%     @ X()62-3L+*T. P  H@P  !D             
M ( !VZ(  'AL+W=O&PO=V]R:W-H965T
M&UL4$L! A0#
M%     @ X()62(#*HX]S!   7A<  !D              ( !%:L  'AL+W=O
M&PO=V]R:W-H965T&UL4$L! A0#%     @ X()62+6"
MZ.PU!0  *QX  !D              ( !U[8  'AL+W=O&PO=V]R:W-H965T&UL4$L! A0#%     @ X()62(=F/$IL @    D  !D 
M             ( !V\(  'AL+W=O&PO
M=V]R:W-H965T&UL4$L! A0#%     @ X()62+#_!04# @  R@4  !D              ( !
M0\H  'AL+W=O&PO=V]R:W-H965T&UL4$L! A0#%   
M  @ X()62*I*L8\J!0  X1T  !D              ( !1=8  'AL+W=O&PO=V]R:W-H965T&UL4$L! A0#%     @ X()62!"&H:9N P  XPT  !D     
M         ( !'.X  'AL+W=O&PO=V]R
M:W-H965T&UL
M4$L! A0#%     @ X()62".EJS2@ @  "PL  !D              ( !^/@ 
M 'AL+W=O&PO=V]R:W-H965TO-MLP,   X1   9            
M  "  >C_  !X;"]W;W)K&UL4$L! A0#%     @ 
MX()62 8B:L:?!@  6R@  !D              ( !T@,! 'AL+W=O&PO=V]R:W-H965T&UL4$L! A0#%     @ X()62!8(Z?'6!0  0R   !D         
M     ( !%R0! 'AL+W=O@"  !["@  &0              @ $D*@$ >&PO=V]R:W-H
M965T&UL4$L!
M A0#%     @ X()62$&I'!,G[P  /*$# !0              ( !HS ! 'AL
H+W-H87)E9%-T&UL4$L%!@    !@ &  4AH  /P? @    $!
 
end


IDEA: XBRL DOCUMENT
/**
 * Rivet Software Inc.
 *
 * @copyright Copyright (c) 2006-2011 Rivet Software, Inc. All rights reserved.
 * Version 2.4.0.3
 *
 */

var Show = {};
Show.LastAR = null,

Show.hideAR = function(){	
	Show.LastAR.style.display = 'none';
};

Show.showAR = function ( link, id, win ){
	if( Show.LastAR ){
		Show.hideAR();
	}
		
	var ref = link;
	do {
		ref = ref.nextSibling;
	} while (ref && ref.nodeName != 'TABLE');

	if (!ref || ref.nodeName != 'TABLE') {
		var tmp = win ?
			win.document.getElementById(id) :
			document.getElementById(id);

		if( tmp ){
			ref = tmp.cloneNode(true);
			ref.id = '';
			link.parentNode.appendChild(ref);
		}
	}

	if( ref ){
		ref.style.display = 'block';
		Show.LastAR = ref;
	}
};
	
Show.toggleNext = function( link ){
	var ref = link;
	
	do{
		ref = ref.nextSibling;	
	}while( ref.nodeName != 'DIV' );

	if( ref.style &&
		ref.style.display &&
		ref.style.display == 'none' ){
		ref.style.display = 'block';

		if( link.textContent ){
			link.textContent = link.textContent.replace( '+', '-' );
		}else{
			link.innerText = link.innerText.replace( '+', '-' );
		}
	}else{
		ref.style.display = 'none';
			
		if( link.textContent ){
			link.textContent = link.textContent.replace( '-', '+' );
		}else{
			link.innerText = link.innerText.replace( '-', '+' );
		}
	}
};


IDEA: XBRL DOCUMENT
/* Updated 2009-11-04 */
/* v2.2.0.24 */

/* DefRef Styles */
.report table.authRefData{
	background-color: #def;
	border: 2px solid #2F4497;
	font-size: 1em; 
	position: absolute;
}

.report table.authRefData a {
	display: block;
	font-weight: bold;
}

.report table.authRefData p {
	margin-top: 0px;
}

.report table.authRefData .hide {
	background-color: #2F4497;
	padding: 1px 3px 0px 0px;
	text-align: right;
}

.report table.authRefData .hide a:hover {
	background-color: #2F4497;
}

.report table.authRefData .body {
	height: 150px;
	overflow: auto;
	width: 400px;
}

.report table.authRefData table{
	font-size: 1em;
}

/* Report Styles */
.pl a, .pl a:visited {
	color: black;
	text-decoration: none;
}

/* table */
.report {
	background-color: white;
	border: 2px solid #acf;
	clear: both;
	color: black;
	font: normal 8pt Helvetica, Arial, san-serif;
	margin-bottom: 2em;
}

.report hr {
	border: 1px solid #acf;
}

/* Top labels */
.report th {
	background-color: #acf;
	color: black;
	font-weight: bold;
	text-align: center;
}

.report th.void	{
	background-color: transparent;
	color: #000000;
	font: bold 10pt Helvetica, Arial, san-serif;
	text-align: left;
}

.report .pl {
	text-align: left;
	vertical-align: top;
	white-space: normal;
	width: 200px;
	white-space: normal; /* word-wrap: break-word; */
}

.report td.pl a.a {
	cursor: pointer;
	display: block;
	width: 200px;
	overflow: hidden;
}

.report td.pl div.a {
	width: 200px;
}

.report td.pl a:hover {
	background-color: #ffc;
}

/* Header rows... */
.report tr.rh {
	background-color: #acf;
	color: black;
	font-weight: bold;
}

/* Calendars... */
.report .rc {
	background-color: #f0f0f0;
}

/* Even rows... */
.report .re, .report .reu {
	background-color: #def;
}

.report .reu td {
	border-bottom: 1px solid black;
}

/* Odd rows... */
.report .ro, .report .rou {
	background-color: white;
}

.report .rou td {
	border-bottom: 1px solid black;
}

.report .rou table td, .report .reu table td {
	border-bottom: 0px solid black;
}

/* styles for footnote marker */
.report .fn {
	white-space: nowrap;
}

/* styles for numeric types */
.report .num, .report .nump {
	text-align: right;
	white-space: nowrap;
}

.report .nump {
	padding-left: 2em;
}

.report .nump {
	padding: 0px 0.4em 0px 2em;
}

/* styles for text types */
.report .text {
	text-align: left;
	white-space: normal;
}

.report .text .big {
	margin-bottom: 1em;
	width: 17em;
}

.report .text .more {
	display: none;
}

.report .text .note {
	font-style: italic;
	font-weight: bold;
}

.report .text .small {
	width: 10em;
}

.report sup {
	font-style: italic;
}

.report .outerFootnotes {
	font-size: 1em;
}


IDEA: XBRL DOCUMENT


  3.3.1.900
  
  html
  467
  442
  1
  true
  148
  0
  false
  6
  
    
      false
      false
      R1.htm
      0001000 - Document - Document And Entity Information
      Sheet
      http://www.greenlightre.ky/role/DocumentAndEntityInformation
      Document And Entity Information
      Cover
      1
    
    
      false
      false
      R2.htm
      1001000 - Statement - CONSOLIDATED BALANCE SHEETS
      Sheet
      http://www.greenlightre.ky/role/ConsolidatedBalanceSheets
      CONSOLIDATED BALANCE SHEETS
      Statements
      2
    
    
      false
      false
      R3.htm
      1001501 - Statement - CONSOLIDATED BALANCE SHEETS (Parenthetical)
      Sheet
      http://www.greenlightre.ky/role/ConsolidatedBalanceSheetsParenthetical
      CONSOLIDATED BALANCE SHEETS (Parenthetical)
      Statements
      3
    
    
      false
      false
      R4.htm
      1002000 - Statement - CONSOLIDATED STATEMENTS OF INCOME
      Sheet
      http://www.greenlightre.ky/role/ConsolidatedStatementsOfIncome
      CONSOLIDATED STATEMENTS OF INCOME
      Statements
      4
    
    
      false
      false
      R5.htm
      1003000 - Statement - CONSOLIDATED STATEMENTS OF SHAREHOLDERS' EQUITY
      Sheet
      http://www.greenlightre.ky/role/ConsolidatedStatementsOfShareholdersEquity
      CONSOLIDATED STATEMENTS OF SHAREHOLDERS' EQUITY
      Statements
      5
    
    
      false
      false
      R6.htm
      1004000 - Statement - CONSOLIDATED STATEMENTS OF CASH FLOWS
      Sheet
      http://www.greenlightre.ky/role/ConsolidatedStatementsOfCashFlows
      CONSOLIDATED STATEMENTS OF CASH FLOWS
      Statements
      6
    
    
      false
      false
      R7.htm
      2101100 - Disclosure - ORGANIZATION AND BASIS OF PRESENTATION
      Sheet
      http://www.greenlightre.ky/role/OrganizationAndBasisOfPresentation
      ORGANIZATION AND BASIS OF PRESENTATION
      Notes
      7
    
    
      false
      false
      R8.htm
      2102100 - Disclosure - SIGNIFICANT ACCOUNTING POLICIES
      Sheet
      http://www.greenlightre.ky/role/SignificantAccountingPolicies
      SIGNIFICANT ACCOUNTING POLICIES
      Notes
      8
    
    
      false
      false
      R9.htm
      2103100 - Disclosure - FINANCIAL INSTRUMENTS
      Sheet
      http://www.greenlightre.ky/role/FinancialInstruments
      FINANCIAL INSTRUMENTS
      Notes
      9
    
    
      false
      false
      R10.htm
      2104100 - Disclosure - DUE TO PRIME BROKERS
      Sheet
      http://www.greenlightre.ky/role/DueToPrimeBrokers
      DUE TO PRIME BROKERS
      Notes
      10
    
    
      false
      false
      R11.htm
      2105100 - Disclosure - CASH AND CASH EQUIVALENTS
      Sheet
      http://www.greenlightre.ky/role/CashAndCashEquivalents
      CASH AND CASH EQUIVALENTS
      Notes
      11
    
    
      false
      false
      R12.htm
      2106100 - Disclosure - RESTRICTED CASH AND CASH EQUIVALENTS
      Sheet
      http://www.greenlightre.ky/role/RestrictedCashAndCashEquivalents
      RESTRICTED CASH AND CASH EQUIVALENTS
      Notes
      12
    
    
      false
      false
      R13.htm
      2107100 - Disclosure - LOSS AND LOSS ADJUSTMENT EXPENSE RESERVES
      Sheet
      http://www.greenlightre.ky/role/LossAndLossAdjustmentExpenseReserves
      LOSS AND LOSS ADJUSTMENT EXPENSE RESERVES
      Notes
      13
    
    
      false
      false
      R14.htm
      2108100 - Disclosure - RETROCESSION
      Sheet
      http://www.greenlightre.ky/role/Retrocession
      RETROCESSION
      Notes
      14
    
    
      false
      false
      R15.htm
      2110100 - Disclosure - SHARE CAPITAL
      Sheet
      http://www.greenlightre.ky/role/ShareCapital
      SHARE CAPITAL
      Notes
      15
    
    
      false
      false
      R16.htm
      2110100 - Disclosure - SHARE-BASED COMPENSATION
      Sheet
      http://www.greenlightre.ky/role/ShareBasedCompensation
      SHARE-BASED COMPENSATION
      Notes
      16
    
    
      false
      false
      R17.htm
      2111100 - Disclosure - NET INVESTMENT INCOME
      Sheet
      http://www.greenlightre.ky/role/NetInvestmentIncome
      NET INVESTMENT INCOME
      Notes
      17
    
    
      false
      false
      R18.htm
      2112100 - Disclosure - TAXATION
      Sheet
      http://www.greenlightre.ky/role/Taxation
      TAXATION
      Notes
      18
    
    
      false
      false
      R19.htm
      2113100 - Disclosure - RELATED PARTY TRANSACTIONS
      Sheet
      http://www.greenlightre.ky/role/RelatedPartyTransactions
      RELATED PARTY TRANSACTIONS
      Notes
      19
    
    
      false
      false
      R20.htm
      2114100 - Disclosure - COMMITMENTS AND CONTINGENCIES
      Sheet
      http://www.greenlightre.ky/role/CommitmentsAndContingencies
      COMMITMENTS AND CONTINGENCIES
      Notes
      20
    
    
      false
      false
      R21.htm
      2115100 - Disclosure - SEGMENT REPORTING
      Sheet
      http://www.greenlightre.ky/role/SegmentReporting
      SEGMENT REPORTING
      Notes
      21
    
    
      false
      false
      R22.htm
      2116100 - Disclosure - QUARTERLY FINANCIAL RESULTS (UNAUDITED)
      Sheet
      http://www.greenlightre.ky/role/QuarterlyFinancialResultsUnaudited
      QUARTERLY FINANCIAL RESULTS (UNAUDITED)
      Notes
      22
    
    
      false
      false
      R23.htm
      2118100 - Disclosure - SCHEDULE I
      Sheet
      http://www.greenlightre.ky/role/ScheduleI
      SCHEDULE I
      Notes
      23
    
    
      false
      false
      R24.htm
      2119100 - Disclosure - SCHEDULE II
      Sheet
      http://www.greenlightre.ky/role/ScheduleIi
      SCHEDULE II
      Notes
      24
    
    
      false
      false
      R25.htm
      2120100 - Disclosure - SCHEDULE III
      Sheet
      http://www.greenlightre.ky/role/ScheduleIii
      SCHEDULE III
      Notes
      25
    
    
      false
      false
      R26.htm
      2121100 - Disclosure - SCHEDULE IV
      Sheet
      http://www.greenlightre.ky/role/ScheduleIv
      SCHEDULE IV
      Notes
      26
    
    
      false
      false
      R27.htm
      2202201 - Disclosure - SIGNIFICANT ACCOUNTING POLICIES (Policies)
      Sheet
      http://www.greenlightre.ky/role/SignificantAccountingPoliciesPolicies
      SIGNIFICANT ACCOUNTING POLICIES (Policies)
      Policies
      27
    
    
      false
      false
      R28.htm
      2302302 - Disclosure - SIGNIFICANT ACCOUNTING POLICIES (Tables)
      Sheet
      http://www.greenlightre.ky/role/SignificantAccountingPoliciesTables
      SIGNIFICANT ACCOUNTING POLICIES (Tables)
      Tables
      http://www.greenlightre.ky/role/SignificantAccountingPolicies
      28
    
    
      false
      false
      R29.htm
      2303301 - Disclosure - FINANCIAL INSTRUMENTS (Tables)
      Sheet
      http://www.greenlightre.ky/role/FinancialInstrumentsTables
      FINANCIAL INSTRUMENTS (Tables)
      Tables
      http://www.greenlightre.ky/role/FinancialInstruments
      29
    
    
      false
      false
      R30.htm
      2305301 - Disclosure - CASH AND CASH EQUIVALENTS (Tables)
      Sheet
      http://www.greenlightre.ky/role/CashAndCashEquivalentsTables
      CASH AND CASH EQUIVALENTS (Tables)
      Tables
      http://www.greenlightre.ky/role/CashAndCashEquivalents
      30
    
    
      false
      false
      R31.htm
      2306301 - Disclosure - RESTRICTED CASH AND CASH EQUIVALENTS (Tables)
      Sheet
      http://www.greenlightre.ky/role/RestrictedCashAndCashEquivalentsTables
      RESTRICTED CASH AND CASH EQUIVALENTS (Tables)
      Tables
      http://www.greenlightre.ky/role/RestrictedCashAndCashEquivalents
      31
    
    
      false
      false
      R32.htm
      2307302 - Disclosure - LOSS AND LOSS ADJUSTMENT EXPENSE RESERVES (Tables)
      Sheet
      http://www.greenlightre.ky/role/LossAndLossAdjustmentExpenseReservesTables
      LOSS AND LOSS ADJUSTMENT EXPENSE RESERVES (Tables)
      Tables
      http://www.greenlightre.ky/role/LossAndLossAdjustmentExpenseReserves
      32
    
    
      false
      false
      R33.htm
      2310301 - Disclosure - SHARE CAPITAL (Tables)
      Sheet
      http://www.greenlightre.ky/role/ShareCapitalTables
      SHARE CAPITAL (Tables)
      Tables
      http://www.greenlightre.ky/role/ShareCapital
      33
    
    
      false
      false
      R34.htm
      2310301 - Disclosure - SHARE-BASED COMPENSATION (Tables)
      Sheet
      http://www.greenlightre.ky/role/ShareBasedCompensationTables
      SHARE-BASED COMPENSATION (Tables)
      Tables
      http://www.greenlightre.ky/role/ShareBasedCompensation
      34
    
    
      false
      false
      R35.htm
      2311301 - Disclosure - NET INVESTMENT INCOME (Tables)
      Sheet
      http://www.greenlightre.ky/role/NetInvestmentIncomeTables
      NET INVESTMENT INCOME (Tables)
      Tables
      http://www.greenlightre.ky/role/NetInvestmentIncome
      35
    
    
      false
      false
      R36.htm
      2312301 - Disclosure - TAXATION (Tables)
      Sheet
      http://www.greenlightre.ky/role/TaxationTables
      TAXATION (Tables)
      Tables
      http://www.greenlightre.ky/role/Taxation
      36
    
    
      false
      false
      R37.htm
      2314301 - Disclosure - COMMITMENTS AND CONTINGENCIES (Tables)
      Sheet
      http://www.greenlightre.ky/role/CommitmentsAndContingenciesTables
      COMMITMENTS AND CONTINGENCIES (Tables)
      Tables
      http://www.greenlightre.ky/role/CommitmentsAndContingencies
      37
    
    
      false
      false
      R38.htm
      2315301 - Disclosure - SEGMENT REPORTING (Tables)
      Sheet
      http://www.greenlightre.ky/role/SegmentReportingTables
      SEGMENT REPORTING (Tables)
      Tables
      http://www.greenlightre.ky/role/SegmentReporting
      38
    
    
      false
      false
      R39.htm
      2316301 - Disclosure - QUARTERLY FINANCIAL RESULTS (UNAUDITED) (Tables)
      Sheet
      http://www.greenlightre.ky/role/QuarterlyFinancialResultsUnauditedTables
      QUARTERLY FINANCIAL RESULTS (UNAUDITED) (Tables)
      Tables
      http://www.greenlightre.ky/role/QuarterlyFinancialResultsUnaudited
      39
    
    
      false
      false
      R40.htm
      2319301 - Disclosure - SCHEDULE II (Tables)
      Sheet
      http://www.greenlightre.ky/role/ScheduleIiTables
      SCHEDULE II (Tables)
      Tables
      http://www.greenlightre.ky/role/ScheduleI
      40
    
    
      false
      false
      R41.htm
      2401401 - Disclosure - ORGANIZATION AND BASIS OF PRESENTATION (Details)
      Sheet
      http://www.greenlightre.ky/role/OrganizationAndBasisOfPresentationDetails
      ORGANIZATION AND BASIS OF PRESENTATION (Details)
      Details
      http://www.greenlightre.ky/role/OrganizationAndBasisOfPresentation
      41
    
    
      false
      false
      R42.htm
      2402403 - Disclosure - SIGNIFICANT ACCOUNTING POLICIES (Details)
      Sheet
      http://www.greenlightre.ky/role/SignificantAccountingPoliciesDetails
      SIGNIFICANT ACCOUNTING POLICIES (Details)
      Details
      http://www.greenlightre.ky/role/SignificantAccountingPoliciesTables
      42
    
    
      false
      false
      R43.htm
      2402404 - Disclosure - SIGNIFICANT ACCOUNTING POLICIES Fixed Assets (Details)
      Sheet
      http://www.greenlightre.ky/role/SignificantAccountingPoliciesFixedAssetsDetails
      SIGNIFICANT ACCOUNTING POLICIES Fixed Assets (Details)
      Details
      43
    
    
      false
      false
      R44.htm
      2402405 - Disclosure - SIGNIFICANT ACCOUNTING POLICIES Earnings Per Share Reconciliation (Details)
      Sheet
      http://www.greenlightre.ky/role/SignificantAccountingPoliciesEarningsPerShareReconciliationDetails
      SIGNIFICANT ACCOUNTING POLICIES Earnings Per Share Reconciliation (Details)
      Details
      44
    
    
      false
      false
      R45.htm
      2402406 - Disclosure - SIGNIFICANT ACCOUNTING POLICIES Income taxes (Details)
      Sheet
      http://www.greenlightre.ky/role/SignificantAccountingPoliciesIncomeTaxesDetails
      SIGNIFICANT ACCOUNTING POLICIES Income taxes (Details)
      Details
      45
    
    
      false
      false
      R46.htm
      2403402 - Disclosure - FINANCIAL INSTRUMENTS Financial Instruments Additional Information (Details)
      Sheet
      http://www.greenlightre.ky/role/FinancialInstrumentsFinancialInstrumentsAdditionalInformationDetails
      FINANCIAL INSTRUMENTS Financial Instruments Additional Information (Details)
      Details
      46
    
    
      false
      false
      R47.htm
      2403403 - Disclosure - FINANCIAL INSTRUMENTS Schedule of Investments Categorized by the Level of Fair Value Hierarchy (Details)
      Sheet
      http://www.greenlightre.ky/role/FinancialInstrumentsScheduleOfInvestmentsCategorizedByLevelOfFairValueHierarchyDetails
      FINANCIAL INSTRUMENTS Schedule of Investments Categorized by the Level of Fair Value Hierarchy (Details)
      Details
      47
    
    
      false
      false
      R48.htm
      2403404 - Disclosure - FINANCIAL INSTRUMENTS Fair Value Hierarchy Additional Information (Details)
      Sheet
      http://www.greenlightre.ky/role/FinancialInstrumentsFairValueHierarchyAdditionalInformationDetails
      FINANCIAL INSTRUMENTS Fair Value Hierarchy Additional Information (Details)
      Details
      48
    
    
      false
      false
      R49.htm
      2403405 - Disclosure - FINANCIAL INSTRUMENTS Level 3 reconciliation (Details)
      Sheet
      http://www.greenlightre.ky/role/FinancialInstrumentsLevel3ReconciliationDetails
      FINANCIAL INSTRUMENTS Level 3 reconciliation (Details)
      Details
      49
    
    
      false
      false
      R50.htm
      2403406 - Disclosure - FINANCIAL INSTRUMENTS Schedule of Investments Included in Debt Instruments (Details)
      Sheet
      http://www.greenlightre.ky/role/FinancialInstrumentsScheduleOfInvestmentsIncludedInDebtInstrumentsDetails
      FINANCIAL INSTRUMENTS Schedule of Investments Included in Debt Instruments (Details)
      Details
      50
    
    
      false
      false
      R51.htm
      2403407 - Disclosure - FINANCIAL INSTRUMENTS Schedule of Maturity Distribution of Debt Instruments (Details)
      Sheet
      http://www.greenlightre.ky/role/FinancialInstrumentsScheduleOfMaturityDistributionOfDebtInstrumentsDetails
      FINANCIAL INSTRUMENTS Schedule of Maturity Distribution of Debt Instruments (Details)
      Details
      51
    
    
      false
      false
      R52.htm
      2403408 - Disclosure - FINANCIAL INSTRUMENTS Schedule of Investments in Equity Securities, Trading (Details)
      Sheet
      http://www.greenlightre.ky/role/FinancialInstrumentsScheduleOfInvestmentsInEquitySecuritiesTradingDetails
      FINANCIAL INSTRUMENTS Schedule of Investments in Equity Securities, Trading (Details)
      Details
      52
    
    
      false
      false
      R53.htm
      2403409 - Disclosure - FINANCIAL INSTRUMENTS Schedule of Other Investments (Details)
      Sheet
      http://www.greenlightre.ky/role/FinancialInstrumentsScheduleOfOtherInvestmentsDetails
      FINANCIAL INSTRUMENTS Schedule of Other Investments (Details)
      Details
      53
    
    
      false
      false
      R54.htm
      2403410 - Disclosure - FINANCIAL INSTRUMENTS NAV Instruments (Details)
      Sheet
      http://www.greenlightre.ky/role/FinancialInstrumentsNavInstrumentsDetails
      FINANCIAL INSTRUMENTS NAV Instruments (Details)
      Details
      54
    
    
      false
      false
      R55.htm
      2403411 - Disclosure - FINANCIAL INSTRUMENTS Schedule of Investments in Securities Sold, Not Yet Purchased (Details)
      Sheet
      http://www.greenlightre.ky/role/FinancialInstrumentsScheduleOfInvestmentsInSecuritiesSoldNotYetPurchasedDetails
      FINANCIAL INSTRUMENTS Schedule of Investments in Securities Sold, Not Yet Purchased (Details)
      Details
      55
    
    
      false
      false
      R56.htm
      2403412 - Disclosure - FINANCIAL INSTRUMENTS Financial Contracts Additional Information (Details)
      Sheet
      http://www.greenlightre.ky/role/FinancialInstrumentsFinancialContractsAdditionalInformationDetails
      FINANCIAL INSTRUMENTS Financial Contracts Additional Information (Details)
      Details
      56
    
    
      false
      false
      R57.htm
      2403413 - Disclosure - FINANCIAL INSTRUMENTS Schedule of Fair Values of Financial Contracts Outstanding (Details)
      Sheet
      http://www.greenlightre.ky/role/FinancialInstrumentsScheduleOfFairValuesOfFinancialContractsOutstandingDetails
      FINANCIAL INSTRUMENTS Schedule of Fair Values of Financial Contracts Outstanding (Details)
      Details
      57
    
    
      false
      false
      R58.htm
      2403414 - Disclosure - FINANCIAL INSTRUMENTS Schedule of Reported Gains and Losses on Derivatives (Details)
      Sheet
      http://www.greenlightre.ky/role/FinancialInstrumentsScheduleOfReportedGainsAndLossesOnDerivativesDetails
      FINANCIAL INSTRUMENTS Schedule of Reported Gains and Losses on Derivatives (Details)
      Details
      58
    
    
      false
      false
      R59.htm
      2403415 - Disclosure - FINANCIAL INSTRUMENTS Schedule of Volume of Derivative Activities (Details)
      Sheet
      http://www.greenlightre.ky/role/FinancialInstrumentsScheduleOfVolumeOfDerivativeActivitiesDetails
      FINANCIAL INSTRUMENTS Schedule of Volume of Derivative Activities (Details)
      Details
      59
    
    
      false
      false
      R60.htm
      2403416 - Disclosure - FINANCIAL INSTRUMENTS Schedule of Gross and Net Amounts of Derivative Instruments and Cash Collateral (Details)
      Sheet
      http://www.greenlightre.ky/role/FinancialInstrumentsScheduleOfGrossAndNetAmountsOfDerivativeInstrumentsAndCashCollateralDetails
      FINANCIAL INSTRUMENTS Schedule of Gross and Net Amounts of Derivative Instruments and Cash Collateral (Details)
      Details
      60
    
    
      false
      false
      R61.htm
      2404401 - Disclosure - DUE TO PRIME BROKERS (Details)
      Sheet
      http://www.greenlightre.ky/role/DueToPrimeBrokersDetails
      DUE TO PRIME BROKERS (Details)
      Details
      http://www.greenlightre.ky/role/DueToPrimeBrokers
      61
    
    
      false
      false
      R62.htm
      2405402 - Disclosure - CASH AND CASH EQUIVALENTS (Details)
      Sheet
      http://www.greenlightre.ky/role/CashAndCashEquivalentsDetails
      CASH AND CASH EQUIVALENTS (Details)
      Details
      http://www.greenlightre.ky/role/CashAndCashEquivalentsTables
      62
    
    
      false
      false
      R63.htm
      2406402 - Disclosure - RESTRICTED CASH AND CASH EQUIVALENTS (Details)
      Sheet
      http://www.greenlightre.ky/role/RestrictedCashAndCashEquivalentsDetails
      RESTRICTED CASH AND CASH EQUIVALENTS (Details)
      Details
      http://www.greenlightre.ky/role/RestrictedCashAndCashEquivalentsTables
      63
    
    
      false
      false
      R64.htm
      2407401 - Disclosure - LOSS AND LOSS ADJUSTMENT EXPENSE RESERVES Liabilities for loss reserves (Details)
      Sheet
      http://www.greenlightre.ky/role/LossAndLossAdjustmentExpenseReservesLiabilitiesForLossReservesDetails
      LOSS AND LOSS ADJUSTMENT EXPENSE RESERVES Liabilities for loss reserves (Details)
      Details
      64
    
    
      false
      false
      R65.htm
      2407403 - Disclosure - LOSS AND LOSS ADJUSTMENT EXPENSE RESERVES (Details)
      Sheet
      http://www.greenlightre.ky/role/LossAndLossAdjustmentExpenseReservesDetails
      LOSS AND LOSS ADJUSTMENT EXPENSE RESERVES (Details)
      Details
      http://www.greenlightre.ky/role/LossAndLossAdjustmentExpenseReservesTables
      65
    
    
      false
      false
      R66.htm
      2408401 - Disclosure - RETROCESSION (Details)
      Sheet
      http://www.greenlightre.ky/role/RetrocessionDetails
      RETROCESSION (Details)
      Details
      http://www.greenlightre.ky/role/Retrocession
      66
    
    
      false
      false
      R67.htm
      2410402 - Disclosure - SHARE CAPITAL (Details)
      Sheet
      http://www.greenlightre.ky/role/ShareCapitalDetails
      SHARE CAPITAL (Details)
      Details
      http://www.greenlightre.ky/role/ShareCapitalTables
      67
    
    
      false
      false
      R68.htm
      2410402 - Disclosure - SHARE-BASED COMPENSATION Narrative (Details)
      Sheet
      http://www.greenlightre.ky/role/ShareBasedCompensationNarrativeDetails
      SHARE-BASED COMPENSATION Narrative (Details)
      Details
      68
    
    
      false
      false
      R69.htm
      2410403 - Disclosure - SHARE-BASED COMPENSATION Restricted Shares (Details)
      Sheet
      http://www.greenlightre.ky/role/ShareBasedCompensationRestrictedSharesDetails
      SHARE-BASED COMPENSATION Restricted Shares (Details)
      Details
      69
    
    
      false
      false
      R70.htm
      2410404 - Disclosure - SHARE-BASED COMPENSATION Black Scholes option pricing model assumptions (Details)
      Sheet
      http://www.greenlightre.ky/role/ShareBasedCompensationBlackScholesOptionPricingModelAssumptionsDetails
      SHARE-BASED COMPENSATION Black Scholes option pricing model assumptions (Details)
      Details
      70
    
    
      false
      false
      R71.htm
      2410405 - Disclosure - SHARE-BASED COMPENSATION Share Based Compensation Options Rollfoward (Details)
      Sheet
      http://www.greenlightre.ky/role/ShareBasedCompensationShareBasedCompensationOptionsRollfowardDetails
      SHARE-BASED COMPENSATION Share Based Compensation Options Rollfoward (Details)
      Details
      71
    
    
      false
      false
      R72.htm
      2410406 - Disclosure - SHARE-BASED COMPENSATION Restricted Units (Details)
      Sheet
      http://www.greenlightre.ky/role/ShareBasedCompensationRestrictedUnitsDetails
      SHARE-BASED COMPENSATION Restricted Units (Details)
      Details
      72
    
    
      false
      false
      R73.htm
      2411402 - Disclosure - NET INVESTMENT INCOME (Details)
      Sheet
      http://www.greenlightre.ky/role/NetInvestmentIncomeDetails
      NET INVESTMENT INCOME (Details)
      Details
      http://www.greenlightre.ky/role/NetInvestmentIncomeTables
      73
    
    
      false
      false
      R74.htm
      2412402 - Disclosure - TAXATION (Details)
      Sheet
      http://www.greenlightre.ky/role/TaxationDetails
      TAXATION (Details)
      Details
      http://www.greenlightre.ky/role/TaxationTables
      74
    
    
      false
      false
      R75.htm
      2413401 - Disclosure - RELATED PARTY TRANSACTIONS (Details)
      Sheet
      http://www.greenlightre.ky/role/RelatedPartyTransactionsDetails
      RELATED PARTY TRANSACTIONS (Details)
      Details
      http://www.greenlightre.ky/role/RelatedPartyTransactions
      75
    
    
      false
      false
      R76.htm
      2414402 - Disclosure - COMMITMENTS AND CONTINGENCIES Letters of Credit (Details)
      Sheet
      http://www.greenlightre.ky/role/CommitmentsAndContingenciesLettersOfCreditDetails
      COMMITMENTS AND CONTINGENCIES Letters of Credit (Details)
      Details
      76
    
    
      false
      false
      R77.htm
      2414403 - Disclosure - COMMITMENTS AND CONTINGENCIES Lease and commitments (Details)
      Sheet
      http://www.greenlightre.ky/role/CommitmentsAndContingenciesLeaseAndCommitmentsDetails
      COMMITMENTS AND CONTINGENCIES Lease and commitments (Details)
      Details
      77
    
    
      false
      false
      R78.htm
      2415402 - Disclosure - SEGMENT REPORTING Schedule of Revenue by Major Customers (Details)
      Sheet
      http://www.greenlightre.ky/role/SegmentReportingScheduleOfRevenueByMajorCustomersDetails
      SEGMENT REPORTING Schedule of Revenue by Major Customers (Details)
      Details
      78
    
    
      false
      false
      R79.htm
      2415403 - Disclosure - SEGMENT REPORTING Schedule of Gross Premiums Written by Line of Business (Details)
      Sheet
      http://www.greenlightre.ky/role/SegmentReportingScheduleOfGrossPremiumsWrittenByLineOfBusinessDetails
      SEGMENT REPORTING Schedule of Gross Premiums Written by Line of Business (Details)
      Details
      79
    
    
      false
      false
      R80.htm
      2415404 - Disclosure - SEGMENT REPORTING Geographic information (Details)
      Sheet
      http://www.greenlightre.ky/role/SegmentReportingGeographicInformationDetails
      SEGMENT REPORTING Geographic information (Details)
      Details
      80
    
    
      false
      false
      R81.htm
      2416402 - Disclosure - QUARTERLY FINANCIAL RESULTS (UNAUDITED) (Details)
      Sheet
      http://www.greenlightre.ky/role/QuarterlyFinancialResultsUnauditedDetails
      QUARTERLY FINANCIAL RESULTS (UNAUDITED) (Details)
      Details
      http://www.greenlightre.ky/role/QuarterlyFinancialResultsUnauditedTables
      81
    
    
      false
      false
      R82.htm
      2418401 - Disclosure - SCHEDULE I (Details)
      Sheet
      http://www.greenlightre.ky/role/ScheduleIDetails
      SCHEDULE I (Details)
      Details
      http://www.greenlightre.ky/role/ScheduleIiTables
      82
    
    
      false
      false
      R83.htm
      2419402 - Disclosure - SCHEDULE II Condensed Balance Sheets (Details)
      Sheet
      http://www.greenlightre.ky/role/ScheduleIiCondensedBalanceSheetsDetails
      SCHEDULE II Condensed Balance Sheets (Details)
      Details
      83
    
    
      false
      false
      R84.htm
      2419403 - Disclosure - SCHEDULE II Condensed Statements of Income (Details)
      Sheet
      http://www.greenlightre.ky/role/ScheduleIiCondensedStatementsOfIncomeDetails
      SCHEDULE II Condensed Statements of Income (Details)
      Details
      84
    
    
      false
      false
      R85.htm
      2419404 - Disclosure - SCHEDULE II Condensed Statements of Cash Flows (Details)
      Sheet
      http://www.greenlightre.ky/role/ScheduleIiCondensedStatementsOfCashFlowsDetails
      SCHEDULE II Condensed Statements of Cash Flows (Details)
      Details
      85
    
    
      false
      false
      R86.htm
      2420401 - Disclosure - SCHEDULE III (Details)
      Sheet
      http://www.greenlightre.ky/role/ScheduleIiiDetails
      SCHEDULE III (Details)
      Details
      http://www.greenlightre.ky/role/ScheduleIiTables
      86
    
    
      false
      false
      R87.htm
      2421401 - Disclosure - SCHEDULE IV (Details)
      Sheet
      http://www.greenlightre.ky/role/ScheduleIvDetails
      SCHEDULE IV (Details)
      Details
      http://www.greenlightre.ky/role/ScheduleIiTables
      87
    
    
      false
      false
      All Reports
      Book
      All Reports


    glre-20151231.xml
    glre-20151231.xsd
    glre-20151231_cal.xml
    glre-20151231_def.xml
    glre-20151231_lab.xml
    glre-20151231_pre.xml


  true
  true


IDEA: XBRL DOCUMENT
begin 644 0001385613-16-000118-xbrl.zip
M4$L#!!0    ( .""5DB6;LQ0?38# *3L0  1    9VQR92TR,#$U,3(S,2YX
M;6SLO6F7XS:6)OQYYE?X]>=)&_OBT^TY  '8V95;9:3+XT]U:(D1P;%"BJ:D
M=,;\^A>02&VDUM!"2JP^766'*!'WWN>NN+CXC__][:GWW=O/D_^O.[[\R@,WY*^J/O
MHBR)1TGWN[_3T>-WOW>3X5_?W6>#I^]^'V1_I5_C-V^F7WK^B7VG>PX82'A"DT00"OPC&"62=(@D_N\)FOS8MS^S
M7OI3^._O_*K[PY\Z@W%_E+W\Y_>/H]'S3S_^&#[Z89AT?G@8?/TQ__!'!"!^
M ^ ;#+\OOC;.,D_DNN_EGX8ODN4O=I.T^CO^@XK'DV^=Q^KGPR<57WCH9EP0!#D2R^:
M?'.0/?C' ?XQ?Z+X0B_M_[7AZ?#QG_$P*1[OQVEG6+VFR4=A27!Y2?U!OS]^
MJGY'=Y3].'IY3G[T#[WQ3R59VIE];_N7EK^0)?=K*6$_^D^+!X=IIYH$_T$%
M ?])Q1?&PS/A@^Z*UHQX^?TPZ5'1Y6/TNFCH\5'TTT [0]'
M<;\S@]RW$D3_QI.GH93RQ\FGLT>'W:H'_<_"'__/^W=WGV&O]VG
M2?;=9!W+)J7 9?3V']__##PA6% &\7_\N/KER3M^7'U)_HYGKU2#[N);/0NR
MD?$.X>>PS( G (NOSS];^$+2[\X?A\C#;_ZV;O%P\:?9^XH_Y)S9P"K2#%:1
M_5A%3L&J*:K^G9N>?[^=>([@X[]X8*IOZ7#VD?WOL:?N+O%.,AVER?!]\O1G
MDIV-R3,.)@]A>9,_3?_6]6_^]MQ+.^EHNJ;ONJE_9!K6Y*O_J4S8]S\7GU53
M]A\_5O[X="T_EA;39'W9'00F^7-TC1"HHNM& /!V"H Z6LNI=QU5D%U\\CJR
M2>W))J<@VTM[IM!W(X^> .&H%P^''^_O1H/.7TLJ'PV>G@;]R<>Z60J_EK:Y
MWI>).YW6GP'-AXE57;-8U1G%>A)M/5BLK;;66:P'&^%66^MJA$,HC9N1>N+]
M@DY\AJQC!I1I.N9!\3SH^W\=5BC"!$0-U8,J\E9U88&^&\E"YKJS)R ^#/KA
MA[)!KY?V'][ZG\Q\EG>5V-A$ZIE@N4N ;:;T1>W!P'-&ZC5N+
M+@Z"2>LYKAT:;Z>NIL7%Y7&Q$%'@4T04I$TXZY-PUF'S^Z 0\U.<^;]=)186
M2;N1 ')MA;U-,RZ;9IRR_GZP,VCE?M[T\M).XK!R4YM;-KCT%$2.6H=0/\.P
M('14&X?0YH&M"VCMP:7MP4F

@CGU=M:R:MT72:XJ!#S:3+0RNT BV&VB7VD"KI:EO ^!;<@6')4FM M#6A$.G28@6^=?(W-^F'ZVHKTZK2T==,-UN*#FY5:QWN];4O[[U*W-J#A>]0' MV8!VC_H6K,'^>]1MD%?S'>C]#7RKZ@TSZH>)N=7!HJ9[+'^^+"/U3DMT]^GQ;OU3_P/+X]Z?G MWN E22:B^/@LX& M7R>%CX;M$>Y [APG&^AMY-;*JX1_-[@?_>U5S#]6_*-)OB:]P>0+T6!XU5#8 MF?K; X8;>QL\&D]XX])OX9^N&0GKR6VFZ"N*#I_C_L.RC-^G_?1I_-0LL<[( MF MOB8X;2N"W"SC^=AT"7J3C]@3<35(?I3W$/3NA82+B<*7SOW^9W=+^.?$V M8YR%RZ#?9HFW>%VCHBECREMVOR2#ARQ^?DP[<6_R8_F-]?]^:^L.$L^*GU98 M\?W/@1<_[<2+3=@Y9(-PE9/?_YRS\J>W]O9PV@:@#0Q ZPJFM4;O7TG6]:S] MU6=P:?\A% [B_LN[4;<9,%EOP#;3=2, 6$U9=-P+=OSN,4E&[P:=28%HR7Y\ M'#TFV;LT_C/M-?!2\'7DS2U$-7W-3$I6V]=;X5Y.N">_++@M-M2UV% KT;?5 MY_-6GVLE_#;XKT_U^1S3;5N?4"N?4*O(OP(N+DZS?\6]<:)?BB#I97JL8LF( MS/:#[[Q9_3 8_9&,/HVSSJ,WM U)"F<@V$3P@N'83G$+FE>#9O;LV_[79#@* MK"H;J4&6I _]7[PCS_KA"9/\V;"3\>?!W!X+*K-[P4JNY_>-('ZU0-+"O85[ M;Y2V)[9/#<2LRWRF@& BK#2^%_X&H?3,6_] MSV?CL.+/Z?"O>=?,[TD<-IOG#][]'3^OV*I?D^Y#VG\PR= GG>7=^ ^#?C?_ MJ&F0V<2?O/UF X..9*"JV;LT-'J5OS<20.Z+Z)5Z5!&4^'_].\Y6/?"MHGJE MB%3)I!;9=47V..P MDA>V2.=,Z5%;DV16UQV\-F_OHTQ2ABN9D^+YIJB.D W!$L?E. OOV,X)Z\ M.Q+X3^1.CK:I=O)C3)?%]+YEA]^\*-7$$ M\FN1O,BPLX)XA=\M>JO,RJV@\$I'@EQ93!T-LN=!YE/I$$HUM8VWV:Z_;M'U M1DBT2ORJB.3W.,OBIMT[WMAX9(G;+7)?A=R;KE!>#,%M)VQ9]-PJ"UQ9J;]""7;@\>Q5F;/'$Y=6>Z;V5([05#3G7/&&@9@?Z M:]?+LJMNMSAHC(;O(=9)%UF_@;]I_'/@0.#\!FH6(WBA<"[?4D-S?N/C($T.U! +40 M6.('OCT(X*9#8$LH-YEP\VE2C CSTW_K]]+A*.E>7S(^F52S*Z%7$_(MJ,": M5HP#]CMNVIFLZU\X^TY((QQ+BRI2H,WA*9I=2+A75)Z;Q0S*:6Y/IT^\& MP\;9P[54YH9Q(YDW! _^=O9,QVXV);W)M\[CO_^/_T]3U**QC5A[G,UY97X? M9/I3D.G5Y.[1P(L\',P+_ NLU2\ZZ7<>G^)L&?F3'8YP,6:2#:?6<=+ N:(' M%3^W7 6:<[7TZ,I/W7EMZ(Y[RO>)Z/'07?^_?)?D^1#_%3YKK3_BU]Y ML[S4-LDLG!G>))HC:<,&P>;QV5;)'FDEK\%%::F+P+B1#/1T)?N;*P&?J?9_ M=47I<]QE6X>\J+D;VHW-BTZ^H5YK6WXKAO=&S=RJN%\?(K]/.]F@_R7I//8' MO<'#2ZBKY4=D&Q8N'R$LW,Z,9L+F!%NVZT]YM.7$O?=M3W7^HWEUQCKX4WI4 M ]OL&D0#<^T+7>W6ILYMZMQ(3._9KU(\\S%_9,;=CA MS8T;S\5#6ZF]$?]8L?]\S1L(UY,=M9L)5YDUUFJ3?L_>I=:37-*37!HLM1F9 MTW9TM!T=9^OH./GAF[JH4:LA]=&0^N:>1T;O:P?05E]7]'J1',6]7AMEGM,KKS"\Q6]['UZ#@\S6)K=7N=3B M*I?&P:'UT_6W;JVS;N\-O"8\7_#>P&M'=3MD_=J'K-<=P>T]4\VH )S_GJF3 M=#B6^E+6#BDV@R?_4=JYBML#-PTNWHG0&^U&V82/:X7#U=Z(V"K[Q97]U*?; M]C#OURK@VS7>^P'@_;CO6?$<]_3@JBX(J:*K!4 % -P@2]*'_B^#KTG6#T\$ MU;D>'&P@[T;@L(?_SYEU]>Y_%SJ;Z?WW%W:K^ T1[4%FO57EUM"W4=]U:/OZ M(277?B1^=8Y(3"=;T&+AM)J.3YW@ MM:*]JMQ]-ZUM/?BE/?A)]'K'&Z#;PDWS&BYVOQ6ZW8.]0,!VZ4%2^VO_U<.C M-C7ZD[<.ML;@XL:@/N:_5>^;,_X' :2-_JX5#ONXARLU#M=E_%<*L[L>M IJ M8+]U'N/^0Y*?_5DY'_!KTGU(^P\F&?I'RR<./@SZW?RCILWGW/E$U%HF;8++ M'@NI9O%\"14\OI$:\Z'(KIPN>.M(/L%TOQ:Y1[?)"X?66N3N>9*O1>X%D5LY MZ*.%[0Z8IV#C3U2_US9%/ ('F7IE6WYO) M&@:!YEXV6]_+7L^\3;)UID84#Q]5OQO^)_2"?(U[GHB&U4&WC\+81.6-U,3W M <>D.>ISXN/]M..CJ<"V^&HQ,NF,VHW8VX6*"F7ATN;)G&N3.YY^ZZ>CX>>[ MWYJ%C"72YB9C(VTM$#8"X1H!<'."7W\8HAA\]E+NE)YO.=X->MT/@]$?R>C3 MV =@\3!9W7O;L"M;[$=]R>)NTG7CQIVPV\BMA:OQMK/K2%6T37O%:[E]0P64 M-0<"7@?U%JW-.39P$@#<7(-BH^Q>?3HFSWR:\?2@OH(6NT9!^?(]?Y=VXI=& M?&O&;]2,WXP6M."]4M!<-/R]FA.W]3>4MS.NHX5M"]O6-K=EV&;A_/QEV*LM MJK7UAQNH/]1D"FQQT;@7P?RI9F%MDV@WD-=YX.K05;?,ZX'8?\-OX\*9F MT42M N<]H=#H=*[-GE[OQ5L$-,%W[Z?5$__6;V!+VE:GW3]_3UJ3=+EU[(W1 MZ'T3K5:=:RE&,YV\NO>YZBA+? )BDOMXW!N%L\-Z_)+V'SYE@U'2J1AS\;;? M&3PE=R-O2\+OE8\M?$A&"_M;OYMDO?"F-2-_[T(E(Y0TFE=#)@Z[):EU5+Q!\2I+4N MJW59K*P?Y9G[57]=:AU4] M*+0%^$F'AC8#T76PX(<4NMNDHTTZ#D-\'2K#UU0GNXH3FFWZ<7CZT1X4?44E M(6\9?8G\KV5Q9]1ZL/7:5\VK^FO;E85K^^!\@M'?DWCTF&3S!RM&OF\">O', MQ_ K'_V*_4?]A^DW[+=G+\GDFO ^ =L&GIT#\,5#6UE^0[C?)TUI<=_B_J:3 ME3:N:>.:&XC?W_K?R#SK/OO7!TMU]#S\NJ"^GETWA?:F13-M":HV&M26H.I: M@JI#J'8,%]:ZKYW=5U-T[ MVA+>Y:F/4MS!?68@^;KM6T] M;5M/+1&]X4ZZ-2T%S;X69"U]UWD[R.K-7JUX+RG>D]SNM5)5VB[AN45V:3_N M=]*X-S?-P^)FQ6L4_9Z4WU"IYL@@FGSIUO"S2'0+G3)T)C'MIPD'$Y^\_];O MI<-1TKU:AS.),7>E]T8 LW\\TN3&U9U,RCG;,FL7BURM\E\JVFR\MK=AQ47" MBMI9AM;N7[-5V*_DU&:L%\]8ZU6D:@%1)T I\2G0W^2K*YT*-!K^>9D,6]^T'V[F,TC/M=KP'^[9W.8-QO MBM9/!%I%92[K'Y>\S9*>9X1143.D[*G[:86Z7+X[D7FIU,U+.1&/'P MT2<_)I[,OH[[?S5$PK,9%FN)*T1=1=UM"?;/EZD" M7*MH5^AKKG!)J[47U]J3!%*'"+;5VH8(=]$D?_8Q8Y9V1DFWF@_;A/\E!"&J M4;%6(?C#2<^!44'[=9CRUX(B?!"7/I_J4#A;% 6.)=FS3_@;5S!_-6H.84YK M:UI8-156)\\JC@&K>7[]+AGY_QT.[J>C/M\.A^.D>X-8VHDC+8"6 ^"%XLUP MOD-Z-^AU/PQ&?R2SRMPM NH@#C478,>.IUJ -1=@)T_16Q=XW2ZP]@!JRP!7 MTB*S,F!HH3_@T\!3\O+EY3E9:HK\)>E/-"1O"GUIFO#7T#=O@*PF\$P]$G68 MP4/WA<2O2=P;/;Z=/94-NN/.Z%W:;]CHG!W L8W4&VFE.0@FGEG^-:.7FP#* M=F)O""ID5ZCD+1Y/3TD6&L_?#T:#[',2@K+NE\'[<6^4!OX5MT$T+O!8BYJ\ MYV,_NL\$H$L/$]HK2ID Z-?!4S+XVWOQ8:&%5XJ8K83>4-2RLXUIHY9+N:+F M61*?!([CD 2$8S*/R[<070$^BLK'6AI;^]$FPI=)A.M@*_8+6S\,)@69;IQU MU7@T>!IXKB5Z//16MFGC-;>9C!U(O2&8[.=26IA< "9U<#![1AZS9/#:4;*= MTAL"R4I1S6M0)Q[%PY%/[Q[3COWJ:5K&R'@T&4 \N.]47R=Z.]9H':\68+:& M69OP=97FL XUP3V1/AE!,;EQV23W26^U?TJ]3_OCX?2A MJQ!FH9WKR&NN:&DKVAJ(]F0G>%NCVVCQM4%3,X*FDUS6LE+AGMVA.YE _O'^ M;C3H+-]O''9L!_W)Q[I9XEY+VX*,2\3=4,6:M%"H Q3JL.]%7P$%=RTTW]HK@^8^U_^= :!O[0T%NOO;V!;.+9S/96]):V];@![-WM:ABDQ:>]O" M^1CV]B23=U>WNQ[C+-%A4/DO@T%WJ/K=#X-^\O3<&[PDR5V2?0V\^.*%,(PG MC- O=^-G3_+BY9CY8Y^RP5=K;^*>SGB*]EW1(37J)Q0*UM]A+NY MVQ+$+98@:I?A[1]QM!"^;0B?\SXV]7><=4OGV2:>R/N>9\^N23/J)Q_AW5#H ML,25N3?>P);K# EJ65^8VX"ZP^DDQNV*@KS5@Y.M,6J-T>62;]P6.]OJT-%L M:QT:Z@Y"=.M>6PBT">A-)Z"U0_%J9W!;%V_KXC=_**JUZ:U-;W#BOUB%; UZ M:]"OHZJY6M)JD=TB^WI*9"MQ>'6]UA;R";SX^!SDTBS4K2FXKJ7K]D+/S0"8 MWZ8^8=55"+^2IMN(UKS< ?DGOFOS[]:I73K_!EX7Y!L$=M2%_/'3&L&W_<[@ M*9DQ[=V@4QY8ED_>]K)6W:>TGWICXA_ZFMAO8?NN89\O'^;;^;>GZ.O<-=_*))LZ0S&C0,9\?R)9>LE.SQ[DH1SM^[ M+,,;B9A>IUJW!O3K$?S;HD1]-A$>Y$M6JY=GW)0[OB^Y-6VYC@+ZQ-3QQNW14L-M8 M@C9KJWUA:UNI^Y?,OR. I5G"*]>X5PBY$3U]70]@ZP);%UA;%UB'Z/*0Q+A- M,ZXPWZ1MKTBS>D5NV#$W!5/7X&.OS-^=:]YM4R#:Q%:)6H%JMXEB;1WAF'6$ M"\VH;,/@1A6'#FIF;85Z5*&>Y):POAKP]8-9\ M@:\8\6O<$J_C'O&ES?G9ILLU!21-+)B?LW2JXUZ8<'KWF"35N\8?1X^>%\-A M,AHV2_+K*)M;B!)IS2V,.IS9 MV"-*:C6CU8PV39]."][L?[MZ/DJ7BB M.X]R/F7I5_^,ZOO?ZJ5#SU3[WV-/[*I(FX+9X_ FCUYV94XS#>5"4/SJ6WP_ MQ_V'Y?,V[^-OZ=/XJ1GHN?1=O3/VS0W9$O]N)!@],2+3?HO(UR!RD7\W@LC5 M8+)UO;?H>D\>T459XMGEXD[:2U=2"9?VO8*G<>_.O[/[Y\N[9#1*LH_WTZ\T M"R%E,N?691 M-_ RBE^>XOZ[]"GU84D+V!, =BN_6_3NCM[_>GX_R![B?A1B[,#/ULJ> K1K MV=Q,K%9LF;5 -8. M\2N'':)!O^/)R"9;*9_3X5_Z12?]SN-3G"T/2;^+>Z5>IHHOER9E1N/A:.!C MP]*S#4/Z%C[-<;_ J"/!>P.;%X:N;^;SF1!>AT,+-4/X0@_+_QUDQDAJ15PU8-;UL-ZW!0J6EJ>)>$ M;I]6#Z]0#RM$>T.*N%IJJ+LBMO[P6O7P8OZP#O6/IOG#5@.O4 -OU0S3+!5I\NKTY4E635#>.M>FJ8/374O M=5"^FE4X6G6ZO#I=61FA:>ZE+2/44BN:74:H@ZLI3<&W\AR9/AA;/9FG.:Y@QA_NM>[U.]UJ'I.H48)M<;MAB;?HK6YAQ0U [9MK0NM-&N-.K M3"#>QYGG8Q0/Q]Z+S'E\.#[#!:)#]*WE,.[WD71K_.3G96O#Y MEJW;?HRY(0B>HB+G/[I/AD&&<>]]W'O.PN3\SISOMX2^XE=VX\D-.==CI@\3 MV_?[(/LKR8;A22_"24VJ#>R\Z=N++VU2T0+P%@!8!PMXS.BOK=;5N%I7ASCO M%&!KJW6UJ];5 6JG* RW*47-4XHZ1'0G EY;(UX&73T*Q'4 W(F*)Q,&JWZW MJ$_Y+SXE61B-UZ)P&85[,NF&DHM30K-%8DGV1Q[Z:CO&H> MM.E$V\9YW6V<=8CO3I%0M#;MPC:M#L ZZ<;_I\>78=J)>R9^BA]NVJCMP94; M36;H%P'V)VI M1:$M,S>KS%R'&M])4X[6'=?7'5];+-BV;EU%ZU8=W/6*3;P;^9\,=/V2#!ZR M^/DQ*.\2YCX,LM&C\F[%?](L0*VE;8Z6,G$W9*'PKE H3@GUNG][ 5T-"(I# M/HMDW5!TM+/XBR?L.-C6JQ%_\<@B6:WX6T=P7D=0!RCL'1.TEN":XH"]Q:^& MZ?59@#E1-R1ZTCJ!.CB!&B6&W23]][OD(>[9"0W+Y8_#7W?6_RMU[\YT;>%GVL4_\[Q?BO^:_3[>Q=^6L-_+84> M\D_TSR_F;%)\A9$D>QE)P-Y@<'0?V0Q607!I?T+^"9O!JCU=+\ G8!5N"*OX M?JR21U= V@P%I/LIX(D*N(U %=T/5?0TJ&J$!Z3[>4!Z"@](FV'6]PZICVS6 MWTYMU3R>'C\]Q=G+Q_NW_:_)W_<])S[^Z^\DO>-+6 M].7E.9GG79^R]*O_6/6[O_5[Z= _:/][[#ESEW3&61J^T;"8_-5\R3.W71ES MNK@^[7N4^6^5[7GQ2:W@M'0V.'QMSJGY#]P>F)9."6]F2PNE%2C9;QW_G8?D M2Q9WDZX;][LW:(UF&PCKF-'"9@4VX7S"H'\W&G3^NEVXE)C0PF35NMQ\H#,S M+6UDLPM@@N5-^P^JTQF,^R,U'":C&P;->FZTP%D!CDN_)=WW\>CF#4TE(UJX M+";D\T?3_B^#7O?VP#))OZO9T$RH+#1#M'UO)Y)?[=H?<"OPV]GU?CO5\%;: M9S#/Y!2>'+?".XOP\"E\ZV&FMMR:%/7BX?#C_:1F4E%0FGRL;D_X^X1_ZUBY M6I=:Y.4-^0C:FIGFAO"''5UISEFRV2+TMI%XZ2PX.$;4.\2P. M$9TP[C[)[*G91&%5,.MO/YP]^A#D.''\2A$ &$#_["P7S<+6OO%X?J,D1E[ WQP)H^],8WJV%&_ M5*%9.DOP:K*/B^Z&)+4US3*/C.YQ/YW*N#]>%8)+^X"GMKWU'+I<)S+>]9.6WBH]FI&WG3!6O-U*YY2>G MZUXOP75T;?G9W)M7_>ZDF23_?._?3<:5:"LX8'_[O/TG0SE ^;=WPPI<+W[X M+@?XY^1^*6WY?FJ^X\[HC= 8$F Q0U0S82P'CL,(4X(5IP+ [W^^CWM#C_72 MCQ=OC,99*#2X=-B)>W\D<6:GX<,.+[?" 1M% #@&!%*$&80NF9DB_!8_X(-;4GDKK+92:8 9 MI11I @IB@]Y]_UTP*).5%484>_64&"_3OH&\6C!";V.$,0X3*P%W6G"O;%@0 M6C "&:]N949X,TF$I ?R86J_/B?/@VSD/PW4[&07I& VXMQ0" "24DBH9\8) M^#]^__,?P95M>]/R:ES:2[+(\_-AD.VB(PP#)_PBH-(".F$H,:Y8A+<2WEB_ MB[.'Y#O5Z22]$'$DW>\F[UA/GRJCXG#^G0ZWA_]"%^VLF$ M(<\G2B)%3<2U-(Y;7"Q'6N=E]_O+KU^^B]2GMU_4N^\^V__UW;LO MYH?%)2V_>7E5_QKTQGV?U$_YN0N$#**2,^EA[<7GA'?M6,_L.K31]S]_&"R^ M?>4-RZ__/>GU_M$?_-V_\['(H)]TWPZ'8Y\O[,"=2%/,'("0.Z6HA7R&9!9Y M:U1"\II7A?5,XJUH2D M;>K_5EXKSM*$'JL(W0*LP@D?XW08#9JQ9Z M DK)9DHEO0;#=GP9_KU>M M$X4(!OIH4UOO!1VC E$ \!3LB!O&E_A29,K@!V^ "Z[L1M1EF; U/( <1%!; M3HDV1D62>A><,\%"3-"87I'Z6#_N?TX7$T_/AWWUOAQ_1Y_E.[@'V9 M(, @U'[ES'M);A4BD= %08IK6TE0!3D[+:^*KBG9TZ]\F+QA<.__E@R?\[+( MR6&^%#CXE(]!A05P@'.)F2&Y? 4@5))EY9]7;F"9(UL)JP$W*O"^R VF&2?0 M(>*0TCKR< \!C'&4,>.#![&6&^ U[)B;Q ^# *>XIY["&;_!?30(J55G-/1Q M0)+Y6'*-&YN1.O^IMWV/SDEN^#D=+O/##;(D?>@7!]S]O_X=9]V5IJ1?D^Z# M7[])AO[1"C<9:=S5,C%W#4W@(4? MG\-;3L="GS%RGQX1*1VR6G+ (UFP,&*XE!I!0 @BL%$\G/C3SXG'8O_N[_CY M=,RD7G.15^:(1P9;I9Q6L%!E#@4K,1-!&"*G>O#RB(QP0 IK.*52*\(1=P04 M-LU!1LJH"G5$0B[&";H'JJ8#@I,XG".=/WA:8#DFH)2(($D(J^>.#)F)*(P$ C[;@ J!RS(66F$1:4J2Y-8>>+(,"(^+-1 8:*MC%BH MW/""==J6#2:&D&+6*!U_._FQX>BS9\=IO8_6WH\;C7WH[+,_!Q6W-#>8 &"I M5IDI(99-\S^GCK,=5CO>B##RUHR!$$J(1M81RIZ6BV+$Y M &F9@9 (WB0&GLU-:&L]$Q&S/O0C7HMQE#>Q(.BHCZ1+YM%SD>U9C3D5)X_( M!@RD==)I()U31OM_T*8 E%( 5T1O@ER*#74OQ ?K6G.6>C@4#ZW4&Q>B$& MED+A PHQ%^'E!.!H%4QEAE=22\PG,'H(B*"!M!6LHT M(,:<-PBCIXX&$8)0.^'C&& D45K;?(/.\X\S40*BST_(OOG)11EXOB(,T1'B M4"IM:>2S62H45D411G):9D8G?V\N^W=I'3:+%)@; (>6T%1G-BJ9(,36T? MY-H 4-V5AHJVM-/Q[)AB^=( F2P7RC#646B""T>T&.(6Y9D0]T$G-)4R@<<4 M2A7'9A)Q<9K]*^Z-?7 S.0L7J/P['3W^UA_\.4RRK_&?/?_JY_%HN/S.S^': M@D/PZ)[XZZ/[_LVSOK^Z;4MU N10ECF MC./O!IVR\9G,IO[X'$Y&S C+WUAABNA2$QFAW%LAC#0PT/^S3_HGTN#,^C1@ M;1/9N=E4(_FL^(79@O3+Y%>G[:&+TIE;:Y?VO5ZEX517X8R'2Q3TM18^N0X'08;F0S]P^&45T505'&299$#6JJ(\$A:X#VOX-2! M*.][MHRJJ%3FPG2) VL7N%0 URWRBP_ZSOY,!Q]&?1-\CP8IJ-9D+L+/E?/90H)K&7( M<_0E2RN3G MO"%%1%7A /XP1^LK5WMJJG<(@J<;#(.LU_T[[58XC>7-)J>M)5B+T.PJ!)"0 MSIC%;76* J"X&F853ZAA&F]FE8F,X)!30C'0Q''' 2E8124CU:RZ(EP53]AQ M& ZVF5DV'"UC//)66#-E,,,8YLPB!JOJ- M0K<%5_:WUWLS:W5HK[C16 M1$1<"T%]Z*[F^%(*5-DM\(.@MX-;D[@%?'JIVL-0!(.< +>S-HC MMG8^FO;I"//)AP[S;1!3LRC3\FJ6<8:/S+*W_)=D7],PN7T0QLM6S 7:K,G.12#4D8F-"/?_ MI#G1!>^,U56:# GQUO!D#%PAZ)*LVZR]Q)BP?6"@H!19;H'546$$%5W:.RI8 MYQ\7M\"XS?I*H8D@C!@4@B'HW0+(2WV><5A ?E9]7<^UO*GD<_(P[DUV)H=1 M_)Q..L_^>^PUNWL_R/*_J*[_4]Q9&1VYZ>K!]4TL[T;='RK:5R9M(:HSZ5>9 M=%=[3OIU^^#BO\99.NRFG=G&<-'3\H\_UN\K,:_KAF,E?(0#5(2Q0R2??^5T M5#Y:.-WW!',Y',"=!=Y.FTG-9"1VO^M-Y603.]_ZO0L;Q).;ZF>[VGD+S"#+ M]YJ[\6BV_;SW^$*IH2*04$"P B0"/G7(I^D8ZU.N$NV$L\7C,L==_=F8LF4K M+\Q7QEI1#(5"W B@<90SQ1D 2AW,6 B)&L^4+3,1;804A%A1(X&/))220N0[ MQ$ *S4M,@> L3"DF*:KNUW3H]6SP%'YPL7UB;Z5@W"$:QL7R"&F#?>Z3;R8$ M^5-5&NG#$<5+I&Y?TRL)V )@HTTX+"T5UT K!;318$8 J7.,!\C8GQ6 K: M#6CM'!<<20RE-01(0 L"(HE+C>]0(L)>3<"T7VAON"C@ VWO/3S>AI8'-EBTCUQ1-'R[%=*EAKV7K4RLFEEU&)K 7104JH\A"*>3QK# M%%IF2E-V.!+H6,+>Z#CZ";=K $$^O22 M,ATQ"XCU4;H6^7XW"U/GR^(D-,QO.-+*-JD )89PX0P&VD4(6&&+V@'D"J * M<8K@LPY8VOS?IZ=^-DW^W=SK%6DCK V-$Y@#X8V<=464$%&[IB<'2K9FQ>L7 M=A1:-G=">/]AN0PW$$0^1/6Q.RV:5TVD,5NS!R+X96C9O$]H #<^G!#<:Q^ M1B$,54$+UZ2J_>=-V/M"AQ/S+NTG@_OIZ66_ALFEA5^2;')UDP^9PDFE3C*] MR67KUL/RKRP?/2UZZ._"11A_OKQ+1CXK^)B_>"73#VOZ>%_Q:Y-Z@8[[?WV\ MS_>@#E';:?O_S)PE,SK$]R&\RR\;AJ_=I MTNL&[D7QRU/.-P>_R*?G_[I M&3?=9OS4ZY28%A)D@QGRFHJ58SR<%2Q QR/,/=,@NC&N_=?S^T'V$/>CQWB8 M!-Q5**N00'E<*6!M9+C#Q$0SL(6K6U[/M_?QM_1I_/1NT'\(C[Y+OB;9!M/\ MRL-VZ\XT"F H]RD%8B$QM\(#)/>X1!HE1;67*H[/K:'A3#3.:['KJ/.D$151 MGVI2J"-O0$S>U>.I(Q&NI@[N2=V7Y.EYD,79RX5$B#U0@3700FDMLU )@LB M_6=1)9$(+!-9(N)<5&X7HE&::^.(%5@Z'TDYS*,91"D#E?3AG>G[,.AWXN'C M-"1)^]XN='-;TW]0X6SHI ;XQ2]V>)]DH\&'<#W YZ23I),S5'O79HS#.HR% M!X9HP"* M H[?-PX'TRAJ'10J"#DE>L\';U;4G&&+7+&.V@.(D\J4YKJ0*\2 MS!!:GD9>>WJWY%W8"N&H"E4CQ@!2ED3(T\ND1MX'LU+I 5%!%_+[8Y$]*64O MWNK3Z8R?PF90TITTL\SO ?IUT M5[7#JI[Q#YH6[OB3*+;746U:G$978)PFJ M.$9JD8U*E!(*%C+?@Q9X O(63G,6OQ8N:IR;K4^3\[:)ZG=_\]9KZ-]@_WOL M#=M\@V#+<5LHA8MHY,-5YIS1AC"KBN.V"(@2GS"AL%E\6IW;E88S@<536P\C M(P\,3!TQ5#IMO''4!8JP*6]MP,F5>+7B#MV@))@Q"S!F4 &-.,$8DWPK%TB) MJ\:]R+H)GYY#29#1))(1U1)"8"3%FJB"3Y&PY3/IC>/3:Y2$02 DY<("S:0! M1 CH"NXPBDIGP2_$EW";W'X^Q$&-F5&A L(4]1&"9#/M%V3U,J>PK<;!*\0> M%G@"\DZO'HYJQ;E4#",?2?C_@\74*&VY5YCF\^DUZD&CL#-+G"3"$AQIP_+M M<<\=PFUI5[%6?-GD/13S:6LDL* (6HS#/^134T-7:MDY4H3J)O:S> _!P@!G MGS]9Q)"5V(?:,_MH:'GP#(2<-(M/KU$/GV=I+H74V&-*+8S!7'*5%UL)2 Z]O+.$$5$81<8 M,2>94T)#I_-!LB$9T5&93N]5-_B3XY/YNAC9VP:KD3:1\EFVX)ZJ@KC0_5%Q M#\52/^!>U,WZ_DPZ[/0&H1MP/ZO&(%/>1V%L#3.2^S@%1+/ E\$*JT;IIHRG M8D&O7OSI 6F8#]S"R6[H\SG$L?%![:R$I'!YD+E_6M:'":^!*P!&>YPBXM-; M8 B)%.(STF6Y(U*RJ3*>B_1-]E)0GXP8:QEG/OF FH:[#L&YY!5=E@!O*%V=FPFO 6^ K6"&.NUM M&+.<4TKFMI:6\A(I-H:4FTC/3X4,[P?97#)W/M(<][M)IAZR9'I49#3XG#R/ MLT[8U-U[4T9C;+1WAM1:P5GD'@TURGW;2I-]YV:D6MGSL)Z),0&8LX57O7O?E6TL8D= >TL7TA(?9"F)CE[RS$.-(4;EMBMQKEGI2 M>F=6?&%+O?BJ&V2SDV#AN$'<3\.)M$_9H#ONC.Z2A\EQA)D_5%^G$T _A5ZB M;/3R=OY[DR^$)I-8I]LLX]M\9)^=C MB]'+SOPF5FL & B^$$?B&&/T^SCP;2RS>PE>H(TDA,IIK MQ*5D$2P ;"% 52.> H#)+?%U,!ID_TH>TTXOF8&Y8//. +8&2N* 8#S,QK02 M2@<+2^&XK3Z[0/BM,OK3X\LP#-PQ\9-?U^YFP@F+1>1""&>LC^< L44D H!W@D9>@%E@A[^QL1#6?F6,(JO_#]7'Z0$W/M=)6/FS#U1IS<_&XD M;W@?]\>L@L"@R&*+.9><<^53BYR]#"-9/: /,'E;W,UK;_LREWLGABF-( X' M0Z$T3I)9XB'HFN-L[,;L@?_H/AD.)Y=HO8][S_D!XS?1VRFZ.QY/D6CV%0[0E+G.MSFH]:<(@.-3V_#3#SH\S!%"KLI M&8:R><5=4K_B;CB](3&(?-#J(22T)8+G3 Y#2=9$5W6N/!Z=R:\M[GH((\D1 M!T)#G\Y:[#.$0F\YH.OJYS7V_T=G\5&+N]*$IAO"#6(,X0A'W(J"WU:ONP(& MWA*_CU/<=:&LJT6$P_PO;B)N>%%-"-?W5L=8%-^2[3BHN!L!*,+44JAEY"P+ ME\_-=B>0,; %\)&*NT ++GR,02'#7/#(H/RB-XR5D5'U-A"6]$89?6!Q5R$J M,&+$"L!I.-A"T:RX2QU>LU=1YQ+ZT;E\E.*N$$*I2!*#I!&*,A":^')SK!U= M%\K5./\Z)I\/J^WZD,$';BH2#(1!*XP9-JN/P74;$P#?B"E^;6E7 $DB[^VX M#14:ZP,U4R#6+Q5797C@!XAOQ/Z^LK0KD37.,2Z%M[[:1V=0@EF/@\75:0>D M^+:8^[K2+HD8]*SD0@!JN'!01JQ(-7P:4@U@(&[$M9VHM$NEBT!HX$78,HP! M%=%\LQBL:Y:Z-9M\U-*NT!8H)12SA")B=+A#99:1P#7#>J"L<37]E"P_9(_3 M8<*4Q-:$2FXD0\-S7H4S/FZN3D3JG/%MGCP9,:H885A%#E@604NC(L/ER%8. MMZIY:9?6K[2+/5N-LQ@2R12ESB);."?.E5MWN6:-RS-'9_)K2[N,0L@PB#"'1%%J"9;'=Q@5? M=SI32;@0=)P18GQQ0"92E+)H=6HG@FM("J?.FVTD9?6!IET"N MN95 P2,@>%&Q:* 'GGNKVL?JW%><'0N'Z6TJX%/"+B!W% =CM4[:PJS$89N MKME"1C4NE!V3SX>5=B'%*-1T)7,^2@;,FPE4;/Y$"JPI[=:Y+>\4/#VX:Q<0 M8;5US@D:[E6"M+A! \O(KBG20%CCZN,IN'M@:9=&G&JAL/69!T7*2:5= 5VK MHNK,#M(;B9"9R'GACH<7A M)2(G-=($^4R/.:@-\WFTG77M4K)FCC\Z\J[\9"9.O'XFSJL'7SGA/&4P,H9; M$>:NF&C:K M#.9N7QW0LCWPZ:(4GH&]^,4GQ!?TR^\=?4Q]>9IW'R6T#O>5[ M3(IGWO:?QZ/AY &X;504%-IRX"3D#!A"@9+Y\#QC 56E04/7S"NT;12L!EIR M1T+?-^!<4:WS@<(FBBRDM\0KO&TP/?(Q"X\BQT2XR,\J&16\=,$"" N-*(M94!776A[YRF1MB(1%9K1(CB$8!.YDX> M 1SN*ZFU^AR95]M,C6 26\!01)!/JA!D,+_*T\,K6IXI=/6\VF9J ,,(0>@B M;KFF(IP=S>_J!DA%KG0;Y9%5<=!)DN[P/AL\I?W339%C##D&*4"6(0 MY ,GMW^40AOIK9!@BU0>M,[CT[EEEIR/19##+)P$$HQ091"FD.K'/ M[?%T\6Z-<*.&1R SED)-'>% YN/;%!>L-+YMHGF+5%2M8O]55J!J<950*L]A M2:5'D20R*$T^$-6'*-263<1I5EF!B<55NK O1TUH_V=$"F>QRM,7KGW<5+J) M8W*K]*E669FZ#GIIYZ4TY7._O'2)9$,,\, )PSXQ2 LV+;)8Q &K M7 U(%U!'GY[C_L(R?_!Z]TD69U"NK0X)ZW24BC)F"L-!:Y5,* M]OW/G^@?^?IW7=Y9Z$G[E?1HIR"+E"+2AW/4ARQ,HV+4)8':>'K0P?1\SB]* M"+?L#,,LS&3XL7\7]Y*/]XL7+/2[)ID$//YWAWM'(1%3W&L"%H8JBG&HLN37 MC3$@-:L89H_HXI7DARSRR!1NB3^X51CZ9,ZZR&?WAAJ1C]J"U"M65+Y3R\L1 MXUI1N"7R8-1RGWH!Z4V%"1=>&FT+&3+_KR5?Z/_#CT;@@X^PL\D&])T']R1 M^[#)CX[G]A$9>#4 M(B(!O+:51MY.[>$BI:]:[ +1:=#:Z?<_ASM"AW%O<%_426V<]9,*,[,R]V&V M8^0&612/8K^RP?-C$O7B]&FH7^9_2COV:VD#=9R%F\.WNF-H'!?"<2LYHLX[ M813F;Q-ML7(+7-L!TJ/S)?UX#1Q2KBU5Y>(5.CL7SAFD<2DA8\8Q@B/B-%0^%O5! MFO:AOF0*E7+/-XB^AA^3ZW\^Q7ZMDZM(PX;IH#]U?^_C?OPP^1V7A$NO\^V' M'=A3_:,SF,Q-E^I^38>#[&66/ZW<_[WFI[P*+GZRQ'H]B+/NQWN39DEG-,B& MT6.<9D]Q?TM;;Q1N\ 14,>G#-PI18/S$?/DD2]KJ/1LPVQ,[A(_;A!#,?11G M6;!!?WN:/B>=P?AY*M;_'GORNO$P_K2P*S2SDW/^AM_8&=3-D-KBC=(^_ ;& M"HE9)+G"AKCB6G!'B(1571'P!PHV"^VX?-\FY?=>+(^]EVO7M>7Y^,BGFYSI M,(K>1L!'K8@5#\+RIUO$1>^>&_=ZGT/-9IYK&%DC991!*&. M<,$\ZXA8,P#S9IA7+AHLZ2KBD==192*((B:-M?GT%(\\0];>OM$DYGV<_7R( MI][VI^6UWY/TX=&_3?FLQ=N+7\+A,>/?-UO9OC!TT&AK*8),.&FU))SGMUOY M5$IHNYQ+^45,5GL<=AY(8HUXNQFE)O2V4>YYRQ5S'#($<,';$-5=,V]S=3@A M8-Q*,%_RE M3)MZ\]?'8.%^YGGYTR1_CM['H_S?/GA&?/D[Z7U-)@G14#T-LE$H(X>;4/UR MTNWWF2UO1 ! @4(T\M&_H=AIS(O;9JT%>&TOT:N7>4J"-_6;24>HSU !$PQX M?;.02S,CV-"UO8<7(WB-'FP3+- ^NO6Y':.8BHCXC)P5?766:[CV.KA#5W<" M\C:)D2+@,/8)#@ZW)$ON95K(1+D?='$F=WZ;F_6D&) ME<*Z,#<9>%$2&L&BV<\**LL=%P0L7)?X^M6>E/!-$H:$0"(]C98JKB)HD"ON M^S;$H8K&5T% +2@_4&,)!!%5RA%G =8&8)Y03#RV4)YLT2@P^E]/;(/U5R@ MJ"9:NPB$"V>5(J M/'VJM2I @D7KY#K071^^7N0_X)+OR:O5>'0@$2-4TQ[ MU=3&1C:?!^15F/C\I=Q7*=%^DMVVWM/2ODG:A""!PQX781!R$V&G"BVVANO2 MWG'H-:T)Z0>JL>6$,T@ ]Z%5Y#641_FP#8]O'(&2XPW2QJ\@^0@ /U"3H37, M&6*(%A\?THR;P)"#_UZD#92!=I%G()HWQ^S U2 MLT#9.]R2.T*"T]V1O&6I)Z-XXP7RPF*DC- :04EU*AH^P#&45>ZC1HALH=\ M3T'Q@1H+N8T8!%)JQA0,43.9>23*76E;/O1J\,,(?1V&#]13/$F$(PRECJ2& M6G,ZHT]35$IY_,]Q<2SZ?NMG"XU.8?,TC,R8]3?%K^NCD\QI'RX)G\81RJ1U M..^C0\8)!TJD^8@2P 6UW&MUQZ)I2^<"O,<:66 B6^HK M>P,%YQ1?F*@MS7*0 ^5M"?:441_(!S6;"0I'Y6:Y-XC1I4QF;Z+R3;6?5*>3 MC9/NI/=(;M3M!KR:SL! &0K$2^0*\E?_PTGFQQFN0Y\VN:4.#_N9=,VWBZN?-9FL_XR1,= M?C2<8)KTA^P9+'ASBUC8#L.2"*Y$I/,#",Q$E)93.98?23GVLL_&BE)[7.EK MNMQ*Y\99?[+SY)]SZ;?P3U7P60I*O%U@5B)AN50^]"0@,CEG(^H#M%+,2= - M,O9=$@^3QT&O^_;I.1M\G1Y?VL)9Q".J<&AB]@Z(^ZP;YM,80ZM]!$H66C)V M@YR]&]R/_HXGB"W^T82SE8/)%T+XNI7/VA#J **&6B:I4L#QPC9846X"19PW MF,^;XE(@,$+* N7C4 FP#W;RJ7Y0P,B6$8> ++F"9K'B7%:2(*8 Q2J,LQ5( M0>54?KQ$()_>E,)B_[<;9.PA5E(@'VT+JYG6$=:1\5Y^QEE!1'DR"LISXMMB M[>O-)',^!T48:ZDL5U89H OC@(P19I71F(C3\[G;34>3"62?XK3[MA_%S^DH M[NT7&V((#< ,8:6XHH8K(*>G["'@-M*E^J /#"E=4<_J=1RZU']WD]0KPT/< ML^&HW')/XJ?\)+DYR9MD^^Q MD3-6*N/5%Q O 1/!0@H"65LZ(DPD*]+1$RWU:%((C64V(AA0PD.#F78DO^5( M0(?XT4C[O^,\]_XR6//\)#7KCJA("+<1Z,.2&U0A)WPH@*EK5VQ MBJ =%W94:N:6KSB@,QU^$40VZ$].\BW*<\TKMDA6&@&ASR=#L1T([AEB^(0S MDB(5E6=,-9$SX>1T."8XZ/RUC1M:,AUV20&C#AD:66P\-S0DD0%.E5QQTS@1 M"AKAF-V@UTO[#V_]3_K K^K$W9+R ,4=43XPD599H9#*E<=8+$%EVT>CF#(U MA%N8$$ZI&N(#M-#OI0(@,)LP(2)0LO)>31/UY',RBM-^T@U'D3P\MH537CF( M99AZI>'$6P_C_W7"$N5=A"6E7.L<[)BTT/VYVF4W.8DU3$?)79)]33O)M($N MG-1ZZ$]^94U3X):= A%QAB7$(2%BD426FKR\002DUI;B2<96?>)I*:H#]\[B MQ8PC6E'EH ]-(L#"H-*\A$>4D 40$9$H! !PP+P5@1'CPB$]#Z.*N8X<;$I=<#?#_"WM )YK80:A M I92SJE3+,HKCH12A,N3O22^)>B2\P4ND(>+MZ'B/KN40@O_\GS@#Y'>>982 MSE821PU<@"*"8H:-_P]7EJ!\4+ /X+7/:&[N""D?")*D5,. (5 MTM "6L2.2-RPX=DV'P\!$'$I6<3"U&T2SCT4@8NTIG1RB:#5+;P;X-YY*BX( M(TF9%(@H""0'C,#"=1I53CA;21PS<"$1(80J#J%/?ZQB5,QR3\CPZJ2"F[,? MYPE<./;!HU2$$Z.D%M 4(A#>$K4B.'[@$LYZ(0414/Y_N$-1X'I>9^145!S\ M:FW.D0,7+9PRFKIPJ 7SB#F%BLI!N%BPZHST19C?ZX6^\J1;/75ART#]N6L, M\Q=*C4CVZ;DW>$F2B:&>3F?8TJ!.E66 N'"&SQD0.2/!]-8ZY/]9E]LG2NWY M.Y%S-@9\]M8Q2\.@GW6^:I'X2$>[WRJX0)9N>7-<*H0A)M(Z'^TSE4]IBF04E=OW<4UX,)V\-K,EE<#-C//&A)M.1<$B9LN('*9Q.%8A@@ MRQ=K3 :Z-X?Z#>9AD0LL\FP@WBLXBJT2ED>H4 +M7UR>8% 7)IS>/DCG0PZJ M$"3$,6*L=OE%T6<8*9!I"$U MBA=!%&2Z?&7CY6(H>G[[8*$S(ER[QA541BJ<3Z4R@-*HQ!IR' ?R=SC"Z@;9 MA\$H"5=JO!O$_:'/29+T:[B;9\M1X/7#KH6/E*WP&2W@@E(LM2MZ^06CN'P: M<860G9=U1'KH9GH@E5(8)R@BWHQA@V%!C]6;2]V'TS-*LOX$0POGN2]X%>N" M.A3+6;X*([_H4*V_Z'";%C 9+L,@1EH('(86D7PHCO>'B)8V=2 JJ\&.3#L2 MIT]S$^7I.4T-!0Q'3OB0S=E(0I/?%.4Y+4G9(4%4]DB'<+H_2KMI;QR^-5^K M_=;IC;M)UV6#IV"TQJ.)S?IX7]1SBEF4TSMPMJ>\KWN+?JG^@?T#H&4CPKS[ M8Y[9RE*H, F'$$%^P%4HL'1Y^#"L8QAF( DH^0+3C\&_ZQ3(UH!L61C&^R5! M(@Q-V* 7TG%MN#?N#GO_%"E3(0S0/#FL)GOU5(R(^X0H#(1 3(>@P:G\>!QD MTEH5M;(XCTYHR2+,2!@?$8$P?L6G:[DNH$B8Q5"#ACD)3, M8 (4GNF$QJ[264"!8"N0XRN&4EQZUBJ @> 19" 2>8N=UQ:^= %X(0P,N'># MIQ3&<)B,]IS5AXEW=,!GF8(1X@VK]W;Y=B]@2I>G@GGH4217!L5,WKOC2HYV M=E=;8IC/#*QV/EZE@*J\UP@+S$7YE!*$C$(*#USYI@/2+(($4V!IA$+U!C,X M.R!-,2X/6$8<(HH.Y>$QSS]KOW#M;4JXO%W$!L3!H96#;\-,^O*B]N6@>RUWF/F=G#; ML5V+&'3 $04,=2;*F/E@N*19,8@+>I*/$ZAS2Q#DBDA/ &0!88<+0\G\8GZ_RT#-@X*T)' M#@790&N#&&B?52F!+-$J&+4 M+^4 E7HYI13!>S2( ]MTEC$G(/5.$6@+*3+: %& @$A5\BJ4$U#E#6O+@&TZ M:P6%B"FEH!+8XHC(XF)'@+% %5/,Z>KLO1T9,'Y*NJ^XO#C_IAMDLRMZIX&# M#T3U2WY;[UWR,+FTI>IFW]D-T:K?G5Y[O'#;;_[%;09.&Z9XY'-+"<*5QX;F M0^ZQ@IJ53TIXF\?+<"DSX@!.D7ISBBI,J%2.^LS#$!$9D9\IP0HC1$KS0#'R M>E6*!H["J0U70=>!4SX%"S-P9$2XMSY:"I"/TL<*^8"R9(,I0#!L*+R"4[_[ M]&V4]/<>ML"@UD!)R*$(WH&Z2.45EC!44I2V^;;#/U_)X6L]CE@GNQ+J:[HT M,VS'F\"7_"GQ3M0'?TIRZ7PPH8LM8HPM1&5C"EDI_*DK=VP_R1Y>7L$;C0WV M0:"2R'G3H+6FV.:\$9%EI7"+T5*H55?>N+3OGTSCWB_C.%P!EB2S;\?][IUW MA:.7W1DE'*-&&1U)81'W"203.&<48P:432>1C4'1S%[&%?9R=Q81;JGWOT(B M1@BPS-@\T\)8FTB7;T\2A!/0%":]CS//@A)[MG;F*^SDPS0T R!J?Z"KA@%4S$$6VW,) N:2- M3P )CQ"R&DB!*(^ MS-$Z,M',10E6-L>8 [DQJJ\98R:CX0[@BY48<0T8YDA*IZ&$>0Z!,:>H[+HQ MJZCBUY@O_J/[9#B>,T]TVDEV52<-1 0845)YPA7Q6L6*X,]#J3PE MU3-Q="N;#'08E M\#&TX=Y)>2.=\\94WEH0F',F3S9KW?XE&3QD\?-C".V6XII>]^^TNSVQA! 0 M9:2(?"",!9#%#JJGQ91==6@:N#2!L[:*81IO,YU."XS#K#UJD"%$J2(!@M1A MMW$2V>4(L^. V6U!5F1\ NMA&$9^1UPBH6A!FD6\?&>?D/A,8?EV"C\,LM&C M\B;>?[(MMK8"@\C#D5#F0>H#(FH+.@$HG[(ADLGR-OJ1""7_A/_<-,\<*^P M,]8O%GK8&9>?A,?$<@%*>P$0BM.Y:O)/M&FMD 6^B:,D4@I&KHGW$T$63O[N MOQWSZK76JW*/C0^Y%:1>24-GM8D4+*K3AG-1,8[Q=*I<\-ZT#BA3)C< M+UTQ.1K[&",J'V>BD[MN&\*1(Y7N(; ^"P/%R/P%$7-#3 M.MN:E>X9X\(HZ+"VE&('+9]5CG2XZ[%DI7V UQ@&':=TSRT&%%$'J8%,>I=& MH]G^CW"NY,CXZ@286C+HP,*]\#F_),A[=0@4TD@+-F-&U7%V'RGBTZ5:-:K< M>_,+*65.A:Q)"8%T?M#1>R@N_W_VWFR[K>1(%WZ7+6Q\)11\&&JM*"P+B[&@M'"-UOSVI>DE?M"X(-W]16(8B[5%O=!3]&I/4X< M+6[NW'QM\GI"Z3Z6H(77V3N"1"JHJ/IGUHPZ-/&/5JIM57\%TGJ,:%*@E+ 6 M1ST9Z3A!=>N75L!V\D3 EKF+<61SHLH]Y0"JL$^R.BF9C]9]!?S@%%^L6H75)#@.4J2Z\4IV>,JTK?># M4P)/IO5E%?"#9HT1'[R 2:XRV]R_W]>-NBV^[V@%_)-+Y\D%?!8#HH[:6,BD MC(#DUJ&VC5MFO,;+3$XNG-,6\"5G)5:Y('0,?(QBTLFO8\E$326V0B&^%DF= MJ( ?O5.^@,E\P70&:U1)ZS<.1^UX IOXT5*1DPOI<05\-L[HLPJ&C-.UPX9, M?VPL1W*-3!R,%L&>7B(G*N!S!,,Y:=;"%+Y:' 1#7V[,'"DVG>4@V N_FKMU MD@(^2%GQBZ!>& C>K[,$#"JKMF-8C5<0.;F 3E/ ]Q)-5$(Y$P+'XXB0^AI; MCC$U>:($K<;*@\<8*SVVA,]V6& L0I80B83GK+\OX2>]!1#'(HW5LCB&.!Y= MPF>O30%=S-* +5EJNY[#--;)=J:60Z/78&N>7,+WH2A.>THU+NRV5;9]"=\[ M"\VJ2V-@M#ZPD<:RGU+"EUZ;[ F%E(;3;,\YX7IF0T37)%D&ZO#+JQ+/24OX M5#NEEKM,N":4MQG&D=*[\_40E_$S.7N!UL0QM:#10^,XM'U/ =\!D.0,((=,!,AKA^H_!IRXZ(IT> M#>:V5YPSW*,/:N! ]_WLYOK'Q?7U"E.^0_B_;GD=P"0Q3DAMM-5>)ZLE!=6% M-%)&0]@".*'$C<[FG<0\DN*!P8%HHS!*$P0;*!$E'SH!$]0I@FW&;J.1XO04 M[WU_X,RJH$A>YQPE1.4UB7Y\($%JKK8UQHPMXKVO$(Z,A10B9XJUV]3$E*GO MS,_@FSC7UL;OD0G>/TI0@(."+$0H;"U%L3%W9T*EB+%)6.HK@!R;X'W73MIJ M_H3TI98"@] *=7?M;(4.:,=XS2:@Z:DI'GCPDYFM=-*6CW+ H W('G]&D]*I MG135(,8]$P.O?I+]*$',E#FY]RYSK@]K@GW;=B_9JE@],L5[KUWF"[?*"#@; MH%0059\_45&6MCW^;8YOG9[B_?=.DF'WK5SM1F)CEDAV49D6J;13GWRZQ490 M/@+%^RY>DGSGE&2O2X[S]P*RW_XI8Y;08FR2-OB(<\P)S\>[O.=C7<[QY^1J MM;?T)DZ6RR^S^8B'L ]Q,'"I K;\8B)XE'G0''T9:@&U1>^K$W /* M#R+J-%R<#+<8738%,WJR)2=$*;NM,!PELY%OW;UZ%I9QC^+J2*.WV@DVH167 M 5T*]_)1]F&]JQ?>"XF3J8WHAR]3%8$K!?.R8K@?:6O7A@4J M9MNN\^2@X7ELSF.$,)N'R?R_AT10C,\>,!)6>*HZ3.SZ55P12FX2 %0;,V;G M$L$^@&IV#Z&4K**K@!0%*'81:T5Q\&E+H@A2/X_A/270?XG1<,JK9#$Q &FO M"/L+3$DT+\7/IKC1+G "148+#A<"ATLI^B!E?WJE;17/)F_C)?@E2^&P&YQ- M)A\ G"DR""JIJF=_]]=)U*4<6* MB"YP&,B$4J30[6#D?P335/\YP]Y$ASV&OE/S=;+;+:1,"6U(*A-I62SVLZY. MB>2;,NJ[0P[VV#(8*(9PPDNZ;L23D?.:'+7IP ,DI93;$)]Y?@F:5:?5;+3D MR-7LF%.=*(1R-O6:E1Z;P.O=(4''V#(8R+8A1% <-WI6K)8AIE3Z6UL\MF6N MBON!A[C@\_!UNF0(,QMC=,)Q6.F4)FMDG\0FF9HZR2')T&$B2+,_9Y?3^>7U MKY/9Y1^+!T2'+W$QOUYQ-Y:0]EB$ M)PE)LBDN>\,V4;M4L HIF I*XYM.^Q?GVZ>Z5[.E)M-(T9O1$6+>0BL-\^ ;@%AQ]6 M:XCNB[(5PM$R>N$;.HR)TBD^:%XD]);CE"C[#1W:NBT+N]@1GEQ(+WTYA\) M*11!@?\SFU@(U@')!N>]EP*:\>ABQJ M.;WU$@-IFYF(*KG#XK++7ZZE?2TU5 4&.88H&,F2599WG38KY:=!PGGVUR^L,UNWCV[/O?&?P_)\O+/[Y\GCX(&>Z^_MYPRJ]7DV[)==ME%Z\FU]>_ MO%_]S(-ON2-U]=>^#2S$_>IFSDIXQ0XEY)PL:-/I%JS F+?MQ^:_(++WY':L M7$84ZMWJ:L[>+_^Z6%S6EH*?%_-IOS:*L9S')$X1>=M46CJ:Z[U 9#1M<+WZ8'Y?4MB^*?6^[TX@XS M%(,&=(CH=*C.L]]9 *9V/:LM\JP%)$,O4ZBOZS#G*$6065(0K(:8M$ZY%[Y# ME.>30!B00"F@@GGUMG/?"N(IJ(F6'@E$E8$H9 M6P)WUL/?WGQ<+&?_LUGP.?7]_^'G:D?\NR"]SE =#Y;3E@3AZG0\QPC M;CO:IU-S=?WGOZM)^N$"H*],T845*1; MFV<7'LQXKI4JZ@"Z@1?&ZJ!2F4V(=ROB R95A-%]342(AU@G)U7J+[3 M^>5L_F%[3_M(%MG4 4AO37!99L'.J!M>XO-,)6PK9J!0JJY@W@>E! M'1N'(1L.M#CFP%2"SDYT3#L=RS;/6W7LU.@\XVB*3IZ]35$RR01)9.G[ZF[= M1\4!]_8K[*35^P[V\S(]J.@4J/;].)MMJ?TNA;UPKVB!;MOI/I.BQW/ ,GNC MK=>H,>IJP&):AY69$ZS'.>#G97KX1B/'DY*")IFRR;% [Z J.H%YG-4^"<_C M.65,K%]!#GS(H!U[+4R]4ZX=YX]SRL_+]*"B98F<1"15@<>4K0-UU&40(D>I MMT73IU#T(R9X"@3^!-^X;).KRZ5SWWXH=-;MJ#ANCOIM_OJC23M9!R&'\C:Q M/2&?DE31@95=WZ^%6CL>F95]OTV7]@\F' MJ1QL$6M^.'P)T_G%QT^3Y<.;_/OD:GJ]43#?\L/-JT>\O;Y9?)HNF\^V(GLP M9Z"]AE(\F[240W)\[+K)>Y"6U'V)S6]77_1OXB_FH7/?+98W([[UYWZ:_)_% MLO_PO>F.'R?+#]/K+?U4#]NIK4X&5?"!/ 8C0]2]L'/V=JNP"0/1?['Q]GR,(F7J$AS:.&$ M2]&FA,Y!+_%@'6Z5^(81'D/BZF5)?.>!A2+02RTLBA1!>^J\,5:P/;5=?%;2 M-R:^TQAD22HA66 &B[ ^21(=4 Y LGF[L)6SWX7]:(,,G%.7.C/C*RA[B,+V M?=<@K'S0??)5Y-+)[R)_K$$.0DF,+&]RWB72 'T?*D<=_@'(RSV)@WZQ$J_1 M^W5])?W=[_N MI^G-QSJYU?]\^Z?3Z<^33_=^UT^SB^5B_L?TXN-\<;7X\.6'^<5B^7FQK._* M Q9*!('@?19@BK>JY [O!I141M(.Y8T>,M++NBZ[Q$?9YFCK-BA?E%)!%N5Z M:R,?[F.YE]X8]8V)[S3>=/4"C\([#O\XAB%?R/3"SN+!)K)[Z0U]%_;CO6E2 MD0\X"@A)9HLE9NJ]J2Q@MGM3@-&#[='/ M385>/J\4R?<7H0&25(JE+XJCMSMV77"$;6X1ZN5G W$+# M()'I=NK?WTR79?;^YN-_3B?+XZAVF4K*M:)5 7LT9TX=0!J4Z*-IB]MRF.:& MI$.8^&'^2 Y(Y8IL'*W+=3D-)RD=VAF4E&1;GM]8A7< /0>2O[A=/H9^'U-( M7J/*4 =D9!):K>G'W$S\'D[_FJ##&+CS7<L<"MF8+5]< ^0-8!*R;Q I MPF_KBGFW$?./ROPNL/B3,*]%21Q1L !JC &14C_[8SWILJV!X,1ZO^N+._%Y M'VR<" :+ JV3 V;I)Z62JOEW6A_Y: M&OLT_6/RKPZ5N4-K/AH5PB:!J)/TGH/0DC1@UX0*V?O4 D43;N!Q[27G*80/ M0;(=#!A*?I^RE_]O)4AP6% Q(@B 6,;+\X ^MN=G9*VR;\?WA4 M!JAY$N%#Z T%M36)#X#26GH+V.U%AARL"@U8J#P?Y4/0U0 T+JYO_*?%\F;V/ZN M/N* MHP]0*)*L2U2<(5MW' EM^OW4WOD63%K^!M!K4A2FCHF3J)L% M0?AZP^\6=)2H58,+@\8X_:+8VXO;P5D,>(,Y^VJRG.'+8WNHEJ!T"RA#9+8? MQN=B;_]6^ERD3Q2C\! Y6#.JWR]&LE!L3B> ,O9%L;<7*81BS4&P"$XZB\^Z M1-5K3QBK6] B:4&^+/8&+*5'*);88) EJ?L<0TI3;+O:70K#@GA!_ U!^Q!? M)R2L88\BA(R0UHM>4FKW8FBK7I+Z!C"!;$V4G,\SKS,.PO:^[;R[>S& K_CZ>9@V5]?3V^N>XS(V?3ZY^G-5H&OBP9A*MB]]6MF):OB\W:>]?5#+,IN=V4A=L5M8.- M)W%,XW"<(TJA8HR<6[IHE/70ISM:9-$\T$BC3\=S'66X(_[J:O'/G7A6NVM MEK+WD 4G]2$E7Q>%V8[Z.J_=F(E]=+?$/)EVVD>[8?^4^5B%BI:@.5=!T==3 M-'O:YJP]A?;/2R9B]8&?%_//=Q"MS1OP(=L2@JVCTQ0L!2VA<.#0V00RQ>LM M3G4SWMM!R2/)':I"*%\<9TH6#/^3LP0'(*!:U1[4M.C4]7XE'27<[^Y(_\.5T=G3*9+5<317]=+J[7=_?+<2Z. MLQ9EHT2J3RT9V8ST&ZTX-M&R<14/:#Z$G%,PL,_7V>A8^(D#X #LY?AFEKOF M&\;EN.J#^RW*1_( M^>__G'P>6I%AO2M\C3.BK>OKC9&FEZ9':J2I$&G3K+YA8?['9+F<#.*MNY10 M*\]I#-]HXTS*_2BN+R:()H>Q@LYSL8^*BL>289Q<71UTLSE)-49 B+E6E2)D M"YV#M\9H;,\BN]/-DLL;EN.A!M+'XFTB=LT0*>=8=.K0$>KBA-+F+,H@;$9V M;UB.QQE(%W2=0X54']-M\%"ZUDZ69M9;'J3K>^2W(\S##&1RLK@0*Q"/=@M(*Z*RI7,#?O? ]%:D,Q38!6L: VBX8/?__1 MM(VAT-T!*2E#.FFP1-FFE+4(O=N*"=N$ZG7P.T+H[@5$(V3V&5=V &2Q?904 M 9HV2N38]*T)ZE#W(^NBR)KK%N-$+=U@[F55,K0K'P!0[;WNKU%8Q_F8% )H M19K(&R347DGLCY9)HO9&Z(C([L1%$U 'ZD6%F-HE&$IO M5MU/):EU+2-\6?_CWV;3Y61Y\?'+C],_IU@K E5:;JBE#)B MK&MP G9Q@%V$F#G^R9@Y&++@(VC;LUML^YIR,C[W3C()$3"7BM8KM30:@A<] MJI1*[<)?B2#WAKO'TW;6& BS2K7SW0*?)1^UB=[WD:G2T';BO0Y^1\K0B5(Q MI:[ 3'7<+4'H5P9;&[-O(D9->PMOKU%6AX9!UAF.?TSVRGFJO< +Y4AO6@.4MP8SFC,P1 X*4AGU-!I;Q,4D%1 M/;MI2Z9X-)]Q<74UN6&:[\TN_K&X,TAU[?!QY:$ X3*@ M\MCNC%.TV2I^*&&G8F=?I(>&9,TN4QU4D39Z@/6CKG;0-"N :)[_QV/G]^G% M[7+5)'.1]]I>=NKL/H@7+*1 M*L94?"YE_? IO!--)=IR%C4J:[_5;>'UQRZN)K-/QU\HYH<-.EL\#YP")5=\ MARDF U"A)O;F$PC#'+54G8*/O4B\$G0VZ*S@()CMEO>IKZ.*4D2;,SG> MCH_'7J'"-BY ( FF$'(8YFBME1A=JY6#KM NVD['T]ZKPZFV=G7=I\P5Y;(R MT]LZE-0XUH.NSG$LK1WD+^\WG->1%J[XX K'?DY7X'=+VE)OX8*P6QY)=Q?M M=]-T$AZ>/YS>2-;6?_X5BF8-AS/]U\7'__K_^5\/)$\/P$: _0IY"=9$@<6* MOIM2R63;5> 2NP*1L>4_+Z+$*7F4,NQ:Z18K6W)7.Y>4']Y_[[^\X?)C&7QU;X= M9Y?0>I>%M76XR>=L:_M0[S:T!5@_XM>>9]%TDRM%[B@F!]I! MC^5E+W"4"Y+3LUB"E]'H&#@BZ_6E*;=-A!;447;P2;R<\%KZ9.K.Z"Q\K(BD M+J1NT2Y?2Q_;V/01')[\6)[P7GJC@[2"H[U4'(?B&F3L_9TH;??.>=B_YYU^ M7MRDZ?7LP[QBROKKOTTO/\SF'^Y]X*_\C3\NKMNIET/ -# %X2P'BLKQ(;=! MYP[9 4+2;8I?!^#-KB3_D42?10*'^?45"N&=1[_N"JUU3_8JCM\,$.[0"=:0 M+ _BCM7W,#5?XX"[3UG@H.TT7]F-=3UR^=IQ7NLY-:?Z&87!]?/9!>=%#50$5I&JH B M=TIQ=6SC("/Q^K6Q?@VL*$.7;-EZ[+?S7 W-844*WD8KH@HB5HPJXS5G++(( MC.M:6$Y9!VGZ?G)[=5.O1+C]PK_RU^7B9GJQ-2EYBE;67_/W"M]W57_3 M*N2\PYIZ>#HZ!/0T_.&4H+8 MU8#YAC1RK\]W; T$1^S-.'2 8,B0)&M-;^ULVJ(!H)V3?F]' S_P=RQ9E+_Q M;SPRQGN"+IPLD5Q=XJTPL/B)L]X:5IAB4]F2Z7]C2CBYE]FMB )!J>!"\D+: M'*5)>FV6L.TL?&???@"PM4%J;$48P7="*DMUC2P5HRFNBC^J/:>.:BB&0U M\'50-I!5'-/7EJ:5%BBR]88&X?*M:^&%)LR/*XKDK#0'HJGVS_@2(@JY3A.2 M5RWP,NY\@_JNXI=4$P'GZB=PQAO2"%GK(C(51L(*5F?'FT%332] GRD%@)+ M:M-@_;X]#3Q/122RE>A3FF2)R8?V,QQ?-51.KB&2^M,Q4N MV42)1NEUZ3QO61FQ$Z7E[6CC62HBOECK,QC4.DA)KJY![0,Q2>W3HT2YLWWK M9:IB %K1Q.@0': ORHNZ.2;U 8L+Q;8G4=[HK-MVCS? 3;; M3]Z.4IZY-E(!,++6J3CT'"[&BH'>Q3%H.:IIKPB(G; \;T@;+S2!?ER-1.F< MM2V^)!N]="ASS.L:"9@VE9;TNH*DMZ3B8VHD0@2M12I)RHP>*VQ>_PIE!>;F M%>K=*\O('Z/7YRR1U%V@WD1E/&7M?-+)FZ]O,+9!7V!#^KJ:1AZED#.62 H MB:BR8O$71]EKMWX?K_N1V@OQRCKD'J. 9ZJ0R$AH;8GH6?0:B_6NBRS(EM*\ MNKPSXNT[G>>KDP@7R)4@6/[.E**0C5,? ZC4/@^_<44\3].(!5FB@22","9K MPA+6F0^%MD(@[["9Q]?%O84J1^)Y6!%=L9*43364U*Z''Q 8?+OZ?=\\VSTB M'D?EJ:9=[_V>(2/G@5U[!H7D4V+#)HSO<3J#T\VM>IWLCQM8CY3T)"]J*%!\ M\#F+C)S@]GCR=BRA20M.F>-[>8P?;*FW=1*\JV;FH-PIY-T"@)X M;Z5")9S7AM8V.H<61%#O&JUX*V([#E(P"V6]D(!\RC0[]9#E&ID'4MOIJ<0* M:W!D"9X!-2^&D(FB<<09)4?)X+OJBDQ1A':]Y\OG>! \.((QI%1@)BT&-#EV M<&8I:3(MF/U9PIDSH.AQC!#(&YF*3PJD0VNP9[P$<]AS_M,XWHN,H22B+21R MCM)7."G=1]DFI-C"2>U!6G@RE>>/LK,S47.2E((IG,5R7)!S#VK*!JF%ZGR5 M[!\9RQV\$$AAC;R<@9BSKK@J1?1PP^B@>035X]CN%R2Y[2]MNT6Z;#E"KMN\LN^:=*332L=&A#". M4WE!\CLD<,W22_ FNI("7U29^M;F*K70+H=7=E<#[%L1VY$;09+1B*N%Y1E( M!)U,#\ZJ*4#C-B0+<)S0_\QPSSIP#A-3U!0K*G!2U.T?J/"SN67\' ?G/,C/ M'I2V#CA<2-Z;$'HH9%5$:JT,Q[JO0M]#T2NGMP:#1H%\M'U!Y_,:WKL8?]B MR\$8M7OIW4;.*1C8%X^S_76< M!N=DI#8$@6):(T ZD(>!W3R!@3.N_7QI)^.RM"C$*H72RD>+7UZJR!:V>=J[">O.B/21"=\)&YXVK<[XH-3LR5=85 M>6J1$1$U#!4FWJI CXO=-?"M!V5RO[YF5Z9)5(!@XI A]5K8J/41O$ MT%>)?$J-*5 @]:[6CK//DD#7NBVWB@ART*V1CS+KK^:^+%&5NMT')W1N2WKI C_-:+$>VK10#NJQ0>"IF M_5"A=3LB;=CN#I6*]TEVMN2 _-?E]-/L]M-UGBSGT\M!3*7?IK/Y]>VRRK3_ M2;Z//_1_QG;O\V3.T@I?.."_O+W@).M#%?/E*X#S_#).KF\G M5S=?UE_5_>!0E4XE!;5QJN+Y!EDQW>\\/7IPBIHJYWUA;>'_>/FHERT?JT%$ M=BTFA$A.EMRC'==B5TC-;3VY?.AER\>Y6 ,1F,Y4I2"+=I]^>Q]NAV2S^VT M+!>?_/OW3./D9M<[]>5T]E\_3C],KO+\IK+R@-')DEFX$\J7H9C7N6J'79U; M9G4[0G^7^J(%Z5L_)PDV@<8W"3Z2&SHA-X*I)U_CRABC16MSR!TW4L7]#<<# M;/RQ6/]5O%U6DOCX_+R87]S]CW&U%,%$<'7=&VI5W$PE_<*+3B'EIUU%K51>#>!8C%.].[!$X(3*_08Q.Z]7FBCY6"%#ZL7BE)(I?. 5*R.8B>Q M]!=GQR!VW_6"1,)+#:2]*EX+"!U.*1.+>7-WSP/)2C,*L7ON5V%YYEQRJ/ 4 M(0@2?8>WK+L*=WL$^Q?W%,.59E>W-[MSQUWDYIPL!6-24(F=661;VZW0EL&Y MI'8[6R%W4]L1\RAZ]SM9KP.$^C>!]9J'N M@Q/L$M )87SA:,;JWI'Q <;=]M:ZL>C=:QFL@A2)[QCX)"6G+\IW]&9"%1[I M>)]&\#[KX M:)TQ=OP!"L=^U6?913=8:O&9!+' M,UV!26KIS$[3.]Z!V.^$?:G5L&1RMMD;X:'NPKSS:XIEO"_$W>>$GT;POALG M$EM@D *5R\AA LFN@L?_([M-J(R#'?'3"-YWY;#N8XO%"G8==5%;)-U'#A6) M:^<)'G#&3R-XWY7C4#PC&;*'? (3^1X#UW3EB.<)35 M=107,&L=4_?(*[W5Z;%.>1O![]_7!HM:D*X3Q7],_E7GQ'^;,L$7JQRZEKYO MRO2R;L6KT\FW-XOEEPM* S_>7+;5 M@?M"J7-4GH40.&D5EF.I[+L]EB:BC_:WJR_Z-_$7O'^EG\[K ]%]^GRU M^#*=_CY=_CFKKP5W8<_TLC(TG5^OON_GQ6IF>WKIZ_/3]:JV?__OX^+ZYN?% MS7].;RH='^:S_YE6? ,F#LH+?8HM?%VE7> MYFW+^^LWW?W0"J/SCX^3>0?#VKX7X;U&BZ/D?N_-B.Y;&LO_\B&D'-BN<%8M M53=YPGF5P*;/&FM?R?TGHV>3S0M5D#JQ@C#:XFP%XTK*4#2YIC&=@FPT+5X/ M?%?07@71B154[TD=YN$+9&*6')&JT/OJ$GWS;([FVU+05Y>[W9SM%*PQR824 MT$:=5RLD=>@$&STD;'I?U=GD>H^E%R##S<&M^S*D7%'>4:?(SM;HF&->FW[I1S#\6 M=Y.H?RPG\^OWT^7UG@&$W:+PGG(PRDJ@A)+MF^KR$BRZM- $4FT*XQC:]O#T MTW1R?;N<7OXR_ZU.E"UG\P_US>PZKB!D?YC_?;Z<3JZJD'HDO<%,[800@O=% M%CFR$B(ZY8L&3RK&#E435%V*U 18.8C*V%MB* Q]Z M,1L(#G^_^#B]O+V:_O(^_]_;V77W^\_=/I].?)I^E72?XTNU@NYG],+S[.%U>+#ZM::S=KN:48_$"< M68%/1M;9'*ER+:7I#F!<@95;=G^0E+LDNE\()Y$;G51N7S\[F_]U<34DJT@@ MH8 S647"F(M*:-CRD\1:.F\B\-48ZLE$=>_O5P\!L^DUAW W<7)U<7O%FN;K MM#K2JP_W3Q6_32^GGU:.H8]E^1_Y+^LOGWR8[A?PZ>;?[QF%GHEUL+W2Q*^K MWOFIGU_^?7XUJ^[O3GO[QH1_^+GQV4RA"]^ @]\\: M46(*F MIKG=NEUWX622.+>5PY=XZT?N _ M9C_#P@7 ]/K .]7Z8W]Q%?S@86MPS3#OFUD^%7Z:L M<%JHJ+S7K 4,%2K9D[");8VB)J?G%(NV2_^$\GE[\A\;:^9AH=-E6Z@D#4IS MR C9W:4NQHBZ:Z55Z:X+]>)5^LOMS2_O7]R=993")9ED;+6+J,S.G:[?62T7ILF&$64^$U+\FS6WR;0 M@902TH<4?9"V[]>/3HEV'QFYTP2I;U@QCS+^-NO:_>800*,P[(P#]3=$FLW) M'S8V[OL%.5 /1]Z(((PV,6:E4BF" U53=R:I'"LTG4CM6CB]L6'@FU7%2'Z8 MG,ZH*E:#XZOA%(EN/0HHD:3;LAQVYY/B:]3(K[>LP5-VZHZWU&7LA.VP1L[^+=W]=O6\4VN_;!.FZL]H3 MA*)*0 U=L3"*;#>GC]GLKFJ%WT5_I '))=MB8JD-UI!*B#)0S4'XH)=$FQ.] MK_5L_SZY>D146Y0T"4R%%W!!*Z+2;[0M%IMY\MI_#C1:@K9BX3G$N$W*^['E7TQS!4QA'U;?ZQ;K M0-R*)F?RLH9.VD!$45#U<:L6+;HZ*$NCA??/)I[S58'1J!!2T24'"RI&(7TO M[L#WN;GDX$9SZR]9VH^ZXSY6:"1I2G(Q%*FRD7W,9!VV,RFCIJJO0[I/CE,1 M%'EEM??1K"+68CK[P1K0F]AZ;\ZNCA>9JF*==3)E-A$A*BE%R:O(U!=R$/>! M&;\2P1[4*3C4[:(!ZW"Q(:I+Q-B&RKX$Z(5J]]N-(Z61&O">)K/SE6%+PE+_ MK6,MOWCO<%V&I2#WP3M_U\'C/!W(9$UDPQN=%>SMM,A]:N8B__YO4N1#D:X' M80IJB=93+'H%I]I'NCXVQ]08&*TQ[D5*[FP&@]B#F6PU&K85G-P:D4RO"3+E M3*[MM>K@408C)53:!1T3QVD*=81NY)U#8Z'%F6JXKU_D3XZ70W2E<)22.6@. MF#0&ZMN !"79S/P!H?YNA9ZJCG-VKI>0O#8F!E>;3"W?-7NG8:,MQ6T:'J^) MXK5K^$C'8G3=[%#7/2C*P/:NW%7S(Q0)&)N.(I)VM.? MRGZ4UZD;;O+'P 4 M6>DT1%%LK&F%!B5$=Y$*>6@?=S.^@P]W11#44B;?6UHUU9X$_JG MFZA+N_9=J-%&#.TU^M4(?WQ<,C@,6X;7*G"Z*H((2R"KL?(&IM?[M M4$G?B#X'"A^<8Y7V 8U$_^<*GYCLCN?,^"$(.KH(V2) M!#YXTQ>A+*GVB>J[%D[Q]@\4-7B=130Y:4A%^O+J@2B-(;0SD0HYIKSBZ;LX6Q!I(4)% 759#=NO7&@*K6Q\8+0QVARJU?!GJF)YQFDNHGH_T H2J=B DIVWZK>6UWZ M*6 /1F[K0%>CS? \CVS.5TI=@3O*(I/1?/2L"G$]<1U\:<;3ZBK7MQ0J'2;K M1[DH;0&LDD0&BHH^2PRZ%VU4V#P?TW@0@J] L$^?H<@L9T\AZB38)PEKU=I! M<<[?!%O?J*2/M \NV5 2A[ )K\0*(M$1M6E!=L=3R8@3\.O?<9ZIN<.E[T0JHH:+]1$X!951WTG?LE), MBP@XGO1/-N5UO>,7G"$5/.+4N^0S6/:SH2 Z*P7<62/"V@[1O$^=0.Y[Y?(, M@C]EB'.XX&-=4Y6.I.=R7^X()PC*; M7H7@C*W@0%T^)L@':)R)Y7,@]/D9C/TJJU4\.=MT"4.*Q*BR#DB%E \VJSI, M=L=F2L:4)EBWR.&F?0R;#:&C,3OV@^9#\&U#,FN54D!-&$Q)LI>?]J)=E_&- MR6];=\6#$I,+TLLL65A:H/=1HEG+3T*#-?FMR T'\9*9DL1&WN%"K=&2<0H%,+&F"%5?913N9\S)[5.!DG M,4@V[]E3 *LRV4Y^&&)IG@J^-?D-&2?AM2PV>"6#9*NN?(S=]L>ZRSJ\JDMV M3N,4C<7P(ZWMKVMGTYY';:LWW[XL_I\OI[,/\K_4?YO6SM;9\ M9#2L$F7A8HE*$N1DJ6L19&,L7;ON%TB3P,?''#[4#(4$(&B MCD&4KHZ<"D:_MYSS[4ESR)8YBI% Y%B7G-N<8HKK@,&+=I'2]S-ZB*43)5(& MXLPVR5 05"Q]^)ICL">P=,\JS7W!&0J^AJIDIT+R=157Z 8!09!#TS1^&*4V M$4A>AP3.:?,BNT>06BI.B33591U2]A&;M^W"FV];FD,VS[H8M,4<(H;DZCY8 M2/T1C;8=%?M^1 \)[D+.#B*[96L0LRW!]$F9*D;LQ2@;19KS#[]-+Z:S5=&T MEDN7JS>P?EW(SXOYY.)B>3NYJ@M&;@\HC]WO5]<18Q%2!U.$QNBBZZ>=3?0F M'L#L<=2-P-ZF#;_/GLRQ0"C!.FU4+E9"7^0TWI86[G#5];SM@CR!R\5*R_%V MN9S.+^[65$Y6&\+[=\TP?<^?^6/RK_:Q"_>/BJ8@C"F45"G,H7:02M=\K$4I MN:E2*Z4V=_(<3MW)F!H 0U#,$.B<"T=T6B;'>NLV/E%6TC9^5RJS.1/S#$P- M#/5F4<\ANJ+1Q+I3$GM-48ZN!>5_APVG7Y]_GE=/G;=#:_ MON4?O9CZ#\OI],&+T)?CDD)C'3BC(5D."S4GB-17UD5EL:FL:]IT>XK2N-E].+YG.V?5_Q\55782^G%S-_N?KAJ8='UXUMDPOA]"%0.7HM:LK M_E((DL_O78X'.MH2V^[A9KCN682T+RZV'+=Y992-@5U$%G$]$\V'VN;&IAJI M\&6P=$:]1\D)4B 9.,P%(TPV::UW]+GQJ]CL0WZDD/XZG5=&_/S27WZ:S6<< MAZR>@O._/D_GU]/C78P75(OP3G!P +XHI3L -.D48EOZ$9M;FP8H.@'Q_W4Y MG?W7C],/DZL\OV%Y/%#?KQ.VES=Q\>GS9/YE*/1#&WV=;XV2DUYMHY!WV2X: M Z9=^8L&Z6R\JG^7_[Y'499BIKK$B/^_SMM$UV7JG,-R%-O0KC?AE\:E'?;1 M7I2WG&,;#U)RPLTNQ6-'._]QVQM,M#%B,2[MN(_V9/E^*)L4>D5.HM,$'>TY MY=B,.6DAX8RTJWVT\Y'VD:1RTH2HH?#=OG/A?*QM;D,M;>"<L,D'3.KSZ8GV&R94+K,L^7X(AT*I M3!T.:SUZ;*L:VJU39Z1]KV'BK")ZL(XX^G*6Z8U=G(:4.?5MGA<([?D,$^TW M3)H/>"&'007)M(,K76Z!=>NX:O&CG#M?T#&0ZGD #OKXGNK"!T>I6ECI(R8- MU)3, 16>\]".K[H.7^[_S8/S'!:3 MY>4O[]-L.;VX62ROX\?*\60^D,*I$$602;FZA$K7.EO7@005(;(]VG>C@??/ M]A91'2U)]08DB7PT*VXVVL17*QM;?>>=)*DDV23#8#=#M5-(DEZI).%!+%61 MR)TDB;$$HS3%]9ET.NQ[/AL68;=UO"P7GR(+;S:_GL7S+3,= #2* *L#I MH:3H,NDX/-BR7)-#'KUY@,[%W@N3ZLEW[D" MGWAJDO1WH#>J(]^B$@:J-C)Q,)Y$=L!'Y;C &ZKPI:NO8 EC4+--"P?6Q M+9]:3(W!>(?.?C?#@Q7HX(4TVDK.QXBS?HX&3']6*^!M>U9!V0UQ\857Z/B][,.M\ M>[I27=@UY#S[EY"(Z[SA9H/ZQ-!*V*!2TM?K5T/$H4@=*=^V&M%3D;HW2#3!&U\[2D%:ZP5+V,N^K%2,V%)6IC%IW1MY94/":*4H MDC9!N\AWKZ<54OM47,>H1R1U;\.Y!9MDJ9C%2+8 VT;1ET DF3:<6>UK'(G6 MH0ZA8IVC9$LJ5A5?O.]OED86<7NS0&ZK$YR*UOV98E*R;FB4L4"TD"1U.^I0 M"QE2!8(["75;:;Y9!6!]L>5\FR M?S2Q7^>.]L\RA,E5;0___>-T>O/CXJ+M8U]-G>T$.+W_7N^C(E]GTI6-FF(R M%2N)8E%%YP"RL1V;,PM;:#^:-1J'-00E43L4F32'B!2HW%T*R-H -8YQ2R/" M0:Q-KW^=S"Z/?^GVL2#$Z"3[/B_0EZY30K++<;I%\L4=M^#N]Q]%VI!#(>P#1AVUQZ,%7+ MZ>1ZFJ;=?]].:USLW[]? =5M@Z4\<2*'ND"-B]@Q2ND@1UE$G\AQ7+DETF@; M'O:S\$1^3YR^U986J(\%'*X":$QU2^@=OY#SEBC0F>;DC\KOB9,V)VT)%CB* M-&@]N@+2]?KEP**YZ.\D@3FAAG^8I^G[Z7(YO?QU<36[^.(O..>[GE7+&A?7 MC^C1X2B(O2$G<)PF::.D(]FU(!)'16W7ZSNSRN3V\#-$XFG9&[!^?.M"(:(2 M@V6;#,';;B8=MP13IK;FOQS^AF(:Q4;BY1U!NJ;8"DXUTZ"U"2L M"19/R=[M](_%&>UM=CIS8A_04 8OM+5Q73BC(IIG-5!M(6(_"T_D]\3V-F:T M)G'$[4A9QUDM^\^^:*2HW5/WCMD]+\,G-K@ Z)RWBDV1**"TS5+W#">KFT*3 MU,[NM[=',GS 0.?11K@,9C= T1AJP3=WO>#)'X'/( M^GKD($]G:TQTAG\ 4C\]KX'#AF;\B?3087T>/@=7?V-P$0M9*C($+"C7* $D M9;D/3C,A C0 ME28D1_&HVNA6TT#P\4EJ#1;_.YTH0[5.MIBU]2"^" MT8&3J[3247BCE,EHI"K&]-EA4&K+(X22IBV-G9K3GQ=LEK]FZL<;6$_&2Z!5 MKSVGFMG%?M4+%5_:&;KZMC*DOTVB3L/"R1REKTAG)O*_4Q)>%^5=GWDJ"&Y+ MYDE#@>"I.1[J_B/.'RU["FE]HA1R/W!:L5:BWE*?L\X^#P\GTUH2IH(D6TQ0 MLHB *:\? 4VBMMP/4L.961XP(<$1VTEK5(Y\T4B[K-6ZE)/;KFT.Z$'D'4*1@;L1JT)&RI4V'KH((1,_<):,D*UED^B M&E+'6)P,7"5!$#(9<+8XC5*G$'L(+>-,BSXCS>@ZN;=VY.@3QM:LV C )RHI MX2"MH1[(9K-EG@/U<8JY1]S)>!HX;&AS8*N65PNYDW6N!+NNE\FV<(W"#=GK M\7D:*L9';]DH5[P]3L"\]&;,';1^?3,/7KY,O*_OVQ",O%?T^7 M:3JYFBZ//WH5-H%JBAG9! 0*5F%?%W,)78O;)J49K!OL(.Y$' VE)#E'<*N> M<+(EEZ*"[]TLI]=;6D,$:APZ>^.R-(2XX'(&_IQ)%>W"AB2$74<.NBV#2,N? M&@KX'L?1M?+YB$G#LED61__DE6)@R!FKG>G2FR9FB [F'*T9#V= MC8%C5CBWUXIDA;]0G+Q'(>T:FG++:MUW4LOVE?P,? R/UO%L?)[,+N\5;_IO./Z!V7$2Y#BGM9'C-"NU"[T] M*\6U"&>U=WR8FQW4G8ZK@<.6BO=6@S1%E!"+8VO0XS+3"E'#KI, M5"ES@%;;,45?\+%;^I7>2:-A**+93MMI^!DX8A306+XF5'.#(+*3JC=G*]#FQC@Y#C/7-\O9QAK]0^U;IH#((B/$4@)Y MI1*N8V2[I2C*?S7H3TY)_Q" =@H8E:X+#)S6OE#M1.P2,:%BVR!$J][KT]'_ M]_ETLIQ/+Q\=>J$MTEFG7%*1'5YM6^LU$*W16U))DC#TC+E)U5-Y& JT:C(" MB*$(0E3L!K&OT;(#T:T65'679^9AZ)%5E>0-96D+Y[^*$_NX#D0<4(.X8)F# M<=7P\_01@S/%ZV1##MIP!!\P0&9JMW)PEH%RF0/,N7UH)/";89*##:#C<7)_DGIQ FA@,*W*>;H MBY(V]O,Z5JO&Z:& H1+$:'SL[9= 2-%IGXH2?,]K2FYZ #04[1U1N.J.?09& M!B9]/''P47%MH,[1Q.S NC7.0H8M8QX(^GF.UL ?D#X!U_9KOKWI\__CR>?H50/-G_HZ;R?QRLKSTMS>+ M3XM_S*ZFX?9Z-I]>#\WIU(WCT3LJ.:/C"-^Q:@W505L74X8M(,I-L-\R=#S# M#?KJ: QK55P$2!6'WY"+EJ.);F$(H&JQ4J %FSTKP^MVA^7B_73U;9.KGR97 MGY<5^_1BNMY-,C2/%9$3.F\X _+!)4NACJK69 *E0&S/NAZ%[0UL6%;DQ>1F MPLGAXO/'V47^LX+ KM56TQSM9[39:O:[_L9Q<5M"4Y4_L/FZ7TTM_L]ZE>'2N2MD6 M8<$AN*>16+R(5 =E-Q630F;U].3,W_W\_>A MN9\$N]Y_IF[O_$K4LX&MDV ?4(@37LEVQ.D<=#&4^,]2L,:V.R$;X[%+2H^5 MY1' ZR],EC':.EDCD_>B>EW(SO1PZS7%;HO^3Q+FHT;&HU3%!Y4L).&TE9!S MW^NG+;5E9<#Z!KN-R'8*>A]90^\-49'5*4J$$@!S4+X?34KL!EJRI+*;9;W' MD#749%R2E4H7",C9A<5,<=TI8-R65032T68OX7ZR!O :[E,F'A FA:.8<_3\ M[]J4I6($SY%Q",'ZYMINH6A7.\DP7?O6/8*OK]I\\ME\A[@K-)2DRR M=NI) <%V=?Z4@VPO+U^>IK!\+(4C\'?.[>Q\"U!EM%ZCSR:XG$7WO),%NX_F MTGX#(AM:P:ZB)38\F>-RQU)S'.6:_I2EV$8X;UE60YO5=5!U9[ D0<)D'T1R M74=3*L'0_NTESRVK_2MQ)8"T12:E1>&@5W?]9R#0R]0\QCDKU&;![@7P=TY3 M@PF,]LXG6?_30%:4>Y'9U,+)? ,B&S(UJ?;6 [)?2VQBC FB&V$'021*4Q=X MR[(:,C4QB%H5YP">HT[)AZO"LW7'JV#;;3B*K&K,__-BONBG%T:?W02J<[O/K+=_$R?6>VL^>Z&%=^H]7D^OK!P+XFM)O^5U#6K?9*95SJDC&I)RC#A%+ M!L\!?0O@(9PP#3S:8;R^8/FL/_N5KN9-)K&ZKV]F%W&Q_+Q@C4^WE5-V-TU@ M;9J) MZTZL06%J9Q3@#J3Y&Q3LO_@GYA^FM:X[O5P!F RB&8&QG%I$K*.3)LO>V[-L MO1-M,YRP#7S3-R':LEA.9Q_F?ZTMT_/ZB6H9A@ AA Z1,"1;]_B4;+/H#Z[' MN 53GH1JX,7/*=T=H>9(?LE"M$YS8LMWV 6G2'?()R!UL6VSOK7@FF[]5R^> M$0QFTFC01^LA@MX^9LC*B ;R++ MT,LVZ]1NV0#5+$OX)D3[*(.I(@A.Q""1307O-;63?NV&R6]'U$B##3&9;*I+<@%#H?XD MQ]+B+M5=:$UORS4#9:0UW45)=MIC[I/LD$1/:^(Z=S^BD-\ZQ7H;&14)4:0?NW1 M0X0VQG?"TA'QTBN2T0@VE, 6308*WW)!(6G7 1UP,!IRVP-L!5JUJ]CY#4CW M:!L*KDY@&Y.DT[YD D3L4U1+L>V$H)VO^F]?O(^QH74A&#FV_5$KAT8;2GT- M@,A">0,A]FCV0DO3XN]*IM:9716SPVG: M]X9>1R?S:@^83D09B)/\CB8KR36S>DRJDCLKS[MH^F'^%:_[]]M_7,\N9Y,E M'QE_?;VX6/VIGU_^?XO9_.9_\\=OEYO &GWU[E3//$)5-"%R=:O8J@SL=?>6 M95D"H6V0Y102&R3V)[ WHISHA'("76I+DH1D!6>+LG!:W0N:6/\\&T"6CJM'ZOPE\ME]<"KL_05F[!^Q35_P?2?DZL_ MILM/NYFX-QGA(T#1*EA$ZYTU7?,NDTWE_['W;MUMY4;:\'_)O;V JH W&0M M'#.>+]WM=#N9U5>S&(EN\XTL>BBI,YY?_Q6HO2F1V#Q)%$5)G:QQ/-:!A0= MG5#U5, __?DC_GI?RKV%6%[#]?5X=O73YS@;GT^N?[JYGO>HU-_U=7IS>;W= MB-R'W 4,SH,'$#87C26#[ ^P5*(-'(PR#>J;!7J<\*O6!I<\>J.0,HB0;*5' M+046YR4%WY+6:ESM/-M+^'6LFMLL=7$^"3:%PJ@H#06O1&^IT3G=>!8<_4I8 MH9!?0YJY3::#Z6YMK#+LV3M9,O>X.0358/U+TC4Y&<. ,6#8//IJB M3>S3-8**;DFOI"5E5EA^'RC3P> ,Q9$4]46.=0IBG7O6Z8SJ&9C646HFF6Q? M 6O"7ZZG9__ZPLXHG_';@&Z_D^NUDB99% 4BDM(I=<\W##5P0-W20CN$%8[; M;1(]6OK#S=,I8(J(63D34*(VRG7CIZV4+K44I)+XV];>TR=8[:9K49N/A0A% M6S;SSE8&[\6UT*X=4P'LB"$<8$4AV1TI^S!)B$K5_ MQX(H-I@(N6KV'@R.%=J\D=*P0JCU8K#85AOLE-"U^)$UKHALM+3RHF]#<*8= MH:Q$;3=ZF5ALK?W5N21E("A1!RJ@Q2#[+A;!8<%N_L:!,=BD?@T+Z"MGK7%2 M"PU>A=@5*[-;#0,$B7*#[3B\X,>\U&B"MMD[JE,':[5K,*HO?MZ$GM\(Z M6NN@G386VRXU:':=7!WL%G.=3"$<0(^%]VD@)0;2KK7*IXW%MDOM;331E1H- M4:&:)92F+^A'=D<.>JF_E^DL7HPF7ZMU[_ZR.H"J100V7/%<2> $YJ13=*!# MT/T+4NT[;4D[.#C51@QNY2["'6Y1:I,W(B0105(J\N$,()7M]@0-.Y&- 590 M^2]/8%&;7*S*+2**8%\^H_.1%;+L=XH#6&P6!:1!#WM8QUW41@L30U6KO* 4 M4B3V#TQ'0H$^HF],HJK9A6&7]RD7M>"&&5W=C"ZN[UY[]MO"RCA*#E-A[SZ7 M;!R4W#\E))5:OI'';>%:J8\ PZ9-3TF3GK];R\ 1#-_1;M:]%%IXW>1='KGI M>\/P]\M*1K_MU][^<^VVCS>S&N3].A[-Y/Z##XQA[[_8F+*'VD5BH/0W@&." MIFE(&F/-L(_U6-F/@\>V^1S&6F6]-R$E/B"5/"+TNCLGTV;"2$DU[&>]##RV MD923J:5(34CIB5BG_G^LMR"GA\G$VFL_H;KQYR73CP\*Y8 M:3A^!+9]B^M2.]/: F&&0@['UH\4_2AH;)L,Y[S,WN8L""W4036Q=W0XUI8# MD^'$ZGSPEX3&-GY*95%D#D"(DLC9F]*-)^"SP4YNJSH46#V<@7Y6-+I*C[Z> M9O_AL!I!>N.L+SZ \ZQ#%W=$:FB<*JV'8[,'2_S$R]\VI0(311^%TU)50B1I M;:\QG7&NG5+13/P]=0"VW ,7C&5_NG@1DF9-*8U;A#]9F(&!I0J&4V[/!,"' MR[-J=L[#S?6/4Q;TVW1V/3[_$'[\N?N!'5^%E^JP2.298 MMU_>W_V(E25,)4I@LT6(0OK<7RU-[9 EI:QVZR.X!PG]Q ALTZY6>6$IV%BL M$X6U;%E$[)1;?O%*$KSFF?=4$=@VIX.$%%*&@*X4=J9L"KUZ=='9E@:5?= - MX>LS(-"0?V_+$BJ4O%+ 0%$$%4*14O5+YKUMDM\*^!<^-BA;80(_T#(WY0WG M SH+!@AULD31H@1:.)#1M+>;_6EZK.5\FF5N,H5:L[^C93+"8RW;@2!Z/YG/ M0$E[G)B&4=:[%JE#%XC")*:V*_S)!E>T\%$#S[H?TXYC#B?)4G M?^\J3@X+:^-"L26DK!40A\L]5[./H76":95RYU"B'Q..Q4O.4GYPP9C>!6OA M>QPD4>]_^#]8TT[.1I?C;1SQD V;0+:'PF76%9[=18.H:UM8SK(=729QE8?U M18.\A6K\-M_:M41\Z6G5MV!:78L< R6^M[7FWB,9QA1+J,,GPAJ6X+>"Z/3K MU_'L;#*ZV)N[G56E,HRF=,$[Q^8B> :C_[=FP+VX5, 3'(E>8$0 MR -2,,;$>EXI1Q.A?3]]!ZN\UJ\9U\=,&PB.M2M'[,)[7U_261^XJEU+C%[I MMA?HG7HC)[;_CK^,^<".+G:=:!)E %#1YQ)!!*F*R*F>5)^C#[Y]?)2FJ8I_ M47ANZ1\)*9$!8U(=5^*#D]056[*#5*OVVHKK5:*'EPC'_I;FA^GU=-81Q'^: M_G!S<3WY*U_?7?6CR$$H52A")-#HK5.VSM'1.14.BYNW7O.RW=#CS65*&BSZ M(J*AVI*3P2CLSJ_.J@WBWLW??=X L@]4CT;(P"Z\39)#1D,I^21[/-/ P"?S MQN#\C_'HXOK+8H(/^TGG-V?7515LFYBFHS0.8T+E9'+$L2BQ!K#L,]F<6B:2 M%V[&CSVH+.H090G.0'4X@XM)SA6L9: Y%&W>-5ZX7[^EW=(;0N'1A!"2QH2I M4H>@JA>;5/&-TXAB=4;52X3C9U-PSL[&8^,"B-/X_9L_KI^LMXMO/V/-#L61-(&PY?A2B2,NDZAZ9S@[43 M;52@7W94\-A-^65R^=O%N(R^3BZ^UZQ!.P/JP!L$H0Z(AB"%S04^6N'')E)2+%]YK[3+E'/@>D!8Q6Y_;F1_N52FC)U3S7@3+ MIK9$JW+64FO;#] @E7S[5OA.-YP'KQ/91WO2X!UD$I$=9Z\%2+:)_8Q@-CT/"]CYHU/[&XF(WUTD+HN$ ;"ASC ,"51/;;88CL0 ME^.>.(6EO-4:H_^=?+WY&J:SV?3?[/[%T3?^RCHR@/ZR+/^.Y3;#R27?GLGH MXI=J8__Y_9:PI?_8[>,:(B:!D"@0,GA>]00Q(HO0W*3;RHT5V'9?Y$F"<^^9 MOY7HSHL)H\M__?39?QW7U_P?_39@*R%35A0J6;L+-DC7TP;)FL-NJ(?=Y-JW MB'*<7$_^R?#FFVIW/UZ<;>M0K]!Z&VT(E9')"G:X>V@SZXHUF<"W".U_?OMA M.OMM=!DKC64]PENU@TPBU9)/5@1D(@9O8D\W)Q&AG6!V.'!_&%V.;NG4RGB\ MA=7OGC>W?ICU'(([UD%__OOD:CK[[G^;C>3J?*U^_GZR;7+S/=;N(E.?8CC4*TX: M[&4S-I:F\ R46J$*V4>V/LHKL^G7-+FZGDW^>3,_%)^F-=5;C2#)>"%0*?DPX[CBMK_F" MS>.J.:U8Y3>;7E;"SZ7KYL_K:-*:C:G]D1\NV;I-KD<76VD9#91,+D(,:)2- MI+NY7MIFB9M&I+X!3.<37R_GS&Y;<,S:4:*::'$Q1 YL2N>R2.V2;YN#WQ:. MPY^QC:'/:5( E7K89, Z,"UVD)HD<^N@O,5;?TMYN/629Y5TS7Z%3-()=OHZ M5G4=,M_ZMWTX?QY?CSA:.,^CV25_R ZS:,A&SV%>'49;:>7Z42GUQ1T:DL\7 M"^:6WL3*59VMH^B159_7(E)'L*=U)-'4=#H4+_EVZN/9Y%Q)[ZR47G@202:/ MIB-BU1B0FNJXMX7I[C99FN1M$BH$8G,!A,;WOHU$V_8/ORT<'V23.>!A2$L4 MB,$5+:6A'E+0IBV$?8N7?B>3#"% JO,^HM ^BQK;]"$-5&[?MWTV]S3): 7[ M,]:!4[F:'J,6"C-ZG5Z/PMS2+)]U"KI.S#'):<6'B\/FWL\+^A49#CR>,99L M-&(L/K+B\R6"4I3Z*"0"-74@;PO3W8VQT<5#1@6FF, QG6(L>W?1I78Z^]O" M\4'&V++)!>>%L@QLEGSW17\T4:IVW,W;@G0G,UPH90(;*M&&S5H ]@E3;61H MZ:O>%H1[FN&LM@&X'%DC"".#>:/X^LXNOKR<3;]?7(^/@_? M_WXU9K7?O6Q>_N;/KB>_#XQJV2$AK;P!97R0/ECV@E-EC+Q=*<;"45O3^2"7 M:8EV%^VP"SK<] PJ6B,5[SB6DDD%4[II/DXE:=O6CV<'8!L3JK?(_B.$7*Q( M20H#G3^.)/CP;CB[S[66@VUF5KS.*"AD5^>$&*VS[S834;95TK\^,TKM'9>HRL<97$G)'(=.\K:#VUAMIH(6F7)0T(=]@E'6ZZE$U4 M;-*>V'T6P8CL;:]S@QNH2)=NA5/Q^!!LT;JDHHJNY!AYL^J@"W*]'74FI+;0 MIPY#$2>QIH-MJPP("5C3 F$D8VR._6T%0= \SH 0S[VK6W0P BB7.#B6PCKA MO(>NNUO6UGD]1'Y!]KDOZX%U< FLI4I,$:.UE<&0U55_66MM==L^(JQZ0@P6 MLT$?H8-CCAXLQY;U^35F'W6?LZRMO]0V&SF@%2[&W:4[[)H.-X(X&2<,"E=? M4X&RDAW=LZI\\30P-'MEBOKQ$=C&,2H=2!N-D\6EFBFT'[XVM+-]WTFE MC#J-11TNGE$6Z[Q#-JJILM.HTH6NRM4"OL8%YNNZ,G_[^!!LT<+&NF M@ D1 M0J50-6H1T6!L!ZZ^JZ-D\236=+!MK6S3D(5QI(AR$1C[(8^.O',MQZB][8\\ M 0?+L^F7\=_G5[MKV<#!\"K8M\)L+=D M!\/?H0M4T*-1HJC,WGLW4I2UI9,MP>#A5W*,)X)2O$P&V8OA,Z5JQ&SM(K5M MW:8\[%%7MTES0T44V\4.*E2MFO/#F4[Y>J9;]B>*66A)-F$$45A M%X6CBGR74M81GW)Y^F_R;YO*GR"6 ,%FF7R426L?N@8@5@!!M1R?=3#&@02# M38*EP!=4UT#:>._XJ/O0]2PB2%7:Z<""8\\F._M R=0FR;Q/7F4GD$*P#E7E MH;F53-?Q4RUD'&E0XV4]4#*]2;(PI\UG4;)%*H+]^N)[S*K?L"H9";('$VR3 M*Z!M DW1%G:-"CMPI%$M7 %J^;SJ9KK&-W^$9(?SL&TJ3FG(TA=VL$VF[K&R M9J]$6YMP^)4N%3\(MW>\W>]*FLZ$&N@+:&(&$RAE50C "+=SP-(6VLPCKJXG9R!;+PQD#F M<"]9:6HE5.QMI2S2#BK^Y[QA>[H""2![04DAJ:B=<=7V=LMSLB4W/>#R<+,K MH$ F$82*RDIRC'2"+LHA&0;>SRHMM6[R8@^4;*,O4$*4E9)/>K:D)69C51?_ MDA F-37:[Y2;SQ@YB&0;?0$MLE(.@%VGFF>*WH4NZTVJ)UC*,?R!.N=;:"M4 MXM,M*BMK-W)9UD?VL*DM[*BKV]T?8)\F5A(4=D3YBF!@P]E'S_5MLFE_?:X5 M/<@?R#H(X%6Q&N3(1$=O9%E$TQ:W5($<;W&[E9@GI[)W',VP%TH%^,@M?%'K M!_38GK_H.'"VU[^%[K6_P^'RX7/J!_YQ.+J__ MP>NXF8UK_WNE1N0?G(W/Q^.OHW]>[#]-U,X'LX.)SL\G"QLENO(5&53)36Z* M#*UD.PXB]_&0.(H6=H ^66-3?97.;-8C]0E:A]BZCF\'SSWB0.MCQDSL3N9H M4B:VV'VQ,26W4>^_;@P?UDBE8^"+6TJB4F>&F2S[: 83>\5O_:+O6+UM XG M_KDM"!A\!+/H=Y%AH[E^W?#M:THA*6.ES26A+Y4 MJ )&M&1ML"9'[(;=*P2/<6# W&IMRPM"8F/6P+)/'Y*$X%.X+8CH*D*4+I1$ M^VI>"V)>*A(;LQ22(S:^&G6V6.W]HFBB[0^%&* ]@,HO]F*1V.2C@W/!LI,>98E64# .Y^X^NK/1QX)::\S\/]+V?)]2 M&^7;PJ&W@^&#?'0?C"Y\*)-V6EL;9:U@ZE)=A"T!T5N[Z#OYZ%[.+W:6'&?' M[,G[U,?>Y'-+Y_=VX-O31S?LBA-D)=A/%:9(D]2"Y,#Y]BWG10*YY:5-LS>J M,A9OY[W.DN'HB@A(VS+PTJ96.V!>$!(;?70!$#)I(0,J5[13?:\M(V&\;JNV M%;Q<)#;ZZ-:J(@+IY'Q,UOHHJ7])Y'!%M3ZZE49 MJ4R*I@MAN*4E[24AL;"R#*(0A%4(.SCN^)MT;;IWP,$!N_ YQM9[_ MA4%Q%"?=0K Q!>6"RWRY7#:A+S%!\''C<^;KQG-W)]W*)+1,Q4F2VI%7TBR2 MEL6U)7UO!\.'57,7K:-R'#&*S/%W2(LV%PW.Z*:N\,W=])V\= =@0T%9V=V, M @-!]Q=;"_2-OGP[\.W+@0(0M5(F*W;#LC/LIRTJ"!2%8P-Y/;[Z>7PVGOQ> MO\2_:#^J\Z@)2O1)0J45QY@)NM=HH=5 R"&15HK'&@$>(-[!:HX,VBR\UK4/ MS"J2@**K\K;*<$AUA.5L(F]G6X!.*)^%HZ ]9NI*HJ1PL:C&>P/D$/KP\AVN M^RKNW=D,TSPL;EW-1/_^GSHA7OE_%O]3;O5%;W MX<>RE.BIC?=>UNH+Z]A5Q&[D@-+"EG#_G'GF_%^1Z:RT55J_$ITRF?5*MUUGE5.]Y+;;F02RR=F M1ZD>L)!X,ZM'9<_UH+&!O:'Z%EYYTX7J"AQY/8G:R76H[4.6T\GV@%55"I3? MQ[^.1ZL<6]M6ABIHEY4LB$;7J>&YJ'YE_&>S4RMC&?87[V&+F][,'K X92S; M.6>!73$06:?2D;- K6UH9SD^>'&]> ]:W*RRRW[LL!@I1'GCE[L1[ MP-H^?6%7:/29':+]UB8B&H6YSK[4WN7*Y-6/Y8FEF.9)7\F'+.U.N@U+^WF\ M&(O8_8;Z+RSR7I76\Z$]?^%3W+];TIHA]FXXO1Y7GR<=O<5>.,*LD5 MX< 4JZW'?O*>L6Z)2&E\,^MG:ZT%9>VZGA&+OUZ?OU\=7S2Z_&UYOFHW#&S; M*%4C$GMC4B:D$H4@ZQ=H.=?VU*Q.5WXU:-U^\C:TK(BL2.JPQA"]5=%9TZ,% M2C8U JL#Q1Z'%D='<32;??\\G?U[-#L?UH-/=:TSL&W@> FZ5M-*C)5>/T'L MIW-EM*XT6RS-@9?)!V)2OS2]3!R^[W\'MJW[KB^85R) ,C*Q&=+*5ZYX ^PFWT14.LA0AI>1K 2;; M4(L#NX00EM*.[95.K-1$;!6NGS/=\ -M0RZ@=R*295>/,+!QMGU=EK"U]:55 MP6YEUO?JY^\GVR;@HA+.9(W:1\4A>B892B^;S>USK02STJFR5;:%YKE-%G:& ML\GR[,(_I"UB\92+TUH1NXD]IXB,8H#R_ITT4K3"KA7H,:)O*>(U.O"^4^ ( M5#C+!CCU ;W_.CS^YV:H6S5H10]*+Z6-C2^@_OI%XU MK$\H^N96WJ@UNWM%*<7'1C#FLL=Y9$/?C2.=$K9Y]0+VQ(\D^982 MGEBTUB;Q83<%A..06_<'/6=H8W*)=L ->"+)-UY1(E>9P+7/$:T*;-A"WTR/ M3OB![FM#Q[JB6VIDHN?P1%2ZJV"\Q\Q*A7K0R;>F\=WQ#OJ6DA9261#'&2*9 MD@2HD%3N&0Q\%&U7QBK]TY-*OI%7DY*K1 _%EE+0@RY:]-0]0&6@_5;+1^G% MCZ/O]9GDZM,TS*;_&L_2>'0QGEWYR_-X,1[-^%?\5,>P3_YO'H3LZ5QYSWHE MH2N897\]NKJY'9V?3&_99MZ5!V%X[(&]C+,6RPG/AEN<* M-.-';8RL<'5\_8O!ZLZ3_W@S._M2TS9;T F10LRD M69I#+K/H9@=(+3C2XR MU&1*3@*:=Q&>;7S_3B-K/VIL%";Q M%Y9OR_Y"'GJ)6QSV6*1-(6E36,<)T*'FG#I.?(Y36W(NI58F9S[_$K<23BN7 MV1N(X.I^*@NJ']$1-$$330''+?@T2ZS)UW$]W?4O_OS_W=Q>NLYYVOM\9J3B M?)WW5^FDL[:EZWT$M";*MA%(&VO=NJ5M%NY *]K:PVB4GT7;*KZ=BR)@*I[#2N18S131K+%IGKY MIP=JBU*2OO)6%^-Y;PLX*I7:9;[)!%&%EO36D%MK]9]T":>QURYG=G S@7$QXH4\_ M,B&+%(HUE5HW!F2[;/OZ'**<=_UX/U-RDX=FPP+#KMN!(/DX MFWX;SZZ_?[P875[S+ZC]%-^^-L6_.W@^F@1Z4RB1IDK "E7!=_/@2%+[.+ Z M#6YWV0ZUHBUFW@N55% <)N@"QFHPNGO.1^,"[.*B'&\MV^AGE0PR&@X8@N K M6*)QW;QIS-J;3<4E!UK+I]GH?%Y??W8SF\=__S&^./\\G4T6>97]!TLJYP$" MNQ51*%8O'+GU&Q3J@T.38%%2K QJ>X"8!U_EEF.8T8"OLVE*X566G&W/PH!1 M^W:\K22A+)[>,K><4,L;R=^5=> HW>F$":B?$II M5D60/;*MAC0/9=Y,3[_ M;7Q^6Q;TX_3ZE_&WT8Q5Z,5W]D>FL^OQ^3PAUTU2'5W)&YGQG,'+]Z M';S11=4R2Q^ECQ"#3&2Q:VM@ MW\E0V[0!>K4:^>EAFEY,SKY_F4^N#^/+\>?)]6U&?C3Y>O7A\JQV*9T_I("+ MHL_>&A6\"$)#(='E*RN+<&ZUO5)6NY56L'R%+5:FKOR,O9/*')!H?L1UDM;'84=R)H-NN8C6?A?5\Z]E2/V9(2G;E MO+%8IWI:8 >N*PB"*%O%3@J$>=;E;*[[9$V@I3*Y:&^]SU!;#;LY*%JD)OPP M1*M/GT=>SD9=8'+BI3A5RUFC<\JZY/O=":R]FVC*:'C.R[.E^@RU116-C\1V MU+(>(!2+*36Q[5DPSLKGO3L;=4$R4F5)*3I=P)+T0O:Z #DP'.B'-,(=X/+, MQI_']=_G^=>/H]E/LWG6^/P?HXN;\9XS>:24A9&U7^XW11! M:K6'_ZF6,O_RE;^Y_L*![?^-S[?NQC*#0B8?!%HHDP*M%C9,=-L@=5).K:!QV+4-G))/H^H&)ML4>0_F(-# M53-P(=3!%D%CZN>]B<)64@W(O47@6S$>*NQ&D&,PPHI0R_TDFS498E__(@48 M7YY*V)]NKJ^N1YR\.K2TO\3W9%DO]OR^ M[E>;6XDR@DDF)I&ES""+Z)6AJ03 FS)![6?O+=I&0H_,!AZCR-E@M,Y7W[IO M^N/SNFE"PW;1ODYNOE;C,T_=W/'$7.W-)!$MYC]UJT>O<_7*:S#_V_ MW3[(3<97X?O'V?3\YNRZH_99?KSKWC+Z[KSOU2$:7=V,+JZ_+WY5]X-;WO80 MK9!0RV"-LDG6D2:=_^PA#PSB0/86 Z*T)9<3$Z:DD>--ACG34K0-0(H79)4 M;9>EE+1:"_=H"3>/KV ?RK%9L[M8S@5L*,U";&+8>2PY?YX0)N#)*2 MREX:3$FCR2JC6C#6HN#PJ;FU?&=7.GP?+^#&L">&8"+'.ZC)&7;DV%0O!%0I M-E&<01"'1G!SAVH0(06JG\KQO:TIF]+3N\J!1[O;]/@32'BRBJ26#RMV:FNC ML8M%5X*[7I$(28TBJ2-,U6$1VI+("9$W,,8Z"!<5^42NJVROS'SL)#:I FU6 M<]2/%G"C'F&/BAT"F3/P+9!9@;(]L32X@HU;Y5C1'?86;$FV!"*KT(60R)!0 MRCK,"[IGVX[BE!SNK_"A/U["C8K$04XE.,_[QCK$:7:@H8=0>M<^.[. \M 8 M;BZ$9L>Y1,6FE4K(=5QF9W#9)3$Y-7UM6EBUTDI[& E/5I-4PK,8:]]:T=&" MI](;?*\RGZ8&(:?88.R/T,?Q[*S2^_PV]AS9?1V??YJ^$ _N?C;'LQ^>O9$ MTMBHBZH6J=.[R2R-I+N[T+-9]X'30=1 TN[\Z9!78 M@_/4 ^A\X9Y#]1U<+0018D"&X1KDJI!WB"97V#.KB,FYT3)[6"& J'8X8=)T6B'\>6^!\'NB:M&S:LCQ%Q M\UM0$CHY8Y,IIE+*6"GZ* (41Y"M@Z?7>">/$7&C?Z)- I-J9SZ4&I(5@;38 M:1/;2 RD'7:2'R7BQO?;F)0C]N!3)3]@ORY#[Z#@4'WB!D?^X3)N<>4)4.N@ M F*AE!P[3EGU(UAT:ITH"5:L%A<>0,:-%R8([9"B5,5'R-8F%KJ7,3K;/.4Y MOM6'UCM;_'E2''&[P!PCX@TQ^,M290"./AQW.+1Y_I8'63)Q@)1 MB/*N%*>HW,Y$DVS55[L\#R'C1AL#@4QEKZV4Q):RM[Y_:W"47<.UO,%C72OC MM]'D?, 1V"_OS)N,#A S(LU8P8X-HP&0UU80>:P1YJ+@;"?-$4JS+ MBQ=A/B(V%EAP@##F;5D9K!;&["CN9#IC9V0RY>\\JVU#D\^3LWEC^ETGYDZ. MQU*YK$@ZL^!>^,K@(U.RF6U2$"2R8:W09 6;![X=I#K ,@;,P?UE"$7!LZ?D M(416:(9<]Z""A-ZK=K!16_VY_T*F9^/Q^5693;\^%0. )X,<'@4 5BY9^OI2 MV#, ^ $+XJJKN[*LO:4\^"*WF'(.<52H)/ YFEIUKTV75I4DBE,#[(E*R-4; M]/RKW%:#GT6A4C/^I$11VGF]Z!)Q!9LN$=9H3[:3][H![]=W/^JHZAA59+T! M'- GEXVI)+A@E$HR.3;)&Y\T]Q+M"59UL"8T$36QM\+QF_&93W[2-D?-=UBR M#\@W]D11V/:N$-DL6(Z?:Y.AJ)-B9*I["PDY#DQ-R')2JSK8WI::5%;.509O MSR9&)*_KWG)H!+R_&SNNGQ&%+7J)O7Q9DW,N>,#:7>PUAH2L?CS%E)O>(+OJ M$3[WR@XW!\EBL39X'UUD=X@](TQU?P5'ZY1".XODJ9%H.JSV9VC) 2F#8/T3 MR#E;0Y'.Z*045*..7"4K78U =Y/M,.O9HHBD\*QO3 XBJ*PXCK%]I036"OMV ML(_A8&>U+?&H"]K6.QI,!BH9>6=*3+7'-_0;9))L%U1IDFF]8_"8!7V:_C"Y MG/+W?I_79=T6LS[ $2"AC&%7(+ KP+;0J^Z)E7W6A.VP(MY4L\.*AJ4[U)JV MG3NOBV,C*'+EG2D!\^?5>9MKP!>D+# M*HYV M:+71\@$R;7RR@#KPB3@L1)!U$J6( ?MG2%R>G-FQ%2FI5G/8^\NT\8E"(>)5L]?H&81XI=E,?U/QL^/[I^[?EX7SE9L8BW\S&_'UE\K_U;]O&E LV M(-%J(7T4A+X8]@4Z%%*& <;E]I:=& CSD8$U&OOP]=ML^ON]!89^^;=)I\VA/A,G&R63\=7:)D@J5YB!08#>R&WP'.L>6 MHOEXUQJ/=ZU+9-=8&AG8BOHBDP?LBH4L___M@3[>M7XH" ^YUD*QG2X$QAI= M>;LY,,7^++ K_YS7^J$P//Y:2ZPM9'RIO?9F>P MG M3$03:V-/U$GVJLB+EB-9-BQ&&T1YE,C'NM!6RTQ9Y5I:I]DD<:BB%W8ZZ^8H M[ZS5G@6 AUSF^GZC,YL@!5$X1^PSWIV!#.TPG8:=\:0@.(!]-B'P/7;*6JU" M%#'VY%[LM$1HXA&.IHZ QR;;'+1UE:&=?&!?HEB;ND)@5CW!QK:]6MACG.(C MVF5"%^=T D9B?=BC:'H$H+#1;A%H: =HBE0/ MNX)C8K.E?E>&PBX=)(G.<5#B?.X8.^IH(9G:]!/"ZOB[EXO-0 )Q:3)@M9#( M\;LRPH:@=>YX;#BFY=O2-%S#O$'C6-!,[AK\KN;?_O/XC(W?;#+ V[+#)2DQ M8UKIMQPUAV01M*^3V%31>V/?JDVG&FTAQ&^FX.WY[\3H(E MY#.!/D&(15CR/^C?Y]22FYPAX;0":.1Z"O^!:Z M-OVU+$0*Z&'R=1C/Z8E:(6$3QY/U(==(R0>ED76+HF['T2NT;?,*'PJY3LC[ M8CQ(4K4IZY$"V*Q+$5%436"U*_ULMD(# T_(@GLR23<=3"IU%HDHE6FG4@18 M@3USGJU#OMMG35SILSJPI/]]R\G_W[>LVS_/YR;_,KV9G8WO9G#^_;+2=I]O MF[M)-5EHO8'W \Q:J_3AQUU:[XSZ'P)_E_]AI\<5,"^54FS:7ZD$.N<&-NWU7RV&"-]T74L9@@NWRN0+"F MS>VKE>J0 PMZN%-&*7NLZE!F89QSV=/BE%4:RH'FWJ<[9-M7MM=2<#*?X/*,LN#F'4 MPBG#MH[/U_[78B')XZ1>N2ABB;%2";80QJ/WF$)1U!6UL5/#7MJF2M?]9*[S MGL\_CC@@_<0_=K,QY]5B]_[YZK\FUU_N_\@._!J#O__N;OTRGOT^ MX2/YVVP\ON/'V/;S5^'[_:\L'>@P'$$=VXHL7#G4C\)Q>4NNKF>3,_Y2'%U]N:42 M^5*3!+^/+MI0;&N)1#18ZVW(L04TBF]HCKU9CU&U^=HZ0T?JE<5MENC1TM_; M[LT_/?RO]^:7\Q?N9IC?SNVXFG:#.VY)9K>56")O>U(F&]1%11 &^V&ZTD!L M>;@JQ?ZJ;_F2X*H#D/[Y_=Z$\ZN[X/J7Z<7YC]/K7\>+$>?;X/-1)V-B"5Y[ M6Y(HE<6F@X_#F+8U1#AAU$O&;]1\_1;17_X]^A:G-_SILV]\Q2=;WQ421PE0 M@!PZ10F0SV#LH2O6-&&L84!7(\.7 MRGV0W['&=G%9^MSZ90B1]2TL0GJ@1+ M6>BH9!VY.\^G;;2$3PG(YFYU GC"%&H MA>Z0U$:XMF895M,V+PF^@VE=)4+1"BT':)Y$3.BT[9&S_&?C]@%H\T*!VT?K MHL.@71;61M9B$((MAK4N ?E:\-[2!ENTC_$:KT>3R_%Y)97D"/2*A;SY>C/W MC]/X\^1LLF>Q$>O2^1C0PF??!"W-@C5(Z 2Y>7U@Y7,[9O"^^-M$.L "#M<& MKE$DIXH**I,F"EYTQ?:6CW%;6?,L"]XX7, "1 *.PJ0,PN>23=> *W@S2YL] M@9HN.OX"#K9C&@/'#>PB6*RL<%91STALI<3V@>P "_Y]?'GS@'Y\9:(/E3?6 MN\3^NA*IF,74,52M*B"MFB3V[6?O(\_!D+9)H1>1PUUVF7/.)G?RUWIH_N$. 52E)%^O0,D&>^JXX$!1;ETNSQL)5%?^"@5E\WP^C M_S>=]=]\SUS^=33[;7RUC5+960J&[63*(D1&DZ/?'D890]NAQHI.J=5[_)IA M9+]V>GF^&YC6!RB1*+F<%8;,;FVG%-GM*GG@$)L[$;TWK%SB+4^G\VEMC9YV<^$02<;<62E8GVD/)N\ MCVB+%4IHGVTB]@H3=,>'_<12VNY^;>K8W4?+=_9/2I^M1R63T,%#D3EB8$R8\]*PW,/WP ):4A;&>$/(N%+P_?4NY!JEI\5JC\!^4&ZC1X"( MPF%VDO4.1]I8]&+T;PAM78R1V"27]Q-GLP>B'1F4BC_91*I$.Y 6%.NYS=:2 M6>WMW%><+:.'-,?Q5%B-0*RM"[Z?^4Z5NK<1IQ:\F\?)LYD/01M2[ LY4VSP M10DT_0SZVGC2[I8R>K5&:$]Q-M(95_8.K;55#H#]$!]2/].7&*BV>@S47,4^ M4I[#L;L*59LN!0< PM:1K;S;G0-B52C-741'CSO[)Z75-FQK(AW!^IQ8(PG% M^M[V*DH7:FM(K663^GJ .9 'DAV[Y)I].5:P!2MI9]?[Q$93#+S.UJFAXG&J M_F7!N(\'HM%+Q]ZP3X+]74EHDNO/)&D:RE2"7GW&>\U@[N&"N%CK8&4EO0"& M*4?53PX%*8O81&H]A.&<(#+4I]BJ=<>75W/1]^>V#74221:",#^2.FY M8"FU/>"*5JBCAN5XN*2'(YJF4%F,HH%8I*C=S*KGID.RHBF<>L*5;>5TS)4O MD#?!Y\AVD:AOUT1V)%J>,^5(/ZFD!]L#F?C4&R\#.TV 6">_+O@!DQL8)/5T M*]M&(2SYZ -KMV*D,&Q\^XXIB62<:YPJS9'NDTIZ.'>+EQ'BG#(+:T-8#K9S M[ATHF=I\U:%6YF>ST>5OX]O&UKMOZ;AN_;]'L_/Y'_^X';AP.S5$;K4)\Y]I M%/G=X_Z<3++MB;6INLG:0VT@,QA=7Y 2B\!@_O3GC^K7;6M^V(I.&ZF_\^9? M_?S+WQO$I),Y"^0++(.IN6C7:25(HGBA7R-BGR;7%^.?/G^X/)_\/CF_&5TL M(==7<#=0$=OSD&K.*UA$CT7TM?')*^\50R5/&:I:!#.?#-D-0;F:-ZM^^C*Z M[$A9RW3V>3SA(_/A\O9SMR:/]KJEPQT'(19/1FF?@@HAVE)=ICFJWL4 ]\WB M55W658V)C* # +T_("]Z'U9UP)H.$,'!J2^"_R]I+Y6RL6L==!EQB3"IWX^M M5N1U[\5C+->:/3!@.!)C54.5A=;&:+MN &]5%F5@#QR!_&,;GN9*N,#J/M2. M9.E,)!2IJYFJ5Z((^3:OQ TO]+_&D]^^L "^=GO]-OX+__+K-+H>E]%D]H_1 MQ= 'NM M6[C^IL%2TKA$#B&3!8[+O!D^X;@>5>*_='UMXG"W<[3(Z)4;V20!+S-0G/M"8.."BH--'\1B703F- MC3A\&"NL-4 $*(+Q(N<4>L85;XP.-+ !];5?'R6.?2U;L-M=4#%F2<(5FTJ( M5M1JPNXN)+=,BW47/9%]JQMQ^/!5,.K2%\H8,^;:^"0ZP^%]SGKP+@ARQ[$: MKV4+=KL+@(Y=,:/9]8JE%MF(CC6%[4*E&QC8"K+'R20\_T:<1/3J4&0#7O@( MM3 W9*5$G__,&N-:AQG>XS/HK)/TM$XJAJV#AW(V,0=!$4U.6?4Q;&'73&S8 M4'H&#?A:-O3PH6PH["^@< $4"DI@/4#OTK&27)M74O(]/H-;]Y8W;Z5"J M"+8XREYKA-#5YG! JXW4&V[F*D[L)OS&+0SA(E\RC8I-F.NJPL$ MET19XCL]=E+A-/=!'_8F1 UUP Y(D^J(CBC9D^\-$"(,/<7667C6_+$#![X) M'H-G8$%I[34F0Q2IMQS2E:'TFJQC&=[N1N!AKP(21%E(695<%L9:3_V+N%/& MAJ&K( QKQC]VX-"99I)4>:TQ>^EC;?9._54HR2TQIO0[P6ZS.4ID\[P;L:>O M>R#7Z;Z#:U)Q.@<$FS$X62=H+![?BE\M,;[W$J[?&WW4#3HUW_88>[=;D()> M^Q)L(8<^%>-][IG!V-1$MS9(X3T\LNOU"O;P [;TMZ!\C'[Y+U11>E <&>E MK%MM:5RJ1'''59!O<>]VNW^>=")-Q7JGO80H_"+H*1[ K=U#]][ 'WNXWQX> MP$N$I8!)%90U6")?8A(@96__C->K_=_+>_>'_7OJO=NQ!,Q7_BK2/GB/.I7( M5J^W?V169U,N%1 AOL4]_,=4I:X95J/9 _,%PYDO1!&2^F-+7T-%N( T99=(3]] M'FQ.<7<.8[^7=L?XP@8C6#$?L2I+*A;[JB#G7F+WBC=PM!"TB&E6*BSE7SF3M34>-6IUJA?*Y&Q]>YWX>OH K M!G9"E%)D2$:H\RCCHK0RZ?6I!*#W<)0"KC\VBM''0!8L4V5X&)\>?XS?^HNI%%+8">.:4%8 M$.1DR91"QY4+[#WZI5[,R_ESZ\$4X*XK>F;X6KZGI7<$9R$9",J)6'+MVK>Y MAR]EY]X\?"U5$RPU+I@ZFH01S%I(CD_J+-4./JLEO@'X_C&]X%]SP1KG(=>W MI&!$(;M/5[BEBR%?2Y7M#!%9"4YH.WO<79L7(8QA$-T MMIP AI5CLLS&XP]U,AS[!KM>9'T_E29#A.K!QEBT5A!1]?7063C(PYH0[%-= MY:$U/3. [36^#Z"H>4BALH3*66HSR=*' :E M&L U(5AS M__,_7O3#P.]]#TM>/SU>C*ZN^'/KSRPSUTZ_?IU>SK_L-S^ 6!M*2D%)$(:L M3=;E+FMH"MHX6"R.ATHQ1@^UT):I Z MZH7LRD^]01W/SB97HW]>C#?4Y-^'Y\./98F\285(DM5(T:[2 ')LV?-/ I_C MX5YQ$'"(6JMU:S@R0+@)H%2B+;5X2;$23CXX3YWR33(%FP8 LB@%'.( '1F? ME7Q)]Y7QQ]GD;+C^;VWLG5U1!4L=X60[';,)I=7 MD[.-S^GK'U]-M$DCQT3"\?=;+?E8LEEPEN]S*NW0[$.9@ST6]?P@#I"IWP=1 MI9R4#>00-:;LM%B\8*?LVY$%\U%Q;P_% 3KT^RBB+3:XB(E#MNB M!HZB?OEG\=OD=OK#5F:BM=RL40/C+ M;'JUTV32I?M5J2OXD@G*6CA*F'MOC$^54T/G1\G#4#JM7\0S8?0D(7M"]A]8 MLUOV>J- J4S/8!H#0SUT %\AP)LOJ6 C2 JLL03 6@R,]/TE=4(,D?;K6J#[ M&C%ZDD-8A_9&@\Z&DHM6WH+I'M]CSLLU9:\!X =4F6Q^_623P2Z_TY'# 5%2 M,4AE44-9ROJ85;T_"&O#,Q+Z')8A;6UUB"N&_;MLPT&:B5\EPO>/L-1& MD0=!,7H?D]8171_]:JG7ZXB*\*L ^*>;ZZOKT>7YY/*W39F$@6SK \.^!.F3Y(9D_3#_(M:0'N(-17ZU9P M9'CT>G@"IJB\8922J>P[PO<-N$ZKY(8;<"4I<8BRFM.!Y\[S7ORNOTRGYU?^ M\OS'Z>7XZ[>+Z??Q^)?Q[/?)V?CJ$W_X%:/'OY\__>;;MXO)>'9_8.[\VS[. MIK7$;[:EVY#O*BD.N -Y4J$HK#QY(%+)Y)4:ZC9\F@O\+-#C^I/)88H66@HE MBI<*$H78=^]3D!8'@'&"#D/>>#KH/-_!M-&03%3(F5"2CMXIQQK"$SJPU@WA M_P(/YGY/FVK]TZ:55B1+OK"1$5Z'H(WL%2E'WFL)0SB*L0=\VMQQ:2>!YH9G M=XS!Y)2<"#4/Q/8[Z]QGA:)&M>'9_2!4YB\0S0W/[L6%)-$$%63VT3.L:8&F M%MEL>'8W;P]-!E/HOZE?UD9[+J#228N4I)R/<37\=Q+:"%L);6KE 6&^E3 $B9 Z52L0>80Z9UK;AOB*$!YZ5#WF& M2RH>?5:L)E2A8@W"XCDN*'^HL9D'7N5I(;PE5PS&S(\NU6I2X^+=4!>=2EB; M*WY%"&_,4S].!;,3EAS[8\[X'*DVB_5\"QRW^O64?_!>[9/P.]P*3P;8S:>6 MBK3)%A^+ . %!>D6.@HKIW@"?2>3@G8W9(G?[OA3YET M1?;K!RD:]=H7GT<"^_2[]3)OUW++#07A4W$E@K18"Z%5Z4KL3#;%#Y7XJA>^ M8ZNE3">_8TN/#B$)4ZSUWID29*923+]?M=?W6??KG]MS1?]<-9OS/RJ7S.3R MMY^KL;QBRWG&7V5SN?6V=3]WMQ&+&H(MX^ZDUU3+S"B[9%0@Q"X03KZ.S^XL!T-@J['-!HE]3D23,ZX<$&TB(+PLXQ1&> M#=Y+X7HNC)C $[XP2%IB@^5Z7+FU^F:YFYN2]JQ=&+NB/:KL75^&G1/%AM5= MTF!E\9.LY+GPVE2(32@+B#K&4FM2WFEG>DLGL)G6MJX0^R7!M9)Y_WG\=32Y M9+,0&;890W(SNMA5.W%,&VPV088L+$ECV5?HLYKLUUJ^BO"K_>%)P-IU&2>' M8JO08@0?K%.&_^N]2#XJ+V5G+[YE[SQ_;_J:8BHG1L)F4 M!I(N@<#U10=D4EG[](7MR]>SK/=44=_\X!B5X9C6!<9=)R-E,GI1ZI&D6EL, MAN_Q]:+^L-FR:SM;=1 UP16+CY+ 9$7]FRYQ>+&V$L&\;[H_CK*X4X%T0]UR M\-:GJ-%J\$NJ\K6";%H59655KXZ7%*^'AAO)U(L,X'N0J:P M_"(.5@4(.?!]SH)]_8R>^M"2[_506Q&KTZ;1_\#K.#Y.K<^YC)/*.5JC"L-% M(3DTH2>_BB4G.41^A[%X71P7A,.8BB5@@)S ;)^3MS7';"25F?#+;4#'-+]VW%U)P'HYCC16!'9 M_Y.1 M_6")&M;/\\AR#6=UG)]V9U1M0; 71S"*BD5E2[JI)-8*30GE1_M2'( MM;7H$MJ6RF< M"MKG!>C]L(UC6;F;_#+X7B?5OB>A2=(P(!CB>M=;V*\[1K>\@>\B*6?*;Z^GL MNS\[F]YQC]7UJN5=/X^OV1\;G^?1K'IE'#U<^]]'DXN:+"O363_[YVIK M(+3B$Z H":55R8(7)J48L*> ]P'%:II9L=ZQ9CG1? "I=T7A[FM?ZY>&?E=W MW0: J*0,Y^/)?_]U_-OH(L]+AN\73(S'EQ?U0OX\GEQ>W/D MXT"!X#H9P_?_O)E-KLXG\UJ\^2?,OV?V_;\_Y+7Y?FN3ENQQH#KW@ MXD^RG4G<< 8?!K83W8F_7I^_/\P>_'^_KB>_MCF%D#CNBK7^+4-.711K^"\% M5O> T#9<02]H%_"4[P.8Z 4JK_*\]=&3Z5GR#7N2VJWNQ9O9@Z/C"W]Y_LO-[-O%S5487;1EY2=O M#U@-:PGK79L4=71HU!$,AH$;T)? MK9^R-WD5=A1-L?ZK@?THFD:K) N) BHDIT FY]V= RJ:!==I 7^4LQZ===&@ M>FBS\:CJ'=;INQVV=+.8GK=85>ILH1P%"8#!6L7;I#WOU\IO# M;N4K!OZI#OM*KLA+IZ.4Q07,RMH8%M%4MH3M_!8BG#LQSP;ZC^/K#Y=GTZ_C M6[=T7?K[=(\YH #TQ7L=/)]V+85;&-.L3*-@'J;25V Z$9B/HL%3-#J@S=*7 MC*BR)J,64>DR@^%ME@;<@S($3PZQ/O&3+)++AMT0AB\+(RA[L0A_M$2]"O0[ M]2 __#1Q/LI1=MH:G4TM*Y(N1">*I?XHV[!:#5??E$X48CSQHXS6.,>N'[K MAD\%+6BA,X);?4'@HRSA-'7&@X ^3KK*(Z6LD\PY20N^@/6+Y'E<)4"JVD*X M!WG6&S&>GOWK]H$G\1+XI^=\,KV?KY*Q-%#+(&N]/"Y#L\O2GAV,K6]Y&0%+(EED2,G)FK'T M/1@DTQ Q-O!=1>.>#(O;O_.9FHU'5^,TOOW?M2[1TQP23<&Q2Y[ USD^)8O0 M=RY99Z(:+'C1FBSM",OP(D\*HZUGA^]1$1A1H\Q><>BN,?<8*2K;2-5/ )X# M3R5;J<&+*OH$?(1D%F2-**'/)EG0:I"5A@,2V/5FO0",MAXA"A"U$3)0$1Z] M")5#N<-(LY-[^D?HP#/%5H^0+(J=3!1.)\>(J)Z+Q#H2-*2% $F3?CT8;3U" M.BG,&+U*28E0>8626VCJK(?HNHYTA'X>7UW/)K4%]7:%\T;5OK5EJZZ>?_NG M[]_&2\BL_,XG)&GR0@K%'B1E0R'6%Q_J*Q=]*,4-N4ED85<#N!&& M.H1G:+X)+(#&D"#'+4K9T%FR7]+BPY_6]9,-@+U&(3; MV98O&]W%ESY-KB_&/WW^<'E>*SYN1A=+/Y@FL_$91]Q;RS,A@ 5+.3GR629* MO59)@O7*(+L>:Z%=?8:C[LB)*6QEDD[([CO[J1PW6W+04YC):-.02R_!R)VC MPK> [:-/^])P=L_0IQR=+S[-9RT$ZL]ZD'*(61>LH%T=P*/NQXE9SF*MRY"H M2$RADE&[_N$L%LQA:&2TL63Q#VB?YJB#J@P3/H,-[#%&&6)?*1&3"3H/'G60 MQ]N/^9\-Z_CQY\$;).$X$L'B.&Y&%\'CHO&6:#"E*8Q::NI[X#J?!JLG'%M. M6A;K*A7ZI.LJJ: M5'GOBUL,DDH[ST;/%:G;C/23;:V7-7GU3<'%\ MF(8MV"YMX._4?6^Z@'(I\/)LB7Q7K.V>XZ56RJVR /WISPBK'87[BO@T"VR] MD/P_-Y/K[_5GV?A<7E\M'0=_?CZIOVYT\7$T.?]PV14F#AP+M70LC&>\=)U, MZ*7$DOH&4ZW82VF($;6#UP#6K=NV[M[\SV^W@*5,R%C04I\Z= K()=U!Q5E:>(J5"\? MIH_\NR^WPJ*L!8?LRZNHE5=68.IA,8&:*_9*]-%J\_46E$"$$/E""9O9FON0 MB^I*A;0T'ANM?5( M0'1TMK0) F%,G^GTS:8RJ7:K]@BR#%"$,@FJ,ADE@< MAP:-B7X=)VA/4Z0PLKXF!18$AY"LH'/O\OW_['UK<^-&DNU?0?2.][8C8+D> M**#0';X1>,YXQVY[W>V=.Q\A$I*P)@$- +:L^?4W"P3X$"A1E 2H')BHBV2 M>%1EY3F5F565:1INFZX'):!VT&7;WG=\SZ5,N(8C;,L0/F&LL?)V&@!H&D5YKZ_SXY?3\J<@-;)NK$Z)"^)[I M"$?4"0*HX;JN:&'D//3H15,1<2C8?VY("54;4\&R$:*A$\\TAVW1O$A,SYJ* M+%]0\*D9DZXOA3 8)8U8+,-E+6/F/#3HP*DH(('EV)('*LNHVKYFBH:"6$B< MGG7GM_AVD4]N(E6 .+O.H_FZ3KS*%/>,G+*!XYN!S6R7BL //*XV+U7ME\1Q M0^FIJ#4UOR/F=_QAT_>\?']CMQ-8.HOR)LN3?\?3+YD;KR]^Y$AS5RN 6S%8 MQ_.L@##!JPE$!L*TF[-8@2>"G7N,R:XX[$O[NE]HJ\2[@Y#>YGJ19"%7*:\, MSW']P*;$)*PY9<6HQ7>MGW)I&JT=**_N\Q-2W+$.=>33-)9-.>&@7-SV?1:8 M1A!:EI".X86&JGC^C#W:3W;GE)W?NT&=2^$0SS"LP'6#P#>%.B(-G3==,^1L M9R[FHW:^UT,PCB\"UPN<(#29X_LP_K3J/'$E6!_.T?>L1S#]2R# M*C-!"%Y#URV?,=\E?-B@,G=5DS.A>4! MH!MA>$RV?&YIR!TAJJ')XOE^-?- 86WF"\L!8Y^:5-0F(O2?RH>UF122A]_[ MEP5P'( FQKRE4*XR6;3."^6 MO=A?6G(K2DA]!W04)A[;L+@?@*6]/+Y.B67[;<:BU!14[(#M5AM>T,*=J3&V MU4^-3Y3>[Y&_K^IQ ^8\5Q#7LP,KL);Q;PX^F..V(C/]].AA>V>VA@9R*7?N"&S)>N:1-FV:8?$+,1.15! M"_@==.C'=#);J-([OV9YE>VD+//DV*4!) 9MP@W&#=\ MZEDJ%UL=O!*NS5M+^M(D!MT1[7AULX\DB*,82 $!W0\=L U"&3BFX\B@V2?A MAKYHJ;YA,\-\F-?N?(7Z?$O+"6P),K2,T+<\$@:JA'0M2 ^HI65I<=-Z.[KY M(I/-$18%WXO1T Q\QPT#;J_6W(D;T)9$I45V6"]G*M)G&8 $IC-++[#!^SE2&!QJ2PK(LPX=)*/# H+0]PW3%2IKP[8[R M(F*T7,F?F(E#UR:A1SQI>YP;X%.H%I;:Q](M'*HGC MS,7")KXI?$)8$-J!Y5MVLZ_1-+C;5B^U2KACY>!,A?K\N3CT[5#PT ^%:_FA M:7O":]QB;OI^^ZR"Q4>,TF/,Q(!\[%-@L"F[F,.W;@NRJN MX*\<%[7KO;7(:((_.%:5?&H=@:C]02$-94@DS+UJJR)MUFXHH:T @?)1K+'. M&CLWYO4P%3M@V1C$LET6>B'Q/&JLSCLRRW5::QG@%AMDK%@]7*@'3,6V8TIA M,C=0.<(]+^3^ZJP&D^U5+K76\F;$^**IV*?,=45(F 6^A4E#F$X:U00SQFVM MU3+.Y5@#-H>+]%E3L0.:: .^7>[)@)L!\J$.HOY4V SE1>>T=U.S0DJ>O!J%@? M:^<.H,0$3GP0H>ZDW4>2Q%JO7O@.]WZ5$:9*+[6^-$G_"NJP;ZN1)US";;5; M/. ^I]PARW/6'!31M,#"5/RMTB<,":;HJ M3RQOZ,5QS-8>6_# S8?AH;IC\&4]_CLKGJ;DK#"?@EDIZ:3IJI;/#3@WKK M5[>MN67]@/WGT*LMX19SE-!-CP=6(WZ3V#OVJH+\D=BWY*_81;UU67G.*8JX MW.NW!*8EO>6)(P^L%^;;04/NPO-:,6W;$$0.EF>R0^.&0+'"K[';)\# MTZZ\%56DM:5U#%31Z@CV64?>VF.]/K5G(@/#$=*@ZKR!%UHN=:P5I#F7[?-0 M1$GWC[$PPP:5PI2-4FD+B.Q9?B3@T&6GO(J/BX1[YMR3@PQP' MQW")PYD ^]643.45\_A*?VF[ C9PM-61!35&X;[*23"%%3A2>K9I<.J&IBM) MH\?<:>?P!7--TC=H4;S"(7# "G--E4LZ-*GC&]0/O,:,@%]VQ.^E-$PQ*!F' M49+O./:ZSQE0"V 6 3.*FUX8"L%#=QWH$D[;&>APZ6+5Y/[[?VJWP#9-AU/" M::#*?)'0I:'9\*7O^2VWH+L%BS$+^=7^ >,V%>H7LIKL/%B9'+^$!=!O(P')M0 MQCCS&+=L+3:B0.Z6WX8N9A?XT]XU'4],Q#<\JEC MRM!Q''OE%W._M6VTPT6'D4O]!9Z%]($Z7&:"QT"8<%P9T)5YK2I,][C4\(BP M;V]GU4:P:/9C>I7E\RHG:9CEO^;9;9R7]UY4+**9VH=5+/(HG<2_I],XOP,E MB_/"6^1JE]T_XRCW9E$R5[7DZC^F_[M8-B3X4^5DW9%]9T_E(RN4)I/,<%QU M)I6XOL/KFKG"-H.P?7;#,$SZ4"^/U;NAR'1/[0[',VQ7,--UI>VQ@ :.7=?- M$M(%=Z]M_YJ6>,BP;TVF>S+>F50EK[=]@)9Z?MC*$PU#T%K%.4[7AB'./: W M#2%#Z;JV93F2$-OF=MB(,W2"]MJ"9,Q^P^+<@W^?NS&VYVYVE_][^KO7Z[\^"H&4IG^FLV2R;TS =>T MJ$[/J/#DHXF0'U^7!9D!0SI@-\I NBI53KT*;GM\UT8NJUZ9W2FTUW?@B)+9 M TX"_J.4JC*ZY1!J.E;8! )MGUNL;7T3RVQ%FLZEFM2AS7#[X'3UR[R:AB/F\^#Z_E3BY>V[_ @M!P+^NL$DG*G M.1AA^RP(6HN78*ZQ [FQPY[_E$27R2PI[\'P"Q>JN/3RH0VTEJ!:&7GJ8PVJ MW^(BSK\^S$R_#Q&$AT(&=FBKE+XDL( S#28<:"&G8$(G\Q2 )Z]84B;!QZG84A] MVV/-Y!1(T@[KJ66K XGYR"+\%)?KN.N/Z22;OR#F$9K"M0T*9IUT2"@,L&-6 MX#3:=949E=0XD+5WM+/[?NZK'DQ(( 0S;"&)2MQ!B1\VDU,0M%?@*6/".M#? M.4H_]]A@GN\3J=:GB,$MCQ(CE'8SGJ'17IUEDMJM_;(]][-:-?CE-E9UR-+K MEWHDAF1A('PS,,"U]RQ.B3":$0U=IYT1B*BQ/ZBC.QO:1U?W**]E& 3<+)@Y M/#::K^_27,>G)P'%MK@[UN]PS5J,:N.W!5 M\0/5]_5=_36/Y\EB_EO\-4YWU7?8H[G@+;I&$+H^$PXS0LMFK)G-7<=N9P<3 MAB7M1R.CSVEBI[W;IZR",BY]8LI0&L3SF<$:9?7 L&N[ 6*Y87\@O=NCGY0: M@GO$5:2@;]\[ETF[YN :P<6NO0.^]*_Z1)V49[ZBWN4F M[5F.ZWMF:).5]TK]MJTNN&BE'S^PC=WV;X]R MSH'&034/==5Z[=\>]>0LM&GH>(8T?>Z$X&G5]6"5E6LZK?X)PNBAT_]K^O=[ M&D=Y"FYL_8S#/$G3\6T"U&E8U"6!$4*'5FX0<$U[1\K+ M"UP*!HT%_6+,]H5-G6 %/LG;F=8IDQ8_,*+8<_>>\L"8RPT1,,]@/DP+ON<* M?SUZ-&B;II3:XD#=?*I[];:9]5:EW<B0/G(B=C7A9*U?[@=;&^"OVSW*3^[YM2@_L2=>L;.JEX<48$*:SX\"H M9=OBI)WSX\OR^=M6F>&;AL.X)0/A&&J5O\Y^Z:F3;FUF//70^>!6%64R\;+\ M-@-;-3ZHNYXDDIFA:3O$,P%G9A#4&<:\D 5A>\81PS-ET\G M;.?S,AA]4.#]R%T,LSQ.KM.7J2R0#P#3D:S:7^V4N&I!N9?./66&&!RF M+HLR6^7K!05SJ*A+H!.?&[0U$;2/C';8RF[G<.%0XC,+["H2^ 'W'==8;G>A MM@>>6GOKPH[3\D?NW$$,0:GC.#[Q_1"T2P!V'&-I0=+ E*Q=@>?D0_>Z.=P/ M!;@!GDFD;W+HL2OK8PG079<8[0BG,*V3#N:!<[@JKNU:KJ^*.<#49EN><%?J MZK77'G8E'SAV#P^>PZ7#'>%(PQ(4W-?0E7Z]\ "=Y':[4D7[^/^1N_BJ.=QS MO8![DBK[VN"" JO6N8$#RR-F6V4IZ6T&Z&L.]Y@(). 17%8W5,E6H8M-'Z7? M]B1@"I?RE9U4S3K0597@MX7,9P1<52M@IEMON:=$P/30YDJ;/3BMO[,1+VOE M6M[-81#W?O7GWY(XC_+)S?U/\==XMCT\S34_IK>+LJ@NH/M8TW")%_HJ\[RO MRF_ 0-4)O_T0)H06JPR_QVQO]B';]DV;AH3[W V#T*W=! IV%Z-M7P\<)SZ& MH>;[N)6Z-G"H8\@ 3$\O<$)1VSL!@2_;UC1C^PS.#CK>FSV@XDW4\MQ Y7>6 MX#N$AFQ"&(XEV^1ZZNZ^:BH1#(P"F#]D:!/7,8W0KG-"@CMH6.V*+X:@>TR# MHW3VH*G$%KXK#%L$7((3XCB>H%;C#DHB6P8[(Z;3 [FH8J MEAG , HI;>4.[@]+:"E:D?V/J=DWP,*]W[SEZWG MN5F43W^Y\I,\GI197G@W0';S*-TA/['I[MB.Z5K24Z@7H<.9SY?! NDP3N6. MY-8FV6,ZOE" 3X?U ^[X/."$>YYC,6$UYA 1S#6>D;NUPU8>U=!@E L1>A*P M&SB2^V%=#Y81@U#9BE<-O\?[# U&I>^0D!$P((EGFJX0I.XQ-PVGU6-@-=F/ M3=EQQ_<9&J$="(<%PI=FX+A@7/B!;(;:L&5[69SL63KHH-N]F1F,>:8P+"+80.$P\S9A!TNVH\XP^+0WVNG=S" 6=:AM68%%.#A)*B&M6'FL=GL*YCU9 M&3TZK-0./?B?+:7O0Q\K(Z/NHK*O6MO'J#3,UT[$RU#0@>O?TH(9S/!<@)NT M#(,[]2YG54G;X^WE?6:JJH!/MW39D)>V]9CSB?0-.PBT]D83C=WS>YF(;* FUXG,!_?-.B=C/Z 0E%V%J -N6^!MW)@H0="M,ES#)989IL.,,:Z=17HL'ML6DX4@_(,00GE%'(J"CA+1-=9AQC.,@=T3^ M#@\"SU-'M4G@B2H=<7T60=J>9[23N<(\M<_?>840G_)YP-T)1>#8#F#5YZYK M!NN2ERYK#_>.'&@=-_68$Y7A!ZY/@*%=[OJ69(YEUID(B'!]OQ4 MPFX!WL" M47_JW;*9^>@JJN^R-U<%G;Q85V[5\UV_Y#,_^E)7_C,M?%V"2 M1$6\+ULYM8G-P1LFGE(KT]L1YLQ"K/TU*;'WRPTH'L0=+U!A_7D68[3>.;$^E+U@BD;SO< M%*ZRL$)U^LSGC;JZG'DM.\LT^1ZO]EBB[<0!I&"B24:L( :=,"K=^DJ4,DL MV;;IU<;B/2&- 0C@L TW5+H.]SCX-HKX12B;[;A>X#KMA IB3T!K"/U_W?YK M83NJ= 3CMI3""4S 0;,#B82[5GV'+H\#YS#3"W@HPQ!L,-\RP?]J:FH *@#^ M[;1#XT#%X5-.8%E&*-Q !M(* 2#<;SPB\/FY>]">T@$(X%4+YHYI&JX7^IXO M5 B.&AC MGR4-P+\K;=PC@1%X?!@6F#BVMQHZIN<(22R0@W0M)[";TYI4 MN?7MQ^/1?=MJ1M M_P\\!>L,==45[XSN7IPK]'""!5_E2)H?)T#!8X$GB M4<=SF;T2"?=W;&[;EUID !(Y$%6"T-XMD\LXIN2!]06LDYS! 3A6NT<8P,7P*N<*8-9 7B51-B"^%352V&K MW<>&V8ZYC$,6!TV7PO%MX$G3$P9,E6KECH3-=G-NM0_QJO">/0:&D.!1LM"S/=NU79A/[?JD!0], MK[TKG59>]@O$\K*UP:<69_L6#:&^S7S.;5\$;N *1SAFO5+*1!BTZ.,[*BUY MG?2_N\(U)=2B;U*N M!YND#B>".F[ P1+SA6E;G)N-:$V?MTG!%(>Z[.<@V)>8=[X?>I03V_,#YCG, ML9AK-Z)E?CLY!26&'(C2=A0."57N0<%E$!"8DZ5?IR-A++2L'5N+"5B]@^__ M07,!3*!NZ*OE=4-R)AP.,^UJ'56TSW6 S3("";QJ>K2DX1'/,WTW$.#G :T' MJUR'/FL;:M1@ [%!NIO/0IB??+5@0DW/_$_7 DA27S0G-CR' J^V02*'3Q0'+38# M.CB#'GN6] B\AKARN=C,;<]E88LJ]^3'Z:W[1U]OEC)PU&8U"L1A^#9Q7+M9 M9S*)1]K'\,#:.#?A]# M!4 VMBM=P57Z5"FXBA+4RW<6;>_ZLE6-V+@6F>V#$/EMF>N6F:J M30BJ:O"TLHP.0:B=N%>&2M[,)+,=DS+7M02U5RF/'7 PVV>5+'DR_[*GY689 MFB*0#%#$),C",CQCE9#4I^W\+I9E'KJN> ()O,J_HJ%O6BIUONG!?T$:EERE M3N:\'= 1H#>#%\FA^Z:H9QA>($*+FL(5CK0MUD##)M:.Y(+&X0O.)Y#"X;N< MA&.Y3%5Z"FS.0?D#:JY.=\MVO@*JZN\,7@ZO\J]\84G#YYXP;# B/2)8P!M\ M^(';=BLL>_BD^9*)DP=^8$L+_"H&QHB4ABI07.]+ 6>\M<5]>5[T-7)X78TH MP[,X<6PA>6"X0RC(:9IMC,P[*@1]52-I-=5> K"P&2N87MF8(6^!4:) MY$T"+V/'@8D=%9Z>;EP>3[(<4/]["NV:)FK)-)HU)M8OE[/D>EDD/IJINE"_ MI&%R5=XX:9J 1A11OB<'P?.??^\!X*ZS_/Z7JQ_+>+XR\M;KM[_FR5>XQDGA M6;.D*./IH6*_6\*)^4NC$D MJ6^E&W!,L)9MQ_=\UU"'CV6P#+=P8@%1MH(-TGZP>OYZ:?4M^\%JO,I>'M@! M#8@K:2"- /2^T7BU3:$5Z*$/SB&?7/;9(A\KW=B&:88.N!'"HH[-P(MJ$I@! MW5#[*0>R T&]3N[02;ANI'(7S ;)2]NV?4,$@1G:]2)(Z G;:Q'.J^3>$M3K MY/[E)LE'*G:/@0$<6#98_PXCPG0"TVS$SAWKJ7V7KY?3:Z3^^2:.2V>>+=(] M.60')6X[4&?+'<>7ODU]GPG/$RLM#VDK+\NKJ7U#3"^2MK^(G:LRSD,8LW^" M1;K;$!ZFL(W0XFIMB+NNJJCD^H;5S*.!3T7+I7F)F%ORV93R/\ +NX%V.Z#O MT77\::&:J_)LS1;P[>>;*(^+7Q9E44:IDY^(;/JNQ+5LT*C =8A#/9N9 M7NUE4(>PK3*Y1?6N=_^76T(*:EKKGA[8QDZ[9_PW_>_'NQ M8W[M1*ER2N&6X;_JGBE5F7%S*-UC3W1/9;?EMA.:H>$X@@EAFLL43=SP0M<1 M.T?/)@S\VZ%TCS_1/4ME*S;5#F53J&J(5FA:=?=\GQ!CY^C9TC %&4KWC">Z M)XG#':!R[H SY%F!R>NJ4C!Z%K7((Z,G)!_,Z#U%+<(VC"!DAN.'G#C*Z6A2 MRU IA;E;.:5E<#D0:A%/4@LUF&]7>PG\P/0=&;@!JZDE]%VYFSE5$74BA]*] MIZA%^-( .QHL# 9>"Q&V*9%%=6K,!I(Q M 55UWDEN$MMP_9W48E&@SH%@3SQ)+5PR ACSA&$XQ&:.=.H:&V Z4C>DN[O' MB"&,P73O"6HQ:2"DZX8L,, *#F08.@VUN&:PE4)DW3W3(N"7]]F]UCUN5"23 M@TVR(+2E8TC'!!Y1%<>Y[S6=,UA@[;99N*1L/['L;F&'77O:'&.^(SP8']?F M0FVX8;2N.*,P"%;Z177?*ER M*S VA*X]Q96&P8E'+)@.0N)9W!!2-&98X/K>SHG\N6;8$;KV%$\ZW.3""0,! M$X /6BB"D#8*25QWMPG&A4F?8:,E>QU,GHVP_$/7LQE5-Q]>87D?HVE,TPI69Q8R0 M@D=.7$,5\&FZ1DT9[N[:,\VN(W3M*1HA/.0!H<12Z:P38=)ZABAY;)FI4L$EJ"/=.UYYM8QNO8$C4 3B6O+T'#8TXMGR5J?5XUU3P[L-&485FFT*1I&H? ES]&)1YHOJB7Y23&99LM*.]G\0_OKN"1WUU% M\V1V_^%+,H\+[5-\I_V6S:/T8_5;D?P[_D#);?GQW7]>EQ\?W#Y+TOB[FTJ, M'R@CWWQ4[?LNFB77Z8=9?%4^^@SU_:XV).D-2*-U7_7Q;OF>RVPV73_H>_73 M"Y\ZR699_N$_EJ?JV^^H^C)5P=(J'OHAS=)X^>+PQT_.)^]'YR?MQT^?O_SV M^\_!IR^?6ZWY'@1U0IDM[XOFMQ__ \R^MK!>VKSJQEF8Y8!X4?I$7L99=:4E9:)<+P%E<%'IUB9?-;Z/T7KNM ]>%!E#2BG@V M*[2O49YDBT*[2M(HG23PI&2-+%V[NTDF-_#59+:8QMHR %_=O:BC\5JLP N@ MU:$)]=ZKY>/5OB.U 0EHZ;)4O\[GV;2^]&I1 ESAC]M%65T]B68S+;NM:E3 MM8L\C]/)O7:5Y7=1/H6O,NA(#H]J\%^LAZMZ6P+RBO+-QD,+9E,=Y%-J]W&Y MZOST8AS#J^Z[S+7)+([R']XI0+W[?B>2!]GZ+QMJEQ1:_.=M!J+7RDR;Y#%H M@98GQ1\P6EJNRI' J%<_J06J.+^-QCUJV@Q*[6LTO@DU[+5 MRDNA[MO0\0M-O3E:K@@">>;_6F,TVW,+?V5QI?SF[7S9G4[G*;.-O>/17 M-9VI)Z\!H^::'*:4 NZ>Q*"?,*4II=[0T&K^TF[B&8"G?-#/99,;8/13K$M) UGE<<8'JU2SY(YXE-UDV55U3 M[2A 3Y*K9 )BV9!;EDYBU=EJQ)1X-UIREY0WU:V@JEOMO5@_0 /2BJ;+A;2* MF]8_[=66]:59^B37;)+ YD!6/06EA^^7NK7U?G5GEA>[%:YZ[(;676@;L\6N MOW""ZY-#YI7IV'"(FIM4"#)1&@=FIK;2BZOE%EBX=;E)6KN:+2;EHF8.&-V= ML]Y2.<"P78*]@FS]QML\F2C$+FU7;0YZM[P%<*)=P@V98K,E_+5I<@4 4GH$ M358TDTQ*!?9DJ631U54\J910@VO <(=&7X/-"PW+-;!G%3:;S;/:XG:IBUH1 MS5:S_,UR2RU,YX!JF,W5?\LM^DMCA8;&]E:RRN8Q/!6PH^;N9/E,@#7,E;P??=M/_]$45N=-+D#\<3-Q?L@G8K M[_'1@'Y,5/*QJ0@%2)IO746^O=#^FBL3:S7;+2W2XY(C%^1"(#L>3=["-CM6 M?:2:)_6;L@O>J;R_K8STZVWHUC[DD;'+9,=]0^P^:4@:1L=B7O(^/)W7&L"_(J.FE0V^S M7OU-K]?A?#4M+-('[JTJ2O+URO\1?2D#?:EC M^N6DZQ#@M]I-]!4X*(Y3[7863Z_5:G+1$-:]%E7\!M-O7)9Q7FQLJ4B*8A%/ MJY685PM@V3M+=AW??+4R#4U3EG-<,CO*V&_.?7E\O8!/67ZOE?FB*'$-&V>F MUMCL351@=74R=NNL]ER?V?UQ^9VRTX8XZ[>H9*EL_OMD(#: MHQ,71QTO2K[IS !_;(RJ'?5JGPZP^\8/RUVS]WH_!L:2[VW9L:.AJXU)G3R) MT@NS.]EOROC_U)*]T$Z+_6YFM.=@OS/H_YQ,\BS5OL23FQ1Z?7VO_9A.VO/0 MR_J!P-\%_#7L.^E_'6$0M..]#AT"GUU8W?QSY[:8.TCA1]_6ZP;\GR^]Q M&_# !R\_JLL_)"6T>[+\IGUV:?5&=9Y,JPZ4:7]+XCS*)S?W+Q;7J,;R6!NM MMSAL]^YHM>MS$N5YLMP9O>:PI;-:G4F*RW80;[VK63UA__K0>W7UM^>VK;3> M4-V+8C"C:XH:F;^G%/DJF\VRN\JOK@[BW.9Q4>_JW^M&J2A@E8^N4MO+^^79 MF/AK/&NF^@U#_:9A(.75=S5[]^-#[HB,O&#\U-&?.']TP#:>WT:3YO$,D M>T[ISJ/\.DF7C8P69=9\D5?-JKZY2Z;E#5P-@KA4B0#S[X!'9M%M$7]H_FAI M^+K=^>JOJ0:70VO3']Y1ZYV69W?UA]7%WY?3]9_YSD=4C?GA';>_V7K"QJ-W M/6U](SWV?7PL#7WI?6PL#<4.GK2#CR&ZYJRO<5XFDVA6L\AE5I;9_.,6B3(@ MQ$V&W/R\O'[KJR6%J6_V-G.#M@<0.MX6]L#DHTZ9JA-!'VZ2*4QEIY?/NKGB MW=/"JF>OM2BTRLK5&H/X)<+<.8_M5J<]IL-+',>6FQBN3;-Y'*ET(+6_4EEG M^PVK1\3\(NSV(>[7Z>YIW8*S>/MNM?/C8I(G5>8*9+;NF8V?@-CVR/+T5/?? MBTSMEEV>1@<']K'P4S11:W?UZ>CBL:O>_U1YN/1;U%_4WZ/H[^=UKO8J]H,51M5^^BJ_9A2+M*.U)JC6J-:'T>MOV1EU-X6 MUZ7+=%[ACF7&R@\8]3AIU.,,HAKO_[)< .IG$\=75F8'3?Y@DKB-L#DA\@P-MYSA]5-A#T;*_'$VMGLMFSQ=&I70] M*(UDE'6F-8/7@,?,=^0;Y!ODFW[YADM=2(94@U2#5(-4TRO5"/+LQ63D&>09 MY!GDF9>9-+9.I(54@U'HYXKPIXT2+?<;:5(P&-U],)J=-A;=/=W8A.CND(GAM %Q3Z="/"TI29T8)D:0$%V(KE&8P@@QA!A"#"&&$$.(H8TX M1'3A*N/'7ZLDP\LRUQ M" F$!$+B+"&!ZXZ/RS9P*]Y-"E5$>E)G*PRE&"8:2!L=#YA)D8PQ(3( M0F1UCRS*=6KCB31$%Z)K')$8A!A"#"&V-8&QY^?G?O/HPA7(@1RG/C/F>1I5 M6TDP^>V?VC1;J#(]K\F"63^TJ@#42JLY%%WK[DSZ[7T@W2738Q)# D,"0P)+"CK@H+ PD,"0P); ": MAP1V>%!0)Y:EM@2"#\&'\QO.;PBQH4 ,Y[>3^\KGY1+ORH%W&]UWF0 / MF>J,LVZ^-Z3$ %V71C7"Y9SAPBS=$IUEJ47$(&+.'#&X(HRX0%SLFDFDSHS. M/,&W,9.,?7%TGX,RGFO-P]*K/20KL7G[@)NA)E^W]V;QUWBF95?5 MAZLHR;6OT6P1:S=)G$?YY.9>BPKU&T\96O>(S#&FX.N/F^^)LWR>33;8A2JKED]>#F,DW@VJZ_Y MX1UY5WT&TI@TGW=(Y$LRCPOM4WRG_9;-HY8U,8_RZR1=-C):E%GSQ9+EJF_N MDFEY U>#(&HZ ZJ:1;=%_*'YHZ7@ZW9O+C>M*<[:N8;XC!6KJC$_O./V-WO9 M,] M[X798SH<*+#JX]W2>KC,9M-Z6_O:,IO'4;'(X\JDJXVS_7;5N \,G-;J/XNW M[U8K/RXF>7);)EDZ7N8:'+,_/U-K#\2U1Y:GI[+_7F0J'>EMGDQBY9\^%B.( M)F7R%>@NRO^(R^*QJ][_5#FP%#=?H_X>1W\_PXN2*Q &/"LKX<;'5#.[+.+\ M:W/R;-<527J[V*O:#%4;5?OHJOV84B[2CM2:HUJC6A]'K;]D930[,Y>H3W?= M*0JPN#Z<0U1CN$C=&]4X@ZC%^[^ ?:^5-]FBB-)I\6:.M1PSYU]7V!R0^ 8' MVLYQ.O@T0-UM=7G%3I;!;%;!1%"X,0_Y!OGF6'S#3-T6'*D&J0:I!JFF7ZIA M.A/=G9P=^N CU2#5(-6%CE4LQ'MU]//KL$DI19=CH MS.XLG>=04-&W#8.H.&-4F+JT.DO7B8A 1(P>$9B0$W&!N-AI/YFF3JW.4G*> M"RIP=\+CLO6R^3R;=NJD#4ARXV6?\ZD88RL+%J-(B"Y$USB,88080@PAAA!# MB"'$T$8<(KIPI?'CKWGR-2IC+4JGVB*=X;KC8%AI=.2#\63$!>("<8&X0%P\ M:YU%ZA;M; !(G7[NL_#X@88Z7C@@N!%2V[HC'46?6TK^X@T ,O7(DT@33RN GC0&[D N0"Y +D N0"Y +D MW8>7N0^XL/G\6NA]1W0&)-;!F_YO)SB7:GP;J/[+O/@(56=8K3Y )X;#1&<;3[ M>$D"]FKMZ+,'=+V'YO4B/6C6&86^XFH:DNC@E!))M$,2Y83JQ!;#$2F2*)(H MDBB2Z(A(M(^](2^6ZBBTK^^8(3(E,B4RY?"8\CW5*1:\W#TJL])"OQ>?N FZ$F7[?UR M$VM7V0SF$%!&K1HG[3:/"W7,1ROAQSR>9.DDF251F62IEEU5WUY&LRB=Q 7< MFVO1;*8EZ=>X**O30=H\CHI%'D^UJ-2NHB37OD:S1:PM"O6* OJ57 '6H*V+ M-+LLXKRJ'0I/N%W S>]_BK_&L[48^;?5.]1+6Q(]L,,U1&M 56*=0N_RJF3>'X9YQJGNL8(;?NR+Q'ZAVZU9 )2C_-'U6+C*5L3 M+ %5VM0M]7GS-6F6SZ/9%G%1=%] MUDC:^=+[Y$C:B>.W^[[1$,6@]7,D>]#'Y:.C?#8L@KT9,+?\0];RV7K>,=6E M;U=]O%L:?I?9;%J?<5#6^_]4UOO/2Z-^:>'_7IGRGS=,^=\W3?D?-TUYC9_; MJ9+!:>S Y#.XG42C0?0>3ZX33/_S$.\6@7K.0!VU#0P7'L-@;H#J ^SL8U7\08'3%2\IQ1O+=)?\^1K M5,9:E$ZU13I[I/ #*B8JYE$4.UA-[_14M2K;S)%@7X:,6;R?[0I_ZY M\762IFKAN][]VA5,!R2_\^>WP2?&[>Y(R"M.? SF4 =C.A-V[R(9RN"K^_#L M&E(-4LWQJ89*W:)(-4@U2#5(->,[U#]T#4"^0;Y!OD&^0;Y!OD&^.6^^,8AN M6]TESQSZX"/5(-4@U:!I,Q:^&Y\B_+6N68V;L_I8:S^W2A)8805Q@;AH MWR=T0CI;,4%$(")&CPBF[+ M?X5L/T>S[L)X Y+9>)FG4R&>MH0LH[HPZ=&TZ[QKRR+X$'R'@(_KS.XLF(+8 M0^PA]DYHBY_]LCI"#"&&$$.((<2& K'WS-"E0/<-34@$'\YO(YC?<&?F,G69 MEL?P^'^K&H)5BM'5Q^LH20OM_2PKBKCXMOHUFF<@E7\OZQ,FZ62V4+4-DE2# M,5#I6@I=2^.R*Q5$+COC%:CWU.ZL>"S:! B7,X>+L'$# ^(!\;"Q8$&8A1,( M3B (F.?^R,@0HW2GFLP-EN46G;5 M?S@6B>F,EX(PN0CB G&!N$!<("Z>=Q1 ET9GH1;<:X. .7? &+IAX^9G! P" MYKF;GW5N=+92AH!!P)P[8&R=HDEV&&!PN^?C0@Q2U3#M,II%Z23N2J\&)+S! M<=/3@LOR:9PWO>>W?VK3;'$YB[7_(-7_7B3 1T>C?INZE<*KBFR63%=O&HJ& M=E?J;9]L7U,+K@]1]K!U@G2W_/1B:8Y"Z_J.FR%#(D,B0PZ/(1G5">\L@H,D MB22))#D(7462'/1Z*3(E,B4RY2!T%9D2F1*9$ID2F1*9\JB.MS Z2X2%)(DD MB20Y"%U%DD1SIS MD@)GEA^X"2I^0/+?AS%*7&ZV^NLER+9K.V%!X*X7-PH7U.TDFL M/D)O[Z)"2S,MFI3)UUB;1_D?<:G=)>6-EET6L94NXR*=9-G M$?1SJP6[7K+1P64=D.G_+JJ.*\FH'^*B3.:1^F8:3Q3KJJ(@[<8[M/:"5H#(U@I&J?[(6UL: U0,%OT)/ML;V0ONBQAVD M$NO=D.]?C O1%8DL 0-2>+3W&\)L)/40M9N XVO T6W -?/;\&>@Z@6@7(,W M*<9M$%7W?7D 2,4>8-LG7R.%H>7GNYMDIH=&L MR+;4]+&IH-+,BM7O-NFDG@YJ .@5RU4/+A8 _'\M0!ZS^ZT7+(_*[WK)W1,\ MM<40#7N. R1=,1KKFM'46'73-'DA.R?;JR2-TDD2S6!>2T$+)C#557/>2;[CF"9'/\DKST?] Z[/TJ(O5PEF+N/R+H;IL;8:]=4PPU2X MYJZ1TW3:/HV*AV =FN U7=5%45B?T*[E2_FJY=671U%*:. M?5 CMU>UV^487B+T#UWHA@H6)%?WH]'E">A&G#_ZVHVG;*VS M$5#X302HSYNO2;-\'LVVEHFHNF;UX*5.3^+9K+[FAW?D7?6YN(TFS><=@OJ2 MS$'!/\5WVF_9/&JM7LZC_#I)EXV,%F76?+%<*JV^N4NFY0U<#8*H%UQ !6?1 M;1%_:/YHH7W=[LWCCNM%&+[S".LS3DQ6C?GAG6%_LW=]9WL)JKZ1'OL^8RP- MQ0Z>M(,CR34XKLT0)STIO6>J.%!"U<>[Y6QQF0FH'1?XM.MI7G66F/O M.7G!<26HA&[E$LT@?VV2!*HTJ/7"5_I*5T:Q7PPI/?HS_ MR,RH3+']49 N!3LFL*_E^OXORUV;V:* *:PXMQA'G^<_W/@Z2=.D^Q2'R(?= MRV$GD@*H MK8I:'L/C_ZV.\5=;;U0/P87@0G = BZ[P\+-YPXNC"!__+)*ZY:D9;:& MV<.\6!@:P- !IDQR(RX0%P@+A 7B(L!FJ8#<@:/8[,N$_CW;[4.2+#CI:?S M\;)[X*VS][418@BQ0U:9#9T8_8>)W\;J,V(/L8?8&]'.C_.RUX-4-0S3JIQ# M@?$Q5'(^7AWQ$TFLAZ,G3&>BNZ,G>RN%CT&-,+2)!(8$-A("HU*W.CP[AP2& M!(8$A@1VQ$PZ1+>M[H[6(X%M^][?5X79=EU_M(9M".T5E>N&UMS^BT8>L31Q M-P47NRI-;%R0SJO[;M0XWZJ7J:\+\BI!3U42?%5]LUYJ?5#K]ZEBOZK:+SRB MB#??=1E?1ZD6U96#FV*^ZFV1UF39_W-R$Z77\6;MV/(FR:?:OQ91#I!0[5%C M=*']+;N#ET&CZA+9LVSRQW>+VZ;8=1X799Y,5)W-8MFA;*LUNGKV_;)'DUE4 M%,E5H@X>%:L^+&[5;75GM45:)K.J/0]>%/]YFX HL';L,5KOP,2NAC2:S>XO MCEE@>%BD /IOC(,5-HK9TYH4*@!IST?J&F&C*DG=C<:\;5JI6VO(KFFDV-HQ MU,E(]5.27-\Z]7K[K,HT6I3'6]6Q-^ZL+[Y:I--"NTO*&YA[-PIF ZX[8BAV M87;*4.O1>K\EZ4X>WEV9[>[$QSL5W[?:- ;S:0XPFZ[X?"W311I-575O^#J- M2R#J(B[7OU:Z4:P_Y_%MEJMK+^_77RI.G4=I=%WMR;MJF7\7VN=L'J]_63YT MR>:K!ZJ98_W(Y011*.7-\HTW9=U(N1_$5M/4;KS=1%]5O_-[-0=MFY&%PK2N M9LBN(-@7'X'I50_BJE=J#I_&\ULUA6]-YWK%5&J>CJ\R&.=* )=JDIZ <*ZS MO#K=KV@H25=S=//P-2O=)'$>Y9.;^XNU$B@A/_+6C=7W]DDV65$V-*M.B5"9'/%$*J1P+531]65$%?E03_M6B7.3QA>8,?[14F[UL M?ANE]]5 =4-/Y@7MUOQ\"YPN+^R.*1V4;Y$J$,9JB])\GM2:G,>SJ*SLW.R1 MB;\RL=<(6YH,.V8(;=?$T-RS,0UH^]G_2_7-9C.79LK:NE'/B.;90OUV"X!6 M,;#FAS7PB\E-/%W,JIEDZVFI$D*J^AVG$V4&P9V?LK(C2[\C95K+!MI:!5RC M:MY+T@@:'?!%U2,P_9^W&O&4&3U\&_]8'DH(;N Q_+X^['X%O?54!:9# M432 >>W;ZNUX=="_&H%I/,GR2$V3']0@+QNTJ:[=(&&MZ0H4T%UE'BZ=>^CN M*O>/ZFR\S6F-I;#A\G3GN'0=67D_M-EL2[K+S$K=28]?B&XGN0OMQU2+ZK"? MKEV-#,4PG^5E\N\*3955F18=>ME=>XG#4]9.'I,F[2JH+[.X-EEH/6]NQB'\3!^TV?'G%F40!W:33R;UG&'\J8)Q2B55:JQ="#K M-;G:$'F0EV]DE-P=^9*.(YS#(]\=HUT,U,SZMEZ&>L)J;@A(&93?GB?=ONW5 MHJ.U_O5N^;':6WULE8K^<1WU''P/1BGQZO(/20GOFS3QW4O%0$69+RJYZ\WV ME\%WZ P ZY1'X_D^X_A7V6R6W2G3;'/9HC7M31^HVH-WNS6.>Z\VSULXSO<\X*5HUYH=W3'ZS=U_N]@[A^D9Z[/O$6!J* M'<0.]OG"D9S]'M>I&I3/NKE\7TZ*K6,@K'70HP=9[I!?;X<;6BY.^TW5H[VL M*+]_KBET\M:N5:)>0=@1-AA^VR<@):;1A ]B)X3J6(8)?D(<5/M67BN6HS$L^WU<#IZMCUR#16G37;>,QJK![W_ MRW(I.EL443HML)AD!UKG9?FM6IJ)EVLA_]ED:J8?M=\O/C^]Y0@SI@Z3XP:? M&[N[=#?[U*K[S*@]Y!(4NFEAA3^D&J0:I)J>L_X)+':(/(,\@SS3/GH? K#4DLW97K[GY>!^R'9>,Q6]/$8)/-8R;YX:?IQ@YB!P?> MP9&L"H[+$T'Y8&[/^K[J(V:2'V3;,9,\0OZ$BCCJ9-B821[!@^!Y(7@PDSRB MYZ2JB)GD!X.E <2YD6M>Q#682;YC\ WH? =FDC]K#'<.V\&?'L%LAYOW,:Z; M5G>K_T,??'4?'HE%JD&J.3[5X,%[9!ED&629WE/C&:S_L] OVJ4]%(W!/ 1( M1$A$?7M63&>B_X(60QG\U]H\&*3&//*GB5Z?7;)3H4NKLP.W0P%'WSX5(N*, M$6%@606$ \)ATT+N M@=V(Z>-[]7O/R[T]8GTT9*0SCJLQ8!X3UV80$@B)'MU,Q 7B8O2X>$]U(CLS M4M$-1,"<.6 8T4W964!E*+I_$N=M0.&2\18%&Y 0!\="3PNNEVSNCXW&*/)S M'R_-^VN.(HPC_[O@.K&Z.YOY8H&.0O'Z=F&0))$DD20'2)+'J_\S;J5#@D2" M'(NN(D%V&)[CNDV/6$6HT_T=H]!6W/R!%#HXI40*[4Z6AJTSRDXOT%$H7H=Q MX,"FQK-_%L MJD6OKRA7O?MAN3BA1>FTR[IQ=U&AP?^7I>.P%-QH2L$9HZFSQ<;24.S@6^W@ M<5XXDAV^X_*>4#[KYEHG*,XQL'SZRD1"U4+5ZD>UGKU<,Q*JQ]HH8\4CUF': M@="!UOA\,-P#KNCYH*58OQ/!>S2U&V;)M >C?5"!-(0$0@+GLP&UM,OY[ 0* MB> ^)W"?WWPW$J=W<#A!^3R31WHI"+JQ+Z'-/ /C#*P6VGV0-"S=)8 MNX^CIRD9M\,-D_ &GQP(:]CTG(QB\!J@[L,3#,@WR#?(-\@WR#?(-\@WR#?( M-\@WR#?(-R/)V'1>D:\PS^95W*O,M*ODZS+^U5EB)N3E,\X"9^B,=':F<"AX MZ-N$042<-2(HPY33B A$1',?H[K-<)) 2" DMB#16;;IA"="&Z^C"M=8-0!!>" M"\'51R5/)KM+(7CNX,*EQ8\_9SEXK#=1VKW/B@QTS@$RF,9Q&04A@9!80X+H MU)(("80$0J*!A-0M@2N+" F$Q H2IDY(9X4RS@428U]9'!R 4'"]" XK@/2W MP1\K@!A"-ZSN8N-8 01)$DER"+J*)-F=++FM$SF 2G.C4#PD223)L>@JDF1W MLL2B[DB22))(DDB26'!S&"0YWH*;)^#(0YK75T7-Y4=U^8>DA/=-ED\*_K50 MU36+>*+*;"9QH6ME'BD">'&/3JZF0Q!W=9_S^F*D-;74[%&U=AI/LCQ2=5 _ M*($L7]6J5_K:%U=/!66XB>L:I: 2VBR#?VZS(E%O+[2[.(^U))W,%M-XJC+D MQH]JTX=NH8*E3H]0ZI098ZDC:8ZEH=A![&"?+QS)%NAQ^:TH'RPILFE%[ZP7 MA,J&RM:WLK7?5#WZ]S2/X=M!5H)ZI,G749+BR12$#$+FV4V>9441(V80,Z=2 MP&$63GNDL>=80&T D6QDF!2N-!6F<;I1VV6 M%.4>NP5W,PR3WP:?@@'S^V^GWR"4Z@8S>I?*4,9?W8=[IY!MD&V.SS:FI5.* M5(-4@U2#5-,OU;RGTM*E[&Y'^3ZAK''3GY@ZUYEGN[!(14A%2$4ODX:TB6Z* MSG+S#W[T7VOV8*SZ8_#GY"9*K^-J;VD\U:Y@M'%AK(>P]=EEZ^%4%U9GJ<"' M@H>^/2F$Q!E#8K6RT%T-4\0%XF+TN'A/39UUEQ(7'6%$S)DCA@J=&YVENQJ* M[I_$7QM0P*A/V7[)RFC6/C2(8;<3A]TP40,F:NAW6X7!=-ON;JT3@RM5\'(W:F"?UL^T(204S)F E=E@+3 M^PTV=QIV$#LX\ Z.9//ON'PKE ^FPGDRLP6F]T-EPUQEAS09T_LA9! R!S49 MT_LA9C"]WW,;B^G]T&LZN7PPO5]?X!O0.C&F]SM;_'8.V<$G'\#4$P_VH5NV M;HO^T^ ,9?S5?;A)$MD&V>;X;,,,2Z>DLP/%@Q]]Y!KD&N2:$VV*ED0WN74T MF;SMK ;(1,A$R$2/^5C,,'6#]<]%0QG_U]H]&*W&!'^8@^:%XC"83IG9E:H, M!0]]NU((B3.&!";X0UP@+G;XR(SIW))=Z\K;=H41,6>,&&KKEM$98(:B^R?Q MUP84,L($?V=)0P=L><1T IV&[3"= 4GG.E$=I8,%A,*($\B3PY"5Y$GA[LE M!%D261)9<@BZBBS98:".$JX3VMTN7&1Y?CK-6W>:%N__*@N_Y"4\+[)\DF_E'"U]F/Z-2[*.;SSZ=#V(1TY MP6PU!#E7][U;BC59B_5=DXL0*&$^SZ;+8Y-1.M5N\^1K5,;5WXMT>7BRO>)P MH3F%EEV=+&>CJ-K78?+&33%4N1KA"Q!% 9V';EYGLZEVN9C-H%478QO]T7)$ M==\)$X.VY_:7Z=9V8M UB-I)0;.'.,5UHRK:=N'"7%X2I-5$?AZ2/F+<2%?*( M"MEDJ=REBI@4\I7"1>L:LT2^3H,P2V3WJS?>.M3?%2P')+G!X;5SB X^8P5F M+-G:*4&83FS6NTR&,OJ/65/(-<@UR#6CR\TP> U OD&^0;XYT59Z0R=&9^F1 M,"TD$A$2$1+1"Z1ARZ,0T5 &_[4VS]L.5E?W_?JL?;X8M^X^;GU^>8RD;C'2 ME:H,!2!]^U4(B3.&!-<-N[-L+8@(1,3H$?&>ZM1JG];![) (& 3,KOL8U4EW M)4>&HOLG\=P&%#D:P+%4#+EA]HE1!^PP^P1E1)>TNST5F'L"61)9<@BZBBPY MT" ,_((6.0"F10CMTQJFM$\E/+]%1 M:%Z' 6!,!'DNK3]ADK>N$@B^*LE;IQD%,=T;IGO#9&$#;"AV$-.]G9MOA?+! M!#.8[@V5;1C*ANG>4!_'I8^8[@T5$M.]C6V[Y6[AHG6-Z=Y>IT&8[@W3O8T< MKYU#=/"'T3$3P58F J'+#FN+#GWP'S.FD&J0:I!J^J[!241G!^0&/_;(-,@T MR#2G81K,*XE\@WR#?',T)\K4I84ILS$8C>GP7Q!'FG 3L\04XIUXG $^3#\%N0)9$ED26'QY*&+DAG84GD M2.1(Y,A!Z"IRY%##0 MKVWY45W^(2GA?9/EDWY=D< MZ.9>@ZOJ>R\7)1 ;7*,>DMVENM*"* 5"3&ZK%'Q:=J5%VC2>J$XN3[G&VCS* M_X 75B?/U07JN_I]]Q?:E_6;5ANPK8^%EB?%'UJRT9R=]VMWR6RF$N_E,?1% MRZ,J[1[7Y2Q6>JQ%Z3VZUU&LRB=0"-N8GA4 M5&S)&CJ<70*^JRO+;/6FS4X_U9YMD8/D;O/X:P1=2J_ASV2BQC>K^Z\EY>IM M,'8%C$6F ;Z!H)/B!L;Q-BN2:E3AJ2N!/_)F?:L;*0BD>A-,;S"%;0^9$NTT MGB4PE=ZK:]2/EXO[.+_0?DFU.)K<:%,0J_JZS*.TB";+1D!C;^-4WS%0ZIMU M1]0S\_AV%DV68ENV 82S:@$\JI+0%.;=[QI9I8"$5%NLDGEH*HN,!D]7V3O4 M+7>3@'"V];\&9]7^I:X5E3HO):#&?:<,+K1_W"2SG>#(UKN6E4JIJ9YX[];@2181VCU#,GMHQ M'@>T?:?/E>E I9!0D=+5"AS]J"W32W0%TP%)VO51L4KT 5< ME.HAY'UV*<3>V[KH+BOTVR \=EK.T-C.UT')T*^;149UFZ8?24B_0%@CMOCD3P(G@[E"/7">TI1>8!8AL* M"OOVD1&<",[31J,0H@A1A&B7QJ\!?GYGD3$T?KL/$)PT#H#GH$;*=0? M*.$ MLD-!X_%2PXYJ6X^TB2Y%9Q'=9POGO!D=F0B9")GH(*E0(G1#'H^(AJ(-?7M^ M2#5(-4@U#_8/6KK@)MH\:/,@$2$1G=+[DDRW"3)1;_&TD=72Z#7G];A;?\*, MW>U#3R_IP+$R=G=:0N5,9C0&S>R(8@QH3ENY^G0 MQU[=AV<-D6F0:4Y@\G1WIA+-'20A)"$DH1>0D E^%V;R?JN'M\=8&P]9^YRS M2DK*=6YB(M9.+2"$S!E#QJ:Z:9.N5&4HNM]W9 (A<<:0>$\)U2V*LPC.(@B9 MYQI># RO[N:1MP$9W%5QHJ). Y+A>$GJC)(4VCJ5G7'7&P]C(?80>P?+J=L< MOD-?1.C;.T6((<2V_%G=%-TELJ(=:Z0L;K+ MZ#\^XF*&J0MI=\91,80@XA]ZBX3-WD1ZN4,13H].T+(Z+>,**4]6W( MHV$*YS!$W%M''!, .8YFX^G]W@%%HD:?)V- LAP=X2 D,V0S9#- M^K/>*->ER87U5V5I^ M5)=_2$IXWV3YI#!)HW221#/-@POR:%(^?9X')?V\]CJ%EEV]NJ19]:B']=D<&.=>NXFF6K484%4J*S.MS$!;M#PN%WFJQ2H5R+U6W$6WA:Y^ MA^N*4JOR[-9?3K+Y/)MN7.7YGW4MNU5%V.#3793G45K"7Q4_PG^O%O#HN*@Z M=97E<(%:JJMU4;M+RAOM:Y0GV:+0KE;*FJ1%F92+ZJ'01&T>QZ4V 2:/DE1; M5U73LLO_C2=E I\OM-]AJ/.JL]#L>34^<32Y4?^%+XMXX_&K]V\+)RFT&-H# M3X%G)^4,9 3OSF%\X U:EJL+LDO0,)!']=,\^B/6;J/[JL(;=/XF@?=%>:Q= MJF)N6I96C[_-L^EB4JJ&1$H$\\4LJIH G8FGE0B@5U5;FX;!?5'9U)0KJJ?4 M)_.2Y3.O5MG=Z_YI"]7]V3U,/*JE>7P%8Y=.XJ;HW/U%6UL'B:S>)XA>6_]C MJJG97RFNKDU!\# <:G3NH3>@5>I093^D<0RNB%+MQY_^L<1L T;0W7SZW6V4 M5RF$X(O*L%+@:(H:*OTO%4H!#E%5AZ74[K)\-KU+IC$\#'A!<0,(J+SYUT(A M*O[S-BLJTKC*L[GV7U&ZB/+[)3?"@U=]5U]<:"#RFKX 6PIAR9_0X!J5;8#O M0'94,5!5LK"^K8%9_+5BF:NZC(="Y")7\KB\KWZ'SBR [R;JK^FB*/-[78N MZX *LEFL0T]4Q2.E!)%6W,:3Y"I1K[Z!OL$%TPOMRPW8F-*EL9 MW2F>4Y2FY%IWOA)3([2)$M52_R,UXHO9%%3JJSIZ:D[?,8MKV:(L2B 1I6U5-590TF6IUJ+C MBJI[=E)L/&4K;C'8@JKS*+].TF4CHT69-5\LO=OJFSYJKI+7UEPUCUV8TL92 MGQW?)X=;ZO,$I:.&M9GKT+ ![E3M*2#^!G7OIP1\__3Z,3^P,L#3R?VK;9O= M;UZ+>MX]3+0"@_:Z[HB= Z1SPLW>1\%1J>'SJ=, MV>7 VM$\6U2.ZV,HVH@6*8<\7U0A+%34[A45RU3NLB^VPI=I7(+'5L1+!=RE MKN_KL*N*!W_[V$59NG8.'YT]#C5GQG?Z?9R;_9$RAB:? 832!BV?P>G/JKDF MUE0]'SKO$GO[G/UU1'6Y-%)M_$" GBF!(<&/3']Z367]*I\!]6=4^K//)WV+ M^C/VX]Y=2L^+9K-F3UBN\0M0S_W\EA8=I!*\I;0A:>L7J568Z :4UC(,^<5)NQ29+\N MRB&:_!QW4HQD.G@C!CRJ3L^+2Z><(RG8XYR97:2X.B6\53&C.F2$[N@Y!7N&;!*>M>@&IW.G"8$< M?L!A<((;C+#&IG%/"^ZH*>SKMU4IX@9;8'@<^>W[$&4/>U*XSG8D5#RZ0$>A M>!@\/<[Y\-OH'@^'#SL.]K;L9=2@H1T/'YQ\4'^>J3]X/!QC=8=(<_.X.'JC MI_9&AR.XT9SI&)#,WK"R#<;C9KI)NJLT=^[[C1!< S))!Z]M>"9[\[[W9KO( M6U_R>#,%*]]@X&YIAJ]*\WU6AV[0,QXN3;\1NQI5YXRW-QI,!UET)8JAD&C? MUC!"XHRW.+ZG3+=D9R8=6FYC<"K[%&*X+)B,4=53S]0#$ER_UM_??_O'&\8PD(B!Q(ZLSD6YR/%\])"C0$,V(3& M.&C5&8Y!2'5J=[:Q?2CDB0'$X=AWXS/C#-F9BX3FVAB<)TS$^"8H:RR".TXB MQK_]W?_^MU\^??_S__N$21G/30$'8U]:5)=6__NKAL+V&'$<@46Z??RV?8[V MC"*2U-"E[*[DS&L%AV;P %S)@60,JD\O]Y0N"/EP:/+!P\RCTZ"!'68>UF%4 MU)\NC8F.,O8,8!ZL[CM>[ITQ.8/OF=29<;PT.F_.[/R^K!+"[+C^:,[LAG1: MI04?BFL+X52"\*LKDA38J_SP7?5-U][YZZLATF^7M1D?*X?XDI;]_MG7?M!^ M_ZSYV6P6Y1^UX/??X(M@D6_JCK]EZ;7V M=_5/<^/??_L'?/_W+(^C5/M'EG[4?OY_G^";G^,_H:^I]FMN.TI7/^2AFD_II/98AH7JZJ=6:HE MRKB-BU++HS+6KI;[.+0\GD4E*+M69MKO%Y\O@*O4@&D__>C^\MOV/<7%.0_# MGF*BG0U#>1-K_Q4!=\=%K/TS3JLZ!.I+[R99?K>(4ET#JLGFX)ZJH@1)NCDT MQ45G1'<"2^R0YFVR+C<[)EVG?'4IVSJ85,_J56NG\20#K,!@?U 3T_)5?CR) MYY=QKG&J:XS0=MSY)1W0*ZU9ARA NZYV1C2R15F4H&4*Y7< 9RTJM"M0)3 G M/G0[:O^[*,KDZO[1<=IXS-8<2QY,L>KSYGO2+)]'LRTKB:IK5@^N[ MM$L]F M]34_O"/OJL]@)4V:SSL$_"69@^#4/%--.@];?I=,RQOX$[I96W43A<';(O[0 M_-'2VG6C-H-M:X.-[/0GGQ&OJQKSPSO#^&:O+;AMK=8WTI?>)X_]PJ/W\#PE M^K+]#UO>"VL%T\\H0K<[-+Q.:>DU%(JQEU/$7MZ@[OV4%,H8?^Y3^U<;3KL?WY4;_*0=C\A]*7)?N(Y]%!2?'AN?,F7TPZ01S;,%/.__L_>N MS8WC2-KHY]U?@:C3?<:.EZ46J7O5]$3(MQJ_6VW7NMS;T9\V:!*R.$V1&E[L MTOGU)Q.@),J2;4D&*9#.B=TN2^(%2.3S(#,!9(8C34&<@HD=^3-T!KP@3J)T M B^E&:X G+R6*O5=XN1BX:^BNQKP!+S1F+^B@(=K[E%X!^\2#GW\^*HE.GP)UR, M2,9A&MN!^\J,6&DZ/TSIE&6Y0@)H70F,"+YB^D/;#4E_2@D(O$?]H3.ZI>5: MT4AJVF&T*H*K3'86C63VCI5-FRW66*BT2>=MM522]X2N?>2CO;91W93\?2VC MW:4*336+S*D4V;B0E/JE/P>LY!$RP.!L:@ MJ2P%1UVF0\+$]N',VF58M"RCU1X0)"A"NZUL*8NB-K14%<&5ET61HKDU4SQM MC,=VRVAUU.7+J'N,A=!5@K59G^R(9M_H#Z@:4LTBF$6*\ \[BNP@B44N"=$\ MD6K"]V),'Z':"B56TDT^A=N4U15-_55'&ZNP;S0[RI;X=:%6"BCJ8^)5SI*S MC':W18B@>.)N\<1-29R6)T,*RDRMD82U8ZBJ"*YJN:PU$IUV.G>8P,?NQPFT M$YPVPJJ:QKTLN"+28C\[&MG;1**_M;P8NDS6Y273?LN^S")$6<"*0L\P>^IV M;>XMT$HH'D5,RSF-G96"(5=?W^#7^[*728-T.XRMG7Q(?[;4'SJ,3:&Y7:1Y M&G'72YC+1W;J)W*SG\&F:>2,[9B[*_O^G#":AJ+,@LOO$O)=#^V[ZB.XRAS^ MT$AF[UC9M/'/+6O"=X*0TSZJ)M=( [?]^1:;2:Q>\N7D=-<4+2 MH@K?.XSU[6RYQ\B&')JAU'(G4M=-/I6QPTEU:KQCTNJ81KM+A[ )$UJ%P0^Z M9Q*LO]Z&"HEO5!4R\G1V00M-HAE&CW;DTAGL0\_4&@FN6.OOOV[^J*',WK&R MZ6,O-HV.N@,%VH?%* A; 0.S/N>NCSJF15%'BCHJLCO5)F\G2M)-/A1"?,>J MHXU)V&H974O98IDNY$D11'T,O.K9<7UU(74RUZK@/5&*QW=!65417'DI'B^O M;GZYN;ZB5(]U4T!M[$O3LHRNNOF48HX$+XHYYFS5=M,P!\47QB([5B-?\# 9 MA++3S 6E#R+ZTDT^=+BY%FO0ZGDOZ\T38H)(-/%?*EE)>HYT 2*\(N M;1N=@;KE\&T%MY-]6@GEV\=X_241>6J8&YU[A=!HZ?NCQ>U/P, Y:, M.?N_-A "CSG[DP3KVY'>I'1@,)O5P JX49M'W O9[XWL#B L',6XH M&P7QV0O@7#AK%VP7VCKK[,1LR/,I!%Y#W;B/?"<=^L%<1*E$XZU M#Y(Q.+;W^#L.Y%TZXY&!H\9_.&,[N(?;PHC9;!KQB9=.T!W&^PQQM9AV#+@I M84&8B*_".^BDC>^'2T+&/?@R6IP:9*,HG+ CT' _TZMC!H^/.7R&JX^FBQJS MQ^)IC]!%;(_-XBEWO)$'&@4D<,4,??/\)=/(#-V&1LCWYR( \-V$\X0Y $X;).,%#SQ.4 K0 MVW]Q!X4;-]@%O&PA-+C5A3<]?984V^(J\7@[%E\Z0'[0B*D=07_@E5ES'7Q4 M$,.5@-<*>><>[2&@1\N'3\/8$T]N M[,>/I>MVM9$Y%-)_*T%G,DA[GVY]*F]$+*O15CHDQ_N9"$1$.[7^#.9-F$ 1R66IRDQ,5CS >7&-F:3R MBRD+_E@_J_%VHHKX-(S0(KV'.5Q.I'X8QUP8MDLK2^S.B6_ M<-_[!A5I)_7OD/W;;Z_C2OS26@LVUF8-67Q<2XY]EIM5T#]V>0PO%F$1F&3& MW+W'.3CGC*N*&].:#NGE"WKY-72$<8:^Z&O64 2FW'T #Q2A/"]PP@EM?BA@ MZ=HT7]N\58#.[K"2K78OQ&:]_(+1M2/4PV.5:EB1[4W:Z2;)A^1#\M&!^VO M[7]R.UH/_M2,PDNUX@B3]>4[:M$\R1,4O&['LTULB8K9C^O*L Q=%/&%E.QF$:VX$;4Q(8!5IW M&DXFH8L;=$4&&%70U$AZVF&V*H(K4NVN>)+?I"U7B[*%I1J*LEHZN-=Q2=W3 MGU ELI53D*9E-+M;!_\V>FJ5I3W[<43 M7.H,EU9;^;XG@@O!I;9P,3H=94GTW@=@:!E:C7L5(\XY-$.I>Z61H+7CL:H( MKNH.F4:BU$X'WV,)A4&S-,VJ]]1+P"/@[0(\:] GY!'R"'GE1RV-9K_XFESO M WNT;/?Y(HP>[IST<:5>,P*AQ5'<'G'<#%-PZ(91(ECHU&DH5"/)TW2B--!SD-[0AH)KNHNDD:BU$X' MWV.,<*!NY\D[CQ 2\@AYNUBC7:-G%7]H6!<8%1WH('01NO+HLHQ.4UD^O-JC MBU:W/E]BSB4PO9DX;)85R*.X$BUUZ>G'D4;5.%)9P+EJ7;!1M!U(N*@Q+HXL M.H:I-"9!:*DS6OITJ&PGM-!2V+;N$>4WU<%KTDAP57>G-!*E=CKX#L.'1[VF M,DN3EL4(>82\ X8^:A^])X@1Q ABM$!6K BOY9*8P1[M*+*#!/[".NJBH;10 M1@MEFGIVI%%U#G&:+6/0H61S2CTR0DR-$6,:34O9H3%=5+]H!XH046-$6*;1 M;BN+]M4%$K06]KQL;\/$]EG$DS0*Y%+82DY%_N_42SPZ-G9P9TDCP57=B])( ME-KIX#L,(6+)NPYE5*0E,@+? 5RXEF&VBS^UJ0N,BG;N"%V$KMQ]_8[1;16? ML;0NZ**%L<]_<#N!7YD+5SS8B?<@]T=2\(F6Q/98916J-/?A^(\I#V)^;+" M4_$[BF9N^];T!W/#],[G[/]IBO_M)T;$3(DDB22))_4C2M+I&LZ;/GY]*47SV N#+Y%.K"^I]<+%JT_K;,6>GX00T< CV_=GH/<\9D&8,(Z9I)@7)&%NQT3,1F'$(B_^BTWLP+[G8BLS?#7F[CT0 M"9NFT32,>=Q@^/B'T$\GG(6C_*8+VX%_Q,Y[]F!'^,\H"B=L"E>$+H/797^Y M?,H#9"<6!FP:)O FS_;S6ZC#Z32,DC00#VNP:HB]LDJ3\5Y&;>(M+G?"R,;S MYI^P(_+1%Z ."0S^##H(6N1REYUQAT_N0)U:IL&LIKE^$G0?21KB-9D*+]9! M>I_C5_7NZ,Z.H5F@5Z#IT'I0*WL"Y)[$Q^S1CIF->NZ#K15_4C$LCL#2L^.0 M>\J*4=2$L+"@:N9PW\^N^?5#\X/X#/.0,_^\ M0>JWW@2D=,4?V4T(.'_:\HD= =AE(^TT">=?2+M6?//HN(MOSZH=O_^=7Y>-5DR&XTR[ZO596& MZMW!ZNUY?(4H=B1)\?%1&$3_=+.@GV=X$5S>Z]MO5YQ,:PU7Z'@ MG0=EJ-:?&V?\/9R,'9;K"Y"JE@NIFR5^EK/,T6AW>0POMA,8 ;!AYD:Y%\1) ME*+)#*;/FL5#9*">#%J*R* ZV%_*BYV+',0NZ96^>J50EH=7O?,?7K*]NE7/ M*BQ^&JG#:0]]0?N:95@#R^_H)S R6#(.T]@.W.UM"MJB^;S2G8:32>AZR8S2 M^&NQHJETP5(7)5.W)OF&)4=]5A6;+:/5H5/%Q#7$-<0UQ7)-NV5872HL36[; M]@9AQ,$<9"X?V:F?S#/:/97?OH,3I]-GA G"^KRVO+E\3&^:2!_ E&8_/$CE M'$)3!9U>?(^G%PD7A O"!86,=I'M11@]VI%+L2*=R*<^.=>H(A&%2 AB12<- M;?5ZA"Z*"FP]YZ=)&JG+8D^T4V.WHF6:1J=%130($X2)Y7'KMM%6E[*B+I@@ M-_MYV5Z*#8YQPB([X<_%X-FN;1J^IK)17 M73!!(8)=:L^2_Z(1!=7'?^GVC'Y;7;;(NCLOA"Y"UR[+\?V.85IT((AB U1F ML'H\5#VZL51&(G5!!/G>! F"Q.'G68UL6RIM50/2>5EPE/^]N///E/_=;!JX M<4N+6D.54#X*G!!15D57B2C5R;)OF$W+�'AY=I)71/H65>L5(9JJ6H8ON* MW$SSW/Z5?5HFDT5FR6\9_^'XJ^01A\\\CC)2']\]JM[V_U>P;9D\9O>@"@:(-%L)$G3'1Z1J6 M25E:*0!3TX14SVJ!XD15&@U^=>FS1H?YC6:[;5@*CXS4W9DA@!' =C%L]XV98@3!H+?[$W'LO92 MW#O;MP.'LWC,.?0G#)C-@&;C&'Z)O;C!\A(;VS&;^MR]!W5U['C,1%**A$>V MSY(P+SP'Q<.CJ1V)/"+P(\!M&D:)$)>31A&(DCW8?BJRC\S%Z<)'N%9>S3 M!YD:1RH\@CP 'I@KXVI6G*=T('3T"0;LZ=2'"0G-EE4XY&\6M$^)$EO*+O)CD:*1LI6WG*YAVS7QD0 M'/O(2/7TSAU9H6Q WL,QV_U_7V1\*XMKY4/>,IZZ$@0F3=67)"NDJ0^2_Y ' M_P]#O=U6;N3$[>?$Q4[DB7.5!&!] 5PK*V=U6@E'+.).>!_ 79A'-\;UQ"/? ML^\\7U03(!N(%/,PBDFV#FGD837R:G5=>1,[SC>8 'F2JE9+5:MCEE]X :B4 M9_NK^QD>;,\72_FC,,KX4I6^Z6>9DS[JHX^G3W;0'($)R;T'[AZS^4XS(CY2 M-)43\&+^74Z_LV*#$Z1Y))]MD6F]!LV"#V)33OMJGDU>&G8._!K9#IAUHAJB&BFH0WQ#? M$-_4EV_(M"&J(:HAJBF!:H[ZQJ#5*TTD2]04)R3E&J-L(PT1$1$1$=$S1&09 MS5;QR<&)B(B(B(B(B)Z7AF58;8M\KRT%4)$%^K*7 J?V3.4Z(-%RC0NZ'5E] MH!SE60#>MX5#B*DQ8@I8C]$% $7'0@D7-<8%S20TDQ!B=A&'TNBW+JI/V7DWJ;_&HI]DGU^LN[?-4RNM=\;S> MO4:[V^GWNX/6H-,SS8Y.>;W;%TR;7/ZUV9ANJ=%IHZ6/4.4DXX%8F] ME96T).^2TAV]?,*;$MZ2KE%B;U*V&BH;)?:FQ-X%Z-7.B;TIJ7=-"+)"6DI) MO2FI-P&XUA8.)?4FQ:R$8I*M0QIY6(VDI-YU5M7JF.64U)OT42=]I*3>I&B4 MU+O^FD?RV1*9E-1;=610GWPAE-2[SA!6CEKM$W!0\I7\?>V>8?;,PD6BR^#C M?93YDJB&J*86I[JTUP#B&^(;XALR;8AJB&J(:FI+-4=6V["ZQ1<06(=-<5+2 M-T$0,1$Q$3'1,TPT,-J=XK/I$A$1$1$1$1&]6%*IW5%V(%?[P7^K]U61)7I* MZUUU7JYOUK"C=MOH#)39/F3B$&)JCAC*LT>X(%S03$(S"2'F;>)0&__61?=I M$B%([ ^)IM&R*-4]08(@0?Z&^KS>\[___LN]'_%/%[87_8_MI_PR>.!Q(DY( M>L$9OTOLP/W-CO[BXJGG_TZ]9/:=.VDDSN_"CZ<@5]L+;B,;=64HSOC"UV>+ M)-"7RS.79U[L^&&<1OP69'GBA\Y?__C/__B[;$$:N/$?7C(><]_]%OJ>,UM< M)")Z\.&&CW[]<'%F- MA;MV:5ZA*=NE2!\SD3(OQTM Z?!(D.TX8>2*%^#;98+U+(+- M$AY-X@8;!C.X%#X -AG_,>5!S.%".Q%7GX838"V\ MX9,Q=>'-R+7[*WP9]P M_4CTT([XHI>&^)1UU67P.X]$*GAOP0+X:R@;FC5,'(JT\<1^G, _\C U]$=> MV'B9L9ZPS@N87Q##%4^6I'0I7O(UC#=QR18TT;P87'3;P[/301N8 O[L=;N" M)JRS4\L\N:@73;RY D&V6)8=@%U[B>B,RT%_;SDZ?DMN[SZG_/O MM[^=7^&?I]>_G;^U-=MV4@OZVV="UX8,ARQ.)Q,[FB&P-Q,"TADR@EH5>UZC M9B#(F/$ B>IIXN:.3-\LZE/ 'ZVWMDGJE1>K+E?QHI;EGK%BF6M;K$)6HC"; M376U)\S6&VM/=*RJ)(9O5:6AU,&#=I!V=FBR@:RN82)*7;;!J$2C@I2-E*TL M9:/2(Z1LI2G;NG]$NTK)]C@$0DV3$C]1XJ?=M>Z&PX,QX_:][0684C:,8X6Y MMC62HG;8I8,YQ:E5%0[F6)9AJ=N7HOW@XWV4%H&HAJBF?*II=2S#;&WMK1#7 M$-<0UQ#7["4-$^R:3K=/7$.AH6U%>#JV@WNQ,RH-HE6'%#\E0D"0>,>0:)E&VR)($"0( M$ODMH)2MC^+(NYNLQM)>1>,U3."6>3X;91:J1C*M+BG5Q\$^@AF\68*'3;%C M A^!;PU\?:-/X"/P$?@.D8>^9W2IK*0B\%'D.;\=Q'8?O#@$=RF,F/9 Y3%(0@PAINZ(Z5E&IT4%F(JW;S7R M.(L4XM7&%,ABSS,Y[R50UW8TLK>)-,MK&>-T MT5=U9[M?D^U;#G\7(F^)5D+S\#XZ@D L605=)994N+'.[!MFNWEXB59"\][*DEO53"RM M83FAK940.KC47FI=@,&*>&NG8!ILY4A[ MDD:!+(D'X'%2><)] NT8^S/Q2ES>1'S UTFXO$B^-PA2VY\_I<%NQU@N,$[] M!%]G.PG^NAXUFM@S]H"EM5P^A<[@M6$ CX['#"?"& O]A2R,6)B*?N"K#% C8V5L($32YO7# 31>7& MI=_H*1H6@0V2]HN--@>-KB)Q1QRU7F9$T:82HN(:B()AI]S!.L[^[.7:K@>S M$:IET=R**KI(CZ(Z]NJ@,7N"DWO,IB!WK$TAM2O:7.[ 8,YS*2AS&2C%G][. MB7S8V(;6W7$>P!V.;\>Q-_(R,R@,X.8)_BEJ J=1)"8!66PX:[K0VKE1-+_? M$=_&*_-V$&;=$+/%YF*C #L*-B(2RT^S*S2;8H)\V= MJA-O7WAX4:OX>C2*>8+VWZ(0^E?/OO-\42W]%DW47:H5#T[-P?#B]*QG-4^Z M%\VVV;QHRVK%K0MKV.Z67JVXV**S<9DS05$V+.H=^-2QQ!TJ[!S3T#EPJKT' MB7O 6A*ELGHV7BF0A$Z @[53P>L!Y\&>3GW ##HV (UG;GX$!TEUH=I7ZN+D MGK(2\-*V5.W$CNZ]0#;23I-P_H6,68IO9#7;P:#1M#JMMFFVFMUFVQJHJVUK M==Y8V];J5J0RZJ B[=SWOGY%VKGW?8=>;0_G'2M+%TC92-E*T_9O&/V*P."8Q\9J5XQJM=3 MI'H5JDWL/1RSW?_W1<:WLKA6$.(2+08^YROR=[9O!PYG\9CSA#157Y*LD*8^ M2/Y#'OP_#/5V6[F1$[>?$Q<[D3>E8_UZ [A65L[JM!*.<.$PO _$HJ8MUM/8 MD;]<3B,;B!3S,(I)M@YIY&$U\FIU77D3.^;VD)"J5DM5JV.67W@!J)0G-CKG M]C,\V)XOEO)Q0X[D2U7ZII]E3OJHCSZ>/ME!N'O,V-3G[CUWB?A( MT51.P(OY=SG]SNJ65% [S2/Y;(E,ZS5H[B,LS;!X]).T<,,4-]QN'Q>@C$?/ M:]W2L,-MRI'M)+AK&^=2<5)2E3&GCS"U@[!RU&I?&T[=4?(WG!37YC"XV3(L M=7NGM!]\O(]R7A#5$-643S52:?J6:14/-UTT@/B&^(;XADP;HAJB&J*:VE+- M4=\8M'JEB:3>*<*)B(B(B(CV)"++:+:4E;TA(B(B(B(B(MI#&I9AM8LOR*G+ MV+_5]ZK( GW92X%3>Z9R'9!HN<[5F*P^4([R+ #OV\(AQ-08,06LQ^@"@*)C MH82+&N."9A*:20@QNXA#:?1;%]6G.800L;[XGF]>XUVM]/O=P>M0:=GFAV=\GJW*Y)U MM^YIDVN?U[LR#=4[+31UL.H=I)QP*A)[KYM6Y%V^V;ND=$>4V)MTC1)[D[*] M$V6CQ-Z4V+L O=HYL3I,^ZJ2/E-2;%(V2>M=?\T@^6R*3DGJKC@SJDR^$DGK7 M&<+*4:M] @Y*OI*_K]TSS)Y9N$AT&7R\CS)?$M40U=3B5)?V&D!\0WQ#?$.F M#5$-40U136VIYLAJ&U:W^ ("Z[ I3DKZ)@@B)B(F(B9ZAHD&1KM3?#9=(B(B M(B(B(J(72RJU.\H.Y&H_^&_UOBJR1$]IO:O.R_7-&G;4;AN=@3+;ATP<0DS- M$4-Y]@@7A N:26@F(<2\31QJX]^ZZ#Y-(@2)_2'1-%H6I;HG2! DR-]0G]=[ M_O???[GW(_[I6AQ_3&"TA^*4KAVX7Y?'=&_QB;?0_1,_=/[ZQW_^Q]_E30ET M2%[_+?0]9[:X1(3@X,,-'_WZX>+,:IJ=_V[_>7OV@7DN?&$[R<>3YIG5.SWI M#;OGG8MV]_3LHG]JGK8Z;;-WUNI>G'SXQQ/QYT7Y2AKE3:-75O9R\7'M](<0 M%9.R>G%,#]#B7:AFE^85FF%="C0[4@[:%GMQPJ:1-[$CN!6/NWG! X\3/.L+ M?SKAA.>.AAAX[GQJ>R[C/Z8\B'EL+ 4P\GXL)_2/[OO$R M,)^ ZUF3L[/^]TZXBDG, *5 M,E#E\C-L1A:TUX,&N(OU%18&+.9.&LF;8A@F0V1?^@V+P8/\3=FR]NDF.RJK MZIM(\;['> ?222I)R&$[!39W^+EZB1^C2-POO(GAB,V\YX M@;6%X=S[',,D%MT#+.7U&;Z%(B:/(7R>3*$/01)_8C8 /78BCCVSH]GR-W:' M<$;0V^S? %XOD=4^<&J,8S'CPN.>;\$4/":LL(%I7I 2Q%."9/Z8#>_!/D-# MTBC 3RX7#P4N^7?J)3/0P_G3NY]S?]Y$*>1:' (K1>#'3?8+30K+X!I&.$OXK!]L+GO=A# M#9GTO7A!!W:R*K"_+09*'N WV./8@]\G]@R&900&"8MA4O!&X-,$"?#R* HG M0DY@#. ;LG/_]A14X@%?@()^M"/!0:(1<-/=;*%.8 6);N&'B9?'][GNK@RFFAW.9CV!T>)O3 @HMWNO](8+\;K8#()[@6C;GB0N%H*(&?_ M9:HCW@#]B1*0'@C' RGY/O-#U%MF1YRA#^1GPL*'KS<'^@-X]VTT!QVXD[OK M8GH*2K@''$\GQ7P?\MEH>L*(>LE8#ID8)&@SHO#9\3"PRYEP,9$-M%UFLKGC MR2/G@9IZ0\ ":F:')%33H!%*5$F+< #C)5# @ID+? 1$!U*5(QQD4!/9J-(8 M++(X9H]VO-2&A <--@P =&DD9OJY3J(.H;,137%&$$FM0 SB#:+J$:H1$$BP MKE@Y^^=V3:OGVH-SR>*R%/07.B@X'\PSGB!'3T*7^W'6@0CY$;5Z210,( &6 MG% L5,1_I>X]*E'>_)+P6;(G?HFT\X O>(9T-J PF"UOEP"6VIH)9(57)$ZR MMH$SEB.[.\[PN\BS?4/(%_,M"A;+" #XV O=E6&;B0M=#K=-8/C<1M4,\:JU M=^C'X=+$A:%8-X!Q1.;&ON!QZ90O>PK.-5]X%.B@AR, 'MH>/AMQ+EUQ^=Q[ M'HC$27/G_65O_&#>WZXA@N?]?XP3I/''>]N>?CJUIP ;@+Y \?7H+(M.R%N& M#F ^]O"GTS">!QRVB!_T6]V33G?8ON@U3]HGW?9)Q^ID\8/S8?NT5:_XP5QH M+"I9&^V ':6!E@\>REB1^'/A>/AOD' M)N3(LHQ9D]8$BY;\?+[#KGG2KHG3"=XW M2L'^A4G:CF RQ-#GQ$LG<39-)Y[C33-CY6G$%"S7^XCC] N/LY\8W-E3P1CV MLHZYO:?"B%,]O5>X0NV:9MDY&TY87UZ28^FY3X$LE\'_L3W?3D<((8=/T6H!C(W:XZ7X?Z%_2_>+LK1XOM!!/+>S(F =KG@ MID@RM1-!)D^:M\)-Z2*XML+4.(.4&J8M*B1=6N#3M"C.7&*BK2C1@M7$I/'+\U& M!77I(I3\)*)4/$"A5YXL>HT.<45ITK8:/;72+M/6!(&WJB;PEF*!HU\MVAJ#POQPD\2X:6Q:X?=%S5!02+#?/NXT(L M(X=OB0BN1A3C\3!P\9]SN/;!]E&:9UZ,"US@XK^Z#>E_LR?][XF<([_C%/DU M=$1[AC^\^'\QR/F_-V";1QZ:^?@J>^V-OXFY+!>3'%@GS?/S4[-]=FZ:[6'7 M/.EW14S2:I^?]89FO6*2:B&X]H[G,7ES_OWVYO+T]OR,G0Z__Y,-K[(_SO_[ M]\O_&7X]O[K]_M;&;>[R.NU0M'7W]N9BB3(R)I;]7 Q83FPO2.#_F<,C^2_6 MGO!PN]9]Q.^E4^XXLD:/6(_&G5X\B\=*ASM^M*=,7,*CJ1WA\H2,7RY+"T0+ M9,L7C+GO8DAR]6'"W9[O(TMCV<(XG6(44$Q"B]($S!%11U3OLZ#%HL7X^C-JR6)B$6V^NG"S]F::>YUL]7XR4KS12C#GXD0M^S) MK*$.:?K-B-JT_N8)#% KI1XN)[G5.-M\P.> R6WNPD'';2&>R_-JM$!W=K7# M7?'8;#4<-U8)/8C2.%E"&UOB\R1!&"(XX %@,![%G+.K$&-D9=E_:GRF4AT/ M17[><8,I"B6NQ F7DY72&( 2":MUE(UL56P+C&6K)!.8;@1)CE;WX'PJW.S( M/6/EF%43&"=/0?@Y_Y( ]T7Z*R>Q3+QF\6!QN = [_O9-;]^:'X0G^.I[M'O7*;C3+OJ];E8;JW<'=DE@!-NJ3P>H9CU"+S'EU/1_[;-$IU*QW M6;!U!YN"](_TKSS]VSH1)$TA-(64".'>2Q N.+]"?8H6"K[3)Q=RD:'ET^>C MH[F39UL$(%6A62.Y:P=SM=#6/@?QVQ-0;P7D*F2?[O[Z/B M/\0RQ#)ELHQI- =-H]>B(F/DWNU@/JXL!BYMQO7E/2^.4W66(E'U%JGU2O#[ M"D@U:5E&7UW5'UW 4K110X"H*R#,5ML8])5-RW4!!$5U7HWJB)/-B^D98VL;G3Y5RB)H$;0JD'"Z]O@B%_VY38GS99\-^^G))2&7 MY&59="S#:E,Y",(#X4%:O:9A-2ED11[Z=H*]#1,1+G_][ #Y$8=<\ES=]MB: M_F!NF.*)A[?L>WQV*+*WB5,6:SLL=5%=10NFKPGV+2NJ14G/!E?L'F5ZUE M>FF=G%[TVNUVKWEFG5H79X.A-<_TE%\='UM9<\?Y:]=OE=Z*"U M@H/6[:J<0^Y4I:%Z=_"]K]'0H;B#G&O=:!2^]Z.M=+2:5)!.5].\0:"EP]2T MJ+?'5ALL$QK\1>MV!XU*TU'%_<%8A:.*[;9AMM;3K],F2"(9[>TE[;7M[3RS MK5I5@6I:1MNBS ODDNU@ XJ=U2)[>99,A]PS]>Y9O?:/=OM&TU*V$T@7-!1M MMQ >ZHJ'OM%M*MOV41W4M(=:.S>)=@C2#L%"=PB:EF%VE9V[H?V! MQ(^'"",11188A"*6!))LMIJ'%V@E%$^AD?[\)NK2&G: /<:[<.0NS2NT5-K9 MLJI=/!8U\7@T88&=I!%?E._;Y%L8;&(']KVH^,KNN.]Q+$HN:O_=P22$F;+% M\\--O(".W \D=TI3KPDQ1W6,7L<>PX\(Q(-8*(.^K)&V\79Y2D+(U'B+X0O M(BQ#&,9>=J$H*P[MNX_L2?QRZ=I"#P#(RK"O;O[/;=MOMX:]?K=WVNV?6F:K M=WXZ.#D3V_;-WMG)8:]O^(K6'^.-\2W^7&&&7W1R;$J=@S6@O3E9I(:MG M*LCC(Y*'P<;00Z7UZQX6I'09,#O3:^-Y<.I5]'K51(]2M $:VP:1MIS7 MMYNF5Z;[<#+QI#V"E\/[H:V@(B"^'4[>YB9XM+HO^JUV]Z+?[W7 [NZWI/'= M:O;[S5;-C.\#GIF]_NVWR]O?\)2L/#I[?75[>?7E_.KT\KRRYV8U,54*59FO M2UX[%;RF6[,K:0 .D](FY_F))::TM+FL(SZW8<>VNUH;&7U@VK(SL/U(\4CQ2E&\J[RGL'0@1F&T<$1 )[<5 M=T6LE9)E3 ;,(0V86AHH^Z:)(,6JFGR(JTBEWIM*[65&:+3/OD(==H M)+@B]>__IGYNQ=.4B[O%YWPA[:N,X(K4OD&3N?9,; S%4%B8CX:)+>'U#8FI M-UE3W"(Q\G#OJC!?CT[MV<0.CME7;^(EW*VN*Z4==E_///(&61TT^8C95&I_ MZ0*.HLTLPH1N\BG6: IX+G5W4ZW11+JDFWSJ:P*]$SOSU$L\/%',SM,HG'(V M]9T:6NK:P7AK,TFI$ ]J/[75VD\4OR)X55YP1>K?M9.$*X54*(1%"EBF IH6 MQ;#4.5;?V&]A=&\'[!1/U\HXELJE5P(MQ:XH=D68T%L^A5*L':1VE%OSLWK" M8.I55URD3N_6_-'3R-1SOU^%9%DM1%,*VP(WM5$*VY[B+7&4PY98DN)!!\XA M4TW!D<;50N.VRM.];?J:@Y.W/NF81'ZKM;;N^*A#9V2R V;?9TE")2_Z4CT/GUB1V4U'H9!3>+-3R7*N]=J])3*^QA/S:[G17WD$9\G M1Q4I(G.IXI?IO!KL]\5O^21?^41ATRA\\%P>KZ2WG*>LS*6HQG/VR2R7Q?.% M7+";TETW6#T@G8@:8:]+PWA9'#(%FIW+US_/:+HDC#*9HF6U&RUBBO+DW;04 M,_.Q)(6IS]U[S..\@FC[WL:DL3(W]'-9EH]L/P[9/+]RQ=(K'S?8.28FS/+F M+NE.I)P5:;O3&+,:1C/&'P0$X5*7C^S43P1$YP"6>8#A$EO4Y9!U,[Q\!L6[ M-!'9BWUY& XP9!_V[)J1@B4[7'YQW(0@#LB.XAM)RNM(0A@-()F8KY^@TUX M=#_/%QX#2X@&VG',L14PG(_<]_'?./2A<[A\Z3,\R+G/V!FD3V#K\#8=.<,^&*"RB\1YX&/5BF[P422(),[469D[-UY MBT3G4UND3 9S%EH4N#$&TSWHY-06B9H=.?G)]-;SF?#1%EFE\3<8DD6:2NA$ MUOU,)<1LN%2U>$79[,-.0,W3JPBS?\:O.*[C'U,39.WFG$!+EXRWNKSGI*1AW,-9D.7H 8*F2C,WFJJ-.QN+/#E\*I8FH:\E]J2CO"=R8'.+K7)B$%^#3OV88@T MZ">>56'9$96^H-IU#41%"1=B$:F3E\HC51"L_C0229++DMH(;!HUTA)YGU%2 M#78I"XHMINW8&7,W]3F6+PL?1?$/40LB,T6DD#,>#)52NF5C@I^N;G\NL[S]E-FWDCT9RFH7&"P2U2WP'V&Y8'#GSP, M6![?^I32A]^$\)3J\&D_*Y(OUH:Z7I^6M$8(BDBJ7M92DQ& M"04I@/G P7&66B-Q(?3%764HD;]T7%[416 +7&-H1S&J)/SIRIJ%!H4ORQ6W MDL> *%N:B+(8.1UO6_"KZB&#LD(RWT3I-R[J:28RI)JE>&'?["@)>!2/O6F] MPS-E38P7&/)(L(XE&D[P[^I*Y,3^B\1O\EO/\:9RUS26Z4R=\=/GY-[RM!&R(>"BRXJ&SK*^76V6,)_4B?P%:?<; _7;%5:QMF2I'.AVCA[M&#?*L\C[ M]LLJ-@$5.ME_G^L8ED[,D9ZHJAWF*I?JUIU*3O>W^?*#&#^SER"' 1BE21JM M 3Q7>OOIOJ;<-/5)K2RH5*"*4H%6_ZVU MLE5[;K5J7D'_6/^J=Q.ZE_F^^K M3.W3/>_KE?(^RN5"!3/5^P*49924K4QEHYP@I&RE*5N?E(V4K2QE&Y"RD;*5 MI&R6LM0=I&RD;"\JVRU(9XA MGB&>(9XAGBF29UH;=KH2SQ#/$,\0SZB41M\BFB&:(9HAFB&:(9HAFB&:J3+- MM$RB&:(9HAFBF6*K>1K=9O%5G'49^[VL6*1%XGHHD1%S_@TL;]C1&5Y+2W34F=! M$JX(5X0KPA7ABG!%N")<$:X(5X0KPA7ABG!%N")<423P0(BBXVAE+@BN:E4+ MM,H-4\Q4^1;0:;]JI&[%\#7QU6))L6MT.^IV?.\M,EVTIVB;02,RT\Z8(#(C M,M/GD!Q1&5$941E160W.X1&5$941E1&55?\,#C$9,1DQ&3$9,=G!58>8C)A, M(W4D)MO1O3R\O'11'6(R8C*-U)&8;"=Q]8S>AF+Q1&9OWZ+QBZAKN>GZTAJ6 M$UJY-5JKU-@C\YB]N2[RH@5Q.GT&(\ &G]QS+E\0K)6KA%M]G=_"=[?O<;3!13V 41MQ@\%\V3:-I&/-X7L!> MUK@5R'E:H1U+6,?IA+OPO9TP>-Z3%T';@I"-O!_B>*XLE#TOM1LOI]?5%C$W MC3PLG@WOFH&Z,BX+WK]5\LZ.A;*7[2>>T/>"[(/KQ=,TX2SB<>BG.'IL&H4.\ %\8P!A>,B/^+HPS648]EPP_5\ [:__? ML+JW%\3 FX&#;!G 2YWYG7!AM/@NQ3XAU0J.:[#+@,70A'G7-L@EYOPO%"M' M*<#3/:PE+ALF&V('RR=B+^%:X"J?.PD;P170.U&H'+[V$O%"V:*)G4!?-[P0 M9.G%0,?P\V0*;[F;R3OB#4^.%LU"[KV'H9--:[ _QIXOI3CR NAT)FL4-5RX M',P8:#L(P@3'?QIQUW,P&8/@?@>F6]L+DMEJ&]T0;I)W^!['R47,'O +_P$- MQ[YFSS;D'"8:X,^DVH!Z&7(.&]MPKXUR +W&87%A?@L5>Q@&3X9XJ;KX MP,#QA&+#Y#)7KW!10 '>E/H@A9>-S.SOO_^2QA_O;7OZZ70Y^PT#]Q3N@X=Q M>!./S[S8\4/0,'X+0#[Q0^>O?_SG?_P]=R<(#SH;@VEP&:"DOX6^Y\SD?Q?W M"#V$#S=\].N'BS.8E3K_W?[S]NP#\USX A3TH]6^,$^:9]U^_Z)YR>#0:_YX1]/J"=/$J\4<-]D_!]V(E@1').28T=?P_B5FB*U-<0+ MG2=NG]A_8-W-Z3$_#)X,BI Z\IR]H#/(FC M"4 BKA+[#JZ'9TD+&+A2]G,/(MF*#E8I! <=1'@Q9[=+.>]BCZ]'W^P(VI0- MWG7@SS8PTA;LTFF:[5;[K&GVSKIFV[).FL.>8)?6H#\\:7?+9!>EL9?-]/+] M])_G9[]_/6>7EWK2B;9V>P'-*Z,PU9>;\_.KKY=?_GG+3H??+F^'7]G-N<&^ MWIXI<=S*Z,+I]=79^=7W\S-V<7DUO#J]A#Y<7EU=KJ)I[7.GDR_ J=/&??_WE^?ON=Y#%E9Y7<<,[[O?&] 5:^[]O1!BM,>_'DGK*R M'M,$G<[K.'[.OT;ZRBMK#29>LWBP"**!5^3[V36_?FA^$)_CJ>W,/^\^;T[L MZ-X+9"/M- GG7\@E-?'-H^3IK7WE:R-%'01%$H7*G MEKL:;0AL$A0GMKQ M6"P).O@'IB!_L'T,]*K"J$9RU Z\R@&K_E<&GH,NYX'VW?)I8A MECE 01IB&7+2MA7AY6*S+MK:<7H7>ZYG1QY79A 2(V^?D;-@IZV P[?MIF$. ME-DUNJ"B:/.%,%%C3)B&V>X;K::RM&=U007%99Z7[54H]I0[W'L0![S(3]*' M@90*\:#49!EF3UT*L[J[!P0N;<#5;58 7:;1Z5*(CYSOK45XEG(VPF-KY'>3 MC[&'.)16D-$%%.1[:XJ+:LS!'Q(UC3KLB#KY>66ZZ MJ>QMXMB#M@6?JI&+J@A1%K%^81FM7D$UPW:1:"4TCP(JQ))5T55B2:4K6MV. M878TR$]:"=VCT)AZJ_RK9]]YF#R)RY1&\=B.^!A^YE&\B(;T/HLMS$8-6%[51%A(JKL\%Q&ZZQJ!/"Z)$ T0#[YD&:,,0^>![R%;NA?#) M$S^(7_3JWNF5993U]1"E0MY^Y:7:)L[>0GT72U.$:\)UA6T6 C>%EEX4X7=: M5M8L^/L>8[RD/Z0_M*Q<(,,SQYYZX-J2V:N3V5N;<_8MH]=45_^X[B>!"5P$ MKMW U5*66Z?VX"*?[O/0E?4Q;9]-;<_]Z 6JIW\BHAJ?M6\/ND:[J>SL@RZH M*'K6)DS4&!.=9M/H=)29N'7!!/G=S\OVAF,A;>XRD&T 3:2E9)T8J$;N@=4Q MK+ZZ(]UU=Q (7@2O'>34[3:-?K=)\"+_>UL1RDUD=&!7.U)Z93-$O7:3],$N M: T*2F&P82?)>]@P0F@D-.ZY9[/8E"+O%(\4?]@YSY]_D+PB&LE<.\;< >9% M9[K20'?%?=5(9J7-82=MLOKIHC\4(R(ZTT@=BE%!T>)#PJUO/Y_[;^=7M M=^S9Y=7I]6_G+'<^CGT;WL"O#+[_-KSZDUU???U3=TQ71-..^(]IQ..8NU@A M-QF':6P';LS"$?N]\;T!4Z?OVU%\3.+./67%;,6Z(7G/GIN,X6H01&8U.3C>TYA_FO^Q-H#+=N=C<$MCJ;4Q\KI% M&$\TYMZT^F8I67W; M88&M#$/F3_!6&(2G'5J5(U3['77J]F368NJV M=>L^\L0SQ#/$,P<[1-*DK"T4D]XQ:TLD ]%47[6 2!!EA"C.Y:)L$(1%PJ(. M3@DAD9!(2-3#;"1!3V5^]&+ VR60+2*A2]\@$(8P01@@C MA!'""&%511A%US]_X0&/;%^D'+7=B1=X<1+9B?? &5=L=E>\?E9 M"7;DAW%\S.[X*(QXEL0?CZDNBA NH!J.H,6!4!8[X2#(]"[V7,^./ I_Z\5_ MM0D=F,9 7=Z,VD<-"%P$KAWD=-0R3(5FQ6MR62I*<;N"E4-RZQP-A#W"WB[8 MLXPN84\1]BA:_OE\S6YG99CK1%[O."IQU++Z1JLU*"LP\3[(C"!'D'O>'S8M MHV<55+>MOJ% PA1AZEEQ66(64Q=E>B>8HO#Z+G6*\H9X\#3X3C&&0^\GHR*3 MA8JO%OD!P-WI&FVKH'78?:3VOATA8CMB.V*[PCS-YL#H# I*-_ >"^H2G1&= M$9T=SLGO&-U!0:'J]TAG=:@/WM]/B/W"FGKP :;&E:N!IO#)JX7RY.3^_^GKYY9^W['3X[?)V M^)7=G!OLZ^U9HRI=6):7E]A]?F;\R^7WV]O MAE>W"CN5KP_>!M.JI$Y^OQW>GO]V?G7['7MV.OS^3W;Q]?J/[TPJ7]\RK<_L MV_ &KF"GU[]]&U[]R:ZOOOY)@%$R$$?\QS3B<+"P1IG#?3^[YMA,>LRO^R&["B;WF]D[LZ-X+9"-%Y?OL"^ECBV]$:6^X&@21 M>0@.CL\TYI_F?ZSI][+=^56TI6/0VK@XNL5"7%9GO-NN2"7U047:2?T[9/]H MKZUDI1%E)35MF0E^Q.<8'8.4['+SKC#)W<\8JVM9]A[C%?4/W7VF<3'B0Q"P)6<2=,' \ MGZ_G4,&?G:?Q;XIZ4]2I3A,>Z0_I#^D/Z0]%O=\FS0-E2]9(NOIB^?WD@%>= M/KGN_A#!B^"URRJ+ZF3)M,I"Z"/T;8L^U6F5WS?Z*!;X^?O8COC'.QNWM#KA M!$N VXD7!O-RX.18E\]7E:.EMF'UE'&2+L@HVK F1-08$2UCT"5$$"(($4M$ M='O*]N;5!1$43GY>MJ=C.[CGS O(E]9HT:=,(98-9O5)M$GC2.-(XTCC*JQQ M%"/[?)9R-HK""17[):=GQX, 'SO(R3+:K>*AIPN*WCJQ4818)/P2YZ27N4'IQ+2&#+62H]M4DJ,[ MEY%[_8&'W7'3-]J=IC(:>T5VV\NAPE1'8"0POB',I\ZFV%)V.UGUE4"P,I.? MH$I0?2:N9;1[ZG*WT;1)\?J=Z@UL"0\N6/ENV.56T\YZC:5)62B!4N"2\WA8AEF5UD M0A?5I] [(>)-T?/.UL5D:0JAH-LKYBQ\%WEWJ.5[, ML:QJG(3.7RR<8JTFBGO2'JIMQ=&W3$L9[^L"%8IK$"X(%X0+PH5"<71,91MN MZX('"JJ]5$@TC.#+1XRBQ;;/T78=>4E6. &KC(Y#W^41^9P:D5)]]A;UE9%5 M[?<6$;((68>UCPEB!#&"&$&,=LB^280W?)I&SMB6$>%3WXYC-F1A!,VUHYDT MNBDV3+[^-MMS>D9WH.S,^5[[;W1!%>U,)<10U)BBQH0+PL7A+5:-/,4#'O8: MT09-O7GJU>,1*H6L\S9WL*/5Y3I[LU3?\09X@CW!OL)&S]Z2K02**;Y.X*X* MN!7N@R%04T3_53?("YR(8TS_R.7RKV/,NRR\(SMPY1_\WZGW8/L\2"C 3V&9 M+4B,@C&$!D+#W$U7=A*=5KH(+'4'"Z7NWPDL%.9_(>_R:D6ZX[,]QT(%Q_74K2]Z#EP^+X GX&(;A>@M@"H;IC>^?Q-.2PUT$!QWT^E M2TF]4-2S?$&9KS=(11<]*-K,(I(ADB&2*2/X0B1#)$,D0R13:""IQB237UZ)L=@4MW M&DY 0+/KP)^=>;'CAW$:\5L0S(D?.G_]XS__X^^YQXG0@+C]>ZYXYW5T#P'_.)8NL&DU?_YIEP<8O?OT+XQ![@O:#P+ Q$0,/) M*2Z[LWV #6?QF/,D9A&?PKTB"G+VVSD;N@]>'$:QP;Y^/5WL2>]]CI=".EI\ MW?V<^Q/NGG^RS,_',G4 AE3L.,87>;(MJPU\A%[RNYEXM1W\>XS@ V6 M$Q8*=RDL;T$WN(DSG,"7$8/.QB@>^,9/7=GOM7&-$_A'\)1\CKC9CA=_);): M,9(NUBD.ME6BQLO'(X/ZDE4H>C2FXCT17+N@D"RTL0/^=?$Z"MX*_8F29>LWBPA(C# M?3^[YMD>7+ M\GO%'E,2-P#[7-GR( 6L2=E>4[8>*1LI6UG*UB=E(V4K2]F4G[@B92-E>T;9 MK"8I&RE;*A44<_ MR17<,(WMP(WI6+@"K;N>'/S7<24P\0SQ#/$,\0SQ#//-&:;1,=6<4=!]YXAGB&>*9P_!, M7UG=-^T'GFB&:(9HAFB&:(9HAFBFEC334I<]0O>!)YHAFB&:.0S-F$:WJ2X9 MENYC_U:FH9T5G[]%WH.=<)&Z,)F)5(:^-_'P]#>>FP]X%(^]:$*\(5X8IP1;@B7!&N"%>$*XH$:A61UVA!4+M#D#MHE:+\\MJO&I67>+X6 M2XI=H]LI+RN]]MI3M,V@$9EI9TP0F1&9Z7-(CJB,J(RHC*BL!N?PB,J(RHC* MB,JJ?P:'F(R8C)B,F(R8[."J0TQ&3*:1.A*3[>A>'EY>NJ@.,1DQF4;J2$RV MD[AZ1F]#D54BLR+K;9?6L)S0RBWP7*7&'IG'[,T%C1LU%@^S3KB_? 9?WBP)95JD?X*>:YXL>Q(2[(RKACF=HTF%)=,U!7Q@/DZM(J7)]QAT_N>+1L7\LT MV,:R;/N,_1[%I/>O_9PO(GW&85R]9/Z\K,ST-M6A6R?=?K_=:IT/K=[%L-GN M]&1U:+-WVK<&Y5>'5L0UXN-:9OI,3&PH:[;C"?.OGGWG^:(VMY9\N:6ANDOS M"BW ?1D@28%E8@=.1F&_-[XWV)?A\)L!3"8' "]) Y'/'LDO7A9]YUB7/>,< M%G$OB('P\%%.IMM@Y(#2!2%35>7GUT=>_)>!Y>7MY:W3 M*'SP7([UOI,HA&^ J_,O:; AD!_6HT>.#.#!SGAQ-^@+L+DSMJ-[9,60 4(# MZ$',O GPI&"!^"10V\3G@FNG, 0A4/P0^%4\??$\^79\A19E M>6?[^&^,Q"WFG4SX2DC0R96]5_+ >7-9/.8 6^CR0EC+KD9(]^Y2CS3M2IS ML\04N@0V3,8P4.$$YF/0.FA\E'V&GB9J.C*?]U@VW:TOU^_5&]1<)4^")K65 M/$B8,: .C_@?L$\00)%G^TOFD=0/O##_QE_. *)#^;ND?L'%2TYX0F'<7<*Z ML2Z,E^?_S=/VZL0NDJ( 3\6_\60PU^YZ[:8]2].NH.3 M?ONB.3SO#2^:O5;_M)O-^B?G)YU6W6;]N6S8A1< D^#(7@9Q$J42B33OO[V] MBTD>F/C?J1>!BLA)/ ;/\%\/LC0]P'<)9P)-Z>P&66OT#R#>T>V%[$'VT^! M"2_1!XG#)T]/@XA##W-3 28-DEB%BU)?S+^C*)S@Q!W27Z2S'@8 M __3B,.7E:,>B._%_9+YK$ $X /)L@:V^XMU(G]&ZQY;R38!/Z/(4"YM%70 MX @#0S32&[$XE$Y7,IL*YV[M2N&_S7VRQ=FXWNNT*5\.Q['O (1G/VZELR0V.E1W^+5[3 #855)\4W M0^$)@<3"(:NJC %U49SG*W&TL>>5;&L6IC<9V**1UB97! M$W MN/?[HSV5[\E/+> XA3 *> T[^G#Y_6SXX1AFRQCNA$9$G&?1C9@[Z+FBGO@9 M8)8_BZ=*.R=_3S[^(!"2X%2&4VR$Z;_P68 4#/'X&*# P(4(8:!"SK 3 4C" MX5$"LIA')$!TCW-C'4SDN7'%XBEW$*,P>7N1DT[ +$-[."<=]&-2D%9["X)&)FG@D [W@;BBC/G)<<'Z"N)RQ^]&'0CO?L7=^3P MB8B1+1LK0D]A\#%[CD"*:/ 2K1C>PS9]S=8'OP@JYDD9O!R1.!+_"O*TX&\X7,*,U7TB+*#)RR91/@Z-O*X MFP(Q27>-/=H1R"F9Y2X$_?SZ!ZBGG(8B9%8NW"E[E7>07F#VDI/7G%->,>7( M*MC.%A.7?_(2>)\CG[2TP!96[]Y=J500O5#K*P\L :%88FC35"QB,D^(U8X% M1I',D':7D6IH"$QW_![0>['^+ -L( _@F,W^@.)$S-!)&@''X@QB,"?B0*-S M\I#? C9/S[Y_.#;8*,48.7+=5!0SA.O3*.*!,T-< JK=_'21,WN65@GS5MY=2:=Q]^%$>Y+,L^, M@27+BP?G8DO9G#9_S>9^S&-'^W1"S,9[]"(K>RF[,;'_VJ$/U0!RA0A>$L]3 MQ*\8/PM$A34SR($O7_:E!*^\X @960CX17]K@9VGJX7<$W2X"=-H4>9! N\3 M=T^CT$T= 0L;70=IY=L3G ?8!.VTJ8_VV8/UW" %O9DQ-EGF\7K0GO8AX]9.L"TQ1-Z:_@^OA+;K*R'X[E MRX4K(:(MZ$Z^'),9^>"S*)UCAYD>H6=C2!=X&>K!9TBAHN(+;8\7SC".T=3V M1*<%=ZW*248:I,-@B[[,(\';MKZZ?+=1U(5,25;[G4^AFVRK!0O.+>L%-\$% M.*%F=K-@&6DYY^Y>>+PK!+.@=#$%",O?27T;O6V7_S#F:=>7_([[/4)7_ID9 MY;E%JVB5:AOL#['PLF&A,VNRG$FR1=>)'?W%DQ7J7PEPYJD363_CU.6>EU6@ M+DW_?&PWW_L #/.1 ;1%FV4NT#RT9XY[3+K6"QY"NJ2C".E^50G MYHH@_*7Y*G(VX8#'=7U[^N%X>5%>;ID]@3P7R-BQ8#IO'ERS!;_QJ0Q*?T]! MEO].N0P=>@&PK[ !17A?SNAIP'],/5R,WMS('0=P=<2\)V.P/C^9(+$+Z %T M>=%A^/BGGT7L<4L@N(Y>7-A&6< MIS;&6#F/\X[%73I[8N=G3H4WR@S#U61ETW/D^1(&.1)MI$F&7MY6>8"_W(\D"'$[J3-+" 0 M_RQ=97, O#"/U@6D<>I$I<2EC!5O[X7YQ3I>F7I7IK9Y\"0;XQBD8KM2O(O7 MY,+BBTEEY\T*.V]%6-G)X,4.Z"98+=0Y%?X.[I+A[&L9)_'T,3':" M??N6>3&+W8Y;[&H8#CLMLV==M"YZPTZSVQJV>FVQJ\$Z:[;:S8MZ[6I0ZUNL MO>-Y9^/[/XVJ#-W:1U&-6SE=C;#0] M4*%5%PBZF?I /4A-+IAM3A*B<<$G4S^<\6R%'0T,Z>+'<@D-N-27EN@5$%MI MSNY T=XUW/NN<)FOV+!PT:M3A5+5=[!_T:3^)HV8B F>9]_F)M.UM,-UZTPE MD7X=L._@J,G=GE83=WLVVT\/=[CL7EAR8*F*D5@8KW./",PHH(ALV*;S84.C M;'ZE$A"VFTT#P*X&T*<^>*Y@3H,G";Y[-)-]BUFV">T'CQS<-B&].[ DE;SU M)[/94-6!*6YEQS;GK-$S&8#&_;%&9D[/]X(KVGBK;@">T:407%Z8-80Y+;;E MSH?"-7)[]+*(J8BJQK@O2>$@F2VCWUT_0ZY4RXX"L85F_C$6-KETQ\5\*WNZ M6)6TX['/X4$+M<1;Q92TX.[PE1::D[4&H:)R?\L(6 V\+3W-M&[HP+%"Y M:2(N=^Y2,J^?9_:AW":8V8WLAH-'ZXE%'C'/T[RNHKW#U1TZF\SWIX=*XU3N M@IZ/1D9-:.0OEVYS\0M<6/ZW"$*'V9)Q-E,^%Z1_C@NSN(2P,9@K%@?R'O]J M]&)YE6Q+%O=8+-J)<(Y\+C;P!SXF"YF+T)K8PHACDVV-742^[>G4]QP1=\7@ MF-B'*-=N22'?UMYM/34,P>=/^G)W?090,B49I3F?O;[1[2LZ/7545J.5G:[Z M5)J<3:MGF'TUI[++TPX0]'IV#\T%;9J&M2'!TCZM/L[/-L]-#L*>%9.3W)>_ MB#%-GYQ'V#3C;)KVYIMG+%R6&$^Z7.^ M,K8X<%Z :C%W,!:;BS)5:+"S9?J(U3E=VCYC,$WE,E&V)>F)J".,68(:/(3B MUFQ7@3AL$J_LIA-9-[*=8QCJ='P[6FZ.FS='=SNB.A9%V>;"FJ'LBI6W^_N( MWV>ZN_6;7EDYVGKNZ!N6JG/9M;8LU,F[V543^2(#XX4FM[I&JZ=&2;:R+_ @ M8!A\G-L5R_6L_"$7>4 DXI,4C\2)F5QLU9 33_S$!'E]#E_:,\^\.[-*XL7^ MLA6S1+PNC#?;13@]B?,/PD3(O&:@2-];3G4C+Q(;00(PBJ(8I9'WG',1U>A9 MTRJ $<0G8 @.RG()IQ+:TC1]%V->:CP&!_YY>H7A8VNI2C"_^;)LZH^=ZMO M])KD-OJ5&SL<;YB+A8&?NJ_19EG/)XSAD2$$K!O 4'*AH3NUBW^[" MMWTQCIH_+E^6[$JD+N_%3&:*EH^;#9/!53[T4@U[+=81G7S$/0N;OU]N T&W ME0J:&.YE:5M*I7V\DDQ/6+P+@MO @#:&>M 2Y@H7>\CFW&I[X>(L1VG*UFIT MU7,H:M)'N5"YB4D-ENWW6,:)8V-%23<::WJV6+9IP2I:UX MQFFP8:QB!]JNJ:D+"'6KVD6VPV#TU#(R$BI&&Q##!G9X W6+Z+XZ!HISC)XC!H[O%97@ZYFP\7ON"S?<\S MI[Y,RC,;:J(@<@V;2.)%4:\7F]]?U,00+XJZIU#4V4GV6OD-6=I;D3HJM_\4 MF&>=T3*J0Y>^LK8D,=-+TK8: S)?2I1V7[&?5(T05?4#;$^YD=F8'E.F"Q!Y M%99[X\J<*>+GIHK%V1XU'/IHR[1[H>^'C_$G%>/FB%2ISPY4[BDKM1N;,+CY MT<;/^=<$F-W'7ZE+:.(UBP>+@EO,X;Z?7?/KA^8'\3F>VL[\\^Y;GR9V=.\% MLI%VFH3S+V3Y3?'-H^5-M+W&75P/Y* M-<'%<&RLTK?R!-&67S_TVC^_6H]PM2IB=J.Y[WU[WUB5^YJEO/"Y<'HIY49G?97.O#R[):+8 *_68B"^*;*NZ^(LN7]>N5"65'"8J/ M:X@B5\_/TO4LA>UM(A:UA7OCRPD MK#TNLI"UINULC2NTX MO3S![:EQ0LY*Y=2R^L9@L+[?7;60=('87L$[@I>>WJKVVO93:6I5!:ZQVHT- MQ_>(:10:2O6RA[[(U(+DM>I+P=J0B]GI&%9[?1?0GK+0!0)%VRN$B>V#Q&_& M1_G&?:.SOEGKG2." A#/R_9_7H^VDR]$H8;]Y'1DFAVCW2[> UA7E>+$I!R" MQUHJ4DHPMT*#APD-T)Y?ET[YC* MWF'(H-5J&LW^^B%(L]Q@1ZC<%ZWF("%\4$:$%>ATF]TG.WV>P: M@PT% =_Y\B-A0MU,7+D)MV4V.K1%A7QN6I#7CG3>H7=]9%I-H]4I[VC)^X[& M$_K(^D-]6LN5]$YMI-UY?6L)S07DW) M? N.T#SQ,>U'%_G\QK4F(7Y+*M#S;Z+TI#74U%V6K>.E*,45'Q9>9?:3:/; M5Y,)_YFR[FR:1L[8CCD+I>[*@E:R#KG[I%S[WV)V.O;XB)W_X$Z:> ^<78]& MGL,C Y^#I=!%)?.Q%V>E<2>@#** >60["55K>*E&M>%17:/FZPVS'/#:FH M;U^:[#L_JU'8,!"ZA^D>YQ63A5H:@GDKUQUN.^-YG^P@\+"**L)0E)&#_GD! M,E17\%1OGN*_+SLK:D>75WW 7-^FME>7914#>Y3P:#E\8D"%AN8^/ZE6DZRH M;ZDE:DRK8:W')??J_A2Z+4F6B.\EB7<:/37$MY3XVZ?HN3AUJ4.3R:K5:*K1 MSF.#R2*\&26=^.!N??SNC$.?QQGTL( ]5LU@D]#EOL0L%JJ?9)0\+X6W-.$? M0JS3ZWO);/D=5N>=0WEN5V0E550-DJ*JNRKF%;4P%-RW,DZN#?>@A05>!SK5 M#$PK#!@@C=KS>3)GKVVT^F(VBL+) M,:N-,U2SAW;>,+U/P;+HJ$.;FH&4E=V>ZAPH,WH(H3BA9^3EQ,8VJ"2':6H" M3HXK?EJ4>5RJ=#80\)R)'>$H9$.2&XS ZF.PN07J MZD=I[88^"9AUGX0F\?/!2K:G,8SU=NR*BKE007$/6D.R5"E:ATF\4&BDJ3$6 M;9I.?2]35T!Y.LE^CWF")=&3\5S-9&DGH4089E*B&%3B246))[/YQAI/G4[9 M)9!:5:G51 VMXI;!:BV;D7RHJ-2+JP4J=Y^0LI&RO:9LRI9G2=E(V5Y3MJTW M-M&^Q>=5\\:+_V*CB',6O5;8BC9"T=G&/4-KC1(WP5;R5,/Z*I\."D3(JS[R MVL4G["+D$?)T$9Q&R.O3G*<&>16)'18IJ_-LW3N_($B^MKY15FUHJ 4\I%H0 M]68;@LM[ADN[H>R\',&%X%)WN'0:RG)*O@^X4"SZ!2-WOND-]R&Q(R^06[@I MY]>A.:J>'OJ&LBAJ_/G,>_ J2Z;>=RG M3)7DT;\N#G+G*?I%6"&L$%8(*X05"A-K:-5FJ=?3B/8L:\%+]?2TBW>TWP>3 M$>P(=@0[@AW!CF!7?]A5-ZEN/BU*NS]5FY4F!\.7_]JW-T]TY^!I>(8BH16; M1CS&'*2)-^$RY]-):$/FX7P8_;H M^3Z[X\SECF]'RRQF*^FBQ,Z9+ U7EK!')DY;R0ET']F8GQ83<^(3,$4:/B&( M\1.?9QB.15+AE:3[WLCO/O;PBIG*S138;'08/\N%K-9VE3)$E2KN\1,X:)9+<0=I= MI=(^;K!A>6F(BTK]G;Q PCFF@H9\?!#5BA?$A!/,C.-53G@?P'/=LKFJ35Q5 M66D35Y4I[6/$\!W/8Q6=9&8SF0<%/MOPV;[GF'/8"X5!659OS88BRTKFYR88 MER5JPG!IHCZ6&5$7[EGF.(C$QE.?"P>/>^ [\.C!*4^?F; M&JU-4&*#&T]U7DHH,M$TX HRRXJOLM(W.HH$??PT\("%<_@/'CD>!F+N9HL( MA4S9O.2@B,>I+SC&"]2D3C<[?6-@*2+0YW+&>\"HW#58 $X,D&/V;9Q&$:(0 M V*8E#KKW9P^'3L>^QR>-Y>,N'5%<&]66-VT,6M/SVA9ZT?_]U*U!OMCS(,G MW_ND*O52F! 909XH>M.RBWR4EM__NH" M"[,=X'DL<'(@ZHZ?X^YYS32%E7?@_V3MC/B3@B52JIZANGJ&^=;J&5V]:S8< M\#ZK*@W5NX,5.0.IW0XPRKTN[Q,?UW*O7TDW+AQM.Q>5W+[ED(=;5,2F$TI[ M(:-%R%C7O#^RY3GM@9$M'VK?SGFH1ON&8C4]94>1B&>(9XAGRFSGLA:X]DU= MUBK?%DYTF/1Y$"\(%A>D4A>FF7J0P2+>RL=M =C;6Y"Z*!8%&RHPRQT. MK@11@BA!E"!*$-7/]*V7A?O"8:'UM"_O,=)H&J;9-5KJ-M#J,O(43]%G&JO< M;&3V&AU"!"&"$+$\8]%3=KJV+H"@T&)I9RSJ&3IL-XUNO_A#Z[KH!(4<*C S MU2>D8'5I#Q*!B\!5C(=DT>99BL3MM-:L^$A(I2V_H^D 0(X@1Q ABFD&,PG1E'PDA0W$W>>FB)A2WT&C.*AICA"O"%>&*B9RW0,S=,L31MO<\6#YI=8S!0EGIS?RGJHFL41#G][EKNTP&#)6/.'K/BO!^SXKA:F29S8 5(4>[3CTF1A-=:WWN_3>S8# M4,3LJ+1V;\JZL$_#/Y4FZE9C?<_I_J(^;NA..T1 91-06>WO=TRC:2G29J*, MYYL,8NY:(.KUXJ?[M/L8;@B=OQ9SSB./../R, W:20UV.^8Q7_P^MEUFK\]H MV1V<32//@:M'I8GC)_#Z%&>YF1@[EIA !& MOZI7I??VT^>PS36C*Y;RQ[*#>5C;(>3TJJ+NH.T-I9#:VF\F;% M5M\8#-97_LED4MSD3LOH___LO6EWXT:2-OJY^U?@Z-KOJ,Y!R5BX5MD^A]H\ M-;=XI%X_/ 8YR?/8X]9SP7QGMYEK?-R4^/HGE;D+-Y MUE43YB(DOR#G)Q/H'Q=_K\.I?@/:++5@3F &M^4/+1GFMS7 M.QV::KWM,6V]WU(UC1*<*W9'""/EHFTHC<\TC>(4B3NS&,N,Q$J+%//<7N"R M-UJUW+KEAE!,X"+N,\'A2:AK;!+"7R&\"PD&OHWUG.-UW$2(F;A2;*RT*OP! M7BK,!X\F8**$]8&/L@<3_!$C:F!!@G@$<\&AYWO)TYEVQ6"R**U.G-D=Q_=& M(_$NC8W@<5O3KF0<<0%J0LRC!W00'KUD7!W],^V/8,;XXGOTZA7X$-RR#:84_GO:;U];;Q)OK 7.,( M(8'^@Q+=_\$XL]0&Y$&!A*J]E]ZL4W5S,S]5!XT5FE;R4ZQ7:4T2S"CSF92T MJ_Z] 6]V8IKFH>0*8BI>\E EIT:Y&" GPU8J*(5Q'J+6E:TO S]@[%5@"&[.G[X6/\0<4PH,7GT4JY5YXR>A4?//HN]^K;]R7^XRMO)"R_]5PE)J.FK\VX92E).'4"[)\7K]>,"\;2E!\7%C@^9(* MFQN.5KDK\-=[N32^Z@J[=E8=6&YCK3J MBG+Q:]W1HS1EJ['P3)JR^DMP$JUL47"-21&R?'F#LF\W0$>."5R4K>A-:K4/ M3&.USHAIU@8,S?15UV:(X0H2[PM7>9U&WKK$.U2"GX ML+9L_UD$,&DF1&&&/:CK<.A3 (+8-A:TJ)K>$4.,9MGJ*RX3^VRR)$GU!JE^ M$^&JWFTJ5!?MF'%%<_Y7;3A8W%%,TQ2*!+Q=3F9;[RQ)Y4&],[>V=4:(H DW+;(W MCW2.<&I]:JG;\?.BA$HUJ4]$RN'WKI$*=&#(.\9I=^O,KA]Z34$13;MIU;V! MO$.K[K0Z2--W6G4G7#4 5Q0$>-6J^V(^09J@[-)1L &@;IAB*K$RJF\*\6HA-P6C=?@7ALR[5>HT &Z^.ZE()O)G>]H'-;..LKS677;ZUA%:$=5I6B:K[35F^J-EGMM:*,V.MFVG\V;:W<89HGKU63C%DF MQ;_G 8^8+Q[-W(D7>%C21N2Q4\H.E&\PJURJ;9BFO(SA9AU8N\\U*-/"RO(8LBS%:)DHJ75574%VI5 MQ:+'(I&]K!HQ5RD$?W6]"%X;1O'SJ;[SOW_^*8W?WS,V_7#IQ8X?QJ#1?XRJ MA:1N,(<^=R_".(EO,0O_.2;A_\I$98_X#H;[W(>V_?KWO_UA7_RZ)(SGT!- D"^".Z9X'W'_&*N'RW*'T!S[SAHU].KB^1%/[1 M^M?=Y8GFN? %[UI6WTS0N[W;):_:[9OC[Y=8Y@ MJX/V0A;G919XMU7DU*)SX1W/5!7_=J7=_:%]O?GT^Y5V?O/'_WMU<_O6QBSO MXK[4^]B?$F+BOD&\3<-45^DQ)$DV 2"[:008UH:"5T2I.C34D2=J MU8VT+.TZ..?@8R/1BFHUL_=4RX)X 6;H%5R&E9:<<5XP3SX(T]X_&M;@ZFF>NM6"ZDK*G7P+JM5E6()*L=!O8O/M&\ T4C4 MMRK4XC[B7&H-WI 7U9*C5QF\$7-$N:O*#;-5FJ8^=^^Q/%?VA%(?M9@[*;33 M@U]!F:3*:0Z+QV4%IAF]EB4HY758)@>O!'A,?>; 1VRTYD"_0M=#1UAV+B_B M%; %%962&"/ %NZ2&B^JBA4*CTC VQ8U6%8U.]-NL= 3OD)4.M."$*Z]ASO% M1!^O#T>CF"?Z2J#X7E8]K'"H1">++B^7"[ZK\.VS4IC@9H@%%G1MM&$6>(_' MG">BTL52JGD<>SXOWSKFOIN+;XE<-WYGQ=L3SQ=ZA7_POU(/7$34G;/2" V2 M ^+V%1(O)+BU.8IMF&%"\02C M50DMPS90S02?N)0;8P3919HMJ&Y[&GS M,.3K8X?5$.05BP*X,O[*(Q&T_ J.M_-41"O7"#.V+R_,OM&SKGL7O>ZY-6@9 M[6L19C2[EQ>=7ONPPHRYO+33SV$"[C*1H9 M67$9_G^81YS0SCQF-7JTK 2/%N1%IC#,!4:J*+H,[(?5E3W'FTJ$5L(%U8!2 MI>ZDQ&EE#GGI^2F^;$G+LJF7C'JY>)U8*QN-L'0UM&9^;0*<; \\Z=.3F]MO M)^^R=39PD@&BX$I/PP0K/,-?L[T0M:)QS?QQS(/9Y0\A&_Z=1XX([8D'PCK>GGR3M>&O)QWY]&A0@FS<:LJ&%J (7A.J,B@Y7(1:J5>.J MHHF?YFK),V&-@->EOR46O?0Y!:DVXEDX2$W*NE3$B"HMD6[XTBY@$RK-C_,0 MEA=)*<5X^V.8^BX*CH&2O\_1LJGI>\%F58*V\7,6&H/^ M_B[ P-T_@AN4 <(?+O@2!E'^$?DHOD,]V\0B&E>V==&Q!^?6]6!P<=7N=3OG MV<*;V>]V>UNWB+472)<%;P7+"%!.0?=EP&!%@+*RFJ"#@B7\/HS@L: ;3^(> M]*O\)6N_8P_8/G+&3XA.!:LV-8;MEKBM5/YW_?*_IF&H*_AK=M]8\=?N[TLA M77M?&OK:^ZQ]:2AU<*<=I%.R#&>O/IWUNM-OVZ]5_(+N[C:4PHN\$0@# M X,$U?5&V+5)M4>^NJO4HITT"16MNDUJ36VU'K MNS!A?JU3IL,*=\@UG@\4]=AIU., HAJG/\@%W3"-6>#&:S,^)>UY;I%MB(=^(;XAOBFYK1! M/;W=H_))1#5$-40U]5)-VZ@_U6=31IYXAGB&>&9'+DU?-WI=HAJ*0J\KPL^> M.,*"YTZ2I\KI"@I&JP]&'UQ!O+YAZ'9'67GGIF"B;@^&,'' F&CK'4N9LT^( M($3L/2)JB.L3+@@7>X^+OM'6^_W%=$E'C@G:EK!:MA>89L%5.D%KD.3VEWL. MI[9IOZ<;K<5$L11!(G01NIKH"A/$"&($,8(808P@1CYB$]%%JXP?OT;> TNR MY*Z!3VN.C6&EO2,?BB83+@@7A O"!>%BK43JIF[8RK;$$20($@2)@X0$K3L^ M4T[:"UC@R$3O01(Q)\'"9@[WB@PE%&9J"!L=3IC),BC$1,@B9*E'EFGK9I]. MI!&Z"%W[$8DAB!'$"&(S!LQ:/S_WT:.+5B ;53-),&TI]\U-TRQ M3,];LF!F#Q45@!;2:C9%U]2=25]7A%N66 U;2OH]O66K8_27!+<7>E2W4T4, M1@Q&#*;JW&]7;QGJLHD1@1&!$8$1@6UU5;C=(@(C B,":X#F$8%M'A34C6Y7 MM[O*\A$1A[TZ>-B@>'V]V=.*\NP?:H]&D['8H +/%H6X]Y%LTCC2.-(XTCC2 M.-*XQ@BQ\1I'B^HKDP?K.!5RM2!,M">>:-,TSW,(@8_Z M^JP^='':,WIZJV>J[GNI['ND 52REFB":&*U"M 9;^("X@+B N("X@+B N(" MFCZ\;OI "YOKUS^O.Z+3(+$VCJN/\'P7':&D(Y0$L7I]AFY+;ZFK5/6B8 [; MER#P$?C(OI%](X@U!6)DWW8^5SZL*?&R''A3]J0R 1XQU0%GW3QM]7H4H%/I M5!-<#ADN5E?OMI5EJ27$$&(.'#&T(DRX(%PLLR0]W6HIFPD>AR79]\71QN%K M7P37K$,6NTD0L&HT]N*\]_8R![RHM7N?4D!LK.EWMIA10&F8<2_TE=;8B$0; MIY1$H@I)U#0LW>QM,;44D2B1*)'HSI622+31P;W72W4OM*_NF"$Q)3$E,67S MF/*T;YJZV59V&(;<335AY)\2L55FR?5;8_>*='POX._'7(R,:1D_[H(SGVO. M_.B)SUX [)Y\L#N@)RK;>S?FVBCTP8* ,FIBG+1IQ&,\^:,E\.-%. %%>RJ< MD.['6/."!QXGV>D@AR7\/HS@L:XV?!+W^/R!^UHX$A]&S(NT!^:G7!M[/&*1 M,W[26(P_+XCH-3VXY Z?#'FDV::N68;94O+4YW,ZKCE\#DB(1RO'J_*4&;MG MP!A7!QT_5U\3A-&$^3.,8N(UQ8/E,#K<][-K?CDQ3L1G( TG_[Q$(G?>A,?: M%_ZHW803MN!-3%AT[P6RD2Q-POP+R7+BFT?/3<9P-0@BHS.@*I]-8_XA_V-! MP;2HKK+EU#7&/%2C3FEQ.[_^.+[#EK%;(;S6W?9^]+0U][G[4O#:4. M[K2#>[+I>+]F7[2B7&EN^Z7C$#.^O[7@C]>\%^8%UV%#@8F/C])[&(:^FVUK M+SVS"6=Q&G'ATF7.V4-.UD:LUF%$D'1QCSB M&^*;;?&-U='[;9NHAJB&J(:HIEZJL72KK>[D;-,'GZB&J(:H9C=4T^KK,(,B MJJ% ]+HB7%6YE.+1ZN/1!Y=0RD3'1K?ZRM)Y-@45=?LPA(H#1D5'[W65I>LD M1! B]AX1E)"3<$&X6.H_=3JZV566DO-04$&[$U;+]B*<3$)7Z22M09+;7_8Y MG(HQ??1@*8I$Z")T[8M-'[\&GD/+.$:"UPM M#7Q:=VP,*^T=^5 \F7!!N"!<$"X(%VNML_3TKJEL!RY!@B!!D#A(2-"ZXV9E MWR/N<.]!9>7W!@ES?]GH<,),EM[JT"D] A>!JX[3(BV]:RC;NTWH(G01NF@1 MDB!&$-N6 >OJ9E==?:-#1QSY<.: M%"]+A3=E3RKSX!%5'7#R30K9$RX(%TLL=:NEM_O*JHH\?0ESQ,/^!:$PYA'HL#EIV":)O!S&#C0"I9X85 \6FP# M@@\W?/3+R?6E99BM?[3^=7=YHGDN?,&P%_/^9"!TW+^/'C MO&*(SUX IB/Y8'= !55JRMV8:Z/0!_,$HM2$"FC3B,=X@DA+X,=H1I!:.!+? M#IG/ @>Z.@HCC?F^Y@4//$[$P2-MD@V2QA)M!..G/> :FF,KXBA7]X(8 QM M32NC!D^ 88NUT\_\@?NE7;/?B7?@2Q>4>L,.9^C/L"K$ZD+O(M&S#^B#2)D\ M@4^B<1"XJUURAT^&/-)L4]=06][:!O&"YQ-/KJD;_T[CQ!L][=XK6[.]#N@& MC]9!Q(R'88#"5Q& GZNO"<)HPOP9YC;QFN+!4J<=[OO9-;^<&"?B,Y"SDW_> M',L3%MU[@6PD2Y,P_T):$_'-H^:V[ZOM2\-I0[NM(-[LLUYOZ:!.UW: M?L%4;"@A\?%16HMAZ+LJMN&8YDN',F9F)=;"3*'F?3K;E:"&7KHFW'0M\]"E M)_A-N'RW%9>OZJAKGZHNGV8?VL$&0OR>R6<->$^@J3X_!/C^:Y-9#@'QD(&X M5Z;WQ8S'-5C>1?%6PH"+KV@8TN7Y+ZAG%16 45\C;P'EG"-!:Z6 M!OZ*]-6DTJ32#5?INS!A?JV.%:UY[_]F@;URQ5Z.@J@4[#Z!O93KZ0_@>FG) M.$QC,&'QH<4XZES%/N?W7A!@!"E;;FR6E3]4J=LOV:9 MX94%41LDM\:1[1%F];1,O=TQ:U>NIL"I;H^%T$7HJMQGZ_VVN@P8!"X"%X&K M-%UMO6WV"5UU>MF'Y4S?,K]INQ&.@W3VCELH(2CA@G"Q>-^IW=6M-B4$Q?LH MM30AAA!3"V(H(OQ,4@#%A_OF1?$FA$"\(%X:*!KFF# M)H/;\5G#--'"4?U>:X,$N[_T=#BS[#H*,!SZ7)L@1A#;9)6YI1NM^L/$Q['Z M3-@C[!'V]FCGQV'YZUSO0I*.Y)8#4=/+-UJJSMZ\F*1 MI'U0(PIM$H$1@>T)@9D]O:OP[!P1&!$8$1@1V!8SZ1AZOZON:#T1V.S<6U&] MR;=6A-QJL[LR]% (U]:>@K[^ON23M?>U]O3]I)X[?\ MOKTABD;KYYXL&NW7=)SD4_$(=E%19X-%;9532?%QH68&%1'="XUMF'QJC78< M-*)W7&1T[4.1!-2# &KCY%,VMT] E1%/TB[UVM6,2HD-4[?/'AMZ_D:E.\D, M'(09:*Z_1D#=N]K1>PU,4KSG%*\4Z3Y6@";%/%C%O/8"%C@>\\7R?L2<),9U M:^Z)D=XIM[]3]K2)\:50 H42=KOT

WQN>047G8YL^^$0U1#5$-;NA&LJ-2'Q#?$-\0WQ# M?$-\0WQS:'RC.$]'TP>?J(:HAJB&7)M]X9L]66RO4X1?T\@9LY@V9]6RUDXU M>(ZF!@_AXHAQT=8-0]F*"2&"$+'WB+!TNV40(@@1A CRG0@7A(N5XNB"I2#? MB1!!B"!+0?ORWR#;6^:K"^,U2&;[RSP'5.7/,O5VQ]R:=AUVF3\"'X%O$_#9 MNM57%DPA[!'V"'L[],4/?EF=($80(X@1Q AB38'8J=72>VV:OI$+2> C^[8' M]HUV9LK495K$X?'_P1J"(L5H\?&>>4&LG?IA'//XG?B534*0RG]D?4(O*)*!8G+#G@%ZM3LVZH5Y;A] H++ <.EW:<-#(0'PD-E MP<*PNF1 R( 08-8#3*=O$5P(+@27=>V+;=($A0!#@%E/'+;9H@F*@@AC@R+[ MM88>(Q;$(Q[%FAX_*B,@1LDUOTE)5HP.>8%$X(808P@1A CB#4% M8I;>MCL$+@(7@:N.A"MFCU+4$[@(7+6 M:C V3!,M'-4?CB5B.N"E($HN0K@@7! N"!>$B_6. NB]EK)0"^VU(< <.F!: M>JM/FY\), 28=3<_ZW9+V4H9 88 <^B Z>LFN62; 8:V>ZX6XE6 #=.&S&>! MPU7I58.$USAN>EYP8>3R*.^]/?VNN6$Z]+GV_QCB_UXEP)6CD;T-;S7A57'H M>V[QIJ9HJ+I2;R_)]BVUX.H090U;)PQURT^OEN9>:%W=<3-B2&)(8LCF,:1E MZH:M+()#)$DD2239"%TEDFST>BDQ)3$E,64C=)68DIB2F)*8DIB2F'*K$^]V M2UDB+"))(DDBR4;H*I$DN9/[RY25O0,_)0SDLO3Z)7___%,:O[]G;/KAFGG1 M/YF?\D$<\R3^G;,XC;C[1W##G32*0!'/6>S%WX)P&//H 5_R*9BF"?PR*K^QT(Z=P/G3]__?O??BX>'48_*!V62U*Z^.V,6W#^_$V('K=[$7FW2//'9"\"R M)A_L#A"ARO;>C;D6\2F6)@CN19V"41H(]62^YF1*JX4C+8$++\()4,23+&?@ M^YJ7Q%J<#F//]5CD@39YL;CNV]GM&7"4[[/H3*MJ/)8[&&7#F#T<;V,1-L)! MLA(5$2KWPX^)>";/1EV+6,+%@X#@N)-H82!^3\K7:"Y<I&Z)HW@H]/NGAUM63$20C/CO"K<,*U4_Y]RH.8OQ,5)$[P GPU\(<@ M?-':.(%_)J!",0ZFO/'L>89=9,G74EF5#S^)5]^Q[Y=>[$ _@6=WD6O=5B4IRV,T(:/S=R!S.(OO$1TQD7DB7'[ M@,8WXX7!_QW@$ER$EJ. M>?,PTQ8=#4,XA(^"BY)0F[(G+6'?)0LO:1/2HE?EN!!:QZ8>UMP1- EVY=G> MBYY[P":!>!\0BYLB*X/50OY#&IQRJ?6B#4R#UP?POF0,S/WHP75!F, [TQBH M-\%G#)'^N>3^&$1PS^ZQY^)FX'-7-'*8QJ 3<0R/2,99W[X%'MYTFPC+A6U= M]7PPIO]&XX$MSL9"V,(1A^&!KF?" ,E)TX&5A* KP/HYI6O_'3YRF$;H\#CY M<)2BU 880I>//&B-]\#1(@0NBT#8TRA\\-"R#)]$>S^!V"*T_S?PI"!%,;LP MAA&_3S-^%\,1IA%8-.YXL?@*9 +-QOOC*7PY\AP-C<.#-+9"K&B10'%2T* A M1]D)(9:*F8\2C- F(M6E0X*B?0(1HLISZ,'$"[)B2S!:8$]!9V'XG[01-"L5 MPM3@ K _>B8C!Q1P*,0$'D,:";LMVBV$F2LE M-'U&)TMZ\>)JSU_J*B@ T:6"]OZ31RZ#V[Q8@"7C,C$$EQPX#B"BEWT27AJJ M!?J(>$\%FP5S,0>=5J$H.&*E\YL#-BH@7T7/-.*Q$WG#"N1NX*:L@44$H?LQ M%E#'J7Z&?$]\([U/EON:B&;X5GJ@@!VU3L-J'\%N__C65XGGG&F_W7SZO&Q< M/D7<%]@.7+T<#7U^.%" D1>/"PN%J >)E \NA;9U*9G6F2(YY72/="$MS\M> M/)'#>NT=)%M3B$ON\,D07 W;U#6I$$ 883=#6Z;;Z CJX M6'_@-7WX\&;QY[+MU2?;W T02 "L++A#[MM5L&GZM0&\#5OI:+P[ MTQ38F%H-B&"=,4,L+&J'T(VG7#&J><[48-YLG9EJU?]Q[,%4,)O4S6LV^A%B M*LS]IS/MG,7P6Q9)]KT_N>^-PQ"[*85RSX-<%G$Z@JFMAU/S.=\ L0[P9)P309IQF%E/* M)=0DYB<+%E#,4(?X$EETN;[ MX:-P'<8L!CGPH%A7.%,7S:WXY,4[$YWC*G/SSYLNO,%>Y M]P+92)8F8?Z%W)0HOGGTW&3\H=\]LSOM7KOXSX_Y1B<']PQ,8_XA_V,!+64O MJFE&RLU/]M+4,6MD*A%-^^6D8_[XXKZJV:U?V8U;O\_8EX92!W?:0OUXPO!M*4'QQ M,?5NRU"E*4W!1=T>#B'B@!%QJGZ-[+ -,:'EF-%"8*G1:X6>-VDZ7:<$/Y4[ MB1<]6?7)(9LCU,:1U09;&2BKIM((!V75A.E(F^JB-6.60QQ)'$DS+5H4AA@LE'*_GZTL !2#$O2$22S.*2 MB+,X#$ =GHI,*"&\Z8&+[*P)- RS=D(#RK1_67OT^7RS(FM+&)7MRQ(_O#4+ MR-%K@OR(EW_ 9+R>LV+3^766 //JN^/%7+O#3#6-Z\Q^B;X X5P^83\.$15A M+#*-8CIYD'@5F=_+#R$FQ/&"/+OM-.(3+YW$VI1Y(D\R=/^]2& JKN&1R/2; MW8&?1);3B&.&7X'!R(O_C#4_=/*,G0O)>66BYBSIYDRK=" "'Y/=\N]\,L4[ MQ+OU6PZ5J,,A/&7(YX"QUU%OEZFVP !\R'55 M>@$C'VZ46=:9\U?J25\"_-HX*?/%2V7[/]5Y[%_T[?;Y^:4Y&/2S$CZ7W4'GXK#J6=QEB>O?9EL;GK(X,_TM2['I__;6 M&@V_?;ZYVD%QAK'(S"_3^,(T 5M2)"+[#>-301B!T-Y?L*$7R*2KBR_5M2G8 MQQ1SMR7AK)D2Y0MD#8+L5E S>'N *?K%UY]1.-B*B3!FNIARZ'GOL,A!-7W_ M;&=Y #"5I05\?N_E17O$Y;G7A5,>^ X:,@+KK&=BT;."/N@#@"7DCJP2!K_C M-]E,*6N#+$2 [>>"N#0WE9.C3"&DI4>?2=0WP#LQ/5LI"$P7.>15APE3O<* MSTV-0$=$;BTOJC!TI1:&:%P^N?(9>&<#_$;^>0Y_@B9A3:5X#%R=>8>R'E*F M0O(AP.:>KUWS893BU2*5EM4^RE3E+4,Q#ZQ1QV#61=M>&0-QTT+YD%L>/7CP M[-.33S>W)^_6+70@DZYB'E/<]^%DY#3DNTSFKZSDP:M5K?E3WU4X4&T/UR@: ML5KU5Y6,.+CR$#*[^;9Z8RGN"\8CYOLCB^*])0$H82B_;P!NR)+DTEB@2*97 MEFEE\QS36>G'TKP\FX/9B\NJCH]C'KPRU77YZ*+^TI"OR&U="1$M"5=K992Z MDJ#T^6!U# .!Q:S0XJH(7(87!O6>;=W;9Q?79GMB^Z5,6A?MO+ZN%;_PCRLR74FL,+MJDCL M&/WN>LLM@L65?T++QAA^F?A#8/MYMX#.@!YM,;APA&3 MRP=>-B,LGR2N$\45A<&;1AYF@P9[[W(_T\=LGIA;/UQS6"D7N:J0A!A6*KJ9 MO\TM.SQ3/9K%Y0\H]P3MO?0LP.3SJ2R;.9H!A6S&4M'+-JQ\5?Z&0GY9R*D: M?192P448_"#S]B=/4]Q0@K4CY0.EG"?PUK$O7(N_0(;@-_CHG4UY(,2.G@./ MH!59?4WI^V"ATQ(<19?*KZYEM*G\HBSW[;-[?8FXHJJ8\Z[-Q-S*#^)1I4B? M&Z=J$2*\5JX=BK!@_FHWC;RLF"RT+5=9(B0%[)3]F0FQ"0?+"$MUB:!H>#.(&.?"M(K M4JI.A;)*86C_W7^G<2(!+M5Y@5.K!>W%HV4]#OB4D<"82_SGQ6JQ1LV%J 0O MG(>%IE1#^?F/DCO$#JKJ&O\P!$G.\2HV?07'"<3GHX/731@6#XIAH+ EU2E0 MM>.>G$KEAF4P%FL'YL_C,(_>00JD V8J'V8)*R.(-2+FF(\AK9@IF8H_[L'&!VTX1DBSB?!2PTI>)L MA('_M&3M"CKDBTE!MI5DL8EA,#L76)@<"&G'6?V@V78(E#T(4&GI%!>[V%/^ M V[4<5TQT11NGVBQ=*HY\W..D19ZJQ*?69V':0) M7UBZC+,P!BXX*UN@@.O!21"790O1\D5>Q>D &_R?!;=#+#*'B2<5WZD^P8O+ M*4AN+N>=EQ>WUF15>D_"ZKZ XL"VL-0G1[CH59<;/SM;*U=**^,/%F.>&.9( M2GJ98>ZI92:RK!N'$S1)(>B:?@NRQQ5,V0\&P<^8%+1_6_0Q]]YO@/5,T[L!&W'(R AYC99*>68=C&=?]\<#UH M=:];[?/V5?]2!).MEM5N#_I;#R8WO9#CKNNA)S.UZ^)BT&7U\.ID)">M7&-B M)?79<*+DC9[6&>N98VV-+= FJZ^9AJ&PWEKWC?76;&M?JG6U]J6AU$'J(!64 MV[.3TR0?*KOT[.Z BS"FS*^D;-M1MF]!OCUKU6Q;;(TG?21];(@^8O3WA1/* MI)"DD*H4\IIYT2I5Q-5FOJZD]\29WNI&2/*N:RV9V*:2B50R\16K9N%D$KHB M JL*E@V27./PJARB5%&HQL3C-63,-2S=Z%NURZ0IH[_*FR*N(:XAKJF7:XI= MME;]<&N*!A#?$-\0W^RJN(QNM#I;$\EA5YXA(B(B(B)ZG33ZO:T045,&_ZT^ MSW$'J[/]N]X#'GW#C=9IX'LQ;JC&HP_)4V6+(L6MU<>M#Z[$GMG3NQ;5:"5( M$"3R^VR]U3<)$80(0D0^539ULTNU6)7.B DP!PP8R]0-NTLV1,',K4&1HP8< M7Z:0VQ8$1_7CZ@O84?TXTS+TGJEN3P55V226))9L@JX22S8T"$,<21Q)'-D( M726.5!B6:^N6NK4;JD5,^U^(0O= *8E"%4[&S;YN].S=2W0O-$]A '@?*K93 MOMV&)WE;7))\30?>F.1-:=Y12O=&Z=XH65@#&TH=I'1OAS:W(OE0@AE*]T;* MU@QEHW1OI(_[I8^4[HT4DM*][=MVR^7")>^:TKV]38,HW1NE>]MSO"J':.,/ MHU,F@IE,!&V]MZ1R#F4B(*HAJB&J42D-4S?:R@[(-7[LB6F(:8AI=L,TE%>2 M^(;XAOAF:Y.HCM[K4LIL"D93.K>F4O3A)AXQN[IE]U2I2E, 4K<[0Y X8$C8 M>JM-Z=P($82(2CJW?E?9N=%7G?YL"HXHG1L!9KTDN6:?;(B"F5N#(D>4SNU0 MF&>#O8)T@EQIP(Y.D)NFK1MM.D'>C'D+L22Q)+%D\UBRI;<-96%)XDCB2.+( M1N@J<613PW*4SJW&:!]1*%$H46CS*-0TVWJ;\@9O/P"\.IW;LK]__BF-W]\S M-OWPJ__^WGQ3N_@G"=I^(B M$&B 4KOAHU].KB\MPVS_H_6ON\L3S7/A"^8D[Z\'%U?V1=L8M#J7??NR9]CV MA7EAMUMF][)MM2]/?IT;A:I$7TAXM6P07TS0IFA4QP +'8[[V*8B3 M*!5YRYX=XQTT?1-[LTGSZDI])S_BY1^\!-[GR">56AF7G?$"K51FLC;EV$4Z ;)^*3>'=CW$UG1^. MALN'"?Q;0$6,V,)V/"T9LT1C$0?^9''LC3SN:BS63I*((9%5+CV1E[$H$M0Y M\(S3-& NIA+D[COL$7 >7*Y-6/0GAR>,P@BX$!Z&%@_:'..7IY_Y _?+(37A MQFF:Q.^6-K':O$(88P8OB:"AT K,W!ACRV(&]A)>"&()XA&/M,>QYXPU_GWJ M04<>O62,:14#KCV!%=*SWB4\FH"J0 >?--D3E"C*)1S&/,*NR\[('N="RZ25 MQG@U@T;"9Q>_<;W8 2N=E *3SQ%)#[,GR>XN[>VB1BP; _F 4B_*5^@:]T3B M2!?Z["3^$PH$M#S[I&MQ"B(!YI0?C%_$[H4X)ZF?>--2.BN:) =3 MJ#GJZU+5H'F$\\07XL2D"]X[$W MC:7*.V7Z +VBJ@" #=BX\I %=EI.OQLQKF9F#)M)#.[Y#AWZC]!B#IHNX%C1 M6,D:50;)F62 AG_-HM9/8NB5C>ZP M#![%1Y'##L$KDX?-,TIFB$'9O4*QXBEWH"E.QB#PEU3%"0>M<+73(;X-/"L> M@"<$MM=!-8,WL$D8)>*E^(V.'6'3:10"< &W[T3+JKFM ^$$%4H,/X43,)#8 MT':)RV*^)N)(1-F05B9DE@R%0<[!%ZW=.F''"\# M"!2^'0=)>$B-:#K$0XLW<8 ..(%G,,<%K09EJO;"R[];U1V&IM.)4K"2 @// MJ]-S\:2YJ-#RT%%\4>#\_.D"WA*!X8:7_\X2(81+D-4=VH!-HDN#_N5YO]WJ MF=>MJ[[=NC#[K8&(+EGV]<5%V]IZ=*EV9V^2B0OG63#Y&Z:"GU W%GS[,?>% MT[4PKJ\"REP]@+90,H6% 1Z1,^.L-D#\005]4(;_+63X;^U-^O2]*45 '3S6 M#F[GA7MR#GR_EMM)/F5SNSO(*=RP%*7H(I%JD6K5HUJ+3C>E_""JWP4>*7W\ MBF(N/ZT[@]URV\KA+H*6C6^I0\5Q"+S;KOW0:$1L5(2"($&0('O6H):JM&<[ M4$@"]R&!^_#LW9Y,>AN'$Y+/FCQ22XVERCF61>9I&&=0 2;U<:K_G=V?K@IIRA^^J#14KZ#H)_$-\0WQ#?$-\0WQ#?$-\0WQ#?$-\0WQ M#?%-LU)['U;DZQJ/86+<*PFU$9[EQ?@7%6&J(7!]<.4"6KIE*"L UQ0\U.W" M$"(.&A&F1?4S"!&$B/P^R]3[%AD)@@1!8@82R@II' HD:'?""W,T,3F#25K" M [5SM 8)<7]92*D0=UT$KM=2EY[]T$-(A"Y"UR;H:NG='J&+T$7HJL.UUEN& MNJSX!"X"%X&K-%VZU5,6R3EX<-'2XL??PXACBNI _9R5&.B0 V1@QFD9A2!! MD"@A8>AF5UEA48($06+_(='3NVU:621($"0*2'1TP^@2)!3,Q"CV04$C*AE[ M,!O\J61LJZVWNE0QMAE>&)$DD2219/-(TN[K1D^9 TTD221))-D(72625"?+ MMJT;767U%8@DB22))!NAJT22"J?;?=TRU>V6(9)<,\+[DRC_M_3Z)7\O*ZBY M>:W,%34W;T/?_1(F_^+)US1RQEC7>9/RFIVVV3J_OFX-+LZO[7;/O.X85[*\ M9LN\,-K=PRJO.7A[J2JJ"+\ ;5*OFJAFN9;7RR>FE7U%A4T MO9D2RMHC%@:O5" NC=E<)?C*/0!45Q=UPY]XHDUS!:+2G*M+<_;[9SVC;71Z MEM6!+O?:32K4V:(JB VY;V\:2AVD0IV'-NLB^5!!C.P^\7$AN?W7*(2)BTL; MQ4GAMJ-PWX*(P]O^ Y[Y/?,"4CQ2O*TKGA_&,2?-:[#F[4^!XE)>6%M*.\3: M33N3*"%4/4)K*>?4,$Q2Q2;U:P97?Z4R4EKD/38_:KX7)R^4H*2UU6;.\AM_ M()RRC5?O.^T9MMYKU9\/8!$W]8E)NT;1O08QUNP&QL4COH=3?N"TV]5;+65U\]XLN,/F M2 (O@5>A'&W=,)6E+W^UV)J"PKKGR 1. N=NHU$$48(H052E\]N">7Y-2=?( M^541(-AI'(#.0>TIUVT 4T4YZIJ"QNUEF]NK;3V]OJ'WVMO+07PVF R]*=I0]\R/J(:HAJAF;O]@5V_;'?)YR.>GI-![:5L7L]P[3FN!YH[F[3 M,)J4K;N[+ZF0C7UI*'7P6+-U;V<$]V3);K]F0"0?RF'[[)(P9>LFA:-LW:1X M1Z5XE*V;-(\2>M-&-@(Q)?2FA-[*M.XBC*88^N6+)T_IU.F>!@,:?\R#H!$60.&#)] M4^_T#56JTA3=KSLR09 X8$BRH MJ%.#9+B_)'5 20K[NME3QEU''L8B[!'V-I:3VAR^35]$J'MV2A CB,W,9_5. M6UT2>S)OA#W"WOJQ)+UG$_AHB521K+98YXH82UU&__TC+JO5T=N]OC+F6E- MATU@!#F"W$IQ=?2.O;5*&4V!3MUS84+4$2,*O>]6;VN8(AM&B#MVQ%EM@)Q- M;N/NY[T-BD3M?9Z,!LFR<62W 7X5Y2)O_ +/]I*4'\8Q$E,WNAW=,M2MP;]9 M;H=M4(COB.^([W:VY[ZOV[:U>YDU17WJC@$1FQ&;$9O5Y[V9MM[KV,V1&OEN MQ';$=L1V=MB[7\+D M7SSYFEGONA\^>O?__;S_DMGSTV]'PO>;H.H^LT22/^-?0]Y^F%^D3+ MQO/%PEN["LMN^'QGIO[6PMM6%^3Z_,?MK3;X]77^ZTJ__[ M]>K+[95V/>1UVYQP,HT\("0M',V6>/M0N]Y4 MGC'CY1Q3^;7^&ZNO=?>FYI>U+PUM=@=I.W)#TL8=V"RU:"[5%5GB1*&E)F4C M9=N6LJV=WY#, 9F#6A':I0(U1[!#3GV!&E:9:BJ+6C9'=HT#K'*0'M$BPB&L M$9BFJ;<5'N5I^NCC?;1_@[B&N&877-/5C9:Z\Q9-'_VW<@U-TCY^.O]R0],S M]=.SHSOL9?9;>JM3TT96.K),F#I&3+6Z.N"*,+4%L]Z@>46=LKT+$^;37(QV ME^[U9.TH=I?:1EOO]]55$*6C041G1&=$9SNB,ZO3TJU6 TX&-45_%+JYZ^V% M;\RFW5?UO#&M'VAQ.IFPZ FWYLK"%#$N5(=I$B"V0C69J$^1?2QHIO:M@*;-IOW O<[NW+5MF]V=-+'=QI M!VGAI"$+M T.WJK6W]!^J:,_ENYAL)# M'S_S./Z@?8;9*(^UB#O(:6)_" 6+E >+7CJ3L'=G#D[QO+*E;!ZU..[UD6]S MTS 38@X:,1V]9RD[=4N((<0<.F+LEMYJ*PN+'P=B:.EEM1"_\(067II.4R\= M/U4JY.QE8F_R\P==MTU^5MO2NU9-U>TVD.KZ$MKC: !FX"]M4B=:>M&9VL% MQ@G8!&P"]G:6^RS=,+=6QORX@4WQ^X^? B>-(BX/#XH0OL\2^)B$S]?^H/#* MJUCPI1W96]]Q3?N%27](?TA_CEA_*-CY3 IW= [@MB?PL&BZU*3IDDHA[C9& MV>GHW7ZG=NUJ"J0H&D'PVB:\3(!76UUF-X(7P8O@5<;K6BV]L_Z!XJ.'%X7< M/GZ-O# 2'K6RHDC$/0>\@ZEMZ+:A;'M)4U!0MYTF2!PP),R>;JG;!4N0($CL M/21..[JI;J<7;7/=APE@[<4;-"];'J;9&><$^XWV;UC*[>Z^T^'RWAGA8! MDH_78<3AP9HXE!@X3UK$'YB?LL0+ XK7-(\E]R^>8^FVM;6T^L<1[2' $>"> M":#JW;:ZZM8$. (< >XY<;5:UK;0UA3@X'U;/TG7H%GX%JOA77*'3X8\TFRJ MA]D==;F_#C[A)L&+X+6!G%17C"1X$;P(7I6<56KK-AXZO"CF M_7'@NA^TSWD2"P=1S(8^IV# ]GEH_^A&MSO*]B8V!1!UFVQ"Q $CPC3UMJ5L M^QI!@B"Q_Y#HZ#U*IDY!W_5E^UL$[BB%?9N9%6IV5<:>?M?<,(4)PYN6K/8[ ME>(/6Y/MBUJ[Y=UJ=<3?VWJ_KJS;FTAT+S2/PHO$DONBJ\22"I=1.BW=:M5T M3(I8DEB26))8J]?T^Y/8LG5$8V?$K&$M.3ZK36L(C3?"_C[,1=\ M:EK&CQ\;)\5-&BL^>P&0>_+![@ 65;;^.HRT9,Q%'BR-PTM<;:'A&SXW0T*F M[*+U+G?"2!RJ^8 "DJ^NQ'ATS3+,Q47LUW1(%]T)>)+GZ<\KCN$??JJB@Y*V MV\:9K<%E_K*C0J]Y8J6B@&@_V]H%;UMFR7T"601(Q)XGQRPF+X*%5L>$31J$/[A#T M_?FR#,\A<,8)Z2/DJAA\W^HI!N&K*$0PKN9PW\^:^\N)<2(^@SEQ\L]+6G+G M34!QOO!'[2:C+0"%[K?Z?;?[D-#3S?R'5[JZMO<5KMSUE?+?^%H->=5>8YI]SS@$?,U MWV-#S_>2IX(8M!"\2B]@/A##([PIX8$VBL()\)31PYN!K\PS[6[LQ>4]^ ?S M@E@#1XY'_A.^![Z+DRAUT&A!2T8Z&$WAAD, ;X=(8;@9< MROYJXQ"P-D/&R=B+7.VOE$4),"AT&0E4UQX!RN%DZG-D,A: L0*C.4W&\#?S MGV(OADL\^(B/8#%\3L12"8HL>^04GOBD\>]34!H=?\!+E_7"\9DW0VXA3T1_I);S=YR5[0O9D"_9$.UR#8K;.NOMA4(!0@+4-=6:D M0J+IU!7>+/R7X?9,[CT@/Z()0UJ$QZ? 8YG!"%QX,E(XZ!B^ 7I0DFQN.03! MYX\-TZARB1=,@0_!T&,A5S-FEY@+%X%(B;W!3ZE-L:,&\# M>$?&OM*+9YEUY'$"7CJ^UPEC>!'/[(KVR.*"GUTB7R+?O2#?P^7>ONI8QKK4 MBWQT[0/'NDPXR^$C$''\7Y+GA(M;3OE923/X?!)0RA-Q6,]LC0@7?9!(DN\TP%34=H Y(PFDCFG?-$A:>- M_?&D^WZ"WOQ](&,=(VT(AFCD)?$)^+0\XL.GBE0T>2D^P@-W&54A%I[S"*P) MB!/?%O,D$1^R%J%U2Z Q 7^2S9FF0]]S8'#^#22.#Y6^LR\#*'E+X[RIHXC_ ME8K,.-"XA9D#W T4A?_BM3&,<81F#2X5@RY?(KJ&MB* YRH9HS/MO\-'?)D. M\G(8S""T&*2437KBJLX40;_8]Y *M!@@B$SK2NL\F7@@5(RHP7#&>F9CR^$2 M_2BB;6BV<)[E"7<@'(UB/*W\!&JI**9X9JJ%HK'P+H01IZD266NRUKNUUM992[FU?G;%8=YBXWJFXX%9 4N-_,$% M<P+_>%/#CLZBTG(5-<$"41)36 MDI1[+L 4(_80BJ.I+T1O O N':"@PN\$2L+(1"6((^D';P#VX+Z'$?M\VE!U M\B.3L*(R\E)U1V-T#N.@9!538O YK25#S 07,#1 M ^43+RVG2\QQHE1EV^T:[.6"V_R"UZQIBYTA*T56BJS4%JU4JP826]-*32/O M 0R*-L4%TN >>'X2)F%U1\N"^5B#_9<%(U1Q9AT1P6*98DDP@OB3^)/XL]'\ M:=5 "FOR)](BGTS]$%WD"4>_VH?7A=/WXK9A&D//XX5HPY G21Z]QQBT6"XM MHO5Y;+N(/@!]BLTG'%'_$1U2(ATB'2*=G>X+J8%T9I=U@&?$1@28] M_8S)) MDR(\P%YTW1KFN9DUA&*>]]R*<&S6KW+W82E)=A]QCJQ^MCU&;09_OGC6HZZS M'7>X@JP]XG^"4 L37,;&!61O!%B'QU5,;2Q#&KC//@M=S2*DHN%OU:EUCX=4 M3BW4<^#@>47+![\>TV'MG"":-V^_F#VSJS].&2D MI'5;&MM&'#)JW)E$\O/)S]^EG]\]ZVUM#Z*^_OYO61H.3_> &Q^EP7OPU\]$ M_MS*OC#TL8K]S L'5#0VPB $PRV+S,.M=N46;#P@ \C!U;#O7IQ4MNZMV 'N M^)X\7).=>2E.\2QL,PQ20:#PZ'#*@^RQ46@!6X=\M)^PD>Q/Y&+!U4:]8*O0V$6 MHE^BW]KIMXZPP2KZ1=\3+HAX$H4.+Q?0<0Q2-]E<: F/&8Q;QO:/OZKQ\9A/VW%8W<<04]SIG;ZELP5[7 A#9$MD2 MV>YZ(X*QJZ..&^S=G5],8TC%P^K6N:5;>'$;UPR'.4A)!=LB@^'V-%R_FS#? MSP\%QF^FY5>3,4M=3\9 Y?'$$3PNQCS$Y8E]>;P^9UUWX@7PAHBA.1+;UA:/ M719;"1GR\P,T49!.92^A],6+_D!O)IN>6%EQA&/)F1E1EL.(W6JSX M]2:K_CTQQ'O$>T?.>^KCX*_>I,S2))R$0V"7@O?TRK+8.KOM%MX8A%DB*3SS M\NPKMTF=KW?B;SW,4Z#BY/FJ'4-U^>B6ZM7EZB1CTRW>9_7ZW//KK2_XX%:K M"3YX8W9Y-',OT78V#:C;*%0=HF9,\AJC8#4D(A;/G5>)Q1(*KWGJUK(,=U2O MRLSM_WG&,6A:FF&5(]?('4"UXNO_K%?+@28_-/G9X>3G:O9HOAH.-=LU1)*6 M4F.<@L?S7B3_TFYA1O%4F3^4.^B?SR8@YRE9W#I+(" 2Z&;!G3R!0)CZKDAE MB\D/L@R[R1B:-0[AATH2 8R*/WA(RR(O99Y=-\O>.YB=P>&/U>0!,ZZ;Y,Z+ M< +:\20W#,EKQ7P,LYY!4P6=%D?ZLR/^"M,0J%U56!L_%.U\#7C M796=14L"73!3Y7(+XSI1+;18Y2:;V62,9>Y$AC.&1PQE37!'93S[U*5+"GE0 MZ'"7%(B#B8.)@P]JK77=W%WKQ?_GUQE&F) ]VTN>9\[-_.)E1WBK'B\2&N:8 M$O2;<;%,GU7F><_XUUV29W9V!U(1[&%K1?EW%>17?'[Z+4%^RN-"=$]TOVNZ M5YY =DVZ?S[3^UI^]YS+O9"N?>7:M,_OO1B;\@ 7PR/O,6J/%9?P4;)H$++S M+<8P\/J\K=ERE668%@4+B+F(N7:;#*:[Q2)!FQU36CQ#2CL%B3"),(DP#RVZ M^ES2$(:5-KMXY"=EOF25>%S.F!?R:U?"I6NDVI:L)L_-! "-ZM5S:V6R+CN\ MIX@,+*Q^5>J3Y8G_Y.+;F+D5?IY)'EY9Q\N>RY*$.>/*WO%L@>R_8IG0>\D: MFQ>O/HXSN\A63*97K*^I6R15O!5PBVF^^LKW2KR&Z-]@J3K&7NS6VX\-/B\H M7O;WSS^E\?M[QJ8?/N?NVG487:=)&O&O>$+RZ3RKQ#4(W&_!E'GNA6"J2R]V M0$)PV1T,X;D?.G_^^O>__5P\+60!WO)9'"Z[$02&2OT%&$.FM<"1-WSTR\GU):8Y^T?K7W>7)YKGPA= 5^_[+?-B<'UA&Y?MJXN+RXM. M^^+*O+#;+;,[Z/_SBGB<_[$*GW;06(GPU M^K:3KDU9\VK=!B:%&A5"S4/8N$D$([AA]"3VY\][%V57@<(J21(P#(]UC>8[PR)>QNVE M3X"S/"\ MI.UZK(WG.+#WN5Q(27S"\U'CC14N@>!QV?(7-M(W1A>5 MF]EM[XBO>&GWJ<\BL72$\_183(L75 \]U ?/3<4B$Q9N].!V+Q)*)_49P1,+ ME<^RIN(F4Q$<%9NXY (+WIG"2/L^=Q)/Z'2 6\&"]V#!T1]&@RU>+AWEO)53 MGSD\SIH%#\<[\EHKL;!$6'0RR/: 93@6\,L7T?!6S9-5X5&7/4 / EIT(ZNN MG@C?PT-_VX&)$2 S$;'8S#G.FRU7YG(J*.<%(BHA#L)7WCG;#_2DT995ZL04 MSQ$S$-%,T154JOQ!X.0$6+S31Z(H;@!'6I#'E,68R)?K0IA5%UR&GF.Y7T0T M/I,0WB@7O^1T MI2FH/R;3(=@GS=67E!06C90V7WY>"("0P2E1@R=\5@@8P3 MH,#L3H9SKO%[$&16\KFZ#N?-L:<03O%BO=PB6&PS?%X!7,SEF^?W&J6HSQ5] M/-/^5RB!&Z;#1 :LXD45R*-DQ:[#7)ZK7QT_*Q <.M!R]B3YL)@]HB#!ML#4 M3K08%#65Y[6>>]-;291(<]E]@Z2>J8.:C,"ZJA7W.HZN+UB3TRPXC4J_Q&*\ M*ZE&3 2A*<47B]AII'-]JD1XRLZ!?5"6&46M=KS+"JXR")_464YN%V4Z,[\G'Q/ M)YI3< /#-/9E_#/V1EXQV1"!O'S%F_GX;U6PNAPR\"DPK)RWA8%/%+P7,A(F MN+S^#7:JB?/@XS0\ L#-(CL]<^1Q3YJ2!P:A(E'-11'*R7R>]'">JC*4G6GG M^21CP@)V+R O];9GF=V/Z*+&/([ERN\B0\:SGF@5LIDE7F*%=0R$U*-Y0FD4 MCK?@G;G4O8NN?3/A_2JO>$DL^-71VVH,^ M_',B$R6 IOD9A$.)46!AF>;'\ M;Q$_7B/R.[BVK7;WNC>PC/9UI]^UK6LSB_Q>&-U>^[ BORAX>$PI1&U6BK7, M==2O(I4F4!"%)TKP>W)YK7APC1U=&$, 2N RC6]_$ MRF_9+[SUO='5-5!U+]+^*;S1WP%@X&\)K^ST+IQZCM:SC',;57RE@ MWH?GG6BG)X/;;UK6OI-WE> -NL<,7NK*%Z.#_23=:\R!B?W-0^0RHL)EV"C4 M)K)?<^%M.8VKQJ!QY]!]D62 B1;+2T]/O@S^>?).M%SF.C[%>!:T@A=-?R:7I(./P(9\0P ,RF6.P"^1U'T8PW,(5SJQKI=%CCTW'>>[?2/>A,I2MK-SL[?+JJ[1-,79^[Y>Z MM#&\A/N%A5ZA37D+6;*6+$%$%3TOE5R(9#1"R__ 17M*]99KQ3&(Z=X+1-1. M;EDKO!2D TD*8A[%172%4^$=P.W1:G'@KD"J7C\0PRCF:!-5"6\7V";E] M1&[,BZ>RB1*".+IYZZ:XC!V(UU0#R*+XNFA+M>/5*>W(B\"S_"ME42+S9\,U M';&1HQH9SL0?%YKFS9)1?K8%.P6#-X()8#RG/C-*@ZI7#),NC[(4(@M'Y(J6RH60KG'"0+8LQ=[$P ,\[S6[W0=6LBJ5]#P]-$ M@3@$6JZF+5$8]-*\0&Y-SS \L^&QW,>Y$14"2!<4H8I69<[./I;&6Y4[:;M> M3(&V/CHIA;;<\NC!P^C->_!"\I!.YJST6ZTY9X4-PS0!7P,(]/UE*M4:%"S; M\3OK;/3!V:B^-N?%N+K];-ZLQ>+1;O[H^4QT,HB5%VK$9,G,*[;?53?Q551: M+W[/GSKS(_ CDG=VIF*^J&X5&J=IX./)#F]2X;IW>A:X1&V'*7IQ7J^Z5:DX MJ@&S=@X&U 6:N/?RA'TP0!-!C\BKTFPXA:]7)/HI-A0- 9RW?-!W"G*WTZ@1%!D$J2D"\PB@6BX+>9,D#,G_KU2_HO&1TJ^2&?""VVSJ%)B-%_/^#OG\\6(RJ:QD&H?\0(7A3# M!A\&@?M5NB3BXQ^C@I-OBQ%8LD]OC3B+=66?6P/CNG_5[[3/6^?V>=^6<9:. MW;\V.H<59U&+N85WK ;A'S>_#;Y\^O\&=Y_^^*(-OEQJYX/;3[?:']?:UYNK MVZLO=^*7MS9O>:?5;8YJXOK)MA;R?XLX#WQ\N7;!IN #^-H-U[7/"1B7TY/? M/M]XX22:H@ID)\+1VG,PVKCW/[- YQZ'O/[W'PZ:N%J?#V',]%CWI M6J4#-^6*7-F#ZL\G[XH=,K%V[X=#Y'J8='KBA /\ I85-SD!C1?G'BK+?&>S M+Q.3>*9=X,*@=EDL+ (-"H,M\]T72G<#)%T0?X0G9V8H!C)N/8PI3 M[:O"_4+'W#;$6,-L%\=:*([/B[*''E92SUVT$&Z,LJ0[VW(J3%/O]KIZVS#4 MN!12-P8:##]8-A"UB##%*M:2UB\]W#]3U9TB1G:&$YZB(MO;M]NLVQE+[X"S MU>[V50[/^<+P@,8)]10K:3&FX=OW 0-P5>*!9;(6W(67)5Z1:*O$QB_S'1)& M3]?^R9'!$NV_01KX;3;I*'@V^QVI@ZTBZURN^J)!R>)1<7YH_Y+[[%$H6M$* MT\A(@\=XO,B+QW#??/B]I<75G M1Z7U_2T4L/=7X:0)S"DVZNO6,73-V M232F]?*HT8'%B<0F?Q$RDS8"7BM.<"1/Q9FI? 4]F]1@]H8LU00&]QR'3RN6 M$'@>/XDXB S1238#-O]V=@OL/1A\11;/"@^65+2T=?GA,!&^DRVIH"8[)_'R M8_" !BY""6.IS9EWD4=CQA[KTL;@\S/WX$P;^/Y4M[CM M)]LLZV1^R'X,3+[G9.84]1(5C'AE,[ X313D;HK D9P7Y0^85B*<9]I7\6RX M\G]8D*(),_.5!'06*QM'\DW.\&20!P9;Y I*=D8R7PK)L] 46QRE9"67B,/SC?(_SN)%E?)3GY//3GUE_WXG=G<55YD=5!T)W9XB6#]%, MP=@5TCR5LGPWLQE!2:.4)W97MZ7ZAU/CK/=.;>/$WAP!P,I1@:* ,FC8.D#, MUYB4-$G4#B,./B!J0-U\U4KWU5U]6$ M+?DJ6CAO<@?% ODECYW(FQ9;"9Y?-[MH]0?G[8[1Z5N7?;/7N1QT^OFZV47_ MZKSV=3/R91//)HT"0$D89S^&^VY$,_].B\=<=#9PE^?R$EEC1$F'"#>1+D@(X[&1 M%_.L_-QDFN+FU#@<);@F"Y8X!8;!#'OB%2/O>R)W1J,?AP4ZW"(X'IW+4L/M MV_(HC#B.M%2N^:\Y+J)*4A\QP&)OT-PQNB([E3 0>/BADD9K5%4QX6B(*<@( M]_SP?##E0D1VA@M34XVY[\HM\0Q/9\]FVJJL,3_)'6C%J1^'19'8-363$2-_ M>[B@4R.1+A*=;YAPX^((%PO?8VWDAX\Q $214[.NCCWG][3K\7Z2,M/HMGJI M*I% J1)B'EA5M?B[\\LHP MMG\NO.E)/-95LKIRT,AH ^:^9(Z33E(YX2_,F\@=@_DQ$SC2J.=N59(!N)=<7R+R+1+/&-3)5O&B"((;H[T7O.&:?NS&\W7WF=M^X7;OL_>EX8V>P0W*_H@H_&S M)T^MN=!\]7,6O:]^)9%JK5/(HL).Z+:B$_9A[+G 2+N8N,X*NVBN??*\K#(. M*B6ABEINL&F2Y1'[KFP0EP8H+L(@;").4C93M]/ M?&ZY@5]F9A_KCCNY!F\$BVFN0@N6E'J-I!JF^*<_R 7G,(WQ).&[>C0+A35D MSI^R -3[;,;O.)R/1CO0MSK74"[F8[]OMF&OU;25 F^*J'Y0(IH7]6I=,*XO M":%U2D71;G=4^3J-'W:\;_,T%@H$0(:-&.9H&>;4;O6V(XT2*O7)1[FFK.WX M$/L0^Q#[;"H*RW@[^1R+?[/YU.JP9E#72[?)O&;V;NUP\JX>0QUK,97(*S'4 ME*&N>RI -O=0P7#:7K)?ZBV>QW%[K0240P6*:73):KS5P6K0I*Y.P2[??JP< M0[,KC.;""J-2:>\4?)9N&):RB<]KQ=84]:+ ;].MV_$@\]34+6LQ]^2K C1O M%=IQNYZ$6D+MND+L=M\^Z2-K2F%&O.\N3)A?@P&P097<,,7#$V_9,M<4,2E: MQ%A71/NPF&'K9E?= M([IIG-=(/'/,!Y.6RUE1TS)CR6X'#A<%![=:(KB[\3?:M!D;\]3(KSU0.+> M09"R(E!P>,_,W/& \[3?4;(AZ:FX&U M^C4EJ#M@AV>MM G+_O[YIS1^?\_8],/7*)R"$)^^^BQ(!H%[]5?J33%2?P?] M/O=#Y\]?__ZWG_.K_Y&R*.&1_W3M!2QP/.9_"D9XF!P/;!5W@$0#%-L-'_UR M:)X+7S G>=^V+L[/C=[Y5?OZPART.]V+RROSPFZWX'_F M>&0^;)1W%8>!_%QL4;J_'AN^-39+ D+[UB=-N$?WP8W=UY6._WV9?#M\M/=U>6B85/2Z\7D$(U(LO$: MS#4FY<8=9IT0"2: R369IF$:\1B7UD1*BK]RA&JC'*(:_)[Z"6:FB#3.G'&> MOB*[-M8XM-;5W#3"AZI4ABS1A%R[ AIXZ[/%@RBS1G,R:W3?F%FCM?7,&J^] MS]B7AK[VOKUI*'5PIQW(UM,(<(T$7!UI01H& MR%*"68Q#3HH(HX311F"4,O<\"]I549W?6>2,-=LDE225;(A*_D\:<,U6=A*/ M-)(T\HT:>5U#CFJB&J(:HAJCF M6;?&;NGMCKI<%$T??>(:XAKBFAUQ3:NE]WJ+I;V):V@Q=;UXE\,WV+/=/$DU MCI&5Y0JL>5M$/8EQK*WE!%Q4F_IXF_+B$.":";B>PGD& 8X 1X![OKR?;O4( M< 0X MR6 &?KEJFNEAT![K53X ;%X.H4XA>>T$Z01C/K^IFQ9M+2)T$;IJ6>+&F3!MIR%X$;QJ6=4U]4Y'78V!0X<7K>I^O!BS MX)[CV>, YK!I )(,N)M/9C&?,8\>Z, L1>641.5LW>K45'O@6,-RA#A"W$IQ MM;>'MJ8 IVZ7F_!TQ'@ZM0V8O])>);)@A+AM;9TP]6Y;7<2($/?:>6^#8DU; M6\J5LV&*UC6)X0XF6M=OZ5V%E?@./5A'Z")T;;:0J[+<+J&+T$7H*E>:#%/O M]^G\(,&+X%4'O,R^WE^_;-71PXL6>)Q@2>D2:%[@A!.NG?IA'+][ MODXPQ>1JH:6]8Y]3JZ7W+&7')XXCID:(.6K$&+IM*+/7A!A"S*$CQNR;NJUN MISU!AB!SZ)!IM?66NKP-QX$86NI<+<0_$OA-RR>(_/N4!S%_I^-.8(IK-8BI M7MJT<$!Q+[V]O3P9!Q\5(W 2.%7Z'[;>[6QM)]:+0NRWD=OI;2V1UY,BE5>2/=V'"?"VB,KF-9;:]([ N3.K;6W,^F@*D MNN?N!*DCAE2GJW>LKZ=,Z0EJL)<5OR"VV]V]K:8D]3 ML/-6(T;KV4ME*SX^B[\D%7\ ;T#NV;AE=5:K2%*106)D@\?H@5D?OM)7E<")($"3V'A+]KMZR M3(($08(@D5N)OMXSE64-/A1(T%+&:MD.G+]2+_82+PR@%7$2TZF\IK'0X6PQ MMCIZKZ7,8M.Q.D(7H:N"+EOOV^JV\!.Z"%V$KN(^V]+-%E5#)G01NNI EZU; M/?(,:YW1'M;$]3<>\(CY8NF1N1,O\.(D8HGWP(N51PJ9[8"2#FWW<$+ MHBG@JMOZ$Z*.&E$]A0G]"5&$J&-'5%NW>W3PF1!%B%(EKI;>[].1,5IG59SO M1/7,M$'".USR.IPH6[^C6P:E/:48-Z&S@>@TC:[>VE[-=X(GP9/@N0$\;9@4 MM':?(I'@2? D>"["T^SI1E]=)3%M@BX!%R5ZTRZ92O+PT96E O_ D7^_-%H'ADY]B:S60)HQZD$2A[^-G+TAXQ&/*;DQA MQ_56@UOJTF"1%T^(.73$V'V]KZX.)2&&$'/HB+$L6V^K.TQ D"'('#ID6K;> M)\30:K 2"8JR.*=R_OA.8TD2><,T84.?:TFX>.CY:(*+7^!J&X*Q8%T-0X/[*5+PAQ'P37&&&1QI'&D<:1QI'&-4=PI'&O$=QQKU.+^\Y9[#D4[M@. M@U$THR*$O0A6&&<=9:&*XXA$$$<01QP71YAG!IT*)(X@CB".6)W-\4Q=N6#B M".((XHC#XPCSS*1<\QMQ!*UZKA;BI>>G"7&C7D2CB(>(AXB'BH5U'NXB'B(>(AXB'=AU1.W(>.NZM4N+C MPCF"_Q5?<%=CT'UVS[4@G0QYI(4C+8R@$RQZDN<*8BV-X3(OT)(QUUR>\&@" M/R=>&.#%/#^/P )7PR,)ZD\DD#58?XOD,>Z$)/TA_2'](?TA_6FL?$A_5+NG M#9H[[\T6_P;)K%D:N%%6S8/)FFEW=;-KZX91?[RO*7#"^RAO+2%L>PBS#5NW MMK##@!!&"#M&A'7TKFGHEEG_VCDAC!!VI BS#+W55E>:Y- 1=MSK+77L8";J M.>#BC.KGH4U!0=VFFF!QV+!0/'DD6! L]A\6RF=\! N"Q4' 0NTT[5!@49F- M_22*-"^[?FL-JPC-]P+^?BPWIIF6\>/'6J6X'EQVUKP:9>EPK,"]-\T5LA6? MO0!(,_E@=X!<5+;^;LRU4>@#,0.#:;)P^33B,;PL%KL<_TI9!"+SG[21%[# M\9BOP>^I#[^/PDCCS!GCYL?*M;'&H;6NYJ81/G1!$!NV,PL,97G A33^?_;^ M=+EQ),D"A7]W/T68;M4=I1E2B8T@J:PL,ZW5FLE29DEJZUN_VD)$4$07"+"Q M2*GOZ;^( %>1DD@I ; ,S96+3*)S>'GA+N'+S[KQ8G,NSP4 B\>Q3:M9<)[ MBTP.*]"TN;,LK"\F?[_S+UQ\GK],%"=#&BXL09;XS?3$Q2OLL3 <_^;+GKDG M/W/.[DT^KY#(33!D*;ED#^0J'M*E!7I(D[L@*FZ2YED\^:*P!N0W#X&?#?BO MN2#&[=SYJPOI*&6'DS^6E'MVW_/1L=D*TUZYDJX18),W\V7/;?_\ZN*UN!". M#[2J/LZLRXWB 9\YKC8WJO<;K$G(7#N'!O)9T^&S6MOU^-0:H?+C4DW+2F.H M,7M499CQ@-PV(;FK7= $C.)/A'X2<5;A)0"I1J@M)7APZ4 -+-*Q:V M!MOG(CV_TZ0W((X%E81*:J*2_YM'C#@F-!(:J8E&7K-1QF19/=02:JF-6IZR MWE@KUUZ^88C#$-^VN]PH=WC_IZ*E2IRG-/)3]+)YAU2OV#V+#M_G&5UC*ZI;$-)^[?_7'0.7 .N =>47"WD&!X:.H!J0#6@ MFI*IIMLV;%/9[J_V+Q]4 ZH!U6R':MJN87MH9EIJ&*S1T:X>VR W6S]):4?( MZ[?+6TA4LJJN!"ACC)K1==59/6N*I]ECC X .YYP-E&N]4%X X *XRP"F< M6 S 7 W"N ,SOJO%L [JTNL$8AN#*%>,DRY(%HS7"-Z3%O6;;1]9#Z '@! M7F7L]IM&IXL11$ 7T%7&!K=KN%WDT@!=0%<9>[JV8760/E*J0]LLO_5D0*,[ M)JJ+(^[!YA&79,3\B2LK^ABSY![%LHC)J8C)68;=MA&30Q <@*L$<"W/Z'J5 MY57H@IVR;6Y :HQ; MIF&UE(^60&@:B&DH8BS+,;J.LHP%792_;%,7F&@P)O9;KF':;:PB6$6 F'63 MG41"E3-E^R_B_33T\]F/$HI1],$2*+L)1&E'1:]D$S0E7 M69W*\G8;'\L"- %-I6$=PU78,O:]%YEN<186 %.@',# MF]=HN;!ZL8.K3(0W<49#DF#^K+;D53^.,BVC;:O+TMJ1\@A@"IAZWB@W3234/[A_R9E K(-S@3WVH:C+M]#%Z0@R@5(O%D< M+<_P7&7S )0*+^D! =#Y6-K@,D (GZ0Z)M=%O*LER: @EL93POVZ/>?_,@ M#;(@COA=I%F*ZCG=6*@YF<).VVAWU4UW;GHJ,- %=&V2.]0R6FT,M0*Z@*XR MT&4;;EO=H'2@"^@"NF;HLHR.PO*,IJ,+^XZ??V,12V@HMQZI/PRB(,T2F@7W M;+KSB)#9%BBI:>G#GF%7US5"%W"5O?H#43N,*.ZFMM3->@&B@*A=1Y1GF%9E M'1B *"!J!Q#5MK%&89]5<4\3U9ZI1L)K+GDU)\HFYBPZU=G>C0_# 9Z IT(Y M=MI&NXTVAT GT*DC.BVC9:G; 8Z@4Z@4QTZ/:-E5M;?K_'HW,R5YTK1,'?] M8GYJ)+EE_3AADT$C&?TQ<>01:ZR>TVI'3?M=PW.4&0[+KWW3YV_"_ IL& ML2S;\"P4NP(3P,1T$6DYAM-59N!B%0%B&HX8SS%,3UFQF2ZZ7[UCIU$@I@*/ M3SAWTTF2W/&+6#] .:Q.1+0[,:V6M_UQ=;K $^%F0%,C:*KS3H%,(!/(5"=' MNP5H IJ IH;0W+?-[6-S-R)?N[Y_>\FRR7;M> ^7?PIS<;>$\R#7B2A+XC 4 MGX,H8PE+T9H84<6U-G--=6U =H., )@=!HS102;N2\-I=DO', /A&99$MSF&;T-&J'^> 6(?E3Y5)2+Y02R+YC=#HE-6MX033-)G7P$'@( M/+291VAVC5:KI(YK*V2CBS:4[?N!:D UH)HG*1^6T?9*:A\'FP=$!"("$:V5 M26,:7J-@\9!XZ!Q^@@.&O<6P>WV1K,\[IBF00_QC&H8#.&*.2'4(1JQ M;Q[8RK)^$/,$1X C&L<1]D$7OO 5=8-%88". (OKU&6?O*96=:!FI7&>':_> @^!A\!# M;XTE==25@.O^ZLL.,H%H0#0@F@KB53!XP$/@(?#0VV)BY=.0+J]^*\&RQL3$ MY,>E7/Y_R2^83RA_?'K'2)0/;UE"XCZ)$_X0-'DLE8WI3>EX1L?L&$['@R<-A %A)2"L;=BN9W1M9?E; M0!@0!H0MK&'=CFMX+42#@3 @K)PUS&EYAM51-[RGZ0C;[?V6,G*003T-'H*H MW@_5!05E+]6 19-AT3:ZIFU8)F !6 6Y7E\@ 5@47]8B-6B970V.? MY*SDE;]?\?]M%J'3N.>^::[G';/#L[:;<\SSIQ6J[5/CHY<4_W?GTB M_WE9W@1#EI)+]D"NXB%]'G1SAX=!Q#X.BA0YRS9__EQI*MZYB_Q?XHC&4[N[GZ=G)V?7WQ[?*]-['ZT0B(2.T2:9!^$@])QG5<$@3_ M7X.,\J0WH&)Y7%B#0HZT!9N9C3$>V)X\>KY2T-)6V)"RS\4- ;?YH@/B!' MTW.%7%SS$N&GX^8#*RHF*&=TOC)SP45!.A0GEU41<_PMKIFP!YKXJ1#8U.Z8 M+ +RGOA;8WTATJ5S9W$$FGK,=D+9)C M&42LWN]=.N2%C"=ZN*Q1\RK97]:/D@3PDV.U#RS"3\7))5+RJ&2_JIOG;V>Y M_$)D3"K626W!>QST5O9F*-%\:^/$D4WPO"FP2HQ.G5!0-A M2C][]U>K7XP?RR!NPL* O]:%"*_TB9X&A<#Y$W&7,11K3)J'F8@KCL/GX_./[X'[RMF[D5GDTY7D$\P+;$#]R6-P M?+'@7BZ=4QQ.8:)X81V;2-KY "OEKLOZ.#8U.@>.6B8N4)-'B22Y%=$$!:MC M<>^FXEO?A1<>!:'*UTR7M]2*]W[T4>SY'1W\?D".69H=D-/I:M=:Y(R$T=Y M&-PD95D62NM=D" WW8=YQIY<8K8A4VP41FRVC_*,QAGC79_BA$7;E8)UBZ8L ME' S1017V:1%RXS"%L-CSUZB1):6>%&F1<8+<74]2%<=/=@'':6W)@+5Z4CL M[MTS$;8>&W\;*4IA #NG^03 MW.4A3<)'PNYIF/.W4Z0\]"?I.X*(BDV,\5[ :N-/Q,K3XM#I/DO_F3C[$UMQ MIFT+>0.UH1I%"U:LAE?D/HM<082_ET<";_C/4BJS!]+3(.V%VZ$M5EXN(NYY%%.C(YUP0)]Q O4N8M#AU>X1:)D&<]?OC!>M_:92+ M_H=C#VC1XA?+3+%@SI*7>RI/\JUE/PG#OA=W?.;%P$7 M.GEYA2]P^OO9Y,5RF__K=[*_-__5WH6Y+-WH<#=X!Y6^4R2P(X3#) M-Y$R_K!\Y>*?IZBB$U2]^&+6?Y;E\XF'$6=;>A-%BH)<2I\$T(KT4NYBDD \ M$:']/C?#Q)USZ9_2^\ G9URGXX2+YF3 #3'^1B8FVO@4A09T;*O].27',4WD M[O8IM]EZ&;\X,CE5W._W/$ES6KC^0O9+BFR(-$N9,B\4E8;<)"I\>?9?D:_$ M#U-B*/('5V-PCG5([#?.8:38DGQ)P8H4I_$/:)&X.<[WDI[A@MX+G2XDP7Q# MH/<_7"<+KI01UQY-$IF'+%*D9C:PS.OB)UJX\/A:Q4[*[.B9(BV=AD/NO[ET M7<1-\5.*A%<9L!&Y9OYS+TQ5Q-=2]JJB9UZ3B YQ"I$[0X(:^>.RF8K*KQ>2 MBN?)!]+A(#XLB [O-^) MXJ*,W"62QI;6B7%> 'VZC(QW/IV;GL!.66&&R5?;9\Q0MR2OJ^?F@66W%*W;E7&S=:#JEN-(FD91),1^2],@_?"2 M*;W"''O&D#:$,2)+] K#>/H/PGGNA;D_F]^PVE+<%U#_,(5X5:(MWW%'D?Q+/S?I\J19?I+G(1Q(/RX4SK@#TY[^=9 IG MI$=EN>+8PR@=$/%-U#,;QAA%]+*H_^!]%=FE2L.&3E!H]::5L3TK1SI[V5,6DQ,;D ]$0C5L3 M>Q/5+9J:!4+EA2' &8GK?B8ZJ"5$I$BSO45?:L-U?I*/*W+K2?P0$;?[\\1Z M"=(T'^^,1+[64K\*X3^8H[?:"[@5.1I+$!N;-.G4V(H[%L96 G'U;'CZSRM MAY7A%^&!L"A5EDVT;I"S'\@"X3A/.0.I6<9\4?J3%"._Y2XCV1^%^:PCQ3CB M.Y.VR/C*LU@TCNV)]EE<9!%[8/Y\FJK8'N/_4N0:3::-%YM>+)"M->M*,Z$*F3Q[.+BQ$7W3IFVNWFYQ-KE$/-5 M%->B@C /V;?^"4T'1Y$O_N>,+UQ\81+AH!NQ#FQ22'%VVK4ZK;.3[GGK]*CM M>D>GQV912.&>6G:GHTTAQ=PY%AI.FYP5YFE"?)Z_2"22=<*%GM26^,WTQ%D1 MW61A./[-ESUS3WY.1;^W\>?-G_XA\+,!_Y,_XZWH*)9\E-5OHY0=3OY8>OC9 M32]?]CSWYU<[52]VO1X?:%5]7*LN-ZKW VXV78EC MHV&CE=8T23 88!/YK#V@>TQ[,TD0V02+3.R/:@9XS^E73YIXY=KJD_#$3+3/ MQBF@@E#!2E5P.0*D9"H?U@V =A/0MI\#[5L523/\[?]4I% 6[G/ZH3S4:31_ MMDPX"B=7Q"MO:?17J@J1&LE..ZBJA:?V0VQ_4B*:5Q5J709;7Q+J9V.YKF$Y MR_FG&%\,DM'>7M)>V][/,^NJ51VHQC%<6]D$/NW?_7N99M==,FD#REXA/95C*\F M$RB6]E%TT5=%D9S7!/L>_ZL,.:I?)BS+-BS/5@;P-TNT%FJ',))N_+BNWH$B MMX#IYK"D;9B.N7V!UD+Q%!KIGV32YLK?OYAUNUGZ['.)MWG*TF_]BZB8I7$Z MGJEQ$7V=%/^?Q\D_(U&C=B)KW,5UBC^FX[G.BJSG33)U3T[/S\Y.S-;QT:G= MMH[.K?/V^8EW=&R>'#FMUEF[\DS=4I/S5Q3:+^G)AN?=;HWHT/5E+)\ M>O+<+:T*T139]E(F&R96EYA-OO-1G(G.R5RL MLB2N^)7H&/3(,K(XT7E.> ?D6-:F3[XOYA,5?2X?1!?J^T#\<]%[/../+2XP M9-D@]KF=BH@?2I.'2*W?^]!8F\]@69K )$H+UI(+UA#1W0;%.;M M=*+);$KP>,&(?'[FQ<8@,Y*=K!R2X">GC?-D[B=!-.)\* :O<$;F=3-::5'8=H6/V+:QX.EX=1L;]#YE-D)JY M_'1&,^+\OJ"L8!Q74M;VB-OO?PUB <9Q-\T!%[EL<" ;A1?CN 2C/8@!JY/6 MHV/+5-)T(EO[Q\DPG8Q>F;=$I:4MGB_SE MB!"I.&EA.X>3;JS%G::36^TGJZ!&8\G>2RI=. MIW'8:?L))>_H@/PC?A 7,[B\9#]3DLZ&(*7S.C,-^J5A4'1*Y1 43#MM^!,4 M8Z#%[+%QH]KYU[4X9EXL6W(FFS0'XGZ?BULTP:"J8HJJAQ_/#Z)>>N:Q0B0Q M5[B%K\7HH,0O7K!LA9@63]LES_M/2LCWD_QN,Q)!DFLQ6SNF:XL]"92.QO/NK%M%I M. ?1&U 2*$D#2E)NN7"FZ-/[N!B>_G+T)N+6I9BF/K4[.26)R,1<$*>@'W$ M9P\F6C-&4[=AWL2;!4 F 9-BSF D9]%EQ8C*9V(R*ZB+U/2K-T6&R.V<6SV>T+"T?:[#_JF"$*LXL(R(XW:98 M$8P ?X(_P9]:\Z== BFLR9^"%MEP%,;"1!XR85>'_'+QZ*,\[#9/^9.G2]&& M6S%O=QR]%S%HN5TZC=9/8MO3Z,-XJA-G)W[]SV155V:0#D@'I%-E7D@)I+.X MK<-Y1B8B<*=?VAO#89Y-PP/T5=--,\O-*B$4\[+E-@W'CI]KEGTXD^2TX?PK M'=Q5,JH>_/EJK4>)@Q?F)AL63?3%!K*<;LA/-[?4ID5(0^39CT-7BPB9T_#W MZI0VDZ@UG=DXKV#3F4YB,;Z^=^2^V5U#S?CDSSZR.WU _)U,2]L//FNR&=> M*E AM"^"$%2D+-) I-K-4K!%@0Q'CM@-^Q&DV5SJWC,9X+TP*(IKQC4OTRJ> MI33#*)<$RD\=CU@T/FWAFH3+MR^'_LZ>01 =_8N-IW3U>G$NIF])HY[+(^6. MDC]WKP,:^3+M4(RPG 5:^*&W;+9^9G&1G\CDB>9NZA5;!V$6T"_HMW3Z+2-L M\!S]"MN3_R!A61+WV&P#7600BSS<>7H68026]&3A8!%XF=8!TB*=[*,0#?EO M'G/&E),T:T??\W[Y0A+VDU0W66(J?;J910<6W\ZES*U-X11K7 H?U!"5-V58PF$A/$_MW0QJ&DZ+ ]-VT M_&8RIKD?%#'0HCRQST^7RLG-TXK]HKQ^PKK^,(CX%1*:R=FF_JJRRVDJH1S] M?L]O49+.7"YA88M/GT<,5MVT8N69$HX5-9DO5[6HKV4Q#SP=:EF*=5:JTGR" MR>1D1874BFP3K)%8([%&;K7!S+;6R#533=99KA:+$54M6.D[5ZST[4M6^3DQ MX#WPWH[SGOHX^)N3E&F>Q,N6VQ=;+MEJX8Q>-&4J+FY<5+5DF= M;S?BKP/1IT!%Y?ES&4-EV>BVZMWE>2=CTQ3O@W)M[J?[K:_8X+:K@PVN39:' MGKE$U20-J$L4FG]%>CAYVBA8"8V(Y7F?JL3RS,VWG+6R+L.>ZEV9)_D_+Q@& MNK495OGFM,P *A5?_^]Z,Q_@_,#YV:+S<[98FJ^&0ZU6"9&DE=28YMSB^2B; M?Y%K[E$\SOD/LPSZE[L)%'[*.&X];B @&^B.@SN3!@)Q'OJRE:UH?C#NL)L- M^&T-8OX/>Q$.N'8]% MPE#Q6^F/B:YG_%8EG4Y+^LPX,(90U%1F6Z>-:56PJ3H%!SMQ3 MP>!@<'"C]EK7[=VU7OS_Z3Y#7S1D'^>23SKGCNWB526\\Q:O(#318TK2[YB+ MB_99LS[O8_[U5_2973>QUO5]FF92-8 .8"0(E,0A G"!&$V+;KZ4M,0 M*B9MMD7)3T[#@E72PV7% '=^G6ED M8&GW:VX^V:3Q7['Y-J#^'#\O- ^?V\<;GY=F&>T-YG+'QQMD_Y,6#;U7[+$% MZ?/E.(N;;%-G^IG]-76;I(I3 2ML\]55GBOQ%J)_QTKEF;7(UJM'@L\KBC?^ M^Y=/>?KQCM+1X75OP/P\9-_Z)R+"EW[K7XRA>3H.U%U$7RB6&^0C^N MXC#D5WB@B7\CD# ]B60L_N&*];_LG9^*%FA_N'_>G.Z1P.=?<"K[>&I;YV;W M^-0Y<9RSDW.K7SD.GN_/E'2EVR-YW1QFZWL9AE7I+"IQ&1+ MDN9#[N[+D6/WL>1H3I=!)+Z2C0 XT:9I/BY*C6>B5I*UU1.1@V0=:2T0@/D$ M_^+S_&4BL:2%4]+@]H0X\9R%H\RF?'+G7))W053W]5:08?1Q/<^KU&.OW&[9G<$Q#F9M?:&G'MJS/ MY);=!5$TKFL522&J@*V13+5#?'6">Z/J23DKE9-C&9;=-3RW4[J<=(&;.&[C MS#,@# A[FYP\PVZY1J>K;-<. / -!#$ 6$[B+#JUK>F *PF MJ5]EBO!"E%+)::*+-5;3/@G]..FS(,OY=ZKT"O2D7C[:L)#=\@S74Y;8JPM. MRE[+@8D&8V*ZT[9^NRG@ KAH/"X$U@K@ O@8L5:X;J& MU_& "6 "F,!:@030M\OVBHWRI#<0G>J6 W^J%$DC6=:+D9JY.;'O68[1'(FG%I-18C)NQJ$X@@MZPM;1+FX= 1? !7 !7 7 M<\>UD-$/. .T^UL=7C AC70TG"TP*@"+H +X*+LB)]&D?:J&W@R,0L3K3NU MX*3%!KW.Z ?QXUR,]YRT "JK^9*E;_,ET1BM;1NMMKU]*9T(%.@&NFO< M=!3@!K@!;BW 74+/;J ;Z :ZM4 WEFZ &^!N*+A+:$<.= /=0+<6Z%;?\!7@ M7G-/XE-&N5Q6_G[%W[]\RM./=Y2.#J][ ^;G(?O6/XF'PSBZSN+>7]_R+,UH M))3P*@[#\SAYH(E_(ZYPP\5Q'/+?_/KWO_VR\B0C_AA1EG[K7T2]>,ANZ(^S M'R,6I>R81:P?9(NG$7G#0L17K/]E[_S4-JW6'^Z?-Z=[)/#Y%[27?3QSCDR[ MU>ZTG*YSUG7./9+P:Q/^AHC/^HQ_\DD@IFQXRQ+"_7HB%$#^UY6/Q_]PWGM/\H*'+V)JS;?_RES!N;,L<+S)561> M9\3G^'X-U_VS#WYF1-7;_)Y<^T?TN0NB(J; MI'D63[XHUF_YS4/@9X/#;OO \5H<@9/__#PA6/["0SI*V>'DCR6TS)YB?MMT M1KK.RL&.:^R\REO[LN=9/[_*YXM+SOC RH\SZW*C>,"M/B"*BS3)RVF8/S.] M70<#?9<'^@K+ \H&9:M*V93G:T/9H&S/*=NR$X7"9M@>VT"H9;T"T7Z3 E>S#*)ERU9O7NJ-XRLWE<;H32(48MZ"G41 MCG<7]]2^EH>[(RT4Z>GAY8 CP9'@2/TXTK/5A9#!D&!(,*0.N@J&5+K+ID&3 MIC<%-&JAJV^)=CQ?*EX9L[]:;UM6=?7;UJ&7J^8W*WA_KFY>/'#*_'$KW>L! M8VM6RO_;9\&_O[([&IY%69 ]'OT(TG^/K_#O[U0DS8J;I-'C[[+,>JZRWFN= MG+7/3T_<\V/OU+)MY_CL7%;6.]VVT[%/JJRLKR(O^[>KL[/+KQ>__>.&G!Q] MO[@Y^DJNS@SR]>;TX'WJ6MTCG'R[/#V[O#X[)><7ET>7)Q?\&2XNS[]=_7YT M<_'MDGP[YX_TV\7US=71Y8W"AYI'I:L.E*\]Y/'15_Z09^3Z'V=G-]>S!M/V M9_+]Z.KLDK_(;[]_/[K\DWR[_/JG?B]Q$ZM-(RT3<=^$I:GL*S$K9! -O?]Y M<'W %]XPI,F*P@;MQ=/<'@V6::KKRM!]9U.&=FU: =AUN5&]'Q Y8)JDH38L M>('*WI?6Z:762= \:-Y6-&_M0#@6"BP4I<*UC?IRU)>_H;ZWD)LYH2&@JQE'"5=CR?B4*=U&X6^K^A6TX[?;V)5H+S4- M!2Q9%UT%2RK=T?):AM52EUD"GD1H;#.K_&M ;X,PR *6ROSE=$ 3-N#_S))T M&@UI?Y8IS=DC@@7J@P6O%0A57@"$BA7H3\WU!X&9YZ4YQ_AP,#3":95"U![ MT#AH7 V6C&:M#&+?/(NQ:UX3@U87M5$6$BKOF4N(W7A&MX,-4= :&"7:0 ) M0_#!WR#;(A^%;_HU=SIA6V4Y?T0I4)>?^>EWB;.FX6Z$UM3P#5P76.; M!>!&:.E%$5YC6UFSX.\NQGBA/] ?;"N7R/"D1T!2.&VMZ>""3_?YB-]8%L01#C2STJ;829NN?KKH#V)$H#.-U!%TII.MO(N$-F@/EYR+[U3^*(,TW*_&,:TJC'K@>,93?BK#=< M!,=AW/OKU[__[9<7#A13N<\Y:5UG-&-B&./BT5S0D9#F%>M_V3L_M4VK]8?[ MY\WIOWT6_/LKNZ/A691QZ_3H1Y#^>WR9?W_G=FR4G<1#_H8>?V?#6Y;LD<#G M)Z"][&/KV#NU+//L^+3CM3S+.S6/6]:)TW*=;ML]\L[W?GWR-N??S$TPY-;R M)7L@5_&0/L^Q'0<0^#@H3W++-GS]7/$O^MZNSL\NO%[_]XX:<''V_N#GZ M2J[.#/+UYO3@19W1Z!%.OEV>GEU>GYV2\XO+H\N3"_X,%Y?GWZY^/[JY^'9) MOIWS1_KMXOKFZNCR1N%#R6\"H:G9HSRYEH\VCRS_)M\NO?ZIX\FVE\&ND;?OLQRAA*2F*YD) >"\/Q;[[LF7OR,U\E>Y//F_/ID"9W053<),VS>/)% M82#+;QX"/QOP7W-!C!?WGG@_HY0=3OY8TN_9?<^'BF9KNK,R0+A&M$G>S)<] MS_WY57-AT6@9'VA5?%RW)O>)Y]OF\V$C%X6,I6X06=9&.T2VDAVB#3:!JK Z M9A(D?W+7CISQI=@GIZPG_1?BK.T" ZU ZW9[EI8 UF59SNUJ+E]",VR+L 4T M$9JHA2:ZT$1HHA::N'81#4P:F#3;=4 :Y6#L_[00V%P.9 *&ZT?M:3H@HR2^ M#X2[=OM(]O,BH]HEBZE(-FY!)N._8GN':RL*PKPIE MAIORQ*1<9T!%H")04=E)S6;7:'7MTF6BR]L7QZ$$ UP#KJF>:VR[97C=+K@& M(>YU17CD_R=/,U&*D8I1HPGKQ5$O"!F)GOJMXI][3^/?B'HCZM2D!0_Z _V! M_D!_$/5^GS3/9!<1D7@PZ8(J"JJX;2&SE&C&K8#8UT]7]6.EES#;BOC)%V04;9A#40T&!&.T?6 "" " MB)@APFLKR\UK"B(03GY>MB<#&MTQ$D3PI37:]*E2B%6#67T'7&@<- X:!XVK ML<8A1O;Y-&>DG\3#4K:O 0 *0&!_7;6/:// /,RV= W3 M5+9$8-]6"ZM^R\9J%B/34E>":DXRBN49W8XRYD*B)= %=,VWLS Z9J/U&\P8N MHGN6EN0L:"13?=D0Z6%(2(3&0>.@<= X!#B?%..0*,Z8:!G)@GLQ$A[N6/7N M6.WV4_8]4UE#)FQ8 BX-AXMM6)ZR (0NJH_0.Q#QKNAY:^UALEA"$'1[Q9SE MWR7!;5[T)$U&89X^39HU1#=T^*0:L59S\HOV;=.PT4,1R7T WS8ZF+:05@OD M 7F5(Z^%KMP(.:O*J0U*W"8'/2$WZ'G+O>.H*WI#'A^P"JR6%48W376=TI'' M!RP"BV]WNHUNMS(P8ME$]'^3E-OS(*)1#RFW6R-+I*,A 1(:!XV#QD'C$/^< MQ3]'2VF0:)SP+Q]$%"VE(1.V:S_(QH,3Q)31 M01SZ+('/J1$I-2>WJ*.,K!J?6P1D 5G;M8\!,4 ,$ /$D"'[+A%>L5&>] :T MB B?A#1-R1&)$WZ[-'DLC&[$AN'KKY.>TS:\KK*:\S?EW^B"*F2F C&(&B-J M#%P %]NW6#7R%+=8[-5'@J;>//5J>81*(>NPD1,?]]GQ5\?1-]EZ1W1R"_^ M8/_-@WL:LBA#@!]AF35(#,$8H %HF+CIRBK1L=,%L#0=+&C=OQ%8$.9_H>_R M. MW3DGBNN,9FS(/;H;<>H;+H?C,.[]]>O?__;+"T=?1+UXR)XYELLZ$@*]8OTO M>^>GMFFU_G#_O#G]M\^"?W]E=S0\B[(@>SSZ$:3_'E_DW]]IPD]T$@_Y2WK\ MG0UO6;)' I^?@/:RC^='Q^ZQ;9G6<;=UY!QYYZVC(^O$:;E.MW-V?NKN_?KD MAG9Y?79*SB\NCRY/ M+O@S7%R>?[OZ_>CFXMLE^7;.'^FWB^N;JZ/+&X4/);\)A)YFARYGOHH>\OKF MZ.;L][/+FVOQ9!>7)]]^/R-S">KD^]$5_U?"O_]^=/DG^7;Y]4\53[VMIL$: M:=H^^S%*6%H4L)%L$.7!]P->%,*1)^G(FP4Z(>^XL"Y:5R7$R MCQOQ>?XR49P,:;A@9UCB-],3RW6)]%@8CG_S9<_&#N=JV-MG1M M)8.[-MBYK<*0^9-[B&)3C1LRIZPG?2#BK!V5 T0!T>U.4BD!HI9G(@Q%-A.*A M,J- (_EIAU;E"-6^O$E=/N%K:E6+/$*CZRD;G*#]NQ?'H>@43 .FV4+M55M= M883N;QX\ YX!SVRI_,JP3!-,@YCTNB*\B3,:DJ0(1*,?;0F1H/>V&7D3:^O; MD5NIR_5:MY%=:+T-+ *+VW=*@$0@$4C4PVP'%K'7M%$>RMF/D:C(QE@^K1BP M,>T%2^CYT?3(!! &A %A0!@0!H35%6&(KG_^C44LH:%L?DO]81 %:9;0++AG MA"FVN4%+VPTN;)6=7,-T.U7%#W0!%\)U0%1IB'*,CEE2PV0@"HC:242UGF%(G+EJM896.;JQN0V(C^ -S=\0S7KFZ XHY'=D4/4NTEDY4[%?G&N]>B;V*7_$>UD71#1J!?0\#NG-S%1->J]/C1[;@BVF([QY8<@FV[]G'G^*3*(=A2'^9'QCK>2-FL97G<:9YP,)-LP,B23FQX MOC$"QM"0=^VS7BRJ>>+H4.A><281G^&N+(^)/U8S_2TKZ<<@7R/3P1;BL^2XQ-%C) MT.#6.X<&.YV*1\?:K9K,N.W6Y#[Q?-M\OK=M"%0RGTT#HVOUOL#IW*H2Q1E? M95)^8;E+P!<9;N+!/ MPRB\4BL.F&P^9^DUIE _^6BG/]/;U6-TO6:+@(CT0]F@;%4IF[*T;R@;E.TU M95O>M(0Q"V,6QAJ,V;KJSTX%*/9_$I'E;!#G*8W\]D#':&-V+8Y32/!E=__[IZEF=A51S6>5CJ(?.UWJ54=TK'W+=LPO?+G>B_# MICPIH5(.3 0FJAL3%4K3L2V[?!M*%PT0QZ&4#7P#O@'?U(%O=CL<7L1)$N8' M(C^\3_,P*X(E!AGE26] 4^:3J5I9G_E=)B-17,7XSV\S1#OUY6Y]]:V* DT M:OVN:R6'S\OP\%O*9@#!BP=]P2X "Z-A8O1:BEK3K0;@,$VM!KW M*A4X9_PVE+I7&@E:.QZKB^#J[I!I)$KM='#]_MC-F5'3-2O3K&8OO0 >@+<) M\.RNNHGD0!Z0!^2M';4TS(ZZ\2J[C3ULVWT^CY,'FOAHVX1-.$U]/FA4@\.D M?#4SE?4\U@45XC@, P,BWF;@N>J"&KMAQ0$N.PP7RS)LK"!*'!N-(@VE>CQY MEB?J!DQK)#7M:*(00R /R-K%&/:-MEU\T MK N,R@YT %U USRZ;*-EJAN#WG1T87?K\X7HN<1-;R*+S>*1F!B!K2YL=6GJ MQT&C&ARI+*&N6A=LE&T' A<-QL6^C3),I3$)H*7):.F@J&PCM& K;%WW"/U- M=?":-!)\,NJU2EB0_'?HQ8E+(/!HD8AM\AFKE.B8SAN.@*I]3_ F :#!C46@(7P 5P M4;;/HU&8H?2],81FL/-5"9";++B::5R<^"R9/+TS^D'\.+\-&?E_3/E_;Q+@ MLV]C?#5QJ,4OE<9AX$^OI(MV_E29;%_5VI=D7((HRVAU;AD=5UV[O'=+="./ MN!;JBNU*<*AV2@D.59CHV#7:MKJ>B&\6:"T4K^S8"4@2) F2U(\D+=LSS+:Z MY@]@R34C:9\RRN6R\OV;9W5;+=+VS$_[' MD7W4:EDG3LNU7?/4LNR]7Y^\M_EW'FW/NO%"15ER(=" MUXI+G;(>&]ZRA#B6083DWWMA>5:#9 -&^C1(R#T-&:J]^:;^T_>9H%_<=U7O["&FCR=SO_LL7G M^>M$ @'A H5;XC?3$TMDDAX+P_%OONR9>_(SIYW>Y//F:OL0^-F _\D?<\QV M_)V'=)2RP\D?2UH[NZGYR/N, L_ F;*=&W[0(MV /VTL*^U?A\CXDF?ZK6 ?GQH:"8VSCTBQ--EUYR,J%0 M5;86/"?HWHNZ]S7@"VATM^Y:7/'=]?(D85'O\=V&T^K3BQ.E^>@9%>&O^/.2 M[3$[;WN4%6%XJX@2\Q.I#(8 N1MDVE>/XNUCXS(61C]?-.B0N\H9M\4U!3'W MXUD2/@IG()CYB<")>IPXP,D*ZVKJKPIW-6(9]T93]HH";N]V]^-;?BWIT+]2 MJKR]>XRCF=NOZ2U.@Q%O"+O5I&BG"C$VH31%.[[63#[URD:#_LQNU]MN@G4E MR^%/W&@DV2#.4QKYZS?OJ!^=J\3>:W&F6:@^83T6W,MM)@"TH00&@J^9_I1: M0?,NAPWZ4RO]>2T@L(OZ@TJEYZ5YGF=Y@BY]6^2[!*ZE*9>ZZ)MZK*KWY$\K0W5.(;KJ2O#T_W=OY=I:A*9 M4RFR[WE&XF)4T+LS610FKMA(7*G)@K C)CQ4I^3]G.V66G:-KME6)8NF+(? MQ/KAS,8UE+)%9\(N(($([;JRQ9P5;6BI+H(KU_P[^^?5I]^.OW_ZQ_^=?D(T MMV&*IXWQZ#J&HVZF9>-C+$!7!=9F<^8[6!VCT\5\AX9%,$N=[S">=SXW[IS$ M$0F#-&.^LKFN:KCC968<3J"=X+01 M5MTT[F7!H:EM>6F7:&KKM@VKK<'PA%HH'B*FU51CC^@C2K'U#G[MEKT,#=*M M&%L[^4!_UM0?%&,C-+>)-$\2Y@<9\5F?YF%6)/L99)0GO0%-F;^0]]>+DY%H M \_XSV^534772-#:P;HN@JM-\8=&,MMA9=/&/[=MR["0E*2GENP2O)2&&771 M-A1PSQ^W;QF.67YV\3)JRA/2]D:A[G:L;V/+/15LR/AM*+7<0>JZR:+RXO/IT]>T2K1Z;IH#:V)>6;1N>NO44,4? "S''.5O5 M-0VK6_Y@+-BQ&OF"V^D@-*YF+JE]$.A+-_F@N+EV&J19<;->Q:G0GW?:!J5T M\*E#OY3J&O5L26)EV*6NT>JJVPY?5W ;V:>U4+ZW&*^?,MEW9M7O5_S]RZ<\ M_7A'Z>CPNC=@?AZR;_U3?C_W- ONV4649DD^Y!9 >L,?\SB,>W_]^O>__;+I M,=*2Y!^N6/_+WOFI;5JM/]P_;T[W2.#S+[B)^=$Y:YOG3NOLR.RVCMONR:ES M:EHG3LNU7:?EN-V]7Y_(?5Z&-\&0I>22/9"K>$B?)].YPY>F*CY]C_)S$'%N MS@X=CVN,RA=[E+U[>N381QMKK+Q;G_5$YX @C@Y%\*&XU"GKL>$M2XAC&41( M_KT7EFKCF.K7F6WO% M4)T[R\)B9?)7._^NQ>?YRT1Q,J3A J58XC?3$TN\D1X+P_%OONR9>_(S9XW> MY//F6CNDR5T0%3=)\RR>?%'0G/SF(?"S ?\U%\28S[A6A'24LL/)'TMZ/;OO M>2]WQG'F2LMN#4=9WLR7/=?[^57Z7&3_\8'66X_K5GW!-Q]8E^,ZE5SP;3N' M"]: O;1T-\A7EA]?:#9W,B%9>$';\()V4/>^!FG&;U:<;]4^1R]/$A;U'M]M MVZR^NCC1^T=E6QB5O>T=F.IAM'WH7,;"+N>L38=QSL\7]Y]#4<[MT"1\% 9S M,/.EH*CJ%?6U-GX[J:CG4Y].N'01R[C'EK)" 5>IZWY\R^]->IWIA^=^%$8#-E9KIS_1VO>TF3%=!0/L_<;N%9(,X3VGD MITC 4-Q9?C;-"0!M*H&!X&NF/\B^@/Y4XI/NHO[4O<1(I?1.:!B2>"3=[7?' M616&5>U2PJH:O43M**,N@JM-K;M&,MMA9=,FCJE/RYM)6 MFPEP>]RQ/56R:,IR"$RL'UMM7+>JCM'NFD"$ @-1(^\4#:EV@I7J(KAJ&E(A MC-LPI=/&;FR9AEW!1$!=&!YAW!H8FLWI0>48;1>3?1L6NRQ3A/^B24*C+"4T M\HF\O93$$0F#-&.^<@,4I*2;?$HW)^LKFN:KCCY&H;)]?5UX%7%$?8&#=H+3 M1EAUT[B7!5=*W]+GWD8M>DI6U]#T/:F9]>AT:CF&O:*A8N4"K87B(7A:37WX MN%<_'']]XV"[92]#@W0K#]=./M"?-?4'Y>&(U6TBS?ER<7BCV_9&]1%<;6HZ M-)+9#BN;-AZW;7BF5;J(=&'O][K, )=&)JGVVH::[/GC]CU,UL1D355F>#P< MQGZ0/9)K470#SUA?FMX1NQJJT^#T1M@().YX(/$\S_($]=$Z1X%T-B$10-1:=?0Q""W#ZBI+ M;->%/!% U,>^JY\9YW:4N4@PU^K@/*$1XTY05ET$5TTCQG_\W^FGJV^7GW[_ M_R[1E+%I"JB-?=FVC$Z[_/PJ7=@>$<<:6*2+Y;?+=;0-BDA:KM'IJ!LY\U[! MP0S6P)74I&/0N'JYI'9!X$/=Y(-BYMIID&;%S'H5HT)_5!H3BCKV:+ .RN.J MZ[U3)V=PW^X8MEM=&YV=,SL_9;(AS*K?K_C[ET]Y^O&.TM'A=6_ _#QDW_JG M_'[N:1;]_^V7YF+,H"[+'?P4^/Z8?)T,J MBM"OV#V+Q,.S'WRUCVAXDJ=L;,W-G62 TDZN: M/$L0<:XN/L]?)A*"#!<4UA*_F9Y8OFK28V$X_LV7/7-/?N8*VYM\WOSYAS2Y M"Z+B)FF>Q9,O"A#);QX"/QL<=KL'';-EQP\L?G MIT"9/<6\HS2S-^R5ML :OI:\M2][KOGSJSA>9)KQ@5;%Q[5K M]XGWH.)Z]8LHJ77M5\>4FN"K:>?+SM9><[L)'55HT)^,)H1QP\LGIZS'AKAMM8-E+^S -0*CP^J!:4*UR5$MY=3!4"ZI5J);3 M,"L"MCUL^UIAP':]T@=5";\1Q-<[)529C[3R'ZJ1: M#]2VO8.UO8=J&PC4 N<_:ZEZ#?/V89/ )GECI7F[9;AF^1U2:J$WL$GJR&\[ M:)-T6@?*VLO")M%$]6"3P":!3<*/<[N>T76[L$E@D]25WW;0)NG:!^7W,(5- M4I<=:I6R^5>1<"S#,K%& M !)8(Z:^Y0'P #Q@B9CBP>C8RL9P Q$[@XCFKA 6G @E@4*-=C3+E.U9GL2C M%>%$'<+]^DH-(Z?6)"/7,#OJ&FJAO;(VZ*K7BM[,YN55[#,"6H#6+BY<;<-U MRD\&!KJ KAU&CP)J9Y@$U]X 'KP[3,65GC%5R0.XV!E<-'>9 "Z "ZP7P$7943I$Q76(BN^4X,J8QKI./Y3E*?*Z M(+^Z&:Z*&NTH$V4)^SJF;5BVNKV=-TNT%II7MBT&EMP:DM_8C4=C:%NFJ;!% MX+L%_-9^/?JR 7H(:@][&$6A'&T;0'#. +L M81S!.*H1@[:6A'&T;0'OL'$TMTGY*:-<:JM^7QD?S4EG MJ3WR AI<_B+*9E,5[9OE S[7O?DM-T;VIHVJ]TB0ID+/[ Z_!?;7RS'?__R*4\_ MWE$Z.KSN#9B?A^Q;_RS*@NSQ7_RM7$3].!G2+(BC*W;/HIR=)_'P[$?&DHB& M)WG*>80EZ?'C]R3V<_ZNCB+_FB7W08^E-UP(QV'<^^O7O__ME^6+? WH;1#R MZYS'R3^C$0W\DY &0W&&\1_^?_CYARS*SGZ,6)0RJ1'\I%>L_V7O_-0VK=8? M[I\WIUQU?/X%5Y6/3M=UK+9]?')TU&J;[<[QD6U9)T[+M3VGY1UU]WY]\B[G M97P3#%E*+MD#N8J']/F5^"55>/KFY><@X@M[=NAXBE_\4::FO?LIZ['A+4N( M8QE$B%6"A_^QO-'YEM,;)(S35)ZS^&/Z8CD8BS>;L)1K#9?^ TO8(@T(G/;C MD%M('$&';\;HNOPZ=XX%U)H36(]?IO@\?Y%(X"1<6'(M\9OIB>5Z1'HL#,>_ M^;)G[LG/?%7M33YOKI:4+G7$UE 5M]9*<= M8)6#5/MF.%H,K=5G9\2RC):#OL[@&G -N*9LKFD;IEO^#&Q=WOY[N09.VN>+ MX\LKN&?JW;-7NZ@N!%"6\PY*=M]*X)ZN:[A>2A3-G>Q!D-X8OIGD(*9VUKN?3:>'..V3*Z767-;M\N-%WT!Z$ET)E& MZ@@ZVTA98;^ M@$9W3.;BQWF69C02 -P@VS?@_YR.LWO30P69^.MOTM19/ MOBC66/E-":G EO/.7.!6IRZILK7)Z<4#;O4!L7&BR09MP[P,Y)\BV1G*IHNR M*=MX@+)!V5Y3MK4# [ ]8'N4BE#+0FH]ME8WU[K?$A'KN:4AC7J,T(S\+XUR M$292-I]-(T%J!U_DONYV[JOJ[07=W[XX#INAX!IPS3:Z/'>-CL*\/-W?/K@& M7 .NV1+7M#S#;:OKK:C[VW\OUR \]/DK2]-#\I5[HRPE">L)3I/Y(0@6*0\6 M-6XNZKZH5U8WP6+YO9='OLJ!M'98#(C9:<1X1L=65G4+Q Q34>,XQIN2UE8 M?#<0@ZV7YX5XR3)LO.A.4Z^5GVYI;$+5Y&>W;*-MES0L80.IUF+L 2*/ '9= M@.U8CF%ZZCI] =@ -H"M [!MVS M=6VU &S$[U_LR17U\B1A1?&@#.&'-.,? ML_CEV1\(K[R)!5_+R*X\XQKYPM ?Z _T9X?U!\'.%UJX"^. '_;(+2RX2SJY M2RJ%N-T8I><9[:Y7NG;I BE$(P"O*N%E<7BUU'5V [P +\!K%J]S7<-;OZ!X MY^&%D-OG[TD0)]*B5C84"=S3X RFEFDXIK+T$EU04/8Z#4@T&!)6Q[#59<$" M$H!$[2&Q[QF6NDPOI+G6P0$L?7@#"<;;P_">->(FI,J,<^#:AEG6S *DR@#8 M /:60M:.:W0[ZG:$ &P &\#6 -B.TS'<;DEC.0!L![<9F#= ']&V$/L\Q+$== M)2W0!_0!?6NCK]TV.NWJFB(U&WV(Y2%K%OE0FUO?'5?9+N)N$ T@L]N0,0W7 MZ0 R@ P@LZZ=:QJF!Z[CM%J;S_9'K@'[H'[*J=GM(U.9_O]:(%[; )DG\_CA/$3 M$UF4&/4>2<+N:9C3+(@CQ&OT8\GZQ7-LP[$K:ZN_&]$> Z >R& :K1;ZJ9; M W ' #WDKA26=1EYXA=/P3EF/#6]90AS,P].*QAJ36>B8 MMN&IZ_W5^(:;@!?@M8&<5$^,!+P +\!KKF>5VKF-38<78MZ?CWS_D'R=-+'H M"133VY A&% ]#]6/;@S'4Y:;J L@REZR@8@&(\*RC):M+'T-D DZ@\)S^B@ MF3J"ONO+]K>$FZ,(^^K9%6IQ5\89_2!^G'.'X5U;5O5NI?A39;)]56LKSE8K M(_[>,KIE==W>1**UT#R$%\&2==%5L*3";13/-6RWI#(IL"18$BP)EJP]2SIV MU^AT2\K^!$L^']'XE,DMI%6_7_'W+Y_R].,=I:/#Z]Z ^7G(OO6_!O0V"(/L M\3Q._AF)V)4P8LO>%B/ [CWE] MNVU:CF5WO"/+]<[,XY9UXK1]L[]WC?!D*7DDCV0JWA(GZ?C MN<-#?L\-SS-6_;%VR[OU M62].9!7-H="KXE)S01V#",F_]\+RK ;)!HR!GD8!+T!H3D'.I5,$(I:H(@]S(YGE/]"] LC>12R M-"7\;,,@DD, ;A\)"_AU$S*B2?8X.RB(".UQ6?@RLO7 ?R-O+V'_S0-^%R2* M^=48&?''B_V7!PFLJ3(]KB8L64?Q%M9:D^O5O**)S_.7B>)D2,.%I<(2OYF> M6#( Z;$P'/_FRYZY)S]S>NM-/F\.F2%-[H*HN$GQ?B9?%.:2_.8A\+,!_S47 MQ)AXN4J&=)2RP\D?2Z":W?=\,'9*QMV5$?0UPKGR7K[L.=V?7Z7YQ95H?*!5 M]7%.76ZT5?$%[_@+DL_Y$@D5KU5926?**+%\V6%]9B3:4H/SX M4"Q&MW'HCPMXBS7\$0JW#0>^$B5;WT.J0N%NQD8?-VW)*;?]H'A0O$H4[W+> M4Y@Y$/TXF3HB&S0MJ(FU4K&,8<#LU$BE*E1J_R<21-SGC_.41GZ*FNO&>@[@ M*JC4KJD4DAJ?5\!C&OTEHLU'0_Z3'C7(Y<'1@3)S6!\9-A_$VE?%J=M#?L<6 ML3:[P)9M&MPE+%TFNKQ]<1RR733D&HT$5Z;^_6\>SNUX6L7FKK(Y.1H)$=JG MH?9U3>+3QY2,Y#RO+)Z/AO%_63]"6[^0F'J3-17JY:^PGQ*\"K]H(K4_^^];+X MEB4(84$!MZ. EHT8ECK'ZCOY/4[N:$1.!C1E11Q+Y=8K0(O8%6)7P(3>\BF5 M8FF4TV1NS\]N2X-)61,?J)-N\FFP^:.GD:EGOE^-9%DO1*,Q"AJCE&C6MA6G MQ*$Q"E@2\:#2]*_)@H/&-4+C-F[^]%+[FNV3]XN=J5[L*+6Z#96HUHTC&AX- MN>YDZ;?^MSQ+,QJ)]W_*[_V>.S?W['N>XX 5#9H8OP^?/.TWM=P7[BWZ MM=!OJL!-Q[;:GU-R'X?YD(F2'W_ZA@E_6<&]U!BR?TM3?EOT>=,R6Z75LV^-"Z;3T:0OE;=93"&VAZOZ ]=N0 MJR+PM)*,:Q,+UPLMHC3KM_#GRO6_W "RSJUI5+H*JR4^,V=38=AP MXR?E%Y9M,;E%PPUBODC?D2!*LR07[5NY(;1D_X ,U),!^L6]N.5!SL354-($ MU:M(]J M(*F1V+3#JG)\:E\;@LXVRTK3L2U;F=9HKP'B.&S&@V_ -]7S3< M*%\?R10R@SS0)*%B?XU&/I'WF;Y[MM_TSM)\](RTN= ^OY#1UQYE1>S-^O"B M%O +P*W3C#Z;TU/%,DQ73-!>.Q-@YYT9 P V\1PL5RCTRZ_94I3X(58P>>; M.*,A25B6)Q%)'^@(88-M4-!"+L9R45[MF,BR+<.REX=+*ZEUW-VB16!JES'E MF8;I 5,(6ZA=_>&,;'D3%WTGT'>BU+"+VW:,EJNLV@>=)\"3X$DM=!4\J4Z6 M7%2^UAWA7IX=*FD>TGC:/..N<.5WSW':.SLX=SVNU MCSOFN'F$V7';9V@>L=P\8AF;;]%<-(_0O7F$99IH%Z%K-X7&/V#]=H4J:A>A MS#2"HX-V$6@748FMOEKB:!>A)QFHJMFO#_;1"Z).>H5>$#6R"M$+HMZ@12\( M[.F_0>E.XN$P]H/L46TZGT;2TPZRRF&J?>8M2K07=MA-QW!:J-$&UX!KP#4E M#Z9V#-M#!17>8JEH<(5^"3VX=$%KV;85 M< %<["(N$#)"^]!:D4]SRM+1,1,A$D"LW BD8SAM9:/?&X\N1 70)!)NQ09] M92RCY: A'C !3$R.L[NNX:IK9=843,#-?EZV%S+!,_@#\ 06U MK(;E= W3-.$2 & F'J M0V;^]P &'SN#418KR[1V)&'.[2V.#S/,BS3@3L$ M3 3D["9:QEMTP8F$")85[;EM6/62(#UI:#F^"]>V^@H[ C8=.<%Z *Z-MF. M[[0,RT9!$&(#:XOP7XQF_%_G.X^)]1^.!AR--:8MJ(Q$ZH((^-Z !""Q_756 M(]L6LQ :0#HO"PX]OLNK?T:/;\LT1.)61^$,2K3Y!E&"*'7051"E.EEV#,NT MC:[9W;Y,:Z%["BUS+< :[:5?FT;+0\%4 @-K3^F9$"C.R:<^SQ*%AU2D8A0^*2( M&JF/&C6N]F/?]EJ&:RI+\5U^\>51L7)884XW(+,&9*Q.VVBWE#D'@ P@TW#( M6&[7,"UT]U%AR6KD2I?; 'B:]INPD&;/7(NQ'K[!_L06C+44UIS_) MOF.T;6496:_*9;>M & /V%NP&XQV%SM^0!?05<9X;-=PN\J,\L:C"W'GV50. M$67FUPPX=/UQ69XAJ_7B/GD(LL$@#L4CD(S^0" :(8)UEOJ6X:R?'KPK$0) M8H+!&XF;7L%U/M:XTFWN F%U&C-M5608)Q Q34=, MVS9:CC*O8\PWFO@*I>%AP&"Y17VXW! OMVQS*ZMKK1 ML^\6Z4;K4"WT%20*$M5.*4&B"A,+17N-MKI0-&:S@"7!DCKH*EA286*=U3$L M5]D06+#DN@&/]T^PVF3!Q&->@$-+Z*^F.TCMM8VGE?E M>-:9[1V=>.Y1YZS3;MN>>2+G5?'_]\X[)\V:5W4S8.-!346]BU#R4<)2?K%4 M3JGZ[T2XI#^1+N'_GH=9*B=9,=H;B+*9N=].ADWY>2).NJ15&]ZG_/BP,+*I MP/RJ21-OD8&2"56O-,2>.\O"2J?MC*HA3>Z"J+A)FF?QY(O"6)'?E#'&JOW. M,59NJRY#D,RZW.A;CZO-C>(!M_J -4D/JI>_!?G,W6ZK^;,R-AF[51/ 83A- M8P%7QOPHS0 YD^#8/2V<(F 4&-4"HQCQ]B)HGPN1_4Z3WH XRAL.0R6ADF]4 MR?_-(T8<9;%O:"0T\IT:>]PC[FZBX4_7T?WE@VI -:":+9DU MCFNTO ZX!EP#K@'7E#Q_T34Z'77]9W1_^^_EFMW>3%T5[^JQ#7*V]9.4=HR\ M?B_QA12FY5+ZDM,BRNC>:WBVLN:]ZXJGV8T7 3@ [B7 =13Z&0 < ? O=SN MT; [ !P !\!5-2+*L*TN (=>WM7U\D8FB,X,UY@!7);=,YZ9$[P OP MVF2_WS(L&ZE%0!?05 %>I>SJ6I4,9VT*O+"K^_ED0*,[)FJ/ M(^[#YA&79,3\B3,K^AFSY!X%LXC**8G*.8;M*1LZB; <$ ?$O2BN5G5HTP4X M99OMW#6W<@MO&-$ZG1BN M,=&ZKFNTN^KL\Z8'ZX NH&NSC5RO@U XT 5TE;'39%I&MXOZ0< +\"H#7E;7 MZ*X_MFKGX86-7.FW!M$]2[,AX_*: BV0,X/)?ABGZ8?EB;.(R95.2[5CGWW; M-3JVLO*)W8BI 3$[C1C3<$QEZS40 \0T'3%6US(<=9GV@ P@TW3(N"W#5=>W M83<0@ZW.YX7X+>/_1B8.(OLQ8E'*/A@B$QAQ+8V8ZK6DA0;%O8Q6=7TR&A\5 M S@!3I7VAV.TO/( MQ2[RYYLXHR%),"976V:K'8&UN5/?JLSXT 5(9?ON@-0.0\IK&YY=F2<.2 %2 MC8?4?J=K=-JH,\1V-1!7D5WH&&VWLLT>7;#SWD4,^]DK92L_/C!Y2[=QZ!PS;8J5=$%*0@K M Q)O#V)YAM=2UL,)D D:@^);MMP;0N0 "0 B^_>9 &61!'_"[2+$55GFXLU)P48]LS.JZR%1ME=4 7T#6'+L?H.NI2^($N MH OHFA[GV(;E8AHRT 5TE8$NQ[ [L Q+]6B;Y;C^QB*6T%!N/5)_&$1!FB4T M"^[9=.<1(;,M4%+3LH<]PZJN%X4NX"I[]0>B=AI1'84-_8$H(&K7$=4RG X* MGX$H($J5N%RCVT7)&/99%?<[4>V9:B2\YI)7 *>@.E*K'3>).9=>2YEEO_S>-Q4 >KH!,7HC MQND:'0^( 6* F'77&#%,V<(P94 &D%D3,JYK.*ZR/B.[@9C-_4*- CD5.(S" M-YR.N.1^8\3Z >II=>*IW8F)V1;B80A7 YH:0G._55D*](X/VP)P 5R5^TR& M[2CKPX95%> $.-7)T?'4U1#O.C1W?0/XDF63_=[Q)C#_%.;B;@F7)G_K49;$ M82@^!U'&$I:BNS'"CNOM!KOJVF#!B@=BFHX8IVMTUTFT<^L]L%R/HJ(S.-D"CP]'HQ[F(LRAK M/KA%I/Y4N934"Z6<'7137>'.VK)I=BP71 0B A%MG)C0ZI;4L@U$!"("$8&( MUK.(K*[AM6$2@8G 1&"B;3*1ZQB665+=\ (Y[OYGB@ M;EPP. (< 8YH'D=8!Q9ZS6_$$=CU?%Z(IT&89\Q'\+6&/*Q]@9"ZU);7U*H6 MS*TR2H1NW. A\!!X:-N1*/ 0> @\!![:=K0+/ 0> @^!A[8=4=MQ'MKM5"GY M<:F.X%_R"^83RA^?WC$2Y<-;EI"X3^*$/P1-'HNZ@I3D*?]9$)%LP(C/,I8, M^3]G01R)'[-)/0*-?")*$M17)& U6#]%F:Z;0-J^T8IEE^O$\7.(GCT+<6"*L.88[I&'8% M&09 &!"VBPCSC+9E&K95_MXY$ :$[2C";--P6^I&DS0=8;N]WU)&!C.HI\'# M&=7[H?]_]MZTN6TD61?^?,ZOJ-!MQ\@1$!L =WMZ(F3)[NLW>MP>VWTZYM,- MB"R*:(, !XMDGE__9E9AY2)14H$L@-DQTTU26*JR\LFMLC)U04'=JII@T6Y8 M*'8>"18$B^;#0KG'1[ @6+0"%FK=M+; HN2-_2R:-&^[_F #*Q'-) M:99MOGI;*Q7W@\O1AE"! M8 8)QF3C\F7((WA9)+(<_Y,X(9#,6[&9ZSO^Q'4\!G]///C[+ @9=R9S3'XL M71LQ#J.=LFD2XD,W"/'$<::!H;0.N*#&E$^"4.1=OD&"RZG8IK4I\)Y#DS<' MX+324RKZQ83U+2\X?B^_Q@_"A>-55)"%U^0/EDLXX9Z77O/+F7DFOH/,GF3? MMU#DF[O@$?O$[]F78.%L*.B%$]ZZOARDD\1!]H.T!L0O]^XTGL/50(BTG#LL MG>GQJC5#Q=>-,RU9CJ#5[5'68\02Y M8T*NVO_'WNBUW0)(%A3\E_23I)M$*"64:H+21YL.U #2IY]8.!IL=T5Z_NF$ MDSGK6L22Q)*:L.3_E_B<=4WB2.)(33CR*U_&7!RK)[8DMM2&+:_Y).7*O=4W M&>)DB!_;76Z5.WS^DRRI$B21XT\CJF7S JI^X7?<3WA$J#R\BCVX"CU69@CQ M#_$/\0_Q#_$/\4_#^8<*SNRFYJ^AJ&$8\H6;+")V#]?%W%>%3(V(J!UDE<-4 M^W.V5/&V?)]EC8RQJ6Q#2?O5WQ6=(UE#LH9D3 VPTXVQCVQP0X AP![F" 4]BQ MF !'@"/ /0(XBJ8X.[9_3&E$M#Z")TU;&G:QO6B-)':G5HV^6W7LT= M_Y;CZ6(?/-C$!TKZ?)JYLEC'F(=W=%B68G(J8G*680]MBLE1$)P =Q# ]0?& M>'"PO I=L%.WS4V0.F%(G5M]PS2[I,1(B1'B#A./-4Q;73CV1'08;=7NN54K M_5T*Q^DDP5H3CK,LRQB,U.59MCT>1_ B>#V!3J.A,>K33BVAB]!5QU[2V.B- M*Q0ONX\=)L.#LW NB_>M!ZT>QYLJB MQHF<<\LTK+[RUA(4FB;$M!0QEM4UQEUE&0NZ,'_=IBYAHL68.._W#-,>DA8A M+4*(V3'0:!5'JI.WO,?PM]_#XCR7W(_[:P!1="D=I)(H> MRR9H3[C*&ATL;[?UL2R")D%3:5C'Z"DL&?M2NIVV(4_8)>P^@8ZV,1@<+)>8 M%"N!D\#Y!)O7Z/?(ZJ4=7&4D_!;$CL="ZC^KK?!JGHPR+6-HJ\O2.I'C$80I MPM1NH]PTC>Y(V0X788HP19@:&9:Z36."%$'JY"%E]<9&?T"8HGUG%;057^^Y M&-)-X$WE@][+K6=EOJI&=-17DCW6A/Z01&P"X;0A%G$<<1QQ''$<<9P^A".. M>P[A:+/F[6_8Z]+QI\P3'Z9_)>G!NS0=,\+\S"0,^51I7B9!ML69X(.AT567 M[Z$+4BC*19!X-CGZ V/04]8/@"!!D&@^)+#BH;+6=00)@D3S(3$TQGUE62YM M@01M9>RF[>7D/XD;N;$;^#"**([H])QN4J@]F<+=H3$LI MN4-]HS^DIE:$+D)7'>BRC=Y07:-T0A>AB]!5H,LR1@J/9[0=7;3O^/97[O/0 M\<36HS-=N+X;Q:$3NW<\WWFDD-D11%+;TH<'AGVXJA&Z@*MN[4^(.F%$@9O: M5]?KA1!%B#IU1 T,TSI8!09"%"'J!! UM$E'T3ZKXIHFJCU3C8C77N'5GB@; M]EGL'L[V;GT8CN!)\%1(Q]'0& ZIS"&AD]"I(SHMHV^IVP F=!(Z"9WJT#DP M^N;!ZONU'IU/<^6!*5KFKG\L=XUD-WP6A#QK-!([/S)'GF*-AY=IC1--YV-C MT%5F.&PN^U/GWX;^ 028%@/&LFQC8-%A5\($82)7(OVNT1TK,W!)BQ!B6HZ8 M0=V^;QL7D:D:]3W[_]Q.-L MNS;=PX5O7H*C92 '@2?\. P\#[^[?LQ#'E%I8HHJ[K69:ZHK W(:PH@ <\* M$9NY5*:5,$&8J&SF6EUE+>E(BQ!B6HZ8@6V,!LJ.N.O"^R]5(K29^U!3FG/I M +YF3AR'[DT2.S<>9W&PTP&$#^RO +ZQ.^['2:@LO520+LSP4I.':ML_(9;V MW@E]&&J4G;U8\I!%)"-(1K1.1MB= M,=4")R% 0N"4A<"YU>DIJX9*A@+)")(1K9,15H=*!"B)P&@4"*R3MM>NE\1\ M2N'3!@I:[<_7J8RMFB":E<9Y3OST%LDADD,DAYX;2QJI.P*N^]+7'60B M04."A@3- >)59/"0'"(Y1'+H>3&Q^L60+DM_E&!9:V)BXNM&+O^?X@<^90Y, MW[GES$\6-SQDP8P%(4S""5G18MS\PK)&ZYCUM1]AI[[?4D8-,HJ?%31#5^Z&ZH*!N54VP M:#,LAL;8M W+)%@0+ @6]7E\! N"1?-A@=JB;XRZI"UV>V,_BU[)6Z_?\OGO M/R?1Q:WC+-]\G:7_KB/^__D[AWCL?].,IO9]C*&;Y\ MX;-?SCY#Z_>7(^N===7M M]^S>^W?6A\'9/]:6J4SR;^Z"1^P3OV=?@H6S&YNEVSW7YQ=SF4EGV>:KM_LN M>^D9%6"9@!KQ#-<'\2"_EU_B(V6]"O8LO"9_L.Q]/>&>EU[SRYEY)KX#LTZR M[T^?_;T[C>?P$>:8EH(&_O><9<3?9!\V)E\,*MPF<<9;Q<,>40,QEE_.!O:K M1Q%917=ZHW7H^P9-&:C>$WQ:% FPT9X0DOBZD;)+F4E'R4Q"SJK6P[ M)FVIQ&T34!<\K)??KOF$8TYX0=>N93!4Q,1_Q']'Y+^]*PZ0"B$5]2$ >?Z3/ 84))'C3_=OI?MT&&JT!U^G:X^^+YMS;\IN5FP9@D_&;L+@ M.P\C%G(/?&K_EL4!B_@D@4>XX+&!V)\:S ]BMN(Q6R;A9.Y$5.OH>#G^SX6V M]DD +S]ONQ>0FW#8=C2RC;&Z;2CME_ZE$4>2,B1E2,H\E12688Y-8]A5UT!= M]\5_J9PY8?>N,!]%/!Y,?\>KV(P>CV.T(X,9FX1\ZL;,C:*$,M(.NIEZ +^O MAEIJMFV,^E1QEP!!@)"*N=LSQB-E:KDM@*"HSJ-1'2,G85)%#-G,@$B MQ!'Y4[K(I/8<5QF.C/ZH_I+,NF"-0A4$K4-!2Q)I9%MV_>S5%GR1BPZV );& MF^ '7N0YYML^T;VS9,(>X.'2"7&7AUP2

ID7?-NR>L@.INH"%7'3"PS.M M7LNP30I9D8>^'V&_!;$(EV='$:1VWJ:FR8\XYI9G->VQN_S!ID&")QY>DO>X M3=-&,!Y%6DA" M-H)124*JDY#C@3'>/]V>)*0^!W7W/F>[ZYCN'?<3_F[U3^>O(+Q*(E@Q'D;O M5E_X,@@QR>0KOUV(!U4._>YQ:O?JW; _?M>WKZ^OAZ.^] M] ]^:K=\ K<[ '@J=37FG,T"#[2)2,P1YW4C'D?P8QC/14^-9<@7;K+ Y.XD MG( W,@N#1:$GTHSPXH?[><"X,YEG^XAX1Q"R11!R>)[C,\M\Q8)9<0.^Y"I8 M "I6?XL8 "R*V#T,..9^_O(W)<6TGXK:D\2/'$QHW-'HA1/>NKXM YZC+/MZW"8<3:DM&1#/$BBSZ:B M-?>LC-2<8YO_!G^$<3"CIBP[4LWV/V70$,35ZM@1XFI$W."Q4M)[UCYH#B"I MA 9QDC).4A:=(TXZ<4[JDDE )H$6\-O;"&]P,96"0HY7C5/C?^Y1O-^[)5$\H7V,.189I[VQ G?S*"9$U-LJ:^ M T?'A%>_WZG_5-\FF]1'(N6 ?*4E YT2\DC+MU[+6P/+Z)G*HI?:KSYI>4UE M33NU?&_<&9&6)RVO,_)(R[=>R]LCV^AVJ>$MR1K2\K6^ODZG&?S0I$5..\#N+I LZZ+0&"Z*$YJ]&V!4&4(*H31$F+ M;J;QF<9PJ.XH#*&3T$D*5%W RNZHZ^5-V"1LDN8DXY8@VDJ(:@I+\C_;!5%* M8]5D!^ETQ9>BWA&ZL).Z SW[4JD)LKL[&AEV[W M;W3AAKI-*!(US1$U-70? M'"JLS;$OI=I]KH< UQ[ D6X_3,[1H&N,1^H.%I)N)U'3-%&C'E4CJZ.NV@WI M=@)L?SLG0A1M(MY.HJ=%O[W4.%PH[#=VNN(?I\YJ0;F]I MFEZ;W_O1GV$/R=@-_'>K](]/Z6,ZOKQZ]_YZ8'ZX&HRNWW6OWP_,<=;']/WH MW7'[F/:0>U1RP)8^IA%;AL&=.^7,839!/GT+,(\CE/8=WB.8$;.]_?A6K^SE;W3^+U?TM7=UWZ>INS%U[ M4I:>4M%SU)M6<6_:7D-Z7(X:,LZV]T2E==#C/EJ'9B?Q'+;/47.==@V,PQ/N ME'42_6N;%14NV/=GV^F/PH+UO M6\-M+%-=KZ 3;_1*P",%3PK^>=3HDH+74T^=DIPA M!4\*7AO^.27@D8)OO8*W!B-2\"1G2,$WH]IU*Q5]P5#/*19Q@DE\XKZK8+'@ MX<1UO&.J^Y:)J5IW'8_;:WE@# ;4:ID@<70/01L%W>TH:[1&>#@9/+1815A& MWU96UHP@T42KDE3$FHI0UN]/FQ5N'1Y(11P,#V-C/"8-08@@#9$;3>H*P;8% M#Y2=O)NV[WT>WBH[9WLB1*M7";>G!:YMF*:ZLM2TG:<-N)JES]NYG6CF@+ MM"@9\NT_@S@(V7*^BG"F;.HLG%NNBH':12K:T:SN\/)D(-%>%3%4MQE&>#@9/+171?2'QKAO$R0($J0B MLL1(LT,VDXI(G4:1\3II^YF'4> ['E/%-"="-]JLVUM%]\;*>@VV?E.A0>AJ MEE)OYWZ=974(6UJR2,NP=8*::] S>D/*-&DANK2S"T]1)1XBW/R$:+,;T0V/# M+(&C(O"HUH*MT%H@*!(423$^6S&:MM'OJNN\0&C4$8W:F:D:(_"H13XMA4?D M"8HZ0I$48S,4HVWUC/Y(728!H9'02(KQN;3LF1V3H'CL&+1&FSXUT59\O>=B M2#>!-Y4/NG*BQ/'4Q:G;3T<%YDCWD'O3CQ"Q"833AEA-4[G'R89X.L=I1SAM MB-58CB,9UTZ.TXYP).-:SG':$8YD''$09#251/J5^SQT/.:YSHWK MN?%J\Z#O M$MI93>U5$=10N0%X(!5Q,#R1&15,59)T*^!NT7'%7'CPU[U*V=M[3ABIK-88W U2S%W\X: M&):Z*L,$+8(6Z:U2.-^P;'7Y_P0N;<"EG5%XDGJ+VC)KR2&DMYJNMRQCW"=P M$;A(;]72F%E9YZ_60ZLA69[U-V96'F%M%Y%H3[2:66EVC8%-#0:UQT2S]'&C MU6[/I,09 @0IB<+)LX?&J$\=!K7'A':&4WN51'>LK@F7-DO<.D"0DCB<)]$' M3V),2H(P04HB]R2&ZB)X;0$$)4D^T)W=6CS;O]&21EF'K!#67/31,DQK)MA!=VMF%)ZBY1J2X].00 M4ER-5UQC8VRJZ]%(Z")T'9]PVB@NA26Q6@\M2I=,.S2K[GS1+AK5K-A/JM]6 MU^H:O:$ZMY6:_.B(QH89 B?;;VM@*W1S"8H$15*,SZ6E-;2,@4UM8=N-1NW, M5(T1>%0ONMM1%Z$B*.H(15*,S5",]JAG#'O4%I;02(I1"\6HK!XJ0?&Y,6B- M]GP.VJ'YZY)/7&K13*W]M":<-L1JFLX]3C+$TSE..\)I0ZS&( MH%H;118)%>TC/)"&*+:K#'NL;+^*$-%$FY(T!&F(IN&!-,3A#J08/:K71X@@ M#9'?9W:4U<-J"QXH26S"4]1<776-1PA;^F"+--?Q M-5=W:)AC\KD(7:2YZBBYTZ&:S;6&70\/*Y4D^S,(O_,PDF@:V=;P+;Q\L>1^ MY,1NX&_F13YW7:)DN8..0*>WGNOSB[D\?FG9YJO28X;+6#SDW'HM!@,/VKJF M>@@1<@]:O'=KV<:@1^D,VD.B679'H\T+FQIR$AY(111'!+K**@<1'D[&9&JO M?C#5E>_19H5;AP?2#P?#PWG/L"UE)M/FLMJ-LC(% KWUL@0!-]U$&R"^":!LF-QU_4 M_DH71/YT<"HU8=>W;]J&I:[6[J.TT84;ZC:Z2-0T1]34$-0PS4Y-C2T?(%4C MLRU>$>).#W&DW \3A;%[AFG7%%XEY4[;' T0-:3<2;F3"V8,?ERXR2)BTX2S.,B^,V?Z5Q+%"[S>8#$/%ZXOZ]_ /1-X>^A,X$E! M6#P@Y'$2^GS*DB5?D^CBUG&6;[Y.YGR: M>/SWV5=^BT/[PIC/@G AWO!NE?[Q&_#!.R^8?/_'?__7W[<\8NZ$ M_)T3\>E5J;S/UQAN^'V)'Z/+"1#0C5??$ #YT\3PXWZC+E3^ 'F=?&A=_W!M*^N>[;9NQI>7E]=]8;65;??LZ_M4;?[X>P?:UQ= M7N)O[H)'[!._9U^"A;-;R3P$BG5I4H9$=Z 8$>\72R]8<\VI@!8SG/))$(IE?(.210YO!9(F8APF M/V77?,(7-SQD7EU_QR9IZ)[Z#/)MGWIW/R MP@EO75\.TDGB(/M!ZECQR[T[C>=P-1 B5=&PZIZSC/B;[,,&KQ?C+F_'%]K7 MVIIOM<>.OAC,+V?]P:M'%7O5]$AOM+K/O;$I]]E-&:C>$Z24DH/F?MH;N4DU MT/)AD_\1T?Y$"HJO]U*ZWP3>5#[H4R(T7S#;5Q<=>'S%DDNC(:(X@7ID= D9 MFYSWI_B!3[4'A@.+YMQR[I3%-)]X(Z=3?3JO9VR9&S[2-\8CZ(FG) M)RVS!Y3;2]ISF[H4B,?8JA'2IM\9J4M\T'WM2=*0I"%)M49&WU27ROX8E1J9PJZL M,X9&X&NN\FI/IVW+ZMC4#9C 1>"JX^!C9T#;C!23VYN$'X)PQEV*RI6ES,BV M;&7R69>%ID"$/NJF<5J%<$&X(%P0+BA,IRA,MW1#A4&Z0Y;B;K.M]FQ"ZL)8 M%&QH@)8['EP)H@11@BA!E""JG^G;+@OW@<-"RLKI-]IZM0S+&AA==0FTNJP\ MQ5/T46.-TT;6L-,G1! B"!'%&8NALM.U;0$$A18/=L:BG:'#GFD,1O4?6M>% M)RCDT #-U)Z0@CV@'"0"%X&K'@_)IN19BL0]::]9\9&01EM^YW;?-$QU)S_H M@ =%(%H>@;"LCJ4,+[JP/L7D"!'/)D>_TZ=SZA23.]X9BW9&Y>I(16B[@],@ MA#570;4G>D 0(X@1Q ABFD&,PG2'/A)"AN+3Z*4+FU#<0B.=53?&"%>$*\(5 MX>J$<45AQ6>=L>C7PV=;FK2W,Q0Y-@?&>*RL].;SJ:@+KU$0Y7B*\V6L]1P" M:L^.ZOHPO%B^-4&<6>/.4%VG!A)F),Q(F)$P.Y(P&W7ZZHYNG+PL*SE8/\<. M3'WK]5L^__WG)+JX=9SEFZ^3.9\F'O]]]G7NA/R=$_'I5;!8_G,3NG1NOON&KO@%=WGGPQW_\]W_]_:&G?796"^['E_=.."T_[7\< M+Q&ON(RB9"%_JSX95L9'\G_ALU_./ERC:_2OWK^_79\Q=PH_.)/XPKHVQSWK MG75MC4:#?L\>]:Y-ZZH+GZX^=+N]T=D_UI:SO#3?W 6/V"=^S[X$"V>W?"W= M[KD^OYC+KJ66;;Y:!]M@3:SA]W4.$M]='R1Z_*:+%ZADJ6]SSG#]''_%D@BF M%\,/[SQ P@4L3N#!+[);/,-6SC!,M@BFW&-QP*8\YN$")BCNNLUD0QG/F^N*/L\ #)8:O$CS:>9"['Z+U M_KUH2T^I:!TS6XZ4_/B]_!H_"!>.5UE!"Z_)'RQFP";<\])K?CDSS\1W$"&3 M[/O3>6WAA+>N+P?I)'&0_2 -!_'+O3N-YW U$"*5?""X/&<9\3?9APU6*\9= MCK\4 L_<&EK;(X0C!O/+6;__ZE%96I7HZ8W6<^_K'OJ%-% E+VS(+G&S3&ZB MSW,W)FPE&Q./T/)A:_(0[=151I.)V8C9'F.VHY:'(F8[+6;;.Y! ^Y"[6?.+ M&WUGLY!S%CHQIR#JL8.HK=R1M3L*-[5;V:[ME98,1,AK/O)Z]5=S(>01\G0A MG$;(&Y'.4X.\AL0.:SUA$L7N @ST*;L+/"=V/3=>D:^M;Y15&S'4!3FDFA#M MEC8$EU.&2Z^C+#^%X$)P:3M<^AVJQE:_+:N1:UGS,6H^01L7\Y#8N>NS%7?" M2%FE.XW(V"P9U4X/75UAO-8GFA*R"%F$+$(6(8N0U11D4=3X[;5[YP)2IVSE M27/]PH_W7;"[Y\_>.?HB!JJ7[O$KYO\^J?X83QV2-'L#ACS]M[^B]:FN3RB)X!8G3(V-P4!9Y09= M %"WM4*(V#_P]6)T'!H17;LS4+9/V19$4/!A-VW_)P]@DB=$888&](5MNPM M$#O$AE9M<".(Z0\Q\K*S\P'D9Q],P=?=\[UM>OY$^K\3KA1J];HQ1KAJ#*[( MYW]6PH&RYD0:D5([@7:"D0"K;PS,,7DH.C))R]!U@D$ >]P9V@0N= ME0FH.8).ZKY%;G>OTZ5:T^1VTZZ[MAJ?=MUI=Y!P1;ONA"M]=;Q&5O61=MT/ MUP3[A 7:$P#:!8!.@P1+B64(;6?LP+8-:ZC.A7DV$77!:-UV!>&S+M9Z#@&U M9T=UI01>+-Z:(,VZ9J>O3I6>O#!37Z=5:3759E5MW:S6:H^N1H/K]U?O[.M^ M[[T]NNR]2ZNUONN-/EP?LEJK8+URW=7N '"MDA>_S3D+).4@XYJ14 M9],D!,G"8KAT@T6?^,X4D"E2Q(!3DL$3O9,9ATM--HYPY_G1[ M3NQS*,#NG8C!_V:!!UHW>O,@"O=-&VT8O8 MJ@FRQNYUAO67-=!E[5\J:2@F1H=C]1?!V@@7J]\W[-Y %2UT@4#=]@IAHMW' M8_M4E9T"$'0\5CNA[XOK4[;!"#$G?#A67O8Z:G;-:9CLXVP MM*E8=7M%V0F&#+I=TS!'0W);=.22EL'K%&,"P\Z8RF913( VY/54ZHW6W98Y M,,8FM< E3-"&?&[/6IT^I:B0STT;\MH)G1/TKL\MVS2Z_<,=+3GM:#RACYSO MLO,]Z-CJ]L/(^=;"EJ8-^6;)G1/>D!\; W6]3!GKKCDT5!:K./G2KP308P'T.034GAVICO738C1C ME14+3EZ8-;*.=5;*[%)6"I-%$]/71_L5J"X5F^Y9_=YEU^I:)O[Y\OIZ<#T2 MQ::MX?CJ:G1YR&+35+181='B\0N+%@_Z>M?F;4P1X<8,E&+9+XP=C8Z;%W*( MPHK_!A6[60Z_UK )<1C5BWZ0)U4&EL@])69[C-F4>5[$;,1LCS';WC%+VI+8 MS9J9K\S2LMJRO5#$@B2.8L?'4;,+!DZ[.]$R )HR?WJ%FCVU&H+L V,P-(W> MH/[TH3H(HEU8JIG@K:O=,N7-/HJ_H6'W;&- !U/U9)26F6ZGB+"!,>J.#,M6 M5KVR]0BCD,_;][,9G\0LF+&IZR6Q>P?V)P_OW EGRS"X<\&2D0;IA=@VDETO MC]H321O 2<$TLBU;F632A2OJ5EUD!+89&".C-Z82RMI#HEE&6Z,18?5ZQE#= MR:6V8(+"@D\RS/ABZ04KSD5K[ZD;PM^#.JVSQQ+FV^E'U6#6/9N0NC#C"84R M&F8HGB9&!W;7L$W[Z$0D?)+52O#NG"3>T+YC3:;&T=LH;&:-@SN@HWNPE9%"8E8 &P^J.^80T( M6!1K54?;2S]V+XK];SSRR((E'HVL&)A:>M/:8-.V+&.DL#I2VYVZ9F*O$<9E M*_%5Q[X$84P;C#7,S&PEQ&QK9%ACRE"FN.3>)/SLX!S=I1-C!#+BDP2N='E4 M0([_F'@)GDF>A<&" 3DFB2?*;N#>OA=$$5MF.9:4-5-G82Q=6*9](9*&V8>- M!@5E'1,P"!@$C&?::2^O(?:$VEZ5XF#\=L']^ M?!B':2M=N- 'K)PF?5 H, MZWWUNI?=JP^7MCD:O[NTK)XH!=;MF=>#4>^0I&N#Y(%*SUWFK&$SY+PVHS^:W*#>R2QZWC>BL&_D,D$QV4<"'P7!4DX 3!9X7W..JR^J'$0>FGH'ZF(N'+T.^<)-% M\61TL(LGI,\L?KB?!XP[DSES)I,@P9Z<^#"V"$(.SW-\9IFO8.#%#7&!J[]% M[#9$7_T>:!!S/W_YFY*P4"HVJ-"DBD*3MOW"2I/=<4/J, X;,LZFT)/608]Q MMGT=#C/.AD3JF[4)1O0I*5ISS_JR5$Y6*X[2P(\FQ#T+<0-%12F; TBJI4N< MI(R3J% N<5(3JN"22: ;??2%W]Y&>(.;/!04.O^)N;BQ$221XT^CO3O.TDF( MW?SWFQ/>\BA. _*J,*H1\;0#KW*\:I]UJJZ?7BO:Y0U'AFFJJY6@^^KC?932 MKZ&L:6=*?[_?4=>,\C$*%6Q2'XF4 _*5E@QT2L@C+=]Z+6\-+*-GUM]B7I?5 M)RVOJ:QIIY;OC3OU=ST@+4_((RU/6OX!7WYD&]TNG1\F64-:O@Y?WN[4CZW3 MT/*T%?G6]J?,JV6[@Z33_JUS:]Z1K,&3MTS#[E$K#\+$T;T#;12S;7=, @0! M@I1$>M_ ,D;FF"!!D" =D=E-XXZRVJ $B),!1'MUA&6-#GIH@\:@37[M34*92P2=@DS4G& M+4&T+1#5%);D?[8+HI3&JLD.TNF*K^.V6-;X0,^^5&J"[.Z.1H;=4Y;0=3)- MITG4M$?4J$?5<*BP-L>^E&KWN1X"7'L 1[K],#E'@ZXQ'JD[6$BZG41-TT2- M>E2-K(ZZ:C>DVPEP[0(COQ]FS%X]W2M31BRS"X<.>PFY,[W:7#O9_U1U[N+ MYBU-LS:C-RN&,\+K\UZJCC_%WV]YA[Q$1;U;2YJ>B3 M"L,-IOC[%/ 7\^D;9<34=ZT/T8J [?W/KV)U/V>K^V>QNK^EJ_LN7=V-N6M/ MRM)3*EJ-.M$J[D3;:TA'RU%#QMGV#JBT#GK<1^O0[)2=PW8U:JZ+KH%Q>,)] ML4ZB6VVSHD!$'_6=(1N,4&I?2ZQ5'VM1/UMBK9I8J\4-;LFV)]M>?PP>M--M M:YAK.RT_A\$2YKTB+*K'8K<&*#Y"JR:8$YKQCW;TJ;7&)_'/Z? /R9\F\(^^ M^HOD3Q/X1SOZD/PA_B'Y4Q-]J/SQ;FI>WKE.[ :^*BR>"-GT$&+:%V>AWJ[E M^P9C9>U+M%]YO(\J9VDH9]I9&&?TX)>*3@6Z_@K<&(%#S)&5+PS:AMW4I%7S#4#AQ'>^8ZKYE8JK67&(,!-58F2!S=0]!&07<[RMJJ$1Y.!@\M5A&6 MT;>5%3$C2#31JB05L:8BE'7WTV:%6X<'4A$'P\/8&(])0Q B2$/D1I.ZLJ]M MP0-E)^^F[7N?A[?*SMF>"-'J5<+M:7AK&Z:IK@@U;>=I ZYFZ?-V;N>9"ONR M$;0(6J2W2GK+VK\J(X&+P$5ZZREZ2UD(DZ!%T"*]53K^V"=OBZ!%6JNAIR/: M BU*AGS[SR .0K:6JV*@=I&*=C2K._P]2GII B2:I90;K7L' MM*5)>" 5480G>X9I*CLF1Y X&4BT5T4,U6V&$1Y.!@_M51']H3'NVP0)@@2I MB"PQTNR0S:0B4J=19+Q.VG[F813XCL=4,SZB:@_" M*0\S2EC+'RP*/'?*_H\I_GD6+=-GXA6;#SQR03'+4-E!XA'B[4^(!HLQ_=#8 M,$O@J @\JK5@*[06"(H$15*,SU:,IFWTN^HZ+Q :=42C=F:JQ@@\:I%/2^$1 M>8*BCE DQ=@,Q6A;/:,_4I=)0&@D-))B?"XM>V;')"@>.P:MT:9/3;057^^Y M&-)-X$WE@ZZ<*'$\=7'J]M-1@3G2/>3>]"-$; +AM"%6TU3N<;(AGLYQVA%. M&V(UEN-(QK63X[0C',FXEG.<=H0C&4<<1S).?\(U)!E-)9%^Y3X/'8]YKG/C M>FZ\VCSH^]R03)0L=U .*//6,US&XB'GUFLQ&'A0LR.K MVLG5]I;\L$=&MZ]LIT*;17YAA%,_2.@E^%M=\J-/W3()#Z0B2OG/QJ!+M32U MAX1V5E-[500U5&X 'DA%' P/YR-+F0^QN>CU20;E*'I-<"'U\3A<3'5G6$X# M+I1R]$#7$"=T?5Y$)%5QUHF0KT'[!4?5\6/#'G5KYRUMN*)FS M!H:EKLHP08N@17JK%,XW+%M=_C^!2QMP:6<4GJ3>HK;,6G((Z:VFZRW+&/<) M7 0NTENU-&96UOFK]=!J2)9G_8V9E4=8VT4DVA.M9E::76-@4X-![3'1+'W< M:+7;,REQA@!!2J)P\NRA,>I3AT'M,:&=X=1>)=$=JVO"IAJEH9OY]Z=U:/-.SU9I&78.D'-90\-TZ1&LBU$EW9VX0EJKA$I+CTY MA!17XQ77V!B;ZGHT$KH(7<M84E-))BU$(Q*JN'2E!\;@Q: MHSV?@W9H_KKD$Y=:-%-K/ZT)IPVQFJ9SCY,,\72.TXYPVA"KL1Q',JZ='*<= MX4C&M9SCM",?G!]QT*]NO(D0TT:8D#4$:HFEX( UQN ,I1H_J]1$B M2$/D]YD=9?6PVH('2M+93=O_RQTOGJOBF!,A6H/"ZL?UWP;&<$256%J(KF8I M]';6BK"L#K4)UY)%6H:M$]19'/79
Z@(]#IK>?Z_&(NCU]:MOFJ])CA,A8/.;=>B\' @[:N MJ1Y"A-R#%N_=6K8QZ%$Z@_:0:);=T6CSPJ:&G(0'4A'%$8&NLLI!A(>3,9G: MJQ],=>5[M%GAUN&!],/!\'#>,VQ+FSUR0;E.'I-@"$%\CA@S(ZR=.G3 M@ LECS[6?H3*NNFHRQ\MSZB2R/K6GQT.#;M_N"X)NXAZ$L4P&X3K9IDN&:^ONP.@.U1V2(5P3KDE;:Z"M!^KV" C4RO<6"-!$'W60[ *XID%RX_$7 MM;_2!9$_'9Q*3=CU[9NV8:FKM?LH;73AAKJ-+A(US1$U-00U3+-34V/+!TC5 MR&R+5X2XTT,<*??#1&'LGF':-8572;G3-D<#1 TI=U+NI-Q)N;=.N?>[?6-H MUM2SFY0[B9H&B!I2[EK8C7NK^=*NQL^Q Y38=OW!A$*)3AME4:I,W .R"U*Z M/@ T?G,A?E$MU514;I%U9.HIW?)MSIG/;YW8O>/LQO$.QX(9@Q\7;K*(V#3A+ ZR[\R9_I5$\0*O-UC,PX7KR_HW<,\$WAXZ$WA2 M$!8/"'F7NG4:M>"]N*S5$[&[]DH@G,@8>5 M&5EC6]V,Q-=[.9B;P)O*!_T:!E'$/F>K^2?<&'.?W:S8KSRX#9WEW)VPRY [ MN(1?W.A[Q#[Z41+RZ;.)L#GG73,L/:6R].;:RN/W\FO\(%PX7I7:>$W^8"'< MV(1[7GK-+V?FF?@.PGJ2?=]"VV_N@D?L$[]G7X*%LV$++)SPUO7E()TD#K(? MI (1O]R[TWC^9CSNC,R^.1C9]@"(,NJ_RK01* S/64;\3?;A[;J2*&91WGDN M4J#LK:E%>VQ>BZ']L9+J;. MJ&Q6S(?H4PQW\*03 /9&AFH+$&J;ZBOK$&L1:TG64I:,2*Q%K%5EK;U381IB M19!M3[9]HS!X_A-S?1;/@R1R_&E$I;84<-T?G:\=!M1D5T[HWMQPQU>%SA,A MH!YB;9_S;IMZ61<:JLO1>8SG]CM#J8Q2-63ECKJ&W576W:#9?(/W-?CPLS(: M:^: M;\@F::)\.T&;9-17F*M,-HD>K$]=Z=^:NS7OB]=Q MR+1G=-7M .DBN^JV40@3->/@J!%(A>WG"! G XCV*HFN95@FZ0B"!.F(W+?L M$!X(#Z0B8.6BJ)>-PP7\\P1\H.RNZDBS9L4;/BU@A=S=+H]2'JJ '# ^PS$K0(6J>H MN(9&KUM_,C"AB]!U@HJKWU'7;HN@1= BQ578A"-C3(J+T$6*BQ17 Z.N[0H3 M7D:NHXI?2."T>!NS-QBJXA-=>+]NS4QX:/$FIMFA37W" ^F'_)BSLL(K!(>3 M@4-[U8,DQ\BV;&7T(%R<#"[:JR8(%X0+TA>$B[JC=!05UR$J?E*$JZ/E[C[U M4"QMZR0XHD([RDA9P[Z.:1N6K6YOY]D4;03GU6V+D90\&I*?68U'8V@? MMIUY;?5Z])4&5$-0>]B3<43&T?-IV;5[AFFK*_U.QA%)21VE)!E'QR8P&4<$ M>S*.R#AJD 3M=_O&4&';"#*.2$KJ*"7).#HV@4_8."IM4OX<.T"U;=^,N O@&?_,9K >[Y<%MZ"SG[H0Y(7=$F]=I MP/P 1K7D$W>&4_96C/^8>,D4;^0,^\$^S%OIY[__G$07MXZS?/.5WRZX'W_A MRP"HZ-]>N]'$"W!@WV %WWG!Y/L__ON__K[K\L\ L,E*_CN_04P5OGSALU_. M/ES;IM7_5^_?WZZ!)E/X 6AP\7[P_GW7[G?-OCWJOA_T^_:@9UUU^SUK>#FX M[MIG_UCCN/(2?',7/&*?^#W[$BRQRG5V$=_%H0+)W:# MAQOU'F'@3]&O3QF>^.[Z8 G$;[H#$ PJQ_L'/#<47,]^O;S\;+!@R4,'^9)% MDN01@H?=. *#O@")B[VN?<>##_EJ2$@"+SFW7*Q4$@&'P9\98"R8R$>&/ J2 M< )_0"PZ$5P2X>_P3O$@?\+A5_$.>2&B'K]=@1AP_-7?(G@$X@8E>3[ AP%+ MG+#?>+\59$Z7$40JK/Y- DL$ZY0M/G "R&58%Q2Q&]QBL,]8%2R,5VE7[2AQ M//CR1%S@,0[1 02C/N10,#O2_SWI3_]Z&,W M>!CT9\_Q(_FH[% ?P^"6Y]N(M% BI2 T]*4&%@ M#,/'"7Z.6"(T*3YDYK@ANW.\!,1H+'X!,QB&.'7B7*$Z]TXX[;"*T.<.&JU1 M]1W(%_!C'+J3&-XOQB*9HORKX*C$1WUQ?O;EZQ_1V>NJR0!&_(8VSW-KAV_% M2Q=P;?;\C7'C&_$G_@/'QM$WR"DDWH)\'3JXG R7-M-3X-J(^^Y@M*FIX093 MA5Q<*YLH]S(/.OIK#BI[X?I;&!,X02PU6X*9!R(*30G)QYM+GR,D@F$+KPW^ M@LN96I[(&G\E4Z'$JRPM;%#T!L6S+Y )<2R+8,H]=O[.2+81*E*2%2ML])#DJ^-9],:0+PG#L'V#)! M)W:9 (BB9#)G3GX1<#A2TL!WS+@;H],KO%GW#AQEQ")<(U&)^!"8O MPE&!0 MK3ILDRAB.1+/ ZS,,>6^:)LJ B? MJ0.SO*,(X:-5I_OSS?SHK9L.H;=,<"F:JLG8'K&47V ;^4,RN&(CDIKDS%3&+ M&PZKLDQ CT]@-O@*>)-PL(!=9@ +%]TNC_NW8$_CI, DE(K$B0(?]/^J(%PF M23.$#.V7V.51R?0O,SI:+)FI#)(OP14Q\H M\09>#[Y L.-D!6(7?D05C P\ V;P)RZ,QN.@5?#2^SDL2<0]9%/_MAC%G@-, M(FF/P1_!G5UR4%48QUW*6!=>X_(H$SQAX4'E0\:IW'- L1/M5*S!O;^#DO#@ MZ9J$WL8333.MFC9>]F$WT%R0I[ :B8C2B 5*[?*M1KQ1-=TF :JM*%=9R&RI MAO"%=-QN&T72FKJ5 B;[FS2GSB-X]:<@?GD7P72G(MU7$ 2>@CT7BJ&_04LG MVTI1$E=^K8*-R;++[OLX8R!1$P?M&?0,(]#MH*W#LHD&$CW3F%&AL_/07[+( MC(>E@[L/P*&A)X12R%/[*M67VZ3:FO54"+7[N0LBON)4+1 'F8%H[':G4F 8 M)94D8E/P')2*.)Q9(FRO\B.$)Q4A]!)O"DJ:X2Q#5^PLN#!P%*=/WE)X>H"I M$I\J%N%R N/R\Z@6Z).G[#%/WP_X'RS)[UZ.KRY$Y[ ^SD%3_>G#5KI"4 M8IFV\9+=0N[KQU\_??SP\>KRTS=V>77U^Q^?OGW\]"O[_/MO'Z\^OO_ZTG'M M.]V6!G)J99H_(F$QOL_$FVZC;J1)]$U$C#@HAES$HS&/J0C"C"E,<3#98RZW MJ5RT>,2&E- #*+FW1-E*.U0@SQ?.]P=4D_3Q'.&&IC8X;A&@T%^@5!7;(+B+ M%Y02WDIH^:YCO!V>XUR&%\\ZY[XL*]3+W2QZ>=!<:VC0W,PV#!RU9? M5/:ZLUC895652TV6*O1M*KQY+D'=QE:M(N;*B>;9;MJ$%=&3\ TQ&QFU_$P]AQ,4X-8+N00;DYC!R,/<^%>Z> .729)#:% M$ +'^];%W7+ #F /9--4"!N!\)"C?>K'<_@>,H]'NNYF-QI!7XJM"@+3H38> MQ0Z-T+I3J6I=7T G@Y# %$*)WX;\5H8GI+>2 @?=,,YNPN [#U.%"B^^2_,! M\$(>"M^1IQ%VJ?D06*6]*?&:.?=$MD#UD3#"PM43P3@89Y0L49&F86FIG%=L M$G*I@E$=1GR"0$:5#?QFNC9:&-_E=.JB48%^H;$QOBWRA]TX M'@;[9/Z-F ",#EP,C.2$L*#_BSK_%@,[08CQX"3*3 H>QS@]E%M ?#?.PDAX M/Y\*R90'I3WC-PD+)BE0"* 0/PIY8,TN(Q6LW@#MD*(RS3A&>Q MH=*;5M5-GPK51 #56R%M"R/:]0&$B=@UU-?K;('V_1SRA9LLV!=^QWU8DR]R MWYZR?6I0NCET9=Y&L654Y$YOR;XKDNC81XD>7*HX]7^W/H=- T V"A^1A2)B MO\4N)&9DHT18!I&;RQ-$GQNENUZYB$H?YT8E#Q8D3WYSKH,U-8P;S"SWF%,9 M8?Z[R.^<,2^(HA*GE'87_Y,$L9/N4N475),MBC"*D+A>NM6\E.B7'"E8"SBA M])0\"O%M?9^@G'9OIGBD M_)BJQ70N';$GMXLN M,HMSE4$AA[&5]$::5;7C5=D;74Y5EB:_T/_3OY(L^B39>4.F MYG(BM?TE,^.W5 C,N<1_D<+385=SQ[^5R2@;0S%2LHL4@O2/4G:( W>#$;Y" 8 "\R$,O,E(H+<,IXG";Q+%PA>.4T9> !6"!=,)@> M6E"IXX-"-5D[:B,%ZZ874^C@9J"\V>D.5UG(JC"-/"^X+XSL3*L6K."6[6CD MM2S=6*C_R^U/1^PCWR"WH%WMX2-"D1.]^1HY@M3> MSG+['O(!JGE\4EI$F1>P,922L1'X,G]CPW^8>,(I )@EX;8AIKR>6X0;SH&@ M=GJ:;&T< F5I.EZRQ 1>9Y7]P2G"$\+L$R.61M7$B4&-@*2=EUTC*0"S[XFP MA++@A1"5I6?OH ?'4TRXJ@$F\V'0,)0G4D5J:[85D%TM1BS^,I%"0";);Y#( M*%( -UE-2$DG],LI7?F;-LSL+]L?(I>J)'[E[$NY8R(K#)3318A9L_DQL&WS MRD3WVJ#@CX[,-$Y,R* M;8 !=QYRL)S2B)*#656OJY% J>&'BQH5-**ZJ/@7/4GG":UUP<)]0 MPP0W0%0GSOVG]2>5CIMDT>@Y\&$Y$IWNEZVR\*,;@CP0:J_T\),!?LWFQW0] M_+DE?K8EW) 7<,$X:*[J-\\I/%%-P-]B&9?9JB3$:)^J*H(;!(NVJJ+1^X37 M?,9#I/WE!%RN2/AM /"($ )?+3L55X2KJM&J[#H1*.=I MF0 \@QC(.-8='I)$72'=5 2]V!>H0J>T;72Y/H8B!@_6//>D>X(5S!$B[IZ76Q) .YX ^Y2S'$(ITP",?&WP_#0C@RXB,2GX$9HYS0 L57R+=,S(RAI07]B[18GCUW MQ(6.!9[*'EI8^;#&\<'2=*[!2\14&M:U\*BMU1<3QS.I2O)W)%<_L,[W7,9- M\M.F2>;R"%;Q^$&3EOQ 3:+5KG6^=Z+<#:=3=2I'ORD6'2\*LNT)A.S,C2N; M"M*$JEA+XDRR"+4*[_CSYDTBRE<]$^I,)F%2VE2M"A491_Z!EI6(4*(I79++ MHA9(&I81;R\G<\E[LW/G0#EWD@I3$1K>F%-%-A7G7BN2&C6("/$<3< HDBN' M&O]/EMVQ&3S)VY9S]2SI<'ZHL2L3XV\.2&ZK8RHE]^O4GUG#"NY$AG=<:J!" M%#^ZG[ET5F7=?RBZE(.U:K@PG1&+YIS'#YY+JFE*']*D)JR6PKB/1&^\L!AV M^B0K#D9MNS-42^U#VII \,WN/IH3O*N8X$96(,"] \]52&I,_]B4UEGI,C2@ MRR)ZTZ%HO%S>MA-'F2H'B*%]2+"\UI]N/,<30[J-N9%Q,TG2^Y2DN3>V(U%, MAH=E@ $7*Q MS+S9C,++_,"9F*&(UZ>SE/D;N9"2?AA*M2WAJ#TWXC6-F!?,V+!MUM^RW$GQ MX3)/?V3O4R[XDCD'>-&7(ABEV_0:*136#CZDU76CPB.KQDCRN$J1BKN>F"ZJ M=6'N%R9^RKQ^CF);#XQD_K-=S MWU4VKC@R40Q;G/(K!!R^OI2FDYTIJ)S&,(IZ=:+@HB@6652D*P)+V\^ E%/! MRT)-BK#TO()(3LN%X\VJ]%DDJHD@E\"(S$#Q.* MW+:(Q[&7)QVF*X()5F+[(S^+DC^H4G1Y9WIV^5TRFI<>Q97XG2M(%\V:8>7+UT5NLI+;=I@;KJ?F!QFA@$ MCDPU%B:/$(H;UE\>*8]DSIF,QTMVR$Z1R$,&A6VYE>$$6=,?5C(=G.%1%2!4 M%CP_&3E0JY4E2R1\*4ZS:#;J1@I72=32H9K2#A<&2[">A;]^3:I@W7#*Y&G_ MO+AN*IOD'=63D+$TJ\K'N-*=KLQI,G!;'A">:5]Q_NI'Z2!K4>$;#T>GGE:I ML%;(12V.*;L5.6]8Q2=/O8L<3Z0U;TQF;^_J'!_V.M/Z2H(S!XKV4(7]@R># M9BI*ZF5Q2&F3]7 +]LZ=RN,=J'JP2*D;+K)30IF"DFI.6!QX^J9(E-ZEM&21 M=_\B;>:$+H!X>561+CUG(E,U)43P#H')M*I=$A5[R#F.*[4\\-;L!%0IZ4). M(S5_\O-0,$29WQJ+8MEYU9#RB+05#):BA$ON8XJ]^"@K 504)"Q.U.3'=DJ' MH/.WX?.RUU4*N*0C2!\JIR\7)S\1))9LNF.Q\+!(6AM)^F!.-+\H?*[RH71W M37H*XN0O-O(T_")^]3 #I&:E/,DB;V(Y-\<;,=$IK;[E.0F:9U5DBZ MK]A5G(.PU9 Y3T\Z(]-OT1BO"U$CDN3*Y1HVL:.EYC*,U2R M&->F[!-+_PSA]TT61\$&)F*?88/[2AL:2B9Q@"R.+/48&PN50XIY6 ?]&FG0 M^'!-6GHB#:FF1W"R>8M4UWO4,R:4/%!5 M;O1Z%*&2SU$8BB51E:+L\6(PLBNN;%6Q*2&CJB5:AFRJB;=H80,#(?5PGNI, M>R%W\L3C7::]GO"NQRINUFCI8-O6@VVRE.%E4?;_MZ+LOVYS:&1(^>.#!6T> M*$2YK5[-T^M=%M?+RI(M-X2F'CI%2%)CVO,7?" M6RD1\<08S"!B[F(!9J'8)I-/D!'H?GC]/OKT2V7XL_USOL/9:?)&(7FDZ,6[MFPEK8FPTN'5$VK)7:N6_N#^ MP+/G8J%T&W$CW%M)P*RWT9H>D (F@T'3\]NKJF&S.E6V\2RV.$1^OSB,N4$A MS)$#BX%/LY:O"1[KCH)9?.^('KP)Z/J\W?/,_5'T4\8ZJ%Q4.W$7:&"4VD%) M-;^$T;BR.FC1&S[KD7XA>J0O>#P/X.^9\G?#3S=5# M872)!9:5"8HQ5+92RUE7V9[OK,QBPIZ=.W;:8:I:JH5\$2LB)$B=6HA)X6X>%C M'VB7.^N8505V:K)(*PSDNBBK+(.ARIL@^+X6TZS(+KEIA(DFHOCK&Q5K.!%[ M*SL7K?24)1:.]6\O<-7?F+#0Y97'[^77^-B:P'N;W1,'2WSPC^+!L?!VL;)E M>LTO9^:9^!XMG4GV?0NU'^FANW#"6]>7@W22.,A^",6PQ"_W[C2>P]5 B!NT M3<(+T8!G&?$WV8<-+B_&'>:?1)ES&*W_RYEEG[$0ED1^R2_^.9X6'\.MCQ"# M^>6LWW]5>4+IT=N>5MQH/?<^^] O//1]W:8,5.\5W,6X*31Q-Q3MK10L8$W& MP>)M15;8@/NR("A_E]=7?I)(Q5\>'69).J&-B1;3F[D[!8ET#"^S2NQ\N-VS MAVF5RJ""$DQX9BQ36370<@O]]E<)2B(+6,/N"<0D9B-F>SZS7>XPO(@!B0$/ MPH!/#U,>>("?*M['ONM.IL$+P6)9N] "Q'@6I31C_/.?Y"Y@D$3@Y$:OZ^$L M)-:-,_E^&V)]U(O4XY],.)_-CL!O=6YX7*T':E^LPY[+:3L)K@NI?E)"FD?Y M:E\P[D\)P75*2='O;[9M?J:MH_VR/RO@J8( I-A(PIRLA#GO]D:'H48!E?KH MHYQ3]C9\2/J0]"'I\_2DM9<+GU.Q;Y[N6K7+@_JP-:?E.=Z[?43G73V&!K:I M"D.Z+'7=K@#IW+:"X;R_);GI)9;':5NM!)2V L4RAZ0U7FI@:>34U4G8[;G" MRC%4W6&T-G88E5+[J."S#=.TE3D^SR6;+NQ%@5_=M=OI(//<,FQ[K"9 \U*B MG;;I2:@EU.Y+Q.'PY4X?:5,*,^)]WX+8\6I0 %U@):S?Z/$7IW77^P@36]XL\)5#!06,>+*AA0!0.J8$ 5#!JY M@G1,D<[T4@4#8K8&,QM5," &/!8#;K[IF8[8T8?W="%\8]B;VGD[#6\),)+#R0V#H)4%8&"PPU3^$Y!#)(9)#:QY8;UQ3@;H6&SS-*9MP M!(%SA"H.XNO&^8D/KN_X$]?QV$<_BL/D\7T0*D"Q'ZG%Y6]<\+7=B7S21_^. M1[&D<#X9UV=?^22!I[@\$FE!IE_;PW @/I*:O M+8\0GP7JQ;V#/]\@;[# 9_]) KQ\&;H3>,9YXCO3OQ)\PFN'EQ)@[\)(0!@JCP!.T M$8XL,_EBY,Y-Z-YS! $/!L!;+>2&<7\W !K (3 M7#$Y$Z0HTB6XB7B(4Y>3D3/.B)92*XGP:@<&"=^G^,O4C29! AR3$TP^1Y09 M29\DI[MUMIL83 .\X2Y3V'.D]A;(4& R]-O!HL2( DP3SJ4 MA?,=+H9K;L( /XG5C8"T,P]NP,G!C3 0250G)?;Z"MK9"AJ"@W%(M]SGH>/! M #9&C_2#]0N=6T'.1>+%[K*@SHXAR<44[ U# *8*X6EQP&XXN\$)^K<=]N<< M*].D-^"E/D@WY\YQ/4F;K=05Q)^F2SEQHCE#_X$M@BGWHFR%HRA9+.7D!4:! M319.G+'CPEGA.*+DYB\N 2!*Z03^16GQ)=%8-^=V/4P,U?:/%G+V+! @* FS M,[%(KC_QDBE?E\, [3M83;%JB5\5B(5P-0#F"U<(/R>,@;VCN;N,),M/@@4P M3'I9P:H @"=(X])#-J33=O'[)(G+K%3"IA2#>W[ A/Y7<#$'3A=P+'&LE!IE M"9))GIT" .;.?0GY3(Z6)XFCV[(V'?8!_K"-NH*X^R[/O8!_:0+I:+=(@O6! M;16SB;_YK/69YW N258?)!M.K,*291$RQ6<$2WC++ P6Q;C@63,L6"6J<4G) M@P/%,8CE3I5/03I067=N%( VDYR=W;$(HCB3W%C12_!!SFDWL2.82KQ<7"Z& M'*8O"( 1$@!LZ*WP>:6%ZFQ602.9]>2T?6#UDG'WN$TG)0^ MB #DEQ K%$X+;N$_+J;9+;@R4I^L_\I7GX&AP0H*\Q"!SU!L MQRO!Z+<^W"4LT&F^*%$F76\G$ :F%33.:.?RM?5CP7T5Q6 BE8 =;PWV7(04)$R#?R=W36 +A"%P):07X( M]2?-GXR=P!J&$G.6!1(FR]>+865NW%EQ3*N&&X% M]=@L9^G2&%(;&^5+>7K%M:#)X$63.!(6F2O,R0Z[?N2QGNOO',D"]1L<,2+)-P&41I3+$B2E.& MVD#.$QE[W_*X9;/@I>\4#ZQ"0022''8; E^GMI%TY<'.FYRJ"8"KGR.0FCQ,$P2B"H)326+^8&]WZ]=U)/Y[JT1I=1 M%&25><_//GZ]OCQ[#99ZA+5TG-N02WO(*-N27@J8XL_BJ=)R+-\3E[Q @1"X M4H2M>(C>EXBSK9;H0@*_":J4B+IU," M5F:=$(")F0.""^Y%*[8L#]"&$9??NU$>V1'+)PQH1PX61X-AGO0Y BEBP 5: MYXXTAL1.(CX F0AX*6>D#?()*V?]@4),YMPVYYZ(6.YZ?X>M.?JKU-ES%\)P M%_\5!;704 JD57:/M,,86"Y),I<6%!F8:.%*B'MV[X1 IWA5NA#X\[<_@3WS MB&0,NB*6+DU9[J!X >TEE5.FP[I@=2*!4>'(QN4M(1@(J#M^"^C]L/FL+*R8A3!C3+P%71,G(O3;8+!$% D#6R3 47)^$Z,NO$)> ZFE9793,GE+$ MW*@J?T [7 P67LG,$W-&XCQD,*J/!FRC6F]"\;V#9=&N">%>6H,%%)>/!AT %P@IIOJM.PU MV^>1FG3/FH30QL^817 #@!+TAFG@ILS^%=A:@L# M;Q8Z*!@KYO7Z(X2COXYVG$CAR*0*(4=_:1LZC;&AV@(6S$-S^:6X,N(IR]3& M!D4#\ &A]$/&"/+)@T"#J8K-]&(62UBS8+JV:<6="-684)["J(Y*"R&V5U(; MNJ1W5]7=YY*V*MZ?"K%M C=Q]*(5Z\!F2J,CX@MNCW!G&-5HZKIBT MD%U5.LE(@W08'#&7;.=BW]$W5]ZIW=QX2"79O1-7H=MLJUP*9I9U+IO2C8C4 M;A92)MW +>[./=Z*@,E%NE !PO*?))XC-M+Y#V-M\QJ@E&W]KPJCO*"MV( O MB=HLT46XYU4CQ&>BML^6U*: MF/T:A%PJNJ3$D=1Z]E]@9,.9\P?-U%,)FCX51>LW6QP?1:R]EX.%]#^"1[J--2HD:6>)8RD(B0 M29Z2"UM.2*ND]>S,0".I77?$!:7U,LU5%HL4<7!7KZZ_BMAB&D'!#(;"7"CB MC)?B0HSI;P]O2&F.)7Q@=2/\$',9#2ZB_N4G"_L$;#\1UBW"W#(*$X1Y($8$ MLR.I#(H$"KE7)ZU;G 5F/>(5.,;;Q,$8*^=1V;&X259K=G[J5+BSU#"L/CN/ M;PMK/=X0]8 H3[Z AR@GY5CD6_*AP,N18,N0+]QDD4J[+(Y<#+TL)&?"(,?- M 9F0Y)9I60K\R_7(4EYV2($T/W.'N$IU +RPDCZ:0;J2#5?V]A[0+_;KBNJM MJ+8L>)*N<014<::2O/EK2F'Q7*DT VBU!V9KS3WX.@?9?/%.+!>*"P[:_='V M2K2[\'09C%M:( )!S;K1'*$)#PLFWX7=X@M +3T %X)/IHT&J#[Y8ND%*Y[N M(:,*E4XL[?_4F!52+)J,6Z59(9& BI1LDQ)4JC9QD8%:DKPRY,]N43W)#*_4 MJG=P!V%'K*;RCID(+^*W<4O7_^(P*"NB.+*>8QM M?HWPJ?S\^1OCQC?*I#:9(>9&!86DGR#L";%OBTN;Y4IFYCZ: 6+'-8U2-8-- MFKWY=ITFL&YA3. $L=2%>9C[7QM+GR,D@F&+/%?X2WJH(^N$_%F(I/!P'?,>%%& M/(_ABIANGA J,'D7X"@]=R._0!!%+$<"QKCGSG)2P<4TABR/M6V,HL/>SV;I 1WA[&%[;:,R M&+QCRWQ1-E2$SQ0L9U"$L(I!*(R^S(@%]G+6A-+?(G:%2=[@?H#G[?I.N,J$ M4IZ!+[A2>!\RZ)+^'448VO/3_/GG_P1?P.YA:W!S^#JSP0O6[K#/L.PA_J&8 M73$0R4US1Z8TB73;90)Z? *SR<)=(A4F2F8 "U=X.=R_C>=B4JG9#T9O%/B@ M_U<%X3))NL$IW]#CQ[B_\0 _RQG(@,".T9>3UW>\+%TC> 98]+A 8/SE6ASO M*2U8Z2Z4'&DH2OA-;B4[JD!E#JH**[ MT^-%<(U; M!.M##AY1$HK-MCS%Q\'^[IZ7H71KP/#>WT%)<::U*J&W\4333*NFC5<$Y'8 MS05YBN$RW.:2"Y3:Y5N->*-JNHD#'R +,Y65GCI)+:CI+MLHSZH4 B;[FS2G MSB-X]2?PU@^V@V-M]H9X#I%?JV!CLNRR^S[.LKB\W-Z,0+?/\!1WR43S5KG& MC'CI$*Y(2B[.UQFE'1>1+PV/3.VK5%]NDVIKUE,AU+*-A9)3)<[790:BL=N= M2H%AE%22V,6%YRS3?%*YNU1YA/"D,#TK2##-$^-3(%-=F?P- T=Q2L=55(2, M/J3I"._3R*5NHVZD]ODVS_;S13X'VCF)/TFS8/*4PZJ-+"$,9H?X MT_PY4NZD3UC/"C%PJP#H;6R<5\G/E\K+L"8/<&YW*^%[N>MX$?A)EY['+L8W+^&!NX37@>G$#<^Y:&%VS-FO%/H>, M1IHJ6K424K4K)HP9+&+Z0,U#S?6G4<=F\"!OV_;HLR(.YX<:.L8%E0SYS>&H M/>P,E%+[=8?]D<=O\N!N@1K)3\LPN V=A2%/@&18J_B\8,O> BSE]2F^99K> M?2 \69@#V'=O,&'&C28A%U9\N"K^5LJJD\>)8YE4@PHNBK(FM<#.L^?/GA;^OCE]^OWV5?;>EO*\,"8 MM!A>Y0PD;E6D40.,8P;%]>6@:0"C=TK[,64""/]'QA(P-+QM[H[OB_(3@OIN ME(L#L/,K!/M;OE RW2=+1<-#)%E$)-.RPV*Z]:RSZL/$E=+ M I2LN)1UQ!M@/B$F; )Q7$^XGZ5:.?)\TS3?)MX=W64R!F0 FJT0QRH M&= ,*:ID1&(OL@ *[GBF!)^!H .JRA7V2R=O;C ?@HL#T%'!#3'W.^S2!] E MH=#T&4^F#G80+E$C""<[C3[. L\+[D5E"UC:3<9:V]NI?6H5/_2GP+T0>*X@J M%$M9B2W=1M](A*P3URWJE[&_ OC&,%\<=X6"+6'7M>.QI2/AU_]\SRYE04@0 MF[_]=E4VQ0HB[3"1X>ZRA9SN'Z/Y*F-8J8BM#C [-(NO%GGUR6]X'E6W";0@-6 ]]]P/4MV_K7!< MAKAFGX&EQ$$3W8;?2$OH MG1.Y$\8S&B]YEK:V<:):+@R&3-)$23\1P?JL;+I?/D>0&R%QM90R"Y(8R\_) M3-TB5SC-X"^H=^UZB2@ROCFR5(>G%6[Q.I0]6>+ [,$S#&>OTQ!65D6!+<'Z M\6-Y]+D\"\S2$YI>YH.*!Y6/$_,?/)RX41;+JY9V+LYM8!FV*$%773Q!UG&N M)K2+2FVRFD:2'7C>F$-:LVHK3<41873#A54JXECY4934>2]'3ZLE1=,7IF^1 M-:BDZXZV#9:!0#LG3?R6)9#D\?2XG/LM#AJE>>OX@CO'DT5QTK*AQ?ME"0J, M^(E/YV&^*1N(\MN[9HGUL];JEPJ=DC-ANFYE!D/']@:4D$ATG*39]3OYJA37 M6:N-&.?E$&5!&1ZG"@X#EG@RQEACD/(@'H2#Y*1T2GG\9NT\PHXI" 5:##]R M14UP40Q,4 F]=7:?9;!A?.B>_1TIEDW[?(P6_N DC^B=^S+\'"V>A, MN'#"6]>7@W22.,A^D&T0Q2_W[C2>P]5 B+3QFR@)N8SXF^S#AO@NQEUN4)TW M@AMO[4:^1XMK,99?S@;]5X^VF*OVLTMOM,SGWGCH^VB@>S%$RO&Z] '5P,JJ M$CL?[NA,/:VVHG@[-1Z1FTJ,YG]S<5(%M4HIJV)?8A&'O9##[$#:6?I5MOG,EW/$7J M3R_2 .=DPOELUC*E^^=ZB&F+3W\A/6%5V%9*V93YTRO6.%^;_N?=@3$8FD9O M,*B=B'401(^MF6.QF#+PJN>K9RF6PU%.&SIUAX;=LXW!:%@[G0AB9+J=(L(& MQJ@[,BQ[1 BCD,^^)'R?[R#FFXIIW]^L(&FXI4C ,9U,;0"79V+9RB23+EQ1 MM^HB([#-P!@9O;$R)420(*.M\8BP>CUC:"L+/;0%$Q06?))AEI];EPDQLL1Q MC=99-:QM;<2RVNE'U6#6/9N0NC#C"84R&F8HGB9&!W;7L$W[Z$0D?)+52O#< MA*=I&]W]=X<)GA2G5+-+GF:)U\-X76"\:9!@'O9+$CNT06D-6^*/T4L7;FI? M,*?19FOKD#4T1L.>T56XV4W(HC I 0N U1_U#6M P*)8JSK:7I:/";*=IQJU M]*:UP:9M6<;(WONXSXTP+EN)KSKV)0ACVF"L869F*R%F6R/#&E.& M,L4E]R;AYQU%+@K(52M=K%6YJ):SH*R9JK=G#HTG'#([E:P9K0'6!/NPT:"@ MK&,"!@&#@/%,.^UG44AJV_4'&]C3*FTUNRN]HL&*KQLG\+\Y/V1!?LU&^Q3I M].CPTJ7OV8J77G:RD>T28W;EK!:.SSY&GH.5_3SG'KM'L;R-0MIDVTA+\:&M M_^MO7V2;@5]#SGT/A\V^8(>,B 4W\%7VF ^PG#R3A>73ZGUK[\*^B6ZY"2(V M&'&6;NQXLH]BM7#B7#;]%MT;8N<[CB0OH?51> M:F!+K C;'U2:S(BBE'CJ*Y*A;WDKL!F\W9_(4O@1^PV)@Z-8B%I+ABBJ:.3- M4$3)P*RG_/IDN>],1&.Z%?/XK9LUCA27NXME@%U0L%$=_(;5]UVLIBC)8J1- M);%-_'(9\HGKI%UW\1=?T#BOC^C(,N8S[.> JS=-L-\Z4E@PA"@9"=<;LHTZ MWGGO>EY!"-FE'E_D@59(2U_C@AO5U08>"=/J@VEO7=Q */KSB,%ES7\]!WR] M2_Q%?GP''X&31$N+-)DE;?Z#]4TPG:]M6![ MIF(Y\#\<2XC&:9WTC>8*W]57&3:(& -5N_(+(2SKZFQS//SSY^ M^7KVNL/2&50*P\-@!-NF(@5&FC:L\%9%HQ08](W @6S^Y,C&KP?L!]?MOWKI MJ\1S3J3B=*WZ\-"Q8U7I^/;,S<89N3(@P]/8]@M:7?+H*% MWSE>XF3]X[!_%%AJ:?OQ0KW(BRHMMASLV25TB1L5?:=$>6Y7/'F!."#^EKE\PK@G=C=,>_# MA<:B4[1,3T>FSB*JE4V:[75^Y:)=&Q@FHH-FZQW0'5RA/!8A'=)2#?O4C1#; M2K>RQ\9&?P(WLP[=8C4DDL#K%<@>%R40^$HS-( DGJ1TJVZ;B M[Y7&J++;@+RPW!A2]'W%%E!!*.N29P,\29>DUL8SETE(7;JXVQX5QHQ 6SC6XJ=%< MNBPYZ];1ZU!S?JA5XO[_[7UK<^)(TN[GG5]1X3/[KCM"[=;]TMW3$4*(&;_1 MM[7=>V(^;[]:UH".1DX/DQ^1?8A)1\X055GGM:2RN*#X\ZH0'/=%.+F%15P&7U9[XXK-#4Y9"IA\!?/4YD9J M_IYI66>(663G\ RWJFMR0DY/[,L?I&C?R9M'UB%W!Q;3U'2:6VWY%,'Z2\L& M\,F)!H4].,G[E=NI:4;M9;1GFT\S-ZOS2TY.O]K].WM1J@IPR M1Q^T8E:2Y0UW5Y)I#"8CV^7A+I"1SXK.DD=-!QF#:5Y4^^9%8_C[H:DP<=*; M*(;AYCQ9&LJS1M_ZP,#Q\/:!5TCQ:P/!!B8O+U.[G-GN>>_KI7.@,_5Z1)LV MVV/53U>W?0*6.BFL[;+\6*4RCUM;&>(4F,$OG)^L!F[96OBYUH_MVW[A,4<" M@T>4T+GF>'PM,_$+[]1R&>:%DYD[GJ]$N"[EUZ_0IK*%T.Y-9 DBJNEY;2D6 MEP67V"R8K^-*]2DP"=9L/P!(=XHCS)G MM_,"VZ.S&5+SI1 ?QKQ.4 ZJA;:"*B8DXR3"JHS'4>F'SB'(1K=L75&RDSZJ MQ<07@KPM]8[7*U6-_3A)J[KE@$ZX1C\#YJB;A*7XDTK3_'DRFL: 1[:7 IU* M6>5JMB,PKSYS2L-4KQHF ?K(*D:7(HO&LY&IM5I80B7P34+G&L-[S)>]$UZ9 MOMI!60KG$B0+8JQV='(!S'E@=^4C:KZFW]@/P1IDB^Q9=;\E"L,J9?G,(>6(;F5^DCR:ZD00+J@"'6T-F;LS 4[J.:AK?'W:,54:+.8D5)I2[$Q MD9"W8(44*XS26+%4]9&QXEU'60JV!A#HVWY6N(P=: L;\V3>V+#8-D?M3U+5 MSRM)?S1H_+1P_+1M2U<^)1Q[UA>KLP?P7AY_B0A(PKT&4V+>KJ5 M2@O5[^53YWZ<7R7E5XY94VDX?)B#QFD6!FPAYT]J7/=&**K6,VT/8-U7!HG6 MG6;#6R^\R?>9\K)Z0!,W_FP9GTV*\3GBJF7SZ,UFN2S^$QU MZZKAYZ[ZXYH^N'[DAD3"Z/RAJ-3$Y%(KU50,5K75Q$?S:<8O/W]\ER5O;SQO M^OYRAI;9>NL[]'$(BGH%@N@%T?"O3[_\[6-U!SOP=PO+;1HG+K=-6'7P&5E5 M-W$2@3\NZ/BWDT&?#?4_U3^O^B?$'\$7H"1OI7Y/-F3-%&6GY_0-V^GU5?'A%]7:YK:O4M"SO;KV>B62U=>,=JM;W\P[YPB6-_/[^R/[^T M%2OZUEDOT<$Z-0N,\>4]6)"/PU_X HO-*$$^=>7K2,J MA4KT(B\>L>?VB[2("8N<>%S#]-[GE/,VF^:U6Q.@OJR<96N&?&[SS#>O;/M\ MHW@0AY?RS:IB,<"=$\G"$_.9:>H]3,KF@ 1&]#HMYF/?N_:#HESPW*WYS,[O M#GQ@IU%E%^2S%;?)V#7U5#C3JL)L+EN8SM.=S2F/&7VQ -IS%$C86?O#J)F9 M\/$@D'O*0R?XB($"U@8L-T$6M9B9$%X&=E[,=V1!?!BARF:-RU:8K@KFY]&$ [#XSDHW*11R".R!/,@![L-/%2$,[(QBND=+[$-U,9<.3XW>6=,%9+_S8!M))%A M2S3)*=.#D_)YK&)TD;A_%@50X]U9%.(\]\["PQZS\*Y0!Q^:@=T=&&\S/^09 M^2.ZASD@%EC-:3I-.15J8<>K,PX=?\(N9_S,N7A@/"DA'E,(A+=PP(Q3^\; M\(CC\C./#(;6IG%6.OAX&' ]3G7^H3SJ(P5:N,Z5AVE>_0GL7?#>6W]*X@RT MY\W.1MLZLYJ*;8KS&)AB_-*(!4[#4/!I$(8^+B?;%5/E(R3D3%S!4H7 R^>#9AD*6+6=Q),I>B&5[NO=H]]4,CQ&(P9IH+"8Y]^ M,3) = M$QHSXP^FCRHBDL+;H>5T#/9]FM3B(N.BN7R6K_QNA(>9\I@@=L[EJ3[-5M25 MHS?OU]R3B^7BR#!;3S5#$IP 6,,H6'M6Y@]J*]\,LLES(/_*=W6M*63@K M#WN]"?W2/5'=;+O=1(;'32Q#F 5OT+=1R"_M6/_=2V/P91 M/"&7;Y79S\O!)["E&IA!M;"Z2]<1BJT2XMV ?K%#@FQ;/&091(+:PJ&1'OT* M<]692."Z8%F0[K-X&_ W2W+23KSU@9SR;:NUEX6S9N;U81K#S,0\*#=F[#%AP#L\K"6* ES1C!J=[JK50 ]J(TU^?Y""?K/2X0- YF=-_=SID+NU848< M O/1*OME.56R0*+%PI"[/ NE"!HJX"&*>K4*/J*X59%4>3Y6F".9!P4F8!8; MP6^HXA/+PEA@4(\JSWGIZ\H"6&"P"*9F+)#];H(T KEF];*TV/GFQJ%MT<1T M LM#MD):J:1WGA_P)1-3N?QRE-^#&[OS38Y99C+F.>%88%MC%=*)@HIA47Y8/[ MHU*#I1<(M3&K[SG75L4LG4UY2S9M;"=#;GJ56GA>.6QJ8>(+^,GCOOT)#V)F M_YZMOX>%ELZ<9V!A\-QA>;*--%H%5>Z:9&ZO4GZ5,S," ,&/\5\T92,01]G- M;1DJ'SR0D-Y$J9\G$X*9)/&*'7YHQD4&+Y7$:^VM5("V/-S/AK/8R8)>\?V$ M<>X#G(UY$3(Z3-D.RVPGIF*664-YN/>(0COYN5./W'FQ3]FI[3$9>T6<0A54 M"TUG)POS'M4Z3J#@&/TNU5(^J+!AIN;KFVZKTYY2' D/+&E&> M_\U"2A0QCT5LR$(:130_,E_T[3&H:EUCW_!M_[$_7!P6)JE"D2;1"*YA^9>2 M+)GF$0?,BF8[TB'7%W:,ASV?Z3?S0;& :Q@=N B: H-T1OJS(QZ-]+2,ZX27 M=S4(*#>#))B=U8:6DJLF9VX0UW%4FS-YRHT#<(DV\AA)4$Q=4/6&Y/VT[5.# M4O;T?%>?$/,Q883^V;M?D3-M-BG4T3OT0@9LMFT ],M/L90:,+>ML2S@L:X< MW*_'K#46(N!/)G3DYQ, #U>977EVS(E:VC24QA%+I<+I+D^-Q4X8)=EDP@8$ M1KS8HE_PDRW=GW_?A(%89+AKQ*ZI M'ISW'S0M**[Y[40\X7\G4V]8_KU]?#I(\L8/\T:" 1F57^2Y<_DW]_XHO86K M01!%Y2584 7>-*'ORP\+)O2LW?4<\[-LK-9>-^>U$-O^^-M'K M?-+8XD;IN?>)NWXA-A0;B@U]R0NQU$5'\HT?696=JKG:R=.RFB]4*"\4P7YQ M[O:GM6F-K;*EO/B?"R>NEJY;4+50M1I1K<4=!%0M5*U&5&OC$D4'8D5T3M]0 M/AOB4=X#'M?(K; MQOSVK$5]ARK/M[EGT/,"'H%:!?1+'VK9^J(QSP37%+ [)-/.(7YW@NM,05A% M$B39$G1U,0J[:3EU!6[LOC8K*"/"NB"XSB!,%V1-%4RKL5T[!!@"K ."*ZS> MXHI')F]GT*>(@F%)@JFW#[\V!(+81&P>+3;SF=%2+80F0O.U0+,SZ(.9454- M03+:AQ\B#!'V"A&VN_GM6 !V(*%?;8KPG!VEXO5*'Y^-9D7]V&'B*!Y3G^4N M>+JF)6[V-$9/!\U"LL:.E386V-L5G+0]ER,FCA@3U4Z;W)@\$!>(BX/'A:(8 M@B$W9J\B)A 3!X\)G"L0%XB+)7.%J@JZN9C\"3&!F'BMF,"Y @- GR';BUG. MK47'7U.*U"%9'A8C'>?FQ.FJ]'YM26FF*NV)J7%DONFD$B'Z#AU]+1@*1[\Y MB!!#B"'$$&((,8080@PAAA!#B.U?4Q!B"+'7!S$,U"P3()0I\(L:-WD-L[+: M1;,>7*0GW#IZC5M'B O$!>("<8&XJ-VG840_P@'A4&UG-X<'W+!&M!PY6M"H M0EP@+A 7;7O\.N1IWW4"3UX'&E-W=H*3YA/T*M.?9!1EK+QGF0*HK>1+4G>3 M+['$:(8L:(:\?RFW(;'.$2BB&]%]P$E'$=P(;@1W)\#=0LYN1#>B&]'="73C MU(W@1G ?*;A;2$>.Z$9T([H[@>[F$[XBN#?B"79=?OK&$UH05^2-_> MYB73)%G\^X?54C2?)T1S9TWE?_LA,%+Z7M$!BTUJP.\QI6' 7DXN*/$3DF37 M_Z'#E 51I[>4.-[#Q O)>1)XX2CY!SD/DRSF>RVGCC?U4R\@\ .YC(([&@X? MWL#7+/2:)J0G$$?@/_;SNVB6[OBY,T9 MN8)?E_Y(_,DT2BCQR!<_]"?99$:Q91]&,43+\@';$2'4_:N*92. M M ?RR<8.>&D$N8H]\CVDRC/UK.B*=[?ZOJJZ?:S^GO:R&.@/8OA6L]YT/O-)?W48WY55:5AS0#NL(]:%81YQ?\' M<'?JI5D:Q0]D6.-FX,YID'5$%+\:IGEF-4L!]">87"-V\ ?FBF(R6$J"0 WW M- C8O^S2IRGSC RBF%^W?ZFQ((:$131 4Q>4B?]7Y4,-'Y26=(LEO_?#832! MF3^($IC*[T&,^Q?-KZ>*:)UI;QI5*:$+'9,DY4QIN%M,23K0-5FVSLR&NP9@ MGH+AZM_1X.%LL9//M;[G%LM6T^;WD2T>PBB%<> 4RH]A3F,Z]6)*$O:/E]+: M##7V0[#H?>!<]AUGW(25UH ?H%,WY-Y/;XES_L7F.@LT#(^Y9_\)(S*!&V)V MZ\@?C^$[6!DDY)JF]]"+ZW;:_E_.A4$V&[*$S2LN!X:=+IM!5MW37SBQG M@F8,O :AU*HN'C:2CMU2?>ECYGOTQ,RBR%K#DR8;&.X)B293+WP 1HEIZH&V MC BH&JL0G^3$!!-0&OM#=@)]'$<3,O4>RJ4WZ)D/BC-**K=*]3!^0OTV"D8T M3LYF+HP_HGMZ1V-@'Y_Y/291DBXVI&[E+S:*$:\?WD&KX%L_S.DMNT[\D>_% M/BMHY%4-RUL,8B3 P),HIHLOJ]]*[J,L&)' _PLF6V#>&>G#>[CCDW5TG''/ M1/6.3?MNAP\UB<$X!QY[-.OEU/.+ML[//?./+II7-(IXTVDZF;X3!=,UM=/ I,FQZO(I8YU)@#Q+OS_(#M M?/&UR\AG)L!UQN3)%@B5;N?[&-XDRA8,@ELO);]?G']FZZS?D%MHS!:LBYD:('\(2 MZH["A.^/ZW-T:;1P+,)U8$[S=WKD.J;>\)8],I^QGCF-TL0D#OL(OO4 M-8#*9T;K\ 3 -(#*=KQ$J@FK0USLKG8;%6P77<,+O8+4)D!GC-* :2:%"S^ M%1 WVLMASK>*+\JU1NGJ_^+%-WYXTN4-GZ:)AXMP0N'.##CYE;)O00)/[WK= M%YL]B9?[[-CD^>/L\FS.+]C!?3)-;-J/T1'?ORHWO/_WV/7/+*W*'Y$4@2G M+XPD^'S P?-*W+==V:63S#/I*-594L[T5M5Y@>6ZNQ,KR6?F$6[$GBIG2K/= MZHKR-JV[G%Y?;4YEL0(%!-J*Y M=3<%Z]>'I< 4!IGO*E2N0V[[9=<\T(?Y_.M[#EQ=RU3!3!EZCVN_D?M;'PSL M6^^.!9I.O9C<>4%&MS(=7NJ,$\^DQ2)AST(G<^"$$2S03(N_KVVDN8 MU_7>BT<)]RK!7VP__X%--TF2T='3R^7R\\=W6?+VQO.F[R_3:/A7(6H7[+'T MX6N4TKZ?#&':RF)Z!7WN!7#-IU_^]K&Z*9N J?;P;7S.MZ[XFN8;V_Z_NO7" MVG?GX04-V.+QNQ>G/DVJA[%$T$R:%W3\V\F@S^#^3_7/J_X)\4?PA3=,WXH# MK:]J?YR^Z M!L'G#[IT_G#[/SZ[Y/RU<%)WFS>DS/':[GC_?N&Z7S^?__['%7'L[^=7]F=R MX0KD\U6_$8?7+KIP^>/+%_OB3_)M0,Z__LN]O/KB?KVZG.5WDC^0;U=_N!?D MZ@_[Z]PEYU^ALY_M*[=/OML75^?NY:'TV;YDW6UV6EEXTQ,+4==QO_1 I$UM M7"_O92-V4;/#T1[,Z[:1VIQIM%RRI_0GF$%)DD=AI+=1EK S.\Q6X0ZO410$ M8!,O)BCMC+@VF$KG'.WB(S\[^[O^FF*14#_>*+%KJ@?S,VMD2(.@N.:W$_&$ M_YU,O6'Y]_9&0.YLRAOIP:J]_"(_E\J_N?='Z2U<#8(HC@H.V?A,$_J^_+ P MK]K3R;.'YXL;I1V?9]\* W%#NZU M@\]+FCEWZ%=>.+U[-+DSE\\C5P]3OL"=+;:>7O=AZMXMY%,U5SGIG!(^K7B[ M,(&=*$%E0V7;C;(-/#\F_V+N/%0Y5+F=J%R1IYH];UGXSN4MI>EV*HEU #N2 M0O]8<2Q):X#\XGH#^X?EZ:]S'I.-2[A@2OZGSL%NR;GW@Z)M7-@;AR_G2^O^^O.U.H0JJJHFJ :4NLBZMZ=H^<(_CTHD"1UF< _/B='N*A5I M>W,/\6X\P)V3#^H/Z@_J#^K/7N33HD=;.F3S868ML.Q7_U,K,QOX++\6KO=V M"%QYW=9RDT+<8JNJ^26.)(B2)*CRXEE@7.4@P!!@+Y:3:8F"KBT> $5X(;P0 M7@BO@_/1'8&5_7-XZX4WE'OB6"Y=&.X$U[][H*&Y",W%(F8'QT:*)&C&XE'Z M1DK#'6^--X040FKU E43%+6YR"*$%$(*(860VI'EW*'5:INRO8I8OB2ZZ[WN M#DGW>.GM>'P%DB"JLF!9S?FZGRNZKN 6G74(T X!U!(UA"?"$^&)\'P-\'S= M\;*UA8,_2[I9+1G0T]$8E6V!0@50.(HREK.L,??&41QGV%1*AW"L =9!IBFH M^F+^Q;:DTQ5]0+;4#K(HF%)C^QJO);<# M8@HQM1I3$BL#TER*0<048@HQA9CJED?^2*SLFGV-_H-]AW>V<02G\POFW9W- M.8H::Y(@BY8@&RUY7+816U>-[T_64VF7CQP[?Q^6S%R\\F7]UZ M8>V[\_""!EY*1]^]F$6D78%8>D$T_.O3+W_[.'O8=!I0=KT77 YOZ2@+Z+?Q M!?7#)(N]<$B_QW3B9Y-D$,7GY7=.- 'IUQ\)(Q(RL5_0\6\G@[XL2MH_U3^O M^B?$'\$7WC!]J]BBTC=L0QTXAF[;KB[U9%\G[(ZC>4/0;QJW.^"_7[CNU\_GO_]Q11S[^_F5_9EF5?_ FM/_]Z^>/"_NJ $G\=?+OX8E^=?_O:8&?X-WX(UE+Z M7H6)K]7.V9?DVX#87_L$ND*N_G#)GZY]<4G4[B]FJF,866L![ M.J+#*/92/PK?LXDC;U;?==PO/?>"*)) &&_R_ZJ\H?!AT5'>B# 6^XN@?XX< M3^G/:4R3A(Z('Y+T-LH2+QPE)!J3'V>79V#>!($7)V]>.HJ[%T_M*7-+ 1%P M6L_N?='Z2U<#8(H+-$A&Y]I0M^7'Q;T>];N^K;+;/].6KJ; MML'.#6_,;R?JW]>:MO,&=G&?(CWSQIW?)QY*0[&#V,&.-W0W+WS>9O/76BO*0WS"'1E#31%;Q%2J'=:][3VK8+([[OQW28 MDILX2I*5_KU*[-/"(8;JB>JY$_7\7E.XIU5S2%E1XS1:?V5^)&%8^G%1EU&7 M.Z'+7I)D$U:8.XXFJZY!W47=W8?N?J4IN8>K4QJ2T@AXVH^*VO#>41./U$[PWB;)\"?44S:81">G&"RV,07_B[+ H-5=4YW6(['L< M3:'_#X1K+?L_<;PD\X+TX0@EV3FZ;7PZZGSL3G/17\<0W)4KC2E+5?&LVTC#[D N>"HN$!2!%@((@T@ M#2 -O&(:4&15$)MS!G5E+)$'D >0![;A 4D4-*6Q*EQ=&4OD@5?# VUX^=WBC%. *.M,58 ^0;Y9A]\(PN&V5P9 MZ*Z//3(-,@TRS9ZBK15-,'80IM65T4>N0:Y!KMD7U\B")2/7(-=@M'4K/OKV M#VB^.N?]\\M\-%*98T6QC_BANN<\'+.?J?;1= M[:/5KF!U#ZSNT;A2'7!UC_]D2>J/'S:9.>=,ULZ6]VBC=H>UI]H=YH[+!NSZ M?3@/;^2K'_5#:>3#U3 Y%07?33BR[@F57]BC*[?C?S$]\MF)<=9'YBM="9=U@S(;4AR)=D?"KZK+K[YB&$TH.64$N>@7PR%Y?NF1?%(2 M=C,KX:@UL2\ 9AM*N- MUJ?J,JZS#8J"39L.!AZZQ!(W#8JLHWGU.A_WB%&OB%,D01%SJX"2$D-E4&I*D"[*(D$'((&0V]0XH@JJ@ M

%AHB9MVXLP;0P^ HA@Y#9U+]C*(*H MX2R#D$'(;&J7J0;,,A9"!B&#D-G0AR"9@M1<]$/G1Q\A@Y!YZ5I&,075PO1? M"!F$S,9K&4DP#2P3C9!!R&R\N2-8FHF(0<0@8C9<_2N:8(@XR6PJ@&9+HK^L M?GF]*/I5[#$=NZ3##+H.U]OAR($A\ORP^,E.$IK.*JJ3%<7/_UT\\=_G596, MJX*IO M](3,RJ,DY)[&%+X8!MDH+Q\\@J&'?Y,TSO@5[Y\$SH:#M";_?NTIQ@VV^\$#RC430 MD#%,+^]O_1%0=;,6W685YSN==:1S\JF:B[5\YFOY++Z)/]J)DO3=IJ;0WEL[ M4PDO+^ZUINY@-]O.RH4AY!'R>U+$'V%,X=O#Q,Z-!VLX! ^"!\&S/7AFA;41 M/8B>/:CBP//C \3-G1=D=%.U.)"5;:M[%;BR;9%K)&T-V;SX-/!>T<@?=/HK M\]FGMU&6>.%H\U+F>(!TM=8Y43QE6S,TWPO)E="4)>D#^7%V>=845#LDS09[9#\^<:H(FM7\( M%ZKA\U*@0]TI4DB'H)B;P0'0ANMI MER#+N)V-X$)PM;$H5;7VMTUPK8K(0^0]GM9,0=4QM6BK*]_C6N!>1:D7+.0R M0E=:8RST-,+F3O$ITY]D%&4L$]-+CO$5#^5)GA;.!79%[YH+-=E4A#N66//D MKFJ":D@[D]M!J%';*QLD,"0P)+#&G"Z*V=S"$/D+^0OY"_EKAWXM0S#TY@Y; M;BJWK3Q$X']I]K_C]9DOKCAY7#4GO,W#31V63SF$F^^VFZL8/8P8YW\$!V M!0]K)8+RP=R>Q7W\3\PDW\FV8R9YA/P>%?&@DV%C)GD$#X+GF>#!3/*(GKVJ M(F:2[PR6.N#G1JYY%M=@)OF&P=>A\QV82?ZH,=PX;#M_>@2S'=;ODQ5!-YK; M_>_ZX+/[\$@L4@U2S>ZI!@_>(\L@RR#+M)X:3Y7;/PO]K"CMKF@,YB% (D(B M:GME)0NRUGY!BZX,_DMM'G128Q[Y_7BOCR[9J2:81F,';KL"CK;75(B((T:$ MBF45$ X(A_H:6<3T\8TNA1$P1PP85= P@7PC*[8.>8S:E.V7+/2'_K3,L8>1 M#1UFHR/* RH8Z'%JS 1&<"&X%N34:"TRA!A"#"%66Y?J.U.LU[U81=PA[A[9 MC9@^OM5U[W$M;W=8'PT9Z8C]:C(PCXY[,P@)A$2+RTS$!>+BX'%Q*@FBV9B1 MBLM !,R1 T86!=ULS*'2%=W?R^*M0^Z2PRT*UB$A=HZ%GA9<*]G<5XW&0>3G MWEV:]Y<<13B,_.^:(HA&>/[[+D[8WG3=]?Q1Y3M$LZS*"5/DWL<.3 6'A^6/QD)PE-DRL0 M0R^(AG]]^N5O'Y]],\@Z9 *]H./?3@9]692T?ZI_7O7_73SQW^=5);&KARFU M?_I)]9/[W\Q/'V;O^L(+FYT0?P2/\H;I6T-734=435<>2)(F:P-1DB5'T519 M&>B:*IY\>C2T]6%:4YYKF6:\VB)RBWZVYW3@<1&Y((+_3*/$9V]?4D>.\O$G M2:4 \(!740RG)B?HFL"[+<6,I87 @C8HX<,9(F**J$ MDT@#Z[4..8S:SP.X<&@0W6Y[=KMA_@',/]!N6(4J"Y:%J:ZZL8Y!GD2>1)[L M'D\V'!"")(DDB239!5U%DFS03R>+:C=H\EDNOH/05PR$01+MG%(BB38G2TO4 M<#W>K92 .VO8AAG7NB'%;1I[K*G]%F'ZG XTF=JO@1$[TH1^EG5FBIJHF[*L M0Y=-#=/[=39W&G80.]CQ#AY(\.]AK:U0/I@*Y\G,%IC>#Y4-0 M08P?1^FS86T_OAJFGO\L'T?FV!KT/[Q)C>[VCQVSAD.Y]\ %-/ M/(I#-RS!TMI/@].5\6?W89 DL@VRS>[91E8-01(;.U#<^=%'KD&N0:[94U"T M*0JZTER5=$SOATR$3(1,])PUEJSJ@BJWST5=&?^7VCWHK<8$?YB#YIGB4&5! MDO6F5*4K>&A[*860.&)(8((_Q 7B8LD:698%Q3";UI77O11&Q!PQ8B1+,-3& M -,5W=_+>JU#+B-,\'>4-+1%R".F$VC4;8?I!"18A,N":#:6#!83"B!/(D]V M0E>1)[L;$H(LB2R)+-D%7466;-!1)XF*($K-1>EBAC^,A4$2[;Y2(HDV&H>C MZX)D=(!%#T+W&O0*K\[QM^SSQW=9\O;&\Z;OK_+T:I>5V]0.1PZ,A>>'Q4]V MDM TN0(Q]()H^->G7_[VL;SY1SCU_-%WD.WPP0D\?\+OSC^,6+*U"0U3]^>4 MA@G-KP)AATRB%W3\V\F@+\.,^T_USZO^"?%'\(4W3-\ZLM;7)'O@]#77M&U; MNK?-C+5-\UI-L'AU2XD330#]#X0F#$)^ M<@NRCDNACZ.8JVP,FIF0:R^A(Q*%[%I_XJ5P033F*0ZS(/\"+DY2]J47!"3/ MME D./1Y^L/RBRR.X4G764K"*(773:,XA2].3\Y[7R].WIP1:!D,?OF>T>P% M5=.\F,X:E,XZ4H5B&!^@>?HNC2?%ZUNLAG7T[ MI+S-0_Y4GHH11@&T,WX@(R_UN#[>^DD:Q8RW"05]C7T:#NGCQN=-C>F=3^]9 MIQ_JK27LKFC$'A$\L)YXE;S9E;//7N+G&/ X1N!!7D)":'&2>/'#&;D$J3Z2 M3M6 (@VE'T([@M!,+4;YZZ'-7@73A*01 MO[[VKOM;?WC+'WE-"?N.R5XHA#!D\](H/^5,B\ZSCP_\]Q&%JR< B=$9XKN! M]E;L&O /,W:E.;MRG2\9MCY<<$-&9\! MB\<_]1[0[/H3B'<34ZZ%R1EQ*%.)M>105^G1>N@O@?T:9,Y!<0YJ][2Y,P$7)6?"T0LR\L>N$-3-B+;YX(,!O8<13Y(*@X,'7 M[)JG>6#1GMO>))LSZ!+Z;>Q6VK'>6--LT54L65<'?;=G]/N.-) *8\U6[+YR M7,8:B(>I124@Y.B&;+ ID)R7YZ1F @:]XPLV3G0S;,),G.:9/N @@-V%0 MO_?36_+C[/*,_&[;WP%1_\TX4D&IO)M\K@NNE MQ!N/ ;T%S92\6U 0L^KX6B@G+S\G&K]XU,A/AD!H64R+'J1@/;$WK[HG?POK M8VE$KN\V>\BJML'$$4THOZ0BFQ$LZL"&FYD:9\1FTT+ [!N@9P;Q+&"-AW[' ME?53GR+.-O5"+5+1')DPF@%%^^O].(I2F"CH9_B#_.1?Q1%3F-LTG;Y_]^[^ M_O[LYW4#8L4(M+;F-& M6O^'DY2H]!77BHL:EE.%DZ:IF'HRF!9>];=\Z+V#!1%5#39 M&!B6Z*BZKKAF_FQ[X,J*L[0]:^YY27L4Q=%=U[:AFZ+8UWJJ/=#XLQ5%%_NR MLJP]Z^YY27M46=0'SJ"G2GW'58R^)9MJWE>W[XK6TO%:=\^+VJ-:JMJ3-5?5 MC$'/LC5EH.>Z*;FJKBW5YW7WO*@] T.Q)5-7>CW#T7J]OFJ46''[DF8L;<^: M>U[2'DWK#XP!B+O7-_2>UI=[DEM@Q71<6U[6GG7WO*@];D]6!YH^,/4^C+_; M=U0GUTU)[3N&M+0]:^YY27MT0Y%[BMLW71-837=ZJM8KN\J#V*HII ;::J2X8LJ? 6L>!:%^2_E'_6W?.2]IC*P+8<$^Q] MI>_8/=$5#;O@6J,WZ"V5S[I[7M0>RX!)"(8=]$'KB[HJNKGL)4OK]\2E\]>Z M>U[4'E@#B:K=MTS'L&7%%"W'*+&K 9J7MF?-/2]ICP4K8U'5;5%[--F"IYN6 M9?55S77U@>44SW8TRUG*/^ON>5%[7$77>K;=-_N6U._+FN-HU;,'TE)]7G?/ M2]IC.P/;[&O6P)0=Z*HST/O] BMJSQZ8R]JS[IZ7M* 229$=>RD?KKOG1>UQ!SW7596>"1:$: )VI1GW&ZZ[M#UK[GE)>QQ9,TS7 ML,R^;;-9R79UO=0%Q3;T9>U9=\^+VJ/I/9.] !X*1 )Z8!2V%1@3MFTM;<^: M>U[2GKYH.);5@_G0DA58N3AJ3RJXS=8M:2G>U]WSDO:XFF7#\F#0DV1=U7M] M101M*'0!WJ8M:\^Z>S9K3[D6M^,AX1OF?$,\O\N+AVO6Y<45[\:L0>6CRMN9 M+^$Y:^D(;BH>]1;LJ$'?<08P(0^,GNSTK'XA=%$%E"Q12FC2'CJXU>*\WD%7 M<=BLKX-D7$563<-494<103)RS]+-)5;UGCJXS6J_WD$%!D[3)<6Q1;A#&\"B M(5=363$4UUUB1NRG@UNY#^H=M'1-LBS=@/^Y?461>OUBGE.4@2PKG>G@5OZ( M>@=UV9*L'JS*!_"O(MNNI)F@HHX#0';,98;%GCJXC8.CWL&^89B*X;B2#KK< MMX"9 /L8-;N:0/$8-;^;@/T2>SE=/\$"?ZK;SP[6#PT=[ E,O9%&&?]*P MBFET;OW\N\P+!3*B833Q0QX*Z8=Y<.(R?D"PL ^JKXR%YQ"O[?43900(>FSH<9K$W M?,BCRO/'#J/)Q"\.JMS[0<"B\UEX/QWQN/B8CJ.8"CQT?9K%TRB9G6CRKJ,[ M>"E[]7R+;KTDCYNEHR)F-@@>O0C:%D9D[/]DAPJ\!QZ FPQOZ2@+:/(_/)9T MOC7U0-4'ZL6$AOSP49\.Z>2:QOD]BB006*WKSU: ;7BS'5!(;XC[TY]%[A+Z MLX (/Y'EI3X[YTID&Z)M12(L M^CND-[SCY-H+O/P4UY2=OPKY\8L[&B=>P-02OISXV:0Z#%+\73^.!:K*$5(/ M)2\.[S$=+Q\04X!?R([53>&R,+HKKH^Y(F?IXNW/EO VVPNM2+A3^K:-J[X= M!,K+IR6?%3<%"B8Q"\@?9XR>F9X$7LJ['M6G(/+YO/?M8OZ>YVO(-K9 *S(Y M^;]1'(SN_1'\Z"?\Q&?,QWT./YSKBR-- %$_^8L?PYC #,)^ [C O'1#HYO8 MFX(^L:-E^2'14<0/AB53.O3'Q>FR0@VY2C'!+LKNT3>?X8]/OWQ\Q_KKOV?_ M_?3_ 5!+ P04 " #@@E9(J+)8FH(9 #6)@$ $0 &=L'-D[3UK<]LVMM_W5_#ZR]T[LXY?2=MDFN[0DNQHKRRIDNRT]\L.1$(2 M-A2@@J!M]==? 'R+)$A02L24VNEL9!+G?7!P#E[\^9^O:\=XAM1%!'\\NWIS M>69 ;!$;X>7'L\?IN3GM]/MG__SE;S__U_GY;[>3@=$EEK>&F!D="@&#MO&" MV,KX;$/WB[&@9&U\)O0+>@;GYSZ0(7^\NO8'UUK!-3 8Q3-/0;O"%UWX0)X M#OMXYN$_/."@!8(V9\&!@D2J0>(U W0)V1"LH;L!%OQXMF)L\^'BXN7EY__,TP MI N@]8909N",Z1; G4M(SSU? K 19GA[?GEU+@SA.\Z 6(!)-TV*G MX 1WF MAD_.8U1O. ]GQH4>.Y0XT#T0/Q+7O@P);S@40Q)7'8947E3 3A9$_'4>PIV+ M1^=7U_MQ$?='/2Y"N$-P\?X"4$N8FIO-8N?P=>, #!BAVSO^=S7.'$I36'HQ M$L'B>\'BU0][L"@Q8[@4,;PZ2TFH@_*AH9808F_Z^?&X"AM)R*$/>$!NZG%2 MGXW\L:-B_PD!!.%W>B1=:+U9DN<+BWB843GTWE0):7EPX1_G,9*:S'B4\A1H M6SG Y@)&?]6)K2FT-D3:K(0PXL?>#,!7:Z7-000D?^W- \+/T&7:#I( "W[O M[1X8($L.OE+#24;2!GBF50BA9<(5A0N M/IZ)0N$\+ ;^;0'G#<]XPR89 NF,0HY0',3R'"G$(&8RQ"!B]L(@"*,&R^2 N:Y,' 0Z#15GPXM237$XB,N+YUJ.)Q#,> ,#\;*N M ]R5B6WQ3^\/CY?T#D?KGAFBT>.DKZRB)2<%"$*2(='8IWZYOKI\=W5Y:9P; M7>1:#G$]"OD?'7/ZR3"'7?]'[]?'_I,YZ UGTY\O=C'LX/9<:(_P+_+WKF(" MX*") G"G)U>&2W>67+#@8:AW;6MT(0/(V=\H(1Z5;=Y>OGM[>5W9-L;? Z3_ MTWHKS<"6[F\LK#1OY.%ME(K)>(R;F%UVA8H(9PDN>JB,] M"RFP* /.C/'J1)I)U&PUE_>-\;=OJ]5@6Y8JT.(!_'Y,.H28W@ M5PN_,BA>O7U[>:-E3T.2,@"V#2LFULYPJ;('8Y"ZHT6'0ANQ ]LZ%W>IG;.# M7XF=)1F#+ R?T,G&:3OHCXNEN)2#X]7;O,%1:<-6#I#8)0ZRQ1SO+7#$W/QT M!:%>ZE^(0V$@/C#R_\3@..6ZDTN TC[#Z6C0[YJS7M>X-0?FL-,SII]ZO7:E M_T4*'0/*I5I!ACB?A[!0&F&)N=[)_E317,;?4[C;VJP%8!(K6AKK4,U1_R MD:QW,M)BNN)19D4HGIFVP,8+ >IVG@W6L:;?C(GO4^C0;UN2OSDV P?G9' UR;K M>'!&QA2MX2TE7W@'T#%)!E8]_9LW.])][!FSD3&>]!]ZQNUD]+^\D[19_?JU M<"$*]7PO+WDSY5*>,5I9U]XAS)-F!)P^=AF5H4+')+G@ZKYQD],W[OI#GF'W MS0$?_Z>SR>-#RY9%\M1X!Q!] HX'/R%( ;566].V)4'1+(K@^MWH ,34'>Z& M][E*%C8$64/2-2+"1DPY.5*=>F=HJO"9F#BBP&+NU_0+/6)E?G&5F7LL\(N0 MK!'1/;E%1;=(//L6CE&57&G(T':-!.63$W\=QJSY.$O#>[7$SAB:3ZG>>[*DKPAQT,3V M'#A:1/F8RW]GQN"1Q\1I W&^Z3#FWH-PJ4]DEI7S?2)D0:PSQFFA7';,RP82 MG)S<)V/%>TIWJL>S=*84R,U2OI-R(!P(,'"J6A3FNX!,-''MESC_N40G*C( M=K^JOV@1+768'_4=)F3 2'+@Y](GCRGQF!'/!&FBQQW:.8KPE_K!>WT_D+12 MX>-D[UU[3* XE0KM>X"PJ'@'O R%[@C'9>?!74"#9&D:4G%5+^D5(7E#TI>% MM,^!07"BVCXY2]9R3\3ACY+3):;%_U\F<8?VDBJT2MVCXG1^TCU\NCLS+S'I MDU<$EM(^8Z! HK+CS>5-SN&"?#NV\%#!P)_,E/_8__'\@:[WNH%8G$YV(7W6 M,E(E=.K=-#_F[*89C*;^(1#_1_=?CU-Y,L3H_3;N#:<]8]*;]B9/K3J35T75 M^D%5!ZLZ?/Z8,\=8V8ZM#)-5=#] 8(X<.93<$2J:?EU;E],K]8),\*WN!0GJ MQH)0PQ&+'#1@X.0C!3;3'EHUD*J'VA]OLIM>-/I\^X;?(61Q?:E]BB4/6CFX M\O]E!]=A;\:S(&X WRRM.Z^2HT7]6*I H@R05UC5NWH5HQ# M&@28/2GY((/';? 1>YH,4[(I&&A"LC4-4->6!M-[LUA M___,67\TE.//K3GMRT-=8S'B#&?RSSWF3P>V*JA5OM M<2"F61Z'YF.W/^MU3S9+JEF_^U7'J4Y"?LA)0BI:\-3_(0ATT\PX-3GH#>09]S.WUNS&; MF,.IV1)OF-8OTJ1\=RS"I8^)-3DI2;*!6AD$>H1A%%M?QWG>2EJ)2%P!Y M*0@/<;-)OR/L=;JHM-Q8=?I7-8SJU#\O]ZABNE./.\2-IA41JJ=]\Y*.:B9L M8\;!*+&@Z^I-D:3 U+'PI]Q8.)N,.KWIM%U3'DFMU8EO66AU+/LI-V>(5=_* MF!7NCNEKJ#Z&46?1>;X^[7SJ=1\'/:/?1B7KNWD&5)T7Y_EXK/)V>SBJHW94 MXN/OE3[>2B=''8)ML3J=OB)S#]\OP:CN$N]S4MB$A8P(MQ$@-WSL+>\LD5IR M;\L\B#&5F$N-FMD=G&_4F(B\4EJM[LCH?5V^CE0>D7;T2QH5&G5AZ9M(9ZKZ]42G08[U8 ME :N&8%B&[0P[* E1@MD 8^O?# M_EV_8PYGAMGIC![EA]R-\6C0%]]R/UG(UVR-V%4%G3*875[GE5QJ>[4SO*E4 MW0,4\S_=,:0RDNW[6:H#$"NU>C8?+[%Z2-?@A(, KS.F0*,U?Z7'EM_OGAU[0]@LQ'[?L6CX '&Q.=>/A./H"//KQE@[LK/ MS'X\8]2#9]),2X?"?V?S'_LQ@7(;PB5CIQ4N!1TAV9OA/-Y B8L]D.]NC08B\V$1Z=F?8AE3PG&Q;1]SAQ<'B?D#V[.8,,@# M7,\AC<34@:AC0TPP]M8?;+(&"!]U]?B.K\=F:JT;)Z Z0\<#Z 0PB6+#H4V8GW7]7;EU %HIKB? MN(GFVUM*OG#.L\+EOVZR*&.*UC!@6/EQSR)A]1$T5QT(B^Y78-?=E\T4 V0N M\?+--'T!FXX8^R#= "I,E)6R!FPCE> !![%MQY'1!LMF&6%5;8XF5"P$M\42 M]O$CII S^F?PO;OP8W>)KQ*:V$Y\=BX2L#Y\_91N33 O=^AV5_JY?^W)QS-+ MQOG#69I'FCGODCU/I#ECQ]HQ'L4RW&L8P$S/ M,)$ "T('HX[+ PL30@ __=X-/96;-S#:D#7/1,6%S:;'R)K,D0/#$B+3F46+*B/5ES)D7,R%+2!8SPH#S1/R*^24M8[7FM43CK;P&=VZ DO(PO^#+J;8.-(CIA5 M8/804:+X*IW4\^>]R,+*S_:439H8=^0W3BU_$GH!>:"0'Z/>E:JDU7^_+&?*Q?BPR&+**0WQ-5E/A"BR^@%L17 M3 !M.-?/S+7D?O4_3%-=[!"@:5(7NG>76/+#Q#Q]Y39#8MHUNIC##( B!51K MV[CY=17?F;6#JHV_*RE3ZPE5&C9X9:'KP1E)3."9KR@V7OZ[RM+8'!*+R[./ M)DUZZ:?P;;/MPY(\=^4PE9 H_VWS1OY=5K.A0M'@6.$AXKZW$)D''ZRBO9D3 M7M&E]S\#=@=M,8CO6 ?):>V^+"(DQGC#R R^LEN'E[VAMH[)P![J M9R&:PUG@ 0+!H'C[@MCJ$9.Y^ RXX+"/-QYSTYUK(G0A JW\ *@4GV?SE 5? M!@T^)-2W\WH7?9KSW ^D#,(HI/+>/N6>R[:%L;@N3Q(]Z;LX^;UD_MHD^L$HK"O]RET1&I@=G8%JM;X.Q%SP.PW M%01,-3M^"IJZOO5V&U^Q"QR30F"Z\6K/R%_J2D'$HNZ+IFDCGYAG)W+)*RPF M"I8^JS1LG@LGCEQF)B8*WC5NRC+!9VK:*^=Y@R>\.+>\A[BP"_U_$4XNPQ+' MN2-47/V4D*YJ^Z/G'))7.5GL!$S*B^M,QM'//5E;,M)%CB.&0+90W:150 4#>EFF]";@_-2I8:J-DI+SN1G"EY M1G87A :/#%M_@A8VUA#]8";MK&>Z0-ZY^+A0B_GL"F4=Q=I^;%D33"I.8 MV?"8B5OD>MD&3>Y1"-\3QRZ29>=M\P3YU^:!T"7 ':%Q<6QF]Q2?JD'SQ!D MNN2J3XNP^["!;",P1^*8BW^PQP-.E55#;:CCAV[!3GB,\ Y8DOL9I&N$):S8 M8V:)=5V.-992!Z1^P _YWU]&XKK%4[V%;[^;9.D!4+$U?M?ATKY9UNCXKO@ MF$C=I2^1!73N@R)G$BT ;7+3H%6:]H$)TA9(YROG"1V[:B;'#L1&"T6 M+F0LN1\O'"W"6W\R(4@3II%!*/A,RF?QN2O_>+]_H"_MAJ6MCN^!X1,1)_V7]XGM_76!&[N4HBV0&!AK M:R, /L8@4D<9'1)? %'P[GL1)5J7BG.W(LGRFS9:T,2(H(I+RF:-"$[!:K2[ M(#1];Y.';1Y7PP4HEY$)W 23YZ&(-6&;NVX2;+[JPH6X%1!;VV3L*7K9V$B[ M\PER&2"!"S:[-S7D?:]\1^BZ.)HVFS*69S$@SW0>L8--S9H_^H!<81<'AB[)=CC51GV_!,4P''D$G9J!4NC?0-6 M%"9Y]]!-@0-'B]+;[&K"-C?;2%XH)$ZDRM>/6%S^;"YY>%GR1SPL8PMMXILQ MXE 4ZV5?-(WM#/*00"C21"S2N, ABS#/$$?YXA-Q51LWV2%D)3L&E&WEE"B0 M5][X/?H!8.!O%[V#X>GDQ))63=AC3] 5L"VZ=P=0N@UV;HLCG][&-ZR_?Y0G MHHY4"MQ0H3F/\BX6WC^3^TCO/,<1 M<]0[EBW:_?>UD']?2IM V[.@_=7TIH6_::5E_-GZ_$N4TX5EY=;-6[>>BN/W M=NYFN/Q7311!GK-X;2E'D6 BS^ECOUC\#,4Z M(*\?_&U1T3GKS F6(] ]UMVC!]-UX#Q'T'8MRHV[ZW6V0C1_^,E]<_QH%QS: MBDMN<9M0L/N3_S6$KVSV IUG*'-L-[B]1AC99?)2FTB^ R!JZGRMIFR9OK$' M_'>JDM\AH%/T.EMQ'I>K&<2U':<:IK^*FG1=1XG@.U;*[(4$,MVA9[B7\U1 M]9=15!WW*<;PG:H%+!BDO"L(X>H/6.58_@KJT7680N"&*:,X01-?;3%S/_*2 M_ZIY=?4CSCE@L?OP^)EE^L-._NFOQ%H8R%U'TP5JW'I)H=6>(+6YLP9;_T2- M!/!VP';,6-JJ>>[XY&^>[\N8,-H]%5+XMN&"\"$1JD1)OV^Z,"]$)4KB;?,$ M^0R!V*P8=WOQJ;^T-.HF#12)4'&[>W*>I/S,LRY0(\5V[!=D9P7;>?SM6/>_ M2^U:*[@&O_SM_P%02P,$% @ X()62(NG>@3W+ 2=P! !4 !G;')E M+3(P,34Q,C,Q7V-A;"YX;6SM?5EW&SF2[OO\"M^:9[2Q+WVZ9XYLEVM\3Y6M M\=(]_90'JY1=%%.3)&6K?_T-D-1.<4EF@K3K5I^6+!)+X,,'("( !/[RG]\N M1B^N8CNIF_%??R)_PC^]B&/?A'I\]M>?OGQ")Y]>OWOWTW_^Q[_]Y?\@]#^O M/O[ZXDWC9Q=Q/'WQNHUV&L.+K_7T_,7?0YS\_B*US<6+OS?M[_6516B1Z<7\ M'Z-Z_+NSD_CBVZ3^\\2?QPO[:^/M=%[M^71Z^>>7+[]^_?JG;ZX=_:EISUY2 MC-G+VUS/ILA_H9MD*'^$"$6,_.G;)/ST AHWGFQ1_C+EG[_E#QZD_\KFJ8DQ MYN7\V]NDDWI50BB6O/R?WW[]-&\BJL>3J1W[^--__-N+%W]IFU'\&-.+_/O+ MQWC-C><"$(7S?[W];FFUY?QKS]-ZHO+$;3[99^"O8E36X\ZRO0<7/6H47\-<+XF7]XFV1; M&NQ3Z/#-FDYA5OR08)8+];2/)JTK<.CF;$GY;0OH2=SQI!G5(2\BK^PH3Y.? MSF/<8G[;E'%8\4YM"PB=QVGM[:BSK"M+Z5WP3U/X.>]0(![,9&]'S=>=\%U; MP*#BO@,UY")VE?5A[D$%_70.77G>C (,[[Q23*^["OU\2;TTX$9S@['],PSM MZ?6[<6K:B[D2MDGD;?+V(^0L?FY.V_HBOFJ;WP&(C9(]EV$8<;9<"3;EZT6X MM_48)I3:CMZ!FMG.^V>C8.OR#";46UNW?[.C6?RO.K:V]>?7)P$60>!.3G9+ MI"VQ[:^&X1I\\UE>1%OK84'MN\&=:AB^P?<^&ZS).]8Q6*-_C5=QQ#Y&W\ W MHWK?]FU1W&!->6^O[OVU1R/6%C28^-G<#K-1_)!N)P)83Y^.D0^S:3;(LWMC MCS;N7UL!('YIFTE6X]_'ZZ^3;M:47A/:MM2PP[\8+C?13 M]+,6IEPP"5O;VSCJ4%'IYM_)\PDT]/?-]!]Q>CJ#?K&3&/H'89?J2D/A1[,0 MPSM8G-RTGU5CKXH*-/\W.\V]A[;>WW3 M2ULW%%J@61_C9=."%?Z+K<=Y)?H5%BU8R\=W*U4_+=V]G@*-_ULS@H_N+\LG M'G[.)YU>6KU#!8,U=SO/Y^:;19U MES**";TE73H45:P)O];6@=65N?FV:7/2 1JW=27%FKW=^-B]I%X: ,;#W?*P MG4-X39:A1-J2'YMS#B7@=GV\,6,OXGUHS^RX_M?F4G-5B&IRV0:#S= MRA6]?0F%!-ZR_WW2QR,U]EH.ODRMK-0@TZR2>[M2R@D M\)9X[UQ0(?&W&XV[EM.+\!]C]L&$4ZCZ&JSN\<3ZS,N-PF[*-ZAP6])AR^P] MB9J--P_5=3O!LVW^(L)NC>].Q101?;NAMELI/0D^;1L?)Y,MUKM5:7L78NM. M?C9++R+=V([O-@GR)&&_U6\)QW/I^Q6FWEJ,>B !7C?CD%7]AT=8=@5INV*& M$GWE29;N3=BFN!)-V23^(,+_$YJRUE^>UW_U@19>R!FG$ MHZUBL(,OZMG%Y.]M/9W&\:OK7^LQ?/=J-H'?DZTGZCXK&;C9'^-5',_BJ^O? M[#^;]O5L,H7)=^L#9ON6.TCCMIS?L3\K6]K*>;[T2L2MN[$+OT]NHLO8NT0Y>MS-&/0/79N$ZU MM^/IB??Y8!XL *?-J-[FOME6F8<7<]N^W:&,X87^V;9C^'-R&MMY%W\\7-WQ3>AGJY8?\EG/G]D7T(_+, M3>+_SO)9B*MM]G6>2S^(,-LR=7VV7D0#JF]E@#U.UVOE6^+Q3/)>1=F.S:M3 MKQ+$VY&?C>:)?X4TRY2YRGUC#"QJB]^F<1SR1O]0]:U$>_AJ5T';:ZW;7M O M5.FV%^MOQ32-9"=N'OMB-D%GUEZ^!!+SEW$TG=Q\DFG- M$2;+N!S_OORX^G 9L]T^/IN+-7D[F\[:^%L]KB]F%Z?V>B'>[/;\ULBZ./KK M3R!+M6,)E?>:$$H(2CH81$/"R,%00UAP8IQQR1OS$(%1CD[2M,O^.#0$[\:? MOS;_B/;N=FMW,.[*J@(.7!, 0XBHD#?*H^AU0"$IQW@4@@JY 99[1#UI_8NF M#;']ZT_DIQ=?8Z;E_)^+ FSKG_#W83B698J7D]G%P@^-ZFF\N,F?@\L4Z/VF M/*C0[N/A&=0:^V/:;6F5,SBP2"SB05MDI=>(" Y+GO5&"NV)LZP3U^@?D&O[ MP'I,;'O;S-K>R'9;6"6PXSYY@@!TA4@("6&5*(J*F8 E\U)NFNY7O9VT.(;4_R98%5991 __S2"KK$70R!OP-1I'H0+26AJ38B6'RC\:P M[H@6H-=->(J9'7UPH_KL@<=M!8M6IJ\",QZ,&8>\D!$I%Q-2VF)DK8W>4:*L MVK3N%6S>?'GYE/=#0EY@=FWMH^R5#8%PK:')#G/$G5%(2D&13!8K!@3RN-M< M7,9N[J%'FR*H'6HT+(VLNNW.EMO<55*)4<4]BD9:Y+T5B$;ID,7],EKOL5;",.:$9 @V8HRC LO>2@$8BI#72N00& MV!&;KB79LA=JAZ5+G?9ARTWNRD@*AC>T&$8%0U3R@%1(8)M'$A3U2H>HC]CX M+$J6/4 [(%=.LIFR#UT>%E#AD+CT2B"C00]U'G#E,$"@\8YF^1CO+#U&/HJ1ZJ;0"=V(=1.A5@YD/?A"_CK.XO0W+>Q"N[:^O]BW^+ ML(!K&+A'J55(5,AL83BMH)<"B8B"0HDD\YK:"/_VFRRTXX#J ZQ<[61Z,A[7 M^9D.VU[WB-C3PBME76"!"]"?E$$*,XV2M0EAQQ*.!OXFXHA-VV*<:8X ^2,< MV1^6!O]0?'U2>J4%X4%PC!*Q#J;B!%,C2Q+6:.>$8\1Y08_8O/Y^"-L']$?) MV+G782C"/BZ\(@E4Q8@IT@0T2= <&-*>!D2UB819Y0GOY@XJ8^!_/WSM ?FC MI.O"[3&80O"X]$K%8)/F'CG%&"*$8$0T)<@0*J,C1"6.C]C)\/T0M@_HCY.Q MV8P>3H-]6'AE@S:*BXA$4 RI)#4RPH%:11U7UGLJ2#>%H(R+XSOBZ_[('Q-= M[YP^FP\*=2^T4IKYR," %R2?VI,)X*(D((.#)88'2FVWO<,R3I&CIVPN%6X9K@O$E1.$&5Y(HB+3&)L M.*(2:Z2$35)B1G7>"!>25I@CC9/+CJ1P9YXSV M3%ELN[EFR[AYNG1(TR<:)8Z!/8J.O^Z@UZ.D%7'0F@ -TIA29#%6B%H&.&FG M!$Y1L7C,7KS.??/XN-;^N!3HZ.7[)G^F59;Q*@W6\QW!*;%YN_)"ZLGTM6W;:VC#_.VG=?NSV^2O#/PG M<=)(*DR!Z-$@K4-"R<-(H$0)XH[9.][#.C\43@4HLFT8Z!7LV)2U8HI+9S&T MD%N.$@9[R!*KD.%11L$2\:;;T:$R$T8/Q!@ H@*6SB:KY7'2RCC-1%08 MJ>@\DHXQA"VL?\[&[ &G7,5NZD$93VX/?=X#) 7Z^"9,)7!RKL%^C#Z"V-DB M?Q_7Z0;K,U;&,^DT+('$RH2LS_=>1(K0;$F8Y$*[U.T*;AG/: _]WSM 15:! M>CR9M=E%DB,Z7<7V@6]FY>2_,D<%YHY(@4FDK='(Q$"0 O4'62-@HA,D,=_M MNG\9UV,OM-=1(T^8 M0#YY,(=A'" +FDXB@$+JN/2K[X4&O0-49E&XM'6XQ^";R6S]@O!,ILJ+D* ] M$ED7!)(IWW^47,+*IXE3U@?I52<6Z.^%!;V"4X ![YMIG-RM6.M5@:>)*YI" MPA)X[ V12%@-6&G*D!>@YU*9/*/=?+[F>^GQ7D IY?K=J-_?2Y6=)B2!M"@E MRU#$)$,#"Q@A!I180;'&W>9T@K^7SMT/C@*]>N_Q1] _/TT;__MY,P*4-SM\ M-V6MP%Q)(<<;THH3%)(+B'("BBR7.'J8K;3<=*ILF$8_E77QK/,\,&,[)]MT M\=!Q'I&?F_=-WMZ= GE E+-WXVELP4Y? TT_%528,LVP="@81Y$4>;E7AB#C M"4S\3,-!" U3"8:0BG ^P1.$)LC" DX]!*MGM3G 9)_X1<*@_ M9(M#8J2(^35D$%9P4#U9K+B#28/_E\L<['\!RCT2E-_!%O M QP!1WJ M*R]L9UI41$PA#%G$C&G*1+""Q2T ;/8.\N] #^< M2CD-MNOSQTDKQ;@'D@)_H^>(62V0TH"3,](+$KC0I%O'%[=^=NN;52Z$_7 I MT-%O9^,P^:\X"E_R[?![[LN3?-1V?HCFI@WK? J[%%.)$)0.1"%+19[@B$.) M.XXDA.NPZ!8WHOC,L!=!!L:L[&[BJ;W.*^1V&XG+Q)62/*9YO&&=0US' MB',X6($LIM[IZ(U+QQQ:MR\B](),D=LO$MLUE;*?7K^UD9D?3ZVU6BU[*KQC6SM 8$&,Q(A,U0TP#?M)83[#Q-G0\ M@5#F!$I?E#H4F*6TT.64./GW/T,)].WMFXW^4IW+ZS2WF.3I$6,VX!(@&'! M'+/(4^ZD,8(JW4W9+7-&IC>KIP1R!>BTTY;["O<1E5%(KV",<.M0U-(@#8,& M80&KK7?P03C,*U*@FBX.M&VU:; B=6524 '^CX21$7&O$N)8@>GJ7-*$P3H@ MNIT&.]0VY6Z=]?1D6 \(/6#T<6W [85.WSLDQ[7AM!9S6_O$[YD-%2O@TA9_SY?=#RK>5WHZ:KP>)F+#ZQM0I M:)8-L-ZW^76,-W'Q>]WV]0[%5%PZ;82C2*>RY$@& M+//AQA LJ%92=S-O"[T^,5BG/S[M.R2D),<]#2%)?LSL&*K3GG)C+\S6=O_3IYSS)]7KAL>=E;ZJZ_!3/=(OK=4V?1]\N1TN!VX=+'54)]@JGT0]J91UW*JA)U4G$-1I"P M#!D*+0157\V;:1/ERMIN'&(_#H<* 5O"$=>TT"?CQ;MF_OIS:\<3ZS/,N6VY M::]B@C2?[;=U'KCM2ZD<8\9@0I&D8$FJY 7"07K$J'(D M*/1*<* B<.@IX@E!$FQ5QU52)G5SD)79N2RE5AT*[!+>XW,P^%]E1_?KYB)O MSFAA@<39HC%6W8Q5E=B<+,:DW\(IL M3UZVT==S"8'(EVT39GX#.9[-4PD:-<-0BQ"&()Q?-6,\!6AB<,Q&[2/OMNE4 M9INR$#_ZQ*\ 11X[-MZ-;XX3W5U'7L.6;;)7*@CL63Z-1%..$BH% MH&])V#M8P ])IM[P/ BA.L>$6T]BBY19(E)R >= N%4XXX. MA/L1"WY(AO4.[*'6O]WCV>Q23.6-49@!S"8Z@5Q0% :?"OFA(L8"XT'*CD&0 MR0_.L%Y!/0B[YFGLCW$2VZO=-*XMRJN(5 X;+1 S 'Q2+"*8 MM@4BDA/LK5Q#B[7!Y9W/F"AL2E0 -U'+!D-="(VDDC#N) M@P@V2M,Q- I* %3);_9(P4R-C*4P^8C MP93E.CK)3+=M&?)#^<&' O,@/-KBTNM.O-JBO"I8JJ.(&!&?7UE/EB+EM,VW MG+ @-F)LNSG)B?S!U[]AT#T")7Z[JS\[E%(1;X/F)H?\9B;'A(@PA3L,Z#,A M"+?:T(Y'I7XH5_NPD)8Y2+<*I\49C#T/:*XHI$H.$Q9$0BIF-XSE& G+*>+4 M!>T93/GBF.-U'?J 9C^0%N 5+.3S^?1S,W?"M?')\S-Y'DY-6]^>]EE#L ZE M56##>,Z41XJ[@)Q0"JG@.1+1AI"2A$\[.E$/NDKNS8#']WF*0%N"<6WC8PR3 MMX#D3:/>-NV3YJRCV99%5(E'22-H!21(A9PT"07!":*1:O09$M/'WUP+?=2ZNP])1E>R<*!ZJI!QF5,@YAB1T HXC0W52S@_K MAIS4AD.VR[GW&\DR-/7X;GK-U]%GV>"]LW*GS<=XN;R;_MS1]X[% ;C6!D]E MUG4I,I9%I!+WRT/^0H3 NM'HH%ZPOFA4&-I./%K.J*#S[4^B#F553EE&L(_( M@*6,"%<,FHG9LIDI6JWW?@;^.U[Y2@)[F.,/J^/R[';V8749E1$N M;ZE2AJB2^<"13=YQ2;7OQJV#NK7Z7N2&Q/- ^SWW'[3<<:OG?M;*V<"M-Q@E M*P620@ED-(796'/!B*-)LFZ.T<.>)!V>07OC>!#B/'H6:;=)Z''FB@9,"?$> M"6TTK2WTLM4!_5"](7H(7_I-W,O3 MD1U/3\8A;T5<[NI"?[:0BBFBB4T2S%5)D8_YK3#J9 8!1TL]B[@CK7YPUWF? MD!YN[V\9TFZ_O;\5A53Y%JUBT&HM(N]T3+1,/Z]![ M?_U 6G@9G(?(^G Y#Z#Z\[?8^GIR=WYPP^JW,F]%35!2!(:,2RP'] 454BJ+ MM.!:>?C*J6XZU$&#N.S=N6O6O+YP/-PFWOQ0Q6[STHXE54YS![JC0U+&A%P" M.*(C&(8NI8SD"-*IV^F]@V[I#4FK85 MN[-WYQS[D.[%;MQN)^^9S)435GHC M(A)1P8P?>4#&2P48B.2H\HSI;E0Z[,Y=[UP: LD[^@P;[O!^N,%%^(:'^7IM-P=DS)^M64S\\(!XPBLL%F.K[\X)PGC:A&*9Y'NL_T6)X_?D0/-^V$I MBX"KO\7I>5:_;T-&K7?0E9*B(MG_C:/))X@MPBXRE-]+1T0$0G7D,K%CIF97 M0CUUY!TQX@6(_RJ.(P"YC'"670*+VU;K:/ILGBH$HRTF! FO!>+8$<29X,@+ MYK3&RGB[=R3R(16+HZ5#,UP/E-!GYY?=%R[,&]%O'\T!M'( M "+S;I%=@F2<6E6="MA[C73P"J6$(TI$ M2Q2DE3!)>L/\WE>"!J10MZYY^G[/WJ@4[.B_PP"8QO%V/7V7N,+YRG@D"84< M[E!+@Q'S4B,"D#&5DL'XF'>)]NRE9_I\+WP*=/K)!/"Y"R:Q%'=-QZ_.D+>V M0,]F#,ED XI4>Q2$C\B9$+CRBO*.3ZF6[?RNW?7XX:6^0"K @-YQ'"JQ^PLN(&#>>R\BDZO@VGW&RACO.5$&S.1$D=(2(VJ80@I[FG325+IN)_++N -ZT>I[AZC8IB!8NDM! MEWZ1C1MX3W)4S&H6C<;(&^.0D ):9E) #&/)F5/)DKV#B@R[XO>XV]8'/"4. MG_[1'SVB M=P>L=18_-Z=M?1$7-_J>>RQUB*K>Y)=N1P/6N.I9]K*UW;[W_E\UK,JM/[^^ M>P#Y7O\>!(G;S[(;NK5^.CE"V>Y]=CS2_0K*VHCEQPO@FU%].$'>VZM[?QU$ MA$_^/(99?K'OENLP<3[EUH?9=#*UXQSSY\!R_M(N B##BG5RTGK\1\!;F^U+?1!B\7K3H0TH3:-U9?E9Q>B?_VCW[ M'LJO)';!"8&1DP0T2VH=\A&45XDQ58)9 >;H0<=8]H5YU;E7G^5)[\@5I<$N=LGN?A1C2*!V2-ST#5Y0U=Y/M MQ]P)GQO0-/,AP@U!2[8KH"*&8N7(_.5M@VC4%#$L*<+*1F&5CJ%CZ)+BK#G\ M*M8ST$?!LJUBI.Y23!6UPH$ZCIAB##GK DI4842MY5X0^(^S?5WS?W3&[07W MX=6I^;P\D.VRN>S*JDB-IAX!3@P%I:%ODH\(2^D\QB:FC5L'0\.V\86NQTDK MXS03$3I>1>>1="S'G(\$&!%-)(QRU34NS#%8*WWWZK,CKC.:1S*J]APXE0G" M,U"*D =U.NO9 @G &&NHY"&4-;U5:3"-.K2D;O9)5T!*\J4N9 /M>+=C-EU M!>3G+:"MH._P% CR'ELD6$B(>_@IB$S8[WVNILQ:WRM=>L;L0(KB!S>JS^8H M9KUC.FO'G97%=455FE("QE]":O[P7 *X0PP!64*#B#!^8NJV3>'4AE6-.<.$P(A)'!-:909XG@U2PFMH8$K%''6C_>^!<1Z"'W/E? MOU5T[SK-:VC46=/6_\JA4.8;@/=VO&YW=P^X0W3/AW8KUYMZXD?-9-:N.R*S M/F-E: HL89[=&-!?-@GD0XHHV$ YQYS9C?ZB81J\LNN:47C?3/\1IZ?+4#+A M==->-BWTWOP Q_J5JFN15<"$4,,CTJ N@);@-5+,@[X0A(F1).]TQY>TBRC) M?5*@.1BD!5:E+5LS/XCYJ;F*+?3=^)?\CW%.^R:Z=?98#Z57"6=_DJ*("VD1 M]H!B?,=[5HOC-;=UO]G M\U3:B1RIU*(@9<@G-5U^&-,B+[0G,/]ZO7$N&::93QX/VS"QKDQ?$;"W<8(* M&)@YB =&4#2&Y3^I=,ERPKO=&"FS:/?4;\TP4!4@^Q-1'Q[1W88'BQQ@DW"G M,3&-8A'?C1]S>KG*'OA,_ ,1'SXE]\@\ M/B9!_6@6SSV(W^PTPW?])D??JMTL5Y%=\3O(^,6Z^[EE<))L#@]Q0QE3QR>>?"X:AOEAJFI3]F M)V\/_=@3-FA*K&&!=TE$BQEG( MC]MAA'$2BR8323WGW9A3QKXLRYQ^@1R(.Y_J;TL!/\=Q']1976"5:$@IZ(!\ MCO23DDW(8(=O8GA0(GVWJR%E[,KRS.D-QP&(8],TMB!6EG/O=6IU8147GABO M".(*=&OF)$9>6SEOJ(W)!J>.V:XL2YC>,#R$MS/' =Y%;D"1" M(LX31]08F$JM""Q(^"4V^:F&4=N6$8WS3O!D^LI.ZE5&L&SB$;7&Z6V*;J*A@6%K4<>Y@CX$?/, M098@8"5#='N'B/EA2#40HB64O5Y9M:'DRFD#ZJVS"-, BY!G'!&6;D*X>05X M[/V(V ]%JOX!'5H/[(U/&TJM>#!12Q<0Q\;E>&(^'ZAB"ZTF24R"[\:E VF& M@W*I?S /YW^>GVBZYSCMY'M\ANF/RWY&*7TV;<5S"%NM>+XH(Y'35B/)[SBXQX#/,+&5_&;;2CW,W_U8PR-WZQ]:JPP]T+JX0*205L M$:&@* %-6'[:(=XH2C9:LO==JB$.F??4?\LVS./%78OK*+*:))( M0IY)L'AUWNDBCBQQC3ZJC@>*A]4FCX$H'?'K@R@[G!K8(FOEH4:9**@H+L#B M1@R!YBP58)NT9=IU"_ QK/97@ 3]H'6X)?ECO 25 AB<+^&Q#1/N>XH0/6^>LB*MS\5_CG;$&T90S=CW$2VZM# MUWX$EXNNWS;ME_&EK9?/VMV^;_=$Z/7!O#N55XDH(A4@8. 6-/YLO"5.)(HI M"*JB\M;1@YQ'_AAA&,]:X&S,42&O8ON K"L?M%J9H\)8B1281-H:C4P,)(6-1S;NHR* M)"N$)CF4$>C:)K*( E8:N: M3''8M76G;=VT MZSI^LNX']E%R]>8% M[,77_;+T4=D59=2#UB>1X8KF]VT<2C91E&*,)F!NI3],S()/L\O+T?QUB0=1 M[*&AIVUS&=OI]6L[F=E1?OUAJ=1^ >NN_=H"H]O)O3EL#^VQG!"58%@8KQCB M6(!.%!R,)&\U8MA'[HQ@DASS6ZN%F=A\1_U48([9L_VW<^CAALK6(E26>A,- ML$,&^(&QQ"@$H5%4UF)LA3?[QTW[_P.E?"\-Z6+>QF=X/RS"0MLY,F_B=^0% M.19-ZF;S8/GU/*A7K^K4J@HJIYR"=4 @S)Q%1"J)1&0"$<4=IMJ2%#8Y7X]E M*>^7+'NK_3W!?=1:_ZO9]'TSO6GINU?O/P[&WNVJK(S/NX.@\@BL\S*#$]*6 MP80N<=*#_4Y6W"/C\V =<.C%=.@MR/D;BJN?/RY269\'PP[YCO.6(GY< MGAN9;\+?[,!_LH^N&0,I[NW*/]>,+F55B3JIN$Z("PM-I9XCYYA:GEB@/&N5 M1[BD]M!O37GH2D0';.8QXQ:&M[_^#);&Q/J,9&Y;;MJK"-9)?IQWS8JW0RF5 M8\P83"B2U&&DD@=](4B/&%6.1"Z#(EWX0U<(CSZ(!N"*%AF@K@PQ) M=PR.5> 46J\<*P]DES.)-U+>B&C'BY"62UWF3M;;A^*70C>W0MNUO!J@EDIB MI10V&E$*HT/(' +?+(]KVB29"KZ;,LX+'(SN;RD\.*K="'?3_)-P54_ '&DN MLKASW)[WXFR=MTJ)8NF)0($0AI+B,'\*=G/7@D9*4K>MM#.H4I-N\5Y$\/6??@QZC_>V9;6%!& MU[?GJ3_&R0R4T2]C.PM V'#(NH^@^4/S[V.6=[D_G,188!"L$^ 3+W'Q7'M:]/"3>CIJO!Q=D&T]W MKU(,/?KO:BI"K[H<=%I)VLH[%;#W&NG@ M%4H)1Y2(EBA(*SD8$X;YPYRZ?U.WT4\?"KRF9:N25YQ*+XP(*.G\N$8.*Y2B MBHC!/ZG648!1>X0[(SWUUN/@Q_T@5,")_3K"H-FZYU>DKJ@(5A%+$?.>H,BX M0(88BPSGC!A!;##=[K\5>OJQWY[O!Z$"'7\R 8!VZ/J5Z2NA%//Y21V)'4&" M)(D4#031?/ ^),.BVONA^.^F[_N":$B7SJ=XEM6JQ1&/>GPVX(+]J*9?8G/6 MVLOSVM\[\#F\:O)(BKOK\O-0%#=]]?>VGD*EKZZA OCNU6P"OR<%5-]GQ?L8 MK^)X%E]=_V;_V;2O9Y,I*,%M>8D&5X;/;1M?+1X4O'..EZ[OUV_;=NXB/E#]=PZ3^?>'@N%.C"_CNH2) MO%**U9\N:#/YV(Q&J?EJV^&]I:OE*#)@7]O+>FI'96HI ^2RLL'AJ\_&=:J] M'4]/O,_'*F&6.6U&,-L]:3X,_):6SG'9%C0HQ]/:JWT! &59'_ M/E= 8SC)$2K.XOO9A8OMA_2F'LUN)\(/L^ED:L?AGBJU0GG>L:1*46Y(2A3Q MZ!+R@<"_I,#YAV64"!DW/C55%)(G+,JZG9DKXUL8M/>;LL!V.V[BV^5=K_E;_3X!#6A\MG *?XKM5>WC:=OD4S?M\V=5!JZX"D;0 M^6MW(BF'M-8&,4;\S>$-S13O]MA#F2L))9AYM#UQ'%3^^>)RU%S'.#\),G<; M-NVS!W *55\9093+!UT"X1YADS22GMR<25+!Q7",!TA_ %KWU1^#^I#6:7-O MZV\ _/S)OX-NU"QN$9^.LI#C^;N4EQG@37LVSV>K+(G6YK-96 B'(J<,:1$3 MXISRY&A,?.,SCX4;.W=Q=6GN/&/E.:$D&@N$4P$IPB0*SGKD#./2,(:IWCNR MW:#.W;XZLQD8MA+N_KL8O&_B)J:)ZW8(>JJB MHAX+0R+T"%$6"2%AWDLD(N%9#)$Q*N7>2M6P.TH#$>^ "!]L/;DY=OKMT&Z* M _MH!O=+S=PD_N\L7Z&]&O;TW^.:!N]6(,_ FPHW-1Q0X[D=)\M[!:_B.*9Z MW7S]3(Z*67?GQ\C*%OQ JH.&]BBCF(P>[\V)"S M<@069>LDBM _B+# 4;0^("JU,39Y#:K=$7MYAB!(_Y -J6'6 B221+[3Y8Y1(!(MYX"00"@8A__]]_ M7"^^^U+6JWFU_.OW\"_@^^_*Y54UFR\__O7[7]_^H-Z:%R^^_]__ZW_\^__W MPP__5[]Y^9VMKC;7Y7+]G:G+8EW.OOM]OO[TW3]FY>JW[S[4U?5W_ZCJW^9? MBA]^N&WTW?:'Q7SYV_MB57[WQVK^;ZNK3^5U\;*Z*M;;UWY:KS__VX\__O[[ M[W_YXWV]^$M5?_P1 8!_[%KM?:+YMQ_:QWYH?O4#1#]@^)<_5K/OOXO"+5<] M^K][\M^:OYVMNP8/'Z8_WOYE]VC3]E'7O^/MLU!*^>/V;[M'5_-=#\9.X8__ M]^>7;[=H_#!?KM;%\JK\_G_]C^^^^_>Z6I1OR@_?-7_^^N;%H_8?Z[)<+N8? M/ZWK\B^_W?S8//.C*5:?U'+6_.'^>Q/Q7T0=K>(0FI'\VZ>Z_/#7[S\NZ@8C M2"&Z1>A_'FZUOOE<_O7[U?SZ\R)"]..0 [/ENI@O$L?WI/&(PWQ7O%^4B:-\ MW':805;7U_-U\_6MFO=5RW7\3N/W.N\QQN--QQ[BRS)^:MM?=H_TI<$YG8XO MUGH=)]!7'^*$.)NOAQ#I4(=CB].3\GT[&&BXRU6UF,^:]487BV::?/NI+'O, M;\<:CCN\UT4=$?I4KN=7Q2)YK#M[&7S@;]?QGUN%1N+%FJ@]__;1<_[?7- MB^6'JK[>VFO'AMRG[3"#W)3OJM?U_+K4=?5;!.+HR/8U&&"8^T&&9R? M+^.$,B\6+Z*966_U&\01N?]L/X C_XW6@BG_B.T81^67XI%_A->57% MOUG,SY6O1W>CB?)+\>7!OYTAQ,&.1AM^L]V>;1;EJP_=1!#7TZ^_D5>;=;,A M;SPA9\AX_MLR /%37:T:,_Z7RZ_F7\N$G=+O)-=5B$4V1 MNE@,@LQ@K\\ U8OEEW)UN^\Q<0P?JWK^SVBNWVP_R =*[M:601 Z]ZUY@7FQ MO+5(WY97FSI.N7%+6!>#?4<)+\HM_OUXWD8+_9=J_9_E^O4FZJ58E;/A03CE M=;FAN%IL9N7L15RE$&\7\NUHTV;NP\_N7\_:99FIOY;'CY4]Z4 M 8!7ZT]E_4 W@\AZI-,,8KTI/U=UW(7_5,R7S4KT,BY:<2U?WJ]4PTAZ^GLR M"/_W:A%_]7!95E?QG]M)9Q"I3WC!:.+V\WP>;SG( %_>VD3;/V;_M;FEO?OC M<[E*_JC\5R_L^MK>=P9OJXCB9;K7J[H_CUD&G!/_9_QU??Q%WWS@P^BMY+W-AED2.W>\<6Q@7SUX+"O[PG'ON>''SY_E1 M!O-367VLB\^?YE>G!U:D]#6*$$^.BN,^^'J^N5[]HYZOU^52W[R<+^/?Z 6;G]CN*<#TG]X.MAAE8 M$TFIFZ-24UTW7LI>GJ7#K48(0O><:GNT'6Z0IO@\7Q^_$['KV<$' M<8JV=S<9?$@GJ&QGBV$&-/^XG'^87Q7+M;JZ:@+SX@+PNEK,^]PWZ]5X_&'V MU>T)?8P_:%?4R_BOJ]=EO55Q4MCP<&\87V __Z.<1:OB!$]16G?CB]*>AOXQ M#/?V=S>^*(-\ZOD_^9YS9_\NAAGRYOVJ_.]-$POQI<^YSK[G1QE,7Z8>;C;( MT"+5>VW GCXWZ,M[XK'G\4&'TH_-NY_>-9"BOFK'W(JM&D2FE0,=#NT!RT''$_\.9JH4>(?9N6'8K-8)XYN;S_C MC+6Z+N;+\X?ZJ)LA1[KM^(?K\OI]6:<. M=HTW$F2^W-X@>QD?N7NP&=*YR3EN7U;^L2Z7LW*VS?\17[>HKG:)M17I0[%Z MOY5KL_KA8U%\CO)!\F.Y6*_:WS33 _D!P+M4*/_S[M=A]T@:W^:+=7G=#6E1 MO"\7?_T^CB'T;!FP 9PPZ:P@3!%*O84(&DP)H5A20A]+NVB2OU3U';:CB7OO MZCQP7G] Z%[M Q.$&\$@YD(AAX7PVK>B0\#Q$='OB:7JJ^^J>E;6?_T>MHWN M>'_2%-WDX1E)>]7X $6!XB^V'^N_72VJ53G[Z_?K>E/>_[):KN/GXA;;T\CX MG=YZB<P%9Y*K6@$SC$@.@&E=F&G93(6)?8: M1%\3XGR5]># 62!]@VS(SH)'LDR;!-F5OWLB_/F1Z=O;E+IM%@0B/,Z>7FOL MB?<$&@-:(0ES+!,!=EGQ_;1_JK*JT<"Y& /L?-48+INZ?!?M%!U?_=O)=-C1 M1V <"J@TD88;R#1&R)I6?.<\G!0WQC(YQX+KGBW__N/CO=XXV[^=7J/GO@LD M3$.%H6&,8Q6_44,5O(4<>\0<^89W@1)9(+RAB&(=)RE$ ;M;\+#C1F4RZ<_: M!?;67M(N\#2 IKH+W"WAD7W@_D9!:86 8TJP.%,)JK4@MD7%\URT&6$GV%O= MO>;W!*PR+/_'[H,D&HCG=!NT$X8(!J32/%I@VAGI6Y TD&RR^\DA%%]=',@_ M6;<3K*GM6Y\;V4X@V=?'@\UOMA+_K5S,YDM=+'_;3X?]#P?$J'0 .&* ,5(P M"P!J!TD@!Y/:?^111S4P:.=H]OW-70;1?KI]\GA@PC@NG=/$QOVZDI8"U0X4 M&.53M(N^/>V>!]O%?!)J;8JZOIDO/VY3Q9UNK#YN'RSU5$9&*\0@-W'"1)RU M>P5C3!);+N:+2-WXC %5;C_$KIB1S@TQP-EWW\(#>=[9MUY 'D?,J[CK*IK! M;8=U%[/8QP]SN&& GB/KB*8*< "EI)(8(Q BB'H8I[@+NV%VCKZ_%V9_\\ ( M,9 H%C\R#9UD1F/4"BZ4SS0K'73"#*6ZO3Z8P> 9UP6S*J_^\K'Z$N>X^2V' MX@]/J1-_%5Z6'XN%VV:2W^-EV?%44 9)* S4$,29/!KQCMM64DJXG;1;90@- M5D-AT]MBZ:O0VY'L/21]^DA00&NH=32Q7+3;H(?2L':XR$ U.8?&69A7@Z(P M>>5-Q2]P$9V=O_7[J3-_WI3SY6I3-\>Q+]>SOQS> AYI%J!4'$-L$9:.""B MIIWD3-)I'#2FPUV-!L5@.GQ1EXMB.;/*)&CR:>,@J>'1HA""&Z,UCK@PW0J! MD4KRS@V^M1]1GV<"DL.G6\0=RI%3I.Z90#&E!%LK$:=8$DDTD.WP'44HCSXO M;]V.4,+N_1X%@S/4J-3 M,8(NH\CL"OPYHGF]N3ZJPD?/!:FPM!H+S"$3@ ("N&K%,%J*2=A$9^%?#2=^ M#BT6?_33XL/G@@/(<(^B#(@Y3E6T[7&WPE@M)V$)#:K%,\3/H,5?EW5YU> X M^W5Y52W;$EUM_9)7[Z,I=YN2YN:N],W-JP^-IZRK<'+$:!KF!0%+2 #&-J)% M,+2.:M'9HC[:C"F\P<_8XKH(K%GX>%":>UE^JJK9ZE7]MJR_S*_*E;KZ[\V\ M+F='8_^'>4&0!A"!@>62*HNEIIRY%CAIJ9FLD9B;.%_Q]H+P_\G?W@!.S23^ MUZ#M^Z\6+[[ MO?K/LJA/,%6.]Q68%-)*C[A$'DMB&6"@^Y0H3)J"Z+?)H&34)D6B^-9R.!IU MO05O&D$^V:)E(K;E*CDJTT]&).ZSD*T#JG B&"K M! /:4XI$MX44:7%#_%LE4BILD^+1_,MP,U+76?"&DHB/N.#@[BDJXK MRF^31%?7-(&$$^SH/&"B-*10&0$ @ \0CV *F,$X+A7]N/N;L M.$Z2>&^;>@NSL9CW5>\!22X)0)PAQ:TAFG#4S>F2.)U$O>?FVLX/Y"2Y]^[3 MO!Z->D\[#Q1 "!2#!&+OH$:"R^YC=5 F>3GA<_.39\=QDL1K]KOK3Z,MMT][ M#P!R*YD'D!)(-%#QD^V\,Y3PM/7VN7G8\P,Y3>[-/XQ(O2>=!VN,U?$;E1Q@ MY;7UW'7*DC(QI]MS\\QGQW%*Q(L;)-7LIOOXQ]([#8AA[@V'1A.M/0,*W^M& M8Y84S0Z?F^<^&WY3(MC#S,OJNJE?->"4]J#78 FQT(*:?#AU<;7>%(O[@>]S\[PI&]RCUEY]\//55;%H/IP#5#N_ M\T")-(!9IYSS'"#*).],7:QU6F3G<_/^9\?Q4L3;'F'<;K13J/6D>7!4:ZD] MD19BS(FG0-Q?UTD_ E(7I<=V-YS,CJYU@-9$LU%Z:P 5'@(8MS+= M5&S2G!'HN?GWAP?JHMRXW:XFD^.^>;"(QUT&5UH!+[DAT1;L;EAJ"I,N^*+G MYI\? :G+TJ/94Z:SHVT=.-06(="'!^J"W+C; M"J;3XW$'@6+")8B ,J2IU8(*XKM+$1XD.7W0<_-TCX+5I4AR*B<"YP 0Y8QF M $L...>^FQ>))4GA;^BY>9R'@.9>XX/GP#V4&G8=2;IZ]<'49=SA7S M;*.$ M=AB^N)HOYNN;ESVRPAYL%XPEQEKAG&-*2>&(%,9P[9SFWK&C]DT^48]E@MW; M)@@K(%7"6J B>@\ )DNA1Y,_SJ0CI[>Q!D(DF*J57<>27:LVLY7 M#P=HXDKC#.6(*V$P](2 %@4GQ!2K[ R@TJZN=XH[F\>K3/%A*M31Q:V$8HTUJ3VY\K$RFU&X77N,'0N="JG_9 M;*[JH_/_L:;!(LV)0YI"X(S E!HF6F&1)62R%L#YZNO!AP&@^L;Y,35;87JT M.($.>S)%-3727GU0UV4]ORI^48?30NU\.!C*& < Q=5,":08E%:V@]0T,<)S MK-5^.,BK@8%)TMZF,2\^S,O%K!F"*6ZNB^7+^?5\7N$$$PFC. M 2D-5P!T)FTBLBD$++1#D;&4>[C#+^GJ^ MW)[+_5*MYU?EZV@]5+-]$\()703(G<2>Q*_*0:^L@M*Q5B#*2-HA^/,@P,A8 MY9@Q'A^ OMJL5XTOJ4 M]57]V %Y!^.#JJ\[6#3*^P(3$3WD$< $"HP0QZVL'(%DWS">G'CY:I:S&<1O-G#JQ\7B1IYNX[#:%#H^'+@4_OZX4 AT5P(!)!1P"H? MM:FYPCJ:L@;QHZ511A;J:'G@1P\&P:5638IB)!!%PE%-7"<,-9D\? %KAED1M[B/%&7AD,#+:T?VZ7'TNK^8?YCV*4.QM$^*ZZ*1"WL3/2#EGO8>P M%0]P9R=[\G.FMKZJ!CXL0-\<#Z9VPC,5]6=7^VW8L7J_V@8-']#UXP>#1)X2 MY*!#S3JI,$&@FQ4]P6DIC<:RZ@=J4I6)[IZ@5B>A'E+OS^:"!E$03 M!1SD&A+N&)$=\9E,RLHYFGK/TDLU/!R7T/)MN:!3]'S;(G!)FLPM6( XP3$' MB';J'BB=J4KU%#2=!$@&7;]:?RKK!Y(?4/+31X-5@'+@$+8&(*D=1O/H#JG=,Y'(NP;W6WL#(9@IP!F7TF,G@-6R$T$8G_2ICN8C'5*9Z2#D M"(LO5I\:CV;\HYE!OA2+KTL3BHC,MHT/9"]-08R&0CQ)G*UGE^MR]EN 0YPX5C3(!4T!G(@":#" M4-6<0W504I]TPWVT^7P@&@P,2@8&V');SG'^I;R%X(#&GSX:)$ 08MED#S5& M*F 8%JTPTH*D+?-HD_Q &CX3A!R'K'5Y/=]<-T=76\OB37E5QB$WYU:_E(>V M5X<;AL:QPS0VU&-$E6/08=L*"AE)TO9H.2@'TO:@D&29S^?+U:9NS@WC4*LO M9?WHO'+G-+ZS12 0..H4E%:XN$[))G]AAYA-2],W6B+(P6;O(;#(,FE_*.NZ MG+VN%O.KFVU1W]46;%.MCDSAAQH&)R0W+!J[3?D%8)3B]_M)REG2=??14C,. M-J$/"$F>Z?US,9\]X&H[21V>VO-JN.X>7\*\?#MZ2ICRA$HYCBT3\/^N.?)B"2=_T:/D+ M!]+OV3#D%A:);1(Q,U-S4CZ"29,]RCZ%X?Q=Q&,WZM^OJZK=/ MU2)B>N=5[W'*V+>+@ WPG!D"!;>*4.3B?SK&$IZ6P.L9'"J/!%!F=IQ&A%:D MN.N/9$?1.$2:-E,4,]T!G"-\6N>1PROJ !/2$,J@]%UQS&\C#-&.^,]RW69E MGZFU+^;U,2?YZ9T%R*VCG!/"F#/-?6LM?/>9$3BM"(6S-+HOR_E;4MBT6<*AL__Z(LZOGRXZOF,N?\G]O+64?M^A.["Q%/3[PTA DE 43$ MF'O[E[*DVY CWGD:CB,9T,IH6MSXJC:+8GY]._;M#[/_VMR>&KL_/I?+5?FZ MN=9=KV],L=H4B^;*SEW;'L;(6?T'@Q2TV"'GJ6?.\_AC!QOD,NGT=L3;3<.1 M[!+P96#=K\OX<2S+60\OX=-' U!",J(XE]QXJN,^$'9!$%RD7= ?[DYZ[B;'?(<_=PT%Q!C@@5@F+!!?<276_P)JTTM2CG>\,J=JSL,>RVTT'(<0DMQ;U\P T' M($26"RR@\M&I]TFI?%33"*^B[2#*>>(HUWF'"^:KX^M3\3DQPAUM7U=;7LI>.GCP8A#63" M,>H-U$8W$^#]Q6SLIW9:-+B"SP0DQX'OK"O56LQG+Y:F^#Q?%XL#2M[3(ABG MO/> <8NAAL(:!KM 8!'7OTGY\D;0]3"X9-EHKR-$Y;Z\VB MR=!BHQ*NYH=6\N.-@Z.1Y A1IZW2.FX\H>YB2#5*NYTZFK]M!"(,#M%%K+J3 MK+FFA#,13>BHAY0I:*SS'OY^LVX\A.^J7ZJF3OLZXAJ'\K$')X9Y08B(6XJE5Y8)P2@C4J-NZN,@ M:748S2N79:;( .,$@M#."#X++NZAM8W6LH];:AIM9FDZK(E*<^V/YM8;@3,# M W3/AN'S#.[)]O>ZJ,OE^E.YGE_=;RZ>4^H_Q#UC$%BFE6:('4?Z<)7TP] M]9]9%*O5JP_;2:%O^K^G;0)BEDLD)%%:"=[D P =)AB0I!")O"D >VMU'SG. MQ"2'(^[!"(\7 /SJX0 E,!H@+PWW2D"AC->M0)Q9,/W$?^DZ>NJ7&PJ=;T#M MV=7=-\_?);5](2_[=J3[JX_L?SAX)A $6&ACM9":$V)YAPTEF>HZ]RWK>(9" M=GK8SX BKV[U*;J]>SB@N+*U 1J!I15*/H]LT*":P[1WR M[A530EH).&1:Q[E/0^0[8@-#"FE'PP1&0C:[)S:#G*E-NM/ M53W_9[FKD%:_AD$; HTBVAL#L0<:.:BZ;UC2:86+39)#9T)Z(>Z\6*TV)_/F MME&@SG'OB-.0$0"\5#IAS3K0*E!/#!9-;A=!@=<2>][-KM:A MI 4K8V3,I:ES)IZ7H,S1I6I/BR %L1Y:")!UC%M& ;Z'2Z"D75?&()MI4"4) MRTO0Y$%URU.X\J!9,!1280RR$E("'#3<="NQ4SQI6.HG.D M-751B]4GOZA^?Y;5$STU"#"J#(BZ$XH0ZI"/-B0#3$EW-'74M$(HG)- 8: ! M8@)I9FCD2RL,C_NI:890]%;!X1"*TX2?? C%6=43E6?*8J6 8]0 RB$%O(.4 MYRKH?D[H1&]M]JJ>>!H>.7SP@U;-HUQ;HB@QS'$5#4ZED6K% T[ Z0=1I&FK M=_F\-("^.1Y,-JKBPNK/KO9?RG5C-;VNJR_S:"+IFU_C O1B^2K.ET53!5M= MK>=?^F9'/+VS@+R)QJG@&FAI+6C^3;> 8"?]Q X]!C,91H%UPEEEND/? *2NP-D*R%E2F4)(Q.MKI6$;J M30#L@PS^N*C+AI<4HCM6-K\)YE.Q_%B^6/ZZK,MBT;@_?XK KIKAEJM7RX=5 MWI:S^[23NZ:JL_H+E%%NN.51-LR8)4XZW(H:-PO32N=Z6657^?%.H=:;70-Z M6RS*5Q].IE5*7T%JQX255#BM!- 88=_:%3I*GN1 &:^FWF0HE0'K#&NMK^IR M_G%I-G5=+J]NWM7%(]J8N7Q?U>EG6 MJ]BP+F=E>7W$+3S,"P(&MJE+X#BRED.K?+1K6N @5$FA<>,5'IP2/2^B@!SN MJN9P2C>YXDUUW:3HW2:!/N2KVMD@0,(P]40A)Y%"4'@F6L$,PBR)6>,5.9P2 MLP8!- -3;/FY+J_FV]%%4G^NJ]GFZ@A9]K8)%'LI/#=Q!E=0*Q,_"M**YZE( M6BC'*Y,X);X,A6D&RD1XXHYD5=KR]L\'@-REK>KAP>C?25#& T2$)!K$O0SB MG- . "5TDK$_7AG&*9%J-) OPK(V^_A]);N3^/5U\P",@BKB*:!"@@&$U?VG M%:W/::60'$.91_ER-F@78)VF!."K':.Q:6\W:,8#6P2 M8T9S/%R$,8, =Q'6))<1/K6K8*A6F'O!',":4\'T@T_(LJ3SW]'\"1=AT: M7FJU.KTP\2G=!,9,%00Z"4<:(%P0J0E(AGM&W_I5:O8<"[C%7=I.6_ M-PN/%5?MUT$PV,C&AZLH;H)@G46"=CM03I/FGM&V]!=AS0"P780OS=Y"+6?; M/YY6:'I3KLKZRVDF4(_^@M-0:DB8H#K.R9Y+:KO/R+"T=+VC;?@OPJ;A4;P( MN4ZHFW6\<6"$0,.;VS@6$Q$G82+;HW@3?YI6=9V+T.9,R"Z][6JK$Z;NN=KV M03G* :)QS\ %15%Z@SNQD?))'NC1LG=>>L.5B-I%R-*CSM1)Y.G17[ *Q36< M.8@M@%HPZ)5K8<'63:LHT$7(-#R*$S"=^U6/.J&7X!"7DG(EF_OK<4YF!-/[ M!5NGY4 %WQ23A@)O4E'>@T1W!R %AM1Z* 'QUD$H3!M18Z!C2:FX1G/_Y(WQ M'0?"RW'H-JQJH)L"!SH+S!LL >4.VB:#80-)M^(KXY)N"HR8VF;LFP+#094C M94UQ"K>B:@D2%K"1CLDR\:7\9&\ M3-S'G0_^7:7KZKH#UL&J!'D@+& &EP)-[?QRQ8Q-.*MXQV M=G91NIP%W$58\DNU+A]$Y9XVOSQM'*Q@R M/X]JIXP3KJ.YVG4T6EB2FC'8P M=E&FG G=A=P][ZJV!NWV7M)=(L43'3Z[.PF615 )1IXQ"9%!ED/4 0#(Q,[" M+NSS&03#2[BDHS"?RWI]\WI1+-=J.6N2<'X^U1.]MY-@.,=0"@!P%-K'15K: MUFEJM>%)E@W\)CW00V$XJ3.Q0<["@A. >DXHLMY9H;W1I@U,L-* M.L\WX+W M>30,+TU8(G7;_(?>HY!G=&@S #AYJ! MQ^U@\T>S)?Q2+)JOX'59SZO94S?6 1:=TDWPBDAMB(_;!.CC[$OCWJ2;=(%( M"AL;L;+58+;QB"!=C"DJ4K^N;R++MU6V3J;(D_8!,JBYE?&?PD"H>-RP=BXM M;F#2^C1BZ:J1N7$>.AE(\7;S^?-M"8UBT1:*>;'\4-77VY1$?:H(]^LA2(\@ M!4Q@CA45D@L+[@Y7N(4*)T6_CUAW:+@R**/@D^7PZ38MWNMB?FC#_/"Q$,&A MU@) @9/QGU1Z@ELAK$)IAP*C*7EHS7QUBI2,3)ZSQ>JZ2*2T2J+FZ@YF1*I6%"SPQ,KICJ[D<\#)[.-H&7E[D-G;#_:T67# 0:FQH5 0 MK1%VE.M62 )(4@VY\9RC(S-@0*12PMR:7*91JLZI7RQG.S8NVPR\'\IZ73TY MR=X7\79FMX%QKC!K'N$D2AR 23O*92KON#M#/AX M%,^CN*#SQDEJ@"'&4;R]NH@CUAH+;Y&PQVZMC"S4B<4%L072&2Z@L) AI[CT MHA4&$)JIW,*IQ05[J^!P<<'3A"^^Z>*"B'NIJ156$F@9E8X@W6*AHR< MXH*]M=FKN.!I>.389:D3WU'"Z6I[66AL"C!QG*.7L%!WO>CQ "2A2@''EL&YR2BK>?0/6I5W/ M&,U]-IB&!X BB[/LT0!_*0_&.7_U<-#$H(:J4# CJ19$L$X@[?2T*D8-IMNS M@;C(59JGJ18/*[M7^T" 00Z>8QYY(2!R5H!4^PCRM6ET#ZO*IW34.7AG(F2 MQDB*$1( U9X"QJU&U$$E(L<[V)!CTXI6&H\%0P&4+7RU&6@3=V>J9=S_;.(6 MZ&XO5"WO*LP_B,]L4W"T07I1OL>]-('[ZYN?R_6GYCY'NY$^DF,GUR@"\88H MBY4'2 H(4=P0=(X6B'52 /UH#J?Q.#I=R',&;=_!>0?S489^U2)$$U%9(+4V M@B!+L&]RP[83.G%)&9M'\XV-S:9SXE2Z"9IY;Z/?C/\2FA\\%1@ 2'A$NF'"<6HJMZOP,).VD>[34@2.2X@Q0 M,NBV.::+9&WN*&\3S_7PU.YK$E1C^0-G :912AHW@:#S+&'JIU6^:$ '[4" M7$#;NEC-KTY0]?;Y0 '0%DKFD<-$0Q:-X.Y3(%8FQ3",YG$]7SE'M)V"R054 M;>>+S?K@A;X]+0( 7EIKJ?'840T,!8)W\;% )$WDH_E(1U=W&BH9%/Z/LKF. M5<[4E[C-_5C^LFF >O5A.^C5J\UZM2Z634V9'C/\J5T%%(676,05TD"M. 8: MH18,B772T5S.?!^I,__(0$V(-<=6BI/Z"99P2YFV,L)'0,$&ZD""9EJ]^ MM!5D/"4GLBD%P\M1Z6["_$J*T\FTKZ<0)?>02:2IL'%:YI:A[CH8A79:-0XO M3:>!4,Q_C?AA8NQ;?^SC$3V3*\5,^;B]]U)2Z*RS)(+KFLT@@\C1H[Z2D84Z M\4HQ(5)Z"'$D"<90.XX[86#C/NO/Y@#7SDL9]+Z:(0>JII*@52QH'IG_%^#QM/=TS#@C2-\.![+KO>[UX M JK/KO('66]_?F2O[KJC^/390)NW%,\$(\=%X]EL"VZQ:/*-O5B:XO-\72R.ZOE@NV"\%4Y#CQW@B#/L/92M MF BJB7D!!]7YD,!DN4&QCM*6L]9S>53QNQL$+9U@Q",>=X(& &L([:9 S]*J MF8YVG#.LQ@=!)$?,1]P1+]='%?SPL0"=,QIPSA2DP*MHUZK.L&60))GFH_EJ MAU7K&3A<+-KCJ'(/-0L<:&:\=M(+9 D!U+F6L8A+E!2\/%I(X+#*'A"7B]P^ MW]H8C]Q=;Z(HOJI_+^HCR5A/Z2E00%6;=>/0>%?M_B .NGB&>$'05#C4 M.*J!H!!:%B=>W (7#>=IE4,:C15?N8DN@&TN4KY8K3;ES&[J1IIM\8-MOZ0<#*I(R*HVVEC];.'>D6P"&$*,=" QE7?8"!1IQX" MS+0N>^7BWH70_?,J2'=Y@6-/F==*8Z.8I00 H5O@$$[+ZC_:K;%B4VEYZ$>[>):-(F= -!&[:KN3>/]T)_&FO$TF4;XM MZR_SJ_+6?'Q37E4?;[5XS'@?^]7!&:Z$I50!0+"RP"O3.9 DX$DKZ6BWUZ9D MQ65$?;QH0UM=;1HQFSM?R_76=NC*NIP67[@G.6'[@F+'"UX>B"'LWSA ZP#U MPHMHK2AH.&?.0X,I(8[+J/ 38PH3!-D7-]BO85!2,P(@ #"2 #35=@UO!7 & M9LI:OC..< PU5".",_DX0[,H5DTT;S-M]8TQ?-HF"(N$\P SQ3W5UB(M78N) MD3A3$O1>\85#:WE?O.&9&.4(.GHPPJ-!9E\_'( F\7LB0C779KER4 /;"F0- MPM./,DS7T=,PI*'0^0;4/MG PDMJ^T(1A=N1JIXAA0\?#DS)YK"!(@2I0((: M0D4K$#!N6H5+SE'(SH#",Z#(JUM]BFYU&VT!M6N.Y07P@(JF5B&EK4 (TR3= MCG8H-XYNTZ#HK=M5>?67C]67N#>:WZHU_O!4F_%7X=;X>%-^W.;O6ZY_*79F M2]_W:,!(-F4L*0#"*8'%3LDV<#D9)*CK6@\7^< R5]QW'ET32*SF31['G(#*Y:TV3N7:[]?'55 M+/ZS+&JWG-EH8>S1[K[' X; 6HFHM H "GE3H[85@V*[W://A(T'*IAH*<<8!!JAU&OO. Q 9F70N,OB)[LAJ/ .0T?1W MZ\ ^/.ON?#90$FT"3PP#PE(E"87W^ST75Y1)'(9FTN@YR(RFVON%P,??[')% M'G@Z0&O;C=N^Q7GGLX$K MKYI5AUK*O=$8*T'N!4A,,?,\/5;G03/6E'[K:WE3?F[N,RT_-L=B>^VO0TV" MUE0PAIQR-OZC2;RLV\U"W-"KM&R!S\UU-2!"(RG\]>;]8G[E%U6QZU+ASN<" M8QPAV,Q$$0$1-PE$M/:CT-:GK=#/TW>5#LN(P7&;\EWUNIY?E[JN?GLP0S^) MB+M[^Y!OLDT*AL6^%YX8N;8IUP\[?WDT[&Y?@V"H59A;:CG#@AL=-8(-0411 MZYM(RX%"[9ZB<3B^;N?3 371E7&,TFOL+)=<8W$W5":WCSILC#8DE1/AVN)+3Z06VG87Y5RO?62A,7GE3 M"4^[B,Y.T-6>I?"GSEIX4\Z7JTU=+*_*E^O97_8&(O5I%K!P@&#)/,"8^SP1O,/'6. 2TAP)X3R]HA JPRY>K(;K , M!4BBSA[9W'N7N0-/!R.CK)(8%/>ETL:Q JFZ"4,3/SES90#$J[%@F:P6IV*W M3$-YYRO-5(M%L6YJ:'^HZI>OS"I.UW%KN5H75U?59KG>GZ?SE.9!2L^UIT0T MT3+:&DI4:])Y05!2F-]()Q]G:J(:'9T4-=]7!WY]ES?GB&+W-FA*#BI'J"!0 M< 8DE%YT;A!M?)*-.M(!QX"J' J/#/E?=R5X6S2&,6L[, MHBR:C$FOZH_%V7GQWZ:QD1G8WY<1 ML)0IX.?BC_GUYOI=>?VYJHOZYF5Y6X%GWPRP[_E@F[,;V^1>8P@3C+6BJ!VJ M43PIP"S/!'"F+W<@1,Y0WLMJ^?%=65_WU-W3QX/TQMC&N4(=<$Y!35VWT#CB MDJRKD8XL1U'=F8",=Z3EY\NX7YXW]SM6T4+89K@8[51KU\M\,:^W*3#^-H_( MQ!7NYCZ]QH,CQ:3SKV&6M6Z$:K4JU\U,^G)>O)\OXB";M;A8;>IR]FKYIKS: MU,W\&A_8)BJZ^]>F/-WJT!';*.\)D4.&,&. U=9IS^*T?CNO,R@@(<<\0-.% M\EA-KL'>$:CF-AK&UL4)5EJL <,MA%Q!FBFKPL%R7A?B3#4-R,<]GAR YOIF MB\CM=>;#R3WVM@G HR;KGM=*6"0ADI+3%A.JTW+(C5P\[ *$V$?),^',L&UZ M M8.>+9X_+JLWJ_*^DL#RXOEY\VZR2$55]/%?+M /I3S:%J)L5X9F(=6:$AP MG#"B<20%5!VX"&DW.5_H@'PY/"E>&N,_B3PHR%-Q!W^#_,W.V]LT@6\;L>X6 MJ",Y/78W"%#0N"VDVL6=(= ,P^;FR)WYY"W,%?K0+Z_'Y=6[LU3@F:!F8(LM MZ_F7*/R7BZUFTC,"(96>M((+X))NGXX4\3+)G>UPV.8DU1U* M>[R__4W^/OT$:#P7$DJ,XA\$ ^R8:F% 5#Z+#>D@:M['HA%1_)*:!R:5HF_D;2WCR-GPW4A M1L D1MRU"D!2R^-^E3G)O.&<,^T[$\^F)>@>?Q.7G1%I<&5@Q&TQDOMRJXV" M&FT<-H,/M K..Z9M%$=JKP"WGCK3BDB\R)1_\)G9OL,!>CG.'+5%#K8+DC0I MPH2GT'!*&6[R(;=B2LBG%VT^J.[Z\>$LJ+Y99DS-*IT>(3[8*#"@.-#<&,Z$0Y Y#5D[:$U$DO]WS'K10^!?C81.KB#H5W%5+=;; MXG;->-T?33FH\J@%>;1MX)("[F 3YDFMP8YCB[LMFF!)E]I'LR.')<-8(%W( M2_&/^?K35R[IU6.?]&,']M;J>E<7R]6'LEZ]6*ZKKZN;]:L/%YG8'[PY.$MUW)!:RD-UAAQ1(GU M6(#N2%[8"$@*+P?/CS=17@Z/[_.:8G^*.FMVCG'+L-C,RMF+I2OJ97QD!?/, MM <&$##2VFD$N?0(22(]PYW#0RB==&]U\&H7$R7VE#0SG3!K\ZE8?HP _!J! M+Q;S?Y:S5LKSXZGW]QV(\E%KVC=;;RY=]R]X,'W!4:]\U0[9PB53!.O=!>4:E6:;V_P M0B_3X/V4%)$W4T#W.U,U12*O(O03N[Q_'XO]LL<5_!U/!^T@X= ZK E61 !K M[HXBJ><*T&,+P-AB';L._^3)H.+LZ*3W@!#$/$12H%8<%N7+=)OXX*7VL[2P M-Q8_1?RI7C"_/Q!M*@,>C4)Z^G!<,YUKRMHHW&3[L5ATB38]CS!D"F ]*?@H M69%?10B.'A-E&DD T89:"W !G0?$Z5BPC%$ MZ_"_XW_V:'A[N\" M,U AB0U%4'K<9#)7O!TB, _*KDSA8'Y(R*OSD,CP[>IBT22H?ONI+/N&$>]K M$IAV!M$HG>!"*-'$7W,CWY\;:AD?"),+*?QHI.?^1L$!*SUB2$(. M9104 TM; 8E2>K*+]_DJZ\&!LT#Z!MDPM:5Z2B3(KOSLJ2.T(D!J8!V'4#C! ME>X <#ZMNN]H9L 0BCPC^<-)4&7EROV0W\Q7OQVQ%0XU"] S!@2#%DN.8?R3 M -N9400D^7Y&OG,TE+TP("Y9E=\Z5AO3^.@Z<:A9,!@9ZSRG5DNDD23.=S8T M89),UFX81G5[^3 85-\H+Z9F04R/#MEI\'JS?O6YE[/GR9-!,HX59MH[A!7' MQD>Q6E$@SU44L:=%,(Q2JB$1R:!<4RP6/;7[]-& '35:>21$4Z=>4Z5M=TIB M(9C6-?-1U'LF)'DW >UY\:L/][_<6J7]S/^]S8.!F%*E"(-18 N10UJW0B,D MI_J9#WG<-Q@Z%SI1?[A1F=B9>@=M_&ZORN;3;0;TZD.S"G?C[Z[]F6+[.9Z6 M C^MY^ -U5Y3$6=QWF2/( C>:I:AN*GCQ_+6Y8>K=S+[?6T#I11J2(WEUD/* MN.9WA0VCR"CB,8'S_&Q:W1>/,Q!X4XT&>"1>(YR^T>7RZM-U41]S%QQK&K!U M#$KGM*!>R[B6NKNB)PWV"F:J@9"6IN1\M3\U+H9%*XW30>:QH$ M\[ZYBB>=QSBNH!)1U@I+K563=2@,I\:C_!@$LF^<)U-S,$R7'MEI\79=7?WV MJ5I$S%>W^;G?5>MB<71C>K!=$YLA/:(60*,4\$@JW>'GF4JZ7#K:[F0XI57C M8721&>*F1^SA@5:!6=#\CVN,C26<:<$[LPX8EZF>YW1-BT2@+L&%7E[H ZV" M<7&+CPD!%@JOC !"H%9$I2EZ3K;$Z7H[QH6S@?HF.?$,[(:+4N$$"APMWOS5 M./H6<=[3,#A-XT"MQ%3+N,8A++CMUC=+IU4K91 M["[J/ P^.4S!JT_E;+,H M7WVX-59^+M>?JMF](%__MBQ_*:Z/&0CG=!N0H5 2B AV?GM%BXGNJ\(R[>@R M5P[5P2V(C$AFH-N^T1Y=40XW#,!J$PUVY %"@A@%".L^5X\UGJRAD4>].VLR M#0SF-\R>J9DDSY$TYYLM/\\C3LMWY=6G9;6H/MXT.2+KIG+ZNIP=MEN.MPS( M*1=79"",18)J3016[? 9($G)X$8S7(92134F1N=9IO/E3]7BB%IW/QT@H,)J M C3U!D4#3ACGVF$ZYI*NN(\6+3&&*@?!)2N@XP@!Z*$TK M8C2ZDG)EGYY';"*6XW! 78X+9^9.5\30)G,( G&)<] !#KJUSE--)VL6#J*[ MDY*HIT'US3)C:B;?] AQ_FH_0E9]@*C"3 #/)(G&+59.T,YMP\"TSJ &PK]_ M5OW3T,GP;;]YDO'LU?+GHOZM7#?KWGW)8%.MUD^W.$TRH&W*^ >_.C 9#/NB M( &'39"2U()+A.*"++HE&6LUK8O8EXK3NBCF&U$>"GR BP?; MA2B/U]AH+AG60"K+27="[$2:"3M^5O+,U!H2PDLRY4C:SH/M@@$2.[N->&X$ M]=BS[BS!2ID4@#-^,N^I,"4!PDLPY3XKZ-_B3C[^58]LK_T["2*:CA(9);%U MV'$KH.U,1^-QDKTT?N+M2W-H*#QSW"E;E+./Y6S7_8-?JO7;\G/1>/@6-V_* MSU6]+F?W0OJJ?EFNUV7]ZH.IR]E\[8NKN]2+![@WROL"!YYH8BRR2$H.@::H M:1CLS3:< ?3Y&WU[SWRG8UG3_*#Z6AXI7'&H6)&E*)/IHSV*O!/=2BM8$:3ZA MB69XSLR8 1',>Y'T-GOTXT334[@S>KC&P5>ILI]FRC[A#NDP;PJ1'P1K1AB@ MB $G&UT;9+ SF"@.CYF44X:S]^W3\]\2N)1QH\P9$AX8:P0B3<*O+8Q8,I:I M5F2_>ZJYF9-6#V0$V*=ZP[5#1-]L,3&+8K4Z6F'_SDIL8^69P*:T^P^"ZZ'.4V_?CP8[@ " M+N()L2 .48U%:S[%/5>NU+9)%8@NH-JO,B&=#6E*J,[K;:JE4BUGO\9MZFI= MSFX#5WN0X:3V 1M)@67>6$$5IHI+BSKCVNF)'G]?FAUC8IQE6LF;0%D1 *"U MA#CKB)942,I; )Q-RZ>7JPSV%*:@D8#.=H/HA"5LSR@$H!KQQDEA)H6"H)5 MTC*8JV[TY?DU+MK/9G]HBL759G%[Q%$M%KZJ?R_JV>A[Q-VO#1YY0:F!%B,G M/)#*T.[KCJA/ZX;=M^4S'D0C.6E_?NGW;3=]J#[0JX)2BAL.@.;> N$ $RV M8!J.IY6;=QJT&JC.[D JF3"_5X]%[ H+CT7R@^\+WAMBJ.&:6B.$H-Z2:-1; M0RB+OT@+=YKX%GTB3!]2+Q.F^XX/^O6FOOI4K Z&GH[QNF I9\3&W8?GS0T[ MBPUO35 B/4RR6B;N*I@(V0=4R[/A>O=%Y^/[UZ\,.DX;E&LL4+11G?=,JV8B ML7$^D3 B_0TZ-R;)^;-5\VQXO]7=VV*1:W[?OBHH0!T5MLGN:B5S@#<_M<KY-GPN_N2\W#\\>N"5=(:3050)FZ &)6>D3AI.$V@EXPG M;4W'OY_P[?'\++4\&ZYO]?9BM=KDFLQOWQ4TU$8+S2AW!##AN*-M] 9A.HWE MX]^4^/98GJZ39T/Q[D/.1/,G[PM$<20U1IH#@9RS C@3S4'LN;(6TZ2;W^-? M\?CVJ'Z>7IX-W6_MLW*]O@T/SV6CW[\P<,HQ8TS8N-]ATD+C5.?);;Q=*827 M?Q(^MV*>#>/O+;6,K-_UTL!(5*O72'J/"4< 61V-1$>$QD!YE79J"OZD_B6T M\VSHO]5>F]/BQ?)JL9F5LQ=+5]3+^,CJT-74/ ,(4L5YAW)OA05$(@;8?6 9 MH&G&/OSSN/7BFDJ)3=XER.]I@JCKJE[/_[G]:_?'YW*Y*EN9YIU,^V*<R&<\[1]#8)$D MVAHNG8="0LS ]O#$>XVU=22MZ.F?A[E34-:S^5:VRGQ7%\O5A[*.4RJ'2\.7D+N'05 2T<=Q[,0U-^%/HOOL\'\"AUX6( M'74>4$*%88PXPXF-6S=(@"60TZ3#7_CGZ6]FO4R8[(<^[E>;]:L/%YGX'[PY M1%US06C\?_PO\$@QT9JCU#N1Y%6%?QX,7TY%$_X:OO[FQ_T&#KXO4*R0D((; M'+=@B'(HF^L8#AK&&;?\YV%Q;L7D3;WV2_'EP;]-(>G:@]R&;KG>WFA[ M]ZE8MYHN?RG7]]6\(BG@<35>. -? 8>6I!-P3+:AK M@EXNG&0M2;C>R=72>P_,2<2X H@(IJ,!!+S@=[!)8&BF*B;]DJKE8LB^Z2<; MS,\@B5KWX]_F91W'^^EF.ZWVSZAVH(-@(+6,8PLEI%)2S!G3'5KL:,+$BZ97 MRT&2_6G5AD/U0@;>ZFL)^N>;ZM-/< I)!+D ',JB +"XA8&P9E[#MG0!E%S M#RMK:!3_94F5G4S],Y--GTN7X]#MKN)VPW T\<:!5@$:AWV+1O[].$@*4,&0$\]Q:))[PT8 M:VU/94RF0L'/QJ(Y&\'LE# 1B(]5?7+\6+!L>2J!LHY*(>),"H#63&A+6U$H M\=/*9C2D:I(R3IZ&5H9Y0"W69;WG@ZMU/;]J?KRO M2S.:S_G(>X,WC@D$!49>8N, M[K[>+G020F^QX\R?99^Z6%5,7G&_[K\L&F. MRTQU?3U?]Z^9-MC+ F84T BI\H9',)7'M)M"FL+!*=P>/R+T67)[ /SSGO>^ MO?I4SC:+\M6'3O!5_+E]TE1-_;"K=7-^O5H7RZ8.[ 4/A>]SGO8YX-WQ=. : M:H"H@(QX;TR3AD-LRYY1C[%AQ\*CQQ;KV,'KDR<#Q A2)R524"IHB/&$W(G3 M7-.2>8RN@X>H9VEA;\[;%/&G>KBIBT7\VLJWG\IR_;)14:./PXZ^?4V"YTQX M*Y0 4%.GA>/:MHA@H9-NS8]\@)FLU&H43#(8%+M&>O18:'^C(#Q$"'$K&>>$ M4N2-!:V @ @Z68?=^2KKP8&S0/H&V3 U]]R42)!=^;FK@FC ,(/ *@1H?BE94Z]^-N*D(?,3,/-0M8":!6^XHH0H091EVD7L!&^%)-[RR9J'\\^%_E,7Z4UG?C^+M[\7GPT?"!YJ$:.P@1IO_QC73Q>G2DPX% M:$':#;JQ%O]AH*]&@2;#)VV*Q>+5YUZ!'D\?#5@(J"353D"&+>: 6M,9+9!G M6L\OH>>!(,FAW^KZNIK-US>MU,?5O+M%L$@9"(!5$&J)N(^&,&M%DQQ/ZU!H M'&T/@DR.\\?;6XS=6."=#0*EPBH)(&96]#>NF,:_NG- MS7SY\75=KEG(^XT?6R$XXI(^FCAAH$W81%_I F%Q( MX4>=I/L;!<^5M!Q[285!3EOCN>R^&*O59%WGYZNL!P?. ND;9,/4'.93(L$% MW&_UYZHNUJ4MWZ][7+?JU2XPRCE#.DID!:%QHPI<=UIL),UU9M+/&!A"75\Y MXH9#)P,)WE9?RKJ!2PNEIIX1S9EP0GO=.2 ))M.: M 88,Z!X)H:R'Y]O/XI>J@;]8J.MJLUP?X,3!=@$2X;4WUE$6/P>LO)+N?A&% M243(< 9W/A&&A"6K]KM4CPD,V-,V&.Q I+>.$R##P"IG[B,/49Q9)WHV-R0+ MAH$F_SS0+YKN]M%@O=6 0.08L1(B813J)C7I85)6^@P'ZBEO:Y>R7 M;<6;..FL]E@G\1E3K#Z9:M'&;D7>RC#;N!Q=6N^P7Y4S?)E5[<+_S M/HW6!++[WG[_$P)@!IBX#?4*>@0EDD!O M$XYQZYK+ L?"X*<+9>]\O^>^(T#G#6244L>I,=&.!P+<0:@PUIEV.OVR_N;E MS+Y[Z)DAG^HEV5P9@('E<3OI%,5 $:ZD%I*W:$$(T^IGC7LDE9< MNAR''J2HA4EY@&$;U2RC(0+C]LMK2B'WP@G2VB%"ZTSKVBAY@'MKKT<>X#2X M+L0(E,0(U$;5*8J\U#SNQ3D4TEA.;"NBUFG1AN.G/,O.B#2X+L2(\W*%<\0! M)](2RHUGGL*[I,F-B J[I&Q"XR<*R\Z(-+AR1"'719.@Z_X(O3E?/12%O.OY M0 V46N.X2Y4",J.54]W4!Y6;Z$IQT@A^WF6Q/8'?5K^X-,[ M"YXQ9@@F4$O#.-Y>I6T!02XMO7BN N87XM;H*!^DW>$TY<7^Q-G]J)3>63#0 M8-Q<&J$4<>"FE]R#N\[@F#G'="M.4 M)Y_4D>TT9I\S,A,WE<6JR?!\%[2\G2$/!X>D=AD,,@@9;G1S M THHQ:WU+3@2ZJ1 L%P5G"]U;IH'Z^D0\563G::+J/ZI^6'9/'MD[S] [T%2 MZ:W2$A ,-#<28G^O(XJ2SAQ&N]#ZK.@Y(.S/)UBN\P%0M[ MGL2FT>[$3H--0P"9@1\/!G>:#7:X80!.2>J%M\UV(^+$,:"MH%REW:*&X-NF MS*"07BI$\T&HXXOETRWJG:/M@M&-]P/]RND7E;J=V^_^XI8*+WM$,B;W&3S M7GI$/06&Q2E!$6IORX]8X:@Y=L-T&A =BU!,ZB\(HSV1+!I]BCE-!+8*WD'# MF5.9*AD>C$;,H/>]=[+&@W*J48;G5MO5(MICTAA,B 7"^[@&DQ9S0-)< R-' M#XZL[N/U=4_#+.L!R+Y*DKU)L;,,I4#2$$Z9$$VV4-R<_W0"&PF>57W=WLH[ MO9!J&DS_ OR86BC?M&B1G0[;@[;EVW5U]5N_;*P/GPU60T,%1T)JSB2@S'#> MBH,,G59!CB'5LRL;ZQG(9%"T^^/J4['\6#;+83GSF^7L>.:/O6T"A% T%]D5 M]\P8I@UJ2U#'3R1^,),*H1A1\4,AE(, ?O=?3K(#!#C%'"QU% [JP5D/A6 M<$C3JKB-MCQ,@"U#H#@)^KRL5H><#OTZ",T)D;/QLP%* R0X,;C=GPM,?:;, MDL^8/@DH/JL(7F( %A9["Z@VD O/!6U%TQ),JQC ! B2!-LDSD?N9=AQT'S! M4Y('@]PQL#YG(CU[",(ZI#@BFF!+D72<<"4 -0P!AM71.]V7$/_8>4>/UD$S MJI%&R%C+H@$=IRQ%6K&M YFNA!X\W1A<@WO]24/!--63BP?W:;O<67UR4Q]L M%R#B$6VCI7),6:B\0[[%!II)EA,?5.7[\QR<#5;.&X*' PVVD06_+JOWJ[+^ MTN"SO>L6_[J**\QBOMWI/Q6X_^WUL=X=@ ;<%T")L8.= M625TTF67\:_Z7IX!3R-F!H12FG=?3^ 3+>RR3G*.SV"(0VF?P%^3,V2 MF18MGNUQ-T#,0(ZHFGE5!D2$7U.^X^#9YG%^=BO=+0,,8= M]HA@[:CO%E1O?%)=VDO&N21K?R"$ ">NP$4U+[)D]6W&(J36W9E!ZG+TH(L M(3)($FZPYIP(9JC\?^R]Z9;;.)8N^B[] 'TP#W?=\P-CM<_-3/O8SJK5O[!4 M$;2M3H7HUN"LZ*>_H"0R1HD42$)4I+M793IE@L3^]@:PL4=9$R\E2W+$9=!7 M+W :I:,VB8BYF\4V7M'?[?3Q1T__K"APD!FEG;=1+;6,2PH%IY[O"O[%BPID M[$+Q=-.H*. %]@12&6_I6$+/(-I7D:J@T0Q,H;]1!KX/4E'@/"BG&I?7NZ( M1HI9"X4UAFMF#7*H1L$JD&0^G61%@<[L[E!1X"S,WH!C#1%.XQ(D!%GIK,/8 M65H3C!6?;BA<'^:=[V%+@^DO(!]7X'B]H%B\4?\+1U!RH:C62D@J-<=5IO5A MPX5J6DWGAV1CDO_E/+3R&>139:3+\,"=1\H)IH$F0#@A/+C(%5$ M1@ K@X3\NEW.;^;?9PM==G'AO_9XH*P2;BT5%E5\+A94L9HH%W7^B1K)!I> M <"Y2B<=@R#>\9P14:2),D@"()ICEZ3E$5_21]MS!Q@ HQSZPYGJPFN[&2-* M4PB-518S((T'LMG-M#5)^<&7],XF:P?]P;F:"B52:JT) ]1(X3$DRJ%&Q^98 M9K(UC)X3GFK&&@*T2?C/AG&V5HTQM7"T4H<%Y20N!]*=IE%C#@HM!6&VD,U'6VJQ-Z_L.,722T)XL):@;%! M EC*:V@ RN6G&\GQVYGO@SA^SX/RK3I^L954:TBHCV@C'D^*N@JF-AQYDD>@ M,CA^.[.[W?%['F9OP+&'+72$:$D-%%5U3 6$KPFV1N%K7>=F;9 M:^7E!\'HI!B<;H6MCO=5/LKDL\8'X(0% @OG%)':,8(0K4F)%\Q,13DNQ^XQ MT4IA_/.;Y!&S_-%G@Y-,*N0QBJH1I)HX9T@S1:4R:8&C&T+.O6 ,!=@0/%4W M-]N[[2)*W.W?5N6ZL[D]_66!*6@@5DQA1S W2ACS<":V!V!?B^E]$*D8 ]$L M8G/$S)[^LF"YHPQ+ZWQ5JE@:!ZBIB124)'4@F*#)/8_8)" ZA-AT:Z#:=6@P M3#EK("15 .F*((&:P*43*L1/$%#^R BT1^_2]G/9*+O% M^OWRH7_P)6W<#[-X-/EJJM4TNQBTN[T@4.^AT\Y8[S$$S#MD]G$Z55HT<6T> MQPL0K^__H[C]&N7Y8['8J<7K;_/O^O[=\J:\*SYMXN94/?Y+-=-=52=;Q*!(RPX!!IZX!2W5A(F#TR(>Y^;0H+4T.)TM&GWQ,">JB7]@(@M MUO.ORQW=+=;TUP<$+(%5BA,*.'!6.>F8.:!!XRTA4U_%LRSJ4Y25<@2P,]C6 M7LZSM;;SL2%! .6A%L!:X!RC4,+#)3,2![DBDS6[]V56*^][ ?3&I&!JQO6I M,#\[TW\KHQ*[GV6'PMFO/!VXQ) )ZBA 59]#Q[RLSWJJA)Q6E];^C"F'1B1+ MT/OKIUN+KG!J6% 8,&JPIQ,4@DY /$B>2 RKII,=K:WIC$,"'E6N3)1_5W- M;G;>BM93X]2PX!P@BJ-X42#& 2F$ ;XFDF!G)ZL_#,.ZH_(P&%1O5"ZFIE%, M3QPNYK*_KR?;V5W_;$0@EFCM&89&<>^8$@RPFC0#W;1<]<,PZ8B3OA\R.9B^ M*N(T[7[G^?3G[/NG8A$_\O7#JMP4-YV"=[J^(GC!B! 24@*4%I8JB!M%2TN9 ME(@WFJ]O'+$8!ZI+R(G>WO<4D]??$#1T4&!%L<&<*B.()\TE#K&T.)_17'MY MI&00I/(E;=?UX>-__CE;M5]33PT+%H"JU[7C2I"();*6/MSIXPUP4FZ]4<1A M0'ARR,!VLUT5[3Q_]%A0$0RME56 2&8AP%#8F@@!TDK-C9:A/0Z/T^'($MN[ M*5;%>O,Q7JNK_:AC3.^Q08%SZZ$G"L?SS1M8!W'*NJB)5;W]*B / /:<6,Q,5 JCEFCHS*%2=(57UP%/X=')T: M3G*Q;4@EGU"QJK@7\= R!_3#A(GG:2X_&8$F15P_$(2Y%"N//OU^_-4_00'!?2)9:;?W'!P5M+9.8 M:N2HCB>9DA! M4+U9R9B:=CD]@>AOA_JMV#QD$NXG4^V>IRU1)P<%P"V+ZK90"L29"D(94(VN MC6E2-N^(I3T&P;\<"9T,:WN73?H^'KN1\.77_7S=O[['-='N]VT=&SCCP+)X M8AHBL*<$0@,:XQO"TXH2&E88Q@(I99D_:#>_E15)LX6Z*[?+3?FEML"NW[ P.&*P2E)U@[$%FCD&R6BS%)*;,9P@KSY6V/B.:EBD7\O5S$ MGZJ2S#6]ZB;^\U!G>@)5(GXYJR3$ ^.A04P:P(2P@F%+$.76"!89H*APJDU' M&INL[D4:#K82)1&R!&J&B7%59Y.:'*FCB&72_SM64DC@PM'EET+^6Z]M@"AS MSD@+*H,XL50J1VHT-$=)86+9:ANG6_>W+K*XYZ&D O3$IF)IA;RK,S\[T_@4(%"4 $$A5/"4)I]02:VJ2 M++/3<@_W9TR' @3G(7*E!0BJ0%A+3+PX,$(]U0YAT"P-*)*.]6P%"/H=ZP/B M%I4+U1N9C:L3\]<<@?,Y8M M$9ACI!S3U#%;44V%IK0F'7.9U%;O,E4$.C,Q,1'X/*2N-!%8<60(H09Y3"E3 MQ%G=$"DTG*J+8$!Q&!">B28".X>8L8ZQJ$L;:HB(!#2:L!))*667R?U/YG$Z M'%>8".R]5,!!%+>-9=L;GGRV[ ZKN/Q(QX:,:C*GT#.X"'GE4E*-HM"D9TX!H MG);=QL*JA+6T/BJ7CDBBD:BA\=IGBI\=J65W9[X/TK+[/"BG&HS3MV6WDRZ2 M:Y53&%?^S(@\JE$@V7)X,[3L[LSN]I;=YV&6Q5HS;DMFQB6Q$%/KA>%* ZZ@ MJPDVFH+)>O7Z,._\WLQI,/T%Y&-JWKUIB45V<>CK6A *(44:"N(!L!1 XQJ,()=) M"NB(27NC\7P <'*XYNKVGWM-J&JC.9_]<[XX3'I6]0.]?;_\6!&RJA2FY>UO MY7)5_Z>>K>=[]>ES5&UUG.,?IQQ\@W\L "D4E(X;(@AVE8F5J1I092:6+YS_ MXG-QQ/.+\"M4[(, M :T-Q5A*ICFLH6303:M:SL6%-S/<.3QNKP!IBM4FLN/I_;2#;)[]KD (!- I M%I57#XG1S)B:+0IXD'103[!Q>JKTC0UHUEO=>E?<:OYE7MSJIA'-=K;X=;:I MJ+NW4?/I?(SW>6U5T5Y#@[6 UAFF/(GG1P,2P$D]/2;8FSU5ZC)BFU4 _Z-< M5#"M]YA]FRT?D#Q/Y+J\*!C/4.7:!4K$+=]B]*"C*,+2ZI&/%FIR22$; 8_B\V'[>KFVVQ=W)ZYA9UZ0UQ1CFB$J<&P:K+8#0182ZOB((2BF4 C&,-?/*5X$_S?+!+NF*.EH@ MS25]'DAJHMDO%LV1:'>?VF\^A^*U9=R=1?_HY/.-?BW@H!$$<08A)%A MBDH%$&W6I,5)55!&Z]DQ.;$<'?"L\OLT)F;]_LO[[6:]F2UO=PFO-?D?RO6. MX=T-?@-]H4JF)L!H[Q 02E3^%E-#IZU-RPD?K=7()64U)\PI<6[OOWR))&\: MVF=/#)*MA).+'HC($'HV0.TQHY(]?L)R4F6W715SU[Y8WJR*JX+;8 M__O=LN;KO2]7OR^_S^:W9C&;W^V,6OL_/"?GEPX1?*-\+S"BC-:> BZ\I4@Q M#0X1F, CU-J69OK0MD7^#?ZM %%4/@R!$3T:-P<+,3ZDCP$J+4@*YA\X*O#" MLO0\W_;"+)AJ-.''8KY<;U>59ONA7,QO[CL$%1X=$R(>RC#G*0.1.4))2WB- MB94*YA'+LV(++R@8Y3BP9KAIO)AJ:ZV((R."E<*+>'.*2@WTGB*IJG;7>]*P M97JR@88#<*N-_[T@>E-2,+5PPNDP/SO3_U8LB]5LT6R.K4%EKP\(%C%/JQ39 M>,$Q$2AMC:T)4R9;!&FW>UQO[I0C8))R7S?EW5T\&^>SA=INRKLR?K[0VW54 MK]K:/+2/K'0S#9E6'EDME/+$(UGK9E*Z)*O.:.$O0[%T''!2>/M;N=R9AF:K MVW.9VV%HH"["PC#W A+L(RG8USM;W.UR-1>]!'>'1R=IZ<[6VUFU651Q!-_J M (*617MB3,#. :0=EQQC;J2E#-=8>"4F%KDQ['(=#I9^F_"O982T25A]M_RX M7;[_\N73/%(9AX&N.W*GUP2D*VL?PUH3Q)053-5I\\ ;II(2A4<+HAAI>QX# MJ0%$8->6KKC]7/X:]?AY9>UHYGB6#+2^)P@(&32$$:XL-YXHJUU-FJ,T20A& M"X 84PB&ABJ#ZOUA57Z))\[.(?3K;/&]FNS\INBNBG=[03 $4,DMDP @'%&. M:FAC8V.)]5Q'"W 86C4?!:,\PO&]6&WNWS5HK,K;[\.*[KZ70\)%H'!HNI MJIJ\Q".04N-MU&.;R6L'DW3[T?SQ@YX*0V.38:7_1S%;;+XEK?.VH<%X+$T5 M,^"H$DIK2TUSC>$FL5C_:.[UH9?YP/!DD(5X-8TLF*TW47B_S6_ M'!L26^O@/[X DE"D/FXL/A3 I@&SD,N[3<=X,A.J%1*;5<']\4""6(L.H M0 @R8ZE'GC4$5D:OR7IP^K.L@PST ND-2L/4/#E3$H(AS J[B-9= 7%;?"FB M%O-IOORZ*/SL;KZXKY2=5H-"US<$K@")"A&555=:3+RT#Q9M#LRTNKT,P98R M!TX#L7T76W@VJQ^-"E *("LSF$'>>Z9QQ*6>-C!T6LG,&=B;CDVJ@7"[V24\ MEU]NNAG[CP\)CGN#,'):8"^Y%40_F"N)J&A2*O=*J M[\V9VG[*ZP+20A@D!(< ,^F),<(W*".0=(B?+RU7>A/(@'@&,7PQS5:E\,B( M@%$\\J@T-EZ=D0;,0M20AHV%D[T?C,O(%_&I0Z+WI@1D:E>&JY"+_%;)JH++ MS:R+$?+IDW&C]0 CXRJ^APIH1SG#VRF&7TH5O/R M]KF.U5'][/.)8+E054M6X*1"S#E%?..,C[>P7%V$NXK2E%)?+L2#E%OOSJ%3 MYU]_+'X4J_5L47[YL"KNYMN[=5Q2R^,M$SH-#I A#QUV0EGNO%?6JR:V!R.: M=+<9<4^:@B"-ANZEK]-FMEI571?WV=6IM^BG;PG0*@.)=,H@@Y'E3(#FO' < M)=7('8 ,M9 2 M'1>RP!P;3K6"430B?UN6Q>6A::L,0&*\RE> _ MF?D_,J]/*0TC0'@-F?L')3PB\/@8_#Y;QCU%WQ_BV#[MYW5& ^ 4 M0)XA BG6B -0(PMX6@GBD?/_1Q2?$RF^(R.;.?G['&K.RA$__\5!$@6<$YHJ M59GH((J4%0WB>E1HYF\9_NY?Q,'"]KM#O9N;M_7=+?BLU# M+?ZX%LN[(N>W3AL>1_GDR("^7WV-.N.^$6#D[:[1U/O*>[F.,]C]>L%/7[+" M;-64YOV73YORYH\N=MQ7GP]26(,,%T(@KI$!"%N],[<;9C'U;7ZK<4A[*+Z\ MFZW>57LYHTO[BU'!<8RMHM![J#UQ1'MA:S*AQ3R/@GRZZFH__APM1-X7C*E: M49MJ_X^!:S&1'AT3, 0">\$MY0QZ33G%HL8DJOQ)E3.R]5;OP>+G8C,00#G" MF!_-L#V"^<7#@4(252%!-08>L:I.'P4U04) ,UESXP \>AZJ/!0Z;X#M4[/C M38+;^;E=L7BKR\U>?P]O!PD,;#*B,#0LX!191)PFJ"O-/3:FL^#F_3H,C VQV=[];K M;7%KMU5?X'U \J=OLWAI^JWX<_=7IS6T+B\(R#J*N06>$RDI!1+Q9N\C@$^K MV?C FOT8".40C=T$]Q/_L)K?5+'JN]].2<.Q,8$#S3U&A$#BN&$*>.-K\H V M20*091,80 & F4\,]S_W.&OG_R-YV-:6>\+U"LK+!*0F(-1XIC MZ?D>&ND!9E-H;C0<>X]:W,9#;*JVN&X4M\8O=GU)8-AI#3$VW'AI%"8N'F\' MU+3,%8R3:*T;13Q>!.*,A&66"+"'&7:(ZGK^<("*4PR9B+: MBDX/#) Q)R!RBA)"$?74:%:?ZQ8^[WQ_89-!'T:5(\*2>=D_6@9IRL-NM3@/ MK'*$ X* Y10(P4!-(L(J22L=N3SN)+2%!/ N)Q]GG1 OQ@4<$;.D:MR%!8XX M$JYY32;12EV;TG >[[K)0R^HWJQD7(D:<4&!.$,0CN1J/X25 M):KZX71ES=:!05LA 64"*LJ)=,CNU*K]Y#7'F4P6"6I!#SZ4(R*489W;XI^; M3\7-=K7+O&[5"U][/$"!-00,&VA4U*2$!4PW6"5VRAFQX^&0;!\0EY2U_*E8 M_9C?%!T7\.M/!\D@EL!Q3: DUIGXA0>9)#BIJ-2(+0T'7[6#P))6Y^E56CX4 MJR]E=:O8)WG%HVH7'NNWB\7'^/QL/8M/W%11LU^+\LNQ .F7=:%&^%B(QQ]4 M7N"H(#LM9'5W,@W@2B75MLN]XZ>;JR<#[/C2]S%>H6Z*VVP"V/U[ 2G-H=?. M."NQE4I8B Y048_IM&)8IB"#HV$[H!A6:2>[6E>^7/TY6]U^+&[*[?=]U;7_ MWLY7Q>VSJ:NO1D^'C3#'&+!C9 (04"48HHZ9Y7! MS/IF 1"2)!LC-C'.*!M#XI;AE'@RT?9CXK7'@V6$8NR85%%+TX)H NJ;+[64 M)GGD1NQ6/-(Y,0 T&?@=2;Z=+[\^V(LJZ]$)AK_Z?%5TP"DCF<.2."*CGBX: MU=QBFW3U'K$5\4@<'P*;2[#<1?5V/,$40H%YI3VU-FD,@ M:=1T>HBS6@$VQ M*M8'V]KCJ9\T"AP;%$\Y0J3#T""$(IF*\,:_Q!3R:45PK\?R.3A"E]L(#JKJ MVD?4'@;>59U^+8T:D_6U[8Q5O$@2INNQ4EX&QO'2 MQC[&!;&:WU2E]V;K;U6YJ?BO2DGZ,5O$Z]&%$HE.SVG'N5\ZI16=\Z+@*?8D MG@6E.G/8\6'P2Q'EL K,VT-]#P^*#A./$=Q MZ5GMB91*(]0L1R05FVS\;W^6=9"!7B"]06F86LSOE(1@""_5XSUN]F*/.QTQ MV&UTD)PH2ZA33A&CN*.(B9H,(UVFAA<=KPY#L*,<&Z,/?/L?%WI*MM5 M\3FJ)CI^^H\3R[[S.P+7'@E&',"&Z@@L5;P^185D,%?)_ZZWRRSJYUCH7>Y6 M>=3FM4I?69!'#4.V=GP7EAO0HMK1E,?5X;SV&#$;(<.1#W M#@R4ILW&(9T5D[W9YA",062Q%] _I?)5L*9VPWYKPMC_EEY]]S^*Q>T_[S^L M(HQZ5?Y1K-8/T2V?RL7M;^7F/XO-A^WJYMLLZ@:G+^[)+PQ4QLLH],I2'Z^K M@E2)'@VQA$XMHRL'6\L+ )LJ1:9<5-[(U6SQ2[&)_UZ77\RJN)UO]C4NVZ6F MTPL"^5 M1X/# !K(G(9 6A/O2Y14#02U05 #Q*>6O)2;T_TA2UWI+RV-^WWITY^S[Z:: M3K'Z/EN=S.I/?E=P\=@%!%+"O+":*0UA([9&RJ2<\1'3DBZQ_D?&= *Z;@]] M-ACK?;77*2^IR^HU=AWJS*FV+]V,@RZD;I MUQX/2C*O&-6"<>HE09H H/Q+@6YG5Q\^]?RQ\1IBHU MNQ((?/AS)0KXD2CL?PT'8F:;*I.CC->EXHC1^.3SP8JH:&FLD>1QLR52<2-K M#!#'F8J*G64/[L?+'L MY*RO W&HC=^]X'D3G)^*A7-:#,]^85"_ZCAA]>M\N5WOY]MJ^#XV) A355EE M4E&OH>8(^JJGMF:"RZ@,XUR]Y4Y?$ ;C4#D**BFFA=^7JRJ;X;3-X,E#05FB MK;74&&@8YTQ0QVHJM:9)K!K<&#@TJWKC<*%0SM1(;Q0)DOOR(6?!]&R!@;F"@-XB0'<8P"\8<@:I*%%OB;0,@ GIW8-Q[+ND;QI M(+U!:9B**C9%(6BJTFM&(4FJ;,] +O+R0]4U,QKD%H+BTLNPBI$V:%+L,"4(8ZHRUD/-ZT-0,BTGQP MG<1S/%?[D(Y.XX$9=UHN^@"57QI^7Z[3Y.'9P%#5=,'$"X^Q4D+2J@%T3:CW M:47PQFM=G54B^D&5XW)2+N8W]]_*141=%\O(BLVZ"BU8S.9WZW?+./S MKFJ$_RA6\V)]6C;:A@;AO!4*(N"9$Q)3[$V]23H'25(>4:Z]H[],# Q/7EDX MS/1)U-%I$7@\(D3M2W"A$ 9( B.HXA TI!F;U,UTM)C6,3G? Y4,#/?;Y>TN M:/+W983XT;2;5CWK7^:S?\X7IRNIGO.:@"FGBHF(+7)0.5W5[*I!H 0DW3U& M"VP=7#1&A"HIS+G1D*HYS9>[8.MC/LE7'PX.&B(<5YHI06'5R),VNYC@+JE& MXF@%] ?CYV" 7&Y;5XM%^6?UX_G[>S,T,*H@\TYC['COL;#/[I4- \,!?"O'ZR821BBM*F*!HXBG),UTT3T8F7TPZ MGE?3R CT5&MKI&*@[S]'NEH<>?U?'B*XWL=+(-6:$.*UYL#6* OEDVY*8]?: MR"-6 PES,M89-+/7:-K/M]73TS8T:.LD-IXQ+)&+UX7XGZPF5GIN)NLAS,GH M#C(V *AO7)*FYBV\9@'*;P*:_ZNX_76VZ=J?_-7G0[S*.(X@,E HA2P"!JEF M4R=Z6J%+PS'IN7%G &QRN K+N[MR^6E3WOS1[AU\_FR(XB\<\)P9Y90&F&#? M**/>F*3PQ-&,^J.QNB\N&=CL_G43][NO1=7)J;C=&1Y;V7UT3%#>.R^=II0R MJQ!E&M=J&Z;*)$4&C&;1'XWM0^&3@_V[?ET/=7/:>?_J@" D\HP#CEEPCD+ MA:NW+VQ@6KFBT>SUXS%^"' R4(>A MHD8;0AD34&F'IF6G'YR/PR&3PL /J_F/>,U0R]O?EXOY.EXX.N_-9XT/5!M* M 8804^X(EY "UIQ!4B>91D=K43L.DT?"*L/.W=Q0'Z;Z@$SK%MYA=+#,QE.) M.@ 9\)HC@N*N=2!9<)NT!XS6SW:TO7QXI"YDWNEBTJ@"CT:P7U>O#8Y:AJQ' M6#HNK+6,:-GH/JK59W7Y._\UN602$)^P6/K9?/7WV6([AI>P>7>U0SC/!<82 M6J(%048_J&;8)AFELEHJKDE 4V&?L)2:V6IU7ZG]=Y76/\8V^N0#P6IA%=8* M5D'"NK(D05@#QY!)4M^RFEBN25Y[89\A4&<^?J3.W)3QEB+69> MF]"G363;W;Z,Z/==3]@N$3KGOBIH#A0PV!MA'$)1#IB5NPY 1"H3)>,B(3BG MJ6BM[-<^.C ,F9=,2Q#)U%&_H%4FTYYL3W!:F_-APVG&8^4+H_[0>(T;%5,7 M#+LMYGN1BG]X+DGQI_!+\76V<,M-O 50T'16<;KR5*(O+L*S['>)J#W&G<24=]]GR_OV4B\OGPY&*R2$$8YA MJT$5!PYY31*G*%>WUM-:?CHCGB=&]D8@ U/W#AWUS_5F-;LY==%[^F! 3 /! M#)>28 (1E!: FA" IE9B/9<6U0ND'.$OKS<_VM0WPC;#5*?Q@3(J#%51RN.Z MJ0+(XI6VV?IPKAYZ'64CE66=VJWV0R:#0#RQ$J@O7^:+>5P5ZT_;?Z[GM_-9 ME:X; 2IO=K]&^OY/&6'^>WQ\NSJ9'-OKO0%K$Y53+"6FUD;-%#K0[+@Z,3!\ M-.OE0 *4$[$,@O5;N2D>53,[G4W_\N$ *(^[+K0:(R6%X@(Z5A-$#4FZ@8UF M$!Q(!'K#D(&O=EOX2/^#@)Y@ZXMG R5.$.NT$80! @DICE7(?)) 92C!50- MQ-6^*&13 EN5OP"0=XJA"("3@@*/.##UQ"5724K?:!%1 [$OB?0,/*M3Y>>[ MTV 7C;NOP;+>1WUT4.F[OB(HYXR/]Q6.L.$1">DY;@16RHD5,\FE[(\$7V;9 M.4],:I((\EH:[ZO$;FR)I%@TR\$)G:MG0C>)&)Y1)R0A#:$\)_?GLCF%3%66 M:;F)>/Q6[FLTG73SM@\.2D*-351#RD@Y(CO2#GW3^R CB- -(/> M88*/!N0!]$A*!"233DN+&V*TPG): MI4^'8,KQC+840'+SQ0DF'QD1-(X 17RX<9)2 M%:\NIK8H:(U 4J35>)&!P_-Z&%PRL/QC%8NT+&[=;+6<+[^NU2X/^N8#P8J M0RVFB'%C$894XOH@K/33I,4_7D+C\#SO#;J>I8B^KQP\%" MS0PRD12CH, "52@1!K&1F .;*7NEJU.V!T->-=;U@&+PL/:T'!-"M(6N:M:N M422@JL'@ZO/+(9"IL?5%C^3^L%P^10%1I:@$0BO-F7+>:51/EWHA)W?$]L+\ M:*Y"$@J39]Y4#LJ+\"S[@=@_OT1:B9P"$&H L0*J2FQN2-(J5V_'<_-+NC*B M0W[)>0CDB ,N-M5A\6%5_IC?%K?Z_O=X?+Q;OH^GSFRSJRNVF?_H&HET_LN" MJ@)GD>&"0!X/(>,!-;610:FTECOCYZF,:3X9'<0\4O5N>5/>%;^4ZU,&D2?/ MQ=L$\A09BSAC3%05.;2MR= .3ZM2[YAL>BD1R2AE\7W_U_:0&?&YK'K-+&_F MN^CXATE_+H?;9,;X7' H,D!,#.DF55$U-E M NR=2[\6FV_E[:.LGQ,BV6E\L,A)83".9SUFF A)<$.VD6D._?'2[B[*^!>Y M5\/CFR,:X%O4 /6LTA>B$A@5AUVCWU/^@5<'!*GBC9UZCRV)"B,#4:5H- FE MT]+LQTNWFY+@# )HG@UH5<1IVF+_[T=H'.*?.AR,W5\2 /9&.VXTL\(2R7%5 M"JT&@/ D36N\[+TI2=1H(%] RL[)%6P=&YQB%@)/#9#62H 1P:XFMPK#GM3Q M-@8;6R2E+V(7V8:>YDZ<(R OQ@8,%%9" BN0 !S!JCA'3:YG/,DA,MHQ=@$! MZ8O8I*Q%@UB) G/QBLNPLD(C3U3\(Q4U -:E:3ZCG5,91&8TZ"XG.WL-?B!+ MXXF7!WGDI;&X4"\R)'UK$K#>6?6\\$!GCUA"Z+ ^O^<(M0-_^]G<>;X78=%]%Z MO8LO?K?<%*N(T^/J+B?]6^>^+% E(8>88:V-B6M5:]CH>]["I""_W$;&,61I M="@G=;H-%D03O.(@7 $8&,-$P[SQK/D_;1DZI(:TG @YCCU5N5-4=SN3.>[^+[W M>W3@:BCV'1X4[#..LBT- 9:2##S&D%#J 66"Z)RA5I.6XB& MQS&CQATG_;'XOEW=?(M7A?=?'N7S=]"PCP\.43> V%H+)"8>48V,L)%@C[F% MULMIY4OF%)RAH9N4]C.(UA,\D00R:0T41CGC&7AP%\1) MQX/O8C(T= UNX"'$3A),G1!85'W8&]>.4C:ITL-HI3HO*#7]<+M8RO\^-&$* M^?[[F?3,]F]]25 V,@5PZASCP$A+I"1<88TI=M2#MA*D>4'HG.G_VKA0F1JK M]I8@*M<6:Z \-#6IUH-)Y?D/R+AC6?X#8#1NCO^X:8) VZ\(U4_28D(L%Z@ MFE*"=:9DWK0TP7ZL.Y$D>!XH%\\S$UAB9(5RGBAD(.?8TGJZ LKK:$+5&?-C M"6=I*$R>>=F9=D:2X.@\NX#%IV^2()'",JNA9EPJQ*,.J1N2F-33L"BG,Z)# MDN!Y"&1@ZL?B1['<=G([/7\T$ "MAXAKIY2 @"%A<0,,0=,*"\V@-_4$*$M( M39U3L4?AMW)9U@%F)X-IC@\+!E#*H?# .$,))4@ 71/IN9M6&$TZBX[V#.H- M2<95WF%U!X.!0<8!)1VD6%HG4"/] +!IYS19Q MKNKV+G*CFN=F_J,XS/R$>+2,###*?J3..@NLM@9914%-*C0R5Y&.;L(Q(.?* M,6'*GO0:5TT\E;;Q8#H$D\>%HHLOY:K8/_=Y]J]B_>M\6:ZBSEN'Y.VB\X9, MG1UU%@%6=3L $U(1R8F 6"+9G+C03FL;&T]2IPOYFTGU=A!1#(2))XIS55*7 M +PF6Q*;=(<=+2XAEZ0- ]9DJY<([>.,K3 0 4:M!,(WHBXQ2+KBC.8''H_G M?4#)X:[[_"0IY"(NN4,HQ6S1TRO7Y3U!6&0) ]Q%-1<3*[P"AY9(Q&'FVK(N MQX&B9D<5DG2?%&8>0)G]YY$%W<+625E])X$RDE M<79>Q9M]/5U*K+H*GUYGS(_YA])0F#SSINS3&YUG5^C3$Y0:8R05GE@,.=$: MD9HDHWU2@^+Q?7J=&='!IW<> AF8^LKQ\;@A\^[<^!Q/:[TX':5_UGN"U1@2 MZ#D!GCCE@9$$UC!4-4\F(0@75\@& _ R $4J Q(4EP#$O?N MI*O ^%FPN85J6!1S&'[F1VP^A^\.\XW3$=\#?NI'AD]<,'S]8S%?KK>KZA3\ ML"KNYMN[*I?M7?W;7K>:%VM]_V%5WFYO-I_VMH0N]K/>[PZ\BL[ST+*JKG_\ MGZ_,I#NK)G)>^[:0PVE!UF9EZ_7>("0#CF//B*4Z;C?".'> RKIXW$S [I91 M'E[$D^2#=ESK7'ZQ;6FUU^>U0=.(*D):0!IU(*(P\+Y&5FN8J1#]6=; 3*(T MD GH)PE "Z-FM8>'"3%I I7XY(3KGE5^LC40,F(W.1,F7G%8R"9[ 7V M3^D\"MA4;+5O62CSFX1752#SYKYNT7V_S]S=SA95D-"!J@,-[1;CLU\6#-%$ MPLJ6ZKUTG#A%2'-@*36MYHJYF/^R>LRXL&:0,SM?%3>;&C4W6RU/UJMZ[?&@ MJOA*8B#AAAE+F*"8UMJYPQ-)*+K\960 [')49RANB]O.\O#*TX%@1)PWUC%, MJ>.,.5K+N(.8)M7K&#%UX5+BT!^Z#-*@UNOMW1GR\.KS01/A%(.&&V>P!D * MW9#%@)Y6E?'+2<00X&5131[/[[?B5.K+BV=#521)6F"5IT+&4S!N?[ FA\LT M!^5H49R7DX6^P&64@P_%ZB;2//M:' 3X<]E-*%X?&"(]5''@+8TZ$F'..(R: M39"E91&,5KGG\A(R"(HC^H?V]'XLOI>KQPFNP[M5GGWH;T7Y=37[_FU^\V[Y MI5S=[3(O+NAQV4>^_&-^6SR:SR'A<1>]'V>Q6LX69KO>E'?%JHNG)?F=(6X8 M2 "#G-&"4TD@AE :A@DVBJ+6Q;9V)[I[LM!/54/3>/B?]BR9HL6]\O1 M,<%BS;TQ5E'NF>'*6^QJ3'S$:8*^E0L+QW-1'0C:'*$\>P%]/-%6:_31,4%Y M9 !P''+CM4., <9K\K"!>K)ND $X]EP&!@;IS6. =XQI;I#P4EK&:@"B=2<%XHQDWAV=F,A+Y/1G_6,TWF^*4 M;O3Z@! E%&E*G#;Q!NR8-%@\8,/5M*KQY+_G#X):RGGZMU6Y7M>?U?=/U,!5 M,5./[*3OOWPN-[/%DQ''SM^>KPV$4$ (BJ120*ER#L.XI2G'&35$I;6W'.V\ MSB?ZE[,%[0)/U\XH^XWL7ZW&5XB(J8L9!* MHQ2/:C0$&J&]9%"%#6^+!AC;T'R"!GW?,8 _X6V!(5?U:D $5 T7',V]@#936VD[6_)Q'/(8->$X#^Z=T'@5L M:@;QMRB4%PAQVD=XOWN@:C?M2O_I''5_?'" ACIJHYI$5?Q_":RH7914">MS M"566*/O.S#T293\8C"G6!?5COE,HD@3BS#<$I*)J J5'%EOOB )>-VJ*@SQ7 MPY5N4C$D>\H<>&7<-A[E@U2=8:O&U+-%K[WDS#<& )&Q'BGKM*RJC&H)=*/Q M8IZDV(]F?AI!E/+BE[*SN&6Q^GJ?OJ]T'1^H9X2C>..!D:BJ7#00H"8%*9'D MFQC-T336KC(26BF,_[6,^/Z]^#:_610?OMVO=_Z7V=WL:W?>G_&*(*'&5"*D M==8 W5P-""=)$V5P]%*VE289=?9*,FKGG>6\MP1G((RX68(ML9H8 M93UK=DN7EN UN92_Q'O,^'AFV'L.S5<:,EHWE]<'! "X[VK3#Z+7Z=+;Y7?4OF-T7W4Z#;"P(PC" B(L&(,$:5XQ'K ^%2 MNZ2* 8/?37*>"J/@ED%@WF^^%:NDRTC+R( %Y4Z9J*AKJP 05JC&$$.$3DJJ MFUP)@9Z6\F$Q3#ESFB*Y?]O.XB0V1=%,)RZ83]M5<<;1D_2R0!B(]S;$%4*6 M(>L05 QE527 M>.SLNF%E(C>&EXC*/V0TZ/M?9_]5KII2 I.H#7.8VY.9-=P\L[, (Q"B7$"%\Z'/\%&<^9I.\?&+IG<%*5ES/?'N*QRHWR4 NI MH* 0&,!KV"R&)L]AT;&FRT 2T*&"R[@P3C6"WY3+:A_<]_+^.%__H>\_QPFW M!.B?&!6(P-J@J&E))X#0%%M+:EP,\YDNK;UKMHPF#L]+9PX&909]]<5DJZFV M1BN?&!4HT]J*2!8U\6K.HZ;O34TB=5!.-E!^$+ZUR4)OH-ZD3&27A9;P]*F) M0GX1..R.+R;=:MUJ&1FTH3Y2"B77QE*&4$2Q)I4)E*M?0.?^:OUY]EP.!@7H M$MN!OM?%\N;;W6SUQ_E:Q9.A(:XBXI W&G%K#;8,>E@32YQ(,G.B-8 :1^&UV%[%Y M,M/6??_HF H=4 "+T!4GR$V E+;&!&CTCY9Q: /JYZ7C1P8G3TU]FJZ_%^GC7MY^3^B2.%DXT,+MZPY'CQ-M6\WK_Y7U4)6>/ M-;Y3)]ZQ,8$ 81F13EA"I<5"2=0<%SA>%R>UCX[M$!X*I@Q2< #@=/VT_2-! MZCA-P.,=3NEJ_O%?S0DA:5H*2X:*G>/P.!&52YBS'HJ%PA-L/C4L*"\=AB!N M>,83S2GU#-=$*JZF%1LZ-NL'1"I?D-?N'G\LA&N 'F/?9JM"S];%[>/HV&S/V=1F^E2]K;WRX/TC%,155O"E(!&^ZK. M&O4:*T4KH^1>$:IW'[?"%$M-1A(9@%6+F)F,8 '"*%%/),5 M^G0!W8R"OUXG@X T*]E:BJ+V0,D<:I&MW* #WIP+]LHO56("^>8J($R5-+)&OES"4A/N1P$[I_R>12P MJ?D?WJ98#F$QW\WAPZK\$6^SJS:;^2L/5RGS6$+AB,884>L-1PTV".MIQ23D M8D@Y,&PYMIJZC:-9S-;KJ&)LRINV$,BC8P+!$%""':.8 ,8=D40>R$-O/A^D4L)*J*#30#J/O%:X M)HOX- YGBU*\U/$^!)27D)!_S#??/A:+'4KK;_/OG\N] ZSU #CS38$H13R# MV#M-K!6<>N1J*(248+)*04_.MLG)*+#]I25I:GK&M 4HN^#8^:JXB1QI53Z> M/A@44!AHK"(Q50"4!TB:FA!,05*IPM$4C]&X5 Z(409F_[U85_$#+7K(HZ>" MTU9'Y8DA+S#A'$E/FG6!7)KKYORBI5>F?:0#F$\&6L^!)\\%;Z+$VBC\'KBJ MO23F7M=D6(3]9/6%)%Z\SL]>4%PM9Z=V?N=G:'_;_]^J"J5VMFFI\?CLL:"Y M) A8[!$5G#C@* /UQ"!PT[K<)V):#D9_"F,.DWZW_,]BMGK?5H/S]:>#I) 1 M2I1EH(HM%]C;1@H98--J/S8 FP:!H3>W/O]9GL&MYND@/-1$1KJ9V=D/ 02- M4N9$:ZOVO.&O0W,K%8;^W(J/GK.Z'CT?! <01?W+6(X@L5 )8QO!@BJII]MH M3;T&YU@R$!DTCKVNW%X5[LES 1M"JL[D1E.N'40$"]Z HFS2G>+\YEI7=J?H M V'6Z)ES87D@;'G[83%;5NE;9\34#/>Y@.)E73#&G6!64T&\0G48*O)PPC;1 M1-DX&D%S<4Q_"NP@X$[MZG;%^<7D]\BM]<=/OY\K+D_'!:6$,[("C*AXE32< M@H>;#J33RBJ=LMCTPC6#^+Q;WI1W11.M]4O%R0J\TS? $Z,"1 8HJ_;UJ)A3 M M@'4T1B'2YVMNAS>\3N,# M5- C0ZVC5$O)*>2LMJ!B!OFTVF$-Q,'7>W$/"M04T_.JY]?J^_=5^:.XK1J3 MKM?;JOE;)R--SV\$29$#!FJME="ZBB5J;!M"V30GT^7NVR-F\%\(\2D8&(^A MNCS&.00]BGQ8X)[]_^-2[J*QHRWJ^)FNXJR M4:RKA5[5\QEL\S[^D<"QM)H(IY5A2 %*4;R+Q5-/&4VU5_JZ;!G3V;T'@_RZ MMN]]"<$\&_7^6X%(IB4'*J))%%=$F9[W)&VZW=Z2EJ37A@ _]4LPWI]73Y)<&$C5X:K%Q.IXEQDLC3>T" M$M;ZI)V3OT6IS 7QY63P[[/%MCA!RG9ULOQSC[>&>)MTA"LJJ8@J#I!<4E)# M9+!-DD+QUY'"$3#.$>"[V#&RN'T=T(/-^%3D;Z<7!(TI%Y!R0#&M.E4*Y%%- M.&$4I@B7?(/"-0J<.:/9]D:!(S65R^6/N$"*O9:P_EQN9HO'?V_*]>:W9C<5-^7<[_YS$.^T'O-]^*U>=OL^7A@M8E6B[WG((4%GJ&/7)>$B"T$@_+ M'-NTJ]!#LML;$O=K8=$UKZ#]\11/H<-/U7.G+EQY)Q*\PEI*!!%&BFHJL4.- M7TP]7PS^/L.L7?+/1 [S/QL MOMII=&-8)GI-*%!E,9$0>*2X9EA0I4VC0Q*?Y+R /]UQ%^+/E!?.@=I=UO:Z MIK;5>CS\UP)P1AF,*94.1U77$@#]H[THK1;-VW;870K\7/+\SW8B_WG*./FQ M\J^O'YH!M4GTT-\+3!&$A'"2,$2-@]H_BF=!:4FR\,VZ\"X,_Y2ENCEY'O5, MJNP$E17J<[&Z:W6NC/+1H(513NDJGQU!9;VJFC'N 9;&NC2]_DWZ Z?"@ZM3 M19X%23759495WM-F$B"1FH*JXBU5W,63TWG1L$+KM"X//UV/N1ESS8:@1QFN MES&;/OI^$$9*IQ !!"F%#,2$U XYJ8U)2UA^BT[/*;+CTC[ZQU.O0V.3??.O MOBPH[)"'CE+N .=*"$WJGB)22)AFPO\+N4.'P_;BPO8JMKV"Z$Z\,D1,JDA" M#Z.JYJ'&"IHZ6J;B2)JMXRVZ2C,A? 5:<;VRUD\LDN^6FXC*>GXSMBK7$6$L4GZ+WJ++M$)B-ZB'W3ZS+F>(Z.J4#%Z M]LJ+;P4L+ ($ %\9962')DZ^$):@=,2"G^Z,(>'_KHD^4)IM!UG$"!@2&!D ME(M;!F<(6=0L+$U0G'@SP7GE 15 PC&@2)2.]V$2TO"99IR_Q;]F1- M_VI$NG> R_@S"!([#ZKF,*1*Y\822=! [T6BX+])1^DD&?*P%O[?__7 BTCM M'[O?GOYT&/F$(W_^^>>_?UT5Q7)136Q5_/L?]_]KQY'7H7Z4(;M;NK;8S.:+ M]=-)%?_:%,O;XO;?IGE[:&1AC&O"@Z!A[RA UA,. !=5_R9CC6">*(RI5FVZ MTDB@#548^11V@Q5?1EP)2[C7#A*F$6&(X1I"3M.<*N?[5&:+Q:@[4F=!>;XC M70CGW9Y3H76[^7]N%F5\X__^M\UJ=YH=?BR7F[@'N,7NV__[W];%U^H/XX>! M'"JQFL5LO8ZH['+X3]<]/SHF. 0PHPQ(9; RDG$>3XL#)@;3M #HLV7O0E7/ M.PO$BZ".8>#,H.(]GF%K.>N7#P=/NY2=8.O3;F9:&.\ IU'/ LPY$N]_KB9#6213 M.'I^R,*5'>=]()R"_^@*>@0RP $6QCDH, .>$.=E#:H3=KIJ1*)LY&@6F(;I M3X$=!-RI*4!7+*?9Y7.8#H5>0(DE1,)Z;*5@$!G38$Q,4H?"ZVIFV9FQG3H4 MGH?G%+:QY,HL32+IY?E::[>,^<8M.!.4<2M)5QR[@2#M4/4 M&JV3RH5>L[GFRE?ON.R_ZM7[J%W@-)?N.1,,R#F)J9(26BD4),Q!4C/.(Y$4 MRG'-9J(K7[VLF"9&D+/65+9B^GE(786E-'R$,_#>:IYB&D)"O%J MX^-F2RETQ$0@$),-^A3)3'&U%TI0Z,SXDPD*YT$X!37S&N*]$30$(.@D@EYH MHHT%S:Z@O;Z2!(7.LI$E\#L)TY\".PBXTTY0N"HYO72"PD[U__CI]W,3%9Z. M"TYR0YAT6GL)J2)"2%Z3R3!,:V9S70D+71E].F&A%ZXY4D<7.^8][B_^&,2J M^]IR?>I*T>T%@9M(J2($0> T%DX0UL ID$U*-IV>E['_S6$4.*=P3+[1!!AK MM6188Z8JDQ95%B%5,\(9F=8%Y W*]:39\C;6QX028##4T% B >'&21D/4-9( M"6$.OXW=?F31O%@"S'G5:^@F]]0081;D1/.Z%E"DFI26. ML)J54- W$AQX%5:%$?GV%UF"$U]W@7N(<%39%<,P_LM0!F#--$EQD@GOFHT5 MXTC\!%?NF9R_ZN7Z%A-@J/4<*PBKEL\NBB!3!-7L,]8DG9+7;"JY\H4[+ONO M>O6^Q008YJD@'G#$XJY+.55"-ILO CS)1S ]'?^;D?D?>X$F-=_/=!9<>%+64%R.C'F,.'! M)[>+ZOZ9C?.*\8=S@1SSV&!&G7+"(TZ@P900I[#';1[/G]DX\2+K@*SLTD91 MQA1"!$#80&A]ILY,8V?C=!:4T;)QSL/Y;67C .>D)]02A@&A$'OD?4V[ 3BI M*-/59.-T9OS);)SS()R"SGL%R0V [T*5$(>*>RD4I9[7H$*(Q95DXW26C1Q9 M#FF8_A380<"==C;.5">7-=6G-OR43()>T% SL1>O+G^*+N"<:XEOYUKI$0#LY"W@OS,M!49@\\Z9B M#;X(S\[@U=?%JJCX02$Z<*/Z)?RMT4X^%O/E>AMUQ9OBE\WMOQ^UM749%CR0 M0+&H2U*/>9RW9LS6$X_43"-G(!WN*2=ED@Q@T%-A!=I59T'OZ^/R,^>@.2X26]FFVT$_5[=W)3;B,+RZX?5+%ZU M;HJUOO\_V]5\?3N_V;'@=%3#>2\*U%-@H'&4:4>LX-J;1I^0[X)EDC$:5( G2#<,5Y/U7$W ML0I/>3AX-BPY2J,F%JTW,FI8Q!H=+\22(891LV,IE723.-^C_&/HF&-D%Q.5K5,E(TLY;V3,/TIL(. .S5=]8KE] +W MGWAR/":PFG!K/..)48$!@913"DMFJ*UZN:M&HQ/"Y3*,7[($?5[13-B./V^_?%O%BUV?EZ MO3A 8K"65!'H#,5&0@)% Q1620VNSD]SOK@>EQ7%"8I;3!^Z=\'@5L:KK;VQ3+_K[4PQP^K,H? M\\B$T[[35Q\.$F .B$9>6&*1E-B8!Z\_F6RD_K@,*0>&+9/+8J>;/HZJZ^ \ M?75,8!@([;VGPD3RF(6V;NT;5XR7279I>H7ZTD 9>#_XQFV'A\O'PY*.(.I M4(A:(1#!B,HF[%)C.]TVB /PJ!P)G3? ]LEI E/@=GXNEW=WY7(W4]5JAGGY M<+"((N>]YE8)P)%@SCT0).6T#OD^#'G.V[Y0Y.6M/H>WNK8!N:AZ>$.@C0J( MYW$)(%@3%-=$DF5M- ?D.+Q-@R(#;S_$=Q6KU2%7]KM^MU]OB5/GZXX," MC3<8R3@G5%-H/#?8-@12AG+=V\[G]2^]TSL&0^5";'^_W:PWL^7M?/GU3-X_ M&AD@KBXOSBKOB ?6EI% <87@'1H4F[;^QUG]_F_EU7LQ,MX8=E-[=@E_)QW!, )9SQ>4X$5$L?C*FHV340P9)FB#[)R>VR0 M>O+]0[R/1N5S]K4HOWPN-[/%?GX?RC^/VUTZ#@_&8H"$IMXK0X")_[/D0(B7 M2">IXJ.58AV'VP/BTY/1'XNO\_5FM2_"L).^]W\NB]7ZV_S[PR0[<+S3>P+G MC '%"6; 2T4-CXI039KS.FFAGV]NN2CKQP J108>SZ.Y;/Z^W*Z+6_7UZZKX M&G_ZL)HO;^;?9PMU5T6\E5\^%3?;561 \9JU;8C7!BR1P<9Q!+ECU$*);6W! M\E:0I&@+=@42DA>W*;J$=HJ.^OY]5?XH;GVYJI3>*LEG2._0L6\$;RA32 !; M_<,C3*3 #7R<)F61\VF+W:5!G$+XV;'PEKT&=BB;L5;;S;=R-?^?D[?9P;\5 MK(S_1[6!/-[NE+/6KF M6UP!'U;EU]7L[ICL?RYU\?#PR3VLSWN#Q99)#Y#"%"IB,47,US IZ7V2T0Y< MAU#E1.YB N;^]7V^UU"K_AIGR]'3X4$@RBGVQ'CIG05,4%)#[1%T2:&*\$J, MO", =#&I^%A4 ,Z77\?:?\[]0+ F;LN".5Z%NY/_O[UK:VX;Q]+O^V-F<+]4 M;6T5KCVI\B39)#/[B%(L.M&4++HIR1WOKU] $FFW(^H"D12=V7[H. Y! M\Y M ,[],$(I;X##E.;Y>M^(]?@J$.;8']XM;JLB?LL6VS]GBY=&DH/]C\\:'[SF M<1,ISPTBP%CBB57-X6HSN>$M6)=[0FA8V?@^_?DU8L>NF//>%CAP MA$DAM0->"64,QHUM36HXCK*XP[!.__ -+\?L6P<%@BPU Q%(7E^FX M?_;01FW19D4O='[A#,@O7:(UR.VS>"RJ%*6WNX=?!F' @_?/H8$!PYU W6(U/588OOK5197/(\-*F5I$""(H$!";BT# M=4$TSSW/JF7:N5?TJHR1#=9 "0EMM4::?]M9&M5B^GE=/9S%5:#+TWYW)0P_%=_6\XW-9[F; M3SV+N[*J9SB-OYKQ?G\<=;",88 J[1 MGCMZ,C_F5+_DO4%IX;@F!" ,1-Q"5I)&V ?493F6X,@#.*Z!W%@8['VQBD)! M>5]L8U(NY:M7KPLIH(!ZK %$A%B2E,AFUREJ\Q(ZWDI@1O^ 79F+/J4>&XMB MZB95,DXOWY80U*&U M7DB4QV5O)=1B> "'4-@FR^_-]#Y.9M,OY<>H2"Q6*9YDLGC23U&E6);SV722 M.HRMORYGT]FDVA_8>/E+@P< I)(UF"MH(EKF14PO8GD1[O"M!%P,!=M8[L3M M4;QOI^Q"E7(/M#.^$ !B5#&C<"I.B;#33(IGJRO/$L30FXG&N :&PSK&XA;Z M4&TBA:>IQ5SQL3TAYXS1@5L#F37$0@\-9]!J[AHU!YF\PO%O)"JC>WR>6:+/ M?FB;V@]MG%[?SJ[UU:SF;"VFF)_??G.@Y]JQ M(<$3$'E" \.(0\QCHNPVELLP;('D1S90]J3;>J@=>CP0 (3D5C">JL1HSJ&Q M]62=4P-UT=K;/*T[H,O.@9CTVCCM@@;=*3SZ2"VAB"#%8\^39K.PK_L;OE#4''RXS0JOGPN.,&QB)H?@M1H MJ:U%0M?+T" O.).J'C!\@>@XLYE\OE[4:QN$MK'^Z>U#0D( @BC].BH M@)A($/_&ZL51)[*.V9XZI?4B!74$S)6H?K047/N@ "P1V*6N.T8""8B+_V\. M)^?'UX"V.Y*=P ,7@?0+=4&@L@=8!J#WQVI65MNHX4_%;3+Z;DR# M&^2G_UHO5UOK2BOY3QH?B-14 4DP3HGBC!D <"/GN)%4C^S<+M8G1CFA<1^K MXGZVOK<1S;BPQ>W33;ELM<3N?3A8Y)GVBAC.":" $8X;68@BEA7:UD_"1N<& MSBX R:-:>3=+'MW[V3+=7\N/DZ=#%NFVYP/V%D,0_X,HSDXJX45C/%#Q7,JA M73_)$SW0KA-,NB"?^Y&J;IQ,O=WC 7/&E+?:(0)AO$ T,ZI9ML]K(]A/BD/O MQ,N#)(=V[U.9P'AD%[/'Q"WO%JNB*I:K3_MS](\-"1X)$-E,4FF4YT)Y;!N; M#?(XRV353S9"YS3L#I8<.OY]LDK5O)Z^%-5]>9?F\CR5-D(>&A.HY0PQ0Y!) M40S,845@3V]MJ/9EO0E@.&;NRWA>$CV*=19I@@KVPTD/9" F(YT4,=1YJVYOX.P1F M0VG&:KDL5N_N'R:S:M-"X/ND^G8PLO' J* A(,QH[7@4\($UG.#&^FME7NAB MY[&QO;%%=\@,0/S?(D1)WO^P^#Q)#6)>W6<'&.#(R$"44,H!%A?)!<*:,BX: M P,V61Z0SL-7>V.";M$9@!$:R>44VO_\<+#,(B24L%HZ#@33A#5:/G,VB]S= ME_+JC=X7(S( B=5\7OZ1[(&^K#;\J!;3FW*R>,&7\;:Z75?58=/86>\)&DL* ML330(RN\ QJ@1@JF,K.*RMNQD?4)U@ \8XN'!"FSUQ@6=H'(%C @($4T ) M\/%^9(8/CM\YU#TV.?2!)(.7B]1S:+ /[GPX2>\H5 #8R)#R.&N4X@&4(H2\:!8JK+5+A_:;9RP+:B^@F2V-'!05."K6, 46Z-XU0A:1KP M",\+4AB_2:\WA'(V\W^O)W%9J\EJ]EAL9J(6B_5D_FZQ7$WF\V0?V#I1V[;W MJ>,#T<@RJ(G#EDIDHUKY''9'/XLGM,* MU'M3KKHG[>N\W-[Q&FMFEHKGP32M,9YGSUU[W(_;^3IN[35=(#)Y-H"S^3BSM(Z'?OR1G#UJUV?Y>&KNON<#! 9XK9U3V#L!C?#"U\M2 M@&=)0;UE!O9&]BZP&8#D_U,DI;V8JL>BFGPK_MP+Y44/!#U9SFX/L,)9[PE4 M4IU<0@!:BB5F7%!=PV!17AN_WDZ&WE2_/C'+L>)M*EDGS6\RWY7]V7;$645& M_AJOSBC[KTJ[VRSN[JZX3?U6TS-?7_8WM3.JN!M)3F^60[*T[TUOAUBZ@OMZ%O$/UG-9/9[XI"(@-I)Y9 M;IA5@E(L&DF',)!U1O96&W_H2[DCU*YF%3A9$SY:L[J3]P>3"N%$Q5HS+:4' MCAIEFGWG258>1F^%]GMCMFM@>25_GY_]B)MJ$Q5V1>=>E%4>BFKU]'$^V7C) MW>_KV4.Z'DYQ[QT?'!Q*=/!,40H(EPY2@*'!E!#-H7+'*J?T[>!K7<'I7KW# MKPC:8BB91Y@R1 5UPFJ[ X!Q>M3#.80KKTLRMCKS.H5IK!Z\UD7JIR]QXD<\ M<2>,#H@:R9,M#'!D#?2 "5WC)(W(:\@RE$>M*Q[XJ2A!U[@-4JVB#8LX@Z/N MBA-&!\4E-E8[YP%6"4!B7;UGL01FM$ZQ3NEY*J]<#-R_!<^,SK/Y(DO)C6/]KBL9B7FYF;OH!F7 MV;I3>KZ6_ M;UW>(?-I1Y\(S #)C5+(>$6-(LP1V( '35:?BN$OGLMY[$J 7O-T>E\<+NS8 M/BQ(ZC5WWCG-#1)LXZ>M%ZFISBKM//P]U>/)=#Y(U^2$?RR+N_7\9G9WR'A[ MPNA@J24>8LB0=Q%"HK4&]9*Y$UGQGKTY_Z[!%]E8#5':I"G#\^'NIEQ\NYD] MUKZ6OQ7SJ2^K?^RM6WC6^* ]C-O *BXT,A899Q%K=@7"64=';RZ['EFD#[2N MY)3;MLG],OG1;?NP%Z\]Y%=K?38@R5T*L:94X;B_I+3 &Q(51X:DE$=EF_.G M>;!3V.OG G;(<\T1BR(KD=IC37$]/>/<0!U,VEN$789IV=W2Q^JXVG0QW.@A M1?FMFCQ\C_MC?L1=U3HF8&HDBW(CX0AIS"VR M688& '8H?3VV7D$W5/3]$N M(!G"4+QEK)<3/>I!:!T3(.(VGNE<$^'NL__&*@Q MF#&M4@%+C#B1#,AZJ@B;H7J=G";==H!X>2$"9Q-K6LRV6S3^\'IGQE^%F^+; M9.Y2A8NGEIMXSU,AS@QP+PW#7 #)#*?)J[2[NH08R HVX-U[.0B=4VX[D]8C M]/4C(55\U\PP87"<=.J%IYHE2V_TDZ4.4S'DP8'0921R F&% 3&>J%X M<\<;J^$P=]X@Y.P#D"'RZ#<)2;/'HKGN4[^,/Y>X4BM?1.AW9?,CA9[^]/ ! M7:2#MP>C5!00193L!%0"6$TUWT&F /59/-1/S>).C%G7@R[G##EEEI/#L_Q2 M3=(!N/W=QRB<[O=*]_FY(&&\4Y67EFE(B7((R@8HC?TXDFX[-IB. \LK,=W[ M3172(?FNY8LAJE,"602%EEH:KXBSHH8+2I:57M9/3>91L5XW<%[)F57_V>+" MVLVHKZ]OM/D>O[W^NBQ^7T=BN,<443?8AP[[!2__7N2\#6?V_H%1.3@%XII2 M3IRDG'H-/770,>$XH?*$SLI].SBA)-PYY(%C<7:62D7KZ0D'X$#2X9D.SI,Q M/>C@/&_I_3HX^S6=QB4Y;F!JSJ \IRXIP/5*H]:4%<\QJ-OR9%(=,)V>!\+5 MK6_",\FQ@YQS+)0&S@%>3S=JU/!-F$Y/QKS-#)>'PNB)-V;3:>\T&ZGIU"JE M@ =2,LXEY(! UJS;*C94'B*]0<6PAER3B#NH?/E7&Z MAN3-A>-XB[PW# #A)*8>4/Q\3''(P.@DI XI=G)<3AY(OQPOC$7@&B,+C"@T MRR"*)-',4*>!0AY)9>NI C]8A-VEH5DG(_YS:-9Y" RP3_5DGL2)S]^+8G63 M $_H'KZDVX:DXFD.QU4H0(3!Q@JO&A'$^[SHA/-M]5>XHSM"Y$KD/GHNMP\* M48D@+D5<,.TB>C9N"MSP,^-HM)?TY20[@08V,P!A[I49[E7=!EK);1 8@L"WNBJHJILTUYWX\ MQ(U1Z&(1T3^4>'YD9) BBBX8$R\9T]YABWT$32J?XLYE7MS:@#%'Y_J7^H%E M [8-1$]GP$.#PQ*81)E7QKYF^B$'H(B+509I24<2:FD[NG?*2I#9).?3?>V MI<$4Q^(T 1H!18%T%$<961*&'%+:Z9%'X>02O!LX_C],=54$)WP*[C6:Q4U! M.(34U)9O!;3)NC+ZZ*0<-#]V_<9BJ8T9 HZ23 &*FG('.U$!Y2[(R__KI M(=]=V,LXL!SR,HMK*V:/1\J<[WDZ& T!T,P*3(R-PAG!J!;UE8WB6@Y[]--> MOI]++!N* :BK;F^K]0O)NECNA*T#-&X=$[1&\= $2& ' +?":%%#E>+\LPZ" M?GK+=TKIK@ 94#>-L]PJT3>SR==X7FUZ]ATLBG9D9&"<02RTBLJ\\!8;A(VO MEPJ1SM)-Q/AIWRTLU^" ?T[FZZT\-)^7?R1[S3E<\//H #50#DFH,:/<>FZ4 M(?62.919(2+R#7+"Q= ,88Q\B/))BL*_*9=+,ZFJI[NR^F-230\YHMH'!2Z- MPR+"ICBG3'*->;- *W1>HBP8/_$[@^2J-(_J]JS:6FD/:Z:GOB) ![EW@D!B MC;9"$"EKOZM"7N<5!7D#)LN> !J .SY6Y6U13)>I=]8+$?9NO3AX)AP:%E+1 M3PJED1X(QQSF'+A&J:$R+P;T#1@N.P0EQ[RPTS[=C]O9,GVYVK^I6Y\-TGH2 MY1$ZM>/&3=W+4[92C*R'KI1J=#B]]QSS^9E6=E\6__\GZ MV?R3D17;;-_XX^71IQN3W<945C MH"I+FVQG?,N;6^-ONZS^W;BNRCOC;V7U>_XU??.F^R.C_6*?%[__*_V?J[3. MC.]U_J_U]C:[2R_+;=JTMF^;YOY??_GEV[=O/W^_JO8_E]7-+[9I.K^,?W7V M-^B_W@R_]H9^ZXUEOW&LG[_7NS\9Q,.B;FTS&!E^_?NSW__FM+]MA6'X2_O3 M\5?K_*5?)!]K_?*_WUU^;OU\DQ=UDQ;;[$__X[\91D='5>ZS3]FU0?_[VZ>W M9]&%O]#?^*7(;BC?'[,J+W>?F[1J+M.K;$]@M)]V6V77+W_$OJH>?0)E**0, M63YEZ%]>^>#FX3[[]S_5^=W]GM#SBP1^ <#-<["ZT+4DO!_^_4_DJ\VA?G.3IO<;N-V6AZ(A M>>MCN<^W>5;#J[JITFVSQDTW[B)BO> M_/9YL-]^2YF%/_&P\)S?*JO+0[7MDA.!1G-SA_9_'$$9 RKC[P.N_^_??CDZ M\XC"VRBE0XPQ^EU?:5:/2_\XN59)_J;W=E_6ARD8A#B.BP39! MDE@!]JW("J*@PX!MQ[)]QAZJUJB^CGJ"TTB+G?$(J7&$NE@1PD7D1+?5$Y!U M]%Y-OI5S-&D-??DH*"%"28@=,_9CHB1V$@:1/8"(HSCF*VP4&]=>X* /[]Z] M_?(.O__RV8#O8P-]:"L<_)Z_O%'-NT(1U4.X+A5=K.[AXU)62/F#\@,IJ8!S M(E(JRB&KEG[*]NTT6UHU#U^JM*B);.=E<1R30NA [%DV1J$3AK$96'97CCDP M@3@(&7NQM!U]_;:'9K38C%-PB]4[K[$UT3.5$;V.OJC.G5)3@U33WU[J\2Z. M@&6#Q(9!X#JA%R/''Q!@*\9\A8M*R]JKED_X$G[!L?$1?OKR'\:73_#]9XB^ MO/WPGK-D44JWG-+IYEF9Z*VB4N%@44 ,96*Q;EV4\HQ1(N798YZZSFYH??0I MNR\K6AV-XFP[T %V$,$$$?8 "&-2'@';]ZS0(K40\Q2JZ.=KG#3M(!DCIL6* MD'/D3$V+RO*YCLXE[\;3J4\UO#!WF^UMMCOLLP_7F PJFH>_Y;OL4_8U*PY9 M]/ N_<^R0H>Z*>^RJHX>1E ]R/I+>K7/-C " 8*)%8$06L"S3&0& [+8L="F M&7<4O-[-9L##TR.;,YLAIKIE[X)17AL]=./JP6C!&R/Z"_J]8\\=/"!YE/IP MOO\N%T5&G5Q9 #DE56OL]&BO/.%3,CUC.%>BZ'-Z_%3\9V>;?2*=D%>03$3+ MND]Y_7OT\(5\ /R>UQL7.!&R+2\),3!!Y#EQ[ X6D9^8//HO8T>SKC^"9E!L M!H5&BBX"CE.PI>ADG0R?ATG>F6\A$C5-<9]E:'(^6Y[7=2B=$D^>S52K8D=8 MF:B]N+Q+\V+C^5$4 V+%0]#S ^B"9*R9/6R%4LK$86K@R6H3#Z&"VJ2) M2T7:]!J-\ZC3D2,>=1)@=J7J).+):^HDS ZS.O7UVC/+[[*[JZS:1,A+B%$K M#"(4>[YM$VD]S).>9)EE%&B9B234Z9Z9"\P M:?R]0S>W5$US-257BEA>B62I\N:I;"EE26+(%V7%]O8NK7YOZSE2R+G83E!D M!W&,G-BW$FLPZV+@2([[^(S-7V*-^%2- #G9%1X&ZB-6NMYBYG2N >$CKOA& MA6(TKT3)E+GS^OA0AB=Q+1N,]M4?\$/'"Y/(=-S0C!('F7B<-0O,2&ZDR&ML M42U3,V;DYE=4S312JU+-UC&$?,(6EYX)$KU6/1-UYU4]D^*)>=DVW6=U7_T% MV(2^A0(_2A)HA4Z"T5$Q/9]K^IWG#6Q+)\=T MG=A$21@F+BF@8DS$YKA#Q.,:CPE\O&8]>+(&+S3H$B&-318T\R4X0[3$(.HY M$Q,J(4';.L1"QH%261/BDX[WZ5WVX?J1N;Y8,3T/FZ&9 -.W;B- C]* MU0V,37UN]E6VN4RKFZQN^LK(0KX38A.'=#>X&4,0>>&X(2 P8Q:Y$?A8S?K2 M@S&NVO4N-CD1(6=:/S3SPB<8 R6O#EBD2=GUMQ.VX_&ER'D$@INDGSI$?V85 M5>H,E4K/LGNA?.[>"\HHP<&R4B@#O)2./X?8??7$BH^A:\?("D,4TP)3E8@F#+H2S4M@V]2[]F!H4>W 7SV;\*$*CA<@YZZ>,;+8YP"5XYA-H*8JU3!(R M&^>ZACB1C.L:LW#(IV)'^D94X^'N MF9@Z%$J!'T^7.!0QPWYS5ZM\]2:,R >908(1C*@%\I]Q4C'T M$/>U7(P?R]-#A.[<$EGBX">'34BTL")4_-7Q@?7Z=QGOWB)Q1-J(P29M>A/&I<>6V/ MN#@_,M=ZO2VNR^JN ]'I8T+\Q]])WR_2_O5@#-#; M>[\'\.IN_9HAR&QRN_[X"M5XZD,[VZ5@TNQ/I(!EH[V.W+$P!PQ7B9L MU:1-1@?DOV;E397>W^;;=-]N@(Z=*$@0BJ$7)#X*8!([>+!'$B57,2UN17/6 M.,4C=*Q!@C]&,9^%.CY!YF%-C\:>(V5*)Z6)7(G6R?OQ5*\4,<-Y7_2IM7[; M,TQL9)HXL *41-CV?=,/!GL.LB*^"Z,%#,S59Q;9O'^6EJE>(TWE2GJ-O!\O MWQ8MS0SS^EI9-;>0% G$4K^=(8X],["PYWI1$ONF8]M1/!CR8!QQ+:SQ?[SF MW/S;SY]_[IYH2JO\ZBI+.4\@BQ#&N("FERO.E3,*QNC1+'0N^3DA4XMEXNRM M0TMD''BZ/";+!=.6SK^5U7[WC8Q"ADNK B\!EA5!/PQ-%Z+ CT>! H[+=..* MT =K5HP1CO&3=?X,AP)^IF5".S5\ G%D16#W)C(N'K]#R4L'5Y36SP M=7@*8J'N?O1_HK,+D+2.KBX"O)1N(*(',-B662['K="A VU@(ANC" 1>Z%J. M98V+*C#FNK=)'XI%E\Z5G-50'A?&:F05(5&YVKV*8QV<9$[50-H#M X5G<'/ MLX=!]#++7HK59$"^&RZ5[.^4W)"JSXX\%T>(6,-^B!QPG"L/8,BW35O0"$]G M%MJTW5VH>3]W&NJ( M2 7RZ5Q]=I'!;/SJUN=^7WH, M8NQ VX$ 6Q9.(C]!U@ JBOCV/FF&LI!&"[U#H3LJ>G5:0T#4*/4B1V3D6-2@ MUISA^;'UFM=918HMQ#&K9G^DF]RJYN'M$5IKFS;R\?Y[#WLQ"A(/DO\+S1@, M)WL]".*$2Y<5F-.LO>TLDS'@Y)-:%62RR>G,//))Y@#..*>=B^R#>YVR"7U4 MR/6;8U5R(=[%%B!'_O>4Y/+:N#K4 MY*NZ-J[+RAC+J^&.V[*H?Y9<6&2GY]P:H@:"5[!69=�GFR-&L?)9 M.>5\-?62; L6VMTU!!WF"^.(>IT5."?!#&6YKI"MJU;7YN69 EXOJTQ5/2ZR MZN:!(0EXB>\&-@P#BZ (H1N:P!QLVQ PG9]3:U&SR'8X.>I+=50R5/.+L,@G MGAU$'96\.J8YZOA%&!>KXGOF]WEZE>_SYF&^:IZ5I'.UO'*25U#)J_>IU-DL M.9+'NY*0^M?L-M_NLX^W#W5[!U9ZE]Z\8#ZT(B4Q MG;14;E1S"FFA&O<]2&/7HN30.:7\,B25I:CERRL=JSU,8\!I=$"EYJ1S#(<7)U+-#KH7D&NT>)6J;F92L\;?2327!:30R<_2LS0 M A%(7!#&.$9F-&[(<0.7ZZ"_'@2:<]& 4'K&2 79PO-%,_.L9+9HP+SZN:+7 MR>6;*5(8K-7.$ZGT\?59(N6,,I7YE\,X,CTBF4" D64!D,2N$[MQY"(8)_XX MT, 1^^JO8KNS[&L9<')4G*KI92CT%V263U)'H(\T5>%4DFKR.2K^!8,@^*IY MV\*W0Q#FJO;Y>#I7\&MB>P4UOR[/2OUME:_R_S4K2)/:CUB&51$S #AVL.DF M ;"2*#;C<6(K,@.NDZ&")C2GEA[5R80N\_W&LMRQ5>HST,:7-P;&COECF2K[ M96(FRFA))M=1)\LZ42IM73P3VFE%1.R9P/4&H1M!%+H Q#!(0MN)T+&T#I#+ M)#0*S.B>M&[!';6&9^Y4CCZ6&>K9F..Z% %9F"EJ.19])Y-CH%IYG% M:66<29XBX.SH.3-0:K)95YYG)M7[J7& M(Z4G"$^2D'BMK&R!D8'#Z15%E4%8Q]2(:J>>KQFJYXQ5 #\TMUDU,2OL "_ M$,4HB&)HFB &<-R^[H(HX%$^65NS+ 9^OL_HCGY>K9/FD4WDYJ203]U:9.O: M+O$*61,RIHKF=>B7,F]*/8V18^8@R0MBB_3/7P\IL=IDV6@_+7:?#U7V4NWH M^B8$L1U VXY]&R>QA^(!B.&282EJ>83_=&O,8( M^$0%Z0Z(#K/TO(*FD'!,+RP?&K%9ACZEY__(=B>3"=OR:U;1'=!5MD_;VU^; MTK@>HUGE]>^U41^VM_36[KJ+X4_]?Z_*8E?_N8UN4Z4[\F%5MLL;V9,X0@2? MFYW0&ZT53%)H=K"7S5>Q_R4AU>CN1=A,S1&1P &W/31+/18D5C%NX8Q\P MO12MS)CFW-;AXRO5Y0EDJ]5GY8XO:770UE6MOT;71+FNC.EUU.OJW"DUM4B^ M=^Q_)_V:7N27%76;N"< A):70.RYGAM$7N!9GNN,^T,V+3.RQUTO#@JX5OR4&-2<@B;?0I%X3E@-V6P%]^P\\V4@!13K M>6>&@;:)XELIZ^LHP-6Z]/3I&/5\,17B3Y[R;-\,2^OT^!I=^<)C8L.[GX%I MFF'@>C%R;2]*_,#V1SS0AQYS7:X5A6:-?/Y:X[.B1?UCC7K#QE#@KR9BO+LM M'K]!?&%TX7LA0MW";_=CYJ>+YXX4QX!@-1%3_: F;W=3_)ZF#*_G!A.SQ&H% M8XMY_"SG[@4B2]=DP--4;;^HX17Y,MTV&QSX$ ,_=#T0AQYPDC!(@L2-@!?[ M08R8KA>4,C#' ND)+N/O S*A)5 A"D56.G53*::0PI1R+D.^X/VKJXTRC*U MI]3X\>+:H3PS_&_U?JG2'1EC?,ZV!Z)L>5;#8M=NV^E_ .LZ:^KN?4J HL0- M_0!%T,>1"YP86CV6P,>0;\I#"P+=&P [1,81J^QCO$KI9YP$69QYOO0@0+KF MUW8Y>)N:%M$:AY7,D^CU\>R;N_H89578M\77K&[:MWW)W[7/1T8@0&&(D..Z ML0F2Q(&>VQL"IHN8ID@D/EZS-AX1&122T-.X(J2QB9YFOO@4C9,J+6KVG) ) MJ9)@;QTZ).- J:PER2@(2IOLIJSR?[0#@>'(FQTB-_!\ %R,7,?VH3L:1J') M59 I,#>;PM2"C[JJH%1$;[2S*:H_#$3.H#XOT<.L1E+A&YJT M6[2L_V[L\[K)=GSR), 9FQKII8M/?#HL1@MFH8VDS^B8$!MQZM:A+1+X2U6- MB$\Y\/?M+6DP&1VJ9;OD4.SJWIY%[Q_$(()!XB/D1\CV_;'.(E47CX*(6]&M M)#VP[MS(SKBFT/AT1()!-CV9ASP^71EYZT 9+:J%!.8L/Q-"(\_I.@1'@1^E MZM;&*4 TES\Z$#7BP<\V$-<=9 ^%)K%:@#>[L]ZOD1$3]YV-TX,/^SPR^Q4UA

F+%IX]:P[2*=;Y+EBW0VB.W#CV>P4_)-3]19EE5_1D*5-;-Q@(.?5[=MQP$ M8BNR8M+T!EN>&W"=N!:SH%F-*89?C/2.[EBGMRALR;_YU%60.#;EU,^9[)X& M^O[X!&5:E.Y%5B943([%=2B4I ^ERG8EJ2R_%57675KREW)/?_1KFA<;'[D( M09 0FU: XQA8[K!A#%@>X-IEH,BD9NTY@C)N"!S.R3)5M H*D7Y&Y97IA. > MI$%1+BQ6+S+'HUYRU*]4SB2=>DW?5'"F3O NR[K>A$D,<4S$UH21:8/ 1Q.+EO&:)@FQPBI"<5YO25EQJ+(/UZ=7L7RB-V%F M.SK*K3_?IE5VE=;9[F/Z\/C0D@\=Y #?]$(7H-@U'1-'"/B)"QW'2I@7^S2C MT-?YCL#IM/>C^Z1Z[.UL#^F2+?PW+7YC<$#@G)Z:OBK']T27GBF0Z^CYCK_3PX/?TFK7G=*Q PAB-T@B;+E^9+N^ M[3L#OL!SF&[HGA_5C&N@ITKR2'%.O:%W)+P@.4;KDNQ91NTAYETE75-TQ5=- M9PBLYG54R3@PK:O.%>MUY)@%_#Z[[CHO\\R9IR%9CUI"^[2N"4JZ;[D]K85M MT_$]WPPAA>CZ5X6O7H]MD+',:48)!1J&SHQTQVMVS@AT30 D>W900@M!V/@ M#X9LF#!=62WQ\3,KC=#!3!'6V$1&,V%RZK+(V>'H"2 MY8+O[&1K#@Y;D+'G) "8-C1]$Q+90NXX//<]FVOX*_#QVG>/M6<"N^X!.2]7 MEV&-44/T$L:I(9Q<:3Q!>Q]>I?UY8]O!J8#$,86<'PS<5V< MA -4#&*NDC4I-&2 5R' M?B]+P=.IJN7CP9I-/F5U4^7;)MN=W@>2 "MT0LL&<>+$(? M&Z$Q<[D(\*0# M,0N:]?P(JIO!X1-S0=+8U%@_7WQR^I2JA0:J+](RH8ER-*Y#U"1]*%4V+,5% MZCD!O!Q/=3H)]DQ2.KN!:0; M$R$X@&8%T%+:4DJ#T?W!A&&O0.O;!VX%#XN M/T,P%56J\\:1AZW,ZS%N:JN9:>\;HAGLG+RYT M5P7_H1]?NRO3HSVWTJ]_NDK.@?;3PS\H&%K<@V$]^WS"CRS7&]Q^2\ M>65=T->>B8;C"X]>-.FN#FF(ZT;O^X4Q>D^^/-!B9=Q$5QM_IXP8/25SY3-- M34US[EN^E=/B, MNA75"R-*]^TC[RE1\.PF+XJ\N%E=\F9M":O)VQK"_\.D[#]<9N[<6C8I0&P8I#XIN,&/O*]<5+:AW[ M=T7":F#S"+#0G0LOYM[JN( SI.$6-^]]T*NA*V?,K]:YL=1O@>@A'R0>"$8>":01*&<#R\ M:6/?Y+M\;36PF;17YOHVUI3;X5Y+QN4-_M(95T?45YYQ.Y?_>!GW<2@7R;B" MK>F/GG%%:9DMXTK%;?F,FY35=9:?>D!*!DB:0!(%L6?Z]/UJ)QD]0$&TEJ3+ MCWPU>7>$OI;4*] *ELZ^FL*_\@0\>OW'R\'/ KI(&A9O5G_T3"S!S&S)6#9Z MR^?CIY/FV E,/X8P,,W$"T++L;Q@P$]J#*=?^L7%XOF8%SG_PN_@I/)EWZSX MPZCH&I?L6%O"'UU!A7E9;,F.+W(K4L^_9?G-+?DO_)I5Z4W63HO&I*!/TKSZ M*[W@^W1[D.V;CH5-%"'+!- $ENN.]ZQ SXU7MN]6J6]_Q(VY T%&SU"W4&10 MC@Q*DM&RQ'(1\A^C^2X]5%N^Y:YU.*>ET?ZH%0M/ZUBVKM'2CO]IJA\][,U? M(VEL!3]2);6)<()P[& K]FP((S\ 4FPUFO&)L6WU,N/XQ7FJ=Q6,N05>_A5M!V MEBX_EFPV:ZU!GNX"_V7+D\?;_QC* M+Q!@Z-E!'+M!& 08^-9P8V*,H@BMHSQ1[=5*RI,U[W=7T'26KDZ6;#5KK4Z> M[IC_9ZM..-O$"K;>JVNW?_3J1!MO"VW>5QWYY:N3?C_D@4CAZ\[9&(>.!\/0 MBD, +=?'ECLXE]B ZX+E'\2EE=0E:ST/H*C=+%V7+-9DUEJ4G!#RSU:/\+2% M)0\@J&VL?_1*1 ]I M=I!W:H9S$ *[2/Z(1R+6*?@:FM(?7>YU4+;&M7J^>+\F]3?[*MM\J=)=7MQ\ MSK:'*F_RK(ZSJ^9=VO3_>I]];[Y\R_9?LW=ET=S6\*ZLFOP?E(6Z(;[F]2:& M /LXPK8;V@@ZB0^"!/G ]G$(/.P[+,/$F:!H'M[U#EP8.P+.X"\,"M]X=Q(FZH'1N6!T M/EP8HQ<&=<-H_5A7Y';EME665I%^I @^ LX<20+J0(J5\MIH^IBVW:T>?:+E M"NU?)*,9Z1@]^IV+OE.2OR&]D>BP4="($S![^KVFB_Q=Z[MQ3;Y;?FN_3WYQ M3X28?.157Q'5MUG6&/<$9D8WN/S,6AO1*-"*Q[/LOMY1$Y<7*I69 [YLC3&W ML^4BG4I?7C_6&!Z(4.BYCAFBZ8)YP_7NX5\%$B MY8HRJB+3_@?)%%^^E5]NJ_)PFWO)OY#2(;2:,,EGX-DCI"$94Q](,BZ-W@N#NJ%[)*TF M@.J2].R!7,%H>DC;]DE'75/F9HF)8!)7&N[UYW.U[G*D=@T\Z\GRQYH#N]#' M;NC&I*T&08"@&Y@]FC#QD*LON;-C6$E.US&@E@J-CH2N)RKSY7$=XVJI(.E, MVGJ"M=#8^L?+S[)C:Q4!_1&SL8"74DE8E%55N?=S_KU'\R4K7J@(0L?RXR1P M'!!&;D#XQ_&(BN!EVLL\%Y;%;\2$XDDKBK:/T8R5^8M9U)7R[*6Y'ZL-"SL M1G: 3."3P7[BQ%$4!P.8V+9];3F='<):4KFN<;5H9#3D<3U!F2U]ZQI4BT9( M8Z[6$ZF%A]0_3EI6,:26C.5<6QV+)MP6N;2 M'1[YY#MG9#1DX"X^!'^;B[7O M\98.F+I=Y&M,"V_$@G!W*PJONM/T,H\YY@"V,8;9JR2??3^5'. E<*',$P=VJ*X9\2,L+ MO4\-C>NXX$#2AU)EPY+L)K3+;D+HM2<2S3B.'>B99A@.QQ)#*PA,J6["9$%S M-VF+D?QX-PVE (/&K#Q>)*U8;/A]?4 M1H 15K7Y6.5EU5VQ^2G;[M.ZSJ_S;7>ARNX_#W5#.V.B+PD MLATWL% V/% $#'1FX,?<<)3!19_F D"''$(Y"<'ZU9_@@:.C^)3#)36M[#8T?_0*^G(N(:. M>+IV0IM)VTHVD6=A%")L>PA Z$"4('.P[4*?J])28U&SOE!T1EKLC/:+$YQ\ M0J.(73;]F9]8/EDZR^EZ](F)P@G94AN"=:B98I]*G8U6A?9]RNJFRK=-MIO" MML$XC*#KXL!W7RS@<,#U0I-6(-H'H@-*0ZMHJ@J+C)8N$!%E$LL2 MI[4+,1O_W/JL.*QKEFW5KC*IN19^647^;5$?*KK0_+'*[O+#'4'S-2L.&1FF MES=%3@?CO7W7Q%:4(,?"@>EYKFG[4306V$[ =,6A>JN:Y;O'9_3XC!. ?*JM MD&INT7S2>6G+!\0P.V6 M[O_)BYO>(H@2$WL8>, +_- /?.2!P:+EL5U%I\*.]FHV?]YE4;;C?7-+BDHV M_9N+1=Y5DR.!1UBK$;@)TB8D3075ZQ Q)9Z4ZALB[\#]/F_2??Z/=H'EPW6< M76=5E>TZHW!+2LNZE4NZ-V8H+Q/'AXEGA9Z#_=AW8B?QQ_E3TTF8SB=I!:!9 MV@:,Q@F\]F +]_!><3PY'R7O:>,;^>RD^$VQ2Y3>=V,[3@9[86BSGP"5 MLJ)91EMLQ@".XRR"''73^C@O:WPB^)@P+J5332+'N8W9R!0\GG$LK>\[/J_+ MRKANJ6YI)AGF*KM-]]?==01=B995%T9>;/>'=F_FR6_36PNJ STK2;Y'CTB> M5/%-E:7M@0]B@$AC4Z7;IFX?O6@_.JWKPUUW\T%K@7QC."72@:*_=-^_/UMV M<,JK?7[3;5NC_ZZRUNJ%\>TVW]X2X_UA$",U]GEZE>_I1_5_NLUV)\9D#XM, M1?F%[*:N9:S@Z(<:/TK5?89SPU-QG^:]+;1/\[N:3B]W7XS[KO!W^C)?UF=% M% 1!Z)H@ BZ(?.0B'WH#D B A&M3E'KSFM/795G7[=I/^\41I-&CI.M$6?4U MZWZ)SCS19P>O]IR;W77$A6V(L'!(^')C!W88!'0HNY6Y[LOG\5G/B(&?Z*G] M7OJBMH[1@DX'G^X;T\TEJSA?EFE!;5]F:9W51$NR_"N5DO=ED6ZWU2'=T]\8 M?N$S*8$.P] %)4X4.::+(QN8D6EA.[$&0$X N=;B-,+0+-;ORR:C*T8#8CX- MUDD_FQ:OA'D^36Y!=RFRA7W"_X5Q1&[0WSO^FM&A7X\\BW,_(=,S!'0=>"4RBGHQZ$Y[U$#41+9!'8&_GAGO#OJ1D3K$<27N9H0.TERUR%DLDZ4 M2AL<[X'0\CZKFH>/I(DU1/CHEK%[6KP^G5L ,+)#C)+0!"@,/<\'83"8]^V8 M:R^N,J.ZYZ'S[W0MKY4HWK.?JFAE$ZE%&.63K0$B42L*LI7\$>9Z)(R5R0E1 M4QZ,=K>>'?#4PAO[+M:O63=P?VK/Q!:V3!-XCH- '(>^'?3V@&6BB&LZ M4]R*=K$KTF*;DU'7V^.U'+S[4X499).Y>)O>4RG*[#IE2 MX,>S/:-JF&$?%%9D6-KDQ.J[K+DM=_6'Z^-B)!FKWF:[&_+5R>]M$B^(?0OB MT')0$GD^1H$[((DCGZL\TV%?^W!R@&(HT#$M 6 =;2[+/>]0=$1Q8?1XZ2KR M$3&]DFC\'>-]V9!_U_E-D=)#4F5E_+^'=)]?/[0W!]?&7XASY-<6UT^!*$P. M;N-8>_D(*5_?$NH*:I_6 ML^,!+&C',(*1[Y#1.P PP5XR(($P#GAT6H=]S3K=0G[38C9.0?/ILQ;BV?1Y M:<[Y]+FC^^H9W1=&A[@=A(^8VX%YO9HB5H#J"1'6&;AUB+!6#\OYN@&?""=E ME9%Z AVJ*BM(;5X1@^FVW?=&@+3_W'?;X)X6[Z[C(3/ -O \FS+M5R(!CR. MGS!=U:X?A>Y1?P?X5R/' MPE1/B++^\*U#FF?PLYR[8W"<:/A -R!WRRA/K5G8M^T !'X8>M"#P(VA-5I+ MV&Z]DK6A66);9%RK2-*D38OGG'SQ2>,I59*G&&3HXSC#,!.-8B<83B[#I+,R M^1V]Y:ZB4V-YD]%=L#EVA;)*^TG.W>>FDQ@:)IV!,P@"+#OARY* MG,$D)O_@TW<)0[.(//<6)C4>($?8+XZ(8Q^+&> MK2)* C(QQ3-OP-=?L[?%MKSKC\<]S5.A M[: (.C8,D>LEON][& [F$?;Y;A)2952SW#_":71 C9_H(>(_\RJ^*I9917T! M@GEU^SFW:Q)A-@(G=59Q#-8BI:K=>J:66GAC%42<5@4I[>J/6=6NJ3ZOUZ,H M\4$,8)2 "-E>&,2#58LH-(\.RMK2+'\#O%[R# +3:''RB9\THVR:-R>9?%(W M\C@2N!ZA>X6U"7U3Q?5LE[U'U8I]>O0 M-,4^/=WSJH$Q5K5[GWT[N?>[*@ORY3:[.[[L\A0&C.W("4(3@20 =AQ:CNT< M1=?W>(1/N7'-&DCO=2&=]O1J_$>@^011/?5LVK@HZWPR2:">9WL]DLG+Z(1Z M:@O..H14GWOE3(U<< ;Y_5V7])[;^%5W5Z_LK%C'X5N$OFN#2P_],CP&6(? MX,#U A>:W ,R 1-SC,F,(R[C[P.RI49CSSEB&9!),+N.;J?$DW/#,FEVF/8# MCN:R^@N]66UCA6Z L9V8V/>2*/9"Z%F]#8!-MJO,Q#Y9; M&C]1TSJCGR-199F)'HYM>UII$MNGQT47VPZ[IUZ>VU(GS,8*]M")8R]5M 8RNTGW[1:+!_@]KS?DHW" +. F$":!AT,8>8,%%$=,XS.1S]4LBBV< M;I<3*?@I(L9.+\31M"+JIH=/#WF8F2BNZFS[\TWY]1?B7%=7D2^>EE,O./Y" MWY>A9]F>+X6\E&\<[+V^^_"XO$OS8@,2/PP<; 5!X 8F1B;P?#Q=I0P54+< M'ZI[S;YOSQT:CK[.Q\SK'5T;*9QK[XQ\*.CAIQZ?Z=Y"I"S?M\5@EY*-@6.0 M\]>LVJ5%\Y=R3Q_*H3N(TN+ALMF]R^ZNLFH30PC-Q Q#/PA"*S!=RQ]U)(:^ MPSSDD;2CN>_WZ#B*>EG>&$9 ,U+&IPP],*-'9O30+@P"SOA[!X]G@"3+)<=P M:49.Q09/;+(_LJC&G&8=__73VTL.X5%$(8.6 MS\\>GZ0?\1FG3W+W""\,@E%$V141S"'P\Q,MIO,,A$NJ/!,3Y\1>+8TKT'S% M#I7:FAQ;!FC7&:N'S5N\0;9GAV[D(P]')K03.X3Q\,%FDC!=2\#Q<;J7(CK> MV#2&AX5ID=9$ .=;BX^Z6P8^TTL&+BD_]$I!.CWGV"YVR.="TP7(03%(X"@&2>)QO5FG$LE(U,5$Y2(_PE;HQCZA9Q0\/[!E%8C1S$(:Q#7'KX)-<1W20*0: M)9)8%U"K16?7#132NEX]XG6$09&$N&'5I),[W8:YL<1U76C:=A+9"#B.DT#( M.X 1_W3-"L1_8Z8$46PJHY$DHA3MPX!DTMO?-L .X@\+W!QZ 5>$EF)AX<-32' 22RR"Y/]TW5/?SS:.T=A M&2TNP?V&'*PQ3&)K)XQSNF0QKL3V9^KA3&SZ^90NX[JL#+V;-D?7S\TW2]&T M@NEE.?QG-G"*,L'^.-MU5E79;C2)O]/W+[(H*[+KO-F$ -J)X[A)Z/M1@IW8 M24@!&,($.;X?1IQ/=\O9TJR[ SRC2;\;/V4=MC\;5QTZWB?7)&EE*^/F9)1/ MF$>8Q)KK MV]B&$8XV3=FD>S:]$K7!)50C'-XQFP*=$B:13:#FX$]TN+NT(O%+D2R;Z] @ M:2_.G6>68H7Y>L[KZVS;C#>#$K.?TB;[E%'G\WW>K44V249(3/>?F[0Y$*X? M'OWR!H,$N!"AR"='G'+%A$[ZUA85/)$?TIP4U:/G]YB.CO;3"LK++#2:5A?JI0>=>COF>[ZR0;["%@( MAC@T+<>'&%D8#5"3V&5?G%D*X*P9HP/(E3&6C1[#(M&/$+AE@R#+-R(^!XZ+8B1W7L8?M9S!.,-/1!@TPQB@"(P[** P(R9!B?R5N9;"B1=Y3Y]X%<5"0;9M&4>\O@4IL?T:"/4 MA='CFE=GSM(SH3;RE*Y#^Y8 (6J$+ MDMA!MH.2P:IE1UR[$F1MS;FK*J4 Q792"5/))D=SLL@G2B.!=+388;LPWD_0 MJ'7SU!E^ /R3*[#FU2YLV9S5-J6!+6J;^F^T,W'[W?E]_HJ:"-%9D0VZ$5 M.;X7Q$F ('('RX$59KT:$1GI $E2L$0X%10MS70J$*XCO?!5>N<1 MLN><\8B9!.,K%309CUX3-6FVF$\8WF=52A]AH&]OHK2J'J[+ZEM:[>I-$"+L M "^)8!!X?AA$3C :C$'$=>^"A!G-,C8B,R@TXQ$VSC.($E2RR=A,+/*IEQ"! M>@XGGJ5G0J@4<+H.?5+AR--SBZJXD5985,(^7J9(V=[9EU[C%[0JHG M&("U:Z"H6\R**,4;JSY^K,IMENWJA'A^LDAP?2B()$?TV*,5HC Q ?:Q$P3F M<"T.3+R0:PU0RM ;2]HH,V MKY)-D32A7DJX78=BJ7&EU-#V.#9(]CLC\/=M7E-3=-/>)HP3-_"M&)B)AY(H ML3UGK! ASP-@0I^N68.&G4H=*&/8JHO?XVR#:1AT(OLGT'.7YB6?ZX MY(M-WQ=6< X;L^LXZ5,#. F-XF%10-,U$2BK[/-S)Z'RFC@4U_KTCEZQ;)37 MQG7/;-8QV^U.RGNT5-"KDUOP1W$?QD+&U8.1OI *C&]Y+"&/P@W2]MC-$3NG6E6PWN_HH>=3!: M=_B>U9TUI&QS(VN+)F?>FR^06B9=%+ _,3&-$) MO?2@BF).T9Z/77%=9B96K\).4L4BHFJX7IE.*G+JG!2JY(Q;[=YE*1U.M4+\ M'$9_63R&=FA; 2 D!AYPH0EB9\ A\+B9X2R[-IWVD/%7I@0C'CG!HX.]FB M4LC#LUXM9*&,11*54K\R953KVSF!U,"@P+S"_:&I6UEV^COQ+82=A)2B3I@X M$$/H(A\/%I%K<3UM(6-'LP9^SF^*_#K?TH>+#T5Y56?5U_XN+ K5^*D%:SCG M[ZE3SRSWL%TKJ3+#<0KLPN@I7.B1C F>V ;.PNRN3,YD/#D_T)5DAVE5[&.5 M?R6C9ECL?BOV>=UD._Q?A[QY^)QM#U4[NNYMFS#&7@@ &4&;9A3Y((J]WC;T MW,3F5;'-,?2VR*,BRW$#@,U\DQ.]!R%^YQ! M7JJYM0'Q^,?AQZ=L6WA M=8.2TR-[\J.3):([1^;3'MCETMW@FH&.K>)'2G OA49;5I-J!W^$5"9'@-+\ MI2 6S-=T'K(O)2QV].*#J"I_SZHX2_=$B\GWT#Y+*R*@'ZJ;M,C_T2X+UO"* M9-1TVVR2"$<0P=@U'1![,( .]I%KN]"+<1(CYMMQM0'0)U($,TTJ=*&SO12D MP_VF!]Y^?X!N/,)N_'U /_-\NC#+$WJC/W+KD)49_'QZN>5,S#)M[&G!?*SR MNZR#4G=G8.S8\R (4)A$#HX#>I\=&"R!,&"_K$3P\S77EGT7OZ>XC*L.&-\I M0BGR&#;ES,";D"HN11G'[IH9J!/;2_,NK6[RPK@JJZK\1K-'FUX>,WHZK#E= M@[DGGWF;UMUQ][ON@]+:^);M]_2_XV>2_'23YD7=//IK^F#@?55^S=NWPK;E MGA8G]$0]_4%Y:.J&9#7ZHWW6-.TE*=?&MLIV>2-]Y/WE:)S;P",9NQ5LUY'U MH%37DCG2P*]5EA7[_.:V^72\2N&RV?W<[_YQ #9=)_03TZ$79-F1B;W>9 )- MQ+2_1HDAS8GAU\M/F$/-I&ECR 1S,L:7$H[(C!-H%P8%)[(74YI-CB0Q)ZMB MV6**74E-?L7Y<^*LBK,5J+0R5TH-;4I6M]_2(J+8Q1#UACW;][#G -,&D9>$ M-HYC])02KCXES.=:>Y:X0Z_V+TFN MA ;)[<'IA-XNY&'LFU%HF4X2N/$P&"<='$;"0V2F3Y]_@,QU)8,$;0*#8^6, M20^-YR)+8EBLG#2Q,J=;YJN-W4OS"Z>CX6=#T]-Q[.GXM]@- ^23[]*![G%$ M3(?3]R2IR)Y7>8E3UJ$M%_\K$'8Y_%/#6@$F6&6[.;73G^1&]*[GT$5V'+MA M3,R9(1S+L,AE.E+JU^[X+Q20HH\-OG6S9N0@"]%&9^(ZZ9.3,:% M*&06V1=\GI!9&8;6(;12'I3JV@N'V*(Q&9-4>_D!U20/-]6A;M+MMLWP?7D> MADD0)9X+(J+Q48P\%[J#:>#:3*^H*36H68[1X\EV"M3(Z_K =26P,G(9U'D) M7OGD^B5*:=77HC0&F"(SD,IXYI#T)?C6MWYU=O6I+[C;\OULEW@IC/?[;'>3 M2<]Y,M)\+JVHCM(*\HQRETJ-K9HC$QTW97WL%TT'8ZX#(78]X%H@\,W0"A/@ M#,8BE+"O8HF;T)QMHK3XW?CP-:MV57H]L1]2*6L,264>POC2R!&3,8(221H2 MS'&DB7D8%$L,8DRRZ?99O\\IM3Q1*]!F!4Z42AN/Q+3+Y7BN&WDQ=(+8BP/? M 0&*7!>/QCR8L#^@(FYBBXBJ[^43)N/-Z$3V"CR M/-,/;==T8RL.QO54\B^;;?. 5@C:MQ-,+5)QOBRM)033@K\:[OG200O7&/!2 MWIE/8LS\_K0 KR_(Y"QA6L>A"[TN/GVC6C^?3'7QN_1[?G>X^Y+=W9=56K5W M\%?TP'*,+6C'(#!CWW9/ MH1R>A3D^^5N8-(XR>!;R1*>L.Q+O']VCDM(SF?U9XX%4(R<)9;\OOW5'+-(3 MWJ_2FOSP)\AS=)VKG*7I74'A+.]#J;+!\:OV95GX'I#_OY.0G[XR6.7;*V\B2GV M,I3Q"[96ZL3??;U[4;.[!46Z1-B)-UTY_':;;V]?5G#RK?;YUC$6:D3[*66O M:+8PP^N1;'$77E!L23[8II^'AE?LVCL9'MX6I*WUP/$GM>XF9!)'EQ\@, M09)$ ; LY'BNBP,G!J]=;Z#.D,;9U!Y>.TSN !HG"%DN*]!%+L\4Z]PD"\ZV MRI/-.._*P,?9*5B57*Y H=3Z4^IJ=8JTJSO["\/(=TW+-"U$)-/TXQ %@U&, M+,"^A"9M2O=2VFM=BO_N 7EV)=.">F(5YX0E.%64#=1SJRD5\+UQ+9 'IF]8 M4$;ARC, IS.L\B_"$>OZ'+T1K"S0G@QQ8+\_PX>AA4'DV;;E 1MXR/7 8,A$ M&/"MO@D8T+ZVUF$R6E &G'?EYCD?$^LR$N2M8]5%QH%264,2[A)1;RBP(NPF ML0?,Q/0 ='S'\P9#MN.)=PE6 _-VB8AO@5F$,+;E8\U,\54RCRE:Z&'+YXRP MR0#X1"8KI(1%;NY MI4=5EV+[[=10+3F\TL.RXB'6H@0K&FOI(5ILO'5*:+LJL/P [/+5S9!*N5WY M0$S (=;!F"A7KZ6/799O.F.?LIN*?/H]*]*B,%I9!+29C ,5;>'"RQ5IVZ"-*J.A@Y$A9Q?'(_[_S:*!&<=9YD0T%O/_7W3#<7HF3Y_BT&NY1L"OP]^F-6 MY>5NJ"D\UX).XB+?I"]"A:YGA:-R8#)VX>W:?)\^5Q_O4 F,& 1)8^_W^O@2 M% !6JA1JP2,.7A$%,;[6HPZ"^%^0"1DF>/3B. Y)R'?JC85CHD5D(!)A4FJ@ MV(]CCYA89OVIP4\>N&SI9$U0.=L(4:L<3'EY1#U'6 MUJ,?PAZ\H"!R;/!K2*=8G:W0IW,6411 /P0(6X$7^*.MT&%ZNUS.PLPZTN=5 M*27A(I!72W1Q)ZT.W\]-N?V]??2^_G!\97;C.Y8#P\BS M7W> MTF<)JDV(;=-#D9^0_TDB8"9V;/?V0.*[,9]@B5J91ZLHNC>_4WC&@,_H /*J ME#";K (U!Y%"VB3 H3)5.D/*I"#)$KD6+9+VXYD,J6&&78'^6NX/19-6W0)Q MO0E@ NFPRXN]($&1XT#@'NW8S.L[8I\^C^*,J+I="QS3*X*J+3KJ$=(69 M*65J\H2"2141I6LMZB&,_YEJR#'!,]XA*D$GFL91^$L5&4;S\ MJ1L]O=CX>K?;Y-]F7:;'P_L&V+UD(XL8 ? MQRX8YH9!%"><4SD\GSR/OG2(C!82KZ9P\<0J)+HH$E(/)G:4*<:)ZY,R(4+1 M6K1!"/LS01!G@.EBA23-J[^F^T-V?%>JSHLXNZ+S,^_2ZO>LH4>L\7\=");/ MV?90Y4V>T2< 458U:5Y\J5(ZCP/;JUS)M^.LRK^F3?Z5?&+=5.TZ5!WG]79? MUHJ%O(^0E?A1USD"0N);'=O?+RIW@Z;9"]\LD M;]_#]^@MO#3>OO_\Y=-O[_#[+Y\Y+B-8+W4L-TBL%[T^O:8^&ZW3%\:)VT9> M&-3Q]JJ$H^M&Y[MQ=-[XJ7ULI?/?Z DP.@;^?-'^^9$%XX0&X\B#\7?*A-%2 MP7/UQ7KCQ7.=QGJ]X&EU8E=T_#BMC^WNC\5B^4+9\X,TKA7<4?(#D%3^4(+! M=Y/?IRPOB)V4!.IHM!YO4PX\)XPPM$,S"''H 0Q@@ *(K9JFQ61TH R*BN\.:SGNV"1) M.VU\0L3/F)Z[,U]@94)UI$A[%G4UO)&TGEMM&!;_G M]28&D65&3F2'@>5Z;D@4+!QLV0';IETY"[J5I>\A:;I+@*L,4P0=^Y2=7'ZKZFN.">Z,DG("\*BAL!EE461#Z7*)B6I+7%Y M1X8N&VB9MH51@%R46(X3NA8 O34? \RTX4[6QB+ZTF&351A6%@4U1@.!*E3F M->[TZDQGG4=I.&EO&:V@BQPCI&@N\B8A6^RXM#W1GMKQ\'R'1\X(?0 M2R(K"FPK22 *(A\$81)Z#MW">(:3:U9<+=M"*W#ZB99(XUNA=Y8U^SDZ-] M'1JGUJ7I-3T5?*G2OGY2#MDPL5 (_ 1!.W1Q8L%A@3' +F:Z]4NQR57H']>L MO6K.U6B@!KIUJ*#$'+\^'3P[]:^)_!]#"WF=XE1#(GY30<9(I)&_Z>)06M1[:4D\63_#$ M+F!B]*Y2M@1=F18K&7X$)>JWHGYD%(;0==P$)(X#(0@] ( ]&$V2.)$0*5Y3 M\\O4B%!*J+@I%9(JG6Q*B]4(;AUR]80K=L$2)7F5DB7LS+1HR7$D*%N7XPN^ MP$2)BR$T46RZ7H" Z7B#.8@QD! L=B-S2Y7 <^#R1 K)E!X.)06*C;XYE.ER MXLEO98RN4HT$W)C6(5%>F%<=RWV^?;@M]X2G*"NRZ[RI8;%#^S2_J]\66WJ9 MRNY]UFP ##$$@6L%,;9M+PK"BJ&>><:%R"=(Y%RY/(!H#QC8 '4KC[4CW^PFZ M]2QE,M(WM;2I.@+KD$#U;CU=^M3#F\!97536K>E/V;;\FE5Y5K=F<1(#:-EF MXF,0.IZ3H&%(B['E,CTBI,S8K)(XZF#5820%"?U9_R^Z2,VGB?)4LVGAK"QK MTT!8UX>[GO*V;%CLT/2+)$XHH3+^UZ& ZMPY?W1:!4\"BO?IV)7K#<(." "T M'=,.300\&%CF: W%3 ^SR]I8O.13(6Y\K')KFC9"^:3L]):'4TB+R=0I"#9U M$F)R=:(DYL5Y+9)@A56"DD.QJ_^2[7>_%82G$]OPILJR]K:6RSR]RO=Y\[!Q MO,"#/B C9!M;$$=N; X;-P/_; JV&/5\LM:Q3G$2LG?M3N6CSAVA7A@CV'D%CX?& M"174$HUU2*,>U\H96C/'(:OC'A$*@MZ 14J9#;:0"W (Q\"SPIL&'ACP0@" MC)D/6XE]O.XEA1%4US_;"_((+HYS1H*T32O<3(QQ+B L1A;'X2S]I(D=TD)I M?=N.$^KCQ8SW9(A&A^.UL3U2>_5@-+?9LW1,V4Z-AGICI-MM>2!#C.NR:G_W MJAOU&^5U^\]MUM[P6'4*DE6RI[U>I/2%1*" _Q6<_I)TH%36%I4,P>%^7WZC MW]SX'K3\!$>.@P-2:,>N[P_7IB6>:3%="J+,F&99_UB57W/:<]HNVM,]]E(F>#J7T"WS M[=7.^?&J63Z1$J.-39BT\\4G1BU1)[==+[/5[B52)E1'BL-U*(V<"Z7"-L4Y M43C<#-U=[0R+W3"J;BVGM&3>?2@^4305O0&ZV+TOBVKX9Y36>=U>&'ERY7,( MH!7B@-1UKH,CV[)\. "%R.-:YE@ GNY)Q_'^>J/'WT]WC3ZTXZ)3+SBG'A>( M*.,$Y;J#R3F-R1_'_G)<0^#Q $53F\H#,#4!NERTUY$2EB3@Z63JTK$03$3V>MF:/ FK+ZIW&.XS7X\JLY1QRN:YD6 MAKYK!XGEHLA'*.AQ0#,QN6XD4V]=<]H97MQB?)&++ZEHB 5;VE@V#'R)X84( M+*WLW/1-:+>^4*Q#G37Z5\[5J/D4]N31,K2GEWI>Y]DN>D!ET3Z!=$CW[]*& M0GR(TR9[,DZ!(: /CD7 BC'R8>*2@2[C%LK$,VZ>_I6XA$\75\_@6\, M^ WJ )_VZHT2FPRO)D!\BBP0F\4E6X;J"?6>)8+K$/)Y7"T7Z"&B\OZ7DNX+ MN:G;&VR_W*;%,?4<0:#$MR,7(!,"4L['CGV<>(*N[W+MW%!L>C8)-P:X%_UM MOPU!?%+0B2JWF@#P:O7LW(NJ\VNTKTB463AEDF&EP5F;\*IU[JS4:N!0H';^ M3%"\+YO_R)J/I*7?IG6V.Y5V[$:VXR''LDTO J[EFH-U)T&F8)DL97/&BICB MO# (4N,A:XP1JW %+,T9AE.)9^DORSC%P9UPOB)NO'GM6LZ/]_BXJ\Q MMC]$EM#I/U\ZT1X)_KQ#1@;TT.<>WM%3GO6'ZY/:\^C#Q[+.Z>\]W:9H>[YK MHBC!M@D@2$+71@.Z*(XC1RS;Z,6D.5)RGK\Z_=+.95.S G MF:?HW332SD_13*,YA+SY93W1$Q\H##X8O1/T>R=NG XD1D=6E'*D0L"4:.8) M\MK2RTQ>GTTJ<[+.=(W'A^OK.FN:<:]*^FCK^Q/[?N2X9!!E1L!V3)_\KP_! M8#\$8<1\NX=2JYK3P1'KR4B#OIV;]1ZV4$O\M,0ORSF?B)_0#8\< MGR#E46G=M'/<-+(8_6(7D,1YO25#[$/59M.\:.O:=I=[>E4>FD==@<3G>IP# M?;ECT)7@QDC)I]6'J__,MHW1E.2#!THNZ%!]?V@SY"ZJ@C&;/J$,]LM)3SA>"&?Z@OI"NXTT>-7J;LS< Z@LAO:CG[-RILJO;_- MM^F^?^7,LH,XME% +Q@,/!M@S[21:[O0M\,P3O@FX(2MZ)Y(.T&TT$M_9[F9 MJE^E^5Q)12KOQ],:4Q$S3%4COKZF%^30J1$ZP_HE_?XI;;+'YTK2)LEV]#8C M.E-R(&0_//KE]^U:&57\[ML?,])0BV9#>[<=VQ:(PBA$"71Q#'JTT I]IMO. ME\:H^XA(^MV@MW"VUQ459?&F!\DUW[TT1RPEZP\20KX"=W3*Z! 9-)P4ZI/C MA!<&J9AZWXS1N:=_1+>,'!M ]\,+H_?R!VD)'%7T#](BQ&KN-;0,MNI97QC. MU=HK"/P**O,UL%"NJSOR7A V#%O'P[.G*SWM:&3C$]/8L0/72GQ2.KDFL$P+ M.9[K!BBT ==;5$H,ZM[/- [>M^,&IBK;9GE[9/C"^+5J'RLX3J2?K++WP_V? M3L;ZG&=2U82$;8UC]F@(+XNW4"Z,TTL*NC"T/YC[MK+769L8LRDE?1W#-[4N M/;O=3#E?_/+86AGMMTWO>)TX3F(OBFS3@9:)8A\ #\'!N!2!Q?_W"N@G'$H4S_WA.Y.RD77ZH1C7OR^:3.[S9JJA5&!O*%)% M[W)B MMZB>3;UN)_ZICO 0"[BNN]#N?&%![K'5>R3J[2-]&N:[]OE:#K?WE5SHOJD M*DB\^K5 ?$3U[<(X@KTPCG#ICH$.,,M!?LTRR,8GDTPJ#LW:9%2U>V=E5@N/ M:F68ONJSP;&7V,@SK<@.8>B:5NSA,0\D,==K@@K-+BR][8-')^\:_=3],-N1 M2G&?[6YXSYJK#(A*L54>"XTR2[&N46 I+FEIY0K$CR2J?(X)R:D =RH7:+K- MT]T>,GA#3P0V1[2;V/)-!". (NQ$P+<(*GO A1-HB@V\=:%9S4A]'*@?Q^D/ M&E9R)&.G;IEGOK"IG-7L4!L=;*/'?:+DZUL8FN19GIAD4%V?^(/P0&BS@%I_4BO+&KZBCI<>K9-W> @\E. R@'T#3 MC"!PL>U2]^1F16GS[E-[<- MG;#=[M/\[F0!#$ G=GW?"2"RK<&X95M,1Y<5FUQ24^=8TA>)@BH551X 3?JYCF7\Y]Q):287 M^3^*6O(YQ:V3 IRI7JN97D<* R>(HS"PO= Q8Y?\!W@#-N#;H=0 6R>P50W( M]:_DJPJGVA6?&4*H:6;SAUK59^-;P>*1FGBN3?MG\5EPV4DEXZR9@^C6\:F3 M[@H >%6WZK:)S0!9$? 0QK'G11ZT79*PG,CQ?.@[(>NI;QD3^F2!"O;)TVG] M[1U_'Y#-?!G7!$<375D%L^OHH$H\*=6W.XY+N3YEZ9YNZFC?2+ALGT?X4'Q. MZ;6S)X\)P6)W[/GU!L+0\X'IAS ,0AA;0619 PX/.$RS@?JL:QZ^#IB-5NM( MN=3"9JR5-'(^+6OKH)M/[$:FNP<\.L#&A\*@D$GA8YP^A490G]S/S7.IKIYP M<-Q/M7A8Q&Z>^G*;T4M6C>KE#D'ONL]/ D0O=]T='3#J^> M_*S<_2QYR90(ER_D*OUQ6<'%4'K]*^=JX1S9[K>B.D%"@93%"8#T,0#+C2P8 MP]"Q0!"9,/%#% X 0@\P/5.GP:SF_(9NZ77)=/7]4#SIVLHA>06[2 MY%BIO9'R360D997E-P4Z5%56;!^^5&E1TT>#RF+ %&77Y'>^I-\WB9>8D1V@ M$%JN[8' =!,P((A1:&V^9M55R;I6J-(R3P<]!).2D= MT5C'')46STK];9E/1]\6I-(E$D&'$/G7?)<5NV[N[+C-XTMW8>R'ZEV6TB=* M=O!XV]?&BMT ^59@ V@Z01Q[T(\&5,@*8YY=&+JQ:*[_!_C=@+UWH+\E_J(= M\)?7QK>\N;TE _AV\)Y^9RU+9PL7FP:O*5)\NOPH2 /V\;[N(_P+X\-]5J7= M>*ZSH4?C9ORV5Z#\?\S@!IP$-ZQX?F M-JOP]_NLJ$^ C;VB1UB."-,3A"$RH\2S?91 .PHM' 1HG('R71-RG!%> I[( M!A/Q?'%Q3!94E$KJ&*G.6\]X9BWFCB'#A-(:XR:5-B[&G''1!JOUQNC=T9 _ MEH\RQ^35BJ,M-KNU5-39YL'4TGUNHFRAH*Y@)FTIS\OENQ17Y3#,,,'=U[PN M*U3>46QM3^MA;BP+!HX;FVYV!7,Q2.C/3[C%."@R[,SRY4I9V98-/_),LI^-MTW_$_*'PS1$W5FH;U,"C7[X MMJSNRZJ%7G71KW*% _W)B:P[=M9#N]Z>LR6ZJ>]JD7D]CG$UO52F+%_O+ MZ4F( :%4=/QW=]%N_Q@B:;J; (>)$[O8# D= 8@L9.+!NIW8[.\B*[2I>?GJ M2?JJNENIN_1E_'0_XI3)93*,"V2YF2-YX#8Q## MT')C%-CTSJ,D0$&$<10FIN-S/:2K!X'F##: IOVT!V>TZ$XW7Y$*\NKAR8__ MWL(_?P9PSB"Q;+M@.Y)N)D[,Q: M")V>;U0XQ&,C5&I,IYQ+F2*)@\8Y!W1B(S@N9M>A44H\81NC"; CJ4Y]&>?$ M*(A= */8 8[G0#>(@L&F&T&H0)\8+2VG4-+#-@%:I51* Z/*=&KQ@=TSGOBU MBI/?5:L5KR]L>B7$T/\A[UU[(\>Q-.&_(F"PL]6 JT%=2$F83Z1(57LW*S/7 M=G5CT%@$E [9UE98Y^$97Q!$:Q0"BR,4P#&+FT68>JS5*0E^JI#)DRK)FO=QS_>@,$,?L M:5?G]+1>S4"GFF"=9/+]@: 52L><$;!*K:D# DH4:YX/>$[$^[M?QC*XJ$TO MHYTY>2Q@)$=2>G^9U]^+Z_RYI1BY?@Q82 (W#BA+>"LX6 H4;L?5_'S;VU-: M5%IJKLN8A(1/0)::;K_@24>K=0E3$.@)B--390T"Y93X=8_?DM^1_"Q <\=Z M4)EK+4;&_Y^*,C_?Y??;%8N@>)*&^EX"L!=0@.*@-PM<$AJ8 I W-M\L@,#H M-"#-S 0H$#QJ,L .M\;F V1HG7).8*!+?5I G>E%SPQHN",W.:#+D^1;"Z_: M_)K7-Y58Z;G.CP^SIOO-YH+_?K;-#CNUJYOGN[I700A7>Z3_SB MRQ/LUW=9?4"]@-#,S =5BNIVURN,B M7^^O\[4,5@^3T$T)2QB-?1KCB+I>AQ6F/H26B@^#".>J/^K6!;LEB,E(&J]" M9@JB_4*D.RXDE1T9R\'E&NK/>Y.(%T@ M$?TC;;O'17Y=[1_:4^[_VA?BYLBG6/'M;=U<@W@ +3Z#-9<2K0CR0]>/PB2* M/<\% <.TWV8+(\22L07-Q' M5S>?7JI3/3C$OVP]&I_>I@ZR?JVSX/@:*WR: MJ#=..IV7SL%-I_?SM%^*-LXV3M M._6O%CGUT%9NN/JT)5%1K9_]LJB!SL0%;DUJ/K[2YHVAE6A@O';J+L9I[G9[ M4K/QGPVS2I:**+-15:RH9FI2RRVOYB)$HM::-5;RSRL)\\7W/,WS_I)5A&A" M0BK>((\AP3%Q@=M;(G$8J#V9I/[Y/&FSU@VQHSE?JW*W=WF\=>LY$HGA(VC.+JE M+$G]B"(>]3A"*0: A6&_) ^#*!H]-AMI?KH=]?<#0G&)7UO3_.SIHP L9&0QUFYP"ZD3ZMJR\M!63\(&7"P.@/.KH.\&)>]F@H,;Q=D6VN M]VU(CZ=BNV%JMMWFNZVS+\5PX]#9[(P43E.K6/D;BM-R*WE3#DI4YD:Y'),6 M<5GNL\U;..(X8@Q@C#!DC.+$1S0=TG,0C,Z*XZS/G12S!OUX"1X9 _V4.!W] MQC)B"]EF0AP9C?'Y<+JHC)B#:\/PL;+A26(5DZ&9("TW%QKR3R(5FF12=L[I MB;5^+$I1 'V?H1C3&),H( 'H3VU#"J'2+5I:!F;+9UK33GH')VG^;;=BQ&D!J+CK5A>\M+L15UQW_:.4J-T/.\:.Y>[33QNT>V37(A?=9SM! M/O^7]%9X(X3*E;E3<6EL]H6>8G'2*\SX-T\(D@EBER%*1CR1O+Q,G9V1XB1V M^ZXBUX]]U\5QXKK,0X110GJ+GD\] ^(D9<>R.'79P.E*Y.YM4/D3.D:H'"5+ MQEDT)DL72Y&E"RU94B)VT;*DYHF<+&FP([_UK.V&[<&"8_M\;!,$,?/=Q/,\ M;A8'(1H,8B]E:CO0M,U8GQ+L=*A_9O-))U/=AJ9/IIPN3<2CFBQI4FAI=]I; M!)W,_E'L[IZ@PM0/_#!E,&6 M0A*Z-.VWZ")QSXR!8LH8EDF6.ZJZ/3HI$#9K'4H[V28+RZC";):(&"O>>O3M M68IC_,X?W($Y]70DW^J5H/%(+D.9)_-6KJ*TQ+*LQM.\+KYG8B/T^6&EY)>L M:(YKD,>_Y>M;/E"\Z%7KKG@@CVT"NMQQ;.VAC.OFA^3QM0^[*+:_MZ]YAIX? MA2X@;@H8#BF- Q2':4 B'D47,J4[#!<$VW+F.(!SSH_7LH2SSD^?FJ?0M=Y# M7A"%DAEG08CM)2<3\;:2?Z9C_T2J6F 36$966R(QU>*[KUJN[!#2?%O\PG CAU200H!8PAZ,9N$O3F MW! KG476-C*'VFB]_Z5/HZ[B6�@.;,\M[76^0HZ8XBGTM5'E4WWM4>+5YD MU>=S5:X[4_FZ>_<@C)N'I!D$7@A1Q% :1[TE',5*;Q#J?/YDH^RM4U8[YX!/ M'!2YZSK5T692YR?^:\?WOFS_HJ9-6B3+R9)M?M44Z3.GDSZAL]>H0^4^TS// MKQ!U0IW&T+H,81KE066ND8V?HA1#O:;^PIR&"&'&"(IA[(8 ,-";Y*69TD;< M48;FF ;4&H2-HU-_ILX*DP;FUF89DITB2''Z2YG796B1&5>!U"0,!!'40+2WF3@,ZJG3AJ&IE.G'ISFD&TWR]L*A MUGP:H2"*8A<& ).(0BSN\^S,DSA6VA]HS*AM56IP.AU01R ]M 61[!]?LTY< MYD8^AG[BAQ G49 &PUJBAXA:46;(YC1RN.ZZ[)8#W9XY#_RW[[+M:$G4Y5E3 M$2>@V( @MB@7J(>OTZV)HA#59+4RK.B]N2_8G[^#E;=[= M!=^9I #0R U8B*. #X4]2N%A,P6)E*X&&&7(LNIU8-Z^2L,"=7*:-AEK:D+6 MP7)Z7,-S+/-(URF63NB5$7*7(5)F7*DL-#Y%.=KO]G7>FBO8D( *4#"DH?;%MN&BRJ:J/$C*2ZV")%44T:&'-IQQ$'I[1"AZJ%:(,6 M].=:H.^_ZH%[<:9?U$%'M4\8TM1- ^SSD6":N)!Z8;^O"A%/;69JA!G+NG!^ M?/&'4S7(%%5B#(=RFC$1?6H*,C#7O'S;PYI)4=YFZ(2^&*!U&6ICPI$W#MJ/ MYD97B?K9*.*Z7AQ$49JB&"8!A-3MC3$_5KJ,2-/$I K4S/Z,TQ]9YO2TQP)I M8W5G(9JCK#>*5"Y3:U2=>$=GM#B1>F_C2YO;_Y'5=5;NMKA<7Q2W=[MM9]%+ M$2 L3*@?)&Z,0Q\-T]X(^X'4-B43=BRK38?NS/FCPW?F9.7:J1N("F\UC&7S MM/A,3:2: @T<]M :"EMPBOLKC'"I\,+%A)SJO65QDMO=7;9S,CYLO=YDVVUQ M4[1[Z=>'36-/KKI^=HA!/"7;GV)XV-$C[)0#$'HQ@CXT"4HP @%0=C;Y4M0^A6IYH&6O!31G(?HJ+R?JT'$\ M+J,,'>G#\YO!#3 B583^(\]V=WE]V 5[9(XKFXM1Q*(H2%V*&" '#=IRRA>PH%$NC&)2H.J=X=;QW@-Z?QQ5US?.569=U?7WV>_YUOQ4EI1K8MK_LW']@#LKN(U*?^4 M)C;-."J_SIL#M.+;#URUBFW[K)KXFY^KFQNGX/_@N?8AOV[KUS^ZR-;=K7KY M=W$>J[J^WM?;OXXL3T^$X*W:U$34%E"8&G&C,MR:U4K2W\03?!NQ+06+-_D2 M,>1ISG!Y@,2)ST"*$_%(MY?B@SDOC".5JE3;B.4\<<#E-,"NQ9J4W?8N=$>3J:T&54J./=J PWM/'ZTYW3(I2BV(?$8Y#PP3<- MN?G>8!(G2N/B$69FTB"M,YUCV-37(0M$FE&B68YTOLV0HAHITKI0P'9%@TXD*H=#'8.$N6E6D MUSQ>HWJ2 ;+;#G2=X.B%*9OA=ABX9\N7%<4]S#,FJ MTV7U/6]V[PJ;_4(V#@+ T@@ET$M2&+N4#)MEL*(FZ7R^924:(+6O^_6+!Y^K MTOGMKY=OSU^8XT].D&Q3IR9#!]8:&9I'>UZAY(3BC"%P&3HSRH/*7'-2W1;W MZN7/S;@/ $+CF"L7"(,D!3&+ 1O6)[#JDUCZ=JQOD!/0G &;TX/3F@X:1:B< MV$S%I9KH:--H:?/LHE;+ J#&=FF76Z"1/ZEJER.^BU4K5 M%SF]TF)(:O?%YWS7/D(GS+76Q;L;70$'0HH B2., ;<2!1 !/$RC^S"6WG\Q MSHQEK>+@G&) Q[]L>MM/&_&HCL(N@I%4GI:HB5E4TR=!X %8]\KH\"J1^GZ, MD4PJ[,B8CE&]/1GCF)7;$G&2@[Q%>/+0U[S M]E7>MD:[-P3[,VHH!!2%E"9!Y*TU*JIN\MFP.X088Z?.I*9*8,?9>R$Z6H.;J748X:]*>R MU3 -/D'ZJ2CSKP(?^J&;)H@@Y%*:P@0-&^ @\J'TR-V@3:Y%-B^#X3E;J"=^;T,)T6I]BU/R!UYJ5;88P_$^UZ _ZKN]QY]H28 MH%VAP M-FHRAT,YO "*M]W[GZ\,JC[GNQ4"28@]-TX#GS# QU;8BX<\ER3IZ'D>HV@L M9Z%V]J%9H'2J\JC[;L5QV^JV+/[=U(3=#+B!&2"SL1HQ.31;F$S,&SDRK]X^ MG5WB.?+$FL5TLTHJO*M..%F)Z8+GHNSX*S--99%IZ;NULZ+^>[;9Y\T!J>VO M>;;=\X',E_)"'$D0M0;)ML7VM[+ZMLWK[]FW#7?@8;_C/^:4%YNBJ7BNQ/=7 M81S3. Z1%Z4@H4GD!80E7N*SQ/=C/AY2NII[0ER6TX-PQ6E\.6O/&&Z=WAV1 M+@:'G,:C,^?8)Z=QRGGJE?//QB_%I81)(RV74I8:9+7D,GU\[=QY;BX8)S+. M'"%?1NZ9Q?/G%[;/QKYR/B*/SRX1"&C(,$V]Q U 1(&/@0]Z>V[D*BTMZUNQ MG"O&WB4R@CY%R;;*G)H SWV%R)NST6"EI!T=%_6I][0H,PX@VQS-]_0^M \J!0"XE 8!HRP@,8QB M&'8 ^+> TDNS!LW:GBWI\1VM?;675HK0ZZF M,>;92"[/H=3,MK% +$. ;3CVYERU8>[,B.2G(OO&=?OHMAP?1(@%+HY 2%B( M8!# I$<1^%AS-=*,[1GD\B%[-*V5&IR;$$R[=)M6S2.TBY3.%VQJZZ=^7#Z" MB([P3DE)Q[(X[0S'IV$OO>=&@4]0@,0;XX#%OI_B'B4.7:4G[Z;&]O'6^C[I MGAV:/.Q33HC8B?CL"W\RP5[PC,HGB4-.<\5_&9EG-N^M3)OH1F':S)5DF^O] MIOGRHMILNB?K5ZF71A F+O4]%J4@Q@E,>\@\^TIMEU\$T(^6T\Z<(T>=?PI7 MG<[765*<;ON8,M]-T#1F3GY:K6+!N?#UB%E/C",;RH^4)<=2825E&HF/*F7,JB"J2^-P;:74D^6U1ED+^OF7\!]>*DW'3QTTQERTQ6/KYZ\@;YP_N MSBO):OLB6[W(<.VR>/.1,^4K0U&1R5%3-X"%Y:7)W7\K%\T3!]OY9_L49S]1 M^MAB3=,D2& 2$DB3*(I@2H,P\6@20,2_X:?3):%Q..?)1$_6*:9)2R/#:3&.#"4M$Q&9(:1TU?>P>^R;;Y= M41BB@'HN3<,TA3'UD[#?4A;$J:LWXS@E0,LSC0.0V49+"K&:?,1D)TR+= M.>^'?E%)Z51XIAD^J;>&CYV2S%!@;QBE&X]I$]*0.P]P"<^6,"1^Y.'$8VF* M"!;YD_(T&KL<^_1)20/D5(GIJ(:>(T?IA&_*/&4YLX: MT3)^I+PUA@8KN6MT7&884%UF&PX3 \A@1'U"$AHC!D+Q59=F4XK1JLQOQ;TJ M5[.,J>0P2HE?W(K?"W>DA;#!,MN02C):DP^G#$9H(>FI&TJ=#O>"T](A+-,, MH=1:P(^4AG3+(?.@L3^<)%&(KQ'R#(MDH M33XJLA"@N9-0-RQZ/^@+3D)'L9EF;*38#GZD]*/EO[W1D58D9AH>=5@#''HQ M\3T2@LACC$: )8G'_#3$E/H0S[BD)(EPJ@2TE&&1;.!F&1=9B-G<.>EH8/2A M\]*S&$TW.E)L$S]2?M+FP.[X2"LBY;O=IOF [2J$H8\0BB@B&,7431@> M=KV+[80SKR$I()UH*N^ :+[U))7X3;^J9#IF"TE8_=J21 -8<+IZ'J*)UIDT MVL2/E+#T2;"XYJ0=D[E6GHX HR @+"5>G*9^$'K HR3@.3:(B ]PBL$"UI\4 MT$Z>NI8RZ%(*Z3PK4J;#N)!L=KPN];$SVFNAFG"-2J-]_$B9;1P1EM>KM&,S MPZ"L?^CLO+S>[-?Y^KQD62U.K6[=58QY>H9A2B,*@MA# !WNF 4PA*OO>?VM MFF%\-@:TBEH>^RV-+3X* >P/Q_R^#ZS*I$V/+1&YYV6_6G+Q,QM])SY6JK^"(UI75TW5ZLWG_,#-ZHG?OX(C>M9'2@B)*H[Z'I=;3=+S%XI M\9;==N:M]!;.3?41>O^L:PQO%ZXKY*41H4D8L]2-8M='H#D4FJ;$)Y0%2H^1 M+0?UDNJ]\U?+N][+R>YJL] T9EFZF*A5S%W>':UD_(B3,!+AG&ZUPT"3^I&F M8HSR8GU/WH6F%CIS S%!A*7 ;C,>= [CM.<9/M85**3#-S$ SB=)O.Q MTY]Q-B88PNE':?HQW#%6Z&,OBJ,P\4&2>C!T8_%$,',3%**0XG#"5#@.Z+P) MMZ49]K78S"[ME!5JXG'\?) 531NJ>^2(L>_X-"XM';1YCB])X]VT_@ZH6AWF?046,)BQ(8<0@]CU,*14[%U(O(-A-_)!-L0E@ M'$++:_]/Q4BN;EZ4,IUDUX(\F8GFQ]8H0QQ,\O2E6D1DU>KR^BY?[S?YEYLO MO K@,,K;3QQUOFYTHQA\#2B=%F8[);EU_MD@_;]J8W(S;,L-L2%$37"DZ+"B*(/W)V1#G:%E:(,&[FILV]#HY;_F M]]_R>N6%/DIP%*$D3D&$7"964#H+E"2NCJM[K.BU.GKLO0H]'8+ MS&CU]_=(L=?C6P;>Z_.*/"VHUZLB?ZW?:WDOV_-_+)&TZ/TCDXXGQ[='I7Q*R?<&;X MO;761,54<953O@6&5$TRIXNF%3$ZLX 4'D QK&$%,_)C!$K <74ZATW\Y$ MD*SGE7?DY^R)^#2^\*[@]-XXO3N:LV)3!58VL2PNIJJ)9;)P6LHL)@)P,K-, M&N&E9)9IG7Z166;@7#:SO+H8^JDH!&.%A3P>(L-*U5L:,6A8S7);[YI+(#.J1S"MS;_$E+G8$0+%'T3+AU4OZ,\28KA(U57*Y;*YWE5<*- MP#3 ( X]%F,7TX@,>UQ8I*1Z>A8L2]SIWJ@F=IH4RBF;??9,RMBTJO4J-R7V_\J(PC4$8 MTH!ZO Q$'DX')"3PD)H.F;<_F4IM!#11D0EH3O4@AOZJ*F6!?ED-FY=Y-85K MT3H=7.<8[]GS,P"M_#4Q$:BGEC]E6D^*H[T@+44Z+7KX0EAMLZDYTFTGJKK2 M\FLWN*/[/-G78KRWBF,_(($+4A<1$-'83>GA# ,D4@]I63(];4GH5,,<*^_E MO NB44/@T;QK#82GI'QL'=E-H?;CX!ZM0\5M)9_S/W?.U1_YYCO_C:KLALED/#NGI>7OU1_7>>U=L5BJ.8QJD7QE[JQP%% M (%!WZ&K5,R:MSYQ*?M<74,KZJK"OE&!M42\)8T]$R(KWF7AH)T&]2+5]4#J M>('5"-"'TE@=__1D5IM)\TK+VV3>(DDI0CY(7#\A/H(400@'))0!I8M(;-B? M66TC6VJK$ '3>FN'?.N**V O6W,'8HVHKGJ8/IKN:GBHK;RZ;!K7WI1WB19( MZ#$8^5[@4QPA0%((O:@'$D10Z?2R!?,S*V]L27D5^#@ MU83JJL?H@XFNAH.ZFJO+I7G)+;[WVA\B+OA^F! .AR ?>7"XDB) D=+%,!;, MSRNY'K EN?+\FY9<*]1;EUR.>MF2V]-J1'*58_31)%?=06W)U>32L.1>W>5U MGMUPB5I%8D>$2U#BHRB-$PAB$ XX C9B9[L)ZW,*[@&F%=E5B8%1U;5$OU71 ME8C%G(I[@#=><#7"\Z'T5L<_/;G59M*PVJZ"D%$_PJE+84H!"#T_#(;99 _Z MJUVURS9&-?9=FTK*.L SI*SB\ZR(ZOM4&Y52HRQ;W':P2-$<+Y72]'\H@93W M2D\6%5DS?^=+>V7\%UX,U]L=+DM>$]?;K'Y<^0 3'[I1 EP0N @$J>?VP+#O M8SOWO6C#L5R[?.T\9/6NY)]X5SQH;>F: M(E9R0KNP,*EIL,K]+U;VHQQ+6]3' IWF58 M'R/SXC .@!D/!'@>,V$T%ZG@6E L4-Z!-$BU;R@[/#H/ MC.3:XNP0[UZ[NV-DO+2E,4J!"P,W( #S/#5L#(1!:'MZ2!G/@A*!XF:]2:)E M;8+(:J F2@5S[>HS0+?9Z2'M8'[47##"X_$31"/9MKE6[%0T"RMR8^3&C8ELF(_YP6U08$:JR.](F#LL[)N7%7'WWI-7PV"G> M;47&GI(O5+-?\FFP+M>)T@=3[3&>CJS$]=F5U>VD*G=U=KW;9YN#];S M=2 #,M\<2&VW 36F&20D)FD04]?WPR"%(**]:>0EXX5T9DM+8]FE21SC.*4) M@%'J A=[PQ/W8:*V<]"$/?N*IKCCSPB)8P7-#G]&]:R!N"@Y&TC34C-URI26N9+EOCI:S=D-&8IE[HXS3$!(,T#I/ #Q)X="5I9$;+% S:%S/%76MF M:!RK9I88-"IG+<9%Z=F!-BU!TV!]Z8JFXY*TI&GS94#3Q.Z"QG+H$NIY;I@D M. 8>38.0#M?.)8':$QTF[%E7--6]5T9('"UH5O@SJV<"XK+DK"=-3\V4*5^\ MF*E[)*]EFFR-E;)N9;TW#OT@C $( ?((I"2"49#VQD$*E':D&C)I6=!TMQ69 M(G2M?.-QIX:3:9&:)91DDQ(U +$2%5[I#EJ%G>2T6)[O:FV^SJ_RO_<$>[D[ROBASY*(0JCB&$/ M$ 3STU\& 3B4L:0K;[G];=*MF8R85&E!QV#D^Y(E^R77]GG*^>"??UR<77^ M^1%WDLQ3&*8Q:BUJC/ M(,32.P#&6;%8#'!$S?[DYHLC;,X_>W03=[O35)VJ$Y4D6&4^F4HGV&?GA<:%A@; M66K\66Q7F/"*AB$<(4R""!(2!;0WF(9JXC?"C&7%.U5L<'B*(C>&SE%5FVDF MS55L)TFEZ%5)AR1J]#4N9%5I8N<%W_%]2Y?OV[Z]>_^FM]_ MR^L585$21 C$F(3,IX0E<=I#(B!6>CW>*I#YE(U6XFR HK;9#8J<^BTF'L;T M\;U06%'(,32>T-!)HK,,E9W&U6J&UB^GU+>;.F_RPM_RS;HH25;^WAOR$(P9 M "Q(0)+$$:( >+VAP VE7GP;\?&3J.K.^28@R0GH&*Y.R^)$-&F(G0 D=DXU MD)Q_MJ D$\X8OM;5]5[,VK9+3S/S]@2,5?Z>90GAG]!^Z'J=\K_M\2MZ;H"> M>57:A .5L::BH:C?'DE=_<[5J3.%HH2%,6,DH,CU<4PAP+TID.!465-5#4RA MJG>BS8M;Z9QO+38-N5 F3D%@;7*F*['?'IT.U!B1569-0V9MLC=6:%585)/: M9UZ_)[:Z)"U(;K5=>$UPQ_$Q;A+T4U'FY[O\?KL*$'&Q[R8(A3[VTR"!V.VL MIAYBP?B94'E;\TT:"(Q. ]+(I*@"O6-F1NTP:VSX+T/JA).D UO*,Z7J/"]C M(&_,&ZDY4UV61B[G[)*LKA^+\O;OV6:?KRA,8N^&S9?Y >T1M9X5#D>M=QCD5Y#TG8F)DEZE$X#:7+';:/LDM$XUB3'W%Z')77?_^6UGLMA>7OW5E(Q/G3E',"$EC%^(@ MBN(P C!!+HD0%V&])2$=2Y:%C@-15+.1Q*DNV]CF3$V]#KB M;INY"O:G^#)?A0FWAH/ >.11I?OF#9FTO=-0@/OYFT#G7!_! M<_(6GYJ*F:)93LYF8%A-UP: SC'-QQ@=]@[-5K1-CK@3(F>8^66HG6FG*JNM M57&?]:LV<5WSYIJ+*5OR>/B5[O9*_$=6KUES3?EYR26[F=K=?MG=Y?75759^ M>1 ?L?V%?\1N>UY^S>NB6J\"G";,B]. !"!&+$6>.\BWS[^AM%5[*: M:_#G MO/HL96)7YK4@<5TN03D7L4M(9 MM]+YPDWC"MJ"_U$$]&DH9A%0S=;PHPNH+BV3">BHN,TOH&E5W^3%L0>^S]+( M1]B/79]! E'"Z#!MX*;>HC14'?ZR9'3 _Z,HZ8N S"*F^LWB1]?3$_JCY-"O_(B]L[_F_\/:^SV[PIN2D7EC0KZG8)":7B,BH0>@@!%X801['; M^^>!T%^4YIIV;AI%[G$Z60O4N15(G;5X0>Z&8W6^"[ _=F'[;JP64/F::T\_ MNI1;XVVFVMETY.=/ UTBVW-9DG#.91#1**0!=ID/?9^ 9)AZ<>&R.7F_-2#-"?PCSZWGEY MD6^$Z'S-ZEV1'RYR0@2Q. )1R#$@S_5#/P[:C5\1\7SWO;..D^&PMRS?01?S M'$= SYP&OK/C^(^_+X[_=2XXG0^S78 VEO130CE5/!AB "!,* I<_H\.5P34'F&SC\;VMJK??OT57_RW\R5USC__G5U> MB=M@+YV?G2]7?V,7SM7?\.*M[K9#Y_=M& G M%$1]0D;!F]2A=\9:31*%9#8F/Z7;7A ME&Q;@Y^K7?[:S=,I]$B<)(2ZF'J4I20(@\$^CI6>:S1GU79U\S=\P9P$?SV_ MPI\4"Q5SS$H6)+.0JEAX'&'\GTZG1@+F0FZ[EZ7P5 UA/ S+4#4+?CVO"2PQ M)S\R?'C8---FO#(Y+[G)C#-S7MY4]7T[L=9KL8LCEG@8NBR*&, X]E7P \9J<8!@3& 4T\2,8!C[Q:'="F.-+HU3J L'I45F?V/GZ]1,3 MDS9B>N?\\^5O%_ASPOA7Z9>+7_'5^9?/JC,WD\7+D/S.$BKC\GSF\"^/?C1X MLI":RU04QHB\\4A_D"1@WF_5)&&)>:G+#S_GN\-4TWEY7=WGGZKMJ]83 L.8 M(HI(ZJ9A@-P@(NUL4PPIA%(7.IBV:?NP'KLZFKGG7R9??F4*=_V99/>TH,]) MK)I7?W'H^67"O_KM@LG)L5W*%6Y M^I#_1(HL\YU3-.B=/*O+?.T(1>7?>K(2LLVO]W71+(*(:XBJ9LGDZ>]<;_9K M<0D15_?B.T?'?_97YY>\S.MLLWD\<_B?'-MN_R 7?\F[*?^<,_[3[\4ZYQ__ MFHD.Y-GP^\.OOPZIO^%@>W;\S;I;T;G)Q0^RK?-'OMF(_]9YMBG^S7]RFQ5E M^XDT_'7D_9;R;>R5.L!6*UW +9@VO*KL M]FT+#Z<=0$0>"6F4>E'H4C?R?,Q0MVD@17RPZ1E_04W>M.T!F\P37Q:>4%/@ M7G)<-A_MBH,OA4?5G/D&6$ITGAI%V8G+0H9*EIS3>7I-ET-921UV;B:"&_&$ MMJB@OMQ<%-O?V[??((0N<6%"0YJZ$(4$4 -L+ M(\^<)QA%OQ8H]=Z?-,"RG%Y.2[":1([GUHHFODO9"1DT1_MIKZ^YG M3H-U[*X&)6IU=S+88G7\[H6.Q9GN[CS)E-(F!1V&EZ%?AGQY=S."/D-2D]&' M4?83M11:V5\82B W0&,?DI@;]OPHI(-1"GWI.>CQIB92K@/09\6#@*HP+VJ M6XD9Z&EI59.NDTSJO.1C@%*%&>9IJ=6;6!Y)L=PTZ+M$O#7[:8[!!4QZ&G2F MLM+*=*?L_N\>1#92Z KKK(2[Q\#43RCB/20_#A6 M>BO(*A#+.>. \LP1F+2>4[<;"=7ISYF#H)MAY/BW/->ISIW4S*?%D"RDFI[$ MU3=G1:WSJW80Z*7)]OGL%: D06GJI<#SHB#!($#>D A\(E6+&S(UN:YJ/>8^ MED\Y[9R0RK'J.,L[[*?Y.:& AHA=AL:9 &B4,-9;8HBY&K/#2I]O M6=R3ZOZ^6C?[+K5F*=6X4IKMM4:3]A1O43H"TKAY737&M"9SK3$W>@97FD'5 M:=MCE]^?J]4B: &*.]:#UV=E1[!A8FM46I19>5UDFTO>KIHS+4G6WI;W:7AE M.4T@20F,DI2%*44L\-QA,B)BH=*\@&TLVX/NOR2%:4X_?"E M_#6K?\]W8@_;Y7 >**FVN^,BR_B'->!W><@S\B M;6QW3NO2TSL&Q1F)]I[!HV]/_>*UR9BC ME.A=N$:I^2*K41H,:6O4;\,=%7^K-N)'?16XBB+(8B_!L4^9ST(:N33I 22I MKW0*S*!9VZMHLK=W[+IN>KCM9*3&C8B$IN!-$X3QZG>(R0&QTT$^'FS/+(QO MTJFBDN-CLE#)-.#8>_IIBCM9,?VZR=>W^7J8=3UZ+>ISM;O,'S*QT6'S>)$_ M5/4N7Q^0IE7]*=]Q>?IRD]3YNMBEV76Q:7ZT"D$:D""A'O7B.'0!@=ZP"\X' MH=+]+/,@G&+9K'GK3BRV7/?7BAS?,+6[RW;.7?8]=[[E>>D\M#2(NYLZN7YT MLD;4=\ZF\7+;?%3CJ%-LM_L3C^M9W^XWH+H]\V+'?JEY29C5B2BEH]F#I)9H6]HG,TH"?)6GH M,/I^:K :IT4E +N>OB[S$[!K8C??\:(>\ST8$N"Y;L '3I!%/NMW:7L^8,9V M[:G8G'28\>R.V_S/ZWS;#!I<\#_$?[9/;K[)FX-.YO;D*85B_-X[6U$POL=N MM@T2DNQI[I;3X7\9JFK<*X7=;_JL67\9M[G*+0A!$$ ?AQZA 4)>&(2M@L/ M8VZH]CZ<5226E=7$XZH:UTU:CIZ<["XG<&IB;#]FRWH+]YTK+J<)XS(T?2)? M3;U_J\&P;?TGCU?<3GL7!Z%IBEU/G'0,@I20$- >6(33>(HDH !GZ9G@S/GV MZ AO]"XSFB">=M."I5!.G!NDH[BH'''@WD*BT CLQ\X6.@X;2AG:7(_)&ZW1 M[N830EGL)RE"?NPQ!@/^3]2;C=-0ZO$L8\9FTOQ! K1N3QI/L;Y06V/7C Q+ M$SN9NAX3IJB=6EPO5QGUW)'0O1$\2<\=%W_FZU^S7;<2V9TZ!RYEH>=ZB1MA M[%$/)!X>*N^ J#V,H67!LG[1_)NX_>!HPT&W%?#,R7;.S3!KK#C[JT>FY%RO M=1X59W8%'N< :*:[X5^EY=24[2@:ER%"(WUX/AUK@!&U^R8/.Q_ZB^8!BG&" M0C>$*&*,NA'KC?F)"]/5][S^5JG=-*EL1*6K'..1[C&?BJT8+[7K2C)[CBU> MCOB8L9RMV[='BN-ZN$O76MOUM8B42](3<:B6J5]NQY\I5[_- MSON[Z\=0N@P),N'(Z[OGQW,C=27?U^:=WQR7Z]_*39/+WI!!2!((@>^Z/@Q9 M$,8N!/U0Q8?^-V-5DR7NE+=LA

[!TF!SK+%%%>6D &7 12$GJ!QWM\9SD*J=(!/Q/V)JD$7KQ& M/FK4;H1FN?)@:H;5ZH2CI9ZC4N'HNLAYJ@8)TDZ4#R8I7T8=8=2CREX#G699 MOMUT*_8+T&R7?1JN2 N2$$5)C$,."T4P)%'L]2@QB"99H]?%MOP%^X-GCG!M MQ"V6D\?=[EK^%"&??&%?*]J+6N9_(RP6UOS'-H!EY)C9O#>T&\!,%&SG+G$= MVXI!BCR:>G[,PHA2B@(2#W.&>)I$)07$B MQ%\@M:#T2B'\V+*NYJHA#=?@U[9@#R=7Q&X,EH:1[\ DY3*_Z5&F' MA'TTEJ7[<,AK&@%7"(-=%;<3@TH\M[1K^&M)W7::M M5^5973^*5;5[L:BVHB2BV"?8C7#,2!JBQ'5[<,A+)CGQIPC)LMR3C/_S.GK.P6W_/VI&&(8\^C@4N0'R0,!8$7TB1"*1]LD#@-E.9@5#_;^D[G'H[> M@6MEJN1$UR9+:NJI0) 5]7O&Q D9T^5L&7JDC;XRTW+4%**]AXWF-]E^L[O\ M(WL@>Z%*7^MJEU^+ZRJZQ=#0]S!#!#)$(^C[,"(0]M;],"9J.Y=-6;6^E;F[ M;''=(G6V'.K6^2;I.="G3A"^CJQGWJK+;3!6W13TB&@4PH!K M "6!RT(7M28PI,A5V_^D\L&6TW:+A5?F?_!Z*"O[)Z7JXO9.]>9 -;XD-S+9 MHDIQQU+W$N/?_V=2DT MJ7] -R6>ZWI>@KV801;&D<]Z6VX8>6H)6L^&]73<;HNL&UQM,IYX8_]KM)S: MTS^*QF5TBY$^/-_);X 1]='O86.$FW@H3@"*>,=$/@T\V%?1&$8,([T1L/SG M3S@*_J2[54V+-]7AL!W*](?$,FQ9'A=_DMBN-8; 9>C)* _>'"/KLB%]D7A= M/>3U[O$K;T [7#8')![$Q-Y5_N>.8?N1ASYVO, M*_/L-O^\%Y79EYO+NZSN+BH\8 GB)$U0[">1AXB+$&,@'+!0I"1U=A!85K\> MM%B+[&$['6ZG!2Y^U$)77#2V$Q')->+9@Z&X)*P2A]GE5(O=4^N]5J.U#-&U M[./SU=P)&%679E';7F[)IECGI5>Q* MO*YPO=MGFR_?-L5M\]!"6FROL\U_YUG=7?KUV,-\)M^>>'(A ;X'<13Q_WGQ M 1-!J=)#7W:16);4(_#. ?V9T^)WA /]17B/3N^"FL1:CI2<["XG2&I2K!6? MV:5Y%-NG]C1,$L5E2/A$OC[?_S AP]*+.OO\JL+E.N4\8NV^;K=L4TP;$53)6@[H9TF M25^&1AKUJ++71#7?KR6/GXKLFY@;>4PVV7;;O.;B>J$7LX3$F"%,79PR+^UM MN@G!6J_6:EFRK',#(J>!I/48UD@JY<1L.A;59$R10+MORK[&S0FM,L/I,E3* MD"]OO1IK@"%E9>HM-E>^9J+^6W\I+\0=B:)$)-FVV/Y65M^V>?U=".5Y^;#? M\1]SOOA?-:7C<]3=JRZ @)"&) ZAF/MU*84H['&#R NUU&TVM+;W5@WW5(CW MD%YT=ZTWI^8G355U/T1TU91[9&#M*KDMOF6RP>RQ7EA&F9^/M[+2_,C4-E$, M]_N^4NQWIP\"%*(4@MB-W)"7^;'O,[>W[$<$*&V?,&#/]L:)PYW7;PR"%7=- MF*!8KX5PCA;TBMCU7V^W177 M254_5'6VR\7C?R^><.!#!Q;Y'DW\! 8X #2A46\;^JZK= #*B$7KFQHZ<,Y: M/(;XG_\1>:[[7\YO?[W\J^*"EQE^)9>V)J=6<1&KP^<FIS][24IXDXM M1!DE?AEZ9]BGYXM+%AB3GKBHZKRX+7^ION=U*>9TA>W^5@8OC<,HC-S49Q'" M,4G3.')Y*8F83R@D2E,.(^S8+N<$)@'NJ;Y]KDH-C1O%I^3X?B(J%4?F+2KG M *O5LYD>>WV;HU.C:0/,+D.PC'CR? 1KC!TS:]R?AA.K$64>#KV !#Z%7LS" M(,1#.8C=Q-PZM[S-):QU?](]P&Z,>!.+WG8XM[#P+4/W#*O?GR1.Q9N.P#)4 MT+A72BOANJRIJ^,KQB^S3?ZUKJ[S?+U=@22 (0S#- 4D26D$$N+W]HF8/"KS M6W&SIJI"CK4KU5_CMK\>0Y3NMCT27?4;3:RJ_DW"Z$@%?$L SQP!U7F7<\L2 M^ Z%4B)H*@Q+DT%C?KTIA&:9,R*%>'>X0-YUO<2+@S#Q21@&$4I@'/?FXQB% MO1)>Z12,(VUKJ.&5YM*XQN.GYB@VH(G&:;4FB=ENMD7*3^N2K%Y2C9KBAOS\OKZCYG?S[DY?;Y>2,_#OR 4CYB1Q$, M8D0" +OS1IAYH=I3178@6!Y5?^:=]ZA7MTB=GSY5V^W;-Q9/&@+)9=[YV5=< M^3TZ(]^^1G&,>0A$!_LOLQ_)U"/XU!JQW8@M0W=M._GFH7J+G*IK,LOJDD/8 M?LWKYC(46FSVO)8CCTEU?U^5S9:>=A=]XGH(1#B(&$H0C4$@YEB;:U$\'R:! MVKX:"_9M+\PG13F0A_VNV;?Y$BYY?/T#FI,*(!6K_)#QQ$-IX *& M4K]'S(<-2CO^Y\1I.4L<(WNR>T;C5-2LX93+!Q\EDFIY0S.(5I3?(L,G,L02 MXKJ,3+(()JKE]3H3F>ES=I]WQP4B)NX/\Y 7()>%2>BG,>W-)A[QQZ<7!6/S MY(@S1T#4/ \VGN Q@F^)6R.J+4OKA.I]H$M9@C687K*.ZK@C)8;:/,DJ&KM_ MV%2/>7ZYJZY_?_),$(JQ!WP8LBB*20(B&H>#/49#IB)E^E9LSX8(0$[WD)6: M5(U@3DZCIB%-39QZ3,XQ<3-M1WV3GQ-J-)[39GV3X-.SO M\KT@3((P0A!$&&W-^NYGM+;@J.-698A<[-ZGW1WIXZ/AZ2J31D*17&; M- IV-/$==D])HZG +$0AC;GS7"C-\B2KER=O_O^RWVUW6;GNSKI?KV ,28H] M%[@4^K&/P@B2'@/U?*6[]\U:MJRDPW,;6??[>KBVWXG%K9V%>V&XNSF)K_>52V\;V*GV=?L4?PQ%@]# MW^;M.86\_EYHQ6+PB1F,(T!<[G^AT$4#: ]1*06F18"U7;AVV 6 M.C%,>6U;A,Y#![%5\)\;AYSLCZR6/7FP$ ;?D?J%H+2YH7?PK:^@NYQP[)ZX M>[IWT#FTBLNCV'=>.L=NGCF=HT[OZ<=J&^OJ>M\@$./M'ZF-/'%,NJU5. M<=1>RJ&,Z,JXO6@(1>GL^"]>9YOK_:8Q<'M0$/YS]O72R;9.YO"_V&^>JDO> M-JTZW[2;('FS*ZORY[R?UVKL.&V#NZ[NQ5:VQH)LM2)")6H0Z'I=!3)-\%XI M61;6:N:M<99&1K7(GCUK%=7/0&YY_4>+6OQ!O5TQ%,2$^#%./(P3@&&:LAYZ M"FDT8RVE!WCZBFH0-_&(P[H#NK2R2C/ZLQ17]@._J!)K<+=I0(/#'[&YS%IO MV6\V>E77PIK/7!75J^&9KJX:USI^R.IJ)"5V:RP3\1HY^=\M/;R8.EM%KI^X M,$4T3!#%$81^-"S9!@B$JUW%B1@U_:]M6ZG^&6 :7@!8M^B-+ 'H1V'4(L D M ;"Z#$#?"<*4"P%OL:F^%# Z+HM>#!COG=QR@"$6)SIR@N^K?;E;)2 -4I!B M@D@#^*-(3)++1D9/CY05&3:3?.A72 M>] ^_WCDPUO'#EM/EK 169%\>P=&%(.[#*6?V&>SAT"T&%=XP'TMSK*OTZ+, MRNLBVYR7-U5]WV'YRNV7.P$O*Q^_E)O'P_N4^-NV>:-X13R/AL1'"4/ )5X, M&?&Z=RIQ#)'LHU\3(+&G. -X9T#O',$7^M(ZX'0>.,*%)^_*]EY,_TCX2-I/ M:,V$,5V&T$SI\,LWPZ?E6EEB2,;[S'5^>9?GNTNN=LTD0WO*&ODN2F.N;"#& M":'(@U':6TX#7^G%61/V+!>-![GH,#H-2&= J7?=A!&F%=5Z(I)UY5B77[M: M^S9I,F)J@/*%J:4)C]Z20V-LR>K=$Z4='F' 7A0E$4,^)8 $*73#WE((/:5A ML\[G6]:SI[6-FFAIT24G4K:94A.E9P7@/"?*7J'DA.2,(7 9$C/*@\I<@1I\?, MQ\1$I64Y'(;++N5(S%"&O614NR8;$9QEJ*<]]Y2JM=$\2J^1;+?Y;CN,ASU$ M0(22,!8W.[J>&U, >B- \8B9XD?;7K5HT"@N42B2([G68(\7Q46#!LAL\W!/ M>3@U?Z]'V#($11?\\QGU,1Q(%V'9]@Z7:_$?]J]]\3W;""G"NR2KZ\>BO&UO MXH8(1@G$O (,PC0E)(0AZ6U'?HI6W_/Z6R5=>QFQJ=))CN'))WJ.K]GJ=BV^ MR ]()T[D,FR=RMY&V5Y&#S/LT_,\;8$QC5?=SDM\<],\:YYO+_??ML6ZR&IQ M+]IV6UTWW^4@_U=5E+N_\U_?\Y:\\DE"D>?'L0\IQ6G@LOYVYA@3G,::;[U9 M0&(Y]1_=4U^4SO8(L_9;;S;"(5<]+"<2:L7&\;MP/ I"2O'Z>S-DVE7.P9$S MY]B5,^?@S%GS1XT_3N_0;*_'J7-_0I6GB>DRU'HB7]]^?\XZP[+J_KGBMB[R MZYPGE6^;_'.^6P$8\G&=2XGOX3C"8>0RU!N"29"J2+;&QUO6X0:14P^0U-17 MARXY2;7,E)I.=FO9Y:US0'3F<$S32MU+3D[HUP@"ER%*8QRHC#4F-?F@^UQL MI#J(V0H&+ HH(TD4( ! X ;),$/D>JFKHA[JGVY9/#B@=A.C?OVFP9B<@-@E M2TT_!IX.:*95CA=DG! .?>*6H1LC\%>FFI#.?.\*>"G#R(L#G\41!*D7@F38 M]Q3B0.4LD>1'*NF#^A&A*_$G3J8]R_L^)2JSNT;9T)G5G6,J]]TI7&E6EM&[ M54&_.F6KZ+-L/_Y49-^X4C17XY?KYG[7NVK#"=F*6:K=XS!3C!E+4DI Z/E) MR+'$:>@/,A+'2OMPC!FU7"LDN!EY(X2=. ,>K3((9^-,@LBXC2S=(ZGS^= MI.GKF#17ZI)E@R9]=5J")*FICRI_RQ,:90].:(H>&PHS)U?5,-)*]K78Y,AU M[#-WNOW'"LH.3T38XK794B328=>SM68Y4JC[EGA$#+$:.2[,8,)C2/? MQX,TLM!7F<%1^=Q)IG$V!JJ=]QE2KG*,DJ-=WB_])OK;0RP6>B @R$V9'W@L]<,D.FP]'(\X>^37$C?V"KN7!/F&VW M0'HI<%,OCCT0HYB1F/J#&8+]&"MN"U;]>)7^I+4#N+F9Q+G.'@I>H:@>I%+E M2DY^K)*D)CK]%:,"RYG3H#ESSK?;_=17P3WGY(2>:-.W#!71A__B*-(H'J27 MGM?K0IQIRC9?LV)]7B9M5UH1GXL3UZ8P83&$.,1!TF^/(<0#D9IPZ%JQKA\' M8,X#1_9S4>J)B3:-DNO7$_"GN*!]($Y $KN'DW>(L[/(_3HSIU:]1W*Y#)T9 M[<7S=7$CK,BJSD6^RXHR7_=WC.'KZ_V]>&$D7]/\IK@N=BO@^A#CP.>"YWK, M0P3&_8EV BA*U03(@$'K6M1C=/(.I)H$F>!43HTF)E--F 86AXL4?SK"YW0 M_S*M2KW/V G!,DCW,K3+I$.5M:8Y=BYHE;@X@=2''@H3ZODNC/U^F5U,0T76(_O,_(L\-_ZO;TN-DSZ8UMD>_.G:RZ'U6=2>)C!)J;7)H M[ADAI9D@:4J7H4MC''AWYD>1"U-;#E<) FD:LIW*VD;#]VE57L>RSZCVXM;1QL)E[28B0MAUU_*"W%/=[NGF8;]N"[N['=%GJ^H'G07%/)G"1C_VP Q#12/5Z)(.&K<\J'AX"X.VN M67N6.NUO9S.D-&^G-D6:)W\9'=Z&8\\W2=KBSDR7?2(O#0HO"F#HH2B)P]AS MXSAE-.Y1@"#P3?9;=>NS=-Z'['%I/?<%<]K=5S\&'Z$/C_!.J2./95%Y$'=> M/NRYV?Q[OO%ZBUX0A('/?)00Q!7#!YCU%A/F*=V:,\:.Y8'697%;%C?%=5;N MG&IW)YY@_+;-ZR:Y.D4#U_FI >QX;R\ZF6=7<;!DF5C=X<^9TP([PN0]:,>/+6Z&(T.V/DRNTL@AC2,$HI8C%*DS ,$4D'@:2^WBR2 MAAW+T03_Q&;E!,/GBE#RR MR1:HFMN$1>TAEC2.%YU[EYRJ/+7PT?@UXD&=B0,^W2J6G5CKUT>3A7FQ2UV? M))[RF2?RR\@F,_EN8=E+-P+*6>IH??@?Q>[NM_(P_=06JQPF)[^Y%:&HRMZ3 MQZLZ*[-C6KXLG*ML(] #ZRW[WY:9# MS2@DU"<>0G[,(&(1<5&/.@X"I8OGYL9J6=4.PE7M=TYU\[&D2Y)D"RIF.KP? M6]",LV%(V^Q$27,RH5WCN&JEU1UPX/MJ7^Y6(8GCQ">^%WHPH*D? ?$00;?C M@L-1F]$S:MKZY%Z+P]EUN,1PL+DOOU_V&RHJUUFW][GQ1OO[S_L'YR&OBVKM M\,_>U<6U"+F3__E0U$WT1\T$C(R6UD!_NC"-'<>?O1:; 3#_K0;RK&/TDV3* M#\'-Q&1A\F[4M=,#:)/\S5!?_I(5Y:=JRVOBZ\U^G:_/R_YPJ;OR/4(8\=PP M3CTO#N(4^3'-MR^'?]YRX%OGIPW' MGF__4G3PQ3IU?R9^AO6>:0(S385JHF4L3,D60HJ]>M5BEJ=>7HAH7SIQ#% ]N.,(/YR?AR<0WBHQF7K[^M1C5 MA:42^_Z>KI2M,SW]\M+Q' N"*4LA82P)8(Q(D&(R;$*G&"L]A3@/P@DW11SY MY?S!'7../>OV&CI/?3L;UM4?C]>C/N*T[LDP3;(DI=,L%B9G\W!@;5%*/R*R MLO=_]EG-N^WF\>A0S4U5WS> :+&]YC4;=V&XQ#=.0EYXBXECEKC,]6.2M$]0 M0T 83F4W^Y@V:Z]F&I ZA[7P(ZS. >QLEU@KDGE"2VR%91DJ8X_@#1J.*6BB+J7N=K$3D#I-D*DS>H.=&YQI*YC-XTVHO*;!-3O=>U ML]->9.-3$+,DC/@HPT4>-QFG46\$!&I/$"I^M.5"X*B#Z-P#ILJ3G)Q8I$A- M1>39L70/ZS$/)R1#D[!E*(4N^!=WKX[@0%D7+J_S,JN+"O]9;%=>F,8$THC& M@4L1C%G@D=X6<=5F./4LV%:)#@O/HAR-KD:H<:8H%=;H4E0,2:;LZL4Q&3*R MH47>PM1#SX>W1&0$(]):TIGXK=P^Y-?%39&O:76?%>6*0"\@'@O#E L8"A$% MB=O;2]T4*>F)MI6)-.7,.8+F_+,%IRHQ^E1*RLPD+.I)C2*!=I3G+7Y.J<]H M3A>B0./]>*Y"AIA1KFH^#><762I>_DE $B0,^@&.0C(,J[R(*DV):GS\=*.> M3[H'R'5(4ZQI[/"E/022HCQJ#[4I4J1G%I894=-*WHH MLTVV/N?BA$QHT[8,D="'_^+IK%$\2#]1G*_S]=)7^IJNW4>.EC. MM0"I^&*Q%G5RXF&/,[V7BP4A)>-<>/Z \7@^ M9#7EF97/^6Y%@L3C8R+J1BB)(8F"" V&"".!RK-7&A^O5'BH/W3%(1R4Y(]W M.H) Z78D,Q8MCVX.!UY*+C?[ M#F"O.^+$?5Y_5QW\&.):3HJFIUE-G7[J ?[%Z2&VYXLZJGN4,ZB6%'6G]ZX8 MI'X9VF;8IY?[6HPSIEI L<:>L..ED$ _89"@"$4Q"2FBO1T40E^G?I+_]"G+ MIY9CO>I)@2^UXLD.59JU4PMFQM)I8$.B6,_,L%ZARIKKNN8. Q@FE,,/\"DP" ,!EF6%/FJA3NTA]J MN5[O+XUZ9[75ZDJBQ JB-$W+:/[JL-]8,53T6[9)D[S,;XK=]E-S40XNUUTG M.JQ0!CY&#" W\E"*(DA#[V@P3)#2ZQKCK5FN0WL\:KG7 (ERZ7=:_M0R<(_M MS&G1-=?.]?AFVZ/P+F,G),<I+Q^T]ME^K37']B*__M2^V MA3CAF53;';ZOZEWQ[^;$9X=GE88^2J+$]X,0IXD/HA3!'D:(7:PB9L:-6]:V M(X3.-8?XSC6/$Q$N)WRSX6<^J5I-3I/B*2U MR"Q#,^VY]^*Q::L\RBKJ+US)ZVS#)1RO[XNR$/(M'B_MK3(2HB@$OL= &H' MXS(^#*RB)&4J CK6EF6][. U=4SV!*"3:Y6)H[F5T\HI:563QF-&GV*;1P;? M8>J$ZIGB>!DB9\R;RDY+-#2D70%(4@A02(D'F8LCKI)#$>HQ%*I,V^A;F60> M1T^A1E W<@!KE#6# ]>%C%9U1JG2E"Y#A SX(3LJ561&[=H?82WEWB55N2O* M?5'>=M/45;DE^4U5Y^WO765_YMM?B[*JB]WC>N7ZZ:''DNEX P+#:[/J$JDC9DG!;%L?SXX5EYUOC5K_Z MMLO^[&53>;O=8OA3ND)J&9#M*7L?[>;J\/:MHX.KSL'7OB&T'CBM"\Z1#V?] M>F+#Q!G/#KR2X8I8E%G]V![2/!,OZ39/5E:;3;L"V?(TQP58DP3V],;$Q36O M962Y13+SZN5?"\.HD8DYLB[C=Y7 RF484Q 3DD2!1P-Q[5\\##@"1M2.P.E: MD1*\,:?@S@\);=A2PC6N03>''+V@Z%WIT"=U2=U\A!>O=LFQK,CO5*[XAS=/ M'\11ZH9^&!#?!7X 8T;1G5MW^XF3/^N);ZB:.1/T_X:'SO7513>ZFBJV<5"XIGGHR^[IBBB"] M4&"G<<3I/'%Z5YKQZ,&9:<763 !."/7$$5Z&R$_M=#5KKU),+L<@5B@ 7I1Z M01BAB(600I_BW@8,U"XF4/ODJ0M719E68TE2;:T1-+(V?5&(\@:93_U<]A-V M3BF:%HL+$28][,_U900#LC+1/^KZ-:\O[[*C%W&P6 @"C (?A[QVM@*@FHCH\.GJ]@@ 0ZL8H]9@?$!<%:3(L10N:T@$9IRK2G.GIB@VR MQBO+>\Q-HBT=" 5U425SF?JB[,4["J/'BJS&_",O;N_XQV/>1;/;_//^_EM> M?[EI+(NW@K>[K!1K/T/IY'&SL1]AQ!*7X- 'Q/-Z&+%/E$Z+&C=N>7S5XW6R M%K!3-HC%N^##7J%FO+5U]EO^:T7I[.YR9YUS6_?\Q\WB&?_EO.^S8B/JIKG0 M5F^D9CYZ,F.6=LSCT9G[;?OC;CL,/VQ M>JRB;YK=58?!D7VU2RXOH*RXT=1%L4=@1'F9%U+D#:\K0I>F!HHJ;=N6:ZI9 MQBJ*'*GWU]%L+[K'CO=.KL\:8E'^]J>BW.[KC%-S>$#<=1%,0X8#!/W BPCV M4=(\(!ZDU$=AI)9(M4Q8SY<7[.KB2\(N+\^_?%9]A4>',KE!AG6NU 821W"< M?PI 3H-H\B=Y7I)R0IY&<;@,#1KGPHO+MD;S(7UU3;&]YF/[?9U_N4FJ>[&K MNYD N,@W8N.?N/5AVT\AY^NOV6-S7N* *J5>*"XZ37T.Q@UP[''-$Z@@0&Z2 M*@J/;336->KR;_B"_4SP):-.\N77K^SS);Y2UBOK09&3MB5%0TT%#\C%#,HQ M=J<#W]R!LSUK9U=^_B8<<'H/9A3.D92?T-BI@KD,.9[,V^?7YTS*LO0[;%6Y M%L=UNL-PPP.15^U.2)3NBB&7Z7H7J&?'G^N)M!AL8J MUC;)'IJCOY^&MVTQ97$ 0L@8"D$2TR".@QX 3 $R(5\:9F?3,E[4]&A'/'1M M,@#CA,XR]Z943YGV257P)8D:DC@B$LO6QS&.28KE:.[D[QQX^GK&YZJL^OOI M5PF ,'2C%"0LX35EX$6 ]";3D"F^:S?"D&5U/'_^AHOJ33IC.)23N\GH4Q.X M(^9:7,T!O@'9U-R5541YVA54W#F_$VVI3K)L)M>W^ MV[98%UE=3'U=X?__+IN2;2A+$;$%,C/C95-JT=.3V+=L,]>#/H@27FTRYK,D MB$#8VXX#2A1?-C9@T7(IR PIETW.92O&J>E6+1U?7'/XYDV&;[M$J\OAK]O^J.MEO=QQ4O26/%_F#N"2J MO+W,;]L5&#&7>5B&"7T7)3%):1*QE #BNPEKEF%\ F 8^"HJ.0$^K*>H4P9.3 MVX7%34V+>_ B$!U\$:_& 6?P0'QK\,'IG>C6;YS9%L'',W]"RR<,ZS*$?DJ' MJ]FZD&Z*Z,P.,,Y+7N7?-Q4_>>Q^>$"34(!(X@$&4))&#)'(\WHT+HR5CI79 MPC!),AC>B__'(1DTBQY<;\A^R[_::@N_X9"HJOU\T="7^ [6D9@?H3X3P>E_ M8SG:KL2SE*#;B=S25-R2EV]*MTU6U?6:E3L^E/A'L+^,C$CU%GQKE M;)K_2U[=UMG#77'M8#X&:,K-8OO[ENN/V 2G>"W"C&%6S1)+CK!:'NF'!^V$ M30?[Z1BA1]ZR$BGM&$7\/$^85S7 MO&\V.T9X;?8ZWV_U]NZE$:&Y:YWF_%'&1[?*5QQ%' M%",*0!BYQ(/("]J]Q&Z0I$3I+L'YT5I.<0(3E\ \=VJ.1C%MS4Z.;/J:':C% MX=#108XG!SZ.W&L&0B\/?#B-CV>.\-)IW'2._#QK*AI'N'JX ?OB5".QD^UL MQ^Y4UEM,NUE(]EL.'\^SX'*0S9<-Q>,TU[M\_?=JPS]FPXN!!CDAI'EI,8Y= M1G@*QS *>^0@9DH;Q9> U_;"^797W#?KX]\'7#/F1=V@SI 9)XCG8G)C[ZMS MAS9>'[ !#F6$9LITDBTE)+DM_>1?U-!?I77]^[*9Y2*0P=1 M@@D%- IL3B*FMF=V1J#6M\@.@B=N2Q0/'#F/>5:KOH Q9R@5,N+R8[B\ M1"A\G"'[60G5>TEOWO:QH%PW,Q&OI;@EQ&;6X1\MOA?KO%PW&1GZ:9+$S \1 M=J/8#WEZQCWN- B5[JZ;'ZWEH5^/Q7DL\HWJ&M[LY,PYY+,6Q>7EN:&1_"## MO>/033W8TVHV"TI_R^!CBH'>B$B]EPQO-W5N!W1:U3=Y(=Y";&#[01#! $4^ MQ%Z8^&D8I$,.!V$D=>'/8L!:3H4'- H+@XLAYYU4N!BR1?\*(\Z-F:H(5Q^")/B8^03B4>TY6;9/9E;W[5-Q0R%+ MM,UN67234E:Y?_T%^)+\D@$0(.F<4S$]I7(ZA;77!M;&8V/CC4!XB(-'/>1D M))QI#UD7J[WXXKKM[ZNG/#%-NL=\O'30UQ MN3F^4=+7R.T24SF:\^YGPLCE-L^J_KT+POP$LS1-24(3@A( VC0NZ ;,AY'L MLG$<-!8CXI$!SM-[8H?2T7VN+]V8[.49,_2?6M^-Z]^9+.)&-OKY M2FT*SL>1GT,:*:6!!WT$(*:I&Y& PHATZ+P8*I59'0N3Y<75EU^OKC[17^C% M5_3Y;\YG>G[QY=?/Z )3Y_R"77[^1:-T]FC>&B-:V''4).%BNEL"9CQ@+6*H M^_A["!D:5AN-&;JLRQ?C:5L4)3 ^9V(->12H,(M",5$.W>&R:IYV* $&MQ M8,P059EYF6_=\ARK!US'Y@9IO6W5?CR@=EK8>L7P+;A%3@6G]8B:,EIPAA7% M5.;TA(K:\\\\E-6B?<58/=V> G_JRUV[/F6NAR$!,$AQ F,_\CLL<90JU9ZV M@V"&2OQ)MWZ_)1^9EV0[[K$ORS*>F5R;/TE4^[?KK(^GT1HV#M!I749UM/K7 M[<,R7[^'J"GTDG5_?%_LM[N%3RCU 8T "0.?@LBE:0\NC3VELK$C0;*LYGC) M5:!LESSZVFS3)^IB/1-W#%'OQ@0I$3]S.DO:WSES&F.F$W1]!T@J_ @>GI_D MCV'TB1@P&N?V@L+Y=K4ORVR=[G<7Q:Z#>IY>?'X"EZ,#D99<[W<.M^X09'X0!O[XP6*- MG*N,1A_#O>.CQB/3- R.4%;\8F/3:>&%*& )\2GU8N81%GA!T$% C)'%KM@M M-^;WFMYM6"FV]!CE1?YTGKRH=F4NH .P)J,[;%AR/0>J>AQATBF6XVH2\4T\I, MN\'Z2Q02?)Y*$K/DF7GHK#7K3CPH89Y%6;5]K^W7?XK^R*L%<8,(PL!%'DB2 M"#"7T:@#E!"F)+P685C68+D!+Y JRJY-S\@I\$RC=7^$RO6CFS]EF??UX5>;W6=J\5O8E6^W+?)=GU9=BL[XH=G_+ M=E=\9-R)FV^_9/?76;F 24(A8(A 1@(8!RF"K <30*ER,98AV#_?O'/N.')1 M)^1!8.]?>RNS3?U6M+C 6O66.!4WY:R^'_N8[9R'SAR%"]$6_75:O6?D*C7E MKKWTY]9+-6RGQ7WF') [7VK7B,UHCM[IX3N_-09(1EG;/E*XBCX/7^E=,+?M M,[DKX]H,OA)91W+)#*YWCV!D,6HW5XRFN-ALQ$N?R\VG;">B2G&#RVR=[\ZK M:M\W[E&?)L GR(4I$2G_?M ONV"02!T#&VYRC&BYZI$^"9&;!G;]['0-W,EK MY(JB:XAZR4 X/NL:@>\ \LSY=&"Y >HT2'5CG"&Z%6/:^+0/B&%FZ)8I:=]%@WB&*ZX=)'3-@ M*6'>0?++"E7.3JTPK/$_@YAEU[[GZP[+3)HZZU]@PIA8[2"60$H9)%$:=\V& MJ:_T@/C@QFPO441ZJ;CTUIT6K]X*O^>*N6JY$*$\?ZV); M>5;6!_5>X@:0D83_.W8Q#A),Q3%#ZD-'9;5 M7-5_=M3E46XI&I MLMW8(#'Q$Q#3(/5]#Q*&(Z\/.)XO5SAMP-?;UNOV>94.EQQVV=* M41Z?D:2S/ZW)ELK[0-99T]MA5F=/\M6=U^Q]:W=X&#DSV/X=:$!AK*.H3:R_ MYCMQ7^Q\NQ8O]^V7FWH2GR 4DP0@0%,WH-5!A_IKO M[C[7"<#%MKK+'[X6=+O+=X_MQ#% *& A\!E- T+B"#*/=BCB)%':/S7=MF55 M.D8F,H\:;)I+;N.\:XK6B)2KGBGIL3V.IIVF347M##E@ICIHRKKW%-(HB[+: M2?(R6W&ZVRD@2[1&?CO98)B+".'S"N922C'S(Y9V;1#/ERJ_H/?-8XU^K16/(DE* M"F"!'TT-F&1Y\H2%]W5 D:U9*8$J]M>U0(L!J5.PG\OE=D>6NZR=:J11$G@N M\9D'12$OE\+0[9H +I6_]*?ZQ2-I0;%U:F2.@*9PH*/,D\3!ETV*U.3@0(G. M89S&/B/]+"QT0R0MBIK?/Y(VGF\=@1R! M++U)4\<3QZ0CE[J4*:CF"-3IB:<6A7(J^KK-;XGI0(9FH*E#+2C,]1==A?WZ M>]&V%#.0!@F?WH:8?W>4N,#M=[AH',F7 -3\_I$5UM.5"P7&5!76#EG#%)9C M&JRP"I3I*JP=ZLPHK!2%&@K;VRREL.H,S4UA-2QX4V%UV=!06.[03LWCR 4> M31DFD0<" E",2:_F $F5PQ[6PL@JZVM+A@IKRCIKB;"!2BM0#==:%>*TU=82 M@8;T5HY('<4]V"VGN1H\S4YU=6QX6W>U&9$]6?DYVXK"36B[1NO[?)M7NY)W MIV]9^R)-VS9 @(G'ARF$:9)$$$1AU[8?@DBJ5H_9%BTK]7Z.&A++YE M:U:4HL:EJ'&W2*!'70S2-$5QFHI$N#AJ\<6(\'7:MZR\+JS=L-7&I3+$CTV0 M'ND7>^$_D3-?"9!]V7^G>*@3"9U;L47>U!FLVGLX#]T]G!_JOU/]:/FJK;Y7 MY=1XGNY44VSM"[BU+4YG3%U#LC-GYG=QW_+""?D?W]/S"!$3V#WTLJXAYM5# M#2[N162KEVRHY(ANZ^*HZ>/A5ZZ6C^)'Z/=EN;YL=/)ROZMV?,CQA<%?L_SV MCDLFXH*\O.6!,BM7>95=E=S$A1^'40A R"+LASZ)090$)'2#F#&?I:Y29M1< M,%N>Z1]+V[&ASI&E=9G!H]]KK75J<\^'NG>?]@$?D)28.8BHI\'G(A]&) ^)(5X12F#$F]=3,!K!%CKLIRHK-( M+"B/WL(Z5W@P9PH?VUDGCN3><1:*>IZ=Q4KQ;3\87"H:G_L:K8$_SFI,L1/,+7J-;K^]%9:6)Z1CV:Y8_:.)EH3' MSNWM55;FQ;K9@#U4.*]_K<;WQ5[^HS,X'9R7G?W=;'YP_\*Q3CC27_2 :5Z5VC M&#EJPMO'*QO(3H.Y.^PZ\T$$ 441B-P>(E KV#,J,,O:CC?YS8WSK4W$ M?*A!..-AVW.AKAOI?3I=_VYCT0=8*K_C" MQC)AB,MG$CLF,=W4XF X_];6!:PH;[*<_V@1Q!P(\3%-^0H%LP0GN"LJ$1/" M[*X-Y&&,OCZXZ: )&>KV,ROG][O"V60W?+UPE]7*M=P^.@_%XZX@>_\S7$CU.D^L)=>?-)"Z,8.C0=84NMP,U_R_+S3X[ M@6?/X2Y8A&D0(9C . E3-XD2&'2(L$],B+X1'+;/*FHA6!W//[/VRD195V?E M.L)5_1 *RA=AHLR^B7;-Z+P9WPT2^M'=9D[I:^CO"KTP8!92+\.TNM8;]=^L MQ=ZLI7)J;X%=6;FG3X_47U^47!1;,?W,FJ5'5;\A?/SGN*AV%\7N;]GN<[8J M;K?YO[+UX9N:OW3))['EU[OEMCW;6"0Q 2STF4=9$KAQBN*#/3Y1.SV8KQ66 M0\VOV[+'^C3BK+@U51-OFJL[VV+[4V/_RWBC%F;FR[9DD)JO ?9"''V6V^6\ MM5=VYO26-S&.KW*>[*5QHYW';.<6##DITGB <_W$$QAXE.OO]$5 MA[%4%9F90K<\ ^BOHBS;JRCM296XQ5D><,XDPFMZ?^*P;M_Q4\5R8>VK ?WJ MT(L^2_2BCQ7!7_7G%&%[6,?ZSF/U0'+&"M F?&@]\8/^ :5Z0FI4)EJ-T MC<:YX7"<;P*/R!YYN>O;]+V1LDDL=PG+>2?SZ0VC9Z@TICM'MK^RUCYS&@*< M?-OO9 O[F^WL#Y+0,LC)-E)?QNEU\XCK(X$+V-&,9)P\SP'XQKA@]F;MJW'OAVFYSW+ '$_N MSHF[#/6BJKY%]T$D[%VV;>B8.1=_<#$S2(0I13/MFVDVAIZ5[>N?PCQL;X$@ M2:&+XPA#%%&^9J L[JU(4SC=IM%P[)8%\.=>Y)Z=^P@%+-[)B/L8SI]BRVE< MO\]I.^I%T=FC-X,_W-&.GF]'V\LRU\MF%'OGR([5/3#37IP\>;*^&=(E?L8X M22CR C?P$/(P\(.@N_^7I!CC6>1,*B$>)0GCQ2V)-RY)="= VS8[[G#18B:Y ME&J=8>J;$;;ZP:QN0=07 [^SVPY'CIOD9H-.QYE'T)T9)Z/=6-#WF)'"),?M M=Y7HUPOD4X\!"F%$W2A"<9P&J ,2)\!<01*]YBV'OJ,WOFJ-ZH);U@$T6%!$ MDW_)Q>2TU$^W'NSL.5H2SN*^^0GFU:^9FW#C/+3?IH$J)41,<&E&E5^-+TV6 M DTVQNM8QTO]).5) MMO3Y=L=-J_)5L^?F(TSCR&.41($' 2$TZD_&8DQ&/5,R MAV9.C0'(Z0A@:! M.; VTNG1Z!Z>U1+AS#GTG@]X/"3C/(MG0D;[SDPBW*PH,7SZ8\%?UO/-WGU, M\7-VO\RW_.>XX(8L5[O]4'5)G=8#J\&^^K^L@=$&W.)@Z4OZUS3YB.3M[)MUCNJ!\^MW@WGKG MR'Q'V/]!,B/U_6LC97*$WC:C,#Y7ADPE68[FS9&7Q\OK3=:^Y^7'Q',#UXU= M)G)$D\C#7?&NA,0^FV MK(!NVD,K 722=:^*_T9=Y%IRW>0K6F'7QWRW\85C M[*]6-3K!C&+:-/;;68=J>V*">/0LLG8KZ:LR7V4+X(9>['L841X[H]#SB!MV MZ#T8DXFBU"#,(RTN?^H6E]U6K7C59;07PTS[>?1H-IJ+9Q+C7BP0.XN=JY/= M9N[![Y0?QPF)1GK2=QW978K+BCG;RLKBX'=X[9A09 MI^7!\ +6E&3%GJ^M!-?)\@YI/^@CPE4ZU,56'.(G8F:\KI(YT55XVS/-3M'S.*=1,386^Q-\PW8T6[IIY_5/_ M:K6@%"4NQ

)(@2]2/.L0&.EHO3A3/MQVI&=]TX,1\K/Z?OIH.-MZG/8] M:3ULFNM+WU,D-!JVFO2\7;_\+"I82Y+\9+;OA255,ZW-T5Y7QM"LINL M+#GR8I.O'M'JG_N\JA]J%?7+JH5H&K$H0!B'%,5QA& 8NQ"'P(,T(&JUP2QC ML1P?.W3.\@"LKI+)A6^;[13#H&V_2(:W&;E$,6P=(W=ZZ,X1]C.G=UD#WSG" M7[_O/?8R;1C;IT++2'Z<2<@8R]KGH6!4EHU)_*=\>9UO\MTC*TJVW^W+K,&7 M9MOL)M]5GXJJRBJ\6>;W%=JNQ7^*!QNV5?8YJ[*2S_(7&"*?12G!+@,I]'W$ M,.B0AP%1NXPW [R60T6'H[X[>OZ<-; KY]_^1^P! M\)]\R76J)-9\W6\HVLS,\Q8B4F]AW34:&[OHU%G)?ZNV\\QI+*V[COB1TQKK M=-;.+'P-=]^0$#=BY_D@87!,1E1#Y>C>,A9.?]UFRW++@WR9W>?[^VH1,<1$ M'>>0^MAS"?2C%/6@!68UEZMP;BDQ6:;<09WJW=(!G M%BJ>\SE$^+5]\T%D7-\^55$>R*0QB6W;_YQ]R[;[;$%7:D*!:I-F"G+9HG1;NS,3T*9=#I%33 M*Q]$2'6M4Y7102P:$U$N'>?U$R7B=\ZWJ^(^6X0N ?R?*(61"[S("ZC'.B@$ M$7^QK7-UQ4.=Q@15!X?4<$^:X?X"LI*XYCTT_E%@N[.QH-3W(THCD ((?)?Z01)U^"*4FMU),(9JA"GPIMT0/;6);EBQ MS3G-D(Q/XB\+VG[8YFXLZ;:[:^<>K.DVNV>F^K)>&!(*C'OZ@\0'\W:K!@U+ MS!N+).B^*'?YO^K/ES?O'#>'2#QA!;!/"?-@$B6,]-&.A9@:C29&D=F^DWB$ M5>2SKM_,[#$<4\RZSU!C"^YYE=I.A!L!P_:E!. MT:&RM0+1I-]06+#/O 7];SS3HY[I&N)5:H?(^3!??1#='FBDJD";X-3T@6CU MUS+?[;+M(D@0 H"D@,8H=&%$DQAV,&+L)39.1*4;MZR^]2N/AT/1WQM4=DY% MY0DW>RQJA6M[YZ*5\]=WO##IP6C'IH&3467'?!!QU39/\VQ4DT=I05W=9>O] M)KN\^9Q5NS)?[;(U7E9W:%O_B_+Y];?EAJ.LOF9_[%).U3\6;@!CF$(7LX2 M)(R2Q*-\R@T#Z,(0 [7M$@OM6Y;5#K)8-A] .P)NO3-;?S@"KBBX-APBJ;D3 M^T)1=A7=X/SV5=27<01VIP;__XTLPNKTGM)AB\Z:B13;M/"Y&EMG4UV0KTJQ M<-X]7O%NO^- !(@'$3#J?KQ(B<];99X/0QX ((U)2NKF@S2,H*>6ZV>JT1&E MMT/*YU8":SWF>[3M8'][A%OF7E5P1Z1=366'L6Q91T^S)B6>AHB?FV*:,NM- MF33*FZPVOMEH^OB5?Q'Z(Z\6'L1)1$E$W<@C&# WC-.NY03'2$463;1G61%/ MCL\S1\!T?A- %:70"-5R*C@VRP8%4(Y@*RHHP=H) 33)^3RTSZA%A;T>:DCQ M1+ND$ \A+%"4^)BDE#+71T)= T+;EB,_<;$1Q5-H;PZ*UT UI7DJ9 _4/$L\ M6]"\]R@>5_4.O.FHG@;K,U<]'8MD54^;+>DU<'&S^WU99B*AK/U(LF_9IJB; MKT_Z?\GJ-U$1BY@;N0%RO90E+"9^$G7M(X#5JBX9:]6R HKR6GO^]YRJA:FX MRC7'KN0R=Q)B%7<36V!-;FWW'T(NIB$)/12-_$"%$6]_K(T4)K[#6C& MLN#UR.K1>=-B4U.](23*R=Q(_*GIVE/J.E@3R=C;#)W0+0.TSD.H3!A2&.]R M:E+T*5M6V5VQ69_?/Y3%M_K\NFO1#8,(A,!/6)CXA"112N*NQ<1%2@<20]JQ M+$8]-"<_PJ8F1H-HE%.CL1A4DZ,#><>P)I*C$Q2=T",3Q,Y#D(Q84ICO=H:V MR#[EV^Q\E]U7"^JY#*4L1!"Z0910 %V_:Q@@"HWLD,DW-^4&F?.;P.G40$UM MCRD0/7!WS ['1D]$9>@==VNL)TUG9TR=\7EHFTF#9/?%=+D:K'1UHN\BB*,X M##%CF"0D020,J=;$3EY)JRO@%6*581'TK=0-TRSYK1#?V?3Q8@'%>M M:BPZ2J7&\]-C(L0NTF$$?(P0Q"C(*0!Z.$![&F47AH-F]00'ER.Z<@<9WUDCYHFCN

5Y=-.>&$@H_NYWEH_?AF M%Q./+T.SVXMLMT@@2R/**$TC[,4A"*';'ZRD,.4K^&*WW R5(G#@#-C,;578G8?:F3%% M=EZKSL]@5?JURF[VFT_Y3;8@D 0,^"#T&.4+_2!-4[=K.:*Q;V3AK=">[=/8 M_ ]1 :BJN%9EU2Z_KZ<[^QJ?L\E/O;9AC^*!\F6)7:,JUF!T!,B9J-F!-1U1 MT^!\YMJF8Y&LQ&FS):MTY_?"JVMY_X2%XC,;-2M*#F&1 M,L!EE: H3CU,/$R)%_8JZ_E*1REF6K2L=@>0XM+9S4'[%%7.$+UR.C<^LVI* M]Y14@?"G&J+38'0$R)]NBO*G_=@E::28.Z%V9IF?A]X9MJFPV5>P=]:I],$ $O]G665QBA,$ D2DG(0(1 G 1NAS-)PW3!US=Y ML?ZR6Y:[T4.@)$85U7MNCOQ>;XU%3("+3L?2Y:8N';;DRI?=YMNM$#3^"TT; M'U;+&DO'D3%%#W]W"J9JOSWQTO+$6+KU,__%776^O:I'5I,702)& T@I)@"Y M:1*B! <=4L_U\>);5EX78TW<=1"JZ-:Q,4,TJ\9YXK&]68K3*^1:E*>/F8B%10.? M:X%M+L>:C_!5WDU67^7KE6D1NR#"+B$) AAZ,$H3&'9(4\)"'2V8 .9D8M&" M57X(> I7CK,):,U]D^\ 'EGFY%OGZ@,NF%]QCL4YZ9"N,),P,R4#AN>DP[TQ M5J"B?SSD9?UW#D@I\=P > '#P/5PPMR$H7YK,G#Q!(%*!^:$LUH.=NPPI>7( M<<*4->=-'J:.+/NH8>H5YU@,4T.ZPO<1I@8Q8#A,#??&=.=2HA1*BK$? PH0 M]0,6@_[\S U9W)Y+T>UZJE.I]Q"JGTIUQA@ZD\JVZ_][&F73L]^'8@VPW_II ME)HG)E"KOV;Y[1V?6:)O6;F\S;I]JZLR7V4B'>"F30>(&(Y2%&%1URD"C/A1 M2EM#TA0BI43<&<+_F/EG9TYGO],2T.]8.S4%FZ*#S2*Q3:)O MH>MJ5RY7NX^;]2;IW7&"M^FN]MU%=^,$V0O_=GPYL_G!PB,$IB0A$4%NQ%$G M)(P[]#A%8-+;GG?+,]%(KW3?^6^FK/"O3 MB*JBUXPI::64_7/2 N;%84P!"SP& &2$KQRCS@+/3=4>%Y@1;LMKJW=5]+V, MP?D[WM"J9Z8^-[_/I M?#]A1.Z-_GZ#LI)?;<9E.QWL.PG-EL@Q'9UM^G"T /U*.N+I>08#,8@HI"1T M/2^D&++># Q#;]00;1K\U$':5AK[Z)U@I# ]I?\G#-2O9L!_;Z%:T;EC$8D11@A/JIYBAP ^\#CW%"9CPVL(@W"-<9E!)Y_D^KC;,/)%'MD]\$$4= MFY6)$GG4O*:DG]?OH[]^ _U%L?V651SS,^SUZ2A9[C*VS,N_B%=4NJSH!<0A MAT]2&"VJGO\MG4]\4< MMS;;$78[PG"GMGSX98EY.4AE/34OY!_CLD1ON'P'F_+&Q*@N?B_ZS[._S6@B M,%."7IL3S!3J3*<'"PB1!T(7^R&?VB0H +B_$II2/_(U+TW, _PT]R9N:[5= M"[6]$6I;OV:G?7UB]AUD;G'=:*_X0/'\>PWBLPC>TIWJOUO0EB=FLF"MZ+MI MBG"_;T7J^C!B!,0L3D%( *2P3V>.4QI/6:![.'H54=8JWBT;IK^#BMZ#)76& M_6)&NCI'=JQ6"3?MQ=&704^3761"!F44KO6BGAO)=]ZXG MEGXWO>S9/%(X2LP.(?#:N>%$KGME0CCW3C3M+'#V[!0?0PI&G.^U=U$4;""1 MGU 7>DF21#"*$8SZG2P0Q6RTV9YQY#.9ZRG=#IHGDV/,\R9U_W2SO-;L6<_Q MS/>G$6=XD_:KZ>=WYOO7.+,[5;?9FMM9ZS[?P2,,*+8<7W5Y<[[E,Z?LZ_(/+O_]P_$Z+W/FAM>1'Q=P%FVZ23#Z8B8<45YLRSFFQ.S^TZ']T?JL-<(0% M3FW"V)>>],D^%6E&<.%,0L<8ECZ/!:.Q*RON>%^6',4;$!8L2 %S"4H]D#) M0CYIC[I&60@]C:>(![8HI0.#7Q5N03H[/O1_R%H]=JX;C...\]-\G1C*AHB> MQV@U94QAI3.JC3G>#EK_?5_MQ%2O^I+M=INF4@O:KG_=[JO]9R&&9:;_4Q' MKMI\1_!Z!/3,.8)ZYBSY4KM%ZQS@CBMY2DR>4$ ['IF'(%JRK1BC3ZO))8'Q=I!%-< R3Q(60A9X?^%RENU8)04QCCC*TR7$F*1W*.0RLP5849ON;XA[JCG<\$3@O;UB^76Y7.0^< M19776\%=Z0\ 8(*#$!*&0Y0F<9I&;H3\U.=1E"5^*KL+9Z(MB]MM'3RQP]8# M=#J$TQ41DJ#MU,:92=;G,>3,FO1\*\P\7_)131RH--/8KB4_3A""C.&((@)C M#[(4-BWY.$AQH'877J<%E1&G=5_]")3::EJ++SFMLDV4FC0=H9E,AEYAY&1L MU^=O'B(SR((7,7TH&[(2<3['H)HI @T#43)@"H[-(I M?[GEC;@:CY,? )V)G S53$E]ZN2DQ"IK:CK2$":CMU8DY#D3)_1#F[1YB(<^ M_,)0Y]&>>2R"P ^1&X51DC"?QBY)D[Z%&#-OL5-9/,M_KY)8J*^4Z\7UL5AH MSS7>9TAYCF&4'.VYQ603"KF)A#1)\] +>1O3QP4K9<=^9_Y]Y?Y:I>M\;*Z M0]OZ7_2?^YQ'T+K9! &,0>0F@0MC#%&<>F'7+(,L4EN #&[.^FKD@-!9<6SU MN5/](3N@''>@O,?9B=%CC.YY#"ESYA26NJ7J"5+)6]CEWS)459EHQO4 \!.0 M>C'&"7)QZ,==,PEQ4[7!IOSUU@?785N->[Q>!U7B*#WC,*\WF>STW=)!T5.R M3IX,:?(ZCU&D#__%V<\@'F1'R569W>?[>W&T6T^'/_<=IKK(=@L&0!2FOGB? MSX.(AH#ZI&L4A('BF!G8V CA*=]6^[*^@'#=7$0X'D)JD]JAS,K-D5&WJ MVP&K8WRS-C["=N9P=.-JT&FF3BB2(8KGH4^FC"FL=$.]')&K8I.O'M&*3RF: MHP1<5%PP:9Q$.(P]Z+J1YV*$(HJZ1F$40M5X/Z@QZ]K5YX4L#]#X1* 2&W?; M$V/-"K-RVC4BI6K:U7/9('..H#DUMFG2;%[G22++9B#!\U N4\:\D6-CA".% M6=?#,E\?S3H2K#SCTFW(NF+]NLV6Y5;< MLN^F"JMLK9KT.X1)Z1G6&!0JSZX$*.=XQMK!&GU:]08]IZ=40SF=ARB9,.3E M5,H,-TK'FNTBDV 4\^5E%"1LYWST,$=E"EAPR=RFC2Q,]2DZ[#9?836^5([ MY*)UR-43ATQ5JEV=UA.*:-%'\Q!.FP86H_5WW9.J3_GR.M_4XK+P"'01""(W M\4**0@B9WTL^#&)?][A*I8U)SJP>EH\S.K ZHDOJU$J'WGD,O8$VO'E^I<^( MT@KFJNDVU=),MRWQ[>UG>+K?YO^I2/-4BB1 +F,@T MCU'B B_ ^#"E@B%23MXT#??8 M_]T%]A @/O4H@RRD+.(?>VP@2D*UB#H.)NL1^%-1-6>TF_I#C]QI;SPZ_.]F MY;=,<<]D)(_)K6SFYRJUQ4Z/P;DI2J9T=CB=(4[_+>.J MO!'R3\C^N,Z=1QP8V>9BRN&D%BFZ0Z5^S]Q%<1(&*(J2"#.8,AB _BI0%+N* M.]K*7S_Z*9JF7JOS)B>]5@E34]&>J6D.RIXS<4+2M$F;ASKIPR\,=1[5-/W# M45LSW5V@*'0C-R H)EX#%!82!7$B?I^VWZ^K/V6;]ZW8MX00Y'D)#-RTO_60>+'B29K)INUO^PJTSN_Y[NZ. M0Q[Y/$:!J5,G,38(G\?0LV/:\],7>_PI;1L?[TZGOA_B((U#ZF.:I#$+TJAK M!JM__>? MSK;89DY>5?MLK?BN@1;=; MQWEHT" +7F;M#F1#NGA_<7]?;(^:B1,,PIB&D&&0XA2'HNYNEY3B,Z4J1,I? M;EF#+LMUOEV6C\\E"&^65>6@_W!.:A%PC\2HT:'ZV*38[ZH=_Y!O;\\P:Z?_P8]O MJZ.=UP6>>?G$*-?N$/,8XOKPG[\9,(P'V<']2[[E76KW>+[E@R6K=@N 8HPQ M<#T^C\$$(A*X0=\,BWR5P:W\Y98']T6Q_:E.^RHV_"_<.GF+2SRK^?>"_Y?S MC2\#]Z7B?J0ZAW(3!ZOTJ\\I$8??F&HGZE6)S[TH:8'G6]7F[V(55=%65=D M/>I07XNGW>D #D("_80A$L9Q",,@2;T.7!JY@4I%LY$@*F.X2IXYO1%.:\4\A=,,^R?D=F3WSD.DQS;Z1?WK"3A_+R#4[T$_ M+=*U?%&DZY?L_CHK%TD4\/ #*:(HP.(JFA?&S6.C: M'>[JU=4?J$2].GLDG];OJ?A5/4Y_GUKGMP;FV]6X[7&\+E;UE: ZKWEV7#]! M-S+GS\*=H$ $,0B\-H0ID/)*?+)!Z;3!QXI%A;T.:+;(Z?DNNZ\^Y=NL_K!@ MT&NT@#J7/?%YMFN35:E-4^_+HP>@H M95X@T;*L)Z-NJ><#I_":0.C74D:53FL)31U[&W3 / MP;1@U_-#,DO,C;NE?7B(+(S"R/,BS!!T.5H$<(+CD &?I"EUE0[61X9F>2K[ M19S&]SNKTVUUR[MJS"UO*UZ:=.M[PO<933K$^FZXLN?G$1FF,M[*[KBF#_02 M0:^6Y659OVJYKM-"KK*RUD:^#D@A!5Y"F MB&$(OBEC7>)@$KGYNJ':3TZ2+ MGATE3OV0;YTU]]:RK)R'K&Q^<5!FJ#[_<@%A NK5A/Y%_BC'R 7#:5 VV:0. MQ^G40*?,)WV+/.D4T\'LST-L31MU,A'5$&=ZXEBW5*$^37*1X@!@%*0,8^ S M-_4H0%VC;@*E3@\--365&!Z21FLUK/^T&B2!ZBSK2)]5@@=*7H/-.8";4N:> M$R4M;]H,SU'6](TY*6<#.1HB8\V%C 6D-&(TH"D( ]>EF MGV#4(DP /E3#) M9J:2KS:WW:ATR3*K+UL62#4C6=/?\CDF2%&J%%F=KTRI&B(A45K<:-P >G-^ MY_HI"DF4A)X?!"Z ?ACW\SLNC53S4I!V>Y8%JX$X; UDCVO)XY^1:58\^#' ML.W+3!I+3).DST/AC%KT]BTH0VQI:-Z+22!D ?9C\2I"#%V6)CZ+^DD@H9[2 MLG)(.Y8U[O6[D&:6E(/H598WJ\P.D;6)5Y(G*)*3,&UB9R==^I:\+5D#V=&6 MJG8RF,0!88 UR,TC$@(7?]P'A%[JJDYFJU83\1Y2Z:&+AVU:=64)PM\#I>F M:0I#O,&-BB8ILCE3/5*UXCTMTF)%6XMZQDGHTLAG84!@ MBEP48]I4Y8!<6F.H>+O$)A++NO?:P[#UZP$]?JWV@SE MVR=6G2>GF//QFYJD6G>9]:K$RFR?D.9QO#@/[1[)UA-ED6TS+'_RVCP7T9=^ M;=+)ZZF0MCO96(P[2( $L(#YC"8T"BH*@!X*0IW8B:[QYZR>U[3,O_[:\ M?_C/_K$7U5-9\ZS+GM9.2KCJ*6X#]NSPE$YW%:9Y8>?\2+\;:?XD[A"JWJ@V M=I2^1CN70>D6!$>PU- MR'69EGZ?.B^SU:Z#1.LGF1:( IP$& 1BUX<$80Q]V#5%_315D7ZM!BRK>8/) MN2W%LY@/[[T89I W.:&U3IF:=K9L];+9 !KYS>Y7*#FA:X,8G(=4#3/A^8/= MP_F0/IG*UH='W=J6 M\+*,.$ACZ$- I#"KLI+@4^9$H'4AK?;S^CNAD9*X%- M7+4MZJ=&5IVH*YX\Z3 H>>!DF3S%*T;RMT4Z4%JEX+8^G*LD'G"'\.TQ9- M)N74Q3Z):OK2XIE685XEY83&#"-Q'BHST(;"9+=2OAU6-W*5\2ZUW2UOL[;U MK\5%MEOP[X8H0J)4-69@4[:UIT?E%#?.\K[8;W>]#O$9 MSC9[NV:V%69ESQQ&(U7U?*$!=N8<,8L.?%Z-(/B=PN\ZV5;9F^7:Y7>7+S?GVIBCOZSK"ES=7RY)#:3::'B^WF\?7 M:G>YKAN%'O72!$413 .&8=#4[D(4(1"KI0[:QV-9!?'E!:$77RAQV/D%NL#G MZ)-S?L$N/_^"OIY?7CB7S/E,?S[_\O4SNOBJFE\X@KU^$4^Y=AL#ZLPVQX_QUX0 M 3]B:>JS@#'>'';K)@/H\]"DE%4YJ"';4C[LC0PP C% :9#P=3\(4]_S".[:IU3Q/51CK=J6 M+N6:U]]!_659SN<\$@?9I5U_68VY]\9H]L?J;O'_\G\6(0;(2WP,/9 P/\9I MB"(<> &"+'*Q> WP_;$G_VV6Q]3E5^P4#V)J)CD!4.#A=)2W0X%:*+^X='Y! MG_\7_>K\0/_T\Y^<7R\^\44L)3\."N55MOK3;?'M?PH+6UGAGY[+26__*S*A MSLVTPU\#;Z';"Q0WLO>[R[I[=^\#A9&/_#!EU/-1Y&-&6=\*B)!:>4;%[[:] M5;W?=4/9^<%7+5JFRI/D/K1%BA0WGCD[#92IG27:) M;Y$AU64])V=2A7A.QLGU@R9O\] (??@O5@.#>)!^=&5UEZWWF^SR!B_W559= MWIQO5V6VK#*2-?\^W_9775A1_KI]6.9KO%GF]Y58K#0?UG_?5SN1S$S_>! [ MI(>EBD<2+PVQQRC&H0L1 &Z,0YH"'*;(CY0V'Z?&:EG#.O/$>49CH/C4F>C\ MT!GYHY-OC^ZPB3L.C:5.8V&S@]=\/%CKM.:V]XP=F1.1>?88.?V=&J8].9]? M/['S>(Q=!YX(07/I.O.(:+-AX_E[,W/!I11O/^5;@;C,UOF.+5:Z2NMW_58LQS@!K-:M&IK38=.K5S* 2[D8,@Z- M:NJORZ 5C7Z3H!/J.IS4>>BB 3L*T]U-<8?@24OHC[Q:<''S4HIAY$4HQCY@ M0>!V#=$X5MLC4/]ZV[L$S\>, *4H.CJD2>X8V.5+<<] C2H[NP8O"#FU;Z#/ MWCST9(@!S_<.AG*AIR"DN%_FVP5-L4_"&'!A(DF<)J&+HJZID"9J=P%U&AA; M11I8@W1$ECH=);' VD M>8^P$=2D@2"M)XH^444 MJ[Q^_)3M^##M9D;M=BB!,$UPXKHX#"'&:2JN"76"IEB\QDB#EE7GD/K<@G0: ME(>U@)K^F"%93H]&YU=-G]ZG=J)C$QG>3DB84=KG(6EF32HL=M/AVT+UO"U" M?@)P#'T:LC!$6-R$[)KS$4Z&[@I)-6)[4RC;\F[C7"SO,ZTEF3YY^MM QGE3 MW 62IVRTC9]W%FB#69R' @TW0V+71X.7(4K3]*9V3D>\- JHET+@4AS[$.(P M[IKU2""5!&JLL6FVH\^<=GSI+>V&4ZRO2];8-;)++4_L:*IU3)BB>FEQ/5\5 MTS-'0LT&\/2>JMUNRFR1+K?_N+Q!]UF9KY87J*NZ"L,PI6I]Q=TQBA; M%ZN].&"N;XE.3=T3,)8ZVS/I%I8)08; :^7X;5M?$6 #Q$PKN28,*(QU$A59 MW8OE[TV>;=:B3;Q\O%]N/^7W^2Y;MZTR/_#= *,4,Q>ZHD@I0/T4-:52JU-3 M;=D6W -"IQX//S0@?W1:F"I*8H!9&24>EU1%67Z/3RV)-D"LBEZ/2["F>&MW M7$DA?Y>$-U7=''USD'B#UA1V.IF"^.-\EU_SYNA>O'=PM5FU3478"P $+F> MFQ <(=?M3WQ0D!!IQ==MP/;A;@O+:7 Y#YN5@OYHLR:AYF,0IGBN^Y(K'='6 M)DU!J<<@3T^>53JM;*CR4FAE([V 3"H-=14%D_^OA%V[OF3C*E>@2FS/",S[_4;9$Y_-)D:(AJ_;+\([_?WZ=%61:_Y]M;O'S@?[)[ M7, H!*Z?$M_W4A8#$/I>#R'TB-29F)6&;2=/MOB&ZY8^M?HR-@JKAL[W6ZQ. M#];IT$XO*.6A;'!XCS48)PR^^<^+\4S M-$7I[ Z(%=:41@F76*1/Q;4AN3R"ZK2^:,!.1;G"PGXJZO66^L=,;Y_T>M'9 M/UUBYZ:QX=2+2W*K?P5BWMH/L,'M#'8(K)A56.Z3BO/Q^M) U06]R_VN$K<) M>)Q#]1,[BR@BH>O%J1?B%'G8]^.XN\O-$/#5-A*&-F8YO*#;VS*[7>ZR[GTA MKH&;!K/XN&KD,*^JO6S^A#F:)>?C8S*L&%0.1+9QY0C=F=/@&WG6_0Y;IV;: MIHB>R>S:F#G/9]1F>9*N-KO)UK=/7KZH=F4=ABLNJE^RAV7)A_GF\7/V4)2[ M;/TE6^W+.IBRHGQZD8KU<781QAR2QSS7=]T QG[H,=!AC1"@BV]9>5U(5ZV= M!*/* #\V1W[F4NR6&T=,S7>/3M5C/N/3=6Y?OA*Y4JME=7=6%_1:=6\XU!^R MHS<<;I9YZ?#_V(M#YIHI9UEU7_CH+&^7.2?,V=UE+S5ZY(*R-AQY0GNF[3CS M$*R).7A>(G<&'E$OH?EE5ZS^D3[BS;*JFL(]R,4HC=PHH23R0@^'?+& XY % M*(6>1Y4N4PUIQ_(\[[@D80W.N7YT:GAZE;T&42HWL1N+3;4YW0 B+1=A?,'2 M"3TUP>T\5-&()6\6+AS*CK1"[9:[/:?Q$:U68H[()XM7Y7(EUL)5^OA?7#FK M-9]'\ 5R??$4,NAB@"D,4QJ0.$H9[D$DV%>KV6NV:=M)24=XM*ZBFV9:4LNF M(UE-WE3XM:-G2DR=DC@[E,]$]2P9]UP(;7)H0AN/(7375R.<4 A8 EA,PSAT M&9?L%H0/J%*55L--VY[C=6B= URGQWOF/!W;6A?G3?MBN'I:=H/BY-"H!T;7 MUY=<:NKK *?,7U^'&*>@KX,Y?$]?ZQ;+Q\7_^MLB39/$\U(4QTF="?#TJ'K#.ME5] M7GK%W=[F7(=N[(DGJOTDQ)#X#,>H;S&.J=3%/Q/M6)_EB$V78VR. *EIVC_S<).G5^/YS5 M>8P@$X8\/TDWQ2*A?.Q^13+; ?J*RAG3D-N..4Q^F%Z@B,HEKID#Q?R=*R1D*W M]%F2JWE4W-\7V[J]OQ1BM_1S?GNWJR[V8G53W/"?9=5#5M98%FX41&&$P\ E M<>+';H0#TK4?@% JC=M\JY8%K0$EYM?9=I?O-GPX?A/XQ%6*1N-4ZOX8I?NT MP$W+M.(:IH;9Z5R#U&F@.@<'_*7G_8^]S8J;.@&\ 715_"[JGQ!?9/A#QA .7,S_ M1X*V:99XJ=2!FM$&;<^C>VQBQ.WJ?/AOS7A\$/C$3Y>;3;M@K;/?CV;:HEOF MVV7YV,["]:1RF$/4HM-HOA@2F)XZI;FDT(ID#70*FO6"T6ATFXA#VK0K!Z!3 MM$C$'B.LSBOLF#'IC8ACD"_58/,YN\VK75EWRR;D7?Z^Y3)]ES\<4"VB*!3O M^P5^Z+($01S%7H^!LE1KQ6.F96T#L1P5#[4='CJ01U4>#O>4%93:NFLD(N>< MO*(62)^$SA[ZF=. =P[^ZN&W-2+J?(E9^DLAT,[);WIQ5W9 ."+7[QLGE<1]@17GO?/G)'Q@^!S+[5C0=RV$S"*ZCF5I,," 44XS%%ERZ MY"!^+HIUA;;KBV*;W3]LBLG@HBV_9FO=H MD;NPY)0O&(8A\F*7B/_'/#](8K_'%T&UJ_6CH;*=OMROV:91!SX7K_=#G0?^777U\^)!_$'EW')#15$1\1N-[8XP-%_+[RX9 M2N UY993Z;ZCNWX>Y_83V/T\E7@BYM6EZCC?&94NEH_B1^CW M9;ENSHLN;UK _5A)&O*5ECH9M$NL3<9L4-7&X? M_[URJCJKE\6G:X'TZ660(W-$89/C MWVM-* M,?T"6H28FQIB/TE6O%UCW@%R\6):[H<<\;1P.V'O ->^:" [Y^_YPLZ='55* M3TBY/??,0ZHMVO?\'I!E)I4N1W_.NM7R55GP=?+]6WK_M4BSPR]S^?=)F##7 M0SX$*" ^]$+684()8\K7IZTA&7V:ORL.6Q"'#O,]>UZ3')>/QMG M*<[AZZ76 8O3(C\Y-1>^O,Z._M;8D_4A9)^:F(_BQ'DH^TBVOG:O?"2&ARD^ M_>,A;W;5R7*7+6(/1M!G 68)H\0-8QAT%U*9!R@8+NR*#=K6[S=TP3G = 1. M$U*M2O401;;(LAGAE29X1&5]2IJR@&IR/F>=U#5)2@X'\35,]3YGHD98OKV5 MEF3,Y]IQ2*,D],(@#"",>G ^A%)W%$:&9%DY#_.FZODV1#/MM3;E->^\(4H[ MJ=],38)[(S[>=%B5?V59M^;@.0N_/:.E0H-ESJ4R*\^WJS+C7TZRYM_Y]CC? ML]AL6%&*/?(%2R,>MA"+L!>XF 0L(*B?KA.YV&"V1_?_D?L ?"??,9YFV_KJ2F?DSYFRY&3]DX1)G=@ MIL_S/":(9DQY^QAL*#]*.P%-K3"R+\5=U*:+ULTWGY]KP2)R:1 F<9)2EZ$8 M8>S[?=9PD@*U%#<+[=N>Z FT]5VYIS4'SIQM5J?QWQ3E39:+XTK)BQ96G:&P MC)_0#SIK]@:NT^!MW]3NBH:=M?_MO#)9F6"!KL;L>ZMQ2WZ:A[):M?"U=;95 M-C5W9%^!L\ ^\;'K!012WAR-V*$:&@M]0A?;^K['^JOVIJM.JU*#/&D&^0N MT@/^:'ONI? .VC[58EIK:]0:NT:V/=_0T4DW,U]A3'ZC<@C=,U)"0P:=WF < MSI7\RF[[C0__O-BV99^/J]6"!8A@Z,9I2GT/0AH"WP5]!BU$H:N6N3JH*=J=$ZUJL.V-K.;/D):\#2583MI&Y%9-U@[ ^@KQ?1W9\PEJ79\FZN1: MV0C#\U R4\:\6"\;Y&B@@N%N (,% C&. S<.8N@F("(D=''7;L0B3V.B-KS1 M<>9I(ZN:"NF#A,TTT<:UK0?LG_N\S-8+AGC3B"&,:>RFD"(4 M]&=O 7"1J7>*#4"QO)CZ)=_F]_O[>@/^]Z+ #9.,>2 M*7+5OA13A<_9[;XIQ%.U +IF;XJR@[3F/UJN'AO>J@-\:)HJ-D<_$TJ'L[,<^F'V:1I6?5P&*T/CW&PJ9= M82]0&M,H#0+7\]V8QV:2!/T)NPNI4OD2NT@L1\7#9'EU-%FN&HQC+&ND/6)S M56/#&2,N:LZQZT"<)]2/@=@\7LCCQC$FO,4"6I?CP"$+9 M(G:R%C+_2;4K\Y7(4A"]T'EHJY3R7UYW^,T)N#D7#A?T2;QG5N [$YS.!H<; MX: GQ1_)NUX<7?)EF=<, <8=._^08-YDA1!AB6_I/(UE==>W<;7,UU^+JV7) M-0PW5;731UQLJV*3KT5:UY?]=96O\V4I7H!@KNLBA&,_0@!S=/CHT4$OE'OB M? 08MI-Q.?*#3#@"N\A8:] [+7Q1S?K8 .?8 L5T-HL.DPL+,_&56C"PZ"8[ MF3K:))_*X['ON7FH_1B&/L\!&HM;H_LNS>3VM8#35BVO%JX70A1BY'MQG'H^ M3<,D/EQ:B\QOJ1O --J2X)7-]6?EP]?BE:7\>E\7YEM6-M8%1KUI<*]G9$?: MVOYIO?WZPJ![F&)&"P0%_H=N$QGT\#P"Q^A6ZVPF&6==(ZF;Q[;+LGXW;OV7 MY6:?765EG?JZB @&(<$! 0S@* 0DC6A_*NSA!ZCV*A%;^=Z&V)+=O3Q<9[EMUM(*/,0C[^,+*-[/NM3JRQN6;Y?;5;[< M] ]D5^A:/)J]VBV FP" 24A@U$*8C>@F$.$01![ 0TCR;$T#AA[@^\8_YGS MQ()Z4^S8!K%AUEOA',QP?NL,&7G,&B'_Q" ?U[GS4(61;2ZF'$XCZ@[)J]6F MJ/9E]C7[8Y=RQO^Q0%$<>,2-D1=#"&./,C_J8#(,E=9ZHX.S/)&Z_/PSNCC_ M/^CK^>6%@RZ(DZ(OYU^<2^9VZB/%EE><8BO,#/'_=Q!Q!IEO,O@,]X/*P7#=9EL1YJ[8< ]5])_[?/?8 MQT "PQC F"11%/H)!#Y.(AK&- H!("Z5318QTYC=8\"LR]D\1OCO3H-QLLFI M%'/O'."98WX>0]VP3:\*N M7@LCJY'S6X-+48XTV9.3(?O$#9.?]SFSHC^OTG)"=X;1. ^]&6A#8;)C:2<6 M=5O_09"R-$RXD$$C:88F+M-.()+_?>M+0Y9.'"+I$TLGRAMX]L-*G M+#3KEHO%X3*I%Y2,2KUH2NWHCTQR7 MGR3JA R9(7@>DF3(EL)&%U23JN>7&-O&TH3&8<"\*"(A=EV" ]@O1ECH*67K M:#9A69P^/[\2KJ9)NKS)B=$(E*FIT,L;U].(S^O$G%"=@4S.0VZ&&E$8[5UJ M M-],) 5U%3 MB0MN3K'=<=/X+]V>;_D8S*JNR4+' KIR:CT:JF+D]A.1VNB>3F%$DG MY,<(M_.0(S.F%!;ZGII0!8[IMRZ+VRE/,0L]>3]@0N)T6N.)1C7&7R G?E-Y0TT(+CK"B MDHJ,GA!.6[Z9AY9:LZX8IX=K/)7]I$V.:[,7[S1=%66=JG>TW/I:O!X4%BF, MJ9?X*79C" 1Q<_]#AQ+0]:^7_9EMRQW=NS.0%6)-QV[[H63P[#J[/Z-3;^ MYS=%>9/E8K&J7"[)O$ODIG(3>T-M-E>#;1^W=AJX3H/WS*D1MX_$_G0M0#O' MJ,_JLMCB"H:$C^P)O1+3[XFZ';?-2, M&?B:6-OD4DF8/V()Y180W6'\:T@LO8Y'J"I M1^!>%=8)I/(47^\IHQ&N9R2$9NQY3?<,,B6?*/;W?;6K;Y%]+=Y(_[CRN,EW M3<7^H^-4U70R8Z3+:=XT?*MIWQ%&<5;]+.O,.62=G3DUU+%SSB09/)E_9MH+ M\U!%"W:]R$NSPYQT/:E\6Y3UQD&S&=#M1#+.!3DJTEN]M7OPYV;[84$\SX? M=U,7AH!BWTV\?FLR<#'1F#..AFV6;1]#U#[MBR/RGA?/#[_GN;ETN?^<: M(7KECT_/J.N= ,7*5Z/Y64ZWY^5;DP?@9TYG2Q-+GU@C]/^M@_,_OY.^9*= MER$_G @.H[MZ'K%C?+.?%P^;AO=A:4GGV_Y1L$]%5?V7D+V_-*IWM2QW6XZ' M_\4R6V?9O=C47D0^@R%+4>IC%!(8N&Z<=N \/XB&)S 9AV0_*T \RO?#AH/] M\46FY'9P(M2(^3NJU"MG^ECS[3PT:&RCI;*'+',NK3_'(!9AROR4)=@+B!^% M 2%QV&L<13!0NUFI]MTJ>J!UJ_+P;FJK"B./[6,V3@U1+=9F,M+TL#\?, ,8 M,+DO5I]'7#\_CZA?O:_R7?8E*[_EJZS9P_NQ1&*"83(=0,? M$9XD;$;6A-#E.$>&SF_S<(C'!NXYCM)9YA& YD.'Q@[GB'X:.2F21"AD)$AC MX*:841BG?640C[H$MTF1=+L>-27R/5CJ*9&=!=**R/_"_\V&-.2F>4C0V$;; MR894XUR^EL]V+29S:_$B)ML4O_<%R[[6:UP6IW% 8\A"X@;4\S$C/@Z\ 6, ML3!(E)X-'MB6Y?VI'IY3/S\K ![J%#N_U1@5+Z@,9E=N?CHFL6K3RV&<6BJC M=)*L$^)IBN9YJ*(Q:UX47#+)TG =J_A[*/9%Y2< M @KX!*V& %T^5T/,C*AI-#REPE5G3@?8^4U =FK,QA1/QP]#Y<^R"PQJH3+[ M(VOC2R:UA'* 0^:NFD-,DY;0P?PIG$*(QJ_*0KQ5NTX??^5PSK>7?%&U%._< MHM4N_U8_*]>7VD:^AQ(/1W$ (B[EF+D0=T 0 M#% G]O0)E2TOS4-V;1KX\JS++I=:!V)B=W&[RC?9DZ.XKX4J5.IQL"ER8^!' M81(C/Z9>'RVB2*G(WR0 +*+#2?)GGJ-W2?F$:.FI>#4Z=8T_E HK-0B M$AF@S0[Y+]GNKN!HOF6M$0OBT23&OH\"YH=^$">!W[>-DY!U>?QRH9_#$Y)AU@?ST ## M-KTLRV.<,>ESY]>O@B<(LA RYI, I7'H^@'L=Q]0"I7J-&HV87E&:#\-2I=: MN=G:"*RJS;?>RB,:^:A=N>;$,![GH4]#C7A^M&V"$_T"C/U-J"T?(K))L\:LG MB)8X-::#/;<'A--JWPO"%"1/G^QY*MT >]X1N*%,Z<_V>,M?BZ-V?1?Y*$Y< M$GNQ&WD (02[=ED8><,F>:JM69[;B=$FWA,QIF,:?.I.[&Q2:60^UY([%R%[ MP9C2W$V7[7D*V0![WIVI#6/*?";-(J1A&(<^(G'JL0#QCS#N !"JMIEFL-DQ MEJWB5.UP?GI\JCIF]LS['C"=-6.4?.O9,G--D3&2&B/MBGDHI0W#M%-A%+D; MJ)W-:H%^'/*E%;@VGS/0P!-&O3N&GP@5_(O$C]VE1Y6_]SG99;N MJWR;5167UNWZ4 'L:#< H@1$P _]-,480I"FH-_69 0@M7>+C3=O>2*)N]JO M=8I9^;#95\_W'S54T(8;Y%1Q8@^HJ60'MMZ4;. Z![S. !CO-@5N^7& M]+K]W6:59+9':&KO,Q]Q.?^^!TPOXXV2;WWY/M-LQ#5P?$QS&U(\Z("ECV,#>YY#F+4]9>VBFQ7(0 MY8-$T_G&?)I?ZH%"NN[)\PVSP^V,)S>GPCK^+?H^O4HMT8 MU?/0/X/V/%^2&V9*1]VZ;0%6E/737:]H[8)00D&8)A@# @(_9*D'< ")2Z(X M0*[2%-)TVY:5S\[+@\8=H"Z"8W,_1!)_Z/<^;XKRQ^;=P5=GE-.)I 2=DI)I MTC'S$U"CUIV04_,LJIXJ\98/#\E>WN#B_K[8UBJ_@+Q=GQ#B)G[ /)AZ.":\ M8>9'!!"6Z%R^,="JQMGY/-ZL-L&XVH&1;9:''1!QD72>T5P#;*:6TQP'O,<85^:W)!@>BE!P'0X,'.?H-#OM M<<[-B#N4[WO ],ZD4?*M[TC.=1O2R/:CM"OFH94V#-/>;E3D3KI .6\=;>N* MOJ)PSS>^P.02WCP=\SPM:@$PXLKMXLAE.$T#ZM((=1"B(&$JZFFTX1'T,^]3 M!-?'*8*UK(K,E_I#=K!$L3ZY43?(2>AD'E 34=PQ7'\X0GK6/>?U2O;FR/7) M%9@\(:16'#(/*;5CVO/ZY/;X&R:GB(M\63YR/6^>X'(9 #Y- A_2./;CP&>X MO]&)$(G;5ZZ^[);E;HB:JK:K,HB?0U0?S\\5TUGNG.OL-M^*BH)BS;B[RYRF MF3D,YV=D*H]C76?,>0!KVR0UC[T8JX9%+#$3]TT13#LY2+V0M6' MZ M$I'L>K> &"1IZOL12V(0XA11%$0L2"-"4\#722HG@WHM6#[_$QCX2J/:E?O[ MDPL+*T/L54I.#*EA%,YC" VTH3#9J50O3';U=L^W5W>/5;Y:;NK]UW7=,EOF M93U"25ZM-D6U+[,%"T,^-OT I D.(Q\R'Y .B$7 =H5.].&F> M:;EE^\0DJRW>#V#%9DD'USG">^8(Q$X-V3E@'ONFI2JG)R30HH/FH8\V#7QQ M,],RE^\IZ^V&?^55R6$?SR+I8U3/=IFCWS#WS!.S$'GH6&@5#(N!!X+7A3I^S5\+= M" Z8-MR-86 Q6F=6?.2MJK+=Z^WY$8$H1#CD[488NXRWTK9'?0Q5S@#U6[%\ MX/=5_)7VFFL]>5W62!7?2M/G4&XE, Y]:K&GP32+2?V;])R8NP^G=!Y3= -V M/'^YRQ SL@K4ID L-^>'K:\OQ69]4>S^ENVNVO2R-2[*AZ+DLEEKIJ.A/4 MQ,V>>^2T;UJ_:$EC#]DYPNP(T&>BTE3MC1[XF=-#=SKLX\JG+L,GU-6ZT^8A MOO;-+$8>#%:DN[X5\:7XEI59?KO]67S8BM^M]\<3F#""TL0-?#>-< )\YO?3 M6N@I5=$? \_(AT"CBO@P1QG5\]%\9%7:F^MCO1G.P0Y'&#)+G3_%_'#)-^+7 M#Z7^9BS6"P0&V9:-"22K=S?R;]FG?'F=;YKX0Q,_@03Z"":^SV+D,O%4?=.6 MSR)/;:ZNUX;UB?A!'%:B>N%RQ:7A8?DHZDJ..])?Y>?$V!W&YSQ&XT ;"I,] M3&W$'+7PVJK;I2B!+&9$[/:YH1_Y+NP:C1!*^QN<\MMQ UO4&$A?#6S-;0ZH MU68_0PF6F]B,0>K .8LXA;@HMC?]#XXPSV(G[S2')Q3,$/GSD#)3QA16.JCB ML]VKNVR]W]370[=K\5[UNN^/7W9<&II"H2)&+CSHDR@@6*Q3 9^ >+Z+ /9A M$ 0T3(-8Z2UO@^U:3TUJ 3J'D7J Z/Q6@WR[;)E]VN7T;RK&U<1P(-EVG@*7 M9^Z$!-K@?QYZ:,6RYR^)6V-/^GK"B7;QLJG6]"G?9N?\9]4B)AX)0C>B$:1^ M0&*&#AC\D"IMFYEM>5*U/',ZP,YO K)38U843\.>D)//Z9Q@4D!5^;=S6T2% MRA.*:LX4J2(S;:N_?@#PDBDID\*5R>J.:I=* MEA(+:P-K;VQL ,7U?5'LF*3?%#]W\99>7()CUX9V%D"RMD]19B41M <,]#5A MQ1A4H67#NCJ [>[P&>9XCQE\7ZWKAV)4\1

M ,-#R%943[7&+R*@'>1#A*2LH8H&D);1^;B75=*75"]13"=9%--3/099K*1J MZM[;JJJ31P5AI2>MLVW]XQR0-(AQX&+'CN(PL +7\3QW *QJYH<56W^(N+* MKBR@J#7JJ[(=I!5V3A/(:NP)QI'7E MO_.FR:M=WP:,'">V<)K$3D"_QI;E#6WXH5B$)O;)AE6D!],]_-J4W^[)EW4% MCH]Z"]?D"%+')RWF6!-3E!['A73D&0L3\B''UC)40Q)[K6.\R"[U#C6%1T6[ M1RO-").HQ\M\& =^F(9Q%H\2!5T8K+X7S6TMOL13;%9DEAPCE%K:'; >U]=? M:CDQS1S7(D(3^JCWU6YEPS"+LP2G MGI]:R$49BM*A32>V Q'WKM:2Z47#B3+VIE@7!#%9J[%S+@PMR!E<.F_W9'G7 M;.F]@%P7V)E@GR]"F(]XL8CA2/@8L".6.VR7.D!P@J8)X=-#[S+43E-?SAXL M4&=(_DC.TXMV$S>UB(+&)-[Q70NC-$GCL5T78CEMDVWM OK6'].90=RD32 J M<'.P+RUR([C%"-T9NKC$3I7JI0F>/$VEQI1D0->N<(9C"]I.ZD,,&Z/,A@HQW-L??N&PC1WO^\W:7VEBY^[U M)UTT_. [NBAHA:7-.5'XTW&%* ^*IWO3!,>AYUC0LM+8<5/?[U\LRJ"?A8G$ M(Y-R#7%-,>5W)2<#B#_E-%,Z)LQIDZ5-.*D^\!T3%F*$ZV):M%Y3/TEBT,_U MMER35KJC**2%, IPZ >NG?AQ$-@)3D(_@XGOIBGB.@:BU(!AIW: !09<8@?B MU-B;CKEG(TXLS+XP9P*WNL[!G=R]K3(<\MW*>J;/)V17"T4+N%E5N0NUQB$C M%NZP^U..I+W?*4I M^'(<,U FIKBOV+K0SN]I8B8B.D4FEQ'2J7:BUCJZE(*Z#^-9N Q:. YB*_%A MZOB9"Q'.QN:LB&NW2;F12P1W'T1/[:I3*17EF6%10Z1W 0*50CXS1,J%?>./"STU9-]U[LU^*]39OV_*N7+.Q MAC9_WW<75JU@%'O(BJ#K>G%B^WY"F!K:CM-(*$S4TZ)A06<@A\>:7\($!YQB MP:0FLOEBR_EY%I-\98J-!)Y5 MMEH_?:C;=H6=S(\S!),@@)9G^3!PQ^6WY_A[-OOK--M)_(!1=,4&Y"O_]B7+?,-Z[HEOT]_X\=]N;YGG]22QLB/ MW^UW^X9\;MY4Y'<>.Q1=N7].XJIU^4AWRH[OXBR[L]9E"[9%2U'EU0AM37^V M_TBB3&7_21WJHOUW\/X.Y%W'R.\_-O4M.S]8=Y^PK\@/EA3[8]TPX 3@XQ![ MEQ7MP;JX(I_P>(:MDNU[U]^J\I_%YM^5']$Z,53.!>AJXVH!H;EB!VIM=N*W;E9MBU+?(_VR$?'Z$P"ZVA+>2B5, G2;9@W"U1 M7&1B#\ 58GFN^!KB[+T<3FG&9@3]4^,M"-,X/,;=W3K)$W(2\U GO3V6+// MMTR:.S[;^[RA'FE]Q&M?$P%V-5@7F[Y^DGB%!MS2R^D!AVVL4'*S?P?93A.'6@;4,KCOT$C1F;#'$= MHU1J8';5[B.C*UHMI"!"W 1*"+<)[J1T^S5M[9< M((N#Q[S<4,6FL?@+U9K&L,?1>A=\+^FBP'F%/HE1+^DH,L3 M0-8.Y0-;2)Q8%72+C<&;W!&74#=7_4J%!/3[EKB;[5/O./:/I%&RXLB_-<7P MGV19\+#?YNKQ_DGS\;H046LOT(,(=V'*@4_/M:[HOTR%CB_KX@6DR'V MA8RP5>:$%G%4D1=0 MO1BNBCH]P<8YK=9!X +T6DLW:LT#2T"W?\MW](':IQNRXJOO:..'ME<>#GS' M3Z"3>,A/_-1%T![7&5[(M66JWHIAY1ZPL44O.R5 X/%,#=UDX1)O4$3]N%WVLJ[S+&-)[__;M*LPB MZ&(GABYTLQ!'F1V-VP!.$+@2C_YJ1F"Z]'$\7?YJ;CUN\W67'*WJZEV/&K0, MMM2KO[IM,^TUEF,6,8\RXCWR(E=@@ P.F.F)]0$UN)XVB\EW?,68G2B^,6NI M913C&.[CZ==YC3(J=(2%G0E^__"8EPUM.KG/FV]%NXIM"_I)'*>!&Z<63@+H MQF-6)O*%;BQ4:<>PV!X @35#1.1VF[.BWET-F!%8=4._;*69R,>FK&C9PW8H M2V ANCYI5K(*GP#/91 QF>V.RC!8X,@N/; +')UF>$HIF5C[O70$/:QXX0HQ'&4!E;HQ] ?2[C]% O)E\3'FUX'OPB^Q*1) MABX^-3+,E)@ '7:F+B0VK]F8T!<%ZI8A*2H=J+4-(S'A0-MM_8,^#I?5#9,J M5&T^U'EU)%EDOE+5SF_KK?;8KTK:=Z-)>+$]$NOU+,LBS06P@PY-GW^ MW;:S<0[P;^T&(6I$() M>95V9I*9K>S]4DH4.)Y-GAJL6C M&:ZZ>MGH*G(S+T"6A8G(!0F.^A#-L91O%A%>N[";?>2G[^'-N2 MVM16ED,.M9V!/HFM1T6UE>5+0&UGX$U.;0?^V E&EHL\W-A_&(4T/YFWX_ < M?T3U+.%I6LYILB*)"]!DU1[4^H:4X.Y)MPL9U]6>!(9)EUM$U>8XT>A!%Z>^ MY7@!3M+ 0TZ4C+4K,!!Z(4M#>WLNU8R^/L*915>WS+7TK-=]N MJ9_LK@9Y& W]L*QY,[+O(P[LM36HFGE8K#80WT]+O#879:Y MJ^F%-."/HXYT^B802^GCG2,:O0CE8AIW#+$3.M ;X AE?UOI16@6"&(O0K=< M6*N%=KX8EI>5LL+&*KL# M_>A![@0&?DB:12A(7 1#' 9VXGH0.IB,)ZX,AED$AOW.\2OV(VQP>"GN"+A8 M-&W('GP!]N5-(>:/!*S07^,/*&S <,_\6(L4MQ-1NUE;+2.0-]S'>L[1+UH9 M3B_A22>Q0PL1Q^UY*$-QYCC$C;,FB1O(;$^L1ERA(<,B M>X/^!]V\__11M$I)._+9[]MV7VSPGM[\V@6EU_AFLF>",6PU9*UWKGYMR79#&V?=6@14'F>M :,,T2'QD9L_8\Y6O@V&"'(BPXV$TBS13%:2;TWMU%@]== M:WW4[_% MN-*?%QPH"W%3BZ#B;#+UXO:1=)8QA?PY?Z);<.A'WG2P/CU2].W?\NV^>WV1 M^/*'[GLO0*+(=H,H#(+ A[X7!987Q3W(. PRJ. >34.[D$/L>P18EZYZN>M[ M=07&?H&CCBEY0.,6EO)Y2S*N'B\G8=>EN35%H_ [LKFLOTC7-5OGIYW5O#90 M<4_''O48Y#F_:5F>XZ8I]+PP\LBZTH_= 9AGJ;LDS7 6L2Y[H59:EEY&;"?O M;"YH-A/+J#,66Z1+$:->T(T8LNMR78>I#G.X"Z-<\[J(-&^JLOK6#EE%@JQ< MKP*(;1=:D6^GB1UG.$L@#)!KQPGV+2_F>AA7K07#0LY S#N73_(P,3W5>%O& MC%/L0ZUS)*G-"UQN][MBLPJM( Z]U(O") IM+W#[%&W-$CA7>6?+?1?GMGGP\^EXT^;?BX_[AMF@^W?6- M=EM7G_:[=I=7])W0E1UD48"0[>$(V0X.L&T% PKDAL&*?,YMS3M_=+,YW![/H_8(K%(9)AN. N&HK=C(; MQPCW;<0X]83.:(I]LN&U#@%#IB0[9_C+ECZ2-?L\/' Q/<4D.%O,[)'!_GIB M2#/ =2M1#3B"O@C3"%R-M @3R5V5=$/?[NT\%,'>$A^U*;JO?J73 M["XO&_ ]W^Y9"]C/>>4$?#+7TXAZ)ZU/(\C MBE,_Q)$7IC$*K=AUW,P9JNVMT_733Y%5+LR!U-3Q:&Q?$.]'[0%9>Z-I!!$-L MH1A'";+\,!@0Q,@9(^L;_L6GSN8E)O&-^ JU1PR*GWU\_0N;SK^>CJ?G7;X* ML#FQN#5ADV4L?8WTK#8_H@53180,ZC[J+?FA;\.KL>^K9TOV_ZS+:O["HR$\@O-L6F*![8V[*NA6$G0+[;->7M?L=*OWBK=T?='%^BI@'[WVGGP/>N=S.GM;20/Y4/F]>Z MRU"3N3O],@-W"RO$9XF M9T(#U0E=AJQIZ,?K=PBU,"-PO2E+RN$^.?>^^MP4#^7^X>C9YY65(!N%;AS: MR E]RW'1H6D2AT5\*0FM31K/0GPI#F\7W>9;^N\6-"- X9M0-;#,)U;ST2M[ M,VJ?#\;'^> !X]&C]+/?D/HF;1.*II7U98B;WBZ]OCE5-U_RDGIG$ U+SB2VL++L239K7/K84YG#=@K(-W_?=QF:(3IC M.CC 515"6>YEQ= DZ3H%\=C_?.&@>R91/$V?D# J6F"IXJC:K3<%4@MO\B*) MB[NB(8OAKEH:K?_8EVU)(].D;G?M*O%BY 99Z*>6&P=>Z,='6HU]6U4L%9LW M+IH#/I ?H($UQ79%]Y]595*5?5FYG(-VG;(YFJ$_5G*$&##(EQ;0:4*%A%23 M;98JJ+JZ]Z:P:N51:>%-CYTVD-/<^C MZ I=U1Q+U4X=7>-9L>OA3UXS/^WNB^9PPJ!M"RK8;A+1D@_DN7[@!REV0F]H MW D\Y5!4JE'C.LE0@9RA415'.5IE9=$-WA G0--,S2>$I[H1$4(G\ MI%#X-G,E+'LW.H6K#_C6FYM(N,_>E:(OF>[%*8SN*;>B'7DRBURR( M/#S*;^(GG.!H3-!U29;748A%9\9S-%#JU=#0-^^* &_3 08_\TNK* M0:Z0V.HTUE*U5VL?WY1B_8S**_.P4CU$P1#:2>!E,,$N#$DP#*/A>&M"O@H% MGP=5;R%G])F9 >2O.]5/&3[]";2J?( ME9;=\<_Y$]US:EB3'Z'G$ B).[;MH,Q24S:9%@V+V\ERH,<.G,8M M<'Z"->Q_&^%6^^;W@/+20G>".-EM;V'BERIW2GT2V?"69$Q>]+)]M6G_6FPW M7RO"ZA$2]*TIV!U&[0HCARSX_=1VL67'H6]G*!VPN#A57F7KP&!\ESE:50BVTRTKC;'SKE,J.?XH:["GL9]IY 'YI]>3@5DA-==IJJ>JJM8]O MJJU^1G5MZPPW-I9$_U,GB"(O0%'B.33V]:'K'=;R<: 6>,JW:SC\[#8?M@= M>G=XA!C6L\UCBEPC>ST?.(B_R(;/$3"%71\96RQ5-#7T3'#_1YX]_9=8KJPH M=&T/9W9DP0RGMATFP\T'B9WZ>+6K=_F63Q\U-BLDCR-"[FG,KO"BEU8>+JH\ MOK[RSW1IY<0T-F"/9.=R_8MC>U*S L"ENFIR^+'!=K/<- M:YC&7G=U<[@18T4O(()VEJ;0#6P?^9$+ARMQD]"-7+$%I@D$QI>7G\GW[W-V M6U-#C!3U@<$#,UIWO".9W!]#S M"JL$JQ,*:])&RY!:HSVLYQOQ@N+;U.NBV+09X6- E=7-*SRK+$H3/PK]+,)A MX 0)#)-D3"^F82RRO-36J.&U);U,2Y>\:N.94U,O0;&@D/80 9V+X)=15\FP M__6$HEZ!Z_NZV;TC=GR864DYN9R23]WF6(AF:N_62Z$TPYMH:$J:/%RB][YJ M=PV[][6[9N]YC!QB+X@].PLB;$4!C!(7#>M<[":Q+W&]G0$4$M&IQ"UWST)4 MZ?N@31I#+$"=VP!J\2F]#O@ %QSP7H$1,4 76O:+4\H1G!JPST)TUF 'SX2F MQKB4B4RYD3AA@*S$2C%"69!ZV,?^@,3RW$0V2-75ON%X%9?M8]T=T-0DN29L M(![ 7H)^E5AVN:HK3BIG4*O;1 O179,]G AUS;#)=3/[ (.245:'"/NZWFY8 M&<5ATWM7?RD>^Q!OA=PHBOW BUWHQ"&TK,P= G#L9([-([U& 9C.%1Q2?_3% MABOV+,-3L0,#0,X*(+-&F-;>Q?"O(KYE=9R&I:C[\I\#;IJZ/2!?@ET$7CY9 M@GWD'C[Y2T//-#T^LU;[?-J\GC7@%_;]EN9^?@4;\L/$?^[N"_)3.3W4"Q[S M9G?(T3W?RE1]U$22ZQ,^#Y ^-=K&><"B)NLU\VD44W/PX7>Z$5.&[J MQDZ$$]]&P8@#199(KL@>K][HX] TU^?+]E3H]YT\UA%O%-(N)=J6,%+=WI>N9>'\D2I-Y0 M!YOWK1ASLA+F..MA39IV">[5:/_JN2:)\H5@_:&7FSINZG\4#2[(^&W:E4// MO:16X***6\@_JNQ\HN<$BV9(%"E?)3\RVORG\RL;]XD?09 M=H5*I%4MM(S0^DDRO531D^T.QQEE!9Y4RA=OZM_*JB8!Z]/U?=X4]R1F MI1J+?1O[T'4RWX]L)W%P8 _%ZSBU8"#V$IW&AD7FHM1KEY.0/YW6$-\EGM$,*OL3AT+'7?TK>/[^&A@>8+O@OO TC8(UCHJV M6(9HFN@81YVC%NZD#^$01(]%LWOZ3(;R#E6;E'SWD16B)T'@VE%(B"2-9B1R MC?!0B([C)' 4*APUM#Y/NCHK?]('#=C]EB#?;,KIQ9UQRCG5 M 8;TBL7K(]@+GZLY2R)'Q:)&2RQ$*PUT[*W#,[JXX]7*Z_WCXY9E/_,MC6VS M;?WC?757-P\LQX-N6U9KMXHRQR8A;^@&+O+"* BQU8>\ ;:1BT6RD;K:-%T% M1UFQ%*%H1E"$)][LGR&*1#-]/3L4Q]P)O0,#D\D[":*6H1YRT%\E MY:3[+[#'4#\4-_G/HF6M./2*ERC"*'+HQ2XD[HK0T(H;NI[@#JS09QM7 PH' M[/*?2GH@R!?WAH QJH3S_Y0E!N4BRO",B.G,OA1E2]$'2?2O\_8*+,BDZ0=1 MZEXS+C:KU$KM*'83SPYA'#MNZ@7QT"2T8"I[:$NXH;FBB:8')*<@:ER*I]6- MTJB22!_Y')!=+F?^DB/.++DTM%<4X<)P,D+X%<:Y]9@!A6 MMQ[^T2%'FJ,=>W!TY!&\ T,O:(Z7]0,<.B)026S<=M-JN3BSB:GIOZ3%!,K MEV0YN8KP9UE!9DM:%4ZKP-?;NMTW!2ODE[-S?4?BE!,O.S0C 70H_$*]PJ^T MKOS97ZF6A"N:YH3[G=7B"R@4GZVK]05FE.!VS?J^V.RWQ:>[I'YXJ*OK7;W^ MQZ?]KMT1? 39EWJ[S>KF1]YL;BB,F^+G+B9$_F,5HPAF?FH[H6=%OD6^RD([ M<3T(81*X"1+:P#&&PO263@^<*D(''3#LX @\H.A!#U]PJ\><=3@W?Q9A&,'M M(%&;@-\9=D#! X9^[ETB69:G]HV,6VX9ZZP9^OER;VDF9GDE/,GW;=%^NCOQ MRF%_Q?@3@?.UHGG99)N7#_3EP_Z+EV\?,L KV[$A2J#M1"%-A6/;=;,D]#,8 M6UZ$+:$'".='9UCRNPY1<3GW2NG0+Q9@=CT#78_ZLR_LRQ//EW8Z=%Y\EF)^ M/M^Q;,N+^90+&MV(Q]%NFPE/=+EQL P/=<'^UTN9D6(>[?@%MWI;KI]NR*^C MGV6[(FVAQ$\SS[>PYX0HPC 8VL,1XKI(2;T5PQ[FV3.&#-D5H-C [Q2=H'M0 MX))/YN>A44RN91DTHK5G"9K03'52EZ%]&OI1ZQYNBEJ$ZX>\K%8X"K,064X4 M)7:6>4Z$/#2TYF)?Z,IWV39FUR'P>X=,58-X.914( /TJ>K/V\S-HST="A'E M$21SH;HCVHNW5$>*%:X]5YI4*!IZ,2W:[^J'FL1E1;QORZIHV]^*A]NB6?D0 MQ;8?H\S!<8A0!C,GZEO-HBAUN;=5-;1E>K4](@0'B&# *+"YIH-6CAW/F1D5 M7,5.D@E^[P!RBKLV5@5V)6=F5V[C495EOEW MZDXM]&GD<0%[.7I[$UM9JB) M%=RP-'+>;,XVZZ7$X_AND(4V*U*.W6R(FZ:6$Z=!%+AND$38\]UA M^9&AD.])#_56C&^X46R[)\"P@0&<2)2JQ"%/U#\7?:*[5CVL%]1)1?I*'(K$ M^'-Q*1G=2W/*&==/=/]L1*^#L@5HMYY^U+H'DU3RYK>:T#@TV+ZOONRK3W=W MUR5A@1C=ZB$XL6=;L>_&,71\A$,?N>X (?$15Q&=D8;G2^L\4+R'-YC8!83[ MZEU]=P=:"AI0U%(I"4TF$,KZS,^^= J(BWBUI) F"TAEB.:WA'*Z2)-%1!-( M7$R]G4W22_@2W)&IKIW.,YG@3\9I?2FV[.*O^C=Z>_X'LKX90?480MOV[03Z M,$ X2#*(<)P.&%+/D_9:ZBW/[;::#C$][?% ,;\CGU.(/BAHR CB?FM>_A4= MUQO4:W!<&FP@[[GFM84FUZ5L$RG7]295G+Y+'^7+@L3.UD0$G5J')#M;N\G9'6KTOURF]HIT5A/I>XD49^2-+K0AZ/LKL,;_G MV78F4J(IW8AAP7^!"S!@4H7B\C1."_VL# KO@XN39Z1.\QPY$X6:RGPNHU)3 MO1NUYG&FKCY]<2C$GI/X7N@XMI]@+W,R?VR0U@ZIZ@]G,Y=1(*E"<14RY57( M (]:=.@B%>/G"1+4(D%6EZM&HAWAT",I;CASN15I:;^F83@N[@H2?%V7U;=M MD>4/Y?:)QFA#-!8@"Y(HS(N@X_HNS")\*%\,K 0*9'&UM6D\?WM "GJHX!WH MT((.+F!XY=*'^KCG2MY>A';1M.V?A7&A5.U%F)=-TAY98,/0@G5W&OT=W5:D M=KCK['#/9P?>)"TO2>?3L]II7L#JVT2O:K.#4\W_?-K=%TW?(GUO)*+[EXF3 M99D?TY>:AA:MQ%/R.2+M7,;/,(2:=$Z(53EO8HI0+1[D8ERJ^0E3G&KP#<+< M2ON!(Q($M%^&NF7JO51/WM!X>7:X:T3VW>BJ[X:\?-]<&F2)XSII'+I9%. 0 MQ@D<]_1"@0-)*HW,4/G10Z.W W@9*L,I*GD+.J8@T7Q^HTE$"A8D3$'D?+% M%T>$OGDL@K^TXDR?IZHH5&E:A$YKZ,;+V@@]O/#FHH]O<4K&G%/1W> 4/R4G MT^).'(:)$X:!;;E^E,$D";,Q">580EEJ(P!,*[N>[3,SW/,EM2].NZ K6,:> MFPQK$SEPHT981G;<;!?K&0>UZ VKI_/WK@.SR(L2[$:)$UL^MIVQ-3?!0K?1 MR;9Q 764VMJ3YI!/ N>@3UWE+K*C=X::"2E3)7,9:J7W9^I@A5=S_KIO MFG*=5\6PIG2AY=<3.B# M-&W+$ AY^+6FX7.Y%R$^E%7Q?E<\M/2ZLR2.,\\*P@Q[#A$U:\Q9.0Y?FO^R M"(VOEO.S;"@SDJ5N#V(?:$;>N:JBV+, NWS'GAG^4GPGBIIOZ[O/3?%0[A]:LMRKBLW*]IW,3MTT M1#A(LPSA#(U7]KB.Q[7#KK$YPS[B&4CP2]/#_)5&Q8\]4E PJ (U/YJ8GM;T M"Y$LIM8O^/URS.\ $J07XE>@NFI^GN7JK'3PS5=[Q<7(N2HLO70NH!Y+5[N5C5%BPRA%B9.X#@[\T!IW%M/ 2;659@FV:]B# M9/OM%FS+AW('MG7;@GU%QME8,:JQ+$N4;O$5P9Q,JP3]1SC[FOBMWAT;Z5,$JS@(8D(_-4!C:4>"E+K+& M([ .C% L,FN.UKOR>\FN.CS:$?Y]Z-3<;\3J,<6$TYO;V,OPD[/W^N6;M1=AG5>/ MKM?WQ6:_+3[=B4-;P2 ,$L^!R+<]/\"I&Z1XO,K-2BV1)8!1((:7"@-VFHN4 MUB.QU859N_$YC\683,QC:+$6^/TFOR6?<5/\W(&8Z,T_9G87*N1/^(A9;+H, MQS!/5^L+S!G3I3H?B]WHEAPO@E#@QA[(1V,I8/0<1UE= \2)9:E -^ MIR$"Z&,$A?/.!HQGJOC&E-UF6COPFFPA139';&NMK)&QXC*T?Z:^*M?0R#,L MM1'ZE@/R4RLEGL>WL 6S+'8RZ(\.R"?_7SVRFI_K7=[L)/9#59L748J72+E% MXR\-W0R]S;J>9FDK2*7*[C*FGW(N7230MK!A= M$:T@PI;GVW8<)]!V$^QC.%XCC@,$ M /\3K&%TKUVX;;4,337<1QUK%4%&N3QKK&+[28L4?34D3.UAH2V,YL WGOMY7:PIVPPI%6;PU/D#:]P(\D6X(;G$LAS[>#9'E(#;G9@:# M4IAJ&UMF]D5FL\'4+LKR!L(R?-@2B7FY0[- B'-ZR\\DXF^XX(=.[ 21C1WL MP#"-O!!FWEB1X 5"6S^+ 7TY3\GZP/RD8*7Q8KB;QTU>QM9B3K*SY;^FB^3F MWYR#U#\$_B7<:\T2RMIS&>YDQOXJ9P_5F#;G +IO?Z8_>5C9V:O03KPDBKS4\OW 2UP; M.B,\&V(\[*W>F*Q^D\0FL0U[([[2H;"TY@/GLYTI[V#27G,[B?ZO:&>NP'%. M<.GNXK01M'H-13O_69V':K>5?8@6WN=P)>,ZB#@Z&$5I9D4(^Q%9X\2AY1RN M)W?L()K9DXA NZ@CD4Z7S68X\VY$N[$NZD4.2;/%KSE.FL"0#Y$Q\I_?A4CU M6J,'D6>=UX%\SI]HRRT!UY4I$ECTBU/G?E"$8L>W4>1Z;I)B)S@\$([C>'01 M_+DG?8W+. 'Q5-,9)]"EF:AEQ7R 1N[Y5'YFOB^HX_-*-S>O$^*LWS;+D%\# M_:I-CVK3,3CYP:+\5J4_U_=DZ!=VZDG?[6<& MC>'-Z1X.8)FX:OU$E/9[OMVS+1[3,;:P84Q%UR9M,IL>#Y8<>K'T>/H%Z5HC M:5F#+D/$9^RO7;. FB%"9!-CH@F/B)V8U;'@2&-VM? MG,C Q9J]?07<"YY;O%SI/Z\Q_JPB(-1'+:7_8HRJGFVT/2O*(LN"V$[=P IM MRQL/0V=Q'#X_VYB2L%3I9.-;S4DL@I\CXY[&:+/Y5SK6R$OL,N:A7Y@8V# M )&0V_.<).:_T$WV\\VM@0^00(?I8O=SGB-GLLI9D<]E3"_U;KRJ(M;"B^RT MH7?VL2O[5J%O1U'J9)D7N3#P_-BWG:$]'&>^V D6V58,9_6NO\;7Z7]]33_> M@/1OY,]KT=,ETNS)J8X9XI1EYW(W/9[C1T!YQ#E=IO1(].,-[9%EAOL1\/KA MH=Z4N[)HWU??BRY,Z)\=]UTW0+&'H)WYMH4ZVA) M9"9)77Y_!$[PX6P5_O@$:"[BQ"3H"!4XP *_=\#F?GSZ/$43*J2#V&7HD):> MO'S.61L[7$]O?-K=%\VAH3:IV]TJC?P(.9GKN&YB>S%,TP0.[7B(WM[Z=E9< M_M,-9[PI!H&W%^4(FI:8>;@1$Q8&YTA2Z!MCJ*?)M^<]B\]=Z2U\,^TM> M5BL?V8GM(A^Y*72#!(5)$@] M].N-\:-M.\X17G 13X1N!P1GPFZ990Z?F9 M5I;Q(\B@RU\?6:)'#2CLRQM$P1G,;QAMWD+=0'(NA8LR7I^CE_\%.B7-'9SR M6B:X-./6Z);S"@>IY[L13K,XLOPH22TO&8"$'AS/*IEP;%P )/;AI5U;5XUN M4DKY.#?AV_21/:MOH[ O;Q"3ODV[8>;U;9,&,N3;:)O:?)L0_W]&WR;6027? M)L&EE&_+\K+Y6[[=%[ALUT2U]^1G$A^E.+%MF 9IXGJ.XT-[:!9%EB.]0)-I MS/!RC$("M)"?\XTY?21*N";3_"D[(L8F0P@.$.9P@ M@]=5J/"X0,>@U)TI-Z#.TT'TCZW_@7SU'_\V?(?\<9NWQ7_\V_\"4$L#!!0 M ( .""5D@$B<29=N0 (7 "P 5 9VQR92TR,#$U,3(S,5]P&UL M[+U;>]LXMB9\/[^BOIKKZL+YL)_=,P^.W=F3*N=+4MVSK_ P%N-HERQF4U*J MW+]^0,FD'5L'"B(I6DD?*BX' +'>]0)8"UA8^/?__>?M[(;F8%O.__@C_ M G[\(9]?%Y/I_.:O/_[V[B?USKQZ]>/__E__X]__OY]^^K_Z[>L?;'&]NLWG MRQ],F6?+?/+#']/EIQ_^.\? MLD7^PY^+Z;\MKC_EM]GKXCI;KC_[:;G\_&\___S''W_\Y<\/Y>PO17GS,P( M_]S4VEFB^K>?ZF(_5;_Z":*?,/S+GXO)CS]$X>:+%NW?E_RW/ZM??%7^#[PN M#:64/Z__MBFZF&XK&)N%/__?7UZ_6XOXTW2^6&;SZ_S'__4_?OCAW\MBEK_- M/_Y0_?G;VU=?U;\I\WP^F]Y\6I;Y7WZ_^[DJ\[/)%I_4?%+]X?Y[%4&=1> 7 ML0M53_[M4YE__.N/-[.R$AQ2B#9B_\_]M99WG_.__KB8WGZ>1;E_[K)C-E]F MTUEB_YY4[K&;[[,/LSRQEU_7[::3Q>WM=%D-J47UO6*^C(,O#L)IBSX>KMIW M%U_G9+KL0:5^#?8O3DO)M&^BHN_-% M,9M.JD5$9[-JFGSW*<];S&^'*O;;O3=9&1'ZE"^GU]DLN:];6^F\X^^6\9]K MA4;BQ9G,SXH_CL)W;P.]=O=5-$-N\]2^?EV[UXZ^^Q15^:F83>+PKE:*Y5UJ MIW>WU(D M>46Q[:+0WMY]VK^L2AOUT;8H2ZWJ=M-)U?Y^^)-.;W-=5G\'H$X MV+-=%?KI3LN5X%"]3CKGI_,XH4RSV:MH9I9K_1SLV+XZO77*9]/R']ELE?]] MFI=9>?WI3DWB(ABY4Q5KB-02V^Z^T)_ ]>^J1;3,KN."VK7 25_H7^!'O^M- MY"._T9O0K_,O^0R_S:^+^#>SZ:GRM6BN-U%^S;X\^K<3A-C;4&_=K]SMR6J6 M7WUL)H*XGCX?(U>K9>605]L;)\AX^M<& .)O9;&HS/A?\Z6Z+59K \/F971D ME],O^>,AM'%R33&;15.DS&:=(-/9YP> ZM7\2[[8^#TF]N&F**?_BN;ZW7I M/E)RL[9T@M"I7QT6F%?SC47Z+K]>E7'*C2YAF74VCA(^-+3X#_UY%RWT7XOE M?^;+-ZNHEVR13[H'X9C/#0W%]6PUR2>OXN+T8=G-JG'2AP80_Y=L66GCSD[C M7TX_K*JEN9K/NI<_Y4L# '"U_)27CW33B:P'&AU K+?YYZ*,7OC?LNF\6HE> MQT4KKN7SAY6J&TF/_\X PO^CF,5?/5Z6U77\YWK2Z43J(S[0F[CM=CX/U^RD M@Z\W-M'ZC\E_K3:T=W]^SN>+V- B+[\<[NHQ;0S6Z99T26AJ,!%>3[,/T>NJ MN.F+LBK:@W"M/S*8V.W&Q_$M=2) =!X>EH=V&\)[JO35I9;\.%RSKPZVT_'! MBIUT[ZJ\R>;3?ZTW-R*C=+:81L_P31E)-%^VVHINW\) '6ZI_Z,;ZJ3[__\J MBX9'.;MKEK@X7E>SY>*W>;::3*--N>+[+KBI<'.WNH7J^=:TF'EM4[ZFKEO%W'SZ5%\+2M/TAG M6^-[5#.#=+W=4#NNE8XZOBR+ZWRQ:+'>;2O;>2=:*WEGE4ZZ5/N.KPYUY%G! M;C_?$HY=Y;OMS+1U-Z8]=< 4\TEEZG\=PG(L2.V:Z:OK6R-9TD5HT]P0HASE M@J2TU;$0[:;D7>4[[LP1(ZNOH34]6G5/:W3;H2^M._*EIPX<"\C3"MUT)[^I M!L5FWW8ZOSG8FQWE>^G,W_+BILP^?YI>'Q]8D=)6+T(\.2J.?O#M='6[^&YOOLE^Z^B-*O%,DZ^K0/, M3FVW%^%:3NY[:W73L2J24E='I::XK78I6^TL[:_58\?T++O^/6HPEEAKV\S&^;K=?Z5'P7[.R7!\,G238KE9Z[/B#S[C^^],4 MU5.N_2$2K;6J.;#DUOYM./T^MLOE37UU5@7EP MWA2S:9O[9JTJ]]_-MKH]HHW^.^VR.XIUVI1V;MY<^MB./,Q[(33?F M^4UU%/HZ^Y _,=:VU9N5Y5?5JBP+LLJR -FZF]M:ZZZ3O^;+;OOYM,'NNAK7 MW6DQ;-?=?K?,RHZ1WM5P=UU_GY>+O-M./V^RP^X6T:;ON+O/FNRD MNPE,6#[OX6&U?WX4_?0Z%KHO6C5Y:G:4S>?R/Y?Y?))/U@E8X@=GQ?4VH=8" M?$2>V1N53\P0;@1#&(N%')8"*]]+3H$'!\0_3&Q5'G]0U%.\O*O/\(? M?XA_\S$OR_L%:T]RH#7'EL^F@ZR\?D;/KRO>E_CY\SK%PT_7GZ:S)D2NRI#4 M#P6*_E&.@O5-KL>1 76"*/7G=+&'3[NJ!*DX4<[1")-P7'%K':V%8\P>&CTO MAT(=Z[KH!=\SD<<6M]ET?B1]-I6"-LYA*SR56M$(G&- - )*[2Z&0*>KN 5G MDD =@#7;Q\PO^>V'O#QZZ=Y4"P(1'@>:UQI[XCV!QH!:2,(*J[@U3*_W;=N':@9L &<,.FL($P12KV%SW,)^- M47:ZN)X5BU69OX\^C8Z?_OUH;FUI(S .!52:2,,-9!HC9$TMOG,>7LQ,U1D/ M6O'K=*@?F/;O/S]UD_ORG;?N>;YL%QHK"WR$6B#GE612.LXVH&-'J3HTB[YD M%UHB"X0W%%&LXZ*)*&"T%IT;=3G^3U<42'*ACT/Y;.O' 2=Z=Z6@M$+ ,258 MG+L$U5H06POH^071J&-]MUHG$A >@$*';D0ENDRG-!NT$X8(!J32//H5VAGI M:Y TD)?C4G5!E.)LP.]EY_,SSNHW:XG_GL\FT[G.YK_OYM'NP@$Q*AT CAA@ MC!3, H#J3A+(P<6P8QA5%AT#?@HK/MS=IU!MQXLGQ:/?:!R7SFEBH_.HI*5 MU1T%1OF+<://QXS3('_1FS2$::@P-(QQK+ GABIX+ZI'S)&+8=E'C>?BC3&)<]<(5[7.]-_. MZ#X)YG-LS&P+ 7O9^S(LKC4:*8[B.B&IE,B1^XU\SY"4?+S[,FWV7X]K* BD MN14>"0XM% @KQT@-AA8(7?@X/YX4*3LUJ7#W/-[;/N$ST'#?W9V'+>TVH_^8 M=H+4T4Q$$"@/N6-00QZMA[5"7'0)T"'?_HQ0M#J,.:JA(..*(QT&EME(2^0E MUZ@&PVIK!YH,ON3EAZ+OZ: ?ECPU OK$_VRS0]LWLBYYWF H6FJ,*V\ JO;U MK3#2Q F6E]F<[NZL'1HB!1+%HJVKH)#,: MHUIPH?P%.0;]\&&G_= 9YJU]T$5^_9>;XLO/DWRZX5C\X2FUXJ_"Z_PFF[GU MVTL[SG*VE K*( F%B9,EB X3U=IQVR!"^%"+R9#[$UVHL.@*T3O^S?Y3Y0+4"I.(;8(BP=$5 31O)F:0O/YPG755%;S!VIO]793[+YA.K M3 (+GE8.DAJNJ1*"&Z,UCK@P70N!D4H\,1W1WG2/7#@1S"'.Z+-H"!V(ZFC* M!(HI)=A:B3C%DDBB06,9.9JZPS0B+O1J!YR*YU!T.!R!\5 J((Z9B81F1GH@ M&'1,T%H$J\W+7RI.T-HVO2?!-H#F?YG.I[>KVX.Z_ZIQ1E0,QQJJ*QC)M)T&IY,4M" M)PPX ;H!&/#;O,RO*PU,?IM?%_/Z3=3ZP;BK#]&^V>0 O+M_:_#NZF-UM-H\ M*7? DNCF P%+2 #&-J)%,+2.:M$8:#X:4FF67Z76^4-?_O9I&W1^\Z]G-!X(T@ @,+)=462PUYFBB/>/Y&=25XLR_6;]O5YW&_!8]R<4RGSQ]PW2_/]^V?H"*6XFUURK.'(9R M%;W26A023=@+.AL<6OE%__H88 K=NMJ\;A'HN+]B@)XCZXBF"G I:22F%I0 MZ'1B?#49WY37Z\+=*_;OWB*K?9+/VO-K=1%"" T$!4[JRSAF0 M3#68 J$2(VE'N*AV18*]W.H,Z %85D4;2#0Y&*SVL0E\E@2RP #S3"D,''JH]_9UQ'BHR)@_&K>'06; MUH*WC&%@((Y>%Z.644H;2*P#B5G9V'<2=H;YF&CHBU79&0N;QD*TAJG B&"K M! /:4XI$L_$C4N.L^'<2=@7YJ#@X_=+=3-@T%CQG<21B;G2$13/,$&VB&0@3 MB3$]XCL'NX)\/!Q\_RDO\^SC+C(>#IM N$.XN%\M!&FP, CC GC2F,:&I&<' TVYZEW+\LMAT)]*BB M6S;9:*_BC%TNEFH^CQ-WNL?B MVSF[&%P'HR3MN^J]MDE?K'W6>D"22P(09TAQ:X@F'#5KB21.)]+VVSDR&5X) MH^3M^T_3LC?:/FT\4 A4 P2B+V#&@DNFX'NX,'$(;M8^^V,/AV3I4&U\&Y2+L^ M&MML:*30\DGUX*C64GLB+<28$T^!>$BY@4PJ\;Z=PZ0>4#XKM=:[#LG,:FH' M:$TTDZ6W!E#A(8#1[6N6 ).Z882./S>Z/&*E@GQ67FVV!9*)]5 ]6,2C1\:5 M5L!+;DBT?9O+Y)K"Q!P*Z-LY]^D!Y?-2J_+=TYE5UPX<:HL0Y,8H"9#UA-LF MU,F0U"AO].V]RIU/KZP8"Q81+$ %E2%.K!17$-Q? /$C+D5&3M8: M\=GU=#9=WAW*,[VS3A VRJ6$M4 Y$@UZ2!&M1?0 #)5D8FS)I5MK_NE]QXZ M'F*!^*J3AYX,?58X0!.7.F"TP98)&+&P4FC)@.*U4,S)"\II0<3$[8IGJPE&IIHE%M&*-5(EYN7(.@]HEW_T;/GF-57O0.[1"9 M'K;,L0>6I%U5 E>XBE"CV#'/F#(&ZV;D864N)]=E]PM31YB>B3"O*T>D/+A4 M':H:+-*+;[ZJ&[S#J&\O)W.UQKZM5A.K_,WT=HN)KL6LB.:") [B3V) M,[J#7ED%I6.U0)21U(B!2R=/SS@/,5-]?=I[M5HNJBW$*G'GH2L3AZH&SBT# M2&C$C%;(8"Q$/=E[!?%EKW<=S$C=XCL F=[,\LE-/FEVHU_-%\MRM3Y^C:/@ M71[1S);Y[.YM_KDHHQ/XD&W?%^77>];W,,:_VL/ 7KX7F(CH(8\ !H!0@1GR M]3&PYPHF'D$<;>8/\01#/\0=@UK.%CZSMG._H7 92P!5!D7_SPGMN'2<,6@P M)41+@.6A#&']0/'PQL,6AE=*BAK1\=._[X&A=1M!\\@_XXUEDD"E ((6UQ @ MR"[GZ* G9NQ\J[U;X,]V]Z^Y]_5+MJPFNKM:PO5XD,)L7H6_%! Y]<% M@^!2J^J9%R001<)13=Q&&&P0-9>S['2KVJ>KS2F@#K"D-/U[=YW/LW):'(B0 MV5H^4 NCX0R!5H13H7V<@4 CEM*7$U:5JLY=K#@!Q2'(<=^[W^:+S_GU]..T MQ1.9.^N$Z.4YJ9 W/*Y,SEGO(:S% ]REYK$8,4G2M/O,7NT&T"$GDS:'6<\+ M!PJ)CK(@@(P"5OGH@NL&(GY!+TIW/8VD0C@ )S:7GEI86%\7#!)Y2I"##E52 M*$P0:##QY* M]0)GBP0E%AU". 77LV_Y(M[!^HP(;:4#EA(I:B/4YY3EHKU M#>Y:)*(',TJ'V#Q-56;1-8H#$.-]F54'#P\[M3;_L(\:6\L'#:0DFBC@(->0 M<,>(;(8-.[A7^)+(<9)6B^[!/ ='-D\J'\.238W ):ER(6(!XN3*'"#:J0>@ M=.*[)T>;&2^>)TEP#L"4J^6GO'PD^1Z*/"T:K *4 X>P-0!)Y:A5C4W-)$R\ MG#["0^4NF7$BBL-:'NTLCD (9@IPQJ7TV E@M6Q$$,8G3A(C3%+0)1'2 1SB M]"1;?*KV[>,?U;&=QXA.7HUQ<.K)0^\!U #J]C4POI]?+?+)=@#U,.E0U2 6-@1Q( J@P M5%5!. V4U"?F;SIZ%7I!).H8T@'X8_,R=FXY_9)O(-C#EZ=%@P0(0BRKEQ., MD0H8AD4MC+0@<7-DE#%$'?'C1 B'B&XK\]OIZK8Z6E[;4V_SZSQVN0KW^37? MYPSOKQBJ36&FL:&^.A1V##IL:T$A(XE<.3H#_POB2J> #K(23>>+55F=K\>N M%A'IKX+$MBY 6VL$ H&C3D%IA8LKK*QRL#>(V=14XR-,A-_9JM,%CH,L-AOX MWQ2SZ?6=NHX+X^: VQ2+ TO/OHK!"GA M7Q!C.@-S +;\6BSSQ<-ZN=]P>5XX>$NDE5X)Q[%%(OZ?-8?D3,'$^62$.=P[ MXL;)$ ZU'7O0QWE4*EBC1'47@,@X_5$2)\0'7U^XY =YCLZX_H(FB73X!HL! M.'CV'Q!&4L#8:4NCAPZ%A:)9_(Q,UOOQA_Z];[IVI/4DW :YH)Q]N ^GCT[4 MNV5Q_?NG8A:U<7]FU.+TOVT3 1O@.3,$"FX5H59.YS=756:CZ;_66CSH11W9 M7(AX>N*KZRU"20 1,>;!7Z L,;7+"&->NN37 $@/:$[=^:(TLVQZN^G[^H?) M?ZTVL1SNS\_Y?)&_J7*KE>J9\SS^ MV, &N4R,J1CE<6>7%#T'^ -P]K=Y'%KS?-)B'_IIT0"4D(PHSB4WGNKH=<,F ML(F+U!Q[HSP,[9)))^(X[!GH_:3<[OCSOG!0G $.B%7"(L$%=U(]& :&)EI9 M1Y]\OC1BG(SD$![@:CY9_#V?37ZK4DP^ZK&J;JVO/8LV2]DQS01,G(60&62M M50A)2D"S,>,E2LQ--S\$ZY%)QR [-FP!1 BRP464/EH@DM(:7/$:[U//"4?X9%'[UO8 MG8$\3"3.1CGK3A_:JMY2.G BJ'=&2:DIB#.DM[Z)><7IYZOCXTT7:GT>A7,B MGD-<<2EN;XMY*WX\+1J$-) )QZ@W4!M=3;P/20BPOZ1SU,[)<2*80X1@3";K M*,-L]B:;3E[-3?9Y&M?W?3$9VVL$XY3W'C!N,=106,-@Z!1YP"?Q0H^ROH-EA BJO!Y#RE3T%CGFR&B M;&I&F*/W;OOWBWK@R\EP#L"/7Z;SHLIL^6H>;8!\L6]^>5HT0"6,,1"@Z/ ; M2Y4E#RX?\GRH[=L7:;R<".999HY7\^O9JLI&\:8HUTI;+LOIA]5RG0RU^+68 M7U=95(M9[,I-"SYU\X$0$;<42Z\L$X)11J1&S93+0>*:=O2N[X7,4 .H8 2A ML">$P 9G%=$V>A>>&4*CCR%-@S51J8=61V\:OTB^=0SN Y,&S:3\9@W?IWPY MO7YPYBXMK;+D'E2[PG$X,X2AA)(X(YB'V&HAX*%MJYX%/S*MLG$2DNC?$4PH MK>[J $QK8:A#B:D=1KD'UZ5J]Z=5/@[402R6^_Z96;987'UU0)S9R[G-T(%.GV[:GHKF8!OZZY[N?E=V=^'@F4 08*%-G$^E MYH18WF!#2>))X2AO'YRBSJW;^2< .2PS]#',N"\<4'2,B';4$(CR0BY30EH).&1:Q[580^2;J1(8>H'O/"0H/O5"[G'@OIB]V:1XJ%,^ M%"#CC"/$C5<4"$84-+(&4CN0&.XP0I9V3ZU>=FX3%3-XW-6;K+PJUR-_L@[U M>).7[SY%1;0.Q=K50/"T>K892>L!%)31.'WX6G FR26YZZ]7<6@#8%&$>V-@=@#C1Q4S?B7]'*B2D?)OQ/5<2;> MO5HL5D=S;E,I4.>X=\1IR @ SL21Q1I[6SY]K+ZW0+)OFF])JA@VD#5AP6U1 M.P"L5;5QR! F!,#HN8MF6H\#;*AGV+\9]G6ODV%I>,0ZNZ=6H)X8+*JD;((" MKR7VO)G5K4.)B^SQ06S?(.U.U,4YZ'9P>=U1(TA!K(<6 F0=XY91@!_@$BC1 MNQWE=>:Q$BU)$^<@V=5JN5AF\PJP8YCVJ%HP%%)A#+(24@(<--PT]H-3/'$Q M/3[P[9N=U=*5,5S@4K-=NKCZ6+W.X6?%'^=^"K[IQW&Q2L^J!6:5,(P2+ 'F M7*[?/O+1FF: 24'=H>.T<<4H.2>!PD #Q 32S-#(HWMA%(]>Z07M1'6ATOVQ M2<>!.>3YX$E/OBO/E,5* <>H 91#"G@MEN0V,6G8F#ERI#I;/?E^'(I#D*/3 M)]\IUY8H2@QS7$6;6FFD:O& $Y=SR'*B=EL_^7XCG]TC:%\_&-!>1--*4%UT!+:T'U;[H&!#OI+RCH[10Z/'U*HF^@AV%>],>* MV_QUL=@W$7U5+E2O)7BK.18$Z(B5UBQ&GV-2#KQ&N4GVJ^#F;DA$>)!U" MG?]R\;ZHGNZ:7T_7SZ<\=/I]T=TDUL?G@K/,>YY.'S-C;ILB3V@N446ZXY5$VS)@E3CIK] :X429\_V$3%?D_5]_X_@C8&Q_2MJ",=G MZSG3J_E76/Y',9TO_Q'17I7YFZQK'*<60M MAU;Y:);5P$&H$F-<1YGU:53D/HOZAMA^K$X_=?42D"ENJX<,UM38MP6YM4* MA&'JB4).(H6@\$S4@AF$62(O1QB6,RI6=J*, 5AF\ZC&Z^FZ=W% ?"Z+R>KZ M -%VU@D4>RD\-W'M4% K$P<4J<7S5"2N\B/,534JKG6ECP'H%N&)CMPBM_GF MST> W*>+;+'EU+Z1H(P'B A)-(@N(.*?5 S *JHBG@ H)!A!6#\,RVMN])ZL>T'/O@PH'V78RY&?AV:,W M0:H!' WYH[FVO8E C5 N^G&$(*N=8]$ J7TZHX%-Y-LH=XK.PK=.8#\+Y^R] M_MX4L^GUG;K^[]5TD\;*%(N]SYH?VU0P5"O,O6 .8,VI8/K1 +0L,1HB=0/H M\CC8*?SG6F<_9]/)XW>W#C^#=TPS@3%3G=5"33C4$"AEG*A!L (DIO]HOT5S MZ1SL#/KS>"+5@TL/YO!BD1\Y VYK(!AL9+7AKRBN(N*=18(V'C^GB?->^^V7 M2^=[AR8(1 PZL+B183$1< (NMX%1-_&NJ]R/ZW M8,Y"N1/A/K>C6[\RGNKEUO6#(J=;=G=_'+[>#"_S]V56)9%XEU^ORG7? M*ROB8U%.F[C=/<1+:"U4$><$>N<(YI I)G%S$=((+!/SD(_RF+=/PCS-]=:[ M)H8@9UE6L$1-T08TSAJ3B0^+CG" M"7!($O8#_H#38NSMPQ6%5_.(QZKZ_1:P6LR*[1L+PE*N*?1<6B YD0:KVCZV MV.C$!W_&>Q'@##-C;]H8>&+L@)_'MQ8$$EP! YQ5RG-'+;-UT)L%%">&#(XP M>^:9ILM^])!R@Z_N507-=/XP:;\K9I-5M;OTL*6T+-[FGU?E]:?H_6_AVRG- M!86EU(Q3C0G2@@#@<;U$6.13$QJ.,$!_ ,(-J(@DQMW/T-$Z/9UN"6T%;*D M'&&'-9+6,*AX(Z*2(''U33T!OHC5=RAEG".J 7HD*6 ,D I'XOU#/)!%//4IR?:GPY>Y$],Q[&?AV*_%,G]T3^"XF>UI MY6 %0UYX&A=^':=V1W7C[5<)[1)Y-LK#W[/R[$3@S[3!][[X93HOHFUPM[X= M>I]K^<@MONV-!,LBJ 0CSYB$R"#+(6H &2P\]XAKI^?>9^O$PVPZFGG=< MA'/1NQI&=0#KOR^ ./6 ; M7D\7!QZ7.U W:. 8Y)1P A1R% HK5&-OQ$'==W3!N;=/ M.J'"'G.O"]3/%TFP#E#< M'Q 06[6@I$V3BFX_1.UF],06 >MB^K-UDN/:Z@ M;P)VKX-APPL>=KJO/CYZU:==.,&.R@%02ESU +EUWC" I:2V,2Z@3LP,_.+" M!WKA7M?HC\JTZ\2D"YI) R5 T:K!VF@%2!/ :[7@B9?9C@\..)=KT0?O>H-_ M /Y5'8_>=_5'Y8%_R6;5"'J3E]-B\G3;<@\#CVDF>$6D-L1'SPKZ./G3Z,XU ME(_0 8UMS+^4Q@(%6<" M-1N8W,#$I?7H.)3/:Z5$W9?+E\VNT_"]&%HQ9BBNGGHW7.!H0%A.&X\)HM3[ M0$?GA-S0RLW[/14;G%3'H3L J=ZM/G^>K2'(9O7#@Z_F'XOR=J/"%H]1MFLA M2(\@!4Q@CA45D@L+[D^7N84*)Q)KA/$C'9*J'VP'.;G?Y'5^DTWW;9L]+A8B M.-1: "AP,OZ32D]P+815*/5,=(0$Z5JKSP[@DU$=)JBCN*URU^>+@^SXJF1 MU3U=*:V2J+J=BQF1JA8%"YSX.M8(=[#Z)\@IP Z\2UJS>1,_TGH7_FFUX("# M4F-#H2!:(^PHU[60!)#$E\''>*S3,WLZ1#DE*+MZ0"!*U1QE9O/)EKV']:,9 M42W+XDGPT:[X[!.;#8QSA5F5P%MAS"A%6IM:<&I2(WI&> ^E+WJ=00L/]!OR MQ?G-[/MU3X9Y;G[SY:8O[7*W;ZL1G.+>02@EY!)H*!FU."*OL?#687+H,*DG M7R;QD7EL@731(8/"0H:B:-*+6AA :.]/Q0V9>^4T;>Y_7_XX'(=P;CMY7QYQ M+S6UPDH"+:/2$:1KL314%_AT^)'J;/6^_'$H#D&.3M^7UQ01C1SG/B+&.+/ MP%H\#WWB3:TQDR1-NZW?ES\.T"$GD]=I[\L[;YRD!AAB',7KM$+-)(N$O9R\ M#EU/(ZD0#L")M_F7?+YJ%8CXM&B@R'OOF(\NME/4:LUY0W#,=>+9])AGC 1% M%IV". CU&*QNGW([_K/7FRO$+ACED9IXI0*C!441.NL%HQPDIC6 MX&AV#'$_)%VI3Y_,[@+*(0[R\LDQ#-E6/$ )*%* <>6PKG*F*]Z,(.M2KTB. M\HV8SOC1 9"#['U^U<%?\[WW?9X5#IH85!$="F8DU8((U@BDG>[]Z=[!XDTZ MX\7)()[E*NS35.+[B=*J?B# (&6,U@!YS@06V+):;*C(4(_B]F^3=,:=/G = M<))QZZZVFV.:L@%YJBF.IIMF@@FI>?7PX+TXC-/$D+;C4^"\O"DF%<.4@Y*' M!^Z_WG%^>O+QM%S@3$,@E9,0(Z2159JYNFL"I+Z!,\)G84]6;Q?X#3#:OTY_ MO>GE_3LG^X?^_HI!>N80(L0"KA&,3IUQ#5P ZZ%2PKPH)Z532 ?2;HG M:9N]KH-U \&*.<"@0,PS02U'CPPBS1*W-\:\&7KZYE?7J YA9JY?M]RDW*B[ M7P7)SK+I[2+.?:M*4P>LSY9-!!L'#(=.,8\]D9 X*D$M?(2Y]U>:!Z-4ASQX M:J7V@_4 1-O[G*JZ+ L:M1M1!)>+X:&!#C@T6FMB[6=X? M@[H"=[#X^JJC58"N*>;1SUQ%5_/>YRSF"YU_+,K\41!XG2"MCN:-\GW=2G6C M:7GW2[[\5-V_K+<[#F1?'*H7@7A#E,7* R0%A"@Z3\U6&L0Z\6;1"+-4UY(V4>SCO83[([FB$A+C'&9Y0O-O?-Q5/! M'>:62NQ7!<#>TY.Z4)#"0XXYT1@"3*ATEC5!<@"AQ/M+Q]^ ?,'S5#*:0R0W M*2)QY\N(TVR]L[N9%E]5Y\D/$^-_%-/Y\A\1PU69O\G*931,%[%BU%V>WQX( M6^_F T$33+!$W@M$(UR044H?MAIY8B:RU.S:_>?DZ8^-9U'(,&EZ'OJ_CY"/ MRP5& !(>$2Z8<)Q:BJUJ-H5(:N!)^VS:%S"]G0+H +RH3J\CT:M$+.M-VBV$#'U@[T[^Y). #H"\PQ,T=EB>GT$3=;E P5 M6RB91PX3#5GT')IA1*Q,#$<:91#LZ:H]P)441,] %#N=K99[+WGOJ!$ \-): M2XW'CFI@*!"\N3 "1.+R<_0V_$60)0W3 >CRS[RZ9)M/5(0YN\E_7=U^R,NK MC^M.+ZY6R\4RFU=/>K98F8YM*J HO,0BKNP&:L4QT C58$BL$\^L1Q@&* MU3/((V+=):/'Y= M9[/U_W6OADEQT?0H=JC*@?Q5A]IDLVM3/\290<"H"\DYPY+".$%P5SGI#$(+ MW*&[FSV+?F3Z"T*D]!#B2">,H78<6UH+4VVJ7DS@5,>ZW9\,XSA4A[R_OI'7 M%+>?B_DZ1V7+I!C;ZD4Q!8B>HW7>&H,I)0 W:&&++I \1ZIW%TLZ0',(]_SK M7AY,D+&U?,":>4F)AI@B!JFGDJ):+&G<4/LX Y+D-.T^]/"L;:)4;7C,9T:&&1X.'4EB+XR5(C*(.\!17*N]A[(6$T$UU(9?_[-* MMWSI$M1![A\MH[3YI-ZB/$B:[16"EDXPXA&/SI,!P!I"F\G7,Y1X-VF$YTW= MLJ43-(>(Q5ECZK)-#@8"Z6+C$>9 IZVMTHTFQ5'0&\J>[ M15TNE^7TPVI9C;SWQ?8)=N^TU<4'@J;"H>I\ P@*H671", U<-'Q'.HMVZ&> MGNJ-5\]FQ#-H9RA:OUHL5OG$KLI*FK7BUB\BU;%)^:2R.O+Y8LV*0Q0^JK'@ M(54F8N&$!@!"P8'U-2 BVT*RAJBYGVNH2?&5* M5'<[=YD2?]^ N8>877TB6(0PA1AH0*/!8C"0J%$/ :;W.[R7.F&>24'?K]LU MM[LX]I1YK30VBEE* !"Z!@[AU(>A1IA-<2A*GT4OX[UUISW67AI$+.:,6"M8 M@Z)3J8\7C3('XV $.P'@D1B4:R_LPU,O[&V^2:R4O\O++]/K?&,WO\VOBYOY MNI5#CD_?GP[.<"4LI0H @I4%7IEFZT\"GF@&')U!\I+8/#*=?=]&;3;JHAZ9 MMT0+"+3QC@K=G*LA!VSB)L'1%Z:'>6K]A6VB'J>;?B/N;7&]6K_7-X]:6JXE M:I[;/"[&?D>F\/H#V98/[(F9;UTW,.J!YQHR:X 4WFLN(#28$E(=%XI#3.] MC%TQ\>TJ!B4U(P " ./8*:XI]I:I*6KQ3,2#_6>TQD)=*2:=T4+G(CL$''0CWIX,&#^ M>>$ -/'0$*&JA!]<.:B!K06R!B6^KC$BJG2HTZ>QT*>B.5B8_+JGJF6<_./" M@2E9G:)1A" 52%!#J*@% N;@W;.7%"A_BCJW1LF? .2PS-#',$/7(750NRI6 M1@ /J*C>0:>T%@AAFLB,46; Z(<9:4#N94:"J?IZ3_QA^\H!6@>H%UX RA0T MG#/G:R%D=*9>?-1#3Q9';Q"WGD$6^?5?;HHO/T_RZ6;RB#\\G3/BK\*F9V_S MFW5"Z_GRUVSK(T^[B@:,)%384@"$4PY#@KUJ5EE,$\.:1V1H]*'*HE-0>^*$ MB?*6V>S5?)+_^7_RN[VD>%(V$"FIY%@+&O_'.5#2-_.H\JCWET4O@Q6GH=HY M+4SU=,=\Z:>+ZVSVGWE6NOG$1NM[!S-V%0\8 FLEHM(J "CD G-& :$I4H2"A_V;UQ*T9BRS%C3S&L") :K')\%_Z=0X#=>> MR;'A;7MZ/"H?)*LL'JVY8E)4KY]2SAI!)$Z,ESO^$='+($@ZLIU31,5>3=8] MFV7;TA,^*Q.HATH (Y B3,;5D).'?3BF<&).F.,SRK]4*IR"9E\[$P_9:MJD MK&Q7,3 ,L9*:(E(E*>$$H?A3;3!IDWID!KX9IG2.<4_T^6<^F_V?>?''_%V> M+8IY/EG?0MMV3G*P3I . 6HT\_$?7@O@D47W @G/2&*L(?S6]C^[@;V)YH.:<\AN:O\ M??&FG-[FNBQ^?[2R#)GK>MT)-9]4=_DVW;!Y5LVQZS?;\ZRZ&GU5WF3S^\>S M%RWR7R>W&0BF5AE83>D*5L]S4ZDWZI& (W+H-'DD$-GH-<^*Q:K<^T1\>JN! M< 2(I/L^RP3O'9: M&64)P-4F.%?8,4,047235OG(6697>-93_/=?']A:.J#J3I3@1GJ-G>62:RSJ MK@K)$S..CLB]'%";1==P=VXJOLYOLMG&:-EQ26!+J<"I(5IRHP6A0$1OF5O2 M=-JJQ">!1\213C16= 5@3P["SBC_IT6"%TIYK3FA'&E8+3'"U]V5G+[\V/Z3 M=/3,_$]"+24>]V_-*OPVG\ZC/9#-K_/7R\E?=L9AMZD6L'" 8,D\P)AS@#1P M]+[C7@$SU#->_:H[355%;S!VIO]793Z+CFVT1!-8\+1RH(A11[$ 2&CJ)7+6 M@EH(*E#B#;!11>?WR(83X4R*T7^R:NU8UG>6#=Y@YJES#&@) ?:+>UT-92HVNKQ@J#$4.D1\N$D+1:](YM"D5?S+_DF9\J;^TR3!TBQLT(@6"E' MJ"!0< 8DE%[@NK/:^$03<(2+0&W[_/9S46;EW>M\\SSP MKKEG5_E@JZ-Q6^789@@3C+6BJ.ZJ43QQZAG[FI/.BR[1/$'QKXOYS?N\O&VI M]Z?%@_3&V&JKC3K@G(*:NL8NB C7'%Z4/N)8/9['.BG\VQ^/:VNDRZB M0;S.Y7?<4> .XFUK^%#"KWUU@G$"< TQEBC^8;6"[#[&6 G*Q"&GIVVWLVFY MSCWX8"HNIG.;?ZCB4'[)RM_S=7*W3?JW=_GUJIPNIWGE3IB\K-ZS>U]FZW?< M%XM\6?W:YN7T2]3-E_R14 ]GP^\CO#KV[?>=F)RK0P$X$.L*UZ@SH:?6AID_CZ-X>TH8^BN]*BDD8:B)BB,=5 MFG'**<7,* _NMZ08Y-P?O(_:C]?0 +OA3#0U7T^S#]/9FEB_Y%E%D\G5_&U% MMLH C076.:OO_U5GB^G.2(3.OQ&HYE9C'QTV#J3%&C ,:@@5I!>2LJX;%A7C M4,( GF\CFKY;"[=)J;4_+>+..@%X5#TGX+42%DF(I.2T%H_JU.3X(^+8&1FQ MBY,G*F%(CFW V@+/&H_?YL6'15Y^J6!Y-?^\6E:IJ>-8GDW7A'@LY\$\C'U] M,C /K="08"A@]$:D@*H!%R']\I,L=-$1P\?G)4?2@D@&X]N"F;#5][M$\P+_VC80X M\"$F"%&MD "0885Y#8 5J><@HXI[&2TG>U/3V7GZE?5T$EF?M120J.*5F#"2 M2P2E],[*&@I 2.(L>O0^ZG?&=JZK8?VCY_LHU>[RK+VSM*>!('2$UV*KF?2, M0$BE)[7@ KC$W!@C.N,9I>?4G4:&I.(]2CLV]]K[1FW:"=!X+B24&,4_" ;8 M,57#@*B\2(>G$UKL8ET/J ])OO5ZL5CC@0XNU7MJ!80(X00[S(QFT2;!0+E: M1.,&NSDY(+&ZU?PN?IT,]9G8!)/8=%\K $DMCQX8&@TU]D&7, MZ^?@;$J#>@ V;5YW;)X?>5TIM]+C?L-L3ZW@O&/:1G&D]@IPZZDSM8C$'SSW M'G_HQ7BLL>[4<#ZF'32Y]M8+DE2W986GT'!*&:[>+JG%E)!?SDK8B:[;\2<) MVI1@K_7KLG7$P<,[L_OCR_=6"@PH#C0WAC/A$&1.P_J84F@B$K?87@X?CM5= MT1.R0P4>7WV.B_9R_5QEU5_W9_5D:W[0'#I8-W!) 7>P"G"DUN#J03_<^"J" M)483C7*OMELJ]07Q\(>M22OZZSW7)'KY3B NFI#,&&"U==HSRT%M/0A(2*+Y M/J+T6N,QN,ZIN#/MDOUSNOST;,][\?6F]]<[Y&MLWI?9?!'9LW@U7Q9K%PBW M&1"]?#@H"YW5%%M&J%%""NELXW5A=3GI9\[$SQ;;=6?3YHB'3:V;NV$&R[[/ M!4R49HI9#!$T?3EX"S5 MT6Y C&'I*'/BD3,D26K"[ O=Y!KGBI*NSN$]D-".JVR@70WM'8 MVTS@6DJ#-48<46(]%J")4Q V C*0'W&&6(]SL[I[[;RLR?UOV71>[32]FE_/ M5I-\\FKNLG(>BRS@,'/\G@X$C+1V&D$N/4*22,]PL[DJE$Z\6SZBY]Q&.BC& MI-7Q!/J;3]G\)@+P6P0^FTW_E4]J*4^/Z-_==B#*1ZUI7VW4<>&B7GES%HIE MZGOJ(WK%;J2#8""%I1S>;!NH?Z0-U+C$E!^Q$$ M,XX[+)&77"J%E89->' $*3'<<$3/]HUC++P$Y8[8S'J^4]"OY[SW>X%1[SS5 MSAE")=/$*]W$)EN5N@,[HI<,QS%FQJ3$,US6KW]GBOGZTO+BY5W65QXH IEA MJGKH6G,,Z7VN%<^$/_A83M_W3PY=N7]2,J@X>SKI/2 $,0^1%,C4XF!U 9>: M.]3HSNL?*5 .$M!5QXI4+W4?C!A\6C@NMWG3 :RM>52_'9'_>?WIGD/QIZ?LN @,.I;%YJ9H_35W%:2@.,&'H;%8EM7_W*<_;1I_OJA*8=@;1*)W@ M0BA1A>TW P00F+BBC/ 0NZL5I2,DST23@Z'CNRL%!ZSTB"$).9114 PLK04D M*O5!@A'.)J>KN 5GDD ]^\7Y'A(\:$6 U, Z#J%P@BO= .#\TW?E+XQ5QY+@ MA 0-1\$\*,\>NOQVNOC]P$*VKUJ GC$@&+181I\Q_DF ;=9X A)=YQ&&F'2U MF'6(YJ"4J7>K*FOOX)*VKUHP&!GK/*=62Z21),XW9B%A\G),Y&Y4O9,_)T,[ M '_>K)97GUMYU4]*!LDX5IAI[Q!6'!L?Q:I%@?P"'EKL5J%%EV@.0 R3S68M MF?&T:,".&JT\$@)J@S55VM93+[<07,Y-\%ZH<2*<@RXZKUM<4]I2.F@'"8?6 M84WB6BSBS.H:D12@B1;N""\;=6^5I((XK)]4GQQ>?7SXY=KX;N#,24 M*D48C /!0N20UK70",E+7'82-+[;*>H*V3.>RS[VYU[VL@X5#5@ZQB4 MSFE!O9;1+'+W[]%$886"+S^!?@]Z?VI==HOQ60A5]_?@-L>AJD$P[ZM[;M)Y MC.-R)]'#N*367LY.:W=J/\BGDR >@$_OEL7U[Y^*65358I-B^GVQS&8'W=R] M]:I3=>D1M0 :I8!'4ND&/\]4XE6^%\&D5(47_>%[GG6N10#3GEJ!65#]CVN, MC26<:<%U8R08]_(?MCW+ZI8([SD8U&KK?D^M8%QT"3$AP$+AE1% "%2+J#0= MZ@'3LRQGQ^OY$'>2@4VY!_,0KO.L'VT?RMY1,3A-8T>MQ%3+.'TB++AMIDY+ MAWK#X@RL2-'@]H>SN\%V".OF^E,^6?YK=GMH MW3JEV8 ,A9) 1+#SZYL'3#0C$LO4 \41GD'WM[ -B/\ )-W5VX.+W_Z* 5AM MHO6)/$!($*, 8S(J;NRH; M8%F]+;W,)_L7R<,U W+*Q2D<"&.1H%H3@57=?09(8NJB$7*G*S46?>)[F@DU MG?\M^I%M[:;'I0,$5%A-@*;>H&@M".-TG6Z MTI #1!5F G@F2;34L'*"-DXK Y>S MJ=R1[MJG(3\.V2$3-&R95YNCY08@DZT#Q(Y+$YW6LS M[/N3(<<3G:HQ9Z[J?&D;5@4#L/7MDT1!5_-?LO+W?%FA]/!@JRD6RZ>>:97+ M8IW3_=&O]I"WVP\%"3BL()-:<(E05)]H%(BUNIS0]L$85XQ(7P,0_WV93:;S MFP=1'@N\A\=[ZX4HC]?8:"X9UD JRTESN.E$JO141);AQVW MK&L3,>)WHS+VR/9%#^=:6+(2ZBS?+)33[9%D7[:[%\ MET?D(UZSN[?YYZ)-O+]P('GFAB M++)(2@Z!IJC9-<6 7V"6WX$I/@:U#3<:-M?5MPJV-I6WP7"8\RFM!D084DBS MZC:L8Q Y9FH;"0&!$TW4,:?N/0^S!U#.F7>SVCG^+5L(#B/*-4 0DKB 42>P MJX\5$08N<7=JS&ET!^9E/XHX1WCEF[RL?I'=Y/O> ]A7+4A2O5+IH_V.O1+< M2REJLZD:?A>8@'9@MG6(_O W%#<);K_.A3OJRXA41>/?6"6E=*A* T<1,\C$ MWV$,I3BT(]#SVK$_:_VS),1?X][ZVN+I7PE3"*I:]/!@V8(%8C8@"UT@L%23.-$&0O)X"W M W[U,I.>K)-!THQ\6#[LZ[1(O/B\>##< 01PCII4GS64L! ,$>@$H!KQQDEA)H:"H)5XN(]YA/&!\7VSP:/O*#40(N1B_J6RM!FA8RSS^7<#CX;.WL9)9UH<\@A<_IS MY>MFV@R3CCX5E%+<< T]P98( 1@L@;3<#S4I<7/T7PH)N^66;E\ 0/D5&+V M]]Q]BE)'/$(67XO8/$W;US#9^[W@O2&&&JYI-!B$H-Z2Z-);0RB+OTB-HCO: MT/H^5LZLV1$/F"U3PIM5>?TI6^R-I^[C<\%2SHA%T'I>70BWV/#:E232PT2K MZV*W*4?[)H..40[G& D4;VWG/M*HF(1OG(@DCTM\W M5L<_7DY6ZXL9,VO=O7Y3)<=Z_WVHG$&K+V:(-)/!,,/DZ\\%JZ0UF@J@3/3^&)6>D3CO.$V@EXPG M>O;M[_Q\'RKCT.R+&2YKO;U:+%9#+2F;;P4-M=%",\H= 4PX[F@=LT>83ATH M8[Z$='DC)%V?+V9X-)/ 0$/DR?<"41Q)C9'F0"#GK #.1(,6>ZZLQ:FO_HWY M]M3E#9/3=/IBALK&M,R7RUG>^J9JIQ\,G'+,&!,V>GM,6FB<:G;@JSW&M,$B MOQM?Y_)3DG7[8@;-@Y$YX,#9]M' 2%2KUTAZCPE' %D=[5M'A,9 >95Z7 ^^ MCYYSNB[)"GXQ(VBMO3I)SZOY]6PUR2>OYBXKY['(8M^]]6$Z$*2*4Q?EW@H+ MB$0,L(>@9$!371UXP3=G1CFH.M9SRGV<;8+\D2:(NBW*Y?1?Z[]V?W[.YXN\ MEFG:R+3SAOS _0@48F*5$QA'8YDH XRG-;00NL13&GBQX98=#:"7H.P7LU U MB_+N.60XRV]W'P*+)-'6<.D\%!)B!M9'9]YKK*TCJ2\&?P\A.(L%V)FB7\PX M6ROS?9G-%Y%L4>YEL4DR,XPAN.7#P4O(O:, :.F( UH)4I^T44=9:@KM[T$& M@YM_IVMWQ,.HF3.&&3S[/AJ:"T+C_^-_@4>*B=J(IMZ)Q+UP^#T2 MX>Q+3[J61SR@GD\;_0ZCO=\+%"LDI. &1]\340YE=0/+0<,XXU:E;C>TCT[X M/GA&HML1#YE=%Y&&O,A&K09" @V!MD![ B&J4Q!1J%CJ0#DZ/F%S.\?-)]]' MR< Z'?$ &=<]-N:L<<13X:C"2%EKJ]T6CXA6T&#N$H=*^^B$[YL YU;J\.F5 M?\V^//JW42=6ED 9B #W" @&!?;8:NZ)%M0) +$\,#YZGGH>I6UW\^4ZI\K[ M3]FR)FG^:[Y\F$+?Y.6[3W&HM$ZHG-YZ9*!$C"N B& Z^M/ "WX/FP2&OOSW M3CMDSJXI83#XATV@W/SX]VE>QD]_NEN;P.VS*>]I(!A(+>/80@FIE!1SQG0C M.$O-?S,BWIV%);M3*G>GBS-9;(OG$K1/FMRFG> 4D@AR$77,J2 *"(MK& 1G MJ1;6B"G9$2U:F$I=H3XD^3;FW,;M/YCT;D^M (W#/HY@+#U63BEBF*M%- 0F MIJ 8,[&ZU?SN=?=$J =@T\.L_SY^\L#:^;QPD)0A Z"GGF)1O;L"&+L72"EC M$A-WCCEPZ0SKY,FX#TXD$X&X*T+01$?X7<\>O0:.*P\E:"&SC"9Z%F..?SPG)[E MH,H:@.=J%A4WSZJZ5=RZ:JM W MXDM\@3E.A^)+,8Q*1C_SOLTG^>WGS8'=8EE.KZL?'UYX[&T^/O#=X(UC D&! MD9?8.,"M;A8X+G3BLU,7Y]> 13>4R;Z4Z&_XT]]WUIWRRFN57'QOA%_'G MNJ0IYNL#L2K<:;',YI/I_&;41[Y:0.F%< !X;S 5Q)/-&^S1*\/J8.[%?B:@ MASO*\U52MJ_&;RK2O"<"6^%$@!JZK1P7-L&)*$3<_J,B"3@*>?N2D%XB!#B5C+.":7(&PMJ 0$10ST4T#]53E=Q"\XD@3H :X9^ MRE #AAGDGD9,.="< Z?O ]?E$'+<,>,2Y U0A M0*LKDZB&0A%R.:>@@S/N5*P'I=U#O]].%[\?L)_V50M8">+3_EY4,OWOV1?=Y_+KZG2HCK+V*T^F^81D\UF5Y];A=@\+1JP$%!)JIV #%O, ;6F M64Q6C3) M\>7L^??#E$Y0'>)H:G,%K=EF/QQ3O+5"H%18)0'$S&HN"?4&P%HPS71B;I,1 M9@/JA2Z=@#H$6U;+59D?YLBC8H$R#(1VR!EIG'48&:T:3!Q(/%0?X4OJ_3 C M'7S8K3T!R &.^+ M939[FT?NSO3(1_NK3Y MQVPU6U;@DD%ZH1'7*ETV@TPOP5 M_7@YO: \ ,%^FT<]S:J^K@^WS"Q;+ [LW.^J$CBQT B.A>4&4*\LD8UP2%]0 M:']7N_8=(7DFFAS<@!I)+^>DIPM5/]N-ZP[9 M 0CTKOB2E_GT9EYU]R!MMI0.5NH0:("LB(]\94CR:+6B1L6*)O/>H-VZZ"#5)!'&+J:*+I MMQV8+][G?RYU_/+O^^:3EDT$+BV4FGI&-&?"">UULSM-,!EJ11KBZO5)NG\Z MO_2#[Z"3SGJR_;6H5)?-U&VQFF^[+-&J7H!$>.V-=93%218KKZ1[, EA(HU& MN%9U2:(N(1UXN;K/-9G GAUU@\$.Q*&AXY+,,+#*F8>85!37^@OTP+MD4#>P M#C__M+-X-D6#]58# I%CQ,HJ^:]"S60J/4Q\KF;4YD[GL\RQ*)YE8IGN?=!\ M:_G@G+%:4 0( $XC[!BK/4#"O$BTA=L?40^=&;_?>>1X1,]YZ_1O9;%8J/GD MU_5+?G'>6^PPS&(9DRT^F6)67< ML]FHKZ$: 0VS6#)#!"/*4((E-)@2PN.@ MY>?)//PHZK^^Z_L8[/4DTVKP[JX>&%/"8<0)](Q;2X" H!9H M^]V7,KK"=WBKH.GZ>F WMDU[6V%' \%Y2[5& "L(C&5"4*-JP:G$O5_W&6J1 M&()?'0(]&!#!&LHWJ6)!7C9=CL5RX!L]M55P M]2':'VM]O2_N@V^: X=6Q&G75-"( DT)8M5K]TXSPJ)A?@^&(>;E[]\.0:Q> ML!X-\2IS]63*58T$9ZE'IKKSBZ22!$!+73/RDJ^9C2B&]]QD2T!YV+O5.PW" MC=-T]?%C]?---HW0/0AZHC&_M^U@(0-&:6&TPUHP&,%"-5S.#Q="_**7UF' M/S]7CW,$]C<1',:8,RU='*U&*NV%:'P@2%-O_H_O)<6S$3 5ZO,<97SMR+3? MQ=C70*#&.\E5E0=W_?RVH\S?"VX=@8DA'",*Q$Z(6"SN:N"RV#VE^,CF]Z-4Q'=.U_=,(K3,:Q-5,N12KS,!\&W-2UU#O0HV);@;CYO(%"GF$=24.H(8Y@K M@V M>#0Q$R\2PV]L []#B$=DN_?D:[9K/U3W\ZV6'%&)@27Q#T%KV 1#J:E0 MDT\ 7O3*.IPBSGFX_"B-<_->2S[1F_?L'F4\?GB%;,QGRIYI3ICR7&NJ(,/0 M(UNEDH[FLJ)('W)[^YD[GCS,K.:3K[+'/7NFN3KJ_W_LO>N6V[BU+OI&Y^!^ M^8EKXCVZ;1_;G8S\PE"J:%L[LN0EJ=SM]?0'D$16N5P228B$*#ECKYWNMDD( M^.;'B0G,VVJY_J$!>MN?^1H#.&\AHU+R<&N.$!@+4$&*LKS^+8T 6':N- M7E@()8,5"$*ZF%Y/7"830!KIY]%^1*7I?;?A(I2<6B76X] M%YJ+>(IF3 HNL:1AD,9R M4ILN.EHSF6R:8*K*Y=B4!_6%V'1>!VZ...!$6D*Y\&ASF):HL,N\3YA@ MVLKEV)0'=4DVG6&@_M:G?^D0OQ- U/!&6^%5/+1!B230N(81L/%#8'_%\\,% M!%> _Q_6L]3)Z]'AD9+M3_#XQ><#-5!JC>-2I(#,:.548W) Y6[0NBO+AN<% MY080PB6XM6]GW8==^S>"0DP1!SU5F#M(XL=KZZU(>Y$;8WNC^FX$?F6)H0## M'J_U7RW??OZ^F=^E1H7[BL]QVOT:,_"H5X\1+*;T'.IX0-7&(ZWHQCH+,P+;> M20@EZLU,0^^=*8$"=-K/J]]^>_2=8#"W5#%E6/QJN#' QV^D7AXVF2&W$THH MF!:]AA)$B>N:EZ(\5HN(RO9?U?;MP_KN\VR3&F\?Z@SN=//IL,O<(8-!!B'# MC4X5=852W%I?@R.ASJQVDYM\\ OPM)"DID/C-ZD75E,&\6_I7Y;IV98[F@%& M#Y)*;Y66@&"@N9$0^T<9493I")Y0UL-54GM D5U-&H5+G@=+L:(28R\4\ 36 MR\*>9S(Q-XWB%^#B$&(HP*XGD^MG=YY^,0"G)/7"VW1 BSAQ#&B]4*YR.Q'T MR*PH%5T\+=8-*I6)A!J_6CZ_&SCQ:W11)GC1>$T9Y(%BU)Q9PF EL%#]!PYE3F M?>^$_%P#LN-HM=WQ "_J<4AM6UJB@7]^.&@1+3-I#";$ N%]W$_)84$"D-RK MC0DQJ)"\CWH&,I$N3ITF#676J8]2^\M!(&D(ITR(U!<9)U]=LV CP?4KIR&$ M?9(W \!:@$<[C]?R_79U]Y]N386?/ANLAH8*CH34G$E F>&\7@XR]'9:WPPI MVI>:"I^!:@&2N+_N/L^6GZJD8ZM[_["\;^][<_2= "$4J?"]XIX9P[1!C#6? M5_S8;B;^8D32#(5N"?(\.[6T,^?%%P+"EE -O:)Q&4Q+:;&N%V8YSPS;F6!X MQ)BT&0+: ISI:^_]UB%H-GO,X$$\F'A$4\T&1B56A-H:'D?-[2BLLF9V*8%< M(CC1K#:] E_3\P'& [#F@D%LA(4:VOAC];*B!9I;BN#Z>98A^;8@Q S +\&C M/Y;K:K9(Y07^OEJDO_K;Z03-;@,$ENJ;*N'C+"!WU@I(ZGL7 :FXG4YR$V#: M$!*8!/5^6VU.[:_=!@C)K>AL_.2 T@ )3@RN=PN!J1^]L6Y!#]P4R96:!/QI_VN(X7HB,F[56+ MIS2EXB'?6NV\!/$#9D8 :A@"3,K6=BAC7TF_A&>;#ZW#VT$SJI%&R%C+X@$U M*BM%ZF5;!ZZ_H,2 DC]Z-ST4O&4KZ#1%Q)JNXZ=BUDZ]%R#B2#JCI7),6:B\ M0[Y>)C0WU*]]4)D?KX1S-L0EF70Z&F47?O+' TW$+GM:";(Z(%8=XS+$Q%0B0O6 M4Z9/>W/Z]K=36Q\6[4L)!>11HTB,':R7C(7.S.N9,B.H7AB5_G;*E@PIY&[^Z7[0 M7EU C/5*0\,8=]@C@K6COM'2WOC,]@N3WK*&9\Y Z);(9%I]B2C,[YK4PI1P MU4/_='H_Q&.0$QA9@PTEB@!KK&B^&0PSJWI=9[A,+JG&0+K$X:[.Z4O3;3_, M_?QTT(H89TG4N@X+ *@DJ+EE%)1F^H['5"\F?[?4OC[\5 M./*2"RZ@QTXP);5/%<3B,94YK"W-S'B;4%/1 M09#M^BY["7SJ%=(O,ZCA"$ M=4AQ1#3!EB+I..&JN:M0N87N)[VEC7FT'Q+LHCQ[8=[O9XOJ[7IU5U7WW9C6 M,D8 AE!..4]5<4Q$%QB-Z^7K M>7!<-4!F?$4<8-"_HD@J*&B<=3,)Y1G(Y6 M)./&P:C,57,+:[*KOTSZ!#@.UT;!>Q)$&RCZSGB')59,&^ZC 8JB^5 O/(HS MT["?9/3=Y:F6@?BE]U&U;=Q9N=OHDR$"A,@@2;C!FG,BF*%2/D:KL$S'=/=S M9*F6VI/82O.!GTQ$WMWBX;ZZ?[4[,C]Y>M*Q>%)+8"D'SG'C@60"@5T=XWB^ M!P32MJR-:210C5/AP@OL$P384"RA9Q#M2Z5%:*!FX/KC4@9DQR 5+OH!?@7> M?(V18M9"88WAFEF#'*H79!7([4P]'085DG>'"A>]D+X!_SXBG +("$%6.NLP M=I;6"\:*7[]R&D+8_?W[_6"]&7<;1U!RH:C62D@J-<3RJ\OK@3N/4J4L#30!P@GAN:T7'?_U=E+01Z37"$ 78-?O#\OY MW?SK;*%77:),7GH\4)8^#"T5%BD2&@NJ6+THQ]@O%0N0RYX!@+U*?RZ#@#ON MC(B? U$&20!$8RJ0W'S=ZPP%.%/S#(!O"7NIIWGTDA9E1&D*H;'*8@9D.ODV M6E2W5_V\IJ8>8]I#YT/[R]7J4=IYRP6WC$L*!:>>NQJ>J)!OI[E;V0N#4@*Y MFEH]4FJM"0/42.$Q),JAY@3-L?QU+Z8R)-^I5D\_P"?ALATF-B#U7=?"T738 M%923J/I)8V,*=SO1X1-@VA 2F 3UAHD64 P912V10%')L'0"PGKA4*#,6,Y) M1@M,D7P9,K@$^;*:/"NA8;2$!:46*$UXU.>X618K=JR<=IV>P:B5 ?DE8P)^ MGVW3Q+_;>?S+^;\?TD^\^7A-00'""A\-:VB 1,YI#7"JU)*"M*40#/_*_7$8T/?U:+;]7OJ^7V\T9]6:VW2;\D@VJ7CWYL;6/!^3 ZH+(G]PPAJ'=J8BRL\8+5&@C*<%4&VH\5]!; M6"_5*)E9,'5"IO$T2)8+^ C<^E"P7.FI(5?O>)D*U7(A'XEA[^=_'2;WH5H.JMU:1@X20V8]CT<$&8\'49+. M-LN/P+09K=-/W;PYB(] K]G'B':<4IKC<.?0EE&#]4()90TBSEELF-5,ULL&(#=JJGM3 M]1LEVK"PC\VVI/7%YW)I03_,)<"L7[:OQ M(F-#C&7 2TB@P%QP(FH$I7.Y[:&[MR.O231:6^CA230DH%?C+9&*[J[S@+46 M*PI /(_4RX* H(7R_8FE:]?3W4.D?8_9,A^\%:@$>[9M/WNR_I3*[NBSP4DF%?(814@@U<0Y0YI/ M2JEB!OAHMS %I;@:%NPA^*#N[AZ^/"Q2K/G?UJM-YX2._,$"4]! K)C"CF!N ME##FT?;\E=/5!F;4&-(H0KDCB1SY@P7+'6586N=3:U9I'*"F7J2@)#-H\L:2 M.LJ0+D,>0Y"N<:O9^>9NL4J=RKI2[(57@V'*60,A26GLF*((&JP7H&1N5]8) M!:I-A$[G8W])-\:[ZNMJG;Z$J&@37(G[U>;-TE:[ \W\6S5MSX:)1S,'G'10 M"0WB<=R1?2X.]$[B5A?<.$>J1_">3#DAG-#5W_]>W7^*;'Q7+782W7R>?]7? M7RWO5E^J]U'(57K\MS337>_!EP9[-]_\I\T=4FX2@2,L. 0:>N 4MU82MJ^F M&+]F2-WU5]D:D(<_%9.8J)0*W#P<%F>KS?S3:\/H8Z\$ 92'6@!K@7.,0@D/1^*X M.,C+W3^,SK]SA=O*E2Q "[#E]2K:.OM9=NC#_,+3@:=03MO2\X6Z&AK-(M6Y7E:F+1O:J=>"BN +EIIK,DDEY #$\\IAD?&+NYU+ MJ"O8U@845%$VFM5R9Y\F9U?K!G?JM> <((HC!!@Q#D@A#/#U(@EVF2F6$U1@ MPXCZ*'_.AK9@.,+W>K*=0Q&>O1&()5I[AJ%1\7S$E&" U4LST-U.]^5A!'PD M_. \5$L0)@IBOK75Q]G#8OO^S]G7]]4B_LBGM^O5MKKK% W5=8C@!2-"2$@) M4%I8JB!N]GXM96::VJ2WQ2$I-0[,E^"8?OA^)L5>'B%HZ*# BF*#.55&$$^: M\PQBN;%3$ZHF4)9A@Z!<@&"'/1.!Z&;L8),PJ5!H2V!'\>M@_KJITO3QX+*H*AM;(*$,DL!!@*6R]"@-Q6 M3!/*[1^7'_E0%@D.C[!6F^V[>$9->K!C4/BQEP+GUD-/%(Y[LCF$.R\P0@ DEVA=E M3!:H68$A.W)N_CE;KV?)Q[B\?Y=\^BW1WJ??"L@SH!TW%A,#I>*8-?8\4YAD MWM],*#%^%"X,CVR)Y.84B/JNBGOCLI/V>/'Y("G@4#* *=2,*,8(X?6R(*69 ME13Z)\%?%V&&Q#1'=_RSFJ7XI,&B9 _IQPL3S7-=F M_PSWZV+!P+@6T!E_+*-D%M_K(#FSF&TV+%X>X MS"Q8-NG[D\DZK@82TH48V.JR.OY2T-8RB:E&CNJX'ULN#_EY<8%&FLS]:X*N MA_-%W($S6: 6<57EM7<\W6[04J$8Y53:M$+D%-&-C1^ANYV(GB%$_9/3:CAD M2Z0_INYOZ9:Q4TN^%YX.\;,BP'G!#$7&4PFM;JX/5#99)NB0&H$LY^-9Y#KF MQ2V[M5+(T;<" -I*&9D/.$FMXIP$KCD'*)^Y-TW:+3!9"VDX.5V.BJUVTLGW M0ORNF-4>.R.$=)XSHU"]3&]RBR9.<+L;1-;=^),%;EAN5Q_K.]V-VSGU[H_MB]U'" 13S*$W3#,&K?74L.9VA3),;V:3 M'%J\JQ)XCT6?O^;;\]BS&R!HS01C4?DK[XG#B,I#<;NXF*C0,^/")K@Q7IH\ M.7!?:IN,J[!-II/:'%3["[A%&[/O#MIG[," X0I!Z0G6#D31*"2;3\V8S(3: M:W/@Y+/S4I*X9"&)?ZP6\8]2.]!ZS>HN_N^AM/>$*TA(AI#GW&)%HFRCV>-E M%"^+(,LH6] 6&#.V?NA>YN%@Q"F)D"50,TR,8X0@;NOE1!I=_]E]0(D>_5QS MH+RB@@F(,N>,M" Y78BE4CE2+TQSE!D7."&.G"W1;E4-^N%X954-N+!&>@44 M-(A+**$0KEZ<0OIV:D^?*]RN50WZ 7H550T4)0 02)6._\8IM<2:>DF6V=OQ MDY\OU Y5#?JA>:55#5*8K"4F&K:,4$^U0Q@TGQ44MU/@=ZB]9T TK[3T . < M(J61@4 "3;R@&#?VG+BA2*YA1-VG]$ _:&\JRY=CI!S3U#&;5DV%IK1>.N8R MTX,PR0X)PU @,\^W'\Y7FN>K.#*$4(,\II0IXJQN%BDTO,7[W &I-""T$\WS M=0XQ8QUCT3@TU! 1%]"8=DID9E]-^D9U2'[D0WF%>;[>2P4<1%%56DLU%M T MQP#):.;!>]+!@0-R93!@2P3?=./*T\<"14!8P2E)%0\T@8Y#ME^$HI;!3$TR MZ<"' =EQ!I17D[@)O480(F04DHXZ+@5V];(@SSUA]ZX3<+6&[1"H3B!UDPB; M\M.Y!I93YPT42C83AB8S"^_:DO_[DF!@6(O>N/S6*[SNT;T-#6+2 ":B-F38 M$D3KFRE%A5.949J3-DZ'NI++!7'RT6W"**XL)41Z3P"SUAI8+\=C5NIVI"0G M,F29&&PM3^71I?3S^."*)1N( MC?3:7W_H\H#L&*3G?3_ B]Q9G=?SWDD79VZ54Q@G/[4(#^RO-M[ MWO=#NCAUAN]YS[@D%F)JO3!<:< 5=/6"C::9KI0)4NL<8??O>=\/U@(\ZMS+ M_/0+01"%I#084X(, B*N$-<+TU;>3G3 D$)>C0!MD;N.7D5>7JQ 0BB$%&DH MB ? 4@"-:S""7&8:/]?:[#Z7,0- 6Z*XRZ1ZVZ/DJY2("1_U.J;2,\AK>.(A M\G9"W\H:3:4$4B*TH.XENY]IZL;^1[,#_$4KN,<_W,J0&'P'PM "@6EXX8(@EURF#!5 ZK,#16.*,"Y MYS$0EY96>?J_L*K=,OY8KOZ]J=;?TFI>+;\^;.-?K^))?S'?,2>#^^?^4D > M*,X0T-I0C*5DFL,:2@;=[=0 NSCQ"XNJA-?_!2!-M=[.YLL?=\D.O.X]5B $ M N@4B\=+#XG1S)A:+ IXD&D.3]#Y5YZY8PNCZ&7/9E?N;_YQ7MWKIA_9PVSQ M^VR;5O?=QM-%9]/CG&%3HP\-#=8"6F>8\B3N6PU( &>V9YI@?%QYQA:42U'R M_GVU2#!M]IA]GBT?D>Q'URX#!>,92L$E0(FXU5B,'NTJ15ANJX4)ANA=DJ C M2**L/GT?%_!ZM?U7M7W[L+[[/-M4]SU5YZD1XM?HX@$:4X-AZM@G""2@7CKV M)O,:?8+=@BZJ)0<40='KL!PRKP(F M&'Y8GG\CR>#R!*PKW[Q:-K7KWGQLW/AOJ_7'U?I+_(].-N;@OQ4$)(H@QB", M E-4*H!H\SU;G%D6:8(ME"9'Z=&%593[/T9];=Y\?/.PW6QGR_M=A8%Z^6]7 MF_FNI&/G4]5 OY J7Q!@M'<(""62Y]G4T&EK-FN?_7#AW,K)WF,$IC&)VQ70 F' XO\R5;M_M!39^=@3;#55CG9C2V'< MB-.D\9.?(_WC_O\^[$WN0_WC=U6Z[.T;>SK4(6[SL$Z[39I9/9$3L:J=W@M0 M(X"<(1%E(!"P'@D.#:8$>QCGT68PC[/4FBC?_6J]S\)]NUK,[[[K:EE]G._< M4'\LO\[F]V8QFW_9V/GF;K%*]_-=]JOS!P\1%^@XX]AC01#& "I3@T8QOQV' MXT#<65U8 I=7&%FU**>L-[!0EABNO)5$&F&%QX=\>$ UE)>)SATT5C9I7 MR[MU-=M4MMK_\]7R*>6>'@R!2,83M/06XD=( MI069J9-7IU4Z,^MY99@+"Z3 8>Y=-:^AVVO,#F'T1]\)<6G*,.E0K>#-\NR(S5.,*X!-=:JZD=>2-8*;Q0(,7T0N\IDHJJ>FG8WE!2YP#2 M;>-+%J0%V/*W:+JM9XOF>VH-DG[YA6 1\S05Q(A'31.!TM;8>F'*W% :QMF2 M78V 9\Z-C5E]^5*MTX6H>MBNOJSBSU?Z83-?5FW=P-K?#(PH#9E6'EDME/+$ MHT/9 ^"E=)EW@A,,$@/6_C^'T5Q=$4(7BU?/>P?//QX_MY7&5\#73=13H- M$Y!.]\P,:TT04U8P59?F =XPE5DX8H)A4B-M*6.@/ !]=JWHJOL/J]\?%MMY M\ETT<^S%G]9Q@H"004,8X?^OOI2K?Z,A_M-/9V.&UOKB\%BJE)?M[AM4VJ\C39_,WGM M8.89:H(1-X/N9$/C6D##_+V:+;:?L_1+VZO!>"Q-B@IR5 FEM:6F.2YRD]VP M:8(!-$.KEX&A+<"CUZME%-]LLXW$_SR_<]\B:BWNIV.O!$8-E3[^CW= $LJ4 MA\T!DT*8&=8ZP:N]Z7B?!I+%A8C6ZG\Z_E(@EB+#J$ (,F.I1YXU"TQ7H3?C M5CA?Q!TXDP5JWAE_%XR]Z^MB(]!QBWT_7WY:5'[V9;[XGG;BUM-]UQ$"5X#$ MW9I*@C##Q$O[>"7.@;F=XG)#B'15 N.!*+,+;>U-DR=O!2@%D.D^RR#O/=,X MXE)/&YC6HI[7LU<5H$8^KKFWA ][Y%/QJLU@9JC@014%H)M"6H<0D3XGV 4T71,KBD( MLO"!HMMBWE;K^>K^.2P=#QGG_$2P7"@%% 1.*L2<4\0W<1?QG)[KS[GMKR"# M>R<.'P7EEW.GLO.#U04QWE7?HJ1FB]7'M^OJR_SARR9N5\OC'9XZO1P@0QXZ M[(2RW'FOK%=-^!A&-//T.TE;80HD'$TRE[ZL,;/U.K6'WY>[R+VC^7&4 *TR MD$BG##(866[6BPB*'_.UO/68>[JW-FH#MP-Y2*79M71\G2C2VF2ESVOJVT'17K6N %1 M0Q2BEDJ'B$A-CJ!IMC&B;B>ZJ0R9SKZ]R9=-Z3-UOO;M,TQ@#KB(.0,6$.\U M\H0UT$>;*],]U)N@7W>W:N^WL_6VF,]Y1,:<.D,/*Y&R)6E2FYUXIOBA$?CI MDC1/WPB60>8,\H)*Y2'P#CWFN$.8>Y3N?K\H]V1;5I]2%N3;F^;<,#*8ZL8] M](8=B+* ,@BU-@1B8YDE37B=Y;94B.&OHP?'$DV)4]/#UZ^+W7U]:C>_JT:> MY!X7U:2F[6H\/$EA_&,9^?#G>IX,,?.P3B+Z5S4[9YN:Z)E9M7N_H5;5I$7-TC[T@*:))_W?_PV/?FX&PY+ZY=_(D0I42,E=8 Q MGII_$=2 !XG-M(VZEXWY\4C[X49U^X7$-7&N-UO6P!K\Q5\(1$KG@526R;CA M:0'08U0\@KG=%[K7L_DOT\>35HER2[/ON^Y><5W)-UL=[=UP@LJ=QPB$*ZDT M8E!)3+%Q-EILS4''ZLSXB^XU=IZ1]49MC['D,4F]&Q^LYI^6[J^[S[/EIV&# MPI^-'0#VAD$&@/<$:RP08TWT"W0T,]9QBM5]KD7+GB>A21)ZC&MT3Q!21 $& MK>'2$<-]\YT3PS)+ L/^#N\;U;@EI')5+D5(@?02 &*APQP("&@#I-3Y%M[R_0>X-(X(;C:.@2!@'I$2,,&X]B4?,!@0BLKM(93H0;Y. (PKDD967 M:E7WI$OGP9R^V29VQG,F*&$,1-/)::3OKG0,PX0S/D %[6)*IS_^)BGF;!?)TM MHW+0WP\52]]7G]*J>O2AZSMLP-A3("CPSDGO(D[*^!HD[5';AWH]K!R1/R=: MBXTLCPF3ME=3N_X#!^2Y\U@J(:C S#!***B!$CB[O?CTB%N&3@-Q.$LX$SLO M_-:A3DK6>,%0J6RTB3W& &@K"1:DA@5"F]F 8H+)]^64;0E!3/)J[UWU=;7> MUB[^7FGX^3\0D"4.46:DXA@!*PS"K@8.4,%O1NN.S*NS[_P&D,XD:5U'KNB' M[>O5ME[E*_WZW6A$[_:3P6%IF75:"0F0%QA(UV@HJG*[!UVY\KX$]4>1U\1L MD,'N+#4GUEJ&.62> ,VE1C4(+DJJ4,Y#65]-6=(.+(/+7U-^^,%1<_UWD2QB MKG4\_E@A#-&6"6(-MJ^VH90=O--"YS]:6ZA-IY M81H=E,Z)MP*,\H;8,0&]QD8X[B6'!E-")(6\M3;0\V4>:P3^\PP2%>U\<[=8 M16Z>5 <]1PA&4YX,*J8]])PP2(2NEV0IS0W[F-YG/8A<5R5 +OYQ7M!-.?PW M:@$W4 MJG(O0:JH0P5QAC2E3#+<6)>[XC;ZK9HOY_U;W?YO-EYM]!.6;Y?M9 MTN^/,TN*VU;K^;J^63^22/K14DJ,O,")GCU M,3B'QL2YP)7%(21VGU]S]_U#-'34#2=[M76S^;K?\P6#Z?NS,X<.4!+N&&0(Z$ MYM92Q70-E8'R=LHCC,')LN#G;*GU#.OI1;6\:Z9W.#P_SO/-UVH=I;C\=)CP MJIGP["0/1_B5( W0GB)FO$):PM3 IK$T& &9E9:ZUQHHG:PW^-Y\47GDT;1> MOKK_-M^LUBD,(TYU)\.6*L9=W@T0*HZ)!H90Y:R0%HG&_K":9&Z^W?/X;X!2 M@Z-\'E%^O%0[3HK]-*/DL*(>0 M\N-_OZNV#^OEVVI]EZ3Q8B)CSQ$"=])C2QR0$6R>;J6 JY>#LN-$NZ>&7Z4% M-"[(Q:__+N<8'/[V3QB M(>(*ZJPUX!:>+AIU2H*H&VK&]LIN#-$7J^6J]KT MV$__:I'Y%S9"74 )/9Y7:GZ\6\_MZBD_G]N:CGR]GR[OY M;/&^[KK4)8I@D/$#!!)" YUEGG(-!2#.[.4H$'&L+4)R@M!U\R>.]5-!<4&0 M!4(A02D5R'G,:T"]H;?3\[8P_U:3DMNE%=H%79O7H=>4=\028+6(QQ=KC71N M7VW(,(MI:_7DL0VF]]O(.?W=+&:;35ONYHFW@N,86T6A]U![XHCVPM;+A!;? M3H![858<-9+.%4&)"K;UNG>3/$RY)2GSZ#L!0R"P%]Q2SF"J)DJQJ)=G&# 1K =8\G6%K,N3/#P<*">984(U!//K'\X>BH%Z0$/!V JX& MD.GSYM?GHEF"'JLO7Z+F33-5^^[SI^CQT\.!<"2%I5@39!A#,AY*:;T@)MWM MM!TZ1YC/>7$NC&5YH?OPXO!PD,9#89" D'- $662L'I!WNG,NYO>L3I%VE*. MPHP\( MO*+]UR%%^\?D0V6Z0X4((Q#4R &&K'RTV/WJ#GJLV/X: M(C!&N?W M:K-YJ.[MPWJ^_'3H@_0Y K=Y7?VY^ZO3UFN7 0*RCF)N@>=$2DJ!1+S9GPG( MK1<\\3TH0^X_&;$CH%N"5KL)[B?^=CV_J^*\=W]VBDG'W@D<:.XQ(@22>&9D M"GCCZ^4!;6XGJ'1@\@P$Z+@7;O_?PVP=D5U\;RX/WE6;A\BQ/Y:SA_OYMKK_ M<39E;MI^GM63+B*/=Y@=[M1ZCA2-"Y"\#1 MY:Z_VP#!.H6DY=A;@#50B""LZ\4S)6ZG5,]HK%@5P/W2"N&"-_"7TPN(*16W M ,*MDS)N L83RQ6&VECF4&L0YSAPO*N^5M".$:P\$ M110QB;35OEX4MVKT CP_1B=?!S\& +( .YY-\'37@I\?#E9"%4\]R0$IXCD* M"DU=@P[./4I.L,K-8+PX&\0BZ6#/ZU[\L:QFZ^4CH4\3I=/[05%L@-8(09F* MI$'N(*V7;2S*=+--,+5K,.Z,@6M!)>-V4^VF8YIG@\2,&2ZM9I@;;JAEHME1 M-2 ^CR;].[M>GXK)Q;!HX@LF<1X.8:6, 5)AIUS#5F=X9IVT_AU,IZ\%AL"O MP->^B[U^\V+@]>E/__2+@>MX6E.24,&!I%TNPEK?#<0;8KGQDGGD./",<-@81 9E;C$3]'>5NAD;&O(2-NAJ,;_[ M_GFUB+*KI]\4[:OKVK:8IAV'B :X=&^0P7CN*#**Q2QY08[ M:SBOP5#"9G8VG:"B&X]X(V->@(!_B]BL9XL(BKK_,E_.$R"IR%4[WUK>#!$Y M) %QG!"."$)"N>9; T!D!K[VO^R[8GH-"_$E+;,F,7U!F+8/^5WZCV^SC,6@H<,M<(Q\JKOH(D%DMXR'T(16;VA](5\M#2;2Z MQL%?U>;W^7*UGF^_/ZE<]>,H+BKD[???J^WGU?V3/R>KKB*?3%Q40O%E\M=T57:L7X?U;SY?8? M$<.'=?5VMMY&PW037XRRJZHO+7GHAHXKTWF>;7[ M%6[IJG?CL?$B BG!Y*?S/T7(I\\%PB21"4+"'0:,2"\;GQ@@,/.8(7\E]78. MH 5XD5S;D>B;.@6C@Y_@V"N1]-A8*Z#B ')M4XG;QIT"H"G6J>MFW ,#(7T! M&J7R-'<].+1[/AXC+,0$2!8- :B]C9\<:99%=>8V-L'[_O,%V\*4'#PO0!,[ M7SP\2:3J0)3#&T$ K@5U5 HC!:0<8=FH8^!IYLXTP1OZT:F2AV@!LORS2@DX MU;WZ5JUGGZK7#RFG_>J?8$AEJ:UL9 E,B(YM6U^O<8(UF!E F93$$:&RG U"I.*4BM5!!9;B%X=-#BW,;IDRS+ M $NL<07!?,Q19'/^EY2L9!X['0C*G M\Z[[%^7N,5[@AG F4F4(Q0U61%C!:V@0OJ%R<*-QYF@)RO'$,*X.>5P> MHP3BM(!(>*0X)UC29%W5,#B8&U(%B9855$A)K>*0F MEI[7T #,2E5)*)&I-A1)CF[\X^%>)$NIR^1;RE1W'R0P[+2&&)ODQS,*$P=T M [>TF9<%;(HQ[-5O?IPN:=747);DQGV?S>,Q:MM8Y/OUB@(RY:*HY M%8]A%-&X*VBV7Z@"-MMW/G$>]17R\PCN(2&]W':7M[_MOC3G@56.<$ 0L)P" M(1BHEXBPRK2D)N@%G<2&E@'YY5C5:S/[Z;V (V*6"*4M%CCB2+CF]3*)5K?3 MLFH067?C3Q:TY]40.?3P_:[2D3S]P=%]JMN+05LA 64"*LJ)=,CN]OG]Y#7' M-W]VZRO#DZV5ST2W2!+NO[>/7<1;C9R7'@]08 T!BV=;H^+6+BQ@NL$*BM&+ MWEW^TB^3- .BFJ-%WE?K;_.[JJ/J>/GI(!G$$CBN"93$.A-_X9'1!+>YPZXG M)G0$?3$(I)>S0'[KT."C[=7@4N=%1RQ&)I5_CBR7I%XL@#HSZ&""_)F$A9N+ M>XYZ.3*%M]5ZY[A^$YQ\6BW?Q^=EF]MAM?/6Q:[6T47XL1,L0 M*B]P!-YI(=-9U31?M5*9%?6NQQC*H,MJ8D(9G[GOXF=]5]T7(V_WWPM(:0YW MC@8KL95*6(@.4%&/::E&6[\&?T>3RX 43CE*9K9>?_>K]9^S]?V[ZF[U\#7- M[%WU/P_S*-!G4U>?HG&2DOX>UY#&V!?,[,GG87\\I!*=$ MNA$0(@A2\65__ M4<%<9K31!"V'HN2^J)#*% Z(,YQ_JWS5H=#/"T\'QJS1J09Y"KC02L93&JR7 MI"7/+.XSP=2!P7DW'*H#JL3?5\OMY\7WWV?+2.?$WCBI1W[W5'&G!PO&8Y&J MK4$IF(\8. C)Y-4D2T,7Y-60F!?8V7Z8:/O6]M+C(57SP=@QJ:)5J@71!-37 M6-12FNFE[E_NY/J(-""L!;@2EYS231XOG=,5] FRO/A\3W2N[#T!2_^S^?+$,A>@C#[2F%]*+-_(S#$+'=QXU4$ >J5]M36 M2W,(9.Y5_4N.7*^*&0;9"T8NQ#_,B%N(?QB4C^I2&FDTMLZD?BVTOOM+97=R MHZC +\2>X>"]'(/>93$HO14$Q!)#J*2!T"&FG=6U6Y4A;#.=U?!7N-,?'MXB M]SUUA:]T\_ITZB>O?8Z]%'=F0J3#T""$XC(5X8U;GBGD28=DN].OQBL(QX M)J)X&75220[0/NM13 M=C\4+4XDVPV/=XF"9@P!HGRP@)/A3+&RD/6 MLA9:@-N)_QU-ZL^36(9!^D(T:LTR./Y2<)QXCK2P5GLBI=((\7J!2*I<"V5Z M5#I?Q!TXDP5JGC?KZ> M:C\;%?\"1'QYUOU*XG0>(W#MD6#$ 6RHCE\X5;Q&64@&2U4D*.,B&X<8JS+8 M7_9X?L$B.6.=TCW""DFH)(OG,:>MP5X:9+35RC"DVJA_:Z=TQ16,V[W@Q"F M%%8*VQH. 7(+6D_0XAF*%F>>TOOA/0$+Z AN;<4#<@<-%A >%2]0"$K)H0?> M\1H@:?WM$'(TYO2TC :3Q63)VIH_?,ZP<3\W&"'+D0-:20R4IJX!R=G;N9HJ M0:1!N)LEF)P[B?2[?Z\6]__^_G8]_U+I]>H_40J/$3#O5XO[UZOMOZKMVX?U MW>?9IKH_?4V1/6"@,AZ?H5>6^GC %B2E[#2+)?26<@)+4&)U :'D,M"L%LG[ MMYXM?JNV20"KCR;*:[Y]M=D\=&%(1U #Q M6TI_*\V2\^'.U3 _W^?N]>'[/V=?39I.M8Z@G2S5DCU6<-%4 12PKRPFBD- M84-Y(V5F*8]))K9=0N^,+(^+79UVN;1O>3, [R&U*B7^(6"M5!XVH$)R0XGJ MI/,C-T)FNR#2;WGZ; GPI>] M:K]&FA9%Q*Y&I8F(&WTVUT*'KDW[AG8CZV(MBN5W?59A-?OL3G_JZ:+SB>[-9[XM2+041T;?P?P3B,)P^H/,;[_C[>(L?;;J!&7VRWIC(_/QX@9-1S MIPB+>PD26N%(F43K+3^]7#^N[ZHC7^>3SP0H-@<8ZVAGQ,$%D1$;6RT$ MRY+4.!H1WO)&4!"@>-SDAA@/,98$"G%8$G/"V:NGQT 2;>-'%IP%;G#4[SI. M6/T^7SYL]O-M#0_W0PFW=4HB.;X M+_Y8KE-JY&G'Q \/!66)MM92$^U1QCD3U+%ZE5K33#%/Z-IW:#&?C>&59:.A MN!")O%02:\R5)J+95)F+!Z&K)\B@)L7 <%YARADQ@'L,@#<,68,TM,C7"[0, MW$X#P/-%W#WEK!^H!5CS=EU]F3]\V;RK[JKYM_2IM%H:QUX)3 $JH_GE,1< M0V")TX?%<:#A+Y&(UEG JU% +>&Y_E&]/H8 S?^WR_[4Y?5@O3&6>X0T\!H9 METHHU8OV1&9Z&2<8D#/H7C4"M!/@4^L>UFV 8)#RT*3"M48A29R'JD:5.Y)K M_TQ0.PU+@YXJ,MI#Q>&[0#(BXYOTB153\-WM) M=[;03W/J')#+,^F/Y2:/2\]>#*E$%R9>>(R5$I(*D>J4[A?J?6X%V.F?ST9F MTWDPE^?3;UU" (^\LO-U$J<4,!80RDVT&&F]..5EYM3O.J[=4@ MG+="000\:Z9_$S H:\Y M !9_,/R?I>_\<GB^3W&29@RJEB(F*+'%1.IQ*C-0B4@,S+@.D;2N?3:D28LS*]FM-#FM-\ MN@KO,V.8)=I(:C N#@7FYK4@M%JL_ MTQ_VWY.:5P.C"C+O-,:.1^5I"6-U!)NG &:&X4RP5U2IS2D7VG$#;>O@_5>7 M"*]]__#ERVS]_;-]O/U?K#Y]GRR9^]6CZIISWO%(![[M"!:>:D ()C M2!F"F.-#34XB=-32;2U$I@58I]29<\<.QB/K/8<* $J-901Z7D,F@+P=+T0Y M26X((HH2!.,I^+I44%N=O'/& M3":%8<:33=HHXX;B&RL%B*4%7H'HZDVHHU9,AGP*F<^YR]/V!DPHGWDW=$.$[LFK@=B<+:$+47H_W]8PD[97@[9. M8N,9PQ(Y1TG\3U8O5OK<*D(W1,<<8G3@Y!E"*'&[.?^KNO]]MCW476N-$GCQ M^1!/O(XCB P42B&+@$&J^8:)OIW0RN$$_/S><@!<2T0#K+Y\62W?;^,YI#V@ MY/FS(7XZP@'/F5%.:8 )]NBP'.R-R8S9GJ"/;32:G(MI 8JXO^ZBGOU4I=ZU MU?WN/KZ5*D??"KC+X6XU7+$4EB?-\A+JBP6]0*E99FE$2?H;AN-.8.!F^-P?5S, M?/FWU:(E1_7EIP,2VBD0IT0]H0Y#18TVA#(FH-(.W8[C;' .#(=JCO#?KN?? MXH%.+>__6"[FFWBTZ[RC]'H_4&TH!1A"3+DC7$(*6+-S2IUY5\E_%8*,A'.! MW::Y1WB#93;NI-0!R(#7'!$4M>5AR8+;3-TC?@%JC8?RA"^S MWU5?5^MMNDBUL^WLMP[1^0/_4B"&,V&DXA$[)BC70C8'4 5$YC7WE1SJIWO- M/8RX)LS\%&L\ LW3L,%1RY#U"$O'A;66$2V;4X[*Y?25W&<68== +,^0UH0I M[6?S]3]FBX[]?#E;WLUGBU?+CZOUE]U:WGQ\NV.'67WY.EM^?[-OJU!/Z_-$# ( SY)". MGQBGFGA#20V;BK2_&0NS),5^ M9+]L3S#ZKY;)H,@Q+3.8'#K;[W6-Y_MJOF==_)?G9(M_%'ZK/LT6;KF=;[\? M"7M]X:F@0%2[2L5Y*TX9TA0C6$]:&'<[[4\'E>!J*$ '9\%^)D<#29\_$H"C MA'LCD /..4ZPMK2>KE+T^IOJG"6CU2"HE2C*\E3WM5?/_/GI8+1"0ACA&+8: MI Q'R.LE<8JNOWU\OA"?EU8Y&[TB,9RGU%T\B7]-DNK6[+'G4$%SH(#!$5KC M$(JG>V9E#8:)Y_V;N7L<8T\IA'H!"NZ#@CJ8_C\^&!#30###I2280 2E!:!> M"$"WU-YQ-!$_[R)P#L EE-7+#>^V]7UAF[NDT_N!,BH,55%)1[6?TCTHU\VN MCWVI':Y$P&BNP#MUG3T/UP)T^N$&6GW\.%_,XS>U>?_P[\W\?CY+%:LB0*N[ MW9_&]?V?U7RY_4=\/+6&.D&SL\8-6)NH_;&4F%H;53]TH#$W=':FX 1WQ8'( M5Q+M J1\O=I63RJKGRYD]_/# 5 >]3VT&B,EA>(".E8OB!J2>5"?H)-K(/J< M#6$!3MB'RL?U/Y+[!"5^>C90X@2Q3AM!& " 0&(::P BGYEH-<'Z80,QXEP$ MBYG,K:9R ,@[Q5 $P$E!@4<N0P3EG/%6 XZPX1$)Z3ENR"[E#=4^+76L&@GZPKSK M1[&F/ GR6AKO4UTT;(FD6#2?DA/Z^KL_CB?D$RS*0[>,I?)AU>R<)E6/7FXC M'J]7^U+2)\.\VE\.2D*-3:ISM;LA<]Y#TGR"@M[.G<]9TO[9H!D6U[*:IYO& M"8I3QYP5&$I'C94"8]6@XWAFKF;_?6MT6V=(:N0#6"*N-,?..:%Y'4> : :] MPP0YC[D1CQ=0T-].K//H>]%@()>M4M)Z/_SLT8 \@!Y)B8!DTFEI<;,8K; L MU36I2.V 41ZO#Y)#IPESM'W]_,DG-GB[6Q^_VH9;?YY5-^G#M8OOQ$TC@!% M?+AQDE(5#XFFOC/2&H',$,[>NN5*F3(,J@4(\RY%52ZK>S=;+^?+3QMU=_?P MY6$7NVZKC_.[^>FV(VTO!P Q58K@^(U Y!#35-;Q 1I85NKV]DII-#C %S%R M>ADWP4!EJ,44,6XLPI!*7&_AR:(OUD9K=+-W!+Z<#><$KO[.N/(+A@'OA1/0 M: JD%"QB5R^6FES/0']?4=$CT^B7,P- 73QUX/':\\W'Y,;WB]6?_TTA.!X? M+@FVF$=%P5*W/H6\$_LL8^)]2@UI^7)&!JV68/_T@9??#%YH09R@GEE 7/PV MO,7U"=PSQQ7VD!IF M.8\+-=00!C0$!EIP0PV*AY+S3\;,,-"6N))Y,L/VEND_/1P@)%80"@A!J1\< M)\E&VR_(:R-NJ'KU^3)]KF7.1;/8C=UNIJIC8>&G#P<+-3/(Q*48!046**%$ M&,1&8@[L#26ZG2',%^_JSH!Q(GEJA&@+'8>$:A07D$K$N5I[.@0R5<,$[_B' MWD;.!_/R.6J(*D4E$%IISI3S3J-ZNM3?0*&FLV1T-$>M%VI7D:,FK41. 0@U M@%@!E>J'-$O2ZOH;E^4+L4..6C_T2N:H_:3J\O+3.@P3L ,&*($)I3#NJ0X" MV$48]U'!D1[1)1^-4VS?OM>O5M?E_=Z^]_Q)6\6K[Y6JVC3%,] MZ^W\6]>XN/Z#!95"SY'A@D ><38>4%,#HE1NS^<):;!Q:?(\QG]L 91AY*OE MW>I+]=MJ;3^O[I]D"IZ@73@E?R><(M9XE.R>>M:+! MLY/\*4?)BR\$J:(A3KW'EL1S&0/1%&HL(*5SR_!,4"U.BG2#"*.,ZEM7<9JV MVO_S"1J'B+H.VWGW00+ WFC'C6966"(Y3L6(:P (S[0N)WA(GA0;1Q/0!1C: M)[.Y]=W@%+,0>&J M%8"C AV]7)3,D/93?G#Z+0<@PDM9#L7](MHP1\3H/IP M[*=W P8**R&!%4@ CF J 58OUS.>Z5REK\ZV2\ M0-_! E429"\.B!GKN7+<*V 5 MQBX:P#4 A.:&O4XP7:<@#T>#_W+\.Z0N#&,3GA@L"*=YQ$ X K"QA@F'>>/X M]+X8'V_:)AQ. "5VZO7JKJKN=[Z9753RFSTZ[J]J?3>/ZSFU,;>]&YPB7A@1 M=P I/$7 &= F&2U&>%7ZUUCN1<@ZDBY#B,% MZZR#3$MCH(4$,Y^:PA!J@>6"J!L*+K\0 8>70<'329STN^KKP_KN"\7L,$Z!1\?L#A@-OM"8..*YJ$#B1F<%6$^1@D8/&B-!?C']#]P !'D+L M),'4"8$%P=XT?D>E;&95G=Z%L[_NA!))L-[>*N_.0_YF"(&MH2']4'APH1:X4% MWB&NL,84QZ.B;,O_'1FTO?CZE^1YZ;V07!^,: GBX==&WBH/S6&ISGIP_:G. MEZ#%L0S& 20PD>H(0 -NO".6:"$1 =:+&@I'L+Z=PBD#R>Y$;81^4%Z\-H+ M$B,KE/-$(0,YQY;6TQ50WF;_WLXR.E8;H1]J5U$;@4AAF=50,RX5XM&DTLV2 MF-37[T3)%V*'V@C]T"M9&^&9HLNKC- Z2% VGLT I\XQ#HRT&&NY& M#PM$@P&!AD'E'208FF=0,V7 P K5AQ@='_ 8%S( MA*Z W'6UK#[.MYN40[F+_71_I0S;3MM,Z[M!"RBP5I!QBXADR##8T#Q] #=O MK@RX[PR-=@%R_2U.>3U;Q+FJ^R_SY3S-[6A J:_&A+AX99'XQ<6=]"%NIH<$LOB1Z>KC:EWMG_LP M^ZO:_#Y?KM;Q*%H'M.]BVX>L3S+J+ ),500!$U(1R8F 6"+96 G0EE*?)LF;3SMT.B421YPL7> M#]B+N]BM\E(:;^)*29R=5X0W2Z;$7G\'H[-D=,S%W@^UJW"Q"TJ-,9(*3RR& MG&B-2+TDHWVFCW1B1,@38@<7>S_T2KK87U!V65[V+N,$89$E#/#X03E,;,3T M48'&S^QVZHR-N:N4@+X U^ 2,\6<2'5^\]5M0])^! /-GIQ.MNPUSC!:@P) M])P 3YSRP$@":QA29;^K5V,CLZ/=#AX,_,MP\*7(F$P:GAPJ< (IT!@YJR$2 ME$F@FJ,'5;EU/2>H"R_&Q"'QOPP97VY?DTG'EL&"X]IR;!&46G# ,:(4UX!$ MJR7SR#?!^^:+$7)8"92Z<)Q?XJ[Q_B%5/!XH8YA30G!%60U72GCY!75(9P;UU2&#BJ*$==RVH-_FLW_/%_/M]Z@= M_<,VZL']TG[T%IO%;/XE^8S3?Q[\QN\B;=;?3D;I%OCU8*C"/EJ !GBH:3P. M>P-KR!FQF05!)G@@G #[BXMK"E_('\MJME[&3WY=?9D_G+S6[3U6X%YYA0A@ M#AL$+,5<-Z)B0(Q>T>M78N^9X$^!BX>I'T+XSV'BCR,%FYIK4 XIC1!80!G2 MLH8":V9+14']"CP\"_HIL' 7[_5C0M$Y5'QAN,! A!Y"KBD'$'%$'/(U*%99 MG,?'[D672E 0U?%SIS-V]=R6G7T*KCB24*7!:?5FMM_/_/03HC7?/T.=W E,N=28T M*]7/[G/$#P7HLC==: M6^FD53*R!.Q\DE4L0I2XS3@ECC*;0T?$O1V MZ$GK*:T(DI )*-(. PBCBNVS'Y&%HK4QT3C@=5V% M_OYVO;I_N-N^KSYU*4Q[UKA!2 8!.)PEG!*YD>M407#[O8D) MV3=8>)@MMH]'\,,:VE,G>P\6#-%$PI08Z+UTG#A%2*-+E,I,BKLAMO8ESL_- M^,85R80U[6\=4CC/'COP5'G<0\N@IB#^?Y\JK^SAGQH%+!/&(@X8892YB@F-:+W3_&PK5RZ86G \&(.&^L8YA2QQESM-;W#F)Z.Z&WEZ/2^; 78)+:;!Z^ M].#2B\\'3813#!ING,$: "ETLRP&=.9V.,%0V,NQ:0C@BQPMGL[O=77JVO:G M9T-JO"HML,I3(:,E&M4NK)?#96ZM@@D6]+L^9JM[\= M-.:8Q55S$7="!#2@!M7+)HZ7ZHA6HK;U^:)_[O$>'-^RG^S?JM6G]>SKY_G= M#VF>EW-T#_@Y6^&=B7J2..*90PXKBO9A3D0C@]L\K",ML/& NEW=N'_.[Y^& M:AW28G:5IR/@Z^5L81XVV]67N.,U>\T^LGO];7Y7]2@".^#OA6@D&RJEU0P[ M)X@A2/@:6FM@6SS2]5RCG$^NHQ5>+B>/$J&E=;6:1P4S6[3XH(^^$RS6W!MC M%>6>&:Z\Q:Y>GH]+OAVZ798=S[DZD$!*\&W_G3Z=:*O#^.@[07ED ' <GQ:K*LD= K10>3I3\(_5^O% M_9]1+QX5]DN/!9^;[3_"R??AO_@P,:VR1\E!8QNH%1&9G!N%.L?##X$3(1K&$3NAI/'>)>,D>,TBLXM'0(&>T MX%02B"%LS._L:@Y3W'HF=7HI);#R+N;V=,R77PA16R--B=,FKLPQ:;!X_-:Y M*I4'5>*FMX#T3[N7\S#/L8C_MEYM-O7/ZN\_' +7U4P]<26]^?@A.69_>..8 M!7WFL(&D;"V"XE(IH%0YAV$T#I3CC!JB2&9QUPFJO7)4NX!0'^9\ M^);T]P3=FX_Z81/_N=G^=TR5RQ@M,.2<\?YW:)Z^_G[9N=[FWV9?>K.FQY#! DU ME@!!SX20FF,%7&,R"$@SO4T3=&F.19WQP+[,3O@V2F*U'&X?;!\O,.V!A$(+ M3X2TSAJ@FV,4X63T^O77S,&2R.>HLZ8BQNR%BAB=-5J_48(S$$;<+,&66$V, MLIXU6MKE9L=.T*PJ?%X<7Q8%=-[?JKC9SQ;-,EJ5VLLO! "X,LXFP-H]* ME1N228P):9\2Q!@O\8[79S),1]_ML\35Y>>=W5?>=J]L 1A&_O_VOG3)C1Q) M\_\^QCY -^[#;&S-<-9H5RUI)%6WS2\8E1E*<8K)R.&A*LW3+T R(D]>8%QD M9IMU*94*1 #NG\,=#C\0$7'!B#!&E>.1UIN%2^TR2],,Z S8I29KA>8=@&W5 MA"+KT+=G9$B-H9TR\5"CK0) 6*%J1QL1.C/[\.-X7==1+@H34JY3@2%)?2 HIP?4)%I/&74U>RRR##%BA_1GD_ M#&&J#8$$>PN=9-*A6J]S##+O8P:9]],LHP]+\3F.O#EZ[LD75\D1H_GHKL[T M*%_(]-@.EY/?&3@ 0')"K2&(:L\X8C4%%5.9+3^&N$FU@:>NZ=]7$L\F"4K_ M^L?HO\I9G>QY*7D[6&&!N(Z*)P)+"&FE,0(Q"B74UO94+O"%'-PM;-"_[EFV M7F-6-;$CWQZBE])X=HP*1&!M4#PZ2"> T!1;2ZHE&N8OQW/4*1Z>EF9O MC %]8"Q-=6_&S8Y1@3*MK8C+HD91QN.!U]SV0>T8&;:B/*X4R'F,M90A%*E9+90)=3L>Q1OC]%$.-$K+Z=6/ MV]'LC^.5W:.A(4H@<<@;C;BU!EL&/:P62YRX[ HS/6J\4[C0"^2J^1ZO^YX, M#8))3*77 !,)M,<&N)J*'.B+5H"9;-^+IY-(W(7W>S0IYGO5WH.G G=@U5N% M:>\5E-@[!=6I]ZZV2Z=P"D#Z/;2)M',]VKHK:."8!2!R3P D2[#V(C(+75 M\K#>ZY@[GUWG%-8^K>7;$#6S4DI&LYMBOKU/[O.'0CQ?8NF DTAX!*R*IT]9 M'STYN)P" @WPI6R(BCFL_5)'<;KYT\&YA1!UD IG35>$&1P;=QP[S,[6@_0%FB8 MU2>3L@/U_LSH>;3Z0R)G#GQ#0)((Q8R1B%C.G%.(BIJ$")]_Y/L0+,IVF-&% MF;E,\O'Q^\>[(IW4[NFQR\S<-B80("PCT@E+J+18*(G _?+\Y5QD-L[OI[9G M0R3N $$; NRN,+A^)$@=IPEX/*4KG>8?_ZBM*TES\[Z.-EZZK;;<#D(R:=J' MC_6^^B[< 9)=PX+RTF$(HLHWGFA.J6>X6J3BZG)"C-N&38-4[C:$:J6?SSY M"D;S@EF?0ERO++ \>0&:E]M/R= MUT!'.\Q51*/9M5,&:%6<#INMX5$=$;^+*Y?C8N2/@NA1;PS& J8- @ZP>*9T M3 N$*M*DT->+<<6TB,LV*=XI&%TS_5V.@FO#WPR,$V&(I)AS(*WRBC%0D=Z;BG_\_G NGXO):)&F-U_, M5[/]EF;[:?1KI=H.L-Q.>W&@/)[+H_VL@;(<)=^1)BMN4< <1?M,E9Z)I1^N MZ9"MZ,0W!V\13PYSCPTTD*AXFO$5N6#C)Z.J/ MN/_&)^8?[];UFL=7<5/_1WE=3%;Y::O?]IEC,]CMRGNKE+=><,"1$=BHM;JC MD&"[-V:[)9OJ13:KV6PTO5GU=(Z&X5/$JC]'LVL_&L_^.9HLBP=,3RX./TNU M'J+:+>:+SY$LNVRKMK\=4-3DPBIF4]TWJ!%EB%0D-]F-5@=XF.T*FD\ML8%Q ML(M#2)-+=G_=%5>1/_\L(YM6U9RZ%)F7OQZTUMQ&2DL)G8[VKZ*"5R0'TF46 M_Q[@2?L2A*81'G8E-M_V+_K;,8O^6LQN=]URM/?1@)VUCGH@TD40L() 1^M] M28NN[DC.P9@^14R&P+QS52IV_'-\'>WM/E3*PV\'BKTQTF'.%!02\[@SJ8K< MGN16E!E@4,PE*903.)@5J-G&&GPY^UZ,%Y$?6V2@JT\'3(B@A E,%>(&>TY\ MO>-$PS8S76F '0DZ%H&!,K /U\R'T2P%&OPLWEPOSV!E( 92(,4%\HBD=%^@ M+?4Z[F1>4+I/ [5^M[H/P/-M"#ZB\?%IWP@0:Q.)& _B6#GMF<4 KDDHH$7\ MIYNW#^6TN+V;E+^*HKZ$B\N;I]+6J[OHY=W= M9%S,]J3TG?;B@"0@U%N)4M,M8X@T3E6$2N'(%P/I'K"UU43M@%,#A'2UFKU9 MA:>].$C((>"6.BTI1UPXQT1%*$-E9EV\(4*Z(T"=B..3V).7\+::PZ=9F8YO MLWTI;R\\G,K&8PF%(QIC1*TW'-6T05A?T+;8$3/+ADG>Q?X6^;?2!V8RFL^C MWEB45_O*Q&P=$PB&@!+L&,4$,.Z()'*S/,1E;J;* &\4!J!H&V)"%ZD+#V:X MOR#,LX>#8IX1ZZ7"V%@'M5&"5@LR@E]._E,#/'V:F' J-3O);+F]+:>KF:K] MM/1PT@$AP[P$FC"NG/ ?U@E)'S(N!QRG,?):P?#U(I8254T&D@G4=>*UPMB_A<= PQ^K9WE=0$ _K U;_&BQ\K MIT]R"_\8WWTMU^'&>W75D6\*1"GB&<3>:6*MX-0C5Y%"2'DY!O>)2-B'JT;) MW 'B['A67$56[M5NCQ\,"B@,-%9Q,:FX@@=(FFHAF(+,_F?G@)>F./PL;O<$ M^G8 E'\6\U7BQ&Y%]^"IX+3543LSY 4FG"/I22U3R.6Z-@=XY=Z_>LLG>W?( MV:NR'CT7O(DXMU%D/'"IWPWF7E?+L-E53 :XP63Q[F7^9Y$NQ\/W6^JG9^.) M<+=O[\EC07-)$+#8(RHX< NYSB4R8^R,=KE,'4SZ7?3_RQ&LX_[ M.L:]_'20%#)"B;(,I"). GM;(Y@!MB_?_7S<; VPN!$2GLSIKW^61W"Z?CH( M#S61<=W,K#P] (+:0G$B-Z)N@*?7ICF=2\+3.1T?/4:J'SP?! <019/$6(X@ ML5 )8VM00I49D#] 8ZYQ;F<3L0/3;&UZ[F\U\^BY@ TAJ?.@T91K!Q'!@M=$ M43;3L!]@(&'_AOTIA!]"S/A6LMPO;'K]:3*:IHJ01P0F-/>Y@.(Y6S#&G6!6 M4T&\0KXBJH<7Y/G*Q-*Q@=[M\Z"+:IW5#7RZT%@G&>_UD&T=$S2Q<5$4>TP, M@=(Z ^LK,H8OZ-S3+SB>ENALB!^=E%2<+V;C%/*]FNQ>J+WX?% VVBK>,Z^- M,$8+Z5!]389A;LWW 9Z]!@6S)GC1/<1^GXX7\\]??C\6:H_'!:6$,S(1C*AX M>#&<@GO[&-++*=,X9,B=Q),.H/=N>E7>%G4$R?N$@D2\W6>.':,"1 8HJ]9% MFYE3 MC[@W-VTQ0V0-CU?@)IC@W](6WOP6+GN."4-911!HGC-JW+T-I#J>+]8);2DE;SK?[CT[:GR M"GIDJ'64:BDYA9Q5CB#,(+^< J<-<;]LG\A#\)9LV\'?'] =XO27!^D9IT)@ M0Y@2T&@O<66.X*@Q,MN/\.&ALG^MVCFWAIB/E)Z?J[N[6?ESE>O\;CY?CJ97 MAQ6*./$;05+D@(%::R6T3B$[M?]+*)M[?37(2H1=@NW47*6&^#7DW7SMBII_ M7"[FB]'T>CR]^5>1LNN+:Q71,+J):JR878WG12IKV$K5E.-F$+!@G$'(/#>8 M82L@E\0R0(3WV&N0*2KGZ%?J0E"&Q,L!:HW_B-M!"K=,E<2OEK/Q8ES,TR91 M7#>H-K9_)' LK2;":6484H!2%#5]-">5T51[I5^/QVLX6J,Q=IV7VECWC.I& M0:R_%8AD6G*@(C6)XHI(CH5E"$C"(14LLV#\ ,- !H'^?KC626IO>?7'6D)M ME-?IS:=B-BZOU];?$^_V:FF_S)1E3XMM'>9 MN%?_V<2$K=>^MUYH0Y\)WDI/+$4>0TZA4QQR4!,1YF;I M#/&>Y RWZ],9-L2=>E.S;KO!WABDHJHED&))>45"0RV&8B6+PA MN!?^=!&D/5F!H+A^F:";2Z]=T=L'O2!H3+F E .**4).I.*!U<()HS /F/(- MF&VSHLMXV+7S94OUUW+Z,PI7L;9LYE_+Q6CR\-]3V(_B\7GXJJ\F8[_ MYR$=UH,^+GX4LZ\_1M/-8?:0>-NNYQ2DL- S[)'SD@"AE;C?(K#-/3:F],XW M43D[]IZS]*W58M1^FU^EYW8=3KN=2/ *:RD11!@IJJG$#M5W?H*)S*0S., X MF4N4LR9X.F2_COOOY7CQZ]TTFI/+5:C(TXWDGRN*O9NN";&B65WMO0T/T$D3 M"E193"0$'BFN&194:5/;O<1G7FS!MVO>L^/MD(5NL]I5=81YM=J]MP/-?RT M9Y3!F%+I<#3/+0'0/]C'<@L@O5T$#XMQ7IFKWYI^GN!*8*0$$X2AJAQ4/L'\5DH-RD.4NX YTH(3:IN)E)(F'M% M\W;-WBE?>@?JB[0]*1AUQRM#I$F*R/4PFI<>:JR@J:*_$D=R?4IO5_ ]<.<, M3@&55,X?>8W?31>1*O/Q5=NF_R&?#U@9)SCRSG*"*+36\?KH)8S-M/?1VU7[ MP#DY9"_3WI2[ST4J;Q!_;\KIJB/KDM#C39XO>[M?/B['GHZI2S876L]Z>?2M@81$@ C@D_=/$S\PPL MM^T+WZ926[DXS)]-((@I0)")=C1DQF'A8170([G/C=5';[?MY\78,]!9#\S7 MSCP+6[\9#6.E@*1.D\AY@S#$L@IUD("07+EYNXD?(OO.2Q,]7FI'"N?)1X,1 M'E'M-< 42(RM\MC6-['.YLK'V_7Z(/EW!@*R#FM>'^@VY1KW1OHV_+G@G)(@ M-?]A'"@BM=-URH(D7.8>9M[NR0?&N;,1AY,#MMJ?09#8>9 :DI%4N@)+)$%- M>B^RA>;M G[XS+R7HW_[^T,^QO7^L?KMTU]N1C_CRLVL**:3-+E9\;<_?JT9 M^C*Y'V3UKT3?%HO1>#)_/+'BKT4QO2ZN_W?++;7G5Y-ROIP5'[\_GN(D97ZG M6)[Y,Z[,U;?YZB2X0W1/>W%@"ALL&*"2"&,)P,!I(Y@G"F/H^;YPKY8VQ*9* M,>_:\AHK]XRX$I9PKQTD3"/"$,,5"3G-O3 ;X'U95U![NI_UQ*E.XHPV-?#- M9#2?QP6NBH_L;H&R=4QP"&!&&9#*8&4DXSRJC4SNSD-$56G\[1LF)I=P*.\ MO2VGJYFJO8U,GC\ 0 MX[AZU_*=I&^QU,(T6Y)!:FM\ Q@PIEAM#:;F6*9 MB1>_9+$+<^50$LM?<4L"$T1[[F@6& M9U9$/CS'YDWZNI.^4[E_U@(XQ/.>PQPPJQ0'P%,N(8:45^2/>R+.$[ZC$W76 MYSTW?1._ 7/_,H1O;QCN8#R=Q\PTH'AN@ X8;2 0"@A(2!TYH2C)#01_ M#,]?B?@.7&:#=MXXBQVT%"FE&1>J-GCB?S*KG+QF#VL[,C- V3\2.V]XDOU?HG+7D/^@//4RQ/V:" 3DG M,5520BN%@H0Y2"K&>20R U(OJ7;4JY'Y%G%SU@)_.:=Z[QQ2PJ>,)8PP9) 9 M7N_2EF>FZ;Q>/_J9"WQKR.FWZ,/OT_'BK>;#\T1\91%G3G').&+46VTC$ $U M#&I!_=Z"!6\U'XH@D0% 0RJD(M[:Y*(W%0D]9YD9$ ,,Y>X*:JW5?#B.4X-- MK'7&^VAD40H=,7%-B$E2$Q+)RTE%[('S.Q-KCR/\$.S;PFI M(D)(7BV389C;SW!X4.L7)+L3;4_BR1#VU)X3;CV)1RL(#+" >,V0]:;>.)15 M;V4UFM/^G7.K"Y-SLH+$I@SBL\6EOM;3^:Z#TV$O"-Q$05:$( BAFR-: D PU-)1(0+AQ4D:[E-4H(\E&_BDAFOJ>! $H@H MC@92C0[I.D[Y_OHF?(/F_UD+WU#SOC%V7D2$8 FQHYHRXVSMLX0>Y8E@;M[W MFP@.'@)G+85#//=!J@V'1A,DD6*04V=$17[-6&:$ZNL-6ANV^)W&_N="W"YVSEOQ+3/YFG@KB 4QJ'%>Z"_]'ORQ0C+24PFGL.4<2(,EH11#L;68#N0OT-+>$\;8Y M=@9[_ /_5IOQQMN_%@2 W !KI8*&(LJUI*PBJ;:>O?E+8:TX64O/"UX"P"!"+B#03(2 ^D5S5["EW \N5FHK,M/L_%5L7;*=^B7 M/7 R@7O#M>(1!]QQZ"WFVFT8HC55EU/&X_Q]MNVP]')DK'_!"LA:JJVTW"K M(\FE9:(BO7G8TN[-]]LVN/N1PR,1, 3AVUIO[I PV<8$L+E9!(\$$PYZ@CR$ MU-MHZN-- M'EN0QW9!< X2^8(3MC_]>-14@B52N+A!:DDLT!8BXQ^B)O.2[.@@Y3>)/!\0 M#$$B+\9?X[D7RBEII,/:>$4P017IH]&2Z:^Y_,N%WF6P%_YW)7K?]B_\VY:% M'Y[F<$"L??>3"=2PR :KJ9!"Q?])(F'%$ 5!YG7$ (^,?5Y'#)FE%R5C@Y"M M0*E"D =S?I"+0U'>NVN'<3+AA7TH,%.*]2>.1(#@#(W, Q6DRZXAH@"GW M%@HO-&064D=K_[30+M,M.MSH]S.2Q<&BX)S4XM,ZLX-0DT=/*CCO3.0/2;5] MH(46*U"?793VK4?Q=^N;.2,A/0T\,-"'B*U$2H(P PYI26&$%K4KGA&GI-Z; M(-'2WME4.^E=6V-C+:NY S)UWS I"$PA1 "$%0EQ=BKPY=4%.AAJ3W>PGCC5 M@9&PGEO\FOIKO*M*R:/G G!.>D(M81@0"K%'WE?+, #;BP%<#YQ_VK;[!,(/ MX99A*UGN%S:]_C0933^,;@M;WH[&TU8"R+9_+@"^:@J+.%3<1]N&4L\KHD*( M,^\+!HCF3"PU%K_5& \Z /;G:'+.QE=1JZPJFORCV).8_>+S@6#GN/)2&^ 5 MIH):IZIE(8@S^V\.$%K]@J)LGA?=0^SWZ7@Q__SE]V.A]GA? MZ!O];$"6&(6(LHA:JQUG1KB*R-I=T"&_2T#N/NCWR<#NI>09/1^6\DO^U34? MYO/E[?IWN7)QXH>"DA!S*3CGC# J.:!2;PBI!?=O^>?-2T*W+.L)^X\Z #Q8 MWZEZ(./E(:*%HGA@(90*22W03..*8!3D8GRHP5'#P7BK;.K@PLF,[L:+T>3Q M=[NY8%JW"#G@PNCQ@T$Z$35C/!0)RBC#&G*UN3A7DGJZ+T>LI?TA\?Y'.8EB M,U_/]T.Y*.[O'P[:!@Y]1_ 4:6F,MC!:!]9Y338(3B10\G(\D+FL?ZD"<0N4 M[4Y >VP=DRNG-IXO=20<9L!8B0&7+IJPS!.EJ1%@7XA3ZWH\84+_,I/1?'[$ MU>O344$!HS1/J[,<,612*\)JF0BY3,T[?%D\F+W;M>B)M#S8[)L75W^[*7_^ M_;H8KY$2?W@*D/BK\+ZX&4W<=)&6^?+UY@M/!8D(4%0"PIBPA@@@**X)P7QF M%8\! J 1SI5-$;)Q[J]GLO5*\>DC04(N%/=<>(^\HP##J#@VTR4"GO^E]DD\ M*ANA6DY,\6^U+OU""!8O'D0#WF<=Z:,5M- M/*XF,Q-Z8.S.8U79&AD;X_^[63$93:^M,ADH>#HX$((=)AQXI)V62#�4( M+T17&8-GB843B=F%KR=R9AD9]DM=797+2(7IS:=D\HROBKG^]7^7L_'\>GRU M8M[N(*CC7A3B"088:!QEVA$KN/:FUJ'2X$R/_8!0U88AT0FM>P;=P]GO#WDZ MZD7!<+J+K_QZ"UE AI)804FG"&M5?U5+VXG&ZB;;&P/)&DK7+_G=O! M_7$6S)932#F$N*\S"-=F5K,HGT@2@.-.&W\4-6N$Y/)B]%8FEKH( MUSZ.!YV8VU&"'RXP37AO).V.48$!@913"DMFJ,7>"%7KG& Q& MJ2+0&8J-A 2*FE XMTO.$&M]M.%XZ)+V P1IM9HCE'O.BT,D M4CPJ&4!EM+$Q-(R@6IHUTID'D$'OK^T"ZD0K%HQZSE\FI4_QY%WN_WX M+SX<), <$(V\L,0B*;$Q][=7Y")CHMME9MDPR3MRM*[,E-7>O]$$!SCR7QP3 M& 9">^^I,'%YS$)+ZBB(5#PI#U%#K./3DL^^";)V@)J',]RKZ9X_')1P!E.A M$+5"(((1E;*6*&PORWEZ(D_+AJG9!3S*V]MRNIJIVGN*?/YPL(@BY[WF5@G MD6#.W2](RJX44Q#27CG%!-H?'<8%N+ F6H MJZ-TUWM*!H?+EFC:$V@>M.$Y$CD/1@:(T\'06>4=\?,/RZ0@R^_Q=\7\KIBMIK;-L7+,.P+@A#-N M& %62!P-LFCYUU&#D%W.U7 S2&F;P"=BYE,QNTKLN"G*[U_+Q6BRGM^G\L_M M?K@#AP=C,4!"4^^5(<#$_UNR68B72&>>CP=X!=$.4AJD[8D@^5S&[!$!AO'$>2.40LEMM6QPEM!,B-'!GBV:A!=W=)\B/>A*\-.W=W- MRI_%M2]GZ8"0$A^:O!K=]HW@#64*"6#3?SS"1 I"E?%_5!O(XRE:.6LMY[7MPG$FGL7K MP7,_C.C,L;Z._UK72%C/^7/D^&PME'ZY6,Z* _;?H]\5(,'2,BLA0A@;YFVD M044.ZEEF#T]YZ;ALF]!=18Y^+NZ6LZL?H]2WNKR9C6ZWRF_@7/4F6O$VM3\Y&H./AP>! M**?8$^.E=Q8P04E%:H^@RXP6A0.,9>@":B<1MS=$?2[2]>QX>M/6OG?L!X(U M41T(YGC*="",4,IKPF%*++$3=CPTJI<(1((B@0$)N+0-5%3///<\LU7EXN,!E;5=- MT_M,C7WO+"0:.2LE-8P+&$^NMQU^-KGYM]X=EO"P(A8BG M/*Y,,P9=ZOQI[NU/G(NMRXZXZX+4@]WO]&BR+_KIE/<&I87CFA" ,!!1_*PD M]9D;4)=Y$P\O-DJO#ZH/!9P?BD6T8"HFG[PNI,@OZK$&$!%B2?(# MU1*KJ,W-XKW\Z+OVB=TS C^G]BW3XMJ-9NE6;?ZA7*B?H_$D92]&H]F.4\F, MZ75N,>E#7Q^H8(1#)@"BV$J'.015OH@7$N4B]/+CZ;HG?A>GX='\1SV]3Z/Q M]=?RTXJX*6AP-/VE?\6S_+RS5Z.N#_]I<$# %*)-LP5 M-)%:YD&B"F*YZ6+P\J/JNB+Y4/3X6@6\)&6;6-;Z!6$W/5!_VZ=BU'\/LY6Z2_7J=MI\6E[5NT1HP.W!C)KB(4> M&LZ@U=S51T)D:I>P^HMGO_K6I(]\9M(H09@ZB=#7"0/S)BXI$')M< M1]KPE$&:V 1CGIJ^KF+Z@>)^4$O"! HIX'35D)&O82&,5(MGEG2 M55O>+K1S$Q!X*N%M$+E'<>ZQ96_34JVIX3*27'&B'(+IL+@VM0W#@K%CI7K+ M]=8+7-_2EW?7XX$ ("2W@O%4N5;SB$%;3=8Y=3G]6)M@6-DX03LX:'U.6:Q[ M2O;6SP045V\(UL!',T Y#-VFOV"VMI/G@JF#A7 M05(U:XZ9C30 F]NJM 1L+Z?)70;77N)[%MDZX/P_QM/Q[?)V+^\?/1>L\EH@ M[74\>QBKE(GKJ3=#ZOW;!P40SY?8I4:=1@()B(O_K;=#YR^G MQ]?I+#X ,UE$[0 U'Q<_BMG[\>C;>+*J2;97V;P\(!BL'"% $ZZML)Q "ERU M,(MR2W.?"5J.96[9 DES8FR?;Y;O=]1FWS *LYAH81AQB47"4]?6$@>1Y M&!A0+GFC&J9A,# MD9HJ( G&J0(78R;RIS;"7&?M03I'40;CGQ7=;IZ^.=O*IUEQ.U[>VN)[6MCT MZM?[6,X?&,U'P2-$3./X^7W<8K MNAW/4X[<_-/HURYW]K;G _860Q#_!U&1,X?O'U)M_JAF MBO'/A+1WTTBZ8K[X_'+1M7U#@D<"1(A**HWR7"B/;>U\0QYG^BT'E&K5#O^; M(VD.!OXQ6J12UK^^%K/;\GN:R_U4MH%@UYA +6>(&8),BG9D#BL"Z^V*BO-O M\-0."AJD:0?'"#^>QA-T"F.J)QE_2KRZ?C?]6:S-U _E='1U-5N.)JLPV5T> MSZSW!>&C"6R1)IA@+ZST4-9&$>*Y$/T:SFYT9'SM&!0T!849KQ^-!"EC#":ZO#ZS,3>D84+Y1:Y!JCJH= .>W MT7B:SE4?IU]&*4;SB0[> 9X](P-10BD'6%PD%PAKROA]) LVF5=W TH):@U MS5*V Q#5EMHAN'G^<+#,(B24L%HZ#@33A-5>'.9L)E2&5 .[-:R<3,T.X*$F MD_+/=,_@R]D*RVIZ_;X<31]@.FK8J^5LMMOE>M1[@L:20BP-],@*[X &J#XQ M4)E=RO,U^%[;)'0'>+/%73E/CH3I*J9ROM+%N^R@EP<$ $!(4BL,3"E M%U7.9:DSKX"&5)FZ-00U0M$>H/+@XO((O#P8%1 @F )*@(\ZV0'*,*_OV3W/ M#EJ]9*]O\V3-\?\DBZN3991Q'^F8:D@MURQ^OE+]Z^47[$G(:/&K 7@5]W;J*"'6$@A68DZ=F +X?193NT[2)+OHCVS?@J%7Q,D]V?+__2\P$" [S6SBGLG8!&>.&K M92G ,[7I@.XN6H=,$W3M8J=YV89XOR/YZ="A 2/"#>$""AD/VXQ&"P16BT40 M93JF!@BB+DVRAJG> <3^52371'&M?A:ST4WQN+7L@U)N>C0?7^W VU'O"512 MG2X* ;042\RXH+HB@T4XLQWB )5>=M&DTTMP'5SXD7< M9[]%BS)*U:*TF[W7"W*]6R_I:YZFP*R:C9+Q1)6M62_%+.?XZO4_#C5 MF'U)2W;SX51MP4A'O00.1@9Q(D1-/,1R8P4&N%,V#M9!,F@8Z*Z,UGD44SN> MI0&SK7>3'7T^.$:DUE@J@Y0R0%'O745(3VWF%?> XAO.#>E-L*D_(V)#U6.: M^AWYIB @-I!Z9GFTTY2@%(OZ $ 8R-R;CX_)*"//SPNQW5!\^-[RO5V'&GE_ M,*GF&_!*,RVE!XX:96J9]20S8VQ 822M [4//O1X"^S'?T6A7,567M"5KQ=( MPGBPAE)2( WFWNEUH6#-#)!]%Z&/)N5=,5O\^C09K4)-4IWTNZ2)#[_GW?V* MH"V&DGF$*4-44">LMA4!.,UUNPSPY-L$"+9>[C9*Y$XJTFR9K_[U->T-ZP.B@N,3& M:N<\P"H1D%BW63+'$N0&P@X/8(WR_U!L91.Z VQ]*;\O_DP6U/2Z^M$6/XM) MN9JY*>>+_=7X#GY'4)Y[P %1 &DOO; X-2Q8+U]!*I,?IV M *#WQ6A>_"@GU^]N[V;ES[4C;2^"=HP*8-4B%&+IF<36RE3GLEJB!"K39A^@ M6[1-"#5'X#[-J4.NWOUVYS7RB9"<.]PHA8Q7U"C"'($U M\:#); )U^*XGU_B<%C=I+5_/&:8]\:3/S?%#L;MF\_9A05*ON?/.:6Z08*L@ M@6J1FNI,=7N\ =?Z+6$?&^/Q!.X31;_/B^_+R?OQ]UW>_ -&!TLM\1!#AKR+ M)"1::U MF3N1F30PH&H ?6(JF\Y=5,2J*[]]_/Z^G-Z\'_^L+NK^O9A<^W+V M^XMEA8\:'[2'482LXD(C8Y%Q%K%:HJ*5?#'WQ2W"JPU*]W@C_&YZ5=X67T=_ M750;4XR4,< +:820\3_& VX((HHA*2W>E_]R> !?1;N=_4N?/A>P0YYKCEBT M]8G4'FN*J^D9YRZG3UT3+"J;HV07]QJ1+2LWU&]%>3,;W?V(V'RN74^AH.3!CG\%#,-$?5@S,R+J[_=E#__OMH99[\29'#U MEX06_ MFU^'=^X%6-S_8Z#&8,:T2N6",>)$,B"KJ2)L+B< J %NE2=2[VA& M7Q?C];X0?WBZ'<1?A??%S6CB4KV97UL4Q0M/A3@SP+TT#',!)#.3KG%^KV>R=;=_^DA('4PT,TP8'">=FO2J>LG2F_-/YCZ)1V4C M5,O)W_EG,;N.9ZI_+R"Q\P*GA'),>:*4)3R5/K1)SL M9MI*T_.W^/(95;9%Q1SF_U:?M#\7X^E\.4OEC]_-BDE*JE%F-P8.&AP$448B M)QA2$!CKA>*U1C-6P[/?X9N!0AO$S$SGJU35K@O]K<\&)+E+U4TH51@3':T6 M4(,VGI S-?J (D*:T>A-$;"+4@NK=+SQSZ*>;NI-];CTGEKX(C)JTRHF'LP2D5S640[5T E@-545UX8!:C/W&,&I&X:0,O3<@R=DSUG-SID MEJ/=L_PZ&R7ENO[=IV)V]?*-?IN?"Q)&6T]Y:9F&E"B'H*P)I;$__S3YYO Y M(#[T!-@/JXK076)VRQ=#5&8"602%EEH:KXBSHB(7E"PS,7/ JKQ_V#;#BAYO MXJH_+^'^#2FL;+3?E;92,1W/8!JM$V(Y= +O"QIL*WSC@ [AMIA?S<:K>F\[ M8SF.>U6P5!KJ-<*$0V,MQX;CBB [R7(\.VL)D&1T]D]G]@=G -^GZ="8?/% M^#9N5+MN A\_&* 50N%X3K6*8D5H0XS@B! % '1\(!#BHO<'0<4 I M 8AI7>_ZF&?>I@PPX+$%W+5%Y0Y ]N BX EA=L%JQZ@@="KKXP05E#/).#-4 M5$N$E&8&6 RHX5*+0&J.KIUHS[OQ8C39I+A\_&XW[%G/5UW%'7:^POXJW_T MK7G\ZX+'3'D*)<6.688M]HS=GU]\9MF5 35M:E5;MD[P'.^F7TZOY_\:+W[\ M*";7^XW\O6,"3:V:!6#*DB@UC%AD?35E*5$F1L1%8Z1IJG;A.9C>C<:;:9K) M:'R;6BMO?JA]'^ZONV(Z+_9N1L>_+!C.N22IMR(1FAEBF*(50;00F8&E\J)A MUAFYNZA[D;IXIV[>J=#"XW;>H]1)<31)3U0/K#SS^Y5B_DN#\5AK#(C32 - MH$,>5@3"7.6&1X%7 (9M;TNYU..U;HG(G M?JV?Q5JC'XZIK6,"<-!! 3%V AK)4-\LSP!@=&Y^3ROPV_?%%D[T6*SJ()3 MX,/\'\7B1WD]__C]GB)1+_\HKF_B3P^>VZGBCGY;\)1;!I63$!NO*7.&DXHD M-IJ@F4A[':[Y]@G>12;BJ@MCZA61PNCC863M.;G;5'QY-TUA-''J:4_>;V9E MO"U$ \&J2'R&HYT@A/*.^HHD2MG<1JZOPTW?/L$[P* O9\7X9FJ6D5?3N&// MXEPC4>(2TGEE]=?):EU'7)!GOS,03 W@3C@D8,H?@:0JYR\@9CXWX>IU>/N[ M(GN.%_;CXD8)*;J5"R@BW_)1,,K<,@W2]DN MK@CCWA7G>+UBUI?EM_GX>CR:Q9E_G*W6VZ,VSB_8'+ MU(9&6HLDQ8) 3S"HR!8)FKL]O0[7?1\LZ 2YMY%Y/Z*16(?:KZ=Z1-CA@:]( M"=Q&*XR4-(1ZQAAUJEJ\<2SS@A*]#D]]2U3N(N7Q28>LPY&U9V34 UI'"\ * MI;W0!M&Z[[J , I:)J!>AZ>^6>)VXD_=Y/84BP3A.+X\E6 L:E,=: M^\4QGIF-A5Z'2[XAJG974NMS<9=J%%72=XN;).Z9,-D5*^(Z;B=.0=X31:;6Y;@O.S@7-1U0?&6]%,?3 MV1XDS-O&A(@2*1WRGDI,.&6:050MT<8#^\6HB=.9_%1<&Z)INR(9C]6CAZ4F MNA3%^F!OQ_.K23E/C1CW2^..48%"S(VCW)C(&L,=3EOMJNF!3S>[_0CD"Q,^ MRIGTPK" #(P'5(A2D9O41 (A2*N%>@\SSV0#%,M&N+W-H70Z9;L1SA[[8C0O MH\@R(XG7C" !F:2>">68<)Q03A38IU$.O&3/[HP!)>$N;L[ ,>JUI5)1N)F> M<" ['/^\).M@'NULC7$<*0\^ [5;U3S.SO&X!Q"OE.?4I6J]U:2-S6VJ-B#^ MG\BK'57-CR-=X_QV1U8U%YY)CAWDG&.A-$@GHVJZ2%] Y=&3>+2MJOEQ5,N) MCVJEJKE52@$/I&2<2\@!@:Q>=RK(=!',SF/4$57-CZ-B#O,[J&HN*?5.:N(] MXU&U.0J%JQ9!+E\.K@5U7&D M.=JV:[(5E4$42:*9H4X#A3R2RE93!?Z26I&=SJWGK:B.HUX'(JY'DZ1YOOPH MBL7[A !$&&RN\JK55IAVD7HVBA*NI8#QS$XH ]Q#3F?Q 9C)(FH'J'F0!K3U8+'U MV6 ](40!A+Q&1F",XY'Z(O5,$RPMFZ5FSM'RY/9( O%H6''B).5Q'X6>NFH; ME<+YS!*, XJ#:T9[-$7 3JH?K.E>SW93#$L7T^+[>-<-QYZ108IH.V%,O&1, M>Y;#)V@ R5 M"M$^.(44\XUQN0,?6\<$K5'AI'B5-$;-# M_T&_Z 9 MDO:!GG^.)LLURR:3\L_D M#E!T,EF[N,BXB_982C9[7\[G9C2;_?I>SOX+%_74WGJUO>'9[#PY]18 .6#N?T\];W:@:=>PH!,1H332 M ^&8PYP#5Q\>J&J\]HCB>LM4^6DX P[5.=%STP 5FV!T,8]+2L>UZT/9?3\B& 0,-9)JQ+#! MS$/(ZO.= [G5 894"KYEIF?3LIL\QOY*QC2?QN@L=YY9CCV,1THC@-/.<.V< M3M$K>M^]6TOAT'6)B)2Z44Y3WOG'[UONNS)*?1S]UJ I@3(UM).$ ,,APQ9M MR"3COG3^Z72-8F5KQ8^V"7_&T1*>Q,T26*41U!Y:!BCBU4(]HYFAFH<;AW*- ML&EQDPKP?CU+H#5*X@ZPE)PS=0/#^9=BL9BL:ZJIZ?7OT^5\.9I$ _CG>)ZJ M_.^ UE'O"2C=5"!+L ,H'K:,H;(6*<=EYEXV().T38BU2>JSCA143AI!I024 M>H8PP5&ZJJ5:JS+#B ^W>2]A_VJ6QF<5_^64= :Q*"H4B[@^0+VHEA;U?Z;Z M.SS"X0E\6@L#:Q,^S=!V]QGJW_Z>'OTVFA?_YW_]?U!+ 0(4 Q0 ( ."" M5DB6;LQ0?38# *3L0 1 " 0 !G;')E+3(P,34Q,C,Q M+GAM;%!+ 0(4 Q0 ( .""5DBHLEB:@AD -8F 0 1 " M :PV P!G;')E+3(P,34Q,C,Q+GAS9%!+ 0(4 Q0 ( .""5DB+IWH$]RP M $G< 0 5 " 5U0 P!G;')E+3(P,34Q,C,Q7V-A;"YX;6Q0 M2P$"% ,4 " #@@E9(X3!KC4R[ "V1@D %0 @ &'?0, M9VQR92TR,#$U,3(S,5]D968N>&UL4$L! A0#% @ X()62#>8HG*'50$ M[4$2 !4 ( !!CD$ &=L