UNITED STATES
SECURITIES AND EXCHANGE COMMISSION
WASHINGTON, D.C. 20549
____________________________________
FORM 10-K
_____________________________________ 
x
ANNUAL REPORT PURSUANT TO SECTION 13 OR 15(d) OF THE SECURITIES EXCHANGE ACT OF 1934
For the Fiscal Year Ended December 31, 2015
-OR-
¨
TRANSITION REPORT FILED PURSUANT TO SECTION 13 OR 15(d) OF THE SECURITIES EXCHANGE ACT OF 1934
 
COMMISSION FILE NUMBER 1-12291
THE AES CORPORATION
(Exact name of registrant as specified in its charter)
Delaware
 
54 1163725
(State or other jurisdiction of
incorporation or organization)
 
(I.R.S. Employer
 Identification No.)
4300 Wilson Boulevard Arlington, Virginia
 
22203
(Address of principal executive offices)
 
(Zip Code)
Registrant's telephone number, including area code: (703) 522-1315
Securities registered pursuant to Section 12(b) of the Act:
Title of Each Class
 
Name of Each Exchange on Which Registered
Common Stock, par value $0.01 per share
 
New York Stock Exchange
AES Trust III, $3.375 Trust Convertible Preferred Securities
 
New York Stock Exchange
Securities registered pursuant to Section 12(g) of the Act:
None
Indicate by check mark if the Registrant is a well-known seasoned issuer, as defined in Rule 405 of the Securities Act. Yes  x     No  o
Indicate by check mark if the Registrant is not required to file reports pursuant to Section 13 or Section 15 (d) of the Act. Yes o     No  x
Indicate by check mark whether the registrant (1) has filed all reports required to be filed by Section 13 or 15(d) of the Securities Exchange Act of 1934 during the preceding 12 months (or for such shorter period that the registrant was required to file such reports), and (2) has been subject to such filing requirements for the past 90 days.    Yes  x    No  o
Indicate by check mark whether the registrant has submitted electronically and posted on its corporate Web site, if any, every Interactive Data File required to be submitted and posted pursuant to Rule 405 of Regulation S-T during the preceding 12 months (or for such shorter period that the registrant was required to submit and post such files).    Yes  x    No  o
Indicate by check mark if disclosure of delinquent filers pursuant to Item 405 of Regulation S-K is not contained herein, and will not be contained, to the best of registrant's knowledge, in definitive proxy or information statements incorporated by reference in Part III of this Form 10-K or any amendment to this Form 10-K.  x
Indicate by check mark whether the registrant is a large accelerated filer, an accelerated filer, a non-accelerated filer or a smaller reporting company. See the definitions of “large accelerated filer,” “accelerated filer” and “smaller reporting company” in Rule 12b-2 of the Exchange Act. (Check one):
Large accelerated filer  x
Accelerated filer   o
Non-accelerated filer  o
Smaller reporting company  o
 
 
(Do not check if a smaller
reporting company)
 
Indicate by check mark whether the Registrant is a shell company (as defined in Rule 12b-2 of the Exchange Act).    Yes  o     No  x
The aggregate market value of the voting and non-voting common equity held by non-affiliates on June 30, 2015, the last business day of the Registrant's most recently completed second fiscal quarter (based on the adjusted closing sale price of $12.88 of the Registrant's Common Stock, as reported by the New York Stock Exchange on such date) was approximately $8.79 billion.
The number of shares outstanding of Registrant's Common Stock, par value $0.01 per share, on February 18, 2016 was 659,733,335
DOCUMENTS INCORPORATED BY REFERENCE
Portions of Registrant's Proxy Statement for its 2016 annual meeting of stockholders are incorporated by reference in Parts II and III


THE AES CORPORATION FISCAL YEAR 2015 FORM 10-K
TABLE OF CONTENTS


GLOSSARY OF TERMS
When the following terms and abbreviations appear in the text of this report, they have the meanings indicated below:
Adjusted EPS
Adjusted Earnings Per Share, a non-GAAP measure
Adjusted PTC
Adjusted Pretax Contribution, a non-GAAP measure of operating performance
AES
The Parent Company and its subsidiaries and affiliates
AFUDC
Allowance for Funds Used During Construction
ANEEL
Brazilian National Electric Energy Agency
AOCL
Accumulated Other Comprehensive Loss
ASC
Accounting Standards Codification
ASEP
National Authority of Public Services
BACT
Best Available Control Technology
BART
Best Available Retrofit Technology
BNDES
Brazilian Development Bank
BOT
Build, Operate and Transfer
BOT Company
AES-VCM Mong Duong Power Company Limited
BTA
Best Technology Available
CAA
United States Clean Air Act
CAMMESA
Wholesale Electric Market Administrator in Argentina
CCGT
Combined Cycle Gas Turbine
CDEC
Economic Load Dispatch Center
CDI
Brazilian equivalent to LIBOR
CDPQ
La Caisse de depot et placement du Quebec
CDEEE
Dominican Corporation of State Electrical Companies
CEO
Chief Executive Officer
CERCLA
Comprehensive Environmental Response, Compensation and Liability Act of 1980 (also known as "Superfund")
CESCO
Central Electricity Supply Company of Orissa Ltd.
CFB
Circulating Fluidized Bed Boiler
CFE
Federal Commission of Electricity
CND
National Dispatch Center
CNE
National Energy Commission
COD
Commercial Operation Date
COFINS
Contribuição para o Financiamento da Seguridade Social
CO2
Carbon Dioxide
COSO
Committee of Sponsoring Organizations of the Treadway Commission
CP
Capacity Performance
CPCN
Certificate of Public Convenience and Necessity
CPI
United States Consumer Price Index
CRES
Competitive Retail Electric Service
CSAPR
Cross-State Air Pollution Rule
CWA
U.S. Clean Water Act
DG Comp
Directorate-General for Competition of the European Commission
Dodd-Frank Act
Dodd-Frank Wall Street Reform and Consumer Protection Act
DP&L
The Dayton Power & Light Company
DPL
DPL Inc.
DPLE
DPL Energy, LLC, a wholly-owned subsidiary of DPL (renamed AES Ohio Generation, LLC effective 2/1/2016)
DPLER
DPL Energy Resources, Inc.
DPP
Dominican Power Partners
EBITDA
Earnings before Interest, Taxes, Depreciation & Amortization
ECCRA
Environmental Compliance Cost Recovery Adjustment
EGCO Group
Electricity Generating Public Company Limited
ELV
Emission Limit Values
EMIR
European Market Infrastructure Regulation
EOOD
Single person private limited liability company in Bulgaria
EPA
United States Environmental Protection Agency
EPC
Engineering, Procurement, and Construction
EPIRA
Electric Power Industry Reform Act of 2001
ERC
Energy Regulatory Commission
ESO
Electricity System Operator
ESP
Electric Security Plan
EU ETS
European Union Greenhouse Gas Emission Trading Scheme
EURIBOR
Euro Inter Bank Offered Rate
EUSGU
Electric Utility Steam Generating Unit
EVN
Electricity of Vietnam

1


EVP
Executive Vice President
EWG
Exempt Wholesale Generators
FAC
Fuel Adjustment Charges
FASB
Financial Accounting Standards Board
FCA
Federal Court of Appeals
FERC
Federal Energy Regulatory Commission
FONINVEMEM
Fund for the Investment Needed to Increase the Supply of Electricity in the Wholesale Market
FPA
Federal Power Act
FX
Foreign Exchange
G&A
General and Administrative
GAAP
Generally Accepted Accounting Principles in the United States
GEL
General Electricity Law
GHG
Greenhouse Gas
GNPIPD
Gross National Product - Implicit Price Deflator
GSA
Gas Supply Agreement
GWh
Gigawatt Hours
HLBV
Hypothetical Liquidation Book Value
HTA
Heads of Terms Agreement
ICC
International Chamber of Commerce
ICM
Industrial and Commerce Ministry
IDEM
Indiana Department of Environmental Management
IED
Industrial Emission Directive
IFC
International Finance Corporation
IOA
Investment Obligation Agreement
IPALCO
IPALCO Enterprises, Inc.
IPL
Indiana, Indianapolis Power & Light Company
IPP
Independent Power Producers
IRT
Annual Tariff Adjustment in Brazil
ISO
Independent System Operator
IURC
Indiana Utility Regulatory Commission
KPI
Key Performance Indicator
kWh
Kilowatt Hours
LIBOR
London Inter Bank Offered Rate
LNG
Liquefied Natural Gas
MACT
Maximum Achievable Control Technology
MATS
Mercury and Air Toxics Standards
MISO
Midcontinent Independent System Operator, Inc.
MME
Ministry of Mines and Energy
MRE
Energy Reallocation Mechanism
MW
Megawatts
MWh
Megawatt Hours
NCI
Noncontrolling Interest
NCRE
Non-conventional Renewable Energy
NEK
Natsionalna Elektricheska Kompania (state-owned electricity public supplier in Bulgaria)
NERC
North American Electric Reliability Corporation
NGCC
Natural Gas Combined Cycle
NOV
Notice of Violation
NOX
Nitrogen Dioxide
NPDES
National Pollutant Discharge Elimination System
NSPS
New Source Performance Standards
NSR
New Source Review
NYISO
New York Independent System Operator, Inc.
NYSE
New York Stock Exchange
O&M
Operations and Maintenance
ONS
National System Operator
OPGC
Odisha Power Generation Corporation, Ltd.
Parent Company
The AES Corporation
PCB
Polychlorinated biphenyl
Pet Coke
Petroleum Coke
PIS
Partially Integrated System
PJM
PJM Interconnection, LLC
PM
Particulate Matter
PPA
Power Purchase Agreement

2


PREPA
Puerto Rico Electric Power Authority
PRP
Potentially Responsible Parties
PSU
Performance Stock Unit
PUCO
The Public Utilities Commission of Ohio
PURPA
Public Utility Regulatory Policies Act
QF
Qualifying Facility
RCOA
Retail Competition & Open Access
RGGI
Regional Greenhouse Gas Initiative
RMRR
Routine Maintenance, Repair and Replacement
ROE
Return on Equity
RPM
Reliability Pricing Model
RSU
Restricted Stock Unit
RTO
Regional Transmission Organization
SADI
Argentine Interconnected System
SAIDI
System Average Interruption Duration Index
SAIFI
System Average Interruption Frequency Index
SBU
Strategic Business Unit
SCE
Southern California Edison
SEC
United States Securities and Exchange Commission
SEM
Single Electricity Market
SEN
National Power System
SEWRC
Bulgaria's State Energy and Water Regulatory Commission
SIC
Central Interconnected Electricity System
SIE
Superintendence of Electricity
SIN
National Interconnected System
SING
Northern Interconnected Electricity System
SIP
State Implementation Plan
SNE
National Secretary of Energy
SO2
Sulfur Dioxide
SPP
Southwest Power Pool Electric Energy Network
SSO
Standard Service Offer
SSR
Service Stability Rider
TA
Transportation Agreement
TECONS
Term Convertible Preferred Securities
TIPRA
Tax Increase Prevention and Reconciliation Act of 2005
TNP
Transitional National Plan
TSR
Total Shareholder Return
UPME
Mining and Energetic Planning Unit
U.S.
United States
VAT
Value Added Tax
VIE
Variable Interest Entity
Vinacomin
Vietnam National Coal-Mineral Industries Holding Corporation Ltd.
WACC
Weighted Average Cost of Capital
WECC
Western Electric Coordinating Council
WESM
Wholesale Electricity Spot Market

3


PART I
In this Annual Report the terms “AES,” “the Company,” “us,” or “we” refer to The AES Corporation and all of its subsidiaries and affiliates, collectively. The terms “The AES Corporation” and “Parent Company” refer only to the parent, publicly held holding company, The AES Corporation, excluding its subsidiaries and affiliates.
FORWARD-LOOKING INFORMATION
In this filing we make statements concerning our expectations, beliefs, plans, objectives, goals, strategies, and future events or performance. Such statements are “forward-looking statements” within the meaning of the Private Securities Litigation Reform Act of 1995. Although we believe that these forward-looking statements and the underlying assumptions are reasonable, we cannot assure you that they will prove to be correct.
Forward-looking statements involve a number of risks and uncertainties, and there are factors that could cause actual results to differ materially from those expressed or implied in our forward-looking statements. Some of those factors (in addition to others described elsewhere in this report and in subsequent securities filings) include:
•
the economic climate, particularly the state of the economy in the areas in which we operate, including the fact that the global economy faces considerable uncertainty for the foreseeable future, which further increases many of the risks discussed in this Form 10-K;
•
changes in inflation, demand for power, interest rates and foreign currency exchange rates, including our ability to hedge our interest rate and foreign currency risk;
•
changes in the price of electricity at which our generation businesses sell into the wholesale market and our utility businesses purchase to distribute to their customers, and the success of our risk management practices, such as our ability to hedge our exposure to such market price risk;
•
changes in the prices and availability of coal, gas and other fuels (including our ability to have fuel transported to our facilities) and the success of our risk management practices, such as our ability to hedge our exposure to such market price risk, and our ability to meet credit support requirements for fuel and power supply contracts;
•
changes in and access to the financial markets, particularly changes affecting the availability and cost of capital in order to refinance existing debt and finance capital expenditures, acquisitions, investments and other corporate purposes;
•
our ability to manage liquidity and comply with covenants under our recourse and non-recourse debt, including our ability to manage our significant liquidity needs and to comply with covenants under our senior secured credit facility and other existing financing obligations;
•
changes in our or any of our subsidiaries' corporate credit ratings or the ratings of our or any of our subsidiaries' debt securities or preferred stock, and changes in the rating agencies' ratings criteria;
•
our ability to purchase and sell assets at attractive prices and on other attractive terms;
•
our ability to compete in markets where we do business;
•
our ability to manage our operational and maintenance costs, the performance and reliability of our generating plants, including our ability to reduce unscheduled down times;
•
our ability to locate and acquire attractive "greenfield" or "brownfield" projects and our ability to finance, construct and begin operating our "greenfield" or "brownfield" projects on schedule and within budget;
•
our ability to enter into long-term contracts, which limit volatility in our results of operations and cash flow, such as PPAs, fuel supply, and other agreements and to manage counterparty credit risks in these agreements;
•
variations in weather, especially mild winters and cooler summers in the areas in which we operate, the occurrence of difficult hydrological conditions for our hydropower plants, as well as hurricanes and other storms and disasters, and low levels of wind or sunlight for our wind and solar facilities;
•
our ability to meet our expectations in the development, construction, operation and performance of our new facilities, whether greenfield, brownfield or investments in the expansion of existing facilities;
•
the success of our initiatives in other renewable energy projects, as well as GHG emissions reduction projects and energy storage projects;
•
our ability to keep up with advances in technology;
•
the potential effects of threatened or actual acts of terrorism and war;
•
the expropriation or nationalization of our businesses or assets by foreign governments, with or without adequate compensation;
•
our ability to achieve reasonable rate treatment in our utility businesses;
•
changes in laws, rules and regulations affecting our international businesses;

4


•
changes in laws, rules and regulations affecting our North America business, including, but not limited to, regulations which may affect competition, the ability to recover net utility assets and other potential stranded costs by our utilities;
•
changes in law resulting from new local, state, federal or international energy legislation and changes in political or regulatory oversight or incentives affecting our wind business and solar projects, our other renewables projects and our initiatives in GHG reductions and energy storage, including tax incentives;
•
changes in environmental laws, including requirements for reduced emissions of sulfur, nitrogen, carbon, mercury, hazardous air pollutants and other substances, GHG legislation, regulation and/or treaties and coal ash regulation;
•
changes in tax laws and the effects of our strategies to reduce tax payments;
•
the effects of litigation and government and regulatory investigations;
•
our ability to maintain adequate insurance;
•
decreases in the value of pension plan assets, increases in pension plan expenses and our ability to fund defined benefit pension and other postretirement plans at our subsidiaries;
•
losses on the sale or write-down of assets due to impairment events or changes in management intent with regard to either holding or selling certain assets;
•
changes in accounting standards, corporate governance and securities law requirements;
•
our ability to maintain effective internal controls over financial reporting;
•
our ability to attract and retain talented directors, management and other personnel, including, but not limited to, financial personnel in our foreign businesses that have extensive knowledge of accounting principles generally accepted in the United States; and
•
information security breaches.
These factors in addition to others described elsewhere in this Form 10-K, including those described under Item 1A.—Risk Factors, and in subsequent securities filings, should not be construed as a comprehensive listing of factors that could cause results to vary from our forward-looking information.
We undertake no obligation to publicly update or revise any forward-looking statements, whether as a result of new information, future events, or otherwise. If one or more forward-looking statements are updated, no inference should be drawn that additional updates will be made with respect to those or other forward-looking statements.
 
ITEM 1. BUSINESS
Overview
We were incorporated in 1981 and are a diversified power generation and utility company organized into six market-oriented SBUs: US (United States), Andes (Chile, Colombia, and Argentina), Brazil, MCAC (Mexico, Central America and Caribbean), Europe, and Asia.
Item 1.—Business is an outline of our strategy and our businesses by SBU, including key financial drivers. Additional items that may have an impact on our businesses are discussed in Item 1A.—Risk Factors and Item 3.—Legal Proceedings.
Business Lines & SBUs — Within our six SBUs mentioned above, we have two lines of business. The first business line is generation, where we own and/or operate power plants to generate and sell power to customers, such as utilities, industrial users, and other intermediaries. The second business line is utilities, where we own and/or operate utilities to generate or purchase, distribute, transmit and sell electricity to end-user customers in the residential, commercial, industrial and governmental sectors within a defined service area. In certain circumstances, our utilities also generate and sell electricity on the wholesale market. For each SBU, the following table summarizes our generation and utility businesses by capacity, number of facilities, utility customers and utility GWh sold.
SBU
 
Business Line
 
Generation Capacity (Gross MW)
 
Generation Facilities
 
Utility Customers
 
Utility GWh
 
Utility Businesses
US —
 
Generation
 
5,604

 
18


Utilities
 
6,524

 
16

 
1.0 million
 
34,797

 
2

Andes —
 
Generation
 
8,141

 
33


Brazil — 
 
Generation
 
3,298

 
13


Utilities


8.2 million
 
56,861

 
2

MCAC —
 
Generation
 
3,239

 
16


Utilities


1.3 million
 
3,754

 
4

Europe —
 
Generation
 
6,781

 
12


Asia —
 
Generation
 
2,290

 
3


35,876

(1) 
111

 
10.5 million
 
95,412

 
8

(1) 
26,912 proportional MW. Proportional MW is equal to gross MW of a generation facility multiplied by AES' equity ownership percentage in such facility.

5


Strategy
In September 2011, we implemented a new strategy to maximize value for our shareholders and over the last four years we have made significant progress towards our goals by executing on the following pillars:
•
Reducing Complexity. By exiting businesses and markets where we do not have a competitive advantage, we have simplified our portfolio and reduced risk. Over the past four years, we have sold assets to generate $3.4 billion in equity proceeds for AES, decreasing the total number of countries where we have operations from 28 to 17. We exited Sri Lanka early in 2016, by selling our generation business, Kelanitissa, for $18 million. We exited several of these markets, including Ukraine, Turkey and Africa, at opportune times, as risks for these businesses have increased since the sales, which we believe would have adversely impacted the valuations of such businesses. In 2015, we announced or closed $787 million in asset sales proceeds.
•
Leveraging Our Platforms. We are focusing our growth on platform expansions in markets where we already operate and have a competitive advantage to realize attractive risk-adjusted returns. We currently have 5,620 MW under construction. These projects represent $7 billion in total capital expenditures, with 85% of AES' $1.2 billion in equity already funded, and we expect the majority of these projects to come on-line through 2018. In 2015, we brought on-line five projects for a total of 1,484 MW. This capacity includes the 1,240 MW coal-fired Mong Duong 2 facility in Vietnam, which we completed six months early and under budget.
•
Performance Excellence. We strive to be a low-cost manager of a portfolio of international energy assets and to derive synergies and scale from our businesses. In 2011, we set a goal to reduce our G&A expenses by $200 million by 2015, and in 2014, we achieved these reductions one year early. We recently launched a $150 million cost reduction and revenue enhancement initiative. This initiative will include overhead reductions, procurement efficiencies and operational improvements. We expect to achieve at least $50 million in savings in 2016, ramping up to $150 million, including modest revenue enhancements, in 2018.
•
Expanding Access to Capital. We have raised $2.5 billion in proceeds to AES by building strategic partnerships at the project and business level. Through these partnerships, we aim to optimize our risk-adjusted returns in our existing businesses and growth projects. By selling down portions of certain businesses, we can adjust our global exposure to commodity, fuel, country and macroeconomic risks. Partial sell-downs of our assets can serve to highlight the value of businesses in our portfolio.
•
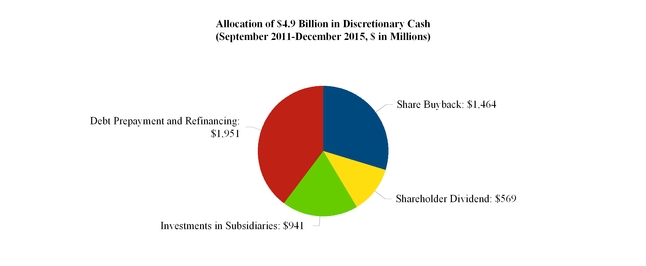
Allocating Capital in a Disciplined Manner. Our top priority is to maximize risk-adjusted returns to our shareholders, which we achieve by investing our discretionary cash and recycling the capital we receive from asset sales and strategic partnerships. To that end, since September 2011 we have repurchased $1.5 billion of our shares and benefited from a low interest rate environment, by transacting on $24 billion in debt deals at the Parent and our subsidiaries. These debt transactions represent $14 billion in refinancing and $10 billion in new financing, and we extended the maturities on $3.4 billion in Parent debt.
Note: Investments in subsidiaries excludes $2.3 billion investment in DPL.
Most recently, we increased our quarterly dividend by 10% to $0.11 per share beginning in the first quarter of 2016. This dividend increase reflects our expectation that we will maintain 10% annual growth in our dividend.

6


Generation
We currently own and/or operate a generation portfolio of 29,352 MW, excluding the generation capabilities of our integrated utilities. Our generation fleet is diversified by fuel type. See discussion below under Fuel Costs.
Performance drivers of our generation businesses include types of electricity sales agreements, plant reliability and flexibility, fuel costs, fixed-cost management, sourcing and competition.
Electricity Sales Contracts — Our generation businesses sell electricity under medium- or long-term contracts ("contract sales") or under short-term agreements in competitive markets ("short-term sales").
Contract Sales — Most of our generation fleet sells electricity under contracts. Our medium-term contract sales have a term of 2 to 5 years, while our long-term contracts have a term of more than 5 years. Across our portfolio, the average remaining contract term is 7 years.
In contract sales, our generation businesses recover variable costs including fuel and variable O&M costs, either through direct or indexation-based contractual pass-throughs or tolling arrangements. When the contract does not include a fuel pass-through, we typically hedge fuel costs or enter into fuel supply agreements for a similar contract period (see discussion under the Fuel Costs section below). These contracts are intended to reduce exposure to the volatility of fuel prices and electricity prices by linking the business's revenues and costs. These contracts also help us to fund a significant portion of the total capital cost of the project through long-term non-recourse project-level financing.
Capacity Payments and Contract Sales — Most of our contract sales include a capacity payment that covers projected fixed costs of the plant, including fixed O&M expenses and a return on capital invested. In addition, most of our contracts require that the majority of the capacity payment be denominated in the currency matching our fixed costs, including debt and return on capital invested. Although our project debt may consist of both fixed and floating rate debt, we typically hedge a significant portion of our exposure to variable interest rates. For foreign exchange, we generally structure the revenue of the business to match the currency of the debt and fixed costs. Some of our contracted businesses also receive a regulated market-based capacity payment, which is discussed in more detail in the Capacity Payments and Short-Term Sales section below.
Thus, these contracts, or other related commercial arrangements, significantly mitigate our exposure to changes in power and fuel prices, currency fluctuations and changes in interest rates. In addition, these contracts generally provide for a recovery of our fixed operating expenses and a return on our investment, as long as we operate the plant to the reliability and efficiency standards required in the contract.
Short-Term Sales — Our other generation businesses sell power and ancillary services under short-term contracts with an average term of less than 2 years, including spot sales, directly in the short-term market, or, in some cases, at regulated prices. The short-term markets are typically administered by a system operator to coordinate dispatch. Short-term markets generally operate on merit order dispatch, where the least expensive generation facilities, based upon variable cost or bid price, are dispatched first and the most expensive facilities are dispatched last. The short-term price is typically set at the marginal cost of energy or bid price (the cost of the last plant required to meet system demand). As a result, the cash flows and earnings associated with these businesses are more sensitive to fluctuations in the market price for electricity. In addition, many of these wholesale markets include markets for ancillary services to support the reliable operation of the transmission system. Across our portfolio, we provide a wide array of ancillary services, including voltage support, frequency regulation and spinning reserves.
In certain markets, such as Argentina and Kazakhstan, a regulator establishes the prices for electricity and fuel and adjusts them periodically for inflation, changes in fuel prices and other factors. In these cases, our businesses are particularly sensitive to changes in regulation.
Capacity Payments and Short-Term Sales — Many of the markets in which we operate include regulated capacity markets. These capacity markets are intended to provide additional revenue based upon availability without reliance on the energy margin from the merit order dispatch. Capacity markets are typically priced based on the cost of a new entrant and the system capacity relative to the desired level of reserve margin (generation available in excess of peak demand). Our generating facilities selling in the short-term markets typically receive capacity payments based on their availability in the market. Our most significant capacity revenues are earned by our generation capacity in Ohio and Northern Ireland.
Plant Reliability and Flexibility — Our contract and short-term sales provide incentives to our generation plants to optimally manage availability, operating efficiency and flexibility. Capacity payments under contract sales are frequently tied to meeting minimum standards. In short-term sales, our plants must be reliable and flexible to capture peak market prices and to maximize market-based revenues. In addition, our flexibility allows us to capture ancillary service revenue while meeting local market needs.
Fuel Costs — For our thermal generation plants, fuel is a significant component of our total cost of generation. For contract sales, we often enter into fuel supply agreements to match the contract period, or we may hedge our fuel costs. Some

7


of our contracts have periodic adjustments for changes in fuel cost indices. In those cases, we have fuel supply agreements with shorter terms to match those adjustments. For certain projects, we have tolling arrangements where the power offtaker is responsible for the supply and cost of fuel to our plants.
In short-term sales, we sell power at market prices that are generally reflective of the market cost of fuel at the time, and thus procure fuel supply on a short-term basis, generally designed to match up with our market sales profile. Since fuel price is often the primary determinant for power prices, the economics of projects with short-term sales are often subject to volatility of relative fuel prices. For further information regarding commodity price risk please see Item 7A.—Quantitative and Qualitative Disclosures about Market Risk in this Form 10-K.
34% of our generation fleet is coal-fired. In the U.S., most of our plants are supplied from domestic coal. At our non-U.S. generation plants and at our plant in Hawaii, we source coal internationally. Across our fleet, we utilize our global sourcing program to maximize the purchasing power of our fuel procurement.
33% of our generation plants are fueled by natural gas. Generally, we use gas from local suppliers in each market. A few exceptions to this are AES Gener in Chile, where we purchase imported gas from third parties, and our plants in the Dominican Republic, where we import LNG to utilize in the local market.
28% of our generation plants are fueled by renewables, including hydro, wind and energy storage, which do not have significant fuel costs.
5% of our generation fleet utilizes oil, diesel and petroleum coke ("pet coke") for fuel. Oil and diesel are sourced locally at prices linked to international markets, while pet coke is largely sourced from Mexico and the U.S.
Renewable Generation Facilities — We currently own and operate 8,145 MW (4,237 proportional MW) of renewable generation, including hydro, wind, energy storage, solar, biomass and landfill gas.
Seasonality, Weather Variations and Economic Activity — Our generation businesses are affected by seasonal weather patterns throughout the year and, therefore, operating margin is not generated evenly by month during the year. Additionally, weather variations, including temperature, solar and wind resources, and hydrological conditions, may also have an impact on generation output at our renewable generation facilities. See Item 7.—Management's Discussion and Analysis—Key Trends and Uncertainties of this Form 10-K for further details of the impact of dry hydrological conditions. In competitive markets for power, local economic activity can also have an impact on power demand and short-term prices for power.
Fixed-Cost Management — In our businesses with long-term contracts, the majority of the fixed operating and maintenance costs are recovered through the capacity payment. However, for all generation businesses, managing fixed costs and reducing them over time is a driver of business performance.
Competition — For our businesses with medium- or long-term contracts, there is limited competition during the term of the contract. For short-term sales, plant dispatch and the price of electricity are determined by market competition and local dispatch and reliability rules.
Utilities
AES' eight utility businesses distribute power to 10.5 million people in three countries. AES' two utilities in the U.S. also include generation capacity totaling 6,524 MW. The utility businesses have a variety of structures, ranging from integrated utility to pure transmission and distribution businesses.
In general, our utilities sell electricity directly to end-users, such as homes and businesses, and bill customers directly. Key performance drivers for utilities include the regulated rate of return and tariff, seasonality, weather variations, economic activity, reliability of service and competition.
Regulated Rate of Return and Tariff — In exchange for the exclusive right to sell or distribute electricity in a franchise area, our utility businesses are subject to government regulation. This regulation sets the prices ("tariffs") that our utilities are allowed to charge retail customers for electricity and establishes service standards that we are required to meet.
Our utilities are generally permitted to earn a regulated rate of return on assets, determined by the regulator based on the utility's allowed regulatory asset base, capital structure and cost of capital. The asset base on which the utility is permitted a return is determined by the regulator and is based on the amount of assets that are considered used and useful in serving customers. Both the allowed return and the asset base are important components of the utility's earning power. The allowed rate of return and operating expenses deemed reasonable by the regulator are recovered through the regulated tariff that the utility charges to its customers.
The tariff may be reviewed and reset by the regulator from time to time depending on local regulations, or the utility may seek a change in its tariffs. The tariff is generally based upon a certain usage level and may include a pass-through to the customer of costs that are not controlled by the utility, such as the costs of fuel (in the case of integrated utilities) and/or the

8


costs of purchased energy. In addition to fuel and purchased energy, other types of costs may be passed through to customers via an existing mechanism, such as certain environmental expenditures that are covered under an environmental tracker at our utility in Indiana, IPL. Components of the tariff that are directly passed through to the customer are usually adjusted through a summary regulatory process or an existing formula-based mechanism. In some regulatory regimes, customers with demand above an established level are unregulated and can choose to contract with other retail energy suppliers directly and pay a wheeling and other non-bypassable fees, which are fees to the distribution company for use of its distribution system.
The regulated tariff generally recognizes that our utility businesses should recover certain operating and fixed costs, as well as manage uncollectible amounts, quality of service and non-technical losses. Utilities, therefore, need to manage costs to the levels reflected in the tariff, or risk non-recovery of costs or diminished returns.
Seasonality, Weather Variations and Economic Activity — Our utility businesses are affected by seasonal weather patterns throughout the year and, therefore, the operating revenues and associated operating expenses are not generated evenly by month during the year. Additionally, weather variations may also have an impact based on the number of customers, temperature variances from normal conditions and customers' historic usage levels and patterns. The retail kWh sales, after adjustments for weather variations, are affected by changes in local economic activity, energy efficiency and distributed generation initiatives, as well as the number of retail customers.
Reliability of Service — Our utility businesses must meet certain reliability standards, such as duration and frequency of outages. Those standards may be specific with incentives or penalties for performance against these standards. In other cases, the standards are implicit and the utility must operate to meet customer expectations.
Competition — Our integrated utilities, such as IPL and DP&L, operate as the sole distributor of electricity within their respective jurisdictions. Our businesses own and operate all of the businesses and facilities necessary to generate, transmit and distribute electricity. Competition in the regulated electric business is primarily from the on-site generation for industrial customers; however, in Ohio, customers in our service territory have the ability to switch to alternative suppliers for their generation service. Our integrated utilities, particularly DP&L, are exposed to the volatility in wholesale prices to the extent our generating capacity exceeds the native load served under the regulated tariff and short-term contracts. See the full discussion under the US SBU.
At our pure transmission and distribution businesses, such as those in Brazil and El Salvador, we face relatively limited competition due to significant barriers to entry. At many of these businesses, large customers, as defined by the relevant regulator, have the option to both leave and return to regulated service.
Development and Construction
We develop and construct new generation facilities. For our utility businesses, new plants may be built in response to customer needs or to comply with regulatory developments and are developed subject to regulatory approval that permits recovery of our capital cost and a return on our investment. For our generation businesses, our priority for development is platform expansion opportunities, where we can add on to our existing facilities in our key platform markets where we have a competitive advantage. We make the decision to invest in new projects by evaluating the project returns and financial profile against a fair risk-adjusted return for the investment and against alternative uses of capital, including corporate debt repayment and share buybacks.
In some cases, we enter into long-term contracts for output from new facilities prior to commencing construction. To limit required equity contributions from The AES Corporation, we also seek non-recourse project debt financing and other sources of capital, including partners where it is commercially attractive. For construction, we typically contract with a third party to manage construction, although our construction management team supervises the construction work and tracks progress against the project's budget and the required safety, efficiency and productivity standards.
Environmental Matters
We are subject to various international, federal, state, and local regulations in all of our markets. These regulations govern such items as the determination of the market mechanism for setting the system marginal price for energy and the establishment of guidelines and incentives for the addition of new capacity.
We are also subject to various federal, state, regional and local environmental protection and health and safety laws and regulations governing, among other things, the generation, storage, handling, use, disposal and transportation of hazardous materials; the emission and discharge of hazardous and other materials into the environment; and the health and safety of our employees. These laws and regulations often require a lengthy and complex process of obtaining and renewing permits and other governmental authorizations from federal, state and local agencies. Violation of these laws, regulations or permits can result in substantial fines, other sanctions, suspension or revocation of permits and/or facility shutdowns. See later in Item 1.—Business—Environmental and Land-Use Regulations for further regulatory and environmental discussion.

9


SBUs
All SBUs include generation facilities and three include utility businesses. The Company measures the operating performance of its SBUs using Adjusted PTC and Proportional Free Cash Flow, both of which are non-GAAP measures (see definitions below).
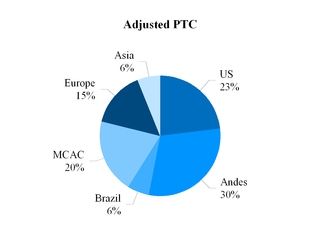
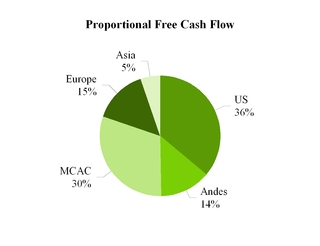
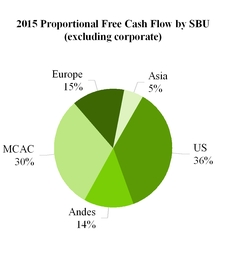
AES' primary sources of Revenue, Operating Margin, Adjusted PTC and Proportional Free Cash Flow are from generation and utility businesses. The Adjusted PTC and Proportional Free Cash Flow by SBU for the year ended December 31, 2015 are shown below. The percentages for Adjusted PTC are the contribution by each SBU to the gross metric, i.e., the total Adjusted PTC by SBU, before deductions for Corporate. See Item 8.—Financial Statements and Supplementary Data of this Form 10-K for reconciliation.
In 2015, approximately 80% of Adjusted PTC and Proportional Free Cash Flow was contributed by our businesses in the Americas — including the US, Andes, Brazil and MCAC SBUs.
We define Adjusted PTC as pretax income from continuing operations attributable to AES excluding gains or losses due to (a) unrealized gains or losses related to derivative transactions, (b) unrealized foreign currency gains or losses, (c) gains or losses due to dispositions and acquisitions of business interests, (d) losses due to impairments, and (e) costs due to the early retirement of debt. Adjusted PTC in each SBU includes the effect of intercompany transactions with other SBUs other than interest and charges for certain management services.
We define Proportional Free Cash Flow as cash flows from operating activities excluding capital expenditures related to service concession assets, less maintenance and non-recoverable environmental capital costs, adjusted for the estimated impact of noncontrolling interests. Proportional Free Cash Flow in each SBU includes the effect of intercompany transactions with other SBUs except for interest, tax sharing, charges for management fees and transfer pricing.
Our Organization and Segments
The segment reporting structure uses the Company's management reporting structure as its foundation to reflect how the Company manages the business internally and is organized by geographic regions which provide better socio-political-economic understanding of our business. The management reporting structure is organized along six SBUs — US, Andes, Brazil, MCAC, Europe, and Asia — which are led by our SBU Presidents.
Corporate and Other — For financial reporting purposes, the Company's corporate activities are reported within "Corporate and Other" because they do not require separate disclosure under segment reporting accounting guidance. "Corporate and Other" also includes costs related to corporate overhead which are not directly associated with the operations of our six reportable segments and other intercompany charges such as self-insurance premiums which are fully eliminated in consolidation. See Item 7.—Management's Discussion and Analysis of Financial Condition and Results of Operations and Note 17—Segment and Geographic Information included in Item 8.—Financial Statements and Supplementary Data of this Form 10-K for further discussion of the Company's segment structure (including information on revenue from external customers, Adjusted PTC—a non-GAAP measure, Proportional Free Cash Flow—a non-GAAP measure, and total assets by segment) used for financial reporting purposes.
The following describes our businesses within our six SBUs:
US SBU
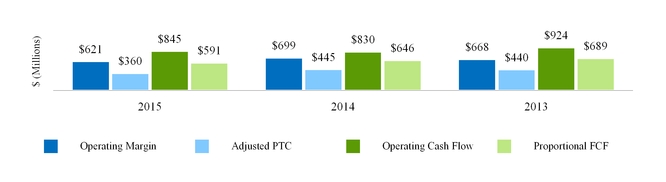
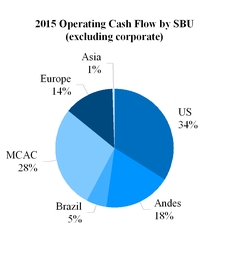
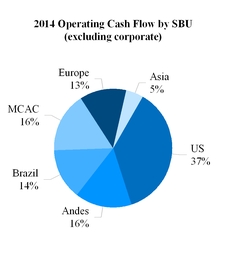
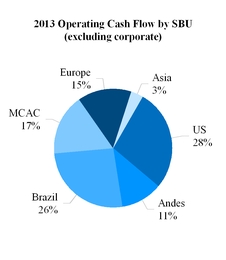
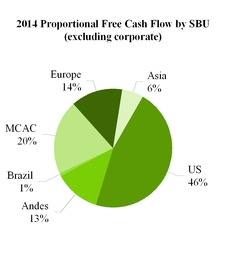
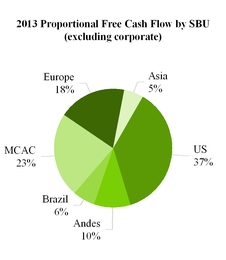
Our US SBU has 18 generation facilities and two integrated utilities in the United States. Our U.S. operations accounted for the following proportions of consolidated AES Operating Margin, AES Adjusted PTC (a non-GAAP measure), AES Operating Cash Flow, and AES Proportional Free Cash Flow (a non-GAAP measure):
US SBU (1)
2015
 
2014
 
2013
% of AES Operating Margin
22
%
 
23
%
 
21
%
% of AES Adjusted PTC (a non-GAAP measure)
23
%
 
24
%
 
24
%
% of AES Operating Cash Flow
34
%
 
37
%
 
28
%
% of AES Proportional Free Cash Flow (a non-GAAP measure)
36
%
 
46
%
 
37
%
(1) Percentages reflect the contributions by our US SBU before deductions for Corporate.
The following table provides highlights of our US operations:
Generation Capacity
 
12,128 gross MW (11,260 proportional MW)
Generation Facilities
 
19 (1 under construction)
Key Generation Businesses
 
Southland, Hawaii and US Wind
Utilities Penetration
 
1,002,000 customers (31,112 GWh)
Utility Businesses
 
2 integrated utilities (includes 18 generation plants, 4 under construction)
Key Utility Businesses
 
IPL and DPL

10


Operating installed capacity of our US SBU totals 12,128 MW. IPL's parent, IPALCO Enterprises, Inc., and DPL Inc. are voluntary SEC registrants, and as such, follow public filing requirements of the Securities Exchange Act of 1934. Presented in the table below is a list of our U.S. generation facilities:
Business
 
Location
 
Fuel
 
Gross MW
 
AES Equity Ownership (% Rounded)
 
Year Acquired or Began Operation
 
Contract Expiration Date
 
Customer(s)
Southland—Alamitos
 
U.S.-CA
 
Gas
 
2,075

 
100
%
 
1998
 
2018
 
Southern California Edison
Southland—Redondo Beach
 
U.S.-CA
 
Gas
 
1,392

 
100
%
 
1998
 
2018
 
Southern California Edison
Southland—Huntington Beach
 
U.S.-CA
 
Gas
 
474

 
100
%
 
1998
 
2018
 
Southern California Edison
Shady Point
 
U.S.-OK
 
Coal
 
360

 
100
%
 
1991
 
2018
 
Oklahoma Gas & Electric
Buffalo Gap II(1),(2)
 
U.S.-TX
 
Wind
 
233

 
100
%
 
2007
 
2017
 
Direct Energy
Hawaii
 
U.S.-HI
 
Coal
 
206

 
100
%
 
1992
 
2022
 
Hawaiian Electric Co.
Warrior Run
 
U.S.-MD
 
Coal
 
205

 
100
%
 
2000
 
2030
 
First Energy
Buffalo Gap III(1)
 
U.S.-TX
 
Wind
 
170

 
100
%
 
2008


Buffalo Gap I(1)
 
U.S.-TX
 
Wind
 
121

 
100
%
 
2006
 
2021
 
Direct Energy
Laurel Mountain
 
U.S.-WV
 
Wind
 
98

 
100
%
 
2011


Mountain View I & II(1)
 
U.S.-CA
 
Wind
 
67

 
100
%
 
2008
 
2021
 
Southern California Edison
Distributed PV - Commercial(3)
 
U.S.-Various
 
Solar
 
56

 
80%-97%

 
2009-2015
 
2029-2041
 
Utility, Municipality, Education, Non-Profit
Mountain View IV
 
U.S.-CA
 
Wind
 
49

 
100
%
 
2012
 
2032
 
Southern California Edison
Tehachapi
 
U.S.-CA
 
Wind
 
35

 
100
%
 
2006
 
2016
 
Southern California Edison
Laurel Mountain ES
 
U.S.-WV
 
Energy Storage
 
32

 
100
%
 
2011


Tait ES
 
U.S.-OH
 
Energy Storage
 
20

 
100
%
 
2013


Distributed PV - Residential(3)
 
U.S.-Various
 
Solar
 
9

 
95
%
 
2012-2015
 
2037-2040
 
Residential
Advancion Applications Center
 
U.S.-PA
 
Energy Storage
 
2

 
100
%
 
2013


5,604


(1)
AES owns these assets together with third-party tax equity investors with variable ownership interests. The tax equity investors receive a portion of the economic attributes of the facilities, including tax attributes, that vary over the life of the projects. The proceeds from the issuance of tax equity are recorded as noncontrolling interest in the Company's Consolidated Balance Sheets.
(2) 
Power Purchase Agreement with Direct Energy is for 80% of annual expected energy output.
(3) 
AES operates these facilities located throughout the U.S. through management or O&M agreements as of 12/31/15.
Under construction — The following table lists our plants under construction in the US SBU: 
Business
 
Location
 
Fuel
 
Gross MW
 
AES Equity Interest (% Rounded)
 
Expected Date of Commercial Operations
IPL MATS (1)
 
U.S.-IN
 
Coal
 
1,713

 
75
%
 
1H 2016
Eagle Valley CCGT (1)
 
U.S.-IN
 
Gas
 
671

 
75
%
 
1H 2017
Harding Street Units 5-7 (1)
 
U.S.-IN
 
Gas
 
630

 
75
%
 
1H 2016
Harding Street ES (1)
 
U.S.-IN
 
Energy Storage
 
20

 
75
%
 
1H 2016
Warrior Run ES
 
U.S.-MD
 
Energy Storage
 
10

 
100
%
 
1H 2016
US Total


3,044


(1) 
In the first quarter of 2015, La Caisse de depot et placement du Quebec ("CDPQ") invested $247 million for a 15% interest in AES US Investments, Inc. (AES US Investments), a subsidiary of AES that owns IPALCO Enterprises, Inc. ("IPALCO"). In the second quarter of 2015, CDPQ invested an additional $214 million and we expect CDPQ to invest an additional $134 million in IPALCO by 2016. After completion of this investment, CDPQ's direct and indirect interests in IPALCO will total 30%, AES will own 85% of AES US Investments, and AES US Investments will own 82.35% of IPALCO.
Presented below are our U.S. utilities and their generation facilities:
Business
 
Location
 
Approximate Number of Customers Served as of 12/31/2015
 
GWh Sold in 2015
 
Fuel
 
Gross MW
 
AES Equity Interest (% Rounded)
 
Year Acquired or Began Operation
DPL(1)
 
U.S.-OH
 
517,000

 
16,714

 
Coal/Gas/Oil
 
3,066

 
100
%
 
2011
IPL(2)
 
U.S.-IN
 
485,000

 
14,398

 
Coal/Gas/Oil
 
3,458

 
75
%
 
2001


1,002,000

 
31,112


6,524


(1) 
DPL subsidiary DP&L has the following plants: Tait Units 1-3 and diesels, Yankee Street, Yankee Solar, Monument and Sidney. DP&L jointly owned plants: Conesville Unit 4, Killen, Miami Fort Units 7 & 8, Stuart and Zimmer. In addition to the above, DP&L also owns a 4.9% equity ownership in OVEC ("Ohio Valley Electric Corporation"), an electric generating company. OVEC has two plants in Cheshire, Ohio and Madison, Indiana with a combined generation capacity of approximately 2,109 MW. DP&L's share of this generation capacity is approximately 103 MW. DPL Energy, LLC plants: Tait Units 4-7 and Montpelier Units 1-4.
(2) 
In the first quarter of 2015, CDPQ invested $247 million for a 15% interest in AES US Investments, Inc. (AES US Investments), a subsidiary of AES that owns IPALCO. In the second quarter of 2015, CDPQ invested an additional $214 million and we expect CDPQ to invest an additional $134 million in IPALCO by 2016. After completion of this investment, CDPQ's direct and indirect interests in IPALCO will total 30%, AES will own 85% of AES US Investments, and AES US Investments will own 82.35% of IPALCO. IPL plants: Eagle Valley, Georgetown, Harding Street and Petersburg.

11


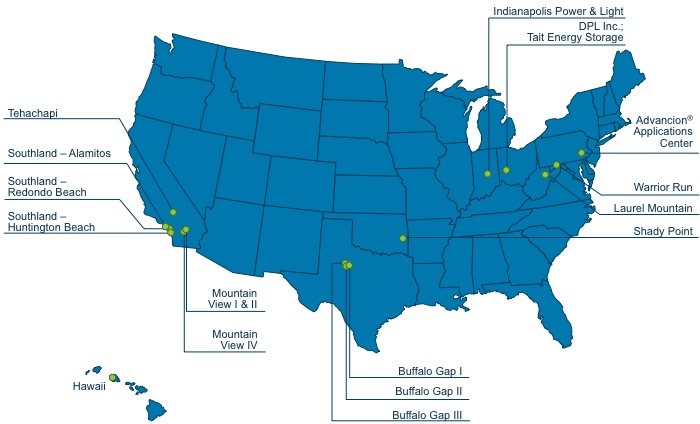
The following map illustrates the location of our U.S. facilities:
U.S. Businesses
U.S. Utilities
IPALCO
Business Description — IPALCO owns all of the outstanding common stock of IPL. IPL is engaged primarily in generating, transmitting, distributing and selling electric energy to approximately 485,000 retail customers in the city of Indianapolis and neighboring areas within the state of Indiana. IPL has an exclusive right to provide electric service to those customers. IPL's service area covers about 528 square miles with an estimated population of approximately 934,000. IPL owns and operates four generating stations. Two of the generating stations are primarily coal-fired; however, one of these stations is in the process of being converted to natural gas and will be fully converted in 2016. The third station has a combination of units that use coal (baseload capacity), natural gas and/or oil (peaking capacity) for fuel to produce electricity. The fourth station is a small peaking station that uses gas-fired combustion turbine technology for the production of electricity. IPL's net electric generation capacity for winter is 3,233 MW and net summer capacity is 3,115 MW.
On December 15, 2014, the Company executed an agreement with CDPQ, a long-term institutional investor headquartered in Quebec, Canada. Pursuant to the agreement, CDPQ purchased 15% of AES US Investments, Inc. ("AES US Investments"), a wholly-owned subsidiary of AES that owns 100% of IPALCO, for $247 million. This transaction closed on February 11, 2015. In addition, in April 2015, IPALCO received an equity capital contribution of $214 million from the issuance of 11,818,828 shares of common stock to CDPQ for funding needs primarily related to IPL's environmental construction program, which IPALCO then made the same investment in IPL. After the April investment, CDPQ's direct and indirect ownership interests in IPALCO totaled 25%. CDPQ has committed to approximately $134 million of additional investments in IPALCO through 2016, which will be used primarily to help fund existing environmental and replacement generation projects at IPL. Upon completion of these transactions, CDPQ's direct and indirect interests in IPALCO will total 30%, AES will own 85% of AES US Investments, and AES US Investment will own 82.35% of IPALCO. There will be no change in management or operational control of AES US Investments or IPALCO as a result of these transactions.
Market Structure — IPL is one of many transmission system owner members in the MISO. MISO is a RTO, which maintains functional control over the combined transmission systems of its members and manages one of the largest energy and ancillary services markets in the U.S. IPL offers the available electricity production of each of its generation assets into the MISO day-ahead and real-time markets. MISO operates on a merit order dispatch, considering transmission constraints and other reliability issues to meet the total demand in the MISO region.
Regulatory Framework — Retail Ratemaking — In addition to the regulations referred to below in Other Regulatory Matters, IPL is subject to regulation by the IURC with respect to IPL's services and facilities; retail rates and charges; the

12


issuance of long-term securities; and certain other matters. The regulatory power of the IURC over IPL's business is both comprehensive and typical of the traditional form of regulation generally imposed by state public utility commissions. IPL's tariff rates for electric service to retail customers consist of basic rates and charges, which are set and approved by the IURC after public hearings. The IURC gives consideration to all allowable costs for ratemaking purposes including a fair return on the fair value of the utility property used and useful in providing service to customers. In addition, IPL's rates include various adjustment mechanisms including, but not limited to: (i) a rider to reflect changes in fuel and purchased power costs to meet IPL's retail load requirements, referred to as the FAC, and (ii) a rider for the timely recovery of costs incurred to comply with environmental laws and regulations referred to as ECCRA. These components function somewhat independently of one another, but the overall structure of IPL's rates and charges would be subject to review at the time of any review of IPL's basic rates and charges. IPL's basic rates and charges were last adjusted in 1996; however, IPL filed a petition with the IURC on December 29, 2014 for authority to increase its basic rates and charges. IPL's proposed rate increase, filed as part of IPL's rebuttal testimony in this proceeding, is $63.3 million, or 5.2%. An order on this proceeding will likely be issued by the IURC early in 2016.
Environmental Matters — MATS — In April 2012, the EPA's rule to establish maximum achievable control technology standards for each hazardous air pollutant regulated under the CAA emitted from coal and oil-fired power plants, known as MATS, became effective. On August 14, 2013, the IURC approved IPL's MATS plan, which includes investing up to $511 million in the installation of new pollution control equipment on IPL's five largest baseload generating units. These coal-fired units are located at IPL's Petersburg and Harding Street generating stations. The IURC also approved IPL's request to recover operating and construction costs for this equipment, including a return, through a rate adjustment mechanism with certain stipulations. Funding for these capital expenditures is expected to be obtained from additional debt financing at IPL; equity contributions; borrowing capacity on IPL's committed credit facilities; and cash generated from operating activities.
Replacement Generation — IPL has several generating units that are expected to retire or refuel by 2017. These units are primarily coal-fired and represent 472 MW of net capacity in total. To replace this generation, IPL filed a petition and case-in-chief with the IURC in April 2013 seeking a CPCN to build a 550 to 725 MW CCGT at its Eagle Valley Station site in Indiana and to refuel Harding Street Station Units 5 and 6 from coal to natural gas (approximately 100 MW net capacity each). In May 2014, IPL received an order on the CPCN from the IURC authorizing the refueling project and granting approval to build a 644 to 685 MW CCGT at a total budget of $649 million. The current estimated cost of these projects is $632 million. IPL requested and was granted authority to accrue post in-service allowance for debt and equity funds used during construction, and to defer the recognition of depreciation expense of the CCGT and refueling project until such time that IPL is allowed to collect both a return and depreciation expense of the CCGT and refueling projects. The CCGT is expected to be placed into service in April 2017, and the refueling project is expected to be completed by early 2016. The costs to build and operate the CCGT and for the refueling project, other than fuel costs, will not be recoverable by IPL through rates until the conclusion of a base rate case proceeding with the IURC after the assets have been placed in service. In October 2014, IPL filed a petition and case-in-chief with the IURC seeking a CPCN to refuel Harding Street Station Unit 7 from coal to natural gas (about 410 MW net capacity). On July 29, 2015 IPL received approval for this CPCN from the IURC. This conversion is part of IPL's overall wastewater compliance plan for its power plants and is expected to be completed in 2016 (as discussed in Environmental Wastewater Requirements below).
Environmental Wastewater Requirements — In August 2012, the IDEM issued NPDES permits to the IPL Petersburg, Harding Street, and Eagle Valley generating stations, which became effective in October 2012. In April 2013, IPL received an extension to the compliance deadline through September 2017 for IPL's Harding Street and Petersburg facilities through agreed orders with IDEM. IPL conducted studies to determine the operational changes and/or control equipment necessary to comply with the new limitations. On October 16, 2014, IPL filed its wastewater compliance plans with the IURC. On July 29, 2015, IPL received approval for a CPCN from the IURC to convert Unit 7 at the Harding Street Station from coal-fired to natural gas-fired, and also to install and operate wastewater treatment technologies at Harding Street Station and Petersburg Generation Station in southern Indiana. IPL plans to invest $326 million in these projects to help ensure compliance with the wastewater treatment requirements by 2017. Recovery of these costs is expected through an Indiana statute which allows for 80% recovery of qualifying costs through a rate adjustment mechanism with the remainder recorded as a regulatory asset to be considered for recovery in the next basic rate case proceeding; however, there can be no assurances that IPL would be successful in that regard.
Key Financial Drivers — IPL's financial results are driven primarily by retail demand and rate base growth. Retail demand is influenced by local macroeconomic conditions. In addition, weather, energy efficiency and wholesale prices could also impact financial results. IPL's rate base growth is influenced by the timely recovery of capital expenditures, as well as passage of new legislation or implementation of regulations.
Construction and Development — IPL's construction program is composed of capital expenditures necessary for prudent utility operations and compliance with environmental laws and regulations, along with discretionary investments designed to replace aging equipment or improve overall performance. Please see above for a description of our major construction projects.

13


DPL Inc. ("DPL")
Business Description — DPL is an energy holding company whose principal subsidiaries include DP&L, DPLE, and DPLER.
DP&L generates, transmits, distributes and sells electricity to approximately 517,000 customers in a 6,000 square mile area of West Central Ohio. DP&L, solely or through jointly owned facilities, owns 2,510 MW of generation capacity and numerous transmission facilities.
DPLE owns peaking generation units representing 556 MW located in Ohio and Indiana.
DPLER, a competitive retail marketer, sells retail electricity to more than 124,000 retail customers in Ohio and Illinois. Approximately 110,000 of these customers are also distribution customers of DP&L in Ohio. On January 1, 2016, DPL closed on the sale of DPLER to Interstate Gas Supply, Inc. (IGS).
Market Structure — Since January 2001, electric customers within Ohio have been permitted to choose to purchase power under a contract with a CRES Provider or to continue to purchase power from their local utility under SSO rates established by the tariff. DP&L and other Ohio utilities continue to have the exclusive right to provide delivery service in their state certified territories, and DP&L had the obligation to supply retail generation service to customers that do not choose an alternative supplier. Beginning in 2014, a portion of the SSO generation supply is no longer supplied by DP&L but is provided by third parties through a competitive bid process. A total of 10% and 60% of the SSO load was sourced through competitive bid in 2014 and 2015, respectively, and 100% will be sourced in this manner beginning in 2016, respectively. The PUCO maintains jurisdiction over DP&L's delivery of electricity, SSO and other retail electric services. The PUCO has issued extensive rules on how and when a customer can switch generation suppliers, how the local utility will interact with CRES Providers and customers, including for billing and collection purposes, and which elements of a utility's rates are "bypassable" (i.e., avoided by a customer that elects a CRES Provider) and which elements are "non-bypassable" (i.e., charged to all customers receiving a distribution service irrespective of what entity provides the retail generation service).
PJM Operations — DP&L is a member of PJM. The PJM RTO operates the transmission systems owned by utilities operating in all or parts of Pennsylvania, New Jersey, Maryland, Delaware, D.C., Virginia, Ohio, West Virginia, Kentucky, North Carolina, Tennessee, Indiana and Illinois. PJM has an integrated planning process to identify potential needs for additional transmission to be built to avoid future reliability problems. PJM also runs the day-ahead and real-time energy markets, ancillary services market and forward capacity market for its members.
As a member of PJM, DP&L is also subject to charges and costs associated with PJM operations as approved by the FERC. Prior to 2015, the RPM was PJM's capacity construct. In 2015, PJM implemented a new Capacity Price ("CP") program, replacing the RPM model. The CP program offers the potential for higher capacity revenues, combined with substantially increased penalties for non-performance or under-performance during certain periods identified as "capacity performance hours." This linkage between non- or under-performance during certain specific hours means that a generation unit that is generally performing well on an annual basis, may incur substantial penalties if it happens to be unavailable for service during some capacity performance hours. Similarly, a generation unit that is generally performing poorly on an annual basis may avoid such penalties if its outages happen to occur only during hours that are not capacity performance hours. An annual “stop-loss” provision exists that limits the size of penalties to 150% of the net cost of new entry, which is a value computed by PJM. This level is likely to be larger than the capacity price established under the CP program, so that the potential exists that participation in the CP program could result in capacity penalties that exceed capacity revenues. The purpose of the RPM and CP Program is to enable PJM to obtain sufficient resources to reliably meet the needs of electric customers within the PJM footprint. PJM conducts an auction to establish the price by zone.
The PJM CP auctions are held three years in advance for a period covering 12 months starting from June 1. Auctions for the period covering June 1, 2019 through May 30, 2020 are expected to take place in May 2016. Future auction results are dependent upon various factors including the demand and supply situation, capacity additions and retirements and any changes in the current auction rules related to bidding for demand response and energy efficiency resources in the capacity auctions. For DPL-owned generation, applicable capacity prices through the auction year 2018/19 are as follows:
Auction Year (June 01-May 31)
 
2018/19
 
2017/18
 
2016/17
 
2015/16
 
2014/15
 
2013/14
Capacity Clearing Price ($/MW-Day)
 
$165
 
$152
 
$134
 
$136
 
$126
 
$28
The computed average capacity prices by calendar year are as follows:
Year
 
2018
 
2017
 
2016
 
2015
 
2014
Computed Average Capacity Price ($/MW-Day)
 
$159
 
$145
 
$135
 
$132
 
$85
The above tables reflect the capacity prices after the transitional auctions discussed earlier. Substantially all of DP&L's capacity cleared in the CP auction. The results of these auctions could have a significant effect on DP&L's revenues in the future.

14


According to the terms of DP&L's RPM rider, a portion of the capacity revenue is credited to SSO customers primarily based on the load still being served to the SSO customers. However, with the transition to market, no amount will be credited beginning January 1, 2016.
Regulatory Framework — Retail Regulation — DP&L is subject to regulation by the PUCO, for its distribution services and facilities, retail rates and charges, reliability of service, compliance with renewable energy portfolio, energy efficiency program requirements and certain other matters. DP&L's rates for electric service to retail customers consist of basic rates and charges that are set and approved by the PUCO after public hearings. In addition, DP&L's rates include various adjustment mechanisms including, but not limited to, those to reflect changes in fuel costs to generate electricity or purchased power prices, and the timely recovery of costs incurred to comply with alternative energy, renewables, energy efficiency, and economic development costs. These components function independently of one another, but the overall structure of DP&L's retail rates and charges are subject to the rules and regulations established by the PUCO.
Retail Rate Structure — Since Ohio is deregulated and allows customers to choose retail generation providers, DP&L is required to provide retail generation service at SSO rates to any customer that has not signed a contract with a CRES provider. SSO rates are subject to rules and regulations of the PUCO and are established based on DP&L's Electric Security Plan ("ESP") filing. DP&L's wholesale transmission rates are regulated by the FERC. DP&L's distribution rates are regulated by the PUCO and are established through a traditional cost-based rate-setting process. DP&L is permitted to recover its costs of providing distribution service as well as earn a regulated rate of return on assets, determined by the regulator, based on the utility's allowed regulated asset base, capital structure and cost of capital.
The terms and conditions of DP&L's current SSO are provided under the ESP filed in 2012 and approved by the PUCO order dated September 4, 2013 ("2012 ESP"). The 2012 ESP has been in effect since January 2014 and allows DP&L to collect a non-bypassable Service Stability Rider ("SSR") equal to $110 million per year from 2014 - 2016. It allowed for DP&L to recover its PJM-related transmission charges, alternative energy costs, fuel and purchased power costs, and established a SEET ("Significant Excessive Earnings Test") threshold of 12% ROE. It also required DP&L to conduct competitive bid auctions to procure generation supply for SSO service. DP&L's own generation was phased-out of supplying SSO service over the three year period. Beginning January 1, 2016 DP&L's SSO will be 100% sourced through the competitive bid. For calendar years 2012 - 2014, DP&L was subject to a SEET threshold and was required to apply general rules for calculating earnings and comparing them to a comparable group to determine whether there were significantly excessive earnings during a given calendar year. Through the 2012 ESP, the PUCO established DP&L's ROE SEET threshold at 12%. On May 15, 2014, DP&L filed its application to demonstrate that it did not have significantly excessive earnings for calendar year 2013. A stipulation was reached with the PUCO staff agreeing that DP&L did not exceed the SEET threshold for 2014. A hearing was held and the PUCO issued an order approving the SEET stipulation. In future years, the SEET could have a material effect on results of operations, financial condition and cash flows.
On October 30, 2015 DP&L publicly announced its intent to file an application to increase its distribution rates at the PUCO. On November 30, 2015 DP&L filed its distribution rate case using a 12-month test year of June 1, 2015 to May 31, 2016 to measure revenue and expenses and a date certain of September 30, 2015 to measure its asset base. The Company is seeking an increase to distribution revenues of $66 million per year. The Company has asked for recovery of certain regulatory assets as well as two new riders that would allow the Company to recover certain costs on an ongoing basis. It has proposed a modified straight-fixed variable rate design in an effort to decouple distribution revenues from electric sales. If approved as filed the rates are expected to have a total bill impact of approximately 4% on a typical residential customer.
On February 22, 2016 DP&L filed an ESP that would be in effect beginning January 1, 2017. As part of this filing, DP&L is seeking a Reliable Electricity Rider for 10 years, based on the variance between the proposed revenue requirement and the actual revenues net of operating costs of the generation units.  This plan establishes the terms and conditions for DP&L's Standard Service Offer (SSO) beginning June 1, 2017 to customers that do not choose a competitive retail electric supplier.  In its plan, DP&L recommends including renewable energy attributes as part of the product that is competitively bid, and seeks recovery of approximately $10 million of regulatory assets.  The plan also proposes a new Distribution Investment Rider to allow DP&L to recover costs associated with future distribution equipment and infrastructure needs.  Additionally, the plan establishes new riders set initially at zero, related to energy reductions from DP&L's energy efficiency programs, and certain environmental liabilities the Company may incur. There can be no assurance that the ESP will be approved as filed or on a timely basis, and if the ESP is not approved on a timely basis or the final ESP provides for terms that are more adverse than those submitted in DP&L’s application, the Company's consolidated results of operations, financial condition and cash flows could be materially impacted.
Environmental Matters — In relation to MATS, 3,066 MW of DPL's generation capacity is largely compliant with MATS, and DPL does not expect to incur material capital expenditures to ensure compliance with MATS. For more information see Item 1.— United States Environmental and Land-Use Legislation and Regulations.

15


Key Financial Drivers — Although recent ESP and Generation Separation decisions provide some clarity on the underlying drivers through 2016, challenges remain for DPL beyond 2016 including the potential impacts of retail demand, weather, energy efficiency and wholesale prices on financial results. In addition, through 2016, DPL financial results are likely to be driven by many factors including, but not limited to, the following:
•
PJM capacity prices auctioned already
•
Non-bypassable revenue: $110 million in 2014 and 2015 and allowed to earn $110 million annually in 2016
•
Operational performance of generation facilities
Beyond 2016, DPL financial drivers include many factors, such as the following:
•
PJM capacity prices
•
Recovery in the power market, particularly as it relates to an expansion in dark spreads
•
Sale or transfer to a DPL affiliate of DP&L generation assets
•
DPL's ability to reduce its cost structure
See Item 1A.—Risk Factors for additional discussion on DPL.
Construction and Development — Planned construction additions primarily relate to new investments in and upgrades to DP&L's power plant equipment and transmission and distribution system. Capital projects are subject to continuing review and are revised in light of changes in financial and economic conditions, load forecasts, legislative and regulatory developments and changing environmental standards, among other factors.
DPL is projecting to spend an estimated $439 million in capital projects for the period 2016 through 2018 with 61% attributable to Transmission and Distribution. DPL's ability to complete capital projects and the reliability of future service will be affected by its financial condition, the availability of internal funds and the reasonable cost of external funds. We expect to finance these construction additions with a combination of cash on hand, short-term financing, long-term debt and cash flows from operations.
U.S. Generation
Business Description — In the U.S., we own a diversified generation portfolio in terms of geography, technology and fuel source. The principal markets and locations where we are engaged in the generation and supply of electricity (energy and capacity) are the WECC, PJM, SPP and Hawaii. AES Southland, in the WECC, is our most significant generating business.
AES Southland
Business Description — In terms of aggregate installed capacity, AES Southland is one of the largest generation operators in California, with an installed capacity of 3,941 MW, accounting for approximately 5% of the state's installed capacity and 17% of the peak demand of Southern California Edison. The three coastal power plants comprising AES Southland are in areas that are critical for local reliability and play an important role in integrating the increasing amounts of renewable generation resources in California.
Market Structure — All of AES Southland's capacity is contracted through a long-term agreement (the “Tolling Agreement”), which expires in mid-2018. Under the Tolling Agreement, AES Southland's largest revenue driver is unit availability, as approximately 97% of its revenue comes from availability-related payments. Historically, AES Southland has generally met or exceeded its contractual availability requirements under the Tolling Agreement and may capture bonuses for exceeding availability requirements in peak periods.
The offtaker under the Tolling Agreement provides gas to the three facilities at no cost; therefore, AES Southland is not exposed to significant fuel price risk. AES Southland does, however, guarantee the efficiency of each unit so that any fuel consumed in excess of what would have been consumed had the guaranteed efficiency been achieved is paid for by AES Southland. Additionally, if the units operate at an efficiency better than the guaranteed efficiency, AES Southland gets credit for the gas that is not consumed. The business is also exposed to the cost of replacement power for a limited time period if any of the plants are dispatched by the offtaker and are not able to meet the required dispatch schedule for generation of electric energy.
AES Southland delivers electricity into the California ISO's market through its Tolling Agreement counterparty.
Re-powering — In October 2014, AES Southland was awarded 20-year contracts by SCE to provide 1,284 MW of combined cycle gas-fired generation and 100 MW of interconnected battery-based energy storage. In addition to replacing older gas-fired plants with more efficient gas-fired capacity, SCE chose advanced energy storage as a cost effective way to ensure critical power system reliability. This new storage resource will provide unmatched operational flexibility, enabling the most

16


efficient dispatch of other generating plants, lowering cost and emissions and supporting the on-going addition of renewable power sources.
This new capacity will be built at the Company's existing power plant sites in Huntington Beach and Alamitos Beach. For the gas-fired capacity, financing agreements are expected to be finalized in 2016 with construction expected to begin in 2017, and commercial operation scheduled for 2020. For the energy storage capacity, commercial operation is scheduled for 2021.
AES is pursuing permits to build both the gas-fired and energy storage capacity and will complete the licensing process before financial close. The total cost for these projects is expected to be approximately $1.9 billion, which will be funded with a combination of non-recourse debt and AES equity.
Regulatory Framework — Environmental Matters — For a discussion of environmental regulatory matters affecting U.S. Generation, see Item 1.—United States Environmental and Land-Use Legislation and Regulations.
Key Financial Drivers — AES Southland's contractual availability is the single most important driver of operations. Its units are generally required to achieve at least 86% availability in each contract year. AES Southland has historically met or exceeded its contractual availability.
Additional U.S. Generation Businesses
Business Description — Additional businesses include thermal and wind generating facilities, of which AES Hawaii and our U.S. wind generation business are the most significant.
Many of our U.S. generation plants provide baseload operations and are required to maintain a guaranteed level of availability. Any change in availability has a direct impact on financial performance. The plants are generally eligible for availability bonuses on an annual basis if they meet certain requirements. In addition to plant availability, fuel cost is a key business driver for some of our facilities.
AES Hawaii — AES Hawaii receives a fuel payment from its offtaker under a PPA expiring in 2022, which is based on a fixed rate indexed to the GNPIPD. Since the fuel payment is not directly linked to market prices for fuel, the risk arising from fluctuations in market prices for coal is borne by AES Hawaii.
To mitigate the risk from such fluctuations, AES Hawaii has entered into fixed-price coal purchase commitments that end in December 2018; the business could be subject to variability in coal pricing beginning in January 2019. To mitigate fuel risk beyond December 2018, AES Hawaii plans to seek additional fuel purchase commitments on favorable terms. However, if market prices rise and AES Hawaii is unable to procure coal supply on favorable terms, the financial performance of AES Hawaii could be materially and adversely affected.
US Wind — AES has 773 MW of wind capacity in the U.S., located in California, Texas and West Virginia. In July 2015, AES sold its interest in Armenia Mountain, a wind project located in Pennsylvania with an installed capacity of 101 MW. Typically, these facilities sell under long-term PPAs. AES financed most of these projects with tax equity structures. The tax equity investors receive a portion of the economic attributes of the facilities, including tax attributes that vary over the life of the projects. Based on certain liquidation provisions of the tax equity structures, this could result in a net loss to AES consolidated results in periods in which the facilities report net income. These non cash net losses will be expected to reverse during the life of the facilities. Some of the wind projects are exposed to the volatility of energy prices and their revenue may change materially as energy prices fluctuate in their respective markets of operations.
Buffalo Gap is located in Texas and is comprised of three wind projects with an aggregate generation capacity of 524 MW. Each wind project operates its own PPA with the exception of Buffalo Gap III whose PPA expired in December 2015. The energy price of the entire production of Buffalo Gap I is guaranteed by a PPA expiring in 2021. The PPA of Buffalo Gap II guarantees the energy price of 80% of the installed capacity while the energy price for the remaining 20% is dictated by the prices in the ERCOT market. The PPA of Buffalo Gap II expires in December 2017. Once the PPAs expire, the entire installed capacity of Buffalo Gap will be exposed to the volatility of energy prices in the ERCOT market which could adversely affect revenues.
Laurel Mountain is a wind project located in West Virginia with an installed capacity of 98 MW. Laurel Mountain does not operate under a long-term contract and sells its entire capacity and power generated into the PJM market. The volatility and fluctuations of energy prices in PJM have a direct impact in the results of Laurel Mountain.
AES manages the wind portfolio as part of its broader investments in the U.S., leveraging operational and commercial resources to supplement the experienced subject matter experts in the wind industry to achieve optimal results.
Market Structure — Coal is one of the primary fuels used by our U.S. generation facilities that has international prices set by market factors, although the price of the other primary fuel, natural gas is generally set domestically. Price variations for these fuels can change the composition of generation costs and energy prices in our generation businesses, and the prices of these fuels have been subject to volatility in recent years. Many of these generation businesses have entered into long-term

17


PPAs with utilities or other offtakers. Some coal-fired power plant businesses in the U.S. with PPAs have mechanisms to recover fuel costs from the offtaker, including an energy payment that is partially based on the market price of coal. In addition, these businesses often have an opportunity to increase or decrease profitability from payments under their PPAs depending on such items as plant efficiency and availability, heat rate, ability to buy coal at lower costs through AES' global sourcing program and fuel flexibility. Revenue may change materially as prices in fuel markets fluctuate, but the variable margin or profitability should not be materially changed when market price fluctuations in fuel are borne by the offtaker.
Regulatory Framework — Several of our generation businesses in the U.S. currently operate as QFs as defined under the PURPA. These businesses entered into long-term contracts with electric utilities that had a mandatory obligation under PURPA requirements to purchase power from QFs at the utility's avoided cost (i.e., the likely costs for both energy and capital investment that would have been incurred by the purchasing utility if that utility had to provide its own generating capacity or purchase it from another source). To be a QF, a cogeneration facility must produce electricity and useful thermal energy for an industrial or commercial process or heating or cooling applications in certain proportions to the facility's total energy output and meet certain efficiency standards. To be a QF, a small power production facility must generally use a renewable resource as its energy input and meet certain size criteria.
Our non-QF generation businesses in the U.S. currently operate as EWG as defined under EPAct 1992. These businesses, subject to approval of FERC, have the right to sell power at market-based rates, either directly to the wholesale market or to a third-party offtaker such as a power marketer or utility/industrial customer. Under the FPA and FERC's regulations, approval from FERC to sell wholesale power at market-based rates is generally dependent upon a showing to FERC that the seller lacks market power in generation and transmission, that the seller and its affiliates cannot erect other barriers to market entry and that there is no opportunity for abusive transactions involving regulated affiliates of the seller. To prevent market manipulation, FERC requires sellers with market-based rate authority to file certain reports, including a triennial updated market power analysis for markets in which they control certain threshold amounts of generation.
Other Regulatory Matters — The U.S. wholesale electricity market consists of multiple distinct regional markets that are subject to both federal regulation, as implemented by the U.S. FERC, and regional regulation as defined by rules designed and implemented by the RTOs, non-profit corporations that operate the regional transmission grid and maintain organized markets for electricity. These rules for the most part govern such items as the determination of the market mechanism for setting the system marginal price for energy and the establishment of guidelines and incentives for the addition of new capacity. See Item 1A.—Risk Factors for additional discussion on U.S. regulatory matters.
Our businesses are subject to emission regulations, which may result in increased operating costs or the purchase of additional pollution control equipment if emission levels are exceeded. Our businesses periodically review their obligations for compliance with environmental laws, including site restoration and remediation. Because of the uncertainties associated with environmental assessment and remediation activities, future costs of compliance or remediation could be higher or lower than the amount currently accrued, if any. For a discussion of environmental laws and regulations affecting the U.S. business, see Item 1.—US Environmental and Land-Use Legislation and Regulations.
Key Financial Drivers — U.S. Generation's financial results are driven by fuel costs and outages. The Company has entered into long-term fuel contracts to mitigate the risks associated with fluctuating prices. In addition, major maintenance requiring units to be off-line is performed during periods when power demand is typically lower. The financial results of US Wind are primarily driven by increased production due to faster and less turbulent wind, and reduced turbine outages. In addition, PJM and ERCOT power prices impact financial results for the wind projects that are operating without long-term contracts for all or some of their capacity.
Construction and Development — Planned capital projects include the AES Southland re-powering described above. In addition to the new construction projects, U.S. Generation performs capital projects related to major plant maintenance, repairs, and upgrades to be compliant with new environmental laws and regulations.
Andes SBU
Our Andes SBU has generation facilities in three countries — Chile, Colombia and Argentina. AES Gener, which owns all of our assets in Chile, Chivor in Colombia and TermoAndes in Argentina, as detailed below, is a publicly listed company in Chile. AES has a 66.7% ownership interest in AES Gener and this business is consolidated in our financial statements.
Our Andes operations accounted for the following proportions of consolidated AES Operating Margin, AES Adjusted PTC (a non-GAAP measure), AES Operating Cash Flow, and AES Proportional Free Cash Flow (a non-GAAP measure):
Andes SBU (1)
2015
 
2014
 
2013
% of AES Operating Margin
22
%
 
19
%
 
17
%
% of AES Adjusted PTC (a non-GAAP measure)
30
%
 
23
%
 
19
%
% of AES Operating Cash Flow
18
%
 
16
%
 
11
%
% of AES Proportional Free Cash Flow (a non-GAAP measure)
14
%
 
13
%
 
10
%

18


(1) Percentages reflect the contributions by our Andes SBU before deductions for Corporate.
The following table provides highlights of our Andes operations: 
Countries
 
Chile, Colombia and Argentina
Generation Capacity
 
8,141 gross MW (6,008 proportional MW)
Generation Facilities
 
38 (including 5 under construction)
Key Generation Businesses
 
AES Gener Chile, Chivor and AES Argentina
Operating installed capacity of our Andes SBU totals 8,141 MW, of which 44%, 44% and 12% is located in Argentina, Chile and Colombia, respectively. Presented in the table below is a list of our Andes SBU generation facilities:
Business
 
Location
 
Fuel
 
Gross MW
 
AES Equity Interest (% Rounded)
 
Year Acquired or Began Operation
 
Contract Expiration Date
 
Customer(s)
Chivor
 
Colombia
 
Hydro
 
1,000

 
67
%
 
2000
 
Short-term
 
Various
Colombia Subtotal


1,000


Electrica Santiago(1)
 
Chile
 
Gas/Diesel
 
750

 
67
%
 
2000


Gener - SIC(2)
 
Chile
 
Hydro/Coal/Diesel/Biomass
 
692

 
67
%
 
2000
 
2020-2037
 
Various
Guacolda(3)
 
Chile
 
Coal/Pet Coke
 
760

 
33
%
 
2000
 
2017-2032
 
Various
Electrica Angamos
 
Chile
 
Coal
 
558

 
67
%
 
2011
 
2026-2037
 
Minera Escondida, Minera Spence, Quebrada Blanca
Gener - SING(4)
 
Chile
 
Coal/Pet Coke
 
277

 
67
%
 
2000
 
2016-2037
 
Minera Escondida, Codelco, SQM, Quebrada Blanca
Electrica Ventanas(5)
 
Chile
 
Coal
 
272

 
67
%
 
2010
 
2025
 
Gener
Electrica Campiche(6)
 
Chile
 
Coal
 
272

 
67
%
 
2013
 
2020
 
Gener
Electrica Angamos ES
 
Chile
 
Energy Storage
 
20

 
67
%
 
2011


Gener - Norgener ES (Los Andes)
 
Chile
 
Energy Storage
 
12

 
67
%
 
2009


Chile Subtotal


3,613


TermoAndes(7)
 
Argentina
 
Gas/Diesel
 
643

 
67
%
 
2000
 
Short-term
 
Various
AES Gener Subtotal


5,256


Alicura
 
Argentina
 
Hydro
 
1,050

 
100
%
 
2000
 
2017
 
Various
Paraná-GT
 
Argentina
 
Gas/Diesel
 
845

 
100
%
 
2001


San Nicolás
 
Argentina
 
Coal/Gas/Oil
 
675

 
100
%
 
1993


Los Caracoles(8)
 
Argentina
 
Hydro
 
125

 
—
%
 
2009
 
2019
 
Energia Provincial Sociedad del Estado (EPSE)
Cabra Corral
 
Argentina
 
Hydro
 
102

 
100
%
 
1995


Ullum
 
Argentina
 
Hydro
 
45

 
100
%
 
1996


Sarmiento
 
Argentina
 
Gas/Diesel
 
33

 
100
%
 
1996


El Tunal
 
Argentina
 
Hydro
 
10

 
100
%
 
1995


Argentina Subtotal


2,885


Andes Total


8,141


(1)
Electrica Santiago plants: Nueva Renca, Renca, Los Vientos and Santa Lidia.
(2) 
Gener - SIC plants: Alfalfal, Laguna Verde, Laguna Verde Turbogas, Laja, Maitenes, Queltehues, Ventanas 1, Ventanas 2 and Volcán.
(3) 
Guacolda plants: Guacolda 1, 2, 3, 4, and 5. Unconsolidated entities for which the results of operations are reflected in Equity in Earnings of Affiliates. The Company's ownership in Guacolda is held through AES Gener, a 67%-owned consolidated subsidiary. AES Gener owns 50% of Guacolda, resulting in an AES effective ownership in Guacolda of 33%.
(4) 
Gener - SING plants: Norgener 1 and Norgener 2.
(5) 
Electrica Ventanas plant: Ventanas 3.
(6) 
Electrica Campiche plant: Ventanas 4.
(7) 
TermoAndes is located in Argentina, but is connected to both the SING in Chile and the SADI in Argentina.
(8) 
AES operates these facilities through management or O&M agreements and owns no equity interest in these businesses.

19


Under Construction — The following table lists our plants under construction in the Andes SBU: 
Business
 
Location
 
Fuel
 
Gross MW
 
AES Equity Interest (% Rounded)
 
Expected Year of Commercial Operations
Cochrane
 
Chile
 
Coal
 
532

 
40
%
 
2H 2016
Alto Maipo
 
Chile
 
Hydro
 
531

 
40
%
 
2H 2018/1H 2019
Andes Solar
 
Chile
 
Solar
 
21

 
67
%
 
1H 2016
Cochrane ES
 
Chile
 
Energy Storage
 
20

 
40
%
 
2H 2016
Chile Subtotal


1,104


Tunjita
 
Colombia
 
Hydro
 
20

 
67
%
 
1H 2016
Colombia Subtotal


20


Andes Total


1,124


The following map illustrates the location of our Andes facilities:
Andes Businesses
Chile
Business Description — In Chile, through AES Gener, we are engaged in the generation and supply of electricity (energy and capacity) in the two principal markets: the SIC and SING. In terms of aggregate installed capacity, AES Gener is the second largest generation operator in Chile with a calculated installed capacity of 3,581 MW, excluding energy storage and TermoAndes, and a market share of 17.7% as of December 31, 2015.
AES Gener owns a diversified generation portfolio in Chile in terms of geography, technology, customers and fuel source. AES Gener's installed capacity is located near the principal electricity consumption centers, including Santiago, Valparaiso and Antofagasta. AES Gener's diverse generation portfolio, composed of hydroelectric, coal, gas, diesel and biomass facilities, allows the businesses to operate under a variety of market and hydrological conditions, manage AES Gener's contractual obligations with regulated and unregulated customers and, as required, provide backup spot market energy. AES Gener has experienced significant growth in recent years responding to market opportunities with the completion of nine generation projects totaling approximately 1,861 MW, including the 152 MW Unit 5 of Guacolda completed in December 2015, and increasing AES Gener's installed capacity by 55% from 2006 to 2015. Additionally, we are constructing an additional 1,104 MW, comprised of the 21 MW Andes Solar and 20 MW Cochrane Energy Storage in the SING, the 532 MW coal-fired Cochrane plant in the SING and the 531 MW Alto Maipo run-of-the-river hydroelectric plant in the SIC.
In Chile, we align AES Gener's contracts to reduce the risk and improve margins, contracting a significant portion of their baseload capacity, currently coal and hydroelectric, under long-term contracts with a diversified customer base, including both regulated and unregulated customers. AES Gener reserves its higher variable cost units as designated backup facilities, principally the diesel- and gas-fired units in Chile, for sales to the spot market during scarce system supply conditions, such as

20


dry hydrological conditions and plant outages. In Chile, sales on the spot market are made only to other generation companies that are members of the relevant CDEC at the system marginal cost.
AES Gener currently has long-term contracts, with average terms of 13 to 16 years, with regulated distribution companies and unregulated customers, such as mining and industrial companies. In general, these long-term contracts include both fixed and variable payments along with indexation mechanisms that periodically adjust prices based on the generation cost structure related to the CPI, the international price of coal, and in some cases, with pass-through of fuel and regulatory costs, including changes in law.
In addition to energy payments, AES Gener also receives firm capacity payments for contributing to the system's ability to meet peak demand. These payments are added to the final electricity price paid by both unregulated and regulated customers. In each system, the CDEC annually determines the firm capacity amount allocated to each power plant. A plant's firm capacity is defined as the capacity that it can guarantee at peak hours during critical conditions, such as droughts, taking into account statistical information regarding maintenance periods and water inflows in the case of hydroelectric plants. The capacity price is fixed by the CNE in the semiannual node price report and indexed to the CPI and other relevant indices.
During November, 2015, AES successfully completed the sale of 4% interest in AES Gener S.A. through its direct shareholder Inversiones Cachagua S.p.A. ("Cachagua") through a private auction. The strategic rationale of this sale was to increase the liquidity of the AES Gener's Share and its exposure on international markets. As a result of this transaction AES now owns 66.7% of AES Gener.
Market Structure — Chile has two main power systems, largely as a result of its geographic shape and size. The SIC is the largest of these systems, with an installed capacity of 15,911 MW as of December 31, 2015. The SIC serves approximately 92% of the Chilean population, including the densely populated Santiago Metropolitan Region, and represents 74% of the country's electricity demand. The SING serves about 6% of the Chilean population, representing 25% of Chile's electricity consumption, and is mostly oriented toward mining companies.
In 2015, thermoelectric generation represented 62% of the total generation in Chile. In the SIC, thermoelectric generation represents 50% of installed capacity, required to fulfill demand not satisfied by hydroelectric output and is critical to guaranteeing reliable and dependable electricity supply under dry hydrological conditions. In the SING, which includes the Atacama Desert, the driest desert in the world, thermoelectric capacity represents 96% of installed capacity. The fuels used for generation, mainly coal, diesel and LNG, are indexed to international prices.
In the SIC, where hydroelectric plants represent a large part of the system's installed capacity, hydrological conditions largely influence plant dispatch and, therefore, spot market prices, given that river flow volumes, melting snow and initial water levels in reservoirs largely determine the dispatch of the system's hydroelectric and thermoelectric generation plants. Rainfall and snowfall occur in Chile principally in the southern cone winter season (June to August) and during the remainder of the year precipitation is scarce. When rain is abundant, energy produced by hydroelectric plants can amount to more than 70% of total generation. In 2015 hydroelectric generation represented 45% of total energy production.
Regulatory Framework — Electricity Regulation — The government entity that has primary responsibility for the Chilean electricity system is the Ministry of Energy, acting directly or through the CNE and the Superintendency of Electricity and Fuels. The electricity sector is divided into three segments: generation, transmission and distribution. In general terms, generation and transmission expansion are subject to market competition, while transmission operation and distribution, are subject to price regulation. The transmission segment consists of companies that transmit the electricity produced by generation companies at high voltage. Companies that are owners of a trunk transmission system, generally high voltage transmission lines with capacity of 220 Kv and higher (with bi-directional flows and relevant number of users), cannot participate in the generation or distribution segments.
Companies in the SIC and the SING that possess generation, transmission, sub-transmission or additional transmission facilities, as well as unregulated customers directly connected to transmission facilities, are coordinated through the CDEC, which minimizes the operating costs of the electricity system, while meeting all service quality and reliability requirements. The principal purpose of the CDEC is to ensure that the most efficient electricity generation available to meet demand is dispatched to customers. The CDEC dispatches plants in merit order based on their variable cost of production which allows for electricity to be supplied at the lowest available cost.
All generators can commercialize energy through contracts with distribution companies for their regulated and unregulated customers or directly with unregulated customers. Unregulated customers are customers whose connected capacity is higher than 2 MW. By law, both regulated and unregulated customers are required to purchase all of their electricity requirements under contract. Generators may also sell energy to other power generation companies on a short-term basis. Power generation companies may engage in contracted sales among themselves at negotiated prices outside the spot market. Electricity prices in Chile, under contract and on the spot market, are denominated in U.S. Dollars, although payments are made in Chilean Pesos.

21


Other Regulatory Considerations — In 2011, a regulation on air emission standards for thermoelectric power plants became effective. This regulation provides for stringent limits on emission of PM and gases produced by the combustion of solid and liquid fuels, particularly coal. For existing plants, including those currently under construction, the new limits for PM emissions went into effect at the end of 2013, and the new limits for SO2, NOx and mercury emission will begin to apply in mid-2016, except for those plants operating in zones declared saturated or latent zones (areas at risk of or affected by excessive air pollution), where these emission limits will become effective by June 2015. In order to comply with the new emission standards, AES Gener initiated investments in Chile at its older coal facilities (Ventanas I and II and Norgener I and II, constructed between 1964 and 1997) in 2012. As of December 31, 2015, AES Gener has concluded investments of approximately $229 million in order to comply within the required time frame. Additionally, its equity method investee Guacolda started the installation of new equipment during 2013, spending approximately $185 million (Guacolda I, II and IV) as of December 31, 2015 with the remaining $37 million to be invested in 2016.
Chilean law requires every electricity generator to supply a certain portion of its total contractual obligations with NCREs. In October 2013, the NCRE law was amended, increasing the NCRE requirements. The law distinguishes between energy contracts executed before and after July 1, 2013. For contracts executed between August 31, 2007 and July 1, 2013, the NCRE requirement is equal to 5% in 2014 with annual contract increases of 0.5% until reaching 10% in 2024. The NCRE requirement for contracts executed after July 1, 2013 is equal to 5% in 2013, with annual increases of 1% thereafter until reaching 12% in 2020, and subsequently annual increases of 1.5% until it is equal to 20% in 2025. Generation companies are able to meet this requirement by developing their own NCRE generation capacity (wind, solar, biomass, geothermal and small hydroelectric technology), purchasing NCREs from qualified generators or by paying the applicable fines for non-compliance. AES Gener currently fulfills the NCRE requirements by utilizing AES Gener's own biomass power plants and by purchasing NCREs from other generation companies. It has sold certain water rights to companies that are developing small hydro projects, entering into power purchase agreements with these companies in order to promote development of these projects, while at the same time meeting the NCRE requirements. At present, AES Gener is in the process of negotiating additional NCRE supply contracts to meet the future requirements.
In September 2014 a new tax law was enacted. The new law introduces an emission tax, or "green tax", that assesses the emissions of PM, SO2, NOx and CO2 produced for installations with an installed capacity over 50 MW. The first annual payment shall be made in April 2018, regarding the emissions produced during year 2017. In the case of CO2, the tax will be equivalent to $5 per ton emitted. In the SING, all  PPAs have "change of law" clauses, which would allow the company to transfer this cost to customers. In the SIC, costs can only be passed through to unregulated customers, as existing PPAs with discos do not have change of law clauses. According to its PPAs, the company is currently discussing the pass-through mechanism with each client. Additionally, new tax laws were enacted in February 2016 in Chile which will increase the statutory income tax rate for most of our Chilean businesses from 25% to 25.5% in 2017 and to 27% for 2018 and future years. See Item 7—Management's Discussion and Analysis of Financial Condition and Results of Operations—Critical Accounting Policies and Estimates—Income Taxes for further details of the impacts of these new laws.
In June 2015, the Chilean government published Decree N°7/2015, which allowed energy exportation to Argentina using the transmission line which connects the SING (Chilean Northern Grid) with the SADI (Argentine Grid). The AES transmission line has a capacity of approximately 600MW, but will be operated at 200 MW according to technical studies. AES Gener signed an agreement with CAMMESA and other generators (Gas Atacama and ECL) in order to export electricity to Argentina.
Key Financial Drivers — Hedge levels at Gener provide some certainty and clarity on the underlying financial drivers through 2016. However, some risks remain through 2016, including, but not limited to, the following:
•
Dry hydrology scenarios reduce hydro generation (See Item 7.—Key Trends and Uncertainties— Operational—Weather sensitivity for further discussion)
•
Forced outages may impact earnings
•
Changes in current regulatory rulings could alter the ability to pass through or recover certain costs
•
AES is exposed to the fluctuation of the Chilean peso, which may pose a risk to earnings; our hedging strategy reduces this risk, but some residual risk to earnings remains
•
Tax policy changes
Beyond 2016, financial drivers include all of the above factors, but also:
•
Current legislation is trending towards promoting renewable energy and strengthening regulations on thermal generation assets, posing a risk to future coal margins
•
Market price risk when re-contracting

22


Construction and Development — Since 2007, AES Gener has constructed and initiated commercial operations of approximately 1,830 MW of new capacity, representing a significant portion of the increase in installed capacity and investment in the SIC and SING during the period. In Chile, AES Gener has a 21 MW solar project with a scheduled COD in the first half of 2016 and the 532 MW Cochrane project in the SING, expected to begin operations in 2016. The Cochrane project has an adjacent 20 MW energy storage project, which is also scheduled to initiate operations in 2016.
Additionally, in the SIC, AES Gener initiated construction of the 531 MW two unit Alto Maipo run-of-river hydroelectric project in December 2013, adjacent to our existing Alfalfal power plant, located 50 km from Santiago. Alto Maipo is the largest project in construction in the SIC market and it includes 67 kilometers of tunnel works, 2 caverns, 17 km of transmission lines as part of the construction, and is 90% underground. Alto Maipo has three main contractors and covers three adjacent valleys in the Chilean Andes. As of today, the project employs 4,100 people and expects to reach a peak close to 4,500 in the second half of 2017. The project units are scheduled to reach commercial operation in the second half of 2018 and the first half of 2019.
Colombia
Business Description — Chivor, a subsidiary of AES Gener, owns a hydroelectric facility with installed capacity of 1,000 MW, located approximately 160 km east of Bogota. As of December 31, 2015, AES Gener's net power production in Colombia was 4,112 GWh. The installed capacity represents approximately 6.2% of system capacity as of December 31, 2015. The plant consists of eight 125 MW dam-based hydroelectric generating units in two separate sub-facilities. All of Chivor's installed capacity in Colombia is hydroelectric and is therefore dependent on the prevailing hydrological conditions in the region in which it operates. Hydrological conditions largely influence generation and the spot prices at which Chivor sells its non-contracted generation in Colombia.
Chivor's commercial strategy focuses a significant portion of the expected output under contracts, principally with distribution companies, in order to provide cash flow stability. These bilateral contracts with distribution companies are awarded in public bids and normally last from one to three years. The remaining generation is sold on the spot market to other generation and trading companies at the system marginal cost, allowing us to maximize the operating margin.
Additionally, Chivor receives reliability payments for the availability and reliability of Chivor's reservoir during periods of scarcity, such as adverse hydrological conditions. These payments, referred to as "reliability charge payments" are designed to compensate generation companies for the firm energy that they are capable of providing to the system during critical periods of low supply in order to prevent electricity shortages.
Market Structure — Electricity supply in Colombia is concentrated in one main system, the SIN. The SIN encompasses one-third of Colombia's territory, providing coverage to 96% of the country's population. The SIN's installed capacity totaled 16,221 MW as of December 31, 2015, comprised of 69.0% hydroelectric generation, 30.4% thermoelectric generation and 0.6% other. The dominance of hydroelectric generation and the marked seasonal variations in Colombia's hydrology result in price volatility in the short-term market. In 2015, 68.2% of total energy demand was supplied by hydroelectric plants with the remaining supply from thermoelectric generation (31.0%) and cogeneration and self-generation power (0.8%). From 2003 to 2015, electricity demand in the SIN has grown at a compound annual growth rate of 3.1% and the UPME projects an average compound annual growth rate in electricity demand of 2.8% per year for the next ten years.
Regulatory Framework — Electricity Regulation — Since 1994, the electricity sector in Colombia has operated under a competitive market framework for the generation and sale of electricity and a regulated framework for transmission and distribution. The distinct activities of the electricity sector are governed by various laws and the regulations and technical standards issued by the CREG. Other government entities that play an important role in the electricity industry include the MME, which defines the government's policy for the energy sector; the Public Utility Superintendency of Colombia, which is in charge of overseeing and inspecting the utility companies; and the UPME, which is in charge of planning the expansion of the generation and transmission network.
The generation sector is organized on a competitive basis with companies selling their generation in the wholesale market at the short-term price or under bilateral contracts with other participants, including distribution companies, generators and traders, and unregulated customers at freely negotiated prices. Generation companies must submit price bids and report the quantity of energy available on a daily basis. The National Dispatch Center dispatches generators in merit order based on bid offers in order to ensure that demand will be satisfied by the lowest cost combination of available generating units.
Other Regulatory Considerations — In the past few years, Colombian authorities have discussed proposals to make certain regulatory changes, which have not been implemented as of December 2015. One proposal is to replace or complement the current public auction system in which each distribution company holds an auction for its specific requirements and subsequently executes bilateral contracts with generation or trading companies, with a centralized auction in which the market administrator purchases energy for all distribution companies. During 2015, regulators developed rules to implement Law 1715 passed in 2014 regarding the participation of renewables sources in the electric sector and the rules for negotiation of excess of energy from self-generators. Due to very high spot prices in the market, the regulator implemented a temporary "spot price cap"

23


equivalent to the 75% of the first step of rationing cost. At the end of 2015, CREG assigned new firm energy obligations for the next 3 years (2017-2019). Additionally, regulation for emergency energy situations, such as severe drought conditions, was introduced in 2014 with the objective of avoiding shortages and other negative economic impacts. For 2016, the most probable changes in regulation will relate to the AGC ancillary services market as well as a general revision of the reliability charge scheme.
Key Financial Drivers — Hydrological conditions largely influence Chivor's generation level. Maintaining the appropriate contract level, while working to maximize revenue, through sale of excess generation, is key to Chivor's results of operations (see Item 7.—Key Trends and Uncertainties—Operational—Weather sensitivity for further discussion). Hedge levels at Chivor provide certainty and clarity on the underlying financial drivers, hedging the net cash flows of Chivor, up to 90%. However, some risks remain beyond 2016. In addition to hydrology, through 2016, financial results are likely to be driven by many factors including, but not limited to, the following:
•
Forced outages may impact earnings
•
AES is exposed to fluctuation of the Colombian peso, which pose a risk to earnings; our hedging strategy reduces this risk, but some residual risk to earnings remains
Beyond 2016, financial drivers include all of the above factors, but also:
•
Chivor has exposure to the spot market as hedge levels are lower in the future
Construction and Development — In Colombia, AES Gener is currently constructing the 20 MW Tunjita run-of-river hydroelectric project, which is scheduled to start operations in the first half of 2016.
Argentina
Business Description — As of December 31, 2015, AES Argentina operates 3,528 MW which represents 10.5% of the country's total installed capacity. The installed capacity in the SADI includes the TermoAndes plant, a subsidiary of AES Gener, which is connected both to the SADI and the Chilean SING. AES Argentina has a diversified generation portfolio of ten generation facilities, comprised of 62% thermoelectric and 38% hydroelectric capacity. All of the thermoelectric capacity has the capability to burn alternative fuels. Approximately 69% of the thermoelectric capacity can operate alternatively with natural gas or diesel oil, and the remaining 31% can operate alternatively with natural gas, fuel oil, or coal.
AES Argentina primarily sells its production to the wholesale electric market where prices are largely regulated. In 2015, approximately 93% of the energy was sold in the wholesale electric market and 7% was sold under contract, as a result of the Energy Plus sales made by TermoAndes. Market prices are determined in Argentine Pesos by CAMMESA, the wholesale electric market administrator.
All of the thermoelectric facilities not affected by the Resolution 95/2013, a regulation passed in March 2013 discussed below, including the portion of TermoAndes plant committed to Energy Plus Contracts, are able to use natural gas and receive gas supplied through contracts with Argentine producers. In recent years, gas supply restrictions in Argentina, particularly during the winter season, have affected some of the plants, such as the TermoAndes plant which is connected to the SING by a transmission line owned by AES Gener. The TermoAndes plant commenced operations in 2000, selling exclusively into the Chilean SING. In 2008, following requirements from the Argentine authorities, TermoAndes connected its two gas turbines to the SADI, while maintaining its steam turbine connected to the SING. However, since mid-December 2011, TermoAndes has been selling the plant's full capacity in the SADI. TermoAndes' electricity permit to export to the SING expired on January 31, 2013 and its potential renewal is being evaluated.
Market Structure — The SADI electricity market is managed by CAMMESA. As of December 31, 2015, the installed capacity of the SADI totaled 33,480 MW. In 2015, 64% of total energy demand was supplied by thermoelectric plants, 31% by hydroelectric plants and 6% from nuclear, wind and solar plants.
Thermoelectric generation in the SADI is principally fueled by natural gas. However, since 2004 due to natural gas shortages, in addition to increasing electricity demand, the use of alternative fuels in thermoelectric generation, such as oil and coal, has increased. Given the importance of hydroelectric facilities in the SADI, hydrological conditions determining river flow volumes and initial water levels in reservoirs largely influence hydroelectric and thermoelectric plant dispatch. Rainfall occurs principally in the southern cone winter season (June to August).
Regulatory Framework — Electricity Regulation — The Argentine regulatory framework divides the electricity sector into generation, transmission and distribution. The wholesale electric market is made up of generation companies, transmission companies, distribution companies and large customers who are allowed to buy and sell electricity. Generation companies can sell their output in the short-term market or to customers in the contract market. CAMMESA is responsible for dispatch coordination and determination of short-term prices. The Electricity National Regulatory Agency is in charge of regulating

24


public service activities and the Ministry of Federal Planning, Public Investment and Services, through the Energy Secretariat, regulates system dispatch and grants concessions or authorizations for sector activities.
Since 2001, significant modifications have also been made to the electricity regulatory framework. These modifications include tariff conversion to Argentinean Pesos, freezing of tariffs, the cancellation of inflation adjustment mechanisms and the introduction of a complex pricing system in the wholesale electric market, which have materially affected electricity generators, transporters and distributors, and generated substantial price differences within the market. Since 2004, as a result of energy market reforms and overdue accounts receivables owed by the government to generators operating in Argentina, AES Argentina contributed certain accounts receivables to fund the construction of new power plants under FONINVEMEM agreements. These receivables accrue interest and are collected in monthly installments over 10 years once the related plants begin operations. At this point, three funds have been created to construct three facilities. The first two plants are operating and payments are being received, while the third plant is in late stages of the construction process. AES Argentina will receive a pro rata ownership interest in these newly built plants once the accounts receivables have been paid. See Item 7.—Capital Resources and Liquidity—Long-Term Receivables and Note 7—Financing Receivables for further discussion of receivables in Argentina.
On March 26, 2013, the Secretariat of Energy released Resolution 95/2013, which affects the remuneration of generators whose sales prices had been frozen since 2003. This new regulation, which modified the current regulatory framework for the electricity industry, is applicable to generation companies with certain exceptions. It defined a new compensation system based on compensating for fixed costs, non-fuel variable costs and an additional margin. Resolution 95/2013 converted the Argentine electric market towards an "average cost" compensation scheme, increasing revenues of generators that were not selling their production under the Energy Plus scheme or under energy supply contracts with CAMMESA. Resolution 95/2013 applied to all of AES Argentina's plants, excluding TermoAndes. Based on Note 2053 sent by the Ministry of Energy in March 2013, it was understood that TermoAndes' units were not affected by the Resolution since they sell under the Energy Plus scheme.
Thermal units must achieve an availability target which varies by technology in order to receive full fixed cost revenues. The availability of most of AES Argentina's units exceeds this market average. As a result of Resolution 95/2013, revenues to AES Argentina's thermal units increased, but the impact on hydroelectric units is dependent on hydrology. The new Resolution also established that all fuels, except coal, are to be provided by CAMMESA. Thermoelectric natural gas plants not affected by the Resolution, such as TermoAndes, are able to purchase gas directly from the producers for Energy Plus sales.
On May 20, 2014, the Argentine government passed Resolution No. 529/214 ("Resolution 529") which retroactively updated the prices of Resolution 95/2013 to February 1, 2014, changed target availability and added a remuneration for non-periodic maintenance. This renumeration is aimed to cover the expenses that the generator incurs when performing major maintenances in its units.
In the fourth quarter of 2014, the Argentine government passed a resolution to contribute outstanding Resolution 95 receivables into a trust in connection with AES Argentina's commitment to install additional capacity into the system. CAMMESA will finance the investment utilizing the outstanding receivables as a guarantee.
On July 10, 2015, the Argentine government passed Resolution No. 482/2015 ("Resolution 482") which retroactively updated the prices of Resolution 529/2014 to February 1, 2015, including the portion of TermoAndes plant energy generation not committed to Energy Plus Contracts, and created a new trust called "Recursos para las inversions del FONINVEMEM 2015-2018" in order to invest in new generation plants.
In December 2015, the new finance minister lifted foreign currency controls, allowing the peso to float under the administration of Argentinean Central Bank. The newly freed currency fell by more than 30%. Over the course of 2015, the Argentinean Peso devalued by approximately 50%. At December 31, 2015, all transactions at our businesses in Argentina were translated using the official exchange rate published by the Argentine Central Bank. See Note 7—Financing Receivables in Item 8.—Financial Statements and Supplementary Data of this Form 10-K for further information on the long-term receivables. Further weakening of the Argentine Peso and local economic activity could cause significant volatility in our results of operations, cash flows, the ability to pay dividends to the Parent Company, and the value of our assets.
Key Financial Drivers — Financial results are likely to be driven by many factors including, but not limited to, the following:
•Forced outages may impact earnings
•FX exposure to fluctuations of the Argentine Peso
•Hydrology
•
Timely collection of FONINVEMEM installment and outstanding receivables (See Note 7—Financing Receivables in Item 8.—Financial Statements and Supplementary Data for further discussion)
•Level of gas prices for contracted generation (Energy Plus)

25


•
Regulatory changes from new government (See Item 7.—Key Trends and Uncertainties—Macroeconomics— Argentina for further discussion)
Brazil SBU
Our Brazil SBU has generation and distribution businesses. Eletropaulo and Tietê are publicly listed companies in Brazil. AES has a 16% economic interest in Eletropaulo and a 24% economic interest in Tietê, and these businesses are consolidated in our financial statements as we maintain control over their operations. Our Brazil operations accounted for the following proportions of consolidated AES Operating Margin, AES Adjusted PTC (a non-GAAP measure), AES Operating Cash Flow, and AES Proportional Free Cash Flow (a non-GAAP measure):

26


Brazil SBU (1)
2015
 
2014
 
2013
% of AES Operating Margin
21
%
 
24
%
 
27
%
% of AES Adjusted PTC (a non-GAAP measure)
6
%
 
13
%
 
12
%
% of AES Operating Cash Flow
5
%
 
14
%
 
26
%
% of AES Proportional Free Cash Flow (a non-GAAP measure)
NM(2)

 
1
%
 
6
%
(1) Percentages reflect the contributions by our Brazil SBU before deductions for Corporate.
(2) Not meaningful
The following table provides highlights of our Brazil operations:
Generation Capacity
 
3,298 gross MW (932 proportional MW)
Generation Facilities
 
13
Key Generation Businesses
 
Tietê and Uruguaiana
Utilities Penetration
 
8.2 million customers (56,861 GWh)
Utility Businesses
 
2
Key Utility Businesses
 
Eletropaulo and Sul
Generation — Operating installed capacity of our Brazil SBU totals 2,658 MW in AES Tietê plants, located in the state of São Paulo. As of December 31, 2015, Tietê represents approximately 12% of the total generation capacity in the state of São Paulo and is the third largest private generator in Brazil. We also have another generation plant, AES Uruguaiana, located in southern Brazil with an installed capacity of 640 MW. Listed below are our Brazil SBU generation facilities:
Business
 
Location
 
Fuel
 
Gross MW
 
AES Equity Interest (% Rounded)
 
Year Acquired or Began Operation
 
Contract Expiration Date
 
Customer(s)
Tietê(1)
 
Brazil
 
Hydro
 
2,658

 
24
%
 
1999
 
2029
 
Various
Uruguaiana
 
Brazil
 
Gas
 
640

 
46
%
 
2000


Brazil Total


3,298


(1) 
Tietê plants with installed capacity: Água Vermelha (1,396 MW), Bariri (143 MW), Barra Bonita (141 MW), Caconde (80 MW), Euclides da Cunha (109 MW), Ibitinga (132 MW), Limoeiro (32 MW), Mogi-Guaçu (7 MW), Nova Avanhandava (347 MW), Promissão (264 MW), Sao Joaquim (3 MW) and Sao Jose (4 MW).
Utilities — AES owns interests in two distribution businesses in Brazil, Eletropaulo and Sul. Eletropaulo operates in the metropolitan area of São Paulo and adjacent regions, distributing electricity to 24 municipalities in a total area of 4,526 km2, covering a region of high demographic density and the largest concentration of GDP in the country. Serving approximately 20 million people and 6.9 million consumer units, Eletropaulo is the largest power distributor in Brazil, according to the 2012 ranking of the Brazilian Association of the Distributors of Electric Energy (Abradee).
Sul is responsible for supplying electricity to 118 municipalities of the metropolitan region of Porto Alegre on the border with Uruguay and Argentina. The service area covers 99,512 km2, serving approximately 3.7 million people and 1.3 million consumer units.
Presented in the table below is a list of our Brazil SBU distribution facilities:
Business
 
Location
 
Approximate Number of Customers Served as of 12/31/2015
 
GWh Sold in 2015
 
AES Equity Interest (% Rounded)
 
Year Acquired
Eletropaulo
 
Brazil
 
6,852,690

 
47,357

 
16
%
 
1998
Sul
 
Brazil
 
1,308,224

 
9,504

 
100
%
 
1997


8,160,914

 
56,861


27


The following map illustrates the location of our Brazil facilities:
Brazil Generation Businesses
Business Description — Tietê has a portfolio of 12 hydroelectric power plants with total installed capacity of 2,658 MW in the state of São Paulo. Tietê was privatized in 1999 under a 30-year concession expiring in 2029. AES owns a 24% economic interest in Tietê, our partner, the BNDES, owns 28% and the remaining shares are publicly held or held by government-related entities. AES is the controlling shareholder and manages and consolidates this business.
Tietê sold nearly 100% of its assured capacity, approximately 11,1194 GWh, to Eletropaulo under a long-term PPA, which expired in December 2015. The contract was price-adjusted annually for inflation, and as of December 31, 2015, the price was R$218/MWh. After the expiration of contract with Eletropaulo, Tietê's strategy is to contract most of its Assured Energy, as described in Regulatory Framework section below, in the free market and sell the remaining portion in the spot market. Tietê's strategy is reassessed from time to time according to changes in market conditions, hydrology and other factors. Tietê has been continuously selling its available energy from 2016 forward through medium-term bilateral contracts (3-5 years).
As of December 31, 2015, Tietê's contracted portfolio position is 95% and 88% with average prices of R$149/MWh and R$150/MWh for 2016 and 2017, respectively. As Brazil is mostly a hydro-based country with energy prices highly tied to the hydrological situation, the deterioration of the hydrology since the beginning of 2014 caused an increase in energy prices going forward. Tietê is closely monitoring and analyzing system supply conditions to support energy commercialization decisions. In 2015, 12 new contracts were signed at an average price of approximately R$154/MWh.Tietê's strategy is to contract most of its physical guarantee in the free market while the remaining portion provides flexibility to either protect against low hydrology or potentially capture higher spot prices in the future. As Brazil does not have a developed market with hedge and options instruments for the energy sector, Tietê does not assume any hedging strategy for its portfolio.
Under the concession agreement, Tietê has an obligation to increase its capacity by 15%. Tietê as well as other concessionaire generators have not yet met this requirement due to regulatory, environmental, hydrological and fuel constraints. Sao Paulo state does not have a good potential for wind power and also only a small remaining potential for hydro projects, directing the new increase in the state for thermal capacity. With the high complexity process to get an environmental license for coal projects, Tietê decided to fulfill obligation with gas-fired projects in line with Federal government plans. As Petrobras refuses to supply natural gas and to offer capacity in its pipelines and regasification terminals and there are no regulations for natural gas swaps in place, up to now, it is unfeasible to bring natural gas to AES Tietê. A legal case has been initiated by the State of São Paulo requiring the investment to be performed. Tietê is in the process of analyzing options to meet the obligation.
Uruguaiana is a 640 MW gas-fired combined cycle power plant located in the town of Uruguaiana in the state of Rio Grande do Sul, commissioned in December 2000. AES manages and has a 46% economic interest in the plant with the remaining interest held by BNDES. The plant's operations were suspended in April 2009 due to the unavailability of gas. AES has evaluated several alternatives to bring gas supply on a competitive basis to Uruguaiana. One of the challenges is the

28


capacity restrictions on the Argentinean pipeline, especially during the winter season when gas demand in Argentina is very high. The plant operated on a short-term basis in 2013 during February and March, in 2014 during March, April, and May, and in 2015 during February, Mach, April and May due to the short-term supply of LNG for the facility. Uruguaiana continues to work toward securing gas on a long-term basis.
Market Structure — Brazil has installed capacity of 140,272 MW, which is 65% hydroelectric, 21.6% thermal and 13.4% renewable (biomass and wind). Brazil's national grid is divided into four subsystems. Tietê is in the Southeast subsystem of the national grid, while Uruguaiana is in the South.
Regulatory Framework — In Brazil, the MME determines the maximum amount of energy that a plant can sell, called Assured Energy, which represents the long-term average expected energy production of the plant. Under current rules, a generation plant's Assured Energy can be sold to distribution companies through long-term (regulated) auctions or under unregulated bilateral contracts with large consumers or energy trading companies.
The ONS is responsible for coordinating and controlling the operation of the national grid. The ONS dispatches generators based on hydrological conditions, reservoir levels, electricity demand and the prices of fuel and thermal generation. Given the importance of hydro generation in the country, the ONS sometimes reduces dispatch of hydro facilities and increases dispatch of thermal facilities to protect reservoir levels in the system.
In Brazil, the system operator controls all hydroelectric generation dispatch and reservoir levels, and a mechanism known as MRE was created to share hydrological risk across all hydro generators. If the hydro system generates less than total Assured Energy of the system, hydro generators may need to purchase energy in the short-term market to fulfill their contract obligations. When total hydro generation is higher than the total MRE Assured Energy, the surplus is proportionally shared among its participants and they are able to make extra revenue selling the excess energy on the spot market. The consequences of unfavorable hydrology are (i) thermal plants (more expensive to the system) being dispatched, (ii) lower hydropower generation with deficits in the MRE and (iii) high spot prices.
Due to lower than expected hydrology during 2014, from February to April the spot price was at the cap of R$822/MWh and the average spot price of 2014 was R$689/MWh. During October and November 2014, the ANEEL conducted a public hearing to define a new spot price cap, changing it from R$822/MWh to R$388/MWh from January 2015 until December 2015. The lower cap price resulted in a meaningful reduction on the expenses of the agents that were negatively exposed to the spot price in 2015. However, due to improved hydrology in the second half of 2015 spot prices were below the cap with the average price of R$287/MWh. For 2016, ANEEL has already defined the new spot price cap, changing it from R$388/MWh to R$423/MWh from January 2016 forward.
Key Financial Drivers — As the system is highly dependent on hydroelectric generation, Tietê and Uruguaiana (more likely to generate during low hydrology) are affected by the hydrology in the overall sector, as well as the availability of Tietê's plants and reliability of the Uruguaiana facility. The availability of gas for continued operations is a driver for Uruguaiana.
Through and beyond 2016, Tietê's financial results are likely to be driven by many factors including, but not limited to, the following:
•
Hydrology, impacting quantity of energy generated
•
Demand growth
•
Re-contracting price
•
Asset management and plant availability
•
Cost management
•
Ability to execute on its growth strategy
Through and beyond 2016, Uruguaiana's financial results are likely to be driven by many factors including, but not limited to, the following:
•
Arbitration settlement with YPF (see Item 3.—Legal Proceedings)
•
Secure long-term gas solution
Brazil Utility Businesses
Business Description — Eletropaulo distributes electricity to the greater São Paulo area, Brazil's main economic and financial center. Eletropaulo is the largest electric power distributor in Latin America in terms of both revenues and volume of energy distribution.
AES owns 16% of the economic interest in Eletropaulo, our partner, BNDES, owns 19% and the remaining shares are publicly held or held by government-related entities. AES is the controlling shareholder and manages and consolidates this business. Eletropaulo holds a 30-year concession that expires in 2028.

29


AES owns 100% of Sul. Sul distributes electricity in the metropolitan region of Porto Alegre up to the frontier with Uruguay and Argentina, respectively, in the municipalities of Santana do Livramento and Uruguaiana/São Borja at the extreme west of the state of Rio Grande do Sul. AES manages Sul under a 30-year concession expiring in 2027.
Regulatory Framework — In Brazil, ANEEL, a government agency, sets the tariff for each distribution company based on a Return on Asset Base methodology, which also benchmarks operational costs against other distribution companies.
The tariff charged to regulated customers consists of two elements: (i) pass-through of non-manageable costs under a determined methodology ("Parcel A"), including energy purchase costs, sector charges and transmission and distribution system expenses; and (ii) a manageable cost component ("Parcel B"), including operation and maintenance costs (defined by ANEEL), recovery of investments and a component for a return to the distributor. The return to distributors is calculated as the net asset base multiplied by the Regulatory WACC, which is set for all industry participants during each tariff reset cycle. The current Regulatory WACC for Eletropaulo, after tax, is 8.1%. This WACC is effective for three years and as such will be updated again in the next tariff review for Sul in April 2018.
Each year ANEEL reviews each distributor's tariff for an annual tariff adjustment. The annual tariff adjustments allow for pass-through of Parcel A costs and inflation impacts on Parcel B costs, adjusted for expected efficiency gains and quality performances. Distribution companies are required to contract between 100% and 105% of anticipated energy needs through the regulated auction market. If contracted levels fall below required levels distribution companies may be subject to limitations on the pass-through treatment of energy purchase costs as well as penalties. As the costs incurred on energy purchases by our distribution companies are passed through to customers with adjustments on a yearly basis, working capital will be sensitive to significant increases in energy prices. In order to reduce potential working capital needs, in February 2015, ANEEL opened two public hearings (i) to discuss an Extraordinary Tariff Review ("ETR") requested by distribution companies and ii) to discuss adjustments to a tariff flag mechanism that may change the tariff to customers on a monthly basis depending on energy prices. These items were approved by ANEEL and made effective on March 2, 2015. The ETR represented an average tariff increase of 32% in AES Eletropaulo and 39% at AES Sul. The tariff flag mechanism, a temporary measure in response to higher energy prices due to dry hydrological conditions, was improved by incorporating i) a higher tariff increase depending on the energy purchase costs and (ii) resources collected by the tariff flag being centralized in an account and shared among distribution companies in proportion to their respective involuntary exposure. Most recently, ANEEL approved the Annual Readjustment for AES Sul on April 14, 2015 representing an average tariff increase of 5.46%.
Every four to five years, ANEEL resets each distributor's tariff to incorporate the revised Regulatory WACC and determination of the distributor's net asset base. Eletropaulo's tariff reset occurs every four years and the next tariff reset will be in July 2019. Sul's tariff is reset every five years and the next tariff reset is expected in April 2018. The 4th Tariff Reset for AES Eletropaulo occurred on July 4, 2015, representing an average tariff increase of 15.23%.
ANEEL challenged the parameters of a tariff reset for Eletropaulo implemented in July 2012 and retroactive to 2011. ANEEL asserted that during the period between 2007 and 2011, certain assets that were included in the regulatory asset base should not have been included and that Eletropaulo should refund customers for the return on the disputed assets earned during this period. On December 17, 2013, ANEEL determined, at the administrative level, that Eletropaulo should adjust the prior (2007-2011) regulatory asset base and refund customers in the amount of $269 million (R$630 million) over a period of up to four tariff processes beginning in July 2014. Eletropaulo filed for an administrative appeal requesting ANEEL to reconsider its decision and requested that the decision be suspended until the appeal process was completed. On January 28, 2014, ANEEL denied Eletropaulo's request to suspend the effects of the previous decision. On January 29, 2014, Eletropaulo requested and received from the Federal Court of Brazil an injunction for the suspension of the effects of ANEEL's previous decision. As ANEEL had confirmed the original decision and the related refund to customers, the injunction no longer became effective. The Company recognized a regulatory liability of approximately $269 million in the Company's 2013 fourth quarter results of operations since ANEEL had compelled the Company to refund customers. Eletropaulo started reimbursing customers in July 2014.
On December 18, 2014, the effects of the injunction were restored and on January 5, 2015, during a public hearing, ANEEL resolved to follow the legal decision. However, on January 7, 2015 ANEEL requested the suspension of the injunction. While the final legal decision has yet not been taken, ANEEL released a new tariff for Eletropaulo on January 8, 2015, not considering the reimbursement to customers, which is immediately effective. On June 30, 2015, ANEEL included in Eletropaulo's tariff reset the reimbursement of amounts previously refunded to customers from July 2014 through early January 2015. In addition to ANEEL's failure thus far to suspend the injunction through the appeals process in the Brazilian courts, the tariff reset resulted in management's reassessment of the probability of refunding customers these disputed amounts. The Company now considers it only reasonably possible that Eletropaulo will be required to refund these amounts to customers prior to the ultimate resolution of the pending court case. As a result, during the second quarter of 2015, the Company reversed the remaining regulatory liability for this contingency of $161 million. Eletropaulo believes it has meritorious arguments on this matter and will continue to pursue its objections to ANEEL's rulings vigorously, however there can be no assurance that Eletropaulo will prevail.

30


Key Financial Drivers — Through and beyond 2016, Eletropaulo's and Sul's financial results are likely to be driven by many factors including, but not limited to, the following:
•
Hydrology, impacting quantity of energy sold and energy purchased
•
Brazilian economic growth and tariff increases, impacting energy consumption growth, losses and delinquency (see Item 7.—Key Trends and Uncertainties—Macroeconomics—Brazil for further information)
•
Ability of both Eletropaulo and Sul to pass through costs via productivity gains
•
Capital structure optimization to reduce leverage and interest costs
•
Sul's fourth tariff cycle outcomes in April 2018
•
July 2012 regulatory asset base resolution
•
The Eletrobrás case (see Item 3.—Legal Proceedings for further information)
Eletropaulo and Sul are affected by the demand for electricity, which is driven by economic activity, weather patterns and customers' consumption behavior. Operating performance is also driven by the quality of service, efficient management of operating and maintenance costs as well as the ability to control non-technical losses. Finally, annual tariff adjustments and periodic tariff resets by ANEEL impact results from operations.
MCAC SBU
Our MCAC SBU has a portfolio of distribution businesses and generation facilities, including renewable energy, in five countries, with a total capacity of 3,239 MW and distribution networks serving 1.3 million customers as of December 31, 2015. MCAC operations accounted for the following proportions of consolidated AES Operating Margin, AES Adjusted PTC (a non-GAAP measure), AES Operating Cash Flow, and AES Proportional Free Cash Flow (a non-GAAP measure):
MCAC SBU (1)
2015
 
2014
 
2013
% of AES Operating Margin
19
%
 
18
%
 
17
%
% of AES Adjusted PTC (a non-GAAP measure)
20
%
 
19
%
 
19
%
% of AES Operating Cash Flow
28
%
 
16
%
 
17
%
% of AES Proportional Free Cash Flow (a non-GAAP measure)
30
%
 
20
%
 
23
%
(1) Percentages reflect the contributions by our MCAC SBU before deductions for Corporate.
 
The following table provides highlights of our MCAC SBU operations:
Countries
 
Dominican Republic, El Salvador, Mexico, Panama and Puerto Rico
Generation Capacity
 
3,239 gross MW (2,482 proportional MW)
Generation Facilities
 
17 (including 1 under construction)
Key Generation Businesses
 
Andres, Panama and TEG TEP
Utilities Penetration
 
1.3 million customers (3,754 GWh)
Utility Businesses
 
4
Key Utility Businesses
 
El Salvador

31


The table below lists our MCAC SBU facilities:
Business
 
Location
 
Fuel
 
Gross MW
 
AES Equity Interest (% Rounded)
 
Year Acquired or Began Operation
 
Contract Expiration Date
 
Customer(s)
Andres
 
Dominican Republic (DR)
 
Gas
 
319

 
90
%
 
2003
 
2018
 
Ede Este/Non-Regulated Users/Linea Clave
Itabo(1) 
 
DR
 
Coal/Gas
 
295

 
45
%
 
2000
 
2016
 
Ede Este/Ede Sur/Ede Norte/Quitpe
DPP (Los Mina)
 
DR
 
Gas
 
236

 
90
%
 
1996
 
2016
 
Ede Este
Dominican Republic Subtotal


850


AES Nejapa
 
El Salvador
 
Landfill Gas
 
6

 
100
%
 
2011
 
2035
 
CAESS
Moncagua
 
El Salvador
 
Solar
 
3

 
100
%
 
2015
 
2035
 
EEO
El Salvador Subtotal


9


Merida III
 
Mexico
 
Gas
 
505

 
55
%
 
2000
 
2025
 
Comision Federal de Electricidad
Termoelectrica del Golfo (TEG)
 
Mexico
 
Pet Coke
 
275

 
99
%
 
2007
 
2027
 
CEMEX
Termoelectrica del Penoles (TEP)
 
Mexico
 
Pet Coke
 
275

 
99
%
 
2007
 
2027
 
Penoles
Mexico Subtotal


1,055


Bayano
 
Panama
 
Hydro
 
260

 
49
%
 
1999
 
2030
 
Electra Noreste/Edemet/Edechi/Other
Changuinola
 
Panama
 
Hydro
 
223

 
90
%
 
2011
 
2030
 
AES Panama
Chiriqui-Esti
 
Panama
 
Hydro
 
120

 
49
%
 
2003
 
2030
 
Electra Noreste/Edemet/Edechi/Other
Estrella de Mar I
 
Panama
 
Heavy Fuel Oil
 
72

 
49
%
 
2015
 
2020
 
Electra Noreste/Edemet/Edechi/Other
Chiriqui-Los Valles
 
Panama
 
Hydro
 
54

 
49
%
 
1999
 
2030
 
Electra Noreste/Edemet/Edechi/Other
Chiriqui-La Estrella
 
Panama
 
Hydro
 
48

 
49
%
 
1999
 
2030
 
Electra Noreste/Edemet/Edechi/Other
Panama Subtotal


777


Puerto Rico
 
US-PR
 
Coal
 
524

 
100
%
 
2002
 
2027
 
Puerto Rico Electric Power Authority
Illumina
 
US-PR
 
Solar
 
24

 
100
%
 
2012


Puerto Rico Subtotal


548


MCAC Total


3,239


(1) 
Itabo plants: Itabo complex (two coal-fired steam turbines and one gas-fired steam turbine).
Under Construction — The following table lists our plants under construction in the MCAC SBU: 
Business
 
Location
 
Fuel
 
Gross MW
 
AES Equity Interest (% Rounded)
 
Expected Year of Commercial Operations
DPP (Los Mina) Conversion
 
Dominican Republic
 
Gas
 
122

 
90
%
 
1H 2017
Dominican Republic Subtotal


122


MCAC Total


122


MCAC Utilities — Our distribution businesses are located in El Salvador and distribute power to 1.3 million people in the country. These businesses consist of four companies, each of which operates in defined service areas as described below:
Business
 
Location
 
Approximate Number of Customers Served as of 12/31/2015
 
Approximate GWh Sold in 2015
 
AES Equity Interest (% Rounded)
 
Year Acquired
CAESS
 
El Salvador
 
583,000

 
2,174

 
75
%
 
2000
CLESA
 
El Salvador
 
377,000

 
892

 
80
%
 
1998
DEUSEM
 
El Salvador
 
76,000

 
132

 
74
%
 
2000
EEO
 
El Salvador
 
290,000

 
556

 
89
%
 
2000


1,326,000

 
3,754


32


The following map illustrates the location of our MCAC facilities:
MCAC Businesses
Dominican Republic
Business Description — AES Dominicana consists of three operating subsidiaries, Itabo, Andres and DPP. AES has 23% of the system capacity (850 MW) and supplies approximately 42% of energy demand through these generation facilities.
During 2014, AES entered into a strategic partnership with the Estrella and Linda Groups ("Estrella-Linda"), an investor group based in the Dominican Republic. Under this agreement, Estrella-Linda acquired an 8% non-controlling interest in AES' business in the Dominican Republic for $83 million and, in December 2015, exercised its first call option of additional 2% for$18 million, net of discount and transaction costs. Estrella-Linda has an additional option to increase up to 20% by the end of 2016. Estrella-Linda is a consortium of two leading Dominican industrial groups: Estrella and Grupo Linda. The two partners manage a diversified business portfolio, including construction services, cement, agribusiness, metalwork, plastics, textiles, paints, transportation, insurance and media.
Itabo is 45%-owned by AES, 5% by Estrella-Linda, 49.97% owned by FONPER, a government-owned utility and the remaining 0.03% is owned by employees. Itabo owns and operates two thermal power generation units with a total of 295 MW of installed capacity. Itabo's PPAs are with government-owned distribution companies and expire in 2016. Since the majority of distribution companies' long term PPAs are expiring in July 2016, the CDEEE is sponsoring a bidding process that is expected to be released and awarded during 2016 in order to secure supply and competitive pricing for actual and future distribution energy requirements. The existing business strategy is to secure approximately 75% to 85% of the open position through new PPAs with distribution companies and large users. Price and PPA structure will be subject to the terms of the bidding process.
Andres and DPP are owned 90% by AES and 10% by Estrella-Linda. Andres has a combined cycle gas turbine and generation capacity of 319 MW as well as the only LNG import facility in the country, with 160,000 cubic meters of storage capacity. DPP (Los Mina) has two open cycle natural gas turbines and generation capacity of 236 MW. Both Andres and DPP have in aggregate 555 MW of installed capacity, of which 450 MW is mostly contracted until 2018 with government-owned distribution companies and large customers.
AES Dominicana has a long-term LNG purchase contract through 2023 for 33.6 trillion btu/year with a price linked to NYMEX Henry Hub. The LNG contract terms allow the diversion of the cargoes to various markets in Latin America. These plants capitalize on the competitively-priced LNG contract by selling power where the market is dominated by fuel oil-based generation.
In 2005, Andres entered into a contract to sell re-gasified LNG for further distribution to industrial users within the Dominican Republic using compression technology to transport it within the country. In January 2010, the first LNG truck

33


tanker loading terminal started operations. With this investment, AES is capturing demand from industrial and commercial customers.
Market Structure
Electricity Market — The Dominican Republic has one main interconnected system with approximately 3,742 MW of installed capacity, composed primarily of thermal generation (82%), hydroelectric power plants (16%) and wind plants (2%).
Natural Gas Market — The natural gas market in the Dominican Republic started developing in 2001 when AES entered into a long-term contract for LNG and constructed AES Dominicana's LNG regasification terminal.
Regulatory Framework — The regulatory framework in the Dominican Republic consists of a decentralized industry including generation, transmission and distribution, where generation companies can earn revenue through short- and long-term PPAs, ancillary services and a competitive wholesale generation market. All electric companies (generators, transmission and distributors), are subject to and regulated by the GEL.
Two main agencies are responsible for monitoring and ensuring compliance with the GEL, the CNE and the SIE. CNE is in charge of drafting and coordinating the legal framework and regulatory legislation, proposing and adopting policies and procedures to assure best practices, drafting plans to ensure the proper functioning and development of the energy sector and promoting investment. SIE's main responsibilities include monitoring and supervising compliance with legal provisions and rules, monitoring compliance with the technical procedures governing generation, transmission, distribution and commercialization of electricity and supervising electric market behavior in order to avoid monopolistic practices.
The electricity tariff applicable to regulated customers is subject to regulation within the concessions of the distribution companies. Clients with demand above 1.0 MW are classified as unregulated customers and their tariffs are unregulated.
Fuels and hydrocarbons are regulated by a specific law which establishes prices to end customers and a tax on consumption of fossil fuels. For natural gas there are regulations related to the procedures to be followed to grant licenses and concessions: i) distribution, including loading, transportation and compression plants; ii) the installation and operation of natural gas stations, including consumers and potential modifications of existing facilities; and iii) conversion equipment suppliers for vehicles. The regulation is administered by the ICM who supervises commercial and industrial activities in the Dominican Republic as well as the fuels and natural gas commercialization to the end users.
Key Financial Drivers — Financial results are likely to be driven by many factors including, but not limited to, the following:
•
Spot prices are mainly driven by the fluctuations in commodity prices due to the dependency of the Dominican Republic on oil-based thermal generation. Since the fuel component is a pass-through cost under the PPAs, any variation in the oil prices will mainly impact the spot sales for both Andres and Itabo, which are expected to be net sellers in the upcoming years. Current contracting level for 2016 is close to 90%. Supply shortages in the near term (next 2 to 3 years) may provide opportunities for upside but new generation is expected to come online from 2018.
•
Additional sales derived from natural gas domestic demand are expected to continue providing an income stream and growth based on the entry of future projects and the fees from the infrastructure service.
In addition, the financial weakness of the three state-owned distribution companies due to low collection rates and high levels of non-technical losses has led to delays in payments for the electricity supplied by generators. At times when outstanding receivable balances have accumulated, AES Dominicana has accepted payment through other means, such as government bonds, in order to reduce the balance. There can be no guarantee that alternative collection methodologies will always be an avenue available for payment options.
Construction and Development — DPP is converting its existing plant from open cycle to combined cycle. The project will recycle DPP's heat emissions and increase total power output by approximately 114 MW of gross capacity at an estimated cost of $260 million, fully financed with non-recourse debt. The EPC contract was signed on July 2, 2014, and the additional capacity is expected to become operational in in the first half of 2017. Based on the increased capacity, AES Dominicana executed a PPA for 270 MW for a 6.5 years term beginning on August 1, 2016.
Panama
Business Description — AES owns and operates five hydroelectric plants and one thermoelectric power plant, Estrella del Mar I, which commenced operations in March 2015, representing 705 MW and 72 MW of hydro and thermal capacity respectively, for a total of 777 MW equivalent to 25% of the installed capacity in Panama. The majority of hydro sources in Panama are based on run-of-river technology, with the exception of the 260 MW Bayano plant.
A portion of the PPAs with distribution companies will expire on December 2018 reducing the total contracted capacity of the company from 496 MW to 430 MW. Another portion contracted through Estrella del Mar I will expire on June 2020, reducing the total contracted capacity to 350 MW until December 2030.

34


Market Structure — Panama's current total installed capacity is 3,068 MW, of which 56% is hydroelectric, 3% wind and the remaining 41% thermal generation from diesel, bunker fuel and coal.
The Panamanian power sector is composed of three distinct operating business units: generation, distribution and transmission, all of which are governed by Electric Law 6 enacted in 1997.
Generators can enter into long-term PPAs with distributors or unregulated consumers. In addition, generators can enter into alternative supply contracts with each other. Outside of the PPA market, generators may buy and sell energy in the short-term market.
The CND implements the economic dispatch of electricity in the wholesale market. The CND's objectives are to minimize the total cost of generation and maintain the reliability and security of the electric power system, taking into account the price of water, which determines the dispatch of hydro plants with reservoirs. Short-term power prices are determined on an hourly basis by the last dispatched generating unit.
In Panama, dry hydrological conditions remained during 2015 affecting the generation output from hydroelectric facilities as in the prior year. AES Panama had to purchase energy on the spot market to fulfill its contract obligations as its generation output was below contract levels. The drop in the commodities prices helped to reduce the replacement cost and the financial impact of spot purchases compared to the prior year. Despite the hydrology conditions, spot prices were down to $90/MWh from $217/MWh in 2014, impacting also the amount recognized through the 2014-2016 Government Compensation Agreement to only $5.8 million out of the $30 million for 2015. On March 31, 2014, the government of Panama agreed to reduce the financial impact of spot electricity purchases and transmission constraints equivalent to a 70 MW reduction in contracted capacity for the period 2014-2016 by compensating AES Panama for spot purchases up to $40 million in 2014, $30 million in 2015 and $30 million in 2016.
Regulatory Framework — The SNE has the responsibilities of planning, supervising and controlling policies of the energy sector within Panama. With these responsibilities, the SNE proposes laws and regulations to the executive agencies that promote the procurement of electrical energy, hydrocarbons and alternative energy for the country.
The regulator of public services, known as the ASEP, is an autonomous agency of the government. ASEP is responsible for the control and oversight of public services including electricity and the transmission and distribution of natural gas utilities and the companies that provide such services.
Generators can only contract their firm capacity. Physical generation of energy is determined by the CND regardless of contractual arrangements.
Key Financial Drivers — Financial results are likely to be driven by many factors including, but not limited to, the following:
•
Lower hydrology resulting in low generation and additional energy purchases to fulfill contracts, partially mitigated by additional generation from Estrella del Mar I, lower spot prices driven by the drop in commodities, and the compensation amount from the Government Compensation Agreement.
•
In addition to spot prices being driven by hydrology since Panama is highly dependent on hydro generation (~56%), the fluctuations in commodity prices, mainly oil prices, affect the thermal generation cost impacting the spot prices and the opportunity cost of water. In the event of low hydrology, high commodity prices will increase the business exposure and the cost of replacement power to back up our contractual commitment. 
•
Constraints imposed by the capacity of the transmission line connecting the west side of the country with the load center are expected to continue until the end of 2016 keeping surplus power trapped, particularly during the wet season.
•
Country demand as GDP growth is expected to remain strong over the short and medium term.
Given that most of AES' portfolio is run-of-river, hydrological conditions have an important influence on its profitability. Variations in actual hydrology can result in excess or a short energy balance relative to our contract obligations. During the low inflow period (January to May), generation tends to be lower and AES Panama may purchase energy in the short-term market to cover contractual obligations. During the remainder of the year (June to December), generation tends to be higher and energy generated in excess of contract volumes is sold to the short-term market. In addition to hydrological conditions, commodity prices affect short-term electricity prices. See Item 7.—Key Trends and Uncertainties—Operational—Sensitivity to Dry Hydrological Conditions for further information.
Construction and Development — Continuing with the strategy to reduce reliance on hydrology started with the acquisition of the power barge, Estrella del Mar I, in August 2015 AES executed a partnership agreement with Deeplight Corporation, a minority partner, with the purpose to construct, operate and maintain a natural gas power generation plant and a liquefied natural gas terminal, in order to purchase and sell energy and capacity as well as commercialize natural gas and other ancillary activities related to natural gas. As of December 31, 2015, amounts capitalized include $7 million recorded in Construction in Progress and the project is scheduled to initiate operations in the first half of 2018.

35


Mexico
Business Description — AES has 1,055 MW of installed capacity in Mexico, including the 550 MW Termoeléctrica del Golfo ("TEG") and Termoeléctrica Peñoles ("TEP") facilities and Merida III ("Merida"), a 505 MW generation facility.
The TEG and TEP pet coke-fired plants, located in San Luis Potosi, supply power to their offtakers under long-term PPAs expiring in 2027 with a 90% availability guarantee. TEG and TEP secure their fuel under a long-term contract.
Merida is a CCGT, located in Merida, on Mexico's Yucatan Peninsula. Merida sells power to the CFE under a capacity and energy based long-term PPA through 2025. Additionally, the plant purchases natural gas and diesel fuel under a long-term contract, the cost of which is then passed through to CFE under the terms of the PPA.
In line with AES' strategy of building strategic partnerships, on January 18, 2016 the 50/50 Joint Venture partnership agreement with Grupo BAL was fully executed. The Joint Venture will co-invest in power and related infrastructure projects in Mexico.
Market Structure — Mexico has a single national electricity grid, the SEN, covering nearly all of Mexico's territory. Mexico has an installed capacity totaling 65 GW with a generation mix of 74% thermal, 19% hydroelectric and 7% other. Electricity consumption is split between the following end users: industrial (58%), residential (26%) and commercial and service (16%).
Regulatory Framework — Following the constitutional changes approved in December 2013, during 2014 and 2015 the Mexican government issued a package of secondary regulations, including the Electricity Law, and operational dispositions, with the objective to start the implementation of a new regulatory framework which foresees:
•
The energy market liberalization in January 2016 through the implementation of: wholesale electricity market (day ahead and real time market), ancillary services, capacity, Clean Energy Certificates, and Financial Transmission Rights market.
•
CFE's, former state-owned electric monopoly, vertical and horizontal disintegration into different segments of the value chain: generation, transmission, distribution and commercialization.
•
CENACE as new ISO is responsible for managing the wholesale electricity market, transmission and distribution infrastructure, planning the network developments, guaranteeing open access to network infrastructure, executing competitive mechanisms to cover regulated demand, and setting transmission charges.
•
Implementation of annual mid and long term auctions to secure supply for the regulated demand, establishing a PPA with CFE as the Basic Supplier.
According to the new regulatory framework, new assets developed under the new framework or assets transferred to the new regime and in operation after the approval of the Electricity Law (August 2014) are eligible to participate in the new markets. Additionally, projects developed and operated under the Electric Public Service Law (self-supply framework) like TEG TEP, could choose to participate. Until the new framework is further analyzed, AES will continue operating under the same conditions. Merida III and TEG/TEP will continue providing power under long-term contracts and selling any excess or surplus energy produced to CFE.
Key Financial Drivers — Operational performance is the key business driver as the companies are fully contracted and better performance provides additional financial benefits including performance incentives and/or excess energy sales (in the case of TEG/TEP). The energy prices of TEG/TEP for the sales in excess over its long-term contracts are driven by the average production cost of CFE which is highly dependent on natural gas and oil. If the average production cost of CFE is higher than the cost of generating with pet coke, our businesses in Mexico will benefit provided that they are able to sell energy in excess of their PPAs.
Other MCAC Businesses
Puerto Rico
Business Description — AES Puerto Rico owns and operates a coal-fired cogeneration plant and a recently acquired solar plant of 524 MW and 24 MW, respectively, representing approximately 9% of the installed capacity in Puerto Rico. Both plants have long-term PPAs expiring in 2027 and 2032, respectively, with PREPA, a state-owned entity that supplies virtually all of the electric power consumed in Puerto Rico and generates, transmits and distributes electricity to 1.4 million customers. On April 29, 2015, AES completed the acquisition of 100% of the common stock of the solar plant, AES Illumina. Its results of operations have been included in AES' consolidated results of operations from the date of acquisition. See Item 7.—Key Trends and Uncertainties—Macroeconomic and Political—Puerto Rico for further discussion of the long-term PPA with PREPA. In addition, AES Puerto Rico has ongoing litigation regarding the disposal of ash in the Dominican Republic. See Item 3.—Legal Proceedings.

36


El Salvador
Business Description — AES is the majority owner of four of the five distribution companies operating in El Salvador. The distribution companies are operated by AES on an integrated basis under a single management team. AES El Salvador's territory covers 77% of the country. AES El Salvador accounted for 3,730 GWh of market energy purchases during 2015, or about 64% market share of the country's total energy purchases.
AES El Salvador also owns AES Nejapa, a 6 MW power plant generating electricity with methane gas from a landfill, fully contracted with CAESS. During 2015, AES El Salvador began operations of a AES Moncagua, a 2.5 MW solar facility located in the east of the country, which is fully contracted with EEO.
The sector is governed by the General Electricity Law and the general and specific orders are issued by Superintendencia General de Electricidad y Telecomunicacions ("SIGET" or "The Regulator"). The Regulator, jointly with the distribution companies in El Salvador, completed the tariff reset process in December 2012 and defined the tariff calculation to be applicable for the next five years (2013-2017).
Europe SBU
Our Europe SBU has generation facilities in five countries. Our European operations accounted for the following proportions of consolidated AES Operating Margin, AES Adjusted PTC (a non-GAAP measure), AES Operating Cash Flow, and AES Proportional Free Cash Flow (a non-GAAP measure):
Europe SBU (1)
2015
 
2014
 
2013
% of AES Operating Margin
11
%
 
13
%
 
13
%
% of AES Adjusted PTC (a non-GAAP measure)
15
%
 
19
%
 
19
%
% of AES Operating Cash Flow
14
%
 
13
%
 
15
%
% of AES Proportional Free Cash Flow (a non-GAAP measure)
15
%
 
14
%
 
18
%
(1) Percentages reflect the contributions by our Europe SBU before deductions for Corporate.
The following table provides highlights of our Europe operations:
Countries
 
Bulgaria, Jordan, Kazakhstan, Netherlands and United Kingdom
Generation Capacity
 
6,781gross MW (5,009 proportional MW)
Generation Facilities
 
12
Key Generation Businesses
 
Maritza, Kilroot, Ballylumford, and Kazakhstan

37


Operating installed capacity of our Europe SBU totaled 6,781 MW. Presented in the table below is a list of our Europe SBU generation facilities:
Business
 
Location
 
Fuel
 
Gross MW
 
AES Equity Interest (% Rounded)
 
Year Acquired or Began Operation
 
Contract Expiration Date
 
Customer(s)
Maritza
 
Bulgaria
 
Coal
 
690

 
100
%
 
2011
 
2026
 
Natsionalna Elektricheska
St. Nikola
 
Bulgaria
 
Wind
 
156

 
89
%
 
2010
 
2025
 
Natsionalna Elektricheska
Bulgaria Subtotal


846


Amman East
 
Jordan
 
Gas
 
380

 
37
%
 
2009
 
2033-2034
 
National Electric Power Company
IPP4
 
Jordan
 
Heavy Fuel Oil/Gas
 
247

 
60
%
 
2014
 
2039
 
National Electric Power Company
Jordan Subtotal


627


Ust-Kamenogorsk CHP
 
Kazakhstan
 
Coal
 
1,372

 
100
%
 
1997
 
Short-term
 
Various
Shulbinsk HPP(1)
 
Kazakhstan
 
Hydro
 
702

 
—
%
 
1997
 
Short-term
 
Various
Ust-Kamenogorsk HPP(1)
 
Kazakhstan
 
Hydro
 
331

 
—
%
 
1997
 
Short-term
 
Various
Sogrinsk CHP
 
Kazakhstan
 
Coal
 
345

 
100
%
 
1997
 
Short-term
 
Various
Kazakhstan Subtotal


2,750


Elsta(2) 
 
Netherlands
 
Gas
 
630

 
50
%
 
1998
 
2018
 
Dow Benelux/Delta/Nutsbedrijven/ Essent Energy
Netherlands ES
 
Netherlands
 
Energy Storage
 
10

 
100
%
 
2015


Netherlands Subtotal


640


Ballylumford
 
United Kingdom
 
Gas
 
1,246

 
100
%
 
2010
 
2023
 
Power NI/Single Electricity Market (SEM)
Kilroot(3)
 
United Kingdom
 
Coal/Oil
 
662

 
99
%
 
1992


SEM
Kilroot ES
 
United Kingdom
 
Energy Storage
 
10

 
100
%
 
2015


United Kingdom Subtotal


1,918


Europe Total


6,781


(1)
AES operates these facilities under concession agreements until 2017.
(2) 
Unconsolidated entity, the results of operations of which are reflected in Equity in Earnings of Affiliates.
(3) 
Includes Kilroot Open Cycle Gas Turbine ("OCGT").
The following map illustrates the location of our European facilities:
Europe Businesses
Bulgaria
Business Description — Our Maritza plant is a 690 MW lignite fuel plant that was commissioned in June 2011. Maritza is fully compliant with the EU Industrial Emission Directive, which came into force in January 2016. Maritza's entire power output is contracted with NEK under a 15-year PPA expiring in 2026, capacity and energy based, with a fuel pass-though. The lignite and limestone are supplied under a 15-year fuel supply contract.

38


AES also owns an 89% economic interest in the St. Nikola wind farm with 156 MW of installed capacity. St. Nikola was commissioned in March 2010. Its entire power output is contracted with NEK under a 15-year PPA expiring in March 2025.
Market Structure — The maximum market capacity in 2015 was approximately 13.6 GW. Thermal generation, which is mostly coal-fired, and nuclear power plants account for 64% of the installed capacity.
Regulatory Framework — The electricity sector in Bulgaria operates under the Energy Act of 2004 that allows the sale of electricity to take place freely at negotiated prices, at regulated prices between parties or on the organized market. In 2015 the government of Bulgaria has made advances toward market liberalization and has engaged with the World Bank to develop a model for a fully liberalized electricity market in Bulgaria. The final report with recommendations from the World Bank is expected in May 2016. The Independent Bulgarian Energy Exchange started commercial operation of the power exchange on January 19, 2016 after successful test sessions were held in December 2015.
Our investments in Bulgaria rely on long-term PPAs with NEK, the state-owned electricity public supplier and energy trading company. NEK is facing some liquidity issues and has been delayed in making payments under the PPAs with Maritza and St. Nikola. In May and June 2014, SEWRC issued decisions precluding the ability of NEK to pass-through to the regulated market certain costs incurred by NEK pursuant to the PPA with Maritza, which impacted NEK's liquidity and its ability to make payments under the PPA. SEWRC also instructed NEK and Maritza to begin negotiating amendments to the PPA. Maritza has engaged in negotiations with NEK and other Bulgarian state bodies concerning these matters. In August 2015, the ninth amendment of Maritza's PPA was executed under which Maritza and NEK would reduce the capacity payment to Maritza under the PPA by 14% through the PPA Term, without impacting the energy price component. In exchange, NEK would pay Maritza its overdue receivables. The amendment will become effective upon full payment of the overdue receivables by NEK, which is expected in 2016. In 2014 SEWRC announced that it has asked the DG Comp to review NEK's respective PPAs with Maritza and a separate generator pursuant to European state aid rules, and to suspend the PPAs pending the completion of that review. DG Comp has not contacted Maritza about the SEWRC's request to date.
In March 2015, changes to the Energy Act were enacted. Changes included a limitation on electricity purchases from co-generators at preferential prices, the allocation of the proceeds from the sale of state CO2 allowances to NEK, and an increase in the Regulator's independence through appointment of its members by the Parliament rather than by the Council of Ministers. In July 2015, additional measures were voted by the Parliament to complement the first measures taken in March 2015. An Electricity Security Fund was created to help NEK meet its obligations with energy producers, financed with a 5% contribution from all energy producers on their energy revenues as well as with proceeds from the sale of state CO2 allowances. Maritza is able to pass-through this additional contribution to NEK since it falls under a change in law provision under the PPA. Following the Energy Act amendments on July 31, 2015 the regulator approved new regulated prices that led to 0.11% decrease for household electricity prices and increased the non-household prices between 0% and 20% for the various segments. On November 1, 2015 the regulator decreased the non-household prices 2.5% on average as result of the falling gas prices. All these actions are expected to improve NEK's liquidity. At this time, it is difficult to predict the impact of the political conditions and regulatory changes on our businesses in Bulgaria.
Maritza has experienced ongoing delays in the collection of outstanding receivables from NEK. As of December 31, 2015, Maritza had an outstanding receivables balance of $351 million including $44 million of current receivables, $82 million of receivables overdue by less than 90 days and $225 million of receivables overdue by more than 90 days. See Key Trends and Uncertainties—Macroeconomics and Political—Bulgaria in Item 7.—Management's Discussion and Analysis to this Form 10-K for further information.
NEK has failed to maintain a minimum rating pursuant to the Government Support Letter issued in 2005. As a result, the PPA could be terminated at the discretion of Maritza and the lenders. See Item 1A.—Risk Factors—We may not be able to enter into long-term contracts, which reduce volatility in our results of operations. As a result of any of the foregoing events, we may face a loss of earnings and/or cash flows from the affected businesses (or be unable to exercise remedies for a breach of the PPA) and may have to provide loans or equity to support affected businesses or projects, restructure them, write down their value and/or face the possibility that these projects cannot continue operations or provide returns consistent with our expectations, any of which could have a material impact on the Company.
Key Financial Drivers — Both businesses, Maritza and St. Nikola, operate under PPA contracts. For the duration of the PPA, the financial results are primarily driven by, but not limited to: the availability of the operating units; the level of wind resource for St. Nikola; and NEK's ability to meet the terms of the PPA contract.
United Kingdom
Business Description — AES' generation businesses in the United Kingdom operate in the Irish Single Electricity Market (SEM) for the businesses located in Northern Ireland (1,918 MW). During 2015, AES sold its interests in wind development pipelines of 115 MW in Scotland.

39


The Northern Ireland generation facilities consist of two plants within the Greater Belfast region. Our Kilroot plant is a 662 MW coal-fired plant with 10 MW of energy storage facility and our Ballylumford plant is a 1,246 MW gas-fired plant. These plants provide approximately 70% of the Northern Ireland installed capacity and 18% of the combined installed capacity for the island of Ireland.
Kilroot is a merchant plant that bids into the SEM market. Kilroot derives its value from the variable margin when scheduled in merit and the margin from constrained dispatch (when dispatched out of merit to support the system in relation to the wind generation, voltage and transmission constraints) and capacity payments paid through the SEM Capacity Payment Mechanism. In addition to the above, value is also secured from ancillary services.
Ballylumford is partially contracted for 600 MW under a PPA with PPB that expires in 2018, with an extension at the offtaker's option through 2023, with the remaining capacity bid into the SEM market. Ballylumford's key sources of revenue are availability payments received under the PPA and capacity payments offered through the SEM Capacity Payment Mechanism. Additionally, Ballylumford receives revenue from constrained dispatch through which the costs of operation are recovered from the market and also from the ancillary services market.
Market Structure — The majority of the generation capacity in the SEM is represented by gas-fired power plants, which results in market sensitivity to gas prices. Wind generation capacity represents approximately 18% of the total generation capacity. The governments of Northern Ireland and the Republic of Ireland plan further increases in renewables. Market availability and liquidity of hedging products are weak, reflecting the limited size and immaturity of the market, the predominance of vertical integration and lack of forward pricing. There are essentially three products (baseload, mid-merit and peaking) which are traded between the generators and suppliers.
Regulatory Framework — Electricity Regulation — The SEM is an energy market established in 2007 and is based on a gross mandatory pool within which all generators with a capacity higher than 10 MW must trade the physical delivery of power. Generators are centrally dispatched based on merit order and physical constraints of the system.
In addition, there is a capacity payment mechanism to ensure that sufficient generating capacity is offered to the market. The capacity payment is derived from a regulated Euro-based capacity payment pool, established a year ahead by the regulatory authority. Capacity payments are based on the declared availability of a unit and have a degree of volatility to reflect seasonal influences, demand and the actual out-turn of generation declared available over each trading period.
Environmental Regulation — The European Commission adopted in 2011 the Industrial Emissions Directive ("IED") that establishes the Emission Limit Values ("ELV") for SO2, NOx and dust emissions to be complied with starting from January 1, 2016. Both Ballylumford and Kilroot are required to comply with the IED. The Ballylumford C Station is compliant without the need for investment. Both Ballylumford B Station and Kilroot required investment to be in compliance.
The IED provides for two options that may be implemented by the EU member states other than compliance with the new ELV's- the Transitional National Plan ("TNP") or Limited Life Time Derogation ("LLTD").
Kilroot has opted into the TNP and this allows the plant to operate between 2016-2020, being exempt from compliance with ELVs, but observing a ceiling set for maximum annual emissions that is based on the last 10 years average emissions and operating hours. Kilroot has invested approximately $10 million in Umbrella Selective Non Catalytic Reduction ("USNCR") technology, which reduces the plant's NOx emissions enabling the plant to increase its capacity factor within the ceiling of NOx emissions and earn energy margin. Further technical modifications are being evaluated which could make the plant fully compliant with IED from 2020.
Without investment, the Ballylumford B station of 540 MW would not meet the standards of the IED following 2015. In 2014, AES competed to secure a Local Reserve Services Agreement ("LRSA") with the Transmission System Operator ("TSO") to refurbish two of the three units to be compliant with ELVs under IED, providing at least 250 MW of capacity from 2016 to 2018 with an option to extend to 2020 by the TSO. These units will also qualify for capacity payments under the SEM.
Key Financial Drivers — For our businesses in the SEM market, the financial results will be driven by, but not limited to, the following, and may change in 2017 due to regulatory changes to the market structure and payment mechanism:
•
Availability of the operating units
•
Commodity prices (gas, coal and CO2) and sufficient market liquidity to hedge prices in the short-term
•
Electricity demand in the SEM
Kazakhstan
Business Description — Our businesses account for approximately 6% of the total annual generation in Kazakhstan. Of the total capacity of 2,750 MW, 1,033 MW is hydroelectric and operates under a concession agreement until the beginning of October 2017 and 1,717 MW of coal-fired capacity is owned outright. The thermal plants are designed to produce heat with electricity as a co- or by-product.

40


The Kazakhstan businesses act as merchant plants for electricity sales by entering into bilateral contracts directly with consumers for periods of generally no more than one year. There are no opportunities for the plants to be in contracted status, as there is no central offtaker, and the few businesses that could take a whole plant's generation tend to have in-house generation capacity. The 2015 amendments to the Electricity Law state that a centrally organized capacity market will be established by 2019, but the capacity offtaker still only signs annual contracts.
The hydroelectric plants are run-of-river and rely on river flow and precipitation, particularly snow. Due to the presence of a large multi-year storage dam upstream and a growing season minimum river flow rate agreement with Russia downstream, the plants are protected against significant downside risk to their volume in years with low precipitation. AES does not control water flow which impacts our generation.
Ust Kamenogorsk CHP provides heat to the city of Ust Kamenogorsk through the city heat network company (Ust Kamenogorsk Heat Nets). Ust Kamenogorsk CHP is their only source of supply.
Market Structure — The Kazakhstan electricity market totals approximately 20,657 MW, of which 17,421 MW is available. The bulk of the generating capacity in Kazakhstan is thermal with coal as the main fuel. As coal is abundantly available in Kazakhstan, most plants are designed to burn local coal. The geographical remoteness of Kazakhstan, in combination with its abundant resources, results in coal prices that are not reflective of world coal prices, current delivered cost is less than $18 per metric ton. In addition, the government closely monitors coal prices, due to their impact on the price of socially necessary heating and on electricity tariffs.
Regulatory Framework — All Kazakhstan generating companies sell electricity at or below their respective tariff-cap level. These tariff-cap levels have been fixed by the Kazakhstan government for the period 2009-2018 for each of the fifteen groups of generators. These groups were determined by the Ministry of Energy, previously Ministry of Industry and New Technologies, based on a number of factors including plant type and fuel used.
In July 2012, Kazakhstan enacted various amendments to its Electricity Law. Among the amendments was a requirement to reinvest all profits generated by electricity producers during the years 2013-2015. Accordingly, the business will be unable to pay dividends for the period 2013-2015. Under the amended Electricity Law, electricity producers must, on an annual basis, enter into Investment Obligation Agreements ("IOAs") with the Ministry of Energy. These annual IOAs must equal the sum of the upcoming year's planned depreciation and profit. Selection of investment projects for the IOAs is at the discretion of electricity producers, but the Ministry of Energy has the right to reject submitted IOA proposals. An electricity producer without an IOA executed by the Ministry of Energy may not charge tariffs exceeding its incremental cost of production, excluding depreciation. In December 2014, the Ministry of Energy executed IOAs with all four AES generators in Kazakhstan, which allow revenue at the tariff-cap level, but all generated cash will need to be reinvested.
In November 2015, Kazakhstan enacted amendments to its Electricity Law to extend price cap regulation till the end of
2018 and postpone the introduction of capacity market till 2019. In addition, the obligation for power plants to sign annual IOAs has been eliminated for 2016-2018. During 2013-2015, IOAs required businesses to reinvest the sum of all profits and depreciation on an annual basis, limiting the ability to send dividends. Beginning in 2016 Kazakhstan no longer has a restriction on sending dividends.
Heat production in Kazakhstan is also regulated as a natural monopoly. The heat tariffs are set on a cost-plus basis by making an application to the Regulator (Committee of Natural Monopoly Regulation and Competition Protection). Currently, tariffs are only for multi-year periods, but with some annual adjustments for fuel cost.
Key Financial Drivers — The financial results for assets in Kazakhstan are driven by many factors including, but not limited to: availability of the operating units; regulated electricity tariff-cap levels; regulated heat tariff levels; and weather conditions, but may change in 2016 due to regulatory changes to the market structure and payment mechanism.
•
Availability of the operating units
•
Regulated electricity tariff-cap levels
•
Weather conditions
•
Cost of coal
•
Kazakhstan currency exchange rate fluctuation
Other Europe Businesses
In Jordan, AES has a 37% controlling interest in Amman East, a 380 MW (gross) oil/gas-fired plant fully contracted with the national utility under a 25-year PPA. We also have a 60% controlling interest in the IPP4 plant in Jordan, a 247 MW (gross)oil/gas-fired peaker plant which commenced operations in July 2014, fully contracted with the national utility under a 25-year PPA. As we have controlling interest in these businesses, we consolidate the results in our operations.

41


On July 2, 2014, the Company closed the sale of its 50% ownership interest in Silver Ridge Power ("SRP") for a purchase price of $179 million, excluding the Company's indirect ownership interests in SRP's solar generation businesses in Italy and Spain ("Solar Italy" and "Solar Spain," respectively). On February 9, 2015, SRP distributed its ownership interest in Solar Spain to a joint venture of AES and a third party. After this date, AES' only remaining economic interest under SRP ownership was in Solar Italy. The previous buyer of our interest in SRP also had an option to purchase the Company's indirect 50% interest in Solar Italy for an additional consideration of $42 million by August 2015. That buyer exercised its option to purchase Solar Italy on August 31, 2015, and the sale was completed on October 1, 2015. At this point, the Company ceased having continuing involvement not only with Solar Italy but also with SRP, its parent, and the Company recognized a gain of $5 million on the overall sale of SRP.  On September 24, 2015, the Company completed the sale of Solar Spain, an equity method investment with 31 MW peak capacity. Net proceeds from the sale transaction were $31 million and the Company recognized a pretax gain on sale of less than $1 million.
Asia SBU
Our Asia SBU has generation facilities in four countries. Our Asia operations accounted for the following proportions of consolidated AES Operating Margin, AES Adjusted PTC (a non-GAAP measure), AES Operating Cash Flow, and AES Proportional Free Cash Flow (a non-GAAP measure):
Asia SBU (1)
2015
 
2014
 
2013
% of AES Operating Margin
5
%
 
2
%
 
5
%
% of AES Adjusted PTC (a non-GAAP measure)
6
%
 
2
%
 
8
%
% of AES Operating Cash Flow
1
%
 
5
%
 
3
%
% of AES Proportional Free Cash Flow (a non-GAAP measure)
5
%
 
6
%
 
5
%
(1) Percentages reflect the contributions by our Asia SBU before deductions for Corporate.
The following table provides highlights of our Asia operations:
Countries
 
India, Philippines and Vietnam
Generation Capacity
 
2,290 gross MW (1,159 proportional MW)
Generation Facilities
 
5 (including 2 under construction)
Key Businesses
 
Masinloc, OPGC I and Mong Duong II
Operating installed capacity totals 2,290 MW. Presented below in the table is a list of our Asia SBU generation facilities:
Business
 
Location
 
Fuel
 
Gross MW
 
AES Equity Interest (% Rounded)
 
Year Acquired or Began Operation
 
Contract Expiration Date
 
Customer(s)
OPGC(1)
 
India
 
Coal
 
420

 
49
%
 
1998
 
2026
 
GRID Corporation Ltd.
India Subtotal


420


Masinloc
 
Philippines
 
Coal
 
630

 
51
%
 
2008
 
Mid and long-term
 
Various
Philippines Subtotal


630


Mong Duong 2
 
Vietnam
 
Coal
 
1,240

 
51
%
 
2015
 
2040
 
EVN
Vietnam Subtotal


1,240


Asia Total


2,290


(1)
Unconsolidated entity for which the results of operations are reflected in Equity in Earnings of Affiliates.
Under Construction
Business
 
Location
 
Fuel
 
Gross MW
 
AES Equity Interest (% Rounded)
 
Expected Date of Commercial Operation
OPGC II
 
India
 
Coal
 
1,320

 
49
%
 
1H 2018
India Subtotal


1,320


Masinloc ES
 
Philippines
 
Energy Storage
 
10

 
100
%
 
1H 2016
Philippines Subtotal


10


Asia Total


1,330


42


The following map illustrates the location of our Asia facilities:
Asia Businesses
India
Business Description — OPGC is a 420 MW coal-fired generation facility located in the state of Odisha. OPGC has a 30-year PPA with GRIDCO Limited, a state utility, expiring in 2026. The PPA is composed of a capacity payment based on fixed parameters and a variable component, including a pass-through of actual fuel costs. OPGC is an unconsolidated entity and results are reported as Equity in Earnings of Affiliates in our consolidated results of operations.
Construction and Development — As noted above, AES has one coal-fired project under development with a total capacity of 1,320 MW which is an expansion of our existing OPGC business. The project started construction in April 2014 and is currently expected to begin operations in 2018. As of December 31, 2015, total capitalized costs at the project level were $336 million (AES share of $165 million), while at the AES level capitalized costs were $13.6 million. Currently, 50% of the expansion capacity is contracted with the state offtaker, GRIDCO, for a period of 25 years, with a normative after-tax rate of return of 15.5% with an opportunity to capture additional 0.5% tied to timely completion of the project. The contract is subject to Central Electricity Regulatory Commission ("CERC") approval, which is responsible for publishing tariff determination norms every five years. The rest of the capacity is expected to be sold through competitive bid or regulated Power Purchase Agreements and a small component in the Indian merchant market.
In August 2014, the Supreme Court of India invalidated the allocation of captive coal blocks. The government of India has subsequently enacted new laws allowing coal block allocation to companies with limited levels of private ownership, based on which the coal blocks have been allocated to a subsidiary of OPGC, Odisha Coal and Power Ltd. ("OCPL"), which is an OPGC joint venture with another company wholly-owned by the government of Odisha. This new company meets the lower private ownership stipulations for allocation of mines.
Environmental Regulation — The Ministry of Environment Forest and Climate Change in India has recently amended the Environment (Protection) Rules with stricter emission limits for new as well as existing thermal power plants via their notification dated December 7, 2015. All existing plants installed before December 31, 2003 are required to meet revised emission limits within two years and any new thermal power plants that will be operational from January 1, 2017 are required to operate with the revised emission limits. An FGD system needs to be installed in the existing units of OPGC for complying with SO2 emissions requirements. The business is evaluating the options and the cost implications. The required design modification and scheduled implications for the expansion project are currently being evaluated. The impacts of these amendments are still under review, but we believe the cost of complying with the new environmental regulations will be a pass-through in the GRIDCO tariff for both existing and expansion units. Ministry of Power has issued revised Tariff Policy in January 2016 to bring more regulatory certainty, attract private investment, ensure distribution efficiency and promote renewable energy.
Philippines
Business Description — The Masinloc power project in the Philippines is a 630 (gross) MW coal-fired plant located in Zambales, Philippines and is interconnected to the Luzon Grid. AES acquired 92% of Masinloc in 2008 (IFC is an 8% non-controlling shareholder in Masinloc). In July 2014, AES reduced its ownership to 51% through a sale to the EGCO Group, a Thailand-based power company. More than 95% of Masinloc's peak capacity and variable margin are contracted through

43


medium to long-term bilateral contracts primarily with Meralco, the largest distribution company in the Philippines, several electric cooperatives and industrial customers.
In January 2013, Masinloc entered into a new Power Supply Agreement ("PSA") with its main customer, Meralco, as the previous Transition Supply Contract ("TSA") expired in December 2012. The PSA is for 7 years, with an additional 3-year extension clause dependent on mutual agreement. Payments are primarily capacity-based. The PSA is primarily priced in U.S. Dollars, aligning the revenues with the majority of variable and fixed costs (fuel, debt, insurance) and minimizing currency exchange risks. Masinloc's remaining contracts expire between 2016 and 2026.
Construction and Development — In December 2015, financial close was achieved for 335 MW (gross) expansion unit adjacent to the existing 630 MW plant. The project, which will employ supercritical technology is expected to be commercially operating in 2019. The additional capacity is targeted for sale to distribution utilities, electric cooperatives, and industrial and commercial customers in the Luzon and Visayas grids. 40% of this additional capacity has already been contracted with an expectation to have 80% capacity contracted by the date of commercial operations.
Market Structure — The Philippine power market is divided into three grids representing the country's three major island groups — Luzon, Visayas and Mindanao. Luzon (which includes Manila and is the country's largest island) has limited interconnection with Visayas and represents 85% of the total demand of both regions. Luzon and Visayas together have an installed capacity of 16,093 MW.
There is diversity in the mix of the Luzon — Visayas generation, with coal accounting for 37%, natural gas for 17%, hydroelectric for 15%, geothermal generation for 10%, and the remaining 21% from other generating plants such as oil, wind, biomass, and solar (priority dispatch with feed-in tariff).
The primary customers for electricity are private distribution utilities, electric cooperatives, and large contestable (industrial and commercial) customers. Approximately 90%-94% of the system's total energy requirement is currently being sold/purchased through medium (3-5 years) to long (6-10 years) term bilateral contracts. The remaining 6%-10% of energy is sold through the WESM, which is the real-time, bid-based and hourly market for energy where the sellers and the buyers adjust their differences between their production/demand and their contractual commitments.
Environmental Regulation — The Renewable Energy Act of 2008 was enacted to promote the development, utilization and commercialization of renewable energy resources, such as solar, wind, small hydroelectric and biomass energies. Under Chapter III, Section 6, the Renewable Portfolio Standard (RPS) was introduced mandating all stakeholders in the electric power industry to contribute to the growth of the renewable energy industry of the country. Under the current draft of the RPS, certain customers (e.g. distribution utilities and retail electricity suppliers) will be required to source a certain percentage of their supply from eligible renewable energy sources. The National Renewable Energy Board ("NREB") is currently developing and implementing regulations for the RPS, including mechanisms for compliance by actual purchase of renewable energy or equivalent renewable energy certificates. If the regulations are implemented, our Retail Electricity Supply business in the Philippines could be affected by the RPS requirement.
Regulatory Framework
Electricity Regulation — The Philippines has divided its power sector into generation, transmission, distribution and supply under the EPIRA act. The EPIRA primarily aims to increase private sector participation in the power sector and to privatize the Philippine government's generation and transmission assets. Generation and supply are open and competitive sectors, while transmission and distribution are regulated sectors. Sale of power is conducted primarily through medium or long-term bilateral contracts between generation companies and distribution utilities specifying the volume, price and conditions for the sale of energy and capacity, which are approved by the ERC. Power is traded in the WESM which operates under a gross pool, central dispatch and net settlement protocols. Parties to bilateral contracts settle their transactions outside of the WESM and distribution companies or electricity cooperatives buy their imbalance (i.e., power requirements not covered by bilateral contracts) from the WESM. Distribution utilities and electric cooperatives are allowed to pass on to their end-users the bilateral contract rates, including WESM purchases, approved by the ERC.
Other Regulatory Considerations — Pursuant to EPIRA, RCOA commenced on June 26, 2013, under which retail electricity suppliers, who are duly licensed by the ERC, may supply directly to contestable customers (end-users with an average demand of at least 1 MW), with distribution companies or electricity cooperatives providing non-discriminatory wire services. Bilateral contracts with contestable customers do not require ERC approval to be implemented. Masinloc has obtained a retail electricity supplier license from the ERC and currently markets power to contestable customers. On June 16, 2015, ERC released a draft for the rules on mandatory contestability. According to this draft, all contestable customers with an average peak demand of more 750 kW are mandated to enter into power supply contracts by June 2016, at which point contestable customers shall be required to purchase power from licensed generation or retail suppliers instead of their local distribution utility.

44


Vietnam
Business Description — The Mong Duong II power project is a 1,240 MW gross coal-fired plant located in Quang Ninh Province of Vietnam and was constructed under a BOT contract (the project will be transferred to Vietnamese government after 25 years). AES-VCM Mong Duong Power Company Limited ("the BOT Company") is a limited liability joint venture owned by affiliates of AES (51%), Posco Energy Corporation (30%) and China Investment Corporation (19%). This is the first and largest coal-fired BOT project using pulverized coal fired boiler technology in Vietnam. The BOT Company has entered a PPA with EVN, the national utility, and a Coal Supply Agreement ("CSA") with Vinacomin, a state owned entity, both with a 25 year term starting from Commercial Operation Date.
Since April 22, 2015, both units of the Power Facility have been in commercial operations, six months earlier than the committed schedule with the Vietnamese government. The BOT Company makes available the dependable capacity and delivers electrical energy to EVN and, in return, EVN makes payments to the BOT Company.
Market Structure — The Vietnam Power market is divided into three regions (North, Central and South), with current total installed capacity of 37,604 MW, an 11% increase from 2014 (33,970 MW). The total demand in year 2015 was 141.8 billion kWh with the highest demand of 70 billion kWh in the South and 60 billion kWh in the North.
The fuel mix in Vietnam is comprised of hydropower 35% (priority dispatch with low tariff), coal 35%, gas 20%, diesel and small hydro generation 5%, oil 1% (dispatched during emergencies or during peak demand), thermo-gas 1% and the remaining 3% imported from China and Lao. The government has a plan to increase thermal power capacity, primarily with coal, to reduce the dependence on hydroelectricity. According to the Master Plan VII, the total targeted installed capacity for 2020 is approximately 75,000 MW, in which coal-fired power will account for 48%, hydropower 23%, pumped storage hydropower 2%, gas-fired thermo-power 17%, renewable energy 6%, nuclear power 1% and imported power 3%.
EVN owns 58% of installed generation capacity followed by Petro Vietnam ("PVN") 12%, Vinacomin 4%, BOT projects 8% and others 18%. EVN is a state-owned company that is solely in charge of buying and selling electricity all over Vietnam. The government is planning to decrease EVN's ownership and increase private sector participation in the power market.
Regulatory Framework
Electricity Regulation — The electricity sector is overseen by several key government entities, including the National Assembly, the Prime Minister, the Ministry of Industry & Trade ("MOIT") and the Electricity Regulatory Agency of Vietnam ("ERAV"), which is under the supervision of the MOIT. These entities are responsible for the issuance of laws, guidance, and implementing regulations for the sector. The MOIT, in particular, is responsible for formulating a program to restructure the power industry, develop the electricity market and promulgating electricity market regulations.
Generation, transmission and distribution are currently dominated by the EVN, despite recent inclusion of other players. Transmission and distribution companies are wholly-owned by EVN and it also owns 58% of the total installed capacity as noted above. The fuel supply is owned by the government through Vinacomin and PVN. The government plans to equitize EVN-owned generation companies and separate generation, System and Market Provider ("SMP") and distribution into three different independent operations in order to establish the competitive power market.
Other Regulatory Considerations — According to Decision 63/2013/QÐ-TTG dated November 8, 2013, the roadmap of the power market of Vietnam consists of three phases. The first phase in relation to establishment of a competitive electricity market was finished at the end of 2014. The second phase: (i) period of 2015-2016 for establishment of a pilot competitive wholesale electricity market; and (ii) period of 2017-2021 for implementation of a competitive wholesale electricity market. The third phase: (i) period of 2022-2023 for establishment of a pilot competitive retail electricity market; and (ii) from 2013 onward for implementation of competitive retail electricity market. EVN as a long standing monopoly in the whole chain of generation, transmission and distribution, is being restructured to allow spin-off of several subsidiaries into either independent state-owned enterprises or joint stock companies. The BOT power plants will not participate in the power market; alternatively the single buyer will bid the tariff on the power pool on their behalf.
Environmental Regulation — Mong Duong II BOT Power Plant complies strictly with environmental requirements involving local regulations and IFC Environmental, Health and Safety Guidelines for Thermal Power Plants.
The revised Environmental Act was enacted, effective from January 1, 2015 establishing new rules in relation to, discarded materials and hazardous waste management. Additionally, new regulations on the registration of effluent and emission waste will be put into effect from the beginning of 2018 with no material impact to AES.
According to Decision No. 1696/QÐ-TTG dated September 23, 2014 on re-using of ash and gypsum discharged from coal power plants for construction material, the power plants need to propose investment and construction plans (or co-operative investment) to convert ash into construction material before 2020. There is no material impact to AES.

45


Sri Lanka
Business Description — AES closed the sale of Kelanitissa, a 168 MW oil-fired business with 90% ownership, on January 27, 2016 with proceeds of $18 million, with the potential to receive up to an additional $1.3 million overdue receivable from CEB.
Financial Data by Country
See the table with our consolidated operations for each of the three years ended December 31, 2015, 2014 and 2013, and property, plant and equipment as of December 31, 2015 and 2014, by country, in Note 17—Segment and Geographic Information included in Item 8.—Financial Statements and Supplementary Data of this Form 10-K for further information.

46


Environmental and Land-Use Regulations
The Company faces certain risks and uncertainties related to numerous environmental laws and regulations, including existing and potential GHG legislation or regulations, and actual or potential laws and regulations pertaining to water discharges, waste management (including disposal of coal combustion residuals), and certain air emissions, such as SO2, NOX, PM, mercury and other hazardous air pollutants. Such risks and uncertainties could result in increased capital expenditures or other compliance costs which could have a material adverse effect on certain of our U.S. or international subsidiaries, and our consolidated results of operations. For further information about these risks, see Item 1A.—Risk Factors—Our businesses are subject to stringent environmental laws and regulations; Our businesses are subject to enforcement initiatives from environmental regulatory agencies; and Regulators, politicians, non-governmental organizations and other private parties have expressed concern about greenhouse gas, or GHG, emissions and the potential risks associated with climate change and are taking actions which could have a material adverse impact on our consolidated results of operations, financial condition and cash flows in this Form 10-K. For a discussion of the laws and regulations of individual countries within each SBU where our subsidiaries operate, see discussion within Item 1.—Business of this Form 10-K under the applicable SBUs.
Many of the countries in which the Company does business also have laws and regulations relating to the siting, construction, permitting, ownership, operation, modification, repair and decommissioning of, and power sales from, electric power generation or distribution assets. In addition, international projects funded by the International Finance Corporation, the private sector lending arm of the World Bank, or many other international lenders are subject to World Bank environmental standards or similar standards, which tend to be more stringent than local country standards. The Company often has used advanced generation technologies in order to minimize environmental impacts, such as CFB boilers and advanced gas turbines, and environmental control devices such as flue gas desulphurization for SO2 emissions and selective catalytic reduction for NOx emissions.
Environmental laws and regulations affecting electric power generation and distribution facilities are complex, change frequently and have become more stringent over time. The Company has incurred and will continue to incur capital costs and other expenditures to comply with these environmental laws and regulations. See Item 7.—Management's Discussion and Analysis of Financial Condition and Results of Operations—Environmental Capital Expenditures in this Form 10-K for more detail. The Company and its subsidiaries may be required to make significant capital or other expenditures to comply with these regulations. There can be no assurance that the businesses operated by the subsidiaries of the Company will be able to recover any of these compliance costs from their counterparties or customers such that the Company's consolidated results of operations, financial condition and cash flows would not be materially affected.
Various licenses, permits and approvals are required for our operations. Failure to comply with permits or approvals, or with environmental laws, can result in fines, penalties, capital expenditures, interruptions or changes to our operations. Certain subsidiaries of the Company are subject to litigation or regulatory action relating to environmental permits or approvals. See Item 3.—Legal Proceedings in this Form 10-K for more detail with respect to environmental litigation and regulatory action.
United States Environmental and Land-Use Legislation and Regulations
In the U.S. the CAA and various state laws and regulations regulate emissions of air pollutants, including SO2, NOX, PM, GHGs, mercury and other hazardous air pollutants. Certain applicable rules are discussed in further detail below.
CSAPR — The CSAPR requires significant reductions in SO2 and NOX emissions from power plants in many states in which subsidiaries of the Company operate. Once fully implemented, the rule requires SO2 emission reductions of 73%, and NOX reductions of 54%, from 2005 levels. The CSAPR is implemented, in part, through a market-based program under which compliance may be achievable through the acquisition and use of emissions allowances created by the EPA. The CSAPR contemplates limited interstate and unlimited intra-state trading of emissions allowances by covered sources. Initially, the EPA issued emissions allowances to affected power plants based on state emissions budgets established by the EPA under the CSAPR. The Company is required to comply with the CSAPR in several states, including Ohio, Indiana, Oklahoma and Maryland. The Company complies with CSAPR through operation of existing controls and purchases of allowances on the open market, as needed. While the Company's 2015 CSAPR compliance costs were immaterial, the future availability of and cost to purchase allowances to meet the emission reduction requirements is uncertain at this time.
The EPA issued an interim final rule establishing the following deadlines for implementation of the CSAPR:
•
January 1, 2015: Phase 1 (2015 and 2016) began for annual trading programs. Existing units must have begun monitoring and reporting SO2 and NOx emissions.
•
May 1, 2015: Phase 1 began for ozone-season NOx trading program. Existing units must have begun monitoring and reporting NOx emissions.
•
December 1, 2015 (and each Dec. 1 thereafter): Date by which sources must demonstrate compliance with ozone-season NOx trading program (i.e., allowance transfer deadline).

47


•
March 1, 2016 (and each March 1 thereafter): Date by which sources must demonstrate compliance with annual trading programs (i.e., allowance transfer deadline).
•
January 1, 2017: Phase 2 (2017 and beyond) begins for annual trading programs. Assurance provisions in effect.
•
May 1, 2017: Phase 2 (2017 and beyond) begins for ozone-season NOx trading program. Assurance provisions in effect.
The EPA has released a proposed rule that would further reduce the amount of ozone season NOX allowances that would be available under the market-based program, starting in 2017. This proposed rule would not affect annual SO2 and NOX allowances. We cannot predict at this time the impact that implementation of the revised CSAPR will have on the Company. Certain of the Company's subsidiaries could be required to increase their capital expenditures, make operational changes or purchase additional allowances on the open market resulting in additional compliance costs to fully comply with the CSAPR, which expenditures and costs could be material.
MATS — Pursuant to Section 112 of the CAA, the EPA published a final rule in 2012 called the MATS establishing National Emissions Standards for Hazardous Air Pollutants from coal and oil-fired electric utility steam generating units. The rule required all coal-fired power plants to comply with the applicable MATS standards by April 2015, with the possibility of obtaining a one year extension, if needed, to complete the installation of necessary controls. To comply with the rule, many coal-fired power plants may need to install additional control technology to control acid gases, mercury or PM, or they may need to repower with an alternate fuel or retire operations. Most of the Company's U.S. coal-fired plants operated by the Company's subsidiaries comply with MATS as of April 16, 2015 using existing control technologies. However, in some cases additional time for compliance was needed in order to make necessary capital and operational changes, particularly for older facilities lacking advanced control technologies. For a discussion of the deactivation and planned deactivation of certain units owned or partially owned by IPL and DP&L as a result of existing and expected environmental regulations, including MATS, see Unit Retirement and Replacement Generation below.
IPL required additional time for compliance beyond April 16, 2015. In December 2012, IDEM granted an extension to April 16, 2016 covering all coal-fired units at Harding Street and Eagle Valley, in addition to Unit 3 and Unit 4 at Petersburg. In February 2013, IDEM granted a three-month extension on Petersburg Unit 2 to July 16, 2015, and that unit, as well as Petersburg Unit 1, which did not receive an extension, is currently in compliance with MATS.
On August 14, 2013, the IURC approved IPL's MATS plan, which included investing up to $511 million in the installation of new pollution control equipment on IPL's five largest base load generating units. These coal-fired units are located at IPL's Petersburg and Harding Street generating stations. The IURC also approved IPL's request to recover operating and construction costs for this equipment (including a return) through a rate adjustment mechanism, with certain stipulations. IPL plans to spend a total of $454 million for this project as approximately $57 million of costs will largely be avoided as a result of the approval for IPL's plans to refuel Harding Street Station Unit 7 from coal to natural gas.
Several lawsuits challenging the MATS rule were filed by other parties and consolidated into a single proceeding before the United States Court of Appeals for the District of Columbia Circuit (the "D.C Circuit"). On April 15, 2014, the D.C. Circuit denied the challenges. On June 29, 2015, the U.S. Supreme Court reversed the D.C. Circuit's decision, and remanded MATS to the D.C. Circuit for further proceedings. On December 15, 2015, the D.C. Circuit issued an order remanding MATS to the EPA without vacatur while the EPA works to comply with the U.S. Supreme Court's decision. The EPA published its revised appropriate and necessary finding on December 1, 2015 and plans to finalize it by April 15, 2016. Further proceedings are expected; however, in the meantime MATS remains in effect. We currently cannot predict the outcome of this litigation, or its impact, if any, on our MATS compliance planning or ultimate costs.
New Source Review ("NSR") — The NSR requirements under the CAA impose certain requirements on major emission sources, such as electric generating stations, if changes are made to the sources that result in a significant increase in air emissions. Certain projects, including power plant modifications, are excluded from these NSR requirements, if they meet the RMRR exclusion of the CAA. There is ongoing uncertainty, and significant litigation, regarding which projects fall within the RMRR exclusion. The EPA has pursued a coordinated compliance and enforcement strategy to address NSR compliance issues at the nation's coal-fired power plants. The strategy has included both the filing of suits against power plant owners and the issuance of NOVs to a number of power plant owners alleging NSR violations. See Item 3.—Legal Proceedings in this Form 10-K for more detail with respect to environmental litigation and regulatory action, including a NOV issued by the EPA against IPL concerning NSR and prevention of significant deterioration issues under the CAA.
DP&L's Stuart Station and Hutchings Station have received NOVs from the EPA alleging that certain activities undertaken in the past are outside the scope of the RMRR exclusion. Additionally, generation units partially owned by DP&L but operated by other utilities have received such NOVs relating to equipment repairs or replacements alleged to be outside the RMRR exclusion. The NOVs issued to DP&L-operated plants have not been pursued through litigation by the EPA.
If NSR requirements were imposed on any of the power plants owned by the Company's subsidiaries, the results could have a material adverse impact on the Company's business, financial condition and results of operations. In connection with the

48


imposition of any such NSR requirements on IPL, the utility would seek recovery of any operating or capital expenditures related to air pollution control technology to reduce regulated air emissions, but not fines or penalties; however, there can be no assurances that they would be successful in that regard.
Regional Haze Rule — The EPA's "Regional Haze Rule" is intended to reduce haze and protect visibility in designated federal areas, and sets guidelines for determining BART at affected plants and how to demonstrate "reasonable progress" towards eliminating man-made haze by 2064. The Regional Haze Rule required states to consider five factors when establishing BART for sources, including the availability of emission controls, the cost of the controls and the effect of reducing emission on visibility in Class I areas (including wilderness areas, national parks and similar areas). The statute requires compliance within five years after the EPA approves the relevant SIP or issues a federal implementation plan, although individual states may impose more stringent compliance schedules.
EPA previously determined that states included in the CSAPR would not be required to make source-specific BART determinations for BART-affected electric generating units, reasoning that the emissions reductions required by the CSAPR were "better than BART." Concurrently, EPA also finalized a limited disapproval of certain states' plans — including Ohio's — that previously relied on the EPA's Clean Air Interstate Rule to improve visibility and substituted a Federal Implementation Plan that relies on the CSAPR. Environmental groups have challenged EPA's determination than the CSAPR is "better than BART." The challenge currently is proceeding in the D.C. Circuit.
National Ambient Air Quality Standards ("NAAQS") — Under the CAA, the EPA sets NAAQS for six principal pollutants considered harmful to public health and the environment, including ozone, particulate matter, NOx and SO2, which result from coal combustion.  Areas meeting the NAAQS are designated "attainment areas" while those that do not meet the NAAQS are considered "nonattainment areas." Each state must develop a plan to bring nonattainment areas into compliance with the NAAQS, which may include imposing operating limits on individual plants. The EPA is required to review NAAQS at five-year intervals.
Based on the current and potential future ambient standards, certain of the states in which the Company's subsidiaries operate have determined or will be required to determine whether certain areas within such states meet the NAAQS. Some of these states may be required to modify their State Implementation Plans to detail how the states will regain their attainment status. As part of this process, it is possible that the applicable state environmental regulatory agency or the EPA may require reductions of emissions from our generating stations to reach attainment status for ozone, fine particulate matter, NOx or SO2. The compliance costs of the Company's U.S. subsidiaries could be material.
On September 30, 2015, IDEM published its final rule establishing reduced SO2 limits for IPL facilities in accordance with a new one-hour standard of 75 parts per billion, for the areas in which IPL's Harding Street, Petersburg, and Eagle Valley Generating Stations operate. The expected compliance date for these requirements is January 1, 2017. No impact is expected for Eagle Valley or Harding Street Generating Stations because these facilities will cease coal combustion prior to the compliance date. It is expected that improvements to the existing FGDs at Petersburg will be required in order to comply. IPL has engaged an engineering firm to further assess potential compliance measures and associated costs and timing. While costs associated with the proposed rule cannot accurately be predicted at this time, they could be material.
Greenhouse Gas Emissions — In January 2011, the EPA began regulating GHG emissions from certain stationary sources under the so-called "Tailoring Rule." The regulations are being implemented pursuant to two CAA programs: the Title V Operating Permit program and the program requiring a permit if undergoing certain new construction or major modifications, known as the Prevention of Significant Deterioration ("PSD"). Obligations relating to Title V permits include record-keeping and monitoring requirements. Sources subject to PSD can be required to implement BACT. In June 2014, the U.S. Supreme Court ruled that the EPA had exceeded its statutory authority in issuing the Tailoring Rule by regulating under the PSD program sources based solely on their GHG emissions. However, the U.S. Supreme Court also held that the EPA could impose GHG BACT requirements for sources already required to implement PSD for certain other pollutants. Therefore, if future modifications to our U.S.-based businesses' sources require PSD review for other pollutants, it may trigger GHG BACT requirements. The EPA has issued guidance on what BACT entails for the control of GHG and has now proposed new source performance standards ("NSPS") for modified and reconstructed units (see below) that will serve as a floor (maximum emission rate) for future BACT requirements. Individual states are now required to determine what controls are required for facilities within their jurisdiction on a case-by-case basis. The ultimate impact of the BACT requirements applicable to us on our operations cannot be determined at this time as our U.S.-based businesses will not be required to implement BACT until one of them constructs a new major source or makes a major modification of an existing major source. However, the cost of compliance could be material.
On October 23, 2015, the EPA's rule establishing new source performance standards ("NSPS") for new electric generating units became effective. The NSPS establish CO2 emissions standards of 1400 lbs/MWh for newly constructed coal-fueled electric generating plants, which reflects the partial capture and storage of CO2 emissions from the plants. The NSPS for large, newly constructed NGCC facilities is 1,000 lbs/MWh. These standards apply to any electric generating unit with construction

49


commencing after January 8, 2014. The EPA also promulgated NSPS applicable to modified and reconstructed electric generating units, which will serve as a floor for future BACT determinations for such units. The NSPS applicable to modified and reconstructed coal-fired units will be 1,800 lbs CO2/MWh for sources with heat input greater than 2,000 MMBtu per hour. For smaller sources, below 2,000 MMBtu per hour, the standard is 2,000 lbs CO2/MWh. The NSPS could have an impact on the Company's plans to construct and/or reconstruct electric generating units in some locations.
On December 22, 2015, the EPA's final CO2 emission rules for existing power plants under Clean Air Act Section 111(d) (called the Clean Power Plan (the "CPP")) also became effective. The CPP provides for interim emissions performance rates that must be achieved beginning in 2022 and final emissions performance rates that must be achieved starting in 2030. Under the CPP, states are required to meet state-wide emission rate standards or equivalent mass-based standards, with the goal being a 32% reduction in total U.S. power sector emissions from 2005 levels by 2030. The CPP requires states to submit, by 2016, implementation plans to meet the standards or a request for an extension to 2018. If a state fails to develop and submit an approvable implementation plan, the EPA will finalize a federal plan for that state. The full impact of the CPP will depend on the following:
   •    whether and how the states in which the Company's U.S. businesses operate respond to the CPP;
   •  whether the states adopt an emissions trading regime and, if so, which trading regime;
   •  how other states respond to the CPP, which will affect the size and robustness of any emissions trading market; and
   •  how other companies may respond in the face of increased carbon costs.
Several states and industry groups filed petitions in the D.C. Circuit challenging the CPP and requested a stay of the rule while the challenge was considered. The D.C. Circuit denied the stay and granted requests to consider the challenges on an expedited basis. As a result, the D.C. Circuit may issue an opinion on these challenges prior to the end of 2016. On February 9, 2016, the U.S. Supreme Court issued orders staying implementation of the CPP pending resolution of challenges to the rule.
Because we likely will not know the answers to the above questions regarding the CPP until 2018 or later, because the first compliance period will not end until 2025, and because we cannot predict whether the CPP will survive the legal challenges, it is too soon to determine the CPP's potential impact on our business, operations or financial condition, but any such impact could be material.
Cooling Water Intake — The Company's facilities are subject to a variety of rules governing water use and discharge. In particular, the Company's U.S. facilities are subject to the CWA Section 316(b) rule issued by the EPA that seeks to protect fish and other aquatic organisms by requiring existing steam electric generating facilities to utilize the Best Technology Available ("BTA") for cooling water intake structures. On August 15, 2014, the EPA published its final standards to protect fish and other aquatic organisms drawn into cooling water systems at large power plants and other industrial facilities. These standards require subject facilities that utilize at least 25% of the withdrawn water exclusively for cooling purposes and have a design intake flow of greater than two million gallons per day to choose among seven BTA options to reduce fish impingement. In addition, facilities that withdraw at least 125 million gallons per day for cooling purposes must conduct studies to assist permitting authorities to determine whether and what site-specific controls, if any, would be required to reduce entrainment of aquatic organisms. This decision-making process would include public input as part of permit renewal or permit modification. It is possible this process could result in the need to install closed-cycle cooling systems (closed-cycle cooling towers), or other technology. Finally, the standards require that new units added to an existing facility to increase generation capacity are required to reduce both impingement and entrainment that achieves one of two alternatives under national BTA standards for entrainment. It is not yet possible to predict the total impacts of this recent final rule at this time, including any challenges to such final rule and the outcome of any such challenges. However, if additional capital expenditures are necessary, they could be material.
AES Southland's current plan to comply with the California State Water Resources Board's regulations will see all once-through-cooled generating units retired from service by December 31, 2020. New air-cooled combined cycle gas turbine generators and battery energy storage systems will be constructed at the AES Alamitos and AES Huntington Beach generating stations. The execution of the Implementation Plan is entirely dependent on the Company's ability to execute on long-term power purchase agreements to support project financing of the replacement units. The SWRCB is currently reviewing the Implementation Plan and latest update information to evaluate the impact on electrical system reliability.  Power purchase agreements for the new generating capacity are currently under review by the California Public Utilities Commission.
Power plants will be required to comply with the more stringent of state or federal requirements. At present, the California state requirements are more stringent and have earlier compliance dates than the federal EPA requirements, and are therefore applicable to the Company's California assets. Challenges to the federal EPA's rule have been consolidated in the U.S. Court of Appeals for the Second Circuit, although implementation of the rule has not been stayed while the challenges proceed. The Company anticipates once-through cooling and CWA Section 316(b) compliance regulations and costs would have a material impact on our consolidated financial condition or results of operations.

50


Water Discharges — Certain of the Company's U.S.-based businesses are subject to National Pollutant Discharge Elimination System permits that regulate specific industrial waste water and storm water discharges to the waters of the U.S. under the CWA. On June 29, 2015, the EPA and the U.S. Army Corps of Engineers published a final rule defining federal jurisdiction over waters of the U.S.. This rule, which became effective on August 28, 2015, may expand or otherwise change the number and types of waters or features subject to federal permitting. On October 9, 2015, the U.S. Court of Appeals for the Sixth Circuit issued an order to temporarily stay the "Waters of the U.S." rule nationwide while that court determines whether it has authority to hear the challenges to the rule. The order was in response to challenges brought by 18 states and followed an August 2015 court decision in the U.S. District Court of North Dakota to stay the rule in 13 other states. We cannot predict the duration of the nationwide or partial stay of the rule or the outcome of this litigation; however, if the rule ultimately survives the legal challenges, it could have a material impact on our business, financial condition or results of operations.
On January 7, 2013, the Ohio Environmental Protection Agency issued an NPDES permit for J.M. Stuart Station. The primary issues involve the temperature and thermal discharges from the Station including the point at which the water quality standards are applied, i.e., whether water quality standards apply at the point where the Station discharge canal discharges into the Ohio River, or whether, as the EPA alleges, the discharge canal is an extension of Little Three Mile Creek and the water quality standards apply at the point where water enters the discharge canal. In addition, there are a number of other water-related permit requirements established with respect to metals and other materials contained in the discharges from the Station. The NPDES permit establishes interim standards related to the thermal discharge for 54 months that are comparable to current levels of discharge by Stuart Station. Permanent standards for both temperature and overall thermal discharges are established as of 55 months after the permit is effective, except that an additional transitional period of approximately 22 months is allowed if compliance with the permanent standards is to be achieved through a plan of construction and various milestones on the construction schedule are met. It is believed that compliance with the permit as written will require capital expenses that will be material to DP&L. The cost of compliance and the timing of such costs is uncertain and may vary considerably depending on a compliance plan that would need to be developed, the type of capital projects that may be necessary, and the uncertainties that may arise in the likely event that permits and approvals from other governmental entities would likely be required to construct and operate any such capital project. DP&L has appealed various aspects of the final permit to the Environmental Review Appeals Commission and a hearing has been scheduled for March 2016. The compliance schedule in the final permit has been modified to accommodate the timing of the hearing. The outcome of such appeal is uncertain.
On August 28, 2012, the IDEM issued NPDES permits to the IPL Petersburg, Harding Street and Eagle Valley generating stations, which became effective in October 2012. NPDES permits regulate specific industrial wastewater and storm water discharges to the waters of Indiana under Sections 402 and 405 of the U.S. Clean Water Act. These permits set new water quality-based effluent discharge limits for the Harding Street and Petersburg facilities, as well as monitoring and other requirements designed to protect aquatic life, with full compliance required by October 2015. IPL received an extension to the compliance deadline through September 29, 2017 for IPL's Harding Street and Petersburg facilities through agreed orders with IDEM. IPL conducted studies to determine the operational changes and control equipment necessary to comply with the new limitations. In October 2014, IPL filed its wastewater compliance plans for its power plants with the IURC. On July 29, 2015, the IURC approved a Certificate of Public Convenience and Necessity to convert Unit 7 at the Harding Street Station from coal-fired to natural gas-fired (about 410 MW net capacity), and also to install and operate wastewater treatment technologies at Harding Street Station and Petersburg Generation Station. IPL plans to invest $319 million in these projects to ensure compliance with the wastewater treatment requirements by September 29, 2017.
On November 3, 2015, the EPA published its final ELG rule to reduce toxic pollutants discharged into waters of the U.S. by power plants. These effluent limitations for existing and new sources include dry handling of fly ash, closed-loop or dry handling of bottom ash and more stringent effluent limitations for flue gas de-sulfurization wastewater. Compliance time lines for existing sources will be established by the applicable permitting authorities and will be set as soon as determined possible, but no sooner than November 1, 2018 and no later than December 31, 2023. Challenges to this rule are being consolidated in the U.S. Court of Appeals for the Fifth Circuit. IPL expects to recover through its environmental rate adjustment mechanism any operating or capital expenditures related to compliance with the effluent limitations requirements. Recovery of these costs is sought through an Indiana statute that allows for 80% recovery of qualifying costs through a rate adjustment mechanism with the remainder recorded as a regulatory asset to be considered for recovery in the next base rate case proceeding; however, there can be no assurances that IPL will be successful in that regard. In light of the uncertainties at this time, we cannot predict the impact of these regulations on our consolidated results of operations, cash flows, or financial condition, but it could be material.
Waste Management — In the course of operations, the Company's facilities generate solid and liquid waste materials requiring eventual disposal or processing. With the exception of coal combustion residuals ("CCR"), the wastes are not usually physically disposed of on our property, but are shipped off site for final disposal, treatment or recycling. CCR, which consists of bottom ash, fly ash and air pollution control wastes, is disposed of at some of our coal-fired power generation plant sites using engineered, permitted landfills. Waste materials generated at our electric power and distribution facilities may include CCR, oil, scrap metal, rubbish, small quantities of industrial hazardous wastes such as spent solvents, tree and land clearing wastes and PCB contaminated liquids and solids. The Company endeavors to ensure that all of its solid and liquid wastes are

51


disposed of in accordance with applicable national, regional, state and local regulations. On October 19, 2015, an EPA rule regulating CCR under the Resource Conservation and Recovery Act became effective. The rule established nationally applicable minimum criteria for the disposal of CCR in new and currently operating landfills and surface impoundments, and may impose closure and/or corrective action requirements for existing CCR landfills and impoundments under certain specified conditions. The primary enforcement mechanisms under this regulation would be actions commenced by the states and private lawsuits. The Company's U.S. subsidiaries are still analyzing the potential impact and compliance cost associated with this final rule, and there can be no assurance that the Company's businesses, financial condition or results of operations would not be materially and adversely affected by such rule.
Senate Bill 251 — In May 2011, Senate Bill 251 became a law in the state of Indiana. Senate Bill 251 is a comprehensive bill that, among other things, provides Indiana utilities, including IPL, with a means for recovering 80% of costs incurred to comply with federal mandates through a periodic retail rate adjustment mechanism. This includes costs to comply with regulations from the EPA, FERC, the North American Electric Reliability Corporation, Department of Energy, etc., including capital intensive requirements and/or proposals described herein, such as cooling water intake regulations, waste management and coal combustion byproducts, wastewater effluent, MISO transmission expansion costs and polychlorinated biphenyls. It does not change existing legislation that allows for 100% recovery of clean coal technology designed to reduce air pollutants.
Some of the most important features of Senate Bill 251 to IPL are as follows. Any energy utility in Indiana seeking to recover federally mandated costs incurred in connection with a compliance project shall apply to the IURC for a CPCN for the compliance project. It presents certain factors that the IURC must consider in determining whether to grant a CPCN. It further specifies that if the IURC approves a proposed compliance project and the projected federally mandated costs associated with the project, the following apply: (i) 80% of the approved costs shall be recovered by the energy utility through a periodic retail rate adjustment mechanism; (ii) 20% of the approved costs shall be deferred and recovered by the energy utility as part of the next general rate case filed with the IURC; and (iii) actual costs exceeding the projected federally mandated costs of the approved compliance project by more than 25% shall require specific justification and approval before being authorized in the energy utility's next general rate case. Senate Bill 251 also requires the IURC to adopt rules to establish a voluntary clean energy portfolio standard program. Such program will provide incentives to participating electricity suppliers to obtain specified percentages of electricity from clean energy sources in accordance with clean portfolio standard goals, including requiring at least 50% of the clean energy to originate from Indiana suppliers. The goals can also be met by purchasing clean energy credits.
CERCLA — The Comprehensive Environmental Response, Compensation and Liability Act of 1980 (aka "Superfund") may be the source of claims against certain of the Company's U.S. subsidiaries from time to time. There is ongoing litigation at a site known as the South Dayton Landfill where a group of companies already recognized as potentially responsible parties ("PRPs") have sued DP&L and other unrelated entities seeking a contribution toward the costs of assessment and remediation. DP&L is actively opposing such claims. In 2003, DP&L received notice that the EPA considers DP&L to be a PRP at the Tremont City landfill Superfund site. EPA has taken no further action with respect to DP&L since 2003 regarding the Tremont City landfill. The Company is unable to determine whether there will be any liability, or the size of any liability that may ultimately be assessed against DP&L at these two sites, but any such liability could be material to DP&L.
Unit Retirement and Replacement Generation — In the second quarter of 2013, IPL retired in place five oil-fired peaking units with an average life of approximately 61 years (approximately 168 MW net capacity in total), as such units were not equipped with the advanced environmental control technologies needed to comply with existing and expected environmental regulations. Although these units represented approximately 5% of IPL's generating capacity, they were seldom dispatched by Midcontinent Independent System Operator, Inc. in recent years due to their relatively higher production cost and in some instances repairs were needed. In addition to these recently retired units, IPL has several other generating units that it expects to retire or refuel by 2017. These units are primarily coal-fired and represent 472 MW of net capacity in total. To replace this generation, in April 2013, IPL filed a petition and case-in-chief with the IURC in April 2013 seeking a CPCN to build a 550 to 725 MW CCGT at its Eagle Valley Station site in Indiana and to refuel Harding Street Station Units 5 and 6 from coal to natural gas (106 MW net capacity each). In May 2014, the IURC issued an order on the CPCN authorizing the refueling project and granting approval to build a 644 to 685 MW CCGT at a total budget of $649 million. The current estimated cost of these projects is $632 million. IPL was granted authority to accrue post in-service allowance for debt and equity funds used during construction and to defer the recognition of depreciation expense of the CCGT and refueling project until such time that we are allowed to collect both a return and depreciation expense on the CCGT and refueling project. The CCGT is expected to be placed into service in April 2017, and the refueling project was completed in December 2015. The costs to build and operate the CCGT and for the refueling project, other than fuel costs, will not be recoverable by IPL through rates until the conclusion of a base rate case proceeding with the IURC after the assets have been placed in service.
As a result of existing and expected environmental regulations, including MATS, DP&L notified PJM of its plan to retire the six coal-fired units aggregating approximately 360 MW at its wholly-owned Hutchings Generation Station. Hutchings Unit 4 was retired in June 2013. In conjunction with administrative agreements reached in 2013 with the EPA and Ohio's Regional

52


Air Pollution Control Authority that resolved alleged violations of air quality standards, DP&L accelerated its plans with respect to Hutchings Units 1, 2, 3, 5 and 6 and those units were each retired by June 2015. DP&L removed equipment from such units so that combustion of coal was not possible after September 2013. Conversion of the coal-fired units to natural gas was investigated, but the cost of investment exceeded the expected return. In addition, DP&L owned approximately 207 MW of coal-fired generation at Beckjord Unit 6, which was operated by Duke Energy Ohio. Beckjord Unit 6 was retired effective October 1, 2014. At this time, DP&L does not have plans to replace the units that have been or will be retired.
International Environmental Regulations
For a discussion of the material environmental regulations applicable to the Company's businesses located outside of the U.S., see Environmental Regulation under the discussion of the various countries in which the Company's subsidiaries operate in Business—Our Organization and Segments, above.
Customers — We sell to a wide variety of customers. No individual customer accounted for 10% or more of our 2015 total revenue. In our generation business, we own and/or operate power plants to generate and sell power to wholesale customers such as utilities and other intermediaries. Our utilities sell to end-user customers in the residential, commercial, industrial and governmental sectors in a defined service area.
Employees — As of December 31, 2015, we employed approximately 21,000 people.
Executive Officers — The following individuals are our executive officers:
Michael Chilton, 56 years old, was named Senior Vice President, Construction & Engineering, for the Company in December 2014. Prior to his current role, Mr. Chilton was the Managing Director of Construction from 2009 to 2011 and Vice President, Operations Support from 2012 to 2014. Before joining AES, Mr. Chilton held various leadership roles in Kennametal and GE, including: Regional Director for Kennametal Asia (2006-2009), with GE as President & CEO of Xinhua Controls Solutions based in China (2005-2006), Managing Director for Contractual Services Asia based in Singapore (2001-2005), Quality Leader for Energy Services based in Atlanta (1999-2001), Master Black Belt for Energy Sales based in Tokyo (1998-1999) and President of Joint Conversion company in Nuclear Energy based in Wilmington (1995-1998). Mr. Chilton has a BS in Chemical Engineering from University of Missouri, a MBA from University of Arkansas and a JD from Kaplan University.
Bernerd Da Santos, 52 years old, was appointed Chief Operating Officer and Senior Vice President in December 2014. Previously, Mr. Da Santos held several positions at the Company including Chief Financial Officer, Global Finance Operations (2012-2014), Chief Financial Officer of Global Utilities (2011-2012), Chief Financial Officer of Latin America and Africa (2009-2011), Chief Financial Officer of Latin America (2007-2009), Managing Director of Finance for Latin America (2005-2007) and VP and Controller of EDC (Venezuela). Prior to joining AES in 2000, Mr. Da Santos held a number of financial leadership positions at EDC. Mr. Da Santos is a member of the Board of Directors of Companhia Brasiliana de Energia, AES Tietê, AES Eletropaulo, AES Gener, Companhia de Alumbrado Electrico de San Salvador ("CAESS"), Empresa Electrica de Oriente ("EEO"), Companhia de Alumbrado Electrico de Santa Ana, AES Chivor & Cia S.C.A. E.S.P. and Indianapolis Power & Light. Mr. Da Santos holds a Bachelor's degree with Cum Laude distinction in Business Administration and Public Administration from Universidad José Maria Vargas, a Bachelor's degree with Cum Laude distinction in Business Management and Finance, and an MBA with Cum Laude distinction from Universidad José Maria Vargas.
Andrés R. Gluski, 58 years old, has been President, CEO and a member of our Board of Directors since September 2011 and is Chairman of the Strategy and Investment Committee of the Board. Prior to assuming his current position, Mr. Gluski served as Executive Vice President ("EVP") and Chief Operating Officer ("COO") of the Company since March 2007. Prior to becoming the COO of AES, Mr. Gluski was EVP and the Regional President of Latin America from 2006 to 2007. Mr. Gluski was Senior Vice President ("SVP") for the Caribbean and Central America from 2003 to 2006, CEO of La Electricidad de Caracas ("EDC") from 2002 to 2003 and CEO of AES Gener (Chile) in 2001. Prior to joining AES in 2000, Mr. Gluski was EVP and Chief Financial Officer ("CFO") of EDC, EVP of Banco de Venezuela (Grupo Santander), Vice President ("VP") for Santander Investment, and EVP and CFO of CANTV (subsidiary of GTE). Mr. Gluski has also worked with the International Monetary Fund in the Treasury and Latin American Departments and served as Director General of the Ministry of Finance of Venezuela. Mr. Gluski currently serves on President Obama's Export Council, the US-Brazil CEO Forum and the US-India CEO Forum. He is a member of the Board of Waste Management, and is Chairman of AES Gener in Chile and AES Brasiliana in Brazil. Mr. Gluski is also Chairman of the Americas Society/Council of the Americas, and Director of the Edison Electric Institute and the US-Philippines Society. Mr. Gluski is a magna cum laude graduate of Wake Forest University and holds an M.A. and a Ph.D. in Economics from the University of Virginia.
Elizabeth Hackenson, 55 years old, was named Chief Information Officer ("CIO") and SVP of AES in October 2008. Prior to assuming her current position, Ms. Hackenson was the SVP and CIO at Alcatel-Lucent from 2006 to 2008, where she managed the development of technology programs for Applications, Operations and Infrastructure. Previously, she also served as the EVP and CIO for MCI from 2004 to 2006. Her corporate tenure has spanned several Fortune 100 companies

53


including, British Telecom (Concert), AOL (UUNET) and EDS. She served in a variety of senior management positions, working on the management and delivery of information technology services to support business needs across a corporate-wide enterprise. Ms. Hackenson serves on the Boards of Dayton Power & Light ("DP&L") and its parent company DPL, Inc. AES Cochrane and AES Chivor. She also serves as a Director on the Greater Washington Board of Trade and Red 5 Security and is a Strategic Advisor to the Paladin Group. Ms. Hackenson earned her degree from New York State University.
Tish Mendoza, 40 years old, is Chief Human Resources Officer and Senior Vice President, Global Human Resources and Internal Communications. Prior to assuming her current position, Ms. Mendoza was the Vice President of Human Resources, Global Utilities from 2011 to 2012 and Vice President of Global Compensation, Benefits and HRIS, including Executive Compensation, from 2008 to 2011 and acted in the same capacity as the Director of the function from 2006 to 2008. In 2015, Ms. Mendoza was appointed a member of the Boards of AES Chivor S.A. and DP&L, and sits on AES' compensation and benefits committees. She is also currently serving as co-chair of Evanta Global HR, and is part of its governing body in Washington, DC. Prior to joining AES, Ms. Mendoza was Vice President of Human Resources for a product company in the Treasury Services division of JP Morgan Chase and Vice President of Human Resources and Compensation and Benefits at Vastera, Inc, a former technology and managed services company. Ms. Mendoza earned certificates in leadership and human resource management, and a Bachelor's degree in Business Administration and Human Resources.
Brian A. Miller, 50 years old, is an EVP of the Company, General Counsel, and Corporate Secretary. Mr. Miller joined the Company in 2001 and has served in various positions including VP, Deputy General Counsel, Corporate Secretary, General Counsel for North America and Assistant General Counsel. Mr. Miller served on the Boards of AES Entek, a joint venture between AES and Koc Holdings in Turkey, from 2010 through 2014; and Silver Ridge Power, a joint venture between AES and Riverstone Holdings LLC, from 2008 through July of 2014. Mr. Miller is the chairman of Indianapolis Power and Light Board and DP&L. Mr. Miller also serves as a member of the Board of DPL, Inc. and AES Chivor. Prior to joining AES, he was an attorney with the law firm Chadbourne & Parke, LLP. Mr. Miller received a Bachelor's degree in History and Economics from Boston College and holds a Juris Doctorate from the University of Connecticut School Of Law.
Thomas M. O'Flynn, 56 years old, has served as EVP and CFO of the Company since September 2012. Previously, Mr. O'Flynn served as Senior Advisor to the Private Equity Group of Blackstone, an investment and advisory group and held this position from 2010 to 2012. During this period, Mr. O'Flynn also served as COO and CFO of Transmission Developers, Inc. ("TDI"), a Blackstone-controlled company that develops innovative power transmission projects in an environmentally responsible manner. From 2001 to 2009, he served as the CFO of PSEG, a New Jersey-based merchant power and utility company. He also served as President of PSEG Energy Holdings from 2007 to 2009. From 1986 to 2001, Mr. O'Flynn was in the Global Power and Utility Group of Morgan Stanley. He served as a Managing Director for his last five years and as head of the North American Power Group from 2000 to 2001. He was responsible for senior client relationships and led a number of large merger, financing, restructuring and advisory transactions. Mr. O'Flynn is the chairman of the IPALCO and AES US Investments Boards and serves as a member of the Boards of DP&L and its parent company, DPL, Inc. Mr. O'Flynn served on the Board of Silver Ridge Power, a joint venture between AES and Riverstone Holdings LLC from September 2012 through July 2014. He is also currently on the Board of Directors of the New Jersey Performing Arts Center and is Chairman of the Institute for Sustainability and Energy at Northwestern University. Mr. O'Flynn has a BA in Economics from Northwestern University and an MBA in Finance from the University of Chicago.
How to Contact AES and Sources of Other Information
Our principal offices are located at 4300 Wilson Boulevard, Arlington, Virginia 22203. Our telephone number is (703) 522-1315. Our website address is http://www.aes.com. Our annual reports on Form 10-K, quarterly reports on Form 10-Q and current reports on Form 8-K and any amendments to such reports filed pursuant to Section 13(a) or Section 15(d) of the Securities Exchange Act of 1934 (the "Exchange Act") are posted on our website. After the reports are filed with, or furnished to the SEC, they are available from us free of charge. Material contained on our website is not part of and is not incorporated by reference in this Form 10-K. You may also read and copy any materials we file with the SEC at the SEC's Public Reference Room at 100 F Street, N.E., Washington, D.C. 20549. You may obtain information about the operation of the Public Reference Room by calling the SEC at 1-800-SEC-0330. The SEC maintains an internet website that contains the reports, proxy and information statements and other information that we file electronically with the SEC at www.sec.gov.
Our CEO and our CFO have provided certifications to the SEC as required by Section 302 of the Sarbanes-Oxley Act of 2002. These certifications are included as exhibits to this Annual Report on Form 10-K.
Our CEO provided a certification pursuant to Section 303A of the New York Stock Exchange Listed Company Manual on May 26, 2015.
Our Code of Business Conduct ("Code of Conduct") and Corporate Governance Guidelines have been adopted by our Board of Directors. The Code of Conduct is intended to govern, as a requirement of employment, the actions of everyone who works at AES, including employees of our subsidiaries and affiliates. Our Ethics and Compliance Department provides training, information, and certification programs for AES employees related to the Code of Conduct. The Ethics and

54


Compliance Department also has programs in place to prevent and detect criminal conduct, promote an organizational culture that encourages ethical behavior and a commitment to compliance with the law, and to monitor and enforce AES policies on corruption, bribery, money laundering and associations with terrorists groups. The Code of Conduct and the Corporate Governance Guidelines are located in their entirety on our website. Any person may obtain a copy of the Code of Conduct or the Corporate Governance Guidelines without charge by making a written request to: Corporate Secretary, The AES Corporation, 4300 Wilson Boulevard, Arlington, VA 22203. If any amendments to, or waivers from, the Code of Conduct or the Corporate Governance Guidelines are made, we will disclose such amendments or waivers on our website.
ITEM 1A. RISK FACTORS
You should consider carefully the following risks, along with the other information contained in or incorporated by reference in this Form 10-K. Additional risks and uncertainties also may adversely affect our business and operations including those discussed in Item 7.—Management's Discussion and Analysis of Financial Condition and Results of Operations in this Form 10-K. If any of the following events actually occur, our business, financial results and financial condition could be materially adversely affected.
We routinely encounter and address risks, some of which may cause our future results to be different, sometimes materially different, than we presently anticipate. The categories of risk we have identified in Item 1A.—Risk Factors of this Form 10-K include the following:
•
risks related to our high level of indebtedness;
•
risks associated with our ability to raise needed capital;
•
external risks associated with revenue and earnings volatility;
•
risks associated with our operations; and
•
risks associated with governmental regulation and laws.
These risk factors should be read in conjunction with Item 7.—Management's Discussion and Analysis of Financial Condition and Results of Operations, and the Consolidated Financial Statements and related notes included elsewhere in this report.
Risks Related to our High Level of Indebtedness
We have a significant amount of debt, a large percentage of which is secured, which could adversely affect our business and the ability to fulfill our obligations.
As of December 31, 2015, we had approximately $20.8 billion of outstanding indebtedness on a consolidated basis. All outstanding borrowings under The AES Corporation's senior secured credit facility are secured by certain of our assets, including the pledge of capital stock of many of The AES Corporation's directly held subsidiaries. Most of the debt of The AES Corporation's subsidiaries is secured by substantially all of the assets of those subsidiaries. Since we have such a high level of debt, a substantial portion of cash flow from operations must be used to make payments on this debt. Furthermore, since a significant percentage of our assets are used to secure this debt, this reduces the amount of collateral that is available for future secured debt or credit support and reduces our flexibility in dealing with these secured assets. This high level of indebtedness and related security could have other important consequences to us and our investors, including:
•
making it more difficult to satisfy debt service and other obligations at the holding company and/or individual subsidiaries;
•
increasing the likelihood of a downgrade of our debt, which could cause future debt costs and/or payments to increase under our debt and related hedging instruments and consume an even greater portion of cash flow;
•
increasing our vulnerability to general adverse industry and economic conditions, including but not limited to adverse changes in foreign exchange rates and commodity prices;
•
reducing the availability of cash flow to fund other corporate purposes and grow our business;
•
limiting our flexibility in planning for, or reacting to, changes in our business and the industry;
•
placing us at a competitive disadvantage to our competitors that are not as highly leveraged; and
•
limiting, along with the financial and other restrictive covenants relating to such indebtedness, among other things, our ability to borrow additional funds as needed or take advantage of business opportunities as they arise, pay cash dividends or repurchase common stock.
The agreements governing our indebtedness, including the indebtedness of our subsidiaries, limit, but do not prohibit the incurrence of additional indebtedness. To the extent we become more leveraged, the risks described above would increase. Further, our actual cash requirements in the future may be greater than expected. Accordingly, our cash flows may not be sufficient to repay at maturity all of the outstanding debt as it becomes due and, in that event, we may not be able to borrow

55


money, sell assets, raise equity or otherwise raise funds on acceptable terms or at all to refinance our debt as it becomes due. See Note 12—Debt included in Item 8. of this Form 10-K for a schedule of our debt maturities.
The AES Corporation is a holding company and its ability to make payments on its outstanding indebtedness, including its public debt securities, is dependent upon the receipt of funds from its subsidiaries by way of dividends, fees, interest, loans or otherwise.
The AES Corporation is a holding company with no material assets other than the stock of its subsidiaries. All of The AES Corporation's revenue is generated through its subsidiaries. Accordingly, almost all of The AES Corporation's cash flow is generated by the operating activities of its subsidiaries. Therefore, The AES Corporation's ability to make payments on its indebtedness and to fund its other obligations is dependent not only on the ability of its subsidiaries to generate cash, but also on the ability of the subsidiaries to distribute cash to it in the form of dividends, fees, interest, tax sharing payments, loans or otherwise.
However, our subsidiaries face various restrictions in their ability to distribute cash to The AES Corporation. Most of the subsidiaries are obligated, pursuant to loan agreements, indentures or non-recourse financing arrangements, to satisfy certain restricted payment covenants or other conditions before they may make distributions to The AES Corporation. In addition, the payment of dividends or the making of loans, advances or other payments to The AES Corporation may be subject to other contractual, legal or regulatory restrictions or may be prohibited altogether. Business performance and local accounting and tax rules may limit the amount of retained earnings that may be distributed to us as a dividend. Subsidiaries in foreign countries may also be prevented from distributing funds to The AES Corporation as a result of foreign governments restricting the repatriation of funds or the conversion of currencies. Any right that The AES Corporation has to receive any assets of any of its subsidiaries upon any liquidation, dissolution, winding up, receivership, reorganization, bankruptcy, insolvency or similar proceedings (and the consequent right of the holders of The AES Corporation's indebtedness to participate in the distribution of, or to realize proceeds from, those assets) will be effectively subordinated to the claims of any such subsidiary's creditors (including trade creditors and holders of debt issued by such subsidiary).
The AES Corporation's subsidiaries are separate and distinct legal entities and, unless they have expressly guaranteed any of The AES Corporation's indebtedness, have no obligation, contingent or otherwise, to pay any amounts due pursuant to such debt or to make any funds available whether by dividends, fees, loans or other payments.
Even though The AES Corporation is a holding company, existing and potential future defaults by subsidiaries or affiliates could adversely affect The AES Corporation.
We attempt to finance our domestic and foreign projects primarily under loan agreements and related documents which, except as noted below, require the loans to be repaid solely from the project's revenues and provide that the repayment of the loans (and interest thereon) is secured solely by the capital stock, physical assets, contracts and cash flow of that project subsidiary or affiliate. This type of financing is usually referred to as non-recourse debt or "non-recourse financing." In some non-recourse financings, The AES Corporation has explicitly agreed to undertake certain limited obligations and contingent liabilities, most of which by their terms will only be effective or will be terminated upon the occurrence of future events. These obligations and liabilities take the form of guarantees, indemnities, letter of credit reimbursement agreements and agreements to pay, in certain circumstances, the project lenders or other parties.
As of December 31, 2015, we had approximately $20.8 billion of outstanding indebtedness on a consolidated basis, of which approximately $5.0 billion was recourse debt of The AES Corporation and approximately $15.8 billion was non-recourse debt. In addition, we have outstanding guarantees, indemnities, letters of credit, and other credit support commitments which are further described in this Form 10-K in Item 7.—Management's Discussion and Analysis of Financial Condition and Results of Operations—Capital Resources and Liquidity—Parent Company Liquidity.
Some of our subsidiaries are currently in default with respect to all or a portion of their outstanding indebtedness. The total debt classified as current in our Consolidated Balance Sheets related to such defaults was $1.0 billion as of December 31, 2015. While the lenders under our non-recourse financings generally do not have direct recourse to The AES Corporation (other than to the extent of any credit support given by The AES Corporation), defaults thereunder can still have important consequences for The AES Corporation, including, without limitation:
•
reducing The AES Corporation's receipt of subsidiary dividends, fees, interest payments, loans and other sources of cash since the project subsidiary will typically be prohibited from distributing cash to The AES Corporation during the pendency of any default;
•
under certain circumstances, triggering The AES Corporation's obligation to make payments under any financial guarantee, letter of credit or other credit support which The AES Corporation has provided to or on behalf of such subsidiary;
•
causing The AES Corporation to record a loss in the event the lender forecloses on the assets;

56


•
triggering defaults in The AES Corporation's outstanding debt and trust preferred securities. For example, The AES Corporation's senior secured credit facility and outstanding senior notes include events of default for certain bankruptcy related events involving material subsidiaries. In addition, The AES Corporation's senior secured credit facility includes certain events of default relating to accelerations of outstanding material debt of material subsidiaries or any subsidiaries that in the aggregate constitute a material subsidiary;
•
the loss or impairment of investor confidence in the Company; or
•
foreclosure on the assets that are pledged under the non-recourse loans, therefore eliminating any and all potential future benefits derived from those assets.
None of the projects that are currently in default are owned by subsidiaries that individually or in the aggregate meet the applicable standard of materiality in The AES Corporation's senior secured credit facility or other debt agreements in order for such defaults to trigger an event of default or permit acceleration under such indebtedness. However, as a result of future mix of distributions, write-down of assets, dispositions and other matters that affect our financial position and results of operations, it is possible that one or more of these subsidiaries, individually or in the aggregate, could fall within the applicable standard of materiality and thereby upon an acceleration of such subsidiary's debt, trigger an event of default and possible acceleration of the indebtedness under The AES Corporation's senior secured credit facility or other indebtedness of The AES Corporation.
Risks Associated with our Ability to Raise Needed Capital
The AES Corporation, or the Parent Company, has significant cash requirements and limited sources of liquidity.
The AES Corporation requires cash primarily to fund:
•
principal repayments of debt;
•
interest and preferred dividends;
•
acquisitions;
•
construction and other project commitments;
•
other equity commitments, including business development investments;
•
equity repurchases and/or cash dividends on our common stock;
•
taxes; and
•
Parent Company overhead costs.
The AES Corporation's principal sources of liquidity are:
•
dividends and other distributions from its subsidiaries;
•
proceeds from debt and equity financings at the Parent Company level; and
•
proceeds from asset sales.
For a more detailed discussion of The AES Corporation's cash requirements and sources of liquidity, please see Item 7.—Management's Discussion and Analysis of Financial Condition and Results of Operations—Capital Resources and Liquidity in this Form 10-K.
While we believe that these sources will be adequate to meet our obligations at the Parent Company level for the foreseeable future, this belief is based on a number of material assumptions, including, without limitation, assumptions about our ability to access the capital or commercial lending markets, the operating and financial performance of our subsidiaries, exchange rates, our ability to sell assets, and the ability of our subsidiaries to pay dividends. Any number of assumptions could prove to be incorrect, and, therefore there can be no assurance that these sources will be available when needed or that our actual cash requirements will not be greater than expected. For example, in recent years, certain financial institutions have gone bankrupt. In the event that a bank who is party to our senior secured credit facility or other facilities goes bankrupt or is otherwise unable to fund its commitments, we would need to replace that bank in our syndicate or risk a reduction in the size of the facility, which would reduce our liquidity. In addition, our cash flow may not be sufficient to repay at maturity the entire principal outstanding under our credit facility and our debt securities and we may have to refinance such obligations. There can be no assurance that we will be successful in obtaining such refinancing on terms acceptable to us or at all and any of these events could have a material effect on us.
Our ability to grow our business could be materially adversely affected if we were unable to raise capital on favorable terms.
From time to time, we rely on access to capital markets as a source of liquidity for capital requirements not satisfied by operating cash flows. Our ability to arrange for financing on either a recourse or non-recourse basis and the costs of such capital are dependent on numerous factors, some of which are beyond our control, including:

57


•
general economic and capital market conditions;
•
the availability of bank credit;
•
investor confidence;
•
the financial condition, performance and prospects of The AES Corporation in general and/or that of any subsidiary requiring the financing as well as companies in our industry or similar financial circumstances; and
•
changes in tax and securities laws which are conducive to raising capital.
Should future access to capital not be available to us, we may have to sell assets or decide not to build new plants or expand or improve existing facilities, either of which would affect our future growth, results of operations or financial condition.
A downgrade in the credit ratings of The AES Corporation or its subsidiaries could adversely affect our ability to access the capital markets which could increase our interest costs or adversely affect our liquidity and cash flow.
If any of the credit ratings of The AES Corporation or its subsidiaries were to be downgraded, our ability to raise capital on favorable terms could be impaired and our borrowing costs could increase. Furthermore, depending on The AES Corporation's credit ratings and the trading prices of its equity and debt securities, counterparties may no longer be as willing to accept general unsecured commitments by The AES Corporation to provide credit support. Accordingly, with respect to both new and existing commitments, The AES Corporation may be required to provide some other form of assurance, such as a letter of credit and/or collateral, to backstop or replace any credit support by The AES Corporation. There can be no assurance that such counterparties will accept such guarantees or that AES could arrange such further assurances in the future. In addition, to the extent The AES Corporation is required and able to provide letters of credit or other collateral to such counterparties, it will limit the amount of credit available to The AES Corporation to meet its other liquidity needs.
We may not be able to raise sufficient capital to fund developing projects in certain less developed economies which could change or in some cases adversely affect our growth strategy.
Part of our strategy is to grow our business by developing businesses in less developed economies where the return on our investment may be greater than projects in more developed economies. Commercial lending institutions sometimes refuse to provide non-recourse project financing in certain less developed economies, and in these situations we have sought and will continue to seek direct or indirect (through credit support or guarantees) project financing from a limited number of multilateral or bilateral international financial institutions or agencies. As a precondition to making such project financing available, the lending institutions may also require governmental guarantees of certain project and sovereign related risks. There can be no assurance, however, that project financing from the international financial agencies or that governmental guarantees will be available when needed, and if they are not, we may have to abandon the project or invest more of our own funds which may not be in line with our investment objectives and would leave less funds for other projects.
External Risks Associated with Revenue and Earnings Volatility
Our businesses may incur substantial costs and liabilities and be exposed to price volatility as a result of risks associated with the wholesale electricity markets, which could have a material adverse effect on our financial performance.
Some of our businesses sell electricity in the spot markets in cases where they operate at levels in excess of their power sales agreements or retail load obligations. Our businesses may also buy electricity in the wholesale spot markets. As a result, we are exposed to the risks of rising and falling prices in those markets. The open market wholesale prices for electricity can be volatile and often reflect the fluctuating cost of fuels such as coal, natural gas or oil derivative fuels in addition to other factors described below. Consequently, any changes in the supply and cost of coal, natural gas, or oil derivative fuels may impact the open market wholesale price of electricity.
Volatility in market prices for fuel and electricity may result from among other things:
•
plant availability in the markets generally;
•
availability and effectiveness of transmission facilities owned and operated by third parties;
•
competition;
•
electricity usage;
•
seasonality;
•
foreign exchange rate fluctuation;
•
availability and price of emission credits;
•
hydrology and other weather conditions;
•
illiquid markets;
•
transmission or transportation constraints or inefficiencies;

58


•
availability of competitively priced renewables sources;
•
increased adoption of distributed generation;
•
available supplies of natural gas, crude oil and refined products, and coal;
•
generating unit performance;
•
natural disasters, terrorism, wars, embargoes, and other catastrophic events;
•
energy, market and environmental regulation, legislation and policies;
•
geopolitical concerns affecting global supply of oil and natural gas;
•
general economic conditions in areas where we operate which impact energy consumption; and
•
bidding behavior and market bidding rules.
Our financial position and results of operations may fluctuate significantly due to fluctuations in currency exchange rates experienced at our foreign operations.
Our exposure to currency exchange rate fluctuations results primarily from the translation exposure associated with the preparation of the Consolidated Financial Statements, as well as from transaction exposure associated with transactions in currencies other than an entity's functional currency. While the Consolidated Financial Statements are reported in U.S. Dollars, the financial statements of many of our subsidiaries outside the U.S. are prepared using the local currency as the functional currency and translated into U.S. Dollars by applying appropriate exchange rates. As a result, fluctuations in the exchange rate of the U.S. Dollar relative to the local currencies where our subsidiaries outside the U.S. report could cause significant fluctuations in our results. In addition, while our expenses with respect to foreign operations are generally denominated in the same currency as corresponding sales, we have transaction exposure to the extent receipts and expenditures are not denominated in the subsidiary's functional currency. Moreover, the costs of doing business abroad may increase as a result of adverse exchange rate fluctuations. Our financial position and results of operations could be affected by fluctuations in the value of a number of currencies. See Item 7A.—Quantitative and Qualitative Disclosures about Market Risk to this Form 10-K for further information.
We may not be adequately hedged against our exposure to changes in commodity prices or interest rates.
We routinely enter into contracts to hedge a portion of our purchase and sale commitments for electricity, fuel requirements and other commodities to lower our financial exposure related to commodity price fluctuations. As part of this strategy, we routinely utilize fixed price or indexed forward physical purchase and sales contracts, futures, financial swaps, and option contracts traded in the over-the-counter markets or on exchanges. We also enter into contracts which help us manage our interest rate exposure. However, we may not cover the entire exposure of our assets or positions to market price or interest rate volatility, and the coverage will vary over time. Furthermore, the risk management practices we have in place may not always perform as planned. In particular, if prices of commodities or interest rates significantly deviate from historical prices or interest rates or if the price or interest rate volatility or distribution of these changes deviates from historical norms, our risk management practices may not protect us from significant losses. As a result, fluctuating commodity prices or interest rates may negatively impact our financial results to the extent we have unhedged or inadequately hedged positions. In addition, certain types of economic hedging activities may not qualify for hedge accounting under U.S. GAAP, resulting in increased volatility in our net income. The Company may also suffer losses associated with "basis risk" which is the difference in performance between the hedge instrument and the targeted underlying exposure. Furthermore, there is a risk that the current counterparties to these arrangements may fail or are unable to perform part or all of their obligations under these arrangements.
Our coal-fired facilities in the US continue to face substantial challenges as a result of high coal prices relative to natural gas, particularly those which are merchant plants that are exposed to market risk and those that have hybrid merchant risk, meaning those businesses that have a PPA in place but purchase fuel at market prices or under short term contracts. For our businesses with PPA pricing that does not perfectly pass through our fuel costs, the businesses attempt to manage the exposure through flexible fuel purchasing and timing of entry and terms of our fuel supply agreements; however, these risk management efforts may not be successful and the resulting commodity exposure could have a material impact on these businesses and/or our results of operations.
Supplier and/or customer concentration may expose the Company to significant financial credit or performance risks.
We often rely on a single contracted supplier or a small number of suppliers for the provision of fuel, transportation of fuel and other services required for the operation of certain of our facilities. If these suppliers cannot perform, we would seek to meet our fuel requirements by purchasing fuel at market prices, exposing us to market price volatility and the risk that fuel and transportation may not be available during certain periods at any price, which could adversely impact the profitability of the affected business and our results of operations, and could result in a breach of agreements with other counterparties, including, without limitation, offtakers or lenders.

59


At times, we rely on a single customer or a few customers to purchase all or a significant portion of a facility's output, in some cases under long-term agreements that account for a substantial percentage of the anticipated revenue from a given facility. We have also hedged a portion of our exposure to power price fluctuations through forward fixed price power sales. Counterparties to these agreements may breach or may be unable to perform their obligations. We may not be able to enter into replacement agreements on terms as favorable as our existing agreements, or at all. If we were unable to enter into replacement PPAs, these businesses may have to sell power at market prices. A breach by a counterparty of a PPA or other agreement could also result in the breach of other agreements, including, without limitation, the debt documents of the affected business.
The failure of any supplier or customer to fulfill its contractual obligations to The AES Corporation or our subsidiaries could have a material adverse effect on our financial results. Consequently, the financial performance of our facilities is dependent on the credit quality of, and continued performance by, suppliers and customers.
The market pricing of our common stock has been volatile and may continue to be volatile in future periods.
The market price for our common stock has been volatile in the past, and the price of our common stock could fluctuate substantially in the future. Stock price movements on a quarter-by-quarter basis for the past two years are presented in Item 5.—Market—Market Information of this Form 10-K. Factors that could affect the price of our common stock in the future include general conditions in our industry, in the power markets in which we participate and in the world, including environmental and economic developments, over which we have no control, as well as developments specific to us, including, risks that could result in revenue and earnings volatility as well as other risk factors described in Item 1A.—Risk Factors and those matters described in Item 7.—Management's Discussion and Analysis of Financial Conditions and Results of Operations.
Risks Associated with our Operations
We do a significant amount of business outside the United States, including in developing countries, which presents significant risks.
A significant amount of our revenue is generated outside the United States and a significant portion of our international operations is conducted in developing countries. Part of our growth strategy is to expand our business in certain developing countries in which AES has an existing presence as such countries may have higher growth rates and offer greater opportunities to expand from our platforms, with potentially higher returns than in some more developed countries. International operations, particularly the operation, financing and development of projects in developing countries, entail significant risks and uncertainties, including, without limitation:
•
economic, social and political instability in any particular country or region;
•
adverse changes in currency exchange rates;
•
government restrictions on converting currencies or repatriating funds;
•
unexpected changes in foreign laws and regulations or in trade, monetary or fiscal policies;
•
high inflation and monetary fluctuations;
•
restrictions on imports of coal, oil, gas or other raw materials required by our generation businesses to operate;
•
threatened or consummated expropriation or nationalization of our assets by foreign governments;
•
risks relating to the failure to comply with the U.S. Foreign Corrupt Practices Act, United Kingdom Bribery Act or other anti-bribery laws applicable to our operations;
•
difficulties in hiring, training and retaining qualified personnel, particularly finance and accounting personnel with GAAP expertise;
•
unwillingness of governments and their agencies, similar organizations or other counterparties to honor their contracts;
•
unwillingness of governments, government agencies, courts or similar bodies to enforce contracts that are economically advantageous to subsidiaries of the Company and economically unfavorable to counterparties, against such counterparties, whether such counterparties are governments or private parties;
•
inability to obtain access to fair and equitable political, regulatory, administrative and legal systems;
•
adverse changes in government tax policy;
•
difficulties in enforcing our contractual rights or enforcing judgments or obtaining a favorable result in local jurisdictions; and
•
potentially adverse tax consequences of operating in multiple jurisdictions.
Any of these factors, by itself or in combination with others, could materially and adversely affect our business, results of operations and financial condition. Our operations may experience volatility in revenues and operating margin which have caused and are expected to cause significant volatility in our results of operations and cash flows. The volatility is caused by regulatory and economic difficulties, political instability and currency devaluations being experienced in many of these

60


countries. This volatility reduces the predictability and enhances the uncertainty associated with cash flows from these businesses. A number of our businesses are facing challenges associated with regulatory changes. 
The operation of power generation, distribution and transmission facilities involves significant risks that could adversely affect our financial results. We and/or our subsidiaries may not have adequate risk mitigation and/or insurance coverage for liabilities.
We are in the business of generating and distributing electricity, which involves certain risks that can adversely affect financial and operating performance, including:
•
changes in the availability of our generation facilities or distribution systems due to increases in scheduled and unscheduled plant outages, equipment failure, failure of transmission systems, labor disputes, disruptions in fuel supply, poor hydrologic and wind conditions, inability to comply with regulatory or permit requirements or catastrophic events such as fires, floods, storms, hurricanes, earthquakes, dam failures, explosions, terrorist acts, cyber attacks or other similar occurrences; and
•
changes in our operating cost structure including, but not limited to, increases in costs relating to gas, coal, oil and other fuel; fuel transportation; purchased electricity; operations, maintenance and repair; environmental compliance, including the cost of purchasing emissions offsets and capital expenditures to install environmental emission equipment; transmission access; and insurance.
Our businesses require reliable transportation sources (including related infrastructure such as roads, ports and rail), power sources and water sources to access and conduct operations. The availability and cost of this infrastructure affects capital and operating costs and levels of production and sales. Limitations, or interruptions in this infrastructure or at the facilities of our subsidiaries, including as a result of third parties intentionally or unintentionally disrupting this infrastructure or the facilities of our subsidiaries, could impede their ability to produce electricity. This could have a material adverse effect on our businesses' results of operations, financial condition and prospects.
In addition, a portion of our generation facilities were constructed many years ago. Older generating equipment may require significant capital expenditures for maintenance. The equipment at our plants, whether old or new, is also likely to require periodic upgrading, improvement or repair, and replacement equipment or parts may be difficult to obtain in circumstances where we rely on a single supplier or a small number of suppliers. The inability to obtain replacement equipment or parts may impact the ability of our plants to perform and could, therefore, have a material impact on our business and results of operations. Breakdown or failure of one of our operating facilities may prevent the facility from performing under applicable power sales agreements which, in certain situations, could result in termination of a power purchase or other agreement or incurrence of a liability for liquidated damages and/or other penalties.
As a result of the above risks and other potential hazards associated with the power generation, distribution and transmission industries, we may from time to time become exposed to significant liabilities for which we may not have adequate risk mitigation and/or insurance coverage. Power generation involves hazardous activities, including acquiring, transporting and unloading fuel, operating large pieces of rotating equipment and delivering electricity to transmission and distribution systems. In addition to natural risks, such as earthquakes, floods, lightning, hurricanes and wind, hazards, such as fire, explosion, collapse and machinery failure, are inherent risks in our operations which may occur as a result of inadequate internal processes, technological flaws, human error or actions of third parties or other external events. The control and management of these risks depend upon adequate development and training of personnel and on the existence of operational procedures, preventative maintenance plans and specific programs supported by quality control systems which reduce, but do not eliminate, the possibility of the occurrence and impact of these risks.
The hazards described above, along with other safety hazards associated with our operations, can cause significant personal injury or loss of life, severe damage to and destruction of property, plant and equipment, contamination of, or damage to, the environment and suspension of operations. The occurrence of any one of these events may result in our being named as a defendant in lawsuits asserting claims for substantial damages, environmental cleanup costs, personal injury and fines and/or penalties. We maintain an amount of insurance protection that we believe is customary, but there can be no assurance that our insurance will be sufficient or effective under all circumstances and against all hazards or liabilities to which we may be subject. A claim for which we are not fully insured or insured at all could hurt our financial results and materially harm our financial condition. Further, due to the cyclical nature of the insurance markets, we cannot provide assurance that insurance coverage will continue to be available on terms similar to those presently available to us or at all. Any losses not covered by insurance could have a material adverse effect on our financial condition, results of operations or cash flows.
Our businesses' insurance does not cover every potential risk associated with its operations. Adequate coverage at reasonable rates is not always obtainable. In addition, insurance may not fully cover the liability or the consequences of any business interruptions such as equipment failure or labor dispute. The occurrence of a significant adverse event not fully or partially covered by insurance could have a material adverse effect on the Company's business, results or operations, financial condition and prospects.

61


Any of the above risks could have a material adverse effect on our business and results of operations.
Our inability to attract and retain skilled people could have a material adverse effect on our operations.
Our operating success and ability to carry out growth initiatives depends in part on our ability to retain executives and to attract and retain additional qualified personnel who have experience in our industry and in operating a company of our size and complexity, including people in our foreign businesses. The inability to attract and retain qualified personnel could have a material adverse effect on our business, because of the difficulty of promptly finding qualified replacements. For example, we routinely are required to assess the financial impacts of complicated business transactions which occur on a worldwide basis. These assessments are dependent on hiring personnel on a worldwide basis with sufficient expertise in U.S. GAAP to timely and accurately comply with U.S. reporting obligations. An inability to maintain adequate internal accounting and managerial controls and hire and retain qualified personnel could have an adverse effect on our financial and tax reporting.
We have contractual obligations to certain customers to provide full requirements service, which makes it difficult to predict and plan for load requirements and may result in increased operating costs to certain of our businesses.
We have contractual obligations to certain customers to supply power to satisfy all or a portion of their energy requirements. The uncertainty regarding the amount of power that our power generation and distribution facilities must be prepared to supply to customers may increase our operating costs. A significant under- or over-estimation of load requirements could result in our facilities not having enough or having too much power to cover their obligations, in which case we would be required to buy or sell power from or to third parties at prevailing market prices. Those prices may not be favorable and thus could increase our operating costs.
We may not be able to enter into long-term contracts, which reduce volatility in our results of operations. Even when we successfully enter into long-term contracts, our generation businesses are often dependent on one or a limited number of customers and a limited number of fuel suppliers.
Many of our generation plants conduct business under long-term sales and supply contracts, which helps these businesses to manage risks by reducing the volatility associated with power and input costs and providing a stable revenue and cost structure. In these instances, we rely on power sales contracts with one or a limited number of customers for the majority of, and in some cases all of, the relevant plant's output and revenues over the term of the power sales contract. The remaining terms of the power sales contracts of our generation plants range from one to 25 years. In many cases, we also limit our exposure to fluctuations in fuel prices by entering into long-term contracts for fuel with a limited number of suppliers. In these instances, the cash flows and results of operations are dependent on the continued ability of customers and suppliers to meet their obligations under the relevant power sales contract or fuel supply contract, respectively. Some of our long-term power sales agreements are at prices above current spot market prices and some of our long-term fuel supply contracts are at prices below current market prices. The loss of significant power sales contracts or fuel supply contracts, or the failure by any of the parties to such contracts that prevents us from fulfilling our obligations thereunder, could adversely impact our strategy by resulting in costs that exceed revenue, which could have a material adverse impact on our business, results of operations and financial condition. In addition, depending on market conditions and regulatory regimes, it may be difficult for us to secure long-term contracts, either where our current contracts are expiring or for new development projects. The inability to enter into long-term contracts could require many of our businesses to purchase inputs at market prices and sell electricity into spot markets, which may not be favorable.
We have sought to reduce counterparty credit risk under our long-term contracts in part by entering into power sales contracts with utilities or other customers of strong credit quality and by obtaining guarantees from certain sovereign governments of the customer's obligations. However, many of our customers do not have, or have failed to maintain, an investment-grade credit rating, and our generation business cannot always obtain government guarantees and if they do, the government does not always have an investment grade credit rating. We have also sought to reduce our credit risk by locating our plants in different geographic areas in order to mitigate the effects of regional economic downturns. However, there can be no assurance that our efforts to mitigate this risk will be successful.
Competition is increasing and could adversely affect us.
The power production markets in which we operate are characterized by numerous strong and capable competitors, many of whom may have extensive and diversified developmental or operating experience (including both domestic and international) and financial resources similar to or greater than ours. Further, in recent years, the power production industry has been characterized by strong and increasing competition with respect to both obtaining power sales agreements and acquiring existing power generation assets. In certain markets, these factors have caused reductions in prices contained in new power sales agreements and, in many cases, have caused higher acquisition prices for existing assets through competitive bidding practices. The evolution of competitive electricity markets and the development of highly efficient gas-fired power plants have also caused, or are anticipated to cause, price pressure in certain power markets where we sell or intend to sell power. These competitive factors could have a material adverse effect on us.

62


Some of our subsidiaries participate in defined benefit pension plans and their net pension plan obligations may require additional significant contributions.
Certain of our subsidiaries have defined benefit pension plans covering substantially all of their respective employees. Of the thirty one such defined benefit plans, five are at U.S. subsidiaries and the remaining plans are at foreign subsidiaries. Pension costs are based upon a number of actuarial assumptions, including an expected long-term rate of return on pension plan assets, the expected life span of pension plan beneficiaries and the discount rate used to determine the present value of future pension obligations. Any of these assumptions could prove to be wrong, resulting in a shortfall of pension plan assets compared to pension obligations under the pension plan. The Company periodically evaluates the value of the pension plan assets to ensure that they will be sufficient to fund the respective pension obligations. The Company's exposure to market volatility is mitigated to some extent due to the fact that the asset allocations in our largest plans include a significant weighting of investments in fixed income securities that are less volatile than investments in equity securities. Future downturns in the debt and/or equity markets, or the inaccuracy of any of our significant assumptions underlying the estimates of our subsidiaries' pension plan obligations, could result in an increase in pension expense and future funding requirements, which may be material. Our subsidiaries who participate in these plans are responsible for satisfying the funding requirements required by law in their respective jurisdiction for any shortfall of pension plan assets compared to pension obligations under the pension plan. This may necessitate additional cash contributions to the pension plans that could adversely affect the Parent Company and our subsidiaries' liquidity.
For additional information regarding the funding position of the Company's pension plans, see Item 7.—Management's Discussion and Analysis of Financial Condition and Results of Operations—Critical Accounting Policies and Estimates—Pension and Other Postretirement Plans and Note 15—Benefit Plans included in Item 8.—Financial Statements and Supplementary Data included in this Form 10-K.
Our business is subject to substantial development uncertainties.
Certain of our subsidiaries and affiliates are in various stages of developing and constructing power plants, some but not all of which have signed long-term contracts or made similar arrangements for the sale of electricity. Successful completion depends upon overcoming substantial risks, including, but not limited to, risks relating to siting, financing, engineering and construction, permitting, governmental approvals, commissioning delays, or the potential for termination of the power sales contract as a result of a failure to meet certain milestones. For additional information regarding our projects under construction see, Item 1.—Business—Our Organization and Segments included in this Form 10-K.
In certain cases, our subsidiaries may enter into obligations in the development process even though the subsidiaries have not yet secured financing, power purchase arrangements, or other aspects of the development process. For example, in certain cases, our subsidiaries may instruct contractors to begin the construction process or seek to procure equipment even where they do not have financing or a power purchase agreement in place (or conversely, to enter into a power purchase, procurement or other agreement without financing in place). If the project does not proceed, our subsidiaries may remain obligated for certain liabilities even though the project will not proceed. Development is inherently uncertain and we may forgo certain development opportunities and we may undertake significant development costs before determining that we will not proceed with a particular project. We believe that capitalized costs for projects under development are recoverable; however, there can be no assurance that any individual project will be completed and reach commercial operation. If these development efforts are not successful, we may abandon a project under development and write off the costs incurred in connection with such project. At the time of abandonment, we would expense all capitalized development costs incurred in connection therewith and could incur additional losses associated with any related contingent liabilities.
In some of our joint venture projects and businesses, we have granted protective rights to minority shareholders or we own less than a majority of the equity in the project or business and do not manage or otherwise control the project or business, which entails certain risks.
We have invested in some joint ventures where our subsidiaries share operational, management, investment and/or other control rights with our joint venture partners. In many cases, we may exert influence over the joint venture pursuant to a management contract, by holding positions on the board of the joint venture company or on management committees and/or through certain limited governance rights, such as rights to veto significant actions. However, we do not always have this type of influence over the project or business in every instance and we may be dependent on our joint venture partners or the management team of the joint venture to operate, manage, invest or otherwise control such projects or businesses. Our joint venture partners or the management team of our joint ventures may not have the level of experience, technical expertise, human resources, management and other attributes necessary to operate these projects or businesses optimally, and they may not share our business priorities. In some joint venture agreements where we do have majority control of the voting securities, we have entered into shareholder agreements granting protective minority rights to the other shareholders.
The approval of joint venture partners also may be required for us to receive distributions of funds from jointly owned entities or to transfer our interest in projects or businesses. The control or influence exerted by our joint venture partners may

63


result in operational management and/or investment decisions which are different from the decisions our subsidiaries would make if they operated independently and could impact the profitability and value of these joint ventures. In addition, in the event that a joint venture partner becomes insolvent or bankrupt or is otherwise unable to meet its obligations to the joint venture or its share of liabilities at the joint venture, we may be subject to joint and several liability for these joint ventures, if and to the extent provided for in our governing documents or applicable law.
Our renewable energy projects and other initiatives face considerable uncertainties including, development, operational and regulatory challenges.
Wind generation, our solar projects and our investments in projects such as energy storage are subject to substantial risks. Projects of this nature have been developed through advancement in technologies which may not be proven or whose commercial application is limited, and which are unrelated to our core business. Some of these business lines are dependent upon favorable regulatory incentives to support continued investment, and there is significant uncertainty about the extent to which such favorable regulatory incentives will be available in the future.
Furthermore, production levels for our wind and solar projects may be dependent upon adequate wind or sunlight resulting in volatility in production levels and profitability. For example, for our wind projects, wind resource estimates are based on historical experience when available and on wind resource studies conducted by an independent engineer, and are not expected to reflect actual wind energy production in any given year.
As a result, these types of renewable energy projects face considerable risk relative to our core business, including the risk that favorable regulatory regimes expire or are adversely modified. In addition, because certain of these projects depend on technology outside of our expertise in generation and utility businesses, there are risks associated with our ability to develop and manage such projects profitably. Furthermore, at the development or acquisition stage, because of the nascent nature of these industries or the limited experience with the relevant technologies, our ability to predict actual performance results may be hindered and the projects may not perform as predicted. There are also risks associated with the fact that some of these projects exist in markets where long-term fixed price contracts for the major cost and revenue components may be unavailable, which in turn may result in these projects having relatively high levels of volatility. Even where available, many of our renewable projects sell power under a Feed-in-Tariff, which may be eliminated or reduced, which can impact the profitability of these projects, or make money through the sale of Emission Reductions products, such as Certified Emissions Reductions, Renewable Energy Certificates or Renewable Obligation Certificates, and the price of these products may be volatile.
These projects can be capital-intensive and generally are designed with a view to obtaining third party financing, which may be difficult to obtain. As a result, these capital constraints may reduce our ability to develop these projects or obtain third party financing for these projects. These risks may be exacerbated by the current global economic crisis, including our management's increased focus on liquidity, which may also result in slower growth in the number of projects we can pursue. The economic downturn could also impact the value of our assets in these countries and our ability to develop these projects. If the value of these assets decline, this could result in a material impairment or a series of impairments which are material in the aggregate, which would adversely affect our financial statements.
Impairment of goodwill or long-lived assets would negatively impact our consolidated results of operations and net worth.
As of December 31, 2015, the Company had approximately $1.2 billion of goodwill, which represented approximately 3.1% of the total assets on its Consolidated Balance Sheets. Goodwill is not amortized, but is evaluated for impairment at least annually, or more frequently if impairment indicators are present. We may be required to evaluate the potential impairment of goodwill outside of the required annual evaluation process if we experience situations, including but not limited to: deterioration in general economic conditions, or our operating or regulatory environment; increased competitive environment; increase in fuel costs, particularly when we are unable to pass through the impact to customers; negative or declining cash flows; loss of a key contract or customer, particularly when we are unable to replace it on equally favorable terms; divestiture of a significant component of our business; or adverse actions or assessments by a regulator. These types of events and the resulting analyses could result in goodwill impairment, which could substantially affect our results of operations for those periods. Additionally, goodwill may be impaired if our acquisitions do not perform as expected. See the risk factor Our acquisitions may not perform as expected for further discussion.
Long-lived assets are initially recorded at fair value and are amortized or depreciated over their estimated useful lives. Long-lived assets are evaluated for impairment only when impairment indicators are present whereas goodwill is evaluated for impairment on an annual basis or more frequently if potential impairment indicators are present. Otherwise, the recoverability assessment of long-lived assets is similar to the potential impairment evaluation of goodwill particularly as it relates to the identification of potential impairment indicators, and making estimates and assumptions to determine fair value, as described above.

64


Certain of our businesses are sensitive to variations in weather.
Our businesses are affected by variations in general weather patterns and unusually severe weather. Our businesses forecast electric sales on the basis of normal weather, which represents a long-term historical average. While we also consider possible variations in normal weather patterns and potential impacts on our facilities and our businesses, there can be no assurance that such planning can prevent these impacts, which can adversely affect our business. Generally, demand for electricity peaks in winter and summer. Typically, when winters are warmer than expected and summers are cooler than expected, demand for energy is lower, resulting in less demand for electricity than forecasted. Significant variations from normal weather where our businesses are located could have a material impact on our results of operations.
In addition, we are dependent upon hydrological conditions prevailing from time to time in the broad geographic regions in which our hydroelectric generation facilities are located. If hydrological conditions result in droughts or other conditions that negatively affect our hydroelectric generation business, our results of operations could be materially adversely affected.
Information security breaches could harm our business.
A security breach of our information technology systems or plant control systems used to manage and monitor operations could impact the reliability of our generation fleets and/or the reliability of our transmission and distribution systems. A security breach that impairs our technology infrastructure could disrupt normal business operations and affect our ability to control our transmission and distribution assets, access customer information and limit our communications with third parties. Our security measures may not prevent such security breaches. Any loss or corruption of confidential or proprietary data through a breach could impair our reputation, expose us to legal claims, or impact our ability to make collections or otherwise impact our operations, and materially adversely affect our business and results of operations.
Our acquisitions may not perform as expected.
Historically, acquisitions have been a significant part of our growth strategy. We may continue to grow our business through acquisitions. Although acquired businesses may have significant operating histories, we will have a limited or no history of owning and operating many of these businesses and possibly limited or no experience operating in the country or region where these businesses are located. Some of these businesses may have been government owned and some may be operated as part of a larger integrated utility prior to their acquisition. If we were to acquire any of these types of businesses, there can be no assurance that:
•
we will be successful in transitioning them to private ownership;
•
such businesses will perform as expected;
•
integration or other one-time costs will not be greater than expected;
•
we will not incur unforeseen obligations or liabilities;
•
such businesses will generate sufficient cash flow to support the indebtedness incurred to acquire them or the capital expenditures needed to develop them; or
•
the rate of return from such businesses will justify our decision to invest capital to acquire them.
Risks associated with Governmental Regulation and Laws
Our operations are subject to significant government regulation and our business and results of operations could be adversely affected by changes in the law or regulatory schemes.
Our ability to predict, influence or respond appropriately to changes in law or regulatory schemes, including any ability to obtain expected or contracted increases in electricity tariff or contract rates or tariff adjustments for increased expenses, could adversely impact our results of operations or our ability to meet publicly announced projections or analysts' expectations. Furthermore, changes in laws or regulations or changes in the application or interpretation of regulatory provisions in jurisdictions where we operate, particularly at our utilities where electricity tariffs are subject to regulatory review or approval, could adversely affect our business, including, but not limited to:
•
changes in the determination, definition or classification of costs to be included as reimbursable or pass-through costs to be included in the rates we charge our customers, including but not limited to costs incurred to upgrade our power plants to comply with more stringent environmental regulations;
•
changes in the determination of what is an appropriate rate of return on invested capital or a determination that a utility's operating income or the rates it charges customers are too high, resulting in a reduction of rates or consumer rebates;
•
changes in the definition or determination of controllable or non-controllable costs;
•
adverse changes in tax law;

65


•
changes in law or regulation which limit or otherwise affect the ability of our counterparties (including sovereign or private parties) to fulfill their obligations (including payment obligations) to us or our subsidiaries;
•
changes in environmental law which impose additional costs or limit the dispatch of our generating facilities within our subsidiaries;
•
changes in the definition of events which may or may not qualify as changes in economic equilibrium;
•
changes in the timing of tariff increases;
•
other changes in the regulatory determinations under the relevant concessions;
•
other changes related to licensing or permitting which affect our ability to conduct business; or
•
other changes that impact the short or long term price-setting mechanism in the markets where we operate.
Any of the above events may result in lower margins for the affected businesses, which can adversely affect our business.
In many countries where we conduct business, the regulatory environment is constantly changing and it may be difficult to predict the impact of the regulations on our businesses. On July 21, 2010, President Obama signed the Dodd-Frank Act. While the bulk of regulations contained in the Dodd-Frank Act regulate financial institutions and their products, there are several provisions related to corporate governance, executive compensation, disclosure and other matters which relate to public companies generally. The types of provisions described above are currently not expected to have a material impact on the Company or its results of operations. Furthermore, while the Dodd-Frank Act substantially expands the regulation regarding the trading, clearing and reporting of derivative transactions, the Dodd-Frank Act provides for commercial end-user exemptions which may apply to our derivative transactions. However, even with the exemption, the Dodd-Frank Act could still have a material adverse impact on the Company, as the regulation of derivatives (which includes capital and margin requirements for non-exempt companies), could limit the availability of derivative transactions that we use to reduce interest rate, commodity and currency risks, which would increase our exposure to these risks. Even if derivative transactions remain available, the costs to enter into these transactions may increase, which could adversely (1) affect the operating results of certain projects; (2) cause us to default on certain types of contracts where we are contractually obligated to hedge certain risks, such as project financing agreements; (3) prevent us from developing new projects where interest rate hedging is required; (4) cause the Company to abandon certain of its hedging strategies and transactions, thereby increasing our exposure to interest rate, commodity and currency risk; (5) and/or consume substantial liquidity by forcing the Company to post cash and/or other permitted collateral in support of these derivatives. In addition to the Dodd-Frank Act, in 2012, the EMIR became effective. EMIR includes regulations related to the trading, reporting and clearing of derivatives and the impacts described above could also result from our (or our subsidiaries') efforts to comply with EMIR. It is also possible that additional similar regulations may be passed in other jurisdictions where we conduct business. Any of these outcomes could have a material adverse effect on the Company.
Our business in the United States is subject to the provisions of various laws and regulations administered in whole or in part by the FERC and NERC, including PURPA, the Federal Power Act, and the EPAct 2005. Actions by the FERC, NERC and by state utility commissions can have a material effect on our operations.
EPAct 2005 authorizes the FERC to remove the obligation of electric utilities under Section 210 of PURPA to enter into new contracts for the purchase or sale of electricity from or to QFs if certain market conditions are met. Pursuant to this authority, the FERC has instituted a rebuttable presumption that utilities located within the control areas of the Midwest Independent Transmission System Operator, Inc., PJM Interconnection, L.L.C., ISO New England, Inc., the NYISO and the Electric Reliability Council of Texas, Inc. are not required to purchase or sell power from or to QFs above a certain size. In addition, the FERC is authorized under EPAct 2005 to remove the purchase/sale obligations of individual utilities on a case-by-case basis. While this law does not affect existing contracts, as a result of the changes to PURPA, our QFs may face a more difficult market environment when their current long-term contracts expire.
EPAct 2005 repealed PUHCA 1935 and enacted PUHCA 2005 in its place. PUHCA 1935 had the effect of requiring utility holding companies to operate in geographically proximate regions and therefore limited the range of potential combinations and mergers among utilities. By comparison, PUHCA 2005 has no such restrictions and simply provides the FERC and state utility commissions with enhanced access to the books and records of certain utility holding companies. The repeal of PUHCA 1935 removed barriers to mergers and other potential combinations which could result in the creation of large, geographically dispersed utility holding companies. These entities may have enhanced financial strength and therefore an increased ability to compete with us in the United States generation market.
In accordance with Congressional mandates in the EPAct 1992 and now in EPAct 2005, the FERC has strongly encouraged competition in wholesale electric markets. Increased competition may have the effect of lowering our operating margins. Among other steps, the FERC has encouraged RTOs and ISOs to develop demand response bidding programs as a mechanism for responding to peak electric demand. These programs may reduce the value of our peaking assets which rely on very high prices during a relatively small number of hours to recover their costs. Similarly, the FERC is encouraging the

66


construction of new transmission infrastructure in accordance with provisions of EPAct 2005. Although new transmission lines may increase market opportunities, they may also increase the competition in our existing markets.
While the FERC continues to promote competition, some state utility commissions have reversed course and begun to encourage the construction of generation facilities by traditional utilities to be paid for on a cost-of-service basis by retail ratepayers. Such actions have the effect of reducing sale opportunities in the competitive wholesale generating markets in which we operate.
FERC has civil penalty authority over violations of any provision of Part II of the FPA which concerns wholesale generation or transmission, as well as any rule or order issued thereunder. FERC is authorized to assess a maximum civil penalty of $1 million per violation for each day that the violation continues. The FPA also provides for the assessment of criminal fines and imprisonment for violations under the FPA. This penalty authority was enhanced in EPAct 2005. With this expanded enforcement authority, violations of the FPA and FERC's regulations could potentially have more serious consequences than in the past.
Pursuant to EPAct 2005, the NERC has been certified by FERC as the Electric Reliability Organization (ERO) to develop mandatory and enforceable electric system reliability standards applicable throughout the U.S. to improve the overall reliability of the electric grid. These standards are subject to FERC review and approval. Once approved, the reliability standards may be enforced by FERC independently, or, alternatively, by the ERO and regional reliability organizations with responsibility for auditing, investigating and otherwise ensuring compliance with reliability standards, subject to FERC oversight. Monetary penalties of up to $1 million per day per violation may be assessed for violations of the reliability standards.
Our utility businesses in the U.S. face significant regulation by their respective state utility commissions. The regulatory discretion is reasonably broad in both Indiana and Ohio and includes regulation as to services and facilities, the valuation of property, the construction, purchase, or lease of electric generating facilities, the classification of accounts, rates of depreciation, the increase or decrease in retail rates and charges, the issuance of certain securities, the acquisition and sale of some public utility properties or securities and certain other matters. These businesses face the risk of unexpected or adverse regulatory action which could have a material adverse effect on our results of operations, financial condition, and cash flows. See Item 1.—Business—US SBU—U.S. Businesses—U.S. Utilities for further information on the regulation faced by our U.S. utilities.
Our businesses are subject to stringent environmental laws and regulations.
Our businesses are subject to stringent environmental laws and regulations by many federal, regional, state and local authorities, international treaties and foreign governmental authorities. These laws and regulations generally concern emissions into the air, effluents into the water, use of water, wetlands preservation, remediation of contamination, waste disposal, endangered species and noise regulation, among others. Failure to comply with such laws and regulations or to obtain or comply with any necessary environmental permits pursuant to such laws and regulations could result in fines or other sanctions. Environmental laws and regulations affecting power generation and distribution are complex and have tended to become more stringent over time. Congress and other domestic and foreign governmental authorities have either considered or implemented various laws and regulations to restrict or tax certain emissions, particularly those involving air emissions and water discharges. See the various descriptions of these laws and regulations contained in Item 1.—Business of this Form 10-K. These laws and regulations have imposed, and proposed laws and regulations could impose in the future, additional costs on the operation of our power plants. We have incurred and will continue to incur significant capital and other expenditures to comply with these and other environmental laws and regulations. Changes in, or new development of, environmental restrictions may force the Company to incur significant expenses or expenses that may exceed our estimates. There can be no assurance that we would be able to recover all or any increased environmental costs from our customers or that our business, financial condition, including recorded asset values or results of operations, would not be materially and adversely affected by such expenditures or any changes in domestic or foreign environmental laws and regulations.
Our businesses are subject to enforcement initiatives from environmental regulatory agencies.
The EPA has pursued an enforcement initiative against coal-fired generating plants alleging wide-spread violations of the new source review and prevention of significant deterioration provisions of the CAA. The EPA has brought suit against a number of companies and has obtained settlements with many of these companies over such allegations. The allegations typically involve claims that a company made major modifications to a coal-fired generating unit without proper permit approval and without installing best available control technology. The principal, but not exclusive, focus of this EPA enforcement initiative is emissions of SO2 and NOx. In connection with this enforcement initiative, the EPA has imposed fines and required companies to install improved pollution control technologies to reduce emissions of SO2 and NOx. There can be no assurance that foreign environmental regulatory agencies in countries in which our subsidiaries operate will not pursue similar enforcement initiatives under relevant laws and regulations.

67


Regulators, politicians, non-governmental organizations and other private parties have expressed concern about greenhouse gas, or GHG, emissions and the potential risks associated with climate change and are taking actions which could have a material adverse impact on our consolidated results of operations, financial condition and cash flows.
As discussed in Item 1.—Business, at the international, federal and various regional and state levels, rules are in effect and policies are under development to regulate GHG emissions, thereby effectively putting a cost on such emissions in order to create financial incentives to reduce them. In 2015, the Company's subsidiaries operated businesses which had total CO2 emissions of approximately 67.6 million metric tonnes, approximately 27.4 million of which were emitted by businesses located in the U.S. (both figures ownership adjusted). The Company uses CO2 emission estimation methodologies supported by "The Greenhouse Gas Protocol" reporting standard on GHG emissions. For existing power generation plants, CO2 emissions data are either obtained directly from plant continuous emission monitoring systems or calculated from actual fuel heat inputs and fuel type CO2 emission factors. The estimated annual CO2 emissions from fossil fuel electric power generation facilities of the Company's subsidiaries that are in construction or development and have received the necessary air permits for commercial operations are approximately 7.8 million metric tonnes (ownership adjusted). This overall estimate is based on a number of projections and assumptions which may prove to be incorrect, such as the forecasted dispatch, anticipated plant efficiency, fuel type, CO2 emissions rates and our subsidiaries' achieving completion of such construction and development projects. However, it is certain that the projects under construction or development when completed will increase emissions of our portfolio and therefore could increase the risks associated with regulation of GHG emissions. Because there is significant uncertainty regarding these estimates, actual emissions from these projects under construction or development may vary substantially from these estimates.
The non-utility, generation subsidiaries of the Company often seek to pass on any costs arising from CO2 emissions to contract counterparties, but there can be no assurance that such subsidiaries of the Company will effectively pass such costs onto the contract counterparties or that the cost and burden associated with any dispute over which party bears such costs would not be burdensome and costly to the relevant subsidiaries of the Company. The utility subsidiaries of the Company may seek to pass on any costs arising from CO2 emissions to customers, but there can be no assurance that such subsidiaries of the Company will effectively pass such costs to the customers, or that they will be able to fully or timely recover such costs.
Foreign, federal, state or regional regulation of GHG emissions could have a material adverse impact on the Company's financial performance. The actual impact on the Company's financial performance and the financial performance of the Company's subsidiaries will depend on a number of factors, including among others, the degree and timing of GHG emissions reductions required under any such legislation or regulation, the cost of emissions reduction equipment and the price and availability of offsets, the extent to which market based compliance options are available, the extent to which our subsidiaries would be entitled to receive GHG emissions allowances without having to purchase them in an auction or on the open market and the impact of such legislation or regulation on the ability of our subsidiaries to recover costs incurred through rate increases or otherwise. As a result of these factors, our cost of compliance could be substantial and could have a material adverse impact on our results of operations.
In January 2005, based on European Community "Directive 2003/87/EC on Greenhouse Gas Emission Allowance Trading," the EU ETS commenced operation as the largest multi-country GHG emission trading scheme in the world. On February 16, 2005, the Kyoto Protocol became effective. The Kyoto Protocol requires all developed countries that have ratified it to substantially reduce their GHG emissions, including CO2. However, the United States never ratified the Kyoto Protocol and, to date, compliance with the Kyoto Protocol and the EU ETS has not had a material adverse effect on the Company's consolidated results of operations, financial condition and cash flows.
In December 2015, the Parties to the United Nations Framework Convention on Climate Change ("UNFCCC") convened for the 21st Conference of the Parties in Paris, France. The result was the so-called Paris Agreement. We anticipate that the Paris Agreement will continue the trend towards the efforts to de-carbonize the global economy and to further limit GHG emissions, including in those countries where the Company does business. It is difficult to predict the nature, timing and scope of such regulation but it could have a material adverse effect on the Company's financial performance.
In the U.S., there currently is no federal legislation imposing a mandatory GHG emission reduction programs (including for CO2) affecting the electric power generation facilities of the Company's subsidiaries. However, the EPA has adopted regulations pertaining to GHG emissions that require new sources of GHG emissions of over 100,000 tons per year, and existing sources planning physical changes that would increase their GHG emissions by more than 75,000 tons per year, to obtain new source review permits from the EPA prior to construction or modification. Additionally, the EPA has promulgated a rule establishing New Source Performance Standards for CO2 emissions for newly constructed and modified/reconstructed fossil-fueled EUSGUs larger than 25 MW. The EPA has also promulgated a rule, the Clean Power Plan ("CPP"), that requires existing EUSGUs to begin reducing GHG emissions starting in 2022 with the full reduction requirement in 2030. Under the CPP, states are required to develop and submit plans that establish performance standards or, through emissions trading programs, otherwise meet a state-wide emissions rate average or mass-based goal. For further discussion of the regulation of GHG emission, including the U.S. Supreme Court's recently issued orders staying implementation of the CPP, see Item 1.—

68


Business—Environmental and Land-Use Regulations—United States Environmental and Land-Use Legislation and Regulations—Greenhouse Gas Emissions above.
Such regulations, and in particular regulations applying to modified or existing EUSGUs, could increase our costs directly and indirectly and have a material adverse effect on our business and/or results of operations. See Item 1.—Business of this Form 10-K for further discussion about these environmental agreements, laws and regulations.
At the state level, the RGGI, a cap-and-trade program covering CO2 emissions from electric power generation facilities in the Northeast, became effective in January 2009, and California has adopted comprehensive legislation and regulation that requires mandatory GHG reductions from several industrial sectors, including the electric power generation industry. At this time, other than with regard to RGGI (further described below) and proposed Hawaii regulations relating to the collection of fees on GHG emissions, the impact of both of which we do not expect to be material, the Company cannot estimate the costs of compliance with United States federal, regional or state GHG emissions reduction legislation or initiatives, due to the fact that most of these proposals are not being actively pursued or are in the early stages of development and any final regulations or laws, if adopted, could vary drastically from current proposals; in the case of California, we anticipate no material impact due to the fact that we expect such costs will be passed through to our offtakers under the terms of existing tolling agreements.
The regional auctions of RGGI allowances needed to be acquired by power generators to comply with state programs implementing RGGI occur approximately every quarter. Our subsidiary in Maryland is our only subsidiary that was subject to RGGI in 2015. Of the approximately 27.4 million metric tonnes of CO2 emitted in the United States by our subsidiaries in 2015 (ownership adjusted), approximately 1.4 million metric tonnes were emitted by our subsidiary in Maryland. The Company estimates that the RGGI compliance costs could be approximately $3.4 million for 2016. There is a risk that our actual compliance costs under RGGI will differ from our estimates by a material amount and that our model could underestimate our costs of compliance.
In addition to government regulators, other groups such as politicians, environmentalists and other private parties have expressed increasing concern about GHG emissions. For example, certain financial institutions have expressed concern about providing financing for facilities which would emit GHGs, which can affect our ability to obtain capital, or if we can obtain capital, to receive it on commercially viable terms. Further, rating agencies may decide to downgrade our credit ratings based on the emissions of the businesses operated by our subsidiaries or increased compliance costs which could make financing unattractive. In addition, plaintiffs have brought tort lawsuits against the Company because of its subsidiaries' GHG emissions. Unless the United States Congress acts to preempt such suits as part of comprehensive federal legislation, additional lawsuits may be brought against the Company or its subsidiaries in the future. While the litigation mentioned has been dismissed, it is impossible to predict whether similar future lawsuits are likely to prevail or result in damages awards or other relief. Consequently, it is impossible to determine whether such lawsuits are likely to have a material adverse effect on the Company's consolidated results of operations and financial condition.
Furthermore, according to the Intergovernmental Panel on Climate Change, physical risks from climate change could include, but are not limited to, increased runoff and earlier spring peak discharge in many glacier and snow-fed rivers, warming of lakes and rivers, an increase in sea level, changes and variability in precipitation and in the intensity and frequency of extreme weather events. Physical impacts may have the potential to significantly affect the Company's business and operations, and any such potential impact may render it more difficult for our businesses to obtain financing. For example, extreme weather events could result in increased downtime and operation and maintenance costs at the electric power generation facilities and support facilities of the Company's subsidiaries. Variations in weather conditions, primarily temperature and humidity also would be expected to affect the energy needs of customers. A decrease in energy consumption could decrease the revenues of the Company's subsidiaries. In addition, while revenues would be expected to increase if the energy consumption of customers increased, such increase could prompt the need for additional investment in generation capacity. Changes in the temperature of lakes and rivers and changes in precipitation that result in drought could adversely affect the operations of the fossil fuel-fired electric power generation facilities of the Company's subsidiaries. Changes in temperature, precipitation and snow pack conditions also could affect the amount and timing of hydroelectric generation.
In addition to potential physical risks noted by the Intergovernmental Panel on Climate Change, there could be damage to the reputation of the Company and its subsidiaries due to public perception of GHG emissions by the Company's subsidiaries, and any such negative public perception or concerns could ultimately result in a decreased demand for electric power generation or distribution from our subsidiaries. The level of GHG emissions made by subsidiaries of the Company is not a factor in the compensation of executives of the Company.
If any of the foregoing risks materialize, costs may increase or revenues may decrease and there could be a material adverse effect on the electric power generation businesses of the Company's subsidiaries and on the Company's consolidated results of operations, financial condition and cash flows.

69


Tax legislation initiatives or challenges to our tax positions could adversely affect our results of operations and financial condition.
Our subsidiaries have operations in the U.S. and various non-U.S. jurisdictions. As such, we are subject to the tax laws and regulations of the U.S. federal, state and local governments and of many non-U.S. jurisdictions. From time to time, legislative measures may be enacted that could adversely affect our overall tax positions regarding income or other taxes. There can be no assurance that our effective tax rate or tax payments will not be adversely affected by these legislative measures.
For example, the U.S. is considering corporate tax reform that may significantly change U.S. international tax rules and corporate tax rates. Additionally, longstanding international tax norms that determine how and where cross-border international trade is subjected to tax are evolving. The Organization for Economic Cooperation and Development ("OECD"), in coordination with the G8 and G20, recently concluded its Base Erosion and Profit Shifting project (“BEPS") with a series of recommendations that many tax jurisdictions have adopted, or may adopt in the future, as law. As these and other tax laws, related regulations and double-tax conventions change, our financial results could be materially impacted. Given the unpredictability of these possible changes and their potential interdependency, it is very difficult to assess whether the overall effect of such potential tax changes would be cumulatively positive or negative for our earnings and cash flow, but such changes could adversely impact our results of operations.
In addition, United States federal, state and local, as well as non-United States, tax laws and regulations are extremely complex and subject to varying interpretations. There can be no assurance that our tax positions will be sustained if challenged by relevant tax authorities and if not sustained, there could be a material impact on our results of operations.
We and our affiliates are subject to material litigation and regulatory proceedings.
We and our affiliates are parties to material litigation and regulatory proceedings. See Item 3.—Legal Proceedings below. There can be no assurances that the outcome of such matters will not have a material adverse effect on our consolidated financial position.
ITEM 1B.
UNRESOLVED STAFF COMMENTS
None.
ITEM 2. PROPERTIES
We maintain offices in many places around the world, generally pursuant to the provisions of long- and short-term leases, none of which we believe are material. With a few exceptions, our facilities, which are described in Item 1—Business of this Form 10-K, are subject to mortgages or other liens or encumbrances as part of the project's related finance facility. In addition, the majority of our facilities are located on land that is leased. However, in a few instances, no accompanying project financing exists for the facility, and in a few of these cases, the land interest may not be subject to any encumbrance and is owned outright by the subsidiary or affiliate.
ITEM 3. LEGAL PROCEEDINGS
The Company is involved in certain claims, suits and legal proceedings in the normal course of business. The Company has accrued for litigation and claims where it is probable that a liability has been incurred and the amount of loss can be reasonably estimated. The Company believes, based upon information it currently possesses and taking into account established reserves for estimated liabilities and its insurance coverage, that the ultimate outcome of these proceedings and actions is unlikely to have a material adverse effect on the Company's financial statements. It is reasonably possible, however, that some matters could be decided unfavorably to the Company and could require the Company to pay damages or make expenditures in amounts that could be material but cannot be estimated as of December 31, 2015.
In 1989, Centrais Elétricas Brasileiras S.A. ("Eletrobrás") filed suit in the Fifth District Court in the state of Rio de Janeiro ("FDC") against Eletropaulo Eletricidade de São Paulo S.A. ("EEDSP") relating to the methodology for calculating monetary adjustments under the parties' financing agreement. In April 1999, the FDC found for Eletrobrás and in September 2001, Eletrobrás initiated an execution suit in the FDC to collect approximately R$1.8 billion ($458 million) from Eletropaulo (as estimated by Eletropaulo (or approximately R$2.2 billion ($571 million)) plus legal costs according to Eletrobrás as of June 2015 and a lesser amount from an unrelated company, Companhia de Transmissão de Energia Elétrica Paulista ("CTEEP") (Eletropaulo and CTEEP were spun off of EEDSP pursuant to its privatization in 1998). In November 2002, the FDC rejected Eletropaulo's defenses in the execution suit. On appeal, the case was remanded to the FDC for further proceedings to determine whether Eletropaulo is liable for the debt. In December 2012, the FDC issued a decision that Eletropaulo is liable for the debt. However, that decision was annulled on appeal and the case was remanded to the FDC for further proceedings. On remand at the FDC, the FDC appointed an accounting expert to analyze the issues in the case. In September 2015, the expert issued a preliminary report that concluded that Eletropaulo is liable for the debt, without quantifying the debt. Eletropaulo has submitted questions to the expert and reports rebutting the expert's preliminary report. The expert will issue a final report in the near future. Thereafter, a decision will be issued by the FDC, which will be free to reject or adopt in whole or in part the expert's

70


final report. If the FDC again determines that Eletropaulo is liable for the debt, Eletrobrás will be entitled to resume the execution suit in the FDC. If Eletrobrás does so, after the amount of the alleged debt is determined, Eletropaulo will be required to provide security for its alleged liability. In that case, if Eletrobrás requests the seizure of such security and the FDC grants such request, Eletropaulo's results of operations may be materially adversely affected and, in turn, the Company's results of operations could be materially adversely affected. In addition, in February 2008, CTEEP filed a lawsuit in the FDC against Eletrobrás and Eletropaulo seeking a declaration that CTEEP is not liable for any debt under the financing agreement. Eletropaulo believes it has meritorious defenses to the claims asserted against it and will defend itself vigorously in these proceedings; however, there can be no assurances that it will be successful in its efforts.
In September 1996, a public civil action was asserted against Eletropaulo and Associação Desportiva Cultural Eletropaulo (the "Associação") relating to alleged environmental damage caused by construction of the Associação near Guarapiranga Reservoir. The initial decision that was upheld by the Appellate Court of the state of São Paulo in 2006 found that Eletropaulo should repair the alleged environmental damage by demolishing certain construction and reforesting the area, and either sponsor an environmental project which would cost approximately R$1.8 million ($461 thousand) as of December 31, 2015, or pay an indemnification amount of approximately R$15 million ($4 million). Eletropaulo has appealed this decision to the Supreme Court and the Supreme Court affirmed the decision of the Appellate Court. Following the Supreme Court's decision, the case has been remanded to the court of first instance for further proceedings and to monitor compliance by the defendants with the terms of the decision. In January 2014, Eletropaulo informed the court that it intended to comply with the court's decision by donating a green area inside a protection zone and restore watersheds, the aggregate cost of which is expected to be approximately R$1.8 million ($461 thousand). Eletropaulo also requested that the court add the current owner of the land where the Associação facilities are located, Empresa Metropolitana de Águas e Energia S.A. ("EMAE"), as a party to the lawsuit and order EMAE to perform the demolition and reforestation aspects of the court's decision. In July 2014, the court requested the Secretary of the Environment for the State of São Paulo to notify the court of its opinion regarding the acceptability of the green areas to be donated by Eletropaulo to the State of São Paulo. In January 2015, the Secretary of the Environment for the State of São Paulo notified Eletropaulo and the court that it would not accept Eletropaulo's proposed green areas donation. Instead of such green areas donation, the Secretary of the Environment proposed in March 2015 that Eletropaulo undertake an environmental project to offset the alleged environmental damage. Since March 2015, Eletropaulo and the Secretary of Environment have been working together to define an environmental project, which will be submitted for approval by the Public Prosecutor. The cost of such project is currently estimated to be R$2 million ($512 thousand).
In December 2001, Gridco Ltd. ("Gridco") served a notice to arbitrate pursuant to the Indian Arbitration and Conciliation Act of 1996 on the Company, AES Orissa Distribution Private Limited ("AES ODPL"), and Jyoti Structures ("Jyoti") pursuant to the terms of the shareholders agreement between Gridco, the Company, AES ODPL, Jyoti and the Central Electricity Supply Company of Orissa Ltd. ("CESCO"), an affiliate of the Company. In the arbitration, Gridco asserted that a comfort letter issued by the Company in connection with the Company's indirect investment in CESCO obligates the Company to provide additional financial support to cover all of CESCO's financial obligations to Gridco. Gridco appeared to be seeking approximately $189 million in damages, plus undisclosed penalties and interest, but a detailed alleged damage analysis was not filed by Gridco. The Company counterclaimed against Gridco for damages. In June 2007, a 2-to-1 majority of the arbitral tribunal rendered its award rejecting Gridco's claims and holding that none of the respondents, the Company, AES ODPL, or Jyoti, had any liability to Gridco. The respondents' counterclaims were also rejected. A majority of the tribunal later awarded the respondents, including the Company, some of their costs relating to the arbitration. Gridco filed challenges of the tribunal's awards with the local Indian court. Gridco's challenge of the costs award has been dismissed by the court, but its challenge of the liability award remains pending. The Company believes that it has meritorious defenses to the claims asserted against it and will defend itself vigorously in these proceedings; however, there can be no assurances that it will be successful in its efforts.
In March 2003, the office of the Federal Public Prosecutor for the State of São Paulo, Brazil (“MPF”) notified Eletropaulo that it had commenced an inquiry into the BNDES financings provided to AES Elpa and AES Transgás, the rationing loan provided to Eletropaulo, changes in the control of Eletropaulo, sales of assets by Eletropaulo, and the quality of service provided by Eletropaulo to its customers. The MPF requested various documents from Eletropaulo relating to these matters. In July 2004, the MPF filed a public civil lawsuit in the Federal Court of São Paulo (“FCSP”) alleging that BNDES violated Law 8429/92 (the Administrative Misconduct Act) and BNDES's internal rules by (1) approving the AES Elpa and AES Transgás loans; (2) extending the payment terms on the AES Elpa and AES Transgás loans; (3) authorizing the sale of Eletropaulo's preferred shares at a stock-market auction; (4) accepting Eletropaulo's preferred shares to secure the loan provided to Eletropaulo; and (5) allowing the restructurings of Light Serviços de Eletricidade S.A. and Eletropaulo. The MPF also named AES Elpa and AES Transgás as defendants in the lawsuit because they allegedly benefited from BNDES's alleged violations. In May 2006, the FCSP ruled that the MPF could pursue its claims based on the first, second, and fourth alleged violations noted above. The MPF subsequently filed an interlocutory appeal with the Federal Court of Appeals (“FCA”) seeking to require the FCSP to consider all five alleged violations. In April 2015, the FCA issued a decision holding that the FCSP should consider all five alleged violations. AES Elpa and AES Brasiliana (the successor of AES Transgás) have appealed to the Superior Court of Justice. The lawsuit remains pending before the FCSP, but it will remain suspended until the

71


interlocutory appeal has been finally decided. AES Elpa and AES Brasiliana believe they have meritorious defenses to the allegations asserted against them and will defend themselves vigorously in these proceedings; however, there can be no assurances that they will be successful in their efforts.
Pursuant to their environmental audit, AES Sul and AES Florestal discovered 200 barrels of solid creosote waste and other contaminants at a pole factory that AES Florestal had been operating. The conclusion of the audit was that a prior operator of the pole factory, Companhia Estadual de Energia ("CEEE"), had been using those contaminants to treat the poles that were manufactured at the factory. On their initiative, AES Sul and AES Florestal communicated with Brazilian authorities and CEEE about the adoption of containment and remediation measures. In March 2008, the State Attorney of the state of Rio Grande do Sul, Brazil filed a public civil action against AES Sul, AES Florestal and CEEE seeking an order requiring the companies to recover the contaminated area located on the grounds of the pole factory and an indemnity payment of approximately R$6 million ($2 million) to the state's Environmental Fund. In October 2011, the State Attorney Office filed a request for an injunction ordering the defendant companies to contain and remove the contamination immediately. The court granted injunctive relief on October 18, 2011, but determined only that defendant CEEE was required to proceed with the removal work. In May 2012, CEEE began the removal work in compliance with the injunction. The removal costs are estimated to be approximately R$60 million ($15 million) and the work was completed in February 2014. In parallel with the removal activities, a court-appointed expert investigation took place, which was concluded in May 2014. The court-appointed expert final report was presented to the State Attorneys in October 2014, and in January 2015 to the defendant companies. In March 2015, AES Sul and AES Florestal submitted comments and supplementary questions regarding the expert report. The Company believes that it has meritorious defenses to the claims asserted against it and will defend itself vigorously in these proceedings; however, there can be no assurances that it will be successful in its efforts.
In March 2009, AES Uruguaiana Empreendimentos S.A. ("AESU") in Brazil initiated arbitration in the ICC against YPF S.A. ("YPF") seeking damages and other relief relating to YPF's breach of the parties' gas supply agreement ("GSA"). Thereafter, in April 2009, YPF initiated arbitration in the ICC against AESU and two unrelated parties, Companhia de Gas do Estado do Rio Grande do Sul and Transportador de Gas del Mercosur S.A. ("TGM"), claiming that AESU wrongfully terminated the GSA and caused the termination of a transportation agreement ("TA") between YPF and TGM ("YPF Arbitration"). YPF sought an unspecified amount of damages from AESU, a declaration that YPF's performance was excused under the GSA due to certain alleged force majeure events, or, in the alternative, a declaration that the GSA and the TA should be terminated without a finding of liability against YPF because of the allegedly onerous obligations imposed on YPF by those agreements. In addition, in the YPF Arbitration, TGM asserted that if it was determined that AESU was responsible for the termination of the GSA, AESU was liable for TGM's alleged losses, including losses under the TA. In April 2011, the arbitrations were consolidated into a single proceeding. The hearing on liability issues took place in December 2011. In May 2013, the arbitral tribunal issued a liability award in AESU's favor. YPF thereafter challenged the award in Argentine court. In December 2015, an Argentine court issued a decision purporting to annul the liability award. AESU has sought reconsideration of that decision. The damages hearing in the arbitration took place on November 16-17, 2015. The tribunal has not issued a damages award to date. AESU believes it has meritorious claims and defenses and will assert them vigorously; however, there can be no assurances that it will be successful in its efforts.
In April 2009, the Antimonopoly Agency in Kazakhstan initiated an investigation of certain power sales of Ust-Kamenogorsk HPP ("UK HPP") and Shulbinsk HPP, hydroelectric plants under AES concession (collectively, the "Hydros"). The Antimonopoly Agency determined that the Hydros had abused their market position and charged monopolistically high prices for power from January-February 2009. Administrative proceedings followed, but were later suspended due to the initiation of related criminal proceedings against officials of the Hydros. Recently, the Antimonopoly Agency terminated its investigation of the Hydros due to the expiration of the relevant statute of limitations.
In October 2009, AES Mérida III, S. de R.L. de C.V. ("AES Mérida"), one of our businesses in Mexico, initiated arbitration against its fuel supplier and electricity offtaker, Comisión Federal de Electricidad ("CFE"), seeking a declaration that CFE breached the parties' PPA by supplying gas that did not comply with the PPA's specifications. Alternatively, AES Mérida requested a declaration that the supply of such gas by CFE is a force majeure event under the PPA. CFE disputed the claims. Although it did not assert counterclaims, in its closing brief CFE asserted that it is entitled to a partial refund of the capacity charge payments that it made for power generated with the out-of-specification gas. In July 2012, the arbitral tribunal issued an award in AES Mérida's favor. In December 2012, CFE initiated an action in Mexican court seeking to nullify the award. AES Mérida opposed the request and asserted a counterclaim to confirm the award. In February 2014, the court rejected CFE's claims and granted AES Mérida's request to confirm the award. CFE has appealed the court's decision. The appeal is pending before the Mexican Supreme Court. AES Mérida believes it has meritorious grounds to defeat that action; however, there can be no assurances that it will be successful.
In October 2009, IPL received a NOV and Finding of Violation from the EPA pursuant to the CAA Section 113(a). The NOV alleges violations of the CAA at IPL's three primarily coal-fired electric generating facilities dating back to 1986. The alleged violations primarily pertain to the Prevention of Significant Deterioration and nonattainment New Source Review

72


requirements under the CAA. Since receiving the letter, IPL management has met with EPA staff regarding possible resolutions of the NOV. At this time, we cannot predict the ultimate resolution of this matter. However, settlements and litigated outcomes of similar cases have required companies to pay civil penalties, install additional pollution control technology on coal-fired electric generating units, retire existing generating units, and invest in additional environmental projects. A similar outcome in this case could have a material impact to IPL and could, in turn, have a material impact on the Company. IPL would seek recovery of any operating or capital expenditures related to air pollution control technology to reduce regulated air emissions; however, there can be no assurances that it would be successful in that regard.
In November 2009, April 2010, December 2010, April 2011, June 2011, August 2011, November 2011, and October 2014, substantially similar personal injury lawsuits were filed by a total of 50 residents and decedent estates in the Dominican Republic against the Company, AES Atlantis, Inc., AES Puerto Rico, LP, AES Puerto Rico, Inc., and AES Puerto Rico Services, Inc., in the Superior Court for the state of Delaware. In each lawsuit, the plaintiffs allege that the coal combustion by-products of AES Puerto Rico's power plant were illegally placed in the Dominican Republic from October 2003 through March 2004 and subsequently caused the plaintiffs' birth defects, other personal injuries, and/or deaths. The plaintiffs did not quantify their alleged damages, but generally alleged that they are entitled to compensatory and punitive damages. The AES defendants moved for partial dismissal of both the November 2009 and April 2010 lawsuits on various grounds. In July 2011, the Superior Court dismissed the plaintiffs' international law and punitive damages claims, but held that the plaintiffs had stated intentional tort, negligence, and strict liability claims under Dominican law, which the Superior Court found governed the lawsuits. The Superior Court granted the plaintiffs leave to amend their complaints in accordance with its decision, and in September 2011, the plaintiffs in the November 2009 and April 2010 lawsuits did so. In November 2011, the AES defendants again moved for partial dismissal of those amended complaints, and in both lawsuits, the Superior Court dismissed the plaintiffs' claims for future medical monitoring expenses but declined to dismiss their claims under Dominican Republic Law 64-00. The AES defendants filed an answer to the November 2009 lawsuit in June 2012. The Superior Court has stayed all lawsuits but the November 2009 lawsuit. In that lawsuit, discovery is complete on causation and exposure issues, but is ongoing on other liability issues as well as damages issues. Based on the information they have disclosed during discovery, the plaintiffs in the November 2009 lawsuit appear to be seeking a total of approximately $30 million for life care assistance and lost earnings, additional but unspecified amounts for moral damages, and additional but unspecified damages for loss of consortium and deaths. Also, in the November 2009 lawsuit, trial is scheduled for April 2016. The AES defendants believe they have meritorious defenses and will defend themselves vigorously; however, there can be no assurances that they will be successful in their efforts.
On February 11, 2011, Eletropaulo received a notice of violation from São Paulo State's Environmental Authorities for allegedly destroying 0.32 hectares of native vegetation at the Conservation Park of Serra do Mar ("Park"), without previous authorization or license. The notice of violation asserted a fine of approximately R$1 million ($256 thousand) and the suspension of Eletropaulo activities in the Park. As a response to this administrative procedure before the São Paulo State Environmental Authorities ("São Paulo EA"), Eletropaulo timely presented its defense on February 28, 2011 seeking to vacate the NOV or reduce the fine. In December 2011, the São Paulo EA declined to vacate the NOV but reduced the fine to R$757 thousand ($194 thousand) and recognized the possibility of an additional 40% reduction of the fine if Eletropaulo agrees to recover the affected area with additional vegetation. Eletropaulo did not appeal the decision and discussed the terms of a possible settlement with the São Paulo EA, including a plan to recover the affected area by primarily planting additional trees. In March 2012, the state of São Paulo Prosecutor's Office of São Bernardo do Campo initiated a Civil Proceeding to review the compliance by Eletropaulo with the terms of any possible settlement. The Park Administrator subsequently approved an area for the recovery project different from the affected area, which was no longer available. On January 23, 2015, AES Eletropaulo entered into a Recovery and Compensation Agreement with the Coordenadoria de Fiscalização Ambiental ("CFA") to restore 3.2 hectares during the course of two years, which restoration is currently estimated to cost R$592 thousand ($152 thousand). In June 2015, the state of São Paulo Prosecutor's Office of São Bernardo do Campo decided to close its Civil Proceeding, subject to the approval of the Superior Counsel of the Public Prosecutor's Office. Upon completion of the recovery project as approved and established in the Recovery and Compensation Agreement, AES will be entitled to a 40% reduction (R$303 thousand or $78 thousand) of the fine as legally provided.
In June 2011, the São Paulo Municipal Tax Authority (the "Tax Authority") filed 60 tax assessments in São Paulo administrative court against Eletropaulo, seeking to collect services tax ("ISS") that allegedly had not been paid on revenues for services rendered by Eletropaulo. Eletropaulo challenged the assessments on the ground that the revenues at issue were not subject to ISS. In October 2013, the First Instance Administrative Court determined that Eletropaulo was liable for ISS, interest, and related penalties totaling approximately R$3.3 billion ($843 million) as estimated by Eletropaulo. Eletropaulo thereafter appealed to the Second Instance Administrative Court ("SIAC"). In January 2016, the Tax Authority reduced the total amount of the ISS assessments to approximately R$228 million ($58 million). The reduced amount of ISS remains under consideration by the SIAC. No tax is due while the appeal is pending. Eletropaulo believes it has meritorious defenses and will defend itself vigorously in these proceedings; however, there can be no assurances that it will be successful in its efforts.

73


In January 2012, the Brazil Federal Tax Authority issued an assessment alleging that AES Tietê paid PIS and COFINS taxes from 2007 to 2010 at a lower rate than the tax authority believed was applicable. AES Tietê challenged the assessment on the ground that the tax rate was set in the applicable legislation. In April 2013, the First Instance Administrative Court determined that AES Tietê should have calculated the taxes at the higher rate and that AES Tietê was liable for unpaid taxes, interest and penalties totaling approximately R$910 million ($233 million) as estimated by AES Tietê. AES Tietê appealed to the Second Instance Administrative Court (“SIAC”). In January 2015, the SIAC issued a decision in AES Tietê's favor, finding that AES Tietê was not liable for unpaid taxes. The public prosecutor subsequently filed an appeal, which was denied as untimely. The Tax Authority thereafter filed a motion for clarification of the SIAC's decision, which motion remains pending. AES Tietê believes it has meritorious defenses to the claim and will defend itself vigorously in these proceedings; however, there can be no assurances that it will be successful in its efforts.
In August 2012, Fondo Patrimonial de las Empresas Reformadas (“FONPER”) (the Dominican instrumentality that holds the Dominican Republic's shares in Empresa Generadora de Electricidad Itabo, S.A. (“Itabo”)) filed a criminal complaint against certain current and former employees of AES. The criminal proceedings include a related civil component initiated against, among others, Coastal Itabo, Ltd. (“Coastal”) (the AES affiliate shareholder of Itabo) and New Caribbean Investment, S.A. (“NC”) (the AES affiliate that manages Itabo). FONPER asserts claims relating to the alleged mismanagement of Itabo and seeks approximately $270 million in damages. The Dominican District Attorney (“DA”) thereafter admitted the criminal complaint and requested that the Dominican Republic's Cámara de Cuentas (“Cámara”) perform an audit of the allegations in the criminal complaint. In October 2015, the Cámara issued its final report, determining that the contested actions of the AES employees were in accordance with Dominican law. Further, in August 2012, Coastal and NC initiated an international arbitration proceeding against FONPER and the Dominican Republic (“Respondents”), seeking a declaration that Coastal and NC have acted both lawfully and in accordance with the relevant contracts with the Respondents in relation to the management of Itabo. Coastal and NC also seek a declaration that the criminal complaint is a breach of the relevant contracts between the parties, including the obligation to arbitrate disputes. Coastal and NC further seek damages from the Respondents resulting from their breach of contract. The Respondents have denied the claims and challenged the jurisdiction of the arbitral tribunal. In February 2015, the Respondents made an application requesting that the tribunal rule on their jurisdictional objections prior to giving any consideration to the merits of the claims of Coastal and NC. In August 2015, the tribunal rejected the application. The tribunal has established the procedural schedule for the arbitration, but has not yet scheduled dates for the final evidentiary hearing. At the parties' request, the Tribunal has suspended the arbitration until July 30, 2016. The AES parties believe they have meritorious claims and defenses, which they will assert vigorously; however, there can be no assurances that they will be successful in their efforts.
In July 2015, BTG Pactual (“BTG”) initiated arbitration against AES Tietê under the parties' PPA. BTG claims that AES Tietê breached the PPA by purchasing more power than it was entitled to take under the PPA. BTG seeks to recover the payments that AES Tietê received from its spot-market sales of BTG's power, totaling approximately R$30 million ($8 million). BTG also seeks to terminate the PPA and to collect a termination payment of approximately R$560 million ($143 million). AES Tietê has placed R$30 million ($8 million) into escrow, with a full reservation of rights. AES Tietê has responded to the arbitration demand, contesting the claims against it. AES Tietê believes it has meritorious defenses to the claims asserted against it and will defend itself vigorously in this proceeding; however, there can be no assurances that it will be successful in its efforts.
In September 2015, AES Southland Development, LLC and AES Redondo Beach, LLC filed a lawsuit against the California Coastal Commission (the “CCC”) over the CCC's determination that the site of AES Redondo Beach included approximately 5.93 acres of CCC-jurisdictional wetlands. The CCC has asserted that AES Redondo Beach has improperly installed and operated water pumps affecting the alleged wetlands in violation of the California Coastal Act and Redondo Beach Local Coastal Program and has ordered AES Redondo Beach to restore the site. Additional potential outcomes of the CCC determination could include an order requiring AES Redondo Beach to fund a wetland mitigation project and/or pay fines or penalties. AES Redondo Beach believes that it has meritorious arguments and intends to vigorously prosecute such lawsuit, but there can be no assurances that it will be successful.
In October 2015, Ganadera Guerra, S.A. (“GG”) and Constructora Tymsa, S.A. (“CT”) filed separate lawsuits against AES Panama in the local courts of Panama. The claimants allege that AES Panama profited from a hydropower facility (La Estrella) being partially located on land owned first by GG and later by CT, and that AES Panama must pay compensation for its use of the land. The damages sought from AES Panama are approximately $680 million (GG) and $100 million (CT). AES Panama believes it has meritorious defenses to the claims asserted against it and will defend itself vigorously in the lawsuits; however, there can be no assurances that it will be successful in its efforts.
In January 2015, DPL received NOVs from the EPA alleging violations of opacity at Stuart and Killen Stations, and in October 2015, IPL received a similar NOV alleging violations at Petersburg Station. In February 2016, IPL received an NOV from the EPA alleging violations of NSR and other CAA regulations, the Indiana SIP, and the Title V operating permit at Petersburg Station. It is too early to determine whether the NOVs could have a material impact on our business, financial

74


condition or results of our operations. We would seek recovery of any operating or capital expenditures for IPL, but not fines or penalties, related to air pollution control technology to reduce regulated air emissions; however, there can be no assurances that we would be successful in this regard.
ITEM 4. MINE SAFETY DISCLOSURES
Not applicable.

75


PART II
ITEM 5.
MARKET FOR REGISTRANT'S COMMON EQUITY, RELATED STOCKHOLDER MATTERS AND ISSUER PURCHASES OF EQUITY SECURITIES
Recent Sales of Unregistered Securities
None.
Purchases of Equity Securities by the Issuer and Affiliated Purchasers
Stock Repurchase Program
In October 2015, the Company's Board of Directors approved an increase of $400 million to the stock repurchase program (the "Program") under which the Company can repurchase AES common stock. The Board authorization permits the Company to repurchase stock through a variety of methods, including open market repurchases and/or privately negotiated transactions. There can be no assurances as to the amount, timing or prices of repurchases, which may vary based on market conditions and other factors. The Program does not have an expiration date and can be modified or terminated by the Board of Directors at any time. During the year ended December 31, 2015, the Company repurchased 39.7 million shares of its common stock at a total cost of $482 million under the existing stock repurchase program. The cumulative repurchase from the commencement of the Program in July 2010 through December 31, 2015 is 145.6 million shares at a total cost of $1.8 billion, at an average price per share of $12.31 (including a nominal amount of commissions).
The following table presents information regarding repurchases made by The AES Corporation of its common stock in the fourth quarter of 2015.
Repurchase Period
 
Total Number of Shares Purchased
 
Average Price Paid Per Share
 
Total Number of Shares Repurchased as Part of a Publicly Announced Purchase Plan
 
Dollar Value of Maximum Number of Shares to be Purchased Under the Plan
10/1/2015 - 10/31/15
 
1,598,910

 
$
10.03

 
1,598,910

 
$
400,312,942

11/1/2015 - 11/30/15
 
1,584,932

(1) 
10.02

 
1,564,682

 
385,040,330

12/1/2015 - 12/31/15
 
4,495,268

 
9.35

 
4,495,268

 
343,035,214

Total
 
7,679,110


7,658,860


(1) Includes 20,250 shares purchased by an executive of the Company in November 2015 that were not under the publicly announced stock repurchase program.
Market Information
Our common stock is currently traded on the NYSE under the symbol "AES." The closing price of our common stock as reported by the NYSE on February 18, 2016, was $9.70 per share. The Company repurchased 39,684,131, 21,900,246, and 25,297,042 shares of its common stock in 2015, 2014 and 2013, respectively. The following tables present the high and low intraday sale prices of our common stock and cash dividends declared for the periods indicated:
 
2015
 
2014
 
Sales Price
 
Cash Dividends
 
Sales Price
 
Cash Dividends
 
High
 
Low
 
Declared
 
High
 
Low
 
Declared
First Quarter
$
13.87

 
$
11.53

 
$
—

 
$
14.94

 
$
13.42

 
$
—

Second Quarter
14.02

 
12.64

 
0.10

 
15.65

 
13.42

 
0.05

Third Quarter
13.40

 
9.42

 
0.10

 
15.64

 
14.01

 
0.05

Fourth Quarter
11.21

 
8.76

 
0.21

 
14.49

 
12.38

 
0.15

Dividends
The Company commenced a quarterly cash dividend of $0.04 per share beginning in the fourth quarter of 2012, which increased to $0.05 per share beginning in the fourth quarter of 2013, and increased to $0.10 per share in the fourth quarter of 2014. During the fourth quarter of 2015, the Board of Directors voted to increase the quarterly dividend to $0.11 per share, beginning in the first quarter of 2016. There can be no assurance that the AES Board will declare a dividend in the future or, if declared, the amount of any dividend. Our ability to pay dividends will also depend on receipt of dividends from our various subsidiaries across our portfolio.
Under the terms of our senior secured credit facility, which we entered into with a commercial bank syndicate, we have limitations on our ability to pay cash dividends and/or repurchase stock. Our subsidiaries' ability to declare and pay cash dividends to us is also subject to certain limitations contained in the project loans, governmental provisions and other agreements to which our subsidiaries are subject. See the information contained under Item 12.—Security Ownership of Certain Beneficial Owners and Management and Related Stockholder Matters—Securities Authorized for Issuance under Equity Compensation Plans of this Form 10-K.
Holders
As of February 18, 2016, there were approximately 4,702 record holders of our common stock.

76


Performance Graph
THE AES CORPORATION
PEER GROUP INDEX/STOCK PRICE PERFORMANCE

Source: Bloomberg
We have selected the Standard and Poor's ("S&P") 500 Utilities Index as our peer group index. The S&P 500 Utilities Index is a published sector index comprising the 31 electric and gas utilities included in the S&P 500.
The five year total return chart assumes $100 invested on December 31, 2010 in AES Common Stock, the S&P 500 Index and the S&P 500 Utilities Index. The information included under the heading Performance Graph shall not be considered "filed" for purposes of Section 18 of the Securities Exchange Act of 1934 or incorporated by reference in any filing under the Securities Act of 1933 or the Securities Exchange Act of 1934.
ITEM 6. SELECTED FINANCIAL DATA
The following table presents our selected financial data as of the dates and for the periods indicated. You should read this data together with Item 7.—Management's Discussion and Analysis of Financial Condition and Results of Operations and the Consolidated Financial Statements and the notes thereto included in Item 8.—Financial Statements and Supplementary Data of this Form 10-K. The selected financial data for each of the years in the five year period ended December 31, 2015 have been derived from our audited Consolidated Financial Statements. Prior period amounts have been restated to reflect discontinued operations in all periods presented. Effective July 1, 2014, the Company adopted new accounting guidance on discontinued operations. Please refer to Note 1 in Item 8.—Financial Statements and Supplementary Data of this Form 10-K for further explanation. Our historical results are not necessarily indicative of our future results.
Acquisitions, disposals, reclassifications and changes in accounting principles affect the comparability of information included in the tables below. Please refer to the Notes to the Consolidated Financial Statements included in Item 8.—Financial Statements and Supplementary Data of this Form 10-K for further explanation of the effect of such activities. Please also refer to Item 1A.—Risk Factors of this Form 10-K and Note 27—Risks and Uncertainties to the Consolidated Financial Statements included in Item 8.—Financial Statements and Supplementary Data of this Form 10-K for certain risks and uncertainties that may cause the data reflected herein not to be indicative of our future financial condition or results of operations.

77


SELECTED FINANCIAL DATA
 
2015
 
2014
 
2013
 
2012
 
2011(1)
Statement of Operations Data for the Years Ended December 31:
(in millions, except per share amounts)
Revenue
$
14,963

 
$
17,146

 
$
15,891

 
$
17,164

 
$
16,098

Income (loss) from continuing operations(2)
762

 
1,176

 
730

 
(420
)
 
1,602

Income (loss) from continuing operations attributable to The AES Corporation, net of tax
306

 
789

 
284

 
(960
)
 
506

Discontinued operations, net of tax
—

 
(20
)
 
(170
)
 
48

 
(448
)
Net income (loss) attributable to The AES Corporation
$
306

 
$
769

 
$
114

 
$
(912
)
 
$
58

Per Common Share Data


Basic earnings (loss) per share:


Income (loss) from continuing operations attributable to The AES Corporation, net of tax
$
0.45

 
$
1.10

 
$
0.38

 
$
(1.27
)
 
$
0.65

Discontinued operations, net of tax
—

 
(0.03
)
 
(0.23
)
 
0.06

 
(0.58
)
Basic earnings (loss) per share
$
0.45

 
$
1.07

 
$
0.15

 
$
(1.21
)
 
$
0.07

Diluted earnings (loss) per share:


Income (loss) from continuing operations attributable to The AES Corporation, net of tax
$
0.44

 
$
1.09

 
$
0.38

 
$
(1.27
)
 
$
0.65

Discontinued operations, net of tax
—

 
(0.03
)
 
(0.23
)
 
0.06

 
(0.58
)
Diluted earnings (loss) per share
$
0.44

 
$
1.06

 
$
0.15

 
$
(1.21
)
 
$
0.07

Dividends Declared Per Common Share
$
0.41

 
0.25

 
0.17

 
0.08

 
—

Cash Flow Data for the Years Ended December 31:


Net cash provided by operating activities
$
2,134

 
$
1,791

 
$
2,715

 
$
2,901

 
$
2,884

Net cash used in investing activities
(2,366
)
 
(656
)
 
(1,774
)
 
(895
)
 
(4,906
)
Net cash provided by (used in) financing activities
28

 
(1,262
)
 
(1,136
)
 
(1,867
)
 
1,412

Total (decrease) increase in cash and cash equivalents
(277
)
 
(103
)
 
(258
)
 
276

 
(736
)
Cash and cash equivalents, ending
1,262

 
1,539

 
1,642

 
1,900

 
1,624

Balance Sheet Data at December 31:
 
Total assets
$
36,850

 
$
38,966

 
$
40,411

 
$
41,830

 
$
45,346

Non-recourse debt (noncurrent)
13,263

 
13,618

 
13,318

 
12,265

 
13,261

Non-recourse debt (noncurrent)—Discontinued operations
—

 
—

 
124

 
322

 
1,369

Recourse debt (noncurrent)
5,015

 
5,107

 
5,551

 
5,951

 
6,180

Redeemable stock of subsidiaries
538

 
78

 
78

 
78

 
78

Retained earnings (accumulated deficit)
143

 
512

 
(150
)
 
(264
)
 
678

The AES Corporation stockholders' equity
3,149

 
4,272

 
4,330

 
4,569

 
5,946

(1)
On November 28, 2011, AES completed the acquisition of 100% of the common stock of DPL Inc. Its results of operations have been included in AES's consolidated results of operations from the date of acquisition.
(2)
Includes pretax impairment expense of $602 million, $383 million, $596 million, $1.9 billion, and $272 million for the years ended December 31, 2015, 2014, 2013, 2012 and 2011, respectively. See Note 9—Other Non-Operating Expense, Note 10—Goodwill and Other Intangible Assets and Note 21—Asset Impairment Expense included in Item 8.—Financial Statements and Supplementary Data of this Form 10-K for further information.
ITEM 7. MANAGEMENT'S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS
Key Topics in Management's Discussion and Analysis
Our discussion covers the following:
•
Strategic Performance and Overview of 2015 Results
•
Review of Consolidated Results of Operations
•
SBU Performance Analysis
•
Key Trends and Uncertainties
•
Capital Resources and Liquidity
Overview of 2015 Results and Strategic Performance
In 2015, we faced tough macroeconomic headwinds, including up to 30% devaluation in some of our key currencies, including the Brazilian Real, Colombian Peso and Euro. We also saw more than 40% declines in oil and natural gas prices, which have an impact on our businesses in the Dominican Republic, Ohio and Northern Ireland. Additionally, Brazil's GDP continued to contract. Despite these continuing challenging conditions, we did what we are good at — adapted to the changes in circumstances and took actions to mitigate their impact on our businesses and on our financial results. We successfully executed on our strategy and achieved the majority of our objectives by: delivering Proportional Free Cash Flow of $1,241 million, up 39% compared to 2014, and Adjusted EPS of $1.22; prudently allocating our capital; and advancing select platform expansion projects across our portfolio.
Management's Strategic Priorities
Management is focused on the following priorities:

78


•
Reducing complexity: By exiting businesses and markets where we do not have a competitive advantage, we are simplifying our portfolio and reducing risk. During 2015, we announced or closed $787 million in equity proceeds from the sales or sell-downs of seven businesses.
•
Leveraging our platforms: We are focusing our growth on platform expansions in markets where we already operate and have a competitive advantage to realize attractive risk-adjusted returns. We currently have 5,620 MW under construction, representing $7 billion in total capital expenditures, with 85% of AES' $1.2 billion in equity already funded. We expect the majority of these projects to come on-line through 2018. Beyond the projects we currently have under construction, we will continue to advance select projects from our development pipeline.
•
Performance excellence: We strive to be the low-cost manager of a portfolio of assets and to derive synergies and scale from our businesses. In November, we launched a $150 million cost reduction and revenue enhancement initiative. This initiative will include overhead reductions, procurement efficiencies and operational improvements. We expect to achieve at least $50 million in savings in 2016, ramping up to $150 million, including modest revenue enhancements, in 2018.
•
Expanding access to capital: We are building strategic partnerships at the project and business level. Through these partnerships, we aim to optimize our risk-adjusted returns in our existing businesses and growth projects. By selling down portions of certain businesses, we can adjust our global exposure to commodity, fuel, country and other macroeconomic risks. Partial sell-downs of our assets can also serve to highlight or enhance the value of businesses in our portfolio.
•
Allocating capital in a disciplined manner: Our top priority is to maximize risk-adjusted returns to our shareholders, which we achieve by investing our discretionary cash and recycling the capital we receive from asset sales and strategic partnerships. In 2015, we generated substantial cash by executing on our strategy, which we allocated in line with our capital allocation framework:
◦
Used $345 million to prepay and refinance Parent debt;
◦
returned $757 million to shareholders through share repurchases and quarterly dividends;
▪
increased our quarterly dividend by 10%, to $0.11 per share, beginning in the first quarter of 2016;
◦
invested $114 million in our subsidiaries, largely for projects that are currently under construction.
2015 Strategic Performance
Earnings Per Share and Proportional Free Cash Flow Results in 2015 (in millions, except per share amounts)
Years Ended December 31,
2015
 
2014
 
2013
Diluted earnings per share from continuing operations
$
0.44

 
$
1.09

 
$
0.38

Adjusted earnings per share (a non-GAAP measure)(1)
1.22

 
1.30

 
1.29

Net cash provided by operating activities
2,134

 
1,791

 
2,715

Proportional Free Cash Flow (a non-GAAP measure)(1)
1,241

 
891

 
1,271

_____________________________
(1)
See reconciliation and definition under Non-GAAP Measures.    
Diluted earnings per share from continuing operations decreased by 60% to $0.44 primarily due to higher impairment expense and lower gains from sales of businesses, partially offset by lower debt extinguishment expense.
Adjusted EPS, a non-GAAP measure, decreased by 6% to $1.22 primarily due to the devaluation of foreign currencies in Latin America and Europe, the impact of lower commodity prices in certain markets, and lower demand in Brazil. These negative impacts were partially offset by a 5% reduction in shares outstanding, lower Parent interest expense, improved hydrological conditions in Panama, and contributions from new businesses, including Mong Duong in Vietnam.
Net cash provided by operating activities increased by 19% to $2.1 billion primarily due to the timing of collections in the Dominican Republic as well as increases at the Parent Company primarily driven by lower interest payments and lower payments for capital expenditures, partially offset by collections on lower margins resulting from economic slowdown, timing of energy purchases and higher interest payments in Brazil.
Proportional free cash flow increased by 39% to $1.2 billion primarily due to the timing of collections in the Dominican Republic as well as increases at the Parent Company primarily driven by lower interest payments and lower payments for maintenance capital expenditures.
Safe Operations
Safety is our first value and a top priority. We consistently analyze and evaluate our safety performance in order to capture lessons learned and strengthen mitigation plans that improve our safety performance.

79


Review of Consolidated Results of Operations
Years Ended December 31,
2015
 
2014
 
2013
 
% Change 2015 vs. 2014
 
% Change 2014 vs. 2013
Results of operations
(in millions, except per share amounts)


Revenue:


US SBU
$
3,593

 
$
3,826

 
$
3,630

 
-6
 %
 
5
 %
Andes SBU
2,489

 
2,642

 
2,639

 
-6
 %
 
—
 %
Brazil SBU
4,666

 
6,009

 
5,015

 
-22
 %
 
20
 %
MCAC SBU
2,353

 
2,682

 
2,713

 
-12
 %
 
-1
 %
Europe SBU
1,191

 
1,439

 
1,347

 
-17
 %
 
7
 %
Asia SBU
684

 
558

 
550

 
23
 %
 
1
 %
Corporate and Other
31

 
15

 
7

 
107
 %
 
114
 %
Intersegment eliminations
(44
)
 
(25
)
 
(10
)
 
-76
 %
 
-150
 %
Total Revenue
14,963

 
17,146

 
15,891

 
-13
 %
 
8
 %
Operating Margin:


US SBU
621

 
699

 
668

 
-11
 %
 
5
 %
Andes SBU
618

 
587

 
533

 
5
 %
 
10
 %
Brazil SBU
600

 
742

 
871

 
-19
 %
 
-15
 %
MCAC SBU
543

 
541

 
543

 
—
 %
 
—
 %
Europe SBU
303

 
403

 
415

 
-25
 %
 
-3
 %
Asia SBU
149

 
76

 
169

 
96
 %
 
-55
 %
Corporate and Other
33

 
53

 
25

 
-38
 %
 
112
 %
Intersegment eliminations
(1
)
 
(13
)
 
23

 
92
 %
 
-157
 %
Total Operating Margin
2,866

 
3,088

 
3,247

 
-7
 %
 
-5
 %
General and administrative expenses
(196
)
 
(187
)
 
(220
)
 
5
 %
 
-15
 %
Interest expense
(1,436
)
 
(1,471
)
 
(1,482
)
 
-2
 %
 
-1
 %
Interest income
524

 
365

 
275

 
44
 %
 
33
 %
Loss on extinguishment of debt
(186
)
 
(261
)
 
(229
)
 
-29
 %
 
14
 %
Other expense
(65
)
 
(68
)
 
(76
)
 
-4
 %
 
-11
 %
Other income
83

 
124

 
125

 
-33
 %
 
-1
 %
Gain on sale of businesses
29

 
358

 
26

 
-92
 %
 
NM

Goodwill impairment expense
(317
)
 
(164
)
 
(372
)
 
93
 %
 
-56
 %
Asset impairment expense
(285
)
 
(91
)
 
(95
)
 
213
 %
 
-4
 %
Foreign currency transaction gains (losses)
105

 
11

 
(22
)
 
855
 %
 
150
 %
Other non-operating expense
—

 
(128
)
 
(129
)
 
-100
 %
 
-1
 %
Income tax expense
(465
)
 
(419
)
 
(343
)
 
11
 %
 
22
 %
Net equity in earnings of affiliates
105

 
19

 
25

 
453
 %
 
-24
 %
INCOME FROM CONTINUING OPERATIONS
762

 
1,176

 
730

 
-35
 %
 
61
 %
Income (loss) from operations of discontinued businesses
—

 
27

 
(27
)
 
-100
 %
 
200
 %
Net loss from disposal and impairments of discontinued operations
—

 
(56
)
 
(152
)
 
-100
 %
 
-63
 %
NET INCOME
762

 
1,147

 
551

 
-34
 %
 
108
 %
Noncontrolling interests:


(Income) from continuing operations attributable to noncontrolling interests
(456
)
 
(387
)
 
(446
)
 
18
 %
 
-13
 %
Loss from discontinued operations attributable to noncontrolling interests
—

 
9

 
9

 
-100
 %
 
—
 %
NET INCOME ATTRIBUTABLE TO THE AES CORPORATION
$
306

 
$
769

 
$
114

 
-60
 %
 
575
 %
AMOUNTS ATTRIBUTABLE TO THE AES CORPORATION COMMON STOCKHOLDERS:


Income from continuing operations, net of tax
$
306

 
$
789

 
$
284

 
-61
 %
 
178
 %
Loss from discontinued operations, net of tax
—

 
(20
)
 
(170
)
 
-100
 %
 
-88
 %
Net income
$
306

 
$
769

 
$
114

 
-60
 %
 
575
 %
Net cash provided by operating activities
$
2,134

 
$
1,791

 
$
2,715

 
19
 %
 
-34
 %
DIVIDENDS DECLARED PER COMMON SHARE
$
0.41

 
$
0.25

 
$
0.17

 
64
 %
 
47
 %
_____________________________
NM — Not meaningful
Components of Revenue, Cost of Sales and Operating Margin — Revenue includes revenue earned from the sale of energy from our utilities and the production of energy from our generation plants, which are classified as regulated and non-regulated on the Consolidated Statements of Operations, respectively. Revenue also includes the gains or losses on derivatives associated with the sale of electricity.
Cost of sales includes costs incurred directly by the businesses in the ordinary course of business. Examples include electricity and fuel purchases, O&M costs, depreciation and amortization expense, bad debt expense and recoveries, general administrative and support costs (including employee-related costs directly associated with the operations of the business). Cost of sales also includes the gains or losses on derivatives (including embedded derivatives other than foreign currency embedded derivatives) associated with the purchase of electricity or fuel.
Operating margin is defined as revenue less cost of sales.

80


Consolidated Revenue and Operating Margin — Executive Summary
(in millions)
Year Ended December 31, 2015
Consolidated Revenue — Revenue decreased $2.2 billion, or 13%, to $15.0 billion in 2015 compared to $17.1 billion in 2014. This decrease was primarily driven by unfavorable FX impacts of $2.5 billion, primarily in Brazil ($2.2 billion) and Colombia ($179 million). Additionally, there were lower volumes at the US Utilities, primarily at DPL, and outages, milder weather, and lower demand at IPL. Finally, there were lower prices in the Dominican Republic and El Salvador (primarily resulting from lower pass-through costs). These decreases were partially offset by higher tariffs at Eletropaulo and Sul (including higher pass-through costs), the reversal of a contingent regulatory liability at Eletropaulo, higher capacity prices at DPL, and the commencement of principal operations at Mong Duong in April 2015.
Consolidated Operating margin — Operating margin decreased $222 million, or 7%, to $2.9 billion in 2015 compared to $3.1 billion in 2014. This decrease was driven by unfavorable FX impacts of $368 million, primarily in Brazil ($235 million) and Colombia ($83 million). In addition, Brazil was impacted by lower demand, lower hydrology, and higher fixed costs and the Dominican Republic was impacted by lower commodities and lower availability. These decreases were partially offset by the impact of higher tariffs in Brazil as discussed above, lower spot prices on energy purchases at Tietê, higher generation and lower energy purchases driven by improved hydrological conditions in Panama, higher prices at Chivor driven by a strong El Niño, and higher availability at Gener and Masinloc.
Year Ended December 31, 2014
Consolidated Revenue — Revenue increased $1.3 billion, or 8%, to $17.1 billion in 2014 compared to $15.9 billion in 2013. This increase was driven by higher tariffs (primarily pass-through costs) at the Brazil Utilities and at IPL, higher spot prices at Tietê, and regulatory retail rate increases at DPL. These increases were partially offset by unfavorable FX impacts of $752 million, primarily in Brazil ($630 million), Argentina ($69 million) and Colombia ($30 million).
Consolidated Operating Margin — Operating margin decreased $159 million, or 5%, to $3.1 billion in 2014 compared to $3.2 billion in 2013. This decrease was driven by unfavorable FX impacts of $124 million, primarily in Brazil ($97 million). In addition, margins were negatively impacted by higher fixed costs at Eletropaulo, lower hydrology and higher spot purchase prices Tietê, and lower availability at Kilroot, Maritza, and Masinloc. These decreases were partially offset by higher tariffs and a non-recurring 2013 charge related to the recognition of a contingent regulatory liability at Eletropaulo, and higher generation volumes and prices at Chivor.
See Item 7.—SBU Performance Analysis of this Form 10-K for additional discussion and analysis of operating results for each SBU.
Consolidated Results of Operations — Other
General and administrative expenses
General and administrative expenses include expenses related to corporate staff functions and/or initiatives, executive management, finance, legal, human resources and information systems, as well as global development costs.
General and administrative expenses increased $9 million, or 5%, to $196 million in 2015 from 2014 primarily due to increased business development costs and employee-related costs partially offset by decreased professional fees.
General and administrative expenses decreased $33 million, or 15%, to $187 million in 2014 from 2013 primarily due to lower employee-related costs and business development costs.

81


Interest expense
Interest expense decreased $35 million, or 2%, to $1.4 billion in 2015 from $1.5 billion in 2014. The decrease was primarily attributable to lower interest expense of $63 million at the Parent Company due to a reduction in debt principal, and a $64 million reversal of interest expense previously recognized on a contingent regulatory liability at Eletropaulo. These decreases were partially offset by an increase at Mong Duong as the plant commenced operations in the first half of 2015 and ceased capitalizing interest, as well as the impact of the 2014 contingent interest reversal at Sul discussed below.
Interest expense decreased $11 million, or 1%, to $1.5 billion in 2014 from $1.5 billion in 2013. This decrease was primarily attributable to lower interest expense of $53 million at the Parent Company due to a reduction in debt principal, and a $48 million reversal of contingent interest accruals associated with disputed purchased energy obligations at Sul for which it was determined, based on developments during the second quarter of 2014, that the likelihood of an unfavorable outcome for the payment of interest on the disputed obligation was no longer probable. These decreases were partially offset by income of $34 million in the prior year resulting from the ineffectiveness on derivative interest rate swaps accounted for as cash flow hedges at Puerto Rico, and higher interest expense of $24 million at Gener due to an increase in debt principal.
Interest income
Interest income increased $159 million, or 44%, to $524 million in 2015 from $365 million in 2014. The increase was primarily due to interest income of $114 million recognized in 2015 on the financing element of the service concession arrangement at Muong Duong, as well as an increase of $54 million at Eletropaulo and Sul resulting from higher interest rates and an increase in regulatory assets.
Interest income increased $90 million, or 33%, to $365 million in 2014 from $275 million in 2013. The increase was primarily due to interest income of $59 million recognized on FONINVEMEM III receivables in Argentina, which satisfied the criteria for revenue recognition in the fourth quarter of 2014, as well as an increase of $23 million at Eletropaulo resulting from higher interest rates and an increase in regulatory assets. See Note 7—Financing Receivables included in Item 8.—Financial Statements and Supplementary Data of this Form 10-K for further information.
Loss on extinguishment of debt
Loss on extinguishment of debt was $186 million for the year ended December 31, 2015. This loss was primarily related to expense of $105 million, $22 million, and $19 million recognized on debt extinguishments at the Parent Company, IPL, and the Dominican Republic, respectively.
Loss on extinguishment of debt was $261 million for the year ended December 31, 2014. This loss was primarily related to expense of $193 million, $31 million, and $20 million recognized on debt extinguishments at the Parent Company, DPL, and Gener, respectively.
Loss on extinguishment of debt was $229 million for the year ended December 31, 2013. This was primarily related to debt extinguishments at the Parent Company and at Masinloc. See Note 12—Debt included in Item 8.—Financial Statements and Supplementary Data of this Form 10-K for further information.
Other income and expense
Other income was $83 million, $124 million, and $125 million for the years ended December 31, 2015, 2014, and 2013, respectively. Other expense was $65 million, $68 million, and $76 million for the years ended December 31, 2015, 2014, and 2013, respectively. See Note 20—Other Income and Expense included in Item 8.—Financial Statements and Supplementary Data of this Form 10-K for further information.
Gain on sale of businesses
Gain on sale of businesses was $29 million for the year ended December 31, 2015, which was primarily related to the sale of Armenia Mountain.
Gain on sale of businesses was $358 million for the year ended December 31, 2014, which was primarily related to the sale of 45% of the Company's interest in Masinloc, as well as the sale of U.K. Wind (Operating Projects).
Gain on disposal and sale of investments for the year ended December 31, 2013 was $26 million, which was primarily related to the sale of our remaining 20% interest in Cartagena as well as the sale of our 10% equity interest in Trinidad Generation Unlimited. See Note 8—Investments in and Advances to Affiliates, Note 16—Equity, and Note 24—Dispositions and Held-For-Sale Businesses included in Item 8.—Financial Statements and Supplemental Data of this Form 10-K for further information.
Goodwill impairment expense
The Company recognized goodwill impairment expense of $317 million, $164 million, and $372 million for the years

82


ended December 31, 2015, 2014, and 2013, respectively. See Note 10—Goodwill and Other Intangible Assets included in Item 8.—Financial Statements and Supplementary Data of this Form 10-K for further information.
Asset impairment expense
The Company recognized asset impairment expense of $285 million, $91 million and $95 million for the years ended December 31, 2015, 2014, and 2013, respectively. See Note 21—Asset Impairment Expense included in Item 8.—Financial Statements and Supplementary Data of this Form 10-K for further information.
Income tax expense
Income tax expense increased $46 million, or 11%, to $465 million in 2015. The Company's effective tax rates were 41% and 27% for the years ended December 31, 2015 and 2014, respectively.
The net increase in the 2015 effective tax rate was due, in part, to the current year nondeductible impairment of goodwill at our U.S. utility, DPL and Chilean withholding taxes offset by the release of valuation allowance at certain of our businesses in Brazil, Vietnam and the U.S. Further, the 2014 rate was impacted by the items described below.
Income tax expense increased $76 million, or 22%, to $419 million in 2014. The Company's effective tax rates were 27% and 33% for the years ended December 31, 2014 and 2013, respectively.    
The net decrease in the 2014 effective tax rate was due, in part, to the 2014 sale of approximately 45% of the Company's interest in Masin AES Pte Ltd., which owns the Company's business interests in the Philippines, and the 2014 sale of the Company's interests in four U.K. wind operating projects. Neither of these transactions gave rise to income tax expense. Further, the 2014 effective tax rate benefited from the release of valuation allowance against U.S. capital loss carryforwards and a change in tax status at a subsidiary operating in the Dominican Republic. Offsetting these items is the unfavorable impact of Chilean income tax law reform enacted in the third quarter of 2014. See Note 16—Equity for additional information regarding the sale of approximately 45% of the Company's interest in Masin-AES Pte Ltd. See Note 24—Dispositions and Held-for-Sale Businesses for additional information regarding the sale of the Company's interests in four U.K wind operating projects.
Our effective tax rate reflects the tax effect of significant operations outside the U.S., which are generally taxed at rates lower than the U.S. statutory rate of 35%. A future proportionate change in the composition of income before income taxes from foreign and domestic tax jurisdictions could impact our periodic effective tax rate. The Company also benefits from reduced tax rates in certain countries as a result of satisfying specific commitments regarding employment and capital investment. See Note 22—Income Taxes for additional information regarding these reduced rates.
Foreign currency transaction gains (losses)
Foreign currency transaction gains (losses) in millions were as follows:
Years Ended December 31,
2015
 
2014
 
2013
Argentina
$
124

 
$
66

 
$
2

Colombia
29

 
17

 
6

United Kingdom
11

 
12

 
2

Philippines
8

 
11

 
(10
)
Brazil
(6
)
 
(4
)
 
(12
)
Mexico
(6
)
 
(14
)
 
—

Chile
(18
)
 
(30
)
 
(20
)
AES Corporation
(31
)
 
(34
)
 
5

Other
(6
)
 
(13
)
 
5

Total (1)
$
105

 
$
11

 
$
(22
)
___________________________________________
(1) Includes gains of $247 million, $172 million and $60 million on foreign currency derivative contracts for the years ended December 31, 2015, 2014 and 2013, respectively.
The Company recognized a net foreign currency transaction gain of $105 million for the year ended December 31, 2015 primarily due to gains of:
•
$124 million in Argentina, due to the favorable impact from foreign currency derivatives related to government receivables, partially offset by losses from the devaluation of the Argentine Peso associated with U.S. Dollar denominated debt, and losses at Termoandes (a U.S. Dollar functional currency subsidiary) primarily associated with cash and accounts receivable balances in local currency,
•
$29 million in Colombia, primarily due to the depreciation of the Colombian Peso, positively impacting Chivor (a U.S. Dollar functional currency subsidiary) due to liabilities denominated in Colombian Pesos,
•
$11 million in the United Kingdom, primarily due to the depreciation of the Pound Sterling, resulting in gains at Ballylumford Holdings (a U.S. Dollar functional currency subsidiary) associated with intercompany notes payable

83


denominated in Pound Sterling, and
These gains were partially offset by losses of:
•
$31 million at The AES Corporation primarily due to decreases in the valuation of intercompany notes receivable denominated in foreign currency, resulting from the weakening of the Euro and British Pound during the year, partially offset by gains related to foreign currency option purchases, and
•
$18 million in Chile primarily due to the devaluation of the Chilean Peso at Gener (a U.S. Dollar functional currency subsidiary) from working capital denominated in Chilean Pesos, partially offset by gains on foreign currency derivatives.
The Company recognized a net foreign currency transaction gain of $11 million for the year ended December 31, 2014 primarily due to gains of:
•
$66 million in Argentina, due to the favorable impact from foreign currency derivatives related to government receivables, partially offset by losses from the devaluation of the Argentine Peso associated with U.S. Dollar denominated debt, and losses at Termoandes (a U.S. Dollar functional currency subsidiary) primarily associated with cash and accounts receivable balances in local currency, and the purchase of Argentine sovereign bonds,
•
$17 million in Colombia, primarily due to a 23% depreciation of the Colombian Peso, positively impacting Chivor (a U.S. Dollar functional currency subsidiary) due to liabilities denominated in Colombian Pesos, primarily income tax payable and accounts payable,
•
$12 million in the United Kingdom, primarily due to a 6% depreciation of the Pound Sterling, resulting in gains at Ballylumford Holdings (a U.S. Dollar functional currency subsidiary) associated with intercompany notes payable denominated in Pound Sterling, and gains related to foreign currency derivatives, and
•
$11 million in the Philippines, primarily due to amortization of frozen embedded derivatives and a 4% appreciation of the Philippine Peso against the U.S. Dollar, resulting in a revaluation of cash accounts, customer receivables, and deferred tax asset.
These gains were partially offset by losses of:
•
$34 million at The AES Corporation primarily due to decreases in the valuation of intercompany notes receivable denominated in foreign currency, resulting from the weakening of the Euro and British Pound during the year, partially offset by gains related to foreign currency option purchases,
•
$30 million in Chile primarily due to a 16% devaluation of the Chilean Peso, resulting in a $39 million loss at Gener (a U.S. Dollar functional currency subsidiary) from working capital denominated in Chilean Pesos, primarily cash, accounts receivable and VAT receivables, partially offset by income of $9 million on foreign currency derivatives, and
•
$14 million in Mexico, primarily due to a 13% devaluation of the Mexican Peso, resulting in a loss at TEGTEP and Merida (U.S. Dollar functional currency subsidiaries) from working capital denominated in Pesos (primarily cash, recoverable tax, and VAT).
The Company recognized a net foreign currency transaction loss of $22 million for the year ended December 31, 2013 primarily due to losses of:
•
$20 million in Chile, primarily due to a 9% weakening of the Chilean Peso, resulting in losses at Gener (a U.S. Dollar functional currency subsidiary) associated with net working capital denominated in Chilean Pesos, mainly cash, accounts receivables and tax receivables, partially offset by gains related to foreign currency derivatives,
•
$12 million in Brazil, primarily due to a 15% weakening of the Brazilian Real resulting in losses mainly associated with U.S. Dollar denominated liabilities, and
•
$10 million in the Philippines (a U.S. Dollar functional currency subsidiary beginning in 2013), primarily due to the 8% weakening of the Philippine Peso, resulting in revaluation of cash accounts, customer receivables and deferred tax assets.
Other non-operating expense
Other non-operating expense was zero, $128 million and $129 million for the years ended December 31, 2015, 2014 and 2013, respectively. See Note 9—Other Non-Operating Expense included in Item 8.—Financial Statements and Supplementary Data of this Form 10-K for further information.    
Net equity in earnings of affiliates
Net equity in earnings of affiliates increased $86 million, or 453%, to $105 million in 2015 from $19 million in 2014. The increase was primarily due to the 2015 restructuring of Guacolda in Chile, which increased the Company's equity investment and resulted in additional equity earnings, as well as the 2014 impairment at Elsta discussed below.

84


Net equity in earnings of affiliates decreased $6 million to $19 million in 2014 from $25 million in 2013. The decrease was primarily a result of an asset impairment charge at Elsta due to long lived assets that were determined to not be recoverable of which our share was $41 million. These items were partially offset by a $22 million lower loss recognized at Entek on an embedded foreign currency derivative and a $19 million increase as a result of the sale of equity interests in SRP. See Note 8—Investments in and Advances to Affiliates included in Item 8.—Financial Statements and Supplementary Data of this Form 10-K for further information.
Income from continuing operations attributable to noncontrolling interests
Income from continuing operations attributable to noncontrolling interests increased $69 million, or 18%, to $456 million in 2015 from $387 million in 2014 as a result of:
•
an increase at Mong Duong due to commencement of operations in the current year,
•
an increase at Gener primarily due to the restructuring of Guacolda,
•
an increase at Masinloc due to increased earnings and the 2014 sale of a noncontrolling interest in that business
Partially offset by
•
a decrease at Buffalo Gap III resulting from the asset impairment expense allocation to the tax equity partner, and
•
a decease at Eletropaulo resulting from unfavorable foreign exchange and lower demand.
Income from continuing operations attributable to noncontrolling interests decreased $59 million, or 13%, to $387 million in 2014 from $446 million in 2013 as a result of:
•
a decrease at Tietê due to lower earnings resulting from poor hydrology and increased prices for purchased energy,
•
a decrease at Uruguaiana due to a favorable arbitration settlement in 2013, and
•
a decrease at Panama related to poor hydrology.
Loss from discontinued operations
Total loss from discontinued operations was zero, $29 million, and $179 million for the years ended December 31, 2015, 2014 and 2013, respectively. See Note 23—Discontinued Operations included in Item 8.—Financial Statements and Supplementary Data of this Form 10-K for further information.
Net income attributable to The AES Corporation
Net income attributable to The AES Corporation decreased $463 million to $306 million in 2015 from $769 million in 2014. The key drivers of the decrease included:
•
Higher impairment expense
•
Lower gains from the sale of businesses
These increases were partially offset by:
•
Lower debt extinguishment expense
Net income attributable to The AES Corporation increased $655 million to $769 million in 2014 from $114 million in 2013. The key drivers of the increase included:
•
Higher gains from the sale of businesses
•
Lower impairment expense
•
Lower general and administrative expenses
SBU Performance Analysis
Non-GAAP Measures
Adjusted Operating Margin, Adjusted PTC, Adjusted EPS, and Proportional Free Cash Flow are non-GAAP supplemental measures that are used by management and external users of our consolidated financial statements such as investors, industry analysts and lenders.
Adjusted Operating Margin — Operating Margin is defined as revenue less cost of sales. Cost of sales includes costs incurred directly by the businesses in the ordinary course of business, such as Electricity and fuel purchases; O&M costs; Depreciation and amortization expense; Bad debt expense & recoveries; General administrative & support costs at the businesses; and Gains or losses on derivatives associated with the purchase and sale of electricity or fuel.
We define Adjusted Operating Margin as Operating Margin, adjusted for the impact of noncontrolling interests, excluding

85


unrealized gains or losses related to derivative transactions.
The GAAP measure most comparable to Adjusted Operating Margin is Operating Margin. We believe that Adjusted Operating Margin better reflects the underlying business performance of the Company. Factors in this determination include the impact of noncontrolling interests, where AES consolidates the results of a subsidiary that is not wholly-owned by the Company, as well as the variability due to unrealized derivatives gains or losses. Adjusted Operating Margin should not be construed as an alternative to Operating Margin, which is determined in accordance with GAAP.
Adjusted PTC and Adjusted EPS — We define Adjusted PTC as pretax income from continuing operations attributable to The AES Corporation excluding gains or losses due to (a) unrealized gains or losses related to derivative transactions, (b) unrealized foreign currency gains or losses, (c) gains or losses due to dispositions and acquisitions of business interests, (d) losses due to impairments, and (e) costs due to the early retirement of debt.
Adjusted PTC reflects the impact of noncontrolling interests and excludes the items specified in the definition above. In addition to the revenue and cost of sales reflected in Operating Margin, Adjusted PTC includes the other components of our income statement, such as General and administrative expense in the corporate segment, as well as business development costs; Interest expense and interest income; Other expense and other income; Realized foreign currency transaction gains and losses; and Net equity in earnings of affiliates.
We define Adjusted EPS as diluted earnings per share from continuing operations excluding gains or losses due to (a) unrealized gains or losses related to derivative transactions, (b) unrealized foreign currency gains or losses, (c) gains or losses due to dispositions and acquisitions of business interests, (d) losses due to impairments, and (e) costs due to the early retirement of debt.
The GAAP measure most comparable to Adjusted PTC is income from continuing operations attributable to The AES Corporation. The GAAP measure most comparable to Adjusted EPS is diluted earnings per share from continuing operations. We believe that Adjusted PTC and Adjusted EPS better reflect the underlying business performance of the Company and are considered in the Company's internal evaluation of financial performance. Factors in this determination include the variability due to unrealized gains or losses related to derivative transactions, unrealized foreign currency gains or losses, losses due to impairments and strategic decisions to dispose of or acquire business interests or retire debt, which affect results in a given period or periods. In addition, for Adjusted PTC, earnings before tax represents the business performance of the Company before the application of statutory income tax rates and tax adjustments, including the effects of tax planning, corresponding to the various jurisdictions in which the Company operates. Adjusted PTC and Adjusted EPS should not be construed as alternatives to income from continuing operations attributable to The AES Corporation and diluted earnings per share from continuing operations, which are determined in accordance with GAAP.
Proportional Free Cash Flow — Refer to Item 7—Management's Discussion and Analysis of Financial Condition and Results of Operations—Capital Resources and Liquidity—Proportional Free Cash Flow (A non-GAAP Measure) for the discussion and reconciliation of Proportional Free Cash Flow to its nearest GAAP measure.
Reconciliations of Non-GAAP Measures
Adjusted Operating Margin (in millions)
 
Years Ended December 31,
 
 
2015
 
2014
 
2013
US
 
$
598

 
$
711

 
$
684

Andes
 
466

 
444

 
402

Brazil
 
136

 
235

 
271

MCAC
 
438

 
482

 
472

Europe
 
276

 
373

 
392

Asia
 
70

 
51

 
159

Corp/Other
 
33

 
53

 
25

Intersegment eliminations
 
(1
)
 
(13
)
 
23

Total Adjusted Operating Margin
 
2,016

 
2,336

 
2,428

Noncontrolling interests adjustment
 
869

 
760

 
833

Derivatives adjustment
 
(19
)
 
(8
)
 
(14
)
Operating Margin
 
$
2,866

 
$
3,088

 
$
3,247


86


Adjusted PTC (in millions)
Year Ended December 31,
 
Total Adjusted PTC
 
Intersegment
 
External Adjusted PTC
2015
 
2014
 
2013
 
2015
 
2014
 
2013
 
2015
 
2014
 
2013
US SBU
 
$
360

 
$
445

 
440

 
$
12

 
$
10

 
11

 
$
372

 
$
455

 
$
451

Andes SBU
 
482

 
421

 
353

 
17

 
6

 
19

 
499

 
427

 
372

Brazil SBU
 
91

 
242

 
212

 
2

 
3

 
3

 
93

 
245

 
215

MCAC SBU
 
327

 
352

 
339

 
18

 
26

 
12

 
345

 
378

 
351

Europe SBU
 
235

 
348

 
345

 
5

 
5

 
7

 
240

 
353

 
352

Asia SBU
 
96

 
46

 
142

 
3

 
2

 
2

 
99

 
48

 
144

Corporate and Other
 
(441
)
 
(533
)
 
(624
)
 
(57
)
 
(52
)
 
(54
)
 
(498
)
 
(585
)
 
(678
)
Total Adjusted Pretax Contribution
 
1,150

 
1,321

 
1,207

 
—

 
—

 
—

 
1,150

 
1,321

 
1,207

Reconciliation to income from continuing operations, net of tax, attributable to The AES Corporation:
 
 
Non-GAAP Adjustments:


Unrealized derivative gains
166

 
135

 
57

Unrealized foreign currency losses
(96
)
 
(110
)
 
(41
)
Disposition/acquisition gains
42

 
361

 
30

Impairment losses
(504
)
 
(416
)
 
(588
)
Loss on extinguishment of debt
(183
)
 
(274
)
 
(225
)
Pre-tax contribution
575

 
1,017

 
440

Income tax expense attributable to The AES Corporation
269

 
228

 
156

Income from continuing operations, net of tax, attributable to The AES Corporation
$
306

 
$
789

 
$
284

Adjusted EPS
Years Ended December 31,
 
 
2015
 
2014
 
2013
 
Diluted earnings per share from continuing operations
$
0.44

 
$
1.09

 
$
0.38

 
Unrealized derivative (gains) (1)
(0.16
)
 
(0.12
)
 
(0.05
)
 
Unrealized foreign currency transaction losses(2)
0.12

 
0.14

 
0.02

 
Disposition/acquisition (gains)
(0.03
)
(3) 
(0.59
)
(4) 
(0.03
)
(5) 
Impairment losses
0.67

(6) 
0.53

(7) 
0.75

(8) 
Loss on extinguishment of debt
0.18

(9) 
0.25

(10) 
0.22

(11) 
Adjusted EPS
$
1.22

 
$
1.30

 
$
1.29

 
_____________________________
(1) 
Unrealized derivatives were net of income tax expense per share of $(0.08), $(0.07) and $(0.02) in 2015, 2014, and 2013, respectively.
(2) 
Unrealized foreign currency transaction losses were net of income tax benefit per share of $0.03, $0.02 and $0.02 in 2015, 2014, and 2013, respectively.
(3) 
Amount primarily relates to the gain from the sale of Solar Spain and Solar Italy of $7 million ($20 million, or $0.03 per share, including income tax benefit per share of $0.02), the gain from the sale of Armenia Mountain of $22 million ($14 million, or $0.02 per share, net of income tax expense per share of $0.01), and the loss from the tax consequences associated with the sale of a noncontrolling interest in Gener of $25 million, or $0.04 per share.
(4) 
Amount primarily relates to the gain from the sale of a noncontrolling interest in Masinloc of $283 million ($0.39 per share, net of income tax per share of $0.00), the gain from the sale of the U.K. wind projects of $78 million ($0.11 per share, net of income tax per share of $0.00), the loss from the liquidation of AgCert International of $1 million (net benefit of $18 million, or $0.03 per share, including income tax benefit per share of $0.03), the tax benefit of $24 million ($0.03 per share) related to the Silver Ridge Power transaction, and the tax benefit of $18 million ($0.02 per share) associated with the agreement executed in December 2014 to sell a noncontrolling interest in IPALCO.
(5) 
Amount primarily relates to the gain from the sale of Cartagena of $20 million ($15 million, or $0.02 per share, net of income tax benefit per share of $0.01).
(6) 
Amount primarily relates to the goodwill impairment at DPL of $317 million ($0.46 per share, net of income tax per share of $0.00) and asset impairments at Kilroot of $121 million ($95 million, or $0.14 per share, net of income tax benefit per share of $0.03), at U.K. Wind (Development Projects) of $38 million ($24 million, or $0.04 per share, net of income tax benefit per share of $0.01), and at Buffalo Gap III of $116 million ($18 million, or $0.03 per share, net of income tax benefit per share of $0.01).
(7) 
Amount primarily relates to the goodwill impairments at DPLER of $136 million ($0.19 per share, net of income tax per share of $0.00), and at Buffalo Gap of $28 million ($0.04 per share, net of income tax per share of $0.00), and asset impairments at Ebute of $67 million ($64 million, or $0.09 per share, net of income tax benefit per share of $0.00), and at Elsta of $41 million ($31 million, or $0.04 per share, net of income tax benefit per share of $0.01), and the other-than-temporary impairments at Silver Ridge Power of $42 million ($27 million, or $0.04 per share, net of income tax benefit per share of $0.02), and at Entek of $86 million ($0.12 per share, net of income tax benefit per share of $0.00).
(8) 
Amount primarily relates to the goodwill impairments at DPL of $307 million ($0.41 per share, net of income tax per share of $0.00) and at Ebute of $58 million ($0.08 per share, net of income tax per share of $0.00), the other-than-temporary impairment at Elsta of $129 million ($128 million, or $0.17 per share, net of income tax benefit per share of $0.00) and the asset impairments at Beaver Valley of $46 million ($30 million, or $0.04 per share, net of income tax benefit per share of $0.02), and at DPL of $26 million ($17 million, or $0.02 per share, net of income tax benefit per share of $0.01).
(9) 
Amount primarily relates to the loss on early retirement of debt at the Parent Company of $116 million ($75 million, or $0.11 per share, net of income tax benefit per share of $0.06) and at IPL of $22 million ($11 million, or $0.02 per share, net of income tax benefit per share of $0.01).
(10) 
Amount primarily relates to the loss on early retirement of debt at the Parent Company of $200 million ($130 million, or $0.18 per share, net of income tax benefit per share of $0.10), at DPL of $31 million ($20 million, or $0.03 per share, net of income tax benefit per share of $0.02), at Electrica Angamos of $20 million ($11 million, or $0.02 per share, net of income tax benefit per share of $0.00), at U.K. wind projects of $18 million ($15 million, or $0.02 per share, net of income tax benefit per share of $0.00).
(11) 
Amount primarily relates to the loss on early retirement of debt at Parent Company of $165 million ($107 million, or $0.14 per share, net of income tax benefit per share of $0.08), at Masinloc of $43 million ($39 million, or $0.05 per share, net of income tax per share of $0.00) and at Changuinola of $14 million ($10 million, or $0.01 per share, net of income tax benefit per share of $0.01).

87


US SBU
A summary of Operating Margin, Adjusted Operating Margin, Adjusted PTC, and Proportional Free Cash Flow ($ in millions) is as follows:
For the Years Ended December 31,
 
2015
 
2014
 
2013
 
$ Change 2015 vs. 2014
 
$ Change 2014 vs. 2013
 
% Change 2015 vs. 2014
 
% Change 2014 vs. 2013
Operating Margin
 
$
621

 
$
699

 
$
668

 
$
(78
)
 
$
31

 
-11
 %
 
5
 %
Noncontrolling Interests Adjustment
 
(38
)
 
—

 
—


Derivatives Adjustment
 
15

 
$
12

 
16


Adjusted Operating Margin
 
$
598

 
$
711

 
$
684

 
$
(113
)
 
$
27

 
-16
 %
 
4
 %
Adjusted PTC
 
$
360

 
$
445

 
$
440

 
$
(85
)
 
$
5

 
-19
 %

1
 %
Proportional Free Cash Flow
 
$
591

 
$
646

 
$
689

 
$
(55
)
 
$
(43
)
 
-9
 %
 
-6
 %
Fiscal year 2015 versus 2014
Operating margin decreased $78 million, or 11%, which was driven primarily by the following:
DPL
 
Impact of more of DP&L's generation being sold in the wholesale market at lower prices in 2015 compared to supplying DP&L retail customers in 2014, lower generation driven by plant outages in 2015, and unfavorable weather; partially offset by the impact of outages and lower gas availability occurring in Q1 2014
$
(53
)
Increase in capacity margin due to increase in PJM capacity price
26

Total DPL Decrease
(27
)
IPL
 
Lower wholesale margin due to lower market prices of electricity and outages
(26
)
Higher retail margins
20

Higher fixed costs primarily due to higher maintenance expense attributed to plant outages and higher depreciation expense due to MATS assets
(18
)
Other
(1
)
Total IPL Decrease
(25
)
US Generation

Lower production and prices across the US Wind businesses
(20
)
Lower availability and dispatch at Hawaii
(10
)
Other
4

Total US Generation Decrease
(26
)
Total US SBU Operating Margin Decrease
$
(78
)
Adjusted Operating Margin decreased $113 million for the US SBU due to the drivers above, excluding the impact of unrealized derivative gains and losses and proportional share adjustments. AES owns 100% of its businesses in the US with the exception of IPL with ownership of 85% beginning in February 2015 and 75% beginning in April 2015. AES owned 100% of IPL prior to February 2015.
Adjusted PTC decreased $85 million driven by the decrease of $113 million in Adjusted Operating Margin described above and a decrease in the Company's share of earnings under the HLBV allocation of noncontrolling interest at Buffalo Gap, partially offset by IPL due to lower interest expense related to the impact of the sell down and increased AFUDC, and DPL due to lower interest expense.
Proportional Free Cash Flow decreased $55 million, which includes the $113 million decrease in Adjusted Operating Margin as described above as well as a $22 million increase in maintenance and non-recoverable capital expenditures, partially offset by the collection of previously deferred storm costs, a one-time payment in 2014 to terminate an unfavorable coal contract, higher collections and the timing of inventory payments at DPL. Cash was also favorably impacted by the timing of collections and payments for energy at IPL as well as a reduction in interest payments.

88


Fiscal year 2014 versus 2013
Operating margin increased by $31 million, or 5%, which was driven primarily by the following:
U.S. Generation
 
Increased availability at Hawaii
$
11

Increased market prices at Laurel Mountain
8

Completion of the Tait energy storage project in September 2013
8

Other
(1
)
Total US Generation Increase
26

IPL
 
Higher wholesale margin
14

Lower fixed costs, primarily due to lower pension expense
11

Other
(1
)
Total IPL Increase
24

DPL
 
Impact from the timing of outages, resulting in higher purchased power and related costs, lower gas availability and higher demand during the peak of cold weather in Q1 2014, as well as increased customer switching to third party CRES providers
(71
)
Higher rates resulting from increased retail prices, lower fuel costs, and higher capacity prices
57

Other
(5
)
Total DPL Decrease
(19
)
Total US SBU Operating Margin Increase
$
31

Adjusted Operating Margin increased $27 million due to the drivers above, excluding the impact of unrealized derivative gains and losses. AES owned 100% of its businesses in the US in 2014, so there is no adjustment for noncontrolling interests.
Adjusted PTC increased $5 million driven by net gains of $53 million recognized resulting from the early termination of the PPA and coal supply contract at Beaver Valley during the first quarter of 2013, largely offset by an increase of $27 million in Adjusted Operating Margin described above as well as an increase in the Company's share of earnings under the HLBV allocation of noncontrolling interest at Buffalo Gap and Armenia Wind of $13 million and settlements at Laurel Mountain of $6 million.
Proportional Free Cash Flow decreased $43 million driven by the one-time cash receipt in 2013 upon the early termination of the PPA at Beaver Valley as well as the timing of legal settlements at Laurel Mountain as described above. Additionally, cash was unfavorably impacted by the timing of payments at IPL for energy, maintenance and inventory and a one-time payment at DPL in the fourth quarter of 2014 to terminate an unfavorable coal contract. These unfavorable impacts were partially offset by the $27 million increase in Adjusted Operating Margin as described above, a $51 million reduction in maintenance capital expenditures, primarily at our Utility businesses, as well as the timing of fuel payments and a reduction in interest payments at DPL.
ANDES SBU
A summary of Operating Margin, Adjusted Operating Margin, Adjusted PTC, and Proportional Free Cash Flow ($ in millions) is as follows:
For the Years Ended December 31,
 
2015
 
2014
 
2013
 
$ Change 2015 vs. 2014
 
$ Change 2014 vs. 2013
 
% Change 2015 vs. 2014
 
% Change 2014 vs. 2013
Operating Margin
 
$
618

 
$
587

 
$
533

 
$
31

 
$
54

 
5
%
 
10
 %
Noncontrolling Interests Adjustment
 
(152
)
 
(143
)
 
(131
)


Adjusted Operating Margin
 
$
466

 
$
444

 
$
402

 
$
22

 
$
42

 
5
%
 
10
 %
Adjusted PTC
 
$
482

 
$
421

 
$
353

 
$
61

 
$
68

 
14
%
 
19
 %
Proportional Free Cash Flow
 
$
224

 
$
176

 
$
188

 
$
48

 
$
(12
)
 
27
%
 
-6
 %

89


Fiscal year 2015 versus 2014
Including the unfavorable impact of foreign currency translation and remeasurement of $87 million, operating margin increased $31 million, or 5%, which was driven primarily by the following:
Gener
 
Higher margins associated to Nueva Renca Plant tolling agreement
$
26

Higher volume of energy sales mainly related to higher availability
21

Other
(2
)
Total Gener Increase
45

Argentina
 
Higher rates driven by an annual price review and additional contributions introduced by Resolution 482
49

Higher fixed costs primarily driven by higher inflation and by higher maintenance cost
(45
)
Unfavorable FX remeasurement impacts
(4
)
Other
4

Total Argentina Increase
4

Chivor
 
Unfavorable FX remeasurement impacts
(83
)
Higher rates driven by a strong El Niño impact on prices
60

Higher volume of energy sales mainly associated to higher generation
12

Other
(7
)
Total Chivor Decrease
(18
)
Total Andes SBU Operating Margin Increase
$
31

Adjusted Operating Margin increased $22 million for the year due to the drivers above, adjusted for the impact of noncontrolling interests. AES owned 71% of Gener and Chivor prior to sell down effective December 2015 which resulted in ownership of 67%. AES Argentina is owned 100%. The Alto Maipo and Cochrane plants under construction are owned 40%.
Adjusted PTC increased $61 million, driven by a restructuring of Guacolda in Chile which increased our equity investment and resulted in additional equity in earnings of $46 million, realized FX gains, lower interest expense at Chivor and the increase of $22 million in Adjusted Operating Margin described above. This was partially offset by lower equity earnings at Guacolda of $16 million (excluding restructuring impact above) mainly driven by a 2014 gain on sale of a transmission line.
Proportional Free Cash Flow increased $48 million, primarily driven by higher VAT refunds at Cochrane and Alto Maipo, the timing of non-recurring maintenance collections at Alicura, a decrease in interest payments as well as a $17 million net reduction in maintenance and non-recoverable environmental capital expenditures. Excluding the $22 million collection delay resulting from the various resolutions passed by the Argentine government (as discussed in Note 7—Financing Receivables), Adjusted Operating Margin decreased by $4 million due to the drivers discussed above. Additionally, cash flow was negatively impacted by higher tax payments and lower collections from contract customers at Chivor as well as a one-time swap termination payment at Ventanas.
Fiscal year 2014 versus 2013
Including the unfavorable impact of foreign currency translation and remeasurement of $14 million, operating margin for 2013 increased $54 million, or 10%, which was driven primarily by the following:
Chivor
 
Higher generation, higher spot and contract prices, and higher ancillary services
$
72

Higher maintenance costs
(12
)
Unfavorable FX impacts
(9
)
Other
4

Total Chivor Increase
55

Argentina
 
Higher rates as a result of the impact of Resolution 529
30

Higher generation and availability
13

Higher fixed costs driven by higher inflation
(27
)
Unfavorable FX impacts
(5
)
Other
(3
)
Total Argentina Increase
8

Gener
 
Lower contract prices, spot prices in the SADI, and lower Energy Plus margin
(32
)
Lower availability
(9
)
Contributions from Ventanas IV, which commenced operations in March 2013
10

Lower fixed costs, primarily lower maintenance and salaries
19

Other
3

Total Gener Decrease
(9
)
Total Andes SBU Operating Margin Increase
$
54


90


Adjusted Operating Margin increased $42 million for the year due to the drivers above, adjusted for the impact of noncontrolling interests. AES owned 71% of Gener and Chivor and 100% of AES Argentina.
Adjusted PTC increased $68 million driven by the increase of $42 million in Adjusted Operating Margin described above, and a net benefit of $45 million related to FONINVEMEM interest income on receivables in 2014 and 2013, partially offset by realized FX losses at Gener as well as non-recurring equity tax reversal of $8 million at Chivor in 2013.
Proportional Free Cash Flow decreased $12 million driven by an increase in interest payments, higher payments for VAT at our Cochrane plant, a one-time swap termination payment at Angamos as well as a $3 million net increase in maintenance and non-recoverable environmental capital expenditures. These unfavorable impacts were partially offset by the $42 million increase in Adjusted Operating Margin as described above as well a reduction in tax payments at Chivor and Gener.
BRAZIL SBU
A summary of Operating Margin, Adjusted Operating Margin, Adjusted PTC, and Proportional Free Cash Flow ($ in millions) is as follows:
For the Years Ended December 31,
 
2015
 
2014
 
2013
 
$ Change 2015 vs. 2014
 
$ Change 2014 vs. 2013
 
% Change 2015 vs. 2014
 
% Change 2014 vs. 2013
Operating Margin
 
$
600

 
$
742

 
$
871

 
$
(142
)
 
$
(129
)
 
-19
 %
 
-15
 %
Noncontrolling Interests Adjustment
 
(464
)
 
(507
)
 
(600
)


Adjusted Operating Margin
 
$
136

 
$
235

 
$
271

 
$
(99
)
 
$
(36
)
 
-42
 %
 
-13
 %
Adjusted PTC
 
$
91

 
$
242

 
$
212

 
$
(151
)
 
$
30

 
-62
 %
 
14
 %
Proportional Free Cash Flow
 
$
(29
)
 
$
13

 
$
116

 
$
(42
)
 
$
(103
)
 
-323
 %
 
-89
 %
Fiscal year 2015 versus 2014
Including the unfavorable impact of foreign currency translation of $235 million, operating margin decreased $142 million, or 19%, which was driven primarily by the following:
Sul
 
Lower volumes due to economic decline and higher technical and non-technical losses
$
(68
)
Higher fixed costs, primarily due to higher bad debt and regulatory penalties due to storms as well as higher depreciation expenses
(44
)
Higher tariffs
19

Other
(6
)
Total Sul Decrease
(99
)
Eletropaulo
 
Higher fixed costs, primarily due to higher bad debt expense, storms and employee-related costs
(142
)
Unfavorable FX impacts
(74
)
Contingency related to performance indicators
(59
)
Lower volumes due to lower demand
(35
)
Reversal of a contingent regulatory liability (excluding FX)
135

Higher tariffs
82

Total Eletropaulo Decrease
(93
)
Tietê
 
Energy purchases at lower rates primarily due to lower spot prices
311

Unfavorable FX impacts
(152
)
Higher volume purchased on the spot market due to higher assured energy requirement
(113
)
Other
(8
)
Total Tietê Increase
38

Uruguaiana
 
Higher generation from a longer period of temporary restart of operations
11

Total Uruguaiana Increase
11

Other Business Drivers
1

Total Brazil SBU Operating Margin Decrease
$
(142
)
Adjusted Operating Margin decreased $99 million primarily due to the drivers discussed above, adjusted for the impact of noncontrolling interests. AES owns 16% of Eletropaulo, 46% of Uruguaiana, 100% of Sul and 24% of Tietê.
Adjusted PTC decreased $151 million, driven by the decrease of $99 million in Adjusted Operating Margin described above, a reversal of $47 million in contingent interest accruals in 2014 as well as higher debt and interest rates in 2015 at Sul. These results were partially offset by favorable net interest income recognized on receivables at Eletropaulo and Sul.
Proportional Free Cash Flow decreased $42 million, which includes the $99 million decrease in Adjusted Operating Margin as described above as well as an increase in interest payments, partially offset by the timing of energy purchases and regulatory charges, lower tax payments as well as a $25 million reduction in maintenance capital expenditures.

91


Fiscal year 2014 versus 2013
Including the unfavorable impact of foreign currency translation of $97 million, operating margin decreased $129 million, or 15%, which was driven primarily by the following:
Tietê
 
Net impact of lower hydrology, which led to lower generation and an increase in energy purchases at higher prices, partially offset by higher spot sales in the first half of 2014 due to lower contracted volumes of energy sold
$
(252
)
Unfavorable FX impacts
(58
)
Other
(5
)
Total Tietê Decrease
(315
)
Uruguaiana
 
Extinguishment of a liability based on a favorable arbitration decision in the second quarter of 2013, partially offset by higher generation in 2014 during the period of temporary restart of operations
(53
)
Other
2

Total Uruguaiana Decrease
(51
)
Eletropaulo
 
Non-recurring 2013 charge related to the recognition of a contingent regulatory liability related to potential customer refunds
198

Higher rates driven by a higher tariff
124

Higher volumes
46

Higher fixed costs and depreciation, primarily related to personnel and pension costs
(133
)
Unfavorable FX impacts
(28
)
Total Eletropaulo Increase
207

Sul
 
Higher volumes and rates
52

Higher fixed costs and depreciation
(11
)
Unfavorable FX impacts
(10
)
Total Sul Increase
31

Other Business Drivers
(1
)
Total Brazil SBU Operating Margin Decrease
$
(129
)
Adjusted Operating Margin decreased $36 million primarily due to the drivers discussed above, adjusted for the impact of noncontrolling interests. AES owns 16% of Eletropaulo, 46% of Uruguaiana, 100% of Sul and 24% of Tietê.
Adjusted PTC increased $30 million, driven by the reversal of a loss contingency resulting from a change in estimate related to interest expense of $47 million and 2014 municipalities settlement interest of $12 million at Sul, partially offset by the decrease of $36 million in Adjusted Operating Margin described above, and higher interest rates and debt.
Proportional Free Cash Flow decreased $103 million, which includes the $36 million decrease in Adjusted Operating Margin as described above with the exception of the non-recurring 2013 charge related to potential customer refunds as that balance was not fully paid. The Brazil SBU was also unfavorably impacted by an increase in tax payments at Sul and Eletropaulo, the timing of collections of regulatory assets and settlement of regulatory liabilities at Eletropaulo and an increase in interest payments at Sul as noted above. These decreases were partially offset by a $19 million reduction in maintenance capital expenditures as well as the timing of energy purchases at Tietê.
MCAC SBU
A summary of Operating Margin, Adjusted Operating Margin, Adjusted PTC, and Proportional Free Cash Flow ($ in millions) is as follows:
For the Years Ended December 31,
 
2015
 
2014
 
2013
 
$ Change 2015 vs. 2014
 
$ Change 2014 vs. 2013
 
% Change 2015 vs. 2014
 
% Change 2014 vs. 2013
Operating Margin
 
$
543

 
$
541

 
$
543

 
$
2

 
$
(2
)
 
—
 %
 
—
 %
Noncontrolling Interests Adjustment
 
(106
)
 
(59
)
 
(69
)


Derivatives Adjustment
 
1

 
—

 
(2
)


Adjusted Operating Margin
 
$
438

 
$
482

 
$
472

 
$
(44
)
 
$
10

 
-9
 %
 
2
 %
Adjusted PTC
 
$
327

 
$
352

 
$
339

 
$
(25
)
 
$
13

 
-7
 %
 
4
 %
Proportional Free Cash Flow
 
$
498

 
$
281

 
$
433

 
$
217

 
$
(152
)
 
77
 %
 
-35
 %

92


Fiscal year 2015 versus 2014
Operating margin increased $2 million, or 0.4%, which was driven primarily by the following:
Dominican Republic
 
Lower commodity prices resulting in lower spot prices and lower than expected gas sales demand with excess gas used for generation at lower margins
$
(29
)
Lower availability
(28
)
Lower frequency regulation revenues
(21
)
Total Dominican Republic Decrease
(78
)
Mexico
 
Higher fuel costs, lower spot sales and lower availability
(29
)
Total Mexico Decrease
(29
)
Puerto Rico
 
One-time reversal of bad debt in 2014 and higher maintenance expense
(11
)
Total Puerto Rico Decrease
(11
)
Panama
 
Higher generation and lower energy purchases, driven by improved hydrological conditions
118

Commencement of power barge operations at the end of March 2015
18

Lower compensation from the government of Panama due to lower volumes of energy purchased at lower spot prices
(34
)
Other
(6
)
Total Panama Increase
96

El Salvador
 
One-time unfavorable adjustment to unbilled revenue in 2014
12

Lower energy losses and higher demand
11

Total El Salvador Increase
23

Total MCAC SBU Operating Margin Increase
$
2

Adjusted Operating Margin decreased $44 million due to the drivers above, adjusted for the impact of noncontrolling interests and excluding unrealized gains and losses on derivatives. AES owns 90% of Changuinola and 49% of its other generation facilities in Panama, 92% of Andres and Los Mina (compared to 100% in 2014) and 46% of Itabo (compared to 50% in 2014) in the Dominican Republic, 99% of TEG/TEP and 55% of Merida in Mexico, and a weighted average of 77% of its businesses in El Salvador (compared to 75% in 2014). In December 2015, there was an additional sell down in the Dominican Republic resulting in ownership of 90% at Andres and Los Mina and 45% at Itabo.
Adjusted PTC decreased $25 million, driven by the decrease in Adjusted Operating Margin of $44 million as described above. These results were partially offset by a compensation agreement regarding early termination of the original Barge PPA of $10 million and 2014 losses on a legal dispute settlement of $4 million in Panama as well as lower interest expense due to lower debt at Puerto Rico.
Proportional Free Cash Flow increased $217 million primarily due to the timing of collections in the Dominican Republic, Puerto Rico and Panama. These favorable impacts were partially offset by the $44 million decrease in Adjusted Operating Margin as described above as well as a $2 million increase in maintenance and non-recoverable environmental capital expenditures.

93


Fiscal year 2014 versus 2013
Including the unfavorable impact of foreign currency translation of $3 million, operating margin decreased $2 million, or 0.4%, which was driven primarily by the following:
El Salvador
 
One-time unfavorable adjustment to unbilled revenue
$
(12
)
Higher energy losses and other fixed costs
(9
)
Other
(1
)
Total El Salvador Decrease
(22
)
Panama
 
Lower generation and higher energy purchases due to dry hydrological conditions
(38
)
Esti tunnel settlement agreement in 2013
(31
)
Compensation from the government of Panama related to spot purchases from dry hydrological conditions
40

Lower fixed and other costs
22

Other
(1
)
Total Panama Decrease
(8
)
Dominican Republic
 
Higher spot sales
58

Higher availability
20

Lower gas sales to third parties
(27
)
Lower frequency regulation revenues
(26
)
Lower PPA margins
(14
)
Other
8

Total Dominican Republic Increase
19

Puerto Rico
 
Favorable bad debt reversal
6

Total Puerto Rico Increase
6

Other business drivers
3

Total MCAC SBU Operating Margin Decrease
$
(2
)
Adjusted Operating Margin increased $10 million due to the drivers above adjusted for the impact of noncontrolling interests and excluding unrealized gains and losses on derivatives. AES owns 90% of Changuinola and 49% of its other generation facilities in Panama, 100% of Andres and Los Mina and 50% of Itabo in the Dominican Republic, 99% of TEG/TEP and 55% of Merida in Mexico, and a weighted average of 75% of its businesses in El Salvador.
Adjusted PTC increased $13 million, driven by the increase in Adjusted Operating Margin of $10 million described above.
Proportional Free Cash Flow decreased $152 million primarily due to a one-time settlement received in 2013 at the Dominican Republic resulting from a fuel contract amendment, an increase in tax payments, as well as the timing of energy purchases at Panama, partially offset by the $10 million increase in Adjusted Operating Margin as described above.
EUROPE SBU
A summary of Operating Margin, Adjusted Operating Margin, Adjusted PTC, and Proportional Free Cash Flow ($ in millions) is as follows:
For the Years Ended December 31,
 
2015
 
2014
 
2013
 
$ Change 2015 vs. 2014
 
$ Change 2014 vs. 2013
 
% Change 2015 vs. 2014
 
% Change 2014 vs. 2013
Operating Margin
 
$
303

 
$
403

 
$
415

 
$
(100
)
 
$
(12
)
 
-25
 %
 
-3
 %
Noncontrolling Interests Adjustment
 
(30
)
 
(26
)
 
(23
)


Derivatives Adjustment
 
3

 
(4
)
 
—


Adjusted Operating Margin
 
$
276

 
$
373

 
$
392

 
$
(97
)
 
$
(19
)
 
-26
 %
 
-5
 %
Adjusted PTC
 
$
235

 
$
348

 
$
345

 
$
(113
)
 
$
3

 
-32
 %

1
 %
Proportional Free Cash Flow
 
$
238

 
$
197

 
$
345

 
$
41

 
$
(148
)
 
21
 %
 
-43
 %
Fiscal year 2015 versus 2014
Including the unfavorable impact of foreign currency translation of $47 million, operating margin decreased $100 million, or 25%, which was driven primarily by the following:
Maritza
 
Unfavorable FX impacts due to Euro depreciation against USD
$
(30
)
Lower rates due to non-operating costs passed through the tariff
(8
)
Higher availability in 2015
8

Total Maritza Decrease
(30
)
Kilroot
 
Lower dispatch and lower market prices due to gas/coal spread as well as lower capacity prices
(23
)
Higher fixed costs primarily driven by maintenance cost due to timing of outages
(3
)
Lower depreciation due to impairment in Q3 2015
7

Other
1

Total Kilroot Decrease
(18
)
Ballylumford
 
Lower availability and lower capacity prices
(8
)
Write down of non-primary fuel inventory
(4
)
Total Ballylumford Decrease
(12
)
Other
 
Reduction due to the sale of Ebute in 2014
(34
)
Lower Heat Rate margin at Jordan
(6
)
Total Europe SBU Operating Margin Decrease
$
(100
)
Adjusted Operating Margin decreased $97 million due to the drivers above adjusted for noncontrolling interests and excluding unrealized gains and losses on derivatives. AES owns 89% of St. Nikola in Bulgaria, and 37% and 60%, respectively, of the Amman East and IPP4 projects in Jordan.
Adjusted PTC decreased $113 million, driven primarily by the decrease of $97 million in Adjusted Operating Margin described above and by higher depreciation and unfavorable FX impact from Elsta as well as unfavorable impact due to the reversal of a liability in 2014 in Kazakhstan. These results partially offset by lower interest expenses in Bulgaria.
Proportional Free Cash Flow increased $41 million, which is primarily driven by higher collections at Maritza and Kavarna in Bulgaria, IPP4 in Jordan and at Ballylumford, partially offset by the $97 million decrease in Adjusted Operating Margin as described above.
Fiscal year 2014 versus 2013
Including the unfavorable impact of foreign currency translation of $10 million, operating margin decreased $12 million, or 3%, which was driven primarily by the following:

94


Kilroot
 
Lower dispatch and higher outages and related maintenance costs
$
(46
)
Higher rates, including income from energy price hedges and favorable FX rates
13

Other
2

Total Kilroot Decrease
(31
)
Maritza
 
Higher outages and related maintenance costs
(32
)
Impact of higher rates
10

Other
5

Total Maritza Decrease
(17
)
Jordan
 
Commencement of operations at the IPP4 plant in July 2014
17

Total Jordan Increase
17

Kazakhstan
 
Higher volumes and rates
29

Unfavorable FX impacts
(13
)
Other
(5
)
Total Kazakhstan Increase
11

Other Business Drivers
8

Total Europe SBU Operating Margin Decrease
$
(12
)
Adjusted Operating Margin decreased $19 million due to the drivers above adjusted for noncontrolling interests, primarily Jordan with Amman East at 36% and IPP4 at 60%, and excluding unrealized gains and losses on derivatives.
Adjusted PTC increased $3 million, driven by the decrease of $19 million in Adjusted Operating Margin described above, offset by the reversal of a liability of $18 million in Kazakhstan from the expiration of a statute of limitations for the Republic of Kazakhstan to claim payment from AES.
Proportional Free Cash Flow decreased $148 million, which includes the $19 million decrease in Adjusted Operating Margin as described above as well as the loss of cash flow resulting from the sale of our businesses in Cameroon and the Ukraine. Cash was also unfavorably impacted by the timing of collections at Maritza, Ballylumford and Jordan as well as pension plan contributions at Kilroot. These drivers were partially offset by an increase in dividends received at Elsta, our equity method investment in the Netherlands.
ASIA SBU
A summary of Operating Margin, Adjusted Operating Margin, Adjusted PTC, and Proportional Free Cash Flow ($ in millions) is as follows:
For the Years Ended December 31,
 
2015
 
2014
 
2013
 
$ Change 2015 vs. 2014
 
$ Change 2014 vs. 2013
 
% Change 2015 vs. 2014
 
% Change 2014 vs. 2013
Operating Margin
 
$
149

 
$
76

 
$
169

 
$
73

 
$
(93
)
 
96
%
 
-55
 %
Noncontrolling Interests Adjustment
 
(79
)
 
(25
)
 
(10
)


Adjusted Operating Margin
 
$
70

 
$
51

 
$
159

 
$
19

 
$
(108
)
 
37
%
 
-68
 %
Adjusted PTC
 
$
96

 
$
46

 
$
142

 
$
50

 
$
(96
)
 
109
%

-68
 %
Proportional Free Cash Flow
 
$
87

 
$
82

 
$
101

 
$
5

 
$
(19
)
 
6
%
 
-19
 %
Fiscal year 2015 versus 2014
Operating margin increased $73 million, or 96%, which was driven primarily by the following:
Masinloc
 
Higher availability
$
27

One-time unfavorable impact in 2014 due to market operator's retrospective adjustment to energy prices in Nov and Dec 2013
15

Lower fixed costs and lower tax assessments in 2015 relative to 2014
7

Other
3

Total Masinloc Increase
52

Mong Duong
 
Commencement of principal operations in April 2015
24

Total Mong Duong Increase
24

Other
(3
)
Total Asia SBU Operating Margin Increase
$
73

Adjusted Operating Margin increased $19 million due to the drivers above adjusted for the impact of noncontrolling interests resulting primarily from the sell-down of our ownership in Masinloc from 92% to 51% in mid-July 2014. AES also owns 90% of Kelanitissa and 51% of Mong Duong.
Adjusted PTC increased $50 million, driven by the increase of $19 million in Adjusted Operating Margin described above, and the additional net impact of $28 million at Mong Duong due to a component of service concession revenue recognized as interest income, net of higher interest expense as interest is no longer capitalized. See Note 1—General and Summary of Significant Accounting Policies in Part II.—Item 8.—Financial Statements and Supplementary Data for further information regarding the accounting for service concession arrangements.
Proportional Free Cash Flow increased $5 million, driven by the collection of service concession revenue at Mong Duong noted above (which is not included in operating margin) as well as the $19 million increase in Adjusted Operating Margin, but excluding the retrospective adjustment to energy prices as described above. These favorable drivers were partially offset by the timing of collections at Masinloc which were negatively impacted by our sell-down of ownership interest in 2014.
Fiscal year 2014 versus 2013
Operating margin decreased $93 million, or 55%, which was driven primarily by the following:
Masinloc
 
Lower plant availability
$
(33
)
Net decrease from lower spot sales, partially offset by higher volumes
(21
)
Philippine market operator's adjustment in the first quarter of 2014 to retrospectively recalculate energy prices related to an unprecedented increase in spot energy prices in November and December 2013
(15
)
Higher maintenance costs
(4
)
Other
(6
)
Total Masinloc Decrease
(79
)
Kelanitissa
 
Impact of the step-down in the contracted PPA price
(17
)
Total Kelanitissa Decrease
(17
)
Other Business Drivers
3

Total Asia SBU Operating Margin Decrease
$
(93
)

95


Adjusted Operating Margin decreased $108 million due to the drivers above adjusted for the impact of noncontrolling interests and excluding unrealized gains on derivatives. AES owned 92% of Masinloc until July 2014 when AES reduced its ownership to 51%.
Adjusted PTC decreased $96 million, driven by the decrease of $108 million in Adjusted Operating Margin described above, partially offset by the impact of lower proportional interest expense at Masinloc and gains on foreign currency.
Proportional Free Cash Flow decreased $19 million, which includes the $108 million decrease in Adjusted Operating Margin as described above, excluding the retrospective adjustment to energy prices, partially offset by the timing of collections and payments for coal at Masinloc as well as a decrease in payments for interest and taxes.
Key Trends and Uncertainties
During 2016 and beyond, we expect to face the following challenges at certain of our businesses. Management expects that improved operating performance at certain businesses, growth from new businesses and global cost reduction initiatives may lessen or offset their impact. If these favorable effects do not occur, or if the challenges described below and elsewhere in this section impact us more significantly than we currently anticipate, or if volatile foreign currencies and commodities move more unfavorably, then these adverse factors (or other adverse factors unknown to us) may impact our operating margin, net income attributable to The AES Corporation and cash flows. We continue to monitor our operations and address challenges as they arise. For the risk factors related to our business, see Item 1.—Business and Item 1A.—Risk Factors of this Form 10-K.
Operational
Sensitivity to Dry Hydrological Conditions — Our hydroelectric generation facilities are sensitive to changes in the weather, particularly the level of water inflows into generation facilities. Since 2013, dry hydrological conditions in Panama, Brazil, Colombia and Chile have presented challenges for our businesses in these markets. Low rainfall and water inflows have caused reservoir levels to be below historical levels, reduced generation output, and increased prices for electricity. If hydrological conditions do not improve and our hydroelectric generation facilities cannot generate sufficient energy to meet contractual arrangements, we may need to purchase energy to fulfill our obligations, which could have a material adverse impact on our results of operations.
According to the National Oceanic and Atmospheric Administration ("NOAA") a strong El Niño has been declared and is forecasted through the spring of 2016. According to local hydrological forecasts in Panama, below historical average inflows are expected to persist through the dry season of 2016 (ending in April). The effects of the El Niño phenomena could potentially intensify the dry hydrology conditions during this period. AES Panama has to purchase energy on the spot market to fulfill its contract obligations when its generation output is below contract levels. However, with declines in oil prices the cost of purchasing replacement power is reduced. In addition, lower hydrology results in less energy available to sell in the spot market after fulfilling contract obligations. We expect this trend to continue through the dry season of 2016, which will continue to impact our results of operations.
The El Niño brought some relief to the dry conditions in Brazil as it brought rain to the South and Southeast regions. The Southeast region has a significant portion of the country's reservoir capacity. At the beginning of 2016, we expect the system operator in Brazil to continue to pursue a more conservative reservoir management strategy to recover the reservoirs. Higher inflows are expected along with an impact on reservoir level recovery and lower spot prices. AES Sul, which is in the South of Brazil, could be negatively impacted by higher hydrology causing floods and other damage which could disrupt service and require emergency repairs. Additionally, higher hydrology could reduce the need for demand to provide irrigation services during the warm season.
Impacts in Colombia are uncertain since it will depend strongly upon the behavior pattern of the El Niño and can lead to better hydrology for just the area where our plant, Chivor, is located or the country as a whole. More extreme behavior can have an opposite impact and leave the Chivor basin dryer but the remainder of the country with better hydrology.
In the case of Chile, the hydrological year starts in April, and given that the El Niño phenomenon is not highly correlated with hydrological conditions in Chile, projection are made considering the average of all hydrological conditions. For the first quarter 2016, projections are made considering 2015 snowpack information which shows hydrological condition lower than average.
The exact behavior pattern and strength of El Niño cannot be definitively known at this time and therefore the impacts could vary from those described above. Even if rainfall and water inflows return to historical averages, in some cases high market prices and low generation could persist until reservoir levels are fully recovered.
Macroeconomic and Political
During the past few years, economic conditions in some countries where our subsidiaries conduct business have deteriorated. Global economic conditions remain volatile and could have an adverse impact on our businesses in the event these

96


recent trends continue.
Brazil — In Brazil, economic conditions remain unfavorable, as indicated by such factors as a negative GDP growth for 2015 and expectation for the same in 2016 and flat for 2017, higher interest rates and inflation, and increasing unemployment. As a consequence, our distribution businesses have experienced a decline in demand. If these economic conditions persist or worsen, there could be a material impact on our businesses and AES's results of operations, particularly in our distribution businesses in Brazil, AES Sul and AES Eletropaulo.
In the case of AES Sul, at December 31, 2015, debt in the amount of $333 million is classified as current due to a failure to meet required debt covenants related to earnings for two consecutive quarters. This default is primarily due to the economic conditions noted above, an increase in regulatory assets due to sector charges and higher priced energy purchases, increase in delinquency rates, and higher costs due to unfavorable hydrology in Brazil and severe weather conditions, particularly in AES Sul's service area. AES Sul is in negotiations with its creditors and has obtained a waiver for a period of two months, that ends in February 2016, when the Company expects to close the renegotiation of the whole debt, involving extending the debt maturities and additional equity contributions of approximately $75 million. Following the debt renegotiations, the Company will assess all strategic alternatives for AES Sul. If the negotiation is unsuccessful, we may face a loss of earnings and/or cash flows from Sul and may have to provide loans or equity to support the business, and/or restructure the business, any of which could have a material impact on the Company. In addition, AES Sul has recorded net deferred tax assets ("DTA") of $133 million relating primarily to net operating loss carryforwards, which are not subject to expiration. Realization is dependent on generating sufficient taxable income. Although realization is not assured, management believes it is more likely than not that all of the DTA will be realized. The amount of DTA that is considered realizable, however, could be reduced in the near term if estimates of future taxable income are reduced. 
Argentina — In November 2015, Argentina held presidential elections in which centrist candidate Mauricio Macri was elected president. During his campaign, Mauricio Macri emphasized that energy would be a key factor in the government's agenda and that a long-term state policy would be required to address the country's energy crisis. Also, the elected President signed, together with the opposition candidates, a statement of commitment addressed to the previous administration, that included several guidelines to reactivate the sector including the implementation of a strategic long-term energy plan, that a fair and reasonable customer tariffs be set for generation, transport and distribution costs, as well as reductions in subsidies and the introduction of a social tariff.
In line with these statements, the Energy and Mining Minister published Resolution 6/2016 and 7/2016 in January 2016 that outlines planned increases to the end consumers of energy that will be effective starting on February 1, 2016. These resolutions contemplate an increase in tariffs of up to 300% for energy pass-through, grant Distribution Value Added ("DVA") increases for Distribution Companies, provide a regulatory framework for an Integral Tariff Review and introduce subsidies for low income consumers. These increases are intended to lessen the burden on the government to subsidize the energy industry.
In 2001, Argentina defaulted on its public debt, when it stopped making payments of approximately $100 billion of debt amid a deep economic crisis. In 2005 and 2010, Argentina restructured its defaulted bonds into new securities valued at about 33 cents on the dollar. Between the two transactions, 93% of the bondholders agreed to exchange their defaulted bonds for new bonds. The remaining 7% did not accept the restructured deal. Since then, a certain group of the "hold-out" bondholders have been in judicial proceedings with Argentina regarding payment and the U.S. District Court ruled that Argentina would need to make payments to such hold-out bondholders according to the original applicable terms. Despite intense negotiations with the hold-out bondholders through the U.S. District Court appointed Special Master, on July 30, 2014 the parties failed to reach a settlement agreement and consequently (as referred by S&P and Fitch ratings) Argentina fell into a selective default resulting from failure to make interest payments on its Discount Bonds maturing in December 2033. The new administration started conversations to negotiate a solution with the bondholders which could resolve this situation and let Argentina return to the credit markets in the near future. Although this situation remains unresolved, it has not caused any significant changes that impact our current exposures, and the long-term receivables in Argentina for the plants that commenced commercial operations in 2010 are being actively collected. For further information, see Note 7—Financing Receivables in Item 8.—Financial Statements and Supplementary Data of the 2015 Form 10-K.
Bulgaria — Our investments in Bulgaria rely on long-term PPAs with NEK, the state-owned electricity public supplier and energy trading company. NEK is facing some liquidity issues and has been delayed in making payments under the PPAs with Maritza and St. Nikola. In August 2015, the ninth amendment of Maritza's PPA was executed under which Maritza and NEK would reduce the capacity payment to Maritza under the PPA by 14% through the PPA Term, without impacting the energy price component. In exchange, NEK would pay Maritza its overdue receivables. The amendment will become effective upon full payment of the overdue receivables by NEK, which is expected in 2016. For the period October through December 2015, NEK paid a total of $64 million, which is $16 million more than payments received in the previous year. As of December 31, 2015, Maritza's total outstanding receivables were $351 million, of which $44 million were current and $307 million were overdue. Total receivables increased by $89 million from $262 million in December 31, 2014. See additional background within Part I.—Item 1—Business—Our Organization and Segments—Europe—Bulgaria—Regulatory Framework.

97


As of June 30, 2015, we concluded that the HTA signed with NEK in April is considered an indicator of an impairment of the long-lived assets in Bulgaria for Maritza. Therefore, a test of recoverability was performed and management believes the carrying amount of the asset groups was recoverable as of June 30, 2015. Management does not believe that an indicator of an impairment existed as of December 31, 2015. As of December 31, 2015, Maritza had long-lived assets of $1.2 billion and total debt of $559 million. Long-lived assets for St. Nikola were $210 million and total debt of $140 million.
Unless and until a complete and binding resolution is in place, there remains a risk that we may still face a loss of earnings and/or cash flows from the affected businesses (or be unable to exercise remedies for a breach of the PPA) and may have to provide loans or equity to support affected businesses or projects, restructure them, write down their value and/or face the possibility that these projects cannot continue operations or provide returns consistent with our expectations, any of which could have a material impact on the Company.
Puerto Rico — Our subsidiaries in Puerto Rico have long term PPAs with PREPA, a state-owned entity. Due to the ongoing economic situation in the country, PREPA faces significant financial challenges.
On June 28, 2014, the Puerto Rico Public Corporation Debt Enforcement and Recovery Act (the "Recovery Act") was signed into law, which allows public corporations, including PREPA, to adjust their debts. As a result of this event, on July 6, 2014, PREPA entered into a Forbearance Agreement with its lenders in order to permit an opportunity for negotiation of a possible financial restructuring of PREPA. In February 2015, the negotiating position of PREPA was weakened when the federal court deemed the Recovery Act unconstitutional. Despite this setback, PREPA managed to extend the expiration of the Forbearance Agreement several times, achieving in December of 2015 certain preliminary restructuring agreements, called Restructuring Support Agreements ("RSAs"), with most of the bondholders and bank lenders, which involved reductions of capital and interest rates and options to either convert existing credits to term loans or to exchange their principal for new securitized bonds. The RSA is conditional to a series of future related milestones, the more important being the passing of a bill that would allow an increase in tariffs.
There has been no adverse impacts to AES Puerto Rico due to PREPA's financial challenges. AES Puerto Rico's receivables balance as of December 31, 2015 is $65 million, of which $21 million was overdue. Subsequent to December 31, 2015, the full overdue amount has been collected. If the situation declines, there could be a material impact on the Company.
Macroeconomic and Political — Conclusion If economic conditions deteriorate further, it could affect the prices we receive for the electricity we generate or transmit. Utility regulators or parties to our generation contracts may seek to lower our prices based on prevailing market conditions pursuant to PPAs, concession agreements or other contracts as they come up for renewal or reset. In addition, rising fuel and other costs coupled with contractual price or tariff decreases could restrict our ability to operate profitably in a given market. Each of these factors, as well as those discussed above, could result in a decline in the value of our assets including those at the businesses we operate, our equity investments and projects under development and could result in asset impairments that could be material to our operations. We continue to monitor our projects and businesses.
Foreign Exchange and Commodities
Our businesses are exposed to and proactively manage market risk. Our primary market risk exposure is to the price of commodities, particularly electricity, oil, natural gas, coal and environmental credits. In 2015, there were more than 40% declines in oil and natural gas prices, which have an impact on our businesses in the Dominican Republic, Ohio and Northern Ireland. Since we operate in multiple countries and as such are subject to volatility in exchange rates at varying degrees at the subsidiary level and between our functional currency, the U.S. Dollar, and currencies of the countries in which we operate. In 2015, we had significant devaluations in the Argentine Peso, Brazilian Real, Colombian Peso, and Kazakhstan Tenge, which had a significant impact on our 2015 results. In 2016, our results could be materially impacted if the U.S. Dollar continues to appreciate. For additional information, refer to Item 7A.—Quantitative and Qualitative Disclosures About Market Risk.
Impairments
Long-lived Assets — During the year ended December 31, 2015, the Company recognized asset impairments of $285 million. See Note 21—Asset Impairment Expense in this Form 10-K for further information.
Additionally, in the third quarter of 2015, the Company tested the recoverability of its long-lived assets at Ballylumford in Northern Ireland and Buffalo Gap I and II. Impairment indicators were identified at Ballylumford, primarily based on an unfavorable capacity reduction proposed by the Utility regulator in Northern Ireland, and at Buffalo Gap, based on a decline in forward power curves coupled with the near term expiration of favorable contracted cash flows. As of September 30, 2015, the Company determined that the carrying amount of the long-lived asset groups at Ballylumford and Buffalo Gap I and II, which totaled $92 million and $371 million, respectively, were recoverable, and no impairment expense was recognized. Buffalo Gap

98


I and II have PPAs that will expire at the end of 2021 and 2017, respectively. Once the PPAs expire, the entire installed capacity of Buffalo Gap will be exposed to the volatility of energy prices in the ERCOT market which could adversely affect revenues. No impairment indicators were identified in the fourth quarter of 2015.
Events or changes in circumstances that may necessitate further recoverability tests and potential impairments of long-lived assets may include, but are not limited to, adverse changes in the regulatory environment, unfavorable changes in power prices or fuel costs, increased competition due to additional capacity in the grid, technological advancements, declining trends in demand, or an expectation that it is more likely than not that the asset will be disposed of before the end of its previously estimated useful life.
Goodwill — During 2015, the Company recognized total goodwill impairment expense of $317 million, which resulted from the annual goodwill impairment test performed in the fourth quarter of 2015 at its DP&L reporting unit ("DP&L"). As of December 31, 2015, there was no remaining goodwill balance at DP&L. See Note 10—Goodwill and Other Intangible Assets in Item 8.—Financial Statements and Supplementary Data for further information.
The Company currently has no reporting units considered to be "at risk." A reporting unit is considered "at risk" when its fair value is not higher than its carrying amount by more than 10%. The Company monitors its reporting units at risk of Step 1 failure on an ongoing basis. It is possible that the Company may incur goodwill impairment charges at any reporting units containing goodwill in future periods if adverse changes in their business or operating environments occur.
Capital Resources and Liquidity
Overview — As of December 31, 2015, the Company had unrestricted cash and cash equivalents of $1.3 billion, of which $400 million was held at the Parent Company and qualified holding companies. The Company also had $484 million in short term investments, held primarily at subsidiaries. In addition, we had restricted cash and debt service reserves of $860 million. The Company also had non-recourse and recourse aggregate principal amounts of debt outstanding of $15.8 billion and $5.0 billion, respectively. Of the approximately $2.5 billion of our current non-recourse debt, $1.5 billion was presented as such because it is due in the next twelve months and $1.0 billion relates to debt considered in default due to covenant violations. The defaults are not payment defaults, but are instead technical defaults triggered by failure to comply with other covenants and/or other conditions such as (but not limited to) failure to meet information covenants, complete construction or other milestones in an allocated time, meet certain minimum or maximum financial ratios, or other requirements contained in the non-recourse debt documents of the Company.
We expect such current maturities will be repaid from net cash provided by operating activities of the subsidiary to which the debt relates or through opportunistic refinancing activity or some combination thereof. None of our recourse debt matures within the next twelve months. From time to time, we may elect to repurchase our outstanding debt through cash purchases, privately negotiated transactions or otherwise when management believes that such securities are attractively priced. Such repurchases, if any, will depend on prevailing market conditions, our liquidity requirements and other factors. The amounts involved in any such repurchases may be material.
We rely mainly on long-term debt obligations to fund our construction activities. We have, to the extent available at acceptable terms, utilized non-recourse debt to fund a significant portion of the capital expenditures and investments required to construct and acquire our electric power plants, distribution companies and related assets. Our non-recourse financing is designed to limit cross default risk to the Parent Company or other subsidiaries and affiliates. Our non-recourse long-term debt is a combination of fixed and variable interest rate instruments. Generally, a portion or all of the variable rate debt is fixed through the use of interest rate swaps. In addition, the debt is typically denominated in the currency that matches the currency of the revenue expected to be generated from the benefiting project, thereby reducing currency risk. In certain cases, the currency is matched through the use of derivative instruments. The majority of our non-recourse debt is funded by international commercial banks, with debt capacity supplemented by multilaterals and local regional banks.
Given our long-term debt obligations, the Company is subject to interest rate risk on debt balances that accrue interest at variable rates. When possible, the Company will borrow funds at fixed interest rates or hedge its variable rate debt to fix its interest costs on such obligations. In addition, the Company has historically tried to maintain at least 70% of its consolidated long-term obligations at fixed interest rates, including fixing the interest rate through the use of interest rate swaps. These efforts apply to the notional amount of the swaps compared to the amount of related underlying debt. Presently, the Parent Company's only material un-hedged exposure to variable interest rate debt relates to indebtedness under its senior secured credit facility and floating rate senior unsecured notes due 2019. On a consolidated basis, of the Company's $15.8 billion of total non-recourse debt outstanding as of December 31, 2015, approximately $3.8 billion bore interest at variable rates that were not subject to a derivative instrument which fixed the interest rate.
In addition to utilizing non-recourse debt at a subsidiary level when available, the Parent Company provides a portion, or in certain instances all, of the remaining long-term financing or credit required to fund development, construction or acquisition of a particular project. These investments have generally taken the form of equity investments or intercompany loans, which are subordinated to the project's non-recourse loans. We generally obtain the funds for these investments from our cash flows from operations, proceeds from the sales of assets and/or the proceeds from our issuances of debt, common stock and other securities. Similarly, in certain of our businesses, the Parent Company may provide financial guarantees or other credit support for the benefit of counterparties who have entered into contracts for the purchase or sale of electricity, equipment or other services with our subsidiaries or lenders. In such circumstances, if a business defaults on its payment or supply obligation, the Parent Company will be responsible for the business' obligations up to the amount provided for in the relevant guarantee or other credit support. At December 31, 2015, the Parent Company had provided outstanding financial and performance-related guarantees or other credit support commitments to or for the benefit of our businesses, which were limited by the terms of the agreements, of approximately $396 million in aggregate (excluding those collateralized by letters of credit and other obligations discussed below).
As a result of the Parent Company's below investment grade rating, counterparties may be unwilling to accept our general unsecured commitments to provide credit support. Accordingly, with respect to both new and existing commitments, the Parent Company may be required to provide some other form of assurance, such as a letter of credit, to backstop or replace our credit support. The Parent Company may not be able to provide adequate assurances to such counterparties. To the extent we are required and able to provide letters of credit or other collateral to such counterparties, this will reduce the amount of credit available to us to meet our other liquidity needs. At December 31, 2015, we had $62 million in letters of credit outstanding, provided under our senior secured credit facility, and $32 million in cash collateralized letters of credit outstanding outside of

99


our senior secured credit facility. These letters of credit operate to guarantee performance relating to certain project development activities and business operations. During the year ended December 31, 2015, the Company paid letter of credit fees ranging from 0.2% to 2.5% per annum on the outstanding amounts.
We expect to continue to seek, where possible, non-recourse debt financing in connection with the assets or businesses that we or our affiliates may develop, construct or acquire. However, depending on local and global market conditions and the unique characteristics of individual businesses, non-recourse debt may not be available on economically attractive terms or at all. If we decide not to provide any additional funding or credit support to a subsidiary project that is under construction or has near-term debt payment obligations and that subsidiary is unable to obtain additional non-recourse debt, such subsidiary may become insolvent, and we may lose our investment in that subsidiary. Additionally, if any of our subsidiaries lose a significant customer, the subsidiary may need to withdraw from a project or restructure the non-recourse debt financing. If we or the subsidiary choose not to proceed with a project or are unable to successfully complete a restructuring of the non-recourse debt, we may lose our investment in that subsidiary.
Many of our subsidiaries depend on timely and continued access to capital markets to manage their liquidity needs. The inability to raise capital on favorable terms, to refinance existing indebtedness or to fund operations and other commitments during times of political or economic uncertainty may have material adverse effects on the financial condition and results of operations of those subsidiaries. In addition, changes in the timing of tariff increases or delays in the regulatory determinations under the relevant concessions could affect the cash flows and results of operations of our businesses.
Long-Term Receivables — As of December 31, 2015, the Company had approximately $296 million and $63 million of accounts receivable classified as Noncurrent assets—other and Current assets—Accounts receivable, respectively, related to certain of its generation businesses in Argentina and the U.S. and its utility businesses in Brazil. The noncurrent portion primarily consists of accounts receivable in Argentina that, pursuant to amended agreements or government resolutions, have collection periods that extend beyond December 31, 2016, or one year from the latest balance sheet date. The majority of Argentinian receivables have been converted into long-term financing for the construction of power plants. See Note 7—Financing Receivables included in Item 8.—Financial Statements and Supplementary Data and Item 1.—Business—Regulatory Matters—Argentina of this Form 10-K for further information.
Consolidated Cash Flows
For the years ended December 31, 2015 and 2014 cash and cash equivalents decreased $277 million and $103 million, respectively. The table below reflects the changes in cash flows for the comparative periods (in millions).
 
 
December 31,
 
$ Change
Cash flows provided by (used in):
 
2015
 
2014
 
2013
 
2015 vs. 2014
 
2014 vs. 2013
Operating activities
 
$
2,134

 
$
1,791

 
$
2,715

 
$
343

 
$
(924
)
Investing activities
 
(2,366
)
 
(656
)
 
(1,774
)
 
(1,710
)
 
1,118

Financing activities
 
28

 
(1,262
)
 
(1,136
)
 
1,290

 
(126
)
Effect of exchange rate changes on cash
 
(52
)
 
(51
)
 
(59
)
 
(1
)
 
8

Decrease (increase) in cash of discontinued businesses
 
—

 
75

 
(4
)
 
(75
)
 
79

Cash at held-for-sale businesses
 
(21
)
 
—

 
—

 
(21
)
 
—

Net (decrease) increase in cash and cash equivalents
 
(277
)
 
(103
)
 
(258
)
 
(174
)
 
155

Cash and cash equivalents at beginning of period
 
1,539

 
1,642

 
1,900

 
(103
)
 
(258
)
Cash and cash equivalents at end of period
 
1,262

 
1,539

 
1,642

 
(277
)
 
(103
)

100


Operating Activities
Net cash provided by operating activities for the periods indicated was driven by (in millions):
 
 
December 31,
 
$ Change
 
 
2015
 
2014
 
2013
 
2015 vs. 2014
 
2014 vs. 2013
Net Income
 
$
762

 
$
1,147

 
$
551

 
$
(385
)
 
$
596

Depreciation and amortization
 
1,144

 
1,245

 
1,294

 
(101
)
 
(49
)
Impairment expenses
 
602

 
383

 
661

 
219

 
(278
)
Loss on the extinguishment of debt
 
186

 
261

 
229

 
(75
)
 
32

Other adjustments to net income
 
(123
)
 
(223
)
 
324

 
100

 
(547
)
Adjusted net income
 
$
2,571

 
$
2,813

 
$
3,059

 
$
(242
)
 
$
(246
)
Net change in operating assets and liabilities (1)
 
$
(437
)
 
$
(1,022
)
 
$
(344
)
 
$
585

 
$
(678
)
Net cash provided by operating activities (2)
 
$
2,134

 
$
1,791

 
$
2,715

 
$
343

 
$
(924
)
(1) 
Refer to tables below for driver explanations by operating assets and liabilities.
(2) 
Refer to below operating cash flow discussion by SBU for further information about the key drivers.
Fiscal Year 2015 versus 2014
The net change in operating assets and liabilities for the year ended December 31, 2015 compared to the year ended December 31, 2014 was driven by (in millions):
 
$ Change
Decrease in prepaid expenses and other current assets primarily at Eletropaulo, Gener and DPL
$
728

Decrease in accounts receivable primarily in the Dominican Republic, DPL and Puerto Rico, partially offset by increases at Mong Duong and Chivor
142

Increase in income tax payables, net and other tax payables primarily in Brazil and at Gener
142

Increase in accounts payable and other current liabilities primarily at Eletropaulo, Sul and Mong Duong, partially offset by decreases at Tietê and Gener
116

Increase in other assets primarily regulatory assets at Eletropaulo and Sul as well as service concession assets at Mong Duong
(582
)
Other operating assets and liabilities
39

 
$
585

Fiscal Year 2014 versus 2013
The net change in operating assets and liabilities for the year ended December 31, 2014 compared to the year ended December 31, 2013 was driven by (in millions):
 
$ Change
Increase in accounts receivable primarily at Eletropaulo, Sul and Maritza, partially offset by a decrease at Masinloc
$
(666
)
Increase in other assets primarily regulatory assets at Eletropaulo, IPL, DPL and Sul
(620
)
Increase in prepaid expenses and other current assets primarily regulatory assets at Eletropaulo as well as increases at the Dominican Republic, Gener and Kilroot
(431
)
Decrease in income tax payables, net and other tax payables primarily in Brazil and the U.S. as well as our sold businesses in Africa and the Ukraine, partially offset by an increase at Chivor
(184
)
Increase in accounts payable and other current liabilities primarily at Eletropaulo, Tietê, Sul and Uruguaiana
673

Increase in other liabilities primarily regulatory liabilities at Eletropaulo and pension liabilities at IPL
614

Other operating assets and liabilities
(64
)
 
$
(678
)
Investing Activities
Fiscal Year 2015 versus 2014
Changes to net cash used in investing activities for the year ended December 31, 2015 compared to December 31, 2014 were driven by (in millions):
 
$ Change
Increase in capital expenditures primarily due to Andes SBU generation growth projects (1)
$
(292
)
Decrease in cash paid for acquisitions primarily related to Guacolda for $728 million in Andes SBU in 2014
711

Decrease in proceeds from sales of business primarily related to $730 million for Guacolda and $436 million for Masinloc in Andes and Asia SBUs, respectively in 2014.
(1,669
)
Increase in restricted cash, debt service and other assets
(578
)
Other
118

 
$
(1,710
)
(1) Refer to tables below for capital expenditure types and other business drivers.

101


The following table summarizes the Company's capital expenditures for growth investments, maintenance and environmental for the periods indicated ($ in millions):
 
December 31,


2015
 
2014
 
$ Change
 
% Change
Growth Investments
$
(1,401
)
 
$
(1,151
)
 
$
(250
)
 
22
 %
Maintenance
(606
)
 
(645
)
 
39

 
-6
 %
Environmental (2)
(301
)
 
(220
)
 
(81
)
 
37
 %
Total capital expenditures
$
(2,308
)
 
$
(2,016
)
 
$
(292
)
 
14
 %
(2) 
Includes both recoverable and non-recoverable environmental capital expenditures. See Non GAAP Proportional Free Cash Flow for more information.
Changes to cash used for capital expenditures for growth investments, maintenance, and environmental for the year ended December 31, 2015 compared to December 31, 2014 were driven by (in millions):
 
$ Change
Increase primarily due to growth expenditures at Gener, IPALCO and Los Mina in Andes, US and MCAC SBUs, respectively
$
(601
)
Decrease in growth expenditures at Mong Duong in Asia SBU due to service concession accounting adoption in 2015, and at Jordan in Europe SBU due to completion of IPP4 plant construction
344

Increase in maintenance and environmental expenditures at IPALCO and DPL businesses in US SBU
(41
)
Other business drivers
6

 
$
(292
)
Fiscal Year 2014 versus 2013
Changes to net cash used in investing activities for the year ended December 31, 2014 compared to December 31, 2013 were driven by (in millions):
 
$ Change
Increase in capital expenditures primarily due to US SBU generation growth projects (1)
$
(28
)
Increase in cash paid for acquisitions primarily related to Guacolda for $728 million in Andes SBU
(721
)
Increase in proceeds from sales of business primarily related to $730 million for Guacolda and $436 million for Masinloc in Andes and Asia SBUs, respectively
1,637

Decrease in restricted cash, debt service and other assets
375

Other
(145
)
 
$
1,118

(1) Refer to tables below for capital expenditure types and other business drivers.
The following table summarizes the Company's capital expenditures for growth investments, maintenance and environmental for the periods indicated ($ in millions):
 
December 31,


2014
 
2013
 
$ Change
 
% Change
Growth Investments
$
(1,151
)
 
$
(1,054
)
 
$
(97
)
 
9
 %
Maintenance
(645
)
 
(751
)
 
106

 
-14
 %
Environmental (2)
(220
)
 
(183
)
 
(37
)
 
20
 %
Total capital expenditures
$
(2,016
)
 
$
(1,988
)
 
$
(28
)
 
1
 %
(2) 
Includes both recoverable and non-recoverable environmental capital expenditures. See Non-GAAP Proportional Free Cash Flow for more information.
Changes to cash used for capital expenditures for growth investments, maintenance, and environmental for the year ended December 31, 2014 compared to December 31, 2013 were driven by (in millions):
 
$ Change
Increase primarily due to growth expenditures at IPALCO, Gener, and Mong Duong in US, Andes and Asia SBUs, respectively
$
(287
)
Decrease in growth expenditures at Jordan and Eletropaulo in Europe and Brazil SBUs, respectively
205

Decrease in maintenance and environmental expenditures at Eletropaulo in Brazil SBU
48

Other business drivers
6

 
$
(28
)

102


Financing Activities
Net cash used in financing activities were driven by ($ in millions):
 
December 31,
 
$ Change
 
2015
 
2014
 
2013
 
2015 vs. 2014
 
2014 vs. 2013
Issuances and repayments of recourse debt:


Corporate — Parent Company issuances
$
575

 
$
1,525

 
$
750

 
$
(950
)
 
$
775

Corporate — Parent Company repayments
(915
)
 
(2,117
)
 
(1,210
)
 
1,202

 
(907
)
Net repayments of recourse debt
$
(340
)
 
$
(592
)
 
$
(460
)
 
$
252

 
$
(132
)
Issuances and repayments of non-recourse debt:


US — IPALCO issuances
$
847

 
$
130

 
$
170

 
$
717

 
$
(40
)
US — IPALCO repayments
(602
)
 
—

 
(110
)
 
(602
)
 
110

US — DPL issuances
325

 
200

 
645

 
125

 
(445
)
US — DPL repayments
(475
)
 
(364
)
 
(948
)
 
(111
)
 
584

US — Generation Holdings, Shady Point, Warrior Run and Hawaii issuances
—

 
337

 
86

 
(337
)
 
251

US — Hawaii, Southland, Warrior Run, Shady Point repayments
(33
)
 
(417
)
 
(190
)
 
384

 
(227
)
Other business drivers
(11
)
 
(12
)
 
(13
)
 
1

 
1

US SBU net subtotal
51

 
(126
)
 
(360
)
 
177

 
234

Andes — Gener issuances
1,131

 
1,934

 
707

 
(803
)
 
1,227

Andes — Gener repayments
(423
)
 
(1,714
)
 
(67
)
 
1,291

 
(1,647
)
Andes — Chivor repayments
—

 
(165
)
 
—

 
165

 
(165
)
Other business drivers
22

 
5

 
(21
)
 
17

 
26

Andes SBU net subtotal
730

 
60

 
619

 
670

 
(559
)
Brazil — Sul issuances
513

 
185

 
153

 
328

 
32

Brazil — Sul repayments
(486
)
 
(58
)
 
(44
)
 
(428
)
 
(14
)
Brazil — Eletropaulo issuances
354

 
253

 
8

 
101

 
245

Brazil — Eletropaulo repayments
(211
)
 
(110
)
 
(26
)
 
(101
)
 
(84
)
Brazil — Tietê issuances
153

 
318

 
496

 
(165
)
 
(178
)
Brazil — Tietê repayments
(226
)
 
(132
)
 
(396
)
 
(94
)
 
264

Other business drivers
(1
)
 
—

 
—

 
(1
)
 
—

Brazil SBU net subtotal
96

 
456

 
191

 
(360
)
 
265

MCAC — Panama issuances
300

 
137

 
—

 
163

 
137

MCAC — Panama repayments
(287
)
 
(35
)
 
—

 
(252
)
 
(35
)
MCAC — Andres Issuances
180

 
—

 
—

 
180

 
—

MCAC — Andres Repayments
(176
)
 
—

 
—

 
(176
)
 
—

MCAC — Changuinola and Caess - EEO issuances
—

 
—

 
730

 
—

 
(730
)
MCAC — Changuinola and Caess - EEO repayments
(10
)
 
(10
)
 
(713
)
 
—

 
703

Other business drivers
(35
)
 
(26
)
 
(99
)
 
(9
)
 
73

MCAC SBU net subtotal
(28
)
 
66

 
(82
)
 
(94
)
 
148

Asia — Mong Duong issuances
203

 
363

 
472

 
(160
)
 
(109
)
Asia — Masinloc issuances
31

 
26

 
500

 
5

 
(474
)
Asia — Masinloc repayments
(32
)
 
(31
)
 
(560
)
 
(1
)
 
529

Other business drivers
(21
)
 
1

 
(3
)
 
(22
)
 
4

Asia SBU net subtotal
181

 
359

 
409

 
(178
)
 
(50
)
Europe — UK Wind issuances
—

 
132

 
18

 
(132
)
 
114

Europe —UK Wind repayments
—

 
(139
)
 
(26
)
 
139

 
(113
)
Europe — Maritza repayments
(62
)
 
(65
)
 
(57
)
 
3

 
(8
)
Europe — Jordan Levant issuances
—

 
—

 
180

 
—

 
(180
)
Other business drivers
(35
)
 
(45
)
 
(5
)
 
10

 
(40
)
Europe SBU net subtotal
(97
)
 
(117
)
 
110

 
20

 
(227
)
Corporate SBU net subtotal
3

 
—

 
—

 
3

 
—

Net issuances of non-recourse debt
$
936

 
$
698

 
$
887

 
$
238

 
$
(189
)
Proceeds from the sale of redeemable stock of subsidiaries:


Corporate and US — IPALCO
$
461

 
$
—

 
$
—

 
$
461

 
$
—

Total proceeds from the sale of redeemable stock of subsidiaries
$
461

 
$
—

 
$
—

 
$
461

 
$
—

Dividends paid on The AES Corporation common stock


Corporate — Parent Company
$
(276
)
 
$
(144
)
 
$
(119
)
 
$
(132
)
 
$
(25
)
Total dividends paid on The AES Corporation common stock
$
(276
)
 
$
(144
)
 
$
(119
)
 
$
(132
)
 
$
(25
)
Payments for financed capital expenditures:


Andes — Gener
$
(131
)
 
$
(178
)
 
$
(34
)
 
$
47

 
$
(144
)
Asia — Mong Duong
—

 
(310
)
 
(519
)
 
$
310

 
$
209

Other business drivers
(19
)
 
(40
)
 
(38
)
 
$
21

 
$
(2
)
Total payments for financed capital expenditures
$
(150
)
 
$
(528
)
 
$
(591
)
 
$
378

 
$
63

Purchase of treasury stock


Corporate — Parent Company
$
(482
)
 
$
(308
)
 
$
(322
)
 
$
(174
)
 
$
14

Total purchase of treasury stock
$
(482
)
 
$
(308
)
 
$
(322
)
 
$
(174
)
 
$
14

Proceeds from sales to noncontrolling interest, net of transaction costs


Andes - Gener
$
145

 
$
—

 
$
109

 
$
145

 
$
(109
)
MCAC - Dominican Republic
18

 
83

 
—

 
(65
)
 
83

US - IPALCO
(9
)
 
—

 
—

 
(9
)
 
—

Total proceeds from sales to noncontrolling interest, net of transaction costs
$
154

 
$
83

 
$
109

 
$
71

 
$
(26
)
Other cash uses for financing activities
$
(275
)
 
$
(471
)
 
$
(640
)
 
$
196

 
$
169

Net cash provided by (used in) financing activities
$
28

 
$
(1,262
)
 
$
(1,136
)
 
$
1,290

 
$
(126
)

103


Proportional Free Cash Flow (a non-GAAP measure)
We define proportional free cash flow as cash flows from operating activities less maintenance capital expenditures (including non-recoverable environmental capital expenditures), adjusted for the estimated impact of noncontrolling interests. The proportionate share of cash flows and related adjustments attributable to noncontrolling interests in our subsidiaries comprise the proportional adjustment factor presented in the reconciliation below. Upon the Company's adoption of the accounting guidance for service concession arrangements effective January 1, 2015, capital expenditures related to service concession assets that would have been classified as investing activities on the Consolidated Statement of Cash Flows are now classified as operating activities. See Note 1—General and Summary of Significant Accounting Policies of this Form 10-K for further information on the adoption of this guidance.
Beginning in the quarter ended March 31, 2015, the Company changed the definition of Proportional Free Cash Flow to exclude the cash flows for capital expenditures related to service concession assets that are now classified within net cash provided by operating activities on the Consolidated Statement of Cash Flows. The proportional adjustment factor for these capital expenditures is presented in the reconciliation below.
We also exclude environmental capital expenditures that are expected to be recovered through regulatory, contractual or other mechanisms. An example of recoverable environmental capital expenditures is IPL's investment in MATS-related environmental upgrades that are recovered through a tracker. See Item 1.—US SBU—IPL—Environmental Matters for details of these investments.
The GAAP measure most comparable to proportional free cash flow is cash flows from operating activities. We believe that proportional free cash flow better reflects the underlying business performance of the Company, as it measures the cash generated by the business, after the funding of maintenance capital expenditures, that may be available for investing or repaying debt or other purposes. Factors in this determination include the impact of noncontrolling interests, where AES consolidates the results of a subsidiary that is not wholly-owned by the Company.
The presentation of free cash flow has material limitations. Proportional free cash flow should not be construed as an alternative to cash from operating activities, which is determined in accordance with GAAP. Proportional free cash flow does not represent our cash flow available for discretionary payments because it excludes certain payments that are required or to which we have committed, such as debt service requirements and dividend payments. Our definition of proportional free cash flow may not be comparable to similarly titled measures presented by other companies.
Calculation of Proportional Free Cash Flow (in millions)
 
2015
 
2014
 
2013
 
2015/2014 Change
 
2014/2013 Change
Net Cash Provided by Operating Activities
 
$
2,134

 
$
1,791

 
$
2,715

 
$
343

 
$
(924
)
Add: capital expenditures related to service concession assets (1)
 
165

 
—

 
—

 
165

 
—

Adjusted Operating Cash Flow
 
2,299

 
1,791

 
2,715

 
508

 
(924
)
Less: proportional adjustment factor on operating cash activities (2) (3)
 
(558
)
 
(359
)
 
(834
)
 
(199
)
 
475

Proportional Adjusted Operating Cash Flow
 
1,741

 
1,432

 
1,881

 
309

 
(449
)
Less: proportional maintenance capital expenditures, net of reinsurance proceeds(2)
 
(449
)
 
(485
)
 
(535
)
 
36

 
50

Less: proportional non-recoverable environmental capital expenditures (2) (4)
 
(51
)
 
(56
)
 
(75
)
 
5

 
19

Proportional Free Cash Flow
 
$
1,241

 
$
891

 
$
1,271

 
$
350

 
$
(380
)
(1) 
Service concession asset expenditures excluded from proportional free cash flow non-GAAP metric.
(2) 
The proportional adjustment factor, proportional maintenance capital expenditures (net of reinsurance proceeds) and proportional non-recoverable environmental capital expenditures are calculated by multiplying the percentage owned by noncontrolling interests for each entity by its corresponding consolidated cash flow metric and are totaled to the resulting figures. For example, Parent Company A owns 20% of Subsidiary Company B, a consolidated subsidiary. Thus, Subsidiary Company B has an 80% noncontrolling interest. Assuming a consolidated net cash flow from operating activities of $100 from Subsidiary B, the proportional adjustment factor for Subsidiary B would equal $80 (or $100 x 80%). The Company calculates the proportional adjustment factor for each consolidated business in this manner and then sums these amounts to determine the total proportional adjustment factor used in the reconciliation. The proportional adjustment factor may differ from the proportion of income attributable to noncontrolling interests as a result of (a) non-cash items which impact income but not cash and (b) AES' ownership interest in the subsidiary where such items occur.
(3) 
Includes proportional adjustment amount for service concession asset expenditures of $84 million for the year ended December 31, 2015 . The Company adopted service concession accounting effective January 1, 2015.
(4) 
Excludes IPL's proportional recoverable environmental capital expenditures of $205 million, $163 million and $110 million for the years December 31, 2015, 2014 and 2013, respectively.

104


Operating Cash Flow and Proportional Free Cash Flow Analysis (1) 
 
Operating Cash Flow by SBU
 
Proportional Free Cash Flow by SBU
 
2015
 
2014
 
2013
 
2015/2014 Change
 
2014/2013 Change
 
2015
 
2014
 
2013
 
2015/2014 Change
 
2014/2013 Change
US
$
845

 
$
830

 
$
924

 
$
15

 
$
(94
)
 
$
591

 
$
646

 
$
689

 
$
(55
)
 
$
(43
)
Andes
462

 
359

 
373

 
103

 
(14
)
 
224

 
176

 
188

 
48

 
(12
)
Brazil
136

 
316

 
866

 
(180
)
 
(550
)
 
(29
)
 
13

 
116

 
(42
)
 
(103
)
MCAC
705

 
370

 
550

 
335

 
(180
)
 
498

 
281

 
433

 
217

 
(152
)
Europe
339

 
292

 
486

 
47

 
(194
)
 
238

 
197

 
345

 
41

 
(148
)
Asia
15

 
105

 
111

 
(90
)
 
(6
)
 
87

 
82

 
101

 
5

 
(19
)
Corporate
(368
)
 
(481
)
 
(595
)
 
113

 
114

 
(368
)
 
(504
)
 
(601
)
 
136

 
97

Total SBUs
$
2,134

 
$
1,791

 
$
2,715

 
$
343

 
$
(924
)
 
$
1,241

 
$
891

 
$
1,271

 
$
350

 
$
(380
)
(1) 
Operating cash flow and proportional free cash flow as presented above include the effect of intercompany transactions with other segments except for interest, tax sharing, charges for management fees and transfer pricing.
US SBU
The following table summarizes Operating Cash Flow and Proportional Free Cash Flow (in millions) for our US SBU for the periods indicated:
Calculation of Proportional Free Cash Flow (in millions)
2015
 
2014
 
2013
 
2015/2014 Change
 
2014/2013 Change
Net Cash Provided by Operating Activities
$
845

 
$
830

 
$
924

 
$
15

 
$
(94
)
Less: proportional adjustment factor on operating cash activities
(48
)
 
—

 
—

 
(48
)
 
—

Proportional Adjusted Operating Cash Flow
797

 
830

 
924

 
(33
)
 
(94
)
Less: proportional maintenance capital expenditures, net of reinsurance proceeds
(199
)
 
(180
)
 
(231
)
 
(19
)
 
51

Less: proportional non-recoverable environmental capital expenditures (1)
(7
)
 
(4
)
 
(4
)
 
(3
)
 
—

Proportional Free Cash Flow
$
591

 
$
646

 
$
689

 
$
(55
)
 
$
(43
)
(1) 
Excludes IPL's proportional recoverable environmental capital expenditures of $205 million, $163 million and $110 million for the years ended December 31, 2015, 2014 and 2013, respectively.

105


Fiscal Year 2015 versus 2014
Operating Cash Flow for the year ended December 31, 2015 compared to the year ended December 31, 2014 increased $15 million, driven primarily by the following businesses (in millions):
US SBU
 
Amount
While operating margin decreased at DPL, operating cash flow increased primarily due to the collection of previously deferred storm costs, a one-time payment in 2014 to terminate an unfavorable coal contract, higher collections and the timing of inventory payments
 
$
65

Decrease at U.S. Wind primarily due to a decrease in operating margin as well as the timing of collections
 
(38
)
Other business drivers
 
(12
)
Total
 
$
15

Proportional Free Cash Flow for the year ended December 31, 2015 compared to the year ended December 31, 2014 decreased $55 million, due to the drivers above, as well as a $22 million increase in maintenance and non-recoverable capital expenditures and adjusted for the impact of noncontrolling interest as a result of the sell-down of IPL in 2015.
Fiscal Year 2014 versus 2013
Operating Cash Flow for the year ended December 31, 2014 compared to the year ended December 31, 2013 decreased $94 million, driven primarily by the following businesses (in millions):
US SBU
 
Amount
Decrease at DPL primarily due to a decrease in operating margin, the timing of fuel payments as well as a one-time payment in the fourth quarter of 2014 to terminate an unfavorable coal contract, partially offset by a reduction in interest payments
 
$
(74
)
Decrease at Beaver Valley primarily due to one-time contract termination proceeds received in 2013
 
(54
)
Increase at Hawaii primarily due to an increase in operating margin
 
13

Increase at Southland primarily due to an increase in operating margin as well as the timing of collections
 
12

Other business drivers
 
9

Total
 
$
(94
)
Proportional Free Cash Flow for the year ended December 31, 2014 compared to the year ended December 31, 2013 decreased $43 million, due to the drivers above, partially offset by a $51 million reduction in maintenance capital expenditures, primarily at our Utility businesses.
ANDES SBU
The following table summarizes Operating Cash Flow and Proportional Free Cash Flow (in millions) for our Andes SBU for the periods indicated:
Calculation of Proportional Free Cash Flow ($ in millions)
2015
 
2014
 
2013
 
2015/2014 Change
 
2014/2013 Change
Net Cash Provided by Operating Activities
$
462

 
$
359

 
$
373

 
$
103

 
$
(14
)
Less: proportional adjustment factor on operating cash activities
(145
)
 
(73
)
 
(78
)
 
(72
)
 
5

Proportional Adjusted Operating Cash Flow
317

 
286

 
295

 
31

 
(9
)
Less: proportional maintenance capital expenditures, net of reinsurance proceeds
(70
)
 
(63
)
 
(45
)
 
(7
)
 
(18
)
Less: proportional non-recoverable environmental capital expenditures
(23
)
 
(47
)
 
(62
)
 
24

 
15

Proportional Free Cash Flow
$
224

 
$
176

 
$
188

 
$
48

 
$
(12
)
Fiscal Year 2015 versus 2014
Operating Cash Flow for the year ended December 31, 2015 compared to the year ended December 31, 2014 increased $103 million, driven primarily by the following businesses (in millions):
Andes SBU
 
Amount
Increase at Gener primarily due to an increase in VAT refunds related to the construction of our Cochrane and Alto Maipo plants as well as an increase in operating margin, partially offset by a swap termination payment at Ventanas
 
$
178

Decrease at Chivor primarily due to an increase in tax payments, lower collections on contract sales and a decrease in operating margin, partially offset by a decrease in interest payments
 
(73
)
Other business drivers
 
(2
)
Total
 
$
103

Proportional Free Cash Flow for the year ended December 31, 2015 compared to the year ended December 31, 2014 increased $48 million, due to the drivers above, as well as a $17 million net reduction in maintenance and non-recoverable environmental capital expenditures and adjusted for the impact of noncontrolling interest.
Fiscal Year 2014 versus 2013
Operating Cash Flow for the year ended December 31, 2014 compared to the year ended December 31, 2013 decreased $14 million, driven primarily by the following businesses (in millions):

106


Andes SBU
 
Amount
Decrease at Gener primarily due to higher payments for interest, higher payments for VAT at our Cochrane plant, a one-time swap termination payment as well as a reduction in operating margin, partially offset by a reduction in tax payments
 
$
(82
)
Decrease at Argentina Generation primarily due to an increase in interest and tax payments as well as the negative impact of exchange rates on collections, partially offset by an increase in operating margin
 
(27
)
Increase at Chivor primarily due to higher operating margin as well as a reduction in tax payments
 
95

Total
 
$
(14
)
Proportional Free Cash Flow for the year ended December 31, 2014 compared to the year ended December 31, 2013 decreased $12 million, due to the drivers above as well as a $3 million net increase in maintenance and non-recoverable environmental capital expenditures and adjusted for the impact of noncontrolling interest.
BRAZIL SBU
The following table summarizes Operating Cash Flow and Proportional Free Cash Flow (in millions) for our Brazil SBU for the periods indicated:
Calculation of Proportional Free Cash Flow
2015
 
2014
 
2013
 
2015/2014 Change
 
2014/2013 Change
Net Cash Provided by Operating Activities
$
136

 
$
316

 
$
866

 
$
(180
)
 
$
(550
)
Less: proportional adjustment factor on operating cash activities
(102
)
 
(215
)
 
(643
)
 
113

 
428

Proportional Adjusted Operating Cash Flow
34

 
101

 
223

 
(67
)
 
(122
)
Less: proportional maintenance capital expenditures, net of reinsurance proceeds
(63
)
 
(88
)
 
(107
)
 
25

 
19

Less: proportional non-recoverable environmental capital expenditures
—

 
—

 
—

 
—

 
—

Proportional Free Cash Flow
$
(29
)
 
$
13

 
$
116

 
$
(42
)
 
$
(103
)
Fiscal Year 2015 versus 2014
Operating Cash Flow for the year ended December 31, 2015 compared to the year ended December 31, 2014 decreased $180 million, driven primarily by the following businesses (in millions):
Brazil SBU
 
Amount
Decrease at Eletropaulo primarily due to the timing of collections, higher payments for interest and taxes as well as a decrease in operating margin, partially offset by the timing of payments for energy and regulatory charges as well as the favorable impact of exchange rates on cash payments
 
$
(90
)
Decrease at Tietê primarily due to the timing of energy purchases and higher interest payments, partially offset by lower income tax payments and an increase in operating margin
 
(62
)
Decrease at Sul primarily driven by a decrease in operating margin and an increase in interest payments, partially offset by the timing energy purchases and regulatory charges
 
(30
)
Other business drivers
 
2

Total
 
$
(180
)
Proportional Free Cash Flow for the year ended December 31, 2015 compared to the year ended December 31, 2014 decreased $42 million, due to the drivers above, partially offset by a $25 million reduction in maintenance capital expenditures and adjusted for the impact of noncontrolling interest.
Fiscal Year 2014 versus 2013
Operating Cash Flow for the year ended December 31, 2014 compared to the year ended December 31, 2013 decreased $550 million, driven primarily by the following businesses (in millions):
Brazil SBU
 
Amount
Decrease at Eletropaulo primarily due to the timing of collections on regulatory assets and settlement of regulatory liabilities as well as higher interest and tax payments in 2014, partially offset by an increase in operating margin
 
$
(397
)
Decrease at Tietê primarily due to a decrease in operating margin, partially offset by the timing of payments for energy purchased in the spot market as well as lower tax payments
 
(133
)
Decrease at Sul primarily due to higher payments for taxes and interest, partially offset by an increase in operating margin
 
(44
)
Other business drivers
 
24

Total
 
$
(550
)
Proportional Free Cash Flow for the year ended December 31, 2014 compared to the year ended December 31, 2013 decreased $103 million, due to the drivers above, partially offset by a $19 million reduction in maintenance capital expenditures and adjusted for the impact of noncontrolling interest.

107


MCAC SBU
The following table summarizes Operating Cash Flow and Proportional Free Cash Flow (in millions) for our MCAC SBU for the periods indicated:
Calculation of Proportional Free Cash Flow
2015
 
2014
 
2013
 
2015/2014 Change
 
2014/2013 Change
Net Cash Provided by Operating Activities
$
705

 
$
370

 
$
550

 
$
335

 
$
(180
)
Less: proportional adjustment factor on operating cash activities
(143
)
 
(27
)
 
(44
)
 
(116
)
 
17

Proportional Adjusted Operating Cash Flow
562

 
343

 
506

 
219

 
(163
)
Less: proportional maintenance capital expenditures, net of reinsurance proceeds
(61
)
 
(60
)
 
(71
)
 
(1
)
 
11

Less: proportional non-recoverable environmental capital expenditures
(3
)
 
(2
)
 
(2
)
 
(1
)
 
—

Proportional Free Cash Flow
$
498

 
$
281

 
$
433

 
$
217

 
$
(152
)
Fiscal Year 2015 versus 2014
Operating Cash Flow for the year ended December 31, 2015 compared to the year ended December 31, 2014 increased $335 million, driven primarily by the following business drivers (in millions):
MCAC SBU
 
Amount
Increase in Panama primarily due to an increase in operating margin as well as higher collections on contract sales
 
$
137

Increase in the Dominican Republic primarily due to the timing of collections of outstanding accounts receivable and lower tax payments, partially offset by a decrease in operating margin
 
119

Increase in El Salvador primarily due to the timing of energy purchases as well as an increase in operating margin, excluding an unbilled revenue adjustment, which did not impact operating cash flow
 
45

Excluding the impact of the 2014 non-cash bad debt reversal, operating margin in Puerto Rico remained flat, however operating cash flow increased primarily due to the timing of collections from the off-taker
 
34

Total
 
$
335

Proportional Free Cash Flow for the year ended December 31, 2015 compared to the year ended December 31, 2014 increased $217 million, due to the drivers above, partially offset by a $2 million increase in maintenance and non-recoverable environmental capital expenditures and adjusted for the impact of noncontrolling interest.
Fiscal Year 2014 versus 2013
Operating Cash Flow for the year ended December 31, 2014 compared to the year ended December 31, 2013 decreased $180 million, driven primarily by the following SBUs and key operating drivers (in millions):
MCAC SBU
 
Amount
Decrease in the Dominican Republic primarily due to a one-time settlement received in 2013 related to a fuel contract amendment as well as an increase in tax payments, partially offset by an increase in operating margin
 
$
(99
)
Decrease in Panama primarily due to the timing of energy purchases as well as a decrease in operating margin
 
(55
)
Decrease in El Salvador primarily due to a decrease in operating margin
 
(26
)
Total
 
$
(180
)
Proportional Free Cash Flow for the year ended December 31, 2014 compared to the year ended December 31, 2013 decreased $152 million, due to the drivers above, partially offset by an $11 million reduction in maintenance capital expenditures and adjusted for the impact of noncontrolling interest.
EUROPE SBU
The following table summarizes Operating Cash Flow and Proportional Free Cash Flow (in millions) for our Europe SBU for the periods indicated:
Calculation of Proportional Free Cash Flow
2015
 
2014
 
2013
 
2015/2014 Change
 
2014/2013 Change
Net Cash Provided by Operating Activities
$
339

 
$
292

 
$
486

 
$
47

 
$
(194
)
Less: proportional adjustment factor on operating cash activities
(32
)
 
(27
)
 
(66
)
 
(5
)
 
39

Proportional Adjusted Operating Cash Flow
307

 
265

 
420

 
42

 
(155
)
Less: proportional maintenance capital expenditures, net of reinsurance proceeds
(51
)
 
(65
)
 
(68
)
 
14

 
3

Less: proportional non-recoverable environmental capital expenditures
(18
)
 
(3
)
 
(7
)
 
(15
)
 
4

Proportional Free Cash Flow
$
238

 
$
197

 
$
345

 
$
41

 
$
(148
)
Fiscal Year 2015 versus 2014
Operating Cash Flow for the year ended December 31, 2015 compared to the year ended December 31, 2014 increased $47 million, driven primarily by the following business drivers (in millions):

108


Europe SBU
 
Amount
While operating margin decreased at Maritza, operating cash flow increased primarily due to higher collections from the off-taker. (Refer to the Key Trends and Uncertainties discussion for further information regarding the collection of outstanding receivables)
 
$
69

Increase at IPP4 in Jordan primarily due to the commencement of operations in July 2014 as well as the timing of customer collections
 
38

Decrease in operating cash as a result of the sale of our Africa businesses and U.K. Wind (Operating Projects) in 2014
 
(52
)
Other business drivers
 
(8
)
Total
 
$
47

Proportional Free Cash Flow for the year ended December 31, 2015 compared to the year ended December 31, 2014 increased $41 million, due to the drivers above, partially offset by a $1 million net increase in maintenance and non-recoverable environmental capital expenditures and adjusted for the impact of noncontrolling interest.
Fiscal Year 2014 versus 2013
Operating Cash Flow for the year ended December 31, 2014 compared to the year ended December 31, 2013 decreased $194 million, driven primarily by the following business drivers (in millions):
Europe SBU
 
Amount
Decrease in operating cash as a result of the sale of our businesses in Africa and the Ukraine as well as our U.K. Wind (Operating Projects)
 
$
(100
)
Decrease at Maritza primarily due to a decrease in operating margin as well as timing of collections from the off-taker
 
(58
)
Decrease at Kilroot primarily due to a decrease in operating margin as well as an increase in pension contributions
 
(45
)
Increase at Elsta in the Netherlands primarily driven by the timing of dividends received from our equity method investment
 
29

Other business drivers
 
(20
)
Total
 
$
(194
)
Proportional Free Cash Flow for the year ended December 31, 2014 compared to the year ended December 31, 2013 decreased $148 million, due to the drivers above, partially offset by a $7 million reduction in maintenance and non-recoverable environmental capital expenditures and adjusted for the impact of noncontrolling interest.
ASIA SBU
The following table summarizes Operating Cash Flow and Proportional Free Cash Flow (in millions) for our Asia SBU for the periods indicated:
Calculation of Proportional Free Cash Flow
2015
 
2014
 
2013
 
2015/2014 Change
 
2014/2013 Change
Net Cash Provided by Operating Activities
$
15

 
$
105

 
$
111

 
$
(90
)
 
$
(6
)
Add: capital expenditures related to service concession assets (1)
165

 
—

 
—

 
165

 
—

Adjusted Operating Cash Flow
180

 
105

 
111

 
75

 
(6
)
Less: proportional adjustment factor on operating cash activities (2)
(88
)
 
(17
)
 
(3
)
 
(71
)
 
(14
)
Proportional Adjusted Operating Cash Flow
92

 
88

 
108

 
4

 
(20
)
Less: proportional maintenance capital expenditures, net of reinsurance proceeds
(5
)
 
(6
)
 
(7
)
 
1

 
1

Less: proportional non-recoverable environmental capital expenditures
—

 
—

 
—

 
—

 
—

Proportional Free Cash Flow
$
87

 
$
82

 
$
101

 
$
5

 
$
(19
)
(1) 
Service concession asset expenditures excluded from proportional free cash flow non-GAAP metric.
(2) 
Includes proportional adjustment amount for service concession asset expenditures of $84 million for the year ended December 31, 2015. The Company adopted service concession accounting effective January 1, 2015.
Fiscal Year 2015 versus 2014
Operating Cash Flow for the year ended December 31, 2015 compared to the year ended December 31, 2014 decreased $90 million, driven primarily by the following business drivers (in millions):
Asia SBU
 
Amount
Decrease at Mong Duong in Vietnam primarily driven by payment for service concession assets, partially offset by an increase in operating cash due to commencement of operations in April 2015
 
$
(85
)
Other business drivers
 
(5
)
Total
 
$
(90
)
Proportional Free Cash Flow for the year ended December 31, 2015 compared to the year ended December 31, 2014 increased $5 million, due to the drivers above and adjusted for the impact of noncontrolling interest as well as $84 million of proportional service concession assets, which are excluded from the calculation of proportional free cash flow.
Fiscal Year 2014 versus 2013
Operating Cash Flow for the year ended December 31, 2014 compared to the year ended December 31, 2013 decreased $6 million, driven primarily by the following business drivers (in millions):

109


Asia SBU
 
Amount
Decrease at Kelanitissa primarily due to lower operating margin and collections as a result of the step-down in the contracted PPA price
 
$
(21
)
Increase at Masinloc primarily due to the timing of collections (despite the market operator's price adjustment) and payments for coal purchases as well as decreases in cash paid for interest and taxes, partially offset by a decrease in operating margin
 
16

Other business drivers
 
(1
)
Total
 
$
(6
)
Proportional Free Cash Flow for the year ended December 31, 2014 compared to the year ended December 31, 2013 decreased $19 million, due to the drivers above, partially offset by a $1 million reduction in maintenance capital expenditures and adjusted for the impact of noncontrolling interest.
CORPORATE
The following table summarizes Operating Cash Flow and Proportional Free Cash Flow (in millions) for Corporate for the periods indicated:
Calculation of Proportional Free Cash Flow
2015
 
2014
 
2013
 
2015/2014 Change
 
2014/2013 Change
Net Cash Provided by Operating Activities
$
(368
)
 
$
(481
)
 
$
(595
)
 
$
113

 
$
114

Proportional Adjusted Operating Cash Flow
(368
)
 
(481
)
 
(595
)
 
113

 
114

Less: proportional maintenance capital expenditures, net of reinsurance proceeds
—

 
(23
)
 
(6
)
 
23

 
(17
)
Proportional Free Cash Flow
$
(368
)
 
$
(504
)
 
$
(601
)
 
$
136

 
$
97

Fiscal Year 2015 versus 2014
Operating Cash Flow for the year ended December 31, 2015 compared to the year ended December 31, 2014 increased $113 million, driven primarily by the following business drivers (in millions):
Corporate
 
Amount
Increase primarily at the Parent Company driven by lower interest payments, prior year swap termination payments upon refinance of debt, a reduction in incentive payments and the collection of realized gains resulting from the Company's corporate hedging program
 
$
113

Total
 
$
113

Proportional Free Cash Flow for the year ended December 31, 2015 compared to the year ended December 31, 2014 increased $136 million, due to the drivers above as well as an $23 million reduction in maintenance capital expenditures.
Fiscal Year 2014 versus 2013
Operating Cash Flow for the year ended December 31, 2014 compared to the year ended December 31, 2013 increased $114 million, driven primarily by the following business drivers (in millions):
Corporate
 
Amount
Increase primarily at the Parent Company driven by lower interest payments
 
$
114

Total
 
$
114

Proportional Free Cash Flow for the year ended December 31, 2014 compared to the year ended December 31, 2013 increased $97 million, due to the drivers above, partially offset by a $17 million increase in maintenance capital expenditures.
Parent Free Cash Flow (a non-GAAP measure)
The Company defines Parent Free Cash Flow as dividends and other distributions received from our operating businesses less certain cash costs at the Parent Company level, primarily interest payments, overhead, and development costs. Parent Free Cash Flow is used to fund shareholder dividends, share repurchases, growth investments, recourse debt repayments, and other uses by the Parent Company. Refer to Item 1—Business—Overview for further discussion of the Parent Company's capital allocation strategy.
Parent Company Liquidity
The following discussion of Parent Company Liquidity has been included because we believe it is a useful measure of the liquidity available to The AES Corporation, or the Parent Company, given the non-recourse nature of most of our indebtedness. Parent Company Liquidity as outlined below is a non-GAAP measure and should not be construed as an alternative to cash and cash equivalents which are determined in accordance with GAAP, as a measure of liquidity. Cash and cash equivalents are disclosed in the consolidated statements of cash flows. Parent Company Liquidity may differ from similarly titled measures used by other companies. The principal sources of liquidity at the Parent Company level are dividends and other distributions from our subsidiaries, including refinancing proceeds; proceeds from debt and equity financings at the Parent Company level, including availability under our credit facility; and proceeds from asset sales. Cash requirements at the Parent Company level are primarily to fund interest; principal repayments of debt; construction commitments; other equity commitments; common stock repurchases; acquisitions; taxes; Parent Company overhead and development costs; and dividends on common stock.

110


The Company defines Parent Company Liquidity as cash available to the Parent Company plus available borrowings under existing credit facility. The cash held at qualified holding companies represents cash sent to subsidiaries of the Company domiciled outside of the U.S.. Such subsidiaries have no contractual restrictions on their ability to send cash to the Parent Company. Parent Company Liquidity is reconciled to its most directly comparable U.S. GAAP financial measure, Cash and cash equivalents, at December 31, 2015 and 2014 as follows:
Parent Company Liquidity (in millions)
 
2015
 
2014
Consolidated cash and cash equivalents
 
$
1,262

 
$
1,539

Less: Cash and cash equivalents at subsidiaries
 
862

 
1,032

Parent and qualified holding companies' cash and cash equivalents
 
400

 
507

Commitments under Parent credit facility
 
800

 
800

Less: Letters of credit under the credit facilities
 
(62
)
 
(61
)
Borrowings available under Parent credit facilities
 
738

 
739

Total Parent Company Liquidity
 
$
1,138

 
$
1,246

The Company paid dividends of $0.40 per share to its common stockholders during the year ended December 31, 2015. While we intend to continue payment of dividends and believe we will have sufficient liquidity to do so, we can provide no assurance that we will continue to pay dividends, or if continued, the amount of such dividends.
Recourse Debt — Our recourse debt at year-end was approximately $5.0 billion and $5.3 billion in 2015 and 2014, respectively. See Note 12—Debt in Item 8.—Financial Statements and Supplementary Data of this Form 10-K for additional detail.
While we believe that our sources of liquidity will be adequate to meet our needs for the foreseeable future, this belief is based on a number of material assumptions, including, without limitation, assumptions about our ability to access the capital markets (see Key Trends and Uncertainties—Global Economic Conditions), the operating and financial performance of our subsidiaries, currency exchange rates, power market pool prices, and the ability of our subsidiaries to pay dividends. In addition, our subsidiaries' ability to declare and pay cash dividends to us (at the Parent Company level) is subject to certain limitations contained in loans, governmental provisions and other agreements. We can provide no assurance that these sources will be available when needed or that the actual cash requirements will not be greater than anticipated. See Item 1A.—Risk Factors—The AES Corporation is a holding company and its ability to make payments on its outstanding indebtedness, including its public debt securities, is dependent upon the receipt of funds from its subsidiaries by way of dividends, fees, interest, loans or otherwise, of this Form 10-K.
Various debt instruments at the Parent Company level, including our senior secured credit facility, contain certain restrictive covenants. The covenants provide for — among other items — limitations on other indebtedness, liens, investments and guarantees; limitations on dividends, stock repurchases and other equity transactions; restrictions and limitations on mergers and acquisitions, sales of assets, leases, transactions with affiliates and off-balance sheet and derivative arrangements; maintenance of certain financial ratios; and financial and other reporting requirements.
As of December 31, 2015, we were in compliance with these covenants at the Parent Company level.
Non-Recourse Debt — While the lenders under our non-recourse debt financings generally do not have direct recourse to the Parent Company, defaults thereunder can still have important consequences for our results of operations and liquidity, including, without limitation:
•
reducing our cash flows as the subsidiary will typically be prohibited from distributing cash to the Parent Company during the time period of any default;
•
triggering our obligation to make payments under any financial guarantee, letter of credit or other credit support we have provided to or on behalf of such subsidiary;
•
causing us to record a loss in the event the lender forecloses on the assets; and
•
triggering defaults in our outstanding debt at the Parent Company.
For example, our senior secured credit facility and outstanding debt securities at the Parent Company include events of default for certain bankruptcy related events involving material subsidiaries. In addition, our revolving credit agreement at the Parent Company includes events of default related to payment defaults and accelerations of outstanding debt of material subsidiaries.
Some of our subsidiaries are currently in default with respect to all or a portion of their outstanding indebtedness. The total non-recourse debt classified as current in the accompanying Consolidated Balance Sheets amounts to $2.5 billion. The portion of current debt related to such defaults was $1.0 billion at December 31, 2015, all of which was non-recourse debt related to four subsidiaries — Maritza, Sul, Kavarna, and Sogrinsk. See Note 12—Debt in Item 8.—Financial Statements and Supplementary Data of this Form 10-K for additional detail.
None of the subsidiaries that are currently in default are subsidiaries that met the applicable definition of materiality under AES' corporate debt agreements as of December 31, 2015 in order for such defaults to trigger an event of default or permit acceleration under AES' indebtedness. However, as a result of additional dispositions of assets, other significant reductions in asset carrying values or other matters in the future that may impact our financial position and results of operations or the financial position of the individual subsidiary, it is possible that one or more of these subsidiaries could fall within the definition of a "material subsidiary" and thereby upon an acceleration trigger an event of default and possible acceleration of the indebtedness under the Parent Company's outstanding debt securities. A material subsidiary is defined in the Company's senior secured revolving credit facility as any business that contributed 20% or more of the Parent Company's total cash distributions from businesses for the four most recently completed fiscal quarters. As of December 31, 2015, none of the defaults listed above individually or in the aggregate results in or is at risk of triggering a cross-default under the recourse debt of the Company.

111


Contractual Obligations and Parent Company Contingent Contractual Obligations
A summary of our contractual obligations, commitments and other liabilities as of December 31, 2015 is presented in the table below, which excludes any businesses classified as discontinued operations or held-for-sale (in millions):
Contractual Obligations
Total
 
Less than 1 year
 
1-3 years
 
3-5 years
 
More than 5 years
 
Other
 
Footnote Reference(5)
Debt Obligations(1)
$
20,807

 
$
2,529

 
$
2,562

 
$
3,624

 
$
12,092

 
$
—

 
12

Interest Payments on Long-Term Debt(2)
7,897

 
1,233

 
2,131

 
1,552

 
2,981

 
—

 
n/a

Capital Lease Obligations(3)
147

 
14

 
23

 
20

 
90

 
—

 
13

Operating Lease Obligations(3)
1,291

 
77

 
157

 
159

 
898

 
—

 
13

Electricity Obligations(3)
37,594

 
2,623

 
5,078

 
5,717

 
24,176

 
—

 
13

Fuel Obligations(3)
5,253

 
1,120

 
1,367

 
625

 
2,141

 
—

 
13

Other Purchase Obligations(3)
9,383

 
1,332

 
2,128

 
1,528

 
4,395

 
—

 
13

Other Long-Term Liabilities


Reflected on AES' Consolidated Balance Sheet under GAAP(4)
696

 
—

 
220

 
35

 
406

 
35

 
n/a

Total
$
83,068

 
$
8,928

 
$
13,666

 
$
13,260

 
$
47,179

 
$
35


(1)
Includes recourse and non-recourse debt presented on the Consolidated Balance Sheet. See Note 12—Debt to the Consolidated Financial Statements included in Item 8—Financial Statements and Supplementary Data of this Form 10-K which provides additional disclosure regarding these obligations. These amounts exclude capital lease obligations which are included in the capital lease category, see (3) below.
(2)
Interest payments are estimated based on final maturity dates of debt securities outstanding at December 31, 2015 and do not reflect anticipated future refinancing, early redemptions or new debt issuances. Variable rate interest obligations are estimated based on rates as of December 31, 2015.
(3)
See Note 13—Commitments to the Consolidated Financial Statements included in Item 8 of this Form 10-K for further information.
(4)
These amounts do not include current liabilities on the Consolidated Balance Sheet except for the current portion of uncertain tax obligations. Noncurrent uncertain tax obligations are reflected in the "Other" column of the table above as the Company is not able to reasonably estimate the timing of the future payments. In addition, the amounts do not include: (1) regulatory liabilities (See Note 11—Regulatory Assets and Liabilities), (2) contingencies (See Note 14—Contingencies), (3) pension and other post retirement employee benefit liabilities (see Note 15—Benefit Plans) or (4) any taxes (See Note 22—Income Taxes) except for uncertain tax obligations, as the Company is not able to reasonably estimate the timing of future payments. See the indicated notes to the Consolidated Financial Statements included in Item 8 of this Form 10-K for additional information on the items excluded. Derivatives (See Note 6—Derivative Instruments and Hedging Activities) and incentive compensation are excluded as the Company is not able to reasonably estimate the timing or amount of the future payments.
(5)
For further information see the note referenced below in Item 8.—Financial Statements and Supplementary Data of this Form 10-K.
The following table presents our Parent Company's contingent contractual obligations as of December 31, 2015:
Contingent contractual obligations ($ in millions)
 
Amount
 
Number of Agreements
 
Maximum Exposure Range for Each Agreement
Guarantees and commitments
 
$
369

 
14
 
$1 - 53
Asset sale related indemnities(1)
 
27

 
1
 
27
Cash collateralized letters of credit
 
32

 
4
 
$1 - 15
Letters of credit under the senior secured credit facility
 
62

 
7
 
<$1 - 29
Total
 
$
490

 
26
 
 
(1) Excludes normal and customary representations and warranties in agreements for the sale of assets (including ownership in associated legal entities) where the associated risk is considered to be nominal.
As of December 31, 2015, the Company had no commitments to invest in subsidiaries under construction and to purchase related equipment that were not included in the letters of credit disclosed above.
We have a diverse portfolio of performance-related contingent contractual obligations. These obligations are designed to cover potential risks and only require payment if certain targets are not met or certain contingencies occur. The risks associated with these obligations include change of control, construction cost overruns, subsidiary default, political risk, tax indemnities, spot market power prices, sponsor support and liquidated damages under power sales agreements for projects in development, in operation and under construction. In addition, we have an asset sale program through which we may have customary indemnity obligations under certain assets sale agreements. While we do not expect that we will be required to fund any material amounts under these contingent contractual obligations beyond 2015, many of the events which would give rise to such obligations are beyond our control. We can provide no assurance that we will be able to fund our obligations under these contingent contractual obligations if we are required to make substantial payments thereunder.

112


Critical Accounting Policies and Estimates
The Consolidated Financial Statements of AES are prepared in conformity with U.S. GAAP, which requires the use of estimates, judgments and assumptions that affect the reported amounts of assets and liabilities at the date of the financial statements and the reported amounts of revenue and expenses during the periods presented. AES' significant accounting policies are described in Note 1—General and Summary of Significant Accounting Policies to the Consolidated Financial Statements included in Item 8 of this Form 10-K.
An accounting estimate is considered critical if the estimate requires management to make assumptions about matters that were highly uncertain at the time the estimate was made; different estimates reasonably could have been used; or the impact of the estimates and assumptions on financial condition or operating performance is material.
Management believes that the accounting estimates employed are appropriate and the resulting balances are reasonable; however, actual results could materially differ from the original estimates, requiring adjustments to these balances in future periods. Management has discussed these critical accounting policies with the Audit Committee, as appropriate. Listed below are the Company's most significant critical accounting estimates and assumptions used in the preparation of the Consolidated Financial Statements.
Income Taxes — We are subject to income taxes in both the U.S. and numerous foreign jurisdictions. Our worldwide income tax provision requires significant judgment and is based on calculations and assumptions that are subject to examination by the Internal Revenue Service and other taxing authorities. The Company and certain of its subsidiaries are under examination by relevant taxing authorities for various tax years. The Company regularly assesses the potential outcome of these examinations in each tax jurisdiction when determining the adequacy of the provision for income taxes. Accounting guidance for uncertainty in income taxes prescribes a more likely than not recognition threshold. Tax reserves have been established, which the Company believes to be adequate in relation to the potential for additional assessments. Once established, reserves are adjusted only when there is more information available or when an event occurs necessitating a change to the reserves. While the Company believes that the amounts of the tax estimates are reasonable, it is possible that the ultimate outcome of current or future examinations may be materially different than the reserve amounts.
Because we have a wide range of statutory tax rates in the multiple jurisdictions in which we operate, any changes in our geographical earnings mix could materially impact our effective tax rate. Furthermore, our tax position could be adversely impacted by changes in tax laws, tax treaties or tax regulations or the interpretation or enforcement thereof and such changes may be more likely or become more likely in view of recent economic trends in certain of the jurisdictions in which we operate. As an example, new tax laws were enacted in February 2016 in Chile which will increase the statutory income tax rate for most of our Chilean businesses from 25% to 25.5% in 2017 and to 27% for 2018 and future years. Accordingly, in 2016 our net Chilean deferred tax liabilities will be remeasured to the new rates. The remeasurement amount and other potential future impacts of the changes in tax law may be material to continuing operations.
The Company's provision for income taxes could be adversely impacted by changes to the U.S. taxation of earnings of our foreign subsidiaries. Since 2006, the Company has benefited from the Controlled Foreign Corporation look-through rule, originally enacted in the TIPRA of 2005, subject to five temporary extensions, including the most recent five year retroactive extension enacted on December 18, 2015 in the H.R.2029 - Consolidated Appropriations Act, 2016. There can be no assurance that this provision will continue to be extended beyond December 31, 2019. Further, the U.S. is considering corporate tax reform that may significantly change the U.S. international tax rules and corporate tax rates. Our expected effective tax rate could increase by amounts that may be material to the Company should such reforms be enacted.
In addition, U.S. income taxes and foreign withholding taxes have not been provided on undistributed earnings for certain of our non-U.S. subsidiaries to the extent such earnings are considered to be indefinitely reinvested in the operations of those subsidiaries.
Deferred tax assets and liabilities are recognized for the future tax consequences attributable to differences between the financial statement carrying amounts of the existing assets and liabilities, and their respective income tax bases. The Company establishes a valuation allowance when it is more likely than not that all or a portion of a deferred tax asset will not be realized.
Sales of Noncontrolling Interests — The accounting for a sale of noncontrolling interests under the accounting standards depends on whether the sale is considered to be a sale of in-substance real estate (as opposed to an equity transaction), where the gain (loss) on sale would be recognized in earnings rather than within stockholders' equity. If management's estimation process determines that there is no significant value beyond the in-substance real estate, the gain (loss) on the sale of the noncontrolling interest is recognized in earnings. However, if it is determined that significant value likely exists beyond the in-substance real estate, the gain (loss) on the sale of the noncontrolling interest would be recognized within stockholders' equity. In-substance real estate is comprised of land plus improvements and integral equipment. The determination of whether property, plant and equipment is integral equipment is based on the significance of the costs to remove the equipment from its existing location (including the cost of repairing damage resulting from the removal), combined with the decrease in the fair

113


value of the equipment as a result of those removal activities. When the combined total of removal costs and the decrease in fair value of the equipment exceeds 10% of the fair value of the equipment, the equipment is considered integral equipment. The accounting standards specifically identify power plants as an example of in-substance real estate. Where the consolidated entity in which noncontrolling interests have been sold contains in-substance real estate, management estimates the extent to which the total fair value of the assets of the entity is represented by the in-substance real estate and whether significant value exists beyond the in-substance real estate. This estimation considers all qualitative and quantitative factors relevant for each sale and, where appropriate, includes making quantitative estimates about the fair value of the entity and its identifiable assets and liabilities (including any favorable or unfavorable contracts) by analogy to the accounting standards on business combinations. As such, these estimates may require significant judgment and assumptions, similar to the critical accounting estimates discussed below for impairments and fair value.
Impairments — Our accounting policies on goodwill and long-lived assets are described in detail in Note 1—General and Summary of Significant Accounting Policies, included in Item 8 of this Form 10-K. The Company makes considerable judgments in its impairment evaluations of goodwill and long-lived assets; however, the fair value determination is typically the most judgmental part in an impairment evaluation.
The Company determines the fair value of a reporting unit or a long-lived asset (asset group) by applying the approaches prescribed under the fair value measurement accounting framework. Generally, the market approach and income approach are most relevant in the fair value measurement of our reporting units and long-lived assets; however, due to the lack of available relevant observable market information in many circumstances, the Company often relies on the income approach. The Company may engage an independent valuation firm to assist management with the valuation. The decision to engage an independent valuation firm considers all relevant facts and circumstances, including a cost-benefit analysis and the Company's internal valuation knowledge of the long-lived asset (asset group) or business. The Company develops the underlying assumptions consistent with its internal budgets and forecasts for such valuations. Additionally, the Company uses an internal discounted cash flow valuation model (the "DCF model"), based on the principles of present value techniques, to estimate the fair value of its reporting units or long-lived assets under the income approach. The DCF model estimates fair value by discounting our internal budgets and cash flow forecasts, adjusted to reflect market participant assumptions, to the extent necessary, at an appropriate discount rate.
Management applies considerable judgment in selecting several input assumptions during the development of our internal budgets and cash flow forecasts. Examples of the input assumptions that our budgets and forecasts are sensitive to include macroeconomic factors such as growth rates, industry demand, inflation, exchange rates, power prices and commodity prices. Whenever appropriate, management obtains these input assumptions from observable market data sources (e.g., Economic Intelligence Unit) and extrapolates the market information if an input assumption is not observable for the entire forecast period. Many of these input assumptions are dependent on other economic assumptions, which are often derived from statistical economic models with inherent limitations such as estimation differences. Further, several input assumptions are based on historical trends which often do not recur. The input assumptions most significant to our budgets and cash flows are based on expectations of macroeconomic factors which have been volatile recently. It is not uncommon that different market data sources have different views of the macroeconomic factor expectations and related assumptions. As a result, macroeconomic factors and related assumptions are often available in a narrow range; however, in some situations these ranges become wide and the use of a different set of input assumptions could produce significantly different budgets and cash flow forecasts.
A considerable amount of judgment is also applied in the estimation of the discount rate used in the DCF model. To the extent practical, inputs to the discount rate are obtained from market data sources (e.g., Bloomberg, Capital IQ, etc.). The Company selects and uses a set of publicly traded companies from the relevant industry to estimate the discount rate inputs. Management applies judgment in the selection of such companies based on its view of the most likely market participants. It is reasonably possible that the selection of a different set of likely market participants could produce different input assumptions and result in the use of a different discount rate.
Fair value of a reporting unit or a long-lived asset (asset group) is sensitive to both input assumptions to our budgets and cash flow forecasts and the discount rate. Further, estimates of long-term growth and terminal value are often critical to the fair value determination. As part of the impairment evaluation process, management analyzes the sensitivity of fair value to various underlying assumptions. The level of scrutiny increases as the gap between fair value and carrying amount decreases. Changes in any of these assumptions could result in management reaching a different conclusion regarding the potential impairment, which could be material. Our impairment evaluations inherently involve uncertainties from uncontrollable events that could positively or negatively impact the anticipated future economic and operating conditions.
Further discussion of the impairment charges recognized by the Company can be found within Note 10—Goodwill and Other Intangible Assets, Note 21—Asset Impairment Expense and Note 9—Other Non-Operating Expense to the Consolidated Financial Statements included in Item 8 of this Form 10-K.

114


Fair Value
Fair Value Hierarchy — The Company uses valuation techniques and methodologies that maximize the use of observable inputs and minimize the use of unobservable inputs. Where available, fair value is based on observable market prices or parameters or derived from such prices or parameters. Where observable prices are not available, valuation models are applied to estimate the fair value using the available observable inputs. The valuation techniques involve some level of management estimation and judgment, the degree of which is dependent on the price transparency for the instruments or market and the instruments' complexity.
To increase consistency and enhance disclosure of the fair value of financial instruments, the fair value measurement standard includes a fair value hierarchy to prioritize the inputs used to measure fair value into three categories. An asset or liability's level within the fair value hierarchy is based on the lowest level of input significant to the fair value measurement, where Level 1 is the highest and Level 3 is the lowest. For more information regarding the fair value hierarchy, see Note 1—General and Summary of Significant Accounting Policies included in Item 8 of this Form 10-K.
Fair Value of Financial Instruments — A significant number of the Company's financial instruments are carried at fair value with changes in fair value recognized in earnings or other comprehensive income each period. The Company makes estimates regarding the valuation of assets and liabilities measured at fair value in preparing the Consolidated Financial Statements. These assets and liabilities include short and long-term investments in debt and equity securities, included in the balance sheet line items Short-term investments and Other assets (Noncurrent), derivative assets, included in Other current assets and Other assets (Noncurrent) and derivative liabilities, included in Accrued and other liabilities (current) and Other long-term liabilities. Investments are generally fair valued based on quoted market prices or other observable market data such as interest rate indices. The Company's investments are primarily certificates of deposit, government debt securities and money market funds. Derivatives are valued using observable data as inputs into internal valuation models. The Company's derivatives primarily consist of interest rate swaps, foreign currency instruments, and commodity and embedded derivatives. Additional discussion regarding the nature of these financial instruments and valuation techniques can be found in Note 4—Fair Value included in Item 8 of this Form 10-K.
Fair Value of Nonfinancial Assets and Liabilities — Significant estimates are made in determining the fair value of long-lived tangible and intangible assets (i.e., property, plant and equipment, intangible assets and goodwill) during the impairment evaluation process. In addition, the majority of assets acquired and liabilities assumed in a business combination are required to be recognized at fair value under the relevant accounting guidance. In determining the fair value of these items, management makes several assumptions as discussed in the Impairments section above.
Accounting for Derivative Instruments and Hedging Activities — We enter into various derivative transactions in order to hedge our exposure to certain market risks. We primarily use derivative instruments to manage our interest rate, commodity and foreign currency exposures. We do not enter into derivative transactions for trading purposes.
In accordance with the accounting standards for derivatives and hedging, we recognize all derivatives as either assets or liabilities in the balance sheet and measure those instruments at fair value except where derivatives qualify and are designated as "normal purchase/normal sale" transactions. Changes in fair value of derivatives are recognized in earnings unless specific hedge criteria are met. Income and expense related to derivative instruments are recognized in the same category as that generated by the underlying asset or liability. See Note 6—Derivative Instruments and Hedging Activities included in Item 8 of this Form 10-K for further information on the classification.
The accounting standards for derivatives and hedging enable companies to designate qualifying derivatives as hedging instruments based on the exposure being hedged. These hedge designations include fair value hedges and cash flow hedges. Changes in the fair value of a derivative that is highly effective and is designated and qualifies as a fair value hedge, are recognized in earnings as offsets to the changes in fair value of the exposure being hedged. The Company has no fair value hedges at this time. Changes in the fair value of a derivative that is highly effective and is designated as and qualifies as a cash flow hedge, are deferred in accumulated other comprehensive income and are recognized into earnings as the hedged transactions occur. Any ineffectiveness is recognized in earnings immediately. For all hedge contracts, the Company provides formal documentation of the hedge and effectiveness testing in accordance with the accounting standards for derivatives and hedging.
The fair value measurement accounting standard provides additional guidance on the definition of fair value and defines fair value as the price that would be received to sell an asset or paid to transfer a liability in an orderly transaction between market participants at the measurement date, or exit price. The fair value measurement standard requires the Company to consider and reflect the assumptions of market participants in the fair value calculation. These factors include nonperformance risk (the risk that the obligation will not be fulfilled) and credit risk, both of the reporting entity (for liabilities) and of the counterparty (for assets). Due to the nature of the Company's interest rate swaps, which are typically associated with non-recourse debt, credit risk for AES is evaluated at the subsidiary level rather than at the Parent Company level. Nonperformance

115


risk on the Company's derivative instruments is an adjustment to the initial asset/liability fair value position that is derived from internally developed valuation models that utilize observable market inputs.
As a result of uncertainty, complexity and judgment, accounting estimates related to derivative accounting could result in material changes to our financial statements under different conditions or utilizing different assumptions. As a part of accounting for these derivatives, we make estimates concerning nonperformance, volatilities, market liquidity, future commodity prices, interest rates, credit ratings (both ours and our counterparty's), and future exchange rates. Refer to Note 4—Fair Value included in Item 8 of this Form 10-K for additional details.
The fair value of our derivative portfolio is generally determined using internal valuation models, most of which are based on observable market inputs including interest rate curves and forward and spot prices for currencies and commodities. The Company derives most of its financial instrument market assumptions from market efficient data sources (e.g., Bloomberg, Reuters and Platt's). In some cases, where market data is not readily available, management uses comparable market sources and empirical evidence to derive market assumptions to determine a financial instrument's fair value. In certain instances, the published curve may not extend through the remaining term of the contract and management must make assumptions to extrapolate the curve. Specifically, where there is limited forward curve data with respect to foreign exchange contracts, beyond the traded points the Company utilizes the purchasing power parity approach to construct the remaining portion of the forward curve using relative inflation rates. Additionally, in the absence of quoted prices, we may rely on "indicative pricing" quotes from financial institutions to input into our valuation model for certain of our foreign currency swaps. These indicative pricing quotes do not constitute either a bid or ask price and therefore are not considered observable market data. For individual contracts, the use of different valuation models or assumptions could have a material effect on the calculated fair value.
Regulatory Assets — Management continually assesses whether the regulatory assets are probable of future recovery by considering factors such as applicable regulatory changes, recent rate orders applicable to other regulated entities and the status of any pending or potential deregulation legislation. If future recovery of costs ceases to be probable, any asset write-offs would be required to be recognized in operating income.
Consolidation — The Company has recently entered into several transactions whereby the Company sells an interest in its controlled subsidiaries and/or equity method investments. In connection with each transaction, the Company must determine whether the sale of the interest impacts the Company's consolidation conclusion by first determining whether the transaction should be evaluated under the variable interest model or the voting model. In determining which consolidation model applies to the transaction, the Company is required to make judgments about how the entity operates, the most significant of which are whether (i) the entity has sufficient equity to finance its activities, (ii) the equity holders, as a group, have the characteristics of a controlling financial interest, and (iii) whether the entity has non-substantive voting rights.
If the entity is determined to be a variable interest entity, the most significant judgment in determining whether the Company must consolidate the entity is whether the subsidiary, including its related parties and de facto agents, collectively have power and benefits. If AES is determined to have power and benefits, the entity will be consolidated by AES.
Alternatively, if the entity is determined to be a voting model entity, the most significant judgments involve determining whether the non-AES shareholders have substantive participating rights. The assessment of shareholder rights and whether they are substantive participating rights requires significant judgment since the rights provided under shareholders' agreements may include selecting, terminating, and setting the compensation of management responsible for implementing the subsidiary's policies and procedures, establishing operating and capital decisions of the entity, including budgets, in the ordinary course of business. On the other hand, if shareholder rights are only protective in nature (referred to as protective rights) then such rights would not overcome the presumption that the owner of a majority voting interest shall consolidate its investee. Significant judgment is required to determine whether minority rights represent substantive participating rights or protective rights that do not affect the evaluation of control. While both represent an approval or veto right, a distinguishing factor is the underlying activity or action to which the right relates.
Pension and Other Postretirement Plans — Effective January 1, 2016 the Company will apply a disaggregated discount rate approach for determining service cost and interest cost for its defined benefit pension plans and post-retirement plans in the U.S. and U.K. Refer to Note 1—General and Summary of Significant Accounting Policies included in Item 8 of this Form 10-K for further information.
New Accounting Pronouncements — See Note 1—General and Summary of Significant Accounting Policies included in Item 8 of this Form 10-K for further information about new accounting pronouncements adopted during 2015 and accounting pronouncements issued but not yet effective.
ITEM 7A. QUANTITATIVE AND QUALITATIVE DISCLOSURES ABOUT MARKET RISK
Overview Regarding Market Risks — Our businesses are exposed to and proactively manage market risk. Our primary market risk exposure is to the price of commodities, particularly electricity, oil, natural gas, coal and environmental credits. We

116


operate in multiple countries and as such are subject to volatility in exchange rates at varying degrees at the subsidiary level and between our functional currency, the U.S. Dollar, and currencies of the countries in which we operate. We are also exposed to interest rate fluctuations due to our issuance of debt and related financial instruments.
The disclosures presented in this Item 7A are based upon a number of assumptions; actual effects may differ. The safe harbor provided in Section 27A of the Securities Act of 1933 and Section 21E of the Securities Exchange Act of 1934 shall apply to the disclosures contained in this Item 7A. For further information regarding market risk, see Item 1A.—Risk Factors, Our financial position and results of operations may fluctuate significantly due to fluctuations in currency exchange rates experienced at our foreign operations, Our businesses may incur substantial costs and liabilities and be exposed to price volatility as a result of risks associated with the electricity markets, which could have a material adverse effect on our financial performance, and We may not be adequately hedged against our exposure to changes in commodity prices or interest rates of this 2015 Form 10-K.
Commodity Price Risk — Although we prefer to hedge our exposure to the impact of market fluctuations in the price of electricity, fuels and environmental credits, some of our generation businesses operate under short-term sales or under contract sales that leave an unhedged exposure on some of our capacity or through imperfect fuel pass-throughs. In our utility businesses, we may be exposed to commodity price movements depending on our excess or shortfall of generation relative to load obligations and sharing or pass-through mechanisms. These businesses subject our operational results to the volatility of prices for electricity, fuels and environmental credits in competitive markets. We employ risk management strategies to hedge our financial performance against the effects of fluctuations in energy commodity prices. The implementation of these strategies can involve the use of physical and financial commodity contracts, futures, swaps and options. At our generation businesses for 2016-2018, 80% to 85% of our variable margin is hedged against changes in commodity prices. At our utility businesses for 2016-2018, 85% to 90% of our variable margin is insulated from changes in commodity prices.
The portion of our sales and purchases that are not subject to such agreements or contracted businesses where indexation is not perfectly matched to business drivers will be exposed to commodity price risk. When hedging the output of our generation assets, we utilize contract sales that lock in the spread per MWh between variable costs and the price at which the electricity can be sold.
AES businesses will see changes in variable margin performance as global commodity prices shift. For 2016, we project pretax earnings exposure on a 10% move in commodity prices would be approximately $25 million for U.S. power (DPL), less than $5 million for natural gas, $5 million for oil and $10 million for coal. Our estimates exclude correlation of oil with coal or natural gas. For example, a decline in oil or natural gas prices can be accompanied by a decline in coal price if commodity prices are correlated. In aggregate, the Company's downside exposure occurs with lower oil, lower natural gas, and higher coal prices. Exposures at individual businesses will change as new contracts or financial hedges are executed, and our sensitivity to changes in commodity prices generally increases in later years with reduced hedge levels at some of our businesses.
Commodity prices affect our businesses differently depending on the local market characteristics and risk management strategies. Spot power prices, contract indexation provisions and generation costs can be directly or indirectly affected by movements in the price of natural gas, oil and coal. We have some natural offsets across our businesses such that low commodity prices may benefit certain businesses and be a cost to others. Exposures are not perfectly linear or symmetric. The sensitivities are affected by a number of local or indirect market factors. Examples of these factors include hydrology, local energy market supply/demand balances, regional fuel supply issues, regional competition, bidding strategies and regulatory interventions such as price caps. Operational flexibility changes the shape of our sensitivities. For instance, certain power plants may limit downside exposure by reducing dispatch in low market environments. Volume variation also affects our commodity exposure. The volume sold under contracts or retail concessions can vary based on weather and economic conditions resulting in a higher or lower volume of sales in spot markets. Thermal unit availability and hydrology can affect the generation output available for sale and can affect the marginal unit setting power prices.
In the US SBU, the generation businesses are largely contracted but may have residual risk to the extent contracts are not perfectly indexed to the business drivers. IPL sells power at wholesale once retail demand is served, so retail sales demand may affect commodity exposure. Additionally, at DPL, open access allows our retail customers to switch to alternative suppliers; falling energy prices may increase the rate of switching; DPL sells generation in excess of its retail demand under short-term sales. Given that natural gas-fired generators set power prices for many markets, higher natural gas prices expand margins. The positive impact on margins will be moderated if natural gas-fired generators set the market price only during peak periods.
In the Andes SBU, our business in Chile owns assets in the central and northern regions of the country and has a portfolio of contract sales in both. In the central region, the contract sales generally cover the efficient generation from our coal-fired and hydroelectric assets. Any residual spot price risk will primarily be driven by the amount of hydrological inflows. In the case of low hydroelectric generation, spot price exposure is capped by the ability to dispatch our natural gas/diesel assets the price of which depends on fuel pricing at the time required. There is a small amount of coal generation in the northern region that is not covered by the portfolio of contract sales and therefore subject to spot price risk. In both regions, generators with oil or oil-

117


linked fuel generally set power prices. In Colombia, we operate under a short-term sales strategy and have commodity exposure to unhedged volumes. Because we own hydroelectric assets there, contracts are not indexed to fuel.
In the Brazil SBU, the hydroelectric generating facility is covered by contract sales. Under normal hydrological volatility, spot price risk is mitigated through a regulated sharing mechanism across all hydroelectric generators in the country. Under drier conditions, the sharing mechanism may not be sufficient to cover the business' contract position, and therefore it may have to purchase power at spot prices driven by the cost of thermal generation.
In the MCAC SBU, our businesses have commodity exposure on unhedged volumes. Panama is highly contracted under a portfolio of fixed volume contract sales. To the extent hydrological inflows are greater than or less than the contract sales volume, the business will be sensitive to changes in spot power prices which may be driven by oil prices in some time periods. In the Dominican Republic, we own natural gas-fired assets contracted under a portfolio of contract sales and a coal-fired asset contracted with a single contract, and both contract and spot prices may move with commodity prices. Additionally, the contract levels do not always match our generation availability and our assets may be sellers of spot prices in excess of contract levels or a net buyer in the spot market to satisfy contract obligations.
In the Europe SBU, our Kilroot facility operates on a short-term sales strategy. To the extent that sales are unhedged, the commodity risk at our Kilroot business is to the clean dark spread, which is the difference between electricity price and our coal-based variable dispatch cost including emissions. Natural gas-fired generators set power prices for many periods, so higher natural gas prices generally expand margins and higher coal or emissions prices reduce them. Similarly, increased wind generators displaces higher cost generation, reducing Kilroot's margins, and vice versa.
In the Asia SBU, our Masinloc business is a coal-fired generation facility which hedges its output under a portfolio of contract sales that are indexed to fuel prices, with generation in excess of contract volume or shortfalls of generation relative to contract volumes settled in the spot market. Low oil prices may be a driver of margin compression since oil affects spot power sale prices sold in the spot market. Low oil prices may be a driver of margin compression since oil affects spot power sale prices. Our Mong Duong business has minimal exposure to commodity price risk as it has no merchant exposure and fuel is subject to a pass-through mechanism.
Foreign Exchange Rate Risk — In the normal course of business, we are exposed to foreign currency risk and other foreign operations risks that arise from investments in foreign subsidiaries and affiliates. A key component of these risks stems from the fact that some of our foreign subsidiaries and affiliates utilize currencies other than our consolidated reporting currency, the U.S. Dollar ("USD"). Additionally, certain of our foreign subsidiaries and affiliates have entered into monetary obligations in the USD or currencies other than their own functional currencies. We have varying degrees of exposure to changes in the exchange rate between the USD and the following currencies: Argentine Peso, British Pound, Brazilian Real, Chilean Peso, Colombian Peso, Dominican Peso, Euro, Indian Rupee, Kazakhstan Tenge, Mexican Peso and Philippine Peso. These subsidiaries and affiliates have attempted to limit potential foreign exchange exposure by entering into revenue contracts that adjust to changes in foreign exchange rates. We also use foreign currency forwards, swaps and options, where possible, to manage our risk related to certain foreign currency fluctuations.
We have entered into hedges to partially mitigate the exposure of earnings translated into the USD to foreign exchange volatility. The largest foreign exchange risks over a 12-month forward-looking period stem from the following currencies: Argentine Peso, British Pound, Brazilian Real, Colombian Peso, Euro and Kazakhstan Tenge. As of December 31, 2015, assuming a 10% USD appreciation, adjusted pretax earnings attributable to foreign subsidiaries exposed to movement in the exchange rate of the Argentine Peso, Brazilian Real, Colombian Peso, Euro and Kazakhstan Tenge relative to the USD are projected to be reduced by approximately $5 million, British Pound — less than $5 million for 2016. These numbers have been produced by applying a one-time 10% USD appreciation to forecasted exposed pretax earnings for 2016 coming from the respective subsidiaries exposed to the currencies listed above, net of the impact of outstanding hedges and holding all other variables constant. The numbers presented above are net of any transactional gains/losses. These sensitivities may change in the future as new hedges are executed or existing hedges are unwound. Additionally, updates to the forecasted pretax earnings exposed to foreign exchange risk may result in further modification. The sensitivities presented do not capture the impacts of any administrative market restrictions or currency inconvertibility.
Interest Rate Risks — We are exposed to risk resulting from changes in interest rates as a result of our issuance of variable and fixed-rate debt, as well as interest rate swap, cap, floor and option agreements.
Decisions on the fixed-floating debt mix are made to be consistent with the risk factors faced by individual businesses or plants. Depending on whether a plant's capacity payments or revenue stream is fixed or varies with inflation, we partially hedge against interest rate fluctuations by arranging fixed-rate or variable-rate financing. In certain cases, particularly for non-recourse financing, we execute interest rate swap, cap and floor agreements to effectively fix or limit the interest rate exposure on the underlying financing. Most of our interest rate risk is related to non-recourse financings at our businesses.
As of December 31, 2015, the portfolio's pretax earnings exposure for 2016 to a 100-basis-point increase in interest rates

118


for our Argentine Peso, Brazilian Real, Colombian Peso, Euro, Kazakhstani Tenge and USD denominated debt would be approximately $30 million based on the impact of a one time,100-basis-point upward shift in interest rates on interest expense for the debt denominated in these currencies. These amounts do not take into account the historical correlation between these interest rates.

119


ITEM 8.
FINANCIAL STATEMENTS AND SUPPLEMENTARY DATA

REPORT OF INDEPENDENT REGISTERED PUBLIC ACCOUNTING FIRM


The Board of Directors and Stockholders of The AES Corporation:
We have audited the accompanying consolidated balance sheets of The AES Corporation as of December 31, 2015 and 2014, and the related consolidated statements of operations, comprehensive income, changes in equity, and cash flows for each of the three years in the period ended December 31, 2015. Our audits also included the financial statement schedules listed in the index at Item 15(a). These financial statements and schedules are the responsibility of the Company’s management. Our responsibility is to express an opinion on these financial statements and schedules based on our audits.
We conducted our audits in accordance with the standards of the Public Company Accounting Oversight Board (United States). Those standards require that we plan and perform the audit to obtain reasonable assurance about whether the financial statements are free of material misstatement. An audit also includes examining, on a test basis, evidence supporting the amounts and disclosures in the financial statements. An audit also includes assessing the accounting principles used and significant estimates made by management, as well as evaluating the overall financial statement presentation. We believe that our audits provide a reasonable basis for our opinion.
In our opinion, the financial statements referred to above present fairly, in all material respects, the consolidated financial position of The AES Corporation at December 31, 2015 and 2014, and the consolidated results of its operations and its cash flows for each of the three years in the period ended December 31, 2015, in conformity with U.S. generally accepted accounting principles. Also, in our opinion, the related financial statement schedules, when considered in relation to the basic financial statements taken as a whole, present fairly, in all material respects, the information set forth therein.
As discussed in Note 1 to the consolidated financial statements, the Company changed its requirements for reporting discontinued operations as a result of the adoption of the amendments to the FASB Accounting Standards Codification resulting from Accounting Standards Update No. 2014-08, “Reporting Discontinued Operations and Disclosures of Disposals of Components of an Entity,” effective July 1, 2014. Also, the Company changed its accounting for service concession arrangements as a result of the adoption of the amendments to the FASB Accounting Standards Codification resulting from Accounting Standards Update No. 2014-05, “Service Concession Arrangements,” effective January 1, 2015. Lastly, the Company changed its classification of all deferred tax assets and liabilities as a result of the adoption of the amendments to the FASB Accounting Standards Codification resulting from Accounting Standards Update No. 2015-17, “Income Taxes,” effective December 31, 2015.
We also have audited, in accordance with the standards of the Public Company Accounting Oversight Board (United States), The AES Corporation’s internal control over financial reporting as of December 31, 2015, based on criteria established in Internal Control-Integrated Framework issued by the Committee of Sponsoring Organizations of the Treadway Commission (2013 framework) and our report dated February 23, 2016 expressed an unqualified opinion thereon.

/s/ Ernst & Young LLP

McLean, Virginia
February 23, 2016


120


THE AES CORPORATION
CONSOLIDATED BALANCE SHEETS
DECEMBER 31, 2015 AND 2014
 
2015
 
2014
 
(in millions, except share and per share data)
ASSETS


CURRENT ASSETS


Cash and cash equivalents
$
1,262

 
$
1,539

Restricted cash
295

 
283

Short-term investments
484

 
709

Accounts receivable, net of allowance for doubtful accounts of $95 and $96, respectively
2,473

 
2,709

Inventory
675

 
702

Deferred income taxes
—

 
275

Prepaid expenses
108

 
175

Other current assets
1,473

 
1,434

Assets of held-for-sale businesses
96

 
—

Total current assets
6,866

 
7,826

NONCURRENT ASSETS


Property, Plant and Equipment:


Land
711

 
870

Electric generation, distribution assets and other
28,491

 
30,459

Accumulated depreciation
(9,449
)
 
(9,962
)
Construction in progress
3,063

 
3,784

Property, plant and equipment, net
22,816

 
25,151

Other Assets:


Investments in and advances to affiliates
610

 
537

Debt service reserves and other deposits
565

 
411

Goodwill
1,157

 
1,458

Other intangible assets, net of accumulated amortization of $97 and $158, respectively
214

 
281

Deferred income taxes
543

 
662

Service concession assets, net of accumulated amortization of $34
1,543

 
—

Other noncurrent assets
2,536

 
2,640

Total other assets
7,168

 
5,989

TOTAL ASSETS
$
36,850

 
$
38,966

LIABILITIES AND EQUITY


CURRENT LIABILITIES


Accounts payable
$
1,721

 
$
2,278

Accrued interest
251

 
260

Accrued and other liabilities
2,436

 
2,326

Recourse debt
—

 
151

Non-recourse debt, including $163 and $240, respectively, related to variable interest entities
2,529

 
1,982

Liabilities of held-for-sale businesses
13

 
—

Total current liabilities
6,950

 
6,997

NONCURRENT LIABILITIES


Recourse debt
5,015

 
5,107

Non-recourse debt, including $760 and $1,030, respectively, related to variable interest entities
13,263

 
13,618

Deferred income taxes
1,090

 
1,277

Pension and other post-retirement liabilities
927

 
1,342

Other noncurrent liabilities
2,896

 
3,222

Total noncurrent liabilities
23,191

 
24,566

Commitments and Contingencies (see Notes 13 and 14)


Redeemable stock of subsidiaries
538

 
78

EQUITY


THE AES CORPORATION STOCKHOLDERS’ EQUITY


Common stock ($0.01 par value, 1,200,000,000 shares authorized; 815,846,621 issued and 666,808,790 outstanding at December 31, 2015 and 814,539,146 issued and 703,851,297 outstanding at December 31, 2014)
8

 
8

Additional paid-in capital
8,718

 
8,409

Retained earnings
143

 
512

Accumulated other comprehensive loss
(3,883
)
 
(3,286
)
Treasury stock, at cost (149,037,831 shares at December 31, 2015 and 110,687,849 shares at December 31, 2014)
(1,837
)
 
(1,371
)
Total AES Corporation stockholders’ equity
3,149

 
4,272

NONCONTROLLING INTERESTS
3,022

 
3,053

Total equity
6,171

 
7,325

TOTAL LIABILITIES AND EQUITY
$
36,850

 
$
38,966

See Accompanying Notes to Consolidated Financial Statements.

121


THE AES CORPORATION
CONSOLIDATED STATEMENTS OF OPERATIONS
YEARS ENDED DECEMBER 31, 2015, 2014, AND 2013
 
2015
 
2014
 
2013
 
(in millions, except per share amounts)
Revenue:


Regulated
$
7,660

 
$
8,874

 
$
8,056

Non-regulated
7,303

 
8,272

 
7,835

Total revenue
14,963

 
17,146

 
15,891

Cost of sales:


Regulated
(6,564
)
 
(7,530
)
 
(6,837
)
Non-regulated
(5,533
)
 
(6,528
)
 
(5,807
)
Total cost of sales
(12,097
)
 
(14,058
)
 
(12,644
)
Operating margin
2,866

 
3,088

 
3,247

General and administrative expenses
(196
)
 
(187
)
 
(220
)
Interest expense
(1,436
)
 
(1,471
)
 
(1,482
)
Interest income
524

 
365

 
275

Loss on extinguishment of debt
(186
)
 
(261
)
 
(229
)
Other expense
(65
)
 
(68
)
 
(76
)
Other income
83

 
124

 
125

Gain on sale of businesses
29

 
358

 
26

Goodwill impairment expense
(317
)
 
(164
)
 
(372
)
Asset impairment expense
(285
)
 
(91
)
 
(95
)
Foreign currency transaction gains (losses)
105

 
11

 
(22
)
Other non-operating expense
—

 
(128
)
 
(129
)
INCOME FROM CONTINUING OPERATIONS BEFORE TAXES AND EQUITY IN EARNINGS OF AFFILIATES
1,122

 
1,576

 
1,048

Income tax expense
(465
)
 
(419
)
 
(343
)
Net equity in earnings of affiliates
105

 
19

 
25

INCOME FROM CONTINUING OPERATIONS
762

 
1,176

 
730

Income (loss) from operations of discontinued businesses, net of income tax expense of $0, $23, and $24, respectively
—

 
27

 
(27
)
Net loss from disposal and impairments of discontinued operations, net of income tax expense (benefit) of $0, $4, and $(15), respectively
—

 
(56
)
 
(152
)
NET INCOME
762

 
1,147

 
551

Noncontrolling interests:


Less: (Income) from continuing operations attributable to noncontrolling interests
(456
)
 
(387
)
 
(446
)
Plus: Loss from discontinued operations attributable to noncontrolling interests
—

 
9

 
9

Total net income attributable to noncontrolling interests
(456
)
 
(378
)
 
(437
)
NET INCOME ATTRIBUTABLE TO THE AES CORPORATION
$
306

 
$
769

 
$
114

AMOUNTS ATTRIBUTABLE TO THE AES CORPORATION COMMON STOCKHOLDERS:


Income from continuing operations, net of tax
$
306

 
$
789

 
$
284

Loss from discontinued operations, net of tax
—

 
(20
)
 
(170
)
Net income
$
306

 
$
769

 
$
114

BASIC EARNINGS PER SHARE:


Income from continuing operations attributable to The AES Corporation common stockholders, net of tax
$
0.45

 
$
1.10

 
$
0.38

Loss from discontinued operations attributable to The AES Corporation common stockholders, net of tax
—

 
(0.03
)
 
(0.23
)
NET INCOME ATTRIBUTABLE TO THE AES CORPORATION COMMON STOCKHOLDERS
$
0.45

 
$
1.07

 
$
0.15

DILUTED EARNINGS PER SHARE:


Income from continuing operations attributable to The AES Corporation common stockholders, net of tax
$
0.44

 
$
1.09

 
$
0.38

Loss from discontinued operations attributable to The AES Corporation common stockholders, net of tax
—

 
(0.03
)
 
(0.23
)
NET INCOME ATTRIBUTABLE TO THE AES CORPORATION COMMON STOCKHOLDERS
$
0.44

 
$
1.06

 
$
0.15

DIVIDENDS DECLARED PER COMMON SHARE
$
0.41

 
$
0.25

 
$
0.17


See Accompanying Notes to Consolidated Financial Statements.

122


THE AES CORPORATION
CONSOLIDATED STATEMENTS OF COMPREHENSIVE (LOSS) INCOME
YEARS ENDED DECEMBER 31, 2015, 2014, AND 2013

 
2015
 
2014
 
2013
 
(in millions)
NET INCOME
$
762

 
$
1,147

 
$
551

Foreign currency translation activity:


Foreign currency translation adjustments, net of income tax benefit (expense) of $1, $(7), and $10, respectively
(1,019
)
 
(491
)
 
(375
)
Reclassification to earnings, net of $0 income tax for all periods
—

 
(3
)
 
41

Total foreign currency translation adjustments
(1,019
)
 
(494
)
 
(334
)
Derivative activity:


Change in derivative fair value, net of income tax benefit (expense) of $16, $72 and $(31), respectively
(57
)
 
(358
)
 
108

Reclassification to earnings, net of income tax (expense) of $(11), $(26) and $(41), respectively
66

 
99

 
139

Total change in fair value of derivatives
9

 
(259
)
 
247

Pension activity:


Change in pension adjustments due to prior service cost, net of $0 income tax for all periods
1

 
—

 
—

Change in pension adjustments due to net actuarial gain (loss) for the period, net of income tax (expense) benefit of $(29), $27, and $(198), respectively
60

 
(49
)
 
379

Reclassification to earnings due to amortization of net actuarial loss, net of income tax (expense) of $(9), $(7), and $(26), respectively
16

 
29

 
52

Total pension adjustments
77

 
(20
)
 
431

OTHER COMPREHENSIVE (LOSS) INCOME
(933
)
 
(773
)
 
344

COMPREHENSIVE (LOSS) INCOME
(171
)
 
374

 
895

Less: Comprehensive (income) attributable to noncontrolling interests
(133
)
 
(49
)
 
(743
)
COMPREHENSIVE (LOSS) INCOME ATTRIBUTABLE TO THE AES CORPORATION
$
(304
)
 
$
325

 
$
152


See Accompanying Notes to Consolidated Financial Statements.

123


THE AES CORPORATION
CONSOLIDATED STATEMENTS OF CHANGES IN EQUITY
YEARS ENDED DECEMBER 31, 2015, 2014, AND 2013
 
THE AES CORPORATION STOCKHOLDERS


Common Stock
 
Treasury Stock
 
Additional
Paid-In
Capital
 
Retained
Earnings
(Accumulated
Deficit)
 
Accumulated
Other
Comprehensive
Loss
 
Noncontrolling
Interests
(in millions)
Shares
 
Amount
 
Shares
 
Amount
 
Balance at January 1, 2013
810.7

 
$
8

 
66.4

 
$
(780
)
 
$
8,525

 
$
(264
)
 
$
(2,920
)
 
$
2,945

Net income
—

 
—

 
—

 
—

 
—

 
114

 
—

 
437

Total foreign currency translation adjustment, net of income tax
—

 
—

 
—

 
—

 
—

 
—

 
(227
)
 
(107
)
Total change in derivative fair value, net of income tax
—

 
—

 
—

 
—

 
—

 
—

 
174

 
73

Total pension adjustments, net of income tax
—

 
—

 
—

 
—

 
—

 
—

 
91

 
340

Total other comprehensive income


38

 
306

Disposition of businesses
—

 
—

 
—

 
—

 
—

 
—

 
—

 
(13
)
Distributions to noncontrolling interests
—

 
—

 
—

 
—

 
—

 
—

 
—

 
(553
)
Contributions from noncontrolling interests
—

 
—

 
—

 
—

 
—

 
—

 
—

 
109

Dividends declared on common stock
—

 
—

 
—

 
—

 
(125
)
 
—

 
—

 
—

Purchase of treasury stock
—

 
—

 
25.3

 
(322
)
 
—

 
—

 
—

 
—

Issuance and exercise of stock-based compensation benefit plans, net of income tax
2.6

 
—

 
(0.9
)
 
13

 
33

 
—

 
—

 
—

Sale of subsidiary shares to noncontrolling interests
—

 
—

 
—

 
—

 
16

 
—

 
—

 
91

Acquisition of subsidiary shares from noncontrolling interests
—

 
—

 
—

 
—

 
(6
)
 
—

 
—

 
(1
)
Balance at December 31, 2013
813.3

 
$
8

 
90.8

 
$
(1,089
)
 
$
8,443

 
$
(150
)
 
$
(2,882
)
 
$
3,321

Net income
—

 
—

 
—

 
—

 
—

 
769

 
—

 
378

Total foreign currency translation adjustment, net of income tax
—

 
—

 
—

 
—

 
—

 
—

 
(332
)
 
(162
)
Total change in derivative fair value, net of income tax
—

 
—

 
—

 
—

 
—

 
—

 
(108
)
 
(151
)
Total pension adjustments, net of income tax
—

 
—

 
—

 
—

 
—

 
—

 
(4
)
 
(16
)
Total other comprehensive loss


(444
)
 
(329
)
Balance Sheet reclassification related to an equity method investment (1)
—

 
—

 
—

 
—

 
—

 
—

 
40

 
—

Disposition of businesses
—

 
—

 
—

 
—

 
—

 
—

 
—

 
(153
)
Distributions to noncontrolling interests
—

 
—

 
—

 
—

 
—

 
—

 
—

 
(466
)
Contributions from noncontrolling interests
—

 
—

 
—

 
—

 
—

 
—

 
—

 
147

Dividends declared on common stock
—

 
—

 
—

 
—

 
(73
)
 
(107
)
 
—

 
—

Purchase of treasury stock
—

 
—

 
21.9

 
(308
)
 
—

 
—

 
—

 
—

Issuance and exercise of stock-based compensation benefit plans, net of income tax
1.2

 
—

 
(2.0
)
 
26

 
3

 
—

 
—

 
—

Sale of subsidiary shares to noncontrolling interests
—

 
—

 
—

 
—

 
29

 
—

 
—

 
173

Acquisition of subsidiary shares from noncontrolling interests
—

 
—

 
—

 
—

 
7

 
—

 
—

 
(18
)
Balance at December 31, 2014
814.5

 
$
8

 
110.7

 
$
(1,371
)
 
$
8,409

 
$
512

 
$
(3,286
)
 
$
3,053

Net income
—

 
—

 
—

 
—

 
—

 
306

 
—

 
456

Total foreign currency translation adjustment, net of income tax
—

 
—

 
—

 
—

 
—

 
—

 
(674
)
 
(345
)
Total change in derivative fair value, net of income tax
—

 
—

 
—

 
—

 
—

 
—

 
43

 
(34
)
Total pension adjustments, net of income tax
—

 
—

 
—

 
—

 
—

 
—

 
21

 
56

Total other comprehensive loss


(610
)
 
(323
)
Cumulative effect of a change in accounting principle
—

 
—

 
—

 
—

 
—

 
(18
)
 
13

 
—

Acquisition of business (2)
—

 
—

 
—

 
—

 
—

 
—

 
—

 
15

Disposition of businesses
—

 
—

 
—

 
—

 
—

 
—

 
—

 
(41
)
Distributions to noncontrolling interests
—

 
—

 
—

 
—

 
(27
)
 
—

 
—

 
(383
)
Contributions from noncontrolling interests
—

 
—

 
—

 
—

 
—

 
—

 
—

 
126

Dividends declared on common stock
—

 
—

 
—

 
—

 
—

 
(280
)
 
—

 
—

Purchase of treasury stock
—

 
—

 
39.7

 
(482
)
 
—

 
—

 
—

 
—

Issuance and exercise of stock-based compensation benefit plans, net of income tax
1.3

 
—

 
(1.4
)
 
16

 
13

 
—

 
—

 
—

Sale of subsidiary shares to noncontrolling interests
—

 
—

 
—

 
—

 
323

 
(377
)
 
—

 
119

Balance at December 31, 2015
815.8

 
$
8

 
149.0

 
$
(1,837
)
 
$
8,718

 
$
143

 
$
(3,883
)
 
$
3,022

(1) Reclassification resulting from SRP transaction during the third quarter of 2014. See Note 8—Investments In and Advances to Affiliates for further information.
(2) Fair value of a tax equity partner's right to preferential returns recognized as a result of the acquisition of Solar Power PR, LLC, which was previously accounted for as an equity method investment.


See Accompanying Notes to Consolidated Financial Statements

124


THE AES CORPORATION
CONSOLIDATED STATEMENTS OF CASH FLOWS
YEARS ENDED DECEMBER 31, 2015, 2014, AND 2013
 
2015
 
2014
 
2013
 
(in millions)
OPERATING ACTIVITIES:


Net income
$
762

 
$
1,147

 
$
551

Adjustments to net income:


Depreciation and amortization
1,144

 
1,245

 
1,294

Gain on sale of businesses
(29
)
 
(358
)
 
(26
)
Impairment expenses
602

 
383

 
661

Deferred income taxes
(50
)
 
47

 
(158
)
(Reversals of) provisions for contingencies
(72
)
 
(34
)
 
312

Loss on extinguishment of debt
186

 
261

 
229

Loss on disposals and impairments - discontinued operations
—

 
50

 
163

Other
28

 
72

 
33

Changes in operating assets and liabilities:


(Increase) decrease in accounts receivable
(378
)
 
(520
)
 
146

(Increase) decrease in inventory
(26
)
 
(48
)
 
16

(Increase) decrease in prepaid expenses and other current assets
655

 
(73
)
 
358

(Increase) decrease in other assets
(1,305
)
 
(723
)
 
(103
)
Increase (decrease) in accounts payable and other current liabilities
31

 
(85
)
 
(758
)
Increase (decrease) in income tax payables, net and other tax payables
53

 
(89
)
 
95

Increase (decrease) in other liabilities
533

 
516

 
(98
)
Net cash provided by operating activities
2,134

 
1,791

 
2,715

INVESTING ACTIVITIES:


Capital expenditures
(2,308
)
 
(2,016
)
 
(1,988
)
Acquisitions, net of cash acquired
(17
)
 
(728
)
 
(7
)
Proceeds from the sale of businesses, net of cash sold
138

 
1,807

 
170

Sale of short-term investments
4,851

 
4,503

 
4,361

Purchase of short-term investments
(4,801
)
 
(4,623
)
 
(4,443
)
(Increase) decrease in restricted cash, debt service reserves and other assets
(159
)
 
419

 
44

Other investing
(70
)
 
(18
)
 
89

Net cash used in investing activities
(2,366
)
 
(656
)
 
(1,774
)
FINANCING ACTIVITIES:


Borrowings under revolving credit facilities
959

 
836

 
1,139

Repayments under revolving credit facilities
(937
)
 
(834
)
 
(1,161
)
Issuance of recourse debt
575

 
1,525

 
750

Repayments of recourse debt
(915
)
 
(2,117
)
 
(1,210
)
Issuance of non-recourse debt
4,248

 
4,179

 
4,277

Repayments of non-recourse debt
(3,312
)
 
(3,481
)
 
(3,390
)
Payments for financing fees
(90
)
 
(158
)
 
(176
)
Distributions to noncontrolling interests
(326
)
 
(485
)
 
(557
)
Contributions from noncontrolling interests
126

 
143

 
101

Proceeds from the sale of redeemable stock of subsidiaries
461

 
—

 
—

Dividends paid on AES common stock
(276
)
 
(144
)
 
(119
)
Payments for financed capital expenditures
(150
)
 
(528
)
 
(591
)
Purchase of treasury stock
(482
)
 
(308
)
 
(322
)
Proceeds from sales to noncontrolling interests, net of transaction costs
154

 
83

 
109

Other financing
(7
)
 
27

 
14

Net cash provided by (used in) financing activities
28

 
(1,262
)
 
(1,136
)
Effect of exchange rate changes on cash
(52
)
 
(51
)
 
(59
)
Decrease (increase) in cash of discontinued businesses
—

 
75

 
(4
)
Cash at held-for-sale businesses
(21
)
 
—

 
—

Total decrease in cash and cash equivalents
(277
)
 
(103
)
 
(258
)
Cash and cash equivalents, beginning
1,539

 
1,642

 
1,900

Cash and cash equivalents, ending
$
1,262

 
$
1,539

 
$
1,642

SUPPLEMENTAL DISCLOSURES:


Cash payments for interest, net of amounts capitalized
$
1,265

 
$
1,351

 
$
1,398

Cash payments for income taxes, net of refunds
$
388

 
$
480

 
$
570

SCHEDULE OF NONCASH INVESTING AND FINANCING ACTIVITIES:


Assets received upon sale of subsidiaries
$
—

 
$
44

 
$
—

Assets acquired through capital lease and other liabilities
$
18

 
$
49

 
$
34

Dividends declared but not yet paid
$
135

 
$
72

 
$
54

See Accompanying Notes to Consolidated Financial Statements.

125


THE AES CORPORATION
NOTES TO CONSOLIDATED FINANCIAL STATEMENTS
DECEMBER 31, 2015, 2014, AND 2013

 
1. GENERAL AND SUMMARY OF SIGNIFICANT ACCOUNTING POLICIES
The AES Corporation is a holding company (the "Parent Company") that through its subsidiaries and affiliates, (collectively, "AES" or "the Company") operates a geographically diversified portfolio of electricity generation and distribution businesses. Generally, given this holding company structure, the liabilities of the individual operating entities are non-recourse to the parent and are isolated to the operating entities. Most of our operating entities are structured as limited liability entities, which limit the liability of shareholders. The structure is generally the same regardless of whether a subsidiary is consolidated under a voting or variable interest model.
PRINCIPLES OF CONSOLIDATION — The Consolidated Financial Statements of the Company include the accounts of The AES Corporation and its subsidiaries, which are the entities that it controls. Furthermore, variable interest entities ("VIEs") in which the Company has a variable interest have been consolidated when the Company is the primary beneficiary and thus controls the VIE. Intercompany transactions and balances are eliminated in consolidation. Investments in entities where the Company has the ability to exercise significant influence, but not control, are accounted for using the equity method of accounting.
DP&L, our utility in Ohio, has undivided interests in five generation facilities and numerous transmission facilities. These undivided interests in jointly-owned facilities are accounted for on a pro-rata basis in our consolidated financial statements. Certain expenses, primarily fuel costs for the generating units, are allocated to the joint owners based on their energy usage. The remaining expenses, investments in fuel inventory, plant materials and operating supplies and capital additions are allocated to the joint owners in accordance with their respective ownership interests. See Note 3—Property, Plant and Equipment for additional details.
USE OF ESTIMATES — The preparation of these consolidated financial statements in conformity with accounting principles generally accepted in the United States of America ("GAAP") requires the Company to make estimates and assumptions that affect reported amounts of assets and liabilities and disclosures of contingent assets and liabilities at the date of the consolidated financial statements, as well as the reported amounts of revenue and expenses during the reporting period. Actual results could differ from those estimates. Items subject to such estimates and assumptions include: the carrying amount and estimated useful lives of long-lived assets; asset retirement obligations; impairment of goodwill, long-lived assets and equity method investments; valuation allowances for receivables and deferred tax assets; the recoverability of regulatory assets; the estimation of regulatory liabilities; the fair value of financial instruments; the fair value of assets and liabilities acquired in a business combination; the measurement of noncontrolling interest using the hypothetical liquidation at book value ("HLBV") method for certain renewable generation partnerships; the determination of whether a sale of noncontrolling interests is considered to be a sale of in-substance real estate (as opposed to an equity transaction); pension liabilities; environmental liabilities; and potential litigation claims and settlements.
DISCONTINUED OPERATIONS AND HELD-FOR-SALE BUSINESSES — Effective July 1, 2014, the Company prospectively adopted Accounting Standards Update ("ASU") No. 2014-08, Presentation of Financial Statements (Topic 205) and Property, Plant, and Equipment (Topic 360): Reporting discontinued Operations and Disclosures of Disposals of Components of an Entity, which significantly changed the prior accounting guidance on discontinued operations. Under ASU No. 2014-08, only those disposals of components of an entity that represent a strategic shift that has (or will have) a major effect on an entity's operations and financial results are reported as discontinued operations. Amongst other changes: equity method investments that were previously scoped-out of the discontinued operations accounting guidance are now included in the scope; a business can meet the criteria to be classified as held-for-sale upon acquisition and be reported in discontinued operations; and components where an entity retains significant continuing involvement or where operations and cash flows will not be eliminated from ongoing operations as a result of a disposal transaction can meet the definition of discontinued operations. Additionally, where summarized amounts are presented on the face of the financial statements, reconciliations of those amounts to major classes of line items are also required. ASU No. 2014-08 requires additional disclosures for individually material components that do not meet the definition of discontinued operations. Under the previous accounting guidance, DPLER and Kelanitissa (which both met the Held-for-Sale criteria in 2015) and the Armenia Mountain, U.K. Wind (Operating Projects), and Ebute disposals would have met the discontinued operations criteria and would have been reclassified accordingly. See Note 24—Dispositions and Held-for-Sale Businesses for further information.
Prior to July 1, 2014, a discontinued operation was a component of the Company that either had been disposed of or was classified as held for sale and where the Company did not expect to have significant cash flows from or significant continuing involvement with the component as of one year after its disposal or sale. A component was comprised of operations and cash flows that could be clearly distinguished, operationally and for financial reporting purposes, from the rest of the Company. Before the Company's adoption of ASU No. 2014-08, prior period amounts were retrospectively revised to reflect the

126


THE AES CORPORATION
NOTES TO CONSOLIDATED FINANCIAL STATEMENTS—(Continued)
DECEMBER 31, 2015, 2014, AND 2013

businesses determined to be discontinued operations. For components that had been determined to be discontinued operations and held for sale businesses under the old standard, the related cash flows are included within the relevant categories within operating, investing and financing activities. The aggregate amount of cash flows is offset by the net increase or decrease in cash of discontinued and held for sale businesses, which is presented as a separate line item in the Consolidated Statements of Cash Flows.
When an operation is classified as held for sale, the Company recognizes impairment expense, if any, at the consolidated financial statement level which also includes noncontrolling interests. However, any gain or loss on the completion of a disposal transaction is recognized only for the Company's ownership interest. Upon adoption of ASU No. 2014-08 on July 1, 2014, the Company no longer recasts prior period results related to operations classified as held for sale. All assets and liabilities of held-for-sale businesses are classified as current as they are expected to be disposed of within twelve months.
RECLASSIFICATIONS — Certain prior period amounts in the consolidated financial statements have been reclassified to conform to the current presentation. Non-cash impacts related to a regulatory liability at Eletropaulo were reclassified from the Increase (decrease) in accounts payable and other current liabilities and Increase (decrease) in other liabilities lines to the (Reversals of) provisions for contingencies line on the Consolidated Statement of Cash Flows for the year ended December 31, 2013. Additionally, amounts related to certain transactions pertaining to noncontrolling interests were reclassified from the Contributions from noncontrolling interest line to the Proceeds from sales to noncontrolling interests, net of transaction costs line on the Consolidated Statement of Cash flows for the years ended December 31, 2014 and 2013.
FAIR VALUE — Fair value is the price that would be received to sell an asset or paid to transfer a liability in an orderly, hypothetical transaction between market participants at the measurement date, or exit price. The Company applies the fair value measurement accounting guidance to financial assets and liabilities in determining the fair value of investments in marketable debt and equity securities, included in the Consolidated Balance Sheet line items Short-term investments and Other assets (noncurrent); derivative assets, included in Other current assets and Other assets (noncurrent); and, derivative liabilities, included in Accrued and other liabilities (current) and Other long-term liabilities. The Company applies the fair value measurement guidance to nonfinancial assets and liabilities upon the acquisition of a business or in conjunction with the measurement of an asset retirement obligation or a potential impairment loss on an asset group or goodwill under the accounting guidance for the impairment of long-lived assets or goodwill.
The Company makes assumptions about what market participants would assume in valuing an asset or liability based on the best information available. These factors include nonperformance risk (the risk that the obligation will not be fulfilled) and credit risk of the subsidiary (for liabilities) and of the counterparty (for assets). The Company is prohibited from including transaction costs and any adjustments for blockage factors in determining fair value. The principal or most advantageous market is considered from the perspective of the subsidiary owning the asset or with the liability.
Fair value is based on observable market prices where available. Where they are not available, specific valuation models and techniques are applied depending on what is being fair valued. These models and techniques maximize the use of observable inputs and minimize the use of unobservable inputs. The process involves varying levels of management judgment, the degree of which is dependent on price transparency and complexity. An asset's or liability's level within the fair value hierarchy is based on the lowest level of input significant to the fair value measurement, where Level 1 is the highest and Level 3 is the lowest. The three levels are defined as follows:
•
Level 1 — unadjusted quoted prices in active markets accessible by the Company for identical assets or liabilities. Active markets are those in which transactions for the asset or liability occur with sufficient frequency and volume to provide pricing information on an ongoing basis.
•
Level 2 — pricing inputs other than quoted market prices included in Level 1 which are based on observable market data, that are directly or indirectly observable for substantially the full term of the asset or liability. These include quoted market prices for similar assets or liabilities, quoted market prices for identical or similar assets in markets that are not active, adjusted quoted market prices, inputs from observable data such as interest rate and yield curves, volatilities or default rates observable at commonly quoted intervals or inputs derived from observable market data by correlation or other means.
•
Level 3 — pricing inputs that are unobservable from objective sources. Unobservable inputs are only used to the extent observable inputs aren't available. These inputs maintain the concept of an exit price from the perspective of a market participant and reflect assumptions of other market participants. The Company considers all market participant assumptions that are available without unreasonable cost and effort. These are given the lowest priority and are generally used in internally developed methodologies to generate management's best estimate of the fair value when no observable market data is available.

127


THE AES CORPORATION
NOTES TO CONSOLIDATED FINANCIAL STATEMENTS—(Continued)
DECEMBER 31, 2015, 2014, AND 2013

Any transfers between all levels within the fair value hierarchy levels are recognized at the end of the reporting period.
CASH AND CASH EQUIVALENTS — The Company considers unrestricted cash on hand, deposits in banks, certificates of deposit and short-term marketable securities with original maturities of three months or less to be cash and cash equivalents. The carrying amounts of such balances approximate fair value.
RESTRICTED CASH AND DEBT SERVICE RESERVES — These include cash balances which are restricted as to withdrawal or usage by the subsidiary that owns the cash. The nature of restrictions includes restrictions imposed by financing agreements such as security deposits kept as collateral, debt service reserves, maintenance reserves, contractual terms and others, as well as restrictions imposed by agreements related to the sales of businesses or long-term PPAs.
INVESTMENTS IN MARKETABLE SECURITIES — The Company's marketable investments are primarily unsecured debentures, certificates of deposit, government debt securities and money market funds. Short-term investments consist of marketable equity securities and debt securities with original maturities in excess of three months with remaining maturities of less than one year.
Marketable debt securities that the Company has both the positive intent and ability to hold to maturity are classified as held-to-maturity and are carried at amortized cost. Other marketable securities that the Company does not intend to hold to maturity are classified as available-for-sale or trading and are carried at fair value. Available-for-sale investments are fair valued at the end of each reporting period where the unrealized gains or losses are reflected in accumulated other comprehensive loss ("AOCL"), a separate component of equity.
Investments classified as trading are fair valued at the end of each reporting period through the Consolidated Statements of Operations. Interest and dividends on investments are reported in interest income and other income, respectively. Gains and losses on sales of investments are determined using the specific identification method.
ACCOUNTS AND NOTES RECEIVABLE AND ALLOWANCE FOR DOUBTFUL ACCOUNTS — Accounts and notes receivable are carried at amortized cost. The Company periodically assesses the collectability of accounts receivable, considering factors such as specific evaluation of collectability, historical collection experience, the age of accounts receivable and other currently available evidence of the collectability, and records an allowance for doubtful accounts for the estimated uncollectible amount as appropriate. Certain of our businesses charge interest on accounts receivable either under contractual terms or where charging interest is a customary business practice. In such cases, interest income is recognized on an accrual basis. When the collection of such interest is not reasonably assured, interest income is recognized as cash is received. Individual accounts and notes receivable are written off when they are no longer deemed collectible.
INVENTORY — Inventory primarily consists of fuel and other raw materials used to generate power, and spare parts and supplies used to maintain power generation and distribution facilities. Inventory is carried at lower of cost or market. Cost is the sum of the purchase price and incidental expenditures and charges incurred to bring the inventory to its existing condition or location. Costs of inventory are valued primarily using the average cost method. Generally, cost is reduced to market value if the market value of inventory has declined and it is probable that the utility of inventory, in its disposal in the ordinary course of business, will not be recovered through revenue earned from the generation of power.
LONG-LIVED ASSETS — Long-lived assets include property, plant and equipment, assets under capital leases and intangible assets subject to amortization (i.e., finite-lived intangible assets).
Property, plant and equipment — Property, plant and equipment are stated at cost, net of accumulated depreciation. The cost of renewals and improvements that extend the useful life of property, plant and equipment are capitalized.
Construction progress payments, engineering costs, insurance costs, salaries, interest and other costs directly relating to construction in progress are capitalized during the construction period, provided the completion of the project is deemed probable, or expensed at the time the Company determines that development of a particular project is no longer probable. The continued capitalization of such costs is subject to ongoing risks related to successful completion, including those related to government approvals, site identification, financing, construction permitting and contract compliance. Construction-in-progress balances are transferred to electric generation and distribution assets when an asset group is ready for its intended use. Government subsidies, liquidated damages recovered for construction delays and income tax credits are recorded as a reduction to property, plant and equipment and reflected in cash flows from investing activities.
Depreciation, after consideration of salvage value and asset retirement obligations, is computed primarily using the straight-line method over the estimated useful lives of the assets, which are determined on a composite or component basis. Maintenance and repairs are charged to expense as incurred. Capital spare parts, including rotable spare parts, are included in electric generation and distribution assets. If the spare part is considered a component, it is depreciated over its useful life after

128


THE AES CORPORATION
NOTES TO CONSOLIDATED FINANCIAL STATEMENTS—(Continued)
DECEMBER 31, 2015, 2014, AND 2013

the part is placed in service. If the spare part is deemed part of a composite asset, the part is depreciated over the composite useful life even when being held as a spare part.
The Company's Brazilian subsidiaries, which include both generation and distribution companies, operate under concession contracts. Certain estimates are utilized to determine depreciation expense for the Brazilian subsidiaries, including the useful lives of the property, plant and equipment and the amounts to be recovered at the end of the concession contract. The amounts to be recovered under these concession contracts are based on estimates that are inherently uncertain and actual amounts recovered may differ from those estimates. These concession contracts are not within the scope of ASC 853—Service Concession Arrangements.
Intangible Assets Subject to Amortization — Finite-lived intangible assets are amortized over their useful lives which range from 1 – 50 years. The Company accounts for purchased emission allowances as intangible assets and records an expense when utilized or sold. Granted emission allowances are valued at zero.
Impairment of Long-lived Assets — When circumstances indicate that the carrying amount of long-lived assets (asset group) held-for-use may not be recoverable, the Company evaluates the assets for potential impairment using internal projections of undiscounted cash flows expected to result from the use and eventual disposal of the assets. Events or changes in circumstances that may necessitate a recoverability evaluation may include, but are not limited to, adverse changes in the regulatory environment, unfavorable changes in power prices or fuel costs, increased competition due to additional capacity in the grid, technological advancements, declining trends in demand, or an expectation that it is more likely than not that the asset will be disposed of before the end of its previously estimated useful life. If the carrying amount of the assets exceeds the undiscounted cash flows and exceeds any fair value of the assets, an impairment expense is recognized for the excess up to the carrying amount of the long-lived assets (but up to any fair value for any individual long-lived asset that is determinable without undue cost and effort). For regulated assets where recovery through approved rates is probable, an impairment expense could be reduced by the establishment of a regulatory asset. For other regulated assets and for non-regulated assets, impairment is recognized as an expense. When long-lived assets meet the criteria to be classified as held-for-sale and the carrying amount of the disposal group exceeds its fair value less costs to sell, an impairment expense is recognized for the excess up to the carrying amount of the long-lived assets; if the fair value of the disposal group subsequently exceeds the carrying amount while the disposal group is still held-for-sale, any impairment expense previously recognized will be reversed up to the lower of the prior expense or the subsequent excess.
SERVICE CONCESSION ASSETS — Service concession assets are stated at cost, net of accumulated amortization, in accordance with ASC 853. Service concession assets represent the cost of all infrastructure to be transferred to the public-sector entity grantors at the end of the concession. These costs primarily represent construction progress payments, engineering costs, insurance costs, salaries, interest and other costs directly relating to construction of the service concession infrastructure. Government subsidies, liquidated damages recovered for construction delays and income tax credits are recorded as a reduction to Service Concession Assets. Service concession assets are amortized and recognized in earnings as a cost of goods sold. Amortization is recorded ratably as build revenue is recognized.
For additional details regarding the impact of service concession accounting on certain of the Company's businesses, see New Accounting Pronouncements Adopted—ASU No. 2014-05, Service Concession Arrangements (Topic 853) below.
DEFERRED FINANCING COSTS — Costs incurred in connection with the issuance of long-term debt are deferred and amortized over the related financing period using the effective interest method. Make-whole payments in connection with early debt retirements are classified as cash flows used in financing activities.
EQUITY METHOD INVESTMENTS — Investments in entities over which the Company has the ability to exercise significant influence, but not control, are accounted for using the equity method of accounting and reported in Investments in and advances to affiliates on the Consolidated Balance Sheets. The Company periodically assesses if there is an indication that the fair value of an equity method investment is less than its carrying amount. When an indicator exists, any excess of the carrying amount over its estimated fair value is recognized as impairment when the loss in value is deemed other-than-temporary and included in Other non-operating expense in the Consolidated Statements of Operations. The difference between the carrying amount and our underlying equity in the net assets of the investee are accounted for as if the investee were a consolidated subsidiary, except that the portion that represents equity method goodwill is not reviewed for impairment like consolidated goodwill.  Upon acquiring the investment, we determine the fair value of the identifiable assets and assumed liabilities and the basis difference between each fair value and the carrying amount of the corresponding asset or liability in the financial statements of the investee are recognized in our net equity in earnings of affiliates over the life of the asset or liability.
The Company discontinues the application of the equity method when an investment is reduced to zero and the Company is not otherwise committed to provide further financial support to the investee. The Company resumes the application of the

129


THE AES CORPORATION
NOTES TO CONSOLIDATED FINANCIAL STATEMENTS—(Continued)
DECEMBER 31, 2015, 2014, AND 2013

equity method if the investee subsequently reports net income to the extent that the Company's share of such net income equals the share of net losses not recognized during the period in which the equity method of accounting was suspended.
GOODWILL AND INDEFINITE-LIVED INTANGIBLE ASSETS — The Company evaluates goodwill and indefinite-lived intangible assets for impairment on an annual basis and whenever events or changes in circumstances necessitate an evaluation for impairment. The Company's annual impairment testing date is October 1.
Goodwill — The Company evaluates goodwill impairment at the reporting unit level, which is an SBU (i.e. an operating segment as defined in the segment reporting accounting guidance), or a component (i.e., one level below an operating segment). In determining its reporting units, the Company starts with its management reporting structure. Operating segments are identified and then analyzed to identify components which make up these operating segments. Two or more components are combined into a single reporting unit if they are economically similar. Assets and liabilities are allocated to a reporting unit if the assets will be employed by or a liability relates to the operations of the reporting unit or would be considered by a market participant in determining its fair value. Goodwill resulting from an acquisition is assigned to the reporting units that are expected to benefit from the synergies of the acquisition. Generally, each AES business with a goodwill balance constitutes a reporting unit as they are not reported to segment management together with other businesses and are not similar to other businesses in a segment.
Goodwill is evaluated for impairment either under the qualitative assessment option or the two-step test approach depending on facts and circumstances of a reporting unit, including the excess of fair value over carrying amount in the last valuation or changes in business environment. If the Company qualitatively determines it is more likely than not that the fair value of a reporting unit is greater than its carrying amount, the two-step impairment test is unnecessary. Otherwise, goodwill is evaluated for impairment using the two-step test, where the carrying amount of a reporting unit is compared to its fair value in Step 1; if the fair value exceeds the carrying amount, Step 2 is unnecessary. If the carrying amount exceeds the reporting unit's fair value, this could indicate potential impairment and Step 2 of the goodwill evaluation process is required to determine if goodwill is impaired and to measure the amount of impairment loss to recognize, if any. When Step 2 is necessary, the fair value of individual assets and liabilities is determined using valuations (which in some cases may be based in part on third party valuation reports) or other observable sources of fair value, as appropriate. If the carrying amount of goodwill exceeds its implied fair value, the excess is recognized as an impairment loss up to the carrying amount of the goodwill.
Most of the Company's reporting units are not publicly traded. Therefore, the Company estimates the fair value of its reporting units using internal budgets and forecasts, adjusted for any market participants' assumptions and discounted at the rate of return required by a market participant. The Company considers both market and income-based approaches to determine a range of fair value, but typically concludes that the value derived using an income-based approach is more representative of fair value due to the lack of direct market comparables. The Company utilizes market data, when available, to corroborate and determine the reasonableness of the fair value derived from the income-based discounted cash flow analysis.
Indefinite-Lived Intangible Assets — The Company's indefinite-lived intangible assets primarily include land-use rights and water rights. These are tested for impairment on an annual basis or whenever events or changes in circumstances necessitate an evaluation for impairment. If the carrying amount of an intangible asset exceeds its fair value, the excess is recognized as impairment expense. When deemed appropriate, the Company uses the qualitative assessment option under the accounting guidance on goodwill and intangible assets to determine whether the existence of events or circumstances indicate that it is more likely than not that an intangible asset is impaired. If, after assessing the totality of events and circumstances, the Company determines that it is not more likely than not that an intangible asset is impaired, no further action is taken. The accounting guidance provides the option to bypass the qualitative assessment for any intangible asset in any period and proceed directly to performing the quantitative impairment test.
ACCOUNTS PAYABLE AND OTHER ACCRUED LIABILITIES — Accounts payable consists of amounts due to trade creditors related to the Company's core business operations. These payables include amounts owed to vendors and suppliers for items such as energy purchased for resale, fuel, maintenance, inventory and other raw materials. Other accrued liabilities include items such as income taxes, regulatory liabilities, legal contingencies and employee-related costs including payroll, benefits and related taxes.
REGULATORY ASSETS AND LIABILITIES — The Company records assets and liabilities that result from the regulated ratemaking process that are not recognized under GAAP for non-regulated entities. Regulatory assets generally represent incurred costs that have been deferred due to the future recovery in customer rates being probable. Generally, returns earned on regulatory assets are reflected on the Consolidated Statement of Operations within Interest Income. Regulatory liabilities generally represent obligations to make refunds to customers. Management continually assesses whether the regulatory assets are probable of future recovery and regulatory of liabilities are probable of future payment by considering factors such as applicable regulatory changes, recent rate orders applicable to other regulated entities and the status of any

130


THE AES CORPORATION
NOTES TO CONSOLIDATED FINANCIAL STATEMENTS—(Continued)
DECEMBER 31, 2015, 2014, AND 2013

pending or potential deregulation legislation. If future recovery of costs previously deferred ceases to be probable, the related regulatory assets are written off and recognized in income from continuing operations.
PENSION AND OTHER POSTRETIREMENT PLANS — The Company recognizes in its Consolidated Balance Sheets an asset or liability reflecting the funded status of pension and other postretirement plans with current-year changes in actuarial gains or losses recognized in AOCL, except for those plans at certain of the Company's regulated utilities that can recover portions of their pension and postretirement obligations through future rates. All plan assets are recorded at fair value. AES follows the measurement date provisions of the accounting guidance, which require a year-end measurement date of plan assets and obligations for all defined benefit plans.
Effective January 1, 2016, the Company will apply a disaggregated discount rate approach for determining service cost and interest cost for its defined benefit pension plans and post-retirement plans in the U.S. and U.K. This approach is consistent with the requirements of ASC 715—Compensation—Retirement Benefits and is considered to be more precise compared to the aggregated single rate discount approach, which has historically been used in the U.S. and U.K., because it is more consistent with the philosophy of a full yield curve valuation. The disaggregated rate approach can be applied only in countries with a sufficiently robust yield curve. For countries other than the U.S. and U.K., the Company will continue to apply a local government bond yield approach.
The change in discount rate approach in the U.S. and U.K. did not have an impact on the measurement of the benefit obligations as at December 31, 2015, nor will it impact future remeasurements. This change in estimate will impact the service cost and interest cost recorded in 2016 and future years. It will also impact the actuarial gains and losses recorded in future years, as well as the amortization thereof.
The expected 2016 service costs and interest costs included in Note 15—Benefit Plans reflect the change in estimate described above. The impact of the change in approach on expected service costs for the U.S. and U.K. plans in 2016 is shown below (in millions):
 
Expected 2016 Service Cost
 
Expected 2016 Interest Cost
 
Disaggregated rate approach
 
Aggregate rate approach
 
Impact of change
 
Disaggregated rate approach
 
Aggregate rate approach
 
Impact of change
U.S.
$
13

 
$
14

 
$
(1
)
 
$
42

 
$
51

 
$
(9
)
U.K.
3

 
4

 
(1
)
 
7

 
9

 
(2
)
Total
$
16

 
$
18

 
$
(2
)
 
$
49

 
$
60

 
$
(11
)
INCOME TAXES — Deferred tax assets and liabilities are recognized for the future tax consequences attributable to differences between the financial statement carrying amounts of the existing assets and liabilities, and their respective income tax bases. The Company establishes a valuation allowance when it is more likely than not that all or a portion of a deferred tax asset will not be realized. The Company's tax positions are evaluated under a more likely than not recognition threshold and measurement analysis before they are recognized for financial statement reporting.
Uncertain tax positions have been classified as noncurrent income tax liabilities unless expected to be paid within one year. The Company's policy for interest and penalties related to income tax exposures is to recognize interest and penalties as a component of the provision for income taxes in the Consolidated Statements of Operations.
ASSET RETIREMENT OBLIGATIONS — The Company records the fair value of the liability for a legal obligation to retire an asset in the period in which the obligation is incurred. When a new liability is recognized, the Company capitalizes the costs of the liability by increasing the carrying amount of the related long-lived asset. The liability is accreted to its present value each period and the capitalized cost is depreciated over the useful life of the related asset. Upon settlement of the obligation, the Company eliminates the liability and, based on the actual cost to retire, may incur a gain or loss.
NONCONTROLLING INTERESTS — Noncontrolling interests are classified as a separate component of equity in the Consolidated Balance Sheets and Consolidated Statements of Changes in Equity. Additionally, net income and comprehensive income attributable to noncontrolling interests are reflected separately from consolidated net income and comprehensive income on the Consolidated Statements of Operations and Consolidated Statements of Changes in Equity. Any change in ownership of a subsidiary while the controlling financial interest is retained is accounted for as an equity transaction between the controlling and noncontrolling interests (unless the transaction qualifies as a sale of in-substance real estate). Losses continue to be attributed to the noncontrolling interests, even when the noncontrolling interests' basis has been reduced to zero.
Although, in general, the noncontrolling ownership interest in earnings is calculated based on ownership percentage, certain of the Company's businesses are subject to certain profit-sharing arrangements. These agreements exist for certain renewable generation partnerships to designate different allocations of value among investors, where the allocations change in form or percentage over the life of the partnership. For these businesses, the Company uses the HLBV method when it is a

131


THE AES CORPORATION
NOTES TO CONSOLIDATED FINANCIAL STATEMENTS—(Continued)
DECEMBER 31, 2015, 2014, AND 2013

reasonable approximation of the profit-sharing arrangement. HLBV uses a balance sheet approach, which measures the Company's equity in income or loss by calculating the change in the amount of net worth the partners are legally able to claim based on a hypothetical liquidation of the entity at the beginning of a reporting period compared to the end of that period.
FOREIGN CURRENCY TRANSLATION — A business's functional currency is the currency of the primary economic environment in which the business operates and is generally the currency in which the business generates and expends cash. Subsidiaries and affiliates whose functional currency is a currency other than the U.S. Dollar translate their assets and liabilities into U.S. Dollars at the current exchange rates in effect at the end of the fiscal period. The revenue and expense accounts of such subsidiaries and affiliates are translated into U.S. Dollars at the average exchange rates that prevailed during the period. Translation adjustments are included in AOCL. Gains and losses on intercompany foreign currency transactions that are long-term in nature and which the Company does not intend to settle in the foreseeable future, are also recognized in AOCL. Gains and losses that arise from exchange rate fluctuations on transactions denominated in a currency other than the functional currency are included in determining net income. Accumulated foreign currency translation adjustments are reclassified to net income only when realized upon sale or upon complete or substantially complete liquidation of the investment in a foreign entity. The accumulated adjustments are included in carrying amounts in impairment assessments where the Company has committed to a plan that will cause the accumulated adjustments to be reclassified to earnings.
REVENUE RECOGNITION — Revenue from utilities is classified as regulated in the Consolidated Statements of Operations. Revenue from the sale of energy is recognized in the period during which the sale occurs. The calculation of revenue earned but not yet billed is based on the number of days not billed in the month, the estimated amount of energy delivered during those days and the estimated average price per customer class for that month. Differences between actual and estimated unbilled revenue are usually immaterial. The Company has businesses where it sells and purchases power to and from Independent System Operators ("ISOs") and Regional Transmission Organizations ("RTOs"). In those instances, the Company accounts for these transactions on a net hourly basis because the transactions are settled on a net hourly basis. Revenue from generation businesses is classified as non-regulated and is recognized based upon output delivered and capacity provided, at rates as specified under contract terms or prevailing market rates. Certain of the Company PPAs meet the definition of an operating lease or contain similar arrangements. Typically, minimum lease payments from such PPAs are recognized as revenue on a straight-line basis over the lease term whereas contingent rentals are recognized when earned. Revenue is recorded net of any taxes assessed on and collected from customers, which are remitted to the governmental authorities.
SHARE-BASED COMPENSATION — The Company grants share-based compensation in the form of stock options, restricted stock units, and performance stock units. The expense is based on the grant-date fair value of the equity or liability instrument issued and is recognized on a straight-line basis over the requisite service period, net of estimated forfeitures. The Company uses a Black-Scholes option pricing model to estimate the fair value of stock options granted to its employees.
GENERAL AND ADMINISTRATIVE EXPENSES — General and administrative expenses include corporate and other expenses related to corporate staff functions and initiatives, primarily executive management, finance, legal, human resources and information systems, which are not directly allocable to our business segments. Additionally, all costs associated with corporate business development efforts are classified as general and administrative expenses.
DERIVATIVES AND HEDGING ACTIVITIES — Under the accounting standards for derivatives and hedging, the Company recognizes all contracts that meet the definition of a derivative, except those designated as normal purchase or normal sale at inception, as either assets or liabilities in the Consolidated Balance Sheets and measures those instruments at fair value. See the Company's fair value policy and Note 4—Fair Value for additional discussion regarding the determination of the fair value. The PPAs and fuel supply agreements entered into by the Company are evaluated to determine if they meet the definition of a derivative or contain embedded derivatives, either of which require separate valuation and accounting. To be a derivative under the accounting standards for derivatives and hedging, an agreement would need to have a notional and an underlying, require little or no initial net investment and could be net settled. Generally, these agreements do not meet the definition of a derivative, often due to the inability to be net settled. On a quarterly basis, we evaluate the markets for the commodities to be delivered under these agreements to determine if facts and circumstances have changed such that the agreements could then be net settled and meet the definition of a derivative.
Derivatives primarily consist of interest rate swaps, cross-currency swaps, foreign currency instruments, and commodity derivatives. The Company enters into various derivative transactions in order to hedge its exposure to certain market risks, primarily interest rate, foreign currency and commodity price risks. Regarding interest rate risk, the Company and our subsidiaries generally utilize variable rate debt financing for construction projects and operations so interest rate swap, lock, cap, and floor agreements are entered into to manage interest rate risk by effectively fixing or limiting the interest rate exposure on the underlying financing and are typically designated as cash flow hedges. Regarding foreign currency risk, we are exposed to it as a result of our investments in foreign subsidiaries and affiliates that may be impacted by significant fluctuations in

132


THE AES CORPORATION
NOTES TO CONSOLIDATED FINANCIAL STATEMENTS—(Continued)
DECEMBER 31, 2015, 2014, AND 2013

foreign currency exchange rates so foreign currency options and forwards are utilized, where deemed appropriate, to manage the risk related to these fluctuations. Cross-currency swaps are utilized in certain instances to manage the risk related to certain foreign currencies and the associated impact on interest and loan principal payments. In addition, certain of our subsidiaries have entered into contracts which contain embedded derivatives as a portion of the contracts primarily that are denominated in a currency other than the functional or local currency of that subsidiary or the currency of the item. Regarding commodity price risk, we are exposed to the impact of market fluctuations in the price of electricity, fuel and environmental credits. Although we primarily consist of businesses with long-term contracts or retail sales concessions (which provide our distribution businesses with a franchise to serve a specific geographic region), a portion of our current and expected future revenues are derived from businesses without significant long-term purchase or sales contracts. We use an overall hedging strategy, not just derivatives, to hedge our financial performance against the effects of fluctuations in commodity prices.
The accounting standards for derivatives and hedging enable companies to designate qualifying derivatives as hedging instruments based on the exposure being hedged. The Company only has cash flow hedges at this time. Changes in the fair value of a derivative that is highly effective, designated and qualifies as a cash flow hedge are deferred in AOCL and are recognized into earnings as the hedged transactions affect earnings. Any ineffectiveness is recognized in earnings immediately. For all designated and qualifying hedges, the Company maintains formal documentation of the hedge and effectiveness testing in accordance with the accounting standards for derivatives and hedging. If AES determines that the derivative is no longer highly effective as a hedge, hedge accounting will be discontinued prospectively. For cash flow hedges of forecasted transactions, AES estimates the future cash flows of the forecasted transactions and evaluates the probability of the occurrence and timing of such transactions. Changes in conditions or the occurrence of unforeseen events could require discontinuance of hedge accounting or could affect the timing of the reclassification of gains or losses on cash flow hedges from AOCL into earnings.
While derivative transactions are not entered into for trading purposes, some contracts are not eligible for hedge accounting. Changes in the fair value of derivatives not designated and qualifying as cash flow hedges are immediately recognized in earnings. Regardless of when gains or losses on derivatives (including all those where the fair value measurement is classified as Level 3) are recognized in earnings, they are generally classified as follows: interest expense for interest rate and cross-currency derivatives, foreign currency transaction gains or losses for foreign currency derivatives, and non-regulated revenue or non-regulated cost of sales for commodity and other derivatives. However, gains and losses on interest rate and cross-currency derivatives are classified as foreign currency transaction gains and losses if they offset the remeasurement of the foreign currency-denominated debt being hedged by the cross-currency swaps and the amount reclassified from AOCL to cost of sales to offset depreciation where the variable-rate interest capitalized as part of the asset was hedged during its construction. Cash flows arising from derivatives are included in the Consolidated Statements of Cash Flows as an operating activity given the nature of the underlying risk being economically hedged and the lack of significant financing elements, except that cash flows on designated and qualifying hedges of variable-rate interest during construction are classified as an investing activity.
The Company has elected not to offset net derivative positions in the financial statements. Accordingly, the Company does not offset such derivative positions against the fair value of amounts (or amounts that approximate fair value) recognized for the right to reclaim cash collateral (a receivable) or the obligation to return cash collateral (a payable) under master netting arrangements.
NEW ACCOUNTING PRONOUNCEMENTS ADOPTED
ASU No. 2015-17, Income Taxes (Topic 740): Balance Sheet Classification of Deferred Taxes
Effective December 31, 2015, the Company prospectively adopted ASU No. 2015-17, which requires that all deferred tax assets and liabilities, along with any related valuation allowance, be classified as noncurrent on the balance sheet. As a result, each jurisdiction will now only have one net noncurrent deferred tax asset or liability. The guidance does not change the existing requirement that only permits offsetting within a jurisdiction; that is, companies will remain prohibited from offsetting deferred tax liabilities from one jurisdiction against deferred tax assets of another jurisdiction. Additionally, the current requirement that deferred tax liabilities and assets of a tax-paying component of an entity be offset and presented as a single amount is not affected by the update. As the Company elected to apply this ASU prospectively, prior periods were not adjusted.
ASU No. 2015-13, Derivatives and Hedging (Topic 815): Application of the Normal Purchases and Normal Sales Scope Exception to Certain Electricity Contracts within Nodal Energy Markets
In August 2015, the FASB issued ASU No. 2015-13, which resolves the diversity in practice resulting from determining whether certain contracts qualify for the normal purchases and normal sales scope exception under ASC Topic 815—Derivatives and Hedging. This standard clarifies that entities would not be precluded from applying the normal purchases and normal sales exception to certain forward contracts that necessitate the transmission of electricity through, or delivery to a

133


THE AES CORPORATION
NOTES TO CONSOLIDATED FINANCIAL STATEMENTS—(Continued)
DECEMBER 31, 2015, 2014, AND 2013

location within, a nodal energy market. The standard is effective upon issuance and should be applied prospectively. As the Company had designated qualifying contracts as normal purchase or normal sales, there was no impact on the Company's consolidated financial statements upon adoption of this standard.
ASU No. 2014-05, Service Concession Arrangements (Topic 853)
Effective January 1, 2015, the Company adopted ASU No. 2014-05, which states that certain service concession arrangements with public-sector entity grantors are not in scope of ASC 840—Leases, and that entities should not recognize the related infrastructure as property, plant and equipment, but should apply other GAAP. The Company has a small number of entities that fall within the scope of this guidance, with the Company's Mong Duong generation facility in Vietnam being the most significant.
Mong Duong is based on a build, operate and transfer agreement with the Vietnamese government. Management concluded there were two deliverables included within the arrangement, as well as a financing element. Due to the contingent nature of the revenue stream, no amounts of revenue could be recognized during the build phase of the contract. All amounts billed during the operate phase are recognized as revenue when billed, with amounts allocated between the financing element and build and operate deliverables. The financing element is recognized as interest income using the effective interest method as payments for construction of the plant are received over the life of the contract. Costs are expensed as incurred. As the related infrastructure is no longer considered property, plant and equipment, there are no longer any capitalizable expenses beyond those related to the initial build, and accordingly these will be expensed as incurred. All cash flows for these arrangements, excluding those related to the debt incurred by AES, will be reflected in cash flows from operating activities on the Company's Consolidated Statements of Cash Flows prospectively.
The guidance was applied on a modified retrospective basis to service concession arrangements in existence at January 1, 2015. Upon adoption of this standard, the impact to the Company's Consolidated Balance Sheet as of January 1, 2015 resulted in a reclassification of $1.5 billion from property, plant and equipment to service concession assets, as well as a cumulative adjustment to retained earnings and cumulative translation adjustment of $(18) million, net of tax, and $13 million, respectively.
ACCOUNTING PRONOUNCEMENTS ISSUED BUT NOT YET EFFECTIVE — The following accounting standards have been issued, but are not yet effective for, and have not been adopted in these financial statements by AES.
ASU No. 2016-01, Financial Instruments — Overall (Topic 825-10): Recognition and Measurement of Financial Assets and Financial Liabilities
In January 2016, the FASB issued ASU 2016-01, which was designed to improve the recognition and measurement of financial instruments through targeted changes to existing GAAP. The guidance requires equity investments (except those that are accounted for under the equity method of accounting or result in consolidation of the investee) to be measured at fair value with changes in fair value recognized in net income; that entities use the exit price notion when measuring financial instrument fair values; that an entity separate presentation of financial assets and liabilities by measurement category and form of financial asset on the Balance Sheets or Notes to the financial statements; that an entity present separately in other comprehensive income the portion of the total change in the fair value of a liability resulting from a change in the instrument-specific credit risk (or "own credit") when the entity has elected to measure the liability at fair value in accordance with the fair value option for financial instruments. Also, the standard eliminates the requirement for public entities to disclose the methods and significant assumptions used to estimate the fair value required to be disclosed for financial instruments measured at amortized cost on the Balance Sheets. The standard is effective beginning with interim periods starting after December 31, 2017 and cannot be applied early. The Company is currently evaluating the applicability and materiality of the standard, but does not anticipate a material impact on the Company's consolidated financial statements.
ASU No. 2015-16, Business Combinations (Topic 805): Simplifying the Accounting for Measurement-Period Adjustments
In September 2015, the FASB issued ASU 2015-16, which simplifies the measurement-period adjustments in business combinations. It eliminates the requirement that an acquirer in a business combination account for measurement-period adjustments retrospectively. An acquirer will recognize a measurement-period adjustment during the period in which it determines the amount of the adjustment. The standard is effective for public entities for annual reporting periods beginning after December 15, 2015, and interim periods therein. Early adoption is permitted for financial statements that have not been issued. The new guidance should be applied prospectively to adjustments to provisional amounts that occur after the effective date of this standard. The Company will adopt this standard on January 1, 2016, which is not expected to have a material impact on the Company's consolidated financial statements.

134


THE AES CORPORATION
NOTES TO CONSOLIDATED FINANCIAL STATEMENTS—(Continued)
DECEMBER 31, 2015, 2014, AND 2013

ASU No. 2015-15, Interest — Imputation of Interest (Subtopic 835-30): Presentation and Subsequent Measurement of Debt Issuance Costs Associated with Line-of-Credit Arrangements
In August 2015, the FASB issued ASU No. 2015-15, which clarifies that the SEC Staff would not object to an entity presenting debt issuance costs related to line-of-credit arrangements as an asset that is subsequently amortized ratably over the term of the line-of-credit arrangement, regardless of whether there are any outstanding borrowings on the line-of-credit arrangement. This standard should be adopted concurrent with adoption of ASU 2015-03 (see below). As of December 31, 2015, the Company had deferred financing costs related to lines-of-credit of approximately $2 million recorded within other current assets and $24 million recorded within other noncurrent assets that would not be reclassified upon adoption of this standard.
ASU No. 2015-11, Inventory (Topic 330): Simplifying the Measurement of Inventory
In July 2015, the FASB issued ASU No. 2015-11, which simplifies the subsequent measurement of inventory. It replaces the current lower of cost or market test with a lower of cost or net realizable value test. The standard is effective for public entities for annual reporting periods beginning after December 15, 2016, and interim periods therein. Early adoption is permitted. The new guidance must be applied prospectively. The Company is currently evaluating the impact of adopting the standard on its consolidated financial statements.
ASU No. 2015-05, Intangibles — Goodwill and Other — Internal-Use Software (Subtopic 350-40): Customer's Accounting for Fees Paid in a Cloud Computing Arrangement
In April 2015, the FASB issued ASU No. 2015-05, which clarifies how customers in cloud computing arrangements should determine whether the arrangement includes a software license and eliminates the existing requirement for customers to account for software licenses they acquired by analogizing to the accounting guidance on leases. The standard is effective for annual reporting periods beginning after December 15, 2015 and interim periods therein. Early adoption is permitted. The standard permits the use of a prospective or retrospective approach. The Company expects to utilize the prospective approach upon adoption of this standard, which is not expected to have a material impact on its consolidated financial statements.
ASU No. 2015-03, Interest — Imputation of Interest (Subtopic 835-30)
In April 2015, the FASB issued ASU No. 2015-03, which simplifies the presentation of debt issuance costs by requiring that debt issuance costs related to a recognized debt liability be presented in the balance sheet as a direct deduction from the carrying amount of that debt liability, consistent with debt discounts. The recognition and measurement guidance for debt issuance costs are not affected by the amendments in this update. The standard is effective for annual reporting periods beginning after December 15, 2015 and interim periods therein, and requires the use of the full retrospective approach. Early adoption is permitted for financial statements that have not been previously issued. As of December 31, 2015, the Company had deferred financing costs of approximately $24 million classified within other current assets and $356 million classified within other noncurrent assets that would be reclassified to reduce the related debt liabilities upon adoption of this standard.
ASU No. 2015-02, Consolidation — Amendments to the Consolidation Analysis (Topic 810)
In February 2015, the FASB issued ASU 2015-02, which makes targeted amendments to the current consolidation guidance and ends the deferral granted to investment companies from applying the VIE guidance. The standard amends the evaluation of whether (1) fees paid to a decision-maker or service providers represent a variable interest, (2) a limited partnership or similar entity has the characteristics of a VIE and (3) a reporting entity is the primary beneficiary of a VIE. The standard is effective for annual periods beginning after December 15, 2015 and interim periods therein. Early adoption is permitted. Based on the Company's preliminary analysis, no change in consolidation is expected although additional disclosures may be required.
ASU No. 2014-09, Revenue from Contracts with Customers (Topic 606)
In May 2014, the FASB issued ASU No. 2014-09, which clarifies principles for recognizing revenue and will result in a common revenue standard for U.S. GAAP and International Financial Reporting Standards. The objective of the new standard is to provide a single and comprehensive revenue recognition model for all contracts with customers to improve comparability. The revenue standard contains principles that an entity will apply to determine the measurement of revenue and timing of when it is recognized. The standard requires an entity to recognize revenue to depict the transfer of goods or services to customers at an amount that the entity expects to be entitled to in exchange for those goods or services. In August 2015, the FASB issued ASU No. 2015-14, Revenue from Contracts with Customers (Topic 606): Deferral of the Effective Date, which deferred the effective date of ASU 2014-09 by one year, resulting in the new revenue standard being effective for annual reporting periods beginning after December 15, 2017 and interim periods therein. Early adoption is now permitted only as of the original effective date for public entities (that is, no earlier than 2017 for calendar year-end entities). The standard permits the use of

135


THE AES CORPORATION
NOTES TO CONSOLIDATED FINANCIAL STATEMENTS—(Continued)
DECEMBER 31, 2015, 2014, AND 2013

either a full retrospective or modified retrospective approach. The Company has not yet selected a transition method and is currently evaluating the impact of adopting the standard on its consolidated financial statements.
2. INVENTORY
Inventory is valued primarily using the average-cost method. The following table summarizes the Company's inventory balances (in millions) as of the dates indicated:
December 31,
 
2015
 
2014
Fuel and other raw materials
 
$
343

 
$
357

Spare parts and supplies
 
332

 
345

Total
 
$
675

 
$
702

3. PROPERTY, PLANT AND EQUIPMENT
The following table summarizes the components of the electric generation and distribution assets and other property, plant and equipment (in millions) with their estimated useful lives (in years). The amounts are stated net of all prior asset impairment losses recognized.


December 31,
 
Estimated Useful Life
2015
 
2014
Electric generation and distribution facilities
5 - 68
 
$
25,427

 
$
27,488

Other buildings
3 - 53
 
1,868

 
1,694

Furniture, fixtures and equipment
2 - 31
 
305

 
307

Other
1 - 50
 
891

 
970

Total electric generation and distribution assets and other
 
 
28,491

 
30,459

Accumulated depreciation
 
 
(9,449
)
 
(9,962
)
Net electric generation and distribution assets and other (1)
 
 
$
19,042

 
$
20,497

(1) 
Net electric generation and distribution assets and other include unamortized internal-use software costs of $83 million and $115 million as of December 31, 2015 and 2014, respectively.
The following table summarizes depreciation expense (including the amortization of assets recorded under capital leases), amortization of internal-use software and interest capitalized during development and construction on qualifying assets for the periods indicated (in millions):
Year Ended December 31,
 
2015
 
2014
 
2013
Depreciation expense (including amortization of assets recorded under capital leases)
 
$
1,104

 
$
1,204

 
$
1,193

Amortization of internal-use software
 
29

 
33

 
36

Interest capitalized during development and construction
 
90

 
120

 
84

Property, plant and equipment, net of accumulated depreciation, of $12 billion and $15 billion was mortgaged, pledged or subject to liens as of December 31, 2015 and 2014, respectively.
The following table summarizes regulated and non-regulated generation and distribution property, plant and equipment and accumulated depreciation in millions as of the periods indicated:
December 31,
 
2015
 
2014
Regulated generation, distribution assets and other, gross
 
$
11,818

 
$
13,103

Regulated accumulated depreciation
 
(4,351
)
 
(4,841
)
Regulated generation, distribution assets and other, net
 
7,467

 
8,262

Non-regulated generation, distribution assets and other, gross
 
16,673

 
17,356

Non-regulated accumulated depreciation
 
(5,098
)
 
(5,121
)
Non-regulated generation, distribution assets and other, net
 
11,575

 
12,235

Net electric generation, distribution assets and other
 
$
19,042

 
$
20,497

The next table presents amounts recognized related to asset retirement obligations in millions for the periods indicated:
 
 
2015
 
2014
Balance at January 1
 
$
209

 
$
142

Additional liabilities incurred
 
43

 
51

Liabilities settled
 
(6
)
 
(11
)
Accretion expense
 
13

 
12

Change in estimated cash flows
 
(7
)
 
15

Other
 
(5
)
 
—

Balance at December 31
 
$
247

 
$
209


136


THE AES CORPORATION
NOTES TO CONSOLIDATED FINANCIAL STATEMENTS—(Continued)
DECEMBER 31, 2015, 2014, AND 2013

The Company's asset retirement obligations covered by the relevant guidance primarily include active ash landfills, water treatment basins and the removal or dismantlement of certain plants and equipment. There were $2 million of legally restricted assets for the year ended December 31, 2015 and none for the year ended December 31, 2014 for purposes of settling asset retirement obligations.
Ownership of Certain Coal-Fired Facilities
DP&L has undivided ownership interests in five coal-fired generation facilities jointly owned with other utilities. DP&L's share of the operating costs of such facilities is included in Cost of Sales in the Consolidated Statements of Operations and its share of investment in the facilities is included in Property, Plant and Equipment in the Consolidated Balance Sheets. DP&L's undivided ownership interest in such facilities at December 31, 2015 is as follows:
 
DP&L Share
 
DP&L Investment
 
Ownership
 
Gross Plant In Service
 
Accumulated Depreciation
 
Construction Work In Process
Production units:
 
 
($ in millions)
Conesville Unit 4
17
%
 
$
26

 
$
4

 
$
1

Killen Station
67
%
 
342

 
29

 
2

Miami Fort Units 7 and 8
36
%
 
219

 
32

 
6

Stuart Station
35
%
 
236

 
19

 
18

Zimmer Station
28
%
 
188

 
44

 
12

Transmission
various

 
43

 
8

 
—

Total
 
 
$
1,054

 
$
136

 
$
39

4. FAIR VALUE
The fair value of current financial assets and liabilities, debt service reserves and other deposits approximate their reported carrying amounts. The estimated fair values of the Company's assets and liabilities have been determined using available market information. By virtue of these amounts being estimates and based on hypothetical transactions to sell assets or transfer liabilities, the use of different market assumptions and/or estimation methodologies may have a material effect on the estimated fair value amounts.
Valuation Techniques — The fair value measurement accounting guidance describes three main approaches to measuring the fair value of assets and liabilities: (1) market approach, (2) income approach and (3) cost approach. The market approach uses prices and other relevant information generated from market transactions involving identical or comparable assets or liabilities. The income approach uses valuation techniques to convert future amounts to a single present value amount. The measurement is based on current market expectations of the return on those future amounts. The cost approach is based on the amount that would currently be required to replace an asset. The Company measures its investments and derivatives at fair value on a recurring basis. Additionally, in connection with annual or event-driven impairment evaluations, certain nonfinancial assets and liabilities are measured at fair value on a nonrecurring basis. These include long-lived tangible assets (i.e., property, plant and equipment), goodwill and intangible assets (e.g., sales concessions, land use rights and water rights, etc.). In general, the Company determines the fair value of investments and derivatives using the market approach and the income approach, respectively. In the nonrecurring measurements of nonfinancial assets and liabilities, all three approaches are considered; however, the value estimated under the income approach is often the most representative of fair value.
Investments — The Company's investments measured at fair value generally consist of marketable debt and equity securities. Equity securities are measured at fair value primarily using quoted market prices, which are considered Level 1 measurements in the fair value hierarchy. Debt securities primarily consist of unsecured debentures, certificates of deposit and government debt securities held by our Brazilian subsidiaries. Returns and pricing on these instruments are generally indexed to the CDI (Brazilian equivalent to London Inter Bank Offered Rate, or LIBOR, a benchmark interest rate widely used by banks in the interbank lending market) or Selic (overnight borrowing rate) rates in Brazil. For the equity securities which are not considered Level 1 measurements and for the debt securities, fair value is determined from comparisons to market data obtained for similar assets and are considered Level 2 measurements in the fair value hierarchy.
Derivatives — Any Level 1 derivative instruments are exchange-traded commodity futures for which the pricing is observable in active markets, and as such, these are not expected to transfer to other levels. There have been no transfers between Level 1 and Level 2.
For all derivatives, with the exception of any classified as Level 1, the income approach is used, which consists of forecasting future cash flows based on contractual notional amounts and applicable and available market data as of the valuation date. The most common market data inputs used in the income approach include volatilities, spot and forward benchmark interest rates (such as LIBOR and Euro Inter Bank Offered Rate ("EURIBOR")), foreign exchange rates and commodity prices. Forward rates with the same tenor as the derivative instrument being valued are generally obtained from published sources, with these forward rates being assessed quarterly at a portfolio-level for reasonableness versus comparable published information provided from another source. When significant inputs are not observable, the Company uses relevant techniques to determine the inputs, such as regression analysis or prices for similarly traded instruments available in the market.
For derivatives for which there is a standard industry valuation model, the Company uses a third-party derivative accounting and valuation service provider that uses a standard model and observable inputs to estimate the fair value. For these derivatives, the Company performs analytical procedures and makes comparisons to other third-party information in order to assess the reasonableness of the fair value. For derivatives for which there is not a standard industry valuation model (such as PPAs and fuel supply agreements that are derivatives or include embedded derivatives), the Company has created internal valuation models to estimate the fair value, using observable data to the extent available. At each quarter-end, the models for the commodity and foreign currency-based derivatives are generally prepared and reviewed by employees who globally manage the respective commodity and foreign currency risks and are analytically reviewed independent of those employees.
Those cash flows are then discounted using the relevant spot benchmark interest rate (such as LIBOR or EURIBOR). The Company then makes a credit valuation adjustment ("CVA") by further discounting the cash flows for nonperformance or credit risk based on the observable or estimated debt spread of the Company's subsidiary or its counterparty and the tenor of the respective derivative instrument. The CVA for potential future scenarios in which the derivative is in an asset is based on the counterparty's credit ratings, credit default swap spreads, and debt spreads, as available. The CVA for potential future scenarios in which the derivative is a liability is based on the Parent Company's or the subsidiary's current debt spread. In the absence of readily obtainable credit information, the Parent Company's or the subsidiary's estimated credit rating (based on applying a standard industry model to historical financial information and then considering other relevant information) and spreads of

137


THE AES CORPORATION
NOTES TO CONSOLIDATED FINANCIAL STATEMENTS—(Continued)
DECEMBER 31, 2015, 2014, AND 2013

comparably rated entities or the respective country's debt spreads are used as a proxy. All derivative instruments are analyzed individually and are subject to unique risk exposures.
The Company's methodology to fair value its derivatives is to start with any observable inputs; however, in certain instances the published forward rates or prices may not extend through the remaining term of the contract and management must make assumptions to extrapolate the curve, which necessitates the use of unobservable inputs, such as proxy commodity prices or historical settlements to forecast forward prices. Specifically, where there is limited forward curve data with respect to foreign exchange contracts, beyond the traded points the Company utilizes the purchasing power parity approach to construct the remaining portion of the forward curve using relative inflation rates. In addition, in certain instances, there may not be market or market-corroborated data readily available, requiring the use of unobservable inputs. Similarly, in certain instances, the spread that reflects the credit or nonperformance risk is unobservable requiring us to utilize proxy yield curves of similar credit quality. The fair value hierarchy of an asset or a liability is based on the level of significance of the input assumptions. An input assumption is considered significant if it affects the fair value by at least 10%. Assets and liabilities are classified as Level 3 when the use of unobservable inputs is significant. When the use of unobservable inputs is insignificant, assets and liabilities are classified as Level 2. Transfers between Level 3 and Level 2 are determined as of the end of the reporting period and result from changes in significance of unobservable inputs used to calculate the CVA.
Debt — Recourse and non-recourse debt are carried at amortized cost. The fair value of recourse debt is estimated based on quoted market prices. The fair value of non-recourse debt is estimated differently based upon the type of loan. In general, the carrying amount of variable rate debt is a close approximation of its fair value. For fixed rate loans, the fair value is estimated using quoted market prices or discounted cash flow ("DCF") analyses. In the DCF analysis, the discount rate is based on the credit rating of the individual debt instruments, if available, or the credit rating of the subsidiary. If the subsidiary's credit rating is not available, a synthetic credit rating is determined using certain key metrics, including cash flow ratios and interest coverage, as well as other industry-specific factors. For subsidiaries located outside the U.S., in the event that the country rating is lower than the credit rating previously determined, the country rating is used for purposes of the DCF analysis. The fair value of recourse and non-recourse debt excludes accrued interest at the valuation date. The fair value was determined using available market information as of December 31, 2015. The Company is not aware of any factors that would significantly affect the fair value amounts subsequent to December 31, 2015.
Nonrecurring Measurements — For nonrecurring measurements derived using the income approach, fair value is determined using valuation models based on the principles of DCF. The income approach is most often used in the impairment evaluation of long-lived tangible assets, equity method investments, goodwill, and intangible assets. The Company uses its internally developed DCF valuation models as the primary means to determine nonrecurring fair value measurements though other valuation approaches prescribed under the fair value measurement accounting guidance are also considered. Depending on the complexity of a valuation, an independent valuation firm may be engaged to assist management in the valuation process. A few examples of input assumptions to such valuations include macroeconomic factors such as growth rates, industry demand, inflation, exchange rates and power and commodity prices. Whenever possible, the Company attempts to obtain market observable data to develop input assumptions. Where the use of market observable data is limited or not available for certain input assumptions, the Company develops its own estimates using a variety of techniques such as regression analysis and extrapolations.
For nonrecurring measurements derived using the market approach, recent market transactions involving the sale of identical or similar assets are considered. The use of this approach is limited because it is often difficult to identify sale transactions of identical or similar assets. This approach is used in impairment evaluations of certain intangible assets. Otherwise, it is used to corroborate the fair value determined under the income approach.
For nonrecurring measurements derived using the cost approach, fair value is typically based upon a replacement cost approach. Under this approach, the depreciated replacement cost of assets is derived by first estimating the current replacement cost of assets and then applying the remaining useful life percentages to such costs. Further adjustments for economic and functional obsolescence are made to the depreciated replacement cost. This approach involves a considerable amount of judgment, which is why its use is limited to the measurement of long-lived tangible assets. Like the market approach, this approach is also used to corroborate the fair value determined under the income approach.
Fair Value Considerations — In determining fair value, the Company considers the source of observable market data inputs, liquidity of the instrument, the credit risk of the counterparty and the risk of the Company's or its counterparty's nonperformance. The conditions and criteria used to assess these factors are:

138


THE AES CORPORATION
NOTES TO CONSOLIDATED FINANCIAL STATEMENTS—(Continued)
DECEMBER 31, 2015, 2014, AND 2013

Sources of market assumptions — The Company derives most of its market assumptions from market efficient data sources (e.g., Bloomberg and Reuters). To determine fair value, where market data is not readily available, management uses comparable market sources and empirical evidence to develop its own estimates of market assumptions.
Market liquidity — The Company evaluates market liquidity based on whether the financial or physical instrument, or the underlying asset, is traded in an active or inactive market. An active market exists if the prices are fully transparent to market participants, can be measured by market bid and ask quotes, the market has a relatively large proportion of trading volume as compared to the Company's current trading volume and the market has a significant number of market participants that will allow the market to rapidly absorb the quantity of assets traded without significantly affecting the market price. Another factor the Company considers when determining whether a market is active or inactive is the presence of government or regulatory controls over pricing that could make it difficult to establish a market-based price when entering into a transaction.
Nonperformance risk — Nonperformance risk refers to the risk that an obligation will not be fulfilled and affects the value at which a liability is transferred or an asset is sold. Nonperformance risk includes, but may not be limited to, the Company or its counterparty's credit and settlement risk. Nonperformance risk adjustments are dependent on credit spreads, letters of credit, collateral, other arrangements available and the nature of master netting arrangements. The Company and its subsidiaries are parties to various interest rate swaps and options; foreign currency options and forwards; and derivatives and embedded derivatives, which subject the Company to nonperformance risk. The financial and physical instruments held at the subsidiary level are generally non-recourse to the Parent Company.
Nonperformance risk on the investments held by the Company is incorporated in the fair value derived from quoted market data to mark the investments to fair value.
Recurring Measurements
The following table presents, by level within the fair value hierarchy, as described in Note 1—General and Summary of Significant Accounting Policies, the Company's financial assets and liabilities (in millions) that were measured at fair value on a recurring basis as of the periods indicated:
 
 
December 31, 2015
 
December 31, 2014
 
 
Level 1
 
Level 2
 
Level 3
 
Total
 
Level 1
 
Level 2
 
Level 3
 
Total
Assets


AVAILABLE FOR SALE:


Debt securities:(1)


Unsecured debentures
 
$
—

 
$
327

 
$
—

 
$
327

 
$
—

 
$
501

 
$
—

 
$
501

Certificates of deposit
 
—

 
135

 
—

 
135

 
—

 
151

 
—

 
151

Government debt securities
 
—

 
28

 
—

 
28

 
—

 
57

 
—

 
57

Subtotal
 
—

 
490

 
—

 
490

 
—

 
709

 
—

 
709

Equity securities:


Mutual funds
 
—

 
15

 
—

 
15

 
—

 
25

 
—

 
25

Subtotal
 
—

 
15

 
—

 
15

 
—

 
25

 
—

 
25

Total available for sale
 
—

 
505

 
—

 
505

 
—

 
734

 
—

 
734

TRADING:


Equity securities:


Mutual funds
 
15

 
—

 
—

 
15

 
15

 
—

 
—

 
15

Total trading
 
15

 
—

 
—

 
15

 
15

 
—

 
—

 
15

DERIVATIVES:


Foreign currency derivatives
 
—

 
35

 
292

 
327

 
—

 
18

 
218

 
236

Commodity derivatives
 
—

 
41

 
7

 
48

 
—

 
37

 
7

 
44

Total derivatives
 
—

 
76

 
299

 
375

 
—

 
55

 
225

 
280

TOTAL ASSETS
 
$
15

 
$
581

 
$
299

 
$
895

 
$
15

 
$
789

 
$
225

 
$
1,029

Liabilities


DERIVATIVES:


Interest rate derivatives
 
$
—

 
$
54

 
$
304

 
$
358

 
$
—

 
$
206

 
$
210

 
$
416

Cross currency derivatives
 
—

 
43

 
—

 
43

 
—

 
29

 
—

 
29

Foreign currency derivatives
 
—

 
41

 
15

 
56

 
—

 
43

 
9

 
52

Commodity derivatives
 
—

 
29

 
4

 
33

 
—

 
16

 
1

 
17

Total derivatives
 
—

 
167

 
323

 
490

 
—

 
294

 
220

 
514

TOTAL LIABILITIES
 
$
—

 
$
167

 
$
323

 
$
490

 
$
—

 
$
294

 
$
220

 
$
514

 _____________________________
(1) 
Amortized cost approximated fair value at December 31, 2015 and 2014.
The following tables present a reconciliation of net derivative assets and liabilities measured at fair value on a recurring basis using significant unobservable inputs (Level 3) for the years ended December 31, 2015 and 2014 (presented net by type of derivative in millions). Transfers between Level 3 and Level 2 are determined as of the end of the reporting period and principally result from changes in the significance of unobservable inputs used to calculate the credit valuation adjustment.

139


THE AES CORPORATION
NOTES TO CONSOLIDATED FINANCIAL STATEMENTS—(Continued)
DECEMBER 31, 2015, 2014, AND 2013

Year Ended December 31, 2015
Interest Rate
 
Foreign Currency
 
Commodity
 
Total
Balance at January 1
$
(210
)
 
$
209

 
$
6

 
$
5

Total gains (losses) (realized and unrealized):


Included in earnings
(1
)
 
198

 
(1
)
 
196

Included in other comprehensive income - derivative activity
(31
)
 
—

 
—

 
(31
)
Included in other comprehensive income - foreign currency translation activity
9

 
(103
)
 
—

 
(94
)
Included in regulatory (assets) liabilities
—

 
—

 
(18
)
 
(18
)
Settlements
24

 
(7
)
 
16

 
33

Transfers of assets (liabilities) into Level 3
(95
)
 
(1
)
 
—

 
(96
)
Transfers of (assets) liabilities out of Level 3
—

 
(19
)
 
—

 
(19
)
Balance at December 31
$
(304
)
 
$
277

 
$
3

 
$
(24
)
Total gains (losses) for the period included in earnings attributable to the change in unrealized gains (losses) relating to assets and liabilities held at the end of the period
$
—

 
$
187

 
$
(1
)
 
$
186

Year Ended December 31, 2014
Interest Rate
 
Foreign Currency
 
Commodity
 
Total
Balance at January 1
$
(101
)
 
$
93

 
$
4

 
$
(4
)
Total gains (losses) (realized and unrealized):


Included in earnings
2

 
134

 
1

 
137

Included in other comprehensive income - derivative activity
(154
)
 
(2
)
 
—

 
(156
)
Included in other comprehensive income - foreign currency translation activity
13

 
(25
)
 
—

 
(12
)
Included in regulatory (assets) liabilities
—

 
—

 
16

 
16

Settlements
30

 
(4
)
 
(15
)
 
11

Transfers of assets (liabilities) into Level 3
—

 
10

 
—

 
10

Transfers of (assets) liabilities out of Level 3
—

 
3

 
—

 
3

Balance at December 31
$
(210
)
 
$
209

 
$
6

 
$
5

Total gains (losses) for the period included in earnings attributable to the change in unrealized gains (losses) relating to assets and liabilities held at the end of the period
$
2

 
$
130

 
$
(1
)
 
$
131

The following table summarizes the significant unobservable inputs used for the Level 3 derivative assets (liabilities) as of December 31, 2015:
Type of Derivative
 
Fair Value
 
Unobservable Input
 
Amount or Range
(Weighted Average)
 
 
(in millions)


Interest rate
 
$
(304
)
 
Subsidiaries’ credit spreads
 
2.88%-8.88% (5.42%)

Foreign currency:


Argentine Peso
 
291

 
Argentine Peso to U.S. Dollar currency exchange rate after 1 year
 
17.51 - 35.44 (26.05)

Euro
 
(14
)
 
Subsidiary's credit spread
 
8.88
%
Commodity:


Other
 
3


Total
 
$
(24
)


Changes in the above significant unobservable inputs that lead to a significant and unusual impact to current-period earnings are disclosed to the Financial Audit Committee. For interest rate derivatives, and foreign currency derivatives, increases (decreases) in the estimates of the Company's own credit spreads would decrease (increase) the value of the derivatives in a liability position. For foreign currency derivatives, increases (decreases) in the estimate of the above exchange rate would increase (decrease) the value of the derivative.
Nonrecurring Measurements — When evaluating impairment of goodwill, long-lived assets, discontinued operations and held-for-sale businesses, and equity method investments, the Company measures fair value using the applicable fair value measurement guidance. Impairment expense is measured by comparing the fair value at the evaluation date to their then-latest available carrying amount. The following table summarizes major categories of assets and liabilities measured at fair value on a nonrecurring basis during the period and their level within the fair value hierarchy (in millions):
 
 
Measurement Date
 
Carrying Amount
 
Fair Value
 
Pretax
Loss
Year Ended December 31, 2015
 
 
Level 1
 
Level 2
 
Level 3
 
Assets


Long-lived assets held and used:(1)


Kilroot
 
08/28/2015
 
$
191

 
$
—

 
$
—

 
$
70

 
$
121

Buffalo Gap III
 
09/30/2015
 
234

 
—

 
—

 
118

 
116

U.K. Wind (Development Projects)
 
06/30/2015
 
38

 
—

 
1

 
—

 
37

Other
 
Various
 
32

 
—

 
21

 
—

 
11

Equity method investments (3)


Solar Spain
 
02/09/2015
 
29

 
—

 
—

 
29

 
—

Goodwill(5)


DP&L
 
10/01/2015
 
317

 
—

 
—

 
—

 
317


140


THE AES CORPORATION
NOTES TO CONSOLIDATED FINANCIAL STATEMENTS—(Continued)
DECEMBER 31, 2015, 2014, AND 2013


Measurement Date
 
Carrying Amount
 
Fair Value
 
Pretax
Loss
Year Ended December 31, 2014
 
 
Level 1
 
Level 2
 
Level 3
 
Assets


Long-lived assets held and used:(1)


DP&L (East Bend)
 
03/31/2014
 
$
14

 
$
—

 
$
2

 
$
—

 
$
12

Ebute
 
06/30/2014
 
99

 
—

 
—

 
47

 
52

Ebute
 
09/30/2014
 
51

 
—

 
—

 
36

 
15

U.K. Wind (Newfield)
 
06/06/2014
 
12

 
—

 
—

 
—

 
12

Discontinued operations:(2)


Cameroon businesses
 
03/31/2014
 
372

 
—

 
334

 
—

 
38

Equity method investments (4)


Silver Ridge Power
 
06/30/2014
 
315

 
—

 
—

 
273

 
42

Entek
 
09/25/2014
 
211

 
—

 
125

 
—

 
86

Goodwill(5)


DPLER
 
02/28/2014
 
136

 
—

 
—

 
—

 
136

Buffalo Gap
 
03/31/2014
 
28

 
—

 
—

 
—

 
28

_____________________________
(1) 
See Note 21—Asset Impairment Expense for further information.
(2) 
See Note 23—Discontinued Operations for further information. Fair value of long-lived assets held-for-sale is presented net of costs to sell.
(3) 
See Note 8—Investments In and Advances to Affiliates for further information.
(4) 
See Note 9—Other Non-Operating Expense for further information.
(5) 
See Note 10—Goodwill and Other Intangible Assets for further information.
The following table summarizes the significant unobservable inputs used in the Level 3 measurement of long-lived assets and equity method investments during the year ended December 31, 2015:
 
 
Fair Value
 
Valuation Technique
 
Unobservable Input
 
Range (Weighted Average)
 
 
(in millions)


($ in millions)
Long-lived assets held and used:


Kilroot
 
$
70

 
Discounted cash flow
 
Annual revenue growth
 
-88% to 6% (-7%)


Annual pretax operating margin
 
-74% to 10% (0%)


Weighted Average Cost of Capital
 
6%
Buffalo Gap
 
118

 
Discounted cash flow
 
Annual revenue growth
 
-2% to 19% (3%)


Annual pretax operating margin
 
-282% to 58% (24%)


Weighted Average Cost of Capital
 
9%
Equity method investment:


Solar Spain
 
29

 
Discounted cash flow
 
Annual revenue growth
 
-3% to 0% (0%)


Annual pretax operating margin
 
-13% to 56% (24%)


Cost of equity
 
12%
Total
 
$
217


Financial Instruments not Measured at Fair Value in the Consolidated Balance Sheets
The following table presents in millions the carrying amount, fair value and fair value hierarchy of the Company's financial assets and liabilities that are not measured at fair value in the Consolidated Balance Sheets as of December 31, 2015 and 2014, but for which fair value is disclosed.
 
 
Carrying
Amount
 
Fair Value
 
 
Total
 
Level 1
 
Level 2
 
Level 3
December 31, 2015


Assets


Accounts receivable — noncurrent(1)
 
$
270

 
$
342

 
$
—

 
$
20

 
$
322

Liabilities


Non-recourse debt
 
15,792

 
15,939

 
—

 
13,672

 
2,267

Recourse debt
 
5,015

 
4,696

 
—

 
4,696

 
—

December 31, 2014


Assets


Accounts receivable — noncurrent(1)
 
$
257

 
$
246

 
$
—

 
$
—

 
$
246

Liabilities


Non-recourse debt
 
15,600

 
16,008

 
—

 
12,538

 
3,470

Recourse debt
 
5,258

 
5,552

 
—

 
5,552

 
—

_____________________________
(1) 
These accounts receivable principally relate to amounts due from CAMMESA, the administrator of the wholesale electricity market in Argentina, and are included in Noncurrent assets — Other in the accompanying Consolidated Balance Sheets. The fair value of these accounts receivable excludes value-added tax of $27 million and $36 million at December 31, 2015 and 2014, respectively.
5. INVESTMENTS IN MARKETABLE SECURITIES
The Company's investments in marketable debt and equity securities as of December 31, 2015 and 2014 by security class and by level within the fair value hierarchy have been disclosed in Note 4—Fair Value. The security classes are determined based on the nature and risk of a security and are consistent with how the Company manages, monitors and measures its marketable securities. As of December 31, 2015, $462 million of available-for-sale ("AFS") debt securities had stated maturities within one year and $28 million had stated maturities between one and two years. Gains and losses on the sale of investments are determined using the specific-identification method. For the years ended December 31, 2015, 2014, and 2013, pretax realized gains and losses related to AFS and trading securities were $1 million or less, unrealized gains and losses on AFS securities were less than $1 million, and there were no other-than-temporary impairment of marketable securities recognized in earnings or OCI. The following table summarizes the gross proceeds from sale of AFS securities in millions for the years ended December 31, 2015, 2014, and 2013:
 
 
2015
 
2014
 
2013
Gross proceeds from sales of AFS securities
 
$
4,902

 
$
4,569

 
$
4,406

6. DERIVATIVE INSTRUMENTS AND HEDGING ACTIVITIES
Volume of Activity
The following tables present, by type of derivative, the Company's outstanding notional under its derivatives and the weighted-average remaining term as of December 31, 2015 regardless of whether the derivative instruments are in qualifying cash flow hedging relationships:
 
 
Current
 
Maximum


Interest Rate and Cross Currency (1)
 
Derivative
Notional
 
Derivative Notional Translated to USD
 
Derivative
Notional
 
Derivative Notional Translated to USD
 
Weighted-Average Remaining Term
 
% of Debt Currently Hedged by Index (2)
 
 
(in millions)
 
(in years)
 
 
Interest Rate Derivatives:


LIBOR (U.S. Dollar)
 
2,639

 
$
2,639

 
2,872

 
$
2,872

 
11
 
48
%
EURIBOR (Euro)
 
482

 
524

 
482

 
524

 
6
 
83
%
Cross Currency Swaps:


Chilean Unidad de Fomento
 
4

 
159

 
4

 
159

 
13
 
76
%
_____________________________
(1) 
The Company's interest rate derivative instruments primarily include accreting and amortizing notionals. The maximum derivative notional represents the largest notional at any point between December 31, 2015 and the maturity of the derivative instrument, which includes forward-starting derivative instruments. The interest rate and cross currency derivatives range in maturity through 2033 and 2028, respectively.
(2) 
The percentage of variable-rate debt currently hedged is based on the related index and excludes forecasted issuances of debt and variable-rate debt tied to other indices where the Company has no interest rate derivatives.
 
 
December 31, 2015
Foreign Currency Derivatives
 
Notional(1)
 
Notional Translated to USD
 
Weighted-Average Remaining Term(2)
 
 
(in millions)
 
(in years)
Foreign Currency Derivatives


Argentine Peso
 
$
2,321

 
$
178

 
10
Brazilian Real
 
80

 
21

 
<1
British Pound
 
22

 
32

 
<1
Chilean Peso
 
84,669

 
119

 
<1
Chilean Unidad de Fomento
 
9

 
311

 
<1
Colombian Peso
 
252,166

 
80

 
<1
Euro
 
32

 
35

 
<1
Kazakhstani Tenge
 
1,691

 
5

 
1
_____________________________
(1) 
Represents contractual notionals. The notionals for options have not been probability adjusted, which generally would decrease them.
(2) 
Represents the remaining tenor of our foreign currency derivatives weighted by the corresponding notional. These derivatives matures through 2026.
December 31, 2015


Weighted-Average
Commodity Derivatives
 
Notional
 
Remaining Term(1)
 
 
(in millions)
 
(in years)
Power (MWh)
 
10

 
3
_____________________________
(1) 
Represents the remaining tenor of our commodity derivatives weighted by the corresponding volume. These derivatives range in maturity through 2018.

141


THE AES CORPORATION
NOTES TO CONSOLIDATED FINANCIAL STATEMENTS—(Continued)
DECEMBER 31, 2015, 2014, AND 2013

Accounting and Reporting
Assets and Liabilities
The following tables present in millions the Company's derivative instruments as of the periods indicated, first by whether or not they are designated hedging instruments, then by whether they are current or noncurrent to the extent they are subject to master netting agreements or similar agreements (where the rights to set-off relate to settlement of amounts receivable and payable under those derivatives) and by balances no longer accounted for as derivatives.
 
 
December 31, 2015
 
December 31, 2014
 
 
Designated
 
Not Designated
 
Total
 
Designated
 
Not Designated
 
Total
Assets


Foreign currency derivatives
 
$
8

 
$
319

 
$
327

 
$
6

 
$
230

 
$
236

Commodity derivatives
 
30

 
18

 
48

 
25

 
19

 
44

Total assets
 
$
38

 
$
337

 
$
375

 
$
31

 
$
249

 
$
280

Liabilities


Interest rate derivatives
 
$
358

 
$
—

 
$
358

 
$
416

 
$
—

 
$
416

Cross currency derivatives
 
43

 
—

 
43

 
29

 
—

 
29

Foreign currency derivatives
 
35

 
21

 
56

 
38

 
14

 
52

Commodity derivatives
 
12

 
21

 
33

 
7

 
10

 
17

Total liabilities
 
$
448

 
$
42

 
$
490

 
$
490

 
$
24

 
$
514


December 31, 2015
 
December 31, 2014
 
 
Assets
 
Liabilities
 
Assets
 
Liabilities
Current
 
$
86

 
$
144

 
$
77

 
$
148

Noncurrent
 
289

 
346

 
203

 
366

Total
 
$
375

 
$
490

 
$
280

 
$
514

Derivatives subject to master netting agreement or similar agreement:


Gross amounts recognized in the balance sheet
 
$
57

 
$
467

 
$
53

 
$
507

Gross amounts of derivative instruments not offset
 
(18
)
 
(18
)
 
(10
)
 
(10
)
Gross amounts of cash collateral received/pledged not offset
 
—

 
(38
)
 
—

 
(26
)
Net amount
 
$
39

 
$
411

 
$
43

 
$
471

Other balances that had been, but are no longer, accounted for as derivatives that are to be amortized to earnings over the remaining term of the associated PPA
 
$
147

 
$
166

 
$
161

 
$
180

Effective Portion of Cash Flow Hedges — The following tables present (in millions) the pretax gains (losses) recognized in AOCL and earnings related to the effective portion of derivative instruments in qualifying cash flow hedging relationships (including amounts that were reclassified from AOCL as interest expense related to interest rate derivative instruments that previously, but no longer, qualify for cash flow hedge accounting), as defined in the accounting standards for derivatives and hedging, for the periods indicated:
Years Ended December 31,
 
Gains (Losses) Recognized in AOCL
 
Classification in Consolidated Statements of Operations
 
Gains (Losses) Reclassified from AOCL into Earnings
Type of Derivative
 
2015
 
2014
 
2013
 
2015
 
2014
 
2013
Interest rate derivatives
 
$
(103
)
 
$
(421
)
 
$
155

 
Interest expense
 
$
(108
)
 
$
(139
)
 
$
(127
)


Non-regulated cost of sales
 
(2
)
 
(2
)
 
(5
)


Net equity in earnings of affiliates
 
(2
)
 
(3
)
 
(6
)


Gain on sale of investments
 
(4
)
 
—

 
(21
)
Cross currency derivatives
 
(20
)
 
(25
)
 
(18
)
 
Interest expense
 
(4
)
 
—

 
(10
)


Foreign currency transaction gains (losses)
 
(20
)
 
(23
)
 
(18
)
Foreign currency derivatives
 
10

 
(28
)
 
—

 
Foreign currency transaction gains (losses)
 
32

 
14

 
12

Commodity derivatives
 
40

 
44

 
2

 
Non-regulated revenue
 
43

 
30

 
(3
)


Non-regulated cost of sales
 
(12
)
 
(2
)
 
(2
)
Total
 
$
(73
)
 
$
(430
)
 
$
139


$
(77
)
 
$
(125
)
 
$
(180
)
The pretax accumulated other comprehensive income (loss) expected to be recognized as an increase (decrease) to income from continuing operations before income taxes over the next twelve months as of December 31, 2015 is $(106) million for interest rate hedges, $(3) million for cross currency swaps, $12 million for foreign currency hedges, and $16 million for commodity and other hedges.
For the year ended December 31, 2014, pretax losses of $6 million, net of noncontrolling interests were reclassified into earnings as a result of the discontinuance of a cash flow hedge because it was probable that the forecasted transaction would not occur by the end of the originally specified time period (as documented at the inception of the hedging relationship) or within an additional two-month time period thereafter. There was no such item for the years ended December 31, 2015 and 2013.

142


THE AES CORPORATION
NOTES TO CONSOLIDATED FINANCIAL STATEMENTS—(Continued)
DECEMBER 31, 2015, 2014, AND 2013

Ineffective Portion of Cash Flow Hedges — The following table presents (in millions) the pretax gains (losses) recognized in earnings related to the ineffective portion of derivative instruments in qualifying cash flow hedging relationships, as defined in the accounting standards for derivatives and hedging, for the periods indicated:


Gains (Losses) Recognized in Earnings
 
 
Classification in Consolidated Statements of Operations
 
Years Ended December 31,
Type of Derivative
 
 
2015
 
2014
 
2013
Interest rate derivatives
 
Interest expense
 
$
(4
)
 
$
—

 
$
42


Net equity in earnings of affiliates
 
—

 
(1
)
 
1

Foreign currency derivatives
 
Foreign currency transaction gains (losses)
 
(3
)
 
(2
)
 
—

Cross currency derivatives
 
Interest expense
 
1

 
(1
)
 
—

Total


$
(6
)
 
$
(4
)
 
$
43

Not Designated for Hedge Accounting — The next table presents (in millions) the gains (losses) recognized in earnings related to derivative instruments not designated as hedging instruments under the accounting standards for derivatives and hedging, and amortization of balances that had been, but are no longer, accounted for as derivatives, for the periods indicated:


Gains (Losses) Recognized in Earnings
 
 
Classification in Consolidated Statements of Operations
 
Years Ended December 31,
Type of Derivative
 
2015
 
2014
 
2013
Interest rate derivatives
 
Interest expense
 
$
—

 
$
(3
)
 
$
(1
)
 
 
Net equity in earnings of affiliates
 
—

 
—

 
(6
)
Foreign currency derivatives
 
Foreign currency transaction gains (losses)
 
211

 
146

 
64


Net equity in earnings of affiliates
 
—

 
(2
)
 
(24
)
Commodity and other derivatives
 
Non-regulated revenue
 
(8
)
 
5

 
11


Non-regulated cost of sales
 
(16
)
 
(3
)
 
1


Regulated cost of sales
 
(5
)
 
(6
)
 
2


Income (loss) from operations of discontinued businesses
 
—

 
(7
)
 
(18
)
 
 
Net gain (loss) from disposal and impairments of discontinued operations
 
—

 
72

 
—

Total


$
182

 
$
202

 
$
29

Credit Risk-Related Contingent Features
DP&L has certain over-the-counter commodity derivative contracts under master netting agreements that contain provisions that require DP&L to maintain an investment-grade issuer credit rating from credit rating agencies. Since DP&L's rating has fallen below investment grade, certain of the counterparties to the derivative contracts have requested immediate and ongoing full overnight collateralization of the mark-to-market loss (fair value excluding credit valuation adjustments), which was $28 million and $12 million as of December 31, 2015 and 2014, respectively, for all derivatives with credit risk-related contingent features. As of December 31, 2015 and 2014, DP&L had posted $8 million and $5 million, respectively, of cash collateral directly with third parties and in a broker margin account and DP&L held no cash collateral from counterparties to its derivative instruments that were in an asset position. After consideration of the netting of counterparty assets, DP&L could have been required to, but did not, provide additional collateral of $2 million and $1 million as of December 31, 2015 and 2014, respectively.
7. FINANCING RECEIVABLES
Financing receivables are defined as receivables that have contractual maturities of greater than one year. The Company has financing receivables pursuant to amended agreements or government resolutions that are due from certain Latin American governmental bodies, primarily in Argentina. The table below presents the breakdown of financing receivables in millions by country as of the periods indicated:
December 31,
 
2015
 
2014
Argentina
 
$
237

 
$
278

Cameroon (1)
 
—

 
44

United States
 
20

 
—

Brazil
 
39

 
15

Total long-term financing receivables
 
$
296

 
$
337

_____________________________
(1) 
Represents non-contingent consideration to be received in 2016 from the sale of the Cameroon businesses in 2014. Balance is classified as short-term as of December 31, 2015. See Note 23—Discontinued Operations.
Argentina — Collection of the principal and interest on these receivables is subject to various business risks and uncertainties including, but not limited to, the completion and operation of power plants which generate cash for payments of these receivables, regulatory changes that could impact the timing and amount of collections, and economic conditions in Argentina. The Company monitors these risks including the credit ratings of the Argentine government on a quarterly basis to assess the collectability of these receivables. The Company accrues interest on these receivables once the recognition criteria have been met. The Company's collection estimates are based on assumptions that it believes to be reasonable, but are inherently uncertain. Actual future cash flows could differ from these estimates.
FONINVEMEM Agreements
As a result of energy market reforms in 2004 and 2010, AES Argentina entered into three agreements with the Argentine government, referred to as the FONINVEMEM Agreements, to contribute a portion of their accounts receivable into a fund for financing the construction of combined cycle and gas-fired plants. These receivables accrue interest and are collected in monthly installments over 10 years once the related plant begins operations. In addition, AES Argentina receives an ownership interest in these newly built plants once the receivables have been fully repaid.

143


THE AES CORPORATION
NOTES TO CONSOLIDATED FINANCIAL STATEMENTS—(Continued)
DECEMBER 31, 2015, 2014, AND 2013

FONINVEMEM I and II — The receivables under the first two FONINVEMEM Agreements have been actively collected since the related plants commenced operations in 2010. In assessing the collectability of the receivables under these agreements, the Company also considers how timely the collections have historically been made in accordance with the agreements.
FONINVEMEM III — The receivables related to the third FONINVEMEM Agreement will not be repaid until commercial operation of the related gas-fired plant has been achieved. In assessing the collectability of the receivables under this agreement, the Company also considers the extent to which significant milestones necessary to complete the plants have been achieved or are still probable.
The FONINVEMEM receivables are denominated in Argentine pesos, but indexed to U.S. Dollars, which represents a foreign currency derivative. As of December 31, 2015 and 2014, the amount of the foreign currency-related derivative assets associated with the FONINVEMEM financing receivables that were excluded from the table above had a fair value of $292 million and $208 million, respectively.
Other Agreements
In 2013, Resolution No. 95/2013 ("Resolution 95") which developed a new energy regulatory framework that applies to all generation companies with certain exceptions became effective. The new regulatory framework remunerates fixed and variable costs plus a margin that will depend on the technology and fuel used to generate the electricity and the installed capacity of each plant.
In the fourth quarter of 2014, the Argentine government passed a resolution to contribute outstanding Resolution 95 receivables into a trust whereby AES Argentina has committed to install additional capacity into the system. CAMMESA will finance the investment utilizing the outstanding receivables as a guarantee.
On July 10, 2015, the Argentine government passed Resolution No. 482/2015 ("Resolution 482") which updated the prices of Resolution 529/2014 retroactively to February 1, 2015, and created a new trust called FONINVEMEM 2015-2018 in order to invest in new generation plants. AES Argentina and certain Termoandes units will receive compensation under this program.
8. INVESTMENTS IN AND ADVANCES TO AFFILIATES
The following table summarizes the relevant effective equity ownership interest and carrying values for the Company's investments accounted for under the equity method as of the periods indicated.
December 31,
 
 
2015
 
2014
 
2015
 
2014
Affiliate
Country
 
Carrying Value (in millions)
 
Ownership Interest %
Solar Power PR
Puerto Rico
 
$
—

 
$
2

 
—
%
 
50
%
Barry(1) 
United Kingdom
 
—

 
—

 
100
%
 
100
%
Elsta(1)
Netherlands
 
53

 
54

 
50
%
 
50
%
Distributed Energy(1)
United States
 
17

 
—

 
94
%
 
—
%
Guacolda(2)
Chile
 
344

 
285

 
33
%
 
35
%
OPGC(3)
India
 
195

 
194

 
49
%
 
49
%
Other affiliates
Various
 
1

 
2


Total investments in and advances to affiliates
 
 
$
610

 
$
537


(1) 
Represent VIEs in which the Company holds a variable interest but is not the primary beneficiary.
(2) 
The Company's ownership in Guacolda is held through AES Gener, a 67%-owned consolidated subsidiary. AES Gener owns 50% of Guacolda, resulting in an AES effective ownership in Guacolda of 33%. At December 31, 2014, AES owned 71% of AES Gener, resulting in an AES effective ownership in Guacolda of 35%.
(3) 
OPGC has one coal-fired expansion project under development. The project started construction in April 2014 and is currently expected to begin operations in 2018.
Guacolda — On September 1, 2015, AES Gener and Global Infrastructure Partners ("GIP") executed a restructuring of Guacolda that increased Guacolda's tax basis in certain long-term assets and AES Gener's equity investment. This transaction was reflected within equity at the Guacolda level, but was not with or among the shareholders of AES. Accordingly, the AES proportion of the increased value in equity was recognized in net income. As a result, AES Gener recorded $66 million in net equity in earnings of affiliates for the year ended December 31, 2015, of which $46 million is attributable to The AES Corporation.
On April 11, 2014, AES Gener undertook a series of transactions, pursuant to which AES Gener acquired the interests that it did not previously own in Guacolda for $728 million and simultaneously sold the ownership interest to GIP for $730 million. The transaction provided GIP with substantive participating rights in Guacolda and, as a result, the Company continues to account for its investment in Guacolda using the equity method of accounting. At no time during this transaction did the Company acquire a non-controlling interest. The cash paid for the acquisition is reflected in Acquisitions, net of cash acquired

144


THE AES CORPORATION
NOTES TO CONSOLIDATED FINANCIAL STATEMENTS—(Continued)
DECEMBER 31, 2015, 2014, AND 2013

and the cash proceeds from the sale of these ownership interests to GIP is reflected in Proceeds from the sale of businesses, net of cash sold on the Consolidated Statement of Cash Flows for the period ended December 31, 2014.
Distributed Energy — On February 18, 2015, the Company completed the acquisition of 100% of the common stock of Main Street Power Company, Inc., which has been renamed to Distributed Energy Inc. As part of this acquisition, the Company obtained additional investments accounted for under the equity method.
Silver Ridge Power — On July 1, 2014, the Puerto Rico solar business, Solar Power PR, LLC, was distributed by Silver Ridge Power, LLC ("SRP") to AES and Riverstone Holdings LLC and was accounted for as a direct equity method investment. On April 29, 2015, the Company purchased the remaining 50% of the common stock of Solar Power PR, LLC and now consolidates this entity. On July 2, 2014, the Company closed the sale of its 50% ownership interest in SRP for a purchase price of $179 million, excluding the Company's indirect ownership interests in SRP's solar generation businesses in Italy and Spain ("Solar Italy" and "Solar Spain," respectively). The buyer also had an option to purchase the Company's indirect 50% interest in the Italy solar generation business for an additional consideration of $42 million by August 2015. The buyer exercised its option to purchase Solar Italy on August 31, 2015, and the sale was completed on October 1, 2015.
In 2014, the sale of the Company's 50% ownership interest in SRP did not qualify as a sale for accounting purposes as the Company had continuing involvement in the business operations. As of July 2, 2014, the Company no longer retained an equity interest in SRP. As such, the then-remaining investment balance of $32 million related to Italy and Spain and the AOCL balance of $40 million were reclassified to Other noncurrent assets on the Consolidated Balance Sheets. As of December 31, 2014, the carrying value of these investments recorded in Other noncurrent assets was $64 million.
Solar Spain — On September 24, 2015, the Company completed the sale of Solar Spain, an equity method investment. Net proceeds from the sale transaction were $31 million and the Company recognized a pretax gain on sale of less than $1 million.
Upon the completion of the Solar Spain and Solar Italy sale transactions noted above, the Company ceased its involvement in SRP's business operations and accounted for these transactions as sales of real estate. Accordingly, as of December 31, 2015, the carrying value of these investments recorded in Other noncurrent assets was zero.
AES Barry Ltd. — The Company holds a 100% ownership interest in AES Barry Ltd. ("Barry"), a dormant entity in the U.K. that disposed of its generation and other operating assets. Due to a debt agreement, no material financial or operating decisions can be made without the banks' consent, and the Company does not control Barry. As of December 31, 2015 and 2014, other long-term liabilities included $49 million and $52 million related to this debt agreement.
Elsta — In 2014, long lived assets within Elsta were determined to not be recoverable and an impairment charge of approximately $82 million was recognized. The Company recognized its 50% share, or $41 million, through its proportion of the equity earnings in Elsta.
Entek — In September 2014, the Company executed an agreement, subject to the approval of the Company's Board of Directors, to sell its equity interest in AES Entek. Based on this agreement, during the third quarter of 2014, the Company determined there was an other-than-temporary decline in the fair value of its equity method investment in AES Entek and recognized a pretax impairment loss of $18 million in other non-operating expense. On October 13, 2014, the Company entered into a binding agreement to sell its 49.62% ownership interest in Entek for a purchase price of $125 million. This resulted in the recognition of an additional other-than-temporary impairment of $68 million due to the inclusion of the cumulative translation adjustment in the carrying value of the investment. For additional information see Note 9—Other Non-Operating Expense. The sale represents 100% of the Company's interest in assets in Turkey. On December 18, 2014, the transaction closed which resulted in a final loss on sale of $4 million. Entek does not meet the criteria to be reported as discontinued operations under ASU No. 2014-08, which was adopted by the Company on July 1, 2014. Accordingly, AES' proportion of Entek's results are reflected in the Consolidated Statements of Operations within continuing operations. Excluding the loss on sale, Entek's pretax loss attributable to AES was $9 million and $29 million for the years ended December 31, 2014 and 2013, respectively.
Summarized Financial Information
The following tables summarize financial information of the Company's 50%-or-less-owned affiliates and majority-owned unconsolidated subsidiaries that are accounted for using the equity method in millions.

145


THE AES CORPORATION
NOTES TO CONSOLIDATED FINANCIAL STATEMENTS—(Continued)
DECEMBER 31, 2015, 2014, AND 2013

 
50%-or-less Owned Affiliates
 
Majority-Owned Unconsolidated Subsidiaries
Years ended December 31,
2015
 
2014
 
2013
 
2015
 
2014
 
2013
Revenue
$
641

 
$
928

 
$
1,099

 
$
24

 
$
2

 
$
2

Operating margin
152

 
206

 
295

 
11

 
—

 
—

Net income (loss)
210

 
59

 
53

 
6

 
—

 
—


December 31,
2015
 
2014


2015
 
2014
 
 
Current assets
$
376

 
$
450


$
20

 
$
—


Noncurrent assets
2,132

 
1,748


211

 
15


Current liabilities
435

 
299


21

 
—


Noncurrent liabilities
1,044

 
935


153

 
67


Noncontrolling interests
—

 
17


—

 
—


Stockholders' equity
1,029

 
947


57

 
(52
)
 
 
At December 31, 2015, retained earnings included $244 million related to the undistributed earnings of the Company's 50%-or-less owned affiliates. Distributions received from these affiliates were $18 million, $28 million, and $6 million for the years ended December 31, 2015, 2014, and 2013, respectively. As of December 31, 2015, the aggregate carrying amount of our investments in equity affiliates exceeded the underlying equity in their net assets by $162 million.
9. OTHER NON-OPERATING EXPENSE
Years Ended December 31,
2014
 
2013
 
(in millions)
Entek
$
86

 
$
—

Silver Ridge
42

 
—

Elsta
—

 
129

Total other non-operating expense
$
128

 
$
129

There was no other non-operating expense for the year ended December 31, 2015.
Entek — During 2014, the Company executed an agreement to sell its 49.62% interest in Entek, an investment accounted for under the equity method, for $125 million. Entek consists of natural gas and hydroelectric generation facilities, plus a coal-fired development project. The Company determined that there was an other-than-temporary decline in the fair value of its equity method investment in Entek and recognized pretax impairment expense of $86 million. The sale of the Company's interest in Entek closed on December 18, 2014. See Note 8—Investments in and Advances to Affiliates of this Form 10-K for further information.
Silver Ridge — During 2014, the Company determined that there was a decline in the fair value of its equity method investment in SRP that was other-than-temporary based on indications about the fair value of the projects in Italy and Spain that resulted from actual and proposed changes to their tariffs. Accordingly, the Company recognized pretax impairment expense of $42 million. The transaction related to our 50% ownership interest in SRP closed on July 2, 2014 for $179 million. See Note 8—Investments in and Advances to Affiliates of this Form 10-K for further information.
Elsta — During 2013, the Company identified an impairment indicator at Elsta, a combined cycle gas-fired plant in the Netherlands that is accounted for under the equity method, resulting from negative pricing indications noted during negotiations with its offtakers for an extension of the existing PPA. The Company recognized pretax impairment expense of $129 million by reducing the carrying value of $240 million to the estimated fair value of $111 million. The Company estimated fair value using probability-weighted outcomes which contemplated various scenarios involving the amendments to the existing PPA.

146


THE AES CORPORATION
NOTES TO CONSOLIDATED FINANCIAL STATEMENTS—(Continued)
DECEMBER 31, 2015, 2014, AND 2013

10. GOODWILL AND OTHER INTANGIBLE ASSETS
Goodwill — The following table summarizes the changes in the carrying amount of goodwill, by reportable segment for the years ended December 31, 2015 and 2014 in millions.
 
US
 
Andes
 
MCAC
 
Europe
 
Asia
 
Total
Balance as of December 31, 2013


Goodwill
$
2,658

 
$
899

 
$
149

 
$
180

 
$
68

 
$
3,954

Accumulated impairment losses
(2,152
)
 
—

 
—

 
(180
)
 
—

 
(2,332
)
Net balance
506

 
899

 
149

 
—

 
68

 
1,622

Impairment losses
(164
)
 
—

 
—

 
—

 
—

 
(164
)
Balance as of December 31, 2014


Goodwill
2,658

 
899

 
149

 
122

(1) 
68

 
3,896

Accumulated impairment losses
(2,316
)
 
—

 
—

 
(122
)
 
—

 
(2,438
)
Net balance
342

 
899

 
149

 
—

 
68

 
1,458

Impairment losses
(317
)
 
—

 
—

 
—

 
—

 
(317
)
Goodwill acquired during the year
16

 
—

 
—

 
—

 
—

 
16

Balance as of December 31, 2015


Goodwill
2,674

 
899

 
149

 
122

 
68

 
3,912

Accumulated impairment losses
(2,633
)
 
—

 
—

 
(122
)
 
—

 
(2,755
)
Net balance
$
41

 
$
899

 
$
149

 
$
—

 
$
68

 
$
1,157

_____________________________
(1) Both the gross carrying amount and the accumulated impairment losses of the Europe segment have been reduced by $58 million with no impact on the net carrying amount for the segment. This relates to Ebute, which had fully impaired goodwill of $58 million and was sold in 2014.
DP&L — During the fourth quarter of 2015, the Company performed the annual goodwill impairment test at its DP&L reporting unit ("DP&L") and recognized a goodwill impairment expense of $317 million. The reporting unit failed Step 1 as its fair value was less than its carrying amount, which was primarily due to a decrease in forecasted dark spreads that were driven by decreases in projected forward power prices, and lower than expected revenues from a new Capacity Performance ("CP") product. The fair value of the reporting unit was determined under the income approach using a discounted cash flow valuation model. The significant assumptions included within the discounted cash flow valuation model were forward commodity price curves, the amount of non-bypassable charges from the pending ESP, expected revenues from the new CP product, and planned environmental expenditures. In Step 2, goodwill was determined to have an implied negative fair value after the hypothetical purchase price allocation under the accounting guidance for business combinations; therefore, a full impairment of the remaining goodwill balance of $317 million was recognized. DP&L is reported in the US SBU reportable segment.
Main Street Power — During the first quarter of 2015, the Company completed the acquisition of 100% of the common stock of Main Street Power Company, Inc. The transaction included recognition of $16 million of Goodwill. See Note 25—Acquisitions for additional information.
Buffalo Gap — During the first quarter of 2014, the Company recognized an $18 million impairment of its goodwill at its Buffalo Gap reporting unit, which is comprised of three wind projects in Texas. During the fourth quarter of 2014, the Company performed the annual goodwill impairment test at its Buffalo Gap reporting unit. The reporting unit failed Step 1 and Step 2 was performed to measure the amount of goodwill impairment. In Step 2, after the hypothetical purchase price allocation under the relevant accounting guidance, the implied fair value of goodwill was negative. As a result, a full impairment of goodwill of $10 million was recognized. Buffalo Gap is reported in the US SBU reportable segment.
DPLER — During the first quarter of 2014, the Company performed an interim impairment test on the $136 million in goodwill at its DPLER reporting unit, a competitive retail marketer selling retail electricity to customers in Ohio and Illinois. The DPLER reporting unit was identified as being "at risk" during the fourth quarter of 2013. The impairment indicators arose based on market information available regarding actual and proposed sales of competitive retail marketers, which indicated a significant decline in valuations during the first quarter of 2014.
In Step 1 of the interim impairment test, the fair value of the reporting unit was determined to be less than its carrying amount under both the market approach and the income approach using a discounted cash flow valuation model. The significant assumptions included commodity price curves, estimated electricity to be demanded by its customers, changes in its customer base through attrition and expansion, discount rates, the assumed tax structure and the level of working capital required to run the business. 
In Step 2 of the interim impairment test, the goodwill was determined to have an implied fair value of zero after the hypothetical purchase price allocation and the Company accordingly recognized a full impairment of the $136 million in goodwill at the DPLER reporting unit. DPLER is reported in the US SBU reportable segment. 

147


THE AES CORPORATION
NOTES TO CONSOLIDATED FINANCIAL STATEMENTS—(Continued)
DECEMBER 31, 2015, 2014, AND 2013

Other Intangible Assets — The following table summarizes the balances comprising other intangible assets in the accompanying Consolidated Balance Sheets (in millions) as of the periods indicated:
 
December 31, 2015
 
December 31, 2014
 
Gross Balance
 
Accumulated Amortization
 
Net Balance
 
Gross Balance
 
Accumulated Amortization
 
Net Balance
Subject to Amortization


Project development rights(1)
$
4

 
$
(1
)
 
$
3

 
$
28

 
$
(1
)
 
$
27

Sales concessions
71

 
(19
)
 
52

 
86

 
(41
)
 
45

Contractual payment rights(2)
66

 
(46
)
 
20

 
69

 
(40
)
 
29

Management rights
24

 
(10
)
 
14

 
33

 
(13
)
 
20

Land use rights
28

 
—

 
28

 
25

 
—

 
25

Contracts
29

 
(12
)
 
17

 
36

 
(19
)
 
17

Customer contracts and relationships (3)
6

 
(6
)
 
—

 
63

 
(39
)
 
24

Other(4)
15

 
(3
)
 
12

 
22

 
(5
)
 
17

Subtotal
243

 
(97
)
 
146

 
362

 
(158
)
 
204

Indefinite-Lived Intangible Assets


Land use rights
38

 
—

 
38

 
37

 
—

 
37

Water rights
17

 
—

 
17

 
20

 
—

 
20

Other
13

 
—

 
13

 
20

 
—

 
20

Subtotal
68

 
—

 
68

 
77

 
—

 
77

Total
$
311

 
$
(97
)
 
$
214

 
$
439

 
$
(158
)
 
$
281

_____________________________
(1) 
2014 balance includes U.K. Wind operations. In August 2014 these assets were sold, but did not meet the criteria to be reported as discontinued operations and their results are reflected within continuing operations. See Note 24—Dispositions and Held-for-Sale Businesses for further information.
(2) 
Represent legal rights to receive system reliability payments from the regulator.
(3) 
2014 balance includes DPLER which is considered held-for-sale as of December 31, 2015. See Note 24—Dispositions and Held-for-Sale Businesses for further information.
(4) 
Includes renewable energy certificates, emission allowances and various other intangible assets none of which is individually significant.
The following tables summarize, by category, other intangible assets acquired during the period indicated ($ in millions):
 
December 31, 2015
 
Amount
 
Subject to Amortization/Indefinite-Lived
 
Weighted Average Amortization Period (in years)
 
Amortization Method
Contracts
$
22

 
Subject to Amortization
 
5
 
Straight-line
Land-use rights
13

 
Subject to Amortization
 
N/A
 
N/A
Other
5

 
Various
 
N/A
 
N/A
Total
$
40


December 31, 2014
 
Amount
 
Subject to Amortization/
Indefinite-Lived
 
Weighted Average
Amortization Period (in years)
 
Amortization
Method
Renewable energy certificates
$
3

 
Indefinite
 
N/A
 
N/A
Land-use rights
16

 
Subject to Amortization
 
N/A
 
N/A
Total
$
19


The following table summarizes the estimated amortization expense by intangible asset category for 2016 through 2020:
(in millions)
2016
 
2017
 
2018
 
2019
 
2020
Sales concessions
7

 
7

 
7

 
7

 
7

All other
4

 
4

 
4

 
3

 
3

Total
$
11

 
$
11

 
$
11

 
$
10

 
$
10

Intangible asset amortization expense was $25 million, $26 million and $29 million for the years ended December 31, 2015, 2014 and 2013, respectively.

148


THE AES CORPORATION
NOTES TO CONSOLIDATED FINANCIAL STATEMENTS—(Continued)
DECEMBER 31, 2015, 2014, AND 2013

11. REGULATORY ASSETS AND LIABILITIES
The Company has recorded regulatory assets and liabilities (in millions) that it expects to pass through to its customers in accordance with, and subject to, regulatory provisions as follows:
December 31,
2015
 
2014
 
Recovery/Refund Period
REGULATORY ASSETS


Current regulatory assets:


Brazil tariff recoveries:(1)


Energy purchases/sales
$
416

 
$
424

 
Annually as part of the tariff adjustment
Transmission costs, regulatory fees and other
264

 
63

 
Annually as part of the tariff adjustment
El Salvador tariff recoveries(2)
43

 
92

 
Quarterly as part of the tariff adjustment
Other(3) 
23

 
58

 
Various
Total current regulatory assets
746

 
637


Noncurrent regulatory assets:


Defined benefit pension obligations at IPL and DPL(4)(5)
227

 
329

 
Various
Income taxes recoverable from customers(4)(6)
36

 
74

 
Various
Brazil tariff recoveries:(1)


Energy purchases/sales
147

 
266

 
Annually as part of the tariff adjustment
Transmission costs, regulatory fees and other
140

 
14

 
Annually as part of the tariff adjustment
Deferred Midwest ISO costs(7)
129

 
111

 
To be determined
Other(3)
239

 
78

 
Various
Total noncurrent regulatory assets
918

 
872


TOTAL REGULATORY ASSETS
$
1,664

 
$
1,509


REGULATORY LIABILITIES


Current regulatory liabilities:


Brazil tariff reset adjustment(8)
$
—

 
$
76

 
Two years
Efficiency program costs(9)
12

 
22

 
Annually as part of the tariff adjustment
Brazil regulatory asset base adjustment(13)
169

 
123

 
Up to four tariff periods
Brazil tariff refunds:(1)


Energy purchases/sales
105

 
144

 
Annually as part of the tariff adjustment
Transmission costs, regulatory fees and other
120

 
174

 
Annually as part of the tariff adjustment
Other(10) 
59

 
66

 
Various
Total current regulatory liabilities
465

 
605


Noncurrent regulatory liabilities:


Asset retirement obligations(11)
759

 
727

 
Over life of assets
Brazil regulatory asset base adjustment(13)
86

 
61

 
Up to four tariff periods
Brazil special obligations(12)
370

 
484

 
To be determined
Brazil tariff refunds:(1)


Energy purchases/sales
30

 
128

 
Annually as part of the tariff adjustment
Transmission costs, regulatory fees and other
29

 
97

 
Annually as part of the tariff adjustment
Efficiency program costs(9)
5

 
11

 
Annually as part of the tariff adjustment
Other(10) 
7

 
1

 
Various
Total noncurrent regulatory liabilities
1,286

 
1,509


TOTAL REGULATORY LIABILITIES
$
1,751

 
$
2,114


_____________________________
(1)
Recoverable or refundable per Brazilian National Electric Energy Agency ("ANEEL") regulations through the Annual Tariff Adjustment ("IRT"). These costs are generally non-controllable and primarily consist of purchased electricity, energy transmission, and sector costs that are considered volatile. The costs are passed through for a period of 12 months as part of the IRT. Any remaining balance is considered in the subsequent IRT, which results in a total of 24 months to recover or refund the costs. Favorable spot market sales are also subject to customer refunds through the IRT over the course of these time periods.
(2)
Deferred fuel costs incurred by our El Salvador subsidiaries associated with purchase of energy from the El Salvador spot market and power generation plants. In El Salvador, the deferred fuel adjustment represents the variance between the actual fuel costs and the fuel costs recovered in the tariffs. The variance is recovered quarterly in the tariff reset period.
(3)
Includes assets with and without a rate of return. Other current regulatory assets that did not earn a rate of return were $8 million and $22 million, as of December 31, 2015 and 2014, respectively. Other noncurrent regulatory assets that did not earn a rate of return were $237 million and $73 million, as of December 31, 2015 and 2014, respectively. Other current and noncurrent regulatory assets primarily consist of:
▪
Unamortized losses on long-term debt reacquired or redeemed in prior periods at IPL and DPL, which are amortized over the lives of the original issues in accordance with the Federal Energy Regulatory Commission ("FERC") and PUCO rules.
▪
Unamortized carrying charges and certain other costs related to Petersburg unit 4 at IPL.
▪
Deferred storm costs incurred primarily in 2008 to repair storm damage at DPL; recovery was approved via order from the PUCO on December 17, 2014 and began January 2015.
▪
Additional Regulatory Asset Base ("RAB") from a favorable decision on tariff reset (administrative appeal) at Eletropaulo.
(4)
Past expenditures on which the Company does not earn a rate of return.
(5)
The regulatory accounting standards allow the defined pension and postretirement benefit obligation to be recorded as a regulatory asset equal to the previously unrecognized actuarial gains and losses and prior service costs that are expected to be recovered through future rates. Pension expense is recognized based on the plan's actuarially determined pension liability. Recovery of costs is probable, but not yet determined. Pension contributions made by our Brazilian subsidiaries are not included in regulatory assets as those contributions are not covered by the established tariff in Brazil.
(6)
Probable recovery through future rates, based upon established regulatory practices, which permit the recovery of current taxes. This amount is expected to be recovered,

149


THE AES CORPORATION
NOTES TO CONSOLIDATED FINANCIAL STATEMENTS—(Continued)
DECEMBER 31, 2015, 2014, AND 2013

without interest, over the period as book-tax temporary differences reverse and become current taxes.
(7)
Transmission service costs and other administrative costs from IPL's participation in the Midwest ISO market, which are recoverable but do not earn a rate of return. Recovery of costs is probable, but the timing is not yet determined.
(8)
In July 2012, the Brazilian energy regulator (the "Regulator") approved the periodic review and reset of a component of Eletropaulo's regulated tariff, which determines the margin to be earned by Eletropaulo. The review and reset of this tariff component was retroactive to July 2011 and applied to customers' invoices from July 2012 to June 2015. From July 2011 through June 2012, Eletropaulo invoiced customers under the then-existing tariff rate, as required by the Regulator. As the new tariff rate was lower than the previous rate, Eletropaulo was required to reduce customer tariffs for the difference over the next year. Accordingly, from July 2011 through June 2012, Eletropaulo recognized a regulatory liability for the estimated future refunds, subsequently adjusted as of June 30, 2012 upon the finalization of the new tariff with the Regulator. The refund to customers was considered in the 2013 tariff adjustment, which contemplated an amortization of 67.55% from July 4, 2013. The remaining balance, representing 32.45%, was considered in the next annual tariff adjustment. There was no recorded current regulatory liability at Eletropaulo as of December 31, 2015.
(9)
Amounts received for costs expected to be incurred to improve the efficiency of our plants in Brazil as part of the IRT.
(10)
Other current and noncurrent regulatory liabilities primarily consist of liabilities owed to electricity generators due to variance in energy prices during rationing periods ("Free Energy"). Our Brazilian subsidiaries are authorized to refund this cost associated with monthly energy price variances between the wholesale energy market prices owed to the power generation plants producing Free Energy and the capped price reimbursed by the local distribution companies which are passed through to the final customers through energy tariffs. The balance excludes asset retirement obligations that were reclassified out of Other.
(11)
Obligations for removal costs which do not have an associated legal retirement obligation as defined by the accounting standards on asset retirement obligations.
(12)
Obligations established by ANEEL in Brazil associated with electric utility concessions and represent amounts received from customers or donations not subject to return. These donations are allocated to support energy network expansion and to improve utility operations to meet customers' needs. The term of the obligation is established by ANEEL. Settlement shall occur when the concession ends.
(13) 
Represents adjustments to the RAB resulting from an administrative ruling in December 2013 compelling Eletropaulo to refund customers beginning July 2014.
The current regulatory assets and liabilities are recorded in Other current assets and Accrued and other liabilities, respectively, on the accompanying Consolidated Balance Sheets. The noncurrent regulatory assets and liabilities are recorded in Other noncurrent assets and Other noncurrent liabilities, respectively, in the accompanying Consolidated Balance Sheets. The following table summarizes regulatory assets and liabilities by reportable segment in millions as of the periods indicated:
December 31,
2015
 
2014
 
Regulatory Assets
 
Regulatory Liabilities
 
Regulatory Assets
 
Regulatory Liabilities
Brazil SBU
$
971

 
$
932

 
$
787

 
$
1,347

US SBU
650

 
819

 
631

 
767

MCAC SBU (El Salvador)
43

 
—

 
91

 
—

Total
$
1,664

 
$
1,751

 
$
1,509

 
$
2,114

12. DEBT
NON-RECOURSE DEBT — The next table summarizes the carrying amount (in millions) and terms of non-recourse debt as of the periods indicated:
NON-RECOURSE DEBT
Weighted Average Interest Rate
 
Maturity
 
December 31,
2015
 
2014
VARIABLE RATE:(1)


Bank loans
4.37
%
 
2016 – 2033
 
$
2,352

 
$
1,893

Notes and bonds
14.98
%
 
2016 – 2022
 
1,474

 
1,912

Debt to (or guaranteed by) multilateral, export credit agencies or development banks(2)
2.39
%
 
2021 – 2034
 
3,078

 
2,375

Other
12.65
%
 
2016 – 2043
 
47

 
668

FIXED RATE:


Bank loans
5.11
%
 
2016 – 2032
 
558

 
750

Notes and bonds
5.54
%
 
2016 – 2073
 
7,948

 
7,654

Debt to (or guaranteed by) multilateral, export credit agencies or development banks(2)
5.39
%
 
2023 – 2034
 
309

 
259

Other
8.66
%
 
2016 – 2049
 
26

 
89

SUBTOTAL


15,792

 
15,600

Less: Current maturities


(2,529
)
 
(1,982
)
TOTAL


$
13,263

 
$
13,618

(1)
The interest rate on variable rate debt represents the total of a variable component that is based on changes in an interest rate index and of a fixed component. The Company has interest rate swaps and option agreements in an aggregate notional principal amount of approximately $3.2 billion on non-recourse debt outstanding at December 31, 2015. These agreements economically fix the variable component of the interest rates on the portion of the variable-rate debt being hedged so that the total interest rate on that debt has been fixed at rates ranging from approximately 2.87% to 8.24%. These agreements expire at various dates from 2016 through 2033.
(2)
Multilateral loans include loans funded and guaranteed by bilaterals, multilaterals, development banks and other similar institutions.
Non-recourse debt (in millions) as of December 31, 2015 is scheduled to reach maturity as presented in the table below:
December 31,
Annual Maturities
2016
$
2,529

2017
1,022

2018
1,359

2019
950

2020
1,431

Thereafter
8,501

Total non-recourse debt
$
15,792


150


THE AES CORPORATION
NOTES TO CONSOLIDATED FINANCIAL STATEMENTS—(Continued)
DECEMBER 31, 2015, 2014, AND 2013

As of December 31, 2015, AES subsidiaries with facilities under construction had a total of approximately $2.6 billion of committed but unused credit facilities available to fund construction and other related costs. Excluding these facilities under construction, AES subsidiaries had approximately $2.4 billion in a number of available but unused committed credit lines to support their working capital, debt service reserves and other business needs. These credit lines can be used for borrowings, letters of credit, or a combination of these uses.
Significant transactions
During the year ended December 31, 2015, we had the following significant debt transactions at our subsidiaries:
•
Gener issued new debt of $1.1 billion, offset by repayments of $423 million which includes a loss on extinguishment of debt of $19 million;
•
IPALCO issued new debt of $847 million, offset by repayments of $602 million which includes a loss on extinguishment of debt of $22 million;
•
Sul issued new debt of $513 million, offset by repayments of $486 million which includes a loss on extinguishment of debt of $4 million;
•
Eletropaulo issued new debt of $354 million; offset by repayments of $211 million;
•
DPL issued new debt of $325 million; more than offset by repayments of $475 million which includes a loss on extinguishment of debt of $2 million;
•
Panama issued new debt of $300 million, offset by repayments of $287 million which includes a loss on extinguishment of debt of $15 million;
•
Mong Duong drew $203 million under its construction loan facility;
•
Tietê issued new debt of $153 million, more than offset by repayments of $226 million;
•
Andres issued new debt of $180 million, offset by repayments of $176 million which includes a loss on extinguishment of debt of $11 million; and
•
Itabo made repayments of $123 million which includes a loss on extinguishment of debt of $8 million.
Non-Recourse Debt Covenants, Restrictions and Defaults — The terms of the Company's non-recourse debt include certain financial and non-financial covenants. These covenants are limited to subsidiary activity and vary among the subsidiaries. These covenants may include, but are not limited to, maintenance of certain reserves and financial ratios, minimum levels of working capital and limitations on incurring additional indebtedness.
As of December 31, 2015 and 2014, approximately $513 million and $245 million, respectively, of restricted cash was maintained in accordance with certain covenants of the non-recourse debt agreements, and these amounts were included within Restricted cash and Debt service reserves and other deposits in the accompanying Consolidated Balance Sheets.
Various lender and governmental provisions restrict the ability of certain of the Company's subsidiaries to transfer their net assets to the Parent Company. Such restricted net assets of subsidiaries amounted to approximately $2 billion at December 31, 2015.
The following table summarizes the Company's subsidiary non-recourse debt in default (in millions) as of December 31, 2015. Due to the defaults, these amounts are included in the current portion of non-recourse debt:
 
Primary Nature
of Default
 
December 31, 2015
Subsidiary
Default
 
Net Assets
Maritza (Bulgaria)
Covenant
 
$
559

 
$
657

Sul (Brazil)
Covenant
 
333

 
439

Kavarna (Bulgaria)
Covenant
 
140

 
74

Sogrinsk (Kazakhstan)
Covenant
 
$
6

 
8

Total
 
 
$
1,038


As of December 31, 2015, none of the defaults are payment defaults. All of the subsidiary non-recourse defaults were triggered by failure to comply with other covenants and/or conditions such as (but not limited to) failure to meet information covenants, complete construction or other milestones in an allocated time, meet certain minimum or maximum financial ratios, or other requirements contained in the non-recourse debt documents of the applicable subsidiary.
In the event that there is a default, bankruptcy or maturity acceleration at a subsidiary or group of subsidiaries that meets the applicable definition of materiality under the corporate debt agreements of The AES Corporation, there could be a cross-default to the Company's recourse debt. Materiality is defined in the Parent's senior secured credit facility as having provided 20% or more of the Parent Company's total cash distributions from businesses for the four most recently completed fiscal

151


THE AES CORPORATION
NOTES TO CONSOLIDATED FINANCIAL STATEMENTS—(Continued)
DECEMBER 31, 2015, 2014, AND 2013

quarters. As of December 31, 2015, none of the defaults listed above individually or in the aggregate result in or are at risk of triggering a cross-default under the recourse debt of the Parent Company. In the event the Parent Company is not in compliance with the financial covenants of its senior secured revolving credit facility, restricted payments will be limited to regular quarterly shareholder dividends at the then-prevailing rate. Payment defaults and bankruptcy defaults would preclude the making of any restricted payments.
Interest Expense — Interest expense for the year ended December 31, 2015 was reduced by $64 million related to the reversal of a monetary correction previously recognized as interest expense at Eletropaulo. This interest expense was on a contingent regulatory liability that was also reversed in the current period. Interest expense for the year ended December 31, 2014 was reduced by approximately $48 million related to reversing contingent interest accruals associated with disputed purchased energy obligations at Sul for which it was determined, based on developments during 2014, that the likelihood of an unfavorable outcome for the payment of interest on the disputed obligations was no longer probable. Interest expense for the year ended December 31, 2013 was reduced by approximately $34 million related to the recognition of ineffectiveness on derivative interest rate swaps accounted for as cash flow hedges.
RECOURSE DEBT — The table below summarizes the carrying amount (in millions) and terms of recourse debt of the Company as of the periods indicated:
RECOURSE DEBT
Interest Rate
 
Final Maturity
 
December 31, 2015

 
December 31, 2014
Senior Unsecured Note
7.75%
 
2015
 
$
—

 
$
151

Senior Unsecured Note
9.75%
 
2016
 
—

 
164

Senior Unsecured Note
8.00%
 
2017
 
181

 
525

Senior Unsecured Note
LIBOR + 3%
 
2019
 
775

 
775

Senior Unsecured Note
8.00%
 
2020
 
469

 
625

Senior Unsecured Note
7.38%
 
2021
 
1,000

 
1,000

Senior Unsecured Note
4.88%
 
2023
 
750

 
750

Senior Unsecured Note
5.50%
 
2024
 
750

 
750

Senior Unsecured Note
5.50%
 
2025
 
575

 
—

Term Convertible Trust Securities
6.75%
 
2029
 
517

 
517

Unamortized (Discounts)/Premiums


(2
)
 
1

SUBTOTAL


5,015

 
5,258

Less: Current maturities


—

 
(151
)
Total


$
5,015

 
$
5,107

The table below summarizes the principal amounts due, net of unamortized discounts, under our recourse debt for the next five years and thereafter in millions:
December 31,
Net Principal Amounts Due
2016
$
—

2017
181

2018
—

2019
774

2020
469

Thereafter
3,591

Total recourse debt
$
5,015

In April 2015, the Company issued $575 million aggregate principal amount of 5.50% senior notes due 2025. Concurrent with this offering, the Company redeemed via tender offers $344 million aggregate principal of its existing 8.00% senior unsecured notes due 2017, and $156 million of its existing 8.00% senior unsecured notes due 2020. As a result of the latter transaction, the Company recognized a loss on extinguishment of debt of $82 million that is included in the Consolidated Statement of Operations.
In March 2015, the Company redeemed in full the $151 million balance of its 7.75% senior unsecured notes due October 2015 and the $164 million balance of its 9.75% senior unsecured notes due April 2016. As a result of these transactions, the Company recognized a loss on extinguishment of debt of $23 million that is included in the Consolidated Statement of Operations.
In February 2014, the Company redeemed in full the $110 million balance of its 7.75% senior unsecured notes due March 2014. On March 7, 2014, the Company issued $750 million aggregate principal amount of 5.50% senior notes due 2024. Concurrent with this offering, the Company redeemed via tender offers $625 million aggregate principal of its existing 8.00% senior unsecured notes due 2017. As a result of the latter transaction, the Company recognized a loss on extinguishment of debt of $132 million that is included in the Consolidated Statements of Operations.
On May 20, 2014, the Company issued $775 million aggregate principal amount of senior unsecured floating rate notes due June 2019. The notes bear interest at a rate of 3% above three-month LIBOR, reset quarterly. Concurrent with this offering,

152


THE AES CORPORATION
NOTES TO CONSOLIDATED FINANCIAL STATEMENTS—(Continued)
DECEMBER 31, 2015, 2014, AND 2013

the Company repaid $767 million of its existing senior secured term loan due 2018. As a result of the latter transaction, the Company recognized a loss on extinguishment of debt of $10 million that is included in the Consolidated Statement of Operations. On June 16, 2014, the Company repaid in full the remaining balance of approximately $29 million of its senior secured term loan due 2018.
On July 25, 2014, the Company issued two notices to call $320 million aggregate principal amount of unsecured notes, $160 million of which was used to retire notes due in 2015 and $160 million of which was used to retire notes due in 2016. The Company closed these transactions on August 25, 2014. As a result of this transaction, the Company recognized a loss on extinguishment of debt of $40 million that is included in the Consolidated Statement of Operations.
Recourse Debt Covenants and Guarantees — The Company's obligations under the senior secured credit facility are subject to certain exceptions, secured by (i) all of the capital stock of domestic subsidiaries owned directly by the Company and 65% of the capital stock of certain foreign subsidiaries owned directly or indirectly by the Company; and (ii) certain intercompany receivables, certain intercompany notes and certain intercompany tax sharing agreements.
The senior secured credit facility is subject to mandatory prepayment under certain circumstances, including the sale of certain assets. In such a situation, the net cash proceeds from the sale must be applied pro rata to repay the term loan, if any, using 60% of net cash proceeds, reduced to 50% when and if the parent's recourse debt to cash flow ratio is less than 5:1. The lenders have the option to waive their pro rata redemption.
The senior secured credit facility contains customary covenants and restrictions on the Company's ability to engage in certain activities, including, but not limited to, limitations on other indebtedness, liens, investments and guarantees; limitations on restricted payments such as shareholder dividends and equity repurchases; restrictions on mergers and acquisitions, sales of assets, leases, transactions with affiliates and off-balance sheet or derivative arrangements; and other financial reporting requirements.
The senior secured credit facility also contains financial covenants requiring the Company to maintain certain financial ratios including a cash flow to interest coverage ratio, calculated quarterly, which provides that a minimum ratio of the Company's adjusted operating cash flow to the Company's interest charges related to recourse debt of 1.3× must be maintained at all times and a recourse debt to cash flow ratio, calculated quarterly, which provides that the ratio of the Company's total recourse debt to the Company's adjusted operating cash flow must not exceed a maximum of 7.5×.
The terms of the Company's senior unsecured notes and senior secured credit facility contain certain covenants including, without limitation, limitation on the Company's ability to incur liens or enter into sale and leaseback transactions.
TERM CONVERTIBLE TRUST SECURITIES — In 1999, AES Trust III, a wholly-owned special purpose business trust and a VIE, issued approximately 10.35 million of $50 par value Term Convertible Preferred Securities ("TECONS") with a quarterly coupon payment of $0.844 for total proceeds of $517 million and concurrently purchased $517 million of 6.75% Junior Subordinated Convertible Debentures due 2029 (the "6.75% Debentures") issued by AES. The Company consolidates AES Trust III in its consolidated financial statements and classifies the TECONS as recourse debt on its Consolidated Balance Sheet. The Company's obligations under the 6.75% Debentures and other relevant trust agreements, in aggregate, constitute a full and unconditional guarantee by the Company of the TECON Trusts' obligations. As of December 31, 2015 and 2014, the sole assets of AES Trust III are the 6.75% Debentures.
AES, at its option, can redeem the 6.75% Debentures which would result in the required redemption of the TECONS issued by AES Trust III, currently for $50 per TECON. The TECONS must be redeemed upon maturity of the 6.75% Debentures. The TECONS are convertible into the common stock of AES at each holder's option prior to October 15, 2029 at the rate of 1.4216, representing a conversion price of $35.17 per share. The maximum number of shares of common stock AES would be required to issue should all holders decide to convert their securities would be 14.7 million shares.
Dividends on the TECONS are payable quarterly at an annual rate of 6.75%. The Trust is permitted to defer payment of dividends for up to 20 consecutive quarters, provided that the Company has exercised its right to defer interest payments under the corresponding debentures or notes. During such deferral periods, dividends on the TECONS would accumulate quarterly and accrue interest, and the Company may not declare or pay dividends on its common stock. AES has not exercised the option to defer any dividends at this time and all dividends due under the Trust have been paid.
13. COMMITMENTS
LEASES—The Company and its subsidiaries enter into long-term non-cancelable lease arrangements which, for accounting purposes, are classified as either an operating lease or capital lease. Operating leases primarily include certain transmission lines, office rental and site leases. Operating lease rental expense for the years ended December 31, 2015, 2014, and 2013 was $67 million, $58 million and $46 million, respectively. Capital leases primarily include transmission lines at our

153


THE AES CORPORATION
NOTES TO CONSOLIDATED FINANCIAL STATEMENTS—(Continued)
DECEMBER 31, 2015, 2014, AND 2013

subsidiaries in Brazil, vehicles, and office and other operating equipment. Capital leases are recognized in Property, Plant and Equipment within "Electric generation and distribution assets." The gross value of the capital lease assets as of December 31, 2015 and 2014 was $72 million and $80 million, respectively. The table below presents the future minimum lease payments under operating and capital leases for continuing operations together with the present value of the net minimum lease payments under capital leases as of December 31, 2015 for 2016 through 2020 and thereafter, in millions:
 
Future Commitments for
December 31,
Capital Leases
 
Operating Leases
2016
$
14

 
$
77

2017
12

 
78

2018
11

 
79

2019
10

 
80

2020
10

 
79

Thereafter
90

 
898

Total
147

 
$
1,291

Less: Imputed interest
90


Present value of total minimum lease payments
$
57


CONTRACTS — The Company's operating subsidiaries enter into long-term contracts for construction projects, maintenance and service, transmission of electricity, operations services and purchase of electricity and fuel. In general, these contracts are subject to variable quantities or prices and are terminable in limited circumstances only. Electricity purchase contracts primarily include energy auction agreements at our Brazil subsidiaries with extended terms from 2013 through 2028. The table below presents the future minimum commitments for continuing operations under these contracts as of December 31, 2015 for 2016 through 2020 and thereafter. Actual purchases under these contracts for the years ended December 31, 2015, 2014, and 2013 are also presented, in millions:
Actual purchases during the year ended December 31,
Electricity Purchase Contracts
 
Fuel Purchase Contracts
 
Other Purchase Contracts
2013
$
2,665

 
$
1,590

 
$
1,743

2014
3,104

 
1,521

 
1,386

2015
2,592

 
1,262

 
2,121

Future commitments for the year ending December 31,


2016
$
2,623

 
$
1,120

 
$
1,332

2017
2,444

 
835

 
1,047

2018
2,634

 
532

 
1,081

2019
2,799

 
314

 
873

2020
2,918

 
311

 
655

Thereafter
24,176

 
2,141

 
4,395

Total
$
37,594

 
$
5,253

 
$
9,383

14. CONTINGENCIES
Guarantees, Letters of Credit — In connection with certain project financing, acquisition and dispositions, power purchase and other agreements, the Parent Company has expressly undertaken limited obligations and commitments, most of which will only be effective or will be terminated upon the occurrence of future events. In the normal course of business, the Parent Company has entered into various agreements, mainly guarantees and letters of credit, to provide financial or performance assurance to third parties on behalf of AES businesses. These agreements are entered into primarily to support or enhance the creditworthiness otherwise achieved by a business on a stand-alone basis, thereby facilitating the availability of sufficient credit to accomplish their intended business purposes. Most of the contingent obligations relate to future performance commitments which the Company or its businesses expect to fulfill within the normal course of business. The expiration dates of these guarantees vary from less than one year to more than 19 years.
The following table summarizes the Parent Company's contingent contractual obligations as of December 31, 2015. Amounts presented in the table below represent the Parent Company's current undiscounted exposure to guarantees and the range of maximum undiscounted potential exposure. The maximum exposure is not reduced by the amounts, if any, that could be recovered under the recourse or collateralization provisions in the guarantees. The amounts include obligations made by the Parent Company for the direct benefit of the lenders associated with the non-recourse debt of its businesses of $14 million.
Contingent Contractual Obligations
 
Amount
 
Number of Agreements
 
Maximum Exposure Range for Each Agreement
 
 
(in millions)


(in millions)
Guarantees and commitments
 
$
369

 
14
 
$1 - 53
Asset sale related indemnities(1)
 
27

 
1
 
27
Cash collateralized letters of credit
 
32

 
4
 
$1 - 15
Letters of credit under the senior secured credit facility
 
62

 
7
 
<$1 - 29
Total
 
$
490

 
26
 
 
(1) Excludes normal and customary representations and warranties in agreements for the sale of assets (including ownership in associated legal entities) where the associated risk is considered to be nominal.
As of December 31, 2015, the Parent Company had no commitments to invest in subsidiaries under construction and to purchase related equipment that were not included in the letters of credit discussed above. During the year ended December 31, 2015, the Company paid letter of credit fees ranging from 0.2% to 2.5% per annum on the outstanding amounts of letters of credit.
Environmental — The Company periodically reviews its obligations as they relate to compliance with environmental laws, including site restoration and remediation. As of December 31, 2015 and 2014 the Company had recognized liabilities of $10 million and $12 million, respectively, for projected environmental remediation costs. Due to the uncertainties associated with environmental assessment and remediation activities, future costs of compliance or remediation could be higher or lower than the amount currently accrued. Moreover, where no liability has been recognized, it is reasonably possible that the Company may be required to incur remediation costs or make expenditures in amounts that could be material but could not be estimated as of December 31, 2015. In aggregate, the Company estimates that the range of potential losses related to environmental matters, where estimable, to be up to $1 million. The amounts considered reasonably possible do not include amounts accrued as discussed above.
Litigation — The Company is involved in certain claims, suits and legal proceedings in the normal course of business. The Company accrues for litigation and claims when it is probable that a liability has been incurred and the amount of loss can be reasonably estimated. The Company has evaluated claims in accordance with the accounting guidance for contingencies that it deems both probable and reasonably estimable and, accordingly, has recorded aggregate liabilities for all claims of approximately $189 million and $199 million as of December 31, 2015 and 2014, respectively. These amounts are reported on the Consolidated Balance Sheets within Accrued and other liabilities and Other noncurrent liabilities. A significant portion of these accrued liabilities relate to employment, non-income tax and customer disputes in international jurisdictions (principally Brazil). Certain of the Company's subsidiaries, principally in Brazil, are defendants in a number of labor and employment lawsuits. The complaints generally seek unspecified monetary damages, injunctive relief, or other relief. The subsidiaries have denied any liability and intend to vigorously defend themselves in all of these proceedings. There can be no assurance that these accrued liabilities will be adequate to cover all existing and future claims or that we will have the liquidity to pay such claims as they arise.
The Company believes, based upon information it currently possesses and taking into account established accruals for liabilities and its insurance coverage, that the ultimate outcome of these proceedings and actions is unlikely to have a material effect on the Company's consolidated financial statements. However, where no accrued liability has been recognized, it is reasonably possible that some matters could be decided unfavorably to the Company and could require the Company to pay damages or make expenditures in amounts that could be material but could not be estimated as of December 31, 2015. The material contingencies where a loss is reasonably possible primarily include claims under financing agreements; disputes with offtakers, suppliers and EPC contractors; alleged violation of monopoly laws and regulations; income tax and non-income tax matters with tax authorities; and regulatory matters. In aggregate, the Company estimates that the range of potential losses, where estimable, related to these reasonably possible material contingencies to be between $1.1 billion and $1.4 billion. The amounts considered reasonably possible do not include amounts accrued, as discussed above. These material contingencies do not include income tax-related contingencies which are considered part of our uncertain tax positions.
Regulatory — During 2013, the Company recognized a regulatory liability of $269 million for a contingency related to an administrative ruling which required Eletropaulo to refund customers' amounts related to the regulatory asset base. In 2014, Eletropaulo started refunding customers as part of the tariff. In January 2015, ANEEL updated the tariff to exclude any further customer refunds. On June 30, 2015, ANEEL included in the tariff reset the reimbursement to Eletropaulo of these amounts previously refunded to customers to begin in July 2015. During 2015, as a result of favorable events, management reassessed the contingency and determined that it no longer meets the recognition criteria under ASC 450 — Contingencies. Management believes that it is now only reasonably possible that Eletropaulo will have to refund these amounts to customers. Accordingly, the Company reversed the remaining regulatory liability for this contingency of $161 million in 2015, which increased Regulated Revenue by $97 million and reduced Interest Expense by $64 million. Amounts related to this case are now included

154


THE AES CORPORATION
NOTES TO CONSOLIDATED FINANCIAL STATEMENTS—(Continued)
DECEMBER 31, 2015, 2014, AND 2013

as part of our reasonably possible contingent range mentioned in the preceding paragraph.
15. BENEFIT PLANS
Defined Contribution Plan — The Company sponsors four defined contribution plans ("the Plans"). Two are for U.S. non-union employees, of which one is for employees of the Parent Company and certain U.S. SBU businesses and one is for DPL employees. One plan includes both union and non-union employees at IPL. One defined contribution plan is for union employees at DPL. The Plans are qualified under section 401 of the Internal Revenue Code. All U.S. employees of the Company are eligible to participate in the appropriate Plan except for those employees who are covered by a collective bargaining agreement, unless such agreement specifically provides that the employee is considered an eligible employee under a Plan. The Plans provide matching contributions in AES common stock or cash, other contributions at the discretion of the Compensation Committee of the Board of Directors in AES common stock or cash and discretionary tax deferred contributions from the participants. Participants are fully vested in their own contributions and the Company's matching contributions. Participants vest in other company contributions ratably over a five-year period ending on the fifth anniversary of their hire date. For the year ended December 31, 2015, the Company's contributions to the defined contribution plans were approximately $18 million, and for the years ended December 31, 2014 and 2013, contributions were $22 million and $23 million per year, respectively.
Defined Benefit Plans — Certain of the Company's subsidiaries have defined benefit pension plans covering substantially all of their respective employees. Pension benefits are based on years of credited service, age of the participant and average earnings. Of the 33 active defined benefit plans as of December 31, 2015, 5 are at U.S. subsidiaries and the remaining plans are at foreign subsidiaries .
The following table reconciles the Company's funded status, both domestic and foreign, as of the periods indicated:
December 31,
 
2015
 
2014
(in millions)
 
U.S.
 
Foreign
 
U.S.
 
Foreign
CHANGE IN PROJECTED BENEFIT OBLIGATION:


Benefit obligation as of January 1
 
$
1,235

 
$
4,363

 
$
1,059

 
$
4,749

Service cost
 
16

 
15

 
14

 
16

Interest cost
 
48

 
351

 
50

 
489

Employee contributions
 
—

 
3

 
—

 
4

Plan amendments
 
5

 
2

 
8

 
(3
)
Plan settlements
 
(3
)
 
—

 
—

 
—

Benefits paid
 
(61
)
 
(300
)
 
(59
)
 
(415
)
Actuarial (gain) loss
 
(68
)
 
(160
)
 
163

 
87

Effect of foreign currency exchange rate changes
 
—

 
(1,301
)
 
—

 
(564
)
Benefit obligation as of December 31
 
$
1,172

 
$
2,973

 
$
1,235

 
$
4,363

CHANGE IN PLAN ASSETS:


Fair value of plan assets as of January 1
 
$
1,061

 
$
3,272

 
$
941

 
$
3,605

Actual return on plan assets
 
(7
)
 
182

 
123

 
360

Employer contributions
 
31

 
89

 
56

 
135

Employee contributions
 
—

 
3

 
—

 
4

Plan settlements
 
(3
)
 
—

 
—

 
—

Benefits paid
 
(61
)
 
(300
)
 
(59
)
 
(415
)
Effect of foreign currency exchange rate changes
 
—

 
(962
)
 
—

 
(417
)
Fair value of plan assets as of December 31
 
$
1,021

 
$
2,284

 
$
1,061

 
$
3,272

RECONCILIATION OF FUNDED STATUS


Funded status as of December 31
 
$
(151
)
 
$
(689
)
 
$
(174
)
 
$
(1,091
)
The following table summarizes the amounts recognized on the Consolidated Balance Sheets in millions related to the funded status of the plans, both domestic and foreign, as of the periods indicated:
December 31,
 
2015
 
2014
AMOUNTS RECOGNIZED ON THE CONSOLIDATED BALANCE SHEETS
 
U.S.
 
Foreign
 
U.S.
 
Foreign
Noncurrent assets
 
$
—

 
$
67

 
$
—

 
$
51

Accrued benefit liability—current
 
—

 
(5
)
 
—

 
(4
)
Accrued benefit liability—noncurrent
 
(151
)
 
(751
)
 
(174
)
 
(1,138
)
Net amount recognized at end of year
 
$
(151
)
 
$
(689
)
 
$
(174
)
 
$
(1,091
)

155


THE AES CORPORATION
NOTES TO CONSOLIDATED FINANCIAL STATEMENTS—(Continued)
DECEMBER 31, 2015, 2014, AND 2013

The next table summarizes the Company's U.S. and foreign accumulated benefit obligation as of the periods indicated (in millions):
December 31,
2015
 
2014
 
 
U.S.
 
Foreign
 
U.S.
 
Foreign
 
Accumulated Benefit Obligation
$
1,150

 
$
2,931

 
$
1,208

 
$
4,301

 
Information for pension plans with an accumulated benefit obligation in excess of plan assets:


Projected benefit obligation
$
1,172

 
$
2,683

 
$
1,235

 
$
4,021

 
Accumulated benefit obligation
1,150

 
2,656

 
1,208

 
3,979

 
Fair value of plan assets
1,021

 
1,931

 
1,061

 
2,885

 
Information for pension plans with a projected benefit obligation in excess of plan assets:


Projected benefit obligation
$
1,172

 
$
2,697

(1) 
$
1,235

 
$
4,038

(1) 
Fair value of plan assets
1,021

 
1,942

(1) 
1,061

 
2,897

(1) 
(1)
$686 million and $1.1 billion of the total net unfunded projected benefit obligation is due to Eletropaulo in Brazil as of December 31, 2015 and 2014, respectively.
The table below summarizes the significant weighted average assumptions used in the calculation of benefit obligation and net periodic benefit cost, both domestic and foreign, as of the periods indicated:
December 31,
2015
 
2014
 
 
U.S.
 
Foreign
 
U.S.
 
Foreign
 
Benefit Obligation:


Discount rates
4.44
%
 
11.37
%
(2) 
4.04
%
 
10.47
%
(2) 
Rates of compensation increase
3.34
%
(1) 
6.32
%
 
3.94
%
(1) 
6.41
%
 
Periodic Benefit Cost:


Discount rate
4.04
%
 
10.47
%
 
4.89
%
 
10.80
%
 
Expected long-term rate of return on plan assets
6.67
%
 
9.77
%
 
6.92
%
 
10.44
%
 
Rate of compensation increase
3.94
%
(1) 
6.41
%
 
3.94
%
(1) 
6.44
%
 
(1)
A U.S. subsidiary of the Company has defined benefit obligations of $6 million and $748 million as of December 31, 2015 and 2014, respectively, for which salary bands, rather than rates of compensation increases, are used to determine future benefit costs. Rates of compensation increases in the table above do not include amounts related to these specific defined benefit plans. A plan with a defined benefit obligation of $742 million at December 31, 2014 and which used salary bands at that date is using a rate of compensation increase as at December 31, 2015. The rate of compensation increase for this plan is included in the weighted average in the above table for calculating the benefit obligation as at December 31, 2015, but is not included in the weighted average for calculating the benefit obligation as at December 31, 2014 or the periodic benefit cost for 2014 or 2015.
(2) 
Includes an inflation factor that is used to calculate future periodic benefit cost, but is not used to calculate the benefit obligation.
The Company establishes its estimated long-term return on plan assets considering various factors, which include the targeted asset allocation percentages, historic returns and expected future returns.
The measurement of pension obligations, costs and liabilities is dependent on a variety of assumptions. These assumptions include estimates of the present value of projected future pension payments to all plan participants, taking into consideration the likelihood of potential future events such as salary increases and demographic experience. These assumptions may have an effect on the amount and timing of future contributions.
The assumptions used in developing the required estimates include the following key factors: discount rates; salary growth; retirement rates; inflation; expected return on plan assets; and mortality rates.
The effects of actual results differing from the Company's assumptions are accumulated and amortized over future periods and, therefore, generally affect the Company's recognized expense in such future periods.
Effective January 1, 2016 the Company will apply a disaggregated discount rate approach for determining service cost and interest cost for its defined benefit pension plans and post-retirement plans in the U.S. and U.K. Refer to Note 1—General and Summary of Significant Accounting Policies for further information relating to this change in estimate.
Sensitivity of the Company's pension funded status to the indicated increase or decrease in the discount rate and long-term rate of return on plan assets assumptions is shown below. Note that these sensitivities may be asymmetric and are specific to the base conditions at year-end 2015. They also may not be additive, so the impact of changing multiple factors simultaneously cannot be calculated by combining the individual sensitivities shown. The funded status as of December 31, 2015 is affected by the assumptions as of that date. Pension expense for 2015 is affected by the December 31, 2014 assumptions. The impact on pension expense from a one percentage point change in these assumptions is shown in the table below (in millions):
Increase of 1% in the discount rate
 
$
(32
)
Decrease of 1% in the discount rate
 
27

Increase of 1% in the long-term rate of return on plan assets
 
(36
)
Decrease of 1% in the long-term rate of return on plan assets
 
36


156


THE AES CORPORATION
NOTES TO CONSOLIDATED FINANCIAL STATEMENTS—(Continued)
DECEMBER 31, 2015, 2014, AND 2013

The following table summarizes the components of the net periodic benefit cost in millions, both domestic and foreign, for the years indicated:
December 31,
 
2015
 
2014
 
2013
Components of Net Periodic Benefit Cost:
 
U.S.
 
Foreign
 
U.S.
 
Foreign
 
U.S.
 
Foreign
Service cost
 
$
16

 
$
15

 
$
14

 
$
16

 
$
16

 
$
26

Interest cost
 
48

 
351

 
50

 
489

 
46

 
515

Expected return on plan assets
 
(70
)
 
(247
)
 
(67
)
 
(362
)
 
(64
)
 
(484
)
Amortization of prior service cost
 
7

 
—

 
6

 
(1
)
 
5

 
—

Amortization of net loss
 
20

 
28

 
13

 
37

 
23

 
77

Settlement gain recognized
 
—

 
—

 
—

 
1

 
—

 
—

Total pension cost
 
$
21

 
$
147

 
$
16

 
$
180

 
$
26

 
$
134

The following table summarizes in millions the amounts reflected in AOCL including AOCL attributable to noncontrolling interests, on the Consolidated Balance Sheet as of December 31, 2015, that have not yet been recognized as components of net periodic benefit cost and amounts expected to be reclassified to earnings in the next fiscal year:
December 31, 2015
Accumulated Other Comprehensive Income (Loss)
 
Amounts expected to be reclassified to earnings in next fiscal year
 
U.S.
 
Foreign
 
U.S.
 
Foreign
Prior service cost
$
—

 
$
(5
)
 
$
—

 
$
—

Unrecognized net actuarial gain (loss)
(6
)
 
(1,092
)
 
—

 
(18
)
Total
$
(6
)
 
$
(1,097
)
 
$
—

 
$
(18
)
The following table summarizes the Company's target allocation for 2015 and pension plan asset allocation, both domestic and foreign, as of the periods indicated:


Percentage of Plan Assets as of December 31,
 
Target Allocations
 
2015
 
2014
Asset Category
U.S.
 
Foreign
 
U.S.
 
Foreign
 
U.S.
 
Foreign
Equity securities
46
%
 
15% -29%
 
44.76
%
 
13.23
%
 
44.02
%
 
16.28
%
Debt securities
50
%
 
60% - 85%
 
50.05
%
 
81.10
%
 
50.90
%
 
78.85
%
Real estate
2
%
 
0% - 3%
 
2.94
%
 
3.24
%
 
2.45
%
 
3.15
%
Other
2
%
 
0% - 5%
 
2.25
%
 
2.43
%
 
2.63
%
 
1.72
%
Total pension assets


100.00
%
 
100.00
%
 
100.00
%
 
100.00
%
The U.S. plans seek to achieve the following long-term investment objectives:
•
maintenance of sufficient income and liquidity to pay retirement benefits and other lump sum payments;
•
long-term rate of return in excess of the annualized inflation rate;
•
long-term rate of return, net of relevant fees, that meets or exceeds the assumed actuarial rate; and
•
long-term competitive rate of return on investments, net of expenses, that equals or exceeds various benchmark rates.
The asset allocation is reviewed periodically to determine a suitable asset allocation which seeks to manage risk through portfolio diversification and takes into account, among other possible factors, the above-stated objectives, in conjunction with current funding levels, cash flow conditions and economic and industry trends. The following table summarizes the Company's U.S. plan assets by category of investment and level within the fair value hierarchy in millions as of the periods indicated:
 
 
December 31, 2015
 
December 31, 2014
U.S. Plans
 
Level 1
 
Level 2
 
Level 3
 
Total
 
Level 1
 
Level 2
 
Level 3
 
Total
Equity securities —
Mutual funds
457

 
—

 
—

 
457

 
467

 
—

 
—

 
467

Debt securities —
Government debt securities
53

 
—

 
—

 
53

 
67

 
—

 
—

 
67

 
Mutual funds(1)
458

 
—

 
—

 
458

 
473

 
—

 
—

 
473

Real Estate —
Real Estate
—

 
30

 
—

 
30

 
—

 
26

 
—

 
26

Other —
Cash and cash equivalents
—

 
—

 
—

 
—

 
4

 
—

 
—

 
4

 
Other investments
—

 
23

 
—

 
23

 
—

 
24

 
—

 
24

 
Total plan assets
$
968

 
$
53

 
$
—

 
$
1,021

 
$
1,011

 
$
50

 
$
—

 
$
1,061

(1)
Mutual funds categorized as debt securities consist of mutual funds for which debt securities are the primary underlying investment.

157


THE AES CORPORATION
NOTES TO CONSOLIDATED FINANCIAL STATEMENTS—(Continued)
DECEMBER 31, 2015, 2014, AND 2013

The investment strategy of the foreign plans seeks to maximize return on investment while minimizing risk. The assumed asset allocation has less exposure to equities in order to closely match market conditions and near term forecasts. The following table summarizes the Company's foreign plan assets by category of investment and level within the fair value hierarchy in millions as of the periods indicated:
 
 
December 31, 2015
 
December 31, 2014
Foreign Plans
 
Level 1
 
Level 2
 
Level 3
 
Total
 
Level 1
 
Level 2
 
Level 3
 
Total
Equity securities —
Common stock
$
9

 
$
—

 
$
—

 
$
9

 
$
21

 
$
—

 
$
—

 
$
21

 
Mutual funds
167

 
—

 
—

 
167

 
274

 
—

 
—

 
274

 
Private equity(1)
—

 
—

 
126

 
126

 
—

 
—

 
237

 
237

Debt securities —
Certificates of deposit
—

 
2

 
—

 
2

 
—

 
3

 
—

 
3

 
Unsecured debentures
—

 
5

 
—

 
5

 
—

 
10

 
—

 
10

 
Government debt securities
11

 
79

 
—

 
90

 
12

 
98

 
—

 
110

 
Mutual funds(2)
218

 
1,535

 
—

 
1,753

 
215

 
2,236

 
—

 
2,451

 
Other debt securities
—

 
2

 
—

 
2

 
—

 
6

 
—

 
6

Real estate —
Real estate(1)
—

 
—

 
74

 
74

 
—

 
—

 
103

 
103

Other —
Cash and cash equivalents
—

 
—

 
—

 
—

 
1

 
—

 
—

 
1

 
Participant loans(3)
—

 
—

 
37

 
37

 
—

 
—

 
52

 
52

 
Other assets
16

 
—

 
3

 
19

 
—

 
—

 
4

 
4

 
Total plan assets
$
421

 
$
1,623

 
$
240

 
$
2,284

 
$
523

 
$
2,353

 
$
396

 
$
3,272

(1) 
Plan assets of our Brazilian subsidiaries are invested in private equities and commercial real estate through the plan administrator in Brazil. The fair value of these assets is determined using the income approach through annual appraisals based on a discounted cash flow analysis.
(2) 
Mutual funds categorized as debt securities consist of mutual funds for which debt securities are the primary underlying investment.
(3) 
Loans to participants are stated at cost, which approximates fair value.
The following table presents a reconciliation of all plan assets measured at fair value using significant unobservable inputs (Level 3) in millions for the periods indicated:
December 31,
 
2015
 
2014
Balance at January 1
 
$
396

 
$
530

Actual return on plan assets:


Returns relating to assets still held at reporting date
 
(36
)
 
(87
)
Purchases, sales and settlements, net
 
—

 
1

Transfers of (assets) liabilities into Level 3
 
—

 
5

Change due to exchange rate changes
 
(120
)
 
(53
)
Balance at December 31
 
$
240

 
$
396

The following table summarizes the estimated cash flows for U.S. and foreign expected employer contributions and expected future benefit payments, both domestic and foreign in millions:
 
 
U.S.
 
Foreign
Expected employer contribution in 2016
 
$
22

 
$
100

Expected benefit payments for fiscal year ending:


2016
 
65

 
268

2017
 
67

 
277

2018
 
69

 
289

2019
 
71

 
299

2020
 
73

 
309

2021 - 2025
 
380

 
1,686

16. EQUITY
Equity Transactions with Noncontrolling Interests
Brazil Reorganization — In 2015, the Company completed a restructuring of AES Brasiliana. This transaction resulted in no change of ownership or control. The $27 million impact of this equity transaction was recognized in additional paid-in capital.
Gener — On November 18, 2015, the Company sold a 4% stake in AES Gener S.A. ("Gener") through its 99.9% owned subsidiary inversions Cachagua S.p.A ("Cachagua") for $145 million, net of transaction costs. The sale was of previously issued common shares of Gener to certain institutional investors and is not a sale of in-substance real estate. While the sale decreased Parent ownership interest from 70.7% to 66.7%, the Parent continues to retain its controlling financial interest in the subsidiary. The difference of $24 million between the fair value of the consideration received, net of taxes and transaction costs, and the amount by which the NCI is adjusted was recognized in additional paid-in capital. No pretax gain or loss was recognized in net income as a result of this transaction.

158


THE AES CORPORATION
NOTES TO CONSOLIDATED FINANCIAL STATEMENTS—(Continued)
DECEMBER 31, 2015, 2014, AND 2013

Jordan — On March 15, 2015, the Company executed an agreement to sell 40% of its interest in a wholly-owned subsidiary in Jordan that owns a controlling interest in the Jordan IPP4 gas-fired plant for $30 million. The sale was completed on February 18, 2016. See Note 30—Subsequent Events for further information.
IPALCO — In February 2015, La Caisse de depot et placement du Quebec ("CDPQ") purchased 15% of AES US Investment, Inc., a wholly-owned subsidiary that owns 100% of IPALCO Enterprises, Inc. ("IPALCO"), for $247 million, with an option to invest an additional $349 million in IPALCO through 2016 in exchange for a 17.65% equity stake. In April 2015, CDPQ invested $214 million of the $349 million in IPALCO, which resulted in CDPQ's combined equity interest in IPALCO to be 24.90%. Upon investing the remaining commitment of $135 million, CDPQ's equity interests in IPALCO will total 30%.
As a result of these transactions, $84 million in taxes and transaction costs were recognized as a net decrease to equity. The Company also recognized an increase of $377 million to additional paid-in capital and a reduction to retained earnings of $377 million for the excess of the fair value of the shares over their book value. Since the noncontrolling interest is contingently redeemable, the fair value of the consideration received of $460 million, net of proportional dividends, is classified in temporary equity as redeemable stock of subsidiaries on the Consolidated Balance Sheets. No gain or loss was recognized in net income as the sale was not considered to be a sale of in-substance real estate. Any subsequent adjustments to allocate earnings and dividends to CDPQ will be classified as noncontrolling interest within permanent equity and adjustments to the amount in temporary equity will occur only if and when it is probable that the shares will become redeemable. As the Company maintained control after the sale, IPALCO continues to be accounted for as a consolidated subsidiary within the US SBU reportable segment.
Dominican Republic — In December 2014 Estrella and Linda Groups, an investor-based group in the Dominican Republic acquired 8% noncontrolling interest in our businesses in the Dominican Republic for $83 million, net of transaction costs, with options to acquire an additional 2% for $24 million at any time between the closing date and December 31, 2015, and an additional 10% for $125 million at any time between the closing date and December 31, 2016. In December 2015, Estrella and Linda Groups exercised its first call option of additional 2% for $18 million, net of discount and transaction costs. This resulted in Estrella and Linda Groups having a total of 10% noncontrolling interest in our businesses in the Dominican Republic.
As a result of these transactions, $29 million and $7 million, net of taxes and transaction costs, was recognized in additional paid-in capital at December 31, 2014 and 2015, respectively. No gain or loss was recognized in net income as the sale is not considered to be a sale of in-substance real estate. As the Company maintained control after the sale, our businesses in the Dominican Republic continue to be consolidated by the Company within the MCAC SBU reportable segment.
Masinloc — On June 25, 2014, the Company executed an agreement to sell approximately 45% of its interest in Masin-AES Pte Ltd., a wholly-owned subsidiary that owns the Company's business interests in the Philippines, for $453 million, subject to certain purchase price adjustments. On July 15, 2014, the Company completed the Masinloc sale transaction and received cumulative net proceeds of $436 million, including $23 million contingent upon the achievement of certain restructuring efficiencies. The transaction was accounted for as a sale of in-substance real estate. Noncontrolling interest of $130 million and a pretax gain on sale of investment of approximately $283 million, net of transaction costs, were recognized during the third quarter of 2014. The portion of the proceeds related to the contingency has been deferred.
After completion of the sale, the Company owns a 51% net ownership interest in Masinloc and will continue to manage and operate the plant, with 41% owned by Electricity Generating Public Company Limited and 8% owned by the International Finance Corporation. As the Company maintained control after the sale, Masinloc continues to be accounted for as a consolidated subsidiary within the Asia SBU reportable segment.
The following table summarizes the net income attributable to The AES Corporation and all transfers (to) from noncontrolling interests in millions for the periods indicated:
 
 
December 31,
 
 
2015
 
2014
Net income attributable to The AES Corporation
 
$
306

 
$
769

Transfers from the noncontrolling interest:


Net increase in The AES Corporation's paid-in capital for sale of subsidiary shares
 
323

 
29

Additional paid-in capital, IPALCO shares, transferred to redeemable stock of subsidiaries (1)
 
(377
)
 
—

Increase in The AES Corporation's paid-in capital for purchase of subsidiary shares
 
—

 
7

Net transfers (to) from noncontrolling interest
 
(54
)
 
36

Change from net income attributable to The AES Corporation and transfers (to) from noncontrolling interests
 
$
252

 
$
805

(1) See Note 19—Redeemable stock of subsidiaries for further information on increase in paid-in capital transferred to redeemable stock of subsidiaries.

159


THE AES CORPORATION
NOTES TO CONSOLIDATED FINANCIAL STATEMENTS—(Continued)
DECEMBER 31, 2015, 2014, AND 2013

Accumulated Other Comprehensive Loss
The changes in AOCL by component, net of tax and noncontrolling interests in millions for the year ended December 31, 2015 were as follows:
 
Foreign currency translation adjustment, net
 
Unrealized derivative losses, net
 
Unfunded pension obligations, net
 
Total
Balance at the beginning of the period
$
(2,595
)
 
$
(396
)
 
$
(295
)
 
$
(3,286
)
Other comprehensive (loss) income before reclassifications
(674
)
 
(5
)
 
19

 
(660
)
Amount reclassified to earnings
$
—

 
$
48

 
$
2

 
50

Other comprehensive (loss) income
(674
)
 
43

 
21

 
(610
)
Cumulative effect of a change in accounting principle
$
13

 
$
—

 
$
—

 
$
13

Balance at the end of the period
(3,256
)
 
(353
)
 
(274
)
 
(3,883
)
Reclassifications out of AOCL for the periods indicated were as follows (in millions):
Details About


December 31,
AOCL Components
 
Affected Line Item in the Consolidated Statements of Operations
 
2015
 
2014
 
2013
Foreign currency translation adjustment, net


Gain on sale of businesses
 
$
—

 
$
4

 
$
(2
)
 
 
Net loss from disposal and impairments of discontinued operations
 
—

 
(38
)
 
(35
)
 
 
Net income attributable to The AES Corporation
 
$
—

 
$
(34
)
 
$
(37
)
Unrealized derivative gains (losses), net


Non-regulated revenue
 
$
43

 
$
30

 
$
(3
)
 
 
Non-regulated cost of sales
 
(14
)
 
(4
)
 
(7
)
 
 
Interest expense
 
(112
)
 
(139
)
 
(137
)
 
 
Gain on sale of businesses
 
(4
)
 
—

 
(21
)
 
 
Foreign currency transaction gains (losses)
 
12

 
(9
)
 
(6
)
 
 
Income from continuing operations before taxes and equity in earnings of affiliates
 
(75
)
 
(122
)
 
(174
)
 
 
Income tax expense
 
11

 
26

 
41


Net equity in earnings of affiliates
 
(2
)
 
(3
)
 
(6
)
 
 
Income from continuing operations
 
(66
)
 
(99
)
 
(139
)
 
 
Less: (Income) from continuing operations attributable to noncontrolling interests
 
18

 
27

 
11


Net income attributable to The AES Corporation
 
$
(48
)

$
(72
)
 
$
(128
)
Amortization of defined benefit pension actuarial loss, net


Regulated cost of sales
 
$
(25
)
 
$
(33
)
 
$
(73
)
 
 
Non-regulated cost of sales
 
2

 
(5
)
 
(4
)
 
 
General and administrative expenses
 
(2
)
 
—

 
(1
)
 
 
Income from continuing operations before taxes and equity in earnings of affiliates
 
(25
)

(38
)
 
(78
)
 
 
Income tax expense
 
9

 
7

 
26


Income from continuing operations
 
(16
)

(31
)
 
(52
)
 
 
Net loss from disposal and impairments of discontinued operations
 
—

 
2

 
—


Net Income
 
(16
)
 
(29
)
 
(52
)
 
 
Less: (Income) from continuing operations attributable to noncontrolling interests
 
14

 
19

 
39


Net income attributable to The AES Corporation
 
$
(2
)

$
(10
)
 
$
(13
)
Total reclassifications for the period, net of income tax and noncontrolling interests
 
$
(50
)

$
(116
)
 
$
(178
)
_____________________________
(1) 
Amounts in parentheses indicate debits to the Consolidated Statements of Operations.
Common Stock Dividends — The Company paid dividends of $0.10 per outstanding share to its common stockholders during the first, second, third and fourth quarters of 2015 for dividends declared in December 2014, April 2015, July 2015 and October 2015.
On December 11, 2015, the Board of Directors declared a quarterly common stock dividend of $0.11 per share payable on February 16, 2016 to shareholders of record at the close of business on February 2, 2016.
Secondary Offering and Concurrent Stock Repurchase — On May 18, 2015, the Parent Company completed an underwritten secondary public offering (the "Offering") of approximately 60 million shares of its common stock by the Terrific Investment Corporation (the "Selling Stockholder"), a subsidiary controlled by China Investment Corporation at a price of $13.25 per share. Of the 60 million shares, 40 million were sold to the market and 20 million were reserved to be repurchased by the Parent Company. The Parent Company did not receive any of the proceeds from the Offering and the Selling Stockholder has fully sold its stake in AES common stock. Concurrent with this offering, on May 18, 2015, the Parent Company completed the repurchase of the 20 million shares of its common stock from the Selling Stockholder at a price per share of $13.07, for an aggregate purchase price of $261 million.

160


THE AES CORPORATION
NOTES TO CONSOLIDATED FINANCIAL STATEMENTS—(Continued)
DECEMBER 31, 2015, 2014, AND 2013

Stock Repurchase Program — In October 2015, the Company's Board of Directors authorized an increase to the Company's common stock repurchase program (the "Program") for up to an additional $400 million of repurchases of the Company's common stock, bringing the cumulative total of authorized repurchases under the Program to $2.1 billion.
During the year ended December 31, 2015, the Company repurchased 39.7 million shares of its common stock under the Program at a total cost of $482 million under the existing stock repurchase program. The cumulative repurchase from the commencement of the Program in July 2010 through December 31, 2015 totaled 145.6 million shares for a total cost of $1.8 billion, at an average price per share of $12.31 (including a nominal amount of commissions). As of December 31, 2015, $343 million remained available for repurchase under the Program.
The common stock repurchased has been classified as treasury stock and accounted for using the cost method. A total of 149,037,831 and 110,687,849 shares were held as treasury stock at December 31, 2015 and 2014, respectively. Restricted stock units under the Company's employee benefit plans are issued from treasury stock. The Company has not retired any common stock repurchased since it began the Program in July 2010.
17. SEGMENTS AND GEOGRAPHIC INFORMATION
The segment reporting structure uses the Company's organizational structure as its foundation to reflect how the Company manages the businesses internally, and is organized by geographic regions which provide better socio-political-economic understanding of our business. The Company is organized by six SBUs led by our President and Chief Executive Officer: US, Andes, Brazil, MCAC, Europe, and Asia SBUs. Using the accounting guidance on segment reporting, the Company determined that it has six operating and six reportable segments corresponding to its SBUs.
Corporate and Other — Corporate overhead costs which are not directly associated with the operations of our six reportable segments are included in "Corporate and Other." Also included are certain intercompany charges such as self-insurance premiums which are fully eliminated in consolidation.
The Company uses Adjusted PTC as its primary segment performance measure. Adjusted PTC, a non-GAAP measure, is defined by the Company as pretax income from continuing operations attributable to AES excluding unrealized gains or losses related to derivative transactions, unrealized foreign currency gains or losses, gains or losses due to dispositions and acquisitions of business interests, losses due to impairments and costs due to the early retirement of debt. The Company has concluded that Adjusted PTC best reflects the underlying business performance of the Company and is the most relevant measure considered in the Company's internal evaluation of the financial performance of its segments. Additionally, given its large number of businesses and complexity, the Company concluded that Adjusted PTC is a more transparent measure that better assists investors in determining which businesses have the greatest impact on the Company's results.    
Revenue and Adjusted PTC before intersegment eliminations includes the effect of intercompany transactions with other segments except for interest, charges for certain management fees, and the write-off of intercompany balances, as applicable. All intra-segment activity has been eliminated within the segment. Inter-segment activity has been eliminated within the total consolidated results.
The following tables present financial information by segment for the periods indicated (in millions):
Revenue
Year Ended December 31,
Total Revenue
 
Intersegment
 
External Revenue
2015
 
2014
 
2013
 
2015
 
2014
 
2013
 
2015
 
2014
 
2013
US SBU
$
3,593

 
$
3,826

 
$
3,630

 
$
—

 
$
—

 
$
—

 
$
3,593

 
$
3,826

 
$
3,630

Andes SBU
2,489

 
2,642

 
2,639

 
(10
)
 
(4
)
 
(1
)
 
2,479

 
2,638

 
2,638

Brazil SBU
4,666

 
6,009

 
5,015

 
—

 
—

 
—

 
4,666

 
6,009

 
5,015

MCAC SBU
2,353

 
2,682

 
2,713

 
(2
)
 
(2
)
 
(1
)
 
2,351

 
2,680

 
2,712

Europe SBU
1,191

 
1,439

 
1,347

 
(4
)
 
(6
)
 
—

 
1,187

 
1,433

 
1,347

Asia SBU
684

 
558

 
550

 
—

 
—

 
—

 
684

 
558

 
550

Corporate and Other
31

 
15

 
7

 
(28
)
 
(13
)
 
(8
)
 
3

 
2

 
(1
)
Total Revenue
$
15,007

 
$
17,171

 
$
15,901

 
$
(44
)
 
$
(25
)
 
$
(10
)
 
$
14,963

 
$
17,146

 
$
15,891

Adjusted Pretax Contribution
Year Ended December 31,
Total Adjusted PTC
 
Intersegment
 
External Adjusted PTC
2015
 
2014
 
2013
 
2015
 
2014
 
2013
 
2015
 
2014
 
2013
US SBU
$
360

 
$
445

 
440

 
$
12

 
$
10

 
11

 
$
372

 
$
455

 
$
451

Andes SBU
482

 
421

 
353

 
17

 
6

 
19

 
499

 
427

 
372

Brazil SBU
91

 
242

 
212

 
2

 
3

 
3

 
93

 
245

 
215

MCAC SBU
327

 
352

 
339

 
18

 
26

 
12

 
345

 
378

 
351

Europe SBU
235

 
348

 
345

 
5

 
5

 
7

 
240

 
353

 
352

Asia SBU
96

 
46

 
142

 
3

 
2

 
2

 
99

 
48

 
144

Corporate and Other
(441
)
 
(533
)
 
(624
)
 
(57
)
 
(52
)
 
(54
)
 
(498
)
 
(585
)
 
(678
)
Total Adjusted Pretax Contribution
1,150

 
1,321

 
1,207

 
—

 
—

 
—

 
1,150

 
1,321

 
1,207

Reconciliation to Income from Continuing Operations before Taxes and Equity Earnings of Affiliates:
 
 
Non-GAAP Adjustments:


Unrealized derivative gains
166

 
135

 
57

Unrealized foreign currency losses
(96
)
 
(110
)
 
(41
)
Disposition/acquisition gains
42

 
361

 
30

Impairment losses
(504
)
 
(416
)
 
(588
)
Loss on extinguishment of debt
(183
)
 
(274
)
 
(225
)
Pre-tax contribution
575

 
1,017

 
440

Add: Income from continuing operations before taxes, attributable to noncontrolling interests
652

 
578

 
633

Less: Net equity in earnings of affiliates
105

 
19

 
25

Income from continuing operations before taxes and equity in earnings of affiliates
$
1,122

 
$
1,576

 
$
1,048


161


THE AES CORPORATION
NOTES TO CONSOLIDATED FINANCIAL STATEMENTS—(Continued)
DECEMBER 31, 2015, 2014, AND 2013

 
Total Assets
 
Depreciation and Amortization
 
Capital Expenditures
Year Ended December 31,
2015
 
2014
 
2013
 
2015
 
2014
 
2013
 
2015
 
2014
 
2013
US SBU
$
9,844

 
$
10,062

 
$
9,952

 
$
443

 
$
450

 
$
440

 
$
861

 
$
534

 
$
426

Andes SBU
8,744

 
7,888

 
7,356

 
175

 
182

 
186

 
949

 
702

 
471

Brazil SBU
6,422

 
8,439

 
8,388

 
185

 
260

 
259

 
299

 
416

 
588

MCAC SBU
4,830

 
4,948

 
5,075

 
155

 
144

 
145

 
201

 
192

 
111

Europe SBU
3,127

 
3,525

 
4,191

 
134

 
154

 
155

 
118

 
228

 
341

Asia SBU
3,197

 
2,972

 
2,810

 
32

 
32

 
33

 
13

 
429

 
576

Assets held-for-sale
96

 
—

 
1,718

 
—

 
(1
)
 
55

 
—

 
13

 
52

Corporate and Other
590

 
1,132

 
921

 
20

 
24

 
21

 
17

 
30

 
14

Total
$
36,850

 
$
38,966

 
$
40,411

 
$
1,144

 
$
1,245

 
$
1,294

 
$
2,458

 
$
2,544

 
$
2,579

 
Interest Income
 
Interest Expense
Year Ended December 31,
2015
 
2014
 
2013
 
2015
 
2014
 
2013
US SBU
$
—

 
$
—

 
$
—

 
$
262

 
$
285

 
$
290

Andes SBU
77

 
87

 
37

 
154

 
160

 
135

Brazil SBU
299

 
249

 
210

 
349

 
331

 
364

MCAC SBU
30

 
26

 
20

 
179

 
178

 
138

Europe SBU
1

 
1

 
2

 
73

 
98

 
80

Asia SBU
115

 
2

 
6

 
85

 
25

 
30

Corporate and Other
2

 
—

 
—

 
334

 
394

 
445

Total
$
524

 
$
365

 
$
275

 
$
1,436

 
$
1,471

 
$
1,482

 
Investments in and Advances to Affiliates
 
Equity in Earnings (Losses)
Year Ended December 31,
2015
 
2014
 
2013
 
2015
 
2014
 
2013
US SBU
$
1

 
$
1

 
$
1

 
$
—

 
$
—

 
$
—

Andes SBU
345

 
287

 
248

 
83

 
42

 
44

Brazil SBU
—

 
—

 
—

 
—

 
—

 
—

MCAC SBU
—

 
—

 
—

 
—

 
—

 
4

Europe SBU
53

 
54

 
286

 
10

 
(25
)
 
(5
)
Asia SBU
195

 
194

 
186

 
8

 
10

 
10

Corporate and Other
16

 
1

 
289

 
4

 
(8
)
 
(28
)
Total
$
610

 
$
537

 
$
1,010

 
$
105

 
$
19

 
$
25

The table below presents information, by country, about the Company's consolidated operations for each of the three years ended December 31, 2015, 2014, and 2013, and as of December 31, 2015 and 2014 in millions. Revenue is recorded in the country in which it is earned and assets are recorded in the country in which they are located.
 
Revenue
 
Property, Plant & Equipment, net
Year Ended December 31,
2015
 
2014
 
2013
 
2015
 
2014
United States(1)
$
3,597

 
$
3,828

 
$
3,630

 
$
8,028

 
$
7,713

Non-U.S.:


Brazil
4,666

 
6,009

 
5,015

 
3,286

 
4,725

Chile
1,523

 
1,624

 
1,569

 
4,596

 
4,012

El Salvador
736

 
832

 
860

 
318

 
304

Dominican Republic
632

 
802

 
832

 
783

 
702

Colombia
557

 
552

 
523

 
446

 
430

Philippines
406

 
451

 
497

 
736

 
752

Argentina
399

 
463

 
545

 
193

 
222

United Kingdom
396

 
533

 
558

 
191

 
324

Mexico
383

 
434

 
440

 
716

 
733

Bulgaria
382

 
410

 
422

 
1,259

 
1,457

Puerto Rico
302

 
348

 
328

 
599

 
551

Panama
297

 
263

 
250

 
1,028

 
1,030

Jordan
248

 
262

 
142

 
470

 
484

Vietnam(2)
233

 
—

 
—

 
2

 
1,491

Kazakhstan
155

 
161

 
156

 
146

 
206

Sri Lanka
45

 
107

 
53

 
—

 
7

Cameroon(3)
—

 
—

 
—

 
—

 
—

Ukraine(4)
—

 
—

 
—

 
—

 
—

Other Non-U.S. (5)
6

 
67

 
71

 
19

 
8

Total Non-U.S.
11,366

 
13,318

 
12,261

 
14,788

 
17,438

Total
$
14,963

 
$
17,146

 
$
15,891

 
$
22,816

 
$
25,151

(1)
Excludes revenue of $2 million and $23 million for the years ended December 31, 2014 and 2013, respectively, related to Condon and Mid-West Wind, which are reflected as discontinued operations in the accompanying Consolidated Statements of Operations.
(2) 
Property, plant & equipment as of December 31, 2015 includes the impact of adopting ASU No. 2014-05, Service Concession Arrangements, on a modified retrospective basis as of January 1, 2015. See Note 1—General and Summary of Significant Accounting Policies for more information.
(3) 
Excludes revenue of $230 million and $473 million for the years ended December 31, 2014 and 2013, respectively, related to Sonel, which is reflected as discontinued

162


THE AES CORPORATION
NOTES TO CONSOLIDATED FINANCIAL STATEMENTS—(Continued)
DECEMBER 31, 2015, 2014, AND 2013

operations in the accompanying Consolidated Statements of Operations.
(4) 
Excludes revenue of $187 million for the years ended December 31, 2013 related to Kievoblenergo and Rivnooblenergo, which are reflected as discontinued operations in the accompanying Consolidated Statements of Operations.
(5) 
Excludes revenue of $6 million for the years ended December 31, 2013 related to Saurashtra, which is reflected as discontinued operations in the accompanying Consolidated Statements of Operations.
18. SHARE-BASED COMPENSATION
STOCK OPTIONS — AES grants options to purchase shares of common stock under stock option plans to employees and non-employee directors. Under the terms of the plans, the Company may issue options to purchase shares of the Company's common stock at a price equal to 100% of the market price at the date the option is granted. Stock options are generally granted based upon a percentage of an employee's base salary. Stock options issued under these plans in 2015, 2014 and 2013 have a three-year vesting schedule and vest in one-third increments over the three-year period. The stock options have a contractual term of ten years. At December 31, 2015, approximately 16 million shares were remaining for award under the plans. In all circumstances, stock options granted by AES do not entitle the holder the right, or obligate AES, to settle the stock option in cash or other assets of AES.
The following table presents the weighted average fair value of each option grant and the underlying weighted average assumptions, as of the grant date, using the Black-Scholes option-pricing model:
December 31,
 
2015
 
2014
 
2013
Expected volatility
 
25
%
 
24
%
 
23
%
Expected annual dividend yield
 
3
%
 
1
%
 
1
%
Expected option term (years)
 
7

 
6

 
6

Risk-free interest rate
 
1.86
%
 
1.86
%
 
1.13
%
Fair value at grant date
 
$
2.07

 
$
3.26

 
$
2.23

The Company does not discount the grant date fair values to estimate post-vesting restrictions. Post-vesting restrictions include black-out periods when the employee is not able to exercise stock options based on their potential knowledge of information prior to the release of that information to the public.

163


THE AES CORPORATION
NOTES TO CONSOLIDATED FINANCIAL STATEMENTS—(Continued)
DECEMBER 31, 2015, 2014, AND 2013

The following table summarizes the components of stock-based compensation related to employee stock options recognized in the Company's consolidated financial statements in millions:
December 31,
 
2015
 
2014
 
2013
Pretax compensation expense
 
$
3

 
$
3

 
$
2

Tax benefit
 
(1
)
 
(1
)
 
(1
)
Stock options expense, net of tax
 
$
2

 
$
2

 
$
1

Total intrinsic value of options exercised
 
$
1

 
$
1

 
$
5

Total fair value of options vested
 
3

 
2

 
2

Cash received from the exercise of stock options
 
5

 
3

 
13

No cash was used to settle stock options or compensation cost capitalized as part of the cost of an asset for the years ended December 31, 2015, 2014 and 2013. As of December 31, 2015, $4 million of total unrecognized compensation cost related to stock options is expected to be recognized over a weighted average period of 1.8 years.
A summary of the option activity for the year ended December 31, 2015 follows (number of options in thousands, dollars in millions except per option amounts):
 
 
Options
 
Weighted Average Exercise Price
 
Weighted Average Remaining Contractual Term (in years)
 
Aggregate Intrinsic Value
Outstanding at December 31, 2014
 
7,062

 
$
14.83


Exercised
 
(419
)
 
10.76


Forfeited and expired
 
(1,347
)
 
17.49


Granted
 
1,859

 
11.89


Outstanding at December 31, 2015
 
7,155

 
$
13.81

 
6
 
$
1

Vested and expected to vest at December 31, 2015
 
6,771

 
$
13.88

 
5.8
 
$
1

Eligible for exercise at December 31, 2015
 
4,292

 
$
14.70

 
4.1
 
$
1

The aggregate intrinsic value in the table above represents the total pre-tax intrinsic value (the difference between the Company's closing stock price on the last trading day of 2015 and the exercise price, multiplied by the number of in-the-money options) that would have been received by the option holders had all option holders exercised their options on December 31, 2015. The amount of the aggregate intrinsic value will change based on the fair market value of the Company's stock.
The Company initially recognizes compensation cost on the estimated number of instruments for which the requisite service is expected to be rendered. In 2015, AES has estimated a weighted average forfeiture rate of 15.28% for stock options granted in 2015. This estimate will be revised if subsequent information indicates that the actual number of instruments forfeited is likely to differ from previous estimates. Based on the estimated forfeiture rate, the Company expects to expense $3.3 million on a straight-line basis over a three year period (approximately $1.1 million per year) related to stock options granted during the year ended December 31, 2015.
RESTRICTED STOCK
Restricted Stock Units — The Company issues restricted stock units ("RSUs") under its long-term compensation plan. The RSUs are generally granted based upon a percentage of the participant's base salary. The units have a three-year vesting schedule and vest in one-third increments over the three-year period. Units granted prior to 2011 are required to be held for an additional two years before they can be converted into shares, and thus become transferable. There is no such requirement for units granted in 2011 and afterwards. In all circumstances, restricted stock units granted by AES do not entitle the holder the right, or obligate AES, to settle the restricted stock unit in cash or other assets of AES.
For the years ended December 31, 2015, 2014, and 2013, RSUs issued had a grant date fair value equal to the closing price of the Company's stock on the grant date. The Company does not discount the grant date fair values to reflect any post-vesting restrictions. RSUs granted to employees during the years ended December 31, 2015, 2014, and 2013 had grant date fair values per RSU of $12.03, $14.60 and $11.19, respectively.
The following table summarizes the components of the Company's stock-based compensation related to its employee RSUs recognized in the Company's consolidated financial statements in millions:
December 31,
 
2015
 
2014
 
2013
RSU expense before income tax
 
$
13

 
$
12

 
$
12

Tax benefit
 
(3
)
 
(3
)
 
(3
)
RSU expense, net of tax
 
$
10

 
$
9

 
$
9

Total value of RSUs converted (1)
 
$
16

 
$
25

 
$
10

Total fair value of RSUs vested
 
$
12

 
$
13

 
$
12

(1)
Amount represents fair market value on the date of conversion.
There was no cash used to settle RSUs or compensation cost capitalized as part of the cost of an asset for the years ended

164


THE AES CORPORATION
NOTES TO CONSOLIDATED FINANCIAL STATEMENTS—(Continued)
DECEMBER 31, 2015, 2014, AND 2013

December 31, 2015, 2014, and 2013. As of December 31, 2015, $16 million of total unrecognized compensation cost related to RSUs is expected to be recognized over a weighted average period of approximately 1.9 years. There were no modifications to RSU awards during the year ended December 31, 2015.
A summary of the activity of RSUs for the year ended December 31, 2015 follows (number of RSUs in thousands):
 
 
RSUs
 
Weighted Average Grant Date Fair Values
 
Weighted Average Remaining Vesting Term
Nonvested at December 31, 2014
 
1,997

 
$
13.20


Vested
 
(954
)
 
13.01


Forfeited and expired
 
(236
)
 
12.71


Granted
 
1,585

 
12.03


Nonvested at December 31, 2015
 
2,392

 
$
12.55

 
1.7
Vested at December 31, 2015
 
—

 
$
—


Vested and expected to vest at December 31, 2015
 
2,105

 
$
12.55


The Company initially recognizes compensation cost on the estimated number of instruments for which the requisite service is expected to be rendered. In 2015, AES has estimated a weighted average forfeiture rate of 13.53% for RSUs granted in 2015. This estimate will be revised if subsequent information indicates that the actual number of instruments forfeited is likely to differ from previous estimates. Based on the estimated forfeiture rate, the Company expects to expense $16 million on a straight-line basis over a three year period related to RSUs granted during the year ended December 31, 2015.
The table below summarizes the RSUs that vested and were converted during the years ended December 31, 2015, 2014, and 2013 (number of RSUs in thousands):
 
 
2015
 
2014
 
2013
RSUs vested during the year
 
954

 
1,037

 
942

RSUs converted during the year, net of shares withheld for taxes
 
1,238

 
1,734

 
905

Shares withheld for taxes
 
549

 
796

 
407

Performance Stock Units — The Company issues performance stock units ("PSUs") to officers under its long-term compensation plan. PSUs are restricted stock units of which 50% of the units awarded include a market condition and the remaining 50% include a performance condition. Vesting will occur if the applicable continued employment conditions are satisfied and (a) for the units subject to the market condition the Total Stockholder Return ("TSR") on AES common stock exceeds the TSR of the Standard and Poor's 500 Utilities Sector Index over the three-year measurement period beginning on January 1 of the grant year and ending on December 31 of the third year and (b) for the units subject to the performance condition if the Company's actual Adjusted EBITDA meets the performance target over the three-year measurement period beginning on January 1 of the grant year and ending on December 31 of the third year. The market and performance conditions determine the vesting and final share equivalent per PSU and can result in earning an award payout range of 0% to 200%, depending on the achievement. In all circumstances, PSUs granted by AES do not entitle the holder the right, or obligate AES, to settle the restricted stock unit in cash or other assets of AES.
The effect of the market condition on PSUs issued to officers of the Company during 2015 is reflected in the award's fair value on the grant date. The results of the valuation estimated the fair value at $8.22 per share, equating to 69% of the Company's closing stock price on the date of grant. PSUs that included a market condition granted during the year ended December 31, 2015, 2014, and 2013 had a grant date fair value per RSU of $8.22, $15.19 and $13.28, respectively. The fair value of the PSUs with a performance condition had a grant date fair value of $11.89 equal to the closing price of the Company's stock on the grant date. The Company believes that it is probable that the performance condition will be met; this will continue to be evaluated throughout the performance period. If the fair value of the market condition was not applied to PSUs issued to officers, the total grant date fair value of PSUs granted during the year ended December 31, 2015 would have increased by $1.1 million.
Restricted stock units with a market condition awarded to officers of the Company prior to 2011 contained only the market condition measuring the TSR on AES common stock. These units were required to be held for an additional two years subsequent to vesting before they could be converted into shares and become transferable. There is no such requirement for the shares granted during 2011 and afterwards.

165


THE AES CORPORATION
NOTES TO CONSOLIDATED FINANCIAL STATEMENTS—(Continued)
DECEMBER 31, 2015, 2014, AND 2013

The following table summarizes the components of the Company's stock-based compensation related to its PSUs recognized in the Company's consolidated financial statements in millions:
December 31,
 
2015
 
2014
 
2013
PSU expense before income tax
 
$
5

 
$
6

 
$
4

Tax benefit
 
(1
)
 
(2
)
 
(1
)
PSU expense, net of tax
 
$
4


$
4


$
3

Total value of PSUs converted(1)
 
$
1

 
$
4

 
$
—

Total fair value of PSUs vested
 
3

 
1

 
—

(1)
Amount represents fair market value on the date of conversion.
There was no cash used to settle PSUs or compensation cost capitalized as part of the cost of an asset for the years ended December 31, 2015, 2014, and 2013. As of December 31, 2015, $7 million of total unrecognized compensation cost related to PSUs is expected to be recognized over a weighted average period of approximately 1.7 years. There were no modifications to PSU awards during the year ended December 31, 2015.
A summary of the activity of PSUs for the year ended December 31, 2015 follows (number of PSUs in thousands):
 
 
PSUs
 
Weighted Average Grant Date Fair Values
 
Weighted Average Remaining Vesting Term
Nonvested at December 31, 2014
 
1,331

 
$
14.27


Vested
 
(161
)
 
16.73


Forfeited and expired
 
(245
)
 
15.27


Granted
 
626

 
10.06


Nonvested at December 31, 2015
 
1,551

 
$
12.16

 
1.2
Vested at December 31, 2015
 
—

 
$
—


Vested and expected to vest at December 31, 2015
 
1,298

 
11.92


The Company initially recognizes compensation cost on the estimated number of instruments for which the requisite service is expected to be rendered. In 2015, AES has estimated a forfeiture rate of 15.28% for PSUs granted in 2015. This estimate will be revised if subsequent information indicates that the actual number of instruments forfeited is likely to differ from previous estimates. Based on the estimated forfeiture rate, the Company expects to expense $5 million on a straight-line basis over a three year period (approximately $1.8 million per year) related to PSUs granted during the year ended December 31, 2015.
The table below summarizes the PSUs that vested and were converted during the years ended December 31, 2015, 2014, and 2013 (number of PSUs in thousands):
 
 
2015
 
2014
 
2013
PSUs vested during the year
 
161

 
85

 
—

PSUs converted during the year, net of shares withheld for taxes
 
96

 
287

 
—

Shares withheld for taxes
 
65

 
141

 
—

19. REDEEMABLE STOCK OF SUBSIDIARIES
The following table summarizes the Company's redeemable stock of subsidiaries balances as of the periods indicated:
 
 
December 31,
Redeemable stock of subsidiaries (in millions)
 
2015
 
2014
Additional paid-in capital, IPALCO shares
 
$
377

 
$
—

Book value, IPALCO shares - noncontrolling interest
 
83

 
—

Total fair value of consideration received (1)
 
460

 
—

IPL cumulative preferred stock
 
60

 
60

DPL cumulative preferred stock
 
18

 
18

Total cumulative preferred stock of subsidiaries (2)
 
78

 
78

Total redeemable stock of subsidiaries
 
$
538

 
$
78

(1) See Note 16—Equity for further information on IPALCO equity transactions with noncontrolling interests.
(2) Refer below for further information on outstanding shares of cumulative preferred stock of subsidiaries.
Our subsidiaries IPL and DPL had outstanding shares of cumulative preferred stock of $78 million at December 31, 2015 and 2014.
IPL — IPL had $60 million of cumulative preferred stock outstanding at December 31, 2015 and 2014, which represented five series of preferred stock. The total annual dividend requirements were approximately $3 million at December 31, 2015 and 2014. Certain series of the preferred stock were redeemable solely at the option of the issuer at prices between $100 and $118 per share. Holders of the preferred stock are entitled to elect a majority of IPL's board of directors if IPL has not paid dividends

166


THE AES CORPORATION
NOTES TO CONSOLIDATED FINANCIAL STATEMENTS—(Continued)
DECEMBER 31, 2015, 2014, AND 2013

to its preferred stockholders for four consecutive quarters. Based on the preferred stockholders' ability to elect a majority of IPL's board of directors in this circumstance, the redemption of the preferred shares is considered to be not solely within the control of the issuer and the preferred stock is considered temporary equity and presented in the mezzanine level of the Consolidated Balance Sheets in accordance with relevant accounting guidance for noncontrolling interests and redeemable securities.
DPL — DPL had $18 million of cumulative preferred stock outstanding at December 31, 2015 and 2014, which represented three series of preferred stock issued by DP&L, a wholly-owned subsidiary of DPL. The total annual dividend requirements were approximately $1 million at December 31, 2015 and 2014. The DP&L preferred stock may be redeemed at DP&L's option as determined by its board of directors at per-share redemption prices between $101 and $103 per share, plus cumulative preferred dividends. In addition, DP&L's Amended Articles of Incorporation contain provisions that permit preferred stockholders to elect members of the DP&L Board of Directors in the event that cumulative dividends on the preferred stock are in arrears in an aggregate amount equivalent to at least four full quarterly dividends. Based on the preferred stockholders' ability to elect members of DP&L's board of directors in this circumstance, the redemption of the preferred shares is considered to be not solely within the control of the issuer and the preferred stock is considered temporary equity and presented in the mezzanine level of the Consolidated Balance Sheets in accordance with the relevant accounting guidance for noncontrolling interests and redeemable securities.
20. OTHER INCOME AND EXPENSE
Other Income — Other income generally includes gains on asset sales and liability extinguishments, favorable judgments on contingencies, gains on contract terminations, and other income from miscellaneous transactions. The components are summarized as follows (in millions):
Years Ended December 31,
2015
 
2014
 
2013
Contract termination
$
20

 
$
—

 
$
60

Gain on sale of assets
19

 
68

 
12

Allowance for Funds Used During Construction (US Utilities)
17

 
9

 
6

Contingency reversal
—

 
18

 
10

Gain on extinguishment of tax and other liabilities
—

 
—

 
9

Other
27

 
29

 
28

Total other income
$
83

 
$
124

 
$
125

Other Expense — Other expense generally includes losses on asset sales and dispositions, losses on legal contingencies, and losses from other miscellaneous transactions. The components are summarized as follows (in millions):
Years Ended December 31,
2015
 
2014
 
2013
Loss on sale and disposal of assets
$
48

 
$
47

 
$
51

Legal contingency
9

 
11

 
9

Contract termination
—

 
—

 
7

Other
8

 
10

 
9

Total other expense
$
65

 
$
68

 
$
76

21. ASSET IMPAIRMENT EXPENSE
Years ended December 31,
 
2015
 
2014
 
2013
 
 
(in millions)
Kilroot
 
$
121

 
$
—

 
$
—

Buffalo Gap III
 
116

 
—

 
—

U.K. Wind
 
37

 
12

 
—

Ebute
 
—

 
67

 
—

East Bend (DP&L)
 
—

 
12

 
—

Beaver Valley
 
—

 
—

 
46

Conesville (DP&L)
 
—

 
—

 
26

Itabo (San Lorenzo)
 
—

 
—

 
16

Other
 
11

 
—

 
7

Total asset impairment expense
 
$
285

 
$
91

 
$
95

Kilroot — During 2015, the Company tested the recoverability of long-lived assets at Kilroot, a coal- and oil-fired plant in the U.K., when the regulator established lower capacity prices for the Irish Single Electricity Market. The Company determined that the carrying amount of the asset group was not recoverable. The Kilroot asset group was determined to have a fair value of $70 million using the income approach. As a result, the Company recognized asset impairment expense of $121 million. Kilroot is reported in the Europe SBU reportable segment.

167


THE AES CORPORATION
NOTES TO CONSOLIDATED FINANCIAL STATEMENTS—(Continued)
DECEMBER 31, 2015, 2014, AND 2013

Buffalo Gap III — During 2015, the Company tested the recoverability of its long-lived assets at Buffalo Gap III, a wind farm in Texas. Impairment indicators were identified based on a decline in forward power curves coupled with the near term expiration of favorable contracted cash flows. The Company determined that the carrying amount was not recoverable. The Buffalo Gap III asset group was determined to have a fair value of $118 million using the income approach. As a result, the Company recognized asset impairment expense of $116 million. Buffalo Gap III is reported in the US SBU reportable segment.
U.K. Wind (Development Projects) — During 2015, the Company decided to no longer pursue two wind projects in the U.K. based on recent regulatory clarifications specific to these projects, resulting in a full impairment. Impairment indicators were also identified at four other wind projects based on their current development status and a reassessment of the likelihood that each project would be pursued given aviation concerns, regulatory changes, economic considerations and other factors. The Company determined that the carrying amounts of each of these asset groups, which totaled $38 million, were not recoverable. In aggregate, the asset groups were determined to have a fair value of $1 million using the market approach and, as a result, the Company recognized asset impairment expense of $37 million. The U.K. Wind (Development Projects) are reported in the Europe SBU reportable segment.
Ebute — During 2014, the Company identified impairment indicators at Ebute in Nigeria, resulting from the continued lack of gas supply, the increased likelihood of selling the asset group before the end of its useful life, and indications about the potential proceeds that could be received from a future sale. The Company determined that the carrying amount of the asset group was not recoverable. The Company recognized asset impairment of $67 million, which represents the difference between the carrying amount of $103 million and fair value less cost to sell of $36 million. In November 2014, the Company completed the sale of its interest in Ebute. See Note 24—Dispositions for additional details. Prior to its sale, Ebute was reported in the Europe SBU reportable segment.
U.K. Wind (Newfield) — During 2014, the Company tested the recoverability of long-lived assets at its Newfield wind development project in the U.K. after their government refused to grant a permit necessary for the project to continue. The Company determined that the carrying amount of the asset group was not recoverable. The Newfield asset group was determined to have no fair value using the income approach. As a result, the Company recognized asset impairment expense of $12 million. U.K. Wind (Newfield) is reported in the Europe SBU reportable segment.
East Bend (DP&L) — During 2014, the Company identified impairment indicators at East Bend, a coal-fired plant in Ohio jointly owned by DP&L, resulting from the increased likelihood that the asset group would be disposed prior to the end of its useful life. The Company determined that the carrying amount of the asset group was not recoverable. The East Bend asset group was determined to have a fair value of $2 million using the market approach, and the Company recognized asset impairment expense of $12 million. The Company's interest in East Bend was sold in December 2014. Prior to its sale, East Bend was reported in the US SBU reportable segment.
Beaver Valley — During 2013, Beaver Valley, a wholly-owned coal-fired plant in Pennsylvania, entered into an agreement to early terminate its PPA with the offtaker in exchange for a lump-sum payment of $60 million. The termination of the PPA resulted in a significant reduction in the future cash flows of the asset group and was considered an impairment indicator. The carrying amount of the asset group was not recoverable. The carrying amount of the asset group exceeded the fair value of the asset group, resulting in asset impairment expense of $46 million. Beaver Valley is reported in the US SBU reportable segment.
Conesville (DP&L) — During 2013, the Company tested the recoverability of long-lived assets at Conesville, a coal-fired plant in Ohio jointly-owned by DP&L. Gradual decreases in power prices as well as lower estimates of future capacity prices in conjunction with the DP&L reporting unit failing Step 1 of the annual goodwill impairment test were determined to be impairment indicators. The Company performed a long-lived asset impairment test and determined that the carrying amount of the asset group was not recoverable. The Conesville asset group was determined to have zero fair value using discounted cash flows under the income approach. As a result, the Company recognized asset impairment expense of $26 million. Conesville is reported in the US SBU reportable segment.
Itabo (San Lorenzo) — During 2013, the Company tested the recoverability of long-lived assets at San Lorenzo, a LNG fueled plant of Itabo. Itabo was informed by Super-Intendencia de Electridad ("SIE"), the system regulator in the Dominican Republic, that it would not receive capacity revenue going forward. This communication in combination with current adverse market conditions were determined to be an impairment indicator. The Company performed a long-lived asset impairment test considering different scenarios and determined that, based on undiscounted cash flows, the carrying amount of San Lorenzo was not recoverable. The fair value of San Lorenzo was determined using the market approach based on a broker quote and it was determined that its carrying amount of $23 million exceeded the estimated fair value of $7 million. As a result, the Company recognized asset impairment expense of $16 million. Itabo is reported in the MCAC SBU reportable segment.

168


THE AES CORPORATION
NOTES TO CONSOLIDATED FINANCIAL STATEMENTS—(Continued)
DECEMBER 31, 2015, 2014, AND 2013

22. INCOME TAXES
Income Tax Provision — The next table summarizes the expense for income taxes on continuing operations in millions for the periods indicated:
December 31,
 
2015
 
2014
 
2013
Federal —
Current
$
9

 
$
—

 
$
(28
)
 
Deferred
(56
)
 
(121
)
 
(110
)
State —
Current
1

 
1

 
1

 
Deferred
(5
)
 
1

 
1

Foreign —
Current
505

 
457

 
509

 
Deferred
11

 
81

 
(30
)
Total
 
$
465

 
$
419

 
$
343

Effective and Statutory Rate Reconciliation — The following table summarizes a reconciliation of the U.S. statutory federal income tax rate to the Company's effective tax rate, as a percentage of income from continuing operations before taxes for the periods indicated:
December 31,
 
2015
 
2014
 
2013
Statutory Federal tax rate
 
35
 %
 
35
 %
 
35
 %
State taxes, net of Federal tax benefit
 
(5
)%
 
(1
)%
 
(3
)%
Taxes on foreign earnings
 
3
 %
 
(14
)%
 
(4
)%
Valuation allowance
 
(5
)%
 
(1
)%
 
—
 %
Uncertain tax positions
 
—
 %
 
—
 %
 
(5
)%
Bad debt deduction
 
—
 %
 
—
 %
 
(3
)%
Change in tax law
 
—
 %
 
4
 %
 
(1
)%
Goodwill impairment
 
10
 %
 
4
 %
 
12
 %
Other—net
 
3
 %
 
—
 %
 
2
 %
Effective tax rate
 
41
 %
 
27
 %
 
33
 %
Included in the favorable (14)% 2014 taxes on foreign earnings percentage above is approximately (8)% related to the sale of approximately 45% of the Company's interest in Masin AES Pte Ltd., which owns the Company's interests in the Philippines, and the sale of the Company's interests in four U.K. wind projects. Neither of these transactions gave rise to income tax expense.
Income Tax Receivables and Payables — The current income taxes receivable and payable are included in Other Current Assets and Accrued and Other Liabilities, respectively, on the accompanying Consolidated Balance Sheets. The noncurrent income taxes receivable and payable are included in Other Noncurrent Assets and Other Noncurrent Liabilities, respectively, on the accompanying Consolidated Balance Sheets. The next table summarizes the income taxes receivable and payable in millions as of December 31, 2015 and 2014:
 
 
2015
 
2014
Income taxes receivable—current
 
$
167

 
$
217

Total income taxes receivable
 
$
167

 
$
217

Income taxes payable—current
 
$
264

 
$
299

Income taxes payable—noncurrent
 
35

 
2

Total income taxes payable
 
$
299

 
$
301

Deferred Income Taxes — Deferred income taxes reflect the net tax effects of (a) temporary differences between the carrying amounts of assets and liabilities for financial reporting purposes and the amounts used for income tax purposes and (b) operating loss and tax credit carryforwards. These items are stated at the enacted tax rates that are expected to be in effect when taxes are actually paid or recovered.
As of December 31, 2015, the Company had federal net operating loss carryforwards for tax purposes of approximately $3.5 billion expiring in years 2021 to 2034. Approximately $87 million of the net operating loss carryforward related to stock option deductions will be recognized in additional paid-in capital when realized. The Company also had federal general business tax credit carryforwards of approximately $18 million expiring primarily from 2021 to 2035, and federal alternative minimum tax credits of approximately $5 million that carry forward without expiration. The Company had state net operating loss carryforwards as of December 31, 2015 of approximately $8.4 billion expiring in years 2016 to 2035. As of December 31, 2015, the Company had foreign net operating loss carryforwards of approximately $3.5 billion that expire at various times beginning in 2016 and some of which carry forward without expiration, and tax credits available in foreign jurisdictions of approximately $32 million, $24 million of which expire in 2021 and $8 million of which carryforward without expiration.

169


THE AES CORPORATION
NOTES TO CONSOLIDATED FINANCIAL STATEMENTS—(Continued)
DECEMBER 31, 2015, 2014, AND 2013

Valuation allowances decreased $103 million during 2015 to $894 million at December 31, 2015. This net decrease was primarily the result of foreign exchange losses and valuation allowance releases at certain of our Brazil and Vietnam subsidiaries.
Valuation allowances decreased $93 million during 2014 to $997 million at December 31, 2014. This net decrease was primarily the result of valuation allowance activity at certain of our Brazil subsidiaries and the release of valuation allowance against U.S. capital loss carryforwards.
The Company believes that it is more likely than not that the net deferred tax assets as shown below will be realized when future taxable income is generated through the reversal of existing taxable temporary differences and income that is expected to be generated by businesses that have long-term contracts or a history of generating taxable income. The Company continues to monitor the utilization of its deferred tax asset for its U.S. consolidated net operating loss carryforward. Although management believes it is more likely than not that this deferred tax asset will be realized through generation of sufficient taxable income prior to expiration of the loss carryforwards, such realization is not assured.
The following table summarizes the deferred tax assets and liabilities in millions, as of December 31, 2015 and 2014:
 
 
2015
 
2014
Differences between book and tax basis of property
 
$
(2,240
)
 
$
(2,364
)
Other taxable temporary differences
 
(299
)
 
(302
)
Total deferred tax liability
 
(2,539
)
 
(2,666
)
Operating loss carryforwards
 
2,206

 
2,224

Capital loss carryforwards
 
66

 
137

Bad debt and other book provisions
 
191

 
221

Retirement costs
 
149

 
275

Tax credit carryforwards
 
55

 
58

Other deductible temporary differences
 
219

 
363

Total gross deferred tax asset
 
2,886

 
3,278

Less: valuation allowance
 
(894
)
 
(997
)
Total net deferred tax asset
 
1,992

 
2,281

Net deferred tax (liability)
 
$
(547
)
 
$
(385
)
The Company considers undistributed earnings of certain foreign subsidiaries to be indefinitely reinvested outside of the U.S. and, accordingly, no U.S. deferred taxes have been recorded with respect to such earnings in accordance with the relevant accounting guidance for income taxes. Should the earnings be remitted as dividends, the Company may be subject to additional U.S. taxes, net of allowable foreign tax credits. It is not practicable to estimate the amount of any additional taxes which may be payable on the undistributed earnings.
Income from operations in certain countries is subject to reduced tax rates as a result of satisfying specific commitments regarding employment and capital investment. The Company's income tax benefits related to the tax status of these operations are estimated to be $21 million, $38 million and $70 million for the years ended December 31, 2015, 2014 and 2013, respectively. The per share effect of these benefits after noncontrolling interests was $0.02, $0.04 and $0.09 for the years ended December 31, 2015, 2014 and 2013, respectively.
The Company's business in Vietnam began commercial operations in 2015. As part of its power purchase contract with the Vietnam government, the business will be subject to the following reduced income tax rates: 0% for four years, followed by 5% for nine years, followed by 10% for the remaining life of the contract term. See Item 1.—Business—Our Organization and Segments for additional information regarding the power purchase contract.
The benefit related to our operations in Vietnam is estimated to be $8 million for the year ended December 31, 2015. The per share effect of these benefits after noncontrolling interest was $0.01 for the year ended December 31, 2015.
The following table summarizes the income (loss) from continuing operations, before income taxes, net equity in earnings of affiliates and noncontrolling interests in millions, for the years ended December 31, 2015, 2014 and 2013:
 
 
2015
 
2014
 
2013
U.S.
 
$
(612
)
 
$
(560
)
 
$
(575
)
Non-U.S.
 
1,734

 
2,136

 
1,623

Total
 
$
1,122

 
$
1,576

 
$
1,048

Uncertain Tax Positions — Uncertain tax positions have been classified as noncurrent income tax liabilities unless expected to be paid in one year. The Company's policy for interest and penalties related to income tax exposures is to recognize interest and penalties as a component of the provision for income taxes in the Consolidated Statements of Operations.

170


THE AES CORPORATION
NOTES TO CONSOLIDATED FINANCIAL STATEMENTS—(Continued)
DECEMBER 31, 2015, 2014, AND 2013

As of December 31, 2015 and 2014, the total amount of gross accrued income tax related interest included in the Consolidated Balance Sheets was $8 million and $14 million, respectively. The total amount of gross accrued income tax related penalties included in the Consolidated Balance Sheets as of December 31, 2015 and 2014 was $0 million and $1 million, respectively.
The total expense (benefit) for interest related to unrecognized tax benefits for the years ended December 31, 2015, 2014 and 2013 amounted to $0 million, $3 million and $(4) million, respectively. For the years ended December 31, 2015, 2014 and 2013, the total expense (benefit) for penalties related to unrecognized tax benefits amounted to $0 million, $0 million and $(3) million, respectively.
We are potentially subject to income tax audits in numerous jurisdictions in the U.S. and internationally until the applicable statute of limitations expires. Tax audits by their nature are often complex and can require several years to complete. The following is a summary of tax years potentially subject to examination in the significant tax and business jurisdictions in which we operate:
Jurisdiction
 
Tax Years Subject to Examination
Argentina
 
2009-2015
Brazil
 
2010-2015
Chile
 
2012-2015
Colombia
 
2013-2015
Dominican Republic
 
2012-2015
El Salvador
 
2012-2015
Netherlands
 
2013-2015
Philippines
 
2012-2015
United Kingdom
 
2010-2015
United States (Federal)
 
2011-2015
As of December 31, 2015, 2014 and 2013, the total amount of unrecognized tax benefits was $373 million, $395 million and $392 million, respectively. The total amount of unrecognized tax benefits that would benefit the effective tax rate as of December 31, 2015, 2014 and 2013 is $343 million, $366 million and $360 million, respectively, of which $24 million, $24 million and $26 million, respectively, would be in the form of tax attributes that would warrant a full valuation allowance.
The total amount of unrecognized tax benefits anticipated to result in a net decrease to unrecognized tax benefits within 12 months of December 31, 2015 is estimated to be between $15 million and $25 million, primarily relating to statute of limitation lapses and tax exam settlements.
Next is a reconciliation of the beginning and ending amounts of unrecognized tax benefits in millions for the periods indicated:
December 31,
 
2015
 
2014
 
2013
Balance at January 1
 
$
395

 
$
392

 
$
475

Additions for current year tax positions
 
6

 
8

 
7

Additions for tax positions of prior years
 
12

 
14

 
10

Reductions for tax positions of prior years
 
(7
)
 
(2
)
 
(3
)
Effects of foreign currency translation
 
(7
)
 
(3
)
 
—

Settlements
 
(19
)
 
(2
)
 
(65
)
Lapse of statute of limitations
 
(7
)
 
(12
)
 
(32
)
Balance at December 31
 
$
373

 
$
395

 
$
392

The Company and certain of its subsidiaries are currently under examination by the relevant taxing authorities for various tax years. The Company regularly assesses the potential outcome of these examinations in each of the taxing jurisdictions when determining the adequacy of the amount of unrecognized tax benefit recorded. While it is often difficult to predict the final outcome or the timing of resolution of any particular uncertain tax position, we believe we have appropriately accrued for our uncertain tax benefits. However, audit outcomes and the timing of audit settlements and future events that would impact our previously recorded unrecognized tax benefits and the range of anticipated increases or decreases in unrecognized tax benefits are subject to significant uncertainty. It is possible that the ultimate outcome of current or future examinations may exceed our provision for current unrecognized tax benefits in amounts that could be material, but cannot be estimated as of December 31, 2015. Our effective tax rate and net income in any given future period could therefore be materially impacted.
23. DISCONTINUED OPERATIONS
As discussed in Note 1—General and Summary of Significant Accounting Policies, effective July 1, 2014, the Company prospectively adopted ASU No. 2014-08. There have been no businesses classified as discontinued operations subsequent to

171


THE AES CORPORATION
NOTES TO CONSOLIDATED FINANCIAL STATEMENTS—(Continued)
DECEMBER 31, 2015, 2014, AND 2013

this ASU adoption. Discontinued operations prior to adoption of ASU No. 2014-08 include the results of the following businesses:
•
Cameroon (sold in June 2014)
•
Saurashtra (sold in February 2014)
•
U.S. wind projects (sold in January 2014)
•
Poland wind projects (sold in November 2013)
•
Ukraine utilities (sold in April 2013)
The following table summarizes revenue, income from operations, income tax expense, and impairment and loss on disposal of all discontinued operations prior to the adoption of ASU No. 2014-08 for the periods indicated (in millions):
Years Ended December 31,
2014
 
2013
Revenue
$
233

 
$
689

Income (loss) from operations of discontinued businesses, before income tax
$
50

 
$
(3
)
Income tax expense
(23
)
 
(24
)
Income (loss) from operations of discontinued businesses, after income tax
$
27

 
$
(27
)
Net loss from disposal and impairments of discontinued businesses, after income tax
$
(56
)
 
$
(152
)
Cameroon — In September 2013, the Company executed agreements for the sale of its 56% equity interests in three businesses in Cameroon: Sonel, an integrated utility, Kribi, a gas and light fuel oil plant, and Dibamba, a heavy fuel oil plant. The sale was completed in June 2014. Net proceeds from the sale transaction were $200 million, with $156 million received and non-contingent consideration of $44 million to be received in 2016. Between meeting the held-for-sale criteria in September 2013 and completing the sale in June 2014, the Company recognized impairments of $101 million and an additional loss on sale of $7 million. These businesses were previously reported in the Europe SBU reportable segment.
Saurashtra — In October 2013, the Company executed an agreement for the sale of Saurashtra, a wind project in India. The sale transaction was completed in February 2014 and net proceeds of $8 million were received. Saurashtra was previously reported in the Asia SBU reportable segment.
U.S. wind projects — In November 2013, the Company executed an agreement for the sale of its 100% membership interests in three wind projects: Condon in California, Lake Benton I in Minnesota and Storm Lake II in Iowa. Upon meeting the held-for-sale criteria for these three projects, the Company recognized impairment expense of $47 million (of which $7 million was attributable to noncontrolling interests held by tax equity partners) representing the difference between their aggregate carrying amount of $77 million and the fair value less costs to sell of $30 million. The sale transaction closed in January 2014 and net proceeds of $27 million were received. These businesses were previously reported in the US SBU reportable segment.
Under the terms of the sale agreement, the buyer was provided an option to purchase the Company's 100% interest in Armenia Mountain, a wind project in Pennsylvania at a fixed price of $75 million. Approximately $3 million of the $27 million net proceeds was deferred and allocated to this option. The buyer exercised the option in March 2015 and the sale was completed in July 2015. See Note 24—Dispositions and Held-For-Sale Businesses for further information.
Poland wind projects — In November 2013, the Company completed the sale of Poland Wind, a wholly-owned subsidiary with ownership interests ranging between 61%–89% in ten wind development projects. Net proceeds from the sale transaction were $7 million and a loss on disposal of $2 million was recognized. In the third quarter of 2013, the Company recognized impairments of $65 million on these projects when they were classified as held and used. Poland Wind was previously reported in the Europe SBU reportable segment.
Ukraine utilities — In April 2013, the Company completed the sale of its two utility businesses in Ukraine and received net proceeds of $113 million. The Company sold its 89.1% equity interest in Kyivoblenergo and its 84.6% equity interest in Rivneoblenergo. The Company recognized net impairments of $38 million during 2013. These businesses were previously reported in the Europe SBU reportable segment.
24. DISPOSITIONS AND HELD-FOR-SALE BUSINESSES
Dispositions
Armenia Mountain — On July 1, 2015, the Company completed the sale of its interest in Armenia Mountain, a wind project in Pennsylvania. Net proceeds from the sale were $64 million and the Company recognized a pretax gain on sale of $22 million. As Armenia Mountain does not meet the criteria to be reported as a discontinued operation, its results are reflected within continuing operations in the Consolidated Statements of Operations. Excluding the gain on sale, Armenia Mountain's

172


THE AES CORPORATION
NOTES TO CONSOLIDATED FINANCIAL STATEMENTS—(Continued)
DECEMBER 31, 2015, 2014, AND 2013

pretax income attributable to AES was $6 million, $7 million, and $4 million for the years ended December 31, 2015, 2014, and 2013, respectively. Prior to its sale, Armenia Mountain was reported in the US SBU reportable segment. See Note 23 — Discontinued Operations for more information about transactions preceding the sale.
Ebute — On November 20, 2014, the Company completed the sale of its interest in Ebute, which included its 95% interest in AES Nigeria Barge Limited and its 100% interest in AES Nigeria Barge Operations Limited. Proceeds from the sale were $22 million and the Company recognized a $6 million loss on the sale in the fourth quarter of 2014. As Ebute does not meet the criteria to be reported as a discontinued operation, its results are reflected within continuing operations in the Consolidated Statements of Operations. Excluding the loss on sale, Ebute's pretax (loss) attributable to AES was $(27) million and $(29) million for the years ended December 31, 2014 and 2013, respectively. Prior to its sale, Ebute was reported in the Europe SBU reportable segment.
U.K. Wind (Operating Projects) — On August 22, 2014, the Company sold 100% of its interests in four operating wind projects located in the U.K.. Total net proceeds from the sale were $158 million and the Company recognized a pretax gain on sale of $78 million. As these wind projects do not meet the criteria to be reported as discontinued operations, their results are reflected within continuing operations in the Consolidated Statements of Operations. Excluding the gain on sale, the pretax income (loss) attributable to AES for these disposed projects was $(18) million and $3 million for the years ended December 31, 2014 and 2013, respectively. Prior to the sale, U.K. Wind (Operating Projects) were reported in the Europe SBU reportable segment.
Cartagena — On April 26, 2013, the Company sold its remaining interest in Cartagena, a gas-fired generation business in Spain, upon the exercise of a purchase option included in the 2012 sale agreement where the Company sold its majority interest in the business. Net proceeds from the exercise of the option were approximately $24 million and the Company recognized a pretax gain of $20 million during the second quarter of 2013. Prior to its sale, Cartagena was reported in the Europe SBU reportable segment.
Held-For-Sale Businesses
DPLER — In December 2015, the Company executed an agreement for the sale of its ownership interest in DPLER, a competitive retail marketer selling electricity to customers in Ohio. Accordingly, DPLER has been classified as held-for-sale as of December 31, 2015, but does not meet the criteria to be reported as a discontinued operation. DPLER's results are therefore reflected within continuing operations in the Consolidated Statements of Operations. DPLER's pretax income attributable to AES was $11 million, $(129) million and $6 million for the years ended December 31, 2015, 2014 and 2013, respectively. The sale of DPLER was completed on January 1, 2016 and proceeds of $76 million were received on December 31, 2015. The proceeds were classified as restricted cash with a corresponding amount recorded in accrued and other liabilities in the Consolidated Balance Sheet as of December 31, 2015. DPLER is reported in the US SBU reportable segment.
Kelanitissa — In August 2015, the Company executed an agreement for the sale of its 90% ownership interest in Kelanitissa, a diesel-fired generation plant in Sri Lanka. Accordingly, Kelanitissa has been classified as held-for-sale as of December 31, 2015, but does not meet the criteria to be reported as a discontinued operation. Kelanitissa's results are therefore reflected within continuing operations in the Consolidated Statements of Operations. Kelanitissa's pretax income (loss) attributable to AES was $(7) million, $1 million, and $16 million for the years ended December 31, 2015, 2014 and 2013, respectively. The sale of Kelanitissa was completed on January 27, 2016 and proceeds of $18 million were received. Kelanitissa is reported in the Asia SBU reportable segment.
25. ACQUISITIONS
Main Street Power — On February 18, 2015, the Company completed the acquisition of 100% of the common stock of Main Street Power Company, Inc. for approximately $25 million, pursuant to the terms and conditions of a definitive agreement dated January 24, 2015. The purchase consideration was composed of $20 million cash and the fair value of earn-out payments of $5 million. At December 31, 2015, the assets acquired (including $4 million cash) and liabilities assumed at the acquisition date were recorded at fair value based on the final purchase price allocation, which resulted in the recognition of $16 million of goodwill. Subsequent changes to the fair value of earn-out payments will be reflected in earnings.
26. EARNINGS PER SHARE
Basic and diluted earnings per share are based on the weighted-average number of shares of common stock and potential common stock outstanding during the period. Potential common stock, for purposes of determining diluted earnings per share, includes the effects of dilutive restricted stock units, stock options and convertible securities. The effect of such potential common stock is computed using the treasury stock method or the if-converted method, as applicable.
The following table is a reconciliation of the numerator and denominator of the basic and diluted earnings per share

173


THE AES CORPORATION
NOTES TO CONSOLIDATED FINANCIAL STATEMENTS—(Continued)
DECEMBER 31, 2015, 2014, AND 2013

computation for income from continuing operations for the years ended December 31, 2015, 2014 and 2013, where income represents the numerator and weighted-average shares represent the denominator. Values are in millions except per share data:
Year Ended December 31,
2015
 
2014
 
2013
 
Income
 
Shares
 
$ per Share
 
Income
 
Shares
 
$ per Share
 
Income
 
Shares
 
$ per Share
BASIC EARNINGS PER SHARE


Income from continuing operations attributable to The AES Corporation common stockholders
$
306

 
687

 
$
0.45

 
$
789

 
720

 
$
1.10

 
$
284

 
743

 
$
0.38

EFFECT OF DILUTIVE SECURITIES


Stock options
—

 
—

 
—

 
—

 
1

 
—

 
—

 
1

 
—

Restricted stock units
—

 
2

 
(0.01
)
 
—

 
3

 
(0.01
)
 
—

 
4

 
—

DILUTED EARNINGS PER SHARE
$
306

 
689

 
$
0.44

 
$
789

 
724

 
$
1.09

 
$
284

 
748

 
$
0.38

The calculation of diluted earnings per share excluded 8 million, 6 million and 7 million stock awards outstanding for the years ended December 31, 2015, 2014 and 2013, respectively, that could potentially dilute basic earnings per share in the future. Additionally, for the years ended December 31, 2015, 2014 and 2013, all 15 million convertible debentures were omitted from the earnings per share calculation. The stock awards and convertible debentures were excluded from the calculation because they were anti-dilutive.
27. RISKS AND UNCERTAINTIES
AES is a diversified power generation and utility company organized into six market-oriented SBUs. See additional discussion of the Company's principal markets in Note 17—Segment and Geographic Information. Within our six SBUs, we have two primary lines of business: Generation and Utilities. The Generation line of business uses a wide range of fuels and technologies to generate electricity such as coal, gas, hydro, wind, solar and biomass. Our Utilities business is comprised of businesses that transmit, distribute, and in certain circumstances, generate power. In addition, the Company has operations in the renewables area. These efforts include projects primarily in wind and solar.
Operating and Economic Risks — The Company operates in several developing economies where macroeconomic conditions are usually more volatile than developed economies. Deteriorating market conditions often expose the Company to the risk of decreased earnings and cash flows due to, among other factors, adverse fluctuations in the commodities and foreign currency spot markets. Additionally, credit markets around the globe continue to tighten their standards, which could impact our ability to finance growth projects through access to capital markets. Currently, the Company has a below-investment grade rating from Standard & Poor's of BB-. This could affect the Company's ability to finance new and/or existing development projects at competitive interest rates. As of December 31, 2015, the Company had $1.3 billion of unrestricted cash and cash equivalents.
During 2015, 76% of our revenue was generated outside the U.S. and a significant portion of our international operations is conducted in developing countries. We continue to invest in several developing countries to expand our existing platform and operations. International operations, particularly the operation, financing and development of projects in developing countries, entail significant risks and uncertainties, including, without limitation:
•
economic, social and political instability in any particular country or region;
•
inability to economically hedge energy prices;
•
volatility in commodity prices;
•
adverse changes in currency exchange rates;
•
government restrictions on converting currencies or repatriating funds;
•
unexpected changes in foreign laws, regulatory framework, or in trade, monetary or fiscal policies;
•
high inflation and monetary fluctuations;
•
restrictions on imports of coal, oil, gas or other raw materials required by our generation businesses to operate;
•
threatened or consummated expropriation or nationalization of our assets by foreign governments;
•
unwillingness of governments, government agencies, similar organizations or other counterparties to honor their commitments;
•
unwillingness of governments, government agencies, courts or similar bodies to enforce contracts that are economically advantageous to subsidiaries of the Company and economically unfavorable to counterparties, against such counterparties, whether such counterparties are governments or private parties;
•
inability to obtain access to fair and equitable political, regulatory, administrative and legal systems;
•
adverse changes in government tax policy;

174


THE AES CORPORATION
NOTES TO CONSOLIDATED FINANCIAL STATEMENTS—(Continued)
DECEMBER 31, 2015, 2014, AND 2013

•
difficulties in enforcing our contractual rights, enforcing judgments, or obtaining a just result in local jurisdictions; and
•
potentially adverse tax consequences of operating in multiple jurisdictions.
Any of these factors, individually or in combination with others, could materially and adversely affect our business, results of operations and financial condition. In addition, our Latin American operations experience volatility in revenue and earnings which have caused and are expected to cause significant volatility in our results of operations and cash flows. The volatility is caused by regulatory and economic difficulties, political instability, indexation of certain PPAs to fuel prices, and currency fluctuations being experienced in many of these countries; particularly in Argentina, where $124 million in net foreign currency transaction gains were recognized in 2015 primarily from foreign currency derivatives related to government receivables. This volatility reduces the predictability and enhances the uncertainty associated with cash flows from these businesses.
Our inability to predict, influence or respond appropriately to changes in law or regulatory schemes, including any inability to obtain reasonable increases in tariffs or tariff adjustments for increased expenses, could adversely impact our results of operations or our ability to meet publicly announced projections or analysts' expectations. Furthermore, changes in laws or regulations or changes in the application or interpretation of regulatory provisions in jurisdictions where we operate, particularly our Utility businesses where electricity tariffs are subject to regulatory review or approval, could adversely affect our business, including, but not limited to:
•
changes in the determination, definition or classification of costs to be included as reimbursable or pass-through costs;
•
changes in the definition or determination of controllable or noncontrollable costs;
•
adverse changes in tax law;
•
changes in the definition of events which may or may not qualify as changes in economic equilibrium;
•
changes in the timing of tariff increases;
•
other changes in the regulatory determinations under the relevant concessions; or
•
changes in environmental regulations, including regulations relating to GHG emissions in any of our businesses.
Any of the above events may result in lower margins for the affected businesses, which can adversely affect our results of operations.
Foreign Currency Risks — AES operates businesses in many foreign countries and such operations could be impacted by significant fluctuations in foreign currency exchange rates. Fluctuations in currency exchange rate between U.S. Dollar and the following currencies could create significant fluctuations to earnings and cash flows: the Argentine peso, the Brazilian real, the Dominican Republic peso, the Euro, the Chilean peso, the Colombian peso, the Philippine peso and the Kazakhstan tenge.
Argentina — In December 2015, the Argentine government lifted foreign currency controls, which resulted in a depreciation of the Argentine peso against the US dollar by approximately 30%. Over the course of 2015, the Argentinean Peso devalued by approximately 50% against the US dollar. Our businesses in Argentina are dependent on the solvency of the Argentine government with which we have long-term receivables. See Note 7—Financing Receivables for further information on the long-term receivables. Further weakening of the Argentine Peso and local economic activity could cause significant volatility in our results of operations, cash flows, and the value of our assets.
Concentrations — Due to the geographical diversity of its operations, the Company does not have any significant concentration of customers or sources of fuel supply. Several of the Company's generation businesses rely on PPAs with one or a limited number of customers for the majority of, and in some cases all of, the relevant businesses' output over the term of the PPAs. However, no single customer accounted for 10% or more of total revenue in 2015, 2014 or 2013.
The cash flows and results of operations of our businesses depend on the credit quality of their customers and the continued ability of their customers and suppliers to meet their obligations under PPAs and fuel supply agreements. If a substantial portion of the Company's long-term PPAs and/or fuel supply were modified or terminated, the Company would be adversely affected to the extent that it would be unable to replace such contracts at equally favorable terms.
Bulgaria — Maritza, the Company's generation facility in Bulgaria, has experienced ongoing delays in the collection of outstanding receivables as a result of liquidity issues faced by our offtaker, NEK. As of December 31, 2015, Maritza's outstanding accounts receivable were $351 million, of which $307 million were overdue. No allowance has been recognized on the receivables as the Company continues to assert that collection is probable.
The Bulgarian government elected in 2014 has undertaken an initiative to reform its energy sector, which is necessary to restore NEK's liquidity. NEK's credit rating was downgraded and its transmission license was revoked by the Bulgarian Regulator, which are events of default under the PPA and triggered additional events of default by Maritza under the project

175


THE AES CORPORATION
NOTES TO CONSOLIDATED FINANCIAL STATEMENTS—(Continued)
DECEMBER 31, 2015, 2014, AND 2013

debt agreements.
Although Maritza continued to collect overdue receivables throughout 2015, collections continue to be at risk, which could result in an allowance to be recorded against the remaining receivables and exacerbate liquidity problems at Maritza if the situation were to deteriorate significantly.
28. RELATED PARTY TRANSACTIONS
Certain of our businesses in Panama, the Dominican Republic and Kazakhstan are partially owned by governments either directly or through state-owned institutions. In the ordinary course of business, these businesses enter into energy purchase and sale transactions, and transmission agreements with other state-owned institutions which are controlled by such governments. At two of our generation businesses in Mexico, the offtakers exercise significant influence, but not control, through representation on these businesses' Boards of Directors. These offtakers are also required to hold a nominal ownership interest in such businesses. In Chile, we provide capacity and energy under contractual arrangements to our investment which is accounted for under the equity method of accounting. Additionally, the Company provides certain support and management services to several of its affiliates under various agreements.
The Company's Consolidated Statements of Operations included the following transactions with related parties in millions for the periods indicated:
Years Ended December 31,
2015
 
2014
 
2013
Revenue—Non-Regulated
$
1,099

 
$
1,188

 
$
1,110

Cost of Sales—Non-Regulated
330

 
331

 
276

Interest Income
25

 
17

 
20

Interest Expense
33

 
9

 
8

The following table summarizes the balances receivable from and payable to related parties included in the Company's Consolidated Balance Sheets in millions as of the periods indicated:
December 31,
2015
 
2014
Receivables from related parties
$
181

 
$
349

Accounts and notes payable to related parties
524

 
567

China Investment Corporation ("CIC") Transaction — On May 18, 2015, the Parent Company completed the repurchase of 20 million shares of its common stock from Terrific Investment Corporation, at a price per share of $13.07, for an aggregate purchase price of $261 million. Terrific Investment Corporation is a subsidiary controlled by CIC, a previously significant shareholder of The AES corporation. See Note 16—Equity for additional information.
29. SELECTED QUARTERLY FINANCIAL DATA (UNAUDITED)
Quarterly Financial Data — The following tables summarize the unaudited quarterly Condensed Consolidated Statements of Operations for the Company for 2015 and 2014 (amounts in millions, except per share data). Amounts have been restated to reflect discontinued operations in all periods presented and reflect all adjustments necessary in the opinion of management for a fair statement of the results for interim periods.
Quarter Ended 2015
Mar 31
 
June 30
 
Sept 30
 
Dec 31
Revenue
$
3,984

 
$
3,858

 
$
3,721

 
$
3,400

Operating margin
721

 
754

 
673

 
718

Income from continuing operations, net of tax(1)
254

 
264

 
203

 
41

Discontinued operations, net of tax
—

 
—

 
—

 
—

Net income
$
254

 
$
264

 
$
203

 
$
41

Net income (loss) attributable to The AES Corporation
$
142

 
$
69

 
$
180

 
$
(85
)
Basic income (loss) per share:


Income (loss) from continuing operations attributable to The AES Corporation, net of tax
$
0.20

 
$
0.10

 
$
0.27

 
$
(0.13
)
Discontinued operations attributable to The AES Corporation, net of tax
—

 
—

 
—

 
—

Basic income (loss) per share attributable to The AES Corporation
$
0.20

 
$
0.10

 
$
0.27

 
$
(0.13
)
Diluted income (loss) per share:


Income (loss) from continuing operations attributable to The AES Corporation, net of tax
$
0.20

 
$
0.10

 
$
0.26

 
$
(0.13
)
Discontinued operations attributable to The AES Corporation, net of tax
—

 
—

 
—

 
—

Diluted income (loss) per share attributable to The AES Corporation
$
0.20

 
$
0.10

 
$
0.26

 
$
(0.13
)
Dividends declared per common share
$
—

 
$
0.10

 
$
0.10

 
$
0.21


176


THE AES CORPORATION
NOTES TO CONSOLIDATED FINANCIAL STATEMENTS—(Continued)
DECEMBER 31, 2015, 2014, AND 2013

Quarter Ended 2014
Mar 31
 
June 30
 
Sept 30
 
Dec 31
Revenue
$
4,262

 
$
4,311

 
$
4,441

 
$
4,132

Operating margin
794

 
819

 
767

 
708

Income (loss) from continuing operations, net of tax(2,3)
89

 
281

 
508

 
298

Discontinued operations, net of tax
(23
)
 
(6
)
 
—

 
—

Net income (loss)
$
66


$
275


$
508


$
298

Net income (loss) attributable to The AES Corporation
$
(58
)
 
$
133

 
$
488

 
$
206

Basic income (loss) per share:


Income (loss) from continuing operations attributable to The AES Corporation, net of tax
$
(0.07
)
 
$
0.20

 
$
0.68

 
$
0.29

Discontinued operations attributable to The AES Corporation, net of tax
(0.01
)
 
(0.02
)
 
—

 
—

Basic income (loss) per share attributable to The AES Corporation
$
(0.08
)
 
$
0.18

 
$
0.68

 
$
0.29

Diluted income (loss) per share:


Income (loss) from continuing operations attributable to The AES Corporation, net of tax
$
(0.07
)
 
$
0.20

 
$
0.67

 
$
0.29

Discontinued operations attributable to The AES Corporation, net of tax
(0.01
)
 
(0.02
)
 
—

 
—

Diluted income (loss) per share attributable to The AES Corporation
$
(0.08
)
 
$
0.18

 
$
0.67

 
$
0.29

Dividends declared per common share
$
—

 
$
0.05

 
$
0.05

 
$
0.15

(1)
Includes pretax impairment expense of $8 million, $37 million, $231 million and $326 million, for the first, second, third and fourth quarters of 2015, respectively. See Note 9—Other Non-Operating Expense, Note 10—Goodwill and Other Intangible Assets, and Note 21—Asset Impairment Expense for further discussion.
(2) 
Includes a pretax gain of approximately $283 million for the third quarter of 2014 related to the sale of a noncontrolling interest in Masinloc. See Note 16—Equity for further discussion. Includes pretax gain of approximately $78 million for the third quarter of 2014 related to the sale of the U.K. wind projects. See Note 24—Dispositions and Held-for-Sale Businesses for further discussion. Includes pretax interest income of $59 million recognized on FONIVEMEM III receivables at AES Argentina in the fourth quarter of 2014. Also includes a pretax foreign currency derivative gain of $106 million recognized on the FONIVEMEM III receivables in the fourth quarter of 2014. See Note 7—Financing Receivables for further discussion. Includes pretax loss of $41 million recognized in Net equity in earnings of affiliates corresponding to the Company's share of an asset impairment at Elsta in the fourth quarter of 2014. See Note 8—Investments In And Advances To Affiliates for further discussion.
(3) 
Includes pretax impairment expense of $166 million, $107 million, $31 million and $79 million, for the first, second, third and fourth quarters of 2014, respectively. See Note 9—Other Non-Operating Expense, Note 10—Goodwill and Other Intangible Assets, and Note 21—Asset Impairment Expense for further discussion.
30. SUBSEQUENT EVENTS
Stock Repurchase Program — Subsequent to December 31, 2015, the Parent Company repurchased an additional 8.7 million shares at a cost of $79 million, bringing the cumulative repurchases total from July 2010 through February 23, 2016 to 154.3 million shares for a total cost of $1.9 billion, at an average price per share of $12.12 (including a nominal amount of commissions). As of February 23, 2016, $264 million remains available under the Program. See Note 16—Equity for additional information regarding the Company's common stock repurchase program.
DPLER — On December 29, 2015, the Company entered into an agreement for the sale of DPLER. This transaction closed January 1, 2016. See Note 24—Dispositions and Held-for-Sale Businesses for further information.
Recourse Debt — Subsequent to December 31, 2015, the Parent Company repurchased $125 million of its outstanding senior notes.
Kelanitissa — On January 27, 2016, the Company completed the sale of Kelanitissa for $18 million. See Note 24—Dispositions and Held-For-Sale Businesses for additional information. The Company expects to recognize an immaterial loss on this transaction during the first quarter of 2016.
IPP4 — On February 18, 2016, the Company completed the sale of a noncontrolling interest in its Jordan IPP4 gas-fired plant for $21 million. Upon completion of the sale, the Company continues to hold a 36% ownership interest in IPP4 and will continue to manage and operate the plant. IPP4 is reported in the Europe SBU reportable segment.

177


ITEM 9. CHANGES IN AND DISAGREEMENTS WITH ACCOUNTANTS ON ACCOUNTING AND FINANCIAL DISCLOSURE
None.
ITEM 9A.    CONTROLS AND PROCEDURES
Conclusion Regarding the Effectiveness of Disclosure Controls and Procedures
The Company maintains disclosure controls and procedures that are designed to ensure that information required to be disclosed in the reports that the Company files or submits under the Securities Exchange Act of 1934, as amended (the "Exchange Act") is recorded, processed, summarized and reported within the time periods specified in the SEC's rules and forms, and that such information is accumulated and communicated to the CEO and CFO, as appropriate, to allow timely decisions regarding required disclosures.
The Company carried out the evaluation required by Rules 13a-15(b) and 15d-15(b), under the supervision and with the participation of our management, including the CEO and CFO, of the effectiveness of our “disclosure controls and procedures” (as defined in the Exchange Act Rules 13a-15(e) and 15d-15(e)). Based upon this evaluation, the CEO and CFO concluded that as of December 31, 2015, our disclosure controls and procedures were effective.
Management's Report on Internal Control over Financial Reporting
Management of the Company is responsible for establishing and maintaining adequate internal control over financial reporting, as defined in Rule 13a-15(f) under the Exchange Act. The Company's internal control over financial reporting is a process designed to provide reasonable assurance regarding the reliability of financial reporting and the preparation of financial statements for external purposes in accordance with GAAP and includes those policies and procedures that:
•
pertain to the maintenance of records that in reasonable detail, accurately and fairly reflect the transactions and dispositions of the assets of the Company;
•
provide reasonable assurance that transactions are recorded as necessary to permit preparation of financial statements in accordance with GAAP, and that receipts and expenditures of the Company are being made only in accordance with authorizations of management and directors of the Company; and
•
provide reasonable assurance that unauthorized acquisition, use or disposition of the Company's assets that could have a material effect on the financial statements are prevented or detected timely.
Management, including our CEO and CFO, does not expect that our internal controls will prevent or detect all errors and all fraud. A control system, no matter how well designed and operated, can provide only reasonable, not absolute, assurance that the objectives of the control system are met. Further, the design of a control system must reflect the fact that there are resource constraints, and the benefits of controls must be considered relative to their costs. In addition, any evaluation of the effectiveness of controls is subject to risks that those internal controls may become inadequate in future periods because of changes in business conditions, or that the degree of compliance with the policies or procedures deteriorates.
Management assessed the effectiveness of our internal control over financial reporting as of December 31, 2015. In making this assessment, management used the criteria established in Internal Control—Integrated Framework issued by the Committee of Sponsoring Organizations of the Treadway Commission ("COSO") in 2013. Based on this assessment, management believes that the Company maintained effective internal control over financial reporting as of December 31, 2015.
The effectiveness of the Company's internal control over financial reporting as of December 31, 2015, has been audited by Ernst & Young LLP, an independent registered public accounting firm, as stated in their report, which appears herein.
Changes in Internal Control Over Financial Reporting:
There were no changes that occurred during the quarter ended December 31, 2015 that have materially affected, or are reasonably likely to materially affect, our internal control over financial reporting.


178


REPORT OF INDEPENDENT REGISTERED PUBLIC ACCOUNTING FIRM

The Board of Directors and Stockholders of The AES Corporation:
We have audited The AES Corporation's internal control over financial reporting as of December 31, 2015, based on criteria established in Internal Control-Integrated Framework issued by the Committee of Sponsoring Organizations of the Treadway Commission (2013 Framework) (the COSO criteria). The AES Corporation's management is responsible for maintaining effective internal control over financial reporting, and for its assessment of the effectiveness of internal control over financial reporting included in the accompanying Management's Report on Internal Control over Financial Reporting. Our responsibility is to express an opinion on the Company's internal control over financial reporting based on our audit.
We conducted our audit in accordance with the standards of the Public Company Accounting Oversight Board (United States). Those standards require that we plan and perform the audit to obtain reasonable assurance about whether effective internal control over financial reporting was maintained in all material respects. Our audit included obtaining an understanding of internal control over financial reporting, assessing the risk that a material weakness exists, testing and evaluating the design and operating effectiveness of internal control based on the assessed risk, and performing such other procedures as we considered necessary in the circumstances. We believe that our audit provides a reasonable basis for our opinion.
A company's internal control over financial reporting is a process designed to provide reasonable assurance regarding the reliability of financial reporting and the preparation of financial statements for external purposes in accordance with generally accepted accounting principles. A company's internal control over financial reporting includes those policies and procedures that (1) pertain to the maintenance of records that, in reasonable detail, accurately and fairly reflect the transactions and dispositions of the assets of the company; (2) provide reasonable assurance that transactions are recorded as necessary to permit preparation of financial statements in accordance with generally accepted accounting principles, and that receipts and expenditures of the company are being made only in accordance with authorizations of management and directors of the company; and (3) provide reasonable assurance regarding prevention or timely detection of unauthorized acquisition, use, or disposition of the company's assets that could have a material effect on the financial statements.
Because of its inherent limitations, internal control over financial reporting may not prevent or detect misstatements. Also, projections of any evaluation of effectiveness to future periods are subject to the risk that controls may become inadequate because of changes in conditions, or that the degree of compliance with the policies or procedures may deteriorate.
In our opinion, The AES Corporation maintained, in all material respects, effective internal control over financial reporting as of December 31, 2015, based on the COSO criteria.
We also have audited, in accordance with the standards of the Public Company Accounting Oversight Board (United States), the consolidated balance sheets of The AES Corporation as of December 31, 2015 and 2014, and the related consolidated statements of operations, comprehensive income, changes in equity, and cash flows for each of the three years in the period ended December 31, 2015 of The AES Corporation and our report dated February 23, 2016 expressed an unqualified opinion thereon.
/s/ Ernst & Young LLP

McLean, Virginia
February 23, 2016

ITEM 9B. OTHER INFORMATION
None.

179


PART III
ITEM 10.
DIRECTORS, EXECUTIVE OFFICERS AND CORPORATE GOVERNANCE
The following information is incorporated by reference from the Registrant's Proxy Statement for the Registrant's 2015 Annual Meeting of Stockholders which the Registrant expects will be filed on or around March 7, 2016 (the "2016 Proxy Statement"):
•
information regarding the directors required by this item found under the heading Board of Directors;
•
information regarding AES's Code of Ethics found under the heading AES Code of Business Conduct and Corporate Governance Guidelines;
•
information regarding compliance with Section 16 of the Exchange Act required by this item found under the heading Governance Matters—Section 16(a) Beneficial Ownership Reporting Compliance; and
•
information regarding AES's Financial Audit Committee found under the heading The Committees of the Board—Financial Audit Committee (the “Audit Committee”).
Certain information regarding executive officers required by this Item is presented as a supplementary item in Part I hereof (pursuant to Instruction 3 to Item 401(b) of Regulation S-K). The other information required by this Item, to the extent not included above, will be contained in our 2016 Proxy Statement and is herein incorporated by reference.
ITEM 11.
EXECUTIVE COMPENSATION
The following information is contained in the 2016 Proxy Statement and is incorporated by reference: the information regarding executive compensation contained under the heading Compensation Discussion and Analysis and the Compensation Committee Report on Executive Compensation under the heading Report of the Compensation Committee.
ITEM 12.
SECURITY OWNERSHIP OF CERTAIN BENEFICIAL OWNERS AND MANAGEMENT AND RELATED STOCKHOLDER MATTERS
(a)
Security Ownership of Certain Beneficial Owners.
See the information contained under the caption “Security Ownership of Certain Beneficial Owners, Directors, and Executive Officers” of the 2016 Proxy Statement, which information is incorporated herein by reference.
(b)
Security Ownership of Directors and Executive Officers.
See the information contained under the caption “Security Ownership of Certain Beneficial Owners, Directors, and Executive Officers” of the 2016 Proxy Statement, which information is incorporated herein by reference.
(c)
Changes in Control.
None.
(d)
Securities Authorized for Issuance under Equity Compensation Plans.
The following table provides information about shares of AES common stock that may be issued under AES' equity compensation plans, as of December 31, 2015:
Securities Authorized for Issuance under Equity Compensation Plans (As of December 31, 2015)
 
(a)
 
(b)
 
(c)
Plan category
Number of securities to be issued upon exercise of outstanding options, warrants and rights
 
Weighted average exercise price of outstanding options, warrants and rights
 
Number of securities remaining available for future issuance under equity compensation plans (excluding securities reflected in column (a))
Equity compensation plans approved by security holders(1)
14,101,219

(2) 
$
13.81

 
15,986,481

Equity compensation plans not approved by security holders
—

 
$
—

 
—

Total
14,101,219

 
$
13.81

 
15,986,481

(1)
The following equity compensation plans have been approved by the Company's Stockholders:
(A) 
The AES Corporation 2003 Long Term Compensation Plan was adopted in 2003 and provided for 17,000,000 shares authorized for issuance thereunder. In 2008, an amendment to the Plan to provide an additional 12,000,000 shares was approved by AES's stockholders, bringing the total authorized shares to 29,000,000. In 2010, an additional amendment to the Plan to provide an additional 9,000,000 shares was approved by AES's stockholders, bringing the total authorized shares to 38,000,000. In 2015, an additional amendment to the Plan to provide an additional 7,750,000 shares was approved by AES's stockholders, bringing the total authorized shares to 45,750,000. The weighted average exercise price of Options outstanding under this plan included in Column (b) is $13.79 (excluding performance stock units, restricted stock units and director stock units), with 15,986,481 shares available for future issuance).
(B) 
The AES Corporation 2001 Plan for outside directors adopted in 2001 provided for 2,750,000 shares authorized for issuance. The weighted average exercise price of Options outstanding under this plan included in Column (b) is $19.58. In conjunction with the 2010 amendment to the 2003 Long

180


Term Compensation plan, ongoing award issuance from this plan was discontinued in 2010. Any remaining shares under this plan, which are not reserved for issuance under outstanding awards, are not available for future issuance and thus the amount of 2,069,035 shares is not included in Column (c) above.
(C) 
The AES Corporation Second Amended and Restated Deferred Compensation Plan for directors provided for 2,000,000 shares authorized for issuance. Column (b) excludes the Director stock units granted thereunder. In conjunction with the 2010 amendment to the 2003 Long Term Compensation Plan, ongoing award issuance from this plan was discontinued in 2010 as Director stock units will be issued from the 2003 Long Term Compensation Plan. Any remaining shares under this plan, which are not reserved for issuance under outstanding awards, are not available for future issuance and thus the amount of 105,341 shares is not included in Column (c) above.
(2) 
Includes 5,494,311 (of which 1,067,734 are vested and 4,426,577 are unvested) shares underlying PSU and RSU awards (assuming performance at a maximum level), 1,451,533 shares underlying Director stock unit awards, and 7,155,375 shares issuable upon the exercise of Stock Option grants, for an aggregate number of 14,101,219 shares.
ITEM 13. CERTAIN RELATIONSHIPS AND RELATED PARTY TRANSACTIONS, AND DIRECTOR INDEPENDENCE
The information regarding related party transactions required by this item is included in the 2016 Proxy Statement found under the headings Transactions with Related Persons, Proposal I: Election of Directors and The Committees of the Board and are incorporated herein by reference.
ITEM 14.
PRINCIPAL ACCOUNTANT FEES AND SERVICES
The information concerning principal accountant fees and services included in the 2016 Proxy Statement contained under the heading Information Regarding The Independent Registered Public Accounting Firm's Fees, Services and Independence and is incorporated herein by reference.

181


PART IV
ITEM 15.
EXHIBITS AND FINANCIAL STATEMENT SCHEDULES
(a)
Financial Statements.
Financial Statements and Schedules:
 
Page


S-2-S-7
(b)
Exhibits.
3.1
 
Sixth Restated Certificate of Incorporation of The AES Corporation is incorporated herein by reference to Exhibit 3.1 of the Company's Form 10-K for the year ended December 31, 2008.
3.2
 
By-Laws of The AES Corporation, as amended and incorporated herein by reference to Exhibit 3.1 of the Company's Form 8-K/A filed on December 2, 2015.
4
 
There are numerous instruments defining the rights of holders of long-term indebtedness of the Registrant and its consolidated subsidiaries, none of which exceeds ten percent of the total assets of the Registrant and its subsidiaries on a consolidated basis. The Registrant hereby agrees to furnish a copy of any of such agreements to the Commission upon request. Since these documents are not required filings under Item 601 of Regulation S-K, the Company has elected to file certain of these documents as Exhibits 4.(a)—4.(r).
4.(a)
 
Junior Subordinated Indenture, dated as of March 1, 1997, between The AES Corporation and Wells Fargo Bank, National Association, as successor to Bank One, National Association (formerly known as The First National Bank of Chicago) is incorporated herein by reference to Exhibit 4.(a) of the Company's Form 10-K for the year ended December 31, 2008.
4.(b)
 
Third Supplemental Indenture, dated as of October 14, 1999, between The AES Corporation and Wells Fargo Bank, National Association, as successor to Bank One, National Association is incorporated herein by reference to Exhibit 4.(b) of the Company's Form 10-K for the year ended December 31, 2008.
4.(c)
 
Senior Indenture, dated as of December 8, 1998, between The AES Corporation and Wells Fargo Bank, National Association, as successor to Bank One, National Association (formerly known as The First National Bank of Chicago) is incorporated herein by reference to Exhibit 4.01 of the Company's Form 8-K filed on December 11, 1998 (SEC File No. 001-12291).
4.(d)
 
Form of Second Supplemental Indenture, dated as of June 11, 1999, between The AES Corporation and Wells Fargo Bank, National Association, as successor to Bank One, National Association (formerly known as The First National Bank of Chicago) is incorporated herein by reference to Exhibit 4.01 of the Company's Form 8-K filed on June 11, 1999 (SEC File No. 001-12291).
4.(e)
 
Third Supplemental Indenture, dated as of September 12, 2000, between The AES Corporation and Wells Fargo Bank, National Association, as successor to Bank One, National Association is incorporated herein by reference to Exhibit 4.(e) of the Company's Form 10-K for the year ended December 31, 2008.
4.(f)
 
Form of Fifth Supplemental Indenture, dated as of February 9, 2001, between The AES Corporation and Wells Fargo Bank, National Association, as successor to Bank One, National Association is incorporated herein by reference to Exhibit 4.1 of the Company's Form 8-K filed on February 8, 2001 (SEC File No. 001-12291).
4.(g)
 
Form of Sixth Supplemental Indenture, dated as of February 22, 2001, between The AES Corporation and Wells Fargo Bank, National Association, as successor to Bank One, National Association is incorporated herein by reference to Exhibit 4.1 of the Company's Form 8-K filed on February 21, 2001 (SEC File No. 001-12291).
4.(h)
 
Ninth Supplemental Indenture, dated as of April 3, 2003, between The AES Corporation and Wells Fargo Bank, National Association (as successor by consolidation to Wells Fargo Bank Minnesota, National Association) is incorporated herein by reference to Exhibit 4.6 of the Company's Form S-4 filed on December 7, 2007.
4.(i)
 
Form of Tenth Supplemental Indenture, dated as of February 13, 2004, between The AES Corporation and Wells Fargo Bank, National Association (as successor by consolidation to Wells Fargo Bank Minnesota, National Association) is incorporated herein by reference to Exhibit 4.1 of the Company's Form 8-K filed on February 13, 2004 (SEC File No. 001-12291).
4.(j)
 
Eleventh Supplemental Indenture, dated as of October 15, 2007, between The AES Corporation and Wells Fargo Bank, National Association is incorporated herein by reference to Exhibit 4.7 of the Company's Form S-4 filed on December 7, 2007.
4.(k)
 
Twelfth Supplemental Indenture, dated as of October 15, 2007, between The AES Corporation and Wells Fargo Bank, National Association is incorporated herein by reference to Exhibit 4.8 of the Company's Form S-4 filed on December 7, 2007.
4.(l)
 
Thirteenth Supplemental Indenture, dated as of May 19, 2008, between The AES Corporation and Wells Fargo Bank, National Association is incorporated herein by reference to Exhibit 4.(l) of the Company's Form 10-K for the year ended December 31, 2008.
4.(m)
 
Fourteenth Supplemental Indenture, dated as of April 2, 2009, between The AES Corporation and Wells Fargo Bank, National Association is incorporated herein by reference to Exhibit 99.1 of the Company's Form 8-K filed on April 2, 2009.
4.(n)
 
Fifteenth Supplemental Indenture, dated as of June 15, 2011, between The AES Corporation and Wells Fargo Bank, National Association is incorporated herein by reference to Exhibit 4.3 of the Company's Form 8-K filed on June 15, 2011.
4.(o)
 
Indenture, dated October 3, 2011, between Dolphin Subsidiary II, Inc. and Wells Fargo Bank, National Association is incorporated herein by reference to Exhibit 4.1 of the Company's Form 8-K filed on October 5, 2011.
4.(p)
 
Sixteenth Supplemental Indenture, dated April 30, 2013, between The AES Corporation and Wells Fargo Bank, N.A., as Trustee is incorporated herein by reference to Exhibit 4.1 of the Company's Form 8-K filed on April 30, 2013 (SEC File No. 001-12291).
4.(q)
 
Seventeenth Supplemental Indenture, dated March 7, 2014, between The AES Corporation and Wells Fargo Bank, N.A. as Trustee is incorporated herein by reference to Exhibit 4.1 of the Company's Form 8-K filed on March 7, 2014.
4.(r)
 
Eighteenth Supplemental Indenture, dated May 20, 2014, between The AES Corporation and Wells Fargo Bank, N.A. as Trustee is incorporated herein by reference to Exhibit 4.1 of the Company's Form 8-K filed on May 20, 2014.
4.(s)
 
Nineteenth Supplemental Indenture, dated April 6, 2015, between The AES Corporation and Wells Fargo Bank, N.A. as Trustee is incorporated herein by reference to Exhibit 4.1 of the Company's Form 8-K filed on April 6, 2015.
10.1
 
The AES Corporation Profit Sharing and Stock Ownership Plan are incorporated herein by reference to Exhibit 4(c)(1) of the Registration Statement on Form S-8 (Registration No. 33-49262) filed on July 2, 1992.
10.2
 
The AES Corporation Incentive Stock Option Plan of 1991, as amended, is incorporated herein by reference to Exhibit 10.30 of the Company's Form 10-K for the year ended December 31, 1995 (SEC File No. 00019281).

182


10.3
 
Applied Energy Services, Inc. Incentive Stock Option Plan of 1982 is incorporated herein by reference to Exhibit 10.31 of the Registration Statement on Form S-1 (Registration No. 33-40483).
10.4
 
Deferred Compensation Plan for Executive Officers, as amended, is incorporated herein by reference to Exhibit 10.32 of Amendment No. 1 to the Registration Statement on Form S-1 (Registration No. 33-40483).
10.5
 
Deferred Compensation Plan for Directors, as amended and restated, on February 17, 2012 is incorporated herein by reference to Exhibit 10.5 of the Company's Form 10-K for the year ended December 31, 2012.
10.6
 
The AES Corporation Stock Option Plan for Outside Directors, as amended and restated, on December 7, 2007 is incorporated herein by reference to Exhibit 10.6 of the Company's Form 10-K for the year ended December 31, 2012.
10.7
 
The AES Corporation Supplemental Retirement Plan is incorporated herein by reference to Exhibit 10.63 of the Company's Form 10-K for the year ended December 31, 1994 (SEC File No. 00019281).
10.7A
 
Amendment to The AES Corporation Supplemental Retirement Plan, dated March 13, 2008 is incorporated herein by reference to Exhibit 10.9.A of the Company's Form 10-K for the year ended December 31, 2007.
10.8
 
The AES Corporation 2001 Stock Option Plan is incorporated herein by reference to Exhibit 10.12 of the Company's Form 10-K for the year ended December 31, 2000 (SEC File No. 001-12291).
10.9
 
Second Amended and Restated Deferred Compensation Plan for Directors is incorporated herein by reference to Exhibit 10.13 of the Company's Form 10-K for the year ended December 31, 2000 (SEC File No. 001-12291).
10.10
 
The AES Corporation 2001 Non-Officer Stock Option Plan is incorporated herein by reference to Exhibit 10.12 of the Company's Form 10-K for the year ended December 31, 2002 (SEC File No. 001-12291).
10.10A
 
Amendment to the 2001 Stock Option Plan and 2001 Non-Officer Stock Option Plan, dated March 13, 2008 is incorporated herein by reference to Exhibit 10.12.A of the Company's Form 10-K for the year ended December 31, 2007.
10.11
 
The AES Corporation 2003 Long Term Compensation Plan, as Amended and Restated, dated April 23, 2015, is incorporated herein by reference to Exhibit 99.1 of the Company's Form 8-K filed on April 23, 2015.
10.12
 
Form of AES Nonqualified Stock Option Award Agreement under The AES Corporation 2003 Long Term Compensation Plan (Outside Directors) is incorporated herein by reference to Exhibit 10.2 of the Company's Form 8-K filed on April 27, 2010.
10.13
 
Form of AES Performance Stock Unit Award Agreement under The AES Corporation 2003 Long Term Compensation Plan (filed herewith).
10.14
 
Form of AES Restricted Stock Unit Award Agreement under The AES Corporation 2003 Long Term Compensation Plan (filed herewith).
10.15
 
Form of AES Performance Unit Award Agreement under The AES Corporation 2003 Long Term Compensation Plan (filed herewith).
10.16
 
Form of AES Nonqualified Stock Option Award Agreement under The AES Corporation 2003 Long Term Compensation Plan is incorporated herein by reference to Exhibit 10.4 of the Company's Form 10-Q for the quarter ended June 30, 2015.
10.17
 
Form of AES Performance Cash Unit Award Agreement under The AES Corporation 2003 Long Term Compensation Plan (filed herewith).
10.18
 
The AES Corporation Restoration Supplemental Retirement Plan, as amended and restated, dated December 29, 2008 is incorporated herein by reference to Exhibit 10.15 of the Company's Form 10-K for the year ended December 31, 2008.
10.18A
 
Amendment to The AES Corporation Restoration Supplemental Retirement Plan, dated December 9, 2011 is incorporated herein by reference to Exhibit 10.17A of the Company's Form 10-K for the year ended December 31, 2012.
10.19
 
The AES Corporation International Retirement Plan, as amended and restated on December 29, 2008 is incorporated herein by reference to Exhibit 10.16 of the Company's Form 10-K for the year ended December 31, 2008.
10.19A
 
Amendment to The AES Corporation International Retirement Plan, dated December 9, 2011 is incorporated herein by reference to Exhibit 10.18A of the Company's Form 10-K for the year ended December 31, 2012.
10.20
 
The AES Corporation Severance Plan, as amended and restated on April 23, 2015 is incorporated herein by reference to Exhibit 10.6 of the Company's Form 10-Q for the quarter ended June 30, 2015.
10.21
 
The AES Corporation Amended and Restated Executive Severance Plan dated April 23, 2015 is incorporated herein by reference to Exhibit 10.5 of the Company's Form 10-Q for the period ended June 30, 2015.
10.22
 
The AES Corporation Performance Incentive Plan, as Amended and Restated on April 23, 2015 is incorporated herein by reference to Exhibit 99.2 of the Company's Form 8-K filed on April 23, 2015.
10.23
 
The AES Corporation Deferred Compensation Program For Directors dated February 17, 2012 is incorporated herein by reference to Exhibit 10.22 of the Company's Form 10-K filed on December 31, 2011.
10.24
 
The AES Corporation Employment Agreement with Andrés Gluski is incorporated herein by reference to Exhibit 99.3 of the Company's Form 8-K filed on December 31, 2008.
10.25
 
Mutual Agreement, between Andrés Gluski and The AES Corporation dated October 7, 2011 is incorporated herein by reference to Exhibit 10.2 of the Company's Form 10-Q for the period ended September 30, 2011.
10.26
 
Form of Retroactive Consent to Provide for Double-Trigger IN Change-In-Control Transactions is incorporated herein by reference to Exhibit 10.7 of the Company's Form 10-Q for the period ended June 30, 2015.
10.27
 
Amendment No. 3, dated as of July 26, 2013 to the Fifth Amended and Restated Credit and Reimbursement Agreement, dated as of July 29, 2010 is incorporated herein by reference to Exhibit 10.1 of the Company's Form 8-K filed on July 29, 2013.
10.27A
 
Sixth Amended and Restated Credit and Reimbursement Agreement dated as of July 26, 2013 among The AES Corporation, a Delaware corporation, the Banks listed on the signature pages thereof, Citibank, N.A., as Administrative Agent and Collateral Agent, Citigroup Global Markets Inc., as Lead Arranger and Book Runner, Banc of America Securities LLC, as Lead Arranger and Book Runner and Co-Syndication Agent, Barclays Capital, as Lead Arranger and Book Runner and Co-Syndication Agent, RBS Securities Inc., as Lead Arranger and Book Runner and Co-Syndication Agent and Union Bank, N.A., as Lead Arranger and Book Runner and Co-Syndication Agent is incorporated herein by reference to Exhibit 10.1.A of the Company's Form 8-K filed on July 29, 2013.
10.27B
 
Appendices and Exhibits to the Sixth Amended and Restated Credit and Reimbursement Agreement, dated as of July 29, 2013 is incorporated herein by reference to Exhibit 10.1.B of the Company's Form 8-K filed on July 29, 2013.
10.28
 
Collateral Trust Agreement dated as of December 12, 2002 among The AES Corporation, AES International Holdings II, Ltd., Wilmington Trust Company, as corporate trustee and Bruce L. Bisson, an individual trustee is incorporated herein by reference to Exhibit 4.2 of the Company's Form 8-K filed on December 17, 2002 (SEC File No. 001-12291).
10.29
 
Security Agreement dated as of December 12, 2002 made by The AES Corporation to Wilmington Trust Company, as corporate trustee and Bruce L. Bisson, as individual trustee is incorporated herein by reference to Exhibit 4.3 of the Company's Form 8-K filed on December 17, 2002 (SEC File No. 001-12291).
10.30
 
Charge Over Shares dated as of December 12, 2002 between AES International Holdings II, Ltd. and Wilmington Trust Company, as corporate trustee and Bruce L. Bisson, as individual trustee is incorporated herein by reference to Exhibit 4.4 of the Company's Form 8-K filed on December 17, 2002 (SEC File No. 001-12291).
10.31
 
Agreement and Plan of Merger, dated April 19, 2011, by and among The AES Corporation, DPL Inc. and Dolphin Sub, Inc. is incorporated herein by reference to Exhibit 2.1 of the Company's Form 8-K filed on April 20, 2011.
10.32
 
Credit Agreement dated as of May 27, 2011 among The AES Corporation, as borrower, the banks listed therein and Bank of America, N.A., as administrative agent is incorporated herein by reference to Exhibit 10.1 of the Company's Form 8-K filed on June 1, 2011.

183


10.32A
 
Amendment No.1 dated February 27, 2013 to the Credit Agreement dated as of May 27, 2011 among The AES Corporation, as borrower, the banks listed therein and Bank of America N.A., as administrative agent is incorporated herein by reference to exhibit 10.1 of the Company's Form 10-Q for the period ending March 31, 2013.
10.33
 
Common Stock Repurchase Agreement, dated as of December 11, 2013, by and between The AES Corporation and Terrific Investment Corporation is incorporated herein by reference to Exhibit 10.1 of the Company's Form 8-K filed on December 13, 2013.
12
 
Statement of computation of ratio of earnings to fixed charges (filed herewith).
21
 
Subsidiaries of The AES Corporation (filed herewith).
23.1
 
Consent of Independent Registered Public Accounting Firm, Ernst & Young LLP (filed herewith).
24
 
Powers of Attorney (filed herewith).
31.1
 
Rule 13a-14(a)/15d-14(a) Certification of Andrés Gluski (filed herewith).
31.2
 
Rule 13a-14(a)/15d-14(a) Certification of Thomas M. O'Flynn (filed herewith).
32.1
 
Section 1350 Certification of Andrés Gluski (filed herewith).
32.2
 
Section 1350 Certification of Thomas M. O'Flynn (filed herewith).
101.INS
 
XBRL Instance Document (filed herewith).
101.SCH
 
XBRL Taxonomy Extension Schema Document (filed herewith).
101.CAL
 
XBRL Taxonomy Extension Calculation Linkbase Document (filed herewith).
101.DEF
 
XBRL Taxonomy Extension Definition Linkbase Document (filed herewith).
101.LAB
 
XBRL Taxonomy Extension Label Linkbase Document (filed herewith).
101.PRE
 
XBRL Taxonomy Extension Presentation Linkbase Document (filed herewith).
(c)
Schedules
Schedule I—
Financial Information of Registrant
Schedule II—Valuation and Qualifying Accounts

184


SIGNATURES
Pursuant to the requirements of Section 13 or 15(d) of the Securities Exchange Act of 1934, as amended, the Company has duly caused this report to be signed on its behalf by the undersigned, thereunto duly authorized.
 
 
THE AES CORPORATION
(Company)


Date:
February 23, 2016
By:
 
/s/   ANDRÉS GLUSKI        
 
 
Name:
 
Andrés Gluski


President, Chief Executive Officer
Pursuant to the requirements of the Securities Exchange Act of 1934, as amended, this report has been signed below by the following persons on behalf of the Company and in the capacities and on the dates indicated.
Name
 
Title
 
Date


*
 
President, Chief Executive Officer (Principal Executive Officer) and Director
 
 
Andrés Gluski
 
 
February 23, 2016


*
 
Director
 
 
Charles L. Harrington
 
 
February 23, 2016
*
 
Director
 
 
Kristina M. Johnson
 
 
February 23, 2016


*
 
Director
 
 
Tarun Khanna
 
 
February 23, 2016


*
 
Director
 
 
Holly K. Koeppel
 
 
February 23, 2016


*
 
Director
 
 
Philip Lader
 
 
February 23, 2016


*
 
Director
 
 
James H. Miller
 
 
February 23, 2016


*
 
Director
 
 
John B. Morse
 
 
February 23, 2016


*
 
Director
 
 
Moises Naim
 
 
February 23, 2016


*
 
Chairman of the Board and Lead Independent Director
 
 
Charles O. Rossotti
 
 
February 23, 2016


/s/ THOMAS M. O'FLYNN
 
Executive Vice President and Chief Financial Officer (Principal Financial Officer)
 
 
Thomas M. O'Flynn
 
 
February 23, 2016


/s/ FABIAN E. SOUZA
 
Vice President and Controller (Principal Accounting Officer)
 
 
Fabian E. Souza
 
 
February 23, 2016

*By:
/s/ BRIAN A. MILLER
 
February 23, 2016
 
Attorney-in-fact


185


THE AES CORPORATION AND SUBSIDIARIES
INDEX TO FINANCIAL STATEMENT SCHEDULES
Schedules other than those listed above are omitted as the information is either not applicable, not required, or has been furnished in the financial statements or notes thereto included in Item 8 hereof.


See Notes to Schedule I


S-1


THE AES CORPORATION
SCHEDULE I CONDENSED FINANCIAL INFORMATION OF PARENT
BALANCE SHEETS
 
 
December 31,
 
 
2015
 
2014
 
 
(in millions)
ASSETS


Current Assets:


Cash and cash equivalents
 
$
186

 
$
511

Restricted cash
 
32

 
81

Accounts and notes receivable from subsidiaries
 
264

 
380

Deferred income taxes
 
—

 
142

Prepaid expenses and other current assets
 
26

 
57

Total current assets
 
508

 
1,171

Investment in and advances to subsidiaries and affiliates
 
7,764

 
9,063

Office Equipment:


Cost
 
135

 
157

Accumulated depreciation
 
(112
)
 
(114
)
Office equipment, net
 
23

 
43

Other Assets:


Deferred financing costs (net of accumulated amortization of $75 and $81, respectively)
 
49

 
61

Deferred income taxes
 
1,028

 
872

Other Assets
 
1

 
1

Total other assets
 
1,078

 
934

Total
 
$
9,373

 
$
11,211

LIABILITIES AND STOCKHOLDERS' EQUITY


Current Liabilities:


Accounts payable
 
$
16

 
$
25

Accounts and notes payable to subsidiaries
 
97

 
80

Accrued and other liabilities
 
204

 
212

Senior notes payable—current portion
 
—

 
151

Total current liabilities
 
317

 
468

Long-term Liabilities:


Senior notes payable
 
4,498

 
4,590

Junior subordinated notes and debentures payable
 
517

 
517

Accounts and notes payable to subsidiaries
 
873

 
1,352

Other long-term liabilities
 
19

 
12

Total long-term liabilities
 
5,907

 
6,471

Stockholders' equity:


Common stock
 
8

 
8

Additional paid-in capital
 
8,718

 
8,409

Retained Earnings
 
143

 
512

Accumulated other comprehensive loss
 
(3,883
)
 
(3,286
)
Treasury stock
 
(1,837
)
 
(1,371
)
Total stockholders' equity
 
3,149

 
4,272

Total
 
$
9,373

 
$
11,211


See Notes to Schedule I.


S-2


THE AES CORPORATION
SCHEDULE I CONDENSED FINANCIAL INFORMATION OF PARENT
STATEMENTS OF OPERATIONS
For the Years Ended December 31,
 
2015
 
2014
 
2013
 
 
(in millions)
Revenue from subsidiaries and affiliates
 
$
24

 
$
29

 
$
32

Equity in earnings of subsidiaries and affiliates
 
859

 
1,313

 
498

Interest income
 
24

 
59

 
66

General and administrative expenses
 
(154
)
 
(161
)
 
(171
)
Other Income
 
24

 
8

 
14

Other Expense
 
(6
)
 
(30
)
 
(11
)
Loss on extinguishment of debt
 
(105
)
 
(193
)
 
(165
)
Interest expense
 
(364
)
 
(422
)
 
(436
)
Income (loss) before income taxes
 
302

 
603

 
(173
)
Income tax benefit
 
4

 
166

 
287

Net income
 
$
306

 
$
769

 
$
114

See Notes to Schedule I.

S-3


THE AES CORPORATION
SCHEDULE I CONDENSED FINANCIAL INFORMATION OF PARENT
STATEMENTS OF COMPREHENSIVE INCOME
YEARS ENDED DECEMBER 31, 2015, 2014, AND 2013
 
2015
 
2014
 
2013
 
(in millions)
NET INCOME
$
306

 
$
769

 
$
114

Foreign currency translation activity:


Foreign currency translation adjustments, net of income tax (expense) benefit of $1, $(7) and $10, respectively
(674
)
 
(366
)
 
(263
)
Reclassification to earnings, net of income tax (expense) benefit of $0, $0 and $0, respectively
—

 
34

 
36

Total foreign currency translation adjustments, net of tax
(674
)
 
(332
)
 
(227
)
Derivative activity:


Change in derivative fair value, net of income tax (expense) benefit of $4, $51 and $(31), respectively
(5
)
 
(180
)
 
46

Reclassification to earnings, net of income tax (expense) benefit of $(12), $(37) and $(32), respectively
48

 
72

 
128

Total change in fair value of derivatives, net of tax
43

 
(108
)
 
174

Pension activity:


Prior service cost for the period, net of income tax (expense) benefit of $0, $0 and $0, respectively
1

 
(1
)
 
—

Change in pension adjustments due to net actuarial gain (loss) for the period, net of income tax (expense) benefit of $(7), $9 and $(42), respectively
18

 
(13
)
 
78

Reclassification of earnings due to amortization of net actuarial loss, net of income tax (expense) benefit of $(2), $0 and $(5), respectively
2

 
10

 
13

Total change in unfunded pension obligation
21

 
(4
)
 
91

OTHER COMPREHENSIVE INCOME (LOSS)
(610
)
 
(444
)
 
38

COMPREHENSIVE INCOME (LOSS)
$
(304
)
 
$
325

 
$
152

See Notes to Schedule I.

S-4


THE AES CORPORATION
SCHEDULE I CONDENSED FINANCIAL INFORMATION OF PARENT
STATEMENTS OF CASH FLOWS
For the Years Ended December 31,
 
2015
 
2014
 
2013
 
 
(in millions)
Net cash provided by operating activities
 
$
475

 
$
449

 
$
418

Investing Activities:


Expenses related to asset sales
 
—

 
(4
)
 
(5
)
Investment in and net advances to subsidiaries
 
(221
)
 
(69
)
 
201

Return of capital
 
501

 
740

 
230

Decrease in restricted cash
 
49

 
96

 
50

Additions to property, plant and equipment
 
(11
)
 
(31
)
 
(11
)
(Purchase) sale of short term investments, net
 
—

 
(1
)
 
1

Net cash provided by (used in) investing activities
 
318

 
731

 
466

Financing Activities:


Borrowings (payments) under the revolver, net
 
—

 
—

 
—

Borrowings of notes payable and other coupon bearing securities
 
575

 
1,525

 
750

Repayments of notes payable and other coupon bearing securities
 
(915
)
 
(2,117
)
 
(1,210
)
Loans (to) from subsidiaries
 
—

 
263

 
(152
)
Purchase of treasury stock
 
(482
)
 
(308
)
 
(322
)
Proceeds from issuance of common stock
 
4

 
1

 
13

Common stock dividends paid
 
(276
)
 
(144
)
 
(119
)
Payments for deferred financing costs
 
(6
)
 
(20
)
 
(17
)
Other Financing
 
(18
)
 
—

 
—

Net cash (used in) provided by financing activities
 
(1,118
)
 
(800
)
 
(1,057
)
Effect of exchange rate changes on cash
 
—

 
—

 
(1
)
Increase (decrease) in cash and cash equivalents
 
(325
)
 
380

 
(174
)
Cash and cash equivalents, beginning
 
511

 
131

 
305

Cash and cash equivalents, ending
 
$
186

 
$
511

 
$
131

Supplemental Disclosures:


Cash payments for interest, net of amounts capitalized
 
$
314

 
$
373

 
$
442

Cash payments for income taxes, net of refunds
 
$
—

 
$
(2
)
 
$
11

See Notes to Schedule I.

S-5


THE AES CORPORATION
SCHEDULE I
NOTES TO SCHEDULE I
1. Application of Significant Accounting Principles
The Schedule I Condensed Financial Information of the Parent includes the accounts of The AES Corporation (the “Parent Company”) and certain holding companies.
Accounting for Subsidiaries and Affiliates—The Parent Company has accounted for the earnings of its subsidiaries on the equity method in the financial information.
Income Taxes—Positions taken on the Parent Company's income tax return which satisfy a more-likely-than-not threshold will be recognized in the financial statements. The income tax expense or benefit computed for the Parent Company reflects the tax assets and liabilities on a stand-alone basis and the effect of filing a consolidated U.S. income tax return with certain other affiliated companies.
Accounts and Notes Receivable from Subsidiaries—Amounts have been shown in current or long-term assets based on terms in agreements with subsidiaries, but payment is dependent upon meeting conditions precedent in the subsidiary loan agreements.
2. Debt
Senior Notes and Loans Payable ($ in millions)


December 31,
 
 
Interest Rate
 
Maturity
 
2015
 
2014
Senior Unsecured Note
 
7.75%
 
2015
 
$
—

 
$
151

Senior Unsecured Note
 
9.75%
 
2016
 
—

 
164

Senior Unsecured Note
 
8.00%
 
2017
 
181

 
525

Senior Unsecured Note
 
LIBOR + 3.00%
 
2019
 
775

 
775

Senior Unsecured Note
 
8.00%
 
2020
 
469

 
625

Senior Unsecured Note
 
7.38%
 
2021
 
1,000

 
1,000

Senior Unsecured Note
 
4.88%
 
2023
 
750

 
750

Senior Unsecured Note
 
5.50%
 
2024
 
750

 
750

Senior Unsecured Note
 
5.50%
 
2025
 
575

 
—

Unamortized premium (discounts)


(2
)
 
1

SUBTOTAL


4,498

 
4,741

Less: Current maturities


—

 
(151
)
Total


$
4,498

 
$
4,590

Junior Subordinated Notes Payable ($ in millions)


December 31,
 
 
Interest Rate
 
Maturity
 
2015
 
2014
Term Convertible Trust Securities
 
6.75%
 
2029
 
$
517

 
$
517

FUTURE MATURITIES OF DEBT — Recourse debt as of December 31, 2015 is scheduled to reach maturity as presented in the table below in millions:
December 31,
Annual Maturities
2016
$
—

2017
181

2018
—

2019
774

2020
469

Thereafter
3,591

Total debt
$
5,015

3. Dividends from Subsidiaries and Affiliates
Cash dividends received from consolidated subsidiaries were $748 million, $880 million, and $818 million for the years ended December 31, 2015, 2014, and 2013, respectively. There were no cash dividends received from affiliates accounted for by the equity method for the years ended December 31, 2015, 2014, and 2013.
4. Guarantees and Letters of Credit
GUARANTEES—In connection with certain of its project financing, acquisition, and power purchase agreements, the Company has expressly undertaken limited obligations and commitments, most of which will only be effective or will be terminated upon the occurrence of future events. These obligations and commitments, excluding those collateralized by letter of credit and other obligations discussed below, were limited as of December 31, 2015, by the terms of the agreements, to an aggregate of approximately $396 million representing 15 agreements with individual exposures ranging from less than $1

S-6


million up to $53 million. These amounts exclude normal and customary representations and warranties in agreements for the sale of assets (including ownership in associated legal entities) where the associated risk is considered to be nominal.
LETTERS OF CREDIT—At December 31, 2015, the Company had $62 million in letters of credit outstanding under the senior unsecured credit facility representing 7 agreements with individual exposures ranging from less than $1 million up to $29 million, which operate to guarantee performance relating to certain project development and construction activities and subsidiary operations. At December 31, 2015, the Company had $32 million in cash collateralized letters of credit outstanding representing 4 agreements with individual exposures ranging from $1 million up to $15 million, which operate to guarantee performance relating to certain project development and construction activities and subsidiary operations. During 2015, the Company paid letter of credit fees ranging from 0.2% to 2.5% per annum on the outstanding amounts.

SCHEDULE II
VALUATION AND QUALIFYING ACCOUNTS
(in millions)
Balance at Beginning of the Period
 
Charged to Cost and Expense
 
Amounts Written off
 
Translation Adjustment
 
Balance at the End of the Period
Allowance for accounts receivables


(current and noncurrent)


Year Ended December 31, 2013
$
195

 
$
38

 
$
(77
)
 
$
(22
)
 
$
134

Year Ended December 31, 2014
134

 
61

 
(88
)
 
(11
)
 
96

Year Ended December 31, 2015
96

 
88

 
(60
)
 
(29
)
 
95


S-7

Exhibit

PERFORMANCE STOCK UNIT AWARD AGREEMENT
PURSUANT TO
THE AES CORPORATION 2003 LONG TERM COMPENSATION PLAN
The AES Corporation, a Delaware corporation (the “Company”), grants to the Employee named below, pursuant to The AES Corporation 2003 Long Term Compensation Plan, as amended (the “Plan”), and this Performance Stock Unit Award Agreement (this “Agreement”), this Award of Performance Stock Units (“PSUs”) upon the terms and conditions set forth herein. Capitalized terms not otherwise defined herein will each have the meaning assigned to them in the Plan.

1.
This Award of PSUs is subject to all terms and conditions of this Agreement and the Plan, the terms of which are incorporated herein by reference:  

Name of Employee:


Fidelity System ID:


Grant Date:


Grant Price:


Target Number of PSUs Granted:
 
 
2.
Each PSU represents a right to receive one Share on the Payment Date (as defined below) in accordance with the terms of this Agreement.

3.
Unless otherwise determined by the Committee, each PSU shall also represent a right to receive an additional amount, payable in cash, equal to the accumulated cash dividends paid by the Company on the PSU between the Grant Date and payout of the PSU (if any). The additional dividend amounts that are accumulated subject to a PSU will be subject to the same terms and conditions (including, without limitation, any applicable vesting requirements and forfeiture provisions) as the PSU to which they relate under the Award. Any payment due to the Employee under this Agreement shall be made promptly following the date vested PSUs become earned and payable under paragraph 5(a), paragraph 6 or paragraph 7 of this Agreement, as applicable (the “Payment Date”), but in no event later than March 15th of the calendar year following the calendar year containing the Payment Date.


4.
A PSU carries no voting rights and the holder of a PSU will not have an equity interest in the Company or any shareholder rights, unless the vesting and performance conditions of the PSU are met and the PSU is paid out.

5.
This Award of PSUs will vest, in accordance with and subject to the terms of this Agreement, in three equal installments on December 31st in each year during the Performance Period (each a “Vesting Date”), provided, however, that if:
 
(a)
the Employee Separates from Service prior to the end of the Performance Period by reason of the Employee’s death or a Separation from Service on account of Disability, all PSUs that have not previously vested shall vest and the Employee’s PSUs referenced in the chart above shall be paid to the Employee at the rate of one Share for each PSU;

(b)
if (i) the Employee Separates from Service prior to the Payment Date by reason of a Separation from Service by the Company for Cause (as defined in the Plan and as may otherwise be determined by the Committee in its sole discretion) or (ii) the Employee Separates from Service prior to the final Vesting Date by reason of a voluntary Separation from Service by the Employee (including any retirement other than a Qualified Retirement (as defined below)), this Award of PSUs (including any time-vested portion) shall immediately upon such termination be cancelled and forfeited without payment or further obligation by the Company; and

(c)
if the Employee Separates from Service for any other reason, including, but not limited to, on account of a Qualified Retirement, by reason of a death or Disability subsequent to the end of the Performance Period, or by reason of a Separation from Service by the Company other than for Cause (other than for Cause, voluntarily by the Employee not as part of a Qualified Retirement or due to death or Disability as provided in paragraphs 5(a) and 5(b)), the Employee will be eligible to receive the value of his or her vested PSUs, as of the date of the Separation from Service, on the Payment Date in accordance with and subject to the terms set forth in paragraph 6 below.

Any PSUs that have not vested prior to the date that an Employee Separates from Service for any reason (other than by reason of death or Disability as provided in paragraph 5(a)), (i) will not subsequently vest; and (ii) will be immediately cancelled and forfeited without payment or further obligation by the Company or any Affiliate. In addition, the Employee’s right to receive Shares in respect of vested PSUs that have not been forfeited will be paid on the Payment Date if, and only if, all relevant performance conditions are met, in accordance with the terms and conditions of this Agreement and the Plan. For purposes of this Agreement, “Qualified Retirement” means the Employee’s retirement at a time when such Employee is at least 60 years of age and has had at least seven years of service as an employee of the Company and/or one or more of its Affiliates.
 
6.
The Company will issue and deliver Shares in satisfaction of vested PSUs subject to and conditioned upon the attainment of the performance conditions set forth below, as approved by the Committee at the time of grant; provided, however, notwithstanding the performance level achieved, the Committee may reduce the number of PSUs earned or terminate this

2


Award of PSUs altogether, but in no event may the Committee increase the value of a PSU underlying this Award beyond the performance levels achieved. For purposes of this Agreement, the “Performance Period” is the three calendar year period beginning on January 1st in the year of grant and ending on and through December 31st in the second year following the year of the grant date.

The value of each vested PSU will depend upon the Company’s actual Proportional Free Cash Flow (“PFCF”) as defined below, over the Performance Period as compared to the performance target approved by the Committee and as follows:
ACTUAL PFCF
OVER THE PERFORMANCE PERIOD
SHARES EARNED
Below 75% of Performance Target =
None (0%)
Equal to 87.5% of Performance Target =
50%
(0.5 x number of vested PSUs)
Equal to 100% of Performance Target =
100%
(1.0 x number of vested PSUs)
Equal to or greater than 125% of Performance Target =
200%
(2.0 x number of vested PSUs)

7.
For PFCF levels achieved greater than 75% and less than 87.5% of performance target, greater than 87.5% and less than 100% of performance target, and greater than 100% and less than 125% of performance target, the Performance Unit value will be determined based on straight-line interpolation. The maximum value of a PSU is $2.00. In the event of a (i) Change in Control and (ii) a Qualifying Event (as defined below) prior to the end of the Performance Period, if the PSUs described herein have not already been previously forfeited or cancelled, such PSUs will become fully vested (for the total amount of PSUs set forth in paragraph 1) and the Payment Date will occur contemporaneous with the Qualifying Event; provided, however, that in connection with a Change in Control, payment of any obligation payable pursuant to the preceding sentence may be made in cash of equivalent value and/or securities or other property in the Committee’s discretion.
(a)
Change in Control means the occurrence of one or more of the following events: (i) any sale, lease, exchange or other transfer (in one transaction or a series of related transactions) of all, or substantially all, of the assets of the Company to any Person or group (as that term is used in Section 13(d) (3) of the Exchange Act) of Persons, (ii) a Person or group (as so defined in the Plan) of Persons (other than Management of the Company on the date of the most recent adoption of the Plan by the Company's stockholders or their Affiliates) shall have become the beneficial owner (as defined below) of more than 35% of the outstanding voting stock of the Company, (iii) during any one-year period, individuals who at the beginning of such period constitute the Board (together with any new Director whose election or nomination was approved by a majority of the Directors then in office who were either Directors at the beginning of such period or who were previously so approved, but excluding under all circumstances

3


any such new Director whose initial assumption of office occurs as a result of an actual or threatened election contest or other actual or threatened solicitation of proxies or consents by or on behalf of any individual, corporation, partnership or other entity or group, including through the use of proxy access procedures as may be provided in the Company’s bylaws) cease to constitute a majority of the Board, or (iv) the consummation of a merger, consolidation, business combination or similar transaction involving the Company unless securities representing 65% or more of the then outstanding voting stock of the corporation resulting from such transaction are held subsequent to such transaction by the Person or Persons who were the beneficial owners of the outstanding voting stock of the Company immediately prior to such transaction in substantially the same proportions as their ownership immediately prior to such transaction. Notwithstanding the foregoing or any provision to the contrary, if an Award is subject to Section 409A (and not excepted therefrom) and a Change in Control is a distribution event for purposes of an Award, the foregoing definition of Change in Control shall be interpreted, administered and construed in a manner necessary to ensure that the occurrence of any such event shall result in a Change in Control only if such event qualifies as a change in the ownership or effective control of a corporation, or a change in the ownership of a substantial portion of the assets of a corporation, as applicable, within the meaning of Treas. Reg. § 1.409A-3(i)(5). For purposes of this Agreement, “beneficial owner(s)” shall have the meaning set forth in Rule 13d-3 of the Exchange Act.
(b)
Qualifying Event means the occurrence of one or more of the following events: (i) immediately upon the consummation of a Change in Control Event, failure of the successor company in a Change in Control event to provide Substitute Awards that are substantially similar in both nature and terms (including having an equivalent realizable pre-tax value to outstanding awards assuming vesting and delivery at the consummation of the Change in Control); (ii) within two years of the consummation of a Change in Control event, an involuntary termination without Cause of the Employee; or (iii) within two years of the consummation of a Change in Control event, a Good Reason Termination (as defined below) by the Employee.
(c)
Good Reason Termination means, without an Employee’s written consent, the Separation From Service (for reasons other than death, Disability or Cause) by an Employee due to any of the following events occurring within two years of the consummation of a Change in Control: (i) the relocation of an Employee’s principal place of employment to a location that is more than 50 miles from the principal place of employment in effect immediately prior to such Change in Control; (ii) a material diminution in the duties or responsibilities of an Employee from those in place immediately prior to such Change in Control; and (iii) a material reduction in the base salary or annual incentive opportunity of an Employee from what was in place immediately prior to such Change in Control.

In order for Employee to terminate for Good Reason, (i) Employee must notify the successor entity in writing, within ninety (90) days of the event constituting Good Reason, of the Employee’s intent to terminate employment for Good Reason, that

4


specifically identifies in reasonable detail the manner of the Good Reason event, (ii) the event must remain uncorrected for thirty (30) days following the date that Employee notifies the successor entity in writing of Employee’s intent to terminate employment for Good Reason (the “Notice Period”), and (iii) the termination date must occur within sixty (60) days after expiration of the Notice Period.

8.
It is intended that under current U.S. federal income tax laws, the Employee will not be subject to income tax unless and until Shares are delivered to the Employee on the Payment Date, at which time the Fair Market Value of the Shares will be reportable as ordinary income, and subject to income tax withholding as well as social security and Medicare (FICA) taxes. The Employee must pay all applicable Federal and state income and employment withholding taxes when due in such manner as approved by the Committee or the Plan Administrator.  The Employee should consult his or her personal advisor to determine the effect of this Award of PSUs on his or her own tax situation.  

9.
Notices hereunder and under the Plan, if to the Company, will be delivered to the Plan Administrator (as so designated by the Company) or mailed to the Company’s principal office, 4300 Wilson Boulevard, Arlington, VA 22203, attention of the Plan Administrator, or, if to the Employee, will be delivered to the Employee, which may include electronic delivery, or mailed to his or her address as the same appears on the records of the Company.
10.
All decisions and interpretations made by the Board of Directors or the Committee with regard to any question arising hereunder or under the Plan will be binding and conclusive on all persons. Unless otherwise specifically provided herein, in the event of any inconsistency between the terms of this Agreement and the Plan, the Plan will govern.
11.
By accepting this Award of PSUs, the Employee acknowledges receipt of a copy of the Plan and the prospectus relating to this Award of PSUs, and agrees to be bound by the terms and conditions set forth in this Agreement and the Plan, as in effect and/or amended from time to time.

The Employee further acknowledges that the Plan and related documents, which may include the Plan prospectus, may be delivered electronically. Such means of delivery may include the delivery of a link to a Company intranet site or the internet site of a third party involved in administering the Plan, the delivery of the documents via e-mail or CD-ROM or such other delivery determined at the Plan Administrator’s discretion. The Employee acknowledges that the Employee may receive from the Company a paper copy of any documents delivered electronically at no cost if the Employee contacts the Human Resources department of the Company by telephone at (703) 682-6553 or by mail to 4300 Wilson Boulevard, Suite 1100, Arlington, Virginia 22203. The Employee further acknowledges that the Employee will be provided with a paper copy of any documents delivered electronically if electronic delivery fails.

12.
This Award is intended to be excepted from coverage under Section 409A of the Code and shall be administered, interpreted and construed accordingly. The Employee shall have no right to designate the date of any payment under this Agreement. Each payment under this

5


Agreement is intended to be excepted under the short-term deferral exception as specified in Treas. Reg. § 1.409A-1(b)(4). The Company may, in its sole discretion and without the Employee’s consent, modify or amend the terms and conditions of this Award, impose conditions on the timing and effectiveness of the issuance of the Shares, or take any other action it deems necessary or advisable, to cause this Award to comply with Section 409A of the Code (or an exception thereto).

Notwithstanding, the Employee recognizes and acknowledges that Section 409A of the Code may impose upon the Employee certain taxes or interest charges for which the Employee is and shall remain solely responsible.

13.
Notwithstanding any other provisions in this Agreement, any PSUs subject to recovery under any law, government regulation, stock exchange listing requirement, or Company policy, shall be subject to such deductions, recoupment and clawback as may be required to be made pursuant to such law, government regulation, stock exchange listing requirement or Company policy, as may be in effect from time to time, and which may operate to create additional rights for the Company with respect to this Award and recovery of amounts relating thereto.  By accepting this Award, Employee agrees and acknowledges that he or she is obligated to cooperate with, and provide any and all assistance necessary to, the Company to recover, recoup or recapture this Award or amounts paid under the Plan pursuant to such law, government regulation, stock exchange listing requirement or Company policy. Such cooperation and assistance shall include, but is not limited to, executing, completing and submitting any documentation necessary to recover, recoup or recapture this Award or amounts paid under the Plan from Employee’s accounts, or pending or future compensation or other grants.
 
14.
This Agreement will be governed by the laws of the State of Delaware without giving effect to its choice of law provisions.
 
The AES CORPORATION
 
 
By:
 
Tish Mendoza
Senior Vice President and Chief Human Resources Officer


6


Exhibit

RESTRICTED STOCK UNIT AWARD AGREEMENT
PURSUANT TO
THE AES CORPORATION 2003 LONG TERM COMPENSATION PLAN
The AES Corporation, a Delaware corporation (the “Company”), grants to the Employee named below, pursuant to The AES Corporation 2003 Long Term Compensation Plan, as amended (the “Plan”), and this Restricted Stock Unit Award Agreement (this “Agreement”), this Award of Restricted Stock Units (“RSUs”) upon the terms and conditions set forth herein. Capitalized terms not otherwise defined herein will each have the meaning assigned to them in the Plan.
1.
This Award of RSUs is subject to all terms and conditions of this Agreement and the Plan, the terms of which are incorporated herein by reference:
Name of Employee:


Fidelity System ID:


Grant Date:


Grant Price:


Total Number of RSUs Granted:
 

2.
Each RSU represents a right to receive one Share on the appropriate Vesting Date (as defined below) in accordance with the terms of this Agreement.
3.
Unless otherwise determined by the Committee, each RSU shall also represent a right to receive an additional amount, payable in cash, equal to the accumulated cash dividends paid by the Company on the RSU between the Grant Date and the Vesting Date (as defined below) for the RSU. The additional dividend amounts that are accumulated subject to an RSU will be subject to the same terms and conditions (including, without limitation, any applicable vesting requirements and forfeiture provisions) as the RSU to which they relate under the Award. Any payment due to the Employee under this Agreement shall be made promptly following the date the RSUs vest under paragraph 4

1


or 5 of this Agreement, but in no event later than March 15th of the calendar year following the calendar year in which the RSUs vest.
4.
An RSU carries no voting rights and the holder will not have an equity interest in the Company or any shareholder rights, unless the vesting conditions of the RSU are met and the RSU is paid out with Shares.
5.
This Award of RSUs will vest, in accordance with and subject to the terms of this Agreement, in three equal installments on each of the first three anniversaries of the grant date (each a “Vesting Date”) provided, however, that if:
(A)
the Employee Separates from Service prior to the applicable Vesting Date due to the Employee’s death or a Separation from Service on account of Disability, all RSUs that have not previously vested shall vest and be paid to the Employee; and
(B)
if the Employee Separates from Service prior to the applicable Vesting Date for any reason other than the Employee’s death or Disability, including, but not limited to, voluntarily by the Employee, on account of Retirement, or by reason of a Separation from Service by the Company with or without Cause (as defined in the Plan and as may otherwise be determined by the Committee in its sole discretion), all RSUs that have not previously vested shall be immediately cancelled and forfeited without payment or further obligation by the Company or any Affiliate.
6.
In the event of a (i) Change in Control and (ii) a Qualifying Event (as defined below) prior to the applicable Vesting Date, if the RSUs described herein have not already been previously forfeited or cancelled, such RSUs will become fully vested contemporaneous with the Qualifying Event; provided, however, that in connection with a Change in Control, payment of any obligation payable pursuant to the preceding sentence may be made in cash of equivalent value and/or securities or other property in the Committee’s discretion.
(A)
Change in Control means the occurrence of one or more of the following events: (i) any sale, lease, exchange or other transfer (in one transaction or a series of related transactions) of all, or substantially all, of the assets of the Company to any Person or group (as that term is used in Section 13(d) (3) of the Exchange Act) of Persons, (ii) a Person or group (as so defined in the Plan) of Persons (other than Management of the Company on the date of the most recent adoption of the Plan by the Company's stockholders or their Affiliates) shall have become the beneficial owner (as defined below) of more than 35% of the outstanding voting stock of the Company, (iii) during any one-year period, individuals who at

2


the beginning of such period constitute the Board (together with any new Director whose election or nomination was approved by a majority of the Directors then in office who were either Directors at the beginning of such period or who were previously so approved, but excluding under all circumstances any such new Director whose initial assumption of office occurs as a result of an actual or threatened election contest or other actual or threatened solicitation of proxies or consents by or on behalf of any individual, corporation, partnership or other entity or group, including through the use of proxy access procedures as may be provided in the Company’s bylaws) cease to constitute a majority of the Board, or (iv) the consummation of a merger, consolidation, business combination or similar transaction involving the Company unless securities representing 65% or more of the then outstanding voting stock of the corporation resulting from such transaction are held subsequent to such transaction by the Person or Persons who were the beneficial owners of the outstanding voting stock of the Company immediately prior to such transaction in substantially the same proportions as their ownership immediately prior to such transaction. Notwithstanding the foregoing or any provision to the contrary, if an Award is subject to Section 409A (and not excepted therefrom) and a Change in Control is a distribution event for purposes of an Award, the foregoing definition of Change in Control shall be interpreted, administered and construed in a manner necessary to ensure that the occurrence of any such event shall result in a Change in Control only if such event qualifies as a change in the ownership or effective control of a corporation, or a change in the ownership of a substantial portion of the assets of a corporation, as applicable, within the meaning of Treas. Reg. § 1.409A-3(i)(5). For purposes of this Agreement, “beneficial owner(s)” shall have the meaning set forth in Rule 13d-3 of the Exchange Act.
(B)
Qualifying Event means the occurrence of one or more of the following events: (i) immediately upon the consummation of a Change in Control Event, failure of the successor company in a Change in Control event to provide Substitute Awards that are substantially similar in both nature and terms (including having an equivalent realizable pre-tax value to outstanding Awards assuming vesting and delivery at the consummation of the Change in Control); (ii) within two years of the consummation of a Change in Control event, an involuntary termination without Cause of the Employee; or (iii) within two years of the consummation of a Change in Control event, a Good Reason Termination (as defined below) by the Employee.
(C)
Good Reason Termination means, without an Employee’s written consent, the Separation From Service (for reasons other than death, Disability or Cause) by an

3


Employee due to any of the following events occurring within two years of the consummation of a Change in Control: (i) the relocation of an Employee’s principal place of employment to a location that is more than 50 miles from the principal place of employment in effect immediately prior to such Change in Control; (ii) a material diminution in the duties or responsibilities of an Employee from those in place immediately prior to such Change in Control; and (iii) a material reduction in the base salary or annual incentive opportunity of an Employee from what was in place immediately prior to such Change in Control.
In order for Employee to terminate for Good Reason, (i) Employee must notify the successor entity in writing, within ninety (90) days of the event constituting Good Reason, of the Employee’s intent to terminate employment for Good Reason, that specifically identifies in reasonable detail the manner of the Good Reason event, (ii) the event must remain uncorrected for thirty (30) days following the date that Employee notifies the successor entity in writing of Employee’s intent to terminate employment for Good Reason (the “Notice Period”), and (iii) the termination date must occur within sixty (60) days after expiration of the Notice Period.
7.
It is intended that under current U.S. federal income tax laws, the Employee will not be subject to income tax unless and until Shares and/or cash are delivered to the Employee on the Vesting Date, at which time the Fair Market Value of the Shares and/or cash will be reportable as ordinary income, and subject to income tax withholding as well as social security and Medicare (FICA) taxes. The Employee must pay all applicable federal and state income and employment withholding taxes when due in such manner as approved by the Committee or Plan Administrator. The Employee should consult his or her personal advisor to determine the effect of this Award of RSUs on his or her own tax situation.
8.
Notices hereunder and under the Plan, if to the Company, will be delivered to the Plan Administrator (as so designated by the Company) or mailed to the Company’s principal office, 4300 Wilson Boulevard, Arlington, VA 22203, attention of the Plan Administrator, or, if to the Employee, will be delivered to the Employee, which may include electronic delivery, or mailed to his or her address as the same appears on the records of the Company.
9.
All decisions and interpretations made by the Board of Directors or the Committee with regard to any question arising hereunder or under the Plan will be binding and conclusive on all persons. Unless otherwise specifically provided herein, in the event of any inconsistency between the terms of this Agreement and the Plan, the Plan will govern.

4


10.
By accepting this Award of RSUs, the Employee acknowledges receipt of a copy of the Plan and the prospectus relating to this Award of RSUs, and agrees to be bound by the terms and conditions set forth in this Agreement and the Plan, as in effect and/or amended from time to time.

The Employee further acknowledges that the Plan and related documents, which may include the Plan prospectus, may be delivered electronically. Such means of delivery may include the delivery of a link to a Company intranet site or the internet site of a third party involved in administering the Plan, the delivery of the documents via e-mail or CD-ROM or such other delivery determined at the Plan Administrator’s discretion. The Employee acknowledges that the Employee may receive from the Company a paper copy of any documents delivered electronically at no cost if the Employee contacts the Human Resources department of the Company by telephone at (703) 682-6553 or by mail to 4300 Wilson Boulevard, Suite 1100, Arlington, Virginia 22203. The Employee further acknowledges that the Employee will be provided with a paper copy of any documents delivered electronically if electronic delivery fails.
11.
This Award is intended to be excepted from coverage under Section 409A of the Code and shall be administered, interpreted and construed accordingly. The Employee shall have no right to designate the date of any payment under this Agreement. Each payment under this Agreement is intended to be excepted under the short-term deferral exception as specified in Treas. Reg. § 1.409A-1(b)(4). The Company may, in its sole discretion and without the Employee’s consent, modify or amend the terms and conditions of this Award, impose conditions on the timing and effectiveness of the issuance of the Shares, or take any other action it deems necessary or advisable, to cause this Award to comply with Section 409A of the Code (or an exception thereto). Notwithstanding, the Employee recognizes and acknowledges that Section 409A of the Code may impose upon the Employee certain taxes or interest charges for which the Employee is and shall remain solely responsible.
12.
Notwithstanding any other provisions in this Agreement, any RSUs subject to recovery under any law, government regulation, stock exchange listing requirement, or Company policy, shall be subject to such deductions, recoupment and clawback as may be required to be made pursuant to such law, government regulation, stock exchange listing requirement or Company policy, as may be in effect from time to time, and which may operate to create additional rights for the Company with respect to this Award and recovery of amounts relating thereto.  By accepting this Award, Employee agrees and acknowledges that he or she is obligated to cooperate with, and provide any and all assistance necessary to, the Company to recover, recoup or recapture this Award or amounts paid under the Plan pursuant to such law, government regulation, stock

5


exchange listing requirement or Company policy. Such cooperation and assistance shall include, but is not limited to, executing, completing and submitting any documentation necessary to recover, recoup or recapture this Award or amounts paid under the Plan from Employee’s accounts, or pending or future compensation or other grants.
13.
This Agreement will be governed by the laws of the State of Delaware without giving effect to its choice of law provisions.
The AES CORPORATION

By:
Tish Mendoza

Senior Vice President and Chief Human Resources Officer

6

Exhibit


PERFORMANCE UNIT AWARD AGREEMENT
PURSUANT TO
THE AES CORPORATION 2003 LONG TERM COMPENSATION PLAN
The AES Corporation, a Delaware Corporation (the “Company”), grants to the Employee named below, pursuant to The AES Corporation 2003 Long Term Compensation Plan, as amended (the “Plan”), and this Performance Unit Award Agreement (this “Agreement”), this Award of Performance Units (“Performance Units”), the value of which is related to and contingent upon the achievement of a predetermined performance targets (as set forth herein). Capitalized terms not otherwise defined herein shall each have the meaning assigned to them in the Plan.
1.
This Award of Performance Units is subject to all terms and conditions of this Agreement and the Plan, the terms of which are incorporated herein by reference:
Name of Employee:


Fidelity System ID:


Grant Date:


Target Number of Performance Units:


Target Value:
 

Notwithstanding any provision of the Plan to the contrary, this Award of Performance Units is subject to the terms and conditions of this Agreement and the Plan regardless of whether the Employee is a Covered Person, as defined in the Plan.
2.
The Employee is hereby granted an Award of the total number of Performance Units (at target) set forth above. The Performance Units will be reflected in a book account by the Company during the Performance Period (as defined below). Contingent upon achieving or exceeding 75% or more of the Performance Target, the value of vested Performance Units, will be paid in cash in the calendar year following the completion of the


Performance Period (the “Payment Date”), as soon as administratively practicable following the end of the Performance Period.
3.
The “Performance Period” is the three calendar year period beginning on January 1st in the year of grant and ending on and through December 31st in the second year following the year of the grant date.
4.
Except as otherwise provided in this Agreement, this Award of Performance Units will vest, in accordance with and subject to the terms of this Agreement, in three equal installments on December 31st in each year during the Performance Period (each a “Vesting Date”); provided, however, that if:
(A)
the Employee Separates from Service prior to the end of the Performance Period by reason of the Employee’s death or a Separation from Service on account of Disability, all Performance Units referenced in the chart above shall vest on such termination date and a cash amount equal to $1 for each Performance Unit shall be paid to the Employee on the date of Separation from Service (or as soon as practicable thereafter); provided, however, any payment due to the Employee by reason of a Separation from Service on account of Disability shall be delayed to the extent required by Section 14(k)(i) of the Plan;
(B)
(i) the Employee Separates from Service prior to the Payment Date by reason of a Separation from Service by the Company for Cause (as defined in the Plan and as may otherwise be determined by the Committee in its sole discretion for all purposes of this Agreement) or (ii) the Employee Separates from Service prior to the final Vesting Date by reason of a voluntary Separation from Service by the Employee (including any retirement other than a Qualified Retirement (as defined below)), this Award of Performance Units (including any vested portion) will be forfeited in full and cancelled by the Company, and shall cease to be outstanding, upon such termination date; and
(C)
the Employee Separates from Service for any other reason, including on account of a Qualified Retirement, by reason of death or Disability subsequent to the end of the Performance Period, or by reason of a Separation from Service by the Company (other than for cause, voluntarily by the Employee not as part of a Qualified Retirement or due to death or Disability as provided in paragraphs 4(A) and 4(B)), the Employee will be eligible to receive the value of his or her vested Performance Units, as of the date of the Separation from Service, on the Payment Date in accordance with and subject to the terms set forth in paragraph 5 below. For purposes of this Agreement, “Qualified Retirement” means the Employee’s retirement at a time when such Employee is at least 60 years of age and has at

2


least seven years of service as an employee of the Company and/or one or more of its Affiliates.
Any Performance Units that have not vested on or before the date that an Employee Separates from Service for any reason (other than by reason of death or Disability as provided in Paragraph 4A), (i) will not subsequently vest; and (ii) will be immediately cancelled and forfeited without payment or further obligation by the Company or any Affiliate. In addition, the Employee’s right to receive the applicable Performance Unit value in respect of vested Performance Units that have not been forfeited will be paid on the Payment Date, if, and only if, all relevant performance conditions are met, in accordance with the terms and conditions of this Agreement and the Plan.
5.
Each Performance Unit represents a right to receive the applicable Performance Unit value in the chart below, in cash on the Payment Date, if and only if, such Performance Unit (i) has not been forfeited prior to its Vesting Date and (ii) has vested in accordance with the terms of this Agreement.
The value of each Performance Unit will depend upon the Company’s actual Proportional Free Cash Flow (“PFCF”) as defined below, over the Performance Period as compared to the performance target approved by the Committee and as follows:
ACTUAL PFCF
OVER THE PERFORMANCE PERIOD
PERFORMANCE UNIT VALUE
Below 75% of Performance Target =
USD$0.00
Equal to 87.5% of Performance Target =
USD$0.50
Equal to 100% of Performance Target =
USD$1.00
Equal to or greater than 125% of Performance Target =
USD$2.00
For PFCF levels achieved greater than 75% and less than 87.5% of performance target, greater than 87.5% and less than 100% of performance target, and greater than 100% and less than 125% of performance target, the Performance Unit value will be determined based on straight-line interpolation. The maximum value of a Performance Unit is $2.00.
Notwithstanding the performance level achieved, the Committee may reduce or terminate the Performance Units altogether, but in no event may the Committee increase the value of a Performance Unit underlying this Award of Performance Units beyond the performance levels achieved.
6.
Notwithstanding the foregoing, in the event of a (i) Change in Control (as defined below) and (ii) a Qualifying Event (as defined below) prior to the end of the Performance Period, if the Performance Units described herein have not already been previously forfeited or

3


cancelled, such Performance Units shall become fully vested (for the total number of Performance Units set forth in paragraph 1) and payable in a cash amount equal to $1.00 for each Performance Unit and the Payment Date will occur contemporaneous with the Qualifying Event; provided, however, that in connection with a Change in Control, payment of any obligation payable pursuant to the preceding sentence may be made in cash of equivalent value and/or securities or other property in the Committee’s discretion.
(A)
Change in Control means the occurrence of one or more of the following events: (i) any sale, lease, exchange or other transfer (in one transaction or a series of related transactions) of all, or substantially all, of the assets of the Company to any Person or group (as that term is used in Section 13(d) (3) of the Exchange Act) of Persons, (ii) a Person or group (as so defined in the Plan) of Persons (other than Management of the Company on the date of the most recent adoption of the Plan by the Company's stockholders or their Affiliates) shall have become the beneficial owner (as defined below) of more than 35% of the outstanding voting stock of the Company, (iii) during any one-year period, individuals who at the beginning of such period constitute the Board (together with any new Director whose election or nomination was approved by a majority of the Directors then in office who were either Directors at the beginning of such period or who were previously so approved, but excluding under all circumstances any such new Director whose initial assumption of office occurs as a result of an actual or threatened election contest or other actual or threatened solicitation of proxies or consents by or on behalf of any individual, corporation, partnership or other entity or group, including through the use of proxy access procedures as may be provided in the Company’s bylaws) cease to constitute a majority of the Board, or (iv) the consummation of a merger, consolidation, business combination or similar transaction involving the Company unless securities representing 65% or more of the then outstanding voting stock of the corporation resulting from such transaction are held subsequent to such transaction by the Person or Persons who were the beneficial owners of the outstanding voting stock of the Company immediately prior to such transaction in substantially the same proportions as their ownership immediately prior to such transaction. Notwithstanding the foregoing or any provision to the contrary, if an Award is subject to Section 409A (and not excepted therefrom) and a Change in Control is a distribution event for purposes of an Award, the foregoing definition of Change in Control shall be interpreted, administered and construed in a manner necessary to ensure that the occurrence of any such event shall result in a Change in Control only if such event qualifies as a change in the ownership or effective control of a corporation, or a change in the ownership of a substantial portion of the assets of a corporation,

4


as applicable, within the meaning of Treas. Reg. § 1.409A-3(i)(5). For purposes of this Agreement, “beneficial owner(s)” shall have the meaning set forth in Rule 13d-3 of the Exchange Act.
(B)
Qualifying Event means the occurrence of one or more of the following events: (i) immediately upon the consummation of a Change in Control event, failure of the successor company in a Change in Control event to provide Substitute Awards that are substantially similar in both nature and terms (including having an equivalent realizable pre-tax value to the outstanding Awards assuming vesting and delivery at the consummation of the Change in Control); (ii) within two years of the consummation of a Change in Control event, an involuntary termination without Cause of the Employee; or (iii) within two years of the consummation of a Change in Control event, a Good Reason Termination (as defined in Section 6(C) below) by the Employee.
(C)
Good Reason Termination means, without an Employee’s written consent, the Separation from Service (for reasons other than death, Disability or Cause) by an Employee due to any of the following events occurring within two years of the consummation of a Change in Control: (i) the relocation of an Employee’s principal place of employment to a location that is more than 50 miles from the principal place of employment in effect immediately prior to such Change in Control; (ii) a material diminution in the duties or responsibilities of an Employee from those in place immediately prior to such Change in Control; and (iii) a material reduction in the base salary or annual incentive opportunity of an Employee from what was in place immediately prior to such Change in Control.
In order for an Employee to have a Good Reason Termination, (i) an Employee must notify the successor entity in writing, within ninety (90) days of the event constituting Good Reason of the Employee’s intent to terminate employment for Good Reason, that specifically identifies in reasonable detail the manner of the Good Reason event, (ii) the event must remain uncorrected for thirty (30) days following the date that an Employee notifies the successor entity in writing of the Employee’s intent to terminate employment for Good Reason (the “Notice Period”), and (iii) the termination date must occur within sixty (60) days after expiration of the Notice Period.
7.
Notices hereunder and under the Plan, if to the Company, shall be delivered to the Plan Administrator (as so designated by the Company) or mailed to the Company’s principal office, 4300 Wilson Boulevard, Arlington, VA 22203 (or as subsequently designated by the Company), attention of the Plan Administrator, or, if to the Employee, shall be

5


delivered to the Employee, which may include electronic delivery, or mailed to his or her address as the same appears on the records of the Company.
8.
All decisions and interpretations made by the Board of Directors or the Committee with regard to any question arising hereunder or under the Plan shall be binding and conclusive on all persons. Unless otherwise specifically provided herein, in the event of any inconsistency between the terms of the Plan and this Agreement, the terms of the Plan will govern.
9.
By accepting this Award of Performance Units, the Employee acknowledges receipt of a copy of the Plan and the prospectus relating to this Award of Performance Units, and agrees to be bound by the terms and conditions set forth in the Plan and this Agreement, as in effect and/or amended from time to time.

The Employee further acknowledges that the Plan and related documents, which may include the Plan prospectus, may be delivered electronically. Such means of delivery may include the delivery of a link to a Company intranet site or the internet site of a third party involved in administering the Plan, the delivery of the documents via e-mail or CD-ROM or such other delivery determined at the Plan Administrator’s discretion. The Employee acknowledges that the Employee may receive from the Company a paper copy of any documents delivered electronically at no cost if the Employee contacts the Human Resources department of the Company by telephone at (703) 682-6553 or by mail to 4300 Wilson Boulevard, Suite 1100, Arlington, Virginia 22203. The Employee further acknowledges that the Employee will be provided with a paper copy of any documents delivered electronically if electronic delivery fails.
10.
This Award is intended to satisfy the requirements of Section 409A of the Code (or an exception thereto) and shall be administered, interpreted and construed accordingly. A payment shall be treated as made on the specified date of payment if such payment is made at such date or a later date in the same calendar year or, if later, by the 15th day of the third calendar month following the specified date of payment, as provided and in accordance with Treas. Reg. § 1.409A-3(d). The Company may, in its sole discretion and without the Employee’s consent, modify or amend the terms and conditions of this Award, impose conditions on the timings and effectiveness of the payment of the Performance Units, or take any other action it deems necessary or advisable, to cause this Award to comply with Section 409A of the Code (or an exception thereto). Notwithstanding, the Employee recognizes and acknowledges that Section 409A of the Code may impose upon the Employee certain taxes or interest charges for which the Employee is and shall remain solely responsible.

6


11.
The Employee acknowledges that any income for federal, state or local income tax purposes that the Employee is required to recognize on account of the vesting of the Performance Units and/or payment in settlement of the Performance Units to the Employee shall be subject to withholding of tax by the Company.  In accordance with administrative procedures established by the Company, the Company shall mandatorily satisfy the Employee’s minimum statutory withholding tax obligations, if any, by withholding from the payment in settlement of the Performance Units to be made to the Employee a sufficient amount equal to the applicable minimum statutory withholding tax obligation.
12.
Notwithstanding any other provisions in this Agreement, any Performance Units subject to recovery under any law, government regulation, stock exchange listing requirement, or Company policy, shall be subject to such deductions, recoupment and clawback as may be required to be made pursuant to such law, government regulation, stock exchange listing requirement or Company policy, as may be in effect from time to time, and which may operate to create additional rights for the Company with respect to this Award and recovery of amounts relating thereto.  By accepting this Award, Employee agrees and acknowledges that he or she is obligated to cooperate with, and provide any and all assistance necessary to, the Company to recover, recoup or recapture this Award or amounts paid under the Plan pursuant to such law, government regulation, stock exchange listing requirement or Company policy. Such cooperation and assistance shall include, but is not limited to, executing, completing and submitting any documentation necessary to recover, recoup or recapture this Award or amounts paid under the Plan from Employee’s accounts, or pending or future compensation or other grants.
13.
This Agreement will be governed by the laws of the State of Delaware without giving effect to its choice of law provisions.
The AES CORPORATION

By:
Tish Mendoza
Senior Vice President and Chief Human Resources Officer

7

Exhibit


PERFORMANCE CASH UNIT AWARD AGREEMENT
PURSUANT TO
THE AES CORPORATION 2003 LONG TERM COMPENSATION PLAN
The AES Corporation, a Delaware Corporation (the “Company”), grants to the Employee named below, pursuant to The AES Corporation 2003 Long Term Compensation Plan, as amended (the “Plan”), and this Performance Cash Unit Award Agreement (this “Agreement”), this Award of Performance Cash Units (“PCUs”), the value of which is related to and contingent upon the achievement of predetermined performance target (as set forth herein). Capitalized terms not otherwise defined herein shall each have the meaning assigned to them in the Plan.
1.
This Award of PCUs is subject to all terms and conditions of this Agreement and the Plan, the terms of which are incorporated herein by reference:
Name of Employee:


Fidelity System ID:


Grant Date:


Target Number of PCUs:


Target Value:
 

Notwithstanding any provision of the Plan to the contrary, this Award of PCUs is subject to the terms and conditions of this Agreement and the Plan regardless of whether the Employee is a Covered Person, as defined in the Plan.
2.
The Employee is hereby granted an Award of the Target number of PCUs set forth above. The PCUs will be reflected in a book account by the Company during the Performance Period (as defined below). Contingent upon achieving required performance levels, the value of vested PCUs, will be paid in cash in the calendar year following the completion of the Performance Period (the “Payment Date”), as soon as administratively practicable following the end of the Performance Period.


3.
The “Performance Period” is the three calendar year period beginning on January 1st in the year of grant and ending on and through December 31st in the second year following the year of the grant date.
4.
Except as otherwise provided in this Agreement, this Award of PCUs will vest, in accordance with and subject to the terms of this Agreement, in three equal installments on December 31st in each year during the Performance Period (each a “Vesting Date”); provided, however, that if:
(A)
the Employee Separates from Service prior to the end of the Performance Period by reason of the Employee’s death or a Separation from Service on account of Disability, all PCUs referenced in the chart above shall vest on such termination date and a cash amount equal to $1 for each PCU shall be paid to the Employee on the date of Separation from Service (or as soon as practicable thereafter); provided, however, any payment due to the Employee by reason of a Separation from Service on account of Disability shall be delayed to the extent required by Section 14(k)(i) of the Plan;
(B)
(i) the Employee Separates from Service prior to the Payment Date by reason of a Separation from Service by the Company for Cause (as defined in the Plan and as may otherwise be determined by the Committee in its sole discretion for all purposes of this Agreement) or (ii) the Employee Separates from Service prior to the final Vesting Date by reason of a voluntary Separation from Service by the Employee (including any retirement other than a Qualified Retirement (as defined below)), this Award of PCUs (including any vested portion) will be forfeited in full and cancelled by the Company, and shall cease to be outstanding, upon such termination date; and
(C)
the Employee Separates from Service for any other reason, including on account of a Qualified Retirement, by reason of death or Disability subsequent to the end of the Performance Period, or by reason of a Separation from Service by the Company (other than for Cause, voluntarily by the Employee not as part of a Qualified Retirement or due to death or Disability as provided in paragraphs 4(A) and 4(B)), the Employee will be eligible to receive the value of his or her vested PCUs, as of the date of Separation from Service, on the Payment Date in accordance with and subject to the terms set forth in paragraph 5 below. For purposes of this Agreement, “Qualified Retirement” means the Employee’s retirement at a time when such Employee is at least 60 years of age and has at least seven years of service as an employee of the Company and/or one or more of its Affiliates.

2


Any PCUs that have not vested on or before the date that an Employee Separates from Service for any reason (other than by reason of death or Disability as provided in paragraph 4(A)), (i) will not subsequently vest; and (ii) will be immediately cancelled and forfeited without payment or further obligation by the Company or any Affiliate. In addition, the Employee’s right to receive the applicable PCU value in respect of vested PCUs that have not been forfeited will be paid on the Payment Date, if, and only if, all relevant performance conditions are met, in accordance with the terms and conditions of this Agreement and the Plan.
5.
Each PCU represents a right to receive the applicable PCU value in the chart below, in cash on the Payment Date, if and only if, such PCU (i) has not been forfeited prior to its Vesting Date and (ii) has vested in accordance with the terms of this Agreement.
The value of each PCU will depend upon the performance of the Total Shareholder Return of AES common stock (“AES TSR”) as compared to the Total Shareholder Return of companies in the peer groups listed below over the Performance Period:

PEER GROUP INDEX
PROPORTIONAL WEIGHTING
S&P Utilities Index
50%
S&P 500 Index
25%
MSCI Emerging Markets Index
25%


ACTUAL AES-TSR COMPARED TO
EACH PEER GROUP INDEX FOR THE
PERFORMANCE PERIOD
INDEX SCORE
 
 
Below 30th Percentile
0%
 
 
Equal to the 30th Percentile
50%
 
 
Equal to the 50th Percentile
100%
 
 
Equal to or the 70th Percentile
150%
 
 
Equal to or greater than 90th Percentile
200%
 

For AES TSR levels achieved greater than the 30th percentile and less than the 50th percentile, greater than 50th percentile and less than 70th percentile, and greater than the 70th percentile and less than the 90th percentile, the Index Score will be determined based on straight-line interpolation. The maximum Index Score is 200%.

3


The AES TSR will be evaluated against each of the separate peer group indices separately to determine the three index scores. The overall performance value for a PCU will be equal to:
The number of vested PCUs x $1.00 x [(S&P 500 Utilities Index Score x 50%) + (S&P 500 Index Score x 25%) + (MSCI Emerging Markets Index Score x 25%)] = Total Earned PCU Value
Notwithstanding the performance level achieved, the Committee may reduce or terminate the PCUs altogether, but in no event may the Committee increase the value of a PCU underlying this Award beyond the performance levels achieved.
6.
Notwithstanding the foregoing, in the event of a (i) Change in Control (as defined below) and (ii) a Qualifying Event (as defined below) prior to the end of the Performance Period, if the PCUs described herein have not already been previously forfeited or cancelled, such PCUs shall become fully vested (for the Target number of PCUs set forth in paragraph 1) and payable in a cash amount equal to $1.00 for each PCU, and the Payment Date will occur contemporaneous with the Qualifying Event; provided, however, that in connection with a Change in Control, payment of any obligation payable pursuant to the preceding sentence may be made in cash of equivalent value and/or securities or other property in the Committee’s discretion.
(A)
Change in Control means the occurrence of one or more of the following events: (i) any sale, lease, exchange or other transfer (in one transaction or a series of related transactions) of all, or substantially all, of the assets of the Company to any Person or group (as that term is used in Section 13(d) (3) of the Exchange Act) of Persons, (ii) a Person or group (as defined in the Plan) of Persons (other than Management of the Company on the date of the most recent adoption of the Plan by the Company's stockholders or their Affiliates) shall have become the beneficial owner (as defined below) of more than 35% of the outstanding voting stock of the Company, (iii) during any one-year period, individuals who at the beginning of such period constitute the Board (together with any new Director whose election or nomination was approved by a majority of the Directors then in office who were either Directors at the beginning of such period or who were previously so approved, but excluding under all circumstances any such new Director whose initial assumption of office occurs as a result of an actual or threatened election contest or other actual or threatened solicitation of proxies or consents by or on behalf of any individual, corporation, partnership or other entity or group, including through the use of proxy access procedures as may be provided in the Company’s bylaws) cease to constitute a majority of the Board, or

4


(iv) the consummation of a merger, consolidation, business combination or similar transaction involving the Company unless securities representing 65% or more of the then outstanding voting stock of the corporation resulting from such transaction are held subsequent to such transaction by the Person or Persons who were the beneficial owners of the outstanding voting stock of the Company immediately prior to such transaction in substantially the same proportions as their ownership immediately prior to such transaction. Notwithstanding the foregoing or any provision to the contrary, if an Award is subject to Section 409A (and not excepted therefrom) and a Change in Control is a distribution event for purposes of an Award, the foregoing definition of Change in Control shall be interpreted, administered and construed in a manner necessary to ensure that the occurrence of any such event shall result in a Change in Control only if such event qualifies as a change in the ownership or effective control of a corporation, or a change in the ownership of a substantial portion of the assets of a corporation, as applicable, within the meaning of Treas. Reg. § 1.409A-3(i)(5). For purposes of this Agreement, “beneficial owner(s)” shall have the meaning set forth in Rule 13d-3 of the Exchange Act.
(B)
Qualifying Event means the occurrence of one or more of the following events: (i) immediately upon the consummation of a Change in Control event, failure of the successor company in a Change in Control event to provide Substitute Awards that are substantially similar in both nature and terms (including having an equivalent realizable pre-tax value to outstanding Awards assuming vesting and delivery at the consummation of the Change in Control); (ii) within two years of the consummation of a Change in Control event, an involuntary termination without Cause of the Employee; or (iii) within two years of the consummation of a Change in Control event, a Good Reason Termination (as defined in Section 6(C) below) by the Employee.
(C)
Good Reason Termination means, without an Employee’s written consent, the Separation from Service (for reasons other than death, Disability or Cause) by an Employee due to any of the following events occurring within two years of the consummation of a Change in Control: (i) the relocation of an Employee’s principal place of employment to a location that is more than 50 miles from the principal place of employment in effect immediately prior to such Change in Control; (ii) a material diminution in the duties or responsibilities of an Employee from those in place immediately prior to such Change in Control; and (iii) a material reduction in the base salary or annual incentive opportunity of an Employee from what was in place immediately prior to such Change in Control.

5


In order for an Employee to have a Good Reason Termination, (i) an Employee must notify the successor entity in writing, within ninety (90) days of the event constituting Good Reason of the Employee’s intent to terminate employment for Good Reason, that specifically identifies in reasonable detail the manner of the Good Reason event, (ii) the event must remain uncorrected for thirty (30) days following the date that an Employee notifies the successor entity in writing of the Employee’s intent to terminate employment for Good Reason (the “Notice Period”), and (iii) the termination date must occur within sixty (60) days after expiration of the Notice Period.
7.
Notices hereunder and under the Plan, if to the Company, shall be delivered to the Plan Administrator (as so designated by the Company) or mailed to the Company’s principal office, 4300 Wilson Boulevard, Arlington, VA 22203 (or as subsequently designated by the Company), attention of the Plan Administrator, or, if to the Employee, shall be delivered to the Employee, which may include electronic delivery, or mailed to his or her address as the same appears on the records of the Company.
8.
All decisions and interpretations made by the Board of Directors or the Committee with regard to any question arising hereunder or under the Plan shall be binding and conclusive on all persons. Unless otherwise specifically provided herein, in the event of any inconsistency between the terms of the Plan and this Agreement, the terms of the Plan will govern.
9.
By accepting this Award of PCUs, the Employee acknowledges receipt of a copy of the Plan and the prospectus relating to this Award of PCUs, and agrees to be bound by the terms and conditions set forth in the Plan and this Agreement, as in effect and/or amended from time to time.

The Employee further acknowledges that the Plan and related documents, which may include the Plan prospectus, may be delivered electronically. Such means of delivery may include the delivery of a link to a Company intranet site or the internet site of a third party involved in administering the Plan, the delivery of the documents via e-mail or CD-ROM or such other delivery determined at the Plan Administrator’s discretion. The Employee acknowledges that the Employee may receive from the Company a paper copy of any documents delivered electronically at no cost if the Employee contacts the Human Resources department of the Company by telephone at (703) 682-6553 or by mail to 4300 Wilson Boulevard, Suite 1100, Arlington, Virginia 22203. The Employee further acknowledges that the Employee will be provided with a paper copy of any documents delivered electronically if electronic delivery fails.

6


10.
This Award is intended to satisfy the requirements of Section 409A of the Code (or an exception thereto) and shall be administered, interpreted and construed accordingly. A payment shall be treated as made on the specified date of payment if such payment is made at such date or a later date in the same calendar year or, if later, by the 15th day of the third calendar month following the specified date of payment, as provided and in accordance with Treas. Reg. § 1.409A-3(d). The Company may, in its sole discretion and without the Employee’s consent, modify or amend the terms and conditions of this Award, impose conditions on the timings and effectiveness of the payment of the PCUs, or take any other action it deems necessary or advisable, to cause this Award to comply with Section 409A of the Code (or an exception thereto). Notwithstanding, the Employee recognizes and acknowledges that Section 409A of the Code may impose upon the Employee certain taxes or interest charges for which the Employee is and shall remain solely responsible.
11.
The Employee acknowledges that any income for federal, state or local income tax purposes that the Employee is required to recognize on account of the vesting of the PCUs and/or payment in settlement of the PCUs to the Employee shall be subject to withholding of tax by the Company.  In accordance with administrative procedures established by the Company, the Company shall mandatorily satisfy the Employee’s minimum statutory withholding tax obligations, if any, by withholding from the payment in settlement of the PCUs to be made to the Employee a sufficient amount equal to the applicable minimum statutory withholding tax obligation.
12.
Notwithstanding any other provisions in this Agreement, any PCUs subject to recovery under any law, government regulation, stock exchange listing requirement, or Company policy, shall be subject to such deductions, recoupment and clawback as may be required to be made pursuant to such law, government regulation, stock exchange listing requirement or Company policy, as may be in effect from time to time, and which may operate to create additional rights for the Company with respect to this Award and recovery of amounts relating thereto.  By accepting this Award, Employee agrees and acknowledges that he or she is obligated to cooperate with, and provide any and all assistance necessary to, the Company to recover, recoup or recapture this Award or amounts paid under the Plan pursuant to such law, government regulation, stock exchange listing requirement or Company policy. Such cooperation and assistance shall include, but is not limited to, executing, completing and submitting any documentation necessary to recover, recoup or recapture this Award or amounts paid under the Plan from Employee’s accounts, or pending or future compensation or other grants.
13.
This Agreement will be governed by the laws of the State of Delaware without giving effect to its choice of law provisions.

7


The AES CORPORATION

By:
Tish Mendoza
Senior Vice President and Chief Human Resources Officer

8


Exhibit


Exhibit 12
The AES Corporation and Subsidiaries
Statement Re: Calculation of Ratio of Earnings to Fixed Charges
(in millions, unaudited)
 
 
2015
 
2014
 
2013
 
2012
 
2011
Actual:


Computation of earnings:


Income from continuing operations before income taxes and equity in earnings of affiliates
$
1,122

 
$
1,576

 
$
1,048

 
$
230

 
$
2,260

Fixed charges
1,559

 
1,584

 
1,595

 
1,693

 
1,799

Amortization of capitalized interest
19

 
21

 
20

 
18

 
9

Distributed income of equity investees
16

 
28

 
2

 
5

 
25

Less:


Capitalized interest
(97
)
 
(75
)
 
(58
)
 
(87
)
 
(152
)
Preference security dividend of consolidated subsidiary
(10
)
 
(5
)
 
(6
)
 
(6
)
 
(4
)
Noncontrolling interests in pretax income of subsidiaries that have not incurred fixed charges
(28
)
 
(26
)
 
(40
)
 
(4
)
 
(2
)
Earnings
$
2,581

 
$
3,103

 
$
2,561

 
$
1,849

 
$
3,935


Fixed charges:


Interest expense, debt premium and discount amortization
$
1,430

 
$
1,485

 
$
1,516

 
$
1,581

 
$
1,623

Capitalized interest
97

 
75

 
58

 
87

 
152

Preference security dividend of consolidated subsidiary
10

 
5

 
6

 
6

 
4

Interest portion of rental expense (1)
22

 
19

 
15

 
19

 
20

Fixed charges
$
1,559

 
$
1,584

 
$
1,595

 
$
1,693

 
$
1,799

Ratio of earnings to fixed charges
1.66

 
1.96

 
1.61

 
1.09

 
2.19

(1) Calculated as one-third of rental expense, which is deemed to be representative of the interest factor in rental expense.


Exhibit

The AES Corporation
2015 Form 10-K Exhibit 21.1
Name
Jurisdiction
AES (India) Private Limited
India
AES (NI) Limited
Northern Ireland
AES Abigail S.a.r.l.
Luxembourg
AES Africa Power Company B.V.
The Netherlands
AES AgriVerde Holdings, B.V.
The Netherlands
AES AgriVerde Services (Ukraine) Limited Liability Company
Ukraine
AES Alamitos Development, Inc.
Delaware
AES Alamitos Energy, LLC
Delaware
AES Alamitos, L.L.C.
Delaware
AES Alicura Holdings S.C.A
Argentina
AES Americas International Holdings, Limited
Bermuda
AES Amsterdam Holdings B.V.
The Netherlands
AES Andes Energy, Inc.
Delaware
AES Andres (BVI) Ltd.
British Virgin Islands
AES Andres BV
Spain
AES Andres Dominicana, Ltd.
Cayman Islands
AES Andres DR, S.A.
Dominican Republic
AES Andres Holdings I, Ltd
Cayman Islands
AES Aramtermelo Holdings B.V.
The Netherlands
AES Argentina Generación S.A.
Argentina
AES Argentina Holdings S.C.A.
Uruguay
AES Argentina Investments, Ltd.
Cayman Islands
AES Argentina Operations, Ltd.
Cayman Islands
AES Argentina, Inc.
Delaware
AES Arlington Services, LLC
Delaware
AES Armenia Mountain Holdings, LLC
Delaware
AES Armenia Mountain Wind 2, LLC
Delaware
AES Athens Holdings B.V.
The Netherlands
AES Aurora Holdings, Inc.
Delaware
AES Aurora, Inc.
Delaware
AES Bainbridge Holdings, LLC
Delaware
AES Bainbridge, LLC
Delaware
AES Ballylumford Holdings Limited
England & Wales
AES Ballylumford Limited
Northern Ireland
AES Baltic Holdings BV
The Netherlands
AES Barka Services, Inc.
Delaware
AES Barry Limited
United Kingdom
AES Barry Operations Ltd.
United Kingdom
AES Beaver Valley, L.L.C.
Delaware
AES Belfast West Power Limited
Northern Ireland
AES Big Sky, L.L.C.
Virginia
AES Borsod CFB Kft
Hungary
AES Borsod Energetic Ltd.
Hungary
AES Borsod Holdings Limited
United Kingdom
AES Botswana Holdings B.V.
The Netherlands
AES Brasil Investimentos e Participacoes Ltda.
Brazil
AES Brasil Ltda
Brazil
AES Brazil International Holdings, Limited
Bermuda
AES Brazil Investimento II, LLC
Delaware
AES Brazil Investimento III, LLC
Delaware
AES Brazil, Inc.
Delaware
AES Brazilian Holdings, Ltd.
Cayman Islands
AES Bulgaria B.V.
The Netherlands
AES Bulgaria Holdings BV
The Netherlands


AES Bulgaria Trading EOOD
Bulgaria
AES Bussum Holdings BV
The Netherlands
AES CAESS Distribution, Inc.
Delaware
AES Calaca Pte. Ltd.
Singapore
AES Calaca Pte. Ltd. - Philippine Branch
Philippines
AES Calgary, Inc.
Delaware
AES California Management Co., Inc.
Delaware
AES Caracoles SRL
Argentina
AES Carbon Exchange, Ltd.
Bermuda
AES Carbon Holdings, LLC
Virginia
AES Caribbean Finance Holdings, Inc.
Delaware
AES Caribbean Investment Holdings, Ltd.
Cayman Islands
AES Cartegena Holdings BV
The Netherlands
AES Cayman Guaiba, Ltd.
Cayman Islands
AES Cayman Islands Holdings, Ltd.
Cayman Islands
AES Cayman Pampas, Ltd.
Cayman Islands
AES CC&T Holdings LLC
Delaware
AES CC&T International, Ltd.
British Virgin Islands
AES Central America Electric Light, Ltd.
Cayman Islands
AES Central American Holdings, Inc.
Delaware
AES Central American Investment Holdings, Ltd.
Cayman Islands
AES Central Asia Holdings BV
The Netherlands
AES Changuinola, S.R.L.
Panama
AES Chhattisgarh Energy Private Limited
India
AES Chigen Holdings, Ltd.
Cayman Islands
AES China Generating Co. Ltd.
Bermuda
AES China Hydropower Investment Co. Pte. Ltd.
Singapore
AES Chivor & Cia S.C.A. E.S.P.
Colombia
AES Chivor S.A.
Colombia
AES CLESA Y Compania, Sociedad en Comandita de Capital Variable
El Salvador
AES Climate Solutions Holdings I B.V.
The Netherlands
AES Climate Solutions Holdings I, LLC
Delaware
AES Climate Solutions Holdings II, LLC
Delaware
AES Climate Solutions Holdings, L.P.
Bermuda
AES Climate Solutions Holdings, LLC
Delaware
AES Columbia Power, LLC
Delaware
AES Communications Latin America, Inc.
Delaware
AES Communications, Ltd.
Cayman Islands
AES Connecticut Management, L.L.C.
Delaware
AES Coop Holdings, LLC
Delaware
AES Costa Rica Energy SRL
Costa Rica
AES Costa Rica Holdings, Ltd.
Cayman Islands
AES DE Construction, LLC
Colorado
AES DE Holdings I, LLC
Colorado
AES DE Holdings II, LLC
Delaware
AES DE International Holdings I, LLC
Colorado
AES DE Manager, LLC
Colorado
AES DE Residential Holdings I, LLC
Colorado
AES DE Solar Access Holdings I, LLC
Delaware
AES Deepwater, LLC
Delaware
AES Desert Power, L.L.C.
Delaware
AES Development de Argentina S.A.
Argentina
AES Disaster Relief Fund
Virginia
AES Distribuidores Salvadorenos Limitada
El Salvador
AES Distribuidores Salvadorenos Y Compania S en C de C.V.
El Salvador
AES Distributed Energy, Inc.
Delaware
AES DPL Holdings, LLC
Delaware
AES Drax Financing, Inc.
Delaware


AES Drax Power Finance Holdings Limited
United Kingdom
AES Eastern Wind, L.L.C.
Delaware
AES Ecotek Europe Holdings B.V.
The Netherlands
AES EDC Holding, L.L.C.
Delaware
AES EEO Distribution, Inc.
Delaware
AES El Faro Electric Light, Ltd.
Cayman Islands
AES El Faro Generating, Ltd.
Cayman Islands
AES El Faro Generation, Inc.
Delaware
AES El Salvador Distribution Ventures, Ltd.
Cayman Islands
AES El Salvador Electric Light, LLC
Virginia
AES El Salvador Trust
Panama
AES El Salvador, LLC
Virginia
AES El Salvador, S.A. de C.V.
El Salvador
AES Electric Ltd.
United Kingdom
AES Electroinversora Espana S.L.
Spain
AES Elpa S.A.
Brazil
AES Elsta BV
The Netherlands
AES Empresa Electrica de El Salvador Limitada de Capital Variable
El Salvador
AES Endeavor, Inc.
Delaware
AES Energia I, Ltd.
Cayman Islands
AES Energia II, Ltd.
Cayman Islands
AES Energia Mexicana I, S. de R.L. de C.V.
Mexico
AES Energy Developments (Pty) Ltd.
South Africa
AES Energy Developments, S.L.
Spain
AES Energy Services Inc.
Ontario
AES Energy Solutions, LLC
Delaware
AES Energy Storage Holdings, LLC
Delaware
AES Energy Storage Zeeland B.V.
The Netherlands
AES Energy Storage, LLC
Delaware
AES Energy, Ltd.
Bermuda
AES Energy, Ltd. (Argentina Branch)
Argentina
AES Engineering, LLC
Delaware
AES Engineering, Ltd.
Cayman Islands
AES ES Alamitos, LLC
Delaware
AES ES Deepwater, LLC
Delaware
AES ES Holdings, LLC
Delaware
AES ES Tait, LLC
Delaware
AES Europe Services EOOD
Bulgaria
AES European Holdings BV
The Netherlands
AES European Investments Cooperatief U.A.
The Netherlands
AES Finance and Development, Inc.
Delaware
AES Florestal Ltda.
Brazil
AES Fonseca Energia Limitada de C.V.
El Salvador
AES Forca, Ltd.
Cayman Islands
AES Foreign Energy Holdings, LLC
Delaware
AES Gas Supply & Distribution Ltd.
Cayman Islands
AES GEI US Finance, Inc.
Delaware
AES Gener S.A.
Chile
AES Generation Development, LLC
Delaware
AES GEO Energy OOD
Bulgaria
AES Global African Power (Proprietary) Limited
South Africa
AES Global Insurance Company
Vermont
AES Global Mobility Services, LLC
Delaware
AES Global Power Holdings B.V.
The Netherlands
AES GPH Holdings, Inc.
Delaware
AES Grand Dominicana, Ltd.
Cayman Islands
AES Great Britain Holdings B.V.
The Netherlands
AES Grid Stability, LLC
Delaware


AES GT Holding Pty Ltd
Australia
AES Guaiba II Empreendimentos Ltda
Brazil
AES Guayama Holdings BV
The Netherlands
AES Hawaii Management Company, Inc.
Delaware
AES Hawaii, Inc.
Delaware
AES Highgrove Holdings, L.L.C.
Delaware
AES Highgrove, L.L.C.
Delaware
AES Hispanola Holdings BV
The Netherlands
AES Hispanola Holdings II BV
The Netherlands
AES Holanda Holdings C.V.
The Netherlands
AES Holdings B.V.
The Netherlands
AES Holdings B.V. - Vietnam Rep Office
Vietnam
AES Holdings Brasil Ltda.
Brazil
AES Honduras Generacion, Sociedad en Comandita por Acciones de Capital Variable
Honduras
AES Honduras Generation Ventures, Ltd.
Cayman Islands
AES Honduras Holdings, Ltd.
Cayman Islands
AES Horizons Holdings BV
The Netherlands
AES Horizons Investments Limited
United Kingdom
AES Hungary Energiaszolgáltató Kft.
Hungary
AES Huntington Beach Development, L.L.C.
Delaware
AES Huntington Beach Energy, LLC
Delaware
AES Huntington Beach, L.L.C.
Delaware
AES IB Valley Corporation
India
AES Ilumina Holdings, LLC
Delaware
AES Ilumina Member, LLC
Delaware
AES Ilumina, LLC
Puerto Rico
AES India Holdings (Mauritius)
Mauritius
AES India, L.L.C.
Delaware
AES Indiana Holdings, L.L.C.
Delaware
AES Intercon II, Ltd.
Cayman Islands
AES Interenergy, Ltd.
Cayman Islands
AES International Holdings II, Ltd.
British Virgin Islands
AES International Holdings III, Ltd.
British Virgin Islands
AES International Holdings, Ltd.
British Virgin Islands
AES Investment Chile SpA
Chile
AES IPP S. de R.L. de C.V.
Mexico
AES Isthmus Energy, S.A.
Panama
AES Jordan Holdco Cayman Limited
Cayman Islands
AES Jordan Holdco, Ltd.
Cayman Islands
AES Jordan PSC
Jordan
AES Juniper Point Holdings, LLC
Delaware
AES K2 Limited
United Kingdom
AES Kalaeloa Venture, L.L.C.
Delaware
AES Kelanitissa (Private) Limited
Sri Lanka
AES Keystone Wind, L.L.C.
Delaware
AES Keystone, L.L.C.
Delaware
AES Khanya - Kwazulu Natal (Proprietary) Limited
South Africa
AES Khanya - Port Elizabeth (Pty) Ltd.
South Africa
AES Kienke Holdings B.V.
The Netherlands
AES Kilroot Generating Limited
Northern Ireland
AES Kilroot Power Limited
Northern Ireland
AES King Harbor, Inc.
Delaware
AES Kingston Holdings B.V.
The Netherlands
AES Landfill Carbon, LLC
Virginia
AES LATAM Energy Development Ltd.
Cayman Islands
AES Latin America S. de R.L.
Panama
AES Latin American Development, Ltd.
Cayman Islands
AES Laurel Mountain, LLC
Delaware


AES Levant Holdings B.V.
The Netherlands
AES Levant Holdings B.V/ Jordan PSC
Jordan
AES Lion Telecom Investments B.V.
The Netherlands
AES LNG Holding II, Ltd.
Cayman Islands
AES LNG Holding III, Ltd.
Cayman Islands
AES LNG Holding IV, Ltd.
Cayman Islands
AES LNG Holding, Ltd.
Cayman Islands
AES Maastricht Holdings B.V.
The Netherlands
AES Maritza East 1 Ltd.
Bulgaria
AES Maritza East 1 Services Ltd.
Cyprus
AES Maritza East 1 Services Ltd.
Bulgaria
AES Masinloc Pte. Ltd.
Singapore
AES Mayan Holdings, S. de R.L. de C.V.
Mexico
AES Merida B.V.
The Netherlands
AES Merida III, S. de R.L. de C.V.
Mexico
AES Merida Management Services, S. de R.L. de C.V.
Mexico
AES Merida Operaciones SRL de CV
Mexico
AES Mexican Holdings, Ltd.
Cayman Islands
AES Mexico Farms, L.L.C.
Delaware
AES MicroPlanet, Ltd.
British Virgin Islands
AES Mid East Holdings 2, Ltd.
Cayman Islands
AES Middelzee Holding B.V.
The Netherlands
AES Mong Duong Holdings B.V.
The Netherlands
AES Mong Duong Project Holdings B.V.
The Netherlands
AES Monroe Holdings B.V.
The Netherlands
AES Mont Blanc Holdings B.V.
The Netherlands
AES Mount Vernon B.V.
The Netherlands
AES NA Central, L.L.C.
Delaware
AES Nejapa Gas Ltda. de C.V.
El Salvador
AES Nejapa Services Ltda. de C.V.
El Salvador
AES Netherlands Holdings B.V.
The Netherlands
AES New York Capital, L.L.C.
Delaware
AES New York Funding, L.L.C.
Delaware
AES Nigeria Holdings, Ltd.
Cayman Islands
AES Nile Power Finance (Uganda) Limited
Uganda
AES Nile Power Holdings Ltd.
Guernsey
AES Nile Power Ltd.
Uganda
AES Normandy Holdings B.V.
The Netherlands
AES North America Development, LLC
Delaware
AES Oasis Holdco, Inc.
Delaware
AES Oasis Ltd.
Cayman Islands
AES Oasis Mauritius Inc
Mauritius
AES Ocean Springs Trust Deed
Cayman Islands
AES Ocean Springs, Ltd.
Cayman Islands
AES Odyssey, L.L.C.
Delaware
AES Ohio Generation, LLC
Ohio
AES Operadora S.A
Argentina
AES OPGC Holding
Mauritius
AES Orissa Distribution Private Limited
India
AES Overseas Holdings (Cayman) Ltd.
Cayman Islands
AES Overseas Holdings Limited
United Kingdom
AES Pacific Ocean Holdings B.V.
The Netherlands
AES Pacific, Inc.
Delaware
AES Pacific, L.L.C.
Delaware
AES Pak Holdings, Ltd.
British Virgin Islands
AES Pakistan (Pvt) Ltd.
Pakistan
AES Pakistan Operations, Ltd.
Delaware
AES Panama Holding, Ltd.
Cayman Islands


AES Panamá, S.R.L.
Panama
AES Parana Gas S.A.
Argentina
AES Parana Holdings, Ltd.
Cayman Islands
AES Parana II Limited Partnership
Cayman Islands
AES Parana Operations S.R.L.
Argentina
AES Parana Propiedades S.A
Argentina
AES Parana Uruguay S.R.L
Uruguay
AES Pardo Holdings, Ltd.
Cayman Islands
AES Pasadena, Inc.
Delaware
AES Peru S.R.L.
Peru
AES Phil Investment Pte. Ltd.
Singapore
AES Philippine Holdings BV
The Netherlands
AES Philippines Energy Storage Co. Ltd.
Philippines
AES Philippines Energy Storage Co., Ltd.
Philippines
AES Philippines Inc.
Philippines
AES Philippines Power Foundation, Inc.
 
AES Philippines Power Partners Co. Ltd.
Philippines
AES Pirin Holdings, Ltd.
Cayman Islands
AES Platense Investments Uruguay S.C.A
Uruguay
AES Puerto Rico Services, Inc.
Delaware
AES Puerto Rico, Inc.
Cayman Islands
AES Puerto Rico, L.P.
Delaware
AES Red Oak, Inc.
Delaware
AES Redondo Beach, L.L.C.
Delaware
AES Riverside Holdings, LLC
Delaware
AES SACEF Investment, LLC
Delaware
AES Saint Petersburg Holdings B.V.
The Netherlands
AES San Nicolas Holding Espana, S.L.
Spain
AES San Nicolas, Inc.
Delaware
AES SEB Holdings (Delaware), LLC
Delaware
AES SEB Holdings, Ltd.
Cayman Islands
AES Services Philippines Inc.
Philippines
AES Services, Inc.
Delaware
AES Services, Ltd.
Cayman Islands
AES Servicios America S.R. L.
Argentina
AES Servicios e Inversiones Globales
Spain
AES Servicios Electricos, S. de R.L. de C.V.
Mexico
AES Serviços TC Ltda.
Brazil
AES Shady Point, LLC
Delaware
AES Shigis Energy LLP
Kazakhstan
AES Shulbinsk GES LLP
Kazakhstan
AES Silk Road, Inc.
Delaware
AES Sirocco Limited
United Kingdom
AES Sogrinsk TETS LLP
Kazakhstan
AES Solar Energy, LLC
Delaware
AES Solar Holdings, LLC
Delaware
AES Solar Power PR, LLC
Delaware
AES Soluciones, Limitada de Capital Variable
El Salvador
AES Solutions, LLC
Virginia
AES South Africa Peakers Holdings (Proprietary) Limited
South Africa
AES South America Holdings Cooperatief U.A.
The Netherlands
AES South America Holdings I B.V.
The Netherlands
AES South America Holdings II B.V.
The Netherlands
AES South American Holdings, Ltd.
Cayman Islands
AES South Point, Ltd.
Cayman Islands
AES Southland Development, LLC
Delaware
AES Southland Energy Holdings, LLC
Delaware
AES Southland Energy, LLC
Delaware


AES Stonehaven Holding, Inc.
Delaware
AES Strategic Equipment Holdings Corporation
Delaware
AES Sul Distribuidora Gaucha de Energia S.A.
Brazil
AES Sul, L.L.C.
Delaware
AES Summit Generation Ltd.
United Kingdom
AES Swiss Lake Holdings B.V.
The Netherlands
AES Tamuin Development Services S. de R.L. de C.V.
Mexico
AES Technology Holdings, LLC
Delaware
AES TEG Holdings I, LLC
Delaware
AES TEG Holdings, LLC
Delaware
AES TEG II Mexican Holdings, S. de R.L. de C.V.
Mexico
AES TEG II Mexican Investments, S. de R.L. de C.V.
Mexico
AES TEG II Operations, S. de R.L. de C.V.
Mexico
AES TEG Management, Inc.
Delaware
AES TEG Mexican Holdings, S. de R.L. de C.V.
Mexico
AES TEG Mexican Investments S. de R.L. de C.V.
Mexico
AES TEG Operations, S. de R.L. de C.V.
Mexico
AES TEG Power Investments B.V.
The Netherlands
AES TEG Power Investments II B.V.
The Netherlands
AES TEGTEP Holdings B.V.
The Netherlands
AES TEGTEP Treasury Holdings B.V.
The Netherlands
AES Tehachapi Wind, LLC
Delaware
AES TEP Holdings I, LLC
Delaware
AES TEP Holdings, LLC
Delaware
AES TEP Management, Inc.
Delaware
AES TEP Power II Investments Limited
United Kingdom
AES TEP Power Investments Limited
United Kingdom
AES Termosul Empreendimentos Ltda
Brazil
AES Termosul I, Ltd.
Cayman Islands
AES Termosul II, Ltd.
Cayman Islands
AES Terneuzen Holdings B.V.
The Netherlands
AES Terneuzen Management Services BV
The Netherlands
AES Tesoreria I S. de R.L. de C.V.
Mexico
AES Tesoreria II S. de R.L. de C.V.
Mexico
AES Texas Funding III, L.L.C.
Delaware
AES Thomas Holdings BV
The Netherlands
AES Tietê Energia S.A.
Brazil
AES Tisza Holdings BV
The Netherlands
AES Trade I, Ltd.
Cayman Islands
AES Trade II, Ltd.
Cayman Islands
AES Transatlantic Holdings B.V.
The Netherlands
AES Transgas I, Ltd.
Cayman Islands
AES Transpower Private Ltd - Philippines Branch (ROHQ)
Philippines
AES Transpower Private Ltd.
Singapore
AES Transpower Private Ltd. - Philippines ROHQ
Philippines
AES Transpower Pte Ltd -- Hong Kong Branch
Hong Kong
AES Treasure Cove, Ltd.
Cayman Islands
AES Trinidad Services Unlimited
Trinidad and Tobago
AES Trust III
Delaware
AES U&K Holdings B.V.
The Netherlands
AES U.S. Holdings, LLC
Delaware
AES U.S. Investments, Inc.
Indiana
AES U.S. Solar, LLC
Delaware
AES UCH Holdings (Cayman) Ltd.
Cayman Islands
AES UCH Holdings, Ltd.
Cayman Islands
AES UK Datacenter Services Limited
United Kingdom
AES UK Holdings Limited
United Kingdom
AES UK Power Financing II Ltd
United Kingdom


AES UK Power Financing Limited
United Kingdom
AES UK Power Holdings Limited
United Kingdom
AES UK Power Limited
United Kingdom
AES UK Power, L.L.C.
Delaware
AES Union de Negocios, S.A. de C.V.
El Salvador
AES Uruguaiana Empreendimentos S.A.
Brazil
AES US Distributed Solar Holdings, LLC
Delaware
AES US Generation Holdings, LLC
Delaware
AES US Generation, LLC
Delaware
AES US Services, LLC
Delaware
AES US Wind Development, L.L.C.
Delaware
AES Ust-Kamenogorsk GES LLP
Kazakhstan
AES Ust-Kamenogorsk TETS LLP
Kazakhstan
AES Venezuela Finance
United Kingdom
AES Warrior Run, L.L.C.
Delaware
AES Western Power Holdings, L.L.C.
Delaware
AES Western Power, L.L.C.
Delaware
AES Western Wind MV Acquisition, LLC
Delaware
AES Western Wind, L.L.C.
Delaware
AES Wilson Creek Wind, LLC
Delaware
AES Wind Bulgaria EOOD
Bulgaria
AES Wind Generation Asset Management Services Limited
United Kingdom
AES Wind Generation Limited
England & Wales
AES Wind Generation, LLC
Delaware
AES Wind Investments I B.V.
The Netherlands
AES Wind Investments II B.V.
The Netherlands
AES WR Limited Partnership
Delaware
AES Yucatan, S. de R.L. de C.V.
Mexico
AES ZEG Holdings B.V.
The Netherlands
AES Zephyr 2, LLC
Delaware
AES Zephyr 3, LLC
Delaware
AES Zephyr, Inc.
Delaware
AES-3C Maritza East 1 Ltd.
Bulgaria
AESCom Sul Ltda.
Brazil
AESEBA Trust Deed
Cayman Islands
AES-R.E. Services Energy Investment Management Hellas EPE
Greece
AES-RS Spanish Holdings, LLC
Delaware
AES-RS Sunshine Cooperatief U.A.
The Netherlands
AES-RS Sunshine Holdings, LLC
Delaware
AES-VCM Mong Duong Power Company Limited
Vietnam
AgCert Canada Co.
Canada
AgCert Canada Holding, Limited
Ireland
AgCert Chile Servicios Ambientales Limitada
Chile
AgCert do Brasil Soluções Ambientais Ltda.
Brazil
AgCert International, Limited
Ireland
AgCert Mexico Servicios Ambientales, Sociedade de Responsibilidad Limitada de Capital Variable
Mexico
AgCert Servicios Ambientales S.R.L.
Argentina
ALBERICH Beteiligungsverwaltungs GmbH
Austria
Alectrona M EPE
Greece
Alectrona PV EPE
Greece
Alpha Water and Realty Services Corp.
Philippines
Altai Power Limited Liability Partnership
Kazakhstan
Alto Maipo SpA
Chile
Anhui Liyuan - AES Power Co., Ltd.
China
ANTURIE Beteiligungsverwaltungs GmbH
Austria
Arizona B&GC Solar, LLC
Colorado
ARNIKA Beteiligungsverwaltungs GmbH
Austria
Atlantic Basin Services, Ltd.
Cayman Islands


Aurora Master Funding, LLC
Delaware
Aurora Master Holdings, LLC
Delaware
AZ Solar I, LLC
Colorado
AZ Solar II, LLC
Colorado
AZ Solar Phase Zero, LLC
Colorado
B.A. Services S.R.L.
Argentina
BaiCheng Wind-Power Co., Ltd.
China
Branch of Alberich Beteiligungsverwaltungs in Kazakhstan
Kazakhstan
Brasiliana Participações S.A.
Brazil
Bridgeport Solar, LLC
Colorado
Brite Solar Fund Holdco, LLC
Delaware
Buffalo Gap Holdings 2, LLC
Delaware
Buffalo Gap Holdings 3, L.L.C.
Delaware
Buffalo Gap Holdings, LLC
Delaware
Buffalo Gap Wind Farm 2, LLC
Delaware
Buffalo Gap Wind Farm 3, L.L.C.
Delaware
Buffalo Gap Wind Farm 4, L.L.C.
Delaware
Buffalo Gap Wind Farm, LLC
Delaware
Camille Trust
Cayman Islands
Camille, Ltd.
Cayman Islands
Cavanal Minerals, LLC
Delaware
Cayman Energy Traders
Cayman Islands
CCS Telecarrier
Cayman Islands
CDEC-SIC LTDA
Chile
CDEC-SING Ltda
Chile
Cemig II C.V.
The Netherlands
Central Electricity Supply Company of Orissa Limited
India
Central Termoelectrica Guillermo Brown S.A.
Argentina
Cerulean Properties, LLC
Delaware
CIA.TRANSMISORA DEL NORTE CHICO S.A.
Chile
Clean Wind Energy Ltd.
Israel
Cloghan Limited
Northern Ireland
Cloghan Point Holdings Limited
Northern Ireland
CMS Generation San Nicolas Company
Michigan
Coastal Itabo, Ltd.
Cayman Islands
Compania de Alumbrado Eletrico de San Salvador, S.A. DE C.V.
El Salvador
Costa Norte LNG Terminal S. de R.L.
Panama
Daggett Ridge Wind Farm, LLC
Delaware
Diamond Development, Inc.
Ohio
Distribuidora Electrica de Usulutan, Sociedad Anonima de Capital Variable
El Salvador
Dominican Power Partners
Cayman Islands
DPL Capital Trust II
Delaware
DPL Inc.
Ohio
Dublin Solar I, LLC
Indiana
Eastern Solar Holdings I, LLC
Delaware
Eastern Solar Holdings II, LLC
Delaware
Eastern Solar Parent, LLC
Delaware
Eletropaulo Metropolitana Eletricidade de Sao Paulo S.A.
Brazil
Eloy ESD Solar Holdings, LLC
Delaware
Elsta BV
The Netherlands
Elsta BV & Co. CV
The Netherlands
EMD Ventures BV
The Netherlands
Empresa Electrica Angamos S.A.
Chile
Empresa Electrica Campiche S.A.
Chile
Empresa Electrica Cochrane SpA
Chile
Empresa Electrica de Oriente, S.A. de C.V.
El Salvador
Empresa Electrica Santiago SpA
Chile
Empresa Electrica Ventanas S.A.
Chile


Empresa Generadora De Electricidad Itabo, S.A.
Dominican Republic
ENERAB, S. de R.L. de C.V.
Mexico
ENERGEN S.A.
Argentina
Energy Trade and Finance Corporation
Cayman Islands
Fundacion AES Dominicana, Inc.
Dominican Republic
Gas Natural Atlantico II S. de R.L.
Panama
Gas Natural Atlantico S. De R.L.
Panama
Gasoducto GasAndes Argentina S.A.
Argentina
Gasoducto GasAndes S.A.
Chile
Gener Argentina S.A.
Argentina
Gener Blue Water, Ltd.
Cayman Islands
Genergia Power, Ltd.
Cayman Islands
GENERGIA S.A.
Chile
Georgia Solar Holdings, LLC
Delaware
Georgia Solar Parent, LLC
Delaware
Global Energy Holdings C.V.
The Netherlands
GNRY Holdings & Investments Limited
Israel
Gray Springs Vista Solar, LLC
Delaware
Guacolda Energy S.A.
Chile
Haddonfield Finance Ltd.
Ireland
Health and Welfare Benefit Plans LLC
Delaware
Hefei Zhongli Energy Company Ltd.
China
Hipotecaria San Miguel Limitada de Capital Variable
El Salvador
Hipotecaria Santa Ana Limitada de Capital Variable
El Salvador
Hunan Xiangci - AES Hydro Power Company Ltd.
China
Indianapolis Power & Light Company
Indiana
Indimento Inversiones, S.L.
Spain
Instituto AES Brasil
Brazil
InterAndes, S.A.
Argentina
Inversiones Cachagua SpA
Chile
Inversiones Energia Renovable Limitada
Chile
Inversiones LK SpA
Chile
INVERSIONES NUEVA VENTANAS SpA
Chile
Inversiones Termoenergia de Chile Ltda.
Chile
Inversora de San Nicolas S.A.
Argentina
IPALCO Enterprises, Inc.
Indiana
IPL Funding Corporation
Indiana
Irtysh Power & Light LLP
Kazakhstan
Itabo Dominicana, Ltd.
Cayman Islands
Itabo III, S.R.L.
Dominican Republic
KA Energy OOD
Bulgaria
Kazincbarcikai Iparteruletfejleszt Kft.
Hungary
Kilroot Electric Limited
Cayman Islands
La Plata II, Ltd.
British Virgin Islands
La Plata III C.V.
The Netherlands
Lemoore PV 1 LLC
California
Little Waver Wind Farm Limited
England & Wales
MacGregor Park, Inc.
Ohio
Maguan Daliangzi Power Station Co., Ltd.
China
Maguan Laqi Power Station Co., Ltd.
China
Main Street Power Canada Holdings I, LLC
Colorado
Masin-AES Pte. Ltd.
Singapore
Masin-AES Pte. Ltd. - Philippine Branch
 
Masinloc AES Partners Company Limited
Philippines
Masinloc AES Power Company Limited
Philippines
Masinloc Power Partners Co. Ltd.
Philippines
MC Squared Energy Services, LLC
Illinois
Mercury Cayman Co II, Ltda, Agencia en Chile
Chile


Mercury Cayman Co. II, Ltd.
Cayman Islands
Mercury Cayman Holdco, Ltd.
Cayman Islands
MFP CO Holdings II, LLC
Delaware
MFP CO Holdings, LLC
Delaware
MFP CO I, LLC
Delaware
MFP CO II, LLC
Colorado
MFP CO III, LLC
Delaware
MFP CO Parent, LLC
Delaware
Miami Valley Insurance Company
Vermont
Miami Valley Lighting, LLC
Ohio
Mid-America Capital Resources, Inc.
Indiana
MM Solar Holdings I, LLC
Colorado
MM Solar Holdings II, LLC
Colorado
MM Solar Parent, LLC
Delaware
Mountain Minerals, LLC
Delaware
Mountain View Power Partners IV, LLC
Delaware
Mountain View Power Partners, LLC
Delaware
MSP Master Tenant I, LLC
Colorado
MSP Master Tenant II, LLC
Colorado
MSP QALICB II, LLC
Colorado
MSP QALICB, LLC
Colorado
MySolar Finance Holdings, LLC
Delaware
MySolar Holdings II, LLC
Delaware
MySolar Holdings III, LLC
Delaware
MySolar Holdings IV, LLC
Delaware
MySolar Holdings, LLC
Delaware
MySolar I, LLC
Delaware
MySolar II, LLC
Delaware
MySolar IIB, LLC
Delaware
MySolar IV, LLC
Delaware
MySolar IX, LLC
Delaware
MySolar V, LLC
Delaware
MySolar VI, LLC
Delaware
MySolar VII, LLC
Delaware
New Caribbean Investments SRL
Dominican Republic
Ningde Dagang Hydropower Development Co., Ltd.
China
Norgener SpA
Chile
Novus Barre Town Solar, LLC
Delaware
Nurenergoservice LLP
Kazakhstan
Omega SpA
Chile
Orissa Power Generation Corporation Limited
India
Profilaktoriy Shulbinsky LLP
Kazakhstan
Remittance Processing Services, LLC
Indiana
Rep Office of AES Silk Road in Almaty
Kazakhstan
Rincon Solar I, LLC
Georgia
Riverside Canal Power Company
California
RMR Solar, LLC
Delaware
Rosamond Solar, LLC
Colorado
Sagebrush Partner Eighteen, Inc.
California
Sagebrush Partner Nineteen, Inc.
California
Sagebrush Partner Seventeen, Inc.
California
Scituate Solar I, LLC
Delaware
Scottsdale Solar Holdings, LLC
Delaware
SD Solar I, LLC
Colorado
SeaWest Asset Management Services, LLC
California
SeaWest Energy Project Associates, LLC
Delaware
SeaWest Properties, LLC
California
SeaWest Wyoming, LLC
Delaware


Shazia S.R.L.
Argentina
Solar Access America, LLC
Delaware
Solar Access CA, LLC
Delaware
Solar Access California, LLC
Colorado
Southern Electric Brazil Participacoes, Ltda.
Brazil
Store Heat and Produce Energy, Inc.
Indiana
Sudbury Ervin GMC Solar, LLC
Delaware
Sycarpha Bolton, LLC
Delaware
Sycarpha Stow, LLC
Delaware
T&T Power Generation Unlimited
Trinidad and Tobago
T&T Power Holdings I, SRL
Barbados
T&T Power Holdings II, Ltd.
Cayman Islands
Tau Power BV
The Netherlands
Tecumseh Coal Corporation
Indiana
TEG Business Trust
Mexico
TEG/TEP Management, LLC
Delaware
TEP Business Trust
Mexico
TermoAndes S.A.
Argentina
Termoelectrica del Golfo, S. de R.L. de C.V.
Mexico
Termoelectrica Penoles, S. de R.L. de C.V.
Mexico
Terneuzen Cogen B.V.
The Netherlands
The AES Barry Foundation
United Kingdom
The Dayton Power and Light Company
Ohio
Thermo Fuels Company, Inc.
California
Tozer Road Solar, LLC
Massachusetts
USVI Solar I, LLC
Delaware
Village of Waterbury Solar I, LLC
Delaware
WE (Earlshaugh) Holdings Limited
United Kingdom
WE (Forse) Holdings Ltd
United Kingdom
WE (Glencalvie) Holdings Ltd
United Kingdom
WE (Hanna) Holdings Ltd
United Kingdom
WE (Hearthstanes) Holdings Ltd
United Kingdom
WE (Newfield) Holdings Ltd
United Kingdom
WE (North Rhins) Holdings Limited
United Kingdom
WE (Services) Holdings Ltd
United Kingdom
Weixi Longdu Power Station Co., Ltd.
China
Wenshan Malutang Electricity Power Co., Ltd.
China
Western Solar Parent, LLC
Delaware
Wildwood Trust
Cayman Islands
Wind Energy (Earlshaugh) Limited
United Kingdom
Wind Energy (Forse) Limited
United Kingdom
Wind Energy (Glenmorie) Limited
United Kingdom
Wind Energy (Hanna) Limited
United Kingdom
Wind Energy (Hearthstanes) Limited
United Kingdom
Wind Energy (Newfield) Limited
United Kingdom
Wind Energy (Services) Limited
United Kingdom
Wuhu Shaoda Electric Power Development Co. Ltd.
China
WuLanChaBu Jianghe Electricity Power Co., Ltd.
China
Yangchun Fuyang Diesel Engine Power Co. Ltd.
China
Your Energy Holdings Limited
England & Wales
Yunnan Diqing Shangri-la Huarui Electricity Co., Ltd.
China
Yunnan Longling Lazhai Hydropower Development Co., Ltd.
China
ZhalynEnergo, LLP
Kazakhstan


Exhibit


Exhibit 23.1
Consent of Independent Registered Public Accounting Firm
We consent to the incorporation by reference in the following Registration Statements and in the related Prospectuses of The AES Corporation:
 
 
(1)
Registration Statements No. 333-203684, 333-156242, 333-26225, 333-28883, 333-30352, 333-38535, 333-57482, 333-66952, 333-66954, 333-82306, 333-83574, 333-84008, 333-97707, 333-108297, 333-112331, 333-115028, 333-150508, 333-135128, 333-158767, 333-166607, and 333-179701 on Form S-8;
 
 
(2)
Registration Statements No. 333-64572, 333-161913, and 333-186888 on Form S-3;
 
 
(3)
Registration Statements No. 333-38924, 333-40870, 333-44698, 333-46564, 333-37924, 333-83767, 333-81953, 333-46189, 333-39857; 333-15487, and 333-01286 on Form S-3/A, and


(4)
Registration Statements No. 333-45916, 333-49644, 333-43908, 333-44845, 333-147951, 333-33283, 333-22513, and 333-180388 on Form S-4/A;
of our reports dated February 23, 2016, with respect to the consolidated financial statements and schedules of The AES Corporation and the effectiveness of internal control over financial reporting of The AES Corporation included in this Annual Report (Form 10-K) of The AES Corporation for the year ended December 31, 2015.
/s/ Ernst & Young LLP
McLean, Virginia
February 23, 2016


Exhibit


The AES Corporation (the “Company”)
Power of Attorney
The undersigned, acting in the capacity or capacities stated opposite their respective names below, hereby constitute and appoint Thomas O’Flynn and Brian A. Miller and each of them severally, the attorneys-in-fact of the undersigned with full power to them and each of them to sign for and in the name of the undersigned in the capacities indicated below the Company’s 2015 Annual Report on Form 10-K and any and all amendments and supplements thereto. This Power of Attorney may be executed in one or more counterparts, each of which together shall constitute one and the same instrument.

Name
 
Title
 
Date


/s/ Andrés Gluski
 
Principal Executive Officer and Director
 
February 19, 2016
Andrés Gluski


/s/ Charles L. Harrington
 
Director
 
February 19, 2016
Charles L. Harrington


/s/ Kristina M. Johnson
 
Director
 
February 19, 2016
Kristina M. Johnson


/s/ Tarun Khanna
 
Director
 
February 19, 2016
Tarun Khanna


/s/ Holly K. Koeppel
 
Director
 
February 19, 2016
Holly K. Koeppel


/s/ Philip Lader
 
Director
 
February 19, 2016
Philip Lader


/s/ James H. Miller
 
Director
 
February 19, 2016
James H. Miller


/s/ John B. Morse, Jr.
 
Director
 
February 19, 2016
John B. Morse, Jr.


/s/ Moises Naim
 
Director
 
February 19, 2016
Moises Naim


/s/ Charles O. Rossotti
 
Chairman and Lead Independent Director
 
February 19, 2016
Charles O. Rossotti


Exhibit


Exhibit 31.1
CERTIFICATIONS
I, Andrés Gluski, certify that:
1.
I have reviewed this Form 10-K of The AES Corporation;
2.
Based on my knowledge, this report does not contain any untrue statement of a material fact or omit to state a material fact necessary to make the statements made, in light of the circumstances under which such statements were made, not misleading with respect to the period covered by this report;
3.
Based on my knowledge, the financial statements, and other financial information included in this report, fairly present in all material respects the financial condition, results of operations and cash flows of the registrant as of, and for, the periods presented in this report;
4.
The registrant’s other certifying officer and I are responsible for establishing and maintaining disclosure controls and procedures (as defined in Exchange Act Rules 13a-15(e) and 15d-15(e)) and internal control over financial reporting (as defined in Exchange Act Rules 13a-15(f) and 15d-15(f)) for the registrant and have:
a)
Designed such disclosure controls and procedures, or caused such disclosure controls and procedures to be designed under our supervision, to ensure that material information relating to the registrant, including its consolidated subsidiaries, is made known to us by others within those entities, particularly during the period in which this report is being prepared;
b)
Designed such internal control over financial reporting, or caused such internal control over financial reporting to be designed under our supervision, to provide reasonable assurance regarding the reliability of financial reporting and the preparation of financial statements for external purposes in accordance with generally accepted accounting principles;
c)
Evaluated the effectiveness of the registrant’s disclosure controls and procedures and presented in this report our conclusions about the effectiveness of the disclosure controls and procedures, as of the end of the period covered by this report based on such evaluation; and
d)
Disclosed in this report any change in the registrant’s internal control over financial reporting that occurred during the registrant’s most recent fiscal quarter (the registrant’s fourth fiscal quarter in the case of an annual report) that has materially affected, or is reasonably likely to materially affect, the registrant’s internal control over financial reporting.
5.
The registrant’s other certifying officer and I have disclosed, based on our most recent evaluation of internal control over financial reporting, to the registrant’s auditors and the audit committee of the registrant’s board of directors (or persons performing the equivalent functions):
a)
All significant deficiencies and material weaknesses in the design or operation of internal control over financial reporting which are reasonably likely to adversely affect the registrant’s ability to record, process, summarize and report financial information; and
b)
Any fraud, whether or not material, that involves management or other employees who have a significant role in the registrant’s internal control over financial reporting.
Date: February 23, 2016
 
/s/ ANDRÉS GLUSKI
Name: Andrés Gluski
President and Chief Executive Officer


Exhibit


Exhibit 31.2
CERTIFICATIONS
I, Thomas M. O’Flynn, certify that:
1.
I have reviewed this Form 10-K of The AES Corporation;
2.
Based on my knowledge, this report does not contain any untrue statement of a material fact or omit to state a material fact necessary to make the statements made, in light of the circumstances under which such statements were made, not misleading with respect to the period covered by this report;
3.
Based on my knowledge, the financial statements, and other financial information included in this report, fairly present in all material respects the financial condition, results of operations and cash flows of the registrant as of, and for, the periods presented in this report;
4.
The registrant’s other certifying officer and I are responsible for establishing and maintaining disclosure controls and procedures (as defined in Exchange Act Rules 13a-15(e) and 15d-15(e)) and internal control over financial reporting (as defined in Exchange Act Rules 13a-15(f) and 15d-15(f)) for the registrant and have:
a)
Designed such disclosure controls and procedures, or caused such disclosure controls and procedures to be designed under our supervision, to ensure that material information relating to the registrant, including its consolidated subsidiaries, is made known to us by others within those entities, particularly during the period in which this report is being prepared;
b)
Designed such internal control over financial reporting, or caused such internal control over financial reporting to be designed under our supervision, to provide reasonable assurance regarding the reliability of financial reporting and the preparation of financial statements for external purposes in accordance with generally accepted accounting principles;
c)
Evaluated the effectiveness of the registrant’s disclosure controls and procedures and presented in this report our conclusions about the effectiveness of the disclosure controls and procedures, as of the end of the period covered by this report based on such evaluation; and
d)
Disclosed in this report any change in the registrant’s internal control over financial reporting that occurred during the registrant’s most recent fiscal quarter (the registrant’s fourth fiscal quarter in the case of an annual report) that has materially affected, or is reasonably likely to materially affect, the registrant’s internal control over financial reporting.
5.
The registrant’s other certifying officer and I have disclosed, based on our most recent evaluation of internal control over financial reporting, to the registrant’s auditors and the audit committee of the registrant’s board of directors (or persons performing the equivalent functions):
a)
All significant deficiencies and material weaknesses in the design or operation of internal control over financial reporting which are reasonably likely to adversely affect the registrant’s ability to record, process, summarize and report financial information; and
b)
Any fraud, whether or not material, that involves management or other employees who have a significant role in the registrant’s internal control over financial reporting.
Date: February 23, 2016
 
/s/ THOMAS M. O’FLYNN
Name: Thomas M. O’Flynn
Executive Vice President and Chief Financial Officer


Exhibit


Exhibit 32.1
CERTIFICATION OF PERIODIC FINANCIAL REPORTS
I, Andrés Gluski, President and Chief Executive Officer of The AES Corporation, certify, pursuant to 18 U.S.C. Section 1350, as adopted pursuant to Section 906 of the Sarbanes-Oxley Act of 2002, that:

(1)
the Form 10-K for the year ended December 31, 2015, (the “Periodic Report”) which this statement accompanies fully complies with the requirements of Section 13(a) or 15(d) of the Securities Exchange Act of 1934 (15 U.S.C. 78m or 78o(d)); and

(2)
information contained in the Periodic Report fairly presents, in all material respects, the financial condition and results of operations of The AES Corporation.
Date: February 23, 2016
 
/S/ ANDRÉS GLUSKI
Name: Andrés Gluski
President and Chief Executive Officer


Exhibit


Exhibit 32.2
CERTIFICATION OF PERIODIC FINANCIAL REPORTS
I, Thomas M. O’Flynn, Executive Vice President and Chief Financial Officer of The AES Corporation, certify, pursuant to 18 U.S.C. Section 1350, as adopted pursuant to Section 906 of the Sarbanes-Oxley Act of 2002, that:
(1)

(1)
the Form 10-K for the year ended December 31, 2015, (the “Periodic Report”) which this statement accompanies fully complies with the requirements of Section 13(a) or 15(d) of the Securities Exchange Act of 1934 (15 U.S.C. 78m or 78o(d)); and

(2)
information contained in the Periodic Report fairly presents, in all material respects, the financial condition and results of operations of The AES Corporation.
Date: February 23, 2016
 
/s/ THOMAS M. O’FLYNN
Name: Thomas M. O’Flynn
Executive Vice President and Chief Financial Officer


aes-20151231.xml
Attachment: XBRL INSTANCE DOCUMENT


aes-20151231.xsd
Attachment: XBRL TAXONOMY EXTENSION SCHEMA DOCUMENT


aes-20151231_cal.xml
Attachment: XBRL TAXONOMY EXTENSION CALCULATION LINKBASE DOCUMENT


aes-20151231_def.xml
Attachment: XBRL TAXONOMY EXTENSION DEFINITION LINKBASE DOCUMENT


aes-20151231_lab.xml
Attachment: XBRL TAXONOMY EXTENSION LABEL LINKBASE DOCUMENT


aes-20151231_pre.xml
Attachment: XBRL TAXONOMY EXTENSION PRESENTATION LINKBASE DOCUMENT


v3.3.1.900
Document And Entity Information - USD ($)
$ in Millions
12 Months Ended
Dec. 31, 2015
Feb. 18, 2016
Jun. 30, 2015
Document Type 10-K    
Amendment Flag false    
Document Period End Date Dec. 31, 2015    
Document Fiscal Year Focus 2015    
Document Fiscal Period Focus FY    
Trading Symbol AES    
Entity Registrant Name AES CORP    
Entity Central Index Key 0000874761    
Current Fiscal Year End Date --12-31    
Entity Filer Category Large Accelerated Filer    
Entity Common Stock, Shares Outstanding   659,733,335  
Entity current reporting status Yes    
Entity voluntary filers No    
Entity Well Known Seasoned Issuer Yes    
Entity Public Float     $ 8,790

v3.3.1.900
Consolidated Balance Sheets - USD ($)
$ in Millions
Dec. 31, 2015
Dec. 31, 2014
CURRENT ASSETS    
Cash and cash equivalents $ 1,262 $ 1,539
Restricted cash 295 283
Short-term investments 484 709
Accounts receivable, net of allowance for doubtful accounts of $95 and $96, respectively 2,473 2,709
Inventory 675 702
Deferred income taxes 0 275
Prepaid expenses 108 175
Other current assets 1,473 1,434
Assets of held-for-sale businesses 96 0
Total current assets 6,866 7,826
Property, Plant and Equipment:    
Land 711 870
Electric generation, distribution assets and other 28,491 30,459
Accumulated depreciation (9,449) (9,962)
Construction in progress 3,063 3,784
Property, plant and equipment, net 22,816 25,151
Other Assets:    
Investments in and advances to affiliates 610 537
Debt service reserves and other deposits 565 411
Goodwill 1,157 1,458
Other intangible assets, net of accumulated amortization of $97 and $158, respectively 214 281
Deferred income taxes 543 662
Service Concession Assets 1,543 0
Other noncurrent assets 2,536 2,640
Total other assets 7,168 5,989
TOTAL ASSETS 36,850 38,966
CURRENT LIABILITIES    
Accounts payable 1,721 2,278
Accrued interest 251 260
Accrued and other liabilities 2,436 2,326
Recourse debt 0 151
Non-recourse debt, including $163 and $240, respectively, related to variable interest entities 2,529 1,982
Liabilities of held-for-sale businesses 13 0
Total current liabilities 6,950 6,997
NONCURRENT LIABILITIES    
Non-recourse debt, including $760 and $1,030, respectively, related to variable interest entities 13,263 13,618
Recourse debt 5,015 5,107
Deferred income taxes 1,090 1,277
Pension and other post-retirement liabilities 927 1,342
Other noncurrent liabilities 2,896 3,222
Total noncurrent liabilities $ 23,191 $ 24,566
Commitments and Contingencies (see Notes 13 and 14)
Redeemable stock of subsidiaries $ 538 $ 78
THE AES CORPORATION STOCKHOLDERS’ EQUITY    
Common stock ($0.01 par value, 1,200,000,000 shares authorized; 815,846,621 issued and 666,808,790 outstanding at December 31, 2015 and 814,539,146 issued and 703,851,297 outstanding at December 31, 2014) 8 8
Additional paid-in capital 8,718 8,409
Retained earnings 143 512
Accumulated other comprehensive loss (3,883) (3,286)
Treasury stock, at cost (149,037,831 shares at December 31, 2015 and 110,687,849 shares at December 31, 2014) (1,837) (1,371)
Total AES Corporation stockholders’ equity 3,149 4,272
NONCONTROLLING INTERESTS 3,022 3,053
Total equity 6,171 7,325
TOTAL LIABILITIES AND EQUITY $ 36,850 $ 38,966

v3.3.1.900
Consolidated Balance Sheets (Parenthetical) - USD ($)
$ in Millions
Dec. 31, 2015
Dec. 31, 2014
Statement of Financial Position [Abstract]    
Accounts receivable, allowance for doubtful accounts $ 95 $ 96
Other intangible assets, accumulated amortization $ 97 $ 158
Common stock, par value (in dollars per share) $ 0.01 $ 0.01
Common stock, shares authorized (in shares) 1,200,000,000 1,200,000,000
Common stock, shares issued (in shares) 815,846,621 814,539,146
Common stock, shares outstanding (in shares) 666,808,790 703,851,297
Treasury stock, shares (in shares) 149,037,831 110,687,849
Variable Interest Entity [Line Items]    
Non-recourse debt - current balance at variable interest entities $ 2,529 $ 1,982
Non-recourse debt - noncurrent, balance at variable interest entities 13,263 13,618
Consolidated Variable Interest Entities [Member]    
Variable Interest Entity [Line Items]    
Non-recourse debt - current balance at variable interest entities 163 240
Non-recourse debt - noncurrent, balance at variable interest entities $ 760 $ 1,030

v3.3.1.900
Consolidated Statements of Operations - USD ($)
$ in Millions
12 Months Ended
Dec. 31, 2015
Dec. 31, 2014
Dec. 31, 2013
Revenue:      
Regulated $ 7,660 $ 8,874 $ 8,056
Non-regulated 7,303 8,272 7,835
Total revenue 14,963 17,146 15,891
Cost of sales:      
Regulated (6,564) (7,530) (6,837)
Non-regulated (5,533) (6,528) (5,807)
Total cost of sales (12,097) (14,058) (12,644)
Operating margin 2,866 3,088 3,247
General and administrative expenses (196) (187) (220)
Interest expense (1,436) (1,471) (1,482)
Interest income 524 365 275
Loss on extinguishment of debt (186) (261) (229)
Other expense (65) (68) (76)
Other income 83 124 125
Gain on sale of businesses 29 358 26
Goodwill impairment expense (317) (164) (372)
Asset impairment expense (285) (91) (95)
Foreign currency transaction gains (losses) 105 11 (22)
Other non-operating expense 0 (128) (129)
INCOME FROM CONTINUING OPERATIONS BEFORE TAXES AND EQUITY IN EARNINGS OF AFFILIATES 1,122 1,576 1,048
Income tax expense (465) (419) (343)
Net equity in earnings of affiliates 105 19 25
INCOME FROM CONTINUING OPERATIONS 762 1,176 730
Income (loss) from operations of discontinued businesses, net of income tax expense of $0, $23, and $24, respectively 0 27 (27)
Net loss from disposal and impairments of discontinued operations, net of income tax expense (benefit) of $0, $4, and $(15), respectively 0 (56) (152)
NET INCOME 762 1,147 551
Noncontrolling interests:      
Less: (Income) from continuing operations attributable to noncontrolling interests (456) (387) (446)
Plus: Loss from discontinued operations attributable to noncontrolling interests 0 9 9
Total net income attributable to noncontrolling interests (456) (378) (437)
NET INCOME ATTRIBUTABLE TO THE AES CORPORATION 306 769 114
AMOUNTS ATTRIBUTABLE TO THE AES CORPORATION COMMON STOCKHOLDERS:      
Income from continuing operations, net of tax 306 789 284
Loss from discontinued operations, net of tax 0 (20) (170)
NET INCOME ATTRIBUTABLE TO THE AES CORPORATION $ 306 $ 769 $ 114
BASIC EARNINGS PER SHARE:      
Income from continuing operations attributable to The AES Corporation common stockholders, net of tax $ 0.45 $ 1.10 $ 0.38
Loss from discontinued operations attributable to The AES Corporation common stockholders, net of tax 0.00 (0.03) (0.23)
NET INCOME ATTRIBUTABLE TO THE AES CORPORATION COMMON STOCKHOLDERS 0.45 1.07 0.15
DILUTED EARNINGS PER SHARE:      
Income from continuing operations attributable to The AES Corporation common stockholders, net of tax 0.44 1.09 0.38
Loss from discontinued operations attributable to The AES Corporation common stockholders, net of tax 0.00 (0.03) (0.23)
NET INCOME ATTRIBUTABLE TO THE AES CORPORATION COMMON STOCKHOLDERS 0.44 1.06 0.15
DIVIDENDS DECLARED PER COMMON SHARE (in dollars per share) $ 0.41 $ 0.25 $ 0.17

v3.3.1.900
Consolidated Statements of Operations (Parenthetical) - USD ($)
$ in Millions
12 Months Ended
Dec. 31, 2015
Dec. 31, 2014
Dec. 31, 2013
Income Statement [Abstract]      
Income from operations of discontinued businesses, income tax expense (benefit) $ 0 $ 23 $ 24
Gain (loss) from disposal and impairment of discontinued businesses, income tax expense (benefit) $ 0 $ 4 $ (15)

v3.3.1.900
Consolidated Statements of Comprehensive Income - USD ($)
$ in Millions
12 Months Ended
Dec. 31, 2015
Dec. 31, 2014
Dec. 31, 2013
Statement of Comprehensive Income [Abstract]      
NET INCOME $ 762 $ 1,147 $ 551
Foreign currency translation activity:      
Foreign currency translation adjustments, net of income tax benefit (expense) of $1, $(7), and $10, respectively (1,019) (491) (375)
Reclassification to earnings, net of $0 income tax for all periods 0 (3) 41
Total foreign currency translation adjustments (1,019) (494) (334)
Derivative activity:      
Change in derivative fair value, net of income tax benefit (expense) of $16, $72 and $(31), respectively (57) (358) 108
Reclassification to earnings, net of income tax (expense) of $(11), $(26) and $(41), respectively 66 99 139
Total change in fair value of derivatives 9 (259) 247
Pension activity:      
Change in pension adjustments due to prior service cost, net of $0 income tax for all periods (1) 0 0
Change in pension adjustments due to net actuarial gain (loss) for the period, net of income tax (expense) benefit of $(29), $27, and $(198), respectively 60 (49) 379
Reclassification to earnings due to amortization of net actuarial loss, net of income tax (expense) of $(9), $(7), and $(26), respectively 16 29 52
Total pension adjustments 77 (20) 431
OTHER COMPREHENSIVE (LOSS) INCOME (933) (773) 344
COMPREHENSIVE (LOSS) INCOME (171) 374 895
Less: Comprehensive (income) attributable to noncontrolling interests (133) (49) (743)
COMPREHENSIVE (LOSS) INCOME ATTRIBUTABLE TO THE AES CORPORATION $ (304) $ 325 $ 152

v3.3.1.900
Consolidated Statements of Comprehensive Income (Parenthetical) - USD ($)
$ in Millions
12 Months Ended
Dec. 31, 2015
Dec. 31, 2014
Dec. 31, 2013
Statement of Comprehensive Income [Abstract]      
Foreign currency translation adjustments, income tax $ 1 $ (7) $ 10
Foreign currency, reclassification to earnings, income tax 0 0 0
Change in derivative fair value, income tax 16 72 (31)
Derivative reclassification to earnings, income tax (11) (26) (41)
Other Comprehensive (Income) Loss, Pension and Other Postretirement Benefit Plans, Net Prior Service Cost (Credit), Tax 0 0 0
Pension, net actuarial gain (loss) for the period, income tax (29) 27 (198)
Pension, amortization of net actuarial loss, income tax $ (9) $ (7) $ (26)

v3.3.1.900
Consolidated Statements of Changes in Equity - USD ($)
shares in Millions, $ in Millions
Total
Common Stock [Member]
Treasury Stock
Additional Paid-in Capital [Member]
Retained Earnings (Accumulated Deficit)
Accumulated Other Comprehensive Loss
Noncontrolling Interest
Beginning Balance at Dec. 31, 2012   $ 8.0 $ (780.0) $ 8,525.0 $ (264.0) $ (2,920.0) $ 2,945.0
Beginning Balance (Shares) at Dec. 31, 2012   810.7 66.4        
Increase (Decrease) in Stockholders' Equity [Roll Forward]              
Net income $ 551.0 $ 0.0 $ 0.0 0.0 114.0 0.0 437.0
Total foreign currency translation adjustment, net of income tax (334.0) 0.0 0.0 0.0 0.0 (227.0) (107.0)
Total change in derivative fair value, net of income tax 247.0 0.0 0.0 0.0 0.0 174.0 73.0
Total pension adjustments, net of income tax 431.0 0.0 0.0 0.0 0.0 91.0 340.0
OTHER COMPREHENSIVE (LOSS) INCOME 344.0         38.0 306.0
Contributions from noncontrolling interests 0.0 0.0   0.0 0.0 0.0 109.0
Distributions to noncontrolling interests   0.0 0.0 0.0 0.0 0.0 (553.0)
Disposition of businesses 0.0 $ 0.0   0.0 0.0 0.0 (13.0)
Purchase of treasury stock 0.0   $ (322.0) 0.0 0.0 0.0  
Issuance and exercise of stock-based compensation benefit plans (Shares)   2.6 (0.9)        
Issuance and exercise of stock-based compensation benefit plans, net of income tax 0.0 $ 0.0 $ 13.0 33.0 0.0 0.0  
Acquisition of treasury stock (shares)   0.0 25.3        
Dividends declared on common stock 0.0 $ 0.0   (125.0) 0.0 0.0  
Sale of subsidiary shares to noncontrolling interests 0.0 0.0   16.0   0.0 91.0
Acquisition of subsidiary shares from noncontrolling interests 0.0 0.0   (6.0)   0.0 (1.0)
Ending Balance at Dec. 31, 2013   $ 8.0 $ (1,089.0) 8,443.0 (150.0) (2,882.0) 3,321.0
Ending Balance (Shares) at Dec. 31, 2013   813.3 90.8        
Increase (Decrease) in Stockholders' Equity [Roll Forward]              
Net income 1,147.0 $ 0.0 $ 0.0 0.0 769.0 0.0 378.0
Total foreign currency translation adjustment, net of income tax (494.0) 0.0 0.0 0.0 0.0 (332.0) (162.0)
Total change in derivative fair value, net of income tax (259.0) 0.0 0.0 0.0 0.0 (108.0) (151.0)
Total pension adjustments, net of income tax (20.0) 0.0 0.0 0.0 0.0 (4.0) (16.0)
OTHER COMPREHENSIVE (LOSS) INCOME (773.0)         (444.0) (329.0)
Balance sheet reclassification related to an equity method investment [1]   0.0 0.0 0.0 0.0 40.0 0.0
Contributions from noncontrolling interests   0.0 0.0 0.0 0.0 0.0 147.0
Distributions to noncontrolling interests   0.0 0.0 0.0 0.0 0.0 (466.0)
Disposition of businesses   0.0 0.0 0.0 0.0 0.0 (153.0)
Purchase of treasury stock   $ 0.0 $ (308.0) 0.0 0.0 0.0 0.0
Issuance and exercise of stock-based compensation benefit plans (Shares)   1.2 (2.0)        
Issuance and exercise of stock-based compensation benefit plans, net of income tax   $ 0.0 $ 26.0 3.0 0.0 0.0 0.0
Acquisition of treasury stock (shares)     21.9        
Dividends declared on common stock   0.0 $ 0.0 (73.0) (107.0) 0.0 0.0
Sale of subsidiary shares to noncontrolling interests   0.0 0.0 29.0 0.0 0.0 173.0
Acquisition of subsidiary shares from noncontrolling interests 7.0 0.0 0.0 7.0 0.0 0.0 (18.0)
Ending Balance at Dec. 31, 2014 7,325.0 $ 8.0 $ (1,371.0) 8,409.0 512.0 (3,286.0) 3,053.0
Ending Balance (Shares) at Dec. 31, 2014   814.5 110.7        
Increase (Decrease) in Stockholders' Equity [Roll Forward]              
Net income 762.0 $ 0.0 $ 0.0 0.0 306.0 0.0 456.0
Total foreign currency translation adjustment, net of income tax (1,019.0) 0.0 0.0 0.0 0.0 (674.0) (345.0)
Total change in derivative fair value, net of income tax 9.0 0.0 0.0 0.0 0.0 43.0 (34.0)
Total pension adjustments, net of income tax 77.0 0.0 0.0 0.0 0.0 21.0 56.0
OTHER COMPREHENSIVE (LOSS) INCOME (933.0)         (610.0) (323.0)
Contributions from noncontrolling interests   0.0 0.0 0.0 0.0 0.0 126.0
Distributions to noncontrolling interests   0.0 0.0 (27.0) 0.0 0.0 (383.0)
Disposition of businesses   0.0 0.0 0.0 0.0 0.0 (41.0)
Noncontrolling Interest, Increase from Business Combination [2]   0.0 0.0 0.0 0.0 0.0 15.0
Purchase of treasury stock 0.0 $ 0.0 $ (482.0) 0.0 0.0 0.0  
Issuance and exercise of stock-based compensation benefit plans (Shares)   1.3 (1.4)        
Issuance and exercise of stock-based compensation benefit plans, net of income tax $ 0.0 $ 0.0 $ 16.0 13.0 0.0 0.0  
Acquisition of treasury stock (shares) 39.7   39.7        
Dividends declared on common stock $ 0.0 0.0 $ 0.0 0.0 (280.0) 0.0  
Sale of subsidiary shares to noncontrolling interests   0.0 0.0 323.0 (377.0) 0.0 119.0
Acquisition of subsidiary shares from noncontrolling interests 0.0            
Ending Balance at Dec. 31, 2015 6,171.0 $ 8.0 $ (1,837.0) 8,718.0 143.0 (3,883.0) $ 3,022.0
Ending Balance (Shares) at Dec. 31, 2015   815.8 149.0        
Increase (Decrease) in Stockholders' Equity [Roll Forward]              
Cumulative Effect of New Accounting Principle in Period of Adoption $ 0.0 $ 0.0 $ 0.0 $ 0.0 $ (18.0) $ 13.0  
[1] Reclassification resulting from SRP transaction during the third quarter of 2014. See Note 8—Investments In and Advances to Affiliates for further information.
[2] (2) Fair value of a tax equity partner's right to preferential returns recognized as a result of the acquisition of Solar Power PR, LLC, which was previously accounted for as an equity method investment.

v3.3.1.900
Consolidated Statements of Changes in Equity (Parenthetical) - $ / shares
3 Months Ended 12 Months Ended
Dec. 11, 2015
Dec. 31, 2015
Sep. 30, 2015
Jun. 30, 2015
Mar. 31, 2015
Dec. 31, 2014
Sep. 30, 2014
Jun. 30, 2014
Mar. 31, 2014
Dec. 31, 2015
Dec. 31, 2014
Dec. 31, 2013
Statement of Stockholders' Equity [Abstract]                        
Dividends declared on common stock (per share amount) $ 0.11 $ 0.21 $ 0.1 $ 0.1 $ 0 $ 0.15 $ 0.05 $ 0.05 $ 0 $ 0.41 $ 0.25 $ 0.17

v3.3.1.900
Consolidated Statements of Cash Flows
$ in Millions
12 Months Ended
Dec. 31, 2015
USD ($)
Dec. 31, 2014
USD ($)
Dec. 31, 2013
USD ($)
OPERATING ACTIVITIES:      
Net income $ 762 $ 1,147 $ 551
Adjustments to net income:      
Depreciation and amortization 1,144 1,245 1,294
Gain on sale of businesses (29) (358) (26)
Impairment expenses 602 383 661
Deferred income taxes (50) 47 (158)
(Reversals of) provisions for contingencies (72) (34) 312
Loss on extinguishment of debt 186 261 229
Loss on disposals and impairments - discontinued operations 0 50 163
Other 28 72 33
Changes in operating assets and liabilities:      
(Increase) decrease in accounts receivable (378) (520) 146
(Increase) decrease in inventory (26) (48) 16
(Increase) decrease in prepaid expenses and other current assets 655 (73) 358
(Increase) decrease in other assets (1,305) (723) (103)
Increase (decrease) in accounts payable and other current liabilities 31 (85) (758)
Increase (decrease) in income tax payables, net and other tax payables 53 (89) 95
Increase (decrease) in other liabilities 533 516 (98)
Net cash provided by operating activities 2,134 1,791 2,715
INVESTING ACTIVITIES:      
Capital expenditures (2,308) (2,016) (1,988)
Acquisitions, net of cash acquired (17) (728) (7)
Proceeds from the sale of businesses, net of cash sold 138 1,807 170
Sale of short-term investments 4,851 4,503 4,361
Purchase of short-term investments (4,801) (4,623) (4,443)
(Increase) decrease in restricted cash, debt service reserves and other assets (159) 419 44
Other investing (70) (18) 89
Net cash used in investing activities (2,366) (656) (1,774)
FINANCING ACTIVITIES:      
Borrowings under revolving credit facilities 959 836 1,139
Repayments under revolving credit facilities (937) (834) (1,161)
Issuance of recourse debt 575 1,525 750
Repayments of recourse debt (915) (2,117) (1,210)
Issuance of non-recourse debt 4,248 4,179 4,277
Repayments of non-recourse debt (3,312) (3,481) (3,390)
Payments for financing fees (90) (158) (176)
Distributions to noncontrolling interests (326) (485) (557)
Contributions from noncontrolling interests 126 143 101
Proceeds from the sale of redeemable stock of subsidiaries 461 0 0
Dividends paid on AES common stock (276) (144) (119)
Payments for financed capital expenditures (150) (528) (591)
Purchase of treasury stock (482) (308) (322)
Proceeds from sales to noncontrolling interests, net of transaction costs 154 83 109
Other financing (7) 27 14
Net cash provided by (used in) financing activities 28 (1,262) (1,136)
Effect of exchange rate changes on cash (52) (51) (59)
Decrease (increase) in cash of discontinued businesses 0 75 (4)
Cash at held-for-sale businesses (21) 0 0
Total decrease in cash and cash equivalents (277) (103) (258)
Cash and cash equivalents, beginning 1,539 1,642 1,900
Cash and cash equivalents, ending 1,262 1,539 1,642
SUPPLEMENTAL DISCLOSURES:      
Cash payments for interest, net of amounts capitalized 1,265 1,351 1,398
Cash payments for income taxes, net of refunds 388 480 570
SCHEDULE OF NONCASH INVESTING AND FINANCING ACTIVITIES:      
Assets received upon sale of subsidiaries 0 44 0
Assets acquired through capital lease and other liabilities 18 49 34
Dividends declared but not yet paid $ 135 $ 72 $ 54

v3.3.1.900
General and Summary of Significant Accounting Policies
12 Months Ended
Dec. 31, 2015
Accounting Policies [Abstract]  
GENERAL AND SUMMARY OF SIGNIFICANT ACCOUNTING POLICIES
The AES Corporation is a holding company (the "Parent Company") that through its subsidiaries and affiliates, (collectively, "AES" or "the Company") operates a geographically diversified portfolio of electricity generation and distribution businesses. Generally, given this holding company structure, the liabilities of the individual operating entities are non-recourse to the parent and are isolated to the operating entities. Most of our operating entities are structured as limited liability entities, which limit the liability of shareholders. The structure is generally the same regardless of whether a subsidiary is consolidated under a voting or variable interest model.
PRINCIPLES OF CONSOLIDATION — The Consolidated Financial Statements of the Company include the accounts of The AES Corporation and its subsidiaries, which are the entities that it controls. Furthermore, variable interest entities ("VIEs") in which the Company has a variable interest have been consolidated when the Company is the primary beneficiary and thus controls the VIE. Intercompany transactions and balances are eliminated in consolidation. Investments in entities where the Company has the ability to exercise significant influence, but not control, are accounted for using the equity method of accounting.
DP&L, our utility in Ohio, has undivided interests in five generation facilities and numerous transmission facilities. These undivided interests in jointly-owned facilities are accounted for on a pro-rata basis in our consolidated financial statements. Certain expenses, primarily fuel costs for the generating units, are allocated to the joint owners based on their energy usage. The remaining expenses, investments in fuel inventory, plant materials and operating supplies and capital additions are allocated to the joint owners in accordance with their respective ownership interests. See Note 3—Property, Plant and Equipment for additional details.
USE OF ESTIMATES — The preparation of these consolidated financial statements in conformity with accounting principles generally accepted in the United States of America ("GAAP") requires the Company to make estimates and assumptions that affect reported amounts of assets and liabilities and disclosures of contingent assets and liabilities at the date of the consolidated financial statements, as well as the reported amounts of revenue and expenses during the reporting period. Actual results could differ from those estimates. Items subject to such estimates and assumptions include: the carrying amount and estimated useful lives of long-lived assets; asset retirement obligations; impairment of goodwill, long-lived assets and equity method investments; valuation allowances for receivables and deferred tax assets; the recoverability of regulatory assets; the estimation of regulatory liabilities; the fair value of financial instruments; the fair value of assets and liabilities acquired in a business combination; the measurement of noncontrolling interest using the hypothetical liquidation at book value ("HLBV") method for certain renewable generation partnerships; the determination of whether a sale of noncontrolling interests is considered to be a sale of in-substance real estate (as opposed to an equity transaction); pension liabilities; environmental liabilities; and potential litigation claims and settlements.
DISCONTINUED OPERATIONS AND HELD-FOR-SALE BUSINESSES — Effective July 1, 2014, the Company prospectively adopted Accounting Standards Update ("ASU") No. 2014-08, Presentation of Financial Statements (Topic 205) and Property, Plant, and Equipment (Topic 360): Reporting discontinued Operations and Disclosures of Disposals of Components of an Entity, which significantly changed the prior accounting guidance on discontinued operations. Under ASU No. 2014-08, only those disposals of components of an entity that represent a strategic shift that has (or will have) a major effect on an entity's operations and financial results are reported as discontinued operations. Amongst other changes: equity method investments that were previously scoped-out of the discontinued operations accounting guidance are now included in the scope; a business can meet the criteria to be classified as held-for-sale upon acquisition and be reported in discontinued operations; and components where an entity retains significant continuing involvement or where operations and cash flows will not be eliminated from ongoing operations as a result of a disposal transaction can meet the definition of discontinued operations. Additionally, where summarized amounts are presented on the face of the financial statements, reconciliations of those amounts to major classes of line items are also required. ASU No. 2014-08 requires additional disclosures for individually material components that do not meet the definition of discontinued operations. Under the previous accounting guidance, DPLER and Kelanitissa (which both met the Held-for-Sale criteria in 2015) and the Armenia Mountain, U.K. Wind (Operating Projects), and Ebute disposals would have met the discontinued operations criteria and would have been reclassified accordingly. See Note 24—Dispositions and Held-for-Sale Businesses for further information.
Prior to July 1, 2014, a discontinued operation was a component of the Company that either had been disposed of or was classified as held for sale and where the Company did not expect to have significant cash flows from or significant continuing involvement with the component as of one year after its disposal or sale. A component was comprised of operations and cash flows that could be clearly distinguished, operationally and for financial reporting purposes, from the rest of the Company. Before the Company's adoption of ASU No. 2014-08, prior period amounts were retrospectively revised to reflect the businesses determined to be discontinued operations. For components that had been determined to be discontinued operations and held for sale businesses under the old standard, the related cash flows are included within the relevant categories within operating, investing and financing activities. The aggregate amount of cash flows is offset by the net increase or decrease in cash of discontinued and held for sale businesses, which is presented as a separate line item in the Consolidated Statements of Cash Flows.
When an operation is classified as held for sale, the Company recognizes impairment expense, if any, at the consolidated financial statement level which also includes noncontrolling interests. However, any gain or loss on the completion of a disposal transaction is recognized only for the Company's ownership interest. Upon adoption of ASU No. 2014-08 on July 1, 2014, the Company no longer recasts prior period results related to operations classified as held for sale. All assets and liabilities of held-for-sale businesses are classified as current as they are expected to be disposed of within twelve months.
RECLASSIFICATIONS — Certain prior period amounts in the consolidated financial statements have been reclassified to conform to the current presentation. Non-cash impacts related to a regulatory liability at Eletropaulo were reclassified from the Increase (decrease) in accounts payable and other current liabilities and Increase (decrease) in other liabilities lines to the (Reversals of) provisions for contingencies line on the Consolidated Statement of Cash Flows for the year ended December 31, 2013. Additionally, amounts related to certain transactions pertaining to noncontrolling interests were reclassified from the Contributions from noncontrolling interest line to the Proceeds from sales to noncontrolling interests, net of transaction costs line on the Consolidated Statement of Cash flows for the years ended December 31, 2014 and 2013.
FAIR VALUE — Fair value is the price that would be received to sell an asset or paid to transfer a liability in an orderly, hypothetical transaction between market participants at the measurement date, or exit price. The Company applies the fair value measurement accounting guidance to financial assets and liabilities in determining the fair value of investments in marketable debt and equity securities, included in the Consolidated Balance Sheet line items Short-term investments and Other assets (noncurrent); derivative assets, included in Other current assets and Other assets (noncurrent); and, derivative liabilities, included in Accrued and other liabilities (current) and Other long-term liabilities. The Company applies the fair value measurement guidance to nonfinancial assets and liabilities upon the acquisition of a business or in conjunction with the measurement of an asset retirement obligation or a potential impairment loss on an asset group or goodwill under the accounting guidance for the impairment of long-lived assets or goodwill.
The Company makes assumptions about what market participants would assume in valuing an asset or liability based on the best information available. These factors include nonperformance risk (the risk that the obligation will not be fulfilled) and credit risk of the subsidiary (for liabilities) and of the counterparty (for assets). The Company is prohibited from including transaction costs and any adjustments for blockage factors in determining fair value. The principal or most advantageous market is considered from the perspective of the subsidiary owning the asset or with the liability.
Fair value is based on observable market prices where available. Where they are not available, specific valuation models and techniques are applied depending on what is being fair valued. These models and techniques maximize the use of observable inputs and minimize the use of unobservable inputs. The process involves varying levels of management judgment, the degree of which is dependent on price transparency and complexity. An asset's or liability's level within the fair value hierarchy is based on the lowest level of input significant to the fair value measurement, where Level 1 is the highest and Level 3 is the lowest. The three levels are defined as follows:
•
Level 1 — unadjusted quoted prices in active markets accessible by the Company for identical assets or liabilities. Active markets are those in which transactions for the asset or liability occur with sufficient frequency and volume to provide pricing information on an ongoing basis.
•
Level 2 — pricing inputs other than quoted market prices included in Level 1 which are based on observable market data, that are directly or indirectly observable for substantially the full term of the asset or liability. These include quoted market prices for similar assets or liabilities, quoted market prices for identical or similar assets in markets that are not active, adjusted quoted market prices, inputs from observable data such as interest rate and yield curves, volatilities or default rates observable at commonly quoted intervals or inputs derived from observable market data by correlation or other means.
•
Level 3 — pricing inputs that are unobservable from objective sources. Unobservable inputs are only used to the extent observable inputs aren't available. These inputs maintain the concept of an exit price from the perspective of a market participant and reflect assumptions of other market participants. The Company considers all market participant assumptions that are available without unreasonable cost and effort. These are given the lowest priority and are generally used in internally developed methodologies to generate management's best estimate of the fair value when no observable market data is available.
Any transfers between all levels within the fair value hierarchy levels are recognized at the end of the reporting period.
CASH AND CASH EQUIVALENTS — The Company considers unrestricted cash on hand, deposits in banks, certificates of deposit and short-term marketable securities with original maturities of three months or less to be cash and cash equivalents. The carrying amounts of such balances approximate fair value.
RESTRICTED CASH AND DEBT SERVICE RESERVES — These include cash balances which are restricted as to withdrawal or usage by the subsidiary that owns the cash. The nature of restrictions includes restrictions imposed by financing agreements such as security deposits kept as collateral, debt service reserves, maintenance reserves, contractual terms and others, as well as restrictions imposed by agreements related to the sales of businesses or long-term PPAs.
INVESTMENTS IN MARKETABLE SECURITIES — The Company's marketable investments are primarily unsecured debentures, certificates of deposit, government debt securities and money market funds. Short-term investments consist of marketable equity securities and debt securities with original maturities in excess of three months with remaining maturities of less than one year.
Marketable debt securities that the Company has both the positive intent and ability to hold to maturity are classified as held-to-maturity and are carried at amortized cost. Other marketable securities that the Company does not intend to hold to maturity are classified as available-for-sale or trading and are carried at fair value. Available-for-sale investments are fair valued at the end of each reporting period where the unrealized gains or losses are reflected in accumulated other comprehensive loss ("AOCL"), a separate component of equity.
Investments classified as trading are fair valued at the end of each reporting period through the Consolidated Statements of Operations. Interest and dividends on investments are reported in interest income and other income, respectively. Gains and losses on sales of investments are determined using the specific identification method.
ACCOUNTS AND NOTES RECEIVABLE AND ALLOWANCE FOR DOUBTFUL ACCOUNTS — Accounts and notes receivable are carried at amortized cost. The Company periodically assesses the collectability of accounts receivable, considering factors such as specific evaluation of collectability, historical collection experience, the age of accounts receivable and other currently available evidence of the collectability, and records an allowance for doubtful accounts for the estimated uncollectible amount as appropriate. Certain of our businesses charge interest on accounts receivable either under contractual terms or where charging interest is a customary business practice. In such cases, interest income is recognized on an accrual basis. When the collection of such interest is not reasonably assured, interest income is recognized as cash is received. Individual accounts and notes receivable are written off when they are no longer deemed collectible.
INVENTORY — Inventory primarily consists of fuel and other raw materials used to generate power, and spare parts and supplies used to maintain power generation and distribution facilities. Inventory is carried at lower of cost or market. Cost is the sum of the purchase price and incidental expenditures and charges incurred to bring the inventory to its existing condition or location. Costs of inventory are valued primarily using the average cost method. Generally, cost is reduced to market value if the market value of inventory has declined and it is probable that the utility of inventory, in its disposal in the ordinary course of business, will not be recovered through revenue earned from the generation of power.
LONG-LIVED ASSETS — Long-lived assets include property, plant and equipment, assets under capital leases and intangible assets subject to amortization (i.e., finite-lived intangible assets).
Property, plant and equipment — Property, plant and equipment are stated at cost, net of accumulated depreciation. The cost of renewals and improvements that extend the useful life of property, plant and equipment are capitalized.
Construction progress payments, engineering costs, insurance costs, salaries, interest and other costs directly relating to construction in progress are capitalized during the construction period, provided the completion of the project is deemed probable, or expensed at the time the Company determines that development of a particular project is no longer probable. The continued capitalization of such costs is subject to ongoing risks related to successful completion, including those related to government approvals, site identification, financing, construction permitting and contract compliance. Construction-in-progress balances are transferred to electric generation and distribution assets when an asset group is ready for its intended use. Government subsidies, liquidated damages recovered for construction delays and income tax credits are recorded as a reduction to property, plant and equipment and reflected in cash flows from investing activities.
Depreciation, after consideration of salvage value and asset retirement obligations, is computed primarily using the straight-line method over the estimated useful lives of the assets, which are determined on a composite or component basis. Maintenance and repairs are charged to expense as incurred. Capital spare parts, including rotable spare parts, are included in electric generation and distribution assets. If the spare part is considered a component, it is depreciated over its useful life after the part is placed in service. If the spare part is deemed part of a composite asset, the part is depreciated over the composite useful life even when being held as a spare part.
The Company's Brazilian subsidiaries, which include both generation and distribution companies, operate under concession contracts. Certain estimates are utilized to determine depreciation expense for the Brazilian subsidiaries, including the useful lives of the property, plant and equipment and the amounts to be recovered at the end of the concession contract. The amounts to be recovered under these concession contracts are based on estimates that are inherently uncertain and actual amounts recovered may differ from those estimates. These concession contracts are not within the scope of ASC 853—Service Concession Arrangements.
Intangible Assets Subject to Amortization — Finite-lived intangible assets are amortized over their useful lives which range from 1 – 50 years. The Company accounts for purchased emission allowances as intangible assets and records an expense when utilized or sold. Granted emission allowances are valued at zero.
Impairment of Long-lived Assets — When circumstances indicate that the carrying amount of long-lived assets (asset group) held-for-use may not be recoverable, the Company evaluates the assets for potential impairment using internal projections of undiscounted cash flows expected to result from the use and eventual disposal of the assets. Events or changes in circumstances that may necessitate a recoverability evaluation may include, but are not limited to, adverse changes in the regulatory environment, unfavorable changes in power prices or fuel costs, increased competition due to additional capacity in the grid, technological advancements, declining trends in demand, or an expectation that it is more likely than not that the asset will be disposed of before the end of its previously estimated useful life. If the carrying amount of the assets exceeds the undiscounted cash flows and exceeds any fair value of the assets, an impairment expense is recognized for the excess up to the carrying amount of the long-lived assets (but up to any fair value for any individual long-lived asset that is determinable without undue cost and effort). For regulated assets where recovery through approved rates is probable, an impairment expense could be reduced by the establishment of a regulatory asset. For other regulated assets and for non-regulated assets, impairment is recognized as an expense. When long-lived assets meet the criteria to be classified as held-for-sale and the carrying amount of the disposal group exceeds its fair value less costs to sell, an impairment expense is recognized for the excess up to the carrying amount of the long-lived assets; if the fair value of the disposal group subsequently exceeds the carrying amount while the disposal group is still held-for-sale, any impairment expense previously recognized will be reversed up to the lower of the prior expense or the subsequent excess.
SERVICE CONCESSION ASSETS — Service concession assets are stated at cost, net of accumulated amortization, in accordance with ASC 853. Service concession assets represent the cost of all infrastructure to be transferred to the public-sector entity grantors at the end of the concession. These costs primarily represent construction progress payments, engineering costs, insurance costs, salaries, interest and other costs directly relating to construction of the service concession infrastructure. Government subsidies, liquidated damages recovered for construction delays and income tax credits are recorded as a reduction to Service Concession Assets. Service concession assets are amortized and recognized in earnings as a cost of goods sold. Amortization is recorded ratably as build revenue is recognized.
For additional details regarding the impact of service concession accounting on certain of the Company's businesses, see New Accounting Pronouncements Adopted—ASU No. 2014-05, Service Concession Arrangements (Topic 853) below.
DEFERRED FINANCING COSTS — Costs incurred in connection with the issuance of long-term debt are deferred and amortized over the related financing period using the effective interest method. Make-whole payments in connection with early debt retirements are classified as cash flows used in financing activities.
EQUITY METHOD INVESTMENTS — Investments in entities over which the Company has the ability to exercise significant influence, but not control, are accounted for using the equity method of accounting and reported in Investments in and advances to affiliates on the Consolidated Balance Sheets. The Company periodically assesses if there is an indication that the fair value of an equity method investment is less than its carrying amount. When an indicator exists, any excess of the carrying amount over its estimated fair value is recognized as impairment when the loss in value is deemed other-than-temporary and included in Other non-operating expense in the Consolidated Statements of Operations. The difference between the carrying amount and our underlying equity in the net assets of the investee are accounted for as if the investee were a consolidated subsidiary, except that the portion that represents equity method goodwill is not reviewed for impairment like consolidated goodwill.  Upon acquiring the investment, we determine the fair value of the identifiable assets and assumed liabilities and the basis difference between each fair value and the carrying amount of the corresponding asset or liability in the financial statements of the investee are recognized in our net equity in earnings of affiliates over the life of the asset or liability.
The Company discontinues the application of the equity method when an investment is reduced to zero and the Company is not otherwise committed to provide further financial support to the investee. The Company resumes the application of the equity method if the investee subsequently reports net income to the extent that the Company's share of such net income equals the share of net losses not recognized during the period in which the equity method of accounting was suspended.
GOODWILL AND INDEFINITE-LIVED INTANGIBLE ASSETS — The Company evaluates goodwill and indefinite-lived intangible assets for impairment on an annual basis and whenever events or changes in circumstances necessitate an evaluation for impairment. The Company's annual impairment testing date is October 1.
Goodwill — The Company evaluates goodwill impairment at the reporting unit level, which is an SBU (i.e. an operating segment as defined in the segment reporting accounting guidance), or a component (i.e., one level below an operating segment). In determining its reporting units, the Company starts with its management reporting structure. Operating segments are identified and then analyzed to identify components which make up these operating segments. Two or more components are combined into a single reporting unit if they are economically similar. Assets and liabilities are allocated to a reporting unit if the assets will be employed by or a liability relates to the operations of the reporting unit or would be considered by a market participant in determining its fair value. Goodwill resulting from an acquisition is assigned to the reporting units that are expected to benefit from the synergies of the acquisition. Generally, each AES business with a goodwill balance constitutes a reporting unit as they are not reported to segment management together with other businesses and are not similar to other businesses in a segment.
Goodwill is evaluated for impairment either under the qualitative assessment option or the two-step test approach depending on facts and circumstances of a reporting unit, including the excess of fair value over carrying amount in the last valuation or changes in business environment. If the Company qualitatively determines it is more likely than not that the fair value of a reporting unit is greater than its carrying amount, the two-step impairment test is unnecessary. Otherwise, goodwill is evaluated for impairment using the two-step test, where the carrying amount of a reporting unit is compared to its fair value in Step 1; if the fair value exceeds the carrying amount, Step 2 is unnecessary. If the carrying amount exceeds the reporting unit's fair value, this could indicate potential impairment and Step 2 of the goodwill evaluation process is required to determine if goodwill is impaired and to measure the amount of impairment loss to recognize, if any. When Step 2 is necessary, the fair value of individual assets and liabilities is determined using valuations (which in some cases may be based in part on third party valuation reports) or other observable sources of fair value, as appropriate. If the carrying amount of goodwill exceeds its implied fair value, the excess is recognized as an impairment loss up to the carrying amount of the goodwill.
Most of the Company's reporting units are not publicly traded. Therefore, the Company estimates the fair value of its reporting units using internal budgets and forecasts, adjusted for any market participants' assumptions and discounted at the rate of return required by a market participant. The Company considers both market and income-based approaches to determine a range of fair value, but typically concludes that the value derived using an income-based approach is more representative of fair value due to the lack of direct market comparables. The Company utilizes market data, when available, to corroborate and determine the reasonableness of the fair value derived from the income-based discounted cash flow analysis.
Indefinite-Lived Intangible Assets — The Company's indefinite-lived intangible assets primarily include land-use rights and water rights. These are tested for impairment on an annual basis or whenever events or changes in circumstances necessitate an evaluation for impairment. If the carrying amount of an intangible asset exceeds its fair value, the excess is recognized as impairment expense. When deemed appropriate, the Company uses the qualitative assessment option under the accounting guidance on goodwill and intangible assets to determine whether the existence of events or circumstances indicate that it is more likely than not that an intangible asset is impaired. If, after assessing the totality of events and circumstances, the Company determines that it is not more likely than not that an intangible asset is impaired, no further action is taken. The accounting guidance provides the option to bypass the qualitative assessment for any intangible asset in any period and proceed directly to performing the quantitative impairment test.
ACCOUNTS PAYABLE AND OTHER ACCRUED LIABILITIES — Accounts payable consists of amounts due to trade creditors related to the Company's core business operations. These payables include amounts owed to vendors and suppliers for items such as energy purchased for resale, fuel, maintenance, inventory and other raw materials. Other accrued liabilities include items such as income taxes, regulatory liabilities, legal contingencies and employee-related costs including payroll, benefits and related taxes.
REGULATORY ASSETS AND LIABILITIES — The Company records assets and liabilities that result from the regulated ratemaking process that are not recognized under GAAP for non-regulated entities. Regulatory assets generally represent incurred costs that have been deferred due to the future recovery in customer rates being probable. Generally, returns earned on regulatory assets are reflected on the Consolidated Statement of Operations within Interest Income. Regulatory liabilities generally represent obligations to make refunds to customers. Management continually assesses whether the regulatory assets are probable of future recovery and regulatory of liabilities are probable of future payment by considering factors such as applicable regulatory changes, recent rate orders applicable to other regulated entities and the status of any pending or potential deregulation legislation. If future recovery of costs previously deferred ceases to be probable, the related regulatory assets are written off and recognized in income from continuing operations.
PENSION AND OTHER POSTRETIREMENT PLANS — The Company recognizes in its Consolidated Balance Sheets an asset or liability reflecting the funded status of pension and other postretirement plans with current-year changes in actuarial gains or losses recognized in AOCL, except for those plans at certain of the Company's regulated utilities that can recover portions of their pension and postretirement obligations through future rates. All plan assets are recorded at fair value. AES follows the measurement date provisions of the accounting guidance, which require a year-end measurement date of plan assets and obligations for all defined benefit plans.
Effective January 1, 2016, the Company will apply a disaggregated discount rate approach for determining service cost and interest cost for its defined benefit pension plans and post-retirement plans in the U.S. and U.K. This approach is consistent with the requirements of ASC 715—Compensation—Retirement Benefits and is considered to be more precise compared to the aggregated single rate discount approach, which has historically been used in the U.S. and U.K., because it is more consistent with the philosophy of a full yield curve valuation. The disaggregated rate approach can be applied only in countries with a sufficiently robust yield curve. For countries other than the U.S. and U.K., the Company will continue to apply a local government bond yield approach.
The change in discount rate approach in the U.S. and U.K. did not have an impact on the measurement of the benefit obligations as at December 31, 2015, nor will it impact future remeasurements. This change in estimate will impact the service cost and interest cost recorded in 2016 and future years. It will also impact the actuarial gains and losses recorded in future years, as well as the amortization thereof.
The expected 2016 service costs and interest costs included in Note 15—Benefit Plans reflect the change in estimate described above. The impact of the change in approach on expected service costs for the U.S. and U.K. plans in 2016 is shown below (in millions):
 
Expected 2016 Service Cost
 
Expected 2016 Interest Cost
 
Disaggregated rate approach
 
Aggregate rate approach
 
Impact of change
 
Disaggregated rate approach
 
Aggregate rate approach
 
Impact of change
U.S.
$
13

 
$
14

 
$
(1
)
 
$
42

 
$
51

 
$
(9
)
U.K.
3

 
4

 
(1
)
 
7

 
9

 
(2
)
Total
$
16

 
$
18

 
$
(2
)
 
$
49

 
$
60

 
$
(11
)

INCOME TAXES — Deferred tax assets and liabilities are recognized for the future tax consequences attributable to differences between the financial statement carrying amounts of the existing assets and liabilities, and their respective income tax bases. The Company establishes a valuation allowance when it is more likely than not that all or a portion of a deferred tax asset will not be realized. The Company's tax positions are evaluated under a more likely than not recognition threshold and measurement analysis before they are recognized for financial statement reporting.
Uncertain tax positions have been classified as noncurrent income tax liabilities unless expected to be paid within one year. The Company's policy for interest and penalties related to income tax exposures is to recognize interest and penalties as a component of the provision for income taxes in the Consolidated Statements of Operations.
ASSET RETIREMENT OBLIGATIONS — The Company records the fair value of the liability for a legal obligation to retire an asset in the period in which the obligation is incurred. When a new liability is recognized, the Company capitalizes the costs of the liability by increasing the carrying amount of the related long-lived asset. The liability is accreted to its present value each period and the capitalized cost is depreciated over the useful life of the related asset. Upon settlement of the obligation, the Company eliminates the liability and, based on the actual cost to retire, may incur a gain or loss.
NONCONTROLLING INTERESTS — Noncontrolling interests are classified as a separate component of equity in the Consolidated Balance Sheets and Consolidated Statements of Changes in Equity. Additionally, net income and comprehensive income attributable to noncontrolling interests are reflected separately from consolidated net income and comprehensive income on the Consolidated Statements of Operations and Consolidated Statements of Changes in Equity. Any change in ownership of a subsidiary while the controlling financial interest is retained is accounted for as an equity transaction between the controlling and noncontrolling interests (unless the transaction qualifies as a sale of in-substance real estate). Losses continue to be attributed to the noncontrolling interests, even when the noncontrolling interests' basis has been reduced to zero.
Although, in general, the noncontrolling ownership interest in earnings is calculated based on ownership percentage, certain of the Company's businesses are subject to certain profit-sharing arrangements. These agreements exist for certain renewable generation partnerships to designate different allocations of value among investors, where the allocations change in form or percentage over the life of the partnership. For these businesses, the Company uses the HLBV method when it is a reasonable approximation of the profit-sharing arrangement. HLBV uses a balance sheet approach, which measures the Company's equity in income or loss by calculating the change in the amount of net worth the partners are legally able to claim based on a hypothetical liquidation of the entity at the beginning of a reporting period compared to the end of that period.
FOREIGN CURRENCY TRANSLATION — A business's functional currency is the currency of the primary economic environment in which the business operates and is generally the currency in which the business generates and expends cash. Subsidiaries and affiliates whose functional currency is a currency other than the U.S. Dollar translate their assets and liabilities into U.S. Dollars at the current exchange rates in effect at the end of the fiscal period. The revenue and expense accounts of such subsidiaries and affiliates are translated into U.S. Dollars at the average exchange rates that prevailed during the period. Translation adjustments are included in AOCL. Gains and losses on intercompany foreign currency transactions that are long-term in nature and which the Company does not intend to settle in the foreseeable future, are also recognized in AOCL. Gains and losses that arise from exchange rate fluctuations on transactions denominated in a currency other than the functional currency are included in determining net income. Accumulated foreign currency translation adjustments are reclassified to net income only when realized upon sale or upon complete or substantially complete liquidation of the investment in a foreign entity. The accumulated adjustments are included in carrying amounts in impairment assessments where the Company has committed to a plan that will cause the accumulated adjustments to be reclassified to earnings.
REVENUE RECOGNITION — Revenue from utilities is classified as regulated in the Consolidated Statements of Operations. Revenue from the sale of energy is recognized in the period during which the sale occurs. The calculation of revenue earned but not yet billed is based on the number of days not billed in the month, the estimated amount of energy delivered during those days and the estimated average price per customer class for that month. Differences between actual and estimated unbilled revenue are usually immaterial. The Company has businesses where it sells and purchases power to and from Independent System Operators ("ISOs") and Regional Transmission Organizations ("RTOs"). In those instances, the Company accounts for these transactions on a net hourly basis because the transactions are settled on a net hourly basis. Revenue from generation businesses is classified as non-regulated and is recognized based upon output delivered and capacity provided, at rates as specified under contract terms or prevailing market rates. Certain of the Company PPAs meet the definition of an operating lease or contain similar arrangements. Typically, minimum lease payments from such PPAs are recognized as revenue on a straight-line basis over the lease term whereas contingent rentals are recognized when earned. Revenue is recorded net of any taxes assessed on and collected from customers, which are remitted to the governmental authorities.
SHARE-BASED COMPENSATION — The Company grants share-based compensation in the form of stock options, restricted stock units, and performance stock units. The expense is based on the grant-date fair value of the equity or liability instrument issued and is recognized on a straight-line basis over the requisite service period, net of estimated forfeitures. The Company uses a Black-Scholes option pricing model to estimate the fair value of stock options granted to its employees.
GENERAL AND ADMINISTRATIVE EXPENSES — General and administrative expenses include corporate and other expenses related to corporate staff functions and initiatives, primarily executive management, finance, legal, human resources and information systems, which are not directly allocable to our business segments. Additionally, all costs associated with corporate business development efforts are classified as general and administrative expenses.
DERIVATIVES AND HEDGING ACTIVITIES — Under the accounting standards for derivatives and hedging, the Company recognizes all contracts that meet the definition of a derivative, except those designated as normal purchase or normal sale at inception, as either assets or liabilities in the Consolidated Balance Sheets and measures those instruments at fair value. See the Company's fair value policy and Note 4—Fair Value for additional discussion regarding the determination of the fair value. The PPAs and fuel supply agreements entered into by the Company are evaluated to determine if they meet the definition of a derivative or contain embedded derivatives, either of which require separate valuation and accounting. To be a derivative under the accounting standards for derivatives and hedging, an agreement would need to have a notional and an underlying, require little or no initial net investment and could be net settled. Generally, these agreements do not meet the definition of a derivative, often due to the inability to be net settled. On a quarterly basis, we evaluate the markets for the commodities to be delivered under these agreements to determine if facts and circumstances have changed such that the agreements could then be net settled and meet the definition of a derivative.
Derivatives primarily consist of interest rate swaps, cross-currency swaps, foreign currency instruments, and commodity derivatives. The Company enters into various derivative transactions in order to hedge its exposure to certain market risks, primarily interest rate, foreign currency and commodity price risks. Regarding interest rate risk, the Company and our subsidiaries generally utilize variable rate debt financing for construction projects and operations so interest rate swap, lock, cap, and floor agreements are entered into to manage interest rate risk by effectively fixing or limiting the interest rate exposure on the underlying financing and are typically designated as cash flow hedges. Regarding foreign currency risk, we are exposed to it as a result of our investments in foreign subsidiaries and affiliates that may be impacted by significant fluctuations in foreign currency exchange rates so foreign currency options and forwards are utilized, where deemed appropriate, to manage the risk related to these fluctuations. Cross-currency swaps are utilized in certain instances to manage the risk related to certain foreign currencies and the associated impact on interest and loan principal payments. In addition, certain of our subsidiaries have entered into contracts which contain embedded derivatives as a portion of the contracts primarily that are denominated in a currency other than the functional or local currency of that subsidiary or the currency of the item. Regarding commodity price risk, we are exposed to the impact of market fluctuations in the price of electricity, fuel and environmental credits. Although we primarily consist of businesses with long-term contracts or retail sales concessions (which provide our distribution businesses with a franchise to serve a specific geographic region), a portion of our current and expected future revenues are derived from businesses without significant long-term purchase or sales contracts. We use an overall hedging strategy, not just derivatives, to hedge our financial performance against the effects of fluctuations in commodity prices.
The accounting standards for derivatives and hedging enable companies to designate qualifying derivatives as hedging instruments based on the exposure being hedged. The Company only has cash flow hedges at this time. Changes in the fair value of a derivative that is highly effective, designated and qualifies as a cash flow hedge are deferred in AOCL and are recognized into earnings as the hedged transactions affect earnings. Any ineffectiveness is recognized in earnings immediately. For all designated and qualifying hedges, the Company maintains formal documentation of the hedge and effectiveness testing in accordance with the accounting standards for derivatives and hedging. If AES determines that the derivative is no longer highly effective as a hedge, hedge accounting will be discontinued prospectively. For cash flow hedges of forecasted transactions, AES estimates the future cash flows of the forecasted transactions and evaluates the probability of the occurrence and timing of such transactions. Changes in conditions or the occurrence of unforeseen events could require discontinuance of hedge accounting or could affect the timing of the reclassification of gains or losses on cash flow hedges from AOCL into earnings.
While derivative transactions are not entered into for trading purposes, some contracts are not eligible for hedge accounting. Changes in the fair value of derivatives not designated and qualifying as cash flow hedges are immediately recognized in earnings. Regardless of when gains or losses on derivatives (including all those where the fair value measurement is classified as Level 3) are recognized in earnings, they are generally classified as follows: interest expense for interest rate and cross-currency derivatives, foreign currency transaction gains or losses for foreign currency derivatives, and non-regulated revenue or non-regulated cost of sales for commodity and other derivatives. However, gains and losses on interest rate and cross-currency derivatives are classified as foreign currency transaction gains and losses if they offset the remeasurement of the foreign currency-denominated debt being hedged by the cross-currency swaps and the amount reclassified from AOCL to cost of sales to offset depreciation where the variable-rate interest capitalized as part of the asset was hedged during its construction. Cash flows arising from derivatives are included in the Consolidated Statements of Cash Flows as an operating activity given the nature of the underlying risk being economically hedged and the lack of significant financing elements, except that cash flows on designated and qualifying hedges of variable-rate interest during construction are classified as an investing activity.
The Company has elected not to offset net derivative positions in the financial statements. Accordingly, the Company does not offset such derivative positions against the fair value of amounts (or amounts that approximate fair value) recognized for the right to reclaim cash collateral (a receivable) or the obligation to return cash collateral (a payable) under master netting arrangements.
NEW ACCOUNTING PRONOUNCEMENTS ADOPTED
ASU No. 2015-17, Income Taxes (Topic 740): Balance Sheet Classification of Deferred Taxes
Effective December 31, 2015, the Company prospectively adopted ASU No. 2015-17, which requires that all deferred tax assets and liabilities, along with any related valuation allowance, be classified as noncurrent on the balance sheet. As a result, each jurisdiction will now only have one net noncurrent deferred tax asset or liability. The guidance does not change the existing requirement that only permits offsetting within a jurisdiction; that is, companies will remain prohibited from offsetting deferred tax liabilities from one jurisdiction against deferred tax assets of another jurisdiction. Additionally, the current requirement that deferred tax liabilities and assets of a tax-paying component of an entity be offset and presented as a single amount is not affected by the update. As the Company elected to apply this ASU prospectively, prior periods were not adjusted.
ASU No. 2015-13, Derivatives and Hedging (Topic 815): Application of the Normal Purchases and Normal Sales Scope Exception to Certain Electricity Contracts within Nodal Energy Markets
In August 2015, the FASB issued ASU No. 2015-13, which resolves the diversity in practice resulting from determining whether certain contracts qualify for the normal purchases and normal sales scope exception under ASC Topic 815—Derivatives and Hedging. This standard clarifies that entities would not be precluded from applying the normal purchases and normal sales exception to certain forward contracts that necessitate the transmission of electricity through, or delivery to a location within, a nodal energy market. The standard is effective upon issuance and should be applied prospectively. As the Company had designated qualifying contracts as normal purchase or normal sales, there was no impact on the Company's consolidated financial statements upon adoption of this standard.
ASU No. 2014-05, Service Concession Arrangements (Topic 853)
Effective January 1, 2015, the Company adopted ASU No. 2014-05, which states that certain service concession arrangements with public-sector entity grantors are not in scope of ASC 840—Leases, and that entities should not recognize the related infrastructure as property, plant and equipment, but should apply other GAAP. The Company has a small number of entities that fall within the scope of this guidance, with the Company's Mong Duong generation facility in Vietnam being the most significant.
Mong Duong is based on a build, operate and transfer agreement with the Vietnamese government. Management concluded there were two deliverables included within the arrangement, as well as a financing element. Due to the contingent nature of the revenue stream, no amounts of revenue could be recognized during the build phase of the contract. All amounts billed during the operate phase are recognized as revenue when billed, with amounts allocated between the financing element and build and operate deliverables. The financing element is recognized as interest income using the effective interest method as payments for construction of the plant are received over the life of the contract. Costs are expensed as incurred. As the related infrastructure is no longer considered property, plant and equipment, there are no longer any capitalizable expenses beyond those related to the initial build, and accordingly these will be expensed as incurred. All cash flows for these arrangements, excluding those related to the debt incurred by AES, will be reflected in cash flows from operating activities on the Company's Consolidated Statements of Cash Flows prospectively.
The guidance was applied on a modified retrospective basis to service concession arrangements in existence at January 1, 2015. Upon adoption of this standard, the impact to the Company's Consolidated Balance Sheet as of January 1, 2015 resulted in a reclassification of $1.5 billion from property, plant and equipment to service concession assets, as well as a cumulative adjustment to retained earnings and cumulative translation adjustment of $(18) million, net of tax, and $13 million, respectively.
ACCOUNTING PRONOUNCEMENTS ISSUED BUT NOT YET EFFECTIVE — The following accounting standards have been issued, but are not yet effective for, and have not been adopted in these financial statements by AES.
ASU No. 2016-01, Financial Instruments — Overall (Topic 825-10): Recognition and Measurement of Financial Assets and Financial Liabilities
In January 2016, the FASB issued ASU 2016-01, which was designed to improve the recognition and measurement of financial instruments through targeted changes to existing GAAP. The guidance requires equity investments (except those that are accounted for under the equity method of accounting or result in consolidation of the investee) to be measured at fair value with changes in fair value recognized in net income; that entities use the exit price notion when measuring financial instrument fair values; that an entity separate presentation of financial assets and liabilities by measurement category and form of financial asset on the Balance Sheets or Notes to the financial statements; that an entity present separately in other comprehensive income the portion of the total change in the fair value of a liability resulting from a change in the instrument-specific credit risk (or "own credit") when the entity has elected to measure the liability at fair value in accordance with the fair value option for financial instruments. Also, the standard eliminates the requirement for public entities to disclose the methods and significant assumptions used to estimate the fair value required to be disclosed for financial instruments measured at amortized cost on the Balance Sheets. The standard is effective beginning with interim periods starting after December 31, 2017 and cannot be applied early. The Company is currently evaluating the applicability and materiality of the standard, but does not anticipate a material impact on the Company's consolidated financial statements.
ASU No. 2015-16, Business Combinations (Topic 805): Simplifying the Accounting for Measurement-Period Adjustments
In September 2015, the FASB issued ASU 2015-16, which simplifies the measurement-period adjustments in business combinations. It eliminates the requirement that an acquirer in a business combination account for measurement-period adjustments retrospectively. An acquirer will recognize a measurement-period adjustment during the period in which it determines the amount of the adjustment. The standard is effective for public entities for annual reporting periods beginning after December 15, 2015, and interim periods therein. Early adoption is permitted for financial statements that have not been issued. The new guidance should be applied prospectively to adjustments to provisional amounts that occur after the effective date of this standard. The Company will adopt this standard on January 1, 2016, which is not expected to have a material impact on the Company's consolidated financial statements.
ASU No. 2015-15, Interest — Imputation of Interest (Subtopic 835-30): Presentation and Subsequent Measurement of Debt Issuance Costs Associated with Line-of-Credit Arrangements
In August 2015, the FASB issued ASU No. 2015-15, which clarifies that the SEC Staff would not object to an entity presenting debt issuance costs related to line-of-credit arrangements as an asset that is subsequently amortized ratably over the term of the line-of-credit arrangement, regardless of whether there are any outstanding borrowings on the line-of-credit arrangement. This standard should be adopted concurrent with adoption of ASU 2015-03 (see below). As of December 31, 2015, the Company had deferred financing costs related to lines-of-credit of approximately $2 million recorded within other current assets and $24 million recorded within other noncurrent assets that would not be reclassified upon adoption of this standard.
ASU No. 2015-11, Inventory (Topic 330): Simplifying the Measurement of Inventory
In July 2015, the FASB issued ASU No. 2015-11, which simplifies the subsequent measurement of inventory. It replaces the current lower of cost or market test with a lower of cost or net realizable value test. The standard is effective for public entities for annual reporting periods beginning after December 15, 2016, and interim periods therein. Early adoption is permitted. The new guidance must be applied prospectively. The Company is currently evaluating the impact of adopting the standard on its consolidated financial statements.
ASU No. 2015-05, Intangibles — Goodwill and Other — Internal-Use Software (Subtopic 350-40): Customer's Accounting for Fees Paid in a Cloud Computing Arrangement
In April 2015, the FASB issued ASU No. 2015-05, which clarifies how customers in cloud computing arrangements should determine whether the arrangement includes a software license and eliminates the existing requirement for customers to account for software licenses they acquired by analogizing to the accounting guidance on leases. The standard is effective for annual reporting periods beginning after December 15, 2015 and interim periods therein. Early adoption is permitted. The standard permits the use of a prospective or retrospective approach. The Company expects to utilize the prospective approach upon adoption of this standard, which is not expected to have a material impact on its consolidated financial statements.
ASU No. 2015-03, Interest — Imputation of Interest (Subtopic 835-30)
In April 2015, the FASB issued ASU No. 2015-03, which simplifies the presentation of debt issuance costs by requiring that debt issuance costs related to a recognized debt liability be presented in the balance sheet as a direct deduction from the carrying amount of that debt liability, consistent with debt discounts. The recognition and measurement guidance for debt issuance costs are not affected by the amendments in this update. The standard is effective for annual reporting periods beginning after December 15, 2015 and interim periods therein, and requires the use of the full retrospective approach. Early adoption is permitted for financial statements that have not been previously issued. As of December 31, 2015, the Company had deferred financing costs of approximately $24 million classified within other current assets and $356 million classified within other noncurrent assets that would be reclassified to reduce the related debt liabilities upon adoption of this standard.
ASU No. 2015-02, Consolidation — Amendments to the Consolidation Analysis (Topic 810)
In February 2015, the FASB issued ASU 2015-02, which makes targeted amendments to the current consolidation guidance and ends the deferral granted to investment companies from applying the VIE guidance. The standard amends the evaluation of whether (1) fees paid to a decision-maker or service providers represent a variable interest, (2) a limited partnership or similar entity has the characteristics of a VIE and (3) a reporting entity is the primary beneficiary of a VIE. The standard is effective for annual periods beginning after December 15, 2015 and interim periods therein. Early adoption is permitted. Based on the Company's preliminary analysis, no change in consolidation is expected although additional disclosures may be required.
ASU No. 2014-09, Revenue from Contracts with Customers (Topic 606)
In May 2014, the FASB issued ASU No. 2014-09, which clarifies principles for recognizing revenue and will result in a common revenue standard for U.S. GAAP and International Financial Reporting Standards. The objective of the new standard is to provide a single and comprehensive revenue recognition model for all contracts with customers to improve comparability. The revenue standard contains principles that an entity will apply to determine the measurement of revenue and timing of when it is recognized. The standard requires an entity to recognize revenue to depict the transfer of goods or services to customers at an amount that the entity expects to be entitled to in exchange for those goods or services. In August 2015, the FASB issued ASU No. 2015-14, Revenue from Contracts with Customers (Topic 606): Deferral of the Effective Date, which deferred the effective date of ASU 2014-09 by one year, resulting in the new revenue standard being effective for annual reporting periods beginning after December 15, 2017 and interim periods therein. Early adoption is now permitted only as of the original effective date for public entities (that is, no earlier than 2017 for calendar year-end entities). The standard permits the use of either a full retrospective or modified retrospective approach. The Company has not yet selected a transition method and is currently evaluating the impact of adopting the standard on its consolidated financial statements.

v3.3.1.900
Inventory
12 Months Ended
Dec. 31, 2015
Inventory Disclosure [Abstract]  
INVENTORY
INVENTORY
Inventory is valued primarily using the average-cost method. The following table summarizes the Company's inventory balances (in millions) as of the dates indicated:
December 31,
 
2015
 
2014
Fuel and other raw materials
 
$
343

 
$
357

Spare parts and supplies
 
332

 
345

Total
 
$
675

 
$
702


v3.3.1.900
Property Plant and Equipment
12 Months Ended
Dec. 31, 2015
Property, Plant and Equipment [Abstract]  
PROPERTY, PLANT AND EQUIPMENT
The following table summarizes the components of the electric generation and distribution assets and other property, plant and equipment (in millions) with their estimated useful lives (in years). The amounts are stated net of all prior asset impairment losses recognized.


December 31,
 
Estimated Useful Life
2015
 
2014
Electric generation and distribution facilities
5 - 68
 
$
25,427

 
$
27,488

Other buildings
3 - 53
 
1,868

 
1,694

Furniture, fixtures and equipment
2 - 31
 
305

 
307

Other
1 - 50
 
891

 
970

Total electric generation and distribution assets and other
 
 
28,491

 
30,459

Accumulated depreciation
 
 
(9,449
)
 
(9,962
)
Net electric generation and distribution assets and other (1)
 
 
$
19,042

 
$
20,497


(1) 
Net electric generation and distribution assets and other include unamortized internal-use software costs of $83 million and $115 million as of December 31, 2015 and 2014, respectively.
The following table summarizes depreciation expense (including the amortization of assets recorded under capital leases), amortization of internal-use software and interest capitalized during development and construction on qualifying assets for the periods indicated (in millions):
Year Ended December 31,
 
2015
 
2014
 
2013
Depreciation expense (including amortization of assets recorded under capital leases)
 
$
1,104

 
$
1,204

 
$
1,193

Amortization of internal-use software
 
29

 
33

 
36

Interest capitalized during development and construction
 
90

 
120

 
84


Property, plant and equipment, net of accumulated depreciation, of $12 billion and $15 billion was mortgaged, pledged or subject to liens as of December 31, 2015 and 2014, respectively.
The following table summarizes regulated and non-regulated generation and distribution property, plant and equipment and accumulated depreciation in millions as of the periods indicated:
December 31,
 
2015
 
2014
Regulated generation, distribution assets and other, gross
 
$
11,818

 
$
13,103

Regulated accumulated depreciation
 
(4,351
)
 
(4,841
)
Regulated generation, distribution assets and other, net
 
7,467

 
8,262

Non-regulated generation, distribution assets and other, gross
 
16,673

 
17,356

Non-regulated accumulated depreciation
 
(5,098
)
 
(5,121
)
Non-regulated generation, distribution assets and other, net
 
11,575

 
12,235

Net electric generation, distribution assets and other
 
$
19,042

 
$
20,497


The next table presents amounts recognized related to asset retirement obligations in millions for the periods indicated:
 
 
2015
 
2014
Balance at January 1
 
$
209

 
$
142

Additional liabilities incurred
 
43

 
51

Liabilities settled
 
(6
)
 
(11
)
Accretion expense
 
13

 
12

Change in estimated cash flows
 
(7
)
 
15

Other
 
(5
)
 
—

Balance at December 31
 
$
247

 
$
209


The Company's asset retirement obligations covered by the relevant guidance primarily include active ash landfills, water treatment basins and the removal or dismantlement of certain plants and equipment. There were $2 million of legally restricted assets for the year ended December 31, 2015 and none for the year ended December 31, 2014 for purposes of settling asset retirement obligations.
Ownership of Certain Coal-Fired Facilities
DP&L has undivided ownership interests in five coal-fired generation facilities jointly owned with other utilities. DP&L's share of the operating costs of such facilities is included in Cost of Sales in the Consolidated Statements of Operations and its share of investment in the facilities is included in Property, Plant and Equipment in the Consolidated Balance Sheets. DP&L's undivided ownership interest in such facilities at December 31, 2015 is as follows:
 
DP&L Share
 
DP&L Investment
 
Ownership
 
Gross Plant In Service
 
Accumulated Depreciation
 
Construction Work In Process
Production units:
 
 
($ in millions)
Conesville Unit 4
17
%
 
$
26

 
$
4

 
$
1

Killen Station
67
%
 
342

 
29

 
2

Miami Fort Units 7 and 8
36
%
 
219

 
32

 
6

Stuart Station
35
%
 
236

 
19

 
18

Zimmer Station
28
%
 
188

 
44

 
12

Transmission
various

 
43

 
8

 
—

Total
 
 
$
1,054

 
$
136

 
$
39


v3.3.1.900
Fair Value
12 Months Ended
Dec. 31, 2015
Fair Value Disclosures [Abstract]  
FAIR VALUE
FAIR VALUE
The fair value of current financial assets and liabilities, debt service reserves and other deposits approximate their reported carrying amounts. The estimated fair values of the Company's assets and liabilities have been determined using available market information. By virtue of these amounts being estimates and based on hypothetical transactions to sell assets or transfer liabilities, the use of different market assumptions and/or estimation methodologies may have a material effect on the estimated fair value amounts.
Valuation Techniques — The fair value measurement accounting guidance describes three main approaches to measuring the fair value of assets and liabilities: (1) market approach, (2) income approach and (3) cost approach. The market approach uses prices and other relevant information generated from market transactions involving identical or comparable assets or liabilities. The income approach uses valuation techniques to convert future amounts to a single present value amount. The measurement is based on current market expectations of the return on those future amounts. The cost approach is based on the amount that would currently be required to replace an asset. The Company measures its investments and derivatives at fair value on a recurring basis. Additionally, in connection with annual or event-driven impairment evaluations, certain nonfinancial assets and liabilities are measured at fair value on a nonrecurring basis. These include long-lived tangible assets (i.e., property, plant and equipment), goodwill and intangible assets (e.g., sales concessions, land use rights and water rights, etc.). In general, the Company determines the fair value of investments and derivatives using the market approach and the income approach, respectively. In the nonrecurring measurements of nonfinancial assets and liabilities, all three approaches are considered; however, the value estimated under the income approach is often the most representative of fair value.
Investments — The Company's investments measured at fair value generally consist of marketable debt and equity securities. Equity securities are measured at fair value primarily using quoted market prices, which are considered Level 1 measurements in the fair value hierarchy. Debt securities primarily consist of unsecured debentures, certificates of deposit and government debt securities held by our Brazilian subsidiaries. Returns and pricing on these instruments are generally indexed to the CDI (Brazilian equivalent to London Inter Bank Offered Rate, or LIBOR, a benchmark interest rate widely used by banks in the interbank lending market) or Selic (overnight borrowing rate) rates in Brazil. For the equity securities which are not considered Level 1 measurements and for the debt securities, fair value is determined from comparisons to market data obtained for similar assets and are considered Level 2 measurements in the fair value hierarchy.
Derivatives — Any Level 1 derivative instruments are exchange-traded commodity futures for which the pricing is observable in active markets, and as such, these are not expected to transfer to other levels. There have been no transfers between Level 1 and Level 2.
For all derivatives, with the exception of any classified as Level 1, the income approach is used, which consists of forecasting future cash flows based on contractual notional amounts and applicable and available market data as of the valuation date. The most common market data inputs used in the income approach include volatilities, spot and forward benchmark interest rates (such as LIBOR and Euro Inter Bank Offered Rate ("EURIBOR")), foreign exchange rates and commodity prices. Forward rates with the same tenor as the derivative instrument being valued are generally obtained from published sources, with these forward rates being assessed quarterly at a portfolio-level for reasonableness versus comparable published information provided from another source. When significant inputs are not observable, the Company uses relevant techniques to determine the inputs, such as regression analysis or prices for similarly traded instruments available in the market.
For derivatives for which there is a standard industry valuation model, the Company uses a third-party derivative accounting and valuation service provider that uses a standard model and observable inputs to estimate the fair value. For these derivatives, the Company performs analytical procedures and makes comparisons to other third-party information in order to assess the reasonableness of the fair value. For derivatives for which there is not a standard industry valuation model (such as PPAs and fuel supply agreements that are derivatives or include embedded derivatives), the Company has created internal valuation models to estimate the fair value, using observable data to the extent available. At each quarter-end, the models for the commodity and foreign currency-based derivatives are generally prepared and reviewed by employees who globally manage the respective commodity and foreign currency risks and are analytically reviewed independent of those employees.
Those cash flows are then discounted using the relevant spot benchmark interest rate (such as LIBOR or EURIBOR). The Company then makes a credit valuation adjustment ("CVA") by further discounting the cash flows for nonperformance or credit risk based on the observable or estimated debt spread of the Company's subsidiary or its counterparty and the tenor of the respective derivative instrument. The CVA for potential future scenarios in which the derivative is in an asset is based on the counterparty's credit ratings, credit default swap spreads, and debt spreads, as available. The CVA for potential future scenarios in which the derivative is a liability is based on the Parent Company's or the subsidiary's current debt spread. In the absence of readily obtainable credit information, the Parent Company's or the subsidiary's estimated credit rating (based on applying a standard industry model to historical financial information and then considering other relevant information) and spreads of comparably rated entities or the respective country's debt spreads are used as a proxy. All derivative instruments are analyzed individually and are subject to unique risk exposures.
The Company's methodology to fair value its derivatives is to start with any observable inputs; however, in certain instances the published forward rates or prices may not extend through the remaining term of the contract and management must make assumptions to extrapolate the curve, which necessitates the use of unobservable inputs, such as proxy commodity prices or historical settlements to forecast forward prices. Specifically, where there is limited forward curve data with respect to foreign exchange contracts, beyond the traded points the Company utilizes the purchasing power parity approach to construct the remaining portion of the forward curve using relative inflation rates. In addition, in certain instances, there may not be market or market-corroborated data readily available, requiring the use of unobservable inputs. Similarly, in certain instances, the spread that reflects the credit or nonperformance risk is unobservable requiring us to utilize proxy yield curves of similar credit quality. The fair value hierarchy of an asset or a liability is based on the level of significance of the input assumptions. An input assumption is considered significant if it affects the fair value by at least 10%. Assets and liabilities are classified as Level 3 when the use of unobservable inputs is significant. When the use of unobservable inputs is insignificant, assets and liabilities are classified as Level 2. Transfers between Level 3 and Level 2 are determined as of the end of the reporting period and result from changes in significance of unobservable inputs used to calculate the CVA.
Debt — Recourse and non-recourse debt are carried at amortized cost. The fair value of recourse debt is estimated based on quoted market prices. The fair value of non-recourse debt is estimated differently based upon the type of loan. In general, the carrying amount of variable rate debt is a close approximation of its fair value. For fixed rate loans, the fair value is estimated using quoted market prices or discounted cash flow ("DCF") analyses. In the DCF analysis, the discount rate is based on the credit rating of the individual debt instruments, if available, or the credit rating of the subsidiary. If the subsidiary's credit rating is not available, a synthetic credit rating is determined using certain key metrics, including cash flow ratios and interest coverage, as well as other industry-specific factors. For subsidiaries located outside the U.S., in the event that the country rating is lower than the credit rating previously determined, the country rating is used for purposes of the DCF analysis. The fair value of recourse and non-recourse debt excludes accrued interest at the valuation date. The fair value was determined using available market information as of December 31, 2015. The Company is not aware of any factors that would significantly affect the fair value amounts subsequent to December 31, 2015.
Nonrecurring Measurements — For nonrecurring measurements derived using the income approach, fair value is determined using valuation models based on the principles of DCF. The income approach is most often used in the impairment evaluation of long-lived tangible assets, equity method investments, goodwill, and intangible assets. The Company uses its internally developed DCF valuation models as the primary means to determine nonrecurring fair value measurements though other valuation approaches prescribed under the fair value measurement accounting guidance are also considered. Depending on the complexity of a valuation, an independent valuation firm may be engaged to assist management in the valuation process. A few examples of input assumptions to such valuations include macroeconomic factors such as growth rates, industry demand, inflation, exchange rates and power and commodity prices. Whenever possible, the Company attempts to obtain market observable data to develop input assumptions. Where the use of market observable data is limited or not available for certain input assumptions, the Company develops its own estimates using a variety of techniques such as regression analysis and extrapolations.
For nonrecurring measurements derived using the market approach, recent market transactions involving the sale of identical or similar assets are considered. The use of this approach is limited because it is often difficult to identify sale transactions of identical or similar assets. This approach is used in impairment evaluations of certain intangible assets. Otherwise, it is used to corroborate the fair value determined under the income approach.
For nonrecurring measurements derived using the cost approach, fair value is typically based upon a replacement cost approach. Under this approach, the depreciated replacement cost of assets is derived by first estimating the current replacement cost of assets and then applying the remaining useful life percentages to such costs. Further adjustments for economic and functional obsolescence are made to the depreciated replacement cost. This approach involves a considerable amount of judgment, which is why its use is limited to the measurement of long-lived tangible assets. Like the market approach, this approach is also used to corroborate the fair value determined under the income approach.
Fair Value Considerations — In determining fair value, the Company considers the source of observable market data inputs, liquidity of the instrument, the credit risk of the counterparty and the risk of the Company's or its counterparty's nonperformance. The conditions and criteria used to assess these factors are:
Sources of market assumptions — The Company derives most of its market assumptions from market efficient data sources (e.g., Bloomberg and Reuters). To determine fair value, where market data is not readily available, management uses comparable market sources and empirical evidence to develop its own estimates of market assumptions.
Market liquidity — The Company evaluates market liquidity based on whether the financial or physical instrument, or the underlying asset, is traded in an active or inactive market. An active market exists if the prices are fully transparent to market participants, can be measured by market bid and ask quotes, the market has a relatively large proportion of trading volume as compared to the Company's current trading volume and the market has a significant number of market participants that will allow the market to rapidly absorb the quantity of assets traded without significantly affecting the market price. Another factor the Company considers when determining whether a market is active or inactive is the presence of government or regulatory controls over pricing that could make it difficult to establish a market-based price when entering into a transaction.
Nonperformance risk — Nonperformance risk refers to the risk that an obligation will not be fulfilled and affects the value at which a liability is transferred or an asset is sold. Nonperformance risk includes, but may not be limited to, the Company or its counterparty's credit and settlement risk. Nonperformance risk adjustments are dependent on credit spreads, letters of credit, collateral, other arrangements available and the nature of master netting arrangements. The Company and its subsidiaries are parties to various interest rate swaps and options; foreign currency options and forwards; and derivatives and embedded derivatives, which subject the Company to nonperformance risk. The financial and physical instruments held at the subsidiary level are generally non-recourse to the Parent Company.
Nonperformance risk on the investments held by the Company is incorporated in the fair value derived from quoted market data to mark the investments to fair value.
Recurring Measurements
The following table presents, by level within the fair value hierarchy, as described in Note 1—General and Summary of Significant Accounting Policies, the Company's financial assets and liabilities (in millions) that were measured at fair value on a recurring basis as of the periods indicated:
 
 
December 31, 2015
 
December 31, 2014
 
 
Level 1
 
Level 2
 
Level 3
 
Total
 
Level 1
 
Level 2
 
Level 3
 
Total
Assets


AVAILABLE FOR SALE:


Debt securities:(1)


Unsecured debentures
 
$
—

 
$
327

 
$
—

 
$
327

 
$
—

 
$
501

 
$
—

 
$
501

Certificates of deposit
 
—

 
135

 
—

 
135

 
—

 
151

 
—

 
151

Government debt securities
 
—

 
28

 
—

 
28

 
—

 
57

 
—

 
57

Subtotal
 
—

 
490

 
—

 
490

 
—

 
709

 
—

 
709

Equity securities:


Mutual funds
 
—

 
15

 
—

 
15

 
—

 
25

 
—

 
25

Subtotal
 
—

 
15

 
—

 
15

 
—

 
25

 
—

 
25

Total available for sale
 
—

 
505

 
—

 
505

 
—

 
734

 
—

 
734

TRADING:


Equity securities:


Mutual funds
 
15

 
—

 
—

 
15

 
15

 
—

 
—

 
15

Total trading
 
15

 
—

 
—

 
15

 
15

 
—

 
—

 
15

DERIVATIVES:


Foreign currency derivatives
 
—

 
35

 
292

 
327

 
—

 
18

 
218

 
236

Commodity derivatives
 
—

 
41

 
7

 
48

 
—

 
37

 
7

 
44

Total derivatives
 
—

 
76

 
299

 
375

 
—

 
55

 
225

 
280

TOTAL ASSETS
 
$
15

 
$
581

 
$
299

 
$
895

 
$
15

 
$
789

 
$
225

 
$
1,029

Liabilities


DERIVATIVES:


Interest rate derivatives
 
$
—

 
$
54

 
$
304

 
$
358

 
$
—

 
$
206

 
$
210

 
$
416

Cross currency derivatives
 
—

 
43

 
—

 
43

 
—

 
29

 
—

 
29

Foreign currency derivatives
 
—

 
41

 
15

 
56

 
—

 
43

 
9

 
52

Commodity derivatives
 
—

 
29

 
4

 
33

 
—

 
16

 
1

 
17

Total derivatives
 
—

 
167

 
323

 
490

 
—

 
294

 
220

 
514

TOTAL LIABILITIES
 
$
—

 
$
167

 
$
323

 
$
490

 
$
—

 
$
294

 
$
220

 
$
514

 _____________________________
(1) 
Amortized cost approximated fair value at December 31, 2015 and 2014.
The following tables present a reconciliation of net derivative assets and liabilities measured at fair value on a recurring basis using significant unobservable inputs (Level 3) for the years ended December 31, 2015 and 2014 (presented net by type of derivative in millions). Transfers between Level 3 and Level 2 are determined as of the end of the reporting period and principally result from changes in the significance of unobservable inputs used to calculate the credit valuation adjustment.
Year Ended December 31, 2015
Interest Rate
 
Foreign Currency
 
Commodity
 
Total
Balance at January 1
$
(210
)
 
$
209

 
$
6

 
$
5

Total gains (losses) (realized and unrealized):


Included in earnings
(1
)
 
198

 
(1
)
 
196

Included in other comprehensive income - derivative activity
(31
)
 
—

 
—

 
(31
)
Included in other comprehensive income - foreign currency translation activity
9

 
(103
)
 
—

 
(94
)
Included in regulatory (assets) liabilities
—

 
—

 
(18
)
 
(18
)
Settlements
24

 
(7
)
 
16

 
33

Transfers of assets (liabilities) into Level 3
(95
)
 
(1
)
 
—

 
(96
)
Transfers of (assets) liabilities out of Level 3
—

 
(19
)
 
—

 
(19
)
Balance at December 31
$
(304
)
 
$
277

 
$
3

 
$
(24
)
Total gains (losses) for the period included in earnings attributable to the change in unrealized gains (losses) relating to assets and liabilities held at the end of the period
$
—

 
$
187

 
$
(1
)
 
$
186

Year Ended December 31, 2014
Interest Rate
 
Foreign Currency
 
Commodity
 
Total
Balance at January 1
$
(101
)
 
$
93

 
$
4

 
$
(4
)
Total gains (losses) (realized and unrealized):


Included in earnings
2

 
134

 
1

 
137

Included in other comprehensive income - derivative activity
(154
)
 
(2
)
 
—

 
(156
)
Included in other comprehensive income - foreign currency translation activity
13

 
(25
)
 
—

 
(12
)
Included in regulatory (assets) liabilities
—

 
—

 
16

 
16

Settlements
30

 
(4
)
 
(15
)
 
11

Transfers of assets (liabilities) into Level 3
—

 
10

 
—

 
10

Transfers of (assets) liabilities out of Level 3
—

 
3

 
—

 
3

Balance at December 31
$
(210
)
 
$
209

 
$
6

 
$
5

Total gains (losses) for the period included in earnings attributable to the change in unrealized gains (losses) relating to assets and liabilities held at the end of the period
$
2

 
$
130

 
$
(1
)
 
$
131


The following table summarizes the significant unobservable inputs used for the Level 3 derivative assets (liabilities) as of December 31, 2015:
Type of Derivative
 
Fair Value
 
Unobservable Input
 
Amount or Range
(Weighted Average)
 
 
(in millions)


Interest rate
 
$
(304
)
 
Subsidiaries’ credit spreads
 
2.88%-8.88% (5.42%)

Foreign currency:


Argentine Peso
 
291

 
Argentine Peso to U.S. Dollar currency exchange rate after 1 year
 
17.51 - 35.44 (26.05)

Euro
 
(14
)
 
Subsidiary's credit spread
 
8.88
%
Commodity:


Other
 
3


Total
 
$
(24
)


Changes in the above significant unobservable inputs that lead to a significant and unusual impact to current-period earnings are disclosed to the Financial Audit Committee. For interest rate derivatives, and foreign currency derivatives, increases (decreases) in the estimates of the Company's own credit spreads would decrease (increase) the value of the derivatives in a liability position. For foreign currency derivatives, increases (decreases) in the estimate of the above exchange rate would increase (decrease) the value of the derivative.
Nonrecurring Measurements — When evaluating impairment of goodwill, long-lived assets, discontinued operations and held-for-sale businesses, and equity method investments, the Company measures fair value using the applicable fair value measurement guidance. Impairment expense is measured by comparing the fair value at the evaluation date to their then-latest available carrying amount. The following table summarizes major categories of assets and liabilities measured at fair value on a nonrecurring basis during the period and their level within the fair value hierarchy (in millions):
 
 
Measurement Date
 
Carrying Amount
 
Fair Value
 
Pretax
Loss
Year Ended December 31, 2015
 
 
Level 1
 
Level 2
 
Level 3
 
Assets


Long-lived assets held and used:(1)


Kilroot
 
08/28/2015
 
$
191

 
$
—

 
$
—

 
$
70

 
$
121

Buffalo Gap III
 
09/30/2015
 
234

 
—

 
—

 
118

 
116

U.K. Wind (Development Projects)
 
06/30/2015
 
38

 
—

 
1

 
—

 
37

Other
 
Various
 
32

 
—

 
21

 
—

 
11

Equity method investments (3)


Solar Spain
 
02/09/2015
 
29

 
—

 
—

 
29

 
—

Goodwill(5)


DP&L
 
10/01/2015
 
317

 
—

 
—

 
—

 
317


Measurement Date
 
Carrying Amount
 
Fair Value
 
Pretax
Loss
Year Ended December 31, 2014
 
 
Level 1
 
Level 2
 
Level 3
 
Assets


Long-lived assets held and used:(1)


DP&L (East Bend)
 
03/31/2014
 
$
14

 
$
—

 
$
2

 
$
—

 
$
12

Ebute
 
06/30/2014
 
99

 
—

 
—

 
47

 
52

Ebute
 
09/30/2014
 
51

 
—

 
—

 
36

 
15

U.K. Wind (Newfield)
 
06/06/2014
 
12

 
—

 
—

 
—

 
12

Discontinued operations:(2)


Cameroon businesses
 
03/31/2014
 
372

 
—

 
334

 
—

 
38

Equity method investments (4)


Silver Ridge Power
 
06/30/2014
 
315

 
—

 
—

 
273

 
42

Entek
 
09/25/2014
 
211

 
—

 
125

 
—

 
86

Goodwill(5)


DPLER
 
02/28/2014
 
136

 
—

 
—

 
—

 
136

Buffalo Gap
 
03/31/2014
 
28

 
—

 
—

 
—

 
28

_____________________________
(1) 
See Note 21—Asset Impairment Expense for further information.
(2) 
See Note 23—Discontinued Operations for further information. Fair value of long-lived assets held-for-sale is presented net of costs to sell.
(3) 
See Note 8—Investments In and Advances to Affiliates for further information.
(4) 
See Note 9—Other Non-Operating Expense for further information.
(5) 
See Note 10—Goodwill and Other Intangible Assets for further information.
The following table summarizes the significant unobservable inputs used in the Level 3 measurement of long-lived assets and equity method investments during the year ended December 31, 2015:
 
 
Fair Value
 
Valuation Technique
 
Unobservable Input
 
Range (Weighted Average)
 
 
(in millions)


($ in millions)
Long-lived assets held and used:


Kilroot
 
$
70

 
Discounted cash flow
 
Annual revenue growth
 
-88% to 6% (-7%)


Annual pretax operating margin
 
-74% to 10% (0%)


Weighted Average Cost of Capital
 
6%
Buffalo Gap
 
118

 
Discounted cash flow
 
Annual revenue growth
 
-2% to 19% (3%)


Annual pretax operating margin
 
-282% to 58% (24%)


Weighted Average Cost of Capital
 
9%
Equity method investment:


Solar Spain
 
29

 
Discounted cash flow
 
Annual revenue growth
 
-3% to 0% (0%)


Annual pretax operating margin
 
-13% to 56% (24%)


Cost of equity
 
12%
Total
 
$
217


Financial Instruments not Measured at Fair Value in the Consolidated Balance Sheets
The following table presents in millions the carrying amount, fair value and fair value hierarchy of the Company's financial assets and liabilities that are not measured at fair value in the Consolidated Balance Sheets as of December 31, 2015 and 2014, but for which fair value is disclosed.
 
 
Carrying
Amount
 
Fair Value
 
 
Total
 
Level 1
 
Level 2
 
Level 3
December 31, 2015


Assets


Accounts receivable — noncurrent(1)
 
$
270

 
$
342

 
$
—

 
$
20

 
$
322

Liabilities


Non-recourse debt
 
15,792

 
15,939

 
—

 
13,672

 
2,267

Recourse debt
 
5,015

 
4,696

 
—

 
4,696

 
—

December 31, 2014


Assets


Accounts receivable — noncurrent(1)
 
$
257

 
$
246

 
$
—

 
$
—

 
$
246

Liabilities


Non-recourse debt
 
15,600

 
16,008

 
—

 
12,538

 
3,470

Recourse debt
 
5,258

 
5,552

 
—

 
5,552

 
—

_____________________________
(1) 
These accounts receivable principally relate to amounts due from CAMMESA, the administrator of the wholesale electricity market in Argentina, and are included in Noncurrent assets — Other in the accompanying Consolidated Balance Sheets. The fair value of these accounts receivable excludes value-added tax of $27 million and $36 million at December 31, 2015 and 2014, respectively.

v3.3.1.900
Investments In Marketable Securities
12 Months Ended
Dec. 31, 2015
Investments, Debt and Equity Securities [Abstract]  
INVESTMENTS IN MARKETABLE SECURITIES
The Company's investments in marketable debt and equity securities as of December 31, 2015 and 2014 by security class and by level within the fair value hierarchy have been disclosed in Note 4—Fair Value. The security classes are determined based on the nature and risk of a security and are consistent with how the Company manages, monitors and measures its marketable securities. As of December 31, 2015, $462 million of available-for-sale ("AFS") debt securities had stated maturities within one year and $28 million had stated maturities between one and two years. Gains and losses on the sale of investments are determined using the specific-identification method. For the years ended December 31, 2015, 2014, and 2013, pretax realized gains and losses related to AFS and trading securities were $1 million or less, unrealized gains and losses on AFS securities were less than $1 million, and there were no other-than-temporary impairment of marketable securities recognized in earnings or OCI. The following table summarizes the gross proceeds from sale of AFS securities in millions for the years ended December 31, 2015, 2014, and 2013:
 
 
2015
 
2014
 
2013
Gross proceeds from sales of AFS securities
 
$
4,902

 
$
4,569

 
$
4,406


v3.3.1.900
Derivative Instruments and Hedging Activities
12 Months Ended
Dec. 31, 2015
Derivative Instruments and Hedging Activities Disclosure [Abstract]  
DERIVATIVE INSTRUMENTS AND HEDGING ACTIVITIES
Volume of Activity
The following tables present, by type of derivative, the Company's outstanding notional under its derivatives and the weighted-average remaining term as of December 31, 2015 regardless of whether the derivative instruments are in qualifying cash flow hedging relationships:
 
 
Current
 
Maximum


Interest Rate and Cross Currency (1)
 
Derivative
Notional
 
Derivative Notional Translated to USD
 
Derivative
Notional
 
Derivative Notional Translated to USD
 
Weighted-Average Remaining Term
 
% of Debt Currently Hedged by Index (2)
 
 
(in millions)
 
(in years)
 
 
Interest Rate Derivatives:


LIBOR (U.S. Dollar)
 
2,639

 
$
2,639

 
2,872

 
$
2,872

 
11
 
48
%
EURIBOR (Euro)
 
482

 
524

 
482

 
524

 
6
 
83
%
Cross Currency Swaps:


Chilean Unidad de Fomento
 
4

 
159

 
4

 
159

 
13
 
76
%
_____________________________
(1) 
The Company's interest rate derivative instruments primarily include accreting and amortizing notionals. The maximum derivative notional represents the largest notional at any point between December 31, 2015 and the maturity of the derivative instrument, which includes forward-starting derivative instruments. The interest rate and cross currency derivatives range in maturity through 2033 and 2028, respectively.
(2) 
The percentage of variable-rate debt currently hedged is based on the related index and excludes forecasted issuances of debt and variable-rate debt tied to other indices where the Company has no interest rate derivatives.
 
 
December 31, 2015
Foreign Currency Derivatives
 
Notional(1)
 
Notional Translated to USD
 
Weighted-Average Remaining Term(2)
 
 
(in millions)
 
(in years)
Foreign Currency Derivatives


Argentine Peso
 
$
2,321

 
$
178

 
10
Brazilian Real
 
80

 
21

 
<1
British Pound
 
22

 
32

 
<1
Chilean Peso
 
84,669

 
119

 
<1
Chilean Unidad de Fomento
 
9

 
311

 
<1
Colombian Peso
 
252,166

 
80

 
<1
Euro
 
32

 
35

 
<1
Kazakhstani Tenge
 
1,691

 
5

 
1
_____________________________
(1) 
Represents contractual notionals. The notionals for options have not been probability adjusted, which generally would decrease them.
(2) 
Represents the remaining tenor of our foreign currency derivatives weighted by the corresponding notional. These derivatives matures through 2026.
December 31, 2015


Weighted-Average
Commodity Derivatives
 
Notional
 
Remaining Term(1)
 
 
(in millions)
 
(in years)
Power (MWh)
 
10

 
3

_____________________________
(1) 
Represents the remaining tenor of our commodity derivatives weighted by the corresponding volume. These derivatives range in maturity through 2018.
Accounting and Reporting
Assets and Liabilities
The following tables present in millions the Company's derivative instruments as of the periods indicated, first by whether or not they are designated hedging instruments, then by whether they are current or noncurrent to the extent they are subject to master netting agreements or similar agreements (where the rights to set-off relate to settlement of amounts receivable and payable under those derivatives) and by balances no longer accounted for as derivatives.
 
 
December 31, 2015
 
December 31, 2014
 
 
Designated
 
Not Designated
 
Total
 
Designated
 
Not Designated
 
Total
Assets


Foreign currency derivatives
 
$
8

 
$
319

 
$
327

 
$
6

 
$
230

 
$
236

Commodity derivatives
 
30

 
18

 
48

 
25

 
19

 
44

Total assets
 
$
38

 
$
337

 
$
375

 
$
31

 
$
249

 
$
280

Liabilities


Interest rate derivatives
 
$
358

 
$
—

 
$
358

 
$
416

 
$
—

 
$
416

Cross currency derivatives
 
43

 
—

 
43

 
29

 
—

 
29

Foreign currency derivatives
 
35

 
21

 
56

 
38

 
14

 
52

Commodity derivatives
 
12

 
21

 
33

 
7

 
10

 
17

Total liabilities
 
$
448

 
$
42

 
$
490

 
$
490

 
$
24

 
$
514


December 31, 2015
 
December 31, 2014
 
 
Assets
 
Liabilities
 
Assets
 
Liabilities
Current
 
$
86

 
$
144

 
$
77

 
$
148

Noncurrent
 
289

 
346

 
203

 
366

Total
 
$
375

 
$
490

 
$
280

 
$
514

Derivatives subject to master netting agreement or similar agreement:


Gross amounts recognized in the balance sheet
 
$
57

 
$
467

 
$
53

 
$
507

Gross amounts of derivative instruments not offset
 
(18
)
 
(18
)
 
(10
)
 
(10
)
Gross amounts of cash collateral received/pledged not offset
 
—

 
(38
)
 
—

 
(26
)
Net amount
 
$
39

 
$
411

 
$
43

 
$
471

Other balances that had been, but are no longer, accounted for as derivatives that are to be amortized to earnings over the remaining term of the associated PPA
 
$
147

 
$
166

 
$
161

 
$
180


Effective Portion of Cash Flow Hedges — The following tables present (in millions) the pretax gains (losses) recognized in AOCL and earnings related to the effective portion of derivative instruments in qualifying cash flow hedging relationships (including amounts that were reclassified from AOCL as interest expense related to interest rate derivative instruments that previously, but no longer, qualify for cash flow hedge accounting), as defined in the accounting standards for derivatives and hedging, for the periods indicated:
Years Ended December 31,
 
Gains (Losses) Recognized in AOCL
 
Classification in Consolidated Statements of Operations
 
Gains (Losses) Reclassified from AOCL into Earnings
Type of Derivative
 
2015
 
2014
 
2013
 
2015
 
2014
 
2013
Interest rate derivatives
 
$
(103
)
 
$
(421
)
 
$
155

 
Interest expense
 
$
(108
)
 
$
(139
)
 
$
(127
)


Non-regulated cost of sales
 
(2
)
 
(2
)
 
(5
)


Net equity in earnings of affiliates
 
(2
)
 
(3
)
 
(6
)


Gain on sale of investments
 
(4
)
 
—

 
(21
)
Cross currency derivatives
 
(20
)
 
(25
)
 
(18
)
 
Interest expense
 
(4
)
 
—

 
(10
)


Foreign currency transaction gains (losses)
 
(20
)
 
(23
)
 
(18
)
Foreign currency derivatives
 
10

 
(28
)
 
—

 
Foreign currency transaction gains (losses)
 
32

 
14

 
12

Commodity derivatives
 
40

 
44

 
2

 
Non-regulated revenue
 
43

 
30

 
(3
)


Non-regulated cost of sales
 
(12
)
 
(2
)
 
(2
)
Total
 
$
(73
)
 
$
(430
)
 
$
139


$
(77
)
 
$
(125
)
 
$
(180
)

The pretax accumulated other comprehensive income (loss) expected to be recognized as an increase (decrease) to income from continuing operations before income taxes over the next twelve months as of December 31, 2015 is $(106) million for interest rate hedges, $(3) million for cross currency swaps, $12 million for foreign currency hedges, and $16 million for commodity and other hedges.
For the year ended December 31, 2014, pretax losses of $6 million, net of noncontrolling interests were reclassified into earnings as a result of the discontinuance of a cash flow hedge because it was probable that the forecasted transaction would not occur by the end of the originally specified time period (as documented at the inception of the hedging relationship) or within an additional two-month time period thereafter. There was no such item for the years ended December 31, 2015 and 2013.
Ineffective Portion of Cash Flow Hedges — The following table presents (in millions) the pretax gains (losses) recognized in earnings related to the ineffective portion of derivative instruments in qualifying cash flow hedging relationships, as defined in the accounting standards for derivatives and hedging, for the periods indicated:


Gains (Losses) Recognized in Earnings
 
 
Classification in Consolidated Statements of Operations
 
Years Ended December 31,
Type of Derivative
 
 
2015
 
2014
 
2013
Interest rate derivatives
 
Interest expense
 
$
(4
)
 
$
—

 
$
42


Net equity in earnings of affiliates
 
—

 
(1
)
 
1

Foreign currency derivatives
 
Foreign currency transaction gains (losses)
 
(3
)
 
(2
)
 
—

Cross currency derivatives
 
Interest expense
 
1

 
(1
)
 
—

Total


$
(6
)
 
$
(4
)
 
$
43


Not Designated for Hedge Accounting — The next table presents (in millions) the gains (losses) recognized in earnings related to derivative instruments not designated as hedging instruments under the accounting standards for derivatives and hedging, and amortization of balances that had been, but are no longer, accounted for as derivatives, for the periods indicated:


Gains (Losses) Recognized in Earnings
 
 
Classification in Consolidated Statements of Operations
 
Years Ended December 31,
Type of Derivative
 
2015
 
2014
 
2013
Interest rate derivatives
 
Interest expense
 
$
—

 
$
(3
)
 
$
(1
)
 
 
Net equity in earnings of affiliates
 
—

 
—

 
(6
)
Foreign currency derivatives
 
Foreign currency transaction gains (losses)
 
211

 
146

 
64


Net equity in earnings of affiliates
 
—

 
(2
)
 
(24
)
Commodity and other derivatives
 
Non-regulated revenue
 
(8
)
 
5

 
11


Non-regulated cost of sales
 
(16
)
 
(3
)
 
1


Regulated cost of sales
 
(5
)
 
(6
)
 
2


Income (loss) from operations of discontinued businesses
 
—

 
(7
)
 
(18
)
 
 
Net gain (loss) from disposal and impairments of discontinued operations
 
—

 
72

 
—

Total


$
182

 
$
202

 
$
29


Credit Risk-Related Contingent Features
DP&L has certain over-the-counter commodity derivative contracts under master netting agreements that contain provisions that require DP&L to maintain an investment-grade issuer credit rating from credit rating agencies. Since DP&L's rating has fallen below investment grade, certain of the counterparties to the derivative contracts have requested immediate and ongoing full overnight collateralization of the mark-to-market loss (fair value excluding credit valuation adjustments), which was $28 million and $12 million as of December 31, 2015 and 2014, respectively, for all derivatives with credit risk-related contingent features. As of December 31, 2015 and 2014, DP&L had posted $8 million and $5 million, respectively, of cash collateral directly with third parties and in a broker margin account and DP&L held no cash collateral from counterparties to its derivative instruments that were in an asset position. After consideration of the netting of counterparty assets, DP&L could have been required to, but did not, provide additional collateral of $2 million and $1 million as of December 31, 2015 and 2014, respectively.

v3.3.1.900
Financing Receivables
12 Months Ended
Dec. 31, 2015
Receivables [Abstract]  
FINANCING RECEIVABLES
Financing receivables are defined as receivables that have contractual maturities of greater than one year. The Company has financing receivables pursuant to amended agreements or government resolutions that are due from certain Latin American governmental bodies, primarily in Argentina. The table below presents the breakdown of financing receivables in millions by country as of the periods indicated:
December 31,
 
2015
 
2014
Argentina
 
$
237

 
$
278

Cameroon (1)
 
—

 
44

United States
 
20

 
—

Brazil
 
39

 
15

Total long-term financing receivables
 
$
296

 
$
337

_____________________________
(1) 
Represents non-contingent consideration to be received in 2016 from the sale of the Cameroon businesses in 2014. Balance is classified as short-term as of December 31, 2015. See Note 23—Discontinued Operations.
Argentina — Collection of the principal and interest on these receivables is subject to various business risks and uncertainties including, but not limited to, the completion and operation of power plants which generate cash for payments of these receivables, regulatory changes that could impact the timing and amount of collections, and economic conditions in Argentina. The Company monitors these risks including the credit ratings of the Argentine government on a quarterly basis to assess the collectability of these receivables. The Company accrues interest on these receivables once the recognition criteria have been met. The Company's collection estimates are based on assumptions that it believes to be reasonable, but are inherently uncertain. Actual future cash flows could differ from these estimates.
FONINVEMEM Agreements
As a result of energy market reforms in 2004 and 2010, AES Argentina entered into three agreements with the Argentine government, referred to as the FONINVEMEM Agreements, to contribute a portion of their accounts receivable into a fund for financing the construction of combined cycle and gas-fired plants. These receivables accrue interest and are collected in monthly installments over 10 years once the related plant begins operations. In addition, AES Argentina receives an ownership interest in these newly built plants once the receivables have been fully repaid.
FONINVEMEM I and II — The receivables under the first two FONINVEMEM Agreements have been actively collected since the related plants commenced operations in 2010. In assessing the collectability of the receivables under these agreements, the Company also considers how timely the collections have historically been made in accordance with the agreements.
FONINVEMEM III — The receivables related to the third FONINVEMEM Agreement will not be repaid until commercial operation of the related gas-fired plant has been achieved. In assessing the collectability of the receivables under this agreement, the Company also considers the extent to which significant milestones necessary to complete the plants have been achieved or are still probable.
The FONINVEMEM receivables are denominated in Argentine pesos, but indexed to U.S. Dollars, which represents a foreign currency derivative. As of December 31, 2015 and 2014, the amount of the foreign currency-related derivative assets associated with the FONINVEMEM financing receivables that were excluded from the table above had a fair value of $292 million and $208 million, respectively.
Other Agreements
In 2013, Resolution No. 95/2013 ("Resolution 95") which developed a new energy regulatory framework that applies to all generation companies with certain exceptions became effective. The new regulatory framework remunerates fixed and variable costs plus a margin that will depend on the technology and fuel used to generate the electricity and the installed capacity of each plant.
In the fourth quarter of 2014, the Argentine government passed a resolution to contribute outstanding Resolution 95 receivables into a trust whereby AES Argentina has committed to install additional capacity into the system. CAMMESA will finance the investment utilizing the outstanding receivables as a guarantee.
On July 10, 2015, the Argentine government passed Resolution No. 482/2015 ("Resolution 482") which updated the prices of Resolution 529/2014 retroactively to February 1, 2015, and created a new trust called FONINVEMEM 2015-2018 in order to invest in new generation plants. AES Argentina and certain Termoandes units will receive compensation under this program.

v3.3.1.900
Investments In and Advances To Affiliates
12 Months Ended
Dec. 31, 2015
Equity Method Investments and Joint Ventures [Abstract]  
INVESTMENTS IN AND ADVANCES TO AFFILIATES
The following table summarizes the relevant effective equity ownership interest and carrying values for the Company's investments accounted for under the equity method as of the periods indicated.
December 31,
 
 
2015
 
2014
 
2015
 
2014
Affiliate
Country
 
Carrying Value (in millions)
 
Ownership Interest %
Solar Power PR
Puerto Rico
 
$
—

 
$
2

 
—
%
 
50
%
Barry(1) 
United Kingdom
 
—

 
—

 
100
%
 
100
%
Elsta(1)
Netherlands
 
53

 
54

 
50
%
 
50
%
Distributed Energy(1)
United States
 
17

 
—

 
94
%
 
—
%
Guacolda(2)
Chile
 
344

 
285

 
33
%
 
35
%
OPGC(3)
India
 
195

 
194

 
49
%
 
49
%
Other affiliates
Various
 
1

 
2


Total investments in and advances to affiliates
 
 
$
610

 
$
537


(1) 
Represent VIEs in which the Company holds a variable interest but is not the primary beneficiary.
(2) 
The Company's ownership in Guacolda is held through AES Gener, a 67%-owned consolidated subsidiary. AES Gener owns 50% of Guacolda, resulting in an AES effective ownership in Guacolda of 33%. At December 31, 2014, AES owned 71% of AES Gener, resulting in an AES effective ownership in Guacolda of 35%.
(3) 
OPGC has one coal-fired expansion project under development. The project started construction in April 2014 and is currently expected to begin operations in 2018.
Guacolda — On September 1, 2015, AES Gener and Global Infrastructure Partners ("GIP") executed a restructuring of Guacolda that increased Guacolda's tax basis in certain long-term assets and AES Gener's equity investment. This transaction was reflected within equity at the Guacolda level, but was not with or among the shareholders of AES. Accordingly, the AES proportion of the increased value in equity was recognized in net income. As a result, AES Gener recorded $66 million in net equity in earnings of affiliates for the year ended December 31, 2015, of which $46 million is attributable to The AES Corporation.
On April 11, 2014, AES Gener undertook a series of transactions, pursuant to which AES Gener acquired the interests that it did not previously own in Guacolda for $728 million and simultaneously sold the ownership interest to GIP for $730 million. The transaction provided GIP with substantive participating rights in Guacolda and, as a result, the Company continues to account for its investment in Guacolda using the equity method of accounting. At no time during this transaction did the Company acquire a non-controlling interest. The cash paid for the acquisition is reflected in Acquisitions, net of cash acquired and the cash proceeds from the sale of these ownership interests to GIP is reflected in Proceeds from the sale of businesses, net of cash sold on the Consolidated Statement of Cash Flows for the period ended December 31, 2014.
Distributed Energy — On February 18, 2015, the Company completed the acquisition of 100% of the common stock of Main Street Power Company, Inc., which has been renamed to Distributed Energy Inc. As part of this acquisition, the Company obtained additional investments accounted for under the equity method.
Silver Ridge Power — On July 1, 2014, the Puerto Rico solar business, Solar Power PR, LLC, was distributed by Silver Ridge Power, LLC ("SRP") to AES and Riverstone Holdings LLC and was accounted for as a direct equity method investment. On April 29, 2015, the Company purchased the remaining 50% of the common stock of Solar Power PR, LLC and now consolidates this entity. On July 2, 2014, the Company closed the sale of its 50% ownership interest in SRP for a purchase price of $179 million, excluding the Company's indirect ownership interests in SRP's solar generation businesses in Italy and Spain ("Solar Italy" and "Solar Spain," respectively). The buyer also had an option to purchase the Company's indirect 50% interest in the Italy solar generation business for an additional consideration of $42 million by August 2015. The buyer exercised its option to purchase Solar Italy on August 31, 2015, and the sale was completed on October 1, 2015.
In 2014, the sale of the Company's 50% ownership interest in SRP did not qualify as a sale for accounting purposes as the Company had continuing involvement in the business operations. As of July 2, 2014, the Company no longer retained an equity interest in SRP. As such, the then-remaining investment balance of $32 million related to Italy and Spain and the AOCL balance of $40 million were reclassified to Other noncurrent assets on the Consolidated Balance Sheets. As of December 31, 2014, the carrying value of these investments recorded in Other noncurrent assets was $64 million.
Solar Spain — On September 24, 2015, the Company completed the sale of Solar Spain, an equity method investment. Net proceeds from the sale transaction were $31 million and the Company recognized a pretax gain on sale of less than $1 million.
Upon the completion of the Solar Spain and Solar Italy sale transactions noted above, the Company ceased its involvement in SRP's business operations and accounted for these transactions as sales of real estate. Accordingly, as of December 31, 2015, the carrying value of these investments recorded in Other noncurrent assets was zero.
AES Barry Ltd. — The Company holds a 100% ownership interest in AES Barry Ltd. ("Barry"), a dormant entity in the U.K. that disposed of its generation and other operating assets. Due to a debt agreement, no material financial or operating decisions can be made without the banks' consent, and the Company does not control Barry. As of December 31, 2015 and 2014, other long-term liabilities included $49 million and $52 million related to this debt agreement.
Elsta — In 2014, long lived assets within Elsta were determined to not be recoverable and an impairment charge of approximately $82 million was recognized. The Company recognized its 50% share, or $41 million, through its proportion of the equity earnings in Elsta.
Entek — In September 2014, the Company executed an agreement, subject to the approval of the Company's Board of Directors, to sell its equity interest in AES Entek. Based on this agreement, during the third quarter of 2014, the Company determined there was an other-than-temporary decline in the fair value of its equity method investment in AES Entek and recognized a pretax impairment loss of $18 million in other non-operating expense. On October 13, 2014, the Company entered into a binding agreement to sell its 49.62% ownership interest in Entek for a purchase price of $125 million. This resulted in the recognition of an additional other-than-temporary impairment of $68 million due to the inclusion of the cumulative translation adjustment in the carrying value of the investment. For additional information see Note 9—Other Non-Operating Expense. The sale represents 100% of the Company's interest in assets in Turkey. On December 18, 2014, the transaction closed which resulted in a final loss on sale of $4 million. Entek does not meet the criteria to be reported as discontinued operations under ASU No. 2014-08, which was adopted by the Company on July 1, 2014. Accordingly, AES' proportion of Entek's results are reflected in the Consolidated Statements of Operations within continuing operations. Excluding the loss on sale, Entek's pretax loss attributable to AES was $9 million and $29 million for the years ended December 31, 2014 and 2013, respectively.
Summarized Financial Information
The following tables summarize financial information of the Company's 50%-or-less-owned affiliates and majority-owned unconsolidated subsidiaries that are accounted for using the equity method in millions.
 
50%-or-less Owned Affiliates
 
Majority-Owned Unconsolidated Subsidiaries
Years ended December 31,
2015
 
2014
 
2013
 
2015
 
2014
 
2013
Revenue
$
641

 
$
928

 
$
1,099

 
$
24

 
$
2

 
$
2

Operating margin
152

 
206

 
295

 
11

 
—

 
—

Net income (loss)
210

 
59

 
53

 
6

 
—

 
—


December 31,
2015
 
2014


2015
 
2014
 
 
Current assets
$
376

 
$
450


$
20

 
$
—


Noncurrent assets
2,132

 
1,748


211

 
15


Current liabilities
435

 
299


21

 
—


Noncurrent liabilities
1,044

 
935


153

 
67


Noncontrolling interests
—

 
17


—

 
—


Stockholders' equity
1,029

 
947


57

 
(52
)


At December 31, 2015, retained earnings included $244 million related to the undistributed earnings of the Company's 50%-or-less owned affiliates. Distributions received from these affiliates were $18 million, $28 million, and $6 million for the years ended December 31, 2015, 2014, and 2013, respectively. As of December 31, 2015, the aggregate carrying amount of our investments in equity affiliates exceeded the underlying equity in their net assets by $162 million.

v3.3.1.900
Other Non-Operating Expense Other Non-Operating Expense
12 Months Ended
Dec. 31, 2015
Other Income and Expenses [Abstract]  
OTHER NON-OPERATING EXPENSE
Years Ended December 31,
2014
 
2013
 
(in millions)
Entek
$
86

 
$
—

Silver Ridge
42

 
—

Elsta
—

 
129

Total other non-operating expense
$
128

 
$
129


There was no other non-operating expense for the year ended December 31, 2015.
Entek — During 2014, the Company executed an agreement to sell its 49.62% interest in Entek, an investment accounted for under the equity method, for $125 million. Entek consists of natural gas and hydroelectric generation facilities, plus a coal-fired development project. The Company determined that there was an other-than-temporary decline in the fair value of its equity method investment in Entek and recognized pretax impairment expense of $86 million. The sale of the Company's interest in Entek closed on December 18, 2014. See Note 8—Investments in and Advances to Affiliates of this Form 10-K for further information.
Silver Ridge — During 2014, the Company determined that there was a decline in the fair value of its equity method investment in SRP that was other-than-temporary based on indications about the fair value of the projects in Italy and Spain that resulted from actual and proposed changes to their tariffs. Accordingly, the Company recognized pretax impairment expense of $42 million. The transaction related to our 50% ownership interest in SRP closed on July 2, 2014 for $179 million. See Note 8—Investments in and Advances to Affiliates of this Form 10-K for further information.
Elsta — During 2013, the Company identified an impairment indicator at Elsta, a combined cycle gas-fired plant in the Netherlands that is accounted for under the equity method, resulting from negative pricing indications noted during negotiations with its offtakers for an extension of the existing PPA. The Company recognized pretax impairment expense of $129 million by reducing the carrying value of $240 million to the estimated fair value of $111 million. The Company estimated fair value using probability-weighted outcomes which contemplated various scenarios involving the amendments to the existing PPA.

v3.3.1.900
Goodwill and Other Intangible Assets
12 Months Ended
Dec. 31, 2015
Goodwill and Intangible Assets Disclosure [Abstract]  
GOODWILL AND OTHER INTANGIBLE ASSETS
Goodwill — The following table summarizes the changes in the carrying amount of goodwill, by reportable segment for the years ended December 31, 2015 and 2014 in millions.
 
US
 
Andes
 
MCAC
 
Europe
 
Asia
 
Total
Balance as of December 31, 2013


Goodwill
$
2,658

 
$
899

 
$
149

 
$
180

 
$
68

 
$
3,954

Accumulated impairment losses
(2,152
)
 
—

 
—

 
(180
)
 
—

 
(2,332
)
Net balance
506

 
899

 
149

 
—

 
68

 
1,622

Impairment losses
(164
)
 
—

 
—

 
—

 
—

 
(164
)
Balance as of December 31, 2014


Goodwill
2,658

 
899

 
149

 
122

(1) 
68

 
3,896

Accumulated impairment losses
(2,316
)
 
—

 
—

 
(122
)
 
—

 
(2,438
)
Net balance
342

 
899

 
149

 
—

 
68

 
1,458

Impairment losses
(317
)
 
—

 
—

 
—

 
—

 
(317
)
Goodwill acquired during the year
16

 
—

 
—

 
—

 
—

 
16

Balance as of December 31, 2015


Goodwill
2,674

 
899

 
149

 
122

 
68

 
3,912

Accumulated impairment losses
(2,633
)
 
—

 
—

 
(122
)
 
—

 
(2,755
)
Net balance
$
41

 
$
899

 
$
149

 
$
—

 
$
68

 
$
1,157


_____________________________
(1) Both the gross carrying amount and the accumulated impairment losses of the Europe segment have been reduced by $58 million with no impact on the net carrying amount for the segment. This relates to Ebute, which had fully impaired goodwill of $58 million and was sold in 2014.
DP&L — During the fourth quarter of 2015, the Company performed the annual goodwill impairment test at its DP&L reporting unit ("DP&L") and recognized a goodwill impairment expense of $317 million. The reporting unit failed Step 1 as its fair value was less than its carrying amount, which was primarily due to a decrease in forecasted dark spreads that were driven by decreases in projected forward power prices, and lower than expected revenues from a new Capacity Performance ("CP") product. The fair value of the reporting unit was determined under the income approach using a discounted cash flow valuation model. The significant assumptions included within the discounted cash flow valuation model were forward commodity price curves, the amount of non-bypassable charges from the pending ESP, expected revenues from the new CP product, and planned environmental expenditures. In Step 2, goodwill was determined to have an implied negative fair value after the hypothetical purchase price allocation under the accounting guidance for business combinations; therefore, a full impairment of the remaining goodwill balance of $317 million was recognized. DP&L is reported in the US SBU reportable segment.
Main Street Power — During the first quarter of 2015, the Company completed the acquisition of 100% of the common stock of Main Street Power Company, Inc. The transaction included recognition of $16 million of Goodwill. See Note 25—Acquisitions for additional information.
Buffalo Gap — During the first quarter of 2014, the Company recognized an $18 million impairment of its goodwill at its Buffalo Gap reporting unit, which is comprised of three wind projects in Texas. During the fourth quarter of 2014, the Company performed the annual goodwill impairment test at its Buffalo Gap reporting unit. The reporting unit failed Step 1 and Step 2 was performed to measure the amount of goodwill impairment. In Step 2, after the hypothetical purchase price allocation under the relevant accounting guidance, the implied fair value of goodwill was negative. As a result, a full impairment of goodwill of $10 million was recognized. Buffalo Gap is reported in the US SBU reportable segment.
DPLER — During the first quarter of 2014, the Company performed an interim impairment test on the $136 million in goodwill at its DPLER reporting unit, a competitive retail marketer selling retail electricity to customers in Ohio and Illinois. The DPLER reporting unit was identified as being "at risk" during the fourth quarter of 2013. The impairment indicators arose based on market information available regarding actual and proposed sales of competitive retail marketers, which indicated a significant decline in valuations during the first quarter of 2014.
In Step 1 of the interim impairment test, the fair value of the reporting unit was determined to be less than its carrying amount under both the market approach and the income approach using a discounted cash flow valuation model. The significant assumptions included commodity price curves, estimated electricity to be demanded by its customers, changes in its customer base through attrition and expansion, discount rates, the assumed tax structure and the level of working capital required to run the business. 
In Step 2 of the interim impairment test, the goodwill was determined to have an implied fair value of zero after the hypothetical purchase price allocation and the Company accordingly recognized a full impairment of the $136 million in goodwill at the DPLER reporting unit. DPLER is reported in the US SBU reportable segment. 
Other Intangible Assets — The following table summarizes the balances comprising other intangible assets in the accompanying Consolidated Balance Sheets (in millions) as of the periods indicated:
 
December 31, 2015
 
December 31, 2014
 
Gross Balance
 
Accumulated Amortization
 
Net Balance
 
Gross Balance
 
Accumulated Amortization
 
Net Balance
Subject to Amortization


Project development rights(1)
$
4

 
$
(1
)
 
$
3

 
$
28

 
$
(1
)
 
$
27

Sales concessions
71

 
(19
)
 
52

 
86

 
(41
)
 
45

Contractual payment rights(2)
66

 
(46
)
 
20

 
69

 
(40
)
 
29

Management rights
24

 
(10
)
 
14

 
33

 
(13
)
 
20

Land use rights
28

 
—

 
28

 
25

 
—

 
25

Contracts
29

 
(12
)
 
17

 
36

 
(19
)
 
17

Customer contracts and relationships (3)
6

 
(6
)
 
—

 
63

 
(39
)
 
24

Other(4)
15

 
(3
)
 
12

 
22

 
(5
)
 
17

Subtotal
243

 
(97
)
 
146

 
362

 
(158
)
 
204

Indefinite-Lived Intangible Assets


Land use rights
38

 
—

 
38

 
37

 
—

 
37

Water rights
17

 
—

 
17

 
20

 
—

 
20

Other
13

 
—

 
13

 
20

 
—

 
20

Subtotal
68

 
—

 
68

 
77

 
—

 
77

Total
$
311

 
$
(97
)
 
$
214

 
$
439

 
$
(158
)
 
$
281

_____________________________
(1) 
2014 balance includes U.K. Wind operations. In August 2014 these assets were sold, but did not meet the criteria to be reported as discontinued operations and their results are reflected within continuing operations. See Note 24—Dispositions and Held-for-Sale Businesses for further information.
(2) 
Represent legal rights to receive system reliability payments from the regulator.
(3) 
2014 balance includes DPLER which is considered held-for-sale as of December 31, 2015. See Note 24—Dispositions and Held-for-Sale Businesses for further information.
(4) 
Includes renewable energy certificates, emission allowances and various other intangible assets none of which is individually significant.
The following tables summarize, by category, other intangible assets acquired during the period indicated ($ in millions):
 
December 31, 2015
 
Amount
 
Subject to Amortization/Indefinite-Lived
 
Weighted Average Amortization Period (in years)
 
Amortization Method
Contracts
$
22

 
Subject to Amortization
 
5
 
Straight-line
Land-use rights
13

 
Subject to Amortization
 
N/A
 
N/A
Other
5

 
Various
 
N/A
 
N/A
Total
$
40


December 31, 2014
 
Amount
 
Subject to Amortization/
Indefinite-Lived
 
Weighted Average
Amortization Period (in years)
 
Amortization
Method
Renewable energy certificates
$
3

 
Indefinite
 
N/A
 
N/A
Land-use rights
16

 
Subject to Amortization
 
N/A
 
N/A
Total
$
19


The following table summarizes the estimated amortization expense by intangible asset category for 2016 through 2020:
(in millions)
2016
 
2017
 
2018
 
2019
 
2020
Sales concessions
7

 
7

 
7

 
7

 
7

All other
4

 
4

 
4

 
3

 
3

Total
$
11

 
$
11

 
$
11

 
$
10

 
$
10


Intangible asset amortization expense was $25 million, $26 million and $29 million for the years ended December 31, 2015, 2014 and 2013, respectively.

v3.3.1.900
Regulatory Assets and Liabilities
12 Months Ended
Dec. 31, 2015
Regulated Operations [Abstract]  
REGULATORY ASSETS AND LIABILITIES
REGULATORY ASSETS AND LIABILITIES
The Company has recorded regulatory assets and liabilities (in millions) that it expects to pass through to its customers in accordance with, and subject to, regulatory provisions as follows:
December 31,
2015
 
2014
 
Recovery/Refund Period
REGULATORY ASSETS


Current regulatory assets:


Brazil tariff recoveries:(1)


Energy purchases/sales
$
416

 
$
424

 
Annually as part of the tariff adjustment
Transmission costs, regulatory fees and other
264

 
63

 
Annually as part of the tariff adjustment
El Salvador tariff recoveries(2)
43

 
92

 
Quarterly as part of the tariff adjustment
Other(3) 
23

 
58

 
Various
Total current regulatory assets
746

 
637


Noncurrent regulatory assets:


Defined benefit pension obligations at IPL and DPL(4)(5)
227

 
329

 
Various
Income taxes recoverable from customers(4)(6)
36

 
74

 
Various
Brazil tariff recoveries:(1)


Energy purchases/sales
147

 
266

 
Annually as part of the tariff adjustment
Transmission costs, regulatory fees and other
140

 
14

 
Annually as part of the tariff adjustment
Deferred Midwest ISO costs(7)
129

 
111

 
To be determined
Other(3)
239

 
78

 
Various
Total noncurrent regulatory assets
918

 
872


TOTAL REGULATORY ASSETS
$
1,664

 
$
1,509


REGULATORY LIABILITIES


Current regulatory liabilities:


Brazil tariff reset adjustment(8)
$
—

 
$
76

 
Two years
Efficiency program costs(9)
12

 
22

 
Annually as part of the tariff adjustment
Brazil regulatory asset base adjustment(13)
169

 
123

 
Up to four tariff periods
Brazil tariff refunds:(1)


Energy purchases/sales
105

 
144

 
Annually as part of the tariff adjustment
Transmission costs, regulatory fees and other
120

 
174

 
Annually as part of the tariff adjustment
Other(10) 
59

 
66

 
Various
Total current regulatory liabilities
465

 
605


Noncurrent regulatory liabilities:


Asset retirement obligations(11)
759

 
727

 
Over life of assets
Brazil regulatory asset base adjustment(13)
86

 
61

 
Up to four tariff periods
Brazil special obligations(12)
370

 
484

 
To be determined
Brazil tariff refunds:(1)


Energy purchases/sales
30

 
128

 
Annually as part of the tariff adjustment
Transmission costs, regulatory fees and other
29

 
97

 
Annually as part of the tariff adjustment
Efficiency program costs(9)
5

 
11

 
Annually as part of the tariff adjustment
Other(10) 
7

 
1

 
Various
Total noncurrent regulatory liabilities
1,286

 
1,509


TOTAL REGULATORY LIABILITIES
$
1,751

 
$
2,114


_____________________________
(1)
Recoverable or refundable per Brazilian National Electric Energy Agency ("ANEEL") regulations through the Annual Tariff Adjustment ("IRT"). These costs are generally non-controllable and primarily consist of purchased electricity, energy transmission, and sector costs that are considered volatile. The costs are passed through for a period of 12 months as part of the IRT. Any remaining balance is considered in the subsequent IRT, which results in a total of 24 months to recover or refund the costs. Favorable spot market sales are also subject to customer refunds through the IRT over the course of these time periods.
(2)
Deferred fuel costs incurred by our El Salvador subsidiaries associated with purchase of energy from the El Salvador spot market and power generation plants. In El Salvador, the deferred fuel adjustment represents the variance between the actual fuel costs and the fuel costs recovered in the tariffs. The variance is recovered quarterly in the tariff reset period.
(3)
Includes assets with and without a rate of return. Other current regulatory assets that did not earn a rate of return were $8 million and $22 million, as of December 31, 2015 and 2014, respectively. Other noncurrent regulatory assets that did not earn a rate of return were $237 million and $73 million, as of December 31, 2015 and 2014, respectively. Other current and noncurrent regulatory assets primarily consist of:
▪
Unamortized losses on long-term debt reacquired or redeemed in prior periods at IPL and DPL, which are amortized over the lives of the original issues in accordance with the Federal Energy Regulatory Commission ("FERC") and PUCO rules.
▪
Unamortized carrying charges and certain other costs related to Petersburg unit 4 at IPL.
▪
Deferred storm costs incurred primarily in 2008 to repair storm damage at DPL; recovery was approved via order from the PUCO on December 17, 2014 and began January 2015.
▪
Additional Regulatory Asset Base ("RAB") from a favorable decision on tariff reset (administrative appeal) at Eletropaulo.
(4)
Past expenditures on which the Company does not earn a rate of return.
(5)
The regulatory accounting standards allow the defined pension and postretirement benefit obligation to be recorded as a regulatory asset equal to the previously unrecognized actuarial gains and losses and prior service costs that are expected to be recovered through future rates. Pension expense is recognized based on the plan's actuarially determined pension liability. Recovery of costs is probable, but not yet determined. Pension contributions made by our Brazilian subsidiaries are not included in regulatory assets as those contributions are not covered by the established tariff in Brazil.
(6)
Probable recovery through future rates, based upon established regulatory practices, which permit the recovery of current taxes. This amount is expected to be recovered, without interest, over the period as book-tax temporary differences reverse and become current taxes.
(7)
Transmission service costs and other administrative costs from IPL's participation in the Midwest ISO market, which are recoverable but do not earn a rate of return. Recovery of costs is probable, but the timing is not yet determined.
(8)
In July 2012, the Brazilian energy regulator (the "Regulator") approved the periodic review and reset of a component of Eletropaulo's regulated tariff, which determines the margin to be earned by Eletropaulo. The review and reset of this tariff component was retroactive to July 2011 and applied to customers' invoices from July 2012 to June 2015. From July 2011 through June 2012, Eletropaulo invoiced customers under the then-existing tariff rate, as required by the Regulator. As the new tariff rate was lower than the previous rate, Eletropaulo was required to reduce customer tariffs for the difference over the next year. Accordingly, from July 2011 through June 2012, Eletropaulo recognized a regulatory liability for the estimated future refunds, subsequently adjusted as of June 30, 2012 upon the finalization of the new tariff with the Regulator. The refund to customers was considered in the 2013 tariff adjustment, which contemplated an amortization of 67.55% from July 4, 2013. The remaining balance, representing 32.45%, was considered in the next annual tariff adjustment. There was no recorded current regulatory liability at Eletropaulo as of December 31, 2015.
(9)
Amounts received for costs expected to be incurred to improve the efficiency of our plants in Brazil as part of the IRT.
(10)
Other current and noncurrent regulatory liabilities primarily consist of liabilities owed to electricity generators due to variance in energy prices during rationing periods ("Free Energy"). Our Brazilian subsidiaries are authorized to refund this cost associated with monthly energy price variances between the wholesale energy market prices owed to the power generation plants producing Free Energy and the capped price reimbursed by the local distribution companies which are passed through to the final customers through energy tariffs. The balance excludes asset retirement obligations that were reclassified out of Other.
(11)
Obligations for removal costs which do not have an associated legal retirement obligation as defined by the accounting standards on asset retirement obligations.
(12)
Obligations established by ANEEL in Brazil associated with electric utility concessions and represent amounts received from customers or donations not subject to return. These donations are allocated to support energy network expansion and to improve utility operations to meet customers' needs. The term of the obligation is established by ANEEL. Settlement shall occur when the concession ends.
(13) 
Represents adjustments to the RAB resulting from an administrative ruling in December 2013 compelling Eletropaulo to refund customers beginning July 2014.
The current regulatory assets and liabilities are recorded in Other current assets and Accrued and other liabilities, respectively, on the accompanying Consolidated Balance Sheets. The noncurrent regulatory assets and liabilities are recorded in Other noncurrent assets and Other noncurrent liabilities, respectively, in the accompanying Consolidated Balance Sheets. The following table summarizes regulatory assets and liabilities by reportable segment in millions as of the periods indicated:
December 31,
2015
 
2014
 
Regulatory Assets
 
Regulatory Liabilities
 
Regulatory Assets
 
Regulatory Liabilities
Brazil SBU
$
971

 
$
932

 
$
787

 
$
1,347

US SBU
650

 
819

 
631

 
767

MCAC SBU (El Salvador)
43

 
—

 
91

 
—

Total
$
1,664

 
$
1,751

 
$
1,509

 
$
2,114


v3.3.1.900
Debt
12 Months Ended
Dec. 31, 2015
Debt Disclosure [Abstract]  
DEBT
DEBT
NON-RECOURSE DEBT — The next table summarizes the carrying amount (in millions) and terms of non-recourse debt as of the periods indicated:
NON-RECOURSE DEBT
Weighted Average Interest Rate
 
Maturity
 
December 31,
2015
 
2014
VARIABLE RATE:(1)


Bank loans
4.37
%
 
2016 – 2033
 
$
2,352

 
$
1,893

Notes and bonds
14.98
%
 
2016 – 2022
 
1,474

 
1,912

Debt to (or guaranteed by) multilateral, export credit agencies or development banks(2)
2.39
%
 
2021 – 2034
 
3,078

 
2,375

Other
12.65
%
 
2016 – 2043
 
47

 
668

FIXED RATE:


Bank loans
5.11
%
 
2016 – 2032
 
558

 
750

Notes and bonds
5.54
%
 
2016 – 2073
 
7,948

 
7,654

Debt to (or guaranteed by) multilateral, export credit agencies or development banks(2)
5.39
%
 
2023 – 2034
 
309

 
259

Other
8.66
%
 
2016 – 2049
 
26

 
89

SUBTOTAL


15,792

 
15,600

Less: Current maturities


(2,529
)
 
(1,982
)
TOTAL


$
13,263

 
$
13,618

(1)
The interest rate on variable rate debt represents the total of a variable component that is based on changes in an interest rate index and of a fixed component. The Company has interest rate swaps and option agreements in an aggregate notional principal amount of approximately $3.2 billion on non-recourse debt outstanding at December 31, 2015. These agreements economically fix the variable component of the interest rates on the portion of the variable-rate debt being hedged so that the total interest rate on that debt has been fixed at rates ranging from approximately 2.87% to 8.24%. These agreements expire at various dates from 2016 through 2033.
(2)
Multilateral loans include loans funded and guaranteed by bilaterals, multilaterals, development banks and other similar institutions.
Non-recourse debt (in millions) as of December 31, 2015 is scheduled to reach maturity as presented in the table below:
December 31,
Annual Maturities
2016
$
2,529

2017
1,022

2018
1,359

2019
950

2020
1,431

Thereafter
8,501

Total non-recourse debt
$
15,792


As of December 31, 2015, AES subsidiaries with facilities under construction had a total of approximately $2.6 billion of committed but unused credit facilities available to fund construction and other related costs. Excluding these facilities under construction, AES subsidiaries had approximately $2.4 billion in a number of available but unused committed credit lines to support their working capital, debt service reserves and other business needs. These credit lines can be used for borrowings, letters of credit, or a combination of these uses.
Significant transactions
During the year ended December 31, 2015, we had the following significant debt transactions at our subsidiaries:
•
Gener issued new debt of $1.1 billion, offset by repayments of $423 million which includes a loss on extinguishment of debt of $19 million;
•
IPALCO issued new debt of $847 million, offset by repayments of $602 million which includes a loss on extinguishment of debt of $22 million;
•
Sul issued new debt of $513 million, offset by repayments of $486 million which includes a loss on extinguishment of debt of $4 million;
•
Eletropaulo issued new debt of $354 million; offset by repayments of $211 million;
•
DPL issued new debt of $325 million; more than offset by repayments of $475 million which includes a loss on extinguishment of debt of $2 million;
•
Panama issued new debt of $300 million, offset by repayments of $287 million which includes a loss on extinguishment of debt of $15 million;
•
Mong Duong drew $203 million under its construction loan facility;
•
Tietê issued new debt of $153 million, more than offset by repayments of $226 million;
•
Andres issued new debt of $180 million, offset by repayments of $176 million which includes a loss on extinguishment of debt of $11 million; and
•
Itabo made repayments of $123 million which includes a loss on extinguishment of debt of $8 million.
Non-Recourse Debt Covenants, Restrictions and Defaults — The terms of the Company's non-recourse debt include certain financial and non-financial covenants. These covenants are limited to subsidiary activity and vary among the subsidiaries. These covenants may include, but are not limited to, maintenance of certain reserves and financial ratios, minimum levels of working capital and limitations on incurring additional indebtedness.
As of December 31, 2015 and 2014, approximately $513 million and $245 million, respectively, of restricted cash was maintained in accordance with certain covenants of the non-recourse debt agreements, and these amounts were included within Restricted cash and Debt service reserves and other deposits in the accompanying Consolidated Balance Sheets.
Various lender and governmental provisions restrict the ability of certain of the Company's subsidiaries to transfer their net assets to the Parent Company. Such restricted net assets of subsidiaries amounted to approximately $2 billion at December 31, 2015.
The following table summarizes the Company's subsidiary non-recourse debt in default (in millions) as of December 31, 2015. Due to the defaults, these amounts are included in the current portion of non-recourse debt:
 
Primary Nature
of Default
 
December 31, 2015
Subsidiary
Default
 
Net Assets
Maritza (Bulgaria)
Covenant
 
$
559

 
$
657

Sul (Brazil)
Covenant
 
333

 
439

Kavarna (Bulgaria)
Covenant
 
140

 
74

Sogrinsk (Kazakhstan)
Covenant
 
$
6

 
8

Total
 
 
$
1,038


As of December 31, 2015, none of the defaults are payment defaults. All of the subsidiary non-recourse defaults were triggered by failure to comply with other covenants and/or conditions such as (but not limited to) failure to meet information covenants, complete construction or other milestones in an allocated time, meet certain minimum or maximum financial ratios, or other requirements contained in the non-recourse debt documents of the applicable subsidiary.
In the event that there is a default, bankruptcy or maturity acceleration at a subsidiary or group of subsidiaries that meets the applicable definition of materiality under the corporate debt agreements of The AES Corporation, there could be a cross-default to the Company's recourse debt. Materiality is defined in the Parent's senior secured credit facility as having provided 20% or more of the Parent Company's total cash distributions from businesses for the four most recently completed fiscal quarters. As of December 31, 2015, none of the defaults listed above individually or in the aggregate result in or are at risk of triggering a cross-default under the recourse debt of the Parent Company. In the event the Parent Company is not in compliance with the financial covenants of its senior secured revolving credit facility, restricted payments will be limited to regular quarterly shareholder dividends at the then-prevailing rate. Payment defaults and bankruptcy defaults would preclude the making of any restricted payments.
Interest Expense — Interest expense for the year ended December 31, 2015 was reduced by $64 million related to the reversal of a monetary correction previously recognized as interest expense at Eletropaulo. This interest expense was on a contingent regulatory liability that was also reversed in the current period. Interest expense for the year ended December 31, 2014 was reduced by approximately $48 million related to reversing contingent interest accruals associated with disputed purchased energy obligations at Sul for which it was determined, based on developments during 2014, that the likelihood of an unfavorable outcome for the payment of interest on the disputed obligations was no longer probable. Interest expense for the year ended December 31, 2013 was reduced by approximately $34 million related to the recognition of ineffectiveness on derivative interest rate swaps accounted for as cash flow hedges.
RECOURSE DEBT — The table below summarizes the carrying amount (in millions) and terms of recourse debt of the Company as of the periods indicated:
RECOURSE DEBT
Interest Rate
 
Final Maturity
 
December 31, 2015

 
December 31, 2014
Senior Unsecured Note
7.75%
 
2015
 
$
—

 
$
151

Senior Unsecured Note
9.75%
 
2016
 
—

 
164

Senior Unsecured Note
8.00%
 
2017
 
181

 
525

Senior Unsecured Note
LIBOR + 3%
 
2019
 
775

 
775

Senior Unsecured Note
8.00%
 
2020
 
469

 
625

Senior Unsecured Note
7.38%
 
2021
 
1,000

 
1,000

Senior Unsecured Note
4.88%
 
2023
 
750

 
750

Senior Unsecured Note
5.50%
 
2024
 
750

 
750

Senior Unsecured Note
5.50%
 
2025
 
575

 
—

Term Convertible Trust Securities
6.75%
 
2029
 
517

 
517

Unamortized (Discounts)/Premiums


(2
)
 
1

SUBTOTAL


5,015

 
5,258

Less: Current maturities


—

 
(151
)
Total


$
5,015

 
$
5,107


The table below summarizes the principal amounts due, net of unamortized discounts, under our recourse debt for the next five years and thereafter in millions:
December 31,
Net Principal Amounts Due
2016
$
—

2017
181

2018
—

2019
774

2020
469

Thereafter
3,591

Total recourse debt
$
5,015


In April 2015, the Company issued $575 million aggregate principal amount of 5.50% senior notes due 2025. Concurrent with this offering, the Company redeemed via tender offers $344 million aggregate principal of its existing 8.00% senior unsecured notes due 2017, and $156 million of its existing 8.00% senior unsecured notes due 2020. As a result of the latter transaction, the Company recognized a loss on extinguishment of debt of $82 million that is included in the Consolidated Statement of Operations.
In March 2015, the Company redeemed in full the $151 million balance of its 7.75% senior unsecured notes due October 2015 and the $164 million balance of its 9.75% senior unsecured notes due April 2016. As a result of these transactions, the Company recognized a loss on extinguishment of debt of $23 million that is included in the Consolidated Statement of Operations.
In February 2014, the Company redeemed in full the $110 million balance of its 7.75% senior unsecured notes due March 2014. On March 7, 2014, the Company issued $750 million aggregate principal amount of 5.50% senior notes due 2024. Concurrent with this offering, the Company redeemed via tender offers $625 million aggregate principal of its existing 8.00% senior unsecured notes due 2017. As a result of the latter transaction, the Company recognized a loss on extinguishment of debt of $132 million that is included in the Consolidated Statements of Operations.
On May 20, 2014, the Company issued $775 million aggregate principal amount of senior unsecured floating rate notes due June 2019. The notes bear interest at a rate of 3% above three-month LIBOR, reset quarterly. Concurrent with this offering, the Company repaid $767 million of its existing senior secured term loan due 2018. As a result of the latter transaction, the Company recognized a loss on extinguishment of debt of $10 million that is included in the Consolidated Statement of Operations. On June 16, 2014, the Company repaid in full the remaining balance of approximately $29 million of its senior secured term loan due 2018.
On July 25, 2014, the Company issued two notices to call $320 million aggregate principal amount of unsecured notes, $160 million of which was used to retire notes due in 2015 and $160 million of which was used to retire notes due in 2016. The Company closed these transactions on August 25, 2014. As a result of this transaction, the Company recognized a loss on extinguishment of debt of $40 million that is included in the Consolidated Statement of Operations.
Recourse Debt Covenants and Guarantees — The Company's obligations under the senior secured credit facility are subject to certain exceptions, secured by (i) all of the capital stock of domestic subsidiaries owned directly by the Company and 65% of the capital stock of certain foreign subsidiaries owned directly or indirectly by the Company; and (ii) certain intercompany receivables, certain intercompany notes and certain intercompany tax sharing agreements.
The senior secured credit facility is subject to mandatory prepayment under certain circumstances, including the sale of certain assets. In such a situation, the net cash proceeds from the sale must be applied pro rata to repay the term loan, if any, using 60% of net cash proceeds, reduced to 50% when and if the parent's recourse debt to cash flow ratio is less than 5:1. The lenders have the option to waive their pro rata redemption.
The senior secured credit facility contains customary covenants and restrictions on the Company's ability to engage in certain activities, including, but not limited to, limitations on other indebtedness, liens, investments and guarantees; limitations on restricted payments such as shareholder dividends and equity repurchases; restrictions on mergers and acquisitions, sales of assets, leases, transactions with affiliates and off-balance sheet or derivative arrangements; and other financial reporting requirements.
The senior secured credit facility also contains financial covenants requiring the Company to maintain certain financial ratios including a cash flow to interest coverage ratio, calculated quarterly, which provides that a minimum ratio of the Company's adjusted operating cash flow to the Company's interest charges related to recourse debt of 1.3× must be maintained at all times and a recourse debt to cash flow ratio, calculated quarterly, which provides that the ratio of the Company's total recourse debt to the Company's adjusted operating cash flow must not exceed a maximum of 7.5×.
The terms of the Company's senior unsecured notes and senior secured credit facility contain certain covenants including, without limitation, limitation on the Company's ability to incur liens or enter into sale and leaseback transactions.
TERM CONVERTIBLE TRUST SECURITIES — In 1999, AES Trust III, a wholly-owned special purpose business trust and a VIE, issued approximately 10.35 million of $50 par value Term Convertible Preferred Securities ("TECONS") with a quarterly coupon payment of $0.844 for total proceeds of $517 million and concurrently purchased $517 million of 6.75% Junior Subordinated Convertible Debentures due 2029 (the "6.75% Debentures") issued by AES. The Company consolidates AES Trust III in its consolidated financial statements and classifies the TECONS as recourse debt on its Consolidated Balance Sheet. The Company's obligations under the 6.75% Debentures and other relevant trust agreements, in aggregate, constitute a full and unconditional guarantee by the Company of the TECON Trusts' obligations. As of December 31, 2015 and 2014, the sole assets of AES Trust III are the 6.75% Debentures.
AES, at its option, can redeem the 6.75% Debentures which would result in the required redemption of the TECONS issued by AES Trust III, currently for $50 per TECON. The TECONS must be redeemed upon maturity of the 6.75% Debentures. The TECONS are convertible into the common stock of AES at each holder's option prior to October 15, 2029 at the rate of 1.4216, representing a conversion price of $35.17 per share. The maximum number of shares of common stock AES would be required to issue should all holders decide to convert their securities would be 14.7 million shares.
Dividends on the TECONS are payable quarterly at an annual rate of 6.75%. The Trust is permitted to defer payment of dividends for up to 20 consecutive quarters, provided that the Company has exercised its right to defer interest payments under the corresponding debentures or notes. During such deferral periods, dividends on the TECONS would accumulate quarterly and accrue interest, and the Company may not declare or pay dividends on its common stock. AES has not exercised the option to defer any dividends at this time and all dividends due under the Trust have been paid.

v3.3.1.900
Commitments
12 Months Ended
Dec. 31, 2015
Commitments and Contingencies Disclosure [Abstract]  
COMMITMENTS
COMMITMENTS
LEASES—The Company and its subsidiaries enter into long-term non-cancelable lease arrangements which, for accounting purposes, are classified as either an operating lease or capital lease. Operating leases primarily include certain transmission lines, office rental and site leases. Operating lease rental expense for the years ended December 31, 2015, 2014, and 2013 was $67 million, $58 million and $46 million, respectively. Capital leases primarily include transmission lines at our subsidiaries in Brazil, vehicles, and office and other operating equipment. Capital leases are recognized in Property, Plant and Equipment within "Electric generation and distribution assets." The gross value of the capital lease assets as of December 31, 2015 and 2014 was $72 million and $80 million, respectively. The table below presents the future minimum lease payments under operating and capital leases for continuing operations together with the present value of the net minimum lease payments under capital leases as of December 31, 2015 for 2016 through 2020 and thereafter, in millions:
 
Future Commitments for
December 31,
Capital Leases
 
Operating Leases
2016
$
14

 
$
77

2017
12

 
78

2018
11

 
79

2019
10

 
80

2020
10

 
79

Thereafter
90

 
898

Total
147

 
$
1,291

Less: Imputed interest
90


Present value of total minimum lease payments
$
57


CONTRACTS — The Company's operating subsidiaries enter into long-term contracts for construction projects, maintenance and service, transmission of electricity, operations services and purchase of electricity and fuel. In general, these contracts are subject to variable quantities or prices and are terminable in limited circumstances only. Electricity purchase contracts primarily include energy auction agreements at our Brazil subsidiaries with extended terms from 2013 through 2028. The table below presents the future minimum commitments for continuing operations under these contracts as of December 31, 2015 for 2016 through 2020 and thereafter. Actual purchases under these contracts for the years ended December 31, 2015, 2014, and 2013 are also presented, in millions:
Actual purchases during the year ended December 31,
Electricity Purchase Contracts
 
Fuel Purchase Contracts
 
Other Purchase Contracts
2013
$
2,665

 
$
1,590

 
$
1,743

2014
3,104

 
1,521

 
1,386

2015
2,592

 
1,262

 
2,121

Future commitments for the year ending December 31,


2016
$
2,623

 
$
1,120

 
$
1,332

2017
2,444

 
835

 
1,047

2018
2,634

 
532

 
1,081

2019
2,799

 
314

 
873

2020
2,918

 
311

 
655

Thereafter
24,176

 
2,141

 
4,395

Total
$
37,594

 
$
5,253

 
$
9,383


v3.3.1.900
Contingencies
12 Months Ended
Dec. 31, 2015
Commitments and Contingencies Disclosure [Abstract]  
CONTINGENCIES
CONTINGENCIES
Guarantees, Letters of Credit — In connection with certain project financing, acquisition and dispositions, power purchase and other agreements, the Parent Company has expressly undertaken limited obligations and commitments, most of which will only be effective or will be terminated upon the occurrence of future events. In the normal course of business, the Parent Company has entered into various agreements, mainly guarantees and letters of credit, to provide financial or performance assurance to third parties on behalf of AES businesses. These agreements are entered into primarily to support or enhance the creditworthiness otherwise achieved by a business on a stand-alone basis, thereby facilitating the availability of sufficient credit to accomplish their intended business purposes. Most of the contingent obligations relate to future performance commitments which the Company or its businesses expect to fulfill within the normal course of business. The expiration dates of these guarantees vary from less than one year to more than 19 years.
The following table summarizes the Parent Company's contingent contractual obligations as of December 31, 2015. Amounts presented in the table below represent the Parent Company's current undiscounted exposure to guarantees and the range of maximum undiscounted potential exposure. The maximum exposure is not reduced by the amounts, if any, that could be recovered under the recourse or collateralization provisions in the guarantees. The amounts include obligations made by the Parent Company for the direct benefit of the lenders associated with the non-recourse debt of its businesses of $14 million.
Contingent Contractual Obligations
 
Amount
 
Number of Agreements
 
Maximum Exposure Range for Each Agreement
 
 
(in millions)


(in millions)
Guarantees and commitments
 
$
369

 
14
 
$1 - 53
Asset sale related indemnities(1)
 
27

 
1
 
27
Cash collateralized letters of credit
 
32

 
4
 
$1 - 15
Letters of credit under the senior secured credit facility
 
62

 
7
 
<$1 - 29
Total
 
$
490

 
26


(1) Excludes normal and customary representations and warranties in agreements for the sale of assets (including ownership in associated legal entities) where the associated risk is considered to be nominal.
As of December 31, 2015, the Parent Company had no commitments to invest in subsidiaries under construction and to purchase related equipment that were not included in the letters of credit discussed above. During the year ended December 31, 2015, the Company paid letter of credit fees ranging from 0.2% to 2.5% per annum on the outstanding amounts of letters of credit.
Environmental — The Company periodically reviews its obligations as they relate to compliance with environmental laws, including site restoration and remediation. As of December 31, 2015 and 2014 the Company had recognized liabilities of $10 million and $12 million, respectively, for projected environmental remediation costs. Due to the uncertainties associated with environmental assessment and remediation activities, future costs of compliance or remediation could be higher or lower than the amount currently accrued. Moreover, where no liability has been recognized, it is reasonably possible that the Company may be required to incur remediation costs or make expenditures in amounts that could be material but could not be estimated as of December 31, 2015. In aggregate, the Company estimates that the range of potential losses related to environmental matters, where estimable, to be up to $1 million. The amounts considered reasonably possible do not include amounts accrued as discussed above.
Litigation — The Company is involved in certain claims, suits and legal proceedings in the normal course of business. The Company accrues for litigation and claims when it is probable that a liability has been incurred and the amount of loss can be reasonably estimated. The Company has evaluated claims in accordance with the accounting guidance for contingencies that it deems both probable and reasonably estimable and, accordingly, has recorded aggregate liabilities for all claims of approximately $189 million and $199 million as of December 31, 2015 and 2014, respectively. These amounts are reported on the Consolidated Balance Sheets within Accrued and other liabilities and Other noncurrent liabilities. A significant portion of these accrued liabilities relate to employment, non-income tax and customer disputes in international jurisdictions (principally Brazil). Certain of the Company's subsidiaries, principally in Brazil, are defendants in a number of labor and employment lawsuits. The complaints generally seek unspecified monetary damages, injunctive relief, or other relief. The subsidiaries have denied any liability and intend to vigorously defend themselves in all of these proceedings. There can be no assurance that these accrued liabilities will be adequate to cover all existing and future claims or that we will have the liquidity to pay such claims as they arise.
The Company believes, based upon information it currently possesses and taking into account established accruals for liabilities and its insurance coverage, that the ultimate outcome of these proceedings and actions is unlikely to have a material effect on the Company's consolidated financial statements. However, where no accrued liability has been recognized, it is reasonably possible that some matters could be decided unfavorably to the Company and could require the Company to pay damages or make expenditures in amounts that could be material but could not be estimated as of December 31, 2015. The material contingencies where a loss is reasonably possible primarily include claims under financing agreements; disputes with offtakers, suppliers and EPC contractors; alleged violation of monopoly laws and regulations; income tax and non-income tax matters with tax authorities; and regulatory matters. In aggregate, the Company estimates that the range of potential losses, where estimable, related to these reasonably possible material contingencies to be between $1.1 billion and $1.4 billion. The amounts considered reasonably possible do not include amounts accrued, as discussed above. These material contingencies do not include income tax-related contingencies which are considered part of our uncertain tax positions.
Regulatory — During 2013, the Company recognized a regulatory liability of $269 million for a contingency related to an administrative ruling which required Eletropaulo to refund customers' amounts related to the regulatory asset base. In 2014, Eletropaulo started refunding customers as part of the tariff. In January 2015, ANEEL updated the tariff to exclude any further customer refunds. On June 30, 2015, ANEEL included in the tariff reset the reimbursement to Eletropaulo of these amounts previously refunded to customers to begin in July 2015. During 2015, as a result of favorable events, management reassessed the contingency and determined that it no longer meets the recognition criteria under ASC 450 — Contingencies. Management believes that it is now only reasonably possible that Eletropaulo will have to refund these amounts to customers. Accordingly, the Company reversed the remaining regulatory liability for this contingency of $161 million in 2015, which increased Regulated Revenue by $97 million and reduced Interest Expense by $64 million. Amounts related to this case are now included as part of our reasonably possible contingent range mentioned in the preceding paragraph.

v3.3.1.900
Benefit Plans
12 Months Ended
Dec. 31, 2015
Compensation and Retirement Disclosure [Abstract]  
BENEFIT PLANS
BENEFIT PLANS
Defined Contribution Plan — The Company sponsors four defined contribution plans ("the Plans"). Two are for U.S. non-union employees, of which one is for employees of the Parent Company and certain U.S. SBU businesses and one is for DPL employees. One plan includes both union and non-union employees at IPL. One defined contribution plan is for union employees at DPL. The Plans are qualified under section 401 of the Internal Revenue Code. All U.S. employees of the Company are eligible to participate in the appropriate Plan except for those employees who are covered by a collective bargaining agreement, unless such agreement specifically provides that the employee is considered an eligible employee under a Plan. The Plans provide matching contributions in AES common stock or cash, other contributions at the discretion of the Compensation Committee of the Board of Directors in AES common stock or cash and discretionary tax deferred contributions from the participants. Participants are fully vested in their own contributions and the Company's matching contributions. Participants vest in other company contributions ratably over a five-year period ending on the fifth anniversary of their hire date. For the year ended December 31, 2015, the Company's contributions to the defined contribution plans were approximately $18 million, and for the years ended December 31, 2014 and 2013, contributions were $22 million and $23 million per year, respectively.
Defined Benefit Plans — Certain of the Company's subsidiaries have defined benefit pension plans covering substantially all of their respective employees. Pension benefits are based on years of credited service, age of the participant and average earnings. Of the 33 active defined benefit plans as of December 31, 2015, 5 are at U.S. subsidiaries and the remaining plans are at foreign subsidiaries .
The following table reconciles the Company's funded status, both domestic and foreign, as of the periods indicated:
December 31,
 
2015
 
2014
(in millions)
 
U.S.
 
Foreign
 
U.S.
 
Foreign
CHANGE IN PROJECTED BENEFIT OBLIGATION:


Benefit obligation as of January 1
 
$
1,235

 
$
4,363

 
$
1,059

 
$
4,749

Service cost
 
16

 
15

 
14

 
16

Interest cost
 
48

 
351

 
50

 
489

Employee contributions
 
—

 
3

 
—

 
4

Plan amendments
 
5

 
2

 
8

 
(3
)
Plan settlements
 
(3
)
 
—

 
—

 
—

Benefits paid
 
(61
)
 
(300
)
 
(59
)
 
(415
)
Actuarial (gain) loss
 
(68
)
 
(160
)
 
163

 
87

Effect of foreign currency exchange rate changes
 
—

 
(1,301
)
 
—

 
(564
)
Benefit obligation as of December 31
 
$
1,172

 
$
2,973

 
$
1,235

 
$
4,363

CHANGE IN PLAN ASSETS:


Fair value of plan assets as of January 1
 
$
1,061

 
$
3,272

 
$
941

 
$
3,605

Actual return on plan assets
 
(7
)
 
182

 
123

 
360

Employer contributions
 
31

 
89

 
56

 
135

Employee contributions
 
—

 
3

 
—

 
4

Plan settlements
 
(3
)
 
—

 
—

 
—

Benefits paid
 
(61
)
 
(300
)
 
(59
)
 
(415
)
Effect of foreign currency exchange rate changes
 
—

 
(962
)
 
—

 
(417
)
Fair value of plan assets as of December 31
 
$
1,021

 
$
2,284

 
$
1,061

 
$
3,272

RECONCILIATION OF FUNDED STATUS


Funded status as of December 31
 
$
(151
)
 
$
(689
)
 
$
(174
)
 
$
(1,091
)

The following table summarizes the amounts recognized on the Consolidated Balance Sheets in millions related to the funded status of the plans, both domestic and foreign, as of the periods indicated:
December 31,
 
2015
 
2014
AMOUNTS RECOGNIZED ON THE CONSOLIDATED BALANCE SHEETS
 
U.S.
 
Foreign
 
U.S.
 
Foreign
Noncurrent assets
 
$
—

 
$
67

 
$
—

 
$
51

Accrued benefit liability—current
 
—

 
(5
)
 
—

 
(4
)
Accrued benefit liability—noncurrent
 
(151
)
 
(751
)
 
(174
)
 
(1,138
)
Net amount recognized at end of year
 
$
(151
)
 
$
(689
)
 
$
(174
)
 
$
(1,091
)

The next table summarizes the Company's U.S. and foreign accumulated benefit obligation as of the periods indicated (in millions):
December 31,
2015
 
2014
 
 
U.S.
 
Foreign
 
U.S.
 
Foreign
 
Accumulated Benefit Obligation
$
1,150

 
$
2,931

 
$
1,208

 
$
4,301

 
Information for pension plans with an accumulated benefit obligation in excess of plan assets:


Projected benefit obligation
$
1,172

 
$
2,683

 
$
1,235

 
$
4,021

 
Accumulated benefit obligation
1,150

 
2,656

 
1,208

 
3,979

 
Fair value of plan assets
1,021

 
1,931

 
1,061

 
2,885

 
Information for pension plans with a projected benefit obligation in excess of plan assets:


Projected benefit obligation
$
1,172

 
$
2,697

(1) 
$
1,235

 
$
4,038

(1) 
Fair value of plan assets
1,021

 
1,942

(1) 
1,061

 
2,897

(1) 
(1)
$686 million and $1.1 billion of the total net unfunded projected benefit obligation is due to Eletropaulo in Brazil as of December 31, 2015 and 2014, respectively.
The table below summarizes the significant weighted average assumptions used in the calculation of benefit obligation and net periodic benefit cost, both domestic and foreign, as of the periods indicated:
December 31,
2015
 
2014
 
 
U.S.
 
Foreign
 
U.S.
 
Foreign
 
Benefit Obligation:


Discount rates
4.44
%
 
11.37
%
(2) 
4.04
%
 
10.47
%
(2) 
Rates of compensation increase
3.34
%
(1) 
6.32
%
 
3.94
%
(1) 
6.41
%
 
Periodic Benefit Cost:


Discount rate
4.04
%
 
10.47
%
 
4.89
%
 
10.80
%
 
Expected long-term rate of return on plan assets
6.67
%
 
9.77
%
 
6.92
%
 
10.44
%
 
Rate of compensation increase
3.94
%
(1) 
6.41
%
 
3.94
%
(1) 
6.44
%
 
(1)
A U.S. subsidiary of the Company has defined benefit obligations of $6 million and $748 million as of December 31, 2015 and 2014, respectively, for which salary bands, rather than rates of compensation increases, are used to determine future benefit costs. Rates of compensation increases in the table above do not include amounts related to these specific defined benefit plans. A plan with a defined benefit obligation of $742 million at December 31, 2014 and which used salary bands at that date is using a rate of compensation increase as at December 31, 2015. The rate of compensation increase for this plan is included in the weighted average in the above table for calculating the benefit obligation as at December 31, 2015, but is not included in the weighted average for calculating the benefit obligation as at December 31, 2014 or the periodic benefit cost for 2014 or 2015.
(2) 
Includes an inflation factor that is used to calculate future periodic benefit cost, but is not used to calculate the benefit obligation.
The Company establishes its estimated long-term return on plan assets considering various factors, which include the targeted asset allocation percentages, historic returns and expected future returns.
The measurement of pension obligations, costs and liabilities is dependent on a variety of assumptions. These assumptions include estimates of the present value of projected future pension payments to all plan participants, taking into consideration the likelihood of potential future events such as salary increases and demographic experience. These assumptions may have an effect on the amount and timing of future contributions.
The assumptions used in developing the required estimates include the following key factors: discount rates; salary growth; retirement rates; inflation; expected return on plan assets; and mortality rates.
The effects of actual results differing from the Company's assumptions are accumulated and amortized over future periods and, therefore, generally affect the Company's recognized expense in such future periods.
Effective January 1, 2016 the Company will apply a disaggregated discount rate approach for determining service cost and interest cost for its defined benefit pension plans and post-retirement plans in the U.S. and U.K. Refer to Note 1—General and Summary of Significant Accounting Policies for further information relating to this change in estimate.
Sensitivity of the Company's pension funded status to the indicated increase or decrease in the discount rate and long-term rate of return on plan assets assumptions is shown below. Note that these sensitivities may be asymmetric and are specific to the base conditions at year-end 2015. They also may not be additive, so the impact of changing multiple factors simultaneously cannot be calculated by combining the individual sensitivities shown. The funded status as of December 31, 2015 is affected by the assumptions as of that date. Pension expense for 2015 is affected by the December 31, 2014 assumptions. The impact on pension expense from a one percentage point change in these assumptions is shown in the table below (in millions):
Increase of 1% in the discount rate
 
$
(32
)
Decrease of 1% in the discount rate
 
27

Increase of 1% in the long-term rate of return on plan assets
 
(36
)
Decrease of 1% in the long-term rate of return on plan assets
 
36


The following table summarizes the components of the net periodic benefit cost in millions, both domestic and foreign, for the years indicated:
December 31,
 
2015
 
2014
 
2013
Components of Net Periodic Benefit Cost:
 
U.S.
 
Foreign
 
U.S.
 
Foreign
 
U.S.
 
Foreign
Service cost
 
$
16

 
$
15

 
$
14

 
$
16

 
$
16

 
$
26

Interest cost
 
48

 
351

 
50

 
489

 
46

 
515

Expected return on plan assets
 
(70
)
 
(247
)
 
(67
)
 
(362
)
 
(64
)
 
(484
)
Amortization of prior service cost
 
7

 
—

 
6

 
(1
)
 
5

 
—

Amortization of net loss
 
20

 
28

 
13

 
37

 
23

 
77

Settlement gain recognized
 
—

 
—

 
—

 
1

 
—

 
—

Total pension cost
 
$
21

 
$
147

 
$
16

 
$
180

 
$
26

 
$
134


The following table summarizes in millions the amounts reflected in AOCL including AOCL attributable to noncontrolling interests, on the Consolidated Balance Sheet as of December 31, 2015, that have not yet been recognized as components of net periodic benefit cost and amounts expected to be reclassified to earnings in the next fiscal year:
December 31, 2015
Accumulated Other Comprehensive Income (Loss)
 
Amounts expected to be reclassified to earnings in next fiscal year
 
U.S.
 
Foreign
 
U.S.
 
Foreign
Prior service cost
$
—

 
$
(5
)
 
$
—

 
$
—

Unrecognized net actuarial gain (loss)
(6
)
 
(1,092
)
 
—

 
(18
)
Total
$
(6
)
 
$
(1,097
)
 
$
—

 
$
(18
)

The following table summarizes the Company's target allocation for 2015 and pension plan asset allocation, both domestic and foreign, as of the periods indicated:


Percentage of Plan Assets as of December 31,
 
Target Allocations
 
2015
 
2014
Asset Category
U.S.
 
Foreign
 
U.S.
 
Foreign
 
U.S.
 
Foreign
Equity securities
46
%
 
15% -29%
 
44.76
%
 
13.23
%
 
44.02
%
 
16.28
%
Debt securities
50
%
 
60% - 85%
 
50.05
%
 
81.10
%
 
50.90
%
 
78.85
%
Real estate
2
%
 
0% - 3%
 
2.94
%
 
3.24
%
 
2.45
%
 
3.15
%
Other
2
%
 
0% - 5%
 
2.25
%
 
2.43
%
 
2.63
%
 
1.72
%
Total pension assets


100.00
%
 
100.00
%
 
100.00
%
 
100.00
%

The U.S. plans seek to achieve the following long-term investment objectives:
•
maintenance of sufficient income and liquidity to pay retirement benefits and other lump sum payments;
•
long-term rate of return in excess of the annualized inflation rate;
•
long-term rate of return, net of relevant fees, that meets or exceeds the assumed actuarial rate; and
•
long-term competitive rate of return on investments, net of expenses, that equals or exceeds various benchmark rates.
The asset allocation is reviewed periodically to determine a suitable asset allocation which seeks to manage risk through portfolio diversification and takes into account, among other possible factors, the above-stated objectives, in conjunction with current funding levels, cash flow conditions and economic and industry trends. The following table summarizes the Company's U.S. plan assets by category of investment and level within the fair value hierarchy in millions as of the periods indicated:
 
 
December 31, 2015
 
December 31, 2014
U.S. Plans
 
Level 1
 
Level 2
 
Level 3
 
Total
 
Level 1
 
Level 2
 
Level 3
 
Total
Equity securities —
Mutual funds
457

 
—

 
—

 
457

 
467

 
—

 
—

 
467

Debt securities —
Government debt securities
53

 
—

 
—

 
53

 
67

 
—

 
—

 
67

 
Mutual funds(1)
458

 
—

 
—

 
458

 
473

 
—

 
—

 
473

Real Estate —
Real Estate
—

 
30

 
—

 
30

 
—

 
26

 
—

 
26

Other —
Cash and cash equivalents
—

 
—

 
—

 
—

 
4

 
—

 
—

 
4

 
Other investments
—

 
23

 
—

 
23

 
—

 
24

 
—

 
24

 
Total plan assets
$
968

 
$
53

 
$
—

 
$
1,021

 
$
1,011

 
$
50

 
$
—

 
$
1,061

(1)
Mutual funds categorized as debt securities consist of mutual funds for which debt securities are the primary underlying investment.
The investment strategy of the foreign plans seeks to maximize return on investment while minimizing risk. The assumed asset allocation has less exposure to equities in order to closely match market conditions and near term forecasts. The following table summarizes the Company's foreign plan assets by category of investment and level within the fair value hierarchy in millions as of the periods indicated:
 
 
December 31, 2015
 
December 31, 2014
Foreign Plans
 
Level 1
 
Level 2
 
Level 3
 
Total
 
Level 1
 
Level 2
 
Level 3
 
Total
Equity securities —
Common stock
$
9

 
$
—

 
$
—

 
$
9

 
$
21

 
$
—

 
$
—

 
$
21

 
Mutual funds
167

 
—

 
—

 
167

 
274

 
—

 
—

 
274

 
Private equity(1)
—

 
—

 
126

 
126

 
—

 
—

 
237

 
237

Debt securities —
Certificates of deposit
—

 
2

 
—

 
2

 
—

 
3

 
—

 
3

 
Unsecured debentures
—

 
5

 
—

 
5

 
—

 
10

 
—

 
10

 
Government debt securities
11

 
79

 
—

 
90

 
12

 
98

 
—

 
110

 
Mutual funds(2)
218

 
1,535

 
—

 
1,753

 
215

 
2,236

 
—

 
2,451

 
Other debt securities
—

 
2

 
—

 
2

 
—

 
6

 
—

 
6

Real estate —
Real estate(1)
—

 
—

 
74

 
74

 
—

 
—

 
103

 
103

Other —
Cash and cash equivalents
—

 
—

 
—

 
—

 
1

 
—

 
—

 
1

 
Participant loans(3)
—

 
—

 
37

 
37

 
—

 
—

 
52

 
52

 
Other assets
16

 
—

 
3

 
19

 
—

 
—

 
4

 
4

 
Total plan assets
$
421

 
$
1,623

 
$
240

 
$
2,284

 
$
523

 
$
2,353

 
$
396

 
$
3,272

(1) 
Plan assets of our Brazilian subsidiaries are invested in private equities and commercial real estate through the plan administrator in Brazil. The fair value of these assets is determined using the income approach through annual appraisals based on a discounted cash flow analysis.
(2) 
Mutual funds categorized as debt securities consist of mutual funds for which debt securities are the primary underlying investment.
(3) 
Loans to participants are stated at cost, which approximates fair value.
The following table presents a reconciliation of all plan assets measured at fair value using significant unobservable inputs (Level 3) in millions for the periods indicated:
December 31,
 
2015
 
2014
Balance at January 1
 
$
396

 
$
530

Actual return on plan assets:


Returns relating to assets still held at reporting date
 
(36
)
 
(87
)
Purchases, sales and settlements, net
 
—

 
1

Transfers of (assets) liabilities into Level 3
 
—

 
5

Change due to exchange rate changes
 
(120
)
 
(53
)
Balance at December 31
 
$
240

 
$
396


The following table summarizes the estimated cash flows for U.S. and foreign expected employer contributions and expected future benefit payments, both domestic and foreign in millions:
 
 
U.S.
 
Foreign
Expected employer contribution in 2016
 
$
22

 
$
100

Expected benefit payments for fiscal year ending:


2016
 
65

 
268

2017
 
67

 
277

2018
 
69

 
289

2019
 
71

 
299

2020
 
73

 
309

2021 - 2025
 
380

 
1,686


v3.3.1.900
Equity
12 Months Ended
Dec. 31, 2015
Equity [Abstract]  
Equity
EQUITY
Equity Transactions with Noncontrolling Interests
Brazil Reorganization — In 2015, the Company completed a restructuring of AES Brasiliana. This transaction resulted in no change of ownership or control. The $27 million impact of this equity transaction was recognized in additional paid-in capital.
Gener — On November 18, 2015, the Company sold a 4% stake in AES Gener S.A. ("Gener") through its 99.9% owned subsidiary inversions Cachagua S.p.A ("Cachagua") for $145 million, net of transaction costs. The sale was of previously issued common shares of Gener to certain institutional investors and is not a sale of in-substance real estate. While the sale decreased Parent ownership interest from 70.7% to 66.7%, the Parent continues to retain its controlling financial interest in the subsidiary. The difference of $24 million between the fair value of the consideration received, net of taxes and transaction costs, and the amount by which the NCI is adjusted was recognized in additional paid-in capital. No pretax gain or loss was recognized in net income as a result of this transaction.
Jordan — On March 15, 2015, the Company executed an agreement to sell 40% of its interest in a wholly-owned subsidiary in Jordan that owns a controlling interest in the Jordan IPP4 gas-fired plant for $30 million. The sale was completed on February 18, 2016. See Note 30—Subsequent Events for further information.
IPALCO — In February 2015, La Caisse de depot et placement du Quebec ("CDPQ") purchased 15% of AES US Investment, Inc., a wholly-owned subsidiary that owns 100% of IPALCO Enterprises, Inc. ("IPALCO"), for $247 million, with an option to invest an additional $349 million in IPALCO through 2016 in exchange for a 17.65% equity stake. In April 2015, CDPQ invested $214 million of the $349 million in IPALCO, which resulted in CDPQ's combined equity interest in IPALCO to be 24.90%. Upon investing the remaining commitment of $135 million, CDPQ's equity interests in IPALCO will total 30%.
As a result of these transactions, $84 million in taxes and transaction costs were recognized as a net decrease to equity. The Company also recognized an increase of $377 million to additional paid-in capital and a reduction to retained earnings of $377 million for the excess of the fair value of the shares over their book value. Since the noncontrolling interest is contingently redeemable, the fair value of the consideration received of $460 million, net of proportional dividends, is classified in temporary equity as redeemable stock of subsidiaries on the Consolidated Balance Sheets. No gain or loss was recognized in net income as the sale was not considered to be a sale of in-substance real estate. Any subsequent adjustments to allocate earnings and dividends to CDPQ will be classified as noncontrolling interest within permanent equity and adjustments to the amount in temporary equity will occur only if and when it is probable that the shares will become redeemable. As the Company maintained control after the sale, IPALCO continues to be accounted for as a consolidated subsidiary within the US SBU reportable segment.
Dominican Republic — In December 2014 Estrella and Linda Groups, an investor-based group in the Dominican Republic acquired 8% noncontrolling interest in our businesses in the Dominican Republic for $83 million, net of transaction costs, with options to acquire an additional 2% for $24 million at any time between the closing date and December 31, 2015, and an additional 10% for $125 million at any time between the closing date and December 31, 2016. In December 2015, Estrella and Linda Groups exercised its first call option of additional 2% for $18 million, net of discount and transaction costs. This resulted in Estrella and Linda Groups having a total of 10% noncontrolling interest in our businesses in the Dominican Republic.
As a result of these transactions, $29 million and $7 million, net of taxes and transaction costs, was recognized in additional paid-in capital at December 31, 2014 and 2015, respectively. No gain or loss was recognized in net income as the sale is not considered to be a sale of in-substance real estate. As the Company maintained control after the sale, our businesses in the Dominican Republic continue to be consolidated by the Company within the MCAC SBU reportable segment.
Masinloc — On June 25, 2014, the Company executed an agreement to sell approximately 45% of its interest in Masin-AES Pte Ltd., a wholly-owned subsidiary that owns the Company's business interests in the Philippines, for $453 million, subject to certain purchase price adjustments. On July 15, 2014, the Company completed the Masinloc sale transaction and received cumulative net proceeds of $436 million, including $23 million contingent upon the achievement of certain restructuring efficiencies. The transaction was accounted for as a sale of in-substance real estate. Noncontrolling interest of $130 million and a pretax gain on sale of investment of approximately $283 million, net of transaction costs, were recognized during the third quarter of 2014. The portion of the proceeds related to the contingency has been deferred.
After completion of the sale, the Company owns a 51% net ownership interest in Masinloc and will continue to manage and operate the plant, with 41% owned by Electricity Generating Public Company Limited and 8% owned by the International Finance Corporation. As the Company maintained control after the sale, Masinloc continues to be accounted for as a consolidated subsidiary within the Asia SBU reportable segment.
The following table summarizes the net income attributable to The AES Corporation and all transfers (to) from noncontrolling interests in millions for the periods indicated:
 
 
December 31,
 
 
2015
 
2014
Net income attributable to The AES Corporation
 
$
306

 
$
769

Transfers from the noncontrolling interest:


Net increase in The AES Corporation's paid-in capital for sale of subsidiary shares
 
323

 
29

Additional paid-in capital, IPALCO shares, transferred to redeemable stock of subsidiaries (1)
 
(377
)
 
—

Increase in The AES Corporation's paid-in capital for purchase of subsidiary shares
 
—

 
7

Net transfers (to) from noncontrolling interest
 
(54
)
 
36

Change from net income attributable to The AES Corporation and transfers (to) from noncontrolling interests
 
$
252

 
$
805


(1) See Note 19—Redeemable stock of subsidiaries for further information on increase in paid-in capital transferred to redeemable stock of subsidiaries.
Accumulated Other Comprehensive Loss
The changes in AOCL by component, net of tax and noncontrolling interests in millions for the year ended December 31, 2015 were as follows:
 
Foreign currency translation adjustment, net
 
Unrealized derivative losses, net
 
Unfunded pension obligations, net
 
Total
Balance at the beginning of the period
$
(2,595
)
 
$
(396
)
 
$
(295
)
 
$
(3,286
)
Other comprehensive (loss) income before reclassifications
(674
)
 
(5
)
 
19

 
(660
)
Amount reclassified to earnings
$
—

 
$
48

 
$
2

 
50

Other comprehensive (loss) income
(674
)
 
43

 
21

 
(610
)
Cumulative effect of a change in accounting principle
$
13

 
$
—

 
$
—

 
$
13

Balance at the end of the period
(3,256
)
 
(353
)
 
(274
)
 
(3,883
)

Reclassifications out of AOCL for the periods indicated were as follows (in millions):
Details About


December 31,
AOCL Components
 
Affected Line Item in the Consolidated Statements of Operations
 
2015
 
2014
 
2013
Foreign currency translation adjustment, net


Gain on sale of businesses
 
$
—

 
$
4

 
$
(2
)
 
 
Net loss from disposal and impairments of discontinued operations
 
—

 
(38
)
 
(35
)
 
 
Net income attributable to The AES Corporation
 
$
—

 
$
(34
)
 
$
(37
)
Unrealized derivative gains (losses), net


Non-regulated revenue
 
$
43

 
$
30

 
$
(3
)
 
 
Non-regulated cost of sales
 
(14
)
 
(4
)
 
(7
)
 
 
Interest expense
 
(112
)
 
(139
)
 
(137
)
 
 
Gain on sale of businesses
 
(4
)
 
—

 
(21
)
 
 
Foreign currency transaction gains (losses)
 
12

 
(9
)
 
(6
)
 
 
Income from continuing operations before taxes and equity in earnings of affiliates
 
(75
)
 
(122
)
 
(174
)
 
 
Income tax expense
 
11

 
26

 
41


Net equity in earnings of affiliates
 
(2
)
 
(3
)
 
(6
)
 
 
Income from continuing operations
 
(66
)
 
(99
)
 
(139
)
 
 
Less: (Income) from continuing operations attributable to noncontrolling interests
 
18

 
27

 
11


Net income attributable to The AES Corporation
 
$
(48
)

$
(72
)
 
$
(128
)
Amortization of defined benefit pension actuarial loss, net


Regulated cost of sales
 
$
(25
)
 
$
(33
)
 
$
(73
)
 
 
Non-regulated cost of sales
 
2

 
(5
)
 
(4
)
 
 
General and administrative expenses
 
(2
)
 
—

 
(1
)
 
 
Income from continuing operations before taxes and equity in earnings of affiliates
 
(25
)

(38
)
 
(78
)
 
 
Income tax expense
 
9

 
7

 
26


Income from continuing operations
 
(16
)

(31
)
 
(52
)
 
 
Net loss from disposal and impairments of discontinued operations
 
—

 
2

 
—


Net Income
 
(16
)
 
(29
)
 
(52
)
 
 
Less: (Income) from continuing operations attributable to noncontrolling interests
 
14

 
19

 
39


Net income attributable to The AES Corporation
 
$
(2
)

$
(10
)
 
$
(13
)
Total reclassifications for the period, net of income tax and noncontrolling interests
 
$
(50
)

$
(116
)
 
$
(178
)
_____________________________
(1) 
Amounts in parentheses indicate debits to the Consolidated Statements of Operations.
Common Stock Dividends — The Company paid dividends of $0.10 per outstanding share to its common stockholders during the first, second, third and fourth quarters of 2015 for dividends declared in December 2014, April 2015, July 2015 and October 2015.
On December 11, 2015, the Board of Directors declared a quarterly common stock dividend of $0.11 per share payable on February 16, 2016 to shareholders of record at the close of business on February 2, 2016.
Secondary Offering and Concurrent Stock Repurchase — On May 18, 2015, the Parent Company completed an underwritten secondary public offering (the "Offering") of approximately 60 million shares of its common stock by the Terrific Investment Corporation (the "Selling Stockholder"), a subsidiary controlled by China Investment Corporation at a price of $13.25 per share. Of the 60 million shares, 40 million were sold to the market and 20 million were reserved to be repurchased by the Parent Company. The Parent Company did not receive any of the proceeds from the Offering and the Selling Stockholder has fully sold its stake in AES common stock. Concurrent with this offering, on May 18, 2015, the Parent Company completed the repurchase of the 20 million shares of its common stock from the Selling Stockholder at a price per share of $13.07, for an aggregate purchase price of $261 million.
Stock Repurchase Program — In October 2015, the Company's Board of Directors authorized an increase to the Company's common stock repurchase program (the "Program") for up to an additional $400 million of repurchases of the Company's common stock, bringing the cumulative total of authorized repurchases under the Program to $2.1 billion.
During the year ended December 31, 2015, the Company repurchased 39.7 million shares of its common stock under the Program at a total cost of $482 million under the existing stock repurchase program. The cumulative repurchase from the commencement of the Program in July 2010 through December 31, 2015 totaled 145.6 million shares for a total cost of $1.8 billion, at an average price per share of $12.31 (including a nominal amount of commissions). As of December 31, 2015, $343 million remained available for repurchase under the Program.
The common stock repurchased has been classified as treasury stock and accounted for using the cost method. A total of 149,037,831 and 110,687,849 shares were held as treasury stock at December 31, 2015 and 2014, respectively. Restricted stock units under the Company's employee benefit plans are issued from treasury stock. The Company has not retired any common stock repurchased since it began the Program in July 2010.

v3.3.1.900
Segment and Geographic Information
12 Months Ended
Dec. 31, 2015
Segment Reporting [Abstract]  
SEGMENT AND GEOGRAPHIC INFORMATION
SEGMENTS AND GEOGRAPHIC INFORMATION
The segment reporting structure uses the Company's organizational structure as its foundation to reflect how the Company manages the businesses internally, and is organized by geographic regions which provide better socio-political-economic understanding of our business. The Company is organized by six SBUs led by our President and Chief Executive Officer: US, Andes, Brazil, MCAC, Europe, and Asia SBUs. Using the accounting guidance on segment reporting, the Company determined that it has six operating and six reportable segments corresponding to its SBUs.
Corporate and Other — Corporate overhead costs which are not directly associated with the operations of our six reportable segments are included in "Corporate and Other." Also included are certain intercompany charges such as self-insurance premiums which are fully eliminated in consolidation.
The Company uses Adjusted PTC as its primary segment performance measure. Adjusted PTC, a non-GAAP measure, is defined by the Company as pretax income from continuing operations attributable to AES excluding unrealized gains or losses related to derivative transactions, unrealized foreign currency gains or losses, gains or losses due to dispositions and acquisitions of business interests, losses due to impairments and costs due to the early retirement of debt. The Company has concluded that Adjusted PTC best reflects the underlying business performance of the Company and is the most relevant measure considered in the Company's internal evaluation of the financial performance of its segments. Additionally, given its large number of businesses and complexity, the Company concluded that Adjusted PTC is a more transparent measure that better assists investors in determining which businesses have the greatest impact on the Company's results.    
Revenue and Adjusted PTC before intersegment eliminations includes the effect of intercompany transactions with other segments except for interest, charges for certain management fees, and the write-off of intercompany balances, as applicable. All intra-segment activity has been eliminated within the segment. Inter-segment activity has been eliminated within the total consolidated results.
The following tables present financial information by segment for the periods indicated (in millions):
Revenue
Year Ended December 31,
Total Revenue
 
Intersegment
 
External Revenue
2015
 
2014
 
2013
 
2015
 
2014
 
2013
 
2015
 
2014
 
2013
US SBU
$
3,593

 
$
3,826

 
$
3,630

 
$
—

 
$
—

 
$
—

 
$
3,593

 
$
3,826

 
$
3,630

Andes SBU
2,489

 
2,642

 
2,639

 
(10
)
 
(4
)
 
(1
)
 
2,479

 
2,638

 
2,638

Brazil SBU
4,666

 
6,009

 
5,015

 
—

 
—

 
—

 
4,666

 
6,009

 
5,015

MCAC SBU
2,353

 
2,682

 
2,713

 
(2
)
 
(2
)
 
(1
)
 
2,351

 
2,680

 
2,712

Europe SBU
1,191

 
1,439

 
1,347

 
(4
)
 
(6
)
 
—

 
1,187

 
1,433

 
1,347

Asia SBU
684

 
558

 
550

 
—

 
—

 
—

 
684

 
558

 
550

Corporate and Other
31

 
15

 
7

 
(28
)
 
(13
)
 
(8
)
 
3

 
2

 
(1
)
Total Revenue
$
15,007

 
$
17,171

 
$
15,901

 
$
(44
)
 
$
(25
)
 
$
(10
)
 
$
14,963

 
$
17,146

 
$
15,891


Adjusted Pretax Contribution
Year Ended December 31,
Total Adjusted PTC
 
Intersegment
 
External Adjusted PTC
2015
 
2014
 
2013
 
2015
 
2014
 
2013
 
2015
 
2014
 
2013
US SBU
$
360

 
$
445

 
440

 
$
12

 
$
10

 
11

 
$
372

 
$
455

 
$
451

Andes SBU
482

 
421

 
353

 
17

 
6

 
19

 
499

 
427

 
372

Brazil SBU
91

 
242

 
212

 
2

 
3

 
3

 
93

 
245

 
215

MCAC SBU
327

 
352

 
339

 
18

 
26

 
12

 
345

 
378

 
351

Europe SBU
235

 
348

 
345

 
5

 
5

 
7

 
240

 
353

 
352

Asia SBU
96

 
46

 
142

 
3

 
2

 
2

 
99

 
48

 
144

Corporate and Other
(441
)
 
(533
)
 
(624
)
 
(57
)
 
(52
)
 
(54
)
 
(498
)
 
(585
)
 
(678
)
Total Adjusted Pretax Contribution
1,150

 
1,321

 
1,207

 
—

 
—

 
—

 
1,150

 
1,321

 
1,207


Reconciliation to Income from Continuing Operations before Taxes and Equity Earnings of Affiliates:
 
 
Non-GAAP Adjustments:


Unrealized derivative gains
166

 
135

 
57

Unrealized foreign currency losses
(96
)
 
(110
)
 
(41
)
Disposition/acquisition gains
42

 
361

 
30

Impairment losses
(504
)
 
(416
)
 
(588
)
Loss on extinguishment of debt
(183
)
 
(274
)
 
(225
)
Pre-tax contribution
575

 
1,017

 
440

Add: Income from continuing operations before taxes, attributable to noncontrolling interests
652

 
578

 
633

Less: Net equity in earnings of affiliates
105

 
19

 
25

Income from continuing operations before taxes and equity in earnings of affiliates
$
1,122

 
$
1,576

 
$
1,048


Total Assets
 
Depreciation and Amortization
 
Capital Expenditures
Year Ended December 31,
2015
 
2014
 
2013
 
2015
 
2014
 
2013
 
2015
 
2014
 
2013
US SBU
$
9,844

 
$
10,062

 
$
9,952

 
$
443

 
$
450

 
$
440

 
$
861

 
$
534

 
$
426

Andes SBU
8,744

 
7,888

 
7,356

 
175

 
182

 
186

 
949

 
702

 
471

Brazil SBU
6,422

 
8,439

 
8,388

 
185

 
260

 
259

 
299

 
416

 
588

MCAC SBU
4,830

 
4,948

 
5,075

 
155

 
144

 
145

 
201

 
192

 
111

Europe SBU
3,127

 
3,525

 
4,191

 
134

 
154

 
155

 
118

 
228

 
341

Asia SBU
3,197

 
2,972

 
2,810

 
32

 
32

 
33

 
13

 
429

 
576

Assets held-for-sale
96

 
—

 
1,718

 
—

 
(1
)
 
55

 
—

 
13

 
52

Corporate and Other
590

 
1,132

 
921

 
20

 
24

 
21

 
17

 
30

 
14

Total
$
36,850

 
$
38,966

 
$
40,411

 
$
1,144

 
$
1,245

 
$
1,294

 
$
2,458

 
$
2,544

 
$
2,579


Interest Income
 
Interest Expense
Year Ended December 31,
2015
 
2014
 
2013
 
2015
 
2014
 
2013
US SBU
$
—

 
$
—

 
$
—

 
$
262

 
$
285

 
$
290

Andes SBU
77

 
87

 
37

 
154

 
160

 
135

Brazil SBU
299

 
249

 
210

 
349

 
331

 
364

MCAC SBU
30

 
26

 
20

 
179

 
178

 
138

Europe SBU
1

 
1

 
2

 
73

 
98

 
80

Asia SBU
115

 
2

 
6

 
85

 
25

 
30

Corporate and Other
2

 
—

 
—

 
334

 
394

 
445

Total
$
524

 
$
365

 
$
275

 
$
1,436

 
$
1,471

 
$
1,482

 
Investments in and Advances to Affiliates
 
Equity in Earnings (Losses)
Year Ended December 31,
2015
 
2014
 
2013
 
2015
 
2014
 
2013
US SBU
$
1

 
$
1

 
$
1

 
$
—

 
$
—

 
$
—

Andes SBU
345

 
287

 
248

 
83

 
42

 
44

Brazil SBU
—

 
—

 
—

 
—

 
—

 
—

MCAC SBU
—

 
—

 
—

 
—

 
—

 
4

Europe SBU
53

 
54

 
286

 
10

 
(25
)
 
(5
)
Asia SBU
195

 
194

 
186

 
8

 
10

 
10

Corporate and Other
16

 
1

 
289

 
4

 
(8
)
 
(28
)
Total
$
610

 
$
537

 
$
1,010

 
$
105

 
$
19

 
$
25


The table below presents information, by country, about the Company's consolidated operations for each of the three years ended December 31, 2015, 2014, and 2013, and as of December 31, 2015 and 2014 in millions. Revenue is recorded in the country in which it is earned and assets are recorded in the country in which they are located.
 
Revenue
 
Property, Plant & Equipment, net
Year Ended December 31,
2015
 
2014
 
2013
 
2015
 
2014
United States(1)
$
3,597

 
$
3,828

 
$
3,630

 
$
8,028

 
$
7,713

Non-U.S.:


Brazil
4,666

 
6,009

 
5,015

 
3,286

 
4,725

Chile
1,523

 
1,624

 
1,569

 
4,596

 
4,012

El Salvador
736

 
832

 
860

 
318

 
304

Dominican Republic
632

 
802

 
832

 
783

 
702

Colombia
557

 
552

 
523

 
446

 
430

Philippines
406

 
451

 
497

 
736

 
752

Argentina
399

 
463

 
545

 
193

 
222

United Kingdom
396

 
533

 
558

 
191

 
324

Mexico
383

 
434

 
440

 
716

 
733

Bulgaria
382

 
410

 
422

 
1,259

 
1,457

Puerto Rico
302

 
348

 
328

 
599

 
551

Panama
297

 
263

 
250

 
1,028

 
1,030

Jordan
248

 
262

 
142

 
470

 
484

Vietnam(2)
233

 
—

 
—

 
2

 
1,491

Kazakhstan
155

 
161

 
156

 
146

 
206

Sri Lanka
45

 
107

 
53

 
—

 
7

Cameroon(3)
—

 
—

 
—

 
—

 
—

Ukraine(4)
—

 
—

 
—

 
—

 
—

Other Non-U.S. (5)
6

 
67

 
71

 
19

 
8

Total Non-U.S.
11,366

 
13,318

 
12,261

 
14,788

 
17,438

Total
$
14,963

 
$
17,146

 
$
15,891

 
$
22,816

 
$
25,151

(1)
Excludes revenue of $2 million and $23 million for the years ended December 31, 2014 and 2013, respectively, related to Condon and Mid-West Wind, which are reflected as discontinued operations in the accompanying Consolidated Statements of Operations.
(2) 
Property, plant & equipment as of December 31, 2015 includes the impact of adopting ASU No. 2014-05, Service Concession Arrangements, on a modified retrospective basis as of January 1, 2015. See Note 1—General and Summary of Significant Accounting Policies for more information.
(3) 
Excludes revenue of $230 million and $473 million for the years ended December 31, 2014 and 2013, respectively, related to Sonel, which is reflected as discontinued
operations in the accompanying Consolidated Statements of Operations.
(4) 
Excludes revenue of $187 million for the years ended December 31, 2013 related to Kievoblenergo and Rivnooblenergo, which are reflected as discontinued operations in the accompanying Consolidated Statements of Operations.
(5) 
Excludes revenue of $6 million for the years ended December 31, 2013 related to Saurashtra, which is reflected as discontinued operations in the accompanying Consolidated Statements of Operations.

v3.3.1.900
Share-Based Compensation
12 Months Ended
Dec. 31, 2015
Disclosure of Compensation Related Costs, Share-based Payments [Abstract]  
SHARE-BASED COMPENSATION
STOCK OPTIONS — AES grants options to purchase shares of common stock under stock option plans to employees and non-employee directors. Under the terms of the plans, the Company may issue options to purchase shares of the Company's common stock at a price equal to 100% of the market price at the date the option is granted. Stock options are generally granted based upon a percentage of an employee's base salary. Stock options issued under these plans in 2015, 2014 and 2013 have a three-year vesting schedule and vest in one-third increments over the three-year period. The stock options have a contractual term of ten years. At December 31, 2015, approximately 16 million shares were remaining for award under the plans. In all circumstances, stock options granted by AES do not entitle the holder the right, or obligate AES, to settle the stock option in cash or other assets of AES.
The following table presents the weighted average fair value of each option grant and the underlying weighted average assumptions, as of the grant date, using the Black-Scholes option-pricing model:
December 31,
 
2015
 
2014
 
2013
Expected volatility
 
25
%
 
24
%
 
23
%
Expected annual dividend yield
 
3
%
 
1
%
 
1
%
Expected option term (years)
 
7

 
6

 
6

Risk-free interest rate
 
1.86
%
 
1.86
%
 
1.13
%
Fair value at grant date
 
$
2.07

 
$
3.26

 
$
2.23


The Company does not discount the grant date fair values to estimate post-vesting restrictions. Post-vesting restrictions include black-out periods when the employee is not able to exercise stock options based on their potential knowledge of information prior to the release of that information to the public.
The following table summarizes the components of stock-based compensation related to employee stock options recognized in the Company's consolidated financial statements in millions:
December 31,
 
2015
 
2014
 
2013
Pretax compensation expense
 
$
3

 
$
3

 
$
2

Tax benefit
 
(1
)
 
(1
)
 
(1
)
Stock options expense, net of tax
 
$
2

 
$
2

 
$
1

Total intrinsic value of options exercised
 
$
1

 
$
1

 
$
5

Total fair value of options vested
 
3

 
2

 
2

Cash received from the exercise of stock options
 
5

 
3

 
13


No cash was used to settle stock options or compensation cost capitalized as part of the cost of an asset for the years ended December 31, 2015, 2014 and 2013. As of December 31, 2015, $4 million of total unrecognized compensation cost related to stock options is expected to be recognized over a weighted average period of 1.8 years.
A summary of the option activity for the year ended December 31, 2015 follows (number of options in thousands, dollars in millions except per option amounts):
 
 
Options
 
Weighted Average Exercise Price
 
Weighted Average Remaining Contractual Term (in years)
 
Aggregate Intrinsic Value
Outstanding at December 31, 2014
 
7,062

 
$
14.83


Exercised
 
(419
)
 
10.76


Forfeited and expired
 
(1,347
)
 
17.49


Granted
 
1,859

 
11.89


Outstanding at December 31, 2015
 
7,155

 
$
13.81

 
6
 
$
1

Vested and expected to vest at December 31, 2015
 
6,771

 
$
13.88

 
5.8
 
$
1

Eligible for exercise at December 31, 2015
 
4,292

 
$
14.70

 
4.1
 
$
1


The aggregate intrinsic value in the table above represents the total pre-tax intrinsic value (the difference between the Company's closing stock price on the last trading day of 2015 and the exercise price, multiplied by the number of in-the-money options) that would have been received by the option holders had all option holders exercised their options on December 31, 2015. The amount of the aggregate intrinsic value will change based on the fair market value of the Company's stock.
The Company initially recognizes compensation cost on the estimated number of instruments for which the requisite service is expected to be rendered. In 2015, AES has estimated a weighted average forfeiture rate of 15.28% for stock options granted in 2015. This estimate will be revised if subsequent information indicates that the actual number of instruments forfeited is likely to differ from previous estimates. Based on the estimated forfeiture rate, the Company expects to expense $3.3 million on a straight-line basis over a three year period (approximately $1.1 million per year) related to stock options granted during the year ended December 31, 2015.
RESTRICTED STOCK
Restricted Stock Units — The Company issues restricted stock units ("RSUs") under its long-term compensation plan. The RSUs are generally granted based upon a percentage of the participant's base salary. The units have a three-year vesting schedule and vest in one-third increments over the three-year period. Units granted prior to 2011 are required to be held for an additional two years before they can be converted into shares, and thus become transferable. There is no such requirement for units granted in 2011 and afterwards. In all circumstances, restricted stock units granted by AES do not entitle the holder the right, or obligate AES, to settle the restricted stock unit in cash or other assets of AES.
For the years ended December 31, 2015, 2014, and 2013, RSUs issued had a grant date fair value equal to the closing price of the Company's stock on the grant date. The Company does not discount the grant date fair values to reflect any post-vesting restrictions. RSUs granted to employees during the years ended December 31, 2015, 2014, and 2013 had grant date fair values per RSU of $12.03, $14.60 and $11.19, respectively.
The following table summarizes the components of the Company's stock-based compensation related to its employee RSUs recognized in the Company's consolidated financial statements in millions:
December 31,
 
2015
 
2014
 
2013
RSU expense before income tax
 
$
13

 
$
12

 
$
12

Tax benefit
 
(3
)
 
(3
)
 
(3
)
RSU expense, net of tax
 
$
10

 
$
9

 
$
9

Total value of RSUs converted (1)
 
$
16

 
$
25

 
$
10

Total fair value of RSUs vested
 
$
12

 
$
13

 
$
12

(1)
Amount represents fair market value on the date of conversion.
There was no cash used to settle RSUs or compensation cost capitalized as part of the cost of an asset for the years ended December 31, 2015, 2014, and 2013. As of December 31, 2015, $16 million of total unrecognized compensation cost related to RSUs is expected to be recognized over a weighted average period of approximately 1.9 years. There were no modifications to RSU awards during the year ended December 31, 2015.
A summary of the activity of RSUs for the year ended December 31, 2015 follows (number of RSUs in thousands):
 
 
RSUs
 
Weighted Average Grant Date Fair Values
 
Weighted Average Remaining Vesting Term
Nonvested at December 31, 2014
 
1,997

 
$
13.20


Vested
 
(954
)
 
13.01


Forfeited and expired
 
(236
)
 
12.71


Granted
 
1,585

 
12.03


Nonvested at December 31, 2015
 
2,392

 
$
12.55

 
1.7
Vested at December 31, 2015
 
—

 
$
—


Vested and expected to vest at December 31, 2015
 
2,105

 
$
12.55


The Company initially recognizes compensation cost on the estimated number of instruments for which the requisite service is expected to be rendered. In 2015, AES has estimated a weighted average forfeiture rate of 13.53% for RSUs granted in 2015. This estimate will be revised if subsequent information indicates that the actual number of instruments forfeited is likely to differ from previous estimates. Based on the estimated forfeiture rate, the Company expects to expense $16 million on a straight-line basis over a three year period related to RSUs granted during the year ended December 31, 2015.
The table below summarizes the RSUs that vested and were converted during the years ended December 31, 2015, 2014, and 2013 (number of RSUs in thousands):
 
 
2015
 
2014
 
2013
RSUs vested during the year
 
954

 
1,037

 
942

RSUs converted during the year, net of shares withheld for taxes
 
1,238

 
1,734

 
905

Shares withheld for taxes
 
549

 
796

 
407


Performance Stock Units — The Company issues performance stock units ("PSUs") to officers under its long-term compensation plan. PSUs are restricted stock units of which 50% of the units awarded include a market condition and the remaining 50% include a performance condition. Vesting will occur if the applicable continued employment conditions are satisfied and (a) for the units subject to the market condition the Total Stockholder Return ("TSR") on AES common stock exceeds the TSR of the Standard and Poor's 500 Utilities Sector Index over the three-year measurement period beginning on January 1 of the grant year and ending on December 31 of the third year and (b) for the units subject to the performance condition if the Company's actual Adjusted EBITDA meets the performance target over the three-year measurement period beginning on January 1 of the grant year and ending on December 31 of the third year. The market and performance conditions determine the vesting and final share equivalent per PSU and can result in earning an award payout range of 0% to 200%, depending on the achievement. In all circumstances, PSUs granted by AES do not entitle the holder the right, or obligate AES, to settle the restricted stock unit in cash or other assets of AES.
The effect of the market condition on PSUs issued to officers of the Company during 2015 is reflected in the award's fair value on the grant date. The results of the valuation estimated the fair value at $8.22 per share, equating to 69% of the Company's closing stock price on the date of grant. PSUs that included a market condition granted during the year ended December 31, 2015, 2014, and 2013 had a grant date fair value per RSU of $8.22, $15.19 and $13.28, respectively. The fair value of the PSUs with a performance condition had a grant date fair value of $11.89 equal to the closing price of the Company's stock on the grant date. The Company believes that it is probable that the performance condition will be met; this will continue to be evaluated throughout the performance period. If the fair value of the market condition was not applied to PSUs issued to officers, the total grant date fair value of PSUs granted during the year ended December 31, 2015 would have increased by $1.1 million.
Restricted stock units with a market condition awarded to officers of the Company prior to 2011 contained only the market condition measuring the TSR on AES common stock. These units were required to be held for an additional two years subsequent to vesting before they could be converted into shares and become transferable. There is no such requirement for the shares granted during 2011 and afterwards.
The following table summarizes the components of the Company's stock-based compensation related to its PSUs recognized in the Company's consolidated financial statements in millions:
December 31,
 
2015
 
2014
 
2013
PSU expense before income tax
 
$
5

 
$
6

 
$
4

Tax benefit
 
(1
)
 
(2
)
 
(1
)
PSU expense, net of tax
 
$
4


$
4


$
3

Total value of PSUs converted(1)
 
$
1

 
$
4

 
$
—

Total fair value of PSUs vested
 
3

 
1

 
—

(1)
Amount represents fair market value on the date of conversion.
There was no cash used to settle PSUs or compensation cost capitalized as part of the cost of an asset for the years ended December 31, 2015, 2014, and 2013. As of December 31, 2015, $7 million of total unrecognized compensation cost related to PSUs is expected to be recognized over a weighted average period of approximately 1.7 years. There were no modifications to PSU awards during the year ended December 31, 2015.
A summary of the activity of PSUs for the year ended December 31, 2015 follows (number of PSUs in thousands):
 
 
PSUs
 
Weighted Average Grant Date Fair Values
 
Weighted Average Remaining Vesting Term
Nonvested at December 31, 2014
 
1,331

 
$
14.27


Vested
 
(161
)
 
16.73


Forfeited and expired
 
(245
)
 
15.27


Granted
 
626

 
10.06


Nonvested at December 31, 2015
 
1,551

 
$
12.16

 
1.2
Vested at December 31, 2015
 
—

 
$
—


Vested and expected to vest at December 31, 2015
 
1,298

 
11.92


The Company initially recognizes compensation cost on the estimated number of instruments for which the requisite service is expected to be rendered. In 2015, AES has estimated a forfeiture rate of 15.28% for PSUs granted in 2015. This estimate will be revised if subsequent information indicates that the actual number of instruments forfeited is likely to differ from previous estimates. Based on the estimated forfeiture rate, the Company expects to expense $5 million on a straight-line basis over a three year period (approximately $1.8 million per year) related to PSUs granted during the year ended December 31, 2015.
The table below summarizes the PSUs that vested and were converted during the years ended December 31, 2015, 2014, and 2013 (number of PSUs in thousands):
 
 
2015
 
2014
 
2013
PSUs vested during the year
 
161

 
85

 
—

PSUs converted during the year, net of shares withheld for taxes
 
96

 
287

 
—

Shares withheld for taxes
 
65

 
141

 
—


v3.3.1.900
Redeemable Stock of Subsidiaries
12 Months Ended
Dec. 31, 2015
Temporary Equity [Abstract]  
REDEEMABLE STOCK OF SUBSIDIARES
REDEEMABLE STOCK OF SUBSIDIARIES
The following table summarizes the Company's redeemable stock of subsidiaries balances as of the periods indicated:
 
 
December 31,
Redeemable stock of subsidiaries (in millions)
 
2015
 
2014
Additional paid-in capital, IPALCO shares
 
$
377

 
$
—

Book value, IPALCO shares - noncontrolling interest
 
83

 
—

Total fair value of consideration received (1)
 
460

 
—

IPL cumulative preferred stock
 
60

 
60

DPL cumulative preferred stock
 
18

 
18

Total cumulative preferred stock of subsidiaries (2)
 
78

 
78

Total redeemable stock of subsidiaries
 
$
538

 
$
78

(1) See Note 16—Equity for further information on IPALCO equity transactions with noncontrolling interests.
(2) Refer below for further information on outstanding shares of cumulative preferred stock of subsidiaries.
Our subsidiaries IPL and DPL had outstanding shares of cumulative preferred stock of $78 million at December 31, 2015 and 2014.
IPL — IPL had $60 million of cumulative preferred stock outstanding at December 31, 2015 and 2014, which represented five series of preferred stock. The total annual dividend requirements were approximately $3 million at December 31, 2015 and 2014. Certain series of the preferred stock were redeemable solely at the option of the issuer at prices between $100 and $118 per share. Holders of the preferred stock are entitled to elect a majority of IPL's board of directors if IPL has not paid dividends to its preferred stockholders for four consecutive quarters. Based on the preferred stockholders' ability to elect a majority of IPL's board of directors in this circumstance, the redemption of the preferred shares is considered to be not solely within the control of the issuer and the preferred stock is considered temporary equity and presented in the mezzanine level of the Consolidated Balance Sheets in accordance with relevant accounting guidance for noncontrolling interests and redeemable securities.
DPL — DPL had $18 million of cumulative preferred stock outstanding at December 31, 2015 and 2014, which represented three series of preferred stock issued by DP&L, a wholly-owned subsidiary of DPL. The total annual dividend requirements were approximately $1 million at December 31, 2015 and 2014. The DP&L preferred stock may be redeemed at DP&L's option as determined by its board of directors at per-share redemption prices between $101 and $103 per share, plus cumulative preferred dividends. In addition, DP&L's Amended Articles of Incorporation contain provisions that permit preferred stockholders to elect members of the DP&L Board of Directors in the event that cumulative dividends on the preferred stock are in arrears in an aggregate amount equivalent to at least four full quarterly dividends. Based on the preferred stockholders' ability to elect members of DP&L's board of directors in this circumstance, the redemption of the preferred shares is considered to be not solely within the control of the issuer and the preferred stock is considered temporary equity and presented in the mezzanine level of the Consolidated Balance Sheets in accordance with the relevant accounting guidance for noncontrolling interests and redeemable securities.

v3.3.1.900
Other Income and Expense
12 Months Ended
Dec. 31, 2015
Other Income and Expenses [Abstract]  
OTHER INCOME AND EXPENSE
Other Income — Other income generally includes gains on asset sales and liability extinguishments, favorable judgments on contingencies, gains on contract terminations, and other income from miscellaneous transactions. The components are summarized as follows (in millions):
Years Ended December 31,
2015
 
2014
 
2013
Contract termination
$
20

 
$
—

 
$
60

Gain on sale of assets
19

 
68

 
12

Allowance for Funds Used During Construction (US Utilities)
17

 
9

 
6

Contingency reversal
—

 
18

 
10

Gain on extinguishment of tax and other liabilities
—

 
—

 
9

Other
27

 
29

 
28

Total other income
$
83

 
$
124

 
$
125


Other Expense — Other expense generally includes losses on asset sales and dispositions, losses on legal contingencies, and losses from other miscellaneous transactions. The components are summarized as follows (in millions):
Years Ended December 31,
2015
 
2014
 
2013
Loss on sale and disposal of assets
$
48

 
$
47

 
$
51

Legal contingency
9

 
11

 
9

Contract termination
—

 
—

 
7

Other
8

 
10

 
9

Total other expense
$
65

 
$
68

 
$
76


v3.3.1.900
Asset Impairment Expense
12 Months Ended
Dec. 31, 2015
Impairment or Disposal of Tangible Assets Disclosure [Abstract]  
ASSET IMPAIRMENT EXPENSE
Years ended December 31,
 
2015
 
2014
 
2013
 
 
(in millions)
Kilroot
 
$
121

 
$
—

 
$
—

Buffalo Gap III
 
116

 
—

 
—

U.K. Wind
 
37

 
12

 
—

Ebute
 
—

 
67

 
—

East Bend (DP&L)
 
—

 
12

 
—

Beaver Valley
 
—

 
—

 
46

Conesville (DP&L)
 
—

 
—

 
26

Itabo (San Lorenzo)
 
—

 
—

 
16

Other
 
11

 
—

 
7

Total asset impairment expense
 
$
285

 
$
91

 
$
95


Kilroot — During 2015, the Company tested the recoverability of long-lived assets at Kilroot, a coal- and oil-fired plant in the U.K., when the regulator established lower capacity prices for the Irish Single Electricity Market. The Company determined that the carrying amount of the asset group was not recoverable. The Kilroot asset group was determined to have a fair value of $70 million using the income approach. As a result, the Company recognized asset impairment expense of $121 million. Kilroot is reported in the Europe SBU reportable segment.
Buffalo Gap III — During 2015, the Company tested the recoverability of its long-lived assets at Buffalo Gap III, a wind farm in Texas. Impairment indicators were identified based on a decline in forward power curves coupled with the near term expiration of favorable contracted cash flows. The Company determined that the carrying amount was not recoverable. The Buffalo Gap III asset group was determined to have a fair value of $118 million using the income approach. As a result, the Company recognized asset impairment expense of $116 million. Buffalo Gap III is reported in the US SBU reportable segment.
U.K. Wind (Development Projects) — During 2015, the Company decided to no longer pursue two wind projects in the U.K. based on recent regulatory clarifications specific to these projects, resulting in a full impairment. Impairment indicators were also identified at four other wind projects based on their current development status and a reassessment of the likelihood that each project would be pursued given aviation concerns, regulatory changes, economic considerations and other factors. The Company determined that the carrying amounts of each of these asset groups, which totaled $38 million, were not recoverable. In aggregate, the asset groups were determined to have a fair value of $1 million using the market approach and, as a result, the Company recognized asset impairment expense of $37 million. The U.K. Wind (Development Projects) are reported in the Europe SBU reportable segment.
Ebute — During 2014, the Company identified impairment indicators at Ebute in Nigeria, resulting from the continued lack of gas supply, the increased likelihood of selling the asset group before the end of its useful life, and indications about the potential proceeds that could be received from a future sale. The Company determined that the carrying amount of the asset group was not recoverable. The Company recognized asset impairment of $67 million, which represents the difference between the carrying amount of $103 million and fair value less cost to sell of $36 million. In November 2014, the Company completed the sale of its interest in Ebute. See Note 24—Dispositions for additional details. Prior to its sale, Ebute was reported in the Europe SBU reportable segment.
U.K. Wind (Newfield) — During 2014, the Company tested the recoverability of long-lived assets at its Newfield wind development project in the U.K. after their government refused to grant a permit necessary for the project to continue. The Company determined that the carrying amount of the asset group was not recoverable. The Newfield asset group was determined to have no fair value using the income approach. As a result, the Company recognized asset impairment expense of $12 million. U.K. Wind (Newfield) is reported in the Europe SBU reportable segment.
East Bend (DP&L) — During 2014, the Company identified impairment indicators at East Bend, a coal-fired plant in Ohio jointly owned by DP&L, resulting from the increased likelihood that the asset group would be disposed prior to the end of its useful life. The Company determined that the carrying amount of the asset group was not recoverable. The East Bend asset group was determined to have a fair value of $2 million using the market approach, and the Company recognized asset impairment expense of $12 million. The Company's interest in East Bend was sold in December 2014. Prior to its sale, East Bend was reported in the US SBU reportable segment.
Beaver Valley — During 2013, Beaver Valley, a wholly-owned coal-fired plant in Pennsylvania, entered into an agreement to early terminate its PPA with the offtaker in exchange for a lump-sum payment of $60 million. The termination of the PPA resulted in a significant reduction in the future cash flows of the asset group and was considered an impairment indicator. The carrying amount of the asset group was not recoverable. The carrying amount of the asset group exceeded the fair value of the asset group, resulting in asset impairment expense of $46 million. Beaver Valley is reported in the US SBU reportable segment.
Conesville (DP&L) — During 2013, the Company tested the recoverability of long-lived assets at Conesville, a coal-fired plant in Ohio jointly-owned by DP&L. Gradual decreases in power prices as well as lower estimates of future capacity prices in conjunction with the DP&L reporting unit failing Step 1 of the annual goodwill impairment test were determined to be impairment indicators. The Company performed a long-lived asset impairment test and determined that the carrying amount of the asset group was not recoverable. The Conesville asset group was determined to have zero fair value using discounted cash flows under the income approach. As a result, the Company recognized asset impairment expense of $26 million. Conesville is reported in the US SBU reportable segment.
Itabo (San Lorenzo) — During 2013, the Company tested the recoverability of long-lived assets at San Lorenzo, a LNG fueled plant of Itabo. Itabo was informed by Super-Intendencia de Electridad ("SIE"), the system regulator in the Dominican Republic, that it would not receive capacity revenue going forward. This communication in combination with current adverse market conditions were determined to be an impairment indicator. The Company performed a long-lived asset impairment test considering different scenarios and determined that, based on undiscounted cash flows, the carrying amount of San Lorenzo was not recoverable. The fair value of San Lorenzo was determined using the market approach based on a broker quote and it was determined that its carrying amount of $23 million exceeded the estimated fair value of $7 million. As a result, the Company recognized asset impairment expense of $16 million. Itabo is reported in the MCAC SBU reportable segment.

v3.3.1.900
Income Taxes
12 Months Ended
Dec. 31, 2015
Income Tax Disclosure [Abstract]  
INCOME TAXES
INCOME TAXES
Income Tax Provision — The next table summarizes the expense for income taxes on continuing operations in millions for the periods indicated:
December 31,
 
2015
 
2014
 
2013
Federal —
Current
$
9

 
$
—

 
$
(28
)
 
Deferred
(56
)
 
(121
)
 
(110
)
State —
Current
1

 
1

 
1

 
Deferred
(5
)
 
1

 
1

Foreign —
Current
505

 
457

 
509

 
Deferred
11

 
81

 
(30
)
Total
 
$
465

 
$
419

 
$
343


Effective and Statutory Rate Reconciliation — The following table summarizes a reconciliation of the U.S. statutory federal income tax rate to the Company's effective tax rate, as a percentage of income from continuing operations before taxes for the periods indicated:
December 31,
 
2015
 
2014
 
2013
Statutory Federal tax rate
 
35
 %
 
35
 %
 
35
 %
State taxes, net of Federal tax benefit
 
(5
)%
 
(1
)%
 
(3
)%
Taxes on foreign earnings
 
3
 %
 
(14
)%
 
(4
)%
Valuation allowance
 
(5
)%
 
(1
)%
 
—
 %
Uncertain tax positions
 
—
 %
 
—
 %
 
(5
)%
Bad debt deduction
 
—
 %
 
—
 %
 
(3
)%
Change in tax law
 
—
 %
 
4
 %
 
(1
)%
Goodwill impairment
 
10
 %
 
4
 %
 
12
 %
Other—net
 
3
 %
 
—
 %
 
2
 %
Effective tax rate
 
41
 %
 
27
 %
 
33
 %

Included in the favorable (14)% 2014 taxes on foreign earnings percentage above is approximately (8)% related to the sale of approximately 45% of the Company's interest in Masin AES Pte Ltd., which owns the Company's interests in the Philippines, and the sale of the Company's interests in four U.K. wind projects. Neither of these transactions gave rise to income tax expense.
Income Tax Receivables and Payables — The current income taxes receivable and payable are included in Other Current Assets and Accrued and Other Liabilities, respectively, on the accompanying Consolidated Balance Sheets. The noncurrent income taxes receivable and payable are included in Other Noncurrent Assets and Other Noncurrent Liabilities, respectively, on the accompanying Consolidated Balance Sheets. The next table summarizes the income taxes receivable and payable in millions as of December 31, 2015 and 2014:
 
 
2015
 
2014
Income taxes receivable—current
 
$
167

 
$
217

Total income taxes receivable
 
$
167

 
$
217

Income taxes payable—current
 
$
264

 
$
299

Income taxes payable—noncurrent
 
35

 
2

Total income taxes payable
 
$
299

 
$
301


Deferred Income Taxes — Deferred income taxes reflect the net tax effects of (a) temporary differences between the carrying amounts of assets and liabilities for financial reporting purposes and the amounts used for income tax purposes and (b) operating loss and tax credit carryforwards. These items are stated at the enacted tax rates that are expected to be in effect when taxes are actually paid or recovered.
As of December 31, 2015, the Company had federal net operating loss carryforwards for tax purposes of approximately $3.5 billion expiring in years 2021 to 2034. Approximately $87 million of the net operating loss carryforward related to stock option deductions will be recognized in additional paid-in capital when realized. The Company also had federal general business tax credit carryforwards of approximately $18 million expiring primarily from 2021 to 2035, and federal alternative minimum tax credits of approximately $5 million that carry forward without expiration. The Company had state net operating loss carryforwards as of December 31, 2015 of approximately $8.4 billion expiring in years 2016 to 2035. As of December 31, 2015, the Company had foreign net operating loss carryforwards of approximately $3.5 billion that expire at various times beginning in 2016 and some of which carry forward without expiration, and tax credits available in foreign jurisdictions of approximately $32 million, $24 million of which expire in 2021 and $8 million of which carryforward without expiration.
Valuation allowances decreased $103 million during 2015 to $894 million at December 31, 2015. This net decrease was primarily the result of foreign exchange losses and valuation allowance releases at certain of our Brazil and Vietnam subsidiaries.
Valuation allowances decreased $93 million during 2014 to $997 million at December 31, 2014. This net decrease was primarily the result of valuation allowance activity at certain of our Brazil subsidiaries and the release of valuation allowance against U.S. capital loss carryforwards.
The Company believes that it is more likely than not that the net deferred tax assets as shown below will be realized when future taxable income is generated through the reversal of existing taxable temporary differences and income that is expected to be generated by businesses that have long-term contracts or a history of generating taxable income. The Company continues to monitor the utilization of its deferred tax asset for its U.S. consolidated net operating loss carryforward. Although management believes it is more likely than not that this deferred tax asset will be realized through generation of sufficient taxable income prior to expiration of the loss carryforwards, such realization is not assured.
The following table summarizes the deferred tax assets and liabilities in millions, as of December 31, 2015 and 2014:
 
 
2015
 
2014
Differences between book and tax basis of property
 
$
(2,240
)
 
$
(2,364
)
Other taxable temporary differences
 
(299
)
 
(302
)
Total deferred tax liability
 
(2,539
)
 
(2,666
)
Operating loss carryforwards
 
2,206

 
2,224

Capital loss carryforwards
 
66

 
137

Bad debt and other book provisions
 
191

 
221

Retirement costs
 
149

 
275

Tax credit carryforwards
 
55

 
58

Other deductible temporary differences
 
219

 
363

Total gross deferred tax asset
 
2,886

 
3,278

Less: valuation allowance
 
(894
)
 
(997
)
Total net deferred tax asset
 
1,992

 
2,281

Net deferred tax (liability)
 
$
(547
)
 
$
(385
)

The Company considers undistributed earnings of certain foreign subsidiaries to be indefinitely reinvested outside of the U.S. and, accordingly, no U.S. deferred taxes have been recorded with respect to such earnings in accordance with the relevant accounting guidance for income taxes. Should the earnings be remitted as dividends, the Company may be subject to additional U.S. taxes, net of allowable foreign tax credits. It is not practicable to estimate the amount of any additional taxes which may be payable on the undistributed earnings.
Income from operations in certain countries is subject to reduced tax rates as a result of satisfying specific commitments regarding employment and capital investment. The Company's income tax benefits related to the tax status of these operations are estimated to be $21 million, $38 million and $70 million for the years ended December 31, 2015, 2014 and 2013, respectively. The per share effect of these benefits after noncontrolling interests was $0.02, $0.04 and $0.09 for the years ended December 31, 2015, 2014 and 2013, respectively.
The Company's business in Vietnam began commercial operations in 2015. As part of its power purchase contract with the Vietnam government, the business will be subject to the following reduced income tax rates: 0% for four years, followed by 5% for nine years, followed by 10% for the remaining life of the contract term. See Item 1.—Business—Our Organization and Segments for additional information regarding the power purchase contract.
The benefit related to our operations in Vietnam is estimated to be $8 million for the year ended December 31, 2015. The per share effect of these benefits after noncontrolling interest was $0.01 for the year ended December 31, 2015.
The following table summarizes the income (loss) from continuing operations, before income taxes, net equity in earnings of affiliates and noncontrolling interests in millions, for the years ended December 31, 2015, 2014 and 2013:
 
 
2015
 
2014
 
2013
U.S.
 
$
(612
)
 
$
(560
)
 
$
(575
)
Non-U.S.
 
1,734

 
2,136

 
1,623

Total
 
$
1,122

 
$
1,576

 
$
1,048


Uncertain Tax Positions — Uncertain tax positions have been classified as noncurrent income tax liabilities unless expected to be paid in one year. The Company's policy for interest and penalties related to income tax exposures is to recognize interest and penalties as a component of the provision for income taxes in the Consolidated Statements of Operations.
As of December 31, 2015 and 2014, the total amount of gross accrued income tax related interest included in the Consolidated Balance Sheets was $8 million and $14 million, respectively. The total amount of gross accrued income tax related penalties included in the Consolidated Balance Sheets as of December 31, 2015 and 2014 was $0 million and $1 million, respectively.
The total expense (benefit) for interest related to unrecognized tax benefits for the years ended December 31, 2015, 2014 and 2013 amounted to $0 million, $3 million and $(4) million, respectively. For the years ended December 31, 2015, 2014 and 2013, the total expense (benefit) for penalties related to unrecognized tax benefits amounted to $0 million, $0 million and $(3) million, respectively.
We are potentially subject to income tax audits in numerous jurisdictions in the U.S. and internationally until the applicable statute of limitations expires. Tax audits by their nature are often complex and can require several years to complete. The following is a summary of tax years potentially subject to examination in the significant tax and business jurisdictions in which we operate:
Jurisdiction
 
Tax Years Subject to Examination
Argentina
 
2009-2015
Brazil
 
2010-2015
Chile
 
2012-2015
Colombia
 
2013-2015
Dominican Republic
 
2012-2015
El Salvador
 
2012-2015
Netherlands
 
2013-2015
Philippines
 
2012-2015
United Kingdom
 
2010-2015
United States (Federal)
 
2011-2015

As of December 31, 2015, 2014 and 2013, the total amount of unrecognized tax benefits was $373 million, $395 million and $392 million, respectively. The total amount of unrecognized tax benefits that would benefit the effective tax rate as of December 31, 2015, 2014 and 2013 is $343 million, $366 million and $360 million, respectively, of which $24 million, $24 million and $26 million, respectively, would be in the form of tax attributes that would warrant a full valuation allowance.
The total amount of unrecognized tax benefits anticipated to result in a net decrease to unrecognized tax benefits within 12 months of December 31, 2015 is estimated to be between $15 million and $25 million, primarily relating to statute of limitation lapses and tax exam settlements.
Next is a reconciliation of the beginning and ending amounts of unrecognized tax benefits in millions for the periods indicated:
December 31,
 
2015
 
2014
 
2013
Balance at January 1
 
$
395

 
$
392

 
$
475

Additions for current year tax positions
 
6

 
8

 
7

Additions for tax positions of prior years
 
12

 
14

 
10

Reductions for tax positions of prior years
 
(7
)
 
(2
)
 
(3
)
Effects of foreign currency translation
 
(7
)
 
(3
)
 
—

Settlements
 
(19
)
 
(2
)
 
(65
)
Lapse of statute of limitations
 
(7
)
 
(12
)
 
(32
)
Balance at December 31
 
$
373

 
$
395

 
$
392


The Company and certain of its subsidiaries are currently under examination by the relevant taxing authorities for various tax years. The Company regularly assesses the potential outcome of these examinations in each of the taxing jurisdictions when determining the adequacy of the amount of unrecognized tax benefit recorded. While it is often difficult to predict the final outcome or the timing of resolution of any particular uncertain tax position, we believe we have appropriately accrued for our uncertain tax benefits. However, audit outcomes and the timing of audit settlements and future events that would impact our previously recorded unrecognized tax benefits and the range of anticipated increases or decreases in unrecognized tax benefits are subject to significant uncertainty. It is possible that the ultimate outcome of current or future examinations may exceed our provision for current unrecognized tax benefits in amounts that could be material, but cannot be estimated as of December 31, 2015. Our effective tax rate and net income in any given future period could therefore be materially impacted.

v3.3.1.900
Discontinued Operations and Held-For-Sale Businesses
12 Months Ended
Dec. 31, 2015
Discontinued Operations and Disposal Groups [Abstract]  
DISCONTINUED OPERATIONS AND HELD-FOR-SALE BUSINESSES
DISCONTINUED OPERATIONS
As discussed in Note 1—General and Summary of Significant Accounting Policies, effective July 1, 2014, the Company prospectively adopted ASU No. 2014-08. There have been no businesses classified as discontinued operations subsequent to this ASU adoption. Discontinued operations prior to adoption of ASU No. 2014-08 include the results of the following businesses:
•
Cameroon (sold in June 2014)
•
Saurashtra (sold in February 2014)
•
U.S. wind projects (sold in January 2014)
•
Poland wind projects (sold in November 2013)
•
Ukraine utilities (sold in April 2013)
The following table summarizes revenue, income from operations, income tax expense, and impairment and loss on disposal of all discontinued operations prior to the adoption of ASU No. 2014-08 for the periods indicated (in millions):
Years Ended December 31,
2014
 
2013
Revenue
$
233

 
$
689

Income (loss) from operations of discontinued businesses, before income tax
$
50

 
$
(3
)
Income tax expense
(23
)
 
(24
)
Income (loss) from operations of discontinued businesses, after income tax
$
27

 
$
(27
)
Net loss from disposal and impairments of discontinued businesses, after income tax
$
(56
)
 
$
(152
)

Cameroon — In September 2013, the Company executed agreements for the sale of its 56% equity interests in three businesses in Cameroon: Sonel, an integrated utility, Kribi, a gas and light fuel oil plant, and Dibamba, a heavy fuel oil plant. The sale was completed in June 2014. Net proceeds from the sale transaction were $200 million, with $156 million received and non-contingent consideration of $44 million to be received in 2016. Between meeting the held-for-sale criteria in September 2013 and completing the sale in June 2014, the Company recognized impairments of $101 million and an additional loss on sale of $7 million. These businesses were previously reported in the Europe SBU reportable segment.
Saurashtra — In October 2013, the Company executed an agreement for the sale of Saurashtra, a wind project in India. The sale transaction was completed in February 2014 and net proceeds of $8 million were received. Saurashtra was previously reported in the Asia SBU reportable segment.
U.S. wind projects — In November 2013, the Company executed an agreement for the sale of its 100% membership interests in three wind projects: Condon in California, Lake Benton I in Minnesota and Storm Lake II in Iowa. Upon meeting the held-for-sale criteria for these three projects, the Company recognized impairment expense of $47 million (of which $7 million was attributable to noncontrolling interests held by tax equity partners) representing the difference between their aggregate carrying amount of $77 million and the fair value less costs to sell of $30 million. The sale transaction closed in January 2014 and net proceeds of $27 million were received. These businesses were previously reported in the US SBU reportable segment.
Under the terms of the sale agreement, the buyer was provided an option to purchase the Company's 100% interest in Armenia Mountain, a wind project in Pennsylvania at a fixed price of $75 million. Approximately $3 million of the $27 million net proceeds was deferred and allocated to this option. The buyer exercised the option in March 2015 and the sale was completed in July 2015. See Note 24—Dispositions and Held-For-Sale Businesses for further information.
Poland wind projects — In November 2013, the Company completed the sale of Poland Wind, a wholly-owned subsidiary with ownership interests ranging between 61%–89% in ten wind development projects. Net proceeds from the sale transaction were $7 million and a loss on disposal of $2 million was recognized. In the third quarter of 2013, the Company recognized impairments of $65 million on these projects when they were classified as held and used. Poland Wind was previously reported in the Europe SBU reportable segment.
Ukraine utilities — In April 2013, the Company completed the sale of its two utility businesses in Ukraine and received net proceeds of $113 million. The Company sold its 89.1% equity interest in Kyivoblenergo and its 84.6% equity interest in Rivneoblenergo. The Company recognized net impairments of $38 million during 2013. These businesses were previously reported in the Europe SBU reportable segment.
Held-For-Sale Businesses
DPLER — In December 2015, the Company executed an agreement for the sale of its ownership interest in DPLER, a competitive retail marketer selling electricity to customers in Ohio. Accordingly, DPLER has been classified as held-for-sale as of December 31, 2015, but does not meet the criteria to be reported as a discontinued operation. DPLER's results are therefore reflected within continuing operations in the Consolidated Statements of Operations. DPLER's pretax income attributable to AES was $11 million, $(129) million and $6 million for the years ended December 31, 2015, 2014 and 2013, respectively. The sale of DPLER was completed on January 1, 2016 and proceeds of $76 million were received on December 31, 2015. The proceeds were classified as restricted cash with a corresponding amount recorded in accrued and other liabilities in the Consolidated Balance Sheet as of December 31, 2015. DPLER is reported in the US SBU reportable segment.
Kelanitissa — In August 2015, the Company executed an agreement for the sale of its 90% ownership interest in Kelanitissa, a diesel-fired generation plant in Sri Lanka. Accordingly, Kelanitissa has been classified as held-for-sale as of December 31, 2015, but does not meet the criteria to be reported as a discontinued operation. Kelanitissa's results are therefore reflected within continuing operations in the Consolidated Statements of Operations. Kelanitissa's pretax income (loss) attributable to AES was $(7) million, $1 million, and $16 million for the years ended December 31, 2015, 2014 and 2013, respectively. The sale of Kelanitissa was completed on January 27, 2016 and proceeds of $18 million were received. Kelanitissa is reported in the Asia SBU reportable segment.

v3.3.1.900
Acquisitions and Dispositions
12 Months Ended
Dec. 31, 2015
Business Combinations [Abstract]  
ACQUISITIONS AND DISPOSITIONS
Dispositions
Armenia Mountain — On July 1, 2015, the Company completed the sale of its interest in Armenia Mountain, a wind project in Pennsylvania. Net proceeds from the sale were $64 million and the Company recognized a pretax gain on sale of $22 million. As Armenia Mountain does not meet the criteria to be reported as a discontinued operation, its results are reflected within continuing operations in the Consolidated Statements of Operations. Excluding the gain on sale, Armenia Mountain's pretax income attributable to AES was $6 million, $7 million, and $4 million for the years ended December 31, 2015, 2014, and 2013, respectively. Prior to its sale, Armenia Mountain was reported in the US SBU reportable segment. See Note 23 — Discontinued Operations for more information about transactions preceding the sale.
Ebute — On November 20, 2014, the Company completed the sale of its interest in Ebute, which included its 95% interest in AES Nigeria Barge Limited and its 100% interest in AES Nigeria Barge Operations Limited. Proceeds from the sale were $22 million and the Company recognized a $6 million loss on the sale in the fourth quarter of 2014. As Ebute does not meet the criteria to be reported as a discontinued operation, its results are reflected within continuing operations in the Consolidated Statements of Operations. Excluding the loss on sale, Ebute's pretax (loss) attributable to AES was $(27) million and $(29) million for the years ended December 31, 2014 and 2013, respectively. Prior to its sale, Ebute was reported in the Europe SBU reportable segment.
U.K. Wind (Operating Projects) — On August 22, 2014, the Company sold 100% of its interests in four operating wind projects located in the U.K.. Total net proceeds from the sale were $158 million and the Company recognized a pretax gain on sale of $78 million. As these wind projects do not meet the criteria to be reported as discontinued operations, their results are reflected within continuing operations in the Consolidated Statements of Operations. Excluding the gain on sale, the pretax income (loss) attributable to AES for these disposed projects was $(18) million and $3 million for the years ended December 31, 2014 and 2013, respectively. Prior to the sale, U.K. Wind (Operating Projects) were reported in the Europe SBU reportable segment.
Cartagena — On April 26, 2013, the Company sold its remaining interest in Cartagena, a gas-fired generation business in Spain, upon the exercise of a purchase option included in the 2012 sale agreement where the Company sold its majority interest in the business. Net proceeds from the exercise of the option were approximately $24 million and the Company recognized a pretax gain of $20 million during the second quarter of 2013. Prior to its sale, Cartagena was reported in the Europe SBU reportable segment.
ACQUISITIONS
Main Street Power — On February 18, 2015, the Company completed the acquisition of 100% of the common stock of Main Street Power Company, Inc. for approximately $25 million, pursuant to the terms and conditions of a definitive agreement dated January 24, 2015. The purchase consideration was composed of $20 million cash and the fair value of earn-out payments of $5 million. At December 31, 2015, the assets acquired (including $4 million cash) and liabilities assumed at the acquisition date were recorded at fair value based on the final purchase price allocation, which resulted in the recognition of $16 million of goodwill. Subsequent changes to the fair value of earn-out payments will be reflected in earnings.

v3.3.1.900
Acquisitions Acquisitions
12 Months Ended
Dec. 31, 2015
Business Combinations [Abstract]  
Mergers, Acquisitions and Dispositions Disclosures [Text Block]
Dispositions
Armenia Mountain — On July 1, 2015, the Company completed the sale of its interest in Armenia Mountain, a wind project in Pennsylvania. Net proceeds from the sale were $64 million and the Company recognized a pretax gain on sale of $22 million. As Armenia Mountain does not meet the criteria to be reported as a discontinued operation, its results are reflected within continuing operations in the Consolidated Statements of Operations. Excluding the gain on sale, Armenia Mountain's pretax income attributable to AES was $6 million, $7 million, and $4 million for the years ended December 31, 2015, 2014, and 2013, respectively. Prior to its sale, Armenia Mountain was reported in the US SBU reportable segment. See Note 23 — Discontinued Operations for more information about transactions preceding the sale.
Ebute — On November 20, 2014, the Company completed the sale of its interest in Ebute, which included its 95% interest in AES Nigeria Barge Limited and its 100% interest in AES Nigeria Barge Operations Limited. Proceeds from the sale were $22 million and the Company recognized a $6 million loss on the sale in the fourth quarter of 2014. As Ebute does not meet the criteria to be reported as a discontinued operation, its results are reflected within continuing operations in the Consolidated Statements of Operations. Excluding the loss on sale, Ebute's pretax (loss) attributable to AES was $(27) million and $(29) million for the years ended December 31, 2014 and 2013, respectively. Prior to its sale, Ebute was reported in the Europe SBU reportable segment.
U.K. Wind (Operating Projects) — On August 22, 2014, the Company sold 100% of its interests in four operating wind projects located in the U.K.. Total net proceeds from the sale were $158 million and the Company recognized a pretax gain on sale of $78 million. As these wind projects do not meet the criteria to be reported as discontinued operations, their results are reflected within continuing operations in the Consolidated Statements of Operations. Excluding the gain on sale, the pretax income (loss) attributable to AES for these disposed projects was $(18) million and $3 million for the years ended December 31, 2014 and 2013, respectively. Prior to the sale, U.K. Wind (Operating Projects) were reported in the Europe SBU reportable segment.
Cartagena — On April 26, 2013, the Company sold its remaining interest in Cartagena, a gas-fired generation business in Spain, upon the exercise of a purchase option included in the 2012 sale agreement where the Company sold its majority interest in the business. Net proceeds from the exercise of the option were approximately $24 million and the Company recognized a pretax gain of $20 million during the second quarter of 2013. Prior to its sale, Cartagena was reported in the Europe SBU reportable segment.
ACQUISITIONS
Main Street Power — On February 18, 2015, the Company completed the acquisition of 100% of the common stock of Main Street Power Company, Inc. for approximately $25 million, pursuant to the terms and conditions of a definitive agreement dated January 24, 2015. The purchase consideration was composed of $20 million cash and the fair value of earn-out payments of $5 million. At December 31, 2015, the assets acquired (including $4 million cash) and liabilities assumed at the acquisition date were recorded at fair value based on the final purchase price allocation, which resulted in the recognition of $16 million of goodwill. Subsequent changes to the fair value of earn-out payments will be reflected in earnings.

v3.3.1.900
Earnings Per Share
12 Months Ended
Dec. 31, 2015
Earnings Per Share [Abstract]  
EARNINGS PER SHARE
EARNINGS PER SHARE
Basic and diluted earnings per share are based on the weighted-average number of shares of common stock and potential common stock outstanding during the period. Potential common stock, for purposes of determining diluted earnings per share, includes the effects of dilutive restricted stock units, stock options and convertible securities. The effect of such potential common stock is computed using the treasury stock method or the if-converted method, as applicable.
The following table is a reconciliation of the numerator and denominator of the basic and diluted earnings per share computation for income from continuing operations for the years ended December 31, 2015, 2014 and 2013, where income represents the numerator and weighted-average shares represent the denominator. Values are in millions except per share data:
Year Ended December 31,
2015
 
2014
 
2013
 
Income
 
Shares
 
$ per Share
 
Income
 
Shares
 
$ per Share
 
Income
 
Shares
 
$ per Share
BASIC EARNINGS PER SHARE


Income from continuing operations attributable to The AES Corporation common stockholders
$
306

 
687

 
$
0.45

 
$
789

 
720

 
$
1.10

 
$
284

 
743

 
$
0.38

EFFECT OF DILUTIVE SECURITIES


Stock options
—

 
—

 
—

 
—

 
1

 
—

 
—

 
1

 
—

Restricted stock units
—

 
2

 
(0.01
)
 
—

 
3

 
(0.01
)
 
—

 
4

 
—

DILUTED EARNINGS PER SHARE
$
306

 
689

 
$
0.44

 
$
789

 
724

 
$
1.09

 
$
284

 
748

 
$
0.38


The calculation of diluted earnings per share excluded 8 million, 6 million and 7 million stock awards outstanding for the years ended December 31, 2015, 2014 and 2013, respectively, that could potentially dilute basic earnings per share in the future. Additionally, for the years ended December 31, 2015, 2014 and 2013, all 15 million convertible debentures were omitted from the earnings per share calculation. The stock awards and convertible debentures were excluded from the calculation because they were anti-dilutive.

v3.3.1.900
Risks and Uncertainties
12 Months Ended
Dec. 31, 2015
Risks and Uncertainties [Abstract]  
RISKS AND UNCERTAINTIES
AES is a diversified power generation and utility company organized into six market-oriented SBUs. See additional discussion of the Company's principal markets in Note 17—Segment and Geographic Information. Within our six SBUs, we have two primary lines of business: Generation and Utilities. The Generation line of business uses a wide range of fuels and technologies to generate electricity such as coal, gas, hydro, wind, solar and biomass. Our Utilities business is comprised of businesses that transmit, distribute, and in certain circumstances, generate power. In addition, the Company has operations in the renewables area. These efforts include projects primarily in wind and solar.
Operating and Economic Risks — The Company operates in several developing economies where macroeconomic conditions are usually more volatile than developed economies. Deteriorating market conditions often expose the Company to the risk of decreased earnings and cash flows due to, among other factors, adverse fluctuations in the commodities and foreign currency spot markets. Additionally, credit markets around the globe continue to tighten their standards, which could impact our ability to finance growth projects through access to capital markets. Currently, the Company has a below-investment grade rating from Standard & Poor's of BB-. This could affect the Company's ability to finance new and/or existing development projects at competitive interest rates. As of December 31, 2015, the Company had $1.3 billion of unrestricted cash and cash equivalents.
During 2015, 76% of our revenue was generated outside the U.S. and a significant portion of our international operations is conducted in developing countries. We continue to invest in several developing countries to expand our existing platform and operations. International operations, particularly the operation, financing and development of projects in developing countries, entail significant risks and uncertainties, including, without limitation:
•
economic, social and political instability in any particular country or region;
•
inability to economically hedge energy prices;
•
volatility in commodity prices;
•
adverse changes in currency exchange rates;
•
government restrictions on converting currencies or repatriating funds;
•
unexpected changes in foreign laws, regulatory framework, or in trade, monetary or fiscal policies;
•
high inflation and monetary fluctuations;
•
restrictions on imports of coal, oil, gas or other raw materials required by our generation businesses to operate;
•
threatened or consummated expropriation or nationalization of our assets by foreign governments;
•
unwillingness of governments, government agencies, similar organizations or other counterparties to honor their commitments;
•
unwillingness of governments, government agencies, courts or similar bodies to enforce contracts that are economically advantageous to subsidiaries of the Company and economically unfavorable to counterparties, against such counterparties, whether such counterparties are governments or private parties;
•
inability to obtain access to fair and equitable political, regulatory, administrative and legal systems;
•
adverse changes in government tax policy;
•
difficulties in enforcing our contractual rights, enforcing judgments, or obtaining a just result in local jurisdictions; and
•
potentially adverse tax consequences of operating in multiple jurisdictions.
Any of these factors, individually or in combination with others, could materially and adversely affect our business, results of operations and financial condition. In addition, our Latin American operations experience volatility in revenue and earnings which have caused and are expected to cause significant volatility in our results of operations and cash flows. The volatility is caused by regulatory and economic difficulties, political instability, indexation of certain PPAs to fuel prices, and currency fluctuations being experienced in many of these countries; particularly in Argentina, where $124 million in net foreign currency transaction gains were recognized in 2015 primarily from foreign currency derivatives related to government receivables. This volatility reduces the predictability and enhances the uncertainty associated with cash flows from these businesses.
Our inability to predict, influence or respond appropriately to changes in law or regulatory schemes, including any inability to obtain reasonable increases in tariffs or tariff adjustments for increased expenses, could adversely impact our results of operations or our ability to meet publicly announced projections or analysts' expectations. Furthermore, changes in laws or regulations or changes in the application or interpretation of regulatory provisions in jurisdictions where we operate, particularly our Utility businesses where electricity tariffs are subject to regulatory review or approval, could adversely affect our business, including, but not limited to:
•
changes in the determination, definition or classification of costs to be included as reimbursable or pass-through costs;
•
changes in the definition or determination of controllable or noncontrollable costs;
•
adverse changes in tax law;
•
changes in the definition of events which may or may not qualify as changes in economic equilibrium;
•
changes in the timing of tariff increases;
•
other changes in the regulatory determinations under the relevant concessions; or
•
changes in environmental regulations, including regulations relating to GHG emissions in any of our businesses.
Any of the above events may result in lower margins for the affected businesses, which can adversely affect our results of operations.
Foreign Currency Risks — AES operates businesses in many foreign countries and such operations could be impacted by significant fluctuations in foreign currency exchange rates. Fluctuations in currency exchange rate between U.S. Dollar and the following currencies could create significant fluctuations to earnings and cash flows: the Argentine peso, the Brazilian real, the Dominican Republic peso, the Euro, the Chilean peso, the Colombian peso, the Philippine peso and the Kazakhstan tenge.
Argentina — In December 2015, the Argentine government lifted foreign currency controls, which resulted in a depreciation of the Argentine peso against the US dollar by approximately 30%. Over the course of 2015, the Argentinean Peso devalued by approximately 50% against the US dollar. Our businesses in Argentina are dependent on the solvency of the Argentine government with which we have long-term receivables. See Note 7—Financing Receivables for further information on the long-term receivables. Further weakening of the Argentine Peso and local economic activity could cause significant volatility in our results of operations, cash flows, and the value of our assets.
Concentrations — Due to the geographical diversity of its operations, the Company does not have any significant concentration of customers or sources of fuel supply. Several of the Company's generation businesses rely on PPAs with one or a limited number of customers for the majority of, and in some cases all of, the relevant businesses' output over the term of the PPAs. However, no single customer accounted for 10% or more of total revenue in 2015, 2014 or 2013.
The cash flows and results of operations of our businesses depend on the credit quality of their customers and the continued ability of their customers and suppliers to meet their obligations under PPAs and fuel supply agreements. If a substantial portion of the Company's long-term PPAs and/or fuel supply were modified or terminated, the Company would be adversely affected to the extent that it would be unable to replace such contracts at equally favorable terms.
Bulgaria — Maritza, the Company's generation facility in Bulgaria, has experienced ongoing delays in the collection of outstanding receivables as a result of liquidity issues faced by our offtaker, NEK. As of December 31, 2015, Maritza's outstanding accounts receivable were $351 million, of which $307 million were overdue. No allowance has been recognized on the receivables as the Company continues to assert that collection is probable.
The Bulgarian government elected in 2014 has undertaken an initiative to reform its energy sector, which is necessary to restore NEK's liquidity. NEK's credit rating was downgraded and its transmission license was revoked by the Bulgarian Regulator, which are events of default under the PPA and triggered additional events of default by Maritza under the project debt agreements.
Although Maritza continued to collect overdue receivables throughout 2015, collections continue to be at risk, which could result in an allowance to be recorded against the remaining receivables and exacerbate liquidity problems at Maritza if the situation were to deteriorate significantly.

v3.3.1.900
Related Party Transactions
12 Months Ended
Dec. 31, 2015
Related Party Transactions [Abstract]  
RELATED PARTY TRANSACTIONS
Certain of our businesses in Panama, the Dominican Republic and Kazakhstan are partially owned by governments either directly or through state-owned institutions. In the ordinary course of business, these businesses enter into energy purchase and sale transactions, and transmission agreements with other state-owned institutions which are controlled by such governments. At two of our generation businesses in Mexico, the offtakers exercise significant influence, but not control, through representation on these businesses' Boards of Directors. These offtakers are also required to hold a nominal ownership interest in such businesses. In Chile, we provide capacity and energy under contractual arrangements to our investment which is accounted for under the equity method of accounting. Additionally, the Company provides certain support and management services to several of its affiliates under various agreements.
The Company's Consolidated Statements of Operations included the following transactions with related parties in millions for the periods indicated:
Years Ended December 31,
2015
 
2014
 
2013
Revenue—Non-Regulated
$
1,099

 
$
1,188

 
$
1,110

Cost of Sales—Non-Regulated
330

 
331

 
276

Interest Income
25

 
17

 
20

Interest Expense
33

 
9

 
8


The following table summarizes the balances receivable from and payable to related parties included in the Company's Consolidated Balance Sheets in millions as of the periods indicated:
December 31,
2015
 
2014
Receivables from related parties
$
181

 
$
349

Accounts and notes payable to related parties
524

 
567


China Investment Corporation ("CIC") Transaction — On May 18, 2015, the Parent Company completed the repurchase of 20 million shares of its common stock from Terrific Investment Corporation, at a price per share of $13.07, for an aggregate purchase price of $261 million. Terrific Investment Corporation is a subsidiary controlled by CIC, a previously significant shareholder of The AES corporation. See Note 16—Equity for additional information.

v3.3.1.900
Selected Quarterly Financial Data
12 Months Ended
Dec. 31, 2015
Quarterly Financial Information Disclosure [Abstract]  
SELECTED QUARTERLY FINANCIAL DATA (UNAUDITED)
Quarterly Financial Data — The following tables summarize the unaudited quarterly Condensed Consolidated Statements of Operations for the Company for 2015 and 2014 (amounts in millions, except per share data). Amounts have been restated to reflect discontinued operations in all periods presented and reflect all adjustments necessary in the opinion of management for a fair statement of the results for interim periods.
Quarter Ended 2015
Mar 31
 
June 30
 
Sept 30
 
Dec 31
Revenue
$
3,984

 
$
3,858

 
$
3,721

 
$
3,400

Operating margin
721

 
754

 
673

 
718

Income from continuing operations, net of tax(1)
254

 
264

 
203

 
41

Discontinued operations, net of tax
—

 
—

 
—

 
—

Net income
$
254

 
$
264

 
$
203

 
$
41

Net income (loss) attributable to The AES Corporation
$
142

 
$
69

 
$
180

 
$
(85
)
Basic income (loss) per share:


Income (loss) from continuing operations attributable to The AES Corporation, net of tax
$
0.20

 
$
0.10

 
$
0.27

 
$
(0.13
)
Discontinued operations attributable to The AES Corporation, net of tax
—

 
—

 
—

 
—

Basic income (loss) per share attributable to The AES Corporation
$
0.20

 
$
0.10

 
$
0.27

 
$
(0.13
)
Diluted income (loss) per share:


Income (loss) from continuing operations attributable to The AES Corporation, net of tax
$
0.20

 
$
0.10

 
$
0.26

 
$
(0.13
)
Discontinued operations attributable to The AES Corporation, net of tax
—

 
—

 
—

 
—

Diluted income (loss) per share attributable to The AES Corporation
$
0.20

 
$
0.10

 
$
0.26

 
$
(0.13
)
Dividends declared per common share
$
—

 
$
0.10

 
$
0.10

 
$
0.21

Quarter Ended 2014
Mar 31
 
June 30
 
Sept 30
 
Dec 31
Revenue
$
4,262

 
$
4,311

 
$
4,441

 
$
4,132

Operating margin
794

 
819

 
767

 
708

Income (loss) from continuing operations, net of tax(2,3)
89

 
281

 
508

 
298

Discontinued operations, net of tax
(23
)
 
(6
)
 
—

 
—

Net income (loss)
$
66


$
275


$
508


$
298

Net income (loss) attributable to The AES Corporation
$
(58
)
 
$
133

 
$
488

 
$
206

Basic income (loss) per share:


Income (loss) from continuing operations attributable to The AES Corporation, net of tax
$
(0.07
)
 
$
0.20

 
$
0.68

 
$
0.29

Discontinued operations attributable to The AES Corporation, net of tax
(0.01
)
 
(0.02
)
 
—

 
—

Basic income (loss) per share attributable to The AES Corporation
$
(0.08
)
 
$
0.18

 
$
0.68

 
$
0.29

Diluted income (loss) per share:


Income (loss) from continuing operations attributable to The AES Corporation, net of tax
$
(0.07
)
 
$
0.20

 
$
0.67

 
$
0.29

Discontinued operations attributable to The AES Corporation, net of tax
(0.01
)
 
(0.02
)
 
—

 
—

Diluted income (loss) per share attributable to The AES Corporation
$
(0.08
)
 
$
0.18

 
$
0.67

 
$
0.29

Dividends declared per common share
$
—

 
$
0.05

 
$
0.05

 
$
0.15

(1)
Includes pretax impairment expense of $8 million, $37 million, $231 million and $326 million, for the first, second, third and fourth quarters of 2015, respectively. See Note 9—Other Non-Operating Expense, Note 10—Goodwill and Other Intangible Assets, and Note 21—Asset Impairment Expense for further discussion.
(2) 
Includes a pretax gain of approximately $283 million for the third quarter of 2014 related to the sale of a noncontrolling interest in Masinloc. See Note 16—Equity for further discussion. Includes pretax gain of approximately $78 million for the third quarter of 2014 related to the sale of the U.K. wind projects. See Note 24—Dispositions and Held-for-Sale Businesses for further discussion. Includes pretax interest income of $59 million recognized on FONIVEMEM III receivables at AES Argentina in the fourth quarter of 2014. Also includes a pretax foreign currency derivative gain of $106 million recognized on the FONIVEMEM III receivables in the fourth quarter of 2014. See Note 7—Financing Receivables for further discussion. Includes pretax loss of $41 million recognized in Net equity in earnings of affiliates corresponding to the Company's share of an asset impairment at Elsta in the fourth quarter of 2014. See Note 8—Investments In And Advances To Affiliates for further discussion.
(3) 
Includes pretax impairment expense of $166 million, $107 million, $31 million and $79 million, for the first, second, third and fourth quarters of 2014, respectively. See Note 9—Other Non-Operating Expense, Note 10—Goodwill and Other Intangible Assets, and Note 21—Asset Impairment Expense for further discussion.

v3.3.1.900
Subsequent Event Subsequent Events
12 Months Ended
Dec. 31, 2015
Subsequent Events [Abstract]  
Subsequent Events
SUBSEQUENT EVENTS
Stock Repurchase Program — Subsequent to December 31, 2015, the Parent Company repurchased an additional 8.7 million shares at a cost of $79 million, bringing the cumulative repurchases total from July 2010 through February 23, 2016 to 154.3 million shares for a total cost of $1.9 billion, at an average price per share of $12.12 (including a nominal amount of commissions). As of February 23, 2016, $264 million remains available under the Program. See Note 16—Equity for additional information regarding the Company's common stock repurchase program.
DPLER — On December 29, 2015, the Company entered into an agreement for the sale of DPLER. This transaction closed January 1, 2016. See Note 24—Dispositions and Held-for-Sale Businesses for further information.
Recourse Debt — Subsequent to December 31, 2015, the Parent Company repurchased $125 million of its outstanding senior notes.
Kelanitissa — On January 27, 2016, the Company completed the sale of Kelanitissa for $18 million. See Note 24—Dispositions and Held-For-Sale Businesses for additional information. The Company expects to recognize an immaterial loss on this transaction during the first quarter of 2016.
IPP4 — On February 18, 2016, the Company completed the sale of a noncontrolling interest in its Jordan IPP4 gas-fired plant for $21 million. Upon completion of the sale, the Company continues to hold a 36% ownership interest in IPP4 and will continue to manage and operate the plant. IPP4 is reported in the Europe SBU reportable segment.

v3.3.1.900
Schedule I - Condensed Financial Information of Parent
12 Months Ended
Dec. 31, 2015
Condensed Financial Information of Parent Company Only Disclosure [Abstract]  
SCHEDULE I CONDENSED FINANCIAL INFORMATION OF PARENT
THE AES CORPORATION
SCHEDULE I CONDENSED FINANCIAL INFORMATION OF PARENT
BALANCE SHEETS
 
 
December 31,
 
 
2015
 
2014
 
 
(in millions)
ASSETS


Current Assets:


Cash and cash equivalents
 
$
186

 
$
511

Restricted cash
 
32

 
81

Accounts and notes receivable from subsidiaries
 
264

 
380

Deferred income taxes
 
—

 
142

Prepaid expenses and other current assets
 
26

 
57

Total current assets
 
508

 
1,171

Investment in and advances to subsidiaries and affiliates
 
7,764

 
9,063

Office Equipment:


Cost
 
135

 
157

Accumulated depreciation
 
(112
)
 
(114
)
Office equipment, net
 
23

 
43

Other Assets:


Deferred financing costs (net of accumulated amortization of $75 and $81, respectively)
 
49

 
61

Deferred income taxes
 
1,028

 
872

Other Assets
 
1

 
1

Total other assets
 
1,078

 
934

Total
 
$
9,373

 
$
11,211

LIABILITIES AND STOCKHOLDERS' EQUITY


Current Liabilities:


Accounts payable
 
$
16

 
$
25

Accounts and notes payable to subsidiaries
 
97

 
80

Accrued and other liabilities
 
204

 
212

Senior notes payable—current portion
 
—

 
151

Total current liabilities
 
317

 
468

Long-term Liabilities:


Senior notes payable
 
4,498

 
4,590

Junior subordinated notes and debentures payable
 
517

 
517

Accounts and notes payable to subsidiaries
 
873

 
1,352

Other long-term liabilities
 
19

 
12

Total long-term liabilities
 
5,907

 
6,471

Stockholders' equity:


Common stock
 
8

 
8

Additional paid-in capital
 
8,718

 
8,409

Retained Earnings
 
143

 
512

Accumulated other comprehensive loss
 
(3,883
)
 
(3,286
)
Treasury stock
 
(1,837
)
 
(1,371
)
Total stockholders' equity
 
3,149

 
4,272

Total
 
$
9,373

 
$
11,211


See Notes to Schedule I.
THE AES CORPORATION
SCHEDULE I CONDENSED FINANCIAL INFORMATION OF PARENT
STATEMENTS OF OPERATIONS
For the Years Ended December 31,
 
2015
 
2014
 
2013
 
 
(in millions)
Revenue from subsidiaries and affiliates
 
$
24

 
$
29

 
$
32

Equity in earnings of subsidiaries and affiliates
 
859

 
1,313

 
498

Interest income
 
24

 
59

 
66

General and administrative expenses
 
(154
)
 
(161
)
 
(171
)
Other Income
 
24

 
8

 
14

Other Expense
 
(6
)
 
(30
)
 
(11
)
Loss on extinguishment of debt
 
(105
)
 
(193
)
 
(165
)
Interest expense
 
(364
)
 
(422
)
 
(436
)
Income (loss) before income taxes
 
302

 
603

 
(173
)
Income tax benefit
 
4

 
166

 
287

Net income
 
$
306

 
$
769

 
$
114

See Notes to Schedule I.
THE AES CORPORATION
SCHEDULE I CONDENSED FINANCIAL INFORMATION OF PARENT
STATEMENTS OF COMPREHENSIVE INCOME
YEARS ENDED DECEMBER 31, 2015, 2014, AND 2013
 
2015
 
2014
 
2013
 
(in millions)
NET INCOME
$
306

 
$
769

 
$
114

Foreign currency translation activity:


Foreign currency translation adjustments, net of income tax (expense) benefit of $1, $(7) and $10, respectively
(674
)
 
(366
)
 
(263
)
Reclassification to earnings, net of income tax (expense) benefit of $0, $0 and $0, respectively
—

 
34

 
36

Total foreign currency translation adjustments, net of tax
(674
)
 
(332
)
 
(227
)
Derivative activity:


Change in derivative fair value, net of income tax (expense) benefit of $4, $51 and $(31), respectively
(5
)
 
(180
)
 
46

Reclassification to earnings, net of income tax (expense) benefit of $(12), $(37) and $(32), respectively
48

 
72

 
128

Total change in fair value of derivatives, net of tax
43

 
(108
)
 
174

Pension activity:


Prior service cost for the period, net of income tax (expense) benefit of $0, $0 and $0, respectively
1

 
(1
)
 
—

Change in pension adjustments due to net actuarial gain (loss) for the period, net of income tax (expense) benefit of $(7), $9 and $(42), respectively
18

 
(13
)
 
78

Reclassification of earnings due to amortization of net actuarial loss, net of income tax (expense) benefit of $(2), $0 and $(5), respectively
2

 
10

 
13

Total change in unfunded pension obligation
21

 
(4
)
 
91

OTHER COMPREHENSIVE INCOME (LOSS)
(610
)
 
(444
)
 
38

COMPREHENSIVE INCOME (LOSS)
$
(304
)
 
$
325

 
$
152

See Notes to Schedule I.
THE AES CORPORATION
SCHEDULE I CONDENSED FINANCIAL INFORMATION OF PARENT
STATEMENTS OF CASH FLOWS
For the Years Ended December 31,
 
2015
 
2014
 
2013
 
 
(in millions)
Net cash provided by operating activities
 
$
475

 
$
449

 
$
418

Investing Activities:


Expenses related to asset sales
 
—

 
(4
)
 
(5
)
Investment in and net advances to subsidiaries
 
(221
)
 
(69
)
 
201

Return of capital
 
501

 
740

 
230

Decrease in restricted cash
 
49

 
96

 
50

Additions to property, plant and equipment
 
(11
)
 
(31
)
 
(11
)
(Purchase) sale of short term investments, net
 
—

 
(1
)
 
1

Net cash provided by (used in) investing activities
 
318

 
731

 
466

Financing Activities:


Borrowings (payments) under the revolver, net
 
—

 
—

 
—

Borrowings of notes payable and other coupon bearing securities
 
575

 
1,525

 
750

Repayments of notes payable and other coupon bearing securities
 
(915
)
 
(2,117
)
 
(1,210
)
Loans (to) from subsidiaries
 
—

 
263

 
(152
)
Purchase of treasury stock
 
(482
)
 
(308
)
 
(322
)
Proceeds from issuance of common stock
 
4

 
1

 
13

Common stock dividends paid
 
(276
)
 
(144
)
 
(119
)
Payments for deferred financing costs
 
(6
)
 
(20
)
 
(17
)
Other Financing
 
(18
)
 
—

 
—

Net cash (used in) provided by financing activities
 
(1,118
)
 
(800
)
 
(1,057
)
Effect of exchange rate changes on cash
 
—

 
—

 
(1
)
Increase (decrease) in cash and cash equivalents
 
(325
)
 
380

 
(174
)
Cash and cash equivalents, beginning
 
511

 
131

 
305

Cash and cash equivalents, ending
 
$
186

 
$
511

 
$
131

Supplemental Disclosures:


Cash payments for interest, net of amounts capitalized
 
$
314

 
$
373

 
$
442

Cash payments for income taxes, net of refunds
 
$
—

 
$
(2
)
 
$
11

See Notes to Schedule I.
SCHEDULE I
NOTES TO SCHEDULE I
1. Application of Significant Accounting Principles
The Schedule I Condensed Financial Information of the Parent includes the accounts of The AES Corporation (the “Parent Company”) and certain holding companies.
Accounting for Subsidiaries and Affiliates—The Parent Company has accounted for the earnings of its subsidiaries on the equity method in the financial information.
Income Taxes—Positions taken on the Parent Company's income tax return which satisfy a more-likely-than-not threshold will be recognized in the financial statements. The income tax expense or benefit computed for the Parent Company reflects the tax assets and liabilities on a stand-alone basis and the effect of filing a consolidated U.S. income tax return with certain other affiliated companies.
Accounts and Notes Receivable from Subsidiaries—Amounts have been shown in current or long-term assets based on terms in agreements with subsidiaries, but payment is dependent upon meeting conditions precedent in the subsidiary loan agreements.
Senior Notes and Loans Payable ($ in millions)


December 31,
 
 
Interest Rate
 
Maturity
 
2015
 
2014
Senior Unsecured Note
 
7.75%
 
2015
 
$
—

 
$
151

Senior Unsecured Note
 
9.75%
 
2016
 
—

 
164

Senior Unsecured Note
 
8.00%
 
2017
 
181

 
525

Senior Unsecured Note
 
LIBOR + 3.00%
 
2019
 
775

 
775

Senior Unsecured Note
 
8.00%
 
2020
 
469

 
625

Senior Unsecured Note
 
7.38%
 
2021
 
1,000

 
1,000

Senior Unsecured Note
 
4.88%
 
2023
 
750

 
750

Senior Unsecured Note
 
5.50%
 
2024
 
750

 
750

Senior Unsecured Note
 
5.50%
 
2025
 
575

 
—

Unamortized premium (discounts)


(2
)
 
1

SUBTOTAL


4,498

 
4,741

Less: Current maturities


—

 
(151
)
Total


$
4,498

 
$
4,590


Junior Subordinated Notes Payable ($ in millions)


December 31,
 
 
Interest Rate
 
Maturity
 
2015
 
2014
Term Convertible Trust Securities
 
6.75%
 
2029
 
$
517

 
$
517


FUTURE MATURITIES OF DEBT — Recourse debt as of December 31, 2015 is scheduled to reach maturity as presented in the table below in millions:
December 31,
Annual Maturities
2016
$
—

2017
181

2018
—

2019
774

2020
469

Thereafter
3,591

Total debt
$
5,015

Dividends from Subsidiaries and Affiliates
Cash dividends received from consolidated subsidiaries were $748 million, $880 million, and $818 million for the years ended December 31, 2015, 2014, and 2013, respectively. There were no cash dividends received from affiliates accounted for by the equity method for the years ended December 31, 2015, 2014, and 2013.
Guarantees and Letters of Credit
GUARANTEES—In connection with certain of its project financing, acquisition, and power purchase agreements, the Company has expressly undertaken limited obligations and commitments, most of which will only be effective or will be terminated upon the occurrence of future events. These obligations and commitments, excluding those collateralized by letter of credit and other obligations discussed below, were limited as of December 31, 2015, by the terms of the agreements, to an aggregate of approximately $396 million representing 15 agreements with individual exposures ranging from less than $1 million up to $53 million. These amounts exclude normal and customary representations and warranties in agreements for the sale of assets (including ownership in associated legal entities) where the associated risk is considered to be nominal.
LETTERS OF CREDIT—At December 31, 2015, the Company had $62 million in letters of credit outstanding under the senior unsecured credit facility representing 7 agreements with individual exposures ranging from less than $1 million up to $29 million, which operate to guarantee performance relating to certain project development and construction activities and subsidiary operations. At December 31, 2015, the Company had $32 million in cash collateralized letters of credit outstanding representing 4 agreements with individual exposures ranging from $1 million up to $15 million, which operate to guarantee performance relating to certain project development and construction activities and subsidiary operations. During 2015, the Company paid letter of credit fees ranging from 0.2% to 2.5% per annum on the outstanding amounts.

v3.3.1.900
Schedule II - Valuation and Qualifying Accounts
12 Months Ended
Dec. 31, 2015
Valuation and Qualifying Accounts [Abstract]  
SCHEDULE II - VALUATION AND QUALIFYING ACCOUNTS

SCHEDULE II
VALUATION AND QUALIFYING ACCOUNTS
(in millions)
Balance at Beginning of the Period
 
Charged to Cost and Expense
 
Amounts Written off
 
Translation Adjustment
 
Balance at the End of the Period
Allowance for accounts receivables


(current and noncurrent)


Year Ended December 31, 2013
$
195

 
$
38

 
$
(77
)
 
$
(22
)
 
$
134

Year Ended December 31, 2014
134

 
61

 
(88
)
 
(11
)
 
96

Year Ended December 31, 2015
96

 
88

 
(60
)
 
(29
)
 
95


v3.3.1.900
General and Summary of Significant Accounting Policies (Policies)
12 Months Ended
Dec. 31, 2015
Accounting Policies [Abstract]  
PRINCIPLES OF CONSOLIDATION
PRINCIPLES OF CONSOLIDATION — The Consolidated Financial Statements of the Company include the accounts of The AES Corporation and its subsidiaries, which are the entities that it controls. Furthermore, variable interest entities ("VIEs") in which the Company has a variable interest have been consolidated when the Company is the primary beneficiary and thus controls the VIE. Intercompany transactions and balances are eliminated in consolidation. Investments in entities where the Company has the ability to exercise significant influence, but not control, are accounted for using the equity method of accounting.
DP&L, our utility in Ohio, has undivided interests in five generation facilities and numerous transmission facilities. These undivided interests in jointly-owned facilities are accounted for on a pro-rata basis in our consolidated financial statements. Certain expenses, primarily fuel costs for the generating units, are allocated to the joint owners based on their energy usage. The remaining expenses, investments in fuel inventory, plant materials and operating supplies and capital additions are allocated to the joint owners in accordance with their respective ownership interests.
USE OF ESTIMATES
USE OF ESTIMATES — The preparation of these consolidated financial statements in conformity with accounting principles generally accepted in the United States of America ("GAAP") requires the Company to make estimates and assumptions that affect reported amounts of assets and liabilities and disclosures of contingent assets and liabilities at the date of the consolidated financial statements, as well as the reported amounts of revenue and expenses during the reporting period. Actual results could differ from those estimates. Items subject to such estimates and assumptions include: the carrying amount and estimated useful lives of long-lived assets; asset retirement obligations; impairment of goodwill, long-lived assets and equity method investments; valuation allowances for receivables and deferred tax assets; the recoverability of regulatory assets; the estimation of regulatory liabilities; the fair value of financial instruments; the fair value of assets and liabilities acquired in a business combination; the measurement of noncontrolling interest using the hypothetical liquidation at book value ("HLBV") method for certain renewable generation partnerships; the determination of whether a sale of noncontrolling interests is considered to be a sale of in-substance real estate (as opposed to an equity transaction); pension liabilities; environmental liabilities; and potential litigation claims and settlements.
DISCONTINUED OPERATIONS AND RECLASSIFICATIONS
DISCONTINUED OPERATIONS AND HELD-FOR-SALE BUSINESSES — Effective July 1, 2014, the Company prospectively adopted Accounting Standards Update ("ASU") No. 2014-08, Presentation of Financial Statements (Topic 205) and Property, Plant, and Equipment (Topic 360): Reporting discontinued Operations and Disclosures of Disposals of Components of an Entity, which significantly changed the prior accounting guidance on discontinued operations. Under ASU No. 2014-08, only those disposals of components of an entity that represent a strategic shift that has (or will have) a major effect on an entity's operations and financial results are reported as discontinued operations. Amongst other changes: equity method investments that were previously scoped-out of the discontinued operations accounting guidance are now included in the scope; a business can meet the criteria to be classified as held-for-sale upon acquisition and be reported in discontinued operations; and components where an entity retains significant continuing involvement or where operations and cash flows will not be eliminated from ongoing operations as a result of a disposal transaction can meet the definition of discontinued operations. Additionally, where summarized amounts are presented on the face of the financial statements, reconciliations of those amounts to major classes of line items are also required. ASU No. 2014-08 requires additional disclosures for individually material components that do not meet the definition of discontinued operations. Under the previous accounting guidance, DPLER and Kelanitissa (which both met the Held-for-Sale criteria in 2015) and the Armenia Mountain, U.K. Wind (Operating Projects), and Ebute disposals would have met the discontinued operations criteria and would have been reclassified accordingly. See Note 24—Dispositions and Held-for-Sale Businesses for further information.
Prior to July 1, 2014, a discontinued operation was a component of the Company that either had been disposed of or was classified as held for sale and where the Company did not expect to have significant cash flows from or significant continuing involvement with the component as of one year after its disposal or sale. A component was comprised of operations and cash flows that could be clearly distinguished, operationally and for financial reporting purposes, from the rest of the Company. Before the Company's adoption of ASU No. 2014-08, prior period amounts were retrospectively revised to reflect the businesses determined to be discontinued operations. For components that had been determined to be discontinued operations and held for sale businesses under the old standard, the related cash flows are included within the relevant categories within operating, investing and financing activities. The aggregate amount of cash flows is offset by the net increase or decrease in cash of discontinued and held for sale businesses, which is presented as a separate line item in the Consolidated Statements of Cash Flows.
When an operation is classified as held for sale, the Company recognizes impairment expense, if any, at the consolidated financial statement level which also includes noncontrolling interests. However, any gain or loss on the completion of a disposal transaction is recognized only for the Company's ownership interest. Upon adoption of ASU No. 2014-08 on July 1, 2014, the Company no longer recasts prior period results related to operations classified as held for sale.
FAIR VALUE
FAIR VALUE — Fair value is the price that would be received to sell an asset or paid to transfer a liability in an orderly, hypothetical transaction between market participants at the measurement date, or exit price. The Company applies the fair value measurement accounting guidance to financial assets and liabilities in determining the fair value of investments in marketable debt and equity securities, included in the Consolidated Balance Sheet line items Short-term investments and Other assets (noncurrent); derivative assets, included in Other current assets and Other assets (noncurrent); and, derivative liabilities, included in Accrued and other liabilities (current) and Other long-term liabilities. The Company applies the fair value measurement guidance to nonfinancial assets and liabilities upon the acquisition of a business or in conjunction with the measurement of an asset retirement obligation or a potential impairment loss on an asset group or goodwill under the accounting guidance for the impairment of long-lived assets or goodwill.
The Company makes assumptions about what market participants would assume in valuing an asset or liability based on the best information available. These factors include nonperformance risk (the risk that the obligation will not be fulfilled) and credit risk of the subsidiary (for liabilities) and of the counterparty (for assets). The Company is prohibited from including transaction costs and any adjustments for blockage factors in determining fair value. The principal or most advantageous market is considered from the perspective of the subsidiary owning the asset or with the liability.
Fair value is based on observable market prices where available. Where they are not available, specific valuation models and techniques are applied depending on what is being fair valued. These models and techniques maximize the use of observable inputs and minimize the use of unobservable inputs. The process involves varying levels of management judgment, the degree of which is dependent on price transparency and complexity. An asset's or liability's level within the fair value hierarchy is based on the lowest level of input significant to the fair value measurement, where Level 1 is the highest and Level 3 is the lowest. The three levels are defined as follows:
•
Level 1 — unadjusted quoted prices in active markets accessible by the Company for identical assets or liabilities. Active markets are those in which transactions for the asset or liability occur with sufficient frequency and volume to provide pricing information on an ongoing basis.
•
Level 2 — pricing inputs other than quoted market prices included in Level 1 which are based on observable market data, that are directly or indirectly observable for substantially the full term of the asset or liability. These include quoted market prices for similar assets or liabilities, quoted market prices for identical or similar assets in markets that are not active, adjusted quoted market prices, inputs from observable data such as interest rate and yield curves, volatilities or default rates observable at commonly quoted intervals or inputs derived from observable market data by correlation or other means.
•
Level 3 — pricing inputs that are unobservable from objective sources. Unobservable inputs are only used to the extent observable inputs aren't available. These inputs maintain the concept of an exit price from the perspective of a market participant and reflect assumptions of other market participants. The Company considers all market participant assumptions that are available without unreasonable cost and effort. These are given the lowest priority and are generally used in internally developed methodologies to generate management's best estimate of the fair value when no observable market data is available.
Any transfers between all levels within the fair value hierarchy levels are recognized at the end of the reporting period.
CASH AND CASH EQUIVALENTS
CASH AND CASH EQUIVALENTS — The Company considers unrestricted cash on hand, deposits in banks, certificates of deposit and short-term marketable securities with original maturities of three months or less to be cash and cash equivalents. The carrying amounts of such balances approximate fair value.
RESTRICTED CASH AND DEBT SERVICE RESERVES
RESTRICTED CASH AND DEBT SERVICE RESERVES — These include cash balances which are restricted as to withdrawal or usage by the subsidiary that owns the cash. The nature of restrictions includes restrictions imposed by financing agreements such as security deposits kept as collateral, debt service reserves, maintenance reserves, contractual terms and others, as well as restrictions imposed by agreements related to the sales of businesses or long-term PPA
INVESTMENTS IN MARKETABLE SECURITIES
INVESTMENTS IN MARKETABLE SECURITIES — The Company's marketable investments are primarily unsecured debentures, certificates of deposit, government debt securities and money market funds. Short-term investments consist of marketable equity securities and debt securities with original maturities in excess of three months with remaining maturities of less than one year.
Marketable debt securities that the Company has both the positive intent and ability to hold to maturity are classified as held-to-maturity and are carried at amortized cost. Other marketable securities that the Company does not intend to hold to maturity are classified as available-for-sale or trading and are carried at fair value. Available-for-sale investments are fair valued at the end of each reporting period where the unrealized gains or losses are reflected in accumulated other comprehensive loss ("AOCL"), a separate component of equity.
Investments classified as trading are fair valued at the end of each reporting period through the Consolidated Statements of Operations. Interest and dividends on investments are reported in interest income and other income, respectively. Gains and losses on sales of investments are determined using the specific identification method.
ACCOUNTS AND NOTES RECEIVABLE AND ALLOWANCE FOR DOUBTFUL ACCOUNTS
ACCOUNTS AND NOTES RECEIVABLE AND ALLOWANCE FOR DOUBTFUL ACCOUNTS — Accounts and notes receivable are carried at amortized cost. The Company periodically assesses the collectability of accounts receivable, considering factors such as specific evaluation of collectability, historical collection experience, the age of accounts receivable and other currently available evidence of the collectability, and records an allowance for doubtful accounts for the estimated uncollectible amount as appropriate. Certain of our businesses charge interest on accounts receivable either under contractual terms or where charging interest is a customary business practice. In such cases, interest income is recognized on an accrual basis. When the collection of such interest is not reasonably assured, interest income is recognized as cash is received. Individual accounts and notes receivable are written off when they are no longer deemed collectible.
INVENTORY
INVENTORY — Inventory primarily consists of fuel and other raw materials used to generate power, and spare parts and supplies used to maintain power generation and distribution facilities. Inventory is carried at lower of cost or market. Cost is the sum of the purchase price and incidental expenditures and charges incurred to bring the inventory to its existing condition or location. Costs of inventory are valued primarily using the average cost method. Generally, cost is reduced to market value if the market value of inventory has declined and it is probable that the utility of inventory, in its disposal in the ordinary course of business, will not be recovered through revenue earned from the generation of power.
LONG-LIVED ASSETS
LONG-LIVED ASSETS — Long-lived assets include property, plant and equipment, assets under capital leases and intangible assets subject to amortization (i.e., finite-lived intangible assets).
Property, plant and equipment — Property, plant and equipment are stated at cost, net of accumulated depreciation. The cost of renewals and improvements that extend the useful life of property, plant and equipment are capitalized.
Construction progress payments, engineering costs, insurance costs, salaries, interest and other costs directly relating to construction in progress are capitalized during the construction period, provided the completion of the project is deemed probable, or expensed at the time the Company determines that development of a particular project is no longer probable. The continued capitalization of such costs is subject to ongoing risks related to successful completion, including those related to government approvals, site identification, financing, construction permitting and contract compliance. Construction-in-progress balances are transferred to electric generation and distribution assets when an asset group is ready for its intended use. Government subsidies, liquidated damages recovered for construction delays and income tax credits are recorded as a reduction to property, plant and equipment and reflected in cash flows from investing activities.
Depreciation, after consideration of salvage value and asset retirement obligations, is computed primarily using the straight-line method over the estimated useful lives of the assets, which are determined on a composite or component basis. Maintenance and repairs are charged to expense as incurred. Capital spare parts, including rotable spare parts, are included in electric generation and distribution assets. If the spare part is considered a component, it is depreciated over its useful life after the part is placed in service. If the spare part is deemed part of a composite asset, the part is depreciated over the composite useful life even when being held as a spare part.
The Company's Brazilian subsidiaries, which include both generation and distribution companies, operate under concession contracts. Certain estimates are utilized to determine depreciation expense for the Brazilian subsidiaries, including the useful lives of the property, plant and equipment and the amounts to be recovered at the end of the concession contract. The amounts to be recovered under these concession contracts are based on estimates that are inherently uncertain and actual amounts recovered may differ from those estimates.
INTANGIBLE ASSETS SUBJECT TO AMORTIZATION
Intangible Assets Subject to Amortization — Finite-lived intangible assets are amortized over their useful lives which range from 1 – 50 years. The Company accounts for purchased emission allowances as intangible assets and records an expense when utilized or sold. Granted emission allowances are valued at zero.
IMPAIRMENT OF LONG-LIVED ASSETS
Impairment of Long-lived Assets — When circumstances indicate that the carrying amount of long-lived assets (asset group) held-for-use may not be recoverable, the Company evaluates the assets for potential impairment using internal projections of undiscounted cash flows expected to result from the use and eventual disposal of the assets. Events or changes in circumstances that may necessitate a recoverability evaluation may include, but are not limited to, adverse changes in the regulatory environment, unfavorable changes in power prices or fuel costs, increased competition due to additional capacity in the grid, technological advancements, declining trends in demand, or an expectation that it is more likely than not that the asset will be disposed of before the end of its previously estimated useful life. If the carrying amount of the assets exceeds the undiscounted cash flows and exceeds any fair value of the assets, an impairment expense is recognized for the excess up to the carrying amount of the long-lived assets (but up to any fair value for any individual long-lived asset that is determinable without undue cost and effort). For regulated assets where recovery through approved rates is probable, an impairment expense could be reduced by the establishment of a regulatory asset. For other regulated assets and for non-regulated assets, impairment is recognized as an expense. When long-lived assets meet the criteria to be classified as held-for-sale and the carrying amount of the disposal group exceeds its fair value less costs to sell, an impairment expense is recognized for the excess up to the carrying amount of the long-lived assets; if the fair value of the disposal group subsequently exceeds the carrying amount while the disposal group is still held-for-sale, any impairment expense previously recognized will be reversed up to the lower of the prior expense or the subsequent excess.
DEFERRED FINANCING COSTS
DEFERRED FINANCING COSTS — Costs incurred in connection with the issuance of long-term debt are deferred and amortized over the related financing period using the effective interest method. Make-whole payments in connection with early debt retirements are classified as cash flows used in financing activities.
EQUITY METHOD INVESTMENTS
EQUITY METHOD INVESTMENTS — Investments in entities over which the Company has the ability to exercise significant influence, but not control, are accounted for using the equity method of accounting and reported in Investments in and advances to affiliates on the Consolidated Balance Sheets. The Company periodically assesses if there is an indication that the fair value of an equity method investment is less than its carrying amount. When an indicator exists, any excess of the carrying amount over its estimated fair value is recognized as impairment when the loss in value is deemed other-than-temporary and included in Other non-operating expense in the Consolidated Statements of Operations. The difference between the carrying amount and our underlying equity in the net assets of the investee are accounted for as if the investee were a consolidated subsidiary, except that the portion that represents equity method goodwill is not reviewed for impairment like consolidated goodwill.  Upon acquiring the investment, we determine the fair value of the identifiable assets and assumed liabilities and the basis difference between each fair value and the carrying amount of the corresponding asset or liability in the financial statements of the investee are recognized in our net equity in earnings of affiliates over the life of the asset or liability.
The Company discontinues the application of the equity method when an investment is reduced to zero and the Company is not otherwise committed to provide further financial support to the investee. The Company resumes the application of the equity method if the investee subsequently reports net income to the extent that the Company's share of such net income equals the share of net losses not recognized during the period in which the equity method of accounting was suspended.
GOODWILL AND INDEFINITE-LIVED INTANGIBLE ASSETS
GOODWILL AND INDEFINITE-LIVED INTANGIBLE ASSETS — The Company evaluates goodwill and indefinite-lived intangible assets for impairment on an annual basis and whenever events or changes in circumstances necessitate an evaluation for impairment. The Company's annual impairment testing date is October 1.
Goodwill — The Company evaluates goodwill impairment at the reporting unit level, which is an SBU (i.e. an operating segment as defined in the segment reporting accounting guidance), or a component (i.e., one level below an operating segment). In determining its reporting units, the Company starts with its management reporting structure. Operating segments are identified and then analyzed to identify components which make up these operating segments. Two or more components are combined into a single reporting unit if they are economically similar. Assets and liabilities are allocated to a reporting unit if the assets will be employed by or a liability relates to the operations of the reporting unit or would be considered by a market participant in determining its fair value. Goodwill resulting from an acquisition is assigned to the reporting units that are expected to benefit from the synergies of the acquisition. Generally, each AES business with a goodwill balance constitutes a reporting unit as they are not reported to segment management together with other businesses and are not similar to other businesses in a segment.
Goodwill is evaluated for impairment either under the qualitative assessment option or the two-step test approach depending on facts and circumstances of a reporting unit, including the excess of fair value over carrying amount in the last valuation or changes in business environment. If the Company qualitatively determines it is more likely than not that the fair value of a reporting unit is greater than its carrying amount, the two-step impairment test is unnecessary. Otherwise, goodwill is evaluated for impairment using the two-step test, where the carrying amount of a reporting unit is compared to its fair value in Step 1; if the fair value exceeds the carrying amount, Step 2 is unnecessary. If the carrying amount exceeds the reporting unit's fair value, this could indicate potential impairment and Step 2 of the goodwill evaluation process is required to determine if goodwill is impaired and to measure the amount of impairment loss to recognize, if any. When Step 2 is necessary, the fair value of individual assets and liabilities is determined using valuations (which in some cases may be based in part on third party valuation reports) or other observable sources of fair value, as appropriate. If the carrying amount of goodwill exceeds its implied fair value, the excess is recognized as an impairment loss up to the carrying amount of the goodwill.
Most of the Company's reporting units are not publicly traded. Therefore, the Company estimates the fair value of its reporting units using internal budgets and forecasts, adjusted for any market participants' assumptions and discounted at the rate of return required by a market participant. The Company considers both market and income-based approaches to determine a range of fair value, but typically concludes that the value derived using an income-based approach is more representative of fair value due to the lack of direct market comparables. The Company utilizes market data, when available, to corroborate and determine the reasonableness of the fair value derived from the income-based discounted cash flow analysis.
Indefinite-Lived Intangible Assets — The Company's indefinite-lived intangible assets primarily include land-use rights and water rights. These are tested for impairment on an annual basis or whenever events or changes in circumstances necessitate an evaluation for impairment. If the carrying amount of an intangible asset exceeds its fair value, the excess is recognized as impairment expense. When deemed appropriate, the Company uses the qualitative assessment option under the accounting guidance on goodwill and intangible assets to determine whether the existence of events or circumstances indicate that it is more likely than not that an intangible asset is impaired. If, after assessing the totality of events and circumstances, the Company determines that it is not more likely than not that an intangible asset is impaired, no further action is taken. The accounting guidance provides the option to bypass the qualitative assessment for any intangible asset in any period and proceed directly to performing the quantitative impairment test.
ACCOUNTS PAYABLE AND OTHER ACCRUED LIABILITIES
ACCOUNTS PAYABLE AND OTHER ACCRUED LIABILITIES — Accounts payable consists of amounts due to trade creditors related to the Company's core business operations. These payables include amounts owed to vendors and suppliers for items such as energy purchased for resale, fuel, maintenance, inventory and other raw materials. Other accrued liabilities include items such as income taxes, regulatory liabilities, legal contingencies and employee-related costs including payroll, benefits and related taxes.
REGULATORY ASSETS AND LIABILITIES
REGULATORY ASSETS AND LIABILITIES — The Company records assets and liabilities that result from the regulated ratemaking process that are not recognized under GAAP for non-regulated entities. Regulatory assets generally represent incurred costs that have been deferred due to the future recovery in customer rates being probable. Generally, returns earned on regulatory assets are reflected on the Consolidated Statement of Operations within Interest Income. Regulatory liabilities generally represent obligations to make refunds to customers. Management continually assesses whether the regulatory assets are probable of future recovery and regulatory of liabilities are probable of future payment by considering factors such as applicable regulatory changes, recent rate orders applicable to other regulated entities and the status of any pending or potential deregulation legislation. If future recovery of costs previously deferred ceases to be probable, the related regulatory assets are written off and recognized in income from continuing operations.
PENSION AND OTHER POSTRETIREMENT PLANS
PENSION AND OTHER POSTRETIREMENT PLANS — The Company recognizes in its Consolidated Balance Sheets an asset or liability reflecting the funded status of pension and other postretirement plans with current-year changes in actuarial gains or losses recognized in AOCL, except for those plans at certain of the Company's regulated utilities that can recover portions of their pension and postretirement obligations through future rates. All plan assets are recorded at fair value. AES follows the measurement date provisions of the accounting guidance, which require a year-end measurement date of plan assets and obligations for all defined benefit plans.
INCOME TAXES
INCOME TAXES — Deferred tax assets and liabilities are recognized for the future tax consequences attributable to differences between the financial statement carrying amounts of the existing assets and liabilities, and their respective income tax bases. The Company establishes a valuation allowance when it is more likely than not that all or a portion of a deferred tax asset will not be realized. The Company's tax positions are evaluated under a more likely than not recognition threshold and measurement analysis before they are recognized for financial statement reporting.
Uncertain tax positions have been classified as noncurrent income tax liabilities unless expected to be paid within one year. The Company's policy for interest and penalties related to income tax exposures is to recognize interest and penalties as a component of the provision for income taxes in the Consolidated Statements of Operations.
ASSET RETIREMENT OBLIGATIONS
ASSET RETIREMENT OBLIGATIONS — The Company records the fair value of the liability for a legal obligation to retire an asset in the period in which the obligation is incurred. When a new liability is recognized, the Company capitalizes the costs of the liability by increasing the carrying amount of the related long-lived asset. The liability is accreted to its present value each period and the capitalized cost is depreciated over the useful life of the related asset. Upon settlement of the obligation, the Company eliminates the liability and, based on the actual cost to retire, may incur a gain or loss.
NONCONTROLLING INTERESTS
NONCONTROLLING INTERESTS — Noncontrolling interests are classified as a separate component of equity in the Consolidated Balance Sheets and Consolidated Statements of Changes in Equity. Additionally, net income and comprehensive income attributable to noncontrolling interests are reflected separately from consolidated net income and comprehensive income on the Consolidated Statements of Operations and Consolidated Statements of Changes in Equity. Any change in ownership of a subsidiary while the controlling financial interest is retained is accounted for as an equity transaction between the controlling and noncontrolling interests (unless the transaction qualifies as a sale of in-substance real estate). Losses continue to be attributed to the noncontrolling interests, even when the noncontrolling interests' basis has been reduced to zero.
Although, in general, the noncontrolling ownership interest in earnings is calculated based on ownership percentage, certain of the Company's businesses are subject to certain profit-sharing arrangements. These agreements exist for certain renewable generation partnerships to designate different allocations of value among investors, where the allocations change in form or percentage over the life of the partnership. For these businesses, the Company uses the HLBV method when it is a reasonable approximation of the profit-sharing arrangement. HLBV uses a balance sheet approach, which measures the Company's equity in income or loss by calculating the change in the amount of net worth the partners are legally able to claim based on a hypothetical liquidation of the entity at the beginning of a reporting period compared to the end of that period.
FOREIGN CURRENCY TRANSLATION
FOREIGN CURRENCY TRANSLATION — A business's functional currency is the currency of the primary economic environment in which the business operates and is generally the currency in which the business generates and expends cash. Subsidiaries and affiliates whose functional currency is a currency other than the U.S. Dollar translate their assets and liabilities into U.S. Dollars at the current exchange rates in effect at the end of the fiscal period. The revenue and expense accounts of such subsidiaries and affiliates are translated into U.S. Dollars at the average exchange rates that prevailed during the period. Translation adjustments are included in AOCL. Gains and losses on intercompany foreign currency transactions that are long-term in nature and which the Company does not intend to settle in the foreseeable future, are also recognized in AOCL. Gains and losses that arise from exchange rate fluctuations on transactions denominated in a currency other than the functional currency are included in determining net income. Accumulated foreign currency translation adjustments are reclassified to net income only when realized upon sale or upon complete or substantially complete liquidation of the investment in a foreign entity. The accumulated adjustments are included in carrying amounts in impairment assessments where the Company has committed to a plan that will cause the accumulated adjustments to be reclassified to earnings
REVENUE RECOGNITION
REVENUE RECOGNITION — Revenue from utilities is classified as regulated in the Consolidated Statements of Operations. Revenue from the sale of energy is recognized in the period during which the sale occurs. The calculation of revenue earned but not yet billed is based on the number of days not billed in the month, the estimated amount of energy delivered during those days and the estimated average price per customer class for that month. Differences between actual and estimated unbilled revenue are usually immaterial. The Company has businesses where it sells and purchases power to and from Independent System Operators ("ISOs") and Regional Transmission Organizations ("RTOs"). In those instances, the Company accounts for these transactions on a net hourly basis because the transactions are settled on a net hourly basis. Revenue from generation businesses is classified as non-regulated and is recognized based upon output delivered and capacity provided, at rates as specified under contract terms or prevailing market rates. Certain of the Company PPAs meet the definition of an operating lease or contain similar arrangements. Typically, minimum lease payments from such PPAs are recognized as revenue on a straight-line basis over the lease term whereas contingent rentals are recognized when earned. Revenue is recorded net of any taxes assessed on and collected from customers, which are remitted to the governmental authorities.
SHARE-BASED COMPENSATION
SHARE-BASED COMPENSATION — The Company grants share-based compensation in the form of stock options, restricted stock units, and performance stock units. The expense is based on the grant-date fair value of the equity or liability instrument issued and is recognized on a straight-line basis over the requisite service period, net of estimated forfeitures. The Company uses a Black-Scholes option pricing model to estimate the fair value of stock options granted to its employees.
GENERAL AND ADMINISTRATIVE EXPENSES
GENERAL AND ADMINISTRATIVE EXPENSES — General and administrative expenses include corporate and other expenses related to corporate staff functions and initiatives, primarily executive management, finance, legal, human resources and information systems, which are not directly allocable to our business segments. Additionally, all costs associated with corporate business development efforts are classified as general and administrative expenses.
DERIVATIVES AND HEDGING ACTIVITIES
DERIVATIVES AND HEDGING ACTIVITIES — Under the accounting standards for derivatives and hedging, the Company recognizes all contracts that meet the definition of a derivative, except those designated as normal purchase or normal sale at inception, as either assets or liabilities in the Consolidated Balance Sheets and measures those instruments at fair value. See the Company's fair value policy and Note 4—Fair Value for additional discussion regarding the determination of the fair value. The PPAs and fuel supply agreements entered into by the Company are evaluated to determine if they meet the definition of a derivative or contain embedded derivatives, either of which require separate valuation and accounting. To be a derivative under the accounting standards for derivatives and hedging, an agreement would need to have a notional and an underlying, require little or no initial net investment and could be net settled. Generally, these agreements do not meet the definition of a derivative, often due to the inability to be net settled. On a quarterly basis, we evaluate the markets for the commodities to be delivered under these agreements to determine if facts and circumstances have changed such that the agreements could then be net settled and meet the definition of a derivative.
Derivatives primarily consist of interest rate swaps, cross-currency swaps, foreign currency instruments, and commodity derivatives. The Company enters into various derivative transactions in order to hedge its exposure to certain market risks, primarily interest rate, foreign currency and commodity price risks. Regarding interest rate risk, the Company and our subsidiaries generally utilize variable rate debt financing for construction projects and operations so interest rate swap, lock, cap, and floor agreements are entered into to manage interest rate risk by effectively fixing or limiting the interest rate exposure on the underlying financing and are typically designated as cash flow hedges. Regarding foreign currency risk, we are exposed to it as a result of our investments in foreign subsidiaries and affiliates that may be impacted by significant fluctuations in foreign currency exchange rates so foreign currency options and forwards are utilized, where deemed appropriate, to manage the risk related to these fluctuations. Cross-currency swaps are utilized in certain instances to manage the risk related to certain foreign currencies and the associated impact on interest and loan principal payments. In addition, certain of our subsidiaries have entered into contracts which contain embedded derivatives as a portion of the contracts primarily that are denominated in a currency other than the functional or local currency of that subsidiary or the currency of the item. Regarding commodity price risk, we are exposed to the impact of market fluctuations in the price of electricity, fuel and environmental credits. Although we primarily consist of businesses with long-term contracts or retail sales concessions (which provide our distribution businesses with a franchise to serve a specific geographic region), a portion of our current and expected future revenues are derived from businesses without significant long-term purchase or sales contracts. We use an overall hedging strategy, not just derivatives, to hedge our financial performance against the effects of fluctuations in commodity prices.
The accounting standards for derivatives and hedging enable companies to designate qualifying derivatives as hedging instruments based on the exposure being hedged. The Company only has cash flow hedges at this time. Changes in the fair value of a derivative that is highly effective, designated and qualifies as a cash flow hedge are deferred in AOCL and are recognized into earnings as the hedged transactions affect earnings. Any ineffectiveness is recognized in earnings immediately. For all designated and qualifying hedges, the Company maintains formal documentation of the hedge and effectiveness testing in accordance with the accounting standards for derivatives and hedging. If AES determines that the derivative is no longer highly effective as a hedge, hedge accounting will be discontinued prospectively. For cash flow hedges of forecasted transactions, AES estimates the future cash flows of the forecasted transactions and evaluates the probability of the occurrence and timing of such transactions. Changes in conditions or the occurrence of unforeseen events could require discontinuance of hedge accounting or could affect the timing of the reclassification of gains or losses on cash flow hedges from AOCL into earnings.
While derivative transactions are not entered into for trading purposes, some contracts are not eligible for hedge accounting. Changes in the fair value of derivatives not designated and qualifying as cash flow hedges are immediately recognized in earnings. Regardless of when gains or losses on derivatives (including all those where the fair value measurement is classified as Level 3) are recognized in earnings, they are generally classified as follows: interest expense for interest rate and cross-currency derivatives, foreign currency transaction gains or losses for foreign currency derivatives, and non-regulated revenue or non-regulated cost of sales for commodity and other derivatives. However, gains and losses on interest rate and cross-currency derivatives are classified as foreign currency transaction gains and losses if they offset the remeasurement of the foreign currency-denominated debt being hedged by the cross-currency swaps and the amount reclassified from AOCL to cost of sales to offset depreciation where the variable-rate interest capitalized as part of the asset was hedged during its construction. Cash flows arising from derivatives are included in the Consolidated Statements of Cash Flows as an operating activity given the nature of the underlying risk being economically hedged and the lack of significant financing elements, except that cash flows on designated and qualifying hedges of variable-rate interest during construction are classified as an investing activity.
DERIVATIVES OFFSETTING FAIR VALUE AMOUNTS
The Company has elected not to offset net derivative positions in the financial statements. Accordingly, the Company does not offset such derivative positions against the fair value of amounts (or amounts that approximate fair value) recognized for the right to reclaim cash collateral (a receivable) or the obligation to return cash collateral (a payable) under master netting arrangements.
NEW ACCOUNTING PRONOUNCEMENTS ADOPTED
ASU No. 2015-17, Income Taxes (Topic 740): Balance Sheet Classification of Deferred Taxes
Effective December 31, 2015, the Company prospectively adopted ASU No. 2015-17, which requires that all deferred tax assets and liabilities, along with any related valuation allowance, be classified as noncurrent on the balance sheet. As a result, each jurisdiction will now only have one net noncurrent deferred tax asset or liability. The guidance does not change the existing requirement that only permits offsetting within a jurisdiction; that is, companies will remain prohibited from offsetting deferred tax liabilities from one jurisdiction against deferred tax assets of another jurisdiction. Additionally, the current requirement that deferred tax liabilities and assets of a tax-paying component of an entity be offset and presented as a single amount is not affected by the update. As the Company elected to apply this ASU prospectively, prior periods were not adjusted.
ASU No. 2015-13, Derivatives and Hedging (Topic 815): Application of the Normal Purchases and Normal Sales Scope Exception to Certain Electricity Contracts within Nodal Energy Markets
In August 2015, the FASB issued ASU No. 2015-13, which resolves the diversity in practice resulting from determining whether certain contracts qualify for the normal purchases and normal sales scope exception under ASC Topic 815—Derivatives and Hedging. This standard clarifies that entities would not be precluded from applying the normal purchases and normal sales exception to certain forward contracts that necessitate the transmission of electricity through, or delivery to a location within, a nodal energy market. The standard is effective upon issuance and should be applied prospectively. As the Company had designated qualifying contracts as normal purchase or normal sales, there was no impact on the Company's consolidated financial statements upon adoption of this standard.
ASU No. 2014-05, Service Concession Arrangements (Topic 853)
Effective January 1, 2015, the Company adopted ASU No. 2014-05, which states that certain service concession arrangements with public-sector entity grantors are not in scope of ASC 840—Leases, and that entities should not recognize the related infrastructure as property, plant and equipment, but should apply other GAAP. The Company has a small number of entities that fall within the scope of this guidance, with the Company's Mong Duong generation facility in Vietnam being the most significant.
Mong Duong is based on a build, operate and transfer agreement with the Vietnamese government. Management concluded there were two deliverables included within the arrangement, as well as a financing element. Due to the contingent nature of the revenue stream, no amounts of revenue could be recognized during the build phase of the contract. All amounts billed during the operate phase are recognized as revenue when billed, with amounts allocated between the financing element and build and operate deliverables. The financing element is recognized as interest income using the effective interest method as payments for construction of the plant are received over the life of the contract. Costs are expensed as incurred. As the related infrastructure is no longer considered property, plant and equipment, there are no longer any capitalizable expenses beyond those related to the initial build, and accordingly these will be expensed as incurred. All cash flows for these arrangements, excluding those related to the debt incurred by AES, will be reflected in cash flows from operating activities on the Company's Consolidated Statements of Cash Flows prospectively.
The guidance was applied on a modified retrospective basis to service concession arrangements in existence at January 1, 2015. Upon adoption of this standard, the impact to the Company's Consolidated Balance Sheet as of January 1, 2015 resulted in a reclassification of $1.5 billion from property, plant and equipment to service concession assets, as well as a cumulative adjustment to retained earnings and cumulative translation adjustment of $(18) million, net of tax, and $13 million, respectively.
ACCOUNTING PRONOUNCEMENTS ISSUED BUT NOT YET EFFECTIVE
ACCOUNTING PRONOUNCEMENTS ISSUED BUT NOT YET EFFECTIVE — The following accounting standards have been issued, but are not yet effective for, and have not been adopted in these financial statements by AES.
ASU No. 2016-01, Financial Instruments — Overall (Topic 825-10): Recognition and Measurement of Financial Assets and Financial Liabilities
In January 2016, the FASB issued ASU 2016-01, which was designed to improve the recognition and measurement of financial instruments through targeted changes to existing GAAP. The guidance requires equity investments (except those that are accounted for under the equity method of accounting or result in consolidation of the investee) to be measured at fair value with changes in fair value recognized in net income; that entities use the exit price notion when measuring financial instrument fair values; that an entity separate presentation of financial assets and liabilities by measurement category and form of financial asset on the Balance Sheets or Notes to the financial statements; that an entity present separately in other comprehensive income the portion of the total change in the fair value of a liability resulting from a change in the instrument-specific credit risk (or "own credit") when the entity has elected to measure the liability at fair value in accordance with the fair value option for financial instruments. Also, the standard eliminates the requirement for public entities to disclose the methods and significant assumptions used to estimate the fair value required to be disclosed for financial instruments measured at amortized cost on the Balance Sheets. The standard is effective beginning with interim periods starting after December 31, 2017 and cannot be applied early. The Company is currently evaluating the applicability and materiality of the standard, but does not anticipate a material impact on the Company's consolidated financial statements.
ASU No. 2015-16, Business Combinations (Topic 805): Simplifying the Accounting for Measurement-Period Adjustments
In September 2015, the FASB issued ASU 2015-16, which simplifies the measurement-period adjustments in business combinations. It eliminates the requirement that an acquirer in a business combination account for measurement-period adjustments retrospectively. An acquirer will recognize a measurement-period adjustment during the period in which it determines the amount of the adjustment. The standard is effective for public entities for annual reporting periods beginning after December 15, 2015, and interim periods therein. Early adoption is permitted for financial statements that have not been issued. The new guidance should be applied prospectively to adjustments to provisional amounts that occur after the effective date of this standard. The Company will adopt this standard on January 1, 2016, which is not expected to have a material impact on the Company's consolidated financial statements.
ASU No. 2015-15, Interest — Imputation of Interest (Subtopic 835-30): Presentation and Subsequent Measurement of Debt Issuance Costs Associated with Line-of-Credit Arrangements
In August 2015, the FASB issued ASU No. 2015-15, which clarifies that the SEC Staff would not object to an entity presenting debt issuance costs related to line-of-credit arrangements as an asset that is subsequently amortized ratably over the term of the line-of-credit arrangement, regardless of whether there are any outstanding borrowings on the line-of-credit arrangement. This standard should be adopted concurrent with adoption of ASU 2015-03 (see below). As of December 31, 2015, the Company had deferred financing costs related to lines-of-credit of approximately $2 million recorded within other current assets and $24 million recorded within other noncurrent assets that would not be reclassified upon adoption of this standard.
ASU No. 2015-11, Inventory (Topic 330): Simplifying the Measurement of Inventory
In July 2015, the FASB issued ASU No. 2015-11, which simplifies the subsequent measurement of inventory. It replaces the current lower of cost or market test with a lower of cost or net realizable value test. The standard is effective for public entities for annual reporting periods beginning after December 15, 2016, and interim periods therein. Early adoption is permitted. The new guidance must be applied prospectively. The Company is currently evaluating the impact of adopting the standard on its consolidated financial statements.
ASU No. 2015-05, Intangibles — Goodwill and Other — Internal-Use Software (Subtopic 350-40): Customer's Accounting for Fees Paid in a Cloud Computing Arrangement
In April 2015, the FASB issued ASU No. 2015-05, which clarifies how customers in cloud computing arrangements should determine whether the arrangement includes a software license and eliminates the existing requirement for customers to account for software licenses they acquired by analogizing to the accounting guidance on leases. The standard is effective for annual reporting periods beginning after December 15, 2015 and interim periods therein. Early adoption is permitted. The standard permits the use of a prospective or retrospective approach. The Company expects to utilize the prospective approach upon adoption of this standard, which is not expected to have a material impact on its consolidated financial statements.
ASU No. 2015-03, Interest — Imputation of Interest (Subtopic 835-30)
In April 2015, the FASB issued ASU No. 2015-03, which simplifies the presentation of debt issuance costs by requiring that debt issuance costs related to a recognized debt liability be presented in the balance sheet as a direct deduction from the carrying amount of that debt liability, consistent with debt discounts. The recognition and measurement guidance for debt issuance costs are not affected by the amendments in this update. The standard is effective for annual reporting periods beginning after December 15, 2015 and interim periods therein, and requires the use of the full retrospective approach. Early adoption is permitted for financial statements that have not been previously issued. As of December 31, 2015, the Company had deferred financing costs of approximately $24 million classified within other current assets and $356 million classified within other noncurrent assets that would be reclassified to reduce the related debt liabilities upon adoption of this standard.
ASU No. 2015-02, Consolidation — Amendments to the Consolidation Analysis (Topic 810)
In February 2015, the FASB issued ASU 2015-02, which makes targeted amendments to the current consolidation guidance and ends the deferral granted to investment companies from applying the VIE guidance. The standard amends the evaluation of whether (1) fees paid to a decision-maker or service providers represent a variable interest, (2) a limited partnership or similar entity has the characteristics of a VIE and (3) a reporting entity is the primary beneficiary of a VIE. The standard is effective for annual periods beginning after December 15, 2015 and interim periods therein. Early adoption is permitted. Based on the Company's preliminary analysis, no change in consolidation is expected although additional disclosures may be required.
ASU No. 2014-09, Revenue from Contracts with Customers (Topic 606)
In May 2014, the FASB issued ASU No. 2014-09, which clarifies principles for recognizing revenue and will result in a common revenue standard for U.S. GAAP and International Financial Reporting Standards. The objective of the new standard is to provide a single and comprehensive revenue recognition model for all contracts with customers to improve comparability. The revenue standard contains principles that an entity will apply to determine the measurement of revenue and timing of when it is recognized. The standard requires an entity to recognize revenue to depict the transfer of goods or services to customers at an amount that the entity expects to be entitled to in exchange for those goods or services. In August 2015, the FASB issued ASU No. 2015-14, Revenue from Contracts with Customers (Topic 606): Deferral of the Effective Date, which deferred the effective date of ASU 2014-09 by one year, resulting in the new revenue standard being effective for annual reporting periods beginning after December 15, 2017 and interim periods therein. Early adoption is now permitted only as of the original effective date for public entities (that is, no earlier than 2017 for calendar year-end entities). The standard permits the use of either a full retrospective or modified retrospective approach. The Company has not yet selected a transition method and is currently evaluating the impact of adopting the standard on its consolidated financial statements.
SEGMENTS AND GEOGRAPHIC INFORMATION
The segment reporting structure uses the Company's organizational structure as its foundation to reflect how the Company manages the businesses internally, and is organized by geographic regions which provide better socio-political-economic understanding of our business. The Company is organized by six SBUs led by our President and Chief Executive Officer: US, Andes, Brazil, MCAC, Europe, and Asia SBUs. Using the accounting guidance on segment reporting, the Company determined that it has six operating and six reportable segments corresponding to its SBUs.
Corporate and Other — Corporate overhead costs which are not directly associated with the operations of our six reportable segments are included in "Corporate and Other." Also included are certain intercompany charges such as self-insurance premiums which are fully eliminated in consolidation.
The Company uses Adjusted PTC as its primary segment performance measure. Adjusted PTC, a non-GAAP measure, is defined by the Company as pretax income from continuing operations attributable to AES excluding unrealized gains or losses related to derivative transactions, unrealized foreign currency gains or losses, gains or losses due to dispositions and acquisitions of business interests, losses due to impairments and costs due to the early retirement of debt. The Company has concluded that Adjusted PTC best reflects the underlying business performance of the Company and is the most relevant measure considered in the Company's internal evaluation of the financial performance of its segments. Additionally, given its large number of businesses and complexity, the Company concluded that Adjusted PTC is a more transparent measure that better assists investors in determining which businesses have the greatest impact on the Company's results.    
Revenue and Adjusted PTC before intersegment eliminations includes the effect of intercompany transactions with other segments except for interest, charges for certain management fees, and the write-off of intercompany balances, as applicable. All intra-segment activity has been eliminated within the segment. Inter-segment activity has been eliminated within the total consolidated results.
Earnings Per Share, Policy [Policy Text Block]
Basic and diluted earnings per share are based on the weighted-average number of shares of common stock and potential common stock outstanding during the period. Potential common stock, for purposes of determining diluted earnings per share, includes the effects of dilutive restricted stock units, stock options and convertible securities. The effect of such potential common stock is computed using the treasury stock method or the if-converted method, as applicable.

v3.3.1.900
Contingencies Contingencies (Policies)
12 Months Ended
Dec. 31, 2015
Loss Contingencies [Line Items]  
Commitments and Contingencies, Policy [Policy Text Block]
The Company is involved in certain claims, suits and legal proceedings in the normal course of business. The Company accrues for litigation and claims when it is probable that a liability has been incurred and the amount of loss can be reasonably estimated. The Company has evaluated claims in accordance with the accounting guidance for contingencies that it deems both probable and reasonably estimable and, accordingly, has recorded aggregate liabilities for all claims of approximately $189 million and $199 million as of December 31, 2015 and 2014, respectively. These amounts are reported on the Consolidated Balance Sheets within Accrued and other liabilities and Other noncurrent liabilities. A significant portion of these accrued liabilities relate to employment, non-income tax and customer disputes in international jurisdictions (principally Brazil). Certain of the Company's subsidiaries, principally in Brazil, are defendants in a number of labor and employment lawsuits. The complaints generally seek unspecified monetary damages, injunctive relief, or other relief. The subsidiaries have denied any liability and intend to vigorously defend themselves in all of these proceedings. There can be no assurance that these accrued liabilities will be adequate to cover all existing and future claims or that we will have the liquidity to pay such claims as they arise.

v3.3.1.900
Segments and Geographic Information Segments and Geographic Information (Policies)
12 Months Ended
Dec. 31, 2015
Segment Reporting [Abstract]  
Segment Reporting, Policy [Policy Text Block]
The segment reporting structure uses the Company's organizational structure as its foundation to reflect how the Company manages the businesses internally, and is organized by geographic regions which provide better socio-political-economic understanding of our business. The Company is organized by six SBUs led by our President and Chief Executive Officer: US, Andes, Brazil, MCAC, Europe, and Asia SBUs. Using the accounting guidance on segment reporting, the Company determined that it has six operating and six reportable segments corresponding to its SBUs.
Corporate and Other — Corporate overhead costs which are not directly associated with the operations of our six reportable segments are included in "Corporate and Other." Also included are certain intercompany charges such as self-insurance premiums which are fully eliminated in consolidation.
The Company uses Adjusted PTC as its primary segment performance measure. Adjusted PTC, a non-GAAP measure, is defined by the Company as pretax income from continuing operations attributable to AES excluding unrealized gains or losses related to derivative transactions, unrealized foreign currency gains or losses, gains or losses due to dispositions and acquisitions of business interests, losses due to impairments and costs due to the early retirement of debt. The Company has concluded that Adjusted PTC best reflects the underlying business performance of the Company and is the most relevant measure considered in the Company's internal evaluation of the financial performance of its segments. Additionally, given its large number of businesses and complexity, the Company concluded that Adjusted PTC is a more transparent measure that better assists investors in determining which businesses have the greatest impact on the Company's results.    
Revenue and Adjusted PTC before intersegment eliminations includes the effect of intercompany transactions with other segments except for interest, charges for certain management fees, and the write-off of intercompany balances, as applicable. All intra-segment activity has been eliminated within the segment. Inter-segment activity has been eliminated within the total consolidated results.

v3.3.1.900
Earnings Per Share Earnings Per Share (Policies)
12 Months Ended
Dec. 31, 2015
Earnings Per Share [Abstract]  
Earnings Per Share, Policy [Policy Text Block]
Basic and diluted earnings per share are based on the weighted-average number of shares of common stock and potential common stock outstanding during the period. Potential common stock, for purposes of determining diluted earnings per share, includes the effects of dilutive restricted stock units, stock options and convertible securities. The effect of such potential common stock is computed using the treasury stock method or the if-converted method, as applicable.

v3.3.1.900
General and Summary of Significant Accounting Policies Effect of Change in Estimate (Tables)
12 Months Ended
Dec. 31, 2015
Change in Accounting Estimate [Line Items]  
Schedule of Change in Accounting Estimate [Table Text Block]
The impact of the change in approach on expected service costs for the U.S. and U.K. plans in 2016 is shown below (in millions):
 
Expected 2016 Service Cost
 
Expected 2016 Interest Cost
 
Disaggregated rate approach
 
Aggregate rate approach
 
Impact of change
 
Disaggregated rate approach
 
Aggregate rate approach
 
Impact of change
U.S.
$
13

 
$
14

 
$
(1
)
 
$
42

 
$
51

 
$
(9
)
U.K.
3

 
4

 
(1
)
 
7

 
9

 
(2
)
Total
$
16

 
$
18

 
$
(2
)
 
$
49

 
$
60

 
$
(11
)

v3.3.1.900
Inventory (Tables)
12 Months Ended
Dec. 31, 2015
Inventory Disclosure [Abstract]  
Inventory Balance By Type
The following table summarizes the Company's inventory balances (in millions) as of the dates indicated:
December 31,
 
2015
 
2014
Fuel and other raw materials
 
$
343

 
$
357

Spare parts and supplies
 
332

 
345

Total
 
$
675

 
$
702


v3.3.1.900
Property, Plant and Equipment (Tables)
12 Months Ended
Dec. 31, 2015
Property, Plant and Equipment [Abstract]  
Property, Pland and Equipment with Useful Life Classification
The following table summarizes the components of the electric generation and distribution assets and other property, plant and equipment (in millions) with their estimated useful lives (in years). The amounts are stated net of all prior asset impairment losses recognized.


December 31,
 
Estimated Useful Life
2015
 
2014
Electric generation and distribution facilities
5 - 68
 
$
25,427

 
$
27,488

Other buildings
3 - 53
 
1,868

 
1,694

Furniture, fixtures and equipment
2 - 31
 
305

 
307

Other
1 - 50
 
891

 
970

Total electric generation and distribution assets and other
 
 
28,491

 
30,459

Accumulated depreciation
 
 
(9,449
)
 
(9,962
)
Net electric generation and distribution assets and other (1)
 
 
$
19,042

 
$
20,497


(1) 
Net electric generation and distribution assets and other include unamortized internal-use software costs of $83 million and $115 million as of December 31, 2015 and 2014, respectively
Interest Capitalized During Development And Construction
The following table summarizes depreciation expense (including the amortization of assets recorded under capital leases), amortization of internal-use software and interest capitalized during development and construction on qualifying assets for the periods indicated (in millions):
Year Ended December 31,
 
2015
 
2014
 
2013
Depreciation expense (including amortization of assets recorded under capital leases)
 
$
1,104

 
$
1,204

 
$
1,193

Amortization of internal-use software
 
29

 
33

 
36

Interest capitalized during development and construction
 
90

 
120

 
84

Net Asset Value Of Regulated And Non-Regulated Assets And Accumulated Depreciation
The following table summarizes regulated and non-regulated generation and distribution property, plant and equipment and accumulated depreciation in millions as of the periods indicated:
December 31,
 
2015
 
2014
Regulated generation, distribution assets and other, gross
 
$
11,818

 
$
13,103

Regulated accumulated depreciation
 
(4,351
)
 
(4,841
)
Regulated generation, distribution assets and other, net
 
7,467

 
8,262

Non-regulated generation, distribution assets and other, gross
 
16,673

 
17,356

Non-regulated accumulated depreciation
 
(5,098
)
 
(5,121
)
Non-regulated generation, distribution assets and other, net
 
11,575

 
12,235

Net electric generation, distribution assets and other
 
$
19,042

 
$
20,497

Schedule of Change in Asset Retirement Obligation
The next table presents amounts recognized related to asset retirement obligations in millions for the periods indicated:
 
 
2015
 
2014
Balance at January 1
 
$
209

 
$
142

Additional liabilities incurred
 
43

 
51

Liabilities settled
 
(6
)
 
(11
)
Accretion expense
 
13

 
12

Change in estimated cash flows
 
(7
)
 
15

Other
 
(5
)
 
—

Balance at December 31
 
$
247

 
$
209

Schedule of Jointly Owned Utility Plants
DP&L's undivided ownership interest in such facilities at December 31, 2015 is as follows:
 
DP&L Share
 
DP&L Investment
 
Ownership
 
Gross Plant In Service
 
Accumulated Depreciation
 
Construction Work In Process
Production units:
 
 
($ in millions)
Conesville Unit 4
17
%
 
$
26

 
$
4

 
$
1

Killen Station
67
%
 
342

 
29

 
2

Miami Fort Units 7 and 8
36
%
 
219

 
32

 
6

Stuart Station
35
%
 
236

 
19

 
18

Zimmer Station
28
%
 
188

 
44

 
12

Transmission
various

 
43

 
8

 
—

Total
 
 
$
1,054

 
$
136

 
$
39


v3.3.1.900
Fair Value (Tables)
12 Months Ended
Dec. 31, 2015
Fair Value Disclosures [Abstract]  
Fair value hierarchy for recurring measurements table
The following table presents, by level within the fair value hierarchy, as described in Note 1—General and Summary of Significant Accounting Policies, the Company's financial assets and liabilities (in millions) that were measured at fair value on a recurring basis as of the periods indicated:
 
 
December 31, 2015
 
December 31, 2014
 
 
Level 1
 
Level 2
 
Level 3
 
Total
 
Level 1
 
Level 2
 
Level 3
 
Total
Assets


AVAILABLE FOR SALE:


Debt securities:(1)


Unsecured debentures
 
$
—

 
$
327

 
$
—

 
$
327

 
$
—

 
$
501

 
$
—

 
$
501

Certificates of deposit
 
—

 
135

 
—

 
135

 
—

 
151

 
—

 
151

Government debt securities
 
—

 
28

 
—

 
28

 
—

 
57

 
—

 
57

Subtotal
 
—

 
490

 
—

 
490

 
—

 
709

 
—

 
709

Equity securities:


Mutual funds
 
—

 
15

 
—

 
15

 
—

 
25

 
—

 
25

Subtotal
 
—

 
15

 
—

 
15

 
—

 
25

 
—

 
25

Total available for sale
 
—

 
505

 
—

 
505

 
—

 
734

 
—

 
734

TRADING:


Equity securities:


Mutual funds
 
15

 
—

 
—

 
15

 
15

 
—

 
—

 
15

Total trading
 
15

 
—

 
—

 
15

 
15

 
—

 
—

 
15

DERIVATIVES:


Foreign currency derivatives
 
—

 
35

 
292

 
327

 
—

 
18

 
218

 
236

Commodity derivatives
 
—

 
41

 
7

 
48

 
—

 
37

 
7

 
44

Total derivatives
 
—

 
76

 
299

 
375

 
—

 
55

 
225

 
280

TOTAL ASSETS
 
$
15

 
$
581

 
$
299

 
$
895

 
$
15

 
$
789

 
$
225

 
$
1,029

Liabilities


DERIVATIVES:


Interest rate derivatives
 
$
—

 
$
54

 
$
304

 
$
358

 
$
—

 
$
206

 
$
210

 
$
416

Cross currency derivatives
 
—

 
43

 
—

 
43

 
—

 
29

 
—

 
29

Foreign currency derivatives
 
—

 
41

 
15

 
56

 
—

 
43

 
9

 
52

Commodity derivatives
 
—

 
29

 
4

 
33

 
—

 
16

 
1

 
17

Total derivatives
 
—

 
167

 
323

 
490

 
—

 
294

 
220

 
514

TOTAL LIABILITIES
 
$
—

 
$
167

 
$
323

 
$
490

 
$
—

 
$
294

 
$
220

 
$
514

 _____________________________
(1) 
Amortized cost approximated fair value at December 31, 2015 and 2014.
Derivatives Level 3 Rollforward Table
The following tables present a reconciliation of net derivative assets and liabilities measured at fair value on a recurring basis using significant unobservable inputs (Level 3) for the years ended December 31, 2015 and 2014 (presented net by type of derivative in millions). Transfers between Level 3 and Level 2 are determined as of the end of the reporting period and principally result from changes in the significance of unobservable inputs used to calculate the credit valuation adjustment.
Year Ended December 31, 2015
Interest Rate
 
Foreign Currency
 
Commodity
 
Total
Balance at January 1
$
(210
)
 
$
209

 
$
6

 
$
5

Total gains (losses) (realized and unrealized):


Included in earnings
(1
)
 
198

 
(1
)
 
196

Included in other comprehensive income - derivative activity
(31
)
 
—

 
—

 
(31
)
Included in other comprehensive income - foreign currency translation activity
9

 
(103
)
 
—

 
(94
)
Included in regulatory (assets) liabilities
—

 
—

 
(18
)
 
(18
)
Settlements
24

 
(7
)
 
16

 
33

Transfers of assets (liabilities) into Level 3
(95
)
 
(1
)
 
—

 
(96
)
Transfers of (assets) liabilities out of Level 3
—

 
(19
)
 
—

 
(19
)
Balance at December 31
$
(304
)
 
$
277

 
$
3

 
$
(24
)
Total gains (losses) for the period included in earnings attributable to the change in unrealized gains (losses) relating to assets and liabilities held at the end of the period
$
—

 
$
187

 
$
(1
)
 
$
186

Year Ended December 31, 2014
Interest Rate
 
Foreign Currency
 
Commodity
 
Total
Balance at January 1
$
(101
)
 
$
93

 
$
4

 
$
(4
)
Total gains (losses) (realized and unrealized):


Included in earnings
2

 
134

 
1

 
137

Included in other comprehensive income - derivative activity
(154
)
 
(2
)
 
—

 
(156
)
Included in other comprehensive income - foreign currency translation activity
13

 
(25
)
 
—

 
(12
)
Included in regulatory (assets) liabilities
—

 
—

 
16

 
16

Settlements
30

 
(4
)
 
(15
)
 
11

Transfers of assets (liabilities) into Level 3
—

 
10

 
—

 
10

Transfers of (assets) liabilities out of Level 3
—

 
3

 
—

 
3

Balance at December 31
$
(210
)
 
$
209

 
$
6

 
$
5

Total gains (losses) for the period included in earnings attributable to the change in unrealized gains (losses) relating to assets and liabilities held at the end of the period
$
2

 
$
130

 
$
(1
)
 
$
131

Significant unobservable inputs, recurring
The following table summarizes the significant unobservable inputs used for the Level 3 derivative assets (liabilities) as of December 31, 2015:
Type of Derivative
 
Fair Value
 
Unobservable Input
 
Amount or Range
(Weighted Average)
 
 
(in millions)


Interest rate
 
$
(304
)
 
Subsidiaries’ credit spreads
 
2.88%-8.88% (5.42%)

Foreign currency:


Argentine Peso
 
291

 
Argentine Peso to U.S. Dollar currency exchange rate after 1 year
 
17.51 - 35.44 (26.05)

Euro
 
(14
)
 
Subsidiary's credit spread
 
8.88
%
Commodity:


Other
 
3


Total
 
$
(24
)


Fair value hierarchy for nonrecurring measurements table
The following table summarizes major categories of assets and liabilities measured at fair value on a nonrecurring basis during the period and their level within the fair value hierarchy (in millions):
 
 
Measurement Date
 
Carrying Amount
 
Fair Value
 
Pretax
Loss
Year Ended December 31, 2015
 
 
Level 1
 
Level 2
 
Level 3
 
Assets


Long-lived assets held and used:(1)


Kilroot
 
08/28/2015
 
$
191

 
$
—

 
$
—

 
$
70

 
$
121

Buffalo Gap III
 
09/30/2015
 
234

 
—

 
—

 
118

 
116

U.K. Wind (Development Projects)
 
06/30/2015
 
38

 
—

 
1

 
—

 
37

Other
 
Various
 
32

 
—

 
21

 
—

 
11

Equity method investments (3)


Solar Spain
 
02/09/2015
 
29

 
—

 
—

 
29

 
—

Goodwill(5)


DP&L
 
10/01/2015
 
317

 
—

 
—

 
—

 
317


Measurement Date
 
Carrying Amount
 
Fair Value
 
Pretax
Loss
Year Ended December 31, 2014
 
 
Level 1
 
Level 2
 
Level 3
 
Assets


Long-lived assets held and used:(1)


DP&L (East Bend)
 
03/31/2014
 
$
14

 
$
—

 
$
2

 
$
—

 
$
12

Ebute
 
06/30/2014
 
99

 
—

 
—

 
47

 
52

Ebute
 
09/30/2014
 
51

 
—

 
—

 
36

 
15

U.K. Wind (Newfield)
 
06/06/2014
 
12

 
—

 
—

 
—

 
12

Discontinued operations:(2)


Cameroon businesses
 
03/31/2014
 
372

 
—

 
334

 
—

 
38

Equity method investments (4)


Silver Ridge Power
 
06/30/2014
 
315

 
—

 
—

 
273

 
42

Entek
 
09/25/2014
 
211

 
—

 
125

 
—

 
86

Goodwill(5)


DPLER
 
02/28/2014
 
136

 
—

 
—

 
—

 
136

Buffalo Gap
 
03/31/2014
 
28

 
—

 
—

 
—

 
28

_____________________________
(1) 
See Note 21—Asset Impairment Expense for further information.
(2) 
See Note 23—Discontinued Operations for further information. Fair value of long-lived assets held-for-sale is presented net of costs to sell.
(3) 
See Note 8—Investments In and Advances to Affiliates for further information.
(4) 
See Note 9—Other Non-Operating Expense for further information.
(5) 
See Note 10—Goodwill and Other Intangible Assets for further information.
Significant unobservable inputs, nonrecurring
The following table summarizes the significant unobservable inputs used in the Level 3 measurement of long-lived assets and equity method investments during the year ended December 31, 2015:
 
 
Fair Value
 
Valuation Technique
 
Unobservable Input
 
Range (Weighted Average)
 
 
(in millions)


($ in millions)
Long-lived assets held and used:


Kilroot
 
$
70

 
Discounted cash flow
 
Annual revenue growth
 
-88% to 6% (-7%)


Annual pretax operating margin
 
-74% to 10% (0%)


Weighted Average Cost of Capital
 
6%
Buffalo Gap
 
118

 
Discounted cash flow
 
Annual revenue growth
 
-2% to 19% (3%)


Annual pretax operating margin
 
-282% to 58% (24%)


Weighted Average Cost of Capital
 
9%
Equity method investment:


Solar Spain
 
29

 
Discounted cash flow
 
Annual revenue growth
 
-3% to 0% (0%)


Annual pretax operating margin
 
-13% to 56% (24%)


Cost of equity
 
12%
Total
 
$
217


Financial instruments not measured at fair value in the condensed consolidated balance sheets
The following table presents in millions the carrying amount, fair value and fair value hierarchy of the Company's financial assets and liabilities that are not measured at fair value in the Consolidated Balance Sheets as of December 31, 2015 and 2014, but for which fair value is disclosed.
 
 
Carrying
Amount
 
Fair Value
 
 
Total
 
Level 1
 
Level 2
 
Level 3
December 31, 2015


Assets


Accounts receivable — noncurrent(1)
 
$
270

 
$
342

 
$
—

 
$
20

 
$
322

Liabilities


Non-recourse debt
 
15,792

 
15,939

 
—

 
13,672

 
2,267

Recourse debt
 
5,015

 
4,696

 
—

 
4,696

 
—

December 31, 2014


Assets


Accounts receivable — noncurrent(1)
 
$
257

 
$
246

 
$
—

 
$
—

 
$
246

Liabilities


Non-recourse debt
 
15,600

 
16,008

 
—

 
12,538

 
3,470

Recourse debt
 
5,258

 
5,552

 
—

 
5,552

 
—

_____________________________
(1) 
These accounts receivable principally relate to amounts due from CAMMESA, the administrator of the wholesale electricity market in Argentina, and are included in Noncurrent assets — Other in the accompanying Consolidated Balance Sheets. The fair value of these accounts receivable excludes value-added tax of $27 million and $36 million at December 31, 2015 and 2014, respectively.

v3.3.1.900
Investments In Marketable Securities (Tables)
12 Months Ended
Dec. 31, 2015
Investments, Debt and Equity Securities [Abstract]  
Pre-Tax Gains And Losses On Available For Sale And Trading Securities
The following table summarizes the gross proceeds from sale of AFS securities in millions for the years ended December 31, 2015, 2014, and 2013:
 
 
2015
 
2014
 
2013
Gross proceeds from sales of AFS securities
 
$
4,902

 
$
4,569

 
$
4,406


v3.3.1.900
Derivative Instruments and Hedging Activities (Tables)
12 Months Ended
Dec. 31, 2015
Derivative Instruments and Hedging Activities Disclosure [Abstract]  
Interest Rate Derivatives By Type Table
The following tables present, by type of derivative, the Company's outstanding notional under its derivatives and the weighted-average remaining term as of December 31, 2015 regardless of whether the derivative instruments are in qualifying cash flow hedging relationships:
 
 
Current
 
Maximum


Interest Rate and Cross Currency (1)
 
Derivative
Notional
 
Derivative Notional Translated to USD
 
Derivative
Notional
 
Derivative Notional Translated to USD
 
Weighted-Average Remaining Term
 
% of Debt Currently Hedged by Index (2)
 
 
(in millions)
 
(in years)
 
 
Interest Rate Derivatives:


LIBOR (U.S. Dollar)
 
2,639

 
$
2,639

 
2,872

 
$
2,872

 
11
 
48
%
EURIBOR (Euro)
 
482

 
524

 
482

 
524

 
6
 
83
%
Cross Currency Swaps:


Chilean Unidad de Fomento
 
4

 
159

 
4

 
159

 
13
 
76
%
_____________________________
(1) 
The Company's interest rate derivative instruments primarily include accreting and amortizing notionals. The maximum derivative notional represents the largest notional at any point between December 31, 2015 and the maturity of the derivative instrument, which includes forward-starting derivative instruments. The interest rate and cross currency derivatives range in maturity through 2033 and 2028, respectively.
(2) 
The percentage of variable-rate debt currently hedged is based on the related index and excludes forecasted issuances of debt and variable-rate debt tied to other indices where the Company has no interest rate derivatives.
Foreign Currency Derivatives By Type Table
 
 
December 31, 2015
Foreign Currency Derivatives
 
Notional(1)
 
Notional Translated to USD
 
Weighted-Average Remaining Term(2)
 
 
(in millions)
 
(in years)
Foreign Currency Derivatives


Argentine Peso
 
$
2,321

 
$
178

 
10
Brazilian Real
 
80

 
21

 
<1
British Pound
 
22

 
32

 
<1
Chilean Peso
 
84,669

 
119

 
<1
Chilean Unidad de Fomento
 
9

 
311

 
<1
Colombian Peso
 
252,166

 
80

 
<1
Euro
 
32

 
35

 
<1
Kazakhstani Tenge
 
1,691

 
5

 
1
_____________________________
(1) 
Represents contractual notionals. The notionals for options have not been probability adjusted, which generally would decrease them.
(2) 
Represents the remaining tenor of our foreign currency derivatives weighted by the corresponding notional. These derivatives matures through 2026
Commodity Derivatives By Type Table
December 31, 2015


Weighted-Average
Commodity Derivatives
 
Notional
 
Remaining Term(1)
 
 
(in millions)
 
(in years)
Power (MWh)
 
10

 
3

_____________________________
(1) 
Represents the remaining tenor of our commodity derivatives weighted by the corresponding volume. These derivatives range in maturity through 2018.
Derivative Assets Liabilities At Fair Value Net By Balance Sheet Classification And Type Table
The following tables present in millions the Company's derivative instruments as of the periods indicated, first by whether or not they are designated hedging instruments, then by whether they are current or noncurrent to the extent they are subject to master netting agreements or similar agreements (where the rights to set-off relate to settlement of amounts receivable and payable under those derivatives) and by balances no longer accounted for as derivatives.
 
 
December 31, 2015
 
December 31, 2014
 
 
Designated
 
Not Designated
 
Total
 
Designated
 
Not Designated
 
Total
Assets


Foreign currency derivatives
 
$
8

 
$
319

 
$
327

 
$
6

 
$
230

 
$
236

Commodity derivatives
 
30

 
18

 
48

 
25

 
19

 
44

Total assets
 
$
38

 
$
337

 
$
375

 
$
31

 
$
249

 
$
280

Liabilities


Interest rate derivatives
 
$
358

 
$
—

 
$
358

 
$
416

 
$
—

 
$
416

Cross currency derivatives
 
43

 
—

 
43

 
29

 
—

 
29

Foreign currency derivatives
 
35

 
21

 
56

 
38

 
14

 
52

Commodity derivatives
 
12

 
21

 
33

 
7

 
10

 
17

Total liabilities
 
$
448

 
$
42

 
$
490

 
$
490

 
$
24

 
$
514


December 31, 2015
 
December 31, 2014
 
 
Assets
 
Liabilities
 
Assets
 
Liabilities
Current
 
$
86

 
$
144

 
$
77

 
$
148

Noncurrent
 
289

 
346

 
203

 
366

Total
 
$
375

 
$
490

 
$
280

 
$
514

Derivatives subject to master netting agreement or similar agreement:


Gross amounts recognized in the balance sheet
 
$
57

 
$
467

 
$
53

 
$
507

Gross amounts of derivative instruments not offset
 
(18
)
 
(18
)
 
(10
)
 
(10
)
Gross amounts of cash collateral received/pledged not offset
 
—

 
(38
)
 
—

 
(26
)
Net amount
 
$
39

 
$
411

 
$
43

 
$
471

Other balances that had been, but are no longer, accounted for as derivatives that are to be amortized to earnings over the remaining term of the associated PPA
 
$
147

 
$
166

 
$
161

 
$
180

Gain Loss In Accumulated Other Comprehensive Income And Earnings On Effective Portion Of Qualifying Cash Flow Hedges Table
The following tables present (in millions) the pretax gains (losses) recognized in AOCL and earnings related to the effective portion of derivative instruments in qualifying cash flow hedging relationships (including amounts that were reclassified from AOCL as interest expense related to interest rate derivative instruments that previously, but no longer, qualify for cash flow hedge accounting), as defined in the accounting standards for derivatives and hedging, for the periods indicated:
Years Ended December 31,
 
Gains (Losses) Recognized in AOCL
 
Classification in Consolidated Statements of Operations
 
Gains (Losses) Reclassified from AOCL into Earnings
Type of Derivative
 
2015
 
2014
 
2013
 
2015
 
2014
 
2013
Interest rate derivatives
 
$
(103
)
 
$
(421
)
 
$
155

 
Interest expense
 
$
(108
)
 
$
(139
)
 
$
(127
)


Non-regulated cost of sales
 
(2
)
 
(2
)
 
(5
)


Net equity in earnings of affiliates
 
(2
)
 
(3
)
 
(6
)


Gain on sale of investments
 
(4
)
 
—

 
(21
)
Cross currency derivatives
 
(20
)
 
(25
)
 
(18
)
 
Interest expense
 
(4
)
 
—

 
(10
)


Foreign currency transaction gains (losses)
 
(20
)
 
(23
)
 
(18
)
Foreign currency derivatives
 
10

 
(28
)
 
—

 
Foreign currency transaction gains (losses)
 
32

 
14

 
12

Commodity derivatives
 
40

 
44

 
2

 
Non-regulated revenue
 
43

 
30

 
(3
)


Non-regulated cost of sales
 
(12
)
 
(2
)
 
(2
)
Total
 
$
(73
)
 
$
(430
)
 
$
139


$
(77
)
 
$
(125
)
 
$
(180
)
Gain Loss In Earnings On Ineffective Portion Of Qualifying Cash Flow Hedges Table
The following table presents (in millions) the pretax gains (losses) recognized in earnings related to the ineffective portion of derivative instruments in qualifying cash flow hedging relationships, as defined in the accounting standards for derivatives and hedging, for the periods indicated:


Gains (Losses) Recognized in Earnings
 
 
Classification in Consolidated Statements of Operations
 
Years Ended December 31,
Type of Derivative
 
 
2015
 
2014
 
2013
Interest rate derivatives
 
Interest expense
 
$
(4
)
 
$
—

 
$
42


Net equity in earnings of affiliates
 
—

 
(1
)
 
1

Foreign currency derivatives
 
Foreign currency transaction gains (losses)
 
(3
)
 
(2
)
 
—

Cross currency derivatives
 
Interest expense
 
1

 
(1
)
 
—

Total


$
(6
)
 
$
(4
)
 
$
43

Gain Loss In Earnings On Non Hedging Instruments Table
The next table presents (in millions) the gains (losses) recognized in earnings related to derivative instruments not designated as hedging instruments under the accounting standards for derivatives and hedging, and amortization of balances that had been, but are no longer, accounted for as derivatives, for the periods indicated:


Gains (Losses) Recognized in Earnings
 
 
Classification in Consolidated Statements of Operations
 
Years Ended December 31,
Type of Derivative
 
2015
 
2014
 
2013
Interest rate derivatives
 
Interest expense
 
$
—

 
$
(3
)
 
$
(1
)
 
 
Net equity in earnings of affiliates
 
—

 
—

 
(6
)
Foreign currency derivatives
 
Foreign currency transaction gains (losses)
 
211

 
146

 
64


Net equity in earnings of affiliates
 
—

 
(2
)
 
(24
)
Commodity and other derivatives
 
Non-regulated revenue
 
(8
)
 
5

 
11


Non-regulated cost of sales
 
(16
)
 
(3
)
 
1


Regulated cost of sales
 
(5
)
 
(6
)
 
2


Income (loss) from operations of discontinued businesses
 
—

 
(7
)
 
(18
)
 
 
Net gain (loss) from disposal and impairments of discontinued operations
 
—

 
72

 
—

Total


$
182

 
$
202

 
$
29


v3.3.1.900
Financing Receivables (Tables)
12 Months Ended
Dec. 31, 2015
Receivables [Abstract]  
Financing Receivables
The table below presents the breakdown of financing receivables in millions by country as of the periods indicated:
December 31,
 
2015
 
2014
Argentina
 
$
237

 
$
278

Cameroon (1)
 
—

 
44

United States
 
20

 
—

Brazil
 
39

 
15

Total long-term financing receivables
 
$
296

 
$
337

_____________________________
(1) 
Represents non-contingent consideration to be received in 2016 from the sale of the Cameroon businesses in 2014. Balance is classified as short-term as of December 31, 2015. See Note 23—Discontinued Operations.

v3.3.1.900
Investments In and Advances To Affiliates (Tables)
12 Months Ended
Dec. 31, 2015
Equity Method Investments and Joint Ventures [Abstract]  
Equity Ownership Interest And Carrying Values Of Investments Accounted For Under The Equity Method
The following table summarizes the relevant effective equity ownership interest and carrying values for the Company's investments accounted for under the equity method as of the periods indicated.
December 31,
 
 
2015
 
2014
 
2015
 
2014
Affiliate
Country
 
Carrying Value (in millions)
 
Ownership Interest %
Solar Power PR
Puerto Rico
 
$
—

 
$
2

 
—
%
 
50
%
Barry(1) 
United Kingdom
 
—

 
—

 
100
%
 
100
%
Elsta(1)
Netherlands
 
53

 
54

 
50
%
 
50
%
Distributed Energy(1)
United States
 
17

 
—

 
94
%
 
—
%
Guacolda(2)
Chile
 
344

 
285

 
33
%
 
35
%
OPGC(3)
India
 
195

 
194

 
49
%
 
49
%
Other affiliates
Various
 
1

 
2


Total investments in and advances to affiliates
 
 
$
610

 
$
537


(1) 
Represent VIEs in which the Company holds a variable interest but is not the primary beneficiary.
(2) 
The Company's ownership in Guacolda is held through AES Gener, a 67%-owned consolidated subsidiary. AES Gener owns 50% of Guacolda, resulting in an AES effective ownership in Guacolda of 33%. At December 31, 2014, AES owned 71% of AES Gener, resulting in an AES effective ownership in Guacolda of 35%.
(3) 
OPGC has one coal-fired expansion project under development. The project started construction in April 2014 and is currently expected to begin operations in 2018.
Investments In and Advances to Affiliates Financial Information
The following tables summarize financial information of the Company's 50%-or-less-owned affiliates and majority-owned unconsolidated subsidiaries that are accounted for using the equity method in millions.
 
50%-or-less Owned Affiliates
 
Majority-Owned Unconsolidated Subsidiaries
Years ended December 31,
2015
 
2014
 
2013
 
2015
 
2014
 
2013
Revenue
$
641

 
$
928

 
$
1,099

 
$
24

 
$
2

 
$
2

Operating margin
152

 
206

 
295

 
11

 
—

 
—

Net income (loss)
210

 
59

 
53

 
6

 
—

 
—


December 31,
2015
 
2014


2015
 
2014
 
 
Current assets
$
376

 
$
450


$
20

 
$
—


Noncurrent assets
2,132

 
1,748


211

 
15


Current liabilities
435

 
299


21

 
—


Noncurrent liabilities
1,044

 
935


153

 
67


Noncontrolling interests
—

 
17


—

 
—


Stockholders' equity
1,029

 
947


57

 
(52
)


v3.3.1.900
Other Non-Operating Expense (Tables)
12 Months Ended
Dec. 31, 2015
Other Income and Expenses [Abstract]  
Schedule of Other Nonoperating Expense, by Component [Table Text Block]
Years Ended December 31,
2014
 
2013
 
(in millions)
Entek
$
86

 
$
—

Silver Ridge
42

 
—

Elsta
—

 
129

Total other non-operating expense
$
128

 
$
129


v3.3.1.900
Goodwill and Other Intangible Assets (Tables)
12 Months Ended
Dec. 31, 2015
Goodwill and Intangible Assets Disclosure [Abstract]  
Schedule of Goodwill
The following table summarizes the changes in the carrying amount of goodwill, by reportable segment for the years ended December 31, 2015 and 2014 in millions.
 
US
 
Andes
 
MCAC
 
Europe
 
Asia
 
Total
Balance as of December 31, 2013


Goodwill
$
2,658

 
$
899

 
$
149

 
$
180

 
$
68

 
$
3,954

Accumulated impairment losses
(2,152
)
 
—

 
—

 
(180
)
 
—

 
(2,332
)
Net balance
506

 
899

 
149

 
—

 
68

 
1,622

Impairment losses
(164
)
 
—

 
—

 
—

 
—

 
(164
)
Balance as of December 31, 2014


Goodwill
2,658

 
899

 
149

 
122

(1) 
68

 
3,896

Accumulated impairment losses
(2,316
)
 
—

 
—

 
(122
)
 
—

 
(2,438
)
Net balance
342

 
899

 
149

 
—

 
68

 
1,458

Impairment losses
(317
)
 
—

 
—

 
—

 
—

 
(317
)
Goodwill acquired during the year
16

 
—

 
—

 
—

 
—

 
16

Balance as of December 31, 2015


Goodwill
2,674

 
899

 
149

 
122

 
68

 
3,912

Accumulated impairment losses
(2,633
)
 
—

 
—

 
(122
)
 
—

 
(2,755
)
Net balance
$
41

 
$
899

 
$
149

 
$
—

 
$
68

 
$
1,157


_____________________________
(1) Both the gross carrying amount and the accumulated impairment losses of the Europe segment have been reduced by $58 million with no impact on the net carrying amount for the segment. This relates to Ebute, which had fully impaired goodwill of $58 million and was sold in 2014.
Schedule of Finite-Lived and Indefinite-Lived Intangible Assets
The following table summarizes the balances comprising other intangible assets in the accompanying Consolidated Balance Sheets (in millions) as of the periods indicated:
 
December 31, 2015
 
December 31, 2014
 
Gross Balance
 
Accumulated Amortization
 
Net Balance
 
Gross Balance
 
Accumulated Amortization
 
Net Balance
Subject to Amortization


Project development rights(1)
$
4

 
$
(1
)
 
$
3

 
$
28

 
$
(1
)
 
$
27

Sales concessions
71

 
(19
)
 
52

 
86

 
(41
)
 
45

Contractual payment rights(2)
66

 
(46
)
 
20

 
69

 
(40
)
 
29

Management rights
24

 
(10
)
 
14

 
33

 
(13
)
 
20

Land use rights
28

 
—

 
28

 
25

 
—

 
25

Contracts
29

 
(12
)
 
17

 
36

 
(19
)
 
17

Customer contracts and relationships (3)
6

 
(6
)
 
—

 
63

 
(39
)
 
24

Other(4)
15

 
(3
)
 
12

 
22

 
(5
)
 
17

Subtotal
243

 
(97
)
 
146

 
362

 
(158
)
 
204

Indefinite-Lived Intangible Assets


Land use rights
38

 
—

 
38

 
37

 
—

 
37

Water rights
17

 
—

 
17

 
20

 
—

 
20

Other
13

 
—

 
13

 
20

 
—

 
20

Subtotal
68

 
—

 
68

 
77

 
—

 
77

Total
$
311

 
$
(97
)
 
$
214

 
$
439

 
$
(158
)
 
$
281

_____________________________
(1) 
2014 balance includes U.K. Wind operations. In August 2014 these assets were sold, but did not meet the criteria to be reported as discontinued operations and their results are reflected within continuing operations. See Note 24—Dispositions and Held-for-Sale Businesses for further information.
(2) 
Represent legal rights to receive system reliability payments from the regulator.
(3) 
2014 balance includes DPLER which is considered held-for-sale as of December 31, 2015. See Note 24—Dispositions and Held-for-Sale Businesses for further information.
(4) 
Includes renewable energy certificates, emission allowances and various other intangible assets none of which is individually significant.
Schedule of Acquired Intangible Assets By Major Class
The following tables summarize, by category, other intangible assets acquired during the period indicated ($ in millions):
 
December 31, 2015
 
Amount
 
Subject to Amortization/Indefinite-Lived
 
Weighted Average Amortization Period (in years)
 
Amortization Method
Contracts
$
22

 
Subject to Amortization
 
5
 
Straight-line
Land-use rights
13

 
Subject to Amortization
 
N/A
 
N/A
Other
5

 
Various
 
N/A
 
N/A
Total
$
40


December 31, 2014
 
Amount
 
Subject to Amortization/
Indefinite-Lived
 
Weighted Average
Amortization Period (in years)
 
Amortization
Method
Renewable energy certificates
$
3

 
Indefinite
 
N/A
 
N/A
Land-use rights
16

 
Subject to Amortization
 
N/A
 
N/A
Total
$
19


Schedule of Expected Amortization Expense
The following table summarizes the estimated amortization expense by intangible asset category for 2016 through 2020:
(in millions)
2016
 
2017
 
2018
 
2019
 
2020
Sales concessions
7

 
7

 
7

 
7

 
7

All other
4

 
4

 
4

 
3

 
3

Total
$
11

 
$
11

 
$
11

 
$
10

 
$
10


v3.3.1.900
Regulatory Assets and Liabilities (Tables)
12 Months Ended
Dec. 31, 2015
Regulated Operations [Abstract]  
Regulatory Assets and Liabilities
The Company has recorded regulatory assets and liabilities (in millions) that it expects to pass through to its customers in accordance with, and subject to, regulatory provisions as follows:
December 31,
2015
 
2014
 
Recovery/Refund Period
REGULATORY ASSETS


Current regulatory assets:


Brazil tariff recoveries:(1)


Energy purchases/sales
$
416

 
$
424

 
Annually as part of the tariff adjustment
Transmission costs, regulatory fees and other
264

 
63

 
Annually as part of the tariff adjustment
El Salvador tariff recoveries(2)
43

 
92

 
Quarterly as part of the tariff adjustment
Other(3) 
23

 
58

 
Various
Total current regulatory assets
746

 
637


Noncurrent regulatory assets:


Defined benefit pension obligations at IPL and DPL(4)(5)
227

 
329

 
Various
Income taxes recoverable from customers(4)(6)
36

 
74

 
Various
Brazil tariff recoveries:(1)


Energy purchases/sales
147

 
266

 
Annually as part of the tariff adjustment
Transmission costs, regulatory fees and other
140

 
14

 
Annually as part of the tariff adjustment
Deferred Midwest ISO costs(7)
129

 
111

 
To be determined
Other(3)
239

 
78

 
Various
Total noncurrent regulatory assets
918

 
872


TOTAL REGULATORY ASSETS
$
1,664

 
$
1,509


REGULATORY LIABILITIES


Current regulatory liabilities:


Brazil tariff reset adjustment(8)
$
—

 
$
76

 
Two years
Efficiency program costs(9)
12

 
22

 
Annually as part of the tariff adjustment
Brazil regulatory asset base adjustment(13)
169

 
123

 
Up to four tariff periods
Brazil tariff refunds:(1)


Energy purchases/sales
105

 
144

 
Annually as part of the tariff adjustment
Transmission costs, regulatory fees and other
120

 
174

 
Annually as part of the tariff adjustment
Other(10) 
59

 
66

 
Various
Total current regulatory liabilities
465

 
605


Noncurrent regulatory liabilities:


Asset retirement obligations(11)
759

 
727

 
Over life of assets
Brazil regulatory asset base adjustment(13)
86

 
61

 
Up to four tariff periods
Brazil special obligations(12)
370

 
484

 
To be determined
Brazil tariff refunds:(1)


Energy purchases/sales
30

 
128

 
Annually as part of the tariff adjustment
Transmission costs, regulatory fees and other
29

 
97

 
Annually as part of the tariff adjustment
Efficiency program costs(9)
5

 
11

 
Annually as part of the tariff adjustment
Other(10) 
7

 
1

 
Various
Total noncurrent regulatory liabilities
1,286

 
1,509


TOTAL REGULATORY LIABILITIES
$
1,751

 
$
2,114


_____________________________
(1)
Recoverable or refundable per Brazilian National Electric Energy Agency ("ANEEL") regulations through the Annual Tariff Adjustment ("IRT"). These costs are generally non-controllable and primarily consist of purchased electricity, energy transmission, and sector costs that are considered volatile. The costs are passed through for a period of 12 months as part of the IRT. Any remaining balance is considered in the subsequent IRT, which results in a total of 24 months to recover or refund the costs. Favorable spot market sales are also subject to customer refunds through the IRT over the course of these time periods.
(2)
Deferred fuel costs incurred by our El Salvador subsidiaries associated with purchase of energy from the El Salvador spot market and power generation plants. In El Salvador, the deferred fuel adjustment represents the variance between the actual fuel costs and the fuel costs recovered in the tariffs. The variance is recovered quarterly in the tariff reset period.
(3)
Includes assets with and without a rate of return. Other current regulatory assets that did not earn a rate of return were $8 million and $22 million, as of December 31, 2015 and 2014, respectively. Other noncurrent regulatory assets that did not earn a rate of return were $237 million and $73 million, as of December 31, 2015 and 2014, respectively. Other current and noncurrent regulatory assets primarily consist of:
▪
Unamortized losses on long-term debt reacquired or redeemed in prior periods at IPL and DPL, which are amortized over the lives of the original issues in accordance with the Federal Energy Regulatory Commission ("FERC") and PUCO rules.
▪
Unamortized carrying charges and certain other costs related to Petersburg unit 4 at IPL.
▪
Deferred storm costs incurred primarily in 2008 to repair storm damage at DPL; recovery was approved via order from the PUCO on December 17, 2014 and began January 2015.
▪
Additional Regulatory Asset Base ("RAB") from a favorable decision on tariff reset (administrative appeal) at Eletropaulo.
(4)
Past expenditures on which the Company does not earn a rate of return.
(5)
The regulatory accounting standards allow the defined pension and postretirement benefit obligation to be recorded as a regulatory asset equal to the previously unrecognized actuarial gains and losses and prior service costs that are expected to be recovered through future rates. Pension expense is recognized based on the plan's actuarially determined pension liability. Recovery of costs is probable, but not yet determined. Pension contributions made by our Brazilian subsidiaries are not included in regulatory assets as those contributions are not covered by the established tariff in Brazil.
(6)
Probable recovery through future rates, based upon established regulatory practices, which permit the recovery of current taxes. This amount is expected to be recovered, without interest, over the period as book-tax temporary differences reverse and become current taxes.
(7)
Transmission service costs and other administrative costs from IPL's participation in the Midwest ISO market, which are recoverable but do not earn a rate of return. Recovery of costs is probable, but the timing is not yet determined.
(8)
In July 2012, the Brazilian energy regulator (the "Regulator") approved the periodic review and reset of a component of Eletropaulo's regulated tariff, which determines the margin to be earned by Eletropaulo. The review and reset of this tariff component was retroactive to July 2011 and applied to customers' invoices from July 2012 to June 2015. From July 2011 through June 2012, Eletropaulo invoiced customers under the then-existing tariff rate, as required by the Regulator. As the new tariff rate was lower than the previous rate, Eletropaulo was required to reduce customer tariffs for the difference over the next year. Accordingly, from July 2011 through June 2012, Eletropaulo recognized a regulatory liability for the estimated future refunds, subsequently adjusted as of June 30, 2012 upon the finalization of the new tariff with the Regulator. The refund to customers was considered in the 2013 tariff adjustment, which contemplated an amortization of 67.55% from July 4, 2013. The remaining balance, representing 32.45%, was considered in the next annual tariff adjustment. There was no recorded current regulatory liability at Eletropaulo as of December 31, 2015.
(9)
Amounts received for costs expected to be incurred to improve the efficiency of our plants in Brazil as part of the IRT.
(10)
Other current and noncurrent regulatory liabilities primarily consist of liabilities owed to electricity generators due to variance in energy prices during rationing periods ("Free Energy"). Our Brazilian subsidiaries are authorized to refund this cost associated with monthly energy price variances between the wholesale energy market prices owed to the power generation plants producing Free Energy and the capped price reimbursed by the local distribution companies which are passed through to the final customers through energy tariffs. The balance excludes asset retirement obligations that were reclassified out of Other.
(11)
Obligations for removal costs which do not have an associated legal retirement obligation as defined by the accounting standards on asset retirement obligations.
(12)
Obligations established by ANEEL in Brazil associated with electric utility concessions and represent amounts received from customers or donations not subject to return. These donations are allocated to support energy network expansion and to improve utility operations to meet customers' needs. The term of the obligation is established by ANEEL. Settlement shall occur when the concession ends.
(13) 
Represents adjustments to the RAB resulting from an administrative ruling in December 2013 compelling Eletropaulo to refund customers beginning July 2014.
Schedule of Regulatory Assets by Region
The following table summarizes regulatory assets and liabilities by reportable segment in millions as of the periods indicated:
December 31,
2015
 
2014
 
Regulatory Assets
 
Regulatory Liabilities
 
Regulatory Assets
 
Regulatory Liabilities
Brazil SBU
$
971

 
$
932

 
$
787

 
$
1,347

US SBU
650

 
819

 
631

 
767

MCAC SBU (El Salvador)
43

 
—

 
91

 
—

Total
$
1,664

 
$
1,751

 
$
1,509

 
$
2,114


v3.3.1.900
Debt (Tables)
12 Months Ended
Dec. 31, 2015
Debt Disclosure [Abstract]  
Carrying Amount and Terms of Non-Recourse Debt
The next table summarizes the carrying amount (in millions) and terms of non-recourse debt as of the periods indicated:
NON-RECOURSE DEBT
Weighted Average Interest Rate
 
Maturity
 
December 31,
2015
 
2014
VARIABLE RATE:(1)


Bank loans
4.37
%
 
2016 – 2033
 
$
2,352

 
$
1,893

Notes and bonds
14.98
%
 
2016 – 2022
 
1,474

 
1,912

Debt to (or guaranteed by) multilateral, export credit agencies or development banks(2)
2.39
%
 
2021 – 2034
 
3,078

 
2,375

Other
12.65
%
 
2016 – 2043
 
47

 
668

FIXED RATE:


Bank loans
5.11
%
 
2016 – 2032
 
558

 
750

Notes and bonds
5.54
%
 
2016 – 2073
 
7,948

 
7,654

Debt to (or guaranteed by) multilateral, export credit agencies or development banks(2)
5.39
%
 
2023 – 2034
 
309

 
259

Other
8.66
%
 
2016 – 2049
 
26

 
89

SUBTOTAL


15,792

 
15,600

Less: Current maturities


(2,529
)
 
(1,982
)
TOTAL


$
13,263

 
$
13,618

(1)
The interest rate on variable rate debt represents the total of a variable component that is based on changes in an interest rate index and of a fixed component. The Company has interest rate swaps and option agreements in an aggregate notional principal amount of approximately $3.2 billion on non-recourse debt outstanding at December 31, 2015. These agreements economically fix the variable component of the interest rates on the portion of the variable-rate debt being hedged so that the total interest rate on that debt has been fixed at rates ranging from approximately 2.87% to 8.24%. These agreements expire at various dates from 2016 through 2033.
(2)
Multilateral loans include loans funded and guaranteed by bilaterals, multilaterals, development banks and other similar institutions.
Schedule For Maturity For Non-Recourse Debt
Non-recourse debt (in millions) as of December 31, 2015 is scheduled to reach maturity as presented in the table below:
December 31,
Annual Maturities
2016
$
2,529

2017
1,022

2018
1,359

2019
950

2020
1,431

Thereafter
8,501

Total non-recourse debt
$
15,792

Debt In Default Table
The following table summarizes the Company's subsidiary non-recourse debt in default (in millions) as of December 31, 2015. Due to the defaults, these amounts are included in the current portion of non-recourse debt:
 
Primary Nature
of Default
 
December 31, 2015
Subsidiary
Default
 
Net Assets
Maritza (Bulgaria)
Covenant
 
$
559

 
$
657

Sul (Brazil)
Covenant
 
333

 
439

Kavarna (Bulgaria)
Covenant
 
140

 
74

Sogrinsk (Kazakhstan)
Covenant
 
$
6

 
8

Total
 
 
$
1,038


Schedule of Recourse Debt Detail
The table below summarizes the carrying amount (in millions) and terms of recourse debt of the Company as of the periods indicated:
RECOURSE DEBT
Interest Rate
 
Final Maturity
 
December 31, 2015

 
December 31, 2014
Senior Unsecured Note
7.75%
 
2015
 
$
—

 
$
151

Senior Unsecured Note
9.75%
 
2016
 
—

 
164

Senior Unsecured Note
8.00%
 
2017
 
181

 
525

Senior Unsecured Note
LIBOR + 3%
 
2019
 
775

 
775

Senior Unsecured Note
8.00%
 
2020
 
469

 
625

Senior Unsecured Note
7.38%
 
2021
 
1,000

 
1,000

Senior Unsecured Note
4.88%
 
2023
 
750

 
750

Senior Unsecured Note
5.50%
 
2024
 
750

 
750

Senior Unsecured Note
5.50%
 
2025
 
575

 
—

Term Convertible Trust Securities
6.75%
 
2029
 
517

 
517

Unamortized (Discounts)/Premiums


(2
)
 
1

SUBTOTAL


5,015

 
5,258

Less: Current maturities


—

 
(151
)
Total


$
5,015

 
$
5,107


December 31,
 
 
Interest Rate
 
Maturity
 
2015
 
2014
Senior Unsecured Note
 
7.75%
 
2015
 
$
—

 
$
151

Senior Unsecured Note
 
9.75%
 
2016
 
—

 
164

Senior Unsecured Note
 
8.00%
 
2017
 
181

 
525

Senior Unsecured Note
 
LIBOR + 3.00%
 
2019
 
775

 
775

Senior Unsecured Note
 
8.00%
 
2020
 
469

 
625

Senior Unsecured Note
 
7.38%
 
2021
 
1,000

 
1,000

Senior Unsecured Note
 
4.88%
 
2023
 
750

 
750

Senior Unsecured Note
 
5.50%
 
2024
 
750

 
750

Senior Unsecured Note
 
5.50%
 
2025
 
575

 
—

Unamortized premium (discounts)


(2
)
 
1

SUBTOTAL


4,498

 
4,741

Less: Current maturities


—

 
(151
)
Total


$
4,498

 
$
4,590

Schedule of Future Maturities of Recourse Debt
The table below summarizes the principal amounts due, net of unamortized discounts, under our recourse debt for the next five years and thereafter in millions:
December 31,
Net Principal Amounts Due
2016
$
—

2017
181

2018
—

2019
774

2020
469

Thereafter
3,591

Total recourse debt
$
5,015

Recourse debt as of December 31, 2015 is scheduled to reach maturity as presented in the table below in millions:
December 31,
Annual Maturities
2016
$
—

2017
181

2018
—

2019
774

2020
469

Thereafter
3,591

Total debt
$
5,015


v3.3.1.900
Commitments (Tables)
12 Months Ended
Dec. 31, 2015
Commitments and Contingencies Disclosure [Abstract]  
Operating Leases of Lessee Disclosure
The table below presents the future minimum lease payments under operating and capital leases for continuing operations together with the present value of the net minimum lease payments under capital leases as of December 31, 2015 for 2016 through 2020 and thereafter, in millions:
 
Future Commitments for
December 31,
Capital Leases
 
Operating Leases
2016
$
14

 
$
77

2017
12

 
78

2018
11

 
79

2019
10

 
80

2020
10

 
79

Thereafter
90

 
898

Total
147

 
$
1,291

Less: Imputed interest
90


Present value of total minimum lease payments
$
57


Electricity Purchase Contract Commitment
Actual purchases under these contracts for the years ended December 31, 2015, 2014, and 2013 are also presented, in millions:
Actual purchases during the year ended December 31,
Electricity Purchase Contracts
 
Fuel Purchase Contracts
 
Other Purchase Contracts
2013
$
2,665

 
$
1,590

 
$
1,743

2014
3,104

 
1,521

 
1,386

2015
2,592

 
1,262

 
2,121

Future commitments for the year ending December 31,


2016
$
2,623

 
$
1,120

 
$
1,332

2017
2,444

 
835

 
1,047

2018
2,634

 
532

 
1,081

2019
2,799

 
314

 
873

2020
2,918

 
311

 
655

Thereafter
24,176

 
2,141

 
4,395

Total
$
37,594

 
$
5,253

 
$
9,383


v3.3.1.900
Contingencies (Tables)
12 Months Ended
Dec. 31, 2015
Commitments and Contingencies Disclosure [Abstract]  
Contingent Contractual Obligations
The following table summarizes the Parent Company's contingent contractual obligations as of December 31, 2015. Amounts presented in the table below represent the Parent Company's current undiscounted exposure to guarantees and the range of maximum undiscounted potential exposure. The maximum exposure is not reduced by the amounts, if any, that could be recovered under the recourse or collateralization provisions in the guarantees. The amounts include obligations made by the Parent Company for the direct benefit of the lenders associated with the non-recourse debt of its businesses of $14 million.
Contingent Contractual Obligations
 
Amount
 
Number of Agreements
 
Maximum Exposure Range for Each Agreement
 
 
(in millions)


(in millions)
Guarantees and commitments
 
$
369

 
14
 
$1 - 53
Asset sale related indemnities(1)
 
27

 
1
 
27
Cash collateralized letters of credit
 
32

 
4
 
$1 - 15
Letters of credit under the senior secured credit facility
 
62

 
7
 
<$1 - 29
Total
 
$
490

 
26


(1) Excludes normal and customary representations and warranties in agreements for the sale of assets (including ownership in associated legal entities) where the associated risk is considered to be nominal.

v3.3.1.900
Benefit Plans (Tables)
12 Months Ended
Dec. 31, 2015
Compensation and Retirement Disclosure [Abstract]  
Schedule of Net Funded Status
The following table reconciles the Company's funded status, both domestic and foreign, as of the periods indicated:
December 31,
 
2015
 
2014
(in millions)
 
U.S.
 
Foreign
 
U.S.
 
Foreign
CHANGE IN PROJECTED BENEFIT OBLIGATION:


Benefit obligation as of January 1
 
$
1,235

 
$
4,363

 
$
1,059

 
$
4,749

Service cost
 
16

 
15

 
14

 
16

Interest cost
 
48

 
351

 
50

 
489

Employee contributions
 
—

 
3

 
—

 
4

Plan amendments
 
5

 
2

 
8

 
(3
)
Plan settlements
 
(3
)
 
—

 
—

 
—

Benefits paid
 
(61
)
 
(300
)
 
(59
)
 
(415
)
Actuarial (gain) loss
 
(68
)
 
(160
)
 
163

 
87

Effect of foreign currency exchange rate changes
 
—

 
(1,301
)
 
—

 
(564
)
Benefit obligation as of December 31
 
$
1,172

 
$
2,973

 
$
1,235

 
$
4,363

CHANGE IN PLAN ASSETS:


Fair value of plan assets as of January 1
 
$
1,061

 
$
3,272

 
$
941

 
$
3,605

Actual return on plan assets
 
(7
)
 
182

 
123

 
360

Employer contributions
 
31

 
89

 
56

 
135

Employee contributions
 
—

 
3

 
—

 
4

Plan settlements
 
(3
)
 
—

 
—

 
—

Benefits paid
 
(61
)
 
(300
)
 
(59
)
 
(415
)
Effect of foreign currency exchange rate changes
 
—

 
(962
)
 
—

 
(417
)
Fair value of plan assets as of December 31
 
$
1,021

 
$
2,284

 
$
1,061

 
$
3,272

RECONCILIATION OF FUNDED STATUS


Funded status as of December 31
 
$
(151
)
 
$
(689
)
 
$
(174
)
 
$
(1,091
)

Schedule of Amounts Recognized in Balance Sheet
The following table summarizes the amounts recognized on the Consolidated Balance Sheets in millions related to the funded status of the plans, both domestic and foreign, as of the periods indicated:
December 31,
 
2015
 
2014
AMOUNTS RECOGNIZED ON THE CONSOLIDATED BALANCE SHEETS
 
U.S.
 
Foreign
 
U.S.
 
Foreign
Noncurrent assets
 
$
—

 
$
67

 
$
—

 
$
51

Accrued benefit liability—current
 
—

 
(5
)
 
—

 
(4
)
Accrued benefit liability—noncurrent
 
(151
)
 
(751
)
 
(174
)
 
(1,138
)
Net amount recognized at end of year
 
$
(151
)
 
$
(689
)
 
$
(174
)
 
$
(1,091
)
Schedule of Accumulated and Projected Benefit Obligations
The next table summarizes the Company's U.S. and foreign accumulated benefit obligation as of the periods indicated (in millions):
December 31,
2015
 
2014
 
 
U.S.
 
Foreign
 
U.S.
 
Foreign
 
Accumulated Benefit Obligation
$
1,150

 
$
2,931

 
$
1,208

 
$
4,301

 
Information for pension plans with an accumulated benefit obligation in excess of plan assets:


Projected benefit obligation
$
1,172

 
$
2,683

 
$
1,235

 
$
4,021

 
Accumulated benefit obligation
1,150

 
2,656

 
1,208

 
3,979

 
Fair value of plan assets
1,021

 
1,931

 
1,061

 
2,885

 
Information for pension plans with a projected benefit obligation in excess of plan assets:


Projected benefit obligation
$
1,172

 
$
2,697

(1) 
$
1,235

 
$
4,038

(1) 
Fair value of plan assets
1,021

 
1,942

(1) 
1,061

 
2,897

(1) 
(1)
$686 million and $1.1 billion of the total net unfunded projected benefit obligation is due to Eletropaulo in Brazil as of December 31, 2015 and 2014, respectively.
Schedule of Assumptions Used
The table below summarizes the significant weighted average assumptions used in the calculation of benefit obligation and net periodic benefit cost, both domestic and foreign, as of the periods indicated:
December 31,
2015
 
2014
 
 
U.S.
 
Foreign
 
U.S.
 
Foreign
 
Benefit Obligation:


Discount rates
4.44
%
 
11.37
%
(2) 
4.04
%
 
10.47
%
(2) 
Rates of compensation increase
3.34
%
(1) 
6.32
%
 
3.94
%
(1) 
6.41
%
 
Periodic Benefit Cost:


Discount rate
4.04
%
 
10.47
%
 
4.89
%
 
10.80
%
 
Expected long-term rate of return on plan assets
6.67
%
 
9.77
%
 
6.92
%
 
10.44
%
 
Rate of compensation increase
3.94
%
(1) 
6.41
%
 
3.94
%
(1) 
6.44
%
 
(1)
A U.S. subsidiary of the Company has defined benefit obligations of $6 million and $748 million as of December 31, 2015 and 2014, respectively, for which salary bands, rather than rates of compensation increases, are used to determine future benefit costs. Rates of compensation increases in the table above do not include amounts related to these specific defined benefit plans. A plan with a defined benefit obligation of $742 million at December 31, 2014 and which used salary bands at that date is using a rate of compensation increase as at December 31, 2015. The rate of compensation increase for this plan is included in the weighted average in the above table for calculating the benefit obligation as at December 31, 2015, but is not included in the weighted average for calculating the benefit obligation as at December 31, 2014 or the periodic benefit cost for 2014 or 2015.
(2) 
Includes an inflation factor that is used to calculate future periodic benefit cost, but is not used to calculate the benefit obligation.
Impact Of One Percent Change In Assumptions
The impact on pension expense from a one percentage point change in these assumptions is shown in the table below (in millions):
Increase of 1% in the discount rate
 
$
(32
)
Decrease of 1% in the discount rate
 
27

Increase of 1% in the long-term rate of return on plan assets
 
(36
)
Decrease of 1% in the long-term rate of return on plan assets
 
36

Schedule of Net Benefit Costs
The following table summarizes the components of the net periodic benefit cost in millions, both domestic and foreign, for the years indicated:
December 31,
 
2015
 
2014
 
2013
Components of Net Periodic Benefit Cost:
 
U.S.
 
Foreign
 
U.S.
 
Foreign
 
U.S.
 
Foreign
Service cost
 
$
16

 
$
15

 
$
14

 
$
16

 
$
16

 
$
26

Interest cost
 
48

 
351

 
50

 
489

 
46

 
515

Expected return on plan assets
 
(70
)
 
(247
)
 
(67
)
 
(362
)
 
(64
)
 
(484
)
Amortization of prior service cost
 
7

 
—

 
6

 
(1
)
 
5

 
—

Amortization of net loss
 
20

 
28

 
13

 
37

 
23

 
77

Settlement gain recognized
 
—

 
—

 
—

 
1

 
—

 
—

Total pension cost
 
$
21

 
$
147

 
$
16

 
$
180

 
$
26

 
$
134

Schedule of Net Periodic Benefit Cost Not yet Recognized
The following table summarizes in millions the amounts reflected in AOCL including AOCL attributable to noncontrolling interests, on the Consolidated Balance Sheet as of December 31, 2015, that have not yet been recognized as components of net periodic benefit cost and amounts expected to be reclassified to earnings in the next fiscal year:
December 31, 2015
Accumulated Other Comprehensive Income (Loss)
 
Amounts expected to be reclassified to earnings in next fiscal year
 
U.S.
 
Foreign
 
U.S.
 
Foreign
Prior service cost
$
—

 
$
(5
)
 
$
—

 
$
—

Unrecognized net actuarial gain (loss)
(6
)
 
(1,092
)
 
—

 
(18
)
Total
$
(6
)
 
$
(1,097
)
 
$
—

 
$
(18
)
Target / Actual Allocation Of Pension Plan Asset
The following table summarizes the Company's target allocation for 2015 and pension plan asset allocation, both domestic and foreign, as of the periods indicated:


Percentage of Plan Assets as of December 31,
 
Target Allocations
 
2015
 
2014
Asset Category
U.S.
 
Foreign
 
U.S.
 
Foreign
 
U.S.
 
Foreign
Equity securities
46
%
 
15% -29%
 
44.76
%
 
13.23
%
 
44.02
%
 
16.28
%
Debt securities
50
%
 
60% - 85%
 
50.05
%
 
81.10
%
 
50.90
%
 
78.85
%
Real estate
2
%
 
0% - 3%
 
2.94
%
 
3.24
%
 
2.45
%
 
3.15
%
Other
2
%
 
0% - 5%
 
2.25
%
 
2.43
%
 
2.63
%
 
1.72
%
Total pension assets


100.00
%
 
100.00
%
 
100.00
%
 
100.00
%
Schedule of Allocation of Plan Assets
The asset allocation is reviewed periodically to determine a suitable asset allocation which seeks to manage risk through portfolio diversification and takes into account, among other possible factors, the above-stated objectives, in conjunction with current funding levels, cash flow conditions and economic and industry trends. The following table summarizes the Company's U.S. plan assets by category of investment and level within the fair value hierarchy in millions as of the periods indicated:
 
 
December 31, 2015
 
December 31, 2014
U.S. Plans
 
Level 1
 
Level 2
 
Level 3
 
Total
 
Level 1
 
Level 2
 
Level 3
 
Total
Equity securities —
Mutual funds
457

 
—

 
—

 
457

 
467

 
—

 
—

 
467

Debt securities —
Government debt securities
53

 
—

 
—

 
53

 
67

 
—

 
—

 
67

 
Mutual funds(1)
458

 
—

 
—

 
458

 
473

 
—

 
—

 
473

Real Estate —
Real Estate
—

 
30

 
—

 
30

 
—

 
26

 
—

 
26

Other —
Cash and cash equivalents
—

 
—

 
—

 
—

 
4

 
—

 
—

 
4

 
Other investments
—

 
23

 
—

 
23

 
—

 
24

 
—

 
24

 
Total plan assets
$
968

 
$
53

 
$
—

 
$
1,021

 
$
1,011

 
$
50

 
$
—

 
$
1,061

(1)
Mutual funds categorized as debt securities consist of mutual funds for which debt securities are the primary underlying investment.
Fair Value Of Plan Assets By Category / Level (Foreign)
The investment strategy of the foreign plans seeks to maximize return on investment while minimizing risk. The assumed asset allocation has less exposure to equities in order to closely match market conditions and near term forecasts. The following table summarizes the Company's foreign plan assets by category of investment and level within the fair value hierarchy in millions as of the periods indicated:
 
 
December 31, 2015
 
December 31, 2014
Foreign Plans
 
Level 1
 
Level 2
 
Level 3
 
Total
 
Level 1
 
Level 2
 
Level 3
 
Total
Equity securities —
Common stock
$
9

 
$
—

 
$
—

 
$
9

 
$
21

 
$
—

 
$
—

 
$
21

 
Mutual funds
167

 
—

 
—

 
167

 
274

 
—

 
—

 
274

 
Private equity(1)
—

 
—

 
126

 
126

 
—

 
—

 
237

 
237

Debt securities —
Certificates of deposit
—

 
2

 
—

 
2

 
—

 
3

 
—

 
3

 
Unsecured debentures
—

 
5

 
—

 
5

 
—

 
10

 
—

 
10

 
Government debt securities
11

 
79

 
—

 
90

 
12

 
98

 
—

 
110

 
Mutual funds(2)
218

 
1,535

 
—

 
1,753

 
215

 
2,236

 
—

 
2,451

 
Other debt securities
—

 
2

 
—

 
2

 
—

 
6

 
—

 
6

Real estate —
Real estate(1)
—

 
—

 
74

 
74

 
—

 
—

 
103

 
103

Other —
Cash and cash equivalents
—

 
—

 
—

 
—

 
1

 
—

 
—

 
1

 
Participant loans(3)
—

 
—

 
37

 
37

 
—

 
—

 
52

 
52

 
Other assets
16

 
—

 
3

 
19

 
—

 
—

 
4

 
4

 
Total plan assets
$
421

 
$
1,623

 
$
240

 
$
2,284

 
$
523

 
$
2,353

 
$
396

 
$
3,272

(1) 
Plan assets of our Brazilian subsidiaries are invested in private equities and commercial real estate through the plan administrator in Brazil. The fair value of these assets is determined using the income approach through annual appraisals based on a discounted cash flow analysis.
(2) 
Mutual funds categorized as debt securities consist of mutual funds for which debt securities are the primary underlying investment.
(3) 
Loans to participants are stated at cost, which approximates fair value.
Schedule of Effect of Significant Unobservable Inputs, Changes in Plan Assets
The following table presents a reconciliation of all plan assets measured at fair value using significant unobservable inputs (Level 3) in millions for the periods indicated:
December 31,
 
2015
 
2014
Balance at January 1
 
$
396

 
$
530

Actual return on plan assets:


Returns relating to assets still held at reporting date
 
(36
)
 
(87
)
Purchases, sales and settlements, net
 
—

 
1

Transfers of (assets) liabilities into Level 3
 
—

 
5

Change due to exchange rate changes
 
(120
)
 
(53
)
Balance at December 31
 
$
240

 
$
396

Scheduled Cash Flows For Employer Contributions And Expected Future Benefit Payments
The following table summarizes the estimated cash flows for U.S. and foreign expected employer contributions and expected future benefit payments, both domestic and foreign in millions:
 
 
U.S.
 
Foreign
Expected employer contribution in 2016
 
$
22

 
$
100

Expected benefit payments for fiscal year ending:


2016
 
65

 
268

2017
 
67

 
277

2018
 
69

 
289

2019
 
71

 
299

2020
 
73

 
309

2021 - 2025
 
380

 
1,686


v3.3.1.900
Equity (Tables)
12 Months Ended
Dec. 31, 2015
Equity [Abstract]  
Schedule of Net Income Attributable to Parent And Transfers To From Noncontrolling Interests [Text Block]
The following table summarizes the net income attributable to The AES Corporation and all transfers (to) from noncontrolling interests in millions for the periods indicated:
 
 
December 31,
 
 
2015
 
2014
Net income attributable to The AES Corporation
 
$
306

 
$
769

Transfers from the noncontrolling interest:


Net increase in The AES Corporation's paid-in capital for sale of subsidiary shares
 
323

 
29

Additional paid-in capital, IPALCO shares, transferred to redeemable stock of subsidiaries (1)
 
(377
)
 
—

Increase in The AES Corporation's paid-in capital for purchase of subsidiary shares
 
—

 
7

Net transfers (to) from noncontrolling interest
 
(54
)
 
36

Change from net income attributable to The AES Corporation and transfers (to) from noncontrolling interests
 
$
252

 
$
805


(1) See Note 19—Redeemable stock of subsidiaries for further information on increase in paid-in capital transferred to redeemable stock of subsidiaries.
Components of Accumulated Other Comprehensive Income
The changes in AOCL by component, net of tax and noncontrolling interests in millions for the year ended December 31, 2015 were as follows:
 
Foreign currency translation adjustment, net
 
Unrealized derivative losses, net
 
Unfunded pension obligations, net
 
Total
Balance at the beginning of the period
$
(2,595
)
 
$
(396
)
 
$
(295
)
 
$
(3,286
)
Other comprehensive (loss) income before reclassifications
(674
)
 
(5
)
 
19

 
(660
)
Amount reclassified to earnings
$
—

 
$
48

 
$
2

 
50

Other comprehensive (loss) income
(674
)
 
43

 
21

 
(610
)
Cumulative effect of a change in accounting principle
$
13

 
$
—

 
$
—

 
$
13

Balance at the end of the period
(3,256
)
 
(353
)
 
(274
)
 
(3,883
)
Reclassification out of Accumulated Other Comprehensive Income
Reclassifications out of AOCL for the periods indicated were as follows (in millions):
Details About


December 31,
AOCL Components
 
Affected Line Item in the Consolidated Statements of Operations
 
2015
 
2014
 
2013
Foreign currency translation adjustment, net


Gain on sale of businesses
 
$
—

 
$
4

 
$
(2
)
 
 
Net loss from disposal and impairments of discontinued operations
 
—

 
(38
)
 
(35
)
 
 
Net income attributable to The AES Corporation
 
$
—

 
$
(34
)
 
$
(37
)
Unrealized derivative gains (losses), net


Non-regulated revenue
 
$
43

 
$
30

 
$
(3
)
 
 
Non-regulated cost of sales
 
(14
)
 
(4
)
 
(7
)
 
 
Interest expense
 
(112
)
 
(139
)
 
(137
)
 
 
Gain on sale of businesses
 
(4
)
 
—

 
(21
)
 
 
Foreign currency transaction gains (losses)
 
12

 
(9
)
 
(6
)
 
 
Income from continuing operations before taxes and equity in earnings of affiliates
 
(75
)
 
(122
)
 
(174
)
 
 
Income tax expense
 
11

 
26

 
41


Net equity in earnings of affiliates
 
(2
)
 
(3
)
 
(6
)
 
 
Income from continuing operations
 
(66
)
 
(99
)
 
(139
)
 
 
Less: (Income) from continuing operations attributable to noncontrolling interests
 
18

 
27

 
11


Net income attributable to The AES Corporation
 
$
(48
)

$
(72
)
 
$
(128
)
Amortization of defined benefit pension actuarial loss, net


Regulated cost of sales
 
$
(25
)
 
$
(33
)
 
$
(73
)
 
 
Non-regulated cost of sales
 
2

 
(5
)
 
(4
)
 
 
General and administrative expenses
 
(2
)
 
—

 
(1
)
 
 
Income from continuing operations before taxes and equity in earnings of affiliates
 
(25
)

(38
)
 
(78
)
 
 
Income tax expense
 
9

 
7

 
26


Income from continuing operations
 
(16
)

(31
)
 
(52
)
 
 
Net loss from disposal and impairments of discontinued operations
 
—

 
2

 
—


Net Income
 
(16
)
 
(29
)
 
(52
)
 
 
Less: (Income) from continuing operations attributable to noncontrolling interests
 
14

 
19

 
39


Net income attributable to The AES Corporation
 
$
(2
)

$
(10
)
 
$
(13
)
Total reclassifications for the period, net of income tax and noncontrolling interests
 
$
(50
)

$
(116
)
 
$
(178
)
_____________________________
(1) 
Amounts in parentheses indicate debits to the Consolidated Statements of Operations.

v3.3.1.900
Segment and Geographic Information (Tables)
12 Months Ended
Dec. 31, 2015
Segment Reporting Information [Line Items]  
Schedule of Segment Reporting Information, by Segment [Table Text Block]
The following tables present financial information by segment for the periods indicated (in millions):
Revenue
Year Ended December 31,
Total Revenue
 
Intersegment
 
External Revenue
2015
 
2014
 
2013
 
2015
 
2014
 
2013
 
2015
 
2014
 
2013
US SBU
$
3,593

 
$
3,826

 
$
3,630

 
$
—

 
$
—

 
$
—

 
$
3,593

 
$
3,826

 
$
3,630

Andes SBU
2,489

 
2,642

 
2,639

 
(10
)
 
(4
)
 
(1
)
 
2,479

 
2,638

 
2,638

Brazil SBU
4,666

 
6,009

 
5,015

 
—

 
—

 
—

 
4,666

 
6,009

 
5,015

MCAC SBU
2,353

 
2,682

 
2,713

 
(2
)
 
(2
)
 
(1
)
 
2,351

 
2,680

 
2,712

Europe SBU
1,191

 
1,439

 
1,347

 
(4
)
 
(6
)
 
—

 
1,187

 
1,433

 
1,347

Asia SBU
684

 
558

 
550

 
—

 
—

 
—

 
684

 
558

 
550

Corporate and Other
31

 
15

 
7

 
(28
)
 
(13
)
 
(8
)
 
3

 
2

 
(1
)
Total Revenue
$
15,007

 
$
17,171

 
$
15,901

 
$
(44
)
 
$
(25
)
 
$
(10
)
 
$
14,963

 
$
17,146

 
$
15,891


Adjusted Pretax Contribution
Year Ended December 31,
Total Adjusted PTC
 
Intersegment
 
External Adjusted PTC
2015
 
2014
 
2013
 
2015
 
2014
 
2013
 
2015
 
2014
 
2013
US SBU
$
360

 
$
445

 
440

 
$
12

 
$
10

 
11

 
$
372

 
$
455

 
$
451

Andes SBU
482

 
421

 
353

 
17

 
6

 
19

 
499

 
427

 
372

Brazil SBU
91

 
242

 
212

 
2

 
3

 
3

 
93

 
245

 
215

MCAC SBU
327

 
352

 
339

 
18

 
26

 
12

 
345

 
378

 
351

Europe SBU
235

 
348

 
345

 
5

 
5

 
7

 
240

 
353

 
352

Asia SBU
96

 
46

 
142

 
3

 
2

 
2

 
99

 
48

 
144

Corporate and Other
(441
)
 
(533
)
 
(624
)
 
(57
)
 
(52
)
 
(54
)
 
(498
)
 
(585
)
 
(678
)
Total Adjusted Pretax Contribution
1,150

 
1,321

 
1,207

 
—

 
—

 
—

 
1,150

 
1,321

 
1,207


Reconciliation to Income from Continuing Operations before Taxes and Equity Earnings of Affiliates:
 
 
Non-GAAP Adjustments:


Unrealized derivative gains
166

 
135

 
57

Unrealized foreign currency losses
(96
)
 
(110
)
 
(41
)
Disposition/acquisition gains
42

 
361

 
30

Impairment losses
(504
)
 
(416
)
 
(588
)
Loss on extinguishment of debt
(183
)
 
(274
)
 
(225
)
Pre-tax contribution
575

 
1,017

 
440

Add: Income from continuing operations before taxes, attributable to noncontrolling interests
652

 
578

 
633

Less: Net equity in earnings of affiliates
105

 
19

 
25

Income from continuing operations before taxes and equity in earnings of affiliates
$
1,122

 
$
1,576

 
$
1,048


Total Assets
 
Depreciation and Amortization
 
Capital Expenditures
Year Ended December 31,
2015
 
2014
 
2013
 
2015
 
2014
 
2013
 
2015
 
2014
 
2013
US SBU
$
9,844

 
$
10,062

 
$
9,952

 
$
443

 
$
450

 
$
440

 
$
861

 
$
534

 
$
426

Andes SBU
8,744

 
7,888

 
7,356

 
175

 
182

 
186

 
949

 
702

 
471

Brazil SBU
6,422

 
8,439

 
8,388

 
185

 
260

 
259

 
299

 
416

 
588

MCAC SBU
4,830

 
4,948

 
5,075

 
155

 
144

 
145

 
201

 
192

 
111

Europe SBU
3,127

 
3,525

 
4,191

 
134

 
154

 
155

 
118

 
228

 
341

Asia SBU
3,197

 
2,972

 
2,810

 
32

 
32

 
33

 
13

 
429

 
576

Assets held-for-sale
96

 
—

 
1,718

 
—

 
(1
)
 
55

 
—

 
13

 
52

Corporate and Other
590

 
1,132

 
921

 
20

 
24

 
21

 
17

 
30

 
14

Total
$
36,850

 
$
38,966

 
$
40,411

 
$
1,144

 
$
1,245

 
$
1,294

 
$
2,458

 
$
2,544

 
$
2,579


Interest Income
 
Interest Expense
Year Ended December 31,
2015
 
2014
 
2013
 
2015
 
2014
 
2013
US SBU
$
—

 
$
—

 
$
—

 
$
262

 
$
285

 
$
290

Andes SBU
77

 
87

 
37

 
154

 
160

 
135

Brazil SBU
299

 
249

 
210

 
349

 
331

 
364

MCAC SBU
30

 
26

 
20

 
179

 
178

 
138

Europe SBU
1

 
1

 
2

 
73

 
98

 
80

Asia SBU
115

 
2

 
6

 
85

 
25

 
30

Corporate and Other
2

 
—

 
—

 
334

 
394

 
445

Total
$
524

 
$
365

 
$
275

 
$
1,436

 
$
1,471

 
$
1,482

 
Investments in and Advances to Affiliates
 
Equity in Earnings (Losses)
Year Ended December 31,
2015
 
2014
 
2013
 
2015
 
2014
 
2013
US SBU
$
1

 
$
1

 
$
1

 
$
—

 
$
—

 
$
—

Andes SBU
345

 
287

 
248

 
83

 
42

 
44

Brazil SBU
—

 
—

 
—

 
—

 
—

 
—

MCAC SBU
—

 
—

 
—

 
—

 
—

 
4

Europe SBU
53

 
54

 
286

 
10

 
(25
)
 
(5
)
Asia SBU
195

 
194

 
186

 
8

 
10

 
10

Corporate and Other
16

 
1

 
289

 
4

 
(8
)
 
(28
)
Total
$
610

 
$
537

 
$
1,010

 
$
105

 
$
19

 
$
25

Revenue And PP&E By Country
The table below presents information, by country, about the Company's consolidated operations for each of the three years ended December 31, 2015, 2014, and 2013, and as of December 31, 2015 and 2014 in millions. Revenue is recorded in the country in which it is earned and assets are recorded in the country in which they are located.
 
Revenue
 
Property, Plant & Equipment, net
Year Ended December 31,
2015
 
2014
 
2013
 
2015
 
2014
United States(1)
$
3,597

 
$
3,828

 
$
3,630

 
$
8,028

 
$
7,713

Non-U.S.:


Brazil
4,666

 
6,009

 
5,015

 
3,286

 
4,725

Chile
1,523

 
1,624

 
1,569

 
4,596

 
4,012

El Salvador
736

 
832

 
860

 
318

 
304

Dominican Republic
632

 
802

 
832

 
783

 
702

Colombia
557

 
552

 
523

 
446

 
430

Philippines
406

 
451

 
497

 
736

 
752

Argentina
399

 
463

 
545

 
193

 
222

United Kingdom
396

 
533

 
558

 
191

 
324

Mexico
383

 
434

 
440

 
716

 
733

Bulgaria
382

 
410

 
422

 
1,259

 
1,457

Puerto Rico
302

 
348

 
328

 
599

 
551

Panama
297

 
263

 
250

 
1,028

 
1,030

Jordan
248

 
262

 
142

 
470

 
484

Vietnam(2)
233

 
—

 
—

 
2

 
1,491

Kazakhstan
155

 
161

 
156

 
146

 
206

Sri Lanka
45

 
107

 
53

 
—

 
7

Cameroon(3)
—

 
—

 
—

 
—

 
—

Ukraine(4)
—

 
—

 
—

 
—

 
—

Other Non-U.S. (5)
6

 
67

 
71

 
19

 
8

Total Non-U.S.
11,366

 
13,318

 
12,261

 
14,788

 
17,438

Total
$
14,963

 
$
17,146

 
$
15,891

 
$
22,816

 
$
25,151

(1)
Excludes revenue of $2 million and $23 million for the years ended December 31, 2014 and 2013, respectively, related to Condon and Mid-West Wind, which are reflected as discontinued operations in the accompanying Consolidated Statements of Operations.
(2) 
Property, plant & equipment as of December 31, 2015 includes the impact of adopting ASU No. 2014-05, Service Concession Arrangements, on a modified retrospective basis as of January 1, 2015. See Note 1—General and Summary of Significant Accounting Policies for more information.
(3) 
Excludes revenue of $230 million and $473 million for the years ended December 31, 2014 and 2013, respectively, related to Sonel, which is reflected as discontinued
operations in the accompanying Consolidated Statements of Operations.
(4) 
Excludes revenue of $187 million for the years ended December 31, 2013 related to Kievoblenergo and Rivnooblenergo, which are reflected as discontinued operations in the accompanying Consolidated Statements of Operations.
(5) 
Excludes revenue of $6 million for the years ended December 31, 2013 related to Saurashtra, which is reflected as discontinued operations in the accompanying Consolidated Statements of Operations.

v3.3.1.900
Share-Based Compensation (Tables)
12 Months Ended
Dec. 31, 2015
Disclosure of Compensation Related Costs, Share-based Payments [Abstract]  
Schedule of Share-based Payment Award, Stock Options, Valuation Assumptions
The following table presents the weighted average fair value of each option grant and the underlying weighted average assumptions, as of the grant date, using the Black-Scholes option-pricing model:
December 31,
 
2015
 
2014
 
2013
Expected volatility
 
25
%
 
24
%
 
23
%
Expected annual dividend yield
 
3
%
 
1
%
 
1
%
Expected option term (years)
 
7

 
6

 
6

Risk-free interest rate
 
1.86
%
 
1.86
%
 
1.13
%
Fair value at grant date
 
$
2.07

 
$
3.26

 
$
2.23

Schedule of Share Based Compensation Summary of Financial Statement Components Stock Options
The following table summarizes the components of stock-based compensation related to employee stock options recognized in the Company's consolidated financial statements in millions:
December 31,
 
2015
 
2014
 
2013
Pretax compensation expense
 
$
3

 
$
3

 
$
2

Tax benefit
 
(1
)
 
(1
)
 
(1
)
Stock options expense, net of tax
 
$
2

 
$
2

 
$
1

Total intrinsic value of options exercised
 
$
1

 
$
1

 
$
5

Total fair value of options vested
 
3

 
2

 
2

Cash received from the exercise of stock options
 
5

 
3

 
13

Schedule of Share-based Compensation, Stock Options, Activity
A summary of the option activity for the year ended December 31, 2015 follows (number of options in thousands, dollars in millions except per option amounts):
 
 
Options
 
Weighted Average Exercise Price
 
Weighted Average Remaining Contractual Term (in years)
 
Aggregate Intrinsic Value
Outstanding at December 31, 2014
 
7,062

 
$
14.83


Exercised
 
(419
)
 
10.76


Forfeited and expired
 
(1,347
)
 
17.49


Granted
 
1,859

 
11.89


Outstanding at December 31, 2015
 
7,155

 
$
13.81

 
6
 
$
1

Vested and expected to vest at December 31, 2015
 
6,771

 
$
13.88

 
5.8
 
$
1

Eligible for exercise at December 31, 2015
 
4,292

 
$
14.70

 
4.1
 
$
1

Schedule of Share Based Compensation Summary of Financial Statement Components Restricted Stock Units Without Market Conditions
The following table summarizes the components of the Company's stock-based compensation related to its employee RSUs recognized in the Company's consolidated financial statements in millions:
December 31,
 
2015
 
2014
 
2013
RSU expense before income tax
 
$
13

 
$
12

 
$
12

Tax benefit
 
(3
)
 
(3
)
 
(3
)
RSU expense, net of tax
 
$
10

 
$
9

 
$
9

Total value of RSUs converted (1)
 
$
16

 
$
25

 
$
10

Total fair value of RSUs vested
 
$
12

 
$
13

 
$
12

(1)
Amount represents fair market value on the date of conversion.
Schedule of Share Based Compensation Restricted Stock Units Without Market Conditions Activity Table
A summary of the activity of RSUs for the year ended December 31, 2015 follows (number of RSUs in thousands):
 
 
RSUs
 
Weighted Average Grant Date Fair Values
 
Weighted Average Remaining Vesting Term
Nonvested at December 31, 2014
 
1,997

 
$
13.20


Vested
 
(954
)
 
13.01


Forfeited and expired
 
(236
)
 
12.71


Granted
 
1,585

 
12.03


Nonvested at December 31, 2015
 
2,392

 
$
12.55

 
1.7
Vested at December 31, 2015
 
—

 
$
—


Vested and expected to vest at December 31, 2015
 
2,105

 
$
12.55


Schedule of Share Based Compensation Restricted Stock Units Without Market Condition Vested And Converted
The table below summarizes the RSUs that vested and were converted during the years ended December 31, 2015, 2014, and 2013 (number of RSUs in thousands):
 
 
2015
 
2014
 
2013
RSUs vested during the year
 
954

 
1,037

 
942

RSUs converted during the year, net of shares withheld for taxes
 
1,238

 
1,734

 
905

Shares withheld for taxes
 
549

 
796

 
407

Schedule of Share Based Compensation Summary of Financial Statement Components Restricted Stock Units With Market Conditions
The following table summarizes the components of the Company's stock-based compensation related to its PSUs recognized in the Company's consolidated financial statements in millions:
December 31,
 
2015
 
2014
 
2013
PSU expense before income tax
 
$
5

 
$
6

 
$
4

Tax benefit
 
(1
)
 
(2
)
 
(1
)
PSU expense, net of tax
 
$
4


$
4


$
3

Total value of PSUs converted(1)
 
$
1

 
$
4

 
$
—

Total fair value of PSUs vested
 
3

 
1

 
—

(1)
Amount represents fair market value on the date of conversion.
Schedule of Share Based Compensation Restricted Stock Units With Market Conditions Activity
A summary of the activity of PSUs for the year ended December 31, 2015 follows (number of PSUs in thousands):
 
 
PSUs
 
Weighted Average Grant Date Fair Values
 
Weighted Average Remaining Vesting Term
Nonvested at December 31, 2014
 
1,331

 
$
14.27


Vested
 
(161
)
 
16.73


Forfeited and expired
 
(245
)
 
15.27


Granted
 
626

 
10.06


Nonvested at December 31, 2015
 
1,551

 
$
12.16

 
1.2
Vested at December 31, 2015
 
—

 
$
—


Vested and expected to vest at December 31, 2015
 
1,298

 
11.92


Schedule of Share Based Compensation Restricted Stock Units With Market Condition Vested and Converted
The table below summarizes the PSUs that vested and were converted during the years ended December 31, 2015, 2014, and 2013 (number of PSUs in thousands):
 
 
2015
 
2014
 
2013
PSUs vested during the year
 
161

 
85

 
—

PSUs converted during the year, net of shares withheld for taxes
 
96

 
287

 
—

Shares withheld for taxes
 
65

 
141

 
—


v3.3.1.900
Redeemable Stock of Subsidiaries Redeemable Stock of Subsidiaries (Tables)
12 Months Ended
Dec. 31, 2015
Temporary Equity Disclosure [Abstract]  
Redeemable Noncontrolling Interest [Table Text Block]
The following table summarizes the Company's redeemable stock of subsidiaries balances as of the periods indicated:
 
 
December 31,
Redeemable stock of subsidiaries (in millions)
 
2015
 
2014
Additional paid-in capital, IPALCO shares
 
$
377

 
$
—

Book value, IPALCO shares - noncontrolling interest
 
83

 
—

Total fair value of consideration received (1)
 
460

 
—

IPL cumulative preferred stock
 
60

 
60

DPL cumulative preferred stock
 
18

 
18

Total cumulative preferred stock of subsidiaries (2)
 
78

 
78

Total redeemable stock of subsidiaries
 
$
538

 
$
78

(1) See Note 16—Equity for further information on IPALCO equity transactions with noncontrolling interests.
(2) Refer below for further information on outstanding shares of cumulative preferred stock of subsidiaries.

v3.3.1.900
Other Income and Expense (Tables)
12 Months Ended
Dec. 31, 2015
Other Income and Expenses [Abstract]  
Components of Other Income
The components are summarized as follows (in millions):
Years Ended December 31,
2015
 
2014
 
2013
Contract termination
$
20

 
$
—

 
$
60

Gain on sale of assets
19

 
68

 
12

Allowance for Funds Used During Construction (US Utilities)
17

 
9

 
6

Contingency reversal
—

 
18

 
10

Gain on extinguishment of tax and other liabilities
—

 
—

 
9

Other
27

 
29

 
28

Total other income
$
83

 
$
124

 
$
125

Components of Other Expense
The components are summarized as follows (in millions):
Years Ended December 31,
2015
 
2014
 
2013
Loss on sale and disposal of assets
$
48

 
$
47

 
$
51

Legal contingency
9

 
11

 
9

Contract termination
—

 
—

 
7

Other
8

 
10

 
9

Total other expense
$
65

 
$
68

 
$
76


v3.3.1.900
Asset Impairment Expense (Tables)
12 Months Ended
Dec. 31, 2015
Impairment or Disposal of Tangible Assets Disclosure [Abstract]  
Details of Impairment of Long-Lived Assets Held and Used by Asset
Years ended December 31,
 
2015
 
2014
 
2013
 
 
(in millions)
Kilroot
 
$
121

 
$
—

 
$
—

Buffalo Gap III
 
116

 
—

 
—

U.K. Wind
 
37

 
12

 
—

Ebute
 
—

 
67

 
—

East Bend (DP&L)
 
—

 
12

 
—

Beaver Valley
 
—

 
—

 
46

Conesville (DP&L)
 
—

 
—

 
26

Itabo (San Lorenzo)
 
—

 
—

 
16

Other
 
11

 
—

 
7

Total asset impairment expense
 
$
285

 
$
91

 
$
95


v3.3.1.900
Income Taxes (Tables)
12 Months Ended
Dec. 31, 2015
Income Tax Disclosure [Abstract]  
Income Tax Expense On Continuing Operations
The next table summarizes the expense for income taxes on continuing operations in millions for the periods indicated:
December 31,
 
2015
 
2014
 
2013
Federal —
Current
$
9

 
$
—

 
$
(28
)
 
Deferred
(56
)
 
(121
)
 
(110
)
State —
Current
1

 
1

 
1

 
Deferred
(5
)
 
1

 
1

Foreign —
Current
505

 
457

 
509

 
Deferred
11

 
81

 
(30
)
Total
 
$
465

 
$
419

 
$
343

Reconciliation Of US Federal Income Tax Rates And AES Effective Tax Rate For The Current And Two Prior Years
The following table summarizes a reconciliation of the U.S. statutory federal income tax rate to the Company's effective tax rate, as a percentage of income from continuing operations before taxes for the periods indicated:
December 31,
 
2015
 
2014
 
2013
Statutory Federal tax rate
 
35
 %
 
35
 %
 
35
 %
State taxes, net of Federal tax benefit
 
(5
)%
 
(1
)%
 
(3
)%
Taxes on foreign earnings
 
3
 %
 
(14
)%
 
(4
)%
Valuation allowance
 
(5
)%
 
(1
)%
 
—
 %
Uncertain tax positions
 
—
 %
 
—
 %
 
(5
)%
Bad debt deduction
 
—
 %
 
—
 %
 
(3
)%
Change in tax law
 
—
 %
 
4
 %
 
(1
)%
Goodwill impairment
 
10
 %
 
4
 %
 
12
 %
Other—net
 
3
 %
 
—
 %
 
2
 %
Effective tax rate
 
41
 %
 
27
 %
 
33
 %

Included in the favorable (14)% 2014 taxes on foreign earnings percentage above is approximately (8)% related to the sale of approximately 45% of the Company's interest in Masin AES Pte Ltd., which owns the Company's interests in the Philippines, and the sale of the Company's interests in four U.K. wind projects. Neither of these transactions gave rise to income tax expense.
Schedule Of Income Tax Payable And Receivable
The next table summarizes the income taxes receivable and payable in millions as of December 31, 2015 and 2014:
 
 
2015
 
2014
Income taxes receivable—current
 
$
167

 
$
217

Total income taxes receivable
 
$
167

 
$
217

Income taxes payable—current
 
$
264

 
$
299

Income taxes payable—noncurrent
 
35

 
2

Total income taxes payable
 
$
299

 
$
301

Summary Of Deferred Tax Assets And Liabilities
The following table summarizes the deferred tax assets and liabilities in millions, as of December 31, 2015 and 2014:
 
 
2015
 
2014
Differences between book and tax basis of property
 
$
(2,240
)
 
$
(2,364
)
Other taxable temporary differences
 
(299
)
 
(302
)
Total deferred tax liability
 
(2,539
)
 
(2,666
)
Operating loss carryforwards
 
2,206

 
2,224

Capital loss carryforwards
 
66

 
137

Bad debt and other book provisions
 
191

 
221

Retirement costs
 
149

 
275

Tax credit carryforwards
 
55

 
58

Other deductible temporary differences
 
219

 
363

Total gross deferred tax asset
 
2,886

 
3,278

Less: valuation allowance
 
(894
)
 
(997
)
Total net deferred tax asset
 
1,992

 
2,281

Net deferred tax (liability)
 
$
(547
)
 
$
(385
)
Income Before Income Taxes, Foreign And Domestic
The following table summarizes the income (loss) from continuing operations, before income taxes, net equity in earnings of affiliates and noncontrolling interests in millions, for the years ended December 31, 2015, 2014 and 2013:
 
 
2015
 
2014
 
2013
U.S.
 
$
(612
)
 
$
(560
)
 
$
(575
)
Non-U.S.
 
1,734

 
2,136

 
1,623

Total
 
$
1,122

 
$
1,576

 
$
1,048

Tax Years Potentially Subject To Examination And Jurisdictions
The following is a summary of tax years potentially subject to examination in the significant tax and business jurisdictions in which we operate:
Jurisdiction
 
Tax Years Subject to Examination
Argentina
 
2009-2015
Brazil
 
2010-2015
Chile
 
2012-2015
Colombia
 
2013-2015
Dominican Republic
 
2012-2015
El Salvador
 
2012-2015
Netherlands
 
2013-2015
Philippines
 
2012-2015
United Kingdom
 
2010-2015
United States (Federal)
 
2011-2015
Unrecognized Tax Benefits
is a reconciliation of the beginning and ending amounts of unrecognized tax benefits in millions for the periods indicated:
December 31,
 
2015
 
2014
 
2013
Balance at January 1
 
$
395

 
$
392

 
$
475

Additions for current year tax positions
 
6

 
8

 
7

Additions for tax positions of prior years
 
12

 
14

 
10

Reductions for tax positions of prior years
 
(7
)
 
(2
)
 
(3
)
Effects of foreign currency translation
 
(7
)
 
(3
)
 
—

Settlements
 
(19
)
 
(2
)
 
(65
)
Lapse of statute of limitations
 
(7
)
 
(12
)
 
(32
)
Balance at December 31
 
$
373

 
$
395

 
$
392


v3.3.1.900
Discontinued Operations and Held-For-Sale Businesses (Tables)
12 Months Ended
Dec. 31, 2015
Discontinued Operations and Disposal Groups [Abstract]  
Revenue Income From Operations Of Discontinued Businesses Income Tax Expense And Impairment Of Discontinued Operations
The following table summarizes revenue, income from operations, income tax expense, and impairment and loss on disposal of all discontinued operations prior to the adoption of ASU No. 2014-08 for the periods indicated (in millions):
Years Ended December 31,
2014
 
2013
Revenue
$
233

 
$
689

Income (loss) from operations of discontinued businesses, before income tax
$
50

 
$
(3
)
Income tax expense
(23
)
 
(24
)
Income (loss) from operations of discontinued businesses, after income tax
$
27

 
$
(27
)
Net loss from disposal and impairments of discontinued businesses, after income tax
$
(56
)
 
$
(152
)

v3.3.1.900
Earnings Per Share (Tables)
12 Months Ended
Dec. 31, 2015
Earnings Per Share [Abstract]  
Earnings Per Share Basic And Diluted Table
The following table is a reconciliation of the numerator and denominator of the basic and diluted earnings per share computation for income from continuing operations for the years ended December 31, 2015, 2014 and 2013, where income represents the numerator and weighted-average shares represent the denominator. Values are in millions except per share data:
Year Ended December 31,
2015
 
2014
 
2013
 
Income
 
Shares
 
$ per Share
 
Income
 
Shares
 
$ per Share
 
Income
 
Shares
 
$ per Share
BASIC EARNINGS PER SHARE


Income from continuing operations attributable to The AES Corporation common stockholders
$
306

 
687

 
$
0.45

 
$
789

 
720

 
$
1.10

 
$
284

 
743

 
$
0.38

EFFECT OF DILUTIVE SECURITIES


Stock options
—

 
—

 
—

 
—

 
1

 
—

 
—

 
1

 
—

Restricted stock units
—

 
2

 
(0.01
)
 
—

 
3

 
(0.01
)
 
—

 
4

 
—

DILUTED EARNINGS PER SHARE
$
306

 
689

 
$
0.44

 
$
789

 
724

 
$
1.09

 
$
284

 
748

 
$
0.38


v3.3.1.900
Related Party Transactions (Tables)
12 Months Ended
Dec. 31, 2015
Related Party Transactions [Abstract]  
Schedule of Related Party Transactions
The Company's Consolidated Statements of Operations included the following transactions with related parties in millions for the periods indicated:
Years Ended December 31,
2015
 
2014
 
2013
Revenue—Non-Regulated
$
1,099

 
$
1,188

 
$
1,110

Cost of Sales—Non-Regulated
330

 
331

 
276

Interest Income
25

 
17

 
20

Interest Expense
33

 
9

 
8

Schedule of Related Party Receivables Payables
The following table summarizes the balances receivable from and payable to related parties included in the Company's Consolidated Balance Sheets in millions as of the periods indicated:
December 31,
2015
 
2014
Receivables from related parties
$
181

 
$
349

Accounts and notes payable to related parties
524

 
567


v3.3.1.900
Selected Quarterly Financial Data (Tables)
12 Months Ended
Dec. 31, 2015
Quarterly Financial Information Disclosure [Abstract]  
Schedule of Quarterly Financial Information
The following tables summarize the unaudited quarterly Condensed Consolidated Statements of Operations for the Company for 2015 and 2014 (amounts in millions, except per share data). Amounts have been restated to reflect discontinued operations in all periods presented and reflect all adjustments necessary in the opinion of management for a fair statement of the results for interim periods.
Quarter Ended 2015
Mar 31
 
June 30
 
Sept 30
 
Dec 31
Revenue
$
3,984

 
$
3,858

 
$
3,721

 
$
3,400

Operating margin
721

 
754

 
673

 
718

Income from continuing operations, net of tax(1)
254

 
264

 
203

 
41

Discontinued operations, net of tax
—

 
—

 
—

 
—

Net income
$
254

 
$
264

 
$
203

 
$
41

Net income (loss) attributable to The AES Corporation
$
142

 
$
69

 
$
180

 
$
(85
)
Basic income (loss) per share:


Income (loss) from continuing operations attributable to The AES Corporation, net of tax
$
0.20

 
$
0.10

 
$
0.27

 
$
(0.13
)
Discontinued operations attributable to The AES Corporation, net of tax
—

 
—

 
—

 
—

Basic income (loss) per share attributable to The AES Corporation
$
0.20

 
$
0.10

 
$
0.27

 
$
(0.13
)
Diluted income (loss) per share:


Income (loss) from continuing operations attributable to The AES Corporation, net of tax
$
0.20

 
$
0.10

 
$
0.26

 
$
(0.13
)
Discontinued operations attributable to The AES Corporation, net of tax
—

 
—

 
—

 
—

Diluted income (loss) per share attributable to The AES Corporation
$
0.20

 
$
0.10

 
$
0.26

 
$
(0.13
)
Dividends declared per common share
$
—

 
$
0.10

 
$
0.10

 
$
0.21

Quarter Ended 2014
Mar 31
 
June 30
 
Sept 30
 
Dec 31
Revenue
$
4,262

 
$
4,311

 
$
4,441

 
$
4,132

Operating margin
794

 
819

 
767

 
708

Income (loss) from continuing operations, net of tax(2,3)
89

 
281

 
508

 
298

Discontinued operations, net of tax
(23
)
 
(6
)
 
—

 
—

Net income (loss)
$
66


$
275


$
508


$
298

Net income (loss) attributable to The AES Corporation
$
(58
)
 
$
133

 
$
488

 
$
206

Basic income (loss) per share:


Income (loss) from continuing operations attributable to The AES Corporation, net of tax
$
(0.07
)
 
$
0.20

 
$
0.68

 
$
0.29

Discontinued operations attributable to The AES Corporation, net of tax
(0.01
)
 
(0.02
)
 
—

 
—

Basic income (loss) per share attributable to The AES Corporation
$
(0.08
)
 
$
0.18

 
$
0.68

 
$
0.29

Diluted income (loss) per share:


Income (loss) from continuing operations attributable to The AES Corporation, net of tax
$
(0.07
)
 
$
0.20

 
$
0.67

 
$
0.29

Discontinued operations attributable to The AES Corporation, net of tax
(0.01
)
 
(0.02
)
 
—

 
—

Diluted income (loss) per share attributable to The AES Corporation
$
(0.08
)
 
$
0.18

 
$
0.67

 
$
0.29

Dividends declared per common share
$
—

 
$
0.05

 
$
0.05

 
$
0.15

(1)
Includes pretax impairment expense of $8 million, $37 million, $231 million and $326 million, for the first, second, third and fourth quarters of 2015, respectively. See Note 9—Other Non-Operating Expense, Note 10—Goodwill and Other Intangible Assets, and Note 21—Asset Impairment Expense for further discussion.
(2) 
Includes a pretax gain of approximately $283 million for the third quarter of 2014 related to the sale of a noncontrolling interest in Masinloc. See Note 16—Equity for further discussion. Includes pretax gain of approximately $78 million for the third quarter of 2014 related to the sale of the U.K. wind projects. See Note 24—Dispositions and Held-for-Sale Businesses for further discussion. Includes pretax interest income of $59 million recognized on FONIVEMEM III receivables at AES Argentina in the fourth quarter of 2014. Also includes a pretax foreign currency derivative gain of $106 million recognized on the FONIVEMEM III receivables in the fourth quarter of 2014. See Note 7—Financing Receivables for further discussion. Includes pretax loss of $41 million recognized in Net equity in earnings of affiliates corresponding to the Company's share of an asset impairment at Elsta in the fourth quarter of 2014. See Note 8—Investments In And Advances To Affiliates for further discussion.
(3) 
Includes pretax impairment expense of $166 million, $107 million, $31 million and $79 million, for the first, second, third and fourth quarters of 2014, respectively. See Note 9—Other Non-Operating Expense, Note 10—Goodwill and Other Intangible Assets, and Note 21—Asset Impairment Expense for further discussion.

v3.3.1.900
Schedule I - Condensed Financial Information of Parent (Tables)
12 Months Ended
Dec. 31, 2015
Debt Details [Line Items]  
Schedule of Recourse Debt Detail
The table below summarizes the carrying amount (in millions) and terms of recourse debt of the Company as of the periods indicated:
RECOURSE DEBT
Interest Rate
 
Final Maturity
 
December 31, 2015

 
December 31, 2014
Senior Unsecured Note
7.75%
 
2015
 
$
—

 
$
151

Senior Unsecured Note
9.75%
 
2016
 
—

 
164

Senior Unsecured Note
8.00%
 
2017
 
181

 
525

Senior Unsecured Note
LIBOR + 3%
 
2019
 
775

 
775

Senior Unsecured Note
8.00%
 
2020
 
469

 
625

Senior Unsecured Note
7.38%
 
2021
 
1,000

 
1,000

Senior Unsecured Note
4.88%
 
2023
 
750

 
750

Senior Unsecured Note
5.50%
 
2024
 
750

 
750

Senior Unsecured Note
5.50%
 
2025
 
575

 
—

Term Convertible Trust Securities
6.75%
 
2029
 
517

 
517

Unamortized (Discounts)/Premiums


(2
)
 
1

SUBTOTAL


5,015

 
5,258

Less: Current maturities


—

 
(151
)
Total


$
5,015

 
$
5,107


December 31,
 
 
Interest Rate
 
Maturity
 
2015
 
2014
Senior Unsecured Note
 
7.75%
 
2015
 
$
—

 
$
151

Senior Unsecured Note
 
9.75%
 
2016
 
—

 
164

Senior Unsecured Note
 
8.00%
 
2017
 
181

 
525

Senior Unsecured Note
 
LIBOR + 3.00%
 
2019
 
775

 
775

Senior Unsecured Note
 
8.00%
 
2020
 
469

 
625

Senior Unsecured Note
 
7.38%
 
2021
 
1,000

 
1,000

Senior Unsecured Note
 
4.88%
 
2023
 
750

 
750

Senior Unsecured Note
 
5.50%
 
2024
 
750

 
750

Senior Unsecured Note
 
5.50%
 
2025
 
575

 
—

Unamortized premium (discounts)


(2
)
 
1

SUBTOTAL


4,498

 
4,741

Less: Current maturities


—

 
(151
)
Total


$
4,498

 
$
4,590

Junior Subordinated Notes Payable


December 31,
 
 
Interest Rate
 
Maturity
 
2015
 
2014
Term Convertible Trust Securities
 
6.75%
 
2029
 
$
517

 
$
517

Future Maturities of Debt
The table below summarizes the principal amounts due, net of unamortized discounts, under our recourse debt for the next five years and thereafter in millions:
December 31,
Net Principal Amounts Due
2016
$
—

2017
181

2018
—

2019
774

2020
469

Thereafter
3,591

Total recourse debt
$
5,015

Recourse debt as of December 31, 2015 is scheduled to reach maturity as presented in the table below in millions:
December 31,
Annual Maturities
2016
$
—

2017
181

2018
—

2019
774

2020
469

Thereafter
3,591

Total debt
$
5,015


v3.3.1.900
Schedule II - Valuation and Qualifying Accounts Schedule of Valuation and Qualifying Accounts (Tables)
12 Months Ended
Dec. 31, 2015
Valuation and Qualifying Accounts [Abstract]  
schedule of valuation and qualifying accounts [Table Text Block]
(in millions)
Balance at Beginning of the Period
 
Charged to Cost and Expense
 
Amounts Written off
 
Translation Adjustment
 
Balance at the End of the Period
Allowance for accounts receivables


(current and noncurrent)


Year Ended December 31, 2013
$
195

 
$
38

 
$
(77
)
 
$
(22
)
 
$
134

Year Ended December 31, 2014
134

 
61

 
(88
)
 
(11
)
 
96

Year Ended December 31, 2015
96

 
88

 
(60
)
 
(29
)
 
95


v3.3.1.900
General and Summary of Significant Accounting Policies (Finite Lived Intangible Assets) (Details)
12 Months Ended
Dec. 31, 2015
Minimum  
Finite-Lived Intangible Assets [Line Items]  
Finite-Lived Intangible Asset, Useful Life 1 year
Maximum  
Finite-Lived Intangible Assets [Line Items]  
Finite-Lived Intangible Asset, Useful Life 50 years

v3.3.1.900
General and Summary of Significant Accounting Policies Accounting Pronouncements Not Yet Adopted (Details)
12 Months Ended
Dec. 31, 2015
USD ($)
New Accounting Pronouncements or Change in Accounting Principle [Line Items]  
New Accounting Pronouncement or Change in Accounting Principle, Effect of Adoption, Quantification $ 0
Other Current Assets [Member]  
New Accounting Pronouncements or Change in Accounting Principle [Line Items]  
New Accounting Pronouncement or Change in Accounting Principle, Effect of Adoption, Quantification 24,000,000
Other Noncurrent Assets [Member]  
New Accounting Pronouncements or Change in Accounting Principle [Line Items]  
New Accounting Pronouncement or Change in Accounting Principle, Effect of Adoption, Quantification 356,000,000
Line of Credit [Member]  
New Accounting Pronouncements or Change in Accounting Principle [Line Items]  
Deferred Finance Costs, Current, Gross 2,000,000
Deferred Finance Costs, Noncurrent, Gross $ 24,000,000

v3.3.1.900
General and Summary of Significant Accounting Policies New Accounting Pronouncements Adopted (Details)
12 Months Ended
Dec. 31, 2015
USD ($)
integer
New Accounting Pronouncements or Change in Accounting Principle [Line Items]  
New Accounting Pronouncement, number of noncurrent deferred tax assets or liabilities 1
New Accounting Pronouncement or Change in Accounting Principle, Effect of Adoption, Quantification $ 0
Other Comprehensive Income (Loss), Effect of Change in Accounting Principle, Net of Taxes 13,000,000
Accounting Standard Update 2014-05 [Member]  
New Accounting Pronouncements or Change in Accounting Principle [Line Items]  
New Accounting Pronouncement or Change in Accounting Principle, Cumulative Effect of Change on Equity or Net Assets (18,000,000)
Other Comprehensive Income (Loss), Effect of Change in Accounting Principle, Net of Taxes 13,000,000
Other Noncurrent Assets [Member]  
New Accounting Pronouncements or Change in Accounting Principle [Line Items]  
New Accounting Pronouncement or Change in Accounting Principle, Effect of Adoption, Quantification 356,000,000
Other Noncurrent Assets [Member] | Accounting Standard Update 2014-05 [Member]  
New Accounting Pronouncements or Change in Accounting Principle [Line Items]  
New Accounting Pronouncement or Change in Accounting Principle, Effect of Adoption, Quantification $ 1,500,000,000
Mong Duong Subsidiary [Member]  
New Accounting Pronouncements or Change in Accounting Principle [Line Items]  
Number of deliverables in an agreement | integer 2
New Accounting Pronouncement or Change in Accounting Principle, Current Period Disclosures, Revenue Recognized, Amount $ 0

v3.3.1.900
General and Summary of Significant Accounting Policies Change in Accounting Estimate (Details)
$ in Millions
12 Months Ended
Dec. 31, 2015
USD ($)
Postretirement Benefit Costs [Member]  
Change in Accounting Estimate [Line Items]  
New Accounting Pronouncement or Change in Accounting Principle, Effect of Change on Operating Results $ (2)
Interest Expense [Member]  
Change in Accounting Estimate [Line Items]  
New Accounting Pronouncement or Change in Accounting Principle, Effect of Change on Operating Results (11)
UNITED STATES | Postretirement Benefit Costs [Member]  
Change in Accounting Estimate [Line Items]  
New Accounting Pronouncement or Change in Accounting Principle, Effect of Change on Operating Results (1)
UNITED STATES | Interest Expense [Member]  
Change in Accounting Estimate [Line Items]  
New Accounting Pronouncement or Change in Accounting Principle, Effect of Change on Operating Results (9)
UNITED KINGDOM | Postretirement Benefit Costs [Member]  
Change in Accounting Estimate [Line Items]  
New Accounting Pronouncement or Change in Accounting Principle, Effect of Change on Operating Results (1)
UNITED KINGDOM | Interest Expense [Member]  
Change in Accounting Estimate [Line Items]  
New Accounting Pronouncement or Change in Accounting Principle, Effect of Change on Operating Results (2)
Disaggregated Rate Approach [Member] | Postretirement Benefit Costs [Member]  
Change in Accounting Estimate [Line Items]  
New Accounting Pronouncement or Change in Accounting Principle, Effect of Change on Operating Results 16
Disaggregated Rate Approach [Member] | Interest Expense [Member]  
Change in Accounting Estimate [Line Items]  
New Accounting Pronouncement or Change in Accounting Principle, Effect of Change on Operating Results 49
Disaggregated Rate Approach [Member] | UNITED STATES | Postretirement Benefit Costs [Member]  
Change in Accounting Estimate [Line Items]  
New Accounting Pronouncement or Change in Accounting Principle, Effect of Change on Operating Results 13
Disaggregated Rate Approach [Member] | UNITED STATES | Interest Expense [Member]  
Change in Accounting Estimate [Line Items]  
New Accounting Pronouncement or Change in Accounting Principle, Effect of Change on Operating Results 42
Disaggregated Rate Approach [Member] | UNITED KINGDOM | Postretirement Benefit Costs [Member]  
Change in Accounting Estimate [Line Items]  
New Accounting Pronouncement or Change in Accounting Principle, Effect of Change on Operating Results 3
Disaggregated Rate Approach [Member] | UNITED KINGDOM | Interest Expense [Member]  
Change in Accounting Estimate [Line Items]  
New Accounting Pronouncement or Change in Accounting Principle, Effect of Change on Operating Results 7
Aggregated Rate Approach [Member] | Postretirement Benefit Costs [Member]  
Change in Accounting Estimate [Line Items]  
New Accounting Pronouncement or Change in Accounting Principle, Effect of Change on Operating Results 18
Aggregated Rate Approach [Member] | Interest Expense [Member]  
Change in Accounting Estimate [Line Items]  
New Accounting Pronouncement or Change in Accounting Principle, Effect of Change on Operating Results 60
Aggregated Rate Approach [Member] | UNITED STATES | Postretirement Benefit Costs [Member]  
Change in Accounting Estimate [Line Items]  
New Accounting Pronouncement or Change in Accounting Principle, Effect of Change on Operating Results 14
Aggregated Rate Approach [Member] | UNITED STATES | Interest Expense [Member]  
Change in Accounting Estimate [Line Items]  
New Accounting Pronouncement or Change in Accounting Principle, Effect of Change on Operating Results 51
Aggregated Rate Approach [Member] | UNITED KINGDOM | Postretirement Benefit Costs [Member]  
Change in Accounting Estimate [Line Items]  
New Accounting Pronouncement or Change in Accounting Principle, Effect of Change on Operating Results 4
Aggregated Rate Approach [Member] | UNITED KINGDOM | Interest Expense [Member]  
Change in Accounting Estimate [Line Items]  
New Accounting Pronouncement or Change in Accounting Principle, Effect of Change on Operating Results $ 9

v3.3.1.900
Inventory (Details) - USD ($)
$ in Millions
Dec. 31, 2015
Dec. 31, 2014
Inventory Disclosure [Abstract]    
Fuel and other raw materials $ 343 $ 357
Spare parts and supplies 332 345
Total $ 675 $ 702

v3.3.1.900
Property, Plant and Equipment (Components of PP&E) (Details) - USD ($)
$ in Millions
12 Months Ended
Dec. 31, 2015
Dec. 31, 2014
Property, Plant and Equipment [Line Items]    
Electric generation, distribution assets and other $ 28,491 $ 30,459
Accumulated depreciation (9,449) (9,962)
Property, Plant and Equipment, Net [1] 19,042 20,497
Capitalized computer software, net 83 115
Electric generation and distribution facilities    
Property, Plant and Equipment [Line Items]    
Electric generation, distribution assets and other $ 25,427 27,488
Electric generation and distribution facilities | Minimum    
Property, Plant and Equipment [Line Items]    
Estimated Useful Life 5 years  
Electric generation and distribution facilities | Maximum    
Property, Plant and Equipment [Line Items]    
Estimated Useful Life 68 years  
Other buildings    
Property, Plant and Equipment [Line Items]    
Electric generation, distribution assets and other $ 1,868 1,694
Other buildings | Minimum    
Property, Plant and Equipment [Line Items]    
Estimated Useful Life 3 years  
Other buildings | Maximum    
Property, Plant and Equipment [Line Items]    
Estimated Useful Life 53 years  
Furniture and Fixtures [Member]    
Property, Plant and Equipment [Line Items]    
Electric generation, distribution assets and other $ 305 307
Furniture and Fixtures [Member] | Minimum    
Property, Plant and Equipment [Line Items]    
Estimated Useful Life 2 years  
Furniture and Fixtures [Member] | Maximum    
Property, Plant and Equipment [Line Items]    
Estimated Useful Life 31 years  
Other    
Property, Plant and Equipment [Line Items]    
Electric generation, distribution assets and other $ 891 $ 970
Other | Minimum    
Property, Plant and Equipment [Line Items]    
Estimated Useful Life 1 year  
Other | Maximum    
Property, Plant and Equipment [Line Items]    
Estimated Useful Life 50 years  
[1] (1) Net electric generation and distribution assets and other include unamortized internal-use software costs of $83 million and $115 million as of December 31, 2015 and 2014, respectively.

v3.3.1.900
Property, Plant and Equipment (Depreciation Expense, Software Amortization and Capitalized Interest) (Details) - USD ($)
$ in Millions
12 Months Ended
Dec. 31, 2015
Dec. 31, 2014
Dec. 31, 2013
Property, Plant and Equipment [Abstract]      
Depreciation expense (including amortization of assets recorded under capital leases) $ 1,104 $ 1,204 $ 1,193
Amortization of internal-use software 29 33 36
Interest capitalized during development and construction 90 120 $ 84
Property plant and equipment, net of accumulated depreciation mortgaged, pledged or subject to liens $ 12,000 $ 15,000  

v3.3.1.900
Property, Plant and Equipment (Regulated and Non-Regulated Generation and Distribution PP&E) (Details) - USD ($)
$ in Millions
Dec. 31, 2015
Dec. 31, 2014
Property, Plant and Equipment [Line Items]    
Electric generation, distribution assets and other $ 28,491 $ 30,459
Accumulated depreciation (9,449) (9,962)
Net electric generation and distribution assets and other 19,042 20,497
Regulated Operation [Member]    
Property, Plant and Equipment [Line Items]    
Electric generation, distribution assets and other 11,818 13,103
Accumulated depreciation (4,351) (4,841)
Net electric generation and distribution assets and other 7,467 8,262
Unregulated Operation [Member]    
Property, Plant and Equipment [Line Items]    
Electric generation, distribution assets and other 16,673 17,356
Accumulated depreciation (5,098) (5,121)
Net electric generation and distribution assets and other $ 11,575 $ 12,235

v3.3.1.900
Property, Plant and Equipment (Asset Retirement Obligations) (Details) - USD ($)
12 Months Ended
Dec. 31, 2015
Dec. 31, 2014
Asset Retirement Obligation, Roll Forward Analysis [Roll Forward]    
Beginning balance $ 209,000,000 $ 142,000,000
Additional liabilities incurred 43,000,000 51,000,000
Asset Retirement Obligation, Other [Line Items] (5,000,000) 0
Liabilities settled (6,000,000) (11,000,000)
Accretion expense 13,000,000 12,000,000
Change in estimated cash flows (7,000,000) 15,000,000
Ending balance 247,000,000 209,000,000
Asset retirement obligation, legally restricted $ 2,000,000 $ 0

v3.3.1.900
Property, Plant and Equipment (Ownership of Coal-Fired Facilities) (Details)
$ in Millions
Dec. 31, 2015
USD ($)
facility
Jointly Owned Utility Plant Interests [Line Items]  
Number of Coal-Fired Generation Facilities, Jointly Owned | facility 5
Conesville Unit 4  
Jointly Owned Utility Plant Interests [Line Items]  
Construction Work In Process $ 1
Ownership 17.00%
Gross Plant In Service $ 26
Accumulated Depreciation 4
Killen Station  
Jointly Owned Utility Plant Interests [Line Items]  
Construction Work In Process $ 2
Ownership 67.00%
Gross Plant In Service $ 342
Accumulated Depreciation 29
Miami Fort Units 7 and 8  
Jointly Owned Utility Plant Interests [Line Items]  
Construction Work In Process $ 6
Ownership 36.00%
Gross Plant In Service $ 219
Accumulated Depreciation 32
Stuart Station  
Jointly Owned Utility Plant Interests [Line Items]  
Construction Work In Process $ 18
Ownership 35.00%
Gross Plant In Service $ 236
Accumulated Depreciation 19
Zimmer Station  
Jointly Owned Utility Plant Interests [Line Items]  
Construction Work In Process $ 12
Ownership 28.00%
Gross Plant In Service $ 188
Accumulated Depreciation 44
Transmission  
Jointly Owned Utility Plant Interests [Line Items]  
Construction Work In Process 0
Gross Plant In Service 43
Accumulated Depreciation 8
Total Jointly Owned Plant  
Jointly Owned Utility Plant Interests [Line Items]  
Construction Work In Process 39
Gross Plant In Service 1,054
Accumulated Depreciation $ 136

v3.3.1.900
Fair Value (Recurring Measurements) (Details) - USD ($)
$ in Millions
Dec. 31, 2015
Dec. 31, 2014
Fair Value, Assets and Liabilities Measured on Recurring and Nonrecurring Basis [Line Items]    
Fair Value, Measurement with Unobservable Inputs Reconciliation, Recurring Basis, Asset Value $ 895 $ 1,029
Fair Value, Measurement with Unobservable Inputs Reconciliations, Recurring Basis, Liability Value 490 514
Level 1    
Fair Value, Assets and Liabilities Measured on Recurring and Nonrecurring Basis [Line Items]    
Fair Value, Measurement with Unobservable Inputs Reconciliation, Recurring Basis, Asset Value 15 15
Fair Value, Measurement with Unobservable Inputs Reconciliations, Recurring Basis, Liability Value 0 0
Level 2    
Fair Value, Assets and Liabilities Measured on Recurring and Nonrecurring Basis [Line Items]    
Fair Value, Measurement with Unobservable Inputs Reconciliation, Recurring Basis, Asset Value 581 789
Fair Value, Measurement with Unobservable Inputs Reconciliations, Recurring Basis, Liability Value 167 294
Level 3    
Fair Value, Assets and Liabilities Measured on Recurring and Nonrecurring Basis [Line Items]    
Fair Value, Measurement with Unobservable Inputs Reconciliation, Recurring Basis, Asset Value 299 225
Fair Value, Measurement with Unobservable Inputs Reconciliations, Recurring Basis, Liability Value 323 220
Available-for-sale Securities [Member]    
Fair Value, Assets and Liabilities Measured on Recurring and Nonrecurring Basis [Line Items]    
Fair Value, Measurement with Unobservable Inputs Reconciliation, Recurring Basis, Asset Value [1] 505 734
Available-for-sale Securities [Member] | Level 1    
Fair Value, Assets and Liabilities Measured on Recurring and Nonrecurring Basis [Line Items]    
Fair Value, Measurement with Unobservable Inputs Reconciliation, Recurring Basis, Asset Value [1] 0 0
Available-for-sale Securities [Member] | Level 2    
Fair Value, Assets and Liabilities Measured on Recurring and Nonrecurring Basis [Line Items]    
Fair Value, Measurement with Unobservable Inputs Reconciliation, Recurring Basis, Asset Value [1] 505 734
Available-for-sale Securities [Member] | Level 3    
Fair Value, Assets and Liabilities Measured on Recurring and Nonrecurring Basis [Line Items]    
Fair Value, Measurement with Unobservable Inputs Reconciliation, Recurring Basis, Asset Value [1] 0 0
Derivative [Member]    
Fair Value, Assets and Liabilities Measured on Recurring and Nonrecurring Basis [Line Items]    
Fair Value, Measurement with Unobservable Inputs Reconciliation, Recurring Basis, Asset Value 375 280
Fair Value, Measurement with Unobservable Inputs Reconciliations, Recurring Basis, Liability Value 490 514
Derivative [Member] | Commodity Contract [Member]    
Fair Value, Assets and Liabilities Measured on Recurring and Nonrecurring Basis [Line Items]    
Fair Value, Measurement with Unobservable Inputs Reconciliations, Recurring Basis, Liability Value 33 17
Derivative [Member] | Interest rate derivatives    
Fair Value, Assets and Liabilities Measured on Recurring and Nonrecurring Basis [Line Items]    
Fair Value, Measurement with Unobservable Inputs Reconciliations, Recurring Basis, Liability Value 358 416
Derivative [Member] | Cross currency derivatives    
Fair Value, Assets and Liabilities Measured on Recurring and Nonrecurring Basis [Line Items]    
Fair Value, Measurement with Unobservable Inputs Reconciliations, Recurring Basis, Liability Value 43 29
Derivative [Member] | Foreign currency derivatives    
Fair Value, Assets and Liabilities Measured on Recurring and Nonrecurring Basis [Line Items]    
Fair Value, Measurement with Unobservable Inputs Reconciliations, Recurring Basis, Liability Value 56 52
Derivative [Member] | Level 1    
Fair Value, Assets and Liabilities Measured on Recurring and Nonrecurring Basis [Line Items]    
Fair Value, Measurement with Unobservable Inputs Reconciliation, Recurring Basis, Asset Value 0 0
Fair Value, Measurement with Unobservable Inputs Reconciliations, Recurring Basis, Liability Value 0 0
Derivative [Member] | Level 1 | Commodity Contract [Member]    
Fair Value, Assets and Liabilities Measured on Recurring and Nonrecurring Basis [Line Items]    
Fair Value, Measurement with Unobservable Inputs Reconciliations, Recurring Basis, Liability Value 0 0
Derivative [Member] | Level 1 | Interest rate derivatives    
Fair Value, Assets and Liabilities Measured on Recurring and Nonrecurring Basis [Line Items]    
Fair Value, Measurement with Unobservable Inputs Reconciliations, Recurring Basis, Liability Value 0 0
Derivative [Member] | Level 1 | Cross currency derivatives    
Fair Value, Assets and Liabilities Measured on Recurring and Nonrecurring Basis [Line Items]    
Fair Value, Measurement with Unobservable Inputs Reconciliations, Recurring Basis, Liability Value 0 0
Derivative [Member] | Level 1 | Foreign currency derivatives    
Fair Value, Assets and Liabilities Measured on Recurring and Nonrecurring Basis [Line Items]    
Fair Value, Measurement with Unobservable Inputs Reconciliations, Recurring Basis, Liability Value 0 0
Derivative [Member] | Level 2    
Fair Value, Assets and Liabilities Measured on Recurring and Nonrecurring Basis [Line Items]    
Fair Value, Measurement with Unobservable Inputs Reconciliation, Recurring Basis, Asset Value 76 55
Fair Value, Measurement with Unobservable Inputs Reconciliations, Recurring Basis, Liability Value 167 294
Derivative [Member] | Level 2 | Commodity Contract [Member]    
Fair Value, Assets and Liabilities Measured on Recurring and Nonrecurring Basis [Line Items]    
Fair Value, Measurement with Unobservable Inputs Reconciliations, Recurring Basis, Liability Value 29 16
Derivative [Member] | Level 2 | Interest rate derivatives    
Fair Value, Assets and Liabilities Measured on Recurring and Nonrecurring Basis [Line Items]    
Fair Value, Measurement with Unobservable Inputs Reconciliations, Recurring Basis, Liability Value 54 206
Derivative [Member] | Level 2 | Cross currency derivatives    
Fair Value, Assets and Liabilities Measured on Recurring and Nonrecurring Basis [Line Items]    
Fair Value, Measurement with Unobservable Inputs Reconciliations, Recurring Basis, Liability Value 43 29
Derivative [Member] | Level 2 | Foreign currency derivatives    
Fair Value, Assets and Liabilities Measured on Recurring and Nonrecurring Basis [Line Items]    
Fair Value, Measurement with Unobservable Inputs Reconciliations, Recurring Basis, Liability Value 41 43
Derivative [Member] | Level 3    
Fair Value, Assets and Liabilities Measured on Recurring and Nonrecurring Basis [Line Items]    
Fair Value, Measurement with Unobservable Inputs Reconciliation, Recurring Basis, Asset Value 299 225
Fair Value, Measurement with Unobservable Inputs Reconciliations, Recurring Basis, Liability Value 323 220
Derivative [Member] | Level 3 | Commodity Contract [Member]    
Fair Value, Assets and Liabilities Measured on Recurring and Nonrecurring Basis [Line Items]    
Fair Value, Measurement with Unobservable Inputs Reconciliations, Recurring Basis, Liability Value 4 1
Derivative [Member] | Level 3 | Interest rate derivatives    
Fair Value, Assets and Liabilities Measured on Recurring and Nonrecurring Basis [Line Items]    
Fair Value, Measurement with Unobservable Inputs Reconciliations, Recurring Basis, Liability Value 304 210
Derivative [Member] | Level 3 | Cross currency derivatives    
Fair Value, Assets and Liabilities Measured on Recurring and Nonrecurring Basis [Line Items]    
Fair Value, Measurement with Unobservable Inputs Reconciliations, Recurring Basis, Liability Value 0 0
Derivative [Member] | Level 3 | Foreign currency derivatives    
Fair Value, Assets and Liabilities Measured on Recurring and Nonrecurring Basis [Line Items]    
Fair Value, Measurement with Unobservable Inputs Reconciliations, Recurring Basis, Liability Value 15 9
Other debt securities | Available-for-sale Securities [Member]    
Fair Value, Assets and Liabilities Measured on Recurring and Nonrecurring Basis [Line Items]    
Fair Value, Measurement with Unobservable Inputs Reconciliation, Recurring Basis, Asset Value [1] 327 501
Other debt securities | Available-for-sale Securities [Member] | Level 1    
Fair Value, Assets and Liabilities Measured on Recurring and Nonrecurring Basis [Line Items]    
Fair Value, Measurement with Unobservable Inputs Reconciliation, Recurring Basis, Asset Value [1] 0 0
Other debt securities | Available-for-sale Securities [Member] | Level 2    
Fair Value, Assets and Liabilities Measured on Recurring and Nonrecurring Basis [Line Items]    
Fair Value, Measurement with Unobservable Inputs Reconciliation, Recurring Basis, Asset Value [1] 327 501
Other debt securities | Available-for-sale Securities [Member] | Level 3    
Fair Value, Assets and Liabilities Measured on Recurring and Nonrecurring Basis [Line Items]    
Fair Value, Measurement with Unobservable Inputs Reconciliation, Recurring Basis, Asset Value [1] 0 0
Commodity Contract [Member] | Derivative [Member]    
Fair Value, Assets and Liabilities Measured on Recurring and Nonrecurring Basis [Line Items]    
Fair Value, Measurement with Unobservable Inputs Reconciliation, Recurring Basis, Asset Value 48 44
Commodity Contract [Member] | Derivative [Member] | Level 1    
Fair Value, Assets and Liabilities Measured on Recurring and Nonrecurring Basis [Line Items]    
Fair Value, Measurement with Unobservable Inputs Reconciliation, Recurring Basis, Asset Value 0 0
Commodity Contract [Member] | Derivative [Member] | Level 2    
Fair Value, Assets and Liabilities Measured on Recurring and Nonrecurring Basis [Line Items]    
Fair Value, Measurement with Unobservable Inputs Reconciliation, Recurring Basis, Asset Value 41 37
Commodity Contract [Member] | Derivative [Member] | Level 3    
Fair Value, Assets and Liabilities Measured on Recurring and Nonrecurring Basis [Line Items]    
Fair Value, Measurement with Unobservable Inputs Reconciliation, Recurring Basis, Asset Value 7 7
Certificates of Deposit [Member] | Available-for-sale Securities [Member]    
Fair Value, Assets and Liabilities Measured on Recurring and Nonrecurring Basis [Line Items]    
Fair Value, Measurement with Unobservable Inputs Reconciliation, Recurring Basis, Asset Value [1] 135 151
Certificates of Deposit [Member] | Available-for-sale Securities [Member] | Level 1    
Fair Value, Assets and Liabilities Measured on Recurring and Nonrecurring Basis [Line Items]    
Fair Value, Measurement with Unobservable Inputs Reconciliation, Recurring Basis, Asset Value [1] 0 0
Certificates of Deposit [Member] | Available-for-sale Securities [Member] | Level 2    
Fair Value, Assets and Liabilities Measured on Recurring and Nonrecurring Basis [Line Items]    
Fair Value, Measurement with Unobservable Inputs Reconciliation, Recurring Basis, Asset Value [1] 135 151
Certificates of Deposit [Member] | Available-for-sale Securities [Member] | Level 3    
Fair Value, Assets and Liabilities Measured on Recurring and Nonrecurring Basis [Line Items]    
Fair Value, Measurement with Unobservable Inputs Reconciliation, Recurring Basis, Asset Value [1] 0 0
Government debt securities [Domain] | Available-for-sale Securities [Member]    
Fair Value, Assets and Liabilities Measured on Recurring and Nonrecurring Basis [Line Items]    
Fair Value, Measurement with Unobservable Inputs Reconciliation, Recurring Basis, Asset Value [1] 28 57
Government debt securities [Domain] | Available-for-sale Securities [Member] | Level 1    
Fair Value, Assets and Liabilities Measured on Recurring and Nonrecurring Basis [Line Items]    
Fair Value, Measurement with Unobservable Inputs Reconciliation, Recurring Basis, Asset Value [1] 0 0
Government debt securities [Domain] | Available-for-sale Securities [Member] | Level 2    
Fair Value, Assets and Liabilities Measured on Recurring and Nonrecurring Basis [Line Items]    
Fair Value, Measurement with Unobservable Inputs Reconciliation, Recurring Basis, Asset Value [1] 28 57
Government debt securities [Domain] | Available-for-sale Securities [Member] | Level 3    
Fair Value, Assets and Liabilities Measured on Recurring and Nonrecurring Basis [Line Items]    
Fair Value, Measurement with Unobservable Inputs Reconciliation, Recurring Basis, Asset Value [1] 0 0
Debt securities | Available-for-sale Securities [Member]    
Fair Value, Assets and Liabilities Measured on Recurring and Nonrecurring Basis [Line Items]    
Fair Value, Measurement with Unobservable Inputs Reconciliation, Recurring Basis, Asset Value [1] 490 709
Debt securities | Available-for-sale Securities [Member] | Level 1    
Fair Value, Assets and Liabilities Measured on Recurring and Nonrecurring Basis [Line Items]    
Fair Value, Measurement with Unobservable Inputs Reconciliation, Recurring Basis, Asset Value [1] 0 0
Debt securities | Available-for-sale Securities [Member] | Level 2    
Fair Value, Assets and Liabilities Measured on Recurring and Nonrecurring Basis [Line Items]    
Fair Value, Measurement with Unobservable Inputs Reconciliation, Recurring Basis, Asset Value [1] 490 709
Debt securities | Available-for-sale Securities [Member] | Level 3    
Fair Value, Assets and Liabilities Measured on Recurring and Nonrecurring Basis [Line Items]    
Fair Value, Measurement with Unobservable Inputs Reconciliation, Recurring Basis, Asset Value [1] 0 0
Equity Funds [Member] | Available-for-sale Securities [Member]    
Fair Value, Assets and Liabilities Measured on Recurring and Nonrecurring Basis [Line Items]    
Fair Value, Measurement with Unobservable Inputs Reconciliation, Recurring Basis, Asset Value [1] 15 25
Equity Funds [Member] | Available-for-sale Securities [Member] | Level 1    
Fair Value, Assets and Liabilities Measured on Recurring and Nonrecurring Basis [Line Items]    
Fair Value, Measurement with Unobservable Inputs Reconciliation, Recurring Basis, Asset Value [1] 0 0
Equity Funds [Member] | Available-for-sale Securities [Member] | Level 2    
Fair Value, Assets and Liabilities Measured on Recurring and Nonrecurring Basis [Line Items]    
Fair Value, Measurement with Unobservable Inputs Reconciliation, Recurring Basis, Asset Value [1] 15 25
Equity Funds [Member] | Available-for-sale Securities [Member] | Level 3    
Fair Value, Assets and Liabilities Measured on Recurring and Nonrecurring Basis [Line Items]    
Fair Value, Measurement with Unobservable Inputs Reconciliation, Recurring Basis, Asset Value [1] 0 0
Equity Funds [Member] | Trading Securities [Member]    
Fair Value, Assets and Liabilities Measured on Recurring and Nonrecurring Basis [Line Items]    
Fair Value, Measurement with Unobservable Inputs Reconciliation, Recurring Basis, Asset Value 15 15
Equity Funds [Member] | Trading Securities [Member] | Level 1    
Fair Value, Assets and Liabilities Measured on Recurring and Nonrecurring Basis [Line Items]    
Fair Value, Measurement with Unobservable Inputs Reconciliation, Recurring Basis, Asset Value 15 15
Equity Funds [Member] | Trading Securities [Member] | Level 2    
Fair Value, Assets and Liabilities Measured on Recurring and Nonrecurring Basis [Line Items]    
Fair Value, Measurement with Unobservable Inputs Reconciliation, Recurring Basis, Asset Value 0 0
Equity Funds [Member] | Trading Securities [Member] | Level 3    
Fair Value, Assets and Liabilities Measured on Recurring and Nonrecurring Basis [Line Items]    
Fair Value, Measurement with Unobservable Inputs Reconciliation, Recurring Basis, Asset Value 0 0
Equity securities | Available-for-sale Securities [Member]    
Fair Value, Assets and Liabilities Measured on Recurring and Nonrecurring Basis [Line Items]    
Fair Value, Measurement with Unobservable Inputs Reconciliation, Recurring Basis, Asset Value [1] 15 25
Equity securities | Available-for-sale Securities [Member] | Level 1    
Fair Value, Assets and Liabilities Measured on Recurring and Nonrecurring Basis [Line Items]    
Fair Value, Measurement with Unobservable Inputs Reconciliation, Recurring Basis, Asset Value [1] 0 0
Equity securities | Available-for-sale Securities [Member] | Level 2    
Fair Value, Assets and Liabilities Measured on Recurring and Nonrecurring Basis [Line Items]    
Fair Value, Measurement with Unobservable Inputs Reconciliation, Recurring Basis, Asset Value [1] 15 25
Equity securities | Available-for-sale Securities [Member] | Level 3    
Fair Value, Assets and Liabilities Measured on Recurring and Nonrecurring Basis [Line Items]    
Fair Value, Measurement with Unobservable Inputs Reconciliation, Recurring Basis, Asset Value [1] 0 0
Foreign currency derivatives | Derivative [Member]    
Fair Value, Assets and Liabilities Measured on Recurring and Nonrecurring Basis [Line Items]    
Fair Value, Measurement with Unobservable Inputs Reconciliation, Recurring Basis, Asset Value 327 236
Foreign currency derivatives | Derivative [Member] | Level 1    
Fair Value, Assets and Liabilities Measured on Recurring and Nonrecurring Basis [Line Items]    
Fair Value, Measurement with Unobservable Inputs Reconciliation, Recurring Basis, Asset Value 0 0
Foreign currency derivatives | Derivative [Member] | Level 2    
Fair Value, Assets and Liabilities Measured on Recurring and Nonrecurring Basis [Line Items]    
Fair Value, Measurement with Unobservable Inputs Reconciliation, Recurring Basis, Asset Value 35 18
Foreign currency derivatives | Derivative [Member] | Level 3    
Fair Value, Assets and Liabilities Measured on Recurring and Nonrecurring Basis [Line Items]    
Fair Value, Measurement with Unobservable Inputs Reconciliation, Recurring Basis, Asset Value $ 292 $ 218
[1] (1) Amortized cost approximated fair value at December 31, 2015 and 2014.

v3.3.1.900
Fair Value (Level 3 Reconciliation) (Details) - USD ($)
$ in Millions
12 Months Ended
Dec. 31, 2015
Dec. 31, 2014
Dec. 31, 2013
Fair Value, Net Derivative Asset (Liability) Measured on Recurring Basis, Unobservable Input Reconciliation [Roll Forward]      
Fair Value, Net Derivative Asset (Liability) Measured on Recurring Basis, Unobservable Inputs Reconciliation, Gain (Loss) Included in Earnings $ 196 $ 137  
Total gains (losses) (realized and unrealized):      
Included in regulatory (assets) liabilities (18) 16  
Fair Value, Net Derivative Asset (Liability) Measured on Recurring Basis, Unobservable Inputs Reconciliation, Settlements 33 11  
Fair Value, Net Derivative Asset (Liability) Measured on Recurring Basis, Unobservable Inputs Reconciliation, Transfers into Level 3 (96) 10  
Fair Value, Measurement with Unobservable Inputs Reconciliation, Recurring Basis, Asset, Transfers out of Level 3 (19) 3  
Fair Value, Net Derivative Asset (Liability) Measured on Recurring Basis with Unobservable Inputs (24) 5 $ (4)
Fair Value, Net Derivative Asset (Liability) Measured on Recurring Basis, Unobservable Inputs Reconciliation, Period Increase (Decrease) 186 131  
Commodity Contract [Member]      
Fair Value, Net Derivative Asset (Liability) Measured on Recurring Basis, Unobservable Input Reconciliation [Roll Forward]      
Fair Value, Net Derivative Asset (Liability) Measured on Recurring Basis, Unobservable Inputs Reconciliation, Gain (Loss) Included in Earnings (1) 1  
Total gains (losses) (realized and unrealized):      
Included in regulatory (assets) liabilities (18) 16  
Fair Value, Net Derivative Asset (Liability) Measured on Recurring Basis, Unobservable Inputs Reconciliation, Settlements 16 (15)  
Fair Value, Net Derivative Asset (Liability) Measured on Recurring Basis, Unobservable Inputs Reconciliation, Transfers into Level 3 0 0  
Fair Value, Measurement with Unobservable Inputs Reconciliation, Recurring Basis, Asset, Transfers out of Level 3 0 0  
Fair Value, Net Derivative Asset (Liability) Measured on Recurring Basis with Unobservable Inputs 3 6 4
Fair Value, Net Derivative Asset (Liability) Measured on Recurring Basis, Unobservable Inputs Reconciliation, Period Increase (Decrease) (1) (1)  
Foreign Exchange Contract [Member]      
Fair Value, Net Derivative Asset (Liability) Measured on Recurring Basis, Unobservable Input Reconciliation [Roll Forward]      
Fair Value, Net Derivative Asset (Liability) Measured on Recurring Basis, Unobservable Inputs Reconciliation, Gain (Loss) Included in Earnings 198 134  
Total gains (losses) (realized and unrealized):      
Included in regulatory (assets) liabilities 0 0  
Fair Value, Net Derivative Asset (Liability) Measured on Recurring Basis, Unobservable Inputs Reconciliation, Settlements (7) (4)  
Fair Value, Net Derivative Asset (Liability) Measured on Recurring Basis, Unobservable Inputs Reconciliation, Transfers into Level 3 (1) 10  
Fair Value, Measurement with Unobservable Inputs Reconciliation, Recurring Basis, Asset, Transfers out of Level 3 (19) 3  
Fair Value, Net Derivative Asset (Liability) Measured on Recurring Basis with Unobservable Inputs 277 209 93
Fair Value, Net Derivative Asset (Liability) Measured on Recurring Basis, Unobservable Inputs Reconciliation, Period Increase (Decrease) 187 130  
Interest Rate Contract      
Fair Value, Net Derivative Asset (Liability) Measured on Recurring Basis, Unobservable Input Reconciliation [Roll Forward]      
Fair Value, Net Derivative Asset (Liability) Measured on Recurring Basis, Unobservable Inputs Reconciliation, Gain (Loss) Included in Earnings (1) 2  
Total gains (losses) (realized and unrealized):      
Included in regulatory (assets) liabilities 0 0  
Fair Value, Net Derivative Asset (Liability) Measured on Recurring Basis, Unobservable Inputs Reconciliation, Settlements 24 30  
Fair Value, Net Derivative Asset (Liability) Measured on Recurring Basis, Unobservable Inputs Reconciliation, Transfers into Level 3 (95) 0  
Fair Value, Measurement with Unobservable Inputs Reconciliation, Recurring Basis, Asset, Transfers out of Level 3 0 0  
Fair Value, Net Derivative Asset (Liability) Measured on Recurring Basis with Unobservable Inputs (304) (210) $ (101)
Fair Value, Net Derivative Asset (Liability) Measured on Recurring Basis, Unobservable Inputs Reconciliation, Period Increase (Decrease) 0 2  
Other comprehensive income - Derivative activity [Member]      
Fair Value, Net Derivative Asset (Liability) Measured on Recurring Basis, Unobservable Input Reconciliation [Roll Forward]      
Fair Value, Net Derivative Asset (Liability) Measured on Recurring Basis, Unobservable Inputs Reconciliation, Gain (Loss) Included in Other Comprehensive Income (Loss) (31) (156)  
Other comprehensive income - Derivative activity [Member] | Commodity Contract [Member]      
Fair Value, Net Derivative Asset (Liability) Measured on Recurring Basis, Unobservable Input Reconciliation [Roll Forward]      
Fair Value, Net Derivative Asset (Liability) Measured on Recurring Basis, Unobservable Inputs Reconciliation, Gain (Loss) Included in Other Comprehensive Income (Loss) 0 0  
Other comprehensive income - Derivative activity [Member] | Foreign Exchange Contract [Member]      
Fair Value, Net Derivative Asset (Liability) Measured on Recurring Basis, Unobservable Input Reconciliation [Roll Forward]      
Fair Value, Net Derivative Asset (Liability) Measured on Recurring Basis, Unobservable Inputs Reconciliation, Gain (Loss) Included in Other Comprehensive Income (Loss) 0 (2)  
Other comprehensive income - Derivative activity [Member] | Interest Rate Contract      
Fair Value, Net Derivative Asset (Liability) Measured on Recurring Basis, Unobservable Input Reconciliation [Roll Forward]      
Fair Value, Net Derivative Asset (Liability) Measured on Recurring Basis, Unobservable Inputs Reconciliation, Gain (Loss) Included in Other Comprehensive Income (Loss) (31) (154)  
Other Comprehensive Income- Foreign currency translation activity [Member]      
Fair Value, Net Derivative Asset (Liability) Measured on Recurring Basis, Unobservable Input Reconciliation [Roll Forward]      
Fair Value, Net Derivative Asset (Liability) Measured on Recurring Basis, Unobservable Inputs Reconciliation, Gain (Loss) Included in Other Comprehensive Income (Loss) (94) (12)  
Other Comprehensive Income- Foreign currency translation activity [Member] | Commodity Contract [Member]      
Fair Value, Net Derivative Asset (Liability) Measured on Recurring Basis, Unobservable Input Reconciliation [Roll Forward]      
Fair Value, Net Derivative Asset (Liability) Measured on Recurring Basis, Unobservable Inputs Reconciliation, Gain (Loss) Included in Other Comprehensive Income (Loss) 0 0  
Other Comprehensive Income- Foreign currency translation activity [Member] | Foreign Exchange Contract [Member]      
Fair Value, Net Derivative Asset (Liability) Measured on Recurring Basis, Unobservable Input Reconciliation [Roll Forward]      
Fair Value, Net Derivative Asset (Liability) Measured on Recurring Basis, Unobservable Inputs Reconciliation, Gain (Loss) Included in Other Comprehensive Income (Loss) (103) (25)  
Other Comprehensive Income- Foreign currency translation activity [Member] | Interest Rate Contract      
Fair Value, Net Derivative Asset (Liability) Measured on Recurring Basis, Unobservable Input Reconciliation [Roll Forward]      
Fair Value, Net Derivative Asset (Liability) Measured on Recurring Basis, Unobservable Inputs Reconciliation, Gain (Loss) Included in Other Comprehensive Income (Loss) $ 9 $ 13  

v3.3.1.900
Fair Value (Quantitative Information) (Details)
$ in Millions
12 Months Ended
Dec. 31, 2015
USD ($)
Dec. 31, 2014
USD ($)
Dec. 31, 2013
USD ($)
Fair Value Inputs Quantitative Information [Line Items]      
Fair Value, Net Derivative Asset (Liability) Measured on Recurring Basis with Unobservable Inputs $ (24) $ 5 $ (4)
Fair Value Derivative Assets Liabilities Measured On Recurring Basis Unobservable Inputs [Abstract]      
Fair Value Measurement With Unobservable Inputs Reconciliation Recurring Basis Assets Liabilities Value (24)    
Foreign Exchange Contract [Member]      
Fair Value Inputs Quantitative Information [Line Items]      
Fair Value, Net Derivative Asset (Liability) Measured on Recurring Basis with Unobservable Inputs 277 209 93
Interest Rate Contract      
Fair Value Inputs Quantitative Information [Line Items]      
Fair Value, Net Derivative Asset (Liability) Measured on Recurring Basis with Unobservable Inputs $ (304) (210) (101)
Interest Rate Contract | Minimum      
Fair Value Inputs Quantitative Information [Line Items]      
Fair Value Inputs, Entity Credit Risk 2.88%    
Interest Rate Contract | Maximum      
Fair Value Inputs Quantitative Information [Line Items]      
Fair Value Inputs, Entity Credit Risk 8.88%    
Interest Rate Contract | Weighted Average      
Fair Value Inputs Quantitative Information [Line Items]      
Fair Value Inputs, Entity Credit Risk 5.42%    
Commodity Contract [Member]      
Fair Value Inputs Quantitative Information [Line Items]      
Fair Value, Net Derivative Asset (Liability) Measured on Recurring Basis with Unobservable Inputs $ 3 $ 6 $ 4
Euro Member Countries, Euro | Foreign Exchange Contract [Member] | Minimum      
Fair Value Inputs Quantitative Information [Line Items]      
Fair Value Inputs, Entity Credit Risk 8.88%    
Euro Member Countries, Euro | Foreign Exchange Contract [Member] | Maximum      
Fair Value Inputs Quantitative Information [Line Items]      
Fair Value Inputs, Entity Credit Risk 8.88%    
Euro Member Countries, Euro | Foreign Exchange Contract [Member] | Weighted Average      
Fair Value Inputs Quantitative Information [Line Items]      
Fair Value Inputs, Entity Credit Risk 8.88%    
Argentina, Pesos | Foreign Exchange Contract [Member]      
Fair Value Inputs Quantitative Information [Line Items]      
Fair Value, Net Derivative Asset (Liability) Measured on Recurring Basis with Unobservable Inputs $ 291    
Argentina, Pesos | Foreign Exchange Contract [Member] | Minimum      
Fair Value Derivative Assets Liabilities Measured On Recurring Basis Unobservable Inputs [Abstract]      
Argentine Peso to U.S. Dollar currency exchange rate after 1 year 0.1751    
Argentina, Pesos | Foreign Exchange Contract [Member] | Maximum      
Fair Value Derivative Assets Liabilities Measured On Recurring Basis Unobservable Inputs [Abstract]      
Argentine Peso to U.S. Dollar currency exchange rate after 1 year 0.3544    
Argentina, Pesos | Foreign Exchange Contract [Member] | Weighted Average      
Fair Value Derivative Assets Liabilities Measured On Recurring Basis Unobservable Inputs [Abstract]      
Argentine Peso to U.S. Dollar currency exchange rate after 1 year 0.2605    
Derivative Financial Instruments, Assets [Member] | Euro Member Countries, Euro | Foreign Exchange Contract [Member]      
Fair Value Inputs Quantitative Information [Line Items]      
Fair Value, Net Derivative Asset (Liability) Measured on Recurring Basis with Unobservable Inputs $ (14)    

v3.3.1.900
Fair Value (Nonrecurring Measurements) (Details) - USD ($)
3 Months Ended 12 Months Ended
Dec. 31, 2014
Mar. 31, 2014
Dec. 31, 2015
Dec. 31, 2014
Dec. 31, 2013
Oct. 01, 2015
Sep. 30, 2015
Aug. 28, 2015
Jun. 30, 2015
Feb. 09, 2015
Sep. 30, 2014
Sep. 25, 2014
Jun. 30, 2014
Jun. 06, 2014
Feb. 28, 2014
Fair Value Assets And Liabilities Measured On Nonrecurring Basis [Abstract]                              
Asset Impairment Charges     $ 602,000,000 $ 383,000,000 $ 661,000,000                    
Other non-operating expense     0 128,000,000 129,000,000                    
Goodwill impairment expense     317,000,000 164,000,000 $ 372,000,000                    
East Bend DPL [Member]                              
Fair Value Assets And Liabilities Measured On Nonrecurring Basis [Abstract]                              
Asset fair value nonrecurring     2,000,000                        
UK Wind (Newfield) [Member]                              
Fair Value Assets And Liabilities Measured On Nonrecurring Basis [Abstract]                              
Asset fair value nonrecurring                         $ 0    
UK Wind Development Projects [Domain]                              
Fair Value Assets And Liabilities Measured On Nonrecurring Basis [Abstract]                              
Asset fair value nonrecurring                 $ 1,000,000            
Kilroot [Member]                              
Fair Value Assets And Liabilities Measured On Nonrecurring Basis [Abstract]                              
Asset fair value nonrecurring               $ 70,000,000              
buffalo gap III [Member]                              
Fair Value Assets And Liabilities Measured On Nonrecurring Basis [Abstract]                              
Asset fair value nonrecurring             $ 118,000,000                
DPLER                              
Fair Value Assets And Liabilities Measured On Nonrecurring Basis [Abstract]                              
Goodwill impairment expense   $ 136,000,000                          
Buffalo Gap                              
Fair Value Assets And Liabilities Measured On Nonrecurring Basis [Abstract]                              
Goodwill impairment expense $ 10,000,000 18,000,000                          
Fair Value | Level 3                              
Fair Value Assets And Liabilities Measured On Nonrecurring Basis [Abstract]                              
Asset fair value nonrecurring     217,000,000                        
Fair Value | Long Lived Assets Held And Used [Member] | Ebute [Member]                              
Fair Value Assets And Liabilities Measured On Nonrecurring Basis [Abstract]                              
Asset fair value nonrecurring [1]             36,000,000                
Fair Value | Long Lived Assets Held And Used [Member] | Kilroot [Member] | Level 3                              
Fair Value Assets And Liabilities Measured On Nonrecurring Basis [Abstract]                              
Asset fair value nonrecurring               70,000,000              
Fair Value | Long Lived Assets Held And Used [Member] | buffalo gap III [Member] | Level 3                              
Fair Value Assets And Liabilities Measured On Nonrecurring Basis [Abstract]                              
Asset fair value nonrecurring [1]             118,000,000                
Discontinued Operations, Held-for-sale or Disposed of by Sale [Member] | Cameroon businesses                              
Fair Value Assets And Liabilities Measured On Nonrecurring Basis [Abstract]                              
Asset Impairment Charges [2]       38,000,000                      
Discontinued Operations, Held-for-sale or Disposed of by Sale [Member] | Carrying Amount | Cameroon businesses                              
Fair Value Assets And Liabilities Measured On Nonrecurring Basis [Abstract]                              
Asset fair value nonrecurring [2]   372,000,000                          
Discontinued Operations, Held-for-sale or Disposed of by Sale [Member] | Fair Value | Cameroon businesses | Level 1                              
Fair Value Assets And Liabilities Measured On Nonrecurring Basis [Abstract]                              
Asset fair value nonrecurring [2]   0                          
Discontinued Operations, Held-for-sale or Disposed of by Sale [Member] | Fair Value | Cameroon businesses | Level 2                              
Fair Value Assets And Liabilities Measured On Nonrecurring Basis [Abstract]                              
Asset fair value nonrecurring [2]   334,000,000                          
Discontinued Operations, Held-for-sale or Disposed of by Sale [Member] | Fair Value | Cameroon businesses | Level 3                              
Fair Value Assets And Liabilities Measured On Nonrecurring Basis [Abstract]                              
Asset fair value nonrecurring [2]   0                          
Equity Method Investments [Member] | Solar Spain [Member]                              
Fair Value Assets And Liabilities Measured On Nonrecurring Basis [Abstract]                              
Other non-operating expense [3]     0                        
Equity Method Investments [Member] | Entek                              
Fair Value Assets And Liabilities Measured On Nonrecurring Basis [Abstract]                              
Other non-operating expense [3],[4]       86,000,000                      
Equity Method Investments [Member] | Silver Ridge Power [Member]                              
Fair Value Assets And Liabilities Measured On Nonrecurring Basis [Abstract]                              
Other non-operating expense [3],[4]       42,000,000                      
Equity Method Investments [Member] | Carrying Amount | Solar Spain [Member]                              
Fair Value Assets And Liabilities Measured On Nonrecurring Basis [Abstract]                              
Asset fair value nonrecurring [3]                   $ 29,000,000          
Equity Method Investments [Member] | Carrying Amount | Entek                              
Fair Value Assets And Liabilities Measured On Nonrecurring Basis [Abstract]                              
Asset fair value nonrecurring [4]                       $ 211,000,000      
Equity Method Investments [Member] | Carrying Amount | Silver Ridge Power [Member]                              
Fair Value Assets And Liabilities Measured On Nonrecurring Basis [Abstract]                              
Asset fair value nonrecurring [3],[4]                         315,000,000    
Equity Method Investments [Member] | Fair Value | Solar Spain [Member] | Level 1                              
Fair Value Assets And Liabilities Measured On Nonrecurring Basis [Abstract]                              
Asset fair value nonrecurring [3]                   0          
Equity Method Investments [Member] | Fair Value | Solar Spain [Member] | Level 2                              
Fair Value Assets And Liabilities Measured On Nonrecurring Basis [Abstract]                              
Asset fair value nonrecurring [3]                   0          
Equity Method Investments [Member] | Fair Value | Solar Spain [Member] | Level 3                              
Fair Value Assets And Liabilities Measured On Nonrecurring Basis [Abstract]                              
Asset fair value nonrecurring [3]                   $ 29,000,000          
Equity Method Investments [Member] | Fair Value | Entek | Level 1                              
Fair Value Assets And Liabilities Measured On Nonrecurring Basis [Abstract]                              
Asset fair value nonrecurring [4]                       0      
Equity Method Investments [Member] | Fair Value | Entek | Level 2                              
Fair Value Assets And Liabilities Measured On Nonrecurring Basis [Abstract]                              
Asset fair value nonrecurring [4]                       125,000,000      
Equity Method Investments [Member] | Fair Value | Entek | Level 3                              
Fair Value Assets And Liabilities Measured On Nonrecurring Basis [Abstract]                              
Asset fair value nonrecurring [4]                       $ 0      
Equity Method Investments [Member] | Fair Value | Silver Ridge Power [Member] | Level 1                              
Fair Value Assets And Liabilities Measured On Nonrecurring Basis [Abstract]                              
Asset fair value nonrecurring [3],[4]                         0    
Equity Method Investments [Member] | Fair Value | Silver Ridge Power [Member] | Level 2                              
Fair Value Assets And Liabilities Measured On Nonrecurring Basis [Abstract]                              
Asset fair value nonrecurring [3],[4]                         0    
Equity Method Investments [Member] | Fair Value | Silver Ridge Power [Member] | Level 3                              
Fair Value Assets And Liabilities Measured On Nonrecurring Basis [Abstract]                              
Asset fair value nonrecurring [3],[4]                         273,000,000    
Long Lived Assets Held And Used [Member] | Fair Value Measurement [Domain] | Ebute [Member]                              
Fair Value Assets And Liabilities Measured On Nonrecurring Basis [Abstract]                              
Other non-operating expense [1]       15,000,000                      
Long Lived Assets Held And Used [Member] | East Bend DPL [Member]                              
Fair Value Assets And Liabilities Measured On Nonrecurring Basis [Abstract]                              
Other non-operating expense [1]       12,000,000                      
Long Lived Assets Held And Used [Member] | Ebute [Member]                              
Fair Value Assets And Liabilities Measured On Nonrecurring Basis [Abstract]                              
Other non-operating expense [1]       52,000,000                      
Long Lived Assets Held And Used [Member] | UK Wind (Newfield) [Member]                              
Fair Value Assets And Liabilities Measured On Nonrecurring Basis [Abstract]                              
Other non-operating expense [1]       12,000,000                      
Long Lived Assets Held And Used [Member] | UK Wind Development Projects [Domain]                              
Fair Value Assets And Liabilities Measured On Nonrecurring Basis [Abstract]                              
Other non-operating expense [1]     37,000,000                        
Long Lived Assets Held And Used [Member] | Kilroot [Member]                              
Fair Value Assets And Liabilities Measured On Nonrecurring Basis [Abstract]                              
Other non-operating expense [1]     121,000,000                        
Long Lived Assets Held And Used [Member] | buffalo gap III [Member]                              
Fair Value Assets And Liabilities Measured On Nonrecurring Basis [Abstract]                              
Other non-operating expense [1]     116,000,000                        
Long Lived Assets Held And Used [Member] | Other Affiliates [Member]                              
Fair Value Assets And Liabilities Measured On Nonrecurring Basis [Abstract]                              
Other non-operating expense     11,000,000                        
Long Lived Assets Held And Used [Member] | Carrying Amount | East Bend DPL [Member]                              
Fair Value Assets And Liabilities Measured On Nonrecurring Basis [Abstract]                              
Asset fair value nonrecurring [1]   14,000,000                          
Long Lived Assets Held And Used [Member] | Carrying Amount | Ebute [Member]                              
Fair Value Assets And Liabilities Measured On Nonrecurring Basis [Abstract]                              
Asset fair value nonrecurring [1]                     $ 51,000,000   99,000,000    
Long Lived Assets Held And Used [Member] | Carrying Amount | UK Wind (Newfield) [Member]                              
Fair Value Assets And Liabilities Measured On Nonrecurring Basis [Abstract]                              
Asset fair value nonrecurring [1]                           $ 12,000,000  
Long Lived Assets Held And Used [Member] | Carrying Amount | UK Wind Development Projects [Domain]                              
Fair Value Assets And Liabilities Measured On Nonrecurring Basis [Abstract]                              
Asset fair value nonrecurring [1]                 38,000,000            
Long Lived Assets Held And Used [Member] | Carrying Amount | Kilroot [Member]                              
Fair Value Assets And Liabilities Measured On Nonrecurring Basis [Abstract]                              
Asset fair value nonrecurring [1]               191,000,000              
Long Lived Assets Held And Used [Member] | Carrying Amount | buffalo gap III [Member]                              
Fair Value Assets And Liabilities Measured On Nonrecurring Basis [Abstract]                              
Asset fair value nonrecurring [1]             234,000,000                
Long Lived Assets Held And Used [Member] | Carrying Amount | Other Affiliates [Member]                              
Fair Value Assets And Liabilities Measured On Nonrecurring Basis [Abstract]                              
Asset fair value nonrecurring     32,000,000                        
Long Lived Assets Held And Used [Member] | Fair Value | East Bend DPL [Member] | Level 1                              
Fair Value Assets And Liabilities Measured On Nonrecurring Basis [Abstract]                              
Asset fair value nonrecurring [1]   0                          
Long Lived Assets Held And Used [Member] | Fair Value | East Bend DPL [Member] | Level 2                              
Fair Value Assets And Liabilities Measured On Nonrecurring Basis [Abstract]                              
Asset fair value nonrecurring [1]   2,000,000                          
Long Lived Assets Held And Used [Member] | Fair Value | East Bend DPL [Member] | Level 3                              
Fair Value Assets And Liabilities Measured On Nonrecurring Basis [Abstract]                              
Asset fair value nonrecurring [1]   0                          
Long Lived Assets Held And Used [Member] | Fair Value | Ebute [Member] | Level 1                              
Fair Value Assets And Liabilities Measured On Nonrecurring Basis [Abstract]                              
Asset fair value nonrecurring [1]                     0   0    
Long Lived Assets Held And Used [Member] | Fair Value | Ebute [Member] | Level 2                              
Fair Value Assets And Liabilities Measured On Nonrecurring Basis [Abstract]                              
Asset fair value nonrecurring [1]                     0   0    
Long Lived Assets Held And Used [Member] | Fair Value | Ebute [Member] | Level 3                              
Fair Value Assets And Liabilities Measured On Nonrecurring Basis [Abstract]                              
Asset fair value nonrecurring [1]                     $ 36,000,000   $ 47,000,000    
Long Lived Assets Held And Used [Member] | Fair Value | UK Wind (Newfield) [Member] | Level 1                              
Fair Value Assets And Liabilities Measured On Nonrecurring Basis [Abstract]                              
Asset fair value nonrecurring [1]                           0  
Long Lived Assets Held And Used [Member] | Fair Value | UK Wind (Newfield) [Member] | Level 2                              
Fair Value Assets And Liabilities Measured On Nonrecurring Basis [Abstract]                              
Asset fair value nonrecurring [1]                           0  
Long Lived Assets Held And Used [Member] | Fair Value | UK Wind (Newfield) [Member] | Level 3                              
Fair Value Assets And Liabilities Measured On Nonrecurring Basis [Abstract]                              
Asset fair value nonrecurring [1]                           $ 0  
Long Lived Assets Held And Used [Member] | Fair Value | UK Wind Development Projects [Domain] | Level 1                              
Fair Value Assets And Liabilities Measured On Nonrecurring Basis [Abstract]                              
Asset fair value nonrecurring [1]                 0            
Long Lived Assets Held And Used [Member] | Fair Value | UK Wind Development Projects [Domain] | Level 2                              
Fair Value Assets And Liabilities Measured On Nonrecurring Basis [Abstract]                              
Asset fair value nonrecurring [1]                 1,000,000            
Long Lived Assets Held And Used [Member] | Fair Value | Kilroot [Member] | Level 1                              
Fair Value Assets And Liabilities Measured On Nonrecurring Basis [Abstract]                              
Asset fair value nonrecurring [1]               0              
Long Lived Assets Held And Used [Member] | Fair Value | Kilroot [Member] | Level 2                              
Fair Value Assets And Liabilities Measured On Nonrecurring Basis [Abstract]                              
Asset fair value nonrecurring [1]               0              
Long Lived Assets Held And Used [Member] | Fair Value | Kilroot [Member] | Level 3                              
Fair Value Assets And Liabilities Measured On Nonrecurring Basis [Abstract]                              
Asset fair value nonrecurring [1]               $ 70,000,000              
Long Lived Assets Held And Used [Member] | Fair Value | buffalo gap III [Member] | Level 1                              
Fair Value Assets And Liabilities Measured On Nonrecurring Basis [Abstract]                              
Asset fair value nonrecurring [1]             0                
Long Lived Assets Held And Used [Member] | Fair Value | buffalo gap III [Member] | Level 2                              
Fair Value Assets And Liabilities Measured On Nonrecurring Basis [Abstract]                              
Asset fair value nonrecurring [1]             0                
Long Lived Assets Held And Used [Member] | Fair Value | Other Affiliates [Member] | Level 1                              
Fair Value Assets And Liabilities Measured On Nonrecurring Basis [Abstract]                              
Asset fair value nonrecurring     0                        
Long Lived Assets Held And Used [Member] | Fair Value | Other Affiliates [Member] | Level 2                              
Fair Value Assets And Liabilities Measured On Nonrecurring Basis [Abstract]                              
Asset fair value nonrecurring     21,000,000                        
Long Lived Assets Held And Used [Member] | Fair Value | Other Affiliates [Member] | Level 3                              
Fair Value Assets And Liabilities Measured On Nonrecurring Basis [Abstract]                              
Asset fair value nonrecurring     0                        
Long Lived Assets Held And Used [Member] | Fair Value | Long Lived Assets Held And Used [Member] | UK Wind Development Projects [Domain] | Level 3                              
Fair Value Assets And Liabilities Measured On Nonrecurring Basis [Abstract]                              
Asset fair value nonrecurring [1]                 $ 0            
Long Lived Assets Held And Used [Member] | Fair Value | Long Lived Assets Held And Used [Member] | buffalo gap III [Member] | Level 3                              
Fair Value Assets And Liabilities Measured On Nonrecurring Basis [Abstract]                              
Asset fair value nonrecurring             $ 118,000,000                
Goodwill [Member] | DPLER                              
Fair Value Assets And Liabilities Measured On Nonrecurring Basis [Abstract]                              
Goodwill impairment expense [5]       136,000,000                      
Goodwill [Member] | Buffalo Gap                              
Fair Value Assets And Liabilities Measured On Nonrecurring Basis [Abstract]                              
Goodwill impairment expense [5]       $ 28,000,000                      
Goodwill [Member] | DP&L [Member]                              
Fair Value Assets And Liabilities Measured On Nonrecurring Basis [Abstract]                              
Other non-operating expense [3]     $ 317,000,000                        
Goodwill [Member] | Carrying Amount | DPLER                              
Fair Value Assets And Liabilities Measured On Nonrecurring Basis [Abstract]                              
Asset fair value nonrecurring [5]                             $ 136,000,000
Goodwill [Member] | Carrying Amount | Buffalo Gap                              
Fair Value Assets And Liabilities Measured On Nonrecurring Basis [Abstract]                              
Asset fair value nonrecurring [5]   28,000,000                          
Goodwill [Member] | Carrying Amount | DP&L [Member]                              
Fair Value Assets And Liabilities Measured On Nonrecurring Basis [Abstract]                              
Asset fair value nonrecurring [3]           $ 317,000,000                  
Goodwill [Member] | Fair Value | DPLER | Level 1                              
Fair Value Assets And Liabilities Measured On Nonrecurring Basis [Abstract]                              
Asset fair value nonrecurring [5]                             0
Goodwill [Member] | Fair Value | DPLER | Level 2                              
Fair Value Assets And Liabilities Measured On Nonrecurring Basis [Abstract]                              
Asset fair value nonrecurring [5]                             0
Goodwill [Member] | Fair Value | DPLER | Level 3                              
Fair Value Assets And Liabilities Measured On Nonrecurring Basis [Abstract]                              
Asset fair value nonrecurring [5]                             $ 0
Goodwill [Member] | Fair Value | Buffalo Gap | Level 1                              
Fair Value Assets And Liabilities Measured On Nonrecurring Basis [Abstract]                              
Asset fair value nonrecurring [5]   0                          
Goodwill [Member] | Fair Value | Buffalo Gap | Level 2                              
Fair Value Assets And Liabilities Measured On Nonrecurring Basis [Abstract]                              
Asset fair value nonrecurring [5]   0                          
Goodwill [Member] | Fair Value | Buffalo Gap | Level 3                              
Fair Value Assets And Liabilities Measured On Nonrecurring Basis [Abstract]                              
Asset fair value nonrecurring [5]   $ 0                          
Goodwill [Member] | Fair Value | DP&L [Member] | Level 1                              
Fair Value Assets And Liabilities Measured On Nonrecurring Basis [Abstract]                              
Asset fair value nonrecurring [3]           0                  
Goodwill [Member] | Fair Value | DP&L [Member] | Level 2                              
Fair Value Assets And Liabilities Measured On Nonrecurring Basis [Abstract]                              
Asset fair value nonrecurring [3]           0                  
Goodwill [Member] | Fair Value | DP&L [Member] | Level 3                              
Fair Value Assets And Liabilities Measured On Nonrecurring Basis [Abstract]                              
Asset fair value nonrecurring [3]           $ 0                  
[1] (1) See Note 21—Asset Impairment Expense for further information.
[2] (2) See Note 23—Discontinued Operations for further information. Fair value of long-lived assets held-for-sale is presented net of costs to sell.
[3] (3) See Note 8—Investments In and Advances to Affiliates for further information.
[4] (4) See Note 9—Other Non-Operating Expense for further information.
[5] (5) See Note 10—Goodwill and Other Intangible Assets for further information.

v3.3.1.900
Fair Value (Nonrecurring Unobservable Inputs) (Details) - Income Approach Valuation Technique [Member]
12 Months Ended
Dec. 31, 2015
Minimum | Long Lived Assets Held And Used [Member] | Kilroot [Member]  
Fair Value Assets Measured On Nonrecurring Basis Unobservable Inputs [Line Items]  
Fair Value Inputs, Long-term Revenue Growth Rate (88.00%)
Fair Value Inputs, Long-term Pre-tax Operating Margin, Percent (74.00%)
Minimum | Long Lived Assets Held And Used [Member] | buffalo gap III [Member]  
Fair Value Assets Measured On Nonrecurring Basis Unobservable Inputs [Line Items]  
Fair Value Inputs, Long-term Revenue Growth Rate (2.00%)
Fair Value Inputs, Long-term Pre-tax Operating Margin, Percent (282.00%)
Maximum | Long Lived Assets Held And Used [Member] | Kilroot [Member]  
Fair Value Assets Measured On Nonrecurring Basis Unobservable Inputs [Line Items]  
Fair Value Inputs, Long-term Revenue Growth Rate 6.00%
Fair Value Inputs, Long-term Pre-tax Operating Margin, Percent 10.00%
Maximum | Long Lived Assets Held And Used [Member] | buffalo gap III [Member]  
Fair Value Assets Measured On Nonrecurring Basis Unobservable Inputs [Line Items]  
Fair Value Inputs, Long-term Revenue Growth Rate 19.00%
Fair Value Inputs, Long-term Pre-tax Operating Margin, Percent 58.00%
Weighted Average | Long Lived Assets Held And Used [Member] | Kilroot [Member]  
Fair Value Assets Measured On Nonrecurring Basis Unobservable Inputs [Line Items]  
Fair Value Inputs, Long-term Revenue Growth Rate (7.00%)
Fair Value Inputs, Long-term Pre-tax Operating Margin, Percent 0.00%
Fair Value Inputs, Discount Rate 6.00%
Weighted Average | Long Lived Assets Held And Used [Member] | buffalo gap III [Member]  
Fair Value Assets Measured On Nonrecurring Basis Unobservable Inputs [Line Items]  
Fair Value Inputs, Long-term Revenue Growth Rate 3.00%
Fair Value Inputs, Long-term Pre-tax Operating Margin, Percent 24.00%
Fair Value Inputs, Discount Rate 9.00%
Equity Method Investments [Member] | Minimum | Solar Spain [Member]  
Fair Value Assets Measured On Nonrecurring Basis Unobservable Inputs [Line Items]  
Fair Value Inputs, Long-term Revenue Growth Rate (3.00%)
Fair Value Inputs, Long-term Pre-tax Operating Margin, Percent (13.00%)
Fair Value Inputs, Discount Rate 12.00%
Equity Method Investments [Member] | Maximum | Solar Spain [Member]  
Fair Value Assets Measured On Nonrecurring Basis Unobservable Inputs [Line Items]  
Fair Value Inputs, Long-term Revenue Growth Rate 0.00%
Fair Value Inputs, Long-term Pre-tax Operating Margin, Percent 56.00%
Fair Value Inputs, Discount Rate 12.00%
Equity Method Investments [Member] | Weighted Average | Solar Spain [Member]  
Fair Value Assets Measured On Nonrecurring Basis Unobservable Inputs [Line Items]  
Fair Value Inputs, Long-term Revenue Growth Rate 0.00%
Fair Value Inputs, Long-term Pre-tax Operating Margin, Percent 24.00%
Fair Value Inputs, Discount Rate 12.00%

v3.3.1.900
Fair Value (Instruments Not Measured at Fair Value) (Details) - USD ($)
$ in Millions
Dec. 31, 2015
Dec. 31, 2014
Liabilities [Abstract]    
Recourse debt $ 5,015 $ 5,258
Carrying Amount    
ASSETS    
Accounts receivable - noncurrent [1] 270 257
Non-Recourse Debt 15,792 15,600
Liabilities [Abstract]    
Recourse debt 5,015 5,258
Fair Value    
ASSETS    
Accounts receivable - noncurrent [1] 342 246
Non-Recourse Debt 15,939 16,008
Liabilities [Abstract]    
Recourse debt 4,696 5,552
Value added tax 27 36
Fair Value | Level 1    
ASSETS    
Accounts receivable - noncurrent [1] 0 0
Non-Recourse Debt 0 0
Liabilities [Abstract]    
Recourse debt 0 0
Fair Value | Level 2    
ASSETS    
Accounts receivable - noncurrent [1] 20 0
Non-Recourse Debt 13,672 12,538
Liabilities [Abstract]    
Recourse debt 4,696 5,552
Fair Value | Level 3    
ASSETS    
Accounts receivable - noncurrent [1] 322 246
Non-Recourse Debt 2,267 3,470
Liabilities [Abstract]    
Recourse debt $ 0 $ 0
[1] (1) These accounts receivable principally relate to amounts due from CAMMESA, the administrator of the wholesale electricity market in Argentina, and are included in Noncurrent assets — Other in the accompanying Consolidated Balance Sheets. The fair value of these accounts receivable excludes value-added tax of $27 million and $36 million at December 31, 2015 and 2014, respectively.

v3.3.1.900
Investments In Marketable Securities (Details) - USD ($)
12 Months Ended
Dec. 31, 2015
Dec. 31, 2014
Dec. 31, 2013
Investments, Debt and Equity Securities [Abstract]      
Available-for-sale Securities, Debt Maturities, Next Twelve Months, Amortized Cost Basis $ 462,000,000    
Available-for-sale Securities, Debt Maturities, Year Two Through Five, Amortized Cost Basis 28,000,000    
Available-for-sale Securities, Realized Losses, Excluding Other than Temporary Impairments (Equal To or Less Than) 1,000,000 $ 1,000,000 $ 1,000,000
Gross proceeds from sales of AFS securities 4,902,000,000 4,569,000,000 4,406,000,000
Other than Temporary Impairment Losses, Investments 0 0 0
Available-for-sale Securities, Gross Unrealized Loss   0 0
Trading Securities, Realized Gain (Loss)- (Equal to or Less Than) $ 1,000,000 $ 1,000,000 $ 1,000,000

v3.3.1.900
Derivative Instruments and Hedging Activities (Outstanding Derivative Notionals and Terms by Type) (Details)
€ in Millions, CLF in Millions, $ in Millions
12 Months Ended
Dec. 31, 2015
USD ($)
Dec. 31, 2015
EUR (€)
Dec. 31, 2015
CLF
Derivative [Line Items]      
Derivative, notional amount $ 3,200    
Libor USD | Interest Rate Contract      
Derivative [Line Items]      
Derivative, notional amount $ 2,872 [1]    
Weighted-Average Remaining Term 11 years [1]    
% of Debt Currently Hedged by Index (2) 48.00% [1] 48.00% [1] 48.00% [1]
Euribor EUR | Interest Rate Contract      
Derivative [Line Items]      
Derivative, notional amount $ 524 [1] € 482 [1]  
Weighted-Average Remaining Term 6 years [1]    
% of Debt Currently Hedged by Index (2) 83.00% [1] 83.00% [1] 83.00% [1]
Chilean Unidad De Fomento CLF | Cross Currency Interest Rate Contract [Member]      
Derivative [Line Items]      
Derivative, notional amount $ 159   CLF 4
Weighted-Average Remaining Term 13 years    
% of Debt Currently Hedged by Index (2) 76.00% 76.00% 76.00%
Current Notional | Libor USD | Interest Rate Contract      
Derivative [Line Items]      
Derivative, notional amount $ 2,639 [1]    
Current Notional | Euribor EUR | Interest Rate Contract      
Derivative [Line Items]      
Derivative, notional amount 524 [1] € 482 [1]  
Current Notional | Chilean Unidad De Fomento CLF | Cross Currency Interest Rate Contract [Member]      
Derivative [Line Items]      
Derivative, notional amount $ 159   CLF 4
[1] (1) The Company's interest rate derivative instruments primarily include accreting and amortizing notionals. The maximum derivative notional represents the largest notional at any point between December 31, 2015 and the maturity of the derivative instrument, which includes forward-starting derivative instruments. The interest rate and cross currency derivatives range in maturity through 2033 and 2028, respectively.

v3.3.1.900
Derivative Instruments and Hedging Activities (Foreign Currency Derivatives) (Details) - 12 months ended Dec. 31, 2015
€ in Millions, £ in Millions, KZT in Millions, COP in Millions, CLP in Millions, CLF in Millions, BRL in Millions, ARS in Millions, $ in Millions
USD ($)
EUR (€)
[1]
COP
[1]
KZT
[1]
BRL
[1]
CLF
[1]
CLP
[1]
ARS
[1]
GBP (£)
[1]
Derivative [Line Items]                  
Derivative, notional amount $ 3,200                
Chilean Unidad De Fomento CLF | Foreign Exchange Option and Forward                  
Derivative [Line Items]                  
Derivative, notional amount $ 311         CLF 9      
Derivative, average remaining maturity [2] 1 year                
Chilean Peso CLP | Foreign Exchange Option and Forward                  
Derivative [Line Items]                  
Derivative, notional amount $ 119           CLP 84,669    
Derivative, average remaining maturity [2] 1 year                
Brazilian Real BRL | Foreign Exchange Option and Forward                  
Derivative [Line Items]                  
Derivative, notional amount $ 21       BRL 80        
Derivative, average remaining maturity [2] 1 year                
Euro EUR | Foreign Exchange Option and Forward                  
Derivative [Line Items]                  
Derivative, notional amount $ 35 € 32              
Derivative, average remaining maturity [2] 1 year                
Colombian Peso COP | Foreign Exchange Option and Forward                  
Derivative [Line Items]                  
Derivative, notional amount $ 80   COP 252,166            
Derivative, average remaining maturity [2] 1 year                
Argentine Peso ARS | Foreign Exchange Option and Forward                  
Derivative [Line Items]                  
Derivative, notional amount $ 178             ARS 2,321  
Derivative, average remaining maturity [2] 10 years                
British Pound GBP | Foreign Exchange Option and Forward                  
Derivative [Line Items]                  
Derivative, notional amount $ 32               £ 22
Derivative, average remaining maturity [2] 1 year                
Kazakhstani Tenge | Embedded Derivative Financial Instruments                  
Derivative [Line Items]                  
Derivative, notional amount $ 5     KZT 1,691          
Derivative, average remaining maturity [2] 1 year                
[1] (1) Represents contractual notionals. The notionals for options have not been probability adjusted, which generally would decrease them.
[2] (2) Represents the remaining tenor of our foreign currency derivatives weighted by the corresponding notional. These derivatives matures through 2026.December 31, 2015 Weighted-AverageCommodity Derivatives Notional Remaining Term(1) (in millions) (in years)Power (MWh) 10 3

v3.3.1.900
Derivative Instruments and Hedging Activities (Commodity Derivatives) (Details) - Power MWh - Commodity Contract [Member]
MWh in Millions
12 Months Ended
Dec. 31, 2015
MWh
Derivative [Line Items]  
Derivative, Nonmonetary Notional Amount 10
Derivative average remaining maturity 3 years [1]
[1] (1) Represents the remaining tenor of our commodity derivatives weighted by the corresponding volume. These derivatives range in maturity through 2018.

v3.3.1.900
Derivative Instruments and Hedging Activities (Assets and LIabilities - Designated vs. Not Designated Hedging Instruments) (Details) - USD ($)
$ in Millions
Dec. 31, 2015
Dec. 31, 2014
Derivatives, Fair Value [Line Items]    
Total asset derivatives $ 375 $ 280
Total liability derivatives 490 514
Designated as Hedging Instrument    
Derivatives, Fair Value [Line Items]    
Total asset derivatives 38 31
Total liability derivatives 448 490
Not Designated as Hedging Instrument    
Derivatives, Fair Value [Line Items]    
Total asset derivatives 337 249
Total liability derivatives 42 24
Interest Rate Contract    
Derivatives, Fair Value [Line Items]    
Total liability derivatives 358 416
Interest Rate Contract | Designated as Hedging Instrument    
Derivatives, Fair Value [Line Items]    
Total liability derivatives 358 416
Interest Rate Contract | Not Designated as Hedging Instrument    
Derivatives, Fair Value [Line Items]    
Total liability derivatives 0 0
Cross Currency Interest Rate Contract [Member]    
Derivatives, Fair Value [Line Items]    
Total liability derivatives 43 29
Cross Currency Interest Rate Contract [Member] | Designated as Hedging Instrument    
Derivatives, Fair Value [Line Items]    
Total liability derivatives 43 29
Cross Currency Interest Rate Contract [Member] | Not Designated as Hedging Instrument    
Derivatives, Fair Value [Line Items]    
Total liability derivatives 0 0
Foreign Exchange Contract [Member]    
Derivatives, Fair Value [Line Items]    
Total asset derivatives 327 236
Total liability derivatives 56 52
Foreign Exchange Contract [Member] | Designated as Hedging Instrument    
Derivatives, Fair Value [Line Items]    
Total asset derivatives 8 6
Total liability derivatives 35 38
Foreign Exchange Contract [Member] | Not Designated as Hedging Instrument    
Derivatives, Fair Value [Line Items]    
Total asset derivatives 319 230
Total liability derivatives 21 14
Other Contract    
Derivatives, Fair Value [Line Items]    
Total asset derivatives 48 44
Total liability derivatives 33 17
Other Contract | Designated as Hedging Instrument    
Derivatives, Fair Value [Line Items]    
Total asset derivatives 30 25
Total liability derivatives 12 7
Other Contract | Not Designated as Hedging Instrument    
Derivatives, Fair Value [Line Items]    
Total asset derivatives 18 19
Total liability derivatives $ 21 $ 10

v3.3.1.900
Derivative Instruments and Hedging Activities (Assets and Liabilities - Current vs. Noncurrent Derivative instruments) (Details) - USD ($)
$ in Millions
Dec. 31, 2015
Dec. 31, 2014
Derivatives, Fair Value [Line Items]    
Derivative Asset, Current $ 86 $ 77
Derivative Liability, Current 144 148
Derivative Asset, Noncurrent 289 203
Derivative Liability, Noncurrent 346 366
Total asset derivatives 375 280
Total liability derivatives 490 514
Asset, Formerly Accounted for as a Derivative, to be Amortized into Earnings 147 161
Liability, Formerly Accounted for as a Derivative, to be Amortized into Earnings 166 180
Contracts Subject To Netting Arrangements    
Derivatives, Fair Value [Line Items]    
Total asset derivatives 57 53
Total liability derivatives 467 507
Derivative Assets Not Offset Under Netting Arrangements (18) (10)
Derivative Liabilities Not Offset Under Netting Arrangements (18) (10)
Derivative Asset, Fair Value, Amount Not Offset Against Collateral 0 0
Derivative Liability, Fair Value, Amount Not Offset Against Collateral (38) (26)
Derivative Asset 39 43
Derivative Liability $ 411 $ 471

v3.3.1.900
Derivative Instruments and Hedging Activities Derivative Instruments and Hedging Activities (Effective Portion of Cash Flow Hedges) (Details) - Cash Flow Hedging - USD ($)
12 Months Ended
Dec. 31, 2015
Dec. 31, 2014
Dec. 31, 2013
Derivative Instruments, Gain (Loss) [Line Items]      
Gain (Losses) Recognized in AOCL, Effective Portion $ (73,000,000) $ (430,000,000) $ 139,000,000
Gains (Losses) Reclassified from AOCL into Earnings, Effective Portion (77,000,000) (125,000,000) (180,000,000)
Interest Rate Contract      
Derivative Instruments, Gain (Loss) [Line Items]      
Gain (Losses) Recognized in AOCL, Effective Portion (103,000,000) (421,000,000) 155,000,000
AOCI before tax expected increase (decrease) next 12 months (106,000,000)    
Interest Rate Contract | Interest Expense      
Derivative Instruments, Gain (Loss) [Line Items]      
Gains (Losses) Reclassified from AOCL into Earnings, Effective Portion (108,000,000) (139,000,000) (127,000,000)
Loss on discontinuation of cash flow hedge due to forecasted transaction probable of not occurring 6,000,000 $ 0  
Cash flow hedge additional transaction period   2 months  
Interest Rate Contract | Cost of Sales      
Derivative Instruments, Gain (Loss) [Line Items]      
Gains (Losses) Reclassified from AOCL into Earnings, Effective Portion (2,000,000) $ (2,000,000) (5,000,000)
Interest Rate Contract | Net Equity In Earnings Of Affiliates      
Derivative Instruments, Gain (Loss) [Line Items]      
Gains (Losses) Reclassified from AOCL into Earnings, Effective Portion (2,000,000) (3,000,000) (6,000,000)
Interest Rate Contract | Sale of Subsidiary Gain (Loss)      
Derivative Instruments, Gain (Loss) [Line Items]      
Gains (Losses) Reclassified from AOCL into Earnings, Effective Portion (4,000,000) 0 (21,000,000)
Cross Currency Interest Rate Contract [Member]      
Derivative Instruments, Gain (Loss) [Line Items]      
Gain (Losses) Recognized in AOCL, Effective Portion (20,000,000) (25,000,000) (18,000,000)
AOCI before tax expected increase (decrease) next 12 months (3,000,000)    
Cross Currency Interest Rate Contract [Member] | Interest Expense      
Derivative Instruments, Gain (Loss) [Line Items]      
Gains (Losses) Reclassified from AOCL into Earnings, Effective Portion (4,000,000) 0 (10,000,000)
Cross Currency Interest Rate Contract [Member] | Foreign Currency Gain (Loss)      
Derivative Instruments, Gain (Loss) [Line Items]      
Gains (Losses) Reclassified from AOCL into Earnings, Effective Portion (20,000,000) (23,000,000) (18,000,000)
Foreign Exchange Contract [Member]      
Derivative Instruments, Gain (Loss) [Line Items]      
Gain (Losses) Recognized in AOCL, Effective Portion 10,000,000 (28,000,000) 0
AOCI before tax expected increase (decrease) next 12 months 12,000,000    
Foreign Exchange Contract [Member] | Foreign Currency Gain (Loss)      
Derivative Instruments, Gain (Loss) [Line Items]      
Gains (Losses) Reclassified from AOCL into Earnings, Effective Portion 32,000,000 14,000,000 12,000,000
Other Contract      
Derivative Instruments, Gain (Loss) [Line Items]      
Gain (Losses) Recognized in AOCL, Effective Portion 40,000,000 44,000,000 2,000,000
AOCI before tax expected increase (decrease) next 12 months 16,000,000    
Other Contract | Cost of Sales      
Derivative Instruments, Gain (Loss) [Line Items]      
Gains (Losses) Reclassified from AOCL into Earnings, Effective Portion (12,000,000) (2,000,000) (2,000,000)
Other Contract | Sales      
Derivative Instruments, Gain (Loss) [Line Items]      
Gains (Losses) Reclassified from AOCL into Earnings, Effective Portion $ 43,000,000 $ 30,000,000 $ (3,000,000)

v3.3.1.900
Derivative Instruments and Hedging Activities Derivative Instruments and Hedging Activities (Ineffective Portion of Cash Flow Hedges) (Details) - Cash Flow Hedging - USD ($)
$ in Millions
12 Months Ended
Dec. 31, 2015
Dec. 31, 2014
Dec. 31, 2013
Derivative Instruments, Gain (Loss) [Line Items]      
Gain (Losses) Recognized in Earnings, Ineffective Portion $ (6) $ (4) $ 43
Interest Expense | Interest Rate Contract      
Derivative Instruments, Gain (Loss) [Line Items]      
Gain (Losses) Recognized in Earnings, Ineffective Portion (4) 0 42
Interest Expense | Cross Currency Interest Rate Contract [Member]      
Derivative Instruments, Gain (Loss) [Line Items]      
Gain (Losses) Recognized in Earnings, Ineffective Portion 1 (1) 0
Net Equity In Earnings Of Affiliates | Interest Rate Contract      
Derivative Instruments, Gain (Loss) [Line Items]      
Gain (Losses) Recognized in Earnings, Ineffective Portion 0 (1) 1
Foreign Currency Gain (Loss) | Foreign Exchange Contract [Member]      
Derivative Instruments, Gain (Loss) [Line Items]      
Gain (Losses) Recognized in Earnings, Ineffective Portion $ (3) $ (2) $ 0

v3.3.1.900
Derivative Instruments and Hedging Activities (Derivative Instruments Not Designated for Hedge Accounting) (Details) - USD ($)
$ in Millions
12 Months Ended
Dec. 31, 2015
Dec. 31, 2014
Dec. 31, 2013
Derivative Instruments, Gain (Loss) [Line Items]      
Net loss from disposal and impairments of discontinued operations $ 0 $ (56) $ (152)
Not Designated as Hedging Instrument      
Derivative Instruments, Gain (Loss) [Line Items]      
Gain (Losses) Recognized in Earnings, Not Designated as Hedge Accounting 182 202 29
Net loss from disposal and impairments of discontinued operations 0 72 0
Not Designated as Hedging Instrument | Interest Rate Contract | Interest Expense      
Derivative Instruments, Gain (Loss) [Line Items]      
Gain (Losses) Recognized in Earnings, Not Designated as Hedge Accounting 0 (3) (1)
Not Designated as Hedging Instrument | Interest Rate Contract | Net Equity In Earnings Of Affiliates      
Derivative Instruments, Gain (Loss) [Line Items]      
Gain (Losses) Recognized in Earnings, Not Designated as Hedge Accounting 0 0 (6)
Not Designated as Hedging Instrument | Foreign Exchange Contract [Member] | Net Equity In Earnings Of Affiliates      
Derivative Instruments, Gain (Loss) [Line Items]      
Gain (Losses) Recognized in Earnings, Not Designated as Hedge Accounting 0 (2) (24)
Not Designated as Hedging Instrument | Foreign Exchange Contract [Member] | Foreign Currency Gain (Loss)      
Derivative Instruments, Gain (Loss) [Line Items]      
Gain (Losses) Recognized in Earnings, Not Designated as Hedge Accounting 211 146 64
Not Designated as Hedging Instrument | Other Contract | Sales      
Derivative Instruments, Gain (Loss) [Line Items]      
Gain (Losses) Recognized in Earnings, Not Designated as Hedge Accounting (8) 5 11
Not Designated as Hedging Instrument | Other Contract | Cost of Sales      
Derivative Instruments, Gain (Loss) [Line Items]      
Gain (Losses) Recognized in Earnings, Not Designated as Hedge Accounting (16) (3) 1
Not Designated as Hedging Instrument | Other Contract | Regulated Cost Of Sales      
Derivative Instruments, Gain (Loss) [Line Items]      
Gain (Losses) Recognized in Earnings, Not Designated as Hedge Accounting (5) (6) 2
Not Designated as Hedging Instrument | Other Contract | Income (Loss) From Operations Of Discontinued Business      
Derivative Instruments, Gain (Loss) [Line Items]      
Gain (Losses) Recognized in Earnings, Not Designated as Hedge Accounting $ 0 $ (7) $ (18)

v3.3.1.900
Derivative Instruments and Hedging Activities (Credit Risk-Related Contingent Features) (Details) - DPL Subsidiary - USD ($)
Dec. 31, 2015
Dec. 31, 2014
Credit Risk-Related Contingent Features [Line Items]    
Net liability position, derivative transactions $ 28,000,000 $ 12,000,000
Collateral posted for derivative transactions 8,000,000 5,000,000
Additional collateral that could have been required $ 2,000,000 $ 1,000,000

v3.3.1.900
Financing Receivables (Details)
$ in Millions
3 Months Ended 12 Months Ended
Dec. 31, 2014
USD ($)
Dec. 31, 2015
USD ($)
agreement
Dec. 31, 2014
USD ($)
agreement
Schedule of Financing Receivables [Line Items]      
Financing receivable $ 337 $ 296 $ 337
Number of Foninvemem Agreements | agreement   3  
Foninvemem Agreement, collection period     10 years
Number of Foninvemem Agreements with active collections | agreement     2
ARGENTINA      
Schedule of Financing Receivables [Line Items]      
Financing receivable 278 $ 237 $ 278
Derivative Assets, Gross 208 292 208
Interest Income, Other 59    
Embedded Derivative, Gain on Embedded Derivative 106    
CAMEROON      
Schedule of Financing Receivables [Line Items]      
Financing receivable [1] 44 0 44
UNITED STATES      
Schedule of Financing Receivables [Line Items]      
Financing receivable 0 20 0
Brazil      
Schedule of Financing Receivables [Line Items]      
Financing receivable $ 15 $ 39 $ 15
[1] (1) Represents non-contingent consideration to be received in 2016 from the sale of the Cameroon businesses in 2014. Balance is classified as short-term as of December 31, 2015. See Note 23—Discontinued Operations.

v3.3.1.900
Investments In and Advances To Affiliates - Effective Equity Ownership Interest and Carrying Values (Details) - USD ($)
$ in Millions
Dec. 31, 2015
Dec. 31, 2014
Oct. 13, 2014
Jul. 02, 2014
Dec. 31, 2013
Investments in and Advances to Affiliates [Line Items]          
Investments in and advances to affiliates $ 610 $ 537     $ 1,010
Gener Subsidiary [Member]          
Investments in and Advances to Affiliates [Line Items]          
Noncontrolling Interest, Ownership Percentage by Parent 67.00% 71.00%      
Silver Ridge Power          
Investments in and Advances to Affiliates [Line Items]          
Equity Method Investment, Ownership Percentage       50.00%  
Solar Power PR, LLC          
Investments in and Advances to Affiliates [Line Items]          
Investments in and advances to affiliates $ 0 $ 2      
Equity Method Investment, Ownership Percentage 0.00% 50.00%      
Barry          
Investments in and Advances to Affiliates [Line Items]          
Investments in and advances to affiliates [1] $ 0 $ 0      
Equity Method Investment, Ownership Percentage [1] 100.00% 100.00%      
Elsta          
Investments in and Advances to Affiliates [Line Items]          
Investments in and advances to affiliates [1] $ 53 $ 54      
Equity Method Investment, Ownership Percentage [1] 50.00% 50.00%      
Entek          
Investments in and Advances to Affiliates [Line Items]          
Equity Method Investment, Ownership Percentage     49.62%    
Guacolda Affiliate [Member]          
Investments in and Advances to Affiliates [Line Items]          
Investments in and advances to affiliates [2] $ 344 $ 285      
Equity Method Investment, Ownership Percentage [2] 33.00% 35.00%      
OPGC          
Investments in and Advances to Affiliates [Line Items]          
Investments in and advances to affiliates [3] $ 195 $ 194      
Equity Method Investment, Ownership Percentage [3] 49.00% 49.00%      
Other Affiliates [Member]          
Investments in and Advances to Affiliates [Line Items]          
Investments in and advances to affiliates $ 1 $ 2      
Main street power [Member]          
Investments in and Advances to Affiliates [Line Items]          
Investments in and advances to affiliates [1] $ 17 $ 0      
Equity Method Investment, Ownership Percentage [1] 94.00% 0.00%      
Gener Subsidiary [Member] | Guacolda Affiliate [Member]          
Investments in and Advances to Affiliates [Line Items]          
Equity Method Investment, Ownership Percentage 50.00%        
[1] (1) Represent VIEs in which the Company holds a variable interest but is not the primary beneficiary.
[2] (2) The Company's ownership in Guacolda is held through AES Gener, a 67%-owned consolidated subsidiary. AES Gener owns 50% of Guacolda, resulting in an AES effective ownership in Guacolda of 33%.
[3] (3) OPGC has one coal-fired expansion project under development. The project started construction in April 2014 and is currently expected to begin operations in 2018.

v3.3.1.900
Investments In and Advances To Affiliates - Summary of Financial Information of Affiliates & Subsidiaries (Details) - USD ($)
3 Months Ended 12 Months Ended
Sep. 24, 2015
Oct. 13, 2014
Jul. 02, 2014
Jul. 01, 2014
Apr. 11, 2014
Dec. 31, 2015
Dec. 31, 2014
Sep. 30, 2014
Dec. 31, 2015
Dec. 31, 2014
Dec. 31, 2013
Investments in and Advances to Affiliates [Line Items]                      
Accumulated Other Comprehensive Income (Loss), Net of Tax           $ (3,883,000,000) $ (3,286,000,000)   $ (3,883,000,000) $ (3,286,000,000)  
Investments in and advances to affiliates           $ 610,000,000 537,000,000   610,000,000 537,000,000 $ 1,010,000,000
Gain (Loss) on Disposition of Business                 29,000,000 358,000,000 26,000,000
Payments to Acquire Businesses and Interest in Affiliates                 17,000,000 728,000,000 7,000,000
Proceeds from the sale of businesses, net of cash sold                 138,000,000 1,807,000,000 170,000,000
Net equity in earnings of affiliates                 $ 105,000,000 19,000,000 25,000,000
Global Infrastructure Partners                      
Investments in and Advances to Affiliates [Line Items]                      
Proceeds from the sale of businesses, net of cash sold         $ 730,000,000            
Entek                      
Investments in and Advances to Affiliates [Line Items]                      
Pre-tax loss of disposed businesses, Excluding gain on disposal, included in continuing operations                   9,000,000 29,000,000
TURKEY                      
Investments in and Advances to Affiliates [Line Items]                      
Investment In Affiliate Ownership Percentage Sold           100.00%     100.00%    
Silver Ridge Power                      
Investments in and Advances to Affiliates [Line Items]                      
Equity Method Investment, Ownership Percentage     50.00%                
Equity Method Investment, Purchase Price Agreement     $ 179,000,000                
Equity Method Investment, Other than Temporary Impairment                   42,000,000  
Equity Method Investment, Net Sales Proceeds     179,000,000                
Silver Ridge - Italy                      
Investments in and Advances to Affiliates [Line Items]                      
Equity Method Investment, Ownership Percentage           50.00%     50.00%    
Equity Method Investment, Purchase Price Agreement       $ 42,000,000              
Silver Ridge- Italy and Spain                      
Investments in and Advances to Affiliates [Line Items]                      
Accumulated Other Comprehensive Income (Loss), Net of Tax     40,000,000                
Investments in and advances to affiliates     $ 32,000,000     $ 0 $ 64,000,000   $ 0 $ 64,000,000  
Barry                      
Investments in and Advances to Affiliates [Line Items]                      
Equity Method Investment, Ownership Percentage [1]           100.00% 100.00%   100.00% 100.00%  
Investments in and advances to affiliates [1]           $ 0 $ 0   $ 0 $ 0  
Long Term Liabilities Associated With Debt Agreement Resulting In Loss Of Control           $ 49,000,000 $ 52,000,000   $ 49,000,000 $ 52,000,000  
Elsta                      
Investments in and Advances to Affiliates [Line Items]                      
Equity Method Investment, Ownership Percentage [1]           50.00% 50.00%   50.00% 50.00%  
Investments in and advances to affiliates [1]           $ 53,000,000 $ 54,000,000   $ 53,000,000 $ 54,000,000  
Impaired Long-Lived Assets Held and Used, Facts and Circumstances Leading to Impairment                   82,000,000  
Equity Method Investment, Other than Temporary Impairment                     $ 129,000,000
Net equity in earnings of affiliates             $ (41,000,000)   (41,000,000)    
Entek                      
Investments in and Advances to Affiliates [Line Items]                      
Equity Method Investment, Ownership Percentage   49.62%                  
Equity Method Investment, Purchase Price Agreement   $ 125,000,000               125,000,000  
Gain (Loss) on Disposition of Business           $ (4,000,000)          
Equity Method Investment, Other than Temporary Impairment   $ 68,000,000           $ 18,000,000   $ 86,000,000  
Investment In Affiliate Ownership Percentage Sold             49.62%     49.62%  
guacolda [Member]                      
Investments in and Advances to Affiliates [Line Items]                      
Payments to Acquire Businesses and Interest in Affiliates         $ 728,000,000            
guacolda [Member]                      
Investments in and Advances to Affiliates [Line Items]                      
Net equity in earnings of affiliates                 66,000,000    
Solar Spain [Member]                      
Investments in and Advances to Affiliates [Line Items]                      
Equity Method Investment, Net Sales Proceeds $ 31,000,000                    
Equity Method Investment, Realized Gain (Loss) on Disposal $ 1,000,000                    
Parent [Member] | guacolda [Member]                      
Investments in and Advances to Affiliates [Line Items]                      
Net equity in earnings of affiliates                 $ 46,000,000    
[1] (1) Represent VIEs in which the Company holds a variable interest but is not the primary beneficiary.

v3.3.1.900
Investments In and Advances To Affiliates - Summarized Financial Information (Details) - USD ($)
$ in Millions
3 Months Ended 12 Months Ended
Dec. 31, 2015
Sep. 30, 2015
Jun. 30, 2015
Mar. 31, 2015
Dec. 31, 2014
Sep. 30, 2014
Jun. 30, 2014
Mar. 31, 2014
Dec. 31, 2015
Dec. 31, 2014
Dec. 31, 2013
Schedule of Equity Method Investments [Line Items]                      
Revenue                 $ 14,963 $ 17,146 $ 15,891
Operating margin $ 718 $ 673 $ 754 $ 721 $ 708 $ 767 $ 819 $ 794 2,866 3,088 3,247
Net income 41 $ 203 $ 264 $ 254 298 $ 508 $ 275 $ 66 762 1,147 551
Assets, Current 6,866       7,826       6,866 7,826  
Liabilities, Current 6,950       6,997       6,950 6,997  
Liabilities, Noncurrent 23,191       24,566       23,191 24,566  
Stockholders' Equity Attributable to Noncontrolling Interest 3,022       3,053       3,022 3,053  
Stockholders' Equity Attributable to Parent 3,149       4,272       3,149 4,272  
Undistributed Earnings Of Minority Owned Affiliates Included In Retained Earnings 244               244    
Distributions Received From Minority Owned Affiliates                 18 28 6
Basis Difference Between Carrying Amount And Investment 162               162    
Minority Owned Affiliates                      
Schedule of Equity Method Investments [Line Items]                      
Revenue                 641 928 1,099
Operating margin                 152 206 295
Net income                 210 59 53
Assets, Current 376       450       376 450  
Assets, Noncurrent 2,132       1,748       2,132 1,748  
Liabilities, Current 435       299       435 299  
Liabilities, Noncurrent 1,044       935       1,044 935  
Stockholders' Equity Attributable to Noncontrolling Interest 0       17       0 17  
Stockholders' Equity Attributable to Parent 1,029       947       1,029 947  
Majority Owned Affiliates                      
Schedule of Equity Method Investments [Line Items]                      
Revenue                 24 2 2
Operating margin                 11 0 0
Net income                 6 0 $ 0
Assets, Current 20       0       20 0  
Assets, Noncurrent 211       15       211 15  
Liabilities, Current 21       0       21 0  
Liabilities, Noncurrent 153       67       153 67  
Stockholders' Equity Attributable to Noncontrolling Interest 0       0       0 0  
Stockholders' Equity Attributable to Parent $ 57       $ (52)       $ 57 $ (52)  

v3.3.1.900
Total Other Non-Operating Expense (Details) - USD ($)
$ in Millions
3 Months Ended 12 Months Ended
Oct. 13, 2014
Jul. 02, 2014
Sep. 30, 2014
Dec. 31, 2015
Dec. 31, 2014
Dec. 31, 2013
Schedule of Other Nonoperating Income (Expense) [Line Items]            
Other Nonoperating Expense       $ 0 $ 128 $ 129
Entek            
Schedule of Other Nonoperating Income (Expense) [Line Items]            
Investment In Affiliate Ownership Percentage Sold         49.62%  
Equity Method Investment, Purchase Price Agreement $ 125       $ 125  
Equity Method Investment, Other than Temporary Impairment $ 68   $ 18   86  
Other Nonoperating Expense         86 0
Silver Ridge Power            
Schedule of Other Nonoperating Income (Expense) [Line Items]            
Equity Method Investment, Purchase Price Agreement   $ 179        
Equity Method Investment, Other than Temporary Impairment         42  
Equity Method Investment, Ownership Percentage Sold   50.00%        
Equity Method Investment, Net Sales Proceeds   $ 179        
Other Nonoperating Expense         42 0
Elsta            
Schedule of Other Nonoperating Income (Expense) [Line Items]            
Equity Method Investment, Other than Temporary Impairment           129
Other Nonoperating Expense         $ 0  
Equity Method Investments           240
Equity Method Investments, Fair Value Disclosure           $ 111

v3.3.1.900
Goodwill and Other Intangible Assets (Goodwill Roll Forward) (Details) - USD ($)
$ in Millions
12 Months Ended
Dec. 31, 2015
Dec. 31, 2014
Dec. 31, 2013
Goodwill [Roll Forward]      
Goodwill $ 3,912 $ 3,896 $ 3,954
Accumulated impairment losses (2,755) (2,438) (2,332)
Net balance 1,157 1,458 1,622
Goodwill impairment expense (317) (164) (372)
Goodwill, Acquired During Period 16    
Ebute [Member]      
Goodwill [Line Items]      
Goodwill, Written off Related to Sale of Business Unit   58  
US      
Goodwill [Roll Forward]      
Goodwill 2,674 2,658 2,658
Accumulated impairment losses (2,633) (2,316) (2,152)
Net balance 41 342 506
Goodwill impairment expense (317) (164)  
Goodwill, Acquired During Period 16    
Andes      
Goodwill [Roll Forward]      
Goodwill 899 899 899
Accumulated impairment losses 0 0 0
Net balance 899 899 899
Goodwill impairment expense 0 0  
Goodwill, Acquired During Period 0    
MCAC      
Goodwill [Roll Forward]      
Goodwill 149 149 149
Accumulated impairment losses 0 0 0
Net balance 149 149 149
Goodwill impairment expense 0 0  
Goodwill, Acquired During Period 0    
Europe      
Goodwill [Roll Forward]      
Goodwill 122 122 [1] 180
Accumulated impairment losses (122) (122) (180)
Net balance 0 0 0
Goodwill impairment expense 0 0  
Goodwill, Acquired During Period 0    
Asia      
Goodwill [Roll Forward]      
Goodwill 68 68 68
Accumulated impairment losses 0 0 0
Net balance 68 68 $ 68
Goodwill impairment expense 0 $ 0  
Goodwill, Acquired During Period $ 0    
[1] (1) Both the gross carrying amount and the accumulated impairment losses of the Europe segment have been reduced by $58 million with no impact on the net carrying amount for the segment. This relates to Ebute, which had fully impaired goodwill of $58 million and was sold in 2014.

v3.3.1.900
Goodwill and Other Intangible Assets (Intangible Assets) (Details) - USD ($)
$ in Millions
Dec. 31, 2015
Dec. 31, 2014
Finite-Lived Intangible Assets, Net [Abstract]    
Gross Balance $ 243 $ 362
Accumulated Amortization (97) (158)
Net Balance 146 204
Indefinite-Lived Intangible Assets (Excluding Goodwill) 68 77
Intangible Assets, Gross 311 439
Intangible Assets, Net 214 281
Land Use Rights [Member]    
Finite-Lived Intangible Assets, Net [Abstract]    
Indefinite-Lived Intangible Assets (Excluding Goodwill) 38 37
Water rights    
Finite-Lived Intangible Assets, Net [Abstract]    
Indefinite-Lived Intangible Assets (Excluding Goodwill) 17 20
Other    
Finite-Lived Intangible Assets, Net [Abstract]    
Indefinite-Lived Intangible Assets (Excluding Goodwill) 13 20
Project development rights    
Finite-Lived Intangible Assets, Net [Abstract]    
Gross Balance [1] 4 28
Accumulated Amortization [1] (1) (1)
Net Balance [1] 3 27
Sales concessions    
Finite-Lived Intangible Assets, Net [Abstract]    
Gross Balance 71 86
Accumulated Amortization (19) (41)
Net Balance 52 45
Contractual payment rights    
Finite-Lived Intangible Assets, Net [Abstract]    
Gross Balance [2] 66 69
Accumulated Amortization [2] (46) (40)
Net Balance [2] 20 29
Management rights    
Finite-Lived Intangible Assets, Net [Abstract]    
Gross Balance 24 33
Accumulated Amortization (10) (13)
Net Balance 14 20
Land Use Rights [Member]    
Finite-Lived Intangible Assets, Net [Abstract]    
Gross Balance 28 25
Accumulated Amortization 0 0
Net Balance 28 25
Contracts    
Finite-Lived Intangible Assets, Net [Abstract]    
Gross Balance 29 36
Accumulated Amortization (12) (19)
Net Balance 17 17
Customer relationships & contracts    
Finite-Lived Intangible Assets, Net [Abstract]    
Gross Balance [3] 6 63
Accumulated Amortization [3] (6) (39)
Net Balance [3] 0 24
All other    
Finite-Lived Intangible Assets, Net [Abstract]    
Gross Balance [4] 15 22
Accumulated Amortization [4] (3) (5)
Net Balance [4] $ 12 $ 17
[1] (1) 2014 balance includes U.K. Wind operations. In August 2014 these assets were sold, but did not meet the criteria to be reported as discontinued operations and their results are reflected within continuing operations. See Note 24—Dispositions and Held-for-Sale Businesses for further information.
[2] (2) Represent legal rights to receive system reliability payments from the regulator.
[3] (3) 2014 balance includes DPLER which is considered held-for-sale as of December 31, 2015. See Note 24—Dispositions and Held-for-Sale Businesses for further information.
[4] (4) Includes renewable energy certificates, emission allowances and various other intangible assets none of which is individually significant.

v3.3.1.900
Goodwill and Other Intangible Assets (Intangible Assets Acquired) (Details) - USD ($)
$ in Millions
12 Months Ended
Dec. 31, 2015
Dec. 31, 2014
Indefinite-lived Intangible Assets [Line Items]    
Indefinite-lived Intangible Assets Acquired   $ 19
Other intangible assets acquired $ 40  
Renewable Energy Certificates [Member]    
Indefinite-lived Intangible Assets [Line Items]    
Indefinite-lived Intangible Assets Acquired   3
Land Use Rights [Member]    
Indefinite-lived Intangible Assets [Line Items]    
Indefinite-lived Intangible Assets Acquired 13 $ 16
Contracts    
Indefinite-lived Intangible Assets [Line Items]    
Finite-lived Intangible Assets Acquired $ 22  
Acquired Finite-lived Intangible Assets, Weighted Average Useful Life 5 years  
Other Indefinite Lived Intangible Assets [Member]    
Indefinite-lived Intangible Assets [Line Items]    
Other intangible assets acquired $ 5  

v3.3.1.900
Goodwill and Other Intangible Assets (Expected Amortization Expense) (Details)
$ in Millions
Dec. 31, 2015
USD ($)
Finite-Lived Intangible Assets, Net, Amortization Expense, Fiscal Year Maturity [Abstract]  
2016 $ 11
2017 11
2018 11
2019 10
2020 10
Sales concessions  
Finite-Lived Intangible Assets, Net, Amortization Expense, Fiscal Year Maturity [Abstract]  
2016 7
2017 7
2018 7
2019 7
2020 7
All other  
Finite-Lived Intangible Assets, Net, Amortization Expense, Fiscal Year Maturity [Abstract]  
2016 4
2017 4
2018 4
2019 3
2020 $ 3

v3.3.1.900
Goodwill and Other Intangible Assets (Narrative) (Details)
3 Months Ended 12 Months Ended
Dec. 31, 2015
USD ($)
Dec. 31, 2015
USD ($)
Dec. 31, 2014
USD ($)
Mar. 31, 2014
USD ($)
project
Dec. 31, 2015
USD ($)
Dec. 31, 2014
USD ($)
Dec. 31, 2013
USD ($)
Feb. 18, 2015
Goodwill [Line Items]                
Goodwill impairment expense         $ 317,000,000 $ 164,000,000 $ 372,000,000  
Goodwill $ 1,157,000,000 $ 1,157,000,000 $ 1,458,000,000   1,157,000,000 1,458,000,000 1,622,000,000  
Goodwill, Acquired During Period         16,000,000      
Goodwill 3,912,000,000 3,912,000,000 3,896,000,000   3,912,000,000 3,896,000,000 $ 3,954,000,000  
Buffalo Gap                
Goodwill [Line Items]                
Goodwill impairment expense     $ 10,000,000 $ 18,000,000        
Number of wind projects | project       3        
DPLER                
Goodwill [Line Items]                
Goodwill impairment expense       $ 136,000,000        
Goodwill       136,000,000        
Goodwill, fair value       $ 0        
Main street power [Member]                
Goodwill [Line Items]                
Business Acquisition, Percentage of Voting Interests Acquired               100.00%
Goodwill, Acquired During Period 16,000,000              
Ebute [Member]                
Goodwill [Line Items]                
Goodwill, Written off Related to Sale of Business Unit           $ 58,000,000    
DPL Subsidiary [Member]                
Goodwill [Line Items]                
Goodwill impairment expense   317,000,000            
Goodwill $ 317,000,000 $ 317,000,000     $ 317,000,000      

v3.3.1.900
Goodwill and Other Intangible Assets Schedule of Finite-Lived Intangible Assets (Details) - USD ($)
$ in Millions
12 Months Ended
Dec. 31, 2015
Dec. 31, 2014
Dec. 31, 2013
Finite-Lived Intangible Assets [Line Items]      
Amortization of Intangible Assets $ 25 $ 26 $ 29

v3.3.1.900
Regulatory Assets and Liabilities (Details) - USD ($)
$ in Millions
12 Months Ended
Dec. 31, 2015
Dec. 31, 2014
Dec. 31, 2013
Jul. 04, 2013
Schedule of Regulatory Assets and Liabilities [Line Items]        
Total Current Regulatory Assets $ 746 $ 637    
Total Non Current Regulatory Assets 918 872    
TOTAL REGULATORY ASSETS 1,664 1,509    
Total Current Regulatory Liabilities 465 605    
Total Non Current Regulatory Liabilities $ 1,286 $ 1,509    
Total period for adjustments to the Regulatory Asset Base (Up to) 4 years 4 years    
TOTAL REGULATORY LIABILITIES $ 1,751 $ 2,114 $ 269  
Period of annual tariff adjustment 12 months      
Total period to recover or refund costs for annual tariff adjustment 24 months      
Brazil Tariff Estimated Rate Change Liability        
Schedule of Regulatory Assets and Liabilities [Line Items]        
Total Current Regulatory Liabilities [1] $ 0 $ 76    
Total period to recover or refund costs for annual tariff adjustment   2 years    
Tariff adjustment, percentage amortized       67.55%
Tariff adjustment, percentage amortized in next tariff adjustment       32.45%
Efficiency Program Costs        
Schedule of Regulatory Assets and Liabilities [Line Items]        
Total Current Regulatory Liabilities [2] 12 $ 22    
Total Non Current Regulatory Liabilities [2] 5 11    
Brazil Regulatory Asset Base Adjustment        
Schedule of Regulatory Assets and Liabilities [Line Items]        
Total Current Regulatory Liabilities [3] 169 123    
Total Non Current Regulatory Liabilities [3] 86 61    
Brazil Tariff Recoveries Energy Purchases Liability        
Schedule of Regulatory Assets and Liabilities [Line Items]        
Total Current Regulatory Liabilities [4] 105 144    
Total Non Current Regulatory Liabilities [4] 30 128    
Brazil Tariff Recoveries Transmission Costs Regulatory Fees And Other Liability        
Schedule of Regulatory Assets and Liabilities [Line Items]        
Total Current Regulatory Liabilities [4] 120 174    
Total Non Current Regulatory Liabilities [4] 29 97    
Asset Retirement Obligation Costs        
Schedule of Regulatory Assets and Liabilities [Line Items]        
Total Non Current Regulatory Liabilities [5] 759 727    
Brazil Special Obligations        
Schedule of Regulatory Assets and Liabilities [Line Items]        
Total Non Current Regulatory Liabilities [6] 370 484    
Other Regulatory Liabilities        
Schedule of Regulatory Assets and Liabilities [Line Items]        
Total Current Regulatory Liabilities [7] 59 66    
Total Non Current Regulatory Liabilities [7] 7 1    
Brazil Tariff Recoveries Energy Purchases Asset        
Schedule of Regulatory Assets and Liabilities [Line Items]        
Total Current Regulatory Assets [4] 416 424    
Total Non Current Regulatory Assets [4] 147 266    
Brazil Tariff Recoveries Transmission Costs Regulatory Fees And Other Asset        
Schedule of Regulatory Assets and Liabilities [Line Items]        
Total Current Regulatory Assets [4] 264 63    
Total Non Current Regulatory Assets [4] 140 14    
El Salvador Tariff Recoveries        
Schedule of Regulatory Assets and Liabilities [Line Items]        
Total Current Regulatory Assets [8] 43 92    
Pension Costs        
Schedule of Regulatory Assets and Liabilities [Line Items]        
Total Non Current Regulatory Assets [9],[10] 227 329    
Income Taxes Recoverable From Customers        
Schedule of Regulatory Assets and Liabilities [Line Items]        
Total Non Current Regulatory Assets [9],[11] 36 74    
Deferred Midwest Independent Service Operator Costs        
Schedule of Regulatory Assets and Liabilities [Line Items]        
Total Non Current Regulatory Assets [12] 129 111    
Other Regulatory Assets        
Schedule of Regulatory Assets and Liabilities [Line Items]        
Total Current Regulatory Assets [13] 23 58    
Total Non Current Regulatory Assets [13] 239 78    
Other current regulatory assets that did not earn a rate of return 8 22    
Other noncurrent regulatory assets that did not earn a rate of return $ 237 $ 73    
[1] (8)In July 2012, the Brazilian energy regulator (the "Regulator") approved the periodic review and reset of a component of Eletropaulo's regulated tariff, which determines the margin to be earned by Eletropaulo. The review and reset of this tariff component was retroactive to July 2011 and applied to customers' invoices from July 2012 to June 2015. From July 2011 through June 2012, Eletropaulo invoiced customers under the then-existing tariff rate, as required by the Regulator. As the new tariff rate was lower than the previous rate, Eletropaulo was required to reduce customer tariffs for the difference over the next year. Accordingly, from July 2011 through June 2012, Eletropaulo recognized a regulatory liability for the estimated future refunds, subsequently adjusted as of June 30, 2012 upon the finalization of the new tariff with the Regulator. The refund to customers was considered in the 2013 tariff adjustment, which contemplated an amortization of 67.55% from July 4, 2013. The remaining balance, representing 32.45%, was considered in the next annual tariff adjustment. There was no recorded current regulatory liability at Eletropaulo as of December 31, 2015.
[2] (9)Amounts received for costs expected to be incurred to improve the efficiency of our plants in Brazil as part of the IRT.
[3] (13) Represents adjustments to the RAB resulting from an administrative ruling in December 2013 compelling Eletropaulo to refund customers beginning July 2014.
[4] (1)Recoverable or refundable per Brazilian National Electric Energy Agency ("ANEEL") regulations through the Annual Tariff Adjustment ("IRT"). These costs are generally non-controllable and primarily consist of purchased electricity, energy transmission, and sector costs that are considered volatile. The costs are passed through for a period of 12 months as part of the IRT. Any remaining balance is considered in the subsequent IRT, which results in a total of 24 months to recover or refund the costs. Favorable spot market sales are also subject to customer refunds through the IRT over the course of these time periods.
[5] (11)Obligations for removal costs which do not have an associated legal retirement obligation as defined by the accounting standards on asset retirement obligations.
[6] (12)Obligations established by ANEEL in Brazil associated with electric utility concessions and represent amounts received from customers or donations not subject to return. These donations are allocated to support energy network expansion and to improve utility operations to meet customers' needs. The term of the obligation is established by ANEEL. Settlement shall occur when the concession ends.
[7] (10)Other current and noncurrent regulatory liabilities primarily consist of liabilities owed to electricity generators due to variance in energy prices during rationing periods ("Free Energy"). Our Brazilian subsidiaries are authorized to refund this cost associated with monthly energy price variances between the wholesale energy market prices owed to the power generation plants producing Free Energy and the capped price reimbursed by the local distribution companies which are passed through to the final customers through energy tariffs. The balance excludes asset retirement obligations that were reclassified out of Other.
[8] (2)Deferred fuel costs incurred by our El Salvador subsidiaries associated with purchase of energy from the El Salvador spot market and power generation plants. In El Salvador, the deferred fuel adjustment represents the variance between the actual fuel costs and the fuel costs recovered in the tariffs. The variance is recovered quarterly in the tariff reset period.
[9] (4)Past expenditures on which the Company does not earn a rate of return.
[10] (5)The regulatory accounting standards allow the defined pension and postretirement benefit obligation to be recorded as a regulatory asset equal to the previously unrecognized actuarial gains and losses and prior service costs that are expected to be recovered through future rates. Pension expense is recognized based on the plan's actuarially determined pension liability. Recovery of costs is probable, but not yet determined. Pension contributions made by our Brazilian subsidiaries are not included in regulatory assets as those contributions are not covered by the established tariff in Brazil.
[11] (6)Probable recovery through future rates, based upon established regulatory practices, which permit the recovery of current taxes. This amount is expected to be recovered, without interest, over the period as book-tax temporary differences reverse and become current taxes.
[12] (7)Transmission service costs and other administrative costs from IPL's participation in the Midwest ISO market, which are recoverable but do not earn a rate of return. Recovery of costs is probable, but the timing is not yet determined.
[13] (3)Includes assets with and without a rate of return. Other current regulatory assets that did not earn a rate of return were $8 million and $22 million, as of December 31, 2015 and 2014, respectively. Other noncurrent regulatory assets that did not earn a rate of return were $237 million and $73 million, as of December 31, 2015 and 2014, respectively. Other current and noncurrent regulatory assets primarily consist of:▪Unamortized losses on long-term debt reacquired or redeemed in prior periods at IPL and DPL, which are amortized over the lives of the original issues in accordance with the Federal Energy Regulatory Commission ("FERC") and PUCO rules.▪Unamortized carrying charges and certain other costs related to Petersburg unit 4 at IPL.▪Deferred storm costs incurred primarily in 2008 to repair storm damage at DPL; recovery was approved via order from the PUCO on December 17, 2014 and began January 2015.▪Additional Regulatory Asset Base ("RAB") from a favorable decision on tariff reset (administrative appeal) at Eletropaulo.

v3.3.1.900
Regulatory Assets and Liabilities Regulatory Assets and Liabilities - by Reportable Segment (Details) - USD ($)
$ in Millions
Dec. 31, 2015
Dec. 31, 2014
Dec. 31, 2013
Schedule of Regulatory Assets and Liabilities [Line Items]      
Regulatory Assets $ 1,664 $ 1,509  
Regulatory Liabilities 1,751 2,114 $ 269
Brazil SBU      
Schedule of Regulatory Assets and Liabilities [Line Items]      
Regulatory Assets 971 787  
Regulatory Liabilities 932 1,347  
US SBU      
Schedule of Regulatory Assets and Liabilities [Line Items]      
Regulatory Assets 650 631  
Regulatory Liabilities 819 767  
MCAC SBU (El Salvador)      
Schedule of Regulatory Assets and Liabilities [Line Items]      
Regulatory Assets 43 91  
Regulatory Liabilities $ 0 $ 0  

v3.3.1.900
Debt (Non-Recourse Debt Carrying Amounts and Terms) (Details) - USD ($)
$ in Millions
Dec. 31, 2015
Dec. 31, 2014
Debt Instrument [Line Items]    
Non Recourse Debt Total [1] $ 15,792 $ 15,600
Non-recourse Debt Current Maturities (2,529) (1,982)
Non-recourse debt - noncurrent, balance at variable interest entities 13,263 13,618
Derivative, notional amount $ 3,200  
Interest rate swap, fixed minimum interest rate 2.87%  
Interest rate swap, fixed maximum interest rate 8.24%  
Variable Rate Debt | Bank loans    
Debt Instrument [Line Items]    
Weighted Average Interest Rate [2] 4.37%  
Non Recourse Debt Total [2] $ 2,352 1,893
Variable Rate Debt | Notes and bonds    
Debt Instrument [Line Items]    
Weighted Average Interest Rate [2] 14.98%  
Non Recourse Debt Total [2] $ 1,474 1,912
Variable Rate Debt | Debt to (or guaranteed by) multilateral, export credit agencies or development banks    
Debt Instrument [Line Items]    
Weighted Average Interest Rate [2],[3] 2.39%  
Non Recourse Debt Total [2],[3] $ 3,078 2,375
Variable Rate Debt | Other    
Debt Instrument [Line Items]    
Weighted Average Interest Rate [2] 12.65%  
Non Recourse Debt Total [2] $ 47 668
Fixed Rate Debt | Bank loans    
Debt Instrument [Line Items]    
Weighted Average Interest Rate 5.11%  
Non Recourse Debt Total $ 558 750
Fixed Rate Debt | Notes and bonds    
Debt Instrument [Line Items]    
Weighted Average Interest Rate 5.54%  
Non Recourse Debt Total $ 7,948 7,654
Fixed Rate Debt | Debt to (or guaranteed by) multilateral, export credit agencies or development banks    
Debt Instrument [Line Items]    
Weighted Average Interest Rate [3] 5.39%  
Non Recourse Debt Total [3] $ 309 259
Fixed Rate Debt | Other    
Debt Instrument [Line Items]    
Weighted Average Interest Rate 8.66%  
Non Recourse Debt Total $ 26 $ 89
[1] .
[2] (1)The interest rate on variable rate debt represents the total of a variable component that is based on changes in an interest rate index and of a fixed component. The Company has interest rate swaps and option agreements in an aggregate notional principal amount of approximately $3.2 billion on non-recourse debt outstanding at December 31, 2015. These agreements economically fix the variable component of the interest rates on the portion of the variable-rate debt being hedged so that the total interest rate on that debt has been fixed at rates ranging from approximately 2.87% to 8.24%. These agreements expire at various dates from 2016 through 2033
[3] (2)Multilateral loans include loans funded and guaranteed by bilaterals, multilaterals, development banks and other similar institutions.

v3.3.1.900
Debt (Non-Recourse Debt Maturity Schedule) (Details) - USD ($)
$ in Millions
Dec. 31, 2015
Dec. 31, 2014
Debt Details [Line Items]    
Non Recourse Debt Total [1] $ 15,792 $ 15,600
2015    
Debt Details [Line Items]    
Non Recourse Debt Total 2,529  
2016    
Debt Details [Line Items]    
Non Recourse Debt Total 1,022  
2017    
Debt Details [Line Items]    
Non Recourse Debt Total 1,359  
2018    
Debt Details [Line Items]    
Non Recourse Debt Total 950  
2019    
Debt Details [Line Items]    
Non Recourse Debt Total 1,431  
Thereafter    
Debt Details [Line Items]    
Non Recourse Debt Total $ 8,501  
[1] .

v3.3.1.900
Debt (Subsidiary Non-Recourse Debt in Default or Accelerated) (Details)
$ in Millions
Dec. 31, 2015
USD ($)
Debt Details [Line Items]  
Debt default amount $ 1,038
Maritza (Bulgaria)  
Debt Details [Line Items]  
Net assets 657
Maritza (Bulgaria) | Covenant Violation  
Debt Details [Line Items]  
Debt default amount 559
Sul Subsidiary [Member] | Covenant Violation  
Debt Details [Line Items]  
Debt default amount 333
Net assets 439
Kavarna (Bulgaria) | Covenant Violation  
Debt Details [Line Items]  
Debt default amount 140
Net assets 74
Sogrinsk [Member] | Covenant Violation  
Debt Details [Line Items]  
Debt default amount 6
Net assets $ 8

v3.3.1.900
Debt (Non-recourse Debt Narrative) (Details) - USD ($)
12 Months Ended
Dec. 31, 2015
Dec. 31, 2014
Dec. 31, 2013
Debt Instrument [Line Items]      
Construction line of credit facility remaining borrowing capacity $ 2,600,000,000    
Other line of credit remaining borrowing capacity 2,400,000,000    
Loss on extinguishment of debt 186,000,000 $ 261,000,000 $ 229,000,000
Restricted cash and debt service reserves 513,000,000 245,000,000  
Restricted net assets 2,000,000,000    
Increase (Decrease) in Interest Expense, Debt (64,000,000) $ (48,000,000) $ (34,000,000)
Non-Recourse Debt | Construction Loans      
Debt Instrument [Line Items]      
Debt face amount 123,000,000    
Non-Recourse Debt | Mong Duong Subsidiary | Construction Loans      
Debt Instrument [Line Items]      
Debt face amount 203,000,000    
Non-Recourse Debt | Gener Subsidiary [Member]      
Debt Instrument [Line Items]      
Debt face amount 1,100,000,000    
Repayments of long-term debt 423,000,000    
Loss on extinguishment of debt 19,000,000    
Non-Recourse Debt | IPALCO Enterprises, Inc. [Member]      
Debt Instrument [Line Items]      
Debt face amount 847,000,000    
Repayments of long-term debt 602,000,000    
Loss on extinguishment of debt 22,000,000    
Non-Recourse Debt | Electropaulo      
Debt Instrument [Line Items]      
Debt face amount 354,000,000    
Repayments of long-term debt 211,000,000    
Non-Recourse Debt | DPL Subsidiary      
Debt Instrument [Line Items]      
Debt face amount 325,000,000    
Repayments of long-term debt 475,000,000    
Loss on extinguishment of debt 2,000,000    
Non-Recourse Debt | PANAMA      
Debt Instrument [Line Items]      
Debt face amount 300,000,000    
Repayments of long-term debt 287,000,000    
Loss on extinguishment of debt 15,000,000    
Non-Recourse Debt | Tiete Subsidiary      
Debt Instrument [Line Items]      
Debt face amount 153,000,000    
Repayments of long-term debt 226,000,000    
Non-Recourse Debt | Sul Subsidiary      
Debt Instrument [Line Items]      
Debt face amount 513,000,000    
Repayments of long-term debt 486,000,000    
Loss on extinguishment of debt 4,000,000    
Non-Recourse Debt | Andres [Member]      
Debt Instrument [Line Items]      
Debt face amount 180,000,000    
Repayments of long-term debt 176,000,000    
Loss on extinguishment of debt 11,000,000    
Non-Recourse Debt | Itabo (San Lorenzo) [Member]      
Debt Instrument [Line Items]      
Loss on extinguishment of debt $ 8,000,000    

v3.3.1.900
Debt (Recourse Debt Carrying Amount and Terms) (Details) - USD ($)
$ in Millions
12 Months Ended
Dec. 31, 2015
Dec. 31, 2014
Debt Instrument [Line Items]    
Recourse Debt Total $ 5,015 $ 5,258
Recourse Debt Current 0 (151)
Recourse Debt Non Current 5,015 $ 5,107
7.75% Senior Unsecured Note Due 2014 | Recourse Debt    
Debt Instrument [Line Items]    
Interest Rate   7.75%
7.75% Senior Unsecured Note Due 2015    
Debt Instrument [Line Items]    
Recourse Debt Total $ 0 $ 151
7.75% Senior Unsecured Note Due 2015 | Recourse Debt    
Debt Instrument [Line Items]    
Interest Rate 7.75% 7.75%
9.75% Senior Unsecured Note Due 2016    
Debt Instrument [Line Items]    
Recourse Debt Total $ 0 $ 164
9.75% Senior Unsecured Note Due 2016 | Recourse Debt    
Debt Instrument [Line Items]    
Interest Rate 9.75% 9.75%
8.00% Senior Unsecured Note Due 2017    
Debt Instrument [Line Items]    
Recourse Debt Total $ 181 $ 525
8.00% Senior Unsecured Note Due 2017 | Recourse Debt    
Debt Instrument [Line Items]    
Interest Rate 8.00% 8.00%
Senior Unsecured Note LIBOR plus 3% due 2019    
Debt Instrument [Line Items]    
Recourse Debt Total $ 775 $ 775
Senior Unsecured Note LIBOR plus 3% due 2019 | Recourse Debt | LIBOR    
Debt Instrument [Line Items]    
Basis spread on variable rate 3.00%  
8.00% Senior Unsecured Note Due 2020    
Debt Instrument [Line Items]    
Recourse Debt Total $ 469 $ 625
8.00% Senior Unsecured Note Due 2020 | Recourse Debt    
Debt Instrument [Line Items]    
Interest Rate 8.00% 8.00%
7.38% Senior Unsecured Note Due 2021    
Debt Instrument [Line Items]    
Recourse Debt Total $ 1,000 $ 1,000
7.38% Senior Unsecured Note Due 2021 | Recourse Debt    
Debt Instrument [Line Items]    
Interest Rate 7.38% 7.38%
4.88% Senior Unsecured Note Due 2023    
Debt Instrument [Line Items]    
Recourse Debt Total $ 750 $ 750
4.88% Senior Unsecured Note Due 2023 | Recourse Debt    
Debt Instrument [Line Items]    
Interest Rate 4.88% 4.88%
5.50% Senior Unsecured Note Due 2024    
Debt Instrument [Line Items]    
Recourse Debt Total $ 750 $ 750
5.50% Senior Unsecured Note Due 2024 | Recourse Debt    
Debt Instrument [Line Items]    
Interest Rate 5.50%  
5.50% Unsecured senior notes due 2025 [Domain] | Recourse Debt    
Debt Instrument [Line Items]    
Interest Rate 5.50%  
Recourse Debt Total $ 575 0
6.75% Term Convertible Trust Securities Due 2029    
Debt Instrument [Line Items]    
Recourse Debt Total $ 517 $ 517
6.75% Term Convertible Trust Securities Due 2029 | Recourse Debt    
Debt Instrument [Line Items]    
Interest Rate 6.75% 6.75%
Unamortized Discounts    
Debt Instrument [Line Items]    
Recourse Debt Total   $ 1
Unamortized Premuim    
Debt Instrument [Line Items]    
Recourse Debt Total $ (2)  

v3.3.1.900
Debt (Recourse Debt Net Principal Amounts Due Over Five Years) (Details) - USD ($)
$ in Millions
Dec. 31, 2015
Dec. 31, 2014
Debt Details [Line Items]    
Recourse Debt Total $ 5,015 $ 5,258
2015    
Debt Details [Line Items]    
Recourse Debt Total 0  
2016    
Debt Details [Line Items]    
Recourse Debt Total 181  
2017    
Debt Details [Line Items]    
Recourse Debt Total 0  
2018    
Debt Details [Line Items]    
Recourse Debt Total 774  
2019    
Debt Details [Line Items]    
Recourse Debt Total 469  
Thereafter    
Debt Details [Line Items]    
Recourse Debt Total $ 3,591  

v3.3.1.900
Debt (Recourse Debt Narrative) (Details) - USD ($)
1 Months Ended 9 Months Ended 12 Months Ended
Aug. 25, 2014
Jun. 16, 2014
May. 20, 2014
Mar. 07, 2014
Apr. 30, 2015
Mar. 31, 2015
Feb. 28, 2014
Sep. 30, 2015
Dec. 31, 2015
Dec. 31, 2014
Dec. 31, 2013
Jul. 25, 2014
Debt Instrument [Line Items]                        
Increase (Decrease) in Interest Expense, Debt                 $ (64,000,000) $ (48,000,000) $ (34,000,000)  
Loss on extinguishment of debt                 $ 186,000,000 $ 261,000,000 $ 229,000,000  
8% senior unsecured notes due 2017 and 2020 [Member]                        
Debt Instrument [Line Items]                        
Loss on extinguishment of debt               $ 82,000,000        
Senior Notes [Member] | Five Point Five Zero Percent Senior Notes Due 2025 [Domain]                        
Debt Instrument [Line Items]                        
Stated interest rate         5.50%              
Debt face amount         $ 575,000,000              
Recourse Debt                        
Debt Instrument [Line Items]                        
Stated interest rate                 6.75%      
Recourse Debt Covenants and Guarantees:                        
Percentage of capital stock of foreign subsidiaries securing obligations                 65.00%      
Covenants, sale of guarantor or its subsidiaries percentage of proceeds used to repay debt                 60.00%      
Covenants, sale of guarantor or its subsidiaries percentage of proceeds used to repay debt if debt to cash flow is less than 5                 50.00%      
Minimum ratio of operating cash flow to interest charges                 1.3      
Maximum ratio of debt to cash flow                 7.5      
Recourse Debt | Five Point Five Zero Percent Senior Notes Due 2024                        
Debt Instrument [Line Items]                        
Stated interest rate       5.50%                
Debt face amount       $ 750,000,000                
Recourse Debt | Three Percent Above Three Month LIBOR Floating Rate Notes Due June 2019                        
Debt Instrument [Line Items]                        
Debt face amount     $ 775,000,000                  
Basis spread on variable rate     3.00%                  
Unsecured Debt [Member]                        
Debt Instrument [Line Items]                        
Loss on extinguishment of debt               $ 23,000,000        
Unsecured Debt [Member] | 8.0% Senior Notes Due 2017                        
Debt Instrument [Line Items]                        
Debt terminated amount         $ 344,000,000              
Stated interest rate         8.00%              
Unsecured Debt [Member] | 8.0% Senior Notes Due 2020 [Domain]                        
Debt Instrument [Line Items]                        
Debt terminated amount         $ 156,000,000              
Stated interest rate         8.00%              
Unsecured Debt [Member] | 7.75% Senior Notes Due 2015 [Member]                        
Debt Instrument [Line Items]                        
Debt terminated amount           $ 151,000,000            
Stated interest rate           7.75%            
Unsecured Debt [Member] | 9.75% Senior Notes Due 2016 [Member] [Domain]                        
Debt Instrument [Line Items]                        
Debt terminated amount           $ 164,000,000            
Stated interest rate           9.75%            
Recourse Debt                        
Debt Instrument [Line Items]                        
Loss on extinguishment of debt $ 40,000,000                      
Debt Instrument, Notice Call to Retire Notes                       $ 320,000,000
Recourse Debt | 7.75% Senior Notes Due 2014                        
Debt Instrument [Line Items]                        
Debt terminated amount             $ 110,000,000          
Stated interest rate             7.75%          
Recourse Debt | 8.0% Senior Notes Due 2017                        
Debt Instrument [Line Items]                        
Debt terminated amount       $ 625,000,000                
Stated interest rate       8.00%                
Loss on extinguishment of debt       $ 132,000,000                
Recourse Debt | Senior Secured Term Loan LIBOR Plus 2.75% Due 2018                        
Debt Instrument [Line Items]                        
Debt terminated amount   $ 29,000,000 $ 767,000,000                  
Loss on extinguishment of debt     $ 10,000,000                  
Recourse Debt | 7.75% Senior Unsecured Note Due 2015                        
Debt Instrument [Line Items]                        
Debt Instrument, Notice Call to Retire Notes                       160,000,000
Recourse Debt | 9.75% Senior Unsecured Note Due 2016                        
Debt Instrument [Line Items]                        
Debt Instrument, Notice Call to Retire Notes                       $ 160,000,000

v3.3.1.900
Debt (Term Convertible Trust Securities) (Details)
$ / shares in Units, security in Thousands, shares in Millions, $ in Millions
24 Months Ended
Dec. 31, 2000
USD ($)
Dec. 31, 1999
USD ($)
security
quarter
$ / shares
shares
Debt Disclosure [Abstract]    
Term convertible preferred securities issued by special purpose business trust | security   10,350
Current redemption value of term convertible preferred securities issued by special purpose business trust   $ 50
Term convertible preferred securities issued by special purpose business trust par per share   $ 0.844
Term convertible preferred securities issued by special purpose business trust total proceeds | $ $ 517  
Junior subordinated convertible debentures purchased with proceeds from issuance of term convertible preferred securities | $   $ 517
Term convertible preferred securities dividend rate   6.75%
Term convertible preferred securities common stock conversion ratio 142.16%  
Term convertible preferred securities common stock conversion price per share   $ 35.17
Maximum shares parent common stock issuance upon conversion | shares   14.7
Term convertible preferred securities number of quarters dividends may be deferred | quarter   20

v3.3.1.900
Commitments (Leases, Future Minimum Payments Due) (Details)
$ in Millions
Dec. 31, 2015
USD ($)
Future Commitments for Capital Leases:  
2016 $ 14
2017 12
2018 11
2019 10
2020 10
Thereafter 90
Total 147
Less: Imputed interest 90
Present value of total minimum lease payments 57
Future Commitments for Operating Leases:  
2016 77
2017 78
2018 79
2019 80
2020 79
Thereafter 898
Total $ 1,291

v3.3.1.900
Commitments (Long-Term Purchase Commitments) (Details) - USD ($)
$ in Millions
12 Months Ended
Dec. 31, 2015
Dec. 31, 2014
Dec. 31, 2013
Electricity Purchase Contracts      
Long-Term Purchase Commitment [Line Items]      
Purchases Under Long Term Contracts $ 2,592 $ 3,104 $ 2,665
Future Commitments 2016 2,623    
Future Commitments 2017 2,444    
Future Commitments 2018 2,634    
Future Commitments 2019 2,799    
Future Commitments 2020 2,918    
Future Commitments Thereafter 24,176    
Future Commitments Total 37,594    
Fuel Purchase Contracts      
Long-Term Purchase Commitment [Line Items]      
Purchases Under Long Term Contracts 1,262 1,521 1,590
Future Commitments 2016 1,120    
Future Commitments 2017 835    
Future Commitments 2018 532    
Future Commitments 2019 314    
Future Commitments 2020 311    
Future Commitments Thereafter 2,141    
Future Commitments Total 5,253    
Other Purchase Contracts      
Long-Term Purchase Commitment [Line Items]      
Purchases Under Long Term Contracts 2,121 $ 1,386 $ 1,743
Future Commitments 2016 1,332    
Future Commitments 2017 1,047    
Future Commitments 2018 1,081    
Future Commitments 2019 873    
Future Commitments 2020 655    
Future Commitments Thereafter 4,395    
Future Commitments Total $ 9,383    

v3.3.1.900
Commitments (Narrative) (Details) - USD ($)
$ in Millions
12 Months Ended
Dec. 31, 2015
Dec. 31, 2014
Dec. 31, 2013
Leases, Operating [Abstract]      
Operating lease and rental expense $ 67 $ 58 $ 46
Leases Capital [Abstract]      
Capital leased assets, gross $ 72 $ 80  

v3.3.1.900
Contingencies (Details)
$ in Millions
12 Months Ended
Dec. 31, 2015
USD ($)
agreement
Guarantees Letters Of Credit [Abstract]  
Lower limit of expiration dates of guarantees (less than one year) 1 year
Upper limit of expiration dates of guarantees (more than 19 years) 19 years
Obligations made by the Parent Company associated with non-recourse debt $ 14
Contingent Contractual Obligations [Line Items]  
Amount $ 490
Number of Agreements | agreement 26
Parent Company  
Contingent Contractual Obligations [Line Items]  
Letter Of Credit Fee Range Minimum 0.20%
Letter Of Credit Fee Range Maximum 2.50%
Guarantees and commitments  
Contingent Contractual Obligations [Line Items]  
Amount $ 369
Number of Agreements | agreement 14
Maximum Exposure Range, Lower Limit (equal to or less than) $ 1
Maximum exposure range, upper limit 53
Asset sale related indemnities  
Contingent Contractual Obligations [Line Items]  
Amount $ 27 [1]
Number of Agreements | agreement 1 [1]
Maximum exposure range, upper limit $ 27 [1]
Cash collateralized letters of credit  
Contingent Contractual Obligations [Line Items]  
Amount $ 32
Number of Agreements | agreement 4
Maximum Exposure Range, Lower Limit (equal to or less than) $ 1
Maximum exposure range, upper limit 15
Cash collateralized letters of credit | Parent Company  
Contingent Contractual Obligations [Line Items]  
Amount $ 32
Letters of credit under the senior secured credit facility  
Contingent Contractual Obligations [Line Items]  
Number of Agreements | agreement 7
Letters of credit outstanding $ 62
Maximum Exposure Range, Lower Limit (equal to or less than) 1
Maximum exposure range, upper limit $ 29
[1] (1) Excludes normal and customary representations and warranties in agreements for the sale of assets (including ownership in associated legal entities) where the associated risk is considered to be nominal.

v3.3.1.900
Contingencies (Loss Contingencies) (Details) - USD ($)
$ in Millions
3 Months Ended 12 Months Ended
Jun. 30, 2015
Dec. 31, 2015
Dec. 31, 2014
Dec. 31, 2013
Litigation Contingencies        
Regulatory Liabilities   $ 1,751 $ 2,114 $ 269
Reversal Of Legal Contingency   0 18 $ 10
Environmental        
Environmental Contingencies        
Liability recorded for projected environmental remediation costs   10 12  
Loss Contingency, Range of Possible Loss, Maximum   1    
Litigation Contingencies        
Loss Contingency, Range of Possible Loss, Maximum   1    
Litigation        
Environmental Contingencies        
Loss Contingency, Range of Possible Loss, Maximum   1,400    
Litigation Contingencies        
Aggregate reserves for claims deemed both probable and reasonably estimable   189 $ 199  
Minimum potential loss   1,100    
Loss Contingency, Range of Possible Loss, Maximum   $ 1,400    
Eletropaulo [Domain]        
Litigation Contingencies        
Reversal Of Legal Contingency $ 161      
Regulated Revenue [Member] | Eletropaulo [Domain]        
Litigation Contingencies        
Reversal Of Legal Contingency 97      
Interest Expense | Eletropaulo [Domain]        
Litigation Contingencies        
Reversal Of Legal Contingency $ 64      

v3.3.1.900
Benefit Plans (Narrative) (Details)
$ in Millions
12 Months Ended
Dec. 31, 2015
USD ($)
plan
Dec. 31, 2014
USD ($)
Dec. 31, 2013
USD ($)
Defined Benefit Plan Disclosure [Line Items]      
Defined contribution plan, number of plans 4    
Defined contribution plan, award vesting period 5 years    
Defined contribution plan contributions | $ $ 18 $ 22 $ 23
Defined benefit plan, number of plans disclosure 33    
U.S. Non-Union Number of Defined Contribution Plans 2    
Parent Company Number of Defined Contribution Plans 1    
IPL Number of Non-Union and Union Defined Contribution Plans 1    
DPL Number of Non-Union Defined Contribution Plans 1    
DPL Number of Union Defined Contribution Plans 1    
U.S. Defined Benefit Plans      
Defined Benefit Plan Disclosure [Line Items]      
Defined benefit plan, number of plans disclosure 5    

v3.3.1.900
Benefit Plans (Net Funded Status) (Details) - USD ($)
$ in Millions
12 Months Ended
Dec. 31, 2015
Dec. 31, 2014
Dec. 31, 2013
U.S. Defined Benefit Plans      
Defined Benefit Plan Disclosure [Line Items]      
Defined Benefit Plan, Settlements, Plan Assets $ (3) $ 0  
CHANGE IN PROJECTED BENEFIT OBLIGATION:      
Benefit obligation, beginning period 1,235 1,059  
Service cost 16 14 $ 16
Interest cost 48 50 46
Employee contributions 0 0  
Plan amendments 5 8  
Benefits paid (61) (59)  
Actuarial (gain) loss (68) 163  
Effect of foreign currency exchange rate changes 0 0  
Benefit obligation, ending period 1,172 1,235 1,059
CHANGE IN PLAN ASSETS:      
Fair value of plan assets, beginning period 1,061 941  
Actual return on plan assets (7) 123  
Employer contributions 31 56  
Employee contributions 0 0  
Benefits paid (61) (59)  
Effect of foreign currency exchange rate changes 0 0  
Fair value of plan assets, ending period 1,021 1,061 941
Funded status as of December 31 (151) (174)  
Defined Benefit Plan, Settlements, Benefit Obligation (3) 0  
Foreign Defined Benefit Plans      
Defined Benefit Plan Disclosure [Line Items]      
Defined Benefit Plan, Settlements, Plan Assets 0 0  
CHANGE IN PROJECTED BENEFIT OBLIGATION:      
Benefit obligation, beginning period 4,363 4,749  
Service cost 15 16 26
Interest cost 351 489 515
Employee contributions 3 4  
Plan amendments 2 (3)  
Benefits paid (300) (415)  
Actuarial (gain) loss (160) 87  
Effect of foreign currency exchange rate changes (1,301) (564)  
Benefit obligation, ending period 2,973 4,363 4,749
CHANGE IN PLAN ASSETS:      
Fair value of plan assets, beginning period 3,272 3,605  
Actual return on plan assets 182 360  
Employer contributions 89 135  
Employee contributions 3 4  
Benefits paid (300) (415)  
Effect of foreign currency exchange rate changes (962) (417)  
Fair value of plan assets, ending period 2,284 3,272 $ 3,605
Funded status as of December 31 (689) (1,091)  
Defined Benefit Plan, Settlements, Benefit Obligation $ 0 $ 0  

v3.3.1.900
Benefit Plans (Amounts Recognized in the Consolidated Balance Sheets) (Details) - USD ($)
$ in Millions
Dec. 31, 2015
Dec. 31, 2014
AMOUNTS RECOGNIZED ON THE CONSOLIDATED BALANCE SHEETS    
Accrued benefit liability—noncurrent $ (927) $ (1,342)
U.S. Defined Benefit Plans    
AMOUNTS RECOGNIZED ON THE CONSOLIDATED BALANCE SHEETS    
Noncurrent assets 0 0
Accrued benefit liability—current 0 0
Accrued benefit liability—noncurrent (151) (174)
Net amount recognized at end of year (151) (174)
Foreign Defined Benefit Plans    
AMOUNTS RECOGNIZED ON THE CONSOLIDATED BALANCE SHEETS    
Noncurrent assets 67 51
Accrued benefit liability—current (5) (4)
Accrued benefit liability—noncurrent (751) (1,138)
Net amount recognized at end of year $ (689) $ (1,091)

v3.3.1.900
Benefit Plans (Accumulated Benefit Obligation) (Details) - USD ($)
$ in Millions
Dec. 31, 2015
Dec. 31, 2014
U.S. Defined Benefit Plans    
Defined Benefit Plan Disclosure [Line Items]    
Accumulated Benefit Obligation $ 1,150 $ 1,208
Information for pension plans with an accumulated benefit obligation in excess of plan assets:    
Projected benefit obligation 1,172 1,235
Accumulated benefit obligation 1,150 1,208
Fair value of plan assets 1,021 1,061
Information for pension plans with a projected benefit obligation in excess of plan assets:    
Projected benefit obligation 1,172 1,235
Fair value of plan assets 1,021 1,061
Foreign Defined Benefit Plans    
Defined Benefit Plan Disclosure [Line Items]    
Accumulated Benefit Obligation 2,931 4,301
Information for pension plans with an accumulated benefit obligation in excess of plan assets:    
Projected benefit obligation 2,683 4,021
Accumulated benefit obligation 2,656 3,979
Fair value of plan assets 1,931 2,885
Information for pension plans with a projected benefit obligation in excess of plan assets:    
Projected benefit obligation [1] 2,697 4,038
Fair value of plan assets [1] 1,942 2,897
Electropaulo | Foreign Defined Benefit Plans    
Information for pension plans with a projected benefit obligation in excess of plan assets:    
Projected benefit obligation $ 700 $ 1,100
[1] (1)$686 million and $1.1 billion of the total net unfunded projected benefit obligation is due to Eletropaulo in Brazil as of December 31, 2015 and 2014, respectively.

v3.3.1.900
Benefit Plans Benefit Plans (Weighted Average Assumptions) (Details) - USD ($)
$ in Millions
12 Months Ended
Dec. 31, 2015
Dec. 31, 2014
U.S. Defined Benefit Plans    
Benefit Obligation:    
Discount rates 4.44% 4.04%
Rates of compensation increase [1] 3.34% 3.94%
Periodic Benefit Cost:    
Discount rate 4.04% 4.89%
Expected long-term rate of return on plan assets 6.67% 6.92%
Rate of compensation increase [1] 3.94% 3.94%
Defined benefit plan, benefit obligation subsidiary using salary bonds $ 6 $ 748
Defined Benefit Plan Obligation subsidiary using compensation increase   $ 742
Foreign Defined Benefit Plans    
Benefit Obligation:    
Discount rates [2] 11.37% 10.47%
Rates of compensation increase 6.32% 6.41%
Periodic Benefit Cost:    
Discount rate 10.47% 10.80%
Expected long-term rate of return on plan assets 9.77% 10.44%
Rate of compensation increase 6.41% 6.44%
[1] (1)A U.S. subsidiary of the Company has defined benefit obligations of $6 million and $748 million as of December 31, 2015 and 2014, respectively, for which salary bands, rather than rates of compensation increases, are used to determine future benefit costs. Rates of compensation increases in the table above do not include amounts related to these specific defined benefit plans. A plan with a defined benefit obligation of $742 million at December 31, 2014 and which used salary bands at that date is using a rate of compensation increase as at December 31, 2015. The rate of compensation increase for this plan is included in the weighted average in the above table for calculating the benefit obligation as at December 31, 2015, but is not included in the weighted average for calculating the benefit obligation as at December 31, 2014 or the periodic benefit cost for 2014 or 2015.
[2] (2) Includes an inflation factor that is used to calculate future periodic benefit cost, but is not used to calculate the benefit obligation.

v3.3.1.900
Benefit Plans (Impact of One Point Change in Assumptions) (Details)
$ in Millions
12 Months Ended
Dec. 31, 2015
USD ($)
Defined Benefit Plan Assumptions Sensitivity To Changes [Abstract]  
Increase of 1% in the discount rate $ (32)
Decrease of 1% in the discount rate 27
Increase of 1% in the long-term rate of return on plan assets (36)
Decrease of 1% in the long-term rate of return on plan assets $ 36

v3.3.1.900
Benefit Plans (Net Periodic Benefit Cost) (Details) - USD ($)
$ in Millions
12 Months Ended
Dec. 31, 2015
Dec. 31, 2014
Dec. 31, 2013
U.S. Defined Benefit Plans      
Components of Net Periodic Benefit Cost:      
Service cost $ 16 $ 14 $ 16
Interest cost 48 50 46
Expected return on plan assets (70) (67) (64)
Amortization of prior service cost 7 6 5
Amortization of net loss 20 13 23
Settlement gain recognized 0 0 0
Total pension cost 21 16 26
Foreign Defined Benefit Plans      
Components of Net Periodic Benefit Cost:      
Service cost 15 16 26
Interest cost 351 489 515
Expected return on plan assets (247) (362) (484)
Amortization of prior service cost 0 (1) 0
Amortization of net loss 28 37 77
Settlement gain recognized 0 (1) 0
Total pension cost $ 147 $ 180 $ 134

v3.3.1.900
Benefit Plans (Accumulated Other Comprehensive Income (Loss)) (Details)
$ in Millions
12 Months Ended
Dec. 31, 2015
USD ($)
U.S. Defined Benefit Plans  
Accumulated Other Comprehensive Income (Loss)  
Prior service cost $ 0
Unrecognized net actuarial gain (loss) (6)
Total (6)
Amounts expected to be reclassified to earnings in next fiscal year  
Prior service cost 0
Unrecognized net actuarial gain (loss) 0
Total 0
Foreign Defined Benefit Plans  
Accumulated Other Comprehensive Income (Loss)  
Prior service cost (5)
Unrecognized net actuarial gain (loss) (1,092)
Total (1,097)
Amounts expected to be reclassified to earnings in next fiscal year  
Prior service cost 0
Unrecognized net actuarial gain (loss) (18)
Total $ (18)

v3.3.1.900
Benefit Plans (Plan Asset Allocations) (Details)
12 Months Ended
Dec. 31, 2015
Dec. 31, 2014
U.S. Defined Benefit Plans    
Defined Benefit Plan Disclosure [Line Items]    
Percentage of Plan Assets 100.00% 100.00%
U.S. Defined Benefit Plans | Equity securities    
Defined Benefit Plan Disclosure [Line Items]    
Target Allocations 46.00%  
Percentage of Plan Assets 44.76% 44.02%
U.S. Defined Benefit Plans | Debt securities    
Defined Benefit Plan Disclosure [Line Items]    
Target Allocations 50.00%  
Percentage of Plan Assets 50.05% 50.90%
U.S. Defined Benefit Plans | Real estate    
Defined Benefit Plan Disclosure [Line Items]    
Target Allocations 2.00%  
Percentage of Plan Assets 2.94% 2.45%
U.S. Defined Benefit Plans | Other    
Defined Benefit Plan Disclosure [Line Items]    
Target Allocations 2.00%  
Percentage of Plan Assets 2.25% 2.63%
Foreign Defined Benefit Plans    
Defined Benefit Plan Disclosure [Line Items]    
Percentage of Plan Assets 100.00% 100.00%
Foreign Defined Benefit Plans | Equity securities    
Defined Benefit Plan Disclosure [Line Items]    
Percentage of Plan Assets 13.23% 16.28%
Target Allocations, Minimum 15.00%  
Target Allocations, Maximum 29.00%  
Foreign Defined Benefit Plans | Debt securities    
Defined Benefit Plan Disclosure [Line Items]    
Percentage of Plan Assets 81.10% 78.85%
Target Allocations, Minimum 60.00%  
Target Allocations, Maximum 85.00%  
Foreign Defined Benefit Plans | Real estate    
Defined Benefit Plan Disclosure [Line Items]    
Percentage of Plan Assets 3.24% 3.15%
Target Allocations, Minimum 0.00%  
Target Allocations, Maximum 3.00%  
Foreign Defined Benefit Plans | Other    
Defined Benefit Plan Disclosure [Line Items]    
Percentage of Plan Assets 2.43% 1.72%
Target Allocations, Minimum 0.00%  
Target Allocations, Maximum 5.00%  

v3.3.1.900
Benefit Plans (Fair Value of Plan Assets) (Details) - USD ($)
$ in Millions
Dec. 31, 2015
Dec. 31, 2014
Dec. 31, 2013
U.S. Defined Benefit Plans      
Defined Benefit Plan Disclosure [Line Items]      
Total plan assets $ 1,021 $ 1,061 $ 941
U.S. Defined Benefit Plans | Level 1      
Defined Benefit Plan Disclosure [Line Items]      
Total plan assets 968 1,011  
U.S. Defined Benefit Plans | Level 2      
Defined Benefit Plan Disclosure [Line Items]      
Total plan assets 53 50  
U.S. Defined Benefit Plans | Level 3      
Defined Benefit Plan Disclosure [Line Items]      
Total plan assets 0 0  
U.S. Defined Benefit Plans | Mutual funds      
Defined Benefit Plan Disclosure [Line Items]      
Total plan assets 457 467  
U.S. Defined Benefit Plans | Mutual funds | Level 1      
Defined Benefit Plan Disclosure [Line Items]      
Total plan assets 457 467  
U.S. Defined Benefit Plans | Mutual funds | Level 2      
Defined Benefit Plan Disclosure [Line Items]      
Total plan assets 0 0  
U.S. Defined Benefit Plans | Mutual funds | Level 3      
Defined Benefit Plan Disclosure [Line Items]      
Total plan assets 0 0  
U.S. Defined Benefit Plans | Government debt securities      
Defined Benefit Plan Disclosure [Line Items]      
Total plan assets 53 67  
U.S. Defined Benefit Plans | Government debt securities | Level 1      
Defined Benefit Plan Disclosure [Line Items]      
Total plan assets 53 67  
U.S. Defined Benefit Plans | Government debt securities | Level 2      
Defined Benefit Plan Disclosure [Line Items]      
Total plan assets 0 0  
U.S. Defined Benefit Plans | Government debt securities | Level 3      
Defined Benefit Plan Disclosure [Line Items]      
Total plan assets 0 0  
U.S. Defined Benefit Plans | Mutual funds      
Defined Benefit Plan Disclosure [Line Items]      
Total plan assets [1] 458 473  
U.S. Defined Benefit Plans | Mutual funds | Level 1      
Defined Benefit Plan Disclosure [Line Items]      
Total plan assets [1] 458 473  
U.S. Defined Benefit Plans | Mutual funds | Level 2      
Defined Benefit Plan Disclosure [Line Items]      
Total plan assets [1] 0 0  
U.S. Defined Benefit Plans | Mutual funds | Level 3      
Defined Benefit Plan Disclosure [Line Items]      
Total plan assets [1] 0 0  
U.S. Defined Benefit Plans | Real estate      
Defined Benefit Plan Disclosure [Line Items]      
Total plan assets 30 26  
U.S. Defined Benefit Plans | Real estate | Level 1      
Defined Benefit Plan Disclosure [Line Items]      
Total plan assets 0 0  
U.S. Defined Benefit Plans | Real estate | Level 2      
Defined Benefit Plan Disclosure [Line Items]      
Total plan assets 30 26  
U.S. Defined Benefit Plans | Real estate | Level 3      
Defined Benefit Plan Disclosure [Line Items]      
Total plan assets 0 0  
U.S. Defined Benefit Plans | Cash and cash equivalents      
Defined Benefit Plan Disclosure [Line Items]      
Total plan assets 0 4  
U.S. Defined Benefit Plans | Cash and cash equivalents | Level 1      
Defined Benefit Plan Disclosure [Line Items]      
Total plan assets 0 4  
U.S. Defined Benefit Plans | Cash and cash equivalents | Level 2      
Defined Benefit Plan Disclosure [Line Items]      
Total plan assets 0 0  
U.S. Defined Benefit Plans | Cash and cash equivalents | Level 3      
Defined Benefit Plan Disclosure [Line Items]      
Total plan assets 0 0  
U.S. Defined Benefit Plans | Other investments      
Defined Benefit Plan Disclosure [Line Items]      
Total plan assets 23 24  
U.S. Defined Benefit Plans | Other investments | Level 1      
Defined Benefit Plan Disclosure [Line Items]      
Total plan assets 0 0  
U.S. Defined Benefit Plans | Other investments | Level 2      
Defined Benefit Plan Disclosure [Line Items]      
Total plan assets 23 24  
U.S. Defined Benefit Plans | Other investments | Level 3      
Defined Benefit Plan Disclosure [Line Items]      
Total plan assets 0 0  
Foreign Defined Benefit Plans      
Defined Benefit Plan Disclosure [Line Items]      
Total plan assets 2,284 3,272 3,605
Foreign Defined Benefit Plans | Level 1      
Defined Benefit Plan Disclosure [Line Items]      
Total plan assets 421 523  
Foreign Defined Benefit Plans | Level 2      
Defined Benefit Plan Disclosure [Line Items]      
Total plan assets 1,623 2,353  
Foreign Defined Benefit Plans | Level 3      
Defined Benefit Plan Disclosure [Line Items]      
Total plan assets 240 396 $ 530
Foreign Defined Benefit Plans | Common stock      
Defined Benefit Plan Disclosure [Line Items]      
Total plan assets 9 21  
Foreign Defined Benefit Plans | Common stock | Level 1      
Defined Benefit Plan Disclosure [Line Items]      
Total plan assets 9 21  
Foreign Defined Benefit Plans | Common stock | Level 2      
Defined Benefit Plan Disclosure [Line Items]      
Total plan assets 0 0  
Foreign Defined Benefit Plans | Common stock | Level 3      
Defined Benefit Plan Disclosure [Line Items]      
Total plan assets 0 0  
Foreign Defined Benefit Plans | Mutual funds      
Defined Benefit Plan Disclosure [Line Items]      
Total plan assets 167 274  
Foreign Defined Benefit Plans | Mutual funds | Level 1      
Defined Benefit Plan Disclosure [Line Items]      
Total plan assets 167 274  
Foreign Defined Benefit Plans | Mutual funds | Level 2      
Defined Benefit Plan Disclosure [Line Items]      
Total plan assets 0 0  
Foreign Defined Benefit Plans | Mutual funds | Level 3      
Defined Benefit Plan Disclosure [Line Items]      
Total plan assets 0 0  
Foreign Defined Benefit Plans | Private equity      
Defined Benefit Plan Disclosure [Line Items]      
Total plan assets [2] 126 237  
Foreign Defined Benefit Plans | Private equity | Level 1      
Defined Benefit Plan Disclosure [Line Items]      
Total plan assets [2] 0 0  
Foreign Defined Benefit Plans | Private equity | Level 2      
Defined Benefit Plan Disclosure [Line Items]      
Total plan assets [2] 0 0  
Foreign Defined Benefit Plans | Private equity | Level 3      
Defined Benefit Plan Disclosure [Line Items]      
Total plan assets [2] 126 237  
Foreign Defined Benefit Plans | Certificates of deposit      
Defined Benefit Plan Disclosure [Line Items]      
Total plan assets 2 3  
Foreign Defined Benefit Plans | Certificates of deposit | Level 1      
Defined Benefit Plan Disclosure [Line Items]      
Total plan assets 0 0  
Foreign Defined Benefit Plans | Certificates of deposit | Level 2      
Defined Benefit Plan Disclosure [Line Items]      
Total plan assets 2 3  
Foreign Defined Benefit Plans | Certificates of deposit | Level 3      
Defined Benefit Plan Disclosure [Line Items]      
Total plan assets 0 0  
Foreign Defined Benefit Plans | Unsecured debentures      
Defined Benefit Plan Disclosure [Line Items]      
Total plan assets 5 10  
Foreign Defined Benefit Plans | Unsecured debentures | Level 1      
Defined Benefit Plan Disclosure [Line Items]      
Total plan assets 0 0  
Foreign Defined Benefit Plans | Unsecured debentures | Level 2      
Defined Benefit Plan Disclosure [Line Items]      
Total plan assets 5 10  
Foreign Defined Benefit Plans | Unsecured debentures | Level 3      
Defined Benefit Plan Disclosure [Line Items]      
Total plan assets 0 0  
Foreign Defined Benefit Plans | Government debt securities      
Defined Benefit Plan Disclosure [Line Items]      
Total plan assets 90 110  
Foreign Defined Benefit Plans | Government debt securities | Level 1      
Defined Benefit Plan Disclosure [Line Items]      
Total plan assets 11 12  
Foreign Defined Benefit Plans | Government debt securities | Level 2      
Defined Benefit Plan Disclosure [Line Items]      
Total plan assets 79 98  
Foreign Defined Benefit Plans | Government debt securities | Level 3      
Defined Benefit Plan Disclosure [Line Items]      
Total plan assets 0 0  
Foreign Defined Benefit Plans | Mutual funds      
Defined Benefit Plan Disclosure [Line Items]      
Total plan assets [3] 1,753 2,451  
Foreign Defined Benefit Plans | Mutual funds | Level 1      
Defined Benefit Plan Disclosure [Line Items]      
Total plan assets [3] 218 215  
Foreign Defined Benefit Plans | Mutual funds | Level 2      
Defined Benefit Plan Disclosure [Line Items]      
Total plan assets [3] 1,535 2,236  
Foreign Defined Benefit Plans | Mutual funds | Level 3      
Defined Benefit Plan Disclosure [Line Items]      
Total plan assets [3] 0 0  
Foreign Defined Benefit Plans | Other debt securities      
Defined Benefit Plan Disclosure [Line Items]      
Total plan assets 2 6  
Foreign Defined Benefit Plans | Other debt securities | Level 1      
Defined Benefit Plan Disclosure [Line Items]      
Total plan assets 0 0  
Foreign Defined Benefit Plans | Other debt securities | Level 2      
Defined Benefit Plan Disclosure [Line Items]      
Total plan assets 2 6  
Foreign Defined Benefit Plans | Other debt securities | Level 3      
Defined Benefit Plan Disclosure [Line Items]      
Total plan assets 0 0  
Foreign Defined Benefit Plans | Real estate      
Defined Benefit Plan Disclosure [Line Items]      
Total plan assets [2] 74 103  
Foreign Defined Benefit Plans | Real estate | Level 1      
Defined Benefit Plan Disclosure [Line Items]      
Total plan assets [2] 0 0  
Foreign Defined Benefit Plans | Real estate | Level 2      
Defined Benefit Plan Disclosure [Line Items]      
Total plan assets [2] 0 0  
Foreign Defined Benefit Plans | Real estate | Level 3      
Defined Benefit Plan Disclosure [Line Items]      
Total plan assets [2] 74 103  
Foreign Defined Benefit Plans | Cash and cash equivalents      
Defined Benefit Plan Disclosure [Line Items]      
Total plan assets 0 1  
Foreign Defined Benefit Plans | Cash and cash equivalents | Level 1      
Defined Benefit Plan Disclosure [Line Items]      
Total plan assets 0 1  
Foreign Defined Benefit Plans | Cash and cash equivalents | Level 2      
Defined Benefit Plan Disclosure [Line Items]      
Total plan assets 0 0  
Foreign Defined Benefit Plans | Cash and cash equivalents | Level 3      
Defined Benefit Plan Disclosure [Line Items]      
Total plan assets 0 0  
Foreign Defined Benefit Plans | Participant loans      
Defined Benefit Plan Disclosure [Line Items]      
Total plan assets [4] 37 52  
Foreign Defined Benefit Plans | Participant loans | Level 1      
Defined Benefit Plan Disclosure [Line Items]      
Total plan assets [4] 0 0  
Foreign Defined Benefit Plans | Participant loans | Level 2      
Defined Benefit Plan Disclosure [Line Items]      
Total plan assets [4] 0 0  
Foreign Defined Benefit Plans | Participant loans | Level 3      
Defined Benefit Plan Disclosure [Line Items]      
Total plan assets [4] 37 52  
Foreign Defined Benefit Plans | Other assets      
Defined Benefit Plan Disclosure [Line Items]      
Total plan assets 19 4  
Foreign Defined Benefit Plans | Other assets | Level 1      
Defined Benefit Plan Disclosure [Line Items]      
Total plan assets 16 0  
Foreign Defined Benefit Plans | Other assets | Level 2      
Defined Benefit Plan Disclosure [Line Items]      
Total plan assets 0 0  
Foreign Defined Benefit Plans | Other assets | Level 3      
Defined Benefit Plan Disclosure [Line Items]      
Total plan assets $ 3 $ 4  
[1] (1)Mutual funds categorized as debt securities consist of mutual funds for which debt securities are the primary underlying investment.
[2] (1) Plan assets of our Brazilian subsidiaries are invested in private equities and commercial real estate through the plan administrator in Brazil. The fair value of these assets is determined using the income approach through annual appraisals based on a discounted cash flow analysis.
[3] (2) Mutual funds categorized as debt securities consist of mutual funds for which debt securities are the primary underlying investment.
[4] (3) Loans to participants are stated at cost, which approximates fair value.

v3.3.1.900
Benefit Plans (Level 3 Roll Forward) (Details) - USD ($)
$ in Millions
12 Months Ended
Dec. 31, 2015
Dec. 31, 2014
Level 3    
CHANGE IN PLAN ASSETS:    
Defined Benefit Plan, Transfers Between Measurement Levels $ 0 $ 5
Foreign Defined Benefit Plans    
CHANGE IN PLAN ASSETS:    
Fair value of plan assets, beginning period 3,272 3,605
Effect of foreign currency exchange rate changes (962) (417)
Fair value of plan assets, ending period 2,284 3,272
Foreign Defined Benefit Plans | Level 3    
CHANGE IN PLAN ASSETS:    
Fair value of plan assets, beginning period 396 530
Returns relating to assets still held at reporting date (36) (87)
Purchases, sales and settlements, net 0 1
Effect of foreign currency exchange rate changes (120) (53)
Fair value of plan assets, ending period $ 240 $ 396

v3.3.1.900
Benefit Plans (Expected Future Benefit Payments) (Details)
$ in Millions
12 Months Ended
Dec. 31, 2015
USD ($)
U.S. Defined Benefit Plans  
Defined Benefit Plan Disclosure [Line Items]  
Expected employer contribution in 2016 $ 22
Expected benefit payments for fiscal year ending:  
2015 65
2016 67
2017 69
2018 71
2019 73
2021 - 2025 380
Foreign Defined Benefit Plans  
Defined Benefit Plan Disclosure [Line Items]  
Expected employer contribution in 2016 100
Expected benefit payments for fiscal year ending:  
2015 268
2016 277
2017 289
2018 299
2019 309
2021 - 2025 $ 1,686

v3.3.1.900
Equity (Transactions with Noncontrolling Interests) (Details) - USD ($)
1 Months Ended 3 Months Ended 12 Months Ended
Nov. 18, 2015
Feb. 11, 2015
Jul. 15, 2014
Dec. 31, 2015
Apr. 30, 2015
Feb. 28, 2015
Dec. 31, 2014
Sep. 30, 2014
Dec. 31, 2015
Dec. 31, 2014
Dec. 31, 2013
Apr. 01, 2015
Mar. 15, 2015
Jun. 25, 2014
Noncontrolling Interest [Line Items]                            
Sale of subsidiary shares to noncontrolling interests                     $ 0      
Sale of Stock, Consideration Received Per Transaction                 $ 460,000,000 $ 0        
Gain (Loss) on Disposition of Stock in Subsidiary                 $ 0          
Acquire addition shares through December 31, 2015                            
Noncontrolling Interest [Line Items]                            
Investment Options, acquisition percentage       2.00%                    
Dominican Republic                            
Noncontrolling Interest [Line Items]                            
Noncontrolling Interest, Ownership Percentage by Noncontrolling Owners       10.00%     8.00%   10.00% 8.00%        
Proceeds from divestiture of business             $ 83,000,000              
Sale Agreement, Buyer Option To Purchase Ownership Interest, Sales Price       $ 18,000,000     $ 24,000,000              
Gain on Disposition of Stock in Subsidiary, Recorded to APIC                 $ 7,000,000 $ 29,000,000        
Cachagua [Member]                            
Noncontrolling Interest [Line Items]                            
Noncontrolling Interest, Ownership Percentage by Parent 99.90%                          
Gener Subsidiary [Member]                            
Noncontrolling Interest [Line Items]                            
Gain on Disposition of Stock in Subsidiary, Recorded to APIC $ 24,000,000                          
Sale of Stock, Consideration Received Per Transaction $ 145,000,000                          
Sale of Stock, Percentage of Ownership before Transaction 70.70%                          
Sale of Stock, Percentage of Ownership after Transaction 66.70%                          
AES US Investment, Inc.                            
Noncontrolling Interest [Line Items]                            
Investment In Affiliate Ownership Percentage Sold   15.00%                        
Sale of Stock, Consideration Received Per Transaction   $ 247,000,000                        
Masinloc Subsidiary                            
Noncontrolling Interest [Line Items]                            
Proceeds from divestiture of business     $ 436,000,000                      
Investment In Affiliate Ownership Percentage Sold                           45.00%
Divestiture of Business, Purchase Purchase Subject Adjustment                           $ 453,000,000
Divestiture of Businesses, Portion Contingent Upon Achievement of Certain Restructuring Efficiencies     $ 23,000,000                      
Noncontrolling Interest, Ownership Percentage by Parent     51.00%                      
Masinloc Subsidiary | Electricity Generating Public Company Limited                            
Noncontrolling Interest [Line Items]                            
Noncontrolling Interest, Ownership Percentage by Noncontrolling Owners     41.00%                      
Masinloc Subsidiary | International Finance Corporation                            
Noncontrolling Interest [Line Items]                            
Noncontrolling Interest, Ownership Percentage by Noncontrolling Owners     8.00%                      
IPALCO Enterprises, Inc. [Member]                            
Noncontrolling Interest [Line Items]                            
Noncontrolling Interest, Ownership Percentage by Noncontrolling Owners                       24.90%    
sales agreement, Buyer option to purchase ownership interest, exercised                       $ 214,000,000    
Future Noncontrolling Interest, Ownership by noncontrolling owner once transaction is complete       30.00%         30.00%          
Noncontrolling Interest, Ownership Percentage by Parent   100.00%                        
Sale of Stock, Consideration Received Per Transaction                 $ 460,000,000          
Gener Subsidiary [Member]                            
Noncontrolling Interest [Line Items]                            
Disposal Group Not Discontinued Operation Ownership Interest Sold 4.00%                          
Jordan [Member]                            
Noncontrolling Interest [Line Items]                            
Disposal Group, Including Discontinued Operation, Consideration                         $ 30,000,000  
Disposal Group Not Discontinued Operation Ownership Interest Sold                         40.00%  
Dominican Republic | Acquire addition shares through December 31, 2015                            
Noncontrolling Interest [Line Items]                            
Investment Options, acquisition percentage             2.00%              
Dominican Republic | Acquire additional shares through December 31, 2016                            
Noncontrolling Interest [Line Items]                            
Investment Options, acquisition percentage             10.00%              
Masinloc Subsidiary                            
Noncontrolling Interest [Line Items]                            
Disposal Group, Not Discontinued Operation, Gain (Loss) on Disposal               $ 283,000,000            
Acquire additional shares through 2016                            
Noncontrolling Interest [Line Items]                            
Investment Options, acquisition percentage           17.65%                
Acquire additional shares through 2016 | IPALCO Enterprises, Inc. [Member]                            
Noncontrolling Interest [Line Items]                            
Sale Agreement, Buyer Option To Purchase Ownership Interest, Sales Price         $ 349,000,000       135,000,000          
Acquire additional shares through 2016 | IPALCO Enterprises, Inc. [Member]                            
Noncontrolling Interest [Line Items]                            
Sale Agreement, Buyer Option To Purchase Ownership Interest, Sales Price           $ 349,000,000                
Acquire additional shares through December 31, 2016 | Dominican Republic                            
Noncontrolling Interest [Line Items]                            
Sale Agreement, Buyer Option To Purchase Ownership Interest, Sales Price             $ 125,000,000              
Additional Paid-in Capital [Member]                            
Noncontrolling Interest [Line Items]                            
Sale of subsidiary shares to noncontrolling interests                 323,000,000 29,000,000 16,000,000      
Additional Paid-in Capital [Member] | AES Brasiliana [Domain]                            
Noncontrolling Interest [Line Items]                            
Other Restructuring Costs                 27,000,000          
Additional Paid-in Capital [Member] | IPALCO Enterprises, Inc. [Member]                            
Noncontrolling Interest [Line Items]                            
Sale of subsidiary shares to noncontrolling interests                 377,000,000          
Business Combination, Separately Recognized Transactions, Additional Disclosures, Issuance Costs Not Expensed       $ 84,000,000         84,000,000          
Retained Earnings (Accumulated Deficit)                            
Noncontrolling Interest [Line Items]                            
Sale of subsidiary shares to noncontrolling interests                 (377,000,000) 0        
Retained Earnings (Accumulated Deficit) | IPALCO Enterprises, Inc. [Member]                            
Noncontrolling Interest [Line Items]                            
Sale of subsidiary shares to noncontrolling interests                 (377,000,000) 0        
Noncontrolling Interest [Member]                            
Noncontrolling Interest [Line Items]                            
Sale of subsidiary shares to noncontrolling interests                 $ 119,000,000 $ 173,000,000 $ 91,000,000      
Noncontrolling Interest [Member] | Masinloc Subsidiary                            
Noncontrolling Interest [Line Items]                            
Sale of subsidiary shares to noncontrolling interests               $ 130,000,000            

v3.3.1.900
Equity Equity - Net Income (Loss) Attributable to The AES Corporation (Details) - USD ($)
$ in Millions
3 Months Ended 12 Months Ended
Dec. 31, 2015
Sep. 30, 2015
Jun. 30, 2015
Mar. 31, 2015
Dec. 31, 2014
Sep. 30, 2014
Jun. 30, 2014
Mar. 31, 2014
Dec. 31, 2015
Dec. 31, 2014
Dec. 31, 2013
Consolidation, Less than Wholly Owned Subsidiary, Parent Ownership Interest, Effects of Changes, Net [Line Items]                      
Net income attributable to The AES Corporation $ (85) $ 180 $ 69 $ 142 $ 206 $ 488 $ 133 $ (58) $ 306 $ 769 $ 114
Transfers from the noncontrolling interest:                      
Net increase in The AES Corporation's paid-in capital for sale of subsidiary shares                     0
Increase in The AES Corporation's paid-in capital for purchase of subsidiary shares                 0 7 0
Net transfers (to) from noncontrolling interest                 (54) 36  
Change from net income attributable to The AES Corporation and transfers (to) from noncontrolling interests                 252 805  
Additional Paid-in Capital [Member]                      
Transfers from the noncontrolling interest:                      
Net increase in The AES Corporation's paid-in capital for sale of subsidiary shares                 323 29 16
Increase in The AES Corporation's paid-in capital for purchase of subsidiary shares                   7 $ (6)
Retained Earnings [Member]                      
Transfers from the noncontrolling interest:                      
Net increase in The AES Corporation's paid-in capital for sale of subsidiary shares                 (377) 0  
Increase in The AES Corporation's paid-in capital for purchase of subsidiary shares                   0  
IPALCO Enterprises, Inc. [Member] | Additional Paid-in Capital [Member]                      
Transfers from the noncontrolling interest:                      
Net increase in The AES Corporation's paid-in capital for sale of subsidiary shares                 377    
IPALCO Enterprises, Inc. [Member] | Retained Earnings [Member]                      
Transfers from the noncontrolling interest:                      
Net increase in The AES Corporation's paid-in capital for sale of subsidiary shares                 $ (377) $ 0  

v3.3.1.900
Equity (Accumulated Other Comprehensive Loss) (Details) - USD ($)
$ in Millions
12 Months Ended
Dec. 31, 2015
Dec. 31, 2014
Dec. 31, 2013
Accumulated Other Comprehensive Income (Loss) [Line Items]      
Accumulated Other Comprehensive Income (Loss), Foreign Currency Translation Adjustment, Net of Tax $ (2,595)    
Accumulated Other Comprehensive Income (Loss), Cumulative Changes in Net Gain (Loss) from Cash Flow Hedges, Effect Net of Tax (396)    
Accumulated Other Comprehensive Income (Loss), Pension and Other Postretirement Benefit Plans, Net of Tax (295)    
Accumulated Other Comprehensive Income (Loss), Net of Tax (3,286)    
Other Comprehensive Income (Loss), before Reclassifications, Net of Tax (660)    
Reclassification from Accumulated Other Comprehensive Income, Current Period, Net of Tax 50    
Other Comprehensive Income (Loss), Foreign Currency Transaction and Translation Adjustment, Net of Tax (1,019) $ (494) $ (334)
Other Comprehensive Income (Loss), Derivatives Qualifying as Hedges, Net of Tax 9 (259) 247
Other Comprehensive (Income) Loss, Pension and Other Postretirement Benefit Plans, Adjustment, Net of Tax 77 (20) 431
Other Comprehensive Income (Loss), Net of Tax (933) (773) 344
Other Comprehensive Income (Loss), Effect of Change in Accounting Principle, Net of Taxes 13    
Accumulated Other Comprehensive Income (Loss), Foreign Currency Translation Adjustment, Net of Tax (3,256) (2,595)  
Accumulated Other Comprehensive Income (Loss), Cumulative Changes in Net Gain (Loss) from Cash Flow Hedges, Effect Net of Tax (353) (396)  
Accumulated Other Comprehensive Income (Loss), Pension and Other Postretirement Benefit Plans, Net of Tax (274) (295)  
Accumulated Other Comprehensive Income (Loss), Net of Tax (3,883) (3,286)  
Available-for-Sale securities, net      
Accumulated Other Comprehensive Income (Loss) [Line Items]      
Other Comprehensive Income (Loss), before Reclassifications, Net of Tax (674)    
Reclassification from Accumulated Other Comprehensive Income, Current Period, Net of Tax 0    
Other Comprehensive Income (Loss), Effect of Change in Accounting Principle, Net of Taxes 13    
Unrealized derivative gains (losses), net      
Accumulated Other Comprehensive Income (Loss) [Line Items]      
Other Comprehensive Income (Loss), before Reclassifications, Net of Tax (5)    
Reclassification from Accumulated Other Comprehensive Income, Current Period, Net of Tax 48    
Other Comprehensive Income (Loss), Effect of Change in Accounting Principle, Net of Taxes 0    
Unfunded pension obligations, net      
Accumulated Other Comprehensive Income (Loss) [Line Items]      
Other Comprehensive Income (Loss), before Reclassifications, Net of Tax 19    
Reclassification from Accumulated Other Comprehensive Income, Current Period, Net of Tax 2    
Other Comprehensive Income (Loss), Effect of Change in Accounting Principle, Net of Taxes 0    
Accumulated Other Comprehensive Loss      
Accumulated Other Comprehensive Income (Loss) [Line Items]      
Other Comprehensive Income (Loss), Foreign Currency Transaction and Translation Adjustment, Net of Tax (674) (332) (227)
Other Comprehensive Income (Loss), Derivatives Qualifying as Hedges, Net of Tax 43 (108) 174
Other Comprehensive (Income) Loss, Pension and Other Postretirement Benefit Plans, Adjustment, Net of Tax 21 (4) 91
Other Comprehensive Income (Loss), Net of Tax $ (610) $ (444) $ 38

v3.3.1.900
Equity (Reclassifications Out of AOCL) (Details) - USD ($)
$ in Millions
3 Months Ended 12 Months Ended
Dec. 31, 2015
Sep. 30, 2015
Jun. 30, 2015
Mar. 31, 2015
Dec. 31, 2014
Sep. 30, 2014
Jun. 30, 2014
Mar. 31, 2014
Dec. 31, 2015
Dec. 31, 2014
Dec. 31, 2013
Reclassification Adjustment out of Accumulated Other Comprehensive Income [Line Items]                      
Non-regulated revenue                 $ 7,303 $ 8,272 $ 7,835
Regulated cost of sales                 (6,564) (7,530) (6,837)
Non-regulated cost of sales                 (5,533) (6,528) (5,807)
General and administrative expenses                 196 187 220
Interest expense                 (1,436) (1,471) (1,482)
Other Income                 83 124 125
Gain on sale of businesses                 29 358 26
Foreign currency transaction gains (losses)                 105 11 (22)
Income from continuing operations before taxes and equity in earnings of affiliates                 1,122 1,576 1,048
Income tax expense                 (465) (419) (343)
Net equity in earnings of affiliates                 105 19 25
Income from continuing operations $ 41 $ 203 [1] $ 264 [1] $ 254 [1] $ 298 [2],[3] $ 508 [2],[3] $ 281 [2],[3] $ 89 [2],[3] 762 1,176 730
Net loss from disposal and impairments of discontinued operations                 0 (56) (152)
Net Income 41 203 264 254 298 508 275 66 762 1,147 551
Less: (Income) from continuing operations attributable to noncontrolling interests                 (456) (387) (446)
Net income attributable to The AES Corporation $ (85) $ 180 $ 69 $ 142 $ 206 $ 488 $ 133 $ (58) 306 769 114
Reclassification out of Accumulated Other Comprehensive Income                      
Reclassification Adjustment out of Accumulated Other Comprehensive Income [Line Items]                      
Net income attributable to The AES Corporation [4]                 (50) (116) (178)
Available-for-Sale securities, net | Reclassification out of Accumulated Other Comprehensive Income                      
Reclassification Adjustment out of Accumulated Other Comprehensive Income [Line Items]                      
Gain on sale of businesses [4]                 0 4 (2)
Net loss from disposal and impairments of discontinued operations [4]                 0 (38) (35)
Net income attributable to The AES Corporation [4]                 0 (34) (37)
Unrealized derivative gains (losses), net | Reclassification out of Accumulated Other Comprehensive Income                      
Reclassification Adjustment out of Accumulated Other Comprehensive Income [Line Items]                      
Non-regulated revenue [4]                 43 30 (3)
Non-regulated cost of sales [4]                 (14) (4) (7)
Interest expense [4]                 (112) (139) (137)
Gain on sale of businesses [4]                 (4) 0 (21)
Foreign currency transaction gains (losses) [4]                 12 (9) (6)
Income from continuing operations before taxes and equity in earnings of affiliates [4]                 (75) (122) (174)
Income tax expense [4]                 11 26 41
Net equity in earnings of affiliates [4]                 (2) (3) (6)
Income from continuing operations [4]                 (66) (99) (139)
Less: (Income) from continuing operations attributable to noncontrolling interests [4]                 18 27 11
Net income attributable to The AES Corporation [4]                 (48) (72) (128)
Amortization of defined benefit pension actuarial loss, net | Reclassification out of Accumulated Other Comprehensive Income                      
Reclassification Adjustment out of Accumulated Other Comprehensive Income [Line Items]                      
Regulated cost of sales [4]                 (25) (33) (73)
Non-regulated cost of sales [4]                 2 (5) (4)
General and administrative expenses [4]                 (2) 0 (1)
Income from continuing operations before taxes and equity in earnings of affiliates [4]                 (25) (38) (78)
Income tax expense [4]                 9 7 26
Income from continuing operations [4]                 (16) (31) (52)
Net loss from disposal and impairments of discontinued operations [4]                 0 2 0
Net Income [4]                 (16) (29) (52)
Less: (Income) from continuing operations attributable to noncontrolling interests [4]                 14 19 39
Net income attributable to The AES Corporation [4]                 $ (2) $ (10) $ (13)
[1] (1)Includes pretax impairment expense of $8 million, $37 million, $231 million and $326 million, for the first, second, third and fourth quarters of 2015, respectively. See Note 9—Other Non-Operating Expense, Note 10—Goodwill and Other Intangible Assets, and Note 21—Asset Impairment Expense for further discussion.
[2] (2) Includes a pretax gain of approximately $283 million for the third quarter of 2014 related to the sale of a noncontrolling interest in Masinloc. See Note 16—Equity for further discussion. Includes pretax gain of approximately $78 million for the third quarter of 2014 related to the sale of the U.K. wind projects. See Note 24—Dispositions and Held-for-Sale Businesses for further discussion. Includes pretax interest income of $59 million recognized on FONIVEMEM III receivables at AES Argentina in the fourth quarter of 2014. Also includes a pretax foreign currency derivative gain of $106 million recognized on the FONIVEMEM III receivables in the fourth quarter of 2014. See Note 7—Financing Receivables for further discussion. Includes pretax loss of $41 million recognized in Net equity in earnings of affiliates corresponding to the Company's share of an asset impairment at Elsta in the fourth quarter of 2014. See Note 8—Investments In And Advances To Affiliates for further discussion.
[3] (3) Includes pretax impairment expense of $166 million, $107 million, $31 million and $79 million, for the first, second, third and fourth quarters of 2014, respectively. See Note 9—Other Non-Operating Expense, Note 10—Goodwill and Other Intangible Assets, and Note 21—Asset Impairment Expense for further discussion.
[4] (1) Amounts in parentheses indicate debits to the Consolidated Statements of Operations.

v3.3.1.900
Equity Equity (Dividends) (Details) - USD ($)
$ / shares in Units, $ in Millions
1 Months Ended 2 Months Ended 3 Months Ended 12 Months Ended 66 Months Ended 68 Months Ended
Dec. 11, 2015
Oct. 31, 2015
Feb. 23, 2016
Dec. 31, 2015
Sep. 30, 2015
Jun. 30, 2015
Mar. 31, 2015
Dec. 31, 2014
Sep. 30, 2014
Jun. 30, 2014
Mar. 31, 2014
Dec. 31, 2015
Dec. 31, 2014
Dec. 31, 2013
Dec. 31, 2015
Feb. 23, 2016
Subsequent Event [Line Items]                                
Common Stock, Dividends, Per Share, Cash Paid       $ 0.10 $ 0.1 $ 0.1 $ 0.10 $ 0.05 $ 0.05 $ 0.05 $ 0.05          
Dividends declared on common stock (per share amount) $ 0.11     $ 0.21 $ 0.1 $ 0.1 $ 0 $ 0.15 $ 0.05 $ 0.05 $ 0 $ 0.41 $ 0.25 $ 0.17    
Stock repurchase program, additional authorized amount   $ 400                            
Treasury Stock, Value, Acquired, Cost Method                       $ 0   $ 0 $ 1,800  
Payments for Repurchase of Common Stock                       $ 482 $ 308 $ 322    
Acquisition of treasury stock (shares)                       39,700,000     145,600,000  
Treasury Stock Acquired, Average Cost Per Share                             $ 12.31  
Stock Repurchase Program, Remaining Authorized Repurchase Amount       $ 343               $ 343     $ 343  
Treasury stock, shares (in shares)       149,037,831       110,687,849       149,037,831 110,687,849   149,037,831  
Stock Repurchase Program, Authorized Amount       $ 2,100               $ 2,100     $ 2,100  
Subsequent Event                                
Subsequent Event [Line Items]                                
Treasury Stock, Value, Acquired, Cost Method     $ 79                         $ 1,900
Acquisition of treasury stock (shares)     8,700,000                         154,300,000
Treasury Stock Acquired, Average Cost Per Share                               $ 12.12
Stock Repurchase Program, Remaining Authorized Repurchase Amount     $ 264                         $ 264

v3.3.1.900
Equity Equity (Stock Repurchases) (Details) - USD ($)
$ / shares in Units, shares in Millions, $ in Millions
12 Months Ended 66 Months Ended
May. 18, 2015
Dec. 31, 2015
Dec. 31, 2013
Dec. 31, 2015
Equity, Class of Treasury Stock [Line Items]        
Sale of shares by noncontrolling interest, Shares 60.0      
Sale of shares by noncontrolling interest, per share $ 13.25      
Acquisition of treasury stock (shares)   39.7   145.6
Treasury Stock Acquired, Average Cost Per Share       $ 12.31
Treasury Stock, Value, Acquired, Cost Method   $ 0 $ 0 $ 1,800
share repurchase program CIC buyback [Domain]        
Equity, Class of Treasury Stock [Line Items]        
Acquisition of treasury stock (shares) 20.0      
Treasury Stock Acquired, Average Cost Per Share $ 13.07      
Treasury Stock, Value, Acquired, Cost Method $ 261      
Common Stock [Member]        
Equity, Class of Treasury Stock [Line Items]        
Sale of shares by noncontrolling interest, Shares 40.0      

v3.3.1.900
Segment and Geographic Information (Details)
12 Months Ended
Dec. 31, 2015
segment
Segment Reporting [Abstract]  
Number of Operating Segments 6
Number of Reportable Segments 6

v3.3.1.900
Segments and Geographic Information Segment and Geographic Information (Adjusted Pre-Tax Contributions & Reconcilliation of Income Before Income Taxes) (Details) - USD ($)
$ in Millions
12 Months Ended
Dec. 31, 2015
Dec. 31, 2014
Dec. 31, 2013
Segment Reporting, Reconciling Item for Operating Profit (Loss) from Segment to Consolidated [Line Items]      
Revenues $ 14,963 $ 17,146 $ 15,891
Adjusted PTC      
External Adjusted Pre-Tax Contribution 1,150 1,321 1,207
Reconciliation To Income From Continuing Operations Before Taxes      
Unrealized derivative gains 166 135 57
Unrealized foreign currency losses (96) (110) (41)
Disposition/acquisition gains 42 361 30
Impairment losses (504) (416) (588)
Loss on extinguishment of debt (183) (274) (225)
Pre-tax contribution 575 1,017 440
Add: Income from continuing operations before taxes, attributable to noncontrolling interests 652 578 633
Less: Net equity in earnings of affiliates 105 19 25
INCOME FROM CONTINUING OPERATIONS BEFORE TAXES AND EQUITY IN EARNINGS OF AFFILIATES 1,122 1,576 1,048
US SBU      
Segment Reporting, Reconciling Item for Operating Profit (Loss) from Segment to Consolidated [Line Items]      
Revenues 3,593 3,826 3,630
Adjusted PTC      
External Adjusted Pre-Tax Contribution 372 455 451
Andes SBU      
Segment Reporting, Reconciling Item for Operating Profit (Loss) from Segment to Consolidated [Line Items]      
Revenues 2,479 2,638 2,638
Adjusted PTC      
External Adjusted Pre-Tax Contribution 499 427 372
Brazil SBU      
Segment Reporting, Reconciling Item for Operating Profit (Loss) from Segment to Consolidated [Line Items]      
Revenues 4,666 6,009 5,015
Adjusted PTC      
External Adjusted Pre-Tax Contribution 93 245 215
MCAC SBU (El Salvador)      
Segment Reporting, Reconciling Item for Operating Profit (Loss) from Segment to Consolidated [Line Items]      
Revenues 2,351 2,680 2,712
Adjusted PTC      
External Adjusted Pre-Tax Contribution 345 378 351
Europe SBU      
Segment Reporting, Reconciling Item for Operating Profit (Loss) from Segment to Consolidated [Line Items]      
Revenues 1,187 1,433 1,347
Adjusted PTC      
External Adjusted Pre-Tax Contribution 240 353 352
Asia SBU      
Segment Reporting, Reconciling Item for Operating Profit (Loss) from Segment to Consolidated [Line Items]      
Revenues 684 558 550
Adjusted PTC      
External Adjusted Pre-Tax Contribution 99 48 144
Corporate and Other      
Segment Reporting, Reconciling Item for Operating Profit (Loss) from Segment to Consolidated [Line Items]      
Revenues 3 2 (1)
Adjusted PTC      
External Adjusted Pre-Tax Contribution (498) (585) (678)
Operating Segments      
Segment Reporting, Reconciling Item for Operating Profit (Loss) from Segment to Consolidated [Line Items]      
Revenues 15,007 17,171 15,901
Adjusted PTC      
External Adjusted Pre-Tax Contribution 1,150 1,321 1,207
Operating Segments | US SBU      
Segment Reporting, Reconciling Item for Operating Profit (Loss) from Segment to Consolidated [Line Items]      
Revenues 3,593 3,826 3,630
Adjusted PTC      
External Adjusted Pre-Tax Contribution 360 445 440
Operating Segments | Andes SBU      
Segment Reporting, Reconciling Item for Operating Profit (Loss) from Segment to Consolidated [Line Items]      
Revenues 2,489 2,642 2,639
Adjusted PTC      
External Adjusted Pre-Tax Contribution 482 421 353
Operating Segments | Brazil SBU      
Segment Reporting, Reconciling Item for Operating Profit (Loss) from Segment to Consolidated [Line Items]      
Revenues 4,666 6,009 5,015
Adjusted PTC      
External Adjusted Pre-Tax Contribution 91 242 212
Operating Segments | MCAC SBU (El Salvador)      
Segment Reporting, Reconciling Item for Operating Profit (Loss) from Segment to Consolidated [Line Items]      
Revenues 2,353 2,682 2,713
Adjusted PTC      
External Adjusted Pre-Tax Contribution 327 352 339
Operating Segments | Europe SBU      
Segment Reporting, Reconciling Item for Operating Profit (Loss) from Segment to Consolidated [Line Items]      
Revenues 1,191 1,439 1,347
Adjusted PTC      
External Adjusted Pre-Tax Contribution 235 348 345
Operating Segments | Asia SBU      
Segment Reporting, Reconciling Item for Operating Profit (Loss) from Segment to Consolidated [Line Items]      
Revenues 684 558 550
Adjusted PTC      
External Adjusted Pre-Tax Contribution 96 46 142
Operating Segments | Corporate and Other      
Segment Reporting, Reconciling Item for Operating Profit (Loss) from Segment to Consolidated [Line Items]      
Revenues 31 15 7
Adjusted PTC      
External Adjusted Pre-Tax Contribution (441) (533) (624)
Intersegment Eliminations      
Segment Reporting, Reconciling Item for Operating Profit (Loss) from Segment to Consolidated [Line Items]      
Revenues (44) (25) (10)
Adjusted PTC      
External Adjusted Pre-Tax Contribution 0 0 0
Intersegment Eliminations | US SBU      
Segment Reporting, Reconciling Item for Operating Profit (Loss) from Segment to Consolidated [Line Items]      
Revenues 0 0 0
Adjusted PTC      
External Adjusted Pre-Tax Contribution 12 10 11
Intersegment Eliminations | Andes SBU      
Segment Reporting, Reconciling Item for Operating Profit (Loss) from Segment to Consolidated [Line Items]      
Revenues (10) (4) (1)
Adjusted PTC      
External Adjusted Pre-Tax Contribution 17 6 19
Intersegment Eliminations | Brazil SBU      
Segment Reporting, Reconciling Item for Operating Profit (Loss) from Segment to Consolidated [Line Items]      
Revenues 0 0 0
Adjusted PTC      
External Adjusted Pre-Tax Contribution 2 3 3
Intersegment Eliminations | MCAC SBU (El Salvador)      
Segment Reporting, Reconciling Item for Operating Profit (Loss) from Segment to Consolidated [Line Items]      
Revenues (2) (2) (1)
Adjusted PTC      
External Adjusted Pre-Tax Contribution 18 26 12
Intersegment Eliminations | Europe SBU      
Segment Reporting, Reconciling Item for Operating Profit (Loss) from Segment to Consolidated [Line Items]      
Revenues (4) (6) 0
Adjusted PTC      
External Adjusted Pre-Tax Contribution 5 5 7
Intersegment Eliminations | Asia SBU      
Segment Reporting, Reconciling Item for Operating Profit (Loss) from Segment to Consolidated [Line Items]      
Revenues 0 0 0
Adjusted PTC      
External Adjusted Pre-Tax Contribution 3 2 2
Intersegment Eliminations | Corporate and Other      
Segment Reporting, Reconciling Item for Operating Profit (Loss) from Segment to Consolidated [Line Items]      
Revenues (28) (13) (8)
Adjusted PTC      
External Adjusted Pre-Tax Contribution $ (57) $ (52) $ (54)

v3.3.1.900
Segments and Geographic Information Segment and Geographic Information (Assets, Depreciation and Amortization and Capital Expenditures ) (Details) - USD ($)
$ in Millions
12 Months Ended
Dec. 31, 2015
Dec. 31, 2014
Dec. 31, 2013
Segment Reporting Information [Line Items]      
Total Assets $ 36,850 $ 38,966 $ 40,411
Depreciation and Amortization 1,144 1,245 1,294
Capital Expenditures 2,458 2,544 2,579
Interest Income 524 365 275
Interest Expense 1,436 1,471 1,482
Investments in and Advances to Affiliates 610 537 1,010
Equity in Earnings (Losses) 105 19 25
US SBU      
Segment Reporting Information [Line Items]      
Total Assets 9,844 10,062 9,952
Depreciation and Amortization 443 450 440
Capital Expenditures 861 534 426
Interest Income 0 0 0
Interest Expense 262 285 290
Investments in and Advances to Affiliates 1 1 1
Equity in Earnings (Losses) 0 0 0
Andes SBU      
Segment Reporting Information [Line Items]      
Total Assets 8,744 7,888 7,356
Depreciation and Amortization 175 182 186
Capital Expenditures 949 702 471
Interest Income 77 87 37
Interest Expense 154 160 135
Investments in and Advances to Affiliates 345 287 248
Equity in Earnings (Losses) 83 42 44
Brazil SBU      
Segment Reporting Information [Line Items]      
Total Assets 6,422 8,439 8,388
Depreciation and Amortization 185 260 259
Capital Expenditures 299 416 588
Interest Income 299 249 210
Interest Expense 349 331 364
Investments in and Advances to Affiliates 0 0 0
Equity in Earnings (Losses) 0 0 0
MCAC SBU (El Salvador)      
Segment Reporting Information [Line Items]      
Total Assets 4,830 4,948 5,075
Depreciation and Amortization 155 144 145
Capital Expenditures 201 192 111
Interest Income 30 26 20
Interest Expense 179 178 138
Investments in and Advances to Affiliates 0 0 0
Equity in Earnings (Losses) 0 0 4
Europe SBU      
Segment Reporting Information [Line Items]      
Total Assets 3,127 3,525 4,191
Depreciation and Amortization 134 154 155
Capital Expenditures 118 228 341
Interest Income 1 1 2
Interest Expense 73 98 80
Investments in and Advances to Affiliates 53 54 286
Equity in Earnings (Losses) 10 (25) (5)
Asia SBU      
Segment Reporting Information [Line Items]      
Total Assets 3,197 2,972 2,810
Depreciation and Amortization 32 32 33
Capital Expenditures 13 429 576
Interest Income 115 2 6
Interest Expense 85 25 30
Investments in and Advances to Affiliates 195 194 186
Equity in Earnings (Losses) 8 10 10
Assets held-for-sale      
Segment Reporting Information [Line Items]      
Total Assets 96 0 1,718
Depreciation and Amortization 0   55
Depreciation Expense on Reclassified Assets   (1)  
Capital Expenditures 0 13 52
Corporate and Other      
Segment Reporting Information [Line Items]      
Total Assets 590 1,132 921
Depreciation and Amortization 20 24 21
Capital Expenditures 17 30 14
Interest Income 2 0 0
Interest Expense 334 394 445
Investments in and Advances to Affiliates 16 1 289
Equity in Earnings (Losses) $ 4 $ (8) $ (28)

v3.3.1.900
Segments and Geographic Information Segment and Geographic Information (Revenue and Assets by Country) (Details) - USD ($)
$ in Millions
12 Months Ended
Dec. 31, 2015
Dec. 31, 2014
Dec. 31, 2013
Revenues from External Customers and Long-Lived Assets [Line Items]      
Revenue $ 14,963 $ 17,146 $ 15,891
Property, plant and equipment, net 22,816 25,151  
United States      
Revenues from External Customers and Long-Lived Assets [Line Items]      
Revenue [1] 3,597 3,828 3,630
Property, plant and equipment, net [1] 8,028 7,713  
United States | Discontinued Operations      
Revenues from External Customers and Long-Lived Assets [Line Items]      
Revenue   2 23
Total Non-U.S.      
Revenues from External Customers and Long-Lived Assets [Line Items]      
Revenue 11,366 13,318 12,261
Property, plant and equipment, net 14,788 17,438  
Brazil      
Revenues from External Customers and Long-Lived Assets [Line Items]      
Revenue 4,666 6,009 5,015
Property, plant and equipment, net 3,286 4,725  
Chile      
Revenues from External Customers and Long-Lived Assets [Line Items]      
Revenue 1,523 1,624 1,569
Property, plant and equipment, net 4,596 4,012  
El Salvador      
Revenues from External Customers and Long-Lived Assets [Line Items]      
Revenue 736 832 860
Property, plant and equipment, net 318 304  
Dominican Republic      
Revenues from External Customers and Long-Lived Assets [Line Items]      
Revenue 632 802 832
Property, plant and equipment, net 783 702  
Colombia      
Revenues from External Customers and Long-Lived Assets [Line Items]      
Revenue 557 552 523
Property, plant and equipment, net 446 430  
United Kingdom      
Revenues from External Customers and Long-Lived Assets [Line Items]      
Revenue 396 533 558
Property, plant and equipment, net 191 324  
Argentina      
Revenues from External Customers and Long-Lived Assets [Line Items]      
Revenue 399 463 545
Property, plant and equipment, net 193 222  
Philippines      
Revenues from External Customers and Long-Lived Assets [Line Items]      
Revenue 406 451 497
Property, plant and equipment, net 736 752  
Mexico      
Revenues from External Customers and Long-Lived Assets [Line Items]      
Revenue 383 434 440
Property, plant and equipment, net 716 733  
Bulgaria      
Revenues from External Customers and Long-Lived Assets [Line Items]      
Revenue 382 410 422
Property, plant and equipment, net 1,259 1,457  
Puerto Rico      
Revenues from External Customers and Long-Lived Assets [Line Items]      
Revenue 302 348 328
Property, plant and equipment, net 599 551  
Panama      
Revenues from External Customers and Long-Lived Assets [Line Items]      
Revenue 297 263 250
Property, plant and equipment, net 1,028 1,030  
Jordan      
Revenues from External Customers and Long-Lived Assets [Line Items]      
Revenue 248 262 142
Property, plant and equipment, net 470 484  
Kazahkstan      
Revenues from External Customers and Long-Lived Assets [Line Items]      
Revenue 155 161 156
Property, plant and equipment, net 146 206  
SRI LANKA      
Revenues from External Customers and Long-Lived Assets [Line Items]      
Revenue 45 107 53
Property, plant and equipment, net 0 7  
Cameroon      
Revenues from External Customers and Long-Lived Assets [Line Items]      
Revenue [2] 0 0 0
Property, plant and equipment, net [2] 0 0  
Cameroon | Discontinued Operations      
Revenues from External Customers and Long-Lived Assets [Line Items]      
Revenue   230 473
Ukraine      
Revenues from External Customers and Long-Lived Assets [Line Items]      
Revenue [3] 0 0 0
Property, plant and equipment, net [3] 0 0  
Ukraine | Discontinued Operations      
Revenues from External Customers and Long-Lived Assets [Line Items]      
Revenue     187
Vietnam      
Revenues from External Customers and Long-Lived Assets [Line Items]      
Revenue [4] 233 0 0
Property, plant and equipment, net [4] 2 1,491  
Other Non-U.S.      
Revenues from External Customers and Long-Lived Assets [Line Items]      
Revenue [5] 6 67 71
Property, plant and equipment, net [5] $ 19 $ 8  
Other Non-U.S. | Discontinued Operations      
Revenues from External Customers and Long-Lived Assets [Line Items]      
Revenue     $ 6
[1] (1)Excludes revenue of $2 million and $23 million for the years ended December 31, 2014 and 2013, respectively, related to Condon and Mid-West Wind, which are reflected as discontinued operations in the accompanying Consolidated Statements of Operations.
[2] (3) Excludes revenue of $230 million and $473 million for the years ended December 31, 2014 and 2013, respectively, related to Sonel, which is reflected as discontinued operations in the accompanying Consolidated Statements of Operations.
[3] (4) Excludes revenue of $187 million for the years ended December 31, 2013 related to Kievoblenergo and Rivnooblenergo, which are reflected as discontinued operations in the accompanying Consolidated Statements of Operations.
[4] (2) Property, plant & equipment as of December 31, 2015 includes the impact of adopting ASU No. 2014-05, Service Concession Arrangements, on a modified retrospective basis as of January 1, 2015. See Note 1—General and Summary of Significant Accounting Policies for more information.
[5] (5) Excludes revenue of $6 million for the years ended December 31, 2013 related to Saurashtra, which is reflected as discontinued operations in the accompanying Consolidated Statements of Operations.

v3.3.1.900
Share-Based Compensation (Fair Value Assumptions) (Details) - Stock Options - $ / shares
12 Months Ended
Dec. 31, 2015
Dec. 31, 2014
Dec. 31, 2013
Share-based Compensation Arrangement by Share-based Payment Award, Fair Value Assumptions and Methodology [Abstract]      
Expected volatility 25.00% 24.00% 23.00%
Expected annual dividend yield 3.00% 1.00% 1.00%
Expected option term (years) 7 years 6 years 6 years
Risk-free interest rate 1.86% 1.86% 1.13%
Fair value at grant date (in dollars per share) $ 2.07 $ 3.26 $ 2.23

v3.3.1.900
Share-Based Compensation (Stock Option Compensation Expense) (Details) - Stock Options - USD ($)
$ in Millions
12 Months Ended
Dec. 31, 2015
Dec. 31, 2014
Dec. 31, 2013
Share-based Compensation Arrangement by Share-based Payment Award [Line Items]      
Pretax compensation expense $ 3 $ 3 $ 2
Tax benefit (1) (1) (1)
Total expense, net of tax 2 2 1
Total intrinsic value of options exercised 1 1 5
Total fair value of options vested 3 2 2
Cash received from the exercise of stock options $ 5 $ 3 $ 13

v3.3.1.900
Share-Based Compensation (Stock Option Activity) (Details) - Stock Options
$ / shares in Units, shares in Thousands, $ in Millions
12 Months Ended
Dec. 31, 2015
USD ($)
$ / shares
shares
Share-based Compensation Arrangement by Share-based Payment Award [Line Items]  
Share-based Compensation Arrangement by Share-based Payment Award, Award Vesting Period 3 years
Options (Number of Shares):  
Outstanding at beginning of period | shares 7,062
Exercised | shares (419)
Forfeited and expired | shares (1,347)
Granted | shares 1,859
Outstanding at end of period | shares 7,155
Vested and expected to vest at end of period | shares 6,771
Eligible for exercise at end of period | shares 4,292
Weighted Average Exercise Price (in dollars per share):  
Outstanding at beginning of period | $ / shares $ 14.83
Exercised | $ / shares 10.76
Forfeited and expired | $ / shares 17.49
Granted | $ / shares 11.89
Outstanding at end of period | $ / shares 13.81
Vested and expected to vest at end of period | $ / shares 13.88
Eligible for exercise at end of period | $ / shares $ 14.70
Outstanding, weighted average remaining contractual term (in years) 6 years
Vested and expected to vest, weighted average remaining contractual term (in years) 70 months
Eligible for exercise, weighted average remaining contractual term (in years) 49 months
Outstanding, intrinsic value | $ $ 1
Vested and expected to vest, intrinsic value | $ 1
Eligible for exercise, intrinsic value | $ $ 1

v3.3.1.900
Share-Based Compensation (RSU Compensation Expense) (Details) - RSUs - USD ($)
$ in Millions
12 Months Ended
Dec. 31, 2015
Dec. 31, 2014
Dec. 31, 2013
Share-based Compensation Arrangement by Share-based Payment Award [Line Items]      
Pretax compensation expense $ 13 $ 12 $ 12
Tax benefit (3) (3) (3)
Total expense, net of tax 10 9 9
Total value of RSUs converted [1] 16 25 10
Total fair value of RSUs vested $ 12 $ 13 $ 12
[1] (1)Amount represents fair market value on the date of conversion.

v3.3.1.900
Share-Based Compensation (RSU Activity) (Details) - RSUs - USD ($)
$ / shares in Units, shares in Thousands, $ in Millions
12 Months Ended
Dec. 31, 2015
Dec. 31, 2014
Dec. 31, 2013
Share-based Compensation Arrangement by Share-based Payment Award [Line Items]      
Period of straight-line expense, 2015 RSU's 3 years    
Employee Service Share-based Compensation, Nonvested Awards, Compensation Cost Not yet Recognized, Period for Recognition 23 months    
RSUs (Number of Shares):      
Nonvested at beginning of period 1,997    
Vested (954) (1,037) (942)
Forfeited and expired (236)    
Granted 1,585    
Nonvested at end of period 2,392 1,997  
Vested at end of period 0    
Vested and expected to vest at end of period 2,105    
Employee Service Share-based Compensation, Nonvested Awards, Compensation Cost Not yet Recognized $ 16    
Weighted Average Grant Date Fair Value (in dollars per share):      
Nonvested at beginning of period $ 13.20    
Vested 13.01    
Forfeited and expired 12.71    
Granted 12.03 $ 14.60 $ 11.19
Nonvested at end of period 12.55 $ 13.20  
Vested at end of period 0.00    
Vested and expected to vest at end of period $ 12.55    
Nonvested at end of period, weighted average remaining vesting term 20 months    

v3.3.1.900
Share-Based Compensation (RSUs Vested and Converted) (Details) - RSUs - shares
shares in Thousands
12 Months Ended
Dec. 31, 2015
Dec. 31, 2014
Dec. 31, 2013
Share-based Compensation Arrangement by Share-based Payment Award [Line Items]      
RSUs vested during the year 954 1,037 942
RSUs converted during the year, net of shares withheld for taxes 1,238 1,734 905
Shares withheld for taxes 549 796 407

v3.3.1.900
Share-Based Compensation (PSU Compensation Expense) (Details) - PSUs - USD ($)
$ in Millions
12 Months Ended
Dec. 31, 2015
Dec. 31, 2014
Dec. 31, 2013
Share-based Compensation Arrangement by Share-based Payment Award [Line Items]      
PSU expense before income tax $ 5 $ 6 $ 4
Tax benefit (1) (2) (1)
Total expense, net of tax 4 4 3
Total value of PSUs converted [1] 1 4 0
Total fair value of PSUs vested $ 3 $ 1 $ 0
[1] (1)Amount represents fair market value on the date of conversion.

v3.3.1.900
Share-Based Compensation (PSU Activity) (Details) - PSUs - $ / shares
shares in Thousands
12 Months Ended
Dec. 31, 2015
Dec. 31, 2014
Dec. 31, 2013
PSUs (Number of Shares):      
Nonvested at beginning of period 1,331    
Vested (161) (85) 0
Forfeited and expired (245)    
Granted 626    
Nonvested at end of period 1,551 1,331  
Vested at end of period 0    
Vested and expected to vest at end of period 1,298    
Weighted Average Grant Date Fair Value (in dollars per share):      
Nonvested at beginning of period $ 14.27    
Vested 16.73    
Forfeited and expired 15.27    
Granted 10.06    
Nonvested at end of period 12.16 $ 14.27  
Vested at end of period 0.00    
Vested and expected to vest at end of period $ 11.92    
Nonvested at end of period, weighted average remaining vesting term 14 months    

v3.3.1.900
Share-Based Compensation (PSUs Vested and Converted) (Details) - PSUs - shares
shares in Thousands
12 Months Ended
Dec. 31, 2015
Dec. 31, 2014
Dec. 31, 2013
Share-based Compensation Arrangement by Share-based Payment Award [Line Items]      
Vested during the year 161 85 0
Award converted during the year, net of shares withheld for taxes 96 287 0
Shares withheld for taxes 65 141 0

v3.3.1.900
Share-Based Compensation (Narrative) (Details) - USD ($)
$ / shares in Units, shares in Millions, $ in Millions
12 Months Ended
Jan. 01, 2011
Dec. 31, 2010
Dec. 31, 2015
Dec. 31, 2014
Dec. 31, 2013
Stock Options          
Share-based Compensation Arrangement by Share-based Payment Award [Line Items]          
Stock option grant price as percent of market price     100.00%    
Award vesting period     3 years    
Award vesting rights percentage     33.00%    
Stock option contractual term     10 years    
Number of shares available for grant     16    
Employee Service Share-based Compensation, Nonvested Awards, Compensation Cost Not yet Recognized     $ 4.0    
Employee Service Share-based Compensation, Nonvested Awards, Compensation Cost Not yet Recognized, Period for Recognition     22 months    
Estimated forfeiture rate     15.28%    
Cost not yet recognized related to current year grants     $ 3.3    
Compensation cost not yet recognized related to current year grants per year     $ 1.1    
RSUs          
Share-based Compensation Arrangement by Share-based Payment Award [Line Items]          
Award vesting period     3 years    
Award vesting rights percentage     33.00%    
Employee Service Share-based Compensation, Nonvested Awards, Compensation Cost Not yet Recognized     $ 16.0    
Employee Service Share-based Compensation, Nonvested Awards, Compensation Cost Not yet Recognized, Period for Recognition     23 months    
Estimated forfeiture rate     13.53%    
Compensation cost not yet recognized related to current year grants per year     $ 16.0    
Period before award can be converted to shares 2 years 2 years      
Weighted Average Grant Date Fair Value     $ 12.03 $ 14.60 $ 11.19
PSUs With Market Conditions          
Share-based Compensation Arrangement by Share-based Payment Award [Line Items]          
Award, percent with market condition     50.00%    
Performance stock units vesting rule measurement period     3 years    
Weighted Average Grant Date Fair Value     $ 8.22 $ 15.19 $ 13.28
Grants in period, weighted average grant date fair value percent of stock price     69.00%    
Increase in grant date fair value if market condition not applied     $ 1.1    
PSUs with Performance Condition          
Share-based Compensation Arrangement by Share-based Payment Award [Line Items]          
Award, percent with performance condition     50.00%    
Performance stock units vesting rule measurement period     3 years    
Weighted Average Grant Date Fair Value     $ 11.89    
PSUs          
Share-based Compensation Arrangement by Share-based Payment Award [Line Items]          
Employee Service Share-based Compensation, Nonvested Awards, Compensation Cost Not yet Recognized     $ 7.0    
Employee Service Share-based Compensation, Nonvested Awards, Compensation Cost Not yet Recognized, Period for Recognition     20 months    
Estimated forfeiture rate     15.28%    
Cost not yet recognized related to current year grants     $ 5.0    
Period of straight-line expense, 2015 PSUs     3 years    
Compensation cost not yet recognized related to current year grants per year     $ 2.0    
Weighted Average Grant Date Fair Value     $ 10.06    
PSUs | Minimum          
Share-based Compensation Arrangement by Share-based Payment Award [Line Items]          
Award payout range     0.00%    
PSUs | Maximum          
Share-based Compensation Arrangement by Share-based Payment Award [Line Items]          
Award payout range     200.00%    

v3.3.1.900
Redeemable Stock of Subsidiaries (Narrative) (Details)
$ / shares in Units, $ in Millions
12 Months Ended
Dec. 31, 2015
USD ($)
quarter
series
$ / shares
Dec. 31, 2014
USD ($)
quarter
$ / shares
Temporary Equity [Line Items]    
Sale of Stock, Consideration Received Per Transaction $ 460 $ 0
Redeemable stock of subsidiaries 538 78
Temporary equity carrying amount 78 78
IPL Subsidiary    
Temporary Equity [Line Items]    
Temporary equity carrying amount $ 60 60
Number of preferred stock series | series 5  
Temporary equity annual dividend requirement $ 3 $ 3
Number of consecutive quarters without paid dividends to invoke board of directors election rule | quarter 4 4,000,000
IPL Subsidiary | Minimum    
Temporary Equity [Line Items]    
Temporary equity, redemption price per share | $ / shares $ 100 $ 100,000,000
IPL Subsidiary | Maximum    
Temporary Equity [Line Items]    
Temporary equity, redemption price per share | $ / shares $ 118 $ 118,000,000
DPL Subsidiary    
Temporary Equity [Line Items]    
Temporary equity carrying amount $ 18 $ 18
Number of preferred stock series | series 3  
Temporary equity annual dividend requirement $ 1 $ 1
Number of consecutive quarters without paid dividends to invoke board of directors election rule | quarter   4,000,000
Number of quarters cumulative dividends in arrears to invoke board of directors election rule | quarter 4  
DPL Subsidiary | Minimum    
Temporary Equity [Line Items]    
Temporary equity, redemption price per share | $ / shares $ 101 $ 101,000,000
DPL Subsidiary | Maximum    
Temporary Equity [Line Items]    
Temporary equity, redemption price per share | $ / shares $ 103 $ 103,000,000
IPALCO Enterprises, Inc. [Member]    
Temporary Equity [Line Items]    
Sale of Stock, Consideration Received Per Transaction $ 460  
Redeemable stock of subsidiaries 83 $ 0
Additional Paid-in Capital [Member] | IPALCO Enterprises, Inc. [Member]    
Temporary Equity [Line Items]    
Unrealized Gain (Loss) on Investments $ 377 $ 0

v3.3.1.900
Other Income and Expense (Nonoperating Income) (Details) - USD ($)
$ in Millions
12 Months Ended
Dec. 31, 2015
Dec. 31, 2014
Dec. 31, 2013
Income Statement, Balance Sheet and Additional Disclosures by Disposal Groups, Including Discontinued Operations [Line Items]      
Contract termination - Beaver Valley $ 20 $ 0 $ 60
Gain on sale of assets 19 68 12
Other Nonoperating Income 17 9 6
Contingency reversal 0 18 10
Gain on extinguishment of tax and other liabilities 0 0 9
Other 27 29 28
Total other income $ 83 $ 124 $ 125

v3.3.1.900
Other Income and Expense (Other Expense) (Details) - USD ($)
$ in Millions
12 Months Ended
Dec. 31, 2015
Dec. 31, 2014
Dec. 31, 2013
Other Income and Expenses [Abstract]      
Loss on sale and disposal of assets $ 48 $ 47 $ 51
Legal settlement 9 11 9
Contract termination 0 0 7
Other 8 10 9
Total other expense $ 65 $ 68 $ 76

v3.3.1.900
Asset Impairment Expense (Impairment of Long-Lived Assets Held and Used by Asset) (Details) - USD ($)
$ in Millions
9 Months Ended 12 Months Ended
Sep. 30, 2015
Dec. 31, 2015
Dec. 31, 2014
Dec. 31, 2013
Debt Instrument [Line Items]        
Asset impairment expense   $ 285 $ 91 $ 95
Kilroot [Member]        
Debt Instrument [Line Items]        
Asset impairment expense $ 121 121 0 0
buffalo gap III [Member]        
Debt Instrument [Line Items]        
Asset impairment expense 116 116 0 0
UK Wind Development Projects [Domain]        
Debt Instrument [Line Items]        
Asset impairment expense $ 37 37    
Ebute [Member]        
Debt Instrument [Line Items]        
Asset impairment expense   0 67 0
UK Wind (Newfield) [Member]        
Debt Instrument [Line Items]        
Asset impairment expense     12 0
DP&L (East Bend)        
Debt Instrument [Line Items]        
Asset impairment expense   0 12 0
Beaver Valley        
Debt Instrument [Line Items]        
Asset impairment expense   0 0 46
Conesville (DP&L)        
Debt Instrument [Line Items]        
Asset impairment expense   0 0 26
Itabo (San Lorenzo)        
Debt Instrument [Line Items]        
Asset impairment expense   0 0 16
Other        
Debt Instrument [Line Items]        
Asset impairment expense   $ 11 $ 0 $ 7

v3.3.1.900
Asset Impairment Expense (Narrative) (Details)
3 Months Ended 9 Months Ended 12 Months Ended
Jun. 30, 2015
USD ($)
project
Jun. 30, 2014
USD ($)
Sep. 30, 2015
USD ($)
Dec. 31, 2015
USD ($)
Dec. 31, 2014
USD ($)
Dec. 31, 2013
USD ($)
Aug. 28, 2015
USD ($)
Sep. 30, 2013
USD ($)
Debt Instrument [Line Items]                
Other Asset Impairment Charges       $ 285,000,000 $ 91,000,000 $ 95,000,000    
Kilroot [Member]                
Debt Instrument [Line Items]                
Assets, fair value             $ 70,000,000  
Other Asset Impairment Charges     $ 121,000,000 121,000,000 0 0    
Ebute [Member]                
Debt Instrument [Line Items]                
Other Asset Impairment Charges       0 67,000,000 0    
Long-Lived Assets [1]         103,000,000      
UK Wind (Newfield) [Member]                
Debt Instrument [Line Items]                
Impairment of Long-Lived Assets Held-for-use   $ 12,000,000            
Assets, fair value   $ 0            
Other Asset Impairment Charges         12,000,000 0    
DP&L (East Bend)                
Debt Instrument [Line Items]                
Impairment of Long-Lived Assets Held-for-use         12,000,000      
Assets, fair value       2,000,000        
Other Asset Impairment Charges       0 12,000,000 0    
Beaver Valley                
Debt Instrument [Line Items]                
Lump sum payment received for termination of PPA           60,000,000    
Other Asset Impairment Charges       0 0 46,000,000    
Conesville (DP&L)                
Debt Instrument [Line Items]                
Assets, fair value           0    
Other Asset Impairment Charges       0 0 26,000,000    
Itabo (San Lorenzo)                
Debt Instrument [Line Items]                
Assets, fair value               $ 7,000,000
Other Asset Impairment Charges       0 0 16,000,000    
Assets carrying amount               $ 23,000,000
buffalo gap III [Member]                
Debt Instrument [Line Items]                
Assets, fair value     118,000,000          
Other Asset Impairment Charges     116,000,000 116,000,000 $ 0 $ 0    
UK Wind Development Projects [Domain]                
Debt Instrument [Line Items]                
Assets, fair value $ 1,000,000              
Other Asset Impairment Charges     37,000,000 $ 37,000,000        
number of projects no longer being pursued | project 2              
number of impaired projects | project 4              
Long-Lived Assets $ 38,000,000              
Long Lived Assets Held And Used [Member] | Fair Value | Ebute [Member]                
Debt Instrument [Line Items]                
Assets, fair value [1]     $ 36,000,000          
[1] (1) See Note 21—Asset Impairment Expense for further information.

v3.3.1.900
Income Taxes (Components of Income Taxes) (Details) - USD ($)
$ in Millions
12 Months Ended
Dec. 31, 2015
Dec. 31, 2014
Dec. 31, 2013
Federal:      
Current $ 9 $ 0 $ (28)
Deferred (56) (121) (110)
State:      
Current 1 1 1
Deferred (5) 1 1
Foreign:      
Current 505 457 509
Deferred 11 81 (30)
Total $ 465 $ 419 $ 343

v3.3.1.900
Income Taxes (Effective Income Tax Reconciliation) (Details) - project
12 Months Ended
Dec. 31, 2015
Dec. 31, 2014
Dec. 31, 2013
Aug. 22, 2014
Jun. 25, 2014
Effective Income Tax Rate Reconciliation, Amount [Abstract]          
Statutory Federal tax rate 35.00% 35.00% 35.00%    
State taxes, net of Federal tax benefit (5.00%) (1.00%) (3.00%)    
Taxes on foreign earnings 3.00% (14.00%) (4.00%)    
Valuation allowance (5.00%) (1.00%) 0.00%    
Uncertain tax positions 0.00% 0.00% (5.00%)    
Bad debt deduction 0.00% 0.00% (3.00%)    
Change in tax law 0.00% 4.00% (1.00%)    
Goodwill impairment 10.00% 4.00% 12.00%    
Other—net 3.00% 0.00% 2.00%    
Effective tax rate 41.00% 27.00% 33.00%    
Masinloc Subsidiary          
Effective Income Tax Rate Reconciliation, Amount [Abstract]          
Component of taxes on foreign earnings (8.00%)        
Investment In Affiliate Ownership Percentage Sold         45.00%
UK Wind Projects          
Effective Income Tax Rate Reconciliation, Amount [Abstract]          
Number of U.K. Wind Projects Sold       4  

v3.3.1.900
Income Taxes (Income Tax Payables and Income Tax Receivables) (Details) - USD ($)
$ in Millions
Dec. 31, 2015
Dec. 31, 2014
Income Tax Disclosure [Abstract]    
Income taxes receivable—current $ 167 $ 217
Total income taxes receivable 167 217
Income taxes payable—current 264 299
Income taxes payable—noncurrent 35 2
Total income taxes payable $ 299 $ 301

v3.3.1.900
Income Taxes (Deferred Tax Assets and Deferred Tax Liabilities) (Details) - USD ($)
$ in Millions
Dec. 31, 2015
Dec. 31, 2014
Deferred Tax Liabilities:    
Differences between book and tax basis of property $ (2,240) $ (2,364)
Other taxable temporary differences (299) (302)
Deferred Tax Liabilities, Gross 2,539 2,666
Deferred Tax Assets:    
Operating loss carryforwards 2,206 2,224
Capital loss carryforwards 66 137
Bad debt and other book provisions 191 221
Retirement costs 149 275
Tax credit carryforwards 55 58
Other deductible temporary differences 219 363
Total gross deferred tax asset 2,886 3,278
Less: valuation allowance (894) (997)
Total net deferred tax asset 1,992 2,281
Total deferred tax liability $ (547) $ (385)

v3.3.1.900
Income Taxes (Income (Loss) from Continuing Operations Before Income Tax) (Details) - USD ($)
$ in Millions
12 Months Ended
Dec. 31, 2015
Dec. 31, 2014
Dec. 31, 2013
Income (Loss) from Continuing Operations before Equity Method Investments, Income Taxes, Extraordinary Items, Noncontrolling Interest [Abstract]      
U.S. $ (612) $ (560) $ (575)
Non-U.S. 1,734 2,136 1,623
INCOME FROM CONTINUING OPERATIONS BEFORE TAXES AND EQUITY IN EARNINGS OF AFFILIATES $ 1,122 $ 1,576 $ 1,048

v3.3.1.900
Income Taxes (Unrecognized Tax Benefits) (Details) - USD ($)
$ in Millions
12 Months Ended
Dec. 31, 2015
Dec. 31, 2014
Dec. 31, 2013
Reconciliation of Unrecognized Tax Benefits, Excluding Amounts Pertaining to Examined Tax Returns [Roll Forward]      
Beginning balance $ 395 $ 392 $ 475
Additions for current year tax positions 6 8 7
Additions for tax positions of prior years 12 14 10
Reductions for tax positions of prior years (7) (2) (3)
Effects of foreign currency translation (7) (3) 0
Settlements (19) (2) (65)
Lapse of statute of limitations (7) (12) (32)
Ending balance $ 373 $ 395 $ 392

v3.3.1.900
Income Taxes (Narrative) (Details) - USD ($)
$ / shares in Units, $ in Millions
12 Months Ended
Dec. 31, 2015
Dec. 31, 2014
Dec. 31, 2013
Dec. 31, 2012
Income Tax Disclosures [Line Items]        
Effective tax rate 41.00% 27.00% 33.00%  
Increase (decrease) in valuation allowance $ (103) $ (93)    
Valuation allowance 894 997    
Tax benefits related to tax status of operations in countries subject to reduced tax rates 21 38 $ 70  
Income tax expense $ (465) $ (419) $ (343)  
Tax benefits related to tax status of operations in countries subject to reduced tax rates per share (in dollars per share) $ 0.02 $ 0.04 $ 0.09  
Unrecognized Tax Benefits, Income Tax Penalties and Interest Accrued:        
Interest on income taxes accrued $ 8 $ 14    
Income tax penalties accrued 0 1    
Unrecognized Tax Benefits, Income Tax Penalties and Interest Expense:        
Interest on income taxes expense 0 3 $ (4)  
Income tax penalties expense 0 0 (3)  
Uncertain Tax Positions Additional Disclosures:        
Unrecognized tax benefits 373 395 392 $ 475
Unrecognized tax benefits that would impact effective tax rate 343 366 360  
Unrecognized tax benefits that would impact effective tax rate portion with attributes warranting full valuation allowance 24 $ 24 $ 26  
Unrecognized tax benefits anticipated to result in net decrease of unrecognized tax benefits within 12 months, minimum 15      
Unrecognized tax benefits anticipated to result in net decrease of unrecognized tax benefits within 12 months, maximum 25      
Federal        
Income Tax Disclosures [Line Items]        
Operating loss carryforwards 3,500      
Operating loss carryforwards amount related to stock option deductions to be recognized in APIC 87      
State and Local Jurisdiction        
Income Tax Disclosures [Line Items]        
Operating loss carryforwards 8,400      
Foreign Tax Authority        
Income Tax Disclosures [Line Items]        
Operating loss carryforwards 3,500      
General Business Tax Credit Carryforward        
Income Tax Disclosures [Line Items]        
Tax credit carryforward 18      
Federal Alternative Minimum Tax        
Income Tax Disclosures [Line Items]        
Tax credit carryforward 5      
Foreign Jurisdictions        
Income Tax Disclosures [Line Items]        
Tax credit carryforward 32      
Year 2018 to 2025 | Foreign Jurisdictions        
Income Tax Disclosures [Line Items]        
Tax credit carryforward 24      
No Expiration        
Income Tax Disclosures [Line Items]        
Tax credit carryforward 8      
VIET NAM        
Income Tax Disclosures [Line Items]        
Income tax expense $ 8      
Tax benefits related to tax status of operations in countries subject to reduced tax rates per share (in dollars per share) $ 0.01      
2015 through 2018 [Member] | VIET NAM        
Income Tax Disclosures [Line Items]        
Effective tax rate 0.00%      
2019 through 2027 [Member] [Member] | VIET NAM        
Income Tax Disclosures [Line Items]        
Effective tax rate 5.00%      
2028 and beyond [Member] [Member] | VIET NAM        
Income Tax Disclosures [Line Items]        
Effective tax rate 10.00%      

v3.3.1.900
Discontinued Operations and Held-For-Sale Businesses (Schedule of Disposal Groups, Including Discontinued Operations) (Details) - USD ($)
$ in Millions
12 Months Ended
Dec. 31, 2015
Dec. 31, 2014
Dec. 31, 2013
Discontinued Operations and Disposal Groups [Abstract]      
Revenue   $ 233 $ 689
Income (loss) from operations of discontinued businesses, before income tax   50 (3)
Income tax expense $ 0 (23) (24)
Income (loss) from operations of discontinued businesses, after income tax 0 27 (27)
Net loss from disposal and impairments of discontinued businesses, after income tax $ 0 $ (56) $ (152)

v3.3.1.900
Discontinued Operations and Held-For-Sale Businesses (Narrative) (Details)
1 Months Ended 3 Months Ended 7 Months Ended 12 Months Ended
Jan. 27, 2016
USD ($)
Dec. 31, 2015
USD ($)
Jul. 01, 2015
USD ($)
Feb. 24, 2014
USD ($)
Jan. 30, 2014
USD ($)
Apr. 29, 2013
USD ($)
business
Jun. 30, 2014
USD ($)
Nov. 30, 2013
USD ($)
project
Jun. 30, 2014
USD ($)
Mar. 31, 2014
USD ($)
Dec. 31, 2015
USD ($)
Dec. 31, 2014
USD ($)
Dec. 31, 2013
USD ($)
Aug. 31, 2015
Income Statement, Balance Sheet and Additional Disclosures by Disposal Groups, Including Discontinued Operations [Line Items]                            
Asset Impairment Charges                     $ 602,000,000 $ 383,000,000 $ 661,000,000  
Net loss from disposal and impairments of discontinued operations                     0 (56,000,000) (152,000,000)  
Income (Loss) from Continuing Operations Attributable to Parent                     306,000,000 789,000,000 284,000,000  
Cameroon businesses                            
Income Statement, Balance Sheet and Additional Disclosures by Disposal Groups, Including Discontinued Operations [Line Items]                            
Asset Impairment Charges                   $ 101,000,000        
Equity method investments (4)                            
Income Statement, Balance Sheet and Additional Disclosures by Disposal Groups, Including Discontinued Operations [Line Items]                            
Proceeds from divestiture of business       $ 8,000,000                    
U.S. wind projects                            
Income Statement, Balance Sheet and Additional Disclosures by Disposal Groups, Including Discontinued Operations [Line Items]                            
Divestiture of ownership in subsidiary percent               100.00%            
Proceeds from divestiture of business         $ 27,000,000                  
Asset Impairment Charges               $ 47,000,000            
Fair value less costs to sell               $ 30,000,000            
Number of wind projects | project               3            
Asset impairment charges attributable to noncontrolling interest               $ 7,000,000            
Assets carrying amount               77,000,000            
Deferred proceeds from divestiture of business         $ 3,000,000                  
Poland wind projects                            
Income Statement, Balance Sheet and Additional Disclosures by Disposal Groups, Including Discontinued Operations [Line Items]                            
Proceeds from divestiture of business               7,000,000            
Asset Impairment Charges               65,000,000            
Net loss from disposal and impairments of discontinued operations               $ (2,000,000)            
Number of wind projects | project               10            
Kiev and Rivne                            
Income Statement, Balance Sheet and Additional Disclosures by Disposal Groups, Including Discontinued Operations [Line Items]                            
Proceeds from divestiture of business           $ 113,000,000                
Asset Impairment Charges           $ 38,000,000                
Number of power distribution businesses sold | business           2                
Kiev                            
Income Statement, Balance Sheet and Additional Disclosures by Disposal Groups, Including Discontinued Operations [Line Items]                            
Divestiture of ownership in subsidiary percent           89.10%                
Rivne                            
Income Statement, Balance Sheet and Additional Disclosures by Disposal Groups, Including Discontinued Operations [Line Items]                            
Divestiture of ownership in subsidiary percent           84.60%                
Minimum | Poland wind projects                            
Income Statement, Balance Sheet and Additional Disclosures by Disposal Groups, Including Discontinued Operations [Line Items]                            
Divestiture of ownership in subsidiary percent               61.00%            
Maximum | Poland wind projects                            
Income Statement, Balance Sheet and Additional Disclosures by Disposal Groups, Including Discontinued Operations [Line Items]                            
Divestiture of ownership in subsidiary percent               89.00%            
Armenia Mountain                            
Income Statement, Balance Sheet and Additional Disclosures by Disposal Groups, Including Discontinued Operations [Line Items]                            
Sale agreement, buyer option to purchase ownership percent               100.00%            
Sale Agreement, Buyer Option To Purchase Ownership Interest, Sales Price               $ 75,000,000            
Cameroon businesses                            
Income Statement, Balance Sheet and Additional Disclosures by Disposal Groups, Including Discontinued Operations [Line Items]                            
Disposal Group, Including Discontinued Operation, Consideration             $ 200,000,000   $ 200,000,000          
Proceeds from divestiture of business             156,000,000              
Net loss from disposal and impairments of discontinued operations                 (7,000,000)          
Cameroon businesses | Noncurrent Asset                            
Income Statement, Balance Sheet and Additional Disclosures by Disposal Groups, Including Discontinued Operations [Line Items]                            
Disposal Group, Including Discontinued Operation, Non-contingent Consideration, Fair Value, Amount to be Received             $ 44,000,000   $ 44,000,000          
Disposal Group, Held-for-sale, Not Discontinued Operations [Member] | DPLER                            
Income Statement, Balance Sheet and Additional Disclosures by Disposal Groups, Including Discontinued Operations [Line Items]                            
Proceeds from divestiture of business   $ 76,000,000                        
Income (Loss) from Continuing Operations Attributable to Parent                     11,000,000 (129,000,000) 6,000,000  
Disposal Group, Held-for-sale, Not Discontinued Operations [Member] | Kelanitissa [Member]                            
Income Statement, Balance Sheet and Additional Disclosures by Disposal Groups, Including Discontinued Operations [Line Items]                            
Divestiture of ownership in subsidiary percent                           90.00%
Income (Loss) from Continuing Operations Attributable to Parent                     (7,000,000) 1,000,000 16,000,000  
Disposal Group, Held-for-sale, Not Discontinued Operations [Member] | Armenia Mountain                            
Income Statement, Balance Sheet and Additional Disclosures by Disposal Groups, Including Discontinued Operations [Line Items]                            
Income (Loss) from Continuing Operations Attributable to Parent                     $ 6,000,000 $ 7,000,000 $ 4,000,000  
Disposal Group, Disposed of by Sale, Not Discontinued Operations [Member] | Armenia Mountain                            
Income Statement, Balance Sheet and Additional Disclosures by Disposal Groups, Including Discontinued Operations [Line Items]                            
Proceeds from divestiture of business     $ 64,000,000                      
Subsequent Event [Member] | Disposal Group, Disposed of by Sale, Not Discontinued Operations [Member] | Kelanitissa [Member]                            
Income Statement, Balance Sheet and Additional Disclosures by Disposal Groups, Including Discontinued Operations [Line Items]                            
Proceeds from divestiture of business $ 18,000,000                          

v3.3.1.900
Acquisitions and Dispositions (Details)
$ in Millions
3 Months Ended 12 Months Ended
Jul. 01, 2015
USD ($)
Aug. 22, 2014
USD ($)
project
Apr. 26, 2013
USD ($)
Dec. 31, 2015
USD ($)
Sep. 30, 2014
USD ($)
Jun. 30, 2014
USD ($)
Dec. 31, 2015
USD ($)
Dec. 31, 2014
USD ($)
Dec. 31, 2013
USD ($)
Aug. 31, 2015
Nov. 20, 2014
Income Statement Balance Sheet And Additional Disclosures By Disposal Groups Including Discontinued Operations [Line Items]                      
Income (Loss) from Continuing Operations Attributable to Parent             $ 306 $ 789 $ 284    
Dispositions and Held-for-Sales Businesses                      
Proceeds from Sale of Ownership Interests             154 83 109    
Ebute [Member]                      
Dispositions and Held-for-Sales Businesses                      
Ownership interest sold                     95.00%
Proceeds from Sale of Ownership Interests       $ 22              
Pre-tax gain on disposal       $ (6)              
Pre-tax loss of disposed businesses, Excluding gain on disposal, included in continuing operations               (27)      
Pre-tax income of disposed businesses, Excluding gain on disposal, included in continuing operations                 (29)    
AES NBO                      
Dispositions and Held-for-Sales Businesses                      
Ownership interest sold                     100.00%
UK Wind Projects                      
Dispositions and Held-for-Sales Businesses                      
Ownership interest sold   100.00%                  
Proceeds from Sale of Ownership Interests   $ 158                  
Pre-tax gain on disposal         $ 78            
Pre-tax loss of disposed businesses, Excluding gain on disposal, included in continuing operations             (18) 3      
AES Cartagena                      
Dispositions and Held-for-Sales Businesses                      
Pre-tax gain on disposal           $ 20          
Proceeds from sale of ownership interest in Cartagena     $ 24                
UK Wind Projects                      
Dispositions and Held-for-Sales Businesses                      
Number of U.K. Wind Projects Sold | project   4                  
Disposal Group, Disposed of by Sale, Not Discontinued Operations [Member] | Armenia Mountain [Member]                      
Income Statement Balance Sheet And Additional Disclosures By Disposal Groups Including Discontinued Operations [Line Items]                      
Proceeds from Divestiture of Businesses $ 64                    
Dispositions and Held-for-Sales Businesses                      
Pre-tax gain on disposal $ 22                    
Disposal Group, Held-for-sale, Not Discontinued Operations [Member] | Armenia Mountain [Member]                      
Income Statement Balance Sheet And Additional Disclosures By Disposal Groups Including Discontinued Operations [Line Items]                      
Income (Loss) from Continuing Operations Attributable to Parent             6 7 4    
Disposal Group, Held-for-sale, Not Discontinued Operations [Member] | Kelanitissa [Member]                      
Income Statement Balance Sheet And Additional Disclosures By Disposal Groups Including Discontinued Operations [Line Items]                      
Divestiture Of Ownership In Subsidiary Percent                   90.00%  
Income (Loss) from Continuing Operations Attributable to Parent             $ (7) $ 1 $ 16    

v3.3.1.900
Acquisitions Acquistions (Details) - USD ($)
$ in Millions
12 Months Ended
Dec. 31, 2015
Feb. 18, 2015
Dec. 31, 2015
Business Acquisition [Line Items]      
Goodwill, Acquired During Period     $ 16
Main street power [Member]      
Business Acquisition [Line Items]      
Business Acquisition, Percentage of Voting Interests Acquired   100.00%  
Business Combination, Consideration Transferred   $ 25  
Payments to Acquire Businesses, Gross   20  
Business Combination, Consideration Transferred, Other   $ 5  
Business Combination, Recognized Identifiable Assets Acquired and Liabilities Assumed, Cash and Equivalents $ 4   $ 4
Goodwill, Acquired During Period $ 16    

v3.3.1.900
Earnings Per Share (Schedule of Earnings Per Share, Basic and Diluted) (Details) - USD ($)
$ / shares in Units, shares in Millions, $ in Millions
3 Months Ended 12 Months Ended
Dec. 31, 2015
Sep. 30, 2015
Jun. 30, 2015
Mar. 31, 2015
Dec. 31, 2014
Sep. 30, 2014
Jun. 30, 2014
Mar. 31, 2014
Dec. 31, 2015
Dec. 31, 2014
Dec. 31, 2013
Class of Stock [Line Items]                      
Income from continuing operations, net of tax                 $ 306 $ 789 $ 284
Weighted Average Number of Shares Outstanding, Basic (in shares)                 687 720 743
Income (Loss) from Continuing Operations, Per Basic Share $ (0.13) $ 0.27 $ 0.10 $ 0.20 $ 0.29 $ 0.68 $ 0.20 $ (0.07) $ 0.45 $ 1.10 $ 0.38
Incremental Common Shares Attributable to Dilutive Effect of Call Options and Warrants (in shares)                 0 1 1
Incremental Common Shares Attributable to Dilutive Effect of Share-based Payment Arrangements (in shares)                 2 3 4
Income (Loss) From Continuing Operations Diluted                 $ 306 $ 789 $ 284
Weighted Average Number of Shares Outstanding, Diluted (in shares)                 689 724 748
Income (Loss) from Continuing Operations, Per Diluted Share $ (0.13) $ 0.26 $ 0.10 $ 0.20 $ 0.29 $ 0.67 $ 0.20 $ (0.07) $ 0.44 $ 1.09 $ 0.38
Employee Stock Option [Member]                      
Class of Stock [Line Items]                      
Income (Loss) from Continuing Operations, Per Diluted Share                 0.00 0.00 0.00
Restricted Stock Units (RSUs) [Member]                      
Class of Stock [Line Items]                      
Income (Loss) from Continuing Operations, Per Diluted Share                 $ (0.01) $ (0.01) $ 0.00
Restricted Stock Units (RSUs) [Member]                      
Class of Stock [Line Items]                      
Dilutive Securities, Effect on Basic Earnings Per Share, Options and Restrictive Stock Units                 $ 0 $ 0 $ 0
Equity Option [Member]                      
Class of Stock [Line Items]                      
Dilutive Securities, Effect on Basic Earnings Per Share, Options and Restrictive Stock Units                 $ 0 $ 0 $ 0

v3.3.1.900
Earnings Per Share (Narrative) (Details) - USD ($)
$ / shares in Units, shares in Millions, $ in Millions
3 Months Ended 12 Months Ended
Dec. 31, 2015
Sep. 30, 2015
Jun. 30, 2015
Mar. 31, 2015
Dec. 31, 2014
Sep. 30, 2014
Jun. 30, 2014
Mar. 31, 2014
Dec. 31, 2015
Dec. 31, 2014
Dec. 31, 2013
Antidilutive Securities Excluded from Computation of Earnings Per Share [Line Items]                      
Income (Loss) from Continuing Operations, Per Basic Share $ (0.13) $ 0.27 $ 0.10 $ 0.20 $ 0.29 $ 0.68 $ 0.20 $ (0.07) $ 0.45 $ 1.10 $ 0.38
Income Loss From Continuing Operations Diluted                 $ 306 $ 789 $ 284
Antidilutive securities excluded from computation of earnings per share                 8 6 7
Convertible Debt Securities [Member]                      
Antidilutive Securities Excluded from Computation of Earnings Per Share [Line Items]                      
Antidilutive securities excluded from computation of earnings per share                 15 15 15

v3.3.1.900
Risks And Uncertainties (Details)
$ in Millions
12 Months Ended
Dec. 31, 2015
USD ($)
business
segment
customer
Dec. 31, 2014
USD ($)
customer
Dec. 31, 2013
USD ($)
customer
Dec. 31, 2012
USD ($)
Unusual Risk or Uncertainty [Line Items]        
Number of strategic business units | segment 6      
Segment Reporting, Additional Information about Entity's Reportable Segments | business 2      
Cash and cash equivalents $ 1,262 $ 1,539 $ 1,642 $ 1,900
Percent of revenue generated outside US 76.00%      
Number of customers that accounted for 10% of more of total revenue | customer 0 0 0  
Maritza [Member]        
Unusual Risk or Uncertainty [Line Items]        
Allowance for Doubtful Accounts Receivable $ 0      
Total Maritza Receivables 351      
Past due receivables [Member] | Maritza [Member]        
Unusual Risk or Uncertainty [Line Items]        
Total Maritza Receivables $ 307      

v3.3.1.900
Related Party Transactions (Schedule of related Party Transactions) (Details) - Affiliated Entity - USD ($)
$ in Millions
12 Months Ended
Dec. 31, 2015
Dec. 31, 2014
Dec. 31, 2013
Related Party Transaction [Line Items]      
Interest Income $ 25 $ 17 $ 20
Interest Expense 33 9 8
Electricity Generation Plant, Non-Nuclear [Member]      
Related Party Transaction [Line Items]      
Revenue—Non-Regulated 1,099 1,188 1,110
Cost of Sales—Non-Regulated $ 330 $ 331 $ 276

v3.3.1.900
Related Party Transactions (Schedule of Related Party Receivables Payables) (Details) - Affiliated Entity - USD ($)
$ in Millions
Dec. 31, 2015
Dec. 31, 2014
Related Party Transaction [Line Items]    
Receivables from Related Parties $ 181 $ 349
Accounts and notes payable to related parties $ 524 $ 567

v3.3.1.900
Related Party Transactions Transactions with Significant Shareholders (Details) - USD ($)
$ / shares in Units, shares in Millions, $ in Millions
12 Months Ended 66 Months Ended
May. 18, 2015
Dec. 31, 2015
Dec. 31, 2013
Dec. 31, 2015
Related Party Transaction [Line Items]        
Treasury Stock Acquired, Average Cost Per Share       $ 12.31
Treasury Stock, Shares, Acquired   39.7   145.6
Treasury Stock, Value, Acquired, Cost Method   $ 0 $ 0 $ 1,800
share repurchase program CIC buyback [Domain]        
Related Party Transaction [Line Items]        
Treasury Stock Acquired, Average Cost Per Share $ 13.07      
Treasury Stock, Shares, Acquired 20.0      
Treasury Stock, Value, Acquired, Cost Method $ 261      
share repurchase program CIC buyback [Domain] | China investment Corporation (CIC) [Member]        
Related Party Transaction [Line Items]        
Treasury Stock Acquired, Average Cost Per Share $ 13.07      
Treasury Stock, Shares, Acquired 20.0      
Treasury Stock, Value, Acquired, Cost Method $ 261      

v3.3.1.900
Selected Quarterly Financial Data (Details) - USD ($)
$ / shares in Units, $ in Millions
3 Months Ended 12 Months Ended
Dec. 11, 2015
Dec. 31, 2015
Sep. 30, 2015
Jun. 30, 2015
Mar. 31, 2015
Dec. 31, 2014
Sep. 30, 2014
Jun. 30, 2014
Mar. 31, 2014
Dec. 31, 2015
Dec. 31, 2014
Dec. 31, 2013
Selected Quarterly Financial Information [Abstract]                        
Revenue   $ 3,400 $ 3,721 $ 3,858 $ 3,984 $ 4,132 $ 4,441 $ 4,311 $ 4,262 $ 14,963 $ 17,146 $ 15,891
Operating margin   718 673 754 721 708 767 819 794 2,866 3,088 3,247
Income (loss) from continuing operations, net of tax   41 203 [1] 264 [1] 254 [1] 298 [2],[3] 508 [2],[3] 281 [2],[3] 89 [2],[3] 762 1,176 730
Discontinued operations, net of tax   0 0 0 0 0 0 (6) (23)      
NET INCOME   41 203 264 254 298 508 275 66 762 1,147 551
Net income (loss) attributable to The AES Corporation   $ (85) $ 180 $ 69 $ 142 $ 206 $ 488 $ 133 $ (58) $ 306 $ 769 $ 114
Basic income (loss) per share:                        
Income (loss) from continuing operations attributable to The AES Corporation, net of tax   $ (0.13) $ 0.27 $ 0.10 $ 0.20 $ 0.29 $ 0.68 $ 0.20 $ (0.07) $ 0.45 $ 1.10 $ 0.38
Discontinued operations attributable to The AES Corporation, net of tax   0.00 0.00 0.00 0.00 0.00 0.00 (0.02) (0.01) 0.00 (0.03) (0.23)
NET INCOME ATTRIBUTABLE TO THE AES CORPORATION COMMON STOCKHOLDERS   (0.13) 0.27 0.10 0.20 0.29 0.68 0.18 (0.08) 0.45 1.07 0.15
Diluted income (loss) per share:                        
Income (loss) from continuing operations attributable to The AES Corporation, net of tax   (0.13) 0.26 0.10 0.20 0.29 0.67 0.20 (0.07) 0.44 1.09 0.38
Discontinued operations attributable to The AES Corporation, net of tax   0.00 0.00 0.00 0.00 0.00 0.00 (0.02) (0.01) 0.00 (0.03) (0.23)
NET INCOME ATTRIBUTABLE TO THE AES CORPORATION COMMON STOCKHOLDERS   (0.13) 0.26 0.10 0.20 0.29 0.67 0.18 (0.08) 0.44 1.06 0.15
Dividends declared per common share $ 0.11 $ 0.21 $ 0.1 $ 0.1 $ 0 $ 0.15 $ 0.05 $ 0.05 $ 0 $ 0.41 $ 0.25 $ 0.17
Impairment expense pre-tax total   $ 326 $ 231 $ 37 $ 8 $ 79 $ 31 $ 107 $ 166      
Net equity in earnings of affiliates                   $ (105) $ (19) $ (25)
Masinloc Subsidiary                        
Diluted income (loss) per share:                        
Disposal Group, Not Discontinued Operation, Gain (Loss) on Disposal             283          
UK Wind Projects                        
Diluted income (loss) per share:                        
Disposal Group, Not Discontinued Operation, Gain (Loss) on Disposal             $ 78          
ARGENTINA                        
Diluted income (loss) per share:                        
Interest Income, Other           59            
Embedded Derivative, Gain on Embedded Derivative           106            
Elsta                        
Diluted income (loss) per share:                        
Net equity in earnings of affiliates           $ 41       $ 41    
[1] (1)Includes pretax impairment expense of $8 million, $37 million, $231 million and $326 million, for the first, second, third and fourth quarters of 2015, respectively. See Note 9—Other Non-Operating Expense, Note 10—Goodwill and Other Intangible Assets, and Note 21—Asset Impairment Expense for further discussion.
[2] (2) Includes a pretax gain of approximately $283 million for the third quarter of 2014 related to the sale of a noncontrolling interest in Masinloc. See Note 16—Equity for further discussion. Includes pretax gain of approximately $78 million for the third quarter of 2014 related to the sale of the U.K. wind projects. See Note 24—Dispositions and Held-for-Sale Businesses for further discussion. Includes pretax interest income of $59 million recognized on FONIVEMEM III receivables at AES Argentina in the fourth quarter of 2014. Also includes a pretax foreign currency derivative gain of $106 million recognized on the FONIVEMEM III receivables in the fourth quarter of 2014. See Note 7—Financing Receivables for further discussion. Includes pretax loss of $41 million recognized in Net equity in earnings of affiliates corresponding to the Company's share of an asset impairment at Elsta in the fourth quarter of 2014. See Note 8—Investments In And Advances To Affiliates for further discussion.
[3] (3) Includes pretax impairment expense of $166 million, $107 million, $31 million and $79 million, for the first, second, third and fourth quarters of 2014, respectively. See Note 9—Other Non-Operating Expense, Note 10—Goodwill and Other Intangible Assets, and Note 21—Asset Impairment Expense for further discussion.

v3.3.1.900
Subsequent Event Subsequent Events (Details) - USD ($)
$ / shares in Units, shares in Millions, $ in Millions
2 Months Ended 12 Months Ended 66 Months Ended 68 Months Ended
Feb. 15, 2016
Jan. 27, 2016
Feb. 23, 2016
Dec. 31, 2015
Dec. 31, 2013
Dec. 31, 2015
Feb. 23, 2016
Feb. 11, 2015
Income Statement, Balance Sheet and Additional Disclosures by Disposal Groups, Including Discontinued Operations [Line Items]                
Treasury Stock, Shares, Acquired       39.7   145.6    
Treasury Stock, Value, Acquired, Cost Method       $ 0 $ 0 $ 1,800    
Stock Repurchase Program, Authorized Amount       2,100   $ 2,100    
Treasury Stock Acquired, Average Cost Per Share           $ 12.31    
Stock Repurchase Program, Remaining Authorized Repurchase Amount       $ 343   $ 343    
AES US Investment, Inc.                
Income Statement, Balance Sheet and Additional Disclosures by Disposal Groups, Including Discontinued Operations [Line Items]                
Investment In Affiliate Ownership Percentage Sold               15.00%
Subsequent Event                
Income Statement, Balance Sheet and Additional Disclosures by Disposal Groups, Including Discontinued Operations [Line Items]                
Treasury Stock, Shares, Acquired     8.7       154.3  
Treasury Stock, Value, Acquired, Cost Method     $ 79       $ 1,900  
Treasury Stock Acquired, Average Cost Per Share             $ 12.12  
Stock Repurchase Program, Remaining Authorized Repurchase Amount     264       $ 264  
Extinguishment of Debt, Amount     $ 125          
IPP4 [Member] | Disposal Group, Disposed of by Sale, Not Discontinued Operations [Member] | Subsequent Event                
Income Statement, Balance Sheet and Additional Disclosures by Disposal Groups, Including Discontinued Operations [Line Items]                
Sale of Stock, Percentage of Ownership after Transaction 36.00%              
Proceeds from Divestiture of Businesses $ 21              
Kelanitissa [Member] | Disposal Group, Disposed of by Sale, Not Discontinued Operations [Member] | Subsequent Event                
Income Statement, Balance Sheet and Additional Disclosures by Disposal Groups, Including Discontinued Operations [Line Items]                
Proceeds from Divestiture of Businesses   $ 18            

v3.3.1.900
Schedule I - Condensed Financial Information of Parent (Balance Sheet) (Details) - USD ($)
$ in Millions
Dec. 31, 2015
Dec. 31, 2014
Dec. 31, 2013
Dec. 31, 2012
Current Assets:        
Cash and cash equivalents $ 1,262 $ 1,539 $ 1,642 $ 1,900
Restricted cash 295 283    
Deferred income taxes 0 275    
Total current assets 6,866 7,826    
Investment in and advances to subsidiaries and affiliates 610 537 1,010  
Office Equipment:        
Cost 28,491 30,459    
Accumulated depreciation (9,449) (9,962)    
Property, plant and equipment, net 22,816 25,151    
Other Assets:        
Deferred income taxes 543 662    
Other Assets 2,536 2,640    
Total other assets 7,168 5,989    
TOTAL ASSETS 36,850 38,966 40,411  
Current Liabilities:        
Accounts payable 1,721 2,278    
Accrued and other liabilities 2,436 2,326    
Total current liabilities 6,950 6,997    
Long-term Liabilities:        
Other long-term liabilities 2,896 3,222    
Total noncurrent liabilities 23,191 24,566    
Stockholders' equity:        
Common stock 8 8    
Additional paid-in capital 8,718 8,409    
Retained earnings 143 512    
Accumulated other comprehensive loss (3,883) (3,286)    
Treasury stock (1,837) (1,371)    
Total AES Corporation stockholders’ equity 3,149 4,272    
TOTAL LIABILITIES AND EQUITY 36,850 38,966    
Parent Company        
Current Assets:        
Cash and cash equivalents 186 511 $ 131 $ 305
Restricted cash 32 81    
Accounts and notes receivable from subsidiaries 264 380    
Deferred income taxes 0 142    
Prepaid expenses and other current assets 26 57    
Total current assets 508 1,171    
Investment in and advances to subsidiaries and affiliates 7,764 9,063    
Office Equipment:        
Cost 135 157    
Accumulated depreciation (112) (114)    
Property, plant and equipment, net 23 43    
Other Assets:        
Deferred financing costs (net of accumulated amortization of $75 and $81, respectively) 49 61    
Deferred income taxes 1,028 872    
Other Assets 1 1    
Total other assets 1,078 934    
TOTAL ASSETS 9,373 11,211    
Current Liabilities:        
Accounts payable 16 25    
Accounts and notes payable to subsidiaries 97 80    
Accrued and other liabilities 204 212    
Senior notes payable—current portion 0 151    
Total current liabilities 317 468    
Long-term Liabilities:        
Senior notes payable 4,498 4,590    
Junior subordinated notes and debentures payable 517 517    
Accounts and notes payable to subsidiaries 873 1,352    
Other long-term liabilities 19 12    
Total noncurrent liabilities 5,907 6,471    
Stockholders' equity:        
Common stock 8 8    
Additional paid-in capital 8,718 8,409    
Retained earnings 143 512    
Accumulated other comprehensive loss (3,883) (3,286)    
Treasury stock (1,837) (1,371)    
Total AES Corporation stockholders’ equity 3,149 4,272    
TOTAL LIABILITIES AND EQUITY $ 9,373 $ 11,211    

v3.3.1.900
Schedule I - Condensed Financial Information of Parent (Balance Sheet Parenthetical) (Details) - USD ($)
$ in Millions
Dec. 31, 2015
Dec. 31, 2014
Parent Company    
Condensed Financial Statements, Captions [Line Items]    
Deferred financing costs, accumulated amortization $ 75 $ 81

v3.3.1.900
Schedule I - Condensed Financial Information of Parent Schedule I - Condensed Financial Information of Parent (Statement of Operations) (Details) - USD ($)
$ in Millions
3 Months Ended 12 Months Ended
Dec. 31, 2015
Sep. 30, 2015
Jun. 30, 2015
Mar. 31, 2015
Dec. 31, 2014
Sep. 30, 2014
Jun. 30, 2014
Mar. 31, 2014
Dec. 31, 2015
Dec. 31, 2014
Dec. 31, 2013
Dec. 31, 2012
Condensed Income Statements, Captions [Line Items]                        
Interest income                 $ 524 $ 365 $ 275  
General and administrative expenses                 (196) (187) (220)  
Other income                 83 124 125  
Other expense                 (65) (68) (76)  
Loss on extinguishment of debt                 (186) (261) (229)  
Interest expense                 (1,436) (1,471) (1,482)  
Income tax benefit                 (465) (419) (343)  
NET INCOME ATTRIBUTABLE TO THE AES CORPORATION $ (85) $ 180 $ 69 $ 142 $ 206 $ 488 $ 133 $ (58) 306 769 $ 114  
Parent Company                        
Condensed Income Statements, Captions [Line Items]                        
Revenue from subsidiaries and affiliates                 24 29   $ 32
Equity in earnings of subsidiaries and affiliates                 859 1,313   498
Interest income                 24 59   66
General and administrative expenses                 (154) (161)   (171)
Other income                 24 8   14
Other expense                 (6) (30)   (11)
Loss on extinguishment of debt                 (105) (193)   (165)
Interest expense                 (364) (422)   (436)
Income (loss) before income taxes                 302 603   (173)
Income tax benefit                 4 166   287
NET INCOME ATTRIBUTABLE TO THE AES CORPORATION                 $ 306 $ 769   $ 114

v3.3.1.900
Schedule I - Condensed Financial Information of Parent (Statement of Comprehensive Income) (Details) - USD ($)
$ in Millions
3 Months Ended 12 Months Ended
Dec. 31, 2015
Sep. 30, 2015
Jun. 30, 2015
Mar. 31, 2015
Dec. 31, 2014
Sep. 30, 2014
Jun. 30, 2014
Mar. 31, 2014
Dec. 31, 2015
Dec. 31, 2014
Dec. 31, 2013
Dec. 31, 2012
Condensed Financial Statements, Captions [Line Items]                        
Net income (loss) attributable to The AES Corporation $ (85) $ 180 $ 69 $ 142 $ 206 $ 488 $ 133 $ (58) $ 306 $ 769 $ 114  
Foreign currency translation activity:                        
Foreign currency translation adjustments, net of income tax (expense) benefit of $1, $(7) and $10, respectively                 (1,019) (491) (375)  
Reclassification to earnings, net of income tax (expense) benefit of $0, $0 and $0, respectively                 0 (3) 41  
Total foreign currency translation adjustments                 (1,019) (494) (334)  
Derivative activity:                        
Change in derivative fair value, net of income tax (expense) benefit of $4, $51 and $(31), respectively                 (57) (358) 108  
Reclassification to earnings, net of income tax (expense) benefit of $(12), $(37) and $(32), respectively                 66 99 139  
Total change in fair value of derivatives                 9 (259) 247  
Pension activity:                        
Prior service cost for the period, net of income tax (expense) benefit of $0, $0 and $0, respectively                 1 0 0  
Change in pension adjustments due to net actuarial gain (loss) for the period, net of income tax (expense) benefit of $(7), $9 and $(42), respectively                 60 (49) 379  
Reclassification of earnings due to amortization of net actuarial loss, net of income tax (expense) benefit of $(2), $0 and $(5), respectively                 16 29 52  
Total pension adjustments                 77 (20) 431  
OTHER COMPREHENSIVE (LOSS) INCOME                 (933) (773) 344  
COMPREHENSIVE (LOSS) INCOME                 (171) 374 $ 895  
Parent Company                        
Condensed Financial Statements, Captions [Line Items]                        
Net income (loss) attributable to The AES Corporation                 306 769   $ 114
Foreign currency translation activity:                        
Foreign currency translation adjustments, net of income tax (expense) benefit of $1, $(7) and $10, respectively                 (674) (366)   (263)
Reclassification to earnings, net of income tax (expense) benefit of $0, $0 and $0, respectively                 0 34   36
Total foreign currency translation adjustments                 (674) (332)   (227)
Derivative activity:                        
Change in derivative fair value, net of income tax (expense) benefit of $4, $51 and $(31), respectively                 (5) (180)   46
Reclassification to earnings, net of income tax (expense) benefit of $(12), $(37) and $(32), respectively                 48 72   128
Total change in fair value of derivatives                 43 (108)   174
Pension activity:                        
Prior service cost for the period, net of income tax (expense) benefit of $0, $0 and $0, respectively                 1 (1)   0
Change in pension adjustments due to net actuarial gain (loss) for the period, net of income tax (expense) benefit of $(7), $9 and $(42), respectively                 18 (13)   78
Reclassification of earnings due to amortization of net actuarial loss, net of income tax (expense) benefit of $(2), $0 and $(5), respectively                 2 10   13
Total pension adjustments                 21 (4)   91
OTHER COMPREHENSIVE (LOSS) INCOME                 (610) (444)   38
COMPREHENSIVE (LOSS) INCOME                 $ (304) $ 325   $ 152

v3.3.1.900
Schedule I - Condensed Financial Information of Parent (Statement of Comprehensive Income Parenthetical) (Details) - USD ($)
$ in Millions
12 Months Ended
Dec. 31, 2015
Dec. 31, 2014
Dec. 31, 2013
Condensed Financial Statements, Captions [Line Items]      
Foreign currency translation adjustments, income tax $ 1 $ (7) $ 10
Foreign currency, reclassification to earnings, income tax 0 0 0
Change in derivative fair value, income tax 16 72 (31)
Derivative reclassification to earnings, income tax (11) (26) (41)
Other Comprehensive (Income) Loss, Pension and Other Postretirement Benefit Plans, Net Prior Service Cost (Credit), Tax 0 0 0
Other Comprehensive Income (Loss), Pension and Other Postretirement Benefit Plans, Net Unamortized Gain (Loss) Arising During Period, Tax (29) 27 (198)
Pension, amortization of net actuarial loss, income tax (9) (7) (26)
Parent Company      
Condensed Financial Statements, Captions [Line Items]      
Foreign currency translation adjustments, income tax 1 (7) 10
Foreign currency, reclassification to earnings, income tax 0 0 0
Change in derivative fair value, income tax 4 51 (31)
Derivative reclassification to earnings, income tax (12) (37) (32)
Other Comprehensive (Income) Loss, Pension and Other Postretirement Benefit Plans, Net Prior Service Cost (Credit), Tax 0 0 0
Other Comprehensive Income (Loss), Pension and Other Postretirement Benefit Plans, Net Unamortized Gain (Loss) Arising During Period, Tax (7) 9 (42)
Pension, amortization of net actuarial loss, income tax $ (2) $ 0 $ (5)

v3.3.1.900
Schedule I - Condensed Financial Information of Parent (Statement of Cash Flows) (Details) - USD ($)
$ in Millions
12 Months Ended
Dec. 31, 2015
Dec. 31, 2014
Dec. 31, 2013
Condensed Cash Flow Statements, Captions [Line Items]      
Net cash provided by operating activities $ 2,134 $ 1,791 $ 2,715
Investing Activities:      
Decrease in restricted cash (159) 419 44
(Purchase) sale of short term investments, net (17) (728) (7)
Net cash used in investing activities (2,366) (656) (1,774)
Financing Activities:      
Borrowings (payments) under the revolver, net 959 836 1,139
Purchase of treasury stock (482) (308) (322)
Common stock dividends paid (276) (144) (119)
Payments for deferred financing costs (90) (158) (176)
Proceeds from (Payments for) Other Financing Activities (7) 27 14
Net cash provided by (used in) financing activities 28 (1,262) (1,136)
Effect of exchange rate changes on cash (52) (51) (59)
Total decrease in cash and cash equivalents (277) (103) (258)
Cash and cash equivalents, beginning 1,539 1,642 1,900
Cash and cash equivalents, ending 1,262 1,539 1,642
SUPPLEMENTAL DISCLOSURES:      
Cash payments for interest, net of amounts capitalized 1,265 1,351 1,398
Cash payments for income taxes, net of refunds 388 480 570
Parent Company      
Condensed Cash Flow Statements, Captions [Line Items]      
Net cash provided by operating activities 475 449 418
Investing Activities:      
Expenses related to asset sales 0 (4) (5)
Investment in and net advances to subsidiaries (221) (69) 201
Return of capital 501 740 230
Decrease in restricted cash 49 96 50
Additions to property, plant and equipment (11) (31) (11)
(Purchase) sale of short term investments, net 0 (1) 1
Net cash used in investing activities 318 731 466
Financing Activities:      
Borrowings (payments) under the revolver, net 0 0 0
Borrowings of notes payable and other coupon bearing securities 575 1,525 750
Repayments of notes payable and other coupon bearing securities (915) (2,117) (1,210)
Loans (to) from subsidiaries 0 263 (152)
Purchase of treasury stock (482) (308) (322)
Proceeds from issuance of common stock 4 1 13
Common stock dividends paid (276) (144) (119)
Payments for deferred financing costs (6) (20) (17)
Proceeds from (Payments for) Other Financing Activities (18) 0 0
Net cash provided by (used in) financing activities (1,118) (800) (1,057)
Effect of exchange rate changes on cash 0 0 (1)
Total decrease in cash and cash equivalents (325) 380 (174)
Cash and cash equivalents, beginning 511 131 305
Cash and cash equivalents, ending 186 511 131
SUPPLEMENTAL DISCLOSURES:      
Cash payments for interest, net of amounts capitalized 314 373 442
Cash payments for income taxes, net of refunds $ 0 $ (2) $ 11

v3.3.1.900
Schedule I - Condensed Financial Information of Parent (Senior Notes and Junior Subordinated Notes) (Details) - USD ($)
$ in Millions
12 Months Ended
Dec. 31, 2015
Dec. 31, 2014
Condensed Financial Statements, Captions [Line Items]    
Recourse Debt Total $ 5,015 $ 5,258
Less: Current maturities 0 (151)
Recourse Debt Non Current 5,015 5,107
7.75% Senior Unsecured Note Due 2015    
Condensed Financial Statements, Captions [Line Items]    
Recourse Debt Total 0 151
9.75% Senior Unsecured Note Due 2016    
Condensed Financial Statements, Captions [Line Items]    
Recourse Debt Total 0 164
8.00% Senior Unsecured Note Due 2017    
Condensed Financial Statements, Captions [Line Items]    
Recourse Debt Total 181 525
Senior Unsecured Note LIBOR plus 3% due 2019    
Condensed Financial Statements, Captions [Line Items]    
Recourse Debt Total 775 775
8.00% Senior Unsecured Note Due 2020    
Condensed Financial Statements, Captions [Line Items]    
Recourse Debt Total 469 625
7.38% Senior Unsecured Note Due 2021    
Condensed Financial Statements, Captions [Line Items]    
Recourse Debt Total 1,000 1,000
4.88% Senior Unsecured Note Due 2023    
Condensed Financial Statements, Captions [Line Items]    
Recourse Debt Total 750 750
5.50% Senior Unsecured Note Due 2024    
Condensed Financial Statements, Captions [Line Items]    
Recourse Debt Total $ 750 750
Unamortized Discounts    
Condensed Financial Statements, Captions [Line Items]    
Recourse Debt Total   1
Recourse Debt    
Condensed Financial Statements, Captions [Line Items]    
Stated interest rate 6.75%  
Junior subordinated notes and debentures payable $ 517 $ 517
Recourse Debt | 7.75% Senior Unsecured Note Due 2014    
Condensed Financial Statements, Captions [Line Items]    
Interest Rate   7.75%
Recourse Debt | 7.75% Senior Unsecured Note Due 2015    
Condensed Financial Statements, Captions [Line Items]    
Interest Rate 7.75% 7.75%
Recourse Debt | 9.75% Senior Unsecured Note Due 2016    
Condensed Financial Statements, Captions [Line Items]    
Interest Rate 9.75% 9.75%
Recourse Debt | 8.00% Senior Unsecured Note Due 2017    
Condensed Financial Statements, Captions [Line Items]    
Interest Rate 8.00% 8.00%
Recourse Debt | 8.00% Senior Unsecured Note Due 2020    
Condensed Financial Statements, Captions [Line Items]    
Interest Rate 8.00% 8.00%
Recourse Debt | 7.38% Senior Unsecured Note Due 2021    
Condensed Financial Statements, Captions [Line Items]    
Interest Rate 7.38% 7.38%
Recourse Debt | 4.88% Senior Unsecured Note Due 2023    
Condensed Financial Statements, Captions [Line Items]    
Interest Rate 4.88% 4.88%
Recourse Debt | 5.50% Senior Unsecured Note Due 2024    
Condensed Financial Statements, Captions [Line Items]    
Interest Rate 5.50%  
Recourse Debt | 5.50% Unsecured senior notes due 2025 [Domain]    
Condensed Financial Statements, Captions [Line Items]    
Interest Rate 5.50%  
Recourse Debt Total $ 575 $ 0
Recourse Debt | LIBOR | Senior Unsecured Note LIBOR plus 3% due 2019    
Condensed Financial Statements, Captions [Line Items]    
Basis spread on variable rate 3.00%  
Parent Company    
Condensed Financial Statements, Captions [Line Items]    
Recourse Debt Total $ 5,015  
Junior subordinated notes and debentures payable 517 517
Long-term Debt of Registrant, Maturities, Repayments of Principal, Fiscal Year Maturity [Abstract]    
2016 0  
2017 181  
2018 0  
2019 774  
2020 469  
Thereafter 3,591  
Parent Company | 7.75% Senior Unsecured Note Due 2015    
Condensed Financial Statements, Captions [Line Items]    
Recourse Debt Total 0 151
Parent Company | 9.75% Senior Unsecured Note Due 2016    
Condensed Financial Statements, Captions [Line Items]    
Recourse Debt Total 0 164
Parent Company | 8.00% Senior Unsecured Note Due 2017    
Condensed Financial Statements, Captions [Line Items]    
Recourse Debt Total 181 525
Parent Company | Senior Unsecured Note LIBOR plus 3% due 2019    
Condensed Financial Statements, Captions [Line Items]    
Recourse Debt Total 775 775
Parent Company | 8.00% Senior Unsecured Note Due 2020    
Condensed Financial Statements, Captions [Line Items]    
Recourse Debt Total 469 625
Parent Company | 7.38% Senior Unsecured Note Due 2021    
Condensed Financial Statements, Captions [Line Items]    
Recourse Debt Total 1,000 1,000
Parent Company | 4.88% Senior Unsecured Note Due 2023    
Condensed Financial Statements, Captions [Line Items]    
Recourse Debt Total 750 750
Parent Company | 5.50% Senior Unsecured Note Due 2024    
Condensed Financial Statements, Captions [Line Items]    
Recourse Debt Total $ 750 750
Parent Company | 5.50% Unsecured senior notes due 2025 [Domain]    
Condensed Financial Statements, Captions [Line Items]    
Interest Rate 5.50%  
Recourse Debt Total $ 575 0
Parent Company | Unamortized Discounts    
Condensed Financial Statements, Captions [Line Items]    
Recourse Debt Total $ (2) $ 1
Parent Company | Recourse Debt | 7.75% Senior Unsecured Note Due 2014    
Condensed Financial Statements, Captions [Line Items]    
Interest Rate   7.75%
Parent Company | Recourse Debt | 7.75% Senior Unsecured Note Due 2015    
Condensed Financial Statements, Captions [Line Items]    
Interest Rate 7.75% 7.75%
Parent Company | Recourse Debt | 9.75% Senior Unsecured Note Due 2016    
Condensed Financial Statements, Captions [Line Items]    
Interest Rate 9.75% 9.75%
Parent Company | Recourse Debt | 8.00% Senior Unsecured Note Due 2017    
Condensed Financial Statements, Captions [Line Items]    
Interest Rate 8.00% 8.00%
Parent Company | Recourse Debt | 8.00% Senior Unsecured Note Due 2020    
Condensed Financial Statements, Captions [Line Items]    
Interest Rate   8.00%
Parent Company | Recourse Debt | 7.38% Senior Unsecured Note Due 2021    
Condensed Financial Statements, Captions [Line Items]    
Interest Rate 7.38% 7.38%
Parent Company | Recourse Debt | 4.88% Senior Unsecured Note Due 2023    
Condensed Financial Statements, Captions [Line Items]    
Interest Rate 4.875% 4.88%
Parent Company | Recourse Debt | LIBOR | Senior Secured Term Loan LIBOR Plus 2.75% Due 2018    
Condensed Financial Statements, Captions [Line Items]    
Basis spread on variable rate 2.75% 2.75%
Parent Company | Recourse Debt | LIBOR | Senior Unsecured Note LIBOR plus 3% due 2019    
Condensed Financial Statements, Captions [Line Items]    
Basis spread on variable rate 3.00%  
Parent Company | Recourse Debt Excluding Junior Subordinated Debt    
Condensed Financial Statements, Captions [Line Items]    
Recourse Debt Total $ 4,498 $ 4,741
Less: Current maturities 0 (151)
Recourse Debt Non Current $ 4,498 $ 4,590

v3.3.1.900
Schedule I - Condensed Financial Information of Parent (Dividends from Subsidiaries and Affiliates) (Details) - USD ($)
$ in Millions
12 Months Ended
Dec. 31, 2015
Dec. 31, 2014
Dec. 31, 2013
Condensed Financial Information of Parent Company Only Disclosure [Abstract]      
Cash Dividends Paid to Parent Company by Consolidated Subsidiaries $ 748 $ 880 $ 818

v3.3.1.900
Schedule I - Condensed Financial Information of Parent (Guarantees and Letters of Credit) (Details)
12 Months Ended
Dec. 31, 2015
USD ($)
agreement
Condensed Financial Statements, Captions [Line Items]  
Obligations maximum exposure, total $ 490,000,000
Obligations number of agreements | agreement 26
Parent Company  
Condensed Financial Statements, Captions [Line Items]  
Letter of credit, fee range minimum 0.20%
Letter of credit, fee range maximum 2.50%
Guarantees  
Condensed Financial Statements, Captions [Line Items]  
Obligations maximum exposure, total $ 369,000,000
Obligations number of agreements | agreement 14
Guarantees | Parent Company  
Condensed Financial Statements, Captions [Line Items]  
Obligations, Minimum Individual Exposures $ 1,000,000
Obligations, individual exposures (minimum less than $1 million) $ 53,000,000
Guarantees and Asset Sale Related Indemnities (Combined) [Member]  
Condensed Financial Statements, Captions [Line Items]  
Obligations number of agreements | agreement 15
Guarantees and Asset Sale Related Indemnities (Combined) [Member] | Parent Company  
Condensed Financial Statements, Captions [Line Items]  
Obligations maximum exposure, total $ 396,000,000
Letter of Credit  
Condensed Financial Statements, Captions [Line Items]  
Obligations number of agreements | agreement 7
Letters of credit outstanding $ 62,000,000
Letter of Credit | Parent Company  
Condensed Financial Statements, Captions [Line Items]  
Obligations, Minimum Individual Exposures 1,000,000
Obligations, individual exposures (minimum less than $1 million) 29,000,000
Cash Collateralized Letters Of Credit  
Condensed Financial Statements, Captions [Line Items]  
Obligations maximum exposure, total $ 32,000,000
Obligations number of agreements | agreement 4
Cash Collateralized Letters Of Credit | Parent Company  
Condensed Financial Statements, Captions [Line Items]  
Obligations maximum exposure, total $ 32,000,000
Obligations, Minimum Individual Exposures 1,000,000
Obligations, individual exposures (minimum less than $1 million) $ 15,000,000

v3.3.1.900
Schedule II - Valuation and Qualifying Accounts (Details) - USD ($)
$ in Millions
12 Months Ended
Dec. 31, 2015
Dec. 31, 2014
Dec. 31, 2013
Movement in Valuation Allowances and Reserves [Roll Forward]      
Valuation Allowances and Reserves, Balance $ 96 $ 134 $ 195
Valuation Allowances and Reserves, Charged to Cost and Expense 88 61 38
Valuation Allowances and Reserves, Deductions (60) (88) (77)
Valuation Allowances and Reserves, Adjustments (29) (11) (22)
Valuation Allowances and Reserves, Balance $ 95 $ 96 $ 134

v3.3.1.900
Label Element Value
Sonel [Member]  
Divestiture Of Ownership In Subsidiary Percent aes_DivestitureOfOwnershipInSubsidiaryPercent 56.00%

IDEA: XBRL DOCUMENT
begin 644 Financial_Report.xlsx
M4$L#!!0    ( -:25TB$( ;/H0,   !L   3    6T-O;G1E;G1?5'EP97-=
M+GAM;,W;RT[;0 !&X5=!V5;$_GUW!6Q*MRU2^P)N/"$6OFEF"/#VM0.H;10J
M:(ET-H1D[)E))OEVY^S[PVC66PVCZ:60]V*[R
MTU-['8S5ZJ:Z-D$4AEFP&GIO>G_JYSD6%V=?M\;:IC8GGQX'YKG/%]4XMLVJ
M\LW0!]N^WIOU=%BOFY6IA]5M-]VR]-/2YL,TOCBYJJS_4G73%,%]&^P&'O]J
M.8\'[[.@&ZVI:KO?M/#39[>TIMU=XS;-
M^+34Y_MI%C>]=KZ81MVK5MB_\6\[:[KYT,;^^H\[YN?_^%[V/L1MUU[:ZJ[9
M6V![M&.:'Y==U?2'CNINL#<_AN'F/;\F9GY7M:E/1SM=:'USX%LR77PUC;I@
MFOJ_UG[^IJP&:UZUX'SA$7\4F\J:^INWT_D>_FW\?L'Q]C&?Z^[_EPY]-^B"
MW<,1D7C3/B+(/F+(/A+(/E+(/C+(/G+(/@K(/DK(/A12-D(1511213%5%%1%
M45445D5Q511819$UHL@:462-*+)&%%DCBJP11=:((FM$D36BR!I19(TILL84
M66.*K#%%UI@B:TR1-:;(&E-DC2FRQA19$XJL"476A")K0I$UH)$69PJBY-E8;HL8<(L8(L
M8>HL8?(L8?HL80(M80HM81(M81HM82(M82HM83(M83HM84(M84HM85(M85HM
M86(M86HM87(M87HM88(M88HM89(M89HM8:(M8:HM8;(M8;HM8<(M8(M8>HM8?(M8?HM80(N80HN81(N81HN82(N82HN83(N83HN84(N84HN
M85(N85HN86(N86HN87(N87HN88(N88HN89(N89HN8:(N8:HN8;(N8;HN8<(N
M8(N8>HN8?(N8?HN80(O_2J\@GEI=_$34$L#!!0    ( -:2
M5TA(=07NQ0   "L"   +    7W)E;',O+G)E;'.MDLMNPD ,17\EFGUQ2B46
M$6'%AAU"_( [XSR4S'CD,2+]^X[8@,)#K<32KWN/KKP.J:P.-*+V'%+7QU1,
M?@RIROW:=*JQ DBV(X]IP9%"GC8L'C67TD)$.V!+L"S+%4EK0VTPAGEN&;>5ADZ3SXB?078VZ:WM*6[13@2=&AXD7U(V8#$NTIO8+Z>@"%,;X[)9J4@B,WHX*[O]C\
M E!+ P04    " #6DE=(C764,OL$  "/<0  &@   'AL+U]R96QS+W=O_O\WXMU[\LS[O3TV&_/CZ]KE=_OCSO
MU^OS_V\VCZ?3Z_5VN]X^+B^[]=/A==F?7[T_'%]VI_.?QX?MZ^[V^^YAV=92
MVO;X_CJ;+Y]_OO;5M[N;S?';7397O^V.#\OI9O/'X?A]?5R6T[I]^Y5/YQN<
M7_[QNOR?VQ_N[Y]NEZ^'V]]?EOWI/U9L_[G!9GMY4+T\J"J#NLN#.F50?WE0
MKPP:+@\:E$'M\J"F#!HO#QJ50=/E09,R:+X\:%8&I4 9BS.)8NW4.I#K.+T.
M!#M.L0/)CM/L0+3C5#N0[3C=#H0[3KD#Z8[3[D"\X]2[0KVK4^\*]:[29VWZ
ML.W4NT*]JU/O"O6N3KTKU+LZ]:Y0[^K4NT*]JU/O"O6N3KTKU+LZ]>Z@WIU3
M[P[JW3GU[J#>G?2LA!Z6./7NH-Z=4^\.ZMTY]>Z@WIU3[P[JW3GU[J#>G5/O
M#NK=.?7NH=Z]4^\>ZMT[]>ZAWKU3[Q[JW4O/NNEAMU/O'NK=._7NH=Z]4^\>
MZMT[]>ZAWKU3[Q[JW3OU'J#>@U/O >H]./4>H-Z#4^\!ZCTX]1Z@WH/T725]
M6>G4>X!Z#TZ]!ZCWX-1[@'H/3KT'J/?@U+M!O9M3[P;U;DZ]&]2[.?5N4._F
MU+M!O9M3[P;U;M)9$SILXM2[0;V;4^\&]6Y.O1O4NSGU'J'>HU/O$>H].O4>
MH=ZC4^\1ZCTZ]1ZAWJ-3[Q'J/3KU'J'>HW16D X+.O4>H=ZC4^\1ZCTZ]9Z@
MWI-3[PGJ/3GUGJ#>DU/O">H].?6>H-Z34^\)ZCTY]9Z@WI-3[PGJ/4EGO>FP
MMU/O">H].?6>H=ZS4^\9ZCT[]9ZAWK-3[QGJ/3OUGJ'>LU/O&>H]._6>H=ZS
M4^\9ZCT[]9ZAWK-D=0CK6%H'N8[D=0J!G2*)G4)DITAFIQ#:*9+:*<1VBN1V
M"L&=(LF=0G2G2':G$-XIDMXIQ'>*Y'<* 9XB%1T!IB8PD6!*14>$:2E,9)B6
MPT2(:4E,I)B6Q42,:6E,Y)B6QT20:8E,))F2R0RAS$@J,\0R([G,$,R,)#-#
M-#.2S0SAS$@Z,\0S(_G,$-",)#1#1#.2T0PAS4A*,\0T(SG-$-2,)#5#5#.2
MU0QAS4A:,\0U(WG-$-B,)#9#9#.2V0RAS4AJ,\0V([G-$-R,)#=#=#.2W0SA
MS4AZ,\0W(_G-$.",)#A#A#.2X0PASDB*,\0X(SG.$.2,)#E#E#.2Y0QASDB:
M,\0Y(WG.$.B,)#I#I#.2Z0RASDBJ,\0Z([G.$.R,)#M#M#.2[0SASDBZ,\0[
M(_G.$/",)#Q#Q#.2\0PASTC*,\0\(SG/$/2,)#U#U#.2]0QASTC:,\0](WG/
M$/B,)#Y#Y#.2^0RASTCJ,\0^([G/$/R,)#]#]#.2_0SASTCZ,\0_(_G/$ "-
M)$!#!#22 0TAT$@*-,1 (SG0$ 2-)$%#%#22!0UAT$@:-,1!(WG0$ B-)$)#
M)#22"0VAT$@J-,1"([G0$ R-)$-#-#22#0WAT$@Z-,1#(_G0$!"-)$1#1#22
M$0TAT4A*-,1$(SG1O(>BZ^/NN-S]>CH^[1_6CY[SKXOSI'<]7T\_GI>/W_)V
M51[QKM^G\ZV6[=O/#W\_OUWU[R7;GZ>L7_X"4$L#!!0    ( -:25T@MB-:^
MA@<  "Y
M-)F4&7)IFYE<.(&TSXHM0!-C44FFH;_^K&1#;;):;!Y.7F++^^FRN]IOM>(B
M,]WS@59SH:T4AKW-TLR<0^.7O:FU\_-.Q\13,>/F'Q#)X.M8Z1FW\*HG'34>
MRUAZU[MPH_3G\U3&W$J5]>YEK)518\MN
MWF*17G0V!3P">AZ*.-?2+GO=0J;:Y&6&,4_%%8S5&_/4B$+J;Z.7N5*S.<^6
MG>+M3F:OYGD^4M?#_>*88M6_YS.C=6]GTJ_FJD0UEQT
MUHW^L2I;?99'O>CLDQ>!Q[IH9[VT7JFWVL)=RTC:5)C'\8!K^S_IPB]JI0F8
M^UYE_:L^6#]+V$UFP2'9;5:,!>:K*F7]=*4RHU*9@'LE[)*G/(L%&[Y38A-Y
MMC_@VS%#"__<+ U38_8(KK@#YK@MQFVW'3"GK3&PHW; G+7&<#-%,=]$)C1/
M&0<7&.:S&==+)S^4DTR"GZ&8VVP!_2J]1+^6D7C)!F!LZSN^^97+N9L+"O@*
M&X3]X&DN@J,96ZSD-F/W7+\*RU]2<",715',M=!R 4Z\$ "!AKR N[E\%\D$
MGX;,P#EAP[(G$0N PQ"X3V_,R/7:3Q;.LPT;*89B'NU4:/:@L@/GPC U&.?F
M#7:W$0R^X;91*ODMT\(X10>WF840+-WJ^RCF24SRE#OCL+XQHESTG>0O,I56
M!K3U@EL&/'HFBX6&',XM1(#: JJZ!/<:2^M] 9=POF%Q3QJ*B0]/;@7?A)IH
M/I_*>!VB<(PCMH-+B'^)W\2@X' P>Q*)@##K?J6VB^%$B[['/&W@#*OI8F]QG-87.E&L.5+MT[Q&<2@
M7R/_"D(G.:EN:U&/\9MHFV7&8VY#-/(O41
MS+'DDHTT> Z/PS,8BA1(%.3_S0$ FY90?@6I @9L[)5F-MP3B0BW'>9%X1,-WV$?GHT_:-R.IO^P-%[2X3
MV%X-KZ(QN"VIS&X[:NL]>2./=H%\'O!3:[AE+<5!+(N,.U2:%75Q/Z QN!_0
M&-P/1LI"M TF=:W3N:@;X (2$^ "$H/[ 8W!_8#$1+@?T!@\'E I;13A?D!C
M0O' I<'.FBY*YQIR+=]TQ;5>2MRF(.@!RB"5>DD4QQ;P6X@->CBN/'$+/7,:V<)<\CA1&
M.C<6J&'[(>0.N$V8C^QK#HH6[#Y@GSI&99,#/^8@U_&4!WBNAJDLI(Q632?1I@XSF=Y
MD?J[3PTP&SW\;(+9=T>CV/H+ADRP0)$%T0&<7J1*X&AX&8C3Q'IP9H&N)]M8-9II8*0^E7AN=X&QA&4/V*56X<^<5=/;;^E
MG;I@%>.Z+C'EOP,?-\H3J7-R'W/PAP9S
MV[^6"PG'Q,10^V<#4YSVG\2%Y 8W!\P(:@^<%X0J)
M=]>6&*_"UI@H4.T+8YZ&S^QJ!PQ^I4-B3%L=#':8VV"'N0UVF)NGE=95K^@8
MSP_#52^((0K/)<(8_Z5EI7>' )P;E6 TP[Q*J
MUO7)Z#10-R Q^#F!O)X+W& @%W2E>'@]6.UT78-4X\:8;7EU<<_7W[SG(W-7
MJDX+$!@W$OK>G 4J"-2EXM1H(Y(U9"C0!V1QN!U QH3R ](3" _
M(#&!_(#$!/(#$H/[ 8DYP^L&-";@!T2-/PK4$6'7@(].E/8A[=:*F0$L%^;@
ML+N1A[C'VN_--GY=UJG_+++W'U!+ P04    " #6DE=($)[?R3X!  !I P  
M$0   &1O8U!R;W!S+V-O&ULS9--3\,P#(;_"NJ]2]N)"55=#X X,0F)
M(1"WD'A;6/.AQ%/7?T_F=2T#+KMQJVN_CU_'225<*:R')V\=>%00KO:Z,:$4
M;IYL$%W)6! ;T#Q,8H6)R97UFF,,_9HY+K9\#:S(LAG3@%QRY.P 3-U 3.I*
MBE)XX&A]CY=BP+N=;P@F!8,&-!@,+)_D+*E?S-;8UE1LU-=5=-SP@ LKU4J!
MO.W&LM^IV!G!ZW"4@QS:T]\_/5"&)7WE/JBAJFW;23NENCAPSMX6C\]T-JDR
M ;D1$%5!E=@YF">GSJ_3N_OE0U(763Y+LR(MILO\IBSR\CI[/TQVYF\TK/LA
M_JWCDT':+BILX,+=DD;2AIKNUQ@=7DY&PO=&AE;64O=&AE;64Q+GAM;.U:6W/:.!1^[Z_0>&?V;0O&
M-H&VM!-S:7;;M)F$[4X?A1%8C6QY9)&$?[]'-A#+E@WMDDVZFSP$+.G[SD5'
MY^@X>?/N+F+HAHB4\GA@V2_;UKNW+][@5S(D$4$P&:>O\, *I4Q>M5II ,,X
M?+&A T%116F]?
M(+3E'S/X%/F7/Z3H=,H%N,!M8('_.;Z?D
M3EJ(X53"Q,!J9S]6:\?1TDB @LE]E 6Z2?:CTQ4(,@T[.IU8SG9\]L3MGXS*
MVG0T;1K@X_%X.+;+THMP' 3@4;N>PIWT;+^D00FTHVG09-CVVJZ1IJJ-4T_3
M]WW?ZYMHG J-6T_3:W?=TXZ)QJW0> V^\4^'PZZ)QJO0=.MI)B?]KFNDZ19H
M0D;CZWH2%;7E0-,@ %AP=M;,T@.67BGZ=90:V1V[W4%<\%CN.8D1_L;%!-9I
MTAF6-$9RG9 %#@ WQ-%,4'RO0;:*X,*2TER0UL\IM5 :")K(@?5'@B'%W*_]
M]9>[R:0S>IU].LYKE']IJP&G[;N;SY/\<^CDGZ>3UTU"SG"\+ GQ^R-;88C'(CN]WV6'WV3T=N
M(]>IP+,BUY1&)$6?R"VZY!$XM4D-,A,_")V&F&I0' *D"3&6H8;XM,:L$> 3
M?;>^",C?C8CWJV^:/5>A6$G:A/@01AKBG'/F<]%L^P>E1M'V5;SCFED)O816:I^JAS0^J!XR"@7QN1X^Y7IX"C>6QKQ0
MKH)[ ?_1VC?"J_B"P#E_+GW/I>^Y]#VATK\>WZV22$KYI9+2,6D$N!LT$DN/R+RO J
MQ GH9%LE"0AMNZ5/U2I77Y:^Y*+@\6^3IKZ%T/BS/^3Q?Y[3-
M"S-#MW)+ZK:4OK4F.$KTL@'37[]EUVY".E,%.70[@:
M0KX#;;J=W#HXGIB1N0K34I!OP_GIQ7@:XCG9!+E]F%=MY]C1T?OGP5&PH^\\
MEAW'B/*B(>ZAAIC/PT.'>7M?F&>5QE T%&ULK"0L1K=@N-?Q+!3@9& MH >#
MKU$"\E)58#%;Q@,KD*)\3(Q%Z'#GEUQ?X]&2X]NF9;5NKREW&6TB4CG":9@3
M9ZO*WF6QP54=SU5;\K"^:CVT%4[/_EFMR)\,$4X6"Q)(8Y07IDJB\QE3ON>;G*YZ(G;ZEW?!8/+]<,E'#^4[YU_T74.N?O;=X_INDSM(3)QYQ1$!
M=$4"(Y4U#VT%SU&\Z.9X!ZSAW.;>KC"1:S_
M6-8>^3+?.7#;.MX#7N83+$.D?L%]BHJ $:MBOKJO3_DEG#NT>_&!()O\UMND
M]MW@#'S4JUJE9"L1/TL'?!^2!F.,6_0T7X\48JVFL:W&VC$,>8!8\PRA9CC?
MAT6:&C/5BZPYC0IO0=5 Y3_;U UH]@TT')$%7C&9MC:CY$X*/-S^[PVPPL2.
MX>V+OP%02P,$%     @ UI)72%Z+Q2\1 P  LQ4   T   !X;"]S='EL97,N
M>&ULS9C=;ILP%,=?!=%I:J6ID*1-VI4@=94B3_\;?S1$R]C:PQOYQ R:Q7C)!O:<\;2
MCXZ33>>N@V<[FO@NXWH/-P3BIZ5CH.GJ9IAZ0*^*0%/(9+B!MFL>RKGIL#=P6;7\??C1!)].'9M9?"][-Y: LSCY<*?$DRH
MQ?CIRU6HK0!BJ"(N $8!1<(8@1CAM3++=2T/[#PN1@FA,K?*4,USZ.I,=!8,
M;3?_>WRZ0-/E0PP/8;P]/&[PO10P!FDRXB]6WIZL4SZXA"10B91Q+=$S"M:=
M[G&I@WSPO &A(:3ZUK$+D^]A&#'>@:+97#P9285TPAB)>2-$8$82@ 6RZ)$W
M.'8*,;X5U^.W:(N]BBP5([ZQ:UM"1='D$Y$W]3*0D^J4:8I=PG9[S^):JVB3
M@/<&:8K7YQC-DA@JL+A3#E!DAM:PDI0].R
MY2<%Z02N6+Z"G574I/"Y0S9=D\[/%]W_G!"Y]NV*GMT2I.ER$0>0CN21^'1A
MO8&IRL1_D&\F[56WVK.7T*O,4M_4#]@[-569* 2,E79BKC1S/^C V -6E$G&
M2NN:*ZUGKK0C"EMX&3%U>E"FZK?MM8K6"!
M,$-)H0&(BOM2Z,9;I96NW3@S7.FR37H9"##V;H^%
M_$Y_$S79((:V;G^%(5K$ZB<$_3.M_P]02P,$%     @ UI)72+*\P]0##   
M0#H   \   !X;"]W;W)K8F]O:RYX;6R5FVU3VS@7AO^*)Y^Z,\M#Y+PX[BP[
M0TOI,M/2/$"[GXVM$$T=.RO;4/KK5W("G#O<43>?VB3DPB_7D8YTFS^:MP^U
M_7Y;U]^C'ZNR:M[:D\&R;==OCX^;?*E76?._>JTK]]FBMJNL=2_MW7&]6)A<
MG]5YM])5>QP/A]-CJ\NL-775+,VZ&6QIS7^A-6NKLZ)9:MVNR@ULE9EJ\.S3[ST9J'@S#,!&@G0Z!>@Z];]XT^RB>I%]&6MK0"-!6A\*&@B
M0!,!FAP$>E^OU@(T%:#IH:!$@!(!2@X#+3-YZV<"-#L4E I0*D#I8:"L64H9
MA]+&X6O41UUIFY51YK2^[E:KS#YZS+6YJXP;VB0*Q"9F7U3W[BAJ^RB_)$56
MQ.2Y=>.@=<4T=Q*W_6%\^*A^A/Z2Q=W$B7%
M5<3<_
MM$MMH\NZ.O+C@3L_=U0??KBIJ]&1^TRBI+2*6/NQKHL'4VYW?F1
M.#J5HY^T-B;67NF[SDVRSK7HM>]CI_,ED_OAN)DM;&Q-HS?2M%BV'DI4/O
M:F4VUU9^3?H9\X'67SOM[BO?+[CP9
M2_5BHMZ5+K3KE/IJ;.O\>S\N=;>-*4QFC:SS6*H7$_6>;,OKE=Z,,1N%Y40I
MG1L1YWK1HHO5VHTT_64B#"G;B Z1_1'<9#] @I&4;D2D.S--W@O4N>NY+40W
M!VQ'EU*B8,(G(I[FSHO&O'S?L=?U]@T)DF*.B)@ DB\D1$HZ8I)FMG)ET41S
M=W]Z:>2WI; C(NR5:;YO3N*K&]MLZWKE%LMK)$4=$5&O?+/N+NH\\Y/0C75%
MYMO7G=.0JHZ(JM>ZU+G'_+]S'&W+QV@[B+NI]0SZ,:GJB*CJ#=?_=+U@?CZ-
M\ W9D4ECQ\38:[?2*#I7/A?1D:O"JO"Z%L]')E%2W#$1]P7E67Z>[0WLK[T[
M9XF2+H^)R\&.8SR2*.GR^%>#:H2OWLQKB8+VE=B\'?N:/8.?1$FGQ__)Z4B^
M)5%2\#$1/'RM9 \[EJ*/]_0$?7<6O;GI&XK?Y+>EX&,B^%.;]COKTZ(W$B4%
M'Q/!7SHU=B03*?6$2!ULV29*HJ34$SKU!UJV22Q14NH)D9JV;/3\I-,3XG2P
M=YN,)4HZ/2%.AWHW=V@2!8LRXG2P=YM,)4HZ/6&#=JAWFTBG)]+I"7':]V[T
M(DN=)W0E]MS$T>]+AR=\ 2:'FM>$J=1X2C2&MHX2I+U38N^FOZ-?E;9.B:W!
M1F\JA^"IU'5*=-W7Z&V/2Z*DKE.B:[#?F\HMA*G4=4ITW=?OD:."702BZ[ZV
MCZ"DKE,Z!+]T?_2^26VG1-M@&SB5&PA3:?"4&$PF*7)$B=0XH0NQ?>U3CY,H
MZ7/"6HQ0#Y7(T3B1?B?,[U#CDTB_$^EWPOP.-3Z)'(X3Z7="_ Y.YHGT.Y%^
M)VPX#J+D<)Q(OY-#6XP$MLE@GXSX'4;-)$J:GA#31;=RYJ9W4Z*6TNZ$V!UL
M5V9#N64G#9\1P\,HV6_,I.$S8G@8)0V?2<-G@6TSCI*&SZ3A,V)X&"4-GTG#
M9\1PV=I=^0TTZUN.SSIK.JM7WIH=YU*VU-I>WIH=YU*VU-I>\JV/X(H:7LJ;4^)
M[6&4M#V5MJ?$]C!*CN>IM#T]=/,XE>-Y*FU/B>UAE!S/4VE[2MOK$$J.YZFT
M/66=2Q %T0=D'\3V$$H-Y=C>OQ+I!_%]S[J-S#EJ"/G'<$\ LF_IIH8QP" 7
M&1+GP[ 1P" <&1ZXJ%3#,< @,QD2[V_JUDWR>Q>7 (/49'C@PE(-IP"#W&3(
M>ID@+ $89"A#ULT$83. 08HR)/Z'82G ($<9'ABD* 45@/D?#0"#, 4P3 !)
M!836]DI!!6 RR*+!, PJ .-!E@]NM@J\KKZ+Z*Q;P/5OO<^L?30@+::&+#;<
M!_N*]_@X 3LD3%PL3M+I*V
M*[]6O/?/D?B&Y\9V3>O:'H!!!; X$7:6/KFN4#>_1^>=\T)'G]&S&+/Q<-;H
M8'5U=]0?Y;RS^3)K\,B@ G@"*6#B8FTG.X!!!;!44NS'UPWE7%]FF+#F!@/LLQ=V"GJ[KS]\#;
MZQ;&/P$&YK,D6Y]VJV^S!^(_@D0DPGT6:"-M!_XTP,)]EFSM?]SMF>=L_
M_U/I",(8!7FG8H$GN0%SU_?5ANF9_P  ;FL]AS!^;_V4Q/
MT6E9UO# #*2?BL6?.S"QD'/7;0XU"6&H8FGH#NQYU5R[R?V\AH=9(!95+!?=
M@?G.KM^DTFDC$^,[4_*J7I@1I/  85P,+2
M4.ZJQM#_0UJJ6%P:AD'_#WFI8H%I& ;]/\2GBN6G^V.2ON8!!A7 $M3]L/[&
M2AC$J8KEJ2&8@CQ50:"J6**Z'W9U_35Z#S"H ):IAF&G (,*8+%J$-; #8!<
M5;%@=3]L_NHT\;E!5@%!&)XF5  +5X.PG=.$"F#QZGY8WUT!#"J 1:ZA=$]-
M8 4,\:MB^>O^?,]-*#4L)B")52R*W0_K/P$85 !+9??'A?U[ (,*8#GM?MBK
M&P!!K6))+::/_G[6U=-3P^XS@$$%L*P681\6"YUO=^3Z]P$&%<#26H2]O(KF
MV:,3!F#X["RI (2=Z86VUOGK)K>@RW#2\L#"C0WBK6'J+L*]^
MR[]? &R/#F!0 2R_1=BKY9R$08BK6(H;RI55 G, Q+B*Y;AA&.P!09"K6)(;
M?%H1GCM2$.4JEN62)Q:WG-?7#"J I;DL0'\.B^L%P* "6)[+8'OV,R#052S1
MW3P5>;K[5"1;Z"?X)/E!ST?VIPLPJ "6ZH9@*H$Y ")>Q3+> ,R_D# (>15+
M>4,/'RA(>17$O(KEO*%'.!7DO J"7L62WM"S# J27@51KV)9;Q@&.0"$O8JE
MO6$8K ,@[E4L[PW#8!T @:]BB6\8!NL B'P5RWS#,%@'S/"O*=@Z( B#"H#8
M5['<-PA+(0> X%>QY#<,@PJ Z%>Q[#?TU(R"[%=!^*M8^NM&,5?H=_Y/ =T!
M7;1ZU3AHIINC>+BS0H'X5VWRW^,MK?^3OD(O3*6+2P=N^E^49V7N_PK2_=,3
MXO'$;S_[UY_KPOUV_^>+@VC1E>5[]]Z7ZE.=^9_;DI_^[O'/?P%02P,$%   
M  @ UI)72)BV=N:' @  GPD  !@   !X;"]W;W)KT^;-74/.P^DX0DUJ@X0.+LWR^@<0RT
MDX?(Y9P^-'1#YQWC[^)*J?0^ZZH1:_\J9;L* G&\TIJ(%];21LV<&:^)5%U^
M"43+*3D94ET%. S3H"9EXQ>Y&7OE1;E*/1 4>3#R3F5-&U&RQN/TO/8W:+5'F888Q)^2=F+2]O3B#XR]Z\ZOT]H/
M]1IH18]2FR#JR=Z)K=*OK'N)QU\2+3!(ZN$^?>.-R%9_:#X7DT^^V_9F&_7SR3I0(,)>"#@
MD8#C;PG10(A& OJ>$ ^$V"($O2MF(_9$DB+GK/-X?WHMT4&"5K':ZJ,>-#MK
MYM16"#5Z+\(\N&LS V+;(_ $@49$H&R/ A@2V&*'CI\%=BXB>D;L740,+R$"
M?8P,/9K0$\M'%Y'" C$H$#OTS!)P$0M8( $%$H>^M 19Y_((7>4LN]#?AE[(1WH%)]&+VMBKJI;&3D7/
M4C9]_=!W)&L?Y=!8DQ7_ 5!+ P04    " #6DE=(>7G5VW@%  #,'@  
M&    'AL+W=OGA?=_M#4CU/0
M=K.0H@B+;;W>S>^6T[EOA[ME^]IOUKOFVV'6O6ZW]>'?5;-IC[=S,W\_\7W]
M_-*/)Q9WR\5'W.-ZV^RZ=;N;'9JGV_DOYJ;R?I1,BK_6S;&[^#T;S=^W[8_Q
MX(_'VWDQ>F@VS4,_7J(>OMZ:JMELQBL-+?]SONC_;8Z!E[_?K_[;U-W!_GW=
M-56[^7O]V+\,;HOY[+%YJE\W_??V^'MS[L/D\*'==-/G[.&UZ]OM>\A\MJU_
MGK[7N^G[>/HG%>O7NJ_OEH?V.#N<'L:^
M'I^YN;'#G7L83TXW:OIOZ%DWG'V[L\5R\39>YRQ9G21R(9%K184*:SXDBZ']
M#Q-"3<@4'R_CA<=;&F^G>'L9;U4G3I(P27:3Q$C0_2 B;TONQ%$G#ITXY>0D
M\1>-2.F5$:))EOOPU(=''ZJ-E8*]3$(G,_ O41T$=0/@+VU47U^"HB
MRCJ)U$E$)U$YB=!(B/K)H"86F;&:J(^$/I+RD: -E9(5*N3"Z96+DKHHT46I
M7)30ABF4TXIH.&\]58 +3+X,AP+AH$H]-@-$B]:(SN#HI2
MS-U;SD:#<'0:C@;))\F5X 9EMG ^ R;#&6D0DDY#TB  OY3.E=H/DY4A RC#
M26D0E4ZCTB ';1$@)8DJIEQ*>,SI8KAY#0EYD+F
M>0M'GB#RO$:>(,R"T;, $?F+2>W:"P>>(/"\!IX@S'S0\R(1.9,K C-5(#+/
M:^8)TLP8'[49HG(^9=QPY@D6E5X7E6?-U8 RNH9BHI2[,YR>0LI*G0."8/1.
M)R01A1P=A--3D)Y>DUP0BX:8054&Y,+!*0A.KT$NI'+TN@:MF"JXG!N.34%L
M>HUQ(>6C";JJ(BI?IAQD.#8%L:G39"7(0QN29E'%9*D,F1)".#8%L9E+2,NQ
M:0DV=#4V"2:W'#AV+2(33V=KRP",91 !JHJ,Q6(Y=BT$<"00XOE
MJ+.(NJ!19Y%A9AC8<&^9+)@<&CCJ+"ZN,0%PY>P+HXLJIC)%YOXZCDV'V(3:
MP1%L%J5^VDPE,>>&8],1;((;LL 67>(1D;$NDY&.<],1;NH9Q1$B)ECO$Y45
MR;GAW'3(S:AG%(<[E&(-+$N9S/E<6KG,5B;2,^I9A6GTINKGFFLGG)P.R:EW
M?U9GS667O1[G%1'EIGW'V>D"T"IFUK..\\YAF:@W&5<."T#HRF>2:Q^F1V)&S2B/+/QB
M4])NJ$Q2)A$]9Z9'9D:-*8\X_&*2WN&NJ,S&3%GE.38]8C-I4'D"1 /;543E
M) <'S['I$9M)8\IC+6D+T:"B*I][[<*AZ1%V2<_]GBS"C49K15312F9SW6?>
M B$X]1!=>60B6P0R&5D$+B[>.^[KY^;/^O"\WG6S^[;OV^WTHO&I;?MFN&3Q
M=;CD2U,_?AQLFJ=^_!F'WX?3R];30=_NW]\=?[S OOL/4$L#!!0    ( -:2
M5T@V"84$J0(   L*   8    >&PO=V]R:W-H965T&ULC9;?
MDMH@%,9?)9,'V/ G(61'G:EV.NU%9W;VHKU&1R49=YBM/;P&N]
M/Q@WD"UFV3UN6[>RT[7JDE[NYNDG_+S"S$F\XD;DS:JO86D22O>AVO=^>MEN%.B:U@\@%P#
MR#T Y_\,H-< &@1D YFOZ[,P8C'KU27IA\TX"K?G^)G:E=NX0;]0_IZM3-O1
M\X+GL^SLYKE*EH.$C"3D4;&""HKODLSFOT.0* 3Q\>48HHC'TV@\]?%T',^"
M(@8)\Y+.2ZHBJ"(B87&*/$J10XHRH,AABD"R@A)<\#A&$<4H( 8/, 8)'^5 
M3P@'(/\1/9"P* F#)%5 ,DB*<;76889?P/,AZ0-5&:4J 545I%J6(!6WFY S
M1L)%BBGS@E8XGWAT>)2)0Z8@TY*#3(PQCG@9TJ^@LD24%YB,GK4'IBK*5$&F
MX+U?5G!+\@K1DM-PG2)*C!@O>5[%F9SWQNP* :NHZ,0,$X:'85W \3!X"4E!
MJM#UH I7G$S0Q)T/$TA3A#0$+AXEC(8X,1G#$]Z!XTZ*H95.F2".NR#./[Y#
M<0/#T,'@#A6P6+@B4$3R":_ <0O#T,/@_C#P')0L?"DC(HQH").-/MM'L9??
M1;^O.YVLE;$G /^=WBEEI)T1/=FZ#O9D=N\TCU_W\
MM_@#4$L#!!0    ( -:25TC1B$6LQ 4  * @   8    >&PO=V]R:W-H965T
M&ULC9I/;Z-($,6_BN5[;+JJ:2!R+ 5;J]W#2J,Y[)Z)36)K
MC/$ &<]^^^6/X^"JUTDNB4U>5S^*HG[=D,6YK'[4NSQO)K^+P[%^F.Z:YG0_
MG]>;75YD]:P\YG*L^V_:#B,*<@'J9F^'?B^?]DUW8'Y@K[/V0TWG^,[^<0]@%W)2'NO\YV;S635F\#9E.BNSW\'M_['^?A[_$P648'D"7 70=
M8-R' _@R@-\'V \'V,L *P;,AU/I$['.FFRYJ,KSI!JNWBGKBL3:_NC@723I(:"0Q5\6\#7Z=@= ,*:GA=#O!2BO8W$K6
M6I+$V 3#T^1^?#0>G^#Q%HZW_7@>YR (1)X&C>LUQUX3.2=$*RV*X\B*LP6B
M('38;PC]AL"OR&DZ:,*Q7PY8^-6BF")Q =<@4LPA]NN@7P?\BEE2IV8Q-G'2
M,%!%QCKA&*C"./'4=00M1ZJDS"A[-P%B&"#^0DW%RN>="YVHEQ5012&+6&L4
M*^8(6TZ@Y>0+997H:<*0Y64"*A=2+"RC6''@L=SU=]3A F#:RAX7Z)D,!;(7
MKJ#.!J$TCN,Y:SW6/QL@U49'WYAOW^T1 P[:1I
M OE)E&FDBB-I&JB( H]IS ?#P+0"(:.+S\HUE$42:5@6D\^AN,)P/X9&2O
M-AHJ=S*#*RA2MR$011[^&TPG$P''LE5?1#=TEXT::(PLGC44^>H"T]  '!JY
M!#":891(PUK#NC^#0+X$8Q0:P$+#TB\ &!L%%: R$O)K&"ORM O"+"3 0B-9
M2(!=%,M"1JI$+=N1R%,7A!E(@(%&,I TMQ0H5TBD#&M-VRP\AC'_"/#/2/Z1
M9I;<*0!)NX20A8Q5GNY&&'X$X">+-"6-J_;^5%LYH HCN?I&JL!Z-G2$R4> 
M?$:2CS2O[JSJR5!E$FD:J-AZ5OR$X4< ?G*BE#2P0#$#D7*L-;ZF3)A[!+A'
MDGND:14Y51A@QV5T88!0[%G)$08? ?"1!!]I7JG;3TM(KCR!YHX\JV7"V". 
M/7E7I:1II>R"W5VHT@M$)O2U-\P] MPCR3W2K (EH44MC%2.M2H,/1MUQM3C
M0&_5R;,38TPA!A0B22$&\+#R(JR0BM6F!L:RGB4*8Q(Q(!%)$O'G) (2V6H^
ME-QZ]3R@ PR2]UO*8,L$$@Q4'$EPPEB^IR&,&<2 09+0*8.-E=P/KX HO=TZQ@#B$-P*OBN%F<" "?)94\JZD8.3!MT^5B>M113[3AHC@0$2Y!/F
ME#]' I#<21JNDJMP"!)QD43
MS.3#^#66D6<-:C$5+* "2Y1=1,DG>=8J,Y./S=8PEO$L1"W&@]4O< Q[:&@]
MKW! L];U9=%YRV=E0-6>M[RM8"QO@>%^;<&&01>87N>K @N_5F!0YBTP# B+
M *$*S'TIT5K5)EHN:V$L;X%A1EC$"+G^N(A$]S'2-%+)Q>(:JHQFRZ]Z&CH]>7[H_4O0<6QU-SOQY>G;^'62Y.V4O^=U:][(_U
MY*ELFK+HWP4_EV63MR:#65L/NSS;7K\<\N>F^QBUGZOA!?KPI2E/;_\/&PO=V]R:W-H965T
M&ULA53+;J,P%/T5Q'YJGFD:$:22J)I9C%1U,;-VX/)0_:"V
M$SI_/[8AA !J-]B^/N?<3$B;W;JU4NT-(YC50+!]X"TSO
ME%Q0K/125$BV G!A292@P/,VB.*&N6EB8Z\B3?A9D8;!JW#DF5(L_F5 >+=W
M??<:>&NJ6ID 2A,T\HJ& I,-9XZ !3D[FCO%^XOS=+'X5
M>]>/<3AA*LPYP3:;].?I:*TRO%=2C^[,>&V;'K=[;>0%LG! ,A& G^
MYDM".!#"&R'ZDA -A&A&0'TIMA%'K'":"-XYHO]Y+39GQ-]%NM6Y"=K.VCW=
M"JFCE]0/MPFZ&*$!D_688(H9$4BKCRF"M119L* ']PD.2T3HWT..2\C3=MU$
MN%IG:/F/=W4^K0M$JP*1%0BG I$W:U2/V5@,LY@9XK!$!.<A5(M&XT7C4:
MKQB==3.+OS6Z1$0SGTO$#S^>&4638TA!5/8^2R?G9Z;,WYQ$QR?C.3#'>!;/
M]%/2W_R;3)JTN(+?6%0-D\Z)*WU)[%$N.5>@+7H/VF.M'[MQ0:!49OJHYZ*_
M__U"\?;ZFHU/:OH?4$L#!!0    ( -:25TAS])Y%:0,  "L/   8    >&PO
M=V]R:W-H965T&ULC9=-;YM $(;_"N+NP'Z!B6Q+P5;5'BI%
M.;1G8J]M%&!=P''Z[[LLV,$S0]2+@?4SL^\LNS/,XF+JM^:H=>M]E$75+/UC
MVYX>@Z#9'G69-0_FI"O[S][49=;:Q_H0-*=:9SMG5!8!#\,H*+.\\E<+-_9<
MKQ;FW!9YI9]KKSF795;_375A+DN?^=>!E_QP;+N!8+4(;G:[O-15DYO*J_5^
MZ3^QQPUWB"-^Y?K2C.Z]3ORK,6_=PX_=T@\[#;K0V[9SD=G+NU[KHN@\V9G_
M#$X_Y^P,Q_=7[]]F->75Q/?*[*._YI6[7OI_YN%@1AOPP8#?#%CTI8$8#,2G@?S20 X&
M$A@$?2AN(399FZT6M;EX=?_V3EFW2=BCM$N][0;=RKK_[%(T=O1]Q21?!.^=
MHX%)>X:/F1L16.^W*3@U1B1Q3.2:.8*R884S&(%H,*36QYHI4JXAP)>T@(AU$.%RI0+@]
MHT8J9RQD"0B8H&0"7R\!B5C1@F-2<$P(CH#@&,T2 K&8F(&7O,&(G'@UM2+)5D0B+F!&:9$"M58&'6
M%"34',1,4"R$/!%$4P,WB8-@0DXJD=15< 1I0 !4L PXF;H1. &8[T8F9R
M,]#YGQ$%0,$"P'#RCE&*(6H 1]N!J )BH@PPN@XPHA# ?)1043WUJT+^R[NT\UJ<
MUY;LC6FUU1@^V!4]VL[U]E#H?=O=QO:^[GNY_J$UIVMK>NN/5_\ 4$L#!!0 
M   ( -:25TAT9,?;;0(  +D(   8    >&PO=V]R:W-H965T&ULA99-;Z,P$(;_"N+>\AD@$4$J0:O=PTI5#[MG!YR "IC:3NC^^[4-(<1,
MD@O8YIV99\;@(>X)_60EQMSX;NJ6;%VU^)T:[-0TB/Y+<4WZK>F8EX6/
MZEARN6 EL379%56#6U:1UJ#XL#7?G$WFV%*B%'\JW+/9V)#P>T(^Y>17L35M
MR8!KG'/I HG;&>]P74M/(O+7Z/0:4QK.QQ?O/U2Z G^/&-Z1^F]5\%+0VJ91
MX ,ZU?R#]#_QF,-*.LQ)S=35R$^,D^9B8AH-^A[N5:ON_? DLD&GBC@7$R=P8NLL'8V:=-"X<\VDL(3W*80+A4C=A;E[&V"W5'@:0[:4K",8
MP@/S])1].,_!]V '/NC 5PZ\FT)I>:2#)E":5BO4D.E2\1)JF0).;!AT!8*N
M %!/ QTTJUD,6P-]JL@>*6XP Q S #!]#3-8A' "C7,I";5=R9:2%^_."QR"
MJ"& NM)0PV401]]\0.-J^62 QK\#&X&P$0"K!4FCI]O_5)$]4MQ@KD',-8"I
M?0GI&JC76@-=:ES]@P+<./<.#]DCH%/2!G C_9BTEQ^WC@MI=%Y(,WM/!EYK
M=L WF!Y5IV1&3DXME^?D;'7JQF^N;!#:>BJ[M&H<5S=)W*$C_HWHL6J9L2=<
MM!_5) Z$<"P8[5=1SE+\1TR3&A^X'(9B3(?..DPXZ2X_"M/?2O(?4$L#!!0 
M   ( -:25TC*V?AM*0D  $4_   8    >&PO=V]R:W-H965T&ULC9M;<^*X%H7_"I5W@W6UW95.U0E@RP]3-34/ 
MF^"]E[S3#YT$/MVV9&EI2;[]:'<_]R]-Y[MWW;-ZO&4:+.>Z33UL\WJ=7MS=WOZ[,_=W6W[
M?EB_;IL_=Y/]^V:SVOW_OEFW']]OU,WO#_YZ?7XY'#^8W=W.+ND>7S?-=O_:
M;B>[YNG[S7_4M]K;(W(B_GYM/O97OT^.E?_1MC^/?]2/WV_28QV:=?-P.&:Q
MZG[\:N;->GW,J2OY?WVFGV4>$U[__COW\M3.EJF]Y,
M'INGU?OZ\%?[$9J^#>Z8X4.[WI_^GSR\[P_MYG>2F\EF]<_YY^OV]//C_$V>
M]LEP MTGT%]-8/H$YI) C2>P?0)[2:#U: +7)W"?);C1!+Y/X"\)C!]-D/4)
MLDL".]Z&O$^0?Y:0C28H^@3%9Z-/ VQV[K]3[R]6A]7=[:[]F.S.0_9M=7PR
MU+>B&U\/QP]/P^GT7=?_^^[37W?*%[>S7\>,>F9^9O0UDZ5#9H$8-626B-%#
MID2,&3(58NR0"8AQ0Z9&C+\PLRYNE^!I&#Q]RL ,,LA(8,Z,/S';$Y.3L' B
MR7(2WQ)DXS1I4 5RTIY&!D&%)N75G-*%=3@X!@;'@."0IB_.S'$V^FR62J3^UZ=4_A:MF8=7L*;]L4+4"9^!@!HZWC?;8W+$(.D>>B 5G2"Y+D2C/
MA(L3%2>4HJ-"S*7FA#49#IJ'0?,@:"0@<\\*28PA=5UPB$9-)$J1J$0B@,IJ
M3<9N#2"51N*6P;AE(&YDVIQGK!1MZ4S$&1HVD2A%HA*)P DV?=>:(L2F.60%C5O"8.3*&Y@4H
MA$XE@"'S?@V0-++R'F=]I%M2T,.D)O,>&@GL0D9*&:ED),A(#1"51M8E%9%S
M"H3%T38K<53+2"DCE8P$&:D!DC@7F0X45FH*2+7'"=1&+BYA+)2-!
M1FJ )"H6%JS1%!!I.7WF>VATN!@N*HUFVE[,J)*1,(H,&XW5G[*@T529]M! 
M<^JII^T&5)).8\\L%I,*J4FV!Q,%VD+):A(@RM!>XB49M@,3:Q-&D6%8L%Q4
M0"\6K,VR%NR184^Z:>Q!P1I, 1%&5^"Y$K7/HD=&YP^>2Z+85D\N*XPBPT9C
M$:6 BBJH\E2B>%G(2 D0Y6E[Q&QJ@!21G:'"(D@!%510Y:BX?F%M%I$2( EK
MLYA-C;*)M%EC+:6!EBKHIJN'1HT,CG1['3J5E9K+G-Q:.L4 *E&.CG%$Z9QN
MCVJ &:-C4<+22@-I55!IU4/$T3!30T,%N"*=YI$:1>PG_74?0V,!H)$ H$Z&
MYBNN4FQ[J;D&H%.QC)2@+*H1 ))1SS+(^=0 ,5FL!["4T$A*T&6AAP9CU/+G
MBU,L?")2RD@E(P'5N'M>:/P I;R.!!!K'XVT#UUB-)<2B78%#:"H298R4LI(
M)2,!U;B;"6D $>5BLQ)621JY:G2]TLBIHBL6@%C\9%]-1BH9":C"U")"C(K9
M]UC5::#JF.6A@1[+Z)E$0)2EUDB-**-C4S9691JI,J(;[B'$9FS9W9*14D8J
M&0D L6S"'LMF&#HL[C00=]0T6FA12X4,H,]547/35F=BI!>;E-V>CC
ME%.:1A%8?$93*5(#S*2QM=UB+6B1%TB7C1XB+I>=DF N$:<&]WN&5<(RS)XE
MRY=L+HL5BT6*A=IK))*".EC%0R$@!"3?P:,,G5=:YAZ+!BL\@AI*NBY4X:NX@)&!8[V1^4D4I&
M D TO<\#F.ASBR6H!1*4V5L6Z,*"'O@&1'G%YAIT?4_'%B"L#BVZ[D8]&BNK
M0QDI9:22D2 C-4"4CO4E%H<6W6BCXL7*RD]&2H D]%IC)><39*1&19D\-F"P
M^+/(U*,NC95-/1DI9:22D2 C-4 2&SD8<%C(.2[D=$K*N8<0NZ0L.W\R4LI(
M)2-!1FJ J,AJ[;#@=,CWH_.F$[VV18^,7N_F2&*I,BCELBH9":/(,"Y813ND
MHJF_U4/$WZ+GWXA*U#0B#1S6I0[I4GIQRHEGS@L960*$WD\I'3@FIRX,8%@W
M??E^F\-BTP&Q23VNN0,WUTS!WKP0L6&%L(1SR'2C^X<>&NTG6<')N91R+A5 
M$DWWBV$THV%KH()=6 T2IV LV6 8Z
M9!)2V>^^?,/-857EN*K2*=V7.2Y2/'NY;=%38\810))N+Y/1ON+EY9G*:6>!
M&W-T_Q4 U.DKNGVJ0<5,JB/G#0[+,,=EF$X-#5+!IY-ZP#O+ZDY4GP
M4NW!4DWO(]P#2*<1Z>;QVN?YVL<$[3V$Z'9L=O4&[:;9/9_>O]Y/'MKW[>'X
M7N'5IY=WO.]/;V33S[W^%KP&WW0-[KXQ\!O;?7-^G_>S\+O;M]5S\\=J]_RZ
MW4]^M(=#NSF]N_O4MH>F:UDZ[9Z8EV;U>/ECW3P=CK]FW>^[\UO>YS\.[=OO
ME]8O;\[?_0M02P,$%     @ UI)72.Z9\E45%%V[&6#WW/'K(
M4 GI"->HXD].F)20\2XY>[0F"!ZEJ"R\P/"EB=?KCGF)*IKCRB'HM'!_@/DN%(0$/G+4
MT)NV(V+?8_PI.MOCPO5%"*A !R8<(+]=T1(5A3#B+_ZC/+]?*82W[\A14M<_,Z/+./!^JYS1"=X*=@[;C9(I3 6A@=<4'EU#A?*<-E)7*>$7^T]
MK^2]:9_$D9*9!8$2!+T _%\0*D%H*XB4(+(5C)5@;"N8*,'$5A K06PKF"K!
MU%8P4X*9K4#4O*V<;RWIBPVL)5VY@76]05=PH%?<:^>BG,DKR&":$-PXI%U]
M-12+',RYBIN+4;DVY$,^F2D?O::!'R?>53@IYJEE@@$S'3)+ S,D5B:7V9#Y
M><]$0V)M< '^D/EUSX1@B&Q,-AJS-3%:4L\F)APR+P\_S>OC@'?WR.R[!!ZO
M<5_HP%SH0!K$@T@CLT-H=@BE0SAP&&M3I66FDJDDXX_T#[LT08$&K5H(@*&5
M-E]LH'4+36X9;<(8H]92VY@@7X.V-M#SPX!>3#:1EM>K\3-J[]H94XNUNGLW
MVT4-SV@'R3FOJ+/'C.\]4!QJQ-^0TNJU.WP[/K5M/_NQV^Z/
MM_.GOG^^62Z/=T_MKCE^ZI[;_?"?A^ZP:_KAY^%Q>7P^M,W]-&BW7?HD29>[
M9K.?KU?3L2^']:I[Z;>;??OE,#N^[';-X9^RW7:OMW,W?SOPQ^;QJ1\/+->K
MY?NX^\VNW1\WW7YV:!]NYY_=39U.DDGQYZ9]/5Y\GXW.?^VZ;^./W^YOY\GH
M0[MM[_K11#-\?&^K=KL=+0UG_OML].:S^_:A>=GV?W2OO[;G.>AH\*[;'J>_L[N78]_MWH;,9[OFQ^ESLY\^
M7T__R8KS,#[ GP?X]P'>?3A S@/D_PX(YP$!!BQ/4YD"43=]LUX=NM?9X73U
MGIMQD;B;,(3Z;CPX17;ZWQ"*XW#T^]J[=+7\/AHZ:\J3QE]HW+MB.5A_/X5G
MIRB]&>Y==GV*BFGR:TW-- 5W1.A<93*071KP"3<0J($P&9#+0.0)!.ND22?-
M?M)DJ8?96HUS 4)26Y%J).Y*O54RW8B!E!I(S72]AZF4)XU>3R7 ?(G(!X7Y
M,E$1N+\9]3>SE\>AOYDYR\(7X"[1B.)J9(92[FU.O-+(6".EL89P4"4A8V( HW1V4U9MD3,^XB^%>^CAF=Y;2$A#9@4DOL
MB3*,+1,)6*J)2"[6W;7'D2SL[-)-"O38V3LD3]%C*_(7E_KL,1'Y2"IU-*E_
M=I[$6-%C;\Z#*X)(<-741.-2B;C+4[\3XJ[AG-BPY.BOU>"JJ8E&8NYRT+A 
MG.5K,J%2$9T'#B.$))A&B9&3AU'L",./;:\6#A)C,]$
MEB'#:FHLB=T/'#_.\L<+HMU9=.#,*J)9Y+@38:(L%F?/&>0)@P3Q[BTY%#05
MT2QRN"=J(BHTXB\GD+<$\DBZTEMN*$ZJ8B(L*6HB6A2Q"',">4(@00)YBP[O
M<%X54;FL0&HR6YF+A9ESR),:1"(YQW,V>%N%>,EPWH$D24DPLU-98J\6D;DB
MCUTO#B1/@&0VD9Z@QA:+1)0AVVJJBGC,<>0)C@1QY E$<%H5$^4);GV9*HL4
MJ)X#R1,@!022MQ@)N6*J9"I-,+LSE<1J"\^9Y F3 C+)$XR$/#%>,UEJH$1E
M(42HY#F5/*%20"IY6M!@R4E4P9DL3T21 EDXE810*2"5A%5&N&]G(M.Q(:(\
MUK'A6!*")6POE$)@,F15W!,R6:J8ZYC*95DLSIQ-XFV:#Q%22*1912J6@!6+
MV$JC,&N+B'(QT[8BYR1VL3B9A) )Z_M2"$L*Y%?%5+FIO)G*N5CV$-)K=6
MQ(+-X20$3HIP$@*GPJ3Z_VC)G9UFJBRRM0T<3\'BR6%U5@;6DS,- *8*IM)C
M*M7( @D<48'T[G)$5""].^LS$2&=:R9*(ADO<#H%4CEAW5D&6^T$;"161(1M
MH0\EU]YR$ 8"0C7QM?A:^,P$F*C,TXJ:JF)/FD+D21%!(?9\RL#P97KF3*6F
MVJ&J(K8N. F#):'+D=^!E%4A-T^X6&,1R\^:JGRD=1XX"P-A(6[JRD J*UQ#
M%1&9!RG,4!);&IR"@5'01)FU ]%?J_'F(:+5N,A6-G#^!<8_W!X%2RS3.2>:
M80N!ST9K*G.Q'DG@\ L,?KA!"NR)E5G(3(3 IJ+(JE"./B6568I[([6XPFQ!
M)+A/K8EF$5D4RIFGI"Q#.)3*RC(D"!$A03Z47'O+>:>$=[CN2K6<6ESN%<_N
M$I4S31%J*]9 5HX])=A+$=)*JC;%%E7%5"DV*FJF*I)8I#GVE& O15:K197-
M Q53F:G53'4YM6NG.?94;;&>1HIUY1!2 B'L/Y3*WG!(L2!C*C$9AZIB#73E
M(%("HA1!I.214XZIG8@"OAA3$Y'&NIO*6:0YN5*Q27,R*"%#BF10F\]-GOVP
M%W>>\4=FKM^_X5!("12P$U>F-IMC(ZXB&NP7U$0C$2JDG HIH4*&5#B+TNOU
MC?Y:D7G*3C2*_BXO7H/;M8?'Z7W"X^RN>]GWXZMD%T??WUG\[,?7Z.!XZ6[J
MT^MU/\VL5\_-8_M[B[Y[?7*=_?Z5S_"U!+ P04    " #6DE=(:V)KS*$!  "Q
M P  &0   'AL+W=ONVO@ SS'OS9ACR >VK:P$\
M>=/*N!-MO>^.C+FR!2W<'79@PDV-5@L?3-LPUUD050)IQ7B6?6-:2$.+//F>
M;9%C[Y4T\&R)Z[46]M\9% XGNJ&3XT4VK8\.5N1LQE52@W$2#;%0G^C]YGC>
MQ8@4\%O"X!9G$K5?$%^C\;,ZT2Q*  6ECPPB;%=X *4B44C\]\;YGC("E^>)
M_3%5&]1?A(,'5']DY=L@-J.D@EKTRK_@\ 2W$O:1L$3ETDK*WGG4$X02+=[&
M79JT#^/-?H*M _@-P&? ]RP)'Q,EF3^$%T5N<2!V;&TGX@MNCCPTHHS.5'>Z
M"T)=\%X+?N YNT:B6\QYC.&+F,TWB1=Z*!
M7\(VTCAR01]>-O6_1O00I&1W>TK:\']F0T'MX_$0SG8&UL;5/!;MP@$/T5Q <$+]YDHY774C95U1XJ13FT9]8>VRC N(#7
MZ=\7L-=Q4U^ &>:]>3,,Q8CVS74 GKQK9=R)=M[W1\9LMB#J!M&(\RQZ8%M+0LDB^%UL6.'@E#;Q8X@:MA?US!H7CB>[HS?$J
MV\Y'!RL+MN!JJ<$XB898:$[T:7<\[V-$"O@I872K,XG:+XAOT?A>GV@6)8""
MRD<&$;8K/(-2D2@D_CUS?J2,P/7YQOXU51O47X2#9U2_9.V[(#:CI(9&#,J_
MXO@-YA+N(V&%RJ655(/SJ&\02K1XGW9ITCY.-SF?8=L /@/X GC,DO I49+Y
M17A1%A9'8J?6]B*^X.[(0R.JZ$QUI[L@U 7OM

PME.$S49'OO;_U@^:?D74$L#!!0 ( -:25TAO!G[&H@$ +$# M 9 >&PO=V]R:W-H965T*D4YM&?6'MLHP+B U^G?%[#7<5-?@!GFO7DS#,6(]M5U )Z\ M:67]T?&7-6!%NX.>S#AID&KA0^F;9GK+8@Z@;1B/,L^,2VDH661?,^V M+'#P2AIXML0-6@O[YPP*QQ/-Z4C@PC;%9Y J4@4$O^>.=]31N#Z?&/_ MFJH-ZB_"P1.J7[+V71";45)#(P;E7W#\!G,)]Y&P0N722JK!>=0W""5:O$V[ M-&D?IYM]/L.V 7P&\ 7PD"7A4Z(D\XOPHBPLCL1.K>U%?,'\R$,CJNA,=:>[ M(-0%[[7DA\\%NT:B.>8\Q?!53+Y$L,"^I.!;*<[\/SC?AN\V%>X2_+"&/V3; M!/M-@GTBV/U#D'\H<2OFHTJVZJD&VZ;1<:3"P:1!77F7Z7SDZ4W>P\NB%RW\ M$+:5QI$+^O"RJ?\-HH<@);N[IZ0+_V1F@R/_>V#++^T_ M0 M2P,$% @ UI)72 N:T>:B 0 L0, !D !X;"]W;W)K&UL;5/!;N0@#/T5E \H&9)IJU$F4J?5:O>P4M7#[IE)G 05< ID MTOW[!9))TS87P,;O^=F88D3S:CL 1]Z5U/:8=,[U!TIMU8'B]@9[T/ZF0:.X M\Z9IJ>T-\#J"E*0L36^IXD(G91%]SZ8L<'!2:'@VQ Y*9\R-E *[/5_8?L5JO_LPM/*+\*VK7>;%I0FIH^"#= M"XX_82YA'P@KE#:NI!JL0W6%)$3Q]VD7.N[C=)/E,VP;P&8 6P#W:10^)8HR MG[CC96%P)&9J;<_#"^X.S#>B"LY8=[SS0JWW7DIVGQ7T$HCFF-,4PU8QNR6" M>O8E!=M*<6+?X&P;GFTJS"+\[I/"?)L@WR3((T'VB6#_I<2MF-LO2>BJIPI, M&T?'D@H''0=UY5VF\X'%-_D(+XN>M_";FU9H2\[H_,O&_C>(#KR4]&:?D,[_ MG\60T+APO/-G,XW49#CLKQ]D^:7E?U!+ P04 " #6DE=(=+GL\J0! "Q M P &0 'AL+W=O.1]9,G$ZF/70FDT-[QM)*8@*L LA*_[Z 9$5)=0%VV??V[;+D YI7VP(X M\JZDMJ>D=:X[4FK+%A2W=]B!]C 5Q&D)&5I^HTJ+G12Y-'W M;(H<>R>%AF=#;*\4-W_/('$X)5ER<[R(IG7!08N,#LRWX@R.&/= M\ MU@FVJP3;2+#Y1'#_I<25F/OT2Q*ZZ*D"T\31L:3$7L=!77CGZ7Q@\4T^PHN\ MXPW\XJ81VI(+.O^RL?\UH@,O);W;):3U_VV#S+^T M^ =02P,$% @ UI)72/G(.1^C 0 L0, !D !X;"]W;W)K&UL=5/;;MP@$/T5Q <$+[NY=.6UE$U5M0^5HCRTSZP]ME& M<0&OT[\O8*_72=P78(8Y9\X,0SZ@?74M@"=O6AEWH*WWW9XQ5[:@A;O!#DRX MJ=%JX8-I&^8Z"Z)*(*T8S[([IH4TM,B3[]D6.?9>20//EKA>:V'_'D'A<* ; M>G&\R*;UT<&*G,VX2FHP3J(A%NH#?=SLC[L8D0)^21C: M10F@H/21083M#$^@5"0*B?],G->4$;@\7]B_I6J#^I-P\(3JMZQ\&\1FE%10 MBU[Y%QR^PU3";20L4;FTDK)W'O4%0HD6;^,N3=J'\>;N88*M _@$X#/@(4O" MQT1)YE?A19%;'(@=6]N)^(*;/0^-**,SU9WN@E 7O.>"?]GD[!R)IICC&,,7 M,=<(%MCG%'PMQ9%_@O-U^'95X3;![]\I_ _!;I5@EPBV[PBV'TI@A2LIM; M2MKP?V9#0>WC\3Z<[3A2H^&QNWR0^9<6_P!02P,$% @ UI)72'HJ$*BC M 0 L0, !D !X;"]W;W)K&UL;5/! *E(E%(_&?B?$\9 M@$[3"7L(V&)RJ65E+WSJ&\0 M2K1X&W=ITCZ,-WP[P=8!? +P&?"0)>%CHB3SJ_"BR"T.Q(ZM[41\P:\&_['-VC413S'F,X8N8S1S! ON<@J^E.//_X'P=OEU5N$WP MPP>%]^L$NU6"72+8?B X?"IQ+>;A4Q*VZ*D&VZ31<:3$WJ1!77CGZ7SDZ4W> MPXN\$PW\%+:1QI$+^O"RJ?\UHH<@);O;4]*&_S,;"FH?CX=PMN-(C8;'[O9! MYE]:_ -02P,$% @ UI)72.S)G+BC 0 L0, !D !X;"]W;W)K&UL;5/;;N,@$/T5Q <4FR2]1(ZEIJMJ]V&EJ@_M,['' M-BIX7,!Q]^\+V''=KE^ &>:<.3,,V8#FS38 CGQHU=H#;9SK]HS9H@$M[!5V MT/J;"HT6SINF9K8S(,H(THKQ)+EF6LB6YEGT/9D\P]XIV<*3(;;76IA_1U X M'&A*+XYG63L1E72@VME=@2 ]6!WJ?[XS9$Q( 7"8-=G$G0?D)\"\:? M\D"3( $4%"XP"+^=X0&4"D0^\?O$^94R )?G"_MCK-:K/PD+#ZA>9>D:+S:A MI(1*],H]X_ ;IA)V@;! 9>-*BMXZU!<()5I\C+MLXSZ,-[OK";8.X!. SX#; M) H?$T69OX03>69P(&9L;2?""Z9[[AM1!&>L.]YYH=9[SSF_N\O8.1!-,<?8Y!5]+<>3_P?DZ?+.J=9)VKX*TPM6TM.Z/S+QOY7B Z\ ME.1J1TGC_\]L**A<.-[XLQE':C0<=I&UL;5/!;N,@ M$/T5Y \H#D[2*G(L-5U5[6&EJH?=,[''-BHP+N"X^_<%[+ANUQ=@AGEOW@Q# M/J!YLRV (Q]*:GM,6N>Z Z6V;$%Q>X,=:']3HU'<>=,TU'8&>!5!2E*6IGNJ MN-!)D4??BRER[)T4&EX,L;U2W/P[@<3AF&R2J^-5-*T+#EKD=,950H&V C4Q M4!^3^\WAM T1,>"/@,$NSB1H/R.^!>.Y.B9ID 22A<8N-\N\ !2!B*?^'WB M_$H9@,OSE?TQ5NO5G[F%!Y1_1>5:+S9-2 4U[Z5[Q>$)IA)V@;!$:>-*RMXZ M5%=(0A3_&'>AXSZ,-[O]!%L'L G 9L!=&H6/B:+,7]SQ(CL.]YYH=9[+T669CF]!*(IYC3&L$7,9HZ@GGU.P=92G-A_<+8.SU85 M9A%^^TWA=IU@NTJPC039-X+=CQ+78O8_DM!%3Q68)HZ.)27V.@[JPCM/YSV+ M;_(57N0=;^ W-XW0EIS1^9>-_:\1'7@IZ.O/9ARIT7#8 M73_(_$N+3U!+ P04 " #6DE=(EV./@:0! "Q P &0 'AL+W=O6B? M67MLHP#C EZG?U_ 7L=)_ +,,.?,F6$H1C0OM@-PY%5);4^T%AB=#[* 4-__. M('$\T93>',^B[5QPL+)@"ZX6"K05J(F!YD0?TN-Y%R)BP&\!HUV=2=!^07P) MQL_Z1),@ 214+C!POUWA$:0,1#[QWYGS+64 KL\W]N^Q6J_^PBT\HOPC:M=Y ML0DE-31\D.X9QQ\PE[ /A!5*&U=2#=:AND$H4?QUVH6.^SC=[/,9M@W(9D"V M .Z3*'Q*%&5^XXZ7A<&1F*FU/0\OF!XSWX@J.&/=\80?WBF\WR;8;1+L(D'^CN#KAQ(W M8M+D0Q*VZJD"T\;1L:3"0<=!77F7Z7S(XIN\A9=%SUOXQ4TKM"47=/YE8_\; M1 =>2G*WIZ3S_VV#++^T_ ]02P,$% @ UI)7 M2(3WD.2A 0 L0, !D !X;"]W;W)K&UL=5/; M;MP@$/T5Q <$W])4*Z^E;*JJ?:@4Y:%]9NVQC0*,"WB=_GT!>[U.ZKX ,\PY M:5F7T/9NJQ-%)H>'9$#LJQ+Z'H7'*PJV8IKA )M M!6IBH#W2Q_1P*D)$#/@I8+*;,PG:SXBOP?C>'&D2)("$V@4&[K<+/(&4@<@G M_KUPWE(&X/9\9?\:J_7JS]S"$\I?HG&]%YM0TD#+1^E>-* MZM$Z5%<()8J_S;O0<9_FF[Q88/N ; %D*^!S$H7/B:+,+]SQJC0X$3.W=N#A M!=-#YAM1!V>L.]YYH=9[+U6>IB6[!*(EYC3'9)N86P3S[&N*;"_%*?L'GNW# M\UV%>80_O%/X'X)BEZ"(!/D[@OQ#B7LQQ8&PO=V]R M:W-H965T0/*#9)FBIR+#5=5=W#2E4/ M[9G88QL5&"_@N/OW"]AQW=878(9Y;]X,0SZ@>;4;Z)R MK1>;)J2"FO?2O>#P!%,)NT!8HK1Q)65O':HK)"&*?XR[T'$?QANVGV#K #8! MV RX2Z/P,5&4^8L[7N0&!V+&UG8\O&!V8+X197#&NN.=%VJ]]U)LLEU.+X%H MBCF-,6P1D\T1U+//*=A:BA/[ 6?K\,VJPDV$[[\HO%TGV*X2;"/!Y@O!_EN) M:S%WWY+014\5F":.CB4E]CH.ZL([3^<]BV_R&5[D'6_@#S>-T):G-+B&M_S^S(:%VX;CW9S..U&@X[*X?9/ZEQ7]02P,$% @ UI)7 M2+;+#:RB 0 L0, !D !X;"]W;W)K&UL;5/! M;MP@$/T5Q <$F]UMVI774C95U1XJ13FT9]8>VRC N(#7Z=\7L-=Q4E^ &>:] M>3,,Q8CVQ74 GKQJ9=R)=M[W1\9LMB#J!M&(\ MRSXQ+:2A99%\3[8L]S$B!?R2,+K5F43M%\27:/RH3S2+$D!!Y2.#"-L5'D&I2!02 M_YDYWU)&X/I\8_^6J@WJ+\+!(ZK?LO9=$)M14D,C!N6? \ZAN$$BU>IUV:M(_3S8'/L&T GP%\ 7S.DO I49+Y57A1%A9'8J?6]B*^ M8'[DH1%5=*:ZTUT0ZH+W6N[R+P6[1J(YYCS%\%5,OD2PP+ZDX%LISOP_.-^& M[S85[A+\?JV09]L$^TV"?2+8O2/(/Y2X%?-1)5OU5(-MT^@X4N%@TJ"NO,MT M/J1'9&_A9=&+%GX*VTKCR 5]>-G4_P;10Y"2W1THZ<+_60P%C8_'^W"VTTA- MAL?^]D&67UK^ U!+ P04 " #6DE=([TM%6:(! "Q P &0 'AL+W=O MPUW$27X 9YKUY,PS%B/;%=0">O&IEW(EVWO='QES5 M@1;N#GLPX:9!JX4/IFV9ZRV(.H&T8CS+OC MI*%ED7Q/MBQP\$H:>++$#5H+ M^^\,"L<3W=&;XUFVG8\.5A9LP=52@W$2#;'0G.C#[GC>QX@4\%O"Z%9G$K5? M$%^B\;,^T2Q* 65CPPB;%=X!*4B44C\=^9\2QF!Z_.-_7NJ-JB_" >/J/[( MVG=!;$9)#8T8E'_&\0?,)1PB887*I954@_.H;Q!*M'B==FG2/DXW!S[#M@%\ M!O %\#5+PJ=$2>8WX4596!R)G5K;B_B"NR,/C:BB,]6=[H)0%[S7,N=YP:Z1 M:(XY3S%\%;-;(EA@7U+PK11G_@G.M^'YIL(\P>_?*&PO=V]R:W-H965T.I/)H3UC:24Q 58%9*5_7T"RHJ2Z +OL M>_MV6?(![:MK 3QYT\JX$VV][XZ,N;(%+=P==F#"38U6"Q],VS#761!5 FG% M>);=,RVDH46>?,^VR+'W2AIXML3U6@O[]PP*AQ/=T)OC13:MCPY6Y&S&55*# M<1(-L5"?Z./F>-[%B!3P2\+@%F<2M5\07Z/QHSK1+$H !:6/#")L5W@"I2)1 M2/QGXGQ/&8'+\XW]6ZHVJ+\(!T^H?LO*MT%L1DD%M>B5?\'A.TPE["-AB!MW:=(^C#?[;(*M _@$X#/@(0'8F"C)_"J\*'*+ [%C:SL1 M7W!SY*$1972FNM-=$.J"]UIL^7W.KI%HBCF/,7P1LYDC6&"?4_"U%&?^'YRO MP[>K"K<)?OB@\+!.L%LEV"6"[0>"AT\EKL5\^92$+7JJP39I=!PIL3=I4!?> M>3H?>7J3]_ B[T0#/X5MI''D@CZ\;.I_C>@A2,GN]I2TX?_,AH+:Q^,AG.TX M4J/AL;M]D/F7%O\ 4$L#!!0 ( -:25TB)*86TG@$ +$# 9 >&PO M=V]R:W-H965T--'*:RF;*FH/ ME:(I, MHO8SXFLTOM9'FD4)H*#RD4&$[0*/H%0D"HG?9LZ/E!&X/E_9GU*U0?U9.'A$ M]4/6O@MB,TIJ:,2@_ N.7V NX3825JA<6DDU.(_Z"J%$B_=IER;MXWQS/\.V M 7P&\ 5PGR7A4Z(D\[/PHBPLCL1.K>U%?,'=@8=&5-&9ZDYW0:@+WDN9YUG! M+I%HCCE-,7P5LULB6&!?4O"M%"?^%YQOP_--A7F"W_VF\!_Y]YL$^T20_[?$ MK9@_5;)53S78-HV.(Q4.)@WJRKM,YP-/;_(17A:]:.&;L*TTCIS1AY=-_6\0 M/00IV!?.=AJIR?#87S_(\DO+7U!+ P04 " #6DE=( M9^<4(*$! "Q P &0 'AL+W=OO&EEW(EVWO='QES5@1;N#GLPX:9!JX4/IFV9ZRV(.H&T8CS+ M[ID6TM"R2+YG6Q8X>"4-/%OB!JV%_7L&A>.)[NCL>)%MYZ.#E05;<+748)Q$ M0RPT)_JX.Y[W,2(%_)(PNM691.T7Q-=H_*A/-(L20$'E(X,(VQ6>0*E(%!+_ MN7&^IXS ]7EF_Y:J#>HOPL$3JM^R]ET0FU%20R,&Y5]P_ ZW$@Z1L$+ETDJJ MP7G4,X02+=ZF79JTC]--/L.V ?P&X O@2Y:$3XF2S*_"B[*P.!([M;87\05W M1QX:445GJCO=!:$N>*]EGN<%NT:B6\QYBN&KF-T2P0+[DH)OI3CS_^!\&YYO M*LP3_.&#POTVP7Z38)\(\@\$AT\E;L7WA9]**%G\*VTCAR01]>-O6_0?00I&1W!TJZ\'\60T'CX_$AG.TT4I/A ML9\_R/)+RW]02P,$% @ UI)72(M[T-"D 0 L0, !D !X;"]W;W)K M&UL;5/!;MP@$/T5Q <$K^UTTY774C91U1XJ13FT M9]8>VRC .(#7Z=\7L-=Q$E^ &>:]>3,,Q8CFQ78 CKPIJ>V1=L[U!\9LU8'B M]@9[T/ZF0:.X\Z9IF>T-\#J"E&1IDGQCB@M-RR+ZGDQ9X."DT/!DB!V4XN;? M"22.1[JC5\>S:#L7'*PLV(*KA0)M!6IBH#G2^]WAE(>(&/!'P&A79Q*TGQ%? M@O&K/M(D2 )E0L,W&\7> I Y%/_#ISOJ<,P/7YROXC5NO5G[F%!Y1_1>TZ M+S:AI(:&#](]X_@3YA)N V&%TL:55(-UJ*X02A1_FW:AXSY.-_M\AFT#TAF0 M+H"[) J?$D69C]SQLC X$C.UMN?A!7>'U#>B"LY8=[SS0JWW7LHLVQ?L$HCF MF-,4DZYB=DL$\^Q+BG0KQ2G] D^WX=FFPBS"]Q\4WFT3Y)L$>23(/A!\_U3B M1DR>?$K"5CU58-HX.I94..@XJ"OO,IWW:7R3]_"RZ'D+O[EIA;;DC,Z_;.Q_ M@^C 2TEN;BGI_/]9# F-"\>]/YMII";#87_](,LO+?\#4$L#!!0 ( -:2 M5T@QIKF&H@$ +$# 9 >&PO=V]R:W-H965T0/"%[L7+3R6LJFJIJ'2E$>VF?6'MLHP+B U^G?![#7ZZ3N"S## MG#-GAJ$8T;S9#L"1=R6U/22=<_V>4EMUH+B]P1ZTOVG0*.Z\:5IJ>P.\CB E M*4O3.ZJXT$E91-^+*0L+(_H&S M;7BVJ3"+\/M/"O]#D&\2Y)$@^T20?2EQ*R;_DH2N>JK M'%T+*EPT'%05]YE M.A]9?)-K>%GTO(6?W+1"6W)"YU\V]K]!=."EI#>W">G\_UD,"8T+QWM_-M-( M38;#_O)!EE]:?@!02P,$% @ UI)72/=TQ!JC 0 L0, !D !X;"]W M;W)K&UL;5/!;MP@$/T5Q <$K^W-5BNOI6RJJ#U4 MBG)HSZP]ME& <0"OT[\O8*_CI+X ,\Q[\V88BA'-J^T ''E74ML3[9SKCXS9 MJ@/%[1WVH/U-@T9QYTW3,ML;X'4$*+:#L7'*PLV(*KA0)M!6IBH#G1A]WQG(>(&/!;P&A79Q*T M7Q!?@_&S/M$D2 )E0L,W&]7> 0I Y%/_#9S?J0,P/7YQOX4J_7J+]S"(\H_ MHG:=%YM04D/#!^E>B"LY8=[SS0JWW7LLLWQ?L M&HCFF/,4DZYB=DL$\^Q+BG0KQ3G]#YYNP[--A5F$']8*DWR;(-\DR"-!]JG$ M^R\E;L4=? M-O:_073@I21W>THZ_W\60T+CPO'@SV8:J<5>C 0 L0, !D !X;"]W;W)K&UL M;5/;;N,@$/T5Q <4ASB]1(ZEIJMJ]V&EJ@_M,[''%Q48%W#<_?L"=ERWZQ=@ MACEGS@Q#-J!YLPV (Q]*:GN@C7/=GC%;-*"$O<(.M+^IT"CAO&EJ9CL#HHP@ M)1E/DFNF1*MIGD7?D\DS[)UL-3P98GNEA/EW!(G#@6[HQ?'"EA<$NSB1H/R&^!>-/>:!)D 2"A<8A-_.\ !2 M!B*?^'WB_$H9@,OSA?TQ5NO5GX2%!Y2O;>D:+S:AI(1*]-(]X_ ;IA)V@;! M:>-*BMXZ5!<()4I\C'NKXSZ,-]?I!%L'\ G 9\!M$H6/B:+,7\*)/#,X$#.V MMA/A!3=[[AM1!&>L.]YYH=9[S_DVOJK U'%T+"FPUW%0 M%]YY.N]Y?).O\#SK1 U_A:E;;&UL;5/!;MP@$/T5Q <$+]YMJI774C95 MU1XJ13FT9]8>VRC N(#7Z=\7L-=Q$E^ &>:]>3,,Q8CVQ74 GKQJ9=R)=M[W M1\9LMB#J!M&(\R[XP+:2A99%\3[8L(%/!;PNA6 M9Q*U7Q!?HO&S/M$L2@ %E8\,(FQ7> 2E(E%(_'?F?$L9@>OSC?U[JC:HOP@' MCZC^R-IW06Q&20V-&)1_QO$'S"4<(F&%RJ655(/SJ&\02K1XG79ITCY.-WD^ MP[8!? ;P!? U2\*G1$GF-^%%65@Z"4!>\US(_ M\()=(]$<8+?OU.8;Q/L-PGVB2!_ M1[#_4.)6S.%#$K;JJ0;;IM%QI,+!I$%=>9?I?.#I3=["RZ(7+?P2MI7&D0OZ M\+*I_PVBAR ENSM0TH7_LQ@*&A^/]^%LIY&:#(_][8,LO[3\#U!+ P04 M" #6DE=( @MZKZ(! "Q P &0 'AL+W=OVK:P$\>=/*N!-MO>^.C+FR!2W<'79@PDV-5@L?3-LPUUD0 M50)IQ7B6W3,MI*%%GGS/MLBQ]TH:>+;$]5H+^_<,"H<3W=#)\2*;UD<'*W(V MXRJIP3B)AEBH3_1QPC M88G*I964O?.H)P@E6KR-NS1I'\:;_01;!_ ;@,^ ARP)'Q,EF5^%%T5N<2!V M;&TGX@MNCCPTHHS.5'>Z"T)=\%Z+[?X^9]=(=(LYCS%\$;.9(UA@GU/PM11G M_A^&PO=V]R:W-H965T)-7*:RF; MJFH/E:(#@E33P M9(D;M!;V[PD4CD>ZHU?'LVP['QVL+-B"JZ4&XR0:8J$YTH?=X;2/$2G@EX31 MKZ"T)=\%[* M_"XKV"42S3&G*8:O8G9+! OL2PJ^E>+$/\'Y-CS?5)@G^/T[A?_)O]\DV">" M_!T!_U#B5DS^(0E;]52#;=/H.%+A8-*@KKS+=#[P]"9OX671BQ9^"MM*X\@9 M?7C9U/\&T4.0DMW<4M*%_[,8"AH?C_?A;*>1F@R/_?6#++^T_ =02P,$% M @ UI)72/)P=!BC 0 L0, !D !X;"]W;W)K&UL=5/!;MP@$/T5Q <$K^W=5"NOI6RJJCU4BG)HSZP]ME& <0&OT[\O8*_C M).X%F&'>FS?#4(QH7FP'X,BKDMJ>:.= M *\C2$F6)LF!*2XT+8OH>S)E@8.30L.3(790BIN_9Y XGNB.WAS/HNU<<+"R M8 NN%@JT%:B)@>9$'W;';$))34T?)#N&P M#X052AM74@W6H;I!*%'\==J%COLXW1SR&;8-2&= N@"^)%'XE"C*_,H=+PN# M(S%3:WL>7G!W3'TCJN",=<<[+]1Z[[7,#GG!KH%HCCE/,>DJ9K=$,,^^I$BW M4IS33_!T&YYM*LPB_/Z=PO_DSS<)\DB0O2/8?RAQ*R;[D(2M>JK M'%T+*EP MT'%05]YE.A_2^"9OX671\Q9^G\_UD,"8T+ MQWM_-M-(38;#_O9!EE]:_@-02P,$% @ UI)72)H'R?2C 0 L0, !D M !X;"]W;W)K&UL;5/!;N,@$/T5Y \H#DZ3-G(L M-5VM=@\K53VT9V*/;51@O(#C[M\7L..Z75^ &>:]>3,,^8#FS;8 CKPKJ>TQ M:9WK#I3:L@7%[0UVH/U-C49QYTW34-L9X%4$*4E9FNZHXD(G11Y]3Z;(L7=2 M:'@RQ/9*K^P_8[5> M_9E;>$3Y*BK7>K%I0BJH>2_=,PZ_8"KA-A"6*&U<2=E;A^H*28CB[^,N=-R' M\29+)]@Z@$T -@/N(H".B:+,']SQ(CL.]YYH=9[ M+T6VV^7T$HBFF-,8PQ8QFSF">O8Y!5M+<6+_P=DZ/%M5F$7X_HO"_3K!=I5@ M&PFR+P1WWTIJK -'%T+"FQUW%0%]YY.A]8?)//\"+O> -_N&F$ MMN2,SK]L['^-Z,!+26]N$]+Z_S,;$FH7CGM_-N-(C8;#[OI!YE]:? !02P,$ M% @ UI)72,I%WWVA 0 L0, !D !X;"]W;W)K&UL=5/!;MP@$/T5Q <$+]YTJY774C95U1XJ13FT9]8>VRC N(#7Z=\7 M\-IQ4O<"S##OS9MA*$:T+ZX#\.15*^-.M/.^/S+FJ@ZT<'?8@PDW#5HM?#!M MRUQO0=0)I!7C6?:):2$-+8OD>[)E@8-7TL"3)6[06M@_9U XGNB.SHYGV78^ M.EA9L 572PW&233$0G.B#[OC>1\C4L!/":-;G4G4?D%\B<;W^D2S* $45#XR MB+!=X1&4BD0A\>\;YUO*"%R?9_:OJ=J@_B(@6K*NTSG T]O\A9>%KUHX8>PK32.7-"'ETW];Q ]!"G9W3TE7?@_BZ&@ M\?%X"&<[C=1D>.SG#[+\TO(O4$L#!!0 ( -:25TC=9NQ#HP$ +$# 9 M >&PO=V]R:W-H965T0/* Y.FBIR M+#5=5=W#2E4/[9G88QL5&"_@N/OW"]AQW=878(9Y;]X,0SZ@>;;PVD;(F+ MJX#!+LXD:#\CO@?C=W5,TB !))0N,'"_7> !I Q$/O'?B?,S90 NSU?VQUBM M5W_F%AY0OHG*M5YLFI *:MY+]X+#$TPE[ )AB=+&E92]=:BND(0H_C'N0L=] M&&^RNPFV#F 3@,V NS0*'Q-%F;^XXT5N<"!F;&W'PPMN#LPWH@S.6'>\\T*M M]UZ*;+_-Z24033&G,88M8C9S!/7L/>G\TX4J/AL+M^D/F7%O\!4$L# M!!0 ( -:25TB% @14HP$ +$# 9 >&PO=V]R:W-H965TVC.QQS9:8%S \?;O M"]CQNEM?@!GFO7DS#/F ]M6U )Z\:67=R?&7-F"%NX!.S#AID:KA0^F M;9CK+(@J@;1B/,L^,2VDH46>?,^VR+'W2AIXML3U6@O[YP(*AS/=T+OC13:M MCPY6Y&S&55*#<1(-L5"?Z>/F=-G%B!3P4\+@%F<2M5\17Z/QO3K3+$H !:6/ M#")L-W@"I2)12/Q[XGQ/&8'+\YW]:ZHVJ+\*!T^H?LG*MT%L1DD%M>B5?\'A M&TPE["-AB!MW:=(^C#?[W01;!_ )P&? ,4O"QT1)YA?A M19%;'(@=6]N)^(*;$P^-**,SU9WN@E 7O+=B>SCF[!:)IIC+&,,7,9LY@@7V M.05?2W'A_\'Y.GR[JG";X(=_%'Y>)]BM$NP2P79)<,P^E+@6\[%(MNBI!MND MT7&DQ-ZD05UXY^E\Y.E-WL.+O!,-_!"VD<:1*_KPLJG_-:*'("5[V%/2AO\S M&PIJ'X^'<+;C2(V&Q^[^0>9?6OP%4$L#!!0 ( -:25TB-V;Z"H0$ +$# M 9 >&PO=V]R:W-H965T M;:*5UU(V5=4>*D4YM&?6'MLHP+B U^G?%_#:<5)?@!GFO7DS#,6(]M5U )Z\ M:67]T?&7-6!%NX.>S#AID&KA0^F;9GK+8@Z@;1B/,N^,"VDH661?,^V M+'#P2AIXML0-6@O[]PP*QQ/=T=GQ(MO.1PJ.]T% MH2YXKV7^P MVC42WF/,4PU;_P?DV/-]4F"?X_0>%^3;! M?I-@GPCR#P3[3R5NQ1P^)6&KGFJP;1H=1RH<3!K4E7>9SD>>WN0]O"QZT<)/ M85MI'+F@#R^;^M\@>@A2LKL#)5WX/XNAH/'Q>!_.=AJIR?#8SQ]D^:7E/U!+ M P04 " #6DE=(Q[^+P*,! "Q P &0 'AL+W=OLTPX[I=7X 9YKUY,PSY@.;-M@".O"NI[9&VSG4'QFS9@N+V!CO0_J9&H[CS MIFF8[0SP*H*49&F2W#'%A:9%'GU/ILBQ=U)H>#+$]DIQ\^\$$H!L$1IXTK*WCI45P@EBK^/N]!Q'\:;+)M@ZX!T J0S8)]$X6.B*/,' M=[S(#0[$C*WM>'C!S2'UC2B#,]8=[[Q0Z[V78KN_R]DE$$TQIS$F7<1LY@CF MV><4Z5J*4_H?/%V';U<5;B,\^Z(P6R?8K1+L(L'V"\'^6XEK,???DK!%3Q68 M)HZ.)27V.@[JPCM/YT,:W^0SO,@[WL ?;AJA+3FC\R\;^U\C.O!2DIM;2EK_ M?V9#0NW",?-G,X[4:#CLKA]D_J7%!U!+ P04 " #6DE=(>PSQ2*,! "Q M P &0 'AL+W=OP%FF/?FS3 4(]H7UP%X M\JJ5<4?:>=\?&'-5!UJX&^S!A)L&K18^F+9EKK<@Z@32BO$L^\2TD(:61?(] MV;+ P2MIX,D2-V@M[)\3*!R/=$>OCF?9=CXZ6%FP!5=+#<9)-,1"Q%?<'?@H1%5=*:Z MTUT0ZH+W4N:?LX)=(M$<Z?P M/_GWFP3[1)"_(^ ?2MR*R3\D8:N>:K!M&AU'*AQ,&M25=YG.!Y[>Y"V\+'K1 MP@]A6VD<.:,/+YOZWR!Z"%*RFUM*NO!_%D-!X^/Q+ISM-%*3X;&_?I#EEY9_ M 5!+ P04 " #6DE=(\X*"P#@# #2#P &0 'AL+W=O^M!+N+55Y4_SXY1M-3RH MD^S,G;WJVTJ;R_Z0#:=>5CM7U#89Y?D\:ZNZ2]>E&WOIUZ4ZZZ;NY$N?#.>V MK?H_&]FHRRIEZ7W@M3X-UQ8B$/\K.5E MF)PG=O)O2KW;B^^[59K;.;?MZ;_.&WA]/S>_:M; MKIG^6S7(9]7\JG?Z:&:;I\E.[JMSHU_5Y9N\K6%F&VY5,[C?9'L>M&KO)6G2 M5I_78]VYX^5Z9SZ_E>$"NA706+#(W<2O1&Z:7RI=K79+^^FQ/E7V%[)', M@]C:0;=N=\],=#"C'VN^%&7V81O=,)LKAB88-B(RTWVD($2QH:"<<#F',^2N MO)B6%QPW$+"!< WX?TN<>4M$F#DFF4&2&6A0>"0(L\ D_A"1+T,#7-L+,,(EU-W)0#AZ8 M_U8 2.01@;&(4QEHX4L,@B(:8]"N3XS"]10!3P@2^3+"@WW->-B"Y3X/ D64 MQK#]6>AMP7RM05!$; PG OM+5@0I0@4TQL. 084# ZN3K#8(B>B.2 W!(K(C>,XX,#IPH\W"(K$&\=QP('3A1]O$!2)-X[C M@ .G"S\.("BB Q[YVP^<+GP=0%!$!QS' 0=6%[X.(,C703;9<[6R/[BMY9!L MU;ES.]G)Z+A]?2*W9_L'7Y>GZB!_5/VA[H;D36FS\W/[L[U26IJYY \F,XYF M@SU>-'*O[6EASOOKEO-ZH=7IOH,>M_'KOU!+ P04 " #6DE=(_1#K[Z,! M "Q P &0 'AL+W=OZ^D@2=+7*^UL']/H' XT@V].IYET_KH8$7.9EPE-1@GT1 +]9'> M;PZG78Q( ;\E#&YQ)E'[&?$E&C^K(\VB!%!0^L@@PG:!!U J$H7$KQ/G>\H( M7)ZO[(^IVJ#^+!P\H/HC*]\&L1DE%=2B5_X9AQ\PE;"/A"4JEU92]LZCOD(H MT>)MW*5)^S#>[.\FV#J 3P ^ ^ZR)'Q,E&1^%UX4N<6!V+&UG8@ON#GPT(@R M.E/=Z2X(=<%[*7;[+&>72#3%G,88OHC9S!$LL,\I^%J*$_\"Y^OP[:K";8+? M?E#XG_R[58)=(MA^(."?2ER+V7Y*PA8]U6";-#J.E-B;-*@+[SR=]SR]R7MX MD7>B@5_"-M(X/Q-ISM.%*CX;&[?I#Y MEQ;_ %!+ P04 " #6DE=(<5VUBZ(! "Q P &0 'AL+W=O+.FZ9EMC? ZPA2DJ5)\H4I+C0MB^A[,66!@Y-"PXLA=E"*FS]GD#B> MZ([>'*^B[5QPL+)@"ZX6"K05J(F!YD0?=\=S'B)BP"\!HUV=2=!^07P+QH_Z M1),@ 214+C!POUWA":0,1#[Q^\SYF3( U^<;^[=8K5=_X1:>4/X6M>N\V(22 M&AH^2/>*XW>82]@'P@JEC2NI!NM0W2"4*/XQ[4+'?9QNOB8S;!N0SH#T#L"F M1%'F,W>\+ R.Q$RM[7EXP=TQ]8VH@C/6'>^\4.N]US+?YP6[!J(YYCS%I*N8 MW1+!//N2(MU*<4[_@Z?;\&Q381;AAQ4\R_)M@GR3((\$V3\E[N]*W(C)#W=) MV*JG"DP;1\>2"@<=!W7E7:;S,8UO\AE>%CUOX2"G) MPYZ2SO^?Q9#0N' \^+.91FHR'/:W#[+\TO(O4$L#!!0 ( -:25T@R!0TI MI0$ +$# 9 >&PO=V]R:W-H965T)" MTR*/OE=3Y-@[*32\&F)[I;CY=P:)PXENZ,WQ)IK6!0),]3+!U0#H!TAEPGT3A8Z(H\P=WO,@-#L2,K>UX>,'-,?6- M*(,SUAWOO%#KO=&UL;5/!;N,@$/T5Q <4QTF:;N18:KJJVL-*50_= M,[''-BHP+N"X^_<%[+ANUA=@AGEOW@Q#UJ-YMPV (Y]*:GN@C7/MGC%;-*"X MO<$6M+^IT"CNO&EJ9EL#O(P@)5F:)+=,<:%IGD7?B\DS[)P4&EX,L9U2W/P[ M@L3^0%?TXG@5=>."@^49FW"E4*"M0$T,5 =ZO]H?-R$B!KP)Z.WL3(+V$^)[ M,)[+ TV"!)!0N,# _7:&!Y R$/G$'R/G=\H G)\O[(^Q6J_^Q"T\H/PK2M=X ML0DE)52\D^X5^R<82]@&P@*EC2LI.NM072"4*/XY[$+'O1]N[I(1M@Q(1T!Z M!6!#HBCS-W<\SPSVQ RM;7EXP=4^]8TH@C/6'>^\4.N]YWRSW67L'(C&F.,0 MD\YB5E,$\^Q3BG0IQ3']#YXNP]>+"M<1OONA\&Z98+-(L(D$ZQ\$OZY*7(BY M3:Z2L%E/%9@ZCHXE!78Z#NK,.TWG?1K?Y#L\SUI>PQ]N:J$M.:'S+QO[7R$Z M\%*2FRTEC?\_DR&A&PO=V]R:W-H965T0/* Y.DRIR+#6M5KN'E:H>=L_$'MNHP'@!Q]V_+V#'<5M?@!GFO7DS M#/F YLVV (Z\*ZGM,6F=ZPZ4VK(%Q>T==J#]38U&<>=-TU#;&>!5!"E)69KN MJ.)")T4>?2^FR+%W4FAX,<3V2G'S_P02AV.R2:Z.5]&T+CAHD=,95PD%V@K4 MQ$!]3!XWA],V1,2 /P(&NSB3H/V,^!:,7]4Q28,$D%"ZP,#]=H$GD#(0^<3_ M)LY;R@!NE<BX#^--QB;8.H!- #8#'M(H?$P493YSQXOYXYX5:[[T4V]TFIY= -,6QT'=>&=I_,Q M/B*]A1=YQQOXS4TCM"5G=/YE8_]K1 =>2GIWGY#6_Y_9D%"[<-S[LQE':C0< M=MBL[;5 0 104 !D !X;"]W;W)K M&UL=53-;IPP$'X5Q /$P+) 5RQ2-E75'BI%.;1G M+PP_BHVI;9;T[6L;EA ZN6![_/W,V'CR2K-3"\FI-DO9$#5(H)4C<4:B($@(IUWO%[F+/I$[TFHS_YC>+ID%N$ OSJ8U&;NV=RO M0KS:Q8_J[ R8*'A MA&@A1#L"F8U3)^6@':F\P/$7F($H;='6[/9.H,M%;$2=Q3FY6 M:,%<9DRTP80K@ACUU2+"+"[1?_0(IQ_0# ^.GF[I68 +Q*A [ 0.'TH\[DK$ M, EN"8-)/CBM%35)$(-R98)A/+C5#33)$ MX+ SP3#QSH1L_G,.LG'/67FE&'O7/#;1M6,\1NZ=O,.+?* -_*2RZ7KE784V MK\V]B5H(#2:5X,%<76MZVKI@4&L[3!/O=EKHQR0:^5T)%!Z9?Q?@= MYA)B*U@(IMS7*P:E!;]3?(_3CVEL.S>.TTX:S#2<$,Z$<$,@DY%+\YEJFF=2 MC)Z+)Z3!QD[7J&\@HQ=*Y#K:)+6WH,W6/\A.=93VOX267==LJ["FV>M'MX ME1 :3"K!@_D_&M,XEP6#2MMI8N9RZB730HO^WAF7]IS_!5!+ P04 " #6 MDE=(M-+[(Z4! "Q P &0 'AL+W=OVK:P$\>=/*N!-MO>^.C+FR!2W<'79@PDV-5@L?3-LPUUD050)I MQ7B6?6%:2$.+//F>;9%C[Y4T\&R)Z[46]N\9% XGNJ$WQXML6A\=K,C9C*ND M!N,D&F*A/M''S?&\BQ$IX)>$P2W.)&J_(+Y&XT=UHEF4 I*'QE$V*[P!$I% MHI#XS\3YGC("E^<;^[=4;5!_$0Z>4/V6E6^#V(R2"FK1*_^"PW>82KB/A"4J MEU92]LZCOD$HT>)MW*5)^S#>[+,)M@[@$X#/@$,"L#%1DOE5>%'D%@=BQ]9V M(K[@YLA#(\KH3'6GNR#4!>^UV!T..;M&HBGF/,;P1WB1=Z*!G\(VTCAR01]>-O6_1O00I&1W]Y2TX?_,AH+:Q^,^ MG.TX4J/AL;M]D/F7%O\ 4$L#!!0 ( -:25TBQK1.(\0$ !,& 9 M>&PO=V]R:W-H965T&T[?P\<[%7F6=BT*SM MX%5Z:N"3F%@(0[Q MNX51+>:>3?XLQ+M=_"R/?F!S :%MA+4#!=X <:LDG'^.XO>/2UQ.;^J?W?' M->F?J8(7P?ZTI6Y,MH'OE5#1@>DW,?Z ^0RQ%2P$4^[I%8/2@E\IOL?IQS2V MG1O':6VBL,#Y%Y$84-NG.[/9.H M,M%+ODW#C%RLT(PY39AH@;DCB%&_6428Q2GZ0H]P^@;-<./HR9*>/A#8H@); M)[#Y=,1H=40,L\%-8M0D1@2V*Q,,$^,F.]1DAPCL5B88)L%-$M0D003V*Q,, MD^(F>]1D_T4@#H*5"89Y\.&EJ$F*"*PO'L,\N'A;W5@%!8C$^NI1T/KNR:)H M.-Z="W!8-*VVEBYG+J6=-"B_[:@F__@?P_4$L#!!0 ( -:25T@-]?5> MI0$ +$# 9 >&PO=V]R:W-H965TVRCR-[D#YFUH;R9PW34-L9X!5$20%H4FR(Y)Q MA8L\^IY,D>O>":[@R2#;2\G,^PF$'HXXQ5?',V]:%QRDR,F,J[@$9;E6R$!] MQ+?IX;0-$3'@'X?!+LXH:#]K_1*,/]41)T$"""A=8&!^N\ ="!&(?.+7B?,S M90 NSU?VAUBM5W]F%NZT^,\KUWJQ"485U*P7[ED/CS"5D 7"4@L;5U3VUFEY MA6 DV=NX+H6%3J7L5!77CGZ;RE M\4T^PXN\8PW\9:;ARJ*S=OYE8_]KK1UX*&UL=53;;N,@$/T5Y \HF#1M-W(L-:VJW8>5JC[L M/A-[;*-R<0''W;]?P([KIO3%P'#.F3/ N!BU>;4=@$/O4BB[SSKG^AW&MNI M,GNE>U!^I]%&,N>7IL6V-\#J2)("4T)NL&1<96418\^F+/3@!%?P;) =I&3F MWP&$'O=9GIT#+[SM7 C@LL +K^82E.5:(0/-/KO/=X=M0$3 'PZC7?-D@S5T+!!N!<]_H2YA.BPTL+&+ZH&Z[0\4S(DV?LT1?KNB;PA)"UPG!:ZCP.93B3\N2DQ@ M\F^2;)-)M@F!_"))"G-Y%'AU<1),&]^G194>5.R&571I@7L:+_X#7A8]:^$W M,RU7%AVU\\\G7G*CM0-OA5QY+YUOTF4AH'%A>NOG9GJWT\+I_MR%RZ^@_ ]0 M2P,$% @ UI)72&VJ+02C 0 L0, !D !X;"]W;W)K&UL;5/;CMP@#/T5Q ^>&$V.V[D%Q^X #:'_3HE'< M>=-TS X&>!-!2K(L23XQQ86F51E]SZ8J<712:'@VQ(Y*4OT;C>BTTH::#EHW0O M.'V#I81#(*Q1VKB2>K0.U1U"B>)O\RYTW*?YYI@ML'U M@"R%? YB<+G1%'F M%^YX51J^\4.N]M^J0YB6[!:(EYC+'9)N8=(U@ MGGU-D>VEN&3_P;-]>+ZK,(_PXP:>)\4^0;%+4$2"_)\2BP\E[L4&UL=53=;J0@%'X5X@,4 MQ1GM3AR33INFO=BDZ<7N-:/'GQ3$ H[=MU] QUI+;P0.W\\YR"$;A7Q3#8!& M'YQUZA@T6O<'C%71 *?J1O30F9U*2$ZU6X857MAPZU8H.2:B.P5UT M.*46X0!_6AC5:HYL[F&+-"QOA]UORTM,3U M_*K^Z*HUV9^I@GO!_K:E;DRR88!*J.C ]*L8GV N86\%"\&4^Z)B4%KP*R5 MG'Y,8]NY<9QVDMU,\Q/(3" +X39TB4]&+LT'JFF>23$B.1UM3^T?C [$'$1A M@ZYNMV<2529ZR?=1DN&+%9HQIPE#5IAH06"COE@0G\6)?*,3/SWV9A@[>KJB MQ^&M7V#G%=@Y@?A+B>FF1!_F!Y.]UV3O$?BU,?%@2.@W2;PFB4<@VICX,#^< M=^HU23T"\<;$A]EM3/#J"G*0M>LTA0HQ=*ZO5]&EF>^(N\*?\#SK:0V_J:S; M3J&ST*81W'6MA-!@4@EOS*DVYKE9%@PJ;:>IF%%OWU/5D>M?P_4$L# M!!0 ( -:25TB'S8IPKP$ !8$ 9 >&PO=V]R:W-H965TR%G_+YH?EIZXK9_5?\65NO2GZF!)\5_L\;V+FR:H 9:.G+[JJ;O ML"PA)*P5-^&+ZM%8):Z4! GZ,;=,AG::9W;Y0HL3R$(@*^$A#<%GHQ#SF5I: ME5I-2,];.U!_@MF!N(VH?3&L.\RYH,95+U5!BA)?O-"".Z/L-/<_^(["+"NR"0/Z/0':SQ*^8@MS'38JH21$1V-^8 MQ# /-R9X23CX3WA5#K2#GU1W3!IT5M9=GW#( MK5(67)3TSF7IW2-=!QQ:Z[M[U]?SO9T'5@W75[C^"JJ_4$L#!!0 ( -:2 M5TAR1S^OV $ $4% 9 >&PO=V]R:W-H965TD+ML?G M,@/,%+.0[ZH#T-XG9X,Z^9W6XS$(5-4!I^I!C#"8FT9(3K4YRC90HP1:.Q)G M 0G#-."T'_RR<+%7619BTJP?X%5Z:N*MR?Y"%3P+]KNO=6>2#7VOAH9.3+^)^3O<2DBL M8"68*+D4OSA6I:%E+, MGEQ>[4CM%XR.Q+R(R@9=W>[.)*I,]%HFY+$(KE;HACDO&++!1"LB,.JK!<$L MSN0?.L'I,9IA[.C9AAY'*2YP0 4.3B#>EAB'NQ(QS'^*3%"3!!$@.Q,,$^,F M*6J2(@*'G0F&27"3##7)$(%T9X)A,MPD1TUR1"#?F6"8QYU)L/G/."*N3[[@93'2%GY2V?:#\BY"FVYS/=$(H<&D$CZ83]>9F;8> M:;C.SETN;+PY*P 0 %@0 M !D !X;"]W;W)K&UL=51=;Z0@%/TKQ!]0%,=V M,W%,.FV:]F&3I@^[SXQ>E90/"SAV__T".M;.LB\"EW/./1>XEI/2[Z8'L.A3 M<&D.26_ML,?8U#T(:F[4 -+MM$H+:MU2=]@,&F@32()CDJ:W6% FDZH,L5== ME6JTG$EXU*5US !TC ED8;VD-QG^V/A M$0'PB\%D-G/DO9^4>O>+E^:0I-X"<*BM5Z!N.,,#<.Z%7.*/1?,KI2=NYQ?U MIU"MJV*4E/GNA!7.<,62#R58$=NIK"A)+<23_T$F"GX"UZ5 ^W@)]4=DP:=E'7/)UQRJY0%9R6]<5YZUZ3K@D-K_?3.S?7\ M;N>%5<.E"]=?0?474$L#!!0 ( -:25TC7]F\1HP$ +$# 9 >&PO M=V]R:W-H965T0/* Z)FU7D6&I:5>UA MI:J'W3.QQS8J,"[@N/OW"]AQW=878(9Y;]X,0SZ@>;,M@",?2FI[3%KGN@.E MMFQ!<7N#'6A_4Z-1W'G3--1V!G@504I2EJ:W5'&ADR*/OA=3Y-@[*32\&&)[ MI;CY=P*)PS'9)%?'JVA:%QRTR.F,JX0";05J8J ^)G>;PVD7(F+ 'POQ) MT'Y&? O& >I Q$/O'[Q/F9,@"7YRO[8ZS6JS]S"_.E172$(4_QAWH>,^C#<9FV#K M #8!V SXE4;A8Z(H\X$[7N0&!V+&UG8\O.#FP'PCRN",=<<[+]1Z[Z7(=EE. M+X%HBCF-,6P1LYDCJ&>?4["U%"?V \[6X=M5A=L(WR_@6Y:N$^Q6"7:18/NE MQ-MO):[%[+\EH8N>*C!-'!U+2NQU'-2%=Y[.N_B(]#.\R#O>P&]N&J$M.:/S M+QO[7R,Z\%+2FRPAK?\_LR&A=N&X]V&PO=V]R:W-H965T*J]'LOJBKEU?"V8R\JTERBQ0[[^(]WAYPYB >\;ME@Y[-(^?\4UP8\^,<\=DE?_>23\TG>%\_F#_[H]KW3]2S9XE_].>3&.]3>+HQ,[T MRLVK''ZP^QF\A[7DVO]&]54;*1XF<23H^SBVG1^'\ M$,BR3Q($DCB0+^8$-D]!#U-O7LS,4U+ !"N08.4)TD]'W 1'!#!9 HMDH$@& M$.! !,(L7$4.BN0 01J(0)@5+%* (@5 D 4B$":'1=:@R!H@* (1"+.&13:@ MR 8@" ,/8/*%P+OJABHH 2C"T(.@A=CCA4K% $48?1"T$'X,ENL>$X B3 0 MM) !&*YKG (480Z H(4DP'#Y8Z"V\S -(%"QE ?P"X"!\BZ^Y $$"O, S1YO MP=3%]R@=U?+:^98XVYWZX)[XQ_\#7I4]O;!?5%W:3D=':6P+\0_]64K#K"_) MD_6EL9UZ6G!V-FY:V+D:>]>X,+)_M.+I_T#U'U!+ P04 " #6DE=("*T: M';P! ![! &0 'AL+W=O%%(#YP3]><,3(ZG:!?= J^T[8P+X++ "Z^F'(2F4B % MS2EZV!W/N4-XP!N%4:_FR.5^D?+=+9[K4Q2[%(!!99P"L<,5'H$Q)V2-?\^: M7Y:.N)[?U'_X:FWV%Z+A4;)?M#:=33:.4 T-&9AYE>,3S"5D3K"23/LOJ@9M M)+]1(L3)QS12X<=QVKF/9UJ8D,R$9$/ DY%/\SLQI"R4')&:CK8G[@_NCHD] MB,H%?=U^SR:J;?1:9H>TP%T?]36JD M-&!3B>]LP9U]"98%@\:XZ<'.U=0&UL=53; M;J0@&'X5X@,4!\=.,W%,.MTT[463IA>[UXS^*BD'"SAVWWX!'6NG[(W SW?B M9#$J_6XZ (L^!9?FD'36]GN,3=6!H.9&]2#=3*.TH-8-=8M-KX'6@20X)FEZ MBP5E,BF+4'O59:$&RYF$5XW,( 35?X_ U7A(-LFE\,;:SOH"+@N\\&HF0!JF M)-+0')+[S?Z8>T0 _&8PFE4?^>PGI=[]X+D^)*F/ !PJZQ6H:\[P )Q[(6?\ M,6M^67KBNG]1?PRK=>E/U,"#XG]8;3L7-DU0#0T=N'U3XQ/,2P@)*\5-^*)J M,%:)"R5!@GY.+9.A':>973;3X@0R$\A"N$M#\,DHQ/Q%+2T+K4:DIZWMJ3_! MS9ZXC:A\,:P[S+F@QE7/97Z7%OCLA6;,<<*0%6:S(+!37RQ(S.)(?M!)G)Y% M$V:!OON6\#_^VZC -@ADWP3(U1)CF"QNDD=-\HC ]LHDALFO3/#JX 3H-MQ/ M@RHUR/ :5M7E"=R3G<(UT& M'!KKNSO7U].]G096]9=7N/P*RG]02P,$% @ UI)72#K17/$- @ XP8 M !D !X;"]W;W)K&UL=57;CILP$/T5Q >LN01R M$4%*=E6U#Y56^] ^.V0":&W,VD[8_GUMD[#4'5[P[5S&'CPN!B'?50.@@T_. M.K4/&ZW['2&J:H!3]21ZZ,S*14A.M1G*FJA> CT[$FRFR3%^1FA>Z8XXA)9IAX0A"C/EDDF,4Q^8^>X/04C3!U]/6, MGJ8;7&"%"JR<0/K/%M?>%C',@DF&FF2(P-8S03#;"#?)49,<$8@]$PRS<-YK MU&2-"*2>"899X28;U&2#"&2>"8;)<9,M:K)%!/S$8YB%Q-O;C=V@")'P4X^ M\F@A]_'"38T1"3_[*&@A_3%Z70]Q@DCX/P *\O\ ,BM"'&3M:JT**G'M7&F? MS4[U_.#*.?F"ET5/:_A)9=UV*C@);4JA*U@7(3286*(G&PO=V]R:W-H965T M&._#38P/^LRVTY8(3"_0K?Y[@6YKU;X ,\PY19]3R;/L'-2:'@R MQ'9*."@^49FW"E4*"M0$T,5$=ZMSJ<-B$B!KP(Z.WL M3(+V,^);,/Z61YH$"2"A<(&!^^T"]R!E(/*)_U\YOU(&X/P\LC_$:KWZ,[=P MC_)5E*[Q8A-*2JAX)]TS]H]P+6$;" N4-JZDZ*Q#-4(H4?Q]V(6.>S_<[$?8 M,B"] M()<)M$X4.B*/,/=SS/#/;$#*UM>7C!U2'UC2B",]8=[[Q0Z[V7?)=L M,W8)1->8TQ"3SF)64P3S[%.*="G%*?T%3Y?AZT6%ZPC??U.X6R;8+!)L(L'Z M&\'^1XE+,;<_DK!93Q68.HZ.)05V.@[JS#M-YUT:W^0K/,]:7L,_;FJA+3FC M\R\;^U\A.O!2DILM)8W_/Y,AH7+AZ >"F&&D!L-A.WZ0Z9?FGU!+ P04 M" #6DE=(L>>L6+$! 6! &0 'AL+W=O>=>[$,!5 MB5=>PR4HR[5"!MI3]I0?S_N B("?'":[F:/@_:+U6UA\;TX9"19 0.V" O/# M%9Y!B"#D$_]>-#]2!N)V?E/_&JOU[B_,PK,6OWCC>F^69*B!EHW"O>KI&RPE M1(>U%C9^43U:I^6-DB')WN>1JSA.\TYQ6&AI ET(="5\(M'XG"C:_,(I%T6$3Z84,OR"XML$L*[*) L2TQ)W&PO=V]R:W-H965TC!":[@V2 [2,G,QPF$'H\XQ5?'"V\[%QRD+,B"J[D$9;E6 MR$!SQ'?IX92%B!CPA\-H5V<4M)^U?@W&K_J(DR !!%0N,#"_7> >A A$/O'; MS/F5,@#7YRO[8ZS6JS\S"_=:_.6UZ[S8!*,:&C8(]Z+')YA+V ?"2@L;5U0- MUFEYA6 DV?NTA1=, M#]0WH@K.6'>\\T*M]U[*/,T*<@E$<\QIBJ&KF'2)()Y]24&W4ISH?W"Z#=]M M*MQ%^.T*OLM^;A-DFP19)-C]4^+^6XE;,?FW)&354PFFC:-C4:4'%0=UY5VF M\X[&-_D*+XN>M?";F98KB\[:^9>-_6^T=N"E)#=[C#K_?Q9#0./"\=:?S312 MD^%T?_T@RR\M/P%02P,$% @ UI)72*Q&Q8CS 0 $P8 !D !X;"]W M;W)K&UL=57-CILP$'X5Q .LP01((H*TV:IJ#Y56 M>VC/#DP"6AM3VPG;MZ]M$I8EDTMLC[^?L9T9BD&J=]T F.!#\$[OPL:8?DN( MKAH03#_)'CJ[N!QV81S> F_MJ3$N0,J"3+RZ%=#I5G:!@N,N?(ZW^SAR$(_XW<*@ M9_/ )7^0\MTM?M:[,'(Y (?*. EFAPN\ .=.R3K_O8I^>CKB?'Y3_^Z/:],_ M, TODO]I:]/8;*,PJ.'(SMR\R>$'7,^0.L%*?' M8=Q91U<:3J!7 ET0R&CDT_S&#"L+)8= C7?;,_>$\9;:BZA MRBS."W)Q0E?,?L30&2:>$,2J3Q84L]C3.SK%Z0F:8>+I^8R>I DNL$(%5EX@ M^7+$]>*(&&:#FZ2H27HO0*.%"89Y<),9:I(A G1A@F$>7%>.FN2(P&IA@F%2 MW&2-FJP1@6QA@F%RW&2#FFP0@>7#8Y@'#^^J&ZN@Z%XB63X]"EJ^/9D5K0!U M\KU)!Y4\=[X5SJ)3_WNFON@_X671LQ/\8NK4=CHX2&-;AR_PHY0&;"[1D_T? M-K9#3PL.1^.FN9VKL6>-"R/[6PN>O@/E?U!+ P04 " #6DE=(,MW_O*$! M "Q P &0 'AL+W=OL.E-JR!<7M'7:@_4V-1G'G3=-0VQG@500I25F:WE/%A4Z* M//I>3)%C[Z30\&*([97BYO\)) ['9)-<':^B:5UPT"*G,ZX2"K05J(F!^I@\ M;@ZG;8B( 7\$#'9Q)D'[&?$M&+^J8Y(&"2"A=(&!^^T"3R!E(/*)_TV5?4;G6BTT34D'->^E>B#,Y8 M=[SS0JWW7HK[C.7T$HBFF-,8PQ8QFSF">O8Y!5M+<6+?X&P=GJTJS")\OX!G MN_TZP7:58!L)LB\E9C-T):G=+B&M_S^S(:%VX;CW9S..U&@X[*X?9/ZE MQ0=02P,$% @ UI)72&15&UL;5/;;N0@#/T5E \H&3*7:I2)U&FUVGU8J>K#[C.3. DJ MX"R02??O"R23IFU> !N?XV-C\@'-JVT!''E34MM3TCK7'2FU90N*VSOL0/N; M&HWBSINFH;8SP*L(4I*R--U3Q85.BCSZGDV18^^DT/!LB.V5XN;_&20.IV23 MW!POHFE=<- BIS.N$@JT%:B)@?J4/&R.YVV(B %_! QV<29!^P7Q-1B_JE.2 M!@D@H72!@?OM"H\@92#RB?]-G!\I W!YOK'_B-5Z]1=NX1'E7U&YUHM-$U)! MS7OI7G#X"5,)NT!8HK1Q)65O':H;)"&*OXV[T'$?QIMM-L'6 6P"L!EPGT;A M8Z(H\XD[7N0&!V+&UG8\O.#FR'PCRN",=<<[+]1Z[[789[N<7@/1%',>8]@B M9C-'4,\^IV!K*<[L&YRMP[-5A5F$'Q;P;']8)]BN$FPC0?:IQ/V7$M=BOB:A MBYXJ,$T<'4M*['4&UL;51=;Z0@%/TK MQ!]0%&"FAO5@W0[C=*"6K?4+3:]!EH'DN"8I.DM%I3) MI"Q"[%67A1HL9Q)>-3*#$%3_.P)7XR')DDO@C;6=]0%<%GCAU4R -$Q)I*$Y M)/?9_KCUB #XPV TJSGRWD]*O?O%2WU(4F\!.%36*U WG.$!./="+O''K/F5 MTA/7\XOZ4ZC6N3]1 P^*_V6U[9S9-$$U-'3@]DV-SS"7$!Q6BIOP1=5@K!(7 M2H($_9Q&)L,X3CN;W4R+$\A,( OA+@W&IT3!YB.UM"RT&I&>CK:G_@:S/7$' M4?E@J#OL.:/&1<_E;7Y7X+,7FC''"4-6F&Q!8*>^I""Q%$?R@T[B]#SJ, _T MW8J>[[9Q@4U48!,$\F\E_KHJ,8+9I/$DVVB2;40@NTH2PUP?!5Y=G #=AO=I M4*4&&;IA%5U:X)Z$B_^"ET5/6_A-=&UL;5/!;MP@$/T5Y \(7NS- MMBNOI6RBJCU4BG)HSZP]ME& <0"OT[\O8*_CIKX ,\Q[\V88BA'-J^T ''E7 M4MM3TCG7'RFU50>*VSOL0?N;!HWBSINFI;8WP.L(4I*R-+VGB@N=E$7T/9NR MP,%)H>'9$#LHQ1-NYX*!E01=<+11H*U 3 \TI>=@=SWF( MB &_!(QV=29!^P7Q-1@_ZE.2!@D@H7*!@?OM"H\@92#RB=]FSH^4 ;@^W]B_ MQ6J]^@NW\(CRMZA=Y\6F":FAX8-T+SA^A[F$?2"L4-JXDFJP#M4-DA#%WZ== MZ+B/T\T^GV'; #8#V +XDD;A4Z(H\XD[7A8&1V*FUO8\O.#NR'PCJN",=<<[ M+]1Z[[6\S[."7@/1''.>8M@J9K=$4,^^I&!;*<[L/SC;AF>;"K,(/ZS@V>'K M-D&^29!'@NR?$O-/)6[%[#\EH:N>*C!M'!U+*AQT'-25=YG.!Q;?Y".\+'K> MPD]N6J$MN:#S+QO[WR Z\%+2NWU".O]_%D-"X\+QX,]F&JG)<-C?/LCR2\N_ M4$L#!!0 ( -:25TA9%"2+P $ 'L$ 9 >&PO=V]R:W-H965TT.I\(A/. 7A4EOYLAE/TOYYA8_FF,4NPC MH#9.@=CA L_ F!.RQG\6S0]+1]S.K^K?_&EM^C/1\"S9;]J8WH:-(]1 2T9F M7N7T'98CY$ZPEDS[)ZI';22_4B+$R?L\4N'':=XILH46)B0+(5D)C[$//AOY MF%^)(56IY(34_&H'XK[@[I#8%U&[HC^WW[-!M:U>JB(K2GQQ0@OF-&.2#6:W M(K!57RV2D,4IN:,G87H:3)AZ^OY3PGU8( L*9%X@W0CDZ>T10YC_F.1!D_Q. MH,@>;TQ"F"]ADR)H4MP+Y/&-R3TF3V]-\.9V<%"=;P*-:CD*WW*;ZMIG3XF_ M71_PJAQ(!S^)ZJC0Z"R-O:/^)K52&K!1X@=[X-[^"=8%@]:XZ=[.U=P<\\+( MX=KJZ_^F^@=02P,$% @ UI)72$+ V'VA 0 L0, !D !X;"]W;W)K M&UL=5/!39]@[)5MX,<3V6@OS MYP@*AP/=T(OC5=:-"PZ69VS&E5)#:R6VQ$!UH(^;_7$;(F+ +PF#79Q)T'Y" M? O&C_) DR !%!0N, B_G>$)E I$/O'[Q'E-&8#+\X7]6ZS6JS\)"T^H?LO2 M-5YL0DD)E>B5>\7A.TPE[ )A@^$45PQKKCG1=JO?>2 OLV#NK".T_G(X]O<@W/LT[4\%.86K:6G-#YEXW]KQ = M>"G)W8Z2QO^?V5!0N7!\\&&PO=V]R:W-H965TF>4JV/0:3T<,%95!XRH&S$ -SN-D(QHLY0M5H,$4CL2HS@. MPQ0STO.@+%SL29:%M.3Q)I$;&B/QW BJF8Q %U\!SWW;:!G!9X)57]PRX MZ@5'$IICZV,06@M H=)6@9CA G= J14R MB=\6S<^4EKB=7]7O7;7&_9DHN!/T;U_KSI@- U1#0T:JG\7T $L)B16L!%7N MBZI1:<&NE Q\CZ//7?C-._DX4+S$^*%$*^$*'7&YT3.YF^B25E(,2$Y'^U M[!^,#K$YB,H&7=UNSQA5)GHITV1?X(L56C"G&1-O,-&*P$9]31'[4ISB_^BQ MG[[S.MPY^NZ+P\0OL/<*[)U ]D4@]0LD7H'$XR#[=D8^3.Y/DGJ3I!Z!7WZ! MS"N0_;S,W"N0_Z!,#R8-OR7!F[O'0+:NQ12JQ,A=0V^B:Q??QN[N?L++8B M M_"&R[;E"9Z%-![A[V@BAP5@);\R1=^:=61<4&FVGF9G+N?7FA1;#]2%97[/R M U!+ P04 " #6DE=(,GXHTA@" #M!@ &0 'AL+W=O8AOITY9PXPX[P7\EW5E&KO@[-6K?Q:ZVX9!*JL*2?J072T M-2=[(3G19BFK0'62DIT+XBS 89@&G#2M7^1N[U46N3AHUK3T57KJP#F1_S:4 MB7[E(_^T\=94M;8;09$'4]RNX;15C6@]2?G:9!OZWH[NR8'I-]&_T-%#8@E+P93[]\J#TH*?0GR/DX]A;%HW]L/)(AS# MX \!N I ^)#T(NS1]$DR*7HO?D\&P[8E\A6F+S($J[Z7R[,Y.H,KO'(DU1 M'APMT8C9#!@\PYP1@6&?)# DL<%7X1AE,$$$YA@Y@NQ3CA@FB$&"V!%$GPBB M"Y,#)G68UF%"6"(!)1) (H8)4I @O=]D!A)D=Y@<,,G,)(Y#]X.5%J#2 E!* M8()'D.#Q?J^VI*#/-KS#[0B:VXV2]"N_Z$:1($ MO4$!%L$:X6]XALL 14 6 MV:7GZ/H5?^D8KA@$E*0^N:_&QWZNQK[-K9 M&5[D':GH+R*KIE7>5FC3%%WKV@NAJ4DH?#"V:W/W3 M&]]I.,S.70S<>%EIT MI\MENN&*_U!+ P04 " #6DE=(+I!DZF(" 4"0 &0 'AL+W=O<>PP'.VFY>)$Y8\IYK\I:;MU3++ M647E V]8K5=.7%14Z:$X>[(1C!YM4E5ZV/>)5]&B=M/$SCV)-.$7518U>Q*. MO%05%?_VK.3MUD7N=>*Y..?*3'AIX@UYQZ)BM2QX[0AVVKH[M-ECWX38B#\% M:^6H[YCB#YR_F,&OX];U30VL9)DR$%0W;^R1E:5!TLRO/>@'ITD<]Z_H/ZQ< M7?Z!2O;(R[_%4>6Z6M]UCNQ$+Z5ZYNU/UFL(#6#&2VG_G>PB%:^N*:Y3T?>N M+6K;MMU*[/=I< +N$_"0@&-;>$=DR_Q.%4T3P5M'='O;4/,(T0;KCJ;U&XIOB37VA"S@W[&Q?=#] M.XL6_(: %R5<@ #]M$/X_MU%L*-0<,?KV@>-)0D&;87"K^@ M&;8/ OPSUTQF'D6A[]\4#7L(028B"Q"PB] 7;(1@'R'(2-%4]-Q)"RP8=A"& M'!1/6/J@6Y\_;W1J54R<[>$LG8Q?:GL7&,T.%X =MJ?>1WB:-/3,?E-Q+FKI M'+C29Z<]X4Z<*Z8K\1^TTEQ?489!R4[*="/=%]VAW0T4;ZYWD.$BE/X'4$L# M!!0 ( -:25T@*\0Q&PO=V]R:W-H965T<##, J*-"O]]=*>>ZK62W-N\JS43Y57GXLB MK?YM=&XN*Y_YUQ._LL.QZ4X$ZV5P&[?+"EW6F2F]2N]7_@.[WZBH"[$1OS-] MJ4?[7M?\LS$OW<&/W=YEZFM_'=(^EZS&SC>OV;_ M9N6V[3^GM7XT^9]LUQS;;D/?V^E]>LZ;7^;R70\:5)=P:_+:_GK;<]V8XCK$ M]XKTK=]FI=U>^G\6X3 ,#^## 'X;P/O&^T*VS:]IDZZ7E;EX57]M3VDWA>R> MMQ=BVYVTNNU_;:-U>_9U'<7),GCM$@TQFSZ&CV+8+2)HL]]*<%1BPR?#.8MQ M @%[%#:!&/>X"'$""1-(FR >)9!J@1,HF$"!#MBGJ]3'1#:FM#%?.*X1P1H1 MJ$$DB&&"V%WE B98.*CL8]18)2/NA@0624 1@1-T.*%;-G07RHB[GCE('8(^ M:B7*P#O_@7%01A(I\+W/Q RQ^.YGTD6LG(I-B#*8$88@440*C "+9HC%$+#8 M16SL/K,8%898B8@4& 26N(OEF 0>.H@=@I3#@XEC6CBBA7B"@U,Q(J)6$9,"\>T<$0+U2DF@:L98C$)'+T-)F*CB5A),,LQ+1S10J7 )/#% M#+&8!([>"1.QR71FB?>&P+0(0$M"^ B!21#,7:S ) CT3O@L=@CZ,+,$LX+P M3("6A'C&"4R"F&&;!"9!N!BG(6@LEII8#(L L"34Y<(@B!GF26 0A(M]$E/_ M1%EAS(H K"3$Y9*8 SG#/TG,@73Q3W+JGQA5!K,B 2L)X9\DYD#.\$^2^'IP M\4]RZI\BZAL%LR(!*PGAGR0&0<[P3Q*#(%W\DYSZ)T9-"X9% E@2XD4M,0ER MAG]2F 3EXI_4U#\IXD&J,"T*T)(0V"M,@IKAGQ0F0;GX)S7U3\3$*@R+ K D M5*/$Q_8,^Z0P",K%/@U!XR_VS]8G&"VC%+HZV-6BVMN:G]*!_IM4A*VOOV32-*>R2R]Z81K>=A'>MXJ-.=[>#7.^;;C=N]ZM^ M%:D_:,SINBAV6YE;_P=02P,$% @ UI)72*-F>YW* 0 P00 !D !X M;"]W;W)K&UL?93+CILP&(5?!?$ 8\!<-!%!ZJ2J MVD6ET2S:M0,_P1H;4]L)T[>O+X128G43W\XY_G[CN)Z%?%<#@(X^.!O5,1ZT MG@X(J78 3M23F& T*[V0G&@SE!>D)@FD*$CG%3N[E7V=3BJAD= MX55&ZLHYD;]?@(GY&*?Q?>*-7@9M)U!3H]7740ZCHF*,)/3'^%-Z.!56X00_ M*,QJTX\L^UF(=SOXUAWCQ"( @U;;!&*:&YR ,1MD-OZU9/[=TAJW_7OZ%U>M MH3\3!2?!?M).#P8VB:,.>G)E^DW,7V$IP1&V@BGW&[57I06_6^*(DP_?TM&U MLU_)\\46-F2+(5L-Z?\->#'@G0%Y,E?79Z))4TLQ1])_BXG83YX>L#FYUDZZ M@W)KIC)E9F]-^?QK!!F E2(+4F3.7VUWJ,IP M X&8!> -P%5DNS*\)K2:48/F>-=(0%-485!\B!('@!)=R!>4VPWP?L3#6CR M(@Q2!$&*!Y"TVI](\5!M614[D$=-E60[$+2Y;1.YP'J% MT&#RDB<3.)CW9!TPZ+7M5J8O_5_,#[28[@_&^FHU?P!02P,$% @ UI)7 M2-41S$R_ P K!( !D !X;"]W;W)K&ULE5A- MCYLP$/TK*/<6/#9?JVRD;J*J/52J>FC/;.(DJ(!3<#;MOR\8-DOP6/CY475/YNCE-K[7195\[@X:GUZ\/UF>Y1EUKQ7)UFU/7M5EYEN7^N# MWYQJF>V,45GX% 217V9YM5@M3=O7>K549UWDE?Q:>\VY++/ZSY,LU.5QP1:O M#=_RPU%W#?YJZ5_M=GDIJR97E5?+_>/B WO8B+"#&,3W7%Z:T;/7D7]6ZF?W M\GGWN @Z#K*06]VYR-J_%[F61=%Y:D?^-3A]&[,S'#^_>O]HPFWI/V>-7*OB M1[[3QY9ML/!V$3800H=I/>G=%?7 MD+*#_R?U@+G)ZE#09/DV ^QF96*1) X^CDK#P)PX%I?!2O*!T8Q9P:6"<< B MF4X+ CE$S'!%879)B5G@<($+ 0MG1(OURY" K6@!B#GJ+\.R8T!WS%%I&%8, M2V9$BS7#TCLR/K4RGB51,DWXU"X 42HP&\+Z(UM_,7,$1%@RQ.Z?$\*2(;HC M Q"(N:+%NB(@&5?))"P9$C.BQ9(A>_,$T0(0@-'8M'E8>!^<[R/I@+D,;;JG.E.]M1Z_62Y8FZ[_YINQ /:R% 3TND[3&W'O[; M$*OE*3O(+UE]R*O&>U9:J]+<"^R5TK+E'[QO^1]EMKN^%'*ON\>X?:[[RY3^ M1:O3Z]W0]8)J]1=02P,$% @ UI)72(NG?:4I @ G@8 !D !X;"]W M;W)K&UL?97;;J,P$(9?!?$ -9A3$A&D)M%J]V*E MJA>[UPYQ JJ-J>V$[MNO#X008_4FV,/_SWP>PE .C'^(!F,9?%'2B6W82-EO M !!U@RD2+ZS'G;IS9IPBJ;;\ D3/,3H9$R4 1E$.*&J[L"I-[(U7);M*TG;X MC0?B2BGB_W:8L&$;QN$]\-Y>&JD#H"K!Y#NU%'>B95W \7D;OL:;0Z$51O"G MQ8.8K0/-?F3L0V]^G;9AI!$PP;74&9"ZW/ >$Z(3J<*?8\Y'26VC=$@84?=EK MVYGK8.^LHM'F-\#1 "=#G']K2$9#\C"DWQK2T9 Z!F"/8AIQ0!)5)6=#P.W# MZY'^C\2;5+6ZUD'367-/M4*HZ*TJ8%:"FTXT:G96 V>:>%( E7TJ 7TE=G!A MA\\%]DM%$C]+#DO)>N6'2+SG3(R_F$.L(G^"U)L@-0F2IT;E3J.L)C>:SC8J MCE+GL!X1=$4'7Z9UXN?-O+R9A[=P>*TFFU6!:X=V*4D2A]4CR?VDN9JK@YHOVKI*_:B%%[7PH#H=VQ6^YQNYM!Y5-E=9&#![C2GF M%S,/15"S:R?UVS"+3B/W%>HQX,1W:A3;R?E(4Y4]NN#?B%_:3@1')M60,:/@ MS)C$"C)Z4=ULU,=BVA!\EGI9J#6W\]-N).OO7X/IDU3]!U!+ P04 " #6 MDE=(^B>-TGD" L"0 &0 'AL+W=OVATFH/[=D+!J)-8AH;V'[[VDY@L\ZD2R^) M'_\9_\:>C#._J/9%'Z0TT6M=-7H1'XPYSI)$;PZR%OI!'65C9W:JK86QW7:? MZ&,KQ=8;U55"$$J36I1-O)S[L<=V.5,7/4E[TH!TY^&>E7ESG^W81 M(\<@*[DQSH6PK[- M9A3-D[-SU&M6G88,-.2]8CU64'R3)!;@1D% "N+MLR$%HK #"CJ@W@$=.& \ MB**3I%[2=%'DK,!!)&,518P7, L#6=B8)0U8.@D?K/*I8*P(6"!5D1*8A8,L M?,22T2#D%1\M@PO$PB,>JPAB10;#I"!,"L!,1).!#K+[TR0''>0?ITD^W@V< MXSS8#4!%\11+ ;(4'Z=),4X 1GF8LI J9Q/?GZMI4!E =R1*+QJNE+$T"VO! M6)63J:S%$U4) S@3NXOADH+_HZ9@N*C@.ZI*KWF7"6F:T7!3 %E&>3K! Q<6 M?$=EP4#1X*@(\Q>483*5-'!QP?=4EUZ4OON@>,9#($!&".4!4#*XUXYB+W^( M=E\V.GI6QEZ1_B+;*66D=8D>K,N#_76Y=2JY,ZZ9V7;;7>9=QZCC]=_D]H.T M_ M02P,$% @ UI)72#T/A&Y< @ 3P@ !D !X;"]W;W)K&UL?99-CYLP$(;_"N+>!?.91 1IDZIJ#Y56>VC/#G$"6L"L M[83MOZ]M" %[DAR"/;PS\XR=G=FLI^R#EX0(YZNI6[YU2R&ZC>?QHB0-YB^T M(ZU\A%UU9(WYO!+TV#V M;T=JVF]=Y-X,[]6Y%,K@Y9DW^1VKAK2\HJW#R&GKOJ+-'FF)5ORI2,]G:T?! M'RC]4)M?QZWK*P92DT*H$%@^KF1/ZEI%DID_QZ#WG,IQOKY%_Z'+E?@'S,F> MUG^KHR@EK>\Z1W+"EUJ\T_XG&6N(5<""UEQ_.\6%"]K<7%RGP5_#LVKULQ_> MK/S1#78(1H=@E;#"+9P@S IE6-E-DI-JMK%0(OC) ^/17M :1U@ 2,I#6=O4IB&0+D7FW"R35 M0:&FXP-0@=EU?"M9$,%8D-3ZVUR"/>B&" +33 $= (0RQ::.-ZL3S>$G?7\ MXDY!+ZU0'7%FG6;D:Z#ZO&'?J=FI^_\]3)YU^$Q^8W:N6NX8_M]\$FJXNI7YNCUC9X+XNJ68=':T_W4=1LC[I4S9TYZ:I]LC=UJ6Q[61^B MYE1KM7.-RB+B<9Q&IA'4_S. M=_;85AN'P4[OU;FPS^;R70]]2+J$6U,T[C?8GAMKRH\F85"J]_Z85^YXZ9\L MXJ$9;L"'!OS:@"]=X;V0*_.KLFJSJLTEJ/NQ/:EN"MD];P=BV]UT_7;/VD*; M]N[;)I-R%;UUB8:8ASZ&W\0DUYBHS7\5X5"$NP3938(4)Q P@7 )Q$V";%)E M'Y.XF,K%$#5**"&!Q (G2&""9'XG4Y@@!14L)YWL8])1)QF6R*!$YDLD\40" MQ1 B"RBR GX1&3A]8,38[6$&DN@(28:2\\0$DMTV"(T8B!"I2#H8O--P3 [ MC,^PQ1!T,YZ$"@:, <(\9\ @ C*&*6, ,\\<0]"X-T)2_<$PLF2&08:@L4/X MDI#!R#+ ;$+-+T:299^P" :. >)\B_C(42H8.8:8\RR"@C)BK<#8<83=U")# MT(WA&3%W'+/)V0R+#$%CBPC"B9Q8^P"_";&P< PG%_,MPC%W'"UO4XMPGSM& M58JQXPB[J4=@$#5WF#N.N/,\XB^67%##AN'D:#'T/))Y'B&MB 'F . T)E)@ M.OGR$WLL#)X X'D>$3YXC !"8.X$XF[J$124$KL0@<$3"+RI1X2_<+(%X7E! M[$W1JCCUB/!WIY+82@A,L $I]3(8SK%)[:H H,GYFQ2AZ!Q9PDS"XR=0-AY M4^=C)P4A@[$3:*?JS=S"DZ'\@=4$+\:V7]WN MVWAOC-5MPOBNK?FHU>YZ4>B][4ZS]KSN/_?["VM.'_]>7/]"V?P#4$L#!!0 M ( -:25TB"@G:^APH (Q1 9 >&PO=V]R:W-H965TK7975T\[?[EVVWO#\V6J_FUIAFOEX^;RZN+X_7?MU> M7_:O^]7SIOMU.]N]KM?+[=^+;M6_75W(Q?N%WYX?G_;#A?GUY?RCW?WSNMOL MGOO-;-L]7%W\1[[=6F,'S!'R^W/WMOOT]VRP_GO?_SG\\]_[JPLS&-&MNKO] MT,?R\.M'=].M5D-7AZ_^_[G7?[]T:/CY[_?>?SZ.]V#_]^6NN^E7?SS?[Y\. MYIJ+V7WWL'Q=[7_KWW[ISH,(0X=W_6IW_#F[>]WM^_5[DXO9>OG7Z??SYOC[ M[?1)-.=FN($]-[ ?#5H_V<"=&[B/!C+=P)\;^*S!_#24HR-NE_OE]>6V?YMM M3]/WLAQ6B7SS!U??#1>/GCU^=G#%[G#UQW7;^,OYCZ&C,^;FA+&?,':,N-4( M)Q^0^<& #RLLM,(>V[R@+9B3 M5HU2\BF9A(S,B-",6# A47U'/AU3B)$1"1J1]&18W'Z(4HBGIGPZA%!="B;D M#!JMNR@YW36HC80E@ADOMF!:SJ#1W.>@6P"RB3!%CIB>^PV MM-^L9GH>IB& M84' :%D.B&ENVPJ_89I;=+-7?M,@X+>O4X))R-A:'%$LB"@M20LX' L M&F(,YK!#'";C\9C#OH+#'G/8(PZKJE/3T^=K!&!H^8L9[ ^)3CWGG785# M2!5>5(:#&KO)'0(P)$1[S%\/^-L2WGG,.U]1BWO,.U]2C7M=:ZMMB2G(V!#, M7E_"7O_UW7<2,C8$,]5.Z8@8T/([AE@+!\RWD,K=T6"^-:B@S=UQ!DVY8Q(R-@2SM@&LC>2VT&"^-15[ MW@WF6U.RZWT&C6J[_"8',(&9@GG;E/"VT:34VWD 1+?S&LS=!G&7Y.T-V?RN MX&Z#N=N4<+?1Q+3Y=A[ L"2UP>QM$'N93S%[FPKVMIB];0E[6TW-D)U'W0*, M-<0C+29PBPC,AH,)W%80N,4$;A&!E4>;5F\5ZT,! M!&*' A$3.)80.&IRZD,! **' A$S."(&D_0]8@;'"@9'S.!8PN (&)P[1$-( M=A4Q?R/B+PD!$?,W5O W8O[&$OY&<&QDE$/ L9&P%8(9' &#$^N"G!U7,#AB M!D?$8.4234YU #T%&9] 8_8FP-Y$%EG"G$L5IT$)HFDL,G3+I4L;N;,.E2R4D/ .D3BP2V@&V>70-0,&P18(XGP/%$[JT) M,S-5; (GS,Q4RIC&9 MR4188D",222W%T,$(::B(A9#A!RF9!?Z'37*E_*C&PBBC"*B$ ."2"(YOA@B M"S$5E;$P=9>@U%IKL[[>VIK&9,8PG1B($8GI;9B^2RJ2:V&Z+"G9X7I'31:$ M".385#.1EP#N)Z9[8S(OJ4BSAK M%%I,HE6FT2H3:0$!ECBETD*HP.YN1*J]HZ,B9>KLFKR="+7%%>3U (?<5Y/63F,QD M$F^ ,BRR.Q/3:TR"^]DBT 3JR:&@GA/^N M)OLG C#Q!=G_ J& ^WQ!C3")R4PFT08HSJ)A-0*1BHFOJ1&(6$Q\08VP0"CD M/%!)*&4I0K6&E0%$H"9 H19Y)R0"^)I:@HC+Q!?4$@N$0@[4U81VWQ0F,YG$ M&Z!FB^QT0(@037Q-Q4%$9()49,!Y116'U[4$6GW@P1"Z<(AP30*H.(0ECD2Z M)J&FXB"R,T&Z,^U @ (.# 45QR0F,YE$G J#F$5!Q&Z2:AZ8HSP'ZG4@/.* M*HZ :@GE/0VB3Y8169P$4&\(JS>(,$Y"3;U!1&V"5&W ?47U1BBH-R8QF

(!$Z0!DX[#Z" \QI=2NBU!T#\J482;1I0;[#'B87( M[J2IJ3>(8$Z@8DZ[KZC> )HYM?8F,9G))-H 75UD2C0APCJI4=8)D=8)U-:I M[4\DG-.KJOSYK1$BL),:A9T0B9U C9UR#!#0:<=,@S)S2(P M,KLHK$H@.CNI$=H)4=H)E-IIQ^C,7A%I$I,90[@/Q'916 I'U'92([<3HK<3 M*+C3;BG(ZB ?(!M1YS&BB MSA,@SXN6Y?1$52>Q)JJ+!DUB3 MTQ,5GL2BG!Z@D/-*Q)J3T MDYC,9!)M@$0P6I;3$W6?I)J%LJLG$B9)/4E$FGG22K0\S M 8CFBD05*$#Q%RW+Q(E83U)%)FZ)6L^:DDS\'?7YA6,VY6]7@RCF&DN4?\?K MY^:@$7EW"]#=J3BY0*AH<_OFGUY)M^ZVC\=W^^UF=_WK9C^T_73UXP6"B^/; M_O+KAZ%\NQG&HS\;;!D^.[YV[_?]^NKX;5W M#WV_[PZ#,#\=UMU3M[S_^&?5/>R'/X<\>WMZ5^#IGWW_&ULE9E9C^(X%(7_2L1[=>(M)"4*J0"-9AY&:O7#S',*S*+.0B>A MZ/GWDX6BB.]QRGD!$HZ=XVO?+UX6UZ+\61VUKKW?69I7+[-C79^??;_:'G66 M5-^*L\Z;?_9%F25U_.I7M/Y17/_4MS9T#K=% M6G6?WO92U47V463F9W^:T)1-7??EQ&/ M%_Y[6]%-L^HU_$'#[@J_J?W^"(X>L>*D.!\^8$T5@@TE&RJ)(VQ"P':*KOS\ ML9TBP!5(6('L*A"#"@R3JUX3=IJ\#U0<&FT%&C''1A0THD!+.*X@A!6$H"7" M:$FO40\NGUADM(1J6(A]S*&/.? A#1]S\@S3ZII*F&5X1M!&!&PHPT9$PT$Z MEFJ898#%T$<,?!C/6,6@6XQL75.-P#9:'B(B!,#(W$1"0)UPH_/60&0$=G.3 M/*;#D[38M0", ;N1:9?1SHG,#D0B81E*#*+NE7%@)K94@4'%)I"*850Q%U;= M1,.Q9$:$:FSQP*QB$V#%,*V8"ZZ8"Z^ R 8LAHG%7)#% )#(4*.:)Z8L7C"V MF NW&(528%H9DPR-8&XQ%W Q2B5B9$PRG&9@<'$7<''*)/.% B1&P=CB M$[#%,;:X"[8X)9*9%:.2H1',+.["+ YX-#>= (TMK!A9W 59',RUR*!WGVMQ M#"WN BWN,MT"(LM\2V!L"1=L"0H@2+N@2%$MD(0(TU@[&Z!(NZ!)HF:A,+\[S+8'1)5S0);Z>;XU*AALB M&%S2!5P2+!1%8'804G%F.-Y(L%AD@279)8:7=(&7I%PRHP\*)[!""6S;3[9L**,I@RTF..L4 MF#+0F(!-FMA\$R 1LPT3G+\*Y:_EL$#AS%/1A)#@S%/@-4U#\O5K>E0RW.W' M^1NB_+7L288X\4+F'HX0)UZ(7G?DU(&#S@_,_1FDXA8LACB'0Y##RM8@G'BA MG! 3G'@A>MV1F"@RZ3&7H$#"S"6=_W @F.GRT)VL5MZVN.1U>Z[VOO* MVP-%X_Z*/:_[,]C/:I:+/@^7[Z?;R?U!+ P04 " #6DE=(-H0.AJ<# M J$P &0 'AL+W=OJ^SN'PP!YW7OVQ-D<55?5OLW/)0Z'AC M&V6I2YX7N%FLRPN_BYU:D[SB9B<'_Q,=ONJ M>> N9NZEW2;)=%XF)G<*O9U/GL3C2D6-Q"I^)?I47ET[S>!?C7EK;KYOYA.O M&8-.];IJ0L3UU[M^UFG:1*I[_M,%_>RS:7A]?8[^U=JMA_\:E_K9I+^33;6O M1^M-G(W>QL>T^FE.WW3GP6\"KDU:VD]G?2PKDYV;3)PL_FB_D]Q^G]I?(J]K MAAM0UX N#4C\MX'L&LBQ#5370/4:N*T5FXA57,6+66%.3M'.WB%N%HEX5'6J MU\U#FUG[6YV*LG[ZOHA\,7/?FT"=9MEJZ$KSJ7#KZ)UY! M%(5'ZL.1^L"JQ $"&" 86O5[-I:MQF>LWG02PD["82?*PP$B&" :/Z-3&& Z M8D:G YL4]MYQNC+R18SSX3 L,OU!VIPU0*'XPBZ*<.B4*F'PRO M0/1&3 B,I@CO<(OA%-$8MTC$O-4%9E@ B /F-4*8+/+&NR5,%HD1;I$HX(HI MQH\0?DS"",- =Q1"PC#0F%)(PRHF>V\ (.GE; 4D3)$A3!T!H +.+@:*@CLR MAH$B4.R&ZP.)N,G%U!$ *F#J#&&@:#K>K<1 25"J!FZAB-O18>HD HI9'A(# M)>D.M\S&$E67@5LDXMQBZB2@+F"JF,0P2+0SY-QB&"2H+@/V.]$UM31EWG02 M$R,!#$' A, P2+1!9&"0& :)JLO ;2L2\LJN]R!"GW&L,#4* !$P=5MA(!3: MX#&.%09"@0HS<-R)>HZEKQCX%"9' 2@"!@K%_"E#^S+.,89"H0HQ<.PCQQ1X M#( *TZ, /2&S6U$8#'7'WDQA,!2H$L._LM%P$R_Z\^M>G31DNMC9(YO269MC M;D^(KIY>CH6>R)Y4?,H7LT.\TS_B8I?DI?-JJLID]E1B:TREZ[%X#W7V]SK> M7&Y2O:V:R["^+MJCG/:F,H?SR=3E>&SQ#U!+ P04 " #6DE=(W !\?HD- M "H9P &0 'AL+W=O;;?W1[/9YNO5\G:Q^6UUO[S;;?FV M6M\NMKM?U]]GF_OUGQ_K5/Z]/CU8_MS?7=\M/Z M8//C]G:Q_M]\>;-Z.#F4P_Z%OZZ_7VW;%V:GQ[.G=I?7M\N[S?7J[F"]_'9R M^+LWER6+4[L;Q9?MVV?2QV__Q< MGBUO;MJN=F_]WZ[77V_:-GS^<]_[J_WQ[O;_RV*S/%O=_.?Z-HQW,!W#?RO!GZR0>@:A%\-XF2#V#6(N>]0=PWJ MW 9-UZ#);9"Z!BFW07O.'\]I3_Q,C[SLT=?[5UYOM@N3H_7JX>#]>.]Y'[1WK+D:-=JUWG[ MZM[G^XT[8VYVK_X\;6HYGOUL>^HT9X\:'6ATJ+FPFE^]S':[\+0?"O?C3$U[ M-]J-[H7[\4//>:D:* M/U O8:CY@*HW.O _43]QJ/F(^AG5^!/JIQYJ/B--@R\9AR]=M^^A'O20< \> M]^#W/;CG/335Z(IZU,2]YFZOB=5N$&__&UU95ND:AY2O09]11LK!_@>\_\'L MO\CH?%T\:L*S]QKOMU6(-G"_D3)-[7?$^QW!?H^=',U[.:EAW:U2HH?['^T9 MJL?G;3MBPS&B N_E2!]L MG)'\(Q8\1OPN^O(Q?^Q$$5[PP[ M'^[DG42()<5ZLFD"Z8/80NJ"@R;&D.;E@W[7B9X?='=K8$=-3"3(11'WH<0= M6N4?M1)WJ+Q\U&\[T>!4R_A&/7P[8B1%1JI)'\0E6C#\*G&)V@'8# 3G:D=+ M<7'RL(FA%!F*9 XE/M%8<-C$)VK'#W/89YT(&+L:%ZBV ^#T94&\I\A[[-B( MHS3EU\<11SDTWHS'MDXT&-Q,0!B^'3&? ^9+K _B**<%A\WR+!IW1H<]!R)) MHVS]MA,-PM.D8QPQJ ,).9&DXXCK7"@H#7&=0Z/3>%1P-@A.CPJ.^-.!?)>4 M]$&\Y H2GB->&\P59T!/#>32$C>Z, M'M@[D? 9B!U#0?@, MQ(XA(WS.@= 9!SUL0;95\)D;8C+:V1@,F#7Q)9U0?BMB2WKG/"+1,92]=23 MD^&^$'O7UKFI(@-VS1XU%(3>FOBQS@F]2&1KDAUZ:^+K&EF6'$]#?-@4A-Z& M^+#)";U(9&K2V&G9Z5MO0VS= ,<*ZX/8L"G(O VQ89.3>8'(WGJ;[,S;$#LW MUJE)V*,V8L.F(/,VQ(8->N1G:H+&3E,3,%NKD[?Z]D[=>J1@C4 'O"LF[4C%*H"K!!"K&"509'- 5;(J :E^BB5PV?K4R7B/D? M@$))24@6"@!)04P6B@!)SN0P5($2H:@\33=1K AP14E)6!:*"TE!7!8&#(GF M3!9#E:V1VNGB75^3-6(0D@ **2GC_!A;)%H0GX711:(9L\87O6IX]-,'S[P- M6*2DC/ICA)%H04X6QAB)YB1EI#(7R'FO&I1H\I&<,&Q) +>4E#&"##(2+8C- MPC CT9S@C%2F1!]ZU?./G6%\%3V&[%[ZO)II ME8^<" .C!)!125G(9L"3N)*0S9 G<3GSS$AE2O2N5PUN6VGZULXP*@&(5%)V M= Q\$E^2LAGZ)#YGWAFI+-35JP8?^:=Q"V$XE0!4*CG:"S.L+XG9C($2GS$! M?=&K!B::OL\P8$H #)4<"] ,<1)?$J 9Y"0^9Z89J<#8[[/Y"F' E 8*CD6 MG!GJ)+XD.#/824+.3#-2@=H$P ]/7CT,GQ* 1B7'8C,#GB24Q&:&/$G(F7=& M*E2A[)EG8?B4 #0J.9:J&?@DH215,_1)0E:J!BH0&#I"241&Z&24G(BMQ A>IG<[2MWY1FN,\,RQ*$7#D6LAE));$D9#.6 M2F)6R 8J4+]H0[8A_+LR JF?GFAB))<@2LNQ/,[@*XDE>9SA5Q*S\CA0@8\L M,1OU$(9R"<"TDF-!G-%7$DN"...O)&8%<:!"M.BM%74I<$ M<,9?29T5P($*U*:VZ >K#6.Y!'%:GO;"G%F7!&_&7TF=0WX@%?B,6V>S'\)8 M+@&<5O(LES,*2^J27,XX+*FSW).S(CNP106\FS=,Z8+*E+TCFC MLJ3)2N= !3[^-S:=L]HPPDL O94\R^4,RI*F))4,SY(F*Y<#%:J-Y:!?^,MP1GP)HKD\B]Z,T9*F)'HS2DN: MK.@-5J,F/U8SX$D1S>1:K&:LEJ216,UI+4E:L!BI0FV0!$5H;9G5$=7D6 MDAFS):DD)#-J2U)&2+[H55E'S4R,N"W/XB^CLB25Q%_&94G*B+\7O6KX!^23 MMPH&<0D"M#S[PWE&76E5LI $HZZTRLBW%[TJXY0K([,4,%5;*Z"*.M M%'!4*9!4J@R.TJH@E2J#HQ0L7F06VY@C50HCU:M>-LC668'J>Q?O?:JP>3=]-(ERG@K!215"FP%(T9'J12D5&5TE,+5E,Q-&*C, M9?2Y5Y6L^D,7: (D50ILN2.Z1),6I%7E*R_EI%6D,C4Z[U4AWVIT,2> 6Z7 MED:BRSEI06A5NDH37*;)EBCC;_C>]*H2J]&5GP!OE0(].F98+8BX2E=J@DLU MV1JA<=A83;-G>)6N^@1 JQ19+PR)4E>2@!D2I6@])UL;H *UF904^*UGT"M]*L=3#)]2@$^ER&(S8Z+4E\1FQD0I M6O<)U"8C-K_I55G7#?,XX*929'&9,5'J2^(R8Z(4K?\$:H-6B;*UR9[45497 M*>"F4F0QF=%0&DIB,J.A%*W_9&L#5XDRM0G9*P(KXZKV&[K6H!5S(J"?S'S3 M'*E29-F;,5(*5HG:8JQ%)-:[['*E232O/'(L(J/$?CL^AJF89 MBW%2BE:3&M^CYU!5CS/+[-DW,-PNU]_WWZNR.?BZ^G&W;=?T?O;JTY>WS+7] M!H?1ZV=R="[@]0LY>HU>;Z_5HT_M!6NWM==:N\WC;:'=%O"VV&Z+>%O=;JOQ MMJ;=MO]*FMFO,IP>WR^^+S\LUM^O[S8'7U;;[>KVI/T2BF^KU7:Y*W+UV^XZ MO5HN+I]^N5E^V[8_MDC ^O%[9!Y_V:[N3[KOQ7GZ&UL ME9C1;ILP%(9?!?$ !=N$0$60FD[3=C&IZL5V[29.@@HX Z?IWGZV26@:?E?. M30#S^S_V,=\AICC*[K7?":&"]Z9N^T6X4VI_'T7]:B<:WM_)O6CUG8WL&J[T M9;>-^GTG^-IV:NJ(QG$:-;QJP[*P;4]=6%R$) MSPW/U7:G3$-4%M'8;UTUHNTKV0:=V"S"!W*_3)B16,7O2AS[B_/ #/Y%RE=S M\7.]"&,S!E&+E3(67!_>Q*.H:^.D(_\]F7[$-!TOS\_NW^UT]?!?>"\>9?VG M6JN='FTB5;,Y=PJ#A[\.Q:NWQ.-S) MXE,WW(&>.M"Q TGMP(= =IC?N.)ETZD2L3*.=M[VG!]KK MUKC-&)\URT- +#1D5D78?0U 48DDGW2GNSN (F>W./HTPP08)-$BL MP?R3P0P;S*#!#(P@O$CG*$<7L4[B@3#+/';F"/8?:8#WM(E#LJ#"B==S[/U"[X?V0E\6>;\4OWFVK MM@]>I-+;9KNYW4BIA!Y,?*CF_./6#/3[)^;?9"*.^]+*IF,=LK=;CW_6:]%V76 MW,F#J-H[6UF7F6HOZYW?'&J1;7106?@T""*_S/)JMISKL:=Z.9='5>25>*J] MYEB66?WO013RM)B1VO[O^]0]:)A-R';:G7W:"NK+[7EJ)I1]^6) C"N?_691I JQY$1R Z M13S:"$;.$+]E<*9!(0VJX^,I#8XS,)B!Z0QLE"$R2*YZ2*0AE8;P@'!C)@!$ M>8*9A)!):#%IYQ+A#!QFX*@:,YO0J\1)$)9BAQ XZJPT/(C&T1#1P\2;"C$=A2@ MR@$U%5S*4I,/@$7C DP986,AX0W*)-A:"/]:FP-F3#:,TLBJ%4 RFX5VT!, M[[X(F;ZXL<%0VV! FPRH2TPN0J9,L$]1Z%..]J".[Q#;@:SVH+:W6'.Y!)GR MP.9#D?D01W-1;!<4VH5#C!3;!;7M H@1H2PQ4MLOJ%4W&^.J&S84"C]\+#7: M9D%8%)LO$02CG#E,FV);H?$MJL2V0I,K5)E<8]H Y39MB@V*VM:3)"E.P;!I ML. &:3+<[HQ<(TV$LJ0Y@"8O#VJJ 8"^$56HLJL_,O0J8\L%.QSTK8(=@LV!4+H <$"HCY M!>V/UMNEJ'=ZXZ+QUO)8J2YX-'K>''G06QGF../W*\;!G99)>T?OI_B?CUC. M#]E._,KJ75XUWHM42I9Z/;^54HEV L%=6YB]R#;GBT)L57<:M^=UOPG27RAY M^-C3.6\L+?\#4$L#!!0 ( -:25TB+2#EO6P( $\( 9 >&PO=V]R M:W-H965T%=6?GF8R]D3S#%];4'7HC M%KVT+21_=ZC!P]9V[5O@O3Y73 22/ F@AO=)?@CP?\B!'<)P4@(-(*C2I$'44 &\XS@P2+J MZ?50O"3N)N!'78J@/%EYCQ\%Y=%K[@(WR)RKR#2"=@KDS4$3PN'I)PW/I+'S M5G1O*;!?(WQW"2G6D#0QF_"-A?J2'\]-)/])$!@3!#*!OSRI4#LI!8HDJ).@ M(.*_,?$Q:X5&K="D%6E:"A3.M+SDGE1DE(I,4K$F%:VD7$U)/<=H5;X15SS& M+9S'1N>QR7FB.8]7SH,4Z$]$F3= PR@U^C= Q#=*R$QEI"82DBU$I*5F.[\ M(:*XAUCX3(T^4X-/3W>1/G1Q#[%P(5JUJ5D!DP]7[U;@N;=P_RRP> *H[#NS MMMLB$0 &0 'AL+W=OKDS_PT_Y0H1_ M@EUVE-E: V/']_XYS-[%]02$J]%VL7(W%@3M(8@NP(U4F&P!2QG M\)H,#F:P(8.=,[ F@]MJ8@%RJT9=9DRJ 0[CP# ."N-A!A8H8PE2%*9=A*!8)&K50 J"^5$4QE!*(PJY4*!+46T@* M1NUUH4.TTB!:ZQ!M[A,UFJ,4'VF,A>+0'HX>G2)/3%T"->>54)W)6Z+JL]>I M"4HQ3(BJ,TXEB-@U*GO86@>K!U3-PK""$::S%""*L79E -6;#I9#@O2PLQPP MJM-H@.HV6H=JI4.UUJ+:/*!J-@F+.4%JSOHF-)9S\HR>$RSH1$O125?2B3-J M]ZX JR)AQ29:DHU1G>FG@UH_0C4_FK"24JBDPQX. MK*3T&26E6$FIEI+2KI)2E[5?OHBK;RU1K'\4*MNHAP.+%K6?:0M>TQ1^H77: M4J#JJZ3[@D%4'=TK00]>, ^HFH5AH:$N*,SN^7BE6&BH]TR#L3Y0J ^=!@\U MQ*H$Z8@5Q1*BS'V;'H;7+P/KMSVJ'/*M>VILQ3G.U!=S MS5H=#[Q2M4-LV>=DO"# OB3C#;+/Z7B!>)9TO$+V-1UOD%WV3SX8H0C,NIUD MF-^ES28G_\!_^>O$Z* MXX?B)A.GVVE*=:0S^P]02P,$% @ UI)72'<3D ./"P (T@ !D !X M;"]W;W)K&ULC9QO4]LZ&D>_"L,'6"(I?S4M,[._-C_6]V*^;A[NKK?RZ\.WB\;7^W-U_@+2S;?OVQY<7+Z[>&WWY>9N??]XL[D_>UA_?7_^A[*=6?8E3Q7_ MOEG_>GSS\UE_\G]N-G_UOQ1?WI]/^G-8WZX_;_LNKN6_O]W?4]RY/_N M.OU]S+[AVY]?>O_T=+ER^G]>/ZX_;F[_<_-E^UW.=G)^]F7]]?KG[39M?KGU M[AIF?8>?-[>/3_^>??[YN-W,&^A= SVV M@=DU,*\-5B?KI[OZZ>\#G*R?[>IGK_73D_7S7?W\M5Z9DPT6NP:+D0=8[NJ7 MOP^@3C98[1JL1AZ@O]W/-VTRYZ@?U_U4J*PTDKY[^C2!/$EYQS\*_?M23:;ZW<7??5>[ MHH_/17J_R.P795@TW2^Z@J+58K_F$W8TVR_*1W3DL*/Y?E$QHB./'1T4E2,Z MJK"CY7Y1/:*C@!VM]HN:$1U%ZF@VV2]J1W24L".U7]2=[NA"7JJOKU?-KU?] MU,-B[S#ZX,61/1^@?W3_?E4!<\ \L I8 !:!I7VV=XF&+]$\7:+9O\2#E^W' MYZ+Y:^=_7QJ)+ ?C8& <@#E@'E@%+ "+P)(9'H37/CU_- MZF#NR.8P#, <, ^L>CZFFKTYZ,$$&J!9!);FPZ.RX%%9T&O[X(GZX;A(3PY& MY>-QS7QV\$#)%C!RP!PP#ZP"%H!%8&DQ/%1+'JHE#=5!KLB6<(G '# /K (6 M@$5@:3E\B2N^Q-68:6 %EPC, ?/ *F !6 265L.7V"\J,&A.QDP$NZJW,X%2 MJ\.D.8&A(.@(>H(5P; [&_7V=);3^7QU&**@<3J ^X,TE,;5F'D!JHXG!B@Z MGAF4HI$$Z AZ@A7!0# 23 =P?]@&0J'2-&R';R!%L9"@(^@)5@0#P4@PJ1/I M4 W$0V7&S!:*LA]!1] 3K @&@I%@4BJO)5F6LT/CN"HM2=8$0P$(\&D M3Z1./9 Z->U*'LT:4'4\:T#1\:RA*;\2= 0]P8I@(!@))GTBO^J!_*IQ$_/H M8BF;$G0$/<&*8" 8"29](HOJ@2RJ1VUG:DJ0!!U!3[ B& A&@DF?2)!Z($'J M41N;^GAG4RV.;C_%3(*.H"=8$0P$X^X4WSP3Y4UK#M=/29\(GGH@>.I1VYQ0 M!9,&=G6X,Z0IPQ)T!#W!BF @& DF?2+#ZH$,JRG#SH^>-K3I2= 1] 0K@H%@ M))CTB3RJ!_*H'K7[J2E%$G0$/<&*8" 8"29](D6:@11I1NV"FN-=T,.%1V8H M:1)T!#W!BF @& FFW6F_"9SR3OY]WOL#-) \S:@=4*@ZGC*@Z#AG&,JP!!U! M3[ B& A&@LFC&V(1V-; MXLG8CG@VM5=3.O^IS8F[J2V(^ZDMB5=36Q,/4]L0CU/;$D]3VQ'/9O9J1N<_ MLSEQ-[,%<3^S)?%J9FOB868;XG%F6^)I9COBV=Q>S>G\YS8G[N:V(.[GMB1> MS6U-/,QM0SS.;4L\S6U'/%O8JP6=_\+FQ-W"%L3]PI;$JX6MB8>%;8C'A6V) MIX7MB&=+>[6D\U_:G+A;VH*X7]J2>+6T-?&PM WQN+0M\;2T'?%L9:]6=/XK MFQ-W*UL0]RM;$J]6MB8>5K8A'E>V)9Y6MB.>J8F]4A.Z C$Y&B>F0./%E&@J M,36:(*9!$\6T:)*8#DVFE%P//>D^BG09$H>^ J?^&)R-$Y,@<:+*=%48FHT M04R#)HIIT20Q'9I,20!0F #$Y&B3(FF M$E.C"6(:-%%,BR:)Z=!D6O*!QGP@)D?CQ!1HO)@2326F1A/$-&BBF!9-$M.A MR72_@.<5?+^$YS5\OXCG57R_C.=U?+^0YY5\OY3GM7R_F.?5?+^G09%KR@<9\("9'X\04:+R8 M$DTEID83Q#1HHI@631+3HF M0./%E&@J,36:(*9!$\6T:)*8#DUF)!\8S =BF0./%E&@J,36:(*9!$\6T:)*8#DUF)!\8S =B61_,4LS3['_QJAXOW_VX_K:NKQ^^W=P_ MGOVYV6XW=T]_I^+K9K-=/[P_G_QK=G[V?7W]Y?67V_77;?_C0GY^>/X;-L^_ M;#<_7OXDS^O?!;K\/U!+ P04 " #6DE=(YO9KLO(! !G!0 &0 'AL M+W=O&"Z*C8EMEO3O:QN6$-:M^H+M\3EGSMAXLHGQ5]$"2.>=DEX?%B.*N=_/,Q)YYGK%1DJZ' M9^Z(D5+,?Y^!L.GH^NXM\-(UK=0!E&=HY54=A5YTK'Q5+[Y71]?3%H! *;4"5L,5"B!$"ZG$;XOF1TI-W,YOZD^F6N7^ M@@44C/SJ*MDJLY[K5%#CD<@7-GV#I81("Y:,"/-URE%(1F\4UZ'X?1Z[WHS3 MO//H+30[(5@(P?\2PH40KH2#*70V9LKZBB7.,\XFA\]7,6!]XWX:JH,K=="< MD]E3A0D5O>:^%Q\R=-5*"^@\@X(M:$4@);_F"&PYSL$]W8LCNT)H=1D:A>23 M0O 7A8-5X6 4PL\>XEV=,R@RH'X!V9-$UB21+4FR2W(/2OS=@1<6H2^)W4EL M=1*O-=P1$BLA^6?&V;D%X\6/.UMH\^=1X(UYD,(IV=A+?6Z;Z/KF3X'^I(4-?XK3(K;ADZ6GH \[>3;@!GY@WG2]<"Y,JN=E7D'-F 15J_>@ MKJ!576]=$*BEGB9JSN=&,"\D&VYM;>VM^1]02P,$% @ UI)72&^77RL! M! JA< !D !X;"]W;W)K&ULE5C;;MI $/T5 MBP^(O3?;1(#44%7M0Z4H#^VS PM8L;W4-B']^_H6"KMGD/T"V)P=SLYPSHQW M<3;E6W70NO8^\JRHEK-#71\??;_:''2>5 _FJ(OFFYTI\Z1N+LN]7QU+G6R[ M17GF\R (_3Q)B]EJT=U[+E<+=\CPI_S[IS)R7,S;[O/&2[@]U M>\-?+?S+NFV:ZZ)*3>&5>K>IS=?79:\F_&O/67OS8+F=! MRT%G>E.W(9+F[5VO=9:UD9I?_C,$_?^;[<+KSY_1OW7;;>B_)I5>F^QWNJT/ M#=M@YFWU+CEE]8LY?]?#'E0;<&.RJGOU-J>J-OGGDIF7)Q_]>UIT[^?^FS@8 MEN$%?%C +PN8O+M # N$M<#OF77[^IK4R6I1FK-7]L4X)FW-V:-H,K=I;W:) MZKYK=E8U=]]7+ CG"_^]C32 GGH0OP+Q6\3:10AV@?@-@PL-#FGP;GUT0R,* M< 0!(X@N@KB-P*R-]*"P Q4]S4A96W$Q/":82,A$(B96PIYZD+KZ%3D/+"8N M1C&)F2C(1"$F D<(881P0ETB&"$:4Y?(V:F(K60 "/$/BR&/>$Q58K!N7KI$2Y!5+V?Q: ) L)-M@) M6(C8*"(&]@(63.E< MNY!;)EC#PM5P+*D06'QBTAQ-#-+C)FGA&BRWYP( XH(P1X%E+$;)6(!1.;3) M PGN& 9"R1CZME 8!F+*3(66,9BU$PM7(G:#1! J.I@$8M1S5B@9FQ3 1C" M( 4V X%:<4R,;1*;@9S2BB66L1PU5TLP5S/KN7L-0%Q0;+ CR%%SM00S,[/) MN!CJ:51B9Y'(66)"@Y)XN)XR6$NL8PG;L5,A,#/; D(8*B?8#R04A^L9 F':J<^HQV>N?2;E/B\I[-75M\NX8=6=,K9MXP4.SJX-. MMI>+3._J]F/4?"[[H^3^HC;'SY/QR_'\ZA]02P,$% @ UI)72*LHE$3@ M @ :PP !D !X;"]W;W)K&ULE9=-CYLP$(;_ M"N+>Q6.^5TFDAJIJ#Y56>VC/WL1)T ).P=EL_WUM0])D/*S42P#SSLQC;+]V M%F?5OPX'*77PWC;=L P/6A\?HVC8'&0KA@=UE)UYLU-]*[1Y[/?1<.REV+J@ MMHDX8UG4BKH+5PO7]M2O%NJDF[J33WTPG-I6]'_6LE'G90CAI>&YWA^T;8A6 MB^@:MZU;V0VUZH)>[I;A9WBL.+,2I_A9R_-PE7NW#]^TR9)9!-G*C M;0IA+F^RDDUC,YG*OZ>D_VK:P-O[2_:OKKL&_T4,LE+-KWJK#X:6A<%6[L2I MT<_J_$U.?4AMPHUJ!O<;;$Z#5NTE) Q:\3Y>Z\Y=S^.;@DUA= "? O@U )(/ M ^(I($8!T4CF^O5%:+%:].H<].-@'(4=A3Q&Q&_5U2^(H:K)#($5PQ.8G 7G]]AY(S.$),98II5X46) M2 @-BVF2C"3)*!)499UY5>($#PZAR3*:)"=)4EB8A>S#].IB3__6AD3MM;W-SWX]GX?%!J^/E M:'_]?['Z"U!+ P04 " #6DE=(DDJVP%($ #Y& &0 'AL+W=O&B#OC#WC\8/MK"ZR?*N.0BCG(\^*ZF%Q5.IT M[[K5]BCRI+J3)U'4W^QEF2>JOBT/;G4J1;)KC?+,I9ZW=/,D+1;K5?OLN5RO MY%EE:2&>2Z%F3Q^> E/1Q5\\!=K]RKW2[-15&ELG!*L7]8 M/)+[V/<:2:OXG8I+=7/M-)U_E?*MN?FY>UAX31]$)K:J<9'4'^_B2619XZEN M^6_O]*O-QO#V^M/[]S;9/8GW:ECW5MOX>S$/CEGZD5>?H@^!K]Q MN)59U?YWMN=*R?S39.'DR4?WF1;MYZ7[)O1Z,VQ >P-Z-2#+40/6&[ O SYJ MP'L#KAFX72AM(N)$)>M5*2].V8W>*6F*A-SS.M7;YF&;V?:[.A55_?1]3;PH M6KGOC:=>M.E$]%9T5;BU^VL;%+6QH88Y'3;P9"H8&4IB4Q*%N!,,!LI:^^ V M!N)YV .''GCK@0T]:-W<=*)E*RI:T;> >>V?%C-0\EZI26-32EBD*0K@,@)13 K-H2HFOYWL0000CB% $3(L@0A$LQQIK\(H XZ'FN,6'!5)D MQK 1"*%'0J=4?Z_2X@[AR$&M,2^[H8-:JL^K81R88X2A.'P]#F:TIP]>'P0S MV&+K#Z8B@5A.+0'Y97@($ X0LYU029@@))E528(XXQ4,0F&\" MJ(R1SU$ $,PP B$667Q@BI!H1B8I9@.%;- SV:LF9!(I(75CI!RE&\5DH@1$ M0&P^,)DHG9-)3 4*J6!DTJ3"-XXS:2J-% )GQHMKV'=,$ K8X 46-E#,!NK/ MR2%F S57%^#5WJM0-1I)1%*\0$)2HK]VAD%@.%$()_WM3@%(](DR; V#A"*0 M$-OF (.$S@$)PR!ADT#"P*3'Y0^4^H@A9V1T2(IR& )F"86A/VBMG*\^%:HY9;YY>3_,?:7/ K#W?D/NX.Y/_G9*#^)64A[2HG%>I ME,S;0^:]E$K4'?7NZL$^BF1WO645+]>;( M>$&DZO*3(RI.R<&0BMS!KALX!5;2-VZ)RWK^K?S'*5_3T1-&;Y[^P@ M4^76M:T#/9)S+M]9_9VV:YAIP83EPOQ:R5E(5EPIME60S^:9E>99-V\6;DN# M";@EX([0)#%)\%J"=R/X7Q+\EN /"$ZS%!/$CD@2A9S5%F_^O8KHCP2M?!5U MH@=-LN:=BD*HT4N$$ I"YZ*56M"V >$^J$,X2KZ; T-S;/&(CN\GB,<(#]U# M=F/(<@&;\,"%>H8_OUNHZ\(*/JC@&P7O/JKY(*H&%!A0:4 O@S1C .(/%CN& M^!YL=09:G4%6)^(*0(7@B;CFH,+\D;@:T.R++.(QQ!VD-4;X&':Z )TN(*=+ M6&$)*BR?2$N7(6@CNH_DU:+Z:QULE!B O PW$X"9;][QN* <@XM3%FH@XBN((@J(3@*0UX:Z/9,ZG!FQL%#Z46C N5 M-XP-P.!A;&/,T*[3.ZX*RD_FW!=6PLZEU$6_-]K=+398'W>#\:V^1E_74W4FY?_2\ M>K7C15H_B#TOU9N-J(I4JL=JZ]7[BJ=K'53D'O7]R"O2K'1G$SWV7,TFXB#S MK.3/E5,?BB*M_LUY+HY3E[BG@9=LNY/-@#>;>.>X=5;PLLY$Z51\,W6?R..2 MT0:B$7\R?JPO[ITF^5< M3>#E_8G]AUZN2O\UK?E"Y'^SM=RI;'W76?-->LCEBSC^Y-T:PH9P)?):_W56 MAUJ*XA3B.D7ZV5ZS4E^/[9O$[\)P .T"Z#F 1#<#6!? O@*"FP%!%Q 8 5Z[ M%"W$,I7I;%*)HU.UN[=/FQ\)>0R4U*MF4"NKWRDI:C7Z,2.$THGWT3!UH'D+ MHI>@,\)3].,$)\'@0IF.CZ\6ZON8(8 ,@69@ MUU(Q0ZH6%&E0J4&^L58;,0HC8[$ 0T**DPUALJ&=K!\'F"&"#-$ P6+($"/! M D.P%A1>+)4DYL_#QE#?P"P!9HR336"RR3V[FUB3F+MK(V(STULD5XF.8:)C ME&B(&1K+0T7O#]A;TF,(!N%!_1K4-=>2IR%A6V%(EMA M?4O&Q4[#(;+A8J?17;)%P,XC4S< ,L\%@.G3#1L+1<;"^CAPL=-DB&ZXV"D\ MU2W=QK8DH2D;P%AE:F-Z/BX9]A6&?(7U<>!*9V2 ; Q7.H.GNBE;A[KU40X@ MH]A0#6&(Z>G>1>-5\&JK.]C:68E#*9OVY6+TW"4_Z2;9&)^K[KGM=;]H9I-] MNN6_TVJ;E;7S*J1J"W7SMA%"RN8W5?=5VO.V#%/M3 M W_^+\+L/U!+ P04 " #6DE=(NV1XZ,&UL?93+;J,P&(5?!?$ -8:05!%!:E.-9A8C55UT MU@[\!%1?&-L)G;>O+X0A8#6+X,LYQ]]OC(M!R _5 NCHDU&N#G&K=;]'2%4M M,*(>1 _.QC4K!U9 M]I,0'[;SJS[$B44 "I6V"<0\KG $2FV06?COF/E_26N4S<;U'/6HC3A?".:1-DVH28M@LF+\IG2X61UKK\.Z(\ M2)2'B'8+HGR]2T&BM0X'B=#L,/;D#+^)/'=<12>AS;EVIZ\10H/)3!Y,:&NN MFZE#H=&VN3-MZ;] W]&BO]TGTZ56?@%02P,$% @ UI)72%.FQ1$@ P MG T !H !X;"]W;W)K=6U+LE5%=.=AU M0Z3UP..%GJ#';[ MLB8-*VECM>2PMA_1Z@G[$J(0OTIR9:-G2Y)_I?1-OOS8KVU7J>?,:7A^/GF_9M*5]!_+1C9TNIWN>*O]#K M=]+G$$B'.UHQ=;5V%\9I?3.QK;KXZ.YEH^[7;B:,>S/8 /<&>#"(W44#KS?P M!@.,%@W\WL ?#+SE"$%O$&@&3I>[JEQ>\")+6WJUVNYSGPO956@5B&^SDX/J M4Z@Y43LF1M\SA+PX==ZEIQZT[4!X!(HC/,7D)@8-"$=0&'A@B,<6&^88:31R M$R.X)E/0$P3R79B*!Y;$4QZBJ8>99'S0@Z\\>%,/6L&V'2A4H$:!/"_2,C8Q M. FUA)?]3-@&(-L 8NMI3#I0,(X"QPC!&"$4P]$M!##296#EJW[E1;K49-4(WU5]:!)D^F-^ 2!1IZF ME&>4!D&4(YTR,BF[!F4 E&"=\K*G*650E!X1AB@;ZHB-0'-=BV#%01X4)]'C M>$88$:P^"Q">8JPNL+2B^I[:PNJ#D2]*0_*\D.0#!1MF6W$Q_^["084C( M@AE!QK"R8'1'U3"\U#&XU/6J]:BQ#"+M]Y(#&'.3LNAGRA>6#.P-MJ8)O/@Q ML/CUY;2!0"C0__7.:'M9D_:H-O;,VM%+P^6F:#0Z'!XV6&Y/M?%<'"H0,"[R M6^4B1W-&,!0SZASB?(;.TG-Q)#^+]E@VS'JE7&R8U;;V0"DG(C'W0?3H21R5 MAI>*'+A\C,1SVQT>NA=.S[>ST' @R_X!4$L#!!0 ( -:25TAUW5\V/00 M $ 7 : >&PO=V]R:W-H965TS+9?=BJ5!XVSXPM7RJ O(#'V;]?@1D'U$>Q>;%!.GW4ZE8? M)"TNIOI1'[1N@I]%7M;/LT/3G)["L-X<=)'5G\Q)E[9G9ZHB:^QKM0_K4Z6S M;6=4Y"&/HB0LLF,Y6RZZMJ_5I+/7@.6N??C/G1OORU M?9Y%K0\ZUYNFIZSQOF>S(__:DO\9L#8?/'^ROW72M^V]9K=5N035=4&=LG;=LB=EL[]I&[MD=WTV.[5M?5\R%LM%^-XR]:#U%<0' M(#Y&O%"$8&/(9PJQ(\5CT"L$)6/0%PI*YS=(:*=[FS.'<^:=O1H/HC"#@ RB M8Q #ACAR8G:%)!VD[" )R37"$4=AE3$Y3NHL=.>[045.\OAVZ%@H>)B2JZQNG"H+D[P/F-4 MZAD):Q"/ 8?RE#7'&L23*3/&TL!II=+533$\8NYB463E"BG=M4)!?.X1;XYE M@4-9(.N;HH#+B$JY7RV 4K$OV5B&.-J7*,]W6& 9$M&4+3C6!D%+E20;8.:I MN^WL0:,M=NKN.R'((V8"ZX* NN F&Z" RXA*N6)V#S5VVG/20=L!-4,\;(DL4;) M*6GNBL-?;BT7IVRO_\ZJ_;&L@S?3-*;H M+@9WQC3:3CKZ9*-[T-GV]I+K7=,^*OM<72]XKR^-.7W<5]\NS9?_ U!+ P04 M " #6DE=(F"1J4.<% ":) &@ 'AL+W=O&ULE5I=(,G>?W\! MB7%F3N.0AZAPNJ=[ND]/S\#T(R]^EZLLJT9_MIM=>3E>5=7^8C(IGU;9-BV_ MY_ML5]]YR8MM6M4_B]=)N2^R]+D5VFXF/ CT9)NN=^/9M+WVLYA-\[=JL]YE M/XM1^;;=IL5_5]DF_[@DKH#H!Y2N@.P'M*Q!V J&O0-0)1%\"JE<@[@1B7X$FYH?(!;Y&L6.P MF?PB2)FCN M@BRK'UR$L+S_ 90P"[,X.U!R?J"E"XFC(V12Q_$83(Z#R5L%H3F[(58AL K1 MJA#FM%I1G!] N@7M6M W$44B:/^L"498'FF$70S0F_CI-5R6V&7IN*RLP>;2 M&4RS +I[0*H3I!(A=-9%$CH3;YU+UTX6.$J-.5%X3A1* XNG"^78Q6/H@ L4 M*H(. )6](=78?(W,#RWSM3,6@[.:N,"08_,!LL_Z$%L?.M9S$5O&AZ[Q MJ4 M &04X/0!T+ W>R+L0 2FWW8@ JFJH .1:Q5,LZ4+Y+9&P_H86Q^CY"$*<=,8 MP&4U&%"*&;4VL_.)<-^!3B*\9H02@GDL'C UG* >#Y E5CMVBU&"&(H@*'<)6D?!& 0SP7YW/QK.0Q7E(T@LQ?2;JKT UTW5(N^4.=H / *D@91?>.A,? MG::S1&T7L/^B>$)4;!$-(1M1L07:^KAD R@W-E"5L./B@UIXH9)S*/,HB%AN MI+O<.&0#&-?_#F1D!SX@0TB\ GCK3'QTFO-!K(<2=KB1/1QSEM^HEPJ26'>D M3X.[[%!&0]V_H9/$$B5AAVL'"!PU2H8CY/;"+M2TC#J4A$L'L1F7Q-(AA_3" MDJC%TJ<7OL&HF!B*J(32I\N]D6Z7RYR#GBXQP8E6_YF0).JK1!VQ?2(ZE^ZI MUK=^WA&56*)B9A/AID,9_1X\!/P!D P?%P)D_ZFZ(DJI0IV[?43Q %':/NHY MAS(-(FJ9@K6,4D)4*#7D&8LBRHZ"3UFL)>1>N77'/7L)))03SU9#.2A%\5I#/UE'*M7*Y)WI7 M#TUP3P.^\,!^K*O=+J%_-()8&A"+!YQ00A!+#R&6)HBE/=;SA79Y)?L?,A&T M:JYW*EP9@D7:8Z=VA4 LM!?_R/K]1UO$BT!'=J2^H[AQ<+OH:83??I:[9,B]?UKAP]YE65;]MW"%[RO,IJ!X+O MM0.K+'T^_MAD+U7S-:R_%X=79PX_JGS_^2;0\76DV?]02P,$% @ UI)7 M2*3ID11A[-39H(R;FL'O&%K84 T(+>#3[]\O+LKHJ6S 7 M2Z"LI)(J.@OP\E24/ZI=FM:S7WEVJ&[GN[H^WBP6UL_SI/PO M3+/B=#L7\X\=W_=ON[K=L5@M%^>X[3Y/#]6^.,S*]/5V?B=N-LIM(1WB[WUZ MJBZ^S]KDGXOB1[OQM+V=6VT.:9:^U"U%TGS\3._3+&N9FB/_.Y!^'K,-O/S^ MP;[NY#;I/R=5>E]D_^RW]:[)UIK/MNEK\I[5WXO38SIH<%K"ER*KNK^SE_>J M+O*/D/DL3W[UG_M#]WGJ?_&M(0P'R"% G@/.Q\$!:@A0GP'VU0!["+"G!CA# M@#,UP!T"W*D!WA#@30WPAP!_:D P! 13 ]J:]Y6S/D/6#TF=K)9E<9J5_;5T3-I+5MPT40UYN[=K].['IC.K9N_/E9"66BY^ MME0#*.Q!\@+D>U+'1!PCSHA%D\,Y$0D3"26+)T>X!P@KT#$/'&/KB#\!B[!T MS)ICE- A7Q$-P3PB#!'UA##D]$>CIR8>3WC#(8&/"Z1PIZB.P-,[Q<84-J:P M.PJE4SA$;0]R.]"A!]F!2\Y)#%">L%TB&J *2<]1CG N,]%U2 MK)B#E.63K#< )&T/%]3%!75Y07VR H0N.XQ-SO&]RW2SA?,!8%Q:3X"A-5_S M=&1 Z\EY'%KS1W LC_3R$\?02D4\'<^E2Q+'"&&3_MIPD.,8KDX/%]-#2PK) M-_3885S6?FL.\GQ)E4]ABD>8-%D^EN4C6>3LA3Y/)G"HER%00)BB*4SQ"),F M*\"R B2+-&D8\&97(J!+'$#9#NO425SQ&)& MTO*EIA&-@/1T#/.: .;%*8:&&8$X?[&M"L,WB2@.=%Y5P!/H<-&#$ !+R4' M"2L(#$D;G$< Z^$Y0LL%5!+ 5.M%% BSR= &+ <@) M:,8 8UA-I<$J)+0*.K5(L'![=&H!()LZ=S2%*1YATH49;$)"FZ!W2Y(OVLUZ M03T0H(1G^U3:%*YXC$L79[ )B6R"#662.X"M'*H-V$004&D3F.(1)EV8P7 D M,APVEDE@.!8UP#5 !33I:!)5/$*E2S-XDX2/'.A0)KGML$="P)GH%#U.$U^G MT249_$U"?Z.CF.0WRL*2=!0#J(#>I$63J.(1*EV:P74EN#67PC".2(/K2N\W MK%L:7%#"&S#6Q\"\6!<##'TT=PVBIVMP0 D)K]+HD@SV MI:!]46=6P%3HPX(U -''O=$4HO@ZD2[+8&$*61AS9<4=A5U2HY!H'!)?A>B" M#,:EH'%13U;@$:U'%7','_3.*II %(\0];(6%^\)\[1\ZUY_5[.7XOU0MW(N M]IY?L=_)]CTCV1^*FR][(TM>Z_>HUW\O^-7J_41?'C_\*./]KPNI_4$L#!!0 M ( -:25T@J#2#[X@( +(, : >&PO=V]R:W-H965T1U.W_=P_<'Y\#()^%BVNV#_MA1LE6DI@YP&*9!0ZK67\S4VG.WF+$3KZN6/G=>?VH:TOU;TIJ= MYS[R+PLOU?[ Y4*PF 57WK9J:-M7K/4ZNIO[W]#C$\82HA"_*WKN1V-/&O_* MV)N<_-S._5#:0&NZX5($$:]WNJ)U+24)S7^UT$^=DC@>7Z27REUA_BOIZ8K5 M?ZHM/PAK0]_;TATYU?R%G7]0[4,B!6Y8W:NGMSGUG#47BN\UY&-X5ZUZGX)>2-&@Y@/ 8A))D M"EJ!H'0*6ML@C- 4\QW 3!&EC8@,(4\VI,BOD$"$Y!H7#,8%*WXVC8M#0@1* MB)2$:"JA,'P=0*D"M0H4&K[:"(1SPUD(4\"VQJ"ML6TK2AW>)J"$Y(YXI:"$ M%+"A,+:UA$"IP]4,5)-!:HP$6V9 0(U\+[_&3"S)04MRR)+(L"2WM*3&[J]M M"#(@Y0!)1I \A4TM0%.+&W*Y++Y2,B2J#0EA,^3Q 76K$-I_Y)#AZ'CHCE1% M<'= ^(8L6FG49&PZ"FDZ:.63 W0+E]Z0M M7,8(J&,KFYZ07:7.XP3#=8J!.K5CKU'PZ3=5 Y)IP=+W\(U]^4Q7]02P,$% @ UI)72%P-M/RL! M(AL !H !X;"]W;W)K8KBX@.WLOU] =*#R%- OK>#)K),I^74A MJUM>_"Q/2E76KS3)RI?%J:HN2]LN=R>5QN77_**R^I-#7J1Q51\61[N\%"K> MMT%I8G/'\>PT/F>+]:H]]ZU8K_)KE9PS]:VPRFN:QL5_&Y7DMY<%6SQ.?#\? M3U5SPEZO[&?<_IRJK#SGF56HP\OBE2TC&3225O'/6=W*WGNK,?^>YS^;@[_V M+PNG\: 2M:N:%'']\J&V*DF:3/7*_W9)?Z_9!/;?/[+_T99;VW^/2[7-DQ_G M?76JW3H+:Z\.\36ION>W/U57@]LDW.5)V?ZU=M>RRM-'R,)*XU_WUW/6OM[N MGP1.%X8#>!? YP:(+D \ Y@<#9!=@'P&C.O=3N]J"]CWTMO&O<55O%X5^^+G@J[3O]< M@Z,U-IR$\^$"6ZH0;"B)J"0,L D!"Q5MO#\L5.(,$F:0;0;1R^!J=6SN$J^5 M9/,E^X[VJJ+5))$6B6D4H( MCCU[T+.'/&NMV7AD'<9<7[,,1-+5'0.1QPV&?6C8IX:9/CT^[8M@NE\@8I[4 M_*),OL%O /T&J,&:ETT VH(7">$B(5K$,*P-Q!&6'#2NH2&' 6T,^!".UOA. MU:_6-7F%>'ME'*UC("3#=&*?P1/#?&(S -5I^M5RSY=Z3Y"*3,^4:N@90XK- MHA1#:/&$T&U# C$=K5#&7,,<,4PJ-@M5C!)&,MTUU0C)=<]4Y#J&H60856P. MJ]@L6"%5GU9#.YA$;!:*V'P6,0PCAFAD^J_$,8TXI)&A7HYIQ"F-R'1RRJ(@ M#+7FSQ%%$Z*A88PUCK!&1K-3]1?2"3LMB48E0[.8GUS,&<=.-='?&:)H0C2T MC''-*:[I/'+*6-+>, E7L!FCG-VP9,7!^RY=O2%_7O8SJVD$F&3R>!MF_ M+:U7E_BH_HZ+XSDKK?>\JO*T?;IPR/-*U04[7^LO_*3B_?,@48>J>>O7[XO[ M(YS[095?'D^DGH_%UO\#4$L#!!0 ( -:25TBQE;1J) 4 ($? : M>&PO=V]R:W-H965TQ4BM7LRL4V >ZH0P2:KH^??C/(J&ZW-+SJ8*DF/[^-K^?+&7U[+Z61^M M;2:_BOQ[1%5G\I+_;LWNS+JL@:][4Z1/6ELMFN*U3DD8SC M)"JRTWFZ6G;/OE>K9?G6Y*>S_5Y-ZK>BR*K_UC8OKR]3,?UX\.-T.#;M@VBU MC&[E=J?"GNM3>9Y4=O\R_4,\;Q+92CK%WR=[K>\^3UKSKV7YL_WRY^YE&K<> M;&ZW35M%YOZ]V]3F>5N3:_G?H=+?;;8%[S]_U/ZUZZZS_YK5-BWS?TZ[YNC< MQM/)SNZSM[SY45Z_V:$/IJUP6^9U]W>R?:N;LO@H,IT4V:_^_^G<_;_V;^;Q M4 P7D$,!&5I #074K8#0GQ;00P%-"D1]5[I ;+(F6RVK\CJI^M&[9.TD$<_: MA7K;/NPBV[USH:C=T_>5D&JVC-[;F@91VHODG4@^*C:^0HF;)'(.;C8DM"&[ M\K-'&W-<@X(UJ*X&]5C#@G2D%R6=Z-QW1"O2%5^C$HF=:.A$ R"8F\)$P=F$A"C8D) M9HF ,/%BXI-"4)@ C8P9+Q@FPJ>)E%Q(, 5$,B8D> 4+N(2]D/CK4U#2 PT; M$KR&!5S$W%3#JT\L1L1$XN4GXX#=;XU4=--)!]$#V$C<@$1R?O%2EW"IQ]0O M4/E^_;7^1%G]N>;1,).?0!X(:ABH?,/2AQ/UZTLD,ZDD9H]$Z9#F!@FS1^HQ M$Q,S0Z(,Q$O+I)]>S+PQ]#5S!CX2PT?"'(0F9M+/,)[$@IH!(LW-*(PQ"3%& M:8"N(84 '#@%%>&@Y%S):E,,E4$,F "E@&F(JI8Z#A8LS\L$,H,URG,72" MX:-#X)-JP PO*D##105S14.N,)NX9HYZQG!%8Z[H(*YHP!6:E0"-8E(DC;FB M@[BB$3)H5@)%#/DUYHH.XHH&7/%.TC[5/'K!7-&(*X8[%\1(:!ACN6,YA1)BA! BK@V(<4 M12J02.9@U6".&<@Q;I0PQ\P8CAGFK#F$8VN@6L2&Q@T<21L:. !$9CD:##L3 M KLU4 '# ';T1SW2,#N6P3PT(3Q< Q4PW(ON;SD\@B,- TV#H=D^'LKZ13 C M#3B,IDCN8>O)MGP[-^V,N'MZN^M==S>S]+F9/Z=N&OAOW""Z M-POT)HF?TR2&;X1[@]IQ_7)ONLOFZ+?AU?*2'>Q?674XG>O):]DT9=%==N[+ MLK$N'/$7MQR/-MO=ON1VW[0?9^YSU=\0]U^:\O)QX7V[=5_]#U!+ P04 M" #6DE=(N@U(\V0" #'" &@ 'AL+W=O&ULE5;;CILP$/T5Q ?)+*+G\>- MZYL<**.9,A1$7ZYT3QDS3%KY;T=ZUS2!P_L;^W=;KD[_0"3=<_:G.*I<9^N[ MSI&>R(6I-][\H%T-D2',.)/VU\DN4O'R%N(Z)?EHKT5EKTW[9.EW87 [@)P M'X#B3P."+B"X!X2VTC8S6]Z,JEW MKRG"T3+QKH:I ^U:$!Z">H2GZ7L-#&GL\"0?J!3-& A]H=9=AQH6BX)1 M/SK,P_&*9W(!C;9%&,@EFG$2@JV$GO$2@LV$0#<%XYY,[81GSBF"_81 0X5C MG2EJX<\5!'L*@:::.VRPJ] SMD*PKQ!HK/$_2(<:-G:8#R459SLWI9/Q M2Z7,'_%@MY_-6VSFRVA_9V:VG3MWFC2IR9G^(N)<5-(Y<*6GEYTQ)\X5U1GZ M+_J5Y/JKHE\P>E+F=J'O13MGVX7B]>VSH?]V2?\#4$L#!!0 ( -:25TC" MV?#Y50( .() : >&PO=V]R:W-H965T<=T*^JI(Q';S7O%&;L-2Z72.D]B6KJ7H0+6O,G:.0-=5F*D](M9+1 M@RNJ.2)1E*":5DU8Y&[M61:Y.&M>->Q9!NI&>?6R9#?!M/_3%MX.[ZZ/[G'-=O?4<4>!?]3'71I=AN%P8$=Z9GK M%]']8,,SQ-9P+[ARO\'^K+2HKR5A4-/W_EHU[MKU=[)H*(,+R%! QH+^3: > MY+;YG6I:Y%)T@>S?;4OM7XC7Q+R(O5UTS^WNF8TJLWHI,$F2'%VLTR#:]B)R M(R(X'37( $8* 2G$&:0?*1Z'!>BP< ZQE-R(,(8A2Q"RA"#I M!#(7^2 Q"(DA2#:!S$4^2 )"$@BRFD#F(AS!D!2$I "$1!/(7.2#9" D<_6+ M#ZVSS&"'%>BP^D+SV01#*8GN:3] Y<-XPHCO:4! YJN5IRK/!@"YY> ^9VV(J#R_+\$SB^!\CMKQ4&5?()! M-Y_OEI[8+RI/5:."G=#F)."^UT; -4XX.VH[3,U8]D>0?J)% M>SU1C<>ZXA]02P,$% @ UI)72/:?RLU- P +Q !H !X;"]W;W)K M1A^V:FH? M=I\9C4H-$!?B./OW&P(Z0AJ-\S! ..=TI]/=(8Y.O/RH]HP)ZRO/BFIL[X4X M/#M.M=ZS/*F>^($5\LV6EWDBY&.YRLF( M'T66%NRMM*ICGB?EOQ>6\=/8)O9YX%>ZVXMZP)F,G MOD^:LJ%)>6"7;CNT? MY'D%80U1B-\I.U57]U;M_#OG'_7#:C.VW=H'EK&UJ"42>?ED4Y9EM9*T_+<5 M_;99$Z_OS^H+-5WI_GM2L2G/_J0;L9?>NK:U8=ODF(E?_+1D[1R"6G#-LTK] MM];'2O#\3+&M//EJKFFAKJ?F30@M#2= 2X + $^$(@OLJ'9OW4ZL\2D4Q&)3]999.RAZ2N M#/(2XP!C3$H!=I1@!A7\% %3REXUPK$ MZ\6DP80*4RB,1ZBK_GJ1T9$D]#'D$M&DT$-VW/=1]WW-_0!Z*>;K/I$ =7]J M#ITA4#^(,.BB@08&JJ\(=$!UB4!#N!G! (U@H"< 0"_C%P%B[):I$#45WE^L M4#/DQ:0_JV:QS*$S!!K%_0DT,S57?357789ZML=!OS Z$:1H!*D6P2B*<($( M%8@>:!@QJA#?;QBS6"\.%XO+' 'VL[WC4OUU@6TU+I+$E/3[OZLOV("9@1V- M(.&G Q)XPR:/=&R"MVQBT+/G!&G%WLV:)7B')?=;[)P@S>B.,;P9$:P;4B(C>B0BAP8 &7HJ$/K*2>#62")MN;RE7&(J$X8 EO&H)4K9:FW]I M4>9]'O!Z!*P>8:!1 5YL0!Z(+PQ\'@'BA]?OXRWJ.IVT/;=K#:]+0.H2J#^@ M@5<;^(_,&B\B0(JHWQ^FH&_I^D==UQI>2V"PJP.R_^%?D%-SZ,((VDS!N3JT M')(=^YF4N[2HK'&PO=V]R M:W-H965T.T%_)#U0 :?3'*U=ZKM6YW&*N\ M!D;4DVB!FY-22$:T,66%52N!%([$* Y]/\&,--S+4N=[DUDJ.DT;#F\2J8XQ M(O\=@(I^[P7>U?'>5+6V#IRE>.(5#0.N&L&1A'+OO0:[4VP1#O"G@5[-]LCF M?A;BPQJ_BKWGVQ2 0JZM C'+!8Y J14R@3]'S5M(2YSOK^H_7+4F^S-1ZB DG14OXO^)XPE;*Q@+JAR7Y1W2@MVI7B(D:]A;;A;^^'DV1]I MZX1P)(03(4B^)40C(;H1XF\)\4B(%P0\E.(:<2*:9*D4/9+#SVN)O2/!+C:M MSJW3==:=F58HX[UD0;C=I/ABE4;080"%<]"$P$9^BA&NQ3B$#_3P/L#Q$1$% M]Y#3(^3E>3V):+70R/&W,WZR2=8%XE6!V E$]YU*%IT:0(D#\:'413./*Y"% MRFD%\K)(%<]^, -9N4E1*!<=U[9-,^\TC*^AO2 +_\$,Z3!3-YDL;4D%OXFL M&J[066AS_=PE*8708#+TGS8>JLTS,AD42FVW6[.7PV0-AA;M]9V8'JOL/U!+ M P04 " #6DE=(0A8FP<@& "M*@ &@ 'AL+W=O&ULE9K=(!!NM?3A&JQI#4[L563 M/U?;LOU2OU2[5/)8-]NR2U^;IUG[TE3EPU!INYGI+/.S;;G>31?SX=FW9C&O M7[O->E=]:R;MZW9;-O\5U:9^OYZJZ<>#[^NGYZY_,%O,9\=Z#^MMM6O7]6[2 M5(_7TZ_JZC;:7C(H_EY7[^W)_Y/>^+NZ_M%_^?/A>IKU-E2;ZK[KFRC3QUNU MK#:;OJ74\[^'1C_[["N>_O_1^NWPO-/^N'[CE9FTTG#]5C^;KI MOM?O?U2'W^#Z!N_K33O\G=R_MEV]_:@RG6S+G_O/]6[X?-^7Q.Q0#5?0APKZ MT@KF4,$<*RC_RPKV4,%^5K"_K. .%=RE%?RA@B<59GMG#:Y>E5VYF#?U^Z39 MCX^7LA^&ZLJG8-[W#X?8#67)V6UZ^K90.H3Y[*UOZ2!:[D7Z5'14S%+SQSXT MZF.I675]WL&**XPZE]QP21[/);=!.P)0Y:XI EQ*O+O6N*1 M)60(+#WK17EOB2E Y#(A/@':$I MAM@26#?6.V(*U_C,84LBM"0B2\@/7D8V M"I*(#A4@$KV20UMR9 OYQ4LHHK;\1G1F2X]\A*0,M<&8E/%?'1P9WRN@TDH1 M+]\@E1<CQK%(9W3(<$F0!C#FG4+ HQ%: 550DF,PS!2B64X< 5YCK@"A(P<8\ M,W#[R(+-52*^M<#YU$6&0"EC, M\1&HP5PBP,%BP%@(&.DW8\#8,8"Q&# 6 B:C?@. X6X#QTN*'?\!D98&. :, MA2=,BIK,5<#D"/(8%FLNTN+HQ#RS(#\SF73LB7GFQFS^'.:+@YL_&FV@XJYS M?/.GV;DF$'EA2^ PS1S<_=%@ Q6P&&SM+(4X% D68W8Z2$4AU7289F[,_L\) MY^1P_\=B#3E$=U..[^VLH9X#9^["JN\PSQS8_ADE)-@.\\R%,9[#@'$7 0:I MC&(7$0 >FA(&B(R6;,:$<8@P2KK.P(3Q8PCC,6$\) SU'5(91;,NS^EAZ'H" M--+>Q&/">$ 8(\UYC^>\'W/!YO&<]S"#89Y#&8RBJ/,@/6&[)"22SKH\9HQ' M]%#"VNB%6[0Q68S'L]Y?E,4@E5'T*-WS#$53U@&-$PCO,6/\18Q!*F Q8(QA MT>8BZ0[98\1XB!AZ%>3YT1"]> 42Z4PX8%(%M&M3=-4*X/K+4/8"41!2E("1 M%]2Q+J^"F1, <^B=3H%$1@O+8X]UW55I M1&1?$LJ?J_+A^&53/7;]OSWCF_W;E/LO7?WR\7+H\0W5Q?]02P,$% @ MUI)72% B\@1T @ D@D !H !X;"]W;W)K(V(@%O&K8AO?U4Z5VFWH M>SNVIZ=:O?/+=];'D!C!+:^EO7K;DU2\N5)\KZ&?W;UJ[?W2/T(\EX![ AX1@BX4FX@U5719"'[Q1%>](S4O"7K&.M5;LV@S:Y_I M5$B]>EZB."9%<#9*/>BU T4#4'2/6+F(&-U#UBXDSVZ00)N\.8U IY'EIT.G M49K#"C&H$%N%^#[6=!1K!R(6U'8@0O H7 "4A!->,.@%0UZRD9<.E RW29-1 M7E3I.F8M)LQ1V MDH%.LCG5RUPG\?B[<3$HQA-6-8R7 M).&XEP"@03>Y=P/W"A3-*5"/&FZ4H7SLQ@6E9*)"".X["&H\>"HBN%\@_$B- MX&\8@1^Q4Z/$"1C'XZ2XF'PJ'K@;(#*K0L3I6\[;\A6DF _J3A4 MK?0V7.G_JOW[[3E73,N%3SJF4A^0;I.:[949IGHLNB-#-U'\>#T!W8YARW]0 M2P,$% @ UI)72)?>(^D>! XQ4 !H !X;"]W;W)KE.J"GU59MZ^+4]>=7\*PW9U4 ME;>?]%G59N:@FRKOS&US#-MSH_+]8%25(461#*N\J!>KY3#VK5DM]:4KBUI] M:X+V4E5Y\]]:E?KZNF"+CX'OQ?'4]0/A:AG>[/9%I>JVT'70J,/KXC-[V0K1 M0P;$WX6ZMG?704_^3>L?_LBZCFH4NVZWD5N_M[51I5E[\FL_._D]->: MO>']]8?W/X?'-?3?\E9M=/E/L>].AFVT"/;JD%_*[KN^?E'3,\2]PYTNV^$W MV%W:3E,'##U MB(F3S'Y@A))1A!D+R%@@QK'%9@3%=^O\03%E%AN 8EE*F$T,V<0.F\SF$CNK M,$Z26UP02K(4O10B,8B>*$/F$12&>#"K$ &*(F;+#G3E>:L9%A9&="4\ M=+ L,* +()SQ@16$I<_D$LL#@_K@ MY!*B;$W$*(\H$M8:BN8D$Z(IUGFAW""D%0(>QL I1;"MB59^LA+#8$>QDGF2X*T!%.+D5B9]+M=Z3T)0%+ M&R$]DI[MDK >D7PFD5@>",J#$Q2$DKX.&XL(P19#V"NE3OCCV*FDU(E_XFLU M",L1(0F1'FGE6$+X,^T*QP7-Y[0K&XB2OI5PV?,YGXF-$ K '(+.0+@N;4AVZ_C(QU\UX!CG>=/K\<:1Z.]==_0]02P,$% @ UI)72,(A M.PZC @ K H !H !X;"]W;W)KW)U81>4+/[-:KQRXJ*C20W'TY%DPNK>D MJO0(0I%7T:)V\\S.O8H\XQ=5%C5[%8Z\5!45_U:LY,W2Q>YMXJTXGI29\/+, MZWG[HF*U+'CM"'98NM_P8D-\ [&(WP5KY.#>,<5O.7\W@Y_[I8M,#:QD.V4D MJ+Y_BGVZJ2K1:ZS9P=Z*=4; M;WZPSD-H!'>\E/;7V5VDXM6-XCH5_6BO16VO3;L2QQT-)I".0'I"\"G>[_!^ MC\>?$X*.$#P1O-:)/8<-533/!&\,"/@A@6\$$!WPKX#SZ" MX+'*%0!*XR>O+2:RF+K%A''Z[!="10C!%0=@Q8&5" <2!.$05@A!A7#^H46@ M0#3CT-;1N,Z0I/ V,;A-##F-8(4$5$CF.TU!@72.TW14)T:$P-N8=PD4)P1Y MG2@53T02SW>+X3AA,L=OAWHP[(<3CQ;#N<,^9#B9T("3@(,O&(:C@,-9AL-1 ML6DX$5H,1P8#<4!XZLS@/.#X"W[A0.!DEM]D_("#J1C$$ZD@<"H( MFF^8P*$@>([A#C5\+R4^ 0D!D?EA4$\J/GI'B##W?%Q-$V M0-+9\4NM#'DPVS=9*]L2/<\3LEAK+^,578E>L7V9=]\BS\[TR'Y1<2QJZ6RY MTBV';0P.G"NF#: 7_3\ZZ=:Q'Y3LH,QMK.]%VTRU \7/M]ZP;U#S_U!+ P04 M " #6DE=(6$&^C% " 5"0 &@ 'AL+W=O&ULE5;;CILP$/T5Q M$JFF_!2(GE-R,$%M$^ P3(.6U)U?%F;ME9<%.\NF[N@K]\2Y;0G_NZ4-&S8^ M\J\+;_6IDGHA*(M@BCO4+>U$S3J/T^/&_X;66VP@!O&[IH.8C3V=_(ZQ=SWY M>=CXHP=Z).=&OK'A!QUK2#3AGC7"7+W]64C67D-\KR6?]EYWYC[8)WDXAL$! M> S 4X#M1&"%3)K?B21EP=G@<=O;GNA7B-98-6*O%TW=YIE*5*C52XFB+"J" MBV8:05L+PC,01MF$"93 I()!%6P(LAE!&CL((I @,@31;9KQ79H6E!I09T%A ME,,R,2@30S()S)" #,GR2E.0((522.\JM:!D5FF:.%0R4"6#5!P,.1J+.P5!)K%Q0&[!7W!+@CV"P(-\]#81\>@.'0(P99!H&<> M&IL]",V2N=6!C85R0"=WY0I["ZV6]Q7#OL&@;^[[.J)N_D0.&=A:&"WIZHB: M_]KO'1S,=KR>G.@OPD]U)[P=DVKS-%O&ULE9C);MM($(9?A= ](;NZFXLA"[ L M!)G# $$.,V=::BT(%X6DK,S;#S?+(NMG0_3!HJA:N_A5-VMYS8M?Y=&8ROF3 M)EGYO#A6U?G)=2$6'S=^G@['JKGAKI;N36]W M2DU6GO+,*?$BGC;:;T1:B7].YEK>73M-\&]Y_JOY\M?N>>$U,9C$;*O& M1%Q_O)M7DR2-I=KS[][HI\]&\?[ZP_JW-MTZ_+>X-*]Y\N]I5QWK:+V%LS/[ M^))4/_/K=]/GH!N#VSPIV__.]E)6>?JALG#2^$_W>@6Z M*0B[@NP5Y*>"LBJH7D&-%-PNE78A-G$5KY9%?G6*KGKGN'E(Q).JEWK;W&Q7 MMOVM7HJROON^$C(42_>]L=0+K3LANA>Z2;BU^9L/0C[6Q-1IZ."52\A1#!LN M$H4X" D3E:U^,$A426Q!00NJM2"'2S7*9-T)^:U0UN7J>_T?=J:A,XV!QD_3T!WN2D(B M=]&$#=R7A)J3-FXW O8;EC9H.)X];=QP!.@X,IJR@:D7P9RT,:,"0LK2YI0* M8:=48$P%XC1BVRT'5=F?+L)0$8"*-?9>:)"=M0D3IH\$RHTF;&#ZB&;4E#!2 M!)$:U[27NL\Z5($U;4P?H6,!*VDO=>_.]\CJ#H-* %1>4L"IW1G&E""F4^7 MF-(<3 EC2@]A2AQ3J:U[$6%*Z2%*B5-*8GS.&1Y,,:42;7V1FK"!X9-SMCZ) MX9,/;7V2;WV2K,"4@2,YIE9N)(94HMTTTA,V M,'O2GU-1S)Z$)V-647[@E?;=36),)<*45Q2<>4-KYY484PDPY17EE KKXZ,P MI I"ZD_8P)"J.9 J#*EZ"%(%SJ?:>H)0&%+U$*2*0THT?CD84P4X9> HCJEU M+U484@7WTHG)C<;L:6]&135F3Z/3*:MH+S6<BY=+;Y):N:N>/=W=MX^X6:B>OH_EH\;;HA]:>9U?(<'\S?<7$X9:7SEE=5 MGK93UWV>5Z:.T_M:+\C1Q+O;E\3LJ^8RJ*^+;E3=?:GR\\?D_3;^7_T/4$L# M!!0 ( -:25TC'#F16I00 -L< : >&PO=V]R:W-H965TK"G^I,EY>3?FK.FI=1[_SK*B>9\>Z/C_%<;4]ZCRM MOIJS+II?]J;,T[KY6A[BZESJ=-<-RK.8)HF,\_14S%;+[MJ/):T/.M/;NC61-F]O>J.SK+74S/QO;_1C MSG;@X^=WZ]^ZJMKD[T-F49[^OKV?BN[]>OMEGO3#\ #:#Z#W 41^.H#U ]C' -Y%>O.L MB^N/M$Y7R])\_)$VLRMVTO=HGJ?FLBJYJK;RO"DV09O[66>M'Z M)J*/HKLB;LS?YZ!HCC5UAM/A!!M7P3PS,!@%Z\:K1P<99]@"AQ9X9X$-\T"L M/-Q$LA,5G4@D1%BQ !$5<^R+@+X(Y(N5LO5-)!ZFL>[:QE5\(<*35@D=D<@1 M9CDBG6E 4J2;%)(H[(N"OBCD"\<6YM#"/&"1+*"%!?+!#A6*))ZF_8=!4";( MAB==Q ,V"0B70'!?")U"1:^2GRQ%(/$N18(1)PSYXN&*8,@)#\D)AI- .H6= M$ZB2=EI&5$-_,*,$0KKPV,!L$162%TP7F4]:*_/QM>)*B/2 3C"G!#%($D_- MP@S2)" G%#-(R92U E7$RMQF3#7T!_-,$<^$>FQ@#FE(K:680SJIVE*WDI*Y MDQ98;CW>8*(IHI#X(L(44AF2%4PAA27.62U(1;B=EA'5T!],-$5$$U]N,8ET M$9 7ADEDL!K:JZ57/2X$I>S:/"(:>H.99I!#SW\VPQPR&I(53\N+ZB%1=E9< MU6+A608,P\H0K,13>!E&C(F0@#%B#!8Z9QFXG2:7"WL9N"+I^]-@&%8& ?.4 M788!8R$=*<. L2D]Z1JJG#^-,=5P&X5AY0A6ZBF]'"/&0UI7CA'CDUI7#OK2 MQ-[^;L940W\PKASA2CWEFWOVJ"'M*\]<^IAKZ@ZGFB&KJBPFS MR$/:5XY9Y)/:5^[VIDHXR^5ST= ;3#5')%(/B0*3*$(:6(%)%),:6*BB=NT= M4PW]P50+1#7U%%^!210A#:S )(I)#:QP>U-WM8R(AMYXGA=!#CV/"P3F4(0T ML )S*"8UL%!%?0_(,*T"T4H]U5=@QD1(:RHQ8Q*VIG;$4.6+6&(2)2317G&] M:K ;XPM/0]<0RB4F$(YB4*H8G:%'U,-_<&L2L0J\\6$694AK"K,JIJRC=PH=X?H MN84*@ZH0J,Q3NA4&3(7L#Q4&3,'GI38HQW"_V[8T?SI)R71ZZ,[8JVII+ MT1WI/5R]G^.]T.XLZD.^6I[3@_XK+0^GHHI>35V;O#MWVAM3Z\:5Y&O#SU&G MN_N73._K]J-J/I>WL[?;E]J9J_\!4$L#!!0 ( -:25TCOQXAX M50( $,) : >&PO=V]R:W-H965TU#I=4^M,].X@2T@*GMA.W?US:$DG!8L2_!ESGC&3N# MR5HNWF3.F'+>J[*6&S=7JEE[GCSDK*+RB3>LUC,G+BJJ=%>9'7L1VXQ?5%G4[$4X\E)55/Q]9B5O-RZXMX'7XIPK,^!M,V^H M.Q85JV7!:T>PT\;] NL=L1"+^%6P5H[:CA&_Y_S-='X<-ZYO-+"2'92AH/IQ M93M6EH9)K_RG)_V_IBD@^1(3SP4MI?YW"1BE>W$M>IZ'OW+&K[;+N9U._+\ +2%Y"A ,(/"X*^('@H M\#IEUM=7JN@V$[QU1'<8#35G#NM []S!#-J-LG/:F=2CURV$091Y5\/4@YX[ M$!F!R#UB-T4$,$ \K6"005 9Q-8GH_HX3'"" "4(+$%PY\.'!Q\=*+:@VH(B M'Q[,[A 0B5)<2XAJ"2U#-&(@XV7N&"*4(5J^'3%*$"_9CGBBT\?72- U$LQF MC#.D*$.ZW.8*)5@ML;F:Z(1TYL]I$H^%Q,>LSBB%F:#!,YK7AH $E-D)"9US6>".(O]TOP0!!8XK='C5_'0;1ZC*\WNNX: M>F8_J3@7M73V7.F;T]YO)\X5TXS^D]Z[7'_1#)V2G91I)KHMNCN^ZRC>W#Y9 MAN^F[3]02P,$% @ UI)72-T[8,L@!0 *A\ !H !X;"]W;W)KGO;JG%URW!XI#EOXJ-,>7L=YKLBJOYIBSW MEYY7O&Y,&A<7V=[LJE_>LCR-R^IC_NX5^]S$Z\8H33SN^]I+X^UNOEPTWWW/ MEXOLHTRV._,]GQ4?:1KG_UZ;)#MIF97;+/= M+#=O5_,_V>5SX->21O%S:P[%V?M9/?B7+/M5?WA<7\W]>@PF,:]E[2*N7C[- MC4F2VE,5^9_.Z5?,VO#\_='[73/=:O@O<6%NLN3O[;K<5*/UY[.U>8L_DO)' M=G@PW1Q4[? U2XKF_^SUHRBS]&@RGZ7Q[_9UNVM>#^TOH=^9T0:\,^ G R8' M#41G(,8:R,Y CC50G8$::Z [ SW6(.@,@K$&86<0CC6(.H-HK$&]YNW*^:-- M3HO-1IL'6=[BMX]KRMEE954YK[]M MV&A^K"[FHOKV<\FDT OOLW;5B:Y;$>^+@K[HAA2%?=$M*8KZHA4EDGY?=$>* M6%]T[XHXLQP]N)HPL(;]2/CQK5$_$9J^XB]7(:P!?W,ED3669W+B7Z&\:KU/ MB\[I1>>-B^#6I%NA'M&M$?6OK-GY4:0BE#2OF- M4 K;9V\"DIZ ="?@+*ET8K%0D^-WE5PS_*E!#"6:@+#!.34T#)Z P,#$ER0!.1M#I)/F)5 E0"AG@B"EW MO%(&P D@B6EJO*$]7E(5@5" .$8@)Y5OAR)5#(0"Q#$*.<7M4(2*:;3@@$P6 M4:&$':I5U7!]5>0+$(H#@#F%II)6J$[5"Q5<*! * ,P)@*5"3E"SGM*M.:"2 M$_W: 6I%JE#5XH!=3E#I5*T5=_O@L6B!JL4!P)SJA I4+0X YE-Z(0=H<@(Z M9^:WW.V'P7"]YH!/3O') CN>JXHBT#((B*0!XPI^R[01("0(I9\LB=\)ERHA!W?' E ER/VEO9+8D.(D Z8DQ92;9.TFV3F@]^,!_"2UWW233*D8N@@!I)(\"**5 M N3)*4=!!9A2!%-V+[KN1.IP!6:DSO>U#$W1HV/'-T:V5,[WL@5:AB*,"I(GL?."$H )^:TOL4 MP$J-Z7TKY?8^S0Y0@E($.!G,$D-8C;K_>:H+H0: U %I3 MJ&IP?-'H;NF4(Z(&J&JJ SI%O%.I7E\>GCF@6E-4:W" T0!5/:59!@#"@-R MVC,/" K!S+VS9US[^-T\Q_G[=E?,7K*RS-+FF=9;EI6F^T0)Z %3&TGV;Y]?2 L88>J-_C /_/-&,:3W[EX MDQ5CRGMOFTYN_4JI?A,$LJQ82^6*]ZS3;\Y,GJQ1VP0X#).@ MI77G%[G=>Q%%SJ^JJ3OV(CQY;5LJ_NQ9P^];'_F/C=?Z4BFS$11Y,-J=ZI9U MLN:=)]AYZ^_0YH"(D5C%SYK=Y63NF>"/G+^9Q??3U@]-#*QAI3(NJ!YN[,": MQGC2Y-^#TP^F,9S.']Z_VG1U^$^=V)E>&_7*[]_8D$-L M'):\D?;IE5>I>/LP\;V6OKNQ[NQX=V^R<#"##?!@@$<#C/YI0 8#,AK$V&;J M(K-Y?:&*%KG@=T^XC]%3\\W1ANB3*\VF/2C[3FZM0%&RSH.;\32(]DZ$ MGT1I.(H"31@Q&,+L,>0!/6,.H C#& )F0ZR'=.*!H 1V$($.(NN /(= 9G$Z M46Q%G1.%)%XXCQCDQ! GFG&<*)EPEB )"$D@2#R#.!'&$TJXRJ((!J4@*(5 MR>PG2C]G@U*8DH&4#**DLW2R_Z>L0HLLG)D7BU='8(+/,=PA *SU%.97+[J*!HM82"2QT1"#4O MU4$UK54\/[U@V3%QL#Y%>R:^=;5F3W;%/[=Q=^R$O\IY>V \J+G4GO2-7 M^L:V]^J9<\5T*.%*!U'I3CHN&G969IKJN7"]Q2T4[Q^MVK.3. $M8-9VPO;M:QM" M61A+7 (V_\PW0_QC9QT7[[)@3'F?==7(O5\HU>Z"0)X*5E/YQ%O6Z"<7+FJJ M]%!< ]D*1L\VJ*X"'(;;H*9EX^>9G7L5><9OJBH;]BH\>:MK*OX>6,6[O8_\ MQ\1;>2V4F0CR+!CCSF7-&EGRQA/LLO>_H=T!I49B%;]+ULG)O6>*/W+^;@8_ MSWL_-#6PBIV424'UY65693)K\,23]SS2!T_M']A?;KB[_2"5[YM6?\JP* M76WH>V=VH;=*O?'N!QMZB$W"$Z^D_?5.-ZEX_0CQO9I^]M>RL=>N?T*B(0P. MP$, '@-P7W@/LF5^IXKFF>"=)_IWVU+S%Z(=UB_B9"9MW_:9+E3JV7N.HB3* M@KO)-(@.O0A/1!B141-HP$C!( 7;!.0K)88S;, ,&YLAMAF:OH00;6=U]J+M M1(0B&!*!D B"D!ED*4(8AL0@)(8@R0RR%"$$0[8@9 M!TAED*4(A#"$@A 0 M',X@2Y$+DH"0Q,9OIDMG0_ ,DBP@J0.2@I!T"2'S1M)E(Y'#!.8[ 'DM7&*B M9+Z(!]6:9I##TPCBS-?QH)IR8E<_L*L1:.O$D0/V-5IE;$!%7+7"UD:KO VH MB*L?V-UHE;T!%4D='-C@:)7# 57B6DNPQ]$JDP,J9S^PS=$JGZ.ET9/4]0?! M5D=KO#Z(ONPD.)U_@8/))MO2*_M%Q;5LI'?D2N_7=E>]<*Z8SA@^Z9H+?2P: M!Q6[*'-+]+WH#PK]0/'V<>X9#U_Y/U!+ P04 " #6DE=(AJ!$2F,# @ M$ &@ 'AL+W=O&ULE9C;;N(P$(9?)Z^KIIO[!RF/#T'0;0Z\+KIOXL@;=6JB;/S%;!A[:AY#_YEX+G<'V0_$"QF MP=5O6]:\Z4K1>"W?S?U'>%@S[$T&B]\E/W,4W ML@]1J,,;7_&JZB,IY;]3T _-WO'V_!+]^S!=E?Y+T?&5J/Z46WE0V8:^M^6[ MXE3)9W'^P:1&.^#D@%<' M2#YU8),#^W"(/G6()H=(R6,Q:8&5:,+@W69LF M>48GP&PO=V]R:W-H965TP."(F\!HK%"^N@53LE MXQ1+M>05$AT'7!@2)2CPO 11W+1NEIK8&\]2UDO2M/#&'=%3BOF_$Q V'%W? MO0?>FZJ6.H"R%,V\HJ'0BH:U#H?RZ+[ZATNB$0;PNX%!+.:.]GYE[$,O?A9' MU],6@$ NM0)6PPW.0(@64@?_G30?1VKBZO6,"9D3]-(6MEUG.= M DK<$_G.AA\PI1!KP9P18;Y.W@O)Z)WB.A1_CF/3FG$8=^+]1+,3@HD0S 0_ M^9(03H3P08B^)$03(5H1T)B**<0%2YREG T.'R^OP_J-^(=(E3K705-9LZ=* M(53TEOFQ%Z3HII4FT&D$!4O0C$!*?CXCL)UQ"C;TU0'G+2+TGR&7+>3;WFXB MM"8:&O[N.='0KA!9%2*C$#XK1*M2C:#$@%H#2G:K9+>0>+]*=@N)$KO5V&HU MMB4;VQ42JT)B2S99)9ML;.[6-[N%[+V5#[1XJQ1X97YZX>2L;Z6^\45T[BNO M@7[KJ_A)]9NQ/3QDLK3#%?S"O&I:X5R95'^2>>\E8Q*40^]%%:M6'7%>$"BE MGN[4G(]-8EQ(UMU;WMQWL_]02P,$% @ UI)72(XD ZN# P KQ$ !H M !X;"]W;W)K_Y\/%Y;)+Y6=:OS4&( MUGLOBZI9^(>V/SN6I+?)*/-5>\_VA50/!VIY%^D?%4W/[<+/U0YB$)L6N4BZ[[> MQ%H4A?+41?X[./V(J0ROKR_>O^OI=NF_9(U8R^)/OFT/7;:A[VW%+CL5[;,\ M_Q##'&+E<".+1G]ZFU/3RO)BXGME]MY_YY7^/O>_I'PPPP8T&-!H, F_-."# M 1\-(CW1/C$]K6]9FRWGM3Q[=;\6QTPM.9OQKG ;-:CKI'_K)M9THV]+%H?I M/'A3G@;1JA?1M6A4!)W[,0:A&"NRS1F?8@\<9LFUA_1SEA/L(8(>(NV!?_8P M->9IBY+8$26&46(0A85&%"AR%#2!81+D@8PPO2C1HJH713A("H.DH.:,8P\3 MZ&&"THR,-"=6FM$TQ%&F,,H418F-*+THOHI""0ZBF$>#-79'21ED MZ9$1RL,"%JHMU0@3JQ%< &'8"<)N[BF#ZH8]A6/6.63=;*5!]:FM'2O,\7[ &8KC.-&!UO;!(,4 M 9"FYO]2)(JMW(*KA]=2U'O]3-]X&WFJ6E6]J]'QO<$CJ8=?8WS%9FN&QFFV M1OINWK-U%"*+:'PU$7RDM)P?L[WXE=7[O&J\%]EV3^GZ87HG92NZ"8&PO=V]R:W-H965T5JC[L/KN)DZ "3K&3=/]^;4,(L8>J>0E@SLR%, M[/S"VG=^H%0XGW75\+E[$.(X\SR^.=":\"=VI(U\LV-M381\;/<>/[:4;+51 M77G8]V.O)F7C%KE>>VF+G)U$53;TI77XJ:Y)^V]!*W:9N\B]+KR6^X-0"UZ1 M>X/=MJQIPTO6."W=S=UG-%OC1$$TXD])+WQT[RCR;XR]JX=?V[GK*PZTHANA M7!!Y.=,EK2KE24;^Z)W>8BK#\?W5^P^=KJ3_1CA=LNION14'R=9WG2W=D5,E M7MGE)^USB)3##:NX_G4V)RY8?35QG9I\=M>RT==+]R:)>S/8 /<&># 8XL & M06\0W R^CA#V!N'-(/S2(.H-(L/ ZW+7E5L108J\91>G[=I]).JK0K-(]F:C M%G4K]#M9.RY7SP6* C_WSLI3#UIT(#P"I0F^QRQM#!H0GJ0P\, 0CP6VS$,C M@(TP**QL1(#N(6L;DJ4PS0 L5Z#MD_MR320:@AY"[2$8>PB"U,BU \4:U'2@ M)#)R6=D@C)!1M34 BC.8;P3RC6R^46 VOP-%HRC&)[2R$AW92?LPTQAD M&D-, ]A# GI(H.Z&L(<4])!"'"*C6JE="[-< 3#/#*01P;QB T>F1T$CJ%& M+30[_ ?4@";F#_H.TQ[U':K@>'E&& J33/B M8] \4]\'@A6/P+D#Z0;VNF& M_H08$*Q;%#W2'%A1")24.:QZU+VV,^.#[D%WZLXF!A&"U8D2B$UFLDEL-FBR M=K"*$2ACJTNIG=)TEV"=(DBHX80/#,L0/R)##,L0@S(TQORB1]UE'$\%@H6( M(2&&4SY@(>)'_H4Q+$0,"M%*V!9B-C$T,"Q##/U_AA.S',,RQ/$C^<+BP:!X MK'P3J\&Q.>"\T=:RINU>;^JYLV&G1JBMU6AU.#@\8[4U-=:7\D#1;?]O;HK\ M2/;T-VGW9<.=-R;DQE=O3W>,"2HI^D^RH =YY!D>*KH3ZC:1]VUW".@>!#M> MSS3#P:KX#U!+ P04 " #6DE=($J]9)FL" #:" &@ 'AL+W=O/OHJ!4.A]UU8BU6TC9KCQ/ MY 6MB7AA+6W4DQ/C-9%JRL^>:#DE1V-45Q[V_=BK2=FX66K67GF6LHNLRH:^ MV\%:>"ZD7O"SU1KMC6=-&E*QQ.#VMW0U:[5&D)4;Q MJZ2=F(P='?R!L7<]^7%JW^51%BI:WW6.]$0NE7QCW7#3 T9<&P6 0?!I\30@'@] R\/JMF$3LB219REGG M\/[MM41_)&@5JE3G>M%DUCQ3J1!J]9JA* Q2[ZH]#:)M+\)3T:CPE/N1@2'& M%L_-HS"\9^SF(HP6]YH]I%G"D03@;@/C(+F/)((]A*"'T'@([CW$5KYZ461$ MC1&%,","&1'$2"S&7)3X#W(1@Y08HE@9W_:B>+(3^Z7LYA*,K?<&2 (XU 0, M-8%"75JA)K.D!P\@"Q"R ""1;T$6,PB&&4N0L808R&(L9XP'ITT7-.A(^Q % MVV?:?QKSH'(@"#,K'>AI#%@\-@A#F-#&X*3$F*0J0O]%Q5:H'XUQ4M&3U,-$C7G?>ON)9.WM M3V+\G6=M,?A?YH7Z< M[IKF^.!Y]7IGBZS^4A[MH?WGI:R*K&D/JZU7'RN;;?I&1>YIWP^](ML?IHMY M?^Y[M9B7IR;?'^SW:E*?BB*K_EO:O#P_3M7T[<2/_7;7=">\Q=R[MMOL"WNH M]^5A4MF7Q^F3>EA1W$EZQ3][>ZYO?D\Z\\]E^;,[^&OS./4[#S:WZZ8+D;5? MKS:U>=Y%:J_\ZQ+T_9I=P]O?;]&_]MUM[3]GM4W+_-_]IMFU;OWI9&-?LE/> M_"C/W^RE#T$7<%WF=?\Y69_JIBS>FDPG1?9[^-X?^N_S\$\87YKA!OK20%\; MJ/!N W-I8-X;T-T&=&E K($W=*5/Q"IKLL6\*L^3:KA[QZPK$O5 ;:K7WNT@7T7(0Z5O15>&UX:_7T.@:2RV:Z_$%4JDP:BQ9 M24D28Q,&=M3T[8GD9 M5N0ID!"KP5CD_2;*R&H"K2;(*BOT92)\4,RL2DG .KP"41Q6.RPB,/C(K.9D M\,5UF)/TKF3LQ($HA9P8[D3)I' G4N*H>@5!]J0T6<3- #AK5WUB]BH$WXC#5TEN\IE("C2!@ZT:LU5_BJWZ8[;>E8R=8+9J MR%9.-"W!*8F&1*YG0&.^:LA7SA MT2GR8\ *-ZWYBNNH0 M67%,WC6FJX[^8 &@,1(U0J)8 FB).U'A]R1C)YB'.OF#58#!'#.(8V(=8"2D MR/#Y6XI4$3GX83#-#*09'W",!)7B4T6D81Q: 8UVC ,&\\Y WO$QR4B8&?&\ M A'%"7<''0&@<[G#S92D?,F8=H91#NQ,KBHQHCG3TL*5''D<(.Y:>"LE(_J M1LXW9\KXHLZ![#;58T,8P@:^,N 0-I*P.N&C:0I4$FXKI'+##0/;(&"[%@B$ M@4UPXLF!31+%1HNE$5*%ONN-&@8V(6"+%0(!&,?"CA29T#$D$L8Q(1R+)0)) MB'+0ID"CC"LU&+3T*=#2QZ %$L?C0H[WGA"TG&Z$*"KHAE1.NA&F+4':JN+*OSI3(C*8K% +>A M+'?$;C]QK%X(4YG@VP)19O(=K*BQ>Y+!B7>S/5+8:MOO,]63=7DZ--TFP\W9 MZU[6D^ZV5]CYI7I8#3M2[V$6\V.VM7]GU79_J"?/9=.41;_%\E*6C6T=^E_: M3.ULMKD>Y/:EZ7Y&[>]JV)<:#IKR^+;-=MWK6_P/4$L#!!0 ( -:25TAV MUJ&PO=V]R:W-H965TW:($] "IK83MO^^MB$L.$.:O> /WCR_ M&8_'3CO*WGA!B+#>ZZKA&[L0HET[#L\+4F/^3%O2R#]'RFHLY)"='-XR@@_: MJ*XIGGMA64K/HBH;\L(L?JYKS/YN246[C8WLZ\1K>2J$FG"R MU!GM#F5-&E[2QF+DN+&_H/4.!0JB$;]*TO%)WU+B]Y2^J<&/P\9VE092D5PH M"BR;"]F1JE),V#N2(SY5X MI=UW,OB@%>:TXOIKY6BVZ__$[F &&WB#@3<:H-5= W\P M\ T#IU>F_?J*!<3E[R5 0A:ES44P# M:-N#O G(FR-VMP@?C1!'*AAE>* ,3]M'%(#PHUJ-&@ MI\2+#%\ $/)7'BQF!8I9 6*" &8(0(;@$P$)0880"DAB!*0'!1-?72,:]Q S M%1&H(@)4Q,8:V^B_*NXA9BIB4$7\2'+$-VL\H0 90B!0M(*U)*"6!(J(L40+!%K2HFH9=/Q=*#(+F8H62@CZ1*XB^/PC[Y%L'5!3CT/S] *88*$4(;B2 M(*B4W.3L@)I%/S"U )BE_8$+"8(JR4WF#JC9.M%-ND HA/QX01!/$% 2@D)N8N^5,[K(6G\A/S$YEPZT]%?):U)?7D5)!)*7[+"D+^5P9 M!Q4Y"M6-9)_U%W@_$+2]OD?&1U'V#U!+ P04 " #6DE=(8P!*MB # !, M#@ &@ 'AL+W=O&ULE9?=$! M EK^/9B9VIY.>]&93"[::\66;2: 7)#C].TK">Q@L4K(30#I[')V)7]!^86W M+]V1,>&\U573+=VC$*>%YW7;(ZMI]\!/K)$S>][65,C']N!UIY;1G0ZJ*P]\ M/_9J6C9ND>NQQ[;(^5E49<,>6Z<[US5M_ZU8Q2]+E[C7@:?R?NZ7K*P^L8ENA4E!Y M>65K5E4JDWSSWR'I^SM5X/C^FOV[+E?:?Z8=6_/J3[D31^G6=YT=V]-S)9[X MY0<;:HA4PBVO.OW7V9X[P>MKB.O4]*V_EHV^7OJ9U!_"\ 8 F!N0# $!+< M$GX8$ X!H1'@]:7H1FRHH$7>\HO3]JMWHFJ3D$4H6[U5@[JS>DZVHI.CKP6) M4LB]5Y5I$*U[$8Q$AF(S503D)O&D@YL-0&V C@_N;$01GB% ,P0Z0W*7(;1D M"-$,(>(A#8Q6]*)8BYI>1"+?Z 8B C_%O42HEPBI)@WQ##&:(<:JB8QJ>E%T M5TUBKBTB@L#2V03UDF!>8L-+@GB9=!8163N;HEY2S$MB>$FGK_&!&%XP46S9 M]1GJ)<-6V5*-HA?V^_7GK/.@^F2A,95UI8F%)V1.?P?5)PU&5;8.$QPL!"-+ M8JL)1POY"EL(#A,=<>\'QPR9Q1DR90C$46SZF:J"+,DL?G#4D%FL(0A'D#6?JB!-;7L0 MQPWY"F\ YPW,X9)?/._-R(B9*2ZMX.# M"]Z;.@W!.04(I\R%76&B*#.]>:/OZIJU!WU Z9PM/S="!8]&;X>@E3ZRF.,0 M+=80(3/2B9S1YR;O_15%?J(']HNVA[+IG&YA4]6%[IHF3H +.P&FZOY]M""7FT*4O!>QSSSWWQCZUXPMO M7MLC8\)ZK\JZ7=M'(4XKQVFW1U;E[0,_L5K.['E3Y4)^-@>G/34LW^F@JG2H MZP9.E1>UG<1Z[*E)8GX695&SI\9JSU65-W]35O++VB;V=>"Y.!R%&G"2V!GB M=D7%ZK;@M=6P_=I^)*L-]11$(WX5[-*.WBTE_H7S5_7Q8[>V7:6!E6PK%$4N M'V\L8V6IF&3F/SWI1TX5.'Z_LG_3Y4KY+WG+,E[^+G;B*-6ZMK5C^_QF*T4W8I.+/(D;?K&:[M<[Y6J1D)4O6[U5@[JS>DZVHI6C M;PE91"1VWA13#\HZ$!V#!H0CZ8<<%.7(Z"23 8/5N'I>.^FBL4" M,_B0P=<,X6T?*&980(8%T!!Y1BZ 4$SU0102X 8@MLT*0!%H:$7$AF@ M#00ML=X0Z@U1]R/,L(0,RZF&P'6-:@!HW-BN&L@TLQHCJ"5"#,:2SR#(6"X; M"/*Q%F5O:(.[B,,H.D6HR6) H/$/W6G^'^I6](PK$20Z,/5TJ$"C:HT*3#%3 M2.C/:8'N]4@HTF+N@1YUFVC&/P@V,8)<+)S9]P3;&/F*CQ%L9.0>)TL!BKJ3 M?QR *G G*P:B9K8_P8Y'[K&\#*$"XIIZ(&K& @AV-/(52R/8T\A=IH91D5D3 M0I&YA8%]C=QE;!!%3&?#J!EKH]C:Z#W6ED$4,5;J!J-F-A_%KD7)L/NG(=A< M*# 7TW=3! I(,*,-FPN=FLMDNZ8 )!.%1B)G=+:L6'/0A_36VO)S+=3A:#0Z M7 12JLZFQG@F+P@$C,M&KC**9F0KY SBDMKEC+YM.!^BDOB4']C/O#D4=6N] M<"'/T?JTN^=<,%FR^R"]YR@O1,-'R?9"O8;RO>FN"-V'X*?KC6>X=B7_ %!+ M P04 " #6DE=(&?X(,]D! #F! &@ 'AL+W=O&UL=51-;YPP$/TK%O?$8+*0KEBD;*JJ/52*>V,\+F8AWU0'H-$[9X,Z1)W6XQYC577 J;H7(PQFIQ&2 M4VV6LL5JE$!KE\09)G&<84[[(2H+%WN192$FS?H!7B12$^=4_CT"$_,A2J)+ MX+5O.VT#N"SPFE?W' ;5BP%): [14[(_YA;A +]ZF-5FCJSWDQ!O=O&C/D2Q MM0 ,*FT9J!G.\ R,62(C_&?A_)"TB=OYA?V;J]:X/U$%SX+][FO=&;-QA&IH MZ,3TJYB_PU+"SA)6@BGW1=6DM."7E AQ^N['?G#C['<>XR4MG$"6!+(F$&_< M"SF;7ZFF92'%C*0_VI':/YCLB3F(R@9=W6[/&%4F>BZ3+'DL\-DR+:"C!Y$M M:$5@0[]JD)#&D=RDDR0/$Z1!DZDCR#^;_!)F> @R/#B&]!,#B:_*]*#,@08' MNDM)6&475-F%5)(K%0_:;53(?PXC"XID(1%R)9+=B-RE65@E#ZKD(97T2B6_ M.; ;$;RYB!QDZ_I-H4I,@^ON371MZ2?B+O('O"Q&VL)/*MM^4.@DM&D'=VD; M(308)_&]*;4SC\ZZ8-!H.\W-7/H^] LMQLNKLCYMY3]02P,$% @ UI)7 M2*CV1G W P 90X !H !X;"]W;W)KZBTVD-[9A,G00LX!6>S_?>U@20P,Z3M)6#S MYLWSV'FVEV?9O+<'(93U695UN[(/2AV?'*?='$25MX_R*&K]92>;*E>ZV>R= M]MB(?-L%5:7#73=TJKRH[639];TTR5*>5%G4XJ6QVE-5YEX M+?8'93J<9.EJVD+75B-W*?F9/&7<-I$/\*,2Y';U;1OR;E.^F\6V[ MLEVC091BHPQ%KA\?8BW*TC#IS+\&TEM.$SA^O[!_Z8:KY;_EK5C+\F>Q50>M MUK6MK=CEIU*]RO-7,8PA,(0;6;;=K[4YM4I6EQ#;JO+/_EG4W?/$.#= OR[ ?X0X(, IQ]*5X@L5WFR;.39:OK9.^9FD; G7Y=Z M8SJ[RG;?="E:W?N1L)#[2^?#, V@M ?Q,>B*<#3]-0>G&P* MR3!D$=,B/'*@7A?OC<<0! '-X),,?L<034LUPQ"0# &A(71!L7M0V('J(0TH M%P$!4Y;=99E(#4FI(245S$G:@X)1$C\&4C$D /.")89J1$I-<)20PY*ED8H MR4,$A*P)3!@!L13&I]7&I-J84@NRI#'* A!KC CSC!B9JTN2)T+2B>8W72! M@" VI2 M% ;58@RTBHSBF?EW,=*]GQDGK"":64N,-E_F_8=W,MI^F?\O[CF@)C4)8-T( M#*H;QLS6C39[1KH]M- !-<[C!6BB,AW4BJA-;J/NIP'?>>[-DJQ4^8UTN]-?POJ M&TH>+Y>ZZ\TR^0-02P,$% @ UI)72*-)C%%L @ = D !H !X;"]W M;W)KDT;0^3 MJCYLSPYQ BI@9CNA^_>S#:$T7"KZ$G^=>\[U-2=VTG+Q*G/&E/-6E;7YMXJ4XY\I,>&GB#7''HF*U+'CM"';:NCN\V1-D M(!;QNV"M'/4=D_R!\UG?Z"2/?'R3W%4NBE5"^\_<'Z/02&,..EM+].=I&*5[<0 MUZGH6]<6M6W;;B5&?1@<0/H ,@20+O%.R*;YC2J:)H*WCNAJVU!SA'A#="$R M,VGW;==THE+/7E,<^CCQKH:I!^T[$!F#!H2GZ0<- FGLR22H#A1:4&U!"-8(08T0TEC=:72@ M8*3Q$,(B$2@2344B=*<1+=:(08T8*O?,@:U!AO62@Y:H@"[;80*X))HI.H:-AOTO^ 3#5L.K)4?7HSY\8G.YPH;$ MH",GAQ=,=3!:SVT)]B4&C#D]0,"86FGFCP[#YL31%YR#8?/A>-$!Q(N_-]BA M&+3HI/Y3CS[@>.;V@%U* )=.JM^#PD]UO-&M6#%QMI>_=#)^J>U;8S0[/#!V MQ-ZJ[_ T:>B9_:+B7-32.7"E[V9[@YXX5TSG@A[U;G/]!!H&)3LITXUT7W2/ M@FZ@>'-[XPP/K?0_4$L#!!0 ( -:25TA_ALZ7&PO M=V]R:W-H965TJ:I]L]9U*4W[6&^B9EJJ#9E^6LO[WJ I]F(4D/ \\YYNMZ0:B^32ZV*WR4E5-KJN@ M5NM9^$#N%YQW$JOXG:M#,TK>ST7.2B:XY'VS.GM!(N^@GEF8' 5S-JSZP"%$-@#AQZX]9#> M>. >#P)Z$/T8$I8ZF00BDCCI7GPANHDE@;$D*)8)]I!"#^F(?$R@APF*(7/R M@40\QM-D<)IL2-J1B!,G[5!$<2Q=:T TQ<@'\_CP$$E&I)Y XAX('9)\I&IE MGIDP>02@U\\_5''N% "K?"O''!..?'C@(9AD(L94 !-(((*]"B 53STS85)) M.J@"2,4G;@6@*O/$@[DGB&GA89I@J$DVH@(4LT@1B[T*0)6O A032\F0"D"5 M<)L05GFZ$,7T4\"U2'W9PUQ3-J8"F$6*6.SG!:CZ>^)7JMMX,-<4;='"T^\H MYIHF8_*"B:6#B(4JX?9,K/+%@XFED%CW(Q"K?*1@KBG:8\7$G0FJ/%V(8?H9 MXCKQ="&&N69C=F*&661P)W9K#56)VQNPRM,;F.=+&>VQO5HC%1>^3W),/T/T M]VH-5;YO$(:Y9HCKA'M\8*[9&*X9YIH-XAJJ$N'6&JH\_8YAKMD@KH$JRWRE MQEBS05@#599YJL0QU1Q2[>E!'%/-QU#-,=5\$-50E;C?7%CEZ78<4\T'40U4 MWDISS]_D05!#5>HVW^CJC*)4]<:>W33!4N\K>U1T-7HY'WJ@]HSC0SZ?[N1& M_9+U)J^:X$4;HTM[GK'6VJ@VF/BN[0Y;)5>7AT*M37>;MO?U\4SG^&#T[GQ$ M=3DGF_\'4$L#!!0 ( -:25TB0X)%=(@P /A@ : >&PO=V]R:W-H M965TFC/H@?RLWK>O/[]G$<=U=_ MKI;/V]OKQ]WNY=-LMKU_'%>+[2_KE_%Y_\SW]6:UV.U_W/R8;5\VX^+A<-!J M.5-CPFRU>'J^OKLY//;KYNYF_7.W?'H>?]U<;7^N5HO-_^;CRW7[P_\ M]O3C<3<],+N[F7T<]_"T&I^W3^OGJ\WX_?;Z;_+IJ[HP:0Z2?S^-K]N3?U]- MU7];KW^??OCGP^VUF8H8E^/];AICL?_KC_'SN%Q.0^U_]7^/H_[U2Z<#3__] M/OK?#^>[K__;8CM^7B__\_2P>]R7:ZZO'L;OBY_+W6_KUW^,QY/PTX#WZ^7V M\.?5_<_M;KUZ/^3Z:K7X\^WOI^?#WZ]OS\1P/ P?H,<#].. P50/L,<#[,+XOILI)/?O_:W$\/ M'EZ*PW/[WFWWC_YQ)R'*S>R/::2CZ/.;2$]$>J[X4BIL-LC74I*&#\EL7^1' MI0HKUP<(1[&&$>#:"(R,X.((K:P@QZ\7G-U$XB)[?1$:S;GQ! MHI"WK!0E)[A>#^OUJ%Z+1PAPA-#1LPA'B"T]>Q/YTS,-0]:R4B-&2#L&6,J M2G%XA 1'2!WMF"8HY#C3TI"CZO1LO^IR/8=Q*:.A**TW4^YCT!HA!)-=C# DW, MQL#FDZ&G*]A^DIJZDEJZ D2L*XJ=K-#)[*:&':C2T14E=T9P:RR["?:S0QXF,@1VHKJ'DAXM=A]MB>^6NP^VQ1@;9E. MBX[4).>58 ];Z&&232SVGNU)L Y[S[4DV#E2I>PN_-F5$=;Y//@C$7L7X[#5 M';0ZL:C#%G4]0==AB[J6H#M'JK)U9=0%K0,BVCKRGA?.""3E..QEUY.('?:R M:TG$(U79MC(R%VVK M2K24VIVE].U57)>25X+O P5;.SP0;U/:G:8X/ZIE3MR\1<7B6EAEXE MV.@>IFHR1L#N"SVI.F#WA:94'D*CFO!'LXP$Q-;OH!>R_T9.J O1>: M,G6XG*F!A,P" 3LXP$Q-[N6!K CW9.J O1>:,G6XG*F!A'4$.S@@!P_D-AVP M\T)/IH[8>;%I53B623CO2%5R7@GV;T3^36P,[+S8$Y4C=EYL6A..E]>$JY+S M2K!_(_)O(NL5$3LO]B3@B)T7F]:$8YE<-5^O0!KBFT@^U4$.3F2](F+OQ9YX M&['W8M.*<+R<7*N2\\^6L(,'Y.!$WFL-V'M#3W(=L/>&IN0Z@%2:7R5(0ZZ2 M 7MX0!Y.; SLOJ$GN0[8?4-3JY+P2[.$!>-BS3]P&[+VA)[D.Y*/0 MIN0Z@%2J)^\\CDT!^5;SL;XB53"L:NSV ;D]D3$2]FGJR;@)^S0U9=Q4!EA7 M@ ! Y)7,&@D[/B'')Y+\$W9JZLFY"3LU->7<5(98"<7< U1J/>L+=GU"KD\D M_R?LU]23=A/V:VI*NZF,LNKR^0>([,DK_>:TH^B4&_&63%,)3P\)30^,UTF$ ME>B#)1@MT8A+E+$W9;U#&B4I3@P!)@Q,Q^3]@AB"3)@N9L(0:,*T41.FS+]E M:TH-;PTA)PRP?S0,OS"$G3!=\(0A](1IPR?,Y87@NB:KAM 3!DP T=#^$G[" M= $4AA 4I@VA,)<3D.\3A"I**AHQ!O2D^8 M%L8V25. M[0G60L@HT99H/4*UHM!1 MV#5T=WFMNZ[)JB'>1CA6%);1"4HEKBNC$YA*7%M&=X"!+CI3 M:NCD2;@L0&S%[59#63.0A19U'9?$AP M,1FZ,CL!QF1HR^P#6 PO.E-JV)5%T#-![%EDA(\0;$R&KLA.P#$9VB+[T!#9 MJYJL&K8A (KLC# 4@H3)T!79"10FJ2VR)X"0Y)T!&G;-$+Q,$%\6E9X3\63J MRNL$#)/4EM?391"[KLFJ(=Z&C%E@UPP!PR1UI76"ADEJ^D8BDH'%_P0R?0Y: M(I'0N$1H-$$X6F1?-A("B$GJV\Z#[>?1].U$)$,M;(C^5VS0K T-5W[BA L34W;SB+F,OJ"-.0= MI1*\31'>%AG\J@1+4^G)\4JP-,6[:Q6=DI@AOBY:.0LPK/0E= M"9*F>)>MLC.7OQ)9UV35D$D H6W1DO"'^+ MEN15I1M\]21Y99MSX=VYR@Z6,M3!RWF_KLEJ)C,%@N2BI6=.'*X]>5_95EYP M+R_0OU*&^G<9/:]KLIK)?(( N>#@ M4D0=3! Y18A<9,"5$FA-;5?<)]":PEW"RKN#!6OX^>=#2,2F)4*_*:+?HF5) MGK!H:KN2/&'1%&X7!EJ#^/2B-#8BD\WYDBU_UTL MH!)*30&E5MQQYDBU_UWYBSP[V7E]-6Y^'/:\WU[=KW\^[Z;+X^31CXWUYX== M\//']]?#IR_315$^-[V@TW,6/^>FYQQ^SD_/>?Q_Y^!C__LX.[_4$L#!!0 ( -:25T@L![PEI0( /@) : M >&PO=V]R:W-H965TQ=LOD)$ MD))457NHM-I#>_8F3H(6<&H[F^V_KS\(2^RAVKT -F_>O!E[QJZNC+^($Z4R M>.O:7JS"DY3G912)W8EV1#RP,^W5GP/C'9%JR(^1.'-*]L:H:R,T9==5B,+;Q%-S/$D]$=55--KMFX[VHF%] MP.EA%:[1?XSD+[[U(;3[QO[-Q.NDO],!-VR]G>SER>E-@Z#/3V02RN?V/4['6+(-.&. MM<(\@]U%2-;=3,*@(V_VW?3F?;5_"C28P09X,,"C O)R+B:PM-<(?V*_(+AX4?*1'3.@[B(N&JR3Q';F,!(#,=%L&M!4&] MQ:NE 747,L*>& "5S31L!/ZI-K,CM>9M98'\C._$9?].90/C$FJ M-,8/*E&ULE5;; MCILP$/T5Q )-7AE3WGM5UG+K7Y5J-D$@CU=64?G$&U;KDS,7%55Z*2Z!; 2C M)QM4E0$.PR2H:%'[>6;W7D2>\9LJBYJ]"$_>JHJ*?WM6\G;K(_^Q\5I^CNTV6-L(!;QNV"M',T]D_R!\S>S^'G:^J')@97L MJ P%U<.=/;.R-$Q:^6]/^J%I L?S!_MW6ZY._T E>^;EG^*DKCK;T/=.[$QO MI7KE[0_6UQ ;PB,OI7UZQYM4O'J$^%Y%W[NQJ.W8=B M@P9$H.D'#0QI[/$L'","$T1@DI$EB,;Z<1S##"N08649R">&E8,A!AGB>0XD M#B<7U8$2"ZJ[2C$LDH BR3Q-$CONFH ,Q#+$XPQ"%$_2G(,2QUVDH$@*B203 MD3DH<;ST-2BRAD3(1&0.2M:PB/$F]/V'D$PZ-< <11RO!3E\AB"=F='F*!(Y M=$"O[1"&OE,\U<$SG2@-'4*P)Q%D2N+XC!#L2O056R+8EVB1,7O4N& 4N@J& MO8F^8DX$NQ,MLB>$2E*'$.Q0M,BB$(HX3(I@EZ)%-H50J<.HJ7F14"+5V M"<%.Q8N<"J"BT"4$6Q4OLFJ/&O]34)(F$Z5@]+^OF+C8MD9Z1WZK;1)XU],)^47$I:ND=N-)=A^T-SIPKII,)GW2]5]W<#8N2G969$CT7 M7;O3+11O'MW;T$+F_P%02P,$% @ UI)72*U((GUP!@ )"H !H !X M;"]W;W)K:^8<(>4A^'*Z>VY?]VC&)R_E^N?FL2BJ MR>_E8K4YG3Y6U=/;V6QS^U@L\\V;\JE8;;^Y+]?+O-J^73_,-D_K(K_;&2T7 M,YEE=K;,YZOIVSL9':PNYLOB]5F7JXFZ^+^=/JG>/LUN%JR4_PU+UXV1Z\G=>-_E.7/ M^LWUW>DTJ]M0+(K;JG:1;__\*BZ*Q:+VM(W\3^OT_YBUX?'KO??WN^YNF_\C MWQ07Y>+O^5WUN&UM-IW<%??Y\Z+Z7KY<%6T?3.WPMEQL=O]/;I\W5;G^VOU]:;[Q66N=K( \&0O<:J-9 #370K8$>:F!: S/4P+8&=JB! M:PW<4 /?&OBA!J$U"$,-ZCEO9BX;;'*8;#'89#_=8O!\B_V$B\$S+O93+@;/ MN=A/NHAG?=:L^!TOEWF5GYVLRY?)NH'\*:]SB7B[M=HZKS_=$;C[]2D>PJW@,W6HNNZ .,Y;JB MJU2D(C_7H#DBTMR\VN2/KP?ZE$J"[TH^PSY%HB]0%+JBKTADLX-HMETVA[4C M\=J1.Q>NZT)@%PJ[4#L7ZMA%B$;N4Z.Q.\UJIR'-U#B&3F,X&P6YT4D0;;/F M7S21J9(TQ^#F&-2D#6''0$ 2AW!I2T1N.Q4H_H=_$^$:M( MHI&$?(G(=R8.!54DYTO"LH0LD]HC"7C2C%D^!#P)"K8(T0;Q JFL8>TE>$H$ M7KQT+EI5=Z7&*:P;CS JT2[ $48E852.85011A5B-"YAERIE5"O;UW-%(%4 MTF12OR*5D6<$)S5F#JJ"*@*@NKB3B.5)SE7$4858O1H']EU0AA58QC5 MA%$-&8T[C51T1ZL)GAJ!YTD)T00\/>8A6!.:--SL1IW^#%6>9'_-'H8A(_$Q M@P:[4M&[4=$$)PUQBO?Q4!7B3?5KJFZ#")H:5=HXE5Q %7NDU 1@/:32WNBT MTJ9'#]UXA&(]9C>L"<5Z#,6&4&P0Q7'E.\;XZ$/U'GTX0I\#]-%!<@0L M)T8,DB-@.7@$&PW2!Y<^Y*6#U(U'&'2 09^1^NP(6$Z/Z3D!R\%+DZCG5RZ] M-1&R?\X)@PXQ2/84CMV?C+E <00N!XI0?$%VTXJ.U[I*GK.;XV8@38Z;FULW MH!2]IR".H.T VCXC@^D)A'[,[8PG$'I0W7P67ZFTJLX0]1Y\>8*K![CZC%1D M3QCT:DS'"8,>%+=D%;6BSBIR_1TGM'I J\_B6WZ?TNKC1\RV929I6:+L-HQ@ M[1'6Y-3 $ZS]J'M1=C$Z!&N?$OA'.B,-UT#+QH9@ZB&F[!Z68!K&8!H(I@%@ MF@Q.2"FE@P.T9' "03E E,F^.!"4PQB4 T$Y#$$YI,8'LM<.A.4PYG$R$)@#V #'HWD=T@,:01[99T>_NWK*'XK/^?IA MOMI,?I1552YWO[.Z+\NJV+K-WFQ'X;'([PYO%L5]5;^LMS'KYD>,S9NJ?#IM M?Y-Y^&'HV7]02P,$% @ UI)72 3VW$6! P ?A !H !X;"]W;W)K MX^VNY O&=&QTO'6?[3&CW[ MY,3+^Y/UESK<2OY'5-!'EOR.U^6N4FOJVIINHD-2OK/C*VUC<+C!%4N*^J^V M.A0E2T\474NCO\TUSNKKL7GCFRT-)Y"60#I"YP,8P0U!S#6,+6?KLUB^\%+V5(X.,)LO!*L6H#7K]2%#FV<1-V;<+J MFQ!BF34@MP9E->C.=X12D#'@"TE\DC&N4"W/B!E;D/,B8XCI"L4@8VS?%XH! M\64)B9XCH3N"G5#&6**>A8SQQ-B7B!ZP\6PZ>#8=K" LW(2+FW"Q@A Z=MF MG NE)N[$PYUXF!.AHD+OBI-F4V6$)PB]9J,GU,>%^IA0(;>A+SFY7];U&]/KK8_KXG1=L30#P1Q<811=L3!]MZ<\HW\99H7VPLCJWU$>+#6,EK92;]U4V=S1:=P\)W93\UJON M\^9XW#R4;'\Z[7?_&ULE5C+;N,X$/P5P?>,Q&X] \= M$F,P>UA@,(?=LV+3MC"2Z)'D>/;O5Z\X-KLX2"Z61%=W-4E5D>+R;)J?[4'K MSOM=E77[L#ATW?'>]]O-05=Y^\4<==W_LS--E7?]8[/WVV.C\^T85)4^!4'L M5WE1+U;+L>U[LUJ:4U<6M?[>>.VIJO+FOR==FO/#0BW>&GX4^T,W-/BKI7^) MVQ:5KMO"U%ZC=P^+1W6_YFR C(A_"GUNK^Z]H?@78WX.#W]M'Q;!4(,N]:8; M4N3]Y54_Z[(<,O7,O^:D[YQ#X/7]6_:O8W?[\E_R5C^;\M]BVQWZ:H.%M]6[ M_%1V/\SYFY[[$ T)-Z9LQU]O)8*M&M82 MDJ6X"(8=Y3$^N>THX0PAS!".&?@V UM#-8'B$52/H#N*L@CS1) G0CRAQ3.! MHFL>SF),$T.:&-%$%DTL:1)47=BBR>5/'$< M8)H,TF2()K%H,D$3.4@&3T*J#!!-:LLRD-U1@9*%1V9I>M1-FB9 D99&27+%$4)HZ*H34]*@(5R2)>:. KMB M"0K9X:4*^YAB5+%P;);59,QVS0"5)&P7+5$F>TQU)[KNXX/GX^HCV6VG-,'F/I M,9!>XGB;&2N//Z,\QLICJ#Q[\\Q >;%8XQ"*V1JY-4(1.7:BC'7,4,?VWIF! MCNUE$&#ZSX+4KEFBE&OA8&P)C+ZYQ.:9I2?8!PS/ '-G?Z 3.;8.C,V%X;F M8F^=9]3-AU"L KMB@ I#4;-$L6V[_M513:6;_7CFU7H;S%=9ZKQN&=G3*?[$H,O_8 >=+Z] M/)1ZUPVW27_?3&=DTT-GCF]'?I=SQ]7_4$L#!!0 ( -:25TBT7T=J$0@ M & R : >&PO=V]R:W-H965T(FP2D;WJZ9UKS M]XS$]"7?_BP>LZP<_%ZO-L7)\+$LGR;C<7'[F*W3XD/^E&VJ._?Y=IV6U:_; MAW'QM,W2NZ;1>C76GN>/U^ER,YQ-FVLWV]DT?RY7RTUVLQT4S^MUNOTOSE;Y MR\E0#?<7YLN'Q[*^,)Y-QX=V=\MUMBF6^6:PS>Y/AA_5)'%!C33$W\OLI3CZ M>5 [_R//?]:_?+D[&7JU#]DJNRUK$VGUWZ_L-%NM:DM5S_^V1O_T63<\_GEO M_;P)MW+_1UIDI_GJG^5=^5AYZPT'=]E]^KPJY_G+1=;&X&J#M_FJ:/X=W#X7 M9;[>-QD.UNGOW?_+3?/_R^Y.Z+7-< /=-M!]&YBV@3DT.#B&&]BV@?W3P+[: MP+4-W*'!Z[S?\G[?#H*V0="S@[#EP[X=1&V#J&<']83OILWKVX4ZS/315+_> M8C_52O?N9#_9RO3M9#_;JO=TJ_U\*]>WD_V,J]Y3KO9SKH*^G>QG71U-N_]Z MD_V\JZBO7WH_\YK._'CWI#?KQ%E:IK/I-G\9;'>+VU-:KZ%JHNNEZ+:^VJP\ MS,ZB)7R QAKA%#@KI!C"%#^^;0+-YV..%(%.() M,CA33&,@Z&:*CTU8;,(V)DS71$"BW4%^ VT:*# >&9(%AT)-4S(!EHYSN^.Q MPQX[Y'%(/-Y![JB?D>]\DG@+0 7.D-1+D*WC,>HX[6.G?>0T>5+F/N_(.4/' M&5"^TV0 $F0K] 2G ^QTP)WV?.)SP/I1$6$6@ E)BB6 M]Y*.I!"'*!3[U&E">%81("4JD#!AHNBBW4&=\K,]&&E$JHEX# MRE@C>"V(GP+J1WN:M] ;Z0$@YC)GQ =0T#Z%Q,^2>3]MJ6.5I1ET!AA-)?T3 MZBXB:^HYLD25]G,?2Q?(DB.6OO2Q=(DL120=_T*6C"./QQ4PY3QBZFLO4]?( MJY!,S+=>IFZ J9#DV_=>EN:*ES>!SU82#BG%5Q)@R@@BKH1"28%*26E:?BM> MWGC4950!,8\!I)RT9 MED@)U4F@-?2AYA<,?2E %T8?R'$'T>;M $'V4+A%$ MGY(K +'\OT:6 D=SED,^RT;.@&P$!655H-&Y!8X[80.LA)I2@:)2L_H!5(*6 MIMH"48:5P="6E:H>H:I4J*RD==II2QTO(:/0T8SDD H]FI$<\B.:D, 0%:Y+ M &FZX[@"D U90H+NZ$[J!HT K4+GBM?-AOJT %! AR !4)6VPHF,4(%K7H&[ M0*C5M% 4:_6.8P,MU*D:U:DTQV) 1;1VFFM>@(X<7;2S$:8(W0+"9"1()9:T'?=1]]C0(&8 MWBX" #*B9T4)A(3"7 LU@$8U )\J3H&PN&ZQL#A2;7YH6 @2#H"TH'\:Z%]H MI;$1Y$A'[W@4C+#P&7#TP XJ8T#Q 3;\7(%6:PO L'-!P(R$#:@1EF(#SB?8 MN6 ,*! 5.'Q0], 3031O$".DC1'$P0!QH&=Q,8! 5'#9IP4AI.@P)IB20I.. MW-%!!WW. 01"0^<<-##.L"P$9K10YAI!K PZ!W$T* Z!H, Y")LMSHS87 %& M6C$$\33PK$31J/JHIX$O"FA8 &)G<@FD J&X,(*(&B2B(8VLCX8:KGWT6',! M&$T++\!8*0D%"35 0ND96@P@$!10/I:$2!UI4("1DE 04 ,%E*T7G )1@:TA MW3\O$!2QAPN]NCA:+KN1":INP":3;HUC (' P+XHI'%Q1M.],[(CY* 5J@R+ MJ@RVO .*1V5!=6!I6 CB[TP!I+2PJ;%"I6%1I2$=+%A!UZU^1R5G!06U:'M% MB_(84&",D?;1=1E!]"@@05 @%'-6>I4.WZ73%0Q0(##PJH"&!132T:@ (TB- M%534 A6EQQ\Q@$!,KVX>VZ#>W*8FR(STE OR:=';>%89 H$!?:./ /[[$(1 M))U<6$%"+9)0]F3UD5#+I8^^PP4(79$!(KW!M8* VEX""B@0$Y(]*J (8A_N M($AZ:V %_;1 /_E!"*! 8%SXZ(D!0)C,O&:E^V&.H)X.J2?=6L> XB$YI'ET MKA!$/S5($"3-E1/$TP'Q9+4.@$!(N>MU@@LH$-4. MZARDTZ4=,?0KOP1"@@P[H;YPYM":MQ&DVP'IIB^58P2%5C@_<(*>.BZ5VJ/2 M Z"J)T$,G*!RCNM72+<",8"JGJ1,$F3']5"4&$ J='2%&1]]);O.M@_-U_C% MX#9_WI3-9Q%'EP^?_,>Z_LR67#]5D^\*7)^K28*NG^G))V3G7$\^H^L7>O(% M7;_4D[_0]2L]^8JN7^O)-W3]1D^^H^M5?D\658[S.U6"5G\:L[ M/KP35'>:OZ48_YF)V?0I?[OX 8O=+F3_M_Y[C\$&PO=V]R:W-H965TJ)"J X&!&98P%W.N#5&(:[SDV(;,O/W(6\9JM;$.%\3+ MUXOZEUNRE\>B_%GMA:BM7UF:5Q>+?5T?SFV[>MV++*[.BH/(Y9U=469Q+4_+ M-[LZE"+>MD99:CN,^786)_EBM6RO;,BEC\?XDJD:>-)1OZO=_HW9F,X/AZ\W[3#E>F_Q)6X M*M)_DVV]E]FRA;45N_@]K;\7QUO1C\%K'+X6:=7^MU[?J[K(!I.%E<6_NM\D M;W^/W9V0]6:T@=,;."<#X)\:N+V!:VK >P-N:N#U!IZI@=\;^*8&06\0F!J$ MO4%H:A#U!I&I0:-YIQPS-CF)#<8F@]Q@K#<,@H.QXC!(#L::PR Z&*L.@^Q@ MK#L,P@-6WNZ>J_:I7,=UO%J6Q=$JNU9RB)N.!>?22CIOKK;/>7M3/IB5O/JQ M@M"#I?W1N.JARPYR1I##0I6YTAGIR%&A-0FY*G1-1%.)&RJ?2&6^Z Q7B5O" M"S"5N=,9%Q7G*^4&,=\H!@WJGF)0:1YF2_,XG_"3CD1(S,ULG.<9)6TYZTY3 MSZ&GGM.Z"%07G';ATB[KP4W4,(%N.\@?,T@+ M,FNL!05I6IA ][,)/5!N.!K7(UE&%.N)'%I Z^[1NGO4 ^:CUN]I8^*,T6%\ M.HQ/A0E08?RYTCW-$AN=@' JUX#.-:!R10WT(=!+$N)6K3,N7E6?",9QZ'1# M.MU03S?"4ZYCO'&4*&#-'RJ?#@+W?)54DHKHI"*JAF@%WT3:] 7G;+2:*8&: MW2:YOV%$*!^-Z[JGE#IS;?$U@#8SD)KSU)X,M)PC!V<,A!01V*; M0^ MQ9]XCF%B"0;^/_9+,-'/@6SHJ-.N0>_H 1+UF6!D8YDJS$3?!Z+QX^ZT[J'Q M] FI[O1,@.!Q]Y/V!!,]'L@FKY4@H#H43.DZT:"!Z-!:AUKWE#(/?8X3^ASJ MTK%'[X:'^$T\Q.5;DE?62U'+%\WV77!7%+60#MF9K.5>Q-O322IV=7,8R..R M^YS3G=3%8?@Z=?I$MOH#4$L#!!0 ( -:25TA7[EZ,:0( .X( : M>&PO=V]R:W-H965TJ M?:BTVH?VV4F<@!8PM9VP_?O:AF2Y#+O9%\#F7&8\@TW:4O;*T*%[69I7KNF64I MO8BRJ,DS,_BEJC#[MR8E;5 M=BA0$(WX79"6#YX-%?R>TE%+*5YH^X/T.>@(#[3D^FH<+ES0 MZD8QC0J_=?>BUO>V>Q,[/0TFN#W!O1.0_R'!ZPG>HP2_)_B/$H*>$$P(=I>[ M7KDM%CA+&6T-UI6[P:JKT%,@:W-0D[H4^IU<.RYGKQF*0R^UKTJI!ZT[D#L& M^6/09@YRQXCM')'$8\CN(Q%;)G+/Q@6S<34]&@<:P H>J.!I!6^L$$[6HP,% M&E1K4.C )CYHXD,FT<2D \4#$^19[D(R >@3S'T29U*V#J,^IKN/EUB38'8 M"OF!%<+1A& T(9!UD$R,PGG6KN4AV"<"?2+(9Y+0I@.% Y_)PFP_1>SF"!0[ M"XT0@Z'&4"/$L$("*B1?Z'A5/F@+<#YODW4/&O:\NY J6MAIT /U7_>H2=L[ MT8(5O T@]X$66/>H8?W<<*'3$+Q;(&"[B)8DX+T ^5^I(/R=(^!#G^]:/6I8 M0G]:0GMP;C3X3'YA=BYJ;NRID$>0/BA.E HB]1Q+*N7RY^,^*,E)J,=(/K/N M..X&@C:WOXO[+T[V'U!+ P04 " #6DE=(E#.\F[,! 8! &@ 'AL M+W=O&ULA53;;ILP&'X5BP>HP82DBPA2TZG: M+B95O=BN'?@!JSY0VX3N[6>;0%EG:3?8_OV=?**=56JT7(FX5DC M,PI!]>\S<#6=DBQ9"B^LZZTOX*K$*Z]A J1A2B(-[2EYR([GPB,"X">#R6SZ MR&>_*/7J!]^;4Y+Z","AMEZ!NN8*C\"Y%W+&;S?-#TM/W/87]:>P6I?^0@T\ M*OZ+-;9W8=,$-=#2D=L7-7V#VQ)"PEIQ$[ZH'HU58J$D2-#WN64RM-,\LUMH M<0*Y$')T W84;:E"M1AG>PZ:Z/H(' M$H[^ UZ5 ^W@!]4=DP9=E'47*!QSJY0%%R2]! M5?0?4'4$L#!!0 ( -:25T@);[SQIP@ ,_ : >&PO=V]R M:W-H965T^ZMMOG+^/QYNZI6\XV/_7/W6KWRT._7LZVNZ_KQ_'F>=W-[O>%EHNQ M-2:.E[/YZN+F:G_L]_7-5?^R7_KT>9EN9RM_[OM%OWK]05=O!WX8_[X MM!T.C&^NQN_E[N?+;K69]ZO1NGNXOOA*7Z;D]IJ]Y,]Y][HY^3P:HO_6]W\/ M7WZ]O[XP0Q#=HKO;#G7,=G^^=Y-NL1BJVIWZGV.M/TXZ%#S]_%;[S_OV[N+_ M-MMTDW[QU_Q^^[0+UUR,[KN'V_LY7^[^OAU^R.1;#!>RQ@'TO0/'# NY8P/THX#\LX(\%/"LP/C1E MWQ'3V79V<[7N7T?KP^5[G@VCA+[X75??#0?W/;O_;=<5F]W1[S>4D[L:?Q]J M.HIN#R)[*GI7C'?5OY_#HG/<6E'%B#W]?@SFL(K*L.HK@7K0XB7R+KT E0)?*1-1FH0BY*UP<814C"LT4#D++_,0&1-P@$G&'!"35:&2H8U9-3DPIJ<9:"17< ) MT#@V8*92$Y3F%AAL <%FUO6W19SDLO!@@8:(530%(J\,R &W"#@&!4R<.$:< MR'-H (V+?#PAD5$"5@A)*&#+ R;9,\%X'C)0>>+S'M:5E2%,D+E?R105XO5R($I$WC04D2&$@]:JKS7A@=>%0@M M"]GSF+TX40QB0$M1."'7,610DW-*R'A1H(!"YBO9477>@Z*;@:CPB*5&'1=X M#2*P"/%K>4MH$;*BCX$J)#$#@&+:#@06;X$ ='I\#L/&9/&(M*XHM2!26-;2&,Q:6P5::RD@X]B MZPQ4T? -S!2H@B%E<7&8-*Z%- Z3QE61QDD^",("C?4<-$BDMAJ#Q@'0.&TK M[Y1;ZA;0. P:5P4:!^#@ O&^0PCA]T)3I$JDS#B'0>-:0.,P:%P5:!S Q\/ M$R02&T M:;G'H/$MH/$8-+X*-!Y!A*=C@,@%WFXH4N:*QZ3Q<$NC+.P>D\8W9>^4]%U= M_@[<7O&[N0D0A<#G&Q0IFV"/,>-;,.,Q9GP59KR$@]C. (T7C08W3EZ[3A@R M'D)&V.K(./!O0[O-RFQO-M0\DW)\V*XA!:X! R74 67@')8 MA0V$"5(%GF.8(E74DK4!\R4@OA1EH@7,E]#"EX#Y$JKX$B05*!C#5R4D2[M_ MO/]0;<5H0T=Y1M!"F8 I$ZHH$ZJ>$R"5?%" 5.J3@H!1$Q!JU JR!^X3*%*RS-$#)O8]$12>219]TP2 M;5=X7@^)Y#-)=.>DI-PC)DV$I-'JP*2)+:2)F#2QBC2Q*D4#5"!% U1ZBB9A MTJ06TB1,FE1%F@12-#S- #16S!4DTI(,"8,F0= HUSMAT*06T"0,FE0%F@13 M-'QU0JK(9^44J1(ILR5AT*06T"0,FE0%F@3PP-.\$R3B#P"G2*3Q-2GN!P@: M;;IAT*06T"0,FE0%FH12-'+"P10-!PU2J2F:C$&36T"3,6AR%6@RX /WADR MR(E;;BA2+GC&I,F0-%JS,6ER"VDR)DVN(DVN2=$ D4S10)&R&\P8,[D%,QEC M)E=A)H,4C3 <@>T,W_H##7EE9QV.&* A MX=22&LVIA>E26NA2,%U*%5T*RM%XWFBD"B+UC531*A>J8, 4"!@ESU,P8$H+ M8 H&3*D"3)%8N/0<,$AD^9!!(E( 4S!@2@M@"@9,J0),D6#@]]B?2Z8?2LZ# MQ7 I$"[*+JA@N)06N!3%6%D%ER*A(#KM4\GT0PES56JVRA:XD%&\CJ8*+V^R M\^0;:S84\89#D6HH5:R.!M"E&+4#%>^A:>$+&<4-:*H(\R;3P/#6@PA$H@=1 M55K4F#&'X_6#1W'IF2K,O,G.<]NBZ5(D;&:H(H439!23G@&T41/H9!2;GFGR MZ1G%J&?JG'KF<^14:*8?:Y@S6H$.-4%'-5C700?8H@5S@(;O9S[6L(@5XB!W M=3'*)IHTMS,U$4?S'T,#LAPUP#=\*;OO<]$4BK0)HSF0J0DXFBT8^8+1P &< MX,\KD4@:6U%-ZE57B(-\P<6H(U A3ILS6+,&5WJ#@:&7KT,3*)(=6,\C77'%&TQ-YF!2W,%49P\F MX.D5*]7GFNG'&A:Q IPF:S IWF"J,P<3\O2*=@/>B'9_I&$1*[1!WN!BE/0@ M*>9@:G('DV(/ICI_, %3[Z45O$8J$FL]4FFO<2C^8&HR")/B$*8ZB_";[/2E MS\L@=L=0)88/5/&+-CYY4WC9K1_WKUQO1G?]RVH[O&][ZO=GC3F!V_ M'=[WWK^!_*.:FZOGV6/WVVS].%]M1M_Z[;9?7@]O&S_T_;;;!6E^VEV:IVYV M__YET3ULAX_#\YOUX17MPY=M_WQ]?.7\_;WWF_\!4$L#!!0 ( -:25TC% M?"9>G < &0Q : >&PO=V]R:W-H965T*3=M")-&5Z#C]]Q4EQ1'O_492-G[( M9\C#X? [,Y?CZ[=V_77SW#3=Z/MRL=K9C^]*LMG]Y M;-?+6;?]=?TTV;RLF]G#KM%R,;%%$2?+V7PUOKW>??9Y?7O=OG:+^:KYO!YM M7I?+V?J_NV;1OMV,S?C'!W_-GYZ[_H/)[?7DO=W#?-FL-O-V-5HWCS?C3^:J M3E4OV2G^GC=OFZ.?1[WY+VW[M?_ECX>;<=%[:!;-?=+S>[KZ/YUT[7+'TW&H^7L^_[[?+7[_K;_2UDVA@WQN8 M>+*!.S1P/QOXDPW\H8$7#2;[2]EU1#WK9K?7Z_9MM-[?O9=9/TC,E=]V]7W_ MX:YG=W_;=L5F^^FW6U,5\7KRK3_2072W%]ECT;MBLCW\^SDLG>/.JN9V>(*I M5C@SE-1:4I5LPN&%NEW[=-0^E)FK\'@ OSN &_94$CVU%\6=:+6_D%B&0EPN MJ,HJBEZOM@\QG@O+(/(^B _$X)R2*,EGED2E9<,5&J[(L*#'7:5.$^4MF&I-<.+AK;7&%$<' M&MCMPX1P6I!A)WE:P)G$S9Z22#P)-6AL9D"8#/^--NQ\[J*1[Y^,O9RMANEL MW"5T/:B.+["93XJNH$IE*9!7 MD\J%W(5S)EC,! E7"[1/,DM)5,I 0%'.,N>!Q3R0<+6:XI6OI&4M2H6R#'F0 M0UHO!K&H,DL M&RVG@H54<"ZSDG,,:U=<#EK'K'8PF]:@/:@&"Q9O9?J#JO1.K@!(YLTSI79LY+ZI&1HEB/!020XG^,C8]I5ER/6,Z4] M55AT'5871GSI5!T65)67" MQU20B/7 \D*N"T%D*CD)(%&NVNTY%3RE@D*LURS7(P.20]7G09-YI'SFE0)& M@N2KUR W2?(516HD@\AE4LQS)'B,!,E7KT&N>OBLI#XI&9KE,/ 8!I*O_GP8 MG)?4(,DDE^_ D1 H$A1? X!<&CXKJ4&2J;6@H%S(6 N*,("\65A MXP)-31K'?B,G0L1$4%L)*!&$7]!X*U?;( HI\SQ%#H1(@:#H&BD0Y!H!1+*' M09*SRV$0,0PD7R.\5%!NJ1XD[6J-RPS@R'D0,0\D7R.\!*B481*IO26_\#HA MDU+3#*93(D<"!$#0:(U:H@K,UJ2FY1&IGS$MZMJ_&LZ?\CAD5 R#JK(YS\RP=-$6F0334669JM[2,!6],WX98HD@ID!.JENDD4AD,(I\K@R:& M<[IHHEC97A-SG:B[YL MUD^[3?V;T7W[NNKZ'=U'G[[_X\ GV^]E%Y_?F:MZO_W_YV%NKU]F3\V?L_73 M?+49?6F[KEWN]K,_MFW7;#T6'[>]^=S,'MY_632/7?]C_^RM]_\$L/^E:U]^ M_$_#^S]6W/X/4$L#!!0 ( -:25TAO_2)AQ0< #4S : >&PO=V]R M:W-H965T3#S,$#1 MAYEG-5$2H[:5VDK3^?N19,>U>/:)J9=KZK=E]WS_7=3O[M5EO M]S?SY[9]N5HL]O?/]:;:?VI>ZFV7\MCL-E7;_;M[6NQ?=G7U,&3:K!=*"+?8 M5*OM_/9ZN/9E=WO=O+;KU;;^LIOM7S>;:O=?4:^;MYNYG+]?^+IZ>F[["XO; MZ\4IW\-J4V_WJV8[V]6/-_//\FHIA>\U@^2?5?VV/_M[UK?^6]-\[__YZ^%F M+OI&U.OZONW+J+I?/^N[>KWNB^JJ_G$L]7>E?<;SO]]+_V/H;]?^;]6^OFO6 M_ZX>VN>NN6(^>Z@?J]=U^[5Y^[,^=L+V!=XWZ_WP,]@DP^+0]V'D MRJJM;J]WS=ML=XCW2]5/*WEEN]C<]Q>'4 QIW=CMNZL_;V64[GKQLR_I*+H[ MB-2YZ*18=,6?ZE"HCCM%LJMQ!255:#F6+*DD!MP(#3NJA_Q^W%&/2S"P!#.4 MH,]+4,(F0W40N4&T/8A,=#KI+U!Y:9)A7P*5#9$9>@O;;$F;34A:?)#8LUJ4 M"ND4*('*2LNTQ<&V.#I^43(Q]+ $/R&& 980,F)8 %'TR:@%,A[:IJ(2B()* MQG\)1$X+W*D(.Q4O!KF@$MJE2!H21-K:DHJ\EQJWMB91,^*F"FF; M@19 T16ZS2,0&09GV@PA$R&TS'4 MP\B8;(^40*2Y$!@,,P-]#N.5#*:+F>)S#*:"R?(YAGH3'6,Z*E1DTLV8)1!9 MPW6;V1K*,#F&VA<9R<80%2G.GA@,,P,M#O-L-)@N9HK%,9@*)LOB&&I,C$CO M1B2RZ08A$D6NR1A")L/B&.I>J"=#(F[U9S#,#-JR44Q_+*:+G6)Q+*:"S;(X MEAH331P#$!F=KCF0R##/(XLA9#,LC@7NA6YZ I%FGM,6P\Q"B\,\)"RFBYUB M<2RS$9QE<2PU)CJD3A6(C!1I&(&( YG%$+(9%L>"S1IET\< 4AG+#2#&F84F MAUD+6\P7.\7D6,P%FV5R+# YZ6JB1*)TA)=(Q,U?AS'D,DR.H_[%DL9XS 6?97,\-2?2IF^,D,BE;A66 MQ)ATCS'D,VR.IPZ&O&$P%GV5S/# G)(K@ MM93P:13!1@[7:8P@GV%R/+4OZ9T()-S ,:_6D;W1S+WL,5?\%'OC,0]\CKTI M@$H)F0X;=2YDV"Y*EA]*QB<.,)W"9?=3 WM3Z#N)^W/AY)Q8S$& [1'S&9( MP%P*4^Q1P#P).?:H#,#4Z#2 0&0\HO9_XB8 M7W'*>BMB8L2<]58!5-'J=.0H$%)KC"2I"00:SXTM!DN\O" K@ ;TZ" :'1E- M-U& AKNCF>.&:,G&;=%*P1T"G+)HDX(Y!BAREFW+=YF#D4YJ8@X+"G7*##(Q MQ_H$6A8E\Z? *L,=@!/,\3]!84$\9(%475WHG2$0+)"JJXM9O_3?,>"Z,K!1(%575VJ2%V='\#?U[FGX^&$_NV]>MVU_ M//GLZND+BT+U1_B3ZW?]EQ?@>C\GK\I^8M*T?E+U:1JGF3[-X#3;IUF;DY?J1R^E+F]G]02P,$% @ UI)72#HI MP),\ @ @0< !H !X;"]W;W)K69K0BZBKEKPRBU^:!K._&:EIO[-=^Q9XJ\ZE4 &4)FCB M':N&M+RBK<7(:6<_N=L\4@@-^%61GC^,+>7]0.F[FOPX[FQ'62 U*812P/)U M)7M2UTI(+OQGU+POJ8B/XYOZL\Y6NC]@3O:T_ET=12G-.K9U)"=\J<4;[5_( MF,):"1:TYOII%1IW/WR)G)$&$[R1X$T$=_,EP1\)_IT0 M?$D(1D)@$-"0BBY$C@5.$T9[BPT_K\-JC[C;0):Z4$%=6?U-EH++Z#5UXV"3 MH*M2&D'9 /(>01,"2?EI#0]:(_,6=&^^P'Z)\-TY)%]"X@@VX8.)^IH?SA,- M884 5 BT@C]7B(Q2@:#82'<)BN.UD2\DM'9@OVO0[QI2,,J:+4%Q'!AV02'C M%^;?@&9^-Z#?#:3@&WY!D&D8 #F^H91_ YH9#D'#(>3%^(\9"#(.V/Y_0#D( M^F0'1Z#A"%(P=_ BC2H'4[KR@D-PTN0O_),PY"29U88/=Q4#6%G?>5SJZ"7 M5JCS_A"=NLJ3IVXZ(Y[);C,TA[M,FG3X3'YB=JY:;AVHD/>HONU.E HB/3HK MN6]+V0^G24U.0@U#.69#BQ@F@G:WAC=UW?0?4$L#!!0 ( -:25TB)/ C" M2 ( (( : >&PO=V]R:W-H965TW; "6@!4]L)VW]??Q "MC>Y!&S>=^:9"7C2 M$>$/4D-(K<^N[KBD==HY#RAIV@+R@ ?;LR0GA#E"VQ&>'#!B"2IBZUO%= M-W8ZT/1VEHJ]-YREZ$+;IH=OV"*7K@/X7PY;-.YMS[YMO#?GFO(-)TN=V5Q)@WH+P]/>?O5V1<(50O"[@2-9W%N<_8C0!U_\K/:VRQ%@"TO*(P!VN<(# M;%L>B"7^.\6\I^3&Y?TM^G=1+:,_ @(/J/W35+1FL*YM5? $+BU]1^,/.)40 M\8 E:HGXMRF0W^9/!G@Q<_- 23(;@;PH>& M<#*$BL&1I8A&%(""+,5HM+#\\P; WQ%O%[)6EWQ3=%8\8ZT@;/>:>4F4I,Z5 M1YI$N13Y2]&L<%CX.8=ORI'[FMU?)SCHBL!;2PI=DFS-$(&QT$#X-ZM"8]<< M(31&"$6$8!U!P@*W\P9&3DC$Z?2\5R*HD6.;THIA^>2 MXJ%DA1H;46,3JM*./-:2J*_/4T6A*[[@W!@Y-R;.4.'T*(0D;HOK FUFP@SXL6GBB_W;![+&>47% TW";N//:S_U!+ P04 M" #6DE=(D)"0=?T" !X# &@ 'AL+W=O&ULC9=?;YLP%,6_"N)]@,T?FXH@-9VF[6%2M8?MV4VOX\!/+2=6SXL^6MN&Y" M%-X&?C3'DQH'XKJ*YWG[IN.];$0?#/RP"1_1PQ87H\0H?C;\*A?GP=C\BQ"O MX\6W_29,QAYXRW=J+,'TX8T_\;8=*VGR;UOT@SE.7)[?JG\QR]7MOS#)GT3[ MJ]FKD^XV"8,]/[!+JWZ(ZU=NUY"/!7>BE>9OL+M();K;E##HV/MT;'ISO$YW M:&*GP1.PG8#G"2DQC4\@T^9GIEA=#>(:#-.S/;/Q%:('K!_$;APTZS;W=*-2 MC[[5J"Q(%;^-E:QH.XGP4C0K8EU^9F"(L<7KZ65!X0HIV&5J*I#["@E<(0,K M9*9">E^A=-:Y%A&4P90Y8Q.AMR20*#< MM4NR?C\HSSTDCR\11"I<$EJ1"D(\YD2@.Q\1ADBK", K4H9+SS>'8!4 BB8N:E*52U02+=[4/0IV/8)L3UW; M6]4=BD29[Q.&G8\@ZU/7^E9UAT(1]:%@]R/(_M2UOU7=H=*(^CYB. 0E #4 M30"K+Q##&8"A#*!N!EB5\P5Z0@W#&8"A#*!N!D"J)/5\ZAC. QE '4S M %;YGAZ< 3B%:KC^!56EYQ\IAI,"0TE1NIZRJF+YGCP8."4PE!*EZR>KRO\# M R<$AA*B=+UD5?]:3;S8&79\.)H-L QVXM*;_?9B=-YD/V*SL_R0U]69'?EW M-AR;7@8O0NG]J=E%'H107'>21'JI)_TS8+YH^4&-IT2?#]/&>+I0XGS;Y\\_ M-NJ_4$L#!!0 ( -:25T@/LJ4): ( (4( : >&PO=V]R:W-H965T M"1%!FI!4[:+2:!:=M4.<@ 8P MM9TP_?OZ00@8EVRP?3GGW'.QY4O28?))"X28]557#=W:!6/M!@":%ZB&] 6W MJ.%OSIC4D/$EN0#:$@1/DE17P'.<"-2P;.PTD;$WDB;XRJJR06_$HM>ZAN3O M#E6XV]JN?0^\EY>"B0!($S#P3F6-&EKBQB+HO+5?W?26NG$<). FE'I0ID#>�@ )GD,,<$J_-)GQCH;[DKR:%1HY9(3 J!%+!GRIH-C,%BB2H42!? M*]8 T;['81$RL1H:K88FJUJ23('"49)ONM7GD,,B9&(U,EJ-3%:U)%DT2^(Z MFM4Y)-:<+B$F1E=&HRN#T3B>N(FU>";ZIR'^&F_VL2'._6WVJN&"1^(T:>$%_8+D M4C;4.F+&.X.\O\\8,\3+F*SXGJDFK!<'MO^L.?1_H/ M4$L#!!0 ( -:25TC>]ZD$$P, -H, : >&PO=V]R:W-H965TZ:)DZ "SF*G MZ?[[M<&A8 ]5+P',F_?&$\_3D-]8]\K/E KGO:E;OG;/0EP>/(_OS[0I^8I= M:"O?'%G7E$(^=B>/7SI:'OJ@IO:([\=>4U:M6^3]VE-7Y.PJZJJE3YW#KTU3 M=O\VM&:WM0ON?>&Y.IV%6O"*W!OC#E5#6UZQUNGH<>T^PL..! K2(WY7],8G M]XY*_H6Q5_7P\[!V?94#K>E>*(I27M[HEM:U8I+*?S7IAZ8*G-[?V;_WVY7I MOY2<;EG]ISJ(L\S6=YT#/9;76CRSVP^J]Q IPCVK>?_K[*]XCI-^3Y< MJ[:_WH8WJ:_#\ "B \@8 /&G 8$."#X"PD\#0AT0&@'>L)6^$+M2E$7>L9O3 M#?_>I52'!!Y"6>J]6NPKV[^3I>!R]:V +$MS[TTQ:=!F )$I:$1XDG[4()C& MAECA9"ZPM1$!S"$[&S)) ,"HV*IZ5;.C*XN4"$M#TL& ?@S@'Q5QI? MH])IKL%JH8\ =QA +<;L?8W*YDI+;@BXRP!J,V;3:M1,BJR2)2G<'@#U!ZMM M,TS*+/-6PV9E#E<&V0Y#P0HR/&^"VPU![<8T 8TR\HZ,2FXU[&O'@^"N1%!7 M,EV V'ZSX ($-QN"FHWI AJ5+NY[+H4;#L$,!X@IA:("0\F;3( -[4[]*,V= M/;NV0LU1D]5Q7'\D:H(TUC=RC!^&[@^:(K^4)_JK[$Y5RYT7)N1\VD^11\8$ ME4GZ*UGPL_S0&!]J>A3J-I'WW3!Z#P^"7>Y?$N/G3/$?4$L#!!0 ( -:2 M5TC-!C=\& ( !L& : >&PO=V]R:W-H965TP^;#*9A]UG:FDU ^( K;/_?@&MM4CFI<#U MG'//O95KT7/Q(6M"5/#%:"NW8:U4MP% 5C5A6+[PCK3ZR9D+AI4^B@N0G2#X M9$F, @1A!AANVK L;.Q-E 6_*MJTY$T$\LH8%O]VA/)^&T;A/?#>7&IE J L MP,0[-8RTLN%M(,AY&[Y&FT-F$!;PIR&]G.T#X_W(^8M5KL_8DGVG/YM3JK69F$8G,@97ZEZY_U/ M,I:0&L&*4VE_@^HJ%6=W2A@P_#6L36O7?GBR@B/-3T C 4V$*/N6$(^$^$%( MOB4D(R%Q"& HQ3;B@!4N"\'[0 Q_7H?-.Q)M$MWJR@1M9^TSW0JIH[<2P2@I MP,THC:#= $(S4#0A@):?0F/+S^L!Y;%3U&$)6L/4[S?S^LU\?IVN[+)%EC19.W:7F'SMU'U88A*8 M.V[![ XQ(BYV&,F@XM=6F3=Q%IWFW2LR=]")[_0<',;60Z8L.GPAO[&X-*T, MCESI&V[OX9ES1;1%^*+=U7I23P=*SLIL<[T7P_ :#HIW]U$\?0_*_U!+ P04 M " #6DE=(SJ'=9G " ![" &@ 'AL+W=O&ULA59-DZ,@$/TKEO<=_/Y(&:LFFJW=PU9-S6'W3 R)UJBX0,;9?[^ MQAA@,I< S7O=KQM"FXV8O-$:(69]=&U/MW;-V+ !@%8UZB!]P@/J^"X%&2NA9XCA.!#C:]G6?2]D+R#%]8V_3HA5CTTG60_-NA%H];V[6O MAM?F7#-A 'D&%MZQZ5!/&]Q;!)VV]K.[V;N.@$C$[P:-=#6WA/@#QF]B\?.X MM1VA ;6H8L(%Y,,[*E#;"D\\\M_9Z2VF(*[G5^_?9;I<_@%25.#V3W-D-5?K MV-81G>"E9:]X_('F'$+AL,(ME;]6=:$,=U>*;77P8QJ;7H[CM),X,\U,\&:" MMQ"BZ"'!GPG^0G ?$X*9$-P(P4-".!-"A0"FW&7E2LA@GA$\6F0Z[@&*6^5N M0GXVE3#*HY![O':46]]SSW&3#+P+3S.HF$#>"N0N",#=+S$\4XS"T^C>?8!2 M1_CN/62O0]+$+,(W)NI+?KS.(8T:9*Q8L)%*YB?%,J7AH@BI?]0R]W4B.CU,@DU5>D1EJ0 M0%'Z)6*O(WRSSMBH,S8?-E5QB38=:=1VAYJ(C/KG&B3&7Q)2+ MHJ)(M"NHG$JI(]1_K([X1&=JU)DN1(T@GG[36^9\?0([(VB%F@*!U?O9(7*6 MG8M:%;[T3+P/*^O2'7>>>'\5>R&ZIL'^G&[*U&#G^C;EU&;!+7">#?",?D%R M;GIJ'3#C_4"^VB>,&>)I.4_\/M3\2V!9M.C$Q#3F&PO=V]R:W-H965T4UW8\,:/E KOHVM[OO*/0IP>PI!OC[0C/& G MVLLW>S9T1,CM< CY::!DIXVZ-L11E(4=:7J_KO39\U!7["S:IJ?/@\?/74>& M?VO:LLO*1_[UX*4Y'(4Z".LJG.QV34=[WK#>&^A^Y3^BAR=4*HA&_&[HA<_6 MG@K^E;$WM?FY6_F1BH&V="N4"R(?[W1#VU9YDLQ_C=-/3F4X7U^]?]?IRO!? M":<;UOYI=N(HHXU\;T?WY-R*%W;Y04T.J7*X92W7O][VS 7KKB:^UY&/\=GT M^GD9WQ21,8,-L#' DP'*OC2(C4'\:9!\:9 8@\0R",=4="&>B"!U-;"+-XRW M=R+J3X(>$EGJK3K4E=7O9"FX/'VO<81Q%;XK3P:T'D%X!D(3(I3N)PX,<:RQ M8VX1;%Q$C&XA3RZD+. @8C#16-OGMXG&L(<$])!H#_&-ARBV2C6"4@WJQU+% M\4*U4I FA6@2BR9U:+ZAS"K9!@ 5J556%Q/!P69@L!D4K,6QSMPX<)+"-#E( MDT,TF463.S09SF"6 F0I();<8BG<"TY3N_( :/%?4(*QE% LA15+>>_E*>F# MFC^"6$J[^R,W&[S4?&A!9A#0?FBA(@B4D4>$[VE @RKFT28!SA>H8+% \3U- M:%#EG"H+\@510;"J(%!6[!8RJ!NJ=#DK6%D0*"UV&QG4#5441 N=A&!=0* P MV+UD4#=4.$!61!L#N_=*80E!H(;8'85<$5EJ*5A#$"@B3DL5;D8H*/$"%2P1 M"-((Y'R[(11.+*9P-B]T=#CHP8M[6W;NA?KJSDZGX>X1JWG#.E^KH4_/(9]N MZNI$#O07&0Y-S[U7)N0THV>./6."RB"C0!;\*,?2:=/2O5#+7*Z'<5 ;-X*= MKG/G-/S6_P%02P,$% @ UI)72'5+\=00 @ #P8 !H !X;"]W;W)K MR2ROUVS>+3C/N&>I[9\7W:O8-H^HN MDV<=.N/?B)^;5GA')M6M-G?OQ)C$RF#PI+S5:CI/!X)/4F]7:L^'@34<).MN MXW?Z!N3_ 5!+ P04 " #6DE=(=NL![QL$ "^%@ &@ 'AL+W=O;7:K,=G M7YO-NG[OBKPR7QNO?2_+K/GWR13U^7%%J\\'W_*W8S<\"#;KX!*WSTM3M7E= M>8TY/*Y^HX>M#@?(B/@K-^?VZMH;!O]:U]^'FS_VCZMP&(,IS*X;4F3]QX=Y M-D4Q9.J9_YF3_N0< J^O/[-OQW+[X;]FK7FNB[_S?7?L1QNNO+TY9.]%]ZT^ M_V[F&O20<%<7[?C?V[VW75U^AJR\,OLQ?>;5^'F>ODG".0P'B#E 7 )(_3) MS@%R:8": ]32 #T'Z*4!T1P060'!-%GC5+]D7;99-_79:Z;^.&5#&])#U"_F M;G@XKMWX73_9;?_T8R-"D:R#CR'3#'J:0.(6E-Z"GA%(AK>@%P"Z17QQ$9)N M(5L7DOX<<="7>ZE9P)K%&"]O1THX@X09Y)@AOLI :13B# IF4&@,UER\N""B M*,(T&M)H1",M&A<4D\(L$62)$(NR6%P04@QI8D2C+1H71*%.,4T":1)$ M$UDT$TB/H&JB818FA20I("%;+1,HNB)AEF4P3R3N$+"$CB812L8,$V,CA'(D M-A-$,8M#6+R$U*N?V$4$[@A MI'V[J[<()GW!'7JQ0PGD/2JUBT HS72 Q XED?=HVS=FU+*-4V*'DLBA-+-Q M2NP^4MS1\Y+Y/8 \0]L;)T#Q/2^QRB54N=WS ,7VO,16(-%/!Z?G9Y3E7 GC M7!([AD2.H;GA8B^0\3VKB&4N%YT5I'M68,[*$@M1+CHJ0!0QS:*P$-6BHP)& M,4NHL! 5/"K8-2GWJ* 9&JQ5A4X*VFY*@&*[7V%!JT5G_QEU70_C/8IY"P#5 M[-2C7)&%?LAL[0KK62$]:RX'%JJ*[GGO@86JT*:M[>,!0*4ILS[Q#77>F MSQCZ_8(?3;:_W!3FT V7<7_=3*]7IYNN/GV^+;Z\LM[\!U!+ P04 " #6 MDE=(>Y'&UL ME5C;;J,P$/T5Q <47PB0*(G4L%KM/JQ4]6'WF29.@@HX"Z3I_OV:2RC8!Q3Z MT( Y,W-F[#,VK&\R?R_.0I369YIDQ<8^E^5EY3C%_BS2J'B2%Y&I)T>9IU&I M;O.34UQR$1UJHS1Q&"&>DT9Q9F_7]=A+OEW+:YG$F7C)K>*:IE'^;R<2>=O8 MU+X/O,:G5*1_[9.OV)6AOWKN_?O=;J*_EM4B% F M?^)#>59LB6T=Q#&Z)N6KO/T0;0Z+RN%>)D7]W]I?BU*F=Q/;2J//YC?.ZM]; M\R0@K1DV8*T!ZPQ<=]* MP:\,VA*YS3,ZKR^166T7>?R9N7-9%RB:L[IBJO* M[:O!NE#U,Y59H48_MHQX9.U\5)Y:T*X!L1Z(=@A'N>]B,!1CQPQS%8,.8X00 MQ' 8#E/AM0=_Z(%C#R[TX-8>>#]/O\>AR:8!>34HJT&N7K#0Q!#,8P%Y+ P> M/M=8-)!%+\*"!QH+$^,'F(8':7@ᖁR/B305I>$Q"!CQ\R,-'/!;80P ] M!#.6QA)Z6#Y2BZ4Q[<;*6!JU\$:61M5]D& )8N+IBB7F^A@),](7* KCZV&H MD;&V4,-)R) )[![/E"$F@Z,!4EQ MDZ!FEV#$-UKWPB@_)?JBQ*#)VN".05'+\$ MO#!HLC:X@U#40OR1'8YA\3,RHS8,*YM!9>NMC)FR-4HSC1ERP=IF4-MZ,V.F M<,=2QI)E4+)Z,VM1@W3TC*<@0R98^,P\8IC-+&Q1#WB MYTCT1FTX$#31-W0,FJH-Q^+GIOBI'W@C/D;._',._1QKDC]T[.?3Y_YA(*Q' M_L"YGIMJ#(P9,+?K,2)8L=Q4K-K2QE8E5BR?HUB.%WE-2NK-\_>:/<]XIE5[]3:^(ZNPN:KPI>;[?H2G<2O M*#_%66&]R5*]L=?OU47E_JFD M^UZS_0]02P,$% @ UI)72$)WG]QM @ NP@ !H !X;"]W;W)KUBIZF'W["1. M0 5,;2=T_WYM0VAB3]H+V.:]-V_&X"$;*7OC-2'"^>C:GF_=6HAAXWE\7Y,. M\R%U^94"[7@Y9FW\ Y-1WK>T-YAY+AUGX--%?@*HA%_&C+R MF[&CS.\H?5.37X>MZRL/I"5[H22PO%U(2=I6*:DI.W?YB!JZ=9WG0,YXG,K7NGXD\PYK)3@GK9<7YW]F0O:72FNT^&/Z=[T M^CY.3U)_IL$$-!/00@CB+PGA3 @_"=&7A&@F1 ;!FU+1A:BPP'G&Z.BP:?<& MK%Z28!/)4N_5HJZL?B9+P>7J)4=^DF3>12G-H&("H1M0L" \*;_$0%", EET M=!^@M!%A< ^I;,@ZA4V$8**AYB?WB3Y0B$"%2"N$]PIKHU03*-:@?@89R=H0 M U'9B-B'G:Y IRO :6H$*2;0ZB9(8"13VI X-:P"*@BV&H-68\BJL?=%; 0T-)RFWSK] M%E'9B#7L@#RX,M7/0(Z)7VHII%Y3/K6=VO6 MO00P 3*$*A"T,AQ[-T=\1]A)]TKN[.FY%^J@O%E=^O$S4BW"6"]4G]:MXU,F MSP9\(K\Q.S4]=W94R :DV\214D&D1_])EK.6?Q++I"5'H8:)'+.IMTX308?K MK\+ROY+_!U!+ P04 " #6DE=("E3U*CT" !&ULA57;CILP$/T5Q >LN<-&!&E)5+4/E5;[T#X[ MQ EH;4QM)VS_OK8A++&]Z0O@X9PS9\8P+D?*WGF+D/ ^".[YUF^% \*9% M!/(G.J!>OCE11J"02W8&?& ('C6)8! %008(['J_*G7LE54EO0C<]>B5>?Q" M"&1_:X3IN/5#_Q9XZ\ZM4 %0E6#A'3N">M[1WF/HM/5?PLV^4 @-^-6AD:^> M/>7]0.F[6OPX;OU 64 8-4(I0'F[HAW"6 G)Q']FS<^4BKA^OJE_T]5*]P?( MT8[BW]U1M-)LX'M'=((7+-[H^!W-):1*L*&8ZZO77+B@Y$;Q/0(_IGO7Z_LX MOW2?8 MV8@XO(?L;QN1NWWF3I^Y[3,RMSZW4I@[;R-"TZ<-^:*?A=-GX>JGL:UU87U=F?'# M[QP0HYB]#&PO=V]R:W-H M965T!>+K3?9(^H9F=>?51'Q@3SE>1E_7 MO3FP@M;?^)&5\I\=KPHJY&.U]^ICQ>BV,2IR#_M^Y!4T*]W%K!E[K18S?A)Y M5K+7RJE/14&K?TN6\_/<1>YEX"W;'X0:\!8S[VJWS0I6UADOG8KMYNX+FJ8D M4) &\3MCY_KNWE'!OW/^H1Y^;N>NKV)@.=L(Y8+*RR=;L3Q7GN3,?SNGMSF5 MX?W]Q?OW)ET9_CNMV8KG?[*M.,AH?=?9LAT]Y>*-GW^P+H=0.=SPO&Y^G Z#VQ .@-R,X@+.(+@9!(,& M86<0:@9>FWO#W)H*NIA5_.Q4[7(?J=I5:!K*M=FHP68IFO\D=[4<_5Q@?^+/ MO$_EJ0,M6Q#N@U ?M#)!-X0G8[@&@J% EAB:0YL"P/01:Q-!M#A3$S))X$ ) MR!AI[./[/$E 8 \!Z"%H/)![#RC04FTQ48,IVU234$O6Q.B+D@*0$ XU!$,- MC5"3Q.(@ AU$(]B*00_Q8[:6L9$FPOK^;#'A$&9M8K122(<0O602,)D$X#." M'4Q !Y,1?"J%A$K>?X+1#M2C"T5ZR3\!6@,@G=1!2#\EBXHA@-? X@+4GQ>$ MQS +2P,BSS!+C,U*8IU88A!RA^F' FL, D0&8XO0(;CX43B&$KC^4?2$V'6@ M@2VR!B!1K&^C(3?]8&&I0:;6)(DM7[C 43*&,[C&T>0Q9^L.U-(_4$L#!!0 M ( -:25TB_!TFGQP0 ,P: : >&PO=V]R:W-H965TE[@9LDYG\QG;=N/8CZ3[U5ZSL6/PBG? MLRPI_BY$*J]/$S+Y;/AY/IZJIL&=S]R;W?Z7?M-,&_2?FK^?*R?YIX30PB%;NJ<9'4'Q]B*=*T\53W_%LY_>JS,;R_ M_O2^;H=;A_^6E&(IT__.^^I41^M-G+TX).]I]5->MT*-P6\<[F1:MO^=W7M9 MR>S39.)DR9_N\YRWG]?N3DB4&6Q E0&]&02!U8 I W8SH)'5@"L#_F5@#\E7 M!OY0@T 9!$,-0F40#C6(E$$TU"!6!O%0@R;G7>8\S<3M4MX6S"JIDOFLD%>G MZ*K\DC2+B4Q)4Y.[IK4MP?9F73-EW?HQIUXUKGDU- M[8CT16M3]*5PZT!OT5(PVB6%.@G[G:Q 4:2%"XIB+5Q 1+3>-I!&ZVP+:;2^ M7B"-Y_5%KZ (F4(&)YRU+L+[%##.8!<<=L%;%ZP?A58/ZTX4M**\$T6^U_YI M,V@J8P()MX!0]]@+WX?#]XWPH\B'/02PAV#$'(:PBQ":0Z;51&@,./1L X[@ MOJ(!^7J.C+X(!=.P[I3^8^7&5.HIM2EZ0XOAH<7&T BE$>RB826(0&]$.@G& M43)D42B5948V@"0(P>5@==8/&L;I=T*AH'F_GP6@(CIT-TK4JPJ/V8J5(( B M#%B?6#800A$^)J4()X@)BGIV_/[ 5TK57SC6<2-0(<$ )*R4*AB0=(0\!$0/ MU?,9 JL<+D-3B46$\(D @/)BBCA!2$#B$2FG" JH-R#E&Z6RSDV_.P0:%(2& MEO(U-=>YO3=DM5-PM>N(HN9"UA$%2)#:L#KK!XW0@)HTJ&L#2RN" SH&!Q3! M 05Q$.@C]DU\6W^S*8(#"N+ R%;P.%L/)5M P@-KT A;*, 6+^:($P0'-!J3 M+00'U-P9F$MKJU0#ZI,AQ& @,?0T,9,8>IH>2[: A%K3Q!#N,( [7HSL@1F" M$T9'I(EAIQ%@>1MI>E4J8".,](9P@ TZN2B5-5D/)5M 0NS)0KC#0.Z$^A29 MVQ!JW7XQA#O,Y$X4!8@/! ,L'%,:" 88>&S12N.9 :<1$ED'CA"#@<30CTG, M) 8Q\JKJ:+!THZ3PKD[5DTW2/[4CJ.(FJJ((83-'R,')F,<'"#DXN!'1,KM4 MJM[&VI97CB"&@XC1\ZI4]\EBX+%KS4T8&0G3%' ,)! M@,1Z/^;&!:L-A!PQ-NW)AVB"+VS>W!4:$"T 4!_H3%_?N^7,FBF/[PJ-T M=O(]KYH:NVN]O519T.;YM=:^)-,5 =K79+J%VNMQ3U_JL9MWZL#K.]TS\J^0 MYK-+K_>M7A$GD>QO7U)QJ)K+L+XNNI8,W_!U!+ P04 " #6DE=(!I8 N( " !4"0 &@ 'AL M+W=O&ULC59-CYLP$/TKB/LNV'PE$4'*AZKV M4&FUA_;L$"=!"SBUG67[[VL;0L!,TER"/;SW_&:&V$X;QC_$B5+I?%5E+9;N M2V!EC276H*HQR?=T++42FKE/YWH;4U- M'(ZOZM],NLK^C@BZ8>7O8B]/RJWO.GMZ()=2OK/F.^URB+1@SDIA?IW\(B2K MKA37J8#-%!):'[10RG\$F C#1P/"3<:(85@A!A= H!&.%P"I5"XH- MJ&YM6KE.$;Z5ZA3Q@N_D&H%.(\AI:#EM0=%PE2BVO (8A.W.0"#DPWYCT&\, M]2:"%1)0(7FF-\G$J)7*YK^([2/$R.<,]#E[IC,SH#.6T2G$-OH(,3(Z!XW. MH9;$L(+>6*&MQ7^F*1UJ:#3R[70!4!@E5L:@TOR.Y3N[(7JF/QUJ5%O[2P(P M,[M% .8EN//'0>#6ND)X8A@EONT73S:4,)Z4& "AN>UX"@K"P'+L#BO*C M.<2%D[-++?4./HCV%X65N2=8\;6^0)@S[2:3I6=RI#\)/Q:U<'9,JI/1G%\' MQB15'OU75<^3NN+TDY(>I!XF:LS;0[^=2':^WF'ZBU3V#U!+ P04 " #6 MDE=(F?37S!T# #U#0 &@ 'AL+W=O&UL ME9?;;J,P$(9?!?$ A3$'ARA!:L)&NQV15WC[P$ZOEESUOJES( MU^;@M:>&Y3MM5)4>\?W8J_*B=M.%;GMJT@4_B[*HV5/CM.>JRIM_*U;RR](% M]]KP7!R.0C5XZ<*[V>V*BM5MP6NG8?NE^PCS#?$5HHD_!;NT@V='B7_A_%6] M_-HM75]I8"7;"N4BE[=WMF9EJ3S)R&^]T\^8RG#X?/6^T;\KY;_D+5OS\F^Q M$T>IUG>='=OGYU(\\\M/UO]#I!QN>=GJJ[,]MX)75Q/7J?*/[E[4^G[IOE#H MS7 #TAN0FP'$7QH$O4'P:1!^:1#V!N&]!E%O$-UK$/<&L6'@=+ MAE^4 -"%]ZX\]="J@\@ @AOA2?>W M& 2+L2*6.1D'6-M$ &,DLY%D-D9^('$ #&AC0T!C'_^= $U9H#W0<9@$]Q"B M'D+M(1AY(+Z1=!NB46+D[0XF^YH9J8U0M1&FUNB>%0J9W8Q"@:'7AI)!3X_T MQJC>&(L2&GIM*$D,9HTZB@RY*!3C>BFJEV(>S"F(0F9^4P>3867$T'N\I*L<:(V& 4I5/_ MA%=CP"ID,#6J\!()R3=R2_"Z1="Z96W1.BK25*VIT CC#;:N%6L.^I31.EM^ MKH7:N U:;R>91Z*VOD;["N99=Q[Y=),N3OF!_THSV"WEY+MA7JD\KGI3B7=B^"GZR'K=M)+_P-02P,$% @ UI)7 M2*7SX,WN 0 U@4 !H !X;"]W;W)KAS-HEA@QNW;%]"Q+M*]$3A\ MW^%W0,@GQE]%"R"]MYX.XN2W4HY'A$350D_$$QMA4#,-XSV1:LBO2(P<2&U, M/451$*2H)]W@%[F)/?,B9S=)NP&>N2=N?4_XGS-0-IW\T'\$7KIK*W4 %3E: M?777PR Z-G@YK]PMBK'GRO3WZ@$8!")74&HIH[ ME$"I3J06_KWD_+>D-F[[C^Q?3;6*_D($E(S^ZFK9*MC ]VIHR(W*%S9]@Z6$ M1">L&!7FZU4W(5G_L/A>3][FMAM,.\TSGX+%YC9$BR%:#6'\H0$O!FP9T$QF MZOI")"ERSB:/SV M$X69FR1VDL0NDM BF47)AR1[S7])$B=)XB*Q3NZ<[%=)8XO$H3D%J/JP( )@* : >&PO=V]R:W-H965TQ[62W4V;=/+YR'1YZX3PY^- M;-5EE>+T.O#2'([?K97:+VS6=['6C^F20^U7Z&2]JS)W$*WXV\J+OVHF# M?U7JS76^[U8I<@RRE5OC4@C[>)>U;%N7R<[\>TKZ;TX7>-^^9O_JR[7XKT++ M6K6_FITY6EJ4)CNY%^?6O*C+-SG5P%S"K6JU_TVV9VU4=PU)DTY\C,^F]\_+ M^*9$4Q@<0*8 <@O ^7\#Z!1 @X!L)/-U?1%&K)>#NB3#N!DGX?8<+ZA=N:T; M] OEW]G*M!U]7Q.B1T4=*RB^23)+<,,@( ;Q\<4C!H@3(3D*BH%4E.\,03>1O.)HHU-20IIQA@3T.$XB%ARPD M+AI'*Q.+**UHKXFW3BOWQC4+ MVQ[&B]/8,>ITO0?>+J/KOU!+ P04 " #6DE=(Y[BQF1<" @!@ &@ M 'AL+W=O&UL?571CJ,@%/T5X_N.@HJSC369 MMMGL/FPRF8?=9ZJTF@%Q@-;9OU] :RV2>2EP.>=P[BU N\M>=&F4!4%M',JUM&.MGR+A#DM U?P.: M#,("_K1DD(MY8+P?.7\WBU_U-HR-!4))I8P"UL.5[ FE1D@?_#%IWH\TQ.7\ MIO[#9JO='[$D>T[_MK5JM-DX#&IRPA>JWOCPDTPI9$:PXE3:WZ"Z2,79C1(& M#'^.8]O9<1AWGN.)YB? B0!G D!?$I*)D-P)Z9>$="*D#B$:4[&%.&"%RT+P M(1#CG]=CC-(%V(P@N0'=$I.7G,Z#O MC!U'C ?LU(G$\'-:0[\]^$XDWT<3R\\=$H5\A]2JD5B%Y5$B<4HT@9$&= M!7U#P$W7 \I0["3L ^69WW#F-9SY#*>.X1&4+8X!>>* ]FL0! ER#'N4$$S\ MAI'7,%H9!B!W_*)560" ;H$]H"QW_7I <>K>J6CQD!@19]N19%#Q2Z?,=5Q$ MYZ;W LU#=.([W0S'WG67*8L>G\EO+,YM)X,C5_J9V\=XXEP1[3%^TN5L=+N> M%Y2B[&#C8N%.]O_7C^*)3_ 5!+ P04 " #6DE=(%Y!"QXH" !U M"0 &@ 'AL+W=O&ULA99-CYLP$(;_"N+> M!0/A(R)(&U#5'BJM]M">'>(D: %3V]EL_WUM0PBQ)[N7@,W[SCPS =OYA;(W M?B)$.!]=V_.->Q)B6'L>KT^DP_R)#J273PZ4=5C((3MZ?& $[[6I:[W ]V.O MPTWO%KF>>V%%3L^B;7KRPAQ^[CK,_FU)2R\;%[G7B=?F>!)JPBMR;_;MFX[T MO*&]P\AAXSZC=86T1"M^-^3"%_>.@M]1^J8&/_<;UU<,I"6U4"&PO+R3DK2M MBB0S_YV"WG(JX_+^&OV[+E?B[S G)6W_-'MQDK2^Z^S) 9];\4HO/\A4PTH% MK&G+]:]3G[F@W=7B.AW^&*]-KZ^7\4GJ3S;8$$R&8#:@^%-#.!G"FR'ZU!!- MAL@P>&,INA$5%KC(&;TX;/SW!JQ>$K2.9*MK-:D[JY_)5G Y^UX$*%[EWKN* M-(FVHRA8B-"L\&3X.4< Y=@&ECVX3U#:BA#=2RI;DJ4P1 @6&FI_( MP B1CA N(B1A;'1JU,1:TX^%9$8W2TAC-*2R-5&R@F%7(.S*@I7E)@;M*%HM MLACUE+8B-4AM10)SQB!G#'$:.;:QE0.9;Q @B0Q20.+#J F(FD"HF8&:6$F^ M&5TO 8GY]P.2$$9-0=040$U\ S7]&A60A :J+7G0U PDS2!2X]O?9C8&,AI? M AJSJX D?O!1J;T"6BU]"#\6 MIL@'?"2_,#LV/7=V5,BM4V]P!TH%D8S^D^SG29Z!YD%+#D+=)O*>C:>"<2#H M<#WDS">MXC]02P,$% @ UI)72%D8=0[$! EQH !H !X;"]W;W)K MKS( C]+#GFL\6\N_:M M7,R+<_.M]*ISEB7E?TN3%I>G&9N]7_A^W!_J]H*_F/M7N^TQ,WEU+'*O M-+NGV3-[?%&ZA72('T=SJ6Z^>VWRKT7QJ_WQ9?LT"]H<3&HV=>LB:3[>S,JD M:>NIB?SOX/0C9FMX^_W=^S]=N4WZKTEE5D7Z\[BM#TVVP6S M&6I0K<--D5;=7V]SKNHB>S>9>5GRN_\\YMWGI?]/' QFV( /!OQJP,*[!F(P M$!\&\JZ!' SDWQJHP4!9!GY?>]>Y=5(GBWE97+RR7^Y3TMY5[%$U:[-I+W9+ MT?VOZ5W57'U;AI RQ[$;T#LBO ;]]<8',58AX#'D!<5@D<:8"=D-T'J*Q!X4]2.A!=A[$R(.P^^F"6!1+JR?0DP5: T\L M(A9'P805"!.%5L(]*.Q >0?ZQ *KJA4 :8%3"6$J(4B%1U8J/4C=1(FUW3H7 MHW6$,XE@)A%JBIU)Y$3AUDV[VSC*GO59G5@#""(EC4(V?&4>I,#L5[MRZ@9V*"R&4AV&U94AN8T[X MP'K+D$S&S@"3?Z[&A5A>U@-D3!$B6RRV#*FMK?S+ 74WVS]"U@#RB6 JPWK, M0K0^Q#AD6$D9DM+8GB\,"*6]"UDAD%9VU0AD*<<+8=EEKNXV==DC M8D"-LI%.70 4AG9="$0,"H:5ER'IC6WI'5"CL6;/UP$3WL&L$2;$^7*LNSQ M^5H3:3F@1BI$+"7'VLR1-FM;FP?4J"]4'"R\' FOIG;26#+YE!TJQY+)D60J M>P!PH(3>DL%@6.1,'M MK$OE6)*=Q5SFB,N:>M;!_!)P7T-4+#!W!.*.4[%PN4/?2P*S1T#V4-D2CW=3 MV",P>P1BC[8'FG#9<[,K'\?!W!&0.P0O!.:%0 .\OB.22'1T''*E>[0$<2^56+B2#ATB(<*B2DA^91Z,26D^*MZ MQ;U-P3@.<2X":,,I"9"8$E)-J1=30L)1X=0+3AF(,)@U$K"&!\2LEY@2,IY2 M+J:$=.>$>SP@W:T:4:W"I%&(-,Y#_8"RGL6IPRI,&P5HPP.">@K31DVAC<*T M48@VSCD?0&EJPZ*,P;A7CC%NRB6$B=9RE,'06I0ZB- MPM114ZBC,'44VF*Y%;LH[3PB^S>G\9DI]]U[D,K;%.>\;@^L;ZY>W[4\\_8T MW[J^9(_K_HW)AYO%_)3LS=>DW!_SRGLMZKK(NA/]75'4ILDQ>&C6_V"2[?5' M:G9U^S5JOI?]>Y/^1UV&PO=V]R:W-H965TPJ8ST8$J4E4=0\K53WLGAWB!%0;L[83NO]^;4,(M=WN)=C#>V_>#,ZX'"A[ MYPU"POL@N.,;OQ&B7PKDFQ-E! JY9>> ]PS!HR81'( PS (" MV\ZO2AU[955)+P*W'7IE'K\0 MG?+<)TV/B1?PN\M>=&J$!0E<',.[8$=;RE MG,_1>M]H1 :\*M% U^L/>7]0.F[VOPX;OQ064 8U4(I0/FXHAW"6 G) MQ'\FS7M*15RN;^K/NEKI_@ YVE'\NSV*1IH-?>^(3O""Q1L=7M!40JH$:XJY M_O7J"Q>4W"B^1^#'^&P[_1S&-T4XT=P$,!' 3(BR;PGQ1(COA.1;0C(1$H,0 MC*7H1NRA@%7)Z."Q\>/U4)V1:)W(5MIY41^L\QP,H+2198T-(S8D%7L M]I$Y?61V1Z+".#J95:SA8I?9+H#9,ANF$^D,N MHO/8?P)J%!GQK;P.QNE]EZG*'I[13\C.;<>] Q5RT.EQ=*)4(.DQ?)"M;.2% M-6\P.@FUS.6:C3-\W C:WVZD^5JL_@%02P,$% @ UI)72/N))>RI!0 M="( !H !X;"]W;W)K22!>]Y^M-FX*C-K) YX^S.SMJ\RJ^SY M/B]^E>LDJ2:_LW1;7DS75;4[G\W*UW62Q>6W?)=LZT_>\B*+J_IE\3XK=T42 MKUJC+)WQ(-"S+-YLIXMY^]Z/8C'//ZITLTU^%)/R(\OBXM_+),WW%U,V/;SQ M<_.^KIHW9HOY[&BWVF3)MMSDVTF1O%U,_V#GST8TDE;QUR;9ER?/)TWC7_+\ M5_-BN;J8!DT;DC1YK1H7+]INULW_R4N MDZL\_7NSJM9U:X/I9)6\Q1]I]3/?WR5]'U3C\#5/R_;_Y/6CK/+L8#*=9/'O M[G&S;1_WW2=AT)OA!KPWX$<#SKP&HC<00PUD;R"'&JC>0 TUT+V!'FI@>@/S M91!Y#<+>(!P:(>H-HB^#T&O0S'DW<\'0&.PXV6RPR6&ZV>#Y9H<)9X-GG!VF MG V>KN,J7LR+?#\I.LAW<;.7L//:JG;>O-L2V'Y8 M(U/6[WXN. ^B^>RS<=6++CL1MT0LL$57B(@96W.-.F*VZ$]4Q&W1#2H2MN@6 M%4E;=(>(@BBT14O4D[)%]T,\?4<]:5OT,& L'S&-$^P)TSB3^XPVZ"O8K%X_ MQT7$\47$6Q?&ZK@)<1<"=R%:%^+$11@Z*^RAT^A6LVTU.J@37?/GC U4BE!@ MRB?$IV:.TFJ_Q-LO0?L9X\YZ?.A$ZB28VW"H.%,:;3BB9,H=#:OE"F^Y BWG M8"$]*!!-!&B['J'2A!': ZCDH?1U0.,=T%@'(MR%P5V8$0LXQ%V$_[^ OX=@ ML;' N]@B/%:$])@3+IH$B6[\P8@^,RI[,+CLC0[=#9V!?H>^7C-BFV$0^;KSCFUT V'S+L)V(Y&E18H\P1#G&"> MCV&>$\QSA&8 XI+#O.P?90)[#K&'''*80K7R1B.HYY!Z6+XL.<3^S%MQ< )[ M#K%'..Q5RDJ71" "> Z!KU$.@Y1ZPD"9"''S"?!I\#*9K<" MN$55@AI< DZ!%;B"*'L$@9P84^(* B>!X@0ZC:D$-=,$= )+H8+(PY* 3HZI M<25!DD3SG5OKH2HAB5 $1A+#2"C""<&(')/L)'6<'53@HBI!)&=)D"111H@] M6A*,2#VFTP0C$JM&A9OA$15=U4N")(E4HD9';BAX8#3>_"X)FB1&$W5&5@1- M:@Q-BJ!)82?&R+V34S Q]86&>XMP/TAJ-XV@3T'Z8(J^4S"),7!%8\ZH=H@-)N M&+$!*&P#D$2F503:*APS1 2P"@(+U^*50DZ0WJ6H";0UWW5 M70(BRC/&\6M 1.OO [&S:"P#2Z+LT,0>H,=<96L";(U6J4[R?$95DJAP- &U MQJ"&$X=<%KM[2#]Q4(G.\!,F]$\;L:-H+/U+HG#2U!7PF/2O"?HU1C\<2W@9 MA5^$(T)TS)\0H?\:G-AX-%9W2Z)ZU,3&H\<<=@VQG9@AA]UK P^[VMMQ0Y!O M4/*)BLP0Y)LQY!N"?(.D=-#Q2P._=&+XL7MV\CWN+GY/'N/B?;,M)R]Y5>59 M^[WM6YY72>TU^%:#M$[BU?%%FKQ5S5-3/R^Z'T5T+ZI\=_B-Q_&')HO_ %!+ M P04 " #6DE=(_._#8M(# !_% &@ 'AL+W=O&ULE5A9E HP+&+/_ M?CG&@Z';@A>YOJ^/Z?Z:D?%!9I_Y5HC"^$[B-)^8VZ+8W5I6OMR*),QOY$ZD MY9.US)*P*"^SC97O,A&N:E(26V#;GI6$46I.Q_6]MVPZEOLBCE+QEAGY/DG" M[-^=B.5A8C+S>.,]VFR+ZH8U'5LGWBI*1)I',C4RL9Z8/]GMJV-7D!KQ.Q*' M_.+5I=+S7V7T[+,B7IX?K3_6 MZ9;A?X2YF,GX3[0JMF6TMFFLQ#K4^+V1RI)A& M$GXWQRBMCX?F26 K&DX 18 3 =A5 E<$?B8$5PF.(CA]/;B*X/8E>(K@]27X MBN#W)02*$/0EC!1AU)=0U;RIG-V;Q01<2Q@Q8X_P:#T\ M6J\3+0,(;B?$>YGU*,V#Z-N%Q$]7PUG=!K: MF!]?GT]VQ]$/(AU&C5W6+1_393%7J,LV^0$^X8D8!0RPE#K#"Q!/1$,R8F(P M;&2XE!%"QVR(D!FA9(9*66]+!,681Q62D"'KZA 8IVI$")$-42(CI,CZ:'&& MH*XD3:B1]9'CC'7UR%QB0@$A2.@CR$?H"M*G'!&"A#Z"? 9$D/I+<8Z B%(" M]?K&-.O9A!%"CL '-!40<@2GQ_H_*51K\E+1$I(%3+*>ML>\5ZB6(V*? (1@ M88A@@1 L#!$L$((%3+ >:"I2J,MNHC(FU J86CTB6$X(D=M#MI2$R'A79&4D MVMRX4ZC+(GM$RIP0$$EEH40&<=$YKF$$4) W!U2 M($(<'!$'LNOW.BW9V?1W(=K"+1 (565"A=Q'HG6HE D5\F#(NA$2XZC$M$5Y M05$.T94.(40'>R-V2N0@6U3]3RV"T>;M H/H>P7KXEO#+MR(7V&VB=+<^)!% M(9/ZV\):RD*4]NR;LMI;$:Y.%[%8%]6I7YYGS?>QYJ*0N^/GOM,WQ^E_4$L# M!!0 ( -:25T@G%[+#$P( .X& : >&PO=V]R:W-H965T:ON#M+/?:7#OM&'\7%<;2^:"D$7NWDK+= 2#R"E,D7EB+&[52,DZ1 M5$-^ :+E&!6&1 F GA<#BNK&S5(S]\JSE%TEJ1O\RAUQI13Q/P=,6+=W??<^ M\59?*JDG0):"D5?4%#>B9HW#<;EWO_B[DV\@!O&SQIV8]!T=_)FQ=SWX7NQ= M3\> "$C)D0K*>??@^@_3TV<]N_J7TVZ*OPS$OC(R*^ZD)6*UG.= M I?H2N0;Z[[A(8=("^:,"/-U\JN0C-XIKD/11]_6C6F[?F7C#30[ 0X$.!+\ M\"DA& C!9PGA0 @7!-"G8C;BA"3*4LXZA_>GUR+]D_B[4&UUKB?-SIHUM15" MS=XR".,D!3>M-( ./0A.07/$<8WP8>+-0:=G,D!%.88*K:%"0T_FH6[L"H%5 M(3 *P2Q*N$CVU(-B VIZ4&PW":TFX=K$3R*[0F15B/XCT=BJ$%L238+%F5E M?OP@U<1JDZP45*#;A4VRVD_X8#PF6ZO)UF;B+TRV MJTP>)*)O&ENM>387N"PV;V43+@OI&60>R8.J]S]1"87\=]P/)VOOK,CYQV5]0 M2P,$% @ UI)72';#<;SK P S1, !H !X;"]W;W)K/E6[1D3UM\\*ZJ[T5Z(P\RVJ_6>Y4DU MY@=6U$^VO,P34=^6.[LZE"S9-$9Y9E/'\>T\28O18MZT_2@7Q475Q;4OPKYV_R9K6Y&SE2 \O86D@72?WSSAY8EDE/=<]_E-.//J7AY?79 M^]=FN+7\UZ1B#SS[G6[$OE;KC*P-VR;'3/SDIV>FQC"1#M<\JYK_UOI8"9Z? M3496GOQM?].B^3VU3T)'F>$&5!G0SJ#K!S=PE8'[8>!=-?"4@3?48*(,)D,- M?&7@#S4(E$$PU"!4!N%0@ZDRF XUD'/>SISS8>)?-^DFFPSNY3S=A (3NTVL M)BT?$Y$LYB4_666[E@Z)7+)D5EO5SF5KD^C-PSHSJ[KU?4%IX,[M=^E*0"XNU\?E^IA<$+EE"X47W7QQQC#A'G3*&5,PJD<, DGWA#H"BPUE MP&Q^PR _!.MM0&\K- !.X/3^P# BS+$',N%%APB,1XPY<@W+,,"G.<"F&@UFM$3VB("PTQH6#*HE#K!)8VG0#9&NN$89U/<:%33"A(P&@Z MH"SIC%Z6=,98EN0) MVR'41P".NHHOJ5":AY0:" @ATSQB#/D+3$=,P@F&:0 M>OI%BKI6-F\C\56D MK]9P\"#8R2,TG :(X3A _,_$S;#9$&RWT>,6H.E*8.P&8;'"_ 'Q,^P\!-MZ MC/$S[ ID^HGX44.IIFBI!DLR4A0^8G7 OXG$5Y&^6D.1IFB1GAB<&!8]I9^) MFV'14W=0W-S;<;N)Q%>15JU]\3J=LW+7?"6JK#4_%D*JO&CMOD3=4_DZ#MJ7 M9+8B2'M$9G'[G>G#_6)^2';L>U+NTJ*R7KD0/&_>U+><"U8K=\9UG=BS9-/= M9&PKY&507Y?MUZ;V1O##^>-9]P5O\1]02P,$% @ UI)72(?%JT/1 @ M9PL !H !X;"]W;W)K9J?9+Z\YT>K%[G6I4ID!<$FOWWV\2$"&&&YHS]6]L3HS3XB(QC0)_U->L5-=S_29"C0P6.(W :05M'%C@-@+W*O"^ M%'B-P!LK\!N!/U80-()@K"!L!.%80=0(HK&"N!'$8P5RS>N50U=)\+6D76Q[ M=)3+8LY3I.*GHVJWDI'+'>L/14J82Y'5:.KEZ(SF1A]3QTG M"A+K75HUT+R&G X4A4Z?60T9NR4LD4.;B ,F,G<&>BW" B!0W&=NAXS7)^X M%QOUF?LAX]I]Y &RT9A'B-$FM8085ROMMZ5Y^C[A]1")(WB!7+A37&40]CLE MA"T\V,)3%F[/(M2;K88B!94*^H$F>DT60PI-G%#K!@C2ZG('&FG] #):ZSU M4!!I+3$BVA(L I1[Z=-8P49>[[6)D/(UNNQAHS<3SK%AY?9!Y8YTBJQJJ&@ M$\=%6BL\#9DPTLJ^'C).Y,'I!G"Z 92N%F950WXGC#:AIR&A36<])#[9/B&< M: @D&B/8(H(MHO_8Q#%L$8\I5SR8JJTWX_?(^DNDSM7J?.D*4NW5 8X9&WHJ MN$6\<^:74QN?V=&D#XRMQIJR/@%?[-#GB/?F)JWU6,N.5]B$G.RYO0W%?U0?!^H'3X^58VYZMTW]02P,$% @ MUI)72"J+7T&" @ 1@D !H !X;"]W;W)K)=IHPIYZ/(2[EP4Z6JN>?)?BI,G M*\'HP9**W,.^'WD%S4HWB>W:JTAB?E9Y5K)7X.8,>%NT3S+0H-Q")^9>PJ.V/'!+_C_-U,?AP6KF]B M8#G;*R-!]>/"UBS/C9)V_M.(WCT-L3N^J7^SV]7A[ZAD:Y[_S@XJU='ZKG-@ M1WK.U1N_?F?-'FR$>YY+^^OLSU+QXD9QG8)^U,^LM,]K_6;J-S28@!L";@E! M\)1 &@)I"7CVE! TA.!_"6%#".^$.I?UWFWF-E31)!;\ZHBZW!4U7Q6:A[HV M>[-H2V'?Z=Q)O7I),)ZAV+L8I0:TJD&X [HC/"W?>F#(8X5'=.V!^QYK$$3Z MH T("OJ@+0@*X8 )F!1B%29]A0A6"$"%P"J0OL)DD-8:%%I0:4$//$+0(X0\ MI@./<.2!88\(](A&'F10DU4-B3H."$?#Z@*@D,P&U05 43!0V@*@F>_#>YJ M>YI >1O$LAJ#D$\FL,T4M)F.;4@GT-IF.BK/ +'^%+%YANC%.0/CG$%Q/OA_ MFYX+-1'_"W\8]* 1(2@./.Q$:%3^!YM%8"]:(@S9#+_I!M7-*0D?Y03N(8A M1L$##;B+H. K>86[! +:!+#A<)17X@\_=Z]SJ!1,G.QQ+IT]/Y?V]M!9;:\, M2VP/I3L\B2MZ8C^I.&6E='9BSJ M8[Z>*%[=;BWMU2GY!U!+ P04 " #6DE=()8IFJ4$" !%!P &@ 'AL M+W=O&ULE57;;J,P$/T5Q <4#(1+1) *4=5] M6*GJP^ZS0YR :F/6=D+W[],P2/FD2P%_A^[!'8=FZ1Z]@;*W)Z M$;CMT!MS^(40R/Z6"--AYP+W%GAOSXU0 :_(O9EW; GJ>$L[AZ'3SGT&VWVF M$!KPJT4#7ZP=Y?U Z8?:_#CN7%]90!C50BE ^;BB"F&LA&3B/Y/F/:4B+M%$".^$Z%M"-!$B@^"-I>A&[*& 1<[H MX+#Q\'JHOA&PC62K:Q74G=7O9"NXC%Z+(/0WN7=52A.H'$'! @1FA"?EYQR! M+4<9K.C!8X)JC0C!(V2_AF2IW41H+334_.2QT-BN$%D5(JT0+KN0 =]HU0B* M-:@;TQC=K-80D!C%6E1\N]6-U>K&9M7H:#F"-HLD86A874,RP^D:\<6IQ%:C M\RAMC'/!WF2+OX1G]A.S<=MPY4"%GH9Y8)TH%DA;])]G,1MYI\P:CDU#+ M1*[9..;'C:#][=*:;\[B'U!+ P04 " #6DE=(D&%9K;4! \! &@ M 'AL+W=O&UL?53;;N,@$/T5Q <4WY)T(\?2 MQE75?5BIZL/N,['',2H7%TC<_GT!.][$L?;%,,,YAS,,..^5?C]PC"^)-W9LK4^0(B<3KV8"I&%*(@W-#O^,MV7F$0'P MAT%OKN;(>S\H]>Z#7_4.1]X"<*BL5Z!N.$,)G'LAM_''J/EO2T^\GE_4GT.U MSOV!&B@5_\MJVSJS$48U-/3$[9OJ7V L8>4%*\5-^*+J9*P2%PI&@GX.(Y-A M[(>5QVBD+1.2D9!,A#C[+R$=">F,0 9GH:XG:FF1:]4C/?2BH[[E\39U)U?Y M9#BHL.8J,RY[+I(TCG)R]DHC:#^ DFO0+:*\1Z3Q!"'.P60C6;21!/[FQD:T M7E9(%Q72H)#>%A+/"AE ZP"2 10_SC#E/2;-?BP[R1:=9$M.9@>VS^YV6279 MS,D"9KV9.2%7C>[H$7Y3?632H(.R[LZ$SC9*67!ZT<,*H]8]Y2G@T%@_W;BY M'F[W$%C57=[J],,HO@%02P,$% @ UI)72'HB_PQA @ \@@ !H !X M;"]W;W)K?MD^NR8X%KQ!S2XD9\.1-:(RZF].*REF)T4J2ZH.O%-9XX:5I+$H/F_M+_!I M#T,)48B?)>[8:&Q)YP^$O,G)]]/6!M('7.$CEQ)(O&YXAZM**@G+OWO1?S8E M<3R^JW]5X0KW#XCA':E^E2=>"&^!;9WP&5TK_DJZ;[B/07EX)!533^MX99S4 M=XIMU>A=O\M&O3O])0$]S4SP>H(W$&#P(<'O"?Y:0M 3@K6$L">$$X*K8U<[ M]XPXRE)*.HOJ=+=(5A5\"D5NCG)1I4)]$WO'Q.HM\WSHI^Y-*O6@7(.\$0@F M4? (VLU!WB/B>8[8)(^0_4OP0#8C,"KY1P5<*_D.HX6;B MI08E"M1HD.?XT&PG,-H)9G;$OD^W5(-DH0^&_(T33[PQH& 0.@MAAT9W0E/8 M$T,[#8I&=L DP_]%[.<(F !@=C4RNAH97(T2LT)L5(@_426)42%9425Y,J\2 MWP&QV<[&:&>SHDIR#0I'=KR%#94U8OH'@!79SWO4.'5>M%#S<.%G TWQA L: MYA:'G^EQ:&YRN*;+H53DT-S!<-+>;QC# M-2?["U!+ P04 " #6DE=(FK(C\OX& !6*@ &@ 'AL+W=O3^.=J'R4W\$AVR7Q[CXSY,LZ_'IU[RAV@7W:>Y MB3#[\RL:1;M=;BGS_&]I](_/O.'EY\KZI!ANUOT?81*-XMT_VX?T.>NMU>T\ M1(_AZRY=Q6_3J!R#DQN\CW=)\7_G_C5)XWW5I-O9A[]/?[>'XN_;Z1??*IOA M!JILH-HVT&4#?6Y ]M4&=MG ;MO *1LXYP;7>;?DW;8.O+*!U]*!7_)^6P=! MV2!HZ2 7_"2;U=8%G96^D/IZBTIJ4JV=5&*3;NND4IM:RTV5WN2T=5(I3JTE MITIS\MHZJ52GUK)3I3L%;9NH2GG%E>^=,KVH$^,P#8>#8_S6.9Z*VTN8UU#J MJ[P4W>=7B\I3_)B5BB2[^FNH-+F#WJ_<5 G=G2!U"5E^G1D!IDZ,D96@SDPD M8]>)*;!"5IV92493'9DC,XQ9((8-:HD876=6C5.S;N[P1B+!'PEZF,B/):(L)NA' MZ8L"-LD38,=E$_BIA9TIL,.#YW,+.S-@)V#3\P78T0X3="X-.3P*O[8QM ] M\ID:W]H86DI#/@OG[VWLK*0=C]>QM62(/%Z@@"%MX6AV<32[*)K9H$:N<,,7 MGD9BTDA,&XE9(S%O)!:2^,!E!HC2>%8]/*L>6-%9;H^\YA(A$5$B)H#AZ3\% M#$_M&6!XVLXE(S)R >QX;+U;2H97\Y5$9(I(ALAFY6@#^NP85G ?B^F#%%$L MK$:^N%7XX+-ACR5#/D\3R;@L&Z? C,VF9B899?'Z*AF;KY<+X$NS"%R"H?/; MR95D-._/6C(>'_L&](=LK&: U0S _;HR!$1^ !W=Q8*":;!J*3\RXFQ;O@V M9@PPZT;Q51Y2K%Y,L2F^BX,0F^@YI%P>'FT<+O$\6)Y5^\?&LH*F;992:T 1 MGY8--*4-VSPR[>@):DE=6RJ;D4DS,FU&9LW(O!E9E$C U!,B8TRHVNAP M;;"DN:@0,ZW39-B]DT+W:UQ4A5S)1)882F1$B42&IKB^$!*)C"B9R+!7/A<9 M3@2_!5A!8S)U)4595> RPXXY!I4-!RRD4=$WK!MDV,B3W,FCHF^WBQ6)9=JY M/%80)6(%FN*Q B$1*X@2N_HV#I=X'AJ+/C)MVSQR))5%#K]5@+:,5=^PV2>T MVY=57^[#1-5O1";-R+09F34C\V9D42*-51]C0M9&AVN#)5'U(6:L^H9-+\E= M+ZCZ;KM,EAC*9$2)3(:FN+X0$IF,*)G)L%>BZL.)D%4?&9.Y*ZDL=_FY!NZ8 MJ>H;-N$D=^%9[C*9[TJ*W5@3#P9$\7/3<4D179-YTHJ:EI1[+=5AUQT>"HCB M1]"+5M2RN5,K:(B?;*SQ?#H\#. #<>U9-B^$]R_NUQ@L$/ET!A BC]1FB!+ M_*P5,#X7%VR'198#5^)I&]@R\[NL)8(NCF3J\VS86%,@BRH_25R54.VP0#P/ M64-*K.\ 4H82H0P;>24W\N1YI@> AIVAHG?<72K38T2P$?'$ 5Q)U8^R#8N? M,MP,*_FX49$V))4RW PK^SUC-MQ<*7!8#L;LR$0P*618[Q58[R^?]M6-&)83 MY;UGR(9BI&0QRGK"<[^D:H>6@<&1(1L5RD8[X(X"X8@LP[QH0PYID$/DFIZ M&W)(OR>'M"&'-,@A7C9F)51_:,VJU'6FWA?3,WU];BS;&))*@V?%_/':'8)\ MTR-,;<@\#;8U_*[]#D"9)T/J:4/J:9EZ?A!P3R _?9M'?._B[9M]='PJWO)+ M.O?QZR$M;J)1Q3_V/QXA^[/J'^)W1]2OW/Z/J,^E_0]3GUOZ+K"^I_ M0]>7U/^.KF?1TM]D$2-_R>3.?K'A+T[VBP-_<:LW*'M_YFDX> F?HJ_A\6E[ M2#H_XC2-]\4;2H]QG$:9"M9-IO=S%#ZHOS M_"KI\']02P,$% @ UI)72(YC%F(N P ,0X !H !X;"]W;W)KA"$L/QUH../.I<^/MTIP55'_2(1.HCGDQ$ MK,E9?QOD>8R6%P1$@^ &#U*@N^5K06 M)!M;H(H&Y<43;277" K\8!+B*AK@3<(@#S"+TOGQ5*:TP86ES< 0"S +TU5PK5\Z/0U_6$ MIA]U0'TUN$^ :13$\PPUI@L &7C^ 6X#8/J 2#3@:8 ; =SC! 1W H+T.*5! M?\(+!$6'C(#@1D!,(R#&$BX4JO](&<@S\&9!L,(.[$F"FP7Q[BDLWM#$;&AS MODN"/"W>@)OWU#WG-1/QW(GHD*/X?KM=9&Q? MRU,JSLOVBZ:]J/GI^H%V^TJ<_P-02P,$% @ UI)72#F'\-R#!@ OR8 M !H !X;"]W;W)K@X_?XFC]VW=/'Q>)P^]ALZ\.']JG9]?^Y;_?;NNM_[A\6 MAZ=]4]^-C;:;A2^*M-C6Z]W\^G*\]GE_?=D^=YOUKOF\GQV>M]MZ_\^RV;0O M5W,W_WGAR_KAL1LN+*XO%Z_M[M;;9G=8M[O9OKF_FO_B/M[D8I",BC_7SVF,_NFOOZ>=-]:5]^:TX^R-#A;;LYC']G MM\^'KMW^;#*?;>L?Q\_U;OQ\.?ZG+$[-> -_:N!?&[CX9H-P:A#>VR">&L3W M-I!3 U$-%D??QY'[5'?U]>6^?9GMC]/]5 ^KRGV4?FYNAXOC5(S_Z\?NT%_] M?NU#")>+[T-/)]'R*/+GHJEBA8K@II)/**G*J>2&W,?E^"I:])Z\NN.I.W[L M(4_=,7H(M(;HBH*@KN4Z0^ M1?0I*I^.$CF[B:]$N40T9>!V"+5#T ZU!)8"]RB4%:CP6;@5B5J1P H]Y,L$ M]TAE2LH0%.72)VY)II9DL*1?K6K4EQEM<7I,4",AJ[6&&E73B].)A,GSK"'T]0A3J,UPIRFCN 4/ JX>F/0_J H MF:/+*>@0@_WJ VL(Y23 \!)5BL9N1;(?_DZ]S7@62W<*X8+CF2@US(A*GJQ@GT20; MUZ6.&R(*A9&C!D[00')EO1<"PC% &8( U-H%G* !"=KO2QT#!*1C'Q!K8UA@ M:)S>@1,T($$AA \(1]@!#++6?N3\#,C/?ESTV1)(1 @+#S5BQ$6!LS,@.Z&F M$1")4NA#CHB$3GL(H4=S#/)7/613S3)VD<<=?$=J(NLJN?UKB:JTHH^(J== M9+1#)A7:P(Q.BK 3>$5$?*QD;(7'<)4R)22DO8;;K]&G--)8M M')L)L0EEO(1([->#GB>B2M&*P1-'9V*)M97@)(Z\Q)Z70!$O(<_T/GA3,K6$ M R\A\*"(ETBBBT4\IC*+>,EX?DQ*BOK,3T@S+.(1D5G$2QQYB10483MB],>* M>%1F%O$2QV>B2;$N7"12+R1%/"HSBWB) S0A0*&(E\C#9"SB$95=Q,LJH?FC_J_<-Z=YA];;NNW8YO_MRW;=?T718? M>M<>F_KN]<>FN>^&K[G_OC^^7W7\T;5//U\7>WUG[?I?4$L#!!0 ( -:2 M5T@Q_M);J $ /(# : >&PO=V]R:W-H965T2V0?=@_(GK3:2.1^:$[&] =9$ MDA0D2Y(-D8PK7)4Q]V*J4I^=X I>#+)G*9GY^P1"#WN"HPZ_P#G0$#K MPG;K]V;\)\? Z?[ZPN9G7OT#4$L#!!0 ( -:25TA:GUMD;P0 #P6 : M >&PO=V]R:W-H965TZM'XF<5K1S;=K'>ZR0JOF1'G5;_;+,\BGL_>H#Q2K@UTA#_'/2YZ/VV:O'O6?:COGC=W(^<6H.. M];JLFXBJKP_]J..X;JGJ^;^NT<\^Z\#^[TOKS\WC5O+?HT(_9O&_ATVYK]0Z M(VNCM]$I+K]GYQ?=/8-7-[C.XJ+YM-:GHLR22\C(2J*?[? :S]\@.P"Y&> ^\< MPMP;PWPN@#OU@#5!:A; _PNP+\U(.@"@EL# MPBX@O#6@GO-VYIS/$/7GD.MDP\V]7*8;Q,TAEPD'/.-VFXM-)C]%932=Y-G9 MRMOE=XSJ50[C*JIJO+[;K(WFSRJ9B^KNQU1(SYO8'W53'31K(=&# E\,F3EE MX$K8E8:K$,$*F0D2CWIX9 @G'#)/E'&'Q%>F%7"&S#-E) R1;UPSB'GA&/10 MKQPCT=#^=6@6?Q>\I$@8#)$5I\5W^5F4?#K)I@E_F$Z*;\+EFW";)F0_D1RD M=-XRJF'2AO$$FN@%9:1"B;VDC/ ]7JW'J_48M0JI;1FOU\L=A A:<%#@([T, M)(3#"U:\8$4%X\2=*])-@')R01' ,[#D&,/H^KQ8GQ&+%NO<-.,<$A(QBEW#QD!+L2*V8I M'TMFJ4#PFFO/91W+(:JK/0;+[JA!7R[)"Y8"-&=+CI*N-,@V&2W0P18H!V<= MU-^0[@(D^I&!($"KXHF!%'JNKUQ#+K*69P82>(?[QD!N@![NA>M.HGWEE1L! M#V__'=2?$(DU+1C(QT.PY#2!P?* KUP>0-"9]<"P=8#!..'_."<8K!.H=U:- MD-%SR< 0\^08-'8K8!S6M)8-[@G4/BO!>,\$:GL!AA8,!!*74BN&2DH58 R0;%L,(QTLF'-2T_N6P4<% M]5%:K@C&^L#!-LI2(5Y[+*4,!:$PV*A@;)34+()N_7=2X<3@*%<(K)JCI&$) M"H-%"&H10BJ<'ATUM#7RJD.8A*=[YI#R<):9Z>T MK*7V[EX//A]$?92#[L]@_ K,_3F,5^VQYF?ST\DQVNE5E.\.:6&]9V69)9Z$>MM6?_TJ]]Y>[C97I39\7)6>STPGOX&4$L#!!0 M ( -:25TA7+860/P4 *,< : >&PO=V]R:W-H965T9:-L>&BH0820Z9MQ]M M8-2+H[FQ0?ZZ]>N%N6AZOIM'C9VC0NOF0' MNZ_^\IKE:5Q67_.W:7'(;;QI@M)D"H[C3]-XMQ_/9\VQ;_E\EKV7R6YOO^6C MXCU-X_S?6YMDQ^NQ&9\.?-^];GS?78J378Q+Z4=8JX^O7+WMDDJ3-59_ZG2_IQ MSCKP\O,I^T-SN97\Y[BP=UGR]VY3;BNUSGBTL:_Q>U)^SXZ/MKL&KT[XDB5% M\W/T\EZ467H*&8_2^'?[>[=O?A_;OX1.%R8'0!< YX#S>>0 [ +P(\#]-,#M M MRA 5X7X T-\+L ?VA T 4$0P/"+B <&A!U ='0@'K/VYUS/D+\ST/.FVT& MG^6TW08&AYPVW- =G[:UV%3R?5S&\UF>'4=Y>_L=XOHN-U=55)6\/MK<&\T? MJV(NJJ._YH"^F4U_U:DZZ+:%X (* ^@S"\Y\9)E6&LY"0!1R"RR>G.%.()RH MS]QSQNT37X4LQNDS#YQ!LB1_26D(\R@QY**>) ;)TOYQ:99_%KSB2!3VD;6D M)7#E742YG+!)$?3*R4,YA2NG<)L4V$L!9(=N6\AOH'T#34*/U MG3$CRW'/& M)R7U54CCDO5_X PX/JD8SK@AV8%'X5Q(JN%)N'2/Y%EP!JF>)6<">NTK08]1 M"L*3=]-C!6%<)8,O9_"%>O"I^[20=[DHQC'DU2T86?RZ9TO M,!&]\P7&8*0HEEOZC0%>7)ZA@H&+H7HY,@&/*>847)1R7['2O@SO7\8#)8?2 MOXS4P.@>+#JJM[[TLCGBT&O^#.FK5?S9>)):Z@ =U:LJZE8"4QD %AHM!(@%Y6F M8)2N8(2V0*UO800SC^BXLI2H(*!]3*!0FQ.,TAA,)(AF91$)S2Q@MQZG,*"] MK(,NIZ,P4@8%4#H1\$Y46:2O)%$Z YC_,76#8M; S9K/W0O@)LLG2P%BH^6Z M@P;-EJ#8-0AVK54-*'8-HEW3^1*XT4Y\6A%+B6+6OY8H\+7M4GP;1-]F_SER MNZ6V+2#H4L4"H]6H8MK 39L/FB#,WL(J2Q,Z M4L4 #*/ "*ZDP;()@DQZ]<&D0I__2K@7*U39+<5+@3BJ,FL!-T@VI9,[0)T=K@3&@+#(J M/HJBCQ+!R*=PE[8K@9E7UI7 3.ASL[4 !5I=*=T!Q>Y APKDCDZ?T D( M?>RXEABE+:#2%I"W!3YJ(K=S8 4A3?-4+VLG> M]V6M]>+H^?W:#=1O#,CQ6W/U9(3C"W.U;M^>?:2?SP[QFUW'^=MN7XR>L[+, MTN9EPFN6E;;2[GRI%GIKX\WY2V)?R_IC4'W.VW=H[9"9[?2\[_ U!+ M P04 " #6DE=(81"(B1X# )#@ &@ 'AL+W=O&ULE9=-;)"?W7VUB-=2>F7M&S]1*JR/NFKXVCX)<7YT'+X[T;K@#^Q, M&_G+@;5U(>1M>W3XN:7%7@?5E>.Y;N341=G86:K'GMLL91=1E0U];BU^J>NB M_;.A%;NN;6+?!E[*XTFH 2=+G2%N7]:TX25KK)8>UO83>W[%_U=*7\ MUX+3+:M^E7MQDFI=V]K30W&IQ N[?J/]'$*5<,'^ - 21:#/#[ /\S(%@,"/J 0XW51T(_)"%%G:LJO5 M=D_O7*A%0AX#V>J=&M2=U;_)5G Y^IYY?I2DSKO*U$.;#O)&$!D(1Z8?:GA8 MC8UGA'O3 EN3\,D4R4TD6>$B?'2BOHZ/)Q,-?3Q#@&8(= 9_W(4(3&33,9%F M&M"I;JHF\24&4T62N+C0$!4:(D)](+1CPE$-%PB]2^1+Q$1FA,J,$)D!D!D9 M)4@$=)I(#)Y*;B)?_)D5'*-28T1J"*3&9A$"'S[">& ^.<($,V)7J-@5(A84 MV:SN/OZ[1+Y$3&0FJ,S$D.GY,:BQ29"& 7?:FHP'WR@D#9FS#_4W@1FEB[1U M!8W2-0M!N1@#]6+,:*%,]8R4/O[*&EM^<^DB\B4ZVXS1/,YZ&!$M.D ZC51$+X[XLP MLQ9*<+LGF-]#$R6(51.X6\ @WU@+&.3-*,9=GV"V#YV4F'YM+(:[2+Z(3+7B MID],UT?LE)B>#5^B+<(D4"V2)ICK+>[^Q+1_Q$X3<[-D+ :3,9J+I F!6F>T M8:YI>]0G#V[MV*41:MLY&AU.-T^>VG"#\8TZ]>B-^&>:+#T71_JC:(]EPZU7 M)N1V7F^Z#XP)*B6Z#[*7)WDN&VXJ>A#J,I;7;7=2Z6X$.]\.7L/I+_L+4$L# M!!0 ( -:25TCW$F\AWP4 0B : >&PO=V]R:W-H965TVQX?YO-GL M\C)KOE3'_-#]YZ6JRZSM?M:O\^98Y]EV:%06G[@6_[UUW;'Y@O%_-+N^V^S _-OCI,ZOSE MFK8JWYM,)V7VZ_RY/PR?I_-_XF!LAAN8L8&Y-*#P;@,> M&_!' WNW@1T;6-%@?A[*,!%IUF;+15V=)O7YZAVS?I'0@^VF>M,?'&9V^%\W M%4UW].?2<$2+^<^^IQ%:G2%S!7T0\Z[[RSD,.L?*J.;F]@1K3;#0D&HDB;$( MA@/EH7UT.U"#>["P!SOTP#<].#%39R8!_4Z M-&+&/82PAQ",.!*C69TA=R5T1BX10]:0)<&D@+%8;0351DBMO$ 14!L)L8") M3"S4(@BKC:':6*NU@IQ#WVL1=$F M0-$(5 MP9#[1 9-="Q5&[# (KF^$$5RK::0(M]4XQA-C%0G4C7K,R6!% T@5= MT]@6"/E"'$C1]EZ\KQD12L6;(1;R]B-"-B1G)L5 1( 5!($'M'8ER@!HJ65CM#-B=3U6"-* M#2U%U/70;E-B[(0FT&X:>M([@XW):&,R,CE8&6TF='VB,?\&%*N[ E*^+-Q@ M8S+ F$+IID9["<(T@*Q^Y)QM&3X3Y"QGS6V;]0I[%KL1195L51!R*+2DS0C "G!]Y!;N9['&J!^I>I!%I2OB+1> M@,6!DHPZ"YQOEK'W653&4LOB<^O['$D!,O.D)Q9[GP7>IXI!%A2=6+K:&E!J M<:6H*_)5^RWV/HL*6')78+5;.96R HA42@4@#CR;+XM=SZ+JE4P"+:@X24=? M T@-*T4]L6]=8->SX)F*KPKDL 3!)$T)0)+T>0-97^G+8AQRJ M6TFK'Z'PSIT+D)FL+P)&[8/F5\_*R[Q^'5XZ:":;ZNW0]D^7FQX,OVS M=G%\10_I^?6$CVZ6BV/VFO^=U:_[0S-YKMJV*H?G[2]5U>:=Q.!+-Y>[/-M> M?A3Y2]M_C;KO]?DEA?./MCJ^OW-Q>?%C^3]02P,$% @ UI)72#6-*"3? M!P V38 !H !X;"]W;W)KR(L () 1M9,K$ZG/70FDT-[9FS:UD0278F.T['A>'%\/9?'8W;3;+K12;K$K-OOY:ME=^W)8+:NW>KO9EU\.L^/;;E<< M_KLOM]7[W9SFYPM?-\\O=7MAL5HN+O<];G;E_KBI]K-#^70W_TR?UF1UJ^DD M?V_*]^/5W[/6^F]5];W]\.?CW5RU1I3;\J%NVRB:7S_*=;G=MDTU7?_;M_JK MT_;&Z[_/K?_>C;>Q_UMQ+-?5]I_-8_W2F*OFL\?RJ7C;UE^K]S_*?A!9V^!# MM3UV/VZVIUOF<]VQ<_3[\V^^_U^^H]7_6WX!MW?H"\WD+MY@^EO,+]N ML-U(3Y9UX_JMJ(O5\E"]SPZG;^.U:+]T^F0:SSVT%SM'=?]K1G9LKOY8:>/# MM$^TZ4*HGCBWS"Z21/L5>XJ'F7"-9@A DQ3%(;&#W*4[R"X2,_R2N>#3C/ MXW?)B&AH#0:9$,DDO*0U9E"K!*]HS*"F*5[I5=<#MBZ:H]= Y*1G16.:-:)9 M*Z$-3*%.F8HUIE!/FHQ[U8 @I>(7RYAJ: \F6B.BM30FS*%V*7[!'&HX!S*_ MY!R/C+GEMFAH#29:(Z*U$]K '.J0X!6#.31P+HR]TJO<3:_THDE>,9AH@X@V MTH@PAT:G>$58$:/9,/;*NE<-Z!"ZP:@:A*H5'@*#\3)9RG Q7@9-PL98];CF/ BB/O7];-+0&0V@XA$VL('V'&$*3 J'%$%H((0N- MH$IX6BP&S"+ G. UBP&S*8!9#)B%@,5/'%:YV"\CJJ$]0@"+2'3"DL9B$FT* MB1:3:&'0R/P"EZ7QZVE,-;0'\VH1KT%@WF+*;$KH:#%E%@:/S"]P86ICOXRH MAGL,F-B,L]CX11A3AEG,4D+(#+.8P1 R]@M4,;^,J8;V8*XSSF+C%ZD-S&*6 M$D9FPB80#".97^#2--Y>&U,-[<%<9YS%QB]"@)%A%K.40#+#+&8PD&1^@8O3 M>#X:4PWMP5QGG,7&+\*[VV$674HHZ3"+#H:2L5^@2@NSA,/$.DY9,V)A!G:8 M,I<2)CI,F8-A(ALQ4HDCQBRZ25LZO6JPG&.;%T D!!A.V).%'$KCP1RZ% X= MYM A=N(E[CU0!>EEZC!@#DQV&0F Y1BP/ 6P' .63]JKZ55BCF#8$P8L1X"Q M$"/G6Z8\Q!@1#:W!J.8(U2#L-><8U9SOPFA%+AX15PELY)C3G.^7-MW$SR10 M76^]#CO"$.8\G]%TY...N$H:CY#SX+LT33=Q=@ZH\EQ@+,//8^1]ROK68YC]I!2)'T^1 M (F8-O(890_6MM>V#-O */N4M:W'G/I)\ZD?3W$"B9@V\AAE#^93JX2UL<>< M^I3YU O9R4D)$L\1Y&DC(!+31AYSZL&J]CKU.TR68@)#RJ0;,(%ATJ0;>.Z# MIXU&1$-K,,L!3,Q6"<];P R&E)5OP R&20F2P*=3GC8"(C%M%##- =0K7*_# MAVU@"D-*>B1@"L.D]$C@LR5(&XVIAO9@H@/8FQ5W]8)0<9"R-]M8"!LY71]/ MOJK;Z8^39\94D45"[8'B7&NQG(.44'V@4O9Q20EU VI*JN3^++N=03JK)GI' MJ$)0G._&.T*,1TJH0U IN[FDA/H!-6D_%\ND,)N44&B@)B%\EMV.M,^J"5 M[TU*OF 9R[Z,RB*;!)@U"E+E5@1*=5(EGU#X0[#RA[]8H$PV68!9HTA4+-43 M:H1()Q7K";4]!(M[P(,!$RALNAF3138),&L4DTH;P214"Y%)B4I)J/(A6.;# M_0-DFFV2KW%K8J&G4#5$!D6G4E$C"75#9%+B4Q+*@@C6!;&=6"1K3(YCU%%9 M9), LT%QJE3>2$*A$9F42)6$(B("5430/UPFID](*!$B5"-DM31M"45"E%0E M1$*9$.$*(+:(M7Q]:FWP\7.!9+F51B84%!&H* +G+-_OC[%M5U]7NKCUT]%15==E8J3XV+GLIB\?+ MAVWY5+=_MLF:P^G@U>E#7;W>]0?)+J?95O\#4$L#!!0 ( -:25TCB1'&" MVP$ +L$ : >&PO=V]R:W-H965T&B]87:3MC^?6U#"$O0OF#/^)PS%SS. M>JG>=0-@T =G0N^#QIANA[$N&N!4/\D.A#VII.+46%/56'<*:.E)G&$2AAO, M:2N"//.^5Y5G\F)8*^!5(7WAG*I_!V"RWP=1<'.\M75CG /G&9YX9,)3P[P4(R[;^H MN&@C^8T2($X_AK45?NV'DS0<:>L$,A+(1(@V7Q+BD1#?"=UU-V1:)?85A?.Z3OKSVPKM/5>&PO=V]R:W-H965T_A) MJB12T]5J]V*EJA>[US1Q$E3 62!-]^W7&)(2?(Q"+PJ8\9R9P1^,LSC+\KTZ M"%$[GWE65$OW4-?'1\^K-@>1)]6#/(I"W=G),D]J=5GNO>I8BF2K)^69QWT_ M\O(D+=S50H^]E*N%/-596HB7TJE.>9Z4_]8BD^>ER]S+P&NZ/]3-@+=:>-=Y MVS07197*PBG%;ND^L<=UX#E/+?SNF79C.Q?W[Q_EVGJ\)_2RKQ++,_Z;8^J&A]U]F*77+* MZE=Y_B&Z',+&X49FE?[O;$Y5+?/+%-?)D\_VF!;Z>&[OS/QN&I[ NPG\.H'T M!*\5TF%^2^IDM2CEV2G;VAZ3YA&R1ZX*L6D&==[ZG@JT4J,?*Q[P8.%]-)XZ MHW5KQ'M&[&KA*?=7#8XTUMRR8U(!$4B0X2%S.(AAA[B"46=00\S ME&@\2-0T4H'.L,P6\,I8L%'0I:%RBP\L0E599"7)\;O M6:R=57^U4C0?6ZT,P\7HGO7:6?47+ LL.AA!AA@D6ZP8+19.*2\FAYGHJ#C8 M,-_(*"\;+2Z&C,5(C _%8D,LI%$U#"1#1)*M/)@V-I]08HY)XI"DX9+JK&Z6 M5&C1P;1QAO*U+$N.:>-\2KX8(0X1&A+;6=T0.X_&'C/')'%(DJUTF"0^A22. M2>*()/,Q1\9CCBTRF"%N,J3>[<,/ #<9BOAH<3%#'#)D^;)RS!"?PA!AA@@Q M9+RF"# TEC1AD B"-'Q-=58W3@_<&[UN?)^XWNU] MF:\6QV0O?B7E/BTJYTW6:L^H=W8[*6NA O(?5-X'M36_7F1B5S>GL3HOV\UJ M>U'+XV7O??T!8/4?4$L#!!0 ( -:25TA]KE(G10( &X' : >&PO M=V]R:W-H965T]=@/CPR?MOY+N-GG"J$! M/UL\\L7<4]H/E+ZKQ??CU@^4!-SA6B@/2 Y7O,-=IQS)P+\GG_>0BKB.^(0NG7BCXS<\I9 HAS7MN/YZ]84+2FX4WR/H MPXQMK\?1[.3!1',3X$2 ,R%,/R5$$R&Z$^)/"?%$B"T",*GH0NR10&7!Z.@Q MX@>/5@R*P-*-:@W M,E,KV34DC&(K6P?F.7&+39QB$Y=8J^R5 26+*'ENB5U#4OMDUI#H'R>3.J6F M+JF1)35=!?F2!I96!\;.9^_ 9)E;;>94F[G46L=79>LHT/JI=@Y,:)?6Y0>Z MU>9.M?G_W-E\?6<32ZP#8EWK_1JRO-9&*U@\2P2SLW[?N5?32R_4S[VPSBWD M!:IGS;)7LK683G!W4Q8#.N,?B)W;GGL'*N2CJ9^V$Z4"2XG!DZQD(YO?O.CP M2:AI)N?,] .S$'2X=;>YQ99_ 5!+ P04 " #6DE=(7!(90)H! "X P M&@ 'AL+W=O&UL?5/!;N,@$/T5Q <4!SO) M-G(L;;):[1Y6JGK8GHD]CE'!XP42MW]?P(Z;I-9>S,SPWN/-8/(>S:MM !QY MTZJU6]HXUVT8LV4#6M@'[*#U.S4:+9Q/S9'9SH"H(DDKQI-DQ;20+2WR6'LR M18XGIV0+3X;8D];"O.] 8;^E"WHI/,MCXT*!%3F;>)74T%J)+3%0;^GWQ6:? M!D0$_)70VZN8!.\'Q->0_*ZV- D60$'I@H+PRQGVH%00\@?_&S4_CPS$Z_BB M_C-VZ]T?A(4]JA=9N<:;32BIH!8GY9ZQ_P5C"\L@6**R\4O*DW6H+Q1*M'@; M5MG&M1]VLO5(FR?PD< _":O_$M*1D$Z$> ;C,6V?@@GBMQ@3\QP%9T(-[[8 MI'YP92C&.<4]WYCUU7/!LVR9LW-0&D&[6=#J%K0?0/P6M)Y S-N8O/!9+SPJ MI+<*W^85TEF%]*L"7]T9WC "R8/2TH:_XRF1$'M0KCVL1G^K"%QV%W>R?18BP]02P,$% @ MUI)72+ :](6? 0( <1 ( !0 !X;"]S:&%R9613=')I;F=S+GAM;.2]VU(C M698H^'SF*]S"R)-@)DAT!2+KE)D"%)'J)(!!1&37E!T;=7O_P7?3[8KXL_L>[A]7J\?U//Q73AV01%P?98[*$;^ZR?!&OX,_\ M_J?B,4_B6?&0)*O%_*?.X>'@IT6<+M_]^4]%^N<_K?Y\EDW7BV2YBH;+631: MKM+52S1>\@AIMHSVHR^3LVAW9R_:B=)E]#F=S^'CXD\_K?[\IY]P"!ZFW8D^ M9\O50P%CS))9^>NS9'H0==NMJ'/8[I>__)C<'D3M8_IR4/[R7]9+>/.P_DVW M^)N7QZ2RI,/]7\N?#>'I&;WQ<1[?E[^]B^=%91@WQU62IQG":!:=Q:OJ<[+% M_^.__;>-2_V8%M-X'OTEB?/H(WQ8 67Y29FW]MF/?RE_%K?9 MO++_T:3\D9SY=7*?%JL\AGDOXD5E=_!B='IY?=7P]BFL-X>UCN'P?X]^35[* MSYVN\[R\^R9([N^W._O==L-4']-YDD>G\-Y]EE?F.8_S^R0:3J<)/ 7/S/CY MIF5GBP7@^&253;^UHLE#G"=%=+E>%:MXB5!L>&TJF\F3QRQ?(;3AA57U=/Z2 M5#Z2$9ZR.5SF.'^)[G!YE<%4Y%+C(V3R=$9P^Q/-X.4T "D JBFWOO;W8O=**ELDJRNZB>#[/GFGS0/>B6;:^7=VMYU&L MK\ C.R=]6NO.R: %0Q2/R725/B7S"@*.80G+50UFGB5W":#-#!8YS19)M(I_ MKZ+'%:!4G,ZBY'>@Y$7U^\O5 R"_XE]<%$G-3NE37/1#,I_MPY;V"P!L=+LN MTF52U(QZDZW@3FX>]2H'YI*O7EK1U1R)! )C!&?VB-!^7[V&RPH/&,T!9G". MT7VRQ+L)Z-2*9DATTMLU\1J>F8;.<*,U9[A>K.>$KK,$&-LTI6'J\'J5KZR+LJ(<_0[BRZ;''/IP51XMG3XA71;3*HO@.[CHL MN K_L^1V%15)_I0""L)"X;?$@ 'WFA5I]4P^9=GL&2YF_2I3(##+^Q0070#K M\=W ,5X@"?L[,WM"]"-&]';_>#.F3V3! &W888'O#VM1AY>SA,^X MX8G+F^%Y$S416G,^'GX8GX]OQE5.YTC 8_R"][_F^WQ-%Q2("9QDT_?^8. X M;^%,5VGU3*\3F"PO$CB\V\I(%]ER/[LY=PO\_O)PH:]7EQ>; '^S9L^&AP*WK4.NW_,MJ^ MA!)9<><%UV@%:UBE>;)X94\5I-WP+ -JNV=1Y$B%2.#"X/:@!)$LIW@ZNT62 M1!<9T(BHS4C0[NV5AD#9_WWQ&$^3__'N4:C%NS]'502<): 4(*0*E&_PY(OU M;9'.4H!@S29^&44JY5U>#V_&EQ?1Y.;R]-=?+L_/1M>3__CW_QV-_L\OXYN* MR"E2%,^RNW-X<-B&*Y;#2?HL-LZ[L,J@+*],DX%UG\>SF8IDD8X7V3,^T#7I_%C"N==A?<* M]"J8$T3;)8Q?)X$XJLOH"'( '. #HNE3$LVS*H>Z >6M6(.86+"("FN> @Y' MN^W>"=R3H]9QM^U V@27=ONP-3B&9WLG&YZM[IW1FG BRT'291Y!*WG(YC,0 M6Q$GD&&N*LP!2<+EQ^*I<9*Q<1/2EOY[#)8[& < MW*SM.53=@)Z-M+YOT. J-.P3>-]= I(<+A]%JN0NDHY]IG(?>>N AXLXOT\K MU^T3*35SD?H7Z9*L*2B_-"IS[DCD@<;O66.L2'7 +R*X,-,RDQ*9NFD_ U7 :$A9A\&9Y4=61*%T K\QI-0T3DJ*PQ7,?LSQ)[Y=R MRZ8O$5JHBI@UNWM8&5QRY)LU-]P)CZ*;X;\&7 CX6C0:7E_ TY/H\F,T_/@16-7PIBK\CIW2 MW[2("P (\T&\3RI$D+K6J#B^NO"&91#,]J*[/%M$F;_3B#II,26)%*FU/VJG M.J:5?9#2" +[3J?;4K5EL^*(.\4%\/PP(XCEZ:36[MW 1[]+5 MGEM73Y:UV^[OO;*PT4W$(*TA/+B0'/@FXI'2X"HE.0=PO8]V&.+,I,HV?GN@3PTH^'-S?7XPY>; MX8=SN$2748VN4:$0GR^_7-Q,MGD5?O_\N:2MU!AG:#/-!^*0"K"IEM1N@O:F MES\,)^-33R;@;D:37X;7H[CTW-XXHP>UDGPG:V%Y&TDI>]4/P0;O!;2 MK&]8Q-F2G&^BG+42@&49#23[#YMP UQ/ Y59-OX]"EWM0,T@KA=$YHS]*(\\ M >.NH-KFMV9_6XNYN(ZA"7"B70$7,S20I'=VC_:$I;4/-S.TZV0Z![TQO0/, MHSGA^JIDX>;<.;33HG(*JBIB?9K-&KC#W9;[JFH#.:C#)!0WPNST 31>5'- MC'5/WP&*J3UI:U - %9''6'^W?8KS'\K6)E)P\EVVSC^SFYGL"<3]EZ;4)0. MMUV_1Y;A=?/-=LW70?BHC_HSB69K(N./<+ZY\SJ@[O-]&+'59#@P+'>-VNB< M!'='4&!TH(TR^F9 ZSD3P#LG"/#.D9/N3H[_@1/6A9;=(>'"<S$ <:$4WU67('*TW MD)+F/;G!MKGN&PYF S;2F9$?>,1*O4<]-8EZ_&MM1DCL,W4(=5[C^RCIW.,&K^R' MY#Y=XE*X0HO &/T6][>' 3H_?\J ?^UVM8 M>01DX#G.9U5;,])24KW:S7;+JW4.T&%+UBKP)%2.ORC6C&(8*?)[DD]3?HV>WK^%06;D MU0,@\4FIR((!)H7#LS]XW"T.8#@%I/3 "+<9[39X2*F&WD6R>LAF)FRM/.A?VQ7"L7D[E1B\+;=3>:^!^K8B1P+I$#[(K4)Z M?ILN:SV1?^V\<1.5X-DM-U%Y[Y29#I*ZT=T=2-^(3A?)6AP4!)'E-'TD MSYK&VL)3PUGV6+>9BA(!"UG/:20"R.3Z*G!2S-8Y?H=RR>HAS6?1OX%P ;#$ M.1#N!R #<7I_<.*-4,,543W(OG35NM\2:[L['Y)OM^X@"%X MVT1+'E";#V[L) -B 4+@,XJ"UZWH_/RT%3T_I-.'Z!G>A@F>TFQ=S%_4_0VC MDII9;+H%5#L MHEL\+^(Y G /@U>?TH+EIBP7QX#$BS6YA-5 6U2<:OM-9OY:M:]>$Z5;Y9VJ M)FK7Q+U5P+2KC&,/48U9"$;)5F-EMGPS;8JT;GC^L11;;>("-P>F-HRW*5+5 MZPDSJR?$I0C4FB5L"!UL&-38H618$0C]X/:[+4=]-< 5%1B*W"<$G:&Y_\5B M!1LGZ[9Q\74T>>WZJ1Y*AP5:ZKJ&2ALQT8O M"1B1WDU1.0JSZ9),A,!$AE7 M-:HA' GH6F44)^-NE7A@M8OMWFC MSQ,@VAQP-"&L/%ZU-18#YR^)L7%'>NZ MH%!H_^2&(_TXOAA>G+YRI!^R/,^>R6:P7@)[PE"=;/Z$(T_)\ /JZ+0QFAK0 MERG8F]]URA4<0+XI*MM,\MJC=LQE.8AK\[BO/GZE#Y.$QW&'*%TF=>DB3?B< MOS'ZU\L!1",QEG\TV:CIU2R3,//U>QNNFJ*M-FF'WI%LQ&KT5S2@M@/95A1K M5_!\SX"Z&=&]%I'\+A85S#(3ZPKQWKH4)346D3W=TUA:3+/3M$H3D;2MWAB_ M;TG(=-N4J\;.:DK+@AFKX!_J*=N,XC.QW$B@_ ")J3J/3W\9G7TY'V&8%P8W#R>_ M1(:379Q%6Q%!2_UH0NLV75!Y43D;7/8\6]\_N LWIS/>*C6E1N:_ M7:_@_JVB%X !$H#R*S:Z<;)>+- 6@\I&"BHA:L*8/VQ4:E &ZL33FD7O\%@3\9?[H8?QR?#C&Q\/04HX00YE>7Y^/3FJR3[QNE M-L@E1;T752MB.QE(U4N@'TAUW[%N249M^/#='AP/7%0]HQ0.SIXM:PE.E6]% MNU,@>C[;Y1W,_"X"!'V'@_M!6;K"]Z/[)+O/X\<'U&5!C9ZEJ#+ 4H!?J\.UI D'KGJ-*[F'<9=HN"@J&^<,.Z#O+6(\\S#' M"#]*X=8#IJTQJ\N'8&KX,>J3 2\$%D#>&P8E@0@>24$"4\,9?ET=Z2#Z+(&[ M,$[33&ZU9+Z8IXL4Q]1%O[B'U4Q!3P0;>V$!#@83[?J D,0-C.AQKY 37KQ MN>P^SF=S-)'!^\\/"8MFUJ@)+TZM!LT23AP]9;2/+*\)_EYDLV1^$%U=CX'D M !6E\-/3RXL)(/ 91TW]Q[__+UIAH)W[/(903S>()EE9B1AV? YLW9T@_;*$ MW@I#A#N.X0Z"+D6ZBH3- P0_L@$+%&9 H^80]VCWW=?QJ'A'7),'MPM^((M4 M]?6'^ GX8Y(L0_C"(2S##1>,>7E*A(UMZU,Z&]S?ZF%=N#73D["8 S:)ZFTP ML@E?;PG=9^Q+$)V6-'EJ%X/VNJB4-NKV#,L4 -I]TJ$(0J('5YT%A2'%Z?)N MODY@]I8C[++\%BTG-+KAS6<#96AXXT11(=@'T=G5?X\7CS^?M^B: =682ZCR MY4.:M6AM:[[P)H62=G2']E=#?+RH3I!:KA<)T,F"8;A(.974/T3W#';8,/K? M,OAS_K*?/:-;THY=V2GB*PI_^["0&$ZH2-F4L:-TPP':]3"ES!Q=T]2"+]_$N\NA#^NA/SIB]NT2I-N:7LW'8>ZMG MZ(5&^O%E0@(92F&?,>S>$3TR]N3.K[\B#'KUD.5VHC$=D9MVX^\ GC>["BRE MA^^31[G9")TOR]2908EL#@&]X5X"#?LT'%X!#47.AKAJ?(EY'T)* MN<.KP&LA9WW&^A1"INH6*>DYXN@40YSQD?B2&AS%<0!RY6I-?@CT-R =7L]Q M0P"'7-7>K#!P.^#D+>1(?T-0 6"+-3",9L *OWO/VXSS_(640%HT+U1>G:%1 M!)/VYAB6A]N99\O[_3E)\@S)G_EG9()?LMMY>L]&UI]+T;+WDC'3J@[DBA'4 M>4)@(/3F" O6Q$*F/=Z.*F>O=2?0"*B+9%!/,Y :C70CJ549\CWSH&Q?KI)Y MR& ,/QF&,'HD2:D>@ZR\^F 3$JJN@S3&2:@H@*JGD0=;D"_;>4 :[ B&SSV\ M/&;J"((989:9@'(5W6;9-\V4?/?+^8>O<&$%_F1^%R8 ,FKR3-*&86SB2T-* M)_L$0@72C:RV) "*TM=D]E"Q$#A>SK3W-C&OI%UW87; MEST^9D79V6Q$E+V?71Q'<(;)\BG-LR5"DB!COL+# :B)5Q _O9?0_WF<+OCP MX!17ZG-H;XE3M4JL2A[O#@[WWD?7CIP%-AZ3 M'8 OGX7D^4#8!5"*EN24H.4=F:7-RTO+^'E$;/*DT<&,.(M9D,F]P 9N!YW*WX MA<9=6"1E#:*T#A &-O@W^"@12]O2#_IC$:2E+"T;4O: HOG.T7S/H<+H+BH M-K+WA>UW[YLI+B_X&45RX[Z&P1^3V7ZV=I[PQBR:FG-@%?A9&9 3(6C4GP.: M!T!88%P)L:@\)6%.:(+&(_"&0^,@F9>L8<)!5!3N0W4)M6;$<.)F6@ X6479/+BX >196)&!,1N)[*C]N'DI7H1"9GN M CE6D#$Q)3TFJ88&\R%2(1 $IO*M>O+0"LZ$P;/E4 MTPP@L>H&]K )VV<9G?<3) SE;TY>#7@^@WV&ZT MZS.X@8*C:%A(@/X(E&1+UIY)Q"3C@2Z@Z5:[I> XYCTR.O@8,,0;4I)@]OF+ MT7TZ/6)Y)E21+T:XX0_..-<8]2/QU( ](=.,&Y9.<3BQ/_&R#8C./TEIGH=X MQAMB$"5D&L K#4-4B0\MD8@/P:1BQ)BE,\(JE/Y9/">(!53$DP6^__DV1$9U M3[.IF*X/_!Z]8,'!^ X#K]!"!-X9T5X3%/[N9T2 _6S^2D6B>6-I*"CUE>H2H> MG;8*$3N:PGLV'9L#HQLRLIO$66$Y\*CR1,C'U66) L< M?^VL)6IK(?70BQ^!QY#M-/']/1I^5TK773P!+R)%O+Q#/?&63<427L2..BP/ M4W;:E>GM)I"H:)@6AD/1=2_8*))XCJ(BQU8A7$!)T70:+PT=23?2@%!J=S&$ M14WI!P N"I O+34^O&9PB.# DKG:FI$GRKD6C3K50?1+]HS154CX7SAY!%8Z ME[ I)1[S1*]1@UR1!O&0)!NKV<]?QZK5"U@CR6/-]Q17T:SU+#.R$U#X V % MQA'96ZTRL DUMJRJ^92 ^I'5IE8+WU PCBY3.*Z/I,*5O[#UFRB]O>6.B^@% M?$[FR&VI@O!!=(UYV9,)^>=8:40FJ?;76DJ6+K?"F:*)/!H".ZZSC;P@.H_F2&,?X_4\4YIKYG:D_@^)&J-OMPWJ(D)0 MZ);?$'G(%"3;1#Q*X9]Z08@3)U@DNE*"K%N6OO5T#9#5 !,X7![Y0[+O- >2 M; +]]@DJO'.!V!\6RO(6>-Y5X%DT +1'R,"0_3@<7T=?A^=?1G2;3$BX=W]- M$U%S5:!Q<0IH1273KE1I1;))D4(("-S,'1FU/-:GS"=R8,YXDH')S>[^-H'+ M#[<1]*MO%'P @M T!7*W$MU8"M4S%MTB@9LK#N>R]M]'[EAW8P"PDG)+,X M;=(^^>83M\<,:W_UI,EL4I/78"PRI$0C3?S;>LF8[/2/DCW:79E:GP .%!O+ MJA&,5"QQ ]SGV?H17U"_@1%^ZY!:243H=*BZ&LR((6C1(U4$OI+X%FU=ST@D MZFXL$PYZ@617/ J6ECW9\#3"NCN!$%"E,]]Y('Z*TSG>'G4 WP')R'+GK\&3 M!,)/+Y 1/"V^<3@._281.(F%M34RW:WG=_!G,F-\DS!2>E6T+1.BL7N7!)X]I#>ILZPY>O?5AD">:D0O4TB HY].\^FW^)[ M"XZ +/DK<"">4'):LJZ[P$@9*DJ]@B'0,B.G&#H;'%L$^'HO;@4J(.$J(72G MZVZ!.^:#$J]QIY[=8L@RT4?%):3GSM+HS_\WM2*\B,UTY;]M1;A"M T8GQB% MQS ,5\GT@?IGB/&,J 75#^>H1%P)X3,N+0DA.%/4JQ]O$?^>+D %H/VN.<3; M;"I=/J[E(/%LRD^NEY5G]<0R+*BMQHT"(UO()4D*#TGD@/%P?G2C_[:>W7,F M,)OH0/%,V-,D.B#OE"[_4ID\8AL%6DU?G)EWCBP53FLH=_7'(KBM\*AVAIQ2=AJ8- 18:J>>*L-]IS>;ZNT\I#>/^"P MN'K^JJM?\80,R]4#@D, A^=/-DS65>XR])P6[T$>^G_=\"@;K9=\Z1+,ULOP MAR!F*D57%&')L(FUS_$(1977ZTYF5@0[B3R>TAHJ0L[M8#3"\HSU?HESLG*N M$O0:6II-@7WR[2O6=QB^1'$3: QVIXQ=)Q92_(4BH&E?+*%ZNLL<1VWN%"5S M8$#4(1#Y%PG')62H M#N*DQ<+OE:@%8XX-:.2P1/S @"VLAP:^XGTQEP70P*A\^#4'BQ>F6F6 MDW8GHA C$ES_98!TW3JD25J2#.ZI' ?Z\*'-R6_ MKUA$JWEZ^>.J*I?(UQB9Q:HI&R(P+$B=HDY9:62M<8T\1:>D-E@KA2&?84!5 M9;!0Z%"F7E )I[HI*A%&EO4204&);[W,J=T,?4B%4SC ![V#8^P]-&EZIX8+-Y=I^R3BUQ%HGA?3\6+#5J?(YS MO7E&0K&>RZP) 3&DVQ_G4 ,Y[R@83S13!)PPD-=8G^$S-E]Z)6&P3F*L1CE1 M/@&&1M O6%T65/41%L#T8;SE$\4S"5+"D(0^B#;&'4,0O+?Q\AO<;S2<<-8Z M&_7D$0[<\,JD45J]DLI\!<[Q/D5O(L!:OZ -(8MEVQU10Y1=Q#7=E!+"2%J* MM2HX!P*=?RYX]A$XU>]\N%:PQ5KRU^-3K/CH('G(WP ?O,! M@8:PTUK<#)X+&6#&M '<]"R/GYEB4Q2F,GDC!-.E 4FXD/"QXH$WMXPI*IPB MIGA@&VQ6E#Y=L$GT]L4Z%5"48\%?B;@VJU%]=#3%>C])H M/A.VCR^BS\/K7T=<%&PR.OURS:7_2]?@Q\)B:F !R1,3F+M>$LA(X+^%[]$# MWG@76J &/P$I8DL3 ]%= 1+CLV7RH@2$TH0.F@PQ=$W9.%7C M;:/HXZGD$@3WCE[QT<'A#>4;^4!2'1L,#Z+/)>.4F=YISC;NG/SQQ+?(4?W$ M8?::J.$#TC$Y@H,85HRI51\!N1-6V;Y_1%@#TH.4":;DT"-ARU"6OS3LKDR< M*NN=9>0#6O$29ULNRS$"[^I <5OZZ=6LT1*D8?7E,E(:M;+$$I)X^E#A"<9U M3LR7)]@$ O B!HF)X3@Y8.P+N-!](G@2_9 M!K"DYQ5E^R[KDLZ![8-+G36"Y7U7)X8%F@/--N- R(M+#%J_'IV.@-\CQ<,/ MA^?GE[\-+X"+?;R\CLXNOWRX^?CEW+^(I-"U&*$,"FH8Y -_7[M,5IS@$Y$T M,HHX*L26*CEI)CZXIE9#R\DC;#EADY1C5PJ+Q)MF*&C0CMP" :J UT@UTD2X MC/,L8 <4*D0JVWW2L(BJ0PSWXF38A)!E:B+9P^E9RL;P'"H_\UHW0%7"353X M4I=-BY' <9%>@!?!0SY]1/+4#$NK66U5#(W&89-OE6N[&#L:+O!8 M4>+B%!3(C/.;U(;]B".0!V6\Y#,#\87UR?#:E/W=!"8TYL/L8B#X39.JS FJ M.&<7@F39J1*$<+HD[3!9.+FXNK_]"U\YU=S0BAG!ZHA"4?..Q$81'DWFC2J;39!ZQ0!+C M'UGC2#&34&K-R]&7G'9)+VW,Y;2I4W[!:.'U)&%.H]!=+,@.PJSU@"MQBB$- M-$.],X]:Q8*U6$K[ REUQI'B-MN?Y7U":9)VU[F&K[LD#Y>=A!^C$ OZ,4?5 M "QGJ=H"*.V(O.ZGF<#7OXG@$HYCI#U'A6/,;+@7555)KTELG:EFUF!-5VO"-Y@"HQ'V'$3GEQ>?]L_'7T%_XG:*A-WG M%<^0ZDR/FSMERM-"FFQ&NE0@*K>QLMDY00W6W?0@.6A%%&>:R%HJ;^\=1!M; M=Y82RNJ>X)Q@;J*U"JM?QPU=1D5GE5QC3@#Q%9;R["DQ@>)D1)JIN9]SAN[H M/#>"4CBWJV%P$ 6]3+61J2MC@*45@-8GS'[)<82X!325&)A\ @FB;FIE:)4 M/"P($<64RL8X#J28-O11+:_2)G %[V@E7E=PHQIAQ9$'%(_+S@HBP7J-Q-5/ M 6).M 2V6PHI53E,XY;9BN0L479NCW' SQAD:8#% M:B]'!V*@",,;J+$A"OB=V]:7;/ W;Q@EE"0(-*S"(<*%*,F4+6\L:%4 OP!^ MIXJ+2@N\@A1Q(\2L_72Y[TXW2%U6>Y@0\:3:Q+?*@.2./TNPH'5>$\F-9^(> M616BHI$$#6OZY+A?Q*:Y/<^ TB^*-UQI;'8O^MM M<_E,@R*)!6A%[%=NI[?'LGY1CE2N*Y9T$-D*<2V)0E:QV6-6/']"CL6\1G(4 M&S,)6^RQ73RN5PT<$!-NL*+C/@6-:$[W4U(17DLIC4#AP%:B-1&1O2YZ)_F^_#H)ZT4BR M/9:"B"1^;3=@R1ENHN1;PN4=6T@$I(A9EL[S&1-MDP$!G::\.#',-4RL!!#_ M)-KE(4T+;@6C5A:B!);?L$M"\8"O)'NY*0*4HX+= @Y*)K8/>?QWS%59UM9W M4.& 3$.;(,U%$NA-*6'BM1AM':TDRB;:^XS=7.2HOS/B.&P,&+3#)]70FI9O M:6]2>P%>)P-T37S.3B"250W^-1N50/&&(5Q@3U'[BH0):K"2J,/K=0I%_'+YKSJF\VK0C_2/#QR1F9:!6\<@P#^GZA_ MR*&5I6 S:P50I0AP0\M6F&1L]KF6EQ3:&A1CZ5XZ#$?_<#9'A056M6H:WBM M<.1_3_(,H!<$>AEQ7F"),"-%?9KF(.1R]G!!GG2TA7NEI9P%7QLVMFL8^YX/ M$L?P%L2E4%-A:M?X4-!A*( M0.EC6JNDY7).I+K\*I6:U=P+Q^4LY%>)%(9"%@:U@("*'Q+*'0C7A)4'&(RRI$F M7$HEN/4I44)XTU50:KI&Y+GS7+@&XPU:HM<%P[S9&E^/:US2@I^C * @-MB* M5;"I:OY+R>+EK(SL[P'16?,2ZA=:O8-4&'N, $V,[:0+0U$>EL]%&G+%8^ D M8]__-DC$H%7PTL0H5UZ@)N0M;7=A'Q[M%U*Q27H*+@;0ZBE\3]:VRA<-1^WH M%*M4BG.([N:0YUPKHV#A H/W_Y,0[VF#V[,SD[)0F'IK1"1@\GL0B!VX M&(33RXO3T62"M=B,D6WB.JXY&'RT)<(_R"CJ -DG 7I"4##917?V: MIO]5;%X:\ER%8PBF_P*&BSK16N27S1CG!6253>5:V"[4DBQ>N*I%A4BH@4@N MA(16B"76V,$#XDTZGSG[=$!MF"Y7*WM)V43G,*!D.[*2U.S%9SZ@3N+=;$;8 MQ$@QDQ];8/Y]N0U(MLS6*K]P^P_8!OE:@QS-?NM5-49*P, =Q)Z%0$,.HK/1 MQ]$UMIKU56)/+R="$MB]X7PEG%>R3$II):FI.>U#:#BSB .;^8*2DE?1>IR! MT<<7B3/>U/]SE7=\G4EQG7R.OR7[SP_9//$E=&O6*>GON"9OMZK-$_5RDX8! MUF=32Z/USZ.;7R[/@E A]586_HQ()C^* BI$XECNTSQ64>SM@K M6/I]":*8:B0+-:EYD?TN2"$)I3##Z%UI3PISD02DQ-C5B/[OX[+A^BRPC*D4 M^:QFP:$X:*K)JK#T:KZ\C5JY(9'ECMKI3!,74EJW:>).:_'OS^D; ;],22T= M).9<"^SB@21)#4[&>N#^(32J%L7L*'HXYER4D,*EHCG? M_E.:/,LJ;#(;:'3AW#[E[(NK4A2XB+7#W;,Q/S<(ENH7B4NF%LY$JQ9$Q'>X M_F?-Z5#,DIGC%7&<(MA!*N5LHIK4#(T8KDM'KSO)D V1P7!DOJ2$3 M2NG5T^CUY4J>@ZG&XHI*"&G$N(.I+9Q9.O!G=[$M-3!^=#1%.9B9Y#?$#KI^ MSRE)?POT4/$KFHZBE6T,J-:/B(Q[?K+UR)00IA %Z;=3RDK MH!QK"((%MT92WZ!Y$T:-I6"P>P:_EL@ROBWNJ(T/51AS4.MX$VO!>C7%NJ T M+[0:7EZ>_38^YYKGXPL0/<87XYN1^/O'%S?#BT]C"C;S6HD%IS?,N-\D> *#?#G;CH3/VDGW*.;+YHVFK!::K12A MO1:.!*\&R7DIY;NX'$3_GE&)+LMS2O$=(=4BJ:Z8G,3S%_'MR/DY!";5 MQT7=G-3'RI:0W3YGG.6:)_;UF/^\%1!3J0Z4V>:5PV/B(&5+@#!F"Q&C)%_K M0"WIE5JEY4+)00>;9"]NRLK"" @OLKCB'*>52R2*A"3 T!6B M\NY+C-"O2_Q)J\=O YK=G2CU-XS#>H(II8>#Z.PM R4D\BZIL X,]R_UC6M> ML-BUZ1Y@9@DBMX@[8QEZ%\;(99K]%97X!5:NT]6:.R:4H&4+U# E%M&R8_9]CP(^=G&;5#2;"IW M$PA\GL0KS6&MT6A:(5A+C 5'6"^968$P+?D**.BT @FY\92]#AF<7,MD =2( MGW4;(6>[&.I*)F'J5 TCM^M,M!OLKRU^K5/998/OQ X5+O!'NQX$::H5O9T/ MLM;[AT@J:Q#RX*!J1 *7.%^X\IAAM$!Z%YP&3Z",*-.L<^/;)S=2J2('N1)% M;-.B9:+O>C Y(+5J\,_X79I*S135Y *WST)K9&(P"0J:%+5-+L5;#0I(EQ)" M0MU;<@XH>3$W4"3=/9]T:U(D)6DVO-^M2DA[L^O,GXYQ3J0++KT08H C)G7> ME3+L7_5&>*52F\*$PGJ9.2G19G/VG/(_9U+W(2>/8LEI;2(M*L=:E:#*;NO; M]>S>N)RXBIM)[U;/7$U>[X]A'1:.L5&57T5128+EIKW^$C3( $VIPEQ[E1_W MUFAI0ZZ\A"43?[=B":$HX0S:SU8OCR)&H=F6TQ\=:6;P:;8XPRM>UL_I"+TS M1\2:/VV.0MS7S':X]1V;^G5/3"*I1'X( HG ***@^@!KO+[>"'D)\CR[S5PJ M?6B?\*G22V/ELBNTN?&LC9K=UKF7642FX+JQU\/.:91JS$PU67(+Y/04%?>J)-OL"NA)$3(4BHB: B]8D]P>.2*@MXYB>8QKG*E M$(1)T,_!LY0$49-?>#7\BTLIO+SY972-7UUC-X;S\?##^-SG50_+!29M2I,& M"BI51?XH3DGT])92OCW%F>+9^')IH5&\2%P_8D=M7!& 9QX.<&-&OF2?#I6+ MB4D:O'"2H71)\L%XW 6% P$PV"G(?&_9'*+Z1"W--HZE7%U8 Y 7&RXA;"19 MWR&E%\IPM&4T*7R&;0#)OBM7K/Y T;@ 5%A*LJ5:LX81"N1Q5BR)\.G+ M^9 RU<2NAP=?/NK0;"IQB/4RJ-C]PZ Y'Q^#O&\1?Z/UB=P=E*XQI)/I&G8_ MJHFS49\=[*#VS0(RY@46I0M.J2'(N+S-,PGZUB*?I_B'QLBZY>1KF.(5@9)]U;Z*4N&K->^GKPVR36:K2& M4"&ZJZ9&OB6]5Z,+CD=R/.'JN*>O'PUT;$GFB_ @ --DO&(DOQC[)\MZG6L)&=*38=FIE4:Z3 M$$(*JQ\XAR<'O&&L.\^ L5=-020>@]:K@$YBIQ$Y?'62KL*;J^$ M1BHR<=@]UN;&E8741@.!2F4H@,Q+63M:>;ETKJWI[.RL-:TY)":>]4=0[1#0 M^QC-51D03\XN#D_/;(DDG_G<.3C4[DN@/K"]GF*@1KD6/A^$$B#+O'"C7[@B MNRNO[Y4E*6NFBB*E[AOSMH\;*E2G%9)+GV@V6F69HK:CMR@=8,Q>.^HW>>PH 7.3Y"$OZ_]I!^L'%#7)XP$ M8\J,85>KLPC2B7OHJ1DKID10.,FO$E&N8OS&DU;*>R;Q13IC&JC4:' MJ-OZXT,*MS-[?.#B$ERDSQ2E\]8J#:2P!Q^>-]Z_6U_=DXJZ47S2&NMZ)\Y) MX&LC(@_-0#Y=V2FU8X6^9>H:UNRS@J+J2B<'D* K^H3F-J?S-G.U]W3YDG?* M#>6U)5,5J6NQ3/NID PD)K/I2J604BUBBGL0W+;7-":R5RX?WD3S7E-I8_(*S?1439N[C-@4QE/*?DX8TD X)X/?N0R]3=5 M7.RH=K!*S\H@&1T//\GN^'2<]XI697=15+<15KRD5C_M/K%5N;K4.ZZ(;(.5 M&MB!KCG-TUND\[?9DT0]^&#(\"V')MG2+S9B M=A?_Z<$_N^UH#W[T.O!/OXT?G, '!)ANU..OCZ*3:+<#O]R@\0+?'. _Q_AT MAU\_@7\&AS0>OC&^.+W\/(INAO\JBM=9M0UGK1.Y)A)?$):"@>$4N*(K/K[B M%$L5=:+#TW_5DJ<"W5R=!""J$]%)\V+;?0.^U<<]I_O6XI?_II]><_ M_52D?_X3_K?ZLZ^OXILX1G\=WA:4&/D_*X]K-9G&+\**+:]7.-D/*IS@)EG^ MH\?8F:/-ZX*&PV03UIE7;CZNJVML7'KS MEQ;I13>D-F% \A7J2F]Z>)N3"7MITFU\0[4%HS=M3%X.C]@T[&XH"8#/$Z_< M"S.63;:*)JF@HL)-1]FX&3KODC#P/\"@D9O["\]]CC&,'J]&VP#"]'[O1_O1 M ,ESI]_J=8[PEZ-6[_A8+'N4D4 AE%UXL-\%K>,8'F^W!B>(P_F22AEA>8W? M?4TC#\(.O-1M1]W#/OQW)&.V<:3#Z/BD'9T<'0K^?M\!=HY;O1,#3"J5J^'S I^.1D@'[I Q\9W3;G;1B[6/FD=$B/LP-0G1_3I]X^IMM+U MTJ4W$I%=K=ZYN L,3;O''<5.6F@G39@@/N N^-6* \^2%A2+N;WRIVK MK1VP&P:Z!/)@YEI5.WFRKN317JOR6OVV0[&Q6D_'UK&1,BXF-VG)WH:[%\.N M561@AX*AV&4Y[B]H.1G5-@V2*X==@X+*)74@^B[P(**UVH<]^MF1G^V3;IA, MU BUS@DPB:AK1,RW@N[D,&IWX*KV-A>)>K4B5(M0MMV);@.4[;N_,3 7]W0/ MC!K+(,V3&98^X1+U6M4 V!YK8'\H_O)= M*T D >8R.(J.6QT@PQ<-L-YR*^U!:W $'.D(%C]>!6X'@-D'N:O=:76Z_28.\,I(->P$47:9_+X2;'49);86B>@^MJW>AC)( M A96R1+';A[_(9N#7;*X.KKIW)&L/M9N- M(-/\4\F>=XU/C9N[' @B34]PH1@3@GV3L H0!TQBX.1"BS\MO4L%IL;29=1+ M(BT6V*#>V:'4P$XTIB1>2>P5YROM=!S[IT+6]^+\,J7: \:WH;M@7REALLW3 M/:WP0OUX.?44CMFG^-1#]R"Z=&T_X1TM972: 1?[2+%8'[V4>G;UW^/%X\_G M9&%=YH($/%C>3[MRPEVR8.,K/1RLYA<>#FM'3T+)U*D%VDWCNZY-LE1O'PL_*K, F%+EVZ@WS;E;H7FVD M%\)@$^0IQK($@SI+*0?"^Y9"[F@GM#WWI\_Z-(CRB0@_[V2\=%8U*_@'@EA0 M$_*W+/^&;UV)$QY^:EHXA2"^CW9WHD#G@]>3X@E[GT5?,&BX!\PF^@$)"5JU M2!R+?L6OEW1Z.-( '^@"=03AJQ-]3N-%BI;R%0U01$=T ,8,4!K7KT!-0( M>Y4!Z3UFWZ2:X5J'?5IO%U?>/2FKY-1X["O:4)J_,8:;8H,IP+?/;/Z&9;(@ M)E1;*;[6O$LQ+3J!HE;6Q%*2+9 ME]C6+G*V(_V'E^@IS5?RV^WLJ3G7&='Q MS=WNGKAL I]5Z7V.=)1:4\8.J#*&[3.F9; E#%9&"@Z<.^!1!+5MGN7C=PTJ M!'W5;EQ,;6EIWOIL^OAQV0^0BIQSRY3EST)WT-_%OG7Y8*:%2%T@5HE)I]\BXD M5K_44]:W=RW"F ,N!YIC-PY"/ZD &O9QKJD4(3'!F00![\]RZAQE0VQ]PD/+ M"8S;=&]%ABN;F=4M%L:HK/BU2=SJ;)$82YT" M"U[K(Z;\Y]?/KT6&9*9TALC%N4UK_#EZR)XQAKQED@AL1P:-I"Y3 8Q OUN) M9VS!'N?F7(*P 4I=6+W_M@'E?,A>?4N@YM;0!R32EMH%->-VV4E4WRK0E_0U M02/:DC$XK0V-SM!Z'_8,JK1#X*J,;VB^1##8T'^)ZM5BENPZ;RCLBE&3'*S) M@=3<+)#))%UN%)I](K(_&$R.^-W$,)^-HUT_A6];A@^<9\M9)A&;H%0LOT67 M)&',HNM86I.?CS]<7F-K'=CS] 'A[]6)G$,B9HGVO[M]X09M"FYZ$C\!99># M$/D *5%KDLS3:;1+0$)J$-UB'@H9 ''@/:VEMQ0(<3@+"2H53/*((.5M-B*# MUL@C9V!X,JU2<18C)DHH(G+KM'#QJ;[]7G:+1%UT-OCB#:TQ9A&TC2]UBV7L> MW$6A>ZRIT%U33B9?)E5M.Q4'>(LPG,I- 61>(YD+1\+!;' M0JH5'[/!@G)-,F*KB:0B*BMM"?JA2(X;Q?2R:&/,75Y0,MUL !9L?7..QN7, M1O/2GV7%@[#)VYR]E#>C1,4;I?7:=3IK7P,^YXBQC#,Y(E5P;B2UR#_:*8:5GA@$CZNXJ7FO(EBP>,,.)<48]+ M7(#;K(('E2AS;&$;@[**=<(PJ(.B.>ZR>9KM<\T*SMX($NBP+..ZL&*_G]YJ M%*[-A%0JX*O#"Y1,K;#*EVL"2[5IW,VM2=YR&DRH-H1Y?SQ@RT6MYPE5+F0_ M"Z?O44AYI9>PRSL-*9'#L\LXHF3A?4X6-BA2JF/F1U*#A8 ^9SU$!G-+H/DD-KC<51=KL&F\6TC( M'?R2*6&0"5=$F@==-WUW;#-QYOWO:*F0@PPMKPE(CE-I;*&IW":,HVD MD#7W]#Q7_)"S=N%MFQ\ 2(6O[(6:/\W#MR26U#X;ID?)Z1P[].[TZ_#='K6IE>1)79ZNS'9$X5PO MN:&ST4@L;CYBVYBJT=(TXI40?@96SG=:-5=F?<[FXDZV ME@L*<+X.2]7H18 IILD2#=(D>GH9T XE%1U]WFFP4;O"'PL'$/*\H'[$?VO_ M]>(Y?I3MBP!I ,(!S&%'\G]PY;8$47GE5S'9LSSX31%D/@7-?$H:Q)O^(*"4L*>D7+\K#>44X:RU0 IC<83Y)3M M]E@\3"U_+U4QP-AS4E_$%_>@#1:LT!?*EUZDTK83KON:;S/K>R-3V5Q?E9H; M8[&P=F:(7+Z;4/Y.TC,E=6Z\=+6EZ_&J)= Q_4I$-W0M,?=-K8\90TM)EZD) MPF9V98+-YPY'I"+_AA4INY,4;,H1D1AAIFU5SDK7E>HSF3G]JM:$-W(J@G,F M[XE]_6* D3FXEH%&FM685Z2TALOUW,0Y6+>C250!\PUY"33VI@$Q6U8^+26Z M!9H<%M_!6J@.3F:]MZ1H8NSA*FH?_K"QA%^=U:/KJPHWGRNES?@5F7ZXF]^! M<_=OM39Y-.J6UCE@1WF-]:=KK3_E%F[>4F(J]%>Z=+/,[//_3:)M^13K=J>= M:X$83=>.8()P(M9CM,==)]+HU NKODK?:Q#_T;X>FJE H>.=7;QNK&J MRPG&-8P?;$B_@;BF2,!KB0:;]]++UQCS9-:U0SKAO$2H6^O%\BFP4NJC/NQ8ZQ# MR<$'U6%M"EYIC,8.]6;% MGV>)8.,V2URYPOCC#85'H8$#2$JW4XW=IIT,D,ZZ!5Q8]^IGZPFACG@L&30X M8,,J:[4NW49?3JD(H1IJ@JL-) 3TI<GTD!J7YD8MP54HDKW7_1]G= M!H]\J[%+0>'=\*UZ/WRI^EOA@A_8 D9(3WD$&($'.%S9O1C3V?M)(13+DETX M.(SZF!\<@_04OOW&\N*]W^BBEE1@[]M^0P@1UR+]+ M=2Z3J\FMHXP-RY1A@_/2VI/)DC(=Q&J:%D$)73GB2KE.$,BBN^09;GF\4-2I M2(322?G!5L%4^^8BGN:95FNNE(ZYS[-G5&Y0(VAY?5][T3F=H57G8&%UI=[5 M\IM6L0-25Z05MT&\P@83K*^QC<.I%E4CJ:!9G23\FRL *Y)DPRA&P2,:8/@: MMQIRFD9IBG+X"*V$+P*F@?LH/:&;)*TDC"+&&[+)Z4'A#4YSYGV]E5)5(M6D MZ,_FN#%V?G')H2"&K.QM#CS-3!<$WJMR&0\%?8A#+5N8VODZH M$:AC#5N3NE5!".(769D!EHB@IC%RY7T?$YGZ-:)-.\WA6PT'U16+.7/#*,XB MZ"R,H0W#MF$&W0K1EGJ!*4VC:/L#3#PE!N -[FQ#=Z2-?4#+J3C(@0)D0"^G MB1+X!9;F$Y?+)@!4T(NN"UO_M2TYH8]34/ZVGMU+,Q;M:_#\\*)MK^VED.E+ M=4>:V?=!=(Z=86IO>.7F$0?[XW#7QX"?VF[LA;26"@H(E6N$5JOF$JDA7S/N MV)#G:K2!=H831LNK4X6G%8CA:-9QQLH:SX9](#"0EWTA/Q8EDY$&ERYG6@4! MV9QVJ50H>^]GD3C>"LCV/IKX(M$UL=7E$F)\S9S@)QTD*J_94.!$2_4PZ+0H MM<1.?IAG&CSSQJ-+'G_1>HDST *YZ2 M+\-CFNC2IN>4-)E':JP1"63D8W\$>96#H"8RU06?2*,O+3&OP>!Y0@6>7I@/ M/K)+Q\>#V5+7+2WGY"(=;UU)[-M4.MP!VI/]0N07^?I!.B/.M5$ ,-5[[N=N M#,FP,U)FLOD:*4)8-#^\24K^R^_(]0NFM2;)Y9H4-W_4=H.B'7(1(S00F*$P M3CM^3&>(D$#@\UOZ4FJ^OABN(^>C/7GKM,R2[$1'@0?&B@;?Y@9J]OR0A 10 M$6#0%VJE*E=. MQBU%P@!H>[SP!,F>5%['$'XC>Y$&7;& M,0BS(4>E\S31#/736@F%3T-.?D:G%[+C6^N&IN M2#"D3# =QH1*+Q!]GA@V8#O,9G,49T)]&QNBO);/$E;L8=:1O)+C4DIP>6L] MAFHVM,84JT=)O4R^CSVN*?.:2S;P.^Z/C?@23-#W$, ^-/V2 H)4> M]H.?1]V>^WES/3P;7WQZ_^H294J9/?R+9U=I:=.39Z/K\=?AS?CK:/(>[0@A M@9V5(O?AI#HG'3IQ>O\XZN!_W0'>)+',E=_IM:.CJ,$NC 9 #)SO%A='-Y,SS7BNH[N&Y KV,JOG"")2..3_KZ\=$Q?H O4F9R MYR2H$A%L=QPP'+L:A\*8U]REXCC=_K'[N'.(FMUV_C6#KVW0V\Z<)ST".2'5+RQ%_W?F_Y'M&48^)!M,G68 MPUN7X^]J\=16WREKM\A>'+T5#$9I=O-=[KAH-WG0EJ%S1=I?KZ.U%NUK7 MD@"S7NJ?>TA:?)D,URF8JIBV3X[UET'P&(O@J /GR0-6O/8E/??#+ #JR_X2 M[7;;4IH&_^._MAZP(DN3YB.!6VZ*$UCJ85=FV85K'LY@M,A=ODM[P45R:VM3 M523Z=V*"Z#H]*;8S0++E$=>KU[MFN#W6(Q6;=T_Z-*A;'1;^"<:H71-JZ?"= MCL++.]%!Z+?&2C^[R H(-8Z($A*V]%Q%VA)ZA)60HK0.)UE@RPN@@YE++:AQ-/S[RY7?;QX---ZSW1]VP]B'/=]*54B>[C4!\ MZQWK@#C90]8'HL8_=KO:?5P4519FU.@/_O@+U@8\[O3=%)WOO&#([0?!U>H> M,E!AV7C!VF^]733JH?[XKFNE_S9?IZTI[7_QJ]2AZC>'YB+!_NHTWU*MV=?$ M!A?*@P\K:*OR2WB,35$S[Z,;$1U\/J[UOGRQ"QB3?WHHKJ<<[CO"W!!.> M85%##IO:*ZG%H43M".;$6'_^X]__=\DX%74.CH]_V#_&?Z/=_D&O\\->139^ M'PWS>W35+I/H*BDR$#K;Y8_@ *FP^!D:MG)_\X*0 FF'UN:R8^VC@S[6C.W" MM,",.H.#P_X>YX7NMH.E&PN=Q 7C@J,?/-%[+Q7CNJXR$C.'TU RHB+RKQX] M&1CF%'Z$>L*F- MA#&F38I1JS[W*G@"+F?.K75V9XG\NN?BX*S[I>0M>RY;+25R2T>ADJ?TVYZQ MY&IM;)OLL S,NEIA7$(T__'%NZ8M=)(A=CU+'UU=LHZR<$">EP5$'U"4@;.Q(,6K&^R39H]7Z2DJ;PQ!$P?:4Z.=RGQJY MVX"<4@SPJ]5<%_'?,(0'AKG/Q3_@FE]*9L57QUW2>9]DJ M.CS^J0/_/R2;3?O$6PWYWR-DIEA#]9]&G^#$:C\?1X8B?R6D3P/55<.XT7"2#GTI!"NY?N$0_7%;P#_-F $SW B72.+M7K= ;(;WR7>E2#,=@R M_&VOD-F.&,_=$HZWL-M-DH0]+W(M"%4LX1X)X4:A59.3@WJ$"&<_"JL(P:&8 MXJ2-@WP,XM8K7*_$V%)G$TQ#/#)AOE"LL%-U80?F_)74UYQSI59DL%IERE]54BJ/R,6-9972>N"O"IU/F'D>W-1P[YEO5U>+H3F*Z[Q?(ZQ_Q"'W6X3F^;!<+03?3S M?5=6HC"Z;6%M_GQ_D#7K#CLY'Y M#(*^7@=YHY/S>[OZN3J"M>.VQC$GC*U0-H* KH&G'%'E@Z)H]V>%V#(U]7M= +G MXD4E9ZK=;QV==/#'2?=$&')K ')$I]49'/G$2WJXW\*U]5J#$W'XN=^JLMN; M=]"G&O6]04G.QD]>W<+@\! ;(AP>BL#<:?5!]NFV>@"6\A8Z_6/XM]]G42(>P@Z* JE\:S=#7N3*=\Q1!1-Y8^OZGDWZT: >!2 M[^C9_9@BF8B6=#R5"7$_1* M)=#7:=FM>UQ*]W%-[2V#G&R1;V>PTU G5CD,S6,,"J=+BK)?-T@,E/@]RBB7 M@/78CQ"4>C1-8A\D,M89?"@J&\YWD2U3#D1?SJ*@;K$!IRVD.FR 7RO:Z0V" M%A/.1N.E^-UWPX^3=WO5BJ3Q3#N@+7!_4E>308UM)DB4I)L!*H[.4?^6.LSQ M-3+ /&?:[O13N9FIP-2E-=F:ON$9>&N89A+O2TX2QD7Y@N>^3NCFX("67E_! MNV[44O&FY.,PRS6M7 ".O#L)#[+E2*G;1]L?!9J?"CCKBOLDA 0.61YFSAD+ M\=(.Z%I7:FN1I12!V\ M.R#>(!!_8!@"-SAUI?9_X=9N<*YCK"9-UJ:2@N\::99V;HH4OY=2?;O&F[@' M(ON@2Z&%]+/3.CZBIEKTL]W&",Q#WXK!/U.SWWKV '> I9]@:IG\B_P+1.,+^+EO)TX' 4^_2"]"I MKN<4M="2BJ-2^L7>A$([4# VF8'=77&EW9GF4BX0+,27&%Y1S0:J7^58<+V4 MQ6DT*Q98*FZT(*E*4B0E-4/3 _:I!!KW)JP#@99*L,#BC+S&",]<0PS>PVQ7B#Z)'N5 _XN;-@\U%M45H]GT1&M])XH'1NUS+17D[55"7-&^_;:I1 M1F\5:S9?$KD3*;=FOE7*E]"50:'4,5?&+"A7"NR[T5E\4'.(E9 A6QO<$0/J M>/K]E&'CK=^X@E) 5[O;@=]4^VC8[2\^GKTUR .1<>': C_[_/5SVWX"I@B MT-XKT-[@Q#%(6K[1BTU#'H-6#\R[W3XI?5N]]B< -AW]-)MGB]M41^GT.ZWV M8( +X.\I8@&;-O?E@U_CO\??'I!QI0 4Q%#LJ]N.^E%["]IQ[:]L755PN2;N M3Q*(-!F'M!A.@$JHO,2M.N(YD-/7*/=),"5'/V#9@B_(=4@[+!^56J+8B6"3 M3]\Q8\V,P8QEN(A9R-&U^8A]DRXT28IZGSN#J ZK*PCI ^%J\;N,K^T-^,I^ MH]W/OSWL(09VWW9Z&X VK8TCWPPMSKNL@]4F*M@^!J@-P^+5URZVV!2"LY:H MC;'=99NHYW--@E)SYDU+*@[ AE7BDM(=\/N+*'/H#2$2I%)54!H+PPOL^^Y% M-1=Q?0:7Q1K48W8/F^J?Y?PZ7V;:5JGPG^YZZBP=:\BUM=K/[NZ,RD]M&JY=/? ]/1@_N!4C?1W7./^%6Y0M6N>>4C# M;;%_LHWWM>\%F39F5NQ$F,G1;9^XW"7*YJ#XO>94%O@:\!BDO$X?>^>Y)!:Q M!.Z@.QC^Z5)@\%&?9B #*\F,0*@MT._@K3.?W)RH0%,PSHSK[E%R3;]+B7-'I3'*^1ZAXPDN.;KA M;93]+D76\K^5H4A']-F_0@"2V4_:&ML,RJD%QQJAW!E(@WNI2H+]'@DK$==[ M%,Y]U!:3N",0Y$I"BQM*!.SO8<>2T(W61L+A/5%P$K>)J3^):>C.Z/.4Y!5N MYTL,PRW-I [+U=60T(2094#8,R 1#[!@Q G[3QBNX0H5G"*X/J)*3>JE:1[8 MQ)[*N:*)VNNFC-&.&(9;G2FCT( 7;[(*E)K)KWUQ!.0J ML$I?]91,5+Q2HU1JO)Y9\%8*)TWBJQLR;AB\D"UPZ:Q@#[8;QIZD!]^1N=5X M8D3>T#KC+*>6#38"D=:FSM5_(4-?32 5FX5WS^5 KZL'>BJP$U-ONMRR,V]U MY+I#H)C]D>)+38!WR>!8^G,3'Y+,'TS.Z$A4>]_D6.F1TX/'_&"[>R*_=(XJ MW<^U7!/;-RFO@O_I"TD1ATM@RKW#V@T::,./XZ*HR3=""%7@.A,\Y3XPQ<*U M;^"8NQVBE)V^HYV5+?K!B)Y6^*FI:U%)7Y'1NV[TC=P8QM_M*+%]RSR@^G&\ M6SWW[AVBP-(IG8@&3@#=QG21[FM'UO9GUG'Y.G#:1XHGW4/)?CBACX\4&?KR MRS%^?^/)86QZ*V](IJ%=[@6]N:BGIKMK6/=E61]TG>D@T@6-PLRHV**_:K<) M*I#Z("PL,?QD"6)ZM'I.YEA:!UY_:/8#IG!M $4&>\[=<5<)IB?:!2K##H:< MV<=*%B8J?P&/M3O!4Q5-5\N73_ M+>?\:'5=8_2R5X:-#"3; -[EJN&:A)X,E*>42XZ*JPZ'2!Z5 MN)0@0!S?M@T_J&.RU#I0W)*QKXB/:?K/6;1/J!7,14XR2E;1AG//;'"C:G4I M<(VW)1-WL59T\H\(.#XFZ?L$G":Y)EW^TR2;?[IDL%$ <(SY>X6 1KGC=4[? MS-KK6#BGM8J*V=F.'3-'Q.S"S4SM3?RR:W,N-[#MRB;:/A78,::!\"7Z 5RN M9#+ 8R6,M\8IQ7VF^Z^A_9OQ?8,:9ZQ,<5%G:#)E%-^.P\9_X\HA_$$:VO\/ M+@C?C%T1=-K;2JPN 7[PFN3WEDN"60'MWB :]-YP45ELHWS$&K' +J5>2-Q% ML;2/GL[-,N) 9?0VG'7#0WT5X3N8[6Q$/!+2C&2&7, F!YC$#-K4D1.K$1 ( MIF D>/=$Z!*E*1XG1;?]J_E9I_2 M4.@\BCXFXC9PN3'4UT_J J--_H1ZY\LSU8ZO0M:7#J_UB( M59R:UE#;>;\2LF6E_#!)S*HQ[=]C'4/R$29YJ?L 2\[!1S'L=$HQ71,4?MP$ M/Q;Z!.[Y#B0I-(PGR)[]7!'-Y;O)5PNK2F&XDG?7 X5<3+BYA#V;BP4L3EVU M0+ R6O9Z/H]\DV9O[S($D/W)^;?]5;:OU3R1Y>R:^#SVI9*LT5R9!%LYLE,+ MA30;:<:"N9?BMPB(MGYBIJVEEL$*T^XKAYEZ/+P3/&R.NS-3&ES%>NL$ MUIW2)OI&] ^76&-3G '>3=%G+0UI4^R/)4?+70"P-7>>?2/LIE!\83'TM5]/ M0C)[97Q1Y\HH$T;D5&U-I)+8MH ^.7AXQ]?1U"!6%-%[1XE#MORO)-FZU7+! M3!_'*1>0*T B5YVEI(&TM%6KU0/,[BBNMX1"WXM!ER6" _5P[ST\E$LQ\ MM2&XZ^/X8GAQBF%8UZ/3T?@K!MU6@KAJ'XK\*G(S%7O;[K0FD?U*9!1#"- E M;:(W,16:NJ=*'Q4-_@PK4A)AJIW[<9UCA,2*@\M9FPH];Z:&*D XFZ]7GM;2 MRC4474G;.1+#:+A(L##QTKP/*[\%JH^RDPVZ\1'HO&B6/YF !C[=6]CHMQFF MS,.NZ[=C?:24.\V-8MY8@Y!],KHJ\I!1)L'1L4^71)\S>9UZ&,7@Y+4"LR3P M@0OFQV9H04>PX@$D[/U-07X'Y?3'ANS' P-UTH6 .B132Y5< M6D38THB#@HHD1(; GZ455W5KIGGN>BFX*T&OPOO4,K^JU+3E;B6N)Z>3I'"5 MTF=P3M66;%=@83Y.34KF3QW4 MM*J!EO$W)=>K]\[%NFN(NRR,P.1]):N'4JY]3_L+>U MK%./Z-JZ _.:$H'Y*K,>WZU2%8'I_H M:AO$X-&D&/LS3Y,GYLFWMF6W5R[3Y8-V;G-(AV$B4N*24A5,'V,^;^[WYFYL M82J*'$0?+R\P%>3SZ',T]'1[&%H9$?_N7=)/GG#?M: @\RM] M*F6M!LS5 PQN68/(./7'WN+RU5+77'H5U2ZU)2TXN8Y1@DUE@[Z;:5Z;'235 MM;$J*-N('45EC)*6GC+.%./(D+U.7Z82\7$?%_MW)*;P5=7XGH Q$YYY-//9 M(H0>3$W)B$F,K B/Y=KC9;T]J$8*0TFLL1*4P*.W*.*FQGR%[0-#4]#*#A9 M_8$')CG:^OS:4KT"R^09[]DZA:,7*F1O@MNS *'&M./QV-F' M[/NF&12%$J%%MQX9_4RQB&<&@D5:"QPJC+_ .NZ!HLK,Z) !113$'WD-$:E? M<&'QN-0ZR3:J*C@-*%W@BLTJ:X_A9BL$E7I/ MF.P;D%:E I E3M>'SKM"ZR80/-X4L[F5QDI8Y/B\ MNGWLB$XIKJGXZL-!'$J:O=?+I%Z!E/#JF9<<65#G@E"H0L>EW,X=+)L?N3,G< M%9=U B?=*I/VJ_D$PJRHL@ (DW*)$VQV1'?(M5B]R["4A@IP^! [21OEO4?$ MMAE+'WHX(8>WN47!"98T.6F?@?W0*=(3]+F0(SYP^Q0JXB;A-[2KP+Z@VQ,A M!DC 2['"2&O)G&;0,O(G AMGM..NU4KU[,(#2H&G=0\0 L!A-;G+9?0O:V ( M*%'A#7X=6B4,[QUWN"Q2@.+PJ@>S>$MJQ$8Z#"TR093;9WK69XZ'3C$O!88E;C987.J" MHM5#I;87/2E8 UMP7"$,3@0/G9*7;E_.B_6#%%/A3(*KZ^AJ#2B71=?I-#.U MN?#G#U'_$/[Y@#-($PA2]G^%Z6; ZEQ9J4-\C/\=S8$2<,H.1;\#HL,6^UTL MGD^CT3]G6(N!B-XL&C$7,N.+O4@JGYWTX 5>SJ=U# +6+.;Z7)@J$W4QDNFX MC['(/V#X\@_1Y=6G4RKA- :XQE'[!".T>U'O!+ZC?YB?&H^8%GEKP[[9(%4J M"$#JC2GW9-[=B094^+_?/0J-3]'7\8A>9KID!;P'V$,A33M59^/#(;&IT'0# MU\/V%B@']EVC'MJ:*1;4RG38ZV&42G4BS;Q 6D/=4;"E]N#HAV@?WR,G@7>M MVF;=[@6< ,[PD'(L=?R6:-'LE4;="Y_W-ZM^43! M_L#)H!4BU'T6+'C51VU M:3:SZ.^=KH_3(3X08B!K1%/P-(OG(MTGOP,M#< ";_#2^>H?!X 63\M2P(,XVRE$Z0?<4B1RPS%+_.8[< MDKV[@D:R%%ZFC5584HT8]%8?6)N2/1]\(4>]8&?@X^3DU5>]]'>O1^3U6YP7 MCN1EIV>FJ%:_OI$]GTKK)W)Q72K&MH/[QXNG*[#*LF]4%$3KF]I^N:W 1<++ M,,@Y55^7R:#U%D'Q?-E>]NB^L'<7(;!S5/*=%ND"H!PO$WX'N["Q!%IEX+ H M0'X9IGOHAA%?BD%"\;[-Z'E"*22#*^SN]Y3X)H%$>R2ARBXTQI[5L<4!2^S5 MFL^,0YR:=]+SS4C4=D1?(R24'1!%7*@/T=!EQE&"KEA>Z7XAG /; A\+UYW= MKPO4E!:D:&HE>XDB(KW)WE'$,']ID?#Y[PH7"$I#.#10_8H'#DIR%8SMD@AGLII:92ZL*(B"+$KA3$WAL0=U0HV0<:]9'%O%QZ,( M6VIF%4##0D"L^L$'12P6&.*^RJ94K^D=I)NM64NA92_W0\6:]3OED:/JBKBBI 8TVQ9=1J M*ZD6),3J&;=*0FTK.C\_;1'9GIF-@J)!4XYN49.B15Q1EP1YQIN?TZ6 MM>@7P!DBTO@H?HK6A7\'$FU+'4:^(="U^'CU(=WEPF)%:TB%K[.H".8> V((T_T=;5/CHQ MIBT?/U-6I 1V=7>?I_BQD%,WBG3HCAV#[,ZF'"X5"8=*+]#G[^B+=Z:49.M= M8&G;8])WNWY!_H5&6++=+267'5'#;:]A\0BBDN-!%M6X<@;<,@S]*$6=[/2\ MN1"-/>M[M$*P_]@O&82\?)I2F3!T;507;8!!99IXF&Y@[G"'_BPM>)DPP>.7 MTU5F)-$#,4,*[@3.<@>8S2BC0H#F=7'#WECZXYF@5MC!8U:P02E0I&*-<5HS M"Z.>ZQ,Y)9>9 LV0:-A#'Y+?!$)AD/JO37\ M7=,\\3B[_CB-+Z.,O7H*TH/YW>ZVQ3$=#>;W-L-;3X@MHOUXH/ M@8I"5="Z[4 .M>NPJ4=@YWH\Q2Z82 MY*L-VM'1JAW(B0;&RV_%C\15:- R_LZRA+5I40=X]UNYW7A#WA)@"P"X6JD[ MO9-2Z&@M^2/Y) 3 @9@3N0*[4&J<+0J*<(O9@)^EZVKJ+5+OYI6F"&)%%BUM M@2'/OJX@L,BF/- R(LD2VBA<>UT[-%#]4BEU*1 MK;(50@B6LPOHS@ZD(8 PU#'"@/SYIZEQ283\T6*!N[SB>-+0[;](8MSPN$S M$FNRG(-1L#H^+;J&%>*MH?5A.)RK1A4ZN4U%=_;9USK/'%J:,W0);_&ROD D MW((Y>I"J!57E)C:Q@6#M7 RUAIP;/*&(<))KCZU1)U/2M.^OIB2,D+3MI*=N MG<01!!3%T6W*OC1?6L)"OW=R,.@T42_>1[,PWND'AA!2I]%HX1/B;% 8WH9 M--VB.N?.P -FMG;-UX@<% ;/)=D732Q!,SP71:\+JN42 2?']-5 #77-#0!J MVG'AE88+4D$7.:N)3+#:=TWYO'2I- A==NO\6\*ZE2.:HO#+<5NQ0I0LC87P M9Q 3I9\+HGD18L>*2WS,CG(OT ) L-(H/HVT0^+"P:A-*2ZLF@\G7\C#BHO= M/SRV^0OQ#'2)I-)+/@M5]!+CASOU8XFXT9I_5(3C.)+ EM-LD2DG>@G%KTW@ M!N $.J:%8\LMPN0R5ZRE2 ](0BWQK8[_>YM<6Q<_V"U'=$S4+SD+&@AXK*UQ M9A;>FVE$ 8OJ==K7?I;OH^PIOAYC8*8RS=C""LBB?+M>UON"@@8 );M.@Z72 M>"$/[#K((SFS_5(^ZQKXFR_A&FRO0$GO:TIL;BQK<2TY:SO1H(>E74XZ6)>H MW3JD9N%4CHARN:++Z]_J"T%:+**M-MIM;' 0^L(RT^UJ2FX#F7EKQZU9S_1YCQF M'/L4@*'7BTZZV D>5G]$S]7F[Y.GUS>CFJ !2APM/[KV&-1B_00[-AU%NWW, M,JQQ]/4IQ$DT:R/GJ+S8Z?7J!40J0V;L>=9WTHCZ41GUC:66B(G+ #!QQ.:B M2!5L&Y]E,[JDV,+@3:2AOFQW2"2:ZZ.3\'9_C_6!5Y4.(%K0K^3"5I^:WQ?& M:B4ST9Z)"8(;1Z%^O1A>3T1L>;4XA]O0D#+%@3BR5Q^AB M6 MSCR,IO!K3AOO!,08;)$;JB49$"I^VU1XVO;2-RS"R6L09R^-;Z@]U,FA% M\FR%B:3;>0$XJ[$DF_(RI?T 705J6$#=@"69_6669QK#9U7MNW@JY*VE(8/& MW6_<^NK1#S6Y0/%@)_0_4_NHU3RJ>H>>,DJ"QX.2-[/>^EK5"T3HS&HD5).) M=%SN>)9N['BFKB*0PA<@,.__VMQI++@;&U%PPR'\8^!&PS-'CJ)MJNXT72J+ M!&:QN>M6S2F5-BV*1;4N",F\%O&>.(SD*E)U3120<3:7S.1ZE(+(=R>XV;YS\%ESQ-]4C4#4&DC362LK%' M3A;5QA4/U"(B$23#E./_!=UL7!N',VSI[+0A3(0(2V3@%&* 0<@D;'F$8XNN MF$S@R6R5&N6'73QW=ZOX&P:ZB ^)T@2LCIW\#L03![BZ&C::JS9C3]MH/;?X MWFSMLXDJFCG(;MXYH84*)2=K5HZ";[?;)>&.XFR@J: M5H@"+%QGQFQ-;RRFR1)_54.X;H*2>R4I/*M"K2P\;--J<>,[U<:,6W7.^'1Y M>?;;^/R<8F!9@AE?W PO/HVQM=%P,AG=5*)GMWG']XYLJO-4BJ*=A@W,:\1/ MWX*:$ 9- -*LY9[0ZTV%JGJA+OEE$@TI*OKSZ?"4"IT_(AS36*0J]6?5.QZZ M?K?4NH$*ZAZ3'MBFTKQM*OXZH.*]K9-^#\FO*TI7L@)2NWU^7:KCXV3L=O[]>][BT/^R*5]E?#Q90LS]L95RS M/_[87QF-("KW VT/*N_"1YOAT@_@E=HP8@#):'7).>58FR1':4*CKK@QJ)O>P([[Q*^(Y;H)Q M'M,SHMUW^LV[O:H7H6Y4RV,1Y4-&6!H>N."<[*')8]2F6KNKPK)&A(QW,>.7 ME;Z@WI[K2TS,O-]1BF6F2ULO<1;GWZ("Y(-X9A/>9CD(+20-Z'O$#40,9B$( MVZMHQC^EX;2D2=BS%N1P$=%24TI\\)QG:ROLK/(ILE<]&Z3!:F37MWEBS3 MXF^;41FZ"CQ?"HK=-]-U3M756&917HNF@-L7S);B/#GR8IIP!DR,(TO+Y*K5 M!'*^S #T*X4M'Q:*O62B6SZE>::52@AQ85U<30@]D8B5H LX+"^!?)4QA6$1 M?([2N)-\;;?:NY64U#_[GZ=HD3Y\%XZ+-(8'K>M((+'W-BR5]C1"*)\XH#14(%)-/GPI48H M.J@)YBP3-1N^LI1?.\PG_ (R[>A9HCXURPE(PC]PIUVR7LWE M9D I,0E90$"%E,Z4;0/&Z^W!?';;OC9U3EH8&]'8G\09%Q%!^^B M@@ BE.VTNT&R21FI>0UE=(XYHW25$E$FW\QRP#A'\;6K[P(=:!&@U&":OZAP#2R4T^<_Z?+D\UB43> M7%3"S5L,!5O$9&$ <95VI^C:LI8,^PWAC O2HN %\'G<@5;;E]4,5;E,EQU MPMVX?3J>0HC[/F/.5I9_HQ*2\6.ZHI8KKC!@E*_#R&5#3[?"@#=(82&R4 #E MFPEV.9@P]N;J4 =JD+,VT:M5 ^502OHVZMM@J]O6[.6J(PO'IZ 3L4J[(7TP MD(JEV[1_+WD4WUB3K\;V0Q8"G<-:,X:VY#/:*/2A[WAEXJ,)@V>N)$O6^MDD M:P[M&#M13XLF[T1=ZK?D_^X<11,BME.LS%1P7.L1%O/&5B+]#GI9=WOX;*]/ M57:U\*.4C7,3=?:B 3Y*984/H\$)_(Z&NE)+P^ 7;>+C4OX MK7,J@5>X+FJP4FJB=:Q";,NS?Z#^I+YES-3OF%Y"4%%D]TU-9(9* 7^QR[-BQ<]F;'00!Y4X*#684 M9'*;02N(/06:QG*[E^UCH@=C*2?(*$FXR?!\F(<-N3Z3#.Z:CJD?(V@">OJ& M$^I*1@RXUR76UQ]\H&2'YD*H=S?E[L*/E-,^X,??"%!3+I!L$/@AT([P@UL[ M8.(QRL71;UP[1Q-U#8[Y >.Q)^(BZBCN!8C#(".H=B(0X;Z@O#R'LY(6@I[8 M'.\K96K_K;3(A*Q@?4E-IAD@DEN,1W)T.@6(K=^5<"H*I#HC:0&U)NQ2-[@E.>) Q1QA>!B4VU+A MK1Q8HW,C.&P?+KEOGP76WN8(Q>5.Q9P "ZCM%-!^!F;FCQN## $CI('K8EE\ MH4U ()*PYIWQZ,G:0[< .A?^GAFI1 M M1("5##_4'(4TI':AI\+5 S7J^^0F77M=D,T6F1X^L.R+I&'79@=!AHH*Y; M/_WID/YCC35T*"#ZN:HDV#=:> EW#TE3W?Z(,3G;)9:TF_K7NFXT1F3TY(@X MI/OI#^=[C0%*N,_I?"_US'!N$_??[GN-[.U@XQI/LP2 <BL,L&[,H%;,)Q M.P2U=K[O*& M!NBV*^LR:' &1\2FJ-9Y5AA!@GW9M$.A]]M)D,"^!UZ)&N8D>[=]-4P *VQ8 M$Q ;G&2_ZL3"/N.:HL<_G16$N"H+N3D>FJ';Z.X;!<3FC!^M4H*.OR%#1HKS M]016_8F]$$B^P045T/KB_4*?:"HJB#U==R_"U OZ?EW(3L8+)QEE M:(D^__&S!2[)AWR^6C>[0V8&F*C3)/H7AWK\Y"/%^D5;(HW E0MS4OYJFM4 MHS$RHJ1CF_;<,O3O!%R> 98V&"WA])G+17FCYMHF.C[](#P$']!0V!M":^"H MDL(ZU_8<6[HX6VG&"/!.&O'VT3X>$,:9N_F;) Y2Q,XY/Q1LS^ C6_P$N%Z MI\#&'\OY%W1)'I^?"'#CWGB?!J-ZW.\W#&#T13V@\DX MB2Y.+@X_M"P[C*^/1AG]'/:G]@JKG5I6I]% S25*FX/O^=[$\V6-1]'%EY7H M^]DUPG81H*E \^F 3/48]_SQE4;4!X'=5;8U QC*P0B3&M+H\SUJ1/2>ZA/5 MJ5#O$^JO)R2N/R1NY3],XA+DDG[)\T5T!OU]++^ Q?"D>@@J)$;#: 1]:M<1 M@0#0-HL^7["GV7UE-,3> ,9L# T8@U(XP03717G-I:0LI2^:N0DHKL'3\T:4 MA)A&'C0$5&PZ[D?9)&NNLY=/.+*<)Y,_;G^91G#0?\'VLFLU487.-TG..!H\ M2^6$93,)S!/KE(;NL9H%%<]X2-SO\0#4Z7/H*_SFL5K+/#'S'+28)[',P5K/ M)5PZTQ1XF<7#&QJBO9\./\UFF(\B?2@9DE_,)!@5'JWH@@?GT,CA3\=G%S_M M*_([#S(Z*3C)'@?8PD>YBFJ?62)Y^SC^'M/&..=C/<)LC,2(7485Q_)25W9F MG 0/*^R,@E3[Q@EDK/90:F#9(,/P=V(86ZUP0%][,!:/)N9_:1@]_(O%K8MU M<<@V!0,%M\9!"2>;FQ$[NC"&D^E+V9-"\/=N5B447Q'N>?ZPXDFO[M'!Q%$6 M7H=4=X> -*:"VT4K9"$',POM\IRU5Z!$*H.N8&A%*W;^N)V;L))Y1$M> A0W M02UD;;N@,K".GNUB!2M'K^#<0\%#3#=)>"CMH 4D]WAI[^,HQSQHL5G7IG87 MKR.(39S)RV+S!3/ M$VQ2<349" /.<1/@AIR)" E<8[-=+S5^T6T*"0 %^R>Q,J[Q#"EEJQ%Y)8FM M97LAFU03DN,[&H9D0D'3QNGW-\T53Q(FUHYFMBFO-]%__%__/?J\%$= ,7>) ME!;_DD KUH5SM]'ZGF/5U)SSXDHDMI'M.SQ.J/:@%>Y>XI;N@G@M5B$?,?/R MM1ULZ;+WQ9Q8PV0W,+X"I'J4O7GOI_>SLR/)53S]?'02K;?$)E/OKPL&:V:9 M!:E6EFY>+ZZ0Y)0"XI?;M<2<,^DT/]TI&V2(N*MKFX#_*NGW)ZPX,6PH-\SS M._2?P2-A_'[1U<<8G0QI@7M$F0L,M],]U,N@\FELW"Z7Q0WLJ7_.EX33QVYF M;.VA3TNJ>UT(Z *1R _?_K2OR8O73HTK, ME9E@]L)?/P2##$E1A(;B_+_+% M/I>B("CY?;Y=K-@E?9HK\:ADW.'3FHC"#@B@=7G!HX;[DO[CI;Z-,Y8/TMH32P.WD&+]0'D H:W00@W/^MF9!LPGM.9JX%/IHCKXR@#K]=*CF3"- MQL^5;]PB*%33L7(!DI[S#W'V"$FZYRCW-%J/Q<8\R#?)D0.0[4;(/K(=>SLP MW(R)IW?C4R;*99N'#0=K516UY^O-.EQ*B5ZAW[>L;BFQ@009GLH- -$:[6/( M]U+R:*2[;2,=RUAN$?3*/C3POF&"(:4+LY3?XYAL)+9DQE+4./E;),M5U:T?UQK#6!_4'")IJ7T#K/2+2'W__D]"EN0ZJX_4S @09U0_%% MPN458[ARJMIJ*3DD1F,2M(CZN5E08\=\(JVM-(6)"$1(.G!D6-@#[!;PDF"CE "'ZW#P7F53*4R#Q+F?J9*-.*HH#EW \BW+PO9A][;+P=N M;>D5,-ZFY?K,N7$Z^JS*#>(3NOHVW99R+,F@'H@%(RO_S$=S#RN7)F[NXL(# MG]-O-;H\UC;MBWT'[>M8;N*/,F)BNZ")7W5^F1(3.Q-Y!J6QUR\:I" UJ>6, M_^C:8$H119?Q>2LVYT!T.- 1I%!^!WIMRC0G"6L\SO%;-AB'S9 Z&\X,/,LA MGQ9MLB7C<];/IA0]:G@[XK:Z2*SMKS' C\:]X?"U&4K&74RU%;7C<>Q/6_AI MFO0RN#ON:!I-G*0Q-UK8"V$.G 6QPPWS6#.8.@\(/?(/<<36HGTX)T-MNW"V MZ(8JGE OL21X]Y-@; BKEML-6ST+Y&-Z[EG$^IA:O2GV EAWU$B;]"CG9TR ME>H>?U1UFEB(<20M@(_;5%LK9Q0X'6 B.Y\@T ]TLMOBR+>PJS*>$:UJ\6V0 M]Z3:-#P$2@QH6^.:605']2^W*SB6Y#[D+0X#I?:1$2"]T^X_D)(6[)[IE,$C MO[_G8\<52GAY=XG.$JNRTMLVTIB&B':,7,UACH30Y!!#BI-H\ M!OD O'5K:E/>T %A< [&9[Y:^@)\ZV]3BXE=HOXR]LU1/BS+8K6]QQPPG>4E M2#,2G'F6D7P9J!9MMLD0HWH+S)/PEL(246JE#@=]#NH3\/-1MH\<9DMM-@L> M^.H66:,:F@$!!0;F['HK$%)> M*=/^1>7%)@];=7'7Y&B"J%=)-N[9FX?3O]./7T 36*0Q#9&J8605(0J>G< MF.?V,0V6^Y?E^ K]W2X'U/,:WD2_]4 $RW:,KWK37YB>W)J-9K. GNY*.PZ MR>OX)B+R9AJ,^<1DPSS_0E$QF$+^*IJ."2TN17"X\61,H9PT&VN.^6C8CR:# M:31*!]%X-&9 OQBSWBK*>.!6*P8A'.)(D0:)Z=LV[XG+3]MGS M@"/>S=Y>M'U& %AGLZ.3SV?GLX@^T51X,M7:P1]JM2&US'74; 4R*$ME*HHO M!1\8UW?7'#=;TTB9(#'C,.?;?/D[ M;.F@AZ.LEXZCUYQ:]A__[?^$7U)*1H_384+S,9FFE&/*PGRYPA +*)_I)+PK M022^;)S!OP@=0-,"BFP/MA)'?(C*>#]"XIH23>]UOJ!27-PDA"\\QY =F70! M[11#-U.()NFE4WHSP?E1>[,HC?OC";9Y/-3$ZZ0W&H8M! $$H1V-)M'[XW^= MO9/A,$,Q[,%Y*1R*)!H.)]$8)+P^!,/>, LO'J?1.)YF<'D\@N_^L!$8NA%( MS0C JDF&4^G]I#<:U3H/7R/B1G3^^2W':0?#>#Q-\,>HWX\^P,;WQJ5_W+%( M<;)2/$PP W\/)G:":?U\^RM$\$U&*?\R&DQ(L"YN#8D;^UB6GMZ-/I @01"= MWRUG5-$+)?N5Z*G]5KY-^%=U=?\GOQ M2S%MA*$SY[=YO$&PB]@?#C;S$GU3"U,06L/.3GM)=*GEP,L6E6"90_,VI$@U MN$R#X %(/LSO,;O4F4O!2"6]R?@U+IM)+\E>M_;ZZST1-VU(9EK_0W!*3)UBL.&M\6Q4'ZQ;^;"Y/;S%5)>P& M.2:C5YMRLQ43_U-CWMLJGIJ37R)J$\S =J$G2RPLO%/%3U@6M)QLE)8X(EQQL '[)71L: M8/3E;I=$A"PZU[S&E\)BUA'9X/:5?H(US"=9"P'4,F)0[FIY2W>I+_4.9*X# ME$RQW-*H85==*VUG7 ^E6POV\_J3V(:*;6I%ES'/D7KF48ZPF-1TU:%'^+,7 MADSL2X1R@=I!@!.K]9J,9%@F<++9" DAWT-, (HR9UV %3T!:WM, 6Q MO&N MAGW4G4?^A1G'-X'%'M8A7]8>GF_(F67GY0ULG_\N3'X4;9Z3FY)5-I;']P9N MCI"%\)JRV' M'XY.6ILTR<8F6:"S2:-^\EU-,MD2W*3S[:*U/<-!^ISV9 ;+\UO:D]6:$T0" M6IJ5#NT=G#[]O!FH-.\V7^5W> MWK9^_SESD$S&WR>FPUJ3/B)%R;LM_CM?0X->P9;L+F&]2#4*5L7B?JSJ\Y$? MJQ010:TLS9CQRO\0 #OPG5]H"GW5&V(!^P@@O>(QY,AA> 81@O2V2W=Q\VG M*AY;.O78NO8Q0(**XYG''4<$)@E8I'/BFICD5DH4@U7\%^90VVC.F^A4V.0_ MY13';K[_W/=&-!X!/HC+]".,P.8?>;3W=KNXP>/ROM.9<-(9#M%].1J.R2#: M8T>JN2*%,RD6\O\%;/CULOTI6'$TSJ+SU0VH@>KW:.\O^3_RWV_101"\:Q1- MC".UGTYV'+"TYMH.J83L&#%"/^QQQ>AUJ#D;\RI/H,4*DGASHYE2"*5% %DK M1F%[%')R29%TFGPY_Q,%GI=SJ5='\D@4B3U-!O/Z=]\^E2)"%K[HRN]8BOL6 MFA3($T>O!]$KB,C6>7-\P*J\ _7/T299NJJ]X?:[_"O]VE3Q[MF2S\';-"88 M.$W9K@3GJZNMV]-)>6!FS)6L,QUVROJFH/N#8_ _K[?T& M8_)KXQFXNBH6CGD/LZG-C*)C("GT:W^$ATF,$RI9P9CU9X75889Y?\^1T[?<>"7I25X[\,4160:%VV M0>?!Y, E?HX' 8/9;7-$-7A?-AL>D"'V;;$#4$N'Z!)M.5G%&P*,,L M[A:S$%^$VWIM0M>%HIG7IC:VNZ6SI!G*,C G.7ZW-N4+Q%S(Y#X1#28&AA62 MB7+(,,L+=)/DCQ0]Z%VH3SEFX)>G5YTD[_>8N("6,>?CD7&('AXJPVFTNN=C M/THGP[P"\N&+*% X"\T#'8\ZV88XTU-=]&!7%QM4(+#2D1:1NFSF&V*'%C20.)$XEQAE3+<;Y$[52;+0NL/%R *P#VL4^6F+< MU"[52;$519(7Y>_%HKQ=<8%8CF=SG[\OG )NJ-1@P%6H_5DY<%]NO6VLI+() MD[3FU'[;7*1/S$6Z0X0#?%88H^MK/O$PZR^.T[I\X(2-UJ!0G>7>@_A1; 36 M9GL0V7CBOR.*W*IJ'=C,K-V1)";B^&[GI>I= B :]\;# MUWR+%H /AH..BZ=Z\4C0ZKN>.NDA5"]')":#:)@,.R[\SK?E_^;;\XZTTF$I;%@#'^UW[AL#?D MUV?/O7 8#<>,M':!.4]P=GU Q!N4JXLUXG6=XVT<;AC)X";3: CCAO_9.J:] M=P+76.W_Z13,U7)[AT%>!$OSL>%AC!,YC)/AI#LRS)#_0P2ATT,(WX<_!_WQ M4\)?#YM2HF9,QUD0YJUILR),@KG-M@>:4.&"4-U!&1O7N(89>$#<"QJG,NNK M%A7# ]ZI:Y$FR>(Y5*)CC-XFDDB1,?D$I2WSTF2B8FD\G&I4K!X1XZ%"Q#48 MAT4+A+7X(U\-C9O8FVYM,6<6%[&*EI2O,*?V)\,>RHQNAF);E42<0R9>'2M: M:O:P>&S#+A"ZLD(%F^ULC9AF+K.>EYJT:>O$V[8.R\_()348!IC9+WU.T@_0 MC54CPBY 4)X^TM.-C/TL[ZGWNVMB0MT-T<[=2AFI(=K>QQPV^9:YMU63A!>* M7[["M>88B#P&.XX3J]\=PZ.TR\Y-R$\T)E_MB=.GGNCD=M0V[%4 DUY]WY ; M?_=W#_G[XG*MI8T-C/3643<0V"\==3>_&;$A\Y_C-N)K7>VX&7SO:L]^V&H? M);MUSS>M]G_**D5FV&^3F:HN-#1Q*"\[Y^W96KHQ.F!",G_E6K**9*RT8F>J M*;,;J@F@I!(]1MCZ>+!]^-Q/Z/L'5%S AE$L55ON7/M" ;G/2^SB:-RIGFM' M<3/KDGS/I_1^D)TZ6//J#4=NSVA/ MU-X!]Y1/Q''SO1*ZH(\D+7GE M)[R TSW"Q\;M5RQ=@F_KUX1D?YNS0]2YM 6O?_MKCIB& M4,OU%1S+-E0&%HND:=Z34MSJQ1SZ(]N&(RA156ZVWK,N]&35+;I>D.G:H!33 ML^YP'5T6KC(7+L,])5? "1YGIYR@/>2>C(788,1D.HVWQ,Y- \]!4X7J;'!\ M2W%5J&,^/!J1 E//"JT;'$#/S#!\,Y#H)$=G*Z[7PB=*SNX&"VQ+_JQ<^_Z@ MI<-4"L^:-HGA*(0F.SSM>EW;](C5THHC8B.H@W(5% M#X-@,P]JV0&*<>S3 ?"28DD/\NRR02)K]4O]*6T.<8V_=?B\D?2!65Q!*!0? M[9?&(-P5ZYM"#MZ&=PDUC;*'L,1B8B ^(@Y5.P, >2)@QC<%'Q'C)O[E93V.W/.841PX$H10%P DU=1(Q/!E6I[ M"O6@#>'5OD4"@!,XNVO.R4$OC?['_^U4B\DR>3F3Z[_EW2:C+'V M[FY:_#"-7NX<$^H.@4A\116'(RQQ87C9N#>$+O=VI45U'(P8[.TYNJ@ER<9H M#\7T\&O=:H^=&HIRCEB/X-K"3'(Z9JQXBZ L)5RMESELVW:]0G]G9Q^CHY-/ M?YV=71"=[L79Y_.+Z'QV]/F,H?\X0A4-IM,I9SZSS_+X^!@)E["R>?%XP'N] M@CF"@KDGUB)-/=[0+2PO?SV>Q6KZAC;VH-]+A];T? 7':=AGA-REX3P]72L& MDW&@[OUT,8/^G/^T+\K(Q -!=A#"P(1 7O5[DXRIOUG W"[+R:\ADM>5.W8M M'DV()[@.[F,?+AQ!4";.MY>$[D#B;UL/)B0\B,"0Y.0_%401OM]_#UV1\<)J MV-EYS<[VEFL5SH]C!+*VK5=BE3\S4^>T )O]NSR*45[?X%?\S.X$K-ZS3-]Z M'\/66$K3U4 UXZ*YDAD@@RDJ0JL0R('Q*JR^]18G"LB5TWZ1/*Q$:3N:<9K_$/A/' M[>VV=*_X"L5,=1238Q8VRB M:N?@:FPZ$0X=#[BGGK;C1_8P%M8;S*TZ:1BF(J-]@1QY. TK&KKP=:R/O>B0 M(J#Q8,M$QR0\$/&@$$1>F,:"7A+$0:7V+1;F:]Q3_)CQ]'J&;'2!-?@8"%B1 M3R [OJ)W'6E6!!6[/JN ^^CDX\?CBX^S3Q<-W@7S5?1A=GC.5H?=Y.C@N:FE MWQH[QZ-8$J(O[D9<845V3W#$8"T:302%-62-B8L3'!V M)3\89*+*I2X'SHI>:75TB#PL]J/%VO:\O! M>)*F(_9$'40&,K*51W72\E?9R'P;(I0>V1%HZW"SHVW56AX<)8X>"IBDA=)M MRZ!X$\%/ ^K:>X9>JC5#<2?$45@2I1OK^FJO_D<*@-!@]> M&:#GB-OF)]*=3&4?T%4&0F'P"G<;%#0-XR0<^*"()1SX>H@^J,H6G"]?Q$#$ MAZ$Z]>-(%F X@(PLU<+>!1KIIJ!Y<'E^"DT3# (ZE7:^OO;"KO%II]<)

JBU\2O!LE9R70@F1G'=YQRY38\N/ZT,9AT<\=0OHJ&8SS! M79P='EV7<>>UIZ>W$]FWZ=A*Q5T6$W#IU\JXHC#=0[M#I#2C?S(#8*! M:H&V#008U>1LD5053I^"V*Y5!(:#,/21N_IYV+J7&\$76RO.%NV2:S[@PS&( M35#GK@O\MK!7XPJ;F0:YAOJW-U6=I/OE6G'LTZ=%XRGO0:-:NOBZ887-[@MN:O:N+?OIJ=E1 .['P15;_F<,3M:OJ"68EW^:#1D;)QIG[%RLI1[E,:#/D*N M#"E#+9V,!/<%KD0\EF24()(.?"GJK#Z?MC?8N_K0,2S *"&8CQAY20C\)TU8 MF25QEF71)!UB8ERFM&3Q*,VB88H-Z'.N%&BY>#R=PE/AZG'*,Y[$2%J#1)>C MX= JO"2+L:(2&IX-HBQ.IT-/BSF&GF64/I4,L5%3Z'3:M#6-;=DT%3]=''_Z M=?;IJ(6_*_C2!.1B4+:NBOV(G7/BU@)97$H2=% ')]I.W27HH#/^<#4('%UC M++A]3D<8<%SCO]@T\^?Y*(1RS.#1]R6& MUPCGD2T%5(":+B^:;Z/'=SIF7+$+@$_"HD(HW[]RZ?]++-=9& X&=>UU]XDV MM#EO,(KU8<<"=Q%HJ0]SB)^R 3> U&A\DC3.*X:BIRHBVH;@G+VFW\BC4*[G M##K,2"F7Q6V^N%;'@J_J:,$G(>!MVW2OX@T4 SE9;_E]MPJF\ 6^N65_)\W\ MEQ(??75;%@^2[>P=HI0<3Y Q!_D"2T$N\ZJLI):&RK#(=3EH--IQGE4FV:@9,H.E.]FVQF#471JIJ:F[$%\,U&-[ R3U M!Y2%)Z5''*I*:NQJ:XJ=8M!BKOIBGU9P\_UJ@^XQ/DG28T('F'NX5/N8%'X2 MSCO)[]78,CE\KKQ#3*'86VJ/R"Q9""R/@OB:"ET9'M\E;IDF':O=94=? >9; M-).'9,8\!(_]+QE-$I*NEW6PA#9 GZ[K(DY93#XGL^?=))N YMO"A H%ZR?G M8CSTRNBC#/],A_^,9A$[,4/7J+NT5GH0_O5K* UVW<*6C 1KL"4/H@/8](41 M@J)&&B#$8/7=4H(K2$F-1%/PSQ$&UNS4%2W:.P([0IX.XO^A\?6SE4P]KRT85XP.%$SN$5E]M(OY!C:B//!; ,J)YJN M(2?X/1_QQ8C7&EG/H[(%:[:0P\<^YDU(#,!<1&5Z(2L3@S8C(M@R7^RJ'&S= M;S$8& /UC=Q'*U..GFX<3_UJ 0M;O)00[EO2&K\F)CY[N.W7O!NALHC?@:8U6 MPW%O^5"N5XH34#M*.T!_JLAD4/V*XS>AZH=W/IJ]LUX7600O6>1?@B0AA M)V!E?$^8\0#SQ\DO3\:E0D_[W'K! MSM,.>2<_^2#F<3^TO%*J:R-ML)TSZ% MU#(8 -NE6-6;-J*M\$FXT*J*9*[6\2#KYEH/1-5&HS$ZQHP.;9HCN]!M>7/+ MK&4UI'])I?1Q,';TS]%$6A>X<\6RBK$.SI4N.G@\/[PQ5O(1[TI>K="_\(AD M,Q7%NAHQ$(P6U*-%%,=O#";7A/]>A PZY=()<[C=:ETWY2/QI[AH+P..ZTX# MY3@(L=H&Z]U!KH98%=Z $'8;DUX23O =90U7.J3\4&+I8 W(,:57 [.+VOW> M:,RV418,<+4*'-J$8B)734"A), M2E]R!Q W+7J>7>O"&]0^WG86OCT2EH>74(M(.NQ_-?]\NC"E MRPK@FQE!)QI-C,T"_9",EL=MZ6#L,L&4FVW)7WJOD\:*E/@:@\C(4;.Y]1WB M%5]KDWP1RSN%)R,@W_8)TE:_48 'CAG2ZF9*]V RK6F_J?G@I3QM%PU\$TY; M*^8^=Z<3M$;/0KO!NY^$R(;-(4#)"^%!Z3C*S[854*$R20([KI9)X_AVV^6JN"85[+E\=AENP5, H?@ZV3AS9>TUD" <6 MPZ'+N9)66&A%."*O&/'']X6V6%RJRK2)U"$EWNQY0*NB^!TSNS"!B:)^KDJ> M>=IHB_X[;&2,"%\LRN(Z0 _!#R0A,02&?,#F+BF0N Q8/Y9S.9Z3W[J\6:VY M )\[AT-S5Q6+!]'T+K$;7?]>SRCAB"SHYF1!:>;\V&+L_T$R,6^U$WM\[6EI[ MH)^. X\T',JA4T-X*.%5)[$DNOF['-!*Y)9Q0^G M)&_'M-+*F$[/L:2HL=#Q;.]9X_I+R0SZ*F*!#L/M>L-$*R%/M:\R%'HT]\RZ M6N"CT3>U960=^\I>8=Q1Z:1W#. P8U6B0W9(DY=IEASPC&,%8&4ZVN M\^@P'.;!8,PRY_PH6B^TP2JOMY<'BGIYHE UY3T\C$<=LX M5Z!\<-&( CT\ M/XJR89_$-\PC0S PUPZU"MQKR/?\A>-;G;M9P-/GK1-#YV4'UPYDC8@O7$N" M2\0]TV+1'81[914,'+E:1OY,*_66L0> Q0[!"\X<\^,93LV6_-BOIF$:NGK? M&V!2-1BHGF&+,XNM)/";0H!2OWB!-6N'(3J:8VSQG&@3P*F"=WEQ1T0LLHOP M6;!#YO>WC43#M^)VQS2LME1#[(T_ 9]YQJUG)1J^G7V:O3^^B$X_''YJA(B# M+Q$?DB3YR!#(4JL:K@#,-ZV0CHX X!2DSA+/$E$;UA^0@Q9_1\JYBR\K&F@4 MB\^]\Q[MUE@9L)032L%9?R()&*\JV5AU7ZLNJSE];:TC/1E)>TPP@HZ0_G$( M?.T>B=J+:8 ]^# =Q;EE:E74VNGXK_'FSB'0%[;<_ YOOM#AH7%!$F4^<;%R MJ"08G_4'VN]C/F$NW)(X6LT+QKFD?C<&RHT06B*+\J840@!/0ULX-#WT"(#! MAQ_1O'-QK:QBK&'Q3_]RNY(=V_$*YQ0 D3#[9;Z^$&2O:.0&RZA':_6Q IY M!>[7:/_,M= G;)*KA'4S2R>E4_,7+[XM#C-&0YR>*M<8P:EW,4SH_KGJ&+S: M*S3,HJ/FZG+,H[&$%34I'[ 9X^B (B%"V"PI/"ME6+W&VJ7ELB3HOK765T"S M;_&D-2>PPO?/P0F,:UT*V^5A>KL4&D5]&IXS$R8@#\$S$KDRG[\5UUI![["D M! QR[8%C,*:#SZX[W52!!SL*6Q;/0G 6_XSP/\I#E "=^T_+7;,G-SD==S!( MX#PRY=HTRNI8I3^7Y[(L.F _'BH7?"I,'F5^XY:/D6SV,T@]*=(]LP/HA"], MTTA(FQO=867;&5 <*G@H:=,0@7I9MWGNG>;.-^UE_^U)%6@/@I&W:&!/BTF+ MGHXM>H!P%W)0!2):^)+XF[CUPD@X=?"]-#KXX^BWPT^_SJ+C3]'IV1F@HG;S\<_WIX<7SRZ8V3LY! %)JEIPMFP4M2S/C+XI09MN(^P4IG\3B; M1N>&1#T:C# N#@V%7XY]T3#\DTVB=#B(P$[.)M-HIMH^7#0^,,R:.<^ MYU72^7(>2Q1@7(BD=& , M2!>G_8&T;6\(MNQ^]Y";*>?\QG%"^8[3<=J8!#._8/C!$>1\=G'^)GJ?EVN? M9DW62Y"K'\YJ?X0_TSBA%TTS_FO4'VJZ*9.K1FH(:=+ &$=EDD3(_)#"&,ED MUC=8Z ;,]! D AK^W G_(;/Z;7,U'24Z4]D ^_C4:-8G#($9<<*22=887X2] M_'1T_.&8%EYT\CYZ__G3.UB5YQ>'%Y_/H_=6;;0^7\ -7Z%T3OF7P3B37^+^ ME) /GT[_,F2[ZD]Y1CC']\;\@^<49G20HA)"($@)=EH/&/(8DQ5* MIM+SA:.;0M3O8#1$9JY,!:'O3$-[M8Q-TH7R/P!+B>OHG^R<01555TP)(W:#I(RVW614^FH0J'#7% MX>ZWZ;LG3Z(DCP]4E;O2!Y=HCIR5S 1:8H2<*:W>/N>"TYLRT;.>[ MH^E/5;;5%I^-<7]1?ETUC3$"RB7P EFF:.("0R+=;%N92^9CT40O=PU:9#]< M.W>OXN;*?1,I\*^0<&:]# EL!P,F $:6S*S7IX_ZO4P_.M-DZ2M[1E=W8Y3V M4KP#I6+42Q/X->U-_2<9\NF>ZEAHHXY@+&K-J;\ZZTVF_.>D#S]GE/F-@4I7 M9Z8EZ.T6TZ@WPL=,>V/\,>I-$WDXON1,;NWJ4KT#X2?ZZV'MM/-8.RA2*+5^ MDK)Y?NC2K:VCL<&2?V'Z2&S0X"LP): ]EW IPG#EY%6@;+7USNF4TF5%Z7.. M>@W?6V'&0-+NAX5YZ0Q-V1$V:X3XU+O5?A3%)!6:;5&EW:-,@SS.C%N@27;$ M7@4>.>JZ'3YV6B&A+?G\*@$]\ZB;[4*45ZVT2JR6=M_JW/_J"JV'@QKJ2CV1 M#/Y)HTU94ZJM)&NVW9!H:R8#D3E>CB=>_UWORB)E%6C3F%HK2%?Q *)2.G9T M=Y3E(1KYFB+BD>(SJA0[["A3@M*JFWV7F[>V]RE,0O%)(YS3ZQ,-C-9JU5;J MH,71TT(G[DT5APQ_&@^\*3B! 2."PF$D3BZDE.%T(Y A> +TDU\J$&ZJ264P MY#M)>0 !W*X=;J6:+49IQ9)/RK1U/A>&:'7)J ;8;V*V1L0;BK%L-)29HPS+Q8\N-:E&P=I/CK>/&B<>&0),'Q20E#+ MYA'R6$%X3<=AS;L5!:M@Q'&4H?MPG&OK,.;M;_X13M\LUY]V=S^(O"M M'.OE"]PJ_,5+6*NL<_X((OLS7Q/=+R5:-!2<9JG>D(J8>%XOY8H"46FX2^G&^(2 M07>J\P'%6O?LE09%F!%Y$T-!,.PNA68>3@+[S[%DYYJP#WEG9NAEXPW4G$#O M!;R6.KK=+FHJHX?+#\S4\C>B]=T1]7/O+YA"0H2%*Z:I&- )_%<>.;KHG(QM M6OR6ROG0Y_>>KA;EE>;8:HJ$S=@CDX"D6"/.[$7"DY&(<@]I,S"MY<' 1_FY MTAZ&[A+QH?@#L]MX:5SE]]+QV=@I6#[? T4'&)J8JR(3B(]'C236UFY7N" M2%9_7CW>W14$(Z*@ \XHDCY<"I2 $NC! ]$Y<5"PA2B);()@J=!"E*^)=SR MM%&C?%EP)@G,ISS-8#->$I79),A?O[=?CBQ>I'MCA:4J1FT"U\V#3'4?.3$XMIT/:C%(*SM6&Z$EDZJ MW(-1(^44)_>[+ZRERDZ4]\5 M3U^;C#L>^5SAWDM'G:]Z[C/@$<_PG:*)#$-KV62[3M?68[KSI!U&&I\^95.\ M\2AH")'%M!]KN\_DP1]!#.=5Q#@Q0P6+X3\)?&%W5"<;14.X;;9SSXWVQN2P M3S+TL>^-Z-^4?.][%"#9RR;D/N6=TAV<&"DROK50^_\]8+'$),+3HXT#0\?0G_F&S:_ J61>W.%\/F'9#.:Q['T :]ETFV0L:4F_$ MCO5TVI15#2=0C$#_P'\_+\UP$GNRBTF26.XMJ,%[(PX+]*5FH(GI1&=/Q5/_7X%%U$P\+ 39^R"FWCH MWEO9,!&UZ0@>>X.YC,_4@3.&$S> E:#.7H,:?!T=)-/749;UQO1!V@/]07_W MR8\WZH%B>:W\W^[N(;H*$8[^()K ,X;]7G\(GTP&O0%^ W]/\>=XTIO@YV<% MEE-0@42$CZ4;D4".W7WP4OR1]+(A_37 'RSF[FHD6NLE0[XLI1\C_#'HC?&: M4'VIA[T/[>J3.[+SEPNUN-D&I]HB*D\A*)#:RPE-5,#U MU(V#-^U^D..(_TT;I"Z)B MW$;0&T'S[G)YG8_*N1\/:#G-C?@1K!9LE%SZYD"2)!2KZ?<+]%J@=\EAK=MS M#?JMX._5G:@WT&';:H.9?>N",NE?I&S=PM(5B<<655T(R>%7$5?F0M,LTLRU M#Y[!!;\&[\4 2C:P0") M0*K%5Q]H\F R^M*=O]+HF.^EG?0UE95B0U:"*1@^0\J>P!=9#R8;9YL#)Y1VK-%)2+^$8%:P;IM M_GQ*K2Z%<,[@PW.6PN >RSGDMCNF_ M-B6%R;N\JW$\85Y0!1S?9_Y-Y5_/O&O@P$F/F7\'??VQ0P!];F((FF MK.601C)4@7P\!IV1$'YCDHH^BS,X[;-*JK^IWI>1_&L-6ZWZ]E,E"KC4R99WR0##OFS."4UG$Y'+C$0A^#4/$>*E3C/I,QKR0TH&M-3N$H)F M_RK;[AH;T!<*3#]^GI<5VJ,N:3R/#&J;-[? 2%P\PI;" =;_*;8B%)L/)$"V M\D8K,L30S#5\*_6POLJ@,@/:KNP=\&WNDLM+Y\9R8429 HF-TAO-3/%^WZ(#3K3K?J#OKX/0]W-I%@C;8Q&*6[B%80KO2B-]@'1P% M@FUL1;I7;:C4L5A0!SU=%J4]L+]W;X)>#H6I=81>C-_L_;P'B+18@HRYBN;00GS=UDAX. \8ZOW MT7JW*"I?3,YT#JVC/PFX+L[NHFYR4=SAMK(C4W,FSG6^6FE#R&F,*X*#? M]W?4&\!Q-^-:X^JA-_R$$DA8GT[ZJ)DGHWK]))L6[9_NJ,F<_)O4V@;MP=@5SVVVO-EP(O6+P5WA>1?M$CEHE)!F5B#7O M%(BG=ZLX!Q[L3_",H*&LE5XEOC;7!^(HY"DVD'W!ESP(0B/^Q=Q1%6&2_@$> MMQF7OLKK">9>/_#B&$SBEHY7*US[4?8:5>OOA=;8\2/.>X>@D'^B/W[: M=_L,$85/>]/70M5IDN%*I,]YN58&M(^D_N0!O+ MY8'4;!&CAMO9>]'?Z$RST09IX'BN-;86W%'"-Q0I'/=[8P(:'(WPEP",4<#5 M&;8"5'CNV;><7'MD%_=<.5[XL>>!XJ0)!65^E1BF=X'#V+09';7D&.9-140+ MG9;\JY9UU2?(\]E('@LC8PJ^*L'>RR3Y$R&U8R4GN>@)@P].A\V' M8#/5+-K-"-R+_DP(9+H^F)V=N:#JBZ/XBN1$7$#K:W 1S[F ;3-C"E0& _*S M4N>VLXM#WTT^0_B^$N",>CA)9U-.?PP]&)*E/W M;!Z_#SFL?%B7N#KH_+6)"LHJN>+1FV^C?]G"8>L*-<*[TW\!;> 9\0;,&8P: MZ/,Y/%S-PABC2KTF;Z ?6S^B@S[/B[1RAD-ZC^!1%3\%WLM?_;3/4>%7&"'U MBDBK%3R+D@"BYH&LODJSJ<5ED-=Y=@/84-GU?>O =_-H,.XA+[*H>%*Y!#)R M""U62K#?M M([?7YWOGS?%)95K,Z0%C&:$BM8I<7EE[4V5>1=E/7"F0TLN:)/$UZN\X>C7) M;(]WZ",N"@Y#ISDI")?GHTZEQQJ:(F;,V!M-?B[V,QU[.4$;NE-Q<0B6\394 MB%BSXQ1HJ+/^2#T8A-&2IJK6;>Z!$9#AZ\O5ZG<]\IR7BB[?$:J.+,;(AC!1 M$%-1L#1?L#E0![)1O[F)(S8"(PCFAEHLIC?[L"].(YBTJS6N7Q$74NS:',_K M%_*#/UE&1QO'BW:,C56=: TT$):?8QXC9%%?V0TN MH:6O 'LAEUC7;(JK$>GW&$%CZ$C'WAPY_K"HB,(HN'49HP8@!N>R;?O[-3F!\K["' M(+@)GVM9HHH;=C.\0\!L/+K#$>%^>[F TYCL9^XT26?O&9P%8+//:2@^P%D] MCWX%#7]/9H\S) _8T7*#W^C>W?(&8@)!D9J\[EZ=2_)+&4"6[N?1[C5)GV%% MR[:VNG?H#=*6VJZ6O-8MT=9.$"X?T@5:&Q(]\,Y7@*/34E! 0AB\8-"7-PR2 MX?>_8M2KSQB\M'/*:M218$QA>A4!,CCFTY:Q"$ K9(!=:EWK%B1'1+L1=S?J M-G_@VA+>$3&MKO]#Q.-Y^VI2P[(=MTC3+N/_)09]=QT.SUQ8R_?-.KS\'A7^ M8HWU[-6J.DU:$^BO&LFPT6$?CPZ/.K78QQS>"[N*'F8(6"[ALTSVDK-,B-.2 M#5M/-O2V S3.3V$]?MC,GVF1AS$U1RD3F(9T((;3=7E_SX26M/2RH55NAJ_- MT2TI]0 S\IH-3X#VD!Z\=3S\^8A&60>2),2*.0.GB<4CF6^8)D+Y=Y;T.TLM MTZ5/([1P- 8&S=$H27J/6M/:L] +54CB#B;/2Y5KS3W4LD,^+>V?.K0,6_4A MQG\>'L67YO$^_ZB!E9T\=WNJ&>V&=XUIF813%V_'R>1!"'&J_7S4H!,LI)Z# MNE5L*%CSM*)%(,SC>'U;H9$C^W#PFKO2=/?H,D%9(NL)+2.[\B4QA_*IB$NO M<(&BC>S2V4 ]:Z 6++O_7-A>)&BO8 O'4,ZD/Z21<:XZ"8Z?/36<7=55MN"X M7#8&\86SUGLR%1Q3P!D[7R)XFF3/)4.M MPQ11ER4%U1L/W"1,&)<\5:S2?>!]7P&K^0K%N&BKF<4K.'_!Q"JQS02[NY3@ MDMB&%O M\(D@37LC@MXZ=, W[4GYFM6388);@GEL3S=!WH24I0.$D,+W''GSJ7#04;DI MF+*\ZDSCL"BHP*.67@0?U,948'K,:.)P#2F"G5+ >"_AKJ?Q9()_GS4&9[6E M!I&$=BKXNE UH7=@YUQ4T>$E/BZ027JP*2DZU(JT#YC<>[PI[M02#GQ;YP[, M'UMWX@EX:\5*+Q+N7VM&G#G!N-DFX1-L)#J!D=IB^E)QMD>O61$#:%AI*EIYVD69>!/\?3#Z6'I<]O-R@GO'@Z]-$2H*224L]75<)MJ]*P'EE03WKD#Y173^F FT!OI-U;,%RQ]G.)9.V!/ MC>Z&-Y&,(#6Y9'.BM0R)<2,'S>\^UJ00RO MQBU![N,8,QQ7C":!7@K.Z$+36QT6E7@LA@SAX-HPQ[EAMN@PY! 'P6#'S, D M7E>;E3JZR<'E[AP,; )#"WBV>U^N+5L\AE#:VC8=G@$-#P_)??Y(4ACD$HP4 MV6+%5^D@4?$44B*H<4;)^G;_"YZ3^)0$'$K\Z$21/[#31Q[#D><9/:IRU'-) M'(^U_*8:Z+W)[UIRYNF7-<*-+V7^\*7BIEWIN_?P.3]I4W[:;WJW3.S3YQ[5 M14?=,!=PL"(WY3+O>B@1_;%O ME'UZ6+?HIM6!0#9_X@L7DH4D\4IY1;LN \OP^3:]8.I\_7)':W,RH(\ M'\[6O)P+733Y72DX5'?Q.5=(("OX0/T=RI'R7EOII\-SMA/2MQPE)8 M5DXNJ-+[!0+'J1/6.8&?),\2'=?)MCZ9N?4+56:Y/X[8A9X;?J:ZMYP2Q$:6 M,;.QOD[7B&YTI[%1JW_J^/ M.D<8I.JY%"$?V,^U/INQNI>W\]*0MDCZ(/-] MUG)RLG[?YLKX1]4Y'FHOC:-+G%I5[<;-[X)RIB_VL9Z(6H<*64@3CXSYK13& M=N6DT][X.>+2; S)"/=!K<-7V<0#X_D[''%?URP("Z(?&G.)DU,JB5A>N6B& M;4OI>8;Z+D^J.0S46LP%RX:]4;W7G$55Z]"@-W$XI#$'DQU,7>OZ2'I@-1I. M[ESYLPW?*>4X593*NK^+5OM5FOD(!Z=(H;@_Y.7"8?*9D6I,D2.7;%L!?;4(#=-= =*+H0X39HS[\6#@3.H !W MW7'FZBRZ$]_/9[]^G'VZB X_O8M^G9W\>G9X^MOQ473\Z?W)V4?"-N^XXWS' M+9PA*JWPU1X::"0,T'JXUN;/$[.D7ILSWB%8NV ^^2PWPE.);E=?:A&E)=$Y MDOO3!LN9H@>!3"456][']L*-'U?8PCCMGW(D1E\=7"_POJ2JWQQ MX.K&2<"<>2\U7^U>@E279?^CY.&$).W&\QHF%IG;&^00M>?%C1=(&1B[<$Q% M-R6MZ0?V/&EPF,)'6,4(NN\M- MHBM8E!]K.5/>Z%II9SNT1U7[T>EJ1<\2D!.9*X=KN7FL)]=T#Q56@R 4J @, M^X)<-^EZT>IH\'#<3\MU".G4@V#R^C1MQ+KTB[XW6U^)S.][_A46S6/(JQ MYU2O.K:S/_M:(Q2L!>!V_RG)R%B//IQ2X"F>)%R?/DK[M0 G_]M^)5D6]*PD M1C3 )!YE"?Z;3L4+S&$J=(S#%6.Z(IW(OU(8B;=G\6@TBD9QOS^-AC&V-@!' M:7SK4A&YOA[I-O"]8^@;O@EHRA'>,) M=-6K%=Z9 ]90?G&@>=J%+KCD&R5OA'*694/X#W\;<,%P1.@T*3&(9$/B#$$R M'B=FZ#! T 6<="P-QDA%-H7_DC'=940*>IN@,,*3$QC<- +Y3>!]B16?%.\; MPO((C?($IK1 M),+63>#OK%4<8 8Y:I1R.#+AG(BQ"_!PVL]>-B5Q&4Z&C*#I<0!W3BE3RH#H M$J=*TA\'LMK\]BR$(0##Q$:_CKSM=M*(OEVXZ)N42,],Z.W0A=[>4*20;,A# MGR+[9F<(?3!B1C$8EL\[;#DQM_:FC)LH^@>']YVWWOYD##=Y/$[5:(#1]V-G MHKF'#?L\_AQY&TYPX"F9:(45=7B<@:?=6G,-\1=MED="BQ-FYP"G)RB8'XZ' M!,DTIE4 EL^;%T8[X^>']4:(=0)R,P))XZCALV+E@_X0%UDR_$/BL,07Q& ! M\7 \8C@J6"XBV@P-\:Y 1N;2I[ %<>TC21DC!FDP'0DXIVM+_39E-8TG&:'B M]N/^B(CSXBFEQ664MI$-69?AOQ,B@!NF&:'#C(SJFL1C>,@XGH (C6%3 I'& MV4=2O\Z\$UAM:4+_GV).5); 5@T3*E.(GKL#$(X#2C^9 MCA1N:##QX-1&T#/,%*.;'/6%H+_)0BD 3L-V$ING@?8=MAI4>Z&^)2VJ4D\OA+( M30ICBEN[3L@PR6A:J%=C'G>L4:"?;-'$N+,?&\B[4I;Z_($.#N04\'ICYA2+ MVV4(Y1=SDKYS4@;FO_H$^>E (R"9H D HX7B#AVVTU$'J-+_W'2T?9G9^0"[ M F8:TRQA1B5?A?A+W<1,43-GI#XF9#NUSPT2M!)J2L:&)EN>.C>8#HD*:RSH M@&2,]6F."$YMV" R])]2PF$]QF5.6F;/()YXA(X2+\'F M=EWL)F'&4(=X]@T;,_EDGF*L,NPW5'2*FYA4-BC+ M@I2*[+QY0QP(:TS8I7.@?_4ISO8:71:G!*3P7_*[^U](N.]]?N2+Y?GSLG2I M*I50\.'Y;2SGMXDYZ4WB/OT]IK,3FF8(^/-&1;EY\N+,WRP>)XB4A!@DL',G M*8&@9?C[" 0-7H;7]/&T!>LA7SSD+&\R=@R]!!\#RP0T;MI4AGB@1T?1T"S.\BL[H ?V$ MCQ PYD-HRG"(<'7+_"X'_8W)9M BLLAQ4N!?Z)O@;J">P]Y MA(,!QK^ IX[!I+HKUBM,!$GW6Q75Y]_7&%P$L[C]>U8\*DV@M_9A QF-$;() MM(J:=^[[ 1Q!R,2/42H&28RI '"&':.],X:M8N+45>?)%C&GP HA\*EAC-RH M*/BSK^(8TTQ;2C0(RTPC4Q7W8A+XD '/>*/AK#27-WPLYP=_0[/A;R6F9WE7 MOH?\1UB[CD3 9^9DH:"H97,?=&Q12J8KKY3JQ+T<-"P3J^IQC. MX?EGF, >#"G0 M88+-MR,9X+?#L]G!V\/SV;OHZ.3CZ>S3>7L*0,=UT?G%R=%?HI-3_..K9 M>72S)EQ- PKATE1\DE%+@I%4@S%F F=G8+60Y&U4FD)\X#(YYIH1UH-]7S,^ M,(Q3YS$/4P8$W^V)!NY()3,9<@30CT]0>"B3QRBUXVP\S[4B5_H'XD;CA!;D MN>DXFZ&>.$XN$LA5JN[.+3<4JO&E&Z2?&9M5*/;J3Y8\%Y<=4Q6>ELW:XD[1 M,:^@F/$'E&6FR$W5U6TQWR[X;/*@$!++XH 3EBDI3Q;!@\Z,>0S'4P1;+&BD MO)/\7L+<1UC;.+;%DE=X+SIL2Q.*:WFT@T:>E^22*N 4I7U]P?Q"GS$DG+#' M2ZKDO2K75]L[KG%'D-*@J6YN'DGNA8X6K=.-P/E)2B7E:B+1:8S!:*GFHZ3[ MF*$2-GI#L :HAK*ZI7LV!M68H@*&E&%Z#737 8.*C&K^+^N*"?R;*O(O/ MVE+"\ -0S&.3)?9VD5_]?G!^!0-1J$HXP(5!M'"K>;'8S93E($2"R/ M3)%"="JII7,6G&*7;_Y88HH9,:C(?^Y2!6%#P=HCD=J/, (Q@GVN^OW@&@75 M%>O2$7S0FQ![C/X8X',-\SDL2_L8;Y6G75VK_19UW@FH3!1H%F5JL)6B@M: ML6UJHN\0H#>$%.8Y3G]?KKXLBOF-0#CXH"KS?TEV!*8AN*QES"PR%\HE"C;3 M)N0[>=VHH;()!J3(9OMWO0U[%<+ [/!Y^+AQY7?[ &IWEU!+<"=HG-8I@;@Y)G? #_-Y #%X;FRV4%AW*G ?P#%,'(^\O4Y1?J M#+U#8 0Y+$;8[@[-Q&7M.MG167%W#R-R+']:L8)#H!&E219E&%Z_6H>C1^A%Y23Z@&2E[.)5K[;\ :YJ?\33MS*)V9J:B)'7-F6.P$ OT!GUD#WN_6E\7 M#A %IHS2@/()^(YB#AK8]9!2/V0$/#YE$P]Z$'C,#:Z/4E'&W)%L?D,7)5 8!W5(] M5@6H@7VQ1UV+: H.TT<1:_RZ"*P07AOW$C.MWT]%& 9>V *U&>TKD&V\;J3. M1#A"\XK -^8,Z?;H"N/4F'%]IMMB9:,M?9:C%_-R"09L<0"V?O&H,K_/>]27 MU78Q9_-46119W\E#1-BU6NTV9RR8VL=>T_+.Z33\MX.):=T>(=[#-Q.1 M> 4KR9$LMJG )>4E]A1:'90NFMF8"^;?UJ(8KWF5$B&]D*X-AKUDPKA[[2:\ MGH $8L^96PJ:B=C@!/!W;9$XK=FBF6%5Y% L14MU#HCH$G@?,<8S*QNM!-Y# M%9'.U^]W[G8[Z_)DE3+WH;'9^<79\=#%[)TX'4_G!MM!G MJORH5^C2D;=RUG"M3F3OI[/SS]5/^W+\H\S4D+Q/11U/A;P\\(Z7G]')HO6L M(_5S^@6=N?#]?_R1FP=*V^S,\@3)Q-B?)VBBO RI3D=+_GQ-W.;+2HPI313! MP!B&?AB#$%K ZTJK>%UJ*9$79C;H.&\8KG& MB%#$\!S?>7#O$( _X 3?^J8GC_+O7V*?!K%2DD?Q[-">TWZ*])XJLH]E.W4% MFRV[@2H9_[C>=QUAM8:'"N>[3['4'YV7P/]7TQ8O&289M=[.]R*)8,I'PZ2'Z0>]L3N> MMEWMLZQ>?(A-8LE8HA?]?_9 DO:&*1](@@WO?[ESB%50+SZ&U%75R\\5]7RX MVAY.3Z5Q?/!R3"K+[U'?898\H5^:^[+;Y>H]1 6 .4;C:)HE]5VT=K';C!W+ MPN;66?F<[SV(DQ23EL9I%DUA.9YW7CG$7&=,$.N/HU-3"OB,0YFM' Q/9:=\ M*H-I77'M<_7<$]JIGLXZ#'[H-2_ZH0_7\C>TU] *Y%A)WF#_=0XE'T#$I_@; M;(?<73VGW@T11BF[DRN>BWRN =M\=\+AY8B'$2L'>EHQ5,,2S^#[;C?C+A@@ M79B[P5*>KU1KL MT&&_'WW>*"/C.<7G05_.BZ_MIU(IT-2J95S5!L=T:9@I@S@CW4N;BI3@!^XS MGW^*!V-W[=[E$R/6.H$Z6=[6%GWJBG5F;X\OWAU"5PKQ>-KG;+#F=X5W+ =>WW6B/[4*_S_]_(X#[&MU6UM!#(P="S]TQN* ,^P3\6:U#A?O(-HK MVIO;D.WQPIRUGY-/_%!]< M2I3P@ZR7.#_8'I;D[$>#46^<=OK@,B)(&.)MZH,;(4Y!O]6!&\18842. M,:P"["5_E <.ZV@GF+@R3?Y?Z7_;'?\_;7&W_2_C;1O^T)C_9'?,_YMLKR== MB*??ZX^;CJA F0BU.R\:(3( ;;CU @[#['.N ME#OGAG*G?OV%XW"5VNSN&I*SV;O9[./AVP\SK09Y'YU_?GM^_.[X\&QV_J++ MCV$Q/\-\LVA;3S 6*525R5-_BEKK21:D /C)",2S>:P(%&M$)0E3:?N,<$3$M_$0/PK>\XM78Z^?=J+H]>I_*!K[O MU2@ O-[UHJ5C<84Z)7D=V6O)B?%<"8-G)[^OEJ+:0USAVEE"I?NBN/0>N%Y9<]*C;1" MSK.U-VJZ*HD](JBB8E% 6J6@J-DE[8_X.U>LO?).GYCL1;GQ5TP MXN;=O#R8C3XDZL7>R[09\$"EHJS-G<1ZZC-1>VZ#:!Z]ZTZ\Y0UWQ3_^D2_1 MQ%H4#X5[TPZF>24M6S-4+^DJ!]W9!N:+\]2)%L5H++(R=!'77XO\YQ1@.>"HBQ'YIDX9B$[II]9M?[^ 0T3K M#+K5S\$5,5QBV];#.[:9#S%G=<&3A,A)G@-$W).,F5VQR^"6VWR'\.KM"L4I M@3L:8:?QW)"V\#W(,L+2[PV_P_3*T.^TJB'!>(8?ZT)*50+R"LFN-U$MY'_8 M1%B@MF'=ARC-AMW&C-ZWZ3_3=3/B_[\&?$H#LN?IN=1<>?CDX^S@@>?_:O6!L_>^YU4? BC[4BSEV?8.[P.P306KV5S,B& M+5R4*F4ACB$RGN>&4XPQ%/(_9/UL+KB#64LHX2L;1M'?DJ M[LKJJEC O!7HL+#VM>.?4$\[)3#H06Z^@^GRWVB9/HV1=-324,P3]9BW8,36 MF1(E;#N81B,$IT'(XM47)SOOMZA'/N.:%G85E%"B)L"'[WT^][D-6.X5P6,$ M2)-9P!&>8HWD< 1^1T!>VH(FOJ32HO&PZ@R60BJ,_TT5D6V,1,F)'IN">7B% MQT'T"A(47C*46Q35SDN5.H%:Q$KP,5ODRD*EQ^:Z!2C/15V&2!#Y$I(.;N=_ MIHPHN"=-O^^/4.^P+ C_;(8G\N$@^E#KV6.$17SP3ZN\Z4R-99!IRJ?!//G* M7L+,&]%Y=E37$82M:#%+.W2.N0($]IWISD6^Y#H_1=KTL"'=[IO#\_/9173\ M\?3P^(R(03I46-=U,A-=_C4_$Z'7Y"_E8KV"O0@E-L3F>[N]OLX7*U@V]]'Q M\7&$?( .J:KWEQ[A+A%T(L,4SBZW&Y;R$?O'9KAMOT6;;T\W5\%_YAO>%A@? MP8C HGCT:'VTCHOJ 9I8U.\D'*Y1=+S)+U?1WCF8#Q]6ZV+YCY7_&EHI 'T# MD0<6 5Y/GBW 2 ,#0Q+:U73H1H2,<9__$;IT-^QIY'WP"CVUJO5A_BDO;D'N M'@6TV^AC8T+4R!<'K'#*Q<$U12081DHV:1S>V","" $H%HU6Z(<#S57@^@;K M&1U;^16^5VQ1C>@90BX$9 HLAO"^L7V/2LML*JE88R]O\.#5RA?)IX4\JM;BO'E MDE-39]5RT;C.&><"$YM H VF'!\D)_$&D\&.;/*6]!JKY-NEQF54UB6G]@HZ M?N'2N\[7Q&!T47S-\?S@.RH>531L4K/IH?XN M#B_IIP!T42/2%>V-C%JS- B\DM.G6)6 M.7I@+*/(9P"<#SS$^4';*;DY\?UX\MCP&A**$CS.S8!ASL=6F&8B M3"<""ZFR5'84""QO5RN13@+FD3=(-M)E(6,W%QJ5_*%TY_"K8KVD'OMQHC)P M^,Q15@61@Y8&B]<+W0^=6@O5:!FJ[4ZZ.\>Z]2OP!B33FH+;9CM6;8F?,B;>]M'+_8LK"] M1EC+5KF&.>3'P"L_E; 4R]PN$<.TJ'GHB!5$F9O(9+6]OU\(&8]/B3-BBR$- MX1*M[]<^22P2%F"BZ*L*6)'PB&OA+9.VLG ZS&$/+.086MD!I(LB1)W!94[A M<#3X_UAKXSF2@A(R&ENQ#QVA',_L +]H:1QY^"R,I9'[!3)!40(&Y40M%BR? M=C> Y?4).F$HH:T(A=2R>F N-YX%BR"Z48@,BB<<.TDP+:46)1+Z:"B,?%XN M$*!*TQLI]1Y>$(M,XB"_<$V8=?:I^'*-4%_U_2C[7N,9FZD/9ZUOM;KJ9[MS M42*B[ 0W^(JE\.M=:[::X*RIEW19(+XJNL\LVMGJY+9<17]?P2I:@*Q]6=;C&BU: MN%7'^@PC.U&J"-FS41A$AVZ-^\<*E!_F;S&4DZ?W;D]2]EU29<;@YYJ28_?\?JU0;8.,RV<@!>PW//XY%%E$)^AK>)RE:&37=V?[MH$,I=Q-]$)I =O M6;?B>/P.&7_&O5PT5S0J;)J7UL\JNR0X"XYW@=B\['#7[>X*1._[=E#_DN4RYLD+X%*3NBP8I[5OV^7 M5U+R(K+NPI">QICJOV#^R+@]WQ3WOAQ/HLPWH)TI9=3,&;%$MAQ8+HOVG214 MR5)#0^FL]8%MO(7\VC_C0OCPZ=?05"+A5L8&&S'5FAC<-PYZXS7Q_D6,P.0P@A&$PM+ M8%;4WSK/P;[YZ?QX]M,^-[-ZA.;=&7^N#$&3K2..M%R,S0H1#3Q@^16D$.PW M*X%01A^>9%!CU=%V*>LJ_+'9K\F]:-KI- ML*CR$6P355?%,H>=O6I;5K'W]H 8MXEWW+7RS(QWK[IPEZC?8AK3[=8PGM;+ M]0IW[?^Z70F%4+EI+.!;.>:T'38-E4:PEYG\\YH3W:R^[S\ !"=76@4MR]A1 M,+4LY$;HC/4-<1MV?_>\N)D$\R\._[69XVR_B\R#3S51Q@$B+(NOF_8<9QT) M)O#56J_"1.[K?'T6@K63M79WG=G[8DY<',3#+NN4<9HX/L=D4^\T'61OR-R, MRVG?$%UE M%$K-B-4JS=)H1J77J*:(1P3]K>0&/"FDC-\XRWYT=+Y=PU-$5O?_\&0* M-Z74*-A[7*4AS.EKJC)\3@*7@I_?M75Y.>NUP, M^T"EZ-.>U<=G9-DP(3@AF.2/_(=J"+55 @6\=G=QJAO?)%F&?E8Y M&T 5FZ1D$ GBU=5Z6\P-I]\'D_E3IQ9R>!A=;#-AUAR;$9@"]]U-_^0?8EK? M^,XT_L>TO7-+?$Y7[";X)(&@K>8Z;G\X2,*5VP@'(TP12@9CAZ??WB![9?!< M:67PT&1$%*73:=>E9C)3).]L>;?VGI\#.V+?;+C6ZN%CC'Y3:S^C_2GO#Z-+9]/?E6EQ.7"69],&4(_2)-(,6AK=.PBIV$9,=#8HZ MX)_]QER90EL+I)!W5M+Q""MK>'CXHZ"]'3!)=(PN\;2$T;$N46@9*).MX<;I M?EVB/H*OR4(SHS7DK4U?G"]@(UMR>CH>L>^V=^;=;:_S=;D3)*BJ'I?K M Q[8,;>TO".%I A:7-T]HKFI4&>L%/WMJ0&.:ZH#1NXA+Q>ZQV@W_KX%4V.N M+#LM;4Y,[/=5$C"&<$.D$]321,HX)LW+@G75)@\M5G3E?*;S,'!LX:5@#E]- MIKYAK<4OXMS!2=-'DB/!+PAV?1'X%_I8NY+VQ Y!E3,Q\> M@Q:@4-?BGAH3BC@T%8< )HO\4LZ#S#T7GC; U0%UJ M0$;X5UT^NGU 1X!5;1OXBN?4VLE/:$M0P O4"#"0=_DR9XY6/]M/3W39 MVI[&K.ILZ7!P;ZHM@EF5Y%8-I]H%HL.\34IX:XAJK.!/N1LJ92*KT!-=B]EYB_;YN%H*@@>6,3-1+3K,XR=!W1;^F(P1JYE/4 M;N'>0UL>D=3[B7-\!=WS)3_PW&%*%R=$\;VOK*/M>RLTJ#_"?V%#.NK4'1&1 M.(^]/\5G#%*?3=D?,FLGL'N=%1L%[L)$)/@BFT;)>$BG[5;#:SB,AA,9#C$+ MNT=G5' MD-L)CM=D$'VJ7[+GIH%F>$A$4/!+.D%'9TT]4+RAXMC!9EUB[M/<>W6PWE9V M"-U!@[U!3QOP?H3B*0B(IU3,(*S'A<<'KDK.<:0J.DS)AS/YW#PIS 3';?TR:1Q[LH-'<4J7VS99'&] M+"Q^JSDT4 ]#MR5/O+!@T= :XP[C"ZIM[G$+$$Q>R[OHCZ+T.#QO&)P\&D0V MU:1E>B87)TC[E#MW%)=+!D8Y_1UEI6B0?BJW^L3 MC"C\Y!?B;],?V$X_]NXT"[*A)C$<>7**M=XAN1C:4($H,<35H8>^(\ 'SJ%0 MXF-7]NG6LC[4VMM2&_#45 M#+=\/9#;6>,H@ALFMJGV"XI8.5OU&&/@ [#IN%$,J M;CQ.F5GJ%OO%KR *P[0/*,^?ADK,*J&"@F">=,3+JKDV)JW"WR53/T:XG6P/ M7O#2)RPTD84]-#CV=X2ZXB;2I:IS*30OE\'6F8,9BN$Z3Q3>OEX#\^_;%F@# M!HPV'-CT1X.$=__A2"R^X1C-@$^KY0%=PXCZ23Q(P;B*1TGJ(IJ#>) 0OT8\ M'!/]8]S/)B;L10'D(.S5%1+S>_G5 @P8J6"IVJ,"@66\75(2>>T,1(=W#.>7J479W$1P&&8?U0L^UT*E!2(:B[+2QT88F/L"NQ]#^YJJ%/>Z! M1M4;L7*'R6K.4N<>?Q4><.+DK=N+97!,:&/CNDYG"K =FDM4QZHZZ;6)I85! MOUWH![3R:AO@(#/;8W.+>''#_,B^I&5/GIA8:=2:_HR6:\K#GBBG_5"DC! % MX*F!$?)MZYG'C)]M6AX'(%+8C;ULO[,C+V)P,WO]YHD!:%U&W2/0W9?:E.RE MW7WY&P<%7?$-G#3,)F]$*=_.N4 $X2Z+-3IA0Y^H*X[@TPA/)^>#T6/QC+!@ MX]IS87"&!6WFBQ+LU=RQ7,/Q$IU:_LW,O5K"%I:3MPF;O8(];2GE+%\--P$A M $45^IE@M'F>J,J"ZU[JVQ?&U ,H6W@KW]0Q+L77W*4Y2[]M4K/"/3C[J3%2 M?(#XHH9R\2;ZL[F$NLWE]N?^I3/STL/U#;9KF2.OPO2 !$Z+3!'+R=YY(^:B8'F^MDB.L\7#_E\M3:?PKD8SO +1,DT#S+!?W,M MDL* @/X%!GE.<11MFGQ!*KJ*]B35A# 6!WQ%=Z2A>UEYC=B]:DAGI>,T6/O3 M8;ABD #K)0JX^W6&3U@-0SH#-_-&NK1MO<,EMC\+VS\:U=H_ZG>T/_:1!ANE M"&,6] R385M_A*M$T9P6L),=S,E&SKY!W[_D:ZF&HN+<%C?-2P<6GD8,JZ( M/1])'GKQ=ZI004;"6A&P(&\[9J#%2/>(7#7)289FU'ST@!2Z\&JTZKQHD=^[ M6#B93!C_(+QS,F$P&^;KAC55>\::#X89OA@3G>\>A1^03ZB6 TRX9[)Y%>'" MPG\30ET9.N!4?H_:J'32""W;432)QK7+PRO(]8I>9U;4,(4(U]U'4%<-.3]Y MT][8X>8CB^7,)T&HZXB;>"6 H@L><+X-[R"47C])T=Y@ZIXXPN/ !YQ5AY,HP,Y+KA' \P63B:?8:-=!JL=4523GJQ *-8P(M:3O!87&\1F_P M5RZ3P\ R2"D'EM6HQ_%'-T+X(%W"B"KZ!:V=F*TE;:6/,OIV\@5&M7!" X?P M"'@OT-R8%(G^A.W:P94++#SYCGNU.QJ@(. M2]FQ&3##BQA,1 R4+-$??6G]I%W6 ",(MYD/2XX>:O!U22+( !+2-4%WOU)/ M_)K=+J8]B!1&\PU+HY[KCLGR#C'@Q/AWX<6_%8OY 1R+#LXQW?.MB[Z^Y!D. MX.I7AH#HSLA_=WQ^=/+IXOC3Y]F[Z.1T=G9X<7SRZ9SP]GZ;?7AW\/[D[.#\ M\,,L>OOY_/C3[/R\F;G?^8R*BIFV5<5G9,:@1CW_J^08D^E#( M*;I*.,W33]:?M\C)$;=4'X-D>0,+--KJGK@KSC]# WIT_4%_HB0>WNVS7-E0 M=^@$FMNQ-M['D-^'0L+X'GHG)9B\Z[C1!7GU4NQ^K8GJ7S#I$JZ TY^W?)O? MP!;Z[]%1CB=*W%FU /?/VR6=7+)]NN \WZ[SZA;$P5_ROKAB<]Z!8?-<4=IJ +X'F4R)3J2![%25I2I!X M+OO5^H5-,U?780^\K+3XB1''KT\Q6#"=CAOCAE3(9(]E_NMO>"U[SH.W)F,* M\J/UAG%BF@MZI)N-<,9>_ *NN(&?@R&:A6Z%$'3[$HQ.4!!./.ML((C>C4I M:[^]66^Q/H:CU][!'N3R(V"ST2OPF;[_372^6A:+F(KTX*8;3KGA%0$GP[_ MV:_$.D>$DN%TC)O;#54\(A8=USS&HN\O\[O+'"^^+?*'Q]I%;%M2>[G26R%+ MK';HT>@[O!@'JD"WF6H!KC1\E?3ML9C"7W" \^=M5 MY@_,CJB);Y=L1*S:YF,B\H6JN8I4'@P< MH<,*9KP;[Z:QB\DX!7O2MPP4+OL!$K$*+O5M>=^V]H.7O\$8P9P=G4?YHH1G M$M+$A_SW A$P-O#5,54/E4L0D-4FE\H\= K11=;EQ)$L3?!586N0D90NI>!7)2-L?#(D1R4Z%I!*IS*D96UN#2$A"!46H M"#(4JE_]#O-KS79?KI]D_=S#/Y +Q2GJD=%_RQ1_BV M\1 R+=+O,].G>88B2C7H.-1='>EY?^D:>PFXK60O\5YPUM*^N'2 (LI*9J"9 MRD<(\Y\5L))$:[4Z@8"4;Y(%9SXQ&!ZU2@HQ?.'7Y^QK;@9FMMA=SN@*YO'N M45E_AL>OLJ^KU#Y?BR"X\O 0J)[)/+\_&5[)*&@2K]U9M MHWPRH8_XG9AS/(PN@-Z1-8(',LP%Y#,QRF2JP*4AB+LM-L9.(LX,P!0Z0K^+ MS7NE,0 %4D5FC*]MU#C9R"NWR%/*$P5MA5+-1#D1=9\G';-5JLWN(^H.$MB1 M,R0A@$SVO3G"=PY%U2(^O"*]13[Y"#/Z3>S*4,N!,F\,AK:\7,Q&JST\\&-: MSD#:*^DB"%A6Q4]EA]!:^9=4[C04:O"8B4;4<>X?5RLH\')=AIR]=\L2<.WH MO1'?A7F]S::"KN+PMI5 MH^V=.2Q_Z/P.C095?8;5]V+<_T9&">:7JANQ\%_3=6;,@=67)#BONM__94ZM MZM2?>W;]#_LGF%U7M0>YT==Y/EXF%J5F_>L.LE[$VN/<[M>=YU:M3:T;KC@/ MNPSI$K'%G(B'@X@#_2!\V*8-GSA8JUTQB=')7Z\GTXD+1)Q.II<7_(.*,(A3 MM4.;A!*55SI8T-M73?HCMLY.G9?TW.-NR32MPGJ2;7L7,/*\:VM,SE'%T+_+ MZ8TC*E)P9_9?26\J3,J.X(671GQ@_X_D#/?9=DS&+A&>7D$4;#0_D\-DG[AV955@;570%T+ MUHU+D87[KQ=X$,Q",:BZN MVCYB@VJW,47AP'(/S,PN'D>:U_]]SZ#V8C/>N#MX+UZ>[7Z@]C:T(KS/>:N_ M*O]%<.BN]M,GZKAPJE^[ZE"@S8O[-#@+#H_)%2'[WAQQ4=ELWU^/CE1-Y<[K MH]4;_+'[0]$^]\Z6M8Y?VJ"LX+UJSY\88948HR*QVYL\2,=QA1?)>G1CZ5XIQW 5^VW[+3H%*PZIJ"6G9:7 ?H4_3 MS1J.^"66XO&NL,&[UN!EO3EQY@#T6\0ARHS\X0%.HO"KES_(3<:057!$A8/! M-'MYP$#GDZQLW23%.RB^:\%P<4-QP3?"6]H=0W+$6E%=SZVABA!5?%IL,)0% MP?*ABZ,BM 1H',EZ=0@Z&(.\DW7FA3LJ4&,4?T]!T[JF9!$1;TIOA8\?E( : M /B!293#I8'!6Z.0/"_)1G=;LS)QCJ:=%(K9<&"%$BZ9EL7AT5.F$NY\&]I7 MEC*45S% Y!%48TCN%-,NV5+8%^;106S(1:**&G>;JOH?X8.?4Z-/0M'L3N-6 M =T:&W8&B>0?S)1\*5FQ8ZFRO#3+.X5ZTI>?V&$4CT=7YY/S3]/H$TDR M9'OJ"A9NP$[?V(G778TQM(T-T: MZ\C?->_0KPCTUM9Y5=<+[RAFP!HS1# G;&X@-EOAOZ7: M89]=0@.AAE7)Z [4W;>6\=.ESNT'I$_^6$H;E;>G?8ER!]R("?B*L_AUJ08D M)C]NU'"-J$PH*V\/OEQ.AYO2U]]A,W2>W_*;#Z/IY"2J.,V3%Z<\5&AAIX!2 M>^(1T+L=*O3R 'YY'!T/(!.O>=2%NHC^8!CUD16Z==1J(O%J-^IW._A$9Q"- M/WX3L>C;Y;1Q-QR?75T:O,!^<>J=)Z%XM[6OPMZO*,TD$LE$# M*^G)&.MX_V(.+?C\^+1JPF180QI6UPX+29\!:D*&-9!AP8S-DR54&L@9VG$H MTF^LHVJ2/K]^S/F=6%0R4I\2B]\#[X(Y""@?75=:4N_YC%<,05P9F-9^9,N$ MX-VW%OK'F#NKJKFT)%VD-Z9O>'NB)I(S:(W3ORMDCUL0=I7KJ0QE=?@%NTB. MK4\M\$TZ3[:4[<(1?:BM.)3[HJ1.7&7%%_JF11* :V'/QW9<\%>3Z:_D[KX^ M/QE?S4:3SZ&QSPC)Q(@PE&\A\ UE#F&J0D<^V=\87/S((A'RD1'1?:- MX\:'QH!*L2K:F!(%^2,U01WE]JN;1J$;F(L>ZE,D!%VX_/\^5WK=V>SK3VE^ MMTX>C39I1)SS8(+AB_X!\*% KZ 7L:WM@30&*@I\CI98*VMZ(<;=>RXQL(.V M!/2T@=1OD597O0JI&P7Z]Q>JX 82:KD.)YW?K_)E?L?@4@*6Y\7642M NP$* M4XQE'$?WSXMU'J.')08S-:$[[";+'Q*P1J$6Q?92V;Q] X,PA1]IV&?<'$8CRNH;@HT6%2V9M7G]B '"CRTA. MA=&)C*UI81&7^) ME%V6-VE"F)J'#GP+*"/Q #N*P"GW,T*R*F-ZY.N?4&I\^'!HF7B@YPEI][Y( MJQB#.08PSW\!LG?!WJQ*@4,44Y6=X] Y8#._!@GX7>NH8_%\N2K3S[>P>PG2 MJ8P1307/BF[:M-H_1O<,K(S0$H&3P\%^"BH>N:49A,(GFT/D\=RBLGH(%9[, M0&8YJ",F.UT=5XO1AM 9>G_1,M:<<@?M1B"9F#&R54OP:,XREM'C;Y23>%+3 MR5B5ES(\K8J^,-XZ2RB]OE@"[9BXJ_J(+(*0BN41]5GE8*N5 [%>30.QA2MV M%],FS]CFV: ;G/+ M!U XWJ>+.P!U3]=W0@)'K[# Y,^(X/&?$5$E[IU,22(+E4S7L.UI$T]/AL#( [-RP M/P4TA3PC=0&^1X)_G3S9DM)"X%@PJ3CY^0TJB^X&1DAI"Q[ "8"T(.CQV*[ML@"3Y!K4 M$12U\L3?MXL[7GC83C@PE.#F-XB*)0@GX,U>^L@(/V/WH0?:CI:^(P"J>0I= MUW-:8A?@!9\2]/C13)77J+GD5X*J -J;J'-0$/HU6Y J2J)G'I+_X6F@W6J4 M$U5?CK'6]%/>FHQ&Q2FQ@"4!+9S"N:/1@/CG',A'; M!LA7L _G:7 9B$J!&T=47%(,T7!#>YO+- ):$#+%]57I-TT:2]V(G I-1IY^ MMY#/WCQKN:\/I+?AXNH[%1H=8#>)G7SG)%&"5^$K?M50D,J/:F&K4%2ZU0+'B(D&.0P05Q("Q MH]02L#]^Q8/NH:MYU[?EB&+%6JT%X9L6$I:'$R)"B-!V[HF. 'ZOP"C@#@*- M1Q('M,4DGATOLY],:D_"\>=BO+'Q_)(.@8G) 5H(;$^9299!WA\]AM 2SY5 ZTU_-X0/YY.J,':,Y%^)9,>#.O;*S MJL\&PYVH?F%&!V&4H1A9Y5OO1'*E@"RSD.)JE0 MLR3-J"*#(R3 G('FZVZX+ M,WE;UX\%!,;7_JY^NOZPS.M=<&U:&@Z:R MS&[6V?:A\D,.NX=/G#V0]#AKGOY+:BMX^P M$?5WF0K7T49.?50%X=-95>_X2KES9,E*3^3F<%X]<%=;;YY?A8;WH+UTK+&/ M/D-0=95DLR! @K0#U[M6'T(O6>DN\^U0T^7@A>H';2$D.D=.8?^O71J(#>OR3^3+_?@_(,"T#L('EDDS?JR-S<$I2^8$XTQ MH'!U6+H45;DFD. #&B-#PU M>Z@-6134@)_'4\5L1CD%83Y:SY8F]:PI298NU33-.H'I0?(E78F,];I\*;N' MC"XKLRW9$Q^2MQH!L<,\G+$X7MK%U A1<&N M>1C7-$L)/EERJC/P3BRS.T^?P.4C)$&[%Q0"D3'3;Q%D^0:$+Z8=*6^\OT_< M:95&_X+'V[6+5B!X;S%B##N!%9QTX>]OBU0;J@""L@"V_(:R;H@IS;ZQ78F' M:YT^+I-Y*DXK<:TER$^ 3@WE$(/4SJ/HPW9YET#6.9S2S^9OFW\F'ME/?FX('PJ/*9JY_VJ\C:0)BN-Y)X8FK)JO@>?M2 ME[J)9QCZ@[L?9FM%F%C&("!_(FX<#.F .9P1)&"#\U6&@'C("C>X'DG$.,- MR XSZW ,9(V.^ =\OJ4N RH8\J<5Q@Q=^1''UBG'P2A1B(1#&==?\R^TQAMO M@%=B*4BW$@<$BK'?VP1VC3,;S*DD2;+.[NY2A"]Q&1;E%\T'>9^H-J0(D?C& ME)BP!'?RCI-5Z&S&)9/]X2T[FXH0@"(=R*UOX47J;A!>%P):?O!784AK_C + M[L79QTI-NIDJG]O_R5U)/N.S$22K78ZN9G^+9E>C\^GHI+*N MM?[)Z,0GQ/05RLMDE3PDM68 S*=2W)&O +PFY']&0!BSQW3H@(GC%YE9E@TY MJ<61@/2Y#",#ZVCFW49:*8H*E>EP()U*[9PCH;\.(J6HFW;,YVDTC^ MPI64:(70NB"=;X@[$=L)MHFL6@/W)NVGZ$,NU+^GN$3YVI)TNQY@GC

3RMBP@MS7!)V@8X08R9B^57QY83:+OK2XDX7UUH/F8Q0FBM8Z[D]SFWW- MYBFC@5G%FPB?+$T2=4?PN[6XG7DJR5Z%:\YIYWL.O+I=YA1D^AF.\&7[ %H1Q@ P&8(Y!%$) M""'@GLL=%RPXW8,J-?N M1KWC/IS(56)FU)XEG?'=^.%D)GKC-ZOJO,R\LA6Z8%W MQ.4VV[H0."U>$02.>):NUTBE6-W%F,#AJ,3(Y?UB^5#GR"BTE(J,""N"]Q<4 M)F%AUG%+E5>]\$UAJK'H9_X58*8LIM(] 8;2PAO[1]GS\&7)LY^[YI6SI76, MTSTFZ57/C%=21J:B)/^5:@)-)S[:J.UILDG"%ZJ>TRFUKG9IAXXR'9^-3T#U M^.NUT3W&5V=_BSY.SD?G)Y/1670ZFHVBQO7YZ/IT8IXY^$,OUX[+)GX&,J.OR5O@J+F:@CP?*9)\"I+1@[,/<0/ M:W)85$"86P5KUFJ1I3/4EJUPX>N?;1)Y&9[0D4)G^+!<@R0T-F+5_88[CY(Z M"ID-D6;B);'D8=F#=.)(EHFO$9P1@/!C!U7=B8># M+OXYZ WPSWX;15W<;395\B]%(2+X9;_7C8[[G:C?&KQ<\F*I:A&7H'5@KA=S MHQW#K=:)NJTZ ';OM; \Y=Q!_[_#]MYAB^^PS7?0JGJBII2\JO+&B/DNL+<< MXW4Z0+!MY#NF,CV_0;NOWE>A;;^Y_,<;.-2\8(E/DTI\S+\0B]O\$["^Z\#K M7_N9<'YW#G?/F7RAXU2Q\U]B1H__A!E]8($V!SR UJ T@/\\\5(UL_T_:V:_CYBIFELUA->(F69/_V'4$M )E(" M+I@OU6CFNF3S74?#@[UK=WR ?Z.N> Q^HC+>9NMB$S-P!YA/ #I,A3<:&*J0 M4'*)_]":"$,RR-!;!::TDVICH2TA4Z*)#WYB% 7\&+UEK&D :8:9'V&0D[QC MA!]&9;;X\VCBID,,;QWQ=55]1T:8J=DLP9B$*!V#,@Y.%0QS-PHX[P62**DE MU ;'FCG4JV4^WVE658TAW TUO>^7F<)?U7FJE/DU(!LH 8-'U3W\:?QY^CR63B.]HW>%1=/L)+&&?@3=,XMY/U MM<[;GO["U% M6\<>RF*KZ0G24([VAW]L/ MT_%?K\?GLVC\F_FO8#5<.=?>Y1K27QZH3MMC.*LK40R5//^M\OD^RJ<#<&%9Q9^,Z5'C\.I' +)=>U@4Y M=55],[G#F>P-WZL ^-Z-"UBZ*.;WZ6)K'IA$A\JI7AU8,".F(Q"VLO>+=HXN M5D:*[Q>H./EE?'I]-C8]/+DX/QV?3\>G*MHP.?]XDN[T8?1F?G].)K^,AZ;2[4F%.BQ/D:CZ12>95P#UCC> M1R=U=?SH-@;/4:_5TJ!)^%RG'0U:5>'#,$;J%:C"+=,9@->-V9,<BM<]OD0M\_]ICFD1>(;-T\:.'7:Z_,MW9J:(Z[S5 MBMMFSYQ-1A\F9P31!1!"T]G%R:^_7)R=CJ^F/T5&+9S,_F:WXYD#E7SO]I4$ MH]^!F@'AD1U$:-/M1-I5DO.(6[;6" M+:<;[+3Z4?=X$)W95%AO9%7? 1_S<&#^VQLVP4$-#YB!4#H39E'CTX0'8=&F MY.6>^2#\[Q43,S"KU(H[/5EGE[:K1](:1F9B:*353_3BH;' CN.N.653A?#V M$UNJ<$:4;F>VELJ;B>",'T+1"R.O#&*(P0WB;G-HQ VDSIBA6]3*ECDA/=,? M?="DP#N\9D/@]AHQ8-.'\^EV;/@?:1Q M%A6CB#IQRYR:;MSNM^NVNN@X*%+<76;4E.\E\:>ST6S\&4TH\T/%>_V1]=I] MQJ8- ;PJ8S/8#-/@G\2)!9,H1 MA2;K#NK\[7W0,$85KMTQ^HU;N(!B4DMS1OQW^8=B,V.@I-%IDCPV_SUCK3#] M!G;[-BON)4J-V:V-5K.'SPX[]+D>LA%SSRU5<><8>]-MHZ#O=HY+G,4E^F,0 M%,UV=-SL0/<##F1FH8^Z$?@[VH.^'R,&E,%W49_BNF:,?_;>.[GX?'DU_L6\ M"C",DW/S[W'TM_'H:AJ-38NGT>GX9/SY@S'90LR^&*\!W(4[-^7Y>";MEH?[ ML;+47!!1N+CG_0N/N70&&XI0),X-7MH#NQ1H;\=$U$.,/$W_8C5[JX^[H'., MFZQ]#(MZE09%M*KD;O\/FT^]:])GPZ\B3*71J8Y9,%77X>\8-7Y5NM[!#=Q& MU>_R=IK'1 M:A_ $G9D#1N==OCA[B R0KYEM""^X>V ?9AH!4K@3647SC/&FUIF3B_A3O)V M):&K<^HGN7[\=,KOLBM:IA,<2',K]BB=4:D\A/V&G\2D6325T7$NT<0W=LZ< M$].](<]SMS3/YJ)O8*#?:)"EUW\ ;J=N&5 MSF#GP^_@ONIB_++3AL CL,K_Z1)_-/TE^GAV\?L?U3;@'D/ST9(!WSPK/!L^ M)Y2DVL5\A6YWB$E0 S;CX+&1?>R]7.T>- B%-L ?0C8E+DV#[N[0%,2-5&<. M&E&("H:Y>PY@.*"6;M=43\E*:\_\M-]M&A,.P3]B #?2$'BO M53WSC2T12Q_PJ\$:=,RL]\W7N^9*<^$M/?L?\O4:$R;-7 E@_H$'4_ 52HK7 MKCLV;<*]"4N9\C?<>-V6SDO!1<=&/V&[L[[IDCT3>3>I5JVH/7M]88 MMO#&:<>M%EL%;3RD9[FY/J/&)C^HT) 1,?H8)'X/+LY+E:PZ+91 W+X<=R#)GTG;O;@4V,+ M:^_#'0A^1H#(";5>K ;(S0-T.S5:J.C4>KQBLS?N MLA66A8'3JV4V?\>8 #M>2,FMKEUE[_"]*=2[I@R\H5@G-]-,#$M=0HR$67E(D2]NZC8CT4$!&DA8 +0&? DL3;2-K2!A7 M1I_YYBJ+UHUR!S/^<;+8(!N'T1V[\ M>H47=DH$&CADJQ\>RL,4HVX=U[4Z. (2*?-@'XNC0*^H?O!L M\N'B*OH_HHZ\,(SZ1A6!_^UNV5RQ7:-''M>VW#_J#/#!%GC6S4U)_ZU^N'LT MH(<[J/_ _ZH?[!WUZ//=?1_LH6X%TW6]8K,+L=K2AVS[8&Y=R/K\:]'6":YW^^_%Z=GTUCHRM)+PC0$R@_F^T6D'-ZVYO&!G#O[U(]1#P!JNHQYJR+69X;P!J<\7P5MZ7@? !T-D<].6S!M,0 M[!^--$.L*19"&:"N*>N)@:1 L<@A%'\CES5X%LV\B#8;7Y'3ZVI\.D'97L6<6,66<.RXG@'OT!U6WCPZ#\OY2#@C:VNO8W[: M(@MYZ]K_SLO:UAF0=!AMCD\>W8G\ 0;;I37P0G>O03>O';?,*_EV6SU_LO-IL_%X0%5@.NH M).%NTW"8S:/VC]"Y]I'1BB %-3&ZQH-8F1Y\% F$'[N(#QZVH,1A8#[>YSW;2()K?FZ<;Q^A(;(.?<]@+%TVG M$$RQ@O]YEX^*&3:BAORM!#-P>34Y/YE>,6CBE]*J;_. M_>5C!NB3*AQ7^WB_!$W,=P,XZ"%43_F:M-!Y@GP:@&T#[ SCB$O.@[S9^.&W MR;CX 7VOU'BH&R85KSMGAV<"F,MZY0]8\-J)<(V\17.4;>32V1:VS_BDZ0P3 M[@C/G(=I R]9%!<$20/EC-3)3'>&_6NNI 4QE'G,9?[O>P:LTX0VKT5?PE)& M'X+(DK?NA" ZO41FJ3.B3M@ZR-*+^RR/!>(N(^>\+ 'A$F-]5 G$4&X2I#U% M?A$-=N4>$OVOIO6_YQF G3$"EFZ[-%)TVYG+[G -,!SDLV/,56^#5+L7!9G, M@=4K+@' G*00ARB5,F#4OI"%EW"JD&+:U=AA]UG/])B*L[7%FBJ2.T8;=#AR MKA>9OW^P*_"S%;&74*C/L>PHWBB(2A%NIR R4Y0Q66@NN=U=)DX5S"@W\AY5 M&>J\LW8K,L#+E_;U= PB;#R=33Z/9F5JR/#W5KP]0OKN6KOQF>1\YW+R.02U M"+8Q]MOM=J%XA)N*UA$92>8 BN)<)=>KS(*OH(!D)A$CK3Z-1I=&6C$@F0\S MB2GN7\QI*S9H6''J&C";,Z4L839X,-BI),%H+ M82T";PE0!!()!MC-=MZ,Z 3Z' MZ9\Q"X@O6]&K2,J$4)(VZNHB%S\+YBG _2D(7\T2HQ[DX?-14@^I'4-/^OE) M.G($%@/WO/Q@W2:<,W ?0I];>E!%%D2-/6"8VV+[U-6YN!OM_OD1_"=$=4/X MFCR5F^@FS[]PSQH__'+VX3=S8)4+38PC2PBJKS" *&.9QN,L\4D(@U5BW0LU MW2TJ?03NM6QUR&C(:+Z!@8A',6H@@>DCUH^1[X9WD5)&#GZV"43>&OI,#=ZO MR"DGG._P4TX[FB^3[(&M/V/'+?EB#"7UZ61J%-'9Y/QZ?*HSA\&,N1J?G(VF MT\G'R7UU_2'G2W^,CX[/?QX<74X'1F[Z5BO:C5G^F,W-2ST*#E_:A)Q+N*7)(3IV&3GT>.>X>? > MDDY87GKP6@KL"UX^]>4_%;_!M0].7#/B?"4:O]DN8U UGZWOP ./Y;2(A6C& MSI"#+MS!04)/Z*H.[>O(W(_@=#)SY<\4.EY)E"]T]^9A]U+J'MZ&CO4> J_@ MXK@S,V/.WRUC-(/^V1 /+BC^!Q!@!LQW&XY=N49_*D)^+2?"Y/Y)UOIB*^K' M.0(J6_ O;Q2]ROMZD4X=1J>M1N"; RGO(: 2\SU2B"0V.K/ MGE!-5A:@/9H;:Q_T0A8ZDAE) [Z7"E.41.@'5]Y[LG+4%&6U6^%G<8;+^I)I MXY9XC?471<@I(* R9NX@K^N!H]3T=BT_&FT!,'IN/,L+50B!1M=O^XCGB=V5 M?IVNGC:?T:=^8WBHK=1MB_'GE*6$-@+'X=C1!3CKLA&J=3"XU5=S# QEC/I/ MITK:147S[T*MQ&H,<%5DJ#:58'./PK/J]-> &5TD#"4!*9(_6P"K%AMW^R+' M%7GM#%XK'' Z*56[/^::;<1_5L7!#9)K-^9@PC'$=ORR:;O_F73AP.9PC$!U M,[_X#!\SFS,F!)3? 0&EX; 7+AD,Y8!E-S"4*[%&) 'HAY .U)UJVQ4,6;CW M!,=>'4VTMX!@XOE?4B=.6>-F]_B79E+3=02-3]R*A^XD7'\&V@9/.@Z(IBA% M+P,<:6"\*@D?["(*'YR3DC]DD6'I&1=D8]DQS)@G10(>/61#?5'(B!FK!D5A M-K]XQ"2D-EN]MU84?,S7):GBMM.>S>",^5M+=<9% MR2#]3)C?+2=,8M.KF8!EK7CI8,M81C5A2P,U):=, _JU=;R(VT:8MZM26 MGGE< #3$-"EP5EASG_DBM"B$NF0CU*O-8:IU ^NR6_8)MT'JPO0 M7[WB>IE-WU]<:9MKI.TLE!W6?!,:[=7?MRN5>%7A';-'IM)#2<1ISL^CI*C( M,-O W3K?/L(+XL54-V75IA8!YKM RXY/U:(_M> ?+SS/;7(#AO$3"(FJ$TN" M U_ BPZ6@JY6)S:K /!O M*,A0AW!SK2W2V^WR-@,@?JX/8*XF>%6@=5QJ1>,V]S8KO6/]]%ND%T:.'GR2 MYO7 GTRBK+K/;C)K!;L$)\_$Q?@5^LQA>P=LS3?+?/X%@'G<='ABR1V!(X[+ M8 B%%&/,O\/"MXUI LPX7D7?]6DU53._+GI4FA5S'8H@M*MK3X%=YJ/@KK&K MGM^ 7Q'EH^PE)#47MX1;_]_%Y'AF!\O&_3:.H(?(P> \] _Y(N48VR:=WZ^R M?VPE$HG28L$I\>B"6-%^SH0RW=7L/R;?LP=($4 F8&E2V>MSR0L+: MA$]N5Z5G9<5R@-H72ZB B#H&2% [0@5. >[_?;NX(TP9LN=MMC0K7BXA-:PI7Z#+R^M)H_%=YI!8(STLZW:)XD!?,^%$21+I A4IE6!DRA MY1F4HRZW2^4XL'5SDI&*N6I)X_KWW&8H-V*UQ<*-%:4<[H\X"O>CUWHLJT"> M%3<7,'D4BDT*%Y5#:Q&VPW,&%H/9-@AG8/EOL;!J;=D B3U;M8K>$:A*-7/+ MW<&VOV+\8"V=0870NGLK%Q:.#&+7+JTJ1!O)'/^5M^DZ59O.SI0G2?E[?^=; MBTEOP859(9K!?PWCV!8NK8+Y12N?7OVT*>LE_&O(",%()5NZR-S"$11KK-1> MK4F%/H6K9/E8E!8&]PQ-5%D'\Y4.N=2)6+?J$Z5\!WWUHD !C6^[ N=%3A2K M72288V:,[)H-F!5Z.4>20':+24!LF<+$\07R MTM6G[AGE3& ]-'4:8RGGHH1H"- +$%;%OP!FFK';LW;,5ATYK%$@WR>H+T%U#P12"=*3,$HJ/4/C9&:'*V%45]L2/N,[N$)]6 MU8/A1,#5;.3(YIZD*.:K4_RKKO):R)>]C!'&H(((@TWV<_426B$N\U].9U<3 MI)*R$XFE7=/QU6^3DW%D'C!_*V=![?VB+(.Z6'!,MJ?N%E2+DN!$P.0MULD3 MW1B8?29*AE+"\= :3;S@9)KBGB9IE6!A#.:/4,,Z]:8(?OI 40"_F-^EQLLE MPDO[[#;*%Y!RZ%R7'/R8O!V"=L/9 U#\ P(R77'^A/Q47E*%S9R;E9M1EAH$S.H\^CJU_'L]&'L[%9VA.I S. MUD^%WOZ>.V:=JNQ$5^SA /UJ#UBLB8QY1NVY0ILB7Z7/(LVPUO^HSBN$9Y]B M#JJC)5^48 UN]CK"F(*)ADIXF)E+4E(D_6/ORE(DB',$+#V>ITQ]WIKQ.OD6 M(XEXB6*([2OE&O.%J;)RL7P=PZ]2:;FN#*YO\D/W"-]3(&0RDMZN'A9NOB/V M355+O%)_%SEZKS?4Q<6>W;*WD@O\@^Z_3A82J0CZJ,W^4?GE<%,J&S>XG[ T M-;R@5- /-0$JM$%B9?&VIW+OW3K2[60OU,8?1A4BV*)4G^/.NLC)!$P[E!^0=A:>HGPF,' MYR1-,"#!B$P+OZ1";R[OSKI&R/BP6%ND797N0UO2 O<908!UA31_N$%B0]B)-_S"8=4Z$*TXV&!+2KC$ M625]':G'56IF1;E,;)4HC3+7J?-#83J5;CDVVB)PQJ,=J/CL(6)F M1H!)%&B?WJ4UG=#(1N0PA[%8A3W%S3A72<3^Y\FD@,2%(O)8TQ$O*-_>;"#= MUG[7@IFXA-R5=!L[PSF[K'*9N\X\=+2#/7R.M4_N+.2KRD%RGD*9WIFK9B7[ M")OSP=4Q"<(6HEJ'_2.T@.&B"1-.SQ/.V_>/91@)Q&F"R(7Y.GM#?I?*%;6" MHH/JCH#8MW83[CBX_5_Z)&A3H"-FKOX<.FWK$I,7C\.3*AZ3*AMQG4J\<0%* MTR)2BUD2!Z +G<\NKOYF*5^PED%I-*Q8%%2)G2[5YC2*JZIV$ /;6G%8;D[; M$3V1:)1*22-'=.0E:UE3C;K*_^54>V($"\M57(?!N^TDQ!);P:-9H ^(;O(C M*L9C)V*QM;ZB@ 082ZV,AKR@G%V,=2\R0F=&FP5W.&K:V[4D$MMT>UL1 C_. ML(R:,DL<&@O=J'/. CK)>7[=FS!=?,$IY=(*?6$/P>&QI!> 78C%SGF8IF_; MNS_SO@\J&#"GD2,5*\\XNG%#P-.B TEUDGX[CIC^P(;AA4\6 M<3^0(QD1-93>'GN1&TZC3]W5+34. +FDPQ=JIYC64-OG9Q?FGP[/);\:4 M(ZC\%Q_ TW!6BJ*)?;<3W2^6IUFR<:7/,DT$\3YS[$#\J*JK\ Q&]E1>A1' MF,"7SF*KA!&,SN)V"[,;DP^OXT8ED-_CW;Z8SV0*G['#\QEMLZ M_YJJ#%QTN"TD-$+5'K>X_KN!$NGBMU!I1ZB]V3IIY)%!P<]0:8#:9JZ*E&YO M#++!7C0B&>\__H'9D%P\F6DE3[37 C-8N'.C[E>2+897AF"Q?S"Z72^:S)_PA30*O#1 MH^A429&8TSM%ZW8[*UE^A1N.[B:N+JNM 8LINLV05F&CL<>ZV6.B("EM[070)U@HXD M901@:AVE6]H.' 4>P _KY)]0!+"JK,$7Y0 ]5[MFVL(+QA9#Q!I!&&K&9TA$ MZ6)H5VNY9KWKG[1Q[&[T"6I212@($U'7?2U[T\H#\+(8P&/BBB$\%:X<'*D8 M*&?@UC1ADZ"*RI<+/\;L9LJ&N[(5V))H2!OKEF<4I0K9G/)A]\F'Y'EG16S9 MDIJ-SC]-T.E!.N3T^L._C4]F +$Z^GQQ-9O\CTI@B1)7),"OR3TZTMH@LY'N M4 4IM&?=(W(&LK6_K+1AUPC,BX.#I(C_!2#6B&06)-]I1X'CHTL%/D"5RE(, M.NR2[XZ078EGS^YBB)?G2S!B$$BGIGEG%)EE_6>ZSLNK\/ER-+D"WSZ4L+^H M^$^\M#FE\/-*P(RC)V">K8T:3)6A!>8ES(DM3=*>@PKGRB2\AKKZ#US-%R0+ MP6[S;1_2][1>QTXG J3P*LH>A);!H2'0@ ;U+5-]1U21X"% M6M;4@G[BR0_)(V$7S6V%'NH&W@QN*+W0##K%PXQ5MDE8/JW< M;/ L2UB"VI#\"0%CV^200V%>+E+]68K%VNIJ58P; _!_\C5?4\#;O<(P>936 M@94[@C@1VW1_RJ=*-V3-"Y>!*]TRJG(RYR1I-%/7&50W0&(9!KPQ88C0Z=ER M(6N;$@71U8Q)?P\8LX5\PQ6O#?-D,+Z+N?0 T24B:%\*NA"T+V],VG("MJ=K M@6Y<-0J+9L(1M&62%4K1K;NG*W:\VI80-@($= HG5.\U@BN@YS"=RLNTUHH7 M,CZ6>(-]EYIU8U+ BG"[=G2TXGC"MJ+W@NY@PB?"]5@/7?@ZKX@KLPER*V"+ M!$D5!U1IP[O3]8/4DX" 6I'U *\2=MO)_%'5<^ $'/"TLB"\=3';'P4^:"7Z95+8"5OL&Z M;3V!5%A3,5(E#=2('5HXBMN%&K-UO)+:F#E_120(D(X(EV:LC&HP_CB^NG)< M)N>?HI.+:?GRKGN.Z''(*2$.VJP,H(JN6L7-X'(&J)2#,DG)U$=-L:1662^% M2ZC@@*,">K*X"-;9)/[:S\F7]/#I/E^F#NN_HI]62^QL_CV2\7IY'*CMC[P1)?O ;7PMFJ1A)#&?_G(VR)$6[#MD'7<;45 M=8P"!:0.W7JZ_+^"5#+'8;Y@"P)4BJ3+J\78A-H)-^@ X M=XP"5RY7@IO&(6E9.?QB%:2.Z,]0&H)!A\%3R?VK&C2Z@[<K1>5*^H08L"=@Z=UFT P@6DS( M#2%A#J>*EQ+258V]+15FT>A3L92EVI,]V%H:J* ?V,AVSE25$NP./'Y/&>J) M@)W-5I_4#0A>@9JJ[>,C4E+EWCSY@P"C\6'?_H?'PM-O2$ 74F6=4UD#:5J8 M"1;F8?UD=)O[A!(B,3"AWC2M)HPH:9^!7W/6#9T6N]0J@,,7N@>&N>MJ 12" M8EM@/4XY^^;3Q<7I[Y.S,\R+F9P;#69R/IF-V4=1Z!3QOP$K;__ZW0L\L?U1U9L.! M!X21,CVYF&]RP)MM052%A[G'3*@6>;.YY#+ FJ1\<%6[;WH]_7!-@5M5D!M 11/$+.Q]L'6H[GW*,RT79NQ7H3?9-0&O@U8B=Z0Q$J6S^R[YM\_ M^YA%&7)G?$G1LB"\_U+S9@\\Y53QN$[UZPG]\X:G&!2X"-3"96GQ2/Y0M@5 M_.0/K*EQ[99.7EU_FD]DR0T\]"A"<^$%6&I<)&.W<9V,$F 7 U4S$V]Q4ODP45 (!"MEE>!"#JCBC'9RGJF6VV&"$)9XN, M#5=;:K5_-/7I^*D=OLGO"%*04J/QKRK#39)SH24I\X*@=_@<8BQR\VJ.S2R* MJ"GI9EY6'$P,7%P@$*6>ORA(V#Y*'A'F #SEA^8&?42Q1YXBF#>O O:6 B40 M__9D+OM_]'2%,2%G(FAU[RMFM_AZ&$LT8Y=N5*VN+_+M2BIGK'4KBOA1PUYZ M*0W[.#T#XZET-HV 7Z?)1NH9*XRFV)_6X&*!%K8KNJR,OL[IXJ!+Q9X27KO* MSDSU5BY62=@5&F[50#"8R-D(@4/+3/446FY5.9AV>(]B>JU=&F6-YU@#VFR4Y27+'_E->X#G:D*.=VVW$6 JX&P7+093&I M%0,B-Q+TS%8<(H?CEZTI8/ZL3B KTP>N %.5RW$!I7^^XU+&;[WCWZV.\!+CU4TG#L4+[<7MC+),EU@(N& -@C?&0 M(.2F(LFE92UK4&'0[6:[N%,.HJ/'\RMH-=40U^#;TKPC:Z=^1<"W8+T/1D3B4@$;_:G@*//1>15 MHI-1[; G,/-OO6CB[+ S M;*6<+U"N5=O#>'-)4I*X8M2H!0:CUY H)81.<$O2#W01,-Q6Y6NMP@*D-/Y_ M@0%8+XUP._G#K8GY[!9(Y7@(RWWV7RKAZ$N-K92<[-;==B/[F <">SQ<0>\\ M"@8V#2@SJ\-A#37I.W(87M*JJN947:FP')+*1P.U^@V0#7*".'>EI(+ZLQ>F MKV:VSN+-W8LAN54<6@X-#EGM./&H8@78$U:P/28YD3?/CTFQB"G<)Q^"!(\0CF4'S$0BET%<"1;2, 6>KJBY'?[,56!>S7\974'!U M!;#>9Y/1A\D9EKG^L;?]RBVA9=<%(Y)6)3(:;EO./86ZJJ"8U\FO.:RT ^+R MO?A%*M]R&?FV3/R)FC,[;0%?4,4F:W98,9$!570Q[X=+:R*T?PJ*0N*'5],< MZPJ-ZC(8*1U-& C-1Y>CSOI=\*F]JYD 8J;!LR03<_&>LT1HN0R"4T@_:A(09"8XU%T%;(N*% *!W!NP\,<]B>@4T$" MMM%?I6$P%Z5-SD!29RA$PWT BB*ED[H4>N7+(#VMD!H65,O#;OH%ME7A1AOA M\@-<@EQA"U>93-R;"[TF51.BN2^%/$58YD$/XJ%B3K-UEG#0P@]QZONH>I2V MEBB_+4TK;5'[%J)I^]ZWBK>%#?O&*;=519PAUCC02QOM''B;KUFG!5 MW!O6RU/>=#;. B&E+2/K@[!G#XS.TP-?';Z/;!'I7<;<;ZC6A)/!96Q>;I;= MFW,J*Z(<&9<0I+,3JJ=?%Q!*BJ:+=+%0$E)?06Y6DKC$CS8^GPJ%'MT8EQ?3 MV=5X-KD:8S[FY=FH1$*QYUN5XD8P:$+F MX03]HUD%57\ N=#LCN0RW4,$K%;*+687(TI[6$CO3S>4Q]NH+R440;8Q?0$J MLERQ;6C@RC;<;CQA"R#ZO(,D>BRF2;;VQA:,RA,!G'HF.Y*H@$9&(X6>^2)+ M:D@"G )S5S (&_8\!'HE):O0?NY*U'G.6"8+UQB?,-&'D+98:A!63G=NY?,5 MHVZV7-H0C'BF<:HKDKI/+CZ/H]GHO_.==UHF_JD,#E3DA_$D8O6-Z0FAML'C M&RH-$/GBHN"%EZ10!:9&D"C,' M"-B1!!M*K'"5*_M=>^!4 MW]=E\Y0,%U!3(W5O7'PXFWRJ)#[:^6RM8EN=Z^)NDUL*YZ&6KN!H<:8V&5&P M6".P+K% O9CI(C!*X(I6Z9-.9=&7B&]"NV)4@;XHG&Q0X+S/DL]NRU6KW:RR M)<+45=I<7I? [DEE^VPLEKU$'<"KI\Q?^J:KG)6Z],>X/)2XXP M2YYRTQIX=X6QI@@F!I/N/813+A/"_MDUC:4J80MKKW'I2_OS_.(<>+6N+L[. M($]UHI PM=O(&..5ES)@\/K>.2JH16%F' M]B._"*ZT6CHVW]J1H0$P/RN>KIO[?'>GN12(D+=,Q$KL!$P<P!>(,IO#:7 M?:U'K9G[''X(\3&!%EB4TP8K>>;\S$7U <(*J9GI!E\9Z)-3C:$+Z]8*[)>8 M\ Z.HC-28"5534CT>,F=-Z>N*[&JO=SUW$_L048T,&+F\?+:0!&%ZHJ[>\2; M8',VKFJS3.K@Y>XA=LARSHJT@ZJU;YE- T:A,7CC>E5H^H1E9%0!H^F.JGTE@,QI)?9F#'4C\(E=:B/ M/F!"S;P>4:/XB<1FBA3(M"!1)C$N6/$K@F5UDE6$#%./@)N!=XV]/NU<^3%E MD%U/1AN\]^8'MPEJ#. X85&)S(]N#R;UO)JBZA.O&X?7;C0?O'$UGGPZCTZNKZ[&YR=_BV97QB0_JZQEW?4L>8OM-H#< .95 M@(L5]=VY)0BW_W:E)(CU)%E:.G?$UZ$"K[% KFA_E_>!ZI<%Q$BJU!ZQ)(^@ M-Z>J>II2@5SB[Q/:[34#2]2P-A9-&[Y[?30]BDX!7W--TGE)D1DPT&JI2LP2 MJOPSUZ$TK=LR$1TJQ(R33, *V6YA@4N%:B0I)K:)/0<=..4(*W1.2#$Y45>X1^J& /W M"G*X46'RYC"Z74)NIHC]E3^@10KG:)4(C&/MUJS:R^$4Z\Q"IZ MWYKU\TCX0(%TRA^">>/U8$$JD+M;RI$J4ZCARF1+I.( MM8%".Z1=NZ[DF0*!^LV.#ED(!6\B M1>,Q&W!S,F%6?/0/J&5#(E[HO5]N&& M2AX7@+.##BM^DAY Q%S.-+ U5$XWX%$L4K"KUUK4(6VO8/<$K[/0)+BZ1P2* MY"@43CH[':'&'KYNA&Z%4U&@+U8>&?N*>V\O ;*2BZDSU(G--W#:**[M1? MVM#9!HMHJ?L28"VXNGY#92FXII#A(OPET^<"^.UH_2%JT_AA,KTH?B VGBNC MW: D0MDO"!$7Z[MDQ1@9\,+5#%[ C'=AVJA,- @1,(O4%Y$Y^5PVD3$RH 23 MS)&;U)T][W%4^E' +ZI?#;:RTN%URG!X;((B:])EU(:GS8A2+]]N@'?%;27" M5V]VH2E M\";"-Z$ARYCA&T:23A83Q\[V@=^T1;,XG:B0X+=#;/["[F5<%A\)BK.4K!V# M+>/]CKLX*5S,'7RZ@ =9^@+>1B0QW!KS*F%01*#T@'P ?9T<)F7L40O1*3EB M-LZJ,:?6J;L/-IC[*.!@<(BW9JNOJ^M[I[^,KL:''T93@+*_^ PA-Z>0ZV-\ MMT:&+RR0XN0T1+DP>UPP[UAO0>!,TT=(MWMD!"X%;D^_X:(2<@L[$B_U2Y(B MJJS>DZS8G<.%#_ ?%)(%Q7U0C\)E<,6V\KB\O 4PR(1X48)O+[A]O(RJ$C9? MWZ:$"QID%I+!^0$2$@^G[R"^X73&;A&&@XD6YF-W_Z)(F2:^T#ZDP@WO.R.G;6ZMR"FJ=V=;XA2)668OIMW2^96HE M2440!,"4\V7BZ'[[@(%027&F!AT34H'WC7?.X :WZ5CD"9'(O\(Y5F5(OG\4 MXEM,[U84.?NP*4ALAVD;T=",! I2Y?2]>WG.*T 4KB:_X?I1\LXOX]-/X'D> MG9B?5>9^O?P&;H#KJJQ%(?"EN]011=*$WZ>+.P1EU->$"N'3E F4%ZDM-?>' M:EM52:.F)'XOOC7-"B\=KB^F"N&/"# $S8GTD2$("RF[J21\VM>KKAQ(HG60 M-"K"J#@PB?M>)G7L.4('+2+;>-=RN?[FP&A\DO@M*4) 7KRV13L6B$:;."%U M(%V8H(D!R!%FRGET&RGZ2]E\#^C/_'!K6'F!L=(]EE$K *E1I1=P8:H=%,O: MY+=!%H"-A*A8]&JAMJ49(OFF]>J[54ICQUAN L*#E@5[ MLE(( K'MM]E5FR5O299N2[9PK?U)2@&7]\'O6+/T\LDVH[#Z')[^% M[!^5V@:011:*(_SJ!5R;_]@FZTUJ]5E$ Y -0*8.$YQ)R@.2B"TX*X7(PJUN MJB']U!#";517M8;S3=Z.!>E^#O+*M493N"&81STB/K OSA.@E;K-4$)%IU") M9ETKGI)'8'Q9YT5Q:'T=_-.2#T3)B%C"6CACSWH3!GD8\#WV_WTUO0&*3[6_ M/9LD8WYFW*%F%Z>,1TZQ?!V;$-4>\'ICKSA C:YB!'ZGR1[%1C#OD,61/T7P MZ\ 28[P-SY^H6,2H3@-'2WE[&-X 1!P'<%,"OF7$.TX!7A,@P@N8.ABC0J.I<"Y2W-CCSZ:1D'O-"T@NY-:>?B"I9GG M*!*Y."2_&1TE!>\"52(7="4/N(3=R+5Z;T/@$)*JZ)I@W1,MF%#_*RA6PP]=N.RQ&@ 3NL"*/5&:[GAYW1+BH MM'38XU@ZKM"2'"ZMHYDP(DI3I,%,EO8>G#4NJ Y6,<8N!X7;)'$40**8P]5M MT-QZ<,M46F&Y;C"M<,YW"\.290^<=T'FB&K/.QV6!*B0*THUA-#,'!A>2<$D M63%B/KJY$N3*TK2B*@SO\([&6(7M'CDYQ<7D\+G"$H5\59YWE,]XT+Q3!2FJ MV3*MM4/$K^;I%;>*[M!(FC]S=Z]VK/ M9*68@UB6.]HUIU]4BB67@&-,H&)&=5\:KDH/1 6YC5PT6 U")Z67(D3,GWU0 M 5@GO8O)'>.3,_NM<)7&>Z=/:OZ ,K5X8.%Z%^BN7(K2I& "??B"UQPG-JHP MF WHA!6 PD=$V@#9A'(%.R>T9UO_DC]!=7K,':M($=ESW!6>VSTF0GU/O&;Y M[6V1"MJ87GHEM72KAUJ'1K-87^?BMJMR23C+@N+17KJ .^MH!.B)!6R#? )C]2DX4?I63@W&?%>^YXEP,SG4Q_G'L/3HQ')),M,!6>%6PM_'0I MD/ :!53?7:L7M0K*\JQ< IY6SU52D6*)R8=(<_<';M(RPE9W#Q> MTY7M:^T^4&0YFZN+:.73MJ(!$"LST> M6"TAK"H!S)>*5[DV_H ]K ^@WB!LZ::4=%RJ4AC_+K2LL(Z75Q?GYN\G8P)Y M'IU>7,[&IV]Z*1I-KZ/S_"AJ-UN]PU8_EO+D&<;#&[/\T1B2_6[SX+T?6HE. M2GJ*K<&C=\=6U3PUDX;).)U6C!_RU]_3*Z-DD3_"EBMUS LRR.I2Q>!+I7\0 M_O5LW3L5U7)Q&=1>U7VQ?>9E+ ,:H77*,3+>W\UI+A:9P(5CQ=R3 MV&P07%F1VULU75%J5\:DM2 8]M"P#XZL1JXNY$EZL&BL^&%B6ROXF+&>CT5I MB=??G\42C)5ERR"$#YPO?Y_=9#8M0C7H#4+'ZNA!,VIO9N1 5ZTA)F:07J#? M">.Z.K6V-.[:[C#PL7P'?G]H#B@[GES]3B)9AK K6#X1/@B63Z52_$,PE@*V M1RM#2KZ[Z+>/"\3K&GFI[%;&0NH5AOG0>(?M[QV,F&'[*>FA(*AJ_ RC5AT% M1Z83>S$2Z/4O['?@8SUH]YQP^#B:?I!LD=*X M1!08M>$KVX$+"%\57!$@A,,A:J;.AQ4@!/&Y.M.&;VU[+P0QZX+U7ANU+J(" M9R.ULT$2?C0]B>Q$4Y%R]7+ T48""#+^0?JLR;]"))T"9,"132J]!?6.U"@" M!(6M(_&+EWN M"3$&96$S<**E, &#E+,S 5B-]AK!7#K+#($(,O<2BD4HB+*/(CAJ]\E"JVA* M/5.&[4M)"F2T 5(#/JH\_G[J@%/;4-O//0PWZX3"W^,QLQN4F!()>962?S2E0-(-N5D6B/I'T#G<,G%MF?8SUOX)8LZ M3&N6P>'**M@$\?VY[?(9%)33+?Q79: RJ39*M=^R=+-*'MB0H13FPG/!'^E6 M=-I>8H:9+1>.V!!GECE3=>Z$](N_!2$VE\\8HLNP_.'3@";F4R['WL.!6NA) M49L%4H!2@\DM&5M'9BPV$4(E?/J6GG@= "\C>4!0,86[(+]5K$M5@/(X M0=$C'7@_/D;0&M(DYV&K5V52Z>7Z-%>BM<37>0M(FPZSN@)9PDT'+AMUU 7/ M4V_&:<^6WRRCZ+F*2U3X]Z#&(=> )/>&<7VI"*-#1I.08O"HLAK132Y1 @DT M-5$HZRK[4;'KA'M>;@6X_<*QITU+]DKT,;)CLR)OTN<ZMB8R?=_H["SC-8Y&D]CQ0JU M@Q&XY%?)TJ)\I>WGJ0GN8,]L>1*@)Y%+X -$.\L8SNX]SOWE^.:NRP:,2W%U]9B$LGVDK^!KKFQ(QKW+FOVL=]5 &H'2'J=]- MXEHS!4+ IZ4GUQMA<,<6'+%/@FK97; -'*;N\>J2+^QNHS4XB!ZXOS;5VIA+ MM-'?M3KJMPZS9EEV2M7[(B;3*2 8?KB>1><7L^AOXUDT_OAQ#/FMX[VH-M[6 MM,VS)Q<[;?Z*4)R#@R%[Q.>YA!(D)S'-R:6)P9=(54]75LNB&["H(;JA$^OI M?<>'3;.W/MJG)RIB#-V_X!"Z:'YM8R"!K^9*X>A =S[[WFK7H")2<#\\4Y:R M,A;XT34:@QNJ %YM@)0;XPD< M5T)V,O9Z.)7-BAOK+;+5XBY5JN&E*=N\EX"WS&:E[B*7(6Q*2,DB0Y*%1JF$ M,4T/.-^21QW@/ESH"%+#929E@WGO%#R*ZD?].$0]\+6 M9[@/%MRP\X#8O%X'^DP#="W5U$3?/'O+#)K.G6!U2M5*T(A+%_R)]6_,,?#APJ!P]).^<#R'P%E[,): >JL@_T(!XMHG/E,00] MI=04YFF6 MDQ:6N8#&5@L4??X<@20%TZHVWBZ_A,-V(%(>4)JS!^NH0\(>O%P0ACETAO>Y M&G#%?AW1CI!>TK= (<),GLZEXV!FI5VP,"U0DH6^59D13NN!&\RZD*$(&_(2 MD>I97GN[7R-T1)H[XX,4UIP@_X^4A/*EU00WY!1Y"6ZM#VODQ"LLH[K #B^I MB'BDJJK-+34UPIQFMMZ+:#O$W@WZ9I:60! /!0Q+?4-3I,S5.(ZBR6;7,1!I M1.Q]0-M(!GFY*;E3<,0O],;3E]'7I;[ WGIQD"2[&]O%JY9M_#2C-( @K&;Q@NN1:,>]JG\+L9*#0TS=Q1((5?)?/^SWXL=\#&2T3X\;IWB8'_5F&YO M-B0,.KW#3O,@>A]=:BT#%GOJ&(H#=?84#-^)>(;)GS *JOS.S 8^S&\/3^B> M]?RFKPM 6.=HX*>'MZ;C$S",;V^5LSZW@%,EE81"9C<;Y]:F$D5EV"^YWZP? M>,9OHC!T)7O3XVIT5YO1>Y(;\&Z*+P83=2WT8-TW8BY>4^E3&X:/9O<)YJ)N M-[CO8#@WP,GQA%8F;Y_ZUL/ ASI4;##-77R4'&;*D+<"O=F)&D6:$L_> 3J, M<%,$4>?(]WQ3,(#C@\YA5KD A>H_J'HNJ1YL:3FI+>M)?L?J< X6;[T#%A. MA%"#'C[2((FSX4^\OX[??G]57$8/(+KJHV#[ZI"NC((^S#_65XID?;WF$FC2 M)<"4&^2W^*0I5(B9@;C*B:'I\-J8!]/\=O,$(L;=#IU>\Q!S44X8B<'<28&B M^#$UG[@$Q%U4LTZ6^7:!H]_B(TKNH]@W%O)RGQW$B'?4# 2(, MRCQ1;<(YE?K'#>6AEUY\022_21][TP'LO%4+>]4)Z=3(^-!=5*7PW#SS]B6A M@ZD[.]6BQ OCP;,*/SE5^3E91<86^7UBK%'>59!?]9YQ#NLQ4:IX] M8NBIV:(Q6GVTOI>AIC@XQ&;[#FI@A:[G]#:E>[VH[G5ZQR^^MU/CJ\",(]Q= M+S;J;5#T!K]&*6RV8Q7R@A<0&M3M-1L@T\^,!(S?9I61X/B8WJPE;+#+'0-? M=NXM%UAE&C=1#=@@J"H/\HJ!;I'.W^0QC?&FLB!<"(BCZ1<4NQPUV@?H7W[ I$L%Y(NM,3R7<@WC9-TG$%\W)]6H!W/."B>7$YATE:P]@'D_,3(*W::@_+T.\G@P)>B&K16]9<0=MDA5\FP)/5ZZIJ]00N<2MIBY/[V>QBM!1Z$9 M55G4I3%SZ;PWF4$0B:P52M#56"B!XUAG'/G5APHZVZDNP6FR5ZC[KL?I(2UC M#\S^X1)"2>3*B?*W4#+&YP>+V!--:HWU6O&GE&I[PS]M*Z;S@M[[G. . &:'.I0@/PE\H)<;G?E3Y5OG_@3(%6);PLL8K=L>H(F[>T M8[B:Z/LH5_W7"D$H)G!Z$F;W)[9X-E]GYG.06>L/NLJ)T;"I_BNL&@4^Q@BA M';!;:$8FRQ3&[+B=Y.V#ETTLP>^J4@+!85.=_5-M>=TGAPQ\'[GA\":!I"Y!]:A'A,J;#N8@:DD Z4G%7>MXOL M6S3]<%U$2_HWO EA@FPAR9$G]UEZ&XTM!N'%K=%?TO7[Z'H:&TUU 5G%'];) M/[-E''T^&9W$T7@+^5W$PV]TWC/W<_#RWZ>)$&C6@2@&(9*- MS67-F)$"46AJ.AB6S$SDMHNS*@FHX$;[8C[P7J71A M=8CZ$3\1$SL2<]<%>'RHDD(%THOLC26&'L1,L%F?VY7%5B_S%EK72$VQ?ZQ? M+Q5 !^W%I0\P(IW1A54])J:Z$BRK;!D;UU;$,GX3#FZ=$Q%QCRK$.TQ]B#3W M(3F-RM>!3D(WA\Q;WALL#R?AQW>2JPBVO=2K'0 FL_1#!2_'MI;F(G&1"IUM MG(5&B(C1P$S<>#E+P<=A-];!EU*5,SRQA(.B*A TOPVKT$M(_@JJ;'=-%7)@ M(!\?;AA@(E'#Q.=9JH/_@7B,F9XF"F@&Z'RJ/J&;!CIR9S8?1F;J@LND>"DX M;A3)_I(BW1_.K1Q7$0!<@,RN ;*/7*_6,&FZ#Z=!2[R2?/^ M.(!;-/DM>R-RN$+(\[;T<79#4NJNXZ^E#/ ,M-]#&9@M<+=$2TK6Z1H3>OZ( MS+17O\Z);5K7D84(596QI ]?FNF: AIU'%T2*NK_Y#]GZ;=-] $P^_ZO\&UC MK9O;'Z9HD2V1D,JF(P-0/J);HV#WD)">4JC*3A>' JWO-CZ^45!L#TU90F7& M\DS+Z.O]2L>I*YA++BO?BEEQ)B 4DD5NO]>/):[:C?0^O$,&;C4TMP\O3:?: M'#BC9M -;*0V\VG/O'V.EV?-V+." U,0*K;*#53,F$/^S ])=BL%I;+;0_YN MNN!?A?LV7.03CPC=_U<#]PC8#>%;0%T6//P_(5\CF@ (=&DGG2 %A[M O#=? MLR4#7=,(-2@H]5 "$0D EF0K%.W$)8E\Z.F" *:$, UK!(VVN";CIUJI)09Z MDB2@'-^Y#!?ZF/846#IM\D:H((<]UK;@(\ ,,1U /BQ@'":J5B+K>G9 Z>4+ MU>$&QJSR@AAS;Q%%\P5T1]/;?'/O!D01@Z!/_(M8%]#$V#%'9'QW!RDI MF]0O+Q>'$/6Z[+=O#8;6 4^%"T/U@YI( 3P(/H*PM$%(X:1Z"XN=0$-.JZGA M@R1FEKXCW @+A7\35JA?A'$!_8"Y,[R,63]AF6BAL'W]$JF)F$R+*/64XP/: MK.*4I>H0YBT!A6_+1%69YPC45?GF=%MT2S/=9&(=U'%1_%1XV)9QI-\U3XN% M)DARQIKE4%>BY/\RN4&GRT*-Q?SP"8\JL\B ,@38;1JVMDA3D+2.8<,(2:.> M&R&X2!X2Q'[+5G]'5$N4T4MC4F)!LS#,PP_8]5%"Z#26**)&F//D\99&CFWJ M:W:7KQU=/)W:!V/P?*591B9F640E9_"3")=&J,DY)DF3?22NO)IEEQJP9)'^ M8\L;@#C(X6..E7IE42#E(#%=S1-7L%EMCFB:V$'YF#S3W<-O)9)1 !189=X+ M:T&:SWUR[H2)PO_?YYGZ^X3?=@[JUUP*92TGJOA1_<$?$[M #94IC8> \5$9CC!PAM M(KR+@_?16!K&9UV5O#$V_%_95 ?\W6E6V-MDP4ABTMV1O6;\GT_L.'F,WZ41 M'/J[J-6!_W3-?QJMZ,#\T6V;__1:\(.A^0%.3"?JTJ_[T3!JM,U?9JC"FS>/ MX3\#>+I-KP_-?XZ;V)YY(UPWG0!8O;_<$W*%?7@&XI^T:@NX,CKV%.'FMV37 MVC:65L4<\A=4^;(7"5T]BPS+H]]77-)X07\4&%^6TNB#J=MGFL9R?SN-\S_^TWV^%0+VV]YJ6MUQS;>LVZF?3? M6@1OH5YU33S:9U D[:,KO6&V+8J-G4J!Z=#P F2-*;1AE;- ,[F[.M5?-M$. ML[4F+A-V<$96Q#""A ZT!H5^=,[;?UC+J] M,MYG(AAX 79&+SJ,CN%4M7MQM]V'O_3C[F# ZAF6?>/MT#$/]CI1*QZ8QUOQ M\1#VI;DYB$+R-ON&C$3!%+;-2YU6U&GVS/_ZW&8+6FI&@V$K&O:;O"??MH#M M0=P=0OMQMS?TF!\]B,#&,.YV0<:8OPR/07R<0V'KFSX).1!&$ WC)LJOMOGT ML(\_?7N;PEVT7;F<=O&Q'4*PR28UVLR==X-.H/*;'?!&E;\L&.4B4M%=N29_ST$=YW76B=U\D#)I1 M+9O4OE"J06D#U2H'5Q4=C'?+FSBZ UA66' MDK;2Z)E_00!:]5D=1>AUMT]]W[54_Y9GF*UQ\01!U.L-^4Y0R2[Q(I]>_K?D MX?'G,V--& &>(8%J9.Q#SHI4X$;DF%#JG-\YEA-9X6%M2_-L[-M_3EP"Z87] MV"<\7F0,8!TRF9]U\M;3!Z+?\_47>.L2_#S0S#J7='0,!KR/&N\B3\LVKZ?% M5T"1BJ[-$\8:;/6C'V%ZP?S#JRKZ%7Z]0H@>:.D8'NB8/6,NIG;T.4L>,H#O MWV #143I1P.XL'Z,VBUS>;4C8T9O@%;,MF'.J_FE><3\WLC#_P'0ZVO[V_; M_+9E=.)N%[:/QP,L9%AF0PX(=TN90Y'IU9M5'AP)PGQGY ML9[?/TL:I#D&<(.IY+R"#O0^-YZ<^1BB^4M$=5W_U;45=^&TW.1A_.QM''BZMH.CH;OZ<:7Q?Z>H_VQ/4*?T*9[V:YT+YZ MAYO,;"BTU_]:42J_/G) N-1WKWK'#[2 M'N@_>GWY XML8+#P[ZY1]/2??2/>Y<\Q(<[H,7_>(C7X[1:2T*D?^H^V_CT\GYI_G#W[O< MO_#)_K%IW4C(/L^.^9B9R?; &.D7,^#IG4['LRD(-7 ?]09X^PWASAX,>_+C M_@!^ "^B$#1265_3WG"M!<%(?ZXW=@N#".V@C=+I#>R/VTT0JNT6>/^ZK6/B M1JN?-2.NT=,VV:[()QA$MC+A.XO*IGNF5N MK4Z[8X]&>V@L/F,3]8R,H;D^FXP^3,Z( E>^]P_?>X9MV.H9=G/(F.E2[ MT?^]Z_^A;!GYL# JGKC00K12G;!>A#(TOQJER+XK<_<(]NYLSPNJB%S!"*BC MJSER^[%9&B#TUUP7K[D6*&5 QQNWJ_P&'/EX7"B':7$QWNT'*' M^@G;E$*B0I)<-D%Y>SZCC9L180DJSXK@%\V3Y7R[% CAA-0$/0*2F6G\\/* MA"MH2T[HB9Q0=_CH8-58$@V0#0?6I !I(4*9 M7 *H38'!Z$3+F(W\EV/OL1VX6X?>II4$ID:GQ?8%_(_^M7>#U4PO@G4HGQB: MKAK;GK[2,*+"_P+;NQ@IH;-TX!TDV[<6FLKXWRD:6Z1UMKML,1V#Z',;U[FC M&JJY@PAIF&0W-X8];-3V#JPWKXW*/@$[G_F=M$+=&THC^+=:< %TCQ>[3Y2*RA2P+7WMU M]\*@[\)JK<'QKA/6_5XGK-6D[PT[;)DU:B?QM6>L;532+ER?1EWY8Z>KU8-. M8<20MD;O^/L?L);9Q^V>_43[C0<,-(9C[VAUFC2IIMMPP%JO/5W8:E/^>-.Q MDO_6'Z>])>U_\:/41F.]J0Y2IU7RZ.Q6$6*G6>P%[;I'J/,EI60K4(#PL"Q< M63OR-TE=?.@]AK_I=[8%Y:BXUAV80 = D<1\O+61)K!*C=\YIS4:44[K06"X M^SJ_%<=3E6ST'__^_X@"49C)2HRMU3X:#'X\',!_HT;OJ-O^\:"DO;^/1NL[ MQ)U*H\NTR(U:W I_9+8'IB.< GO1VIUKC^Z9"]E:J-\9'?ZH!R'+COFLN>K: MQT?-W@%6UIB-XG4=0<1TOR/H)W":-_=R.(4!,PW4A)60)P)CP3M0;=-+ M*DC!Q-N=NF:=OX8]-6? ^;M$E'>>%9(A*PS\+\A+\VNV7.?Y)FH._M(V_]=$ M&[@U=%X8^F\?! L$&3YL;V^391Y]2AZCR602-8=_Z33IO39[(5!>&SVK9:X# MS(KY/8.J=AUZO62>^8.H>6S?[Y"-WQ)+G_;:;^RA[+3)TF0?3TO\&YP6[:$' M&QMGFL,!F3Y"@F.S_1?33>KCT':1_VK1CAKF6%AGP9^;? M_X+EK'?.O68Y[0 :X\0(J0_FIC!SW/E+!P?3E10FMKN=!M:.QN;:2MUR=*.A MFZIN'QP'_,30/L'^-IR48_ TJ-4^3Y]N,],_7&'S?_A"J^W-I/GGJ2:Q=;56 M[Q%5X21Y2,WF]'BVU5@Z?6JNP_O.[)\=>Z)K]D2VA+3*JPR84"\1?$R-MZ,< M6^U^!_*[QD;8?X$1MWOT3+O%VX\==497#?;/V?@*]AN=I2ZZS[TAFW_K(Z2& MP\Y(VX7!'GZ0:9J2)YN/!<71)BX?9ZSX2&^W:T[7L'F:1SC/KA52E[Q%N7 % M<+6-?/3 EI>5&_70/'^('LRLB'R/ B/ ,:? 8DQ77'WVE M##4HQKN]12=+NJ.;N >D5=K=)&,@;GIA*S]?GK.>:H<5U K0-(>K)D>XKL57 MZVGZROI3536^\D0T!> *Y9673(+J0ZFN6=15ZEQ1[[4\_"]*6;DP\4X\93PI'8&-1@(U0)5R=^O\:7,?'8+N9S;JL=$ #_M& M_^/'N/S4%1Z;-;DS73KL=_'Y5M.\T#3/AR.A/%FD]Z#\&-.R%BUP!;^F?VWZ MW-!\KK-']]H#>J$'*FV[NT\'3=-U OJ]=V&;J_DU/>]@1V2>7NIXBQ[O'4N_ MI9N\3UMF7*+>MLU=7U)N*T'+H7B[1LGD,P,>!GI5CZKO"GE[>P M*4.CQ9XK?+6H5E1+U1\O1C(M'P,V35(#XV&DT[;A_WD2/$/=R+H6_=^'C(H1S[M[(6^>H1]##]HWL< M:/SPDQ>'<-QL0NY2L\FJ>SON&2VL$W?-M(1#:/<&YK^]'BEM[F\O:SDSJ9TI MC<@/!$CYE*0"+2QVS>CSY_%T1#'[9 'EH>;D@D]+MO_3?;Y,43O1C(F,60L) M2FR')\PA%> KG)?@X9QR(8 L*5#&B"L7N3%V8O3[9/CV M4<[XA9EE&^[^:)8&V$SQ@1G'H5WK;TBZIT0[+MEB9#E<<, ;^CC5&0)5^6"[ M8V6QS!M/82?2Z6+X@T\UWR\J.O#.G/!ALXU_]HZ'^&>W>5P?K_2XAZ /0E\Z M7+):VMVR7WV6+SG$,3&G(=OVOH'WA1%[5 4M2L[B3.8Q!\M M;O^)A6F"#47P*1.S0-_0;@PT:5L_$M5NJ??1V>3#Q5744%[, W/E'7#/N:/XI_&X.Z"#W)\?45O@N?RP/RL'?7:7?OG<33H@*?2G^#I4X(+"UASZ,Q^\T- M.S4B 7_+P,"%15"&)RN^MV%T6"F;62 (X!-6#BO1R&AJM3NKC/Y1BH+N*\:K MO045>V3G%ZRLP3JBMPN>G4)E9P^". E(CTX;G-BM_@!<-%2UGADA<)6:K@V: MX#'[;\O-SRWS*W,_&M%^"PR<'_3]Z;+3>R'&V"KY)VK&H$ M6H,0F&HS@,1Z5O7:DR K*I MUH\6,ZPAI%J)>E$[[/=Q /P].6(PO;$G'_R<_BW]>H_G8@Y$P0V V6IAT(/[ MRW;1=&DD@L+?Q,MP2:;H/TF]45@F9=!F!(.0''D!^E%[W^3K/PEN_@3A(HB) M'WC_719%DWU,SUGM1OPRQT%M;W]UUBO,KB+JFIJ# GRPWR1YD:TL<1$YRI.) M$VBL\KB[PF%H?ZMZ2Y3Y/:SA=S90M\[^?'^ '!SOMOHU1)]X P#KJ?UM,0,Q M[J-UG9 .AW5!=MJQ8=TRQX7;.R:AO'\N57,>_WP M:J-+&CW@\41555C/4*7$5S8RM?5IRYQ$2V0&,E<%-GF@!ZZL;+,K5+/A2J?:>$BT/$<3:X-Y(.A-&P]^T^V!VW[ M7ABS-K[V38#QO'$XTA'L%--+$1C5 42'AP$P[PB1;W(W5C>X../'2- M8A<45A?"&"RC3C2$,SWIH]X9Q'!\*_LP+Y&,;]C5 S0S;K =O;OQG1@,/&EM MWJH9;P*RXR448MV+*7UB4&JC'+%;M%[#)D?GH1TGV:+8*/[I-$7WX0E>X=:4 M/Z-*RO_^<<;*M-4H!X<.58Q9U)<<=H'#P@0CXDKD=8*#2 :A2N%7 D(*2TQ) M/;'K/(O<:-<*#F.U9@1MDZF^7ICX+5V!K6164 45#2CKQ<68V(28I4_IV$Y02E3+A0G5LWFQ/'YT2E?C-1H2X7O#="U!8)5P88[&5Q*B>2F M9B.E514*>K$U#1A5K384*8@ -WV'&QLM@/)26-8 M6LM([-0XYP(T15N84*1=EZ_Z%S)9>J)-V/3:.I4%O707M*1CY?.BQ?K*E'N! MQ;0B!-R6?8M 09Z:NSTQ>R73:>G/NF-/0L4QFC>2,,B>%92OEIP>'/*#83R2 M7Z*!DT,]$=\@6VHI$)=_]!0*ARI>;@F16ZP)I*(1^'$<%*7VDC! X$AV MD54MHWRRB!,Z1#6/FLD5WMH85U^_.W?:^+&=;5 C?YQ)A"8)1N^POFPPACN+ M&^\AV,[:?V7[M2HWB@\.PMTC.V^.&EW9NLJG*]]M7M][]V%XRR&@LP9?20W^ M_\%NXFW4$O$>-CVG=9Y8?]MYM\N.PH#1$"Z._62'7X;(>@D#-*4)EU:[MGGQ!D'^85,NGW<%<6!SA@H_(>,2P]P- M37PTVG[)8),0:HC:A2L,1L+/V?N!EVR=VT^AFG2W]0\>R=<74]1.AF=$G=)( MTVM=AR%5)6^X6")9"C2"J"[NJ;1BLL9ZHK_YA:2C3<*(G&ZN&"DAD2[7AW6Q M )URO'-%N/.VL)="!/)U(0*YBJ,D^M' TVCQ15AT*HR-C-\KU!OM+L=:K&-P MS!VN MEW!K]..#PMN"UHYAB'>%]F6?2XK**($7>#B?-NED,9NFG$B!KLH@QMO4L(?F MU[<,&71^\>F(8NU/@*YI$([0*)T@-.U;_L$6*NM\4MDX(?1/T"?&B%P^*0@-+5]++[%TL>,)A#BM?W4U2?*0Z,]^ G+*8)A# "CFR MN-?0*)8C!:,)7UB;! M<5->(\A!^78S]_-=(1:[)%%U$9%R\H66>!U['(+K9A'I3(U!$-^*8[#3746Q MKPJ-K#3CJ4I"(!82M)R/(D)R;'<)D8>\/:3%!>?E$/ZP%Q&$3C0B)5?)UL\4 MJFOKJ)C;W1NA2#596%O/C:-B("\Z>0B\K==5T=W4F1/Q&[5#-&BU!^C="PEY M1S5E^[<2PD :J8RMS_X"$D &D-:C&.&68L2(P^U%/#B4\5D*%YA MK1B4FK#%?Z=3&@C':(1I?"!Z>Y$G9;\4CVY.TQ,G'A'!3O1+^(3FTY:CU$=R=NG:WH=FU.8B&3)#NM>(1KE> M38BF&MH'0[P(=5-*_5#59K%QHK];)'!7%*""Z/ARQ04;J4ZCE&GD"HTET VO M"AZ;;#D*^B3W]'#$X)DC=J*A6"!7>'L$ZI#M-7/1QENP]7K*:B58+UUM2F\C M>CS?.I7+M ?" _O#WO AA@2/(CMS4K4=]A.K9=,#?5P_S\3,DV>I^@RA*]2 M^I@K,81[UM;YQ719-[U'D9E?$@]+\\-\%&=^"0S ,S],9_;,CS\VG#[AFMI. MRE[8=]Z%C^KITBO099 4Z$(T&871=IKTX[B2)H->KT03="^7V(P5^#X?.V&O MR47W_4**+'$Z07G;Z3)/M6,7C4"VC=J/%'Y'H7= Y\V$(['>P**IG V"\)\O M2C7Z,(&V/ RUM77YN>O[7)DV21NB5&X5S8?&1"[8R4-%>!*U/IA&8@T!Y_>$ MMVPX8/1EO$["@:Z%Y?9..:%R/J7H\5O[0T=R[B$,M7&4<'!R4GY4C*UN78[I M'=-Q*JM?[(G R6$4J@^;QPOPY13Y)@_M\JY]EDAS@ N1'TV@I(PA5&0RQB&)AC+"0$NLRDUPA!B M,IN&%IYHE"!8&.&,P;SC/LK_WI"FDC38$\YT!2L#D^T&"B_CSQB(HQX0E1#^ M$1L@_"/U*P18*;:^T>/L#]6!,> &!@,3[!1RL1OVD$8$))&PUY3G@OS2)$B9 M-H*2RSJ/P(!'F.M>J6A]HC+AF"@4Z(&BB-T@TWPJ*:G96E#\!$2PDQ6-EE]$M@C@T M,*Z^'@T2C4B&I]@\>^+<1[:&32R(X':0*63K%$\,/A54-@8:KJJ.A3E:.B@U M3&:>,W3YALO2&6R$VN-NK-0D=P>_?^8[-?O/7L'<0'J]@!\]MRLGYM/<-(29 M+N]11$'P'6626UUQLOS>D6$.&D#Q(.(16.'NA:_9F&T)<(2'K3S5>G#K7:;8 MW>$,4T!06!Y:PA)$7=6KGW\_IO]8-/:T?5-]KF0?'%">(--ZDKAR_35HK0;_3\L @6>XPB=%$4('C[2XSG1U6VSE9HT8]X3IK/F1GR] M?X#Z^R#1+^_% 1BV'<$=Y$>M?@C'1;@+!0,RFL\KUG!8 3"#S.L&:_=W79H%.GWN;Q6KSNRG[#! MW3V[TY) [A9%B6W-O#4TH6^#?G#]M!"#Y/$MNO$HO@;DRMTR?5 $&:E;5G/Z MRB#*1*!DW\)HPAB1H-$2%0=?'E$BWF+*G+2H[OSE.5%!A7J.Z_8HO>2'<5R$ MZ32[M"^L$W8/T$4"FV&K>"AX,?J]H ]S\LN( @.,ZTHOM4*@V0 &, "A<(Y& M^QD6A#1 GCNMW! $5[A]W:BZ-)K_"P,!$1L/ND$R3-Q]MON"8Z)7-/QQY\LH M@'OX#L=+W6XB+]I>G#,(PD8BI^C:BF"=6*8XLJ=8-B)L#ZC ;M0.&Y6%N+0. M#ZHSA.O$<:$P8I,#_CF5?%Q=;E16<7S'P!P_C3\?'Y_^=*#F("FBHB;=9PID M[)J),[;X\*>3R^N?#E2F+!,9;0@F9UI%2*$OS^1+:H (NG)S#)YBJJF-2M16 MBO_:XAC1R^ A3#IA,$7E&K;N\-\6.)E9IBJPJ\&A&IB9^ >*&U6W1!@'B-L' M&/#]JLP<,-<.T.+9RI>ZL2*S3,>J(L/F9I7]=8.$@E>5 5J96E#=#-@.!>V# M=B:=LJ&#*7#TT'.' QT>IA^H37N^"?_^-_!5^LDL#*^S6W@D\) M%F69:2,5[>\IIL 2\W"5:75\%Z\32GK0#M>=Z*W+1:U%3BV6^5V. A^A6C+? MQ98>^YA-*9553@/KRHZ!V'(VMW[Z>'QY]!-GL%]\.3H/EIL99J:7YZN]HRM+$QAF!9 MNT,6G.C2DQ>FZ0-:G1#\[>+TW]3N>R:7'M500B/5MSP-T+ZP-+*'9KFPH(/" M0=L$;]UD=W"FJN(:; 7&T5I%,,O&C^ ]2KG63Y?C]S]) '@:W&HQ/@7]C"^3 M\Z(<:%G@?50>X/$Q2V<'.",XRN%$?4PWLP5;C"]2E18PS1D.9.&+,)PNLE7U M]F*PWVO;>O[LS^@@>[,2L*0TJALQ2V@8LU&!U:79:* F-)IM.[@BKM:;8>Z5 M2MPR*:A464(G:Y",7N:Z@@49A7COB::!1XA4PBSI"L78.TL^:]5@@[0D*@'+ M7\@4E7DN+R2J%Z"4\$CZWZO?:(L;"L!LRBVKUY6Y!(0%;C* MPVCSU3U2D!D96N4! &OU#] C2Q,RF]%'Z;;0 M83=#EU.8=8:),F3=@5=6F8@-,ON4AH/FCL)5J,BHY@94D@3\-4D2$)>_8S4U M1VQ0%7** [7-*ZP_V:>(;7LBA^*B3C TX$_28_('"MA;>;D5S1^@I/UQ,R/) M&;&*9CA4M$"]S$$+O_])RU,\AI3@-BL!%QJ4#=F3>+-7#+*>4GP$A^&AZ=Y( MS-_9M<.9415A]&A7@A%'(9C,'4@99O:"]&5QZ?:_1E:3;6!&\D0F;7@[Y?!D M:%J1(^1P\L?'F0"G:6/@[S#N?$'P:;3FFH#\^CR3<^BC_66H]Y9Z NAMC5RU M.;6,CB8W ?Z;'V;?@>78><''4HIQ-#0#T6!DYU\:9^MX)8$Z3_9;-.\9*>X@ M?><%B2[-VD-[LON@C9!G?M]K6/7!FT,5$3:5NXVZ;EY,D'MTO4'^S$B)+)-4Z MG$5XYD.^+5J\0[1T[Z84F.A8.]0V0'$/(DU*LL^=_,S^H-/KO;5(F7"HHQI% MZ7K<-K:YI#!57A Z9!\: M%R">),2<15[IN-"ZZ)K"U% N*1 097X2$#*^H9K3T&M9(!M3T[N(;6/R6E,* MI<*>>) VVK/ MXT@W<*HN%1"-MFV0]62U=BP$9!'!' EK-'J8J\)5W8*TYH?%8" S4!0@N>.W M'^!I!E(&IV=-2M_X)ZA]3V4,RRQ_N$%CB9: L\4$*\>J]"76R5#GQJF;0[=D M>I(1T6ZWMJSZ6IF^;(."LCAI:,ZTSN)< 1$CM>.(V3ILECZWWN*RY0^+;ZDR M? S8OE5ROK*)T71(L:MA7 A3A;&/]E:0IS!-QF5K'!G*SUR/V4 MZUC5#(/5?8HQ !.0/(C0IVLZ"+TP@)Y6)"YDPQHQO5*L#7=>*T&+[[[SLCJ[ MW$B:AQ'*=#[A#LHX!<26WT9TF!6AU"F23>IHKP_5=0,4;L@$XB9';8OCV!Z7 MX,](L!.F]\F2=F=@?6)'6C1^4/;-U?LOF* TH#2E&+.2!E2R-&S'R0"3(?"! M?J\;#,-1T(_#8- ?<&H$?M&R3+ '"EMO%!;SUK6KE3T>[!X1SX<+H7FSKHP6 M*1?#0-(CV"C1$_-[=%T&;&8+G$8YZ:049UZ*C<;-J7J:.^4B:E?T\_GGP\OC MH_,OEU?'P8?C]]=NK%015/Q,H8U6\,*?QIGQ[#=KH_94_<^G7^%4PE$ M29!TXD'PED.!_OG?_T_&DR;0X![5T6P/1S%%,3+KWBS02P#[9S0LOA5APE;($TO-ND<(U=9R1/#H('W.\"E==&B89R3JHMINAU(JVDD$D) M!]O\*\=^1)UX1#U3UAB--PGB=GBJT-^KT>\41 KL!B_;[P^#CR?]^ M_$'(89&BUP&5OTB**.CUAL$ ^+E,@EZGEQ0?'L3!H#U*X/%VOY?\. KT- 5B MBP*P1Z+>2&8_[/3[I<^N1E-V!4N7G(+L-KC] F#+\3;M7C0B MQ(KV:$BX4?0ZPD2UHW[,O_3#H<:#+R+'P7F@,Y8-_'?)P:(]759ZL[D6<["6 MA4=N97RE\U)_!I^6WMUA M!86UA3VO2Z]8*6=DBOA.=SXX<=[$G2BX$2<$_-\5"78!"&]%$J4S6 ."!N:+ M!Y ;:$&$B1I?59%^(FL*,UUI8Z3!N;)?MZ#:;S(ZF]NY:L]])R MLZ<&WT3Z4AH/KT*JND:@9'/B%R@5=88#*DHU[$3)6^^LOS_F2[+Z MP\9*,8\@RM@W>6;M.-GMJOH _X4:@^3E%#8KKAJ_!G=U>]_"G^[V-#8YA6** M0$CY>N.'T= Z!\)8:#&.?VP]G=P:1+[L')>-8!NMI%>Y9J6@NVO ZM0N2*C= MCQKXI:1OB.O_S$@+HC^>'B@S*+(4$VXCCB\%':$WXBC3$4A4BC2%,P.4!+JV M(1SWH8F@*$WRC8@MKQYP@BKB+6B!ZQT _AL$XII\=0-TX!D;D&LJW3=; MBT[P8:-K8\NK#'Z]RO0MHUQ?B90/$=/6WG6&\RZX$!R(SP0![^G?E#O6=,/, M*=$#SX "Z[^E0>O]9G:'4@$QF+YE\Y10:GL]JA'>P\2>&3Q#VJ'U1 Q;#S-B M?DYAE\[]K6!L("@,5XL[$*"KKT'+ /X7^H)SR](.N_&P-@R[L&W@QSK-O5G% M-I[1_LI=28H7 [J];RBCE=4Z3[2G;]&L7,C\*^R>4Y@.%0\*9MRYLF@,^B] MY5=T@5O0JOT/C]3#?4E>K6IUV.EVW\KV'H9!+^I5/,@E;OY+$+_E;3\ _0S_ MJV\6Q$+2A]M#9;.#3CP4%1#X 0NOT4__PPF5&B=M"?4X_,__(&ATW'W2],%> MT!MPBAW5,#A:S+]A!@(E]2\Q49! %-#H[)Q\3NN'U>IL'$&<"^T$#[Y/?PW[ Z*O%-QE3"WA__^/\P M:]E<\LB<$;2FFEL<)DG:"=S-DO8@"7=B$GZ/ZJR-G)2-0B(S>S"L4[\L=7<4 MMV7]F8S.;54/>6/-7T^[+=XHM)\71;#RN-#5_18-2!Q$+:9:I698$KVDU. 1 M>*%'I S^>%*+VP(JKC?6\2@A#<1^=M%1I#];"\'ME)H6]4MEE5PED6X)92J$DN7ULWIOT$- M\=JYKH 5LIGO<[8J>;Z@D1)R3;_'MEHJ (+03S'/* := XV"/3I1XV%?= MX M$BV&41_K_(;PI;#AI,2&]FQP=F72\76S'\4,71)Q]PATPXF-[21)@B&B1[6[ MB4IT;/?C).@11E67Y1H66QR,L%P9/#V(F4&C-F8&8;)_O]>S&35*VN&@CP.' M0S9IQZ->8.J@P,RH/@NH:3BH$4S:07P^4K"@D[ITQR,#'FJC2%ANKCW22B_2 M)3>H+K5%B%+=2R%[K?(&J\['VG/'^,[\ Q#]!/:/*76.5E$4[GC,:8N,B;'F M6ELP*%44LO#RXP(K06'#0%6"45$15CJHD,=,B4>F-!]EE;*IKR+V7.)9,2Y+]##J8$H^ M5&8H 99N<#T=.*X)\I9R7BV,682\@?V@HJ<[P7:&5+Z6SQOB% 0",*8[50[V M6)'_DE81)W&,BHQ^U%,*SOSUJ<@-ML" [8<9:[#]PN 0P>XXQ)9<_W8!RX>Y M&+<1@@,S=^#'4;&(#\=I9^LUN71OE7D>9(:T#NQ_ZGQM&&+%^KW2[N7[VW3" M?EH0>P,J5!9>QU.Z1-)(Y6;+ M:*IAD 156)R15MV8 A2FX[S'W83-'E@E.JV'EOGJ:RG-A:-@T#Z-E0G+.(4_,O2MJJ1W<();5=/& 85H3 MHJ248VSOY7TM\BL5^%5(Z84_COXP_OSI.#CY'%Q3 MZ^#\_>G)I_'UR?GG=\%[-T9: L0DTIS]I%%,);C:,7MEVMT>U\L>)".X;IK8 M4<0\"'M4<*1O# #T30+''=P*>YC\-PJ.'QYGB^>L'.%+(#N,LDT+",(+! TS M&E @&#+^#WUE*N2M^%,;'DWFA>%.^31H]4-"8>]2R94>^9R2$.&#QCJ,NX5Q MW <4PPW/B $KVB\0JZ:U-"$O#B/)W8Z"1+.:RM)@P#5CI'G $#+SI@K_*JNZW M5J.^QK9+")AO&S7+"]:-.(\R&B8.?=$F^_GHY/2$-EYP_C'X^.7S!]B55]?C MZR]72@"QV/"V+T85K/DQ5,64!HG\TN["7:96RBEUJEAPHH##MH?*YZF<)]Z_ M.K@W.P:E5"BG(#ZU?$19_NJR='QV_N7S]14MS:?/)_\.BP$K<_V'XP"6ZNK\ M].3#F,3F&';8T7%P]8=CS-BOEKDN6JU&/QSH7V$-QY/)&2UH#_80X!_@@U?J5X'NP(8PP&(Z\V78=>SFH6>A[E;S$@ M'O*!#'[+/:,Z.,:U)\:#BF>JI7\4KWR]H3=*0KR99>%N+(1L4J=4G@ZQO4J]W#8_C)[]CG%R)5GUSB*_YS7[H.D/BP<-RK-Q M?:\\,01>[(R(HQ/,?1X'10# :+2K$'(#2 M8$H)(\[J:4EKU&)_V"\FCX:=T 1NW%IA#VBPV\Q%$-;/6 =1%Q,LK'#OVI34 M4D9J[9Y>P4Z4&N9?5EFY!L8V0[R%[6:*8*<2=)9:;6]6EC,ZG4T$& "'X-O4 M&*BN4Y?A4%#/H,KYZ@=&M0!P-_V[0+G=)#(EZ208U16&'!5'8$.=+GW4[23J MHTL.H.'4'=@!BK.E]'OY5 MOM&R=CFQ=!_<>(GEJ12:)($IIX'-S*O.%MY8%>8@*B4#)@$$BW6Y'(MRGAH*@02L7% M:FB:BZMDLYFR^ZI_3FZQ* ;I/K\-SF'7@.";D/V0+W@(:FL.%M]Y93"^'TLI MUI(LCW"EC]PJ4OYQD:,EFYOGY5D53Z^<:F,]S7VFZI*2>:(8$*%?WJH7I@4I MC17V\$X*J[CUV6A0T613&=Z*^Y5=-6TC[F\SM-F'TCX^!AU[JL_ORO/?OF;6 MZ@)%/]IV/8!<4T>%@9!KWW_P5FL-A3\*9C0L=$Z!+\KSR7^21ZK>L);TX8K9 M,R=XE0F'BP\G5#"P3S]C,G^TR$;50H"N$C0J*KT.JD' -9]QB_GL)+R6[A M9%9#O]<0@6)! \+ EH&=^D/%"JU+::'8@?Z-;=F/&GZ :$5F%U4E/E"5+2+Z M-782.\HJ",8JL"IMMNJ-)K54-W,W6;60_X>YH*HDIYUU M>PN2#)85]Y\7%=FZ@[*_&#??,KM'-OB6Z9J9IU2/:+S[0,J#J-FF%^X6T-50 M>U:%88ZOLLB)U"N"AJ@"2@1Z3W85;7^D$I[E&K_XQ,#J@IYRN!)1<-;![Y4) M=\RI?SF7R%:X'61J)0_6'B+8VW%EJ^A %@M5F^PHO29;FT?UO9Q?F1(:' MS%2\SF2AAR'#RK8 TIB.%+1Q0TDMM2!7)@(SP928L/I F&_"V\'PQX6).QT,;]H&'9"+E#8&>&_@V%G MB)]?9N@U0P,I'/KP-[V(8;!\;8).*7NHD_3HK["G2PSJIS%FLA/U^+&8_NGC M/V%G@,\4A:PR*76ON!X9'BHOD8L,PK#'F#6!=H$1$11+DIA6M3 M"IR:R_6GW(+O4@T,]BZJ>":,>0?6SZ')'!%43/EE"@U(OY)4QW*+ MG$?<1IFGBZ \PEZF^%S6BSG:GB\)A[184]!D_X.OCRN*MP&I_A^;.5?KHYN5 MLN&BZ0=WWPRS0.!94P >7IE:*/\J38?+^\VGFQ56X%PO.4UVIZU,'&ZK"!;N M/?GO=>4_SC/%H:E"#62W-]:Q^QPN*LO)_?-+'O2=_ZNS]P-C!^_@GC-N9$GVEY?\?Z;2XS MI_["_%6[7S1S8 $IT_P;'3&EVM,)=9O_+Y=AY0:C@O_).H?D2 6.[T)1E0#B@*7)*Q;'&;P M+V&Z][KV5_V0Z%$@D#"D4D_*A+9@*![LUXREIOQ&*@$'JK I!5G,GEG/4E-U MKIUD">;RMN?% ^C]LSE-?B^,UY)SPPLY;VTK2DO/[K1=2_DUV !N2:[O^0,6 MPC2:O=7($Q6AI1C%_&\$G@$23N* \)Y*A"N)1C2<47U*.S"*BAI*M <#U>$% M'1063*5[2-<4'$Q0%R69-$?]B6M>PP2 Q]:[BB)[XO]II9'6!W^00**B]'.$ M%)Q@U<510;'DOVGSV!_"!X7M$EJR!G^/!F9'X^\75.->ER]5!RG/IRT]; M&=/B6/ZVZ0G4MH@?=F/Z;Q^A'%J_72CX-2I[1_%.L>D3EBLV#-"+\/]2:UI4 MNKZL2#BR)+U?>BH!27!AM2.X1#50/;RS M,P5,:O@SMX+RX *04WB*(;:-+LPC-U@?BZ4-"'A=E \:=EB5KEO9D(FFQJ\4 MO:6ZT*$%N^D'NAR=?%8[T#HX,?BUB$Z+-3TX&H-$Z:ZZ^E: MX&#P"7*OL,6W-42C@HK 1]PXQO0FJ',=C,5)4RQV"#KR5L)36]S300%ZAJY) MZIACH2Y6>?%7^\.P6AADC[%>*3D%5>9)C1VE MF-11M&'4]LS8QFQN)J@6N-WK-\H#X))REO&,TRG><0M]8/'^D#,F2 611(G^ M*(B&DK@S"+E8-R9&P!6' $?P:G#(Z8KQ$',E^T-GO45S:AKC*V;"<"*9SE7WXA3+I\VXCA W917X98,:>'J4&MZX8Y#O5#?N<8,2>MG_'\9Z' M:#*19#&'10?1B7X;D.LB;OGAW9EM)T8# M*4&(3L-NCRBCJU.*7GFYC9P512D#VT^/^F")B#NNFJ.9%%UXS;P,OKUN@0:1 M!P,T*5[/Q=JU*MJ-M2OB*=@VXC^5@9R*0N.MMM%4<$CHG)!<% M5$)4M'&2#&&NGE Q:&[5,7ZB5(=^+7Y[!8E7N&&CPP)3\]A)TD+=AGZ)]"=4 MLD9#D19H+YX28>*;# \XRZ.C+/NM/H>[4F'@$?Q) ?QC'?#J=P"IZW."]JD( MS5#;AR ]82IBB('HV,\1LP\^G&D]-[7B!2S\24E,GV7DHRS=X^&#$DTE/->B M)I*K1^I;3-I2*^*IQ^WA,';=0I'[%]YUI0YUHV[1405 MT,MNL+EB%CDV;.W7,1$XP]J.19 +$'36YTR5G_DX[YQ.5 MEICK \A*:].L1)PM =?D^R8).J4RO9)O94K6L]6DHE@R^0,I>!M66EK!H@SI*M^EUK$414>([R8Z4X)S02 MM:B3/@V$R,@@J]X4>Y$T7#61M'%6.3'46(D/W.2WMW3'Q+$->C2'*#+A]Z;V MHIYR&*)1/@EI.;> M;"5P1\LE!*2*]UY-3;!NU M[EK2$:,\4D<_@@T3/.R!R7=G0\5]7?DWUF$7KG)1/-:T7I>;=:A5[S ^1'43 MJH@.6LGM)??&.H4;C7.P$FBP- V0H78U1._T#B"W:[@&DF <,_G9$&V M+QLWSQHCN5J#*6DLEW(>_@7U]&-73V=>4D_1P:?Z./X.?\RM;TLJ2?V? H?\ MAB!QZ"AN#R.VN_?C;DF?Y)_^)\=S#.S%MJ(VQ@]&[7X2$8S%2/8%']PH*N") M 3T1#^6G!=VY(@(<*KF3G6XWBMA5QEC"=R_AKC >' ;ZZU,I2"%/N4GCBH!T2 MP#5\,NI25FIDZI$06A4E[Q,G6\$K"P:#M(4QUK IY7"PS%#JV25,Z-H]< M'U4P7>&1/3FOCWR6)#WXCZ!1V%+(]=EC2JA*>I1"A3F/FLT26&9T)N&BHTT0 M97<"BDJ"!:OA+8NE8+81,B,6(J9B\,"_$?07V>P3XWMPM,3( ,. _)9!#$_% M PZ,M9@%4[IBC)>%K_%_ [(EXTBP!#('+7GCCYRK?41L:P>6\K(6"LC[TAW^C0>7U@U6=' 7'.I"/NL#E7=*EC*$4L/ U@&M O& MT^F['?6_=G-%IX\^7.";/G :ZU&-;@]4%ALQO'^(9LK82 SHWAOT.7@G45!; M$A?S 1%%)KFQ+Q8T?04!=FS7$:PZ4O<35J/V,*$X^FZ[VR>T@_:(;)8)7623 M'LLR_#FDK/U>G)#7NV^)KF%[ (T,VL,A(K''F/**JX](",-^,$I _^Z"< ,! M;PFQ?CL!Z@SI@!JV8W@U'*)/I$N@ZNCW0,9$KM0B+6D/@9,30GR'DP/[Z'%E M\S"AV<%R1E2KWI)M,:S" ]Y6.>$#T680MA+^&44C1%*OM#(.7AE-"" "3QY MA[#;XHC^'Z,)*D$\45A064+T(1X"F_=A,\Y6K9D7$7M$0QQ:-; 5K,$ < MD7C BP(,@ +1XA3R@2&:/BX$_!N#HA'W$^NH(_P>*D(/9]T 4RF&!5T(X8;0 M@P8G#>A*>IU#'#MB'?=0",1^K28R<2,(^@\TQ:-=X[Q&"2T+S6K =$]BWNT) M:S1M/-E/K #!7+;Z]!O730+19@X1=<3 0_J4H0!^M-*\<%%"Z[_R IGE0"4@ M&J(* -1"=H<)V\M1#KQ1_^GE\'V9V.L!>@6L-!5B[ZH;/('.Z(49H61.2'P, M27?RKPVBZI"[-&%%DS5/M39H?4:!-9!82E+&NK1&%";FP&,JQ11=GA<7_UOZ M\/AOQQ2ZB+?,Y?.VU&X=7Y&7KF<3?K^-4<]2F+& !6=NI=:)@W^MH_5SJJ2YM&'2>"?[)P2XYU^WD4HS<%6<<++/M+\.' MS_2D5&$R75\@KRRQW#S&N*P#6@O:&H_&WKSS;O@RS_75?R5X!GC[&\CM;VC= M$X?M+OT]H)L7*G88)_!.;03WWL9NFJ0]B#"F Z--$8$QIM P0F/LCPCH%Y_! MVH)V2?4!2(PA"/\A"+\8\0]!,_N .%X88H/W_LW-+)^ ?@./P$F*CPY@:^*I M>K28+1YN8-_T0(7L43 ;[%E0TQ.8Q@6,(W]\I/J92;=/-XX$IHO]#5"S7]Y1 M#< 4Y!JFR.&^Q)T'1(.S629("Y?DGPISQ;P[L< MWAB;.'&JEP,C-Z#WK /T\>**%QL\1/K!U3(/3M/YUS1 8L#500+5$;#N(5LN ML QW?. 5$ M43O"H0*/H;8T@(/&0NFONA=CJ KH,!2STFLC@$T!Z$YY+C!!/2JB &#XNOJ@ M":1J8HN=(B: E5@/-ZVI]'"63P__C$K'G_/YM%@+5^4"8K!?A6%5I9M/N+ ? MQ>XU,_$18Q@1\VB)F$R)F&I :)7TO;8RI;$D)I:OP5S%JR^P@!TBR&&WU]8) MK$>F7-MX26":/+8VAT0^+*;L@J5RM(IX.RAE*HO?!!00=]DF^2N*JWDN MAQ2.C:OU @@U45$&#PN*,=7G%H<^>KD$V*);8A1,P'A]3KE:S+.98HM\]>.Y M(JF:,9K*=IE?;$_CYSS[M@ M (HR/;#R+)D%P_#*')TM\8S!^2I<@DZXH8.;\48([ M,+F%V]T"H5 9>^N'KBB$7;/6Q\6P[A!<5$/P6E'*=6!!=IXH-X#4;%M!V^]G MZ>3K(= J[1*7X=82Q4? $F4S>J3_'70X[<%!@,0OBKG35*.96QCY4@@^#3_ MED\Q7N,YQZA;2JN4__2C,FG*DFD1_QT$: KMPY99?3V\10VX6/PJ[ PII53] M$V*[%B)5NK8H@+*K0_;FN$.F_J@3.3C1#F,$'JZRI.M'[331S&H'9!08Z,6X M#A2_)9Q:@&VQMF.F$"4EV$L@.)8%?,.:.XCQ JW,[JNN8U#B##'5%@:G_+! M=_DO0INJ=E^W0N72H!]7A7'+RX5X,6R _U-5#W(T/%?UV#Q-'MK.5K*+-5HZX&>.Q"'O+ MP<$7+M$Y<:ITGCS?+$Y.1QO--7*TF@-QR&*S8N2F*4(T+XN1>(@H]TBX![IS M=L8>O%/C=ZMH'BNB75#99N?[2UVIW,:ZIDH_Z& 4B3#6]0!/]*I+UF%]23^T M4;*5,TPZPU@/9XI&<'3%AUW,4/^X6-YFN0)IY.)W4X*L)5B0<-!)1L$G L2> M8K5.O-&$"!2VI?L>=!^2YR>,.\,P("4]^!,S6R&D':M_HXCS-M)O#]BP!(W M;:DSI&:.9_E=KB"7-'-Z&TC:T4B(@!>F#C7V@\7@98:5N"=\IB./X^42."1' M-EMCY3-,F3S2*9.O@H!C59%K(#=Q/%IV7EY]^*N_*5%ZPYU"QVIJ\6M(LF^8I=> MMF4NAE#@9XZ$)+$3?*"*=3K;VO.P_:(C&&(T-%5 MDJDU(C\M?-8-JV1C1!E38=0!R60D([ITX;-N7-\OYIK&+)&B#MIC.@,M%7U/ M&Z/USK(S:HL!F#KZ+3A-C1%MRD=JG^T($DJL0,!$W\R$*6;8[-Q2)9I=;,1; M&-&55GKOE\O?(*>@=6X0(.1K2;:4'M8B2O(Z,$N=\O%H$Y&?%;%FT=PWB)-@ M!.MV5?ED#WV,:%KM#OYU!]E_FE/LXC<\O"ZV'%X]LBU@Y+>K\>M(IHO*DRN1 M_^+RP77A/;CD:90-OG/KPN+=6(QF__D.K)K3ZN7GU,5+SJD+CWBX^)><4S'# MA2>=2)\5K9#J'H3]SB"N/*<22H'IX6OJG.IC:%2WT^UO.Z7@0.N%?'B@X[$3 M_:A3"EWW6,$-X8)_.'/9P]OW@+KXS0XH'P>Z$JGR@$(6&?+:7+ST=(+C!MWD MV%;UP=3'^!02-*ZS66?E7:FLO"L[^6_K U6FS6NXQ2R6N/\EEL#4;0Q^&=^L MZ&+M1 9;W54D]^X77ER-9[,UF_2&D[UV0:79FE)9+!1D0=XU38JE($Y5M^+] M8O&5SX?R4X>5J:C#N/)\4L6:LR7$5BDJH MG96])'4/J@("V<%WB;,1>573R<(RVLC:X4HT)HMS_+./5^*J4H%2H'2NRIJ# MMLIGO^Y-JC5/$P:)VEW3F@3"OY# W1XJH4MP,LZ+2@>)3. \,%JB7FW% $'44#J1&X0:HJVX2A!VWD#>6!'ZFPK@&FPD>*EQ?"&K1H;P(N M^$&Q7:$;)^1;,%GDWWK%5+PN+0;.7*XAVA:6EYM8)$;[)?SP MKKX&:I)YT@*,"E0SYGT*@R,XNX$#2L&8HE88\K9MH;)>82+66_#7*8)NGY)D ME!C,/Q"."\R>^.SFV0_A^I=:M;VYOT]D"V/$Q M.#DY"<+0X()]Z?SS:A=+0_LM4W&&)6?I/"7/K!"1R]BZ!UE%!6&F0 _# M4%:6%Y/Q[TQ6F[6N'+5)P20C9S>(I.,@^:K%- _I=3^?^Z/N=RM\I)'I%TOK MXIG1IO"'[(O 'K.0RQ[IL5 YG0EDPHX#%.'*]4*2GB M_!:#1=7LK#7C$AMHP\)D04:KPK-1?4=H0KA0:H"$&O.T$%AHVGD[ZHH^D"I< M*JYV@F70U@AZ>"N#M8P.Y!C6.7]*V\STH-4SY"9/[4(&)FVQ:2K G@QTI<>O MB*T''A,\L?[!?"(9$7(GL=_1%A5@E[=D37E+WH"WLB$YH(-1E50\<4RE8Q)Z ME'Z:L(94']YV@\AZ;^$2.8&[$IZ]V+'*.EG)M_R3WWJ?3CE?9(I5?O4YHA^B M\1V9>A'0W"Q]DF^YL T^\6FQF#XA3I?E>58!.H>NY M"0-MZU@2-9*:=V\1DY!.LB<\R:3D%JC7G[.<3A"-$5C0S>\0/7^)[D>T1SKI MV-7V,A _ELRY2)]I-5"47-)5R..IV7(Z%$Z$I6Z$4=BE?1?^M"90VK8VG/@; M_Z>I5OB&X$41@'2@XQ3\ [*?++0KHRPT&O4ID6,TJGK4JGL88XJ#IV\U>VX' M(2M<%[!8$<]OS1F#"R-*%Z[+J=&P]S %3%6KI+9+X#C"UA80\ZQ:)3LMSX<< M1 "FSZ$E(5L_81F'&[RO,VKY=PFM7&#Y#@X%I9.[C:F/G'G:CJGH!VM+\ 8G MHFGKRM3JH!4QI@0&,JO3MS ]79:2T'X8T".B(/(#I?L@LCFJ\Y-TN7P&>8,1 M:"L$$^UBW?L(;B,J(+^@--1 L2?9JBD2(/=!7=ON[)0[977 JV MFMLV%2Z!S!\$8G"/':!0DQA#J5KI:+N^%:4/;$U$; JN5:[WL\4^JZVSC@&6 M-#0LSQ$*C$2O+SNJ1R P)KR=/'M1.XS[@J"KH]E]J9-N28_O?T_U/187ZH\;.)5 /VO@F\/#O.!&@;Z8+(]67ROIBX [35]R M[-HHJFT,$&=RQ%UNZ-#6A-)5H'? MN_P!)Z; KY'\K;)'<.'X(T_>B7G>3EHQG\(V Y$PHSIUIB$[^<0\6THJ,4,K M)>>(CDLFVI">*"]8H8H,DD=5P6[D).,5]E\Q#%(;^6PDH$NP1N"9C=VSI82_ MRMVR$O.V1S\I-Q>VD;)7GQXA,+5<"*&3R,"#FFB[;T MS:3A2P1@9>"86/NFIYQ<=AM"C%]3YI<9H^JFA+O#O1K[/\ M X9\!V;&L2?E3BY\2"V">K8G>Q@=0L, 'D!#4V'(/L/KU![?F]!;U78 M/0S$",J\>T2 M!!+K;6*,+-@@9[/*\']F(+D9<0(-;\)B#LVP.>Y,G=E4Q:]H]!%,#4-SI5:C M[6/8&F89W,D@KGF.Y4#J=1!3>["H6A$#*%CX9WMTF]ZNLV6QUVA .NM@?]"J M+1VP%8N*H$>NLJ23E2_@/79,5^T)SZ/O4PSB)64JGVW6)- K+GME/JZ1X_/- M0\8P]V09S[ FT)S^5H*>NF6S.7=K7^_9'43F^\W:E/':;B':3X_"&WUF>,D* M1G'GHK(_#E7VAWBN]$MRO](S[J@(#*XEX(WCYNE.TW7ZKFENK7#PE?*,/NH5 MW>>;]^.KDZ/@>'SY^>3SIZO@XO@RN/K#^/*X 3Y'$URSB54ZY'XQFR**+\,S M]X>X>;H= DX8@$ 8D,N+"HVA]1N+5,3T! (+?/QX?'0=G'\,/IR%P6"XR%6UCM_D+('%P#N-05JD"PN951!F:\C_$H8! MHRFB]K!RWHKC+F%;1(.^@\\1]= W"ESI '7 (38*G.6K7@MC2ELI$]L^MAL= MFV$9L;@ZL&5:(_#I\@H4K:X52U\HU[GRV.AVTZSM2=,HR\/"'$_2#9.1RI%5 M-^>U92WS3 @10'I]-^PTD_3'_PHJ_!JS]JS(T@\@8QMM(]_+%OA?HYN.%_)/ MKZ;D%::;*5V__JH[Q Q9+!IPSVIMI,L:+'B)2U"*S5PC<;HX#V #CH:VY%J ML4H-5BFX0JM Z:5UF:54T40X1$Y%B4Q3+^,3!L1X%@65$.A*T*2QB(D:3,$5]*."3 L:2- (_Z+N&.N"!DEP1"+T" \ M27?8>*V+DB1JQPAOZ7OYU8@5U?O90:)[JL\(>C5YM$ZB+!?X;6?1^#?&" M;0YE N'0F<"_3KSX*#OXK2C[.F+&1UMK"KN(&4RGB;+[%\W@J-.%.L#YTOIU*O"V-V ME5)*&J>83FS0& L'9U1"63)2[5C9+3D"F8.I=8")@92#^U4ZYTQJ]G.SI9/> MBOC27AG):$<9HV*Z(;0?CD;6U$P5/:G4O1,*\B8:NE@Z3!$A@U AJ0PMJ8P\ M5X$DL\7$Q@[BJ$5/.+8]AS(W5(Q^,'S9X#G"RXTXT:.56LH6[*UEF;_U6.:; M3LBB$NU*Y.W>2,_&\OC 7Q_//Y_\Z?CL^(P"/Y?6[3)=TU8UWC@5751@944& MN.;,5@N#*:69P_&:E)"#:7AAMU\Q/NRQ>HQ;AJ1IS5&JR6.*67[ OS@GN8X&&K\S=.%98DN,9W-0:SYN16VW(SA-V M(&O(SNL"9&?EOH\;2U'$@;8D)Z+.V6*U)$<'HY=+T>3_;5*TTDYR$AQ:U@JO MH812Q[B>876X^D?5ZN8''KTQ%VWYGT,.@Q0AOQ;V0@_T=LY14\Y0> M\DP"JFZ<8'E#722O%2 Z)Y/6++\E&"IM*[.M5MN?KEJ$E=7*MT(K?S6MI*J5 M[?EHQ5!^RR/\OER,[8++AQV!(+G+!*APM2[D[RB+U)^!>J6+=OBS#:@ M[^4R9<>F3)GT4TR2T3.RI71+.?55 __68L"3&DK[-A&C; UD/BF*)*;35+W M=D(/],.@->0*#JB\COKUSB#X'IYN48@/%[1Q4P3V!"9LP5[.,=Z5$M=+NC([V*E)^SIYIF@'E-''?A,57'KXZH M=6UO;[IME2_1 &\4-/*?*$_F3\W26@JS[&?&T,SQ] DZ:/4\SA<$<Q8M[LD[]NF]E&Q 4'2TDOEQ]"%IO M#E#%OLN&5S^PN6D;WWWF.S[%@CIY M;N:-*\PK34$+^_)(L!$KT*8S%SB?Y(8'#>'X_77CM[%\\&OP M@@F>+>"E#QO\>64*^U:20Z_\-)OE&.B@;B^HY=\M,R;,K\$>?-6,G$P".;)- M%OVJK-[LOG$XQYN+H>7\,U^]=@KRF6&]FU]Y]//G_Z M<'[VPNY-*XW[!QY,%?KAE"\+8S3 (&*LM47W&E7#ME][K*^RH'OV]8/F\D+V MV+>SQK,9_R@6:M+PJX[R59AGGXY^Q"Q>R#9[]=1X'F@-FU/&JCE[#@-1[.I/ MH8^;;&;E(RW3IP /,:Q3ZSQ[A74\*;:&S;JKS>/CS*/.E0N$J.)LC-W?*B(T MJ%HN![N/O;Z?NKM-[9ND0CJP$IS=1791#CI%C]#B=OT$-"''DA-)BV$LRWP2 MW)&2H8TE4ZS%JRJQW::3"IUXQ]>!72KNU4HOF=;=@WO^F^T>@_!?G?M#?P>L MTMYL\AG:CK=]73W)N%'SU>/K533P<;.<4VTWFO;'_#O7>:O:B%L>KQY_M%?W MU?.)PSJ"5 Y#?^UOM14>_./OY!)HPA=6TJA&<$%S.T:T<24]\C%P<<_##<@W MM9\DYY$\F''1NHYEP?0'A8S3?_S=23DM&=%WE%.%^G_:N'ZEQEBH!D@ ;9:( M4*)[#ZE6Z%9G)C#M)->I4&],+%F M*MAL4[ASS1:/.MUD8@$)5=%=BKNHBHU6]2B%2T3Z,NN$#OT]U.1QS_8//Z"TVOO?>1&@ZN1ZHC/ZMO- M?+G#TUN(QEXB*U7Y_&:6WW$\AI<@?M@A;P-PBU_,9IC*B^G-P1AX\QDSPG^Q M/W8&;#P'$@+M]&B0Y(J)[&12<: 5:P?(PK).S; R\(,5Y<^Y/4PFJ$R:K>XH M'OI&G^F#?()E#VX1FLHYL-D'6S5[FHZEO"ZLZFKV3)&\G/:P(SN*)S MJ6LMW=J698W:VO5F NV@V-NO0=6H+!0H3)X-$L\#!FGMSXOE5_1C X4QRMDY MEA5E'??%H-/MOG6L6I3/KRB@:EQY.$\+6/O,*3_W,TYB3K'EGF_[WA&E# MCKMT+>BF V(6)Q,B[OO>OEJC-[RJQ[CG>^??\X<'S%7ROQ,-?>^0?_ A)Q>V M\QTENQ=7FRCJJ&@:01=/$10CN '/X-C=\";SB\(MMS+=:%L9>=,BHH?J@2)* M3+]R>BWU!^\)1Z/6>6;U90V;W4PW>X>UQ_ THCRV:.L"68[[ROM[H+=C_IZCWN!4Z=GS?R7/>\7T' M.^R#B4BJ]G0YCT![1QB$.$5J:L3!W1K02B+!.IG(*(^,]_9/LLL36=7P_8_5 ML5D-6ZA8T=J'7X-PIJD7DM :TPN):5IZ+;*Z"?UU#[\>6:/7(FOT:F2-7I&L M3?:_>?CUR!J_%EGC5R-KO"-9%6+2S1JC\Y2$_378[]QX66O5TN>5VG6VWRNU MZ_!?#7_!2PU.IYT;J*;=_DTYY-J_*9="&"Q(D3 JSH]BI@O._+U8\-4:KJ'H MJW?A4OK5NW!6X-/B6[:AU^2"_.4OR07CPG MUNM(X'W;J=/\7EOJOKA%AWH2/L2 [B\6(2]KK9J2K]2N0\]7:K_@5VG2H6*>W-E.;=F^AFFHO M:,NAU@O: 1M8YZZ3A0M4"\TYJ'3 MQYHL6\I:IP;XU&_6$U.7:R KC6Z+>^1'CL2U"U(E$([?+>!Y*X@QO\D5$^A6 MG'9+#H-E)HY&7#0$=^0_#]ZYWDG3A3BY*"(FE7R$FOCCWY8N%I+BOW8@9/^^ MS:AX]'I1*91^C'W8[AYK E1*D?\KUT%B6 &]EVBKQ[E"__FJT74 MU&BCY.WQ]PG[#[>^4VG3250TK!_B?0A1M33QXM?GO M9G-[23>[+_U+>MN%;7QT/G2-=38&[58^>KV6]UFA5^IWWR5[I>Z;K:&M&W$> MUYK9PDKE;>S@MQJ3+5O59$/?I2- 5GYOZ;E[+/@$2'4I1JM+^S3\<[/3T.G< M,U:O&]._1M61? Z!V\$QTO=9)H A/Z3YMSW)>R]ED3J)70@*V1J=XL3'/F_O,H>X9[^7O_SC9@YO]OU?4K/2I_NEH8J_6$[A ML/ %TU2>#0YL!B,6N%%ZNK8@%H.MW(G4FF7,F%MC*3_\Y6>N:-CZG#W=YMEL M>E = RJ/?K!"=B\$S$=;],LOJ4J+58W>2+W%.ZFW6&F>OS@]OBQ_:!5KK%FM M:K-9X1E,8'4+4(Y5 4I[OU'-QP:[9Z=6RY1Z_7%7T;K&N>(O1= VR$R,\;04 M[*:,(#%NG@D,N: AIP\9S&YNX='_P+Z62T8FH=S=W[CWPN)X.J[Q%_WF0VA: M)N,'#J'*(W"6K>_)NF'PFJSFKQ:H!5P]XO6\:A_^$E?Y".K;!G4W@0+'!5YAR#;^]*F?EW6KCZ@?U(]S1OV@?E[ID"KOQQ] +W_[KTK5)E;9PX^?PZOQQ%;KVJM1:VM/KT:URG/N M]2>UO:O?<%:OQA2O?2/XEXYP=_NQ1A&W'O5:\G_I>5(AW'=K#/[^K@AEHUKW M][WD:GO>$3=[=<8PJ%!:;15^_7'=_W9'GL]'XC%BF\;Y'P!;/PM;+[ M7'RM[#XC9TU?M#I5;>VS4E5M^6.I3?V.\)___?]JA/V?FP =)XBZ%17:C*'- MJK+=54WR?-CKB:7$0;8=SDBV"1C.?<&/D=M%! 4_B"&DUHM@EXQ# M&&*IHD1J5Y185U:4J*5#8O=)FPZT6LV:?_IL0(1[XN>UY0FG)@ MT>M2I#7P4M]+$@\7DAQ'A<;'S2\;>5-:QKZA1HGO4R_5&WEGS-9HXI)MQ7Y> M#_V?A]'^X])K0/#RO8C0I::-F;KBUU98]\*CM4JSH6 MJZ2".\%55U?'UU?.IVZM%QB5J6U0?IZ! N&=Y2KS5NIA6J13JH>>?F\0W>2F MX;G/."HAJ7'7]Z "^ZO4@B-%H4(08C4VU MK_KTP2WPHB6-\HRH1,.QDD*;H"36996VB>VLFE&83O-]'5P_9;-OF81MM@.3 M+DF5DTC=>6D_5'GH^@E+8"X7F[O[X"/0X56ZNE0Y?Z>4!=C&F%=!/V5F6=^G MJ%4^8,7-Y;-U60&"'F,U*BP"!VQ[FJU6,+QT[A"5,?(>$6\OFTK=>1P'@4V, M/UY9B;WE5[<,00_:6O\=Y\^#^Z*3':G)!5%/^)K\(I9&6V%@V?7S8T'6__/_^+]M M&=\.CDX_%C]H#A!Y_.4R:$&#]75NH(.:&=>I^>:Q-IP% A^:>H^5T_P&:(P; MN6E:C3II#]5)>YFAA1"IBL1SE(<*8.>WJE:?3]XQIZ];6C^WR6P?[Y,@?ACJ;2X.,"N6U!;*"@H(Y4 M=D!%]DBENET!YCWPZD.JDHQB7#QE=UY%3R/[$-'3S(\EE5(06>%WQA MA )H%'#JY[-G#>J=,I"M8% *2#7^J7:,'-D/HL):#>L]MFSNLM9\\?@G1; MKAG;VD<#GDZ16H1\70EC!L\(E*\>V%J.SJ@;QZ)78-Y"K5ZQHYQ6>2.:1<791GO?% 2^N\O3XL?C"^O M=C@6*C2HR@,"1EC^"&91_@@&Y;SH'B8P.>>8OW1N&)_>7P2M?_Q/=R1;MKF3 M_7/^J-'"!>ZA[MA*Y7!9ZL-%L6#50"A="Q=LK[[?+]._H;UT3BH)+>M>[5#N M$TO0/=X^6LP6#S>YGLWYGK,I);$A3^[53EA10/(]ZF^K^^ "5 K0W=[O.EP% M]RF+=A#4(*5!T[Y1.+TIU6)% '^6O Q^CY?3I\5FAG#_ H4 ,OO![UZX+)X4 MAJW7V9ROJW GKRO4O0J>E(GCYIG:*%:Q5G.B&:X*N):\== MH(5WU.^XQ5?+ MFIW)+KLCU935Q5X53/0TV[9GLNZ.Q> _7!Z^!JV5'YMIR.]:D%@]K73E MF9EKRRN0HM$[E6GMK];0/J-ZV95@M[?WF.O.'>Q#@T9)W#^DT7U&J^ \ZM%3 M]N8NIX%]QO@""93;$DC=<5G\:(/P!^\EZT721P%-'?F-]]:#&FNHRKGI4'@KH=L"5J0>"%@8:C^/! QL(]$N!/<9):9E<"[JD#5K '\D/85 M4ZVP:#!58+I>(* 379S'2SKEO/JEB]>"3'E^>XLGP!>J8;5C,S:;O;0MM21V M'0X.Y;):'A-6'99^G*%/!5389ISPBJW2.)OT^K+=O./>YRK#^/0%,A&7&#O" MHD4?9XLGMDN6MG;Q6VRPTA_B'TP1Y*M.U3#/X2!,D6AR8)T?G:HJR=;X?4VL M"FW,0'7);W/<4^A*P':*&Z=!J_#2"6P]O+60#;#@DUUQ%:J%E!7G0KN<0');P@3Q.'"5SA. II*N:01 M7_AF&1>'7P>+205RQ5&IV=24Z"JT1S!YCN-_U_F33PI+?*.OI[D6!OM2_.8G M!L 2=JP5%]:X,%U]V_VBRUQJ/KH[5?$:V M7:JA-.&&BL=+^C>J8<062C6#9O:L*(FXN7P$30G9(^6HT-SRD ,W3NUXW(6. MQ]V/N_R7"7LN^URU*Y>X@8A[:?O[B/N&?3:[0OZ+^]]%0#?LMYEDWK>QVD-A MWT9-755J_OR5FR_@S 8?<;A M9-O#5Q/0K3>L=OJ'6!OFKM\P(77.NND:JA\7(*V^P3#@%J3&@P=VY>!\+[1I M!;(ZU7];CX3VG;+28QJK'V6WNC_EB?C@Q6Q:K M>.=350>7#4/, ZP$ ._U6=M U\=*+C;XNP\KC%](.CJ4,U\%UL49).?J'K13 M3G,H%G?7VZ(3-,HLVA:,64CON2ZD]QQ:%W4YA$UE8[W 7/!=0HS)EN.-Y:S? M\ 2<&<95")>S3M"-_%_:T\EKLY5J+2'H>+5%>Z5.OIB3_Q>V$1]L3(6V11E) M/D&OV\US<)'Z#)V#T%ONUT$_'CE; M!M?7]>%[FSN>K=:I\Z$/="T9=?HNI/&G30I":IJ:I:O.@/"&U)U??'(FD'@S M(!J#GIRA2 *=(H,S^;$6TVWDS;^H9"^0P3O,MRBC@C^='!//<^S VL2N!??0 M(!JSOZ7+G$Q/.CCK9K-&88-V*'R!H]>>09K!Q3B?X-C\80;%R+B%9C;H7D\@ MYVQ$[;X='U]Q\? V#*4_>'NXH.+1$SN6?:5ITC'/8_NKH->E4$[5/,6";69D MNZ:-3L^;Z[Q_3-! '+_U9STBHX F@U8^/!C3V>$M%3S/OL,T5V*Z(TO^ABSG M4Y/'SN$>ZFN*CY.9Z4KF:$,%\LY(:O'54P7#84BJ-FG267*'1Y[1>?E\<'W? MN\CNJ\T#+:U1="C,Q<#)+PIV!$J4-2S:,"*?D8D3/VPQR^W0+[>!-B#QJ[ZT M*K)OK4S!93-@-M=N6HEMY( I,\9GKJ9?=96X2)^9QGB 3$B_U<]F?*70QQ\N M<^55]--L<<-47Z;,&:#VXY&P1EYUNI5\1K)8R9#(CEKQ'')P>;JQ:Y2EUL5G";7L%-%CFH/:, MJ_3/FG.N/N>@>4/(-'2-14P*RGVH/8X/07-(9\XA:#\CCQ!_4':8ZU*06/:" MAP[TZ,4D)UZGV@D4NZXI W<3)?5@,<@I 3?B(]9!G)4C.E":Q/SNT$TW3"7= M$#UO$[D<'^5+V&P8*X=2Y#3C7 K@_&JBWBGI6G50O02^U9^[87:OZP5D%;?GUZ"_S*6;FX8.P/+9]\"R?+Y;JRC*U M5U27/3K!F%Q8N;GUJG/?5Z776V2_OU'FS/^Q66 M\-UN3CL=:VY5@ZH'"T& >&&'HQXT D=M: )CT=)/V94.]W"6&!25VI*)MDYF MG"@!ER?T&2]OV+91U5U;J5;3X,.&H"D!2,_BZV[WN\L_ ].L,E;_; M0!EF0;@H1[12\C#YP)4U;I(T7 NYY M.TZ@44*"$^UT3D]:MR#*^L0]!ZOLCKZT[;;3S82#==_TACK/EVR%\P4U"#>; M!>1AH3B9;%S>--Z)\)4G5I#G3PJG(]OMT&MQN,+(]5SK*G5HZ3#VV MAH#S>T(3&&Q!;2G;;XLX'^U3M#0'7LA$F7(:9#VR.OF>$UC?^[>"O:4DRBSU MN:2QBXHF,)_QMG:$*$G5E4%1S;G'>>959=;US-_1(43/!+7X[GY=;5;Y,SH6 M@B4]Y%Z&^&YM7;HKGF0E'FN+P<[UNT),PL8C7^TJFCI+YRF'Q%4\H(/\G"\V MJS4<6TO> #@*.%#4K7I2]=88N=]G&"=+#QD.;I2%6"7E?>G\W&%QD ML^P.4RJ9%V&.8K&!X"5*&[YV"2@2RZS2;%7,PFAB5:!"^FZ-=#>:GZ0!,FW_+IQO*<$(_,?4!9\M M4>PAYBU!.JL0I'4J1H/7U>#\.JQ+OK3B^4N]6L>\6D?6:E4#TNPW.*VCU;_? M=G%R0/[#@1^H+D(7B0,Y7<5*,K-)K59]##R!EJS< ]QY:.2UR,U<[TL$)<6%&5SGB6 MG_# >53@K;\&%:T93=L TCBW8:5D$V^IL ;K[@7=_6FQMBT&U?Q9BLAX$<.4 M8@-J=:I=Q4N!0:!]ITEWE^O"[14))#N/@>WQ;*QWWL"FTIN<=KR M/PY7^!U>.;\>GP:7QY^^G(ZOSR__$O@QK"H'8LUDI]%L?8_C,SB9A%)[M1L! M58GRO! 1* M:7Q[A 1>/Q)\@[4S]]&3\_N3TY/K$#720>NJPH.E\3K@W<&## MQ=<,S7'I5D61%Z;'*M0"[=X+5 !O,5>;449IY@T[BY**SCA ([CF!HY7Z_R! MKD@I7I'-?E;MLX;"5:4I7+4WZM/^CT>H[?MF%CN.DH"V'KG..HD[C= M'-^B[Y7B"^':<[=,'RC0KHHP?CX:5W9:I.M?!L[KSH27K6SJ%7>BT[\QLZ,SL(INO*DG^R^B_ MM7\)NQ[-E^RUU^GW;*6Z(^V4;.3J7ES17.@)*[_-EJAPGN73)PX@FV:/",," M;'&5+;^AWY"MT(MEQ4C#:/N:^T^67T*WQB*_JK(SEZ8)T=,I+%)=JD%FPSV) M,7! \"XST/H<>PZW:, 47Z71UO#@9![ &?^,YWO$V(4&?41N=KJGH(7?_Z0I M\M-!D")>,>H[%!E"LCZ?P!O?\NR)- "\3Y.G/44(@$>XWLWIS^-9MEXN'M/- M;/&[E>J"< 61!Y4)<)IA.!NJ?@))A%B]8G/ &;(QTFJ+@RQ\_:_1U"C"UHP$ MC89+?%MB':%I18Z0L9@>'VDX\HT<''; ,HI+(+J+2\TO;=J7%;T9'/ M(X###O63#N4V+-&X.'MN%RFXE4A+DT:1VEO F&/4&#*M ]QN*(2"E0ZX?6'\ M$$R&8VH4G(K85;#;?_P][K9Y/3>/8LV&2RA.U*]=74#M S2*90^/O$5@O=+2U8!5$8N6HK&K42A(#K$ZM0U8&'[* M&D:[8F2T<%4*&G6P9'Z:\_(LI\3#CI0R2P1BRE[3HD7+()&Y%JC1P?C!AB>5 M"'76(XO146A8VRR%7_,'DE+,%T9Q$F@2(*M$@LHY"P-Z3)=KM<2> MG*[R*#K3U(;3;:M#:VUI1HRGNX*'-+/068D]6_S^;8&3F3'@C#6X1SQ?38@B MW5?4O0;&88#?/'P#M'AV]U_)P"L;S<@E?%5M?64LQ_A%6'Z\4T'[^B+DOUFM MU02P&,2W!2_ZZA$M^ PWS&BM.+MTMEI@U^0YL025DI>%E85Q&8DNR,T:.QCD MK=(!W!#R5A@>6"HW41'HLOA&^2)(:CGQ%Z2^D-,1=XL)=!*3O%'X%T;A1[<# M&@;-$9CJ_+F @%;3Y912LQDDQ]N*;]!18=!PI@ E\]4]]T/[H" W]&#I0%!\ M&6S6+/@LAY,H)\K?D#IR#<6%V>.8AP.;DH>!!+)6C'4[#9.D'^/5G2TFRF6] MVCRBFT9MD7FV?EHLOUJQJ^F\("[5L"TG#GQ+/B!+%YIC'!SO&1]"I5F)XZBZ>.2U,(I1R-2+#9K M'7OD\QWJ*^CM)E,"36L@,&/4,XYG__B[OFL75[JTC.IHPRYE2MJY6&S%$NET M4/I7BGR]]HMM072U!VTTF#*4K.9SFW_$.6[-5RV\]9&<3.:,*ZR,V3_VDW_= M8&3\DM!QK7?D)L<;R5F"7T9NYD-R<($%5U$OG$]SSIY<^%(?IHML57UI=OOR M6#1:O8-KV_/[[#^ R!NJ:$_'U6-F1"\F75ILR0D6A7-.)Y&QEDWH0V5#0) I MP'+[5@?DW,SMVQ,NWQ(-88280_U+&)!H7,A>8CLIZ4PE3=LLG5:1Y,:%WL5. MH$Q$F43_R6K+0&Y(A9-K%K+K[U9F<+-G8P(PM-(WB8XR'CV;HE54SHK14SAV M 1?VF8#Q5$-F2*1IZE#-AW2:JFRA2?[&3; MU5 9I4\#???/__&_OLR-ATA%9 6]EKH/(>7QZAK1C&6+FWU_I:G 1[%2Z.?T0P7ECDG'+1-/M\-7&+GP1_3^09E M&EFY8*P6=D*%P_>GR_%[("$;D8);?:>?9I.QPV5QQ"*E3'DB M3PBO5:=A]90^MN$*]ATVP(/4>BM4ZHA.[L_#VB%&8O.XWB[F;(Q@FG=&P M64OT#TBF%DCU.Q 9<)G+2'$\"![0KBPP*VW4M]"R,V$0F10MM63'*&0@@_8W M_^KZ+Z/_UO[%=6%&G7C4;)!>F(XPZO3=J(6/M,#-5J?7"<,PA=J_3<_G$ M;>6W('3/1U%W*%YR#CO]OO.NS\I_[915 ;&@<_JE*LV-<\77AF4+ ,!X24FG M F53W]48_DK0,TK]Y50NB71J;([WM&Z+;_X:=" ME\Q!02 :N91L,* TW%MZ M!Y_RG7* MP&H-"!J8+Q[R"5U48:+&6E*DGVA5A9FN])W7X!S:KQ^:M;K)<%#W7)!JM>#E M,*OF+#>KP/@FTI=2=W@54M4UPO@:IU2!4B2L<2N0A/5-^OLC)K=#6RJ8>TIM M4EN$:6/7Y?'8RLZL#<5;7]=!XK_0R)EQYG%A+^("\FMP.;6WY:KM[C[K5K>" MVQ(F%R,R<+[>^&W]5>>Y#L)5T8Y['./D(TUOU^Z^YEZM:%1W .0:O 5M;8U2 M9CR99#.T[A4CUK=K$5-IPU]Z[0R6(K?-C@3XL9F_3F:ZTQ)A1"O?[)AV=7(Q/X9Z) M&$E+./VD9.:D4P="Y33"#GZ^"39YOA@XW^2-B_'G\9D#".=[\CJ'N_R.K1EOBX,:?%N4%+7WP1==!QM<[RY]5[OZ MAZS(]?*#@\Z@]Q8N\',T*WV94UE7V/649O9AD[%=X]?BM;/RHN>[5%$'>_3J MI)TT>6?;2$?;V^CO\TZC?EV-O]O=TO!@GW>V#<9;T]3?Y.G)^_/+X'$&*F#\ MEISBT,'H)>^6!X?E1/%!QZ1#Z!@KN,*D4^>"LSM5HNX^[VRCY* 3#[>TX=0K M;_).HWY=Z\5P6\..KM[DG6V#H38\E_)MU'7PO9J\LVTPU(:_8=/BBKN8DUV! M&3/J!;]\6*!F]=^V==$G>4" 3:!"?,,T2^3+ZR7F65NERV7(SF[9]?U&XW'L MGI;=G3! -QY$$ONA"] K-[E33]EWWN$]X4+?QY41%(=[CJX&+'-.V8U[FT/+ M_>VDA8\W=YT@ZE6!ALX[0=CW?WF6/L.;W:HOEYV@.ZB!K9.08C_@7=6 8/<) M-VXT>]I\"=) MP06J\W_Z/6^I:S6LML;J%>O$@D(O!3$NV*Q4,!=< ;P*?]\+ MDOKC^@_R6_X7PS]U01DX8&>8E"9 M"XYH-T<,]5.U82L>@W&!4O+6-R-7$61S-@4$<,J ]SZ\>T\H9RJ$0'5C!=6\ M,.[>'D085;;6-X]5#;+D3Z/R&VCI.,+@4V Z3B?D9K=Q2?6TMC)8\X5TKKS\ MTI40AX$A%W@W)9Z\0'TZHH%)B\.=IM'PLE5N8Y^+$Y_E6Q6=HI'S]Q@GO&3' M ^)MH2SD1\F1?WV_V*Q23O+1SS6L?@[:XQE'U!^C]=D=KJX8T.U6UE:39\+1 M:"3/J.%)5*.9 O]T+,49Q2H8>L 51\4Q&.6/HC+((KZ2;-;'S1)Q7S7L:[ F M.OZJR>.<)CHT99H]L*>%D!?(#?&J@_C!4WQ,*>"%J?J#^V)_BSY)?PW>>%3( MG*-[*<,M%8AGW3^<;D!U"D4U^2L<\ZM:)3\*#HEB;1HOAVZZOZ-.Z#HS7]831YE7\H'2,D0J/#+Z:Z$Q37$* MCK2:_C5XR5:=:S@4D0"&X!APBC#J)@[[5_60J_L]/.227=8Z16,ZXD)R9*?2 MQ#0"-4CFSE@UA-5D"UU79?&\MC\ "X M *M!@:[LS$,PW['K?\S1._R/.TY]#_L,XA\Q&V'[ M6K$W;?MS!?ZJMSW4LY+:Q8:CJU&>S#.\:3AW;(Z[*:NH1$JMZWU MBB^OS3"B'A5J::6_T]U5[KY%RX1>[%_0RS M,Y\[BS99OJ3KU?()GY[@'\.=:E GD\H&:R(! B&COT +\N$6:2QS1!GTGA+' M7KORKA!K.Q5_0ND=HZFA#%0U#D!-9G#Y!TCEF7MRM2(&[TX@% M$/"R6HI_ODH@$J;JGQ++PXU+MH(.8#N=Y0M:7=H@>$'GSW5UL[%PT3#KJ6+2,M\-8!/O5D/0PD_+:%3\\8KPF-[ M3%-N\B5AI0T)2#XR[3Z\G[BX_1 MS=GEQ8?1QXN;:T>3/G/2C[L6U R_Y6=67J7WCN'^.'EZSE:O22ECUMF3&6(? M)3\&)'8H.,)]'LAPF#6SN: MS]=;Z\'0*?)__/;[TEO2QQ3[\>R($%D?S43%F!? V@!U!C-"0&.NXKQ5X\)= MXS8L#A)T+RI3IPO%4@D60(^N3)TNE%)AD!H $N8K@->4#HD;Q*"%7I=*:![5 M7WL/:IL)6\+Y+K.U0X[!=]_D? HM\+NCDZ-BTG:_US=Y/?=65@Q$IF^7,I4D M/'@-Z%.$8[3@X+B*"[Y4\/#F+FUU)P51/.%;\L>UN4OVL@(KWHDR@\E^' MO:&;+C?L';@_WBJC&2+5+7.U$2C6O_SU8>_0)7'8.W5_G"H04347P&L-S\(= M[XF;:*>1_4VP?0D6(/PX'O6.W/3/H]ZI6XWX5I*MQ1A>TF=VJ:EZ&X%3\@&L M%UB&E\MZ9/6EFP"Q6F/M][D4V/Y!;\AQYM#ES%%OZ*9TBO8GKNGNM'?,=^7N MF"/N1W%9C"(4VJVYJO+J5O;AHL1_&PL*BDR5KIOCH05GT0PCHHMW*V$PJ+6C M6 6Q#W6!TG7P6(F/ ;Y!A7!IT ^%\J)F(;'_PF@'.W>$3G)[>BU6S/!1:X3?DY5CS.G0M9PNX^NEFJH$)9 M/2!=^M[FQJJ[30BBIJ">R0M80S^N9&]YP#.F$^L >_1[M>B+T(.H,O :-.%[ M:?EV\OVW),;85UB9H87X-%89VWAI>BF[4JV2+6I-H%S7Q<5:JVH!LBUGOK#P M-+'2MU' RE^JXAP*!LWM,Z"35997KWTZ&E%U-:\P5;6 >A=U,HZN M4OQ=##.#!PG8H*IRL*KD<4^EFVHHN,98%XT(H+5TIS!"L17*';#U^N#)@<(3GE'[L&]^[@]Z!F\TB M?CUUQQ3L!\J%(P >!U;#3'# :2IL799@MRRTQZ W<,D,>D>'+E9(2%NNL[[] MP][ )=L_Z@W<'"UW+W1]+OP^FR_!$O X[T\Y E73K=@L)_U>WR5Z?-([89(M MV1E4#2"PBPXY>*+#7I^!Q*GHQ+-GALPZ]H[=X\9.K'0=606FB[=+&Z@+>EC\ MKU_P@%P"BD?DV()KM!FT:.,D/ ;;7&TEX"VC;]=NV'*.+(EF4V9)-./ !T# M0Z>\PHGPG;V69%IRIP;!9KRJ0; 9YZR;HN4<.0K-)L51:#:+L4()P=PLJ ?S M$F><(ZX=E9:LV<4==KUGB08RM'8)>V[>?+4FD\?99*8VZ$WL F;=MSH]Y+V(I*8VX(!?0% M;M,$Y>[=6K?GB(=.8YYXZ#0_,79I:4SHQ4+D>R*SPSFJ(-C\2%40;,PYDSEI MTL3V0:,]SX+4&C,L2*TQM^I+H^TIM>=<&YET#S0;\QT9R!)IS[LPN<9L M"Y-KS+%:LGP;(HTG5DNBK[S%Z@KUK0GM<&4W%^UW)]E<#%!%(98;'LFX,8$= MA $OJ>;R@)=4RTN&MP173*03(&F& $@U>CJ-NAMOR_$J5%X@1PBA&:9^C_D MV29#WL+7X= M*_+<0Q+8F:PK=I7$D,V $@YVS:0K@8-5QJ/@;EBIO9)O1._18Y(1SC76GX O M%HQY7N=7=U4E3"P0:L46+YDJ[$7>:*>OS$36?Y89[;6=H)I0PL5?4X$2-Y%; MM]*!-RK_'S:*MB M^GE/09GL]>JE%_5/>""T]\F=^&,_@)+6]Z"D8)?$"_-?K#LH$VM4)G"AKZ;HYEGZ]; >D1R&@1US MK@'(?Q3Z,LSV>7N7I?.:;.U&-SHATW*%W[V6]R-]YISV K3*(L6T+3RS@F4* MXH5=+9T2W8W.MG R:<80J*.A LS0S'!G>*E, 92$7VHC%X (SG;L$DF!"F_'XH'?3F;A?(K,+"?C:/=IB6;/5/' 2AJQO]+RX/<[D]NB:!=?_,Y,U>$V%ZYK$ MX-V9RK(/5E+_)T">&'TOIV7.&P,_4>3?$CMKY':M%%?!$PW1=8+L2 M2_P+TXW8U]Q-K:\>%3>0_C%7@JD>K:A%B8$6O(,HGDJAP*J.-XW3Q5O!,HUK M8]+ RG 9N-YG%[YSP6Q#101&;J-C%0EPGJ&GB*7C39EY> M@;CE]^"DJW["I:(B__,60W8+,:/1:$.:% ;=B_L># ZP5:RGITVN M6EEZH]03Z"B-LF.*YD;$3:>WOU#^-1P8!8+@SJ^^X-F3K M#U(9&JKBP.DL[Y3W6QE>'L;.:D*IJ_-:QPH] (^<3'LQZ@(==+%C/\9?=^QQ M3!_#7\:F.!^0MV4,W&OH GD/QL\?H*1D&V-N\ EOX15P=6%A1;)>W:*,PIGC6 MW@O9(Q(I;:'9A8DC.66.)- CVU"EG4LV6$FE; -U#3I[.+K9XGQ&-^/+=O6B MBMO<\!G@UI!RO9-=47CX[5HC4*T)@#3:TZ(OR>PN0$D(_I*($T>D?O_U.\X.38G!A=35%_*I_(#[[L%HM MOH!+S%S"0NF PJ\@GXXD9 _\$=L,^J(-Y:1=&!XH/#CT*<%0(9)&:)_;/.?2 M:4O)OHJIF&SGUN0=G!QJWBE.$6LD/R0[AJ7T

HO[63&A%XVR?*42U:V-X:!LE2XC'%[_X,@S/NC1/\:*(6E.'PM& MDT4:J[E8%.HR%6XH'.JPSXU4"N)5+XQX1M9P[%>$HB4WC#3""[47=5EL(D,X M[,M*+,@DRS>5"Z%G?2)F?6&%\5\LH3JFD!!>P)@$8-K1R RM[OD_M,]_^$KM M'UD7I5AD^U8M7ZK'ISO?J668GO\_=RK$[:B<9 C$05,21,G /Q<8?PRA)0!\ MI_>,!5"&U;ETJ5EM?'8C7HK&M,ZY*E/@$SR98BQ!:?1FONEYK?'DQ#_D3>I@ M21.G!YGW4H6=+S,=I/=1SP(=D=$,1MPE%7C*H 22&W:=:'.2N)D?UO%3U[9J MQ]O-HXH#8C&U/ZXQD.55#0)S*[O*N;#HHJDVNDH$&6<$4SN,XS:Q[5KVS,)= M6ETI8"GL4K. G[?5W53-^U97E!Z9:5L?\JCB?GH6%4_3TF)7;--R3TVV:^,B M05@$T!?!0B,2BPL2*FJAQ36I$QLB1^1Z#8U3VD+C5P.]5>%O7=TENEG$YBO541$'$]0NVT"HB(C7I/"2 MA#:P!)YFW&B**Q^=\)7)5PP*R*(@ZQBC!LTG5J$XDF?OT;AI5''SU"GF(E<; MJ,*!3QW)E91FWAF,#\=?[2 IEKPE(_#4@#T@4E5>&^P4D+,VX M_MA/O?-AOY;(DG4_OQJ/QO!QU)ED$%OV$B]6;H$3MJF?G?PT/#QF/Z[!>'1S MRAM=*"CIDW1Y,^8TSX?>90BU\*Y&J)%_44*MZJU-B()_B8)3]*Q4J$V-!=O; M:RAUH7,HS#%/C?>S8/^#'Y3'$=6B14I9@:V11WA8I. HG/N$&1#+93"C^.S/ MQ7H*[M^-XIW*$2G%>V,KWA[A5[0Q(1R79*YUKTL,BW]4%B.P/ 7YHO12BD8V M6%<\2_>U453%"N0!#5D(KV/0#-:OK7P>)(C0XZ=%C#&6B@%S '2$E=DN,=Y: M]AF2;4!;4(HT(Q-8?X1X)C;4R[-;L8Y!;^96A'E,W<6R[A?W"+;-'L!8[Q#:)FLHJ\LTF<;+ M^,EI0.&&Y5]_BO\>/WZ&ZD#.+KR]B"Y'US^-W$,L%GO%'6[ZO?Y*??J\AF@& MS\_UZ?R<)ALQ9=Z-Y=L(Q;_6[ZS3?Z,+)DF/'!K=!D6[VL UP&-%,\@9P8"P M$K;M4&';'I:Q;2TSMQ#!%[*#JW3Q]A>X!W])P48GDZ6 MC*I@4^=SLH%2K%X;TQ;:)7F&'!X463(\_A8\F:V62:88D.9_^OR'OOGW3XZ; M3??0GM9/:?*R$CK#,ED_K) /M^G+RHPV5"#PHJK]QF%X-'LDSB4/5S^MP?O(("34"C'$->-=MQHM,;" M;S*?##,0GU8+>E+7@#.OM@KD**:J(L:/\7(+@6L:C]@XK\#^C#'Z9'Z>;9^> M)*CU3&BBZ!*%Q)/+]W+G]6%L!A!O[.VGN MC4:06MF-^ '178KF8O'0/[P&T(%U6N#+"F*&N-)[ S;O97#(_:K)RH R@80?WA&[;@%5$L7VUG929YC^#65OEN*?I'0=WEOU;'R[;K-P MZ6%RVA6@SSU%9L%2)\,V>/$V41ZT)85E;=RP+/HP!7O6,A>Z@'-P MJ&4Q>5PUHK1U5_;+'Z6'&"QX*O99]8#FOG&=+?[):B7?2SK'XW9/!=OG*#R&U/Y$XZC*6D%X-A( M//(589^HW>']XOUJ?9^D=(4MJ.IOX.L/6"_6__?24&5-HXI!_DP@"K)_C2D- MF[0^D4F6DI<9WF"]96LW=PK-*,Y1EJKGXFNW5/X7TEXN_U>^)?.W,,OF_Z9B MZ?P-&RY?8/9UE[#6)+INH8>U]M7.K?K0]."*]>7?W,#T]M7%L="QQ->/]3BR MKUZ'IYY>"TPL/SU,-- MP1V0^?>:;*P,PJY\FV4L"?[,6;S!#,2>%&19C1?<#(]_%/@35>O>]USUP1$4 M[E/?::[Y69U;_T]?V,K7';D4G<-!LE3*FH^\GY?!JUE50X9KV=EAOA<@>)#S MR%J%L;J+V%,M#RYS?MD]+>>WH 1@9=)@/]5W8/EKK=;(3@$@!^&'T$K"A1K, M&GW(Q!0(-KKO M@3-P6]OF_RC-463\>48E*,X5>A&BN)%H\LRA^(QJU'\O?K.&>S,/H",51E46 MR=18Y1#A8N*DG#MXX)/"Q0B?T*1Z3R\P8)NP!K9W7*48?*.6\HVR MPMXM*["J,HQX9#@XMO:6WE[S5B3Q3?/=X\Y<#GOO7,.@E)?D/1C3>8J74/_) M'"O1>TTEFWV&V>OH%T!7NZ(=!PZTE-VYTOZB-BE"LLEM.E>-F"FAT1\@(LB\ MM87C:#;F5FR:)PMYC]_-'XC%Z=(O"EAV5.O2MTX4=<\>J".V!)"-!Z9Y_@5 M2.!GOSF M$+OIL-C4W^AC\@114&L=0QXRAYN/983C7$R:B0T$S!?,=_D_E,,K^F'6" ?_AR&F *$WF6W0ZZO08V-2PPO2-44'4#%SCQ*P'V'64YP>?RJB(69X=_!Y=F!ZWR1D/-+/LU: M70F:Q]P.^2U_7G.5-)/F!E[!L @BM\02@C:U#VZ=U^26^QT_22M:N80S=>$O M1F-G5:,$JZ+".D(K7.DH4)7NWS@\2U+6OMMN=!9G>)?.'I-D(T/A.*0C\$D4 ML;7R:KRQ<L$I9$4$,D^SQ-CI+X$6#QSI+G,VA\!MU#BH;':?C=LHLXX: M\'_S5_2YKQGX+]5E\A4^W:;YHT('!$\=<&R%W65I? <>7^[^0%5L)8OW< /Q M+SS]A=4S:RWY)69'2HX!Y85:12_[+I,'0 _3@+QU%BXT98\#TYN:U[%^$X-T MPP5_0)AA,9=/H!J)G8F_MV#.:72%,GDT@6 *]ZACQ,IEU)G$.:)F+!PS=W"W M"D8E^8OH6\Q)$7.#DS?QW2KJS(2<>RG$WN7?5WPP*F/'Z&ZI2N?RZAG(Z"ZAZ&T ME9S%J+'S,)YWZ^[GR^W3=;],=YEMG0H.S@Q.3 ^QL!,R+W&([4,;0@J"RCYZ_1 MY&XKE 8OHI65<15UBB6@=\S&>I\ T&7F&)8D@) KS9)(Z%H&Q&/I$)' 0<[O MQ?D0M).%Y )!&\44JN+$/+RG\S3@T;#Y3D!3*_;4E2F?@?@EF.M62$VOD60> MOG&<,6)&I08H@4D:MNPVGLB4#D8_.>>\TV=_)BY2Y!OF>ZGL)K?]D*?+_PQ; M4V8C9-GJ"PA KO@VE]B_,!L- ^%<__&""@N(YV/+XBB; O:(51!_<>0+E=5N M,O79:_"/WW[GP(OTXOM6:G#,Z9?ZI$E!IB:?3UA^?OH)0XPAFQ$O$;](CZ ; MA6]9,-SB*;*V]31^E1 8@D3Q3"GP]EADLS!7U7V'_),W.G"U\/NE$6K;59Y@23FWYGDJMC%DTIQ/P]%8;W,.7A>F,!=S23?AGE7Q M+KS;:C.6=N0#,!$ IHAKJ"P!UUQM [)87ZJO9"(+;TTU4?JV\)W2SYRMPUXV M!'M4+]N^L#3 _( M UQ2C"]9ILA&,'\8*&7!?HDYV.8:*>6#2IH\U]VB1T7?E1:1"B4O^#Z" H'Q7:%3^DJ2U=K3\BUDB::-[4 C9TL M^8T!LW2U,5U^QSF@\;,*SP7I$/\7,ELWOEQB>Q^T\536ME<[)<0LB<"V786L M4-K)T5DD]']OH/LZ]Y$1<_,"T)CX'5E%1;X*.168'8*VYER6KQ -UK#:\I9: M7,[T9/O)O@SQX%[X20&GD3,56:G>QK MQD[+,(HNNEWNDA+4'E+I M<@Z(6D/R[-B:3$VQU\.U:)3)LCEBITIO$(=MK(9L3\LY;?\!TH)XLDZ :U#U M#@\CRG/*U!'Z^F'R,KD=7CLX/OFRKHLB);9T+-#JU&@V.3:-:K0MJN6C4UN<]TIB;[QG,S\RY60BP%4K F8']5 MP)IZ9+D@"U5&<4T3$J;![ )'S2!-](DTT=1"5.D,7:$1T!,*4+ON%BJ4:K/+ M@=D%160HD+.\)B(I@^< ;1[XOT?D?>L:):5E\(S-24+S4+&.6K#%Q"OH% )^7?3DY[?28TB1O%R;!W MQ)2CDZ_FKU&=>1YY2MI];4#CA(UD&\%*IW%T!:*-$*T="06=XZ9.W5UUG3K/ M5F2.CACYM;;>DN60N4$;%G(#*\S<%"\LU'6S$]FUTX>$-57HM&H /]BX1:$J M:KG]OI]/+R>WWX;T3T(QQ''9Z/#*RB=!_8H.DU:S 7W)OAIY)>X*-@U( =6>![3O%U'ASP'M5R MF%0I2FKDCY(Z=((=2Z-=!TL4 6 M"B3S049-+3Q%%=5W!@A_H7:J+7H::VZ98%?!Q"S(VE6C!@A@YE^?W7 _"ZT1 ML@(8,*X"%U78F5NN-,+J71XBE?Y/?]3%M[Q7O(>Z.&EO&=T_YZ8-5#\UX[HI M[FP[0G/*/]2%BXO^4;ZS:JJ%V@IAD0R>:;X*9;$BN:H2R 2D:(QRP"J453_M MVL:L][)AGUT>GY*G8A7-O%@ IMU]&AM$?HV&3A8@XV6#[39?2P./5>.-.IDHY&RXJ),G3 M-, ^3X-B\$WKJ7^$PD_D6"!Z=(; Y@+,1HEW3P,J*X[(4#",R>IU ) ?9YF& M6 &F_T+&V[QBZ.U[9$%2+."O^CP+H%?+K;/C&DHJ^UM%19!=1Y,";4/C^"Y2 MK,>;S@G5"[['(T YP&\"UZ]:T/%/+@K MXD_)E!R)55JX[)#2BT([@I"K[4;[L)G15O@I87=@.'?SW5H8H2EO%B6%$E^>>0@3<1";*#6$5.W(6 YFIH40X5;^( .&H2=$Y>@D##$ M@?//;*[1@=%7&!.&HHR;[A]\C^G *Y(^-QC8H_KY-?*MR54LMN'? WJKK[=WF?ILI_,;<"BATG$@X D7?"CQTY32A%BRV2:$L5J'"=GB(M](#-Q5J M1:$P:H?!\+E<;$^Y)WF1J_,PW#LR^\ ]TP]NXIO@^/0I-%0MG?[.'M%RZ MB20I4[NI_'VCFCD P?](U?*4MZ)8B%XT\HL[LT2"IOZ-\@>SUTB6K0,34+R) M]Q3?%.S'OK/]47N,,Y&UCX20(<]Y7-A0DVM3C%UV7:,FNZ-AHMA8)*/%#U^V M1>5,ZXRD!3=V)TLR?-WIZG)J$">2Q>AT$A_/26]B);0+M_S?LS2]X5-::5LN M__ MCS^Z::'^*E>&KN +=AX;)SD3Q-&NI\C9Q70Z_%9&\ZH":IQ1_4\>@G[G M+L0* OH";(N%YYJ!7#5T$D>=@A6\1?S$V':!N9%K)IQ95>6(K:HX0LD)=*;N4F*$\GGURLW>7WNN@K MN>L[\IZ,K6+2<:E<]7?'[ZA.P$F_"/?OADL$Q:30S&;)$H*K"VU,NHZ*5*S3 MRKG!MOB-Z)PB\V&&U #SLI,[01^]2)[V>SFW\M?'9",DNZS-*68Z-F#P8,Q] MKN'6\NR"KG?Y]\2,MCPTOL "VOU._"N[&>LRSXHF]J19JK(^SC&NN#DG;!VY M!@2* ID3]L:68PF*,L^S6,5>**6H7Z7HI/O#JC#BOY,9JI5>='DSM?OG/CN'_3=_QC0[_<$;8.ZAXF[G<%#1\1239G()"HH@9ZJBA@+5^I9,!C*E MC836(8@T ^@5@)M;PXY'3[=2:5H.4&PZ,<13R9IA%6N<-;&MOW*0Y;>X.&@8 M;H/AX>))#G;>58SNF]T1.[^%),ZQI,F- [X:N>RZ9OE4[+RU2="4^2AH&(,D M/<'"3TO)[!)XT&B=YAA(0LB24[DIF)CT_; ,W++OL]67W9XY3:;-2Z=P\B0 M*9L\G!B8NK5Q9K-W74 M,7MATSS?HL2/J'-^#;'U+4'*SK767:1F,[,U&_QK&\ JS =7*K?HW,MMP-WWT=R:)\0:F\MAR$NS(0-]"O30'B+,(WCW6D,',!<=RZ')Q4T M'$3>,HUA[Z2*QF$5C7>]=U5SJ>0IT3"-QX@:AX]4U=ZQT%DDWVBA0"YA,R]K"N.2 Z9 M;)C5)1N$ZH+)@S.F6FKU-JN3Y.$0.:TFXAA*'2)MMKQ#9)?5:#$B]P Q#&Y^ M@APB;8Z00Z3-&?(0:7N(''*V@(D&Y2T3<>>TVL>-NP^BU2>C3'0O)V4?C\4> MB-;8_/MX3BJ)MCDSJ(UK;5P""3?0EOQHE(B0%EXYXI?]Y&ZP-=S_0P!1>!3C/4D\<2 MXW8MT9 YON4T/VQCK%4C9W69;!!*&-1:S /9)W>W&7I@W2KR<1Z\'-@BD>7 M=YO:30RZHLXH@_ I_0]7X(6AH:R.(^M&]TE"4.(^=(%@$QX*P/##_Q?(L2NL M5&":79T2?[%$316BVR:22ZZAQ&Z8F@:*K4+/D5.E#,[-HSC5W_55Z5MGB4JK M2SF=F..B0ES$J)*G)84B=BA<'>*_?>$=.Q.LY)U9,]J 57^O)(AG;0R(+1N M*\#'7&WS&U\OM1I5=FT.)9Q*"TYQB7$K67K_2A8$Z81K?(]3M8O215\4V5[C8+=HB5!TU<@VNT:#PRAF5G;\5WB7-G M37AT9[9*!E90]QZ>.,G_V\K&N;G7N3@72Y.)XR3B_#7/-__^OU!+ 0(4 Q0 M ( -:25TB$( ;/H0, !L 3 " 0 !;0V]N=&5N M=%]4>7!E&UL4$L! A0#% @ UI)72$AU!>[% *P( L M ( !T@, %]R96QS+RYR96QS4$L! A0#% @ UI)72(UUE#+[ M! CW$ !H ( !P 0 'AL+U]R96QS+W=O&PO M=&AE;64O=&AE;64Q+GAM;%!+ 0(4 Q0 ( -:25TA>B\4O$0, +,5 - M " 549 !X;"]S='EL97,N>&UL4$L! A0#% @ UI)7 M2+*\P]0## 0#H \ ( !D1P 'AL+W=O7G5 MVW@% #,'@ & @ %^*P >&PO=V]R:W-H965T&UL4$L! A0#% @ UI)72#8)A02I @ "PH !@ M ( !+#$ 'AL+W=O\! !>!0 & M @ $%.@ >&PO=V]R:W-H965T&UL4$L! A0#% M @ UI)72'/TGD5I P *P\ !@ ( !*CP 'AL+W=O&UL4$L! A0#% @ UI)72&MB M:\RA 0 L0, !D ( !A%4 'AL+W=O&PO=V]R:W-H965T&UL4$L! A0#% @ UI)72 N:T>:B 0 L0, !D M ( !#5L 'AL+W=O&PO M=V]R:W-H965T !X;"]W;W)K&UL4$L! A0#% @ UI)72'HJ$*BC 0 L0, !D ( ! MFV 'AL+W=O&PO=V]R:W-H965T&UL4$L! A0#% M @ UI)72)=CCX&D 0 L0, !D ( !*&8 'AL+W=O&PO=V]R:W-H965T&UL4$L! A0#% @ UI)72(DIA;2> 0 L0, !D M ( !0'$ 'AL+W=O&PO=V]R M:W-H965T]#0I $ +$# M 9 " >UT !X;"]W;W)K&UL M4$L! A0#% @ UI)72#&FN8:B 0 L0, !D ( !R'8 M 'AL+W=O >&PO=V]R:W-H965T&UL4$L! A0#% @ MUI)72.HUEQ^B 0 L0, !D ( !57P 'AL+W=O&PO=V]R:W-H965T&UL4$L! A0#% @ UI)72-UF[$.C 0 L0, !D M ( !;(< 'AL+W=O&PO=V]R:W-H M965T&UL4$L! M A0#% @ UI)72,>_B\"C 0 L0, !D ( !^(P 'AL M+W=OPSQ2*,! M "Q P &0 @ '2C@ >&PO=V]R:W-H965T&UL4$L! A0#% @ UI)7 M2/T0Z^^C 0 L0, !D ( !&Y0 'AL+W=O&PO=V]R:W-H965T&UL4$L! A0#% @ UI)72!$V:#JA 0 L0, M !D ( !JID 'AL+W=O&PO=V]R:W-H965T&UL4$L! A0#% @ UI)72'8:)5_B 0 J@4 !D M ( !9Y\ 'AL+W=O&PO=V]R:W-H965T M&UL4$L! A0# M% @ UI)72 WU]5ZE 0 L0, !D ( !A*4 'AL+W=O M&PO=V]R:W-H965T&UL4$L! A0#% @ UI)72*]? M18C+ 0 X 0 !D ( !(*L 'AL+W=O&PO=V]R:W-H965T&UL4$L! A0#% @ UI)72#WQ>Y*P 0 %@0 !D M ( !%[$ 'AL+W=O&PO M=V]R:W-H965T&UL4$L! A0#% @ UI)72 BM&AV\ 0 >P0 !D ( ! M1K< 'AL+W=O&PO=V]R:W-H965T&UL4$L! A0#% M @ UI)72$'Z[I:A 0 L0, !D ( !8+T 'AL+W=O&PO=V]R:W-H965T&UL4$L! A0#% @ UI)72)K KU*R 0 %@0 !D M ( !V,@ 'AL+W=O&PO=V]R M:W-H965T&UL M4$L! A0#% @ UI)72$+ V'VA 0 L0, !D ( !D\X M 'AL+W=O&PO=V]R:W-H965T&UL4$L! A0#% @ MUI)72"Z09.IB @ % D !D ( !N=0 'AL+W=O!@ &0 @ $+ MX0 >&PO=V]R:W-H965T0( "P) 9 " 6OC !X;"]W;W)K&UL4$L! A0#% @ UI)72#T/A&Y< @ 3P@ !D M ( !&^8 'AL+W=O&PO=V]R:W-H M965T&UL4$L! M A0#% @ UI)72$8L\)C\! Z1X !D ( !^/8 'AL M+W=O&PO=V]R:W-H965T&UL4$L! A0#% @ UI)7 M2 ;0RH\K P #Q$ !D ( !R0T! 'AL+W=O&PO=V]R:W-H965T&UL4$L! A0#% @ UI)72+@Z9]R0 P WA$ M !D ( !HQ&PO=V]R:W-H965T&UL4$L! A0#% @ UI)72&^77RL!! JA< !D M ( !62D! 'AL+W=O&PO=V]R:W-H965T M&UL4$L! A0# M% @ UI)72"=&>41U @ APD !D ( !,34! 'AL+W=O M&PO=V]R:W-H965T 0!X;"]W;W)K M5R 0!X;"]W;W)K*- 0!X;"]W;W)K0 0!X;"]W;W)KBX M 0!X;"]W;W)KW( 0!X;"]W;W)KK8 0!X;"]W;W)KG < &0Q : M " =KV 0!X;"]W;W)K]ZD$$P, -H, : " 701 @!X;"]W;W)K M,Z @!X;"]W;W)K%J/JP( )@* : M " 0D] @!X;"]W;W)KP_ @!X;"]W;W)K M!Z @!X;"]W;W)K! @!X;"]W;W)K


IDEA: XBRL DOCUMENT
/* Updated 2009-11-04 */
/* v2.2.0.24 */

/* DefRef Styles */
.report table.authRefData{
	background-color: #def;
	border: 2px solid #2F4497;
	font-size: 1em; 
	position: absolute;
}

.report table.authRefData a {
	display: block;
	font-weight: bold;
}

.report table.authRefData p {
	margin-top: 0px;
}

.report table.authRefData .hide {
	background-color: #2F4497;
	padding: 1px 3px 0px 0px;
	text-align: right;
}

.report table.authRefData .hide a:hover {
	background-color: #2F4497;
}

.report table.authRefData .body {
	height: 150px;
	overflow: auto;
	width: 400px;
}

.report table.authRefData table{
	font-size: 1em;
}

/* Report Styles */
.pl a, .pl a:visited {
	color: black;
	text-decoration: none;
}

/* table */
.report {
	background-color: white;
	border: 2px solid #acf;
	clear: both;
	color: black;
	font: normal 8pt Helvetica, Arial, san-serif;
	margin-bottom: 2em;
}

.report hr {
	border: 1px solid #acf;
}

/* Top labels */
.report th {
	background-color: #acf;
	color: black;
	font-weight: bold;
	text-align: center;
}

.report th.void	{
	background-color: transparent;
	color: #000000;
	font: bold 10pt Helvetica, Arial, san-serif;
	text-align: left;
}

.report .pl {
	text-align: left;
	vertical-align: top;
	white-space: normal;
	width: 200px;
	white-space: normal; /* word-wrap: break-word; */
}

.report td.pl a.a {
	cursor: pointer;
	display: block;
	width: 200px;
	overflow: hidden;
}

.report td.pl div.a {
	width: 200px;
}

.report td.pl a:hover {
	background-color: #ffc;
}

/* Header rows... */
.report tr.rh {
	background-color: #acf;
	color: black;
	font-weight: bold;
}

/* Calendars... */
.report .rc {
	background-color: #f0f0f0;
}

/* Even rows... */
.report .re, .report .reu {
	background-color: #def;
}

.report .reu td {
	border-bottom: 1px solid black;
}

/* Odd rows... */
.report .ro, .report .rou {
	background-color: white;
}

.report .rou td {
	border-bottom: 1px solid black;
}

.report .rou table td, .report .reu table td {
	border-bottom: 0px solid black;
}

/* styles for footnote marker */
.report .fn {
	white-space: nowrap;
}

/* styles for numeric types */
.report .num, .report .nump {
	text-align: right;
	white-space: nowrap;
}

.report .nump {
	padding-left: 2em;
}

.report .nump {
	padding: 0px 0.4em 0px 2em;
}

/* styles for text types */
.report .text {
	text-align: left;
	white-space: normal;
}

.report .text .big {
	margin-bottom: 1em;
	width: 17em;
}

.report .text .more {
	display: none;
}

.report .text .note {
	font-style: italic;
	font-weight: bold;
}

.report .text .small {
	width: 10em;
}

.report sup {
	font-style: italic;
}

.report .outerFootnotes {
	font-size: 1em;
}


IDEA: XBRL DOCUMENT


  3.3.1.900
  
  html
  1440
  886
  1
  true
  359
  0
  false
  24
  
    
      false
      false
      R1.htm
      0001000 - Document - Document And Entity Information
      Sheet
      http://www.aes.com/role/DocumentAndEntityInformation
      Document And Entity Information
      Cover
      1
    
    
      false
      false
      R2.htm
      1001000 - Statement - Consolidated Balance Sheets
      Sheet
      http://www.aes.com/role/ConsolidatedBalanceSheets
      Consolidated Balance Sheets
      Statements
      2
    
    
      false
      false
      R3.htm
      1001501 - Statement - Consolidated Balance Sheets (Parenthetical)
      Sheet
      http://www.aes.com/role/ConsolidatedBalanceSheetsParenthetical
      Consolidated Balance Sheets (Parenthetical)
      Statements
      3
    
    
      false
      false
      R4.htm
      1002000 - Statement - Consolidated Statements of Operations
      Sheet
      http://www.aes.com/role/ConsolidatedStatementsOfOperations
      Consolidated Statements of Operations
      Statements
      4
    
    
      false
      false
      R5.htm
      1002501 - Statement - Consolidated Statements of Operations (Parenthetical)
      Sheet
      http://www.aes.com/role/ConsolidatedStatementsOfOperationsParenthetical
      Consolidated Statements of Operations (Parenthetical)
      Statements
      5
    
    
      false
      false
      R6.htm
      1003000 - Statement - Consolidated Statements of Comprehensive Income
      Sheet
      http://www.aes.com/role/ConsolidatedStatementsOfComprehensiveIncome
      Consolidated Statements of Comprehensive Income
      Statements
      6
    
    
      false
      false
      R7.htm
      1003501 - Statement - Consolidated Statements of Comprehensive Income (Parenthetical)
      Sheet
      http://www.aes.com/role/ConsolidatedStatementsOfComprehensiveIncomeParenthetical
      Consolidated Statements of Comprehensive Income (Parenthetical)
      Statements
      7
    
    
      false
      false
      R8.htm
      1004000 - Statement - Consolidated Statements of Changes in Equity
      Sheet
      http://www.aes.com/role/ConsolidatedStatementsOfChangesInEquity
      Consolidated Statements of Changes in Equity
      Statements
      8
    
    
      false
      false
      R9.htm
      1004001 - Statement - Consolidated Statements of Changes in Equity (Parenthetical)
      Sheet
      http://www.aes.com/role/ConsolidatedStatementsOfChangesInEquityParenthetical
      Consolidated Statements of Changes in Equity (Parenthetical)
      Statements
      9
    
    
      false
      false
      R10.htm
      1005000 - Statement - Consolidated Statements of Cash Flows
      Sheet
      http://www.aes.com/role/ConsolidatedStatementsOfCashFlows
      Consolidated Statements of Cash Flows
      Statements
      10
    
    
      false
      false
      R11.htm
      2101100 - Disclosure - General and Summary of Significant Accounting Policies
      Sheet
      http://www.aes.com/role/GeneralAndSummaryOfSignificantAccountingPolicies
      General and Summary of Significant Accounting Policies
      Notes
      11
    
    
      false
      false
      R12.htm
      2102100 - Disclosure - Inventory
      Sheet
      http://www.aes.com/role/Inventory
      Inventory
      Notes
      12
    
    
      false
      false
      R13.htm
      2103100 - Disclosure - Property Plant and Equipment
      Sheet
      http://www.aes.com/role/PropertyPlantAndEquipment
      Property Plant and Equipment
      Notes
      13
    
    
      false
      false
      R14.htm
      2104100 - Disclosure - Fair Value
      Sheet
      http://www.aes.com/role/FairValue
      Fair Value
      Notes
      14
    
    
      false
      false
      R15.htm
      2105100 - Disclosure - Investments In Marketable Securities
      Sheet
      http://www.aes.com/role/InvestmentsInMarketableSecurities
      Investments In Marketable Securities
      Notes
      15
    
    
      false
      false
      R16.htm
      2106100 - Disclosure - Derivative Instruments and Hedging Activities
      Sheet
      http://www.aes.com/role/DerivativeInstrumentsAndHedgingActivities
      Derivative Instruments and Hedging Activities
      Notes
      16
    
    
      false
      false
      R17.htm
      2107100 - Disclosure - Financing Receivables
      Sheet
      http://www.aes.com/role/FinancingReceivables
      Financing Receivables
      Notes
      17
    
    
      false
      false
      R18.htm
      2108100 - Disclosure - Investments In and Advances To Affiliates
      Sheet
      http://www.aes.com/role/InvestmentsInAndAdvancesToAffiliates
      Investments In and Advances To Affiliates
      Notes
      18
    
    
      false
      false
      R19.htm
      2109100 - Disclosure - Other Non-Operating Expense Other Non-Operating Expense
      Sheet
      http://www.aes.com/role/OtherNonOperatingExpenseOtherNonOperatingExpense
      Other Non-Operating Expense Other Non-Operating Expense
      Notes
      19
    
    
      false
      false
      R20.htm
      2110100 - Disclosure - Goodwill and Other Intangible Assets
      Sheet
      http://www.aes.com/role/GoodwillAndOtherIntangibleAssets
      Goodwill and Other Intangible Assets
      Notes
      20
    
    
      false
      false
      R21.htm
      2111100 - Disclosure - Regulatory Assets and Liabilities
      Sheet
      http://www.aes.com/role/RegulatoryAssetsAndLiabilities
      Regulatory Assets and Liabilities
      Notes
      21
    
    
      false
      false
      R22.htm
      2112100 - Disclosure - Debt
      Sheet
      http://www.aes.com/role/Debt
      Debt
      Notes
      22
    
    
      false
      false
      R23.htm
      2113100 - Disclosure - Commitments
      Sheet
      http://www.aes.com/role/Commitments
      Commitments
      Notes
      23
    
    
      false
      false
      R24.htm
      2114100 - Disclosure - Contingencies
      Sheet
      http://www.aes.com/role/Contingencies
      Contingencies
      Notes
      24
    
    
      false
      false
      R25.htm
      2115100 - Disclosure - Benefit Plans
      Sheet
      http://www.aes.com/role/BenefitPlans
      Benefit Plans
      Notes
      25
    
    
      false
      false
      R26.htm
      2116100 - Disclosure - Equity
      Sheet
      http://www.aes.com/role/Equity
      Equity
      Notes
      26
    
    
      false
      false
      R27.htm
      2117100 - Disclosure - Segment and Geographic Information
      Sheet
      http://www.aes.com/role/SegmentAndGeographicInformation
      Segment and Geographic Information
      Notes
      27
    
    
      false
      false
      R28.htm
      2118100 - Disclosure - Share-Based Compensation
      Sheet
      http://www.aes.com/role/ShareBasedCompensation
      Share-Based Compensation
      Notes
      28
    
    
      false
      false
      R29.htm
      2119100 - Disclosure - Redeemable Stock of Subsidiaries
      Sheet
      http://www.aes.com/role/RedeemableStockOfSubsidiaries
      Redeemable Stock of Subsidiaries
      Notes
      29
    
    
      false
      false
      R30.htm
      2120100 - Disclosure - Other Income and Expense
      Sheet
      http://www.aes.com/role/OtherIncomeAndExpense
      Other Income and Expense
      Notes
      30
    
    
      false
      false
      R31.htm
      2121100 - Disclosure - Asset Impairment Expense
      Sheet
      http://www.aes.com/role/AssetImpairmentExpense
      Asset Impairment Expense
      Notes
      31
    
    
      false
      false
      R32.htm
      2122100 - Disclosure - Income Taxes
      Sheet
      http://www.aes.com/role/IncomeTaxes
      Income Taxes
      Notes
      32
    
    
      false
      false
      R33.htm
      2123100 - Disclosure - Discontinued Operations and Held-For-Sale Businesses
      Sheet
      http://www.aes.com/role/DiscontinuedOperationsAndHeldForSaleBusinesses
      Discontinued Operations and Held-For-Sale Businesses
      Notes
      33
    
    
      false
      false
      R34.htm
      2124100 - Disclosure - Acquisitions and Dispositions
      Sheet
      http://www.aes.com/role/AcquisitionsAndDispositions
      Acquisitions and Dispositions
      Notes
      34
    
    
      false
      false
      R35.htm
      2125100 - Disclosure - Acquisitions Acquisitions
      Sheet
      http://www.aes.com/role/AcquisitionsAcquisitions
      Acquisitions Acquisitions
      Notes
      35
    
    
      false
      false
      R36.htm
      2126100 - Disclosure - Earnings Per Share
      Sheet
      http://www.aes.com/role/EarningsPerShare
      Earnings Per Share
      Notes
      36
    
    
      false
      false
      R37.htm
      2127100 - Disclosure - Risks and Uncertainties
      Sheet
      http://www.aes.com/role/RisksAndUncertainties
      Risks and Uncertainties
      Notes
      37
    
    
      false
      false
      R38.htm
      2128100 - Disclosure - Related Party Transactions
      Sheet
      http://www.aes.com/role/RelatedPartyTransactions
      Related Party Transactions
      Notes
      38
    
    
      false
      false
      R39.htm
      2131100 - Disclosure - Selected Quarterly Financial Data
      Sheet
      http://www.aes.com/role/SelectedQuarterlyFinancialData
      Selected Quarterly Financial Data
      Notes
      39
    
    
      false
      false
      R40.htm
      2132100 - Disclosure - Subsequent Event Subsequent Events
      Sheet
      http://www.aes.com/role/SubsequentEventSubsequentEvents
      Subsequent Event Subsequent Events
      Notes
      40
    
    
      false
      false
      R41.htm
      2134100 - Schedule - Schedule I - Condensed Financial Information of Parent
      Sheet
      http://www.aes.com/role/ScheduleICondensedFinancialInformationOfParent
      Schedule I - Condensed Financial Information of Parent
      Uncategorized
      41
    
    
      false
      false
      R42.htm
      2135100 - Schedule - Schedule II - Valuation and Qualifying Accounts
      Sheet
      http://www.aes.com/role/ScheduleIiValuationAndQualifyingAccounts
      Schedule II - Valuation and Qualifying Accounts
      Uncategorized
      42
    
    
      false
      false
      R43.htm
      2201201 - Disclosure - General and Summary of Significant Accounting Policies (Policies)
      Sheet
      http://www.aes.com/role/GeneralAndSummaryOfSignificantAccountingPoliciesPolicies
      General and Summary of Significant Accounting Policies (Policies)
      Uncategorized
      43
    
    
      false
      false
      R44.htm
      2214201 - Disclosure - Contingencies Contingencies (Policies)
      Sheet
      http://www.aes.com/role/ContingenciesContingenciesPolicies
      Contingencies Contingencies (Policies)
      Uncategorized
      44
    
    
      false
      false
      R45.htm
      2217201 - Disclosure - Segments and Geographic Information Segments and Geographic Information (Policies)
      Sheet
      http://www.aes.com/role/SegmentsAndGeographicInformationSegmentsAndGeographicInformationPolicies
      Segments and Geographic Information Segments and Geographic Information (Policies)
      Uncategorized
      45
    
    
      false
      false
      R46.htm
      2226201 - Disclosure - Earnings Per Share Earnings Per Share (Policies)
      Sheet
      http://www.aes.com/role/EarningsPerShareEarningsPerSharePolicies
      Earnings Per Share Earnings Per Share (Policies)
      Uncategorized
      46
    
    
      false
      false
      R47.htm
      2301302 - Disclosure - General and Summary of Significant Accounting Policies Effect of Change in Estimate (Tables)
      Sheet
      http://www.aes.com/role/GeneralAndSummaryOfSignificantAccountingPoliciesEffectOfChangeInEstimateTables
      General and Summary of Significant Accounting Policies Effect of Change in Estimate (Tables)
      Uncategorized
      47
    
    
      false
      false
      R48.htm
      2302301 - Disclosure - Inventory (Tables)
      Sheet
      http://www.aes.com/role/InventoryTables
      Inventory (Tables)
      Uncategorized
      48
    
    
      false
      false
      R49.htm
      2303301 - Disclosure - Property, Plant and Equipment (Tables)
      Sheet
      http://www.aes.com/role/PropertyPlantAndEquipmentTables
      Property, Plant and Equipment (Tables)
      Uncategorized
      49
    
    
      false
      false
      R50.htm
      2304301 - Disclosure - Fair Value (Tables)
      Sheet
      http://www.aes.com/role/FairValueTables
      Fair Value (Tables)
      Uncategorized
      50
    
    
      false
      false
      R51.htm
      2305301 - Disclosure - Investments In Marketable Securities (Tables)
      Sheet
      http://www.aes.com/role/InvestmentsInMarketableSecuritiesTables
      Investments In Marketable Securities (Tables)
      Uncategorized
      51
    
    
      false
      false
      R52.htm
      2306301 - Disclosure - Derivative Instruments and Hedging Activities (Tables)
      Sheet
      http://www.aes.com/role/DerivativeInstrumentsAndHedgingActivitiesTables
      Derivative Instruments and Hedging Activities (Tables)
      Uncategorized
      52
    
    
      false
      false
      R53.htm
      2307301 - Disclosure - Financing Receivables (Tables)
      Sheet
      http://www.aes.com/role/FinancingReceivablesTables
      Financing Receivables (Tables)
      Uncategorized
      53
    
    
      false
      false
      R54.htm
      2308301 - Disclosure - Investments In and Advances To Affiliates (Tables)
      Sheet
      http://www.aes.com/role/InvestmentsInAndAdvancesToAffiliatesTables
      Investments In and Advances To Affiliates (Tables)
      Uncategorized
      54
    
    
      false
      false
      R55.htm
      2309301 - Disclosure - Other Non-Operating Expense (Tables)
      Sheet
      http://www.aes.com/role/OtherNonOperatingExpenseTables
      Other Non-Operating Expense (Tables)
      Uncategorized
      55
    
    
      false
      false
      R56.htm
      2310301 - Disclosure - Goodwill and Other Intangible Assets (Tables)
      Sheet
      http://www.aes.com/role/GoodwillAndOtherIntangibleAssetsTables
      Goodwill and Other Intangible Assets (Tables)
      Uncategorized
      56
    
    
      false
      false
      R57.htm
      2311301 - Disclosure - Regulatory Assets and Liabilities (Tables)
      Sheet
      http://www.aes.com/role/RegulatoryAssetsAndLiabilitiesTables
      Regulatory Assets and Liabilities (Tables)
      Uncategorized
      57
    
    
      false
      false
      R58.htm
      2312301 - Disclosure - Debt (Tables)
      Sheet
      http://www.aes.com/role/DebtTables
      Debt (Tables)
      Uncategorized
      58
    
    
      false
      false
      R59.htm
      2313301 - Disclosure - Commitments (Tables)
      Sheet
      http://www.aes.com/role/CommitmentsTables
      Commitments (Tables)
      Uncategorized
      59
    
    
      false
      false
      R60.htm
      2314302 - Disclosure - Contingencies (Tables)
      Sheet
      http://www.aes.com/role/ContingenciesTables
      Contingencies (Tables)
      Uncategorized
      60
    
    
      false
      false
      R61.htm
      2315301 - Disclosure - Benefit Plans (Tables)
      Sheet
      http://www.aes.com/role/BenefitPlansTables
      Benefit Plans (Tables)
      Uncategorized
      61
    
    
      false
      false
      R62.htm
      2316301 - Disclosure - Equity (Tables)
      Sheet
      http://www.aes.com/role/EquityTables
      Equity (Tables)
      Uncategorized
      62
    
    
      false
      false
      R63.htm
      2317302 - Disclosure - Segment and Geographic Information  (Tables)
      Sheet
      http://www.aes.com/role/SegmentAndGeographicInformationTables
      Segment and Geographic Information  (Tables)
      Uncategorized
      63
    
    
      false
      false
      R64.htm
      2318301 - Disclosure - Share-Based Compensation (Tables)
      Sheet
      http://www.aes.com/role/ShareBasedCompensationTables
      Share-Based Compensation (Tables)
      Uncategorized
      64
    
    
      false
      false
      R65.htm
      2319301 - Disclosure - Redeemable Stock of Subsidiaries Redeemable Stock of Subsidiaries (Tables)
      Sheet
      http://www.aes.com/role/RedeemableStockOfSubsidiariesRedeemableStockOfSubsidiariesTables
      Redeemable Stock of Subsidiaries Redeemable Stock of Subsidiaries (Tables)
      Uncategorized
      65
    
    
      false
      false
      R66.htm
      2320301 - Disclosure - Other Income and Expense (Tables)
      Sheet
      http://www.aes.com/role/OtherIncomeAndExpenseTables
      Other Income and Expense (Tables)
      Uncategorized
      66
    
    
      false
      false
      R67.htm
      2321301 - Disclosure - Asset Impairment Expense (Tables)
      Sheet
      http://www.aes.com/role/AssetImpairmentExpenseTables
      Asset Impairment Expense (Tables)
      Uncategorized
      67
    
    
      false
      false
      R68.htm
      2322301 - Disclosure - Income Taxes (Tables)
      Sheet
      http://www.aes.com/role/IncomeTaxesTables
      Income Taxes (Tables)
      Uncategorized
      68
    
    
      false
      false
      R69.htm
      2323301 - Disclosure - Discontinued Operations and Held-For-Sale Businesses (Tables)
      Sheet
      http://www.aes.com/role/DiscontinuedOperationsAndHeldForSaleBusinessesTables
      Discontinued Operations and Held-For-Sale Businesses (Tables)
      Uncategorized
      69
    
    
      false
      false
      R70.htm
      2326302 - Disclosure - Earnings Per Share (Tables)
      Sheet
      http://www.aes.com/role/EarningsPerShareTables
      Earnings Per Share (Tables)
      Uncategorized
      70
    
    
      false
      false
      R71.htm
      2328301 - Disclosure - Related Party Transactions (Tables)
      Sheet
      http://www.aes.com/role/RelatedPartyTransactionsTables
      Related Party Transactions (Tables)
      Uncategorized
      71
    
    
      false
      false
      R72.htm
      2331301 - Disclosure - Selected Quarterly Financial Data (Tables)
      Sheet
      http://www.aes.com/role/SelectedQuarterlyFinancialDataTables
      Selected Quarterly Financial Data (Tables)
      Uncategorized
      72
    
    
      false
      false
      R73.htm
      2334301 - Schedule - Schedule I - Condensed Financial Information of Parent (Tables)
      Sheet
      http://www.aes.com/role/ScheduleICondensedFinancialInformationOfParentTables
      Schedule I - Condensed Financial Information of Parent (Tables)
      Uncategorized
      73
    
    
      false
      false
      R74.htm
      2335301 - Schedule - Schedule II - Valuation and Qualifying Accounts Schedule of Valuation and Qualifying Accounts (Tables)
      Sheet
      http://www.aes.com/role/ScheduleIiValuationAndQualifyingAccountsScheduleOfValuationAndQualifyingAccountsTables
      Schedule II - Valuation and Qualifying Accounts Schedule of Valuation and Qualifying Accounts (Tables)
      Uncategorized
      74
    
    
      false
      false
      R75.htm
      2401403 - Disclosure - General and Summary of Significant Accounting Policies (Finite Lived Intangible Assets) (Details)
      Sheet
      http://www.aes.com/role/GeneralAndSummaryOfSignificantAccountingPoliciesFiniteLivedIntangibleAssetsDetails
      General and Summary of Significant Accounting Policies (Finite Lived Intangible Assets) (Details)
      Uncategorized
      75
    
    
      false
      false
      R76.htm
      2401404 - Disclosure - General and Summary of Significant Accounting Policies Accounting Pronouncements Not Yet Adopted (Details)
      Sheet
      http://www.aes.com/role/GeneralAndSummaryOfSignificantAccountingPoliciesAccountingPronouncementsNotYetAdoptedDetails
      General and Summary of Significant Accounting Policies Accounting Pronouncements Not Yet Adopted (Details)
      Uncategorized
      76
    
    
      false
      false
      R77.htm
      2401405 - Disclosure - General and Summary of Significant Accounting Policies New Accounting Pronouncements Adopted (Details)
      Sheet
      http://www.aes.com/role/GeneralAndSummaryOfSignificantAccountingPoliciesNewAccountingPronouncementsAdoptedDetails
      General and Summary of Significant Accounting Policies New Accounting Pronouncements Adopted (Details)
      Uncategorized
      77
    
    
      false
      false
      R78.htm
      2401406 - Disclosure - General and Summary of Significant Accounting Policies Change in Accounting Estimate (Details)
      Sheet
      http://www.aes.com/role/GeneralAndSummaryOfSignificantAccountingPoliciesChangeInAccountingEstimateDetails
      General and Summary of Significant Accounting Policies Change in Accounting Estimate (Details)
      Uncategorized
      78
    
    
      false
      false
      R79.htm
      2402402 - Disclosure - Inventory (Details)
      Sheet
      http://www.aes.com/role/InventoryDetails
      Inventory (Details)
      Uncategorized
      79
    
    
      false
      false
      R80.htm
      2403402 - Disclosure - Property, Plant and Equipment (Components of PP&E) (Details)
      Sheet
      http://www.aes.com/role/PropertyPlantAndEquipmentComponentsOfPpeDetails
      Property, Plant and Equipment (Components of PP&E) (Details)
      Uncategorized
      80
    
    
      false
      false
      R81.htm
      2403403 - Disclosure - Property, Plant and Equipment (Depreciation Expense, Software Amortization and Capitalized Interest) (Details)
      Sheet
      http://www.aes.com/role/PropertyPlantAndEquipmentDepreciationExpenseSoftwareAmortizationAndCapitalizedInterestDetails
      Property, Plant and Equipment (Depreciation Expense, Software Amortization and Capitalized Interest) (Details)
      Uncategorized
      81
    
    
      false
      false
      R82.htm
      2403404 - Disclosure - Property, Plant and Equipment (Regulated and Non-Regulated Generation and Distribution PP&E) (Details)
      Sheet
      http://www.aes.com/role/PropertyPlantAndEquipmentRegulatedAndNonRegulatedGenerationAndDistributionPpeDetails
      Property, Plant and Equipment (Regulated and Non-Regulated Generation and Distribution PP&E) (Details)
      Uncategorized
      82
    
    
      false
      false
      R83.htm
      2403405 - Disclosure - Property, Plant and Equipment (Asset Retirement Obligations) (Details)
      Sheet
      http://www.aes.com/role/PropertyPlantAndEquipmentAssetRetirementObligationsDetails
      Property, Plant and Equipment (Asset Retirement Obligations) (Details)
      Uncategorized
      83
    
    
      false
      false
      R84.htm
      2403406 - Disclosure - Property, Plant and Equipment (Ownership of Coal-Fired Facilities) (Details)
      Sheet
      http://www.aes.com/role/PropertyPlantAndEquipmentOwnershipOfCoalFiredFacilitiesDetails
      Property, Plant and Equipment (Ownership of Coal-Fired Facilities) (Details)
      Uncategorized
      84
    
    
      false
      false
      R85.htm
      2404402 - Disclosure - Fair Value (Recurring Measurements) (Details)
      Sheet
      http://www.aes.com/role/FairValueRecurringMeasurementsDetails
      Fair Value (Recurring Measurements) (Details)
      Uncategorized
      85
    
    
      false
      false
      R86.htm
      2404403 - Disclosure - Fair Value (Level 3 Reconciliation) (Details)
      Sheet
      http://www.aes.com/role/FairValueLevel3ReconciliationDetails
      Fair Value (Level 3 Reconciliation) (Details)
      Uncategorized
      86
    
    
      false
      false
      R87.htm
      2404404 - Disclosure - Fair Value (Quantitative Information) (Details)
      Sheet
      http://www.aes.com/role/FairValueQuantitativeInformationDetails
      Fair Value (Quantitative Information) (Details)
      Uncategorized
      87
    
    
      false
      false
      R88.htm
      2404405 - Disclosure - Fair Value (Nonrecurring Measurements) (Details)
      Sheet
      http://www.aes.com/role/FairValueNonrecurringMeasurementsDetails
      Fair Value (Nonrecurring Measurements) (Details)
      Uncategorized
      88
    
    
      false
      false
      R89.htm
      2404406 - Disclosure - Fair Value (Nonrecurring Unobservable Inputs) (Details)
      Sheet
      http://www.aes.com/role/FairValueNonrecurringUnobservableInputsDetails
      Fair Value (Nonrecurring Unobservable Inputs) (Details)
      Uncategorized
      89
    
    
      false
      false
      R90.htm
      2404407 - Disclosure - Fair Value (Instruments Not Measured at Fair Value) (Details)
      Sheet
      http://www.aes.com/role/FairValueInstrumentsNotMeasuredAtFairValueDetails
      Fair Value (Instruments Not Measured at Fair Value) (Details)
      Uncategorized
      90
    
    
      false
      false
      R91.htm
      2405402 - Disclosure - Investments In Marketable Securities (Details)
      Sheet
      http://www.aes.com/role/InvestmentsInMarketableSecuritiesDetails
      Investments In Marketable Securities (Details)
      Uncategorized
      91
    
    
      false
      false
      R92.htm
      2406402 - Disclosure - Derivative Instruments and Hedging Activities (Outstanding Derivative Notionals and Terms by Type) (Details)
      Sheet
      http://www.aes.com/role/DerivativeInstrumentsAndHedgingActivitiesOutstandingDerivativeNotionalsAndTermsByTypeDetails
      Derivative Instruments and Hedging Activities (Outstanding Derivative Notionals and Terms by Type) (Details)
      Uncategorized
      92
    
    
      false
      false
      R93.htm
      2406403 - Disclosure - Derivative Instruments and Hedging Activities (Foreign Currency Derivatives) (Details)
      Sheet
      http://www.aes.com/role/DerivativeInstrumentsAndHedgingActivitiesForeignCurrencyDerivativesDetails
      Derivative Instruments and Hedging Activities (Foreign Currency Derivatives) (Details)
      Uncategorized
      93
    
    
      false
      false
      R94.htm
      2406404 - Disclosure - Derivative Instruments and Hedging Activities (Commodity Derivatives) (Details)
      Sheet
      http://www.aes.com/role/DerivativeInstrumentsAndHedgingActivitiesCommodityDerivativesDetails
      Derivative Instruments and Hedging Activities (Commodity Derivatives) (Details)
      Uncategorized
      94
    
    
      false
      false
      R95.htm
      2406405 - Disclosure - Derivative Instruments and Hedging Activities (Assets and LIabilities - Designated vs. Not Designated Hedging Instruments) (Details)
      Sheet
      http://www.aes.com/role/DerivativeInstrumentsAndHedgingActivitiesAssetsAndLiabilitiesDesignatedVsNotDesignatedHedgingInstrumentsDetails
      Derivative Instruments and Hedging Activities (Assets and LIabilities - Designated vs. Not Designated Hedging Instruments) (Details)
      Uncategorized
      95
    
    
      false
      false
      R96.htm
      2406406 - Disclosure - Derivative Instruments and Hedging Activities (Assets and Liabilities - Current vs. Noncurrent Derivative instruments) (Details)
      Sheet
      http://www.aes.com/role/DerivativeInstrumentsAndHedgingActivitiesAssetsAndLiabilitiesCurrentVsNoncurrentDerivativeInstrumentsDetails
      Derivative Instruments and Hedging Activities (Assets and Liabilities - Current vs. Noncurrent Derivative instruments) (Details)
      Uncategorized
      96
    
    
      false
      false
      R97.htm
      2406407 - Disclosure - Derivative Instruments and Hedging Activities Derivative Instruments and Hedging Activities (Effective Portion of Cash Flow Hedges) (Details)
      Sheet
      http://www.aes.com/role/DerivativeInstrumentsAndHedgingActivitiesDerivativeInstrumentsAndHedgingActivitiesEffectivePortionOfCashFlowHedgesDetails
      Derivative Instruments and Hedging Activities Derivative Instruments and Hedging Activities (Effective Portion of Cash Flow Hedges) (Details)
      Uncategorized
      97
    
    
      false
      false
      R98.htm
      2406408 - Disclosure - Derivative Instruments and Hedging Activities Derivative Instruments and Hedging Activities (Ineffective Portion of Cash Flow Hedges) (Details)
      Sheet
      http://www.aes.com/role/DerivativeInstrumentsAndHedgingActivitiesDerivativeInstrumentsAndHedgingActivitiesIneffectivePortionOfCashFlowHedgesDetails
      Derivative Instruments and Hedging Activities Derivative Instruments and Hedging Activities (Ineffective Portion of Cash Flow Hedges) (Details)
      Uncategorized
      98
    
    
      false
      false
      R99.htm
      2406409 - Disclosure - Derivative Instruments and Hedging Activities (Derivative Instruments Not Designated for Hedge Accounting) (Details)
      Sheet
      http://www.aes.com/role/DerivativeInstrumentsAndHedgingActivitiesDerivativeInstrumentsNotDesignatedForHedgeAccountingDetails
      Derivative Instruments and Hedging Activities (Derivative Instruments Not Designated for Hedge Accounting) (Details)
      Uncategorized
      99
    
    
      false
      false
      R100.htm
      2406410 - Disclosure - Derivative Instruments and Hedging Activities (Credit Risk-Related Contingent Features) (Details)
      Sheet
      http://www.aes.com/role/DerivativeInstrumentsAndHedgingActivitiesCreditRiskRelatedContingentFeaturesDetails
      Derivative Instruments and Hedging Activities (Credit Risk-Related Contingent Features) (Details)
      Uncategorized
      100
    
    
      false
      false
      R101.htm
      2407402 - Disclosure - Financing Receivables (Details)
      Sheet
      http://www.aes.com/role/FinancingReceivablesDetails
      Financing Receivables (Details)
      Uncategorized
      101
    
    
      false
      false
      R102.htm
      2408402 - Disclosure - Investments In and Advances To Affiliates - Effective Equity Ownership Interest and Carrying Values (Details)
      Sheet
      http://www.aes.com/role/InvestmentsInAndAdvancesToAffiliatesEffectiveEquityOwnershipInterestAndCarryingValuesDetails
      Investments In and Advances To Affiliates - Effective Equity Ownership Interest and Carrying Values (Details)
      Uncategorized
      102
    
    
      false
      false
      R103.htm
      2408403 - Disclosure - Investments In and Advances To Affiliates - Summary of Financial Information of Affiliates & Subsidiaries (Details)
      Sheet
      http://www.aes.com/role/InvestmentsInAndAdvancesToAffiliatesSummaryOfFinancialInformationOfAffiliatesSubsidiariesDetails
      Investments In and Advances To Affiliates - Summary of Financial Information of Affiliates & Subsidiaries (Details)
      Uncategorized
      103
    
    
      false
      false
      R104.htm
      2408404 - Disclosure - Investments In and Advances To Affiliates - Summarized Financial Information (Details)
      Sheet
      http://www.aes.com/role/InvestmentsInAndAdvancesToAffiliatesSummarizedFinancialInformationDetails
      Investments In and Advances To Affiliates - Summarized Financial Information (Details)
      Uncategorized
      104
    
    
      false
      false
      R105.htm
      2409402 - Disclosure - Total Other Non-Operating Expense (Details)
      Sheet
      http://www.aes.com/role/TotalOtherNonOperatingExpenseDetails
      Total Other Non-Operating Expense (Details)
      Uncategorized
      105
    
    
      false
      false
      R106.htm
      2410402 - Disclosure - Goodwill and Other Intangible Assets (Goodwill Roll Forward) (Details)
      Sheet
      http://www.aes.com/role/GoodwillAndOtherIntangibleAssetsGoodwillRollForwardDetails
      Goodwill and Other Intangible Assets (Goodwill Roll Forward) (Details)
      Uncategorized
      106
    
    
      false
      false
      R107.htm
      2410403 - Disclosure - Goodwill and Other Intangible Assets (Intangible Assets) (Details)
      Sheet
      http://www.aes.com/role/GoodwillAndOtherIntangibleAssetsIntangibleAssetsDetails
      Goodwill and Other Intangible Assets (Intangible Assets) (Details)
      Uncategorized
      107
    
    
      false
      false
      R108.htm
      2410404 - Disclosure - Goodwill and Other Intangible Assets (Intangible Assets Acquired) (Details)
      Sheet
      http://www.aes.com/role/GoodwillAndOtherIntangibleAssetsIntangibleAssetsAcquiredDetails
      Goodwill and Other Intangible Assets (Intangible Assets Acquired) (Details)
      Uncategorized
      108
    
    
      false
      false
      R109.htm
      2410405 - Disclosure - Goodwill and Other Intangible Assets (Expected Amortization Expense) (Details)
      Sheet
      http://www.aes.com/role/GoodwillAndOtherIntangibleAssetsExpectedAmortizationExpenseDetails
      Goodwill and Other Intangible Assets (Expected Amortization Expense) (Details)
      Uncategorized
      109
    
    
      false
      false
      R110.htm
      2410406 - Disclosure - Goodwill and Other Intangible Assets (Narrative) (Details)
      Sheet
      http://www.aes.com/role/GoodwillAndOtherIntangibleAssetsNarrativeDetails
      Goodwill and Other Intangible Assets (Narrative) (Details)
      Uncategorized
      110
    
    
      false
      false
      R111.htm
      2410407 - Disclosure - Goodwill and Other Intangible Assets Schedule of Finite-Lived Intangible Assets (Details)
      Sheet
      http://www.aes.com/role/GoodwillAndOtherIntangibleAssetsScheduleOfFiniteLivedIntangibleAssetsDetails
      Goodwill and Other Intangible Assets Schedule of Finite-Lived Intangible Assets (Details)
      Uncategorized
      111
    
    
      false
      false
      R112.htm
      2411402 - Disclosure - Regulatory Assets and Liabilities (Details)
      Sheet
      http://www.aes.com/role/RegulatoryAssetsAndLiabilitiesDetails
      Regulatory Assets and Liabilities (Details)
      Uncategorized
      112
    
    
      false
      false
      R113.htm
      2411403 - Disclosure - Regulatory Assets and Liabilities Regulatory Assets and Liabilities - by Reportable Segment (Details)
      Sheet
      http://www.aes.com/role/RegulatoryAssetsAndLiabilitiesRegulatoryAssetsAndLiabilitiesByReportableSegmentDetails
      Regulatory Assets and Liabilities Regulatory Assets and Liabilities - by Reportable Segment (Details)
      Uncategorized
      113
    
    
      false
      false
      R114.htm
      2412402 - Disclosure - Debt (Non-Recourse Debt Carrying Amounts and Terms) (Details)
      Sheet
      http://www.aes.com/role/DebtNonRecourseDebtCarryingAmountsAndTermsDetails
      Debt (Non-Recourse Debt Carrying Amounts and Terms) (Details)
      Uncategorized
      114
    
    
      false
      false
      R115.htm
      2412403 - Disclosure - Debt (Non-Recourse Debt Maturity Schedule) (Details)
      Sheet
      http://www.aes.com/role/DebtNonRecourseDebtMaturityScheduleDetails
      Debt (Non-Recourse Debt Maturity Schedule) (Details)
      Uncategorized
      115
    
    
      false
      false
      R116.htm
      2412404 - Disclosure - Debt (Subsidiary Non-Recourse Debt in Default or Accelerated) (Details)
      Sheet
      http://www.aes.com/role/DebtSubsidiaryNonRecourseDebtInDefaultOrAcceleratedDetails
      Debt (Subsidiary Non-Recourse Debt in Default or Accelerated) (Details)
      Uncategorized
      116
    
    
      false
      false
      R117.htm
      2412405 - Disclosure - Debt (Non-recourse Debt Narrative) (Details)
      Sheet
      http://www.aes.com/role/DebtNonRecourseDebtNarrativeDetails
      Debt (Non-recourse Debt Narrative) (Details)
      Uncategorized
      117
    
    
      false
      false
      R118.htm
      2412406 - Disclosure - Debt (Recourse Debt Carrying Amount and Terms) (Details)
      Sheet
      http://www.aes.com/role/DebtRecourseDebtCarryingAmountAndTermsDetails
      Debt (Recourse Debt Carrying Amount and Terms) (Details)
      Uncategorized
      118
    
    
      false
      false
      R119.htm
      2412407 - Disclosure - Debt (Recourse Debt Net Principal Amounts Due Over Five Years) (Details)
      Sheet
      http://www.aes.com/role/DebtRecourseDebtNetPrincipalAmountsDueOverFiveYearsDetails
      Debt (Recourse Debt Net Principal Amounts Due Over Five Years) (Details)
      Uncategorized
      119
    
    
      false
      false
      R120.htm
      2412408 - Disclosure - Debt (Recourse Debt Narrative) (Details)
      Sheet
      http://www.aes.com/role/DebtRecourseDebtNarrativeDetails
      Debt (Recourse Debt Narrative) (Details)
      Uncategorized
      120
    
    
      false
      false
      R121.htm
      2412409 - Disclosure - Debt (Term Convertible Trust Securities) (Details)
      Sheet
      http://www.aes.com/role/DebtTermConvertibleTrustSecuritiesDetails
      Debt (Term Convertible Trust Securities) (Details)
      Uncategorized
      121
    
    
      false
      false
      R122.htm
      2413402 - Disclosure - Commitments (Leases, Future Minimum Payments Due) (Details)
      Sheet
      http://www.aes.com/role/CommitmentsLeasesFutureMinimumPaymentsDueDetails
      Commitments (Leases, Future Minimum Payments Due) (Details)
      Uncategorized
      122
    
    
      false
      false
      R123.htm
      2413403 - Disclosure - Commitments (Long-Term Purchase Commitments) (Details)
      Sheet
      http://www.aes.com/role/CommitmentsLongTermPurchaseCommitmentsDetails
      Commitments (Long-Term Purchase Commitments) (Details)
      Uncategorized
      123
    
    
      false
      false
      R124.htm
      2413404 - Disclosure - Commitments (Narrative) (Details)
      Sheet
      http://www.aes.com/role/CommitmentsNarrativeDetails
      Commitments (Narrative) (Details)
      Uncategorized
      124
    
    
      false
      false
      R125.htm
      2414403 - Disclosure - Contingencies (Details)
      Sheet
      http://www.aes.com/role/ContingenciesDetails
      Contingencies (Details)
      Uncategorized
      125
    
    
      false
      false
      R126.htm
      2414404 - Disclosure - Contingencies (Loss Contingencies) (Details)
      Sheet
      http://www.aes.com/role/ContingenciesLossContingenciesDetails
      Contingencies (Loss Contingencies) (Details)
      Uncategorized
      126
    
    
      false
      false
      R127.htm
      2415402 - Disclosure - Benefit Plans (Narrative) (Details)
      Sheet
      http://www.aes.com/role/BenefitPlansNarrativeDetails
      Benefit Plans (Narrative) (Details)
      Uncategorized
      127
    
    
      false
      false
      R128.htm
      2415403 - Disclosure - Benefit Plans (Net Funded Status) (Details)
      Sheet
      http://www.aes.com/role/BenefitPlansNetFundedStatusDetails
      Benefit Plans (Net Funded Status) (Details)
      Uncategorized
      128
    
    
      false
      false
      R129.htm
      2415404 - Disclosure - Benefit Plans (Amounts Recognized in the Consolidated Balance Sheets) (Details)
      Sheet
      http://www.aes.com/role/BenefitPlansAmountsRecognizedInConsolidatedBalanceSheetsDetails
      Benefit Plans (Amounts Recognized in the Consolidated Balance Sheets) (Details)
      Uncategorized
      129
    
    
      false
      false
      R130.htm
      2415405 - Disclosure - Benefit Plans (Accumulated Benefit Obligation) (Details)
      Sheet
      http://www.aes.com/role/BenefitPlansAccumulatedBenefitObligationDetails
      Benefit Plans (Accumulated Benefit Obligation) (Details)
      Uncategorized
      130
    
    
      false
      false
      R131.htm
      2415406 - Disclosure - Benefit Plans Benefit Plans (Weighted Average Assumptions) (Details)
      Sheet
      http://www.aes.com/role/BenefitPlansBenefitPlansWeightedAverageAssumptionsDetails
      Benefit Plans Benefit Plans (Weighted Average Assumptions) (Details)
      Uncategorized
      131
    
    
      false
      false
      R132.htm
      2415407 - Disclosure - Benefit Plans (Impact of One Point Change in Assumptions) (Details)
      Sheet
      http://www.aes.com/role/BenefitPlansImpactOfOnePointChangeInAssumptionsDetails
      Benefit Plans (Impact of One Point Change in Assumptions) (Details)
      Uncategorized
      132
    
    
      false
      false
      R133.htm
      2415408 - Disclosure - Benefit Plans (Net Periodic Benefit Cost) (Details)
      Sheet
      http://www.aes.com/role/BenefitPlansNetPeriodicBenefitCostDetails
      Benefit Plans (Net Periodic Benefit Cost) (Details)
      Uncategorized
      133
    
    
      false
      false
      R134.htm
      2415409 - Disclosure - Benefit Plans (Accumulated Other Comprehensive Income (Loss)) (Details)
      Sheet
      http://www.aes.com/role/BenefitPlansAccumulatedOtherComprehensiveIncomeLossDetails
      Benefit Plans (Accumulated Other Comprehensive Income (Loss)) (Details)
      Uncategorized
      134
    
    
      false
      false
      R135.htm
      2415410 - Disclosure - Benefit Plans (Plan Asset Allocations) (Details)
      Sheet
      http://www.aes.com/role/BenefitPlansPlanAssetAllocationsDetails
      Benefit Plans (Plan Asset Allocations) (Details)
      Uncategorized
      135
    
    
      false
      false
      R136.htm
      2415411 - Disclosure - Benefit Plans (Fair Value of Plan Assets) (Details)
      Sheet
      http://www.aes.com/role/BenefitPlansFairValueOfPlanAssetsDetails
      Benefit Plans (Fair Value of Plan Assets) (Details)
      Uncategorized
      136
    
    
      false
      false
      R137.htm
      2415412 - Disclosure - Benefit Plans (Level 3 Roll Forward) (Details)
      Sheet
      http://www.aes.com/role/BenefitPlansLevel3RollForwardDetails
      Benefit Plans (Level 3 Roll Forward) (Details)
      Uncategorized
      137
    
    
      false
      false
      R138.htm
      2415413 - Disclosure - Benefit Plans (Expected Future Benefit Payments) (Details)
      Sheet
      http://www.aes.com/role/BenefitPlansExpectedFutureBenefitPaymentsDetails
      Benefit Plans (Expected Future Benefit Payments) (Details)
      Uncategorized
      138
    
    
      false
      false
      R139.htm
      2416402 - Disclosure - Equity (Transactions with Noncontrolling Interests) (Details)
      Sheet
      http://www.aes.com/role/EquityTransactionsWithNoncontrollingInterestsDetails
      Equity (Transactions with Noncontrolling Interests) (Details)
      Uncategorized
      139
    
    
      false
      false
      R140.htm
      2416403 - Disclosure - Equity Equity - Net Income (Loss) Attributable to The AES Corporation (Details)
      Sheet
      http://www.aes.com/role/EquityEquityNetIncomeLossAttributableToAesCorporationDetails
      Equity Equity - Net Income (Loss) Attributable to The AES Corporation (Details)
      Uncategorized
      140
    
    
      false
      false
      R141.htm
      2416404 - Disclosure - Equity (Accumulated Other Comprehensive Loss) (Details)
      Sheet
      http://www.aes.com/role/EquityAccumulatedOtherComprehensiveLossDetails
      Equity (Accumulated Other Comprehensive Loss) (Details)
      Uncategorized
      141
    
    
      false
      false
      R142.htm
      2416405 - Disclosure - Equity (Reclassifications Out of AOCL) (Details)
      Sheet
      http://www.aes.com/role/EquityReclassificationsOutOfAoclDetails
      Equity (Reclassifications Out of AOCL) (Details)
      Uncategorized
      142
    
    
      false
      false
      R143.htm
      2416406 - Disclosure - Equity Equity (Dividends) (Details)
      Sheet
      http://www.aes.com/role/EquityEquityDividendsDetails
      Equity Equity (Dividends) (Details)
      Uncategorized
      143
    
    
      false
      false
      R144.htm
      2416407 - Disclosure - Equity Equity (Stock Repurchases) (Details)
      Sheet
      http://www.aes.com/role/EquityEquityStockRepurchasesDetails
      Equity Equity (Stock Repurchases) (Details)
      Uncategorized
      144
    
    
      false
      false
      R145.htm
      2417403 - Disclosure - Segment and Geographic Information (Details)
      Sheet
      http://www.aes.com/role/SegmentAndGeographicInformationDetails
      Segment and Geographic Information (Details)
      Uncategorized
      145
    
    
      false
      false
      R146.htm
      2417404 - Disclosure - Segments and Geographic Information Segment and Geographic Information (Adjusted Pre-Tax Contributions & Reconcilliation of Income Before Income Taxes) (Details)
      Sheet
      http://www.aes.com/role/SegmentsAndGeographicInformationSegmentAndGeographicInformationAdjustedPreTaxContributionsReconcilliationOfIncomeBeforeIncomeTaxesDetails
      Segments and Geographic Information Segment and Geographic Information (Adjusted Pre-Tax Contributions & Reconcilliation of Income Before Income Taxes) (Details)
      Uncategorized
      146
    
    
      false
      false
      R147.htm
      2417405 - Disclosure - Segments and Geographic Information Segment and Geographic Information (Assets, Depreciation and Amortization and Capital Expenditures ) (Details)
      Sheet
      http://www.aes.com/role/SegmentsAndGeographicInformationSegmentAndGeographicInformationAssetsDepreciationAndAmortizationAndCapitalExpendituresDetails
      Segments and Geographic Information Segment and Geographic Information (Assets, Depreciation and Amortization and Capital Expenditures ) (Details)
      Uncategorized
      147
    
    
      false
      false
      R148.htm
      2417406 - Disclosure - Segments and Geographic Information Segment and Geographic Information (Revenue and Assets by Country) (Details)
      Sheet
      http://www.aes.com/role/SegmentsAndGeographicInformationSegmentAndGeographicInformationRevenueAndAssetsByCountryDetails
      Segments and Geographic Information Segment and Geographic Information (Revenue and Assets by Country) (Details)
      Uncategorized
      148
    
    
      false
      false
      R149.htm
      2418402 - Disclosure - Share-Based Compensation (Fair Value Assumptions) (Details)
      Sheet
      http://www.aes.com/role/ShareBasedCompensationFairValueAssumptionsDetails
      Share-Based Compensation (Fair Value Assumptions) (Details)
      Uncategorized
      149
    
    
      false
      false
      R150.htm
      2418403 - Disclosure - Share-Based Compensation (Stock Option Compensation Expense) (Details)
      Sheet
      http://www.aes.com/role/ShareBasedCompensationStockOptionCompensationExpenseDetails
      Share-Based Compensation (Stock Option Compensation Expense) (Details)
      Uncategorized
      150
    
    
      false
      false
      R151.htm
      2418404 - Disclosure - Share-Based Compensation (Stock Option Activity) (Details)
      Sheet
      http://www.aes.com/role/ShareBasedCompensationStockOptionActivityDetails
      Share-Based Compensation (Stock Option Activity) (Details)
      Uncategorized
      151
    
    
      false
      false
      R152.htm
      2418405 - Disclosure - Share-Based Compensation (RSU Compensation Expense) (Details)
      Sheet
      http://www.aes.com/role/ShareBasedCompensationRsuCompensationExpenseDetails
      Share-Based Compensation (RSU Compensation Expense) (Details)
      Uncategorized
      152
    
    
      false
      false
      R153.htm
      2418406 - Disclosure - Share-Based Compensation (RSU Activity) (Details)
      Sheet
      http://www.aes.com/role/ShareBasedCompensationRsuActivityDetails
      Share-Based Compensation (RSU Activity) (Details)
      Uncategorized
      153
    
    
      false
      false
      R154.htm
      2418407 - Disclosure - Share-Based Compensation (RSUs Vested and Converted) (Details)
      Sheet
      http://www.aes.com/role/ShareBasedCompensationRsusVestedAndConvertedDetails
      Share-Based Compensation (RSUs Vested and Converted) (Details)
      Uncategorized
      154
    
    
      false
      false
      R155.htm
      2418408 - Disclosure - Share-Based Compensation (PSU Compensation Expense) (Details)
      Sheet
      http://www.aes.com/role/ShareBasedCompensationPsuCompensationExpenseDetails
      Share-Based Compensation (PSU Compensation Expense) (Details)
      Uncategorized
      155
    
    
      false
      false
      R156.htm
      2418409 - Disclosure - Share-Based Compensation (PSU Activity) (Details)
      Sheet
      http://www.aes.com/role/ShareBasedCompensationPsuActivityDetails
      Share-Based Compensation (PSU Activity) (Details)
      Uncategorized
      156
    
    
      false
      false
      R157.htm
      2418410 - Disclosure - Share-Based Compensation (PSUs Vested and Converted) (Details)
      Sheet
      http://www.aes.com/role/ShareBasedCompensationPsusVestedAndConvertedDetails
      Share-Based Compensation (PSUs Vested and Converted) (Details)
      Uncategorized
      157
    
    
      false
      false
      R158.htm
      2418411 - Disclosure - Share-Based Compensation (Narrative) (Details)
      Sheet
      http://www.aes.com/role/ShareBasedCompensationNarrativeDetails
      Share-Based Compensation (Narrative) (Details)
      Uncategorized
      158
    
    
      false
      false
      R159.htm
      2419402 - Disclosure - Redeemable Stock of Subsidiaries (Narrative) (Details)
      Sheet
      http://www.aes.com/role/RedeemableStockOfSubsidiariesNarrativeDetails
      Redeemable Stock of Subsidiaries (Narrative) (Details)
      Uncategorized
      159
    
    
      false
      false
      R160.htm
      2420402 - Disclosure - Other Income and Expense (Nonoperating Income) (Details)
      Sheet
      http://www.aes.com/role/OtherIncomeAndExpenseNonoperatingIncomeDetails
      Other Income and Expense (Nonoperating Income) (Details)
      Uncategorized
      160
    
    
      false
      false
      R161.htm
      2420403 - Disclosure - Other Income and Expense (Other Expense) (Details)
      Sheet
      http://www.aes.com/role/OtherIncomeAndExpenseOtherExpenseDetails
      Other Income and Expense (Other Expense) (Details)
      Uncategorized
      161
    
    
      false
      false
      R162.htm
      2421402 - Disclosure - Asset Impairment Expense (Impairment of Long-Lived Assets Held and Used by Asset) (Details)
      Sheet
      http://www.aes.com/role/AssetImpairmentExpenseImpairmentOfLongLivedAssetsHeldAndUsedByAssetDetails
      Asset Impairment Expense (Impairment of Long-Lived Assets Held and Used by Asset) (Details)
      Uncategorized
      162
    
    
      false
      false
      R163.htm
      2421403 - Disclosure - Asset Impairment Expense (Narrative) (Details)
      Sheet
      http://www.aes.com/role/AssetImpairmentExpenseNarrativeDetails
      Asset Impairment Expense (Narrative) (Details)
      Uncategorized
      163
    
    
      false
      false
      R164.htm
      2422402 - Disclosure - Income Taxes (Components of Income Taxes) (Details)
      Sheet
      http://www.aes.com/role/IncomeTaxesComponentsOfIncomeTaxesDetails
      Income Taxes (Components of Income Taxes) (Details)
      Uncategorized
      164
    
    
      false
      false
      R165.htm
      2422403 - Disclosure - Income Taxes (Effective Income Tax Reconciliation) (Details)
      Sheet
      http://www.aes.com/role/IncomeTaxesEffectiveIncomeTaxReconciliationDetails
      Income Taxes (Effective Income Tax Reconciliation) (Details)
      Uncategorized
      165
    
    
      false
      false
      R166.htm
      2422404 - Disclosure - Income Taxes (Income Tax Payables and Income Tax Receivables) (Details)
      Sheet
      http://www.aes.com/role/IncomeTaxesIncomeTaxPayablesAndIncomeTaxReceivablesDetails
      Income Taxes (Income Tax Payables and Income Tax Receivables) (Details)
      Uncategorized
      166
    
    
      false
      false
      R167.htm
      2422405 - Disclosure - Income Taxes (Deferred Tax Assets and Deferred Tax Liabilities) (Details)
      Sheet
      http://www.aes.com/role/IncomeTaxesDeferredTaxAssetsAndDeferredTaxLiabilitiesDetails
      Income Taxes (Deferred Tax Assets and Deferred Tax Liabilities) (Details)
      Uncategorized
      167
    
    
      false
      false
      R168.htm
      2422406 - Disclosure - Income Taxes (Income (Loss) from Continuing Operations Before Income Tax) (Details)
      Sheet
      http://www.aes.com/role/IncomeTaxesIncomeLossFromContinuingOperationsBeforeIncomeTaxDetails
      Income Taxes (Income (Loss) from Continuing Operations Before Income Tax) (Details)
      Uncategorized
      168
    
    
      false
      false
      R169.htm
      2422407 - Disclosure - Income Taxes (Unrecognized Tax Benefits) (Details)
      Sheet
      http://www.aes.com/role/IncomeTaxesUnrecognizedTaxBenefitsDetails
      Income Taxes (Unrecognized Tax Benefits) (Details)
      Uncategorized
      169
    
    
      false
      false
      R170.htm
      2422408 - Disclosure - Income Taxes (Narrative) (Details)
      Sheet
      http://www.aes.com/role/IncomeTaxesNarrativeDetails
      Income Taxes (Narrative) (Details)
      Uncategorized
      170
    
    
      false
      false
      R171.htm
      2423402 - Disclosure - Discontinued Operations and Held-For-Sale Businesses (Schedule of Disposal Groups, Including Discontinued Operations) (Details)
      Sheet
      http://www.aes.com/role/DiscontinuedOperationsAndHeldForSaleBusinessesScheduleOfDisposalGroupsIncludingDiscontinuedOperationsDetails
      Discontinued Operations and Held-For-Sale Businesses (Schedule of Disposal Groups, Including Discontinued Operations) (Details)
      Uncategorized
      171
    
    
      false
      false
      R172.htm
      2423403 - Disclosure - Discontinued Operations and Held-For-Sale Businesses (Narrative) (Details)
      Sheet
      http://www.aes.com/role/DiscontinuedOperationsAndHeldForSaleBusinessesNarrativeDetails
      Discontinued Operations and Held-For-Sale Businesses (Narrative) (Details)
      Uncategorized
      172
    
    
      false
      false
      R173.htm
      2424401 - Disclosure - Acquisitions and Dispositions (Details)
      Sheet
      http://www.aes.com/role/AcquisitionsAndDispositionsDetails
      Acquisitions and Dispositions (Details)
      Uncategorized
      173
    
    
      false
      false
      R174.htm
      2425402 - Disclosure - Acquisitions Acquistions (Details)
      Sheet
      http://www.aes.com/role/AcquisitionsAcquistionsDetails
      Acquisitions Acquistions (Details)
      Uncategorized
      174
    
    
      false
      false
      R175.htm
      2426403 - Disclosure - Earnings Per Share (Schedule of Earnings Per Share, Basic and Diluted) (Details)
      Sheet
      http://www.aes.com/role/EarningsPerShareScheduleOfEarningsPerShareBasicAndDilutedDetails
      Earnings Per Share (Schedule of Earnings Per Share, Basic and Diluted) (Details)
      Uncategorized
      175
    
    
      false
      false
      R176.htm
      2426404 - Disclosure - Earnings Per Share (Narrative) (Details)
      Sheet
      http://www.aes.com/role/EarningsPerShareNarrativeDetails
      Earnings Per Share (Narrative) (Details)
      Uncategorized
      176
    
    
      false
      false
      R177.htm
      2427401 - Disclosure - Risks And Uncertainties (Details)
      Sheet
      http://www.aes.com/role/RisksAndUncertaintiesDetails
      Risks And Uncertainties (Details)
      Uncategorized
      177
    
    
      false
      false
      R178.htm
      2428402 - Disclosure - Related Party Transactions (Schedule of related Party Transactions) (Details)
      Sheet
      http://www.aes.com/role/RelatedPartyTransactionsScheduleOfRelatedPartyTransactionsDetails
      Related Party Transactions (Schedule of related Party Transactions) (Details)
      Uncategorized
      178
    
    
      false
      false
      R179.htm
      2428403 - Disclosure - Related Party Transactions (Schedule of Related Party Receivables Payables) (Details)
      Sheet
      http://www.aes.com/role/RelatedPartyTransactionsScheduleOfRelatedPartyReceivablesPayablesDetails
      Related Party Transactions (Schedule of Related Party Receivables Payables) (Details)
      Uncategorized
      179
    
    
      false
      false
      R180.htm
      2428404 - Disclosure - Related Party Transactions Transactions with Significant Shareholders (Details)
      Sheet
      http://www.aes.com/role/RelatedPartyTransactionsTransactionsWithSignificantShareholdersDetails
      Related Party Transactions Transactions with Significant Shareholders (Details)
      Uncategorized
      180
    
    
      false
      false
      R181.htm
      2431402 - Disclosure - Selected Quarterly Financial Data (Details)
      Sheet
      http://www.aes.com/role/SelectedQuarterlyFinancialDataDetails
      Selected Quarterly Financial Data (Details)
      Uncategorized
      181
    
    
      false
      false
      R182.htm
      2432401 - Disclosure - Subsequent Event Subsequent Events (Details)
      Sheet
      http://www.aes.com/role/SubsequentEventSubsequentEventsDetails
      Subsequent Event Subsequent Events (Details)
      Uncategorized
      182
    
    
      false
      false
      R183.htm
      2434402 - Schedule - Schedule I - Condensed Financial Information of Parent (Balance Sheet) (Details)
      Sheet
      http://www.aes.com/role/ScheduleICondensedFinancialInformationOfParentBalanceSheetDetails
      Schedule I - Condensed Financial Information of Parent (Balance Sheet) (Details)
      Uncategorized
      183
    
    
      false
      false
      R184.htm
      2434403 - Schedule - Schedule I - Condensed Financial Information of Parent (Balance Sheet Parenthetical) (Details)
      Sheet
      http://www.aes.com/role/ScheduleICondensedFinancialInformationOfParentBalanceSheetParentheticalDetails
      Schedule I - Condensed Financial Information of Parent (Balance Sheet Parenthetical) (Details)
      Uncategorized
      184
    
    
      false
      false
      R185.htm
      2434404 - Schedule - Schedule I - Condensed Financial Information of Parent Schedule I - Condensed Financial Information of Parent (Statement of Operations) (Details)
      Sheet
      http://www.aes.com/role/ScheduleICondensedFinancialInformationOfParentScheduleICondensedFinancialInformationOfParentStatementOfOperationsDetails
      Schedule I - Condensed Financial Information of Parent Schedule I - Condensed Financial Information of Parent (Statement of Operations) (Details)
      Uncategorized
      185
    
    
      false
      false
      R186.htm
      2434405 - Schedule - Schedule I - Condensed Financial Information of Parent (Statement of Comprehensive Income) (Details)
      Sheet
      http://www.aes.com/role/ScheduleICondensedFinancialInformationOfParentStatementOfComprehensiveIncomeDetails
      Schedule I - Condensed Financial Information of Parent (Statement of Comprehensive Income) (Details)
      Uncategorized
      186
    
    
      false
      false
      R187.htm
      2434406 - Schedule - Schedule I - Condensed Financial Information of Parent (Statement of Comprehensive Income Parenthetical) (Details)
      Sheet
      http://www.aes.com/role/ScheduleICondensedFinancialInformationOfParentStatementOfComprehensiveIncomeParentheticalDetails
      Schedule I - Condensed Financial Information of Parent (Statement of Comprehensive Income Parenthetical) (Details)
      Uncategorized
      187
    
    
      false
      false
      R188.htm
      2434407 - Schedule - Schedule I - Condensed Financial Information of Parent (Statement of Cash Flows) (Details)
      Sheet
      http://www.aes.com/role/ScheduleICondensedFinancialInformationOfParentStatementOfCashFlowsDetails
      Schedule I - Condensed Financial Information of Parent (Statement of Cash Flows) (Details)
      Uncategorized
      188
    
    
      false
      false
      R189.htm
      2434408 - Schedule - Schedule I - Condensed Financial Information of Parent (Senior Notes and Junior Subordinated Notes) (Details)
      Notes
      http://www.aes.com/role/ScheduleICondensedFinancialInformationOfParentSeniorNotesAndJuniorSubordinatedNotesDetails
      Schedule I - Condensed Financial Information of Parent (Senior Notes and Junior Subordinated Notes) (Details)
      Uncategorized
      189
    
    
      false
      false
      R190.htm
      2434409 - Schedule - Schedule I - Condensed Financial Information of Parent (Dividends from Subsidiaries and Affiliates) (Details)
      Sheet
      http://www.aes.com/role/ScheduleICondensedFinancialInformationOfParentDividendsFromSubsidiariesAndAffiliatesDetails
      Schedule I - Condensed Financial Information of Parent (Dividends from Subsidiaries and Affiliates) (Details)
      Uncategorized
      190
    
    
      false
      false
      R191.htm
      2434410 - Schedule - Schedule I - Condensed Financial Information of Parent (Guarantees and Letters of Credit) (Details)
      Sheet
      http://www.aes.com/role/ScheduleICondensedFinancialInformationOfParentGuaranteesAndLettersOfCreditDetails
      Schedule I - Condensed Financial Information of Parent (Guarantees and Letters of Credit) (Details)
      Uncategorized
      191
    
    
      false
      false
      R192.htm
      2435402 - Schedule - Schedule II - Valuation and Qualifying Accounts (Details)
      Sheet
      http://www.aes.com/role/ScheduleIiValuationAndQualifyingAccountsDetails
      Schedule II - Valuation and Qualifying Accounts (Details)
      Uncategorized
      192
    
    
      false
      false
      R9999.htm
      Uncategorized Items - aes-20151231.xml
      Sheet
      http://xbrl.sec.gov/role/uncategorizedFacts
      Uncategorized Items - aes-20151231.xml
      Cover
      193
    
    
      false
      false
      All Reports
      Book
      All Reports


    aes-20151231.xml
    aes-20151231.xsd
    aes-20151231_cal.xml
    aes-20151231_def.xml
    aes-20151231_lab.xml
    aes-20151231_pre.xml


  true
  true


IDEA: XBRL DOCUMENT
begin 644 0000874761-16-000077-xbrl.zip
M4$L#!!0    ( -:25T@UMM5 W(\' .#AGP 0    865S+3(P,34Q,C,Q+GAM
M;.R]:W?BR+(F_'GF5_1;GU]W Q*W6OOT+!!0V]VNLLO8O<^9+[72*(VU2TAL
M75Q%__K)E+@C0 )=,C)CUIG>W48(9<03$4]<,O6/__-S9O_R3CW?NVU2=M$TYNM
MZ&8_7SS;^LC_^0M[:L?_2*C_7Q_>@F#^\;???OSX\2O[[U\G[NRW1JW>K#>T
M^H?E=1,W= )OL;Z6W^)7GTY^G;KOORT_Y%_2;FKUFZVOA9['A''L>\M/^1?U
MW2^:U$K^#OL@X7+Z<_*6?#W_)%K-[AIRAU@3/_F9HH_X(]5W'\EQ'2><)?^&
M&7B_!8LY_8U==,.NHIXU67_O_)=VO^#1UZ,K:?W&/EU=Z%N3Y"6P#Q(6X =S
M[\CU[).$+X3^S920^?H[K\1_B1YD^4&"LMDGGFMO(7W[.]$GR5_B\8<[EP:)ES;C2X/M2ZU3 '7\@#B3->1^
M'D#TAQ9=7>]VN[]%GZXO][\>2-SLCF8NO\Q3?KI_G]?_^O
M?_#?^NA''SS2UU^BW_[X%N&.>:6;E4?ZE3W'A^6G7 W_]<&W9G.;K>@W?I?8
MPTU<)Z _@U\L]LBC ?_J5_U_G@;\=U:7,/]K!0O^A]5?+)/_[=6BWB_18]"=
M%:Q@:=S^^>'W&OM_G39SP/5__+;_Y>@W?MO_D>5OS)E-N>;VKS()>,& A8'?
M5W"JK6^Z^6SK"]0Q-Y?7&PQ]FU\S5Q>O_K3^O=4?EI))%M4MNV?K:WW\1CSJ
MWX;'I+;N&F7\PY(]G4;^_,&SB^^SQ
M)R1@'/?^-?IDT?MI^:>_O'CPK!GQ%GWJ4/9MB_WK9SI[H5YIHEX[63KEA#OZ
M4_PWD_WRS[G-GBJ(G^D7TV*7Q"1^N:J/EXCDP^\GOWU4)O_X+?&QXE7\=K ,
M@4"D(XB4 E'N#G@0@P@"0=.S$30]9X(6B4J#(2HMFZBT(D05T_ZU@QD'[)8<
M_,/_A&PMACN;NP[[3W_'#3UYE/BAMQ@'[N0[+%]S)Q<:TE $>+Z[#[^*YMLU,;I4/2 F84TN%F2=?S#N0C"+'0#):,1D5(6#H&# $
M#AB%U,0N\@VH=94\P\5%+O;GF>O(RRH.UJ=(@>LV]AN8F4+)3+>"B"9,UH'>
M0=Z,XZ)P@1E'N1E'U6'D*:/C ".-E=HQJ!FC-V6D=#@6 H&F7]?A1
MN6#Z^]GC,"H73/3-;KE8:R^SUEZ(15^@="RQ"%!B$00,R+\!JCE[FH51'$QR
ME9VBX50%<.)V09L$B1OT//N"_;^H=.B6GCURHW.''\]%/ 6V!*0+ONPR]DS<
M.J^N-XM.CNXO1I9#G(E%[+4]W+&LY);]ZX[%KP^1_CEGA@0L%\^PX(WA)ZY8
MD?;W%F@(];\]LKOUYG//)9.W"!7\CP/+)].I1Z>\=K%]12R2_-%V&*,^47?J
MD?F;-2%V]/WEZZ2^/8]%AR:3X,=]L7[XG?_UC%Q/(5 XD[@D'.\K]=!<:C#A]XU?XZ^'#"E_0S@E
M5*1':'A"&]ZG/AJ>9(;WJ:^>X:$)(9KE0;,X12[1D0TJ/<%2KJ HE\K9JV$2
M&&3@Y"K)E2]%C$ZT)"5[C0Q-#8ZI24KF1#,B9'*B]5$4B28"4C@,*##*73#[
MC]@'% (F4KE7='- \%MUBBHZD.$09O3($)DRY*D,9,HXD5$5!1+?;A"_0/!;
M-062"O4R\R4TM8M,[6!K^9OK!4_4FPWH2_"TF-.=LCI7TOVKX5%S)0_1(;_6
M>=*Z-H7LPX45I_^B-XUOJ[-G_COT _Z0_LCUOM ?O4D$<.,,7R84(C@13VBWP&4NAY[-E[OD^A% 96 #BVP(WA'UNA(NY_"Q0FM;[=,0Y@#Z,U
MK!W"9]>9#D+VCW'XXENF1;P%#!"P!7W<6U!LXT=7I)[2UT=\$6>Z&^H_6XXU
M"V&D5*2J ),81PNMFSV$+VRUSX%ELV4\TNGR#&'OV?%6_\'+CN'^R;JK
M"]G/1W*&A>-,J]X^:S=YV3 +*_E 8>M3M8W9D4^_1)2JBXBRW)"
MC[+K1M9/_F_ >E*9P'%\N>JIOA]:;+W.E%VV^M?;V=QSW^,6GL0H2+5RN(#0
M$1!@ 5%\+1^#@Z#!02C5(ZV$1BN%@L_1:Z,)''ZYS(XD]>KA N-2THG $ <8
M96S5*@0;LFW_*!]#&1X.]Z;D@>WCW%*V_0PE4.XKT8N[*\K,!I3&=U%9 UI 
MR1:0JD*D--2OKJ$AIB7QZM)3<$&].K+R2C).Z3V["!DG>O?2&8OT;KQJQH+^
MNIPJBO1 KJ2*@NCEX!JP.[PS"OA.;QW&^4*^Q$?+_[Z#0,.=S5R3+=5@=_/(
M!%B?]-0:-X XLDB$QDEHK-Y$Q(\OW17984.M":%THSY!S.H@Q
MK?0$%.,JL+B*E1158FF^3G*R?:$57;AY"G2*)3G%#%I0Q D*4S94UD!$*Q.B
MC>1>]9$0VPBJBASOR;P7,[B*B@J8QU6;Q^F8QPF6Q^6^Z5,DAREA0 ?K()%:
MY.(0L74 V3E>5,O$L068%3VPZIBQSL +K8')Y?9/^(GHQD6$3?_>-"GP(
M.%B,0L<\\=WUO_Z3Z9UXD[?%'7VG]FZT65USZ\S#P(\N:,""8VI%;+!Y3A,Y
M$:BC>MS:0+:OR/Q_^@0,MD+Q<1S(X9MSL L-EEWD 0%-)H^MGFM$+[#G!00(
MVFEN<"D\Z[#@*4'D+O[W+S;7,LA EJL\!2 D$&8>0RTS)S)#D),F_G?7+?J>=P
MZ9CT)?#7-QFX,V(Y2))AD63>%#RM48$,6"JB+'F&"RS@@C1>,!FN5)%73H(L
M95*+!%G8/%;.^%HN009FLR!C+"B"+%4AJICX>(00 Y]N%C(.':.K4FV6S7.6
M7E!J""R5$V&7K9#V"")]*_R=:-?;%A1#*!B$8JL\KW,J%,2- @X4^42%? )8
M7T,SCT7Q+
MB[7@)N>!Y4,X.0\\*Q)CY  IL2"6BI18Y)@JR38716(C"#JK;I 2/Q5$H(N:
MMXF-;!&[G0HS+Q4:J$BZ*CVC%A@S@L8_).'=>$"I GQ&^.-;I$H 9$ 5%6_%P(F)UB+H0F*NS>"JS!5<19*RN_J9#881$.O'V(''ZDFBD2
M*P>3OVPB<.8C59E"S/XFV@K,< 1AU!6\^1:_Z0^9'\"P!+[S*4Q8,EQO[GHD
MH!B:Y E-)Y4JD!E+%9ZP"2:&Y6(3#'Z%7<"8BUQ24EQ+5;H3*@A!P;,R$0,.
MCD494H "814F"F1&+_)W2=F%XG,I8A^[AKR[R!J4Z,>N@2\B"S,RECQM+[%9
MB5/JS;[1 3%]\1@D]D-@&@FV04"=_PG,-*!! &CZ>\1/GRS+08$0*&9_<2%4
M; 0+^(8P*/!5X'5>< *P )F@&@5TNPO5$!5_?*W&U59(NF2(,#D2&
M@]RRLNH H?ZW3^X[]1PN'9-ED_[Z)@-W1BP'J:;8QK-/.)E&/Y[6J$ &C,P3
M%O,$9L#(/&4R8#DC<%GS64A<<3Y+EAE^V4NRP H\6)(%7=$1T$2QH@,[,&)H
M2IT0@LL!@=D+OLL6S13*>+?"I1HA[2/WB7&)JS.23$]BRB8!BP3?#Q>314(!
MMQJ4#X[G5J Q)F52A(TQ&!F2@"-9$#(D8#8KI'U SY# FRF<.KO\!0E &1+X
MRD!E!;P2CG&3OY: Q[B)4;P0HP56_,$3"ENG F=9H(&*SAFK?ED/T4F;4XHA]]<: (_;B
MI'$"EO[%+H%B;TZH6"5Q5TZAU R*-:F11\D<7,JJ$4)!M)H%/3@^.G^$(S(!
M.CUA#FM&IX=.3T"$8UM=[(P/:R&5>VXL6DH2 +!T*5)])-VF (QHA5==RACL
MQ]@J;&P5="N?7#8FU;X[.(%(W(Q?X9DJT!P21R%52__P+6N2F3"^9:V$*)R9
M86(Z* A5Q710Y'100,H,X6 (8)8JI'U /Q@"JS:X5:CRZ"I5(4CBG!;@+ETH
MA@)U/DF,MADX-PZ,>JDQJ8S4"\C&'#PZ#Y!]0,^0P%<=Y2]D $N*T$R!YT$"
M1E- ;V@$QGU!M_4$[^B!;Q((;;1H80):F-AX%G??#*9BBN1  NX'RWW?# X^
MRN'\D[4ID.&"SXH$,]R"-KRAS99MLV)N>%/<7,4_3D]^%HK'Z2$5SCFB8E04
M)RIB:$H_* CJ=1W (A.^K@,#4^6!J>H]JL!L%D2 @[Y'57$S+FK<1&(; S@;
M(C:")7^Q&["T"IDBY%1.C'W4L/=\ 1N8PCU?.#8%)=7#8RPE2>]$;AF W^@C
MC+D>/:4&;:P$&[OHC""QD2W_%C;Y@Q# ^H?$ 4B],7N%:S.@PYG@C0"IJC0"
M)'G8R)/#;(6?N59\PW@.ADNH_^V3^TX]ATO'9'[:7]]DX,Z(Y:"E%6AI3/P?
M3XL?$S[I';X\9]_+_/YH^?,%?'^TQ"E"Y4RCK+P>$P3,ZW' #U+S%BT6F[=2
MF&OE93C,YC&;%S*UPRTC:#&X940 ,ZYLRT@)%1KY#18K-&*8IMS)7BEO')1_
M6$J%(F"BKI8D"UL^@:-3+11&40R[@]3
MU$($YI 8@F!Q2$S_D$/*E01*?L EL&B+!UQ"CK"%EU:W!/*9$C_T*'_@/O&M
M/1;K!]:,!/3^=?V-];\,+']BN_R[L$SCS-JW2%^&QM0D% NIAYV;&RN2E;RUO9@S@T_,_3 /4MBKZ93KU@P'XP]OJU.ON_]1W7
MGVU]@3KFYO(=@*P^*1\@4KPZ(1U&*GIG@10P27%R>C35RW*5N4??N(+X_2;N
MC-ZY$[). GG]YMB%2_U,EB>#L]]P?#OZ*OLQZYW)6494%GX >AJ]Q&68:Q6C
MB U=1+R.)/%R8?F"2H5\E.M0F:_6&S5*Z-3S* %19R@
M&-:!+$)$:T$*4;+U*(]EA$;*UPJ@>RVW=(!.%EB>AO4P%7.VW,M;RJ9MHI6S
M,'-+82/("C 6J\-JE?7- K)8=,^YNV<)X8V@RB$5:GYM?#.I]>V.3HD]C!:P
M!L[SG_^RV(_P"4IWSA?[X+G_II/@Q$Q]PF#^G>M,[YB(S>@S_Y_4-GN.^>Q3
ML[!)7Z6'XI@V/^YI,[:",^K,R=6?&>H_AX;\GZ+(J6%%9A1KK1NMEEL^'KN=
M^GAPU/&,79MXXSD#9>HM0+M[]S[3X,TU;YUWEG/RQ1=W!A.ZFB17LZ_ XGW+
M[FZ_(_H7R+FD..U%%>?2N*EU\RWV-6.F?,R]],/75V*[4S*_O;U-[6'2+H>)Z(F1W$K[>ZZME6^S'LNV.11(N@*'M)*[[BA3?
MW)!^2[%%2 [ZK:&30?I=Z)9]19Q+OO1;#N>"# :="S(709V+/I[3B47LT5\\
MYSKJ9P8/=YD=S"?7-7]8MHW5PE(]REI5Y;F274T+Y#NP+KC.>FI;!9E2ZH)_
M6K;GNOMC)(I6!'>$(7YQ0KI:8"."U[[$GA9SFKZH)T]C']/]__K 3>08'DJI
M[N%D 58? $P6:">J#T6$^,Q.R2">M["Z_B5P0- 6@WPN"I/
M)U"<1#V"-7*6T#V!?--
M%%+L!"RG!@K67L#7%.7I$:9!\_4,%"Q2A69T\J!0@(0(B8SH<%>'L.2;,< ?
M \&B XZ!8!E"J#$0^$X%>R3H5+ O(I13$:RVB70%:Z5(6F0JW8HXXZ%\X4')
MF0R090F)SY%7W@J5.IH9HO65_YZCHNP/[:,\^Y"G1Q21-_W$QJ.Q9;]3[]$R
MI_3!_4$]#!KE&$6BV &8ABJA0R]B8[Q^9F1@;E]@@+(,#6P6+V(?-<>0(,(;
MJ/6O]7/UPD]D7L#$ #8>BBL/KC4FH@%AMZ&J.*;E?O*2?J+;,'P) XKUOS+,
M?DO46/$3B#CF/SE]ACC&H\%?Z ^&-/N$U:@W+KTK$_&M1"*:F0*W^<<*L' %
MYZV;O%7$)
ML=^RG)":]^RY2,"T$,%LY'IC8M-[CUTR=QG@[E_["_X7X(:\*ZKR2AP72UJI
M"%IU0>#2V(E'2\E"2DN.FGBD5'7U#@%JC E"OPWH+*Y +;=DH]V+:_>GK2R-
M=M4([ZLM2_$F8WZO6K?1/&Z9[)O?BY\AP4RY"*O?Z$[:011,DO,(]XUFWOW$
MXP-J8J"R@>@SC]@1T1MAH -$<'F'Y;E
MA1%]:70*W2F,>0',G<@*90*-(@Y?E6.2 1,"G&3 1$"D289* S>Z$20"Z#= 
M\I*S#<7R]PAA:J#"'B2%$HE<>WB"M130,!5K 8"TP'QK[FGV"!6T<1^LB0#<
M""_/-AH@) _32"2-F'2*F73*>(P?CK-BU[I4?X)SK07MVI?A'"WT*G*E#^A;
M9.(JP';<8$J$.VXPTZG>>X!LRR,3P;8\L@X1VO)5[]1#^H$5$N0A$FQ$K#:+
MP2$!J;,.D",!Y6ZL+_]%EQBZ"[!AQ5ZR6+!"GY6\8DZ&?@5F'C"$!,PPI^AE"E1NQ
M8XKE2^R52E.] #EZC9U1'+W&%BB.7J,'P=%K]"(< ^+A(,;-Y*PW>:7W4D
M&?E:.<;6_+'?W!V0RBVV#J+0N>\LGQ9SFK[X?RP@_VG9C%(&R.2+,#(>-8^I
MK932_=%8OJ-V@<(HNI*5*ZEU9_OG?.F0;6$S#+AI!I++L*B'W$OO#8UTO$ODJ-94G:K06 (V=2
M@%LY<&\#&%)P!/OH&($Y1@B,$6LS6"D 0PIRQCZ2 B0%8+"_30J,T/.H,XG[
M )/E?WP;/C]N!@O9#[R3P'IG^O$#+^0+>K3\[[LVX7K4FCK#GY,WXDRIP7[2
M(Y,3?QSG:%[ +8$) X8E(.H2G?HC_VSG>Y\MQYJ%,T2GH'YZ
MK;'-S^ZH#*81#&(CX,>F54)N#NW@7^Q;;[R \,[([Q08BU>(MR380Z+JBK.+
MG7/=FMG.=6L6<:Z;2-&$_,1H LMZ=E0F331)A?);=@^/^L$CLT$U D4Z)!Z7
M"SKQ(IQXJ?@%2?C%Q6U)9%PHO I&.D![9+7)1\E>7ZV4%J2G5SN553&:"&@X
M$F6QJAA..5FLZ(938-H T28$3AO4QFO9FZS/D*/U7_GS1$?N/-')FV/])Z1[
MEC-Q9[0WGWLNF;P=7@S#.L3=DUC$5NEK6%:>E&SK:320,=] 3E>X+$'!0]
M@E(>(7,= CU#X9[AZ/'*KDV\\9Q8V<]=3'>X&9*%5,"*WIGO1>;M
MKWTA0>AMOK@W1GT_YRZ5./PM@#^(9\(!29)HEH$Q238YQ:QDR<:_FTJT$F/2
M>+-L2IQGQS*).: CER_"->Q71.<62LY("7%:/$Y=VYV]6,1YH+YKN.@\=^"9
M*!Q$9>&H'(:>R_X_@G$+$SLR00R6%<$CT[?1+R:$[1W1(")+R'/(WY;-PM$C
M)7;?LQ&3.XE.DG 0E86C\D_R-_G^QG_*>J), '_^O=]3.P+,]80/N]@TJ7GZ
M)%P9,'I45 7#=#U]DT'2$B.VYTWY8SJ4![">MS]+IK8?318.^M&\4&FXLYEK
MLJ?9R&)3NWYP?U#O\X^W; YT?4M8IV#'&7:R-&)([(JC)"=Y1)HPD;?7/T?P
M(?@$[^MR/WEL4&,PM\?ABV^9%O$6,'!V=&(A82UP78Q>S $Y2??Q/Q'+N7-]
MO[_X)S6GT5O)[&@6PG^SYKNNB?AO(]O]L;QN[^;Q1,4X8#_/[WOG3J*[)#[C
M\.><*13(E(Y@Y_)(RTM5X**81 ,<[,SDCPV/@7IW)6A'G
M$!TZV1Q42HFBTQ("_^G.7D;4BW">,F+].JRC>\>$$!3*>>U$NZ!VX?K!_>N8V!3(T(4H*5BR [[%?_^M??Z
MR@?= CG-L_ ();"5IE*W0IV'2PRVHN@9?\Y)SLAS9_=LL3'!N7\=6#Y?F.6$
MU.R'ON507TK#53*N7J)VA0SXDM8ATE\T4^GH;]6MO@+[^ 79)';II;=,[,&#
MBI*;B5\,D#*:(<9&,":(QB>;\:EI=GOMD>Q6 P7].:-/LL+\)=XWW>A#P7YX
M^1"K>9E5GQ,6-L49D1#<1Y_4MD)>&U!9'JMZDMJD$%4] 4OL2*'*IU B^.1+
M!HV00B&%4I!"B9#QZ.BUJ_;: @9O\;VVHD-I"GMNT>;2H)(M[*278*?82:^N
MDRX"K0*7!6$\Q7A:;3P5P6QA3:8I:K.JQE;1#%8$ GQ)!PCC+,99A9C92
M)+NR&2(>M8-FAV:G@-F)$.V ;&/$[%))VQ0\NX3:6,')HA*,5=7NIPB312)$
M5E@C?XJV.U4U4M%ZG2)DH, */]CKE,LDJ^YU0C5!D5\XT-=E"KZZ""-7N1>JPBF'R*JK/*;^$1^/4WPM4_97O7,%)&C!U"4T:H1B_"
MFS^Q1[)G5'*_.U2FEHH(9E]0KQ-C/<9Z,0Q=M%@/I(^*N:+XN:((98=+X@?2
MQJH1CK01,&T4(8(4=V9>Y<:.#08T==$:#$ R122-XI-&$:+')>UI)(U5(QQ)
M(V#2"#571-(HFM$C:01"&J%&>@SN0M@YQG.,YS+%<[FL4\HHC,$/1/"3?)L4
M!C[<3R7%<"R:I=AF*5F#(.]S;S#.0=T.C $.L!E#;<[(99R2MU8D(X50;09[
M'$I:GXS=#A'< *#<,//)K(P.A2^^95K$D]KTT=K3G.IZ' T*,679]DXIDO>B
MA8N:_HK0M,G[T'2T9JQBH1F#,&,(L1FI.%JX8%0AZH&K/*6%%GWF6&O RUQ)%
M%_B]"!$('J BIER6B$%-\'H?K)=YRV4<6.\3WSX@D#ZYK$(B\B89BX(ZP(@S
M_4J.0N:=.HDPTR^"&X!0+<H7XI^0'WFU Z-8O5W
M:O;\Y:4;5<,REN25;K"08JG%8<1BOT38MPZ]]>J3_%1^J:N&HNA"O*+\ZE70
M)50=/Y5V27I6S&9-(A''529Z4+"M"X%M],?HCRO&;&8.D;,__N(ZYEJ^,N)6
M+/^;(&ZX7"(S=I$^B-?$A^)]Q4#P%8Q!>D];'4.0RJOJZ>N$@"$EJDI!D3PH
MRBZ-J<&Q;.3Z8B((75A.+BS=H*+JB"UC#%%4G!;.Z.4%E[(J+:G, !@:0,H*
M4B&T*&(G%^9$XO?"]I_D4GE5XQYBJ#<7"JQC0E:Q8=
MD6S5'Y/$\>%W_LF^/'("7;(TKV748OO().S%+"OX3'Y:LW"V1N'RSU]<;H[$
M7D(1@7L2N(>RC"&<*,PK<8Q&(X71&&^638GS[%@F,0=TY'()N(;]FLV&).F$
MBVM09_14DGV)U/L':&QWW"<^^R;&IZK-:5<3&)TN,IBM ^TPQN24;:"?C[\E
MTHEMJ=)F!#F"7"#?G JSJO,1Y 25<0*$GI+0$RJNI\4J%A:5+>Z!Q&O?LP++
M?WMP0\?\]#)/!UK^Q;UFV_T\RL<=D_W]!_& ]!=/8S=1-@4#F/]N*M$BCG=P
MW/.F?&D.?:"^V_-\!/(6H)*%@T@6$LDL5+JIZ8,B -Z1">)62-Q>6=12!,G5
MEK,0VY>R9/*W95O$>:3$[GLV0GJ')B<)!Y$L))(-UW9G+TQ9G H:+B9\.\XY
M43B(9"&1_"?YFWQ_XS5HZXDRH?WY]_X\])F2VY!=;)K4W%PVLIC0)Q:QM]ZR
M(P.NCXJJI&I<%DDCRI-8=>20;/36"51Z1S3HJTN?=MC>S+)^"]@GZDX],G^S
M)L2.,#EQ0R?P%M]ZCZ*#;H6!HVOY\/MR,1][CZ4T7@O?)XIJ ]$OSVYMSV.)
MU/8\5L7:C,\2JVP\HC(I!O*"/NPN*\_8C*X*K0/VD C\3
M_BL>I<'<_4$]\.I+7 _L6'=<>4.;_09XE6VM0D8KVSDX<^U5@#0,CJAMY\#+
M_37):FU]XGD+>0)=TG+@VM]IU=W/IQ-Y-)>P&KB*.TU/,,()XQQ/*PH3 > *
M1!<)5'%(2P16W7%:@FD!&(IRFEMB!06P\L:N3;P'OLZ'Q[L[ [SR$M<#5WFG
M(Q\J#VCL6S5YGH3OS1W1UJJQ\P2T'[<<*_WZ-#B5>[,O? =O5%NK*$Y7>].6
M]5J%TY:Q;K5O)K6^W=$IL8?1\^]ZS?&<17D8NF7K^+BWCBUWN;60TM1;Z]XT
M]/3JW;D\%_7J7QN]N6?9]?K6P2 3=T;7O>@^L8DSH>,W1N-ZCMDS32L^"'%@
M^1/;]4./^OT%^X^YZQ/[D^>&$3^:\>X4/Y$S[W_,"$X% /2/JR.?ZC#*$MRTEGI582?O6;&@OWJ=W3WN4Y
MX5?[([07C5/OJDU,NA\^_*K=9ZBSH]IT([E^>=OIUOJ(-7\>Y"
ME$IR.)&J\W_-X)[!ZSMY0:4F.EGTOGUYKOOUC]7?8!GVT>I;)69=-=M:VC76
MS<6PW>Z-5LM;N9'M5E!5!82:*LJGE< QBZ_1BSHT S.[:JHPY<^B(!,4-C%/
MLQ62.M0;AR^^95K$@Z^]Q/7 5-Y69,<*J&1Q\I*>!7841>M1I-A@@NY55&J3
MN>AQ> [$\#\AN]QP9W/78?_I[XS(/Y#H%9\@-)Y#O21#!G92?IMY_&T!*E2I
MT3"9QV0^QI>6#8Y: 22E^;4^HB]>R)Q]O7/448+<37+4Z56YEZ36N*EW2DT 
MDS>,KOW/([79'TT^]+=X\HCCDTED%_W%]B?R$I[L^VDSN*_TPJV:?A7Y?LQ-
MJ%O)GSGER'V_!8_N!IR[*?/,>?0>D+U'(6VT'/D*(J3Z.D[5
M?"7GI!LA53VD1$BZ<2\WD'!R?N@-=072"K>X DXTRA:U;V/EHF9S=K%:)2X6
MYTZ5<[RH#W%U%9
MTK")OSNB;+![>F02](E_^"T8L%@ER!F6OYDP3K%^A>8ZD>(YZG6>?/EK3-RA V93@
M,BUWXV7VUJL(8(Z^JK@?^I9#?7\OQLY%&(#*# 7,KV2%0_8.%KH% -VK
M[&I%9@=(M=F(&A8^9:9IJ%V,S9B2@7/C%]DZ!FE9;?VB:AQ2<1DK<1=! 5F 
MS'#(7K!!(H"A @&AAH?8SQ,NV0"WW.8#]@]T7^)%
M=E_:GD11[7WM]$,_<&?4B]ZWP:W@S9JK ( 3ZX;K 78/.HQ L4'A(N\0+RG'%QE7L0X0B,,@,&4D;Q**-0
MP2(^X-XATZ@H)[W>X^/LDY8+-S3DQ1-691.9];_/$?;6K!X(N/T_>.Z_Z208
MT'=JNW-E_,#I9:L)!:P6@E9]7H4C# 6 J> UW0(,!56% N&@@%F!DJK'*8)J
MIPB$! -.$4CF$?"86X7K@ZA\<95?PILNL7DD1_-(2*C@M % Q2_'T+\^#;Z9
MU/IV1Z?$'D:/M-;K8&Z/PQ??,BWB+6!HEBWEX]Y28JTEK*4XO>V-E]=KU8^7
MUX]JN1^^OA+;_43FP%6\OY"2[+*F%;6Q])C&AB]A0($K:VL-)=FA"/M^]-,.
M%TWQ6A5G]?HZ] -KQH1E
M/K)_&&\\FU]_ 9;.CZQX6]MIEUP*"K2;6ONFIA=GY!N!1!%PM^>Y]R&P6)^P
MM*U&9O+:0)KV":6B78MIUX4/N:!=EV_7A4\D'%/JT!X3^YV8KA>#_)%.W'?V
M4]"RLZ.:/;= V=1[VFUO5A\GI ^A-WDC/O5E=]YI%RX_'/9H"P!:?H/IS
MBY1?S4C61"!K D!@+S+VF=/KF?\._8"O3#KMIUBM*HK?#WQ/'G'\F17MUS5<
M/_ WMQA1ZO<<,_*:LGN&:P4"%SYI\WQD"*!S^30UN@%]I9Y'S<^6^8/Z >]M
MS:G#A3^FWKLUH?=S7K=VO<@NH*I]+Q6\9-%P87 N^U]]]A#+3Q9%KSX\7!9<
MQYVFD(,6+9)%5QJ_D?Y!IW^5MGF&KZ]L7=29+!X\=^J1&6B/D0"'4PN46[VK
MSR,W^D@#RXNF&.Y?;&L:32G(I.K5!6D6*YO:D>8!4V7"M"56=X6L[@H]5XEQ
MO5=7&.K[HY/@$B/%J\-"I.D]+M@5[^
MU.WX@N56_ZTS<6?TB?RD_E(8?!?QR'-GJU/WEU8@B?8SKA>N\M/T\M'V1;#]
MRD8YL)H'L9I7&5PP5%0?*@I+#./1KI=@0%]): ?]Q>;\UO;ZV\83&H.>\"_+-<&=/Q"//)U5!C+-U,=2N,4!%+^;*(LXQ\\(DRX
M%"4M[CXSQQS\391'W(X<$&O%^#AWZK%?_*X\V'8%@6@K!&U_DG?B.>C9=N2 
M6"L^BDJ!FM3Q$(X"/Y,@9(M:]!?_0XFWM>EB\Q'_X.F'"TN/A^M:;:PXLC"E
MU#ER0R!)'3":)9/(]2 P/_1]R4D"N'*
M@L"JT9,DPOA7$V58G*'MO1 GT\Z>O%^($S?_^)G+BT9SC;;AS\!RIJ'EOT6C
MKE$E9>ND?6AP6R'@V+)69^B7!X'=M^>T;QK-_,/G,4=S^]"[,^[9'ZDW]RR?
M^K?.Y%5'HFNB6\T5,UL&5\J2E$D(D4V99OF!K1ES70N AN
M^:OO0KZV-"T[V611W?JT=Z*N=%L3K=VXY#'RA1TV)
MD'Q",(4#>?UNKT.YEN>&]4QNF%VNU7)#\UDZ^F31@*K.#1*%(!L[*)""QL&^
M\4?HT'HK>#OG*V-W,(XM\HG)YLXESMUM__[QP0[]1KL9.XF.VA0@FY2DYP2M
MFWHK R?8OCR?MR2>2;$PKU737W'$XB/-9O
M9MY\&Q9"CKF:K&(JE-&MWP^]+V60CF=9O/E,%HW:^=I-- NU%'[OQ7VG\7 4
MN]];5)L8V2[A+IL?V;I2"Z\+L1_IILTWX#JX8_"]7FJ%IRA5UG::-XTUGE/4
M=K8OSZ]"OH*EP;B$%8S(Y/#$/<.-=#OA&Y=X-8>90(!L7>$0BLB74
M9U+'T7=GF[U(IVSS$]
M*G<@/NH7M].&TT;W!O:W7UF\[6[M84]9OMRXO??3"TZ23P
MW#D);5?-$LZA!&0KY!1;V:[5ONI_$"@H>#\'].;@_YYHJJ):M"JJ5O>T1
M3SE0Y90#D<9&ELC4.#)5<)"".ZEL4*AUC6/R5*W:*1.FR[>7&<_CP'#Z8>[5Q,YA:F\$J/C[_-B O[IA9
MO>M1YV]%BS.)0I -:"(%\VLG6]JKT)2Z22=S #\I&NFB=I5ON/G,C'D0LG\<
M+1WB$2OGG.U1&>:$5#S3I>ACX%+N%\?S-@3;\BC1?O!1C$-]Y1^WE]5?['C/
M^^"->HD&F/3E6WZT-_5W'?!?Q+/(BTWY2#,<+"X=3[)H8C0R(+;XI/;)\YW
M'YWDAC@>%0_ZR2)C]^?0#BR;+=DC-L;MK1PJ42Z(18&Q*&>\KA:(5<7JBICC
MIE!$G%4P4AZ%F^++OE!D1V%A^[$*1Z&4<;EZ(%88ERO&(F8OF+V(E5=CE0>K
M/.(P1\RE14UAU/.,^<5L^9RC, $;_2-&ZNJ=HU29=7K/B)DU9M8B>$2S'"==^H%%I>\%_I!M+O/"BSJ
MMY8[ QI=.%@[M>3ET4^9U@S7,:4&08H](7)H_LK-+V*KNYE6W<\.F;D,^W]3
M\\&CL]":R:3C8ZM3P)DGP%OOK-R9)I.2TZQ4 4M.$$.T%W]NA[X6'Z C5>1.
MOUZXUGZ-\@]L0,:W#93C(5(\B+!O%1 .ET0$'5$!J#PXRPU1F:T"@JC,D:5CJQ0X
M9[]JP DK;FHI'$LPX-2=ZRB$M/JN9O"IVFB.R6X%R6ZU-IY*#NHF%E?#!%.+
M2YW1UL3QP/(G_-U>ODS0.KX^!=P.;I 18H., '0#A\=P>$Q !X6;MTK>O"5<
M=7V_":^N'[IR0@&R$ZH6E=D8@[H S8]9(58+[$_* 391IJV%:_QA.QK;T>(U
MJ'"*$*<(1<0EIA>87HB'RG7JKWSG)X5P$)45#9D@*A4!GG/X%X"T/5WMH^YW3L%UC%=)SK^\84XW^]?7ZD7G_D8/8;D.+]@
M_+<"M&?XR7T];Y]LFT+1Q=DAO0]17F&F]#FTX"CR]]L?FZ$WAD F5F<%OO%T@AAL9Y,<#M3.4%E>A]
M$2J#Y)0 8,*#)TQ:G#"A,Y'"F>Q0?2T;U=?RIOHYPVL44EME7)U8OT* TO,#
M%$:T2B+:#J3T;)#2BX!4$T.@K"%0A&I77@0W^=,)6]Q4!,:GV[HU-B#Z-'VIG6>R >>U#F.^?$6<#0
M*UO.Q[WE;(;2$M:C$$-H?FU\/:+P92TE\-PY"6UW[S"56V?BSN@X8(_ Y7#G
M3B(#V('*ZHW>PY]SI@H*&"S+@LJN+'*:U#DAR0U*$T59'D[U3#BMM6ZT6K[$
M0T?B(3#Q*&B$/9MK$EVI^3@6M&MDEZI8="JR$8\+3T.;?6@^TG?JA,@T+F :
M\6APDAP5KTVK6AABL:CTAL>]?[*4A,I/=&5?O^3X-QL2FCS02WZUCTID3
M;3J  46N_/1K7IXN>&[1,-/@*V!@$/_-<&TN#8_8_.QJP?_>99_>HN1* 
MC&!(N72E(+&*7I]"XK$'H+(Z@U5XV5^GDLJ.82^WP:^9;,):82H]849D0%\M
MAYI]ZK!_"1YLXOC\F&W;]1E5]Q,^W8'!,PN$U(RHEO\0RSFZZ/[U>1S3O=T[
MP #*2O$7R6:#F\N$H]!L2:Y0'+D>M:;.MJ 5QEY*:2@$MB;Z/?1[HG2CT.\I
MX?=$ )N.?@_]7O5C5;E#$?V>N'ZO:K#M#W2ATU/&Z95Q\CLZ, D=6)EG^"!P
MY 2.X!X' QG,0%:!/^HO^#^CWO=RSXA%=\'$SU7;'#H8+QL=7#I@'I7N!HY)
MXLUI/@8=[I7EN>/&L=GFRBZX==ZI'VV\RM<\5'/C)ZQELZLV2=YBV(MH@46X
M"N45]K;ZSB,E]M#G(D9+*S8N[4L:;4QX&\N#[:&!H8&)9&!E;@<6+#M"FP&4
M+*'=8.(DHN5@XB2/[:R^,_Q/R): 4:>LJ),L;[0=8#4[-!\T']'-1YIZ0BD\
M3^7^$01B)W4'Z7S+'GNK6"X 8!F%O5]/4,M B@;(4$0C:*+;#28WF-R@[0C5
M^T0F)FJS$UD8=FF$,!,(R3Q&$X&8&,84L:D71A:L"V,H4=(Z!'UU0E]CH>-T@
M45UB6%T.82G#PZ;#RM;3'0<+&KX$AJ^AX:/AIS5\#;KA7YL_\I>G]!R3_P_/
M=-Z)756%'WU -L9]2G/H#L1W!T(FS ;U.*HG/&&Z?QW0N>L?V"+1J%C
M@C=\%5C @;K0\,6/^$(ES]AR!V7XV'+'B)\OU7_PK'?V2<6!7TIC77WIF(BE
ML5FY+:3:;3Y(B648_887&,'7P*X>/A&FG92G"V@HX *4Z%"5[ X:T!-D'#]1
MWB]@SPP=!%;0%,\3L(*&B4*^S$","AI6T+$HITHA7:@$09#X+Z6QRA^LY;0)
M">?(9.;$.$<&F!,+E0ROB^0P3
MVSJ G]\CM6%@Q!"Q"XE93[&&@3F&V-8AX?8VN,:">]&48ENX 02B!>(&$ RA
M9N6'+AQ5&3H 1>=8)=D$*J7%[J3J
MV$@":R-R'CDLVE>1Y
M/X\*T1'?SP,O* K92A)P8AF;RS@$+8R# #^/*("4
M!JM&T!:;(^=SF@E6C[%ZC#:QQJX I_(C:7V/"%K !(M*],! 
M#$"Z8U:P^X
MG,1)&:A!4L@T6;:=,C)7RM= QITR0$OE0KH /(,1J!_ ,QBQ>B9AWTQ*FU6C
MR26V;%)J2\,S_8?\3CN]'ZE8ZT$KL (1-B
MV5R "FDQN@!,CG''OHH>0(U9!HD=0 7-(\'-%7R;5W+KP-:J**U5#)+8K<50
MJ7"H!&^T:!V0K4/) R# TU,\  (YXLXE#HY:Y%C[292M
M-%8J9YE5PBD+%8(B3EE@,,SQ*'2Y6+$*@Q;(B@'/6@@\9RF/%U"'!J +@,<%
MA$P"Q#@9$8O2V9R ](IC:/]8U9W6H7H(,2O$8A;+)3CO8DJ. -\;R) PQ>R."@@,Y#:D&NR
MC+UG4/:/O6? O><*JF1HJI@>JVP=\KQB"!ER-H:LQ%N+D"5G#Y8FM;[=T2FQ
MA]'SK%GPT*:3P'/G)+1=[*L> HG)[>.>W&(^>B@X:>Q+_."&:$8TEXYFH2H8
M:V 6>6;QLV,%U!SSE\[XVRJX?WT>QPC"SH;<1QA?A@"!R)ORN^Q*R.6J=Q/@
M*RI2I';@G07X+3G7LHGG\9-'"=/V@B%M,PXJ@+>0VK1/BEU6VY8[[!8U68"Q
MM@R#%'3"  .LV $6EB&#[X>H93O@1]H%?5]U]8:H0I%+S-=7@W<*RI>W!*Q_
M2VW':A6K(9-1R-4>S%>Q@"1:J 4_%9C/D:VB1%DDX%C2$L$M@&?@R"+012"+
M0'=1<,+.QS.C$\+X!;?.._6#&4ZB@/(3?%#TN K108!+,P1_K6CUU@P^ZJME
M.\H?:Z$&%Y5_^!Q"\)-TT)#1
M=M2R'4S7E2BB8;HNA+M0OKHGX*PK^@D@@\"6%Z"#00:CB((1*,5;?D?;5#N"G
M=/#5#C@Q5!%KD-8IJ, 7T"D@4\!B)'8RL1B)[4QL9V)"@0Y"$  <.'H(K.:IXA2$W%XJ;,(AM36KF!V(;4>X"Q,K>UC9DZ.R)V2R+J"#
M0&N6QIKEMAUA22KVLI'W"A9HE>^Q2UOF4L%!8)D+O%/ ,A!CF9]TDI8($,I/!HRHS 
M"P;,@<0F4JNS_UO?H8VXNW[&HU2>Y6I1Z&$?87 (;'6$##39Z-MCH
M)< &XS?&;[2HJ])G+;<-HFA.:$X5%I>T(HI+I5L'0KGT(0C!@:/:M(\LLS6Y
MPRI5_:JRCKGT_@UL/[MR7RM<\2$'*XK?(3NFD]"S O8AVE+.MI0L8+0H:2UJ
M0%\"M*?"["E)O&A-TEE3*6>WJVQ/$$Y61XLZ8U%1PLC7%;,,PYW-78=K<0?F
MOQSF&A_.2:-]A)MVB$3FKH?*'!)V(Y=Z[O
MCSQW-J ^,TW^P;WW-22V];JPG"D?6AK9[H]_4G.ZBL[R NMBD2#L4L,N*4@H
MX[E2+%YA*#%MFJ%-[U]C>7ZFP9MK;JC,X5\I_4)F=,TO;Q]Z=\;]D/V*-_EQ'ZU?OMPMP9*?(S)VM+ZA*4O$SI^HS3H.>;&M+8J@OT%^X^YZQ/[D^>&
M9ZZDO<_
MV#_\-VO.-$J_F=3Z=D>GQ(Y'B=; CRX=AR^^95K$6\! .5O,Q[W%Q&A(7$UI
MJJ_7;^J=#$%Z^_*\4C_M:YZT]C/Q+<=V)_LBSTD5Y"6 [4P)8Z]YHM?SI[#&?.'!GEF--B/-(Y^$+$P0,
MI![UBD?6 Y9DZE_K@\=Q[VZ(&BS)7NM92$U!N^5V(EN)B<4QMRTZF*I(!2X)
M#M^*INSI0$<$9U9L9
MG-'VY;DX(P26),#:.7AL!R^(]+MSFGL%5;_NBFVFBV9S122+FSRHE
M)RL4W)_(8[LQZVK\$3JT@:Q+*M;5NFGDQ[I*':G "22<0!*NB-_D#(?^I-Z$
MR18+^:4$QV:VX)CW'-EF0&C\]&=^GJ\W'#^/-]>K6!4]*H(RQU[JV<9>ZCEW
MB)8CO>A)2E)XE1.I6Z.&1SS )FAN_GY_.D,&._1WQ .<$0'.SR6G;PQ7XSF=
M6"P;9O>*AN^R)%K:RD-+6-QJ^^Q1=L6<0CC-,1R
M5"I7'(5M@ER4J#J(Q#(+GN?!O+6*O+7 69ZT(7UHTTG@\54MH@T++! YTX/62)S%G37CA\%B<#_C)3-*$L-\41,DN]7
MX'!$^9B_7YO<$>FZIEI&7Y#MGL^(MC"C3(Y(U,0P)<
M;[O+@&EK)1]+)KJN*^@O/
MWT7*7$X]J_JS9/?.6WZD$YOX/A/X),H,[\/@_G7K0/?HC2N\.^71-R[==QHG
MIWLG)5]VD\LV?"CTAH=KM+-]?O(UZBEYD /.RRI$L&9-(FN6Z,492MNM..\ 
MT;)9J%;"V>UHH6BA:*%"I4 R62@R8IGM5G1&+((UR\2(T9K1FJNS9F3/^5JS
M!*^R5=I>\:V\LM6/,9^5PS+%R6=%J G+9*$8,V%;9O4Q$RTR"1!H//D8CV1 
M%:]X@D 5#J@BU 7$ RIR'('1+SG'$<$BQ:O4H?$(%SK$.(AQS*=^^0"H-WD+
M7)/=LC2H7"JX6K9WA14CN(9Q:T03TR_AXH5,OA^&/(-#\/YU'+B3[SN6S( W
M6 BIU0<\RGO4'%CO?%DF^V_^ 0#I
MU;,=N5W/]#G/GIIAKTP>(,@MEJVL%_+?RMF8SP045"[.PF;1>QN_OHD
MY,JOA$@1]>T&!%'IV8Y$B=ZBD^>;W&-4:1!$U'6*W[E?%(S?'/*5>A;
M#O7]<9SA;H[RZGOD;\M>G9B[.@0?3&G@U/KBZD#R M5M.R,DJH6$@.TDA$2U
MD!!A\CBSE^@Y)O4E1D3B^A3Q$;@XQ*.BSS/GFX>(4\@9-] : O$%3"&_0\RTB
ML3](6IXB'N$B. QG5&8X)"U/(3AD[EA@C*@ZRQ"PJV$P&;BV94;2N&7RW-TV
M&+T??KGR+;$=VX(H:3$\64B;'1DGI70*6[ +\J*[Q#/87KZ=S)FN))D9U: ;
M?N= ?40\Y<&YRG:C")Y:1T^-GEK"+DEV%G*]IX:<"@GOJ#$10S^-?AHY"/II
M]-,"R]3^$1[=@W1<1?':+2?*0:3$/>? $$U15N !$!U]74]1#7,N-:A)I>V5URN2O5E;-L
MK%%7XJ=5RR8%\=V84U9>1\&I)UFGGD1 )F3R)F3P\)R7GY9Y=$@0/ZWXH&F\N-C$J<7@F":\4+!F47OU0K^U9.3['@*\@$/!86Y"XL
MP"N98?E7:,]=(3.!Q[AQ_E=P,"O\DK4*FQD2^V=1*(?:7CJ7AK,LD*RV_"L"
M 2T[:&-G2\[.E@@ANYHR 1YJ(NNA)B+XYVHPC>TYF=MS\'"-O -YARQ8QOT8
MH/VV8.TY>/C'P[F%]N7(2W"\0F9\H_^NO F-^_[EW?@>
M$:!1S50PEHAE+1&+T/;()7S+ LAJ.[KJNCBIA[$$\7*JCV3EB&SED2D9-,HN
MV\C+Z"I/7['=CU.G(GC(G&.WVD?#[(7NM< ^47?JD?F;-2%V!,>)&SJ!M_CV
M\ @%@$?7\N'WY6(^/CRJ&XJ/JYI[GK\L&CAD!LOEG- X-_6=-2EDXWI6&W\>
M2Z#QE8T_CQ6I,=S&-I[2P'O>E"_0(5*9^-ZJBM.\Y3#]LF\=VNSJD^L4J:,B
M2U>DGK5
MI%+GP;H4L>7+:F$]";2^KH7U%%%U>K>]TO/=GQ+I^>Y/F"XZN]H^_[=$:OO\
MWS#5EJGRC)J[QK&*4&O.K&KTK1!5G=T9?^I+I.=/?9C..%ME&7,)5=_9W=1"M6+,ZD>/;!\ ,@TAH,- ]E8U_EJ]A
ML+\LN%$\<[VX+]/L9!]G)[&U+ZVKOFAN$FM9$$E9]CQZ<"^1G@?W"D5@U!S4
M")QI.@.ILVSJSQR+L84(-1:G'ZG#34IY1.;JA^E0C_(XZDR*Q[TK[&EVG%"W+AVC87"*HX^?_<(2TRDYYJ5Z4!TC5+UL3C_;3BDDVQ*I/GL;0J8^
M<6G37R+$]DQ6CE.>O;F).57V*"Q 3QI+7@*H+7-W"D_T
MDB.V9J91.+<'4=793Z?'K2R"Y+29+13/W(-HH1<5'-%(+U%UU07'S#DM[GF1
M*;.]R-)Q SE$2\_66L"C[06F8AGW3&!Z#+K$L7*[SV,)U+=RN\]CA;ATIFH6
M-@WD47SF'C#:.$06G2T>XQ8J 2-R]J(DMOC ,6$\X4%(V\N\&Q%K4#(5)BZJ
M0>$$%4157Q!E9:HUEC2147&4Q:ED0>-LM@HPE@T!VR'VWP6RN^P#;;CQ.B?"
M(T(1,%-J@]5?U9@NE@3!1UMLF L>@;.I$GVPD$J\J*&&=:)+HF?5#;7,M D/
M,5&5.N')A()3J/2JQ/?02:),?)^[0&J[J+V&FI,[!8_1F2P8^P$R6?&IN-T/?9[:^^-XF7X$@=55 \OG
M-[*DL3PX??591?+
M 1D" DP&@(G@P8XEF0@P"0!6=6I[&X=(1)^J]NMZ,.!,Z#MS)]V?'"H"5,'86M9R^/[XJ13HS"8X-E:^2Y>NH
M_&J4+R!AWU7^ZJ^/U \\:Q)0@%$ BJ>8231!"!H 8I
MW)_ 0!24A((R)R50J>4K->^)!NZQZU_KXS?B4?^%,D9+^5]0QY6Z[WHV][UW
M>?[;BI)1,)S-;7=!X_3G?LY+;5(@X.BZ0%KX&64>3=!_6,';U@>&ZY@6>!4?
M3=Q/KQ:FXE.S<31D>5GX!98/6O>5E>8JM>2CNOP7\VN?B?>=!FN7)JE^CZ\4
MK1T14A5"!"1V>S,#C\29[M*!S^2G-0N!O<@HOS"0X4?7LMMPCAWAP<35Y4T]
M]"58ZL?$4HC$4BAJ2#K#?4_M:_UQ_(SM
M#4':&[5=%9_S-+7*YE6P,"HO>4TUN88 D)=KG)]/0>V#F4O1<"ZETKF4PL_P
MP=X58.ODBC2I]>V.3HD]C)YGK<;;N3T.7WS+M(BW@*$^MI2/>TN)E9>P%MA*
M6V\L9((V0YO>OP[_$[('^TR#-]>\==Z9X^&/?OA72K^0V<98;Q]Z=\8]DQ?U
MYI[E4__6F?P*0]OKC7]7R& )C^-"@ F3I ,("D3*X3[7^&Z&.YN[#MW?.=LS
MXS(:L1^(Q7[,(',K(#:B+A7JLCSC*75L6,I)?2B2>:Z*G!@-X500+U&:+/7H
MO)2K>A7Z+(8&V3 $:43C*(82UHR#&>5A2 H_5"Z&Y/=#&6.9%'ZHW%@FAQ_*
M6-*1W@])SH=*+PMB+$,,E>R',):)'\M$]T-28$CRO*R0,OAR%OH8C/J4O%/O
M+V+;%'I9[W I)=5N19AB/J/FZ*4!M[,YL3R^6N":3ER-0LK63BO[^<]_68[Y
MA?Y@\K=-X+I.6DQ)JJYZ&"R%7?]IV9[K0K?GG56@':-R9;#<,\J]#M1YV\7N)(35Z.0LG6D7VK,2:10]I#X09__TL,=<$4?K 25O'XCA^M0_]UB
MN29\-2>L12%%GXG3PY

TM<$4GK$6AN'Q&T5@#DTG9YSK-:-5JQ&E4M"IQ M&F='5'#<6,^6P6F?L67L-4.VX',U;+1@":+Q.=J%T5@*-9^)QE@%DR4BGU$T M%D<44G;!\_]-YT$_L"=$Y@9JORSM[VPR MKK5NM-IZP85OS,+^8W8E%;3S2<,RI7"NM=;=LL:\8FOC*\;6ZF*KG@T K5P! M$!^RJR&-+OP@W1W+S>N,QA26BR-Z.90HL]BHGK>-IHC&Z*1ECM+G#G?" O6U M24XAIW%ID7)&Q.*UV)#V%SW?I\'.8>=WKC.]L]ZI&7WD_Y.YMIYC/OMTZ>'2 MI$GK4RJV?NDS)7[H18>W]HEO[1Z@._0#:\80>?^Z_L;Z7P:6/[%=_ET82.*@ M.2;A&%+G1'P*824D@2E^8G6DQAG];KT((H."RZHBY,]^SH1$;,D"#7=+YSE& MU19@AIV;1B??.*>=(";8;1/V%2SGRNF8-EY;DRV@<-X\4:G!@JR /&7_Y:>W MSL2=T2?RLQ<&;ZZWTM_FXX!Z#K$?6<+KA'1,O7=K0F\?QS#TN>*?R:O<\-,S MRX2<\VU4S99O>-2T H-XWN+5]?A+H7:T_8DZU"-V/_0M%EJ O>/JZ/(V:DY< M'TSE)KP6??UVE$_4G7ID_F9-B!WI=^*&3N MOOWU91L,#]$OKMUUKU%K=(AC MOM"%ZRP#$RP$'!7 A]^7$OCXUY><4M\=^<4QXK@ 14V3"GZQ]IG8$JFKYYAW M+E/3'Z%G^:8U@??NRW.QY1R*H+B33U9O#FN>'TC?UK!Y:] M5Q]E$H2G"!8S1IB1ZU%KZABQ6F#![%Q825H;S%B2/D^)NE?4Y!R^9T<96V"] MT^4+!MC78&GX1,(2-9'.+A2DNN-BG]8+IZ$?-!K\O[Y9T?LDOVU>-KE7^EOU MV&'H-U[-Q]W5;!?_=I=35O&O<]-H5&:TL;/:9K] E)G66(\N$*21)I*^:U^X M^YGXEF.[$VCO'RLFD^BNR7"CC56KB_*)8R)4!)>K6,81M?;S MPY]SRR/D6+MYOO$)LZ$CM\H#7J.N7E9_680SN\O MV'_,79_8GYACGOOL%G9H6LZ47\-^SW)":MZS9XL4Z:\Q^N"R>YOP4J;=HD?1 MHHJA=TQ69L;S?>IY#H8OMSS^$3HTOS*9P?[# M(O&_MQ9*5%S3$*/^&^!1V!!KLR(N2^C\N#9N&EH M&>#)+M?SAN>8SKGS#-S/41.G$I#"](IE0K02_QF=\93)?VIY-M8'F^RVHOK7__SQ#W,F(\SMLKHJX[CK41D@>#>D;\915;,EUHW6U+0PL MM0A?:JDX.:ZZIWNL<;1^ED?B3.G.;I[/Y"??_H!HSK,9EV$I:XUL-B'MJ 1D MJWE]^ Q6B(!4B(H^TF8;#-OFRO=O[XT#.Y/0\]@C1P?Y[?DO17%T3&*K<>,$ MD>7DGA#! C24,=$^&:&AMY ALL9XTRQB4B#6N*T2D*QQJ[*IW31:59A"C_H& M2QG)E#K8&3H*[D,IE5K93-T;BB]OY9K>[^^RKZ(.!7#[?B5U*%G.!1BLCTI> MH6U'(H9-?)\I:"N32KPN_@\FJ]?^8DQL^L4-DD6X%_[+]+^0YXK.*&43JJ_1 M2DX$HM1P4>&T5/.FULYVR/GVY;GMSM^>EBK1G "]9:\*8);R K\].-9K@AT6 M@<1%.%R62UR$.C5BZQ7N5W$=_OZ75]?SQ:0Y?U)V;W8[WP>695Y&<=(K R"[ M.=!E>;EPQE9W_I;*DN&*F V&$N%#B9Z->NO%O/060XF@5H"A1)A0(@+ID]]2 M%:QM26VM%9>UJK38N!'".]:-6O"&E2WAL%E*96NGXU&OWS1R?O.G5EFA"M%5 M/;I$2G97+^63F)U@'B$/,RDQC]A_[6R.QW[&64%]>1^/3SS);("#N0WMD&TT MO0/3V])B>2W%[5B'R3M:)UJG0-99::(^V)U8Q$Z-N-BLME.S/:^8HE.S?3DV M_3&$8 B1MO:Q;/3CS!B&C^/A(PM =9P9P_8A!I)JSQ!5.:1@=T>P[HX( 43' M "*R 6 $2J B&&QC8J&CW&7N-"[Q"L^X+KZX:C>1L76R8VS];7.C]UP7_NA;SG4/V)_ M$AVRS=WDNCJ?YM4XF_PDM/]+E-Y-:W^[HE-C#:"EK:_U, M>+K@,]Q<1@2UQ->;-8C9MZZO=B[%V>SWLQFE]UU'3A@^@[ M+"&?;'MOQ+7'GLBT[#"PWNF83D*/&3'UAS^YSZ7FR'-GACN;AT'D;.]?A\1S MF"OV'Z@W?B,>[2^2;[ 3;0W7>:=>8+W8=$!?@LU5,)"Q!._G^S$B _SA^AH&N*%\Y XJ3"U0CP]D>CD%( MB $)$:8OTD,BDM/]G#MG>6!PL"B%5-]$;R"2-X#%&= ;2,8-TGL#5+V<5H\I M+::T8OLH#8&*0!6=6I^O[C*A_ UDD.5$57=K%3"KN9D4M7$ZDPD?M/6_N 'U M[USB^#W''%D.<2;,8A[IA%KOA%E ?['Y]W7_-'K+%O$#,Z3>^E,@KN1Z*&3Q M5U=(>?GBK2-B!HG5F* WC%O#Y^[X)5R\D,GWK?S<9C[+?&">;O'D,6&12=3; MY=+9?+)Y]^4;$Z2U?G6CX7IS-^X&LQ_8GP3@O_=(YZ$W>2,^??#U,&2"O'Y2LMSPLRKQ[Z434L7^B>2@_EY33- M;/W59B']U0O,8^WE7U\MV^*?Q=X.AHN^!,=KCYNX8I#>0A?V(*? R:4/6P,;3KA?2;V]T_464Y@ M/MC,UWUQG2_AQ*;$V^/?RB'P0'H;H*477TZL&ZWA^B(M6@-:0T764'4E.,$: ME ,P@N;ZU 5=*+I0A7,R??>UR>O-4)\H+W+.WZP)L2.\1BT#;_&M]P@%FT?7 M\N'WY6(^]AY+4W6F5Q(7J>JXI/[M=EU9WQS99;/G@N%_XD5\W%W$\F2MS2K4 M4.YR?^WMPX/.]TY*O[.6+Q2WU.*6V@T.\NH#"KZ7MG%3;Z9U,GN7Y[:)?TXG M%E,?NU?4+#]J8G*9H.C(R$(C(V0TM+R1882SV9PX0 H=B8-YZ^K'X7I@SW2@\HI7 M7B'S&(VXJ(GZ*R.N-K(1KD:!56Q4>#D%GNH+M1HJ7)T^U6WLTE';)<3C1A%D M2D/EE:(\K4M_[LSG6F+-&=\3UZ.SN3'NG$#3T_VKP7;PVTG.D?H6.Y M'LL"78_])V]#\H_5PT.&G#I)P'$].+.$X>9J'*'[H.HO;OE1<.%.2V],^?*? M'9]O%Z4FW_&E=]K-04@;M8:VQ*YDCFH?"_N"66[J22&9*R$KI,A7 F]44,TGA0,HK$$-&)]4N'ZI'1HS%9:0@17A>#<:UC0C>::9 M;GDJW M/(5+MZ[&(WIQ(!A&-YYG;U9;*;J.;ORT9 0R 4GPV&O^VJRMA>Y'.G#X =I1 M[;S1C \!5A.1Z62#F,R;ZD9R3W 'L2O057:2J40C(R*K);O/#IFY7F#]3F UB-B@0]\9L M$+-!L;PDUG E8==B>\AK\(B3CPI//@K7&+X6C9AXP4 P)EX%N' <%U9P7+A: M0H'M#I7;'85A3\(H+FPX$RXCP>([%M_1:'!;!&Z+0*-)_7K<#'8SCA7]Q$1S MYQ(G.@3@P0[]QDKKG?),:/V=OXAGD1>;/I)@]_Q_=C/3=6[9JKT7XGR_?WVE M[.'Y9=&#RV>):=6CME%F^,E]:&V6F0I;Q;D&H5XNG!MKO;#/B 'XA##5MG6Q M [". 5@N2\0 K&0 KOH=#Y7O<<8(C'M*X87@RN>1T&R S#"AV0C4K@=&G M1Z.YNMY:Q)&TF.KE;X7BGX:+:1[667%"M(# BQ.B8@?>[;%J@WU@.=-(ED[@ MD4D0$OO^Q;:F)&!B\?N+@W>(?PJ)QQZ 4HEG\]*+90/)?;D(!'^QIY4OP"*_ M?"-OXI@]WZ?!F+!X26W^(I%;QZ0SQPHLZC,IO5@.-1&M*T=VF>00SR+B&?&9 M!I]2 L8@_IOAVEPJ'K'YE/@=#=B_^_>O!J-D*P&@QV/7IQ,5NKCBZ6,L>(1H M$H5,D@UB,AF3(8L!$2!#W]S&PXP2GV6DOUN^JS?J[8_/X\'J'JN/-G?E-TF^ MY0/UQF],/-NW-JUW!H_M-?%O?&&9L4<"=ULE*1_C?^T\R.Z-MGYA0!UWQE^0 M=^0WEEKAC^N?^Y&]>ZT^6B_MC&3B'TF2]^F'.'/;X?/C*1VRCS/?\I5,+)MA M,NF^W#Y7GV>^L7'_<.I9V<>9;_GG_WTZ=4OV<>9;]A_O3MV2?9SYEKSD.-UU MOML"M>*/L\OS;G12GG>CS+><_7A+NF48>'3Z\?._WBYXQM,ZO\NN\][C^-0M MV<>9;^F$^\%QUSCG[%\SW_13_^32V<>9;QG5#$^8YNKSS#?^#TL<@N,(77Z< M^;9DZE'*(]ZQ&Z\OR'SKN>?^FTZ.WGCYD_V6>8;OH0^R[3\1,_/ M;[KZ_ (L3$])=OGQ!;?UK.0X%=^5?YKYII/0#]S9<7RM/C]_X^@4I.*Q&],!C?_W M"Z-%3S^H_4X_,X[TYO^RI$J/]'6+K:_8]( M_9TQ4/X3JZK^H^5_WZ'AHK=I &]2;ACYH#Y@C MZ@_U[JC7K.EZ]\,O7,K1ZB-J>*/5HO_WC]^*E#H K8[8+UI39_AS\D988B*" M+HU:K]W2^MJP-1JT^]IHI.G]6)=]O=MJ-?9U66^@+J.+1#-*@ZVAUFB-FGJO M.=!J@WI7Z\2*'';;PV[SP"CKM1:J,KIH^3S5ZU#KUIIUH]]K]YLCKS#H#T8]+HI>K=9LZX,#.-=;]1U97/>L MA2VY>6+)0Z;[=IX.:<;!DO5W4DF]G]A $?B G<+Z[#5^:YMLV^NO*$.ZOELV7:5_V+^[[E,3D$QP$#*+]S MGS :/*'C-TJ#GF/V3-/B)D1L?M**[7+>Q@R,_?XM)G;9YY5A:C-&/0&;:[[88^ MJC6'=8,]*PM8M9&A->L',:MY(/ITC^P;Q/,63/@,^LPL-@ACJO%XKNNQSPZM M5?NJ)1;&.<1NF7+=,6%Q@''TO]UST;G;Z/>;-6TX&C;:G4%/UWM]0ZLWAAVC MU]6&!UII: ;QGU1J_; MU!CM.;#;0\.]0*;UZVE&#QP 3#13+\3VC-N:BRA;R&WA\. M>FUF$FU]-#)TK=^HQ]%_-&AVFOK^>IK=3O=P15F>+^>596XB'9-$OS_L=@;: MT.AT!\/A@+&?VI++#KK#=JVS+XFNIHLCB%,AOL'6TAO6&4NO]YO-_JC;UY8J M'FJ];NL@5#(02Y#KZ/!"+93(&F5L!L<]'CE&]KH^T7JTS&/1Z6F?4BX3'!-GJ M'GI:V:3&_CQSG7'@3KZ?DU2GV6XR'\28VDCO181EP"758AE9LZX?8Y/22"J9 MNI\16J/9K[,H/FH:?;W)O/JHS\#&X=5MU7O-VH&7ETUHC),3/A6V2BW/B*O3 M&0ZZ3&+M9G/8-!K]SG!4B\35'#;T8?/ E_W8'D?]/B\2%2LKW_('5K3;A=VL3X,?E#J[#)H%W-LC\CG'C5K=0:>JO+_&KS($U9KB?C8^6\FM+Y MC-9BZ4^G4V^T.DSAH]:0"2J2TD#7&-@/BE\@I70166EU=:/6Y^6"0;=1X_5! MK1M)IM=@Z>+PH#P%43+I"4G3Z(TTO=MB-*0S&C9&C,0-(FEH1JLY,%HR2.,B MTJ'7N^VVWAMV:QI+)6M,%LWNTGTRWY-0,*_M% ] "2@CP>C665CIMVM&HU/K MZUI/JS5K$6;Z[=% JQWT."L62449)?.T3:/=ZO9J;:W1TCO]48U)J:OW>MUN MO]$Y*+J E-)%'KBF->HL"K6T8;_1:+6Z?4:[(LDT!\U:9R@%?M)[X%Z]7FNU M.RVCS8A-M]'66ZT6ET9WJ!N#1OT8!04EC8L\\*C!T="K&;56K]L9]%L]?;2L M6M9'[>XA@=WMWX$24$8//&3Y<*_'Z'V;,^%^O]MMZ9$%=7K=5DL.S&1)X]IL MTN]=IUQK,G_1Z;;T;R:-1;_'>D&#R:%83D4:]_DC3]&%_5.\9S?YHT.D8 M3$I&5^L,C5'KH#T(4DH7122&%MXHJHTZ-:W+*$QKQ%)D)IG.L-]OU6M2X"=# M1!J.>@UCU#&87ZFW>!FIWHJDT>EJ-98NR""-RR)2K=]N=)OM7KO+4FCF=!LU M8YD3=.O,YQP.][5$B$@7"2AK1!J,.G46J]NMH='HM9N#7BNRH&ZMW69B.U;8 M!B62+!&I9HP&PWZ[WZN/AK5:H],>\!R)V9#18:FD=I ^YB(//H'F,/_'1P:> M7/:'S,4US6#67AMUZ_5&EZFPKG7U94.UI_6,^H$C;#3;26GOP8-<^J"'&NHO MY_+'\1S]9M:AYYC4_T2=Y1#$N>RLQ5:J#[N,-K6;O:9>TYK+.=W1J&$T#GH* M>KLNRCI]BZ1>YDAC^=6HV>PT#4:A=:/5'[16,Q#,7 _*.\UVDL>J8IE]C_QM MV:D7VFT/VNU>3=>;K7Y7:X^:_?9RH?W:R!CV#Q;:Z0BR4,/UYBY;(XU8'4-Q M]+]#VXHV-7('<,[5#$>U1K=CM-H&RX^:-984+/,D7N34#T?.=4%6/IS1]$CN M=SL]K=UI,*HZ&(XZW69C9*P\TZA6/RC;:KHH!OMY0B;I<F-N@.]V=4;@_:PJ7>U_FJ1S!TW#A"K M)_*HLA>Y'F%/G+G[)[7-D>OQZ0Z,^;/7:HVZ[WM%JW6Y_S8*:A^E@NU:H0HHB!]W>L-UI M#WO=5KO>:#:,=E<;K;:X=+JC ]CIC8*X7N9E9B0'K>%HR)*VNC'HLQ6,6&K2 M7)*#WH %RT.R5R_(WV1>Z/7D8,0"H5$?U/MMQG6;_1[/Z9<\EX\''(3-FB K MST0.1MU>6V.+TFL=]O^-VJ#9;B^W>C2,8?-@HT^C41#[R[S,3.2@WA[66+2L M=5FNTNAW.FU-ZZ[9O'$X^E#OBN*7,I #O=5LM+HZG\1D"VR.!JW1*@4=]+JC M@[Y94Q,AR!1'#E@:KG5&[=%PT&DWM>&(N>G:*K/I,/]UH'2M&'&S6@86E-G"33S+[UA M:[7#M]YIMPXRS:Y>4-3,OLXLY,!@MM?5ZOV^K@^[M0%CH7I[K<_!X&"9Q<*N M.&[0Z+*HV#+J/;W>,#JCQJ!96ZNSU]4/?&JC*XHZK^8&W5:CRQA1@]GJJ*Z/ M=$8-FJMS!T9-XZ#.7T_JKU:Q\DS<0&=+[/5&AJ9UNCUCV.\;1F\K:SD,FG51 M_%(F;E!K-=O#1MWH#4>#9G_0ZAC-]BIL=OK]P^2L5E#A(/,RLQ0.=+W1&/:- M;JO?;6DUO=?MK&,AL]:#Q*S3$F&1Q7&#FE9O--J,"#+=&WJ'!:65/(9,_\UC MD_'GY;#994\W'=4GCS@^^UGV'P_1:79G.9/()S\2*_U]%&[SQAY/*LRT$9=X\/O#XW/*^&G$^Y:&='9)K?.%QK$ M3[J]&?K)C3>)#4+VK]$M7JG'E'G!>,;QGI#6Z!HL36X:@YX^,+3^R%A6IX:# MD:$?M+(ZM9UMQ7D_?WER.<-X#6UD-(V>,>IK/:/3J7.>N]0Y"Z:'V* MDLNJ>>F^!N0G]5WG-3XFARX[N3[S*^ZKM?R>Y7PFS&?UAN.'@-X%YJ_GG=WD MC9HA\U:O<;?T<[2_8;,1X/"OE'XAL\TQO]$/VNYD'+[XEFD1+V%S8V.[M]QM MM!J-AC%HZ)U6J]UH#=KZJB:^5XY;'1AW4_OU_['WKWBN^8+&B3\0#>>3,9_XA=H9O'O M[K_U]VWHY>H+B88DZ:BU!.),M"J6Y&, 6[-!E=SX7*^.7N>2I#N)7NUT.KX: MYD*D_QS>?YZU=L_G2!S6I$(I,,T8VDJ\TVG"V+\PM!C.K:ZKK/F:J,,6/_=I,[H=X(M].&CR"B.3[&9??L)F^FD[Q M)L>+^@Z%&]R^?9CDN[NX !\F#VL<'J^H,>9W'IJK5MT978;EU6]IV=%)@5@% MCN*=@IZK >Z.*TBL34E6%"[BH+,.84JR(6WKW]KS]OX!K'].,)?$YJ;7#2R M7+^0&X?[F5M6Q7<)E+ F4J,9QI]@">\27?B/4#5TZ%/238;_FHR?@]@X?;^UE/UF'GSPCO(@.2F0^L M,L%S8!W07J4-'#F$K41'U:\_;%WM=;#TK:AV\SMA?EW\<_ 5+?6@\]KR?\D\ MTV]NEG_%(B;^VHP&H_O_&(YO]TH?)L/1]'_/ M(C]ERDIM@K1<<8G>1& >Y1WM_?C&<50GJ^U:E1GK"?L'P^W MWT LA7[+G[-S5&\9P"[6 KSX5_82'H;3SRVO40O;KG%F6XVZLH08QSW5Z*TD M%ZR,\U22C5!;2UE9BUY(G@\_4_"3Y\*/RMQD[6(2U@I%B'.E?M8&I455)'H) M^)U,>)DS DDECJH2/,;(UI:K5NE4,[0P.)7PZ!Y>X;\&GS#,Z5(_;0GK^*8C M4)V;&/3_9I[@Z-.2&[V;$O*008%;P;%:HYN468I"E"[@'\HS=4C1&;4AQ"._ M2K$)FL=*NQG#=Q@:3H97.055+.ST7X._AE\>OKS+/S=N%>-^7+([3X"9D=9Z MR91P5%$2N4#]*BZFQ..U 3/UZT;(#A7N (@PTEQ\2I?TS!'G[(/NQR5]T1'] M/0%LB1/T>4D +IE/7/@YL6N(5,9-JD9_97O#=J# ^T/YODU3=).DQI/QY!7^ MMR557M;[MY/Q5=-<3S].,Q'%N^9N\&UK;'Y:=/'X6BL5F""TDQ#LTD%60F[* MU>!!WA?=$V#PI("_6CLXP^EK#*+O/P]&X@GVPMD$&I+CA%OEB%2IM+!'='"] MV[@7>QN(\\*SO$T+3LJ<[E\W$GMT-5C@-CD@GC N/1I':[H$HM%6UP1" &+] MZEU?PV'KZ\NP4\<86$X )"XP2>!=LL!(S6/]=J?X:=?7D^F.TA!%+;IM,A@) MS&K5/12;W.%2^[VZBA%VK>]],_F*W@PJ&7[13,M+=FCNQM/A>F*^C_71*NL) M& M24LJ\@+7AEVXP MNMZ\44O!]?I'3Y>T?,/?KCPJ?T1!F^OVX.!MV8ZW:[_IS1 J7S M-W$:6%_B\"Q(QYL;M(IO;MZ,FL[W*A,(7HU:N_HP:FLLWHPZ +IBAH/= 4NH MI1(U+()U47NE26DXTY'4#6>@=DM_[,*/@Z+]I!OT1QXFHT=#H02&D R]M0A, M6\9%BJ5867L.=?:T1Q&.7?@A4)3Y%"?6"CP/5C*>8E(4@O!,^?)*K]$@51"H&R=7>.5_DMK7KF9&R;B%L6=!H)+N8664OA&4M) M8HA6 .HX9:8T)GE4&$LK^,3)T%O*>,[OFNS2?D)G/JM.^U?#3LE>D!>4"*'@ M&490&$;)W*S($A'>J$24<:)J'U&\QPP=!-0:WNO/]C9[I__15AE]VE9"64S+ MTAGC#NU&KDO.E9XNHKZ4(D\9N/FWO[T5_[6R^OY?V[/.%?Z)@],M@G+(9(!& M9D\A 4T4RDN'BJYRCF ]\NI=TN.6WY.-<4Y$A6&XR*>2@-5C!"GKNKY- M"G3&Y?=Y9S2 5RZI/!\% B3 MWYK[;&3L9)*+6UL0-M\=.9NSX9N7RAAF!7TYI9R3/1_&&[Z[KW..JPN615TA3QH27 "'5A*&EYQF&Q5JJ/ 6DXL[\XK=X7T\PIB=.ZZOTF# MX:2MF)W5-.4A?^^:JP:7=+U)!V%NY)>3WRN-)"WN\^DZ[6E9J[)Y=%F]QS], MQOTU?SYQXX!$HP3)_1M:L7)K1'24JP>2U;>F,\.[<1MQ\S?_AN9^.3^?K\P- M0Q/!WDV _0+R.5XL;)-GHN57T%+!NKT2SR@\- Q]99:T\0HD%'H5)KFMLORP M?6,. .P@P-_\.6HFN;VJ5#&\']^NGHBNB,H^?'J8W@/D/SW+0]$_=S\4K6F=PX_H=X#ZH@1SH;@8!5ISZ*D@N866(..BU02NB<* MKY,0L+'ZPX@+!%O\3KMNE)"31&BTG@/T?XPGUX,-ERM=[C7'6 -=151Q0'<1 M6," (S+"M-).;()M--?B4GAGPX$^ */;3NZ]R;?'CBS) H>?0@?,P/:UIXI0"K9$T[UW+D@GM29=SET<+$)\4MKE4"+UP]1A->4_2SU7[\14V>>LZV>$3J@^ 6.VM ?"LAW MPZ^C7B];I\2B)P8/=K(J*9O*2[]+Z'Z(S4CRYU#)YQM#_W:,GWU=1^2+80,Y MC;?R6M*UG_3!+Q1S+F;*A! =C11=$=ZE&FG4&\/)K,@_T>]!?];%TML/R7.Q M(53[T^TJ6EX,9'M"1ID&2=EJ$S:_^Q;%# M)R)M;DU:N I/AJ=8\01O\;/RXZ71# MRG8YW(\N8N!#C,Y%V)3;EGE6)"K1+2%$\\TIEL=OUWA>??[V87+U>3!MRK^[ M5QM[_3\/&V8&=Z\5_W@8-2"64E=/PNBS6J43 S A&=,Z6.-<8H6M+AD35!7" M<+%:(W(4%CN1;*9O\POX>+0@E?EXASI\]1G]J5;EQC>^F>2A.&TWU,/5?=LY M&M'WOAHV(_QG:SLQ?5ZP.:$.& )*;>"R4A#*6BQ,VK+W>#X:32[2V!\[)Y%C'SC[97O61:4*,:Y9)R %-9*(U+LCJ]-)F[T<3/]&=M?TBT+/8NL MNW4W!*, /?JH39Y(*!4OQ6M&6>+,9MT]8%.?4M3=^FMXB* 4%U9+DD3.I)+R M/N-5VOP^MOX]D-=-V6D,Y80I?_WH^G MF8OBOYK[_+L_C8;_UURW-)S-]8=Q1T+6_>N_FL'D[[E7N'\<6_O+5MJ>T1=" M?_%+Z_)E,H=<--Q7AB*9$]8+S45$S8$\NR-VL2&1VE6IWI5&L^=#Y\7MSYPI MI2PX;]";NRW<0V+YB5(&$:/UU%@3I*;1*BCQH[=U+V!'/?1SA_ XY#_L;G4X MS2GBGCG%? #@3H@@@V:B#!!1-M;.XV6^.$H$EQJC(Q+9,.X,6L?-W0F2A MIN"7EWF\VCZ=_QQ>-XOTRYO1WYOQI\G@[O/PRN;FF.R!C!Z:_'H5_[IO)B-< M!T;FZ+Y,IH7[./_.CJ;)Y]+ )2*10_TK%3@(:+E#?33H/C+=72Y!H^G:' :I M+C'_% +-P6L#_E>C,FGWS>,E4:TC"BK)_'S1Z@9O2E;G7KRU.*+$XMO0!*\Z(F23N - FT;5[OY5EM;4:?H M53;0HZ5?SX#-LZ$+"J%M=:;_D\GZ1M?_/6Q_^+\7G[%X5Q[>8N#S;GC]J7D[ M_K.9]-:"&NFE\$J')+25-GG?O6G$9#3;_*(DEA'84YS=&,R3F7BG-/;3I&FJ M'$E8XBM\% "K%H"2Z#W8$"6:3:EB,,+DJ!RH,;(ND*%J@Q+L)\VI$,A*0-M* MX[U0>(478-]1B(DX&ZBV>,BH@3PEL45!@2",B\KK72T3>@80^)NK7$8_H6P' M"&@?FK[!Y5Q'+Z-#W[XM[8HLTGD9#D6S6,^X%\\F^O(=\#BI5; D1:?1Z4+M M=PD8X>74.^%JR_]XJ>=-$)GS+#MAZ)J];VYO7]3KY2J(VBAIM<.3XK5A$;S* MA$M4H#=!1#VY;[5\<1L>%5[_0M?K8<8EEE-<'T?C/S+;51Z;\6IT]W _74V# MOZP MVJEQ3D%V@34]_)>\:SX]8"0PGGRK?MW!]7W C-(MK[BSN<85K6O'NYD8L;*> MPR7[0#NM0,\/W6%CD]"G^S+&H_ZMM.SU3A9WF5PN$"":0";&2Z7RE07+>T+- MG_BOX]]%=?&OJW:0S[Z[X)3@,;#\_FUSY:XNT^@2>%:7@_Z$_^"I8=M+<7F4 M3$'$?^.ECH&N#1W;2N+ ZWG7/P3V?4Q&.E#)*9?:,HB"RBA$X:3,4Q5[>GE_ M!.S.:[8IR<@32JR.,8*-AL\W ".TRF#\W("SV.TDP#J&7BQ#M2QV5$QZ@4ZB"1H#4BDHZ;J,8K3I$K#/!%"Y[.G+/,KSX]O;9H]1 MFMKC-\X7]Y!+MS8/#9RGIO[X M-EKYAG'^"_POS?UB+&6.%+__76OO9O8S(^.;# MX*]!1\Z\\XCUM((!. 8!W1F\)+0/DODY-YC+PYVK8>3+=\.AJSN=5+T,7$2* M7*-HB,*8FAGT.LJ(AF#CM@/_?/+TL82&G$/RP7NF5: QS=_0I1#&Z,Q M="6:1T-)$)*34%2>X#JJ[D=]NJ7U-I>22)1SS@9&O Q<>#6?8F-IG>*HCN/V MI8U'2\VGXYOVD7FX5"V>K[#)=1ZO8-^^\E6&6/Q.V[[JN4%KV^@WO1SMU8*] M^HAM6#*!<4WPQL*#&PQ3T>)M;0$AL#4?,%\7^S#A3@1+WPMB!B*,OPQ'PZL! M^@1W#W_<#J_Z0DQKHQ>@"'@J@\Q$45V2RZD@1S-S$YT:WBNX>;F\'M M^.^#N]Z60$@D!LFY=P9C ^OF?IR1PJSP^-S-EO)O?^MWS%]9HBF- M?]T-9XG\EB_C=7[U>SW\,MQ10K$XRYJC#Q'RGG'KK&"JM"#ETEQ#LA/:^: ' M_>H#UOOQ[F[_]2IC@^*1 (8&P6FB$/9"S.8=;]=K]E_PXG?O6G#7G(@_V[ZN MM/USVU!>)EY;-$N4R&=U7K'[ME*NE\?B9*\>%S89W.:ZG-?-/7X]+2.=>]_S M>> T:4^\DQ*8H:4")E+T0RJ[O,+-<+CRN 9 M< :V.!+6."_JE^[O IZ9"NVI05XQHP4U-$GP"5+0*A:(\+ZOWPR>%J)MEN(1 M9ZYUO+(/UI7 O1I=-U]&K7O=@Y6F+*9,;$4]D-&0'6RC)HY0B>U 8!SN![I,K MT3U0PRH7:K5)\L7B9^9CZ([G)3YUXOV[E>0P2J-T91Z)V@R?2,=0_X>2#8!G8P>N[E M\EW+97E@("$. SZ3% U)RZZDRCNK2#4:9[6.\/3+%3W:FVBR*F@!6CN&B"Z& M[V& 49-JZ7.O=K?N1F&])MQJ)B IE3@IJ[7.U!E%=F;5%;M5UP/>6)Y:CVS)?&V+=:H]!;5'9U(&?_NGKRLR1*[8!%X#%H[W( M4:HL#.&U6>5T"W:'KJLG.1MR36\ S="X,PK!^/D!3S:$ZL@(P@];U_@F3^U] MG1G:9NG;13_-[,EK7O_^NOG:;#:H/96LM]/[#90D:P7L*)41&(%H8((X@, + M(Q7'O:F2T!HVBWF@.',\VN+4W!,S\_P>\G3U>6&I:V[&[5EHYATR^17VPWCS M\]L1LV>(\89)L($I*9Q&1RIU^2 1I*E<9LE6?.;3KOZI,.DYD98+O,' *ZZ M.*](*%V!,>(!K?) 0NF7CTG?E)R0YI^S@8Q&BRJ,KI!"<&RM9$+$S"@&\)Y51 ,UK(RNWDYJG+11%_F%%LE M>'7U&[$FT&'K.Z%@?4J77S4U1=?5,95\YG;LK(4GW->-@;]42O=LDO4H(7J1 M'L-SW#GC'/<,!=+%*\(XN/8BUZ_+TP@V'!5CV'G,>9CY$?I',G4PQD9X@&PV M;*'DR]J6OGKLYKJ5ZU_4(R7H4;3H(O,QH6$CVF+D 9Z7(:K!!5./SN'K5_79 M)>A1* C!,X\Q/\3,AHI*)'1LG3'AD]XP_$>><@^N!M//>//2'H95% M4BTWS$)[5EEZARZ;7$^@\7KQ41&-@8YI9>$6S9>H)PT#W:UB^\FTJ%M]_^?@ M;MKFA=_<+/_W:1K^U5QW^>,#L[Y,@74*;9?W3CCI RM97^MIVLC]27XE&G@1 MZL#E'2'7C!3V0+D A5*<&J.9]AA].V!E%++3SFZF[":@U<%RS9:WD*N$SZ]& M\TAUG\[R^5RY@SM*5P67#H^9!&(E-R+1%)@H5 MO;>OX^8:NL&\67LX__SQW6H/=CMH!&^J^;=.,\_/]/[S9/SPZ3/>8BU4+#,@ MR.AYBD8O.U0"N#L6LO+F[GMN^;N.A] M6YLK9B _].9!$1!S36C-URKY'J5COCSHF\<\U?^ W#:?-TN[<=,L(D M=UHRJQ/^RPI-8\J=2X&[I"!LYLE_:LC0N&\SQ@N%JSY^3RNUL$W;4;):2I/3 ML&C8/=,\,1VS2:=,"![DYJ$D% /+HW":3A_RF7ISDY\U'B9'9AR255$HBFZX MR:]=S$1;TBCL#<>YGV$\08N8 MR_I\)L6;W __N,W?B*J136CA:[G.38++]PKC'_,X7UF)[AM%CD&H)<]2$!!2_LB5,LDQL>,VE*R_Z3REA0;6M MDI\V]_>W6YAY^J;=,8TF,"9GDU 6HBD2[>,DK9*2:RD5-=^^=YKZCLKQ((& M$GF,*G+A\^2QLB;\O[HBD9YB47UM120J2I@@4F*TD+@UM$R]2H;4327[ 37- M^=B:L^T1<^FH2Q:\U8PIY_%FU(X4.E^N=*Q*:%;-S!XK>M3B^\;/Z3RZ@V2 M)0;K27HHECP:7Y=\4/.4B^][2B+X+41[P@+A1@G0JHQ!$I;HRGI29V&H7 MF^0)7KC$&;Q;DZ/1D:!+;PVC9K./0$ 4.7> MBFQX/BL4%D4]'[_>LXJ^BRM,"Y4@5VMK'H1#F$28GTQ.ZJZ M:+84XH^'GW* ME_M2P["=3L=7^7BW_D#VF.9L N^:Z@EZHP9GY;ZH RSB+'ZU(5IM]$F:EKJ94P?!-Z];J? M$Y'TT-P>"@5HU"*.X883@1!)/7.E;XD2Q2J&)XP.V>4CT=8>' H%"32'Q-XD M")2DE.?P=5 0(TE=O\+TR:! VXUVW;;M,=L\[^<^-2DQH] J^Q O_8>BO<5 M 8.XRCZ#E&(_?):EOR"LCCE/@G%MO$[)&YK)4+FRY=V/ZLBJ C5:6+1?*DA' M'35+$K/*6A9 (32*>Q>* 0:BZ]YDQ?<\:J=$B5_&L<.P/P?_G"N*+@_Z16IN MH?$D5G$UHV3/N^I"L3KFV$F\PGT>7ZV25HII&FPI<@8/-?DP(DE?-$C'W7#6 M^BBD\D'+F"QA(I0G9[3H<<.$ RV?'B5Q$S.XN6]Z1AP]TXD#FC $"8E+I9F'_!12_$L6 MF:QL.*"UW],\+22_#)2..6L!==D!:"62\"1/][*JG#7/?)U?IWQ/+;HT=(XZ M9(I8*:,@/@"7R6)\HLK=1C,#1Y4.86;/Z.00>'+F9#A*PZ]-'I"U.5OXW.<, M71\561Y6$"ESB5$OBM$FT==&&\PJJ?#>TE\07,<<.,5ST7IR/)C@HB::E%96 M/(I>5J$M\N%Z:B3ES!TPVL_R12QZ\8W$:/TPN M]_31@$8\6DE!Y^?&8!.5!2V7ZA$ H,S&Q&VO]!<$US&G+UJTZ%9:XXC303LQ MGPX;22*;PMX]H][+A>FX5 IW)F&8YIQ.1AJ@HRC%:.0BL3O:+@>JH!P&9NYL\6BE" MT,/T7*1BGP!OPBK+2POY[PO%Z*A#IXW&8)=3B=&;1!\*O"]7'I%!5 ](E+$] MX]ZC0/KP>=)M.7&4S3U.YNIB M;4JX>AQ,T^F,&=^.KDN;RR-F&U!A($!BT@H,O01WA5\1W4)5,4:*-;.Q8RU' M+KBG-#6WREIE\5N-BM8[H@K%9< 8R=>)+77N!?>4HU*6HUNK,;1UA 0MF'+S M.0@B5!T'7!^^X(G/S]FZP]>E[ M*]%[,_C:Y,%!MTW?X -F!;,$-T<*CD&ZS(]HG2892Z#.>ZSZR?N*4&3N"E7? MMXTU\Z+2+^-12XW?MD#\<=M\O!N/9@7\4_R ]H1Q(H=#$P)Q;4)&#!9K3"V M[$ZXLHPMEY;-^GSPD'=J-Q/NF+46.7]K[EMFX<^S5N_E!C;4B-RECR!E_7"/ MX'80AND8@W31%+A>D>D,!,I>D8>5'0\9&ZA MKNB4H-VNB"M6>VF>6[B^3B&6WT$DH9YR_$HZ.F\; 8TW]A8FB\=)]2&W/=^@ MFGX8YW:94S&S22?RX&EO$T]2B^C%/(KTB83*@#"YME'[K>L$@O1L2J2)2D>2 M4EH123-K=5?.DYQ!IZ Z3F+]/!TJR9]=)33^[=O)>(1?7K6%JJ.. CF/ZWJ8 M9+MSW74PW0_^&K1WR'AR>]@P)[)\&4,R+',,42I"4CPE(XD+VE.\]6RHRB5I MD?!4"YY#T ZJF_>Z^=G/'E:8GRQ$'I46@O&$%M%9TG46&0P3:EY6:E;9(C>O MX8@5SGW9_QA,AK.Y?!WK3[Z3E#TR3?7 MC!K\Z3WF&45)DR$J#^F2 ,&"<=U#8B#$0)TDY.3TH.QJ*L# C>'E'"->S$E1 M*G-90==U:CBM8SFQRGI^LA5>U+:IB-Z-9\'X_ R,/C[WM%SI5J>ZI%"RHT'! M/QYUX)2/*>))"YI+%B@>O<+RDZ31K&X'87+UZ77K.HY;Z&5M("0G/?4*;(YR M=%)EQFI 3\;5.57"=AV\1V&SZ_A%HY4"1A+QT5K<3X"RB8"'L0Y_&>Q4M<)](8$"20>WFOC"-<@*\;N#W[NU&$YS*F%0$C*=%K@,M MM#N)!I]J-1-EB9O7N$+KO??RVEAS[;O7QJO\*W?<=,-5\E]W)"$;?K#LVM"N51$BHKO"4I(E$AK M#>HQQ:!#.Q-\ 2524]=;L;5 ZHE0:7-X^"V3I6\YHZX0EPB@DV]$(.@P!^%) M@84RS^L%3=8:DW'6SGP681<88 M@ZV.EO6,FA*<=(P[YT4$FIE @XAS35'U8% EU\+"EP')@7I"''>0'XR]R#=E M$HZH@HK?0'62B;*>"Y7?QO=-0>7#V U&_SL]H[YHIT";F(MZJ0O.1V5(02;& MFNABC4WG90%SH-:(P+C2*C@7"-BH"86282%P+&F@6BKG)5 0NE!V MYJD9=;C,V07(A9_99T1()A%0B:CDO$Z9EDX5N7RJ]\NR.%,]O!B8LR@.>':Z% M*;@0O/)VEX(\!2Y/'&(F+Q*&F"0)A,9[A<$FS,^/X%4Q#[IR3WY^GC[$M"J; M5J\U3V"XU=R$>;#@C:^#!:Y.''COC\K3AIB.:1O0EU(BHH\(" :=7T+6UP2/ M0CR;NCQYB,EU+@DUX(P1-DD;"2U:D^LMZB0P$X?X+!O>\\L(CO" $LY*O8:S M!XI'E/80 L0*03+[) E49C8(+K7C7L4@=&42%JL_73U\>6CGUK=74_ZV2?.Y&4TQ')QQBO?Y:.AS6,\2-YHXI0&C M79JQ$R3%/+GU.\9N3ES]=C"\?C7R@[LAZF]?$;K@B8)/N:=!$&921+"@!:ZMM F@TE FLV^*6C]JZY'^2I]87 LN\(.@"N=*"*2"\!E+.A M5:_D@O"FRHQ<)%#\>%+7RWT_>.UO[JD'[I@+Z#P@3(8Y$D6+$94Q#PC] M?C$ZRMPSJWWT)/E@$JD@C2"Y8R,\R MPD?3ZI=G+5_P]ZM?'_(O>IA\V^L4@J(\12JY1>-$\8OL="%*FLH4ZUJZBT1) M/,^MF+O 4L#XEP)&(D5%\&0[^47CM?RMR3YPT45CO@Y*4"@!77F>3,RYNR1)+EILCV!.B&OU M'9NL0RY%S9PRVFBM" ..=Z)TNCV$"=T)ZK:VCCT>I;;'Y\W->_SYV\8_3._Q M%II,/WP>W,\'.K2-GZ-N^.2;R;_&DSR-*>=0WS5?F]%#4^>2V:[!NR+%/(*; M$4\97EILP>MN+8B5DIRK;D$+B4^QWC,+SW<*3] SE(0&XBAX&F*:%[<(F8Q_ MZ<+O'+D<&%,VD&!U\NCWXWW_+XU\NR5WQ\&$S0*T\Q>,'ZXS[Y3&'X=7C>CZ^F'\:O1U_'_ M-FX\F%R/;P+^JJO[\63:4GG@+WOW<+M9N;[V_UG#!/PFCK*)=6&&.5L MTHXDP[CC-@\[6X+H_\VDP,MTY2X]O;@7@^2K@Y",1&76"T*MB4DJ#41F)$UP MWJ:5\93?)Y+B5$A&Y_&H4I82%Q3U4<901MT[)5?X+!9(/AF&:3S*\WF^-%_F MPV_V:A)>E9%&*[U$-P,4QPO( BMT]#8X=-269!R47_-O?V.K4FY:RC[+S5#8 MJPR.1Y]E)NI>S>FK,CC)(G="T92BYMQ0[W21(CZW?#KYLJ3==4-RD2\I )0K6E MTD$J/,K.,.G\/M#U8%-!.2E31K,7_[Z95(WY?0;HH$LQ219"BBK9& PZ#EJD MSC4.*._*J^VT74MU,CF]Y<.#1W' Z'UT:O4P;A!*'"U6L MK9_EV/ (SXWMJY'%'QY,SG"]'+2[ULKDG$M":@D19%1!=>PG3 =B][A>3B7E M.GH??_WGK_\Y'%V_G8S_![]KLYW@OS/[\ D];X#\IQW3XC[^<_G#>L\UZ(#1 M;IX_&#+%H$BEA#R@'[W2F7LW^\@*ETWK7Y=Q^>\WV$#^V_@K(\]A ]^.\;.O M#T%,*^#4!LT\20$=/6,*X3Y>+H[Z38C1-6]O^?>]&*@^OC\$)B5S]B30F ,P MPD2,K+"(:,E)W 03VQ^EZ^86#^ D%[+A'3(8S7V-@X:QMJ7=8Y3\ ?]OES$A M*V]-EGKJ12*:Y-!91$>)\S%H9Q(:W"7)C= M)H7H+"1L%6UF"@+&W[?CN_SQ!N0#H#\H\+DH*NEKG,!=S;1]WB5%$?O/'[?#3["AU_&?QK[OV)![1 M4B<='AV#AXI2M-7!*BO"?'(L^N7;IGMV]J=G+8]9MQEKY,/@ M=NG3UDKE6_:^3*_UKFF?YEZ-KILOHS;)TE>QBYZ\58)0IQT>1/1.9PU"B -W MM'X@!W7!,+049!CSS-I+\JC>V<3F:1G9W,?-39A'19")!J&9C7A&=5$*PZ&> M6PHO'XS'S-9>Z[5!W5#H >8DCJ&6<&7FA8!;I%X#VT10Q28T. M!J*P47G&[*R/+:N1=;$J<&+2G$1TW-0VA).7>1377&NK!;522,,- M#=KH^1M%\$K6A(%4[,9P SA/C^0V53HA;-(;Q9/-U:X!3V"2I2_.) YV SW\ M"X)MIG+GTCAPWMOHM7922:.TLJ8CIC)>J[JJ!WI.[9[0#4=;OOEU,\W/:J,V MH+N>S?%[2>=YC3(Q*)>GT$BF^B5ONFEY]L9"5*O9+CEWOV>'$M_QLD MIT&:Y+773EDMV3Q&HFYE$O02!O3B(#@B5EP%PE/E@2M)03H#EG,B2B*<<^;Y M9B#XQ0%Q7*BSHSZ&.,ZB"1@Q$Y-[K3"D+OE*ZZW8HB#BHH#9)VQ9\QTY1FL> M S?N @CA3=.%;[CF&1CSEJ6NE33TX M!75C%E^-KGQH@"6YU?GR,1E%=F!B"A5"/M5QMK#_/DGM'"5#" M''AA) BO(X;UA:O6$5]SU4KUF"6/IU,_F$R^W8PG?PXFU].9%]"9L0_C]M'U MS5W6L]!3K\*IY]>Y]GX/OF,."I1%40SC"'@8SS1LQ'UR1?YR56Q=R]F*/7W'/R!-IS M3Y,4"E?N4O !S'Q,L=';.F#/M=J>0^>B](PJ9HTV5-%$2)F\$E*DO)K;=L1J M9V?@%.H@K(Z,!6EM0'V8-W T!F+P--'U[?4G(6 M>!DK$97:,+:K%F/;6AZUX%DMU-H/K9)PY2C@!K&Z;U[G(5J+;YY-#>M+L$0F MO07#&+HMWN1N/Q%=:DM\I0C5*1<'R[V2C2A/RB$ON;EN=;Z!ZUI(4@[K6R:QI.4RQFN\'MG M38*M;4;MK=/">]A95+#$>.YAHF!TE,F5Z91!4[1;U0Z8E1S,?JMZK Q]U[#4 MB9G$L@!$9F_8E@(\9=$,5S* ?GH9>DP H7BQ87S,B),T.4!'.,UY?#6O:2M7 MR5./EF%1W)8+['(UT]?\T^CZS4MU-LYJVC'+[YA$(+I]!H5.GJ&\+(&-A:(2 M71;T5*HQ5D"VZ>%^$IT0"GY:*!Q+BBIKO;9>4$X#)<6I]!Q#T\KS,9<"Q(XB ML&. 0/=4)+SC,^^F#$ Q..A>NKWW!NKK'4ZD$GBKC*_'-W8T>AC\!U&&+YY@YHYVB,5!3>N"B2.[?_O:6PK^Z5>[\9>M+FJ*O M-?ST^?X6KXIFYI)G!7S[_F-_5Z?-8=]*>@\_%:/!+VTQ8P[_/B*<\QM[D5XP MEFGT3"3^.QGAB872ZY4X#Q:E8?^U*LR.9>XIT;O#)5HT\.;B]ZO[KIJZ%0H_ MKI(+%(_$!12.!N%\DE24U)3D5NO]Y7JW+-JY9Z+CB)UI+,T1 2X6'NJ0IJ:[IY0M7I%M?G M1A,J&>JG!4>)=HZ(DD)((DI;&0RQ.C5FY]KN!W\-VX!G?'/=5O8VUW_,.ROB M7UUU[R<,&\:CZZ[T=]@6_6)@,>I*?O$[QO.:WU[2KB2T\A1_67W'/PN&JQN$($R_S^W!E?2UV(>VO2#D%G/-"3C& M>&D>0BVOE7_3[IP4P"?=&W[11Z<=\XFAE7:4 47#SLJ[EV52TVIO?H%UH_ES M<\YV<" _W2=A,F>&NC$=8H@ M6>)E>F<(.8%1D_5_1WLD7L8>A>"%L 0 F/3$F1S*%_K42.JVB5]6YZN>=9?& M5TUS/,ETD)SD(]QH>#6K/J M>ZSJD2+T>/-*19>2-E%HRA6E/,2R99J;^E[B5)FG%J'O(4-**P C;*">"M1 M(N?Y2Z7K9T,.7)]$A':F0/[B2?-D(=-59B>/&B*"LGAY=4YX?B_5E=+]0E>9 MXGLE>(2HI\Z#^2BBQ1!.!D&2C7H>S7G% >K!2Y(]E:2G3G19#),M=UX9QY0P MRK BJ?%:;'M&/DK"=\W]PV3TYJ;+#I]=87.KLT\$!0."+G >GE)F@^L89!4U MPNIDZ1U+/TJZ$^MH9FDP447%G=$L"I*IKV;2<2-TY3NJ]53-::4[L5Y&$@S^ M([P%IS3S&#)"H?+@-E:U4&OS]PZ0[B9K[N"V&=]DQJ?)]//PKK"]K1Z_L-JF M?_E.D9*4./0.2"Z*-<2C49L[KJ'N?:!BX^VT"Y^CL=SK>3!IQ\%9+AA8!T% MIAC-L_"<9"'6W4)DHX-POO7W>#@6HP-O$G!JC,0PC_M(\_HQEL ;-%7/:GKC M'7*^Y>.)_?UR\Q;@K38\*!<3PRLJ>W.;6?[RK^LE7EQUY1.'!'F"J)2!6"LI*Z\T6:>KME"\ MC?$2OOOM#/F,/Z\ROY1O+:>FC M%H[:HT6700KO4R(QDU[.,#P M KQEMXK**:J(R(.#2N6.\XY5-!F*R^_*\#X>\B.L@)$T!,Z-5BJ:R&2^SDMR M0(BZ8A)/Q/IC[].CCM_^YF9I2D)H[B8HWDS>\>3^T^!3<_WVMKG^E#'#2#Y' M&!_&KX?-IM+$=6_ +%S59+SR/D>&) 5HW ME,L 64$I:*D@X=F5@=.HRS1*'IVOKFX*3PG0\C!'_S"95&5'O=Z@"Z5TU4NGHJ5R'W#[S]T:80ZEY]GO'O';8K,2>X!1*X]]L L<:$4OQ/M-IR.DZ*SZP)/0C)M M(Q/"8-3M B>R<"4XP=.V&4XG6-(E;QBJ+8T1HB/!,@N202S\0<)PMRU!NBK18PQ$KO.2M4RK/\;$T M2LXL)YHZ7\Y:H*P>W,;%*IO::4#:=>0L#2SI1'5,A%@-7++.9_:2<[4IRRG. MLL)+WD8&.:2(2CBB>0HT^D)-'$,$4IW [)H=!](6?JE=!S'Y&*5B#/U B7$. M^N.LHYQVSC%1-\""V+JX%2JH_=950>V^O1JAR_BP0AEKQ:^"O&\R]A];"O5) M'!@CPW@(($2QA+MF@J;:!!<.%="QQO+YT33^DQ-93]+P2GNXE%!C> M"1)4H)8 D?DN2$19XZ5&9ZV>/_]L6$C'CSCP9)"I2#KEH MW@4M2!X=;AE"XK3%$TOUMB&9EP3%02:M[^G1>DC*:#PT4G-"$LN% J"\#J!% M_7;QE'!L."9<*S$[*JQOGSD7BE 97%!@\G:[4NH)$B._2U#]?00\F>)S4,YH MF<<-."ZTP=NG2\1&JZFO/+$+ 42Q @CM,W9:,1'PT@43./HJ)*@2ST4%5)>#I;I]%_E"*"8T%;Z7F*A8\/_T/-!7DQB'2 4-%7_F*DUE2QJ%U@0)PU MT94M-X9438T[@M3GE.]T5&%XO2OC\VLZ3&6@X)OY4Z"D05M@@7HG/5?LO+E.]D^PU$)\])TM([2?+D M/$@E*9=2'<1="!ZFV#O9.SV;6$W0EA,IHU84@I!EOYUT]84E^27*=[K]]E90 M9_,< .J,3=;Z^7YK6;.E7 @>KU^Y-^_N;A^FK UXK92@CQGJJ%= $"0-7C-YY3$K)^J'Z.6#) ME#9^//K:3.XSO\B'R7:*NWIR M@*!;L\1G$_7C:/!EC&+^7W/=EHT]C'HK&_&4.A&-1"_< ^5 >Z!H*."[LJ<'J\S9D(PP/J+= M*\PX6M=UT5SQDT)31$V#X>0_!KUZ- M[A[NI^TWT#7TEC[R7^T [*Y2^:.[3[A>W[ M"+4)Z)3*1-&*L+J!3^JT[TG/LL>.9.(A9IFB5@G%/0NZO/"E M#53LISPK.Z=Q45Q-(!17IE7@)C_QE7DWBHAZ73N>9X]8UVP*9K[Q!O?9\_OF MOOU7,Y@L!F0N_=6'S\VD&=S@W=JG8(#N@1!21)TP-(@LQ+E,C.OJ/+$UUK4G ME"G_11I^[=,>]-DE1>"5B%*$1!@M$XN-D1 KW9-%QX[1@%*E0[<-=3DJ0FBPVBONZ@?QXY M/GR>-'V2$"N=Y#9:8@ECZ'?/AW(8I;VL.AV>29(_QWW/DS$8C!2B-MDW47G$ M:2ARD VD(%2?W :0(TX!8=KV0ELXM7*U49A1,^RYU6PM,]8JA, M4JF2 "DU2(J&Q)2R91I)G0UZ+D2>KFB!<9-Y<3B&.7B!A&A!DERT@%<(]US6 MQ3NGRP2=&I)3%B_@H:%2.D*D)%Z'Q!GCN7@! T%G@ZO.SG/ \J@B!L>322(I M,!%O)2V4BB4M%D#6O87/<12>M(@!J/*,4ZZDU6C^B?>FW-#@@%^$;7A4$4.B M*IF@DW,H*LU3*U0L.ZY)[8*<\LG^I!*>CN)".@@,?;&$]V.T&(*YPG"JC0O; MQE\]/R+[%C$H+FU4$BQ>^#3G]6DIS/$TD5#EOB],KM-=M6C!HAOCT 4/4AH\QE8K(XJ'1R#412K/X,,^9=$"ZKG@ 1V7 ME*F\O7!L:71X$M4^7Q@>O44+,1F;&.$1(R_BB&#8GZ+R"\0W95-DCYG MUN"BBA4H,^BY<#BT2"%ZJSAJ9A >("3C.2O4 MOIFTKBHO/>%K_!G$/-FN&X[^F8U&"M1U&YU(5BY*5.IW@.> Y41%"D&C]RFT M\M(3S2)JNBF4];F_NKJX3EBDL+>H3_">3XUU5D&>PJ-%0 ,>9/'3)'.TLG>_ MG/()Y& 4WDZ:+P_#+WWDPQA=4*&,]\H[O+!\(J0<;O#UG7U:F4['(TMK>$IUFNC$ST 77&RA?29#L*BUG =/P6ICYTK+Z@*C7;UYQT#S MO11;H%K%Q"E+GN>1.Q0M0.EQ1##KHI7+@^]9BRU \C9?Q5$-\P C2)(6^&PR M58$^^L+R0M7P68LM&-=)!8\V&J31W@)&U 5'GVB5&#T??$]3;$%SD,RE$-9D M,F]'::D##L;4DY].;=B?98\]!HI:.Y]TLESA7HO2W(.NEP_5Z_(!9Z4ETAE/ MOKT>#O[(-#SH!:Y/%7K;3*[P7X-/C2VNQ HVKUI>2/:/A]L%//4'?YM?96XR M^+]A-[NHP'/]#O_/?QZ,/C7S'ZA!X4:B-#$!&A&ERX. ]"(L%Y2. MVIEYJ/J_HH,K"B3'2?Y8Y%Z-?D/<=DZ)>AX\T>OS1FHPB*J->,ID"@7/Y%:8 M%Q9X,N"/Q',S'@N4N\F:,W,Q?7/340$L?MV,8BF-)__Y>7CU^;=Q1QT[6@SQ M"AC=9,-S-<:PY]ML.-.KZ=O)^.OP>GV8Y7I-U=KO61UFN;Z(OJ#):=5.[$.O M04AF&!$E&R84JT\QK'G69X?B65$79T(].KPG"$ 26OO(HY!E8J5KRX@KUL6+ M ?VW\>CJY6J[#Z"=2D"") %CL'PCS>T)J4=_*;8;^'.@\=S8GTOGO0(5H]0< MF/;<>V;FC^7"T?J=!9AZ3O#ONM&+CQ^R(92,R6>N VC'@X(/\]&NX&D5VS*V M3A^T=2U'+;>';AJ=-^>!&)>K9P%DT+',[F0 ]7@&]/7I.9?;0Y#LA9:!,O2Z MO??$4AZH*L,SI*Q-*6,4'K'<=X_1!*VDER(HQ)'XX*)5KC"I2\)A ^\KW:H) M[QZUT!X=\))[$JR6C#MA+7H%A8,U,(>.0G56Z7HN]50+[=G]@'MN8AZNH;3B MTOU:]'(IQA1=Z,KA*[QA$XU(AF"',U_21Z^28&Q:P M6-O79H0A\V3\92-!_>R*>?MY,&W>/-S/KAC7W(PGS8P;_\/@KX--!^="1Y6O M1&$8:"X$*T1])/"ZV53JM5?:1R_YK-+WV"-0>&N"LU)8F7).TY0W7,/XAAY% M8.R,TD^F@]LW-VTFW;>?]:D977T[?$M1 !HT\]X2!5J+Z$AI,,2+JV8#(>LR M;5[(,4OMP5]3+R*1RJ+#K+CPP$M>%,,84;=&4'V^I8K?X?E;3N8BM)G(DHO*+:41ORH"8(@)%DG>C@M+#O/*N'1"_PGX"VG<9'6 MT6)6@C:\S\X/;3I)DEE1^^-9,W=QG6#^.W#Y.KUGBNSQ;)/X*Q%=[O MU00D-(Z_C;_.M^/]U>?F^N&V>7.36:AS7O#^,P9F\["M_J]-\]O@R^(MTD[P MVX:#?^7@$'6AWL]7OZ7E&\52E0*Q>1(=QUC'N.BV]?QZWG!0\)!M!7@Q%ZO2W'?9\I<(P&HJ*"(*,!$Z@IM'_5C ;H@2PT^PIU?](,YJN9?AYD23_C[__T.317 M[0?EL+:W%LX[JF0,T1F2^2.U4'."+N4WY+\H7+K:B[RGS5_-Y&HX;4ZF^@FL MQ/C7!"T5!I4T<,_;^DBC%'K;-=&1OGR87KU]_1QZ_^JM?>W?Q+S$NPGN4?[! M7T^D^WMH?(H6>*X%TU1+0[CRFJ#S2J*1)MI87=R,F\O?RO=W>1K#;4#4+()Z M>[I;])EWRUK+@;/$\I#-0""S0PN7.(;Q 1V9.E5ZT;NU:?+U2]^AD =Q" E2 MXYW!.%-:1=PA@4&@8M36+*[L66^0[G'WTKS/($AF'>'!IFBB1]\3

MOOTQN/K?[2G"/*6':Q9CM$;1I*UB$;T+C)\DRKM\<\Z6@K$26=>0_99Y%L'J M,^1O!]/IFYOW]^.K_UVM'AI_^3(>M?^]K]T_8%@14N:4D$ 8")XL@J*)5(IS MD!M X4\ REW6$_R&JM #87F_$F#"2GS)\HA&AFX15/P>="TGAX_I=499 M)54"38+1UM!4&CAR0T?=7YCI9E?D/]G2GPZ,)5LRFHYOA]?MA[]"PS.MDU73 MV7+B[?!+KJON'S!' F&S DPP&4(-SL^?0!14]>8_.I"U[7ZK3+Y<^D3^VJW,,I+C'$7HI):!0F6=>]_7D1?%]G\ MLCJ%_.<>]>]1_-+L;\&X8-[GCF8;O>82@@BI[ ?!,+QZO?BY&X?MQK^N!E?[ M[T9N7$.?E46!NX*AD4REFC=1I>N'Y)\7RH';\7%_7RO2R&CBTC-B?N8'_V&L_>-WXL# P68Z-N&$L#Y: DG@V>CJ40-5K*(%@!_GYGW\ M7CPZ:!#>.AT51MG1.&FXRIW]7=]#DE ]HO\BX8>)&AZ_/0?%"\D$=$F%3"1W M=N!-'K4L"2C.3.6ALM6J\Y\[<;I806H&W*#90F\*.(]SADQTJC"4WMH,]',G M3AHFD$SG:)B.>!JY![R?MP:N?4YSXF:8A5&HV+L9S. M1P%H)>LQ2DQ]/]?PB;U+8RVE44FF\F,YB9&41S";%&P8"P+_S@OO)'-YX)WV!CT*PJ!T,R*0&_P[ MI7\@? ]RT Q)7!BMJ?3@>80@78=E4MK6#/),_$@F]" /*PDN8C T@7;2QY MNI90G[W:#:F2[R<#>%(7249JO8JV?2L5D8*)A9.-RRAK3K:7#&1?4[P1>'ND MS$3#2! J1:F*4A$#=5:9P8L'X[S%*3) 5.B!$_1@&# +B196!!=#_>C[HP-Y M-N\]&BZ42RX"T89%+A(I_/:$$5792_E3K\^87K9<^R"H5.@-0"08!HCRTLZ] MCK7/^G,WSIIBYIYKHUU I\)9PU5DM+"A&$KJJL07_.SR//OQZ#!$NL B^L/. M0<(MH4&4.;W!4:FKGK9?7K+K_#Q[=% H8T.@402T5\PS[QW)9Z:[3Y*H<\TO M..9^GMTX+!HRRH#P/!\/3S"J9&*>YTR$U??)S^O]?$EGHR1Q+A=D&QU$R\Y> MVF_1^:4UC<8+SCD?MAF'UJ8HT"F%I%4+G+:9K:)3:VEC;61^I'CLR6M3#/-* M)1 "+;[-3&"T2_];D#Y5%S#_N15G"AX(6)I2'KNG'"@=N1+EQ3TRO !J2N:? M&W&FN"&!DSKF&D1I' ;8WL0N8103#?6A@)=<)O34>_'HF(%SA39+TH3_ 'BJ ME"K\A@+ 55'=+X+],('=$Y>F>*TBC>"U=S+W%Q!-N@'+GG%9.ZB,O^!'I*?> MB8-"!0)YA1 CX.CQ!@ */.3 O$U5<:/$T@_:6F*=3*!SL_6E!-#O 31U?H: MZ;2OWAKX2R[6XFM:YNM9*)FNJ^I=<+W4PE =X2%II MC4<[0+Z)(M/ 2C5&2(*H>O24>,''NX?N53K.$F>:A.CQ2@[@R_ARKS/%:=WO M*%YP5ED\066*2BRB87/@$T.T?(JJNSVL-Q"J+-J/#N3Y*E.4R WN4EI)O/,^ M^%(B9&TDMO(XZ0OVW9]I/PZJ33<,E$["6VJC"&B 56&Q$=:GJA_X!?L!S[,; MA]*F&*X@>$4-)4I:K=+L-3'/S U04S&^X&S-\^S'H^,0ZJG.[Y+26Z7RB% ! M76E*I)SP:L+#+^*G!3MK&R3)!',6SPO&W\R#57&>X12ZKN)]\5[C19>F<) $ ME!!*Y,$$!.-&5DKK@A:L?L-_P='0\VS' 2&5\GAE:*MTIH&/@H,NC_C!<+.1 M??$'V8Q#2U,L.JQHYK67RMC\RAB%*,FG0&V5(ZE=I0XVGUI,7UCZ[6YPH>!)&2&T>Y! ?MA:NZ6"XQXNKIG^8%EZ8\]48< M^OB@-4]>IL"H G )"N#VY-C-?VE><'E6D^]%8\.&8A2QL6(_T>L 9*\XJK< M'H;1ZO;XA?.?VW.FRA3BDN!>Y^FG5E&E$:B;@?P%RRW<.)\4[:FC3E);_B/_5.'-(13)AGW)@$5'E"M-2DHQ%*@/]? M&2S2ZKDPQ+Y@(Z' L#_$M@4IFC& & M_1DG.!'.=D4^ ?U_6Y$G_%!('N@<$AJ"M@* _RKXQSPFM/70(?G58RZ%*.)G@*55_:BZ8'/!C* QPD M\)93RQ,C&&&SX/X_>V_:W-:1)(K^E0E_EV]M6/ MZFA]]]Z@P0;0**-Y72!-D:N((NQ-A P:#7E_H*MG5(-X8+ VPY@W4+G.J+GV M@R]Y3_2,%\-AI_]I)C1W]Q]YV[G+/[)_=(;7LP51+_NC\7 RE::II?CPN=.? MK6L;X1N_-D-DZ,O^;-_\UMD^T^=^N+N]7S*%7YS*1U[=F;>0_8ZHMED@OGP% M)J(RTAJK.*1$II(T!YC650.C+%Y^Y$EZ!O0%B88 O="^YUQ0ISB(!#IA2#HYUK..$\@ M=*D1=E9JB"T\8%K]X,'Q3X/WFH1$.2>2'FR5,"2" 3Y//B;B36H+3NCT^O,'OQ[%KT>>,@;@I.:!1NZ, M2B2680I.F0!MKH.ZC._P[+AV$E?/)&4=X7G2)-B\FB79N8=A(G*PC5_R(L'G MM\6NQQZR!)[Y8(T7T48;\I['F>]!O91M01((\UUS[<-@W.FE3G?XMTYOTM1Y M170\CL:JE5G12=K$0@P<(*\:,%+2XB8:2NIMSZOW$IM))N<^_#DX"(;HO L\2&0&2$X5D^6*BY&5 M<;OW^0ESCOS$1M(\(\X\SE$@P1,O$Z-"4%1F2< LKYTO>#B#MKL%1L]RN? T M^?/WIOOI<_X%GNO.I^97?-$X=,;-04IOCT/%EN^#.#.*<$.\PGA6QN!Y<>[0 M2CW<8XDOF)(@MX[\;-B%V+:5;M\&1_<^C"M\!1D4#?A\J1CQZ,*G>3F <CMDDD"VQQ_()*YA)YW64:/%V*/\Y4!4&< MG8(*D$5+G(=K*B"/K5!7Y M^5R.PY-13$_(OA!.*:/*6?">8N3J3"HWYS1(]CTP;?$D.QI-OLS>_>"M]Q\9 M+P X\!XJ?KGM#>Z:V;&:8;J91>C+126EIDE%EK01>M%LQU'[A74L8C\S_D@6 M'4B9I\.1G>XL]N=(3-Z31/&DN,AR57"RI=,]*;G6*>,_,_F]' G" M!?2Z2*3)1!XBGHO2\V@L/$SV+)\1HIXI1U:4Y*8DVU&+&5:Z@&DN&E$R&6:9 M$4E9**WQQCA>Y4 ?:S V8/R$J+F7#*^.&H H4Y3 K3"1@*)F<7>MM(I5/Q<[ M2L+RR5#U:/4 *^TR,E#BHW6$171S\AAG5WKD O7K;E*^"YH>+JD2F +-J=(B M"8%&T)6%CS8E4V\A^L8D]6AWZBLM$IE=VJ64^S]BOD8J&3ST^"!4DLJ_(YH> M+JD6*4HT\\RZH%043*7%OBQ*334_[<)4C:,Q8H%?2H/A3=,=3X;-._SKZT'_ MS^5IB*@TD^>6@Y1>RT7-6Y)"+]>U]Z=9CAP.4F!Z$]6V M8W9.RNPE4,NT$1@J)P(I6'0U)= MFQ93R(P]PW19N=\PC)]5'2" /@\IE E M *']_+RAP=46VNG#86.DNB=]/FXXL1_O[C^R/1DQOD]&3#^%WQA,QN_RPXYX M#N\IGA^\PH/?.G]VOTR^U#1_^3HM-PWJ:*BQ#*U&-$"IHF7%;(K4KLSC*51? MOO0Y"\&^619U^[NPB*#A<8&!2(1+&T&A+UH2;3)$U78POCT63^; U MM83Y_Z1\US<_(R]7#F.=/2QFY,IRYI*,V M3I?=G\2L5#C<93FZZ/8_O9OTFM^:S@B=HORQX[;\;3I!*LGHT,GV8A3@GE1[-GAF778.T:Z8_\)W^QV91^#H>3+^V&I3F!_;8\[ CRA(L+0^UD>/49*7D[''P:=KYT MKF<'O=/K3,:?!\/N?YKKSI?!I#^NA 506):>8?'SZQ.L)C) ?46=-,2CL;%Q M/I79)&UDM7RWC- B2^CM 6O!\4/G3]?TFYLLE$VO,TVSXL_R**;)Z,W-?*8E MJK67?9^_-^PVH_>3C_]JKL8?!N^:Z\D5?J/S9TXCK6TH7G]11VE0S@<.3!.K M9-32SX/!?-]4K7=2*R@?$_3SD$-L)D(.FV M5(TGC#XGRM7T'7?__-OK=>0TP*@%8"99([S6@3J?V#07!A)IO8&<] SD;+[D M2:G#NUFH:?O]2:<7NE^[UTW_^EV#/YR%E.T]G]=-]Y^OFD^=7NR/\[=+1!=N M>PC J'O=Q2=OFVG).$H9D9;$Y#&&0$\GD:03&.L9;*D=V17\TZ+[<@]TK6&> MQ^@HEQIQMI'3^=6F10^5U"/2+X,N'(N[Q O/%37(2C<=G%VJURSAJ9Z>?2'N M;D)W'^XJ9[BD 8C+-X1XQ$.Y(HS"\7IN\".Y._PRC\ZZ'WO-VV%STPR'&$DV M5Y,A>O;-" / +X/^U/N??3!/SIQ&,:VJ[R4UQOQ5A.9JBF7>[-6NTS3G0DM( M4GCBA.(D6E(VK\IDZ-K27/B9JH+LXX%_)"'>9:WY,"PCY*_B_W3ZF1(OD!#Y M!QMRYAQ#SL!=XAP#$I%;H,ML0B*9;;NOHC\+1N6C:#"%>W?<%Q+TL%)X([M7 M$0W!.\@B[+GA)KA$?%FU:T&;]LL!(A7LBN@RD+NC]G(TFC37[N[]+<+=Z;V= M#&\'HZ8,"/XPG(S&NV/\8J4Z!V5;)HM110C.RKQ@9#X //C@5RJ:1C-P[K+R MFFT6V17I'< _*BW>=H;[G_M505!.">X] 8@R,F.99_,]Z@Y9V.[I[>LXP'X\_-N^;3!-WM MP?!N.FPZ%TRMCS:7\C0NB5QC;IU&'T]XJ6U2(C+I*!#@/_WR5LPSM7N__HAP MPT.XT7*[E!MM8M2@M712SVVZIT;[>&2X\??-U0 Y.4"&W$SZUU>#T7B4'S=U M>\:=8??FYO[16XNN[]_ZJMOYV.TM>W"SU1H?IH]<5+EE2^,_YYSXX@M5UET9 M014DU.KHU46F4Q*EKMT;*\E2UOUPU$Y!G(J[U FCHA% 4DB">FE-P02LXRIC M(GX[%BJ___S^Y_Z@CP=YT)^=R,$-GCW43-=^:2+^VUZGOWV._*KZ $'S_JZ M#DCD1(&>5WCE'3+6IN4TZ"T^?E&"MP]("S3>AT&OUQF^[%\W?TY#[)=]._R$ MB';[G?"$C@K_C0K\W]_>Z[[NC?*Y<@">G? M_=2/?UY-)74**5+A\(K&91^'*3SI'OU687AB-C!5]J9%&TEDK4X=AV+'-U+G M&R#ANHK#U4+E"#X B" I:$>RKUA(B*ZQ;2_$54"_"Q(^J)3;3$KJ&$N2"PM$ M)!>4\6 MFR\A10R<,)+'/[A(@BXZ)X&)MEIW2:5\'-SSXU^4R6-$A3F?-%%3OY\93;F, MI>E%H-!4MW8O5I>F[@+3X^#?(C/9(63<6FUY]-,\2)GNF0C$5,-/5X=&GAZ! M+<+#P4B7=SIKPR18&[P@!0&C2;6,ZX59(SR[P7\U^-3/GUZZPK"HD:^ZM[-K MC'?-:-(;O^R_;L88.T[KJ-[+E&=LB\S1,F+X3BQ2@\-\-TS,-#2YD5?#X['!PR81KU.7>2] M@\XT/*_)PFB')2.(RE5VBYZ6H!\.CUDTM)P ]+-298LF=DE"5"DO$>/9"_0L MS!.T:%B,KIJC7_ =Q.K9$&=K<8RTQ$ T >TK44J%Z,J@CL!U52[VHO+(SDN< M#Y\[X[\/)KWKEU]N$?YX<]-<9;]D?FO]-F_9&_3SV;7CN2<\^GLG5S1.7SWI M]7*Y[:S.L=<;_)&/=.L,L*1BH:1!)JQ;]_E]4G*3Y<3H!!W]9#A)/FJ&IUB6 M4B4!P&K?Y)*4O&ZZ_VV_-/WKG$%(O0C$#+[=69*W@4;/T?%&>2'_V@EE)QCW?JF!V#<%P[,JO;?3,:C M<:=_C8=X]>8.09*E;6'I0^LS\(*SH&AR/' 5A;8> 9TGZAA#%=^ZEL0HCO_ M"OP;0'R S.SL+=;MSBK?=B$M3=%J[\#1)!1&=J8L24_@$VK07_[1C%9@:GW3 M*C2IVVN&'N7LTV"X"W]%'O#-J-+@?.(N&B=2J0D"*NU/O[SJ##\U_V6OKII> M+N5KKO]K^HYEP%9>N@K/V\G'7O2* MT2A!Z:=?;'S_7_[-N[?+[U]]S2H(?QOT)OUQ9S@CWRX2PR)!&2%)&B)# *N5 MLF42M$^@?_KE]6#Y[0_>L/KZOS>]WE_Z@S_Z[]%='O2;Z^F=_7 74N34F)'& MVQALB$2P6%AC/-JG2G#7O*K @ZYX/E;O[[Y\'/1V,@8D<0AYXI22G#$2@RJ= M-)9YF+)B]OZ51^?W=?M?F]'XO^^SBZ\'?3SH3:;2Z\&LX<36+3&+RXM\8SO5 M#=>(UU*.\KY?O+];O'G'2:)XD MLP >Z6%E+(-V#1)D^6KGRQ^?E[?#[$Z ->3:2J,5H/7*_ OT&:.@5'%T*/)0 M>@VEN$)'6J7B.2.;P#X&K+.2T27>S'7L/)>UX.K\Q^6)<^8^_/)*XZC_C(>N MT_^]W[WN7(S9Z2,1R,1B5H?8D8H"T:3\L#=I,40'I;"]':D!1! M/SU"26J#T ^;+G*&R_R@^2-IKD%R]."UH512RYCB=.XTH?S+N!RO^U=IT1#W M'"D>)QBXG_U(? !5#;J9S#N!D0!#Z^==,HNK)1),E:L%]H.NN]"5:BVM M$J"E\$9P*[DO=!74J&6U'']_A]*JV?.EZZM,U=]'UR>G:M2.,9]+54!J(J*5 M;+ZU([K$'U:AYYP=/[OB7:%,J4=HWC:C@1T^G'JUAD+YFP\J,&:=RA@JX<]S M\_2V0:)(#2]%8J@L,:R5:*9*&!0TP'(ZV+Y[CX3B]]V2WQ6ADA,T,1&(PW_; MY#'*+1/>G':FRIMC4'=1.LT*&[N=_KNFTW/#WKGH9$C>-D&!>SQI>/9G;"29=8$IQ(KE^W!07W9?N%3YW()]>CS M6_SZ]:\?;\]%)1J]X88Y0JAG6CIJ:#&.CBNZG(;XU;U%*IW=-CX%*OD\K)@2 M-EU0);E,NF0)DP\8>*R+["Y$I7F8D/6W[YV-2)#S%=Y;SI1QTY",A,6,+*.K M\)?2RSH$%Z*21=GA-!E@7N?\CTT+[75>47)Y@,TAJF-7J;5$G!I"K <)7CB\.6,BRW(3.;$.?4]& MN+5.V.)@:45LI:$ND""\%&F0'BQ%E:8C^!4D@H=G3AK4XBL-OY?*\3TDS6!G MNAPARA,:8J#!YH*:YE,PFPR+PN*B$ MHJK2./>M*!>ASE\Z_^G\^W,NUNA^:!#;O_SG83/8EO,5\=.$F$,R;/>HR).::56%@TYTE5O_"#9ME7PMB%29Z4=H2@3ZYX6*01 ME%@NWOG+__V0FX?,92.9L]TF*)0>XDD"B3:?8JCG0J&,X-I5M[@H;ONHJ#ED M_VVOIB/#1F\[=YV/O69^O[)GB:TWP?"HF' "(II87]:_Q%S%5Z4Y&+O/4V^& MXT!(6V3OY5FTG?ZV^4F.*T'1WU+>6,ZE"*E$0.BBNI:25S@=7IM* M)[9H$D"6Y>FDM\I-75$U7WN=V30'HT#D@+>;@J1E+39)J!6)8V MH.>+$7W=77@X7N^:JP8/#'[HUQP"[C>6Z[?.L#O^3V>;PYKMJO*282A(A'', M+ 2*2E4W2W)8RZ<'T)X6H?OAR/-'HT9I1J\&G?[(HE,Q4_S]3_9",, M!!XKCX_E,6O'A/KUH'^U2:4OFO_+,'MWM_CC_W2;86=X]?GN5?.UZ:W."BB? M>=F_G8Q'TP_0!S*]],BEK06N,^J.5CV>^:R6-S>+;RS^$+JCJ]X@?W=;I1!E M )4U%H0)XDVLLP5B/B_2E5OH^\]W9X2B=DE21PI1O^<"4D#,UQXU*OSJD-T M3$@]Z^IYDIA?DL3,1N](I,HZRR5EZ3XEE4?[M*B+M7;YC*3>2!??&0[OIC8L M%]LWUS-?>7_2!#1+WEG&A*$*9<^CPS*7/J1,W0G*8 =[=5G2'$5D7,R31@C5 M0C@5F?(7I,SG7AWQN,#A^.!SG MH2VN/EX2B6]N[G]\'YVOO&J;1\(#I5H*Z3TDZZU '[@,V>$IU&5(;=38"<7C MD 7.0Q8OG03C>;#".L.B%67"&RH8)NK];&V'YS"RY'EH5X,ON%T&MR9K M5:@'+IBV],=> !Z6IU$8)[HH=4(GR:?@9,DL1N>#KA/LN\#9GNW8%=R-*5Z% MGEOB,868[P.\O>\PFJ?%$<"=TLTL;ZN#T [9AU**$,#94"6U1(ICX^H M^R&VP[M! >\,\B8B)ZK06@AF+2H&HE125I48)8*H9)>WY?OW@;G,^NT>*,20 MC*(I",=<3-QA, XEV6BU$[4'P%E;5-4.RN'P'BW];Z1@6G/K:1XQHIE1*I11 M%-X\W%:32];72='1T-LD/PB4%7F74RY6,CQJ3WQ9,6TA5%? 3/"3L^.8MS&: MXB&0P3D55-)*.RT+.Y)E]0X\1M8IH:WH3;Y,IKN%T#<>CKO_F4YX>7-S?YC* M[/39W4/C\R#HT\JB2-H'X!ZL(\&@ST"U+:.>/2=58E^W&=Y#T#H)98YZ21<( MVB6O$A7<1JD<3;:DO"):V6HU8IO:/")E0G,[S%L(\B/PS[UF.AZHO_+HM\/! M;3,Y AIRTS,W:KY M)ADC+#25K2= QXT)2 PY3"Z S.L49 PJEKRN98GH MRB5_P:&ME.E)TG&^(F@^/?5M_O54_J??>8LAT1!/Q.QN9;HZZ#!)9"XY)U'Z M4A[/[(.-I83-Y!6B5='E"V8V172G0.BBM-N8IV4@%?=:2N]8RA4R5)>L9R2N M2@&]8&I33/-$:+=^E+9=;-LZ3-:$DBY:[Y7B4A#&=:2NS+6#F"J_^06#@X5M M'RS.3J2-U9D!G6A@E$GNG>6*><'*I8],IKK0?,$9'&H;3DRD VVCI))KAP?( M)RYI$A'F0SF,B*EN2$("Z$,)<"KDCA8>D&B-(,D)"<8ZL-;9,AJ9"5OZO2>^.]:__.>M)^N?+Z7^R#EG MCCN]NT[_^OTMNE#;\EHD+Y&P0N7UYMPSCT%P=-ZCRR=%\M4I$&W7]X<39KK^ M/">CN^/F%7[^^F5_C"Y@W@,[W3,Z>K!M[O=1K>K!T]?%\KL_ZA[NZW MSK\&0]_KC!Z4%,V[RO)ZT^I;U2)1(S'&,(QSJV74R@2A7/1$ IKAO!WVIU_> MPC^6"74XMBM4N[[NSAK1?%Z.-\:/]NRG3QA4XI\793Z[*\]II]YM[_WDXZA[ MW>T,MQTG*J27P W3WCC&)/.ZY%4\6I2ZF:B2F)T0. ;*FSISMJ"\.AZ=\J 9 M,0XB&@>+?V:Q;,CVVM>^?)U)>@3.;SM=E!3?N>WBP=[/XJLH<\: 4)Y0,D.$ MH'B)XM#LU4,/1$L;33L@A\)ZO&L/03 VR"G2J$U2*(-0=CUP9U4]Z?S$N&TL MB*+J!,YQ83T:'R(W-%>G, QPE8GH4PM8 M.%*R]C4.Q:W7&UQ-4VIYK\!40V?XT,Y,W>KX9_YCBUG@JV;!YL;]U5ZZ9G@S M&'Z9;@S+>PM^1VBWM=-)8EFNR*(VYJ7:N>MZ?E>;;VY]A7,=G.Z$SZ:&0%F8PZV3K\EZ$=:SV7PEI 481R^@A-=>'7$Z? NR:O8[V:IFR+ M$+Q[__LV*AB@@*A'%'0'*:C 1=FO(I2NUXU>D SB% AKX'WX0>-16$668T-9QF;SSQ<3B3VUU$.K(XFE1X+"#H D( M:KPW0I (,2IN>2DQ4QAZ/:6# *E_R$\7_ M\(,@DJ(!P(?$E-1,)TE*>BUY6]^\7/ @[$2!PPZ"Q !0>VEI3C9X'9*)Y2!0 M+>LMC?1L9&A/MIS,12()O?*@D/=H%Q-S0O#2"P^Y[N](XM":5S@E/0X_(!A_ M69$W8I.H?$ 5$2P<\,!G&2>6!,TR?TWZ'P6CXMZ5FF3)W1N3N* &2<] M"H.RREL:\P*\LMW,)D=\97B?T+DYD4.69,B=$8Y:QZ0C6GI>UA\+)=D.K4-/ MFR*'G1OA T]2IJ0H+L=Z/W1/*A5*X\SE!AC.2>) M41Q-05EF%8@G]>5#2W'7/L =$:M-Z>'HA=4^>N+1LB&/C-&E(XA'6=]%M]1N M'(S52J/(PPNI=9[@^H18(C8":AJ3+X4,H4K,F\:1$ZKN_6.U6=H(T&- %YM! MMSI9#8*(W"67?-8/@!/!CIL!CTZK9,"(EF4VIA<]%RHKJ*I MB_5:)BSN SH*U9N;T.U-^^9J,IRVH"U9ICS/KJCG_)F%?EX;6DROY*I' M'D'?*P$J>:4IV*@!70$G@Y0T,:8) 5NE:%>)\@A4GP;1=G<7O,PMYDRIO)<@ M,;085""AHO6 ?F:L O9G02AQ8NG21MH0/*,,57:D!./7J721".AXU5-;OS&B M[2Y=8+BBEN>EZQ*LQQA%0I8N([VV4FQT0)XLH>#$TD51EQ-+\T&T5!-NT$!E MHB5EJ8B;9_!] T3;7;J8(MHI;7ART2BTY#EA@(12G$IMW<9YD,&]G8&?:[_4\C#':G@43;-.T=/"Y+3=X=IL%)R--& MI3)95;<9CS MUB8CN(B+25*0VD2T]JV?%2F>AXAZHZ.V@0M+)7(CH/Y $67.8'S)5XI8GK^( M;HF@>#+4 "=YXU0PZ,S)DA6*-J:5^=B%%G41T[,BQ;,0460&B5&"SF/ ):H. MRD0(TENI%8@5]_J<(IJ#XI=?;CO=8:[!]OBI3P\&?,VL%;.W0Z9?,+.TPR(7 M1.>NT/GHOMXTR?VY:7*3Y7T9W/V4OI&[P[_<#D:=WJ_#P>1VA(] P!'"_)GI M@+3)4B?IZ'XW2;?YVD&WI?NUOW4Z9"!:>*'!&X?DTY;8Q<0==*LJ]XG7LM]* MDH.()EX/OEZ"7F\'^.SKOW?[UV^'@W\U5UMO'!R)BO+$# @@(B0EB9GGU_-@ MWKKVJ9;,YT^UW]_O03&I.6DEM*!KLI@1>VI'HMBXJ_T M?7.;23<>_-89YI]<@GR^\Z49#K;&-Y9XPF00@07O&=-4E*[FF/M*ZSK#EGF% MQZ#<3@&)IT9HE[P#RPACTI9:^0A:\RK2QSCM=+!N\4R3@3Q23,2HDT(P?1*% MKAA?TWI474MCT)%A77O1LRHJ;3-AIR^JNUK:1?!_FE[>8_:^TVO>#&?"B[^^ M<7?Y)]O";9ZTL2 %-Q")]QYX&=,B@9)ZF\AI[,4NCAV3*C%M%3449%YHZ,H4 M6TLBU)W$DM37H+O!^F[1)_SF8Z_[:4KE^AJ(;YKWPFF,28M@DF0) ?2>S@V* MRN7UU2EOF;B[#I(#P=UT%Z>%C)'DM@H)A@4GHBH-[M2$6,_H;^F_.#*X&R_9 MT#Y[2WUT'# <3S3$!7517=974VNLS\'@YJ%]S0X%NNLUJZ-,1H74I1:$83G; M53#PHD4^=A>/A[ =":$MA],$#+JL)B*[40)/GJ1ACI!$=ZJ2H)9BR:,B-%6[ MO;O[9.WL^FMS4]WZKC$?0)MI:;B/1(!"4SV_K$Z@3#W$=Q>\MH%X(CQA$Y[( M*TI9OG5T/A?[DCB=K!PTCTZ0EH&=.W/Q.-C>3\E\.9N#>+WWT>.41T:Y](2F M:/ $>E4:JFGPO)[ T^[3[ C>\=#:<@!5Y$'9:;)-*9E$\)H5C:(25+Z:V/T M'@&M]\UXW#N 649$[CQECN.'.9XUB*JH%2E%K2JT-DQ0:JY M@K043*I;B=LCZ-V@.QI2VU*)7EF-X6U>42:9SFMD:$'*1:BT_HO=W8P=D&H9 M4KO)Y:12&I2\(%*7@>B:*5%Q()?'M)^6VB%N!V7I=J_$UY-1M]^, M4/@^3;?=+B(>#+:;T:]-?[YR M*DQ&W<[.B @,EZ)403'+4LA[ R,K%>!YHGJ]M+:E1O%$B+AAYS_=WNX\$12< M$RQY:=#E-C&5N41Y@X:I>X.Y;@\53X"*'PQO!\.\)26/K2@3GV*O^Z7;GX7( MVPIFLM;224?JF4V)2.93.>AXB"J-;%IFE9X(M_BEV5W>-!4.75,;LM$GN1PV ML;+"(P&K.PZH.1LBOUUUKG9&!*+(C<@7( M@\IJ4ZX?8S;VQ&0?4YX$,<$1*AWZ5C0P1*O,**%!UB/GF%&/.,K[(;*G*:<: M_5GT-%"[,O R)12J@HH.=1>6%KP]W7<"5!YMRE-D>5N1%8#:1MLH69GC8$-> M+5V?'7XV/NUERT7VXW-A!_I=7.A(D&MS$Y@HK?OP.;34@I\(D3UMN7+!871B M28P^4HP22VB8@JBW80@CSJ8"]K#EGDA+T$A0A] QX;QG)0489-!MP[):5EN< M (_3&7/%*3"!OA?-XQ71"D%/H3U!MK<@15 M.KPDJX,.+C4\(H ZYBPE00/E/$LXE\Q2B^Z(*<6<5/@JS6AXRP+YO2 _E0D' M):FP7'L0(G!I/%N8<.]L/0=!*U%W9)X*DWU,.$D,"4^X%2S(')9+52X0.?HH M]1P#:MH3.B= 9-]HW&5G)"J)$;F/RF-TI(H)5Y)5J$C1L@7V1*@\VH0+- R( M!?Z_SE,]D\I^USSXXU1542R81Y[Y$UEPK[UBP7KB>$J&2,5Y21^B-@UU!$+9 MV>1M+PN.3B$@['E E,MU/PRMP3P?1P3409THM15G0&0/"\X3:#3AZ( 8QJD/ M,20H:44J4ZV2]7D4V>D,N(C6HG((PNFS7X'M0RZ^+ MCJ S3@/ZXF"B1-\VEJG5DM2+=Y5NZ<,V> 0+GL M"!FQJLB2HG(^)AX%YOOAP:.7TZT?UU]S>=OHP\#>W'1[712ZD<=_?1H,YPVA M2[WF_\(?CN_>_-%OKN\_O>T$!2V%4BRO_#,8/>KY):-)N<3*5(F))X1OMW\ MOII*'HPFSNF$_G[PE,_S=Q&C,EI7.:[S/O?'>Y-;+(3#J#4ZFZQ%V\B$D64@ M$\L*N;+^>EUFZR"XCN@CBP 6E-4Z6:%92N4B%)U])2KR ED3&!Z&QL6.$:HU M#RIH9U$KIX#,E.48489BMJ;*X@FA?=!I\C)Q9@AS47.,)),ROMQ04HU>4N4/ MJ7VE=E%-S[S&T]N"P5%07C^!Q _0.?G:[?6:\/;5MDG: M04CPB;%(B6#H49%4EG!X+XG;V =\)ES%7^E:7-WDYJ;3&_S:N=V[#/?7P>#Z M#Z32^B\N_O@_7?3CAE>?[UXU7YO>RE,6GWG9OYV,1],/T/6/_*WI9(1G9>RC M[BI$I8C@SNL9!J$_&+H_0_DE&1J0HT9$:A/AAGCG]73HO+,2 M*'B_<4;%M\[0C=3WG>'P#N%]U]P.AK.EVI/^>'\&>&N4U\!L=E -6D!:KK>3 MDJF.8-D:A_6R?#A__\DW8R.IMCQQC'PQ%.$8N*!A-(M^&0B5F_>#\]^*,54R M-^X)GD-6ZJ-VTI?[/^F\J+*'G*])'OZ0@&=J?9G5/%$5K?;4>D>!E^Q7=IM] ME:[XP?E+F6F,71CC@G$CA? $?297)B];#;3*4_)UM3J7Y5CLC,:NZ5\O@O$= MF):_]VK0_S3=2C:#*7/*]J]_1_X\?VM,EB]T70J*>?!@E+)> E/EHE#F";!/ M_$ ^!_9>U.2*:)P-@B"7#3I;SAI==C/97+JV6S?:#RX_.;.Z?(B!22(YC5X& M%P@STJ=%![I5Y*DG*<[)WK/83N;0K1$*)+&)4Y:()[:$N(R)NOCX@FXN6\^6 MCY/Q!B_D.S::'F-7=%B5$8GDGG\!FA?^)MBAJ.\'8Y^HN>2">@Q*2&0B:(,^ M$3)ZP=E0-V__X.PS,9&"LT 2]]YIHXQF08,HC%5 J]Z#->,NO@O^GL5&7"]5 M$SQ_>[E:K:$]#<"#44)HKTV^.2M12%"I8O8/+C]'XZFITC1HQ[U@%(26H;3/ M6T=!5NG='UQ^)H9T-8FO9(C&$A,"YX)[K51)X>8KO7HSR+JFC.^-VVI/FZ^>.FBQ[+MC(J%D/NHTEY MQ$B>W9&W;,[+J *D6#EW%T%V?971/'_DG*.F7]#%S@V3PA%CB&(^41Z$6DFZ\? KEB-\6LR];S\\T M."($BR;WRG&K7%GN$6G+5?F/ WZ!ZW,J"=?YUASC>.\XQ$4X'Z5H&=MSL0IQ M0!?R=![+O-;_4^?VY?(8Z%"H%IPS[5EX&V48:&QF9-5_/+-\GA+3'IR1C!'".-$&:NMU338 M2)3GE#C%F/?UR(;+1?:P(;)O.2F;]AE'S9R%J"!ZQ\!$(Z2/*'DZ6:A, ?*F&9*GH8%$WQ"C75+&.?KH[1.) 9X[@R];!^V(2I1Q&2 )PB25 M:MYUZ!,/8NOVD>^*PV?Q\BTW>5B7Q8C,)6"H7=/BS$G.ZLKTRS6#K1O8TEJ\ MO+[SF#MN/15<&6FCT524(IAH#2?UQ?E30[=(P&PHW8.1)4]0X5RTY$G*)!V/ M-+L.( @5U"H?%8D2%)7U@)H??'Z>A@6U%1>240I>H6V1*<^YBLAB;4(0K.IH M7+?VX >[GVHPNGJ;AK&G-49RKE10)N1ZXL)N'9Y$\_I3X_-9O EII0)!.8,8 MM5":1Z*SNE6*1B'K@:?K)I:?ASW?RFE@GDBC@D;W!:*EFN9*SYE+PXVN=XPP M>HFR^GG_66H^,KW6CPNWO0.* +_1,59>2B*5TXX[Q4QB/L"BQI-R<^$V_6?) MSXLZ*8[Q/'-8*0"KY58$YPSEE$4C321H[!;# M&:BY M]P\./SUCN=*LS\ET?'"@WFHF7'*A+!!T@4!U;?E=,_@LUC/D_3=:Y#*LA&?. M!OQGSA%#;+UYA5XB5I^%ZO1]6-]!-NAUAN]O.]W]QX%]'UV_5FM+E8O$1I)H M8#PEF([[=$)(8B^< O\V&'Q1VVG1.;(A0AZ13$CBAC&=&9RX0!5K+CSM^MM@ M\$7C3,+SE&OB+1!'P*-Z3HO:*QM\E55EEQC2\+3X?)[A&1!D@$B!:A$ 8Q1P MNO"%$]NR2?5B?.'(E]/5Q/VEVQL.!N/G?^Q6.A)4L(EJ#GD+M+ $8\Y%5MTI M6=E-M6:WR9FXNQ-OUL\9M51R%CAZ@ZAF@G$D+S;Q(1$9G:SW>S\'9)]@!';) M) KS0#1&UM)*ZGDRZ.W'["8H!RXE^@2RE<^;MQ=NY":2&.8@29J>/?G\F7M)0\24,)Z(!(Y[T%SD5:+YX&KG@O*Z *7BT^/T>>YH* 0.&<2 M;"+&6!.\='/&,!5"I7(9O9R-%7,&I;]E%JTOM]ACMOKNQ1;/TJ :CSZ3R D& M'6WBN5Z#^8@JUUO HWCA8:3/F*N7K<-WE(-4UD)*E*I@*//(U8@_\"Y>>@;@ M,^;J14TDT&1LL)$3#P05 Q&JZE(_&AEWJ^;-1NXIQ1M/HY#<].9],;N[OWDXZA[W>T,E^+^SM?. ML-^9$R__)%\ZO+E9^M[BLW[PM>EW^N._=0>]Z7*N;97O 2Q/>&2L?^L,N^/_=+96>%.NT?EDQ 7&'',"H\HI_)Q9 M[2IU*6$-2X^/P/O!)Q2&T;]/PK?HK7.:$,^T12^;&TYIQELJ)Y&)%=YK&OI/ M@/6D=__3DZ N("IK!$GHV6H96%(SEDMNC"&L7H' U]P:MB,_Z.=3C'JH;=+B M?2*(UG6C49$NG;FUPU$OD?P,LAW^P<@;_/49R^M0FPE MGFZ+:,^19U'IZNJ%*K%.X@]$'R[)>TL$!,5"1 ?0.Z:4,+R@KRBI=PVO"^0N MC?U!S.=$1TH\)8PZII'QUL[K["(-(;6$L>NZXC:AC\IINKFRT_MU.)C?NWU\$N4X MO=_ FD2T]1@\(>O3^VB0=R, BMEH]#LZ\IU>_N(K_-LJK@%QY7\5__@0UM]S M()K48H!G103$-%F768[VB"K0L;K8V@G-%L".B)'8C%%D6DV'FZ#S+R(>;L5$ MQD@E=$2"V!B\/AJCF\%P5'_QW=+7FE'\(\Q =O]FGALUU6_%J M:CX.)_@BNKYA\K<.!L7C8=.,;^_WU2R3CBVK'J=0K*@FG$/PVFC'+$ ,-"@E M_3VMH(H$]\'I0%I,A>], M!-&:*8P0C=-XG#1W1"F2I00/&Z&FGEWS&'K,\-I"E'?-U>!3/Q_)E]VR!A&3J_PQQ@"3;VXT6CR!5V5SN@S_B)?)W[%-K'L%62].KW-]I4=]"Y/?-;0?9T_3N[M\Y912BAK\> MV>OKJ9!U>O=9VM%+?%F.5K-/B.'@./YYV_1'#Y19%?*^O_K<7$]ZJ##:+WKK MGS;-Z\Z7^\+PEV_M*_\FWRT/;X==5-(8R_S\(!O^?HS(W#\-,;T=]#,=5G+A M]UB][73Q9;YSVQUW>MO2A2)*+Z/V&A"U$%/TEC'&C<2@5-?-@WH75A^5 "L#9$-W.H%(Z4@Q M+)]G:%(*M#HF]<+S?6#;&Z>7_45TOQ]>4>5MI33(W..FH\3X39:$3#*L+LG: M>!1V@>\0W :3X0&X"8-!-35<>6=UP'";0TDV)4M=+8$'XU;@.P"W#Y_1)A^ MG.*HJPES.@!PP< XMSA>-+8(9!4Z[ W@(=C],3@ -RE4M"2!Q6/F-/Y9!5&$ M4@BH=]1LU'D[@+) MY#UX^V%6PIU9/A4=M7[YS9XGSWF;4 4"1OW&6(<1&EFD>4D]O><0--?#NA_. M;_$A^-_II?V;F]?-^,'O][03-,4D42"#\S00YIE4!7/%ZGV.]:7SXR%NP7^6 M[/QR.T&:O1_?E$QBGH&M8#,Q PCI>,*5K:Q7CTL65278LG?!ZT M-VD]4(FEF$\?ETX:*J/$.LI*K D.ZLLN5M]EGQ&/H[$/&/X3 M+/J!23'/@P/J%@&-%;78ZA9'\"AHOVV&W9QCO1IFSSDTL__N[=C*(!B/B)#P MDBO+3$AS=1(T6O1*'E\PJ HT]@'PV(@=C;,>/&&!9,9:RXWR6LWK5'RNM*IB MN!>TK@"^#"&V>/LN2N8\&!T<F^MYT+%N:1[AMY%E4=[P>L+X<<0(G2_=J^;_O4H M7TA]&*R [N[R/>J@U[WNC)OK16%XM]F_&@=R 1):("WP/PEL #HO 3;@M:^O ML.HE=H=#>RJZI=+[2#@/>CW\_;#3LST4_.N[MX-1;C[Z]&F(IW9\ MWP6VN^L\'QC^L$%B_='VC,9$O$:G67F(7I(RE :4IK7;7%%B5QR.A/BFVH1] M$'=6H'&:+D85@4QOK(MRIX[7S0ZU"!R&^)U:&TQ+C3TW_JA+C19BW M5*$/Z$YZ;GE 960#P[^4"UR$_&%R\;_^''7_N]_M_7\_C8>3YJ?_^E\'@P$K M8#@!VJ%NX" C6.>)"/.;!S3\]13HK6 ,^N_'@ZM_WQ^F9OC^,QZE?,+RP6K3 M:/2OF^H%G?8J;YI"596XB!Z"3.A^&DICT%(^X&QYWT^_D)\)++-W.VS'P(5M MQ$7%Z# 2U!$=RL1S E"X*2Z")N9"?%JX\(VX!&J$X3"=@)I-+0BBI[B 5LIP M_[1P$1MQT8HFDLN:HK/)H,L FF5/BE4-I^61'4PQ@LJ+4LZ6.6)+$YFGIEV?@G#2*/7>5AA M/#\LY7?E2_CW_(OUZ''#7-)<9T\J))58)'-_TE*)/N8&]'9D50'I4>BM"8%6 M<3& \0 R1R"'6)Z@I)IK_P15C#-QR62^"RNG1 M0T.4K&,>G6?0I78AIH>5VLNXL+/CLLVC28Y3J2Q:32&X)DJ$Q5V0Q& I/9F# MO\V=<1:HBBP&KB.7F@GNV3Q(9> >KD8^P =X9OAM#'A>IHM*5_;>NO]("#SP3!K#2,$765I M+5.E7HYRJC:9R'8\UL'U:#1@$QJ6V>B\-I(P*;W'N+)XRD%XQC:XDL=!8_J[ MD9V,/^?1"FU-*QNYX**)$*,T6NM 7 K*%"YPZ5>V+8RF;[JON27MROM Y&D9QK ),#W8 ^2)GUX!,Q M*P-+"LR:"N"&"KD!Y!DL!X&[D<2>893$F I:A&2#0P-6"AMX="NS!._!!2VD M7*,T=P;WS60\&G?ZUZT[IC>2V"0@J B#%\Y9$R*ZI\6/$-0ZW0(S\D0#9:8] M&*H .ASPC<3645JJK48'&P-0 3[WELP )T%$V0*XS$.=M#*;Q'D[X <4+&&4 MJ<#F.5,AB20(T6PN&,9170^N:TG$K[Y^;]".=D\:0#F;G&><$94H$:F@$J10 M=3'SD5'95%=DJ6*21>LX**^8\#R5/3B"@JA*DX\/VM&HK+1@Z-MX81F%:84O M+>TXT>F/^I^;5[VKP9? <#/66&V$A@R5<9C=0,RHI-RX4CQ U=]5:TG;7 M?P*HM]SI)E3(=CJHEGK/F>>4Z4+KQ.OBVQ>AR<=5/WECIBRVJQ)"&YE@&*=9G1XT ^*?9;Q#%X M(I@F1FJG/9%$BW)9G[+)J@H41%W-^H21WR+5(2\5D9*8[-MY8L )51+G$GC= M5=G247(6[!>#L][FOHY!_S!JL".7+1GK!)X6FY-9&!RB,9ZGYZ+PJ1Y?O9_^ M/03ELU)S6^>5>IL43N<*26II4QQ MP] .LE3JL!/:&%55K?*6HM5G3YVCG43'DI::*S1-.L^$2-384M4NJ7ZD3_'D MJ;FMSA0=0Z=)=#E^-R3AN5P8>(^Q44N%=-V[\.S)<[R"81 M,BS/A1^]'_2N8Z^Y0D9='5 5C&926V)94C%E:2IDMBI J(9!4R9%"YU;@3D( MWBV6"Q+W 42,*E^I@O=2EBIFY4AMN7)[?4N(?#QXMV@_[8BS6GEGB!!H66-B M;/+: M(5T&XS @%ZKQ7;Y?P8_>=*^F[=1O)O@$>W4U^3+)]:FS<6(M^FQ%OQ[ZD,,& M3-T_-S0WW7YS[9H^_F'\MM?),YW^-9G-O-K6=I*<,LQ[9CGJ/DFE$R%RHES4 M&"'S>N=BBR9Y+"^V!:]&H2/I:5#,8<@14>(-:FW,5R#RWZ4GT]5QK M"7*-K7D\D#\$AEB/IAPHA*!]<.AF65E:X94P53Z_+6K9R(L9D(AKO+E!BY6' ML/R!L.?=,]G!'';[5]W;'E)BUB>%!+L>W-;3/+:.4+,.0PQN19YTBFZQI]-N M+A<@&L1CT^;APT$\(:*'2\-F*=O@4P5K!!@;3:[DJ0JDN\+&^;*<,1) M^S@E%%AT;.H6^&^,4.^:<2=KZM@9]O%MVU9V2$L,P1", R4L\61L'JEH/"&2 MY+[-.FE2!SG? -4^#*=KS>YV$; 0"8:#3DD0C&LM':-I*F!HU:2'RF$^ :FF M4RE3DZ<>]SYT_IR/9IT;Y_TO6+G'>%Q%8XEP,2AC"%GT\$52)\[J'1A;0'H4 M]-NFA5'"&?<@=+#,6HQF=,G?:.H?UGH]8,?IH-[BH5J2!X$)"XIZDG*+*"^7 M*CIQ637/UM=Q^\,^&#;=3_W'RXM%8>$I,9]G$E-%1%M,P$/"'TV^0F%_X&)K753(NHA5XL M%]/$UEM'H64ZUM[03W5HG@4^N#J&ON&6^,08>G]YR!<$J8@M.(",]:S4-1AL M!NL(>&Q+2RA \7%X!ABJ23P,2I=U5YJE>D[AQ?#8%BU#, MC#\O3/?JLQ9-[-,YN?,-$O;CX&LS_<%O^+S/KUZZ-^]2;]#)-C>_Y_5@W.0Y MK?]GTF_P)>9!L/QJT/\T;H9?\IOR=L3%._(T]Y:2/V^Z7<'P^FJD^;Z M Q+JU:#3GQ+Y;6\R8@J0M/A(/2?KGA=4A[!A\9UE+%=>A ^[SO<>^,"/G?Z_ MWZ [AL#GCTT!W\9-)Y324>*A41C_!\Z"+".1I5+MM;HMD5$E]2S)^+CT^#+@SYBQ:4/"5C0.25CS:+@&)TH MHL[!&82CF>TDWV\B#CHUP[+]=#MM9QO&-W@&JQZ]Y\Q);1B@%0DI]X_Q& 0W M(JD023VJLAX=M0[)XQ.B9330$>CQH%W$Z*"-(^@A.>6)EN!E\90DE77-6'U? M<#Z"S*[(![>=26]P&OGPS'''J$:KE =P4QGD7*%9C/=<7?0%U576^ ^WR-(HXSW^?)886R,@SO_OG6'ETA$Q,3#YZ"XT8G*804*!7,RI2G@-8+ M.\ZACY^0%HG.ISQ@W*8 >0(%]:(L-$D.2+U6EIU.1&;EL/2WSE!M2Z'E'6%O M!UU\%/[A_S;#P3R=-HM#2M*,$29.D3 C6C,C!,DCAB(C@5HH(Y0,EZ%:%Z;@ M=$+U\IFE'E>[!F226CG!A0@$% \JE.W8,M$ZP%#J=/[T['"R][<(:J<7D !' M$T((@R^=;G\SZ1:WPO??WD(]YA2SS'F'45D2 1)/,0:&?[!>1%)Y ' ,ZI6" M]RPALYOB3(7%.N3V]NM#+/"6AR+:A M47^K5"T7,>(IB'9*.J9\<8)^KK9.H^-&RZ9%:E>*0I:9L/X&Y9DRX:A$-7G< M-IGN! [!">>C+&L==5#:?.M$A:<@V31*:J)&]SGF=>R0^[O+R"4O5@9N?]-, M.*XEM(G::)7UP*FB7EE1=+;,=1+?*%$U(3.BJJ<@V83)%),W43'!)>IOH1:# MEHB*:YB@U\.B1!/3O!+HDH21[N^&LF'!:Y-DJS!)9S MMAA. -*N\;.?%U%S(9\?]+\VPW$WS]@83D;C:8U?=]QM1K)$Z"NK^.2ND:B?F\N*HH%-$.G)G#1'),1-QS_3(:Z0FKSRU&/TVB5U6/LL%X^D^77WT-B.XG MIM%($.^_+]YLR9G.FASSJ>@LK60?:DJ MI"6VJB+KE^%\J5:X;K*D,R@$[ ?J"LZ;.W0ON_"^^:S;Y NF+7ZF^\35I69" M[2-U$[#F2LW$:C#XD'F#F)XDH@>44Q>R>BG(E7-2OX^N;RJNSB$(MV@V' P? M%ZKS;^@)-8OK;:$-J;&:#;33A?N0@MG8>C*G['\6'3V?BG8(O:8M&LGVC3 Y M4+\XOS3!%-T&T9Y%/\^78#JS?AXQ9!,3EBJN]*(L37/FI(*O&T1[%ITGAV7A ML!V 51+:%-12N[[<.AA<=DF5EFS=<()V_*C.JNN!,C@J(1HD4;$NP7W88-NM MMB^T(2*9Q0']04DXK+T@0Z5P",%E["V +4^;3O579E/_W[&#.J^NA][.#;7O ML C,G*-&A],V$!"_*<\^%ZC/>=0.C:R7D%IE2*86 MF\NRE:&(ANT;FG0>^ZC]P^K<^\&UVZZ"4?RWZ/]Z[VL(U.2?_6[=^_.;W_H7 M?_^V?[//[,9*V+=GV8HC"[!$-<-%-$)3;Z8V 3!7\1$VW2S8##T\\<$$,"4-(09HM MU8&AEE>;-YWS&_S*CBKZ""@LKPRWQ2\N/4Q'_WH&L5&F]G;1#7T#(O4<*-*' M7;1IIA!%$[^LC?SQH-SE]C6E?S,#D'^-W@\&I*3J7'04*477R,!JU;'$&O*7 MA)O/"^/S7F+W&N)$3\%K>M0'1527EZ4L*BB\0=7]SOTQ*'^!"/)F0 M5>N-QQ9*(",8U85HAA0E4=B4O>_6A#Q;2)UY1*_[1 O MLV6*,Z&KT9HN_D!>>9+5_/C8(__Q9=PP /GI7F;;>/#:4B[0-**& #D&[U>C MM8VA893S*Q\.^"[GEV>7KQ=]6<_-+[]]^ MF.&S;395(A=B];T7+6-A)3:;PBF[1")I&!@S;"G>]A[;WKDOK7SZU_:A&&#$ MT#@J]0;[WO+"&7.T*@CC:Z\9#[CU779_]>\6:^8QX8:15#MVRGP^K3Q2OZ7A MJXU]"IMSZKJ6N[T* 0_&)VS6UDTO\(5ONVD UT/>UI9<3$[-0W:N%:@TO6UE M!!Q&1XU[VQ_VMA^6 QS*87!QS*&P%(]")5OW85]IW[F@;S5,;'PU[N_;[+&,0/IL,>\%4.)EI!LRO,-HL+S;GBN4VQ"*I!6!.+C&M:MSS3%SW^MFTD M:K(M 5 ,AI#!VVDNCS@U:,,^CW43.Q_OX;?(3U#+Q+:RU*3&2**#:8F-1B'4 MAH=_M6Y$V\.?_MOSLU_Z4+_SQ9XKG[F&!KT*9ZMW!;.O'V6FU7&UM0MA8YBT M[FD>_M3W+GV.!JW:').8&FN8[>*T_1V<24-LUT<\?>E3?[;2XU JZTNJ#$$H M5@U2-$!+'_>_!$YF,#N;WF*7ISO<6VW19*G9!_5EUB1U<<%"\)-0)8(URPWG M\5;;UDKWI3 :4K>L;&7.@3&L=H,9WJCBAWLM_1#=W"PT%/^P)_%;#4?Y[/KZ MS[=7U_\XNWZSI^YG]=RHV3=%:YWS,?L\;:_5@')<1FK'W=,[/]F!7N<^HQ!\ MAL;!%7T+R!Z]9GQ+J=,_H4&7-ANR+WN;#1G/?4P8IW@7X_I$NJ2>.IB65X-S MT0P* RYN]-R?/\=#GO0^D&VL%IQ%)T9B%H@:-DU..L8\@.Q2V@[S]B?=E$IM MGO]=H]J?7-1)>%3IECS=#18GZ$>_YC8'IY\^Q?Y/>1^:!:5H$$:^]K4/J;;F MIP&/$',8!R;GO#%5W^&PJU0J&6)C52KM9C M"F&:UT!^##P?_U$/QD:#%$INT=><,:(I<;(UK"2-#OE3A#,95 MKY;':!@:!::8-%'(P]-JKKF+['Q\G"]\\(/1XKEXQ*9!JV^A)!-P.LAC1TX& M.Y#B$[[HO;[+:NF3W^B ]^,(;Z'!^UHQK;+_@3;__?7%]-]7["^/35L1JO%T\B:;_WG@W%?SZ M';8T:-3='8EMK['YX0[V3O?)8+;DHBI,)M6B%EK(JX0O9WVQ\9W,]OCIH>_4 M)SCL1TE4G0 L'@@1HS*"XJ;JI?%Q7$@4MJO0W6,\Y$'OC:QR"51BT8C%UJJ. M ^M2=M13NC(4BYW=6"#8XT'U%]/O+;.YKK#Z\UG?JZ 9WS*YVU,11/.S;*O& MJ-D5J9HDR')<0XY,>3S7V"'RVOE1'^N%[V7/BKK]')LFG(FBJ"&8\B%/E(8U MW'9SK?_17_C'QOWZ^KV^S7[LVDB!/ #DVH*UI26_C. X6VOK M:!*V9RH[/>9CO.B]"7H0R0%=ZVK)(37@:7IL"<:.Q:[\%"_Z_YU=O/\@ A<7 M5__HYT)[9IH%/(021:BJF_5]M\FTT422&W*&G+=74<9G^N)7N(\89]GF9LA[ M,CE7DTS$20(9\GB.D[?[V9U?X<&E:\W4DGI3EDCH(#FL,.UJ1I?'\A6D^ZSB MENKOEU2K:R7]FSU20X.4Q1E<=F;F &'-IJC-)QO[/NB#DQELM@4L1GQ,IM2, M=2I,J-::T0"[N.,S;XTA=WSZ^P#W&F5%[UW5)Z\U)(@T%38UVLKCDB&3-Y[& M//SI'Q!>)34FQN9DO% ?+YKB=!^O]"DC0SU(\\W=GON^T&7[(]_KJMED1.N\ ML<51D!"F]<_9^FC'@#;?YZKW?^0?KJ\T^KW]\X>+L\M;M?GR/^_/?W^WM\"7 M%JHQQ;;D%'>GF89,KT$.>,@-'83[;. N#WC0=[N/(G*H844_L% ?15ES7?.Q MK2N$,1:>TJB#O=OYY6(*K_I'U2^_?_>^#S:+FS5_^ED.O3R:_T'#!/V;/GSU9U^R):]6[^YM%M-*32DV M9]4:KEP]M"$.1U7F-4#N@<8\!X.QP.+9Q*(D&*-KOB"!B1-8Z89:EF3C-JUO1V/ >N=C^QI[/7BM_ZB M?RP^G":7Q5N5);75:MIL5B7Z,'%Y9LS9U^@)XC@/H M \MS!>=++$FBAFJ]X% H3S\\J97.QMG2BI M&HP,YW5SY^.'Z_.KZY\6UW^GY_;]V<7/RYNWU]? M?G_WYA]JDYL:&F>B#*$EK K'@N 2TMC)U+:Y>./S6@?DXB6< ';[@T15 B$Q8Q' M-VFG\.6($#QT$!Y2<>(T!'?.!U-"F)IH2E'M'UHT7NV4^1P2SY]NSR\N_GUQ M\68>UO+CY\_.K_OATJ+\N?KEOY\OKL^N7__VY[>+/Q87GW_[Z3/?7/[^_O;F M[@.P+32DH%(>$XEM+9/Q&IDLR0FQQ:&0\BI] 3LKG ].TW-8D*>D*4G.OD#P MU \PC;D+X9G:Q!J88!6QE3YBKB7T1 MZ638#8]-\[N+^J<@S NS0Y>OT7L;DO,Q12DU4IGZHMGT!75C'6MM4]2C8SBK M@")5!4HD)C6TD*2FVJ:"B.&8QY!LYQAWOI@=6NXHIO F">&!Y9&#RQ)U&">#=CQD?K53CO7HD,[*&><0 M0\F4?#5D:VHVTNHR;F8[G"^_6GLA[[@Q/+!8DG668HTQ4VU E6N=9K>#"VFH M\KZRLQ#+6?EJC,BQ2 KBH5*WFRRK@7C%CV.!UMXF.&X,#RR68$M*$KK'CHW[ M49Q+'R]\NC%U<;N$/X> ='W!=>;^/ "**<;UE89!:L0FT_0.37#<<+RV!XSK M\9@]HH>NH()!=IF=%T>D$KIJW5: 31S2Q%W.9YX)YEEY?(F^U0Y6"!HUI6K, MJO<_E>"&WI)7NS3LG *P!Y;?OFA$?5?+T8 IOI\$3#T\Q3H:HM-="D7/!/.L M0@,*:&M+D8BR5W2II.F*7K'BAHCU]!$]^-%5:5#0UUHL5@U@(RSK<]4(V"%^ MW3LA>"#,[R]O?[XJB^7W6KQIUU?O=CC1[?'(=PI^4T#/+OYS<78];R[+V46_/O73;XM-\R3GH2JMM2*%:RX9$K>J&3=/ MPS,XI[&)QYJU%_SV0V2V6?_H=N#N#%>EIO_'\O>W78Z4NM3-'&R&TU8;PX9X8I M&#MA>3\NSS[J2 DWY3;ADCH.8O^\4(3XKI?$PIBY?0*#;3 M1[3XA'$U9QVICM>PPRXIRI%B>>CD#WU#-:-!7(U%E5^FZI DP[!G6?,+,7W_ M[O>>,=[\_6;QAL\N7O>X]_SRU^6'/EY>ZG!U2]T7,LS,KGZZB"+GD(E-J@92 M$M,75R^CU=PTX5N_CL8:C%LP?@A,1X?]E\OY9WMLHM/@%G(?>&L+.36_.!T= MI]@VK$)#@\=+Q;.:;_PL$"9;:[\,1D*!*[1IY0>9FNOZK6'6PA&KP9S,_:=4 M:) '-1H@3ZP$^%2+3%1H#+AAF;R]?7B[.;.?L&YX(Z M6S(E]=X@2F#=LNA'O;%]@T$*: _$Q&;0CIR7PRI,2$0Y&ZIWGVF"74#>H#\U6??E]P<7U^]>;\]?+S_41KD:L2=ORO@?#=;1$'#A!<:"A@+6.'=2&KD#,T]13P;IA M(RRF? J\//=Q[&?92G$Q4[.QI68,5XS3S=CQ,^[ &?Q3\](GB[Y6N/H*U+ZG<+H=-M?;Y)]EE;6YEBVX M/K8QE6 DRJ0RA=Q&E3DH-?<#>$)D'5:M4 U<,S[XGMY>;/B,333.UZ0E:N2ZK$]=E(.JQR4>HC@;,/B=%3K U"G.H,$MR&NO:#RW3'P]F>59#[ MLH:B/WET)M5FI_7:I9&,.\.L\<\"X'S:_F+IJV:3:$KAN6*UK:V&P%E'PPU1 M7+]JZ8@0._1\SUBJ=9 X]ZUTP;MBZZ2SOJQ;80$[W%H\/(#SZ>3+/C*['&PH M2+454U*81"[G/"XBRO%91&Y.!VJ?WX!P1BR;%LA$*IE9H9N&NE'*X_I0NW8U MXD$ O/GA['PFH]ON6F^H&0+P36.9B5PO&;!)]K=-?3N_6>#U*&OLU;O M*#IA8R2R;16GS:AJVPR,/>&[.],OQNVYLYK/XPY.;#3@@!J3M5!\LCQ)6/7C M];CBMLL%MR."[\#"&#C;&!P3!TQ-(M'JPF &2^-,[AWLX2'0[+_UP]GU[?GK M\]_/+N=X&/WYO(AH-"]KUD,00DA@<"64QKC!1.YPA74+('-&\] ^VW&&4CFJ M8VFHWMNGE?_1#'@ =T:PSLIR@J8E4J56@405-*1FF&:3]B$G&X+&$T7ST /Y ML 3C8L[))_:YB21<60 ?ATK@X\$ZG;>V][>*P_0'9W_V_84W[?R/Q<>9#3<_ M_[:X7IR]O=VP'7,F@JLQNL>^,"(6;NBK4:V?UH>JU1UJAC:D'6*FA^%T;-@? M6LR;IY!R3)@<(%1'=BH%@9J1-X1%P2#:F^VV4>\E[H' G0!Q]##<00*$O(Z##TWL$) M]YIP'*VV0]+[5+!W3>EZ,V>Y#LC]^AE701-<%^@,KZ&UKB1"4ZSQ"4/)*SFN,N3+NYQ]/ G,5^]G'92P;3EAPY3NUMU'4\I4 MQH$^X'JW!>$/067FP!YZI'!?6%-M4OP<)F\RKY;60$QIP#GN4*%X"IA__NUZ M,6L#7#+9%-'$D"W'D@6F27(:6* ?-]SO4DG;#9:Y0WOH3QA2#IH(0F7Q M"5:A1-^\-(02LP'Z'U=SEN!63;3!5I.*.-M%6%;)2.31-+A=UEWL LJ\83UT M %%ZRT[63"YF%J[6XRJ 4.,Q[F-Y4I!W69@WJYGNK08!%Y@!HC>M99@&]!3K M8%PVBFF'8O%F-&:*XJ&3M;ZY51R9?C??0\R%EL%8WW>'@R\+,\%T5H<8:#2Q M]2Q!#,<4L%)8#D M[V,]'Q/369U<&(\!,HE!#,U;"QI*+4',A?UP4YLNRVW80*_:JPVE9! M=MZK%E>86$Y2A]:[%Y6>,=G;0A07V&@*G4S [%VNKN6[ 2A<3<+F!_M]A"Q_ MTJ'T[=79Y4$)_O+#Y@H^%05:6$S*2>#C8F3]88@0=ZALO+#P!*'_-E<9 9!; M22XT4#XCB[ /4;AI(I9AN WYPNAS,[K-+08GP?1B1'90HK20HNN,2K$N5AS< MX@NCS\WH-M\7$F=0$BG55+QM!>VRT-0(T[@,]'B-[]\O;Q:OE:4W=?&+!CF= MKUFY0;;9HZWH76W.,6.;F)#<]'?'<04O3,Q&S;:YPNPY19^(1&EK8$JP40TG M5VF.+>RWL_2%U9FX0XKL>F^.:BSD6B#&J?U7BL]C&^J+RLZ(W&V>,>=4"0.V MVN?_EF*HBF:%1 $=DSUVE9V^AL]N?J/+-_TG^9_WYW^<71R\ O#%"6)(WCI- MR)UW4(L%S<^7:D98QB[[HRQ\SX^/I_2/"?NZF=H86*HM$21/8:CT8\R>GJ=TI9;0 M]]'$Z&,+K33L$U,_, ZFI:'[Y87QN3.^S;,V,9I_8O2F](8GS51\(8<) MW<#X"]?SY7J;HR63I$$IZ!D<>"P)TAW7TJM*]=C/*E=<+ZYOS]^>O^Y$?/^V M+GZ_NAG0?MZD-!:.+&0]2RXY86):-AF2K]&,389';6;G0L>3'E\*28X6:T)P M45S-5.YJML67['#HN'OA=C[<;CW(S,$7Y99+\]D*EIAEJMQ2&HM[+]H[-X:W M.4I;V .'D(O$:"+8A!_*MX#..MAO,-5\N>V1T.V?[?WEFWG5;)O-E6-,8H,U MSMJZ:OLFK!7&R2CQJ/.09Z;A*=VB:Q3 J"^TB6WU)H/8J51+P(/I?&%V+LQN M$:2:P&BI5FPU!?0A.;6;)G$[E8#GA!C=Z@2M$R?<[XB$9I*Q3+4SVFI. M.8ZME2^,/NX$]0+-<85:2F9++C8_5>92X\$GXB[W35]8F5\)UI>:;(R8,X$R M[+ROTV(K]'7-&($7HN=)]-8S32^Q!1=$*.;2!QST#FMLK:7KZ_>+>978Z'UT>NOOI]9 M]>)WTS0RY4#@RE26 Y"Q%W:7<>LOU,RT"-NP^5P"9_&D60=(C#15VYWXL0C[ MPO:,V=[F3DUDR]44C+E%D@JQ]1DNCOIQ"^53.;L\<9:W.55ISOA:,H;62O/J M7QMUEHOQ_4KF<()VK"Q_"&?^=O7'XOJR3V2JBU]N9UJ=)3%D;:IHB^U+R(OU MRY'9Q%S&/EA[G)>@9TS-DR:ER. (E5G0!*M9E\T\AQB&$LDR)YIOEJ0R;D(RG8S2L(8^:SZIZ MU[R$4QD#7N&C6=R!^W M4KJQP?RHZS&SXN0IO6-K?=XR>E#GR,+%H4&-1Z&U'@35H>KVPN^\^-WF+$5) MM5D,5:NZ[(5*FC91>B,T7@-Z4>,YTKQ]@+JJ,(5&P5'6&)?X@QJ+"]&&?"I5 MG[__]//UXDPY^Y,NWWQLM9H!V9L;HXA,\E"+^D_GN>HO)P6$B&B'8XVC3N[G M2]"3UF =MU:S+T@U0_)H\VIJ?I4Z5'1>.)\_YUM'PC9KF1N+FELCWG%L/'%> M?#F53JVO@^SM*Y^;:\WK#VA<*Z;YTJ\+&1]=T SV.+I=G[*Z*J:)F&Q4*Z"9 M!NH/I\/]R#A.? 79]SZ/_-ZRS;WQ&ACCC%!C)!B+ 1V.3.'@@UFF*KBW8SK M+3/G8NO05,G%1J%40Z:&WH8R;2]/1>*8GX%_(>.QS'H,'IO^X'(#C=2;M+@\ MB2,A:L.X-L@SSI:?,>>! -DJ>(TX"QA6VS_M$$*GT=%8T TSGBUS7*'+-N-/ MK1GP/I&EWDZ@J4<+4S[*>5RU9HU]X>:)G$$JT5-(474G&*2,(FXJUL4XWO;P M,[X+>US,;#VB4N^WYZ_/?S^[O/WVZNQR5OV.K$!7 M3ZIBAIS+ '$U'[)6R4,1Z'F;3H^S[,D(E\Q(9,12M,< M74]AZ#U]UB'))T#$4WK"ZH)UZ(I7FF.^P9>'R2)+W/I_']A=;_V_V!R MK$[]83],=J%"FKK%-'8^W&Z=(J::FCU72:9%TYCXPQ0Q@X&+'7?U M'!FKT]?PV=63*MFJ.7TA=\;D;KTGSF!:#DB6J?AD0D[M+EL$ MFP.XN>Q,>B'W(0ZR<;^K4Q(;YZLZ1[8%.KDY,GO7YM)E>@3D'OHTTOI:;;8< M0.TJNLAYM1S">SGV ZK9$_.4[M-1K(<2.+30O7,^7ZVW> M-*<^E%. ()A2:G,MQ7Y*U8!(J,UE#\\+UX%MCC(833Q)4'.;UB@7)3S(CI^%)3RRY;QM$] 6Y)626.EV3 M)+%VW(_TPNQ,F-W:P\.WXOC#XWHUM+L8E, M15\9^X2L1NKXL#,*M;K*[=C[[!Z;T4./6:G1YK[4$1D+I6I=\*O;(!;'=:W^ MQ7+.LDBSS47:%#3$Z6N1H@$T4J5,<^E ,\=Q"_,+T?,D>NNB)&4TDJ=BH,8< M.(>[M3K18_;5OWC,V1.\S8%F+*&/)\.2(/1+R+T+LQ/,MA@+IT7P3->K M"0V]JYE;%8.F+=M\7"XR<)"/WY:>SL:5;:ZR9,T?&SLNE?JL%]_"-.<%'8R7 M)E_(G1&YV]QC::&Z%@P;MC:AK8BFIQ^V%FNEG4K#P:G1NG609XE!\TBT/;?$ MAJ'>3:L'('6*+IY*:;6=_W/QYIO+UU?O%C.LKY82Q:9JN+6(DJBDR6X6"W8X MG++Q>62>OA*.^(G"J_6_PRD%N414,G?K*PC -KH+L>+@M@O[%HLZW<+.U!-L7SL4DC"Y5 M2EC13K5V0#NN!GEA>\YL;ZW#"C5?4BP^J5Z'#*%9-;>VJL5M]62N')PXR]N< M:J4:H"_6RBWU:R4-:NTL2[*639S+7NTO9OE#./-Q3@,9<:&S#X5 U.W>@<)([+)8]:UYZ9 MA:?TF-Y""K8XU2C5IZ*9J.6[.7>8315>TRO[0NPLB-VZLC R5M75YC&*8?VQ MTMT @QPP83F5^MX),;IUK \#F 0U6NL@5BC)9,PR@5%!CD[Q<5,;%(@UV\ZBO9\V$C"?M^BG5Y\H84TR04VK0G ^Q%E>\ ME7PJPWU.D-FMD^]LJ :2 V;OI3BCZ<1T[ZM8'OH27C1W7OQN5=FGP8;3^D@-?0TH.I%H*$/)9&&Z/L<8&$(EDYE]L#I$;NUK.J+;;:/ MN:_0#-="/G5B1445\(6$.VK7-'QK,8KG49KPX M93C7+*IQ-OO4K*-AVM(+H3/W@Y$9"4CZ!;M>)>^M.YW06#UI?G'L^T).C]"M M-R5#\>*MYPSQKC;*J^WI%*(;SXM?+._(ZZ%;7ON0*X[/.NKNG%EQ\I3.D33W]R907T?0J-^Y"_WT'JRRC"F>2C7U9/G=ZBM!-'1- M7$VWJ#59#6FG7F9H;C@->5'C6=*\S8-2\-*JRE:R^LK;K0")QQ4D-J@C[5 MMMQO3S[G\9*5/ MY#:26#)@])R%S-;XWT,33T V0RV-BY&^M0R'USPD1,-/7,'I^2#K^3WU]>+R]=_ MRC]?_W9V^>OB1T6,[WYUL_SP][]9!6FL0B MR84 $G'JN=.X:-^!($\/_R;7/#M+'VPKQ-[V72_"U7.-RX"S4-"4=Y!XM+M, MM-\#H%.#^DDCGVALSX(A>,;*I=B\;,TI01(,Z<*KG8+24R3OP/;):'P4I4KJ MMX)+SGU]X&2?#+8]&S-F OBL7+&':,D*@ZNF>,\M3&-22\-UKCB'76Z;05.!=O&+ Y.]UV M-Q+\H2.GG0%_?_GFPUN^O_F068\U"YS-@1B56'PM6*G5 *%F8R;C0VQ@31Y@ M\BYYP #"G$ [=(MJC62JRZ4XSR9'%R1,N12!&0X57]F=&H"VF7@4&SQNS 8I=-B5$T#B8 P_YNWM)*=9,;(K-7 MUC^*YM[JN].[J^O;\W_=993?O_W;V?GEMU4X)BM!"XK M!Y)AE,&=QM/? \=L@3RP8 9]O)8@8,B^Y5R+*OFDV\Z.@OF$@/YP?7YU_=/B M^H_SUPN^NKGEZ\6;\]N9RZEU(0A4(XT;VN)==E.MKO5_OQC/]:@<";J'SG?9 M21^O7G,P?0Y!M6DEO!#3GF,$#P3V-PJ@0G';/S_""7,25@)IU9=<.&L81,U& MM?$*P Z%BD/A-BN'FUJ#)"IED!.HU8^B1FB-Z!Y8](Y:^ CSFVOAHG$DVNP;KHAFK6 M+O-+'A/+6?E5@HK<>P(,*'0N884P#>1B+L-8M"D=/@WT#ET3I'ZZ'!5&DYNQ M*I5U6H[F4@NC6C^S),[*_SH!8ZKO9=76YVO:.OG?HN$># 4$BSNH<^ M)JE0DHD2H92FKIG*QXT7KK1QFN4.LUO]/KU^W?O+_0MIT]] M;$JY^>92_OEZ<7/S:6LB_?KK]4+_?''?5\[YK,6TS*$X7TL*12A[G"8"4R6B MX:@0\BX+*9X&UU/G]N"WK2E:]M[' #7WOA597FW*PE!&"^;,#J'PUTSU?(ZN M6/-!,<&0#>0"(F!;C@=NM<_\'H-,OX-S?^%VAFJ_+G+GXVH=)/8-4I&6BLE8 M)"[KB?HOCZ7^?B_JA20K$;"H39CZU3,;D9CXZ'^_\24;D;UM'D]=(-/J[ZY;&+C MV%RQIH5EXU0C [(FNX4GC:".B^;YN%META47(E'!EF+*+B[5MU;"NB:S33O< MLGGA=6;J"['U\1?D2^SU*6-5B:=^Y1K#N*K3QATNG,R YOZMWBTNW_1)8#.Y M([=Y-DE+-MELDL_HHK*U8'%#+UW MB+D4RRFKO0PU37:2Q,N@HKO$.'M"=V=)]S2?.T:6;Q;G__6M?L'%!V3N@#Q; MW/R77*CMO;[Z_>S]Q=6S[T5)G[HM#3=B9.O1J)]R_3Q]FHI5.-6Q/V&96FQG MY" H/RN9\[ U .)0(AH)04IH#&PFADQSP^8:-+"C:7YAZ%$L7*1<.3MUHXY, MB59CDF6UM!IGQF;M'1.YHR?,'Z-]= V;0 :"1%$:&N9D-"*BVK 6.YQKQ*_# M/,XGO8Z2;!_!WJB:PMTJ^KN>,#(&8W9#-=N%O$-?TPM#CW?\JXQEM8JVGR8U MY"1AV<176W3C@-H=$^5Y$W9TY[G$)J4BIFJ\(9*:#S2-$4[D>%RTGAY3K1YR M:G L3!WZ G-I:OMLYA;0@NJ8H6G/-D8LX\SAWO?SFX6-S^=72QNZ/+-3XO;VXO%C"J\3SELR(&)-EB?DYM3G0$&D4@%2"I@#!2:9.GY+$,#]EF(_G)0?%Z^O?KT\ M_]?BS7>+VVE.0GV_^/GJDV]A9WXGKC@;4_ )&(ISF)),!U0:T:UIE+\7R]T0 M.0)4#]U^$X(#;-B7#8"/%CA,]\V;D-E/8)\3Y%D=ZP4 LI&CMY8M]"LV9*8; ML.#KV#&\W4*?#+:'3A]S;PB=W'D36 M;,)Y,M1FY;U)3)1@0J1&^D^*$)=UCMX:E7"4-=BN!I2SI#L'B<@CC[9#30_#0EQW1UCYY7F42C;>A07,*J"N0-7<; MR\$[M! ?!-9-1R6S,Y(<8LPQN>K=W:TST^YT.C149UW#T%*X*W2[GFX\!V:' M;I)UV"+Y!+9Y@5PR^78'H24C0?:K%SP>A+,RA)Q4/_OTZ6ALCE*<0M%$TSV-U!2*DW" \0[F?Z=@7RY[/K7Q>WJT_3 MQ<75ZP_GH ] <_/2^]YV^/WM;XOK_H%O+O]8W-S>/>8,MMU_2M WW[5/CYY] M:#$48&?0%P3I-T"78U)",9\6:B[?WWVK_V7^S;C[&-H,]RQH^O@UO]S^M'C] M_OK\5O]HUB1QQFA[5F4<%1-9([3I)DW5K"&M)36FY M3^V?A:W[L:\Q^H^S?YZ_>__N^-S3 V*NOW#DG443$FARE'W4++Y-VS[0N++> MU)D'VKI/L9X=7T_@I[Z8+;!54".'2!HL).\)/IR0]6.>2I_-\?G(5CIEMA[5 M8WTQ7[YO?&G0,O9%6+Z(^J4E7Z[4SZIC'_ER^83Y>B37]<5,%=)(/%MB\+7F M@&H)IR$/*/A9+^\G=A">FZGSRZ_4;T'SD(,UW >:.^.M&L3EZ5KMI]_K^/H2 MLCX /3NRCL%IV9QM]0;9"1L*IG^DBL2UZK6 \/THR!KWCY+:KTK'C7? M0XM4P4\[I27_I3G^(UWVBV*,F?,U5Y^56BHLL49OF6,#9WAJKB:H-C^+#;S6 MUWB[N+XIB]M_+!:7_[$XZV!T#W+7,+Z]CO\$7>G6H4GZ3P9K@T )^>.%@>)X M. 7>H>5@ZWL?'#;_Y+!E[PU7)YK'1W*^#\U?+756^=OO\/P+ ?L_JCJ_W2[> MT!_ZBK\N[B^[;+_O=WSA$'XV^:>F?O%%)%OCLY<6<4HSP,KZ2IBQ\=Y2RQ:$ MOR9ZOKPP]BE;6#4 *M$#.0>FQ19JFE(-T#1D0UDLW)ML' =;\PQ7/U,E @M) M"J% \M!,F28E5\@%UD<_,=U?8WDAYU$4B3(;TVJ$E# 5"L@X55=B$'3KCVE, MOM?UQS7&S-)\_[/%SPY)/M2S:P@@UDW/(PNF\"@_7E M$P/W9^0OQ!Q<@;R&6<0'0F++],T").@; CK\&AX>DJ9)Y7 MP"5:#L'/45Q<5]FP_[8M13]6+ \KIIH?II L%LTH2F/G@IO&;0&6LB[ G1NT M]\\5.>Y4WC2K42V'[("*^-IBXBDYU#1C4W*(,TH.9TW/896)14F*G9TD3319 MM-.:XF(I^$ULN1G9_(>R-?]4/I;<%Y9KVFX8*!N;_'+H0%,?XC8T2UA[ I;N MZ%+Y&&)11Q]KM,''3EI:9(T7"#:F\PQ=BGE2!,(EDC/U"!KKF?>B5_P_>R)MJ M_8:P+A\-3T]9!1&55L?5+^\O;]50.3=[Q=7?RZN62&]/O_E_7(8YG<*;U/4 MSB[^NAYWV:SP(J./#_L#7&ZMF M P0-(1C&(BGY$B8J?$G#Y'&WP[C= S#Q^[4^[H:+\A_&'VV>CZDY3&+IK78V M0ZO8[/*-"#V%<=NG?FI\IX\/L/N#X?T/5DUFSBW5TERI DX IP>3;-8L,S1K MYM<\Y,'\_0_F5\VE99B=U-6D<]FH?]F!T^8;>75W?GO_K8J&3?[9W+]=F_SB]V?NM8 MG8;%U*)&'M&SYY:6D9VF.#8,8\&)MF)9GM!2\)I[#T"L&6\Z QSDW6)WD==7C@4J2W0@ MK8J7,I'OA=.P;-#Z-4VT,WCI_WA]]GKGEU9SQLV1<['E&E%,JDOCIK0+C,8- MY_G2?]_=GC>3I:;0HFT^4A64:7D9:?K&0X""N";Z?>977L6R&K_I-SJ_?+]X M\_WOR_>_^??%Q1O-$?I,\>^O]2._7]WH'[\M?_;?V;ZK(T5T:L\U#8N:XYJX M.O^IY(.H_]<:O26C*S*QGI R1,TU M T5US89Y&K"O?S*^-,[SI?>(3,0092JD3%N?B*F_.,ZWRP&8R#?@PV3B$J2J6K36_?' MQ_DRJ@T*ZESZ!IQ8J,8\G<,RIN">Q_GN_E>5+]Q<[7.7!JBVH$SXFS*V;:P*AY5,V#JKLGM$^/YGRC M:C>W[%O4%T^V#Q"=XDVN=LR089[6;2_GFV(K2ZT/ M?//3^U_^[^+U[<]7:SZ]31*L+\G9/F^YQ%)07])-M[PHM+% M$80/G^7_=[3 M/]%[LJ/L.(,FS>2"2ELQJ_?,..[3A37%[MW?D]]?7^M#K:5U0*S)AS"P76' M1'L_Z7=7EZ\?!*NZM)A-\UG5.H U-H7I85,.8WG?;!7QCX_RT >^#UW-(X() M7E,+C3P@5+:TD@-C:1@^[=)66=WZP!^Z17Y?F#50? M]/+=NZLW=UT TS?ZJ+0_7/UCWYS6\_7+V_?/.W7WY_/'S4 1%D0M^WTJC1K#P-%14/ M&>-,\>'?SB\69Y==P?CB$>'1S,A$7\ XJ 4R%V?]! _:G.8-S]\OS]^,AU9L+)'H7&-7P&-+8($Y(%9B[(#T4J94ON[ZZ608VK__\1I_C M>G%S^Z.F-!M]6TZ!DZLY4-/_Y6 #31VAR"[=F>XY.C>^NKAZ]\OY4O>N'E'W M^E1/35:,(Y,U6M;('5>Z%[F%F4J4Z!?_W]3( MD]1X#20[)F&>F%SM#,A#9"6TX#6?Q8K%M"("ZO?[S0M_S?__KKXO?MPB-Z(??O%F\^?BQ=JXXO3X_N_CF\N;V^OUG^?)' M,3*1HKCB1=,CAP4#X0HNYKE&1=]VQ?K[S9M'4*S::L#BN38KU7N;_E ' M>8DGJ?HXRI&2;YH!W]S@T^-R3^C\V'J/D?M36'\]O_GO=K8C) M%OY5A##>PHWQX/'ZE/_OGCSJPI07=SH M9S_4:#^_;OWA]Q=OZ&;YT8]_Y;;&:1"-<8,7BUB=[UT+RYHQ-^=E:"7[JH#] M[JJ?-B^QW79)1#3][)4+3P6M\0' 34#FS.,J;'A&&[87E'<'D#MJ*I6JN:6Q M.4=)[,126(F3"2,*Z[H,C@6$IU!/;BT6=)I')V;7]30]T4L\2; 3Q L!V]\-JK.P;A4JA0KTVJM)H:'8!G<2>#Q%.8S*'Z&59^"T7PD^63B M-$A#.)6AKSE]3<#N8XC!NMXP+(&@&4TZJID&F+$@Y#5^Z/D,\>,%RRVCV)B< MLT%M>K*D>>WDCJ"% 04\%GEZIF"Y^!0"-E,T"?'1!=M#4' KYBM@U<^BB/?8G2V$+[_/@]HCAIG.PUH H"EJP%K^)45W!4&G)9 MF#\<^TB#C9K#,[<(,<56^_'>%$<(N#J$50!/$D?0NZOWE[??7=U^__9M_\]? MS\Z54+ZZN-!WNCZ[>+ZB;6,2YT+PN1<^"GN[6H?B*>@<9R[_,!^>WYV2_G%^>W?^YWWD$1L*I*9>>=,3:X M2-,+>@Q^J$IXNV^9;/5@!WN9)V$^^0:0@B-,GJ!$+RVM@ $WGGN8?6W.(P"S MERO?N;EBDU6V06QK!?KJ7:G1DUT6!*M)L8Y7*_<-G(\$H*<( !([YV)))BG& M;+-:\6G3NW$2AK.1KQWK?:(+\9$@BL,0K4CST8!,T46Q=L#V>$!]6-4&H%^5 MYU2C-*-"Y^NJ:J,_C .,_)I+>\<+RY-DAZK!4CW&5&)O,(HQX82P(3M>B]PW MG#\)A/?1X=0J.@?D4Q+L1W[!KG38V;&V^)^KS!>4IM%BJ,]$EB@&"X3R76U.*JINNN!F#0_V@?+5DH?KP\?FQIQS-5 M9%UN+MPMJ.)6?,HDLJKS&QS'>'U%L.ZCI(XHYAA#JVR23Y9S]2LE+30D?=,L MX#G@^)CYF;H!,ER@68<1:T'\>!QG[#B*)1\/+ON(!Z'/T7N/ B:VJ&&'GZQ7 MK03C3=%GCL/NZVXP:F\IF2"08NK-&M&6J?8G<>QN>'9.GZHHF@)[\MY:1V)< MJ"KJ']L^\E@4U<3Z^8%YTM)8*$%(\V;.08+)-13KIG*-1C*#E;QO), Q _0D M;<.2O/KOZC1L0@J9<'4VUJ"D%ZR_I#06*@"J *=:+:70+.95T!3#,,#G>$!] M6&DL6N,0(9>H/L'T&L.T"8$EJED<2F//G/$=7U^3/K1H2H-.Q]]&V^=&] '^&4W-P1MK M,]K6T-I@>=+CZLW@,\ _ZO M$-^]RMLJI@YB8*,>Q]U-])VZQ269.!Q&'P^.^Y3&- (QCB,S&Y=CU=0RR4<4 MQH.I=4LFC@V,I^DN4Q\!5#6J*=XJQBY,-9UJ$XPW4Y[YP&^N38L^D0LF.2_@ M8@ZIQ6FR DL+8]?5G#SM8R9H9/LF( O>%\4'?9"P2M"B'\L%>S<7/Q\N^XB' M@6: <]3<@8R^>Z-I_'XUR:_!X4G5;+[-C(F;I@(NA6(;>* ^8^'CW,%QN!BPG\S:^)M^P;=7 M-S<_+EY?G-W]^_RYGO^1J.RJV\N7U^]6\C;MXJ* M?H\?^OC0J\OO_MJNO&:'RJ-48^Y]F_+GTK[\N+BX,RXWOYW__OE?=W;S6[NX M^L?R=37D]=OECLIU">?TR--?O:V""=!+^>S45!67;34U3ONN>SUW MD(W[.O /R^.+K#R:K$S/*/_\?7%YLVW(;S]*58/,J1E;07)F7&9YM3+*D$6_ MNN\P\&N5D=WJ0<\N&0^S(L*^][95+MXE=.17T^NJ1/UQG\SB:Q60.=N-990B M__->??PWEW)VW4K]T-V""8:98C$Y3\::M1$GC5/L:D6EBJ^A.DVDH# *"#W5=^^5OFXKU#Z[(*QNPMQ+@4F MB(5CB9&M+W8IP>SI6 R"6$AG!32^ K#R*B%@:Q1J E!QF I*5,:6U?MN@GZM C)G>_'E)9)0C*/DSU./3 \-0G9/U]LXB4;#OW>4K#&-^0T11S>^['D>.+YXJE*Q'XQ M!KF P4=H##5(]%6,7QUO\CAU[)6];^/EBUS,5RX>6'+L/4G59\'DF @K^C2= M;K*3=/^2VZ]=+F9=7]K==50(S=3H36(J:#R)69UP0QR75KRXCB,3A5V$ %I. MZ#4?C4:LMRT1V4'$LE5B3 MQ3Z9O1BH#MNJ.<%A_NK2QE.5B/U"C=:B)4_%!JNA!I> T\3.VA>E#06E5]:< M^*V;4Y6+!U8<769-4-BBIK*!3/*TBD5+M76\"OD2BQY7M6F/PF,*0'=CZ7J' M#$,06;7)U[9&%$[];LW)R<(N4N!3<&H4/( T$_17:*^4G_A9]@Y" M\&B5QYP(DH%BV 1#FA Z/_6ME08XC-%X%6=Y0^'JU\OS?RW>?'/YX;M]<[GX MR_>CRS+FYN?U?LJ7B_W:'>\1VO81E^LZ[;<-4JE M3(*#,?BA@+"'P!R4S".7HI,N0DG.CEJ.GK+E0+YPGEI8//MQN_2+#)WN_7D3I.$3I87XL1&.M8/4)&4/V5%=7 M\/#_9^];F]N\D73_RW[/%(!NH($O6X7K;/8DL?0\%6Z46PP8'$)"RD M!*:;GYS01VC7F&SL0EPJU_J^C#E[>Z.(V?FZWZK49)A-726,+C(U>Q!^Z$U( MW\BQ*+2AV&W..GGO0&O*V?L9& '9-')LGB+I1>D\T,@.$K 60J[[]F(4WF9G M('8)6 W0KF/OU=*ERM)V9LV'H.H@*VVD\(2!K.[JQ!CHEO7V:?>"J=) F5VO*.WM.^T#*0UR-:#,FQ]$@EG5%!:;9@ MLYQ1B.(UO6>]$)V'$&UGSI)E>Y85B)Q1VQ13C=IVV"A#.UVEQT8G4%M0MYXD M8;V,7J0H02KJ'%C4H-JXVL9C4H_/M6DQSJ?/X^%'%N3)#US\>.[%(0NTH 7# M3E&'(9&",AMX&1A'[&( ^S:4/P_.'@]&+JGMU:QU;9+1"C#6%A.[1N&$*'92 MY'%Q?#RU1PFJ:)^=24$#6D4N"->5VV4VJ8TOJ#?N+;U<9AZZV'+)0ID8-=2^ MWP ,AQ@OAUF9O4%L9HYOGU@X=Q[NC04)4Q(%I"9="BHJMG3N2PPN-OTO6XQ6 M.0\FG&L.>4E+M0;O?9+>1$F>7!%=.4'$).9T-EVHBCROA.[B0IVI MX'4A:;KP9Y JM0L:U(7BT#/*A"T&H=8%8R *;8&\+Z(\-Y@5:J-&/^#F4](O MEYLG V!RECY9.5DT:;6725*< 1BEFV@ ;A_#.7LZ>)H3Q M*FHR?)T0@A0^2N6IXZP\M;>I(]KD#&5'(4==O$BS)CLK[)RV M5[%]%O7BN'DR"(9$II@BHY=@"EM2&6R9/DFEA&N>)'Z_3W*/GIT1PDIM7;0;LFATWA)OXP>EJXCGQW@P.F$S5>%'ZA6P)IB8U"A9HB,447$ M#JH& 2CGK,9:SU_8A!$]5W=9251240+(!5(&=$[LIILI1U$'U20'S7?!T#6P MRLF^T;K_U+OH?,A&4_).I6F"/T=P9=L$?\_15[[/#=N?1!8ZI&(2&BJ^N$C3 M=UDDQ78B^)I]!F?.Q66H+W=P]#J_# MX_U-+5Y9E;#2"AU*KS5[D<8A:]]IR"U(8]VO+=KLVJ')\MR9MCG-%X/[Z*DX[4V" MDG7(*:=IDLX!EK;Q5:U7&G%"M-M?:OQT\;V,RGA')2$8"A)$F2+#J#6%A9/F M>Z:>J O.+U%%*B*K4@0:5%%.HV>9_RQ[:GBX63?:- 9HP]),/^H M\!.5R75Q,H]^XQ+=GI4'=;Z#)*]L$DHE=K]KL;57G?,MA&VW^*T7SCYS+EZ" M\VV*QXP4&#H&JY5,14[;[V.M2FMK"M<;K-ES]D"^M_"U>\FI6#R_49ECZ1(0 MF;#,ZMZ%H(D1^;\5$ M9[+D9S?U(!%$.XEXO0KLT^79#IWO9*+.%,"C%8'=;1U@.L LH[=MAX\29^>H M[:^JZV21?<(B&,1G'8R6=+6A1DDZ1 $Y!C%MHN M&.S)-S-&U?E%%O=4IG>RCS-3%,(G!O4A: 1M8IY.) @05&S08<_*DW*[?0Z0 M43BC*&")X-GOGEI,[5QH0OT7SKY+\+>UH:P<,U @QAC98.;2!<)""AL/E^E9 M>B!'&R+CF6!]K:R51I9":0K\?41P[0J2LT/^9\*_S1UMS4\N*QD#""@U$)UQ M"FQ"'8';]EG*LPN2G!GOUGIP.:$@326Y3*2BL5T-=8 H?%L6='9507I_KK84 M5A4FE2JR@),J=5M1@Y"R[0&0]E"N]D\W@]\9NS[<#.]?$N3'I]A#!WKKM",_ M'ES]KX^__W-X]?#;:,ZG5RD$B2';Y#"#M5"*--Y,6R2,$= V M>=(23^>K&VUQ97V@*T^6'SGG/ 2C,-12GZXKQ!313KG"9<[=)E=^$1V$HB1++%J7 LD@L#:?YJ4AY3:% MLFR QA9T^,K]F[F%G06LOB)_X//H?G#[TE.T36-=VF4G3II!V>X>#D@>7DR>PDV:\C<*2"@SU!7;" MP9)!OLDW=![;A5!'+Z=.)!TA&JE*I@P1R<"TC-1+HZEY.B= E3=W*[Z8G_"; M]]\28_J0?AG]L/P^%#'<5Y?3UY_(/;^DMN1_>/X^%]^-+] M[K^.1X^?[_DK;A^O*UR?=Y!G[/9VQ-]]_5\W=]=OQZ,*WE;NTR#21GKC-3B* M*3GIW*QUU.MU=K/LA(9[YLHZ^HT]E9P#%2NPCI'#(*SNJG4!6R_F!ZG/GAC[ M\ :%$T$'4LD8B9ETF*QP>!K2($V+_2^!?,\;?9_"#V\>^0>_7NN[H&OZ!9&W M_9)O(B(S1?.4R:D_,+J;>7C=I[[ZWC1\?W,WO [#._Z'A[>L0>[]]3\?[Q_J MEZRJ*C$^JZK9M369K,>80@9!S'?/RJ1QG7IF'YG9O[$/?_\T=6!M)H-//C'F M$\Z+.J7*N6K$!=G$7KY4;=47M-'HLV$V_DW][2MF_WKU<7C]>#M\\_Z)PC\/ M'SZ.KG^\^V/X1+KV3X?#7P939D_"*?POX]'H;N6H(I=EB,YI0LMNEP M3$D772IR-BP";..OT1FC&;P@#?T:<^Q4$#XF3S4X:+POK$:Z^MP<9MF>/L_MQ<#]D6K\=CF]&UZ]-8@AOK3/)RTBDR(92NBA]"J:TG:%S MNF#V=YNC$6V%0X8QR:S).^=B="&A\5-/HN3B0I/:6#.S<=I$VSJ.S$A,YQR< MTJ2U":!RF2I8KPWH.0,"UG/E7WF/P]-IA5213Q:<#R!(JP3*"^VZ5HYW)RIF/NYR5&(M>+9):$\UI9"$Y2U4B7J!OHX"UFV M.Y/6LX!G2JP5C\]DZ:3(WI(1PK%0R=AUM%A&$!L_OB-3:1ERV_C5*< <,X@8 ME2@8P8G<]::2ISG#]>5Z68%M+W! RJS"2Y[1=U&%M-06C$3]5)KG2D3OVM#, MZ]71B=!EQ6NB9, 6;3*KH!R#F!0,/^%(6Z1I+/Z!*/)<9[&\S"*.V*N[GGOY MIVH[=?"LD2\V^5B74!8)*3 ^"%,,Y4P!:G+MW7Z+EY3=B@ [)^)3I9[\]3-? M=7";:K_AX'9XC"J:_QR-KP>K2)\$6B58@'-=?U<(S$0;:F$E%2I-EFK.TIA= M4[[6RZ_GO3#G^OR8Z;)JK H ELVFZW$HAS[=)%Q>/(B%KHL)"?7:J)(WH:NW2YJ1B+=)RWDB3 \.W.I[U*2ZFO(%&FRD[SRWH*?^/O_^? M#:HO=1:1?'(B^N)T"4J7KBI6$;2KQVA>"N]DB,[H[TA$S[\_/JSJ;D>'%1VE M;(2W+HIB.E?.U\Z8-O([KZCD];3^@\WXW?5]''WZ-+K[]6%T]3]UU\O&SE=% M>JB!K$TDI9?>H$1CLS(J"5.63CA<<(;7G'/[[,;RK,GB9H1_Q[_[5MZXJ9K$B9N4\J&2M# *C*A,9!]1DS=)Q(L>_Y[MA MA9C#ZVZ.RHK+RA(LYBA MBTZ>7[$QK*E%(LQLA2N+/8:$+CN]_W*CX&X(M*UK-6:GY[153@D$@I%]G7 M.^U[;JAB!2;V8(L-,GH!(-D!P(ZI2LP)2=HY ;*C7WH3%5L8"KODXG%8LX^3K;[#Z[>#\>*Y0\_O?_;9 M+Y-"3SYZ#6V%+U__S4MST(WCO'X:9;'*]D7M*:B2@V-GNEJ";L-HRNQDS!E: MTFXAFG>O+2ZN#WIQFT+M:X_\!DU1D9W+;M= REI24^@L;3N#:*N++YM!-'<. M27=!_GG^N:HT!WCL<__J1 MSQ@&]S=7Z^37U(LU SZQ[R@=):F3UM'-ZJH0Q+=[BKI?Q=['7Z1^/O/5PV>:S:/; 0"$$%3,S= M)B*9OO7,GL\J_R)H]V?52Q]7!L,V.KA"=6%QT#KGU"TL2^;;A55@*UQ76L!08JHG>4GULVN"^K;^;TO%*R$O1QVR>,JECRJ"IB, MPN@CY-F"'))2EL6$Q==8KG1S^\B6>5,[ZV4*"?B\)% Q]F,-VY%6V0!N.SL[ M/L>-UYE^D& MJR5IR_9,"[:TC KXR75XAKV997ILB=U]Y7F7/#@HWK-/A8ZU&=8F)F$[ :[+ MTN02VVOV<][E]K> +1+Y5!8-=YCCL[;S+WAN4%)"='3 :R$M&YM -# (V>FH)??\N ./>4W=S7?Y>^NZ_^K*;D_!K0T9RJ&/JE[[8R]R;J@V1#:[*.55K)JF<+1J$DL MG2-UG/NOJ/O) HO77M91BM&I;!+JV4:W\*U'6/G:A!>/>:^=\56CK#72Z!DU M*&(=#%TN.&K^LV4SCUYW_UF!TF^#/]]-UP#>W#VR*G_N8MC49Q(N9:E$[38K M)ACTUG0F,!+@UV64=X\3LK Q ?CV2NL<;5<76HY)7=*"??Z07FWJ?+_0B#'#P"ZVP^>R".\:GI("%*R@&4EU87P2MS=P+H3S^A=HZGK\. M1Q_&@\\?;ZX&MY/G=U5[)\=?_O%_?WDNYQG\^32;X+GCKW[CP\?QZ/'#1_Y' MVS[/%TZU-J+8D.H+K4NX1'""C2GX& KE.)]_=M)BT//O"BO%8Z-3[YT(K5EY201B_CJTC-8Q M>P61K?\4_O@D4)>+($)KBEX2 0.& #$YH0/#AF1==NJE,D0IQ K1_O MTO#]<#P>7O.'_/W]\.&^+D5Z^H6WMZ-_U7[23=$3DC/"$R;2R0M I;!;FP;: M4=C2V&Q]_H.29CD.BP Y1<8N$M E 'Q*T$R I54O$LD=:6I<>R5N.0_:+(=T M0AL-3L@8T&AG!:H4ND$KPI!:0)L-G]$>:?/4C3SI(WCSOML>O>GC,;XX=B$S MNU :K;81EL':T_]QN34? .R MJ;(XY'67"WF6)3(:?"+=\ _6F,#- MO.$$*WQJL")Y+[7UP5 ,7FG;&4D?S2+!QLVNONK4^Z?"PQX/O;%FSW7-*@,BJ3 ;ALMH9@M[E:47ZV>^NK3:[-+?'G+WEUPNWYGO$C)) M]&S*A7>>W_GS9K*\P&?>4+_M_Y++Q=S >;L3\7WM M)=\-/P\>QM/O>C]]#%V2:V-([X)Q(=>4E#="9?YOQU;%E,#=X-:E1][S_5?$ M3YU@/8U4,$CK6;*AZ_")%*Q8P/$-M?8QK[]"X"GPHV8]+;)@X*+9:X&NQ$45 MY7;RJG=Z_4GDR]]=_S2Z&MS./O=MQ]1JP><; LMZ+1_7%BE)Z73'>"IVD>!O M^-87G79_MUZAQ2$$-LE)^&P1V?VJ0\NFH#S&/"^TM<5S/_RMETNY!D*%5BD? M&(:D"/$I15NQ>90+;[VAZ[76K6_Y:\8W5V_'H^O'20M(_O/S\.Y^K5#,MZ.H M3429H,1$L78\=,53WKB8FK8 ;=N)$0M/\ZHC7\;FD->LB;$L:ZEN:V9'/[@L M6;= W?D8029/[639IA.G9\QBQOPR?'BQP'JVJ.G-^&^/@]N;]U_8K-3DAJN&@Q@;)V%%L&[8G4,*F"=.2.(L4%(.349[KV_HU45)TJGNH4(*)(' M"[EHWSU]3]B\_0)@TW\Q-G,AFA)R#HT9EH3Z)1H>Q1[ MQASSZ>IE,@7J516[.]-\9!W$1LKNG=-O:HHB8V)UB(%-O?>RU)!3%<1 MJ61J:NBTAJ8;<#]'O@P)>\W3#XEJNM1))[1VSNI*G*="P!*2;W/6Z.]P4_<>]( MN03" D:8-:@Q!-"I*3.5DRZ0!0=^>99M3MNV^KS44RG[VKB,,1232VVGZL;9 M443?%$^B,@M?PRX.^VW;PZ7LMST' MWPQV+<8S+)69.:Q"J:UUW6%U4:UO@;C7PW[;BR[..SR%X;*JD*A"!;<;"<2.:5L2M!.TZV=P_L\[-(75BR:X" @ MHT*08-%13DFAR3DJXQK=!5,AV-MAEVZ]HW7V1D<[6Y'@DVV>G;6T4$?L^N@K1$44G[2?S/TE$"PV M+-C/&P?:!6EDS$*YWN#H?V7@/QZ\1ERRH"38?$A%F$-FT4[=9DZEH1VN3[:= MG;?D/*\\=N\++!J$JA@[,:QCHYI+'9R.. D!LGN@9+OSN5UMO ^>K7C>VF4* MP0GALF!\7;-9'6!11MAV,I!J9TWN[]B]J"U(W%!FW0"*89!,0EA6T##;(4^Q M">&TN\_VP;,5ZM@5AD0F 5O";)1*"6TNS:UYQL>XOJ[AL_'-'X.:)RV#FW$MO*U;')N_G-3E M+I\FN+K!Q;];/+Y6Q:A<*-XJQT^*M.B*L3V;9#UG$UKK;6QQH]U31.^*(EZS MGV",)@6&D MTVPRF4(=VD"::.'\VE=Y28#/MZ,OP^&OP_$?-W69U]-LH.%U50VL2)ZJV/E] MLP(:\L]>5RV0_QR.KV[NF<23$=QO/B]M>WU6*_\:C*]_^_+YI6:;G>#YJU;- M3!?!QL#:G)U?!K/ E.H67F<6I$:#R%:#[.[6!R,F[H>8*F=?=Q@'!8I23$6G MW,T8\[X=T7D1M-3[H2787 (3)X(FF]A#A.>Y8MJ4)N[1^EA'I.4OHZ>UQ=<3 M:MS_-GH8W+[XM:/[AU]&#_\]?*@51A_N;O[WV]DIWQJ'EV2M+9YOA^/WH_&G MR=K >M:_,SE6X@47I".5P->AV Y-? J$UV)0#;D=7;\54;>Y_'O)9?R, M=1Y,L::$0"JXKB^F.,KM.)@V(O/=$?G=L(9OKO@7/8ORNU__ODI%H!;LNL>< ML+ G7Q11E]]C7 C-,@DYQ\Z?,Z6?>K[+:#S]H_HYN:&"7JE)G@/1A?5%J#/F MB9%FM 6Z)C\F-ZOF?_OWMTK\? #:SKWVV1!\#;WRU4!%8Q"*14$IY!PBR_@4 MG 5EHJLD5SW)UR7Y"BWS' N1K$^BPT>1*=C@?LO\V^'-: M[E(1SM=_LVXYZ6[ !R:ILC-UP*(M-:QD4T=6%<6WH[BK7[:-MEYYVZ/3;WMD M(5UPAB3(5(Q#9!U@ISF38+0+[=*6"Z?@=K"!L0$YS'7F!X))/M@P-63)0?*+ MXK/G2,6E?NZV[SB*@G52F-?:BA)B0#6EGX].MYF[.8&FBZ#?]N_8 P$JPI"@ M[B=RN2[IFQH88#-_0>]X+0IN]XY%H60\149)P;'W*HOIHBU4H%WW=\;O^'40 M?J$4&F=2@E@,^:@3H\OI"C!?DT&7)(5[BE%%;[V)-8"* .0Q!-OME3"BS"DP MO7 *;O>.(TM?B'7_#23! -MA5U"1V,;DQHT_Q#N>9/1^'CY\'%W_.,'M-1GQ MR_#AU\'M\/[M>'0U'%Z_C(5.*SO_\_'VB_K'S>1G_O'\H[.'^NO-[1_#\;N; MZP_#MZ-_S1O*]C+$$4H&80(ZKZEXJ.N0IB&.$HMORA8DM:.%U[K+#FZO_P9S M9Y).KCVZ'8Q__3RX6?6D+")E9QVP3Z S"T36PF>I1<[D!37Y"&C?U([N.\D" M__9Q9*L-5.UU%\:88 MHRA:-%I:X>2T8R5@+NW*7M.F-C>^SPZI\35Z7T*(V_N'P:I@=7"1M*[KL#+6 M/3-6J:Z.POIO-XNP[*LU9?^0E'@J]GZE2/!3<*'H+.N4?+"8?.S\/AUM:BEQ M@B*!*T5B#4(4@=*'%*7+F%4(D>*TWB'XTFP8^;=_MVW$]_0)L:&)0".+3LDY M8;0!8X&ZL$JN+8F-^<36']L'3?YU-QS??[SYS,CTBO]]\&$XOQYD,1W"8#S^ M,EN2N'QZJ97"%VD-!3)$-FLY:Y9/6?AYT_GD7]:@07N+@UQ]@7I4+V)!TCK% M;H[(T2.P@G"JN[$3>O[D2GVR-_[KX^!J='L]6)/?;!)LK&MA25MI+>-OT17A M)F'*_$&5+^9VGM3M?V9@Q-!Y.'SX//_%OY!U5,I:JMWL",XH1L_=W0M[=&L, M:CJIN[_Y_.%J3:Z'((WE.ZHZ?TPJ44L6N[(O@2[-O3FZ4[WY!!1/5/S;=S_] M%)??G8%00/*U?5E6$&"#G(WKS<;-Y_HQW[O>F7(GX_BQ"^>\I2"\%?PO7<"1 MK)IW]>,J]^577T.Y4RALS:),K-P$1AMC]#/U5M+\+0:GR^P-E3MSFWT>:X%A M/M8MQW[6IY>S*_-%_<4.AW.X_3:KHR=?5^MT?WW\_?[F^H9!V0J44)#82A6+IROL"AG)V6F,C.QDL2B O7!W7R!*D0'8(J:ALYD]M='BJ=]_ 3AIE M=!W'2PR&750E>N@00K;2SQ_2>4P[N?SF7SE$/SX,;E>(/-;JE*"MR.P2,0V" M,<8E1YB!@BKSYKZ=LLAO!!*BK0OKDJPOG8Q&%7/N[ :(O,;\]L/=_0D?P3]K MP/3N^E7^\ L2. PU-.#K/FI;9(! S'Z3L_7.VOE3J8_$_C4@:KQ8O2!ZC"VU2F8#:^QF@3W[1.';0#ARQ%F.69;A .0!D1M M?P'917G0F[:_HVL#7W73-2+A][,^$";"U>WH_G$\1XV]_HZN[I&7EM RYLM! MV&RG:?$";EXZ;3K<7P_ MK'_8TNWE%I,U,T"Q0"MO.UC&H;"W9/*O6?CW=#:1X^KB+6$Z%^ M'5X]U@48P_&GGT:#NY]^#&_>O;U]O%>DG\AG=T>^E^E(D36%6LANHR5VT!A< M=IZX3K:)-<_)R.R!>#\/OBAQ\K13=3Z.E)KJVF-)2D&6'>W8T6^'4)JV^V+7 MQ--_D[]^YN,.;E,=;?MY?'.[W^?:?>#O=_=/?%B#<-D:"-YI-O"@ X5L=,QU MO!"&6#=1M!-0VHZ*$R6<$FGTB2'&?@@7998NRI)3$ J5Q9!,3B!%SF!TFTN7 M<^::[(%PVQE/O4\10RN"B#%F80G83PA6 %.JCK#"NH"SI52+/(Y!*3>/4N;I MLON4+*V<+_S. BC46EJK:Q<. /LALI1V-G6=#;9O>ID73_*^%@$]7Z[&RX;_ M[Y&_(__!_]-4+GWS]ZLF/*"HZQ)3]:X)= 0A8A$551D5DVG%95L0,<.M/]Y] M?GRXK^BU?F39KKN)8,Q^+GR9M&F_J!7\:73WX:?:\/BT/>L_AK?7_N[Z[_?# MZ9[(A4Y9>'S_?G [^C#X_..//WX;Q*R[N5Z0]+^&-Q\^UGX'=M[9=?SF\[.= M7;\-KS[>W3#I7_SP=&K#Y\_CT>#J8_OAY3& HJ+5Y(S/R2I*[!H[B29+&[)@ M7;A@Y\-7\:\E=#]=]OR?F]OQ:/1PRHRI[0I612V8@C%DW%#$CQ;=Z$H._3SX\^;3XZ=#SA/-(R,V_O*;^_]96;0='\?CX=W5$YNN MIO_RC_SW=U_AS&ZNR3/:K%_]@EC=?I\_KR8+.2/_UC&383.MMBB:+6RF.C.R M**=D*I$=/XN$1OF09('YTBZLM0NI^2V9+HFB7VNC111EV.-T"5EE8-AJO$\R M3"AJK%21%FR ^DXI.E>++*)L"EXA&O:MO5-9E6)T%Y/W3I3Y:\2/1MFUZ/8C M?P?[30_=ZO;=/6SI?(ZA@CX5(+ $&ETZ8K'+N "37R"QUGFS4'1PBHS#X+0M M+&8Q=L0*P2Z0+'5QQ-KH.5K/!CA+@1E%9JO9&+4I^:UQLB#<@6O7: M:DQY.COOK^/1OQX^GH6??@1GH[#9<1GK+A9&3DFH8D+US[6LW!+S:Y?E8O]\ M(?$ODV&']T%"9D==.F4A>Y0Z)8&I,@RM5U0G8LS?K[?X97U?'#NB;V)41 1# MWD.=#BX@JJ>GEIRAA OP-%PLX]8-DAU!*Z; 3 FJYE%SL,F#%].RUQP'5XY%B,H>.%=-/S$2,=H<,HSQ#+7COUP ICCA)AV1"T)40(J MD8LCJ'MNT.+,B4YJ;B/M7A[< __,VW'=K_WF\V0L_=V'GP?C#S=WTV+DD\?\ M1U"6%$'E)#+*9#(E$"&8BO4)!16?S%S>Z>6@9!4?+IZ-1]"?D V[;$4Y+%@8 M6X+$RD9CBTW9SF/C#^HO=KFS_;WS\8@J58*Q$8(-Y+*N^ZY<>GJ6R=0IH_/[ MT!1^9^P\8<><80S8X)"BA9150BOE,Z!1-#]NP>THE MZH"B0Z2@I)J7&6!$2OT3/#E=*DJ.QA#[\F1K%AM#*!TG?2GS,PLHQ5VQ#3J-S65H_ M*QU,0LPSCZQ=Y7)_OV?E,=5L1.LL(0AO)=ABP$C1(9Y"9GZQQCX@Z\_#06W6 MK 3[KYN'CW^_&_U^/QS_,?C]=OK-M0'K[FHR%.&F;JZK)4/\S6%P?W,_XVZQL!V.&FYNWFX6;G.4"I@ MYT@YXT3V)$C8/%LQ$FR[C(R@:2OIZ;Z8[FOHK,F F1$KG+MZN>OA[P_WLR]Y M:BA:_&KJRDE99[1:-$6*5 QV8_4%BJ8W5#?MC3WO]LR[>5\R^\?_N&&M/+[Z M^.6GX1_#VY?5E-]H\_H!N>(M,_=)* 51$8!%U)&FL]I*3"XT/>F]')RG'*A5 MK8))AP)L-8.Q6;#KEE*7*D@^$4?C.L[W83*S8'UH5K=&NFQRRJ1$3A!TYZ[K8G.[+*+M MD.[YMW_^'=+" WAFOV:,[I/QF3U&([NG'(QJ]@#UHG"VHK#*R ,BAF@B.,'@ MCGUG#=/FCFB5$,U4G5X[G+U(K#+T,5JL\Q$B4'#LR$<9NRVXH6C;B$0O"KL6 MAD%&G0NF.75+IQUTCT(:_#L>V09EUZKP%M'4N5R+(W5L)L M?746MIGMTDO N4G *FM>RU.,2A@A67;6M&B M1"(9P'@/*6GGNS4;)9-WS'>]RH*7.O>X%&0_76A?AW'1 M= AH)"REX54[DZIGV7Y8=DCK[?B=UEXD]$H'7:M^NQFZ_*?Z1<-$_V+/C_TK MH^W1&V6U]]"F%#G=EL?++M?GJ2?AE(9@9-KM';_; _*MT,:\(12HR 54E8B M8A360!=*)?"] ;\ &5AEQ:U,.EN3@8B00;T0,G0;L6UR31U4KP[.5A16F?(Z M4-FCS\5%6Z(+K -4IPZRETWY1"\#NY:!R1[U:]-FP _/ND!:=E7.069>ZIT=@E"ITR=%$2II&''HQ.$LQ6&G4027G MJ4A0$(OP>3K'MV;8"%U3+M%KA;,6AY4^NK 2,V)M,;",ZQGHITXK"&QW"/1B ML+48[$NQYV0PY.A\J)L66:<+["+N%DIN^D1Z%AZHA9ZQ$K3I7^-<%CX/[UU%7RK. M*_3"D7(N)9-(=YFE2+ZI$%*V63+8T_F9SAO5]'WZ-+JNDXA?S$U>O&G.%5>G M?BI*&2-K+$AB5L%#WG[+J79?6L^H73+JH,ZFBIER#DI3B,KE[&9>AM4E]479 MY\CT52@&95(RJN)]%$9F933.>JQ4\(WI@[['ZFQXOPKV.+ .T82DJ V1JDJ&29#19Q MHMT;:OO'?UX2L,I::RP>)/J16!3$=A;M%<:,C9* MY4"CL2:$+OZ1G$ZZKX4_/,M6Z5N%TE,&)Q/_1Z>LG>T2\=;/Z4'4?1W-@3BW M2D\"E*0*A;I=+Q>3=9"^RXXQXYIA0JHO@?J:Y+^-!]?\6_S59(_HY/?LL_5$ MI8R!@K/9NVRUP:*GN#B"$V M0<>>_^?%_Y5V5B0 !Y15*)FL+[7,Z8G_9%*?"#];QJ\RTXF*+X9L1*&-C 0Q M3"L@V+\!_#Z*U0^@8*5GGS&:&+2RT6N)KMLP7E(LMBDAO&0%>P!])F,11H$0 M1FNEI4@&1.?JP1P\0_:"&^ /$171R0:UV?#?-(-9='G'V6**T.+&&FDP@*2 6(US44G>K M!D0JT,ZS%3W=3V88<4BEEH"%E(PB19ZYUR'2@JQ>%A4K];P[&.\.B9]JQ1J$ M[+VV&L&1%1%GM?=&-!51O1R)[881"THRF0A"J11=+$& M[H81$V/DQAV&'IJ=^;C1E76OIBZK\0S7*4MC+$"<%5:Y@)<;@OS^1&'E#*0, M4MJ0H4Z6%U30.//<;PN]=K@\D5AEZ L;B:R+PL1>H-3B[[-I[AGN= MXQZCZA'ZV4O RMQRE@1)>"^,"Q*)G?9. I)RI6D[['7!N4K"2F^=R+)S5]=+ M6%7G4$,W)*_N#LJ7V]IV,A*P?D4864H.I16R;O:M@RA+E[2B4FP3<+VTA/7I MLNR0UMO&F+2 1(F=,)%*?;E=79A'T3OEY\W^5:8[D \JB:*-BH*$S,ZY+JVO M?9N$ZY7 .4K!*K.MT&L3(:B0*/H"R1?Y7!RJ+K??[<38O[;WK:)%Y;QQT3MI M@RH!NWWNVH)K?*[^V9[M]-%5!MQG%8U+VA8R#DPP7G1UAS&CZ?/F%R #*XLA M,<:Z5J0XJ:)C>TZ2NF"<=MC40?7JX&Q%866=IK6I^.0EHJZ%WB:+V213P4B_ M5P>G-XPXIMKS" RU?"HQAJ!3[,H8K=--U 34A4T(.7W>';02SJ547$Y%69OK M NX$LTZ"G-OD:"\&9RD&*R=1"/;!1 F"*.3DG3"S^MA,0C5BT&N%LQ:'E?GQ MY"$K;:0!=M -FB*[/7_.LZ'OM<+1QY^NCK4ZB@I+-L87TC)AUR(6R131M(GT M+#PX"U<.(ZZ.-B)Z69)(QD:MNGBI4Z)M@^H[3DYV&#'94J?W1T9729HDD,AV ME<7L-E]N8^SK6+C^,&*9$9U [2TDZ4R(V'5H$B7;#.,!ZI_*<881QTA@C3+% MD9(4C,F=4JL+44H#+;!ON3B;V:2K, FB4JB3T37YYX,,IEM>5:+&W"0 >Z:? M =-7EE\'2:0MD+*,3[*(SF'7KYRP-.DCO+ U-Y?,^U6PQT;R,D.=:T@&ZO:S MW"VO=%;K9OUP'U0XYC#B8I,NP2CE35%6)2FAZXHM6<:&6WT0Z.SFD:Z>W)4R MNYF>C,[54=$9Y:Q$)U-OH<^7]:M7'VF5$EF=P(F4@B^B V>!U4&3S.N[I,Y- M E:NH&,1L'5#C,K%&0?,W,XUXS^EQC533O4BQ[H##R.N<]*4"IJ*D:D89&@S"SA2:I_>OBR@.BX9"*Q%P#.L6Y5 MWJ1LD\J4.HD$;]LZ);FS!<-+;W$<,LUQ47^\NW\8/]9?^>[F_G\V2M+ML69& M6*.C5P"9 5$N)(+J&C$CE-"VX^XLV]-S[:2"AX5(IUC Q+H(.(:47)?W2PK% M/A!R+P$G%8LL#,E,$2@=A2PAZIAFF=]"I5W8M+-89"\()Q7:% PAR6N;BG8J M&UF$@-F&/)BSN:N7@TX.QJ/[^\B_87AW]>5'_K;Q\/[AW>!A43YOCX8=V)Q[ M;ZRTI+T)9*74LRT\+C0CLM3. &O/Q9,V])HTU2W#-GKA(R6C\VR2 X/R?4S/ MZR7BI T_F:)CQMHX$G,"B,*&KD O:M&KBDL5C)4=@%XE9T"R*V!BF 0\0@<$ MA---U*.7B'4+>?;IT7N7A4E68C$B2V6R+L][5T73Q:MW5K_3\^X$S3V)VM'/ M#Q@EF=[Y!#25&G[*V9;E?T*4-HO( >\G4?.JY;3YFT ;)6*.:;$YAA MUM&/J6T'QSY*=UC.'=255]DX6U1P:(V4!K4(7553++IQW'HA.$,A6&78H>2L M&78E>(YRM,*P#[,F%DH.+MNZ3 A-TF:T%=WY.)<[W4?=P6L]FY4R"PN93"V!. MDBPHM(Q=H(NTSM];3/RTF+?* JK:^,3:.>E,H@BA6GE4;&QQ':ML^M?X,D9 MKI*T3T YEQP3Z @VSAJAE&D7JROU71BN ^@^Z:.5;+*4@X"4 H'%66 (Q/>F M^PZ@L((L%I4Q20OG).,'#;/AV4F;IK[B.U%8!] RR8+3T0N%[#H+"F L=;EO M0^5[TC)Z22VO+8*TR2DI8A9Y(46W KL$Q^[F'M>KG2"93JT4;'%LD( A#[@H M,2? X(,MS^&@U#A_<+$A_A/DVB%-NH,\CY7;@$ MK/2)ZIP>XY4+J'5@/\AW04'&UW/[57I5<):"L+*6-^6CDX'1J>;5.DM%J2=XDQ>"53-=;5:+3]!WE[L^ BX9DQPGI(5CD)(1BMC>F2BZSH MFZD*^F)3^R?+NT.:>R&E+5JXK(IWT:'5J2OU<*A:,-_+P7G*P[:>J].)R@:2>!T616 LFZE!7#O%!FX;XY98"[F[US M]N)P7+_>JB1JY0DZ=*!+DM@UWM5$2VZ*>4'O; ]*S[E3,^X0)2.]XHK)*5?$ MEU0W?B%G@_O8H]L+P:E9=F!UG6)-3:,P%FPNMAOA'+VQ3=Q>]_':LY6%E:,+ MT2L70]94K-$!DJ-992DD:I8W@O@NA&&?]MB7[$4*BGTLI" 5>P2Z,G(])W6 M/9S6LUE=SZ80BU52Z^*,559UHWZ+LR'N8YEUS[R=Y:V)2MT(Z(TNNAB(A;J$ MAB\*YLR@NMAY=*?+Q)6UO#9Z=-ZF$$4)-J&";@(!*5D:-0KJNTA"'$#WY5B@ M3FA44?,_:"#,,X?2"VCBQ3W%7ZNPLE8RL84I.0A+V6AC=1>* 5FW2)1L\_5L 83+#=_9#T]]]_>:;2;^K M#O'7P+K%W4G2V&"_YM@7? M%@>)%H_:]\4EBZPC!984D=QL5SG*2$U([H?%\[2^>Y;IY79(8-9:6!TC6W61 M@Y$PK7/,)075F/0?I%M<\- 3^P!VR"DLD,#79$6Q-MG<[7;.K.#FS(SNV;5+ M=FUGA@0!&1N<*R$ZYRD6VSTSHW)N?!9^9HOSCCW?#F.&-)4 Q=LD!(54&$64 M:62L%H'H!O%]]R_MS?Q\./P[G["D*O1IV']U%Y!^^SO%Y_@:C + MV V&]PL_.'W>5].:5/X==_>WDQ_E7W;SQX1G$T%H9L7"B6MUU)P M=.9?8XC/&F4WQ]=%25DG;40-8 MD\&46PZFYFR8O M]H->/9^>HL&1IAFM8IN:0J[^A\.E/I.;X. M(:S#,E,J.GK-+"8#9A8'9F/52$%OD(XK!+MX^IB!':#B!$H"A0)3-S6?GWZ4 M;7QS20?>T>E[+ES?8>#ZA/0'@UA-V>62DW"IF(2I"Y7K.EBK=ZPO2H1VH7VD M)1=5M(:BPQPEHJ).9%+V:RVO/SIS+EEDSB46XQ !V(1Y:T&%8H+-ILOX. 5- M*X$4O?]S,0*U"TTD,EGC(#A9IYLK;4(W:(8%R.FUBNJ/SJ)+%IRS",-@U'4S M@;*6729?9)%V*D6I[IYL$\^+I](=G6V],!TZ"I,I*IE+;9>V[(8QD-:="F*K MUHQYAR-GP"]0>(ZO0<"IG$MT@"60"@#%3'LB]4&_\Z+.WGW_(T:;S?0DQ@?(Z5(\F2%2% <5WC))82VRKE MGD]'; 1 EW621KL8"X: FN(LK"R+:08X=>G(GEV'K__/F&Q(J%U@Q[>(E!/, M:NB"H\;Z'#3MU3QA9-RD3]61'BIBQ**0F)]ZSYL"^!@%F);.- MH/@WLUYRJGM#N3;K'C>?=(E\VBK_'?)D'PT)$"6((&:*SI!S;23='31N>PI< M>O/X\.;]EEZ(+JB,]QB<-J )O>[F.A4HL552/QPT-#7OBJ=(WOT:$HM.D[0E MVZR%*2&$680<9/'-?-R>.0?W1)P)A;!6B$M=? 8C=;_5J1 #J7H)4-T;/?G8O-@#II*NR,^+8>IV?.P1V2J%7.TB*B-%;E K&K M&LDYD&@,??^,CN*2% 0KDC?9>N$<&IGB+'FH*!UK1N$^^3-_+46[A /^ADN: M>)/7DGSRE)TPAK*?3<%BKZ[%2#O-(LV_P1'HLU\MG\#DFCZJM094)P-)*K-J MFJ@:A-/3>%ME7Y41U M(*-C)3)K@(C0UB))L=,XW6E0&I,ND;J[>B<(L<@ ;O?!B-NO# M!VSJ0978*0H^4UIO,](_&Q&5LRHXH45)4F?7>1O&N7;MEMIM_OPT**V7*-;: M;NRT!(A!.1.5-#3;5 %*MX6;NRU\.AD"/6O-Z>2$B>AU8Q3^X=_]>I!TG2F25?D;(J44=1.9'87B -6^3&X4;P?W]PMVOI:; MNP'[I8/;Y]]Z/_FA^Y6>M:J#%KRT.6!2RH?2L9AB2G/:9B[\P>T%RT3O&2JR M>0T:@V-7,?C2Q2]*-.V"W)[&VV(9KTQV2&@H*"C@3.JP#,G2;K94M--ZYC.E M]38-*XJ2QABM"QF2Q)K/[D0Z,^'GY-\.K3EN^ ##G_@;K_E^+$-UH?;DR_]^ M/WS_>/O3S?O5_9_OJNR]H-7/@S]O/CU^ZLCS/)!#A\C@.0$;00JH).DNKZ^2 MP?AO__Y6B__^ZO)K'.\0U^&OG7<=@3F)4H@=?@A:HS-JZGX%YF.JUY%[NSP3FR1L5I?ZTR9LY>>=UN M/-OXB'NXX+,Z7/Q]XFVS.6BPD$(MW&/.D M9:,CFR3?DNVRJ/;KX'9XSP;C:GA_SU^^BEI&^DC>$].F& )1;)Y2R['W2PW8 MQ LBUS-T?#*OCX/;M20LNBB$-<1 462M/8E8IOOF5Z+=*IJATY 8^!EMD@!A$\8IW&9THDH[_;B-9UT,S=X-G^8MWG^\^;R* M;BID'YS,*F%&R*78;O*1*T:(1IO!!=)M,LOOVT^OPL)!62K&,#82_%Q#8>PQ MI5MF+Z0!&VTZX.S)QBAO+75F8^'_A."S16(B)?0R!U9M2@)XN[0>[.A$6A:Y MC*"C*E:7@LZ79(OSI@.<>4XEB6O]SE.XWZ'P9C8RY@PQ2!N$%F!,UP[N14IS M"F].T*R]AEQ;XDU5L$3KF6A*RJ@S&=^U=MGB91.1/4$ ]1JJ;8@W'1G,4@'# M2TG9*Y*IE&E=7$PBSADNO!$J6'W:/=_[4&A!AEB(4:ECYM,,.-W)H%I]R3_<\&$07*4@I$V--*X)@ M9W V\24E< W97OGH3I%JKWEDY*2SRENEA);\X-@WG)(O"5/:]KJ-H,#>R#=Z M'&_VN&2TB60&)[4A$P2_M3![7(PB]_*X^)1[NN>A'A=EC,26RPKP%D5&Z6\[B/Z]7D^^WC>+BA MZ:*Z8<=+;WV)6; W40O^G^Z9BQ5-_>]K\>/LF/NZZ:'>5PA%LU ZZ BK&B3$>: ,GK\2(NR+@OT8; M.FC""INLU!8B7RSR/V*GARVCXKT\L'^-]G/+0STNY7WQRBC603*1E3;EFSUT\KI.BV:L>EM-U@FCQ8! *J@R89@\+VV%ENWA8:Q/OK^-F[=RJE:K23HW"$*=B<'=-(/D"@HT2D'U M4(B4\%HQ# G!8,T5-(.6U";%73N@PS*_(UBV NR9LF5DYF7/9G(:P @.96[B M/PH/+-@'+#B*@?U+&4 "%A%8A$V'(!DU"=TV!FT"B8],BBU1D\U@;12L\JS6 MAO\[];"\$-JZ=A+E&5%D4U^S.- I%F4"U#+.Z#H'W667VT=.FSCH1R3%MJ") ME5U.1@M?A'=9LJ;#W#V65$P3;S<'!@D'+_#QI0"YP*ZG""*15:JCA^,WTZZ$ M/3"(/$;Q3M'L>CMGG-;!^: =F XT)4BZ 0AG)B);)0P(8A0&$X-(+ZW1->@W M52/HRSH+[TZ:)NMB)@*H%4HI"%W0U(F'=496#HPN"DM'XX/NS1W_9?BP69S) MU<9-ADK\UD5A].LK(Z?>H@U^SBB438PB'^>5!S\46@J.X:ZT3NK:T*9<+-9V M74=(80X=SH,,6R(EKR@R=6EXCR9CXR?C)OKM2&38%B*5HG3,VI(/*4?IC4,UB[/EV-!B(TAP M;%IL"(^*T!4)A&PLE*Q-M+/^)Y?%G-JG,W@>KX%&D1WI&'UV'DLHF?^YZSM@ M*L6V7&4C7_/(]-BJ8+E6=7D&SQ L*+1!EEE]O ';.)KG)!_K8B*5O;(:/-G@ MBJR6M*:SBL@8;#2I*=+=*([T2AHLBR%9D:QA0"^4C+*0*\26#QB-38$! 59]%@+-'%9%RLL2/H!J0Y:I?:ZDV"Y$!SCE: E5K/.G2PI<4A#=Y1 M8D6,"(TF#<@@L?#+@-+%BIR09NG\]I,EQ%:3 G0!E9/WWOBHHS"I*[5TC)OG M=*2>D<)8%PD%DE"2IBA"9-,A%42=62P$Q5BT:Y3F1M&AN32XG5O&=/7_'F_& MPVNY-MYSL->"3\.O^Z^#F[J?1_7T8ON?/_#;XLZ46+-]4(Z/0SEN2*%,VRGD( M7;>B\OR_[4C7]CKK'V_'MWH>G#:\JCR^>7]S-=%ZDXT/7_4!3I1!''WZ/!Y^ M'-[=W]1Q>U>L)E\(Q;9?\LU@T%\?^,,5J65F99U!^>GSZ&XR\?/K7_;5]_*C MZ&Y/UAN!(-6Q>$=TI' M:4I"F6-6&=BE@< 0J 4^/[1.P1%XNF(S'V2CK4_*J,Q^JE"Y-IP\O;M8BEJG M3/=HE^H%=<$4>6$+>!>UMB@9DF;ONQX.96-HM4\;ICL"3U/?-SU4 MMI)2MR-ERW95IY_^!V51L<.I.35UL&57^I3J1+$(D 0^@,"'U C%69M,>#*I MOI_4+5Z_/)?94$CXT3HEG3>U22!DT\[&[8"&^^UI_<,W\Q+]OOD0;J]G\^FW M[X<[>/I21>%\>2NQ.EF>0-0Y E$$"HX;W-(XA6U+V6^Y0^8^IZC0)*>]Z2,K<4H<==+]V/O]+]F,U_GU[?_./UZI=R)C?9B41_X5^#0^<" MV"R-*30' KER0E?>5@G0\O(V>:JC"]6W"2YH,LK(?7:6_FN4X.M-R%9A;$Q9 M^XRRZW+?+.]_ZOW-XN)?K^?O;W^]GEW.)LLONZR6,VWB[\NGY[2Y]._;\BPW,ZN?RLGX\V'./WU82AW=_#Y M3Y.E?F7NL4#_>O.5_WESH+S]"WL_G<\6RY\7-]/K>#NEOVV^L8U=7[GY"64@ MVNWR>EI^<^A5I.QK"HK%R)U-0GKP-5G&8IM!?<6A,7&#NCA4<>*GR1?!;GX; MTMR=UMX72NKIY2_3Y:M+:)SF5FCP6>MY .W;=?[JY84 M]832KXR'N,,ZE]/9/WZDF7/$ 3;R=D)N^*5!C,O\R]/+.,K"0$(3P MY?6=+'D-34(95-GNMVX@WZE%'D '+D29N342-.&%H!R\$+UP&:3B304;+ M7-[EG3M*W:V,6!2P)H'"$E MS!&92*6Q-);>&91)FR:+_TH\P5'HO0VN#>-L> M]S@B=%[@U3&>7RYK++G9Q1\7\X\W!$+*3_SER^?IYM,_+^;+$0A->N=Y4L8R M3H@<6"H=0$H&GQR/J0.A/;IY&]!._'SU%42?1DG.&L,L>.58P$1 SV,))$66 MP !EAQ\[,QW],)U/EZ?6$H)S/)&Q J;LTR>UD5Q4E8F0\JAM14M]^H3J^GU M6_\COBDA]_+S"*4P2T(&CQG\5IU,18>2VU42HD^7D@"U[41.9*@:=(H'6_9Z:E][W,KDB?.(O/\WF,P+@JW%>:XJ0DX?(B3N^FJG*P)6F-15XS3YS M),#7UMRTX*5?A(.D'8B.8R1'6=)C('TTJL27NL[V,0G#:O M8USF8^[20/J"T7IEU,C+]&%@OG0XU4J,$-H6:&Z;LK33K_YH]B#S:)7020'= MJ:@#L[7H/"35,3B)=^1J3B_MG_Y&.5 !E K:ZS)%S3)I337;%#W[XJI%E:>7]D]_E8)'*[F6+&MG5,XBU/%=.=G4\L!W9"9&[-)BZ#:Y/*$KZ--U=E!PP\,(Z'QT"6I\"8W4&=##0 M^S1_0AE^NIA<["P#&$^:1TF!"T@AT#NL[4;H"9:U[4:/>K3^MOLEL>!#+$_\ M-IM"'V) NBH)"=8Q'*]UE:,DZ>OO)Y3+R(-IKR3/0:LD-N/N-C+94?0S M=C4GM#^,;#QPC#)X,C\IR-IW2X<_M5Q_A]J?D<*,L3\2$X6^/C"2P<;,P;L- M=T:"=C;LH?9GG"BC[ ]R@5G80%B6EQH^RRMON$L4+O;-.#RE#*/L#W=*!V]0 M9.4P,YYA,](*E6*MHS[4_HR3983]B61S4DJVE!QYQ1C0WE1) O=-1I3,[6&2 M]'73NJ!1K!K#!!T*89+5MRWKFPEGK*=*ARYA]9AF3 ME&1E&*$Y*9)O>KBA[6D;O_!3&4[F*>J,(CH;1(P4W#"S\4D^JN,#MY'"C#&< MY$YC!.ZX1N<4!P+[M;<.I6[9^P\UG.-$&64X#1E-1AA:D2?6=$= V&HX R>8 M?33#.4Z&4883%5CM(4?I$QH309M4P2=(UM$O_ZA':X3AA)21">^T+J?+NBPV MI#>8*-H9GM;>)TCM0XNWR]G\X]OI5)M8?S_,0=9?(9-YG0 \%BBEAH MES6%?RMQN8V1M734YR?N*.]@RUN\!<'(50M0%(T:NSK,"9DUMHERSD_<$0Z$ M_#@DEE1*P3AF- 6H@H35W@FIN&PI4PXV6'DR6_[/Y.IV&F?7%U>+Z]MEQZ ; M^5?>AXB[W,?KG_-]_\%-,(%$@G)4,.:#%' +JH'+E(0J9 MA28@[8'L)Q9KC+77+K+@+2?!LO=,EG*FVLE@L8-H=RMX/ZU0XVRZ#8& +QF7 M8 MK/!GU-1-,$%:I]M[;MI;A4:0:EY%E @./QA4>,\UBD'F3D:40K+GU/<#^ MM%*-L-!9*L=B01Q9F$P[18'+AN>9=Y#;Z^WIT+%"[6&&'\)A*8-3A-<9LRIS MJ]R&D,O8V%'-T$ZRV'_I/?8WN\S)-$D;K2,$AVQS3)+E;6<6V(ZGX?W7=;I< MSO"?//T7LI=>G-<%H$PP56-OL8M3 =)$-;,YZGE6J4_?6\<&>BU5F@4<*P M*.2]IK^64^MX]O=DN6D,C!$RYLHJ(10@=[S:7QUB:'F%CVA_^]+40&@$:4D, MO'/EC=ML;"NMCS>MMR$2/ &*D8'^09NZ52ZU M#21'-&(GS Z3&"I;PP2%8M&K*-&[S2MG"BT3[O&,V,GRQ#(;GZT$HU"H!"+& M7-F.R:>JEBM>F_$1Y^M/GR?)2:I@HZTY. E"YO3 M%71K" 1T:IY"IY)^$@'GNK,,];#6,,:0HF M\>1S=&AE+G@WUO[N*$$WM_/9:&&4Y?59);K.60#]:H./%$UM&)^U;9_^MX?O MYZF-41:;T(*-241&]T-X(:11&\A0$/:S/1-C2BC($8NDA-8\.>D -&S>91F% M4(VUY"W1\6,KHS=&!X+=%$%XE8SSAOR4V5@[KG+77+RMD.D1Y3F9]3>!FPPH MN+;""HD@=;WQ")F?D]T[82Z@4%H(H5,J#]FHR"'FS2F'('9Y:#Q/+8RS_F5H M<)0&E'6H2F2A-W,2/?G&$;C[/+4QROJ3F= RNB@P',;2",U0%>>M=.4GXT6 M1EA_,@W:@DO2ZB1##!Y,309$"CE;6C_8_I#W6,KH2VY$88R7W+E"%:4"CU 3 M273/F6TIYXQJ.V,?7YZ367^@0RU4R>)BYBA=:0"H> ]B2\'W?-0PQOI'4=R? M+W&023JB")MYQP%C19&6?_ !$N$>+5A'",SDE12D8!V;3[\#*S_*6OY M2O6>DD$C&DWRNZ_8/WK7SNQY-EH88_VETMI'!YAL)I,9@MS@@91EBY7)7Y[@ M2'1+ODMC/5KDI>'7>J=I)UFL?*C)LXZZ 3 #)_J0M+ M'R:?!TE>%8M2.9$)H-#FZYQJ^DHSW?;4\('PY80R[?24*X3+/I';T9+$XL%L MLJ):"=G8WIZGW&/((X^R1S[&8')BA0?9664Z;>RE*G M7,K!&LL)Z6+(83.>!;)T'85:6Q.XQUKKSOK_.J6CEE2%+ZM)%^U,CKJ"P4JC MG"D6-@F9!A]]-GI#2>R[IO>=]'(-T9W5RW5\/9C2R>ZS9=:3Q51!L5KFEC4' MVQ[@$]_*4Q89BT)XEU1AB7 1R*A:N\EY=I''G(F,H_I$,FV/HLTDT2!Q;:S9 M#/*+"G?I2GL"$4>BURBB06NC(X%23BFY6OC@.TCGSD/$<9#4!.1DGH*,&5), M9*R_OF"S=H#4>8@XIB3-<1=$H0&1PJ: M1/])OWGSY2P4G]L/EIQ9W-]Q!76D1F MR5?D%+0JFZY,%=>0'MIY/.W;R!YBWR61MJ/>P@07%8/2%).D N5,)2!SD3>V MS[@6%.ZU*M&WJO)*[APW!)-X9K)0W*R=3J#_8,LBT,%QO=>JH&]563"*=VR( MP$$EQUSP=0<->&AVT.BCW-.[M-GV'=311RL2RLT;5 =)&-5UNT(,-KAXRWKZ8R:<]YQ 49[R7PV#EDE M]$MJ^HU:EK9E9O4#M!' MU"$:&Z.0A;Q$Q-2\C9F.=YC]5M5GU))E$%V0GL)V1LZ -%'#/1TH@&CSU_I( MQ_UIC9H/F!PA!271LBS08Y4[\0BJY<WTV._Z_IU65>+/_6S68M^A*E?_OO MO\_FES]/__@PHQ\RY*T+E[(A*9TE/)T-;8FN@W"Y;7,Y;>O93D(<1>K^;,#D M^B9,YY?Q[8]#&3K0Z'@HY70F:_06:@L-1F9=1]G-X2*OZ(KK_&(DT6;SV]G\ MXYO/ZVS-^%(+D^F6E]&S&)(H66VY::8E:QR:DREL QV&5W4<&;X.BYM=?UY< M3TKCT>UG?$#Y_.#-],'GBD8_+);T?Z<_+VX*A^[YE)]BR78ID"E,2I[@ '"0O M54?C;]N.OKR6!7)+/*RA4Y&UWDQ^O9K^LOAY M,2^"+A=75_2IN^32Z*0,]SEX\EL6+1I@4(K:UDD9&7ANDC)2[F$_AM?]6'KX M/@4,(I=&BA185H)C8A%=&5&9F;*!MP\"KV /6/E]PX^[X3]/;\JPW:JB.+V> M?9ROOG#YU]O)U>S#%U($3JY_RU>+/_YK>OEQ^#5,:M#@>))!V22"+<,*Z1@$ ME1CH]A7PU3[>Z!R.P4 2(T5#T17C#%.9EF3=IK/#$[H537X3VJ&GSTD/+^,Z M'#2B-]N4$T9K,SI#_W&BMBVE'%-K_]JJK.\;_OSMGQ3"2*ZY9;F 'L&DJM4 MI+O4IE?$,[WW R$_*4'Y&#%$KH3W#+);&([-42J9XK_OD^!71>$@ 2- MDH+08 5GSFI9B]UT$+E)%Y0I@M\W_,79/Y53:>H6H5!:95OZN=9N,$3-6MZ& M5VUMVN,?@S#]L%BN5?K+Y-_3ZTC_<'TSNQ@=]EHI;2PC[H.(BB46A&)U0'>. MOHWME6D*V0]8[\G$'D"[L13'!P!AO8F1E;>[V@$KR]2N5NRUM3]SL0>+Y>5L/EE^>4V&X_KA37I- MREC2%[5J$<>=\TYG)+'D1-9H(D^EG:X6Z>L<3//@^XJW9;8GE/_)U-Q3Y[6/ MFJU)(3DD39M(,2DSWM="0U1DJ=J$_I]"R^K(AYDK8UVTFI3'"\$,><*UEJ/@ MMAU8RHYA$AY)RYG^+R&$T6X1 K<(HV<;06DT]!!)\S%V[M%!&EE6U=8@>3R?D)/> 2I3%90G9*)>'1&!E>II.>B]"U%+[>%C^_?/A3[G#U3].;WQ:7(VO3OQD( 654C\RH MT"5#_^6F=K6BC6WA+9-[P.2CR7=F:GT9L=6''Y_BANY8 0!Y*&)]4T(1@E"B'RAL(@JN.#'8[4.//>*H& M8$! \G 27 D*-1 "YU";?4TT+9,_X<=CP( 7HM:7<5D/L?4Q&,=SF1&..=D4 M-->APD@595/^]ZH=&O#]^#SOXW-\6\\#T(F"I$5@H9!O6U8/E36AY7-[U<&X M_&<\58/1CV?.,;JO6J>BV(SKACHO16AI3/AWM;ZX-Y5#;+V%TE25E+%ER@/: M8#G4(@*3>)M0%L=X/?A^?,[H^!S?UIL, ;&0\D!*0IB0*[4&_=>S%D LDQ!,TDJH-8+/)F;7<#76UXE1 M"MQ'DJ?3U8:F-%%BG8T@J1I>=H8BS1\7UJHY_+61G@W!.*K&R&K'B4%.LF M)MVZCBAZ[G73S;)/\^_S454O9Q:B@:@=61\)&CPXD3=5%]ZUF25A]ZBU?CZZ MZF7RDB5)'KTM].Q9:#0N5]+$,E6RI3]MB0!?DJYZ^<4DUT9[EKV7DEDK24UK MFKZHG//-%13N9>NJM\])I,QTE 2L64R6S+NH#'$V9V@2*9SOD]U]7LIZ&3C@ MH)RM9<$(KPSY+RL8A-(#=1=RJ9!X6]$$+]HROYQ#<8*&*1L"^*A"9EG'DGS= M- P4QNLVY>->,. 9H"YU8D6BBMEEAL[GG-@:&P819DJUYP:# H MZ4.,S@7". (97V=]8M:V'2$KVH$F+TE7_>!0B."MC%C*M)"K8-/:7$IC'P^NNH%AREX+@5(;9@%L2H32(5\-O-H%>2VL><%>[:!UZ RR85S%S7( M6.:9@J@]4-E0;-LR+>L7G")Z23GZ0Z!A-LX&ES5P)T5Y=XUV'5RA-")W-,B\ MX'CA)1V*XT/#Y)CP$9R2UF;KR)3D&D48+MN?)TN%D%YE,$:;F(=CQAHQUW>)M\K]A=FSD7 ;X'H?0&3MP91 M2$+H$&V0 &^$YI!0JFBK?T> MY//%=OGTV1S0;P&?>!!'"/#HZ9,R,8>"0\0Z+H+%;Z?-/-@_=S;R]1@8R3PF M\D1D93%D)[7-&Z(.P6W<)A__"S^3\]D&S>)!I1?+M@1\5B)S03(4:A/;P+=X_]I ][Y\8,ET9KIZ@?Y%]H7'FJQVEMG0XR#.9__Z[(M BN&9( O#M)/2 MN)A\K=[P+O79SS/Q#VU ^6#_O*)K9C(O7+]2RZ"@##-1&+0NW,4]#I##V0C8 M8V"R$\:13$YR'80!#'+=$$CG5@!LWT"I'D^^.+NZ):RZ%T:3BB/+CMTU>RE& MP4V=T6>8S3U'=#1&N[_,D\CX%=G_,5E>_O+E\\/@(GWZ?+7X,IV^OUE<_.O- MY_*36Q!_7S=><^NE0"4< QMR2 !*96.Y"@F_Y<.ZKYMQ,/X,=/..(H/E[*+\ ME**=,@7R^MW[O_7K1RKO4VG\EEX+Y-E +N2V$D7V,:%['OKIQ_B>9$'4,6:, M2A&(2D;4D@;O0SHFQC^ID+TXGS.OT#ONK0U:B1!T;>(7RO8%:J-QQDEE[//% MY'R-0TXFS>JT&BS(UE@_VT0PL@?KG]4^]OECY87745A-P39Z=);#6L9(:/'; M@>$'X?W3RMCCL(SW!DW,*4NR-UI*J"-_O4C!]&!^=G8R'MUA)?1"?O9*<:6:L>F4G M<>M&[A$XGE3&7H?%!!->,F6$)>/FN8KKX!$]2];V[*,^)QG['!8O W213BP8 MXPJG=G9 :06/FH>8:N,^P20IQ6RQV,QSCC23726'!4"YS[6F3C9L]CCE:4\ M-QF/[;&RD(S>_QQ.KM]I&Z>3H MW]EZF^DDVNA$G083*8[JFP+^5/+T5L24,M\<, H7* #V3@A3GRB%C2WE^9/+ M,U!E%U22D6!_), 0"0 :;RLP4CJHALSQ#.3IO48RE&#&)Y$)&E (0T"H3IW/ M,KMSE&>HE4&AM=*%E$'QR+6O90$0":F?H3R]]R=&RZP/!-PB1,C68!9K M1B(_L3PG:2G-C)?1 $Z"-$DXBD5JEL4! ?:VM&.@Z/=P$1Y7/0-=%J>=0:@O"K[#!+TT]0SQSG)+?B9QY@17H)7T;NUQLF96-<,ESEXO[Z:? M2_71WM.&R%0$BH0,.5\>5:8SD[ ^XH-N(<4K;@9:M ]8_2.I9. *&6N"J^H]QR$[LMI!BM$S%QH"TEQ"O>C6#]LH-!:]>7"F#AGH?N2 MG,A 2ILY"/I78@9-K> B?.7Z"BSV-7:/(W-?TI/"2L+&6O&4#"LM&"K6+GF1 MM=KKV?PL9.XQ8U888[5,%/%(:[F66:I:Z>7$MWS*#P_W&9NQ_I<8!]X'D HP M9T[FFTE7Z<3!"]-3?GG.&SU0TJ>S,D($:[5'99G3L&&4(II1@JHZ10D)"-/$X(\DMQ]ELVPX'5PFH4( M$*(/RFV>7PBK/FNY^PR;3BQ;EA@XBD6\LX^PR:52BYB M0HH^F+920%KG5!PBZ>%9R]W7MY*TC2*F""Z+!#)&86H".61S&J2ZF]S'&L.C M>%1:>6Z,F%$4.I+KX.7B($.34MB_6ST\-/%Y&)G/5B&DDN1E"K% M\BG8I*H>HH-V[L+S,9M_V]UY2 )"F4G0++(4@HTJUKH_NBNM%WT"\>]2$/^8 MK3[SCZ\?_7KZKZYO)D.S;T3DRI;;;Y(FZ9A/K';Q@?RV79D._1"%V4GE[1\W M@]JFC#$R(U7D$$.N#_M>V*9,B@^429U:D._X=4LU8& I1VE#%@))7][4T#J) M[#OPZT#]^J/MX['QJR4=""S\5G0_,RA0P5>V)Q-\2RXX0)AW3HH8@U\Q83!E M")!,R!5%,BZM#P22;_HVJ?B4^'6T'D;BU^2]$,8Q*W)F B!&M3;6Y67T6WZL MIW)*CXQ?I:5C80P/#FWTJ+EVZ\>52+>F!?6OG@R^CM;-*/BJ*(9Q2J#/: I- M7GF!6%\39W-JRX2?+H$S6A&C\"LG *NL 9\!C4V2<$Q]?!'6?$N^\#QNR0CD MZB+GTGN=@BK=1)Q9A=5<4DC7#&AZ O$':E,5@&5!!8A9B9!+WB+5,0*H7$?" MXLE.\KI1\7(Z^\>/TX^3J[O"ULVV_7 [N5A<70Z!<&&!8D_%45@=>+*.">47CVG;ZV%[H%ZS"'H%$JE4$25M&U M]@4L-E?\U9.!>77:J(9E"8)S()16:":RR7Z#YIUO><#MDX5WXQ4Q*JHA=%IX M*+T+F95.=.5%K>L4PC=8_LE0ZV@UC$W*.\N<4B9S[65*@8M0BSU]-+')0#T' M%1P>YB$H#)UA?N:E\ M:&.:IPO]1^MA5$B3".=D11@'P#%D/)I*ZH!9DX:>XQT9$=+8,BG2J&"X<100 M.,-,]1EE4CL>7_Q?)O].__Y,D&*ZGFO0"BRV0^&'B+; C\EWD"U")*K%HH1^!8Y1R[IW[GV;*LHF^0D MR"U^_)BK?1G@\Z"9Z10LD,\H='[")&E5<*M!O/0_'IQNPJ-78DM\]'U;'J-2 M1VO0)@N>(#" 8-1JL[Q?)0!:2IMMP=UQ-FMHN*.)A3#=HM4,.1J 6)LU%'>R MR;/*;0]LQUSMTV/D,9)FU#IPK85S*@ &T2+4IQ^ORP-AF$K=DF8^YVJ/9,TCD\PU9 MZD 7103C"J'X.M\4=>I('#Z"<"_BWAQBS9*0Y$]21B\]AEAN2NW.U\G(G:E\ MON_*Z:V9T%%Y*;)P44AGO7*UU2%[9+N>DZ&Q;?/W#=/%Q.?G\&^G[:J6< MB\7M_&;YY1__\_-V*!=24JOP,96A>R!BLEF8+ 40(FU)X+8]F>\F&1V)Z>SW MP@#S4*K7=PYUNPDCVRRYBA"L YMMLFG=HNI98K80 MN?)D4;.C4"L1@G>5B59C;! \UWLO<7K]=C(KQWQTJ)YBYD +LD;94DIEUC0[J_BKV6^/1W%L2UI*RP4@9LRK3JE@M=M"RXVSTW,V]11J(ETH[ MOTH>R;2SJ'@6*M=9:*"=:SRPM"=0^Y&C)$VGW&*PT;A 9Z@,MZAI:1Z-;1)Q MVUZQ#A%I -8QC\9&'P39,V#2U&XI&4I MN>$HP$"207)O@S-BG:],"#$TM['/4OOGC;/+K[&IV,YN.;]3C-E!8)8TIUU#%S$(=FIM#C-A>0K+[';+L ML=13"#M@13U#([4TBB-=8T$RRO5UCM9)V>9E;%>4=B:R#C%9NN H#E7E?AO- M&?FR6HL?3?BVR91,5Y=3.YFHVV[>#B>VC#9E*%$E;@%5)#A=BQ^85+%-#/#. MLIW!A1TNR,!I%)#+=,S21"=3$AZQ%KX[V5" M+ 7V*>JU"8D&HVX8=\&,L""[RE$>X.8WB^4^-M D23"6++AA@95RB9#6F#8S MA);VN7MP^/8%';#R@2.$R@7D&B%HPBA1LEB)V\@/Q6_'9GV%A:=?^,"9 <9C MX6LR2,$7$)BUK+8C2(OM&W1G=(YY M>"19!DZ6S]8K)D*QHV1A#H%HF3NON"GLY:C1 MEH[K7%\MC&(M1',[W/*MRSN:5 -G+K.$%&]+"KN3=A&,WKAQR,HV14EJ%Z-[ M>JF&3A\%KE85XAY460;O[:;M5T7>(DP%HV_2SE*]74X_4Y06IQ^FR^7TYH]'3$F'] 9&6/2D$,5,)'GZ2@]A5WBA5V6>@IA!\XHK%JC0E#>&CJ5 M.5#M=TC/4?+Y7) M"9%(KTQDV3L#1D)-[BC(- M<) W&5**QIL+1@'O4ZS_:/M% :W. :*-F$OZR%.T6!LCLV[[ 5_)P^4M+W.3 M*UK?I\5\Q=]U_7 2 DZNKN[&^5V3:?W[9+F<[,/9Q;01Y.VX(!^?P0FT>1W' MNQ0XW$^^7J]6L2F1_D:V_=9[,K&')N*PK.GVE3F0%!](0M@;%KI <8YYKF(/ M(=7@*)!()"(Y? K'@3!.915E6?H.L9](X-7O!;HHEV\G7U9-;^4'?9SV$KEL MK\T3/)5Z"<^MD"*6D<.VIDR2>=#16N7NA@0'+?O42A@X\Q$(P);@F-""+;I@ MK@X&8S8_2#U6)71#V[-6PM#CGH"DK(^,50F7 MI1YH=C/]D@4O65/U[_WM>KJ;KB*P2,C#J3)Z1(<< ]^D&3H:LN#, M+F;?4SE%-+D\Y7OGI$^%:Z8.2W-.HV_2?+HC6_3$LCVUT0KF06B(.83( MH-*!NT2!2/.2RSM<]7-6X0BC4XH9E$:&/$J)GF]X]B@<-=^.8R--G=]%>C2C MPSWD%#4*'SF!8&F1U]GE*74, H437+@&B"9E[+R+J2O^H"#.WK>(=2;G' M4XYZ7.40XE7@I94Z81+UV&59QQ"D#V09+X7."F561N9DI:B5XR[%9G!&J?7J MR& =*LC/TYL#]T/%( .3 $XRPY40TFT&_#C#FX=N80?%Z%K4X4+T[04K+T[& M<30)N?9&&5ZI6+2";P=RE1+6CO32:"%6$Z-Q<7US_7I^<5O>VG#R>78SN9K] MI\MB#.7('*(#(&.7DDY>:8K>ZB@U[3IH=;I$Z%W28D1*(KC"?U!&HF6) MD6M=E^]#:@U45_!YRO4/)*9X0*&8!B9D #I!/GU5/TNA>5-Q1UG^^G'VY-P4 M$LL;0YE$*8.AR#>YFGCVH% T.91"F[U%O/621TDS] B2T&BE,C/6.,LP95>3 M9#(9UY8/2=N1%#QT>=_;Z+:\-C(;938NJ<1,P.29E87DP&$L3.H=T*,CPCO: MYAR;S,WDGR$?#*C316NYD9"3D$V M2%C,;Y0EVPYL.UB&W=]X+N[N"!K9@%0ICHJ3OI.G]&-L0D3>2/ V12^!PHG- M;*IBL=M+WI79.-;F'!LG<GPDE:V\)1 MJ1TJY52DV*@2%7BO0VR?F(_J5T\]=$)9:S,CHX%!K1H8<-2\ D.O98.32N[K*04>QZAJC& IL"Q2LHH;';"> M59=2.QV@JS'E$64;A9,B*W4++"6I0@I6>0YU;H#3D3?WD'=U-3ZB<&.&.CAA MF !;&#SH6,K,K*L0D,F6;E-TM4'O+]I ]@LEBS:!\X5OTE.T:"L_JX-LH ,G M'3=!=.2"89%R>3U23.LZ/"F)/S([/9=8I<99-,L8SGEBNA->>3'9;#J%.>?2.C)." M3Q8\ U721\IFK2IG,$K EF/S%#;LA,.Y./TK.>5"Z5IB$$+>-'8SV\[/AJXV M@T<4[V"<),BM,B@P*45=AK*@V ##$$QS5@&>]JR.PDG&R +\C/0ATD$E3%'+ M1DEHW]+:=/41/J)L(]GD+2#%*!)<0!DTDI^N>0"#+442-T][4D?@)),G=&8'6VFE3I*D7BB<(MK*[B.V.8FMI=)M.+MJX1' MO^*"<&1,T@2+1CL9N->A**%41\H4VNKJK2_*QU/"H]_P9+S#K$CF+$N;D 2V M.@D&%0;1#">6A-:IR64T!PJJ.9U4L0?,PQV%[RJF3P7"G MY1VQ6Y\+R;+0N19G!,*5)D M$*WE9&"T* -+*S\QV&@[:M:Z&.0/7=[Q!A 9@8@L>J$]^JQ9R3^LPSGI7 ?[ MX-9PKE>:%0\AEO*V^3="#16;2FZ (SGA,O99 M:%]!:3*8(V?."&L3"UX[6\E&M=2^[:3KNX7;%WK'G?:E.1Q#>LR,0@.;G0 + M!*"<,&%]K;+R5K:Q+>NP85^_?/=%]1*TQL2MD838/:?O\YQ7:OP8K&=-TE6; MCLLTL*AWDS]^*IU),_IZ^LR;#^^FU]/E[]^21@V>P[BBW[('AB"RX3[$ MI!/F9+TE)[69XF5,FQCH-%U/*>Z8%X=RA6RP(EDA,-O,4JZ]A10\M51-CW(6 M3_<$44:S<9,D@ T$FL'+R&MBE^>V4%!TS4M]4H$/?I2(DH @D&2*P4BN6LO8GDS"FTJV#=!^W;::&=GN0)A1U7_VHLLRR4 M>E#Z,HT>0ZU_54RW#1Y=2:\GE7;$ X97CDM.T2U:QUW(R=?!SP@06HMU,B$' M,@T:72(OXB1%OH#2,IDK&W0PV;4,XEVQ[_'7>S08X[P-LA2!N"RDI[ D^\T\ M2 5YIS3S"<0[%2R($4/6.@,%-:BA\'MORL*"CDUHW35[^&G%'0,+F$HB2BNM M29FG&3$*7J&>1\::/>T:2/"DTHZ !8*^@($C5RN" MYXY%B!M9DQ+-%3Z9D ,Y\6ADDDSEE'4(5B4P-?/IA4'>1/]*="21C[_>H\&" MJ"V6AD':"Y\)D(&L)<9(-E.UN/MQQ#L5+$C6T>U*03AOH' *0$6C(8HDF@>8 M+O[!IQ5W7+\K-]R)I)7DTCA-3J+6124;.N90\!-CVE.7+$I/SM"!<,K:&',! M19NFR4QNL>V^.S$P>/PB1A\(\94':HO:NZQTC)O">LG-MMCR;!0P"AZ0 09, M!/FR89K@$+K:\NP#'=!Q"L:MK/# ,1,:6?<6\OKU?%.G5L4L8W^>OK MQ<7J=^D2_I_%;'[S/_3QVV77(PGT/9*8(!1%)\IRQQ."S:&^0GM ;&M[6%\. M3SU=A'8*@^B:*_8BU#:JL27-7* ME:A<;'MLQ$N]KZ.0D/6BO('FS"6B(;T95N=&1&O%;LFOYZRM,>\O$36%?BD: M7P89Q13J-"9/8; >DT$[+XWUE=106!<)0MK,C4K1E8?R^NA4QJRT@_WZJ@+. M3NRC)7^8CS&BBIX+PTM[23!U:F[(MJ68=840\!GI:;;ZD?_X^I._PH/)O7;2U?7-9,@&EY@[RQ5U$*C$DZ\< MHZ04;,?^=O7U/D?=_' [N5A<74YV/3R9%QI3C&6J(4^)&[WA4DE1MH1ZG40' MSU%1/TUF\^N;Y71Z\WGQQW0YE*J$,D8@RHPBB$BAWR95Z9-C>DGC>? M/U[L>H:$T\Z59"ZDR)CS3FVR(2EW])GS+@*7YZBD][.KW\OBKH65Y/EVW+;WK[[ M\4<M=I& MO=A)4\8]"%:8GS7R\L9<\W?,M>, GIFE/UG^3I79&!2R:)>@L&1GBGEK1@ [ M*+-?G+X.SM\9YY,U0M'Y,Z8,RC)Y;>1B*;MIF_]>YKD;E;V+.@JF-)>.I4!P MGOE:'()>9-^ UN<5 YTH>8<"64 K@?"L2XH7CH_:TEM&A[_XJSHB>0?> Y0W M'1ND)D#K U0.5 M3-41DW?>9PG:!LXAF, M&%[IW@/9[L9@&_-\PAQUO.2=\)))%0OW:91.QJAX M+92-=M=*@N>DG5V2=R)R*T72GJM20F/A!,U%QQE;HMYN_AK MGJ.6QN3PDK-&L MSIZE%# 2AE9!LX88ZOGK:53R#KP!HY@%YYU(QO"DW-=G!?:RW-I^:3M-VG!H M(V865?'_,MC-"U5JAWP])_!\LK1=R9ISFYV/SC$%.9+GJPDHBM0Z/-ZS,E.G M*KN3@($P=Z (%DP2)7%7NT07^*J'(00HCE7"R4'[DRAZI4=6J A?QJY M"Y$ /T5-.G/13E3J)I,ZBM)6?W#UY7LUF=^L!E*7WUU> M_S;[[#\5T2^N+?=O.X8/$?5,5/;?15OS@%:.R7!7F ^Y]:_?%05(! IRH9T%I89#;QM [@N_\[ M^_1INMSMM*'0((""]W+J(/#,:MV(4\C:<>W<-MURSUQC71]*5].+F^7L8K;F M+/\TN[XF79*]B[-K^H-?;XMJWW^Y)N0WE!?)-B;F0BZB%A6B9YDFPS&@ M)T4.SDN?LH\\2B9BJ-&,EDFU#1?[F\KGI,+QR$>&E!P/Z(T1/C#Z9ZA&4QKE MFYQ]FU-]D8H< W^RI$OL*&:),OF .0==PQ=M1%L_N'OBZUFK<"\()&5.FO,R M,H)YK[2W=Z/N2DZ,S&2KR]US8L]:F6-P$%E"I3C&;'"R,!4FXAX M^>[EQ%A(:^ZDLS)I6;J)V*JC=)/Z"5CT# MX.:^L MG 'O^$ YF*.6&E%J(03S*'2EOY/D'UVGE/5U);A#ZS_8%&K6.6C M-_31./WUYI;O7XWO5C<+J^GY0\&@;G7.C/MIELF&1*Y3*"D?22I=J;VY W0Z_?@)1C[FS!7#1W;5)@.#1@ 99Y[X3 M_LIM>=Y!XOXXF5^.8Q?S3"?/763)&Z]0&&4VN+>^\J7#B^CK MDK1(RR!%I;"J931T*&I:WB;>LG<8WCRL-8N8WM#67;_Y@,OIY>SFS>W-]0U] M9#;_> =0NW=^#0]OZ&.K SV_6=+Z;B=7;WZ]FGVL5SO7^(9V#7NL\&@[ ,(::9)7)<]MG)%DT]?WQ0N5 M&^82J9O\PG$$JHM_6$4[O_27OT_F%]/K7Q9?2VJ1_N?C8CG[S\J\W^L:_2?] MYLT=?-ZY3RM@&4P6%W'"]M1(]B.JSA< WW6L+SO2\%,1!N9C6 45J03#;GC]KKU&L/]5WBT MZQ92,JBTIO HEL?-\J)4H30=P\: 0(LMCR/0DUTWYRRW4?-L)"2 3,'%NI0W M"?1M[[_H\\Y/K("];EUY?O E#>>4CL9B<+7%,7$6L;6XT#3K[:R!GQ?SBWW\ M'%,KJN+@R1U# ,V,TQO *W3+&BI5+VC\NH[]%GJT^X=H A2.4Y%9B6;1L-H9 MHZP3+9*7IN_\'2S7DUU#YCA2V":U3B*J4D-:N9?11Z]:)--GA\Y"#7M=1@ ( M&"F2=2)#F?7!E:_6R':P0;G>RWB0'OH<(>@08@"P.O,"/CT!M?5N&1MERY4) MA.).N-#C!0#D\R)FG2* -^CI;E8VKA U=HV%/=E!?%*W2)&J#BE$T)%)$Z-0 MOD9"(EG5ODVW3:'GIH>]+J2F.%V@2H9[3F<;#<&%ZAVS;CND.&M?F,7/VP7-Q^?CV_N+HM:1GZW8M55NEV>OGF\[KMXS5YFE%!UMC)">&P,NZ/6M3IF"CB9AS/O.\L&2 MKS.OJ\SOY.9VN?JI[Z:?)U]6Y_K-A[?+V?QB]GERY3_<3)?_WW2RS+/?MSP; M'_TSJ^.6/Z=7OTY]( M-[^=^-G!*I691V<,1:,*G).V%CXX,I%]0Y$.DFIO]3S.R5&8")93Z"1CC.0< MF%1KY.8(N;5JD;J-VO>1ZC"U+&Z7IU5+0BEL)+<89! \DLL,E8FB$(LW#M28 MUF_L(]5!:OGEM^7TQ,?% U,J*182UYD,E(",&7$KR,%HRLE4"<^=Q -]X. ME3N2.AY\_.UT.5M<$A!:3B?E1?ONUW9"*O3/%@^VC!5@M,$ZLK[2/N1"N-R?XE7F4/7XWH5_)3M+OSGZ]FI8__6GR[]FGVT]' MO>AI_OMLN9@7JSRY&KKKAG/G32&4,,PZ3;"\%C8;CJXER!S0TW81GUXOO0;0 M/FR^!,4=@G:D% ,\U@<8#S)#VSR]OB^/H9?9_.GT$E0V )HND?%H-86X4=?L M::$J;*L,]M++G8C?ZN7-_&OHNUHL"3.Y_BU?+?[XK^GEQVF\G?ZRR(OE]&)R M?3.]7-6?3U9M;F^7BU\G],/??/AYL[UN\G-M%;AW&FQ]^=<_S"9S8M4X4M9/"WGW?3JKFJG M5*;?_X;[0M+GOOGA=].V-S1:/RXNOJ:COEUC^O?GZ?RZ@S+W]<_Y >68,YGB M!!60?(43P4"=4)05X_T!Z/'WZ?'/@?JSGH.'R?=,D8*",AD]DP$4<<5"MP+% MEDY&DWQO'\).?!AJIK6*-7)8*;-94,B<@U9) AB]Z;65F9GF/9+BR29=]^T* M1J_NZ1+O.F(6* -JI4T&^@=5Z^-$-NV+X-E)O5>:W6B>9,Y,9> :&$I3D7 2 M3K*VG;UY=3E,^-['+K"<&V69DB)+P0A\L-IBQC"T3'Q,-*#UX-4]X4N0\BQ3 MB*)4)C\CHXMUDCEZQ4W?>\%Y2+W7@<3L/>HD$B25LHZ.;:XA3RKW4?&.D;K& M)GFY^'2_$X\$*T]%Q5\MKJ[(OM:_\%]WI83;@NN6O_.NZ+ DHQ;S#7]G_=2] MYKH5TV[YV'+Z&SFAE3,LGFN0<)=,E,\L)D6'GBY$3BBUU='PDJGHJU8[EB[. M6;^7E[-5E\S5V\F, E*!<&4\*!MQ!(TDT[)+R@7&S3_Y](I M_?:GQ7Q55SO(D2*LYUPY]&60H->I%)A8C>1JI&CI0/]<>NS^CJ%ZP M>6FLP*3X8N6.\D-Q9!KFX\04L*F)J$ MZK/5I'PB;P]TVYT795R6HZ-J*#Z3VDGC& C?FX'X,^AW+V\?A#-*< ?::Y0R M9L?92JK@(ZCV<>S/I<>]O'WB MD@$K34,IDH-"[J&^R.44VJ'5LBVZ_A.H=J2W5U$4'@=-ZHRD5FXQKLZI,8)N MOV\>=OY/O#2:$^F,P0' M+"5;9H=JAW3)00K[3*ME+CWLY?73>Q^1,J3? H+SW MN*:K"C9C.[P-[#,/\?=2[=@0'[P3RJTX*;B&%*P(JW.:E @F]!'(_@F4.<;I M>Y> ,'[VEO1&H9-5&5>:]-KRW+8>/:$FWTTOIY\^KW[BZ&*X!$I$X[E*B17! M1/2$:6S$9 D]AN85=$YE,2B+&HIW(F"HO$<]: M._OABB3!6 = VBBT.UK41\I@$6W;FC[&9I^%7G8'!38Y;QG%!CXKR(SB?[NZ M.\FE4F"Z;][_++2PGTMG3G-6VJ:M3H0HA?9BD[7'CG$X3WDX!FIFDU7)B. T M [!912GKC /1IA'ET^ZB5+*TX(6=O>PC<\X;()VXZ 5+-@'&:A_I]U_"L1EA(-&;)!&U)9?A0@HJE2!4.\Z, MD"WEPW/2PEX&DH(+R,#%L!2@44*L2I$ M)FS.,J\LB,VA3(M\SD=D3+B!9<@C86_+64!K"RN%7%T5@:EP:9V)'@;:+H!I MBI84!%ZXNI60'.H$">,RVS?\W%&*#4'LV^GRHO0^?)R&+P_OZ=U'=N=:*85= M_4#3]+U:SG,O^?VZLO M7-W\ME5#]QCQZQSK^<>W*UVM.S=_G'V:$03[II[[_<5OT\O;4OY\9V-^FM[\ M5GJ-:GUB^[O3Z<^33U^97W^:7,_F5XN+S1SFCA;1!^=69QW)+:D2ZGK.K OK MR(X"'"=UY][(Y[TYJV^93^Y@7I[-2ZTG+I:?%_?'C3_=E@1FLK)E1$? & "9 MEK4"'T$Q\YQ,R9TEX1M4/=NH[7CZ??W6_XAO4EGGY^7L>GI-0N0H M:C> =/>-0"U8$&@D4PQC/)[\D2&#"'++K) <5Q2 MZ]ZG )++[BMW?T[$(\O_K:5[,EO%"Z%:!*=45MR:"&9#:8LFI>Z#HY[NX*SM MT>NW/]Y\[3EZ=%/TL/$.RXAW<"9HI@P7D'(IT>(<0#K'L&N.PI,K\&.Y75L= M+$XN?IM\O)VTDL/]/ 'PDBFQ.BGFP97\J4W>ZJQ2]IEW#]=PSATL^\_3F]*- M]G:Y^'UV.;W\_]E[V^ZX;AQ=]+_<[[Z+!/CZY:Q% F2/I]/M).[,N??3+,4J MVYJC2)Z2E)[TKS]@J;9LAUNUJTI;59+L>7'\(I4(D 0>@,"#_,7D'U\+$[GA$&TI%9)W1;>ROZ+NR*/% M=]8NS'VEH:?&/Y94L^VMH%%?R!5$\@BN$#&0LC7 LA+X9_/!*F,A@L+)@ ML%@YM0Y2TM''-/#H!ZN[C#9T&;ICB30?MB'V>,JH5.()HM+1>4;K8]=6R(&+>>XEVJ$*6O[]74>Z612MO#ZV"*W28FZV-N(^6K($\,!$/CJ%/)=ZG3 M5\X^&:'F8\>K AV!*(EGHLJ^=Q6 ',:L089VZ_W/5%0S^]%;V7-Z]0LVUL&U)>@8.- MIF1M4<*>P<^F:/O2*[/UQCZB#J:J)EQ##3DYB> X)T5E* ^JD05)]?P*/;WK ML82:+^C)H42YKM9HRKH:%50= )2'OJ_:F(X^[_ ZF+#%R03?]M+&"#4P99^& M\14HL7OG7T#W''+'$FH^\N(V1MNV-UH)Z$TJR@R9;>W%R_>;]%0=6?:B7V^Y"I M6@).:+(F:V3[JK)*>XG2E:_!9_)]AZ*$.F.>Y86H:?^B.%Z\;Y4L>7$AO[EN M VFOTNE_W=QF@")>*MQND9J&Y,;4%%] MC6J;%O9]9_J=63&UW3+5;7TIQ$8DK#=MI1(@Z0(9 MJJEU>) ,,<4N5-(XFR$Q/^&FE0%9 0A%"=2+#@H$">F&E3'U>4(39M29V;0R MK'*VBFJL=MZBJXQZ&/!GM>^C$%!C:8-]5[8)P,24K#*U,,BYKR6&[- MJ8CU_1"#AZUL/BQ,3A5",A@X%.OT>NQY:DV[(P6+\TORA,SH_?M-A3E6!9BT MKIS1E76B0_X_A(YTXY76,Q_%IZ2FXT QSQ%)5TA4R%0YFC4/G1RNZM2%XZ\& MTN+O6_"X4$S55O(LT,L5K5RRWJ5U9K/Y/-_Q48V0M'_?F/V06!;HE8,$AI[8 M:&.2P+&UAQ10$3H/.3(18%_5VPDD)C]=18<<0JW6956'#")A5+EOD3"S'0J[ M&8G95JI!\$''FI"2@-J%PL=;6-M;:63M843FJNN=1F%V2)V1% M-P1X)284)"!;W@KKLAG"* I>V][@]1.U7XZ6CH/#E'4V2 CK8HQ6?E_)Q*%> M"$QC>S\"A-=!A4H&;(9HI7X MU@ZSY!"I#ZC,1!IOFT7.+.%$FD9#-0:R&"K=R/A#=74=MB>/6%_/;= MZKZ]6=+'-A/H]<677[ :+'B^H-O;)I>VO'^_>"?K+IU.Y^>TX*3N)/]!&JRDH M$ .[>AW""BE(Z*LMQ)'WH)$3]>@JFV6'5I.(;T>CM=DOYY=7-\LV)_+WQ<7- M0JSSY8>+LW\M3M-O[5MW@L>KOI3+BP]\([]L:DQ17X5M6HN%3<#%.5&^A$2D M)-Q5"GQ.:A-?ZV%4,(/2AYU-IY>K-FE! O(%@P?>K;N9V^:4+97[V&9+'J M!K3U'"3^SD:#I2+W"*P#W0_&@Y%TVC>LZBV.]E>9N$"&/4:+F+P5HU0,)(CH M6#L/J9_@.@9>GK:Z!Q]]5QCV\^+JYOSZ_ABJ&9TV>RY]^K2\/'GW\;,E^O!A M*7Y4(I0O_[F;'O?^VL_?P,XEM38YLT@3* M>0EV6J13VJ!+(M-#86%0IEY?(*XY*2O\JZ;R;ZOKM/ N8J MDWQN">I6Z0XVZY)M T&H&;(+/8?!-XV"#KYO\UA>,H)Y5 RJL;%X9<5O^K;) MP')A(77O92,OS-_W^"GL\08##*D(<"HYB?$UBKPB<[O'(>18J$\?C10$O;A- M/@!F-:2]S0S5H]A,"K7X('I')"X5^^J&L4*L[WI_9.C)VF%K%0JFE@(Q)DWI M=I,*!E/N[5KXODD'A)#%>U="HLS)^((%;:;U38J0S1B]W?=-F@\)-B"0:K0) MJ_PV*RZN(7CK.7)5_=/2*_U=_T=#=):5BQJABL-O++%4:UAM5DIL3!YA<_J^ M5\="9D8V!'U-3C"X@(* %&[WRENY#%K_?08@_J MJ"=GR_\X.;]9B'J'W_[;F7SX\MW'/WY8_+XX_TJW=U_S^N+3S?75Z@OTGS3\ MQ4?^;37H8R5>/KDZ^[I&N%Q=BXZO%V_>WWW'W6\^5X=-S@?16MQ,4":&(ALB M<&#-R5+DE]BU17VY%5_KZ9@JA*.J4,!MR F3]]E60Z' NMBZ:B^&JH)?WQ=;A2<3I;+/U:VY-/E M\GHHO]Q==A9_%3P9"9XXJRC ?)CP4K@-NNHKZX:7UB,*/\NN)\M,%75P+2S) M@G!A&$C!Q-"UBK37CEFOD'U1)MWFD!297'R.[?T(^,7<%FD]3A4G&-;J2'_.DH\Z@F7:+6:GQ213!>+"21U#"TO>MY*Z^,A#M+C[WIV2F." M2$2&E"ZYI#I8(1M,_X!M(_9H?Z/D[TZN/KY9_GBRO%[_(;W[[YNSJ]4&FB)4UI3U%<#6GQ1*4A/![@B(X"]GHX,B+"[NM\!$$G M.M-L KF+.GI.2 8GSR./7$Q%THD'-9 \)L$2L43DG\'*8)U,K MZ)%9PF,X8WY!^6S%F7PM%^O6UDBL>GEQ=7:ZN!T9)M=@(5^RQQ'.E8,MM0U< M\MI!E8A[30U5H)2;=>Z"-*/'&6.5;VSKCL30UB@8RF.G#*BLWM+JW9 MZM(^!<&GB,T=*@',U2G9ZH!D,ZYA"\<\POS\6!+W+9JO+SY/W9XJRUC*R?N;.E+T19M/:FZ*+EYH0CVR3Y4PX(&J[4N%9*8 MC$(72+P4#>TUQ;JH+%H*KE31372VL2NVXR3WT3JD/I'6D_H\9YWM..$Z$EB* M1J70TB425V2-J\O'(3H%'07@2U'3+M.OBW?!4N/?Y58'$E6[A$U'6B(Q6S=V M'#^^CMZ>M$& MYQ,MR+O39VAC=R56"T:*%!5K+Z-.P_LL11'DYY_WW4^MKP' M]_\QN"#!3RG,)BD-V<>RTJ,%EX@>=JF>CQ[W0@-%(BE/01LDB2(!%<":,"RG M"+FGB^M+UE^."G> "-FV<0^ZV PU!?(QK:YNM-0F$G0%.2]37WL!!JH!?34D0TZU@^9V+;/5Z.S(1YDAJ\)Z%'<3; >J"$N_9Y*%8 MCW7 #MGU5:DPFGY^(2K<'CN8&EN=FQ$ D4HJ*IFZ.G*&LRJJ/BP!\VSTM9=? MJM55K2LF*-6URO7BAUQIFSO1%UOXODWKY:AP1Y?1H*K6* @5@E%5&XZX,G7. M.@%9SR_HL3_G;IX._-G/ M Y%X:)^TI8*YM#K[F"T !"H2NNJ>S@_]6)'"]XUZQ(1G0B?^#7)D=G*%:C"V MX=2H-6=?^@E;SW:+#O78I2S4*#8\:F^32U0*B4T2[:H,IG:AV0O5XU[F(F7, MXOL@9'".&SM#*@-\,* [#XCP3.##(S^(!3ES2="]9A-1Z:1*M]3,)D@[Q6I8#BH[09]OF"G,T MW+*LL:7Y*^61N9DOVWGL EW;)!^H-E*H:&J($G3&U95-7*)RG>H>26-?\GB. MEZ[?1^U!BN,95_7DAE!":H(9"?3BH1NWYEXO<30#[$]PK MP"]__=]G%Z?<*GDO/[6]_7%Y^5^+=]=7?/F;7((-#=DI6C88R6.,L2:-WCA6 MZ)-7F;K\^&A;RB:9+HL-@OS,PS'ATQ_TP/4[S3%$+A+(; 4G/@;=)J4D87:_M)JS#V MY/)]LT8V:Y\Y'^Q8T)3XLB);$ 57L8]M.T(2<^W+-J-O9MR-B;),WP8B<=:J MC4<4\UDPK0M1HU.I]R,X,@MW]M6^C+,S_T7WLC$2&$J,'57+D=I$_@YL D[D MJ[YOTDP77'$1T!IR3'*_LVI]".M9R +$P':8?ZR2>;;-F*@^C@$L54+VE&V" MY 'U,/J.5!_:C;[AS+S8EW%RYK_>.L=H:XVH0T8@;I,>AQ+Y6G0_/_@ !^ME M[-4^M[R-K7023VGCT KH91/7QE:B?>H)JW;=ANLV(Z;5ZK,:GV<+IN?LQI&Q7-T2]EC@#A04Z>?[$W=.PEFE"GLC<0:2 M@J$;,5M3^]%H,#*"Z\#2Y/NE*3&JHFS1X%:U8RF$.VE\&7G%'"F9/JPP]+?[ MT=HPX/3($TL/0_"6,?L M8879=)VA9#(B16$E-[I->[###1!!-WNUPTJQX1X[ J.]DCA;#!()Q.64FU$J MZ$I6T#V2P4CYXD9A;AHT>//^CI'H[>)#6^M6^/OUW^N7R1E9DFD-1['5_X?H M0\DN6Q>@U0=]U:Q\=?M#_I__Y;Y8YWTKF6VY7XW/0U!.62]8HA@=HV&V-E,J M).NGKP+,!R_VMHN_*7_OU:HLUL23M8%C$KRLHV*N1NR.HV3N\_-O9Q=EO-[_]>/+'ZNOY9K&;N6\(S=U6X]>4V@1W.SQ4)J_Z M%)&&ODIZRX7M(8U4%$F6Q*M9:Y#4@Y8J,75J[?\G9;75[R/7Z MHDI$\?\O3I:CJ?X-WKF6Q"8E4MY%#-E'O88-3')7NMYEWWF W5>XGWR7-\L] MY*-8V)02$H/\QS8H- R%%C?1,\"%SISNOL*]Y/O'Q^5BGPVLH]5[%Z2D-[1QWL2=$&^P/:A4\[ M+W /Z?XAP?WBY/WU8KGC[F'1E#-X8U5JS^H1[J03M]J];X2XKWB?5S@NGH3Q M*Q*:]Y?+?YXL3\=WZ0O.QI:[^,?)_Z2;ZX^7R^'QKE067,ABI\1?__D!5\!W71QV@9BGO_[S?+LZO3L M7BPV":&+1+%>:H00[V"Q$[%_U@ME;\)9U6STEO_[MT\G9LMT&^GBR M_+#'NS$5G<"7(L[2Z.HA1CVL.AG;QQ>QRWUL6,T#%WWO4WY>G/R^:%1*YXNQ M>_@U4TVK[B^4@E;%@\#,NW=QKVWL@D'3Q>G'D._F_?N3\\L/)Y]>OWX]U?GH M@(PJNK4MFZSD#$8OH56.QA8BO8ELXPB2T>7%XNKW,]DX_O&'*G:^O+R<>CAQ01")6$6GVLP> M%#?&>F5!,,BF]43MQY5I]5F?/V;JB<[:8(RK/IN2LO%X]U 1*Y3Y]D'MX M"6\+U?Z^^.?[L\7YZ=3;MD=VA3VHA$8LOT&NZSM71>Y-I<"/(=I$]0I$ZR3H MT:45CEI7)?!)0Y5:\;9#Q2-9E$=;]!QH(_N2 47]#E)R$0N'N);/"AH\M 6< M$FP'F.&S8%C#UKDD08P+(23;C(1)Z,C'[OWRN)+M C.4HEIC(T!8]1K7Q'Z= M82>38S^8][B2;8\O&A.C%S2H*D7(%IQS-,@%V%-BZ*ZL[1CB;0$S= K6> .: M2HE%V9HR-),7G<1?@H"[2H3@NV&-L3U1I ;5FM%0_(_%@?&5)/$*S^M M,[D=S(C([+DT.J66$8HF45Y9D.A K)FK]I\!@S6MMM&)H3JX4AFQ/Z$.TZ;DV@(48WK[^ 1$W!=\ M*&^K+ZE@->C9@K=FN(!9_JUOS'HX^+BZM_!G8R6Z1,S>L./L4(O!J.:NEHE: M^-+MBNGG$G0?;]N3$]K=36*_S^]HXO\O(S]UCEZGHE*<:)"+G:K]@_"&._LPH3:=$%\"%CD-I))X.DHUJZ'$UQ/7 M+MX6G+D!>CUXG;,I7S&35I"R%_2/T:5:8*B<:=3D,RE_I&.';EMOY,]?3_D< M'03Z]X7\^S]._F>/<,=Z'S,'[4-M4\&.=E(Q'Y(W?C-GD^"(RCG"]:< MH;?IJEXN[Y_*>G7GG3Y_P=OKDXO3D^7I+Y].3ZX7S0@H.Q6)F1K$X+L20GM7 M-ZDJN=$IL#C>FD:N]DO6_5/U++IH3E(-&0X6AK=$YK\=5#8MWH[QLQ8S^FE1-?C(6& MV=B3+((&()&BJKTO>PK6IK_D\OWR69?+=0$D75X)HEPN3L^NT_+L2GX2WRS; MSUO(%YT./ZS? ;@_ZM@'*!2":$-N?2F)G1SHD&AH"W*"=O8XQS.)?E0M3Q0[ M^N13T/10=/.4K<)=&Y7.FA!]-%A5O&72]4UQ-!A1<78S-!!LCM61GS M,#R^N-9DUA$Q?(/*F^V@RB>6%,!%[[&5E#COAS'CIM'=/%-E7\FW_W)Q\MOE M\OKL7XO3 7<>T\FC556)&2 )D[TSJW&*:Y. RO5Y[Y$NH4<4_WAJGO#RT5HG M!C1RD:#6AZ#C,"ZZD:52WWHSTCWV(O4V-?&U^AAR0:.]#=Y;#NE.;Q*C]NR> M_?CBEZRWV:ZU]J+00&1+404H*%'P8$!C[O'4J^TCH^>MYPDOGS(I:UPRE9P+ M/F<]4"%4I^3(=G5_X_GV%ZJVV8ZGU:TY%7-CQ&G,$^'SPX:8A]HS)+\HK[./ MPVE,L)H:WPZW.I!:T\ #QEJ%VN>T1_I='T>4(VIKMO/(.BGGE2_5I6*K\LZN MSV,M*?8C6LUX >(+4>Z4#[>*"UE+QOJ84\C)#O3FV=B>&> 5C#]#ORAMS7<4 MLU*F8C+.QQ97.HU#)L0"I2Y[_.H@ .E8RIT*RL446FWR?+E*6N^_*\6L*BA*LA.0#II@"&Y+FBQ=/?\*=WR@4=A]3C][H_5V\+) MJL,^77SYTO 40O!0M<^EU. MR7D&%P:BC@1(J7/MK\!M#=9GU,/1U3Z5>(]. MM"4Z]*H$7X,-:3TG+NJ@^^Y9@53C59^\%=8M_5W6 0KZD MOE5!(O2MDV\O3XVS&8&HB5R):#"[Z&TQ1KN!Y]?;/C7_"MUXM=$+5_L$("C6 M8*JI8C!>V5 LYW68%,&&T)7UO=*J'[[S[>AQOH"^=>D6[U+P <1RJ#:S\_;X M!HS4TU0[/U[P^335/OD#]G%8.C6*?H4^RJ%M?6\A#+0QSE3?6UJ]=;)I7QF. MH9_YSF!8T0H2 07#)C?BP>$,IM!7R[XX?4YX]NI-BKED0?%LN6J.9J!A NM# MUY"R-9Y_3MJ9,<,>2XD<$#@J6X(*%0=M(N4N3G]AVISPPRY29I]3- YU-3:S M&9@_=6M[W?\!]SFI9[;#1HF-1#21P-CHM':1 O55M4]#G>V[\^*]_(0_ MSWBXVAO@Z1J4UX20P2?QF86#&PY6=:'7A-O^B6:+]3ZRV,>I'&XUJA+GF2** MC3F&0F8=.1?6$+J^ONT1\W/6Z/R%P0&3UHBY3565Z"3"'1M;1FNI'P*V=7[B M.>MYG[K?JGRCW.)< B@54@IQ_00AAK+H$2NP?;@QHRY9K.7OJR+BJ\]')EW= M'I8#YA=K)E#-4Y0BQXY*BD-S/*G:M[KMIJNMA'QDC4U$6A!;'VQ-N1:-7 RQ MRT/524G4LSR:K=':T]+ P2>34R,^+=JDK,@ L3B.8>10Q, ]:?US/5N'F57> M2DY"008.FDB.:PQ&0$U,1?2,DQ0_+TV+M/6T<@8(F4Q@9@5>%Z_:C"[1G"N& M0^]:7[KF]II;CFBJ$8=0B&)@;RKC4!Z>**9^7,/6SU#/6I<[#C"WC1NCBOY4 M8\134: 'K8XB&6K,)M_:4=QE@CG:0,9F94(V)C+[FF"ENUA-=L_: $XEYZP$ MLE:B6:T*1D<8X]W#14;7$>2^ KM3%/9T5# ?BX F\9;*E5Q=9N=UQJ$_S7%( M8QT96]?$/3&5'1K6N>J"J]I8%:O"J*M30U= ]*4?/??MJ'8O7&9X.4 M,QOOO)@UB3VJ(#P)QIZ]67LT7(=B%RVJ3 V*M(!"M\HXT5QHDQ;,)"W32]/< M7KA.K&+T+>QWZ!3K5()?-P/D9D'[QUEMM\X?/VMM[HCL:N80*.7 ,0!32L:4 M=A@K:EM"7VWXTM6W"[)SC6LR-KNGY PVKAE4JXMVPAWEV4>A# M,^9[@CI0B4 W9I)B0."R4>K.#31NDF]5L7M!NJPL!JTMV!31^I;MC&+/"R3 TU>FA:WAW0E9=;9LT^0(F5G*(65YJPN&+X]S>T%Z;2ATNHKJD,=(3I= M<2"GX\99UY>+/KN\^U[*W!'1,3*# 9-]]48'Y8*^RE:P*$3045S W709S M-Q)&Q?X&P_9M= \3_1C*G7C -60:VXJJP;19?:8(=AZRHUAMW\Z.N]F[YZBL M@^-'TYB8%'L*1>M*Z*H>RE>"3SVA^;=P8@^"-L?,WH.\=4"DI;$_&AB3VY +&J-4#LBV.N;I);OMO5\=[X5_T M@%T;K_F*FB/$UCI9\LI4VQHYY.E!?R]"RU,=IHJSK9I+:]O)MXO9Z6^/LFS(24:]790:FE8'(2+!H+W%Z9<@T6(>R;6_P&]+T] M4A;$X#14BI0SL9A)2C'/ 2V-E:HD]BQ(U>'7 RQ:J0.Q?Z7=%[%02X @5MT(4I M*H&!3L65&5D9;/PVS,C4W$[4SN;04NN!@ZN(.)0.@*)>1SNQ63Q7;:L? P"U0!YAXJH]FIP_H;T/N.4#FQ MCB'Z$#QXETO%U-*=,0>-D-Q>(X*^$47OE%0."H/7-K>\4G+%9*@K,\(AB"WI M^O*>G9;_W&C_^2 M4*F:[CB.2GS9"TO<8]F4F=3V;79PH#LF-ZK?:HHOVG"5F\CB\ M)P#;?J#I*[-3=\/W7=GKE8<5U6P,D H2SP>Q6-'?E>S$GD=TIV+C[WMRD,)3;[UG9Q(BL4==1RN6)D4[5SUG(.PXP2 MKN:QX<"WN1OS=2U[5H$P->A6,N4 :D',PR5^/GLPGT,*'#5!*9EM]0Y(#[Q?57!Y_QCV?<_VV+,) M8*?:M +#F1F-_ ="C7IH(P,?]^4W^;X'CPCDH/D;M-I4 >7*QD!6#R9Y-PK;6\8'H2HQ$6>DXD-!E00+4T5-_WX.]]V"V>V.4LXTV(4>,Q5?* M_C:(E0 (8^*7LV<'2Z$U@G8Q1"HQ040TP7,8!E-Z4%U(B3OQRNP*3_?..457 MV1M9XV'X2$A3/%I)/-QD&P$8IR Z624KD+-R0B.8Y*)N!?+ FU@+_$,5CK70*H M0_9!9]4_V/O=: +G%F2^P7R.K4JF:(S5ZPA*A%]O()@"(V7KQ[KS1ZIZ9@<8 M7"S.>VL,15_JT).>K2D]S=#S4M!>M]XJA]60TPIK2;5XJ\LP)4)E'LF@;C^B M<%Z=3 U&!BNH!T/K3:X6_N*B=OT%VW[>X -%/XIV)P*/T)Y1R84J2*2HBJW, M:7A6-0;Z8:$&OP%U'=SHU177?;8">8J8OU!*&4K--!7;<\]^"X?V('6K&H"5 M\[%U>C57S E6]-I4/-9$^W9G?!,:IZTK5Y6UXL9-K3:J*!#6$L65E@-ZKWHZ MZN]:?B!B2)P"M/'/"6HEE(AIL.N9"D,_N'0HM?BN^?V9^K5HUD;("A11([Q6 M9G7(*\LIWYN)[IM0]2[UJXUL(D#,S#XTOM?6=;/2,S%$[,N(7JB>IR8 5*N2 MQ^*3$B@<$Y2[E+(C5EW!'+SH^S]S\J[FZJH1V!! XM.J,/FAUPO8]A.@=DI, M/5/='AHS^R#:QU!=!/02K<1HANKIJ"7V^[X'CX.8(R)$%D,K)J5&;UQNU%;1 M@(%&O[0O4>,WH?$=$#/HA,'E[#V) ??LJ5&)&LU%*1?W+;'X)K2\'P6N%HA, M-6"R7&KQ,1$/W5XU4O<0I7=Z3_LF]+XC7LXA WF;;"TU P2M?5H9$F=BKF7? MRJ]O0M6[X.6DD*ED#*;:K%V@W/C:Q)34HAWPMV)*)EZDA=&GAO]3@R"SU-;\PV-#=%X4UH;I\ S]M6D]<,E!?9^9![9BTYP'NEM MS7D0#Y=063:FNESC\#:2$WGLGX^_[\),H#F@1Q6QUHH",HP.L31?1U -@.WG MS'_7^#Z@.4*JQC@J*A;R6D4?;K7L-:?8YSR^:_F!H#ES(]Q%=IF"!6ML*&4P M* EB7\1D7S1J/@1'@L?D'5D,:"UD7[6);6H8H0Y%_N^[)9D)-=L2@H$ I" X MG0@1],J69$/M6?8%Z/F+W[^63[K\??45\I/*^_>+=]<[%Q-45ZQG2X0J@T0: MV233YE)X@7P5_+XM<'/)\U3T-Q\YKUU5! F0LY59F>PJ*_E+ST!4'S]'].3U M/?%$ A:X9$J9V8:<<@F<5N=U14.S]S30EZ:_VW^T;U-Q\_#Z*)T94* MZ /6!)I SFL.)2E4^KG8A^FVKS<77XS).EBE)BO?ZGR5-1B2"]'17?!@6[%0 M3T<*.[7U["GWP=4Z@:I<#"D#RP',3F,)U0X=,E$;5?M2'HT[U?P_%S5-./,< M:@FVY)RH%4D+=J]W]0ZQV)&.@A>LI?E<=M*N9-L&*UL--IBJZM"EY*%_['WE M=V(+?RY:G>IF<8"N^N!9.:!8 .FNBKJ-X^M[%G9*@SPO+).O4Y594=._L!Y M35H@5S-T609X3-MV%-7,UYNDG*TF*D@QA9 "EH$W)5H::3; G9Z8G[8J)URH M*B66PFV0%T)($9.)=V3+*G4S.^\ M4Q-0"*$JYPT%4Q))B&*"'IC4JB76I57R MK6,?2*:OF]J-D>"[YN?#N$81IZR+,9E,B*XHM09R $1]AF2WQOIO>:RM(%.-JJ&R;)69HG>\J6B?3 MLT]\=R-?+60?W\W4)GXDQIR5RY5C&EA8&24J>/0 \=IJ!\^WMS@2KXS=:)?+*KAV\EODF-=$/$0UE7TKG+Z]?9D 3*52K*:*0C@4"?N?(/9 M&BCM+_2A53J%)9-M@]HS*^2L0^%X-R8((ZH.K$AD]O)T- $Q H-'G4,"ERE7 M5XKE.\XO-5)W@_;%*FD^E"PAHV= E2"6ZIR->:C2R392GP;38>OLRO-1ZE2= M1/)BN6J;8DK,3(SF;K2:1]MS\]FMX>UST]&,/,)0@8ALS39YL H8AI=K3#S2 M@O-<5;I7B43QH)UUT(:-I:!,5@//K$MR9;L7UZV?%?=:_\$5,V.!1,RI$A*3 M-1Z]+F$];H(PV-@U\+X<14X1F%L@[W(.SE%&%ZT?JI0R>U_[EZ?M*^2>AV;F M"ZZ+,AH)N,82J08R97A)LAQ]_WIJ7\P9F_";1J>44$X7UN23(5M\&(HC,H^\ ML6W_?O \-#.?&6N=)MD%$ZR*7GF*N0S^P.#(R-VM6:/F4N35M02VY7\^R6]L3UM#$&#PY]/VX-]UC8U/E%$R6L!A=2,;GFXNSZJ21Z2KW&W/A) MV'MA\P4512!- =,&81,[158/T:P7']V=:!R_B'L(,G'5*$6?"F1>]<28I,H0 M[22'(R/3W7BTL_?"YF.0]++YLOT4 M&^M +80Z9F^ E1VF652KNSR]'G>GMZO=6HBI85JMK* MW_?UC^.'9,=53?4G66>]S;5Z*%6#6*X!W2:-(_/Z-,RBJ[DKF#FS*%.BO^K) M@*DE#V&@J-QVN<-Q [>C#%./1>#%T 8.%;+QUD]XT>5>BYK/ M'KADH0U@*%99\6O)P3#AS!I;N^.QV^GXX>SDU[/SL^NSQ57C>5D-"OQ3_^SK MV\-R_^-#PH0V>5F=YK;O,,QI98^FSZPCP'B@.[J6!ZQXOEZW(H%!&[@0+&IG M&)U=XQVV3H+Y+>NF9Y7/;MB12EII%M/! CJL7$#6P\1I$E/7'YD0Q[W(W"N> M+UH3N0Q:%1QZ\?;&L%GWU5$*.?;N93R,V4Z^]D\G5Q]O;]#:L>[L>T@+&A5P M@J#!5T>.?1XF2FM'??W8/6.MQA:SYXHG_)*Q3C<> <$=8-@6,41#Y33%--*[ M>$_^:L853V% + D,EE();$W5X="KQ4!AY*GEGK;Q;5=\.81B^QX*C*WA!Z+Q MU4 ,8AGY+AB7X](_2MY3(CVREH>L]S_/+GY?7%W_Y^O5?]KC^>JBGBRN_E/N M[6**($EG!ML8$<1.YF(EVM'.6JRJ% M&3[)1'$Z:MV?GOR^6/Y^=?EC\>/G/ MQ7*J[S2(E_,U!N<,F2IV1ZZYCSYAYO6.6O_5H3JY:N49I_SC#[<[<.<3ZLG9\C].SF\6^8]T=;6X MIE8!?/CA[/?%Z>K?KOYM<7Z:+DY_N5J<3B4P;$D^>"JHC!>7J,1# M#I0 V?=51/;Z\5A-.,\!7 E./&J 0I9.\1M*<4X4M/YTC0S]C%_ M6Y'#W581G5R=?4T==_=U?';U[ORR?>'KZ\5OZ;?+FXOK*[[\[>3L8@.XMT!* MO*NI6 R2I2AV$K38E1A'QCOK\8#T8.K^;/VW4/?P%;?,>W];7'^\//ULA*?H M##'54$P-%%009^Z,N'7C7 OAT!ON@[=Q"'LHU8R[DD?7DDJ0G*)69J>B%2SL MX77<>_K+W_]WV<7IW]?_//]F5R\PY@T:R*ZF T57UD028IYP+%. M+ESGM0]D[#=@K/.KZY,I#T;.Q>2A%*Z^*%#LATPW&G"'PUC3TFR!&#.GXA.E M##4GKN2-+0*L2A:T5:AOKCG079\-.$I42@"Z5=1559$YB\D7^3C;*-O8!>2/ M?4LGXJA@67'5@I$86-7LDKG+2*K8$SL\\CKOM2;YYOW[D_/+#R>?7K]^?1AC MTN!_":V_1:)=#!E]75_O/L?(JYG 09 M.HGQ7 +K'^:NLRI6:$>Y'RF MDIVA+&Z=@AW8SP)1Z'S\/?GI!R]S8M_;JX\AZUNA0!6KF2&DJ))7OLGC#OT5"O@2^5]./)'RO77R^7XB7?+1:G5ZTU;_W^W)"! M?%=Z=WWV^^K);>=+HWTQQ84**K?!+:$]FZPC^:Q2Z###J] =QQV7.*MT4UG[ MJ'-&T.+5+;>"T1W)N&8PDWVNM$N;X9]&^BA9)AQQ!Z+G?2Z6?Y(A8RI S=!UK&OBCV*S%,-@E7B M:#&*)FB)I3&IJ,M0/<1&L@O&2$RFVA.TLHPQ#>37$0IU48[NJW0VK^CA:Y^O M+MIB"38$B4"LY^;3!L9E\@'T2%[P@+).-:HE%[0J[,0:B%''[+0::G5C&(F: M3%=B^-AKGX^A0EM%W&I2J(V#5WA7(D1!KE3_&'1(6:M;% &DY:,;> M=C MW1_=3+-IU5^OY2'KG:\66=R19U) M'5.]0X"A:M??GBZ*G%>\J=258U5J]D%)\*&T')TA"<^QV-I/;N_I+!YCO?-M MAS(EF!R2M\&(KZV:[IQ.3?U44[@WJ)I'O G[!1%R#B" (!EQ,NC\;>NAV"]% MJ1]U&P^RW/DZ($3IV1A.8@.\CRI;3<-N) $\DTG=7:3[QV5Z]]\W9\M%OKDZ MNUA<72VNTL7I,)SU]<7G_/M70DB?EF?G6F]XX/[+S MC;.8LLF@C'4VX*[/M6O#=F" M\06BSH;DA'/R@X<*,)*"?8)W?6:OIAU6,%:%6*!R)H5#XH6]7[-_J1/VE=>K9Y'[GV!^=O)V47C!5Q]N'T0?WPVG]: $DE%V=P4L[@^IX<[ M+JBYA\S3E_S/,CQ0X+G[5IWE1J8;, ;C0([YD*0BU*8_WSU]T6,+//.%)B>8 M#2SG@.1R$O<&0V529/GM 7;XTV)Y_4;2-T[',.VD[UW>7$)-#=52 95/)B1LM$%78ZO!*-DF"4\E+O!B0(?F1R[RYTZH#4\0#Q3J[Y'BAICNF[.K58V@R@3YXTQ)Y^44VR]H#HO M1G"8CNK%XW5)>K&11Q-EZI1Y-MKID'7*JA4'*#=8-D-9C[R7J&G;MKTH?SN[ MN%R*97[[4:SQ1PF>%\O=3Q:+\U$0!5D;+8$U%#70$HH=*+;+L-F>"'/SBAZR M]HFC5+A-0O$;Y.;:ZHXJ!(D&Y9 M%U\DE1-TO@3[61,[K'T33S4OW@L\//V2KIIN&]._Z%8?YSL8X,#(1WQN3KL: M^=>O&]HNEXNS#Q?K1=Y^]U??,ME<:8IA,(6*13(24PTS;;AXWP^C[Q]8'JR> MYZ/L7T05B]-5Y=?5EQI_\_Z7M[= ;R?=!\@N.8RF):I<,-4/?(!M9$3/4*N4D\VU=NY;TC9,Q]Q*%Y[*B6P9M+!QSLB MC1@@F X@/QFMST"U4W.0V$VWC"3:*/([*$,J6D*W?H G]IUDLRS[,'IX(K>= M,S=B0X6M.S%C-IP&SCO3PJ\^8L8^>OGFM#[SM3H(9!H@'/&8)AB=$-!OARZOB _]H7E2!V[@9+%/F?F>?_K;4_K,]]]5V0+0$IJ!Q&@U<4ORW4(N( M] M,>%!]F#Y3O[JY,/BS7M>_'K];XO3#_(1?PQ/&S^+[%\P/8]K>]6E>_=%^8]_ M_/%IOM#]QB MQQ^:%G^Y^C.KQ^Q:#"WHRLH'$V-:=;2X7'PZ.1NHN =+ M@HI1 LR4S4UR-V2BFT5<-KDB'OF]P)#TX+<*#)9Z3ZI&\RQS(YC,CCPZGR@*G ;E^:Z@HV8;^L?>D5>9Z65^[M7BLU6;5K,!;]Y_ M?@;O7O)Q5:$&X17$+^Q$:\F\:Y',)^*AWRW>?EPLVMO/YZ;(+Q!*_D/^\.GR MZN3\+\O+FT]7\A'G-Z=MUH)\C?S(LXN;Q>FZY_/RXG,3^E_/%K^?7)S^?/;[ MQ6+J]5BCSQ59'&)V+5>LTC#PL!%7].E?/9I M8U 8:!.F^%6L,SJJZI(C6[&JQA:^KL 1G78*'3%OCZY.\Y/FG]^F'\K]K"N7 MOYU=G+T[N6A--[^>G[V;"C!T8K*-NQX4.,\Y\3!)F4/,78#1$U4?1NRZ^'5Y M<[+\ \PQ#M/;DYOER=5'@0B3#6^53+(NENJ!4W!I2).1SAA[=1Y'F_]^TN-S)[P]YZ([ZLV%JB22Q^0P=KH[;]W.F1A,,AM G_?G.Q^-Q*_^[C MXO3F7+YIG)VF_]O%XN\GOWT1>,D?EI>7%Y,M>B47]&@AJUB8*6=]9_^U'>%O M'$$G!] ._OO-^1_:7G^<3T-_.Y&?=W[Y[NW-KU=GIV=B%:9:>KBB4Z:--@$, M.1DWS/!I4GG)W\K?'*WO%TW5\<%T!3A=8[%Y$$46CM MF6-IN1O6_60XUZ?+'W_CW$_Z]8\_FJ;P%[]]3= __?1F.A?_?=.L[>_RRUTV MY9Y_G]AQK^2&.F[TIM42D295F*)K$\%SYIZKIT^0'F3'V_Y%,9!'PPIIIS90ZEAMS(8;OM'Z&/F7W[ORCSO]JV)^T( M6_27\\M?3\Y?7[R7\&)-;[3X\61Y?;%83J'C0@&3,8UQB@J#4]7DU@ 7(X&3 M&*3SC_U M ?H\3&V8[MA)MI[8N4071;T2Z[@T!WE50_E] B=SQ.4>HH[1L58 MM4T6H"(@FP1#=W=*;H2L/:A]8J&#BSTU8]8Z8N_;;'9VROE66C:D9+*#7NR1 MZH?YI7Y]=773#,)A*9 2Y9*50O9.DZW:U6&B&$&(>D07FU0Q*L,#!9ZY/29S M=$53LMIJ+@+^Z:[2+1N%?>W+H>6=N3LFF>P:_QIH9UJ=2008^)U]9NK>5S:B MYCWE;22HK>*\O4T]^HG6%EO9-C$YV>!,)@Q--.2\\EW_T_!2,2GREU(\5.:9 M#[4&PU4UZ5"A3E6<]Y ?5.WG]5F;?A#DXPL]\\EN+Z:(1@Y0<"9X">6'ET,* M$%R76;=C;U(/E_GGQ>EB\=O)K^>+'Y>+]XOELM6([,,N%63C;%4JM''=5B4O M?VC=$%HK0R/,R)-RW+>R.66:0!C..J;685U6,Q6SJ2ZO.CS$V1@PW<%\$C)- M#67+@HZM")-"-2Z5$LE:V\JDJ1Q[5'7 M/\4#V*BN2C*.HW*E",(.=T,)+8Z\K(^5 ^RW_B^X]%8%!'W$VXHTM5O@(PLU7Z:%JKE91L:$-!9#?YR1NVHOIT^*B M.@_U1+0P.48S)]*,7F6M6$P>FN'$5OEE"^;EXPLW'Z4EUE0JU-J*>@HB" 9I M6VPJ.R>@Y(EN\53S(!42J2 F1^VEQ-XQ/Y56LMI)]>I);?'<_ +BUIUVP$&U M#JDV,[.!;>.-L6*,^T&WFQ.1#]#&SXM/=XQ:/[0T@\1A A+.=F<:J%F\3)O= ME 6V"#RKA8)72!JY6[EDL@ M@4/&WN5E!,%O[.1]B,3M%>W-^_3[R=EY"ZW$[+:_>;MX=[/<#^+Z[ 7&U4B> M)>3(20*G@5U8D%T?T\I?;;Q_4PN<3[ )NT)JE3AS,26&&CAPAF$VBM7]8!QC MW<;#>3C!IG@TR%NG*#OGQ((@%A.&011.)=>SFT35=YG.)MC!*;!\,,@N8@"R MA03+@!Z&LK*O+,CH+E5C9&?="(;*,7"#=D^2E"O^.O-H:A MCR/RS/:5J>A0/4J8G2%@=#JM(5VNJO3$;C/*.@\%4;$Q!1N+D:UB;2+%P3]H MS*[G[<'->;7[ES:',%.F-(**T7*V$B](9!@9UQ:'O=&FJUTP5FU,2SVN,%.8 MQ4>3=4B!96\@^("TMA_RO[YO6#%AI%5Q'V'>GUW_\&=BQ*V.4DC62E >4O6> M':/\NDY"F9)[3GP[NM[U3]]M35]4>]Q)]?IB5=_Q>\OR-AZFNZ=@DE\^7"[/ M_O6Y*.BV$/6_5CF\-_^\6)S^>>[@_84;@BKEWE=TS<+%&(N[B]F3#IW03T78 M=<)R-V$%[%L$5S!9#P[%1-":%B9:$$S=[?#8[7J8S#\OWGU5T_7FYEHPP;MW M-[_=G(L$MSU9S70O%Q];G^[OB]L"H*\,_+X?\N?"J^T&K7W^W+%>Y]/_NKG= MPRE'HVP1!"R0RJ;4)B(%W^8#^)(S^=I/!FFC#^96_LX";U;D!DM2Q(RCCT5, MOH1LOB6V7;">2@#?.Z4CR+C7]+QJDVJTP*W:@R ;#[6*7%[NE?:)-DU;/Y!< M7Q083 66,>50,^80R!?;BN_M2I;(+>$^$5@>0I;6;-\Z@2_/SU>S&&^K@J:Z M"WR(XFL+M-?%R$;BY0&U5[0C7K>?E'L@\7Y>M/+MQ6DY65Z(?%.VNPU_LC&R M0JI6A<3!K+%YCEAP9(K2&#@_A&#_6"Y.KFZ6?VQS"E5)7#)6T 4UI-J,QNH4 M4DHU]#2G#Y+&_*1_VE1)( %>0/3&42W>NTPP9'<5QJ)D7%%<%MH&"_(!?M1&3!:K+'SFG"CFDA,G3&H;:PJA( Z#Q&3;Y6 />G9 M6&)_YS6936M2SE>?Y,!; Q"#1 5VZ"GR.D"WIO8U?Z1"SN#*3)'QM/6AI(\),28?&W3H?,:8A;-(]3Y3T78O?"T$[LE MQ[MH4DE#Y%*\'H0%4OU5&$O\/4SF;Q9/(SK/5L)4$P%"!DCI;L96<=AAL5?] M3.H'*_]0>#HK4MYZC4;5$M"P"\&XB%"],:4'-4>0<2\\'7*M+C>&8R>@T[;7 M_]CD"A7D/SPOGMY+KNWQ=-(A&=D0C^*DLU:QI+*2);JH9?..+\M>>%H+MM0V M>#(YF6!"DE!A[5ES%)_;$2+[V3SK(^-IKBW1+2"/HQ43 HWY>=V&C*Y_C_*C MKS:'$&P7/)U-T$5"W M$M^@K3.$QB6#H :03S8XVS,KC":]=U[31D"MJ;0Q$]2: CRE4KFN7VMC!NP? MO\P,J>"IL8&E^N),-M8DDZLUC?KO=NL$Y->1"SM# LT>&4Y[EZ@D+4&@%A @ M@3\4=P>G"W3Q\0PAZ8PB[P6J#8/7WJ'"%(O(G.+@<8K"L>NP/GIS"OW-HNH" MC4[.PXJ M54^5>25+"@*W8_( $!84(.;K"H;J!8-$Q]W'-:+O2(\G8G;N_+"X_+$\^?12_?_X%;<^' M1:.>F"*M(Y,*6Q4EV@Y83,W@C1CQT(9:6>ZG5P&,P=RCBIIOSC^<+,^F)(V* MC2TA5Q*H[FJ5\/2.=C1J/=+T-,9B>UQ1M^2'*SZ%BJF1U^;6ZQ)K7=O[%"!/ M);J.*V&C'I^J;8BZM6O*5B:O&+4N9:@K2;++G=4W2C^Y0_OOE\O3DZE]Y% \ M8.M_B+5U((:ZNIRM--L[V_/\F3"6/CBJG'\]^=?)__G8F.VF$F2%.%8K"-*N ML#&A7[MRCL&I/GTSZLJ/*NLJ,!" ]LL4;-%@0QM3EG*VA0FM<@.?A_:UKP(= MRW$>5=(?Y9:>??K4*ONGHH/&50D&;8A(%148CG*$33;C)+6'%7:7_[/LB'P*8!$Q+I0 M5HV!.D4.(=2!'EV7GNOV"0GX'V>+ZXN3WR8SVS5&&TJNKEI!MSH))"^J8K6) M;=\5K$T\(,Z=EO1=XVM<_O&?^>?[JQB,KPF3C8G(AMP,S_!VGB5B[-VH'^4C M.;J(]&;#4$@'%31$;V*6Z-!:VQRHSCX'=*4SM&:4)^WH$O+]$K:L++)R57/; MN (.\*X\QO;H$OXE;V""=B9H<.(KHUS#I"*MWU#$9ZJ>I1SA28&@ M0<(?_KJ!4Z:)1A9U$!L"9.+0%)(T9=.]MS^IL&20[V__WP9B=!2;F;2I4&)$ M=J;<31=&VU?=>7Q2X?0@X8_I?G>86%7F&',(((Y04QFZ#6NPW'L+]30-S8_W M>PLLZ-D*DDN^,E79T.&)KLW!Z0L.QMLUCB[AV_^X/T& 1A7#F9S2\E\$#$-O M!E7K.JB*ZDD:FE_>WG\1!8>KFE-(@M8J9@5W*9!LC>DGROE1)L%'$''3O!B= M0;$F1 $H8OFM,T-E(WDS,NT$((P^$SW.LN=KO78Q T&KUH2<6=H0FAE\M8B^R)[ZU1J,6$PQJGV2M99R_CD1-TRYVA;L;RSP25; M'8G=9#O,IH^(?8VWAM&:S:.*NG7.T7&;#"KAOBNERH:"&9)R0=,$8\=Q)=PB MYXC:A1RC(!DQ1 F+>/4P#-'+4/M4G(T'M$$SYAP%4K=$C2X^%0NNV(BUY1Q% M2%_S"''>*,GR4>7<.N?(KF7@G(905P3VFNXPC?7>=.^BVCRY/=TZYQB=KB$X M2\%F%KNKU?!42B;4TD/4)V>(MD\ZHO8"PTO,E@6&5@B%N24=T7'BFON :I1[ MYZC";IUT;%-L)-*O$DNQ\YX,#=/T8FW#VOLS[,.!DH[;2[M=TE&U+K1:L WE M)5N+R#LD'5'0PT2UZ5$%W"[IV*I-!+1O+Y/0"BAOXQ20N+G/YHR.#3RZA!LRCBC. MHG ;I>HC@@MP-WB=-8;05PH<*O6_FX0;,HX9G$AG!.)40F]!.UBCV:S^+WMO MNN36D:2)O@JMKLW<.V9%=NR+ZDZ9Q5K#:4EDDU35]*\V*/.01!<2R 8R*;&> M?MP!!'*)@^4 !T@D6=5JBLHUW"/"_7,/]\^1]OE,+>D.N48(.BA2FQCCL24[ MJ51X3ZW4W%:2Z5.F"GK)-6*TG(RF!"(L(C1UC-P]O=G:"U+"SLK?[Y!KQ.8L M"5>I%T)50Z[[7?ZW&E_G;X0B';\&7E;^^OKJ>3K[,3_+6 )]-)&C47-]/AQ5^:\7(*V8?I8#R[&LYFV$ SOHS# M&7S^UUO\U.H';:L:RJ=(-O'5 UYGI8?/OP2_?.L(9 M5(&\CB93[AASRBSXR?& 2)NK:,]VR"3VJY;YL/1?;H8CL*;OFD_+-I_I+^-I M^0]TA;>/6Q7*%Y;1?MNB>PJAH&5!B\"8CDC0)TL*68E49<@IIZVMEV>KD7N? MW54G$(5@A2#@ 4:94-%QNZR$Q!<24P\VT;RU-^5(.MGT+*E3UL3Z((("<)8U MB*!+XHWY4$$X9KJ4B/6Q]/[F)S ??:8Q>)(\S9;10I3I#;>L?L;BNQ>*]2+H MZ8&"()+GH -F=R+%BL %W2;:?)YJ[E!JU F=W[XZ.0I0T#ZF (3,=+4'4/ QPRGP&L' M P7LG(\T$9%HQK=RRV1:'1";*DMJ3FU'3PP4 D'>"$DLST09X?4J_YCGO!$U ME9?ID!XX XWL 10"Y4G";<#J>BF"U)XMGVJSR[KF3Z%*Z:.!I\YMD]P'CIPD M<,\ULXH;364YXD0'+7'&4I\T_MK3EZ21H1 MI5 NFJA5 F_J8CEZSCN'-_3Y*&\]+-WC8'&"!,V2.&M=D$$XZU>WTL6,!XO3 M;UTW:XX-X392<.8R>^N)\2FIU:4CX!-!-^SYJ&9G%+^/>8K4&NF$TLS$ %XP MQ;LJV.104Y)\9ZI:N)[WTN M_]1J>1I^+24-28Q:+H6T^)YIR@1)J[SF%6RO(/OWJ7+XR7\9#,=(HX,+B\UL M^&F\"&S_[78P&G[\"K W#&:?\VCRV_]J+C]MYZE6,?B8D$ 7 B.> R]T^C%[ M4M/IBRJ>_SYW8@[\1@N>OUT/O=#:)QD<_LF-MQ!/D-).:6+:U)M^/"67H?'M M_%U+=0RF4SQ9[@K+*[IE&!QV)60=*/$Q0$!.E$VE_0(P;?5P7?/F[K/&H\AX M=UHN/C>7MSB&:O&]/S4WGR>7=PR1]4>;YN?!DA81JVY?OW4_AC<)%W ]'>@P4UI'$>L($Z O^784R<@ MZ-:E=LS$FB-7UOP49R/DTQX3;X,@!)M'($3B.F?KE9^8=YP-QW\8SBZRPAL\[=":*X<1*Q$IXC5DK*,K\%)(C7MC*G2 MK:>4[J>+P<7.LBFFDT4^$@L6"JXOLD(5V;"4MZJKJ%Y+3BG:+[/=!1. D928 MU\]$JB2Y&XY)HV.5#U.\9\DVF<[$+$4S290AF4J,QF0I>V?F'O[GE%F=*\-T MRY"NIQ2MPX6)T>-[$LBG?*8,?'FIGL%0.U;-)JHMIMY=LB7,[>9H,@ .@!$J M*QL DHJ45X/$/'=UF8RJ)Z2M6<>^2WW\,%N^Z='5^3"8#C]^A(A@\@5P?3-+ ML"F?OKZ]G5Y\'@!&F'_+MDA$10-8"UR03#X'0 R%AS%Z^& %$D1-77,>LM_/ MOX?)[&9V]^VY 5V,%Z'1+CK)@#4XR89!&"R2LS$4X!&=L;[2B=IZ&8^MDC1Z M/QA]&5Q.IH_5LCWHSU)(02$2%I0D@(:E4PH<2=TI95O2+Z<5=;Z+CW_B-N+& M3 U@PXBT,-QI%SPM\R3@C+NJ8%ZVA!3]2;FQ8D]FE2P)'HG]P?3SE(NY]-*Z MFOZD[LWK>:FG,T72&14HP1)4N' $O*!:/4/';&M&X[HOZCQD[]$4,>$28&G. M/<2^8)\M]C0N3VYF=:*H93K+J76RMRU2Z("8L8(!]N&!,V.623$?K*J+L;=C MH&.+NH\ML@++?AB.9F.."1FD+UQQ,3%5 :*:0VBHG-QP:^_?*GX>5OS>SF]?BR MN6[@C_'-^V;Z97C1+.K])M.Y?K8=#TL]N&OMC(B"Y8RCB,MM-C%5<1NE6V/2 MTVAA\2KP8?![,UN>#DSSX6-"N)W=P*>F2]&WQ7=.&I#:@[FF1%FIM"]8&4+R M%G+/,SD%>\%(*8R2T0FIJ7.6),N*,Z9.N!9:@:>7=541@(]!RSN_;4L9P*^$ ME(E$"0C9L?ZS8%#GZF)X7L\1[5_.C:!993!&,7/CW13V\RD-\FNK@M8R*5MPG*7"5"33]$17^F1NRD4/ MUDM$HX,1/&JE5Y4]7EM3]4+5;%M/(_\^;DJ&Z"A7W#("8K"D31D7&#VE];L9 MXV>PV7OX*1((Q7J"X'%R@Z:1NQ7VXDS7DTOKEJVN4@)5PKSS2$@5 $XY7%Y#5LW5;5['',C?%>U1&:8CTC""/238D MJ]43BPYU%R6CFU#]P>L\WEL2X#B61<(DF]6. ^)9/4L0+W5-2<7KL/+DL[(A&D#6&JK=#*"BO+&3"RG=:I4 M'6T'-U)#2\ZD-"EFBE^9E E\]6II0TW7H6M6\A[7><3G6?"OR&+)-7@?P:U+ MLJ3OJ/*NML5_+O()HBJ9S[5!*Q[R/AUKS=;R:P4+D!T"F!'ZNQTR3Z!$+3N M]E-UG_+ZI1RPX!:0L_J^1S?K$?CP$.SM7$#*N47B/\,B/A" P$$5AF @J"M<=#B3IHYQ=P!M3ZN)'3, MNVJ(1:L22Q 0<4+Q;)? .5U:_:F-.6I-90^?AQ>#)OQQ=>W4R2YN]HE M./+1,(B&HA, YP-QTKCBI[ @IV4BQ?D(_"CHO>=)MM)X2 ?.84$=P'^0[#" MK!FH@BM2.8436(1-V##DR 0QG-,H"<122I?D%/(2RNI8"G4")]8>J1_#B1&? M0DP,M@RPE(5P6-I5TYTBO@["=@F*3RO^P4Y,:>4T)J2YEDJ9E.VJ $<%4D18#F#& Q,6C+G( MI3D5G]UJ6UY&"9^%AO;R7B(DEK,S:U>!]_9> M0EF&XX;FOM_Z$$I=5%EIG%L.80>A2UJDN<-E M+1,[-K9HM"SGL'6?R(\QEU*6R25\6W$A@9N.*_P=Z\$[:H<$SU/HX/TUR#<8 MO?EU-/PTSQ=L'V)"9")&4)0Y5;XQ1EC*[S5,OS[/"3OR94EY13'T1B$ M*J/!?XO"61^#"O4K$ZWYI,]3'ST[-.&T3#RP8*A*6FH!'KT455'K*]Q;$TT] MM9KVB\DX5![,.*!$S:656Z M_'VTHN;/.RO)R^?GGN%=.ZF2\$\B%P14+OICX($++0UG+/)PCKOM$'EYDIR$X]Q8L M.0D)*VHNY/U3N'[.AV,,-OX M=C#%K5GP+KR>K_+-Q_>#T>-'X[@H3GI )G:?%+>5V1 ^?O=P/"?O@K7\?'LQ M:@;3Q]QA=\OY.C^O;HK,#%2R>M8*Q+\%P2TVBS'DIHM:%*=!D7=?2\39>@^,J M^#$=WO-2,)@$ HK-CD'LF[7 H>)%P0"9*X_(VY!#)P5?#[[.*T'>?/P1*T/> M? S3YG)XL\XTK,>^5A(EDHF*VB YH!Y>"-IB%C4O&):8UDM?LYH]ERPV+YF3 M1%( SP/@-0%2M3H4;\2BXC5;.V_)2_6[XBW,@]P09[RF1EIO/?@060C!HLI< M54JV;10$75<\&7_ZT$RO8O/KVE/1WWP../%L#@-10L$X$66V,S>F96H5HRT7 MH'WQ^PDH^A70<:1[AW-&F'1,&L![)0FL8JPGE0$VW+R%!PLHUPN(6 \P?&*<35$$KXP40==, M-&W^^H2ZB->C][>_SH:7P\'TZW%4 I&B9%KB("%K$B 9GY8VR3GK;$VOJ%NB M@Q.J9.%%)]>#V]'D.!J)P7.C29043H:%:,F79Q.774O9$FO+AYY0(W,P<>QC MD@R6RR;N(UP<3T MRL#-T9(G2D3]""C:"OM.J)0-Q'1]J\9P8W&6 PU&"88C M.JD U5B&)1..UL]LI.55^(2J>7][=*-B/ M21X@]2; J".H\VEG\?PH7J:;, M:$M,GE E'X;-37-T2ZN(DL8)+41D- (.%,O>#A=\;NFU84^GE+MARGUK01NG M,\3!EF!QD4TY9@;'PFO#L)BDYIEHHQ<\D1;VP5N"&Y\\-E$ =K>!X)SI)=YR MBW:+UMIP=-:&*9"])XHHV4LA2TQY1) M50=G6K# TVEB(RMC#&">54J4TYPUU6G%DZ%R2S#*;,M!?5+1>MMD3K+TVIG( M$TZ8PC?%4++$T=>6N:U#Z !-W R0I3X-IF/X_.P1?_W%XZA]*VM@H@X@J708 MK 7_^PVQE#0=8OW" N$@I7D#P%["_3.C2$)4R5W4S M4)MI6;/V/05\WB\N/DAK;99<$D=33"R7=$74'KSS6F*C(VJTYXP=V+%DL":) M.1M%%@8S5@OTQ0$XURTR+0]V1Q'PF1Z98#0-P0FB@Q4F>:-M+H]T7JK:VE#3 M4O[8KT9[#CI2@*"#>0@\/*<6.[NY6]6ENSK>;B/+/8J S_3()$^3A^@M*0.! M*EIN6PHFI&&QYBTB]J!+N-9,KT]22NXCA>5Q;WU0UIE2XFP9EZK.9,N6T;_E MMW=9T4JE 30^&0TOYQOV^J:Y>CB)9CZ+8;;H^DZCX=5PO-/P 2^%S%Y:'25- M4H@8RBP6$+AN8W^YUKJ?7J@.S>\0(#2[][\3;P2?\Y)S)[6P#M.*2Z4$;M:,C=3I4M$. 7J-()^9+KI27#B0VS]Q6PT4X"FB7$#*$\7 1\94&CI# MBH15QO+E.O]_UFI*5\WN%PCB3"<%=4E0EA4GR1A3GH4#,YO[.\]?%]V&7)@H M)+4L"X_5PYKQM/3VSIM0/X$^3_O:@7"%),>%C!1C#Y>UBK0TA#@&)F4S/=/Q M-+$<>#_^5&3;9A85P'V QI0K+:))6JGE&;>!!E=7"$E+3KJU:P0Z&I 0R1$B M,T!$!K$R)\+RTA;I,OC3FNVMC8+OK/71!42PE",$ATK@N"2-\[Q6%608(58@ M0K;-@#EG;72$$: $JXG4! G,9'3*L[MKSVAU7T!M+4\"YZR0@Y$$RS0JKA*@ M"4V4TLKDU51O8NI N^7M\ISUTPE"B$22I=Y1PKBS.9-H2O,1B:I^:&CG*CQG M=71"$5G(9+57SC.?$S;:%LIUL#%!5$Z3:=J2U3YG=71 $)X;ZS5342J-U$;( M_ESN20IU)RU7;77%!RCC;H;E[/48+KJ[_#(87S2S#Y-5*F@6X(]/D^GP'XLA MN:M='_PG?/#FZYO?QLWEW5=O Y'.ID28<8Y$1Y3&^4S++".5J9Z4MB[/?WIQ MA^,]Q,U)*",USH5S63HX\05*).(SJ9.JZS-D^TG<-S;B6@3ON8^,>^(27,Y8 ML%',7M0I5-4VX/6X G4!-YI093E@=\L-E9%EDY>5VT'[S.MGX)[!3>_H1'D9 ME G!.!D,HQ"Y^V)? XY].3HZ.0&\$!$P%P%/(B 6=2IG3P0/WZ^5[]5%6POP%9MF("B.S"8;2O23)-4UE.W=16^69O55BP_&X0Q_ MWA!^\N42R:RN4_T3_])@;^SUY^'%8'1W.P=7S72R/0HB7F+'A*"(863,O/ W M6\-2JG"]3+##96AZHC>!4*R>U\2+)4.8B.AQ#5:>8VJI9GXE62DWP+^_7A\C3X/I<)L048'W54RHX(0V62L(298[@5V% M=5M/&]'JT838T13S8"))67L?A% Z(D%/L3@VLJI$]42+_SP<;;,+"6<32F8) M5M-21P6_8]=G*=<%!+*-0_1H(OSOR?1RL#6_(R!4CU3R:'P$>&,T>$.([BP1 MA A3YW?$*8_0OP[^,?C[Y]G-5C% _SI%:N95HG"5U2HO8[UHR8+(MJ!M=DEF0[E'&N3$ M 7Q&;$A-A&%?/R>F[B-KXU@[FAP?)C>#T2Z[$80C.@MPYR(8[B-.-%K>;X!' M]0 3REA;]_G1!-D-O6A!DLYPOS/"E: !V)4',K@<=>'Q:=;^UV%S,QY<;:L4 MTCQF@G1]60#RPL& $0Y2C)($Z^L,X_'77O"1?[<>']D@"-:K2-"XUQ!IE!Q& M"A!;5 [M>#F,M:L/;];G_&3V&!A9@:30SE'J":B<,&LCU[0>5WXR>%<6']'(0S+=P+I_)F9?%_\>MC4L[@HBI8-\.N2FE<:4G. M#.!=2S+O2+G)M8O_\5\WM#=$S:6@U#)I %%GG?@J$^E%S3YUZE/ST__9P#,' M>"'D>5Y?9#@TU*ER:@C7%3V*:!O3>-3%OW7K3TW$$9-P4+(-)-) J%K6#68A M54W>P8Z5 EZ_^/6FDE-!B="(\X,'_7,L;5[@'6$]JYE_VCAKC[KX]W]=GQ;P M' "_I,IS2P8E9=Q<#9MA+NE_?ETB]\0Q%/A5>"&\ #QB_:<)Q56W3FA'F%T M>&)P"VV.4U%1)B(ACAF("*TI3S,.(L,Z(TI=8[..^L4X2"2 MB2Y0PVA))TN1ZV0_.Q +]"C4T9[AD-4UZ B'#F =;"^#J&<)K)D#D%TI95TG MPWGKI,M+7@0TSI(321('-R Y*TL :P--53[JF>FBXS,@Q%J&Z !:\ #_.1A6 MO4S/!\M5J#SR,]/&P4^(7C)&4C+:2960A$/[0NC&HZL1R\M#JU">1D^='B*= M!,1@I:.."1X]$UBJM#PSX-JJI^.7Y^,]CO66:3F8U^R4Q$HM?/V#L*@T4#BK M*I_Z\L!HZ&E4TN4YU$ 4J .Q,= LK4!7FI2P060DC M(.@J7/Z:^GK(-F"E0S.%O0AT-$"1A45>5I=89%9QSR3 MZZ,+F, Y11RK$R5UECI-[FI\YY/G>\\DG%H;'>&$E( @&$3X5#'/,\,^PU*U MF5RHKCU.=7Y>"CD841!#D^#H81:X73 ;1B"@%VA!"V>D%@ MRCPSZ]H!0H!ST1[@9,(F 134ET -YT:JZFV+FS:&MP.4H"[B1)@<2K30IA.API$<9.)V" MMZ$*:OH&-[VCDY1(R$)S9GRB/&)$4G@H@@^LJK+O'9V< %XX$1-)8# (AS\! MKC-1GEA\#,>V(7UG&JB65'$/!D*%*)59A5\X2+B>5P#PH-_T2\_^W5AI9W@.,XZ"0,P9F@B7,JK-].^@S M+7D6U) 0",Y4D\I1KJ,J'. \\5"]1+!^'GS.M8J52RJESMDXJQ+-3.HR+@GA M?NU&CF21#BIBA=",*R=Y!K\>D?P_!RS> X2:DA!M(]R/9(<.*F+U27N0@06M MHP8\S:E9!>?9U4("4R2(\4*())7RH;3))J=$K/S;B1:_0Q$K MQ/K1>!E(2DA!QYTP9;ZW8[Z&NU2MY14[A@@[%;%:B-.5#)Y';X2V09*,>,.K M9, SUV4$3)WR-N]%&89U)D;.ZR5(=6/S928K=BU@5\MAKP[GWA#"DV L&#A7X2F7 M1]150?*4N[%S$:LQF.+T*3FA4A *PMLE''+6"%$?*H!-1PJ8#BAB55QD&G* M("D1&JBQI2LOQ>!(?TT"G=:^6Q%KX@("O GB.28,R$ P# :6I',(.1:S<\LA ZPSL3X MP$$CY7%?>5O7E;6-&CGJXC<4L4K' M'#A?)20 .E2V9R69P4&8NH'[6*'Q/D6LD5L.NO@-5:P6"U>=M%$KZ9PD M[J[Q12=I6QYP3WUL-E2Q>B0=LW#DM=?6:!93*!UL)&E7CU<4IW*P.U2Q,L:( M86#@.:,6+$\TJC N9*'JPNV#2^8[+WY#$)^1MI<1J;FBEF:/S45W8Q!2/2'< M')JLWS)*$5M(-=X[D;7,E1J*,]K,!5T7 9L$7 1,443I$I?=#@^JJ]/IC&^(F4 MTN5Q)LNH@P_"">QIM'/PJE(CP*FDX&>!J> #<14KJ+TA-ZAO4C_4^ZS+6J!UWF>$P M/2\D21"XEUDB4CA2E_8^2TO;Z7V*&8"OA,;YM-+@ 2<63A(7O;"543FTC/5I M5-+AB8OA+&^ FB$)8\&L4KVJR!!&R/Y:>KMIHFL9JR;>*0C/A7)4$^4!PA6J MI21(R\P.20X-N'H1Z'BE&@I4:VN#ELSGDG1))J>Z/)D)3ZZ,1N MYU4T$'<[ 6B3N923+U6]GIA8/=$I/(R5NY!!8$RGQB.F*+",5)>MB': MJ4(UH=2!+]NG5LC!B()G[DA&J@,X/#XJ\!4K;B+\IPH(#\S9GUI!G:!$<6AW=F/T$H$M'N2(R0\#&H^>YQ":9Q[J, ME1_:I'YJ=70I8U4I>@CI)=,AL$ A4"LM MRP5/E>+FV_RCAY&:OPS$:D)78@ M,A74ZM(HC_/E6+W]_3J3D]>QHJ,P6:0 )%SAQGL0MX+,(M7WD*)?B]_W^ H M "*T1EJ71)!&9,-=F=_*):"C>O]TO^"H9W1#JX2 MZD\BJGJ(\(D%[-;FHG.D23+J0E#&V428+1/ B:FGF-.#B2T[R]/)P2?BX=3% MC+STU 3.8QGQD\ UN /'/RI35X7=GW*@J2)P852 2P<%\5?A2!"/>^K=P_= M3XUBS%:HC$DM[[$)SR9N\94DQ1 L-S7%RZ$4\IVDV+%&T;,8HDL<^R=U\$E2 M4YXGF72F,FW\T :H3D+L6*/HHR1<2L&SA-,4K#>%5 &?AV5_I K=%K]#C:+- MA/M,D2_$X^N3YJ)X%L&\KM_E#R8EZR3"3C6*V4?/N#7Q.*@]L%.TDQLXUBE8Q MGHF/#!D%!8E,%[((I'P,;3TW)Q-B]Q+%#"OW@A,FP:!2$0B'.#;!GWC40JRD M$.249 ME-X54B-BZT**TZQ]MQ+%P(1*=E[R#>L6$JZ$QQ)%G3Q<]7J('CNT:FMG&78H M58P>)\.J[ P+3@%^B"$7!CP3?MN L[ MKWU#I2*@.1'L_$4GTY2%SJL.7L=56]76J:W-IDI%G!_*F)$0((? /"B\O,\[ M,*-UI>*AW-;=%[_>5$+\'AP7++%L00+P3*F\J/&079WU/;2TN//B-U0J*96%"7)X]22BAR=G_J^;JA4M$K#%63.L02QEHPTB5#(?1-U;='\ M3N?F_6#4O/GX_F9R\7=\7AA>+I,+[YJ+9OBEN7S;3#],!^,9K $^^D#&A8AT MGI# U/)T]GEX/8.?]Q^7S? _?FP^#48)(OR;KRLP,?_2][>_PJ\9#J9?M^4# M \@,^(%E(R%,8XHD9/1SRFA*;K?[%Y^;RUO\ MH>F_;D$I/S4WGR>7=UG]^J--\S,$YG<)D_3^E_=W7_]Z?/%J:^H$H H@ \>C MQ 9/XY40BA+P5U2QU/)B41V9)U'@+G2O)NDL;6 2!W$;91/.T\R94T>8#74< M>18R;2G^30D<0(*@.#((!:2'(!]='(,P33M>3X<4-2'P4\O6WW%__=;]&-XD M+(ZZG@YGS6R' Z\!,I*H!,G99J4- _?$&'.1\R@T:REP.(X"X8LN0,;!)_C MRC*ZCSM6,0FOZ5N#/61VP.)Q=3T!#?YE.;J_#:#";#3^"0UT]?+9^W>(_FLLW M'_U7_&D_3W9C"H"S-[EJ[M+S@Q&^O;[_W#0W\Z?8RR%^UV"$/VPTF=U.FYG_ M^N WX_$=W5X.QY_:?^&]<_]6/'ZXAUUN_NL6;PTX\)L/7Z^;AYP'#S]?'P5V MGZ@M6PBT'+')DT!TP+D],=@0C(A)*MUZ%+@ZS4GPS9=&9"8A(G1"Z,9H*65BJP>2U9X,IW+=/"[O]]>Y+W@Z^XH?<;X/IY?R/OP(& ?,,%WRI3G*ZN1Y.O33.W 6^N[S_3WJ4OM.$V$>(2#\*HQ'.I W_-_OR=RC5&>FK7?P0Z;#BYOF_U)KC$L=$[4>PI>4C"2\ MU*OC\&-BSEUC"[#[>@S2WL[?\^?O3!\^#\:+(S++D^G'9@AZ>#U>_-Z."IT_ M^S13\"Y7>S%CH=[S8XH+B#P2S0I8:0(A@CB2A%4T@]J:E8[,L]3??L[@JCZ;\WP MTV=8@/L"P/E3\Q?XX3<14'D>#*=_'8QNF^-=G/L@6DJ)1"(Q\XV[OY6).(,N)7++G!#)^#G\%8X0 M0)(TK=U*]DK3[W,KY[]W=F)7I3Q")<$I4F?97"EH9*DI&/+7E!I3H4;GGXS]C!P?*\[\[?A MS>>?!M._-Q!ZC1=)J"V>2QN6 M%J_O[3W(?RD50Y3",R^%CD1SY@JU1H0HDZ[=4/J*VG]NZ+X;*DYT7ZTE5E&3 MF:&&V>@S*VS$V#'PN OG =+\Y_8>:7L/NJ\L.&^H%@*"!JV\RFE10@%XD^2< MY-H-%:_4$[C/;V5#CQ$%1BMHEA"IZ\"U1QIP6JKZ*5>/F<+O;25Y1=0_M_*T M6]G=] 9NDC;.80$*A=N*?K7D:>NFC;OM-:\8^^?NGG9W?X/=O?>)U19OWF$7 MK/;,*.-",MHZSWDA$)')&;L!.YE_.M?C;/%!SE4FSY@+$@+3J)@SU#FQ=*Y, M&+XIF4/X=[NA/T\6!3B7/\^?M=N?,_O-YDA"<#R:0,I1)QTU3I6'!Z$TXVT9 M!#XGVSC%+CU2R-GOPF'9',H885K[)#-XNZ@E -)E4:]6]D'5U&HO[+RZ]/O= M"]G[C3 D>"6DS#KJ3)C+*I<)1]'Q!XF9NYR:_+YOQ/I=..Q&1&U"HM8Y]"'* M61+($OG9P/F#GIJ[1SC+OHN]Z.CO>W,?#]YL)/8AQVR3TQ2\2&*N5"YQ%\^X=!-4$%]RHY(2FVFD6LLYY!=5@-SS%7=W? M/9I%=@E,7LQ&!IQ11'1Y .?:K8V- 6C3DZ0^OH_=.RP3&<&KV]_#-[0TR'& 1]Z,5O6NN!L,Q?#S WDU!N;>#$1:/;F\* MZW@;[\V0=-DPJB*G4@5BB2_4QU%$8^T?_OR6BI].L4M[:.5;V:[.=8Q1XXLY M(=DIN&W*N3+[V08*?X=-8^3[WK2_SB_\^JJ&_=[)M^!]"'2ME,ADY3,)-H)O MRR4/J))NRT:W"85="$$NYXXHDQ;352D:V]!'!9>';TJ16BN]F+^:<62>K0WM( MU^")M#H:B":Y9#*Q%%>])-H]+D3#,+)J4WL2)9WC-O7L4Q[Q"(;D"8E4.B-I M JM60):RUM6D[A5WSC^WZ4AV[N$03VT5 .)LHW$F@-=1I>O3)EM/8_R>;].9 ME(/!EG$7"!&>A\R*)1VBFQXHB G:0UZB@U=_30WF]U>+=:1?K]N4+=Q^&5XV8POW\%O MW1-[;&B@7M/0D*.D5B')4<#AJ2[$4(:G4B7:J4UZV9Y=-?'$:M\)2W16NU?$ M**L%XY0(;5C6Y0$(3* W[30BWY/:#Z4+6%-R;().UEA!8V*!)D!GA7=8"L(S=L*4:876/)B)?$_UXOM2_7',#;'214TA,(1_ M4[#P4I28GI"T[M3W\3A\!JI_-YS]/4^;9CZ@$Y#6LY*4R23* H=A'TNNCO,/R,\W;Z?!BKV*VSB@E2$V3#<(X93QUPAE=4@!*2[^^#U.\ MTL?1]R:5'&$7FMF#9"R8K.EP/!M>],HUL7487$A66$M3])$%HCQS)2&@+*G( MB_M7_$8MG+G6][?D0H#G!+U+QKG(H'*J5C5EBLJ*'K+F2/\NM-];JX3)-6'W/W7?X\F7*G'MH\Y:1:^%T:*, ?&"J%P_D7V? MVN^M).;!R>=>6J%3,A ?)2Z]X:Y43&KB*Y[=?^J^SY.OEL]=^_>F]<(-V/UR&.*QD)Y+I8QC*N8L2U;!L"!;.\G-G%6^OSTX OM?W3.Q MR>X?*V7#HP)DGTEPWD:(M3(6R"_/N"*ZFB'J3A/J4Q\#^1Q"N9!'LST\7#4 M325GL0M'R$8")LPTN.13XIY#5&K2L@P0_F75^M9H_LKT41_S=+NP*$=;()_Y M0^V'"7[HWDK M%HS<>AX5\DIW>3OO53F];LM&3KTGV1.:YBG1*!-3+(I@O2PR925Y)GC7 \7159T.5PK2LV] M;2TCX8_1;]_2GZMZ]VJ+T#YX:[/$%!LH-QNI"U\@]>3!B^-S4_%=RNY8F;-[ M0^Q-]H% H):E=<'*$)9V&^($IW&F&26/AYKU(5,OBMI4GHEL(2T3X0Y]_[Y' M?2-175J _G34PBE6^JR4E(R#YE0?BMLJXU-I\M#WU#M-ILRCYU1CL:FTT6&A MTI+J049-OGE-]G:;58C!Z:@"@L!]% 4=2\XY<3,<\R2QKB4,V7;0\F !1 MN2Y<2,[YB-95V,<<5:>5OD_E=R?"8LPU.(WF MLC;>[)[Q7@VY7W0?HQ"3,<::#S0''[Z:C.=Z:S'B\GZ&S]%L :&EF' D%64X M@6R1X0/ F]O( M,>UI6^Y2B5X$XT?N"]%^=X1U=;T8(GI13!QS U+/H2(1>\&XO(D'->\;)A5JHT2R5 A MGTBN+AM&8/6.P6T"L^M]A LF"E<-\T:T4='1OFR'/.*.(=&N"AR'!V-N':*P M8(KE\%FU51L8*OLYB=WEZK)C,A/E6)(LB\0]\@*R(IG-C+=2I0G;BMM;)9M, M;]"WO9X3 \]3H*UG>6M& MI^];0K2/AF:C(K7>@<$FJ=@UYZAL>QMDZK$>NLMY'FKJ=.F,YR9*(7F $-@+ M$O,=&3OX[Q9%O;1GJ"AQW/-$25).*:R> ZND:%RQ+WO//6\MW67?BIJZG">1 M G>194#GC!,)/HGPU73[D-O&G[RLZ&!4&.D!$L>V,JAY11,&]YY2:M(Z9B:NDL K!ZR3UVCA?$75S<7MV.X$LOY[QM^&73YC/\ MEN&7YO7X8G+5;,E_4Y$P8>(5 XS,O'""F+G.J&4\T@H'?@,ZNUR,[1R,W@Z& MEZ_'87 ]O!F,MN@I0K@1* !Y(;0!*YP27<7UT8H*U/.:TO1YJJL#]M$23HYB M,8$-]EQ:KP5\( D):-%R]^T=I7?-S6 X;B[38(K)T6T-C3%+ E=**\VSML8+ M1=W\KA'AL-OKVU/0-@?^H/>$9 6GQH"MILAI$64N3^XDRA9NYS.\87O!YAZ, M.)PGD@P#C)AD4"):$H2R4D6FK;#DK _6?CK;RXAS ((J.R*3$S$HGG@JW=S8 MC),K(_Z-G+#--OP!P3I+,1J&R0\%(1FQA&L\21#V2RZ4_O9.TL^3,?Z@Z60T M6C2=S9F8MC5'$^X@JA""1T6BTEI;,K]P*6704T5P_OS5U-'5N>BU]"J2[!V6 MJ1H=%PKR@"NC2=^>@KJX.N&\UI%10$74 7B,N3#O>@L[WWTXO, VT5*'_T^6V,4\HG MXC3)B3J1"#'1J1B,"0%":D4KQ\)4_2C>GPH_3T:7S72VN-3=2A"D)EAMG[RB M$?YG*!.%K3+@7/OJ=9_I]L>U!VO88X7_<=D,_^/'YM-@E,8W\$4/-N1&7U]ZH>7H_=^-)=?D%Z ML]F'B?OX<3@:PH&=!?CC$^[WHD"SL*']-/A/^.#-US>_@<.Z^^HM*H 8@=N< M,@<#G#1'&IQEW4NB09/J@K^49ZR!X7@/#2A#$>Q%8HT4'*R:*E5HB1'WF(05 M)[?J_C6PR08'8K1C'H!%S#ZIX$PL+1I$9%:=4MY6F-3'"GN[=Y1XG[B :,3D MP)('I)1+KR,UODZ9'4VBI[MW7,5(LM$JPS4C3D@7RJESOLYER.,[=CJK M(+'RP%(PJBI[[LMP#"98#9PH80>? 0B81[=8B?YV,IV+<',S'?YZ>X,]'!\F M[4F[/HJS#X_B!8TBL&S!4U$-,%JDQ,H[AO2I2J&^7'!R;U/7/@HY4Q7O%?03 MYR!TU2Y&%67,QN" HF7.C I>F58C64U#_ UK=??<0 C<@$UW$E^PE53:Y+L# MFGRMR>])C7L]!RAJ J Q;[142@HA(R_%-=DQ5N$29L5W=38[YF:,%IG&$(-P M$+DD9PTI3)N.2EM%+R_7Q6'?J#J[9'( (7M/M##,(7[A-D5;Z@>=S'70H,TS M=D;=>WL.]_>,&P*X"&Y\D($FL*&RM&A!E!(KA/R2&;-#8/8-J7B_M_H X1.1 M2,(@"81WB;"2Y#>>Z8I)S8@U^:QO5*N[^_MD38XNJ2BL=TXS(WA)YH;(0O46 M\(S]?7%M'3%1^5SZJB[_7T4& +D,@2@NO@Y6F^'NOO:K&A;RDQ.P0 MK)^K,CB1C&*P^B^7..&+MWR1X.?0P++/(@H^** M6Z0M6#6%$6M"513]DC/3_E+XK:IX+^@#2I720LQ#,_S#J/"K^H: ?;PU]&GI M(/V&M=HAU>&D9XIQ%<#,19^S"VG5*FQ351C[C*%/=S7N!7W@7F>>1%"<*L%I M%+X0HWGKJ:M?.(A\QK"\NU([0A^N? :W9+-*)F2K(_:M+9%D (!9O2W09QPZ M]D_D\ !%@B*-)I%XRFCD%GU^R1I)'>NL$>7Z&:/R3<^03C+'F-9$P]U4@=!< M6BF2I$9721]%G[DF3M]Q02#VX]18++ @VL0@5\TJ^"Y?(Q]CGK$=W$/%^SWR M2,:)H2YAA:?F26>Q+'&(5"135< :39^QR^Z;_N5!KYD1V.5B8H8_1> ZQ,*P M%'DR55_G=Z7&O9!/9"X ^!'2:)\38$FVFMKN@_.5?^&$/6-?W5VI'9%/EIB? M8,2I!'=8I\#+,[EWC*=ZNN-S3N_V3XCT@,O'>*\@!DQ*$6/U?+#]:E1C4"W( MQ_ =:E0.5>:'P>]AVH ;"(/I].O'R71.KSTO=FS7$%:HK+[ICE)Z5;WR\^3N M@]LR$^ Q/.6.RI2M"@%NZ!(,.NF4K\J[*_.W8?%'E?'?F\$4OE3?3!AA8B'E MW:%H_6WE6_-DV@P_C?_W[70XNQQ>S*D8MMDT+[.(S$?B:";@(92V9;"S3*J* MYECUSGHL/>TH<@/'=3!R(SA]8U#DE^:GX7AX=7L%W[9-=.=-Y-ID[8*#>-;! M(2G5X$RPNJKKS"3?8[.59\1RQ;2Q+F9NHLI+7C+A;/T.Q"OW]70BEZ_X2S/& M#?>W,W ULZV5>\9('DCTPC#AA&,K9J !(SX=3+\N;3I^,59[ MS[]P'SO:D7*.2!M)D!'!"0#^M5:]X6^+U M"#L!AI=#6,,V8&(@1E;!*I$()S+DX#7HDFH9.2>A'GS\G>GR=0==&A>E,3D& MXDT2GF>1">H23F:VR5:Z5-6[WO/7Y:9$C7(:+5,0)AFG5 3HQE(&=F0I5 M?OI;O+?KJM6[WEN3F6/9"@97UN)-Y=+A69.99$/2=W%O-^FRR[W5!CQFPG(Q M%Q)Q$5P(^A,:?71"UP4.3WQOWP$,7 RJF ^:*L.N#O81=[$M$JL_ "(_#7Y' MG%GK\?7/^?X#%,?Q!HY; ^=1,06QAR'9TA0RCC;:,#FMBG9WD_G,M+1 X]NT MI &VN!B1 G+.LR4E4Z@E+;SRU-#U6JK2UN>AI9:[=OA9BMIK#--4SMGG8*+E MV)82>)8VL0UG::NE>QY:VNTL)1(=H8J(Z"PUWM.8X2S!7Z(@-O.X_BQMLV%' MU%)''WCX69+&AR+SCR4HP1RZF MDCY/-B5/-EBD<]//46P15NDA"6+2-EL?X5BL*B ]5Y%OL$7/7#^[G1]!:&1< M0S"N/ " +'UAH\W$DFPV6*&#]#,=(*QZWUS<3HN7VQ>/V-1Y"2Q M(!(++9P&1(OKCT:!6W!5A'7R]6_A44I!BBRX8!;L-.9JDY*P?CA2@ #D8W=V M^/KOO3JX"SAVT]4,H#"9W;3>L(44=/Z)):O!S>1R<-.L'>Z9)5+N>[ @+/$8 MI18KI@I .&GMY6"O^'WSNN-B>Q*0A==A3HW\Z^W77P<7?[_W\#6O)'@[F-Y\ M!6V/9X-%.M9_O?^9E;T)GX=C4'WIX0V3*5YR_ [X!8_LSWV=WJ,;*3]J_ND[ M5HSKQ:?AQRR7&"=(.[%N&P!N:E1^ZVQX2;#X9O$WU^ MVW!47247!-><92:,3%3AV.6$LV_@O+*J&^4\=*7^C8;;J_*EH&0"H9])KY/\IH(^R:M2_6T7F9 3 Q#Q(YC@KN,7PM?O>1=&!91OY9#T&9$!"\J >*Q@AF26&^S8;9![/ M>>M9 \>BY7_ !>8AU(F20#GRT M U$E>&O'?2$0@#"0M#E+)H]\V$\S5BE09:SR!.R=1HB2G,F%B4*#O6N3G#Z> MTW4,R5O"W/OK-A&NH$U811U83MP#""LAH5"A;7H/MZ>XG$>?6Q2%3CH0(3EZ M(\4<=ZNV!>5UV_7L1_(Y%6>W,A.WL986]Z1SB9NV=22F!06)!F!B7-BK!L8I'D:CQ#KVPMPL,0M!BFB MXE3$9+F*%@*<0&*"P$=5E8Q,[7!I3ZO[XRI()A.0^(!@2W@A W'^W'++4XNN:9ZF6OQD)+97)6 M4!=E<$%#C&'D7!<*&9 VSC4Z8UUT;;G2"3 *22%ZY>?DX$K,E: SLZ"'YZF$ M+IU2(0JII/4R KBW<#V<*WP0 "=H/<6Q;N$[C2:>:)"<@8@3/"/W*2+YO;/> MS<!ZZV#UOR. ( M4 _B.O@7R]&# T'Y 5\[D1Z_TC\7^?=J_;4^TQ"#(BY$B8/:OQ9A M(WG(05-<0X(8:#ZT$ "T==[KIP?,)YRQED(06<%ESU1B=R& )8JZ2!%NNZL; MJ)^'+G;W?CI!$(R3FB%.,-3ZX)/%^6#$L2C2Q@&69RQ_5V).)W"&L!4N6^,S MW SAYH<@95",>Z:'H(O)S\PX:0V)+#FL#P*IS6KJ0*Q'=HN:VKFK)GX93Q]5 M:+X9WQOYL=WO77QN+F]'S9N/"RTL?L/=3Z@_VC0_#ZZ:NX+HM^['\"8A-+J> M#F?-#(SGJ\?YW2.:'B>T(!D?K)U6*22(V;$!%S"G(DG93;,+M^CN(#4_/FO/ M70# '3VN-,4S6[51[K_4V%R@*<<*^MGMZ ;\ M9YY.KMY.AY/I8K@E?.W;R6Q^%;LW6@2((^$X.^H(Q);8;%&FL@#<2JDEN-A- ML$ZK/KX6MK1K1$IP2@5W'M_XU )]+EA+M(%D]%UOM:I_V6_\)%;/EMOB0G?80F@KFB"?!MMR?8"R<$D$U/FXF';%>J4S*)$K5=4K5P^:I%;/(3^#U:P#&X3>Y MBXOI[>.*M&VN/'ML?);2<)L)=3")5^QTG636?CQEPD0A*CN/4"ZS646':*XK265"4: M7N[J^-BF111:W#0 MF"@,O)3E<:EJQJVCR]5BE\+M%*OR>@"G,7+-HD8T9H2(/'A=>'E)MF1O0-)Q MW:?0Q);S; T'A,YIA&MJ/%A:6?JPK,RIKB.J7@">CR:VW !/N#?4:I\@N'4T M,U.F]B1''%_'[74VFN@M<*/6*WP=E8QFG7#.3&%:IBK428E"-+*G(O9'ZP>J M8BLJT>>AABVWPE&9-3Z5IA2S%EF& M7-RYD\S6LY)WQ>3]JV'Q](T9NZ7CV1-T4CCP-BC+);@"&3/5*A5>44Y2#3IW MW_GU2^Q=PDW8TQB74<9M?MLC?X'#>40J&")/M4D:O&&(0FA MI;JPZG,+3F#?F.?(.OKP>7#SM\GMZ/+UU36(D3Y^;"Z0&!V^Y-W@IJ6U:],K M5B3>@1XR$QX'^H%_*(/-H\TA5=$[KXE ]UOF,03=A&&T2& E.;4Q6DZX#%2O MN-'!FM8/2VK7<.8)!-W(.,R\$ASV3R YKB$TA9(A1*Z0VC[68S<.%Q2K(!9C M#T:CR6^#\443FX\-!'CX\]QLUMR$S\B\]GKD+DRQ8^V7X%G+GQ M)=BS9OH%_GKYG[=KRRBV^&_)F$K)9V7@GY0TA]NXS"H$$>KS^;*NT-]Y<3U) MM.U)4R1'%.#,*(@*G%D HVH M-QDN32GO"#%6275;.>%32;$Q6R"]%=8+;J3A$()DEF.9OIBMK(SST8\4V/'I M)S#K$RPXA(_OG2*0%*Z+9(3#)9$I>&?*6$D;4CU6DE=YD+W6>01!MR7Y:08C MC8VQ+'%GD"RH\%PXET*%!NONZ7,1=(LE5X%R(I,$$"%LR=\TA_*D2 M6Z?>T;@*EKI7C0C-*-$.U#TO^O"#V?!A06Z: MW8#,&+NOOF/UESB<78PF^+U;9Y?#^359)(9/S$IK&5,AV\'JZ'6Q]T,-;93V M0-7(IU*-MMRRK#*$>2I)_!];J48;60%0UGJU=U;-WYKAI\\W*R[2GV]Q<6\^ MQN'H%CZZH%MZ(J R55#4OX#5]^"%O.@._)0'W^E(MDB1&W#D2 %^'+!@ M&Y^>KO-&G=;8HW#;*I2\MA*@K0T4=E#*8 IEGJ.9QK:]TS4[Z%,)M^5@(I&+ MT=I'P2D$B%D0L;QY 8MH9>O!K*QE9^$&S>P'=W&!::/9V\%7-*W@F^=MF3B[^OE_'ND3TD*80.$6MQM TJ^.5YM!"T M>_:'/__WT 2Y7UY M,[G^P5S__B=<[\OA^!(-NBAF-0S?#F\??-__.WQ2_^=3*Z M7/P@%\*;7W[^\/[%6_?OSO^87KB?XXLW'_Y7>O<"/O7NEQ1?_/C:^=<_OO[P M.KU_@;_W7_ G[;F(Q>('5]=_^G\,H^Q/+\K.OKA>;"WN&/AY^,#DXXO!U>)S ME[?-BYO)BYOIX!*^8#Y#-J,_OD!NK9MF MC)CRCR^0\6P,:_\Z_\D3/,,OIH/?7B"*F0[ARKUZ,3_8+P;+TH+1W=%>+?;A M$H;S9]07-_B.^D?XW9^P;1E_P[UO_>.+$7+MS6\#'+5F?($_#Y?07%V/)E^; MYF71Y<4$=3\L0]505;QM[ZJ#L6_P'E__/?__U\.NS![9Z/S8.S=74UF,+7P=5KKJ?(((:: M?-$L4P/_W]WYP(L'MV=Z,_S'XFOPVF+"'Z\GW$- Q> 6+N%(7RRV#HXB5A[] MCS]6WX;W9#H>C%[>PJ^833[>_(:3"/"X#<=E&/K=]H-1P'V'!:XV?OZU%_>V M_@7\\U^W\/4?<5Y@61?>45SV];S4"0_[Y?!B?IQ!KA>@L!':BO_QP\9CO6G_ MYOL%O_73^(>+!I>^RRDHFSYJ/M[\0![M.O[W_5\SGDS!03\X*!2_9O6#%_MX MT8Q&RZ_YGW\@?YC_]^QZ<%'^N_OYA6/Q:3A>+')P>S,I'YC.ES7_R&_#RYO/ M\-6@B%]Q_ZNJ>KO^%6_E_VWK6Y<=QH&_Z<_ J4 MGWLJGBK9(U)G[\Y6^9C,G=F9B:U-WOUT%T1"%K,4J9#4>)Q?_S9 ZF1)M@Z@ MQ,,UEM&KO M%EJ8:WI5:[,;C0/?U\Q)/_%^QWR_==J>X)DLZX@8S4T0UO.CR!_^M$ P5U6">DGDC!& M/V@N=QV;_;]X)9B&+%_7O:4Y6+OV22L2J@95.XRJU:%J4+7#J%IM4U%N9Y&0 M3'Z2F<=[XN3# M]#W!,F 9L$Q*+&."9< R8!FP3+JV3&?C15SI66;[56R1%JN7F^S'PO>DW_=D MON%[VD566WB2='..V=&E)$7A%8"AM&"H:9M] 0: (>]@: (,^UJ<&5KIIF>* M?MHQX _NA R1DU8A'I&U.E4LH($KX$J[;\H$L L $L[L-K85]K!_OZ@SDRL MO'[M<::]CR--SS7)8H*V$SW?T*M^YS+767CUW'T>B:V/+W5N6S?&9;U=N^Y< MULQKXZ9:30I67+>N;JO-U(\OX?B+YN,OS7U/OU0/?7HB+\=MC'JYSEVT=N/; MUMH8T?G#%@QA\/GQ FX?>YPY^4!_[RS =F9 M ::6*YLS7?.KI9E#\>:KU\R?4-&N>U_\N%0QU.TPDT:FB2Y]=;L7,ID+=78F MV:X(ADO2W?Q9S;7/DNV$X]$K&X%+Z^Y9LXU1I!HY->+#0M30CDZ1+"]S\H4= MR"=K"YJ#IX\UD-LTQ ^4J*O@.K5SL6?!@?VI+^N/_&J^PR_W7MDZJ:ZR6.)M5[.^B08N@B6M[3]ZZVVP\,IP2\-O M:7]\1P,R/>>"/J*2'=A+=*FXOQ,7T"@0H:IT)5.(!A./$(N$YP?RU)P_)LQ/ M?>+VS"?.GI(]"=9[5C=;?D!MC?PX3?QWWQT/Q21#\?Q]@:R-+,!;$&X26K-A1,PD@N9&]*(;T>=C-_HJ\PD+ M5V9]EC49MHR?N;ZYNR,UKE<[U:N[J_:=46TGZ7\OK]J=3KM4Z7\7\VJ'XU[H MV X/GAG-9VU= M5!*Y;%G5 MV'VDOWD1MV13W &Y)LKPN*>-\S(DM4@YJT]M'L8NV?,!_Z_C MYCCV.4=&.R:XXB931&I1H %H2&ZKUY!U>F_3(D/K)'V:\7?^G0<>_(A9,4DR M)+7\LG-14M49=9R( ; +.W :B$')%PP*UTP_F/@>.$?[/3O_+_\CT$8<0^^ M&/ABCK_9D'JD7 &V%3844?9/0FNK!/*62(HR2X%=2NO;6CZ?!\]6?CU;Z4TS M73_2EPLO0Q++'-% <.G;?S6:R6U_+(\=[F, (AIE$\D6/5S%J%1KVF;1W:59 MBH@6\*,&"_;-0Q4'%&+F!;=G$9?-,D?,\DQ,TE'$!SL^.[SGN$[DB/ RNN-. M\$_NCL47$5T]7W&7>Y9X& @17;L\#)T^C>1R$9@-DE)F95S'22GN+HUF(_VB+O-J=(RD%"%+$J^PN=P2+])3S)*FT$6RX,Y0)6J) M\T_(2T=T@6^']*LM!T+8%=9W@C"2&5F>!H(N"9@?,,^/Y.7/*M6#+4+"G;R8 M#83]*#LTU[A*#N'-WS^]<9(30C7H33XER25(>NK3Y.)PW/NWL-3/0QY&U(XG MHD@^C#\&0L0O0BV%#KT[#^:_/:4G4PLJ'8T[%FA_1FS/6]1[J8 M6Y9LDL34IW[R^=$(7\\-@]07!TQ]83;V3'UA(H-%5N[#"V:EHWA!O&":#\Q) MAH1L+0L@G\W7FX:!-":H9 (Q$'^ M7.(@:!^T[Z#:IS5^!+H&7.@<= X:%R*)QIV24EBY'>EKVZ[\P-: MZWM)"+VU4$85#KO#D-K>D3;Y/S:9WALC0P"R90#]0+^>5ZX9R'T+_ /_I<6_ MJ:T8!_ /_ /_.<._MEQZ0#_0#_3G#/UF35L*=> ?^ ?^S["RQHI =< E<:L.ED5*65. 2 MN 0N=\=E';@$+H'+S.'2U)8F"K@$+H%+;7:LMH@8X!*X!"ZUV;'ZRI*6'9?[ MEBUMY]N7K3(J,*XU!0 8:QO,::K0E UU.ERMI?SL+!ZP9%)12!D, X8!PVS. M,#5MD _ #EAZ3Z3O7I.^._##,-6BJ-@;U9'+J2BYFFJIJU51 M& NX JZ.:?D#8 8 (:)"[@"KE(\(JCO$#)P!5P!5S ( 3 #!-7AG!5\ECV M.S\0U&RJ3E8PT.8,E#.BJ6G+-5@4/@$82@L&4UM:/( !8,@Y&!K8Y0<8 (;$ M3$+H.\ ,,2W&=I*8@$, $/.P= P 89]'7(E"8;TAT/?=B+$06:5>LI2T]+0 MQEFEKVD)7 *7&?0_ I? )7"IS?NC+SP3N 0N@4M-N$RI%"=@"5@"EGLL+U.J MRP)< I? Y1ZXQ'R9D:!3LYUO5W;7C[C+7/U%DD!;VP /)>X*7N*N7M<6=U*: M$G>@&% ,*&9SBDEI+Q , X8!PX!AB&$ZJ-,+B@'%@&) ,: 84 PH)H\48VH[ M] "& <. 8< P2R=)])VK*@W%S.W#?8@XO>'*Z^?^GGLOU_'$V4 H(C',ZKN? MYE[4$K)$Z-HNS[6R@,$J:9-JQ?&(7N+/\X_Q_&#(W06=-.0UTX;5.S!+N&YR MS<>3ZHGZ3 -D33ZO$'+7&8J0?1%/[-X?\B5F&_+@T?'B3O)QY$^^B&E4??/D MV-'@HM,Y;U<;U6;;-)LDE';CW4292$E2/GUXJQNPMYK=$9\K56KGW MO<&NJNK:QY-&\]V;>KL(DN1&X\#WM7/23[P?WB^]YVT7(P&;$/+93#[3[K;V MC.M*.7QKR8;8PT!4GYYB(Z+GNW;4'+H&5KM6SC M50HF $P J4*S=@1HOB'+8X/U,@Q%A'!,*-LAE.TS H"A<: W*%LQE6T'>DLK M]]%!E#/%U$A;I0655+)-N$0/+)#,)7#V*7Q&+XEO *X%&LM M;<=O=A=74>8"T!AH##1V#!H[9"HMT!AH##0&&DMEIP4T!AH#C8'&BP:"];C+/4NP<" $T@7DD>5*XWTH@',!Y^Q ,: 84$R* MN\E-< PX!AP#CDG1C-%W;@$4 XH!Q8!BEBBF"C,F/==7@3U64J[]%4(IBQT%A@'#@&%FIQL, Q0#B@'%@&)2HYB4BC* 8< P8!@P M##%,"T9,5DI5Y-RE]36BGR8Y/$(6#7C$!MQF/2&\"NN-(\8#P3R?N;[W*((* MXY8E'6#"9GT_8#R<.RR1W"YOB'QJ0?K*2*HR5PA]IG'S2 (AD]2J,H<$8L@= M^1V+1#"4X37R6QZ&ON5P^81OWRZUZ7EV!A-32WG.T94@WZE1UW?0KO3Y3D%C MA:"QY&GRUM1,JG*07"J2U$Z!:56.VT:8A] Y$"0($G9>2>V\YN&<#K#S0&.@ M,=!8&C2&*D.I.%4_1)Q>?>7U*_[^^0,7X<6LOL5E&(HH_.SPGN,ZD2/"R^B. M.\$_N3L67T1T]7P5>R@?9)+A:Y>'H=.G 8DN;_WQRY__]+-J MV@DMZK_CC87]=20"=6EXZ=GWPEJX/?SFNX[U/&V R=OHP[WH?SRYNS&K1N,? M]=^[-R?,L>D+;D5GC:K9JC=NZ\W.9?7FKGIYV[RZ-JYNZYV[NWK=N*Z?_/)B M".>'H^L,1CJ=N]UU/'$V$(J]#;/Z;@%M;8*64A''LV6YCYK$ MFB8=41^?X@?W?->.&[KY]'#]]4OWTY??;F_8UV^W]Y?=3U^_/+#++S?L;[>? M;\[NOMZ?/5Q^OF57OSU\^G+[\'#[P)8T:O?I0L7AL]M^7U@J1<__CMUG9E08 M#56]HES(U_Z0\/3,1H$?CN*KZ!)N^R/I5;Z,/=C2[_P0<<_F@1VRWT8VCP0[ M/;E\^.WD/?OBGZOVSJKMRMY]CS_*RR^D*L DE]>: MU?<7[%Z,I/^=WM.>0P.;P4'=+)'B^N&8>B-[01]'?LA=]4$*DD@A.?S*/79+ MC43/6@:SPIX&CC5@(3&;0J,7T2!9 ^[)<[1R&$>!([<89L/U.'9LE6NCQXA M'DFZX<#I1Y.M$AHBZN23X[KTX;N@46)#_F_Z2B@%E5V=-OJ7<*ZG2OC]Z9C3 M<\8N=4+NG@1JX.B]Y/;*NO>\'/K>8T@/4#LXL=S""R9(%ZC[0T'O*G.T?Q=A M%*N2ZO"3"*1@Q7?''X#,QHAP<8C*4"+ M7BIT%%"DU'IS(G+6JL)/ZMJY\7T:R)>?#7$@(N[0F\UI($L:DF])LO/=[]/* M2O'=+\9/G0>7UG$8JX \_DV]$ZXSI)%5NV2!/R0E>/1ED_-WT_^205>*-]5* M1GKFA33/R+==$)LM2%V<"5VL5PR:'.2?W'6?*TFWP_%PR .U%3EY2IW<^<%6 MVF[[:D2VE6!,(3$%Q4A9I?T5=O/M\^V]TH._"V)C:C@,.3N->8W,PH&$H6KG M;Q.E?I!*/=5_4EYI8,34+J^[#$C,],.O\F&DG!7VV_G?S]F_Z'79:4+YD%*4W8\.3HS_"^.ZU7"=B+4\CY*T?OC0!&\X]&G MH1JU\U?-\RP8CHE](Z=OHH-% XVOT47VI"AQ"N$)#4V,.05HX2AA3"(4$IV7 MS?051U,3R[.)DJ.:3922*T*<;]EVXKP=XLO$X;B-\.3KG M[$I0"PMR_4L8F]P)VRY99+%Y1QUQ_-FLI.P3FI@7+'=)PF$<11*(OJL&25:> MF<*-B%V&D- G.[$IUG+[G9R97DP3,W7:L!DEL475FNO,>#I]T)I)3IYJC5%) M9.E)^D M\-12^GSF9>O*^)K'QT \RL5.+/-I6AO5F]FU3I@DLF&]9]4?C_ZD?@:"TVQ/ MKVV+Y&_'BQMX.:6^)J2)]4]/F1DAB@!",>+2TIX9#1.K\IHD+\]B*@'.K9'D M0D4^_TZ^P/GRE)1)=OS70*B5P8S_G%>Y:W%E.RW#%#*'OG$"Q3>2P+R0+G7D M2H:,/Y[8V_."6V'6,5(TX28CHHRS1!]ESEM/#FC@NV[,;@00TC<2\]_\)[I+ M1H11?QZYU,J N3)?4F)+2I2Y8@+_-0:NLU!22BW2Y!LOTHC_Y(F 5EVCZ?/) M1E,+@_7\(GNQWC,P#6B33^?T/HML-%F,3=!*9#!O,ZT?I3>T[X7[:U)(^Y4@2E:S_=6C5L=!0*-XQ4,G_,WS>Z$(ODOOV2=O-([N%PS[1:_: M)DXQ\[)V:5Q6FU>WK>95M56_N>K$3K';NXYYW2R,4TS=)XFT3YCPGU3XHA36 ME,C4NFY>EE([)7G.I97F:I@40[JSL2)K/1XL"=P^#2[[+D=7^1!DF_'PL9X< M/R:I]''!"AG/#2DAA<8T9*>?);1GK%Y[/\67-$!"6@O+:6=?>S5Q;R=^;R5Z MFA[\6*4OI&,Y,:"%)88]$1K**GUZ>S*=!+YMOGD5C* M1,ZH)5?2P?MSUI4I*VBQIH5E,BB/\VE6DQ9]/P<&*VT:A/_IPS M]1)3C'XC-B3]'2GK,'%2*/,O<3--_3Q3[8O=!JLT<)Q8;A9WK;&DT\0%)&AM MK_0[Q@BW_SV./56[+V_FMDHL*7L*'/+@T?'B3O)QY$^^B/=TU3=/CAT-Z&H2 M1+(SI1(5CD)Q,?GCIY>;2;-^S\?$SS:DFBN3>FP05J\Z\_&D67WWYE[7XHY; M6W\@BE(.S7!;PT([9V$W%KK8@_)8LS=D^SO*X@"P0\0>=>T;D[ M/Z"O/'9-:R/A6*H\\K; MDA!"Z5O[7^Z->? \4U-MH>T(+]XCJ#W[T<.GIK["(J7.)(H#$"D=@ !%9J MS*J^%)E%/YT C@''@&.VEX6^P^Q@&# ,& 8,\_*V;79*KHP M9*Y./[BS2\C8?Q)A:?G@LV?4%_H#_0'^@/]"># M\DEM!ZR=;W/JT]PY[4D^WEUT[LVZ^ F2;?68T$P9W3T54@N MNG< P *P,)EA,@/F,HHYHX/-M .YNHNT-DMR>LF$'V(@O# ^_TF?!3M;.$8< M)WG8)@IY8PCF#&FG->TQG&6>Q3!9%18IKZ7)VE%;BC(% 15 !5 !5 5L*IV ML:JP[[3GVJ:?'.>UDN.\<:XP-TD1D^)JIR@.!YP.@!\O0]-=46!U:E3U576' M]QRH ^J.LR;#M : 6#3::VSG,$2L]HAUGV%7=X%XE%F^?2#9W8:9[E]/Y_B M%CX5>!KA:82G$:@ *H"*#?P.VH)ARV"' 2E "I!RS)VJO!\X?Q!1Y,9UA> X M>"4-5?I^@[)8;W#( 5>S6:P%?QQVF8"Y0V+.P!$-X JXTHZK6OH1$T7!5=FS M?$V+V:MJ6E'<#FD$C>\JNK+, M@/#[ :!;+,GT'5+<5V1%GHP!6H 6LRIF50"T# #%K)K5)>[AT7J0&LHWPA+# MG@AF\-67*V91 VND@;8_[KEBKQ+?V9"@OC)@F\HH^^7 3FM5??&DFXJER"0% MCS7X!_RS>31[2U_8[5M2*7++$#+5089CZ+ Z8TC+A4I\M7UUH![CS+[ZUP1 MYY=M!T)F?_4>Y3U):+BL^CP?.S$0KBT]4K))0;_Y_;G>9)I.2U.R_BWA%:"F M?>H[9-N(K2Q&8(8X%]8AZ*Q =&:T#^<3 XV!QD!CH+%,G__:7UI%7BZ#X4WE";\_I]4*ZJE=?/_3WW7J[CB;.!4)QDF-5W/\V]J"6\2 1K MNSS7R@*]RG:E36]69CR?-ZKLW-741+\F-QH[W MM0[\O(/?=VB!'OJ^9D[ZF>WWVVXSY6@;O*E8-.K34\S7/=^UXW9^IPF*W7IR MEV022,MJ1H6956.;?;SI^]3V#(-/0=BO"WAI1FSM)N+66A%_D@\08<3N>21T MF4A8KD#G7M&YNZ1^Y752OQ)J![4[@-I=^\.A;V]7&A7Z!GW;5=]4%,@.:VI$ MTJP\2O6_W!OSX'FFIMJ3EL$YN(-+.ON^OU.CJF]_ ]L7V+[0OGT! BHT 760 MXQD4 XH!Q:1',:@T!(8!PX!A4EQ%H0AZ!C+CY#['ZZJ34:?38TWRT-+LE-/[ MBS0\D8?Q-!:?NPLVMT%_H#_0'^@/]">#\DEM=ZR=;W/JTXI#Y+OH7%FJ[9EP MD\!-9EHL^"W;&;&KA.X_D=]RB_VP79[PQ!'.&M%.CH00+(JQ!E24%A5D::$*%LGZ MS3(/L>^EN@0JCA<"3@AX][(SX14%5Z=FXV!Z5>09$J #Z(Z:V!VS&@ &@$W7 M=^D'+Y5A5L-^UG1Y%XC',:W7_."9G<958][/EXR!4P6N1K@:X6H$*H *H.)M M=YXV]SO # # 4#0UK[37D_$?X@HL@50^%%.+GT6FGL*MQJ<*ME9SXJ"JZ0 MU@1[1<#<@3%G8(,6H /H#KLBPUG"])9JA5J1=64<7U\$(?/[+-X78J=S^T+O MF>-%/OLLO@N7;1/#5E1G!_SA< '"!;@TX6CS6 , $/.P8 I J@ *C!%8)=( MPYID5; :\\>1_"W%59- !0 +3Y ,6]F9(XQ'4>#TQA&7RA+YZGIKP+U'F3!UKJ3QR[8#(1.F>H_RGB346M9 G@]L& C7 MEJXFV:2@W_S^7&\R39BEJ>[^EO *4/Y=7_*QG855%.[%GE:>K#Z06'%(S-"8 M10$T!AH#C8'&CG)^/CO2*O-.(A@.# >&2\=0RP#%%<50F_/U?5 .JI77K_C[ MYP]L!D59=\= )?_/\ M7BB"[_*IG[S1.**??<^BNU29H*[\ODNBNW)]ZX]?_ORGGQ<>^+5_YWB<+N?N M)R^,@K'*$O?%CZXY/4+8E]'TTL66:+ \.2+WHO_QY.[&K!J-?]1_[]Z<,,>F M+[@5G=U>=JJ&>7-E7EYV+INUN^;E[95Q=5OOW-W>&8VJ'ZVN,Q0A M^R*>V+T_Y.O9=NYVU_'$V4 H)YX):_](8'D^2\AZT^&;IU?,QKPB/% ,,^/V#!1(.GHG&N?NA:W MZJD 2Q[1%9/HNX>!4,VJ(V%+6-A22@GR$TI08V&3J@9*32\DYF)!3N+]9G-B MS:@PJ6#[]D UKX1TJ'>A7B\G/]NEUQ76&T?*3?XT<*S!P@"&S'9"R_5#89^_ M2EBO866.72U261%L@K@%&Z+Z F'R\_QC/#\83 MZHGZ3+."-?F\/5<,>?#H>'$G^3CR)U_$9J#ZYLFQH\%%IW/>KC:JS;9I-DDH M[<:[R=1&X^WR42@N)G_\]'(VFKW%_%[/+#[<6!F4O<%VD>K:QY-ZX]V;D^7B ME)W<:!SXOG9.^HGWP_MEN9_9?K_M-K<14@/Y;":?:7=KB55=_2J9Q9*XU1I!HY->*SU=30=(#A\\@7 M^Y;F&'7^3TF;+7WI;(I^"!H< XX!QVPOBUI=7^8_< PX!AP#CEFZ+87">> : M< VX!ERSM&;"D@D4 XH!Q:2X9#*Q9-I4 @^6CQ5,\N/=DRR*1@98P<.^@/] M@?Y ?[(I'^@/] ?Z _W)0032YB?3C?RN3=1M7WSO+!"6/PY"P6S1VR9]&MQ& M^R+US:R".H6X16()[8G^&Y56!^X28 O82@-;G5H'V *V@"V$+ !@ %B. &;4 M*LT6#$-@"]C2'P-3,9LM0"LU!U&A_$#W:?B P#J;LT[.R*51T9BULB@< CR4 M%@_U2K/3!!Z !^ A+<\)4 %4Y!P5F"6 !^ !LT0J_H@,.?^.4$IAAJNDIL)R MT6LX59&+-RN"RXRPH''0.&@<- X:EQW!0>.@<="X[ L.QYI14R$3J"PC^* _ MT!_H#_0'^I-9^4!_H#_0GTPL/K*W!D9-!=D*:BH4AWV1O&_+8(,CY@=MX&0$ M. 8< XY)D6/JVD+]P#'@&' ,..80 93@&G -N 9< ZX!UX!KP#58.V6<8Q"% MA.(*V(HKVF0%_8'^0'^@/] ?Z _TY^CR@?YH78&@N +<1L?.E5&4/)]&H]*L MHMXML 5LZ<=6LU*MMH$M8 O8PGXB : Y0A@AEEIU#!Y 5O EG9LU2KU%M9< MZ3F("N4'0G$%I$7=1E\:%;.A;=XN"H< #R7&0Z.AK4@8\ \Y!P/*7A.@ J@ M(N>HP"P!/ /F"6V\T=\B&1ZF)77S_T]]UZO)'/9=\3^[[5_K[Z;>@EF"==- M=/#C2?5$?:81LB:?D][,JVU]E"3>27K7=88B9%_$$[OWA]S[B:T3_RH_SI-C M1X,+L[X)(RQJW>87;^U*VD9G7QG;%KW\ @%4Y5MN/]BM>2%J3QND+_1/=D"C MZ/:15'<@0L'XBJ1.H\#Q+&?$7?>9OG9Y)%CD,SZ,+[3'@O4#?\BN+W_]]?;A MLL*B ;5C#QW/":. 1W[ _+[Z\FG@NR+DU*1PA14%CN5$SVS(@S]$Q!R/70:/ MPHL4G:V[UE_$E>?>%$)'YK&CZ6I*EB7*7674AB M]97Z'>SY8/48^0)*,"3@(0WP,ZDXN_:]T'<=FT1JLRONDSIK:S?LT,[%5+%<$2(=KX+]_E31]0R'A)HPR]^=,V#P!'V932]M"N;ZY)M=.7ZUA^_ M_/E//R^T]& -A#UVJ<7?/+\7BD"AZ),W&LOV/ (6,0(!=+$9XF9/VEOWHO_Q MY.Y&#N<_ZK]W;TZ88],7W(K.;JJ=>J/6N*I>WM1NF]5ZS;B^-:YNZYV[V[OK M=MTX^>4%H;]F%:PS"EZ;#^:MCC;-G?/Y_VKFZ,?:1GRJW>,MDGK*I_ ML2QM8?DTJ1'A7$B+.!;$,UG(3'B2="?09QH0/Y/TQ:N8>DTAYA8(%HE'!)NH MU9()-J]&\O/\8SP_&')W0?.,!;-M*[-Y"T"0GCTZ7MQ)/H[\R1?QBEE]$]O* M1I4$T?,#6P1RZ]?EHU!<3/[XZ>42:K7Q/;/+C)6KS0V,9]496@ WWFUIMR^KY.3?AJM S_0K!_Z#;<;BIV2UL)'!?ELZL-[LWY-S+6))(S1#Z:6.6PR MD^IUZ2W-:]JS'4C#<28Q94)"K0X#NTU5Z2A9-M+7/*EKRMID76$-/.<_T+RL M:9[^/#_IJ]7\LI>I=2^T*EM:55 ^N^?>HV"G_U+?"WLFWTL2%W\4[W=P'L'& M!7@/;^.F(*LMP;G'CL]J<)XZWDQFB5L]W!B14"[(!_*!?" ?R&=_RU/_Y/8_ MR4BQ)KY]L<_KOC!KZ/790,KU6SH2C:ZH^D]\:ZCTCI2^%2E)-1@'_> MY*,/#3=.J,YO"%J_\W# I-3S*Q?HS:'TYM+SQMQE@?@NO+%@9(0^18/\"@:* M<[3Y^*S=?B=/\#7?L=.SUKMT0RZP8,)*$X[OK @N,\+*F\9!QMSD2!)+3B*Q:S]4^4>N^4CFB\JOS*!31[,FF^_2L1\WCS/.>V#% MU;C?YZ[/_LI'!5S(9 Z:I2LQ8QBHW01@P;62KT"'# D,FG9T34LU-")#$H.J M9<_"/S-C=W'G'3NMP5U:=QS-0W N5.]H$18U%5^!5 ['5SC(!QYD MZ _D _E /@70-IY$\@H5,EA T4'GLF<]&^:A(GESCLZNCTR#F5Z@9D--2EA$SC1:NEZZ M+!$AP#_D _E /I /Y)-%^7%T,R+N>L,14#7A2RB MGT-2?*=/(*#6QW/R98X2,!N'PJ8V G7Q9_%=N*S&;'KB=QXYWP7C82CHLE/7 MX3W'=2)'A._I2^G*6-*W+5\A67@GWFTE*%M8OMPT]+T+:9"&:: M7C,J3([^OCU0S;]^6/.UL9XS4BT:7Q%LHC$+[%-]H2'R\_QC/#\8,PMX;K)-1]/JB?J,]&1-?F\O:['6[9Q)_DX\B=?Q/RGOGER[&A 5Y,@ MDIT+&E"7CT)Q,?GCIY=F_*S?\SZ&&7E65VY";."F4)WY>%(SWKW)RXLS17+C MH>]KY*2?]?JA.WJ8!^ZV/?S&!EV6/&*MW>86>9OZ]!034,]W[62N>1X)R?HW MT[D!]ECV]H@/LQ7\VL2G7?&DH+I9[HW MCUJ6C^DNA_*HV$RL_MR2YYY[CZ\3X+%Z?3K)6C7K;)*^"B<_X.;*!MEDX^3' M:[!L[B:@YGI8.MY,9G2WZ_A>N#$BH5R0#^23#4NHC.&]J26&.82JS42P;_3% M)SE+B#!B 8^T+7\S)*EL*5T:I)5R?I3,1#2]J539#W4ZK57K!Q/'#"^YB7[3 M9CR"@+857&$GN(=Q+W1LAP>."&-YM4VC]1.S F$[U-@H$-P.H7C']@BGEO?L MB)&MY^WVN[.V_']VVCBOFYL?+BU]4K0\G!;0IREW?B#H/9B,9Q*>]8STWH5U MT65./M ?R ?R@17%9G%2R95+2 MTBVQ6F;$ 66TSAL&.V.UQGF]SD[-YGFU 1?4@5Q0>;,_;\>!-JL39+.!<;FK MT_*(!N2IL?_^Y?QKEWF/$A@IJ#-_NN/X_)=P<9L1JI-=KV-&3#:Y6ZA;##ED MV12SBF5HA:1/7M?^<.@3T>C;.3+E\+RSAJ,NWSU]^W;B^OJM=WIFFT;ZYZ5RW MJZVK.'_YY4VMV;HZ:/[R]NA%_G*9>EKG\,K\Y7$&ZYX@#9*5@T-Z4)RYO!<( M_H?M/WDRZVQ_(EP6S*3+'(]-,ENQWC.)=^Q%P7.2GERV,:)'^[:\T";<1,+> M/=GW!L);L[G?.F435JS7K#-.M&R]27Q;NS9Q+O9CLGR;&-6EXZ MFNT7S$GZQU0L>/5I*7G?I.0!JQD5. WUFU3Y3[.M7>56UM. JD'54E&UC3T^ MN3^"G)[?9W*JC6,UGL/]N-)XL//OH#9KVFJ@%OY8'C@&' ..V8%C6MH.EA2> M8W(1QID>;*[Y4 2^[^U3@'&AW$ X'KTBNU<\H8U1%._@&O$>)#6D4XD;/80\4@@/7:6 M**BJ6(\ 5\!5#BS?P@.LY O^JX#_U]%VD &D4]Z#G!UME(.3G !3N<&D M+URF+&#"L<0XZED>2V2N+WLK@N'JV&:L/8Y]- 7'%E,47A%V;#O-XXNK*%,# M: PT!AH[RII08W!;Z6ELZ].'FYTXVW>,_^^U?Z^^VU:'T.:5OCXY*KCF4!I; M)_Y5*X/XR)HZ?KCE>:2T#B'1*VZCLZ^,;8M>?H&#F_.' #@"5H'\F3^O2J-!G>7 W=(C;>.3XGJP?TQ/)8DW8\A2J M636:K!_X0W7J-.2$F>0$ZC18JS<.Z4W",#ZV*H] G+,K[M+*3S G),KA8>CT M'6J/ARP<^$$4KP[CPZSS!\+DS8US]B $^^)'@IG+^=FV>_GXD[SZPJ&EJ6,M M[53<.&$LC3'U[^LH$41XKHT7D]/7;QZAGAZVCDNR7B>E>V[HK;Y3G[Z+\.JY M^SP26Q^\KK?:-_6KQJ5Y/BC8/=BR!U/ACQT13#<@Z_7/U,/7YL[\346=EC8 MI3K)M8Y[[FV),?;PO*]&[^E<:D?4="TLP@ZN4\^"!YLK5*X#%@NV]L^09#.' MZLT7/T@5#8V#QD'C\J=Q$-PN@M-@P>3ZK,4D1Z9@WT3HIZ9NI=>S@V2O.[[Y MJSF\>*T:93]LV*S43",]010E(!A, B8!D[Q^CC;%S)?@$?!(AB66)JHV3M^4 M:R>G/H'%258<[K%[@:JQ!_4AE27U4QLIU8 KX$K_6C2]A2AP!5SE37!I)R^D M6S<&W)Z9^W)G0SJ1$P[8-ZD'QW1X% QY&\]H>9NX3%U*4I;Y"6 H+!AJ / MW0TF86 E: 5>X%E^8X[K1,^,V_\>AY&P*^QIX%@#]B@\$7#7?69/_MB5P:Y6('@H9('CX?XU@+65 MG05"LXU0L]P(E>7 @VGAHTAX$HQ]YH\#B4M50,&:%%"P9P44V%-2/8GUGE4; MED\7A2/?D^,[!;>".F%R_LXAC\9T*=U%!L_C8#DT?8<7,JOFI66-AV-5&^TK"3FX]HM2PS>B.RZ_7 MGQGW;":2X:+?IU7O9"-B,GAL%(^>Q.$,.-1&& 7CH4(MM?>?Z<@RBX:6R<4. M&]#@RF]4T[)_ V<4R@Y;[E@!DP]ID:%@SR/"<"#!;[D\#)V^0UWI!_XPZ:E\ M2$07A!$3/T:DEYM'MBQ(3'/-%+:B40JZD#WE 8HL[R<>1/_DB7E.J;V);Q:B2())*@C2_N7P4BHO)'TM3V&KC9^9Q M:JUT VU@O$QJG>>EZGPS)_W$^^7[__R]J! M[);,!YO="$L,>R)@-:.R]_(5(2!+YHEA'*&,=Z:*=LNE:3@3XNGG9*ES/UWJ MS'YTO-G?Z 2WQO38?HJ>IVL9BVU );KQ6M:!\NW5FO7 MAXC^$R]/:7G]E5:#\4(Y#>D?1KJ9TT[PY29\N>AT>4&5HG:EEAZ1-3W$[ H]S((>9FSJW5QV4-+R*.G&DW:NSP"FE\__ MTYKPF&WY3HZIMP?&F.&9X24] FG7E M/0@(! 0"2I& Z@@0!@8! 0""@U01DMD! &@@H)^<( MBT\^!9//QC$GAXGUS)Q\H#_0'^@/] ?Z _D9!<)D1%C0.&@>-@\9!XR"X[)C"7T3$Q'_&LO"-X\U*!OA]QOM]QW5X MA+/$F5IO%J48HCZ/3:D#3( Y8&YSS.'(.C 'S!T6<\OUPH Y!%)F8H4#^2"0 M"?H#_8'^0'\R*A_H3Z[DDYZE*"M<,-]3H9/2/>EXWT48J0(K^157YM2IL&$O MVK/A%GFQ!:"4%BBQ,-JF86J;AF /FCK0G@(H/ !@ -EN_P%.'(.&,KET@'P3I M07^@/] ?Z$]&Y0/]R95\TK,4[_Q 4+.S&(LHX%[(K04F*D:,LL *0 *45&BKY0A3(@!9'$F]FYB"7.&#MI5\4C MP[0=0E0M4I^;^AL!&\BBR>0"X 6Z;J11B6#"9'1)=>1%;"F#[78$B&=;7_G#HV[)B M1PI>?S!/8;<>Z]K<^$7A$8"AO L4"# !#SL&@S?($%DJ#A8S))\4*>;YW M%HC'L6%MN"RA284FUKBTD%JP*,.0<##6L/0$&@"$)_<)AB;23 M.F!G!5M21ZQ/[P>V"":2,$8_6.B[CLW^7U7]0_UZ:"0T,M."A49"([,E6&AD MP05W* ^FY8>1+* G"^GAL&"6EK$'I<2CGH'6%^JTK\B*O'(&: %:?: %9H%9 M8!:8!6;W\U 7+1RYZT?_<_!9:1? M)-H)O*5MJW!CJ129J4$_H!_0SQ;%EO3%[8!_P#_@'_#/-C(Q:IV#205QA: 8 MR ?RP12%*6JK%7H+%C(L9- /Z.=(H10-\ _XI]C\DS0JKUC>>LR&@F6*G-*0 M5PJ%,#+N6\R!UNVR1?TAXB2:E=>O^/OG#UR$%W_ECO?9#\-/WJ5EC8=Q).G7 MB/IU[0]'@1@(+W2^BT^>Y0_%I6??\L C:89?O=M^7U@R0]4W/Y"97[_V_S$F M4?2?Z>=K'@[NB-G^)NQ'$79EM[HDJBO7M_[XY<]_^GGQR;,V/WEBQU9IH#PY M&O>B__'D[L:L&HU_U'_OWIPPQZ8ON!6=MW;4OC:O; M>N?NNM:JW]1.?GDQNO-#U76&(F1?Q!.[]X=\/5?/W>XZGC@;"*68AEE]MZ"9 M;5)#I3V.1]1/%\@O=$X W8%@?=\E<=$CF=(,1N,9TL-"=NIXC%IP2<#A>T:C M+7^*^(\7V7M9("S_T:.&;49WB&2$@-]>D1J@OR<=RR_+$7 MR6O#B'LV#^R07C683YK&Z/M)BQ7UHWI)NL"W91=LHAIZ@XM74?;:6,XAWZ+7 M$L$F&K$P0U9?:(#\//\8SP^&W%U0&D->,VTX'E-+N&YRS<>3ZHGZ3(QE33YO MK\M#'I#8XD[R<>1/OH@I5GWSY-C1@*XF021<2CSI\E$H+B9__/22&V?]GH^D MF?%K8V4XU0;!.*HS'T]J]7=O4O?BS)/<:.QX7\T\\ -WO:^=DW[B_8[Y?CN= MQL:B"?*!?""?0\1^&\:>P=\IQW@OV8&MW>0E;U.?GF)#L.>[=MS.7V/K_'-B MG=\O6.>35=0."T?P/?"J33[3KN][5D.7+#=VX:0/X&N7AZ'3EXM/N4@FU%[3 M0E>^M5I//T3TGWB53.OGK[1K:P9Z*\$988]D3 M:D8EU9GD4.C7X8K%Q$3_QG+"N?S MYPG\/N/]ON,Z/$*]\S1\X@4KLY6">5R4*0JH*"TJ3@W=2E)FUQ2 4EB@:,-) M428-[/FNO.W.#P0URZQQ$ C/>L:V;X:611D2W $U, JX%W)+18\OGM4NH%PS MIY";EZ$H2ID)?4G*L0T*S %SARWM LP!<\ <]MLSLF@LDF5^'9#9G>K*$#R4 M-?GD+[P7.@0G9EF $]L"VTQBM-6 S)+',40X$ M!\%E27"I9/M?-QHY2,A^N#( ^YPIR$5]@&9V1%G:L@$@3A GB#-GQ*GO4#J( M$\0)XLRV2H(X=4FRKB^,;6=1'D#A,N5$VZ\8E8Z24*\5FOKB>W^+JP-]FI4F MVKJB5*U]4VM?7K:NVXW+Z\N;6JUQ9\85I:ZJC6KKLG@5I3QZP-O%I+:N(K6F M5)3G1_132*JN+N3AM$C4_%6$-1'L6!E*?N!#J5?_Y9.Z53WN$ R\)GK>X\BJ$P>2'V33U&EJJ8/0MFI[10^IV6GS$-7@:KG MI=Q1*R?]Q/NMOJ^)LE-Y74M!/I /Y*,G!"1WA4+V6"VK3YN7G9H)UO%F?Z,0 M%1" M"BU!U0ZG:BBT!%4[D*JAT)*FH[ HM)0QET*&!)>_D]@9$EZ^M$YKU%] /Z.1;]:,M24FKZ0;A 1J@'\LFGBP-%F([C M+T12/H=:H%E^&,G=KI"[V.B" MIW*#\\B(RH=/'T@Y9.(0 5 *3!0M*U]2KW$@3\!CIC2"BZ]">P^W952AF28 M.>4KG1?P-'WO.DQ)8 Z82R7) # 'S %S&YU(3EVK2KT2!*0@GWS))\W*#)8_ M%'&"C?>L'_A#YD\+$\K5G.V$%MWF>&-:XO7&H>,)F8HCO[+,G*X5U6V)(U] M!5"QM)YJZ5:2,B^; )3B L70%KY>!J1@3ZRD6SL07.8653)GADQ.L,1=X)I+?B%19:_2V'XO @]<]JZN7/QC<*K17$^IK!LVUET95GO M : Z,8 ;>G;'@ N@4O@$A-G9@&Z?2*3(JTCNG[$7;C*BKJK!_D423Z+7%TC MKK;]<<\54[+>>SHK0+W13664_;JC1CLE,WR%5(HRFX-B0#&@F,W# *N@&% , M* 84DQ[%=, PN[LD/D2?Y>UQO&:7_Q#A-_XL+[GT['MA M">>[NG[A)B8W%>G#O>A_/+F[,:M&XQ_UW[LW)\RQZ0MN16=7U=N;>MLT:X9Q M=VM4S:NK3M.XNJU?5JO-1KM:/?GEQ=#,B[GK#$7(OH@G=N\/^7IJF[O==3QQ M-A"*20VS^FX!*VT"AAIZQR.FC"YJ$BDZQ[X[$,RC!S U<"P<#X<\H$M"%M$O M3AP+&TGALF J4[5A.XJ%+6L@T%-<%1W+U=[M#5TX[(E@QL4UH\*6M&F7[LH! MT]*0>@5=75K.Q+Q+0Q>OXFT3C4FH9JHT,5]8I#@BV$05%V:RZ@O5DY_GG^SY MP9"["]IJR&NF#<<:90G73:[Y>%(]49^)YZS)Y^U!1 I*Q!!WDH\C?_)%;(RH M;YX<.QK0U22;A(6)75T^"L7%Y(^?7C+JK-_S;M4I*W=6^M$W<,RJOGP\:;7? MO8VW//<849/FZV;HT#>UAJ:M/3_$\ MU/-=^Q7C *H&54M%U38NOX'2$Z^=LWNYMIB+&8C+7T?:UN/9D6KFL'YP?*<< MIY%1S]@.H3[9]Y@936T'N$H?W0,. X>!PX[@]3? 81F)4#1R;M>J$,5UGG,L M3[%IFTU:S_6F;6HF:(%W;4$QH!A0S/$MQ )3##R?;WL^DS *N#TS1_!P">RA M5#D@]*:V NJ%7]*#8_+ ,8E=(6]-S:@H! .E(BC]@M]_J MP/SLE'TD A%&]SP2-_1FWWGD?!?AU7/W>;3]&?O69?.FTZG5JT;5[%Q?55N= M6\.H&IUJLVW0^>,HC+@G^\P\7Z9")XN>-%P$S(G"N1M#=;!=WAR?61+V&2<< M\4?! C'DCJ>Z(()A>V?,$$80GTE!AM8?EQNO8+J=NQ#%;G!-!WG#\0 MCSRP2;#JK9X&@D00*#G,9$-+H&DN"<8#E;K@/V,">?]92L7BX8#).9<-XM03 MU*@;IYT?.*-P]^/Y.(L_N.ATSMO5!N';-)LDE'9#W\E\L[KGT7S3+.01]"/> M=VB!8B!R/A!&K9B201J(C 1-%$P^T^XVL[TGLF3OM'835VOM2?QK;%Y#MU+2 MK5_Y#V?CD/6\H78J$/O%B,NG&5)ZR MZ\ /0Q8;$=;S/NZPYMJGRG;"\>B5.(0EE]&LV<8H4HV<&G'A4VIH.M[@E-S' M%VW/.0>U@&:N_DV]GP?MWI?$%0XTZ$=#_K.^I8@&-M$\U@VX%[HTG=@L\MEO M#S?013 SF!G,#&8&,Q=6%[.F?YM'\Z2OB_^:!%Y<)H$7]]/ BZX(X$V$?7 ( M+7PWDZC?G_U](WI1XNZ(W&9U=\\FSQ8Q]'R/H^Z7&$F#LY0K 3 M"X]TJAQDO&66Y7X[['2NU,][J%!1(79PG7H6/(!"89?L,/+9;9#4CG1 MLAJ]#!"XZ!QX#AH7(XU#AP' MC8/@(+@""@ZS:OJ.@:*EB?S\Z>KK/3O][?SAG-W(D[@!/'(9=O%F)*^'66G6 MM"4H*DI^#N A-WC(:DX@, 8 R0SQFQW=*6N15X !XP(^9N1@0#@ $RP #: M7 W:RW5J2P8)MIMW4*8#7ANIL]WZ3DO,^1 3T]^M[_=QW[-VW'@ M:W-H9DAT^:(CK8++#$_I*]11],S% %;>-O6.6/^F8:) )X"%&0LS%H"52V!A MQ@*P *QWD M'H %8&5 <)BO *O2P KS%8 %8.5ZOLIL?(UQN$@(*%IY#*/6X>*V2A)@\R'B M/5>LO'[N[[GNOU)B9=_^_]]K_UY]-_42S!*NFPS.QY/JB?I, V%-/B>]F1_/ M.@W>?.^ZSE"$[(MX8O?^D'L_L7487^7,?7+L:'!AUC=1B$55W?SBK?W)VZCF M*V,K2S L$$=3ON7V@[U0 4)[56-])"H[L)?HUL-\CR(8ZK;N0+!K?TA]>?Y+ MR)Q)DOU )MFW9X7L'"^,@K%TJH=L%#A#'E"[]*WECFW!N&4%(J+15&6L^="G MM_^O_.@E]>_"PD"P .X@* 3LAZ/*0_ M?$\Q92#BPJF.*@8H"4'\F-&CL'BH?@W#,?HQJ65ZYX7N3$15A]:CN0 MC3KRIB?Z(-3CDMF0#7A(L\_:*3'<'_N3ZW_^P$5X,2EP(^O;S)6WN7KN/H]$ M5][7I8&Z?Y2W_._8%],6/1/B-/ZO+%^XAK?#D M2-^+_L>3NQLYO_VC_GOWYH0Y-GW!K>C,-!OU6L>X,:\;QIUQ=WO;[C2-J]MZ MYZYSW:#O3GYYH4JO\=$Z.GI-$U\:TZ]5_UK;Z@+VJY-6I/)X\>?YQWI^,.3N MPH.-ZCQ?:./G%STG"^K1\>).\G'D3[Z(5XKJFYBDC2H))JD9:LE5WKX=EB]P3P / ^TW9H")+5M M[Z_8ZK9R?Q&J!E5+1=4VC@$O MZ G#SFXRG=[6%<&07?N>>G^Y(= -QF2>/ A+SAF."+5-PMF19N8PGA?!O0;N M?16Q>=YJ;!R9ER.90=GTAUWOJVMFU4S_B -43;]ME_)YDGWU2EL9KC>5*OT8 M]'UET3!:J4L#IXC ,> 8< PX9JOU[V:'619C^+8)R)L$\7WVO4>YOKQUA14% MCN5$S]_&@37@H;CVAT,GDA'>6\?RU6X;5W>=NM&I=3KUZYM&_>:F$ MFI=7!XWE:[^(PJN9DY,RFH;]THK&W&6C1&XA(PT5@0SG#(425D R4>&B*L3S MF;0C9(*NV2NX?/;\R0XC6[6QN$N#>KJUYR&&64,5;?U9]D3MUI\]SP6HIN;= M94D@Z*2;^QQ>F!M%'@C&W=!GR=D685?4D0O'=1W?>R/Q\H8QVXB,U1(9:^X9 M&5OK'#@\DM0@)W&."$^[)L\14SC7*D956W;THB #3JW2XH$, M5=, 'H 'X"'!0ZVM+4=T4? K_,ZDVH;3^+&D"E*N0RSTNB86)[ "9*=V:@H MT#(J9A/0 K0 K11F+4/?BJCPT$*@X7* 430.Y F$R3F.Q3,(,LY0QAV^>GQ M0W#-88)G,D=7&=.[S,D'^@/]@?ZD)!_X2=;Y2;2YU+"C7>@=;;/2-+&CC75M M#B=ZL$QN6,:@)3ZB\\ R8!FP3*I;R37XZ--;.Q5LB;1-PIZB1E^8E7H=T7GP M2B$:*;ZM7=-V5 UH !IRC@:C4JUK2VM7%#S Y[S.H%JN_8THAWE':TV;I57X MQ0E<( @@VAA:#:SZ 2P *Q7[KXW(/#C4-K3_MBED4=0EDUEI=;05]"@*,N!" M*"T>:EL=@@<:@(8BHZ'=TA9K510TP)VVQIS:*F"F=$L3L]+9RM]8[J4)5OU8 M]6]ALF'-#V !6-J!U6P@#RZ<:9MH2I=^$;P?B2 5/*60!OZ8IF"]8K2TG7=Z M2SA% 1B\$ #4^H0,=7TF(/ $/)4;3_5*K://\BL)GN 77&T9^A%WT]&E&NF2 M[8]EP)%874X"[:W7H DX')=A=6HV(V M].6Y )&!R$!D(+(C$%FG4FN#R-)89GZ(.+WZRNM7_/WS!R["B\^^]]@5P7"N MTO*DUNCU-!]E5[;;)2%]MIU1HWS3OC M[JYU9US=UCMWE]>=SJUQ\LN+ 9D7;M<9BI!]$4_LWA_R]?0X=[OK>.)L$*?A M-,SJNP7T- DJ:L =C]B6+I!?Z!SQ[D PCQ[ U'"Q<#P<\H N"57&3XL'P3/U MA?$A:6W$3AV/49.NXWOA>\8]FT4T7"'S^XR4Y2Q(1H#9- 2,J^]E,R-ZO&^' MC%Z"4!,)^^)5A7I-.*^5NUTKX@66K[X0J?P\_QC/#X;<71@%0UXS;3B6E"5< M-[GFXTGU1'TFU%J3S]LK!PG^T?'B3O)QY$^^B"=J]!KXCU9F/)XW&NS?I:Y%$DQL-<]<;#WQ? M)R?];.>DG]E^OW7J/FTAC2C:54;Y$0Q(]6DI)?27KU_.[F^OO_YV_W [L]%O M;J^Z6UA.\]L5&XOR0"767Q=O^F75_Z6^$#:[)#'P1\$^R2>*,&+W-%MN(>2, MZ6CF%HM94[S-,9Z^$O[*HS%=^PQUT[]%V\KV%FWZRC4I%S 3XQ9U ];-R%/Q MOI7,^U!HSI# MRSNA6"+#9$,55NE:AMO:NY4;R5#[F]]GL=_7MY_NKSZ?,ON M+[NWR_Z0S5MLSGB>E8\J;,6FF,(M7(J?%>]84:VL;Q=[0 ].VQD3EN MR8RP\D;*$!P$EU4S !P'C8/&'4MPY3[O=,6]/YCKGAPTZ\0[. ,.,YD=E4BTGUV2I<]F(E)_M4W#F).;6:UI"Z"!;F6&AK,: ME):?B<>LU!K:,JD6)4 ,# &* T#&)5V!QG*]EZ:9<@]D!X\OOB1"%5$9<_W M;&T+M_22O1P15O7S3OK)RK#6@V.N"(([]NK03+^: +2Q?-F_C$J]A0(P@!:@ ME0*T.@9*P*2SGCF:FT.?>LCC=2SRV:D?L,?5)=*IO'V1IHV@Q:Z5=BB%[5*M:7-^U44 M(PQX*"T>S$JMA2KC>RU*2K/)\C4:;)4#O'Q;*^9Y,_VL^K#^X7$K@N".O;52 MUY>Y*CM"S9PVEL[_6]<6+UUXYR]P!5QM7K"HB1)[Z2U@BK1.N?OT_]W>K#D8 M?J05_ANBR@/AP$,$^4 ^&3BJ"OZ!_D!_TC[1G*&U1YZ..A?1K=LX/T 18GAU ML=XO@N".[=6M(6 >WJ<4YH &O$\ %H"E'5BM1A7 @EOW>&=\<[TP:6B/>2WS M^@/S3];D<^S51 O)F1!#^Z8)4^G4$5,./ /$SPT]=DE1<$#4O?C!&S6?"<9 ML<0:&H_&8G\E'W22NF^/E2/N\V=0MAC*O.C#K9$T^Q]Y5J6O/A%5BW=K< MHCENE63MFJ:-I-\23%',&X )8%IG\^A;))0$3#A1LO*VA]^NNE^[EY\SOR1_ M0X!Y(*O,""MO+ _!07!9M2L*XG8T&I56!VG0@2U@*PUL-:LX-9&>I5XD@_RS M",,+=CT. ADC->31F"Z4850I QV.)PJD _D Z><%NH^-2L-\V".N1QO5;X' MV "V?<%F5#IM?0M6@ T>\M7R@WL\"V95AE0-@H/@(+A-Y](:S:6V/^ZY8B]+ M(V6OU[Z3Q/\<3'AOJF7V S:-6L5LZBOFL+/$BN(P!9.!R'W+O)[;N]58MC9\<.QI.O5^38Z\5;;J\D+;VG]8W73^OOV*^]4"R[OI?0UR.SM1LPI[=U!X(Y7B0"$48LX)%@ MOL>^\\!1\%%?V#++0R!&=(GPHI!%=$OD1]QE?I_QV<66/QP1KJD+T8!'S E9 MCX?"E@U: ^X]$HH/CB M[O")C^)4-9SHC^XD/BS$@] M>30*_!_.D"YTGYD.M?F?VKG)>H[KTD-UM"<%2<1Y%@C+'P=A,C#^. HC>G]" M(2.IWPA+#'LBF)D\-:.BY77,JK%<$7&'=M2(4N_G!HI>R/.'$C D>E( I6(K M](J&*7JIKZ$4B_Q69AB1"I!<-+G];*;#/2&%-!#V(VE8Z,=J.M/F)1BHW]6= M4N]Z0GB)=O+)HP-2:]EF/_"'*6B0>=YN+1_>VD5U(E]+A]KG9EU+AU8IP8^1 M$P@I6SET_CADMI*QDJTF!5X^:+*3, =D:3T.-'6JMKS>W46@>QM26QE,,)#R M:R"]DE9%>Q!2./;;/0H2[Q@)X21DXTEG-:N#^Z)]?__(&+\.*+[]TG5H3,X77C MA);KA^- =.4]71+FE>M;?_SRYS_]O.+R7Z>A9_=BQ)_E6W1%, P7;Z8A].2P MW(O^QY.[&VD^_*/^>_?FA#DV?<&MZ*QN=IKF7;MUUZE6&T;]MGE[U3"N;NN= MN]M6Y\:X._GEQ;B_1COK6.7GI NOE>U>4.86[+U8)-17Z+@^5&6G^-)N_ENRVD[N='8]3[S( _<*<=C06(;U*>G& X]W[7C=E;R MTA83__1%WBIJED8TTO8Q$*\QC7;97GK>F*R+7[<.Z49@SLK;5J[T#AA(6)J- MG/SOT^@-S"W1+DP)#^ 0K;1VF?$*EA3&UY45&66;B;3;!RW< M%)# M5D=,/YMB:1M5*>KTT]%79JZ\N"C)Y&-NHRHEG'SJM?3+89<79$7"4I=^$;P? M;957N*A34+O2J&H#3GGQ48I)J*MBBY;BMK31[D$#T9.GJ5VQE/)!9L>YF6:4 M>AJ"S'CBKYW%>0"ERQ1[;A;?_FI QV81&G/A'3)6(_!=E]3T4Q(&&7XC05O/ MV\1SU"YK5WM.\ZYEW+;OZB9=I>(Y.K7Z]5V],/$Q@($<6A20N_/T3TGSAH MDQJZGL5VWZHVSV=;Q)CA=%@@F#@MPHX$,-*Y(G7D47EQ+<\6+S_1IIA\T_CSPZ-=0Z@=-Q];8 M5;HZ/90QNXLT6P8Y\$=181;-WMR9AM$G)R_^0H(S3&_R;L29%. M;AD%?M^AMQCP0"E5(,/C8UBLC/=VJ)]272?W!_2*3PKX\^DSC\@'3G22YAU4O-7S]# M)75ER*@[,VDP>2A5W4&*+B8BF>O1.;OSU07T:C/Y5.8EQ\928O*+OWV^^B<; M"AI3.U9A1\&82Y"$Q)'RQ6=G".:.,JR7ZWG3N4O!TWQ:V!?'%' M1N?14\9!TI?9L,[F@0D3!LPEG,H(UHG6R*G9&$NR3'T2#!?DH M-7'%HSK5,>%SFIRDM54AA?%*C)QX=SU,Z MWU>24Z<^Z",-FN/'W$Z/G3*)B(\5J9,<\25OA-*^M*HV,(PF9M2]>(PA=NG9 MRAY+/GX+?'IT]/R-1B>BW^2VK MN^;5W951&/MJ>C2M3Z+WGY3^*0T*Q\,AH>"_\NS-1+Z3V>ML]LTW[GA?7OJ9[?=#V.^ZL%^V7;1OQ@26N>0BB(9> MKW(KCZE U:!JJ:C:QD70L;^U\K;[%49W9='BYK0HCN:..%88227<)F_]X<(Q M"@9^'&TH[]$&PZBT-::@*GI\#V@&- .:V8%F:A6CJB]G9]%IIMQAA#-K<9V3 M%2L__2N_LA6 J%=J#7V!S2@ ; !;*^ K5T'V%!M)9..)D_HB[3.CI"+2WY% M.5K5JM2;V^0*2$=H15DS 9J IC9HMBMF\V#5X0H/S7*[,[ZLB3H[[ 886*ZP M)TV-9J79TN9<+0KI !#'!<3F)_(.C)96I=;0EOFO;.<.X6Q8-[&GO5>1(9'F ME\C*LGXY;52JG90JB^T@M2)[8H%;X%8G;@WS8!LEI<8MG!([.24T;I: $N[ M(6P8E49+VP&.MX13E'48 5 K0.463%K %29'!L:C0$1,2&3Y 2.M;DM@ 72 MD6/F45\^3>$5(>J^4ZG6,Y"NN:M2-9J?>K!NU9MNX:=Y;H0!89#J92G3?9W9E@7Y2457G/G$C65J_\XN'QYNNP^[$&4K2[7A<@;R[&@=!%<(P>T9YV44 MC>&NQX&JA[#D)GK=);.C37@8FR];&@=##_H#_8%\\C'C;6<_M',[&ZK;K@+^ M7\=E$0^9\G\+QZ!7+8FDS8]9*8Q3%)P",.(*=&IJ. MIVX_S0%-Q.K&YHR_Q0E% PK*: __+@W]2V70O\ _\%"D]2MUUZ MWCBNQ!NJ"KV3ZJ6)OX3;_QZ'D8SG3<_RW,R(S[M)VI4ETH=.*,-BJ1.J;/G< MADQ?B-T.VFU^_+4@"3/,IC9"+WS0/];/&EQ=90%6$]5Z@"LX] IOV'RQO]2V)\6@[?>;>.WT%2V1<1Q+CS"\^,S>#%!4,'6V)&P"& MTH A8_));XK_QYA,)1$J*/93;77[:9=^H7DM3I\,G@@/N,NL M=>?7CC%%Y&PF:-5U%SY:*YFR,#Z(O;1H:M8.5KT7:"H-FB ?K2;19H9EX6RE M+[ZWUE!*Y: _CGCE<[63.<%!XZ!Q$%SV!8P #4!#OKT7.=W+*55TT2?/\H^>_+-WBRJCKB^S#ZBHSBX1LT549@64VX0X$L."V2'_2ST JQT(9 M44?/V)@SIC?J55UX+0NA@[<+C : 6#(M[.GL+9*J:)M;D1?!(&PV:^._23" MB'UZ^!K;,TO"/=KV3 O1-9O.*_J"-+&>SLZR,'-34?F 91@ %H %1U7ZCA6? M]02S122"H3Q.E:J-5RA3+E]I&9$_9&DSI*;/>$/^$'@-RHVFUL&R' ),I0%3 MQN23TRCG$N?AB7,6>J]DXSD&M1=EE=XQD-H6J_CC3Q, YHO;VBUMU4L 3 "S M\.ZU; ENSU"OPMEP7[N7G]G][5]_^WS9_7K_.[M\>+CM/J1#<#4B.-L?R_P' MVA;B^:\PO[&,LE^"WJ@T-=8L?DLN99D$RT[9(!F0S +)-*HI;2Z 9$ RD,]! MO:)%,ZCG3.G/GRZO/GW^U/UTNXT]C1S16 \?R<,'C8/&07"9%1QJIBU.M=?+ MVXZNPWN.ZT0K4S(A=0TL8Z0^@OY /KF2#PZ\;9R.,!31:R<*-W^"YO#I]J[A MT]J!D?*.>G;\O6_I?_;]O#%3M$W#3']I418O+]96X!IPS?)M+:3N L7 [Y4^ MZ72??/9,FH>V\ =XG#4$Q/D04 ME9Y-H3_0'\@G$Q%I*,:'Q=7:Q56U@<55\=8(V:*K4@*KKB\/!8 %8.5=<(7= MP$(QOI*'%Q@FBO%A_89@FP0-+53C QIR[NTIK+%2JFB;C)5P,:JO[\7LTC'D M4]:@)XV#58K!2CX["]+,S8' Y8O;FOK.Q &7P"4\;+L",?7Z-0O"*ER:J+A, MS8H:-7/)HHXQ3^1L.J@W]6U5H@@9/ _E1E-3X\8_T 0T03ZHZZ?+8/JRLJ)? MVJDUD5PXG^N>S D.&@>-@^"R+SB<7KI4I\\#$3F!D)N.S._18WCD^%Z&LOL8 M^Q]B*EB014O?EA469^4@NR*CP6P!#4!#OET5*8;!T"O2XKDO9*R1RC>3[OGN M<@07(95/<<_NM)&,%XO/#-EC1<%5TP"N@"MXPU(W3I#81Y=]%XZ$Y7 WHXXQ M$XZQQ=MJ+9S%R_Q2-W,31E'14&_C+![0 ,?8NH/N/NL)9HM(!$.:;6UXQ9 . M$3$=)5V,94YPT#AH' 27?<&5/%O0X5(NYFSQ58,G(O-KBVPQ28'!8)AMH %H M@" *:W(5,60& M=>)SMR[7E@.D+),*YH["8L'0%IT,,)0&#!F33]'MI7)$T2!Q]9[.@)(DR-7G M*T!^W-PLB?]_]MZTN7$CRQK^//TK,O2TPU7QL&2".ZMM1U 4Y=%,N:I:4G6_ M_>F)%)$4T08!-A:IY%__WDP )+A(XI(@ ?!X>FR1Q)*XN.?<)6_>S)T)!"R7 M'4G $K \.BR+(CBTK3ZZM-2G%]I6.V_U8CR&I2B:0:C4-+840+==)!].'4_- MZL'V[ &>3@9/D(]6]ZCL3N8+;M.7N]XG=C/X[=NGWMV7FW^Q3]>]B^M/UW?7 M@]ML.*M.G&6ZX;TM]B+TC*/)?4G_KP<3WIMZNZE5W%Q6^BUDNYE1&F(;@9V* M[E]>>7_O?;/J\^F'H(-A6W'K^F7L^J9^DSO9)A\CD>3?MF-U9W+@)[LLQ@_+%>W41=%C5[\X.W#@*W4=Q77G>;'GX! M22WYE-N___9!VXGL.*Z]^$@.?2^AOVR^VKMA;G;:C1A*;E+X<;VX.XSZ-!4> MBUK'6-QAGU6?/6ZS@2V&@6<-6;S(O/>@BHO?G?4^#P:?SMXG,Q*R*Q\+QD2_ M#V-5E!05*[&[J#:I-ZM-HE.O;^[.WI^SN['P152>S+@G&%V91B;KF\BH$H4[ M@>?:MAJ<7 \V]:P)78Q^II]\RU?E3\F:=Y.)>*!6\%QA(AILD%IJ5E$7\>D@ M>N[HIL&8!^K.ZH+DEM!E'EWY,+90PTL-;BI;2YNS)QS117C&34= M5V$3^F[L+]>(DIX/[SWQ7]"^<+H MU I[&EO#,9WLAS9)A [B+%"34YH>OK;J8>[Q\(%+0U6:/M=R]5CJA9ZS*_[H M1B#PIV[ 2*_^$'0OV39!O6UN^ZX4P;])7>3%AJ2\[D0DEUK4=)(/4[>*;A!Z MOHBE3G\$9$Z2SI_G>QMLOL3PO=%X%(9OX;1+,1*>Y+=1*.R8UZUH6MUD M]\],]ND=V'/?^I;;C]PD\I!$:)D661[)#;[O#BT>T#E/5C">F1^)]]CFC#QW MHIA@_=52=*.,FOM$Q!%9/FE#V90X63+4M;/V A5U:7/A8>9UOT1/4Z)H^LM7 MQSW2J!7%WXO@28B(V?DPD(8Y)0<>DV/JJY@]Y_8@JC'V([,XNZZ5/O(_(=D; MX9&!7CA'&@UZVH@#08&@0'T4^,9V&J# A=.NG:$=FA&+"<*X8C")??F'&Q(A M,2(AQ66>"$+/.6>J"IZM*3Z*+Z$\:-,RR6,/F.">LW(-1OPFM'B(?^TP.L0F MDM3B*A3VLR)!MOTUU4 MAZO9. F'J[ZWQZ4@U&TU:CEP]6#)?*GE^Z&($F3#H>N9*DQ2GI8\[(IN[7%)YA\PA^$! O9O+\E^;QG]D1N/)]./?IDLD>+,U6Y M,\]O*LM$YBKQT9G15JYY0X'U7CQPA_T/=T).UY(>.W (')89ASV243QIGO+K M>FI'X@LY1_#N[*9W06Z=0A!GH]DOH!^;'Y[H1QK\J!-F1[G M*]E;)OXC9^7I4'F?J2<>9=\$W(SW >*A*.P.,YZQ25R MLL9 >(_6,"E>FQ6Y298:QK%R/)QHWGY6TQ9*!E/TEB%W8>! M(LMG$LO\0O,AJ=) BXY218<3;HJD@F->P+A8MD&/)2]H13.@*O.WFC[G4EBN M*DE,7S\Y.1$7W4H^M/ EZ5K^6$HP/#W1E%HC)E.)%NJ5)7$,G.#0R MNAR=XHLXY3)T)V)I.& B,)$V)FJ#B;9Q+=,;W2PZ9;/];=A2AB?Z666(KK]^ M^C&JX;>&UC3R)./"RM\M\XD(@UW??HF+2=-SE5YJC8=TI4SWE=!S$U],U7): M$^D46_XZSPPD Y+11C(=D,Q619WL?T);S;#4HN+P>0P45Z3/7!KV3OY^-LM. MRQ*#9()G[G580^E56(07R5)1(IJX@=,SDP?B2->"/J;RSS_ZR2UFH5!"1S.. MB.K1B:L>K"0>EGP4A5/I7#:+ O+5^P?2K8H#K?E(Y"25)\_FJFA*7CH1AZ'. MIP>TKPJ_:,Q\R.3(TC>J9$GUS3G M]Z'8W8P=.OI_YX/X3D0O631)\I/$5+6<)^+JE#BVG+VA<]:+).>0.%)GJ>>V MU=H!BN^=A9Q!?-GTT)[2]U#S?V8H;5&RJBDN[E>KVE2:8^9ASEU2AU28>)_+ M,:G*%GH0^[FR*,$WA93.9:QK9O@\&P/9-VNB5"KQVZ.E5Y74TC39"ETM?HBR M*J0E\K:I8L%J)7JORLU72QQDD8[U9V1-X]J=E&QGA3JI-Q I9+2"+*5$2JBK MZ^;H=O75ANP)'F1F@?SX""KTWN**A]EP=+!=JWW>;/Z@XTJI=]M0@JPGTEA: M0EB9+SR1W^JX=[UVWM#S%)47WI12:!ZM4EUY8>I!O0AG.@;AN%I>R"R'^$H_ MT.>EZ<'"E./"C80;J<^-?&.?*;B1B\4+*E^E4OS"DO[@:+9*?BF!-:LLHH_6 M1'F/D;V>[SQ&;".3\=%2QGE6?-V2=$ >D-<&>7V;I)P$YC==79)J-+Z^"4?Z M (I)%#6DVG$DRYM=_.KCPA MXLIYV3[DR^OS?3P,QJZG(@T5\<0M(%2S"QKV\DINU3B"'BL]FMDP_84%U$]C MUQ:R5T1R<+R>.WZ"1 (J)EN_O%OFUR@"DX^7>JC9.NRAK/,RXS%XPIK1IPJ6-)/"(5 *6BF.3GI&-*>IEWTB!$?$\O M'&6IR>[Y)'<\T:Q6RY$1L>E0:R0#;SG#03JBE UT#[K72/=H_;05W:>P.E++ MH";N(T\:/L3YNFBJ8,QEL:F3)DE;/-"Q:Z$O_;JD,":FJ+5E-.K(EPD$Y !R MT$@.:(^S*SFDRR$(SZK1VT(4M^@Y)9X>(U=$I9_(,R0_R(^*IU0*/\X-QE41 MZ2A3)ACGS@BQDNDZ\3 D$:5:<"7SE5'7N/EA4;LNZ1/%,2J]\:E+46;LT3CD MN;G>'S*,Y?.BO53PF@S;G<9.FFH?-A%$5*D9 T<(,W:+U+K29-WGG 6M]9([ M9[(;6^34WMR$B+@"1_2^?8YR'FG,WN MQ8/EJ!@VF1YK[(_MY/B??^+"_SA?:*36&?E$;9_FP?B=//&.I'Q!]/C'KW_Y MKY_E.;=#HJ?0%E]&O7A1_+5#/MJ#10='5[EX_IW_V_7Z,HA;O$8T@?4]N!&C M7\ZN+F7F_^^-?]U=GC'+I"_X,/AP66O4J\; [[6;WLG?1,/K&Q:#1O>JV MC&[]XNS7);UXC5U>(I?7U"I-:'(38J5FEF.2"GRLUQ(Z6W/1S15M?IZT!R-7 MUH='\[KWLH.D'TYDDN1/63Y#YI ,TP.]H4I<\6/-I#TK/$Z:$\3)CU0%((W; MBBS;N[]*98S[M/CO7^_KL2'LAD*6'FXBY05FJRY)57Y.W\9QO0FW%UZ$44VS MX58&:@O]B.H+HD'R,'"3+Z(FWNJ;R 0951)$W(I^*)O,3GWQ,?ECA9C6V[0Y MVU77[L.U@4U2@_GEK-[^84MS&)]H['C>H>^W\WG=TM^POM6).VW8?NKM[]-8 M[>9[E[X50M:^-=864_A:-B&##J[H8/T(.OB&++?4RCW\\_5:&4T_[QV20-DV MDL\1%&SS_7JR5[;;>5*IEZJ_^^G:45EL*Q ?/LGL%-01ZG@ =?RG^H(BO)Y< MM/$@%I22?8WBP'<4^\GB6_\]M!):>1B+/%?"WT4P=C?FPT+O4JO%]5:G]>DK MN8+4/R9B3V8?QA)LL[BZ_8]N86 +11B]H@A.'[!>\/=+*#,HV_ZNE6Y:WSBO M5B!Q0<_RIV>WY&S*2WZ0,W'9N>I'E9EF[_,3)Y4(?<'4P+;QTVH.\:U3*+JOL MLO#EWIH1T"K-(SJ!^B+6705V*LYCCO!7+(K/D>#TX>X?W)/]FTHH(RA7H1V+ M @D,FE9H33OM?.2=&W [&^>K3LZ7Z89RV86V4N825 UL*J/\5P\TJ@<3RJEX MY[!>D _D _E /I!/'N7SYAKQY;^Q*ABK@E\Y#ZN"'MI6?"KXCW68+%6&1@Y@MHMKU7. M)3:P?AI(.3I2-BX8/M8 3VA-=W8SD3?"$4\J;15WFQU*08Q4RSZL^\:Z[TUD MH6W)# M1YX;TKX"O'6H!,"I>*6@Z+S)1Q]:L$+\Q%0G'T8\?W*!WA1!;Y#%+>BZFY-) MY[XEO!+D>XWN\:5U*KYWCNBK6!82@H/@(#@(#H([0<%MO;!H<5/*?3:87+-) M9;2WK^4Z7T9?;>Y$5[AR/4&OM7@TZW>U'O&=5!Q[@PC)[1B':GO+RX M:%\TRK<[I>4\BF@#5*8V-Q4/S\GFQ:-(B&Q*8O69+\0?T=;'_+LUH0O%6R[+ M?=M3%WD:6^1ARKU2Z1AZ$N99_A_1QLCT-L.),.-=WOGLQ;$Q]YDM?%]NPNSZ MH2?D;03IAMRE5&YKJ1Q9^>70=GUA/],8@N&8_NW](;=A=AW3"F;[23OD+$:; M,,L'&'(_B#=F7MJ(<[X/IZ\>M^]."('//_H+#YYLPIG:J5/*)_7$\IZV>!2V MVN_:BC9M'G'+8X_<#@4;6\+CWG#\G-Z@DRZ;B#G:RM.?[^6)O3MSLTJO7M]S ME9Y1VW&-5ZUYX$5EA[[?H<_#\^5CG'@^/%^>QXGG.^;S89UH*>:S?^7"; M^2[8*<(6S] WZ!N:![PF57T3J.ME&N>WF,QX'74A45EA6_QV"]IU[I/,<;E*YW:D9M_YFVG+V+ M[-;R]-W)Q'7H)'?XQS$I]&26/!5_19.^!4U8KY0;ALF=$P*&.5V&T6G)P37@ M&G -N 9< ZX!UX!K$#F!8< P8)AR,DQ-VZPO* 84 XH!Q2!@ M> :\ UX!IP M#;@&7%-:KD'HM#%2"K* LR#T*_&0A?:TCQL3']:7V>YO(723WT7".JYXT@ # #P P MC3,$M1: !6 !6 6@ 5@%0!8< D!, , / +!B JQ6UU:5!6 !6 6@)7U M_.5Q5EAIT0SU:C/=!WMMGEVE)6U\^WH@>,"!ANR-FBJGK6T$6;%8PTD+% M$2J.4'&T8LJ!!6 !6("% "J "E@(8 %8@(4 *H"*+5"A;4=#8 %8*#@68"& M"J "%N*-Y\2JMH,U+,R1U+*;]OGFJ#DV83)3W LGH#\SZ6A8EAELU%ZA1"27 MAKTL &L"5H 58 6[!8 !8 4"&.P68 58P6X!8 !8D0!F5($KX JX@N$"P "P M @$,AFMC] M2+8B>EAZ3JSWPBYF>Z+J]S (N4%A6HH086@ 58"* "J("% !: !5@(H *HV 85VF:=@ 5@H>!8 M@(4 *H *6(@WGG.[*9R<[9>E12_4IZ=H%=.]:YO1=6X$MYGP QX(MB++?-!Q MV5[$LMSW$+OF16P&%K'E4,W+0L$%PGEQ_10 # #P "PMYN?-H KX JX JZ M*^ J_[B"0PB 6 & &@!438$85'0X + +P#HBL+:?!RWH+)OZM#+=&:W5 M6A'6D=VELJV(ZW-_S+A#5"3_$/\)K4=N"R? JKA,W.RRA6 ;-=[N1HG[8ZEK@=SUTH_>QZ@=">.YH$P P P TP>P>ANX JZ *^ * MN *N\H\K.(0 & &@ %@ %@Q =;4UKL(DDC.EWYKNV9;+_4U7_%(UW#'W[&[\AF++0#Y@&8#I@] E4 56G MC2I]K1^ )6#IM+%D= $F@ E@@KL'5 %50!50!52=!*KT]2P'EH E8 E8V@)+ M6'!XL*F\#:56+?8DWYT;<)M-;>YL/].W!2+KA$C3#>]ML1=593PCOZ\P_WHP MX;VIG)OR_>:RTL[]-6W+R7<75UGL DR ;A, &@.-;30/4&G5,II7 Y&!R$!D M(++#$%FM43V^N$!CH#'0&&AL#QJKU#H9I15!9" R$!F([%#KF!!6@L9 8Z"Q M0M-8K5)O@LA 9" R$%FAB:S>S6B!)V@,- 8: XT=B,8JM;:^#ADG3V2I@KR? M DZ/OO;XU-_J(#84MAWKR"]GU3/UF20P3#['3Y%6JP;I4/JI[JR)\-EG\<1N MW EW_L9>>KQUA8)/EAF,/]8:F^CEHCYL?O#6VV=OHQ.O]*]OT\,OL%Q+/N7V M2M)."W'_;OK&8C=]O<6*>XGN97RU=X/7[+2O\[I"YHZ8&WKLPN-_6K9%W_OA MO6^9%OF"(1'9],H0I\T2%W4??:-V@KSQ>QA(8(W(;_ ) M/8%X<#TZP"2@$D+OZ7)B&'H1,0Q=AP 52#!/TJ>-"/I/8XO@NGR&Y!K%%9XU MX=XSH\.%9S]+M$<4-!%. (0"H;OMDW,2"/TDMRIB@SJ\M:U6C^O?&ON\LS9IGT!9W]H=F^K%YU._66T:EV>JUZ MH]ON&!>#1O>JV^M>M"[/?EUZE:_QP4MT\)HFI".)#J%&:89%Q.<$'^NU)+30 M%%0I-\NE%_"D/"C%@WXX(;*EXWS%O5])5>C"?7="FO/\HZ+Q6.3JSUCFS)T+ M79(_D?R*QNPRPDLQ%)-[XH"?BGU\02>BI;\@^S7U)\7WJ^J&T8"Y["+E'N!.Q>RPO0I\?E&,[X82V M<+)X\M0-Z(+2?TXN$_G$R<&SBY,G[+@!#= ,AW3>_;.Z.(\>JL*L$=WPN4)? M*IB'-AU"]Q9#F2R3KK.TJ-%XZ+O0(Q>;K#&1ETWX]XB0_E2OE*3C/EJ^>KFQ M>.:/%(TLOJ5TP>W0% OZ,.'T13RT1>$IXR^_-BT:0$"#<\3("F*'G]E"CD\J ME.]2-"$E\V0%40#AN,Z'V:"5YT G632">QD/"&(1+5H89T/B-(E"HTEW]=2C M?91YB#BW93087<>F;_5HYJN$NZ$M&4J-]C;AH05K75WB'?DY?1O']2;<7J J MHYJV\-H\JJ61$S$]6$XT2!X&;O)%E#!6WT1NE5$E0<1)+Z7-4U]\3/Y8L;;K M_;29">^N77B[@9NEQO++6)NJW\S6#*> MU6K6/;Q2]>DI(I)[US:CZ\P=.9;RY%C*E=O;24<7@Q5FJQ^AB\$;LGQ=#5<, MFG9%C/Q!*-LQ9D%SQGG9*]OG4,8VTDWM/7A"R'06> ZJ=PC5^SV*).=R'<0A MY?R;&QFBSC_*4&T@9U5FNKI#3@C;%P#?A_=CCN^GM'834.M%_+ZSG+G,XL2# M_Q[*!?!!/I#/\4'1,O!5]S9P!OO -E_HNKU3 M>GAQZ1..JKUB/K=E/8C-HVH84TP<58^Y(K/M0H7L2O0+&Y3ECB$V[F^^BZR. MV+^\UM:E)*?BL $,>9-/ENY7<:4"K3F>+[4YJR*WM_:TOEQOEJZV)8?+%D$@ M:U[=$1MZPK2TU:+D2**Y ^W&?H]6(1YSAUE]2\N1V@*NBBZX0FR=E!]Q0<]R MZ(VIS-::=5$%SFQEYWE]6O:R4DNA?.%8KAH MW=SK*M=N>JV,^OJ4=SL]@"E;/2F5QZ4MUPNMRIM\LO2?E'SLV(^J;5SZ@=36 MVM/4?I4E]."+A5!TF"6H<6MTL9D4,H6%I[$<23;+*@9]C:WS(Z^":2($ MMV/?KX.2\C8=MA;?G.S'E^Y]\\&0[V4^L'W[L)!]KRBB\K+OF=/--RH!V3J(,_R_Y"- MKU1#25/UL0I6P^TW>M6]T(=NNU9RJZWH!J.1& 9?1E\<\55X,CKE M#^*K:]'UQG(A];73IW?-+=G@+IQ,=VM/UVEUKNJ-1J/6O>RVKZY:1K_=B]K3 M]>O-VE6]?.WIK,F4'EQVZIT*1W8@D[W/Z"_!1IX[89Q^$?13(G VE1)G0R7R MN%=9U#6"3YF ?/1)Y/,*GZNZMT!BM96 MX9*=?#2K2H8+[?.]^*!1YDCABI+Z?^[^N&F$>!&G98;=6!> WV5UL'21U(E=+ VV\'RI9F. M_6Y#=6K/,2^B;3V^\FO-J@.!DTY MW5&K7E2[K48MWI7G\JK3,7H'G?98GB$\QJX\P@_4%DVI+0NC:;=OY[?G:G)N M%&V@I&9+AFH_FLG4=I^%%^W:D[P<=>SLF)%Z>[-=6*;Q^ZHP@M*8F>Y$WG>X MOB'3PJB:T)\%F+N%RQE3E8D>63X_.GDFT3#CR 5[/D"+@RR3@ M.TQ ESOY0'^@/SI6\R$%D H^$.#GJZBA+#59K8W;]IV\QPE< 5=;=$SH %@( MY38S[>@;A[+$-PTUUGT # !#L@@*:$#@O*%US=X1 ].R+T< T MI^?@M^OP[X$KX$I[WXHJ F<$SAN:=K735+6FK?@'A%/:D*'>T>8'EH4^@(:3 M18-1:770(.IE<[IG@ZC=FSFM=H:*+O([IW^K33V^C&[$T T]7UR*^V#K5E#- M9JO9JE<[]49[T&BUKCJ-03=J!=7K]R\N+LNW T9Z?XJE-E!3SW*&UE3NUC*1 MW8M]9H:BPAP1R-9[H4/?DL+_*?&+8":]B=FN+0X]$!M9 MCT*M7(HZ1 5R'Q8^"NA$-'S*8\.GQKZ;8!R\(5(;G8TRCC+4IY5F()=B*";W MPIO[$W6CLHM+@48K*[+]+(*Y6+_.R+D7D?/\I\MPXQ[SR(MGOA)K%[E@.?^6 M\<'QEO-'L.O4C%KV&=\2AA(GF9G;:BU(:8/L#FHV8(TS*.\^N4DAF""8H$RK M*LMJ@MKM!DP03)#^0JF3,T$-K)0IE>G1IQEWL]P^#,[?ZI5F%U$/3,Y&P'$# M;B].HFFCV(7<>7WZG9EN*.>K]DF>O_A2XKNI.;*5-'T^9*TOH?F69/?)>&8A M2-T,UZQ4#7W=IG:6Y@%T+E?$N5U%QCIC7]0:AIN%*@/NR]*$M9.0;$6LN]RN MMDZ]=[D0LWSFQV4L)@M<8GH^'+-)5,GR+)]DZ@E?3BJ:R?Z'Z5H-+842Z3 1-4!*B5#%%E*(_8 M5PPHCX )VA0PY2Z/V%<^*(^ Z=E,4TI5+K&O,% N<4 39!0=.:I> F42A4AL M%KU,8E])HDRB &42RXTKMNDUL=JIXK,(KIVA.Q&](&IXH8YWOW)/.$'/,>\\ M[O@CX?EW[I7G3CZ[CFQ7X;FV3?I]+:?(A+_<#V.#CA;M3F?0Z1FM5J_:Z;9[ M]6JS'W>T&/0;_8M&YATM%JH_JIJK/V0'BQ&)R'TB(<7U$4M=+&2["DL)GO&4 MY&7)A3R[-[AE?=>;NAZ7+4A4/PINVRQ(7@=[%[COV8A>"7,6W@E=-7XIZ6*, M6:.+*0W:->5O)D$V$";Z6>2F+*.[;UE&Y]#]+'8\KRCCS/?S%:1:)7?]P2"? M#>/V]A%J=G)5H9-4/[$MBIZ 2J#RJ%NWGV EW=KR9Z@:5"T35=MX^G$G4U"( MF;E]U^-\WBKZU9:1RH]H[D _V! M_NPLGRR3 =5BLWV<#? $]X6E7GKO.+F&_2,!+ K@ZVA@:N#Q89%]Q9Z M-"SI$I +L.025-CUU]ZG_I?8!ZC,JN6\I)>1*<0DJL8+9)UBVG.PA+]/+Z96 M^JG\Q6DD*:YW2E!,0V\XEF]<]#>,_C-VO%E>1*F#.P(=@0[%HL=.U5T53NXH_]R5[6##>RU M[EEIU9:;G,UOVMY-B NGZ:A BLJA7BI!VF%@MT*PSVX@]KQ6]$D>_5'.LUK# MZ.K[5&_-AKBFP_HN;^"5.38MSWJ3827;["GD_/4H] (Z@(*XD>S%IN(^^E^Z M6G]YVGO+HKOSUZ']0M/#+-H6KC9'3#=2O!0!M^RM&QU6C>I5U>CT6_5NYZI: MJP^,VE74Z/!RT+OLMC)O=)CFF>5M+XW65'_CP_1VD$M-#X?<\YYE3H!/R$ % M[%VJ0^'[*)\@O(G:+'-AAV'YA3R_[T[(+#W'^VFBG6&^VQD:M3W[&3::N_;1 MJQ^Z46!1.A,:A]E(L_0/6) N;P?<*?1FT/_R[>9V, _,+P<7=]F$/0?I-+6Y M:+/O.I5X+.R&KW&?,?=X@(30R>G7,=Z=]AM)I4[JC3G@?9TY[O8:MW5R: MZ6SF^)8$RY+V NHV1UWAFEH>98]WEEVCR\+L/[=OVO]6.);KL6^.+X:A3(>M M37X6?YXO.PFVS]O-'THHL=RQ8U$$EV4)@TZ_(S\2*Y:J:9UCSP>'H0MDMHO/ MRKZ*!5P#K@'7;"\+HZEMD];2L4ZVOV MDQ^)Y4[53JZ?MM%!Z@O K"T ZM9RWZ*N"S 0DX9.>4-!/7I^N++S9Q]_F^J M"@VI9J2:=_*JM6TG L4I;5*MW=9FRLMBL8$&H %H0(H9*6:DF,M UD417*;. M<*U:0HGE3M5.+A/6:&'/1@ +P-(.K!92S$@Q']\3+Y.@VN?U#G+)R"7OY#YK MFTF'XI0V>V94JE5M8599C#/P #P #\@G(Y^]\T(_8+?2 M/[<"2_C%C?^S$UH+;9:17][5I4;O"V34WG20]?4=+(N9!AJ !J !^>57->6; MPRV 6F#W\6L:C0_9T@XHRQ0ZWWR[NOMSU M/B$A4=:\+N0#^91*/J5-^%6J!MK= @_ 0X*'6K,#/!PH!=XIMA_[2?C^1]8/ M/4_0N1,>:"[D0' .P4%P$%S!!8<\V@%J1T\]HP: J#Z)J>,YO%SW:

? [-^ VDA)(8D(^D$_1Y;-HY^IDYTPWE,M<$D.WMP]P-)[^Z\%EI%\DN9XX M>%,NIQ*E@&1 ,B"9%,D856T+$DZ&9%)!U4\!IR=<>_P+?Z>>,3W>.VLB?/99 M/+$;=\)?IHG4Z;;EB ]CH5C)J%5_6-"[!BE92H9#X03"V^2J"P"O)E>Q'.*N MZ'/ZMH[K3;B]<&-#'C.[L!(/&PK;CH_YY:QZIC[3NQ\FG[>7QX1[#Y83#9*' M@9M\$7&T^N;),H,Q'4V"B363-,[F4U]\3/[XV[*6S<>=#I;GFEI?FS/9(-Y6 M@_GEK%'_X4T0+"(N/M'8];S&H6]X\"?<];R#W["<#[A=A@EN&.0#^4 ^D _D MDV_YS(;;WG/.+N.IN17/?H^84'UZBES[>](XNE!Y+:YCBS!^RUO('P W;#B[RI G2N0#KW>U2<^PQUT^^!U(_@@;PA MRV.K6TWCY!A4#:KVNJIMO(]*27L9=7>3Z>RT4^F5GSM<%T5PKP%Z7^5KZ^QP MFB.90=GT]T3=5]=TNB4YDEBQ5&T7^62\?&-?O=)7N_*64F5?L[*O+- 8'HMW MP#7@FD-PC1.Q:[94+9#Q1/Z M5H?F1V*Y4[7-^T/EI/_3WKY6!WE5 O T@ZL9@W;T6<7W2"(09JDH/+),B3Y M='WQY68NI/^;6BBF,UB!4N5-/MF&'MA='$G;-XM[V]A[''H7!V MNI%'CH+]#.=7OEWA'2@)7SD6I#TA7P@'\BG\/(Y MU5QO%H4F)Y+U!:J JI>F*HWFP2913F&R$A,L:T^[3'AOJJ5^3R[?4U4["^Q48DL0&8@, M1)8-D36[^IK$G3R1I2+WGP).C[[V^#5___P3%_['V^%8F*$MOHQNQ- -/5]< MBOO@4@3[HV2]L=_C'KW_YKY^7S[!Y(,ROW N>Z6QA/"-&OYQ=7=:J1O/OC7_=79XQRZ0O^##X4!OT+MJ#[J U:/:[U=;% M9;?7-RX&C>[51:??&+3.?EUZ+VD9WUD3X;//XHG=N!/^,DNF3KN^60Z0;?*Q+".E\\7=CP4:N3<1.MV3JU3$_G$RX1\?Y+*"? M[[G-G2%]\&;292//G3#NF&P:B9D%+OVL7@1]Y'%E[1@+JI++T5^3M_&<;T)MQ?>HR&/F5TX$O-0V'9\S"]GU3/U MF> _3#YOKU[TUAXL)QHD#P,W^2*R^.J;)\L,QG0T"2)F+2(=FT]]\3'YXV_+ M1#,?=SHI-R.KSMH,[ 9I/3667\[:W1_>I,%%,HY/-'8\KW/@^QWZO,,\WW;) MVCST[5NRFIW=N%.>ICX]16B_=VTSNLXE\>/D7GBL;E2V<"UFXZ\?8?;D#>&^ M+M 5_M0N4FF@=7EIB)F@:J^KVL9=.$LZ4;6'3-5I*?<[\A"77,)C(CGC$&Q? MT>D+WH\?F^\K"Z.#DEUD$ M8+ >.*0S'U!O8*#X[;Z=,3DUO&/564NDNQPW( MMWDYZ;6++YZSQLS[RJNIKYE]60"$R/1TT=!J PTOFI-]YXJVF/E9G3BZ'7-/ M7'!?F')F0C@^#RS7N1%^X%E#NNYM0*=]T'$LSS)]/7VF_R#!^Q12599VR?A"2G(2,#,##TU246'/Y/N^4PX"+LT!.+&.<)32SFSH6&?#2%&*SFAA[C^7^@%@ M%1M8'6SAE4OU *Z*C:LL.BN5'6"G75"B7.H79[4JS!&!G OQY?2DSYZL8#P6 MMLE&KL<"_AWM*/.<,LT)*75;NH10%LH!&$X6#+4.2G" !J A,W^U+*A "GCM M:;=9.Z(YDF*Q:*B,\70+>:I\/ >K2"YZU7B@Q:%X-!MU&[[#4[G6:MV6LWVG*E2*]:K1K=:K]<*T5Z M\=J0YZ3Y%X_E-ELAH"*0.%^^M ADSEGY6PT2-UKSL>+A5%8\-)N'KNRO%F0I MP<[GU8LRT!86/1S;W81\RE0>W-Y-@.T7RX.E[86JZ5>UXC>7TZYJ_U1?"',N MV![)AC\(]IO'Z?*7/!#LBEL>^P>W0]1X'"PA<7A5W#QL/Z9:WH@)MQQ9F"2C M9/G?.^%-=HCO,9,V/^VSS#-$W0V"%R)6G:NCQPQ +C7D ME*"UBWS05K$X+-,XKVFKM@/+@&4@.*V".^V5%]&$'V+K_)KZG)BQ=QJ7(:^^ M\NSDH!DO&V_<#:CH2\3O#9L#>WRM\_;&339.I9(<>(!\#NNFY7;G> M2%A)=UCQ?6IY^MRY'$DP7\IXBMG2=[5&]NL0X!D"=7IJ-S)#X(%]R2:RA\@> MELN@E4EPIYT]5)4Z2!\6N30G)]YEJZ:M/\M;4CH58P8_6\"CP! M3X6W3F62'S*8>U2 'B[U=*KJN1V\ZP1OTPWETL8$WV5,>AJ59E-?B>C.$CP5 M$PMP9J5:6HM,X[NIMDW &@M1.@;5S(Z-88AMI'D#GP(^G MRX\YDFR66#ZO(;&]>5GL82(28+>T1;/H+ M4%!\5>77-P0/@ ?# BCK_4*C[7W;>;MAL&4#\0U:>]<:K4:K>E5KM]M&>S PJD;K0K;V M[EY=]1K5ZE6Y6GO?C06+6D3?"U+:N-$W'>.K?MXWLAEV,":7_7'NT3\)3[R\ M7:9?H/[?^L:SVB)NM_%(^>H:T^HB\%TNE.Z-?H/>Z"7NC=YJ'[@C=[<@G<,Q M3C1&1QXU/[%S[KM5[Q%5JT\K;8$QX0]5.YRJ:>MW#%6#JKVN:ALWJL)$V]K3 M5$06Q^9+@3AR:V5*2N9D*JW;S+X9/K+] -;) [*"\5C89K3[+?^.3<+RG"W-"1D9E5I= M6RU:65@'>#AA/+3KVD)*X %X*#@>NE5M$SUE00-2OVM/N\W:"\V1%(M%/V4, MHIN-+H+H/.H'@%5L8+6[^MK; %@ UO$%EQ-@-:J83]G!Q3[D,I'M%W#H7S+R MPMJ4#5:*7%XV6\U&K3ZHU:XZO7[?N+BJ1BM%^K5!US#*M5*D%Z\->989<)D2 MY['<9@L#5 2Y\H+M B$QFT34?M8Z' J"QV:M5(6YA_QO&91!MK!4H=C^YJ0 M#XJ"7RD*EJ87JJ9?U>I0M655^Z?Z0IASP?9(-OQ!,+6S%+OD@6!7W/+8/[@= MHKSC8-F(W&WED1.UO!$3;CFR)DG&R?*_=\*;[!#D8QYMVQU LB][!RN<7H[2 MJ'2[R%+F4D-."5J[R"=C;(!_D M3[?FFBO7&PDKM=V#Y>ESYW(DP7PIXREF2]_5ZMG72L,S!.KTU&Z498N'VGE; MWR;DR!X"6A ZV$E5ZB!]6.32G)QXET:EV=&W_]P;VSN M+,%3,;$ 9U:JI;7,-+Z;6NRZX!71JW[<3NU39>=(9IN[6G41RJYNL< M7[![,7(]07$E!:Y";B^,!!7F#S!_D.$^RYG+ G,'8!@PS.DR#+:;!L. 8< P M&>Z\#8;)+ (M4Z!YQ[]3@.F(D14@.Z0_.W1B_8;>Z6M2N:%@3KE%+(!VND#+ MJ!D)@ :@ 6BP:!D!#;,];\WV5)@C E6_B'F>H^=(LN"RD\FAO"$[Y%@TR*HL M.9@",5B6W0&REB+H#'0&.@.=@EQ].7\E[K*P(G%^E.0WBU%24=Z$+Z:15) 7T MRZ=DUJ,X1@ ;, /]1T?_*;5)/Y(X\AX+GW:[FGO!5IU 5NDU4 M']@D@HO:CNAFVMCU(=]TUO7ZW;K#;&5Q<-ANM M3K\ZN.C4C4:W<=5*&NSV^T;OH UV.]-R--@5DZGM/@O!;M!I=R<+NH62H=-N M&3JUXOF*_7P%J9Y"I]WRQ/?H28E.NU"U(ZH:.NU"U=!I-^_>B3KM!IUVRU89 M=2IK>(J_1F=S]CKY>1E0#"@&%+,#Q>CKE 6* <6 8D QH!@TV]VM8AO-=M&: M4)LVO3M8AX-5A2G,FF?T 70 #0 #4 #T$X,:)CP>6O"!\UVC"*DL2!A0&"@.%'9["ND>7%1@,# 8& X.!P8[-8 59%:)Q[FNQI^[- M0D_=U54@F]\!375+8'?V3E06WWP4QPH8VK8O+PN; _Z'EP\:8!:N 69-VQ*\ MD^A["58!JX!5#C\S4&Y6P;3P*_'I8C?=&W33+3:9GTKFL?B91=30Z\OA@V) M,:"858K!8F-0#"@&% ,O)@<44^@^T_52]IEN3Y?[3"MH;:\E[8-.R>XXKKSV MF6[OALS9::?39_K-)L]:6TVK>W^9[M9+NGK9N&KW6O5.I]YO=CN]JVJ]%_62 MOFC2O]HGWDMZD^[1L\[1ZF#F1F\"+:2W-XY;Z!9:2)>A!3&>K]C/5Y!BP4Q\ M&O4)+:31;/4-C5NQO-IU#BVDH6J'4S6TD(:J'4C5T$)ZOZSO5T\$_/MBX!IW M&- %XAS),7?HQH3+Z4ZX8$H7# .& <. 8< P8!@P3!$9!C4CV<6?90HST3T: MO3;U:=,[0QOMH-.H'7 M=$-9'8D>AAJ$AWR+#F&5)2$#$@.)@<1 8B QD!A(#"2VI; R"MA/D<1.?&I, M->^RG,"S'-\:SCMXS0-UX0TM7U\?+W"_?OGD0Y=.L:&SKD73ZKY MYAH#?GKSHG$2':.A^* MT3>O1]$IQ",6HF#)"& %6.5XR@NP JP *\ *K1%^65A&&#A9+&@+6@$%H"%@F-!WTXM90'# MUKLE9-"&_>4&Z*M]UN^X]R""GF/VAD'([:\V=WJ^3]_8=#S?K8=Z_:(^J%]> M75WUZO5ZR[B\:%[UHQ[J@W;_JG9Z/=3GCE6$974"/0>] ?J)JT;Q\K&G= O7 ME+W;30)\($QT;L]/Y_;VGIW;Z_5<=^+>_[SNH<=9+8A@,-""#K0@W>E/RWM_ M0U9%D _T!_*!? [ /X:1[T8AV3=!_RH\>1/^H*8Q9+3*5+CJQV%'LMW(7,YU MH[)#[ [[N(M^-@JFGGNDO]:K9Y1-F0LQE44!'^K7MV;!] T[W4"Q"J-8&^]K M4Q"SF4G!Q7KI*9>$]7D@'ESO.8M(,__[WV@7ZK?SVXTWO>-OA/ M: 7/S!?#D(ZPA+:D979+<(ZW\KW1.IAT"MB^_(=VF(Y?B/L@@<5A@W[59U2V$ M4_9/8=7R)I\LDWJM:CJI-_^STX1"Y5BA7?C-=J@_;PH#U!7;-35SVM M'5 'U!W8UC7T[30)U %U0-U&MDY?>ZF31MUIUX9]">@GY,3U)>E. 3*8.RJ: M?(Z064,YV,'1 < M! ?!;6I:ZV1:33>4>[HFMK6,4WA&M7I>U;9H97\1EMEO 7*!7" 7R 5R@5P@ M%\@%#+-]/ 2>QK#U^S=\__\2%__%V.!9F:(LOHVC3U9YC]H9!R&VY M*;#:@"^U^>J=O/X=/?,%??7'KW_YKY_3EW!'5Y9C!>*3]2A,[IC7CBE&\V^N MG8 [#Q9=(=IJ>/%B)&A'2O-&C'XYN[J4.W+^O?&ON\LS9IGT!1\&'WI71O]R M8%Q=U2]ZQL5%M]F]Z!L7@T;WJMMN=(S.V:]+;R3JD*>KM6_24#AW0HB]T4M'=6+"12[)_HELR]6:9 M'TXFW*/C?!;0S_>-Z$VXOO#=#'C.[<"36H;#M^)A?SJIGZC.! M?IA\WEZ=Z"T]6$XT2!X&;O)%1$3JFR?+#,9T- DB)CBB&IM/??$Q^>-OR_0R M'WX$D^ M'Q14R_T*LG=S[D*G^7"-@FT5KGVSW$LQ%)-[X:7Z'1@5AIWIH6\'UK>R;5B? M7R6L8P/*9:W\S7-]/XE%07S0N0/H7&\X#">AK;(@O8E+4OE3I;N@?E"_ ZC? M9Q& \*!Q,++0N1+K'(PLU*]81O9DFXVLE^!M>/]O,0Q8X.Z*WXWU$PLDP&_0 M'^@/] ?ZDR/Y0'^@/] ?Z _T)X?RV6DR,D=5[5HB-W7:5\]5@9HI'H7M3B<4 M6S,UIM55[IM?O94>E!].7XF"5^H\YU=I3@-UD7?&>S46NM#L_1V)(UY4@:.' MX>JTO^J2S9NJGO]5!=GWB]?SSC70'YUW[[&A+;CWRYGC.N+L)YU R1'OY&0<31@&7)+T'_8!^0#\9[A, !P<, X8!PV37S;0#B@'%@&) ,8BA M$$.!?D _9:.?6AL>SH8".-D"QZB>D=NJ5QU9693?ES+BNZ:[M6=&\,Z.P:I1\6 MZ2UM#F+I,]0%0GMQ#659KI5WRX?,&; %7"5.(G:YIZ M*^ *N)H[B=D;+#B) !U EW828E 4C MF"4[63"\,[2Y;_#2@)02(V7S;7Q@-@"&DH.AKJVS L ,!0<#.\,;6B #P6D ME!@I^B8WRV(VMD]/Y2@1G!V9?.*.R4)?9)BU*DTN&!UH,A< 3-+IX2J24J=F MU++7+P , #LY@,%P 5? 50:XTK;P";@"KH K.(0 & &PY4G7)UV55NR?!?5 M;#I+0_D>9. MF:5WICMM,M&D;.=7P+Z*3_9S,9[EGDZT_5,X27OPIA^ M9[YK6R;[/U7U3]' ;>BKNWU#,&7!>/[@7& 362XPO=,7]FTHF%-V4@&TDP6: MOE)?6"V Z<3!5 .8 ": 29,+>+!X"BX@@';"0--7@'DJ5BNS LW.(8"7'1O= MAO>!&W [$]"59@X ,]J9"P#6[/2 ]:ZKSXYA1AN@ ^@VVLX#Q?P %H"5P6)J M?;E$ O K!F"[.;V7?,A9\(U %U"UN6H/0QN^SBX1&5"?^H3T]17>*]:YO1 M=:X=4XPLQPK$AT_6HS#9M1-PY\&ZMP7K^;[8K7]A/8,F"F^(M C$A#DBZ _T M!_H#_<'6R]1[JM'_R0'@9I@8+AAOL MAK'M<\*ZE!8,&7AI0 5047!4P$0 # ##K+ <8 8 ;X2T %4 $3@4*UW15E M?0OV S0,*TO2USA8U^;2)X4QV7*(R983P646LYT * *@,)P I? 96EQJ2]T M!"Z!2^ 2#BT "H"> $!A.'-3'HB>\COK5L% U]*W".M$-G+ K"# E!\7$Z@" MJDJ.*I@H@ E@T@2F-C;N I@ )OA[0!50E4]4P42A-E.+(MUMF0/<0I?JI$NF M&\I^\ON@+.-$]+X"_.O!A/>F/NK? T5[]P+#.+ZXRL)HF%C6 MSBU1]Q87]L("Q8'B0'&:"TT,?1N+P5,#C8'&0&-'H+%&O7M\<8'&0&.@,=#8 M'@&GSLV5$7&"X\!QX+B<<5RM@[F!+&8[?PHX/?K:XU-_IY[+MASQ81QM%VW4 MJC]H?,?_[[5_7GTV]1!L*&P[UN!?SJIGZC.]H6'R.1Y-6ND;I.'IT=U9$^&S MS^*)W;@3[OR-O23^=;/$3Y89C#_6JYN@9E%?-S]XZXGJ;73VE7?;IH=?X."6 M?,KM7W8[+40_G+XRP_[*:)K3(/9\(M--%])LE^0 ]A+=R_AO[P:3V6FUJM%@ M]]SFSE PRQG:H4DZ^^W\?\_9/RW'9.Y4>#RP7,<_9]<.ZX4/H1\P=58P%KY@ M7.W?SIZ$)V0YAUEA]V' 3,MDCANPB1"!/) -Z?XT!LX"E]T+YHFIZP7"I-/I M6']( [.<4*3OQ^2>@W2JY='1?FC33;@GSQS98BA/?;*"L>6P^%S2I87!W@K! M/KN!8"MO;Q_=$*2"^&T0TN+7_J^M9\MVPJ>V90_ M3^@4GXT\=Z((U1,/H!6/T&XK7=P+K]^&MRPI[$U'#/+ESZ$ M;U$<1U[%.#&9OC29Y)ZX(W9)P)S<(13TK3Z0_OX9D4G)YA1$\1"+_"Q,3R?<(3X[;M/DEVC##]R#W+#8GV8N % MW'FP[NU9H"<31)(39]Q)4:+U:)DA7>>9^?1$ZAY.L+]?DAS_\T]<^!]OAV-A MAK9P1U>60\'D)W*53!KQM6.*T?R;Z]F(>VK =_**=R3N"]L=_O'K7_[KY\6+ M/7([5,1"E_H//80U>B8MYL.A&SK+9ZM8DS[7TA+\O?&ON\LS9IGT M!1\&'RX'O:O&A='L=Z^,7G4P:-2; Z-J7%ZV6XU:;6"<_;JD&J_QRTOT\IIF M+2>D4IHV) ]2>)M<=0'+U>0J]*;I"NIS^K:.I&9[X<9&-8U_;7R[-/()]QXL M)QHD#P,W^2*:XU#?1*1K5$DP<::6@&KSJ2\^)G^L8'$]B\^7_U37+L;9@(75 M8.@"M1^V- #QB<:NYS4/?<-#GUXR WW,X!/-KBSDS< M'_7I*;))]ZYMQO4,EL/H)%L&+=M,S<\>H'Z$Y9YO2/=UB:Z8^3VFTM;+]"(. MIWG +@197(?&.O>NR3F4":JO=#G7W-O5Q@)D:.3;&MD?D^LGS+E< Y?U73^0 M(E("ESG+;-.WF-Z+2Q]K1>DM)5DRA)+C.>7Y;) MN-49&ATJ?D#1%H$;UP8W6;FTBA+"PNDE7)D_L$QA>&8NKY.8: 8 M4 PH!A2SDH#6N/T0F@V"?\ _X)^M^*=6 _^ ?\ _X)_CI''J^C;'*'N,M6^M M1FESQMNHT+S/00;3%4?G2P:6MH:8 ,, $/!P?"NHRV/C5 . M2"DS4O1MJ@RD "DE1DJW!0=KW^@\1SG!HX3MVQ3P;(PCK4(M!+)# M3F2SO5-?VA)CFUTL9GM@A/>^95K<>[X-Z.M+RQ_:KA]ZV^UWT;EL=ZXN+IN] MUD6SV:H9C6;7N!@TNE<7W6ZKWC_8?A>Q[B_WVY"?-;UQ]7&ER^'-X'(P^+UW M\6G ;N^^]/^7?;EBM]\N;J\OKWLWUX/;5U5ADP=+GB*]!8?:14BG(M^-9:] MV3:0;LFB#3O\<#+A'AWGJ\Z,?7="('O^4?81-(681,=(S9';P?B),EET>+S= MEA]OGR7/GJJ^CM%N,7('&O/CWH*)W_CZ34X6.'/=#B8;Z-J;URC6+BC=[GG# M:-:JC5:[4V_5FFU]>Z)T]]P2I=TIR#8.11EGOI^O(+M4Y,Z5A'PV=+7;1^C& MG*O>RPM323MXHWF&92;Q\ O.W5N>SJZ[R^1,I/E%,OJJKRCEEC/#4#6HVAZJ MMG'5_$[68[.G4C%KV4"L+U^R? M>2BZBWCANG\P.8LGEEQ"]D'U7:VY>R,);U^X6,;MV/,T1\W<:B]V%-; M-]&W!%,6I@*8 *8#&OX3056&N:/B^@7K4W)W;L!M-N*6%[D+F(D/$^8<=$&8KO# MR\/87@0<>0LXCMG+%3TJ@*L\X>J--#UPITUB9<%E0=9:9#Z1\8KKL+S68D6T M^9G.J&4RG0$*/NY<:^&TS"NA=Q@7NQ6"?78#L>?% MHD_RZ(^R58$UC"^O8XQ&Z[4R0"WC'/PGM()G+:,=N1X;A5Y !S#+&.7UN[YYZ\J?Y$4^(W<]RX*?",G MB](#^$ MO2)[-PS\@#O2F"2+)>5BB(UG%'9_!VF3MM*;4QHTG?3Y)?06)T)DN2,]-I.E M%V-N[B2'/=[3?&1_;7>2[E=:KL=X,-L$9^XLKFUAMLOEUS9.VFV[1691V'NY.RF-KX/6\Z'&YZQ/7AFWG)2VJ';:2Z2A M-"&=[G=MJ0TD>'FT.XU6:D?2?HN]TSYT21<#P.7KFF-8@OF4_P0J)YQ,P;PY=4L O_2'*2_ MK(?HW-#3(S6Y/%D,0V7M_A-RCT(@_YQ=<)_&3FJY1GSQP_S(^+UEJ\!J6PG* MRUH^&UH>F5II3X>BHNXD03)9P$/JWI'S+,^+5U1'+^]>J/<0@TK&=58T[#BT M6T86*>XZG5BZ+@W#];CWG 2/\K2YL8KO,!%__LD=\MF8+1[%[$Y]NH[,]87>(PF_$,'3"P[G918.YZ56A]/0'%;!X2RPPQF,/9&UQQDQE\GNGTF3U8N7 M__^I0G3[1%QL/W]PGQQY\&S+&'D14OKCNZK&@5Q5J;M*[:3&1(^=%M6*1"?\ M6=J-B#OI6WGAU/%DMF*OC(R\*8AN)Y83O0%IW->8-.FO">^#LE%I*Y:1$[>Z MT?NQG;CJ:K.J_9RX"IO:H;^>&F?NUCF[IG=D1@U\*\OOL$?:+;=N[LG4J1UA MZYI,J2=-NWH]TJQ*_YTT_]'R56(X&$?O9Z/!+KH/JFGF[N0Z[TNY;1*[X&^XM'%./WOX<$3#P19QB?2=U#NRB.W MU1UYVZ.9^I%+.D W,^WW,_HP0_L@BYME?;F M9F=R6[30__# ^?1C;S;&_I@[#\+O.>; \URO[WKR'4L8;[-+VL6@WV]VJ]5J MK5EM7QH]H]KK1[ND73:;[4;S8+ND9;V9F/JX,E/^>?!/UNOWOWS[?'?]^3?V M]>;+9_J[/_A]\/GNEO4NOWR]&UP6-9[HW7YCG]USY2!\,-H5Q?\3P>[X=[E! MR)T[M8:LW:B^_[B(%-:WN>];([D=6DP'EPE@U;FY%T@TS3H:24"0>5G8-TX:0'\:'2HS4R:Y/])P+DLO\:*5[QC;2DY4;B:R"?AW\IE\$3.#;454 M37Q [JKM$G4HSI&W),Y1##7;'5%>R7V*V)A8=1B_ >F>^8J 0KH%R2 V#O$^ M=D3,]+[.68_N2-?T0SNH,,%IF/\F)O)-2Q$"W9:&Z;A/=#8]X)B32+28,M?1 MY/X[I'2IAUR5*",:3N3Y'/FX,XHV71%EHX:*$2,WX[OE*R)/N?K1&U,BB%P< M:3)'='%U8&R\^(+D_A:=8]$+'"IED4&*DB9=,O:=QM:])5_ER',GZ0LN/$1* M%^(#R7 MO"/^0-?SUSV[LNR<'E!.-*?/H?=N)MLWV,^13BC-<03$*(N0H MPZDTT$IOTT!4_DSD65! 9C]'KHH$X@)$*S*R((5(=FY4$9RZC?GOT*<+%#8# MM,@Y=7+JZ>1'Y2-'+^J_A?D@WTQ,WAVC2>3=(UFEN%I*]+/:\Y%]#3T"A1^? M'']YRV4X<#MTIX(-O@]%Y/.1S).$_D"^!HK=Y+ON2\>'' 4_ Q;(<:;X2H/4UXZVJ:331=>6?RE MKUZ9KUZ9F+VRD 3ET;#[;*8->FJ77DU2KM=(37-*=Q+P*NR@IXT@K&Q M5?2C&-@-;5,A_EX%$T,[-!,&5L0A);^93$4: ,E+HE?RI.X_>UGJ_@ZY$625 M QEQRJNKFJH):4\,/)'"33#VW/!A7)&&RQ2V5!L5LG%&CCF/K;($E,QD.0I3 M(L+41&$JLG$S29!4Q,R="8F4E=(J\R)[[7$NCY^W=Z$14\YG/E*\^V! MA^G@<&0Y)#]+/HQ\HU$R4(E6>8 S,DTIY/YV)2ZD7;<7]/%,3>-#E>CP5GB/ MDLR(\96:T_/W/$]Z5)%H$I/3K+^^G6!N^'[N__\/=T*93UCK_:_Q]R.!1/2O ME",F@.%\QEN):C@7%4^+2KGYT_">A/W!5XF7Q'5ZH*.BG&GLLLBK*5HG79-, MWFE4L^?P3T*2845?'G61GF,VDH]'W.P^.'1&DFGA40IGY'$_\,)A$,KDNYPR M)AEX@73M;)6*H8M*#W8J!4H141@D5XTD6A50.\3LQ8!/ZEDMN7%ZG)KD]#(LVR3#-I7/']D? M90EE92Q_\$04=,RD%TN$@@3V(-?P./+G26\=)+^#<*.@!P9N>1LR<_QYI+6GRIA'@](3A$^ MN\J,N/Y\)#%"*(X*I)<6TXY*5Z@LODPTJ'2"+Z*5V9T],8JS%VH/S?G-5+9'J9(J M8Y"O/C)&*^[IPMS%[=PII5?:EQ>\4A=<\NR+84P6$G8R7DCB%&51)JX9Y3H] M$"A8]O?.V;=7W?K('XR#AOAEO_!6%O/D7+V; MI;O%V8!($616=KB23=5'2GK<) J>JKP'[I9:CTX9+=2TWO1GFYY +T MDKFJ*!#96S4ZG8MV;="M M=8U^O]9J#BY[M6ANM=^_:%8;!Y];S?2]]&YO!W?L^O>OO>L;.7W*!O_?U\'G MV\'.:O;:?N(ORF!A67UU23GEY_1MHF36@I@,>V M"A^J!E7+1-565U= U:!JF:C:QIM9%\0ER9W^03X;XM,PCKLCU K<]F@5M!YN M[RPGR9KYKU1&.1MQVV6]\RJZOKY'YT9_Y*=E6X(;1TJ4E9:$0H.%DT9"!Q04J@ J@ MHJRHP(3'VM.^G?_O.?NGY9A($>2(=LJR2WV]C7 8N *N],^? 5? %7!5 /^Y M] [[3SNX#Y ';:2=T+P66+T7]P MVQ;/B-P1N2-R1SX+J J@ J@8D]4-+"*8V]?,T?A779.:)\$Z3_*[O[([N:7 M?1 DGVZ0#( !8 8 : Y0%@-6V.=>EQ==K9W>N W[OLW2UWV"?7$\Z?KC:7 M&KQ3VK@=V2R@ J@ *H *H.+-2A[D>/?V.',4VV7GBGZ1VX8B&LX1T[RU74-9 MHF5#7P/F7256%FX#+H'+/#O4 "@ "H#J JB^CD:G#LO3SD+?N0&WHXW$U4[L MT:;+3'R?"L='1PE]#+8%".L$0M,-Y1;(^VS/%E]4[:Z\ NM\:)^^YNV;"O# M\M(^N]C1ME'GFR([@/XA1X_):E6C66'!6+"^.R%]>V:! M\ -AJJ\\,92F3MBMBL)TWJD U1*P6<\8/$8*XR3UA(F&'=,YEKV MAY'ET8%3F]-8+4==4O:!K["GL7#B.SR$-@]>-10^&]%1\IQKCXYBMS1Z0M; %L. ?I?'_O'R MB6BL\@)#[GG/\N'YQ UI:/1<\NLH1R)385/VQ'WFN,%< K:(KAL_Z\K!Z?NX M;,P?Z7ILQ"V//7([%/(>6M[A7]O59!-F/3H1^E(2\ODM9^A.:-C3J>?RX?B< M]>CMD@3\T X6541*Y<&A"YDO)I;T/;!1,[0^\?GL'5H^/Y+.=:R6:(Q/+6QN#'8E@+**4M22S-%Y)-D\D+<*8-Y%O M[TY\Y_XYNYYK(OU*)IJXQ6=$)Z3?4K36R*++WG.?_NTZ=!%3#.7KDI<@@GGB M'A%61#^A]TBL,R2$VW3PDQ6,U9@=LCY,@EVJNN7Q@!13CGS$'UU%%'2*$WA\ M*!]RR(FJI,_L;T]++W+0DBB.QT6&T3DU,C):FLEH^66N(:5OMZ= 2+,=8MB[ M2_$H;'>J7N%7S_TWF7A_M78^.X8B3B"R4.AQ7$5'Q ?3T/,)/%J&$3RY>AY' M4> T%E':QYI3'.%#RG'F:3V3 \T]XL&AHBZ?^5-Z7/HH'Y=.)[@D%ZS$@)-2 MLB19CD+;3N'K5;KEMN^F.9=83LLSC]QPM91M)^&YLBIN280SL=%OEC("GGPX M,Z61Y*@&H:^<7,E(DG1\7_T2.Y*V]8>PK;'KQN0NB,"2.[ G-[3) (E8GTSV M0(:.9/MH19:$C,=0>(Z2_?R-C3GI('U'7.>X$WI7]%^?A.O%[U!YW.IQ1F1X MZ!UL;6Y\.7HUTN@I_ 6'V)<^NT4_!G(ZD2ZCAT[K>NU')=*\%:-Y3?)]>"!Y M\D!4EGW]6%T/9S2S,ID3%?[,3*;4"?*2Z!--8/IU/[N9(X@I)CY1%S6J7C?$'Z%&M^V@&^%^3&"_6U M;%@>);YY5WF$3V&J#:TLO7!/;08 C%1#2ULCG-JW1B)B7S!U) M-G@2<4IHC90T$6^UKI=ZN0H_9Q;")C> -,4/I &1ZJF1/W5''601/Y."3>[) M8UB%-X5>%/,F0;I4[@1'ED-J3?&[Q+4"^#F[%8*NI8M^:@W=++;O]5Z@W$O+ MG[J^I1A$CSK)_*8T(_*2Q$#$(-RRR9'[ZEDR\^FJ%R!?1B7F5DD6IV'?4J;^ MLW@BNV.;[P]H[K9/B5N.IK YQ=KY M3SG5-'/_6C =/A=^+%?YA;TL\N8])\.?+\7P4MY2'AE+Z\>.28SE[N_*-^JZM*.F2[-W,7UWO%2V<=_@L>N>E\H&$ MW5K9S^J]VE%\)X5<3VGU"ENXEYJ/&[NV_?PA(J-UG/55.([_;#]R1Z8#A'KE M\OW06^0R1><)H927/@ONV<\LPC*7>01ZRU^_]N;3<.YH%/ _Z/YT7?$]2I!& M+C2SP\GT@Q].V)0_:PZ,]4Z^1R!('C*>1Y0/)Y\T(N](?SGS+4*ZS-DKG] , MA^KP6+7C+,1\LG$=F?(8%TGF6+*&L]8 1F1!F[%4O\O+2H>X3L2$6W>558O*>T7MLU'O8G;]6&MVW7.?O.X&:H(/O*U MU,1<5%00ES)Q.>E@RV59<:T3C=2:$,\IY,[@O%C_9*G)H7^'3H3]&1.F;QZK MD)1'Z%"02,!26=+;0$R9,0.7X\CQ/9#O]V0MS.@IF:V;$"$_<*VONAA@4FA* M%#R1,ET1\,I=N(J*=:=)9VIWJ)CT3^%E%962YSV4(E@H)*$7:T:9@KQ&K#7= M_)EZJTFT=1 )8]^^OP;<9JP9SQ*YZE'.H_^H^!I M.3%S$)W>AD0D'ZY)\:6(AY:LTDHJ/4U.D?O9[?7@['TT3/^9AC=)59+&:G'I M$MBEP\1NQ#2\)V%6(HZQDDGXF$'DA,Z<;#WQ*!Q"X(.KXN:H)$R2BR5=I\DD M=.)YHXB/)_>)ZZ;X.*D7X":)R9_%<,3;45YW[63SO7C=$]N)71,W+^*1:*:% M]&,H'$Z1D[^.?2OSZ@?BF'7<4WF)H%-O_&5R7O3RED])#>;E.>U4X=Z]YTKW M_S^AG'M04WK!"L^/XU1L9G-*-<>(4F-D4$FLFZ7S8'NWU>1%#K3$[ MO_=[_9T,3_+WSS^%_H<'SJU(L\U*J_IA[#\*_(R-S8;O#/W[]RW_]O'#H MC0C(*Y6'?B%>>XBFL;^Z1''/*O-/)]Z(T2]G5Y>RMNWOC7_=79XQRZ0O^##X MT.T/!O5^NS9H-:_Z]>9EM7MY95P,&MVK?K57[S3.?ETRCVEAW5D3H:8VV(T[ MX2^O ^7'RZ_JUW=_WE\ZU^ MJ[H\=^^9_@L1KVTE9C7.8H@'\M'=V0N6EL)3+UXE2R(D1:I(AL%RE6+&15HR M/S(_T9+655DF,F3_E$LO.'/H#<[OJ-0[0>G27#"?*E?D3^''%1M^X*^.F:QV MG%I.J/L%-]X3MJ*T90,6F8B%(?$A73"(;*1D\;AZ(!9;5%47/7F2&9T/UHQF MXBUI#^@\\B'DA:0]4@>F4M;+ XM'\VU*DJ._ END:_OF8ET4D["M*%/E+PE& M56&EJPKIL0(9?265 M$[K9"I>XY>$[V=!T[ODK3 =GU_)S)YA2'2;-(GR]YS M3/F?P7]"BP0KJS-NR/!0R$G"6/_[QDQ3NZC6.Y>]>KO6Z75K;:/5[C=CIJEU MFYU^R9GF9G![=W/=OQM\L\0L0147%<\J)E)H)T4?JPIL>?)/%X!!+^("2RE9L=WI,_ M:PGNTANJQA%R[ M(3$EYQ7DU=/?)NLS) JEKY@JG_4KZ=S,2P-.#3-AC7A63$Y$*':\ESZLD*7! M$8ZE$LHU(U^_]K;$\SX8?1OKWQQ/%]H;1KU-_U>]Z-1:O4&GW;SLUB.T7[7( MPRB[7S&#N/IC\/=OU__H?2+_(F.G(HGS9%XHA6<%>3(X8V5_9M@ALW+/G3\D M".0*9K4((%+8^! %!7],#FVDKU$ %CNW"HF6I! 9Z[J>]6#)2J6)Q'WT@[*2 M! XVH4<81[HOR^*B*%<-2MY _2'F.K9VUD!=3=' C+I4'/A=!44I#VI;"[D? M$A8PY4XF5J"80![NRJ*;!YFQ$/XEQ<]DOHD09W[\!ACJURYJ5YU>=7#5J%\, M6OUJO=:)+6:W=@R+F2UDOGR^N_[\V^!S_WJ=$0Z.L9QO8GRLT,ORC D-OGE9TK/2#_*/)ENGLZ>O_6A>NL5R7?T-AZ)F).W$;E4<0I/.204:(2>^DLY#Y9<>^7]?NMG$E7?CS.;\"*R>]MK..XM;5DM/3 MLY9C*[L]D]@YMGOFG8\0!5G8H4@U0=IQ__JW"B ITI)M209EBJQ9TSN6Q M0 MJ*=N*%2A*9<;^CP $1E(W$#W=3(]B'-\N_"FYGTH;/5([^&7J7ZR6?E[B8]V MIE+Z3?)C]*$?<>+%P.#HND%4_\6L\[BZ,"M]LTR[&8,,GQR MS!59DF?X,.,J)RR L6,\ K8PW3 \91(JP5N<(#\BX.0+_&6T6>9T\#A1LN9< M589][G3^)B9G&34)ZV-'3,#ZV(E(/NCCSCZ@5I^JL#6^UK&]X;W@(I=!=>C[ M= PA"0:<;! M?(QF^9L7QWZ2QQ@()Q>G#Y?)SL8X^-!8/C.$<2=47^G. M+7YGQ$:0\6/EWT9>:-6A8N=97[^8DAE98B$G'GZ6'V9\G'KMCY1Q_306MO.T[^S#JZK^?"N )Q7!%)HW&, M45,]M4]8\B>)\W?MQOFWEB"9K6%'*^%US.Y$WZ M8(,=1[AN?,WO[YKO]&>%FYKQY\T=!A!,X."90?(H]),O3/4X_VTMP\5^)3\L?2YOEBW-EJS&F]J^.51;?7J.>LQ_+[NV[KEQ5K>L4W M[OR^YKX,M+?C%[:/-[IQLP+?:Y9%+U,-\/YVED?_:<=[856<9JR*S%[!\R$5 MJE*Y 7W2X79>V=J@ %H^SX9+"LTZ(QI[D)C-&K.5C<'6EWG%,]M%I,^/8$@E M#9X0ZQ'K[8#UOAE/Q2+KZY0A@HR?Q>R"]!8JI -3T?P9^BWE,RR>TIN'QKUH&:<"'F131Y&$6+_I^3:T>L/> MY6UKS[BVRM.!>UQY&MXBROKX^MK,Q1 M*"4\K.2MJPM@X0+S>WR8=+F&]=ZX J5#[?I65P&YFF]H?!W9,[Y>($Q=;# " MTQXG.]N&E[58+W%5V>A3I/VDZ>/&=E1[[=0/"FVMO.T&V_)6T(+?+X3FY7X' MY/[8C_!L]FL$?VU2V%XB7@5RW+K'S;,\#/)DB32>H3/F_I*A3TJ<[[L-R8&I# M :UU>]! 3>4\[I^65':Q]!4^]@.[QTI^2;.EY*) JA],YOK&F6JN'C98 MX>Z>%%\[T='GU07.7K&@BQ=8JY+V1'G*<;E:*&=+*6)]?N\N[MZ9%@I'3C5A M?F2=,(A[%NJ2;/ZBZFB2^HKE@$U[;%T^3??)P6)K<8FSM%+<4L:&;I,5*:S- MS4<@I@^35D9XM2Y?:.I)6IEWP17R\DT%YEPF&2J9Z4[P MMG^QPQJPNG80==BS,Z+%8LVQN*WG1;.D&8,?A;JDJF>Y<2'[;"; M65#4.9GF34E/$VFGU&.\BVZWHZX]DMIN>*V[V,Y-=6OWH:&MMKA@-RJ_'--G M^-GTVT&5)I(>$Y$7%_S6*_&X6&?^26@+*J6UZB.@8!L:>:=7LY%V'$UZ^V0P M"N:CH%08-J*8@[F.K2P(MJJ$F55A %V,8GPM9#W_Q H!O5B U-S\_T MR<'ZVR,AO%PC(AF:UD1<^1YX.2!C?*4DAB+2;J$)LV+['%UL%1FD3VI2Z:=W<18E<[$DDC3;1;23-CQ-=33K3A"1M>#H6 AXU\N'F=$)& M(3P:4_Q#(WXG/ F5U92KN'L=SC*1'CF+0#>M<]UDU!B'6#1K@<=; OS@N+3V MPK'MH>VTHG;];-V\19;VU4@$N>Z/%K?\C)W%4U )F,BCX?G9-"5BUU.!X;:X M,<1K1V8^XN6Y#M GB5I)6[1DL%>>!7IB])=ZQ,!K2>E^VX,'KP\\0[ :L:$5 MW([+AB(];;F1J.6LQ%JXH *L7?\![9>&+G0?]U4/^<],7!9F@-USHM 8B]BF M)#"MGT'E_"L*I!HGK>(.Y@$\0LZU)_PYX']+]\,A.XT56EQM?]'0(!LQ:[#L MO7"UN;VA^7$L)F"P@V*@7; M U#P B7$#W H$ 9 .R#0# 1"B"'H,9_Q6Z%][W^!QZ&;\@#%I)@TT( V3&B^ M,,_/Q?VF_ Z'ZTG-LP_Y?IAQBQ>D_)V\]0,_PC9"9G)(FID28 28.6)SH&01 M,QI?OQ(]%J-:P9/(=-.)C=M'#$@+0K?PC3&4DO(%\X M>*;[U$+89WJP+,3^HIT33"0T6S"'[ _P@?.>[6/6V\[#53BOV*-:N*2@P.58 M]Q.9\#L_T/?%P8'4QM7%R_#ZV"/._1KS:8SQTCK$);%=DF8P\;3S%K99<&XL M_2>6'WT_3SD!^ M />!%!.WL 1WTG=YH@5!K/MS'P: .B&V_&\C\SO<\TCA/=*!"?\9WP.OB<*I M;SH^_I9]F!\\)!?;BC.L""/D6ZXJL9+D3ZR6"4&,1'B/0+1D^!^VV*AL/LGZ MC70.NU9';S&(TE@913%F^A/K^^B!"R;^F'#-8_0FO9 S(\4N?,B+?A0L@JV: M\=/>B:]7Y'%BRN!1[LH;=*E>8-?B9IN)$<4;L2").WD1D-E6X%GIL="6UG88 MVD>6_7(=Z#/>>3ZI@G\ M),IX&NH?*18>-9C.T$KG>6BK3 M;](L;N>>"@:*]5_-P'$3Z?$16PN:F_5H@ M)Q/]G/_@7H0. *K/!CNY& Z_@M%GC)_%I=IM^AG#%CN+18'V"%)?R;P4], E M/#+R!.LT&[EG/M[7CY^+>2^Q3A!R-L)(GDD*\'-S6WAVBXYR=])X$N;5AF:+ M&6O1?ZL]-QB0:R9XF&'1GI8WR(X*3$O=5S2VKI+6HM@ U .+20\(Y9FV=CZA(.>ZUQL20U\6Y J\2%22N@^>O>F[>N3MF]VN3,.5PJ6_/IGU_J0G62C MEWG! V9ZLF:!P(:NN/PK19!)K)(JM[;V=CZ/[.Y>(%\;+C:B!O"%I+60^/($ MT\2* UYPA?"(+#4<'=F*%1_W[8>*D\Z/!9'T7'?Q5<#[Z(FILE'TR'+3Q;0= M:$[)(>!T.VKM2-\O%$5&9_EZ8W=9<&3:I1J7 N4/C'>A9D!/.#HT@,\"?XO/ MIQOWC]^HZ_N:_>)-<_E->L5W>L?=SG&K?_*YVVZVSWI'G\^.3:_X+X/CTUY_ MY[WB=VNWTOXC[3_2_B/M/]+^(^T_TOXC[3_2_N-K]Q\WLG0?V:M/6+DK[.%U M+%OPC4^/SGJ]0>?L2_^T?7S4Z1C+]NSDJ#7\O'/+ME!#]O3RV[?SFV_#BYOK MTF\/KY[!U^')]7!Y\-M(TDRPZ^;1=B::WSF0ZY(D9G<9XVH?,>"FY:>#.'2U M+>D*XTIJ;]"<5M+A$9. G3%BYU$ 7B0*'&X@!QZEEDAH$TLM;0#K_ER@Y0+7 MFP>CPYF_0JW:_$MV%&!0:B;A1: J<$GAY?X$5 A*.I.^#=/6 M)Q[,LY:>GEPG3+@@/0J(IYY4$<>>&!AE=M2]+5O,UKFKLMF&-NW5Y?X;6RW9 M/4#!4B#);FC.TNJ][PW*ZMQUCPH\C *F85:&K1)9RZ**@26"4;B<1,[8BW<" MQ*RKY2GZ#$:L+=R'A2!-SWTN#<.X0.E&(3S\>X#WA0\-]MWE\9F687IN-':! MW@U=F%D@G=C.3(,K8]R4DZ/(?*%/21^^T[;C;8!Q$HQ\)%E$>;&>G*DNX)Q' M525J"1UNBP*L;_=PF$5),;![H&Y%D(+I@A.XJ>??L[A.@=G,C/T5W/Z>1;,8 M.N"0&+O+[&HN@*]=VSSB%P'$2-V]6Z$%1QJ C-^<1RTXC\^__M$+ M^=Y4!="TL36DYUC/ MU4)\TK',%3MI/O++\'/V-6;W(.?*M?":],$&=^#9N/$UO[]KOM.?U9P[R>?- M76+0];?2,X/D4>@G7YA".?J;>SD.IW U$"*N#J7[:,R5^)3\\=OC6F&+<6<+ M-:95=@8K2P*O4>I1C^7W=_WN+R_6[\F7&HIO;&U[7W/7+]SU?;MYX68E/*DX M[!)R^N6NWVVS5*S^M!1O^J+MC 41,P''Q9>@+]*5%M VO M=MZ 5U^@\EMS;^+E?M4FZ 9$+1D[EE= $M,M,=TB<+P9VU&][96WK?2A=HC< MVA2%WO^:SSMHMDX5G4GYD8BIKXCI6^O!4GD14^\^;&"V;,(J5>U/W[+6$:PJ ML"#OLK9@Z \(#.3SKJ<\-F&5VC7Y;K7("B-'KSQZJ"JXZJ_='+#VN*J]=[,) MJU35H&M9ZS%7%5B0=U-;, P(#.3=K*<\5J0?DA56@%:IO!5&W@UY-^3=E$%S M54E!W:09[87 Z6US1FVCJJ@^V\N$J0JXR$ MFF!5$63U]FN_"J4^L?,95K8SI=FP C*9Y>3CDH_[AC[N2V?H=G-&KEST(:]N MY6W?ERJQ^+H1],HZ+&2DDI&Z$_78L^=)U]Y")5=[!QIUET0L/>$RJO977?=H MU?4[@\)SA:&RB['[TKNGEQG-]?VF[?=Y(J$+^JVO5R#-^E'F19T4V$0 MZ=KD6$/[7\(QK;1T&6Y=,EO7N17!G72P562VUB18$R(NYRBQ[F.F)%Q\@^G) M,8\"9\I-UXW,#7$9;>'JUF9QW?%&7)U[,4RL- G3PI'IJN P-UUKZZ^(>Z$I MVPT3F0?IZ_ &T]]+7R>Q*.9,ZJX9,G"BF0IQ7DIWN#IDP\R TH$NWKY<;A/' M>0N#CXFV: N:5-TT53;S2Z$KXP'SF;*_.#J@?^#/=/N]M%9;N]D>;%;&SUE4 MUWFF0)\IK[=$6"J8N?9PJ,#?NL/*%_C#;F]AA!UY8F@]Q8Q4'7O+!U6S.G96 MH<:U%Y-A6BJ8C5J"N\I/Q*MN^$W%*$M8C++5?F4URL[QCHLUMBM?C?)H7P:Z M[7U]*K?Y)L4-E\R%L>D!G-@&L6E -1"+6X*L1_0]\8A.$TO-5EB*HD_$A,^6 MD14N<1]QWQM5Y-3M#+9G/]J,7'G;2N^-RN;9WT+<_QW"=N/H:#E 0NFVM =( MQ3E)RMA+ENU9S-0C*4-2AJ0,29EE*=/O6K-[*R]EZIUQOW(?KGZE@3J-5M-: M;?ZJ((."6K7% QBJ;6NGN@@/A(>]QT-G8*W)3U7P0%'GITRJ32*)M:MKT&[T MCJTU7:B\>T)!D!UHHZI J]5H'Q&T"%H$K0*T5LN>1U1Y:%&BX>H^U4L':+)Y MAIAW^.SQ 3JJOZVX*AG?E8X^Q#_$/\0_5"IDQW$2ZIM-.]IK9N>U:4>;_-H] M5/0D9?9&RK3 Q:?L/)(R)&5(RA2ZE=RA&'UQOE/%7*1-*M=5-?NBW>AV*3N/ MHE*4C61N&W2L'54C-! :]AP-K4;37J>4JN"!8LY/&52;]*^J89;#4<>:I55Y MYX1"()1 M'X-VU5UF=J-_K&U7N-500:% M$&J+A\Y&A^ )#82&*J-AT+>6:U45-% X[0ES:J.$F=JY)NW&\4;QQGJ[)N3U MD]>_@JM6AO=UMM/K6SCM1EW:* M0M0=4(U6UYX)2'@B/-4;3]U&Y]B>Y5<3/%%<<+5EZ(?<+8:7.L!+8S_"AI.O M 5IM#DR]1+P*G*CJ]!N]8WM9BUM3K"I"C<)%VUL/),E(DFU/K%ZCW;-7YX($ M&0DR$F0DR-Y D!TW.@,29$6XF;^&'*:^\OH5?__;KY'Z>,OY_-/IHO#DF52. MZZLH$#$NQ*3'Y_]^4, M2Y[_O^[_W)R]8W(,7W G_-CM]7N?OWP^.VOWA[U^ZZC]I?VY]7G8/?YR=GS2 M[P_?_?NC!<@2\T;.A&(7XIY=^3/^M#C,W.Y*3WR;K;C$;)GU:>PV8\^"'"CWX@L8/OF%U__E,=LFLA&!(7Y\1=F+)R M(J5P@OY$UV,]-7/[AV+S0'J.G,-5YE$*9LDN_% \HU*W&>F**@_;*_I!N]5^ M];#,1[S\DPQ!*CKF#=?B%D6(9H5_"O\VX/.I=-BY-_&#F>82*Q,Y9/\MPRG0 MVH^"DO$4\E"#W0LVY7?"SMC">]_.V(!=@4\?& H3A=P\BA3^J3[!8N5@_*>& ML10 AQO@^,RO>&_V5A8I@9+A7HX%"[AWJW^=1,)5^DFA<*8>*-U;>!@#"1#+ M"\&$*YPPD Y*"Q4Y4\852 WN-M@M!PI.'\:!#X0$D=; X# /].-&$N2]@F%= MPLJGHUR,1BHM>@*I ,^98>++ISQDH+8\!8JN@;B&UX^B4#3TDX&;'# O./XK M R>:J9"#HH.AI$/6$N\0N#F5#XVL0( E!ZK.8TII68"_!G#[/2IE($@@N*:H M@OE/ !-:8CAN!+2;!_Z_@"(J7B583'P SE\/3Y/@L/3J8EDNK-:'EX9,WJV> MW!#,!7\&@@+-"64'-1EAIWDX622S0$(OCQ*@SE#&P[^N/\?A"#,4^/T>TQ= ML#N!+Y+QP;]FX?5: N]'W(6%FOGPX0Y6"!A2(*-YR2.!"],G'K(S$<)X_7CF M1F=DG^E/0N$Q\7/N*Y'C+ ".9B4@#W+U6#C 2K*4,O4;%Q M! \ _/"9#V_R=?_X"9A=?@ ,S<>HQ05<&CEAE.=6+$#NCPVJ\)G I+!V@(DH M $9V *MS/TS4W2$[216E^]!@,"KXF"I#KFUN_=A;UQ\);15*3P^-A<@10K]4 M!@S!-N;!&&4G:(PI7!JY $J8OA-J,<]'QK* 6R?20V@RL.GOP^D".>$47G@+ MD@3,>Z6ECKDG@S]AU M/,Z,@L>_\#_VW?>#?VBY^OGS1X2Y%D8X#3Z9P ?&0\K)@2" HG^JQ\ $X!\ MPM?&C*3'D\Z4AUK,B1"(#VH&;"O@514RS=FP*GH45F"4%)Q?3+C3:K"5/8RV M>?SC91C;&?7[UF$'=(7KVK(XD)Z1AS0&E86VHL9:"CKQ5R3ON(O>4_EEM%G7 M*$#NLD(9. _#Z\/-3=P MID!:@H/D<,0K:/C8<<#G:)AZ/'8LLI:"TEH@TIPEO:P^ @$"OK;6'O^=%Z!& M3CVAQM+;\$I0*#@V'$(J5N:@K- HUZ-># 6MF]6#;+ YQ^A+!'8(J#R<=?IC M(Y9@B3[/RBR8>RJVGIA:@\&%7+HYV@7:%- ^I1<;9J&^UAA,\ "T#L,I+ ,8 MI6#2Z9%\>A9].C8"9I[KQEC[_5WSG?ZL0,\DGV,NR<*QFZ#OB?@#>PJ:JW;] MP50.IY^Z_77"%Q)* /N7_NHX\#,P#&!RLI-AHD^FD/&4C&:,*("\BK6X#"ZZ.' M!!>"2XGA BIG84(GV-'^V%2,;\'#!DU]^X#^-+@#A 9"0Z71$( MG@EZWP8=&"+0+L.S_XT4"\X&X);@XTV,SW1,B-XSV1"AUU=-D16 0A@E"E(32% MUP 4)NXBB MV4SONX+5%OAS[:O@UFK DLU*^3?/[K9R@ Q $ "5V'0+QX@T$N&GVOB)O'M, M?_%N=5HD0"+#_(W,!\9O312@P92$I_(@R=F.1-^YP<:6)@8F0-S T;*,;W 9&(_ M_O%^*K0$6/&C'F5F^CA#T,UW.EW:7$+B@,1!I<5!+@_!'^DC!(L4Y F7YN@" M>GB&D].4GFR $=.R9]+#4PE<)_7B/:ZXY2Y3#RH4,P(2 :G:0%JQAYM1IB'_ M:2+K#P0$ D*E@3"6DPFF=6H+"U!@+$3E=X3AN?A0U\>]JG]%@53C.'3Y&RH= A>!J\K@FOLAP$,F M+I76.*A;,,8(-IK 0Y\ZAI@>402PS!",/^NS#E9*/Y_J= M]&!FG!F9'.;1)GER>M*<.=1'MAT>X<%*/7CTP),< 7V:$'[*'5+)/]J<%7IJ M1HO3F>90=?9>E;QV])#-.")) %WZ9%1>: LAZGX:7%!N>>G)V\U&?Y,DY_3).&SH70 M&L3DU*FYCV)DGFQ8H1Q$.;+P;UQ^'Y_823"OG*F8Y ;<][2U M!1?K$^'F'#>PPF2B8W'F3Y"::/R9"-U$R_'T #F@'/1>*K\7 CMS]GJU4$/S M,G\P>R8 4/-H!$Z:EO^>'VGQ$1\ 3.[B'GD[D"&0_(#.]-=P7U84M8F#"5AADBPX#NI$K.O>=T>BRT[I/CC>+1 MP4<_+3SQD-V:-W=EBUHDJX!:1$6C?^D3X'YV%*"*I-#KKUGD#@-"CU=AI=K, M'($<12'S_/@(I$8U'8$DXWQOC?-'F!YCP8Q9;&XVX".8A3)!N.."?M&66&KO M^"K4ALY()'55QEA7!K3A;!0%2O,^[E# C1^3:A'Z)@HI$;#J!:PLDG(P,T " MZ]YWW00PGN_EOB+,$&:JCYD5^Q$8* )SE%B?6+_2K/^,NI@PC*"%2=!LQG5D M$/]!/^2O"$8T>=#5_!;/2(-8N GNRE$@HQEAB#!4)PR%X*'C#MXD",@$PG+^AV*1-Q9!?(TK,.D1'1),J#*;U/[:#44), 28?01, MUG3R[F3@ZTT:S/=8A,"S.P39R+C>W\$O0Y_]\X]_,C&3*@UUQYMXV7#R2]LN M>[J-S?C(OQ.)K8KF:3;U!4O7SWAPB]M[$W.((0ZUXR9L2IFT&BWW5L?D5^Z, ME'\;RWS$RY\OT_PEWD@\3382"RK0C T&TL+,F5V59-\YW=!,RUKJFMB8CY[9 MD#)[)QC[U5M79CL]NUW_N.#QTCYIOE+,(?ORZ(;5%\(KPWLA/%,&] R#9";E M%[EJ A_]^T<5-\Q('7W$[>D1XMF U?6=/^E')SOM@LV%\DTIW<\!_QL\+*YW M!UWSW9F/B<7(PU?"[,YE;AA&0?S7Z52Z BY:_';JNYCMD?ON.UPEY_/DK>D\ M_Y/_S7],L8XS"P509A]!8$1(DK]@G\W//9;44]8EE!N/EC&S'P].-#+P$H?& M8=A4,AD!9)(2.!A2\T X,HWC+G-)>M)#EZV]9F/#K0 4O0?Y4\[,-G6G^.?!_R"_KAS"C,2 M>NGQ6#7>JWSW3E-B:7H9ZNEL T.@I!6#ZR-+@9F93W7 ;A_8L<-2Y6';+//: MYSW!XU_2.L?5HO_$%[B)^>6]WLB M;4SB:AI2PE2=.]-S1@O5;9.T&AGYVDC%FF;I_)'B?91LJ]5[KI53 6K]+"[U MCPT TFXPNJ>.;B,4:A#+4.56(7N,;>R#3,"PHH8P?I-=6"<[?+UM%:G0G\&C M]4$[6+$XE5/GO:EH/G Q*B<\7_Y@9EIVF=$P27(;&C&N*[^)>?L+M[^#ZPR/H] ^"626$,G'CH. MZ9#] <8L_-H .@%UO%OT:^-AX#$D?5Q/*Q+6 C&,H5KL5H&/\(U'8?(A2Y?4 M9JD8/(QGN??O5I+-M]1K"$:TW/MNFP>57Q#I^S#9-9/YAR!X(J'LL6,::_]$ M=\3M1?060Y@8 'CV/$5=(K63.OGC-#OMB8NU4)#X*4E?,U?Y8"7?YL)1&O\Z M,WDA3,"H"830:76'['R"U?^C$9K F%Z>K?Z?%S0+'9@\]%>M-!?/U1FG6,!5 M=UI#41+'Q\0X+R#O$Y?GL7=J$CSQ4EA:?7P*SQ0#]=([(B\Y#!R(N&SX-V\\K6,F MW$F-DF0<#=V))IMY#:SBFS8P+G_(=.EQ79-0:4 3ZOXY)A*46E5,-[6)HQYP MF2O_BN38Y)NK"'Z'$2PJ#OF320BV%^B1B^%_[E<+F9C6V'LG0XE8]ZD,20RN MK+SU?:?7LIJ/WD!Z&Y?%T@";?;L)\YIX:(B,(W%H9Y 7ECK;<8RQZ!9*B)\1 MQF(R^?I^LN&0@T96C";Z0JL!M/*#6&!F@":Q-9L_POM7S+[L C#5Q(FHR9VM MU7G+)HB ]I*FHE9[*!(P:LST]K\YF*XUANX=@Z9[7&5?"3PRE$0E@%:>P T; MK 2HKP>E"]P#H@7U7R*(#N,O8L4>'[?"-CMC_][3W;?,21Q\4=RZS[3B! F. M:>OZ6K!@_1]&D(6Y"5XE.TS)L/2!'A,0UEW4)AQ%XV*["=2Q,2$">7LKL!Q; MIA'H\HWPPECT9)X1Y[K#1:,P:Q\48ZO9YI 3%SOJW$[3B2TL*5TU1*,A$0(Y M1,7IM-B.Q\2(%M!1+-NW"(T5T]XGW^MM$9['8'L*:','HCG0W) )(P5B%A]N MS4$;3Z3\!-46C#"ZNM!ZB%Y7S+1ADTQ/&ML,?-$H/M*&0B[TS9:D;M67"R: M _G\9LF*QLHOMTM^U%YYC*P]_I*<@,MT3[V>^[!=]^4O7YJ? M6R='[?Z7X;!W-CSN'?=/3/?ETT&SU6SMM/MRJYT7A$@O$5@U_99"'S=_#/6N MP^GEU??+JY.;\\N+(F3Z+J9R??K'\.S/KT-V#K.Y.!M>7 _/V)?SBY.+T_.3 MK^S\XLOEU3<]0W;YA7T_N1I>W&P]UQW/[?/)5YC&D%W_,1S>7.]@U)FGY#:O MFX\D+W[.OL9#B+IYMFYF][LWRCC8 &UF%],,DD>AGWRA*P.8;TR:0:L)A!BA M% T^HFSFBR_O^NW?]DPXR&^L;7K^W;^ MPFI.<+,TE)$?AO[L4?H(H"D+K^QG7*,,NZE"1X$CP+A6?G#>#Y BW?&K K(Z#$:A5AM?@MVA%8>D79 M^'!YAY3T!.F),IIQNS;3^MN1H_\DV@XPI]5LRZ@/Q< .4]M'W/EQ&_B1-T9G MWP\^_1_'$6(R>0-FVZDP.[F^?BE0M $R2T3%\D+V17V[0R+N ^%*0RSBN#IP MW.:Z8_>L9D4AF)16G2@?LA.=JOM\+2PRT0I!7QU!1OQ#_+-;(5TB0\&B],8T MX?2H&Q8+N>,NIL^0>;6' NQ)8F_I/3XZ9OU:9GN_,Z9:-S:Q/BDTRUFD16MP M5#@U[*RZ!7# ?2,L'REX\/L[S_?$NU_3>9*,(1E#,J80&=-KM4C&D-.^XK:K MN'VV,(8?.5WVG:[VV^ZKV)8EG;8M)JF*Q" PU!8, VMZM2I@H'"*V0Q-CD!B M2,7S0Y$[#*E;L&2;"),#5"(99)6(;RB!!TT"%KG3 M*VX[$Q,1!/HXMX.EAD+^TYYR)U%363_BN;IS-7=&U^LMQK(@0559_Z77')#_0F@@-!AOOM'JTW8Y^?.K>./< MNQ,JU 51=15*+/]YAT4H=5G8[$ZY^7$RP4X[(6VE37M%A"O"E75<=0E7Y/>O5.WZ#!65\*;]L]W2 MA_B'^(?V7RT5GYB8_N7>+;Q:A8H=@'O&_ GCF: NG_E E;]-ZW7X[7V_IU-K MWP]:#6P(/\<&\G?"?; 6ARH1SL<4"5 MJ>C4WB8I(HUFFTZQ$AX(#^:V09]J4I'[_5+HE&S[$DF8NI2WL6?ZU[VZ#<&2 M8$FP+!TLZ^6QFZ)3IJ@EE9PJJY3:-V'4:/:MN?,OT:8JZG?R2-XXMRB/N@Z@;NQ'V*/K-0*I-JUQ7R)>!7KG'CE__G'Y]6QX=?T/-OQ_?Y[?_ ^YW/9= M;DH))_XA_J$C!464=(M;7GR5?"1=&4IA[U18B0A6+M[;!)N[).(^$*XTQ"*. MJP/'[8,/8$\;G#@.K'NHV)P_-)SQE[_FA2,VHQRVNR-TI4[Y21;*0CZG2,^&*<&7_/&"3 M<$7!DM7Z/HBPT ZH>Y/$[RZ"Z.0Z[5[B[)E@:3>M919718 0&NJ+!GL] ZJ" M!O*K]6W7PI-^D/>H#70&P#2_.?$.]AS+W=GK7U(B4NZO#*K+"> ,.UKCO[J? M!2: $D#M[=GUZ) ^>?G;<(XYI)\8&>3ADT^S/N]T6M9B\E41'H2&VJ*A>T1E M)LG#7\497WT2EJN"!7"Y]VW]$6L6J",/9TM,=PXR^Q72FL1@)+XP"^^JW M1,3<7SE4E5V9GKWX:.5W70A8!"P"5BD,@GW6^[L_I$3RI[(.QL!>WI3#3.[V*MXPKEUSAN4JHRX8'P8&X[:G3[U@X,504/Y,J; MY+30=WY,?1>L*_4/)OZ*9/A NPI6&6,1Q=>"X>CE>I_YLYGMP$V@% MLBS)LGQIRY2L2L("88&P0![6TSE*, PLY<1=-N=R_%%ZS.%S26W50A:!*T-H-5MVLLTJ#JTZN4X7XF02T^,V9 ''@R(]BG)8W@Q M/:)+"<>$!D)#6.M+6FO<2*U( M=2;W98_$F54BQR_#*Y;?])9=%AJM[ML?9UZ?.GL<7B505PW4;UJ>M-VGX\YE M21X8[*&!0AZ4->FT ;@Z *ZQ'V').&MNTYLY!N]W3B/[)+$MF(_!J;2WA_,2 M7:HB@$G(D) A(;-^*E>KT6X5%+JJL)3)F'F_AKHP^ZKK,W]GYN5*3WR<"BU+ M6NWF+V\_L><&EUD%1WBA"*P.]UH(=J'+WX8^NW:F8AP!MYP?/K\.JX>>?>>- MG,$S+\0]N_)G_&F9^]S,LR!N(60+(X7^>&]>/?+=<6Q;_S%D)\-K=GIY]?WR MZN3F_/)BZU7,SF6P^ZE:Q M.37=3)XB/;! S.?L>ST_F'$W_V:\)GVPEG',$:X;7_/[N^8[_1D$N)-\WAR( M,Q[<2L\,DD>AGWQA+"W]S;T.WQZIB,>ZL#[Y0 M-YV5\98UW'@]F-_?]0:_O*C)\FHSOK&UZ_MV_D*:X%Y.<+.XU9OY4H4X!ZOE M^A<_8.%4L/\!2TJQ(0C.,3L3CIB-1, ZK08YI/9C\B\6>"D@;^ %6C[/A$OZ MV#H;MINM'K$:L=IN6*U+K$:LMAM66SNTO2>F2>GXC^BS)CY;K;<]D+@$M_YV M].@_";<#Z3&XR96^I^J1@U?<+L*5N!->)-@D\&>Y3EVZEQ>?3*0K>4@-1?92 MQ!6':R7F*K\.U=M:[9JY9.22,20B"$1LX6(H:)))&)(Q)"(*?#4A+W4 MZZJ+F'TX$5X<:(;ZV!<#1U[$A=J8/]F%_TD"NK*5JP8]:P9.580,H:&V:&@U M.NMO2A >" \5QT/WF#H#O-H$+9'?6YQM>H[[5T*%8)TZ_DQ0S*!$0J]=7'P9T*K@JMZ!W7\*3P3<-=';\4QZ4H4!#[$^ MN/@Y%YZB4"XYZVN4(.Q9S]VN !086@4FFHV"MK6P>H4'QX MY6V7NO?-.06'RR:.JN)L4W"8@EB$JQ*WAB=8$:P(5FFF$:DKB@VO;S@/31B8 M_'7RUU_RUZUM.M7!6R>@U! $, M+Y)J.A/P$'_"QF(4DI-=(OE4%2?[H-6T5CBQUIV8"76$N@U0=VRO9PVACE!' MJ%LOI8ETW=N8[U6RTM-S?((BSF5M.[IODJES9&^SBQJC$]0(:D]"K=O>61]? M@AI!K=90Z]@[WD=0HZCY4_8X9DRS ]=7Z@,;B8D?B+C&!@OY3ZHQ7BX95Y%@ M0J=)-2D)6 0L^R4!FL6'Q@E8!*S: >N@U:=-)PI_6S*WP;(&6]L3$VDM,86$ M4FU#!3N+?M=%\Q.6:HNEEL6B6H0F0E.]T=0>] E--:K_;(]S+@25>MZ=?-H M>1U WMB/1JYXE5"J3?^HEXA7A093S8)LIDW(517Y3V*,Q!B)L;<08_TC>W7* M28R1&",Q1F+L+2)8%DO_U%Z,9;SQ7T,.4U]Y?>;OS+QR!D\\T+< MLRM_QI^6E^4@A?YX;UX]\MVQ>=#-'T-V,KQFIY=7WR^O3F[.+R^>)?=,S9)=?V/>3 MJ^'%S=9SW?7<;DYNAM]@P-7%VS M(:S/&3L;G@Z_?1Y>L4ZKP98F8.5U[69K^;2>E2<7..)EO65IQ"<79\6->CDM MQ,J3EP>\ S63>6S.C&PF3Y$>6,CF<_:]GA_,N)M_,UZ3/ECK3N8(UXVO^?U= M\YW^#(:!DWS>7-G,>' K/3-('H5^\H7Q!/0W]W(<3N%JH$QLSX YXO*Y$I^2 M/WY[;((LQIT-P2_,F/;*/94UHOAZ,+^_Z[=^>=%"RMMI\8W;WM??\?MH?OLX MO\WVGFA[=TDP=-Y@>_<%6C[O<"WI@U=XGQM8(I1)0*Q6"*M9;U!%K$:LMJ[= M;R6C@_AOV=QNO6V]RR5VZF]'C_Z3['0@/08WN=+W%)UH?67FT/!FG=A0P;J@ M-CLJ^[]A8C-]I>K[(;2M6]"V+LF82LL8F[DE)&-(QI",(1E39.)'U67,:T\A M-_?;1_KB!^"">LR)@D!XS@,+ ^XIEX?@@#+NA/).A@^?BH@5[2865'VY7#&] M1?Q#_$/\4Q!]"@L4#JJL!?:E-JRJ&L?42FY,I22VW/S]4HX+E=*3F"2VF0-?29XX,%8-S!9 MP4A]WS0&ZR[LU6K5MS$";]!NM>WM;M2DS@T%-0A53R5D4$%# A.!R1*8J)YA M62JP[?FFX8T?]UIFQ^^@T_I 26IKFZ_6"IG4VG@EEY%9PCS\N;=6(JABG M9)J2ST<^G_U("\59*,Y"F-LEYHJH?%1UI5;S5+'%"89Y$GE9E(M@XTA@[A@: MH-P)(QY([K);#E5=7>15[9G6&Y9VZ>H"E(I E%; M,!RLW]AS72ZIL]%(2*DL4OJD-BCPN-TA ;#+DD,"B>''9SY0Y^_T][PAB";@ M!B:?/DT0QRB4X25 5MV]G2=&5=P8IVE*"-.JJP+)E[XPLX9)P2;BTA4M[ MN=5UQV7-D]4>'WN(O FLM1BGL51_!*_5UO-; ';/<-FVMV-8D^-(%.7GSQ_"*G5Y^^WXU_&-X<7W^7T-V?@&? MA^S@Z^7U]2;"BGR^Q^KPJ 31&-*4%*DAU&YDQ'9W9L82:@FUA%H;7-?965D9 MBJ^^$%_=;XO8CBV\ 8=U@,/&?C1RA3UO],VH]W[G-+)/$OL=IIH%&13/D*7. MA@/9!R1_2/XL3*.VO6X%+U&E*C80B1@2,21BUL]NZ164#EIA$9-QLWX-.$%XK ZMROA6 7?B@4YFM?.U,Q MCF"%S@^?G_OJN63?>2-G\,P+<<^N_!E_6LB5@Q3ZX[UY]75]\OKTYNSB\OGB7+NG,9['XJUZ=_#,_^_ IN,,SFX@Q\XN$9^W)^<7)Q M>G[R%9SC+Y=7W_0,V>47]OWD:GAQL_5<=SVWFY.;X3<8\#6._?3D^@_VY>OE M?U];6:L-^2[SV)Q>;"9/D1ZH?/,Y^U[/#V;DDGS<'XHP'M](S@^11Z"=?&--&?W,OQ^$4K@;*Q"(=1+7+YTI\2O[X M[;%X7HP[&W=:B/C.R@#C&J$K/9C?W_4&O[RH/?*J*KZQM>O[=OY"FN!>3G"S M6.V;.2^%6..KY?J7N#C _X!9IMA09\:>"4?,1B)@G5:#/$#[FU OE9XK(OOJ M!5H^SX1+^M@Z&[:;+6M1%V(U8K7G6C1_])N!U(C\%-KO0]M?;N:%&9SKW]]13T;1\B7(8 1P,I4$H]JA1#F"'/K8*[X_<4Z8*[F3>I,C Y; MTF&596P@HAN1C.^XYYB#;RH:*3F6/+"8-$+RJK)=D@[:]HI-UT'^$%3J"Y4C M:]OWA!1"2H61TFY:TRE5B<]0?/FIWGMA%.B.>@Z?RY"[Y'R72.Y4Q?GNV1-( M%$DF8!&PDMOZ77O%Y E8!"P"5F)"=PA8%!->BU7.A!,(KG3?O4"H,) .)FK@ ML4+RUMXJ.[M&-+H"/0Y1H( M$>@(= 0ZTG1["+J:1XP/OD>!,^5*?-"G^##[0DW](&2A"&9,ICG&JH'IQ10J M> .!54 9UXJ=Z'N!0E6).1"J"%5/6@.[ E,=; ("&@'MJ4YRI+3*$2BO9+GG M@TC!']+[$%O>D@H_EU:N522.T*$J@?8<$0(6 2O-A]Y!5)R 1<"J';"Z1]92 MLRH/+*IKFV^^*#WN85]9JFM+=27?@#[$/\0_Q#_$/U37MAQ6@K[MLQ_ ,&!D MBAW,^8/>[?[ 8-+"=&H.Q)WO G6L[H"31T,>#56YI9 ! 8P 1@ C@!' :@>P MO<@\+<3,]B?,\T.A&)C;?.0*?3#,!UL;J.E'<]]C(Z IANF4<*+ ZN8W2:?J MGE*UU[BW*C*&T%!;-+0:O3;A@?! >(CS,:B(0;4BPO98XTHD<=\W-4W)HR:/ M>G&BX[A%;6+H5#6A;K>H:S=:K3[ACG!'N-LI[EJ-=JOX,K=UP-U>A)6+H]-7 MGWN*'83^!S8)_!DU0:,HP1MO9%4E6D"HJ"TJVD<=0@.A@= 0&ZN]MFTV(8NT M^F'FI-06!IE#[-,0!0_P"-_Y03YUB:1197SJ[L":F*JU1TVH(]1M4 RW67Q! M#4(=H8Y0ET-=FW0=18]?;Z('/JSU6)G8L50JXIZC#7;'G\U\SZZY3I*JLC&" M+L7+" N$!9.)3%@@+! 6#!9H(X6BPRLYXS1C8#)X@P0K6;)9FK;=]K5%7]_!P=BR/@I2YUD?9)(&^\1!+II9:!U?'6[650OI9D59:!!%H"K36N*Z(" M[+:DJ\K6. &4 $H +3% 7QD.KTP/XT7?XFPWXT5HA1EDG44A:AMHR@"& &, $8 (X"5 6 'UHXSUWKS M^;69Y/MM@I][#A8 %.Q@+,Q?'Y@T9K?N.*/_$']%\HZ[F'!.X87="ZQ]DTL= M>^W>ZB" ""JUA4IG0*W@" V$AC1SW-J1Y#HH#HHJK[SM]"G;M<%&XE9Z'J63 METM,U27QK=>RY['7/>&-@$G M ;,5H> 2< D8)8.F)VFO=;#=0=FO>/6K+[8/.Y?XXCYT6 M]> D_!/^:XO_/K5:)/P3_NN*_VZW3?C?46RX@EZ7X\\$"_E/H5+/*Q 3((2U ML[@4/-FA&"XXS[ T\OE%IBJ_X*8*)I3^3;*&9,UN^HOMC!A5/A)+XH?$#XF? MS6EA,86RZA9.QG?]->0C5ZR\/O-W9EZN],3'JK2?>>-G,$S+\0]N_)G_&E9MBXI M!D520G]<3L,Z_6-X]N?7(3M_EAC/S6#'([ZXO!E>LYM+9F'H6>)W@?B%#KQU MR$[FS=.(AW/&=!S :C/2XT1BA M"=]Q0P2%U^!33V"E3_U@[@?FU@.\*/%/V\W?XF><^C,0J@_I#ZW?/IA#;R"J MN?38%-9 ZO;@>)T4ZGGDEX&PJUDHPR08);N.1DJ.)0]@2GK")Y.)="4/5W#. M]O:4C@3<+%8LIC:;@DEK*3*CA&64%_S5R3#!S83 MX=3'MC7ZRTG*+'+!+/NZ4.&&5.0TVBL)D,A,B-#H!F\A%4QW(* ^PH440#D!\TT!^^1:/!8%TGY M? !C8X2L961FGIKSWIN/<(:?LZ_U4.>X>=<$KTD?K+T>$ NN&U_S^[OF._T9 M7#HG^;SY&L]X<"L],T@>A7[RA8FOZ&_NY3BS._ONIU?7O1M\PYT?&-KV_NZNW[ASF>X[7T[ M?V$U)[C9_CPE[1!]B#Y$'Z(/T:?<]$F'VR]W1[\ER][ZJ>,S\.QF(Q$LR-AI M-;;8 B'S@."Y&_H4 4EK>:#% _8\/G['KG@HB.>(YW; <]]X&,&U#\1N]BV0 M%P]C[Y[UWIK=VLV6]<9!Q&K$:JM9;>U#N14M9'2\'4W3V^+]CS\])9PH$&.] M$V)-\9:'@J7#];X0[CE OY;Y^H?]WB\5I!DQV^N9[7%N[&MYS:994B**[1>K ME3#__+5\5:7\\]?2@H[:T5$[DC4D:W8A:UH].NQ2G.]++BY%J/:4/D4ZK,O:%<$5Z!X/#9I.VLXC9=N1/]"M(L=*QVMHF55F:=;_:UAI07)6 1<"R M#JQ>N_C\@ZH BS8L:,.BCE%GZR[)U_//EU<+(OW?S$$QF\X*,579Z%.LZW&\ MOX0I'>-4-6C;[UNS=ZIBUA :" V$ANV-_!+YTWMJ_9>(@J43/?M".-K"(&:K MAA_1;E:08J5CM=I%6KM'UOS3RD=:"5@$K+6!=41;& 5Z-^3$4)AD3^E3;)& MSH V*NK .@4X&-9R68AQ*AN:;36:36N.:%7,%\(#X8'P0)L5M%E13N&S+X0K MTC/H'@[L>08EHADQ6RE]B4X%*58Z5JM=3+7?*WX3K"I&& &+@$7 *H5W0TX, M!4KVE#Y%NB2]PQZ=JJ@%ZQ3@8%@K"M?+Q5 (6 8NZ MYI3*RZF2,_.GQV<^S/!O\&/F@9C):,8.QE(YL.*A^D"!DZK&GXD^1!^B3XWH ML[XQ5$#WYS>TB0[:UDRA-0FS8)A-*?-F9@ I>@+:JP][[ IG]?4\2N3L%[B_ M\N?GF\N;DZ\4(:$H-Q&."$>$(\)1%'@#!=IM=(\'%/\E:!&T[$.KWZ6F-L4Y M.'EV&.RW(_-5*/6)G49!(.#>&0\CN% *1;$6"OH2?8@^1)^]IT]=8[U%))K4 M).I+J")4/;55V>KM;!.E#IN5M,&R\K8;/^0NA49$O[EERYMZJV)EA=?$L29"3(2) 5(\AZ MQ_:*Q-5>D&4\]U]##E-?=?W.!I8AFBL]\7$JM,AKM9N_Y%@4]RLM45%_O#?O M&?GNV#SH/R)=>N(Z0@Z1'@_CZA.*?>E[+YS?6G=:79C6 M_OFN_T M9V!R)_F\@L0W<@84NA#W[,J?\255,^/!K?3,('D4^LD71J_I;^[E.)S"U4"8 M&)L +9?/E?B4_/';8S@MQIT-/2T@V5D9:%PC>J4'\_N[;N>7%]&>ESGQC:UM M[^ON^H4[G^&V]^W\A=6$#S?(O)G!Y+6$@.*!^PYOD"HD%UQ*F1/ M/+<3GOMF,N4?B-WL6R"=-[! 7J#E6[-;N]FR5HZ06(U8[7E66[LS R4OKDY> M%,&,G?J>GC]N"-P$$9@GUUB+V^KIJA)1LW08WQ?"%5F)^^BPWZ-*W,1L.ZK$ M?5Q!BNT7JU&*SRN8JOP9/+U6OW!J5"4]AV0,R1B2,21C* 5P50I@-LNMTRXZ M)_#+GS=_7@W9MQ/XY_SF?'C-+K^PL^'G&[8TH>UEG#[IS:Z$XT>!$FPL1B'C MBOD3MG)'S\ZK5P;FMGD0DXHI9RK&D2O&+/19(+@S32JR/.!,YH%0Z"&.,7TR MG IFL@U' E1'-J/RDQ4NH8S* C(JNZ],J.P?[3BKKMVFK+IU=%&YLA HQ/TL M;4\\+^(N^[9QM2N*=S\1^FD=D7=!W@5U?RK:RZAA]R<0+ILXI&O7Y2DX3]%Z MYX*!M;([]<5%7;3Q)L?5:U.IOS-S MS([WAF)U,)M*5 M/'QA;VSC9(("4D[T?:=<3=DXG50@'"'OQ-C,SO$]SK"L[B2#O M^]U!DH%AY8&6$E3>#P9-R^-"_K TMI9=FK&)'^C,F >0#8H!*\"")SOIK'Q) M/_;&LQR9>>.UA3%U+(TI$&HNG!#P[#X<,NT1&>!Z/G.>PSU/A1CCC@/Z#O&/ M+#)ZT%PB_HHPM6HFPJD_)MZI'N\! M&,OG?:'R)I#^\\^3JY.+F^'PV@I?9+: SCTT#SR4+[['[F4X90Y8U5QZ2#09 M8MJE_R_XF4VDQSW,. 1.=T!R*(FW&+:?^R"0V#P*G"E7@O';0(@9D$8UM$@Y M]6=@*S\P^)&)GYC'J=P'!O8WONF'\)@K9Q*%DS\"FYGC<\WZ.?X,?HB?-/-5 MB(.ZGTIG"D-U7>9[\)P12++)Q$A(!D),_P)?PLK/X@*?X[ M)TVB, (Y*N[P!5JTPN"?'8/XZ;@1,@(\S8>+=2(DO AL_;_A/2!87S84IWC([NV5"#BA&-<;2N/M)4JO:"N 2R((;0 ,*F+AM!$2D0M".P<."93+BXYX'J)'0VY)>=ND2>TMQUX "I %\?2"]1,3X M]QXHKZFW RO]!&*TZOAV?F-;95X$NZ)Y,VK5EM.Z5';+KB! M=]V%&18K13\*50CP0#;7=H"!@M"ULR-/8:D(X-CXZ@EWP)$)'PJ0R)<7 61188[Z"0#_G0[#X YXY6\]-R',ZD<5PN0&["[/[N^\^/?__?_^K?,X^+-'KC] M._SE/*37(7NCL7XE)K^_^W*&W/;_NO]S<_:.R3%\ ?S^\:QSW/YR/3=J]U>M+Z/.P>?SEIG_6:PW?_OL-PX>Z=B^]7YQ>GY]^_FB/:IY<7UY=? MS\].;LXO+^R?U;[1$,WLS:4_=?Y4+W[@"K".IR1OZ.'DMVHB98*-CW=K,&!@+H3?]\"7-[ONWS7[XW]? M&R [87JA(1:0]G(J_8:F8F1L);T>AEDT[2<8W[V%Y8^Y._8*$_4,4ED$/C"# M7NV95"I_41+)>>+I__+AH_OP$8,NX]RSE]8$D846Q$<8" =>4E(_ >>38^5) M"F>5POF0G<8F")B!*/8!D(:U@7AL$@D7GJ$RX:%DPMI1EAA0U0-R09[KEP"; MX65Z^''$"(>$P72-(QDP?,+M [ 2OQ6:"F 2S6 (^,S%*&2>T_50\#LO](,' M&*2+S(LA6P"R:T@>FT'P&!7-YVZR$@Z?2TP^0]:*,??BD#'"!40.QMIDTR:S M&?QB]S,7#XM7;@ME^Z1VS&K1,S$*5RC:-13H<:_5/VX=]5J#LVZOV^P=]TZ: ML0(]/3GIM7:J0%N%*TRL8F)%^!P]$CZM(\M#UY=_0L:4SA.3N;B\^'@U/+W\ M\^IZ6%!]%D2?!].,BY>H:(;0_UL8W>'P('A8V)(8#%XTBC/J+MEF\7SO8["B MV(O6E3 4?ZRTTZDAMWU)%"J!4K:FMB5)=E/+Y/7W'>_). =[,LYRS^\I M=D^?4,0ICE59^Z6I?9-50XO(\HN:]NE#,&N390>BHODS)XV7HBF+I_3FH7[( M0>N#'@L\*%VSS0W\TBSG/LB6TA!KWX0R$8X(5U8S@&0<<1QQW%L1;K^+%+W6 MM/S,O1_,];EGK;'AJ^,/VY?R>"TQNH<=:PU4EA>\.#I8Y@EK;0=))I>-/@6" M1U>27Y HR1MH9>C6;G:6#X?O#>VJSUOE$#_62E/MC^)I-SJ]MJUI5Z78$TD MD@"UD0"MQN#8FFZLB@2H:(GFU_+*A1_&VI*/"ZPA4 M9U^O1,C;+S5=(L*]M7?8MF8#EXBHI>/&O2O9_WK;JFNO_47EB_83M A:&T#K MN%6\T*X*M/:D5:X]]L"CB'AD\L /%@4NL-3@!S:+W%#&Q5(:NJY($*9E!V^% MYV!OUQ2#<'^VW,6(>S^6_9[U!V@Y#ZJ];1Y46>(WUJV]PXZU+CGD7%&HLWST M*=15:K=>WDBS9M 2;Y6VZ=)K.:G3:/:M1;^J8H01'FJ+AW:CT[=VTJ4J>*!- MEI6W76+YJ%+&3$IBIK3:AT?V^E[1U@I%W&AKI;BME:ZUY((2$;5TW%B[^&_7 M6KYTY8._A"O"U=JX.CHJ/FNE*L"J]P&>+^?_W_#LB8/A;^3AOT"J?1 X%"$B M^A!]2G!4E>0/\0_Q3]$GFDOD>^S34>]5\UIG_X/T3]GH\];> M1)^*,U$.[8LF3..X2SGEA ?"0X*'(WMV257P0*7[Z01LV6(G);'$>A:/QM+^ MRGZ(D](IXWTA7+&G;#L[/&5;(J*6CAMK%P;N-(M7 54Q)0E8!*SUA7J/@%6, MCU:U_16KQWOWV!T9'!X=V29#G;T.TCIEH\];[ZITK5?"JC%OK6_1O&V79.N< M9DU(OT28JI@W!"8"TU,VCSTGH29@HA,E*V^[_O/SS>7-R=?2N^0O$' ?A%5I MB+5O4IX(1X0KJUU1D;!CJ]?H'U,9=,(68:L(;!TUZ=1$<99ZE0SRKT*I3^PT M"@+,D9KQ,((+,8VJ ("1'4Y!%:(/T8>")6E47#4 MZ[5*XOW.B/2OMW3^JWG3^MO.:Y7H1B'_BJB/XW,_G; 3&^[F0HFO5 $0H4LX*%@OL?N M>" U?/078ZSR$(@Y7"*\4+$0;@G]D+O,GS"^N-CQ9W/ -0PAG/*02<5&7(DQ M/M"96/S4Q>#TXR;RIQ@OGG7(<(2G\)%[#VS*U:.[U3V? MFU)R_CR4\"I^&P@QTP,U;^.W\,TM7NOY> 6,>QY(SY%S^(O/0&:&^LWS>>#_ ME#.XT'U@-MCF?>>PS4;2=>&E-IZ'A 3!^3$0CA\%*EX8/PI5"/,'%#*@^IEP MQ&PD@H7)TVDUK$RGW6PM=T3'0!;XS,G@3\K@(/:AX/^\N&M;5@G]*T,:'#8[EH9T"HF^#F7@4#:XM+Y MD6)C36--6TL,O'S09"MB3L'2NIU:&E1GV=_=AJ"O-J0V,IC(0-I? ^F% "9*K@86JW]RF&KER6/!QJ=B5L6#P MV#93$H;$ WB+"F48H4Y3KT?W<\3+>C\#8%%-3#3+O/!3IYVX0Y8C7S& S"HS"!Y%/K)%R:FJ+\Q&J/5!$+$81&0%2YX >)3\L>2.%BM@E(9 MTUVY([J&!M%C^?W=X.B7#957?&-KV_O:.WGA5I4.*[+#KS_=&SB,?'=LGK-2 M+FV@_M*)O-3:JXB^)Y$>C8;QLG-E-ZRLK;5OH[.TRGJ\UV MQO[O5MA-3ZW17D0-CZ& 6.EOH_$J5AJ[U6BVK269UA<9=='$FVP%U^\89*-# MM0U)_:R+I4U8I:KJY]A>L[7ZXJ(FRJ>]":O44/ET.\4WA:XOR*J$I1OX1?!) MN%%UW:JJH$&CU[0&G/KBHQ9*Z$9GV"QE+UD3NSM-QX[?IG?%"JJ*6)[@9I&Y MVD40LN3EK[8FYPZ8KE32\^DL[YT-K#0Y$R=[DQ/18"?#:Z:BD9)CR0,I%+N7 MX91-N"-=O:G',%T&5L+W5!A$CD[9G/(QXYF<8EN)E(MQO6\?'EG(Q_R/P)!&8(X<\J5(=L M^!/3C#"]--2YDL_2< 7A-54+(677+BDQ3YMY$?*V7OZ47EFRIK2."8R(5$A1 M%QH,KN XWI'T>"8C6>DG MP!M*+W/,1[S\$])0.N9)UZ RY 1T&F;X!]Q37'/>\]OTZ\PGUH:#1V99X6+U M+ IB=+$'T M,Z$2^1,RR,DK7>Z%AC4.>^*ZKN9"IS,)H=L^N#B94@\&=$PW/ MIYYM=7(J7L,"#D]U!U7,#=:SSWDEG2VS@Q\?N#^4WB M3ZE4!'CU@+G,29B))077.FQ957"@$B83)4),"@[$G#^8 P_6QMMM=Y($6CL* M^7XJG6F2Y@P2A+F^TN=L8$V!7R.IIK/X/(YERA];G-=L5$89MNQ,A84C"L.K"\#IRBY.$O99=,ZMPLW!P M5!%)V+4K")^/P) D)$FX_Y)PZ(HP\.<\Y8%R,P/!!9N\8HVKOIV1_Z&;B:)1!*))!(WF.AW[O$9+U J M-IM[Y6BV!W9#A&^X_V!9'9$P)&%8<6'XS?=NV5F$_SL.@+SEDJ^PA%.26/5 <"6X5AVN-U*$9K+M3O>W G,H>K:#Y;OR[( 'R @@J4)2 M99,$=0]TORI0F@SVRR-J]:NR]68[8HZ9UR0022!67""> XOZ;,;'HACY4IF, MSX'5>;Q=G=S64>'G+[!R[E5R>O8,5^'4OQ,>!\YJL"L!3JU,4OX]/,8PX9$+ M3&>%L EP6^W?=$.&4 0SE93:C[LS_$.M:$^0U$IV +Q<8@%]&+ CL?4"#!*O M7WSC)--)3^$D7S .MK\K9S(TE7;3PPP/#(\YW.ERN_"\._W-S(]/=63//"P_ M<\8?DN$U]%$C?(GGAYD7@=?!L2T CE#H,S[Q-'('B18S"/# #Y9[EIZ<13/F M8IUG3:='YY+T??H]W"R9CVTQG"C0)U*0S^)6%(Q@,'E%ZGKO+<'+(&(-[ M)0>GJ4X43>(LY:>N!^\P5.-'F1[CU.RA0+TR><,BN M([ I,^#+W $ORSW>X,4H]T+.+-L]L5Q$HZ4"]-N>,/%-[C2K<>Y5-)L!:_PM MU%-<^;#2VH1_M=V[LJN$%:*N7GA[:\;.(I$@*IX,J):\6N%9K1)+-C0>$7Z9 M/EA+!**>$Z7I.=%JOK+IQ-'6/2!VTSS"PGW-?1EHN2>X)VT\2M@($6/"SH>H%M.P0^?E6=)1T0T+JL"/KOAKZEX\]TN/TW MX,]2M8[9P":S4K>Q#JV.KE-#>QN6I/Y&*YAT4P%8,N8KKP D;EOBMHLDSPMI M>J*C+H7*PA*5L;5"59/BZZBW21]"$EV6[/VWZ>EB MCVVP1M3!YX#_+5UKUCP9[:4B3ND47%5; '4Z'5M<4A5A2FBH+1JZ'6N^5%70 ML-?ML.QQQG_R.QYX%$A@=42 M1%(%)2F\H"LMQ/7[TB\/V8GK)E<^78\B?H(N 10"7]_"'V.L.#KATHT"7>0! MB]&X#Z;HD*EZDZEYYHU_]?$+SU0#P]H7SA1+61Q@M;)\I;(/V:?.A,!:&!.L MJ*!K03B+0G'ZC2(4^3KH\![S>J"34"%00NFZ2/#_KNL[ND!.*&>B89Z=U(Q) MZIS![3/^4_^Y7 PM?78@_HID8(HEX>L7]9=6EU8:^TZ4%D[456OF"2I"@?'N9FXN$/F"J=]'$,U#Y\&0 M.8P"7>X.A*TK K.^<"O/HP+CC'UAK FC/ D3%D))T*(.? _,DS+^B-BIOP. MEM640\*:*;#\FII84SQFKGSUHG]@52.LH*0KAHTE%C$"U&D83@)_QD:1DEB4 M#X@*.--/F,#0X9$JQ&G LP#8"=JP2* "#^JUGJ$;,U ML@6OTL*O]Q(4QBA7PA+($KD\2!@"J*:F,-:I[^*$-3&%-U;,2 7\S_LXA]>" ME,?7(@H/879YS:0+@&4$QD():03"_:8:)SYQQG5!2I@?$F;%J,M?/7.\6PMS(<-?\Z%!QQC!079$JCI&T3\AD0$/("5QK 6VS@M$,82+.JZ@\ M MD6/, "NC>G]DMP4G#-#E,8L:U(&9K;@V=S@(-T^$J&! $P3"F [(E%B#SGW0 M$+WUX(%CE+GR,9& E3-M2;$@JUQQ%5()59JV$("+D+\-6$(?W@R8C6O7:5V& M5W-7^?% 5Y3#@JGZX\.MEJS[>,F**$W7M5L".;N AB9:2BUHF1(<+(@ Y+7" MFGP^2+TPKE")VFX>:4D0!;U1@+ M+ Z,>AIM%[S9QZIL=\+UYT8:CB,MZI' C=3N@87](5PY]?VQD4D@^B?\#BP) MM$[\* 2!O5BTQ"1'Z9S,QS<+GXX^.U@>;@LII:R8?"23?H\J'#@\"7:S4 MU/Y[7-<0*\XFM;A76DB)Y<-3+\I(1*5--NW9457 \E0%;+^R*F"WMVU)N M>X;GODCLV?$MCM$2T]G?E'R+4JQODW:WFL->7^F2DED)=96OKUBTY?8D#-<^ M\D3YHZN/!IE]EC^]9*?EPK=GO=6"@OW#?N^7"E*L=-)Q7PA78$ZC5;NC/!3; M+U:SFI)<#AE6BAIX)<%89J^@<*K4Q;8G64.RAF3-\FVM7HMD3&$.7)6\C$+] MM"H1ZMBF.T;JJ6ST*=:YLE:A@!BGLB?S"_ /JJ*B"16U147KR%KQL:J@@78< M:,>A$ H.#IM-VG%X:]NW1(0KUB@NONL'L5K]BI6V!A3Z(F 1L.QWF&L7OT5< M%6!13)EBRFL0ZNOYY\NKA?3YOYDL- HU4ZAY*ZO:6NL:8IS*!M7Z?6NJO"H: MF]! :" T4(B90LP48JZ"L-X7PA5J#+>+;PA&K%:_2%CWR)J35?E(& &+@+5^ M(Q\*,5.(^>TM\2H1JG_8&5 LF6+)6YG/UG;2B7$J&SUK-9I-:VY6590SX8'P M0'B@>#+%DPNF8/=P8,^\+1'%2B>N]X5PQ1K$G0I2K'2L5KNP5[]7_#Y%52P) M A8!BX!5"A.]2G8DQ9/7)%3OL&-G%G5V550S MH8'00&B@6#+%DO?'M"T1Q4HGK/>%<,4:PU1PNTQV055"7CU[AYDJ'_(B8!&P MJ'Q[J4SU*MF3-R*8L5/?T]/$YK8W0:1"=HWVN0RE4/OK_Q='M",JLTSQY6U- M:JI]01&U%PUD>W4'JZ*F"0V$!D(#Q9>?Y90_/3[S8>I_BS$[.)/*@?F&ZL.O MWP,QD]',FC%;(F*63@H1X8AP1+B](-SZ\;$76BY7)7YVT+;&=J^EV(+%-B79 MFVG?#X19PNSNSS*^.63KZU14R7>X_O/SS>7-R5<*2%0UKDOT(?I4BCZ5#?@U MFBTJ=TMX(#PD>&CW!H2''87 !_MMQWX52GUBIU$0"+AWQD/+B1SDG!/AB'!$ MN#TG',71=I [6O>(&@&4 &IO_M8=QVVI^H=![_Q0^Y24(*"F$0?HL^^ MTR>OYSJ@Y\9^A,=<$D7W:AO@S>3T^YW3R#Y)2KUQ\")=ZN*ED) A(4-")B-D M6DUK!Q)J(V0R3M6O(8<9KKI^9P/+$,V5GO@X%5I.M=K-7W*P#6*A?#3/)">(^?<97RFSS*P<20:S!,A M\RG'1KP-; 4\Z. !0*^"Y1@8S$*V<0/]$,]F!";R#O!'H!FBG%O MC-\'@D]"N%%Z#(;M2M]3G[8F8H85'2"<")ZD6N8I.3G9?$1Z_)Q]C><',^[F M5JN%UZ0/-F1UA.O&U_S^KOE.?P8(.MU(V= _@MQSZ[\&5_2/K ^M](S M@^11Z"=?&%6GO[F7XW *5P,A8H #<%T^5^)3\L=OC\&Z&'2[8_.<,^&( MV4@$"T.GTVIL$WCMO#+P6@"5GZ?LDJ2Q3ML+$2[(^CT5SB=&."]^.HO6+FM& M1_E6WM9NMH[>TH$I>&^J/(;Y2\Q4?H.86M@;4-Q?KB MHB[:>),$5"J\1BJ(5-!+B-JD$E1555"_;ZW?0GUQ41,5U-ZDS'SM5%#WR%IE M.5(])5 ]]CCC)HWMD\+YK=/H'9/70RIG[53(_"::-1%;1,[ DXL2OTWOD2V% MZHM>:Y4@G./LQI: \M9#><>.YD'TF7@Y?8:.NG@ MU)_!$C\PJ50DQFQI'MN\YGVOWTMR%:P\D/';VT#<\G Y\P+S+:R\8W4'GZU& MJTP[)<\/A4X,8=BQY1#+N3OQ\=][&4Z!_%+!\"?P(.\VOQJ!& LQ@_6XDYR% MPB2.X)7*T@IUNMWB5PB61H:*B9]2A3!%.T,?'#8MKU.4MKW*KEBKW] 9.';H MW>H=V:7W7M.VW3QD)XIQX',5N1K#R/TN#S'1*0RXI[@3 JT>H\+Q;SV=5L69 MZRM CP<4P/E'4DUGPH@#G51E2RR\'[3M+EPXY2%(6P8@<:,Q3$5Z\20]K8L! M0F-V'<(_R7PNYR+@2 UUN#PG*]ES3?MZYAL/G.D*/9-*-ICV)')=_:,MC+7L M+M6(N]QS1((U*P_MK^Q181MBET[HCP!*2/\DC] 6E8\L:XXBJ'R\$RJGMM31 M*G$&GFE&DJD2B+)VIT2B;&\DV1/.!"=W'FXVZ#.$E]/7)]K! 9XRX++_R/R-*L?'S(\M6-^& F.)V: RX4*&? ! M-[?9XM;_G[TW;6XD-[9 /]_[*Q#]9I[5$11')+7V>!RA=:Q[Q]U])?4X_.D% M6 6*\!2K.(4JJ>E?_S*!VKA(HB@454LZ;+=(U@(D\AQD)H#,@27T\F'P ';B M.!1B=P(7C-EOUV=?;CH(6!&Q/\'P@#YXLU<2[Y1+:\-^>%1NY"(9Z'28(ZQ\ M"$/MIQ1V7",*LVPQO"U6 -2@L=$[7,4-B9(4+==03+CT<4P*QB*?3L/@NYS M2[R9+4?DI!25>EF3RN%TVXO#>23(Y< MH^ 7Y@8'_D]&;,0=ZXPC#;,&9DE',<\+& M; <.5V-X7^ (X2HV"H-)_JP)3@)#@1:D)Z'Y0R(3/CW_%Y;?1G^X:X'G:*^P!0=-HPCY%WFR8F,M.IWS-\\>TF 64N0]T'% MA.N#-N$EPMH 6F7@;MN\^,PM^7GQ*VG1D#L-F*B$BI5E=C ,/R0W&2\( MN.:!XL\8>P3\$H?.F"M\\*(0)B*\%TF"%>[ #4!LR1P/O*4#@8;\H-D"']&9 M-W%U_(6/1B \GDY P6BTFWK-:BPP$0PT#<;V 7H$RLA#>,*]F8',Q&>D-)(P M6([4^UFGF#0& US8B;!ILQ7W5) K;-[O7&%-O]/Y*#6,]-0F?3.!I:9'+C54 M&%68RGB!T>#6+ :(KPE1Q?4='728G=C3=G@69>LDCA%P!NJ4,F8\!]? EY-X MDC!D8A<58.3^&^ '#PJ,#0^MF&O#_-5YBT")[P5VVS1#3XM%=K;EW?2Z XLV M=[]W\',VMZ5Q6PSQY^9&;MBO-P'F%FY&)H4I M"_DZB*/"!%.7-_]@YU\^_WYY5M(?X4 DKSC]?7UQT ZB.8 =YLU_B=:BKTK "3_S0 *ABB*Z&M6;PW8:7? MKR\[:12UA.AV;Z\[L+Q29BW,=;!\5'.C!H$[P1ZX%PMVA^[;>>#K8PIX .%K M*$8B1*S>(F:U :/N MZ@Q]>I+)7%U[0]*SO+ZFPR'98B$(.+6$K>WNM]UB6[(\M+8=*6>9_XGU_',; MX[D9L#K1@BBJ^X48@I1A;LHVR9RP'9Q./IC6Y*G'L@L!! G[#&?(<-UB !.' M+HT0JY?X#]TU7/ARBE'EW#96^=X&K10>>#5R)),G35@2M%8D_CO*\B4(8>2_)OI:$XL?)-Y!;Q!9Q,3DT,_SD_V =1%VND8: MQ)Z;KETFBWA)?,8MA!3GH'T[S^_/6[#Y/(U61L7,/&!&W2-#^4GG4M\_V]^I M[;>DHF5&(0\XA8E=.WEZ_2N83*!_V?(7C"AJM^"@'28$^9=4SW%_ M@S85TP,8^5M[>C$YO8T75,6$SI&GPQH]Q%M6["?%'/1_,#2>.I4'XL !K]/L1P'"7 M_@W#6F:DP<@#!],5.I9EE"599E"YLY,]T,[8[G$R6L,S\52(4Z/)%1$@AVT8DN^L3Y*@=. M$_'4VI+CBNQ-;^-7M) !#'K5(QD9L**38*Z;!W-3HQA<4R:^B]"1Z**BT: S M+^12R +FV3)0[F4X :HK&-["5F\_>Z=&%+KN(]9*"7CK2#PS1CX>.!+B" MZSZA7P;$W''BB8Y/%Y5,+QLYH=XD99K6R0[9I;V:<+T] ?G"0UT-]&C.O\ZX M;CD==34?H3Q,*#J5R?SBIA$*OJ.P\A4EFZKDQ 0ED;+RG]$SS66VH'IZ_70H M!(9@I/L\+:1___6G6.W>I3/+KM0A7/AP(T:_?+BZ0/_D__;_=7?Q@4D7ON!.M'NT=[YWVA\< M'1_W!V?'^P?G_?WSWMGE_LG5R?[5Z=7>A[\M4%91:5^H&O"A2HRG/RXGCK^\ MNKRYN;Q@5]>?3S^?7W_^E9U_N;TK(>YZ'B@3.8]U $_'TWU?Z(AVNNM9H4P8K0QM.LR:L0-D:V+DZZ?>/ MSZY.!T7?]^R:X_W][=?/O' MY6< RNGG"_;WRXM?$3JGY_"S7K,#'?'QYA>;WP .UT;Z)T999/6P[ MM(-&@0?@T\#7._U8XGQT=.QL-A5FKV^*D<["4ET01[B=3<_^N!M>Q]_,5(>S M:WYC5DZ'&?$)=Y>G&P*R8P^:R+B5X'Z2="G)JZ3%"*9 8+;X?L+$08G&K@SU MV8O28=PR=/6.+KWO6^AP)\JAL#E%YLRC*1)($,P=3XYF\\OD8\-)AL(Q8#F6 M4RI&]*9B1".]@[W#XW[_$(1R?&"O-%%_[XVUB?K]+=H-F2J8FY<'J5?"4Y),W]_ =BJ2]I23:T6;B.GK2%3HWZTJD6Z1; MUG7K'V9]A72+>)WD4PGYE%H6X/7%/ZLEGXV,S7>HHKIVY0GKA'Z=AMEO<*D+ M(V7G(9Z\-T:$\Z:=T8=/OA6?H^+I$^. Y0R60D;Y8P^FD7[(3N^C;AP\*!MO MXI2M :*#B:5*TJ#7]SN'@Q)8<[ #!P@C#?<.0.9[@X2\?,(?!AY^R[A >FH0'RR3Z@VT1 M$ ,0 Q #U&M&/#[J$QX(#S7% \V(Q #$ (U@ &NA!ML(Z2W7QZR-6)JO-A51 MDOUCVT+(![PVT^=R*FYKP,#!ZD/^W1'^(?TA_B'](?D@_)IT;RH?G+JB];H8A2>;& M\['T!/?9-U^ZW&6N8%:AA@6Q>7HV652FI'PV#5NO7*WH&UDWL$ M+ )6!01'\Q7!JC6PHOF*@$7 JO5\5=G]-;WM[80@16N/872TO7U;+=E@\U/$ MAYY8>7WA[T+SGRFQ\M;V_W_/_>?9ONE.,$=X7C(XOWS8^Z _PT XZ>>D-<7Q MW(?!*[;N3DZ$8I_%([L))MS_F3V%\57!W$?I1N-/_?UU%&)>5=>_^-7QY->H MYC-CBR48YHCC$'OY^L&>JP!AO:JQ/1+%!KQ)=$_#_ U%,/1M=V/!SH,)M&7V M%\5DFF0_Q"3[;E[(3OHJ"F,,JBLV#>6$A_!<^-;Q8EP<-G;!I M&]E01(]"^&^M#*4E<"$<,1F*,!_O0:_#^GN] QM/UQ*)=-^C&*Z9L6"D/Z\4 M;H<]CJ4S3@6K@#'"1QZZNRKBH1;PZC$QXIT?/7RQHW?[.>ENO_QF!=?X]WA+ MWK!H#%/8_=B*4/M[@V6C;5/QV6E0?_D,_P;/Z8"BJJEP4(C>K/OF2?)5DPU- M+O6=7/HMG5RF(L3*35A[$ICO 28.U/C=9((91@D[80' L2D *!4;<@5_!+YF MRE"8PJE2%P-$0A#?7)*!,YER\ST6OBO.2Y+M:_F(5YXRISF[X'FZZ>@Z'SS MN?@:/P@GW)OS27I[1;188Z>%EH/]<"]]TT@>1T'ZA?&3]#>&HGI[((BD8J:# MF8"G2GQ*_UC2W-6N 9GZ<;\\N'@Y,=7TF5R8V_+]QW5I)T;W]>O M2T,/7G4C%0:E776EKLZ]E&S*S#. MX#WY8;-"T3["MGULOUA$J/*%QZVKX.O1&SW_UPTL).A(N"!?;PP6["[FO MC'L-+O&WVPM2P"TMJ%;9,BA? ?^IOQ#N[BF(!V-#-V+"I8\1[CL13M[ UT^_ MLY0X7IG6(V&(Y+/N)'=4PG&IMTQ9;P@=KT;O#BY52<^#>4M1-;#&(FSK.C43 M/%Q?H>@$7G5\_PI)MG*H7M_YH:J;I'&D<:1Q]=,X$MPF@K-@P;R##*V8*OJV MT_ >[$IP]-E7HA2,F(29I%Y/TCJR56R,>(1ZID\3*1-5>*X*<]@1V%O+_2$]RG]V(%5M( MR#&E)!)OSO&_-B8IAP3ABG"UMB]:GB-*N") ] QX-0][:,UK=)BYKU3#;,C\1&!H+A@&!@<#P[DL%;3:]JFG# MEE0^H-3] .0UM3<:<;S?.3RD;+&$+<*6_56M'@&+@$6AOF;8FW4.]3U9A6KM M+&'5\UXJ!\.FACJL36)MF:L("XW%PJ!G;?66T- :-%1,/O6VPRIDT%HTT* G MDZ&D2%_U9JBF1"/Z!_U.[[#\NB)MF=<(7 0NVBQ+N*J,(5DAP=7;PJRS(7D9 MA];,1P)<<^,8M'V)P$!@2,"P=J)U @.!H9KRJ;?%52'3U9[<_I?_A_\Q5A'W M);L3_KUHH*%?.5BV+O+0ZQR>T(E"@A9!RSJTK)F%!"N"5>T%5^8^&+D'O>C#T&L8>;79U0<*4+ MZ$ZH*#8AE(IBKX-04]TZ+7P4"1_!.&)!'.K*UO#RI#JV,RM6GF:/2?4D-ISI M9SA!B%7I Q_'-P.WAKJ:JUG-)CR*X5*X"PR>^_'RUO0-.M3?ZR_O>-G@.6_G MC34'E*IIVZBF??C&8MI'>]NNQ3RH2]'H_286C2Z%4?4G>T5^JR>URKG2I2Y0 MOB"K.LB']*=6\MEJO;'%JI<;&#S-K#UN7=+GP602N.BZ4M'Q]UVGJ'QQ9>NZ M]V31<5*W4B:-2A-=^>J654[.)?O&$LJ'3[ZKE+ALF9,@88?D4R^'9ML%<'.9 M477EQH./JBO7,4'AU^!1A&SG'_\<6X-FA>16+\R6M^^J#I6!:!,6X:H&N*KL M)JS!!C/ATYNPM@: 1N_P6M ?VO15[RTE+=_T]+B:^_E^0A\.*)6+63 M).3^O6!@XNLM)?A4NWM*>LLU0#=X3KE[2HI4WL$+_>+]V8UF]UED'NBGGZ) MP2DIS^E%ZMX^&_AZ)\G7$7P M'%]$1AGO0R%,1^!)2D+?>5C\=@?>' I#7CA>"A\"8[\;C$9 9QXT/?DF\O0M M* T^064')A*. )FA"8":,N4S_3>8DKHKP3QQ?=0706>'W..^ X/B!\P+@,R@ M108_(";<%LN+HZ&>9Q+:>;;%G6?]@S=N/>OWZ[(3;.M[Y*B#U$'J('70_@MI M_;812TB5DT_>W-X[[$5ZRW+N&P)FJ_T_VO=,:O8.:K:_09"%I@#"IGUL#FJ_ M&[4$L*:Q'U(X4K@M*-SG(,IE2MI'VK=5[;L+(MIY3[I&4RLI7/,4CJ96TKZ: M3*VTE7L]H9HM#K807"$9UAC:6Q1B'017&6&1QI'&D<:1QI'&54=PI'&D<:1Q MM1!<981%&M<&C7MC3?3U]?=O5,PE<*6"W'5)[\TZ;=].>'VR+H/JGT)?/ M>U&!.$(_H;\=Z!_T3@C_A'_"?UOQWS\B_!/^"?\MQ?]R!1%"/Z&?T-\.]/<' MUE+0$?X)_X3_VN&?YO^%?I:U@;+NZRKGJ[*8V5(>6@7=0LF/II0NMV>S;"RQ MII =X9)P:0V7*S)'$BX)EX3+=\;E/N&2<$FXK!PN^];21!$N"9>$2VMVK+4= M,81+PB7ATIH=NW:^.\*E]2#WO*X>L_\+AVC*J_LKBH*2@PPJA-(64B6&(88AAUF>8@;6=RT0Q1#%$,40Q2Q1S M5%*(EBB&*(8HAB@&SU\2PQ##$,,0PY2VS+Q?TGH640Q1#%$,40Q0S'%)6[(; M3#&4J'OQ-OUI*5'WN@7(:=>!W5T'E'./LCR2QE59<)41%FD<:1QI'&D<:5QU M!$<:1QI'&E=]P;4\6_\0B*U/G'5P0,FZ"?^$_[;B MWPS_<;_7MS;^Q /$ \0#->,!L@,(_X3_]N)_OT=I.PG_A/^VXI_\ .(!X@'B M ;(#EOI)Z;N?2-\=!DJ56A25UD9MY')J2JZF0>EJU13&(EP1KM[3\B> $< ( M8#1Q$:X(5R4>$;1W")EP1;@B7)%!2 C@-'$52%&I!KR6;(8#()7!G1/LBJ4D];:EKVK'%6ZVM:$BX) MEQ6,/Q(N"9>$2VO1'WO;,PF7A$O"I25XV]^WMN^D-27NB&*( M8HABUJ>8DM8"B6&(88AAB&& 84ZH3B]1#%$,40Q1#%$,40Q13!TIIF_MT ,Q M##$,,0PQS-))$GOGJEI#,85UN)\B#CU<>7WA[T*_/.F+W;'01-+K[_WX1Q%*1?&!K5WSQ*-QI_ M.CGI'N\=[!T>]_N'()3C@Q]390(E\?A4B4_I'S\O*D;>B^*2:*Y<1RO7OM=8 M5=5-^^7#P>&/+^KM/$B2&WM;ON^X)NVD_E'_RGO?Z_9(D$U(\EE//EESC]ZX MKZOD[5M+-L0;#$3]Z=$8$U+*U MO12: &@"*!6:@W> Y@NR?&^PGBHE(MJ.2&PM96_C#_ 1 MQ1#%$,6\7A:]?7N;%(ACB&.(8XACEM+ZV,M30!1#%$,40Q2S;,;8.UC?=(YY M:ZZ3>H>N/@>^8S=Z1=1K+S53R9LKK!\B.;97U_,%R32%?0A-A*:GTO+NVXMW M$IH(3>U&4W]O:UFN"4V$IH:C:7!(YE]^LJ6,-#&L?_)R.R6:TWTH0'!!3IG M1Q1#%$,44^)J\B%Q#'$,<0QQ3(EFC+US"T0Q1#%$,40Q2Q2S1V9,>:&O!D>X M@A%SLW57)GT5A3$NI"KF!Q'\.E+VPES$T>N?-JO9:;*=GK5T)8 M#.QEL7VKR)ILT1!H";0TJ]*L2@!M T!W^EM+W=?J6;7E"\6?190$ R@$:8W, M7H%&2]D6JJ%,VTNJ4)]-.X.2$2OV.1"">XO0:_Y4H%CN3XAJ]?3ZWI>74&DZ:6]IRC:T&^ MT]Z^O8-VK<]W2C36"!I+WH:WEF92M8/D2I&D=0HLJW+<:X2Y#9TC@B2")#NO MI7;>X?:"#F3G$8T1C1&-E4%C5&6HE*#J3Q&'KJ^Z?FL-*PC-D[[8'0M->+W^ MWH]S"GH,VJBE*GT7*V3T\ M+8C4?\?)/,H)1<\R3+DB$,E\Q)!KX&.T\ MQ\.$5T"M[.]X>%"QI=YMSJEZLSJ[&PLV"CQXA8ZRX@@I-@V%PFHA.])G\#0/ M6J,^ZM K_!+Q[^R>2U^Q'2]02L O\RF?3[^<_\:X[^;QW%!X.EH;!?HA(NOJ M-._J$QEUX'E_QB"ET0S;IP]7XE3#QB /_$8_&MLWEE.%#7:\&(1(8F@Z#"9)2_$E$5R@(B:^3X6O1+'!V6\A?/-4*_5+0#8/,HB5 M-S-A\4)(/.F"#HC/]T&DX7)H\\>.B9:/0#6SY-GYSS#,(%4>NDH_IQA51VDG M$NGH'_58P06!B[US@9F@.\\7>GD.&P6&<00*Y$DP%)XR-X_N+2 */Q=?XP?A MA'MS(.SA-=F#M6HR1WA>042[N0$)/19/+*;8,*7K),) M#T%LII$\CH+T"V,*Z6\>I1N-X6H01$+H^GSO5(E/Z1\_+W)PWN[B4E*^+?]H MY5[X-5:C=&/@GJ,?7YPBYB>J],8MWW=8DW92_^K=O_YQ31I:%X%2_]ZS?Z_; MC/!NFZ!*<5GUIT=C%PP#SS7/^1>8DXI=@OG@L@OAB,E0A&S0Z]CRU2AN4FAN M[XW'!DL^';ADA%K7ME_1P\F%N/-;XNK<9*Y._J/T\[_1I2"-M*:16=/?>H[5 MEBS7IL/R5?0\\68=[0"COW@.?C#V6ONNMQ'\8]Q3<*^_@#=H'.4RI+\=Z59. M.XDOU^'+^:#+ E462#0*\D^72>AH@S#C^N;2MCBCDN;4W6PJD!CR"L(T;=DG MAI?**+Z#"KXW4_3W>@>D:J1JVU&U?5(U4K7MJ)JU0WVD:E53M<+.R>575$T/ M:78E/:R"'E9LZEU?=J2D[5'2M2=M.AVZ\K;K)[;'O";,2/M<-P2^==9LS3;6 M^N]2W>GME5\B=1DOY0F(\D 3 1$!U8B ]OOVCOL0 1$!$0$1 ;WJG,Z!M4A7 MXX_A$,>4Q#$5$MP6G/SD?$P#A5!"(@(B B(".AU!-2WES.RS014DW.$S2>?ALEG[3TGV]GK63GYD/Z0_I#^ MD/Z0_I!\WM52_!SXNZ&XCTU"*R=0$9[Z4]RSMT6/U&G]>LN;R.I=RR;;5I(F M.UL$% (* 86 0D!Y!BC6CZKL4VS!^4K'OE;>=AH!1SXC 4OC.C;-T5Y:;& MK#ST][:F5TUF,P(=@>X5H"L_*RJ!CD!'H)M+5T3Y&@ET%0[$5TAPE*:X25K7 M/JJW%L@GIB?,$>;>:4V *CX0P A@N?]"D3K:)%Q1WX7D0YOT2'](?TA_2'\J M*A_2GUK)ISQ+\2H(!3PVWV,1A=Q7W(EDX+-[+GW%=KQ *:%H+R3M^MKB!HHV M>%^$E!8CQ5IF 4(*(:7)2+&W5:$-2*&=Q.O9N;27N&+L9%T5WY&SMK Z0ORK0),/Z/)A, AS2X[ZU,'Y3>(3 T%XP6+-B"0P$AIJ#P9KE25AH#18J)I\2*^0%_FXH[F./ M1\)EH7@0?FPMMP4I4F-)==_:EEAB50)#S<$P(-^3P$!@2+9^T6&)LI,ZT,H* M+4F]8WWZ('1%F$JB-_W.5.!)E_T_>_H_5+^>-)(TLM*")8TDC:R68$DC&RZX M;44PG4!%6$ /"^G18<$JN;%;I<1W/0-M;ZO36T769,^90$N@M0=:PBQAEC!+ MF"7,OBU"W;3MR'=!Q#W;"QHM9K%7X' .'2#>.B)#(AO9JAWTZ,?MBXC^R*Q M3N!'UI8*UY9*DYF:Z(?HA^CG%<66[.W;(?XA_B'^(?YYC4QZ@Y.M287V%1+% MD'Q(/C1%T13U*@_]B"QDLI")?HA^WFDKQ0'Q#_%/L_DG>2A>L;ST6 T%JQ0Y ME2&O$@IA5#RV6 .MVV2)^J>(@VA67;^U<$5!-I[TQ>Y8Z''I]?=^G!N88Q@% M+3SI _-%GP8X+#;Y[VXLV#04$?_.N./$DV2+;!#!+3"H$_AM+'PE'P23/GP6 M)F7M1R:^3X6#ET8!&PH6"B>X]^'9+N.*<1^O#@57<+TKS%\?\=+D(:,PF,#C M_4CZ,?25!5,1:1"(6*&(R%8&/AW@O5L=7D00D-=D+0Q3R_LGKD4VL-[O7MMW>TF!$ZE3'W M75O-/BQ!S%F^/6RGX0;3\FX]6.XJ,/0Q XYF E[BLA3K+('X?B?E09.2VQJI M_&!W0#K @?KT LPT2*!A ,\&!DVQJ]@C_(M\['&EY$A"7^&W@$'7?;A0$R:' MWU7LZ>>@7%RI$C+FOB/P6\X!A-,R(8S?;5 33)O#\ HD3[W/$ P3"JFS9$$ M]H=9008NVX'WN0',3J <.,&8]\$,(:;Z%#I[E-%8 M^C@KH=+A3]RS,[C18V#E.;MZ,IOK-*),\!&,:I?=X=]:[%;>YMMI-%.Q,P9] M$!/-$BG U"J$67FAO9D8>0R>-N@N-\P&@?6.[1&8^8B7?Y(1V-".>=*U+T8C ML,#0,OL:A"D.SA&U5XC:OVN"MB/X_S>O'8*Z",/MP2L0:]J41N94T&_%=@!F M"=N!C1CEQN5\N8.BN0AW9-2DD6ML2H/PO(_3O(]YTE>X0D6AY@6%#_HS!@&- M9MBP>?I:I 6<H9N KP,#.(B1!>]!/J A/'25UNQ"EEFM.$IG/[V\)KL MP69,'>%YR36_?-C[H#^#B^>DGU>HT!W0EV*?Q2.["29\*5 SX2&(S322QU&0 M?F%\4OW-HW2C,5P-@DB<3W L/;#JQ*?TCY\7GK!R__D:NY=U M8W[Y,-C_\45?=]Y53V[L;7C?H+_E%VYZWW%-VDG]>\_^;92^AJ+,)!^2#\FG M1/GDS>V]\;1\ZNQSG]+K/.;.>O\,K'. M-XBT$]\37JW))VOZ6P^WVI+EVFM>Y0/X/ GV.=K#1=2>@Z.+O=;^]&T$_Q@O M&?SG+]EB"VDGS2;VE?%?.@AXB4' 7)3%:&"I,\FVT&]C]=NZZ.]F4QV^O\@B M5@1QFJ#KEOFN!%F^-R>N7+H@52-5*T75K)5V(E4C57M>U=9.S_#Z'#$5RO14 MW@;&Z[D]5R74LZR0%"N'[;H(;@OJA_LY?67-7:B0\.JE=1N=#BBWW'%U3@:\ MI%0U.*Y4?NUX.J1$]$/T0_2S\K9\(U_I4FE+/A'B&N(:XIKEV_;MY=YM.L70 MEHF*T O)IYYAC,\B8N+/&(^H%<\3X$&FT4AZDD?V FJD5XVM2UJ">=R4*8I0 MT5I4[/1L*TF;0U,$E,8"Q1I.FC)IT)KORMNN%M- T+)O==RB"@ENBQI8S-@P M?U:[@7*MG$*N7[>K*76Y[%5UH650PAQA;KNU\ ASA#G"'*VW5\1I;))E?CZ? MTK $SY!XJ&KRJ=_V7M(A"F*V)8A)6&@M%FCERZ9G1$!I+%!HXP2M@;U.8^Z" MB'L4$J%42K3HO"64J<[Y4#>K59:">J/6$Y>3 MBE,-[J[^M'[=J%RPTL__IDI2A. JR*=!E:2L0[K\2E)K M2W\[TJV<=M+\0I6DMKDFL%KT5$EJ&Q"O?TT1ZXI'E9)(U;:G:E0IB51M2ZI& ME9(LG66E2DD5"RE42'#U.TI=(>'52^NL;MNJAHY1^0!*G4*E2HAKB&NVRS64 MCI"VL!/]$/V\%_U82S/2:OJA[0(5H1Z23SU#'%1%Z7WBY90,J"W)@ @5A I" M!:&"4&$]9PMY.*U=&:9Z2A5VD"HD.*JGU!*%7'NV;$J=B7ZO_!!B6ZQ- A8! M*\^&OV\OJ2 !BX!%P$IN.[27F5DV>3 ESA+FUM2:8M&.;X?A4Y(/K64S[8<-"=0$:YV*>[10A=%*M;[M-K%H7@"!6):*[CR)K";N5:WV! E2))]ZR:?,R@Q.,!$FP<9'-@J# M"0NRPH3HS;E2.7";]&-P\8:QDK[ 5!SUE67E=*VI84LZ\D6H(%0L^5-'MI6D MS6X3 :6Y0.E9V[[>!J30FEA+EW9(<)5SJC!G!B8NG'.KP)&:!HI[^NRAG$RY M#+-:\'-.5K!)8?BZ"+URVKI^*L+$!?G\BD27[$71!QCT)E35W5(_DT23[S7#T KG:#>.B)C*S? M/)TUH-[HNC*J?MW1WG%)9O@*J31E-B>*(8HABEE_&^ >40Q1#%$,44QY%'-" M#+-Y2.*GB$,/5UV_M885A.9)7^R.A2:I7G_OQSDU/ :=TU*5/I!0]&FP!U]8 M$JOYB)=_DA&,FF.^>31-&0:>:QY]'@I71NQ&JC]V;X0Y-'@>X++G/32)70D> MQ>$+6TO7Z6\:+EMDIR49].W)0-]W\543,O[O-S;FBCD %5P'QCE@-QJ+72>( M_4C (&>9://\LPR7@$/N1(K%T,"03;C":WT1H8@8OP^%,$O&T9A'^G)\^#0, M'J32^W7U]R&6:P@%FVM-%,#CI+F!^TSZ#T)%^+#=^Y"[@DFE8FR7&2)JR6^D[\R_YBTJOPKZ/N.<)GPT%S'V%]S']ODXNFA&T&ONN M!3/EP"U"87/QVY7"&7/XB)V$)PI<2I] T&93%)?_S[038\]3XO=1_U ND%] M"T$[_Z/7UM/W3GCX!RC'+OXK(H;K]6QGQ&7('K@7"R:^.UZ,&I3* ;\V3^#N MOV/3)_6QPQ['TAFS1^CXDOZ^4I622&Y"FUIA7>$$9D_ )^2%9#[K'S-XC@?? MOO65^GE:?EMK?*]ON?%Z(\6VFG\A'#$9BC WP :]#NOO]99/J+[;4"0^1&\Y M<_HF#^H Y-14. A&;]9AHR!D@/!B_FSV**-QQA?(\J%(CX9G+#]*6+[+3FG$ M2AZQA?G(9=- 4^;60%YG@CJPVO9%^(#F.UR-"Q,3-_7/\X,M/)?YP=([S(R^--=*F%8+\_Y]--%ANWK'-JGOOMWX0*-W)_B8R62P854 M#MC ,$'?@?#/O,#YXV___5]_77Z.^C(:*8/O*["6?T=C^72"*%=? W !9WK. MAV?D>#L[.C_?/+JXN+PX/]H]YY M[^QR_^3J].#DY.SJP]\6/+ZBL.[D!+CKLWAD-\&$/QU6V]A!MNT3 M*?=GVC\2'HRFT)R&%!QH>2)G%IDXY5F%[(N<.I(^!P<,B$Y%P'AZ((&$81X( ML2LXM42%%[D!" G?D#Q>Q>"DK'P^UY76(_.2W/_!.G]F6-D.6GS)WWI6X%.@ MXN]R@KY7?LM'T%0GN/>A]ZZV$O&).FZ%W83?/"XG2Q/3#L>?!+1KZ,$CDMN" MH2?OS9RB[P7+T5]UZY3/S'VK'>47__[.2\=W&\9W!QM7]QVK]H#"Y6AXDN+F^N?S^]N_[]\I:=?KY@ M?[^\^/7Z\Z_L]!R^N[Z[AJ^M4&IAOQ;[IO4&52XQJ5!O &&^RT-7:34N.CHX M/XP-=\[C+5-]I9VC/&BA 3,1(DKB&H!CF=I*O/#L#D8J.2]KWTH MCD .)Z#PTSAT@$$$HB3Y"G-N,7@#QF2F^-P.7B^D+G%D["V\VI-\*#W-]"FA MG /X<4^9?L<9]SA&=6[' N_ ;DX$Q^E )0TJFH;POASV778K1%$6?U%%'IF: M20&?^#F(1#YQ[S^W;>[-@4@]T A7IO%JQSK0KF]N?.+AC5AA Z&_YYK'DY& M&5AH H1=-(J+$L,IX>O74R/H42Q@'./I%#R 0JA/H-V,82X?&' XF],V#E:Y M, $I;2AG;X1QTF^;K:-RJ!AI+!&M*M>%AQ6TO9/J$=QGHEQIA%$),.B1_0M! M,>A)#B'H(C1:S+\N?@/6T %)9<,>M@IG5-7:%YC@] MKOG3C CA2W^A1PFYO"BGYR?L*LQBB4>2:^PT!)LHA#N,6VRR(DJ-8Z4#Z8"< M1SZ%X7/"0*E=)PY#X0,[)M_"X$$WP-!)OR^0;B=1S.7E V7X).4&S1O*T,8# MM":(YUQ\F)9\!2.;VI9Z]4[#"* F=$! ?)]J3P"_3:/U29@<@WNJ4^CH7.]6 M]&"^T7"?(\Q#NNPFX\QY$>'/\Y.KCN_'(2C;4$E7PIM!V/&0F@&MTY?+UA7!GAH]!P5[&G ME1Q')^=0K5CIT^8&33&$=\AA2!)R.U7P2RP1;+$70 X\8>#%C,,X5= M:B7839J,M)3T^"U=$DP37\?7GLFCGF^P4XGJN+B,@Z$N%X?3-0X.**O6Z7P@ MC4,#PY>&MPU_ XT6&]EEYRO0/?*+,2X(=;G7Y1>O]"Y5*J:?I4*',G- MXAA*$U4E4R*\R@LX:CY8BW**!B6?)8[DM9]9-G-+=$NPT^P_I^BYK6N,A.=, M"J,WTR L6D;Y W)>,7ZF'A$_T*:42 *A^:!JVP0N3!SDV'<2"P!Q%#@8'LRN M'9DG9EV9I9[F_"5(@&)2!,4J\EJ%"7UO(O112I>+NHL7F0=,WAIC!7''>Q;:-\PUF.U^'S.1C"3.&.I]#RA1*BM, Q5 M(7*!GH/[D$_AH6@)T@*9*M$"4"'\#%_VEK,=&%EWV3X C&D!FD1Z=ML38! L F>0>1@5-.ESKG;>* ML\D2NY#'96 *&:%3AGY4,:ABB%Z'21?U84&Y7@A25,;FN=O A ?%UG.SH^?T MQ"S-YB8T<#TYTI/9 EVD]Q<=4#""\;R\ 50V+PZ%WH* 0^/.VT2![YG8V^+T MQ[3A*J$Q<@)^V;F>2/*8VWPX;,Z,0C:!^\8P!%YA,N_,S;?0?=,QF5+?0@,2 MY1Z)T- I._UR_ELVB1?B:9II!0]]Z*)^%+;/='7>I..Z)=FEP!P^6FE9 Q$X MV/"Y9^=/SC95>+,NN\J6>E=T:98)6\U;:^EV$ZT.&*-P T>/VYP[G'0?@3_7 M-)C"(S/<6L5"5^,I61E[O=K!S#9BIY>WN6NCEN/*%019-'3"G+ ZJ&3K= MXD[:\+P=CQ)$A Y6,9<#\&@A:J\EN:1[2 @PF3MH)AZFDF-P=.,@&:L8 7)@MWQK$K/&\.'=!1-XD? MIQ';_$%P=^QCJQ2NYR&-9_Y@ZHCGLN+)'4MBU?8ZWI-H-+XD;YZVD#"D#-,7 M\GZJ6IIWC0&@)XC 7Y:[GD0TT.9051/R_>=8>N))CPYI V>M.0M-!P5"KNT9 MF!/19@$54YC_,3<.LCL]>2^1J?&NQ5%Y@2*+(,1G/4T<*[D8UYIS_GF"HE+C MS$.VT)$I4+(5PUYLRPX8O,EN+N0S$]$T%O]")Y*HIXX$ 2>D"F:O\567*3=&C/:H];6^5R4XN_!(SPM["0-,_Y( M.EROZ;<6[Z)07Q1$X7UID#19'#-D4ASZ K46G[I;]$9T@*%HY*K5I-2-J=*@HV7R!TQ11NDH;I$)EF,7K&[M$6,!M)]):QM.&%@(<)HFC9 PQQ3$RP(^E1*FR/ M.W]H61;C"5FL!!RP)+26+;W@[MK"!.N_:/K@TY\8@D2L_Y9^XX7_[C\?'?+KF]OOUU>L+-O=^SSESOVK\L[=GEU=8G+F9?VES+O-&'AW&)4 M:86AG.^RTMN^7;/!*IWY9T +NGM]_8YZ"+.XL.=_=Z'7:5];*PD<;^&):T$/HEB7#LW 53Z;#C M_L%N;^_C)["DM V3+>#]8WX*S#M]:E:2\9K\R]_R1>7*C[.^[]IG_\/!Y0AG M>F"-VWIU>GN6P('AL&=#GF_L-Y- $ON>8(A,I [(G/@6+(@<&?/[*D,=R(MX M>"\TP286-;HBWZ69"'X]/?UJ0ACWL30N<.(Z*8;_1K.Y,!%PO:M#&W-N5Q+6-VY>,I$7/'?S8B$^)@N+2:_=^6T!R9[PW%LH M_#1O.IOU5\Q&_[-I.G3)+%S&2B01'ADE<5.SRFN,?O/BPOK'G*0++U3)@V&N MU<^>Y0O84_12"Z&)_$D\5_GB[HGA;&Z8'8P4!N$L75J8K'A(&JA:V&0!DL8= M$=F9EU5$NM3PI+U9!_027&)L8V@M%" 99?;RZ@3_VN^?C[='@0XMFT63)T)= M:9=GB39DMA]?N#$7^&X6^RV/9NSTL)HN%??$X1*(D:ZQ MW[)6S.O6$\&A8B>TF6-8GBR)W/X M ^\"AOH_F7^V2O$,KV2=!B\WG_2'XE[ZOHEJ@5"U+2LG&-J6V#.X*32&JM[\ MG>[&9K#5NJ9S*,8B:$E//5 B/AR)KQ M-2=HYGD,ITLA_2Z[1&8R/@W*%1HSQ3Y$T1+C%IP;/5#S7I'1'=,U'WS9S&I3 MXW0K64J&-!^*NZYUA#WI9[ZNB&)#_C*"EBJ3[#S?ZI'6 M_9R_"CDQM8D-B6=:+PVC9NNR^58[XM6$(0XZ^7[6ZS3N4Q>G\'HRC7/#-VO^ MSFT\C,RL,#C8'>PM%R+8I#^?RNK%UZ(!CUB'YBL\(PX/7W!G+S!@>PU(U<@\ M!P-)H6.;;IG1%L]OJ&_!:#=)67!:.$%0>95-9[C3^![W+#P]O145.-VTX_$P MG>&2U=';RW,,WHY&Z7Y;/$TR_+=>BPN671*S=#^,](NTA!TMX<(6)B\1;N(? M%(]G)*%0XR^EB^LJ&THDZZ+?)J@?CS0&JZW\7LH$EG'6A+ M9G3L#=B.$L)D3_AHZZST-L[.S6\"P$/'V;Z&/.2^4B540:+H?.:GBV"0K;3- M]H%--)E"-^$,L(%*XK;$K4\W2>F 1,7..?[0WZ^Q:/T64]Q(E6[57+H& M8ZZAT$EQ<*N'B3WA'5OUS@XW]\Y6N%H3-'J> M A=G[P!Q#'W7>X(4*_HEOP:!:_Q*&,0OFE"+/VN/ KS8W6\*C,E@%#VBC96[ M%X.#O=U])(1S&+A@(D)P'!="3E<"7OF5RV3K][D7Q*X>Q%A?4K#.*R_LS#B? MAM);ARWV5MCFX^ 1%-=(R^S#TQ)Q,HG,F=2)"9H?ZBI8O,4KT_T;N,E1I>,$ MZJ#W).E=A/-!JVR5:C% GC<-'81"C&KQJ2K9)>4DP>XAAGFY%]S+_VB\!8M[ M/3.0 _H\H$CQ;!3[;2&C-W)2UB3SO1$9KF3I=94"*27;\0M?:,N7.^.% UTZ M *-EFIYT2C9S+MWX@FFQ462G360W:$,\I_J;,E[/E8,G+*O%Y=U5 8KA+"$R M,]7SZ*4P!B\N8.MK\W7*8?;.?#O<,%E^4[C\9O:2FY1/<+.;; S3:ZO:K -B M-CMD"_'SM$W9>SKIT9\LFJ!_U]NJ8S]=XWMN?T+&J&;S_'*'TUU!9OMUOKN1 MP^UNMM*A^26>(C.\#R,;$S+;'%$@6[-I7B]PK"996\%_&/ '/&:+:_').D"= MPS9/QVW*"LY8#B$47.TDB+ JD&(Q!C(X.-Q.#Y;B%<50PV*802?. 7Y)]RIY M^:[EXH:6=XE&E)J$>,7$WB],[.=SFYKJ,KN?YK2;F,?S_3@%^WD&,T*VI-]; ML7)3M;%+)_HK,0S3;7G/+4YXGI;#PL-/[ MR$;HX4[1P]6&A2L<=MM/_ MJ/=OP40F3!Y)'^X:RZE^&GP-WF1QZY46UICC(2 8(G#L'$/TNFLHIAT\\%*8 MMI-[96IAX6%D-'Q\,9*..5J=W+ZF1; -S^RL>&(T7Z@&21K?-C0>Z$PG5\'\ MF=DFMWD%DBIWFWAZ)GLA)Y#)HZ?2Q ;IEJXF^$C[NWLG!2J]24X':5Q@1OVJW<%ZUN3T%JB<_F.[)L,I+?IGG^#0;-NJX,. M:8K6QSE@IAM/7'V('Q,*BC1W2V%/:=JTHF,Q"5SA95FAG7DEF(L(I5NG-9^& MB2>3>BH+?4Z22,P)1Q M ::L)>]'@[>D/MLQ+C-W;/6FK\0X0BI"%ST !,P$#SN%C=M)' (QOP2TY!"= M'4_]Z+4SM!\\%IQNG::!9P?;@U#"ZZ A"YU>M0ZUD^P9T9,W[C>6:6X8W2P= MG>:>P#YK\>P*;0":NS^^'+E-,RJNBBC@FEO@&J=KG8#NF*OLO)5*=[YS0QH) MIYJ3&5J8VUBJ>GY:7G7><(.3A/-'$3$-C?HRNH8NR! O_C+Z+?#O?\,T+^:T MT=^%YY[Z[CB<9=3#:[('1R;CBO"\Y)I?/NQ] MT)\5*$[Z^?7]-TGH32-Y' 7I%Z9.FO[F4;K1&*X&020%HG3BWJD2G](_BA+2 MQ9[R=AX-?4^FZ.C*K'$*M@_))85=# MM>S5E'])J:I?2[[7[Y4NC:84D2>.(8XACGF]+)XK%D9<0UQ#7$-<0USS?ESS M>@^T28[F63P:<2]@O_(IN[Z^ILB/_E6>$GH,@U8,$$Y2BN]5E'W*2V^LD$\ (8 0P A@!K H ZULSK!N/JW9' M=Z\C/@S8SBWWV6]!*/S_!-9,:N*=QOKM%,TB5! J"!6$"D+%BSMY*,;[9HNS M0KY=>:;H%RP11]YPA9CFI7(-3?&6>_82,&\JL:9P&^&2<%EE@YH 2@ E@-H" MJ+V,1FV'9;NCT'=!Q#W&L4BQKLIL2AKK^NV^HHP2]ACL%2 < C=(,82R&\I MSY8\5%=77H)U-;3/7O+V=06X97E97UT\ME:H\T61;4%_WI_]B;F(N8BYML!< M)R5%>HBXB+B(N(BXRB,NLKC*\K=_BCAT?^7U*_[^ZT^QVKWG?/KI0D1<>NK+ MZ#KS6+^,?@O\^]_D@W!/T9E5?Q>>>^J[WY1PSV;ZJSL0RID7.'_\[;__ZZ_9 MHZ1RO$#%H?@R.@\FZ/7R2 ;^C?!X)-SS0$7J=LQ#<<;A25_Y#%^FLD?!./@H M[!LQ^N7#U45_KW?P?_O_NKOXP*0+7W GVMT_O[PZOSPY.CRXW!\<'.R=71R> M]\XN]T]A4'N7@ZL/?UL8O.) W,F)4.RS>&0WP80_S:F%VSWIB]VQJ<[;Z^_] M.(?#8P"=)670'Y>J -_^_?3FG#!!-]&O1+[\[=E_/_95^^8A=NV5(G-I_*=&B=G5[>LON0@T:Q8(IJIU@4 ML&D<.F-0-Z90\>"G$:C99!+X\"K4N1AZ'R9_F]O8U./F7C&9>L%,P%W<=QF@ M8/$4;@4IB! +#A;?+(> #<9=VB+2H:*2=^.))&WK#RH8ZT]^W9&%E%@JTD#.TT: M\P?0+CNMBL:A6([2;O*DW1G,Y^Q!J C8EBEG+-P83!.4'WZ)J@93_6XTEJ$+ M'YQ0Z)F0H=6O\5')_@#@9 !(O8,&JCE,):. \W<(T[3F)>!"Q*6=G@C?CKI@ M/X"R3R-V(1PQ&8HP=X8&/7N LT4 ?#H-@^]R KP)-&B'Z \97./!N-D1:3)M M/0I@;-!C+GW4^5$0,O[(PP+1&IKMLFL@;\]CC@R=>*(B[CL"YLEYA V3=B@!$9>68&&8-9D3Q7.RD=!F\,AF"FXQP#-W5P:@1+-;UA;HH' #I< MC?4]N%_++-KHR1=N[5;>P#++3="K4>!YP2-*7)O_,-W"A(94@ETV%AB($5/? MX#PY @.?/7 OUE.FX,XX%8@6N"8HO%&/F3?#QRX] R053\PP@7YF]HIY $[P M'18KW2#X]LSCSA^[MPZ,EDC-LETT"?""2> *[]/&LB[X96@'B' =@WXN$+&W M,$+XN?@:/P@GW)L;U!Y>DSW8R-P1GI=<\\N'O0_Z,_B33OKY]:X(V$[WTC>- MY'$4I%^86)+^YE&ZT?@36FVIIPM>K,>G2GQ*__AYT7/-VUU?&DULI:U$P?5-@^M9ZSJVTIDG52-5*4;7E2 FI M&JE:*:JV' &C@U:O64N\_#X5#GJF#X''(^G)R%I>UPK)K[JH;DT2$GMKUB]) M)%>1UXKDW5"XO&A$F"/,O1ESUNPPPAQACC"W%N;6-D@)/CW5C(6LD5 ;N(9PTEJ<6#L!0C@AG!!.""<4:7[9J$TV M2^F]C3MZ+R%5;J@2-S7%%;>7D*3I"4<(5@2KM6%%V>0)5@0K@M6[P:K=L>$; MJ?[8'85",(G;:_ @5,@CRHM%3OR+3GSWV!K)M,&/)Z@05 @J!!6"RO-067\/ M+D&%HL-/R.\J/U3+H\(Y6/*URZZ&ATR#"S%_< M8W_XP:,G7)/Q4?HCS,]D4G;""T-\HLX')F (E3"9J7@T=V%RR30>>M*I<9XO M%4\F/(3K3*8O!T8>%-8W*-%)U"'EZ4#";B+>8V71!]*)S@WH?G8E[" MI42DOCZ7KQ\QDC[W'1P4%<$7)G\AW)+DEE.4UXOR>C4T+Q3UK][]H[Q>E->+ M,N \KW&4UXM4K4FJ1GF]2-4HKU)=DIJ2+[TX*IX4D3:\ER"&@$- (: 8V 1D"K!]!HK6?E;?.EN9-5 MG@[S1:1W;_+O%"UYYVC)/'@' %XWB'%WY%MHK37AE)>$1_$6&\)J2D"&2(Q( MC$B,2(Q(C$B,2(Q([)7"*LEA;R.)M7QI+(BXATDZ0^DKZ23)C< ASQUU,]"-73)&H.WD(>;PJ:$_NW+)YG#\8H5$WC[N*$4>526.;8Q^L0KQ"O$ M*[7@%7L5[%O!*[18^XQ;F.<.*GJ$F!G(GCM8(7%6CM'7WX_2D/(R=&2$8$6P MJO"2%\&*8$6P(EC1&LLK].217WOG)U?Z;^[#+_!$-L)L M[?###.2DF(#^N"Q-0IMC=V4VVDTZMC+7Z"8/LM>>Y824FSP().I::](R36SR MH"X[U4GH6S2_M#"JB1J^UQ'XA'_\RX@KI_.?Q*?UQ MWF61DWPL12Q:F(G]"ZV;4-[_K6G;/U-OZC3QIB[3A;ROH72L):XG+:R< MYJT?!MV>%N:"3=7Q1DRX]*$;[!SN#,$-C;G'[D0X83O@MVG7FK*&$5=N0TM/ M[^]#<8_U1J^S(Z:_XX;B=>5+^[-7WO8ECE3$?6P;X]$3X22;M9 J)-7*$< [ M;79[OS,F1YV]0]K\5DD-:1.T-CK3UI8D* W(<;+?/:8#(<0R39K 27 DN-?Y MC%L48N4%U^YC!)>4B:GZ]F5%;*>=_=Z);3$T.6<[067]*:MI6Z;WND>'MO2D M+=X$X8'D0_+9C@M EOXZEGZ%O,WR[)FK(!P)J7=R^R[N^Y8A9>)Y=S)KXA+/ M3J\SV#_:FH3:[%L0[BBG2.Z-''7WK7GNM.A!T"+!D> J(CA:]-B.*]0DC^?7 MD/L6LXT2"K>_1;4B'DVOP5UZB.5*NEH.47]ZRAZW+4Z1W8KNNR@03;8H01.&M1 MMKA0H*@LAZ$ZQWG*K&E@Z/$6=([XL;G\6!W!E0A5:YMI*R2N M>NF9U6FV:3-I P[&EBZ+ILQD[5X[_5T7:DRWBF8I@K%^XW:B',33[^ O582D M#CM'1]LSV)M"6(2HYB"JLA;0NC*J/LE@5& Y]3R1#)%,U=RKRGKK!RMJ-]1& M+LW7FX;-/36:6FQUN2FS!FT=6'G;)3Q4HI6 55ZRDJZTB:#*1-S*303[G?Z) MO:2=M(F P%DC%[XUJQME[A.H")'U]KM'>^\O,"(R(K*Z"*Y,LZ);_G(D:1JM M]]-Z?XFR:,I<5L]BWZ57J+T;"\:S2BPRJ\3R@)583"U7P4Q!4SX$ZF.AF(9" M05N4^4E7*(:O=B/^?>G^';S$E:.1"(7O"#84T:,0YJ'GP00T:?87!:(+%!ZO M,-6+IU@IBP7F(H^KB$4AU\XAD?L,8@]EXWY TH+1!4*1\B'_"%)H=QQ MX(%QJN!"EW'/6_PZ;8QNF@SSDNU^+>H+=YG62UT,."V=_+26/DH0@#/F_CW( MC&.G$^T9<>CZA(=_B"BY-'E6KGM:Y^Q4DS[>!E:3EH,,9"1AX&=Y36^UHC9X M(@BA(CG11<*+.JBB,)YH)&. \G$LG;&^.A1_QE))D+02X0.B<54E<>AD*-PN MN_8KICP==GIY"\!0A6ZO*'0^,@GSXA Z@UIEK>+Y0;=__*,=;L%QF:_I?F^2 M7B S5TOJ"%F9B]R 4BO*@^8A.6(J'BI0+= X:/X(JVAK106X@#T2"64(4&/= M%*9[4EF33(?P/D_^(0 $H)1FFF&C,)C@?/0@@SAOCNJRLR(SY)JQH :=(C\D M2J_P\?BG#^QN15@_#+H#EI1!MZ,I6#L=;@HY:ODN\A12(0@(W17XR7?!^"K\'+MOATVD8?-<# F-I1\*];L^NA+%*/;;Z(ZBTQQ,F7 U. M-P[17D%-TOU$KG3K,?%:FPDM37SZXU+MP)O+V[N;Z_.[RPMV>_?E_'\K/W\_ MT0V@(3 6465NM2)]@UE=V5$)HV7'_5[_9S9G."@5 ]6&^:N-#L?ZU3L?;FZ_ MJ0\?X2-,[PR_\@*4#Y8(G3,OIA[WC9F&=S ._'DO?)A:T29)@6"LL7BJV0D MA%4E<>Y-S+ I1U=40KLB,,7P8J:XQ\.9>;!IDC:%*T=@NQK8N%]:>R[.6+@Q M^DC@#.A-U# _@W$/5KX,<;)V0F$F+TW'V/=*]L<0+CX&]&0>43$ [!8[ C#G07&B]$_@8 M$]%&%5+Z&'JH.HE?%^,MH/@"O5!?@86!OK#6SU#;Q3[<$8/AG(@$1UF+(IX3 M(:B#$1X\E(\ 38\\=)4VGM%['L'D$LG( MTUU*W#]CQ"/7=!BT)!AZ4OM-<%-'3UHB2F]8^29LKUUE:;ELOV;=8F/>OHR,:"-4FJW"Q5 MUMK[A/J@SP&*82TV\4.OW]VSA4!++=KO'BXOV6\D2&MC^T,/O,?E!':;B0E@ MCD$$^0"^;8T"C:/ \X)'33PZ^J_BR82'.LRHF138$ QR:E.,-]61S339<="BL$0)&83\%$;*0/=I($5@>#*4KL:K@E\?;5IXV% M7%B_0D]%A$]*M?"4N176O86AP<_%U_@8]?+F#2&\)GNP$;8C/"^YYIQ_T M9S7E3OIYQ7C>R0D,S6?QR&Z""5]:EH:QNY>^:22/HR#]PJR!ZV\>I1N-X6H0 M1++UQ0$=X%,E/J5__+RXPI>WN[CO-U\E'*S,@;;&UF'=F%\^'![]^.("Y/PJ M9W)C;\OW'=>DG=2_]^S?ZS;*5^%,D;V]&ZM#8*D5RU8:KW3:*(ODE990OX34 MPR_(\GF-6YIYK>LJBU[KJ1JI&JEJ-JR9T\']EZSFQ)#+>DZ?[)0 M('T3_.??;<&X0I*L'+YI*W.+MS*OS5ZMW\M,%$,40Q2S <78.^1,%$,40Q1# M%$,40QE8-U*4._X=?$Q?C&1$ 2+[ :*65=S;L><\K2F87&%JDZKL(P&-@$9 M(Z 1T AH[0(:+?B\M.#38;XP9\UIJ>?=@R1E<%EK@B@OR*X)09:2/I,?&/I\%_^E(-I9$)0/1-?@0?9G)!HWK$OGX9-'_69!7K6 M2CHWA[68-9,]U;U5[K%)F#G86T?G MYH>[K(R!T,77Z,0S:Z!'T/DY@M+YVC?0DJ.M+LENV*XWH12;_B:I/PW-H\V0 MF=UV:BJH%6KVK2B)9I+MNDD-++,.KV3@/Y^L>!WX/M?I(BJWD= X%.R1ZW(- MNK1!K)("/J86@H[N!.&*"FH.G\H(!@?S$L/]6+(DS7AL*JR-=-4++)"@ZSY0 MFO9FIFGOLE.=ZKI%X_E#[]!RD;)14B\T]@O9OI%#A; MJN^7%!=#?-HO+];KVDD/GVN1YHRTKLPC_A]0U21PY0B+X^GR8D83_+*I!B%G\9S;+E@"+?UTC^26Y_Q7;R HL&9V@*!+$"]E4?*8U^ M==+H[[TQC?Y!?\OIU$]JDO9]X_L.ZM+0UR6VK\E6Y.8'^AHFGW?-8O""+)\/ MEI6?N!FG7E(U^ZI&.<*75.V?B9.4"_8T\99^U07(+C (=(4AHM]U 3)2R^W, M$.^@BNLO%[RG6MZ("9<^^KF_)U43[T0XV2 P2=O;\ML^8XA7Z5A)](3#:K-N M185D6C-6L"FXJJR*=DY.CDH74%,61@E:%7+):.]%?5AFT.W;.PE +$,L0X*S M*;AVI_[^W>HIDK;K4H72"5C/@7IR8+UZ8).SG!)4[ 7BWPR;K5M\>SU;>M(6 MPX[P0/*A^.FKN>8J"$="ZOBI[^+.-!G2H>!W!VL3HZ4[_8&U_$HORJ?-EB&A MSL;>C=(0N&5;LM\]LF9+4O20H$6"H^BA-7;2.W4H?%CGK3D5L2Y[G8-CVUGX MGI136Z8[PE-K2Y:!W;BWM:IEA*?6X*EF6T>K)3^*8;YA#Z@]ZZ Z,JV6>KX. MW@. MQO$>+9Q[4HB-31,^YW!B;WL.1M+L"U3+(&S+-6RNLVT3>FHWTY[=4]D MW>\>E.2;OT::K(J6X-"04SO7A*"G0<3&,49 MD[Z,)/>\69Y77JU(2Y]4RL!$=!.=GSY/GRU]%87QQ)38"$+V.);.6%\=BC]C MJ60DF!+A@W3$RFSVT,E0N%UV[5LC%7A6ZO2+8_,D)!8KT2.F(J' M"C0*% V:/\(TZ%H_ 258)@#4-AJ#HYEDJX^Y][2.)D=8X7V>_ ,+(X NNG(T M@HM'83!A4WQK$.?-45UVQK$92SA8&/V._CD%E]%U7;T __25J&IU"A\T&T3$ M4;=WD9W8D"N03U)APLI;HG$HA)WVZJH#296+Q8H9J8I3D8@M3".FV,!0P)2? ME(S0$P@*70^&AN1#'AK2U3U,G:458T2%@][2GNH5#J(J&\OR:F:5C<,CJK)! M[:0:&W4),C9,/E1CX^D,\[1SC%1M>ZIF/6DCJ1JIVFI56_N\,>W86'F;]L@2 MWWS!$;<%X@K)L7+H;MV>#(L9?6FME(!5 <%5!%B]SMZ "LM44D,(6O6&ULF^ MO=MMV59HA:18 M+_IIHA-]L']"3G05]8. 56]@'9V47R*'@$7 :AVP]O=H/64#$YL.V>G[],>E M'2M? =2XJ]QW!+N- N]3*@9#?UIXM]+OCO6[=SY\ MO?VF/GS$PS/!:"0=$2KXR14APY^] *4EPLG\B<"IQ_TNPSL9QW-/0D6AU&?Z MBL\.1LE10"L=/-BS=!0.FH5!>=-&_LA#5Q^'<[S8%8RS"0__$!$&\EVI.XNG M*LQAQ@F7/L;TJ]6?O.G%0<[:WV68F 6;K4_4!8X3AWB83A^3FTX]("Q]D $> M+?T81"$F4R^8X5&Y_"%FG''TU4@F)WEV^,=\+M'^8R95%0__+9P(E0J_7!(I M?GD71-PS.!@#1$#A;D04ASZHY-WM#6@D7'=Z>9N_ C1P M\9#1/?@4-=<\X( M+D\']3:"EL&(Z@9^#8+P+RI_P,'>'OL620_: (BXA09"HZ]!U[^;4V[X "M# M8N^RFG>&ZX[Q2_U)=2PCI+RH]G'GJ_CO66\\NSZ[O+DZA MER)22\^)>'B/"VUG[@7M(+Y'=]B<-]I/C8PV.W#-[JFYL->;(IGP5QQ* C]_;./MLB1]!, M*P_J[UEJ40?&8IH/LSFL/);B06N//@3/@:8=&3KQ1$4XD*ICIMKT7.MPIL^E MNP'S@PA4)I*19P8V(5(]6Z'QT6$ UV (9B.>J(:;.B@0):+TAI4S-XZRP]58 MWPQ7@6HJ)%4L+*1GA+8+$U#\%\M6&TCN7,F4#!'6NEBOB55LG0 M%8^OAV+DF6P*,E$FQ"20[(C+D &88Y&JF:$:%S3!L(:!=-95O-98=_G9=OR^ M\" >63J]?MSM+^^JV4@$R%.:O#K(7ES3FBW,'Y[8M3CS&=#Q H4M-9B;AI@9 M(QDE-\D@H4K$S'-7F:CU/_%.AZG7T*,QQ]'/<5S$)@+A!B9L6Q.P M/8Q:&MH?>@?=WO(RPD:"M#:V/_0&W?[RCIS-Q 2$C-E"Y(/P9H:BBR1N.$3S M :[:/>7N/:LDUI2CU^L>6QH+I&TO]2!28DPH<9$W#5\^,9^E<_50>&A.I;09 MX30Y#8.A=G.S##&KA9H(,@_A^C/;OXD.- M'P &W6AQ&GW*''GD2EMTVBLW]L@3YHE),A-I#_K)D?[:C%PH[#&(/1?4^D'@ M'!@*G88';&!+FMSM6\9$!LAB;"# E+X]C1@. M/<2$29A>:96^&Z\Y54L=Q=$A'U:,]&ALJS3@H+/'Z*QB899 +-N_@!ZI:YX- MN+ 3*'@,["BQ26Y32&"59$;&W@\%M%[[8S/H.BK[L)@B1_KHLYG]&CAQ#07( M!RX'9*N1")'6M)!"G5W-AVMC9YP*28%SQJ)=($OY"#",/6@:_3?JV>37:'FD_FPMN%A%*H=)I(L^1XF:=5 M,.<#7Q^W-?G I _\+S&H$L$7)N48W)*0C**D-]5)>C.H6]*;3>\[KDD[J7_O MV;^:).D_K2T9)L:R&RE74P;L.\WW$^2-7= B2TH70^I&J7K(55KO*I1 MNIZW[4G$]?@TBW02,Y"^B07P[[9@7"%)5@[?UOF/*KW49D,P57DAAB&&(88I MCV'H) \Q##$,,4R)AYJ(84KS0)OD:-[Q[^!@^F(D(XH.V8\.O46FU)\L= M2^L\[Q\C*8/+6A-#>4%V%&.Q(*NFQ&!JQ& EZE/I4B0Z(SHC.B,Z(SHC.FL\ MG:V]!9'HS*K7_FXQ,XN+8OJT]?SIZNR0YI+4UG_!8;%=*IX^$_=8.A&8/^5@ M&B6A*1-W@0?9I%4*"MB73\-FC_I, M:BMTWAR(5(A4BE1J02B%O-]%+:?YG:U:-C9>Z(A$8)AM:X:?6/UA9.59? M?U=,:74SZAI4:WK0C&!%L-I^F()@1; B6)5I<#<=8&M5>"K^_:H\@45]P9R1 MQ5XMY@UD3W5OE1-@4@;N[ZV#T?GA+BMG&G3Q-3KQS((/ZO,<\GJ'T^]O X:W MA?6G#=OU)I1BT]\D]?+B95)P)H4*]$^;!#.YVEU A7!U5,)/J_$S*QP M_Y2'6<$/_3O\C8F!L8))E@C79..M3PYLJHZP1N)M=JIS_+9H/'\XLIJZ7,-& MQX]BOY#N>!ERA?S(28)Z?5+!B;*4NSDQ",,0H?.;W:7Y\#<_I- R^ MZY(SGJ6T[KWNQ K(5WVD/.+5 MR2.^]\8\X@<'V\Y#O5>3Q-<;WS>H2T,/FYBBNW)A+I*/K3!@Y5/7'FTF0+Q- M?UJNVPUS+ZF:?56K?Y9DZZKVS\1+R@5[FKA+O^HR7Q<8!+K"$-'O&!LBM=S2 M#/$.JKC^;O1#C9(#!)FWCRVSYCB%>71N?1$QZKS6(9:I[P3> M),&U.__Q[U;WRK==ERIT=MI^(LA#:[;R\I#7Y@PYY51]AT!\S;;=]@Z[1]8. MBK3%L",\D'PH?OIJKKD*PI&0.G[JN[@U389T]/'=P=K$:.E.?[_\PH!D&1+J M[.S=:,@1KMX!10\I>MBL":U)@FMW]%#OU*'P89VWYE3$NCSLVZL)^X*4VC+9 M$9I:6[6IM]?=(SP1GFH_.S5)?A3!?,,.T.V%GMJJGJ^#]P#@[08Q'FUQFV9+2,#9EJF.4%$95%35-"<> M(!X@'FBY?"BJ_JP!:S8%9_DJ,=).\69Y+7:U( MQ9X4A\#<:Q.=DSU/&2U]%87QQ%25"$+V.);.6%\=BC]CJ60DF!+A@W3$R@SN MT,E0N%UV[5LC%7A6YS["(>^HM#:'M2*L/*V_"PR?&/5AZEAT%G M\KXW>\0QHS>*!?/*R[P[[%%ZGAF$!XEU,.2(J7BH8-A@-.&F$>;7UDH JHCY MYT$WHC&X,$D:])A[3RM"'%BN>N"#]H"$.*)^%QF #;D"\225 M"ZR\)1J'0MAIK\YFGU1/V"FA=L(/O>ZQ70E#8W6K/RY5CDAQ0,42MC"UF*3[ M0P%F0%(Z04\J*'0]&)I!'O(8B:YR8=5;>V,?[1C8>5MVB-+7/(%_]L6B"LDQ\JANWU[$NSELZ5E4P)6!017 M$6 =E[^'C'!%N&H=KDK81-YX@+7[%)LVJ9]HP7T2X%J+&/!2*/ M:VJ)\^]4N.JMT\+*Y74#P)6O8%% > W6=I/'[]; M]?=??XK5[CWGTT\74CE>H.)0?!F=%TZEW9@#'N>!BI2V7/7)H:]\IH\?W8%0 MSKS ^>-O__U??RT\:AHH[OT*(I^J:]_Q8M0U? -T1?JQ<+],1:@?K_+W9L_" M8"Y*^T:,?OEP=8%[Z?YO_U]W%Q^8=.$+[D2[)V>GE^>]T_[Q6>_P:M _.+\X M/NJ=7>Z?7%U=G5R=#S[\;6'TBB/QPF[P58/_XED/2]J@/R[MN[FXOCW_\OGN M^O.WRPOVY>OES>G=]9?/M\]JQSJ-3\!_O, /AV6?73E5S(5ACY4R)^8^!Y%@ MO>> OXD8]>6?9 28=CB>T].E1,[?7PFG;&C^?7O!D!*U,6V;($R2*VNGFE+X@786&MM8&,#V&N=J+6% M:B'/@-^IQ3\B8I%DO2RA5B:#)J0B/$FH/FK1CS%TP3HF)[0K+S],)14B2/1[ M]#OI@GUV\<"-HSA0 U8YN529<*Z(U*B*]")?G)ID89JHR]3'O@S)ORH#3\O\ M^*J49RW[F,/V00'=![C/'L+ULHB%601R<+**LYQU3U5EZQ-=G^/#%I1@KO:S MW8:#\MJ;EW=X3CJ=H_5=N0H/K575*OWW)SX4L20J["0DVDK2_C>+A&;#R@$"#9WT?@/+V?!5WID-!M1Z$M !=&@Z'7[[(^9J%YHL#<(@ M#42)"^'9>Y.4JCL3[VE5L%?)=-AO^%K:KR06=R+*Q*Z*&LBA,)L6 M32,.D^]3_J/8>,ALO!$,1SR(52!2?PQEDJC-?_P\_J@B#CP,'PR!3"(9>I.E M1Z(9>H:>KC%[]"23/9I\MD--F.^L8W=OC?E],E:(46*OC055G&C R9I;;1P? M;GI+B59-]K!PO((UV?RBDFRCY9,)_]1;/5VNL-73"HNDNU@DC?7XET1=C-GE#IA@GK<0BE(]DMG>[*C,5!NTZE1S7,KT+&(&,O-];1 MR>GKFZLI,K;=R[>O3'!O1T7OWLW'_E0T;B9\-\T9VF4]T9>Q*$4'7W/8Y88Q MM_#4P<.6K3HW14\050#]MX;^.];&4XL0KTV[OV3N$%&@A3Y(:8+Q)1'*=7<, M;%:060MB"MM5DKD!:#?>N#?=Y/15S!6+^24*<; MQMY<1+,^PX6.M;VKGC0*P@E;TYN PD!AIAVIS4D,.DR.ARSLV>NK2$V"L^XT M35*<9].@&]2%PFQQ):Y#$M0\[[MBKR1JW MTEY7&QLG/WO-705[*IF/ZO*9W8XFFY*4-E:R MIL\O;7R'";^S()T3-UCZB2+),W/S:8* ME/=6HN\*LYZQ:X)(J%8BZIMN8[TBT*SQ'.^RO\=!+Z!?V2U/S/)$A0S6ST3( M9!"R4>"NWA394N':AT=6"\=B MX8G@3L&:FHSD8<^,LF[5\E/Z,PG\/)"M\&VG#@<'=JN02M83TXH0?@@Z1_OL MHTCOU49B0R'TUF<*.&IOZCVB[9Y&D$?/I.=R=<\L][4Y!S))0M<1(QKF4J!:ZS&(Y$NSZXV_Y3V:MMKA5+;1?5T]8VI^H"E_XJY?* MISQA-'6&"[YP6CSE & M92%+^R6#Z!H^@M?SA"2I86A=LI%0%:B=V87E);"UUH53*_WMX&BH:Y0,@M%L M/\[*TW5GT!+>RZU[1G:/?!F9SF48D)VC@*3@"_]#D&>.4OKI2OWX2Q"1C,N4 MFPU,4QD/S457^N4\Z\=M(KN3'\]9,1-[)+4JS@JK;ZDY>(I4>-I2@.$S$@6]&KSPCIC4URHAFCC'B< M1H3S=TKVZ"H135K;#_I]NC'RU-:PIE-'7P,HN9+-$A*&]XG?M#F8><-EJLVNQL"E< MA:ZZ8QN\L[[ZV5W,WZYKZ["->Z;G&D=(#!U.MC76#3UQED9%>]F8+C5=&'D7 M^,:CYOL,$7Y'6>P->"+*DOM7YYQJ(45ZNRKE ,A[_**4@P?1L@[K-Q%%R3B\ MX^I"GM(5_>"'4)<$GLVQTJ%ENIZ/J!(_@B%I),'6DJ;8Y5Z.-3>%84:^%.A] M0:XHS@,F/ REV3.KV&Z\V&C\9L(4ZG?&7J#D4=4RYXGJ^'#BB=+)PXE/>"@: M%FH]/:0Q!/5I]+[R5BJW)#G63F>_U+,WQR8$)A52U?-_5,_M,_7R:DUOV5IW"=L]9P4,GUQ)T(YTN.H J6O$;NOH*_.E^[ :,E9V1^! M3<>V^^S*]$W)+\4^^Y.ZY2I3B@J_R/"J8]='=KLUJC7,,'\BB?<#,R@<&SC- M'A>B1YNJ,;-$V:6D7$^%XIH9.E[SGW)1I840%IW$5B4O+9!BBIK\)/)0KQZKPI M4F]V1NX!B2T7W.91: ^<)K9LMVF;FKVP*^+*PZ8UCDO;U/;9#WBEBV]?+K_; M0>><)YKL"*M&T2^=%5H$H<4LF\+"'3TT/5@WX=!"0+ZJ2V6+5+.-XUSV8#ZJ'H ]$6^S33 M&1"NI6)FYUM3UUZ6,E\2'2*9ZAD47:_)A$F1.Y'34X7P']A9?-\4YZ_)Y.@S M'NL87VPV+*+_J-H)7X_XJ$+Y,U2]2ZLAC<]17'Z MRI&RZ(\BRW]^EN'\\EKWXVPY6\OI/W:*M=/NG+ZS/[RQU+^W6[""?F.]J[-8 MW-798'LRQV"ZEH3+R3&#I7D*Q0M-I-G FIS.59@''NE'V>^\'5LVSLQ4A:K& M@F5,Y:=1R\4!D5(OTB%E!X\G Q.D41H6*R/*R"_-I*G>2>P;W\T]+\[RV*?4 M0;8PX+UB$+&,VQ\YC;4\BZ].B MQ\\YP_R@>WG4NCSX>'%T\.GR\KS3^G1\:778^;?P,\TK3)C[R)/ T M0/T@U(Y4Y!94QRJQ1-E0:W1/G2^?AZV9&=P+?X_?4;O<"A9EFDF$;7V'1CEQ M8JA2L5-E=TT!F:J4*![._B2S-$FYZ;'E09GIJ4XJUKWLKEU-Z5$6$W+,ZWPU M4!T&D7[,@W79+<[ 3O1+S.G?^?ILNL>,?2==2U/ C&B0[!:E'4UG@@E,>JF8 MP;Y'95>]2*,4YLG:(IDW>*CN@9$.75@5$3%53V/!">'C_**A2 >2;&\D+.CO MY>^E>\Q/N]KQCD8$=<7#Y_+O"NP.OR_/O7JZ\_7[-O- RX_I_S[Y?.SZU +92 )R!WK+S M!P,U@E #]LBC0?EDW9:J-T%,=0+("AJM(I+4V/IS?D%O%2@;:YL'*P25#S=< M/MA8UG=5KP_.%PYK*_LJ2J%?>:86N>81Y;R/.IV$+#JKC@PD5JW(TN.W M7C?FM_28II=9\5X-8 LH39*_DR6P71#.7"XG-YET\2FX]]GO*L7:#)1+QUHR M\<,3H[2$;!H&\Y>?=5EF_L%L0&GAQ*P'7>[,=@LXZW+VH+3NFH===C=]V.5! M3;5NS:6#,.S5J^Y;:^=_( M'50-9E2&KHI.I ;?% 7_M3T:W MCC]SS@2TS3[8UCTOIX%@TQ.4CZ>7 VQ0-CM@^\O4HBHBK[$'Z %Z<*HU!AN< M*IPJE U.%=#;!/3RM^@\@(57.(5+%SWNZM:K+4S=<,?U@:F+OGH+8 HUW9R7 MK_4I=-6=VO+Q_/KJ$WMF2OI+X;Q!@]9!!YPQ5FT%]$D_#\0!<9MUV4 <$ ?$ M 7$U1AR\*A 'C7/9<,X8"X@#XH X>%4@SAW#0>->8KCGQX=GK-2N>1SXZLG- M#>8W/E-[,JC-SS[)>)2OXI_9L&(@0U_$ZT\J#0D=H7@1)MTP[5]LF\!^C34: M+5:YVSJRI?1VVM""HH0O.%P>62;KVV?S_+?-AJ.38[ !;*@I&^ -UZUR:__ MVOI?" $ )0,P$X/CD%_\'_FO+?.ALZ+; !;*@I&^ -UZUR>[\- 8 0 "V M50 Z)]8V+0+_P?^Z=X6*RW]+;+SY\O M/]VP7S^SBZLOO]U<_7[)KB\__?;]ZN;J\OH9&$*&D%7514[:ZHA#%B00ARS( MC7B+JGOA0%_]T>>%8ASQW#0N)<8 M;LM7[UV7SYNN0M[6GE%ZW!RVYU0,@$XZ[8XUS6K*U KF5C=O'T=F&L$*L&(# M76'X"K "K KP(JM9453>U!M< %<@(> AP KP JP JQ OPG])G !'@(>P@8K MJEKV4??IO>\B2>/ 2X4RA9KIRZ(@K62>[ZD3QZQ..C>+A"\V75/8BZR/JM)E M7HV4K[A'P*L;#[0$+>$WYV[;:>VWK WFUC;:%&75"9OEKMP[T!:T17<7?G6K M">HH*5_QP(17-QYH"5K";Z*[B^XN:%MWVJ*["[_J$D$=)>7K=7>M[?\*6H*6 M\)OPF^X2=,V5R37/7-#[5%Y>L,OS[U^OOOY\S;Y=?F?7_W/^_;(:@'4)8+[, MU!&E!<(VZ":=VPSWN39RO^=@\631)ZW2% E"LF%S),;^V:36CB8#G\"GVO$) M+KMRB6GM'U0TWH?&0&.@,= 8JR>L0F(@,;63&/MGM,)E@T\-X%/^4'7%8O 9 M_GPC]K)_@&QK<]Y^ P""=$&Z(%U;(5T6C[Z%-56 M#2)2M_2LJP!LTZPW \$(,5X6%RKWDW2>,+@GIK5:>MFNG4$=6"\5X9,E8QW;+9?88XO<\]A,FLS1) MJ:34VJPO8Y82*,;4_ D3D8W6SK,^/:%)V,-N3-%F3R34'ABV!/QU/%V MV[NLTVH?.H*052M"15X< [XN?JA(BPM07V;%6"0CX:7!G0C'NP06GI)?R$*? MC61*(A7P,!SG*L)Z/ F\95(21!IF_2S-8K'/SDGSE!'5O;N5@+ >"-L"^% 3 MVRE3^]"N)GHRTCTHU3?R18^@3-!,V+T@N,IAD"JGV(_E4$-S":1+?G2?*<K[L;F>$]/V-,N(B/N/=X/RO__V/DOV;CD? MG5WFI?\FXFM5]AN2LH\AE?:___,__C:YZ,\L2,>_B'0@_2LJ>)(.J<3)-^H? M>F-5%R6 WT7_PYO/%XI"_W?PSYN+-RSPZ0ONI7O'W?/+SN%Q^U/WX//QX>7Y MI\^?NNV/EP>GGS\??CP^/7KSWW-=H7)+W01#LLQ7<<^^RR%_>&#G0D]*?[PW M+^[)T#N*JJVZE1Y$9/![' M8]T$0]48^^P? Q&5WD--*'X$29I0XU(128_4[;*?:]',S099ZJGTNF"HZULJ M&KT[IGX1(>G?] .A+:!J![$NU[UZJWID*!/=-I-;?"&&=+E4-MA3Q=Y+Q9"0 MPN.Q;L @RA62;OI5742(C/8DV9)K:(D?(Q$EDZ[%3&-JT:_F'KK M-(L?]/MD=]5:/9'>B[R$\Y56A9 9(9TD) [U+[GY\U=&(M6MF4[L9AI$B"5\ MX46#3R\RPJY(-BUYDO62P _("+NZ34;I% V*1A-X$*O(F>@JSH+B5DK_GARE MLK'B<"SN G&?EZ+4,F'PAYA]=W'G_K2_Q'X;T0NY1V^("[Y/4;=+5:!V3$4\ M)#%>@EA]N1)@TA@U"B_,I0F:))D" !%3"Y-2,/6]ND?U(Y-E[20XB5OI'<4- M"X#-<2QCU7V59K"C7\[("L4K)RW9#R(B+W5E20K*R%EHTQ+.Z5:%#@6"*2PF M_01%UXGJ&/YH%@3]B6$6B_.X7W?!]TVB"(6T^4&BG$0092+W,J-16.A87M%9 M?-Y/=*@L7K'P,X^L2FK];Q'+2<,6[\G!K-7B7GDN3P[S3AK=,HKE'>&,QA>Q M5HI2>V8C11MU4;DQ9_69,)(-5RW_/(L58^D*JD?SS]NM(]YM F>]648RGO=L%I ":A#'M-U!A>Q",6=ZKP)DDH] M2"\:6MY'(DX&P8A@0 )-UC9CDD(HM7XFD['W%(Y!J2\UU^53CG )F/A$*PWP MDJ*/\128'K-T*;KL"56#5=IK9D*E-=<^ZG/Y-9&,ASR<:=*VNF;R8&-Q3X1A M?LV'-ZTW^G,RXE[Q^?E(HP:\#2)32)ZELOC"S(GI;^X#/QW0U62(/%[O$1#X M*!%GQ1\_SQO"/EJY#7V%ALR[,AS<'[;=/3@_,3E3D-[8/7WKC MAN\[J4DYFUZ_4Y3SQ?L-O-K<_,/3@:YMJ-1-J M4#U T1$HKJQZM1]26+?>>1&L;RZ;-XK&3RIN&(_AANUKW_$K:)]32OK?'9E^LW;:KSPZH>CUM"_K_[];\\3:8[EM&=9?L>^#)!MK-.6&T[C@JWCO9G85=3X'* M_?UTJMA9N^D[9T-KH#70FN?;PM[1R5 8*,SK&\X16FW2A2]BI3H[65;BE<>S M(!_(MS*J#EO@G 7.U60FQYYE/JK@[X)U5G_04?G]239Z)-JVD),\?@ MM[A;"=JP/RKT+MN!#RR%_<7*?^=G/.CZR> =^0$\P/%S>BP^0G> 5>K\=6@%?@U>L;SI$!$>8UD4L SH%S->3<\X,3=8Y!7 1)&@<]??C!923BV_ID M%=0F#%MU'H#9Z-5:X &^H['SG.UC6R#9EE$-R-!8,F#2'ZS 5.;\;:?6-XUJ M\F !1-E:HE3@/K:!,9C[U[?]G'%ZE>_0]'^GDM&V0XU7'?@_#8+0WI99[EC, M.5^R=?.3W0-,4()8();]S01.[.U8"F*!6*]O.$>&1=WJ,]6V89@$SH%SJW.N M>E^V#9S;KIG_7[_]_,F=Z$,7<_U/M-=5Y >+X:+:&,8Y+]'4:'5&>]W'@VH"SO%:UD?MQUJ.VO4U+GK+* MMG3>(3&0&$A,:>M,:YM>0&(@,<\>E&WCV OX 7XLC=W?IYP4=MGU&Q-&70+F MB3#,[?KA3>N-_DP&]8K/>4G*K7- AB^7["88TKC[J[AGW^601S^QAXJX+&!Q M'_CIX*QSL KP9Z&V^L7/CID\AX*/I($?4^5G<-Y2M7Q^0Q_;34J?VX#.G@RJ M JQENH<[#\GJ5JZTJDZR7!+X6@FFY53T3*R4_;%DI.9/] MB;EW&2E;%J9$#A-"U^46_;[PTN!./-!&] ;!>EVK=2';)VR"^&)88^LW6WO MLDZK?;"K:V(:R<9;CMO6C%^"]&M:_]".]>'RX/)>M QR*UR>6HC*!IR\7408 MEU3D?A"3)(D?5+PDD!%U(^6_B.\LBWR2+U_@*4W*>7Q3'='H[52^A6NBF5U$N]I:OE2,1MHS?_/8>)QX3E(5UY#%+EH;*:;=<0"ZB-H_2LVRK&SI:"$ HH?1F& M\EZY$B.H23:DX0E=E[ A_Y>,F4=]E%L9!_0%N1"NK:TQ$](X)PB#5/TRS,W/ M>,KZU#(T#**F(?12[RLJ-0CKJ19A?J8_Z.$0E4[Z^H'TD>X,%939?9 ."&KJ MBM+S!@'A,/8&8[9#/U+]0H7)=V>/8G%%!GM"#=A6:;0%C2PWDOI-_IAM_WTON.:U).U _U<[F< M;M?O>7U_3!W!/JO99U+T=1=.V++ERHD "_VR-<96^M.]Z9CU9.B;Y^1C!S76 M8!?4VP7L[,_HEKN%CD#PM6'WBS4C:)U,5R%.^&V3MYWZ%^+.@'N)?2H^ ME? I7[>TZW3^T=(8>SJ* QT!AHS,)M&C GG7:G>JI!:Z UT!IH#;0& M6@.M@=94J37']DX$@\1 8B QD)B%\$P'X9E5#;!^?F3=)VD^9OT^#R7[F8_8 MU=75:VH,-+BN4R^G[[LMJU,O@$^U1Z@]8_F_;;!TN@>V4-(4+P0V;"T;*H@] M@15@!5@!5H 5#6-%NWT"-H -8$/.AB.PP4(T:SMRD7_;__L^^T<0^6SG8GK" M&OMF#E=+WMF"$B8EZF^X*B-E1[8C90[9S3G K>SZK!KQ%7UBUUH'L?$S/^ 5 M>(4,,1 ,!'.!8,A8 *U *_@M$ P$JQ/!NL?@597!R4;%(']-Z2=;>(':N&:? MBHY,T;?]SN- 9M:.J !X&CLMUK5V:%-3' _(L+5D0!X16 %6+&1@6XNV@0P@ M0\W) !)!A!#G9F3L5;-LK"_.Z[QOG6(;*T3(5YI$/46$'&0 &3") M"E: %6 %6 %6H.,$,H ,.*X9PQ%A 'Q %Q0!P0YX[A@#@@#HASWW!(K[GXIJVF_O<%HM-O)K$!E?:1^;MK6MU9H2$0<;MI8-F"<"*\ *L *L "O "K "K,!X M8FTVE$):[U/>"\72ZTM_E^JUD!3RV.ZWLT4N/64&0RHI1S\EB(@)YG/Y-9&, MASR<@5E;73-YL*X#\T08YM=\>--ZHS]3 WG%YR5&O@F&(F%?Q3W[+H=\@81# M'M\&D2DDSU)9?&$8K[^Y#_QT0%>3(7HR]D6L(J8A'R7BK/CCIWDH3,L=+^5? M=RE;5@A)ZL)\>'/0>OLD4F=1G]_8?N%]IQM^WTOO.ZY).5$_U,_EL)T/?/.<7P9,L%OIHW0N>"L"NDEE[UR#XVK#[Q.-X3&5BYT.9D3$K M(/-FR.HNZMKM5X#:,\(%-D]<60ZRSSR(V>\\S*!J4+5- .Y;+%+^XU%COE;1 MOLADY;.(:M(/?SA09]U=_5/PF%U&OO#9A?#$L"=BUFWOLDZK?0!MP4#&N3S0 M#0UD''+V7\2="*=6M;8;/F 'V*T..VM'N0%V@-WJL.L"=G9@][RNKUIK[]"Z ME4H6$BS'WWF2B-3:X:8.V= M.,)P,)S#?A>KS8 X( Z( ^* ." .B /B7#(< M$%=]!.!U)[_RM.MVEVZV,MC/IPI538([X3.NA_EL($+Z._)9E@C_;,&2J[_# M\AZ&[4KV,(1TP#ZPSV99*RCR+RWR%6AB#C$O19/TNS^[ZK]_JSEM'LD-WJ!;B7V.=!8[LA;G_9 M&*A679WTBKMJ5L^PIFQX HF!Q$!BGF^+"G84@]9 :Z UT)J%VZRM>8'"0&&@ M,% 8]&:@-= ::,WK!&?0G5G5 ,^?R&G4?,UE+\-^:2ZKKKM3+4?ONRVK4RV M3V.W03\]M062IO@=D&%KR5#!2!"L "O "K "K&@8*PYP? S( #*8VPZMA;6: M0@:D(6\@K(59AOH;KLI V*GM0)A#=G,.<"O[-JM&?$VG9VT7X,;/Y8!7X!7R M,4 P$ P$ \% L(83K'L$7H%7X)7U[+E#\*JR^&.CPHR_[?]]G_TCB'RV\U7< M]P,1VMOI ,KCFGVJ3::C?Y%,AVFPC69W-\4-@0Q;2P:D#8$58 58 5: %6 % M6 %68#BQV:B6>R'D"L_5N @2C[X-HDSX3(Y$S-- 1HE#YVET*CE/PZ'6=4X8 M83@8[I5<,4Z% N* .)<-YXRQ@#@@#H@#XH X=PP'Q+W$<%N>=/.)#T4L9<1Z M61)$(DE$@BCG9K2L63DWUL\* 7P:&R3O'B-*#C: #9A(!2O B@=\1-=:3P)L M !MJS@;X"+ "K%CP$2<@PSK1+/>"JA4FVUS^F07IF U%.I ^"Z([D:1#>D_" M%HR[^M,MI]L<(-W&I0@=# ?#89K&%<,Y8RP@#H@#XH X(,X=PP%Q0!P0Y[[A M7A2@F#54ZS4R;BH,3%P'(56;?0_\6\&^R7L1(_2Y&7EK5@8.CI!#Y'SER+F] M;=F:$CH'&[:6#9A=!2O "K "K KGF)%Y[@+-H -8(.^[0")_#8"7"N&")L6 M^;J,4O&'+0 A5EU_PU5[L%SG$ ?+N>;OFG+,0:>-D^5 +!"K#E$($ P$ \&* MV]H=G- #8H%8\%P@& A6)X*=X,C&2J.2KQ3_J2;6^+.4_GT0A@L66_U9EA?[ M'5:RV ]""/O /IO)[-[&!&[@!_@!?H ?X,=9^P _P _PX\0"-C467"W<4O>- MI"^^?;G\CC ?=\Y02X/XLH5S8AV$5@&L4 LS(B"8" 8" :"@6 @ M& @&@H%@&'NY0ZPM/[KN8];O\U"RG_G(%F2@.*[9!T?6U0L^35WHWL%1$R # MR%#9* BL "O "K "K KP JPHN&LP'#BD6#6^Y3W0K'T^M+?I7H]LMIJW8;Z M?X_]\VC=="68)\(PA]Z'-ZTW^C.UD%=\SDM31NO!*%_WEI?N)AB*A'T5]^R[ M'/+H)_:0^9<% >\#/QV<';16$8)9U*U^\;/CD,_!["-M>TR5G^%]6U?S^:U] M;'=A7WMV89^]*)PJP%JV>U@ CE_&D\EMUT*PKS(5ZQRF.'E89W$OI9Q.DF27?X8B2@1-@I/)(]9/XM3NH(% M$7T:\C20T?[:>OHL78(.U5B'.M"A-75H<:M?%W7H(D@\^B6(,N&S7T.2S<_^.1Y[0 MJG'>[P=AP%.QU@'>D^J@OP5=6E.7#IS5)4=UZ+06.O2KUH2O,MK+^U;1[49& M>HLFAO1 >E;:2PK2\]3#VJU::$^Q:YGN_1@ANHI2'MT&BMGG9JCE=/>GN/YO M[[-D[Y;ST9D:.?ZN!HZF^+\(GF2Q\'^-2&)CX65Q3.SZR),@N:'N],=0>G_\ M]W_^Q]\6;E?#WE"J>Z<7,C40I@_?1?_#F\\7G5;[\/\._GES\88%/GW!O73O MLG7P\?+HX\?3@Z-/'T_:E^W3B\/VQ\N#T\^7G[O=R^Z;_YZ#]&/"^) N/L:( MLWHKZ/OWQWKRG)T/?/.CS^=5W]OOYE]\N'VW)5*PZ 7PH,QJ<[#-5(AJJZ*O]4MD253BZFWV20Y+,\5^3!PK&!OQ.L)X0$94@ M%?&0VL!G6:+?#4#OR(8__$.EL'^'CF-T%<6KL0*]*1%$L>IRZO2B7>6>/ M)_1@&;'!>*1JK*6>I3&/$N*&BAH5 9FBI*0+^N<^66?&E*I>6:+?ZP=]^EFU M0%Y$NC<;CLSSZ+7OZ2%Y.>@K-A3I0/HRE+>JZD,^-M7G3)4S5LTGZ'E>JLJ9 M/F#:J?&;@.M%]5_.9J5[QH8WPAM$P9_9>J/?^=GY=3W9LRICI^!S:C TWD1/ MQW#/4QA1++C- E]%#HA>B1<'/15"&,1"<2J(#-FY-S"!!?,(=5>ZH#3+Z7O& MU)S?I--5D"!_ZBY3D?C)KT'DR:&8_*J?I4):DPM47'3RLQ&7N2*%QD]D:19L^\WCY\Q^\P+U!/,I?0G3]F] MS$*_>&TX)J&E%_R9!=2)454A1Q%R@AJ/C-W,XW,74-2"K)YJRT]"7*H=?8+Y M'15=.Z5T!GOT,#;I':FR!53NAN-=>IHR<"1TL[+[(%7@BC+3FN*. MWK+GT_/)R033.4LQ:2O2=(\:1Q$BDM%3OI3Q>-(D_K+"1J7>7%'>&^V@"#)A MYHORI,&D2YN_;"?8%_N[! 9)0^Z4ZD8F58RF,BA+CU31W^VRVW+W.(@6GB+V M;^DI:@8B4:8ANB2FHJ&Z07DOG=AC*G>OO$_^Q2X3J;?_;E\%'@V#PMVR)Y^Z MZ62)2CS6K,:IITM(K:Y,%QFUJ_HI"M)T>SC6)5)7S9BW1 V-^17:;Y<1:'(1 M+.F?:E6R5$)*0.WZ$QO(>T).;"IO*CAUQQEYPGA9F15]9#\5IJA#Q2QBA6&V MMH,JY-1FK^?$V[8[X(^'L6V[ZK*R_'563AZ@9@YF4BW=RHF>B3-(U$JO.\@% MS=(Q=04)8[G<7\Y_]9@&D'>BQU)=P/BQ(7IUD_*-7UYJ999I*\0BH\]>J9282-Y09]\7FJZ MZ_D(0-O@5N5#1EHF_;DWJ.E-UALSF<7L8\S_K:8B(I9D/:I$0*]6]OJNO8YA MGJJP,H-Q)UH$DS3.N15 MI*3K(X_^8+_JKKC/OE.%=I7P?[GZ^.MW8CNYJ<@;*/LKI:1K%"G5\.:>S*Z; M2>@:]>@I$W/K*]4WC-[H:ZG1#?A./?E:$,C9CC:28B3KR3B6]^HJ]>!W^O_U MHTSQ]]EG:>1B 5PE($0R?1(,RJ+]_%ES+;-;A@C)4&D\I3M IE<3)/E0)\>C MSU/.9$\Y/V$>G01$1!Z7U7,93*?=ML[J>&VPVEV47)UUM3LGQUO@8>I3%Z@D M?G@#Z@F(/>KE^FK +H=#Z2O F7Y?HAO8($ZU4<%-Y;1Z*B2@E5"-"[33S3&B M/*8"04(L5UXY'VSGB#6]SIRUQ7B9_C8]\U 5VO1_Z/KI8#^:7JS&Z^F]^K*H MH7J;^;O3C%&N"4B1Z57/H]0GVC5]52T,/SRAXP9ZL$7-[85$0-)GG5A2F&;W MH3Z'TK#"J>3*KT6=VEMX/-%#P;SO3Q\'3.6ZET<25-Z8&EUUF:E1=<=Z,DC1 MC3\:$=+-D$A]G _-:!GADV''=!A$/XA\%*,Z0QJ1TF; M=]375C8DB$S8E3]4/65*,./7M=#KLIAK)LV;<*H/=0L5!I)%,Q7< MZ\LPD'N:K%HB8A)TP@ U,/7S:51++,V2\KAX^OKRD)N:ZR[PBR+RR&B *> ^ M^\> .)Z0)76O0X_6=N,N*YH[%;6Q& M/E08'HZ30 _E\_A!R=F1+7+)G)'4"\0ZUX$IV<2 MTA68J!09&6=<8C>!7X1+6HO35T'L[Q% M.>1_B&2^'V4P7JYNF1$$'!G[QB,: N9AF1E^Y:HY7^(GFD9Q9H7FF:K?MV_G M>0\RHZ^3C#2=-( HDO?U/>JL[^9C;_VJ MHK,\5>K<8VA)-Z$L;[QG/.%,%&I&?&D(3XVK-)GNCL5=(.[-H$$,1Z$<"]V1 ME^PVE#U]_9!0="ORMBZ"&$\4@A&H_IAVN*I! - MZB[=Z)J5.BO*)JER(;[*^LUT0NTTIC3Q#[I7\-"(;ZXC0-C('?V[V5BE?H^A M.U=XIC8KH9C[_\I,M(%Z"I]^/W_S3B&AF$0NBE>4K%0%!<9(1KG4Z+"\"C>; MYZO6GPV]ED@PG4\BB[J[]V"I@9@[*=20U4 MK]Y,Z"YQ(\9YD/ .:# A8^T0I['5LI/+,15-8@1:P1^<]-N6.MV$-"MY;VF;EZU2/Y0=>/U C3^&UB[9TH MQM21T%,HJ2Y5*0$@BQ;J.QU^:!@NC!%5I4J4(CU,PZ(#)B<#]HDABH'E-3% M#YSTC->][@1.NH(A#6/2DO5TV4W/23=,3J#B!3.CV<)05/">&,O"/YCAT$@& MIF=8ZN"K$?B_)PT7TV.T%QY1*U-SD9PJ-U,,W>OU,:ZF!9Q[PT)W MF;(;ST[R47"W'QJQT<#0\LGS.<#EN-K-K5, IS>)59#]S5][G@K;]J01'6VM M0H,G#F0WG^$LO/G#[4Y-5 PF'RE1X;=U7SL6_9":Q9@R%^G%+H+6'17C*;]S M6JI,XR9OE1QSXT"$N26UPA8QW?P=U%E6WLPXQV6!6A.$RKVUBED\X@)-U$"_ MI!C:>T52CC%-F6FDRM'"M^J9I?CR3(R@S]25J/G,_57'QA9B1UQ#:. S//R(>J(?^M8_M) MND!@W8LLWQZ4NX$3VBZ;DESVK,7BS#QODOVF4D'TL[-1+@KI>)0OC^318B[! M7"*ANO"._(81-@6GXETT^ K5,'":E)@[#-45F0^7] ,U>:CO5Z_-]79V4JPT MA?_@Y*P2O-(8Q:?/;][EL<3<"ZEWT->3 *-Y:W&_*<[">&>F/SZ1 MRJ(7FE=_VEW=53)8_%?S@ZM)&&GZ;!H*C".3(+EX[4*. M9N'D_A JP2Y-ZF8\;BE'( M7I)W>Z@=/>HRF0C[S'0S-;:G6U22-)$'T57^;?]Z?[<(V^H,(.-Q)Z/->%RJ M5JB[+G3!LN89J=B+S)*PE/N2QY@6GZ2540\ULY@&"M-$V#)$'J7MR*>3AEWV[M,I:A; M>?QLZ*9 ]+U2SGPN+<=..8FMY)M5=\^DW<[I13$!IM!&W:T\\Z 6)FFP&RXO MEF"_E#,/W,\'MIC^^]D,%!Y(A=/#])D Z4)RW8/9(N:>A:#]C JZ1ZH?;YK*W)K]+)K-'5I'J)*%M2)VN4LPV?D>>O(5IC(TH!*I8F-\BRF2<1U2(WW0UE3:>2T*,I^ M,Y,,TT+VJ;WT<+JG!A>WY+C]?%HKT"&528@E;^+IG7H>+5%C/]87]^3,^+" MSL( 48>45 !EFIX[F8 :9H**KR9#=2QVTFD87$6*X?9LH'Q M/XJ83C&P?. II7B/UH!2]TUW/::!A[E7S"?RZI(8(LC[J+1@)N\>Z$ZY,! I M3;L_-KNN$R@G@313K\;$29\KN0O+(>C.4K[^ TL13+I(:/*IR\L2YA/S9I+R MC,#EP$D'03(CP@5>>L+CZIH@G28JJU%'CQ5'OGWMI M(??+<^YUX'^"U 6YUDL^[X.$N&8*.XDY3&-V\])8]F$/)6AO,1QGUGG,^W\: ML.=3S:61/"^6=.C&FUN>\UMNXE*KYV-?E?#N!7I,MG#_="E1,"VCFCT-8OJU M6"M7E#B?.'OD*9.YI\E3N= MVC6SM1-G8](F(B_/C2--EN3!/%&XW"%7(T_YI $6>*)Y;^:9SY=X:_)W&1(L6(M,E,_>18FF48M MGYW 'I:Y,'6NHXEGO552[ R75\,M;3S;BD#.5UF$)U M.@*=%:$@EB>QY@O7IE&1CZ&4*DYBT@6_BXP:.E').N615QGF]_FD7PF])B"T M9&:O-&31(\)2?FO^@*)8NEL[' 5FRE:H#$4E_.7^_$(G>FD[-'J"Y!=3W:E, M5 JZO"\I)E";OG<2JB TY.F9HI2[HL*S QJN>#J/92IA>5A=NZT\+T;YR5W= M/RK2@_6\J,E%T:F1,TLE].SFS#+RW#O53 =\9)@I'UWPH+00:R+118=L_IY6Y[%C3)%XA(ERA7,P[)Z M-6NHY@I*CU*KBODH\!5QJ^R\.[M0 6GX3.DV6H"(JHD9AD>966UNE$^ULU@2KCL6=[;T\E\DR0F_8;EKRV/K4S6PB21.2H>-DGB#.F)RH8J2J!_VE7[;ZE< M SV+;#C+XUB%\>97:Q1R%'&=Y*E5)U$K?2)ZJ);UTGVSD6$=/$Z3V0E&55@M M6&;V9S82?F9O,$3Z;CMJ,T=V# M"B*+-6K3)>?%FNARB^@,(!HGC_+TLL5EL47T0W>+9Q,1BFBQ3F&??]M,4J8] M8Q\\9.Q"L(\V/W3^OG2B;^T:+ZM>-;MU2=6AT7[<+)LS.T$HY2W8I7HLCRR9 MUKD1_F1*B*[4.P&VJY^F_-E07HO&=3;4TUXDI=>E;MWY=/[IFPS5>(YJ9L7# MSG8[G]R294?-N9#_5.KZ+N]/BB>V:9G;HZ64.6>2Y!*=D:-32\Y>C+B26GFZ M&[;*QGDS^VRVYG"J/I=?$REQ"F>@/;LUI[6]4.=*3H"X#2)32)ZELOC"',"E MOS$;HIZ>[I^T#EM')YW.$1GEY/#M3SV]*&Y/>_11(LZ*/Q;4??E^JY.=.+O= MI4=9K;!?JB[:AS>=D[?/W*HUO[&]X?N.:E).U _U<[F;]QMP4[=$/%>4*?/9?+?U/U8>A M+G3AUX#3\@%OD1?,'DP'!LP ,^LP.UC5C' < 5,K/["L1\PI:O3=6YS187 M#X@%[ "[RF'7 >P N\W#;O$86L .L+,/NQN9\A!8 ];0H0/LM@)VZ- !=NC0 M 78-A=VS.G3//E/WIQ[W_KB-91;Y*H=%QF?_Y7E"]/M.A3I/7V;4TP>-:G97 ML\5@AVQ88VIOT(AU,)PSQ@+B@#@@#H@#XMPQ'! 'Q %QM3"<,\8"XH X( Z( M ^+<,1P0]Q+#U3YU7\XY=+]OG7[^SZ_,OEX^LZ,1M1"2FW MD7O #_ #_ _P(^S]@%^@!_@!_@!?MRT#_ #_ _P$\-8F>K9PBV-X(U>R$T M?01FHC9.T_NN+<;/5G_F<;DH239ZQ)8+NZI-GW(X2O5#=MKO=%GH09,V0Q3> M#<% %!Z( ^* ." .B /B@#@@SBG# 7% '!!7"\,Y8RP@#H@#XH"XUX^SSEII M_L"82K!678;B;Y&.K>IC?WHB4J<765MN#4[:MX\;J/F+;1/8K[$&D,4J_W^/ MG'[SPLK;:4L+R*;[>C'S0L'C#V\B&8DW[R?5@0Y !Z #T]NZG6/P'_P'_[>4 M_^@'0 >@ ] !] / ?_!_>_F/?@!T #H '3AL6=M.'?P'_\'_FO$?_0#H '0 M.H!^P$(]*]ODON8Y%Y]4Q?M4]50D3/:9+T8R"5);\$&.U HY4IU-YD@]XYR* M&G1/'C1-4W0+! /!5B98NVOMP'00"\0"L>"Y0# 0#)X+Q *QZDDL>"X0# 2K MTG,=6HNU@E@@%H@%SP6"@6#P7$X1:\M79O^LV!H-!=WHS^Z!:0M!$*!G"% % M!]HWS-$_8:&FR!)8!58]P*K."<@$,H%,<%%@%5CE)*O@HD FD DN"JP"JQQE MU:&UC15 )I!IR\D$%P56@55P4:]-)JP%7(ZDZZR7RI2'UO"$; -D&R"=!^D\ M(-@&"'9PV@*Q0"P0"YX+! /!:D0P>"X0"\2"YP+!0+!Z$>RX=0IB@5@@%CP7 M" :"U8A@\%RK$VO-Q7_MC5"JNFG!RS^S(!V7UOR=V4(.A&?U@Y(KL%4=[ /\ M #_ #_ #_+AI'^ '^ %^@!_@QTW[ #_ #_ #_+R*?9!HOSRB]DN69CQD?:JF MM0VT$-W?P-*@ID3_7V$E7N-G"4!0$-0:0=OVCD, +\%+\!*.$P0%09M/4#A. M\!*\=(^7<)P@* CJ,$$[<)S@)7CI'"_A.$%0$-1A@L)QNK+0HN[3PK;W7X-: MO>ZFD/DSU15/;*;8_"[%RJ:HL7R!CV[S<2O"TB 3R 3G!N<&/FX7'^'<0":0 M" MA+P7"M:7,4MX**SA"\D<2.9PN2?1]*P.$!0$M4;0PQ;2K4!,$-,Y8L)S@J @ MJ,,$A><$,4%,!XD)SPF"@J .$_2X>P!B@I@@IFO$A.<$04%0APD*S^G.XMB: MSQ)_/[^X^OHSCAZK0*VP=3GP _P /\"/4_8!?H ?X ?X 7[1E<$(K$649".>LE6I^6,8O69KQD/4) M# DF%>QS<QM@<#F2J[[H/B\OO5[^[@?!0+"5"=:U-\T&7H%7X%5^6^>T M V*!6""6=8?5.0:Q0"P0"T,M$ P$JQ'!VB?@%7@%7ED?:H%8(!:(50&QND<@ MUHH&6#/'ONX3@Y_D<"C](*UD1A#:L[7[9V)76NQ*"U;99M5!&V0"F4 F*V2R M-QT!+H%+V\VE WN1') )9-IN,F'L!%:!5=;S3]#? YE )HR=P"5PR24N'1R M3&X<-=4YJ?=DGCEJ"DO[ZBE;3UJ#F""F<\3$4!,$!4$=)N@A'"=X"5XZQ\M.!\0$,4%, M]XAYT@(QW5C:6?.5G3>_WIQ_8>?7UY34X M_67C-K)ODKH<=;?$*$W19"B,@PJS@4-.&R4_5=C+>N3EI**UPDM,AD-RH5SH M&SDB3H[H3V7)#.@<06(@,9"8]*>34XR_(#&0&$@,(CQ0&"@,%*:&"G-\@G$2 M) 82 XFI7[(/) 82 XF!Q- X:;?503_&F7TL:INYI#_="UV@G@Q]\YPO >\% M89 &V-%BHTF93YTPOTDCUL%PSA@+B /B@#@@#HASQW! '! 'Q-7"<,X8"X@# MXH X( Z(<\=P0-Q+#+?=:S$O+K]?_7Y^<_7[Y?69+8Z"BJM3<1L9!_P /\ / M\ /\.&L?X ?X 7Z '^#'3?L /\ /\ /\U"1BMEK L5WS6-I5E(I8)"F+>2IP MV%7-%:WB30C=R?5^"E3NYWA7L=EZT[>@A-9 :Z US[?%H;TS42$QD!A(#"1F M_K9N"QH#C8'&0&,JU)C#$V@,- 8: XU!6 9: ZV!UM1::SHM>T?'0V.@,= 8 M:,R"QK3MG8 &C8'&0&.@,?.W';31CUG5 &NNW*M[NM&G6"8)\[(X%I$WKB+? M"%J\^C&P+['5*Y[F6D%LIBFR E9L+2L.NB #R RP$6 %6 %7 3( #+ 18 5 M8,6SY@FLG3< ,H ,-2<#7 18 5; 16!1^D>(!7H%7X)7UDQ[MG24+7H%7X%6QXP4R$L$K\ H#+1 ,!*L3 MP>RE:H!7X!5X5=QF;>X"M *M0*O).*L#7JUH@&U?^26'0^D'*19]O;;TR)A: MH+!$>_2#)3(,?/9?+?U/W12HBA'I$Q9JBB*!56!5Y;D^(!/(M.5DLK6U+5Q!MI[#NR[Q MSI=9+Q3V,E0:<,#JJC9R_Z#5RH,02ZS3%(6&U$!J(#6O/W4/B8'$0&(@,14F M(4!B(#&0&$A,A>D4D!A(#"0&$H.8#*0&4@.IJ7>*"R0&$@.)@<14F*P#B8'$ M0&(@,16F'3588DKI1>]33C5<>GWI[U*]PB 2>P.AA:3=:;V=A\8!06-:YI.7 M5?5D!7E8_6G'Q=/^WV/_/&H\;27FB3#,J_OA3>N-_DP0\(K/2TIS$PQ%PKZ* M>_9=#GGT$WNH/9?E>=T'?CHXZQZMPK99G*]^\;-3S9Y#@@6PS#;*C!+K$PE> M@)7CLA63;/1(DMPCQ3D&/1%/;=MM[[).:\GA MI2]X.N.1;Z685*!%S_*"Y^ROKF 3UA*'B2Q80U E@);O0(_CP)$I8EZN^$2!#TB5STWBR2O43$ M=UJA@VB4T1MVOH@[$98 ]H[*';.4RC\FGYDP019:"R;:*'GR<=X[T*;WR0:Q MKO^9\LL5(G[:+.M"_EEU69,6I5+OY,BAAE XZ8U9.AX)!9L29(*(T9-"*D/R M;I_=Q#Q*^H(:L"?2>R$BIAN:=;4)S-\=QF-!CTA%/"2V$*H2]4S5]M3JQ9^Q M&"G-(RR-Z&72UP\8$="\8,3#<$P7)%E(>(SED'D#'MT24*DPZMXI^CQ=W&4( MS!)ZLJ, MZVW-"8?Z7'Y-).,A#V>TIMTJ>VMKW:.YD@]Y?!M$II \2V7QA1G'ZF],'ZG= M(D/D_7="&._!K#9?WIWNAU3X:^>,0UQDK+37RE7B!HV/2=O+RM4!2" MO,#<(YC[+&/Z*F*?:&PD(F\,V %V&X#=Y-!-X UXVP#>]+[0+PB?V=U I3:Z-LL:.$ &VO '5:]@X0;OK>,= 8: PTYOFVL'?, M'A0&"@.%@<+,W_:<&9?M5I@U][]KUSQF8\Y#N^5!E+"=4":)2-ZQG5C0RU22 MGDI5R:+BX[NS*J*-FXDF-E^>&^:^@!_@!_@!?H ?!^W3U.-EU^U.745>F*D4 MJ"!BU"&-J(S/.6%V]9V^'=G)>^WI'GNGI&.R!V&2:G?7;PCGVJ#LVHL4RK86+4I+@BL "O "K "K$"OZB6]*LP[K3FV MZ>?+>;U\.2]+U3XW8;Y%3(6CG:8$'+ Z '$\A]Q=4VBUTV[9.U,+T7.P#JQ[ MG3$9W!H(!H)-W)K%@T^VV:MAZFHRO(O%K=KE4\9CMF-VN7U7WN(6,15$&A%I M1*01K KP(H5X@[6DF&WH1\&IH I8,IKSE35?<'YM4C34*AC"+ PZK%MJ*J/ M&VQ+[PT!.?!JZL6.$8_#+!,XMTG.M;%$ [P"KZSSJEM]QD13>+7MNWQ-#K.3 M_>)HQ)W2I-$[%D2I+$ZX0[#CIYU3:SOHH3N(L&"3F8+\=1 %1,'\*^9?P8J7 M=+2L!0>VP7]@5FF% R*>TM?> M7C&S".P2 GV9]4*QUA'?;EC0WC%@J]K(_>/ =KHM>_FDJYJER2*%B#7T!_JS M>C;[L;VTVZ>LLBV#%T@,) 82,TV&A,! 8" P$)C*QE 6E^1A"%5=*D/- T!+ M#V3NRYBE \%&=)=4NP MGC+(>)K&02]+N0)2*O7UWH!'MVKWU](ASO//CH7: M_36Z5??DJ>'JU.=R[L1 A+Z*2*E'"OI-]DNE<5I.M^;(^J>,UX S[2N?(7N. MV;:E$^B0YJ)W"#EKD)RU3S87$X.,0<8@8Y QI]=_K6^M)@^7H7!0."C,C#&;"VU363!YMPFR?",+_FPYO6&_V9&L@K/B\Q M\DTP% G[*N[9=SGD"R(YY/%M$)E"\BR5Q1=&D?4W]X&?#NAJ,D2.*X)%R$>) M."O^^&D>"M-RET.N4S@=+4VP7"%JJPOSX]YDRJM-\%;2H]&?[HU>]V3HF^?\DQP4NXS4+$F12,NZ M[5W6:;6?,X\WJ4]WS33X"HS]N($7/.+QRTQ\_*")K]0+1)*R[SP5MKI(&*X M />7HHWG07R@C$U,FF6+J7Z M7QYE/!Y/86I]TS($!U\0DG8_]K?3;MF;W\#T!:8OK$]?0( :+4"GV.,9$@.) M@<14)S$X:0@* X6!PE0XBL(AZ [LC%/[/5Z7K8S:F2QK4HN6IJN%DYA=F'KXFT9\/3S5;Q>OHJ7I>K\9K4/ ML8PJ'0(U)PJ!( 2B>^XXO*;P:J=SN#%<-=E#@G0@W:MN[ ZO!H*!8)/Q7?7) M2]O@U3"?-1G>Q>(VH_&:C,=LQYP:\ZY\9 R"*@@U(M2(4"-8 5: %4^'\ZR% MWT$&D %D:!@9JIIOJON*\&N1IJ$8BBC%RJ7'CL9N(:R&L)H[_J@IO,*V)I@K M NMJ<$.Q,,1 D0(<,'A6(M8@ P@0\W) !:JU.@.YG-@P$*&O0DWJ MD8)^D_U2:9P6S*TYW?TIXS7@^'=[FX^]V%A-T5[,:=6IUP<1:XZ(M2WNH@ 9 M@XQ!QB!CK[)^WAUK;?-,(A0."@>%JZ:CYH#$-:6C5HKUO=CL#T -"H[9J$)&@I6==!4^;9KT9"-:7(8FFCK_IR%V2#8<\ MINL2'6-+J#V#/F&*GIY%LI>(^$Y?%T2C+$U8E@A_$A[,5Q[-' 2[;/,$KM

70;3)Z=K+-[0X/2R- U;&W?^UF@_M;'>^0NM\TZNQME[YR[P&_4^.KK"D; MG'7?O$ W<*"X, E$S;6Q0B!/T?4&=U@M6]ZX\H"-_4<4^>.E-ZKK MG,HH\A E151/>31&2?4DF&%C7)#-$2^M70->6J;/*]/:$&MR44:X?D>V=VV[ M5@:Y9/A,KDFHU=8+@;5JE5.L#%V5-HUSTDHU]LPR6^R&B;+9NG9SXCY)7J.+ MM>8>X[(%KZV";P:#2X[-ZR[[9!LY$*RXU0 <6I!(H3$C87-^C!76PV>E7L2C M]91D5#,UJQQK7[!EF[ _R\FYNC&@-8VD!T 8A9=YP;G:V M]70_5RY;%A5[TN.:Z@&M]NM1B%4CW'J)7,1%@@UML7Z;F ;%4J!)JZZE'';386R-C K1@O(66F,N%+Z8=UWA>$S]'M9Y._R;; MIH-#+79M;83P=-B4L\CJF6XEV;[1%O)$M.+W&MNAY@\TGE-'!)NORQLQG94; M90.((HUZ@5?<7%EBI]D'AUDE*:8)MZ:#+$U-ZC:7_,87?>//7LC"T%6(\5D1'?Q%NXS]$+9#4NN M6O,I=CHIG$-TMRXYY4%0)1L-V&#M@1#O5Q4*6R2 QL[1VJ)29+0^;!)K?@J4 MNE2TK8!>RHIFK]@ Y)[$+2>UN(%U8L5-"NJ0B?Q!GUD'/=G82XR_-I!@,F>0 M$'LDFLA"J$SEMQ^<'!\,SL]QB/"J0F;* +-,1$O'OT5TQ8Y^]53[67LPZ M38/Z6),KO07@ID$9^H1,?I=E%&#IGS4CH!0KZU*+%3'BL=8Z! ML9!497#[E)+'B3M84WKQK^#+X.*WD\/ KK9:22JAU0*8% ZJ&\*+EXV!&E4V M9'6:8AKQ71114KJSC4".IS7G#:/%B.:V;-3=:YDG;^&0,VG0I!JKL/P#E"0T M($+TP%X(,GK"T8@&U775TKZMB[C31+F\3;(X6T<%J0%HD+'S37M!%BTG,Y]V M8:HCKF%JQE!':IA.TBXUW^'VUB6[(>9.D5J+B:<"J\9W,G(:$+KFL&5QJ9QA MK@^2/3:%%5TE+70#MPW<;0J8@CF,4N_3062NTD*[7$\\,E;KC4.![$J:"[(= M,6A%J>VJ=+[MT*0CUS)S/*6_2/#+3Z)!HEK@C'1Z:ED)T4(OH;IP\Q!-&0C= M\2*F4K='=S*S?%Y41Z300YL(90,I=$M8G35^F8@KN0N[J6SRK3':Q+1^U=Y_ M.5Z'IDO;.;B,=3TX@A5;;;?U53)/V(@ <-O5Q0'L^ [E+K3=$U546=^XP4-" MK77*6"6U#7=KNU+4)$#L0"0Q::"L!R55S'2.250Z?<6$Z#9C6 M7O8M]-RU!GU)*8/9YU%HVXPN?EYI/F0S+RN;&L,X^F*M=K2(S,0MKA(RF:>8 M^\6OJ(YU:DBB=9_U#,E&F>KJ,EW^C!&!Z6WWWZ1BQWG%LJY4,]+RJ1ZR(=O. M-&M*P= I)R$7WE/6G?4FK(KYH61VJV?PS[+*C(E;XZ.5G2C5/-,F\ 8IC5,% MR[JDGJ:/P YM5\ ^G9P<_O/H\V&6&7DH.6ET?DW)"49D=?'*_ MM=FHUIM'WU%Q7!V9^^$?:O644HW[@OXB:R2K,B$&FSI!LSF/-+\ MIAR9*?4+:0=7+%["="YSO^3?Y^X$< 0F]HLG'S_Y8!>.A-KB5&RJ8Q)Z#ES+TCJX M)F,7H$*G^9QC8KD[+8?= 7J^F#7(<*'9$WT *R/U^%B3@XDM5-HZC26+UV\W M,M $QN%W*GO%"'SHCG5/J($_6*7&O=Y (I.RYDY!S #EK:A^.<]$,4ZL1%KS M%:>>BU3*_N#Z@* MH0A3TW'*DL7C3)7\X4/550ZL75<4M66:WY(MIN&965UT'>%M$8W*W=#9R$H'FD=.W4J0&Z3(]'P'BPP M$)!"A0@KU;^VQ6O0<\':4 5PA3IC]0(,5ME,!;7SGF.%+KUEXT-R;JYGM2AI M,>S:#D(9PS(DUXA_ ZC/<>7MMGCT-<'F'K^VLW#*)8DB]E+N!G^Q]X,@I0TC M9]4)5ZVI3HBD<@^2AVFH6DJ<'FV XA;M]&;*5/2UE!SA:5/R8!) ZG7@G]6DLFRV6?E8G<,?*FRR(,2K2.JN:?\ MJ:'*;,8D)TK61_)+"D[=GUL4*,VS5Z;/KM4X4K82=>F[M]"08'F>D+D=*Q,C MF?)P#!<#-#-I2R5IPO[&U(M'-K/G2[XP-_Z7!5U1BS^.KJ?4\#*6XT,*RO%J MI!%:.>T+N+>HBS83"8=U/+:2@'@:M-5V6N5*M;1D_<6=.<35#,KWIY1ZV;^T M$*#,9H92EVA3R[J\4NF$?-P$QS<8_97 8QW/,(!0ID$W$!N=_-5\)A52#-!R MIS\M/QA\JHLUPXL<-RW?U-)(^R5#U?K6N@J94,BR,?K&D^(Q\T"=B?DXDF/# MA2[S@LO Z8K.OB0SMH:2%HHB'^:ZQ;?KGC1=;C/+W6WOT.[9S7X>Z[1M"7]L M;-PX!V$=J&]I]$1[)3[3X1=S_U=I%?]2WL8O8I)C5!D1*.4Q)1D7"$GI%R%U MAG]A]RU&M6)1_VAQKG [F!7X5I:+#2(I][A+6Y20,M(BR7%7,Y9 MJ]9%URO9UX^8@P<:KJ[F#3H\"8!<350!),:A5*V^MAT;;R9;6:([DAVVO^7[EYV[:1VD2O.4=$4]2>;*80)BH\NMX;H1XJ>98^E&24NAOF4:F>C6SU>\'-!' M3"F.INU0(3W8-#]8]3-#9\MX;I4*C2@_G%-TL0S!:?;;LWOUM#=$4GT[0SDG MU9V@S)MUMV"R")%^K;1P9W))*L;43(TH"SB2BDE*KYK84+",5/Z.= \ J'"@ M>4_YH521DX0\?O61J @:H&M9XCW$>SAFO%31,/RX?)5D6I.CB1 MI=OC2=E=6*P=NYO6- (6] MHLF@D+= O12T_U8&O=V,'ENI:;\ W>2+.KZY-\X<0[^%.7^-@$#+VS(UC^<( M+>\H*:/:P]39F%1K>]3T+Y-SD3!GN7#>T([G17K0<7K,FZA9&I'&(/VM=A$? MA@_H?51,@-,F92K;(ATM D/VEW,*MS391-P4 M$<1&Y/W2(8Q@?*0L_'1PS'4<6FDY/3F_.!M<')T-,$TB"S:ZUBE:7"N%[0_X"UBSLBROW1!173E2+ HSA?\JU4MY M*, M,_6.)7#P&15G:(G[L30!Z,,=^;* E5 T>@X#A)=#FVEG=M#S"GP3W9& M:0<.6ZP1%;"6CJX@I";V&U@%L[ @WIR].;P]ZTADGJ2ICFFK4!^!>OU)DK.# M=9[UWT.0&L"5MGN8IO_:M279>@;.BU[!."G#\1@+*RK+]22'URFW&_7:M<*N MIMZB5!Y"*5[I-ZH?U0(L)79)])4XMK% .C*P]77S?).>^KKY#[06DM)Q!$KC MA/(_52Z[1 2=6H>566^V]U=?%(&PA=,1,EE?.S-'^R!U]FZ2@PGH3MP!C)6#N3P M)V4/DR/9,"!,R]Q>N2GRK4[^]JKV8LZD(1DY-<5_B*$B'ST";Y?&(9U+0["S M85TN ML=:WL,&GY'W77V'TFAG908P2D*Q6[$AIH#63D$K:DA%F54)$-4UX;Y MI3HM$IBJ6X;*WBS%?=:A $_FQ_)L-IY:E#0]M;]DC6.PW%M6^P.02W ML?,I31#@389UE:M?4#R*?\.3<+>W !!#LK0W:!+:K!3OU3]L".%22T;KZBFN M.WO.>%=]'S>/QJ7-P#MO_GS'J;SJQ?N^M_70'WSH]_8>RT;O^=Z[1[)/CZ$> M0U?YO;L-'1_F595/&\/"03#9DLK^F9]W?L6B9.T7UP-+2DD)BNW9]X"LZ%>7M M_>#U=GGAN*-YFXX-974'>'I\\_AV+WS3T;>[()SG>C^(A;L_ 0EO@.4=T?+- M_0#X9GGOE>6>1,\'/08^ ;V%?IY[//8]^#8=Z1]>>S'\VCGTQ:R,Q;Q<' JX*F 8:ED=>#K& ME%>>_7CVX]G/ZMC/WH[7<#R+\2S&LYB5L9C]U6LXGL5X%N-9S/-E,2_?>2.J M R/JD61FKC+Z](^[1)],$=4-H=$5I_UV34Z=!5:>BUSVXO?)TD)G$0!/"YX6 M'CDM=.>K?@[:E">49TLH;[S0\+3@:8%>Z\PT][3@:>&1T\++SJ)MST&!\EG2 MRT!X@7,&.G-Y.GG[N[/O09S7V.+H1Q+WEUZ#_!JU55HH$5@/Z';G6;\)LC_B M>E\%(#O/GWS]\T'Y BW_CK%&G'%M5,V/'/TS/&G,,>W/Q^4GCEZYNB9HV>. M:\<G1\ M;!$$?A;CJC5D6)6TS*">[93.S#(9KY%4U9O9J( MS!X%F";?1#KGH7HX$XYG9*)G@/(UP%(#9O MN]ZVJRD$'3 ;/Y*1?U\S-5O6!:J9+QZE<#')"*F@SE*< MC*Y'AJB "Z&UU4!F6-/Z.GPJ MQ\LK$07A3_J:EBV#@P9I:B;LQ(PDU*-HY0[4^D)/*FT?<%ZZ$\[7_^+;.6C_ M_'QP$5ASG$\^?#[ZU+\X.GF(:C&AT8.(SP"9S5)T^N!JJ;S<8\X#+!J;TT/Y8^2F.B\<&Z%*,ZA<^-1'-C M5.O,\#5A=,(DTF0*;K"24S#E@:SV2-[&:$DJ3,U/>G[[37C - MYWQ-<#MC&H+-0[0?*YT=GX"J* M/$T1WQ0S9(GILO40KG064L]DAR_BG.5JWLK_%H:LQ]?QQP,S%'U :VX:8[@/ MUX&8@[.'>T"!6K3@FKB=0DQPI+3159K*4W;=2>4P3)I:R6<$E6!4Y%-2R/1^ M;_/=_ YRX.X0"?K(5_3@S?PJ$T4Y26:L*Y7UL$SB!,=] S=+A>0ZYM1&'=%B MC_@72G<12\:!+$>J+WCMF;KAJ@BS$B@0^:*M?MH?P ,MA?1+*??Q)7NQ?P-- M(YI)J5N&*7&6)-O U6$0JCGD:)9B5>;P6>>EFO/6AZ:*S=CKI=MI0?:H,A8 M+;WNN5^0_20EC;\F30?D0!WQ^O\11;[^#(;E=EI-\GH\Z2'.C 7@3)CVV@YN M\,G@!]Q_6."L=]*=P'"/:N;VFC.;MP"SL85V. :FK)1&R?V-#C>L0= )ND"D M/;CC/V@0;:Y? 35KE, I)F%!2%44B/!Z?C.(LB <%T(2"IDTA*[J?= ]Q141 M/A^6L SHNI+[)!4P%B58[3SUG.TJ,D'R2-(F[)NE)0AAPHE+@?//2QR)+ECE M=YXW5 E;F:((,M PTM,6F]:.>.AX14P7&T<2!#Z$)Z70X35WR'(V./IT'!Q\/3L;'!_\*[@XZQ^??R8MOGL%HZ_1&5!D5&<12_& M+<2(E%7""/6S1E7 79!CH%IG^32)X (NDR+/IFQ66MJZ6C_(2:X*.3^\5(R. MC'OK ^TO2T8AWT;+-(N1VY63S>!O)GDIEATLM(Z%,]K9 MRZ#&8!OMYA G,1##Z!C)!@93T" M#3V4=Y'DM.C2 =E@;L_25N1VB"6A'0:O37%ID"1UP< RZ*58=YR+DKQ+^)F, MF K;1XH%XA=+(8BYL3NP1Y\(TS*W?4K+SR!WE2 VHN+JP# 8I36:3E*R9>Z! M@/'D;('1!Y9C;1N:-T$<"X1(0JS5Z,N@N$91/96:0SM\E]P?G-[8(:C(&R4\ MS](Y2T#E!@QJLCU)@RSX![S4%#:%OY#Z9)406]!_:9$6+.X5MPGUEEF*,(&$ MUI&NP[H%7RS*2$",I&!?(MY?R:\:U4*A#JJ>L-%I4DF]-@QF*=U'*#VA40AB M6YK'[1MB];@)2*76/59!=C;X?7#\=1"<#0Y./AT?K49^G4DF2#155YH'EPWK MN!#C6K&Y.S@"W?7Q/67]H#P:-]Q+#:>59(2&W?"[@ 2%]-!KO8L16W%TO'E4 MX.N*F-(<* JD2\H6H.-PR>KI$#@ O!N'M,[E[+M@(=6C6Q@V2*#Q7 &]SP!AE_QF9A$@65NQ1IRMN?U04P M6_SC++]"AIG3K^E.CX <4)E 2C^?EX &\O[!E A>OC@Z/RE?O*+'ST E)=Y* MTFR:E.1H/BG&(5R^9-TO7YQ=X N;L*X$(L@!,I$;UH*6U"-M6#A,/V=79A6 M95C Z=G0'0K#39S'R5(CD16WO]I 99K<'K:+\$"$JRPQ&*4R%@1FA&9U$%QM12L))(Y^$U0 M6Y8WE(12Z\8G7XN0R$LT"2B MD)\LE=XU=JE)8BZ50Q@ KH %DUN4_E(#KLL0,> YOL5N O-'YIS*6FA*$]K.1DP*Z4(01_H/T&M@ M(AG VXJ:M;"RK%M9Q,UH7^#295(A!^-I]RQ >PIUC8" ,XU$@OIW(\8M/2,? MTC#ZMG$>3?(4[889>Y8 2,1 "L_SGH'Q\&_<,O1\='YQ=G@.>_#X+!_T.<7T7FQ2>V\]GZC)&+(C90WH)$ MQ%*IXX#]Q2SGN8]H^Y)YHQ^R0L?F.1"NHY&V?*1S 7D^?0&H@3T5L&%82$0U M?1?H(F06WY,^=[#GR(/5"R8U_!5I"X1GI+P5&1$385-)2H+#'%'MBA/ ^0H= M8.1SE%XP6,/X,$HQEE+%#9=@8@7''H$SYS*>AX%VZYAZD1@X?)K/B.;$"+;5 M&@P:WPSSQXK#AX.SH]\)9\\)CW\;''["*%S_ 'X'5L8J4/@K:2?2A$.U#=D) MJG5QB%%O5.'@@>22<8Z@/A'Q&)YRE3[-%DMYZ:SN2._ ,K7%6KN'?@,QJY2" MKGSD4ED#'$VUMHNL6OZ*#(^0['(QXP@O/ ^,%.E+NK$LQIXLR9=HB1=:SF:E M[+) (*>1X:V;P;EP#&=T-QK.*_-&<,7CO!+& [5G7<./7BO_B(^_IU!Z)!VN MN(W?<1N=X T'YC2! V,H0:,B6P'GVA:Q2SKOAW#4QG*PJ"JGP%^&>1IP2=0N4LW5D =9FC#JEA>T]A4?P M'K-$DN=DC\AXM)5RAOQ(DQ _2>-K4XD[9.Q5,Q06 MYR0K;D7H^:@"Q3[FZ"F[O)3:Q?XBYZLGJ&7]NPZ+2FB3#T2400#V!I )I6U. M2$XO=DK.(2=I/7I4V$CF^!$G9B]IL@J0E6AF7*GAT8 M5B9Z4GYS-"_G="TG<#?-?B5:!"U:Q3-=$.&?&QX5U!CKP@UYF" 3.0?_(^BT MI)[1,K$85BKM A,PF-DA/"-I.^08_68,STUF2)FW7!GHD& ]]-#KP1 $%P))KPDWRD@BH(:K'$E1]P7];5(F\XP..N8 MQ/SPZI1WHZ%)8%P--W_%]^U"&PT-X!BK:MWV8A9P?TM/**L/KJY MO+@B>4,>2$:=6*46Q'B=,0?> 5D)I\U%DDF+UV?9*\Q&[4UN!@_J$?.2739Q5\;7(XXSH&L.'1@5*!2D!)++W$3;\0 M97+NJ$0B_'*KF+']Y&A@FA"I 6]><,89FPWD@@2\*]F_S9TB=F6&P&_Z2$6G(=7Y(@4J2Y!G8C_C4%U*\H26+$/HHXC^C>''-8'A\)W]E:);A*"GE]A'$.+F-*9&;: M7=$.)-LHZ _.C6E3&G/%NL\$G2S$.D"F-"^5KXYVW%,;-_N@5 TL))2I<7& MR$=5#9>"Y +N(4, 80Z_KQJWV*,M*V>V++Y@MJA7T?4,2]9@V$H;L519B$-E M::K2@$@*0+Z+"@L"QCK'R%[/H0XX:"R+D:0'D<7E<TJA%?%:MW, B;2(D MU_E2QM'*BS&Z;_C/$A:EE#-*:"?/%"!9R[7;>WG)40CZ,! K>S1-QH]U"+O4 M<"%F_AD]],'NJT7FK'?78^\;/F ,5'>548[5F>5[HYFKJ)U37*=C)0U?@:.* M7)(N&G^@2B#D$Z17L76ME!D3X7&\%+_E5[!: MT9,;:TD#O.6Y6\(BMP"$]3WE),U'HU(ZHO#.S=5;K-5>=<.V1LC!8.L&P0W#46[J S @PG=ZE"R ME%>J5B8S*"$N;3PD0.M&UF!^(_D(<*O-J[!3[F[(P*(E/_*2I9NW@9=UB>@S M1EV DZ XM5-NW')XL!.%8*_RE(G2Y(D4L#%F3+"T_0G:5R*X2JZT0B]AY0C8 M[$;5AXL56J] @M5Q.K44=V72<6*#X)&(HF:NEI#))E18KA$W$[;]9)4Q*Q&R M6*E=4M9J3A:X=+^BDJ M> 7"LEHHS%D-LFRMO-9R\,^@?W!P\O7X J.\IVG%X/# MM2>$):''_OG7X#C?#':VMOUNOWKNQU^!@ M0:75_2WHW;4'"+TWT*;3(9 9;+N;O<(&BXU.W92$,;Y#!G( O2<\*.B5;), M;^S]@5D8.9EIZ+6B4#UK,"WM,GIHQRWMJ2#]#4Z-%C JXPGO<7WW'\#XRSAA MCB];9EPI'P2 I)-@=)YU%-1&]FP=LJ7KAYT8QGZ5,2;M(PPT,Y8N>/;'R$8G M\KI(H:(;(Q#,T PG90#9M[2@J?5$Z$#N5^5CZ5D^(X(F+"EK%2?),-'9C=:" MSB'LW =^,!/N'2E!T89-E%_)RJS]3C/3QR[^63CWTNV0H\=\!_^^ 8Q?^IU- MI7>HRA\0/Z71GAK$Z*2W9A!3:D( MY!9#0G1(E&)_7&&9Y#%0XCV&- 6?V?^&(_]J#FSM 94&_'J,GW8B C_WS#RJY= 'XBN&#'7$IO5 QQ7LLT,4508"01W:IPEO%U2#5>ZW*-_*I2&L(ZPZH,2KHR MH:^,M;+^^4&@L6'U^4Q+,+(3.8",'0A>.551"A;LMR861NR'.##GWG /*+1( MV?(CX!/C4,'KFV$J; *PPIM7]'TW@RX3%*FJ5+Y+95=JN,$T^'O!-??D%J:L MESG7;ZF:<4E0/4H;0IJ2U3(8"J(0*0-E'W M1O__>YC5&&YOU?Y;]'T&"+-_0@[) !1_4(4$)G;M&,.LYL]JL+*CC1+V '0C M52=*^<\+X^G&U8BM ZXA)W^[M[5Z'OX9*X'*7C?$QGXNFSU+;F3UT_N/3"<1 MJDAR5(3LD**J:4RZ0!\<)B%@>:L,QH,&.^,L>JQ5E*NR8LC*\*=^_W2Q6@]T MT"G:9:9Z4>^,]CG"/TIMANHF%?R)UI59T3/Q/L- OJ 1=UCC?ULE;J,P4@4K MP>^)J+)P*OV"7"-9.KD!FXN\O:!-51%4D0&;$$E_($_ZL3Y*RN.I(H4H2C-ZPTKF8+B2SZI^SW M*P%(1LBXX.O=!*CJM%NK L]U-*N@!Y")"*>]]1*P5EM1M4^=KFRY*:U>#80T MP8S5"#?E"A.+4KVD+-&U7E6(QB\OKX"D(!R_+HE7K2D;]:#]N=@XU5P,H3)O MU.1C"N?NF=LLONDF,X2EW4&)?&ZU;N]G]#C]C.SF0S$25??93!55G5&8/3(0 M!.4CM787,L ]R%6?,QGBD_M3?0VE:KB$-SLY"93J%5-,]P:&S83,0DZ][31% MI#P<77LU%/.9\C+P]S0!3P@%'5[K<+F35T.P?AS!Q M''9H+R@[A20*AFS)UUF(RIQ.%G+*Q+[K]"V,?:/#CU-(JJ:^)WM2+E7K>W;B MI+SL);?B^LE#NIO&UZ0W0*6*MB6(=,*$_[2]N4_L#A;MJ+0(4?5:PEYV&>0^ M;,@]V8R$4I=T-Q(9;^*&@R:5#"/MYO'V?C#= >[E]MM7P;1#R.E2XBK\SARJ MHQO>[7B;IJEW^@CBN^TAN^7ANJ/S\Z^#P^##UXO@^.0B^-?@(AA\_#@XH KD ME53:62EW'9^ARNRKT]D,K=RF>SL;VQCE/7,ZBZ/5_W% MS?8QA^Z;**+YY6<3M%G[>U8.=R4;\6+;/>[ZRMG=@KH!>R9EF<\4JP&4^\ % M7R-9RFYO:W!&.F*!-1=CZHD=R>1!S+I444+C2-!*BH[SZLZ6IK+HI5,FKN&:VX<5[,5175M&41I5@WZLD!TEC\72H-KXV1+FQ<=4ZW&D-C31*' M=-H:0).-YI8653E5T3A-3YM9_:;I22.6%#9>- #?T&4N7*##^6B83?0BO\KD M+U^\,FV.Y9'L)"FL]F+H2@-2-U]W<&M)'KQ]"-:LW:$7%AFB#5;FS %T4*/1 M^MT.6>-"[$"UG'(G;TH8C3+QJIK&\D4VP M,AD)4S85Z-7IW/6+8AHQ9P9@38',.I$.B9##QZ;M?J ZH5DY^L960A5&IUQ@ M-T4LXT,_H'[M_O&71Z*3WA2X!U'W0754@=,/91<&$T/9PK#].8!)A=T03GTC M%1#[+.5@XY1;_O5-5\>U!Y32 ,Y!4#+6+H^Z:ZC)D L#)I%\P>+_&VILA=7> M,C%U@\*-M?;EE+RFJ[EAMTX'@R*O%I?D)E#*B02 M7K_88JM;T[TXJ=QB(M$8%F)6N8[]M'%9ZB^29=@]L=D6N[3X58,CX/D3:=USI)SGC\4H/)K.:J/XZNV_/*^'%4N%W?V-W:W%X/I]SO-^5:<(@Q=Q5GHKIV/-!T;6;YZ,U7,8OS28Q:9?&(.!EKN?ZUT;.T&+TN!BGB:7[VB M8%A7;F8E&PW+4MGG'3ES%Q.Z9(:O"4^VHD1I012-3U-N I?-ZIU._M6DV M*P/N*^)MTJQ7_2#((=%=CDQ'D-U[Q*"U4OR[A"XWP[=S0IW*QE7G]*V%:K2- MU3U8Y8[.,6EF[NYNM9B9#2FMWUI[.&B?GT*UV<&>$:HKS<(SZ'/E(164]\"^)WSC0:VSU_>W MSEI,K2DJ/VP:2*@I^!B8-YIV :@):34*J9T^DXSV.V M*^$23XBAVG\FBP*LV(VO)2B3^:BZ0AW+F!>[^UL;5.MW(#NP@^'8<#E]%/#) M4QS$2[Z0@S2O8[K$FAZQM/.U![96SF=%DMZ&6VRUZ.:3_,KTJZ< #4$DTA!Q M5&JI@IK^E9;&:S^I\@JT;(W12BO%9:WJVL.I/DY;::,Y%X_;Y\'(L MLVGUP*768=MJ3_H[/=7E4'L3Z._40:I66&4%-4ME0W@] MUI$.XB^J>O9G<&16(:TB>,UL*;):4X"CGE$:'.D=.@#V=U__3 G6/!7V*Z&EIEZ/!_:2:=W^ @EV?P, M;T37?51N$NP[EF _<)*:'HMT[QNVJS/"[7/T07^>8WJZKL1OB=RLV]TI0?]1 M# N5EG==2![N44U]#K\AMU-Q8+NWX\&>M&& *0]28O)M%6Q @\OMU\%([1P9VCADF(1BXABOQMXOH): M]*H94=R#N$!-1"6!A::[NRK=Z04O=UY1_M:4FH!80[UI-3GUS4J](F!-0JS- M@2L"PRZ2?3?P: BFE]C;SQ+;\MU$:5@\&7DH,C%*(NXB+5^_I4;P$);9![LY MK@E4 R39MBW8 IW3'(DLMY+<7 1*2F,VA:K]=&/\29KSC!C9PUVE=#T%&VEO M8^N=Q4J=&8MN9P[MU=$WP)B1OM76MY$#@6O#2RE;QJ :F,!?:8 MF"'6,OE&Y=J&W"LRLPHM)=W@(CBHFK*"Z57I6I,X9S*RSS21GJNT-%*T[)I0MYLO):(FC5K)!L_2AH7Y;F6-P-8K MTPX RV5+7E5^C,UW<^12AI,3* Q<9,X7&WLZ]BX_9;E^AO*7J1)/9L0#EP_F M5,_<^!;-,+A#/L#>C]?U+F$B=V85[V6/-QQ=P#AK]4\#5;8CZX>(=T5G[D:Y M-(VR6I.^I'*$K A-=.SC-1=AT;,2MZ4? FE^@=!DO]!N+/4W=Y70V /.&-W4 M"BW4/;SS(H'/82,:]]!M<:B7NB]:1LVKTT2-P:!MD7F<"S(4@!Y+=? MW>RY5T,\E#FF7/]^= MS@%H()5XDV%=Y>H7U/J8?W.5Q-7D_;MWFUL[^[M[V]N[6Z^W]G;>_?G7(0V6 MVZ"FQK-2O%?_L.&%"UNG*/2_:'(Y[#W[VXOMG1=! =?%/^B'_U+%YI]%ZQ*T MM;^]>/WVS\X*UM)MJYD7M^_YWD-_[Z'?\^?KXGO+L%92Z:4 =134.$DIW+ON M5X=M[#0:V=D_RUYW]J^8:/$W-V[38E1-:C4HW-N0E]EMT7UP-29[C(IL7KS_GR@28C3Z"5C9"0SI->61M"VMGTFM2X'\T_443GGH"C8W M(M,U,+HG* C5.H3%SM;*@='-I7? J>&]81%$*6BE?WN1Y9EX\1=]SH? AF;XLYKH.W)[7>%[C>8WG-5W!XK579U9G.ST17R6]]@DG3^09!;XH!MU> M07T+$W[G!A/^/E"[@T'>-05MO^N*@IX*H7A_UK,EAM=O/3%X8O#$P))AQQ/# MCZI0:V2W=8<8?35LE]L>U%@X\A4K%@ZYY>*!/7GEY=?SX&LEZ[>N+_*Y)UEU M"N.?26]OO"WCW27K(ZZ>"EUU9N!XLO)DYK+SG[9;)"IPN/J>"GJ(, M4V]=K2)*]E3HQ?L7O?7"=X0ETC5D)(*ZAC^XGT MM--=:/8&P#P5NO)NBV?KMMCQ&:6>&#PQ2&+P#FWOP[L-HES0G'N[4=9J5(Y= M4#GBO,9V4S^BC#V;&JF;@/<$BJC>WKK_PNJ@]52XFW?3W%\'6",N)K]&C?I6 M9*,]#Q:W"D!V7^C06:^C^\/R 3#.UC+^"S4$ M;GO^P39F >UNO;6[;A5.C]^FM[;LMKZJYMI"+M_273O-2YP3V])>.T[*6]5PJQF':;*5-_;CY$6J2S=X WRK;M\KVK;*?="OIIWX^WRK;M\KVK;(? MK^WI4,8OQ':$\B_$LQK.8U;&8_6W/8E9F43T\;^G04&H$ MJ.:+8;7GE\WM*QN\0\M7-LB\D,XDAR<&3PR/G!B\8/AA96F-++35-D/\@\4XETA:RF?/(%Y O,$Y@GL1@+S+ORGY%_SK7A^-CUU%W7WG7B\5^)I M>R5\ V%/#)X8O(O.N^CN@"=V(QY9\K<:E<-WXND6>$\@&^/U&I1:/Q7VYKTT M*\H(\[TF'B6+>PR])KJ;O^U;37CFZ)FC9XY/B#F^Z6[BIF>.MS2,E_?A:?OW M7_]2EQOC,)R])V_^$;5Q[6W%QT.L>/^_O7]='+X(DAA^$4;51O_- MWH>]W<.]M[O[@X_O!N]VM@>#[0^#O7)_&[=B0_B&=BEMEWIC MGZ".;IE^7&P"=/';X"PX/CG>.#D=G/4OCHX_!8/_=SHX/A]<>_.^W\WU_6ZV MM[:ZZW#S]@<;W+Q]Z 8I;QY)(Y?U/I]O '/;!C#W*K/PO1)\6P[?EN/IM>7P M^+> ?V]6$)6\O55S1U1[=9S/-E,;X2PZ>,WPUCSI,43AB<)?'X+BE*3S7!;V^G M*[IY*N3A[\D[<-:M6S.2U V\FHNUO=)>6R MH@1_$L%56'8SA#/+.UGF.LTM&.5% '\.YG G@:!\O$X^JI+Z# ?'[+[6P63W M67[S*> ,_XB/J_FN)C.C^S&NAW6!%X^9@3VZ\H-\"@QJ#J@@HKK"@:E9$(X+ M(:9PT*#*@U*D:9!4'6'SWKO-USM_[@:C$\PT$F4%_P@(7#@]%GZXA-_1[L,H M O,3#X4(#H:H8#07_ZZ3:AY,137)XQ[]L9,=_6E[9U^E)G6#X'PN+',HDQ+N M(!\%65C5!5ABXY"GZT[F<9&+5$15D41R,"^VU Q&892D2453=6=I#4_#.B#/ M1DD!$(G%I4CS&<%I5N1_P/L\2E!T(Y5&8%,%EF-8"MXT8Y,#=OBAU@72@0D3Y.$MP>.^L$%7X M/4A@1TE!3RJ.!2MVXG MBQ T21E\S(MIL+VU\0^BP5%=D(Q*LA$6A" 2KY[#/QQ'MT/5#\C8KZ'C'Z/8 M\[-37A'7:F4(PU!B-P 95&F:UQV$P[RN6CZ'OY&,B'#P"$ W)TP\!^K/^%- M/G5*#!UG@X=150,GQ&?@S1G14@1;&#/6PHKP@2HLDM&HW SZ( T*1(!T[D+H M81G.WLX*&(XU$1V.DX8((H! 7G.'?:[CX M'6:#70KG-^\ZAKSGT,"AKR_6>5PLFN*_@=3E/@@=+1@FKW1;7 MD0P30 Y,CW;5(_5M.B1&'LW!?$8-4"ISLS1DGHR+'PN\(_A-7#+3A&N\I2;, M[!7W2OPU$V.XXTODRPE663I\/,MQN9B/!D_F52+_^6A4A=^ WNFK M<$*X36"FR*0DPQ??0:W%!4Y/^Z[Z^;!,>7NG6]X0#/$$<4U0PX-&85',\05K<;9[D9 *])IB1&7"G=$;BWMU<@!+4IV[;WND3H@YHP#(=H%LUE M80F*G+K"^G) W$D23;BF?#IC(7H)VD,.ME,9B0S_BVM9?,WZKRW:Z7/V6:4D7VIWE9 <4 8\!]?0"#< 3$V%)S?XOJ^9WM MCUL''_9W]C\<;@_>OM[:^OAVBZOG#[=?'VSM/*WJ^0^#X\''HXO@]'/_^/R' MQ5J;#-M^O4H9UGZJ0[A_%!HT=R,9UJ0DGH)\^&%B;O]>Y^+3INUR!A(F+SKR M1HU 0>Z&;<82R)$-9!3+9?#R!;(%!'CYXE6+NG0OD%QUY!4."_;^?MT\WR3G M<)WASI'_Y7.!KB-@^LP7._E@GBWF"=QKXPDK%7JC2J,XA1/!<@I?4$^.1%&A M!4EG//_P-1BB,!!E*=B#MI8'.SS]; [7$=:<=+5'1&P0A%%:QP!#T-\G >,- M@K,%BU"+/3K]O&['6$JTZA):CG&(Q[A0!$WT\^\:N"\I\:Q8EX(,<1/TV-O: M5NAYA%9O%J;!F;@468V,+1:;03]-&3T7\%DC,GQ(I,DXP6 CJ!JS$,.3R0RT M%*7XAS/T@A1H!3)_%]\C,:MD= >L:VOUJTE.2T88N(>=@[Z*]D6*?F34^(=A M,0::03U&1P-Z<+X4R"8H:V ')DA0SD0$YX_"%.QVV,)E@EBAG$WZHPA48PS\0>*EO09"N+=W6YW!BR) M<)'<;#.6L^G\QR-@L21AD8!.,PDO#8,< MRG/.I$N3>20I5"AS\,4*1&I":A'\EQ$VYOYM%5^Z<=2Z+.UU"(VY&"P!VD2< MH.PO17&91 *8W=@$T(PH)TJ _1;X9W@9=3GXR@D_V G0=KOA+AC'2]H RQIV MV9G?<>7BM9M86W>6/:BY:%68\SK8K#3$0DREJC_3-DU(9@.07>90P ]LK5$C MAKM9#>_;W>D^H0^ D:;Y%7E]J1R*/G_V7O3YL9Q9&WT\SF_ N'3=<<5 MH7*+VNV>F@B7[>KQG&I73=G]WICWRPV(A"Q.4Z2:BUV>7W\3("51UF(MH,3E MZ8B9DF0N0"*?!YD)(--1CDZ:+P:1,C0(^F$4U&+?V)+19<+EQ"R18JTEBJU0 MJXS58+*\(JR+G06#9)V:DW4:W3VS=;8[!WJ[Y=WO]ZPVSOV[?O7?]Q< M/=QOEP^_5N?:0>6=P.#/8#"K$(@LN-L*!QT#AH'#0.&I7UZ>KQ)/M[&\@_N1MQ_FRXBK7;- A*$CM/IF.1)><0FI+'$B?4SUID3*3&' '#"'Q0\L?@!@ M !@ !H !8 #8WEYNF9S9)#-QP,;MNE&4;N^<+$#W/(W4?!?!X*%G_&JVT6!3 MX539DP78*@LV3&&8PH J_7L:.OIR_6 "PTKNVOV[S.O3T[E,:,MX(#W@:V&* M45_X,] V]1E4^9%L[OAN"R W"%]Z9:YK_$L5$S MNMJ2U^PNL*K89R R$!F(+),,7+7SKK[E4! 9B Q$!B([BD76:.HK20TB Y&! MR$!D1R"R5JVI<8-:Y8FLVCMMKOY^>??K#;N]8]^^7-ZQR_O[FX?["UW:!:Z? M-;>9P0&V-V15!/E ?Z _T!_H#_0GG_*!_FBU'7/D%F=G5'[FML^>N!,)N8 ] M5A5P@D"$0;*D_0_N1MQ_F 8\ Q65HRG;J^S2)E9YEJ+Z&J''P. M\T48^2[SW'3 "X%H_8'HLF4"U98497' LR-<''\&4 X=P^RA&C30 #0D:&AH MVP,(- -!4=#4U^>U+*@ 7L3EMYV,QH[WHL@P=+??+L?R:/V2)F>)^XI2[K+ M ^1I* M9 5? U>9I9+45&0*N@"O@:G);NP-< 5? E?90C<9SYV4'5K67$A/G M5&3CG()[2AO_RB#U:UD8!:BH+"JP0@(L N8(8 *H&)%+AU@85__*T>ACNP< MLV]R2V<@PM 1(^'JV]>9(^$5EW/*$BHP7 # M# #P "P8@*LVJN,2:FI@(VY;2%(AB#96WZIOM11\#^!E#(CI5G7=@X%4 %4 MR@R5MK9=W$ *D%)FI+0,;?M'JP 5+&$NWULZ& @SE.F7!YXOZ 7,C'Q?N.8+ M$S_,(7:*LMPJ'(YBE7W1E"78!H "H/F/DO)-16>L=9%9F M*P:H!6HQK6):!4"K %#R\;6E@<2TJC4X4*88P%N%F:Z%*49]X<] K2^'#6AO M&]AJJON<#[4[7'GG[$22046FAK[\4&_)I2I&%T@&) .2F=[6J#5ZVHZX@61 M,B 9D,P22T9C;4F0#$@&) .2>9W*16MIR:J0#+;"++WM^\W5U[NKVR^WEP^W M7^_8U\_L\^]WUS?7[/[A\N'W>VUJEA]9YH[;I\UM'O*8UAM"+(+@.?6OT<'EA&9RQ^ M#CGU?MGU.X'=V6$Y/"4;QW;%AZ%0HC<:]7=SLN^1H)7P;)=(*KQH2LGKI*J' MH6 #SR$BI%HO5YZK3O'P MD'[[Q!WNFH+=#X4\NV&[C%[NR%)A=*>C+@D]==M@+KCG#=2/\MQ'4&.D8$-2 MSY$(2)$9=ZU)8HA:$@54UU)W/$N^PR)MIR=?["SLE&::)&#AKY1NZBES9%M_ M-43R>_HUKN>/N#,WJH:\9OK@6.BF<)SDFH\G]1/UG1!E3KXO&=<'F\3$[L0S M^^Z-^,(41F/X:+MQ(WD4>I,?8I2K7YYM*QS2U22(A"0(QPX?!^)B\N&7U]B= MM3L=EI[AO[LTSKY!9%LUYN-)N_/N36J9)[_D1N/ ]_4*TD[T#_W+[GW;K5,= MS=S/Q )1WYYCFN][CA4_9[).Q9I&C<%!TK^.W-WS?/;>OM)Z_5JP([1K6*.N M/_D:% N*)15KX[A7M3[AWLF=^W^>G?[?V^NV=<[]O#W&W;U]>[^ MZY?;Z\L'^NW3Y9?+NZL;=O_WFYL';7MX@=DM-A5E@-GM]Q8=%,6_G]V?0=6@ M:@=0M<]Q< ;:!FT#L4'5RJ-J6Q(;SK0MO>W.<^-\SF&2TDD7>G,DO=S!6COM M99PU,3\+R&\I5?X7CE%W#3DSP37@FD-P34=?&Y'-%5 M92KT99:G"Q7Z@%J@-B/4=H%:H!:H+1AJ,\L)!=0"M4!M9IF4C&8/N,UE&*%, MT8([$2:9DM*)DGC(A&O)O$4O@ON(7&HCNBU@BFQYI<^6AVSE6$\$_X!_CL0_ MR%8._@'_@'^0K3S7N@/^ ?^ ?Y"MO ,5,QLY8:4=.;IREUZP?),Y5?>B$;U MY2\!DYF"TMG#&3?-:!3%:<@G&WJ\/HTQ#VW/79=;G)VF4IF_1Z;Q\F0:[S0. MG)&Y*)G-B](_C%^Q^[?=^"'3N*Y,XTAXC$S:R*2=FTS:^^XZJ+KB%61BR)?0 MD/]S+7Z1:A:JEL]4L] V:!N(#:J6?U733&PP@W6:P54ZQCN-_']*(O]?IY'_ M8U(ADL,59HG3J!GM>N;RJ$KFC1SQ3KXH'"Q3:99IU,Z;R$()E@'+@&6RM&4: M=7TG(L$R8!FP#%CF]6VM6K,.6P8LD[N@UYS$C(('MV[=@=STJ?:PTB&C6 MSKO:LL@##]7 S8>+ ?39V[[[(D[D7BUI34+HBE+J30#@2,$CO(UAY<'6CC8 M"V@!6MG,6AU "] "M#((6?9ZV*\ :.7.B9V36!6.<++QFIWT.+]9Q!TU94(P M] ?Z _V!_D!_ F_A1"AX"]816"9G M+-.JU9M(^%U"EBF[=53Q,Z8'W<55& _G+6UQ5N !,S80 MEN5&8R ,,T[!\="H]?3%W($'S#A[^X@_A[SOB*77ISZKBY@I'"<1[,>3^HGZ M3E(T)]^33J6'IT623XOFP1Z)@-V)9_;=&W'W%[9*H9;YKL^V%0XO6O5-1G-> MOS:_>&OW>1N]6C.V7>K\_!9MZ8COH&K=3%7MM8+MV*Z]:$$V?2^IKX9W=S=X M3V_[J=/K,+K(6;;99X?G,>Y:3,>#?C+.#-;7V#!OP,*A8*$7Y(F21.XA< M2UAO;+L/F!7)V]B-(T+?&_/(\>1F_$\^_X_M,*[VXU\+4XSZPF=-H\8:=:.M MY$ ?6C7FBV!,C[>?A/-RMC?AK5.3-(_U"(Q*;6SJHQM>-!L38M,TB3Y(82J6 M[0NRQ%@0C4;> E-4>$ CHR<^JC21?3L#@CT(&N*+16,HW8%% ?R!Y MRIL(,J9,MR8%3U)=,AQ2K'+PQM0NS[+-Z36F%X0U1A/JD%D>43;A3UT\\'QZ MNUM+!DJ^);XWH)?2 V1NM_5'*#8$IDE2%OY*$:>>,L>:]5?C)+^G7^/*8R/. MW- :]331;C73K9O97K6C#H)HN_YEO!EK-SA MXT!<3#XL4-?R^7+&A\VEQNX&\YUJS,>33NO=EE/MY,8=[S-VO*^!=J*=FJV[ M'/H?>SB@ZEL\=U#/'"M^SMQ4NXN'WG[K8&],98ELC/$/%GB.;;'_J:O_LO;@ M%^81[1*4]DEQ7=W\AGZ@6&3O0K'T*%9!B#]?0MLJ?T,&:-S^"-E!\?G[V?W& M#BA4#:JVAZI]CMUN:!NT#<0&52N/JH'8"G$HN[A1#W7;IR2J_74:^=XIS<]! MG9RT*P7[^!X'X:7"PP5PSAK:MNS#JSD:S]) M/O:S-W*8$28GZ&N=U3%1%1I\F*@.-5'5SUJ8J J-E;)/5%B?67K;=^F5RO,$ MIC>2I1PF)1I,7_! Y#(VDA/.:YXUM9D';\JGREQ8"!SF@R2SSN]81AQWSIK9 M9WP&CG.%XV(Y!F5$7?/L'+-GQ5"'V;-\..ZPG2YDP_T!_H#_8'^0'_R*1_HCU;;,4=F^('V+.;2 M@J '6!7)"^Y M3,[PS8]QG%/;\60'A#]2;K'<,^F+,/)=YKFJVME,L%N7/2OKOO#.60?;P@N] M+3Q?3%1BJ)R?=0$50 50V616.=>V8Q=0 51*#!49*L4A5F %*Z;9ZM?WQ"/$ M*3J< \@G<14"AC@'4%0D^7&V?/0-H&/>EB[HNX+'KHD9++ MO3.DYVP0A9$OY@J>!V=L?2:R8%)9/9YW>)^F3V9YS/5">8T36?3C2!Y:":@C MCBR&+E]*=P2"R7[)$NX+0)/;=NC5E^H#>[;#(>-KT*@-C-U60Z_6AVRNFK!4 M"J5A\0BJ(4@/H[R!1C!DEHQ;V[)V/^7?EXS2BF;6 M6#\*Y:M3.K/Z]7N]J\54=P4;3X[GIY5=/7MRE1+@WE;:5M88K*_B6E^9Y6O. ML0UU&V.5D"8)9>#$R!MP,U0HXV',8#'C3S [G6:60G"."Q9O70[V_6&Z3GYI M'ZE'NJ;D:;OD&H87S<;$:=+D(#ZD+% 1R#;:P5!.LC1]TG=[Q%_M>)W;ZL6GH)\>,3)S%'03(L-/?'4\]D;HZG;O]1*(Z5MS/N.)X9CR6-D2QX M2+Q+-](L04^@ 8M?&JB)3$QVX2:CFOQM_9#D2MPCF@>IY2-Z@9PFY1RI3(J9 MK5^+32'57\?F?=NQ0UL.BO00Z'I+W4K25\(6H?(E2);1:*SN5_.PFJ:G/TWE M/QG48.)_C,G>IZEWN.%]#2;.Y/WB"?U]" B=:'I-+%3 M9H:?%(D4TH5J/NN*99U>,2E3T4F S52# ;4(Y8T(S8/U>-(%K*] MU)JD#=3HT+>)$Y0B^8-5>VYI?)J#S2!!$.?Y'PLQ-=3BZ8$O,O,ZPN98W8]1EY?DB3 M!>FPNK] (H^52N&(A!61'A.2(H=^L6SZDR+#@>^-TE[^7X*YD9)N$3?-:!3% MCHH4")<2H;<11FAFGI^\% 9J\H&^(-M1U-@C34X^@?&%\5C'YU_F"]-[=-73 MY&"X@3*G%<+F'ZQ9[JGI?VX28/B_'Q M6$I)*C1_?/3%HY+XG'K+:WR/2^&003'Q4^4X!L)_LDT16^URE&Q9E9> -+/C MY8RYX%9.F%.ZE^J^,5W^(06:^"^)[Z$B1/*JW\_^E_Q@,9#^M?%7>?F%+6G C-_P:ZS52A;WT6B4A,ON2:FD^TYS M#;LTU;C)P?GFT8UR?M32.SF6@\A7P0WB,L\?Q1.8"B8H+O5B!]8<$ M6A#RNI=:2:"QP]=!2&*,B0GL9QI+^30R]F^+Z?!E]%(A-)H M5%SJIV(^21_ZLJ4TS5MVPL$A>Q'<_R#VB\/-Q+MG9'#V(&75$&4Y@:?Z)UT4 MV4=+-OV)R#](1H7&SE2VI%))J:,TH83V6$9*XGFQL3/V+0'&9!Z5/)'_+F4[%/L$G%/M?NVZ3#7:G=+15.K2H.+T%Y'R%6E6 MI?DX1_K-KIRHG+F)Q*BG(U7:(H.O6DZ3,U%.W$@>A=[DAW@Q7/T2 MAP>-.LFF[_GD$LHU=X>/ W$Q^;!@-BZ/-TY#4>VE^=JMGP\Z?7>;1FI M3&XT#GS?^4'>A]W\2V^[G5HY V:\6VK?[!UOQ8:4_02WBWQ6"CL?:O?3P90J M_SOB3E&499UXWN^P%%'!W!W7XF!$#K[.-A7O6XEW,^2BAK;$#'I0H6%XZ;Z^ MSTQ'ZWF&U0B4/9@5H8INL"Q4)RNS'U MP@VG.YM<$:[8=TO$-8GSUQAIS)!9WDBNXL;+AG)K!6E#+=FL+-0"83!;_=Q] M:0#K )K7 1K[+@0T6P59""C*@@7ZA_[EN9WHWS'[MYW_=#2+/Q,72GV+SQ=1 MSQQKZE/-C@S!1]+O(W7?"O'$ID@B"6/\@P6>8UOL?^KJOZQ]J 4[4+N&+=U@ M!,6"8FE0+.TY1:%84"RI6,T=(B2P*-1SKJ:1D)D:>H/9YSL1SKY,ZH;/?DD* MB,]^V+:2>,XDGU^<-X^ \S=D>6SDRR,P4#6HV@%4[7,4(=25_N*Z7+D4?_^PV7Y>%E0 M9NS;GL^"#'*G@*1*N^:$>J' K"0%D:O832T:0M0 504'!78H0,L N)YZ9M M6W\5W#, I;) P48V8 %8@%NA/8"7HT#ZX2)[LDRTXP78V)DG%BK+:D0C^WV= M9:$KX JXVAQ7VA(B %? %7 UN6WSNIO %7 %7&V0.U1U'C7/D?ARQU];(+))B+2\J.^(O4BK,H7=WA)>&2J_ M9>2H;".MLDP+8#&P&%CL*-$6C0EQ06.@,= 8:.P8-*:O#"]8#"P&%@.+'8/% M>OK.CH+&0&.@,=#8,2)C,,; 8F QL%BA6::.2JNT2H8473:F>.L7Z,!1LX#E$FO1*I@3# M@F@TXCY=%S#;9?0(Q_;<@(5T*1^1BH0!\\7 B>M5TA677Z^^T+^F$\EVQU]Y M&/IV/XH?&'J,Y&+2ZWUZE;S&=D/ABR ,:K+2I7SR%;U";CC@\J&?N,-=4[#[ MH1 AXX%,F70M3#'J"W]&Q$VCQA:DO(L0&O4E=5IW>5"-NL)#-N1/@GHV*@1VJ%7C&76LJ<3$I$$K"[ OY M0(<'@3VPXY](^5P2K!HQ*4Z7E(8-[("8@%K!_8N=U3$%:E/(85NI?ZFGS$U= M]5=*++^G7^-Z_H@[D1+? MB6?VW1OQ!8. M/S1=N-&\BCT)C_$UH?ZY=FVPB%=38)(.)0HT.'C0%Q,/OSR MFO9F[4YO,)E19V?ISJ$-]JBHQGP\:77?O&@EV^L4+ N1O MSF!+,70RMCQG4IR8H+-?0F_V^951NORBM)GZVD3=P9/+,P?G5[.;1]#L-V1Y M;%W__>S^#"0*53N JGWV?/K)A;9!VT!L4+7RJ-J6Q(:#6$MO^Y:KFI^564XL M_FIA%F="R[XHB+T-&>UM ->4FFM.M54#JW2U<] /Z ?T U,'I@ZX!EP#KBD+ MUU0[._GO;FJWG]SKR[0 MC%K]O &P 6P 6R$-RHKD;@2J@*J54YB^XKR8O[ XOR9+:C9ZAO._>H57@M!3 M5O[O+M(J,]DA-)Y1:!P,!X9[._"0@_2?8#FP'%@.+%?0B$\5\[F SD!GH+-2 MA=I@L:T,PB%EU<8IJ^)D4B,:V9>_T#?N/\HM&'2YR4-9VVC@^3G+&J7R/$U* M+XT=[C(>!'.-KC'2XB&!8R0"@I&Z81 ?MZHEZ;%DM^,L4O)PO458"X6%K$_Y MR?K4W3/K4[.Y8X:;7D%2^)PCZ1,:6JJ&(E-)QHO8& 4B@7%VEBQ-B[V4)!I,Y,(^G+I*9.$ M7?%0/'K^2Q:>9O[S>6D7*E+''6O1]2#JM3EZLU3?81\ZYN,]KO9K+[T#B'XI5*\?)"]JVS+O@>? _8'11V1O.L MT03L +N*P"[QW-7A UUILS*8"NOZDO-IQ606X@-@ =AB ];HG#7T'9$$8)%E M>LEMUZ(?9A X++#MVJ[K%D*5[5/,:GF33Y9!O4X]'=2;?>RUH5 Y5JC<,.]9 M7?NV:) OL%)"K/2,,P.&"K "K&PTKYP#*\ *L/*VCG1[9SW88)F&CW(4 $S?HJ'/RBEOL6Y #5#3 MX,;K.\X)J %J@-IJJ'4 -4 -4,L>:L995]_^&T -6^&6R^_!"[DS+'MG@2+*3K!IY#'$-M8XXG&RC\$;/=)Q&$(VH;\_K_%F9H MT_>+M?)0(\),X3A)5S^>U$_4=](J<_(]Z4=:&KU%Y6Q-Q)%T]<$>B8#=B6?V MW1MQ]Q>V2E;+HK_/MA4.+UJ]311^'JN;7[QU 'H;Z"VHUZO>S].GE)V&F:'7 M:'3VGQIDJ'VOKJZFG?U!,N*V&PJ7NZ:J#1Y$@X%MVE+G;=?T1H)QUV*._6=D M6[+("<%FS%^8+T+;%PH:?>&*@2U+B=.%GMRSRIQH-*8GC>2E\II@8QFN9+>= M@ 4@ 4@' ])LWO!YJ+!$((E\EW#$Q ]3!('\3LI$0-,%XO@*2L((81@%-,80A;H81 M]VWNQ!B2\Q!P!!Q5!D=DI8W)')/>R>NIQW-33DPPA9CX(;=#3-$E_J3I: Y> M3X0G+PJD;6<.1]S_0STXV+@LY4I<;>(O3MRAS'U#M1>$<7+\S'@.M@,2W),M MGHE5QG2K9TEM<)35:PDI;&HSXV3:VC%!+#SA>6B;0^5@!O(F@CM_I%&Q W(X MA[X7/0[9V/-#\C9M>B2-F!_89&_'-TL#.N1_$%F022[=4].+W+#&^(C&.C&M MQUX0V/+5 Z(]SU=#2.WH>T_B@TKW9*5\U9JT/4S/_7?DFG'S['#(S,CWI>$^ MB%Q+.;SD SMTK<^Q7(B826M(XC%37Y&&A5RVG8'FTW M;B2/0F_R0QQ24[_$4Y)1)\$DH3JB18>/ W$Q^;# ?,OGN"F=-IM+MS=M,$>I MQM ]QKLMI\?DQD9GQQMW?6'[P.\[]'WH7S[:B?ZA?WEN)_IWS/YMY_+AK ;D MLYE\9LUMO[5=/NN#+4O$E=%1>_7M.3;<^YYCQ<^Y%J88]86?2FAIU%BCKB\W M#/0-^K:!OFV<=Z\@DT(FFS"6RU2%*[[)30/ K'[,-H\ V>T/5AT4Q%]DP&LF M50-J![4[O-IIS[@%M8/:O:UVVA(O0.V@=FO43IT(AZY!UV#00>TJH78PZ*!V M,.B@=B55NZT,.J1)VDRH-W]&\L!'(,R(;K%%P!8DO-UKYO9G&HW]E]VJ,#;J MMM^B,.*.VK"7_]156S"#[G.HK797UXRS4B1Z-$+#).+L<%P3)\#USL55 99. MU@; # # #P PF(8 %H!5;&!U "P "\""20B 6 & &@ %@, VW!%9E M2QVK;TL.L_3#N:5'SNNU7R72NRIEAS8LM"W(J& >UM>U!*0O38*]- M9<&0@<4+5 50 50 524#!4PG &@"&Y35\@ V & H.!MA+0 50 50 %4 % M#*=L%WJPK+J?UN1(A>LBI\5ZUA1ZT MY=Q0O77Q=B]S_2X+718(X+ECQLH!"SNZ # # #P "P8@(,IB& !6!E :RN MMO5L O K!@$@)@ !@ !H !8,4&&$S#S8%5A&-J6C1#?5LXEO9=<(?=J#K+ MN;3-%-F=;$N).PL"*QA/88=1@4!1W&F]8*AHU@$&@ %@P!0!5 5F"( M!H !4P10 51L@XI&!V & &3!% !5"!*0*5U'92%/5M8=7H:TC7YFZ]J KC MH6Z[XL&0<9>827X0?T;V$W>$&Z*4&G:=8-=)T:P& P \ , , / # M# K*AU'K%7O5[\$+NL+'#7<:#0&RUZK<%(IN$2,N+^H[8BZLR M7J+?5Y@_'4QX;RKGIH2_N:QTD_]Y1U]UEYW%599Y 5. [BD - 8:VT18[8Q6 M L!B8#&P&%BL)/$MT!GH#'0&.CL,G1FU>L,XOL! 9" R$!F(;"\B,T!D(#(0 M&8BLT$36UE9V BP&%@.+@<40)@.=@6 M;1I\MJUP>-%H;:*7\_JP^<5;5T?81B<*ZG0@Y8JV([MVGO/XUY27PW-[F[(G-[V M6Q1&W&$#HHZ F3P4CYY/%UB,!\P2?7J<,".ZUR80F)X;V$'(O $;I6\;>#Y[ M'MKF<.$.[@L6#@4;^_:(^R^,+A>^\T(JD\J&8ZGFR& M9?V7B;XI^:1Z+-_IB"?AL&<['%)KE>RX[;,G[D2"#6WA<]\T)@X<4N# MB9C'-#Z>)?MIV?(5UL5:#=L0>"8U3?@KU27UE#E6K+_2.?D]_1K7\T?!N)A\ M6*"FY?/AE.^:S:6'(C:8SU1CZ)[&NRVGTN3&1GO'&XT=[SOT^PY]'_J7CW:B M?^A?GMN)_AVS?\A,F4'X#_))-;>=[Y.U"W:[]KJ+U\(4H[[P9W)L&C76J!MM MZ!OT[8#ZMO&9[X),"@>LG?HYB5!\DZ$9P%8_;)M'0.T;LCPVCK_(&-=,JMJ6 MBZ!V4+O-U:X!M8/:'5[MM)WMA=I![=:HGD=%W/&8Z(T)K@&7 .N => M:\ UX!IP#3PG, P8!@Q3+H;1F!P5% .* <6 8N P@6O -> :< VX!EP#KBDK MU\!UVA@I!3G 61!ZD7N-RK2E*)W4;0OA3)O[5JWL762UQ1Y"[;DX.UU=Q%(6 M_@!55!8-&5CT0 50 50 %4!%R5 !RPEH !JF\8GNQ@F6@ :@H>1H@,4$5 5 M0 50 53 /KM,1]JN9/<& MU,&0A.T-F"7&7F"'6;!9P4@+.XZPXP@[CA:F *N *N,'$!8 !8@0"&B6MC]4 Q,Q0S6PVD7Z7]4,5L3U3]%H41=]B >K6X MHK/Y\S37,&N@AMF&X],E0.646LWL6T?T *TBN#? F M& VF[NZ;6W)40 M0 O0FOE;, H!+ !+/[!JC29J;@):@!;\+0 , "L2P!JU M5EO;49#20PL'SG#@;#66OH;T)YPUPZ8@?7,UN*.TJ, >:F !6, , 50 %9@A M@ 5@ 3,$4 %4;(,*;:M.P *P4' L8(8 *H *S!!O]'.[)9R "X;RX M=@H !H !8 #8V\E/6\ 5< 5< 5? %7"5?US!( 3 # # #P(H),*..# < M%H %8!T16-NO@Q9TE4U]6UCNC,]J+0CKR.92V4[$7?%@R+A+5"0_B#\C^XD[ MP@UQ*BX3,[LLW(3]2D %4 %4 !5 !5 !5 50 50L6D0!%@ %H %S!! !5 ! M5 50 7L)I1HRP%RBB(X?9CZQF57;7I5R!R/NSFJT];$$;?CF0NE7UTO$-IS M1Y, & &@ %@^@#6[ )7P!5P!5P!5\!5_G$%@Q \ , , "LFP-K:Y'OP0NYP\8.=[=?Z=L" MD4U"I.5%?4?L1549K\CO*\R?#B:\-Y5S4[[?7%;:N;^A[3CY[N(JR[R *4#W M% : XUMM Y0ZS0R6E<#D8'(0&0@LL,06:-5/[ZX0&.@,= 8:&P/&JLU>AF% M%4%D(#(0&8CL4.>8X%:"QD!CH+%"TUBCUFR#R$!D(#(06:&)K'F>T0%/T!AH M##0&&CL0C=4:77T9,BI/9*D->3^'G+J^]/K49W41,X7C)#KR\:1^HKZ3!,S) M]Z07:;5JD0ZE>_5@CT3 [L0S^^Z-N/L+6]6]91L%GVTK'%XT6IOHY;P^;'[Q MUN6SM]&)-?GKN]3Y.9;KR%YNKR3=M!#WSZ9OS&?3U[M9<2_1K<97=S=X36_[ M-MM7R+P!\R*???+Y?VS'IM^#J!_8ELU]F_28^X+9[I,(0F'1!S;V[2<>"E40 M.U07R!+9WF@D?-/F#O,%_1]=+:\)A\0PCT/Z5R0[&:V1[=I!Z//0\^73XI>> ML0>Z8L!MGSUQ)Q*R271/("9-M -FB5#X=#>U(@I(@]1#;9?>3%>-Q[['S>'T MA=QU(VJ&_)W; 7<"UNE1$YAE!R81G^R/*NTM;0BZ@SLO@1V<[*.XO-&H(&_\%H426 .R&P)"3R@>/9\NL BHA- ^/4Z8D1\3@^FY!*A0@GF4 MOFU T'\>V@37UW=(KE%TQ!(^&&0"@0NEN=G$H@](LL M5<1"CXUG]8MB9*DYF9 :4F.#L)9@4,V=/PAO(:GV; K>'V7KNI\VGWND*DH< M-J'=#2^:C8D]KOYN [95;?EXTNV]VY+HDQN- ]]7E';FNW\%R=F92;1/ M?7N.6:+O.5;\G&MABE%?^*QIU)BNR!;BS+/F-H]P*/D-6:[7N(6)2;O.->I& M&ZH&53N,JFV\GW5KQRQ/"VW9+1!]XF1FFT(:UO_@;B1]?GUG3_,CP-S!6COM M568AL@3KC!JW2Y1]$1$< XX!QVPOBW93WY'%LG/,]J;A/'AZQ38!+TVU-.2+ M,/)=N4";BKRN#X;"D\O$DSN,IY8[^4!_H#\[RR11W)SF;7#-7W M !U IQ]TO2Y IP%T%7<2OT6^.>2!"&HLX$ZRZ9C,B- 1R*$,;^X7FJ M8'240>&%LH2A@(K*HD+;DFM9L)#9:GW!I^$'G[O!0/CJS-!I[,B_9X[-^[83 M[^"W7?+PDQVO<"AR1$EE<2BR*)U4]A4F P VWSI%K""3[Z)HEP-N?LHF!4) M&=47/\SXNR\/_L:?M94L 0]5MA#5J='(*/OU:M&4.9 (J %JJZ"653K :B(- M6_[?VO*?.A\&5^;(.YR0GBQ+X95@2R^JD" B QH#C16ARB0CKYU>,XC"R!>L+UPQL$,VYB_)]AA2TB&IYTB^ MUYQ[?BHK#7+/(/=,.7.SE+U_!% M44?VF>QLQ5*:A*\CIBH6.[ #ZCI[(=$RXSCX>=M"6Y)3,QTT,,3%,] []S#OL>N *NM$_M/0 +CO.&4[LV50'3 ME-97Z")+), ,"2<>:Z-,LN"!CC.*V97C?FK\B.PXC)-60S\;O;Y=G;2=N M6?"P43JE99__^G,4?'CD?'SQ3;B![;F7KO4UI(9^\X+0%Z'MJS)9G^)#+L&U M'9B.%T2^>"!I?'(\\X^__?=__76C9WQSN!M\\QS;?%''I^D!W\7@X\GGZT;= M:/^S]:^'ZQ-F6_0#-\,/[<[G\V:G<=5M7-4[[9OKJT;[QOATTSK__*EK=,\[ M)W][-3QI4;^1F&?9Z*[-^R3SK6>5]TE]73BW_^WF[O[VZQV[O+MF7Q_^?O.= M??MZ__#]YN'V^\UO-W#X6LRCHIO.R#KAO M6O.[RZ]67FDPW+\:A.J45#KU )&_@(3.)(N@!LEGA M3 Q_D8]YC!S5YRB&0 M#/W'X20#E\R"'YRQ2\=)US-G7/Z)7N5+^=&K!YS>\,2=2-"U-_=)UK X1=A( M< E1]28Y5FSL>T]VD&H=R^-:31?Y)]# MNO.&NC26UR\AL W(Z+QWWCH_-[J]ZT;W\^7-U?5EHQV3T>=._?I3X^!DE"WW M?/_Z[>;[P[]JBF0>% ?=_//WVV^2>-8.7A[X5-VW01X]D^!-\ZP\L9E@0DBF M\FV3/9*Z^DJ5E69;=C#+]9'6^)BO$E6K*>T.XZQZ$W5CIZDD>>]C&HO)89;& M+PK$('*(,Y^H9?)Z";O@_9GB8CZ2,(WA+UF3KGL@\5TN[D-BOSS[S9#/>OE,FYY% M7&&9K HFGVESN_FN 9-][KE4D8Y:-NL"0.5FJTF'SWNX>2PM>SV\F9K:ORM3 M>R;@+_9 [ +M?"2:3-ZB+.:%5^2*":1/C2E8_Q0#/=Q:#UO9S$25V95VLTF0 M9$!^>1PGU3:%Y5*V.C56W=:>\<&'V<<#9#( J^J?=9#W<4N'Y8BI9=NU5D/; MB>;2[]X"S8!F0#,[T$RWUNHA+5%V)GB9+&VUVLWZD>W(YFFSI,ME,#>7&LSZ MRE%CPBKQ1L*>/L>J+)0+/%08#YWSC:-C5<$#HH!+;_L<^:XMMRO6V,#^(3\$ M\QN?2NA)9FG&-)::,4UMB1-R),;B\GEYSBDBY32 !6!E "R$D!';V3BV4UR? M+$M3R%@>T=%V!!;$O 4Q'W>+HFY^[IWK,ZC?D$Q9:!IH II6H.F\JR\]5470 MA&C2TML>O) [NQV_@Q]W[+WE$!P136;?X]+S6:NGCZ0V%,U.:[';# M:N:H]P ;P+8_V,X[#8!-']AV.H"?(T=EUO?S/45V)T)-,:G-7WZ^ 0ML_K1. M6@)!-%YC_"XD?IH]I3T.8ZP9L1+1@^#DYL#&A."TT'R3:-[R(IEC;)])L#*G ML-X27@F.:1GGM7HK(ZMB&XF5)18#)@.3@Z*3*EL51.7N81QDM1&:Q.M7Y%*4',R2^KB-@JWQO?I4N?G M.'0N,VU>/#%]\XILP%ZB6PW>[F[8[>[MCC/;-9W($BQR^4@F:8_3P8?"=ZG? M42!8X W"9YEAV?2".!WT'D[WM,$_]9J3U,\Z'J7DC+_X&D] Z8*;I_]CIU],KDDS\ MD'42A,Q\+F%J)Y4B$JC&U\ATYS&JIR409"$)FB_YV)9[QVC:#$3POK9PVW*< M2T50?Q%!.'F&H@4K\F4#+$$#XL49W.6UIN<2P41F_%27_1G1]8,7>6G2KKB< MA&!CDHEGR;(4%M&J7'Z=RP!_L7:,-R16)&+7DHB]N6=OV&][R3YZP+_CD:@=SQ@G;>K,Q*7?$7XHR:4=68+OT+%/Q@ZB;K,[KCA#^&$')%3 M6;(YG>O+G5EV!QJX JXVCTTU "P "\#2GSL=ZTH[V-\Y."2:FT-!WWQO3 KQ M4F-CAR=V]K1>6(VY(E2[E59D+JSM><9LUHZ?C ;K[WW\;?:\?8^5I5O6UMNR M9QXP&8!_Y(_"DG(7%GU@GL^"J/]O888L])AC"S?8_Q#?[+69G.++0MY[GN.; M/6B;@WRYP>,;A_1\\9C 4,J;R.;#[)=UQV_'ZV"NOJV".$N=E$OT<>F1.ARB MR\TANO-]S]#U"G(&JRCMS'?_<,;L]7YX'"S#$0P<+(.JE5;5-@X;8-5JZ6W? MEQC=M?4);VJ,I!($" -B&RRVP6:XU>D8/45'0#&@&-),=S31K1AW;[;,S M(\MI+:X*LL+ST^_Y5:WH2JO6;!^LDO:BTF3'W:AP!+#E#VR]%L!VM I'"#2M M"S2Y(H3_5R#R*\MNM&ZMU5*>WC4Z-0Z79RF!B!R!8ADUE.;1Q>FO&.BI5MKMK4=M]Z\EP6& M$H(-&TSL6:]5Y$BDQ26RJO@OI^U:_5S?MHY]I5;F2"QP"]SJQ*W1.-A"2:5Q MBZ#$3D$)C8LE(,#*+@@;1JW=U7: XRWAE,4/ Z J)4I8VJ-)@!5I<"&1F-@ M>57J-VP!.$A'WC,_C](FH=3R(GDP?Q\.J\RF^K>$5X9=]^>U>BNC9>QM)%:6 MZ0),!B8#DQV#R1KU6NL\H[UR560R9'=;>I_,)N72"Y)$4F-?!/2>0%:CC-RD M_.2C:\NA%QO&]$-H^T+EA_+Z-.K*A [FTD$-/']%,JC%5&#(!H5L M4&7(EE3V_A4D&U2Q[$'(!QEYD/P)JI8+54/RI_U\MT_9@Z8,BX!AP##AFAV4FC6M,9>>8:N\Z MO*1FR; H=YAC\[[MT#K#L'YCK ;0* RT65J]A-+3%A9!OI](A@=0)B6MABE&?#((I M(ILX(W'L_^:A\%GH"QZJE_1Y8+MQ)LOXP2/OB3O,\V7"RQ&] MPDD:,V F:3>W73:FQR7)+\6?D3V6?S]CU!E?L&?Y?PO2WT4X/S4FR8*T/$YV MP!&/W"$)^4*F\C15I9(XD>=;ZJ)QY(^]0 1R9-1&;,+=6A"<98)JHZ?F%'1(7 MFTE8^]D5?C"TQ[*K5PF*KCR:)S[;$M2?N9GL2"\&;UU_4_HL__>%#7G :.:R MGVPYU-ZTJ[9,1T% 4VF_M*C6@.A,CXZ:4O8#)?M9BE\VF X#^[='S2>FD-V1 MR9#"89SGET5A,TE=L[-K\%ZP/KV>W4I[09#X_[?N3+SW MPG^R3&^\MZQ68MHGX1/)$T!?N=6(MMG.7^H-OS9=+U2D9 MTVLG]\ILW"S!OLSLT^J59=P-8 );^R0S%K($KX$I_%!NPRLPU*Y4'=A]&G+POK/],9R1M MF=WA12'(5^8@G[Y 1%GF$J"ALFC0%R & "&HH-!6P"_+&# M!R3?F_]F@D M?-WN1QF7?1J'6Q2KLL."*!JB:*EY+'O0E66& [ K,T/0.$$%' %7.F?L+"< MFIU'=GA 96!JGF'+5Y6TUMD7@K-P(JVAD MOP5]H1*U7N&5(5E0K=[6%Y"O?"UJ$!F(#$1V%"+3>#8:- 8: XV!QHYQ!$G? M8?/*LU@JIO&S*DN]]/HEG__Z.1\?#$I8*[*EUVZUK1X^;4=F(X71+YX M( E\))P[2=A,1X$(IS6L&?C:?WZ\;1^O9@,96UR-2%(D)KRL1URAY&V M!K+R/%UJNR%W'VT)NN32(.K_6Y@A"SW&1Q[!]C]J\S,[M<_$68T-;-<.1=*6 MA;O?GZW5_-R,H;K\0@K#-N,G?5LG1_T#NOYUW!?T<%4)CH<$P(!&TA4A\P:, MIZK$6:DJ<6?L82C4I?(J7[CBF3O)&(](29Z$?'+ PB$]D40KZ \AW1$%8A"1 M2M@#(6]L_ ^VNF^NLAEU\-$70<#&_$5)I,8$J; KZ';W40F0 M?K)=XDWNFF+R0\ =[MM"_2D4](!8-!Z)T(^O899-@Q$Z+R1\&A[Y,(*0F7ZW MG7K]*U$R*U+O#]4@IMM+[?*LFKSQR;:$E5PQ&CM"_9W&3/Y"?U:HM:D=@H;: MDK_TY8Q28YY/ SX6;A"KD[P\)-)5'Z[H2=Q]H9NH5R,20Z(AEG@2CA>/NM0Z M$I>I G9>#; MP1]!+$797T_>(:O023V=];R64& L-2\0Z3L>I^3?9(W^Y::CD@YZ _)G=2_-RB$OOEB M(&6@)A!2D&#(I'L4L('OC>@G68):B9T>^62'U/Z"$$VZ:B=-O8-0Q'(EE?-G MZL^=)Y(_(Y6,A!)'/+@^:;4O8L#UR5I5-TB^"93*1:'"M#TB&B*.B8()6]"H M<=G?#[+O;"0("\1+-+#JKU*4(S7L4Z(G\4Y8(]:R&JF939B4XSKE 7H&J9UZ MM:=PHW2$OKBRA7T>V,$9^XTKW5-$&0_LF-M^0FY#[C\F&A^SC]054J=( H&P MDQ@C9+G3U9)>@C2D?4_9P_-_EA\3PT?ISA90.F.W<9]G#XQ%&P^/U.19_Z@A M"94F RH2D4KU3\^8\1@K DX>2#IOQHT+XNK!*UX\86GY51'L3-*JP;6YIRXT M9#(+Q'>DFT3$[<:\T1=2D$/A)"B=-: @>'J835!_"=@GG__'ELP[X;5D0HZ5 M=V(/DS,Y7*L.IGJ@NE/R%)?BBZUC3S)V$%\3DSUIS151&9>JE@ I5FYZ5#QM MDW9/(3-GCTV57I*K'*U5S4_/8F(I2M\F5(7E$?G)TL#S:.!3Y)[,^-+>2YZW MI*/QK+WJ$;%\Z-9@Z/;*$2>;Q![0K!G/"O$,/WWT>@7>PDE^Y>QNY"!OXQI_[C6:5Y\_=8WZN=&^ MOF[2UU[L&G_N?/[<:)?&-9X"=N Y-)DK?8X)/!K).>L_2A_$C&.GZKV-/32S MN=>#XC1='I0]V\0)=)?MKYH/Y?4O@OODP,XA(>6(3?POQY'3,($ZGK;)N:(I M3[W4\8(@L:L>W?W\HW755%>._5Q@MOYJK.7W]&MF]0;/(8'WI=I,-MA>IQGP\Z33>O1ETG ]])C<:G5UO M//!]O8*T,]_]*T@)]&*M24$^LZ8?JCI\P>0S;6XWWQN*%Z;S/9;CEB]'7 M3 MC/ID(C6-V@[K4&"M;)8W]6B:MDW(V>OAS=34_EV9VC,!?[$'8A=H-X\ [46! M)V]1%O/ZS?;''@'ID&(*UC_%0 ^WUL.--_!F=LJCV(<\;C8)D@S(+W?4@HFV M*2R7LM6IL>JV]HP//LP^=O)9Z*=DK*I]UJG,7L/B;R5LM&NMAK:*MJ7?+0B: M +Z9%F: M0L;RB$Z]N-(J,#&7*^=I[UR?05V17*= $]"T DWG76V<7!4T(9JT]#:5.'BW MXW?PXXZ]MQR"@P,\#6/V:BV--E;9?6!@"]C:(KA4:[7U93PL.[:J'5^Z7)&< M#6[?8:PBR*>R;O'I>:W5RB@S[6KA%+ 6_7N #6#;'VSG'7W%? &VW0[@Y\A1 MF?7]?$^1W8E04TQJ\Y>?;\ "FS^MDY9 $(W7&+\+B9]F3VF/PQAK1JQ$]" X MN3FP,2$X%)9 88E,=D*?U^JMC*R**A:7 ).!RR38J MDW.PAFV5&36MM*UQDFYW1:94MJJ)RUS".$EJH[6)UJ]():@YF25U<1N%6^/[ M=*GSG&=DC-ZDC%!<,$KY+_8X" MP0)O$#ZK4@&J&(@WV*?,SK3!/_6:D]3/.AZG.J2E78;1UMLP;2*;9(Q,'X&J ML:79XXXIP:5IQ'9X3HWY(A@+65U$."_:YJ -LLTOSS-/<[EM_AXFJ;NV+[]V MT[DRZN?GO2OC_*9U:7SJ?KZYCG/,7[:[W=Y5:7+,JZ\+V>6^W_SZ^Y?+AZ_? M_S4IOW9Y=\V^W%Y^NOUR^W![DT$YME1ABJ023I#F/\?F_60TXQH(I&^1$TXJ M&_R;Y[],FA2SMJ,J4XVI*3)7_:0.2\*]ZIU#_B187PA9_R1/*\Z:1$PXLJW1,%9)%2HWQ5[B&N-S(K!/7KY+T2<'2S&S RLY+2 M,OY",^.R0I/*0+*6D)*RJQ8#5"?O92;^24FJK^-D*@I4?G]JSK[#''^5E\]5 MAKN=%/RZ5:60M"C3W#"EU6796*7* !X*-36G=/#5 $Q&3TKX]8C'%7ZF=]$5Z9:ON#LIL\;Z+]-:.U)+ M!D1H:BW*&YJ[0]8.4_U:Q,.T M/(JLXA"I&5."=BQ[* QZ4 P= M&J4GVXL"YV4&&S,NL!C749D58HO%G@!_J?B?26&H.?3T02+N*?QM=U*+2]%( M,KZJ$U,D;%T69>W4DYZD_AEQGV#@O'R.RZ5QY]8=R!(2\KW;3%;M]J?S[M7G MRT:[V6M=-7N?+J]NXLGJYE/GJG-]\,DJT[GI_N;+S=7#S37[Y^^7WQ]NOG_Y M%_M\>W=Y=W5[^85=7SY9F_ETDR*ENL*ERL&L>\FSF MW5?U98)9@9FX@)++(\N6"/MSVBR:1*RX_.'RZ21X-9],2C9-IGCY74M?]C2I M9P_:UZ:>:](^1G6J2:>3HCFIVCLU)GZ88AS*:HHL&*H*VBQQ?;VR[256^T6SFE*/-:8*R?35I3 V.F+VE(1=KB/)E[=&D$2CVDY]B M/YU]B_TMMW6;T]VJ8XVL'5L)K[U!9E5X)M:LW:>4];ZN&=Y56636K8;GN0[;9@ M,;#8*Q;KM?45=P&+@<7 8F"QP[-8MW&P-)E@,;!8 5AL\PK'H+BU LY COKY MKU4_6&+38VK<\[B.+]Z+L$OZM6+J7 UHF9<$8%E. IE5H:A\L MY@HT 4TE1U.GJZWH+- $-.4!39L[(0>>N(S#A=GAA^4_0(@5(=8R MA5B!*J *J *J@"J@"J@"JO+@@.4H2)*=9R;3B=O+\Z@684=Z/H18B$WG.=E7 MKG/A$:=J$.;=U80 AX'#=N8PC6N\X#!P&#@,'%;DY71P&#@,' 8.*_#FA*I3 M6+7W)\RB8.S4\8+@/>-A7$EO4L]&5KJXO+EG5YX_]N+M"]GHGJ;JM?F0Z^&* MU!:'M(P#EM0N"SMA20P4 XK9_ SN.1@&# .& <-D9L3T,LH-!8H!Q1R28JJ; MTFXW_BE"ZKK3WC95F?2(; ; TVI2_0-C!4ZQE&(G0EH2C+!E*CY"=H_3G M$@J$[=S9"0 H J J * *@ *@ &@N 5KY5?6U>R5Q$C=?P;42'6+1N0"/ M4RR(SX-CP#%9KO\ QX!AP3);;", QX!AP##@FTYT*V9RJS8?RX.#LOOL8 MG"@4%H[.YI;X\Z.%N1,<- X:!XTKA.!R(RQH7!4TKO*+?#@ZFWMWM3C>*([. M(J"%@S.5)@ @7757,@1QA M.W=V @ *@ *@ "@ "H "H H )I+@%9^5?V-W9(X/)NO\%J)-H3C\"PB]#AT M HXIRBH_. 8< XX!QV2YD0 < XX!QX!C<'AV1T'A\.R^X: GF]C/"I@E3(?[ MPE*Q(-,;C3PW#@GEFL(R#E@6A]O>U-;\DU[F\>YMQ%85PRM'+ >+#'16(CH[ M:"P*/ 8> X^!Q\!CX#'P&'@,/+8L;F\<7UYEX;%4/.UGM5EHZ?6ISZE^.;8K M/@R%(B6C47_W2ZJCIG!#X:]L M,WUPO.')%(Z37//QI'ZBOM, F9/O2X3\8(]$P.[$,_ONC?@"2XZX_VB[<2-Y M%'J3'V)*5K\\VU8XI*M)$(E>D5HX?!R(B\F'7UZKPJS=Z6#F3)TZ2_-(QWKVIJ?-X26[<];[N@=^'_J%_^>M?E;>GJF_/,5WW/<>*G_//B/LT M(; ;XG6+->I&:XLY?//,8V_LB\Y Q.O%NC -:A?L;]QG36T&$;P3*-L:9?M' MY K6U!9&@+9!V]9HV[T8A] V:-MAM.U:F#.9;CZC8D/*TMN^BR?A1AEM.M&C MC]4,"NYPSC+_,<%6K=%I'%U>98D)8FWC(&L;8#&PV"L6:QH9+6V Q[[-^O!>DBD+QK#\ 32M0%//. >:@":@2<_ MT'2 Y*8&T7B-_[IP-F+VE/8X5 \Y;=2:<=X3 M>M26;+HY6Y0DB7)/GP5;]F!+@9B@P+-P27#5Z.E;JP&P "P *[FMK=&N!; M+ !K,F.= UC9>(IE6W=;4=[QV*4;"X:WTT9&&4Q72Z;,"4P1"@725B$MHWSD M !J !J =MR);62Q*H JH JJ.[Z?E*"22W5Q_1W[:7('#;/0JZR2#R=M4LK*, M5#BG6\,U9R#,0I"Z6;!SN*)"QU2XXW-F@8+&64ZZ64L13 FFS"B0WVT?7Y:@ M2E EJ!)4F6^JU+F9 %0)J@15@BI+2I4ZMX> *O4&+4L=FV0\#'V['\45"$*/ M/0P%N[RY9U>>/_;BO2>YYL]\R!5EA!=O.VT?CM.P-0"+F* ?T$_J-J-YN!KF M93&.0#&@&%#,YNFV>H>S<$ QH!A03.4HIE$_W,Z,LE ,]J4MO>T3#VSS5?1G M+'P6#+DO+K;0LFD'WJS'"8\ Q MA=AR (X!QX!CP#%9[FJH#,?@D.V*/0].% H+QVQSR^WYT<+<"0X:!XV#QA5" M<+D1%C2N"AI7^44^'+/-O4=:'(<3QVRQ,(=#-F ''+,% 8 0 "+:U[:K ,0 M @ !% X L Q6RT1B!P%PG#,ML3G"G#,-B^1@!PA/G<& F"+8[: +6!;=-CB M%-_A_6L % %0(OF_Y;+S5V[LQ(';?,5;2O1_G 5M/3IF8WAXUJ- V=K6+9"SFG\FC0'_U/.N92$7A/9;N MK1MR]]&6!MME$(@PT"-9^0)MTFTLGA3.HW25_-CM;%9/=%6+#"1]#R1!TYA9 M=F!&04!3P]GBL[^]X/ M>\1#LAXTV8Z]IE;;<6*AQ2998H?)MI,)U2+KQ^'R-$_HJ8L"[BAW@3-RZ&4V M"]^CEM $:;MTEPA"^L!^XX'M.IZIK"5]?&QT"L''-W]&=OBB;6B6L>]KERY# M;>MJ]>EV4S;Y^?>S_SUCSS;-[]3%?Y,]'FC6KD:K$-IU;0=C+["3S#$DCK\+ MQ_I 8OUP+Z7U*2+H";((@DRG_X68P@S]ZM"?KH!"^URK]OGD?3ZZ])O%/)=] M_GIW^W]N?KOYC=W>WLJ_"?M)6B4R(X\ZD7CI/PJ9KX=+4E-.[)RO.E';,W;I M!)[L^JM)@*1'TXW+S,CWA6N^,(M:]L2E*SF%K!8Q&76M7OLK.KY;5&Z+1 MBM'%C>]YA.AGTAA7FK#L^TQ.!YT/Y)%;;>#@>W8-!T$9-?Y,@CCN=*VG4P.5QYY/.[+7X+D6+&\Q65<.4.I$"=! M^<8)PC5ROR6"Y1H]WIM4^/NIJC1;W"ZLU6*W!:@U6 M:_(KW6.LUNQM8D^N_^O/4?#AD?/QQ3_C"_J/V#,CPDA=]C<*O@TO3C$:1"OHI39-.G2^&)! B\+B4 MTX-LR/2)JI@3??DN!A]//E_+5?Y_MO[U<'W";(M^X&;XH=FY;G^ZZG0;[>95 M^ZK=.._VZL:GF];YYZM/O<^?C9._O3+GUOD$JUR"==9@>FM9CRQGM?9G.Y\2,MF?)8(TEKR/?^UG(5%P!7>$X M9/BR4_*/$U,B>+^^^NFZOJ""KY&6F/R>?HTKM^KLM'=3)C3O>U^X<^(6[WM( M=X^@A/KV'#-OWW.L9!%*A-QV G;9I\EF[_ +$XXT3& M"Q2UQ]&;511EBE&?_*"F4=O!_]DT@TL&8LQN'NCL)N3.2B$K'T/Z;)XK5Y& MY,,P7;&T3KOU<3D8")-\V)E@OY!_./MV&XK1[)OMSCZ3*SS[KA0;GWO4 M?4C?XS51;S#[^>NT7!.47/]T]6:)]\,K_+'GKZ7G5Z!J4+5,5&UQ\:TT4Q-4 ML5BJV-S76I_*M[M*OH?.O;A>JOHR-BPN.2V7\N?7^U)#G[N!H^P;QJU_1_&N M,%5T4ALQ(.N(!D8XKM+F3G"Y$18TK@H:5Y"E@'P)#?(IFGRRRR;UJSKTXDX/ M=O6GIY6**ZWR:U,^=$=;)K+BY!-;MQEMQ\Z7)3D8> \4!D>T!:= _J!?J"_ M8.@_;>CNA;_>C^,!UZ+&' MH5!Y$Z\\?^S%+EUQ)58LC5&6-"X*F@&$&57Y'RH385W"S>VCA]!LZ* /Z ?\G@ MWUPL,0'X _Z ?S7@?ZIM]L?6OQP$-DI%)!!<\05W* _?] )5PT;FB<&A,&R? MSV"FU)CRM,K;YP$Z@&YST %SP!PP=UC,Z=M65&7,80DW)[$ER*>8#MZM3!TO M@FD9^^+**'PA.!*+K@L]S^JE/FJ,EI2^HR: MF:I]QOIB0!XB"_D/$:B::>+/R Y?F.TRLFA=NEJ53N.#@>W8/,0:8+XFXK*$ M2[NH*X-%0(#NL* S&OK"-4 =4 ?4;82Z+C:\8&DPIUX1Y),W^63N')+KA^-Q M.,BPZ0J?MGTM6,$#& H.AH:VA0. 6 H.!A:F!ET>"@(%B#*4EG!99CJ4818 MVLJ!)FK;8U*:>.#!MDQ6.EH(S *S^C"K+>,Y, O, K/EVN19:.#" 9" M/Y457':@_2*"X(*=QJ[5^W7'WW@8^G8_"GG?$2STF.NY\D+?YFI5EJTTP!5PM?FVS.RK3P%7P%7E<*5O[W_I<85EL%(L\T ^ MAUH&D_LS[7@I[+5/]C 4[/+FGEUY_MB+';?B2JQ8&C6_U:$Y_L$L+Y+#LD^F MK^2A\HJL\CKNJXT_'5R !Y:7_B(.^GS9346V532Y $I7X%69+$L59.WA@.) M<9OEJ,IHISXHK@@4!\.M" H&5MMZF;\!R^WHFP2F#>^N"B52]P\:C#V4_.)O M\NH+.Z2'F_$OST(UJ^\Y5OSDRY%'\OB/\O[EJ4U+#&Q76*PO7/H4,IF_1OZ) MFV'$?9L[3%:UJ#%7A(B%'S 6WCQD+'Q['JE _%T>:99M=C_:DMM&5UK\(.4B1NZX :#GVV(($=RS)T"5FY+ M?O8%G,JR(Q^P JPVMT!1CA )'(&YPV(.9=&0@#&GO@ODDS?Y9(>T7X4K?.ZH M8MC<&MFN'83RU-F3F)1)PVKO,::Y-[+N%FVV.UC:_RI,>@ :@+;J_)@25J]A M-/2%"MZ04%5")D!595%UJB\5"*8OK.!5=2$*@LN=^_=F/G[6%P//5W6S1:"\ M1-25.[[B5B]Q/KU%C/\^R M@[$7) ?^[-&8V_Y(N*':PTE_2]Q 867@!4+)*AL7Q;$DK#8 5?E-AP0L 4O5 MQA)F*"SAY06#$%S)!:?7N8N7\4HHIMSI%\X?%&(AKTSG#P!7P%77$5I]NZ8! M5\ 5<*WF>F&9X(K%Q%(LED$^QT+:%Q$$%^PT=D'?K\LCP\/0M_M1R&6)]-!C MKN?*"WW/<>25MAL*7P0A5AN/,*$6+%9K:,N=7980+,!073!H\^H !H"AX&!H M @PZ/!Q$*1#>J:S@]"[.V?$9N]?>S\-0L,N;>W;E^6,O=I%**,J"Z>#SO$B.USY;6E:.1@'":-J*\;XIV3=U]L#QR*+4O]A%E)4-]A:(./-]8!(L M"A8]SH:3>GYD"1K-/XW"_@1S@CD5J6-RTX2@Q MQ=_DU1=V2 \WXU^>A6I6WW.L^,D/'OV5^<)T>!#8 Q) O'8\\'P6#@4;T[,] MJ\9<$F8G ME&(&(6:FR)(GYD.PN2*J3 2FWS36>(PE$QXK@MX5F.5@9!5"P\!LVS.;Q@)! M8+8MO/N?U3K_TNM3GU/-)X=5?!C&[K#1J+]+-:2[6_NGM_U_Z_Y;V[=XLX(I M'"<9NH\G]1/UG0;"G'Q/6I,>[18-;;IU#_9(!.Q./+/OWHB[O[!5%+MLA]*S M;87#BU9]$U:?5^C-+]YNDQ1U<1O5?&-LY_C:Z,AN[C':\K8@&J\)(ZUI3GL< M)L01*ST]2/,D)ANPE^Q6XWQ?G%R.O$CF0;-=-N:^<,.A"(3\:LDPE&"6Z-OT MY]!3D:@KSU6A2/J+Q>Y#^F>:1>WK],S#F3;J^.O/4?#AD?/QQ?=7P;&O4?AU M<&F:T2AR9&.^4NO\*V\T]L50N(']).*S&0_RL0\DO4^.9_[QM__^K[_.GF@) M,9)_OIL+H-TF\;/Y.]7I#OKR70P^GGR^;M2-]C];_WJX/F&V13]P,_S0OOQ4 MOZRW6MWVI_8GXW.G?7UY=?/YYG.]T_S4:EXV3O[V:I37<<4JJEBG)&DNZA&@ ME-+00-((733K$W+29.+)G5P#DICW+(..,6<&T6C$?;HN2)1E1"K^\I> ^5-9 MTVND-$E?@J@?V)9-U]/E?>YPUY25EI4NS8*>,TVT+M:JU2:"2:;@UD0V,:!, M(4=\GI#JK\2W3GJI-[_YC'337,\?<6=NU(QZF@>WFHBV4"8:HT?;C1O)H]"; M_!#;,.J7>/8Y/S]K&>U&O=7I]IJ=1KO[;F*Z$'TY?!R(B\F'!89:/KE-:>]\ M:4!^@[E)M>SC2;?W;LMI,;G1./!]16EGOON' ZNE.)"9._E,F]O-=]JW9([2 MMRJYL 9Y+4PQZ@N?-8T:V\& RS,LLUO<71#C][$;/*.Z\$D=EJ%DRS,$=-N:V12XD M,_E8;B*JL=MOEU^NOK)@R'V!4F5%-*)7"CL?RJ=OR6F/[:4Y64QJ=O75"=:_://!3=1/SD>7^P)^Y$XI5)R#ZLVA(.'U"_ M#UBQ>A&]C [4E+=,!, $,*'X2B[F_QPY( =2;L)V$MKOML_O[.RO?+YVC?FP67-$>L7/Q2Q2 \9$#G+L_/E81/+G]]H4E>X?)\&%C7PR$[PLKV;0!W^[PW%8< M8T'=IL\T* NK P \"0?7RBZ'/O]6'F7C@<>7,XCEDM0M^)8#CRP%7F"QG MG3:)E067!3EKD?E"QAK3X?59BP71YFWYLIJU7DTNL5^P=>N@G]!/ZF3?]3# O:;'E M,Z4Y2?6X#M^)A#Z@7^2>,7+C!>S(FT6?Y-6+>B?1[77TT6AL"P/4TL_^?T([ M>-+26UFY91SZ,BDEL=VQS/2G(NW%_\W/ZK'HQP*?NIR:4;V71SN8O%G.97M6 MS2P!^!W?]R$ OI,; 63$Q#R$;+&]%P8\H*X<3!:')>5AB)UW%-[);&J]SEJZ M3X[1]>RD*JWI5^H'3\,5C/1L;CH>#_V]4I/VJ^U*LU,NU]KU2O>JWFEW*RVC MVZ^U!]UF9U#O))Z:5--@L7F8O>M_Z0S[/?*UW-_<$4 M6NV_S%6\EEJUHN^!5+LK02MJNQ)\7BA0'7+1'1YEY25?J4NGM*12I/:\J>T* M KH"_S,Q_-NF*@CUO_2_](^)!#H1$)=I?0.;.LX3\1Y=@>S1$WF0DW8W2MW+ M;,44R_:9&B;$RJNDMWF5-8(7\%Z27VMOIG: MG$L.TP>?S5,.*['T5-_?ZB=YG-CF1!EA0;[H^7DHOEXQP@7I!"1X]!8F?Y#] MBU1CW?J_L1^VZ476]\;C@/[!?/%@/YAOVN(QN)!!E:+8E170QT[(7).5Q#T" M(>O!HA.E9P/[3 @.%SUX5JB71OLKZ7K4MY1.]=0K\GS1W:&Z;-D#^8C4X9ZX MHQA7I'X)(T\$(P@5ORQ00AWU]GT^L6?/8XI\(F6*Y>^I5WLUL1W1[4>IA]YW MVV(R^1 UY7@EW\C\Y8FYI;"]>B;QPD+Q"]07[^IA_GY$!Z0I;?>[^"7YU?QM MV**WIBF33HM>2JV.[B,M.A\3IRR8>)9\XOF%@GGB#5F+E$C.4VDUO_"BDYR8 M<^*(D67F^8'JK% L&G6)<.9_MV628=$USL3+ET89$YG>FH['MF,+%/%Y=[X+ MO?="O@*XB^V1:?NH7ZSJ,5S+O+Q3PFY94.ZG._80%2HZ)9&1$W+/PQ*GRPEIE,KM=NSVR,M^'\(E8@J7 M@,KD7&6,%DY&0F6@,E"96%7&0"*U^)95>5H]77D\D)M3]]1A7,,:*J\95ZI5 MI%R!ZPOYAQ9L,, &L %LB)RXS0;8<.RD*D6+N1C38"X"P:Y=TYN^#O]&!JDE MJ;3M]N9^!0,_20)C4EYX9:"^'G@%7ND?K^!Q@\=MKSE@_\>,N3R626#&N%/5 M5N0L+Q2!-Z&P9- 6A0(N@ L9YX*V6(F\<&&G1 N)=2Q59_!6CM%%^=3"Z93Z MXCJN3LF-J$-=>1@Q*KZG+AG[WE0=6IS1)_5%X&TX<3<_JF>[JX<@7Q[UZT:W M)_<3QH+U6$^'*N7%CI"6VZVD4Y;Y-$7WI\)T41)EY;08,M^7J5'?L'R)T(!0 M,O-M4^U+1??3]K1_,:H7Y=>:<\R.:KSM);P5KTQF7-6O#UA KD'VNG? MBUL\W_[B.=&\'@,9K\^Y',G-8^_WAN8_RWE'( ;%" M7T9&1!FAEVU-,YQGMR9BHF:JK/R>2H3NSW],3$)4#O-Y1NTG%I"1K?1)_-Q( M:+ USZ)-W%#M&HJV%GWBZNK%E=$%8H *)M'@*Z30GJK'I5.Y+%UY"HLYMI@Y MLN<^!Q-/*+VZITI/OMY<9I5^8"OCF!F*07 J_Y!&GR=)%F.=^O4+TK/'8W%W M%0DR8L$C8V)@F6?3EJFVG^\+RPAA\>0ARJQNSV5%_DV=2+C+6818E!: M36#^*(##Q/A,N R*B")-YD.76'Y[CS(-MZ>^5N_T6M!AQA0GR/T3%S"8OW_/ MYV*F='U_R\5425Y^QQXB-1JN)FN_]1^H>/GS'-/G9W=#V6">/%X:4>9J5T$P MZ_F\Z<(W,,\HS=?3PLL73(DKWOS$"WWQ].*URY?/3!K*2R&XBP(G @; MKYN^@/(;R=]?TD;,A#\MJ2.ML [X"(SA+"H[,1. 74))7OV<4GV>OMQ24R!? MY2 7M^^("OU U;-^O5KAY,I M$]?);RTVMB/U5HG6Q7]'U!9W$S-].=&,?E/E4[>%\%!_+;^[ -K33"ZG9#9V M689@&D[G+6?T*1(,94Z58%[]MGP1*P92TA/97;T6+IY/ZN0G*=;SERI7U*J[ MT9WELTY<,9;O>/Z6?!E#)9&@GOZ)!/2',CR7 MKSL"BJL6T XS5:9Z^2P+,@O +DL+^&QJ!T&4+ M^XM(-#U?=%;J]_,;$*JDS$Z\9[MOB[\CYRN!>A\1C9>::#RC>6S>_$K"X6J- MC(359>7Y\/ZR_7S[O3^$86X+PSRHAD#S!,%Q:0N%0]1E#'M; );&^@ G"%'- M%/ R,C"DRVB(D=[*7[F Q, J"4 M4'DH@#:@#8(&Z"6'ZAI%C9,@W5.@PMS M5&ME[X7,-US(#)^+G3!5+L MHP _P _P _RDUC[ #_"3NIW7:B/;L]/G@VX;9IUP(\"-L-O&:[,"-P+<"-D; MX: RF5&92JG1TE9?#"H#E8'*0&4V;;Q64;$:*@.5@IS? MS&)$39X8#/P /\ /\ /\I-8^P(_6&6@QME%P?A/1R#B_"1]"^A4<*E-HE:F4 M&NTF5"9_*O.V&1N'67&M&0]G6^9XKRKX+N]2GP7J)N?&1V5;<2/H%G0+)T*A M6Y@=0652IC*U4KF*A-\Y5)F\SXX*?L8TT2CFC,6F: U6+HIT81Z48SZT:]K\ MK. #1FPP+,Y 8S ,(T[&^5 IM?3YW,$'C#A'KQ%_"NC(81NO7_E;741,YCAS MPWX^*Y^IS\**YN+S_*%67T]-6'[5-$-[RCBY88_DSIM2]V_D+4!M6KL^VE8P MN:R5=WF;Z_C:_>*]E\_[X&K+NVV*AU\/T98+\0.@UHP5:B\!=F"_CI(%V?6C MK/XVO9N'T?NYV5\:K081%SF;@GT.N!^AKD5TW.@OQH5!1AH[YHU),&$D\ +J M$)<%)'3'H6LQZYVP>TZL4#8C?8<%OC>CH>/)8/RN3_]K.X2J>/P>,]ETQ'Q2 M-4JD4C;JR@[BCUJ)^(S/Q.WM[\QYNM F>#__%/)/#Y3.+N_-";-"A]V.5]*5 M=5SK.:YK7@]]60Z=#^4=AP)47<>O-;H7A_"MO.O/91)Y;^,ZN M7=.;LB\>?W$K 6Q7@O6.C3^?#7K2$O^L_3[LG1';$E]0,_AD#+KE0:O7,JHM MHWEEU&K]9LOH]FOM0==H]3KMLU]>L&&;&K\EQMO(M*KV+2%9BERV0((;7%8K M"_G7--48"LB9$^H^B&X+T'1NK[Z0T9,PTW0FIAUN4%)0E-BD/Q1FQ&Q$VM#W M!/+=!]$F8 ) @6H]YRE7)T@DF(\@ANKBW+5=5O^)#&$QT_,52B[EQ"AZBB9/*5[X+L MM=&W_ +)\O/JS[CR^)&S!GZCO#I@[S5CVH.34^H_V&[421H&WN*+:**KOHFF M2499&&+D^1;SY9Z+0V><72[^>#4$;IYW+UQH<]IVSS MAL:A[1+_P:3;9::CA[8K9Z6C![9+!J'[+6C@@GJE?>\=CIEK[-P2QNP'X9YC M6V0QGB9S>&;;D'?$JD9]>HS&O)'G6/--5L\77[E+NYJA[S/7?"*!3UWN1'-] M:OT[Y,%43LN65XKY67;]0@!IAD#ZS?69^*W_BH6H>'3[.Y5K1N*(11;C:IT M' *'B>!PX1B9)RE8ND,XA#$K@-2SGQ0_VH;2(7> 6TSK&\Z!, ." !5&@.8^!;4I_,JAD [$ MI4*=XK"3_KE3J=)*Z>PI SC;6=DRD=!V_2=?1CM]4M_HLYV*$U.Q3<^!8N1< M[E]\)+8*&",C-O9\1GQF.I1S>RPLI-S*ASA*66 "D5^J M:)N;@R@@2HZ)8J#6(,@ ,BPF6 UMI>]5(>G:EXPF!E#<,L>3Q( M")+<PLY3? EV*D"RC8OEJN:I9IQL.?VP!QJ!1AL7;-JR_()&H%%A M:73>,$Z[J9ZG*1]VW#<;\"I*1"G78^+9F*D2)M)Y7D69&)&:IMR3%WTG,U^L MU>R9L\]B#8Y?.'X/M96A>SH.SR\\O]B[@H0E)V$()8*60"'Q((?7J209*YU3EV-5UAG>G8L0)1#R1J/::!%S0%34%3732MZ LV!$U!4] TKFEOJX7Q]!0Q M)+M52MZQH.CN-4#?*"?JB']3R=YNQU_%4K/#.0OVKQ[:ZO>N>I6K6JLS* M1J77&]2CZJ']2GU@#/)7/91*0Q'Z;#Y9D=9GWVWVJ"JTR+6YY(GS))-06"Q@ M_E3TF5#"0SNJZ?CJ#H\3VYP0SM@?7#82IJ /C/@V_T,L^'TO?)B0F><'8\$# M<4OQJOUEJCY5I#2@?ZAZIJ+Q//2F1.C4DP4GU!F*F0"%+7]Z+-Z9Y_.2Z-]145SQC[8KW_R_0]>,NF<'$Q(5Z J(+$4CXWH<]ITYXEJ3 M\@F1NB^;6+;*'JCZQ,1G;VJ;ZH-X(2$/?%G>B[D6OR#2DE&53GFSR"X\G$ZI M+RS.5?/WCBCMY8W%UT6]4)4S^FNJ9Z M+1Y$WFE,;9]\IT[(R,1F/O7-R=-:_=:H:/#2N2)M*=^B,,SA-417D5E;(#,2 M(]04U5%3M%H]LJ;HP14P*TG7!JUGI"(EG@_/E^9^XOGP?&GN9[J?#Y6 4U(X M(&?V67:W?H+JG\=47SS"C: ^O:J^V&,FFXZ8O[1CU2@1N?(&WH"W!/&VLR\_ M(X-"+*[ S395[@KI4].6>Q2<75GU9[Y M'; ?9$.KZ55M9VD!NP N]UAIRWE M&F 'V.T..VU[F8 =8+<%=D,OH ZP!JQA0@?8%0)VF- !=IC0 78YA=U>$[JX M4D'ES??9_T]H!T^$,S,436S&R2L+[_:W>U#7BY/[<+E(/)'$>(2?$BB/W!P@&@H%@(!@(!H)A:@AB@5C9)%8# MQ *Q0"Q,"4$P$ P$ \% ,! ,4\,"I-'4@A3U:<-AEE&PMO6H>=LP)\93S7Z5 M2N>JG!G6NMGB$*>,:9"^A(-Y41K$VA26##',>,$*L *L "O BIRQ A,GD %D MF#?3Y\@ &4"&C),!\R6P JP *\ *L (3IW@W>K"M>AQJ4F0X?:3:>AQL]_LU M5KO!P]F6[;)7&=&7=ZG/ G63K5K=!N(:U.W7U2$]Z&:75$^(=05RB3_8/\)[>_486Z M4FJ(.D'42=9F#2 8" :"@6 @& @&@H%@(!@(EE."U4 KT JTPK@%@H%@(!@( M!H*!8)@8[D.K@[)M@E);M@SSM#,8;;S%_80YC]H-PS[$M M\C]E]9^L:4\<@_L[%LJ+&$%WP*JW@HOT'4$'F4"F8I,)0Q18!59AB *90*:4 MD@E#%%@%5FD?HO0Y1D$FD*G89,(0!5:!51BB3DTF%,Q+;&]O1ZNULKWK-_0" MZI"90UU".6=[[?KMP+? M;NBK[G*PN?(R+F (T#T$0,8@8[L8JQ[33@!4#"H&%8.*Y<2_!3F#G$'.(&?) MR)E1*E>,TQL,0@8A@Y!!R(X2,@-"!B&#D$'(,BUD=6UE)Z!B4#&H&%0,;C+( M&>0,<@8Y.V9UV<#J,H[@O)\"*AY]X_4K?ZN+B,D<9XZ1SV?E,_596,!,DQOV2.Z\*77_1MYZO$U!@X^V%4PN*[5=<+F.A]TOWKLZ MPCZ8<&R7?9I$A0:,2OG#RLMMBH=?4SE#T6]_E#17KQLSG9K^%04@=,A;2P8E) _;@^>("BU!. M+#82MV-F*-K:@@2FYW*;!\0;D^EJL['GD\>);4Y>M: ^(\&$D9EO3ZG_1,3E MS'>>!&16LJ%<:!.!GW\*^:<'2F>7]^:$6:'#;L<=Q_'$<]F>>SO^ZE"WHT(Q MA[+Y4%BU*_[UCU_^_*>?-[2<"D$-^!TSO0=7VN3:[5)Q!Y/=3Q@+UF\AC2/? MTAT;?SX;]"IEH_[/VN_#WAFQ+?$%-8-/C4JKV6_4.M5VM5JN=3@5,!#7<84*&AF8^,\6)IZK_N5*($T&F0L\6F1N=**LS@5PB/AQ M1[Q0V=)1EP2>:B;AR"0):1!R"5.%/=&:EX@8/ 4^/6%%P4Q5ID/ 5AC'+4FH M+ZX5C^-9\C?#\\7W>QE)J9=@?:\> M,]ETQ'Q2-4JORWSAC."AGI[G[C;3?4;PU3Q".\+DM!7 K#B -;.!U+W+_>8 M$]57S3J_W7Z[&=Z3N_[5[:\WU_^WWR.W-V3X]SZYNKVYO_URW>L,Q7?=SI?. MS56?W/^]WQ_>@[/Z.5L] 6??L>6I6?SMXGYG9PV@!J@= ;5!Y)P!VH V"!N@ MEA^H[2ELJ'V^L=F-YYJA[XNWI3NW1GJLESI::Y>]P@2\9#^>!;66$'T'K8'6 M)*$UC28D!A(#B8'$8#H#K8'60&LRK35U?>< \BXQ!=_Z-4T_9!89,9>-[8 X M-AW9CAT\K8Q6_PH:VL2A&&#P0O'+S.2Y%PI-7(I]0Y M0Z/7ZEB;Y5DBP5JP5A]KFV M6 O69HRU1C.Q8HU@+5@+UNIA;&YU"9T>]!44]K/=, LN>R>V8G59RZ _T!_JSN_XT6FWH#_0'^@/]R9=G"OH#_8'^0'_>];&5VUB!Q>1+ MVZV0PM;R=5[UU5*^5*K]]O]3O50:_:K-6O MYDG56YUVMYN_I.I15N\1$Z+],J$Z%\BRQP+YXLY1XAGI*11LH ],YDE96)J$ MPM0RD;IL)'ABAH[*D"_=B8N@)&\DWS>=K3(\'R*PNK\EV M9O7JD9G5&[4#,T(GG9&]@GZBG\@\GECF\><'J",!,C)KQQ&. &#MD5D;P-IY M<91FX4^7T70&!\5@RU/S$ZEE ;5TII8%VH V"!N@EGZH0=A..,TMS+'<[MRK M??OL^=[NHSZ4OPG:,O50Q)&,)$8,( Z( ^* ." .B /BM,Z,\S0![MG[OBSVD4-^9Z"OWW PCL97XDJYXDL9A1EEK MQL/9EF'T59#?\B[U61 % U>B(%=Q([#OU4!5QD"5:?)AH$IJH"I?U#!099HK M>1^HL#^SL=F=7)7*\P2F-YTQET>'$VS7]!GE+)6^D91H7O6BJN\<9PXS$6G3 MPDSP,!TB:<0\F\\CCQL7U0IX7"P>9VMAD$?652_:&#T+QCJ,GOGC<>.B%G\E M1O X53Q.U^A9[.WEKXOT 8M RRN/![&$6"+F(PUNNM39!_@!?H ?X ?X2:=] M@!^M<\<43<,3BEE,Y0(F):M?G2$B6/UB]0N?4^+1)J =: ?:[3;8:4R<#]:! M=6#=;H-=JPS:@7996B7G:3'<_S%CILSY['CR 9@_5*Y9.90 M=VE8RCD+<-9/[@XW$!:>Z;#P="E1CJG2OFB"*J *J+++J-+6%K$+JH J.::* M=)7B$"NX@AW3>/%U-U\1XA0=S@&D4[@R04.< \@JCW$.H'@\3M?,I(BLP^A9 M/-9A],P?CQL:5^G@<39XG*[1<^\2QGM5:UTU9FTV+]\[WER]E;QEB$W^AJAP M:[6\B^W781)7Y4KQB/N@8(NB-L7#K\&R,?MQ""R:L>K[2WP=V*^CR"V[?I31 MWU:NYF%4?&[6(;*D#^'AB-N63?VG1>WF*V\J.OA$)I03BXU%CZP-9:)5:B8= M-OY+@XA+''%+'7=3!:FU=*M9:^GMF++8HK3J4@8E&?LB[B$@3-THI?6;;D]Q M,?595!8]\ 3(9>R,P#D9AT'HL[6"Y_R";,]$QA>5U:-QAX[$\$DLC[A>(*]Q M0DM\.96'5KAX$$<60Y<_*EIP1N1SR1+NKX@FPW;$3W?4'^31#B:$;F&C-C(V M:Q6]J _(6C5A"0J%L.@-JE>P^AIE _$& V))O[4M:]>+448\N[_-CRW)M>&7 MZA=D*%[,]J823L%$_)*RM,T7+\U:O->H/I7X3(6XTP>V^#YZT]%;ES<1JF^& MXOW*_LI_W_"6WNAFB8S"0/[T"F;>_OFC?JM&U.,R,EL0UU'7!5,DX(R=B+FC:D9*);1(%*P2/$7G'T>9C92 M<$T+7C?=3/;C:;JX_N>?0O[I@=+9Y;TY85;HL-MQA_-P.E.3OF^B0T/9;BAL MVG4\\X]?_ORGGU\WN1*#\ .[=CNF.JXIH-KG@3T53_#<4#RM*]_,'1M_/AOT MI-K\L_;[L'=&;$M\(6SXJ654.OU&O3YH=SM7Y6ZE4J\:Y6ZWU^L;G>K J)_] M\N+5;]./M^1C&W)65XG9MF17Z^*0[YIZS4%*[^PK?R\^C.NYT^IL_8Z MC/*JZFD;95[T?$K]!]N-.DG#P%M\$3E6U#?14&.4A2'FM3J%/#ETQMGEXH]7 M"K1Y[%HF#*AM/,R_P]BC.B/:-#_L.>PM&A[:KIST#R;=KI:5CA[8KIV1?@*A M0&B9<]_-9FDQ_=_1:"'@#WM[!V[7\ M.<:#O0 'U3L2A=43@/ =6^X)RR-\(9MAV;,Y?7CPV8-R>2LG[&(9"QT$ A- M8&=_?3\ MG$F@H<#C'R2FP!(3_WDD2 PD!A)37(DY1\* +=;Y"/F!_$!^8DQG'W_5;\QP M(#&0F.)*3#W^&0XD!A(#B2FNQ)RC)(^.151&(C/CW'WZWWUVGY:'J&*HNKK' M1J?VA&JZV%24<1G#;VZYH&T' %P %S+.!7V^ZB+,ID"4PA)%6PTC#!K@0L:Y MH&UI#BZ "QGGPCDJ=L7MCDJ1BSP^$PZ]@#K:7)YK:%,<71,X/Z; MKV'^:RJMTJLC NFPKC[/^GN6/<;U'H.YH>^@%M;<&C:]=RM!NZV:T@ZE MD=ZIJ<0Y"^Y88/MLRMS@]KD*U'IAIAWJ*U6[G:MVVZ@W>]5FISD8&)5&W^CV M:^W!H%%M&[7\U5=RQ0_,2_;-?,:9+,JX+,YH>@^N:&.MUFFDTMKBBX6YUTJ@ MKM1/>JZ_%%7UDO]F"1**NUR^KLR(RDHGJJS4/K*P4K.5D6(I6>EGNI\O(X?O MLC5=AGWRE+]5>S63C76L 35 +1:H[7R4<.]JOVGRI\2WANI2A[HFDZ6F_T'= MD/I/2Y0FET6MP/S6KG](L1%;T+YN[U"E''^.#7B_H3'0F.)JC(%LA#M39?\Y M8IZF@AW1+>D6I0YQ;#JR'?&)23^H&?H^L["FT[^FR]E1S!J2'($,($/43%^* MSKR0 2Z8CA"ML$2+C-6J&!5M?J'W+%3&9D%6E,VI#_Z4;A'E[EL; =[ MYP?JU(Q&KS/H5OO]=JW=[=1KY6Z4'ZC7: [*Y5SG!^+A=$I]<0E7:7WFD3,J MS8^M["NN^R'^T7.5)6TW%#TEWHSY>R4'VHHXY 9*,#>043TR.9!1/C I3:.6 M9N1I ;YD "U M+.1# M0 M>.@MG. >4XWE@Y%Y?.[&#"!&NJ\GH@05'A_O*S!;" M3B?4S,*X:+/O@46RKL3 4.!9!Q2FN H31_02M 9: ZV!UKP*2:[HJY5=Y(-' M&?&R9T1[\G: I,?&;,_LB7D]A'U>UY: J BZ @DI+E.,BK:X+0!7LQ6PVX'U X:=F SMQ!0O:0%<@G )IF>B %J!5J 5: 5:'4DK.)#A M0(8#.=$D.D58Z4-!"DL45)X!%\ %< $>X#V ,O!\)NX+'S!\P.E5LWH9F6OA MKDK1;" OQ*K5XT_##F*!6(4C5EUCVJJ\$PN>8'B"3^,)SED6:(U5%PN2_!DJ M S*]0:86R 0R@4R:]C"KVL*540DD/F>VD?&YXM +J(/U_*F6'AL9BIS>>HV7 M@S/8M49,=:&*F-,;,@89@XR=1,8,E": C$'&(&.9EK%J;>>4II"Q9"NL[%L< M97.-E<4.BFBL:K7PCFM]L>G(=NS 9GSO^BJ]?K52Z?=K@TZ]V^]4JKUFM1W5 M5QG4C7*_E;_Z*F//$7HO?G)SD15K;F!96H5096)"78LX2R.OEE4IB6N(-]Y8 M5W%#?OY#.KTQ^_HA-U+/H:M+K[-T'W*CPVO/K.*FML!-)"2H1:.C%DW[R%(T MS59&*IEDI9_I?CX$?J0D?V7.[//<750P0%T60.V$4-NY+DM.C^<<'?QFC\72 M@KFFF.N-6/#(F$M&GO>'FI;+U<:(SO,O@*JI3_./N/S!A5FO[[K MO=CJAO\I2_*6E]/V8D54KR8VR2CTB@F\!6]U\K;1T%8>"[R%I^,M3\>,^320 M 7R.QSDQJ>\_C3W_D?H67!PG$+B,Z52E5"EKDZF\A#J##T7F0T7;!D1>^ !G MP<9F5W1F2W=!? -OBLR8707*RY)"XW(B[V>5P"OP:O?<Q>D=*E% M+#8*5(RJIT(,5,CJS/>^VUP>@,,* RN,]^2FC0H68 /8,%]O5\ &K+9W08CW,%E>U _$!#&U$;/:B"FS;@&)6?#EOCIQ)UXPYQNRS6*=@W7.NQ&[K18B MV,$'\&$^-)7Y#MU0AK8GDNH3 9/Q7(?BXH4"5!1%A7G MK;:^W%\X,0O6@K5)L+;=UA<_#];"3[#-3^"R %Z"3,A;QE3,*+7;B248R\NJ M"GP"G]X^1]_2%ME?%#[!2[&QVW$015KW&RT-.]WHM MIO7A(?;*\P(1&@>-@\:=1..J+7W'6Z!QNTV1CZ]"O5?YZ# MR(Q?NZ832@N+KV6U:=L-F37/T.BY/*IT?1_00)UC[5)'[K7=3Q@+Q"]WQ+N1 MEU%'MG8\'OJB#WM4KVZU>T;MJF$T.H-ZOV=E'C/K^;Y>[F^8%$A\I+*\V%/9]3V MU;EC5?E:!BIY+K'F+UY6J*..(S\_O_&5^Y*9;WL^"3Q53IM:WDQMM(I&G?MO MY,:[(+*6X*=R2_3=5]>(IK9GR;+:EA"'0-SM?*7"]L?#:T2_KI#XLK[S#N]\ M;:1#C>@U%T_KV!K1]:1K*)R8)$> M,]ETQ'Q2-4KD$-58 V?4!,W>H/4-L*M9UC_>' WMCL+II[PAT!=T0R MFV_5F$[G[&.NO&S*P:L*KRID[!0RUFC%=/JWB#)6[.C!R/-*SJ7W[N-+WY_T MQJVY[T8AMUW&.>,E,F)CSVVGBK8'BV\0*_F("L;C(=X*''L:$[)RNDSD!2!S'!_I"#X/S^DQ0'?=([ M.1QH#UCLTW' _!C6^K&X.M-A[.0\FME9+E22"WB'.Z$PLPDH#!1F.9%*3F(P M84JYRT*?O>1)2Q7@K"9-SR'.ZV'0.9I"8;H9S,X2!Q M.9(XHQY3CAIHW)OS00W'#),Z([CYB&*?^J[X.?Z5^?<3ZK,NY;8I[M6SG3"0 MAQ]73SGNX>F9QCAG9FQ6OYN+TX),Z>,/4P9M78-_S^>>TG^N! MLK(E'CKZR4OIXXE,M#C@LQP1Y4D?"9UC>Z!NO^'04$P/LO%4S2%=5N]7RYTV MGKXXS(J/XA^? ]E\-A/*H59SKV$;G0%AUBGGH>T:&>EGWM]?5OH)G&7[_66EG^G&6>8S!S0/6U\UMV8.T)4X MP"BG.^GJJSFK=FMN7(1A"_[A0/$$X/9ZP9_YA"?:\1=Y MX*%M^L%VBASX*0>;VI'15EP=8(.R;0';7Y86E1YYA3U #]##H)IAL&%0Q: * M9<.@"N@E ;WYKZ@X@.UUJ$Z-RS2.N+M;+[,P3<=PG!V8IG&L+@!,H:;)C?*9 M/EP67S!VMW-_?47ZG;N;ZYM?[\G7_AVY_WOGKA\+G!,T:!9T(#7&RJR OCO. M W% 7+)#-A 'Q %Q0%R&$8=1%8B#QJ79<*DQ%A 'Q %Q&%6!N/08#AIWB.&. MS-9J9-P/?/UN<@,:!+X]"J.CUH%'9$Z&3O^>7'G^;'Z*7Z9,F(K_X8%G_C'Q M'(OYQV\J304Z''80)M-AVN.SZ[PP0?ISY%3+VM* (;=J80:NM/!??PDU;7E" MP0:P :-AQD;#\D5-V_E?" $ *0,0%HZJNA"OZ#_QF?#CAN;]0>#_M60W Y([_K+M^'UO_KDOG_U[>YZ>-V_WP-#B!#2JKJ(2=L= M<8B"!.(0!9G(:!'W+!SHRS[Z4F>XU!@KLXC#" O$0>/2;+C4& N( ^* .(RJ M0%QZ# >-.\1P!3^]=R\/W!%OID[JQ2%O1^\H;3>'[CV5"$"MBE'1IEEYV5K! MWFKR]DG)3B-8 58D,!7&6 %6@!5@!5A16%;D=09E@ O@ D8(C!!@!5@!5H 5 MF#=AW@0N8(3 "*&#%7$=^\CZ]MX=XX%OFP&3II [?:%K!['L\[U7<4SKIG.^ M2'BPZ?+"7D1]Q!4N>3,YXY(+*4]GOD7[G[N;ZYM=[\K5_1^[_ MWKGKQP.PJ@"8Y86R1.D"80D.DZE+AKNOC=(_<]!86?1=J^1%@A!LF!^)T5^; M5%MI,O )?,H55[QV/F,\3\1>^@O(EI,;[1, $*0+T@7I*H1T:2Q]"^6"-OO'[#WS__%/)/#Y3.+N_- M";-"A]V.^]1W!:KX5^;?3ZC/NI3;9L>U>K83!LP:ROL/A3&ZCF?^\B/._.^R];4["P-^-:'N ^/7[E>'NAW.6<#7 M[RU>B"NM?L?&G\\&O4K9J/^S]ONP=T9L2WQ!S>!3N]]K];J#2J_6JO:-3J-> M[EX9W7ZM/>AWC'K[ZNR7%V]Q]8T,[2GCY(8]DCMO2M^6UY7FCNVR3Q.FU-RH ME#^L4;(E^*=08KM"K8/+JB2D3I@,)XR,/4>,".(GB7K19.8S+GZ,$TI\)@QF MVHY-91D-XHT)=1PR$]8E5)F73!GEH<\L0@,RIK9/OE,G9"3D\GY\^;)(N/*V MB*U>%SG_PKXSAU0_BB^(Z*LC:W6(_O@D$/V:B5Y[%A?_9HE;")Q<;@7O-INN M,,T4C\;\7=[,VN!2?O$FY.?5GW$]?TJ=M9=GR&N>;QS9UF2.,[_F\UGY3'T6 M"F$N/N^/J2GU'VPWZB0- V_Q130_4-\\VE8P$5<+0\RU2^B20V><72[^^-M+ M+5KV>S5"\UG/VAM#(\51]^7S6;'UX5RG7-7O>T$BX75;ZF>[GVR_B]V2S MXUAF=.K38Z02(\^QYE' S&33$?-)U2@1K">TK2>>N_MNK;!WHO!CL.5VQ+T: MF+1C3DYW #5 +1FH[>S5C2O%97:'#-6L2\4TVV1R8OT/ZH;4?R+ZSMVGQX"I MH[5VV8OY/%=ZG$WO@2K],3[5MKZC-'D_Q0>-@<9 8_:W1;U:AL;$-C5<)T\K MVU/ CAF$U"$^"T+?)9Z[ZGG=[@S%2BZ6E5PR*[74V0?X 7X.MD] MC7_=^QHCF3E>B)2-(%T,I&LU03H-I"OX(O%KZ)L3RADO$4X=Q@EUQ;.S('#8 M5(;QE(C+ DSVD]>IC,D1BO"!%6#%JX.5X$(RR_FL#\-#G[I\S'PNHV3/HX7\ M1^+8=&0[=F S&<HEH]L7*$16 :0O[?"_E?.1^&I!G3FT!'2_:;;9EU[._B+J8W94/ZXXX&[&XM\\O> M672Z[6:ETRE76[7>H-VO5COU6EUFT>F4R[5:K=[)?Q8='DZGU!?7;_T3&3'"'.L16+T3<[T?D.0P\U>S*FPI*//V5$[9X=<_7 ME B5OS=COCSC31^8_*WY?<:^-U6OSG9#V4]/7*7ZP\F(C3U?W84A_\Y^:#Q- M_AVC?&P"GG(N$\V@GTC<@\0]65RZG-2SO/\9*R3N =1R"C5MZ=@!-4!M.]1V MWE3#AM'&9O?/:\;!?,VX6 C"VWIJ;VML,6\G=!#&'P"7X=WO)88^I!)$8-^! MALM"!ORT4C,#U1; 6_ 6O"T$;X\-2\_^:F&^R:,.A M*Z.8F+@_8?/:2+=VJMKW!\#NFG;](-UJ7! M<&EA'4AWHOE[GJ;I_Z).&)V%H/+8A#SU#!*AWLU.76L1BHT#\EQ6:G#@T03J0#J1+UF,6D\NL\*1;F9;_I&K;;[K^('R+=B.?F ZC M_NU^H^Y/;G1FU#=-(A=R*RTFY4C&=3NG(R8[XL MP4H?&*$CH6?$YH3.9K[WPYZ*58CSI.F!6KJ>QV>.Z)=% D\9GE-A9S8YH1X MCRY_HR%?X.[KQ';LV4QP@9<(=:TUFVQIJ^7!QE[HZ['0MXO_O2"/@JQ$O,5_ MBY4POR WS);;G+P>K M;EFSZ@ZETGHRDZOX2:*&(P$8@0TW$/ ?/1&'?6>. %(P>=9EVR??Y6L@$YOY MU#1E,Q55= D4>_# MZ93Z3Q+>]T*1[;&8BHC?Z)BF%[J!?+ZOGFAH2V)K(=FZ&HQMEPI R\XH?*H^ M.4N$DG-A%W%/1[+MH[ E#/,YO*Q[^)F[7IK;E%SB5GU=_QO7\*776H&W(:YYO'"'/ M9(XSO^;S6?E,?1;3.G/Q>7_&"4 \V&[421H&WN*+:*JIOGFTK6!RV6Y?M,KU M7BC[^]G$XNGV+5S?H\):U6-U9OW\%3J[KV M^:S2^O#N;'=]/CYO:"3>#\^7YGZF^_GVV_<\F:LS":>4 M+A<>',$KW:V?[>/O?!V><+13>#N87DWACX"3^O08S>%'GF-%]^DQDTU'S"=5 MHR2]8=J+.P!F@-EKF.U\F <# : &)E9/0$QW['EJ:GZ17H)EU;57L,$L /L MWH>=]J-K@!U@]S[LM*?P ^P NPVP&WH!=8 U8 T3.L"N$+##A ZPPX0.L,LI M[/::T.4TP4C[,*.VWS1J%!RHB\$ILF&&J9V@$;-@N-08"X@#XH X( Z(2X_A M@#@@#HC+A.%28RP@#H@#XH X("X]A@/B#C%'A;(LM7V556]ZE M/@O43^'0(!KSP0!P0!\0!<4 <$ ?$ 7&I,AP0!\0!<9DP M7&J,!<0!<4 <$'=Z/^NZE5I)8"V^",5OKO*M,HM8;,3<0/RI[;@U.*G?/NE MS5]TFR#^"GK'/O+_T5^V7L^[U(!LYX!2<] !Z$ 1=:"JKWXM^ _^@_\9XS_F M = !Z !T /, \!_\+R[_,0^ #D 'H /ULK9TZN _^ _^9XS_F = !Z #T ', M UX]9VQ)[C,>I49&!Z M\J9I\J);(!@(MC/!C*JV@ND@%H@%8F'D L% ,(Q<(!:(E4UB8>0"P4"P.$>N MNC9?*X@%8H%8&+E ,! ,(U>JB%7PD]F_2K:Z4R8:6NLY,'4A" *TAP#%4- ^ M9P/].Q;*BRR!56#5&ZRJM$ FD EDPA %5H%5J605ABB0"63"$ 56@54I955= M6V(%D ED*CB9,$2!56 5AJA3DPEG 3Z'D&&R5!?L /\ / M\ /\ #_IM _P _P /\ /\)-.^P _P _P _RIXB8$3! 5!4TQ0#)QI.6B1]6UAW?G7H%:G M30HYOZ>\XIUDBOF?4NQLB@S+%_B8;CX6PBT-,H%,&-PPN(&/Q>(C!C>0"63" MX(;!#7P$'_/G^P4-04/0$,,B^ @^IF#-E]S(EQHSI 4!!4&T'K981;@9@@9NJ(B9$3! 5! M4TQ0C)P@)HB90F)BY 1!0= 4$[19K8&8(":(F39B8N0$04'0%!,4(V=Z#L=F M?)?XKM.[OOD5I<=B4"ND+@=^@!_@!_A)E7V '^ '^ %^@)]TV@?X 7Z '^ ' M^$FA?7#:8K,?K?^?T Z>"&=F**ZP&=?F4'4#;[T@:>S\1MB1GZ/G/-)V*) M*[_3P/[.M"6;PRZ!CEV"G.P"Q+&'EW=W/P@&@NU,L*J^;3;P"KP"K^;-*NT* MB 5B@5C:!ZQ*$\0"L4 L++5 ,! L0P0S6N 5> 5>:5]J@5@@%H@5 [&J#1!K M1P,<&6.?]8W!*V\Z]2P[B&5'$-I3V/R9R$J+K+1@E6Y6U0R0"60"F;202=]V M!+@$+A6;2S5]GAR0"60J-IFP=@*KP"KM\2>8[X%,(!/63N 2N)0F+M5J(%,Z M2DU56MG>S(M*3>%H7S9E*R_1!VE*WYD7Q0-!05!]DW=]T4'@)7@)7FH[>M@& M,4%,$#-MQ*PVD=,:Q 0Q4T=,+#5!4! TQ02M8^ $+\'+U/&R4@$Q04P0,WW$ M;)5!S'0<[UV0@F+M0[FJH)SEA2.'Z0M-.1F<_I*X MC?2;)"NE[C88)2^:#(5)H<(D4.0T5_(3A[VT>UY:,9T5WF R%,F%ND4KF">4QJ\EAD-G))?7IDJD,CS[&B^WRQZ$)\&#,6N,JYH M,2@A): ZV!UNQOB[J^FJB0&$@,) 82\[)9M0R- M@<9 8Z Q,6I,O06-@<9 8Z Q<,M :Z UT)I,:TVEK*]T/#0&&@.-@<:\TAA# M7P4T: PT!AH#C7G9K&9@'K.K 8X\N9?U<*,KW^."%J\>QG8 M0VQUPFJN,?AF\B(K8$5A65&K@@P@ \B (0*L "LP1( ,( .&"+ "K-AKGT!; MO0&0 63(.!DP1( 58 6&"!PJ/PPI \]GXK:Q[O-@,UZ# FDU8KX&[-SO1(-@ M(-@>(1[@%7@%7FFO]*BOEBQX!5Z!5XN,%XA(!*_ *RRT0# 0+$L$TQ>J 5Z! M5^#5HIFVO0O0"K0"K9[7617P:D<#%/WDES>=>I8=X-#7J:7'\\4;6%C"F/T@ MW'-LB_Q/6?TG:PH4QXKT'0OE19' *K J]E@?D ED*CB9]&7&!9? I6)SJ:K/ M/PHR@4S%)A/63F 56*4]IDM?[ G(!#(5G$S@$K@$+NGA4A-D2L("6*"F#OOHE02VT8!,4%, M$'/G4(&VOG(M(":("6)BK0F"@J#Y)VBEG5B8'8@)8H*8.Q.S@BDMB EBIHZ8 M=0,C9DH.=V;\;.?P=MCY0KY<=[K77ZZ'U_U[7;B";.W#NZK@G>6%(X?IBU#) M08'576V4_D*KL3LA-E@G+PH-J8'40&I.OW4/B8'$0&(@,3$&(4!B(#&0&$A, MC.$4D!A(#"0&$@.?#*0&4@.IR7:("R0&$@.)@<3$&*P#B8'$0&(@,3&&'>58 M8E;"BWX*J'C"C=>O_+WR7([MLD\3IH3$J)0_O(1&34!CV>?688_:VD$>=K]; MR1WWI2Z?R-O MO<]-<5Z/MA5,+JN-7=BVCO/=+]X[U&P?$KP"R_I+65-B59'@ *PT5ZW(P]F6 M(+DMW:G/ G63<^.CLHJXD>;A27;@*-N]K2C-PUCVW*PS]417_\MD5"L/")W- M?.^'/:6!^&9,;9]\IT[(" V(#A;VF,FF(^8O;5LU2J12WE"\]("[$^I:6KHI M.O1Z9#G@/A?:5/GGGT+^Z8'2V>6].6%6Z+#;\4"\GG_)M]/AG 6\XUI?;#JR M'3NP&?^-41[ZS+IU[Y@9^K[@6I=RFP_EW8<"3EW',__XY<]_^OGUC7_U/.O1 M=ISGRP0V7 G!.S;^?#;HR??US]KOP]X9L2WQ!36#3]6>T2V76^5NV^BT>_U& ML]>H&]U^K3UH-VOE0>WLEQ<8WZ:4;PGE+F.1G+;(G$B*,K8K)JWB@L;:R'3\ M*#R<,*'FCI@8BY\DT0C!P^F4^N(Z3@+QS^:$N@_B;]N-/E+??Y(7TZD7BA_T MQN1A;N82&3T1G\T$$:,;L8>IZ+7X 5\U?1)#/2=,/,I1Z%[V/A86+F]_+ V7 M=SJ2ARM=$F]!7.38GLNWDW)'%3;%"V+^+D!=&^C*+X I/Z_^C.OY4^JL8=DH MKXZ-VB8C+WHND/M@NU$G:1AXBR^B5:/Z)IJ1&&5AB/EL60QB#IUQ=KGXX]4X MM7F*LSP_4=MX:&&'*8KJS.>S:NW#GK.C>4/CP':MA'\OZ79XOG3T,RO/5\GY M\^7S_>VW\(/S\=7 53U!NM=W;+G=#_5JOG*$=T9]>HPF+"//L:+[?,-1+0 M M":")=2[*/0)KB6#MMZO.%: &J"4 M7[H>S,&L %L28RAW*: &J"6 -14@O]= M;1E;E80D8/GV)MVQ6^%=ZE#79(1RN6_PIOM^GT-PNT,V00-G@>NI,59^11*( M ^* ." .B /B@#@@#HA+D^& N$,,=VQ:QW*V5["+D,)3.IW280EM!SF2.Z=Q M["-72HUZ2]=CY^4@!MRJ4(#"*$"KW0;_P7_POZ#\-VK@/_@/_A>6_RUMR2# M?_ ?_,\8_QM8_H/^H']1Z5\MM>O:4K7D10%BBW7+^%9!QS3#:>BH#!3V=$9M M7YV&=SS.]SKWL3QEG),J;<<:]KQ2,NH5730\VFI+W&5&NC]J,Q[VE\';_1)A MH6 XRI^"H" H" J"@J![SGPU^I\Q[P5KP5H,JQA60=""$_2\4JI6X5!*8F ] M,GQ-=O=S01;JBC&L8OG++!L06@PU@ R)MP0:P M(0$7 E@!5F2<%8C&!!E AL6$J=2H:/-AY84/B$W<#);K1.(1\^(>-AKZZC,6 MV?F+39LD-FURPKHX=DVQ*PJ"@6 @& @&@H%@(!@(!H*!8" 8" ;/1YK#WA*A MV\G+?NP#M9V3]\9@QRQ(%7:!@!_@!_@!?M)I'^ '^ %^@!_@)X7V0=2(MN(7 MA7.9:*T1 6\DO)&@5@P'I$ L$ O$BN&L%8@%8H%8S\32%Y$/8J6'6&^;L7F8 M%=>:\7"TW1*.[;)/$Z:Z;E3*'U9N5)\%\XW;:&M2W ML3?XX&*54:KAN.;. M""EX;&(B6?,S1J#SJM'4Q9\B^-RQP558JL2P2,K+P )6@!5@!5@!5H 58 58 M 5: %6 %EN"9"GO+NGMKD=Z/4/,_H>TSBUBA+SI*@@DC3T*7XN!:;AS)..$> MNP$PAA6/5X@L ,% ,! ,! /!0# 0# 0#P4 P$ P$@V\CA;Q"H<<="CW6#R$; M"M7L3S>(-? #_ _P _PDU+[ #_ #_ #_*#08XK6<2CT^+Z-*J5&LP:_"/R- M\#00P"L JO *K JJZQ"349,"T$U#& 8 MP,"J3++JO%)JUO>'(84>1,69?^+%F_$MBQGL7 MEOHYJUO=:L;IK564201V)Z%B4+&T1]-"QB!CD#'(6,9CER%CD#'(&&0LCWYH MR!GD#'(&.K[!=H=+! MY2>C);[1]]"R&0]G6S:GMUB\/@OF07 ?B;*)N-/&EWE Q[I>,%%EBP3/."_-&.'L0?WCA'YG9,282WQFA:9H M.7HB.OK\EWJ+B&LS R(YZJG<5GPRAQCSU?_-G_$"S*< MV%P\GC0,)X%'^J,P8"7R.+'-B3" 1<:AXSS-328L\+"H'"5,ED93R/?]2+D, M)Q$OVI4Y:&L7V]5L_O?//X7\TP.EL\M[M\-NQXOL2$/!K*[CF7_\\N<_ M_?SZLFO7]*:LRX1U6?3WD/[HB?_A@B0=UQJ([P5-AE(@GV\E5-^5C+UCX\]G M@YY,EOO/VN_#WAFQ+?&%>)&?JM7>H-ZO=?N#1N.JV^P9E=J5T>W7VH->N]/K M],Y^>:$JJU8:VN+WR0U[)'?>E+X]<=M%E*0&M5XH3+6R)C#'CT5#@R(1\!+27]MF83OF0&^GKS^NL6(?<2)E<5Y=> M'[X[Y$:7!X_C*\.TR21N=B'>VEA>?D$T^7GU9US/GU)GC9N&O.;YQA%U3.8X M\VL^GY7/U&7#,'$!]N-.DG#P%M\$2TLU3>/MA5,Q-7"$//)L9C; M.G3&V>7BCU<3F66_5Z/@EG/BZL:HQQT"Z51G/I\UFA_>G6ZO3_KG#8V$V[4R MTD\\WRF?;[^P401NPSZ[V6?G]+%Q!+:_8\OM7I%7X^P13B+UZ3$::$=B#;%E MZ@6H 6JQ0$U;KEE #5#;#K6=4Y7$EC\[VV=5OEWJ,, 8( 08 @0"<2H*:^S M%%J!BU^R]\=Q/ M.A>L4.7"9H,Q2LVJOI)8R*X$/A6;3Y6246V 3^ 3^*1I?&I4$DO#GA<^Q;7' M8V1\WCST KI/@53X..+P<>!H5YS&RX&7Q"C%EF.YB$>[(&00,@C9:82LWHQI M,0@A@Y!!R"!D20E9N8:L(MM_U:.M!9U;?.O[ZG;F!YS_=>*X9^K[XL/=1 MUVZ_4NN5&X/JP.@-RA5Q3<6(CKKV*VVC,BC<4=>9T;MY%5G1. MSE?.H7XD]/D NZ5.L(I>"_H$S,(IQM2<8FP?>8BQF97#0L689YTS2&M7X M3BCBVQ&,/) 54?BUVW&MCO5=!=H-O8V:8.L=VQC >4Q3L6L8S+ ,AZ M^<,GSQ=JR_DG[]%EULMR'5/Z;T]TX6G^KZ$LWJ&6?ZK<#P]'W+9L\9,JM)(& M1+H'J6G*BCCBWV49CY"K#HJ?G=<'F;)@XEFK]3ZVITU!,&6"P925VI'1E)5J MTM&&Y8R$-^(!\8!I[R@>\*0/6.389 T^?L-(MY,__F#'E?DZ M"CX.(&Z)N-\6"X0(;M_6%@A+X]ZOK!0.6+X63@TW&_OW]\HA'H)AQ(SC> *. M)V3A> *@!J@=!S5ML>2 &J"& 1102P74,( ":FD;0!%-N+'9'?O.W)"=DK"% M"1?)?C1(HV;$;HV\!'L@9BVFF#5H3*XUIEW1ET!/%H6 MG8O: S8[YX2).3A7NY>AKHT\>>$(-OP+RX9*65NA+[ !;,@Z&]K:XO' !K A MXVPPM(65@ P@0\;)$!FC53$JVM "5H 58$5>68'0YHW-;EA ;%7NDYP['N.7FPE)3 \Y858=<29@5?@E7Y>H0P7> 5>Z3_B!5J! M5J!5!MP7(!@(!H*!8$DY#E/C8Y]G J_/]&9PCS<]1PQFRYBI@"J@"J@"JK)@ M*J *J *J@*HLF JH JHTFRHC"\,$,[TCNWM\MD5R6F0,17+:7$,MAU#*XUPM M.X JIG9AF 34,$SF%VHYA%+XBFI\$\HY"TY:/!#9>_:,A#A=]IYJ M$_%\B<&AP",<-*:X&E.KX^@8-"9%L^@DC9@%PZ7&6%E#'$:UXHYJ%0QJD!A( M#"0&1Q:@-?G0&DR@DW%'Y\GK?..YYJ&.Y[RFHJJ4C"HR.RW8@%.K:I-F.&U3@^_TB551216!:7I0:PTS9&P'03$0&S #A?P S5="1?05A@,:@HV9)P-C2;( #)@:H'@F02\'>);WW,< MT3UBR[1BC,=S7 A>;'BQT^" S:RN%X5@AK;9#W@%7F%W"($T*3%2,8YDR(J-E1H^X#S_QCXCD6\_E?"?M/: =/<6AZQJ3;*)4KVDZ, M%$6;(<&YY4.[ADTOL &;7HBG@9H>KZ9UB"G( #)$S<[KVO(^OG[C^S[ZR=9A M'\$43#L2=G?\%-"1PS9>O^'OGW\*^:<'2F>7]^:$6:'#;L?7[G?&@RES W[M M=ERK8WVGKLGXT.N,Q[9CTX#QC5OCI4-EZT(S(\1GRX8^//9X.>+.;YS]KOP]X9L2WQ!36#3T:O M==5HEKO-SJ!C]%N#>J=5-[K]6GLPJ/>O.L;9+R_>UJKEA_:4<7+#'LF=-Z5O MO[F5YH[MLD_SFO-&I?QA#5(M@18E(;8K@!!<5B5\=,*A]U4!0O[_E[]R$KJB M9[;%+.()(_I\8L^>HXC$'X2'YH2,J3D_1T5H0%[!Z*!N;"KL3C;66CWD]L06 M7>5D[#F"5?QR*_*WO9IM-1O??,%KFE%^\4+EY]6?<3U_2ITU#!CRFN<;*P82 MDSG._)K/9^4S]5D(BKGXO#\TI]1_L-VHDS0,O,47D6JI;QYM*YB(JX4AYM58 MA6XZ=,;9Y>*/O[T<[Y;]]C?IK5'?J(4[.%M59X1@-SZ\._*L:_V\H5$^M&%6 MVE6RTM%#V]6STM%#VS43^<']MC,P:=Q[>97^TM7-PPPHFZE/K^H-KTXKR/V$ M^@RK%?W ,XP3("^].%NN%@Y8VD#Z('U:('F[6#A!\9+WSQ00;[_Z'N=$^3F$ M B[->\_\[[:)<1

B MU-EG]S5MYM>LYW^1.RFBF2.8QG?>QHWMR'LKVZHEI)_Q[\*:C'P3JD6T);6+ M[U#)Z8H=)W 6-\,A%1]2"9V<*;UV<4>M]-XM_ M^@>%@<) 88JK,*@F$Y_+(E>>B?^53@F7W XQR?<*K6 MM)UPRLM8 C84E@W(JP$R@ P+,H +QRXRBK$O^ILM+B$#SP_4OB@G34)=B[12 MZ1Y*R0*E&O_^!%8N\"QJ&;?RDO.R8FB;WN7>H09B@5B[#V;:IHK@%7@%7CU[ ML4&KV)9FN5J!W0F4^;J7'WG<]JDDMRE6Y 4+O&CPHJV,8_&3 M+B\C'(@%8NU^ HGH, K\$K_@(7MU/A69,D3*K[Y\M"G+I_:G&/31S;[3GW; M"W?.PE44KP5<>!J'F-.F.=8^@ZMJ&VG>,0S(!#+EG$SZO S@$KA4;"Y%QFI5 MC(J^)79!6(5-JC<62UY G=2['=ZQ7A8T*S7&RIK8[R%?52%?EA?* FW'*'QA M<@&]9[P\) LJE>OZ'/('&RPOPRB$#$(&(3N)D&D\&PT9@XQ!QB!CISB"I.^P M>>%53&MA^/=KMV^N^7[#@BYSV=@.KCS^LDS\#N7>&[5!?5#NM7NM2KWY55.Z]WVL:M4[LY=YC+>\^G+!YU7-!1Q+5#N?A=$I]<1TG@?AGTYO.Q*L7 MEB;>6'WCLH#,Q"T]RS;)*#*NN"RJ +^H6U(B OD3@7EA <$.E5MF[/GBP=R2 M_$/=Z4D@BXM6XD:R,A@*KZ>F\'KEZ,+KM8Q4T6YEI)]X/CQ?FON)YSOE\Q6Y M.*'Z]+KT-S/9=,1\4C5*1->D'NOK97>;Z=[3E!=J -@@;H)8?J$'8@#8(&Z"6.ZCM M*6RQG57)K+] -;MG_G?;9"H20A=Q4V2XU#%:N^(5)HXO^V%Z!I+L0V(@,9"8 M&"5&V]XN) 82 XF!Q+R6&*1BA,1 8B Q6"A!8B QD!A(#"0&$@.)@<2L-ZM M8G8U0+%S:U_+K5+& ZV;KZ J7RP@8$R&]LUO\Q8V; +.*S(/1= MXKEDYE"74,Y9H*T 7(I,F5T-RDM1SO.FME5<'DNW?P3I0#K]I*O4FF =6 ?6 M)"ERI"?GV9-E MHAV/([ S32J4E]V(2OQQG7F1*_ *O-J=5]H2(H!7X!5XM6BV>]U-\ J\ J]V MSED2?] S> 5>%8Y7%8Q7X!5XI3]R">-5?&[6/'E3[UD0.&S*1,,':KO$9Z;W MX(I++%T @OSL(3\Q%(7,U^;.>Q;*BRJ!56 56 56@55@%5@%5F645=I"0L$E M<*G@7,((!5:!56!5:EB% -6-S89>0!TR8RZ7$:HZCYJGR'RITZ\]&%D5C+2\ M<.2PHT2K,(7=WC->'BJ_Q;10V<=:>1D6H&)0,:C82;PM&A/B0L8@8Y QR-@I M9$Q?&5ZH&%0,*@85.X6*M?2='86,0<8@8Y"Q4WC&,!F#BD'%H&*95C&CJB^I M>.%E;&7?]Z> BD??>/V&OW_^*>2?'BB=7=Z;$V:%#KL=W["@RUPVMH,KCP=\ M*.\W% _?=3SSCU_^_*>?-S89".LRZSZ@0?BBB;"K*XUWQ\:?SP:]2MFH_[/V M^[!W1FQ+?$'-X%/',.J]?JU<:[2NFE?M=J=9[AC=?JT]Z-6K Z-R]LN+E[%J MV*$]99SM 1)U,NVQ1.YP655LD;G MVQY.&!E[CM!R\9-$O2]URL(LG%D0@U+7$G7SQ(&Z)4"Z3+\G6,_'3GL6)> #!EH!9EUN!M,TP*Z@WA3&8 MOXMYU[2]_,*<\O/JS[B>/Z7.VALPY#7/-XX,9#+'F5_S^:Q\ICX+MIJ+S_L# M8TK]!]N-.DG#P%M\$0W/ZIM'VPHFXFIAB+G("(UPZ(RSR\4??WNI"\M^KT9@ M++6EN3&T9H<@#M69SV?UQH=W96M=/.<-C83;M3+23SP?GB^^W]LO).MDT8^Q MS(K5I\=(YD>>8T7WZ3&334?,)U6C1'3- ;$>6W:WF>YXT5?S".T(DU-, O MB@-8.Z]:,R_\S<.LUWS3>N>V2T0CQ_9@)^OF/+4S/VV\7]!: & MJ"4 M4'DB ':@#8(&Z"6'ZCM*6PXA+:QV=7?.S>_]LGU#?EZ=_N/_M6PWR/= M_DU_<#TDM]TOU[]VAM>W-]L]]=BY3ICL"1HQ"X9+C;& ." .B /B@+CT& Z( M.\1PQ4YV.P\T(MY(W#TJ(!:%L?R#NB'UGY;VU%[*M,!,U6Z?=(!)6_QEAJ(H M2Y4JBI=" : 156 6JG:T%:R PH !8 "9$P!C%*YWH8"0 &@ 55@%JI68," M'.U829%S+\[R0OYWVV3(@IFZ++XY*72F,5=0WH]M@E?@U>Z\TN;G Z_ *_#J MF5?Z\A" 5^ 5>(5Y( K>[@.4:QF_S'B@=4D*Q=E=<3(F++467%T@ \B@FE7K MV@*CP :P(>-LJ&M+\ LR@ P9)T.MA3W!HQ=:*7)IQ+<"ZT]GCO?$F,K4Z-NC M4 9B?$*_9\8BGOFW3T$@H%@NR\(02O0"K3"N 6"@6 9(AAVX>-; MQ.9IK?K5H2ZA4^9:XO\#;8M42$YN_6 X'PLN@ M1LPJX "Z "ZH9PDC !7 A M:G:NS6WX^H7O^^0G6UKLG),>VXAO+\TX"P*':5V;I-'C0WEN7-K1G MJ"[R^A-,R2]3JF5MQ[1 %5 ESU31E]@53 %3\LR4FOZ2[WFF"K8P-S;KF$%( M?9LZY/R!VNY'XG@<^YAITJ6\>*3.&]KBC["1"=*!=#N13A@(K /KP+HD66?H M*U"4^TT7$ O$VCV"O0E>Q;;>S=.RMC\>,S.0=57'GL_$#Q S]'WFFD^$_3 G MU'U@Q*XYMD?\IJ_]D39OBB+AXQT)YT2JP M"JQZ[4'DJB"RY84CAQTEIW=2W'0HA@Y!!R"!D M)YF15:KZ2E)#R"!D$#((V0F$K%:J:@Q0*[R0%3O2YNKOG9M?^^3ZAGS]TKDA MG?O[_O#^4A>ZH/7+[E9C.,#VCJVR8!_@!_@!?H ?X">=]@%^M,X=4[0LCF]2 M.:"V3[Y3)V1R WNF*N!PS@(^W]+^!W5#ZC\M[8T-[2PJ76&<"MGW&1BELKY\ M7[EW"4!EH#)0F?UM42U5- :]0&6@,E 9J,S+9NT:9C+0&&@,-";.F4RCK"]8 M).\J4^PM5)6#SR$^"T+?)9Z[ZO""(UJ_(SIOF4"U)45Y_<+C$UP,],6%8\6^^/0KE M47ND3$^3]N0EW64">1KR(E;@%7BU>QI9;46&P"OP"KQ:-*LWP"OP"KS2[JK1 M>.X\[\0J]E;B?''*XEF<0GMRZ_^*(?5K7A0%K"@L*[!# BZ "Q@AP JPXHU< M.N#"L>NO%+DZXEN8?94AG9P%@<.FS-47UYDBXV57<_+B)SJ/O^PD0D3!.7 N MYIHY>??1@F @& @&@H%@(%@V"5;L7<9YJ2E.9M2VX"2#D^R]=:F^U%%8?X(I M>69*M:SM' JH JKDF2IU;5'<8 J8DF>FU QM\:-%H JV,#?'EH['S QD^N6Q MYS/Q \0,?9^YYA-A/\P)=1\8\6G 2/0WMCC3)%GO%0Z',TN_Z?+B[ )!05!] MDY%V(Z:RU@?8+,^S&+ 6K,6PBF$5!"T"0<4:7UL:2 RK6IT#>?(!O%>8J<=, M-ATQ?TEJ?3EL('O[T%93W>=TP"ZY\L[QF22&BDP5??FAWK-+429=$!F(#$3F MN5FE5&EI.^(&D8'(0&0@,AMF,AIK2T)D(#(0&8C,RU0N6DM+%D5D$ JSL=E= M_^KVYNKZRW5G>'U[0VX'9/#MIM?OD?MA9_CM7AO,TF/+U&G[K21[3>L>( M63!<:HP%Q %Q0!P0!\2EQW! W"&&*_B>L !DP]+@Q#[P"G0-S@VBN38.#?J MR3E/BQ#A _V!_D!_]DCNH+&<$O0'^@/]@?[L-?]I)A>A OV!_D!_H#]K^E,J MM[$"B^F,Q4\!%4^_Z?J#R.XW/"K-!AM^,;%D1.NGOEHQM*DPY%3[N. M9_[QRY__]//&)E]%1SS+-N?9_JX\'MQXP>\LN&.F]^"*OEGK=U)%Q\2'.S;^ M?#;H5],V);X@MJ!I^N!E>=6F-0N>IW!X-VHU]M5CI&MU]K#[I- MHSNX.OOEA<57;3.TIXR3&_9([KPI?7L82,T+&TX8&7N.&+G$3Q*%9,+#Z93Z MXCI.;)>(6SBR0AL)Q*5TZH5NP(G/Q@XS V;)*SJW5U_$_YI.*/L=?:1!5-M- MW3#PB "RJO8XNWX#,>\!+Q7'7G*_$3\@@7E3?M4H>Z)B/W$\:"+?[: M$GD%N$.,(&&@Y48E\2@T(!/ZG8DG#LB3Z/V(,5?8:X%'^32F-YT)8DM#B@=S MQ46S.9#%U0K)XA(N'MRUGBW.?LPB@PMCCIB\H4,YM\=V])50"U<85KTQ:4Y7 M@(:,;2[46_2"^I<'Z\>*V)I,OK9=0+TV?RB_ +'\O/HSKN=/J;.&>T->\WSC M"$4FDH4/Y@NU$G:1AXBR^B@4M]\VA;P41<+0PQ M'_?$T.30&6>7BS_^]G(X6O9[=:=E.:0U-FX=[;!9HSKS^:S6_/#N:+D^GL\; M&H>V*R?]@WA S>TRT]%T/^!^VZ@G6XV^/4%N'C9AD,W4I\=(LD>>8T7W60S+ M1([&&P?2';;RFT<>D3]ZN;K=AJ_&/>U6[)AF. T=.?E9SF]NQ4#NBXG1=.:S M"7.Y_9TM__%:S*>FC)Q_\3B'WR2&\!)@,IIY+JVXF((NOPF\Y=\O)J6;+UJ= MIKZ\&3L6 [/WCIQ+%^K>+^PN(**"6 -0&4692H UH@[ ! M:OF!VI["AG-[&YM]]6W/___9>_?GMG$L_?OGW;\"Y9E\QUVEN$7JGDRF2I;E M7L^FDXSMS%;_]!9,PC:G*5+-BQWW7_\"("E1EJPK2/'R=.W66(IX.SR?!\#! MP0'QF?=D&4R&@8^);\85#HLSV;O)M8H_R9M%_4O4MRR,XA2N*836U%=K3I5M MUE'K0IV0'\@/Y =='71UH#70&FA-5;2FWHO-OSNI;#^1W$>-(*2>16WR0"V' MG-H[3MDKVTD@XREI]NC_<+^TAG;[]8-J)V-GRE:A%V;R-(FXU4@])35^'0,\A9J4)M MZ+&]&81[N\;8#@6V=JZ6M;KNEBQ+\,5UW"GS:,!-//XQ98[/SE]&25VC7>IM M:9?=<;=W?MD::^>CH3;H]=K]J-[6^'(P'+0RK[>% D>*"QSU#ZQOU,^[>$SN M]90J^7PEJ(PMU6 M^<#VZ4IO2@,N69IO6]DJE:K@@7%E;6'(H#6I"A48#J\>#MM^0+,@9U-$4*EU MJX7^U9T[M8#S4VEJWT^F.^H/!L-<>=N*JE MMK"5^ZU&&]SZ9"&S CNB'I(P/!B<-?5.JZUIK6:WV=8'"O='U0_,'^[V<\ZO MS?MZ>1^'YT-^=)[YT?L$P)"SNBIG55F=?HRXX&K(Q(>K%<+5,LK$+]@TL+KX MP(A_Y?%Q(>&O9F(Y?'SI'G7_260LEB:TI#V26)6E#NH*IU=]+(-P20[- M556X4I=+"ZR %;!*QDK "I&W+9,5^'TQQW@A'N,/Z^^TY5I51U:/F/$\9/XMZ3@/X@U#'C,@BV M1>_B2!Q&-DA@0NB@9.T7 -@ R (>2-V)P2/Y%5*C(!*8-U;$?D2<]H3^L- M.Y>4F"N$+6H;ME!7O @P (:RPX" -F)XNY8KM62ML&RZ'-@ 7*WQ*K"(JK]U M_87LK%45=4.89O\^0(%4;/O=)2%QBK;I/&:Y566UCO:W90X>!W6$.D(=H8Z[ MJJ.RHH-0QVU'QAF4L'Z[ /6:"M9?DZ-'KA\,'7--'>PMREBWSML#7>^W1OKY MX*(_;G:U82\N8WW1[76UXY:Q%E^H= >4L489:Y2QQO,5_/E0QAIEK%'&NKSC M0K@:REC#U8K@:O4H8YU=S.:SZ_NS&FUBU8)I^5/7%].B>Q1L4PYS;:8\RS^C MV5:W12,F+ NC/(5K#R$Q-9885&N"Q$!B(#'924Q'@\1D-J+*7UL4#I38 Q\4 MB?DV*RZLL\\@OF*9UEAU@( 65AW$.1O*6@[ !A*#@,:AH,[2P4:H65;J/" M715K5V0 53P0"BED^P3 !@ V ; 4,(OTKQ-93).39/ZF;=424'48EJ1R50 MW!

!;(QN@58!ET5>4.4)J.,,-2! M**7$E:$.A+J]L5$& N((<80X5D@<>^IVPX0X;CDP5E0C9X<2-ZL+Y?PKI%[ M//OETG*H8UC4OG+N1:44D4!R*^YQEQHYPT[W=BXNQWAWWM?-!5"-G M/#S7SKM'K9'3$CRJ= =1(R0+]>=5<@A_/R1T:&A: 3/)'XFAQ0[S MIGA)IMQK7C@Z%3^X"?C_3&2U'?>>Q"^6_T#N4R_.)5XI=5[DYR6/V^?^5]8R MV.=$_K3&1G& M/WZD3XS<,>80C_F!?"^!R_^^MYD1B"6]4=YZR+]WYV^(7X+:MCBKY9H^F?)C MQ9)M4]HE.5C\@IK_"?T@>LD.,YCO4^]%'"[>KSNU''XZ\?:Y^],'Z0SR;5-R M3RU^QXF'R,W1^!'\.J$=1!YBB37BUB2YB;.UFH1*3.LK,6G-IL+:2]U#:R_E M7;NG5Y(:0W@^/%]VUT-MJ==E0N+.8EQ=:L=22*B_\K9A?Z6B1I>J41A"*7"V M-<[VS]!A B=A<)F*A8E"Q5RK6[^2VE 0J M!A6#BD'%,E"QGJZN@!M4#"I6?A6K;TZ<6HDK0TIIV]MZ'R70!)K* M0-/V@Y"<&RXMOS [QF'%CURI\ZQHLW%R[[F3>)^"4 S0Y@L^&L1AT2(,^F/) MO-M?L)N^3S^%T8" M2MQP5P6L+L "6 !+/5A-=0-+@ 6PB@564<>8[>PWLKRP:L'446 M-!A4L0TE$&)%B!54@2I0!:I %:@"5:"JDE1A@?/*P[[P 9@E9_ORE,W2E_(QO<4 M[6M4#+OFMT-1>41+:^NY6:4JZH0I,4@,)&;[-;C*-N2&PD!AH#!0F*5.3#^C MVE"0&$A,KON_UK:DW7[Z4X;2=:?]779E4F.R.8#5<+J?L@L<%2@:GIW]SJEO M&:]B2K,]-S_LX)ZS!]BXQ4F.9BU_6U(<'RR!Q\#AX7"D,5QACP>/JX'%U MW@]6'G:UT)][NSS6-M.'>RY^5F[K8EA6V2"W/#&TYIFN+(B&&%EMFBX(0'4$ M0(, 0 @ /45 +T' 8 0 !J*@"GO N@;!G&7E-1Q7CU&/@\>5PG"%,18\K@X>5_M) M/BR=+?QPM3RC42R=14 +"V=J+0!8.@L!@ #46 #T+@0 @ !J*D 8.DLELYB MZ2S6%:@W75VZ P5BNW#]! *0 $H 6@ !2 E 6DA :S^KOB%;$HMGBQ5> MJU!".!;/(D*/12?0F++,\D-CH#'0&&A,EHD$T!AH##0&&H/%LWL:"HMG#PT' M/5E<_4R?F,RPJ<=,&0LRW,G$=:*04*$E+.. 97FT;:.W%E_T,H]W[V*VNG2\ M"J1RZ)%!SBHD9[G&HJ!CT#'H&'0,.@8=@XY!QZ!CJ^+VVO'M514=2\73?I;) M0BM_G_H[]5RVY;#WCTR*DJ8WWWU,/:C!G(!Y;]YRZBP+/#>YG\FS6 Z7JNAS M^C*.ZTVHO>"MFOC-[,11PI/!;#O^S:>3YHG\S%^0D7Q>8>1;:\)\\H4]DVMW M0I=4UPOY^OA^?!\Q7N^.J>GRD_/ MD5S?N;89G>=?(?5X@T#&7-=-HC>U]@YM^/:5QS;D16=@XO5F76H&E1OV5^J1 MEK(.$48G<+8USO;/T&&DI2R, &^#MZWQMALV#>!M\+9\O.V"&7.;;M^B(B%E MY6'7[(DY849))VK\L9Y!P3W6618_)MANZ%W]Z/:J2DP01)3O5&*ZI[PD^UHYINKQ85*:+<5]>#K7JPI41*4.)6N")V-[QV%LWEHRW4SVC"J9O6Z;*!4P1 M"@5I;Y&643UR@ ;0 -IQ=V2K2H\25($J4'7\<5J!0B+9M?5?^#AM88/#;/PJ MZR*#\=5DL;*,7+B@J>&**Q!F84C5*MC-;U.A8SK<\36S1$'C+!O=K*T(I812 M9A3([W6.;TM():024@FI++94JDPF@%1"*B&5D,J*2J7*]!!(I=J@9:5CDX0& M@6?=A=$.!(%+;A\9&8YOR,CUIFZ4>U)H_2R&7;&-\/)AIYW\- VI 9C$A/Q M?E*'::W\]C"O2N<($@.)@<1L7VZKGU\/!Q(#B8'$U$YB]&9^F1E5D1CDI:T\ M[)SZEO$J^C-E'O$?J<<^[.!ELP?8N!]+CF8MO[ 7QP<+9SAX'#P.'E<*PQ7& M6/"X.GALE8=M6TQLFXF^/=>8*[=U,2RK;#A:GM'F:?.LJ:Q,*.;D$,V" M.E1('9IGNK)M;:L2:X( 0 !J) !=91->$ ( 2@= *@*ZMH7!4!*'M=\]PK MV648B5!6Q*0J92?%@/[XVUHB$E HX@O700"V*[ ]_CZ.P!;8 ML=O.X(M<0J M7PP:@ )0 %I@0&L_ [\VKQ+K:XL5:ZM0:K@8)&"%+6;SBQ/+AP#52H":9QK6 MOV&^$!H#C2E%R@$T!AH#C8'&9)G54!N-P2+;-W(>[#!@)I;9%E;;B^.%A3,< M/ X>!X\KA>$*8RQX7!T\KO:3?%AF6_@1:7D&G%AFBXDY++*!.F"9+00 @ ! M6)[S4M8[@ ! " I1, ++-5$H$H4" ,RVPKO*X RVR+$@DH$/&%ZR 6RRS M!;; MNS88A5?_N-K I 6C9QK_5&N:NS:S$0MMB1=LJE!^.A;9Y#P?0J8 M08"PT!8SAM 8:$SID@Z@,= 8: PT!@MM@8= PZ!AV#CD''H&-UUC$-.I9%/.UGF2RT\O>IOZ.,(H/9=NPBGTZ: M)_(SMX"1?(Z?(NU5;>Y"Z:>ZM2;,)U_8,[EV)]3Y2-YZO%5QOF?+#!X_Z.UM MW'+1'[;_\,K=G:27-J(?3M?$ M2-?<36<:1&D_6I3/PD^TTK_VO*^#*!:WKM#HA]CXRC'LT.0./?580'\0:S*E MEC=A_$3LQY0Y/A,+RU18[:]]PG]BKTK@V^-L#37WU.H5\*;TEJ;RK@AU3++< M5.]QII;>56NN>]=OW;N@%C^2/D'H!\WQ5 MOJ@W5[3%>SV!Q_PI,P+KB=DO9^2&+4]7[';:Z)/X]0]$&C^SDS+-T+?YTW#V?*Y=^W$[]191^>\O)US?;%SKBXJ4\0N-DTZ MV0_4A6KSWH]-Q6J> MP)4_\JDMAPN4\ &]J&;AN?Q.> -I.?PHY@?\#_(K]2W'=@W96U*GQUJW%'H\ M_B.T@A=EKV:5^KX>TF7H;3VE8[K]G$W\_?WL?\_(L\7;=_Z(_^']<5^Q=^GM M4GC7A>5/7=^**\=P<_P/L\WWW*SO;X2USD..'N,] C_3YG\IIC"G7R[Z4Q50 MZ R4>I_'1Y\/#O_.)*Y#+K]^N?KW^-?QK^3JZDK\&[.>1*]$5.21*Q*'W@,3 M]7JH$#4YB%T8JR9N>T:&MN^*1W_5"'#K\>;&(4;H>LBW>'/B\7^>)((SKB+YMTCB,7#[B M<5[^YL?+BL4A#J%R,)0*<7*4Q[8?;$18J9\N+P(KHI]>.4]]U+YR^(U,9"6G6W&66_8C.+==X_=__/=__7WY!-?L(;1IX'HO MD7/Q@?3BXOQ 3_O]J_W5Z<$,OD7U C>-\: MM)JC;K_9'']IG8^;@\NSSN=[NC\Y!^O>G+KA@-OC0;6=033667] M)*OL\'PZ^?$YNLZ=:YO1B:['OWS_/+S]>OT;&=['[U M^>KV:GRS]OWO\CPR7]!R3.ZX'UJZN@>4Q]W.1_7DD?HR4N"9C(^89@X2C>^C MP*<]]Q%RRD?W<4?(_XEW5_BHWXIZS ;_=>"2*3^0?^^YX<.C^&SQKSD>@3L1 MO1A^-#7$Q<3@ESQ;P6-#7L(/[T2HF1_02-_$U'.?+#^*P/J\2V3;?.BP?L?8 M=49.)6$:3 12MW&]I?%9^M6(S^G+. )'>^%M:@MC.F5CZ%=W/J'>@^5$-TG# MP$V^B-+%Y3?10%IKU:YY M_YX;YN5G/J(+>6_[&S_2-?<8JZ+5=MWM:&Y?DJXC0Y=A4+#POZU7E$ M!N%Q\#@8KAP=@J4A<+M=[D9_[##OX85,0\]XI#[S?Q8KY9:7F.38VRR&7915 M*RM/S;'VBE6Q>SYT50J'830%_NO#_XIUR^ ?_)?*/MDIPM!Q0FK;8D: 3*D7 M).4$XG@)-?\31DL@L^MY;M>)+WN7]-:CCC^Q9,(YOPE?K!%(3WWE4FZ)4O$8OQLX)05UW ZK; %;A"0*_J?:Z5O=B2S_*- M;7)#[2=JBO79KZ?ZELQXM)D^_>"9ODV-44PD]PQA_\5$%&9 M7.1SNW?\:C3>JX<( M5IB&EKZ\HPEH VELD])YW)JE5UT%6V"&] ?S$_RM.4&"_>>.YEO.U&HOE,W M\[Y359(/6NIFG)!<@*$HN)I-Y8(K<(786"4Z>I7JSZ'&)NH6%V3X5SC[P'_@ M/[!/(6:DZE-LZ.#ZE[4;7&EM=9E]&%T59I!0++FJ(UAZ%^% @(6P1?:-?@%* M.5:J$W7TBHTE4WJMW53%:UT$';I=81H V H=["GLGV56F7;7+![YGG,)+]: MYC/S W)U\S7JSRP9]VC3,SUDUVS;KJA+TL1XNCC#PL(U1?4#2], %L!"H"K[ MP(I+[A@Q6<"\B5A.E6D?KU)=N7*5943]D*7)D):ZSAOJAR!J4&^:>KE5.01, MM8&I8/8I:99SC>OP1#4+G375>(XA[549I0\TE+;%*/[XS03 ?'58OZ=L]Q* M"3 K'UXKEN$.3/6J7!_NZ^WP,[D>__+]\_#VZ_5O9'AS,[Z]R4;@6ES@3#<4 M]0^4#<3+O\/\UC8J_A;T6J.K<,_B37:I2R-8=\F&R$!D%D2FT\QH<@$B Y&! M?7*-BE:M0YWJ2G^^&IY??;ZZO1KOTI]&C6B,AX\4X8/'P>-@N,(:#GNF+3:U MH^5I1]NB=Y9M!2M+,J%T#7K&*'T$_X%]2F4?+'C;NARASX)U*PJWOX+B].G^ MONG3RL'(>$:]./'>3?Y?_#AOI!1]7=.S'UK4)>&>AYKCVYNZ#1R=%JVDQP&Y[KTM7J!*%NK0: M:!PJ"X,.& ##T0=C16W=41\L]W#IZV6*Y([ZK)!Q4RV'NA,5696E=5$MK((C MT<(U3/4#2V\!+("%V%C:"$K(^CXE@4ONW=!+>GM3_E/71&QL[PGP>^XAV(P/ M&46U5U/X#_P']BE$1AHVX\/@ZLW!5;.#P57UQ@C%DJM:@M565X<"8 &LLANN MLA-8V(ROYND%FH[-^#!^0[)-3$,/N_&!AI)'>RK;6:E5MDW!MG#1FNOG8O:Y M,=135N GG=QVBL%(OC@#TL*U@>#RU6%==6OBP"6X1(1M7Q SW[]FP5B5*Q,5 M;5.S8H^:5+&H8[03)6L.VEUU4Y78A R1AWK3U%4X\0^:0!/L@WW]5'68OJS< MT2_KTIHH+ES.<4_A# >/@\?!<,4W'%8O#>7JAE$]UU^[T48P7@\\"]<>JPE57 U?@"M&PS#LG*.RCJG_G3YEA4;N@ M@3$=@;'%PUH]K,4K_%"W< U&56EH][$6#S0@,/;60G>7W#%BLH!Y$][:FHB* MH1PB%JH"R5&5R!J](;KK)=KBJF MS&"?^-*-RY75 *E+HX*VH[(L:,JRDP%#;6 HF'VJWE^J1Q8-"E()]E':/JM[)?*/;]/5V^)E2AHO_7W(RWT6^W;16W MMY7Z%K+7R2@,L8O!ZM)V%DCIBM5H0,@@9(?E&32(_\W=B))_C MNTF_[/;RRQ9?I6_XUIHPGWQAS^3:G5#G(WGKW:T:@3U;9O#XH=7\[AY_^ 62NN(I=W__O5S+B>QY7P?ID;CU@XS^=O/5VX^YV6'7 MS!#:)/EQO;@ZC/PT91Z)2L=8U"%?9)T]:I.QS8S LPP2+S(?/LCDXM.3X9?Q M^//)3\F,A*C*1X)'+K\/CS(I*4I6(K=1;M)PEIO$#[VZOCWYZ8SG) MA'J,\#/S.Q/Y3;Q1Y1+N!)YKV_+FQ'JPJ6=-^,GX/_-_\BU?IC\E:]Y-PN(; MM8*7!F'1S0:II68->1*?_X@_=W31X)$&\LKRA+Q;PD_SY(J'L9F\O=3-345I M:7/VA/?\)#2NZ"CN0X7?:;J*LY )_^[1?YTCQFU^QM_)"W]?$VHY'&)R1VWJ M&(Q8?MH EB-_[X=W/OLC%"^,']H@SX^6\<@/]D.;6X3_B)) 3DXI>GA]N8=Y MP,,'+K]5Z>ES+Y>/)5_H&;FD3VX$@3]U \+]ZG?&KR7*)LBW36W?%2;X#W<7 M<3*#.Z\[8>.Y%*L/IL*;F1C9K[S(4C:OE$&TJF7).% M0ETY*T_0D*;R!7CA&-!K\:2,-A 1" M5)X(;M M-""!"X==.88=FI&*,XE_[A/_$YB*II*FZROMJB(Z[HC[U M!3/8Y(YY\V:DI36(WM26EQP>TX+\AI1T_D49$5$K/K">F/V2.._JY+EC^*_> MZA73@WLM>'"!/3AQ7W&W:[UY581DZVVZR]KAZK1KT>%J'=SCD@@-NFV] )T< M=9V:[PZ=N/SF_N0#$-OE''#M9-^%#I3N!"C7^""TQ2)'A().Q232T MX]6")>*GE^R&+ M F2&X7JF'";)GI;XV26_M">BJM%8\7J.\,B=)#6Q3D\NQ]>CDY_D?7S[/OI* MO-!FU8\>@620'$-F4,][$3%JXY%Z#W%!.(/?.N5@N5&K&,\37%!YAT M0A^8@(6W>1^3>-X+>>;=>#J=>OR329XL2F3FSCR^*5LFWEPE?72B]637O"UA MO6,/U"'_I$Y(^;E$CQT<@L,J3/&"( ! ML#J .P!XAV<3T]GI2*IAN*$3B*&G'_!^+/5$6,BVW>=DXEWL4D?O, LMC<@K^CCG\1T%JMUK1X[YCLF/->]"F"(_3I>@M87^(67G^4W&=J<>> M1-T$WFT/'7'@@R/'Q7+NWA.;X3[PD7 T+(ZC7G&*G,@Q8-Z3923):[,D-Z%2 M1CQ6CF\GFK>?Y;2%0L&D-OEG?#@=/:(4-W\VU1_?R)W,N7.C>7Z1L_ W?WYS M_*[G._K-;)74*W@Y(]?)&(-+8#Q>$=%K]T[(6(/A>"ODN/+):1>2!CE;XU8@4+IT+B4BBG M9&'J<47C0NHG$P%3H42!I-]+*U@\(1?0'TPF2'$QHQ/1C A9>TMV&[.T"\OA M$L?OH3&?6X@3B[DBW;GN[^_YF4G )E,^7N27-+G6\ ,W R6"$BE3HAZ4:)>N97JCF\5.V6Q_&_(JPA/]LXP077W[_+J_12:SQ$5\ITUPP]M^F+R5Q.:R(ZQ9:_JF<& MD8'(*!.9/D1FIZ1.\L_0EC,L>I0 ?4_'GO_G))69#H42.9AH1Y:-SK7JP MDO&PT*-H.)6.99-H0+Y\_4!TJ^*!UOQ.Q"25)XZF,FE*G#HQAR:/YP]H6U'O M*UG$X_^-Z^B3*WIVD=+.#!@=[K!HOHIZ?N/#FG.;\.'[N; M<8>._[_SGOW@0B]4- GR?T->3\GQF*MBA9U10G]\M5;3+,,>MASKND#G=AKOM4W)/, M;.$/8K\T%BVXT4CI6,:J8H8OLWO@[9LUD2Z5]-NCI5>-U-(T40I=+GZ(HBK< M2\1E4\F"S4;T7F4W7RYQ$$DZUI]1:QKG[J1L.TO42;V!R"&C%60I)Y)&75XW MQR_76B[(GO @(@N\'Q^APM];G/$PNQT5:M?MG74Z[U2<*?5NV]*0K<0:KY80 M-N8+3\2W*J[=TL_::IZB\<:;D@Y-HU6J2R],/J@7<:;B)AQ7R0N9Q1#7U -] M>34]6)IT7'0CT8U4UXW;/+.\UF*,=H\P7$LU$J/[,8D)FA)[J0T6IH\5>2FW]Z'0].=*0(YZX!(0L=L%O^_5*;EDX@C]6^FYFM^DO+*!^ M?G1M)FI%)#^.UW/'3Y!80([)5B_O%O$U/@(3CY=ZJ-DZ;$/D>9GQ/7C,FMR) MFA*ST:'M+H.:N$\T*?@0Q^NBJ8)'*I)-G;1(VNR!_W8E^J)?ER3&Q!*U,HU&_O)M M 8$X0!P4B@/*X^PK#NET",ZS+/2V,(I;[#DE/3W"NR(R_,1[AKP?Y$?)4S*$ M'\<&XZR(]"A3!!CGG1&N2J;KQ+(S*W_C4 MY:/,N$?C\)Z;Z_TNAK%TGK27&KPFM^U.XTZ:+!\V85RH4C,&#F-FW"V2ZTJ3 M=9]S%;166^Z,W+ @L".Y\Q_YK1+7X+ULKKAQ?W)N+W[/J!(&'52J@Z]JY*BK MNEM@-;N>E\&:A_3]9 AT/3R/"QF*_DFT&L=YG8CAA;;,=TBM;Y-3.V*DQ4$2 M_Y:.L<^'F',UNV,/EB/'L,GT6/MPMM<9-(VRV'Y7&MAR3/[P'UIZ O(*5KMN>F@87BCG Y.DH'5;N^US]XMU11I)WK;HI^=)]9_W&K7W>^+TK%CY$"0NR5FHX$<&_ M/YF_A0?3'\Y+SQ!,Q56!:LA^WOFK-EHV*P41B M[9NBESK+0KO=?*6W>G7G4?9,=),T#-SD MBZA$O?PFZF!I36Z(>*,%0Y10GOKL0_+'4K.[NL9VZ+')6_FTTFK M]6['SEY\H+;O<>V\+X@'Q ,6\0%W&PL=;9.]''>&FW7F1>+*#D.@V0/TBKW- MYU*;I]R"*[-]L)_COF-K.%;*L;;>9:HDPE9<;VL=P=LVV/+8_O>Z:,LNNZK# M[^!W"OSN\YHH )RO(LX77T7&#=;O=%X@SRRB(FYO2'AL_3QV#RW%]NHK#XOG M_6_.OQ^3_]KL*%S^#8,'/77[GF,WX,(H3.&:26A,C36FM;Q;)C0&&@.-@<:H MLD6OWX/&0&.@,="8S#1&:[3:4)GL(C15"L1\O]DQ"#.[47U#'#'CR6/5T'0[ M357(5(4,S /5EH:^-@ -H $T1&U#2UGP&32 AI+3T.LJ&UQ4A0;,\JX\[-?1 M<"2&%^1T;),;:C]1T_5^R@*A34D+2LU]1/;:+67C^GTM5A5F$5W,H6FK"Y>1 M%?NZIF#_20 *0 &HZKE]=>E#X!)<@DLTG(4%]- 9K7ZY1YVW;D#M;)RIQ9W) M=$-1BT'9&LD*3)EO:Z,R3)UWNUNO&#W8+E41' 2#(3(0F1U$IM?):#@"D8'( M0&0@,D)D.DUE.1P0&8@,1 8B\_HPO:%M7V '(K,3RPM1H.M?[=]N+TZ(9?(OJ!&\'UUV1YV+T?!<:U\T6X-1LW/9TL[' M[<'E>7LP[FDG_WCU2M+FW5"6U2U"XMX'%XP*+<:+$?L"0E M_E"[5-ET)6J7EFQT"<="[=(C>%LQBJ(5RO\*7JD/?E=]OT/MTAHX7RDK0191 M$5&[%!Z+VJ793P2A=BGJ\>RV]@"U2W=1>RPNV+.9A,;46&-0NQ0: XV!QJ!V M*30&&@.-*:G&H';I+BJ#VJ6H7?J VJ4Y-2,5:V:K2@-JEX(&T#!K&U"[%#2 MAB2$@=JEAX\A"A2[0.W2\K"'VJ6(+I:I::L+ERC!!D !:($!1>U2< DNB\%"[%,%@5/R"R*!V*40&(@.1*;/(H'8I1 8B Y%! M[=*"B4RFM4LW5BNU13',;]0+7FX]ZOC4"$3ES%MQ'[N4+NUTNH/S[JBI#?1! ML]4>=[51/RY=VNOJG5;U2I>.W GWMY>_^?PO1X84A27)3<#_1Q0BE:5'OTZ9 M1Z5%B>48=FCR7P2+=4]35B?/5O!(O.B=D"E_*:+,:;J@Z;WKH9SIUHYSI'*F M^H'E3+O]G&M%YGV]O(_#\Z'49Q:U8'[C+;Y/QHY0]8/+?A:C$$^A:NV@$&B5 M:SX5S=64C5S@:G"U]:ZV==HN,LE7'G;-GI@3LE2VR!?7>1^/?9EY3)"Q,+XT MX2JMT1RHBXE7/8T(>7X9!.X4Y8%NQ49?6GKFRVM_(C&,1)F)FM/3P_.47 MYCYX=/HHWLW08W3W986M\: [ZO6&_8OQJ-F]U-OM\U:TK'#8'[9&%5Q6&*V% MNV-<:LB4]QGE2D++N1=KZ,2;:I"[%VZXT F\EP:A=VX8R!6!\^6(1GHYHCM? M@"C6#C)J/(JI7W%$\.@Q1E[D&A8FU[ L>>2.#Q$/7>+4;6DJDQEN= ,?A.=' MSYFLE9GKGE@TLW*UQSYF7+'^9I_3K%P2L-_]4.=PX[Z=.[[_/5&Y2+4BKUVI ME=6\^?3:W3,2ZR>Q?.()^PCD^ \$BS'0XN,SE\M'8@7B9YQ-A_\H>E5"4PGU MV.:#^9\WVS*3R?-*?Z? MC/\(K:FHN-,@#@OVB*H46>[>#DSU]K-P;VTU"Q2SR,R!4O2 M)8KFAP6K=+&][>"D]7%29?D!$,NB^6'17 WM,ERM:$WO7N.3 F6G*C&C/.R[ M8\T*J_I+YMO^A-WT??CA=$WNX=(\R/PLG6D@3W*J13O7\A/-7ID"!TNHUF$]N_ 2V@I1RM3D-A4CW0 M EI :YYUHO?1(01:0"N#L58/.U!D%-6HVB3AZ-&R4<9;[#O9T5')>\?G1.-2 M81ZZNK+R"N !/)2>ATX7U>W! WA(QAB= 7:.! _@(>&AJ>G@X9"A=?%"6=D- MN\>VV+7^B9JNATC6FG3X%D+$F1L K5+]P.JWE#56 M@ :P96%WLI0JP );Z M? %-W>IN@ 6P %8"5E/9/$_EP:IWKL"%.[$<_GP.N6;3\,ZV# 3^/G;5C:2J M0@G"X+6EH=\$#: !-"B/LH$&T%!R&GI])%B"!M 0TX">TN&CZP(%LM1YQH@_ MR>3.H@A:K5F8V5&W>T35@U:(!B,:O -82 P 6 !+/5CJEI+(6[PE0=K#(D!JCSC&^/EFU-IY:S8A_3^D7RVDTLA-OQ.=&<5)>& MC@8:0 -HB&A0M\LQ: -):=!X7).T :RDZ#NJF6JM!0Z@R [!+OA]X#6@_4"^;4HK'K7$OA&'3I! MCD#P44_ MJO!0ZAP!=;[Q3]KCQ)2V04NRAR?^+?% HH %L#"K8X"=/PX?ZABESA.7[[QZU'%:< $L;M1@P8Z#H.='D M@0I0 2I !:@ %: "5( *4 $JU(8 BA=X4^B;SDI>B37\0W[4MD_RE*?^K3(Q0W6JG?0U6%=DHD4*4MY6M#9;*WX$Y5(,.$"(!Z"ZA6HZ7EUIP!* !5=:#TAJZP[BZ E U M!ZK=Z/710@$H *4(J%ZCW0)0=2I>DG$$(QM?:G%?,MWPSF8'D99Q".U0 _XU M-^-M],=MY6I[6V70%QATE57>V]]B51$U3(KLWWV DD')#NJ$J=SL $H&)8.2 M0=%=O&)-8MF>_SA%V2N*YYR M=R?IJ5W"JZU?PKOG?1U$L;CU@XS^-IF]_<"<'3;^8=BAR1W<8T_,"1EQ[P]9 MCCT[[U]UPG]B6P<5V9^=C5#'),OMSQYGTEM*[^O>]4CPR,@+ES6?,,=DIA+S M73"#3>Z8-^^YM+0&T9M:6YDYE5BSJ2W/!>UQG@9W/W_*C,!Z8O:+^&33@)LR M<,G(=4S7D7?\JV6^_S_F!^3_+,=LD.='RW@DU&/\Y_#?C;]HGER#=%#<.=N&R)D\NY]]L],X5+2B3^+7 M'ZR 6\.('N&&>4^6P80<&,SW.?1DZ'G4>8CD0(W""1$C$]>T[BTN-AX+/#>1 M/')'?R&QC<[(#6/<" %3HMC+0Y)]8%E3XT?)"_F%.5Q];:GZ M-^%D(NS!37/#W9>;SQ!N-N0Z'CK22[YQ"3LP.QDT6/Z:,7 M2PD?!CRXLIFYMIX<=_85HC_0Q,)I8@>:J$X3NU#$!46\H:%'_>.QG_")CG4'L4^H$[89X_=,S/ MKO/PF??CS:'OL\ _?_F%N0\>G3X*,(8>H_ZMN-0M=^USVS5^_\=__]??EZ]R MPQ[$DUVSJ>N)8-'5/*IS_A+_X^P41-B/?[AF]Y].+B]$^.U?[=]N+TZ(9?(O MJ!&\/V^-!\-SK3O6N]U+O=<_OQRWF^?#3O]B<-[IGY^?_.,5B^L$_2T]WV8 M(::J^\GXP>(.[00?6OK"<.'P6?M;[C?WKFV[S\)IY*OUR92/L410]]YRJ&-8 MU$Z'RLC="_$CL\Z@XPYEN:9P1)._.^%QI]PG8[S]GSZL'W%MJ6L&OR+SMC'I M0LO1?&5"\3E]&4<\F+U@=:V9;FV4M>ZO[GQ"O0?+B6Z2AH&;?!%E5\EOHB9^ M,#AK:QV]V>[V^JVNWNF]2])%>"-ATZG//B1_++4#JWL0L\:EU5VY2':+'H"\ MM4\G^N#=CIV/^$!MS^,Z.5\O[^/P?,6X3SP?GJ_(]XGGP_-E=[VW6OW9&;+8 MTV95>OGZ8?"\1W5 -J_\]!QU!N]MNVX9G@GO_$1+1G+ >W*P>@. MP8>Y-;5BUV-9ZNLKMVI4%G2;MXR*/[O$M^!B,Q>[$A>(A\KP,'B8>@]+HFJ[ MZMA;S?L\+G $RVYPTV/;6L0*0;%ZBN%JJUQM.7L'K@97R\35E-7Z@JO!U=" MPM4*X6IH0.%J:$#A:M5R-32@<#4TH'"UPVP97T6F.JTO)E\ /]RZ=47U^)6' M?;\A-^??CPES;:I>E;^H5:O1&:BK_5[UDE4HOK=_DPB5J;/*]'5U-4"A,E 9 MJ Q49EEENJTF5 8J Y6!RF2F,NLJ94%KH#70&F@-M 9: ZV!UD!KH#70&F@- MM :S3E 9J Q4)E^5P:P35 8J Y7!K%-15&;WG+TJI>8-'5%7<[?LO-F]9E&! M98?<3^7;*3;:_8$J;JJ"!U*K:\Q#MZV#!_ 'A(>6F@?P -XB X[U92-,I;? M>';#+<4]Z)] "DC91(KRE8P !:!4$93EK4,!"D !*"MB53V,1< #>)B/S?O@ M 3R !_" \AP[^2P3D-AQ4:@!;2 %I:G 3 !L & #8 ,@ $PQ R!%M!"S!!H :W2 MHX68X2YHU7O]Z*^CX0C+1^.4BU9'60F9JM"!%*0:\]#M8_DH> /"0\]=?LT M@@?P4'(>3I4U#ECK U "D !*#4'!:M' 0I V2Y4I8P5#$7 0^EYZ/:5U;(! M#^"A]#ST-(1N7STG5H^N/&P<>NZ48?7H>BMI#6V@K,=5^3EUI*L@764'M-KJ MRG("+: %M.9HM=H]H 6T@%9Q2X)NM$B=@]A@#LS-FE/7HP$CU#')UX#_, M^[ES/9%YB$&WZ@_BN;9GD+TWY M7V7FS5OJ%I'N:[&J (M\E3SR56K"I<*"Z> 27()+15RJRS$#EL 26*I:B:V6PFY >3 M=C1[_35W&ZDWB?HYWD:SF=&$T@K#U*6Q1YL.E8'*S%6FU]!Z&65Y066@,GFJ M3'Q2\8OE42XD*!=[9= +&C3STZ<<7 CB!?%"%ZE$7:33MKKB^=M:I["+3-X_# 8G+6UCMYL=WO]5E?O]-XE7LH]T*93 MGWU(_OCXVNOF3Y%.<)UY;JN],HMYBQQ9>6N?3O3!NXU0+.(9'ZCM>5PGY^OE M?5Q9GJ];DONL^GNH^O/!SXIQGWB^8S[?6ZWP[ Q9%%-=-1Q=W^=5TNN7GYZC MSMF=:YO1>8;F?T(_8";YYK& _B C_BO/N@L#RW7>ZG7^QC^3,>_VF>2"&6QR MQ[SY0+:E-7885,R?NWG@TL^,EYHM]9*5OXEHW=#\?=R.$#-1%C.!G\W\[$I< MP&%@&'J;5W3ZV/H)Y-_CJL0VN-]45A07*<+7U MKJ8L(QJNIJ[R235=35D*!UP-JH8&%*Y6"%=# XH&% UH>5T-JH8&%*Z&!A2N M5GU7V[H!+?6F?$IL* _[?D-NSK\?D\^,2YH6)U%UD_L4/T>^U56WOA"%; NC M)H5KXZ Q]=68=EM="05H##3F^(8K#%AHO OI'W4""XUWI1MO3=U&&) 82 PD M!A*S)#'HQ4!B,#Q0SU7V>^F *W"%IKN^37>KA^$!- 8: XW),,K9P?0!- 8: M XW)4F,P5MK6 &786U2=9PP=D_D[)E1MG1%_<' A9TKZRGK[58$!Z:WUI4%7 MUF: AMK0D"T!1XP$=90M= (-M:&AJFV#IFSG<, &$H.@[(2_&"A-BQ4M9ND M#0 #8$##$(V@!Z !-("&))Z$00-H W*,XNJ0@/J&\C#SCWZIV5G-26772)P MOOPHW%BJZA/:2)K)H?FI"E=Z&QFO .O( ; JKE;1L=*TF/Y1,;#JUV(!*V % MK)0'*( 5L$(W$%@!J_)A5;O6:@"NP!6XRB *S)_ M'0U'6) 9#9:0,K3KA@U@ ;0D(174>_NU7-B1:8\ M;!QZ[I1A1>:&47<+,]J9&P#M3_W :K65==, %L J@.$*$AI3& T 6 ++59R M&+ "5L *6 &K$F)5NVZ@LAQC8 6LT%K-EXYAWW. !;"*O!4-P )8 "N#!3:5 M!ZM>:S*'OD6Q)E,>-D!R]8[/B::DLC"T 0-@P$J#>*6!NM+1H*$V-%2U:U".I:$$BZ 3#$L20LQ@0,@"&));5!P^)S8C&F M/&SD>E/7HP$CU#')UX#_, M>[ES/9%YB &WZ@_BN;9GD+TWY7V7FO$_;;74[ M:1YJL[EO93>>>\7UH?;[29GQB@-K>5NYVE#;::G+ 0.UH!8+"510V=65]5I! M':A#6ZFFK52WP =-): %M+E JRX5&] "6O1OE4")[BV@0TM9K):R/5!7'@Q- M):@%M;DTI7UUU5Q +:@%M;D$>-553 >U:XQ7K]7%MVY ;3(T_Q/Z 3/)-X\% M] <9\1]ZUET86*Z3!;3[6"QV6O&+98\]9KI00^NHJS:S]4.6.)L(N74@:35) M+5UU0A!(JCE)1Z3GB,NA&WI3]WNO5?P[HG;4'O!_S7Q MF]F)I8&(P6P[_LVGD^:)_,S?OI%\7F&H6VO"?/*%/9-K=T*7U&%"O0?+B6Z2 MAH&;?!%)D?SFV3*#1_YK;HC8+[G/V73JLP_)'Q]?^]G\OKU5PJ#I*TG=8H)? MWLRGDU[OW48,%GF+#]3V/*Z3\_7R/@[/I^)Z;WGM[*C^6RUBWN4X5@C67!D& M^S4-XC#YZ3D2M3O7-J/S7#/#=0S+MJA(5B&!2ZX8S_"*W@A8RIY_"?^L2])\/[>WE2YG]0UO0B MWV]SQZZ5YX8?NWMRL0Q7AERUM_N)RK7@B^N\_V4X_!;GLTUX=V@G>K=VPCKZ M&D:G\!_X#_RG/&U=@?I;ZH)!WQV/\4?\DYF$CY>M)]ZE?6+D@5J.GT46L^H@(D09$&K;? M+KBK+D\;8 $L@)6 I6XE4=6Y*D,(+[LNX=5D2BU/Y"LA@C<;;'6:RDH^UV&T MA;A$?5%I:XAV Q6@LE7Q8V5E5.N "F)X*P_[S'MIQ'4(OP"_O=#R'V7GS;TG M)KL+,AD3U:7.L=;']I)%: 0+Q'%Y6\?:4*OWU.W/ VI!+:C-A5H=.X$4LQ== MI<[R-X^]%[L*&"YV%=@^^U-C3-#PLE>D2O,"[1XRZ5Z E$B9X&H4'4<925R@*7\+C(,J"+*\=AFKJ-F8$6 +8"4M5DO=3P:IW MA/$S\_T/Y L+"(LJ.5H.8:EBCG16S#$3WC:$ODN&G=;,;5*@*O0A9@*:WJ)I M )@ $V!2 E-^T]55@0E1R->'R4]+I8-WBTC*HN$*NYH[N&J+NZKIAB(0>@C$ M&0^(#@7]K[D9;Z.[J\]"R6#/,EU=;'=O@U5%,A&CVK]C B&#D!TB9)V>NC*] M$#((616$+(=LB7JH7!GV<]8:S;:ZZ<2]K5FW#!WL$EBO70);W0-W"=0'E=QE MKNJ[Z.'Y\'QX/CQ?<>\3SW?,Y]MMN@03DDL=*TTK]HSD4O=9^4S2K1M0FPQ] MG^V4CPX/@X=MZ6$7;.HQ(][P6,Q$#B%M7 YN-R6+C>B4TO(VOC' ME#FF%83>]O/;)6E3WXY4]?:S9N]-:_[&J$?&CLE,^Q9."B=5[:3*UN>@MUDT M/RR:JQ6LT8:K5=?5"M;TPM6JZVIH0"OK:J7JR!6L=<5H TY:^'893@HG/:!% MQ\J\E8=]OR$WY]^/27IM5I24?\'(H-%OJZL[C_4@A=&7PC6)4)GZJHS6;#2[ M*)X(F8',0&:R[,P,4*(5*@.5@*ZNIRSGJ"HTH%+&RL/./?JG96JSW\BPR:%%J@I:_4:[I6P@ [2 %M":H]52-]<.M( 6T)J'HI5-4P(L M@ 6PDL/T+E9D BR I1ZL#D99 M@J0=K + %L!2/XFE8<$9P )8ZE>+(RJX MM7_4>R7GKZ/A" LYH]:HT6\I"TU4A0ZD&-68AT$;"SG! WB(.U6-)I:N@0?P MD,R0=D #: -,0TH @,:0,.,!K0-H $TQ!.(32S6 0V@(6X;!EC("1I 0TR# MAK;AU7-B(>?*P\:AYTX9%G*NMU*KH>D]5415?O(;627(*MD!K8Z.13% "VAE M,->N#;")$- "6NH'6-@Y!V !K"SF_P$6P )814ZL 5@ "V#-8^U8%@.P );Z M! <=8 $L@*4^Y-Y&5'!; ]1[(>?0MR@6DBY M P_@(>&AKV&A/W@ #W%_"8T#8 ,@ $P (9%&%J 3 ACB1## !L 0)2SK MV)L6-("&Z+!.#_N6OWI.+.)\8YK.9X%/'IEMOK]WO?<^M5D6 %5E GR "N&9 M&P -4_VXBJS4US4]>_\"8 "L=H!IC1ZRC8$6T$+;!< 6*D .\T^Z7C9178U MR=&&\#^!.3"G/H2(-9_@"ERALPC %B9 %.7%@&NP!6XFG4(E26B5IZK>J_\ M'+G>U/5HP AU3/(UX#_,A"O7,YF7&$2;_B"^:ULF^4M3_E!!$VBJ-TTZNGJ "3 I@DE=U5_ !)AJ M#A.Z>8 ),"D*0JC;]PLP :9ZP]3"F DP 29%+1/&3%@^K,*1;MV VMGX4HO[ MDNF&=S8[B+*,DPT.->!?1G]4G^BNO _0;?0[&?4#=K%8540-^5_[=QV@ M9%"R Y2LWQATU962@))!R:J@9/'5Q*%9#27J(7-9&%)YR;9FHZUE--^PBSES M<#H() 02 @F!W#F)M9U1H [Z"'V$/D(?2ZZ/>EM=E0+H(_01^@A]K)0^#M!_ MA#Y"'Z&/T,?EP_1&NZ.N)"KT$?H(?80^5DD?.X@_0A^AC]!'Z.-J?>PIVW4, M^KC6?*G\ZY\#RNVRZO>YW5C*:+;EL/>/3"JIIC???4Q9T6!.P+PW+YLZRX(( M-;G_R[-8#M?7Z'/Z,H[K3:B]0)$F?C,[L300,9AMQ[_Y=-(\D9_YVS>2SRL, M=6M-F$^^L&=R[4[HDK1/J/=@.=%-TC!PDR^B=D1^\VR9P>.'P>"LW^PTNWU= M[W*C]#OO$B_E'FC3J<\^)']\?.UU\Z=(Y]G/5VJT5ZZ;V")57][:IY-V[]U& M*!:YC0_4]CRNF_/U\CX.SU>,^\3SX?FRN]YN"Z"PQ'"IX=*T8J\Q7.JL'- ] MEI^>H][*G6N;T7FNQ 68'Y KQW GNVPS"2>#D^WJ9.,?4^;X6WM92?3M[3%: M;S]+]MZTY&]\1$3&? ABD@MFL,D=\TA+:Y!]_+)U!+?<8.AC.ZK>U)0E+T$" MX6KK74U9'!^N!E=;[VK*]M^ JQ7-U;8/-1? #PO6NBH+T\-)*^2D!6N7X:1P MT@-:=%1)6GG8]QMR<_[]F*37IG9(^4N#8(-(9$_EV3!":Z UT!IH#;0&6@.M M@=9 :Z U9=<:O8O-BJ$QT!AH3(8:TU=7>P8: XV!QD!CEC1&X:;P5=>8W>>> MJC3%-'1,YN\XRS1?4[5A2C3CIU/24[;M6%3:0:55;&/J 3 ANBP%F M#( A.DSK*$L^! V@H>PT=)4-M4$#:"@[#2UEP>VJT(#*E D-[NXTSCT MW"E#$MH&GE315/DH+J9',#T"K( 5L#IBF Q8 2M@I;PXAK+M>< 5N )7R6$# M9;$*< 6NP%5R6!_+$+(+#E8I!CCT+8K0=[:#HXQ<;^IZ-&"$.B;Y&O ? M9H'/IBW)JQ+K53?EOZ_!JL(KIECRF&*I"9;_+X.=.P$H 6@ !2 M#J ]IJ MJ:N@ S !)L!4!>8 8 ),@%DX,-MM=;LKUQW,>N<%WKH!M;/QI1;W)=,-[VPV M[W"C]SKO$F;B3V'3JLP_)'Q]?.\;\*=*S??,IYO;*>=TM)@SEK7TZ:??> M;?3;14CB [4]C^OF?+V\C\/S%>,^\7QXONRNMUL:!GKG2PV7IAV8')5Q#M12 M9Z6WG[W$8?+3<]1;N7-M,SK/E?/$_&#"K^,3RY&+#H?F$W4,WN<(7#*\O[=L MBP;,Q^ 0[J?>_<9_A%;P,K>BYSZ/O-_VF,,461]?'L8 MIMS>O_'1&!GS(8Q)+IC!)G?,(RVM0?;QWM81G'?9T/%5Y(!KZ1*'^/H!P_[5 MMM>;ZHKHY6V[TDHLG'1G)U66H @GA9-FY:3*:LZC/PH_1(L.)ZVRDZ)%AY,6 MWDFW;M%1.6SE8=]O=JQ5KYSTC)<]%BR/*PEKI"HE6! TE6M:5![_= V@ #1$-[3YH V@01[65Y:E#1@ M0\EA:"NK 0,8 $/985"6DEX5&)#5O/*PK]10 ?HMH<.S*E@KMX9;D/?HLAPBSJ' Y1EV_$YT>Q4 MF ;,08$&T!#3H"XB!QI 0\EI0(E"L 65(>4 0-@ P5@P%Y:RL/&[G>U/5H MP AU3/(UX#_, I]-NZ17)12LJYGIAO>V6SF:/M8+CZI^,6RYQ;#B.IVEM[6@#G;2[6V=16NX]EDLAS\ MI_BC!70PH%Q0+B65*)1M=@SE@G)!N:!<>4UE-IKH=4&[H%W0KO)I5U/=4EDH M%Y0+R@7ERFL5)H0+P@7A@G"53+@4%@2"<-D+TXP_!Y0__LK?K_C[[S^'_OL' M2JKIQ[UYO0P'*=\Y?X'V^Y,K*"EUMQM[.S\5?@ M"#M?L_M/)Y<7>E/K_*O]V^W%";%,_@4U@O>C\XO^2&OJ@T'G_'+<&?6&EVWM M?-P>7 ZUR^[EX.0?K]Y;^AW<6A/FDR_LF5R[$_JVG*8.MRV'O7]D4KTUO?EN M <$VYTWZA>5P=0X^M 2 *AUC2/QP,J'>"W'O2?#(B"O-1VAL/L)?C?S^A7L. M8?PN3'+!##:Y8]Y+WHTGU@. M?R(W]*EC^@V.LVU33WP[?QY^>EO^E/TPV#0@4W&"V# 3-W0"_Z %3GWU(_OCX6@GG M]YU.<9BK:7MEHLL661+R9CZ=M%OO-@KU8I,1'ZCM>=P@Y^OE?EQI;K0L;R*? M^]PMFPB#%MAG._LH2X_,P);K>^)++71O/P.*P^2GYZB)OG-M,SI/W%^%MZGW MMA:\[;6W_9_\@G?BA]PD](&1\0_F&9;/R#?/,AB\\!B!K%P\;_OH0WY>.#=L MXH[7;$(MAS\&&?$C/3X,#:E-;IDW(:=\W"9&H;ZR%0WP4FCE&B\=/CQX[$%4 M";GBKF@YOF60?U,[W%HE47UEY6%?P\ /J"/NC=#@C7"2WM2RW]X' I"CX0HR M-=!K-+MZY@:J2N ?:!4H*I"QMQ5GEG*34Q5?9;3V61_;/D)EJM2 PW PW&YC MQAR-6'C#U7NE=A)F-!&[*6[_LB!]I].VNKS3Y5>>G1V*6K@%J%2XXO59#UN# M@(>C-QVP3ZWLL_40 #W];7KZ!1IM9M>?N72]>V:)W -1=)_]F%J>NN% @2Q8 M+&>LXQ3/J=9HM=55.JES?3EPET?68T6*/FJ]L[:Z%:.8] !:,!P,5PS#8=(C MGZ%0E48\OWC4"3#E4>:DZH*,:+1&OY/;IC%UZ6"!I^,NS#KF2$4[RV\3)O!4 M&YY@']@'\RJ%&4P4:$![_.4TZDHB%<>JQ7+0PVM)57 RIM?0.CE6XT+4&' 6 MJ+;@6V\#10=WD;V25R/46F?]C/;BWL6:M:A4"'VL_N10EGM[5=!HV>KW\ M.NQ5$2P051VB"ML#4K"!04%$1D0%,MHD'2(#D2F,?;+0@8A*[OALNQ6G&4_'0E/PWP_YOLSM$55 MVC*U>^SNN4'NINUVO]$7L3WO\)EZ9OIL8E\4>8FA[X>3Z+N=M]YM\3[+L-ML MGI^/6LWS3F_0TT?1UKN7YQHQGU_, MEUON/B=[==%XQ ([:S9=1X3':E?1 KS66RA#B0,\(\^T6<=ND< M=/Y^&OQ#LNUO= *3!JQ!0E_>$/_VW.;0O>=^X-KK,X]2++ZGUR;!I9M!2^( MQ>9(=5V*TNKYI:R4L!#T.S 'YM0SE]_6S6 .S($YP5SVV\W6@;EZK[J==K$K.*[ "5@6JS0BL@!6P E:(#:\X M[-KR?W]_[S%&+)%>(PHQ>C1@&,1C$+]I$'_65R8R=1C' Q6@ E2 "E!9C\KV M.;A !='A-^QW.5]42X/4.EB,M;.7)N5RA,(0FZIU^JS6\C,I;C49M76OE6MY*$P!M M7X,I-U?9]O[[6=Z^_+BTZ/MF]#_CB^^?Q^3J:N]'R/F6_SW\_'UX>_7U"QE^ MN2#_^C[\?'7YV]677\AP-/KZ_6 Y+UW/ MNQQ4IR3UI_8^KE66&]WWN-+<*![PC>/:J*UVE-IJIY9#^$&VZ&#NDE5>H2H[ M!XRC5MOTG-K4,>2\S#GC+:[#[W4^.H\KEW[CIW.Q-#6#^6)XY))'COB \X&9 M<[L&+AFYOBR]._]2+#AQ?&3&P2?S\,GA1,8DR/_Q P+FI 7R'BX(%\S!!6\] MZOBVC)>1H?F?T ]$, [.!^?+KY_4:D3JU\K"AV+Q M]M#%_I$T#HX3CQG,>A+!.#\3%\_1M&70AL(8J[JB"H^#Q\'CX''P.'@ MI]YPARXM[I=[)'%JA)['XBW,'->)/V8RD5)']T*(!?X#_X'_P'\*:Q_X#_P' M_E.8[G6!AGC9=;M_8]0C8\=D)EG8&W*7[:VP^"7#.$+Q%[]H@^SW5ZK*VA>$ ME0K4_$-C2J,QK3XD!A(#B8'$9"8QI[WLBY$LXY*=?12["NKD0W^@/UGJCZY# M?Z _T!_HSW'".*WLM^RMRABKWF7@U\2,=W&A>9V#BE6E50=257C!Y%UM:>@J MV[\/, "&DL-PVE<6Q\90#J14F10-^[Z"%)"RV4<&RLH;5Z6#A52O78?MNR3P M;,U1579'5 =8Y>-BB+WGT#Y5A2MU8R%P!:[ U6SHU&WFYE=U'E,!.D"7RMX8 M #I !^AR'9EAX,9'#-UW9>6N453NLN/>7EF,%[+/UQ,PK)Z#.@\7O:^C[ M+/ OPX ?/YRX_&7]*2\55]1=W+EEBRU7+D>#\];E>?>BU>D,NH-11],'T98K M@][H_/(\\RU7TAM:M 0P*MWB]E%4WA-%^/@+(-'V%WXXF5"/_\Z7=0Z9'U@3 M&C"3T)0Y"8OL2>Y>B#4S/J'"^L3@/W]PO1=9U&_)P_:Y3_YFEJ,H^YR(/Q+' M].%1U6WIRWWE?4[T82V'&]WCC4*9V#7E&+NFM+IY[]C0+,O6$GA /&#!;[38 M#XA=4[!KRE(SK]RF*WM;R!PX>%P-5UOE:LJ63<+5X&KK74UY]B1<#:ZVVM64 MA?/A:G"UM:ZV(@2%Q+9=I@%NJ,U\$0HVF.^+<<0^KEF7.9/LBUQ49PU0,:@85 PJ!A6# MBD'%H&)0,:@85*R4*J:N"")4#"H&%8.*0<5*K6(*2^"IJ%VW4!.//4R8$URS MJ3C(>5A10F^+4G?];K,];G>[S7&GIU^,6\UF7XM*W0W/!^UA._-2=VFN^E-E ME>[DQZ6%LS?C7WX=?[F](<,O%^27\==?KH??_N=J1*Z^7'Z]_G5X>_7URW*1 MN&VKLKU^DH4B?DUUCQ9-M3PRXD<>0+S$!?A)O- 0GD1"/R[E-W(G'+V7O_G$ M]1ZH$WL7M5._I3ZQ I_<"XZC0G^!RT]Z;S,C((_N<_H\A+]G^A"?^R[TN1%\ M<2E+K'GFI[5?&H0Z)K%FUV.FJ!?XP-P'CTX?+8.?^4$LN"7/_,,CF7KNDV7R M<[& GX'XKF&Y[Z>N;45ZQ+@+NQ-^%+\WYOF<&F%CXMX3-_1F-W!&;E.W^/K: M2V]T'X/[U@\EYR$WY]]]8D=W)I[AF\=\2SB)M-OHT6+W9/R#&6' A8)\O;^W M#.9](-]O&F3(;> WR+E'_[3L!OEU-!PUR#CTW"F+K#[T+2HO<$:^^\).XBW1 MJ,:F^/@06B9U#$;X.U[RGL;">S89?QT3;EV3?TT#[B'DD3M*L6S)']RC\LG$ MTQ?KWB*[1M4U(U.+]>8>?]M3-W)B3IG@3KXO):K3?JTZNF)!E3__8 6\M3:B M,XU&+QX&]ZY4L2I[,60TY6/./9 M"1G:OCO_G3B(NY$=HPL)Y1-R=PQ:!!XUET8^0.GR' M>,/BAZ'C,>[XHE%YX*]9-#*$=[C$DWG,EF^*'\-;*>N)2NT.^"OV>2=+G+N1 M/IP_(7\I_*V&7 X4.FQ<7#M^*[YGL+A9+"_V="MS]N,DX3?*5\-.:["Y8;&-%6R"J9T3> M+UN(A==[QZ^=]"&BSH)LP&U1]'E^E^FWS2^S\-ZB3H3X:N+*<]GLB?+;B=^Y M1(*WFUX$R&)7)^F-$'Y(7'8Z.3]W$GXYB__;JXL+;TPTX&P^;!]R8J(>D^C: M//#WZLB?V@)KXH1R2ZR4Y5EBULG49C^LX&6Q65UG,_ZXE#^L%WO.E(M!ZGGE M[^->$ALQ186CM0D=4^/5#@DOY$'[H6!>#G"$7C_SGUM M.^XUH;U@@@U_'2I&\?"R_RI2D7D7^IKQ=QE&HO[*=P6@D1,ENI3(L00M5OVX M5O;]O>@G"P]*ZWX:_J@5DJNWYLT,%Q8V#62Y[ 36QJRU$-\FS4G4XY9W<<^$ M.(@;%E=^YD_&WKOW]TL7OZ.V<&OQ6^Y3TREOKH6F<26U;?%+C[Y/'DS/>G6IYQ'W'<,6_/R-7XD(['QZ(U+!4,\;_=>9HI6G-7E5-ERV++]_+ M3%0L1VJ*5)R[>;,FWJ

M;'=[_597[_3450AO=0^L$*X/)Y\/S%?D^\7S'?+ZW M6OW9&;+8.7S5=/?Z.38ELXNKYU3B8=2V'=<,[V3%9M7S86I+:ZR]Q3=6@FE: ML9>"+?7UE5M5+NHAV[QE+#9<'PR!B[WA8E>I2 L\#!ZFWL/&/^* \(XZ]E;S M/H\+E+XZN7);BS034*R>8KC:*E=35E,%K@976^]JRLHDP-7@:FA X6J%<#4T MH' U-*!PM6JY&AI0N!H:4+C:8;:,KR)3G=87LRN 'V[=NJ)ZW@,U)7-K/HR6A0#V+])A,K4667Z>A)FS7JCW1^H MXJ8J>""UNL8\=-LZ> /X"'AH87V 3R A^BP4W7[82V_\>R&6XI[T#^!%)"R MB13E*QD!"D"I(BC*=KL&* "EPJ#HC78/8Q'P ![F8_,^> /X $\H#S'3KX2 M[7J;U22@4A,>D:AVH]M%[D[F!D";5#^TNHUF4]E@!F@!+:"5'-9I**S8"+2 M%M#"\C0 !L & #8 ,@ $P (:8(= "6H@9 BV@57JT$#/NGTL'P4/X"'AH:=NGT;P !Y*SL.ILL8!:WT M"D !* "EYJ!@]2A 2C;A:J4L8*A"'@H/0_=OK):-N !/)2>AYZ&T.VKY\3J MT96'C4//G3*L'EUO):VA#93UN"H_IXYT%:2K[(!66UU93J %M(#6'*U6NP>T M@!;0*FY)T(T6J7,0&\R!N3ESV:_% 7-@#LQAC2DZD@ LM\AB'V,TH 6T,HDL M8E-HH 6T$%DLV=1SE6:8A[Y%L<94'M;M*PL;5H4-I"G5EH9.!R7N00-H2&A M"BMH V9Q9U!!:@ %: "5( *4 $J*DX%8DV@ 30@U@0:0 -B35@>NI^GC%QO MZGHT8(0Z)OD:\!]FP<^=ZYG,2PRB37\0W[4MD_RE*?^KS+QY2]TBTGTM5A5@ MD:^21[Y*3;A46# =7()+<*F(2W4Y9L 26 )+52OQ=&71E(--AJ5Z@!;0;E5> M5=UB"$ +: %M'M"BH06S8+94S!Z_F<6@%5@"RU>'*:N("RR!90Y85@0[=;MZ MU+J'6N\UQ+=N0&URS9Z8$[)L=+S%==QTPSN;S83\8-*.9J^_YFXC]291/\?; M:#8SFE!:89BZ-/9HTZ$R4)FYRO0:6B^C+"^H#%0F3Y6)3RI^L3S*A03E8J\, M>D G[ZE(,+0;P@7N@BE:B+=-I65SQ_6ZM4.30$^8'\0'YV2%[,*-D?\@/Y M@?Q ?C;-ARE;>POY@?P44WX0.:I@Y*C=&'0SRFU#Y CB51CQ@CX5M>\D)M?: MZG:!P^0:5 9=I))(4"FZ2)U&?X#)M:P*,_T<4/[XJWZ?VXVEC&9;#GO_R*3^ M:7KSW<>4%0WF!,Q[\[*ILRQ(1Y/[N3R+Y7!5C#ZG+^.XWH3:"[1HXC>S$TL# M$8/9=OR;3R?-$_F9OWTC^;S"4+?6A/GD"WLFU^Z$+@GRA'H/EA/=) T#-_DB M4G_YS;-E!H\?!H.SMM;1F^UNK]_JZIW>N\1+N0?:=.JS#\D?'U][W?PIT@FN M,\]MM5=F,6^1(RMO[=.)/GBW$8I%/.,#M3V/Z^1\O;R/*\OS=4MRGU5_#U5_ M/OA9,>X3SW?,YWNK%9Z=(8MBJJN&H^O[O$IZ_?+3<]0YNW-M,SK/T/Q/Z ?, M)-\\%M ?9,1_Y5EW86"YSEN]SM_X9S+FW3Z37#"#3>Z8-Q_(MK3&#H.*^7,W M#USZF?%2LZ5>LO(W$:T;FK^/VQ%B)LIB)O"SF9]=B0OX[&'"KP0/R\##M+I[ MV/@'OX"SIYB]U23/Q]9',.\&7SVVP?6FNJ*P0!FNMM[5E&5$P]7453ZIIJLI M2^& JT'5T(#"U0KA:FA T8"B 2VOJT'5T(#"U=" PM6J[VI;-Z"EWI1/B0WE M8=]OR,WY]V/RF7%)T^(DJFYRG^+GR+>ZZM87HI!M8=2D<&T<-*:^&M-NJRNA M (V!QAS?<(4!"XUW(?VC3F"A\:YTXZVIVP@#$@.)@<1 8I8D!KT82 R&!^JY MRGXO'7 %KM!TU[?I;O4P/(#&0&.@,1E&.3N8/H#&0&.@,5EJ#,9*VQJ@#'N+ MJO.,H6,R?\>$JJTSX@\.+N1,25]9;[\J,""]M;XTZ,K:#-!0&QJR)>"(D:". MLH5.H*$V-%2U;="4[1P.& !#R6%05H(?+-2&A:IVD[0!8 ,:!BB$?0 -( & MT)#$DS!H V@07EF455H0'T#>=BY1_^T[*RFY+)+!,Z7'X4;2U5]0AM),SDT M/U7A2F\CXQ5@'3D 5L75*CI6FA;3/RH&5OU:+& %K("5\@ %L )6Z 8"*V!5 M/JQJUUH-P!6X E<9A .Q.!5@ :P,PH$ :UL#U&M%YJ^CX0@+,J/!$E*&=GU. MM"75I:&#E"'0@)4&,0TM)%>#!K0-\;J;/F #( A&EMC129@^/_9^];FMI$D MV\_W_@J$M_N..X)6X_UP;V\$GK.><=L>RYZ]\^D&2)8D3(, &P MJW_]S2H M?(B@0 H%"B1S8G?&DEA@5B+/R4=E56&<5'D&3!H0#.@9JJ2!WW(&H@'1<.IH M,#!K0#0@&NKR*IYW]VB>N".3#?,763HGN".S)>M6<$6[=P6@_[D\8"DJMS - M@87 &H#B!E(:XU@-0& AL-!CU<,05@@KA!7""F%U@K"ZN#"06X\QP@IAA=YJ MM74,[SU'8"&PAGP5#0(+@87 ZF&#S=D#Z[+V9-IY%.*>3#;,PN;J ^>)KN1L MP: B&! ,N-.@VFG [^AH1,/%H.%<70->%XM80"Q4I6#$ F(!HR3$ F(!_<)Z M+0F/<$$P(!BJ6A)NQD0P(!CJ6I**:-B<)V[&9,/<-)NG65@0(4RFPL<"/M@' M7L9I-B59K0!I_EW(TSB:"O\ALO^*!2E[E%K8@Z1!WZ2CZ^DM\&'W25"%H$ M[5% RZ\5&T&+H,7XE@LH,;Q%T*&G'):G5"U^QX.AJT34(FJ/XDI-?J>Y(&H1 MM8C:HQ1X^9V8CJA]0GF7M;OX2UJ$L6!/_[W("S(5/F6D"+\++GPPB\:+(DJ3 M/D#['(U51DL_L6VQ+]DN-)(T?J?-[#W)$^XFPMXZ1%(SDA29=T,0(NG"D?2" MZ'G![= C6>2]\HA(NG D7:1/*C5ERI+,;WD&\81X0CPAGA!/&.DAGA!/ \73 M1?HGK.8ADA!)6,U#)"&2AH,DK.8]>[_ZST4XCDG3YX\FV)K2XB@A;^X( Z,D MBS_^LJ;%"4D*DNW\VK6G;!BW");+GA(E -'RY_6O2=)L%L8;]B_1SRP?S!0D M3$@<5Y_Y]97XBOT,;W]2_]R@J"_1C.3"!W(O?$YGX18[S,+L-DI*(<-%D=:_ M**F(_>8^FA9W\&E01&678'-Q.,_)V_H?OSRVLY7<61,Q2'(C4O=8X&?"_/K* M,'YLA<$FWJJ!TC/':4?^OF./P_GQ^+Y=5KL<9>[RB,<^CJ.!L%;,8#W/-=!A M[*?[DM3&:3PMG_.93-)D$L512)M5A"(5WB63=$:$FRR=L4:6*%F M,+'.4YZ"01/##VO^=T5NOW>#YWZ\#>]8G)^N4B1)&X-;P@5A,HY0X7? M>?67@)23KMCUIS\ORN=I'M&EZ)_#R1^+J/PWUO!:;RGB=R[GN6=$6&G 2L/^ MUP7K_/JT$5@(+ 16#2Q^.XG.'5>G4,+K+R1\-YN'44;[E;""MTRV-)';D<^7 MD&UA7>)RH:)*6.U&J"!4]CK\F-LQJI< %:SA-0Y[#U&:D"8"? &(MXCR.Q:\ MI3?"E(R+7G*B2SGG6#+Q>LDA.,$!X?ATO>/%H%8V^-W/@ZA%U")JCX):&6\" M&684?4[!\J>,O*&W"DQ2O%5@_^Y?WL@\[Q-?L*2#.&H:)HU$"<].0B0ADCIW M7ZEX+N8A.,+*:>,P>SI]NW%$#XT*JR-ZTJTC>@IZ1,]("(LR<&0GE16I &^# M!9-I'--Q$3TXC>0%=D\^H7B=X[7FY]Z-@E46[/(Z(%7C=S$C @N!A<"J/9;" M;R7PW(%UV17&]R3/WPH?2"&0\B3'*!'(VF&.X?(PQU[PUE+Z/C'82>+1%@7. M!7U8,T$T[4*3A6!","&8N(#I>,O5YP(FK$(^'L9^VCHZ^+"*)#LTG&.H>8"I M*F"JTW1!"Z%=0-QS0M05Z#\<37FMYLZ_"Z6'.\MD?K7=9ROL7"@3:U3/#TR0 MR)#(NA"99O [IA>)#(GL'(CL"-T2E\%RIW"?LS0257[+B<_6YJ5UZ. M@9=U M2Z"B=[PE4+;.\I:Y<[]%#^>'\\/YX?R&*R?.[R7G=]AR"2Y(;@56DC3L%%N:1>48FU87'="72GJ6@B#_# S?6HLFA MR>UI'03&U@3AM-[7Q-;6"N%TWM?$T-'>C9FMI)!7(#\ZZ8 M;:"1#MXOHY&BD7;PZ+@SKW'8UVOAVOGZDDB_F!TEI[]AQ!J9*K]SYW$_R&#X M97 N$5GFBCH,VW!>\;,(<&?R:R\X% M'K@/Y6+Q8(Q,D]O1M(@'Q,/)XT'1N,55B ?$PXGC03*X[2)$-" :3AT-)K=> M3D0#HN'DT8"1$J(!T5!U^JO<+@5&-" :3AP-AHB1$J(!T5"MU1G<>H[.!0UX M4D;C,"<+_XSBOA;KN*KP!?&DCU2.ER.?^^HW=M@JJ!J).+6-<0#XJ%>(=40#8@&1$.%!CP$!M& :%BB M 7T#H@'14"T@BKA9!]& :*A\@X4;.1$-B(8*#1+ZAD?SQ(V)!'EH$M=X@'Q$.-!U/"C?Z( M!\1#%2^A6/YHF;.'B8+@]7 MI99,69+[MR\$& +LX@ FC0SL-D9H(;30=R' $& G!;#7_3<=;YO(H2IYL13^ M)\0<8HY_"1'W?"*N$%<8+"+ $&"G!#!^;1&(*\05XFH9$')K1#U[7%WVSD\W MS>9I%A9$").I\+& #_:"JS2;DJQ6B#3_+N1I'$V%_Q#9?TX.7A:W+4!MFCD7 MF&&#$Z)IYVJ7Q&_C!.()\73A>+)D?B5X1!.BZ;+1)&.HAV!",'$"$[]3?Q%, M"*8+!Q.&>0@F!!.G(@2_>[\03 BFRP:3@CD3@@G!Q,DS8JU--Z MPR'J/(+1(4$B02)!(D$>W,2J]E2H0WY$?D1^1'X\<7Z457ZG%" _(C\B/R(_ MGA4_6A@_(C\B/R(_(C]N#Y-'JL;O2%3D1^1'Y$?DQW/B1PWKC\B/R(_(C\B/ MS?QH<+MU#/GQ2?6M]5__7(2@EZ;/'TVP-:7%44+>W!'&I)(L_OC+FA8G)"E( MMO-KUYZR04(BV#][2I0 OY8_KW]-DF:S,-Y D40_LWPP4Y P(7%;75^(K M]C.\_4G]".^223H[Y)I)-#(TLD.-S/\^)TF^ MMY6="+_MSM&,YVG2V*G)?T%&)/B0@DP%CTS(;$PR09%&PG/L4GD!LVQ1]$L; MJBQ*W)J7D +1U)XV-6YU?#0U-+6G38W;_1MH:D,SM?U+S0.PPX%Y5VYE>C32 M,S+2@?EE-%(TT@X>'4]):ASV]5JX=KZ^)-(OYNR0TS\:!"^(Q.ZI8SI&Y!KD M&N0:Y!KD&N0:Y!KD&N0:Y)I3YQI9Q\N*D6.08Y!C>N08D]_9,\@QR#'(,<@Q M6QS#\5+X<^>8P]>>SFF)R4ZF)#]PE6FUIZIE2;3GIF#>J#&XW;MV+MC 3JN+ M!8.)8$ P(!C*80J" <& 8"B'21JWYD-$ Z+AU-&@YL9A3A;^&<5]59ZXJO %\21;_ X*._="+BX6'<$?G0VP5 06 @N!Q1]8 M$BX](K 06/QKT.BQ$%@(K!Z I?"[3!B!A05@AK!!6 M+U@F0U@AK!!6W _'X'8]#^(*<86XJH=9W&H5B"O$%>*J'F;B-H3^BH/G5 .T M\RC$WK.R(L'O[KMSP08N(UTL&K@5$A +B(43QP+V82(6$ M59H%!$H(!P5 % M20@&! ." ?=N8=_9 8;BIMD\S<*""&$R%3X6\,$^X--V)?FYU'KY+?D_5V'G M@E=<8CG&$LN%P/+_]'!S)P(4 8H 18 B0!&@YP]01>%W@@X"$X&)P.0%3 N! MBVP753I!BDF ,.U^TIT$&*08I!BD&**7Z1#:08I!BD&*28 M_G:FU<<)>3-'6%4(LGBC[^L371"DH)D.T5>>\H&"D6P)_:4* &" M*7]>_YHDS69AO&&5$OW,\L%L#L*$Q''UF5]?B:_8S_"")O7/#4K^$LU(+GP@ M]\+G=!9N<=LLS&ZCI!0R7!1I_8N22-EO[J-I'\^ON^P]HP,#K?J*U@Q7B>ON@P]M-] M&:V,TWA:/N==\HWDQ0R^)Q>BA&TZM*??PF0",4>1"O;-311'84%R3 [1_/B; MG__'(BH>5EJ,DM6__3!+0/9\]9O7[],\)_E/S\@AALR/N],P[OK^%V1C@@\I MS%3PR(3,QB03%&DD/,=ZE1][V.)S>A#9S.H&>A-YU<2Y]"+@'O: MA$[%P]].VC>#LZ[VXH((+*OOCBIN;0EPAKA!7JRW1.@(+@87 XG[BIXBX0EPA MKGCCZK7,[42;5I6L;.10G;Q8EK[W?:,(.@3=_J!#S/' W&5WN-EY%&*'6QD< M6G@LVX'S1+=SQFC -2A$ Z*A0@._BARB =%PXFC (PH1"X@%WB5E! ." <%P M9F# OK7&86Z:S=,L+(@0)E/A8P$?[ ,^;;>DGTLI6.+7+_!"2X0EPA)A.318RJ:%P$1@(C"'!DQ^_>0(2X0EPI)7IQ&W@G]GC9US)Q)B M%C'+#[,R@O88H+WL]L$O:1'&_=B9 G8V31?CF"P-[3F:JQY*/[%MN<-0(K^; MI?=5X)'UQ9O;=([[>-I4=@3[&7ZV@ $&,A3*+A==HS,AQ=F$B<2%Q(7$A<9T8<7$\$ B) M*]Y89ORY"&'Z39\_FF!K2HNCA+RY(XS[)%G\<<. 3;!6IM4H 6XKWBK4?'FJ M]A%:;N#[WGRT&U!O&3:/OWY^3*%.36&,WGM7+7,Y\T#< 7X4$SQ=R5\)M]( MLB!"E L9U0^%''R 8K$"-/WQ_BX"C$8%_1A@,X$/E:\J)\ $84;:!\,O']@G MXW1"6>#JV?2WYD0FP$0DV\EW:T_9B)K$1Z1)?U[_FH026[S!LQ+]S/+!)2%. M2!Q7G_GUE?B*_0S.;U+_W/!BOD0SD@L?R+WP.9V%6['H+,QNHZ04,EP4:?V+ M,O!EO[F/IL4=?!H44;EE,/4XG.?D;?V/7QZ[V97(2MF/]V7'GR MQ]1)_U_P_UA$\QD(,!(24CRC!#%DNMM=Q3&>IV%CIX;_!=F&X+-"0)VI"31! M>XZY*B]@KBV*?FD#;LQSD1D[,^,P3&W_LNT [)#;QM1CZPZ-]'*,E-LM=TB6 M0[/#H9D:^F4TM:&YWF?E)P/:4\U%C6S8UR2B*YG715B0?$M]^S]07Y)"!=J,\8V!+(8LABR&+/9\%M.5GO:0(HLA MBR&+(8L=@<7,D8BQ&+(8LABRV FSF#$R^"T87CR+7?8ID!_2Y,W7J^NKMP?8 MT]ZK7L=9U3HM;D??A_:#]H/V@_:#]C-0_:#]H/T\6S^GWLK37ZCM9.&?T2$G MKN]_,<*97'R@CG2=WW68YYZXGA"HAD51EP@M?22*_ XD0V@AM!!:U3!MQ+&I M'J&%T$)HK;I.9!,#0H060JN'7,O@>-#CN4/KLA<)W;LH/N2@D[W!=&*8D4:: MS&WA_5R@@07C"\:#+G,[7@'Q@'@X>3QH.K%!'FL4M?4<\(!Y. M'@^B)",>NJ36PRME]9=V^[%P'<;?PFF:827KB79X!4O$O2L O=+E +SB^3.A>48!G\8M%@BH@&1 .B@7N5#=& :#AQ-!@F M-E@B&A -%1HP4NJ>70^HD,7/,ER8R6PF)CIL;O]HAS+UIA-1BKP0< M"QL#$%@(+/[ XK>]#(&%P$)@+3NO5>P116 AL/@#B^.M,.<.K%-H#.!G&9_N MHCB:SZ.DX1[3RZODJ2)NA#MPGNA.SA<-FH1H0#0@&DHT\+OE&-& :#AQ-'#< MSHEH0#2<.AKX+;6<"QI.N@.@O\9[.[LE21$EV!+PU#X6"P]![UT!Z(XN#UBJ MCBN7""P$%O^6 !5/:49@(;#X']9IH<="8"&PN -+EK$[M+]:QCF5++XF44&F MPM]!MFDZPVK?+PH>EXNU;ZQ]UZF/@GM!$0V(AGK3#;>SS1 -B(831X-D80<9 MH@'14.4-> U3]\QZ0$6L_E+NW\CW:))B^>H)+/$[@>;LRU=8%\:Z\ %;Q? , M6006 JN'S0\6*UOOY*%LXBO@VS M?HXZ/#'<*";N!CIPGNA>SA8-JL0M[T$T(!I.'0W\VBX1#8B&$T>#-)(U;EL] M$0^(AY/'@\KO-/1SP0/V"#0.^[2 B:?"9VP4:+D3$_>Y]*X =$D7""P5;W%& M8"&P>F@316 AL!!8_/?FX+%2""P$5A^;WKAM\SE[8%WV60*?PB2<88] \8N, MITECW1OKWC4:^)U+B&A -)PZ&C3LF$$T(!KJ-5&17T$,\8!X.'T\\+O-[USP M<-(] OQLXV]I-@T3+%4]$5OAJB76@(?D? MW!$V94D6?UQ[BC8OV$->RS\Q6>!!![+AN58793S-_=!YHHL[6S24RC!E2>9F M+8@*1 6B E&!J#@S5."Y'H@%Q,+R' .\^:-[JC^@JEI_6P+^'OX9_GZ7%]BW M\"2B-+Q@NG<%H$>Z0&#IN'<-@87 ZL%CX;'L""P$5@\-00@L!!8"BW\%3T1@ M]5?,.*>:Q746">_#Y'<\R:#X1>56F#@7;&#A^V+!((EXK >B =%0#M.PEPS! M@&# KAE$!:)BQQV#B(6NB?6 :EC\[,(-9R1+T^V>@/V?Q7FK@-+[5H%SJ:/U MX.G.OIZ&A6HL5"/ $& (, 08 @P!A@!#@"' $& (L"&77DZYPO+U]RR,$C*< M HN*9S'@B@&G>:++0U0@*A 5B I$!:("48&H0%0@*A 5?$L PRN\\3.2CP7\ M2?B0)F^^7EU?"<,I$VC]]V&DV91D]4N1YM^%/(VCJ? ?(OO/V=0(^>UV>J[" MSH4V3H@A3M?+7@PLN?5$(BX1EXA+;JW*_ Z*05PB+A&7O/9<6HA+Q"7B!)TDC1CU;<.1>0X8(( FH7H)21 M(AW-G2&@$%#G#BAY)',\=Q8@%+YW;RWO,U=BZD MAHLBSP\?D,F0R3H%83PO.T F0R9#)D,F>PDFTT8FOQLQD@LED M>61*&),ADR&3(9.=-I-I(TG#F*R/XO_/10A3;_S\VK_9AX0)B>/*2'Y]);YB M/X,&)O7/U2S6[4H%(UJ?U9=H1G+A [D7/J>S,/E%V#6]ID6)^VA:W+V5S'T, M<],>]O_PP>LBA]C$$YMF#9C\!LWI=):'&XG!=PNO]/06WF?*U0G%5/1.2M^- M3.-YP%P.\[]/XL44##PCWTBR($)ZTV4[]O*Y/\@"?"2..AVROWR:$"938=O_ M/.-)LL)5KILT$XH[(CP K>4"2:9DRD5]'IF0V9ADJ\A%D4:"+$HJ-W5RT:8H M;:\%/>,Y(S"_?$XF1?2-Q _TIS@L0)5%*KAI,DT3)O%OT?3-_Y"\$/XG2J8C MX?XNFMP)84;@XS M ] 6?3A;*V=?=EW _\Q(4N04!!^7(_?N"M_IHP[R1>A[3M?WR)N^AU_:,6 / M\BFC("L M?,XA-%LUO3_!?+'(II30%%8 J1J4A,J+M, DY7WH ML+,L3&Y+.N##<)3$A%DZC6XB()N,%%E:4YXP#O,HK[3TMS!9A-F#4.GH2K@F M!)10$"Z,O9V2/ 41UVE"XCIIB/(GQ,NY+W.UG^/R+<4J 32@-N4N9G/T;)^^D*LUF'_1'885*\5<2-*+_[8OL7>-UYJ3DPD4IU\)!L,2E MT\(BKTJN;FD1?X$7G]V&2?0G>_%AO/99,*P(#..&]A:POU)CK.Q.N$OOUY\C M@';"V^K9XT4.2LCI5T7P>C)X+$W)J"^/EM\'UC=^$&Y)>IN%<[!J>/(M,]K2 MQ.=9^BV:PK-( 4\0\G02I6_F\/9+=B3PXM,9C +92)87\&PZ43#B=)$M!;@2 MOJR)^/B[.^!TI? \^L[E.<*U\S47XE(R.H=/D,]&4U9"![VY=Q&Y$?SO9+)@ M9>./-S?1A&1OA:_7(\$&'>0CP]\U+>V "&LOH2V$-Z1D.XKSXM\+4-(T@*\8P:,%3\ H5$: M88[O/BKNF%VO> M.5DZ<[I6P<58MEP41V-9NJB:39@[LJ?_7N1T0I^^N+73F6<16_JIV0C>$EN3 MH;J9D9!<; X'HX&4G;_YJVY_J3XPHY4_)#6,KH-5U'@OI=Y B_$[?53H# M]6;I3*BB*.9*5H81%D46C1>E/0 Z;?]:("SZI1]<)!D!PZ=.Y19>,W4R L0U M.8N,ET$<>*GH6\BX&P*Y)(?0A#Y[M#X<9@@O!=[J N@@F3P\?MYHZPNF"R80 MQ'_S-(\J:<$8P\D?BZC^!=AU[1!+&R2 D=&C1] EV"BK+#VI@53]D2H.PF

FVJX9),U MF>Y":I @R"U884%?3KT6_UAW8#6+>$,%+?_J2D95RZOYJ(.Z]Q#Z$D@,5F'[S/$[#N-<]#Y:[ 57W^2GA'O^C@X04[A'.RGI,N M#>W)%+0UO6S,%S<3S!AL[[9J.( 8VIY2E$#^PVC:_SXG"4#D\(S34W51T57/ MLC71$&U/MC2_S#@MU7=4]64S3MZQWWWYQ>,TGE8='/X'_[/]7K _>(+M_?;N MP[OK+Y_M+^_^Z0O^__WD?[@&[\DE%EP/!=?;1L*-]PB *E]D#4\:;:_%;27\ MEA]:<]FKST%^"6BZ6223E8N%KR@B]@T IS)"OZ[\NF/ MH^#5-)W2L*O\ MTBH48N*\H3Y*N(%06: AY#(\I0V/X.UH9!Z%XRBF/T"H7F0+!J(HSVEIM@I> M <3I;5F&8JV!U+RIQM_0UUYU!-*,ECTY(V4H3UUMV:L(TD?I="0DA(47,$\@ MGZ+,'VY(1&MWCRI?+,T*!2<.)[^_N9[X[KJ3X1\=YK[#V__'UW9=_'2M0EWC/9Z/JM&.&)2R_ M; 7='R#?@A%9ROQ-&;S2M)BG,AXOO?65M>PHP97E8.$S62_P\V?L=PEK5GZ< MSM(TEZU.E43,EA2J"CTMGX!P.; DA$B4J6A"OWI%5090)O!)2I.?Y);Q3WH/ M<4%^%\TIT5;OKV0Z+M/Z0>;1C+%6K%SUM1=TCI636)_J?;CA#F#"X3)L$^9A M-'U#JWSAG+[8EE[D(:Q![3!%%L_Q-[V/">#X6[FQ0#)'#78(624U02[?K/[( MQR@@F?B=5A$8#DK-7%_95\+K5^R'5S_!#+)T<7O'O"J7[[2L*XN3]!2"$%$M MQGDTC6B%EM::LIPQJQL"5&\7(09MV7.S3F&?D6I8L\?JA#.F"Z&4W8: S#/E*^49H^+LO^$% 5BPK3 MJ])<%0S2O"XLOX25:]Y0W18L-*6%81J.03!V)?S/7127,1G[[)1,X,\T//U4 MU@-7W%B7C*5P+W>4;9$MTJVAA M52M>JKJNABUQ4=K.-+JY(;26WW5W[;J34ODZJ3$I[FF!;COE8%R7!&%YKI"DQ9SJ"_^^"^8X7MNL!ZF"/\D-:K-W1% MI%X0:7@(%;-:X*$ESRJT6'KD-:$Y>->V0/CE8L&_I=DTY&0OCSSP;V$&KY0Z MWFWW6Q;#6.(KA+<9*:O5 *R4*BV7 M7^#OU+C6.>(Q,U0??_?IDPHVF[^YB>@*5;EODI]OY+)I9O6\1PYP%=4#Q@,R MSLK=BF7DI?/9KKCZ4.<\BUNE YP/OHOS3JY]&'$E25OFF^:.RI 3L7I54 M:4&4O1KF]U9A#">.5RW.58JD?@-UXDGIG/Z:?*]J+U3YG-)HR;C2>4&A*JBP MC)JN0 LVF$]<09["N'H/O##\@RQQ#KZK*'OHEE$O1*Y7YJA^_\*"@C%KL*I> MQGK@4YM5"DD&GSG*ZI7%B7FNA*]SMHI$+:1NBLW(+"Q;96AB'Q5UIQ.GTH7" MNW11O81'NL_7E'\/WU>U67 *RWBI_Q1K[6R<_3B3)/GCKCX^]F)R9AN:B^Q. MV(5[PO;4+?-GEC'3#+HN-K'E069JF^N+(>UY71](854-X08>Q>!9:RWC)F+L!/='?&-&=-QFN-,11C9$8[:B#JKGB9E:5JO=2KZ#>K\#RB;Z!N MN%QKA7/*?CWA^HX06H[F,I\/*1\+.ZCR5JS7$6C)>ZU-MPP/]JF!VW1)9Y5M ME\7#LFV2@IDU115D!4^*X>6+8D?*T9B0><3QXVZF709>-2O.">T780U1U3ME M74\; JS5.INL@'UO.IDL,GC9= 7AACWD_HZU#E,S @L;EUU=-%M;@V[QH4G@I[4&;@%/[3.:+,?R^EXK%\HPT>D:+X.=%1N(X M9";R'B8;"G^%Y&S.RNK+5:2J+8J>_SNO*XT-XK+M !FO+,CDE+WM="G)1DLC MR9^8&;^J@,GC6)]]5A6KLQZ\B)VT M1]>2LDE$V8YM2HXR8(H)[6JNBF[L\,AS!X]D]D-2[ "!1;77N+$/(LHWBC^[ MW]-=^(UMO*UJ#KS">FY0XN!U3C.Z*:=_M-J%S+D6R6TG]P^\J__[M$()15T2L8/SCKTCNCHSJ:39R$(>[>%=RT3HF0>[ MZLWOH3UEMU%<32?TX_Q7,A4 M-=XY"TSWWW37ZEK[8KT,SC:*D/62QU5I-/#*I4:C6;6+,(16IENRRSI%4F9; ME@$GB]DB+C>14=X"PYH0,N58:545'N=+K2NMW%=(@PE.GI/O6UVKSPJ+>5H? M"747D6_+C?SUR][LU2?TD)F()/2$[;+@_[AUO:%LU.X\/NR(P#@NL_&M %=K M 1L=A\G:1.LN#):#\.?"'^1CUB8>K0%-2U-@>[7OHFPJ_+$(LZ(\VX!"OK2+ MJBY>E_B7J%W;35N5_DM+G*QM#)^2&Y)!^''"4;7-@IV*[];T4(8^:YRX<@M5 MRR"7]ZE)O'(CTMA''B4K]@8HK";!RM+K 5NYY[G<5\W.3RD7CUB;8U7WXA,> M\)IQZ>4AKO3IB21T*V3Q4&TF+R\8*(/2VJ6]CV9146WD'%0M=3D/JNYWY3$G M5781E'O/EZ%VD/Y7[-G;4*5CJ5#F#?+G*6VX) MIG^;1G0);/JVFPK+3@JZ[Y9D.W6X]I2-(UG%1W1+?U[_FH2VLL8;#"V)Z\>X M4[>UO_8ZC59 MR;U^$N[RG%9KX_S6Y>MH/TN7R?+K*\/\\$ MXJ6]J)\6_2S%-5X]K:O-&V>E^7>!^?).]QLW4F#S_;-;3J?#?;SLIZU# =9K MJ_LJ$%&)J.P5ET"J'1SFN7/B3F4/PP*W[Q_IRZCV#7;W5P4S.8ZZ4$2]=VWP M>>L

4TXYBA'Y]83H]#7BF'P-I/5*^^OSLB9''Y"J"!46FSD_SQQSN\SK>6BHXO+ M*%*\>U:!8KDG$HL4 R>QMEZF<\FU>F"_9ZON7&@3 8H Y090;F'\Q<,2U]'I MRLH!6P8Q><+DJ:W.H.W=_HQE!D3*,0. 9W40EL]D.XNW'OB22XW\.G+;HH"] M-7!ID<" HO;^F,RMKFUA4<'A9Q(<]CZPZ:[[H=L; M-Z=7)\E)^KS'$[;9;[:.AK GU9'$,/&/3&OTT,2,W)$DIZ<4OT_SIW/@YTY6 MD?E-EHVCV7YYGRL[1-#^Z+ZG)T;28TO3A%TBO#K)GI4!#CJ"L(-M,A$KMU9Y M+J:(*9E458FWE)K+63P 50L$5#3M^HV=^>4@N7=?/\-G'NS@WC"O3JC,\0#( MP1P *>D=3X!4]6.?D'CT+SSVN),1]+GCQ%,1])GCCF.A>.S?Q9\UUB%O:PXH M@S2#7ZW=$#)90%1-C\1G,79<+<,L[]D8K3X)\1FOB@,:*1KI$T;Z-:%7=D3L M!@@8]*V\D85>,$5W8*$=HAT>RPYO%C37$^8TW:9EBC%\5(?$>"(&V=/) MT-RM[0N]LG)?11T6&]("[8 6\?I;7ZKOK*\N,!\32+#I;>S+NX'8514OB58\ M7ZZWADSN?:GR2+/XK;*U*>22>U8'1$Z#>8=DJ^5D6P.-'HZ 3O;F]D.+T6]P'[HS:]\W.WTAOV& MG^[*5JW)1JO6:[I^\5.]&6I,;M+RKNLXS//HAEZ<2LO*SRF4GMMV8-W _<"X M'QAWSN^SYZP-WP*]1X^.3Q@P,L5B.7(9?QYS+5 M?'%E(84AA2&%(84]5U<]G=F$#(8,UD?IYEQ.^-:X573.'E<=UZM?I&@SL.7K MH111AWK4[HLO89]3?PFN5"#(&I-E?C?G7L(Q=@@CA%%CPB8AC!!&"*/.(9_T MLHOJYQ3RX8K[CIL5RL,@:3X&T**>QX%(:M1,AER&7(9[^'\_/C M$^>$=,':2-B-G/5]FF6J2^_:G-+/D>GC&QZ%UVO7-]CT>_ MO$\[E?L>S1.1$^?WDO,[D5L;CWJUD4>*,(ISP1Z#L\%(^SB+:J@?U,^^F9HD MO<#M?UUN7^N01NRBJ/*&=$&11L](,?9M4S_^)8H=_(#^/"7K.Y7,<@PWG*?0_YX>JG=P69K7Z*UBY'AE1X]8,+F2Y5 M6[CQJ.L"?J8W)4,B?;/Z]4?(H \^T1V-?$]W=?IWU7+W7[(H<3\,'$T-3:W9 MU'I:TOM2OL4N_Q[X^^6FM\EM0*7^BGWX;%?#PR0XM M!VD&OTJ$R2++2#)Y$(HL3/*8Q3="./WW(B]H!#02.-Z$CKW4/!CA98UV<(H; MC++0XB[!XDYD*6!82D/]G)I^^FOV^&L8)0+$&'D8$]JC,%[D44+RG&!59<#6 M- S;X;;!JK\9G\">SW/9]X0\@#QP,3S K3J'Z$?T(_I/#/VON5W!\*P>\F&\ M]YZ.&L12$=;8+EUQ_$#Z@10"O59 N,G2F3"-\GD*F;X0)E,AFLW#**O[*NC? M)BD]UW)!ID+*O;=B0-H=G%E>W%4J?9R<=.['BB# $& '[(3D=\UAFTK..71% MT"'H#CG, T'W4ODB @[UEJ[+0LZH6/WCC]>O#>"CRRODXA&VY3'5XDA0R&#(8,QBOSP>/1!E.3 M0%9#5D-6X\)J!K+:2Q=]<.M8V]:QKTE&X,]_DJD UA!]*R\OO VC)"^OE"?Y M3[AO#'?Q#%MQ@U$66MPE6!RN,9Q%#1WU\U*!W89.16WI7,@0>&?E&D@6W M>Y#1D+!9_&R:Q55N)Y)C71[AC_ _,?@K(L(?X8_POU#XO^;F_;'U;P"%C;,B M$E3OK>B2,8=+N .I+:%^3C/!>T>/CB>0UI'O#HIGDZ* .OU^'P)O1JN@ TS:T']#$T__2&M^=;=<,)NW=T\ M0>%TU3LUM<6U?Q9QS)(E 0Z#M M IJ.0,.EN\'"$A5WYHKKL_^1'9G/;D:KKCX#,=?N/A/&Y 8R1*$(OY.V!F")W'I,SJ8>>+26 MR8NN%B)F$;/\,,OMQ'/$+&(6,7M>39X7C5EBXE2NK4 M1XH[!8K#P.T4# Q9[>!E?ADCMQ=O$E@*;NPJ)<+TCUJ,/9;^RI_HI]]&!3Q\ M4O[FGC"QQFD\+9]LSU+0QY\L^Z>[-J?D)DK(5!B3!/Y5"/3\&OJG<%(LPBP* M8X'>:C$2$E)@+?R(M7#EF+7PPVUX<(H;C++0XB[!XG!=XBSJ[JB?EPKU/I/; M11P6A!)07M!(A%Z3C)MT!FQ*PS <;IEI?S/F?[0%MU/=+Z&#'+D!N>%RN$'A M=H8&<@-R W+#.7&#@=R .\\&RB2HN--77(_'3*;)FZS?$L& ]#@X [RXEOS^ M+W ZEXY\A!7":O\(%*\CQ ,<$7/'Q1Q>BX8', XT=T']#$T__2'MKR0A61BS MR[##Z2Q*HKR@N\Z^D?J:-%SM?0DWUW+J[JEYNZ,=^W\)3@^!AD#;M7^,*I"%"IN<.E?ZWG\PIC^5>WG OKUS*K[GVHNNE)P2Z89^R<7D(5/H_OQ41."@$HMMCO]I_2_Z1 M$6D,%)&7<(8!EHJPE'9&^ND]PX3\L5Y0/%TM#[C'M VAN0H+$STGB M0L))@ Z7\H:%0*7_JZT0@8-"(+J]%P>=UO_N]4L '2[(G<6"$^KG6%D>O6N. MG@Y?YGG3*)^G>;7A+YK-PRB;D:1@/9SPMRH-)-,>LD TLHNMB^*V)%QM0%0- M]S@DQ!)BZ;*QA!X*E_"&@D%4W)DKCF]R5R[CG:&:!F=?N/_@)!;RSFG_ <(5 MXFIN2IW'_Q M'%5>;+'WA(ASV!LFD46115^FX40,+'&:3PMG_PEA;\*&9G$89Y' M-Z" :+^5,*_ M0>UXT?BS7,$;_7L3RFG6818A2(-3QR&8@=%5+THC']HS'$;2R\\=@IV M=\(LAT'625@8,MOAS,;Q@B!DM@.R^Y_9.G_CY]?^O28^)*SDS5V9#DNR^..: M(,;SY%\.^W]/_>?)N97-"A,2Q]6K^_65^(K]#"]B4O]<2;/^ME5XM>O2?8EF M)!<^D'OAJN ^K;QKT_A\^K$D*IGB(:;:\VPV^ MEG0ZS0YOFP[+%_,GRDA/B*/-BXHX2J.'!W%V8E2 3KK;C?.N.+%GZ8*>@Q8E MPCS,2%+T#$6$*1E'\.TN@Y>$RR0:1EF#E,J39)33+1O'=!-9[,T ;VFD]\%+_H6 M@2337-A2Y_-#,G;0"^O"@N\"^WN EQY-A>GRN^!%5497>@2)+EPG21T<]1>[V)LKP8"3F9I,ET M!+^*LBDKFMZDBZRX$_Y8A%E!Q\"\95'26,EUI8TI++W)X=WF^\1RY?$Q/ M[_\ER$FX9B"BD_MX/>L%[;.7&"G MOX7PELQU$_W$_-:2T< 2YS&A#BI,A 4H++N'9Q0U M?EZO?F)7N\_G6?H]FH&3 _OF,A==%. S<5/7Z[-4PRR4V>9C+A3&#TPW M7TB6T14EX5WRC>3%K%34LOFVFO@U*=>.KE [7XSS:!I1E=5K3*!7 M>+9[%R7AKH<"0D(!^'%"^!& I%PUW(7>C0&NP)*9E@;\$LS'XG!6,$+M\@]R$PZ)-DWP@3>DQ_K)EJ6N-EDTNN6*CTB%^F$5US M+:@[(-$W(M#?I:4= 6%,")E69P[3WVQ0)?U% ]0$D$"X6<3 ,DRC%,L0[?Q. M:-A!N^77@7VU3KCW$<0P$-3D2R8;42]T $72/Z[44,]CD&_P";);JKM)NVML MM/+]/'E)W+Y*\#F/&K'@$WQ6>'N;D5N:?"W?"V#]V RQK@Y]54RCB@FAC$/]04%W/Z'&J0\#ZH8P]C3O:GBIQRP\J(R^B\ MGE1>TUCS]$?"F#)EG2).%K-%#''+-ZHUVH=#0[^55M&=VL$ ML/:194A!%4.2"2MTUL12:P7BL[KV(\(?LG1Q>[J-ER%(JG:E]V() M+/SHY25+5V9-3)RP1NT1'-,WDH6WI,?H3KYJN#3L64I^#F[)< V=V4UJE9)>XM;3$\"@UP>0_[SH6NP' B+WA# M0X^4%N!**B3H0HK'1BBA6&069S>/T@1 6T)NHD*8QR$][@U> M-M XO4FJC" V7OC5QM(;A6I92"HBMIR2/.S&-< 37!Q\SYC<@N?;%86TK+U6 M__[/GQ?YF]LPG+]=*Y3D_A^+J'CXD!;$BW*ZO+'(R!=X"4X,G_FO__V__G,Y M:#'.R1\+(#?_&UW^77Z(%8GAA\_DYM=7@4>MZQ_JO[YXKX1H"K\()\4;PPP" MRY54SQ)=6=%<0]94R?%5*P@[M+.NOEFS*28;2\G;6M5FZ5U0HPG\!"4Z^VMR'R>#%] M)FS6R29LTO:A(\=*V+:,B%=V).MJ']E1OI8<;6=#PC6$-S0DXD1 B>3,#GW:*!'6/,(P;9'Z#OBV\;\:K%7C]9YGGWZ9/:2XBX:CXW]^>< M<->Y+[0<3)G_;VDVA5?&I+X-\S3>2?9W3F+:<@M^4LZ"1F84)K M(_1OY04RI&PJI:_LJAP'6(/8(\V*[9( M5P-L4=2T0!&/MAIPE(5;^OI"QJB@J#@*UPU\3&ZC)*D[A4D9L875YCSXS")9 M,O&4'?U4K3NQG7L5!!^?&+7:QC=]^VS676O_FK!L=1\];^SN%!_IE?Z\_C4) M=9#QQJN0Q/4-H0?MR#W 0L"*0>FED.&B2.M?E)NYV6_*;;B2"(JH=FU/@&_# M>4[>UO_8:I!;R=UXVIFD-!Y&ML>^7";,KZ]TX\<#MP17 Z4CCS-/1$Z+U#L*G'3@>,'. ?MK/FVP\]6/[_,VC'TFYY7BYFUQCO0Q- M#4VM%U/C=I$AFAJ:VM.FMO.0=AZ&15T:7UGI=@LO MGIU_W&/QN!Z-/PR#XW?@78?#[0=RE)UB<0O*>G[K', 1]WPV+G(,<@QR3 /' M\+ND#3D&.08Y!CGF\3#5P#BFOSSTG-)-N^J<*9TV,G:6DY+\)B M4;!_QM$L*D*N>^,&I,O3):BV4Y?.)1GG6'3NJK%S9D3$+&*68X++;X\!@A9! MBZ ]RDH3@G:8N<H94\Q: MMODSN^ZL\?,-_UZ_NV^_:_F>OLK/_PZ33;S#7^W6]W<_0CGS+FZSB=6U[NC?VT]8M,W];0R>&E"\1 M4A[E,J/]#:[_BXW 40O_8A[F>N55UEQW?T7N :U5]7CT7W9+W782^.I4%OX9Q>AKCX/!OR:1 69 M"G\'V:;I[ Q)_[1 .B#%G?CBR1F"]+H("Y(+KP,R)5D8XT%!Z#F?ASWIN=CC MUU/34,Q^W&KP\MVW8]?/WRY%NP/GO#AXQ?_6OCL MN_Z[?]K.>Y_]TG[__N/_V!]<7P@^?A:\CU^=+\'7]\)RX):9/!^4[(Q5H7Z9 MK#&$AA+,4(/DGH9VQ>7$ET(YI-YT!=!Z$.7Q= M.J5XC1^$,,\)_3_6!4V;;LD$C!6RC(+U4H?UEZZ^:D2M)X^ 2^'U"#=@+&F6 M"_EB<@%B:3:DZA9"V MDK,-U_1*++K'H;A9Q*OO91=EP6-(7D2SD/J415*+S829T<_1Z8?S>9;.LP@^ M="6X0(MAQ.:?+K)E/SDH>W(79C"WB'(4/%2 N3=-DD1LAA#6T'F"?62@[07H M#(;-<@&DNH>_D_)Q]&TL'\AZXB<+4#+KBE^VLL_I$Z()"/RIZX* K<*SPCQ-8%+, MXA89F;9])2@31+NK?@L:(5,J-%!&-*5"A*UPN =4%83*=$/UQ&1]8'])4B%. MDUM0ZI20&0/)\F5>/@8D<'0I25P'>L(' L MT;,\JZ;BP+7$,Z?BK]>^\#$0_.LO[WZS*1%S9U9*CO.,S,-LR5?P,G/"B([V M-3/(WX#?3281F!X]]ZT\QIAN!H$/ 3_,*&'> UYKPZ1P!"* $?,8WL M26CP M2>T?4I,Y?6"U]60S2H7OMF>$,J/P^M5?;?O3JY_ KO]81%G%T36+%ZDP"W]? M<5()! JNV;S04/J< M+ICO68UARF9N[0K\)*-($'T1%Q1?BYA."/20"3=9.H-A:;ZF-V 5$"A?WR#$ M*&RW8N&EQHLI>5M.$YSN _W^V@E005=^(B?4D\1 7VPZE';>T)^FE29_*?\7 MQ"W@%5.]".D8(M@RQ/M%B.!M1UGY^QOA-DVG]U$_""MWO/1VI6-;L6;U[@EH"@BZW =5"5FJ>D(3D+7H(".WBS@$1_ZP M\<%J^A64UCZT9C'E)V]@;DPR9C4K(XF2O,@6E>3;']QEA!.&$X:L<.7S)K09 MIXR9RX?-P!DM:F7?@#=(F&\%'[#A0^GXTLCN'N8TUF Y#GPC?,NT4F4AC-/T M]TJRUZ_^^[WS3P!LI7^JW4D5 T"(0NZ9:RJ9@ T'QBG@A_PNFE?SG!+JVNO- M:2ES7"P&"(4\C,D3XN;44]:1&7U[J3 F:\.BY U8.*"/ACG@CF/ZFBA<7P/Z MTOD<,,$&@9^OK(A=E!0RO_[3+P*%'I5IXQV2Y%N4I0G5)-/,VI_HRUGNOQ/H M;TN;%B9Q&,W*EY>O#H0_U.UN>E'J7T$;O[^]2=."!@/OX0?A._L5* K\PEU1 MS-_^_//]_?W5]W$67Z79[<^R*"H_TS__3#_XJOI\\3"'SX.+(^#AIJ_@T=6S M(=6J/G*746_]'\P[BZ+N:)*BF[9CVK9F&Y(ME=[9,RW#"NK'0F!*XLJCMXWY M?_$XWA0'OIM"Z)7P<[L\9J#8EJMIIBH9JN[;=I6XN;+I.COD>7I,)WD4VY4# MT;4UT1$UU[;$P*V>[=N>JS3*TS*FDSRJY4NNXP6BYLN!IT PY6NZ*5F:&4BR M;3?*TS*FDSR:KIFR(^N696GP[\!5J^C.515?]!OE:1G331[#4LS - W7]GU+ MD6W7*Y\=2)X3N,WR/#VFDSRZHWM28,JN9+F &L]PQ2KZ]5W=:Y:G94PG>0P= M8G'1T3S'M2S)"!S3JNDPW>3S)TUU%E&7/M=S $16V M,]X6P6I!"'M--'E=514W2/,]T@>Q-U:YL,_ ,<$O-\CP]IIL\GJD&OJ('HN1J M@>_I1E#%5HIHJD:S/$^/Z22/HSIR(+NNJRFFI@6:(QHU][NFK3?*TS*FFSR> MYU)S5$Q75@/15.0JUO,AIM":WU?+F&[R^-0P#5O2) MI\=TDP=L4'8U5[,,PW8!'8988U=7G6;[:1G321X(793 <"&.,2W%D#S%7G*; M(AO-_KUE3#=Y(&#P'-,'1VWKX* #TZEB*UJ9;+:?EC'=Y/$]TPX<3=541P%' M!#$ZQ.:R:CJR:') J"&4,); 4\MJ6K-78ET;:;\^66,9WD"53)LT7#T7U)U&W- MT.T**P&$@$9SOMPRIHL\D@C3,TS?56738P&65.G>4E1);LQWVL9TD\>45%]5 M#0C&3<4.7-&L7I,-WE<-P@@B[( J);L0>1IU+5)S5(;ZU%M8[K)X]ER M(,F>!8&=#,&+HM7<[T@[_$7;F$[R: %$OYYM0_(+$9^H>W5L16N"8J-_;QO3 M41Y7@IPI$'7-MD5%590J=_%M4'XS/[>,Z22/#DK695/Q("16+5VVM"IV"&39 ME!OK&VUC.LEC2)8M0EQNV6";BJ,K3I7[ K&)9C.^6L9TDT?V%,O7?<\W9& S MQ=&4NK84@,MLEN?I,9WD,4W=-E3-U%774A5;IP%-.5=5LHS&^+!M3#=Y;"50 M MD4@=\,V[3LNK8=Z)KF->8[;6,ZRJ/+M& !CAHB&==0=:G.71Q?WB7/DV,Z MR6-)$/,J@2CZKJTJFN58%4LXRN!+S7;3\N83O+XMN]:D-F)$$CYONMHFEYQK6JH3K/]M(SI)@]X M( L4+TJN;$)<3HL"52RC&%)SO-HRIIL\/H0-LF5 X*)",@?@]>JU6=?6F_FP M94PG>0(]4""@\CW-=C15T6D27CX[$*V@63\M8[K((XN*'/A& *H634.#>>O+ M6J CB8WUP[8QG>21=%&![,D578CZ'$7SM7JNOKYC?:=M3"=Y9$]W95T)@/U% MT98E0ZG7BH%\U69Y6L9TDD=1/%/WU,"5'=D+%-%UZNY*WQ+51OYI&]--G@#B M%TU7%4OS1;8$8"QC&:F9G]O&=))'A0>[BB,[GN':@>+90;V6!40G-_)AVYB. M\OBRX2N*8WJ.$[B0Q52QC"L&EC'=Y'$DQ81GNXZJ632$D"15=S3#TB5;:Z[WMHWI)(\.)*O*@6QYD-J9 MMF;Y-79M5_0:ZS]M8SK) [F49[NFKEF&J>BN*5G+6I>E-J]_M8WI)H_BBS!= M'?P1Q!&J:)H.K?T#3B35=QKSY;8QW>11(>14 \U17,U45!481:7+$ X%L]G\ MOEK&=)('[-&"\!>F[(FB95M:O79M^X%K-.8[;6,ZRN-"W*"YGJA ^N(:X*#K MV%SVK,;XIVU,)WG@]:N:%]" 1K54S].D>J.6!\%Y<[S1,J:;/$ DDN';IBO9 MKB-IBEGGFHZFN,U\V#*FFSS@LJ'Y=FS0A"6V6Y^DQW>2Q*&G(KJIIGJP!SX&#U'7'4N$/:G-_7=N8;O*X MH&V@$]=V=-OR3-.L8SU5\G?@JV5,)WD\"93OZ[:DN9*J&):[W-CKRZ+=S#\M M8[K)8^F^#(]1%"!9Q54L4ZU[>7S#;,X'6\9TDL>GV:5HVZ(.09YJ*)JQ7.N3 M8<*-\K2,Z21/ &FF:5.82)*K^89NU[F+&=C-];&V,=WD,7W(XL F(8\RX/\L MN:ZU^X'7O'[1-J:;/([CBA9D#([N0]ZKVW7LX+B6:N^0Y^DQ7>0!-PC1KZ)* M 5W==X%SZ]J28YMF<[S1-J:;/$;@^C ]4[/ '4F!:!KPWS+ML!8]=8<\3X_I M)H^O.E8 P9ZNTBY"QU7DNC?$DIO[:=O&=),G )0&/F#%MR ]\"')6_;R!,WU MNK8QG>21 1V2[S@29 FJZ$J24:\=V;1LV2A/RYAN\OB^IVL068FVY0.Y^6K% M_1!&!'JC?V\;TTD>13<\S:.)BRS#"Y#M>BT=OD17&O'>-J:;/$!GBFQ"K ?. M$-)Q5[?J6HZFRXW]8VUCNLEC0QREF;YC>[KMFY99KSU",J4WKU>VC>DFCR^K MOJ&*OJ[[CAZX2KT7QW?$0&ZVYY8QG>11)1<23!&^P0-JM2!<".I<(?"\QGB^ M;4PW>535<76(8437HSMRM+H7PS7IO33-\CP]IIL\FFKK@6UI@)- W9;]AH M[37W([6-Z2B/;JH %HM&G2:$ZE;=BPHQLK)#/T^/Z20/Y1'-ES0(B3U-EC6M M7BNF+;MVXWZBMC&=Y-'=0)+40+%%T_-L6X$(C]5N%7!+5O/^IK8QG>0Q)46R M--TV: ^Q0>=:Y>*.+%IJL_VTC.DFCV: -8B6I02JK4BR;WITKKKG.9JD-JZG MM(WI)(^E>K87.(&L <>J'KR%>NW(<7RW,=]I&]--'LOR%$VB?E Q# 1)U@&:)N+V,KO[F>T#:FFSRJYSB61*W MTBU?%$VWCJU,:9<\3X_I)@^8@@Z^D7:B:;9D0<9+:_^F%\"SF_OKVL9TDP>2 M.S4P71,>'4" [ON!JNN*2OOCP6R;Y7EZ3"=Y*$Q=7?9\U0LLU8=\P7<5$;Z, M9J%NL[]H&=--'A=(1 *W+!NRI2NF(=5[217?<9OCPY8QG>1Q34_T P.2*%6% ML%AVQ.7><3S(#R"K@\!.DR77%SW7HK8)N:;I2,WY>]N83O+X MMARXFN.ZLFHY=%7+T^O:@"++S7S8,J:+/*IH^J+E@6\&FH540884IEZK48/F M>+YM3"=Y)-W0;1&83*7KCJJSS.T\S;*:^_W:QG22!_0+SY<@)!<5QY!%M8P] M(5>01:EYOW#;F([R.'3+B^O800!9@[/5K&=))'-2'Y-D1%MUQ#EV3=JO<"NKZM2XU\V#:FDSR: M;]F*9RD*Y"Z*'SAJH"Y[&Z7F?H"V,1WEL67/-G4_\ -9=R$DKG,77?&E9OMI M&=-)'MV2%<_P T^R3)%N1-;$NE8!OVS,W]O&=)1']X%%',B!?4W7'=>L:A6T M.N@UVT_+F&[R>*;MZJ+A:[X3N*X*-%?-%2;N-\:';6,ZRN,K)LW$(7#Q;5,4 M):5>BW UK]E^6L9TDL?PZ.H1) JF+6NN[>O>\BP?&N1CB0+RS71GQ;:LR_VL9TDP<8S;%DVM)L![KMBU+=ZR3K\!Z:Y7EZ3"=Y M;$/S%5<&B.B^H1FJ)E;8=7S)S9X2FW9"V]KX* :Y6D9TTT>7PX@C8,P#X(^#Y)@ M:WEVEV<$C?U1;6,ZR>.#;;HF3!2"!U5S)5OT:6QNBZKD:UIC?M$VIIL\E@-1 MKQAXAJ70AA[+K'O!; B%&_.+MC'=Y+$#"/ ,AW;'N;JEZ(&DZ9KD:1 @>T&S MOV@9TTF>P#9T(P J"3S151S/\]M0VR,Q]K& M=)/',.'YBN6KAJ1K$%') >421P8D>V;C^D[;F([RV+XIJ[9J0O2IT*VWE6W2 M18GF\U+:QG221_$"R=<-R;9U2])IG:*J5=BBH36OG[:-Z22/"G1F.>"2C,#3 M->!:IXYE=%=S&_/3MC&=Y %B]1RZ9&UJMB7Z"H3%5:Y@J49S_W/;F&[R.%(@ MB9YD>'1_F>?8FJGIAF49D*+[U@YYGA[321Y=$2%R,"1(5, 43 4XI-(]1,;- M\5C;F&[RJ&;@N+[C.A!ET9-\5(>N10#569[=?'YFVYAN\D!V &F!;]O@G W7 M4>JSWUP'THC&^+!M3#=YO(">;\HFU,-WD"S31I>5T1'5O5)'_9*Z?:._K]VL9T MDL>DJS*>+:FJ1KLL=5]2!!,ZV(.J5=-9^"KD#B\T5!P+1 MYO[,MC&=Y+$ $$"U8)^V2A?W)$FN:R? =\WVW#*FFSRV;-%-I)X.1DG3R_KL M <<'*FF.5UO&=),'2%66#-^%$ ML(C#T:JZ!:;O-YT.VC>DDCVWJKB1*KNNY MP+".X]2]19[E!59C/:IM3$=Y3 BI DN379->N&$O8T]/MMQ=\CPYIIL\CF2: M,J1Q!OROI=N*7.\54!7%;US/;1O321Y'=#S7\11%4QS(G13'TE3=41P5XF(( MAAOE:1G331[=LCS?\E13]$RZ&]I8UI(#O[G_L&U,)WE<@*MD* H]X)4NA"YK MDY &JSOPWC*FFSRV+IN:98DR;=^S/%KO*FW3EYWF?NRV,=WD 3^D0"XEBS!= MV8?,*EARK:0WYSLM8SK)XRD0@@/)TTP3LBI1DNM<052UYOT@;6.ZR:,Y@<)< MH>F+NJ%[GE&M[<.C[69_VC*FDSR^(DET^ZBL2+1L2M=*5K43I3G_:AG329[ MURP_D!U9UOW U/6@[C5P/%UL/G^L;4P7>73)5 )5D^GY]@X0'=!']6P(B[WF M_MZV,9WDD668KNHIAN'1@-CRK.59F)ZA-/8#M(WI)H\BRBZDX+HDNBKM ;/J MO2^T'Z*1G]O&=),'$CG@#\. A->5 ]=>]LKYIF0W\D_;F&[R^+KH.SX]@,DQ M_ !2/1ER<=]W)-GPFO.OMC&=Y%%417=5GRYCR9)HF;I:G_VFTYUXC?*TC.DH M3R"Y@:O(0&V2*T$X4\6>ON?:S>==M(WI)D^@ZYIG! X$GA"!FIY5Y^*R[CC- M^&H9TTD>B.BH-=*2(,0UIJYH92YE*(XL-:]?M(WI)H^G:*83 *&XOFA:IJ_4 M9\G;]+^:Y7EZ3"=Y=-]T%=ON6!]L&]-)'H.V54OT8#Q-A_ AL):U'-T5I68^;!G331[7 M!"]MZC)$Y[+O:IJHU6LCEM7[5-J3F_59M M8[K)XX*V9?!'D+EH4N"H4GT6G0V3;ZQ'M8WI* _X(5>QK<#4Z.$]JLZXQ*)G MJ_K-_21M8SK)0X_,$!W?E"?[6';FNXTR],RII,\KB.ID@\6X'F.8LO^TA?YOB8WGS_?-J:3//1. M4U660=LV/;3/L)UR+T7@.(&C-,?/+6.ZR:/;EFR:EJU+!CA*;;DW.G!59T=\ MV#*FFSP.[5KV(=YS34M3+=NH>PF=P-":^:=E3"=Y:$>:;%JJ;+IT:SU,N^[E M<2T]:,P'V\9TDB=0+!?B35F2= ]>@!?4=[/0PZ6;SSMM&]--'EU3Z:$YJB/2 MZXX4L5Y[!*@$8G.\T3*FBSP&/9H&GOK_N7O7)CN/&TWPKU1X.GKL"%O.^V5[ M9R,R@MWO%E;Q)C=ZR>]R.9<_JT@%4WU61P@T3)II]Z1X!&K.NS M+W-*'^V;+CVI)#V8?/6J7VLG:YM6_=>1S"E]3,ZVMB)7UL[*4UL:N>OSG2.:!S*G] $47UK6Q(#]0*Y%ON1^ M=M/M^ON"(YES^F1P<1C<(J6D"XZN'5B88C*K\? CF7/ZD#+ >(Y]T: Q8+SC M;@3(W*W&,X]DSNG#^!0@*1_Q3ZFFM>&+"1S3I_LL!UJJ+!JI##A M='VK#2BZ[B\.9$[I W]C6DW!@ALX;,_(+-RW&0H5/UG5YT#FG#Y2JZ]FJD4I MT\ PV["US9JV[B\.9,[I$SF#^2IM@1XD7:Z/VA6Q][2.-PYDSND#3*<4L56" M-94#-!YG%^1E??\V,V5]?KP.94_K J!4M@>0( M< =H;MRHA:E#6*\_?R1S3I\&=)=[0 M*.4HD<2\1FR[K_=/.9(YI0]AO@L,?LY5FOR0&ER3>TAYE2\?R9S3AURQI657 M@P=9D4<5TLL]2LGINO[^_4CFE#YLO):2[1Z.IW0 X\$UL_QDG9\>R)S3)UO2 MW11JY/K2"V7TU@A=K_=#/)(YI4_#D3 D^8U+[Y'>KK6%7,P;\8T#F5/Z@$(1 M6=^R;W^9( MYIP^QGOG<823 R)6*8_>ADV WZH]/)(YIX]MW9F(0:H0"U9_]#*5RGU]0Y]] MF7/Z^,;99TH-M*KX)O6.+K;$Z/7WPDR+H^ M^S*G]#%!,2E55#6V8:.Z>*VED6D=/Q_)G-+'&LXE=FV-I:Y*DR+E(W:[49__ M2.:K=&M,K? MCV1.ZN.5U&TN(.7 ?N'YV,6Z]G^^1S$E]"*@J!R"]V+UB.W*=&%9F MPQX>R)S4AZT"<3$A2U\?J\=>*,3)K/.= YES^H#P K5(K!\,3\.JC%AR T5? MC:\>R9S2)Y)IQ)&[M#QSR=>\<"G\5X'M7;<_!S(G]6G@"%DX%!O@X3IZF18* M>;V^\9',*7TDSN4MY^A//L"ZE]!+.[JL^!S"E]0)DR0*\I M5IH/@)F[Q?;7AEU+=GV]#F3.Z)-5BH:J:[T;9J"^/MZ6"9#(J_&Z(YES^@"T M= &:A7NV8/Y7M_^9K?>'_9(YI0^IBJILQVMZRI(/:IV\8V@=K1^7W DC7 MU^M YIP^E+5.R1JP/)>5+I%'K*+E=;Y\)'-*'UB/0BJQLI)<5%P=M31R3W;# M'A[(G-('&%BR=UPQOOI>.(R[(_RMCZM\\$CFE#YD8$><*@EXV-C8J[9++19. M.:CU]X-',N?TP5%Q#-R96NE6TAD--8D+%%_3!CX\D#FG3V/&'C2V:"U,,[3K M72C.T<;\[,N^Q-SSZOW7DWT_'\B21S2A\/&\(P'AY84]5F[>CUD?%-Z_E11S+G]+&F M1,!,KJIA.W#A4>LQ5[.>[W2R]>W2HKR>C[)D6-XG7G-5@M;K^8=',J?T >^54A'+5@ ]\,"@E[V0BMG8SPOK=2!S4A]2RF+AM:88$H/SNG=7MX('-*'WD4F65#1&G,4D,9O8]@;%U8 M7Z\#F5/Z=)U45AP[?$")A3#?E[.K8BNK\80CF7/Z1&[1R[-QUT$:.+EKKF6U MZ_=Q1S+G]"E:HJ*ZPR9S3ISF7='2-0#1M M*N"8+I#MP:?*O*'/OLPI?3 R;>1V367PS.P ^<9>B"#$J_H/W]\I',.7U:):<=-U:8?AWZJ,6+LZO6^W8/=6[>&1S"E]8/*Q!7T(@'?2(]-<;;_U/:W;GP.9<_J0*5'B M$ZGB .N.33&X2]7K_?6.9,[ITS,87:L]=(\)U\7#6:INNQ=8NNI/CV1.Z0-' M6)*!)3.*012<;2-684I?SP58?I=MUOM8ZPFY8C:\>R9S3 MIP4IFI.#+2!X *$T?*,/:KT>VI',*7V2TS;"$;D ",':V&MN?C:DUQB75=:_'V5JU?7Z\# MF5/Z%)*:BAE(6">QKG7D7C%'IG5]#F1.ZH/=$)SJ(4]T"MO MX+$#F7/Z)(/#R@7\I9(J7OKX7;">V-;B?*@U"H7J6>5QUD!'HWK>/5(YI0^4@H<)R0 \''WQI8T M:NT;>7>VJL^!S#E]P)AB38"1NB/VU%J:V>34?\DCFE#Y)!95-]8"<'6C* MV/'VCIH8>7F[H!K9@NVZKL^^S"E],BF50FQ+ M--F7J&B\Q3&]N?7Y.9 YI4_)P [>2.'4F'FY1A^V-O1U_',D0>LUY4'"@U+KY@4*\7U_,,CF3/Z !^T6$N4_N1PCAA@5$LMWBH?K5?O"XYD M3NFC/5LK#?.Z%.#.3*%>8DLF\GK_Y2.94_H8\M(07%<%HV^JLJU>[R+*>KW< M(YE3^E@E422MK#3O8BEM.+B4!UQ?C3\?R9S2QVGO5#3R,E*1(_B!\391*C*M MS\^!S"E]0)BDCQ=93KE%;- ZWFKWHGGU/NY(YIP^;(IW7)J*)R9S3QRF'DQ):*[4T>$8N(]<@<-S09U_FG#ZAR.R3S[ =&6S% M^&LN85OO?WHDYDCF7/ZD '\K,OK5A<+\\BM MQF*4]7SC(YE3^A2_)%Z1!9\+69ZY7&]+C M+;)$EU?CX44I"JX/'@+7C=L"8*+7-=G7^:4/C5FW:63*]29[7[]^/9$[ITQI.B[3/4C8K[(D$VA!"+4$* &SXTP.94_IT+25A MLK3PLMQ3S?Q>+83U]XQ',N?T":4;;FR]EV@D3)T>6"9KM1J/.I(YIP\F&!_= M0#*K#M1!>$>L73HSK>NS+W-.'Z#AZ@EKT-A[G=S(/>_>VO5ZL$^2?CYZ1U#3<3W>>R1S4I^JF[S"*48Y"U>IRR6VI&U:KT=] M)'-*'^L48=TE_XI[5ZIH+W=K1;*Q^GJ^WY',*7V"!06/)K%QTMHGDAEW:U*$ M>_V\'\BL5)#?NC[[,N?T*<%J7T Q0Y+&<,ZD@?7" MEOTYD#FE3PQ);O.E<#)%E958.*GMH5NT?KU^RY',27W8,>6(F6^MPTV:D3M3 MDE[/USJ2.:=/ 38OTJ:F&NI:]N2%*R13U_/GCV3.Z=.CYJX*>*7T:U!MO V2 M5+FR?MX/9$[IDZHQ5)H\70#7;268P35KM^O]"XYD3NF3E2ELLW M'+UTP,37\VV.9,[I4V,'( <=KUU"_]S<G[+DDA:;:'U^#F3.Z5,K]>@<@#!P ME5$T:D&!EF_^B?;V_KY.I YIT]4T5>KC.5J MLU0RO+[E,_ 4+)PW57D"3%]?KP.9<_I$\!0+MM Q:MVRO^:>!V77^SLC+.6"#SS.3'741)>9V_'\FE@?2M^M,C MF5/Z@# ILI$K>6E'H'NFI5965D*(5_W7DFH U)EQ3L^V=KH^GK]WB.9<_ITGX'T M:U8J(*WKLR]S2A]L!2,%9[VO K"R';DSF2VOYQL?R9S2)\@3<6/)1&LE%9[B MR)TASG7U/N5(YIP^WI!R[%VWX+HD1:^76N#%9^"(5?QS)'-.'ZG&8BGX!"N2 MBJ.G7J^29L1YPSX?R)S2!VZGYHX-D)W)*2D>;]W(1;/^WOQ(YI0^8%+-=^/8 ME:1!&@ @+K%MK^-Z?;8CF5/ZE$;>^R2%&)IT$;W69I#.'^M\\$CFE#Y5 7Z" M\W8#*L6FQ%$[!R:OK-<;/)(YIX^VP"Z2QMBUCMB.AD W&_Z":FOKZW4@[K%:;7_?O!S*G]"'IE!>]%+AN/4<0WF%KX:W7WW^V)K<\$I7M7G0.:7#_>O(?C-V[??_1^__>T//_SPQ;]]^?#ZB_N'KW]KE+*_O?S& M;[\2A<9'#?&O'NZ_O>BJ5*A>VR"/FG'>8 K*R%U(.?[L[=,]A"X?!:,&IIN; MU,)S7)Q3R54/NFO%<>NUHD)0Z9,,4.Y*,@QPAM=F.SF &D!H=*62=NB MI9H.#G4IJC 6-:45L_N)!NARTU095AC^B6WF+!<[.OO4M2EE8/9-2OC9;#43 :=:!U*88PPYVKQ6.O-O&*#Y" .,3SV= M/-PIX'3L=93(!V)K.P-TP99:K6^2G9(E0"IN(D7IUEGA*9[-"G[H &%4 EGM MC'3RAH&1PKXR0*-+K&J-;'RJ <8$FY"EN:615RMV.'K)@FE^?DY950?4 M$DMC&[L85K$UEDMVFP,LM@;O)8W4YY!R)7D;4:F!T$H%D17Z^JD&"#2+O::, M89(+1F5'63@TO8*)I 16R2*184=**WT M 7N 2D6M'%."*U22 ALM M!FBJJ\:DM9+-GVB Q92@2.KWJ(QMRK#SX^I1JM9L;]%8ES:6<'^P*8KQ!X : MPA;/ MK=\R?R-%_Z "G81/% HP20+)1O3C2P8WB\LM]X/Q6M!"4\]HS)P*Z M3JZ,Z#E'E[=7[/2*IRPS3C$T6['8E'B-IM@QIYN-=F0B"0K)SI? MFTU4M IK[VH^T0#%ZG4#%;U-\%^^JM&_65/Z&>N9$HM*132Q*YAZX[I*UK21 M<".EVS8'"-;7X-+AY'L /THFEPXCXX)7I4;[?+9H;6)A8M%!YUP-^]$1G'/ MZ+<'",/;Y!4:_"B!@?BV^$'+%"*9M52 3S5 &!.#E?#@JH5@-^-XDAJ"J]MG MR2P^91MU&S+%>MZTHVUR#=4[J\RJ+J8E,G:*7VKV0^S L^C$&*$"R M!V[-L;4%X(Q35T912JIQW38RL[ )#! KIQFV0L/)EYK''7UGB<]LARPTE6HU M 'H*OH4&#"3UQYRII*7*^?,98(4[2\J2R7 6UK910HXJ]F[='B!\B).BS5%; MSL9UZ>E1FP&!ULF$9X-D-+"GI!!W24[+AA40V,B3\=EMW]%/8V2@G>G:<%95 MPN_>^@'5I#G6MI&99H"@X,_1KZ0C?[(!DG92.4AR))1UUE[BH@UV,F\C&<[ /DTI7\%TX5(*2UR4 MM>TXR&"6SV: \OXLF&29HW$YF#SJVG1CDMF^'_PH20@?(2;SP0.-VR&*:%12S;KM)"F@F MEI3+2,;KH'N\'1=5KE@'DMM:,EJ>$5:EL8+= Q[@)\_'BJ82C%P2@BN![E)T MHUH9C&$SVP-,.+B%@46SL9+?QH3I@!^4AZ; M<_'#V:=LB1SJ4;%69]K'NG7 M #=^&ZI]E&2\CS) YVJFF"KVIC=!^9&K1LG'SR A5I?BK4M2WX)CBDKU$1<% M5MMS$]-8T6I2["'D7L46UN[-> '8 $BV8S+38-%J83W! DU5E9P\"ALABP1$ M,G_H7M>;R" ^V)^C.(R;0&*FAR!+MU3HN?X/$PA$K8N>&=):K60[>@ M\0TPI'IG@]RZ/ VPJ]RW5W"6 1IE36]1VBBJ%#U6,URS+*I6VUD6LX!M(WWM M$DR,(M])&+H?*]C"7D+L-"MH.) )<,X)AJ88'>UX^0)HX[8'.(N1,=9R"E@! M,M5PMXIJ'B]?,BC1]& ;1 (W\SOZ#% 05?6UL2U=MEK%SY(JO^\',E'S[+X"&%#@QTE,0NOV=6@ MI4?R2(@MNH3M,VCE^E UV)-<*Z>47'*^=LVJ9\-KA20^T0I^Z "S!\!K"EL[ MM-9BL-QD@,8E=CZGYV-%?=4V88#2'B8++5PJDON8@RY^)Q'(D0?W,]ZFZ, G M3;M<2P&E4]#Q^9Q!:;#I3#>9#=A@\7F4P #'5SQ_&HF)AKD0G+749PB4=+[> MT6>WD](\SP!M4UC$ , -;@AKGY:B,U(MT;6ZH8RN)=*&JX==&Z+YZ2]N.?AJP M78"I%1:C5+!Q;4#L!]C6U>ULT5DJ(6" K?M6<)#D84ASX1IT @;HVU9TEI4BE)+TT8R6KIJ"?1EIT7H+.X"2D0X"1H"#*HI;*,&G?T&*+;28B= M9H"MU*SA$EQSMO6>1OG@W(-2VV%#DL>4JK?::@6'K-%Y>7W&+IID[%H?QT\T M0/(JV21-^C1);BSK)D@FPBQ*">#Y5Y"DA50)T#+K5&%%KPVS@=SR_&]XS5(< MW1HI(,_&P^D#<4L%<(P1H&4'D'-!*O.=L&RSB_D>E.&MJ* =6:@+=" M&7'1U,O.%?8T=*DG<%:"<>F4(_X_7_L.MLX[R7C3A"QZK00UV=?0O,4"#KI4 M";QG>X ! !80O?I,.<%4:<=:P':R)CNSUK'ITPP0N-HW99WN\KB'@&C\M MZ>>=[?YJ@"GZI(OMI'1N,+XI5QE@(>FWMM8BXE,-,,I;<5V3SX"CNJL4GUJ# M2TJZV[FC_QCU9#[* )NKN8/22\-?79B2^M9N F075"HG)_/ )W&?%N%83* 2P9#&CV9HK2] MGSXF8['#*L&C944L54;]>'U&"1^T?84]S19UWI702X8_,]W#U5^?]@ #[#QQ M!4^R8" UPCZ%KGWN+F& )=DJI@> PPX-29E"58D0SF/:B2LFYV_&HD5 M'^B;E@[T[(WQ?CPKD+(R9;N ZBRU#0$H.[@<-I5*S*5@VY4EC<0"EN:="K&S MI)'8I*W./I0HA7.BK.#E;J(:E=W.,_-)PH8V^2BMUG*VW16K34LL*QB8J]=N M.]MPFA7,,/+<:S<>",;!H=F1+UIKH_DS?@5UL/5:@+6-L5JENY>K6MB/$LHV M'YR&+A6@41-@^EBEB!.I0KD2WK9S^3++%3:P-M>:M9R^+*DO*HUVRR7IO=NE M22Y?+/R6&$ E;ZY]T3FW**EMTG;(8AHV 9"E&JA )?" R*:J:U.;S&8;R63"1K0E8X9B!9(I M6HQ,LXZ:-EZM= _]1 -D[:(S$I_P1E-33%FL:%<^5;US^3*-%6W%]"688ERN MDAH[VMA+$-]L(YE9^*!3P%N908^ THIN)IMKH0#7=Z)JLW3M<3K$4!1PBX15 MDJO7R#8#@>T4"ICE8<@'#W"6AR$.YPR#E$.D;(U&.3]:IQNE=QIJS&)D,, J M53>IEMY)^WHMWKA4@]LV,J"0V8-P)#B79(FZ,&=LT0#_DL@]'R-C#4X-%*S2 M3Q%..WDW K\1E'YZ).-<*EY'94.6/LTFY%%GFUH)>AO)3#- WW*QG,'"C;&M M5]?=M9:%_H]^VO,QW(2'I^>20NNMFT 1+NSBZ(.%IYO?37SH *=Q$R$;R[%U MUCDI:1?BU;@ Q5]N7Y_5IK/1$9S"FF8;4TE-+D"]2TL_M6OY"X2\ O%18_9U]Z*$WI\4C9!&S7Z5.Y7(F^63(PGJ%%'YU7:O0?U+G. MG[/M8"L[+'Q@WYTR ?1P-/ONEMUG< 8I2_366?AI'"4+%S; =O% X//SP:5S M4DE%M]04!Y:4O,O[08Y]^Y$RY6 (WA(V6*K>PT?P@F1TH"9Y&\]F@("1FA*6 M#X30>=)%-0D;PCKJYOW\E?%=UDZ0TNUYBB!UNL+,B6SE7/=H221WJZ=,IX?8J#EOO M, S*D39UY*I)N].P?09G03)>.6CDC,W!.5(YNVJO5]A>;Y_!6=[1>RW]2PH, M)WGX><\8*K4$JDLQUKR-9&:Y )6ROL%*)C-75E+9HE_+CI6HYH^J>1,3!FES M1N,(Q"XM'O/"N8Y=V$=_#MN0*2QL[! \G4P0<#>9H_=.\!6[C* M@Q=)(5!-$IH)+#6W5.+8,?<%+-7.(,[437;@,S)4I9>WHBE75;+Q!-,@%58(ATN"3K8&8,WM 4ZS@AFF$D &AJ8XR4+7VHSK M,SC_;2,S2]C0YV*R%+GG .LBP>S1EJAB^[7YPX9>((O1L1%X+\YBC\&,5M% MS?-GW?N2@$.4!H\CX)=:ZWC#RYE[GC^=$@-,X+D]>T,)G$>5:\B"083FO^'U MI>J43&>,*Z4&5(O>]<3!!*=(6N"1QJ0]FT0@#W>7N65V27&2%AKQFB?3VTZIAVG.(,$S MZ&AM4$222Z;%&@67G(%)X/X67K(E2M$M3S%Q?C*9\ F&B9?JK\;T%85NR3G M_71]9K?CHM,,L#>?6S?5&##Q%$(?;YW#!)=\0E+AIM-3\WAE-N4;A +]<*O5%3*:=FR\@7E?^: MW\B$EN0*)0HN2:DZ.Z!:815VC$S+H1@'7,#.6@R0 MX,4 LXTJ62OVTN4F6N 8HKV,WUDRG>0%;\PP$C;Z@+W5\_5^, !E;CMZ:Y4E MN7P#6"L^66;J,#)2M,52#<_F:4^(E, C4C#LDFF D3](7'6OT;7G8T4385/B]"0& M78)R3H]^] 5+NO/,?!8KF@@XE&S)/7EI^NG"X@>QJG!J.X^SIO&#T@%,53!6 M0"S64LQGZ5[7'06?XF?@Z$NWILN*M>*B3:&/WF>EP"C.GW4?J&JG&TX><[7% MM"L6;Y1)'H8#:HY^_R6F0I\DF268=29D9T[JYE>PY>\F(D8&K@H$TQ1HG?PS5C"GK.?/%XTJ2V:O%' R5&WUCB]&AABG MOOGK51TL40,VT M"LU/*G4=.IQK#7GF\6(P._D(.5S#3K%9OL1JD'@)NT MFFE$7&>X"J*500;,4H>X9\: MMOW@+'<3T=7$$20)_TR(R5!,9CL1:)8>H#&0 M,F#RCGW16(<::"3CA4INIU# ),_,(QA@#Z"W/N*?4D%C!Q;-2?F="K&SN(GH MX!U4]_+,7+< .CB2\9Q-=?L, O/$R,5*SW.52?FLL46+#47N4-D\GP$&;EB+ MS R7;^$IXJCQ6RB7;48_2RGX#Q[@+/>#,6: 1U7AP70GA:FG:\>0_/,7.E.R M"0!J \ EMY;=P9!&9KF;:(8 IXFJD6I4SKK;4!U9HU;0>+3A*Z MEW3F[$!WM 4CE)?F?;0&B[VGSX /IJZ54L1620Q&N1A'YZS,R>^D0PC:2F>5A2,1@K $X M=EG)]: OHQ)"35+S=7XK6GO72:X38&@<"3D?==58=?X/[E;P,08('N * &C. M<-'!D!JA>^[R:F[[#$Y2"CX2@=V4EET-7MNE@IP/24?0)W#S[2OL:4+W;+S& MO@2-*ZUT!4:O1B=EZ?>V/FV^[.);">8",X^4VHQNB*5>M/P@T;OU;J?QLB$R@6>/@%] MXE0Y?7WBVITSVTD(%5/AEMVM[=*#JC?I&"+%!70RX=FP"?"&!#)8+6'!P,8# M)S?BHMKOU+*8);+]P0.<);*-T7G YF8CCF S79HQC'?T\M1N^J 3CHMB4JJH M:FR#277QVAHLTT[0:1H_: WG$KNVF/BN2@ME7( "0>?M 4ZS@K9ZJ:N&;2HO M(WU-X_U@]E'5[9C,-&S"-L+>]#$5E2NEFJYMB5IL>MO(3.,'G3$I17G: ^ < M3*$ZKL]ZR&'^) 2I.1:X%>V (*6RMLOQFM),-'\W0IVR%\!)V7HEQ_OJBR>4FS^I4TZJRBB9>N[@6 M207>'. L18R3(W DE13<6L<:Q'9MJ)&BSO/?#Z:@)4D-]H5KJ')C=AV@O"+? M8Q-S7)\E:4HD1ZG W7>P CO>\#(\Y(ZC9RF;:ITCUEI9>9W U"E* SQ)@GHV MY58P0+;*=V-"SMX5J\<9+"0-3+V[U8NUA('E[@+/T/DN]Q@Q#88KEXD$.JUNP:&TP M/V3GOS[+*D5#U;7>#;.GVD>-7R&'>3L)818KFA68;0<)I%;!D'RL^MJM(#NW M'72:I=1#-A4062"EZRI([]UV81,M@AK,3YZIAM]>U M9Y)\T8P5L\ P$D[3@*' 6Z. JK=Y!ZK-4JPC8U]9[RML@W.])%"=RQEDW?>Z M%4RS186TU@B\3#W &GK]5,P??A!.W\[OZ+,+V&&F>%U-,<[3TC_KJ5)Z^_D5 MPXS="N#U0)""IX3]Q;%IZF:9W M7H#.)R>30@NW21 '6Q=C UR2$5IAV M>F'/O A,RXY:B+%>W036='N+SL+HEV?E M.B5K$I8A*UTBC^LS.+3M%9SE?C##\Q52B965-Z[%U=$:+'=A0=L#A/]DI4WP MW:90@X:MD2K-_JG9[?/Q@\6RO/ETQ?CJ>^$P\D7QMS[.GX20R< '.E4P\2 \ ML5=ME_9\G')0.V6H9VG/EPE&U'%7(;72K51W,-3DXJ7XFG88_2S79YD:,XR) M@99:XMJA7;/N86'GSW3*3"YK$Y,"%.W9*%?&NXG4]#9(IUD6L5;"A@LI'FSS9 M09? +K:-#-4.H(V#BJ.JNZFPH1+X91=-,M8]FU0NZ>5FHBK-2&\B4[%C1S42 M,.&=QUFSQ&0PP&95J4"@TA:E )2.NFI)QCW]]5FQ+05P<(MAI6B#7!1>.RG; MG6?FLU2(+4X' .U&'<4*VS=E MPTZIAVD&B/,">*6]+TJKVJSUHQH)AKOSAG<:*^HMG%9KF:MJ.(9Z#P>9VFFG>9NLU2(+?*LU;-<\6JI7]& U495KN+* M3@_02:[/2M"Y]N:5\:8$WPJ8[Y*SC0$HVND8,HV1@;/64D_2=6#(DER^%E!5 ME/=>GTU2S!\#)+B#YKF3;=DG1VU ->*\4T!U%JB60G Z^Y"DCW+D;L.U77L+ M9N>)ZR3=ZTI*97D)4 1QL;&]>^&##6P>B['M)J;A@ZE66]@#5?; 4FO[^KPN M:+U3*& :(T,J25^IY0@V+$0HHYY,*F;'R,Q2E:N0Z:9('@$3=$V"3);^@V#J M1G\&B4#8G:D#;17=!9,F\M=J)-*L8/Z[B<(PHMACV)&4*M!7>,K9EHQ?7?M. M"=Q)"N9@@(3?QX'3FF)(',(E(99KK'KG O1C$-Z/\':I<,6,.]A/@G7@&"+; MZP!SVG'T 6 5!Q5(R$F]"+@7Z<.KNU()P.\9;=$/'&!CW[PT1-519R:6FA'2 M4"/F$D/ISR8)H4C%\"R6!N?&AAJ*&D6,J;DP?QEJJ1JGLN+8@4E!\0CG[N(' M56QEIP3N+'2I1V[12S<4URV 5G+76A9PWO-G_.*T:$D8T4U>IFJNWD0@;P6G M*&^0YV^H4;$2U:5N2?X-R]8S+0\D8Y6BZ?,_D*PJEMA,]<#6U;CJ0G'OE5O9 MCJK-LD6K2C 5,3??5*P$JYB>L"@Q*&S;OEV:!8M6[5-SRG<%K\8%IV^D4W9M M@]^K93%'\<:JFW-)@X-3!#=/I?>T@*W@4V7>"=V;8CL&QE*$!M/B9"E+=LWI MZ/,S.H-8+VTDYU?E5$UVY$:6A8_4M['H-&?06 OP$:/WB[&!.1S)>+7P7CN& M27J^5-,J.>T8I@&[5 =YD?1TA>VB,CMAPUFVJ)7KLRY!(U?@NF%!W;BC!PC8 M=O24@R% XL=_0Z ,/^O-W/IQP@$!ILB0\A9D]! ;T,J&9]3_,_ MKZN.3(ER99; Z90&0?4L:?K9%$EBD!+=*C2I+OML!@AD79*!6S<*=*1S!*R MJ+$%Z8V9<:2TLHHC#;#M@]II]CU+(I"D.-D((.H"6!-K8Z]EQ[K!YMMF]).4 M':L);%[6;9E[24\SK>ENI,26SFVO!.Y'*%KU408(;^=ZJ#7%Y0K;*W_-^+5^ M>XM.\S)%I>X"S7)]A@#B%P:F.L^/AW:L=N6HMM9TZ MV]-@T:I#PN# >95D5 +4A/$X2[F=:B0FY*;PGPXN"/#)5250RIP 85.'?7T^ M X2CT(D5]1Y= Z!)[5KKWNKM^\%9WDU4J>CDO0.X]AW0&;;FP@I:<0L<"9ZPGR;H/@_#F%K:-S"R)0)6[J(9Q M!EFP0GXT6.S=\>< MAN 55)P\@[FU$3",H[:AI5W$H&FB6QW1Q4#C)'8:2?= M,O7HPPNO-G_0"3Q'!V5#P-R'6L"98@)Y4L18$1?F[V9.8#PD)5**ZQ4DEVBL M( 9(.WYPEJ1T##" Q?<*FR&U1=@I[#,IC BM=.R*DQMKC-+S MJ(30HMG>HK,X>G(AL- <+PT9LK7Q6D^&N>VT8Y@ERX)\*U'*I5OE(O6L\K"B M/<#3;3/Z:;9H\$YL9P"MY^Z-+4F/_H-2/79^1Q^""K&F:FLTN1MB/\*&1=N\ M70EAEAM>X-"@LJF^!UB'+&6=1C62)AYD_BV:*FQ$-%;!Z*-IC>WO8*S=#,GJ5*4O(%6)69>WH0,)!/Z'A^< MY0R2 704XVFUAMM.Y-I80=OU]@ _BA7]"#G;1-%*TCV0C W2!<7TR_49NY)W M5M#J"*_9I/%-K9Q D 3)=,VJ9\//IR+0!P\P>]C>I@QH?VLM!LM-!FA<8N?X;7C;D2Y.*E H@U%1E6[TFXQ6_C60,\+D1 MP-I[$^\)Q.#DY8OUP+;6?IB;^ A^\(,'.,O;);9*+JNULHD))E6%,"+;OKB^ MG>DT2\8O.^V=BD;,@\)& _ >=;:E>>W\#R0YN! ,.[*<+ M"0*MP7CA7EH)7BL0)QQ+B^5S^=FDQ/A"#4V) P@Y5%NI1D#?S;_"DII M0^!0JC%1=5XYI9\ 2>>",PW6!C9%&]*CWX0D=VWGJC6# MF6([14[())]"'++TU!-T\FW1*+APLP=;GGA)X3I=2S4#.#;:&5-S9HK8& MG+54L\\AY4J"ARJU#OS0!KS#@W%JL@2=I5>DA>K"AYWGG:,XV;: V. MHNF"06:%LYC(@P)7X3^>=MC$++=+W+7T5C; M=I[,+'V7N'/ X2%L5;ANKY,;==6ZMU9O)R',\KRNJ5IC2J%UU@2X+!?9TO,% M'M'#06X/<):>+TUQK@F4L&.Y]*(TL1KQ3E6N: >H.)F]: 8\'%*'BP 59LBU&-9+0XDY-IUF03#/)"QDT+9O>I?)8 MI9'*I>-GD,HE;1ATD]*IQ2AGX==TN=S1:YOR9[""\G(3YTV>FG,'6RW:2U)Z MD8?G_3,H]2"YNBU&D]@XE:*\,A])Z47J=$U_N]1" )5P+74%KA3E\: ?B4 2 MH9D>JC5!'MJ#H^J08B#E3!HAB[#G!V=IJ-%B2/(<2U56%%56XNZE>YUNT?J= M!HO3./H8V#'EB W:6@?N-N.):TEZYYGY+$]<6RRI6]!58#5#78MQN<1%DZD[ M==7F&6"/FKN"-?E8P M#5W*RA2VV6/#25$$R1;N]1*!90A8M1_:)XL:QPY%[U4X7Q:04IIYXGK+,4Z6JZQ)P<88FJ77#QN;GGYDFUKX3-X M =JJLK9PAL-.UCB0P]&>+^=@=[#H-&>PIDR]UD!.RI$X JHMLHNT5G,9- MU%JI1^<()AYP"WCYPB8JI=V'(599\M$R-FGQR4I-#+D E0)F5,/S@6H2]VV4 M2_5.L"CXSFA+E&QOVU9T&L++46&O685#5&VF:O2UQJ_3.UU<9\GX;4T:U!J% M\5 C(_6/M-P/PC22Z7L9OY/<#[8.Z\XUN["\Y0&#[7#WWE0H7+3?WJ*S7&$W M&)BB; =JP5KJEOVU[%A0MOX'OYOX"!>@'SS 6:J1M [O8)1FN82&732MCE0N MF,2=;,-9_&"'BGKIUXJ5=+WB./61;6A_+*VPO!4N34<^&30AVP;B]3-=@Z,/J=&6-,= M/S@+H\< 8S6N^9"=!6.JR6L)/T70GF#T=LABEFHD70-SJIZ,,]8U>3_H1[9A M@?O>(;R3A.XQP&QQDJKWK%N3!ZYQE-]DM\,FP!J*<> ;[)R-U:?>G=3XQ00% ML.AG6RY<.-FBPNPQ;Y0M;*WSB":=G$R"I2E)U>5>OL4NW&$"Q%B:,'*/Q_ M<9_!&:S:@O])V8JN=81=,40M-?P%U=:VM^@L0:=>@5^X1IC[R-"R]&M"+'RX MWV83TPR0D@D^>@N$W7J."5QN7)\IO=,291HDP\5BZH,.&)D4M@"ON""97. P MYK>BS*Z"WDAM%1DEVR3YHEVISIIWPH:SY(OV;CPUGV*!!023"_#W(\LB-MH> MX/^^VH:77WK]XLO;UQ\X@P>3\303/YN$)Z4>;A_OWSV\E+_]]C5T>//U?_G% M[9O?_,N??_%__=+\ZA__DP[JG_[XW-/[[X]KM_NKG] MG^_NOOOV%G]^\7AS_]4-W[Z\_?;+VX<;JW]]8Y3V-W=O7KY^]^KV\>;M-[[^S4UY>(!.M_(]C[^^P5^\N/GV_M7=5W>WKVX>;M\^W#]^=_OR[=WW MMS=?OGB\>[SH\M]>O'GWXN''FXLF7^"3;_%5F&O]C_\I&6W^Z;_>OKE]>/'Z MYL6;5S=_?O?MM_+;$/SSW==O\.$O99CEYWQY+X-_AXG^9RS_,M2G"?CJW0-6].&OYN"FO[A[N/G^Q>MWMS*/ MK^_??/V;UUB65UB1Q]NWCS??W+Y^A8/X\)O'%Z\Q?8\WWT$QK"I^X\WMLB]> MWC_B]][>WSS>OG[]X9/Z=]SZ?MQ)_=/M98A/!^#A]ML7=V]D-[V]?8-9Q(CQ M$3*AM]AT-R_?/3S??FZ2^^ MO7O]6C;,92[P]S<_WKYX>/S5'^]_@ *__/V_?G/YD59/_VL_>,4IZ":/HV$E M*66 VFBEK0I3B&3^^M[@XZRXMO]^R5^\^A_O'M]^^[3\]\OJ_:E4[(+'=Z\7 MFR).".8'O_@M)O+Q[<,RV3P8B_Q=???WCX\WGQY^_7=FV6G_;=WKW]/3CY?C_;M_^^N:' M;^Y>?G/SXD%.[,M[.19?PF!]^>[MS:M[.7(WV,;BAO!%BZF#%WKW /XIZ?? M_O$G4[88N?LO1?[7RP?(5[Z]^W99W\?ELWZ$Z7MU^Q:GY^[-[:L/7Z6_(V'P MXZS2. '__,?_2C??B!=^(XOPXO5OOKI[@ &[_;?OL(@R]9B2_P&7?8,]BV5[ M=?O][>O[!4W6# (P@MA4=^]',M6OGNX>[WLZ67Q,8]/EO,M=CJ^ M!*(0PJE8#L'-_4^>"W^"5#HQQW][)]&/9&8N<[P,_LL7^.'+VY] UK]\\?]\ M/]ZU=/N_/5W:ME3WY[ M>_NT55\^W&%GWKUXFDYL]._NER7!ZKYZ'QZ\-\FR)! %%'@R=(^7@_35ZZ>% M^>'N[3=8B(NL'(3WE?T)AKB?8,AW]X]W/WWX_SU@Q)\%1M1WCS@W&,TV,/G@ MY?X[KB0_UG+_Z3T#=/]P,?3+GS!I-_7AQ?^Z>WT'%_*'%T^N63S#R[E*\72/'+7Y0_M/;??_$K?,37[UY?UFI UGJ\@: ^?7-7UX\W'WU MU4VY^BZ(_NY/?_G%KP;$N%A=K.G73P :I^[-_9O?R()BF*\7Y62=<$IA4._P M8SG L,MB%K_#4&$;Q!Q<%+T35G'[I.S;]\S\KY<0O8=P78/C-B[?+-R\? M"-N!C_G^7@;S^O;)=/RDW'>RPU]=1RA[XX7,V=W]*]%#&X#X-V^_6>B". ;Y M2YD&C/4+S,6/[X&UZSE[?/^++_[C\=V7C^!!,E$0';YC;/T[<1-O[]]B8O'Y MQHTO77SVLK(_K>H%WF$ J6_OW]:=&S^MQ?'=".X^6ET+UX_WLM7+W82'S8\ M_^6C_GIEH=?-\E5/7_#NX?'V,MK'Q1G=7N;E\<-/RM]1&_?CG!3_J[\L 'O9 MV_=PP2]^HF[P(S@S#Y@5;-;['Y9I>'7[E;A;C/S))2T;%G,/5PYGM>S[+[$I MO[K#QOCR]=W73YAA6,&7$HU8K."+O_I.,:K"BK'<%\ ',/C]W?V[1YR"=V]$ M$.3R?XGHR[>@IW?XQ:^QRYX,V^O[Q8Q=S@[VQ5\#G>ON_VL?-S;2^YO]G2#_ M!9Y@+_WQ,D01>_.X;./W%/ER.8SW3YM9R#V TE6YUS^^!TVN5^C<8Z;>W6.A_,,G>7#C;8BX7J/K-W<.K&VQH M>/V%KRX0XN$6\_VT_Q83*'Y8/D_\P' #3PP&4@*N\7V_?P$__?K^Y?N!F'!Q M\>U_OA.^^;[_%G3Q;O$# F N(]C7/Z9SZLN_+PCJA[OE!"X@]'\C)-D;TGLS M!9:WJ/,//E_'\]YYQ9_Z/__A=_]O^WW[_U/:GV_* M UPS3-^+X:2^NA<=?CX1\'/B1N[^W0;9"4A<)_\?M H;^LDW;NMXH-)UMN-E MLCO&\>:E;*<_O??/65F" 8 MT9]%72X;A\#'7[SY$0;S\1NQ+2+RYN($)-9Y]_ 4&WT+4 8;\S>//%U&_KLW MW]^.^(& >&RT\NI[@2*/-W^YORD_J;KN^[M7[Q;?]_A3*/C#Y_+O>$3T<>8R_0J;9X2!S*^7/?B3>[U, MY]6)WOQ2?OZ+/XT_@S$L=O;[VR> ^@05P2\$V-S^L,RR!+R>XOI+C IS^F;Y MXWM1JO_\.+[BZF4'5KX"@Z<@*;"NT/;_O[LK[6WC2*+?]U<067MC ;1V[B-9 M!. <7!AKQX*$['X><4;2P!1'X)"2O+]^Z^J>'G(DFY3() L$243.T5W=7<>K M5T7V;? XLJ4VGL6N_M#[0=^WRH9W(WDH6DX4%)PF@$V"J2M WB96)\\TH3H&0=A:P9)5CQ I MD9+A:: 3-Q[1#$!)&6Z+7B%0XRPY."'F733O.6&MX#HN>NZH/-8WVK:6\%>%YJ'J@HM%];@BD/>44B=+U)9S".^N=A*2Z2:;WIWV M._480#V2^2^UR\OAS]@(R^"E#,2RPXZI(7BM ,[6F-=T?2=V"Z*"8E[_E]U] M<0H,N2)XL2E]WHPZIN[_B8H#&Y;4#-=<,) MPE/??VO(TZ,)N&H4&R'K&!$;AJ/Q4]2A'^Q/B^;AFF$Z<-P5!C62XY"_< M'+2@Y>@:S#[8DXH/\J6Z#;;LK?$4^-. 16$Y%U],I+NMP9+._ M!%,?++OCNU'H38/ R4,[%!Y8&MCAX24(?MT<[#%;AF2B_,S1H8*AH#+ M]9(4Y%,._K==J<)TI59/NE*O 2+N0AH_U/[=%[ M< +3/F =$ M:8#&(,V^0GB"X.SG/=W8^'GW\F"H-APK$ M $4$ID$-C@@=;G(ULML*@GC43FKI]EZ#70K8#@7DHG[641XGCA;DGI)32Q^4 MU>6J4]ALTS5V6'07=YX-04+@\F@09W:#5 G&'1<;[P/7MGID)8*/NZH?*;$8"'1QYF^X3Y$'#:&!0\9-'<@DI! M3QXF2^(7NG(IV2MAL\" M004&&\#=.]WN.Q (QI:?Q;EM1U;B(8]T$GNY9X=^? 2+H?-@1K9=Y2! =+BL MRK_9 &XK(J1P(C!@L6QB0&D![EL#-UUV. [? )8E,7(!8K18([8WL%7>8R3S M%!G*1)*^P;'97]/M0.P][,I,Z,"3Y,#$P(K@5N7X>B:'I^YX$2E,NIG7)?F] M%ROX#^]GD.,K2"5PK7"2!XD?IW'D9+;M93;20R+7B3VGW\OL0%*Q3S[K- ([ M&>"L-V"2!3:74)CI!3?%?2504C.K229ST*QDC%5VPLA*8#)6TAD2&PXF/QJ% M30T^Y072C4(_LD$CI)8=YW&:1'&"TIVDV)LR.<:>!BXDD:*3I%$A*BE M+^-TWKR9*4RZ7=^AV5'(S*):/33++P9]HN!(L[XE6$8/V\C!P[>4PC?0C 5$ M'"T;>5)2HNR,;50/2P[5UFHUY_W2WL!01\T,PC[8LM5"4HJ:JUDM7I!%W*6Q MWF&5E^$*_;CI"!E8>$V\%-947;9;A7YP"/&DH=N"&!-'\B9I3Y;CM@#[OKXU M'ZP=J UO$+SJ:QR(_AXS@N"NW34U)2Q7#^A/#+M(BIC!O$#:,%>2"AV8D'+7 M=7( 5-8#J)'W1,K!60S+@:?4EQB^>+9$('Z0X4CL7CR?>F"FCT)W.Y83(9:A MF+[SKWMOLEU(VTAFU7ULPA)BOTI#*7?&5]YMV733RLK]( M/,N-IOA#@$X63&T_GGH1N'.3R$VPQ^D1"'[JW%$N1JECII>LE,8KD=DGN5R= MZ-6(B#ITZX4<-/+R8!?"*7F_;I'D=+5Z8.Y(RX[%&R/?B0]Z8\,AT1\\@U7) MEK2]U]J2.S2O.*S\S^:%EJV0DY])Q'-DSN[T'9WGBF/W6K(O$&2!\9DQC #_ M0O.RJGK MNEZ.+4#"( [=>!K]#G'SZ-\?<@K2V-RO3 RHF2-EJL-,M%5'6H^PESFI5%/Q M#!.FX+@O]]>%N[3'/NQYR1]UZOF^6K#V>>.X5O\(>.$V:8:J'- 5!E4R:$$\ M94'<_NX?F]24BV91S<==9KICT#Y#OI54#L9_M(AX6 X;6\=9%&;>-+;3) <# MFJ?>%$FR=A)@,[O@"!5,[DE'<1)6,X9U*&+\GP8VZS95G[7#0/9*'L$PG="A M!^G^S)U^$_7W@^-T*G$?'T(&AD2JEX\-/-P-A>V^RNC4T/"J9T.@#VS@J-[B PR_%GQ2K]2RD9S0.[K@FMQNPB$9MH8U4IV:*BY2PAN%KH^D+&N)8PUYLC%.P#$#>9Y/$A G(^'@"2I2=%G-ZE8R!HKQ0!R0=QLU0#!L M<#Q/-C+1^RN[';JP'=8Z?:2\,B;K5%'30HCOY&-3.@$W@#X*71ZA-5SJO261 M3D*(#V,O2GS?#=(\"K#36P0V.\1Z_\.[,ON/?(?& H==P^$B'CA[^7EG]@V> M1K]^]CNR#+]_"'WEN4,KN,/"!9U)V0DR M>14A9.[436S'3FW7LI/$FV A39J!)H SD1\EHST9_79Z<=H!H#IU8M)E= IV MJVR,T>9@(Q3SHI> S6-#,8,[0/!+0O6PXO-)2JR+1J)E*3>/[\PQ3VL.("T$M,34H^6V?$=/K4+,!!>TTEVM>4A<53"DJ.IF^(;%4*J(FT&[A>#RIU. M'YP[\=:VW^0+*_?96QDTPJHYG&&MF:.:EJL;@!3&.;8!/2^^?H7O]B!6W8#:/ SX,\ MG7I8P>(Y26IGD7,$V'V H42E<51;.=_, >L_203,L&N9!X*+0C0Q+JL49K4P MVE5XUY5B/S3K>8D!,F\OD/7M_E+,,G#7\R1R@RA-\8>!(%A*$

_#MD/]DDWU3 /AK3M>2K 6G&(\&U9D_L1/F#[70\2.AW_\ZJ$][I/OPE\$ QP311@!6[X_ :Z*; MKE+IRCJ'&@'QY4 $)A66^>6(L,POP5"+@(3*(:OC=@4MLJU2&NF;E,5]LL.% M\875&X%)A?7[YR/"^OUS<%9!YR#SWKDZ!8Q&$-5=M=)QQFB2/CW92=_XPNJ- MP*3"TL>60?TI1),.# MYL8S+2F@6#,IK#.*M7L#Y$FJS.B[XQD$GH).?Z?3KW?U@..0EHMYM+[C^-7U MJMIEMSG@@3K6)$1E'"/ED6)QIX\KF1-6-OT%DI81*#.E-$=&J+]$]WS4+&]N MJHL:U8_5:KZ\/"#8#BV#UK:^#LR=LX@1K:@"K6=-:U1&&<6IY3L^4.-.W/H6 MF;K8W1-NNI4RF_>^)T"EZBPD&@H=-0_F,:;-R"@#)$GI&KTVXCFG^!BP9=B\ M71S!Y65U^1#5\Y !^NKE7VZ#S8YL[BFO"X(33J%VT=)04?O56I-F,:1"LZ3X M^-&K*.;8_#.@EX%233Z)=XN+Y==J6[3\"&/V/!T4H$(I@>(FR;6GT>"$M!D2 ME!ZF$&+T:HDY"#$9[D8";/^BLC/U:):;2^FF]GM[&*^^?Y+=3W[YVRS6=?II^;;\[RK MYY6U8MG#J@E ]\:$!%UX33"E3:>>*9$ZU*ASH(DIHQ>XG!J)24OB!-$ M].Y!9*+@WAU4-VIQ^?GNZ]?9ZON'J\_SZ\7\:GXQ6VSN2U;$GGQWFWH92(@<'LDU5/UYJ(L?5F:;:NC=XO$3 M\RCIVYOJ_9$@Y-'>'01$PDG*,'+"2R&-M0KXJ$IA#+$^>=^C+,A.124/>F_P M<<-0@@%IO,/"1>W#XP8J97W22CI2(/(9^/#<9Y<1VO$CDT<*4/BR7&U^JU9? MZ[O<=4*R4W%-^YX/AD$NG33.<\&-@?41%/ (8609XRX3S7K%-&42_O/XA1'@ MRQ&V\KR;IX-6]K<(7%NBH?;" 8VQY\K+J/Y$%5132:@BY88O#9/4*;D/@N=- M,:"XH*4B!)]=X/5V^N%J%[IY,BWGRX<#91P;;B&6<3C(8 *CJ1$!TA+8:'-F MV@*ZGN8/EU_"?+OI]J$F0WA@/O;6$$XZX M08]]7L-^/A."9Z'%RS3_<*!@N-$"[ZUMHO5T>TI1,Z8Z_W!(-5'?_JO89>64:%\*Z! 0"4 M%$(P<07E\RB24\*:@5VUC?7A:GNP$<$]795]S^.! 225YYAS!A0E1D'%FD$1 MP"BM:>-EDASA%O5'7!7 M7OJ5B:7ZO$C51 "^>=Z4O5^52Y?\AV/-O?;/%]5BMIHONR8#>?Q\X$HC;0"S M7@D)H6=Q,,VPN$^K4](_%/\5;$9CP)>#%?>]^WVQOJTNYE?SZO+TH>FA-D$S MK#2.TTA!QPWS)(ZT&1X"[A7D_4B3UHM4@N,"].9X4-JF48KXLXO=5E?5:E5= M[N)>*[-<;^Y+=6Y.7:T]U30XZK"'W !B-+71AJ.6 !\[XC'UG)=UN'Z^@+Z1 M<3P3:1X\QBF\>=8Z**+K@@$.<.V9CE.&.%F'--2C1EHDF;R3.>'+HLXP*'/< MX#\(UU&TW-55=;%Y\!']U]TL/E#'JF\>:7^]8I$'?"^@:#ESC-*R+U*O;V]5R=O'E2';T MYX\%'Y=$ 16P3'!/J%$&VV8PEJNR$Z&/)JGE: CUOR+Z^(-'$U>_?# 0)H1T M$EK*!*IS_C%.F[[Q2/;BG!C#$#X@ID%@E"6P4KP-YY334/G8^7IV?;VJKN.G M+Q]__VCJ\!.M@N&2:6 M ]&B-=&6Y;9=2Y069=0U&HKX1@8(!*T5I@X9EXV1[P3.9;4.3FW<&?&7 M>:C[(3"IL'[61X3ULP[0T3H%,XGC9ITPGJ&#.^IPNJ-0(9% M]=WB:KGZNO50Z^_WB81F-^UBTWC33BA@/=X2.$<<,X8CAD(QQSGQOH' :)QD M/DU\$6%ZE6PZ +-PJ,Z]]]#9KK<8C[8+1B*ON23:$0==M$LD!(W[UB$%BU76 M)I'E"[Z,#]V;94IIJESY!!GJLM'5(H*ZV9[M'W74O'PP:*H9M-AXI3B@R"(M M#00, PD4%MG"L+HI"2/!O!P1D2S3>)=TU?UU&RE_.F![[_/!8\21(PQXXTSD M-8%&-NAH)Y)N)$ZF#8XKZ#&!.4NP?J/UZ.\=,IEU:1X01EIP08# 0HJH*QDE MFD$+33)ES"],+9P N;/2I5-ZJR[- U52.@LLH!HR": U\8?[05-'0;':X;@B M[)R1;2ER%"* MN6+*:@>TMM&P@9+Q4]&&;R+@4@"L#()1$W3<>NRHXSL(E!749KJN.CC@LK,D MTP,N>P$U?L#EZS&G.#,1(ZJE=] 0CQFBK$'*4\;R4&HJ.;Q_U[EY[QC+?(CO2JBU73I7G@B'/@#<*$:@-$5%$@A-I12>J0 M>7@JY\C4<_W(&+K;-:=>$JQ"GD+F+,$2>JXQXN(>!%:G8RW L!E7F B0:*>-)=#D./AETA6W7 M3A[W/GHJ2.8X94J*>B?$AD,C:3,$2( IUK!(D,(^.0Z"X55*M#25/Z\@LPOP MEXCFU[NO)T7XY+G@N=,&4<^%@XP:H0C4S3 SZ^. M*=9=F@=+%6,1/A_-/0-0Q%#)^T$+K&FNU);=9#ZI(.X5/QA&5!-FVQ6J* ]M$,D00!P*.)HC1K MH+*0)R5$+:Y8;6<^C%JLMA^TI=KQ!\)=3UX#.M@J*!]U;6ZMQM91RA"-OP#: M4NV=AQ9FVKUOR ME^7BVM[%?WR^^V,]OYS/5M^/7IH\^'RP6CI-XM*"L'9,"8R8KWMJ(&'>BS*< M0^GX+L?'((,F-&8Y<($E5]XZB!6H85*FAFJW;Q#(WEX5QU0K:B0$ST2/(06@ MN6:4&JYPY+[Q%GF@6L2\,N7>C!LNLNZ5H-- >H-L*&7C+I$$V84_?F'H."HI M(FB.:2VDP%3548F[(0KB2$\8) M58BTRZR ):9A.(^".26L&=A5WT@86A4:(V,]!W&R4*>Y<]J2%CKF3+D9NB:2 M79?RT&F8O1%"E*9L%LR#H3ZEAY%\WLP6E[/5Y>^WE[--5?L" 3V>/+U#T^"9 M=QK4UU 080YX35Q[N&XI+RM+US )+">%9@S1KMM>8 A[RG9/VR"]]=)+2S%W M3.D(DS7-"!0M+$_KA,(=CDUV/?%$[>C.>N*I&M04&J.DPAY2*BQR!DO1DMR: MI+S+19=4'D=/'!?6LUPB'K-.NY2424&)<-+$R0,(KWWUN^%B2-TKT2!'DVKO M@NUI +YYWI2M:)9+E^PTV5O#^@@U]M>\=D9Q)A'A]79?*UT0M;X;%M%,H0-[ MBYO1&/!E24DP9EUWYRSC5K(ZTSZ#-NIRJIU.,J)7["8S4%J="[RG ?3F>%#: MIE&*^(?:JX>7NL5=O2LMKQ:M7_[ROCCX9O;7;'M6LUS=/+CJ#QBUXWT@<*6D M]Q)RP9V&G@F#(Q;6>4DL,3+7<6FN"ME]KTB<%>T$YMUWZ+*ZF7^K5MLDBG6Z M_=GUJJIVURCV$^I4NV MA@A&Y0Q;K84QEOMMD)%V'$GFRKIY>2:>C QBAOTF M,0VIV9']8Q67UTL[7]<7>>Y6U?I3]:U:W%6?JHOE]6+^/]6E^EHW/;)YY>E MP*C.?FJ]A@Q#YNK246X7<(=0+9(\463%LK=H:90[#9KDM8TK]K_N9O&!^J+K MYI$I-'YZY?W?"Q@[K@G"BCNBG%:1 +QUU&*59!3V/\E^JR0?%?QR.6WNOM[= MQ"%]>Y%KVOW[;K[Y_F'U:W4?502G6->[?ST:!IPIXBB"QHNXBF F; ,Y0&F+ M>G^/_%OE^X2BR!599I9?;U?5E]KZ_%;M+I$=&M5>".( /US]-OMKKQTVT9<" MA%))ZJ@3EE/O$1=8M5!JD73.U-^U5SRKSPO[^=-F-/]^VJ\V*\9]YU(ZLEQ> M_CF_J7NRQ?AY&I/L'ZQ+15ULMLKC:C/_G^UV>U\^ZHUGU+242,*$0(HP;;"D M #I "#2"H_I*?_=5"[*O!DU$>+$@K@F*.DL]!(S21H0I/.93KZ&9]3L+,ST MC)K]H"HU$\>18>KOO\S^>[DR-[/UJ2#@'F\)V%A+L?5*>!/Q4Q IT. &HR:? MAV)39>7LS(K.V::&(IA!_SO2^8>N_SK[>CHK?,\W!6Z\E\!*0+D'E!E,@6B@ M,-J5>QMM$GEWY]2(8/[0_"KM4.\UTBI_\-#=>A.-E]6GZF:KWZZ_S&]/WX$Z MTBH(#AFCCG,I'%&*&!^'>S]$!%!9YWJ3R>]YO-!H@/4_FOL\NZG69AG-XW4] M;XY7B=[_<% LOI0)!J#$U@G "#=-'[562;KP9(=P4PMU-)QRS.^H2J]F%YN[ MV$1$9'9VFIH.&R&2)1,RH\QV:%/+CZ,!]AY54E_M[E;57L< M7^J/]9;P:7KER=<&)*")MJ&)6YCU%G@O$&Y 0JBUE!%C"PAE<3-Q1'M^YO"+IL/=8RV>M B" &*$ M99&['$L2]\N:1[OA68]**(DR0"8'HRB&@%!JR$1[<4[?K2-4Z_7GW7=/!4D< M;1>PIY9MO:< (J %E/X!:P!/\?^\81&)8CYT?7@$@')<']WU[O25T)IWG,A\!G%HVGF M]C\8.!4 &XNA9U )3*F%I.D;Y+ L1WPBK,L1$4A(+A;5T*X"VOML\ IJ0015 M%$D$A#)4B::'G+(D\WHR)^)P&8T!0G\Q_7(QN^@HI7V/!H"C16X@I<;7]I(V M&+6F3 M:C1/YJ<:+J,1,$A8[M;SKC+:]VC@SF(I9)SG4A "N:6(-OTSVB8M=I-Y=D98 M[(9CT%D7G+;BF%34&:6M)MAR9K@SK-65$"=)+KF)*XZ-9.&58G2=16:#E8X_[C:',RP^ M>R*8J/%0+"4 BFEM'=&ZW5XA\9FN^O2M%]89P^48H\[@O&C6\W^NYIM-M?AP M=;4-R:XN?UO6(;T?KAIS__>(=@>G?:?W!(N8-0(JJ#Q$R$,*N&M@T-R694R/ MY_N>$J2,7'ETI-2!$8^>#D9(!J1AR" "/5(<>=7J"PPGV7Z3&>CCRST=BHS2 M_7FU7' MSN:KZE)=7.SR,527NU_MZC=WDO3)=P3NB4:$<,:YCI9779^B]3D1CI(V\\GG M]9@L&!NBC SI0(!0Y\I#0! 6S3SHE79Q".U6I$!9/KLIY-L3@>P3O/=L;GD) M&>*&4:<940IJ)S#W+2\)+>O:RG13-Q&/C()6%_^^JY<8>[>JL\]L4_QU$/>^ M9D%H"@BK"QY+C#5$A)K6C-$8J*)\AU,(?014\H=TO0A/:P9QOKBN=XO[<9Z^ M5_Z^0^A7RNM"U,*)14902CU6VG).^"X2SPG!R*D\75-'AYT84_>@L2XO"G7: M3DL] -P+HBPB"+<7]QW!F8IC'8TEFU;(!\/-)H!O_"BTO8ZUAZ[N,ED?.&LX M]&@P$'F*?-S62'PQ!?$_[1T0J7S2:5ZV\+%QQ;8<%:K^/M+G'SWHNC[\<'#( M*0WP]F12DCJXA1\\L MNK\@<*61B2N1T=8+# 4EMAT+!SC3.GM"JQY#%LL,\)SWCLY$^>V(LUZB^M)[ MA-,;@^O(A_;N.TQ**9OMZ'^2G7AZ%,]+I(ESD&W3XTJIN*QKJ.$X<05MU&*M M/2].%YA4W@.3D:6!^4/SJQ15Y373*CN=FB1->K;NH0SU:!V\0(@*[;'0F#IH M##/MD#T$99WO3R;/ [FQQ@,N U=Z.&M.Z$D]WQ2LHUA0A)"F0&%N(N"N@4)* MGJ1-]S]S*E%7FA;)\Y.JYYZ6\+8 ZLLKW'MM@(Z3#%K#60.)8U@4JS=-)OM^ M'!L1U+_Y%J$I38]ZS30;ZC+Z5"VJ/^L%VBVJU?5W4ZWNJTM5QSU%)]N%.G>R ME1IR:!45F &H?*LY,)WI<*:C6C2I:);3P?8F%&@,)8)&<<\TUAHK!A_T0(9\ M63<9B7]6->NK2U77-;ZNXC2XNKMY/[\Z%D(RY+4!.8\X<4 H)Y$D MR&*D'T!*TUS/M1.-R[&,L&:UD8[.FDYVT=$W!%)OSPA[K TBE%CG68NWTFE9 M&LZUIXW+J&D03#PTGS\[))X=9L#)-L$+[2%%!-2L9X 2#=MMGN/_G[TW[6XC M1]8&_]$=[,M'K#6^K\OVV*ZN,_,%AR93,F]33%TN[G+_^D&2S)0L)X;L]N'HR:%H>[OT++SH];[>ZJ-YI,3 M+'I[)-8T[PL"1)'AFE.ND42&X*B'2H"]4PI8#>&I4.HR>!P*,LWW\$ \@-HQ M)@'W'%.HM5 M#K!8HX*]@:>WXGA]8Y#SAZ?F4C6:_L!/!<5&L]%\7'WZ6E6K MN->HR60C!Z.9G2Z;9:\75=QSXQ\>Z^6HR;=;/\:]9SQ;3Z;S^V9,W?3C75>3 M]X^[ZB"GKZ)*+"!@2U$4#2 @4HQ[193!G:!XD=06O:>XVUO(Z$_*SP"94D#Q MOHB$LRXH$I\8HG*A*3-66ZDY=ZK1-UIHJ'1ZP)=BPQ*=^I;\^(_(/H-H>/=J M?TM)O=8@_5!'G"9_3N>3#XOZ?ZKQB9CM0\.#,=1[QS$"UC$+E8PF6[M.24VI M:]CSS-#>F5%G1^QRSIJX[D5]HO[=CX,"=TA0Y[3D2'-+E2.^:Y@U@#3RA76!B(.O'5/*UR>D\!]P-0P?M#]I<.DK::.6&] MH)PYSBE@'L(6"FO5\$H"]LKO*Z.ET\#\6\O7T)3VL(<*QYA(@GMG(=6N.1_B@M-7>&%+WA-?E/,[1.)X#()55 M42$#WD2EVH@GRTPA*P>ENY;@:1:<"L;\7=\X7@-.H0140\\L;@QRTFGV3(,D M$1A,X_A+12 O6)=_T[^/YJ/[ZLS]>O_@8 W%BB!+C $< \0C^9VZ;5A2#<3! M='Y/^::SX'0Y+]W#=+.'J-FL_E?C5SO.S4/# R4,2D.,]-8I!QRWJ+O@4U0- MJ[)^"7YF0FK8D;: 0V:U,@X:A+U$#G<;#? VJ20:>ZU,SP-2B5-YO5S5#]6B M/3[..)7WSPC41&H<8,P*;J@AA"/1^=L42>(_?^W\SP-603G8U--NU,BOT\?S M96'/K$!D4PD2.$<)5%Y"+_&3 HI=DM$M?A5YN!ZP C*Q-VCMI$PONZ)A%2?[-026C7\K"'# 5^&@_ M+T:3ZF&T^.=2S2>;/S0TG_Z$C\X+3"FG&B&5$+ HL]K+SHL+M$\RC >5DI[Z M0>>$+3%GKU"A6PT,U5)* [&'!$ 3=?R.%NB3>,(?/?$*P!$,)K?,2*XHHCDAT,8F8BB0WZ^6B\UK, MX'Y0+2%0V\7M6?9)V^/4U(#B/DJ ]'Q3; H2K>,WU%TZL>'6O,W.S9?2T@]R MO[BX#,TN';R4W$HZ]H?,G]1FSY@=C*!6($$Q!RSB*IR!W;TF]'9872SS,7"_ M9&1$ZK9AN>^JE?JRW%Q>#!HP"!&Y<:9[ MKY#>5I9.=<4]-34TM:*AU5)!(:E%CBG=F122\*2@HEL$\R8Q\'SY2 'KMI+Q MK.6K>J@7J^F_-QMFFJP<>%@ $0H>#06L)%/1+J6$=ENZ%"+)Z7*+L.&>I2VO\-Q?N]31,QHW M7_JH8+2RA!#,3-0=.5*8R2[X W&6=$N3?7\9B';3,[A%)&W/H7N9?)WS@, U M,1%62;$1T (447VZTO)IV;?9=Z/!2%4/D-Y EN+6>HTD[9L>&!# (>8$TQXZ MQ2E1W=T)@K20T_AURE$&0)^DJ%1IP7>C1>-V^%;=L+5UN\:W9_2M_FELB%:+ M=39J%<9Y0"Q22A 0-1A-.">(G@H5[24A:+=9!. M9%J="XZS#^%S>;A=R<&;D9=#@E/06R,Q0 @@IHAF<=V[Y3+*Y. NS*["O,Z* MPN"9-Y3KJYOP[-J@&;V^NQO-ZM]&CT=#8UX."PPCJXFRGG'MK-(<.MZN2U%= MJ++G"84T'OER "DB'8]LUQ!PJ@R'&/3&B/,X(A01#AB%M":,R+>JHMTO=_-R_"HV";#Z#L7%?U-QXZ3E733,G@:GJ9)1B MEE2'NK=[U_RLO)#^ LQK=Y!-SZ3E!MH/U6(8?]1-Y-R;^:I:5,NS MNENE/3!(H)QA'#B*A'70*-2:P!'9:$(-0O7*+QA%T"JX![0KM.M%7'@D95H? M$Y9CTP+A43,UCF-NH<)"XOBUM$0ZPI/NVGLK+Y5_K\B R>6Z^L]GSN._6 M#?'UW?.ZYP=4^/,?$+B642^AD00,+8S_IMIU>Z%-Z]G:6R6IZ_G;*SH)G*[F MNY!E,WH(+>:COEWX%30"C(2Q^W MD'^,9NOJJ0G*&9S=,RMH2#2$B%G/&V^#I%9U0 %FD]STO=5KRL_GZR$I'_GQ M=&U[)'SSAE$A1U;U]HQ D7.F!TR,DP(Y#IHR>\SK)DDX6E42.Z.Q/&4S]!T[ M M4W.8)BE@4XU!&$\8T A*U^+F)4JZI"H6U9)/*JYH G,9@K?-J^BY20<5B"-* MN%4HJL("$&Q;N*5#G@XNR*97?E_9K2,-S+^U? TE#N@UBU5Q<3+U?%G/II.- MN;W1%TX<;_LG!*4C>D[$K9XI@J.Q8*AN"?-Z4&W."IYD6<"ZB12?5\GIHN_P06%R$%8K4'=K.G8I/*?:>K$'V;%00VC% D8:. M6 JY@K)3:@S!>KC=@A.XL(^/5\'P*CDZM'VX+".+,_!YY9_W=R]WHB,\/3XQ M:(^\%,[RQO30&$C&U M;^;QQ^KSZ*]^GVWJA\=ZWJA-#?3=KX_?B6=YLZWNJL6BFL0_[,IMS2?/?O=V M.OHRG6T+4?:_&'=W5S6%+ZON=Q^K<3T?QQ5LY/+J&($VH7U/2PUHI!SU#\)K%WV",+KKGW MOX*80W?Z^P<&1IU@SE",L<2<0FPQVQ%A,>"WK R1 _HZ(_%E*D(DL/R N;)W M7("86P,(L%I0982/,/(=ST\7.Y_UYMX M^-77>O($P,^_K3:M?T[=X5SQV* T!8X@AKB)UAH4U&K7@H0U3LH<[NG&/].I M>P/8"LC6H=6>O HX/C$(V71GIX08;:2T*NJTLOL:H22#.\K+LKL]!^U*]"?OO#?R"B;*?+QWI;HNJI\."50KOWF8%&K2B:IAA2 M0@6V'%FKM_ 0( A-$L_>"C^]$O',@?3EOI=S5O;G=/7U:SUK^JYLH/E6+9:C MV:$B1%<\,0AK%/=($RW>5$ MO)]MSS[.?JX&=\6FM_=Y@2/<4(JD%H!'0X]3;[M/$;.D+:^W"EZO8,O+@?) M-KQ-R*^:_,]ZZ\Z]=H][^;@@&?$"8(DE("FA[UF43533A,DX\K;]5*>UGH@N],S,T,S I(_ M_>S9-=3VQZ:]A8]0[#N,=-7L1]V4 HE3W8\?1M\WB7"JZ4K\="A7TV^;7Q=8 MRG5M?@]LIRV27]6' M\JZ.C@\P*DG8,& M"2>BR7\8%^+9Q;"U @!MG%'(,:U;VA5WA0(XSPH/S\3$.A\O/SV?G,>[ Q.:)H&,<@"5U1@"205B[5HEHR+I3K&W"+5,G,N#18D\R;:^VV]5 M?;\8/7Z=CD>S?6,OQY3G!2*BND54!ZS7S$#\&6/$.'G+MX/$1%9=XQS*UL5TD424K9ZZER=-Y#-Q\H5[#.C!:+[W?UXE^CQ>1I#;;)&#BT M@UXT/R!LH^AAC:D'BG(1*6@U4*X+J-3-_*$?I<'E^+:__ MWVJTB+_DJSI:=>2H#;QO:% 40:*QYC2J$00Z2DQWAC"7UN8E^RG:$^1U5FP2 MKNWKI_4?Y=S/ T-< '6,N24%@ XBS1MU^:028JYR.YOZI]O5R-3QFW_,P*G MK][VSPF,,:F;SO5026$MALS:ECRO[)#*N?=V#9<%FEMQ_JQB.B=F!N@,T=)) MZYER!B(.<'=H06[; M!>P='S3@G!AED%46>B$8@KB-=O%>E>KH>/9=1AX>O>Q5G@&:RY6Y7343-5M5 MB_DF NWWB.7#^B&2>52Y.STQ(* A0M0Y3H'G42V-"V[7CB%,BMSO\W(Q*UM[ MP2B!O]L8[_]>+Z;+R72\B;0\SM>#$P)50JNF1H-#L/D_B!BT:S58#B-@NE=^ MYL*FP,[<:;!JO?I:+Z:K[R=T]_T3 A1$",DL\L0[ (@UBK2$66*2\@LO3]6_ MH>*>!9>;,/RD0G9H2HA:"A/"4J,LHQ 2PRWK3AWEAMN9Z5IFG>3]50#]8E(P M-'U\*,R_ =,W"L:L*= P7U>?JL6WZ;AZ\_'327W\Q,S '8,*8B*MQEBPN'V: M3CU1F@SKMO)ZAOTD 3G1*15WU!:!>ZZFG!2$$S.#UI+B)IP1 PN\18!XT)(* M+$T*-^N_9%\N0I%>\7ON6"% M;L!OQ?(,D-PL&?_'A/(/BVF]:&Z*\E7VW/?(@!D7 A-(7 18KA^8,_%C-HE1./M>?5O7XG^\?-[?@U62]]8)]KO5FJ[N?3__=]%E5 MC]/Q 0=C_A<%ARQU6A/O*>=*",VP:+$1CB1EL61/_.\GZ??F:-XL$F%#WL6Q M")M9P5GED6D\[S@JA81[Y#L2H5/#J#_:WS:3#YH"W/^YNN[+ KQM8=Z3(G'I MHX)FR!*FC,9***^:U"+:@N%$6@O7[/5$^Y.3GO$J(#S75>4^I](SXHH2Y:VD M)EJ$AA#E5$LR-S))1++7]NQ/1/)#E!0XO"NSMNR.N_B[38>.Y?N[YQ77MN;\ MM%I^6G]IZN1\KC\VA^%F_8W6?21+(-LK@K5"028\04PRH8V5GK1X4$2&4;*S M'W7EACB6O'SYL?C?.7+0X6+^GA5<-)PIYONP)(S*2),U'?*&Q!I8?'9:V4.?VM) M!+3 %O/'?-'9:\\H?BIE5LU'L]5T5\ML6\I1C<>+=34YH^5=AJ<'YB7""L=C MGB-D!(8&LLY'Q=(2Y^ K\@.7Q_"68K==__OY,X?VCI@4,3O\M"! &) 'R%EO!>5>6.@- [[;DY$91L/Q80A1 M7BA33IV497VH%PU"3;]*M5HMIE_6JVKY9]-4H8FBN_?KV>RLF]_"*P@$2X&Q MT8X*28UQ!&G>G>%1=QQ,O%L!P1PV]MDD6<4UC:>/VPN*C]5R/5N]F;^K5K8: M+ZK1LGI_=V!B0]YT#M'O]7SU=?G^3H]F#1V?OE9QS4!$2>Y ME]\:4MJO;\LUYH%S\C2 H$A=QBR1BBG')K; N!4K90&::]'=-ZYNE/X6?]0#8: M:&>U7;S4A]%B]?US-)J6HVUZB/[^_&].U(\Y_R&! :>P=2@./]/5)P9)ONO->4WE0@_K;\LIY/IZ$CUB(-C Z!8.*6= MMXXRBR16SU8(R# N;7(@7.=%HEB.0M>,0N^QHEAS8:W!6+3 6Z,+Q1T, M3,<8)/8ET@ O(>&L6L:)3PP2&,FHUPY XSE1# +90F.@D(/5=(8F.B_S$(OR MXS\B^PRBH2EE?U-)3930ML?9='/X;%N<;7]^V>%L^]MGI]2!@W[ON,"U101@ M"RV'WAG.J3 =7)@.J9]6_^=Q#HA*B7T+LYO> M5\-[TNZ^#(;+&?5I.OM6+3Y.)_?5A_I?)]IX[Q\<@'#<8R@8H20J$9I%C:([ MT1$KU->Y(*NRX)# JWHV6FQ>^.'CV[?F.*OVC0U:&V0)]QI"SK36%"+8K M9 0E^26SA^EEY50&&"YGE&ZNH#O=ZBB?]@T-B,JH"1/II1:& "2B!VFI%-FKF65E13+Q"9K;>C2N M9Y/1>=O7@=$!8T85D%9#*35SBC+2W1(1GI:7F;V:6%;M+0L0E[/K_>/]^#Q6 M[1D9N.(".^8DE(0C+"73G<:"B$[:U+)7\,K)INM!*. R?;_Z6BV>7#,GJ][O M'1^@D<921X&Q /M(8<2HVRB@&T;IK5R\S0G%Q6Z+\;:V_M9OL?O#2\?%[M?A M\\<]C'SZR^ ,\IIZ&T]9P[QV35FXSH:(!G^2V9N]\E4NMB43?OE&^7M\%3@@)8:1MMV"3=+A?DT_EI-UK/J_=U^P,_*@SG_(<$+&W41 MC@&0WF% J 0,&*0(A)N.YB\!P7(;:?7, PV95!@J9[?$ T\] M2\I4SIS^T@040Z&4\PTTD( X!IE!W'6DJ")@:\D?N5L3IP(=TB#XU5R=MCQ M*Z486O9N,&J 3#OO/$"<:!:-6L_;U0ACAAVKG M/3(0#N,_7B+K+54*8>U1JQ]KA<'@3OI2PG"U[%T%\'^D\ >0AJ*5_&K"=_6M MV,YKWWB\)F=<.9^<$XQ0"#GB7&.F,T)MXXG;K9AH5TH2\CD9K^-+W0]N*?>? M_W,YIX_-"5A#SHPQ3&JCE!:2$=.N&#B4= EVT^N)?)S.B%N!@^1C]:V:KX]> M9+5# HP8$"BPMQ$310@B@K2+%TPFA:;V]GD7<#,F E. J[\MZN7RPZ(^WKCO MV:@@,7-::(L<-IXI@*%6'0D.)?&VMP^Z &_3L2G WNVZFF[91[C[-"@X A2' M'!O9'#3, :DZ CRQP[K\*\#<9&@*\';;@=:L%R="5GX8%VP\\9F.ECAPS$LG MO1"N)>A(,>OAJ@LS\_ZS/>.#YQ3HA!@%G!NG%!-H&Q+EL1I!G7V5(K;<#X9 MI1L$I5X0>1J0BOL5PX!BQ(CSFDNON[/*L*1F>=G3,@JR_$J "G#[TZH>__-K M/8M0+[=3X![--N=;,G:Y2,WKD6HLL=9'_, M)]/EKNG&Q(T6\^G\?OG^[H#7;EOOIHI4?VS"ZN9/4P[XTG(]/HA(,L4,.FX] M1HAZ+7$G^TJE53?.GB%20%9NB.KETF7;93;5D#Y6XVKZK9KX"->!I1Z0HDL? M$QR7#B,"N"):$D6<(*U2Q+T3:?ZZU^BP*X#>Y5*A1\OITD[O[N*Q-A]7NEK] MJZKF;05[]="D1VU:-+8 '!"+BY\3!/&&, *\=<)@A ENTN.VE#GATV( 7Z.S MKP1\MXP&__[^;E\P^/N[_=D3?[M^"40"Q #3"@#4M#GUE&U:QCLDO57XU"W6 M[:#(UR^!,ZJP@U@0"04E4:Z=W4%@ 2IU99NQ7\+9/$WNEW 99/V&C5]CM>QJ M2VYW55,_/-;SAOH3 7%'YP5%N,01=BR5ESBR@EK?8N,U+12AVE.%Q+,9_Y-! MDP^R8HEIW2I/!@[M'1\44,)0SS@E@%)!F>"D):NQV@<;FY:)6WN3S?* ],O( MP- BPX;$^O*7RIO\[),%1YX/"]HI2)7UB%/#%)<& =?MB H7:H)SIB%Q)1]> MWB&GXW!Q;LFDFC9\),T/#?O(,_;%7X6WU?UHYN:KZ<$&1WM&!:&@)=@0Z UG M'%C;*$V[19NH1)4)^1C(67T]0-FYNEW)P:WWY9!@M=1.(@2EWQ3- TZWFJ^U MF*'!G;A785YG16'PS!O*47D3GEWK:FL+M)U5SJZM&\4=L41XA!Q7\6E2<-&N M"9J!E'E)1W)/^;HDPA.8<7UY:.0P,88!P"1G7FO,.GFC%":%LV5W7^9A30;Z M+^?0IG#NI\>XZ--EAI\-"\@QJ3&WLHF4Q%XVQ5;:=3$&DQ2*[&&&6?AR)>DE MDHLOJ@J C<'$:F605P1RB)I*E:VV9%F2'C^8QA:7JH(Y(!ID^K@0WG-,B1+ M"@D<94TZPY8$"8P>G()X)2=.Y)&GP?$J.3L4[?&V#+V2D3E+?5H""1,8:&FH ML=1("&JU8Z\QQ M#HMAY+;EXDTV'*[BU9O5:';<$M@_."#@N-QT)[5"*.V!\JW>Y;2D2=>7Q9I: M7,FK=!RNY]5H/CG#0#@Z*1##'(:>.V>-E]Q&O9NW:X8JK<%NL4X7.7AW%1XI M 4?7=2:AW!L#A# *(H(TQU;0=GU*R*3(Y&)=,%+XE0&%R[ET6?4AA;&03=:# M!@1!"*##K?'J.$_[AHJUPTCA23KQ":RXJ#.)EU112B1U& ,N;---L5T-IBQ) MI2O6]B*)%V M[99'ZT9&A9EPQPSUVK+VB/"<\*1\O*BBDZD9=AH__B.RSR :BE_S;RZI5VMWL_K+)D-A,5JN M%NMQT['APVBQ:BKQ']?X3DX,',:S2F-IG2""B:8[0!O?Y2VTP[C'+\:@ND?L M^C:PA+66&B8@9U$9YCXNK)-ZK])JG/26M522D^D@%3A,U'B\?EC/XHXXV31H M:^(O%]779D/]5FWWRZ80S[MJ]?[N\^BO(X?(A4]JZH!8+1@#CF/0[)> M/XT M3P0=UI=?)LFE7PB+Q:67:IH3,14 22EULW%)Z"SNR!=:)1ER-ZUR>+T$]05> M$??#+^## M>C'^.EI6'Q;3<:7N%U5U)&7[DD<$C[%2'LKFR@%S1I%HE7T%&,9)232]E7;K M5T!ZQJ[ 'O1;!+$Y8=_//XV:E':]7D8TCM9Q/#0E*.D,,1!$A=%);:PVV+;$ M<0R3RCOT5@BNS,Z1":O+-X6W]?S^<[5X>%:@JMNB)G].5U]M]675R>7':KF> M12/@_LUVM7J6;&L>?JS&]?V\:?FWW10[9-Y6WZI#PI3\ MO. \W+1I=LII B##@OJ64DUY4J>;WHK1]2\_I8"\G5756(B?OX[FGZN'QWHQ M6GQ_(OER\^K(PX+E3%(NA:?$0VRU9J0[IC'CPZIY=U,[*Q^*"3M1MXQG6OD> MR^]3/9L$3 $K&*-<*4V=PTPG>M?0XE-97I+>Z> 7VF_ZP*Y)=_GW; M1*I6XRC:BZI5S3867%O<\;FY=V2+N?QAP4(O )46-Y5"*?>\"ZY3($*>5N>F MM\IY9?:8WF$L(5>+>EQ5DV53RN>?/1+#>L>MI]W]_]H]Z:"3M:=I_6 MOA/QN@?&/=X(: D70!(@L')4H188:V%:,=!7[IXN F6Q4+G&TFP^F0.%#T]& MNIV8'Z*6:%FD,JH$0 -%)8.X)9M%NI,DZ-4[G_,C=S,3[EVU:AQARW;_O=AL M>_F @)C6!FMKJ)7,22F)!2WA1I*TT^V5NJ-[A>YF,O.Q<:U\63+[6-9;A8 M>@X_*CCFG":(.HED-%LQ1[Y5)"$7-*TV\2OW7O<,XN46_X=%M1K]-8LOK>\F MFY=6DR^=QN;^V@6UW,>5U?/);E737:'M^-]MI$L<47>A+@<< SV\*5".$3)< M1WT1XWBF ]#Y_.-O3%J.[2MV>-\>XR<)+%D+>1.W?JBJ\6XYU[[Z]]'BGQ'= M^*)/U7B]V-PFE'_C\0+./;ZX)X@W[LZM0A9YZ_YZK.;+JLQ;WM7SG9@W]D+S M=S>MCMUW6'&WLYRT*8JL(EA, 16JOE^, M'K].QZ/9N=7(7\X)%#B&J!"6*8B9)D)HUV+BH"M4FO;")+R!B\ MOA*!_Y0'R):]J1PG6!IMC>>:( *DXRWP-/XA1?0NO[;[I32307+N;Y6I#2(. M1BH/C(-2.,S-TVZB* :#59&&)CJ94K;3^/$?D7T&T= TN;^II%Y[B:6JI1DM MFOB/^?'R43\/#%1*PB23LKGL-X R)D&[-LS9L+3$WAE09\3J,F]L6Z;7^Y^[BN$<.^+^PP;C!ID]W$^IW//[XLMH"=Z/RP:77GU_4,4 M_D;LFSCRQ^=9^OV_:6/G?:Q6T\7F.WS_93:]WWX_?0G4P:4\=>U^?_?A\99A MFP>7^/:,:,O3DP-A"E&&M(QZK_$0&NGCJ>,M4HHP<+( 4$_1%N.OU63=V/X' M*3@5Y7CN(X)%V'K,O(B&(?%&,XW$#@#$+4M+(LD;IIB3C2_C,/J!::CA@3^< MVF8V6BZG=]/Q9I,Y<:]_8F8@4LEH+3IL"$:&&VV!;/$!2B=56.LY5# _[X_= MYER-6>E[Q1\7?-D-XKZYP43=#RO5E IKVL(")B5MR456NL%>;V?CX_GR<15D MO[RD#.U6>;@"2N;OR.U;MZM=\V/'B=?.43@\8.0 .A DAJSKE" ML-VU,1&\5&A"PKWS=9P^)D.]P5>F2LW^0UI__QS7<$)_.6-VH!( A;!D&'+" M++7,L)9D:%W2C4//086]ZS#Y<;NEJ#1+/GD^G3$[.!;1$$FMB1M\/+=W('D'AM$$O1>N MORS\40[%(O71IK/F/B6NN_WQS=5IK/FA](I \H" F0G$2]TC'9 MZ7A-2>9!A6SU*3Q]P%5 2OQZ,=\4 8SK]M._-KT;3HK&X4E!:@P=@PYRY1%1 M5&'4P4>92@KAZRT.JT]YR(;1+167;:'CN(S3,G'V,P*,1B$0\1,@D GDD<$: MMN1;F28BO45E]2DB?4%60&(^CN;WI^SE;DRPACC A3#"4@84Q]*:SA' ::'@ MS&%9Q:GHE&+NR0_^V:@ $(%6*$VD%0(1%\44M'=GD:#A]K1-X,(^/EX%PZOD MZ- LS;*,+,[ WR.:#^N'DRS\85QP$EDO>%0ZM?<,QYT)\I8,KZ$:E&67A'^= MC_P27!S]=1X7GX\+W&" C27< "P4LI"CC@PKTS[%WDRL+%R\@OR;:\O)*G)@ M,JH+LK[7'@)JL,!60AV?=7&WUN*B:UE7-I5OU.*M6 M6\>1>J@7J^F_-[\_&29XO.?N5:\(WALL/+/&6\DA]ISJIX\)DR0'J@&"8 MT>-TM:UAW<3FKE?5XE-]M_K7:%$=EXKC$T,\UWF3^B5IU+44]S(*?DLHT"@I M4:&\.^=ZD<@*TRTWBC^6U=UZ]G9Z=RPX^(S900FIG(#8$40;-=!BV9W43O&D M&*S>TN=NL5DD8Y4_(^7@&I\?C[O\B5:LGY^0<--I:&4OJ M:$)"'ZRL"X UU+2$0\2>N*,X-BU(!)UG$"(,^[OE6M\@80@N5W[[HVB(W MS\\4J02X"F@XAU9[,A3K^,3@D,94Z @@1(QK8;Q2+:$6H^%&[N5AWYDR<158 MO[!T#.WF9(A"<8$P["T88NIYM?PVG]PED:3"2("9 M!\ZW*^35R_GV?YH7SILZ A&YHUS;,S((I[ETCAK)#*5& M2(?;U4DL<5)MC=Z#XX/#2 @# M4#1]@74^:B;4M2MUD W+M=@#]W(A6"84QMRXN M4WK1F2>*JZ3SKC?_7P]\NQZ3RSGV_TT?'JK%.1S;,S) #XAF%F"D!'1&&$@Z M>8JG?))=TYM?K@>.78])8?6T#4R/M!^)2/_T?;FJ3@<77/?@H!465 N(@,?: M:L$OJ9_>+.\#ABY\3 MM$=8<"@(98Q#K4$4UY8RH7S2Q5YQ$RB#/[4$>C?T=W17)NJAZ4K37)S,X\:U M'C?$_5DO_OFF"7^XCR"F.%(O>'HPT4+1C'-/%$',4< 0VT&FE.))9=Z+VV\% M'/C]87I#,6RN])KKQ'H^6E4=A9^^CA8I%T)'GA:@Y5X#:Z6*9RWA0A*"6DBT MT$GEJHH;F@7$+!^&EY]Z3]NK&3V.QIM^[/>C/T>KP^7D#\\()C[>2*[B?HRX M,-IZ#]K54@=H"L>+FZB93K)\.-UPL_AM42^7/VV#.Y@^58MOTW'*KG'.8X.C M7DKMP2^T4)YU+7)G$:G?%K><"VTD>P/(\VA)QU[?@!:"B(P M6^(9091&GJFHW=J3!2OZ(;IDP55,G5,*",,Q,P)#0I'= M 4 !\H4J95Y;]LQ:3^)$3VA*N"-2##8_JB;\O\XS[1/%O)$9#BZ-Z M5=)S.ZGI5GJZ',&!*0$99:@%4-F(F4=04F):XBA5A>K-GYL0G9EAA^3A.I * M2, ^XD_*P.%) 5F" );(1**XU99:PEKU$1.2=#W57UI\OU*0#::;)ZBF6(;; MO'"B(9+&2V$$D9AJCC!I"?76#:M8OD]TL$W_USK\[G_;-LO5^V:$KZK5DW5GA3:*+NG0)2"DP$MEY#IEIT@+%)Q35OF6U_J;@- ]>"CMZ>.I-]K"95 M]= \^].J'O_S_=VG]9?E=#(=+::EW_9NM&B8]>V6_NG/U<-CO1@MOC>XK[Z? MXY4^-"4P+5T38J^=!\@0&;Z-.3 M@_6*$.<90A 3H*.]2MV.:"8=&H+_^7J&U3W#,E1_<]?%^7D^,LKC(Q8%5#17ZSRI(=O[_C@C&)8$&2 MQ)H("QPC+5F8>#A8OW F;KVL-I\1I%]&!H;FU!T2Z\M;YEW?Y@^CZ>3-?%?@ MY:33[NB\8#REQCM!/>>4*,$ 8CLRN89H6-[;*SGUTFS."$P!_C]=J&YA^+U: M?:WCLK]5R]73-_'\MU7U;O1PJB[X-8\-7"-! :-2-U+?OD6# MK3[UB')0%CMB?E[MF6?-H8F!(Q6_IJ9D/A/"*JHCU"VA\6L;[H5T&?;N/9PR M@_D+2\_@5)97*#37NGG??%!OS7O7!)0^+J;+:OEF/OZOHPF/1V8$#J6"U%#% M553M7#R6F>U6BT52'8F>-93KD:_[P.;LSWY9C?_KOO[V?TVJ:?/%D^:'ALWD MV8<>?Q7>5O>C65Q9)/F EK%G5%"J:;*C(#=0>26H4DYV4NW3*FOWW'^D!Z7A M>F2RLW.[DH,[],LA03"H"'72<$.C $+K2$LR]]P/K__W59C765$8//.& MA&=7GX"/L^Z:Y?OQD^_GD4%YR@PB4AG4-#)R#'#PQ!UEX12>^:5A>WR+>!)B5J79Y[>6O.X%I=2;+VH0Y9FT O'K<2 8BT D0BT)'AG MU.!TD2NX<*155AH,KY*C0U%0;L/(X@Q,ZWEF);$"0\PEELP::'&W-PD1#Y-! MJ#)7X7^TY]EEY)?@8E+/,]4TRR"(8T@U5%P@:%J53"CNAE4*)@L7KR"_4/#^ MMK7#;Q&1MTUF__S)I7A,%SHQ,R"*(5-,&4Z;4HD*:=^1:@BS@_I>LT<5Y46G MQ)W@J/$L;W3!INK0=+*+O?Q8C:OIMVKRH5ILRN"-QB<*(5SVH 4$]A(QI07 MW,37L$JDOW5AH2^J^=-7%M$,[[DOBT!L;MF'RT6W^-O MM\4:CBEM"8\+2EH #&!Q*\7804[3?4',;X:7A2;!@2AMM/< $RP-@^WMB6 Z M33GMK1!5WR&TY0&]W'77UGW\$(=4BT63PAOWX$_5\\#Y X4V]TT)7$$F(>$\ MKA4:!;D5K7H8?ZV2PF![*QZ530 RPW(Y&U]0HN;S]6AFI]_B03J??*SB+Q?5 M@1RR2Z8'I:$E/!ZR2!,7]TXIN6CIL#8M5J"WNDQ9V=L31.7/E.:@?'C<9JU- MQU74K$[5H#SO 0%KY0'AC-.X26%N ?:\)5QKFK3W]U9%N>^]/P](Z?MYHT57 MXW63B/3_-.7[J\7RS^GJ:[U>-9&9K=PN/]?1&*O_6>EZM)C4=S8*\3AR9;G) M/6OT[_7!?, >WA0:,!"6&%I'/2*"<]#>0DIB?%(^H!B\" T#S719:Q=JMBFS M3>Y;N\XWD1.+:K3((6BY7M,T^8&<(D6PHZ#)CM38=M\@DDFFMGQ54G8C*/,G MFAY-Q3SZE[UEHF[*5-2+[UV"[MOIZ,NN@'KAUR6EH.[OH+.+N:SO7KYQ],,; MWQY)-4UZ3G .(&H!4=A)Z!C%4D'/A '&"<]/7C!GI>Y09NG%SPC R>Q-Y09 M'K]?(QQ4.ZJH-*!0+8^]":8]LZDN ]E0DT]?4'HJSN+GT<'9>*Q#2YD'.NZS M*I[KH,6!TK1V]#TEFO;(Y/U5HJX JHB3^(=%GEM'[L?QP<3-BS596 1QB:B+ M9.$=60S[ 3=GO8I'Q_E]%32_#.<'%[YQC?T]GGJ##>Q>UK7'_; M>//<.BL1>TVR%C\9U!W MQE>RIBZ&4R[^/V^#9NKE:OF$@*^JKB9/JEQ<_OC@O.,&6D^ 8$QZS"!U+0Y. MP(%%D_0L+[WC=[DS;:%(O7B[VJ'ROILRU 6R^.?\RICPJ&.A1W+P"40D9S@Z#V+7W$B"374&]7K/G$H !6E\O" M1E%XZ;F1;+#?EJHF(RR:M[<,\(TF%87J[(,W'V7R0%+746]_4 MH3SL$S."U1QH)[DCU!A I:2NM4UXM$T*E>\>K)_N&K!N(P<7>&U>S E<"MC$ M.&M!!6G^D;@]L^+W0^4K\-DE\NLT_Z^"Z)>3A.'Z\&XM #E].6ZYFCXTQ;T_ MQG^9KTUZ2[>%K-Q]\WG:-'#Z>U]V-3 D< @T83TH@IZP@SZDG^@4TRU@IXW')P-B,N MJ5_Q"Q5%CY:5FOS/>IM4=,8'?,;\P(5'#E-.G'5(B*CO2-12HA!,JN19P+>6 M[]O-#U)/%S"7;]WG/BIP!J5QQ FOC<"88(P[<48F+:>F@-\M]P;>$UZ%+V2N MD9.T5X0FX-LS!!U&<4L$4+/NNI-3S9+ZJ13PZ?4G/T5P+& 5;+;$C]5J%_7_ M_LML>K]M.G^6B_^3E:&9LR@=C+7NW C( %YI!&\Q0T.3U<&P#:ZP?AI1Y&:8'QT.*6 M[8B16O!A> INR_H+,;J-6_^2@^#EI, %@( SJV&D#%%LK9(=@9PDG079/06W M$H(KT;J-.%QX(NR9%R#75DABF5'4:!!U*]OJ/I(9G%1P+[OY?W.A2 8LH4Y" MO1K-'JO%M)[!ZP""Y^3O .81 W/2\IEQYQTP;8AI/ M038,8[Y<[E?? -YDR]A?,^7H^""P X8*8^/A"(DP$HGVXDM"#8=1->'66\3E M0%V^-7S8"&-]MZWLL?5;/MUW'-@'CD\*6AECHA&M&%&"1#/8VZ"W?W^V4V)=X^'KQY]?I M^.N[^F.U6B_FSPM=VO4B/F%W#?)]^QV\67Y8U$W5A)Y'+5Y/J6$VFXW^KOW^L'B-YFZ)5VXHTOT(1)\4M M)@QPZY1VD@JO 02$,L(-4M*]TB).4!@.F91,0NQ)E'1-[(XJR)U(RKJ_:1&G ML]F47,3I,LA& RWB]&DU6FW>J-?+"-YRN?M4EZ<:@Q^;%XBGP#%&D4 8$.0! M9JK%AA)1J.A'3PEC9S/^96. C) 5\ FW>_:I!*$?Q@6")":""ZPPD=8U01(= M&1XK.]CTL$S<>(,[?JOFNJ\@9P9LO!P?BJ$32 M1"KCH>@4$$WCL=W9" 4M57SKO!"_1'A_"M2\$H7+.?7'\DPN_3PP..,05YY2 M;C Q47>Q4K9K(QXDQ=KWEI)U/8>N1N!R[OP^'HW/Y,^^H8$J+*R.4N,TLQ)! M!2EHUP=@6N!S;RE5UW,H P8#CWS#BE(E$>" :RHA\)9U J<2Z[4/Q E[J2V4 M":-7$[?@XI?@93SYE4>&:,*1-2U9#,FDT*:!.$BO9WTZ4*7=4;V509\U^=X? M1HO5]V>-V\J]J.7Z^[OG([;MY#8D?QA]W_PWR;V6ZT/4V\Q]0PX3$"IWQ3/5E,>YGRG&V-__/9WQQPU5WUO""T0IP@1%'\ M*@U3K+G#VD'C'$L*U\[DMLO/WI=V5P'$ANJU.X_BD]6>SGU(4,IPHIEK;DH5 MTX91:5K4%!6%+,:S_'F%Q..G\[(G+(LH44\K/*,I818GC$X+U MV&J*L$0&,&$0QK@[QSU7A?K G)TXG,Z8E[G].> HP&>[WE2B?4;Y<5MY[_C M$#4<$HNLD(XC[:7R&[*DB"Y"0*/E?%9.V)E/ M" )P):0&DD,#M(3&/ 'IO3X5%5&ZAEA_8M$#6GWX42[Q-#P?\8NZ&"#32@GA M.2:BZ<#AN&V^7(&M5!*SO[.+@;FH^W# I8(J"JEWQND=-)PPF!8^6MC%<#9[ ML[@8+D-LJ"Z&38_?C]7CKCS:KC[BJ:B@@Y-"M)X5) 99(H1# BFI38L*\Z44 MAP(NA+/9_U+8/&V:3$D9Y:2MQ&';@6L@(2L%O X$DRU[>MZ/-FT_;B_=VGT>R$&)R8&Z@B3 %#J<-"*2L0I*H# MD/FD2Z7;A1VDBT->G J(Q9OYJEIL>B,W';.?(W-$'@Y/"@![@0D"SB.HC8'> M8=82"+3F*8+08X>SG@0A&T %)<#]]1@5ITM%8,^L *G01CJ!-3.0,J H>MK[ MO!]:@[.>9>!ZA,K%'17.W'K^\Y_3U==/T_OY]&XZ'LU7F\N8K_4L,O]7C77" M1$6ALM8##)2@3&GM'#(:2F@]/%G(]U>.=5+($.B8I41PS85V<;_<0<,T3:QF M5CC6Z6SV9HEUN@RQOTNL$Y0&&X"4B=:ZY@!#;T6+BD+NUXEU.IO]Y\TI:9K :KZC@1MK2EV"9XAU.IL;E\M 29(F&@U4>^F#: MZ9NO-+A^ 3D8FKHP3/9?JS28K]-Y?$_;=,#4B\=Z&]03C[6C=>7.F!DB]1X( MQP4SR"IJ%._VQZ9W5%)+K9*WFV>C7_>)R^TTA#258/,-2$114XT4>P$ I0@! M@5I'CI,@*:5VD,%/F76 !/!N)Q\7[?L_S0M ",FBAHRI=H1II!1X[7Z6I\M#0>F1Z(9@PP;A9 F5 M(#&Z!-):]LL":+&*1!ZH> MHBNFRW\V)7'_F(^KQ2KB]3S*,E]0Q;ZWW#!4XH_Y>KD>S9IEO5\\+>K[.;$2 M)^<&1CS"BC.&A6]"YHQS%-!HTT*I.+6G8HK*DGPJ*.+HO("8H/&% E%A6)1D MKSG MAO.70[&(3?M\C6>8LC\/#QZ1J%I!U[2HX!H(8V!'E+&$#-:W48:5/]FZV2#\ M1>1C:!Z.UR,6UUZ)?!@M5Y-UM7CJ4'#T'N30\ 4HMPQ8#F&$@A O>SV4FC3 M^G+TZ*2X!NDZ.QQG?\7+:OQ?]_6W:(1,FP^8-#\T/"7/OMOXJ_"VNA_-MKEF M!S2"/:,"!9(2PX 1Q$EJ@>,$M(MVB"1IE3U',N0]X*\')3LGMRLYN.N^'!($ MCU:RT]Q1!*EF4#5UC=K-QW,^N)/X*LSKK"@,GGE#.29OPK-K3[K?1XOIZM^C MX^WCGH\)'G"B,131,,4*24L][$@R3)4*VCA^IJ7C6.>ANX *>FB7U]_?C5;K MQ2FK]YSI@4+J$"0.2HHUDXH1JEJB/41)V(85;AY4$>+A53/*R]$QYR0#=WT1NAG*LOQYQ*2XF:C:K M_Q6M_\K7"UNOOZSNUK/62?!D31[SO)[U@$"-T)C&+5LR12$G%DK?$DXQ&U9Y MU?Y<_+V@54),?EKC;XMZ>8Y'_L6,(+UD4CH'6!1_HK#UHM7B%,8Z*9BTMRO^ M'@4A"SP%./]NW4#T_N[]XZ9,X/R^[5=_A/<'YP2&D-'>)[%+U- M),F1C_FL^0%#;IQRR&M*9-1Q:,2R)1O&/Z9(!'T]$M$G6)=_Y%NWR9_3266G MR^;V/RJ@[^>_54VBX^/7Z5@UD43/ZG59// M=517JNG]W#1GUF):+3]$8WY_TZZB[P\>.2DX44P@("PGC$/='9< ))TG[/6( MW9#![E]LW5^K:C$?S$D-X9*D2B@(AA8"=\6=I4MHU M_[6%M0#.J3K4^[M/<4.?5=W2/G\=K79J?36):_MK_X/2[U_=WG>A41 MW5)W5..Z\MD!4Q5/%N48THARB(ASK0]#L:B>I$B:>%V2=@L@\X?3MLEL;TP] MGS2EU-I@C='LS?RN7CQL=N_W=Q]&SWMH9HNSO>SU>C1K7!N?OE;5ZH;!N-U: MGZ_GTVJTVD0Z+LWH<7/BO3TC-O?21P4O*1%:0"ZAL-&0$Y1PX..):01&&IYR M<]T"D%,!NV?,#M [)3663&//F69<>]N2C?G)H.@]Q)2$PT>A$&DUTC5H0A8(!5(S;9KUH)/-LIK\8'PA06B/ MN9)8: QE%.F6+!Z_CT'Q/I4E>SE['1*_S+4)%P)2 3Q&%BB,"8&&[LB6 /I2 M$327"$ RYY*N2BX#J$C6T++IG+>J)M=*R(5/"B)^;DRYN)=ZJZ6)R'C30H%8 M6K15;Y$3>66E7Z@*2(W=URAGA\X1$3DV+7@.&>0<.PX1H,A98'%+)#$6#"J6 M(J\\9,2E!/.KNRHN;?)Y]-<6AG?5Z@S>'YX5C->"&-;TU>+<:^\XD=VN"' 2 MZWN+O\C,^FRPE##T%M7C:#K9M4&)^];[U==J\0,@QPR_T[,#]+)IJX2DMLYI M*PDCG;!#AY-N>GJ+N\@K"?GA*6TWG&LO!+R)#.%.,H&]X@+%,ZTE R.0%#39 M6YA#7BY? T0!?K[I2H0NW\R[=HC+3^LOR^ED.FJNI2,%]7CSVRBC_UU'5/\1 MAZ\71]O.7?7<@!#$7$3YCC!+B**5YENP%?8LR:[L656\VJXLB5B1HZ-^K!:[ M=M]QN8VV^_APGK/AY-Q A$!,4@BED=PQI2!R+;D&^Z1KF9YUQZL%)#%U6SES6U1*O'6;7AQGRB'NIH#/U[\_N#Y!W3.S*](C &%"%> $B\989! MXVC'$Y_6?JJW(Z@_$;L1GK?OJOGXZTU=OQ#/SDW:"J,(0(H )S&TFO%6B]MA-,- MJ_[S5?PZX,/*!Z%^(C=@=PXX+L]4>/E"]]=X MMIY,Y_>7F 9I#PK"$-HT3X(44$,0I)CYEC8"75*(4F^'>@Y6%\&IF(OZI&\Z M&(J)U%II(A0E-O[;HW;A7H%AI7QF#5ZYD/0"/'L['7V9SJ;--6@4KDV%^%T# M^4;05M_/4,S/?41@F"B &(C_%@2A:-T V1%O!^9<+A:PUA-\967G_'BVPY." MAG'?A(P"XCTUG--&C>T(1*6Z_IPG'_G9=E@NK@.JC']Q4Y3DP^A[D^5PQBWE MW@E!QF_%:XTPI2B>F4HKLLN.D !%:V:H$I#,H /%7:Z"I4Q4TN^<(TAPVU?X%5 JT!'D@DG)2 M>C/M>N#QU9"4Y?&3O^$RS?WG>2'*K_!TD]8:J>0$68Y;,IF5PPHR+ZF\7XU5 ML:W];3V__UPM'C9;U,F]_8?101O.'%0<8LN;A@Y,N>ZT$E25*M1^,?NOX<[> M_?T:6 IP^K_7S2(_K;]$C*?S1M\\E^LG9@:VN7,R4#$DXS9'+6FW3 D!\TFA MY24V@(P2D!>BV]AQY]W-'9L7N!4^*B^8VZC=<+Y)PFK)M,@D^?E*Z/09)2$G M0*7NZ/8B<>JB;N^DX 7'U"MH/"=1H>5"X$[GB9I5DE570M7/* '9T+F51GBI M)ABXIQ@S2S!S7J"H-$O9&3.$I=7R*:'[9V1Z#F!*J'LIUSQ'M&3G>5-W6CLG M'*7.6=J&JTED@$URW)?8\/O1_;,!52)9O7YXJ.=/C:&/\/_ET!"-5R4=B'N9 M$MA@)JQO/Q+$M1S6=4T.IOQ4K^LJ0$JX:B>3#<"CV8?1=/)F;D:/T]5H=H3) M!V8$3KU!BAN#"1>,(,5H>P.!B"7#NKKM@==Y<"E29:"I@5E-W&@QG\[OES^$ MD=]-Q]-C6_SIR0% U"@K1H)HOG"/(!'M688D4$D.OMZV^AX$(3M$9;,_-EII M4P]I47UM*FI]J][,Q_5#];9>-G&$[^\^C_XZ?H]SR9."4%PA:Q&VT#(.E%6H M-7B1$&I8H5Q];!N]XE5 =#XW9977B^]G:0@_#PZ82][<7L?-T1+F&9;_/WO? MVN:VC:7YCV9QOWS$->.=Q/8Z3F;G$QZEBF5KNRRY)97;[E^_H"2RRN621((D M!"GNG>VT'9("WO< . ?G!MK]T4F0="TXF4TP@0 ,AN0LUD O*R!H%Z<$!%"0 M>N"15M"V0FLQ3.H3.%F.^00<#X:D@#"_ >%]@4*B#>0,0R&@=XQC UNUU^BD MT.PW[&@.M1-LY3&?QI]./N;SY6F_G-[+Z$.MWMP <6Z>[RG2 T5EIQ MX0VSAC$1=P0$M:,28@.@.-7[=J*]>T_FF[MCDSE5J;O'5P*QPGA81YI#S&T= MX:K@'@;MF#J+-R,%4%:&X$B4<> ,@K"(R%#JIFN XH?!'ENSMC?J@4 M=!H*Q9.7G;0>Y;LGYRR[%CZ\?#<"@.GZGIE&@T(2'?^;-X<5Q[R,,)MT(CJ4 M[^Z'0-[;M:<%.=[+03A"=%TJ75C/,7""T!:::- F&6+3 M%P2?5$G+ ^6YC30[_S*/3]VNZ]JFW]4M6]P^%C0[;K'EZO7TR\-L-8OJZW9P MOU:;3;2,H^85"9@7T?LIJTT)'#&6$ Z4,@13Q3TRP#-I+080NE/;^;78E!@: MJJU15IJH4R,-6/S_>Q@$A)DVKA%MRLZ\#K I^X$VODWY8MT LVT0^F%[:B^V M%VD/L_LW?]W//^RZA>IO[^-P#MB3_3X0O./6Q/\C6AL!;03!@ 8 ;UFF9,') M3,W._"XSH->_@L2IH1RT8;J_' 20%B*.H(F: 76>1%VPA4@"5)QI.A5'/41@ M$'27*0:E&+F7PWYV(^I1*SQI%C]_-& M$#7\7S[=-BEPFW_/17'3-SD-KTCP46 M3T;CA38:(J8(8=Z)9HX:@S+*@$U(?C;HW A>>CQX[Q!0EB/! ME5&>,"1;F2?0)D4UW*UF]_-_5\\-_*,[0,>W M Y4,.*LP0R+JR()R@5NY!3HMVGST>(.)E_PT6(WNKDCS(1K)/%82(\9EG7C- M==VWH/'MZ,8;=<(C.[H;RUCGJXUB%AD QR.*(F^$RY"ZC!7!GS _Y MH])0*)Z\4LRKLW!VB3Y$0J2BU%K@ 0!6Q(,'-U.*4)71.C*=B"X^Q%X(Y,C: MF$4UX< )^<,S05+(%?282EF'$ENKE&^&+Z5.<@+WUW&+.1^' I2+WY.+]@N!-S LO\3@(AHMDM)1C]#Q$9B?PMXCFIX=/ M)RG\[KE@M)=0:2P5 X@"*_VC/L$X+ZM 91+^R_&FGX/%V==N+#Y]+C@"%?&2 M&NQ G C V\K9>_^7+Z%CD]?'CP'P8/!&K:&=T? J\5M'6;V M$.WKO:"M?ZW6Z_#?2"2OQU!C5@TWH&R&AO2SJ#V=!9Q\W_.(V X M:-GI>)P=WD*ZO!B4AAU0AJ%S=Z(Y2I&7KT^3^5))>WGSS M/#&%(V/6?U_XWA7IJVJGT>XVKP/[P=%W@M:$2LK6X*3=R>+?I; \ M6<;Y]/O F&"-1N]N0^I'[^Z=@ CUSE.D/(@'EO102MJ,V&F3=+_)KX[>)+#. MG:G0\^D&R3=W;SY7J[W7O( D@5WIEH$9 B<_$HB4Q&/DJ42.,L*]-,YKC[U! M$,&3JF]>$$XE!!Q]+T1KU6&EC:(\2C"2T7R%^ZD"2D4FIU2W%( 1B?NAI-QX M&%UR%KDF1GM$#1&8XKJ"-D.XP8]:D]0#?.+0_I&H.Q+ST0^4\X<-&*VQ$ )) M[JR"6G+33!DJ+T1Q'JQ!F!^,'TA"H7CR2G%6G86S"XSY8)8@ZI"PCH(ZL]5# M8-LI(954FSE#S$=7(CK$?/1#((<'N?I2+1ZJ.F7W^T+QQ_S)A]X)+-H S", M)!%,$*!(M.$;C4.AI*NQZ;TCTVE28R'5WQ[>E?EZM6@JA+ZY.YB1?< Z[O&% MH.K4(&T8DQI8XJU@AC2S 8(EVR>OLI MDE 7(]S,OU3NZ^<:HR/"<.+-@# C6@B(%91107( /0J\XBK)NSJ][V0ZF1@7 MKPRBL2T@O,/CB!@\>2H8:"6I"YD0Z+BO.\WH5N5Q4B1M ],[0Z:C/!V;7/3N MA>^8"OC=]J M_6;AOM;980_S]M_CIVVI]\-UC"*%!8.&(,)8!ZPQK-%CF1%B$UO=]D MPBU^9,2R:($[S>3T>?_LR1!'[9@4C@%KA/(80H.:J7#@D[(BQ063/PR?+%0W MY?]K(W67*_H01?31TZ6KN^5JWR;@_>QKM8XRO)KM>@NNOFWAJ9/\+\=\\% M025E-BKDQCF#+:'QZ\TTD(-).BR\Y+O+(?"20&I!]$9P\CJ%/S$=)$4AZ//(VDX[ 9+I?H,NI^=,;\4#Q!&@K%DU=R M#,CDG%U@#(@V#&E#L+2,8$UY-"%;3!0B:7KVY#$@G8GH$ /2#X$9-1/(42&78E_^:U M\O$N#O2$2O;\T0 XQL)X(2&3E$KGZ^IE^\D@E-;QNJ#B;*GJV$"<,I-^\B#^ M\>'@@2)Q3D3@N$Z8Y PJUDP(8%FN"I9.S1&.!X%R!6R7IG*=D^1SZ-6WR\76 M5_[7;/&/-W=WU:JZK4?\ZRO]YMWIRO)=W@^".<]-W1"\[O%.XHFHV\,14)BK MMV:W WX(;3\JW*.C,TRQT]]>+=:;U4-]3AWI+77LE6 !0Y9!!N, !1< U.U6 M]N-U4B:EG/:/CR[FW!X9KV'\/O[TT79!QUX) B.#J8%QK$ISHI"4O!DO(ZR\ M=-3Q&#A Z4@0E4]M*6=Q>8P.97(7[?%'W'EN'E:[X [.J7VH:O?347NZPYO! M0P^ 8)X0K+W3FB KFM$;J\LX8,?C8#DE.N-R2Y.YI8W-3[R7"),X8* -I!J( M5CT04"0%^4W2MRDKMVGHC,*M;,; ^G+[_,U ),<<$VRUPC1N9-KR5K$DE&:Z M BF$VX'HC,)M/$EV8^!]N7W^9@ 4&$NUX@ A0:,1R35H1F])6O.(29HOY>!V M(#JIW/Z^&\'[:O7IU^5LL;6ZWMX_K%$C:J(#S5T_$I2WCABNG./,8^@1>S3D M$-9)C(^>13@AXQ,!-!'?RO72>% HV<+ MYM[)$]$91[O&^QT%P=[J]?-7@T)U>Z2Z60,TVLHXO?8DLA#HI$*XHZ<#9M.O M!\(S"KU$-(/ ?>G]X=7 @(RF@<.0U97EG/> -F>-M_O]X.9U$G+VUU $2/7E=V>SDHPHD0VDF/A12:8,>:P >KN4TJT#%^YMMT M)(^-4'^6_UC,/BU7F[J!KIVO;^IZZ(<[T!]_(4 L;%0@0#Q /"5$8UT7%MF- M53*3%B]_&7=:HZ&2P3G\_:2;A.K:?>GN[JJ;N@;0VVIU$__=[,.QQ+=>WPF2 M(57-;M\LGH8LP%/1!P](M1A)Z2-UC2FD.= X9_!HV)U5C=LU/1NHPSW_2!#2:&<]8I [$=>/!\RT5PK*)N5L M%-)S:'P%;B!Z&<3GQX2$.@6B=O)L*Y05G5F^5]UD=B;HPWJCKX8N%5*&8",8G&^ MP,'X\ZT1 ]):G$Y?I&]2V1@5L7/W=C6/:'VNRR.] MKKYNWO^KNO]2_;9<;#Z>RNU._FY0G#K&'5%2:QJA<8RU%]X8BZ32>Y-F%(Y! M^1%)FAK!T@3M?ZK9ZOV_EF/)U_YSP5)%K!& ;[O6Q0U:^G9CQM8G76E.FL-X M;K%* ZY(:8J_?DQU3OM@0$I1'0][2B5WD0D+5>NV$0HEQ?1.=MM2C$0E0%>B M3/GEPXFTJ_[?"UI":5 T22G'%G)E'C/(+==E)Z]/$>&K.LNOBPPO86NJYE1ISX+T3P-4U?ILI >22,M&F M+V#;F8@.!6S[(9"!U-?5ICXLWJZ67^91C]7?_MAVQMAWN%E\4'48W_Q$5^/N M'PG**T"H588S"1BGT +4 , 5*Z./=5:-:S+PSB<]NW:MWXV]@^NU_\="7'X4 M.J>9!Y@RSJ%TI,6DC-\\@3>.!F..@62UOJNIVVW3K]UE='BG^S>W# M-J!8K=?5YMA>=/KE4%^W,TH!4]ZQNC4]\.V$M1*9-/N.4C,EH<\/K+&AZQ]( M^G9_C^27J\>>S^M7BVV7WR^SQ4VU?K]\VA3\0(QI[^\$X9"7)"XSYB!!+NIL M&K0SL_!4AY^\6TD&H+6Y6U:P.DM[]\]7B701C-;_9[$[9 M(^?$J5=#E%R)-,4*$4$=EH3 ]@36U"7="$[FELQX2HP,7!;#=;>-O5^JFW\^ MS%=5'W7BU+M1*?<0"@BQD89QQ!1I#7W"'"G+VYA3FQ@9N7,(BGY81XV\[C\= MC[PF/CJ>?W=W\_OY['B8$Y1 M&AO*HDSE44SD0"7TS"-&(,=(>F.]Q"T 4"?ERDR?%5>&:=P3O/-)S]Z'_73L M+W6I3K]\Z?D#01%$(2:&46DED])@VFB("B1F:$V?Q'<&J9L6V,R7-$_C/VK$ MXC_,JKH]VCR\T_O!<(\-<#(JDG%-&FG5 M>OU07RO$03\)-.HH12^_'"#V"%C@6#1:J1 (\!9.K;0JJXU/02(T"IP9Y.<[ M4>\F-8=>"8 QI1@0 F-/M+<2MMWX].GY>+WS?+F'QU,^<,O!R@AP5Q()ICQ$DE,%6TF+#1*2F+(?0N4[909 M&\ZS:2D=Q>?4NX$ZARU%B!GJ(5$1/^S:+9.D]9S+??%S7ATE'/Y*L%#7G=>Y=EXI#[CV\'%R2";%44Y6M: 8.1D$8N8CZ-D'>!QZV4>M 8"9RS):SI]-:8R+HI[@I=!>G;U/M_[.HIZ,66]#WSF),C,M3G,X%!AH1!D' EB/5 2=->9C($D^[[ MIB_G-&G^WW3PG4V&5-Q85ZMO<0_]SNX;>)YD@W=PFW?\0F 62FL4Q)8Z M"!TEDC97$B;^BZ3#:OQ& 5EE9AKHL@2=[N*-WL[FMU%I.QIC^MV3P0C)#<,. M.>YA_&]&51.4%.U46U8-^='Y^2&.= @X>8*+EY^J][.OU;H+U<\?#@@;C^H# MTDBB(-?*N!888],N=2=S/$_/]D!\2BH)LOST>55]K)."OU2[B950'*1+E<]C MND^O:J$(J4@WQ8Q *SDE3","O+>(&NP=/I5#-=%YOF>TINCP9$Z5"NGQE1"- M**TY\,!+#ED\[2AE#0P(V4SIK-W*AHS+Z_/3?#+0+KF&"(,&H;JHED128,80 MH;"9J74R4V/[7C5$)B'R2#V1?A"=O22%)0AS0"%6T92AG"/AX./ZD.PBZHET MQOQ0;8HT%(HG+SMI/>J)3,[9&3R<0^N)>$(H)D@#KBG23#D+13,E@&%:P[:Q M->QT(CK4$^F'0!X_TDXC_G6Y/N$J>GPN6$P4< HYJP4$B"+.:#.-B%"A54$F M5:B& )2!YZUG\P5#R"]7U?S#OEW1S;?WJ]EB'>W&FIK%[?9/]SN#\O;_/>SR MR>-$W]Q%P_#E.^8.=W"YAQ(0DUP90SD%1DJO/!:N(4.;M-[JA?2+2Y76PCFX M@ 7Q2R2S7NIJ-5_/%Q_LPRK^]PZ$!I()UT"'7P_QF**>68\M9-HC13UY/&L\ M2'+93[9)ERN0(Z^<\9D[XV*I)])UXN^JF_O9>CV_F]\\8ZP.PE%OS*MWU>R^ M[FC[Q^?E8EO/9O7K_)\/\]OMXP,6U1E&&;SE0"(NG5#<;?=EV"@ 1!I3UIES M\8NO?(8O9)'^R.3$Z^W''PQU=V%E@<-( HX)%93*!EA,?%F9\'^KI3.8K#.N M AMA_3*KJYFL_\]#7-]W=9R#6O]G=?NA6D]FTXSPJX%) 3W1&&J&5-QMO+#- M_0,!#B8EQ!;2+WEL\R4_W&>4Z#\6J_U!U>B4;Q9/ !C7,$G_L:"Y0P(*!1RU M!!F,E,8-H(ZSLLHW%B%9':4]&R=G5EY.:VS?S7N@YI+X:T%+BH"LJVPRI3VT MJ"Z;M(<4@C1S.[O&7Z*8YR/ES'+>"?Q$J>[T[2#KP"TCD),DVC8R_M/Q1[AH M4N)9=M6[5!F>@H*S*M21[.I65XOX/S9O[Z.5D,%),,*O!L@4BOP"A2*QQ@FH MVNLU8C1)*B,[?=&K,RG4N>$N2J+C#-^NZD[JU>K+_*;:)I;NZC*-JUV/],LA MGG648X$ ADP+Z:62NMT\/"FK_%81,I>\#G(05-1:J(^H/Q:S3\O5YJG),?5" MZ/^S 7,#(\<&(LNUTZ@8EYHUL!B;UL6XOU?B @ZA\<$\DXR=VG .OA,8BI 1 M;[Q #AKAA1&\42:9YY=T'(W*9@?9&0+@U*172SV&1C[V^_=4+\; M_-&W=BIV"05PYPL1&0$!I",4#4?>8P8X)91)S3[>K1<3T5J[^, M3?,A*9H0Q;^M4)6F[%R4+)U/AEXM/C]LUEL\\&DMY_!;P1EMHW)8U\EG#G!C M@?/-%($$F5P*'36;B=@[)".#X>HL$=,6:/2*(Q7'ZJ/ZYT!4]# PK=IG4*:. MC\5H)\,A&IW7OC7^"*P;/RG-ZXM"38CS5C;#5820XE2%09@?*O:7AD+QY)5R M))^%L_Q.C\$%&H6W'NJXU3BF,1=* >W:,P&CI,RHZ0LT=B:B0X'&?@B<,8;P MI9H=)RM,C5>4K,M/!1K)D QR9)TQB'F")'L$$R3=)112)C(UW./,&%](&:*! M-9J*+Q.V306##B%.G+;<:L",\+3=M;0624$IA52E''MQ%,W,156 R57\99N" M0ADR.FY/T59UV&D!9*M@Q3TKJ01>(76+QA;P' 7GTGWW92SU6^I@32:"A?- M $X, YQB:2UM%SS223ZQ0@H"3+$53X[PI:2C/?G?K^*7EE^V3\3Y[CI[)@KP M6#\?0-TH5%D/N$&":B85U8!2"YQQUL"DR[)"4H.F$.LSX7ZA2?[Y\_OK?01: M #&+9'O'K#%$:$N7KM(3*@N,$6_)H=(@1%DA&H% MHFS@^/]:IZ$4(*E1U?3-M O66+)Q<>[^7?RY[:*$:+\DXU\$6_VU MV6?OM>2]L%0./1JX)Q0RA15TQ$M@O"8, NB-$<;PDTIWWS$>2EY[Z;% H/"& M*VSCP0VQ(%P@THQ-.Y0IKO+%[+3A>"Y'F_BT&6;3>I(YT@8;Z(%C7'CNHE%2 M=^H!S#(J2:X$Q$Z>Y&%,'7$5]\/@_-Y&8;PUDB$$E<8B:MAD-USG%%=27X2K MN#/F!]V.22@43U[)KN+).;M 5[&)EBUPF&F-&&3>24IU/25I9=VYIHS>Z.E$ M=' 5]T-@0KUO7H=XS?:ND">E96]NE@]1Q3Z@Z^T',^$/'Z_M,/WO/T9>'7_N MJ$H\8)@[92?^Y"_5\L-J]OGC_.:)0I[[]R9CX_C/IM@;(Q6UV WL7?6YOO"H MBZFT@SIFL/1Y/7@!'>1U\ G&T#$L#71 J[K5*P/F9#;-1!-OY?[('/2W_;_L M7M6C\]>"(MP)+07G$L2=T&!J8 N+M)E"M8]6]QB7WH-%/:;"K-3B'F:Y6"_O M]\[T+8@GTI)>?B$(#RW#C$$,C6:<$:58BP8JO&3'!*3_4%]J!-0RZ)D_CO-D M4LBA5X*W@(&HO"D)",>88T-(,SD.<;E)T4/).LG](("N3 I*L2-+(S\[Z>T= MOWY8QP-UO=YO?*<.A*/O!6RTAQAK&?=,S22%WM!FFO&LSM17L]AS84SP+PUX0TCG#&@:B]1NW:L*/8@&(F=YYR/ ,[%2Q?MJ]; DMXG%47*5FT@PW8^"*Z\S)]>V,^? M#WC9^-X',2V_ORYN2[ M 5H-/8]['F ($T"(5NAQYZ-)Q&=+V,ZZP8\"X+GEI<_6<-"4KRKJ;LEU/T3ZBC2=]7-=R&@NHHO[\-!XRO5"<]T5J]D M,^3Z>(D<^>7J33RK9O6_>KM:WLTWV^3'*$'->;-\Y+6Z37%DCO2+ 4E"E(UJ M$(.DKO/+*4* 4$8M99#[4RZ::>!M)[<7@.-36W\_MU.NT.$?#]0XR8RFW'+J M'3542=B AIS)I CW\HQFEY?EF5&_=M\JXP92RY4 3!$KK&'(-VAH34L*?3V' M#'1SM?8#\<*<; @B;S7'1'EAJ+=. M-B!0K6P(>2U=7;E@;0E4E!:5IU*>1G M)[W=#9O][V1$[X$W@A.":0A]-#F )?%4EEPT4S.(Y+JGZYQ7-I"@YREDHZ"2 M@?!M7[B]UN'NYY_FBRT&)VD_^EY 6D.G,2/:*RTUH5:2%C;LDT+TIZQ(,R[Y M8V)SL>$5IFY0;Y' &"E.H <"M9).,4Y2#2<.KSBC:C@FEL5ZX*6Q#& (!1'$ M$,^ >C3;F&+EZH(CL7/4%9\&SL5R79K&5P+%/:A],4?YC_4OU6*[91TYP%]^ M, #GZZPCBH@G@!)@M,#-V*R6N8(ANYW8B; N1T2@/SMJ<5MU)>C%9X/72BB) M'4!0H"B&1$K;C- KD=2@>S*M:CA'8X#0GR:]FOU[?M^1IY M&\[1"!@D'$SK>5>.7GHT2*=EM([KFL%0$F* @[2]T[ LR=*;K)+6",?2< SZ M7"X8NZ/J\'J1#V&!F/+;3Q-"4U=]J18/U;'[F>:1P#C!3AI(.45&<>4P; =/;+:"&;U(+G$JR=Z>VC8X M.\?C@-F?ZB/1H(=#DNKYNZ^;:K68W9OXS/)3M3I4)FV\'P@$<2\)\H92SAW6 M6-K6YQ6W65K$YC&8R&4!V&4Y-0;<8I8)8@ 57[0FNF$BR]R=3 M8TJ0@]&P["\+=K[^O%QOT5ZKFW\^S/?_>SN& T)P])T '16,*JBU5TI"R!P! MS8@YX9ER.(MG?TP0^]/^ZM/GV7Q5S^GHMYR-W(&X)R[CZ*RJ[38'JHYR^]&C04!@8)8U+2^-^@[5_](T:H),Z M-TYV17O&13L#Q]88QC#DE!JK'56^O>^(1TG2K=%DU[KG MXW4P<@D[\*[/7YQ/_;/SQ4.IC+ M^^U%2QVD5JTW!_?O47\D2.&8M0)'A<1)"^I>4ZVDD#HKKDYGQHEO!3F MJ$?6];$_KZJ;'5GQ2;5KS-3\TS>_?U<[6XG6\>5D6E+4]13!EC!Z21 M!#@M)'106"> <9Z@Z,Y=:IJ\$03/WLQ9$8HI]\.LU(3?:7(\O.3 ,&,T 2K:KU!HY!ML."=)<8X%EE;N+ *] MDCKZ@5=LH+\#5O)X<%(/,=68 *%X,PVH/;W0I([.[!R-^$\#YV*YSL[QH*2. M/!0/]K@-2.K A &$K7 $($BCT09(Z -4 \SA9$/_/RUJH3#-&;VQ2#^Q, M21TI1(V"0OZD#HXY\Y8ZH#&62#F)G6O&QX0NR\LXG*41,,B?U$&=!Q9*9[DV MPDL-/6I7N_>LS)74D M'4O#,W M\O'-O#@ 22KZU!<2X[*? ;:$$_Q';_O[9?R+0R?V@<<#4M XSX@5$8[X!R > M-0U 05)<[=0W&>/3.Q(\62*:FJ"27>!)$XER-/SHY5>"BF<59QXSAS$DSM?7 MH^WDB"WRAF2:C7TDB++POQO95E37QT(WGCT9B"6&4R^!P\YS@KURK-54"$IR MHT]]US(5VT.0R;K(UZ\6C_&5=:^,^>U\MII7ZZA^+F^V?QL5D?^]C##_&1^O M-ZY..T'"=X-$6OKZ8AXYSCFR"%.YATE(BI..BJEO8J;>+J;',7N4[-#XUD,A MD,A85Q=+@)9S$3'@A)#]M*40:>7*IK[CF4I\QL>KN)#1?463VDS:6LKZFUD^ M+#:K;V<,"FVJK+Q81R&.]-F]W*\= D53/QE -!&=U-YHHH &TCL(:GHIDU0I M\NL>1IGPX4".L-,A**:-&QK 7#.[!B@O#)-TCCAQ2.KT@' PS MS0!I\1&GCWO0[+YKM.GS=P+!VDL!K+,<,P:D(*[%1"E6=J3IM%)P*.AT((;Y M@A"?#K1K0.*/[X1XU-MX^EK!K<< \7CNFV9ZCC!??B!J.F,O1RB.!M+5R4)V M&>@:J%J ""12OZYN_N/#\LO_NMGIDC7SN/E#33I^0OK^K\,?O[_ [N._##@> MM,1@3P#A*BK=BIKF $:,I-FU4_NTAB"^'(A _\OJ[5WJZ^7BC^-NY>>/!4VC M8#IJ&8Q6LE160FR;<7GBBO0\C<#,"%A,NJ#TNR,+2K\+T'L0K57(C2>6$"N= MU_NA8BYP&4V9AH&\'#CI!(?/Q_F)*)LG3P1!@:;,&XF)L!P!)W2SHC'%(NEJ M?Y+B=H,I&#;S2=?)[W\>62>__QD4DIYP+DG4PJ52* X;-4.-NT49L=ZCKI/> MDYZ4'_OF"#_V39!UA6= ,'9$446!C4(@QYX^BY)+.F=']EZ/RTWO2D_+SBS["SR\Z$(D$T+N5Q^J.C9X=CS:_ONGH@IJ$& 06"(9QAI* MLDL$V$J-(65$48^F#PR;?7].WD;]8_[Y!DZ_TEWL]_^[Y'=[+?_&VR,,(C$6;)FJ!+8I+(6 MH\EB!U MC" 5$(<81OF1G%@"I"6$R6:H#N*TS/TRKPF29]U_3_O?$8G9\63(IX\$";@R M1M5U(C@QC#&W2Z2MQV-I6A(D+/,>8.#<^W/Q7[-_S_[Q<;TYP MARH$2W/?E'T-T'O6*?D%GZK5\D1.]_/;]&?GC'ZLXK>,N@.^>"_8BPA6F;6+E6_Y#) M]Z?CSWFU6I.V495K[ ^9?'\ZMIFV MIUW,SQ\+#E#%()-Q%'$O11Y:U5QW$P5LF@I!<+-?9.1Y43C(/Q6>C]L7*-R>K"W5XN[XWC4:2LL0Z)H@V M%)!F/Z35P\^WM_6R;0%:GP'VN1?5U=2R1_=AK 3.$$*7*""(@ M99PQUVC#5#*=%&PP6:QH=ED8$;JS91H>_/=OE_?SFWEU**5P/]BD@=U7-YOJ M]O\\S%:1I/MO?KZ8+6[FLWL[V\PR_]PYFVDT*LFO'3(B?WPX&.8]%)![A[1! MSG&"HMQ23"P36*(S-W3]+V#]PEO/A<4-XQPK1F MGA-/'(&$F';. F72'/O='22RMAP/A]X^H00:#UJ"!YX,2#*,)(T65)RWMIP" M+)LI0.5)<7;_0"8.\3D(CHMDMA0K_[R$#KUE=_?KS?%8K2=/!.ZCKFJMQ @ M2TPT-15NSAP.3:Z;E^,J^6 HEV-,/N?%^BBI\E HSKT7D%&*O!-&6-!,#QB2 MY%N<^D)]V*$X-B;Y;M5&2G>VVAI"M+4&<(BM!MC19GH0:%G=MX]6H59),>UG2'WOC/AR M( (9UNFN.-BC$VAV/UO<5+]_K*KZWD[=WF[QCE.?KVN3NJXHI[_MV@',[G]9 M+1\^K^,G[A]NYXL/+]_\GSCS\PP@("N!<% Q")@#5$BM6L[BGY)VD/Y!K^=0 M((H$.(-D]YK"Z]FGZN3YE/C%H*@35#KH!>51PZ>8>=CN^7:*!D' MZ5M*(BF M4D*FN.>6FT9%%[DH\'8WMN MOJV+T$<\-E%R_WK8U+OEXOZ,(VHWV\+U'?H S/%#P:-I*&60XLLL77G M#,QUNW0<3_+R3=@@*H?<%8%T=A$^H-U5FS=W[V=?.POF\<\$"J%!2GC.&6)* M,JA!"X('(,FRF;!A57YQ&Q6_/,' <7^N1W\\]'?_4$!:J-HXP'4+)BRI-K9! M25+*DO:;";M6Y1" 9'0RT!L%[U$^CS#\W7/!B6CX(1=%DWOB,.8*\F8:4*ND M<)X)FU7E('D(0#ELEMEJ$0^K]=MJ]?O'V:K2L_7\IH-!>_2]0+D$$EG%B7 V MSE8#VVIM0NBDQ3Z=4CN> 3LF*D7HLG$BVSEL9S-(2?WN2X$8XPSATAL8_Z=A MP-,F3$M:)S*U[.@H(".QVEO;' )986IDFASU^&:PV" AZIZ?'L;5ZGWQP%9X3$VD(?3UP4%TQ]:K?3HBYIEYG,QIU&)L8 MY@Q\V_G]0U3-$A219V\& B%%W%ENI33:*B.!:J;JD"SLGF,Z5608+J4H(_M9 MC**.//U6D(AQCSF&Q +- 10(@W9%<%B6RV4T;E-4D@&PE:>4),E3KZ\&":C& M/!ZJA'&)D42:L 8BZE'9BLDTDC4E@.<[K/H?4D$3C*B3G"JL@# 0:M N'XM/ M9MB>5T$92S;& 2<#[V;YZ=-R\?MF>?,/._\ROZT6MX^#KF[NXS^."4&7UX,& MBC-@B':&"77M%P<=L91K$0498-'XJK6'*BD4<#H/R'!%=&1 -OEZ^ M7('GEPA??8Z]632/=PT;[?[%&FO#(8Z+11HCK.#2-0%56F-81HN<"8R6/'AE M44-WSM^=WK,MWWA4O?SAZ2")0U9@%'^ P_A?UM#&WZ"E.]EH/+,K93P1&(Y% M#@TPPG%[6]W::C7_$H7R2U4+Y9O%CW]_3"GL_)& O>+60&9KV>9*@&AL-0"X M*.PIPC!Z1> I+C&F@BB[)5I7;MI\^ZW:?%S>/B:MGT[H.O%^,-Y+#C@6$KHX M:$*0&-9=)P![6C$AA$N#VEZ$T$6EO"^.0,UX>F M>+(ZUUB_$0BR &H433?@(8_[B4)J#R'T&*3UE>J] QXO[)514)Z'U)\)Y]FD M-<3297LWH3C$$^G4WST7K&:.*,D 4=8[AP3@OD$?Z5P)&8EUR+,1OQP/PARI M/D&DI)@#Z^/NL <58%)N;9=$V7B^N96# MZ4^!'07<[()Z(A_Z@N7T#)V__9JOZGRP!?_"=(#CAB&!"G%1" M@;HMLVRG9]/BQ:=+@CLKP3]A"8(\TI]T!"H(D =9OQ/>1*N*0.WN<3XPGME.*XN#3QKSUL]5W3G\O[V3Y+ M=K8Y:H)/_^OQQ*0&8&[B-H8D$@H:SQO(O>:9C/.IQ7\*&9QR?8Q"UJ6NCR:B MX!RKX^EO!T^\YRR>P99S0)R7E-H&;BIQ4D7ZZ9)D_FYK8P!5N5;&7Z>G_%>? M*;^O5I_@J24QR8\&PRBAP"%I(81,:*QT:UG!;&4%KV4ME,#1I1T/[^;K?_A5 M537Q!SF/AY=^.RB!N/*"68@4\=P)"!KS#RO'DI)7IHL7*WU)%$15_U#$46?P MW]7\P\Q+\O].881%/""0D6X5U$K%G/#KV6JUC13Z&8UP\/)&*6N9,MYCA#760%*$ !,> M,\>MQZ?N7']&(U3!<<6TM9Y!1#3G6@G30 @8A9D2VZ>.1N@L*)-%(_3#^;JB M$:+J#3SSA"/IA=#$("*;N1OIB^QLEI_XH]$(_2 LP9:Y .>NP(P!YES418SG M5,CXQP942;2YD&B$SK*1P\N;ANE/@1T%W+*C$2Y*3B\\&H'2>.P0'$T;I15! M(!I@+=;$X+):EI^7X,[1"/TPS2 R[ZIU76.X3CRO!_M'9&S][O<_3HK-T?>" MB':OI\(:+*1C2$,KV7Z:##E76('?DD1G3%S[7[J]K5;;*H!U_XOVY_][OOGX MVVSUCVICEHM=,XSC30%Z?B4 &7=TSU&<3UP#U#D*>3,K2TU2O,CY'"$YI&5Z ME$>2G7_%\3SY%^V@^LO/\2\%A*G@F$ %J:0,8B.5:68'HYYP69Z#L\K0J$B/ M)$?]Y64_6B85UL@ H1127DN.1&,Z,X[XA5VGGU4NDA#-H<+4Z)RX3&J?"=K7 MGEM%XR8H(!=&$DZ;X1-"DDI23-T-^.P72:GPY6+_M+KZ^%304BF(D%.8$@X1 MM8+;9@K>T7(32!)8>(G'03!<)*.EW6GD)3([@;]%-#\]?#I)X7?/!02HA1)I MPU"= E!;.+J9!H.JK Y 2?@OQYM^#A9G7[NQ^/2Y8(23E% "#*R#WQF2%+33 M\""I&OYDEO\H+ Z8?D)4S..-TC;XX.UJ?E.INE#833SIW]SM;+_MWQX*:.G^ MA> )9L0@[ Q' !DDO";[V1@"A2YJ29[!Q3LMGB4X-([:&W]6ZTW=%ZA:S9>W M)X-H1_J9X##E/"XG2>K8&@JT]M],A+U"/A(LGQF]$L6:O?U M\WQ7*'"W8*<0Y.>_$9A1RG!.-7$0:^:$$;+"]8^H_ .1+QD_>'U M0TW7_D)KK;[,YO?U!95?KK9*U!2ZQ(F?#(X8 N(^0)R. / N6W!)<(GU1LL M+_#ZC'K%N 3D#*>H5E^B^GX@QGJYK;U7[8Z:];;,[]-_;Y;KS>OEYG^JS;OJ M9OEA,?_W\:KI4_UF(-@1RRAET&# $7?8ML8'9FE5$Z=*\Q76G9*UP*8] R5DJ9 MB\;!IUDHEO^*0SP4)M84H6M..0R4]\P@T M5XV&,9$4[S)=_=HS7:OE ;>_$$VV)MY5]_7,WB_-PVH50=S_XW^JV4X_.B2& MYQM0V#:D)U9X79MY$9\E;W__XY#,=G@S>*X-49 2!9B7#"'N&]>HI9PEW?,^=D6X$ND:'\A+ MVA'C[.L_%+2HD\AXQ B+BC4_7"@[21/C:'&B71E.BWGGL O"O M Q> N]6MJ[OEJMK^A9DM_JH#,K]4JSBSS7)WE7),/YWP9P,F2B!)N!-6">.@ M@T0TN&E+TMS#U^2**Y"%C-*[:U#Q:A'/IH=M;.*VL8@!C&QL7_:&Q$W%T\I+S=;)1("FR$U^0?O!AN2I+_G:8W^[9\V&R#4;/+ M_/,!!,BQU<0BX!4#JC:&H&RPU-RE%5JY)C]AT7R4'//Q\MS?/\Y]9Y6_VD>[ M/"N[UM9::^NO31$D,O88@\!$Q#,92805H]0::@!@*FJG CG.THJ!7Z.O\5(I M*^DTV[5R>;>-83^:-%#PD(-C #(%,+'.&&^)4,HU.Z2 B5U3KM*? M>AT,9EQQKQ8WJZAM5O/%CQ.9WSTOM/!ZN5&?/]_/7PSP.LLX0NW^UG7S.H^T MA58K8D"++%%IU9ZNS45;.BV/ C]MN=BWZP=ULYE_B>O]9\'8@Q(&+!8""@X- M0XC4HB9W)>&9)I'/4TMJ(M NJF L%L[2VNE&),,6PMIHWT.(F:1)H=;E%8SM M+"B3%8SMA_/LJ@K&0FX%)PA)'(UDXX7#4C9SYXY?=_O:SL0?+1C;#\(2KAXN MH/YF/-^)I ME)R.$) Y8NDTA!S&#$LJ#.!.@CJLI(4.IO5JNZSZKYWYZE@ZK1^B)>Q/R9>N M;<#>N^7]O5^NZI?.N09\SFF2DEQ>)/2U+)U!Y%WTRMGG39YY M\?PPBD"T1Q8RS8WAP +MQ;X-=Z1 $YED:Y078WTMZV]A+X/)RD@""E M )F-EB3C@DOGW%/M'A*9E&967G#VM2R>0>2-5?1@O%/TH/V2[\<#188QZP&C M"!AAJ$20-!@:0*^DM$V>!5 L;>6)OEKP5M*P#4Z:2ZVN4%H%[/XAB'QXM6L5JN3D83%G.[W&>DP0A"C61148Z<1ML3 M6-52":A**OM:WFW!15P_3\C;WV0)%K[N E!4&>P88A)PB[30#NY)HXZ!O]VM M]C027^#*[S!:W\\6'9[B\JVH1C']OEHO- M:G:S>9C=OZ]6T^183S'.8)%B3'*-C+-ENQKF9ZU MC 42ONM&L2NT_K-6PD%AQ(Q+ZQPWT-;5.)A0>_\Z]D8;<\J>_%DK(1Y#%@J$ ML+("^W@*4:"LW4.H/1-I->2+JY7065"FJY70"^?KJI7 %5-$TPBTQ\I[A;T0 MS=P=L)GJ<9RK5D)7XH_62N@'80G:X@6DGEN D340$BLDDXXJ25I0K;?@0FHE M=):-'#GH:9C^%-A1P"V[5L)%R6E9M1(\A0I@Z*0V2E+O:!U*NA\MU#SIPNBR M:B5TYJMCK81^B&;8G]3]EK;J]F7X]L;@,9VKTP<"=\0H*CT#+,Y=^J@6FU85 MABBMT'S!%Q:IJO\D<&:0HT[]KM[/ONIJ$:G<^(AY/SD;YP>"5<)R ZS67AFB MD!*^!!:XB]GO7E>;-W=Q=H/WO>9#@6"@,!!>\)LJ#!!SN8)*PE-SCJ*ZR% )_1V?7H/&_;3OYT=AV4 M)^%QW2=$8A=U.4*H!VCOLW3,N9,=PGXZNZ*Q%H&32E#JC.#,$P[ WGD=[7^F M,M4:G=K9U5E0)G-V];CQ^K^UN_7+V??:U>LL2+ M&%<@' HB$/&2,6HHF?CCO3%[05B"Q7X! M-XK 0AXM/,2H5,H8@*FG#:A8<'@A5^"=92/'U6(:IC\%=A1PR[X"OR@YS2Z? M[ZIHRLSKBA&/U[7O?O_CX*UYI_>"5<1HHA".6H]GR&#-63--*,'?H*EF9Z*7 MT^&:Y$&))NOR+HYA5M#,@#R72<0I1)>'<*^V( M;T9/'+RZ?I1]U?]I<"PEV:,ML[-%:;V-#GSZ[\URO7F]W/Q/M7E7W2P_+.;_ MCKANT?#+U?ZOZN?@D5TI[T "H\I'U!$E&$+F*%:H7>0.IR5"EGSIG&K/%DU+ M"4K@E38@MHQ8 0!$#@$!B8@[5GM<,0B2%,>2KZ*3[WM*IN4ZUD=!#8B%4\YQ MZ873&A);%W\B#?S>BZ3RL^6I01.+YMD:$/=C[Z(73WE!+#[*A7'Q/\(KH&3< M7+5IQ4-#=1T*U[4LG4'D7?3**;4!L;+84.$%P%J"J*(PS55[?V#36G*5IY!= MR_H9RM]%+Z'R&A 30@14CCL%!?- ,] [[$+JG%9'EISM>R> :15U(\6CD- MB#4B#$CB&==804LE?MQ]M#!)#O7R%L"P^]LBJ2A/G"^CJ3##F&K+ 2!8>DJ8 MM>@199+6KZ+D6@$E"OPXW%RR$^0<_H[ -2'21V/-$4 :EX5;:.MZJ#;_)*=2A>^;B?D_J(7[35VPO: :6FU80IZJ:S&"+8N>:E54DND\F[T_S9+ M=UKZR_,BE-J+]S3RR"FB')&" $>8)!RIUE]J($[R+(CB%E[9GH6Q62IO?5QS M\VH/.;...$$%@E9AK6V[=QDKD^Y4Y<\55!9M%ZTP7G._:4F\)91H!C&Q@CEG M4:O[$(*3W(,07-'RNP;:,E8=>OK'GPVG3PFC<(C7_;X8H8IACS$0NU8*%!)D MS:F;TI\%B*K <1: 8:I!-ABB(Q6>PBQ)1XG;6"]]Z_):_!W%93I:O#WPOFZ M"A!AYK'AP!@H1&0!4V9D@S[P(E.^^[EJ\'3$MVK %$_7#.(3ZY^U009+X63]345]5A+*E@S M<2M)KAIH^:HJ)UH.D\!92O1^ ?VJ,1%Q\4JFF ->&>NE;9>UTR#)<51>D-1P M.3P+W,7L=^/WJQ88 4R(XYXBH C2R*,&"$EE4J1 >4$^N?:_1%A+\C#^4.A^ MVI:^0\<3)&9UPQ5@N!30<40 H W2PDJ6(L#EA;JD"_ EL5."V3Q27.S)57/> M 05HM(]6A"448RZXBEM5H_!33652L:J24V"3;\PO@9Z,#KV?3;7[2)VGV@$% MI:<&0\X8X7MS*!I#&I[L7O73H5<% *7QS#JC.;*<"A3!VT,H''-7XM#K+"B3 M.?3ZX7Q=#CUEK5)QZH9RB T@T#/5S#TJ*9ED[$P.O<[$'W7H]8.P!$7O OPC M0D=.H'#:.*E\U%>H;W8%80CR%^+0ZRP;.1PE:9C^%-A1P"W;H7=1B>SGT^N%:PO9V1>6,3=3CA8*>>ZB PD@1 M!1IM'CF<*ZXAV^5*LO52)B%%7\>?_P(^&*<9L\@@99 $SEJ 6KJ)3NL"5;*O MLJ]XE\U'T=*]_<[E].3FECFDI8"4.VZQE88W&J.D3">ERY3L/2U\)8S"4J[+ M]*W6MIO)S][<)R6/&^=LE#5+F.;,,6N)M%9H2>K\)O:S-_?IBSZ'(1444Q"- M 0FXB8:':B!T %W)37IG09GL)KT?SE=VDTX@)%1Y;YV+%&BL'&[F;K5)JAET M,3?IG8D_?I/>"\(2+/<+N)A$T?JS"FFFO/&(:ZHL;$"5#IM+N4GO*ALY;BC3 M,/TIL*. 6_A-^B7)Z?EBTA\M@).WZ ??"4XY CR$4'N(H=906-U,3QAS81D, MDQ)\*)9\(*8E;&E'8:MO0^>+#SLC^5B?Y3%_)C"LI !2$B$PQ"":W=);ZZ%0 MQ!@E,NF"^2Y'DBV/\X%>LN3^6 YEXB8!1W\P6"&TCPJ]4)PQ'D\UAL">76E1 MFD^GY$OO[-(\)OR7)=?3]3 ^]%O!,(0$(Q990Y25W$#F-$PL4M-) M>!(;.82[UHA>K=5MMA.)Y]1P7\#F^J36]:Z6X7RU_<*D?4>[_G;P'E$M MC-2.<6E8Q)CQ!F[.3V8%7(C7L,S-=VQV+F Q3-]Q]^76K! @(XA$&GM.H '( M*]H *2"ZDLS,,L5\$!47(-,'ZM3F5*J[#B%@(:@52CK%K::$&(UQNZ$HDA04 M7=YV?W[+<2)"+F U[#6YV@DYN=C_\%O!*"455<01Z3T7!@/*6NV1DRO9Y\\O MWT.1OP!!/ES[N#%6WJ[F-]MN'7M7+^!1(4$U!1IP!#M7A@;IKSE@)BX)4X@C*(YGE644_^ M2E@Z![W(SZZ^#O54&FT%C3J00)R5T"#!N$#*&4Z5YPT1@O(K*1)7X$(Z)XTE MK*>AEVIG.J &C2MH*)TS=>M#H*#AT #:TH29/A5R?B%V>X&KK2!62UA\IS:? MH]T!LYUDW4<1%)%0"DH,X!131PU0HJ& .7XEW2D+7%AGX["$933X]O!,A]BP M@07N( :.6ZTH0PP*';>^/5'08I-TBK'B%MOYKR2RTG0!Z^G);>69%D['$02@ M(O(1<$,$EHHSC2%JH(_:>%(L%/^Y0C+QD6LI_'5ZXG_U5@$.=?1#IY9%WM$$ M+TRD1%H'(7/6@;I71$,)8B(IS[WDML:#EDC1W%S /QN1;7V2B[@#5W^&P^Q^)*&$V@6%+$D4$L M[H $ *:4;"D1/"D*H>C.Q>=:1M.3#% "7YA6!Y'M;SFS!C47 !$G[ZM%0?/JRJ#[--E6T%)(\I M>&V@<@1:@IT0'%E$6YO2(YD6@E">Z_3\*R0719>E4WT_U4RJT[,?C8>PLT8[ M*#P'&AO-C'R\5XEV8](:*,^A692&-(R#,Y2B>_K7^Z9F/ZO2'90P:I47B$* M+:!.>D.%VU46])QQ>"K>>4XYU+*9GA+D;]#7I3/!G:O2]<,T@\AT:XI]3$WK](&@ MG%94QYU MM7ES%V-]K/A0,(9P (B75O&Y9X0&C[8)E\$HR47+M?XFPEF B]$U#VW85 MS^:>Z_+S@5L$H<482HRE8,CB5HD1Q(FKJQ:1?/-7'AE'5\"XG:.^\R9N1^YG M\]4A 9[JIT(=46DMP4@C AQPGJ+F!)+ Z*30\)+K.?05UD* +T5%-;/UQW?5 M337_4MW62DVS!M_$S]S'*QF2\>JKA#5OO4YB[^[(RC"$1[P F'TDOD@ ;0P_@/IH ! M5FMU*I[J4FDXY1;/-(+ E.(. %OO,]YZ[ T4#?R"V*3ZR",[S8N4QN4ET%6J M[WUZM$XX]?,,(+BH+&BI+0>.$*1D9$BU;"F9*2*E5[1 <8*E])$UPP&M$P8A$RUSTBA1;*A!::*S/"4*AR'POF?K9> MS^_F-[M;NN-:^XDW S>6:*X\ AQY&B=,)6FF"I!)BBGK+Q57I6Z/"_EYI:N? M>O'2NZ&NL:F@2\@K'[ M0]Q0[_2WWV?WU>OEYN5]]F2$ZY#/!B6(4X0IBI7"DA"H'^\E$;%I&9=9%)YA MG!^3IFDQS!6D\Z[Z_+"Z^3BK:Y8M/ZQFGTXH08=?"A)#XA"1"'J-/>4,HW:" MWI(DFZ9_<-=5Z3^CH7TV<>J6WG'@M4 D8RQ.%%(;_X=#0"C?3!)C56Y>T1C$ M=9*%04!=J524IMR4)@SYA>#["(<.::\'W@@04JV-C7/SQG!AF=2/)[=-*P+< M/^CRNLZ84: ^CQ2=WD<.O1. YP1 ::0P0+*XVH S?2<,*KI'/CYR1-23\%&!>L?04I^%*3'TDW/3P4D(&;4*2N!@818I!%N_1%49:HE MUE%,+B$(?V(&,HCC^U4UB]A]V\YA>\6X5C=Q@:ZJ8^W)C[P5G*?Q/Y ZX@GE MPBLI'YU>T2@M*E+J$H1L/+!SR],V'[89JUFN-[M-OZM@'7@].$@E<,IX+#FF M#$'O'F\]E$V*Q9NLI,3%2=@XJ.O1_NAC>8BC79HP>IN M7PAQXM!Q:YSRC$?UD@/\.'5DD]2KR>H^7(+ 30-\0OSV$Y51W?W_ZJZLMVD@ M"+_S8V#O0T)(>R(D1!$@\;@*Q4TMVKI*4HY_S[J-G0ABM]ZL'?>MJ=;CG6_& M<^R.9B[*JS*BUGKOG4O_7%T=LEI#203H*1%U>L*=M9(B1A1L^#$0D11%&JTG MPYP5:63DIW:4C;G=#J.IK6[<_[VO?ZJS["$1(*#>U@F0L2;NA@DCVXIL9,F\ MYJC.6>U&1OYD3K.=?K0SP;LUJ7[T*42#AT!RR3A5,1%"5L;$OY6 Y2@IEAMM M@.ES4,W)9#'%X>COB,_RKEQ?UG"?7=CBV^9ALWT'HYT/!Q"WZTC$.MU MT7>'^(2G@ZR#"ZJA4Q!!YR&WKF69L;06FZ,-PWP.ZI4?]/QMB^Z;?YUM+HO5 MA^IFR_S-\ICQ,X>[T6WO1ZJ+YEU5\ZX'26[?^+ZGV4X2G< <=5(Z!"V@1EGM M!15.&\>A)9RKQW*6K-QU]; 93",@)K2D3#J!F1%$>;CC2A$]T8W)P2XT(XNI MF@:R<3O!K(OSE\OJ9P2TM@JU$\#;OVOEPGOF_^&_>\EB1['(P75!$"H9BK 2 MRI$R4A)O&YX) 8\-29JRG\J( JWR0?1D1W^$A#OOSCM6!N.Y])02[*$F&GO% M &Q8H)S!V95:'"F)+GD>!<>SE.QDL7]E8$SHQ"'$"D M<#0Z $HLR=YN)NI1]4B8?#2450[FAXOB_3&)HUDSGZ#FU- 67!(^&RNUIO^/B1[*P+A,7/REEBK M!)(,.L);8^"DGDIY- .:+A$9 M$;N$S_)@ >+']D"U/"_4]V (E H3- &T4-]XI+SH#@;1@N8%*, MDMW<3J<+(V(W7!?>%C?;XRRSN%V<$:ET)PA04B$ M0%#:[%8ZG33)/;L)GT[2^: Z2:'V_9%W#<^7R\7-E^+ZMEHM5G_>7=\NRE6' M;4@G%ABD *H8B5A.48U&;?@:@ %.:N^2O09E&MV9#,5P M\4(XK "C'K3@$926X68O*3FU]\@#WLFLS(=B4U<:KYO[D,&6Y5\"04(?PR8> MV;?(4^4))ZIA'%F?U)\T>T7('*S)D0,N5 M-+I-LX!024XF>S7&M&J1":N3V8[AQB(&7P12CJ5"%@*.4/R)0<.:L2;I "A[ MG<0UXJMU]_G#%.$ D*.2@UDXS8ZF@/,971+>!.F#S*'J8A:X< MCUY?]<+K5_7";S%%?O/B+U!+ P04 " #7DE=(S%3S19<0 P &K2@ % M &%E&UL[+W[<]PXEB;Z^_X5O#T3=ZHCY"KP!9(] M,[L!XE&MO2[+:ZMZ9Z/B1@:52=F<2B4U2:;+ZK_^@F22F7ID"D^2FCO3NU4N M6^;YS@?@.P? ? O_^/[W=KYEF^KHMS\ZY_<'\&?G'RS+%?%YLN__NG7S^_0 M9WQY^:?_\=__V[_\7^_>_5OZZ;U#RN7N+M_4#M[F69VOG#^*^JOSOU=Y];MS MNRWOG/]=;G\OOF7OWG5_R6E_L2XVO_^E^<=-5N7.]ZKX2[7\FM]E[\ME5K>V MO];U_5]^^NF//_[X\?O-=OUCN?WRDP> _]/PMT[^1/-?[_H?>]?\UCO7>^>[ M/WZO5G]RN(>;JK4M8*3_\>_/?OX/O_UI-TF2G]H_'7ZT*E[Z0?Y9]Z=_^^7] MY];/=\6FJK/-,O_3?_]OCM/1L2W7^:?\UFG^_>NGRY/HDI^:G_AIDW]I^/Z8 M;XMR];G.MO7[["9?;A]]H6$H:1AR8?-(RYZVAT ML[+1?Y]^UC!VLY"M]HRRSM:&>\:S3Y[$O&Y^ZCW_U?X'FZ^?D=_6^%Y4CSZ< M?Z_SS2I?M:+YZ--.L?K7/_%?+7;5NR]9=K_XE'_9K1N05_?YM@TI%;JIZFVV MK!=^&%/7 UZ2QB[%;@)]QD 0PB#"KA\1L&@_N<@W[W[]W -H?\NE;OML@M/'%L3G3NX_WU Y1Q@.;_UP/[??_GIX,XC%LOE2]VBA7.;53UX6C?I1+G==\5'/09M METZY7>5;GN;T?RG;+E]ID/U/_+0L>>R^K]\]:ILFW;'@26F^VW7L<&=>8F88 M2UE>+9IT9;5;Y^7MWFZY?4!5E==5QI6UR&Z*=5$7>76=W:SSA1OCR(5) A/7 M9X&?H#0@O?V(QGA1#\'DY/ R;U5FL-4GHMV9$=>#=AS:;H'SVC8M^7)*][9X7^WG2>V(G2G_CS!.U Y/XA GI TNKK #U%O,PQBN/B6;V_*UP*1&5LRX^\8EO#PZU$Y/2R>[7%@@DIG MB%"QC'D\)B4CB2!S5G+DLZ2(D? MQ%'L(S](2).:L\$&\Q$1R8?5OFP[YQU&3(='5FWD6!)4%VL$J:K):]S8T9-C M&L[IAQ)=,]$+->Q/]4&# 9&Y<[K-_EZL?\XW^WGZ+_G=3;Y=!#1,O 1ST4F! M2Q&(0=QG1)X;A[[H)%GQ\Y:5H4/E?$Y_%9]JJ1+U^EQV!([DQ&%/SSOG@,GY MK4,E,3=5)4Q\$CH"<6JSS7?OG _E)O^1_]-Y] 4GYU&=J^YMN77JKT7EY.LV M^/_HO'NG-=M\F8H3TTI-WJ:?/^HZ4!KK0^)"^VOUS C%U(L0"\,(^P%F*2!) MTAL)& C%IH"*'[<^Y_OULYS JA#TNKA:9D9.6#DEFJ*J0I*XH%HFZZV(Z7,: M3@BI!E_3BZ@.^-)(GQ$7SU^6V?*9F1#Y,4FY-M,4DL1SD1N"W@QPD> *FO+G MK0OH+QCA1D*='RC/5;/UMVQ5;O\LKA5JI+TNJ=;9DA/5EB9-656C2EQ8K5/V M5J3U)2).B*L69]/+JQ[\TE#?,;^)_K[8Y)=U?E6VF-[B=%KB%G5V)YC"WJVZG):SNK,^E$*>)@PB)K\)O1< KB>Q2AT4QHF/DS2- T$QXFF%7L#I@7F=,C:G+_' M-MF9C_-4G1E'ACB>QX RY4QII1_J#+'VO_:625$MUV6UV^;7^?\#'">(00B^!/0;B$R 3U,U:MASLKZ[_2C\YEQ_PU2_401^(0__M(_WP MF\-DJ\C;F#QKJEWW&WNLS@&L\UL#UVGQ3JI_KW I+(>FVF2.ZFC,M[-B M:99!4>TD^;;XEM7%M_QRPT5ZU]4?;U9_S5=?BLT7M.1_U*9'!TB#FD=!$C+( MF!_ D"4!2M%>S4,_)0"Y@H/;)@1[0_V VCF"W0[Z/7#G@/S1R)\H[]&@^8P* MC-%X\]"$43PMQQ\:55\V;0_VYW$2FF \1"%L> T= '<0Q[P,PGJ4QB-B%,RUE< MXYG3N>8<^7;A[+US6O>G<5+NT.D,N!6,*&^D]>4"SJ@- M;R4"V6N6,P%J!GUA'O%K#D24LQNGXD4R'_*Z;F+N=LM'97Y\3B^.0I"Z2=J< MSDD C%+06W(I%3I#I_-]R_%F#\LYQB5U@E>+N]?K5L:@34ZHIV5,O,AD#.;4 M2DDN-[?E]JZK1LQNREWM;/:<9D=@M4I%3CA_HB!$EZKIRSZT/2C-=1P=S=T? MA@0 1"&C$2818)Z/PM1GO:D@2:BZZ H:&%]U)8\RZ]&GHKL6F-,6WE%)TY%> M"^29TMX_ON;M*O9RGWA57(5SI]K=_'O.IQ-UZ=QE%>_B+VKTCX9%^N2I<2.L MSE&F95TXJ]-*?(@(=9^45Y^[;G%=OA D]O7K+H8I26D, '89<)GO^?'>.@Y2 M(GR^W*1-RW(^0'7V6)WKTGDI3Q27*:.,OR[W4Y$M%P&$>58X)V24'58>SI$COIK5C\-'WD3<99Y,VT?8LC]MOQ6-)=\:T80"?9. M!!4;_$\?9ZQX5=KMM:H;F]6PS/1^J#:/>)0#*8@A04&*W(""9+#) K&+0,U8 MLAQY'JT4'Y:0%0[%&")6=D_8-J>JN[X*=%K>UGV!*:&-6QV&Y[&T;9)D4%:8[)&G7(@BR)ME'7I$C) "J5$Y-^U1].*DZNBP(J\W1Y7PO7IP#]KJH\*GK 19IE)9AR18M*Q% MSQD2$B0-8N>F2CJNG)0F;7Y4\Z$/W/V]0"0. :*]U3@"H7;")&%KDIQ)7YL4B=7(G"QQ:B)YFEZI M7N1)-H528'ANFJ7IC4@BIG- M^S1UC:J=N-F1%&_= [*F>A),&U$^.Q2;2.6>*^#PA[-2P0&5NA+*-\*;4$,% MM^04494WD?J\YU/E^NKVEO_JUPUG]87:C 4(<.1&//=DR*<,)6D,HAY#'!#A M8RWF+8^\XE;Q:5CM=)B=%K1FY9Z%MC@OGM,W@U[^^!9:0+R@;]J6T"[KJ[_F MSFT3S+ZUA2_E[7&A7]8U5UOEMRQWZY7S->._?9/G&_Z3;?OMVO8[4S+NW#0U MY_DV=S8EGSH4&R=;+KGXMV=<_RCJK_S+=_?9YL&Y+]?%\D&O0%"Z-4Z4"=IK MU>F+!2WZ5HXQ+E3"Y*.%F=> N("Y,4: !C3V<,PH# 8@- 21?*PT:G[\I>#F MRA-KFFVV:61"YV2MHCT#>4,-HA)))VL8N^%T?=1Z;S*FRK3+JX'52B//*;K: MBNW&WJ 2'ZDA6;JL;E>IWQKIZM%Q0"' 3 12XEU,4AQH$[ MI !>*'5GT"B 1B\7.5YXZM ?!X*] \[! _.['OJ-:&Y79-3V,[EKHM5TDVVG MO$:WYG:+L=9\$PN0AEU6V*XQS+?I[9Q7X1$6Q@3Z/H(N_S]*&65]#35)8B)U MG_]HH"8IY)DT:AAL4+.[2J.VI>E=IS<7081I-[!59:QEWT0DL>"VXE:78=Y5 MR\H7OLA0-EPZ0R$.NZ$:C;1R6YZS]^MC> 6?PH'UW-JN<[.CF MZXOFCJ&;W!D\<1I7G-X7\0TOZXWW^E;DG-I-3B7_DS:9^&;EG)I.;==RE"84 MV5_4I/+$1N-8#33]CN-HGI;C=W_Q6#PD:QJHD >Q3T+H 3^$Q UB (=Y!TU2 MH6O$QL)B.28?KSJ.*_*C-.3KL7EN;2@7G_^3-Y]XG)Y;,ZK%ZM&:4R1>&Z#T M1,P>L[&FC]NC>EM.,R3D5N@^;LO[?%L_?.2=OVX>G/V/77'?C);A%;34"T* M_,0'"$0TIJ$;QH QXB'DH90RP44G?4/VI+O'=N&TZ+I7EGM\DSTW^"IC9Q:H MS+$]C\4J@_Z4MOJEW,#[O/R:KW;K_.KV)(+N'2;B-0=Y(8M!Z@8,IS#U!O,1 M@;%,R84QHY93X5<&I,J;>^;X%M.[2:@V*GM3/' GRMH9Z3-._#P4T+Q;I>4. M*[E56%3W996M?]Z6NWN\SJJJN"VZM^NZIY$2E$0HHCX.? ]'."4@Z:T"E J= M$#)ERW9!V1Z>T^)S'@.4>@?-&+F"&XLC\BJYQ:A#J9TMQ_-_&7D((@$D2]G8](O;NFCEKTRJ9U,MB!BG6 M5C,+[!K5L]>('5O13CXZ9I[KV:N:K#_BNJ;$E)*R_35?-RM7_#_S#V7-_ZAY MGZC8[/+5%<\<6S#]VS2I3X&+71VV>+?A!'0%GO#&(8504OG ;Y M.P[]78/]HJTG/X;O'/!+/K)EO:T4A'.B9M*14[,M9%]KQ2D656 +C39#7;;A MY3FUML:J]F)_^M"\!=_FQ6$" /+\!/IN%$ 2$HAA;]DE%,KHM0E[4ZXT7C@- M3*49MQ&J-7=6++%L<)%1C.!Q=U<.K*GLKRAP/@]E-.J1Z!Z+,EO:BM?8W>?+ M%')II2%76^S%_/^E,/!ZRR 2>TW7I+TY*)[2S-P(V9J:9XEG"YHWR1Q=@#<5 MU5-@?>:JI^*1J.HILR6J>G2=+^MML?PYW^SSRNMMMJGNBJIY$)A#X;DG__.; M7?-' ZQ]ZLE@Y(,@Q"P(DI#@YAT0VD-B%$@E@%:!6-;)'KOS90#?#N35$63G M-EONS[K(2:7=%A+3T-DTCIRX#NURP,TE]0AYVTK'V(\WM2>9K>LP?4:.1VG M>>CT.*Z6$PP0.65/=\5ZU=PNMEGUO[R\:YYZ?_0>>,"- .2Z 4BBP(T]"I-A M]=11*5?:(?]6RBK5 E'9\)8@1$RL[G,B)D1 = M5E1F\/Z,BL@S- ^54,!=ZO8-A5&^UQ'@!2Z)41HD)(Z]@'(Y 7L+ ;N= FLI"ISSC\] ODPZ)+FVJ\ ;0BS5NYRZ([ M(I[?K_.ZJU[<7S/8_OY)C O&L!\S2# C2>3Z+ K30V[I!_YBDW]IK(C)WVBP MA 9QT@WB8P^$Q_*1)\[JR!4Y01ROF<2DM,)[[ <7 MY,?2?/%8F\=58U.-<$:W1V_G>2C\^&Z7$X\ODXGPA[Q>A"$+TZ:6G0&2PCB. M@Z&L/8!N(/1^BCEK4T[X+YP/LB_!&:#71 9LFED;2? Y;B=(@3D7>_XV+PN;RM_\BV>6,TH$$41%Z:A"R. M4,02+J*]49!Z@8RJ:9JR+&E'Z)SE'IY3[?%=.!M92=,E5DS/1N143LR.Z>R1 M.9\'.D=7L?-$G9$P0PS/0[],.5-:Z86&4K)?J_QVMWY?W.8+%">(QJY/ R]L M"D*(GPQ+"!1%4G=*FK!G>Y6RJHN[=G[787(:4(8R,1E6-7,Q2X0:S<9$"!XW M'3NPII*0*7 ^#TDSZI%H4J;,EG!:5M[=%75[G)#;Q>UU:%_RS;+(J^9ZM'59 M->=[^H<8?!0C'! O=H,0!+&;4(K;%U!X]:2;T\S$XL,&AW+U_GW.N7\_+Y *<,,1"A-4PPB0&(7 M@!X$0Y'4W07@Z<-+'_M45+]W+[?$042"@&L_ M"C##'@, )X3$*4>/8I^F4G=QSP>V9;T^@'..7+UP&F>='QIW_ZSV)-6,*!2] MV7L^B.U%$1/M;>?2[]'8/Q-W9M@%YA&SYDC,T]O(9PC1TG,4@O8BC_&R9>+)2J\SR1VO/8* MF=VF>*N:+N>DMCXK<"JJM2]8VU]:#/F,!T!(8((BDB(2P13T]E(_EII&J%N9 M1#&5;@O08%),%L%Q'@*CZ<.S$AM]1G0FD\T$MLVI(A#%* "N%S"? M8"^)(^(/\]G9I]J6;?_NC9&#<(O9#PSP?,30,?Q2 @O4E,Y>Y=T#(TGCKU MX%1?C=:B4U:=+#.IK$[B)%I6I^<$":F3!J]S4R<=5TZJDS8_HNITN>&C.:_J M3UD]&-TG:P2Y$ 8^C4G*_Q2GPVH4]*2*D37,6%:F'IG30!O&E9PFZ9 H MID@C\2>G1R]3-]&4[31#9P3) *WSD",3CI3&NYSD^E!S70;>;;?Y9OEPQKK+ M?.@#X&%*$ PB&.$DZ*U3/PJE5HP,V;2]AM3 ='J^>6J@SS/P_],^[5T^4L*ZP)/Z)4;O/BRX9^7WYMK@U^8C.,XLBC M$$91G!"*(6. ]C8!2J1NM=*S9%D%]^"<'IVN\FG2*J9WXS$JIW(:9-IY5ND< M3V?TS R_\U Q0[X\?5_)($.BBM7> O#4$B-A%(2^RX+F3N,0^RC:6TK3()7: MZ5/YOF5UZM[S49M *M$EIC^VF9)3G<XLN8E(O%NG8L;XVU4!S!FQ.#TYI7T^+ M4-%EJG&XE%VG4J31TD+528[.KE3I,SL/-3+BR;.U*E/L:*K3?JT>>!%D ?3C M,(D0('PBF/0%5&F0>-" /@E:FDZAE';W-&G54BD+C!K3J4EV^<[R)*]5DOS. M6JUD?1'3*R6&9'?ZZ/?[?%/U;T]1C&+7=>/$\V$(7==SO7[ZEX(08)5-/CD+ M8^WO[5&I[>Q)DB:WJ6>/+\7]O#V@B7?R'M$BL(FG1N-<9$;+AQ-;=SJ,B-\6 M4M57MY^S]>&YV@1$?H11PB;=0O$P'82Q5/(C_W7;.W$.BTDV3L_ MI)D2W%*S2I+DYMDQ/U-MDCWEX]QVF#)W\Q .#?S/[M#08^(UPJ'RPW-MIMB\Z6ZND6WM\6ZX*E0;S<)$IC2* IHR&) "4V]O@XSC;U(Z&IJ M<]8L"PH'Z70HG MMUG_S'A^A$V*[[SCN]@X><\WCP39@>]MOBR_;-H[=K.*_UP[W2VWSKHIN%CM MMLV!G_IKSG_NOKDZG__7?;XMRM6/HO&#,]8&!=?;AP1A"E\($>;IGS9D6/"G MM-51Q4,*:MZQNKR[SXIMTVL?I[P^JP8C3VY$'&*.(6PH,>@>#08C4FU(*#.J(B.GW/^A'P; MX6MZU3;C1FFX'\FM$S03"SZ]V-U4Q:K(M@_];1C]'K+GI2SV@A2ZT'A0&:\L6YJ$BJG6>%S*B=8Y&J>MO7V9JC.*98;B>0B6(5]>KKTUPI!,IM5; MH'&4-A=K\/_%OINP%(3]>834!ZG4^7*9[XZ00TGNODBQ(IX7V2!$/@F::J=% M;(]%A:=YB((2\A=2%C7OC5RF^K[8Y)=U?E@JG)F1!4_#3M1EYO]D8:[^VW^-=]4[5]H=J;H[6V^;/[^QV8SJMRT M3P/&0>2S@+ H3KS$;;*V(6.+8U=JF6H2@)85]S#8T!^W<'^ZZ\@Q9U_4W/W\"\T_P=NJ-MI)-7+8[A9O M(,Y8IT F*HW3'J9BV#JKJN*VR%>,4XZ6R]W=;MV\IWJ%+R\W=7D:KLMG(M0E M$+DQ)AA[<1P."Z4P\LT]I& 3Y BQK'H4S 9/G*:+MP&-RUY=#O5%UL.;O08W M$^)FT=96PMS3MC_XYG#GNF[0N?5"XLZR98+[=Y5N4D[_[](?]>7_^1K[_EOY2;^FNU M -1C.,)I0KPP=U.EV0)V M?ECMH?_9V32/;KJ><]="ERB3FJQUST>W-].P=KRZ_5#65]SS;7/N8A%A-XC2$#",XSB%# 1AOPB/ MDR"2.@@^"4#+"5(;)*75-?_#+.7+, M^7C4]-PWY^K5IK>R-&"C>6,1J?X4L C/&BU*AKKV?H8 M2GLX2/AG+XK/:2=A6FZ5*L>Z\>]3W"SZ)[#J]D]WR M<>7DFU43:W+8P'):7,X1,.>W'MK8)Q;.L'0F%35"[CQ22C.N/#VN8(X?Z3&5/J3= MJM[G9E'OYVVYN^>)Y763:RY0$C(6^92&'FU.3,"$);UI/Y2[4LJ(0GT0)W?6JBR;QX8H5M2RL9B6E72+IP;99;MRML9YD1DS@3Q,Y,[ M(RZ=DCUS?"G(WR]YU@ANDS2G6554[>W%B.(H)!Y+(7&12S%B9!!=/L&6>H1/ MUY9ET3O"Y+2@E&XYUR946MNLG6WK>G)8L RQI M3(":(QSHKMQMZFI_?7$<>S!@(8T@!BX*8@CP02B)W.7G1@R.EZP=CSVU"]#- M,*P\U;1+KO*44XK7L2:2;N6%6\/U%;:[\&2-[]GV^T#GQY_:F]KS5>=.)]& M@3P/NR )$B^-8$Q($H!>KC$%L=29(].VK6_9=G"=#J?DO?&F>1:3R"DIEI/) M'N%L]%&2NC,:::L1YJ&3UKQ[>K6]519%]9)6=7&7U?G5K8!D0XII@E/D1I0" MS#R0 -I#8 D4.J]BQ?!HDVDYD31+KIA"3L:KG#SV,)M:B%FED3+\G=%(*\TP M#X&TXUHY0C=6W@49?OG7(M_RO__UX7W^C=/=+&JRD#5/& %,,?1!Z"=Q!/;& M"4J)E"@:,CF:'%XX SK=?1$MBJ6W1\9B5WWS5YA8VSLE9Z@2VS QP?4\E,^T M4Z>W3\QQ)JUV1R&X>@YCO\KI>;X?Q23&7'CC 1!".,> W21W/W"1BV/MZ]R M-$+U=E7,,"ZI@:.3K;S/(L&S72T4H4Q$$HU2/S-E-.O;*8&TP*"T3EYN[G=U MUT*$/$W8L:V"+Q7$5U4Z%-TEMLTR9 M>E+7 ;MP]@Q.=;/Z:9Y$Y$N#W9F)E8XGIZ1)FQT=(?+V%IF'XB1P0PJ8&Y P MH.&P5DB2&$EM >O8&46(/'TA$N9-78AL4&9*B+P9"9&G)$2R[,Y7B*0]$1 B M-79TA,COI<\GA#%$@<_"T',QP SV%FF,M3,B43NC")&O+T3"O*D+D0W*3 F1 M/R,A\I6$2);=^0J1M"<"0J3&CLC!?%9LLLVRR-9'MPE^*.O]1'%U5)%RN<'E M9M4\+;CBOZC*==%_I\)G M>SFL=^OXFM+V&I'>,P<]JA.[W#B#>\ZQ?X^/.E4*3V!,V@W.Z_%;Z0&2.OY? MC=\UOOBM!V^A$ZA=DO#N'6_Y3?XC_Z?SZ M._KVH>)O>ELT=>D7EY.MVX>Y' MY]T[K6L.+''Y0L"?0\M-?XG"Y R4\QE'4R4FP[EW/TT13YNH%\88@S2!/ALV M 5/7%[XZ>")X,TQ+FBL\!:/3Z_=+S*8;C)V76.D!]M.2_YR-/U5>8J43_/\S M+3ES?\P,VNT_6U(B3X"UG$2Q+407;5%5'1N!28)#&$6^[X* 8!PE&/=&&&12 MQV D/VTY%4"?/]/KSW(KL[+DB"W&6N1%+D!V0":[)NLQ#V?65Q4)F\>2JBKX MTDBGD12#Y;(]POPI7^;%M^9BF0]YSWC-BP)[?,X[9S/@DQ0276(%E65$3B6EIJ?S *U]=NK"^? Z MI7;4YSQ7Y^3($,LST2=3WCP5+*,LB2H8-] \DKC;-N\>W-0+@OPHB6,O<&'@ M1B"@B*$@\J +*(V30.JZ%]EO6U8H#N==C\=I ,E)DC138A)DDR0YR1'GQXJ^ M/"'BC)ZH4C8/_5!&7YKI.)*ODQ393;$NZN+HZE"78(AA"K%'_"0 ( F'VZA( M&(129QA4OF^[)N4 27K12HLV,<&PS9B<:$B29><%C.>,G%$/'?[FH2!:'CQ] M/D*;#9&]G&.ANB[K;+T(2$JY6J4$16D:PA"$47_RE$8,X\6W?'M3BFS$R']; M9C0%$,470EG&8HLO;Y+89<>.;%XE%TX+1JK[(@OX]ME26T%_E$O9+9I?BMK?[Y93%W6NVVV7C\X MU8[_O56Q::X.J,OVKV6WMWSH\]^HFGGZN^VQ/;V'%)[1>6(57IWVZ1?0-;"7 M)CJ>7![7+I^CU2I?76??CZ:8A_EE'.(D26CL$L1X.'BXRN2^:F\$=4 F6^QYS,.9\:%(V#S&@RKXIY>!Z7 @ ML0DN\MYV]^Y*"'P*8>I&&":1&P=!Y.,> I_<"!T+LF+8_O9XC]5IP3J/T#H= M7.>'!O"?U1Z#,ML.PAOHTS2!]&ZZ0?9M;:\+,WE^K]U\@\Q#$^VX]GP7WA9_ MHGKZN>;6FYRE4^\&0;EI4ICV$C, "*I6Q/U+%E6 MS'V><0"E=%&B)IEB*C@>CTJIFCB%5I3M+#MGI,P,J_/0+D.^E#;ZGRGR6"+^J[G3BJTC@/O='TX<5II!XC"K/)]B'P=;MIBE;_OJO:A9S]11B1RZ(4A!3[ M%/DD9%[@IKUQP#$ISB-U3-J>07[+BG63=KZ[+;?O/F?KW*GRY6[;UFY<.)M< MOL3:"-'2$\6Q.%:?(K)RFQ=?-@YN]S.6#\X!IX/J>EO<[.JVP+TN^[WW::[? M$6-5;+IHHEGF(7ZFG3H]133'F8(\?LCKG[D.-]-1QCD@><7[;#MQW?ZO7;8N M;IM'4G!6?67K\H^_YJLO>;6'%@HP"R+*V_ M;K8YQ_=W/O1YURR^\0;]ECM?N"^5\\.:NY-7?]936(MM):V_\V@F=77^T#SH MSAWHE^L: 7 :O$X#V.D0SU:GE=D74W'[C3L[C1_!Y=,18"R^%>(#R6^+3;Y* M\PW_1?V1CZ?J69 "Q ^0GZ1NZD64Q6%$PJ@'@=Q$JI3?L&GKFG^[VS3%2_?- MVFZY<6:V;01WJ55?6S*U?5[C]390W5:K&\AQ1:@6$RD3;;5[.38 MJ'.GA=<\AP;WN_O;.KTH"OG_TM!+P@AZ"6&TMQ_C6#7/UK0Z\4YW$RJ-;VR+ M$FYL5]L"UY**>H4O9ZN4YUG3V[Z69'YV^FC*+_F-:R7F#%A@0)*HKN&:,SZL:Z+WLI:[V&L5H69"=]K!:&B32%%/6![T_ M]IO+AT_2&OKVZOL^\+1EV08-^+XB#A MN7+HDP;@/G..(G=QGV^+#0);B_[ M:=YXOI8]G39)=S :%B;K Q8CA]F&GS+"R+2.?A"RTA?>5)RRPX!:*+/8&H:C M'>Y^B/\>_LH';5Y=;IXLU3]>E*>WM_GR@#WR $DBX$*"HC#$ 9)<,!.B;7X M9QGW'"/BP65G[[-3;,1V^2Z(YQ>N^>DVWZ'W_LX>,-7>L36'N]Q6@TGD47 ML1J'+?2+*6.N:H/I1UOK7>5-Q5G[;*A%V)%:R7!L'5!XE.&$)BR*0X)=[,):Z M;M$F#LN5$ )C_J;UP'GF@KHJ6VTW,86>2Y/)J;7MUK*BW1I4G]'Q,1IP'IH^ MBJ?E^,-#3NN?VFN6T@2B4+=5QJ<)39XZ0'2IYWDA\F"$8@3"D$4D[B'B5.ZN MW5&!68X&3WWI5N_%'<9M:+%[,MI7E LCH#6PEHIALC#,A M9I(VGT?,F<;U<@9CSMP,Y*5BC6Q9=ZM5YTLW AC["&2Q"3ADZ:(AM#OP29\ M B5WE_)$(&543.D.9N6BK\[!=L'<=/7?5!U"?]8SDYY@?$)DLPN,/E]2;R3% MJ=0(O6(>$6]J$B0F8*.UB8DH2(8+/:K#@7Q4==4/AUI%X*4TQL"/D.MA%L* M]I>U^)!#-A?PS."90VP[\L0YN.)DU5!D92.(&6I/_7@U?D,:#TU&6G#T&"1$ MO&*X,=NH\X\LAOV5""(VF#81+\YNZ+]\V\ ANM$$LC\$:\51!_/VV*S+.[7>0\_KQ: P1A$">7XH!_Z M-/$) 2BB+G0##X=2=^^.C6WZN+$_P,WEI_.H.?M]\,D9G#I6J5SRXLG16UPO MILRAL8W'&,/M/&J\46P0A?ACN^GG'8^L>R\8G\9IA2GOA4O] +A!#-PDC*'O M>2G"0V2%*:/[TX-TLQ*+6U-@E#]?V+MCZU3;?UT-9OUB+-%.,0^AFY2!$:X& MDVN->5T-EE"71&$<$G@^WY@20(MHYZ?*/[7]4YSO]Y)M$^] M*4T=BY-)KG>2:[&Y7.]$O-!C00))A$B0!C'$H#^\'2" 4DN*:PWO_+3VOZ[P MF?H*']$^\Z:TU#X;(U_A(]=*MJ[P 82GRQQ("ER0 !C1",,A>_9\8DD/A>W/ M3]]FKE<6KHT1;:,WI2?RWFE>&R/'HNAX)_E-38IJN2ZKW39'-UQOLF6]B)D+ MD,]\;@GSF3'R8^RY*0T3-W6]-!1]O$KQZ_86^1M S@&1\UN/:>075%XFYLR8 MTV1R'D-+UXG2:._2&2C7^?CE*U M87D'E-#T6FZS4IDL%5FQPY.FKC2@G!;5I,HR<",L+?)LSE%;%+PX*RZJK(BJ MR^>:YP%-CG]UVX5^/@-X(2$8-,[S4>J&.' AH7X0N9#/!$#H<12A&\-0]/2& M:;/V!MB M-U]?RF_GBJ42W)X9B#::HUY#%!KWI7C]&G) ;W\FJ]VZ_SJ%I>; M%3>XKM^XG-^]PA2WR4R*81)NY;3 MB@&@,R!T#A!Y"&U 2CXR:91V00V=B'$Y_=0DVXYRBC-W3C4M\#\3Q;3AV5.U MM,:>^,3JZ>/IZ4/S3U15>8TY@B_EML@K]+VH%AY*O2"F'HY"R$A3D^2B'H$+ M4D]NLF7.KNT)6 ?UT<['A=,"=0Y(>0;$L4H*IE'V16=OTQ O.Z,SP;FE*9XP M@6>G?>:;81ZZ:<6S9]-#6^R)ZN8+UDAYEQ6;10B#&,((PB3P8HQ3PI*PMY?@ M5*J87]V*94UL@+TP'#MPDB*H0:68Y(W#HIS *1)H1=%.\G-&O_0YG8=:&?"C M--W;=#.XZK!R]G2#N[T^H%%%'$7(0S#V$Q0Q%\$H26&/!9/8U#.5Z1MI)->L;NXGT\S]3K3-25BA L%1^:++!YJ&]EGU\-6U2W,H'VB@UNQ113@V]U?35/M;Z&FF)Y M- U]+0_5)WZ^6BCIAX#>J3 CJFG[8S_[&LK.WB,(O^1W-_EV02&*0DI]%U'L M^R&,0M_KK5,?,QF%,V73LM[UI_I>S&KDE,P8RV*Z-@7!V&?>JM-M)Q71OE1>+]_F7;$TW=5$_M-DB0Y&'(DP85U@* MN);Z _*BCTJHFTJW[6L7RT41(>>:=5""WFIWSG$1WWW\7TR%;B!%[HHC9KU MO#0(*"-] 8N/@D"H E7ZHY;'>]^?I>9:\LR\/M"MD2(WRD7Y,##"CST^,;R5 M2)E^;*O!+C4[@^2N7GMK6%.OEFT>]EE#S AS4Y>+!TS]*$8(I+2W!'Q/ZH5& ME>_;WLEK(3E[3)([=RIT">[9669*H.304S2S_5O1.BLHS2FBG2>:AD99\ M*\?HU&;N7#U]VU1_%PK:%E6Q^4)VV^;2O?:4>7.B-^198P+=R",48P^RP$O@ M0?Y!8O")'FL8A?1!^VV>?HEUV5]*5Q]=2I<-=WIQU2BZPT"UJ8G<%[QP=:1V&/,U M[J>/CA]N3VR?'[_"EY_R;%W\/5_]>E]N/F?K_&K[OOB/7;%J?[QQSFO>&H\" MFI*(I #BF(7#*DF:QI[A9^AFY-DTD?'"V3YQK7GX(,^V&][G+,3'F9$^XMO? M<^E"LW@K_"D91S<%=]=B-GQ<.#TCSHY3XC2<\,#A'+$RHQ ^;E]0"/PS[:SS M3A?F2IJ%)\]';W/=U.37S78/J,^8KC9'3_.>2)^B$'HXY3E4Z@'JTS0&R;"[ MRA,K8###L -PG$3A\&+%:D#LW&;%UOF6K7>Y^/:D^]PFS4L,H!$V['6#>L<^R[X(A;(P6,#%)?CU\/L+=@,1I&%,O]:, M0Q"%?D)(.(1++V6&)[L6$(X3BPZ@)IBMVFA7_5GG5&UI*RH)30B?!*D9A2.U M)E&!B9 D_#[[T:\O^9?*;^U/<-#=&PP+$%,<(L) MA+TX3&&"PA2$(0$44X)=:CA0C89[G/#UDOS]T'G[9Z?Q5^T1@X\\U]DZG_/M MMV*9\\]7M?,#WN:KHO[S>66<<3_2#XSSZCO&PN64_67T2&JJ#17CZ^A=:/Y1 M=WQ*)&+Q1.VE&Z%?..[*A^FOF^RN>1[Z:+Y[8HKK$N#ZD(0^HY!@'*01('T^ MP3",^J"L%X]MHU0(P?K1U\ 30D<,Z%::S*O7Z(7@67076Y/4B?O)J'%8LR$5 M0N]876?>T78T%@0#[+BM,LY"K'#"P,KMT1.%C3M!$ON>"X,P12 @L<__E_;N M)#&(1U^RM>C+.+/CO0,7SKY'=J9+>M=MFU*_=?MO&>:!5Z;_66, MI>"I^\BDB\;R8?N63Y.?O-4[H\!LN\FM+4J/T OG'=KG0Y/1A>[1VE7X0&-V M7]39^GV>57G%=O5NF_]2;(J[W=W'[*$]]T%VA_<\@!=$$?,(##&C(')=0A.6 ML@ CY(TE7I-PZQERP<:.WR-PMX5W7&85OGV/CB=$W^1/,%HEGJQX#@=ZW(1 M[3&S%\Z^ ?98G1XLGQ+F_ ^+:LE_]O_DV=;Y)>,_V-W7,LV;15(,GSO8:*6E MYJ'ZEGQ[>K#1(H-&];4K-ZT7)/4CW_<]'(1)RJ'XJ0M[""SQ@\6W?'M3&A58 M4=,R(_T8I?" YZ,)6M!/86H-RJ<-3BVJYX?F.<7K/_(UGS3\4F[JKZ+A+(H]'WJ FZ?8"]B,>Y1 MQ#CP+>BEA/4Q)#.R()DR!!M434O,6A/.IMR?(VZSSCDJYH%/7=%4:)DWI)LJ MWJE(IS*+IM63]\2\P\&8[S$:D21)8C^*P@BE=%!Q#!,[^BEN?PP%C>THJ 3) M9C74#KMV5;3!/&<='3@UH*3R[?.VM%3!/T4U5672L)XR/@KV,%#,2 P3 E)& M8.ABF Y)L4>QG714W/P8:II845,)BHV*J1UNK6II WG&4CHPJJ^D\HWSIH14 MP3TU'57ET;2,%M_V:A[Y"$<,0)+X%%$44.BC'D8*DMB.C J;'T%&/6!'1L4I M-BNC5KBU*Z--!<6,9;1GU(",2C?.VY)1>?<495211Z,R>OTUW^;9;9UO%Q 3 MY('(1021)&((T,CO400H(!945,*Z=1$]8+$@I3(T&U122_S:$U*!1IA.10_@ M=$54H5W>D(:J>*J M7[4H5=HT@!-7RN:O6!#)UYDT*(U&2;0FB#-405WM$R;^#2F>N$\J.B?)F#EU MN]QP;IRT_\)%UR/T=!CB0>"V$5Q[(;IL"&%0&0Z6=2 8CUS M?)]7U5^__'W[)(DC$E(7 M1OS?T <], R\T&P"JPW'.;NFB$>ED%$*(Q=0Z U[>)A)O6=IVK:4U!L[HS5XH79*RW@#B$GZ ME-S+Z?=3?M_262U)EL^(M:WVFH%:JRP:UMS^+$1,$Z[[+I\,I "G M".,0#=5G"74]N<43P\;'*/J2/+=EFEZC@FJ#5ZMZ.O7I+3E>]154MH'>E(!* M.Z>FGVH<&I;/H_,0/D2)BU(40H_&21B'/NSW^Q@C3/+[K)"M&E9M<.P=6&=ZHR7 K%&Q%6^F=Z:O"IX MJ"RPJFP:E]C#:0F?A2QV,8.A1YCO>CB)!B!QDE)+"BL.8 R!E3SO98-FP_IJ MAU_;\CK5L2]Y6DV(JWP;O3%M57!055I5N32OK,,!"I\R%WDI!+$'O32.*:3] M3AJ+*$AM*:LP@!&45?8(F V:32NK%7ZM*^M$)\'D:36BK-)M]-:45=Y!9655 MY-*PLAZ=JW 9#GT(@CC&*8%>B#$(AN4)KOM6A%7"OG5=53T59H%JH^)JB6.K MVCK5X3!I2O5U5:%YWI2LJOBGIJK*3!H6U44,TYCZ_)_0\T,$@M"-R) LDR26 MJ;(U9=-R*:W"03%C;!I52Z-$6MS,#5[>LV&2;99&M/Y95T3Y?,)19(9S"( EX^@JAGP001+X+//[?;IPBY H. M3R.V[(W- 5Y36SX ='J$DQ4IBM!V9E0:97T>0]*L2Z7%7BHW&%%5Y76UK\X9 M;%%,0>BYB+(P\'&:@C0>;/DAC65*NM4L6"[4=[I&61N@GT$@""-$G#(/1"X/>V$PH\*94Q8]&VZG!T M[3-GR^87^0&G["E (^R*"=+XQ,H)U,!I^XLCB!=.5CL]RNX$W]@G]028.R-A M9IF?AZ09]NG9D3KSC(E*WJ><*VJQK/.5& KJ(YZ_>1&*4!@F-$HB.J" J8]D MQ,^T;(#;"J&<^!GG64P&IZ183A"/V#VCC?L\8%Q%E"3QC#;::HYYJ*0U M[\IQ.K7D>M#79,E %UV%L5>H.3<(I@.@_/0 M(3T7GBYRZ?,AO*BU7)8[_OE/^3+G6G:SSC_D=7\"S:41\@,_!*$;N&D$@Q3! MWF3H^9[4VI:.(\$]4]_FR+K[EZP?)Q3*MIA!<,QNK%227SGHV/QTU $FRFCE^1.6M$= -)_*!6UHP2%+&$C].TRAR Q^X M,>E-<$65?%!+ZM/6:Z<&-'*:(\>/F,98(T9.4P88K9*,*R#'%)P1#"6FYB$0 M:M!+ SU%3@!(?IMS@5E=9]^[5?UCR4FIF\:(D0A1@!,_A- ;YF@AE+R$7\>2 M=7GHP?$9U+*\RYTZ^YY+3J&TF!13CK$HE!.2@3L.R^DW^3YTV6$SV<_:^@/4 MYXD3Y2QGN#NC0"88GX<@&?&D--\?Y>3JXS:_SXH5_7Z?;ZKA)I"(^4F"0!"% MC%$?D]2CN+>%81C*S,/4+%B>@.U!.7F'2E*9%$D3TR3[?,FI44_5'M!$:O,B M*V=T1H_%>2B,I@^ER7XE639=?\VWCXH:%AZ?7S&,(0Q]2#'&,0W[; M!!N5N MHI3_O&4]:1$YRWTA3M9"DZR-5J!,3% LLR6G)AU13RJ71JYL?L;'&1W1(&\> M(J+CP-/29%TNY H?KVY)4=V75;;^>5ON[KM+UXO-%_Z[W/>ZV.SRU;Y:NMP, M=Y@A""(/!4%$$$P]-_1#T ,B"7#EJR.MP+"]OMPB;^8+7_/UZMUMN7W'\>?. MS:XJ-GDEG?#8;!#!=>1YM(7D1&X/UFG17C@#7N<8L#,@OIA6&-4Y?K78TVK# MS4-HQW#TQ;+1$;A5JEA?0/ZA.$$^_[@;@) 0+QV"0QA&OLRA.+DO2\FKXM$W MK6Q/DB@9C;3!D>3FVO0B)JI+LF3-26JDL9\K.I=D0$X0/G"WGM2V)\0/HYCP MI#$* 7$CBEB_FH4B0*16F)2-6,["/EQ]T#_+HL*=C%Q8IDU-.0Z@)C[4\IR= M5R5%@] YJ8N.&R\*C38OXDO:)<]VZH>/O&O5:+-JBB;OFY*F#_G!=)I +G5) M$$> 1BE,8AP,IH,@!G(KW 8,6E_P[C!>."W*MGQHP"GY!HH9@D57PT?F5G9Q M_ RMW:;=5 (FPMS9!72#Q,]#V,RZ]&QYW3A?HH+WGO>Z19B0P/,22H+81\SU M6!"%_:=Q J3.K A]T+)@-1CD9$F,!C'9,G]/6X+IP6V<@G:4]3 M=$9/3! [#YDQXLG3L[+&V#$Q9UI@'/H)9C[T4<(0HR$7PMXD84AJ'5?+D.5E MW4,R?S\D\_DAF=^<*>JU0*K^_,@HGZ;G1?.9#"E.@H39G8=.F7%%8M(CR8]" M:=$+*TJ(SZD2C$(40>AA#!AR!W6$24(5JXP4+(U2<-2ADWW"5H]!,5T:CSPY M87I:S1(D5)FD0/ ]M,N3+Z7(E;89DCG_MS\]>;M#M;;$NLCJO/N]N MJF)59-LBKSBB)974[ M],<)KL(5M]:PX[5$Y=.MG@COSA,XNM(Z:,\VD8.>5\H4U0 MUR9-DQPQN9&@!=D.][)-N%9[G&)Z;8S@\XH\!;=RFCM3 M6E?E*:8\[%*S3\C.\FO>_,7-.A].:=/O^ZK[P31U41JYU$,Q(RE+F9O"_OHL M$F/,Y";S!@R.LB)9#$CWD?%PK]62A^;=.FLNO\SNRFU=_+V[R*"]T"KJ+K1R MPUCG1BLS#2,ZCQ^Y362GZT-#'%\A\<. T>E!_GGL.?CKO)V=:AND?1YR9]:E M9Q-GXWSI7(5S6(E=)#B",?)I2EP:P10E'@YZH]A+??W;<"2,R0S$.5V((\.G MF*Z-2*3L9%CR6IP#ZNEOQCE@.:-MAJB?AZJ9%-;@Y/G3V1E[82_)U;3=-F9?@5-VX/27%\Q4->S M (@ @)NCJ!Z*8@ 1'*XG(I$70LDGJI5L6$\-NYGSYE"+HGE_D Q_8CFA?>+D MQ/94%<\,2G=D2W:$69Q'5J?I@TB)CB0C(CG<4Q/##/AD >,"$S?&'J"8IY,T M\7T?D/YZ: )C0$2*GBV9ELK\5&^WZ':Y9)3(%M&O9X,3?=4T.JZ:GK81Q%/,B1M#,?O%4Y7K%==UAPMTQ3U;.>U[]TZYR9V'/-LV?W23/Y3\\PW$3;F]:T;O M\+#X\F'9O&U0W#KK_:3M4'AUC=YK7-[R.B5B^;<%-E2"UA0WL)S) MIR59F4<"+0OZQ;M4)'T6ODB@R&Z*=5$7;7W,Y[I<_OZ51Y]\6S4*4C\<+FY) M:$J0%V#&?()XBDZ0?R0COM1E Z:,6EX0?7^)TLOWE]>7]+.#/A"'_J]?+Z__ MC^05!<8(%M.-2;B54Y8CB,,I09X 3W4<1Y2Q,[)DG/1Y")=YMY[>N6"'-P7Q M>_H0NX>"" (D);/0;,6!:X_JZZ(Z%35C=I!J7US"9Y MR@HVW'DY!_UZPI"88JG2.CN-4G;DM"KI<2/[0.;'[*%YL:Z_G],'(.8?#5(_ M#M,4H"1@[MX8#>-8ZF2SH@G+^C.\R7C?P5)[S%*6-L$)F'W&)"=D/5E[1!,_ M7/F8EW-S-CTBYR$SNDZ<>*92BQ.)VN6<]ZOZB;$ T\0' 7"]J'GX!9/$[2]K MH,0-I&9TBB;LR\MVURZL=NBD*XN5:!.3EQ$8DY.7'M#$\O(R+V?D19/(> M5'M26;Q80(FI\^(R!D5RDC)PTQZH?TU+S' D7C%AFRNUDHCKIA9BOYIUWQS7 MZX[J-44&_+>*^N&?*F=[W.=^=!YU0:>HG%7!?Z)V;LKMMORCV'RIG)N']@L? ML_:[N+R[SS8/734$__GNULO=-ENO'YQJQ__>JM@T919UV?ZUP\4__]342[Y[ M;%^KLN&%1CA1NJ#37-/7)FBA+\UT6G$=_U!N7C(4>0F+>(@@/#[0U(U3%@U3 MXS2.4W$I5S1@7'Q>MOFO[HPM'S+?LFW1 MI/S#G+<;N<)IJ$X+O!XB1J!>+DIP0(YFI%!E2SQ8C,":O7CQ7+.=9QV]C0,Y M_Q+OP_MHLAO#&]GMC;X7_JCJ+^6N_H0 M _=_^TEH.\P"JZ.[JO1BU4-9Z8E&C%Q,PQ!B M3! &#"2(](>R:1PBJ+CK; 6+[=J;HR(18X_:6F\?Z3WMR9M&+E[*/V\[_9*. M)MMBF^A6VW$>RT.C>7MZ.WX$EM5KAQ81 2AV79Q" #S7]P$D:6_(@\B3*896 M^+R4(.N^@*N\OJW"F[2JVJ!,3BAG)7M22B;+W>S$2=J!5\M_)+E0D) 7;BL/ M7 !2EH @<0."O2@B87_FFB'@8\5<4,&2Y4SOZ,U<$W6(*E1*"XQE%C6T9@;O M&YSE24R$-/B=G1[I^'):FK094EB+_7!(JAA( Y>QE(0^@U'J-@K9VV(I9LK+ ML1(V)EZ1C2#8WV!X ?R1UV1E6D)Z6=92$^BNS#:_H[LZ*\.;\@*M)?[4UVB; M-=C_6J>=8IWVP[EE!#-=9W:KM2H^G%ZP569$MF;DR!"E(?%QFE(6 0I#!L*@ M3_=9$ :Q6MF(A(&W4#DBPY=<\8@EHG3J1Y1BCRI;:F4DEEBS&W7^DU:3O"K[ MF@TWO>;K.G"BK$29"X4+BE^<3"T\#"@&"4U2D&(_Q@CY?4$+(QZ*E*\H5C-G M/1*8O:18D5.Q]9=1R93<%SN^J/CQ>DQ>S^):XA<9.[,88XSL>:S'F'/G].7$ M)G@2?KT[W[3W<^[?M/E8\LB7USQ:-K&:8^+SH56:;_@OZN9*H.IE;$$," 8> M2'V/ W(3'%#08PL1D*HW& >1Y;7HO1-'4\-[[L>[@R/J&U\CM9B8E,ZOL>3T M]KB=NIM!'[O@['UP]DZTM^M53ZH1IE)E(^2?D>YQ&W<>^CZRST\?19^ <:E; MEE\V2(CKQRB)TXB .,$T)K O@F,1#I'"59J?,YIH@-1Y")T)1UZZDMD$-[;+9(^U,DC<*($1@!3%*2$I\0=@ M-):[O& $.+9+*%X4MNGK9F4:3+H&8PYM);E*H%<].Y7@ZG-NH896H4'G(>!C M.FRHDE:9:ZU*N(5+7$P 1BQ&+ !^',=LO]_G 9)Z6+&>5L+"*"6U)K)210*E M-=<2=W(R.C=1E-4Y!1)G)UTJ/H@4LTDR(BHPN+R[*^IF-MY<-(I;A?N2;Y;< M]B(&(8C\E%OC&6T0$8;=N+<(F-BK;B;L6,X1CZ"URV:/P#D_5'G.QU+-?^EV M!XW=X/0KL>8Y%E.BL>B5TZ.SS(ZK2F<(.J--)FB=AT(9\:0TW^GDU.I3OLKS MNZ9DM!'&IH*N7/,?_])?Z]5=CHSWKY:@]M&2!8FAVY1%^6%(O12&+.IOU/$ MC"&2D3$K "SKVP%S5XS8S'Z/Z_KDQ,Q.$XBIW.3LR\G?$?&/\3H]X(O]%>\7 M3@_:Z5"/*XXJO)Y13:O-- \YM>MB.6*WEQ/@YS?1#Q/DCUTE&ZKK;7&SJQNX MU^7+@(>#&1@#%"5>1!.0QL1C"0U8#S*.9/=91@9G?6]&Y56-L1M(3+AGW#)R MDG[LR#\-XGU8KMQ[XQR[TY18GM#_R4ZBF6V0,[%@HI:?1Y28ROER%J-/-[(, M!F$8$ QQ% 3,ARYV$Z_?_O= 2% LD\!KF+&/5Y_0]>75 M!^?S]17^?_YZ]9[03Y__[W^(/3?Z9Z6WEG3(555X*[SJJ_4S:=X7S,]'B954 M59KMN2JDO".OJITB-S)+J.6F-?NW;+W+%VF:-._!PQ2YA-$4)A$+AY7:!(2R MZZ92'Q]AL93G-]U"P@__"'X$KG.?;9UO#;@+Q[W@7[\ W?]WJJ]\;%5.MJN_ MEMOF)==_=F(WO(@#> $]URFJJK\;'$)X$8/X(DJ 4^[JJN:_V;X[VQ0L+O.[ MFWSK^.Z%TPRB]B_$;G 1^LF%&\#C[T3 OXA#CB*)7ON.RBJN7#.++]U::V'Y M]5K>N)^[(ZM_ZYKTLF5W_-7:8TY>6:)5HF\> J@._X7%6 T>A-\T6*V*)F/, MUA^S8G6YP=TQYP7#$&$?IS -F[S03>,8]]:B E>>Z!KQ?J4_ ",JUZQ>M>^ M3-UBDWS,0)5&,4T9@S\Y:3DBKH'4/.F-7R'.SC,&+S-S1F!TN9R'SFA[\?0! M R.LB._[U%E3*DZS[:8Y[(J6R]W=KKT@H2DB7Q8\M\,H\%'*YZ7(H[X?4^0/ MZYTA2"0%R(!!ZUK48W3R/4C9C1Q]3D6W;48E4W:39L]BC\[YX0B?LP=X.E>T MM"'S&F-GMU^,T3T/[3+IT+.M%<-<2;P-U1MJJ\R;\_K;_&MS7.9;?MF>.'Y? M5M6'O+ZZOAPR!9[^GEK=X=??47J=3=2_-*)/6]M"FWCB3 MVC 3IG0>@J/CP*L;9))MSU*:"[NO/EQ_NGK__O+#S\[EAVOZB7Z^EKRR6YXV,5FQRI<% M43E1,S6NRCPE[8S&*/,[#X51AU\:ZF=3E*(N8,+E+O%1# /?HR1P*1NDCV!& M]5(@*Y!&29O,I$1VFD0UC9J\-?154J/8=.KT3(5]ZY6EPLT[#Y$>VVDKE:22 MG"N;U0M9;I0BXF&& 8Y92@+F 4@&LX'RL7DU8[9%_.H:O3]^-L9!'XA2 M[:@^K6)R/2JC&FC.G=/G[DWP)'[S M\OTV7Q;=I>9>0%W(0@0CER4^M^72V$UIF/C$C5+ 9&I'I3YLN6[T&(N3?[_/ M-U7N_'!X-":[:^+'W[/^,O3NF8SV&G3>GU;.;K-J-OWVCVJL\ZS**\F] #F> MQ43+&L5R G4,8^R+E ^6STB0$D_SD!LUZ,\N0U;V7[@,O1L;39EUL_>YXX/T MB&P(\P1;UU%OA2"F/*IF7Q04_$I7UN:I.M MW^VX"%5[P)+5X*;8%M.9*8B6DZ CA$X/T>DQ7CC'*$>N)1>C[HQXF29_'KIF MW*NG!>E66!-5PWZNB=_>#=Z^1%9NNK=BS@U42Y2+:>&H;*N+ MX$!ZB_-XW0ZMU^4?&1^DSFVY=1A/;2OGUZHI-NV:!(LT@16M?(W:,R)IK%7F MH8[FW"DM]5[QQ]P^;LO[?%L_-#>LUWQFV\QFVP'?%L,]*GD]9*F_<(G^DGW) M5Q_7^8K_ZVK[>7?S[_FROB[?%WSVMDB!3P(7A83Z 05^G*0^[G%2Q"(1 9T. MG67%[9UR[ANO6F'->[\NG$U>MW/_G+UC MSA7/H/>-?ETZ[]]$HXN_T3?_QE=[XJ^[@*D9X/=[#R]>D@$%%;B0D@&1M_FL MM,$+6<+T[3W]RX 3^U_.9>3)'OUKD7S,.-[K;;:ILC8OKH9+'5A B>M"[&,_ M)CCPT]@CC/FQ3Y((^4BT6D#;CKVHLH?FM-B<8W"3W5KR&EMG)@K&B)['1,&< M.\^.IAGE2;BL:ODU7^W6^=7M*0#IPZ,_:7;Z%Y B'$4@2I"+ L88Q33ML030 M3:6N:+*"P'+"WX-N(OKI\7K1O-+[^(]_:^&?'KYC-I)@7=7D[2-91F6K:>S4 M3:FP>ZY,RFIKS4.#+?OXM AJ!$:%U;HY*?,0 M*2F0BAS:T;^3#)T3.7U:9Z)D!AQY*E>FN-'3)%+>9<5F$:1^$B(O=OF_8I]B M1D'2F_2]D.BKDJ"AR72IPV=$F40YU=$F"W2:4J?7F!Q1GSHHT@HE2>Z<-4K6 M%2&54N)'9$NL-;<=S-UWYO EOMD]W&3+W_>&(0H\Z"8!0!Z*4PR2(!V2-C<$ M0C< TQGC]/A0)T]4DG],LGUZ]M)$] LIV4S9UA\[V8"IM4V M8\PP+K*5(D;)B;T1PWQ.O]EAVJ'26M^32VX_[F[6Q?+7NCDG\- FT1'F42D$ MC!$7)0GT:>JQW@ZFA,IDM/)?MUW'T )R]HB4)M4*C(GEJW;)DMSXE^+)2F+Z MC(XSV:@Z=?-(037PEZ8ZD9QN["VT.ZY[@7(3C\5!BE-*W%=+$M,,R7W+B(4F5%?5X3L@9^=!@;Q[ZH>- ::PG MR2D(7>?+>MM<2?KP<[[9/T#>FOU0;C[LENL\V_[27I:W2.(8-&<3 9\R,PC] MD$;]NAY*/2+U (5!LY85YPBIQW>[C.;QU@234RV0!B*C41]W+J M99!V*\HF3N(9Q;/0$O-00AN.E=9[L9D2LL?;M%WREX0>Q@$D)$D2$D8A9L$ M((ZDE-.@6)"^*V*VUL^QVULT4W-L[A]LA8 STN@ MQR*?I;&/<(@]KS=&PU#J!+6B" MZ7FHESEWQ*9?JCR)*]JW?+/+&7?T"$&15PL:1)!_.H1N"HGK^SB,^U-;*/9I MNMCDM:B0J=H0&F7#BT"UK'ZUL-JG-;Q_;M9_/^5?NN.DLJ*ES*&H6EDE4%&F M6DQ.,T0>'4?BL,86IQ/LG%4E74;G(D?:?CS3(3/,**14S76F[94$EYOFTIFK MV\_9FML-40 1P&%(_1@APD=KB ;A@TSJ?)"^-N@J5W0I\*>F%R-1)R< M3CWA[.+Q*>]I+MA[3M 973+ ZCP$R80C)Z[3T^9&5H)H=X?Y(XMN&*CANN!4)+RZ62(4@9= @*7IG[" M4A: (,$X#L3'D=KG;8ZA!I$S0)KL$JP3U)P=.WIDSF7<:'KQ;,R88$6VCGI? MN+U?F!F,>I1!DN(H! P'*/%(''J]T33TA8[\&C)E?:.IA?,7M2IH5?K$5&=$ MYN3$IP?F] NU4XG/>8;.:) A:NE0Z'-WJ+U'41IBC@$YL(4,ABZ(+>8H@" MI5Q)Q8YE16HVBK:ZJJ3 GJPFV25.69&.#H5-K$?/"!)2(W5:YZ9%&IZ<5")= M=O2F;8LH\H,T\'@*Q@ +4BY[,>R-(>8AF3=]%4U(J8_J<^S;5T:.4J?RW)5?2[7J][V,,TC*(U< M/\'8!0FWBC &\=XJH:[D2YF:MD:JCZF:S7O)%2%M&L7D9DP&Y72G)Z_%YC3@ M+IQ!BZ9:'WJ%KC.Z9(KH>0B4,6^>/F]IE"4YR6H+F>^*JFJNZ0M3 "/B,9CP M?U"*($GVJ^3(\T 8+S;YEV;B(J-34@:$!M9037S 8GM%2(4K&2DR3Y*6^AS# MF4)JCNV_JBY*W,U)4-0<>%%#-+B0G3Q]W):K[EW1_?[T H>,I1#3)(B\F- ( MP@#T]ER/A7+JH6['NH@86,118$]N)F6)-KW)U '4J[4^5N=5S\@1F%JI$SH/ MK3'@QXD)EBXSFG.L1\:G5;.82\G/H839G(?\:'LA-F>29$54>G[>EE7% M=>ZVJ!<1@FD2IH&'(0B(Y[N$D=X"BIK'D,1U1N:[EM>&K^[;M??-%^2E?A^1'/GMGM0:;59H M=5=LFKUR/DJ^Y7VJXWLI26'HA] C((B2&/CQ8)5/NN0F/;K6K$]]]@#;YZ>S M1Q"=O,,HF8IH\RLH)F,0JR8P1XP^QC;-'.D5ILY)D2&.9R)/IKQY*EE&65(\ M:K0(PAB[@#*4@"2(O0 F4=!;B;"/Y61+]NO696HX&Y,;.%+T.EEB&F2%)2-' MAR8]*W1&4509FX>"**,_?PY(D@5QA?C&;32')KHS%+W5!0S:J5,<1R'7H@3Y M ?9Z<\ C4I5YRD8L[UD/ Z)0.@NMRIRH;HQ FJR ])"&D] ]JK&UY&5NSHJ* M)IUS41==-Y[)C!%>A"=66;&IWO/I6UY=;>CW9N5A5U1?&_M7MR2_J1=> GS$ MK270A4GS7([O1\-23BI7,Z-OS;("-=B<GW7)Z2BTY1^W_Q]Z[-3>.:UG"?P4/W=]413CKX_W2\P00 M8+6GG>DNI!04NTS2F9]!&IS'3_^@%XD^S4!0 !DC[3$2?J.&696'MM M<.V-C9N>T=4YQDZ-KY2Q/0\%4VC/^S&68J9X->VZ>DHW;9I6+H+ M"S7<"P3 MVZ'G6@:,8-<&QH;@:AJQ9VL?8=5PY(97@BSQ29$&>J1DI^&%G*N%:1&7-QR< M$!(YKN8A&I+8"Q6]14(,FE1J06(38N0'!/L8F19Q;6-7U,$.$DEE1)ZK.6EI M.KO,F$F(' $%T,"+S/M_YD@M?6]_T_"Y=U^0I1F]^:+(#[WW4M;SOO5?BKSH M9E+WTI"%;SAFC%S3\['K.Y'G!KA/." RA&[HE&U#LQHP*"S/9@M26'9]ORVS M/"V%IX2D*>33B3'8$].,?43@[;AE7 DY0LT).1E*YCRD9; 5A=HN)EA)*8K5 M]VR]OGQ^2;(-&^2PYA:8F#B"'C9-G[@Q1*9IF'W9!IG]G=SX1)9/SIJ)1@[E"B4MH NP@P08II$K(P=Y.54.&4;D/)1GJ!'O M"Q\J.!$:X$ J;-6NN>@IV3Q2I4.A9SA!$-AF8"-"F<%.KW0.1J%$[4.R)>V5 MD!K78-$91*; $DGBP,&3 V)>P+4 IM@"'68H7-#JH&\SD.-E%AR:,BEA!U> M78J+39H]YM%VLTGSY?Y5+2P78X*(T@?ZG;ODQR((+(2PY<=.8!N.;1MVT,VE M.P3YCLBP3&6[FH=J+52P;+&":N\2H\=F!+(^,P+1SSV?K$U%NYC,=8QW,-]< M&U6/G.LAWZ\7X+Y&"RC<<<5/@,<38JC#&_,01RV6%?K[LD12MS]^[=TU79W$KOLO!; MYGM4!M/R_Q4ZT]'<^S)):WSZU[SB(>S M9.;@G04SPR@1M2FR-CE :9ZR+9D>@;;GNP1;=F!$061;7G<"C>/[1' %G&PK MVH<,K5A5R0_9_4:2](D$'TV\#0D4%%(W/@"_M*A&GO$^PLU9K95G';)U191-0R.!Z>W1S/8*;/0H?GC4.;G MI'#*;#J9LZEA3%V-A'YCO:6CI<>OQ89] *OFAH?D?IW>%6\'3OTV+S,T("&1 M$]HA#B+3-P(S[L Z*! Z_GPBB%-7/E37,?3X457)8G(7ZJE.U,6'QC#06@;V M30-5\5%J#S(>&E1FT-HEYAA7QB=!N'@P@D]X(Q?.RF6#,%WU -]:+MA M^)^2,KW>5E_335:L:+)[_<#F02%&.'8C)PX0Q!:F\=;I2QKL^B*1-'\2@)I' M!9WNK7>Z5^Q*L6R#\9Y%>XOV+T">UKMDLY_*&^S3?S(NP#]9]D5]<-$_6TB4[RV9]_/;A&?4+OC@X^RXA%@7WL>Z"7E]PWX^.A[\*&L- ;=FG8EN! MQK8+\*7I+J,O7-'AH1-1<-(.,8\8."T%Q8Q>4 7QKUO9BT4N?DV<XX M8>AVYRZX3N!YXM.RF@'ISEW?OEM9BU3TZL1Q?",R=S CMTC-%+3X><7P NQ9 M,=E=C2JH/SL%,))GYR',XYI\L+P_*M_JIJ%/X27TZ]7KPC=,BT(S/0-&F!VV M%>$N3D'Z62RS0E S).W+":_2LOP7\$MC3%N+7>YF*O>*]\D[9*E?,M%TL.ED'*K@["-7\= M8!(9.#!\P[4=RW(7# M$6,311$, VR:L>L&#K0['"@.8HG;:M6#D(@_TO?8LHG7=M953[31X".^<#*1 M7]1,"\PS$@A3>D+J];EG'EJNT;[WYYUJ9E)*C1S(#3T269'MQ%W9 M"\6&(W11K]B31YO1!/#N[N82_7$'T14!=]?@[E_I9^061-583?K[^X\O=+8] T9\_?Z;_=WMW M'?W;OUY?87)SJV[R4X73!L]ZCNPOI=.=C23.?G;S/,5RTYH*73:4)PBL3T/).#9O>XW3 GW51CD/#,G"!7^N?=WHGV D:.&X>. M:04QC (2A&PXWR7CR!7:DS(>*LUZ>G9^396>:O6<[KDSG4Z;9M)L>K$>P+^6 MR3%9'\]1^D>Q6]ETV##F>0,):0^;^IIN;I]H[T=)F2W[]!U'R/5@2!NP;=O$ MEA4;W5G!"(:>4' 8UI)FP4?P]C+:'7+[E=R VW^%-T2PG#&033[!'H](,1'N M<+%]Y:!&=@%J;)-5'4XR=4(NU3 \#PE49$NAHP^J'O53-#60&M(".8A PS-# M*_!=P_,M+^JVW47$0-;B6[JY+]05 <1:%WD/]X&JJPG\-&M_]Y0V)=YB0T-/ MUQC;B6F.>6WWA#:&# MB@URKIF']FJS3K@,,81%'36)MW@,8ME6Y)J^;\=^:!LD=KKC%J,P<-PA2JT2 MAW;-%E_7.[)F*_6J^OJ$/G?JJD?4YY&9A!N4&TS,!-XSP$;: -/&4%049DA0AGZVV5KOHBAH.0[V$_ M(I$=^AY-E4G4%3$B([#L(;5/T;8T5S_QY=4?=P2KKW\*+W=BR8M?"IA4YW2;8"+,;Y7162(60_%>-5+%GM51)M;ET?G72 MV<0#(:>HJY5*N7J.,4*3I8\)&ZP%7S%"$%6>*4IJK.H6Y9$ MX>Q;MDKSU:[E=+FF_[=:Q&%LA[$?(\<)H65CR[2[^@=FM\J*%%*5-*B]FOJW M2TR^X%N 270%;PBNZZF=.+&R*O@ER\&J6%.\):!A!93,@.-7*&LDGT^Y1N== M3,8:>*#&QP2L17CQ1M9:F./J&@]Q)T1.*>_S4#RU)A4:^ZF8%MXNG]+5=IU> M/]RD:W:PTM=D4[W>;9*\3)9UVGA7+^Q/?U2(\O'7PC5],_ B*PQ#,_8\X@2. M9R+BAC:T0A();5%5WKAFC>SPLI%:BQC4D,$^9C$]5.\ /FV2C'?Q9 M P8,,:@ACSQC)03"3;I,LV^L[?)K\EK_ M_SLDM%G#\7S/0*9#2! 9D6%T2##DV\2DL_W)I'8/.NBP\TFN5G><5MVY>$*5 M\!YR@H@ C^>75;'E]DJ2S:OS79V]N&F?,I>ND,(_N%CRLK9-?"% 5V*T;0BFW@F1"AV?=,(0]]"CNV:KB]6J9D*I>9X^L:P M"\!, Q6%"!KC0&T=V)EWT9XJ 'H+]VX>:HUD(M.:V4Q@-0& 4_6GIYR[BO01 M^H1HZ6D&W4%3Z4J3MT[6NZ;N(?,8U\V AY\J:Y,CDBS'D;]OL^KUWYKAEWD @R#+G2G 8@FF/= M#B75(8H)_,E0"88EO9X0K=%-[ 31]3%B_&NNQHESQU69T^B2>:CY.*8>K=AI MYY=[)!5=$Y:T MOFRR,BTO\^5OG]/G^W2SB$T'NM#V#"N(W*[$BD)M'Q)+)>%JE;&.E*R_)AF-#%'RDE7)NFTS@)[C^^R 91O1GYS M@L2 IH=\%SE^Z(ADDL-:TBS7.W" H?N4Y:#%)R@XBGCERRC'HU1,O(>PJ26U M/$G4BZ\6&[X1^$'N& MUPHD](P(B^WMDVQ$Y*62VK;7X0+]E@,Y@9(ED4^91F!/3)(D:-.B1(>).2%! M YF/: 9Z^\6$6$/1N&WD1@7AWF4<$FPD7 M(RPFD/60W!W%CHE=UP@]TW#HL^T(AV$W00;#P!5,VL6>K3U7_W+\9O<#9VE\ MA$MW>2F=QTLKB?WDI;MB#/"^%%\WQ3)-5_59"5^35U;?+>^*SUE>;++JM=YV MUYZNTA^'YALX-DTZL'8(\:TP"MB9XRV0P#==D$$2-;IJ':NHTL!BMRPLF)6^Z;-=CJ>QOTJ1,&;S;A"T!:M*H9C*]^]8" M!C$FR(;(-0PWF$'B04%$276"D2S)K?I3HV4_G HQ_EO)7AI9P26[8S M0[$!9=)LZ2K[?+4YR4%PY[)>+_*I^&P<**;G1S2[GB1N'%H+_6WKJ';\W,#O MOSUR!CN Z5,)[Q@.G(?2CV/J^W1Z/'YYU;\+.%TS.-V!N4E7Z?-+

Q;42V M'QJV:40H]KTHQ$X?>V+/L!=Y^LBVM=WQZ[VJIKF4(6R4X2>4 BL%9=3]A3[M MB?W5<(57YBD^,1_5.VIUNX/:Z/8>6"HKX.N>1_KT?%SUYJ3VA%"K=LX\-%FY M587>+LV_(I1M5.I&[7<%:^]P*"@7ID="$SH>#%WDNBX)#6SU-18,N=>'JFMQ MA,RYZBL:O[!!=/W:'BEI\*]]5,CY:<6M;?E@W=][#A8-OZG(_P3;SR;C7MI^@#]_4N2OX+5MOG- M:#%?M1>.I :3.7OZ#&(ZTXL9O&PR=];<)3]P?R#:[EZSP/3H$-L/C-AQ0B-&' M"G8&O$R[L^)")_)BVARR C..?,=!A'1-QO0W,C<\23:E?7U9>Z7''?Q?1/"" MCF$42@N2'NZ4*-)DAS2?HDE,E,39G:TJ29AR7I9D^9&]8*B70=<*;,]Q'1(% M7D!B2)!)8B^(#+9@A02\ET=(/U_?R_3SO3>SN9Y7XEY>84+G\?X,-^/,Y3>2 MO(@?,0?S*ENQFW:R;^EMNMQNLBI+2_)CN=ZNTE5S[>3SR[89O5X_O,?9G(-' MO!!CB,P Q[X=>"Z.';,#&?D1ECMT;A1HF@MV^Z=G[]L#=@:!SJ+N?MC>)O9' MAUYWF1-6Q_8XG[[.V-EBJCR%GS4?F:?"(R #[O-2 MOB>;U1W]D_IX/]LA!!IA%%NF9WN&X]J1T[9A18XM=CZ*T),U1XH:#&!HI(XJ M%62)3Y[U$22FKOS5EK$MQL6%FZWL^ 7G??:?S;!A,)N MH7I.; MEL%, U*Q.[;+SYD64._)S&K]QYJ%S=YE@C4#(6WKR2 V,GLHFIW3@ M/!1\6@K>9Y;3^X/_;*NRVF1+=A4ZNWSSCSRKRIO;/]H3;J#IQ YQ$?;B(*(1 MS K4",#OS :?YWL MI*L37)T03S4;K*AS:C^V(;N0,D"$ M8 _'9A"Y75O$,83&OW(M:*^8-ECD+NR0XXPS2=1.EVC-D8\I/?G=(3).)6B# MR)N'M@RTX7V*I( 1_OF>IHD_\O(E768/6;IJ)6W;"LC:4ZZ T3-R' "U[ <3&#D$>(Y=M>(ZSA",\>"C]:L.10- MJ.$('X8DQ ^?IFBD1DQ(>E8F&B*])>*$8D@R-@^9D 7_\UE!\AQP3^\-FWE$ MKX(C@:^)6B6I/>BOD.;J$)5B"Z3GK MJ(PY7&(HS9/ Q1K?TDV5W:]3G-Y7NY;;#!]!C!S;AZ;A&1C:R'/#/L,G!N(Z M!4A56YKU; \>8/C>I$Q2U_L,)I=/S,;D54S+!E&JZQJ'4UR=$#)5+,]#QY19 M\_-E" I9&JEB<-7?MA &-H0F)DX<^[X9FS%VNK31MCSDCU@>X //" ME>R]/N.Y=Y1R@1[/JJD-:''J'"L*5QQW[XSNYWG$AO'-5EL8D.5=[.@#=A%) M X6BS;<4P/5+VIRLQ9"@I,R6-9R%%80>)-"- SLTL.MZ$,<=BA [ADA04=VV MYMC1[O/_A0'^M=.4#C/8@;ZH):7&W0C+%-O_N5D](1FZ_#,/9=!FW<%S W2Q MR'-^X7D$F E4NEH@"WLV-GPG,H@1&Q@'R._:)@ASI8QJ6QSGG69(FY/D#K[1 MH$7+?YR<0LI/IW'3L2V6HWT HOD/Y)N&<+F3]EKBZW"UW'%>[#@_<=C>RWI+ M?[_Z/]NR:FYCH@UMUQ5[0']+5E*6V^:,;W9%9@7Z3'RY5S I=UGY]W33_RY= M75 D_2GRWQ.V@Z)JOY/^2#?+K*R_LVF>7= &-^TY_\V7,MHZS?"W+W7SM"%J M5/F0++LT?TE;2=CU 47>W"L^\!1 ;MIO&APXR1EEPO06/*A*BX-9'WE%D'GSF-$-;+-:@LM4HPKV]1_;+OH M=9,<76^KLDIH!I,_?MG6G>T,$ M0_OIGL$%^R:!/9O _2O8_UYK5[.K_ *TIM$?=L9=@,8\Q0<#J/<]7_R9M]O% M8M%4'I_F< %1QYS:.C)9)YA'S)K0?M$S!31[8JQ8]K>TI(,UF*_(CY>4[3F^ M*]A'/\-WL6%$#O:1YV&3>*:)3*^#[X?0$SMX>3:P1410ZA!GE5K86%W?KM+9 MS4I$?ZMO!)P\-*KK2N-$S$GZT'2!5%GGF664Y76FQN"KO#_]8\1D];0H#M6: M_,9_]$:Q_.NR+IQC.DS.'^D8."M6->3RL&T+["!DAM Q(F3&EFU"#_:YA&?[ M8B?(:6A_C!%EV<\VY/0-J.4QR5_9'<6;XB&KFH(D>*%_*'JLAP9_<$:TB5TA M&)SJHX@:N*#!"QK %TU *B_ L0!V4=\O5CRP_;D/:59M3UT5K>E,$6&N3\4. MC9Z;21C0:>%/IY7H9E/\[/IHDZZR"E,@WQ)6U"R;8XBC $:86%%HF%[@^M". M Z>^:L(SH\!V([G3Z"4;TRV[W;GCUP^@00ANLO(O<).NV87S[2*"1Y9\QFE2 MO]-#SX^799U3;\0S?U<>V'Z3JECZJ8GHD8*C/GZ"'I2GCB M68^&7]:WV_LR6V7)YK7=2T'LV,5Q9#J>A0/B(@.[8=>*9?.=4"S[;,TBAK]> M@1TF_J5-4C2=7RVFFR$QU7E+CN#>-&F6^)=ZZ69+;E$73LOE)GOI)M77Z6.R M!O0I676\?_&L;CI@[9%U3$-XF7[%TB#TA9K>(;BW];TX7_4; SPW1'84&(YI M^9B@R(FPVS5HD! *;6N5;T:SBNZE?Y].IG]7LCNSAE#,E_V-Q*Z8 A_*]7@X MU+.E]2A#)U(]!;3.(\E38MMNG #8L/8,ETGB!W?122,C Z&Z1&A4ZR4-ZY9U%A):MW! M!"\MS@NPZNUH+CAOUC,+'F"NWA-\*C>I$P2SSQYJ4Q[LT8*OO2]ZP( A!C7D M<451E- 34JG--_,04'WF%2/U<=$33]8L$]HD:[C>I,F*(6 S2S^W#^W #&(S MIJ1:R Z0:9*X;1\'/@S%SCY1U:KNG+$'RK2598P/Q4:-N"IDGC-WG(1TP51R MQW<+$C0HYZ"BW 2>RC25.V$>NJG!KI_.4M'#'$^],4K*IUW[-^DRI>]^NR)\ MF],/7Y(-6RN^L+!-;,MVZ C>)XCX)/2BKFD4V19O$5)9@[KUD>($>R]MA[3; MH;F/E;\BIX[N\\7,29@6%,69D\Q?"YV$;+D"Z1W;F-IIRPHD]>:.>C\H\\9R MYXU-YXUVN]F^'6RQ&FU@/V'HAFCE!?C^E"V?0%:"Y3HIR^;*@*3>(=O=G,3: M&K;;E)?Q(T5:Y0Z;OG*KWJ1"8P<7W&FZ:K8H)^N]:/ES@/1-@NS0=WT'.SBP M7>Q;0=^X[8O=$:RF2QI>Z8A] 8/ #V#L&R0*46RY,'"(@3QH6AZ%8?!.R4@_7^-"G 82 MZ#&!/SM48R^_.4+.J64W0_F M_])^8^!J0X7>X=2[B1TC*(5:?*)YJ2(WL5RK%]6[:28*J]/"HVL<=;$I<$1] M6:RS5=UB/0U?W_ 1Q";VV*$3MADAS_<<"+V^,0MQ%1X'-J%]*F8/5;.T1.H" M)ED">2=9M',G.J,B3)NNH^8/$'-RIF00D_/0J*%&_'R>_'!.Y)6FO7LCQNRX M^BB$H>'XMNW;D>-TS?FF+70LO'0C4ZB-U"4^\C3**HX&!A5HSB17]1PC1TAW M!/FZ1XX=]BW-[^C;9EEJ=EV>96C>+9$8I-VT8A3:^0%[IF'+E= MFR8QA0X1']:2[C%EBV7:.^P/,7-J[*&$T7F\1XIL.7:WO0*&N-^H[7VYWXIO M0-\VH!UYGA_[(8E,0KI6PC@6.E!4]-FZWYH='*DQ@C!5G*43C2P)ED7X"=*C M+&^9.*4EDIS-1#UDT;_7BT$L2"A$&]NM"&.?RA!VC-#V N+& >S:BX9GV8[A. A:NTJH*ZLBDJV-J"JJ:I8**!;6G1'8E=>AN50US_+%IU0# MN9Z=<@VUY[B2*6%*B;*UFAH%<6 X7D1 MHDU@'>,@UF>B>TI-.K.^40%?/%O[Q%;VW*3?TGR;U@M\[M(?%:+T_+7P C:N MA@&*S<#T'$)BT^Q68"(8V7SGS(^%1N1-ECH^OH4%T&Y!70V1?V_:*$XY+9YS M](:@KNX=?7E:8_<_Z7!N7I3=CYB5(%TWQ^4J*Y?KHJ3_!LE]L:WJ#S>M']EQ!6FR?*(?,*.3YBK-VM(+MMDP M 24E@GYXS^QDJV0K:O2P/8<*"#\05\=VY?0[%4>UMICFA=$5J&%]Y6RZ^KJA MR'ZP8][J&VKI5]X!=2SBX\CTH0\]SS.1;:"P QISWQ$S(4#MX;Q#"BC43Q0K MV >[OVI>:Y!7YU#5<7\23XZ0"ISV^W@)@CK/Z\H9)ND!HZ012=<'7F@?J&@? M6.[W@5_85W:76#RG2?WG-(EH4XSN7@N:A-!'E[]*IB,7(,O9)9RLLR;LP 4: M.[-UEG2GUS8)S_L'EO^M0U2R+[V%TEU3GM9'WE+PR[[81JW-FBO/[U.*-^W^ M1 8442;AK[GXQ!&R+-(S!8W!I;A MF;[G!&*7\FF#H3^MJI%*%DGT>X&OM#P+^L5RH9N?PD?KB?K\GLX7-#SL Q=) M=[04HV6)/E&@UNZ[>12M]9M9C/Q.:-W(WZ,)0BLP7!C'CND:MF-BG]3;.@+L MA8X1"IWWJ0N#[LF_ 9O'Q4=&VAW&.5LX U])CFYUN6D.V_TY!%VWY^:AY]JM M'+;U7Y)5<35OZZYU8"$_J+JQXY7HB( .53OT]+1XW MRL+KFPTS[5-O6 MCA?J8+)O'Z@-G%%<4>TMKM S61>96W2:CHBC 6QBW_#,\O6G 380/C<%W-5U M_J7(-^ERNV%7JZ*DS,H_\N*^3#??&*++_&5;=;<-0ARPW>B>X>'(H^,I.PYB M%#N&&7FA&2'>([CU(]$\>MD=L=E5.#H;P'4.]JT M1E@WP[0&")V.ME(#CP_ M@3MEN7FA66D\KU5?%EQ7-09C+M_O._D8Y:AZ8U;8/FW<:S/J1*:;Q MO#G];-*(MA93O"]B@]6_=?WS+ET^Y=G?*<#ZN"KD6J&)XL#'A'@A]'UL=(V9 M?B1T\(1D$YI#;X\*]+"D]GW*$L@WKAN!.['0)T&;EB'486).#'\&,CF/H.L]DCQPJL^E_4",?A"\_AD^?1SX]V]W@0[ M'L*F%4-6-[%-&YE=XS$*N"H3BIO4K$P-2M#!! =?M@:JH%*IHIQ/MR9@6TS% ME!"M1=7XJ#NA<8JYGX?BJ3:JT-I?Q=2P'XVBUWH\&K';S>K<+\:&[T#?#DUH MV-B%86A8O?KZ.!(10/E6-&M>C0;4<*3&? /HXQ.S<9@3TR\!TK2HU%%.3@C3 M3@1Q3[Z1&G=.Y3U PY^RY 7H[R6A7%ZD\@CV5'V>F]Y/1<"Q<3.L7 MGN4)[U9(_&NZ7L%\]4>9KMJ4VK))2!S'# PC#-PPWY=P*BLBBGR' GEG[$?E5BY"?F;](7^MCY9 M;\W6\JUKKI.&ZR?&-5OFMZ60ATVCGZ/BR"RY,@:GGP179TJAH8>)#2U(O=7W M[!<3 @8';-GT[$#O\(R*2?T ,K6DXB=Y.I%/J^%W'DFQ(EL*'3UPG-6S=7V& M1#:)+,-&;HQ@@., 0[N%%'BVSYV^:@?R(=;."E1_Q_'>^0QY5HX3D]5_4)^- MLVQ6N>_^:]4L'^D:%LT*^7+ZX<)XIBI:,BO!K^[@?73!"PDP"GW#C6P7DMBP M3>QV"UX"'!I<=[5.!NXC!/GAB^^F\[W>=& 4MT^0(GQDCX^33(SB^<%50)8R M['*!JO?E\!*@#NXTY F#W?2Q/,$Z08TQ_H=+L" 8:,7ZSE:3L?8D=A M3"Q,'B)+8@)*GC7^,#4*>W*A9H_%)6/Q@;&8L3-.#T:=*EMG_TF_>_\*]HY5 M'1:(CK%S))@,)G/Z@##>P7Z9I&2 S7]\,@ M]!T#F8[5S6L%D1EAD3DFN18T2W,'"K2HQ&:2)$GCFT'2SY>8,+^G:J()HX.T MG)@H&D;C/":(!MI0J.Q8$C6E=G74'?W+NGQEQ8AFE)$;$YI6^J891KOR56Q9 M@7!=2+2!\6H[Z+49[ .&3;[ +\R@0'5%)WG2%9*I>).H4>CD3R[YJWG\5O.X M/X7!DCO&)CLNGB%65&=X9_^Y6H$L7=.G=\--.#1F'\:'YMK^V56N ?)B-V(W MXR$C= (SP+#;41^X#N%*$*?&./]*/WAW;GBOCC(['Z:F6V_E?]3>,/H$P#]6 M1QAE0F#4#C%X7F#)@#6K"-K5P<]='V$KA-M[F9$'--()BK\@OD$Z[X2SV7#.&F.90%O0BPXH-HQO.AIX=<,TI*&AFU*71 ML+L$:NAZ:'X6^4I9(Q$H%HX/K81.IZIJ'6=(: VT,*WSJ&^I,.3LZF=);GA& M6/^6K3=%4;7/=VS7]R%AMX6[V/<-)W*ZI=4AC VNC=OB3]6L-"T8B9DX07+. MCP[T\2(F(*-1PI\GZZ-&+K/EIH@G3WUCW)',4HZ Z7-!2=S%4-?S:QS:/CPD MZ^(Q>;F\O&Q;L4W?BMW0P+%#K !! ^^4U+&)Q:MT,L_6K'?W#21 ,0$*2N(E MER+LO/KIYDI, R>BB5\1==,EIXO"M/'HXP%3CZCD$%*FU\I!Z LU74/@ZOAB MG6QN7^@@N&O"\PS;-ZR1)EFESR55:3<.L1&;V/:<, PCQ^QQ^3$Z+?WWTGV31;@]CNXVX.D#VUV-3??[/,)RG+8IG5%X=_ MSZHGL*IG8,!S+>DE6*440]-:00$6&_"#8;)=2+T3U<\> M2G20Z6/[R/8JVE@DR[3PN:MM)=NGMMK!G_?%-^KIQOZ%BSB.(BMR/5A MZ!*"310:OMN7^V$D-!.HK-'QH; $W.-RGTPCYE']68=.U]4+6\#5))UR:^;]"[Y6V%5 M-ZOOI=M'"G90ZU7Z'5C0H 5_=GA'7E0JR.:)UU.77^;QRFJSKABG=XN]VK?+ MIW2U7:?7#V^;O:SKT#3[.0RSN=;MMJ*:PVKA**&OPS*]?4K3BEH 5ZN,?2U9 MXZ8\O:7OSEWZHT*4Z+\6EDF,*+(M0H>U$;1=QW-[2USHUYSK!_!&CM"VS/*TWD?4_@5-;@'Y\9+F95K?ZG#Y_$)#"N/AIS_> M/5I:)H0?K' WID.P0Z :=CL-#\S=GTZ6K#-")MA M#< TO A4R0>*VQ6O]+N_$211,7S:^X+UC3W7K(N_S/E#NUWH/+.C0 M@H@&1S9.0@V6SHG]1I8G,U"/C^E"V?ZJ5V]#/F M2VHE2!XW:;/"[Z7S;+KG[H*^L2 !5#&S8L6>7&5T8$__AF:@[ J2I%G/]YHF M&]#>29*S-8%K4/3!>/FZ7*<7('NH;R%,-Q?MXD/V._8';+5B?:-) S!E%0.: MR++D%7S/UFMV\\ESLJ*/>,[R['G[#/Z^39@%65JRS]9I65$0].<:7(N5E427 MM0O9FL3DF96N!]]R*-A5CBPEU-GIIE\XJ-6Z8IQ75W#:(KVO+O.RVFS[)AKWE0TXU?ZQ2[7Q+!@((=TJZ$(WA3 MHA2=G#,]FID4B["*2-0SB_,S4Z=F:@;P.H]QQR +WL^X#&:#^RBB'RS";K/R MB;5T_@M+O82U:^.R+&M MPWGDTYU1*!03'SGV]!Q#=(2=$X(SF-!YJ,YP,]X?0*2&ER'ZP\Z4;<]?LRUL M!#%5MQA'V(Y)'%EQ+WJ^ 8>JD$!3DVC117N0M- !F:JXE51D?3 MJ1U7@FHE0?)\-4O&& [EDN:(5[_^R$NVH2Q=L=;:[>>6&]BFZW@!]"&R;,.,Q(D[,A3QSW5HIDKV%'(ARG@*]3_;>:0. M/X"0ZB2LLV9S(L3.S(]OTH\C!!E \W M;-MA!U\+G5XA_G3=D_TU(% CDBP823#&)RQZR1+3%#&>].Q9>4_'"1F1IVX> M"C( __O=& .9D%LH5"=$INE@V[8LY$4.-OW(BHQN7@Z2R!"ZZUKB\9J5X]U: M%JFACPQI?-JAF2\Q\1"D:H1%/V?&.P/8FX=^##'@Y(H?"2[D%.1+\MPG.I9O M(PMBQ_)C,[!B9&.K:P[A2*B2(MW(N&IR 1@TR>&./)$RVJ*)PT$*PTO?"$JS MHX=;;R08G:/JR)AQ4GND>>$Z1SW[EGXMLKQB/_SO=%.TAU7MY4]XFUJ&Y;80 ML.]B([(\%+L0QR0(O+B'8%DNURIH+0UK5BH&$]2 0?TC@]P="P?>#!,H;,!P MR]RBJ]P;YZ?;)G6$F-Q]4!\('%D^I2_D9OMT^(3K8'!!JHY,&&IC?/KI1'VF M%2/T6/X0!OW??/=]>Z;3#OO=V'=A0,S0S6D32_NBNPH5'!A@&'#E^,-.!0%&U$J1HZX!!E?/J8I,\TF0&' M'']< X[@-^.G0.FWS?FQ']%G1]@QO[PQI!'-$8E".YS8 M^0)I\B 2.08;8_$G%E&.4RQO#>^4 R,\>)A1M%/I.(36,XCS^"S&]SX(!?LE4[X'QLG9![L3C*1;OO]J1+!$S5[/,'QPF](!<(1;TQ*-")L7,D MJ&FB>/H ILNP0GOW% U,_;$3+"#Z7:MN-S]FN0ZD+<26%X5! &/ZA;[*2,>T M8M%H6%MC+C;8G:;"H'9OG"LJ>P/)Y8TTX_$J%5[>D>GO),R5#B@#F16-(N,Q M+!LI*=F8V^^5OX-,G!?'C)"\G@X8: M1N<2*119\U-X4,F29$P(NU:]+A)YIFM[/G)\&Y'0,1R,NJ5N"/NV-2 F"+>E M.2:$YV."-TBYQ,F5B@E:>541$\)=3/#4Q 1Q9@?%!*T,?^"8\)X7_I@@S>@L M8X*\-:=CPD"69-<%6$:[[CDDIA<@$A';"EPG]*$?^+MAB<]UG,#@1B9:%V 9 M$OLPAK$IMT! "Y%J%@A,P.&P!0):N%2[0("'4]D% IWY @L$A!F;7L#5F'%F M@8 D+WR27=:-;;M0D;-65\VRA"1?L<:[,43H!DX4^X9G.Z9C6+&)NB-&$70" M[OD&A4WJEO-_!@U4T&,%-5BPZM;7L"N9FO=(8O&2.NIYU'X2U@6U_\,0+A(: M)B%>,E"H= !?Y.!EYV@<44[O'***>J,*K5URZ&[%KE 5^U'D!%X4^+83$"\P M8-0O@2,QY%YM-JR5,2<0WBS8E"ES#R24(W2,QJ58M)@5C4.W+>J@4_6V10Y: MY;'81\3W M^K51V':Y55Q!6V,6_M^\+;ORM$SA0@7+'-(^,L%B C]G;@7T?F2.Y51?#==< M\G^>CV-!0"&3,P@%*JTI]/2W(2?Y765Y>EFES^7"BK#CNG;H!"8=6@0F04&W M=QXA; H=6B[;AN8P\--1EPP9J*$-.L5/@,33:C\F?V(J+T7=""?X]=P<4"-5 M;,[Q_#X)*TX>WR?+"D\R>IDO-VG"KGII_C_++W/Z]J9E17Z\I'ES!\S""USD M^J%'_,#Q_-CW2-R=?(PB$W$?G*&F-DXY,L)E?SYI<_+1V?9[G$5 W?/(DI%R-'4E.U;$Z?G"JVI]#5[\02U(-7 M23\7V[Q:Q+$50^+%#O)\3 .5%7C=+3Y1'!G^XENZN2\&W2_/UY#(&[6/22S? M8O>*9'E2I2N0U+@47"[/221?GCH2@V+:?^P"9WB:PO%NF*]QG,A7%; ZCY15 MA2$\]\S+<",W7.Y4D&TYO:W8F]GN3TT>TP6"V,=>8)BQ"Q%Q;!PY7>8<49$< M1K',^'HT=@<-N2]VV10#>@%:XG=8IQR' MG^*0>VBNQ!'SD#X=AIT)&GCTP<^<1G M>'M<[U/8O$_[T+A?*X8.U)N WH]Z5@*E%C4OUEFZ3KQAZJB>QZNFT)Y"5Z<< M$NY14F;E[[RLZ+*EFF4K-=5<9-6V:8YCVQA0Y=$KA_% M9HB\T+6@VQ\_%MF>S[VW7DUKXZZNN -3L" @JH #=1FV1+_E)LBHL]/:8[/ M\4 -G!.]_#.:X],L-Z.IA&Z>"4TN0HY,:*HE<_H)3<7V%+JZG6R9_1%.C?BO@-,89.:(\9- MNJ2_*M-Z@@[T\.K=:[]ODPW]1YJ6_R*K9L/8%HT8HQ$]*&R /9A[C/_9(158 MH:V2;-GX,1KI2H*(//GB@>04,US11 FU7';S/<5#E+QD M5;*^K8KE7\5#7&S2[#&_W=Z7V2JC(Z.TK ^JS/+'Z_MU]EAWZG(11[;K.)'E M^S'&EF?XEA6T #$*+$,N &F'I3E([?"SHNJRL0"4S 3VP4-C!"CWK !E:P8H M=G;("JM^MXI&NEEY=. @ZJUW6VO ;>?=UB"P;Q'H3 +7'\&[LJ%U5EY6-(;3 M[FWQ.#V49JY8/IHOYQ;OQS/\:$XP,O=J!J6WR9K";<=@Q:;87-+/]G#N&_5U M4RS3=%7^4:8K-IQ^25[K6:C(BWT[LB#TH>V:H4%@W&U?PP9QN ^;G@=:S5E& M;\L%**DU3(T>.WOH"P,R.DYXDV*\O)&RE]8JL*5FL?+4AAEV>@IXKMU"Q5"@7.DBQYC=HRYY4^3\R%4:AG?4[/)MB[KE3]5$27E4[PNOF?E M55J6U5.2NXO0=TW3#9 %'0=Y0>@&1K=-"YNVQ7VH[^P-^; Y&LB:Y7KLTR4U M'#Q0RT%6@C6U'3#C@1RK,WZLO')0IYQ-[GG"MU.FI2JZW/\C&:L2JL9.9M7Y5TV>^SG+L^?M M\PV3GN+AFJ9']?VM';RJZ#:Q14_)YI$^,K3#.#(\QPVBR"2!;R*[FS+%CA=* MSDB. DUS+MKB93*3.[C<(1Q_!V2KSKTF=KC>C4NY\-5F1*./2>8XVUWZ$S$6?\4*Y MB&8?*,HNDA][(-]F/@MHQ(Z/H>]$/L;(0C",N[L5,3%-4V$F,02&[JRAP;;+ M&GXJ.BD-&8,^G\:"<_'74JC^5ANTQRYY=VG*$:?X%$^ M'JMPSH>(O4H,%8NSZKCE.YCU&P7!P)09;7\%5]\22EQ9%?#A(5MG297NEB\' M$<+8CC!Q[-A#H>&Y=FBX&(:V%9B1?VZWL?+V],GS'DQVB"7;C=(A96_O#JO4 MM@FUI(L<)3H1^;(GBBIT M_!HOS\'!%/+11/+Y5ZS"HT=TVQPRWV(%SF< ?A M;@_"'=M0O@A=(W!-']NAYUFN[_HXPEW[$&*N:U/4MZIYX"#P-M9X!8_35\C^ MZ2@T+?':PM 9SK6<>\%-X0&QU.>&>9Q\H<&N0G<'YD\;?T_S=--/1;VVEU@9 MKAT0B$B,B>MA*[2A:?6Z;#C<9UW(/5VS_M6@=G/8KQ)7UTFR=CZKUD^8F&Y- MQQ5_,JR?,[FL]],G\*7(T]_H?\&;)X#T1U;20/!0;$#UE)4@7:?LE[^!3Y\& MI;T'F3B2WPYC;?I$=B#^0E7_$4U-E\5S9?DV7;5E_"(O(>U; MB]CQ7#..;>C:R \PCFP[Z,#CB._^E9E!UAP4.L"@1@R^),\I'8Q28,+9[RS8 MXDZ=9X%68W5>W*V:$NPQB#Z9G<_*TW-)[>=%RD_C@GG!$SMA5 0'>R_;BQ)# M(PH]-T;$,*/8=Z!G&GU)*#(#L8L7-&$8-1:5[+* %CG8APYVV"]:91.ZF56[ MI_ABT!R_IU4'S#ZC0,)JFU9:!V L5'452!UJU,;!I$=OR M;>([!G$#UXE)UXIMFUR'?,@^>T0M$$J2I+D2U ,--,DKPH!<9H F',U-AI(U M,UT017],&:18X)D3NLW6W]+-3;9Z3+\6W]--5Q$-B!_;9N YKD.'BLBCX\8^ M&;$\KDOE!SQ>LT(TJ$ -"]2X^*DG?X8:4"CK*0*J6JR33=W$UYNKJZAM!Z'(PHX? M(]/T/820;<5&UX[G6)!;5*6>KEM3&:BVEW^]N0 4F(!(R/'%H:G:J1*4U)]9 MDM%4.;H$)%4[;9***D,?EZ0>,OB8H@XB9P:".@Q_H:J;\,LI2C:;UWY]5-N, MY8:1&3AA'*(@<@PK(('=->.3*.!54ZF':Q;3&A._'LCQU$_915B<=(N*(G [B;'HU'0:_4-1W^+64K,LJZ1)?,XI,+PX] M"[J0&#YQ2;![NLTU_RKZ3,W*64/A%P0A-LX+IBXBQ'2R1B&ACD)D\(NB+E+D MM)"3'!Z1VS/LB+;)F#Z]I$FA+H8Y7$# \BK]JWTZFS%UH8G#*+9"QXB<*/2[ MI\>&;RWH*=-)] /Q]E($1>&]%&.$0,4U4"(H80R$C8B)D"(B8 M)E(^2D*W9_\QK9-@: 9:)X.Z&-8O!';L;)-EL5XE[]-"V_9<:(08F6&(/ )= MSX%=2X[O<$_/R#Y?4@[G&SS+,U M2^_UU]\%YFVDR#FOK[IY$=-61LD@795BB5]3=;/U4?3T ]'M'0(8]/KZ"#T MA9I^([8_Y+IZ2C>[_>UM6V841M@EKA%APXYILP;IVXI-PK4$<5@+NK64@7IS MWH.0= QD[[3,CD>+72O$V/ <+W)LPXHBZ)I=.VYHOY)ZN^)7E MZ665/I<+%"$8AO6=,;$=$N18N)^4\'',I;9Z6M:LQ +'\#',H :MX?Q# 5?P M#=FF\X*8NBMVP&2'(?99?VCU:[*A/RZ@84,4^@CZ@0]]QW,MB R7V"$B, HBKF,3=;2K M656_T#Y3T!%#L5ZS,THZQ!>@Q[Q_1^#]*VA@B\FJ4C_PB>I4+A"35-7L:]%4 M 2I/**H.A\Q#3[585NCOSF):2OZ^I>U_3JNG8K73]@,X%HY-91LB'-K8]@+; M=2.RJSN8A&M;G/I6->MH Q0T2,$.ZN%764P^%5+/)Y[3L"XFG8H(UZ*8W/R= MT$OU/IB'6FJPJ]#=>\64\B9E5-0I;E;DUP]_Y!OZR6.>_6>ZNDM^H#1/'[*J M)#_:DZ3@,ZO9LGMDJR3+Z0=W!?F1/-/<,")/CU!='9M-!M$0BW8X[$@;D(+=]W4>S$Q(H-'*#0<,VN->B8\>(EW63%ZK9* M-A5?B)1M242SWH/BEB^4/F9Y+3_WS1'#8@%(FD6^N#$&=6)R?U39K_6;3;W\M MROK,[W)A62XQ;?H_B#T#Q59L&J0%9SLX%%HH.1(DS5EZ=QYZLXIXV< $KVFR M 15]1U\ZG$K$3;F[!FGAE)Y2))WU(>>U$: W K!W'[1F@,:.^H^^GO7EF((K MR+ZX/NMR[ZSE7)O1?.JOEW,MP>(K!;4Y ,WUH.F9<4R!$=?$,;11%\=LV_-- M;:%"%M"H@>)-;&!#]Q>&NHX;.D.%M+,T!(HQ_*0]3-1&?+0@<81Y52%BJ&,_ M8( 8;/*0\*"&[X'! :.9!1 M3.W[Z;>%36I],8\W4./P]#:MJN;(E_+?L^J)?I^M$MA63VS% ML&?0C,>JYWRA:M"JS.M<4S7R/+2^2L7U9^*SC7R(JQPC-;\27]#I?U"62T MTWS=%#G]<=DDF'!5O-!L!=Z7U2995@L2(I.$!K)BPS1]/T).$!G(@Z9K^4YL M>!Q%;(6MZ8O:%"38H01O88(6)_BS0RIP4)9*LOFKR!.1+E<<5D8^3S67GYDC M15H-U$Y?>]5A5*&U.XKE""< 7&^B)]H;T\M\_QM9OLQ>UND=RV46#C10[ 1> MZ%!>?8^F,,CK,&'3%]K)JQ>)YHG7TV]JL0&- 6P:Y\W76AO G[45@KMO-?N. M;Y Z'[>I#&S#/:8EI1Q$]HG$CXU+,?X>=?!LBK[W4C78,&JBQ M@1TXF=->Y6D\/T 8AS\QV9P!<0)'Y8Y"H.1QN7)$\SL(XG[<)JFS],5 MV%"H[#AB63AJZE.W3VE:73$6:4^"/[)R$=BA#V/,]G89OA,9,(J,/NDW/:%3 M':4;T9P[M[A #0QTR.BPEF(3S(CE>>1+=D>A4$R0Y=C3DIT>8^=$XCF8T'GD ME,/-*!1WM.'Z@XOG),L7/O)<-_*A3<4NBK$5&[!//6,8&4,5B+.9B32H0:= MA7C9E-B1J"( @%86"[$)&NQ<"1N*I-LAW-JM15VV&.3DB3"F;GH4U*+#ETN9L2=B35Z2I+[K-UO>JP:S9&B,#0 MP@:D/T08^2'JFK6L ^0*/'&QM:I/81JQ$J"7RG%TDOM0-D28G4,[?J)+7X! MDR=ZEBHVP)S34C:4)UX]@ZO_LVVO.XF+S:EI:38*1;Z)_,AR8C_T'<]W7&@Y M_2@T,(4&A6I;UJQT>V#K4QE.SR+*E+ 4.X)/!:?S@9@D*J5?BT(*,7E"+O5X M9![:J5DF54JG.R78)0 <2-"@!@_G)<"76)ZAA^;0:34*P8,(U7V[YEX&,SK'-R0TE'V[MFFV[88QCL,XQ*[M$P\B&IYP MOY '!_F0^^0"*&;9F4A0IQN MN1AQ@!#N(#&$S#E&B4'VG P3PYF2*_B>6(%>ET?<^@(D:,>FZP;8(I$=!GVL MPE$@7_ =VO+(!=]SNT(&5WP'>T*FXCNF$X95?(?Q/T+)]PR5W"5?52Z91Z%% MDVTG2[YJ&>35U1.M=GH>NEX8N$Y PHCJM^'X; EYTZYMND1$2X>W-C/]E"H5 M*^"<3S7'I5NO4DY28CY+X E]5$?^/#11H3V%KFXZSF;RJRQ/+ZOTN5P@,X"6 MY^(PL*R(.+X=P;XF0BQ;:+^+?C2:M7/P%F5F":A-&6EGN8 C^01W7CX4$^11 MW#>K;>8]ZR=4?#R/SD/E1[17T99S6::'G;"4;UE@*A[R?NG;*GU(Z0^K*OF1 MU MZB\UZMQINX4-V(W-H^H%/D!E[0633]!V3.'2P$X5<:]!&AC1AO+@ C35L MF<'.'M 95)\GWYC$E&G/*!4'.JGW[?G*^4S=JBZ$_(-Y5,417I-Z5OT17^H] M/.P<,%%ZC\P/3."_Z2<1IC":ZYPQS9QS)04MA%6ZSKZE&W;B39GE29X\;M(: MXP)CV[3, %LV1BB((NS']:D+B/A6Z!&;.]8/;DEW".]?^'V(;(B0T/]U* 44 M?#BU'*%V5%8%(^C\"!6(=*,2*QG AA',%9'.T7 LT"BC;P;Q0YTMA8X.IJI0 M>')D^N8*=)R5RW51;C?L5HAO:;Y-;_IC@F%]F];"MF)V WJ,3,\V/1)8)B8U M^-BRF%EJJHFC0IYP"'F^9'71WD!7=?>;[AG,3OFO308[FR] 8[6JXN2XG6=H M!7.V_4;=&'6"+C-R052E$Z6JII/THKF75JLN:\F(5M$Q\YE@U]XD""H.=BOU_*9D.AKS=?TO9 (G-!(M^##G$M,XH#&JIM+\ =@.!1MI**JRSV@>AT[47<8>A*KK*7.*I2+NTS'\ MU-!Y/G2DC*]WK:CZ 4Q7)N=_V<[ 39]PPXQP?55<1:)2>P+'<8W%4;- ML;:!W5R[6G1 RWI>9\\$<+\MLSREG:"\H&I:_PE;AI#^>$GS,@6_W#>W\_TJ M%D+E_L800_RHKZ7=Q< VS[Q"[/LUZ9K'/Y#T)@':OL^%=NN MFCMNC-3DIA-Q<>J.,8]8.#D+Q;Q>5\TQ[Z4HD_7UP\&_6QA&B&+3#F//LT,/ MQYY+O ZCC0.H-=(-0J8YOOV>T.3_E_5.R58M7I#D*Y ]OR39IADMS#/B#?.Z MIC@WFL-U1+>F1[R-;4V/H+\\_(B9Q[-3[E 9Q92X_8/&+C6V#XU8"CW &Z=N MET_I:KM.KQ]B*I5_2];;M!D,PGSUYI3BA$U7KJ[SFY0M**5A%"5E5M87&=ZE M/RI$Z?]KX0=^1#"!9@P=UR#(]HR@QNAY$3%#H1'9N,@TQREF OC&; !/&?7H M9OGT6N_GW72@P7-C2+./K&+HQ6+/R)[DBSWS=:)8[.GL8$&D]F5MRD5WYP1+ M-O;/<>_L857&WB)0F]1>,0N85: V:^1M@$I=<2?B6POYO#R\>\0 MZ%%A.A+[5M>VU5,*'G:)[UZ"VVPLZ?M01E]IC7JT3HGVWW>UO&^"GI6+_1IE\O0,+2Z?V^1YMA(.[3QRS/V<-8 M$VF^8C_>-U??4:QE^I+005:Z?@6M >SWRWJ:K 2KI@C.GO/2+&9.JFJ3W6_K M'!U416,G%<;B._WBOX!?S%_IIU6R!H])EC>[. M6:>I):9_SRR9-UFS-9PUK MFW?__)5!>MRDCTG5M$RE^Z=G9?ERO5W1O\URD"8;9AWE@OZ^PTT_S].JY9:1 M0]M(*.OE: =C=5GFCF1=5^7*;DKU) M\O*!#LJ:_4FKO0_8I 5MN0M?OS /I#^2YWIYP.YKJVWMR#W#&/BNK['^^,H> ML]\5F]YWO#[(LP5J-*4XLI5J?DHU_9:L&7)2S#FV2*3[NW')3Y!^&G3X(4$0 MTU;]V/5";"$+=RB,P(XD$G>%K6M/P6]/Q[Z+7?E((J=2Z0:!C'HB_J5SX[[T M<_UP(-L5JN>,XPN)3'4BGTCFG,G]=IULZOF\9A<-*+?/S\DF^\\N43N4)VY+ M=KA&T:6A?4[PP+;&+C.:KM'TI]K4@,K?U,1U?E[/16@-'II1K-5AW:&HJ8U% MWNF6=X6X7:C^4N2;M]6W720.K2AP,;&)%\401C0>NQT2&#M"IW3K:'^JJ9-\ M#_+@V1,MCN&;(YG:)]*1\?,>YQ=@'^WDDQP2G)Z8RM#IH7E,6&BUL!BOORL> MC>PC>AN#RF0(+ Z1+X1^HI')@.03#]*V5=JQ4/?O(KO7N+[5[!<)V4[C5X'?C;!FU5/[>N] M]]V^D*(H_DN[Y5P*H-_?,\H"1C#V4"(P%L?<=VUU86@/UD.Q>:[?MNN'KPD[ M2"LJGE^2_/4Z7[_N3M."]Q1^LJP6#C&($:$@PH%O8?J382'#M=S0M&%$HG,G MS8^(1%_LZ,&_B1L]?"8.C0&@M0 P$_9.Z@-_=E:,?9W48-I/U/)&].D\2GMC M&OS^QJJQN>89;K!5#]M-F>+TOB(_V!(G.LCY']L\*S:WVWOJ#HJ5IKWLU^VU M6AYR7>@:T##,P/.@B]F%*2T&%/"=,Z"G9F%KAN2V-L%2T#&GBJJ&!KT&Z, M(&@1-F+T2PWR5^$QE!I1XN+NA$ZIY7X>TJ78ID)G;Y4K!Z+7W01(G9%AP[.P M9WHF?7[@!X;A&U'7' E#3Z;R)]S(J$4^]+HWN2PTW!I.IE@%3RN/0XIU4U(H M5X#32J5UKNJFR/*TWVN[FK))[MJ%WT]&]8G0GFPW;M=NN0F\V+7C<;/VR>_!37'-4Z:??,JS G;\:1 M&MQ 7D2CPZZQ-ML.;"NRWK[+MZFU,=..VR(S=@P B]V'!O%!"''PD&_ MB@ C[IO&5;2E6;#]WWSWGT$#%/1(V2I1JD#;%#"D_(JCA-SSTCTVKV(*?IA, M"K G5&+V70FS_)(^-L-RRO[I$]N-E/Y&_PO>/ &D-+^KNA.4=F=._08^?1JD M^QR\')%_E8Q.'P646E/HZ7>#8@(=#32M^FVKAFM$V$6076P3N(9O^\CH6L6. MS;VJ2T5;FF-"\)MAG(D)_B#E$B=7*B9HY55%3* >T+5Q 1Q9@?%!*T,?^"8 M\)X7_I@@S>@L8X*\-:=CPD"6)&-"/;/PLMZ6]JIN/&P;]Q$=ES@6<6F_(*Y# MXL#&_4(,$A@#0H-LDYHCQ&$YJ\$"AA;8_UP?DL@0#](S:) M5A-!I!D?%$C&8%XNGJCU@&0\.4(/?U@9RN\LH\M@HTX'&36<#1Q_6$;;JFE% M9F2QNS9#S\&F&UEVV+4*?>0J&']PMS7Y^,,RE&3)_.0.&G]HX57M^,,RU(X_ M^)E5,O[0PO _P/BCXT5\_"',Z"PCA+PU?.,/299DYRGLMA1FF6VST*(CGC@T M(3(CA$.*JA_V8-- )O]!)DJ:$WF[I(XJ\7^S@S.1P1Q64Q>G6&ZZ0BNW2N8K M['["PC(535B(DSMLQD(KR1\X//Q$C,"XAP?@O.A0A[D(I)4"P5(O1R MJR)$,(0]IVI"A 2Y@T*$7I)55IP$R9:,##_QP1\9Y*F<96088,[IR#"4)Y[( M -W?7.- VTV[W42ZBWS3I&UCB!V$ HCMH)M(QQ;QN?9UJFM-LISDLMUUZ"QW?"0)$PM@.P@ Y-O&ZPT@P\G$D M%!V&-S=*>-@)6(,3U$#;^3W+E5B#KXILSD@Q+L\RH6*^% L&BW&IEHL6BBCG MCAEG.3D5--01.I.HH="@]V%#-5<\<>.//'DN-A6[$C9 M'=KIUY1V,=I['M-%Z%FV[T6&CU'L0=X/'-#.AI6_LT00>P/CU& M[%0>Q2R?EO?IZ153_7>[EB_ &Z(O0(\6[.".>U:/$),'U$ZO1^9Q=H\FVXHQ M^K3<:0UW196L%YX=.482*FSP8&8#^RO5V& =&.'&TW[)C\!49.8+BF@W$< M.MBS+=NRNE:BV#(6>?K(CA_^DE9B_9FW :X>'38]^AT6[FY]E9;EOX 6$7A. MJNTFJ[+T^,!,M&^WC^;HW:*TS*M_"Z,_TL/E6!#MXW0PU#4$/131:&";0609 M&+K$)=NGMDD4;E KHU=S\*V:46.R7(CV^R'D"@6.I5Y:%N:7X/V MQH1R_\:$IH;-+B];I??4"UOZ]^ E>16_RWTPT7PCN#$Y%ANS';J0HL94W]*^ M%%,<-8.T,V2=&):IHGD> S%EUA1Z.J/PR=!U&\UI?)^;=.VUO[S)QQ#"R+ B MZ-&V#6+2OM&/\ P?"1X)/:0IS8+&T'VB?_?"1W<"VR?)E]I*L+T"G7#_U[?IE_27]4=]_3 M];?TUZ\6M>W DE5)]4@TBRA]7SQYF=- O+@* M3LOY,)'DB%+LIG!F 6A, (T-T\FG,-VFC7HLPZ&1Y'E.K>E MR&*J4#@GZQ#72++1_5NN16.=:E9J(UZ:YRCL>3 M709]YJK+(*H472%O?5#-%;-QJ.1*,*I/<;-OZ2+V A<[06PYL17$#G8=V*^Q ML2'1F^MR(="NN+SG0&HF6I?BJN9X1,6ET.>NN!2B4L45\=9'55PA&PTDV:,$3:U%>0 M=.4"K(]O_1I<>^8#R/ ;CM4HL9S;/IP82YHIK\=#>.65Y-^+8O4]6Z]AOKK, M*_H29/?K%)9E6I5L]^2Z*+>;M%^9X49&Y+N69X3(=EW303%R3$0HAL!Q8M/A ME 2UC>K3@0YGO>!UAQ0T4,$.ZV3+E(28//&VZ_'(/%YQ3;858_1I#2_S7?JC M0I2?OQ:1:3FVX5BV0^S8\SPC,F$'PJ,*([8567'C(F^UU%[DWZ^O\;]?7ET! M^ 6#Z[M_)3?@\LL=_/+[);HB -[>DKM;L4Q+-?T*Q50/[]K4E,$%-=XYZFE/ MYE!!%??*!U)4">-D)%660UY-_;HI'K+JJBC+A15ZCFV[R($H-GWHNLC$!A5R MXL;(("'GN?\2#]:NA5_('16_Z/HS&?=UVW%PXE62(&H>KXD,\&)P)Q'KWM?5 M4[J)BN?_R]Z;-D>.8]F"?P5F4_,ZTDR1PWWI]PD$P"Q-*4-J29%E;6EC;I0[ M);'*1:I(NC+4OWX +NZNQ5T ")!4UK.RBHS0XCCW7.#LR.EH;/ZU;N["@:M_;*J:S5R^I?7Y[77R MXR(MLX(.V&69)NS07OO?;>9C$Q3:H4]-L.S \.F0-?W>#"<4.T W._":2T"= M76#9&0;JG2V &?B4U<__*9:TS(Y#SK1G=KCU)4Z-J>"%K: U%GQATO#3">A[ M1F\VV+.[R;?V+ <[TT\ -9[5L:CYD\UAQ_;DD5 SVTXUCX V7WJ*3R(.XP;G M7Y(L9P(!RZS*\CN\*>F?K26]70O']C!;X_%#W\&NX;I!2#KDR/2(,V8\5H%W MTA"\[3;5"4JS.? E_?%(Z4E_8M__BWD"_O+%IQK.9/HO MIG$":/./[45,Z^=Q@[F2#C-._!Z[KTP;LIFUW6^"SF+0F@Q:F_<*WQR. MU!BQ57:C/T>05LJ(XKBLWEM#0S%#PXO^,EVNDZK*;K/EJRPCIEZ$Y^CT,DW6 M[.+2[X]%?I6LT_/R+/O7)ELU/[ZUT(2A:4;8C[S8"2TS&PZ).<] MU9_1 P-#_!Q-^CRIP)N.N:,$L&@ &"ELGTI+"]A07@ CAH8>L$?-_#*&"?J% M1&8QY]X[[PQDULQQ9BJSMF'TC.9MG61AQXX7$<^/?&*%1"$+\5N+F/EB4+7(6$SR?-;QG7K+(#7/SG$_M,,W=8_35=W:459U77B0/+]?T0^EX$$?;,(-@BMFU#Z J1 M*7%JKHGN3%"]"#F*$X=-9N;F/^63DST#P M/BZ:O0"_16I@"&/D1!:-ODYD& 3"8(L4VJ;B13%=,&>TN+47]%X&NR\FBV]_ M^6)Y/W4!S]$3\+3VA^%K6)/V 5TACVMYZ54$G%^L&^ >R6*E[LXP[V@W"@," M96Z7N>:<1!Z,:F"PTKE^'YL:I5%35H1EE 66[G;KL) M&].@W4QN1FLG7+Q**H]:G\U?9Q3;*Z J.I@>OLYQF^7I*FK+$A=TH%3"N]<- M$CJNY<;8-WUH^KX9>6Z/V#=LH2> IL2IN5ITP>Q1?])J% \.7>28E_.&9[U? M6L-^ FQX M&I4)[N6/L;VC/L11F!THO+9^R98KH6*U0F:ZR^E@Q"V*,XMAW S/R0]\. M M]"VPT(GB]T=>?46$=;&'GLE7&W)0FL:*9=%^"Q;-X';>T"2VK8F!NC1^L5 MJD/G]!UB\O#)0F;# >A( (P%\*6EX=,<<5+D6R4A5F^O^FQA5C,;TJ%V#"]I MF%%2)-_SY*$HZ_U5I&.0<8!-:,(P-&P;N4:,#>1TD+%E.)IBK0:@MBS;AU9?M<:>%>/1]T_H-FCZ MG19]>._Z7OM]JJ$OP_VZF6%]N">CB>>[>T38YHSIMF1H[XQC;-Z810><=)N' M>.+ \E&6">PE#/-+#49QO[9M)&-URWDG%S/C2NG6E'$]K"(]X4;\SK' (/(C M*["A$Q)VS-DCOKU-I@+#@]O$0\T.%YU095(*V>TO[Y0+YJ.N TB6U,TQW#I_ M11R%!0&M&\\K*E1LMPLP]$W#*2_)5\NSK]C=#D[?SJZJ=);@7GH4Q2)H09G_^8%S=)8 !+\L4[&M]I MM6^1_FN]6;':"YL<4PVIZS*[V=3)S3J]+KY1WHJ\IAS23[\[S>N4=N]Z$84N ML0@T;&1[GN6X7D!1=R@=[ L-W+&Q:1[C,J-['C[CF^O/V5UBL_>C\_;=7/H$ M;.T"G6%@WS)667II&^B-&U?.%7OFB/)/U0?F$20FL[Z8QTA4%GJX4%E&9*'0 M-"*3_N%#TR7.%E4(_>TEG(.#C1(T$C-3L?!REE;5?[[>))1UFX225[*4OY2E MK+-"<&.8=@\.#CSCN4YOH/EL845?&%'JT=F'#;76\H<)#2PK" L++W(LW_<- M/X@CZ =A'-G]X4!L6S!2-+OXL)WI9@H 7E]?GD;?KR%[(_'Z'%S_E7Z-7 %T M?GEQ?@FO3\^_*1/QC_D>+-!*J1Y)?"^2,LWGH[5R.LI-_.PUDM\2?OT39(=7 MV]I&Z.>S]Z:7:?;$NM0B"D(#V]")8],V@X 0+\:Q%R C(+'GF('(3DVY%C1O ML3S=[IE(*U!N8?VO_RNP3.M_M_>O'AY/*IGDTRO])(HI5<=? PCL$)UTUY6/ M+$7OLG-$A(:Q.0_Y&6A#H;)_24K.7DN6C7S/-NTHLCTC1BX5-;=OR8I#0R2- MDOE\S>E3NSR;O2\ZDC(CPIZ@R&@B3HG$3*0L8KHB0>#,5$7&@D.:(LT&KZ+ MY;+O"T )YMH<#%\6^@VS+<0V?&'U[H>T)'3F1;V7,9.8Q>1Z:R0R@ MDT]HQF%23&XZ3&!?=B9*9P[2ANK,-%2-6K.J:C (3(S\, M'!08-+DR@PAN,RIBA4(3JT$-32=)^1;D4%42X556F#11JD*;OGU,Y$CRM$,B MI% 2W,Y5I&1,^5"GI/F1EZH%Q,1P5@G3D.UZ&/B9!5(*6?#=6=JK1%2&&[NYJHK_ 9\J":"7/!JR*]97I19_=RO MP5VW\[P(.DX08C?R_= T0R>,H!%#+S2PZ;F$B.0Y#WQMTAZ_Z M4LDAGZ+HIT],5&29TZ(O[Y)S1&*&D3D/E1EH0Z&R>XEIS65:)^RD-ND.R_Z: M/MRDY2+$)/3L*'*Q:<<0^[X!G;XQU\&^B-A(-J%9;7I4H(<%OE"!WSQLUFQ7 M%F 'V)=9_=.X8^=]JHX,GH'_&4EC<%[S@:U)3(:-I'-3P&M0 %P_-&GI,*C3V0NDH\J)AG"Z;9FV3=9 . B3(=I%G0##H(5^$$H&4V&-SQR5'D]^'K,P#9/V$ATI85/@0^$ \VX] \+.!\R/SSV M*'"!= P:UQ5J8I$"ETB$I0^9X@M/Z@B?79A2:-KA<*6:O^&3GQ<@^M@),3&M M +ML!XOC$0/C8 O"I=#43(.DFIY\0O1ZO"J;''9_%5&'8W/,[JUX+7)*J]C5$A9/]?,UBMX4%>ES\XUN:LH^E;PRVQ%3P+5$2BBC-&+\XCL&J3Q@Z '5'$K+] (ZV()"72?AE]5?DRK+J0E7FYLJ6V5)^=PKN.$0VXWL M*(XAP2'&A!A]4QYVN3?Q2C>@65A[7& 'C%\GY%G[6%I'(4Q,6]_A2D)83VD,T'E'8P1=-+[7 3"H5=9E!ENFO+I_DQ08%A1S9V;"]$ M-NKS9=LE-M=1R6$M3%-C'E2MY.5.JD*L@38U96")C3KRU VJYFJ@4.WBI)JM M-8<,YR^W"A(UO0 KL.%XX52*$4X)CDJJ^.LLR9.N!NM'1FCZ@>]9V'?M*("Q MU6^N<0@)1=;^A#][!-G=89);)!+GBTMPM5(E+K7CLR2DK5K9DE=5$=8XQ?2U MI8=E5)J360BH//I"3<_@%TVR3I=UR:ZR>/XES=.2]I/\[J(I3+";\9/\^2Q[ MR.ITUT@$&'&'20 M^<5%.?L?R_.4Q(M)MQ#G$KFS*2&,(M"#J) MB'4$+LZF9Q>ZA!B M.4P=O(.>(00-Q('O\0@0>CSXC,NE6)P91.,HC_-L67I'U-0Q.X^+_!78\<%# M/;+,\*K2>7V?EI>TH7*SK#X (-,#$9DF:03X3&($],@L1YTZ([!X@YHCI#J9R'Y@RVHE#; MP<3T!F?58U$EZU_*8O-XFB_7FQ5MD7Z51;4LWZ2K\\>T709$-"/+5MT_%LB- M#40@=@)D8=LAV(6XA^-BC^MDMW80NJ?Z'6[0 &^.+;30P3YVL 5_ E[ %],U M?9[B$[Y9.$FP"*#)/UKT4Y;?(P*KW67S4&#]9A8C#X5A,]GS/W*J9??9XT5* MQT5>)W=I]/QRHM+^R"(D481(9!!(*)8X,AW3[/!X)G;-(3-==2BFF0F?@*T% M8&<"N'D&KWZA_;%A_FH>LCV/G! M;%\7L[S*?E$6RS1=53'E!F>L.IK1*4%Z?AMMJBQ/JXH55$,CMAR#&$%LAWX< MT+_'?IZ(AJMH3[-:]Q !ZR]@M0,)BEMPT\$4$V,E+//)[M@$BPGL2V[Q M2VYW",=54 [*CFBE2L+GH8I*+2KT=4^1\R&O;M],V!,,5;,J]+@5WH5K8!2A MV#&0&=B6[0;F-GGV')?_(+BBYC3KW-N+:4_ 'E"P0RIRFD$-T1_O%9B 8S&I MFS.](J=%1J=9]KC(8+KYCHOP\'%@=5\QF=.OZ*LVJ-#6\?ACQ56R3JODKDQ3 MUGBT>4[+=K- 73S2OG>?5&G1)^U9E\6G/RBBK$I7B\C'R((>= T[ID$+A\&V MANZY*.:^CE0O"LV1I6+@P1;]"6CP=UMN0%V W@2PM0%DV[GVU@Q^7=3LLX^C MT7S<)1:D_FR>X@]L\_&87+S3[3F>8#B(PP,Q4Z* JCD';,_A(!+X#(%0FT^E!H M#K0,"8"O-: U %P7H#=AKWZ]JVDW9H#&#C']UN@TOD@[#W^)1=H_G:O$0NT\ M7"87:K6[CC?62I-X)-;J=\P\8NT(=A9C=WG^6!MO6)7UY;K2FR6HF^?\Q0\T MV0!CMRX3-O]F!K =" ^/Z[1.%Y:);.2XKF^;H13(P?R".F=.WTV<6DUA?S&&#\F<@O2481M/L;FV)^<7M5 M%\M_9OGN 8;+=,D\MJH+>'&*%B%R/-^VS, S?1\BST"NUX. T.*^MT]#TYKS M"(:8"@38P\PV2C2H ?W6#O<)Z)&SVA_#SA\X=+CDXR1@8F^(Q?C/ZPC^ #VQ M0^3BKQ;'\$17<;8.!$^-M$\?&W4:5XS2=64V&9WF\/:6W[Z;YN_V=5\5Z MM3"-""//]F("FP?O;6AO=W/&#@S$MQHI:'2\#4>G.=BB?7]S-0,LLS%&!?GM;4H3ZZ=T;Q,2"U(U_5[2F_ ?%7@J MFNO2^[6W9GZX8O-&]H-E^EB4S??I![ +UK^LLI)^[/J9*CC]G?Y?/RG:WO0Q MNQ]N(1;Q/[A&!V[FF]XSD#5W\'N+P#-?M7%)4'0AOFGF?/M#I-K 8 MK0\/#'YI=<$RKN:$-4N\:-/?'XL<+N^S]*E9V"UN45K6=.[YXC(-0H/W,DMS M^G]VAX]O1XYG&I[E^X%O&]#JIYF^%6,R*#Z.@G":$)HR06B- SOK #,/[-G' M?J6S\-7]-/LV#M3U<3J"9#">71]0$J___=P_,/+/KALH30[&Z0[2N80*\D72 MC5&=/=.,9%P./DI:)O ([PG_]Q>$3_-EF=+LBIW#93O/SF\ODI+")/_:[-U. ML(CLV+9=V[2,V(@,+W2,(-Y"0J:_>$K+FX+W\+]6*"+BM(]:;!LH59AJNZ0 MJGN*M&+K2:^V=O0UO)%/L@\A^!T!&M5O\SC[/HZIQ03C8L"M?=^*^MVKI]BR MVUE15>=Y_^.+*(CII"RT(79C;#C8-/$.C1D+"H8N%-JUXO6])3CST>4C_[7W\%!^1==U.FX>B:[?RV-5] MVECEU?$^047%PTW6/L!XE3XF%$6Z;K9$W.79_Z2KZ]WNOPINK\MGT-=%13/= MZK2J-NVCC32IH5:1'X]ISLX%NB&R'=-U<1C%, BB&%MA#]LGAM %?Y.#U5SK MZNT#>P:>@)V)8&TO8ZYD;$>F/%XL?DU',&FLEQZHM( M\^@=6F*7;J\="7*SZ3#SB(;SH:.8Z< 6BZ_MQ*S9;/CB(EZ*.,V>TM5%6NY! M7H0V0=!F"U86)G9DH3#>!GF#>(Y(M%3D!+G!#C\HCJ:W+*/#1)?2,F/+&YZ&^"8.M3WS%7:)&>[5Z0XOT\CMB$N5]3>@ MX97VS>?077GS!&5W((^\JKNK;%PDV>HT1\EC5B=K5#P\%'F#CLJ]@X/(CTD4 M0-^VH@#Y_<6W 2:(Z_ESA#R$[V=B#91);!;,>ZF)*JH)E/.T=F M6$PM!Y.K11T_INR('BKD>QX*J-*@0EO?%%,YM@AZ7K;+H'O">[IW:'MAQ)YA M6$'@T[26Q%X8162KK^Q17!&94]&>9IU[=Z?!L5L-Q 1/">-\BC_=.K)UZYT;606O.=#II^-".B,7#=E9]VF](W(@9Q9> MDCMQ\[(VDC9[BW=74- 8V+]X!U:-F>GJYX$':&3).GA"1CO[ MK3A4_I+F_7O(R6.RI)UX$5JF[7I.:)LA,@++B:"%MI,6S+$P/F6T2%1$-7LG;ZJZ3);U AH8A7'D$(A"QPTPFTM*FQU+V%"3J<(,E7H$$*]J""WWNP_]_(56\!'H_5OW6X M8QZU(#VFO:Z)Z^./>^?%?5'6UVGY@-.;^IK^*OR150ODF7Y(0D1B/_ 1,DU" M3".V+-O"GN<3KN+/L!9T[Z%@H+[27WP #-8)8,#H<*30#@]%E01R;H;0SIW@ MC@<9VO3L:GB/F6-;%P8Q.0]-&FC#ZTT("AB15AEJ.J)6?*0[4JSP*L]9EJ?GMXA.E[/ZU_3A)BT7KN?;R,>F'=)F+'9>33EE$H%%,8.?:TZ,PA=HZHS6!" MYZ$YP\TH%'RJ*H%<8D=FSXR'!2YV/<,%SM4 M]@PSMMW8]X4RFL&-Z5YP[/"!#F![Z\1)/\9.0(-2\%JKP03S"=2HW JN&0ZC M5<]=5!_0=42YE#$]#P539\[K:Z34\C1$T=CUA/LM0R=RH&L2PX]B+X*1[9"0 MS0=9XU84<+U=I;*]B71M!U.9M DS+:]N.DE6(W#\_(ZF<:]($Y0Y6/7NMV2]:=;D8;[ZKTVRSFZ?L_RN6_[;+?&%,,9!9-.6/)H_VG9H M^@9-'MV02BY56]Z!J*@U?6-Q"[!9%M]!!#W&R1;&^:@[,B(5IZL-.Y!Q',;N\J_K]$<=K=F!M3B.J4)0?7"1&_C8#:68>:%;@_%MP==O [0P\:^&,OL:.P*7"K_=EMD]==TO8J+LCE[5^+ND,GY;?3,OM*5[ZS ]6WH M$1AX06C8D>61V A#WS:#R(">*S3EU(9"]T3TW:WB=*;$L'^]+1^FZ7EZ.YV.38.V^FX>ZCV#GVTOF M1V&6^RJ'HEC]D:W772,((2\*L$50%'B^A\PP=OI&(ML/A6YM$/MHS1K^#12(T5BPL?/CIYK$U[P<$28) F;A]K(@G]][\$0#GC.;9X5^=T9NRBV M78C=$Z>N21+"@'YZ$#I6:&),Y8?^OVT2V1!RW>VBI"'=&[\H/M [/<9,(B M8FP"/O^YON&,'M>3T!249#6$\I^(')78P4AD_KO9*4P7^TU MOGLQLX,1>688.;8#8XK&\"+7"((>AA'Y6."8OOK&IYG1-[7 O_8CK-&V'7*A M8^ :W/%Q")G<$P-FZ\5+)[R0N>U5**GH/DM]WA ZD3^M5^1BTM>O;"- ^C/] M$[SX!)#^R-BK1LP[]7U6@73=/+3[,_CZ=>A!>V&B#L0HK9Q/'[?TFE>,U'?Y MXQM)JCI*\Q6^..O:@+9A6!9T8Q) '&*(PKAO WNA[? ]=RKWV2)C3^H14P8) M,$R @I)0/ FZ/@XN>GD2BQP3$,2O]WJ)DA-S0<)XU/J-F0>D6)Z.Z75V /9" M18<04,B;3=W/+WPCL@,"'8*\P(Q=#X41Z3\]=&+"F]B+?*;F?+V!(C/016CA MT$!-C BJWQAD".B=)E(DE8Z/'"Z%VQEV2-LD3)^!JLF@+H8YG%_)OO_M[UF^ M^I;^<9O1'+-OQC5BAP21:?DQ]*#C&E9?),T O!S$SO7 .@U\HZB&B M4HK3IW1=/+(..V,$E9Y57<<0N4$>"YFHGI>[D\]$)!3^#OQRAY2,NBZ!OP0X0MY#D1AM! MF%@8A7T#IA5RG6Z6^%C-R4>/9F\-DS\\BC+T<6:AD1RQ1&++B_C\3905_AQ! M(SMR*0$_2SS2]]*\ \(GR<'TLB<+O!CL?X$R?5ZG_^R725V?V(%IVS;Q+0PM MZ(1V_^DQLKAG7R*?J;M,SZ ,J[GNC#E4$B%#8%.4)E(^S5ZGG?V'MC!),#2]SDFA+H;U"WZ=BS:WM\FZ^"5Y[ ]E M06+91A"ZL1/2Z;EEA]Y62@W/L'C%3OB#-2M>AP=00/Q#79R=C\5/*S%B"KC' MB80.BI/#+X9:29)31"&R> 3OM8T'5$^:BNFE3QYZH: K"*P*_7SU,RM97F_* M&U:1Z.L[D>=;)C1BRX4HL/W "G'74!SA*.9>#)+[>-UK0!05^(-5U^L.E\ B MA21A'.L\^KD27-YA-#6+$#TDF?5U2;X$UG+T\R:YA"/!']?"S;L&'UJO&<;. M]$HZU(!"64\16)1)-F52W==ELCWEY?F.[X2.CSP4!I"8T.J;0);+=1.6U ?K MKO&T+Q4_I/5]L0)9_I16]4-S=/&+\Q._2(CS];&<:J5*3$AW4"0$5)P;?NG4 MRI&<:.X@G8 $5)N;*EME2=D\]\E> D7%PV.2/P\[[/K:[D/+?K+T3*^:\M + M!=U#0"FS]5-:7F:KN_2B^&,[V_<-: 4P"* 7N9[KT.26]-N?V(4(IL BMEP# M^I>R&UR@ 08:9(I6M-^U]U ''T;.#+KY0 ,*91U%8,KUSS*AV)M>;H<:4"CK0P)R>\6F?/T^O*Z9 M /F1[=/NQP"6B'%%D<0JN;)T&9O6KK M,KL-M>(J*\64@,;J9DRRIB7,')>*OF/L(0T=PLL,%'00_$)1_^!7SU_9Y<14 MJ'_+TC_Z1FPX+XR0^6K-R]H@ @\0O!3(Y8B;6^G MA/GJ+$MNMC/RA#U'L3K/OQ5YF;)GP++\+DJJ;/?FD.V'V+4=2/]G46TE-O8[ M2*&!39.[:*D=B&:Q9/B;5V32_E)<:@+8LP'T1H#S'.R; 1H[>![TFL!['ZOS MK!PG)NI_4I_Q1Y%9^>ZS%'R'DG8@KHWFB^G#X7BF%A/T=;$7.UHT6W"[1Z#V M@2S"$-E68",_] /+MDR;-M^U;<:A(_1^N9H6-8?3!B2X90+]U ATO@=.[*T/ M10P?CX33D2L6\EI\)V O].TPGKR(<>.^&<)%W#O2J8?X>;PPHMBF0F=7E5"] MTX='VCB+R>@^*>^H1CM440,4$A=9@1<87NR%I&\L0 CQ;?H9V(CVC3^MMNV M@0Z9A*Q)4"B@8WJYDQ N$=+TJ=0;6CZ2)7D>9Z1# XQX3WB&L>%,COR(_'-*_2A6>@R#8\(W(=2/.W($)&G\Z9AF]RWI(SN!GM:M,@8^G3 MURTV.C5JP(T[=@Y1=&3T#&9U'N-GN!F%XMXF]ZK@;LR>%56UB +?M!T3(\MR MH VACW#<-X9=E^N(V, F-,]"MN_H9;NX,\G8>9^>(R-G()_S&#=#C3CPTMX@ M3GC'S&6Z3NIT=9&4]?-UF>15LFP>RWCOE6'G]W^#Z$GZ[@NCZ]/S;E5@FK)1JOO1X*I;% M[*84EZG#X]%F93/[5'"7;W5 M1YSFNXQA]H\2( M0X&#<\,;TSZ[O228D%]A=$; U?4Y^ALXC\'5]^CJ%)_"2\*92*AB]N/%\I$I M%=.E'3C0H!-.$K20*G"6>5QR)3=+[3AEYYEW$1>LTCK)UJ!D 9D5:>IB__#S M(]7]M&1;$:K&-UF^7&]6*3MR#QZRO"A9(,ERFH:G5=V\F\ MN*G2\BFY6:>G^>.FIM^F[-'?:D;&-?OZ D9A"+W0L]W8#Y$?AI[E&:$5VS:T M38*%-AI-A7&4C4@[X_H]28?V(UV^VHRT;R-HC 0OK:0BSKXGLU=ILFXAL9?I M,W0/N=@QDVXBM$E*DS<^VD0U=2>8/CS-AXKW-F%-#DI\$9'=.U.F]VE>4=2G M^;)X2,^8?VG;\$=6+4PWQ*[EQ)'I0"-T; NZ1M\T<:$I4L55TJ#F\FV[L/@" M)&A1@AXF^)T!Y0PX:LGF*PZ-SK-87J" 8GU+N1_0]M&RKBK6YU%24FO2>\N] M:OE2I7S=JT:&XT2^:WM61%NT,+0]]AI,V[A!_U2I?9Q-SD']A!Y 4TVY&@74 MP+8 \#6T<%3SXBIHF[C^'$HH:):B%4ISQE$B:AI?[#6=-P[M,EM7QGK+Z MN7^7(_8=Y =&:/@V_6L]021VK5 M^^+C\M.D;I"1S$_F ?Y*SZ2>D*O M#F#R6'P=PT$SB;>CF/HZ_H['+V]IC2)Z*%:T%53DS7ZQOK4X@%[H&H830>*X MIF.1L&L->L3D>H1L:!N:H^@6%NAQ"6KL8 [YBF-CT"<6S&28TU+\.D#-D6K7 M4#+G4=X:;$6AMHO-8H_/69:GIW7Z4"V"T# CC+'CA<@VH.$ALU^%0)9+N)\- MFP58S2HXUG8.9C!H+)['UA^!WC+IKC ]'66>.\,^<1^9Q18Q/7U%;K;4^#)C M8$"9TJ2W8L=6;[,\H7"3->@"7?5B"W$":F;9S^#ZGO[\[F>2,@6;BOY,78!5 MNQ4U99]:E,W/TU^]+>;7T\_N8S\>XU_5QO7G2,LPE-UD^CYV^[ M:\V,F)B&$[B.A1"F6$T/NSU0MI%NDHR-'][GS-$&7ATY<@\8.0O3X_Q9Y%V? MR^\3959Z_/_IKA=52N48*8NXW_YD28H$ ;K2$EE?\!:OMV"_I?4KO#W<9\D< MZK)8K^.B_",I5PO+M(+8L2EVRR:!$2,2V#UX'/M"M?"90!XM83D!U- WT0M\ MV1K[TRYX%6^"UPE/U8#9#3K#!2OW,_$&YT+ 3-".D>_,IMMH6;88QY%'5D%F MUI/FL:@R-U**68_^"2-U]1+]+TF6LSO43KM*XFE.DC*GOUTMK(CX, H"W[&C M*" 00X1Z8UPOCA=Y>L=*A=<3!7!UEG")F;@G9<)8K[ +3A#[1^YVL\L%%':U^><'W,X>*U]0W_O^A/F#!I)TYA.Z M?#K/_.+P\:^J6GC(0&[D!1@%)LVE+!OYVP3*]G$X^YQCD'7_3GG(D4.A[4_/ M.4$9UH?GF+3H[[>?.)&1[ZM_@@SG6,^83=:CI/O^.V9":HB;-#M2Z'O>C&EG M5 _G/-]]C5J]MW8#L0M-Z$4>HNU[H;G=!(P(,;B>E%;?JN85C.NB3M;@CH*L MP)__.G_Q2+] JYYPO$T] N%B=W>%Y&,1H) M][_%0NA45U5STW@DJ*AWQ3PT7X-=A>Y.++'MK=-\MLFB^GM6WW^D]2\CPV5Z MMUDS-SV_651?N $,''9?G.E"9$$+&K#?JX 5@1F9"ZZ6WO.V;!YA]'!.@-[O?=E:^LV_N<_4, MB8UPGZ.'R&V*N][;[[8[8L!V\>\RMZ($;>[6[9!+P2,-&,7J<"9W I(RJUC_ M82$.K/9N16F[#_OY/7$!#_V,/7GQ4C [B4!1]9WQINF,F^:#-_N].&M[\9>S M](EV.9NV_\=]MKQOCCQD[VM@3E-9Y^LVG*Y;O&351)5RF*\VCY#$[5D:L81%S/CTU$2-!;X3NFT.W1<\/^B;?[O]7A+0'L MI:D"=#.G^81RJ&[1H6F=ED7LJ&\6?U>Z6C]EH6 M'E5^(^4-9?MJ76QJ]K#D?%, H9XUHQQ >6_Z5$D 9[?ZO&G GGNGS@-D>MJ_ M42(@1<\4F8"\'\=(!=Y?KEA8GAM8ENNXIF\ABP3$B/'V6@)DP;'F_)+P/LFT M_F#$'R]@R_I??T@>P?73!%UQK\\NGK[O&TT1$E_,88I[ MT6QW.Q9X>NBS!RL6^&V(4&\;?W AKV=#?:J('_2>(BW[2D MY0#T)( O/0TS.EXFV\VFG_&.T,/F/.>5Z%RSB])R+IYHWCNPOWW^**^;H!'G MODI\R9LE_-SZ)3-XCO*J;U2><6Z1@"Q7L804[L).='Q(D\XA$Z7++//1%FW7%.)U; M;&1?U4G=K(Q<,Z%90 )-PXIL[-C0,7WB&)[5-^*&'MJ%.'^" MTJ&5.C$5$6%-KXZ\)H5'4J2)G)FZR-MQ2&@&,L.M.>G=Z]9P\X#. D<8.4Z$ M,3)\T\:181.W;\\THE!($-7YB#<]NG.(EF.Z M,YC*F>C.<#M>ZXXB9C[2G66QR>OR>0$O%ZX1$X@-/_0L)_ ))C$F_0?;$>1: MDQ#X.,U* B]_(=^N3[]!/O40X>&X3&BB0$P//K;^B 94Z?+GN^+I_^DL81)@ M]_]@H]_>&_T[:]\9YA)43#N>90 7TF[GO_WD^]_^GN6KB[+X1[JLJ^YM6 AC MQ[61%2/+AG& 48AW0F#YW$]V27VXYM'[_6^ @0(]*OZ+(N2H.CZD1V%);("_ M)DCPY6QYIO@OP=#.F-RU%>+,\5S@\)ZQ[RCB8%ZFOR1A&/Q"4?^0K.2<;5]F M1%X;LR..R"MB;R6QI@ &'RC.R7/#79=94I=+5T16K[3I5$! S<"(W#$T/^C%; MJ.KKT8%%O%BL5J.R9=VZTX$%'RT&BSZ JFQ[4U_2QR"OIA(&H_,844.-*)3V*+$Q\DM9 M5!6=(]UF]2(. P-&V#:,$"/3QB&=)O4MT'_98@-#Y).UCX;SQ[2DDI/?@8>D MO,OR<8?%'A5'QH(,8?,8 %+(B^'=1:RK[V[Q@2#S# M]J/MN"0^%!LU$X'4/@#[ITC6S97OS=6KRZUQH-A:=P+RM#F;72<_QAVD>I@_ M,MXG=O4\I&-J$HI9#;\A@L:VL[9XT]4.[K>T/K^]3GXL7--$%@QBW_ M&1E;"+%A>$-D:F#3VL5G'Y^HUHS /%^18#+*Q6H$+]Z<:H7^!?WG>_1_:^FG M@$_ =ER!;F"!_9$%Z@*\'%N@'UQ31HGC7N#6?D7.G*.BJS+MJ$XKY8]7?>G' M[[WA1(+8-"U"/]B/'6+;/C3]O@TS@HY(15;LDS577-D8S5XD;\FK<7E]GP)( MK@ JRL>BY7[<,?F"KR.#3H[7>8PJ2>R%BIXE6'7K'H*]2,NK^Z1,V4F[Y;;2 MY_KLH1X,?2<@F#8=&7@[M0N"2'"V-*PM[7E' ^?5Z*'R!"J&]?"38GI*<\>H M.E:A4T+Q/ :1(EM>U^L4,J2NED'1-$ :2 L'(8(?,8WMJL$RX2#&%1Q^S_ M)1YL(RL(8L^A2N18)(X#I\^'(82.*Y*KZD.A.:\]4!/X3$H@P+:BJ:BH M#EKL'#!)'<+LH,Q\05 0VA$V8SH3L*@VL=7W;5LN02)J(->"[ADLN0:GW]#Y MKP3 Z^O+T^C[-8S."+@^!]=_)>W@/K^\.+^$UZ?GW^C??_V5_N?J^AS][:_G M9YA<7LT@4Q?-T+E)G\?@'&@#3T8NR(CLH,+9>E.GJVW^[YBF:_D$^S@,480A M"@W8MTJL<."$5[2U$4KM#:"93GI?T24PJ&2)GN?PDK;F@X$VC"6ED]\.2AM/ M0\OS8]NW30<;D6^8@64;VZ'OF['BZ:]0V_]G JQF KQ/^M IL)0#YS'4-=HG M,PT>P*2FB?!+1(8;V3[-L!W/#VTKM"+'ZQ&YL:5S*BR$X_],A@=/AJ7T08\7 MYZ@4FBP=-B4>P.[ _'T1.;;EDM!WH0V- )EF9&RU"MMBY_=DV_@_$V.>;%X\ MB^3I/''5<\E!T99$H9 MG\>(4VM2H;&'\M_Q95>E"F-LM=%G:QI<\@@)G&PZT#RZI@MRE=-:6K\!=4:S^R-;K=[[_\Z"+2(Y1 M^DZ04.:%Z2\F46-&H;AWBM9*VDW3[3SLO+Y/RT7H$ L'MD5=[9OT#XS<_O!M M%-+P(U8#$?]\W;+?00(MIA/0H!+=[R]!VW&='XLQ08D7(TM37><-(T?K-?+\ MS2/9'&3!F_K*4#:XZR8/-^EJE:YV;V[\DF3Y>?[VZPL[ACY&IH<#'/@^# PC MZA=>(^*'0K=9*VQ6L^[TB/8>^#D!#"Q[R^>=;XHIDDKZ^81J(N;%]$L9Z7H* M6-P4'JMIJ??#/'10AV&O*U^ZN)-;JR+_VC2O$]7W[)6A)ZK;+!FL%BB.0]_P M[2 T"6TY\E'4%^(BBV*2>*)>3<-B=3'9=^79D:.T04BG/"#MJI5LQ+>_3U6:=GM_^TLVBK],?=42- M_^?"LKS8#\+00P$.#=-Q VB;$7%#EP2A89E"-Z\-:$=S\M)#8X.N!R=XD=H0 M$ODRDK'X$TM!WJ.N>_$','R@ 3CVQ6B'J3HB6RH(GH=8*;'D]15GRMCA*=_W MK16W<99G=7I&DY15DE,Y7*6WNZ_0"2#MC!GM;,T3B%73[W:X$#%P8'I&; 0^ M="SHA7&TQ84]@[?./PZ:$46N->-K@[HIH.XLZ;ZXLZ5]IU7@SO"1?/?QPL+\ MW":OK1(>$Y'AJ9S(O[@Q/V?*K8*,Z%2>!0XEM!Y8"1G79=,OF8QL;S'5X! / MX^>W<$DG->5;"-'SK\D_BA*MD^HUG#"(/6(2(S)"1.B$QZ;0>CBQ$06BT5L+ MB!&#=H_^'5&(GD%C 6A,$%=Y/?[AC]"3NT8R,)\+>$5).-;C*/$H/+G#Y(+O MWJ/9; _W?=KL$DB6=&1F59TMJ_UM!TPWV57?RZ0LG]D7GMC#ZR> ?GZVVFRW M,9R /]+L[IX= TN>TC*Y2\&F2F\W:[#.;NF/TX:R7==(VJZ1]+UFM6'OLS=0 M'IOWU\'-,WAH>LV24?@S@/O_!%G%MLX]%A7;NO[>)]?W24TAY^ F!7=EL7FD M/U@7=RE;'*-?6R84'&ON&224A2I[R-9)>0+2K/V!9Y G=<-/\P_ZQ:QD]K#: M) .YMUV^9Y#"2?+G8?LLAO2K#[(/K5UU/DF'7C/?R35&X%6TA/DB_7F-*MZP M?@T?V'U[_]-TX6X?RBN(Q'$B/[*P&9+(-J!'_Q'V$ WHB[T,.B:P$5,1!K!Y M&F$?=;]-3JYR.H[OQ$JMLW.;HOK!FU3E!+36O.O/V91S5;B#H_X[JM?G53 > MU_0#%>8)^.=?T-ZNQN'TIH;YJEVKNTJ7-(^KL[3:'@9'!%D6C6@QLAQHVL2U MNDAGVPZ=7O,^[J6P19W[Z+8@3P"#V12S6J!@AW2RAW+X23RZJJW<$_,8_#H, M>[.^K8D[B8%[FG<0?DW*?Z;-8=\W8/(52LLZR?+K,F%SP59[=K/'G<[@ .+8 MBP)B!3#R[P5 M8WZ?++?4Y2F^0#)-YYA=V)F(AL-!:DJ_\(:T.,G*WUA%JYI&%80 MPL"DV:]C^*[9M&G@.$"^T"[T82UI#BXQ/+T$O\&S[T0LA RDCR\.C,>@!W2V:P0^)2^?XC)?FJN_OI-9K(#T)D!+[INQY"R/%LJT%C$F0B0^CR M,UT8-$MH#Q90M*"!"]KG?"A@T-]RW$"6U53%+A'5U^F\(:^U;YURTGDEV?/* M?+17B&,N'=;CM;EILB8K#^JS3E8%[LECR[;-"BYM^C*MLS)EM;=W$FN(S3@B M'J'_=X@'H]!"MA$CTS0]:-M6S"D&*IO4)P#[*)MQOL,YATFE (E'1K@.5\QC M5&NQ[.V5>IK8$\^T,#M?D*ZB-*=_J2]H5Z[V"TU,2IKWH(D=!(;MV*9ANP8Q MK!Z#%?)=MZ>GY1&WS'5P08<7-(!?55\99LY-X9H\(9I6C>T$^61J./^:LR<. M*KER)I4NF8>F:K+M8'ZDGD&>LU)DG2[KLGA,-NOBU_3A)BT7@>LZQ,>!C0T/ M.[$+B1GVC1A.!'E/0$E\M.[YYAXB_E,P,A0=5[01V!&3K'TPX/<6CL Y(1F& M^$__:&9*[DR/&&,\AU'>FOF.\ [D8_J#(T/ %TKZA%C.^9WM"5Y=U>P^I N: M_M(^TDCS^>WW*Y+76?W\4K<[, CZ+J$8HL"QL&5%$4V#>S .63KZ_0JTJ(4E2TW>*4?G MD014LW_FD8GJ-K(8M<^+Z>_;K'B7%)_1[YS6Z4.UB*,@,B*$_- )0C.( M,( M^K8#2+BNW%';HF9U?4]87Q3J&%+00!6Q^=:3$V5T*Q%2;F8.R*< M:IF?ATXJMJG0V5>'JB!GZSSN[:V50 Q^:GN]%D>6:B&#' MQSV(R/6$CH3NW;)F^+\J%=:*9_ X_=%/6Q61GY(V./[N0@ MV9.1FTY&BJV!S975C87-:SXL*6OOH3G\]/G\NH-L.)AG3U 1._:K%5U7.!Y. MFC.!9-L1FNR\O[!PHIT*&OTE%*#&[R5SC683,/%AZ)O*.U/&R;N[LGFMX*(L M_M%FY8>6Q>Z!M$S3VAKC!5#H),%,3= <7;?(WHF:T\=&%5U@ MNK YLO=G%E'IU*XG .QZV?RF>&/X>>1(K+#C_7F#M$J21HC?RGTZA]!^=$8? M1F$ L8F\&+J.9WN>"\EV?1[Y0DOBLS5BQ/+FG /\L(XP?8@?K0_,.,C/NY([ MCJ\G"O1*NM^?/]2KH6G$8*_0KW,(]]M+/O:_NT"N@2(7LQ<=_"BB_X<6WJ4M M%II+G)=#KSG -U?D-#>^OZILSR>V2WI]^J"NW^$SCN9[=R^]_*$_3R!_U[\3 M1?!A?>W/'[H'\C-BS%;AR0'!NC= <%G M=S0CGP363XQ3-MR'7N++T3&T$JZ M)E0S6'H&CT?=?U8SA-B@4^SMV<;T'3;_7&@ M&H7Y\0)0'S;?*6='KFU8D1.C$)NN9SN^N9W?!H3O8;TYX/S,*[CC.7.LN#.. M'R>,1/N3N!F6856Y2VNX&MY)_BP!3 $3RD.:*N^,'^3>GQN&) A]XE.L7A11 MT+&SVY)%_Q"ZV&]JK)^VW#FN1\>.=OJ=.9.(-]^RI4K/C1+\AO69/UL ',B& MMB"HPDO\%^8OBX>T.>C-+D#IKK&^ND]3]@@)7*TRAC=9[UU#%+$KR!^+*EG_ MPE[YI;9T[Q:SGRGR.LLWZ>I\^UIO>VN1@PPGABY"I@N1AR&T?!A'L1T3/W)) M%(F]5C4/S-I+E&-J6SO?B10#"9G^ MJKTAX LEG6)NTY&S[34MV'8,T\"A'_IN9,6A9;IV;X%GFT*']>>$^T\W+3F3 MO<=J3EZ9S?Q$3T<2"X'S[$.?=)JS=>BD4QWQ;O7O,MV18&;T*8^L]WBF/>?U M?5JV)B#:,MNZ)J,8T?D5]F,<&2$Q;81CA+H&L6&[7-L4%32C.6KV MD$"]PP2^@BA-GM)F=6.=/O-/ 892^O&,:40VQ4)' PQT >0KV/*ZAVX\'OFG M52/R*3?%>L%KF;8G#>H"T"^_Z+/%+4C LF<]J:IBF34_VZSQI3^R&C"1I<(- M5GV0X8 M''!^^]%. "44\:N\9JHDBV(.5+G&$KE/&H2@ZTHU'8P M_G3M,J7361I1SF_/TKMDC9I*PUV:+Y\7L8G\T'1\*R)V0&S?L-RHSPU]Z'N\ M:=N )D:8XW=0Z,2F1'),\N1TA\T^D-LIX&GZ'$^%$872OB,V93XKJJK(R0_6S":K[EF/*FZODQ]) MOFJBP5F6W&3KI@ZS, )L&Z890].([ A+XC]'D($G6!!P=\4O%-JI4V+C)Q] ME,)3[O0%7C8AJI,?S3I4T>1"ZQUHL(50,FU9KMUV*%T@9U+UT<':4WSX !!;\SJ(("J89N/FT.JC6I$)C/U6E?JQA7#PD6;X(P]BBJ2IR@MBUC3!V<03;IB/311BJ43^! M!J=4OY-N6+90E:F?"-U#U4\3TPK5CY?DD=5O1YR4^DGP/G?UDS&)6_VD^1JN M?F?; S $Q\B)L&LAU[5]2*?K$>E;#CV?J!$__O8FS?SDSUXJH7JH\.EA6676 M-]W!1 [6I$1/G/.Y:YZ$1=R2)\N6TNI@^J..*!7_7%BFYP5!9 9>Z 6N9<6& M$S ,F&*Q*3SE%4+NEF=6)00,.6B@ZR@8\CM$8=%0BR_T%@ZYW#!=#;%G=&@= M4=@S\U!43;;)U!,E&>39;L?.OZ$B?TK+.J-=\KK<5/55NMR4S18)SW?Q)K4, M*^SN33$1=CPJ[+3]F(2.&X9^3+!E.5$0DAAS2:R&9C7KJ_>S[_[?S1E=L <: M-*C!#C:@H %#S;_!2S7]QP5U8N;%U/1CNBG8+>42-U&IYIY_:]V$/I#;6/?U M*SM.D_Y,_P0O/H$=F:[JJGF,J+[/*I"NFTL>?@9?OP[:4R=&T8$==9IXGGX_ MG2[#"NU]E#\R?<^3AX(V_C_IZJ),'S;90W]WE^G[, YL"P969$.#F(;1-T4G M'=PQ2+H!S=%F#Q?H@/&+FCQK'X>.40@3"Q+O<"41">1)X]?\4]KZYY3SZ*-\'5]\.V[[]!P]W_>V2 00,=MH''SM[8>J#/ M#V%E^NX^"'VAIF\,?3KG6UI?I&56K+)E]U545/7VF;H@-NT8AI89V*%O&G88 M6)X9$3:=J?U\T#)Q0KZ,&"_CD4!G?PVZ%#7AP^Y*.517F>OTO(I6Z:L M[843V99O$^@XQ/$B(W;""&[;#%RA+3K#6M*],M-" 4N*9:A*"A$H*XFZN%.A M?SV9Z!B9(^G<'D]"HB;#[UP53,J6#^5*GB%Y;3K-Z=A.JT88%P3%EA=8H6W" M. J-@$0X[ANU[5CHH,G IC2K4X]%B3R)<2BK3]KH4R%06S[GH%#[3 E)E!3% M<]4H.6,^%*D!',FK%/GQV+RK?9G6FS(_S_>>U\.!&Q(76XYE.LB+<6"&6Z&, M3-OK:S6RJC6@:8D:CIB*]=A V8!C-S\H?(=U".FR(J>;;862MR7_DJJQ=QA!%& MH1.&R'6@A?S8P"T8FGM:,!R6^2F!H#DCW,?8/&C-4()*X2Q6C2-DE75T'ZC0 MV-=.:6"_F V#+RWTGZ867!Y^A:17JBESB&C[I$830R\I<1"CR+.Q@B%TK#EUD$HQZ.(89^ );-[1C&6>/QPY2^XY$ MN04_5%-5N4168,=T@T*UW<%NUK7WK^YD>[KK NS!GUI\^3@64F+%;INK+*LV M\T.-UL*KZMU%"\>)(838)L0(3.QBESUET#7O.YCK%2CEC6JN+;07_CVF><42 M+!6U!%ERU>X74LJKUGU"4\OH^_PIV!3$[8*YRN10LR0W 0GRQBN#%PG;P=EM M5HX(-%V(8\MWD0?]$%D&,9"!B!5B ]I"R^E"'ZQ9SEHL@J<-Y!CBTRMMY(AI M$B\O6C1GGX,CNB)%U3RT0PYZH:"K"+SAL4F6Q7J5]&?#?.)@)X@MB_C0M.PP M\(.^ 1,A_B?X^-=,C=CH'Y$5@:F/>.[ W@8/HS)K+ B\'^YQ>\JVS]E):7V>HN/:63G.>N(2JD?F@'!$8X M"& 4&S!&74,D"EVN-RH'?+QF 6Q1@086^ H:9/RC79:RC[5P!+;$-/$]HB3T M498Q?IT<@3DYO91CD$<[WS?Y@(8.Y&=Z+1UJ0*&LK\AK:Y*OKAZ3+.\:=)!' M;#/V"<$H#GU,HLCO&S2APYU<#FQF1*WM^S][R*J!*"\AHER*BZ]&&N5%^ V# M"M18E$IY5=9(Z7!UEJ!61J9?8L0 MO(0(>HP"4V8%I'(4%\;E4TS7CU,I4X90P*E :6)<;B7?U1S(,5<1XT,B#A4V MU#$XO=*K-*;0TLO$5H+@DO:WS9IMVFG>$F,W2I3I/5L#?DK;A\78^ORWM#YG MKW0N?-?'4>!Y=!9A&\@-L>'T<8<=^!1:%U?=MN:8L >W>Y_V!>#NP>VS4/#LVV?-\=3VJCF MD=UB!2U8L$-[ GJ\H $,MHCYLQ6UY'^<"T[&NUA6^'DHYT\5)Z->+FE4Z *> M_%&$G0.9I!:"I\\I]9A5:.Z88GEFO]'S/+]*V&7JT:;*\K2J%C DR$&F$=J$ MA!'"$;)QWYQOFX%(0BG=B.YJPM[>Z2('.*L>BRKKC['T*,4V*,D3>CR&C,JE M8"5A&(U:LNU#-!U)JP;@9A>(>QY\1GQ7Y';L_^RQ+;K)U]9?<_NN=Q*XF5:;=;MB_(-OEM4Y#6E:F&;T*%)N>_B.+ =TW%,-^R! MV89A\N;*(\'1K'+,BO8-ACT[P,X0P"QIKW#=V@*VQM $!#!SP/DMZ SBS_C& M\N?'Z?<,72DFLO\&7N3/Z&?H3;E<__H^![:&AMKS7R\WO-QLO/Q M'\S'"5@Q+R=;+V]R&E+ '_?9\A[D!6 OWY19L@:W69[D2_8W^MG%8UHF35=8 MITO1=L\9LR\\)H.O@E;CXP,SEI$[T/1SF;$-+B8;K/S9QNG#8Y*5 MK-'BEH$\RY[257N]SNXP7#M'@WT'/TN?:*0AL6G%D1L32"+',#T[<.,>2^3Z M-F^"H0^!YIRB!4X5B:'^VL#N;JX"?TW7JV87P_9B?9;M^V GX"N K7%#AKP MLW .?XXP#R?)I04:G<43>J6I.Q!M];MB^@ [@HW%F)U;K(SX?B6S65>[OD_R MZ_3AL2B3\GF'>X%]+W3],(A=)S9M'$6>LZUGVIX?BQ08-30_V=)6NX1=4]A@ MBULX1.KT"U^=U RW#]V-_N6(5&C"'762N- MS6O6X1XQFX=TF,$.=#-OV5Y.SMZDW@(7/;:NWB]\.CRQ2\1T6+TW-!V6%^7T MB YK=- \=%BG@6^.YVOFDEN'RV*9IJLJIFS@C 6$C&T=W2V>O0!4O4#D&22V M8F3&Q'-(: >F9W:G;*$9N['0PVDZ<>A6Y@XZ8#VJ*2I7R3IE\^&;+?:3YH)/ M5H].JGM0%6O!2^FTNHE3GV?B(4&A?N&-=B#?0)VP)ELM-#WY*('+Z;INGS$)^B1, P=;/2-H] 1RK@5-3E9^9D=CVJ@@AZKBHJS..5#JLQ:V595618@>L1B M\FOJA O(TMS/0RU5&\55*![(V3 UO$R3-5LMW&WS;3=P)^L%\0B)',LEH15Z MH6O[5MS71DP_<(/%4UK>%,.4<4#S(J-V'ZF"P=NC!N_N?4\X]TKH<\P0]1S) M(ZIT5-H5(ZKJ84J%]56!=^:LM"K,X])<93SR[#2\*-,Z^<$VSQ:WJZ:9=+6K M8I(?R_6&;89C#VP4^:K#D>7LRRG]!MMMF^4;^A/=+MXB9R^GV):%_,@S ]NF M"3-U07_Z@GX%>;Q[$*? IKUTG'ZE-FUW*_=FO:@<;RUKWS6ABM$;=P)Z\UC% M@I'G5M'>9-C>CL+Q9=D&1L0V/!2X%C2L]AD,9-J!SULUUXQ"7^#9 6>J MLP\==-B;]V.H^#3POS;XP7:;R^^]"2._]C",[R-SEI$<.8\9S%C&OGZC9DR. M>77D:GF?KC;L>'C3=,2:W@<'RY*.F_81L>AY]S,=//A'4JZNDYMUNG L;)@1 MA6@:L>DC+X86[/'%-M_A[?%1:9[1](8PE=E7DA>*LV\-.XCYCN2 QB3P>V.4 MX-,[([J8+VK,T[MB 61DQVJ))LK\<"2PC._K><28">PNIAYE@JL:#X_KXCE- MK^IB^<_S1P:INYDS\!W?U!H65>Z%=V1@0$"+2+1 MI5IYYCC7%T8A37 AH<,$]HF;Z-&U@_P<6Q48S.D\A$V!':_K_(J8X4YY/Y+# M0VIXEN7I:9T^5 LS\FS'CK'CPQ@XH_EK^-Y=1[Z/J;!KS/6L;G6'C'B M)"M_2]:;%%;5YJ'-]6"^:M>TBW5Q][PM[P2V;T6^Z\=&:!J1$QA6:/?(84"$ M[NV< ]ZYQQQVPTU6@L9:L&=N<_1ESV">6N]\.XWFT#51?QDYMJGL*O.*@/S^ MTQ$B-?2>3QY#=3"B*LAJ\]8D49C\>$R7=;KZK5C3CUEG]?-E4J<+'+G(L'T4 MN+$56@$T4>SWR./(%UO$F %>W<<1.E3@:0MKPB IZ],)@N0([IQ)D&3[M[I. MLC,6,&L_<8Q\WWUCQ=/&".',J(S1BKQUJ0Q$F=/V2K-5PWNV(ECW\.$ M8-\W'!*'KHM[W&YHX\DCI!#:L>)CDN>;9 U6'3;PG*6B=UY,3]:4@5*;5^<7 M)GM3_RQ!$HH.-Y\C/M&!#>[(=U<(,]U7(-8 M(39-TPLB&T9Q#]@,PE X*DX#TZ2L?I((AA.Y4B *SM^+ M\PM_S,8)HIX65WT4[J;M'S.*T!!6SFG.>.$LB.:YWF!WF3QE: M>\-!9_F+'ZQ!8SW W!G9+!TC<'7$[+"+="KY]SG3OJ+P1]\=DJX[W.XDIWEA ML^EVC?)43(/8G>4['1IT@<38U+^3;LVZ!TQ_]<1\J2D^P0@6R,>ZXXC%+1MX M#?XD7_UKDZRSV^:;WC%CB\OF=(I Z3.\'$EA%YH4D@6R_@/9(XH 5]\KD#!7I4 MDQV<.$S0D;JE E;G47!484BAO,>)#2)$$UK:TJH9RTV;S[MQ:SN>@V+7)!@B M,W -/X!&WR2,'*%CVH,:TIPF7ER>?D.G%V?D"IS' )U_NSH_.\7P^O3\F]B: MTS V^41I-"+%9.D%K)-6FI[![]U_)3(#-0IUC*TC&J6$Y'FHE!I3"@V=4$RI MOE?I^2VIZNRA?>C*I"P?D%N6R2H2L OV%P2= 9O+HZC4]1 M^U7^@HQ&KWQ<*)N'.\3D;A\SV($&D!UO> U;2 /'] U_O6P>/I(KF>&T6I;9 M3?/Z*Z"_G=7/_U'U-3(V77]LO7-;E/0GGMDE[#O?[BZ\;HILY6MS?P9L2>[0 MKW2?O-K=RMQ=JETUBW$4](9&L':Q;OM+]%\)6!8/CT7.UH39/WO<]+>2&J09 M_>42W"<5N$G3?'>Y//N<$F05Z$&RM<$*W*?K56-=\V!Q=9^LU_07:>N/15FW M5\P?,B"[!3=%??^?X$OR4P/Y%1_-.\>WZ^*/!C;[@1WP^^0I;0%^H6W_D36M M_@32=?:0YOSE))7UKXQ+[FE.>1!)#^# MTQ<&I.MTV;XC3]EGN<+>'DJVH)O3_(E]\X G3D!64\\5&^K)KC?1#Z@/=>/Z MGG:"ILF>E%4W")I?>FA?+6(]JP73 +YN>N3+_MU_Z(MNRTPJT_U>S=KL?K$I M0"\W9_!0_+,>N$JN[U-VQ]FO>&U=':. M>"PSV@0[44&'[GN?^C/ /2W,Q2Q]*=E/+._94F+S.:\L:TUJRN4Y63> MK]89\R@'*+:IT-E]!1=&:,9)A9?]ASVD]T136MKD]YQE4F7&@O'[/]&!89-H%A2V?QE#]D)V$ M.!J3XV%:?\D'R8.A1RR'6 'T;-=$EF,8V\P[-*WA2J\(B&:=OR17UY>GZ)IT M2L\D'Y/H&ER1R]].$0'T!^C?1->S]/IFB.I/X!9EFG_Y)U!\/OZ%]5ZQ6^>L M]JI-Y=)Z+?SR*OVO2?G/M&:[$Z_2Y:;,ZBS=3B.\.,1Q:(0!CB-DN)89^]MI M1&!SKOLI:$A[Z>+T&U7AZU]9#@Y.OX%?X>7?R#6,S@B5:O3]\O3Z5%2DA]#* M)\$C\2DFL#M08(=J/K)YF+,CHJB Z'E(G@I#"N6=4$RNKLMDE5*)/&<+<=W> M4"J@RY2*)471M6U&)D$T'S9L-\:6ZP0A)GW;B,JG2 :JID7-J29$Z/P[4R^6 M8WX[OR97;%,".?VM$3'V17AV=OYW^(UFG?'Y)<#GWZ/K^/L9Z']13-T4>8%/ MZ,9W@)CF-?B:?+%!"'J(8(=Q/@K(1>81,53KC'GHHF*;"IW=5TPM3_,GFD 6 MY?/KQ3$G1(%G6T[DV:8)+3^*D;/-)CT"6F8%M(\]&I0RP=D:;!Q,Y#C8:;42CN<&*:SJKLKR12;FF@#F6EA8 .A"]HGN3KUN7M-LA%S'=3QL MAH[E>)[>!8AZ &T>#9+6J&)-^G)Y\?G3E_,_, G(;FXP;]PECULVK9J$5C[M M:B$2Z:(@JSBL@SD?/6-E\HB^2>^,>>B=?+-RQ8.8-P;;DO&:DE /EF6R+:,T M2[?)E_1[LFIB/R/0(\@!A>&O*H[);>/'YO%J6 M5@H(;KX%_X'#6W![">#7R^O;\_]/X)RA!)99P[:-XUILH 9W!FIXGRI\ M\U'#DR0>#?-D=< \]$^B/6\"/[E,,2O>XU.<%E1A+PO45&A?KK_DV7W5=@WF M;3"*S?4S XN/<'1 J;%EQ1R+9R=FLY&/P4X/B:I*KML)BJKU,37PJN>3U8M M1LDZ*8ID%3[$Q7WRIE'L(PUYNN\Z$)EZH.EAT#F P JY\H #FU*LKPA'^/J: MZ&ET?@$OPO.+SR"\O.$5UJ%TLDGHB$SRB64+##3(YJ.(QRD[HGV2N)Z'RLDR M)EJ-.7\@@1GYQ?GM[A9\K[)$?)IG4SVV81O(N+Y M5+ %66V1O),JG(L4LI-Y1!<5],@\1%*%8;GRT)V^C4(ACBQ"J&O;MN]Y&/F1TY9'(VPBR'Y+D3((RNN8NS+ *_B/ MKO+O\O9W?$T+_:[IU45?SF%P_H6CHEEMIQS7U]GT!I_2=A6 #>;J5J#Y(,]^V!QJU3(/6YR/=\!"R-2]R M<= VZH21R7>X9V!CRAWC-?[\[0NDQ:!MU0'UC-R^4!:W;*N*$4GE\V\U,- A MF\_:X3AEQXJKY' ]CS6"+&->%U+)Y(A9QI*LI"\3-6IZE9?;(J&WH%457&18 MMID<(S0@]C3-"CW3MB,-&[BM9D6>YF"NF']U>7-[ MC6_/KW%52G#U!;+>1BJ?<$:5FX)K3KVK(?;.^+Q$696>SDD%&2D]IH>R>V4F MRBC=K-<:J88W]F+39?Z8W,8_7XNS;CI:Z.F.!6T?6[JMN5$KSM@- \YP3[@9 MY8'>^45X^16#6_A_>&,Z<>K8=&X4SOATK88$"*;Y:-71RJ9/HS+*F4^ET, >&^B!FX]RG2+PB()) MXWX>2B;/G->/@R N7NKDQ7:5P, MWNIAX_' QH[D3IA^&T>V0;FR ).E]%E9O-I#F]H]8T!ONJ]]NWK_< M'OFVY0>$1\US0L,/"3ROB^ MC^OLO#H4BF/LZ/(:GW^^ .&WZVM\$?X#W%[# MBYLO J='%78$6_ ]CS[@\UD-9M""!GW45:ZTCWLV8;HPU4?B=_7=-X_ ?@0[ M7U]X/Q*SK))]G7Q/LEURG2SS^RQ][ZU/+W!(@Q#Z 6D/FC:*++-MU]1\ET>: MA[>F6(*O\1_XXAN]R3B\_'QQSJ^\$OAD4]AQJ>13T@8;Z(&;3UKC)'%'=%$> MZ?/0/XGVY*J&)Y^>W3S$11+$9;(*\T?Z&%HEII=/VWH3ZYS00M9#WY,76U>. MJ>E1Y#F&#TW-11%T[ 9)! .-\W4C%0B4)S]N?H?7^%, ;^C=[I=?Z3Z\0-BI MA'PV.9R:=3Z!K-!^NJ-P01_O&:@1-T<:&LSU=OQL!%2 ZB.2JK+CYB&R2BW, MQYL&G$*<5!F(STF6%#$]>@%7CVF6EEOZY-WW!-& M'=AME!O9$>(Z/J8(@N(0]#.^P->P/DD&T=?SB_.;6_HX\Q\8X/]#A9FW$$!5 M3S *\_2=P*G--> ST$"NM/@E:-"BGD]4*T;S,5U6VV\SD6;%1KY6YS$X9;]) MI4B_5^V^:="%&$,3(0UION%K$'I:V#:H.R[7=?,#FE$LM A?G_]1"6M=/?\[ M1I_ISA\,R9\)%-$/(91-2T?BDD\O>Z#F(X>'F3HB>1+HG8>LR3#DS94IDK@1 MD*?+];I,MG07LWLN%#[61Y/J"!:Z@85"V[>-$$+=Q4%(L#0((I/O*4Z9[8XH M8)=1=(-O;ZE^[=\MIO>/\C^&(95Y;F$;E?0!2K?'"7IO'#=09RF$IYAE4T9I M_3,[J91GV6'ME,P>A=OHDCGJFN5VK)B0;W ?[8/"%$AO;J^O""_#G']D!I$EU>W&'%6 MN\IEGDU.IR.=3U#W.$$#M+[NGD(%/:S@K^F*8'FH/%81JZ1+YJ&ABFQ[72NK MD$'VH)16V579U,OU1?)CC^FJR#/RRV55QUM>Y-M_)%NXRI^VR6H1NFZ(=:3[ MD198@6\:GME>*A-Y5A3PA:GYS0R]Q";[=TE?>P#_P+"/9#B^]\H,@!CTM?HD9$-#@.=F"!O:$8BQ$\]&P5F6W MS4.<%=OX)M15SRC[#M0];>LZ>QXJ)\V:U]=12V6)5=DNB_LX2_]553>%W9$U\IL@ M+M/RO7^'U/^B+3S?GGR_.H_,07MR^R*E>?CD/ MN;?6)^YN-GW^=?J93]W[=IV!%Y:=@N:7@HT%Q- M=S#V(M^+-"<*(HM,"6B9$57C-.*D] M0KRPJL]%GJV:II+5U^3Q+BE(1 61#2/2$K9<-XA"QT1-2X'A>%PU2R+?5UV9 ME&^[*9.L0%R"=B*=9^6VJ"X,XM,>(1+99$0!;F\0<9^6]YULJ?Q.C:2N%!B[7H (GH!0"['&(JUKB1 7V!6=#9%: / &I54OB4+E= M4C+S-2@I/DFB^\;B4\(K3M&,Q'> $>\)\%!.6$2XODO_2UZ6$;'I\BDIZEOG M+MD-HBEQ :MV9Z.%$1 D4>6\JX7TGM" M3!\".;:2=!6>.*A;MY6^(# M1?T14-Q@#YQJ4A]ZM__)+DUJ.N2TXD_>%WR^0*P;!%R%FOY@=R*3]XN8>VG[ M9U/U#]5+D._[AWB;5;]_[IC[A\4+B5!VP#\I97]ZSZ76O'RD42QZH< ^[T?/ M(>QS@[!L,H.]'_@(;M^);N!;H=&3 ,VZ40L@A$L6L&5*%1 M[ \IE%J&$S+1FWL>_T7F-/GCMB;P#+R??$UZ94"B=Q,HZT2V'/>\^H_/A^ZQ M]U+@Y8&^>IDH)UVZ[_B/I'^3P]L.BN\S$.3]2()]O#Z=1SI^1'L/WH@P#M/, M/J+GE#IGU39[F9&_?LK)#JP9R50V:/C[%:5'+S^O8 M3+32J A4X; Z6&6CDBD#&[GH7M2+'E]I%0:.RR9 M8I1N=C12NTF6NR+=IDE9%9;Z1N %D6Y[]%I2QT*!J:.V(0U&/FLN6/#SBO6H M107VL+@JRH<0=SIG.P)GG"O*">EB3ZF.0)O@XWW\]+'D0]^W]T#& P<#%7AHO[ZXKC'/S/7;I];E_UXJM"&4 98P9+ M*5M\L0TG46IR5:_Y.):A$N9N'HHR /_K;-1 )I@O,WM\VN3/2?*V/=W2=%U# MNH%"T]8L#[I>&Q9@S; C/A238\?H6 M+4G,L$ZF*F/RT5D1]CR3!/9CNYZCH&BT&[:B@P7+8OJ]95X$^:/CWE6MPZW1./O=EM:/G:; MA_%FLW< ?\9%$6=$\S7'"LW LTQZ;6E$U@N:8[2(L.Y9/'JK$H=B]>U!!S7V M=JKWT8-MOM]9;L.[-: FO8CD6JO$]5EIE[*I]5QZDT^[U73DN.H^@/DC6C]& M?\Y#^4>Q-!]_MBCP"M6?$=^4K*[B9_K#D&*ZK]_R6KB^C;U0QPA!)_!\:$(= M=L \5[YS& 9GSCZB^LE/=]0TT-@&^L8I=A4#^UFBQQBOBT=T'*=Z=X;^XV@_ M#'4C:_8"BLS]21%<[^#HAJ@B2K!?8(7.QS8EEQ]V'W!:Y/$0'CD=#7M]ALT?;O\ZFP2OQ4I0CK!PH3I7/ MZO35J@IL.GCGB3S&!F92FT;?I!P6#C9L:&'/"EPG,$,R^]NX$FH^UBV6^:>J M;<4SD3.%UY@A/9\JWC6#,JJC](K2G"JG0"K-JAYBDS^O.KA?YA$1*;..+;ET4MCC,0&,ZXZ6N=?6KY%X,M#X8 M YU5V^"M\%;01U\E\3%[?%&DJ)?F,>,5VO=VR:.42=99?YL\/N5%7#S7]>OT M]I!-7NZ*!-Z5VR)>;A>N05\DT)%FA%:H><@WG""R7=<.?629R&5TX<,;4N>T M.VR@J>+?HP-_M?A&+A4\R=>1:2J/ZWE,2XGVY*I&)>^1O562/-+$Q@6A@,Q^ M0L>FNBR,N**DW%9W8>R?6_1U'4*HVYKN6I%KN.37?@,"NRY"/)Y6P> M+7@)%[1XFVMAQ%\_E]T7;'HX83?PB:/<'E!TPI*'RR/"J:A3YJ&BJHQ[JBN'?=.T,D-:?DJKB<_,\\EO49?4?DLOB2D@A]]?(VRPBYFF^X/O:@BVW+"0SB1VH++3\,Z36U]_0N MWF$*/$?+F)2ZN^]V3P)'U/?2$%H0D'2WHK.J,]'C?]-J;9ZE-$_0M0(2/N+H'-6PCRPA- P9F"Q2[ MCBXG!E<(4'G('3[0(AGZJ,5J_VK".DX+\#W>[!)V+;>(EMMZ+>8?3/WC'/5< MO*,$9'F$43%O=1V# $:1'*TO9(3)IU7Z!?@]4M\V-!\[AN_ (-*1$3A1BU0G M_2HOW%6%\!<)6S_HQD>:5S#;Q,('TYBEW@WH*\$X5/7(F+?BC<( 1UPX3F\, MU3Q$)E:6K()ZAEV1"4N 7!$1+FZ2XGNZ3.A[H658)*MT>TRI"63;-3U#,W5: MXQOYT \ZU)%ER]&_L= JU\(*,RAKT/5CN?3*6&(V>*J@_GW6\9+Z3$ 3QQXM M\];'T=E@U,II>DF^;E(%_Y;%CWFQ[<>ZQR";;J@'5A#J!G(#^C"E[^VE'B$H M9X4\"M01U\I4 U_M28'5KCH6134S7FYW<9'&&W!?/2;8/!8KJ*X?7!IM^DVH M:' ^M7$5245PLJJO'_&68)?U0H LU7UG2OB((IDF];GU/KF M1GE!#.D][5C;Y%I19+FZ%OA6Y+M:8&H0-3;9H1.$8R[65=LR_K*>R&:[K&]U MN1EQW=^_U&FJT!R*7*W_FXCW@SU+01ZEZY5E"<8:DO.6])EQ)37S,&X/,U_? MO[LKDW_N" 3\G?SGEOSCZFDDRT2Z'EJ6YSN.[L(HT Q:$46C;7!6VHFTH M+J7=PP(5+D"!<;UR-IA$MM+8,?CCJX$5HD[-%?_OR.0\%'6S%ZTO_ MI; R0'6:%X%<'6$O]+!N&A!#' 4.]MKV<*!Q73TCWLHTRL/U\I<$*H751P&+ M4O3G%(%C*=#!Q\'D<3I;%>*UX[0."3$CJ$3M&PU1J&O(Q[KAZ! '9JA98=N6 M:_#=1BO6PM@*)/B2D1A[0L*C@+B!HC/1HT;OT<*N-9PTSE)G>&TXKC%"C+#J M"TK+I[R,-Y^+?/=4_R997:Z#9UIL>)%OZ0G+^K S^>/NK',#">E8"PW-]'03 M8^C9CF'H+:3(,FT>&5(*1+%:M=A!!9[>$E+#I[FINV= +3@#Q ;0-Z)_[Y*8 MNJGM.S81G$VW\6FE^AY3HJU#V#XBP:-TXCR4>AQ3\PDF"?M->;!X3+(T_DH? M92"1:]..B:&A&9%N("<,L>99FA[N5](69'T!7.SKBA6Z 05:5.RO5PN2=5P] MQ^&)3Q)?4\3IE 9PQ?[,MWK.Q-[XYN>.Y2;%=ZU]1\:',S/]#8D#\>>RQ@B[ MBM[D6;)IOAY%D>V19;YNA)H16(YC8:?^.M)SJIXH4,:4$5W8.,L^?? M!JE?S]H#FB?"Q_1*)X0Z'S8*V%7M/XOT+NT>9#<=4X]PY-JTT,=WC0"U7[>A MQ:QJ/-]4K&H5%/:)S,7&:553102?JE4H!%2-BPQV55-%BIBJ,9+#(F ]PPX( MF(CITPN8$.I\6(>S"QA*[^+'N[@5R-"/?-/6_%#'@6>8H0O]]OLX-)@7M7Q? M59YNK,"PSUQ.3DX+F3HZ>--X%0X!,>.DA%W.U%$C)FC,%+%(V@OC#HB:& '3 MRYH@[GQHU[-+&[V?K;I18@O+,FGWA0+7(ZM9J$'+MBP4VH'NA6T[@68Q5:2( M?UVQU.U!@0H5^P07).NT]JGGB4\#7U,D((:"7+&+HGK.Q,21GSL6E7S7V@-J M.8R9Z55S(/YF.%6+F M=2[WEU6O=O> 1-9[_$0Q+(&5-^!%FJJ<4_+3J2)0@JD[G5I@X@BP!DAB"4+7\<$:A+Z@1 M"40%..*(1-5R)1B*BN_1(=-IJ?K.#\Y@B+RS7%6*MCT3P$+ KHGIG:L3/"IG )&Q-3M MTR?Z/$%D/Q,2Q(IUA<7I25(-M7I_-_ IT^#M>^DYG'R,P^MXP6= M#QH3[-K65TX[U!#V73^P,3)]'%I>JB.K1>5E M/!U06CB;MU#I?8:]FMJG&BU/:8LTRD]+[31L\PEQG^C+->A0@O,,['&"JPF) MYJDOFH)P,9&_3I[(WU:7R;YRG)^*<_WIL#=PE]OW)5 MF9ZLAM65,Q-XL+Y)=@=,[T,4V)2K'+(<-5,[ZMCR=?U>FI>R.W2 PN,H$1K"XVDW,A:% M?(YC'NQQE%F-Q*)@L94@FTPE5X.?S>:?CF;6+RUV3\1J,@S(C?2HS8G;3@F9*Z-G1RH\J7(R^LP.A,/W']![\;(/NWM!"\, M/0/45/!'_5Y9;2V]\?@R'RKR&8#E. MQQZ/<6;AN31D=\(YOFJB'YW$GW-A&O[GN1:3A6Z+O0UTW/:;,"9@!UYA/V4AI3[ UJ MC%0]:I2=.I# E (%'5+V58P7"2@?$OK8WK9Y^10DV0H\)G&Y(SI"_WA];)S3^['IQTCK MZ7;@'7^'^#[@%P9WS_2^8+@)N<3ARE]'T3\:M_!US4&6C0,["+ ']0CI[>U= M)C0CA[> @NOCHU5."!X,%F.,O51"&5FB-1(O3K.JYHF_*$(97T.K(=AXXZF" MZ)MZHOQ!B)7I9708_'<*'@;PP"*?GY.LV1P(XZ=X21SG5^*P_XRWI#7;MPW- MU4W3@@@[FH&LL"UZ,S7#9E;1(6TH%E/"[&JWK,K[6VS@P]<_/[*KQ" "3XOJ M6-SQ:>L>U9XVB@M4P$8BCUUIQR)13' %R631W2.&'Y!?&51-K\)2K,CE#B". M"_S[:9)@]YP4ET^T[=O\B@RAA[A,NEKEMCY9"TQDN,C#4 ]\-W1A8'0@*##F M>_[E-ZUZ(Y0F!N,6\AFXHZ!!7J&F*\.G!G>OGI_[X(J*#CDM_1/W!><&YHO\ M[!FH\((:,$VIM)![AURXC[6HZ :.1PZF[0[!MQ#D=PO3$PG<7!UP1PI)G]Y+ MJ30N'V7@"]?3 Z@;MFEX8M&"XO-\=>?L48,&-H"O.NB\YAI'YJ,.;TVN^JJ>B-;^;G&Z)$1A%0J^F M)G^W3 MY5Y,P\/.7' 7EZ2U%WOFX"Y9YZ2#Z9^0'\SOZ=7.Y%^2%MX&G\,VV-G[Y9CO MD]NQ,_%UDHUZ[=M4<,9TIC99)P49F%=%ODR251D1RU]0@U_:[]2=T,?OQ6(EM*E[CM5#IAGZ%%="AT5PMTMW%<]?@Y3B, M*)/VTRYN*L;Y?%Q'=@L34)S@U7T\>Z@3T.R) B7N98^TI,4]&B\A^Q 1V%H1S#4H(%LT^L.,$8N9O81O-]5[ LZ.*"L\+"+ M$3=!IW5=)3=\^KVGY48U+>Q:K)(>*5=H9IT$+U\-*YIBBGMW9@[+&[TBXH#2 MBM(UO:(*(\^'#Q:^JSW.LR5IY$M>5I%]6%]#DF;WW3TD)7UI6'=M1W,]VPD= M>A4;;D][6';HA6Q[$A(;5+X?46,$'RC*CW4&9P]T?\70V_W&J[C@*+J1F,>ERW(-"A7-G(Y'G*(MPE\>BKR>/D ?Z:D"3/0/1UJR/'=2 FZ;3P8Q2AOBBF;')X7CV M025)@C$-#UE,3SN\LO% N"),Q?3QBCCT7,)0$%-#E#_&:;:P',_SL:\CV_$, M#3N>X]IM(ZYC,C]J*/#I<16Q!B4X[5G)XE-%!3P-TL51*!+31@54B:EC2U+U M HY2J:P;8A!+3F[F)9>\X \(IA 'C)=@=T4GJWZ+S9L\H>L[U7:-1E:3H4O^ M'X)MBS#PF--B0]M1O3'?A_=ZW'._H3685(8M^!'YY-QVGQ>57+2B)M>N:59DLL?5AP%Q<>:BRSHF:'F(!][CAT25^)U+D37 M'8WYH,V01A2K.92G/\.X/*WCH]'()^*S89"C"'@L)@4/I2@5[F/&'U!M*7Q- M+]ERS,@ECR,VL5[2VMSB>?'M9N$BEQZ_] P=(2_T A/Y5O-A[)EL>5N.SRD6 MX&\7Y[<8@9M;>(MOV*2"AXOCLJJ(!CX!96/@R(Y/F2Q_N\^__WMC#=WP,=O? MT/EO]O9Z]A:_,]<%Z)AV5HL SH6[GF^F?@X6.K81]D++C1P<61&R-:BW'X:1 M';#M=W)\4/E^9C-6__/\XC.Z_,HW75D(89NNDID0FJZG*) \7S\'1^8K!Q_S MF*\\@'/AON>M7UCGQ6,5J07/49K%V3*--S@TBJ>#BSHT (*%U"\7'N+2OK@N)9, M33^?Z,AD7E'M"#.-1XM(Y'?&7*I)%%CVIJQ$%7LLJ:0@R9)UNJUN]VV60($= M.#HRPPA"5[,-9 1^J&N.J?D:-#T,%-/&IV!34,2>$5),E5@>B),REN3/6SL/I'P&$#)]HF<(^%S*H. - M/>L;0_#/IR0KDS:!9!JN@2U'BT(<$GVV]-!O)#H*L&?P5LN*M*%\0=G" @TN M[F$N*WQYAYVC@D5\N*T]\ M680/9'@EYUG_!U(2"#UM$KQ>)\OMY;K^DYYGNMK MEHF0Z6BN9K1HH6GY/,NZJ3 J#GR(66 /&[PPC Q94..F#Q*^^*G&NC-0VU>] MZ53_)%G0=#:"QDB^1>-DHX%M@?DK# 2^4&[:,:!$_Q5UTA$/,O6PF(M$?N M4A+;FH;ON(8>6+:#;=U#V/,=/<"V[]BN&X9,M1TCP%#LS2ART$$'%/O^\!5H MX-.$6]\ T+> SU6I[# V;S23ON)S. J[28DW$2?YB,,8H>?FX1/&,#0??59P M*GN>K>@R:D6119O\1Y?%O:4G1!>Z;IM>:,+0\\GB*G!"[,,HB$RRJ#(-QK,J MLMI2K=$M/%#) 78V_7XJ\+(N+^_&NMQ^&"I_BKM HA9RLS^R-KYE4D@H!W3(W%5SB&G, M$CJ8/_;,]Y8V?E7D-%A=!<_?")SS?;X!+K/S58Z;(P[Y*+<0>4-\U M:E[UV/Y D8(T^]A+ZL+3O"O*Z[*R>#15*[TKYJ&:*@Q[DU!5Q-U Q3S/JIMG M^P#@7;DMB$ L+,^Q=8P#)]),VW%=W<=6)]T6Y(I#%32OO,BS@=:;M/];BEH. MXGR0:HY%MU3U?*\CP%\M[I%#4'YB^0551B_-6EBE&,@FL/*X9!7:_KW>](G! MRW7[F/;WI'YH8J&;B#1M:PZ,L&/X+M:BKN$ >CI?19.$!I67-S75,"4HDDVU M*;'-ZX=90$D063S:L7#V)4+YK2FYX[@*!&.*X^GF;LB!Y* MI'L>^B?3H%S9T&2O;;^*GZME?I07M;!6OSO/8+:"J^\QX:2\S5]L"WG8B'R+ M+/H=K%L&CGP<:!T&I%N+K#XX?%SJU+3--#7]>FKV87*&D-5>0IJ!.%N!C"A> MW*"E&EAR;Z$KZH;C>C@A_V+2V& %!"SHH26_!@0O: '3IY[YJQ@4=0%[E?ZT M72'ZAEM2)Z3RW79-<\O$_>?+M H&?J3;!S)#]MW4S)9#,V785=G<[!TX&J"N M%Z8_.:#0MGR,<M MV0YB/K?L6A4R>F+/%30A\F\/E/W=ID;S)XL HTG5/U\W0#QW7<*"E MA6V[#K9,M@R*O/:49TW@:I76E49DV?=4T**%[?,9>"(_M*V6A0D!_O1X[%D8 M550S9HW'X7A89H1PVZ";/&5\BJYC&6-I5,]#WB3:\SI?+)DI88';/U-(EOGM M:6FRYE^OTPT-_'MAN \367$,3B.,4H!@GLOMP1?[B MH0I"RF:'IWS(BRT@B!_[.;,SFEN>>.*>))5G)LOKH9E.;8D&GIKKLKF47W2T ML'T]MA&9JAAW[,Q<5,A1K[95GU!#[FV>'&I>)O*ZTN#O"CR'Z0S2O"A M!?D1[#(R6IM-Q._YAGSY^"I9)>N,JKFL[K.J M<$Y7>7J0.L;BT^'4ST--)=MTI 15%F,B6GA>ECM:+$1:SK/[VZ1X1,G==J&; MD:$A#3L08]OS#,WM1#B 40\<;"$YA3'N#T%)!,PR[=D)I(NH7<:5)LF.9'! M BSSW1.].CV)"QI&E)1_"O!3E:*E$*<3PO99F0%$7)UKSTZ&C@A=/CV MBH6;4;Y%_"+N4"UVXFRS29Q:FL5> 7_![Y1B=HB<(Q(VF,]Y"-=P,W+)XTRL MJ/I+'F?U*:5^(7>(C8"$A<@RM<"P C\P;=2VJ2'(="N'G)84QV45*/!AFW^L MHP3!$S_#"3TN1N-S*1AJ5777-:G5+P6/[PSG4ZP&6SVO:BJQ-Q7C;T:PO%KL M=XEAJ,@>1NB\ZK('VG*@.EL&0[S5/E%>$'?3E*Y$D6_XI@WMMF$O,"*Q>L8!#2J/5ML2'AI+;6EQZ:YX!B7%)E; .(1< MQE7W2*P.*V%[PA"-/:XKCVI>YK[27^UK6DU!$X(93 M/"2KJ(I=64G%"=7M%%_<&441KF>B;?+L8#:#H.U]RA@"MH%-E MEU?"5# Z6+SV58GA4>X4:]5+;IA42I#.N>F3J!D'E6D0+R(+Q][J]9+N4;Y3 M6+@P" S/<& +0LY8>#[5GO0.$"1Y8D7\,EH77DIWZL2L[Z,?005['?+@\57 MFE+ZA'_=.79G#%F%#N\%YM##H>VZNMF%RY'E6GR!JM2FE4>I^[>[ MDP8O* A@4/^ZI$]Y\]^^)9=]-N6$)0J0TK#D)OZ3\!J][%A_2!CF\0CLLXGH9,3SB>A!I3P# M-5;PSN6'XS\9SLKD$155TB'S4%$UIKWS$+@B_H:I*"0!M'BJ,-]LXV([1$1YV^69Q*\A\L_GUXIY!NZ2 M^S3+"-PY3-]7Y''/6U'RYSQAA6UBFJG#&),[12,SH*7&O@$#TS,-%#A>US;V M([N9HCAC+/F5TRK_!&T!RIB>2;;ZF\Y-5MY_I;G);)/0W.1CC'5NWNR>GC;5 MH\SQA@*@[S2?9^N\>*P.AG17E3A(]U$(=1/96->Q;?EV6U(6DK^P>(I69;6I MN'3UYMO5U1?\%5_ MR,DN:V(D[XCZR:9_'OHGW:I<[:#E?3&BONGT*DY7%\EV$7J^&SHF-K ;Z>2_ MC@W;2TY#QT9<#QKS?ENQIE73[:E?\I4V *LKCVCB-'[,=_0OFV=4TG\EG'6L MW'2R"9M*)OD$K$4"*)0S<#'VA;-A" L<[\[DC\EM M_#,IVX8,,XP,FO0(?0OJ;@!#W,E5B/A.^@A\?@(MH1C!EH+L](0,_%VVXLS. MBI#)*B-*>>15DHJP"LUT:O*:D*."(LS>7#1%W("W3\$,XX+EBHRN$926RTU> M[LAHNJ47V"STR+3,T,'(MAT[B%PG-",MU$(4.IZ.$9.X#&M!L;[L)P?H00-_ M5> .+PQD4GA<4L9C3U15)B.._=:+<0@4N^U"D$B6.RT.FOV.^,JA:?H[+"38 MD,L<.'SQ'6FIWMB"/]-R8=J.8R+D:5H0XA"2(#((VC:@B[GR87Q?5JRZ=+ W MN[Q_43R,>B'($EO,IHX@/F%EYT9)I/:"AB-!FAA=\XC/!+'G,@:,H!Z@_#%. MLX5A($]W33V CA]![,'(#MM6#&A"(45@_/:(FE C$E4%5JXX=4$!3>+*<(HA MM=I0M\ZB#IRDS4P?>-$?4@@A%EA6;I#VU/:AR'?W#^27WM?D\2XI%IZO^]"" MV#60986.CGVC:TC3$?.-AH*?5ZP4%!1H4 $*"_Q5 ^-8=H@2=WJQ-@)G?+(Q M)5WL2[01:!-;GPG0Q[(V>]_> PNS@>1,ORH;:D N;:#P::O?-62X=4--9#YA\1Z,&,S4.FAYN12QY)7))M>'&VNDN>\VSUHC$[ M]!S;U72( E/7?-LSG+8QW[&]B$.P19M0+M>&5Y5XUM &"HTPCTQ2/0:%O$(] M"_:X1'H,%D4E6I1-1H$^8/IA>1[*U2S$>; 1N=3QPR;,2UKJ53PO_KA8>.03 MM@D#U\<&]BT=VA W'\::C9C2EQR?4RRX?YSC6W !O[(I P\-QS54$0-\>GG2 M^",9R#)9_G:??__WQA":@#3;W]#9;O9RCWMCWYG; DQ,.X]% .?"O.-W& M/^LG\O#/I[1^0;3:U?#,2'<<[(5F1!;6V#%=Y+^/L.=0XP)[ M8%Q;DH/(.QTJC<$;_R;$A)2QQT=C4"<6''WZ!"[R+/F-_!>\^ )(","FS''[ MD)8@J>O5?P.?/@T*F YP<2!:&LK<]*'28 MR>>-(0(2K,UED$/R(B]6^511O MDW8CR41$]LW M",-VJY'VFR3G3A %G-9GKP6QQ/J/M2^!%&PG#O'DDGGD/-1 M^186^/E2+> &1J7\EW,,I]@YY2JDL3LCYR'/IO?9D M[6\UBWUH&[H5F(%K>Y9IT?-N8;>8<+#.[$N$/J[8;5!,]9[M-J<[!3:[6(EQ M==H%**>)3^U;AMR&(4L@WRE&%;N$*Z?L5U'K]X@X(,R#.)M>@X?!SR6-'79E MOG^-BZN$BV. MX_B!:SFN#GT/(5-W$&K;BR *.6O>!5N9*,$A>#Q&E,KC>CLNBW+2%A.=H7F? MGW>$1AZGLZF='VK'VRIZ*S)N)')_562 M8MD@%-J%;\&AEX 8U#D@9PQZ#OX]#&J>OO,2:BY@.HXU#Q M<2C\9=3[(!V'5'LX?S-0:PE&Y%+'E."ELG"W?ATMHQT640;;DP CD\6FT"&]JKY5]P1"1AJQ*$K9H=P(JXU30;4P9'C><@.(7)L7;="%SE=Z@%B-$QM&!N9 M1&^$=E'$>135' 44RE"=2;9+#K'#I3RWC-.*D^0KQP/<.1Q9OKY'N2 M[9*;I/B>+I/SZYLFPG*QHT/=M'P4F*;GA X.N_4O#"RN"Q:'MC5.-E+@W8TA M_+'*SWC4\:I0C0PTT$"##7P@Z#Y.M!]R@JZCLB2'Z+FHDR1KWGO<0QI+S,^F MD=5Z K/5%\+JIK\<;'=K M\VZ45GIH:T"!F:%6EMJQJRF:ZTD=668JVJX%47 MBE0 7V2'.%]*&THJFX"-R2>?@!VCI:J)L^UGW7@0:V(T]OFW(]A^E"B4$-C)3P?[%*X5,H,=[8 M9$DY96+)_E=KNDE$Z#UJCBC/(";G(3?#3,@ECJQA3Q5]2;/D?)L\E@NR8#1M MW?5L6],-UXBP:W1QF&6B8,AS1>RMC)=%>O%@# 4(*H0#G]_AX//T)N-X5 IG MDR9G<=A#1FK8%-MR[--7;2^._+I1Q\6!_48Y_$V_Y2C)CA,O'8DRPQHAXO4Z M6=(RE*[Q:Q*H7B>4@'235D/OJDCS@I[B[;V$MS =EP"R= L[6NB[H>N;S3ZH MJWG8,WBB2&4@%+N!#G=_CE'HX"7V,U"A!]5)__Y;D&?T,9$EF>)\X:FZ3F,+ M86?17WR^9H2N4A(2BU)])&Q6WGOS"*W5FYF//"MD*'N89]LTVZ79_>534I\I M+A>![V,[],S #* ;>O1Q'+N0 ;+(*,&RCXU/ H=0R29Y(['()W%[ BFJ M%Z?Q#A.H1,T.TW-$O21P.@^UDF%(+GV\L6=2#S<&'VD2]SK9$&E8WVWSY MWY=/U>V$R6I7%R3?YD$57=YGZ;^2U7D&G]+E AO(QD%@19'MNM#S L?T6I > MMI@?Q9H VH2J!^+**%#45M&+^$IJ%\@KP\"JLXS^U5U"?K U#J09@%?G(7NF M/YTDGGF'RQ-H4-L#&H/ ;0XJDT!M$]@;1?\JJ,/6IJ_/25\3R^;=U^RI M[)GWN5C^^_8A 4]Y4?5EO@8K$F.6VW1Y1G/AU4XGK;LHNPJ,356!D1\1AS,R MX>F_K9:)216]DC^+O\?IAF;0J2(4E)0$K'?;7?USU5^D]?IGEQ$W")(L7E;2 M0CZRB7\0(7F(MR M^YIS:!Q2G#_2S>9]Y0$_'I*,_'F\H7\Z*)\O?T G#.*1;;DV%H5\X<#!ZYYJ9#.XYZD&2S:I%C"=#^= M"#NLFO1'O-G5#Y%L-OF/F%B.DG52$!#T'$59)MOP@0S!A AC#2-P#&0Y, Q, MZ,$(TB?=[!8&]ER'1ZBD-ZZ^7(:$)V4"/JR2^EH[:-I])&7W".BJ:R?YJ&DZLS+1QKO M?)K[NM'R+:Z%X4+;@A'R[="!1FA9$,.V93?TG<7WI+C+68561HL\<[L/3F"* M"\JH%%[9E'-L0OG$\JTNDH7^.PHZKB R<'9$ V4R/@_9DVI1KFY\YM?5[FG5;./6BX0\J#N M>)%E.+[C!2'R(ZN%9QL6TYTAHX,:8?E\UQC33[C19%Q9&413A7EG$HU.EZU1 MH*RMVB?Z5EW%",=%4N-V\NF$_VS[EW]MW]K1S^G3/Z]M 9=KL+>&YO [>T!C M$/T'C4E=NFLP/R?$)G13;F'EB@YC\#_GC.AS@=+Z]$!R?I)A,WU:?AJS\XFGZS11RE52W#S$1;+ ?NCB M0$.!Y[N.[]F11OZGS #^4>K?+.)B]Z??IS& M][&/BG'#&R4#8BYA#BW#!95Y<^_T:0(?)9TO+P#:S^1?,13Z;3:Q4-O-(\1$ MW"/J[Q4;\9NO*$82[ ?6=/6W;%^KTX/=E;U?)5F\V1)\,%M5MQN1.0&7RV*7 MK.!=N2WBY7;A1+YA0C.T+-]0^; M=(94HM.: AI;_C=?M?6V6PH/Q#4^26(_I ,&BOM(W$L4\WV/] _0MQH^$^$^3*N(4$OH MI)D+LPP+6858&IOR0_4&AA%8CH-U2X\<:&H86E;4'MEW7.(:U,3EC(VKK^9K MLQ!/^VA-JMP*TRX[D%; N-JH>5XB>X!/*:$P9]?,7%X'FR<.F -IS/BE< Q'MV%_-%TBP6$(.9!C;*G(@#:*%96C(PV[@Z[[G M!XYC1EY;D>EHIH55Y4!8VY\J!Y+4^-3E0)@[0'X.1 7WZG,@^$2/3)X#:0!* MRH'P=M+,A5F&A0-R(&)L2@_56Q@VTDWD^2%"@6L'T$:.I;4PL(NX+LN2WO@4 M.1"Y8GL 3YEA,*\73-S>1ULGFB0*\8C2\WLMZPIM:+- MY65:E:; U:KZ1;SI7?3=A=5NZ)*8VK>P"2/=(E#LL ,1^#Y3:EE1T\HS&VU= M6C6?6\Q@#[I_@3UC#D-5+QQ7V1ET *_&\G#/DH,8I1?82T(G[HU?Y?EX?IH. M%$PJY'OZ]BQ]VWYKE17C)'T4R\SGK8)'="K:8D).5@?/F]B'>_IGO-JOSQR_Q5]5) M@];A8_:/I-5XW345:%"C!ONW &Z;XT:S4,T3Y/*+JJS>FK7F2C.239+E"S3F FHOV!L,]A8#:C+715'S'C@\697YP%:?CJ%7BS1KL#NJ M1V<@7?%X:%?1?BP @L'=H>M'4? M-9:$KLW^9O9<\4\6&,9[R^N;#:HK#(C(9LD6M'<1']?R'Q4'0#? 8\7"&7BL MK1[LVR?O%O$ <7+H4P2+/:/KBU2JP72> 6(X:"VGM[ <_L2?W6"J": _W5 M*@X )0%\_=N,L,&1Y.0FC!-5-IK"%%T>%+5X@*Q5T28!,QK(:C2N.C!U/ M'*FZ5_EBRMF,L=G&E_-AZ'2L.1^L\XT[XY^5);Y/0%N1%]@V"::#T-&]=M,K MA'K$_%C@7/'_S>+.VNH91P6LPVJ&<:>"$?4+QIU_FQ$VX[A3P4@;$'?6:.88 M=PZ[&G"B;IU+X,DYR/XO##QY&9HR\!3J3=8:)9J230LJ'Y<%2LNGO(PWE^M; MHA3IW2:I7\'85QIVA8;80J%FZV;@^KYA.C@R35T/L.WKGNZ[8@^83 C00J8RUH)N7H[IU4M/=F1;C-TC]2^*NVL>]2^JCG4>#F T:]^\ M/C8FRZPNX6;YD*QV&Q*_5K=E!R2475W%U:WND+ZSVWL>O/=<6EGN'NL_JR;% M'J1A^9Z'HC!R]%#W/&IMAAM-90S:GL^71'#0*-10#6 MCU971H'&JA?O$^X-XW,=8_9<>?R.1:)_3JYBY';*4<\SD2]/P\'-)7Q M^2QF(/O&V7L P_R1GN:OL-SL'A_CXOER':59G"W3>$,?BJA.RM(?RS/Z7DG? MBE>(?5^S[!#YNA'BB#A0J%M6@UBG;T2P;I!-C7-LQP4J"T'?1-#82'^FLQ)T M9H*]G2^%D'TS8FJ2&;:UIH8X@H^[9!@"EWQ#@,?IS6]4L&]%30U5_9933P/H MID^1_'.7TO>V5[VK)8KDB?R?I#Y8L:^3KQZ>JD9%WHR*9BNIJI?O1E/9,D+? MN5IN=M4S5.2#G^@NU+(_&)O;FLZJ_:GF-^!#LU'UD9;B;XLT*]-E55R?O&T_ M^9D4R[2DM?UKLEK;_UC[ _21JV35O'Q5/A 8^3))5B6@#O_0QP;M>BD>00=V MM^8R;J??Q9H-$_G\5&5XTN$%ZAX@2,\2I-OG5\"@AE 0VI&A(1@9$30#/VR! MN5' =3G%"' F2B[TK7BS!FU-&9Y.D-UWXBF$";M-3MJ J<=FF2C@HYXS.:"H M7^>;$%!E,$,20"G7HRW\KTE\5J1+$J-5-GS+FEJ,?+?]&A?_G9 ?S>J[EE[[ M/$M@M]\../S=R??/M9$IDF]/7N[L\!_DG)6WT>U*T>8[W?J).@TR?UQ >/RK3 M'NH']=\D*S("4;*3)F/UK8R F0/K@2#?L0W7T;!A(81\5P]MR^@P:\A@NK1P M'DCG$/9R!QK=PK\R5EZ0,<+ &!Z^SFM,*(A0Q8>#R@!TA+$A+\:@*KOZVU/MQR M?2M50K^^VY(8,ZOBRKB^Y.HNN4^SK/H#TEA"_K>!\)S$Q5D=,^X!'0YU]XU4 M^.BF6QU7GM%C& 3=.DGIOUGMBC9\IBW\!N"FS)MPE\38AZ@@2.[OB^2>6OUZ MX^]#\I-&.!4%69X][>XVY.]HG$[?COAX]CZ-1?(8IY7AI"NJBOT=B8R)NWBL M/G27;Q\.V?J"1O+M S]&+_YZ[F\RTHA]V9S.HW_<]D'5EXVY&_)K\C?=4H#^ M^7Z%\-1<,JXT6!\\$07C\?$$8/XA]XA<<$358_?0N('S']5,A1GYY\V2^15X MY-M>A+Q =R-+1Z;O^AILP>M(\\:/H =#_@5#:5 ;#8C5H#-[BIAI^'@9,[ > M=:A,'V&_.TIF$FP/'SA31-VC#B"Q\!N]B!ZYD[+]>K!NR+P*6&<2>9WJ#.4A MF+31\'>*Q>21HB0HD]QGD]Y0LE^(Y@S(!BA5G'"0;!N)G&N6WDRQH2ZO.)$PP-)5OX_[-__S_[ M][_H_OTDF_>2Y_W\H^BQB)"0(5;2-R/&PB?SV98;11;R'0O;@8TCC(,@:I'[ MKB'M&-A8>'^UZ+C=A(W'W:J7/DQ&BYA''2$3A\[SV:&7/EY&#Z=''3>*]^9_ MI8WY:7?E50V"OTV0)8\1^=&6Y-YB";O.R;J.3CSZI"M*BO1[3-]X+8/G6_*) M5ZW;T+$,%$+?UMS(, *H8ZQKFFZ&V F192P(YKN<)7B2V2J/3/4!,JM4"[9^ M6;P'%P3/@ +F/;XCE?/3<HTZ]2[YVV_4KSMBSRALO=T5! MOTK==?M^43_EDN44:;PYZY(ZX&U2ITKDT"\\)<0 8MU]U?+WN$@IOD]-RW=; M0-3XGGYB>^"=HC- \T[%:I.4U=WQ/QX2\H-%G;GIH!.;B&SOZ@U9&MVF&?CG M+MZDZ^0.$;.@0A"Q=B;/@I08E6N M=L:R>^,H+\CPS\)JMBR?3P&(=$=#H6W;(0K]2#=1Y%H- ->,=,CND"4WK-PG M-WA!"UB&6Y9-_FG//"'K?,Z9B>XA_EDV]^PN>L(^&,-+O_#1ZZ8;EVTWKI(L M?TRSYEHZZOW><\K$17YOG.-+9]R]!/C.A]]WHDH=L@(WS#F>L MRK!<^?1D=\ED&?^8D^7YR::18T>NBUP+1B%$5N"97M V;?AAQ.Z,I36IW UW M2&7X7WE,G_:\DU#,YW./#>U-+ZR+ L*\ 11+:A81P9 M+ MI.M/>^^Y]SF?HY?=V4-"@TDZG#V*F'O'CQ-PU$ON?9TH#2=>+JF7+T<$B1!X M%^2DN:>8)M0WSU7MY(%_OTI*LCJ+JSBF[**,%RT0< ?^,0F(3G]@6)2B8, < M"&BF')K3QSZ36I_/0R#8(ZK/)-#_DI?E>0:71#!VM$!X=4DC>%HT4"0/2582 M$\XS$OPGQ'?CN* +@_(RP]5Q0_)W5T0("-3+]?_;!?EA7#Y$F_S'[W3SZ_7A M)1.Y)O(BI$5Z9"//\:&EM4;XIF:Q!UPS!*\\'J,V VHT."?!U-YL4-D-7A@. M:LNKF*NU'5QFH+,>-.;3JKD] 8 R "@%H.: -U:;8;\PA'(S1*TNTIMD& T) M!V?8.QS1X@S13Q=,5J%DN8\EW\E=O1NFU7FL>T)E"3YL")M)^9%\=YG?9^F_ MR-"EF:;>2,ZKD;Q\,9+3>B17__IC?6JF'=#M6:3F1_9'9%Y%L%7>JCYELS]U M3[_]U$R"PR$N5]%&%>O2%I[(Q_(5_='H./W+$VK.KFL'A)$#>U5.=#A.%XM$?K/K:K&H;J(NYPMM9'!],FP9 MM4/G%)*,:_B[X<8$W(N&$A=Y]GL=X)_OUP*OD'B&9F)?P_2"2]<.R._"L$'B M>3 (A\0,,MJ?*C@@V$$#'O30RX@ I'2+F*L?NT>NP> M^F42+$/2)4/VWM1G0[@ZGR,VD#F4YAD$2+7PA+>7SR:+6X<9&:"?DRPIJD'] M-:&7!BVLP#(B'4+=U'S;=DU+TZ$6:B&*0@.9ML.^D27V?>5[314L:Y/GV@TD?Q&_@M>? $D M/].RD_N]>_L-?/HT2.C?9>* C ]C;7J1'H@_ES5^V 46/R;QFV9L'&E(]S%R M@]"+_$"/C*Z9*((VN[X*?5ZYO.)=D9-HC$M?Q8@Z+:_*&>)35_P5PZ'B*D85 MN[8JI^Q7D=;WB#B@K(,XFUY8A\'/)8T=CKBU3-\VXT.7OF87&"0\UEW;TRW' M:)HQ#<]S.<)6D<^KCUH)*LZ@58@FAIA5-3^<(2LE9FC$*D051\"JFK)?153? M(^)0N#J$L^E%=1C\7-+881/57?GI/HZ?%O2ZN)P^O;%+5I=/38OE[\EF%>7% M3;Q)+@OR(T]$NU:7Z^"9_DF#!WF&Y[JA9;L.A+YA(P=K6F@%IJ.'AA=Z;.JK M'L<(,ET=(W@@6#^1V?.IC(]D]%_-F 9.!64=EW<5GH:3?Z=3Z=^3S;9L_Z2: M7)\T_5,SO0:3]\X\'*]#IIVP(]J9CSW4V>.J+WEV_R7]GJSJ0=P#T309F$B+ M,+20YKB&X6A(TW"K.I8+3?88:W!3RB6">).VM[^43=..87F:C;T0 MV9ZM.;Z'@\YSP\@U6??$I36H>!.\PUGMK54@>2Y2D,7JZ67-)(3R+77V7-;G M&6#+*.C#%%C_R..9Y\**"?@66R==]S:A'Q+09#B_;9N#;V< KHMT&;_S)_O M_0S\F9+NZBU3JPO:B;FT/V_RS:[NO+P. HCS*9/[:A_PK-GR7N75IO(C/4%: M75Q1I&0^DL7O-@?QAM:?T>5:^^0';:&ZV3G.ZB,#;SX,FKWG?^YB^NQ'O86] M)=ZJ?,@WJ_9UDGRW6;5/]75G5OM/CNPRXAZZ;Q9)=6" /O*Q7.:[^AV_^UVZ MHD^SCJ9\X M29J!7A<@$$]9YAO"$H4Q]-X0MGEU(+:0/BVGCS'DFY0KE#&^)7L=X2PLRW[T'>95=- MFNXP=<<2<1((GX<62;'D=3)-&CMLUW;M6XM?MD8S#B1 IJMO=/M.,].L9^0:JF,+AYHGMZAFC MML:V2[GQ7*LDNR].)PRFX7^P(KXC@[_W=RO 'O&4_//<635A/PB^RR2Y/]AN M:N*CZ<#Z4!G;TZ\3U9F6CS!:.7+5\5-*%E:5]J[2[8X,U&JEM3"@'N+(L9"G MD<4IU#5OGQ;7;,UBSDV+-J Z%UWC GU@'$E28=H8DL]C,,:9;'Z'+%"!&H,R MCCSR&-2)GF1*P+;*852WHN2[;74QRGLYR'CYSUU:OU-,DY";/+O_M*%;6&?@ MZ>&Y3)?D(W&]#UGE96DB<5?6R>\>*3MY!E=S=!/='G3;0[J14X"[G-Z MR(@ZG#(IOJ?+I/X-S9#2I&:V(A]L'L4F(O3_]+*R/?SENP84R5/\_/+Q9?+7 MRV80)2PSCBF[>:"W#V4SAPZ.Z;W2[NS)=I7%!+YMM0Y 2 M9JO_R$GT\@?Y<>K/%KX1^)$=:*:!7=OJ,#!EV[; M\DZK#GIU@R#-,:R^TZ"L"@CWQDSED@089?);*GMJ+G-Y%%L/>D#U#+/K!/7% M]#!]1%C"9 6U??Z:;!_R50_MP@@1)D[:UI'K>@2(:UE6T[;O>5'(HP3'V3&?@ZNB,ELGU7&:N5)O>S%#YC+'.Q#9?&>:/=VW= M"[PKMT6\W"Y,GXR1R#-,R[-#VEX8AI'CA9KGP\"R3]TW)*4-=7FR%A;HXP)_ MM[6JDH7Q!G6E MF&7P7)\5B3>?BWSW1!PU3=\1)_#^*9/J@ID%M+W("P(/86P9&M)L%&H-^B"( M;.Y4S#Q0CY#9J6Z(ZBQ]]600K +NUEK0,Y<^+]0:#&J+06;)*& ^PVD>$C<[5MZ-1&:$C_UJ@8( 3N.OM'(]3MO3MJ8#'3N$ANE% M>@@=)PALU+03AM#B> 9>[/O*Q:R!!5I<&R^$%ODUJ\H- M;TFQ]+4 ^\<-.XCL\U\"HZ=5JDJ3+^L?5_2[I,@)G14V:BO<>JRE=%ODR2 M5;7YB%*ZX5C5EUZN>V<9;!1HD68'AAEYT#(B'*(VZ$>F'3 FTF2VJ%P%6Y" MCDO0@TGKI/F/]LA1+ ;FCBB-3-[GH1!2+9;I>TAS(L,U @L'D1>U;1LP1.S);7EM*I^5_7EXN08=6/HX MT!XN:/ ..W?'RLJ!=8A\5J=?CRBP*57&DKRL< M\"Q->BGS!H]XR.X'-W[#S<]#E**!X#EY'A5FY MXJ')ZWN:Y>!%OGUW'=CSA_51CIM\LUH$NJ%[MHEPA%W'\"SB%^UN21CP5#@H M!*$\*MR'@6E[*JDDP"1,1Q$^CDY.I03/9:JJ-?+-Q!V!4Y9IW"X8*2-4._+U MFY;+1>!CW]$<$[JN$UFFY7NZU3:+7(,Q+RVMN9'3*)7KS%^NVQJH[ &,')Y/ M1XNC$\P7)H@-!SE!Y+9H(F@P73NO&H/BS,-5D7S:QC^KEZ#I MA7.K!M?HS[.(D'3,BPK5\DS]>KYC68NVY% MB7\V^WYT8.=9.ZR;NWM6]!]6N,E/[&\Z7]@^=%&$$2(!;(BAIT=^A]/V X,U M]S@-NI&DHGD&GKXLWQ@&]I:=@)YR:9 "P1+9S M[WO>4/A_NITK[)Y[]XO&Z1,. [807P'Q!]<$4W;R'!81D]J?SV6ZL<%H3(KY-'%&61S2 M,>,/^!4I?$WO'N28D4L>1^QB_?XU,5TZJRF4B>^3JGU71YH6N1B&01BX&$'7 M;V^Z0(;I^*SJ+;=5Q7+>7*GT6*$E 5T+]PSD7>KVJ4-\?,=0-?^G%7\ZZOE< M0,-Z#12<]UC?)\SW8#F=@F36V;W$=.R+N0V9O<#B2+CX.>!9U' \O:M19%>N M>G2*'R.HWK]>'[K)+/1"'*'(BP+=<4T-ZK;6.D-L&*[.LZ4AKU7EF+UL]A&3 VZ*,>.D@/_CSFA:ZF7LD1\2QPD/DOQ.F,>ND0*[CASO MD,D:LVS/3?$883-P W,T#6"H*U+PG:D9\@B=,()N\C<&= MG,AZ9-GB%ZFA5,Y#D@9;D^9*1=^<3AS.HE/X(IV7EX@ OK [2& X 9=WT7M(F\.'<-[,&[B M#A)+,U[31S'+ZK$2FM)X.ICDH+]NG26XKWJ5/EY'["Q3X@-(GZYZ5O^F_N3. M.WP>2$LJ[Y[I,Y3J3>0]LS.<3W4'[ZZ*-"]N\PI3Z$9>H&F.Z41A&)H1"F%[ MO2LV+<=7??Z.!XMR)]HYQO<VQZS=KK'J-YB/N5TGV_B!^68^O@0[3B#$OSS"T4 M^#U.-_1A@2@OKL@,>HC+!&XOGRK<:TA?:"Z28J%C:'F!X?F^%^I:8&/-;BLF MR2\MQ@=3ID*GW'NW2/Y7"?(*7/4 =0,8Q/L;'\==%?L+>5>7_.Z_? MV02(4:"U"L MJ.VB-V^UELV\MR6'"1/VNI3 X?@LKAZH3TL0=_U/WY3O).#N M>?_B/;%NA'"!C^XA 82BCOU%0@I5UO,&&4I[@27L"';/25&W):,8 MZ"KCCB)_+V9HT). HFCQ=V+#[C=4],GI(&#B[N#S\178UCF3'KAZVP,=Y,[- MGP&*>MI^8'?/$_>'F/=5T2\LSI6?K .^4R'KT[M&E<;EHXQ<=L?6MA=V1PG? M+.CQSVV2E03E54*6]JN%9;I.&$&3_*]!EO'(#_UNAUKS3::;1Q0UK=BQ[6=G M_PCPVW@Y:6'38R0$-_APESSGV0KD60*>D[@X_'3W*!UTVLM-W#=\7F[?+7NX M[R6M.\2@ACQM)["[N(D[0\S%2>\4%O_&S]0!_Z:0\NG]FTKC\E&&+>_S0M_) M\,V+Y^OXQ]>8M)S&F_(BV5ZNKY,R*;X3K)'N&A%T:4&WI>N!IB$-Z@&V?4(H:)32GV(]%.\(2O;HXWSZ0.+2(?X#'%BA?K;4,:H][HXE8Y?- ';@S M0."!#M]958=$EL(MQK'?,3K%V9$*4(F$SZ/F4Z9!;Q[[D-FGR MJE'-@9'EZQCJ1$0MSX/8Q6VC5J1Q71(XL"G%DG;S%!<)(/_9UI>REPU(03D3 MI)-3RM0S*2QC+;2Y*-C_S]Z[-C>.8]FB?P4?[B,KPM6'[\>YGT K,X36>D\ MF:[NN%$?%+1$VYR620\I99;GUU^ +\FV).-),GON1$^WTP_MM1> A8V-#> D M53SJI<;QPI1+T9ESJJ6#(V'%HL96-+"S:;!G$]=SO,CQ<)(XO0D78J9/U2[; M"NH3SP<+J=&(@3\#SOYDII%"W><9%R(L+6P4"$$_U^?%_>?MX5^+YE\-+#=_ M4*_J75;0U<_1*Q&) Q/;#U/D)W1 1;Z/(VSY5AC8L8.0ZW'.(6I&S$TA+:YV M!GZ!3.(M%#W#XB)/%\:)'GZ7,7 T^5*9Z(%B0^N/-'* @".TU"N[<9>@X1BG;5+!D.=GMP@*&CW>=HJ#V#/UN$G,\^ M:>*53[*FHU1,LE38-*)9%XFZH%EZ"%Z&9FGRI3+1!<4T"Z[7U;[<-9^K7=Y\ MJK*2B69:E%FY+LK[K_DZ+[XS\\GSX>L;:@'^5; SWT[@)C!P:!BVD#P:A.C'XCJJA"W071G*1% MEJ&IT[A:S=#C!1=H+PSABE5:K%*Z_(..36),[#"Q(H3LT13"GB>BM%(&IE/0 M/SM$@O(IQQKG:M8T8=)R]RY79E:M)_BXM%A5H6\9VJ3FPNNEJ3H?7.^X9,UN ML\_KT5KS>\[N^EU9T/%#$E@X=.W8BBP_C<= TL8Q=^FOM '#6L)P 0H,'"$# M?W;8!!X[_\KZST^MT$M<.T*$N-")L9_:UBCL ;3YCV^*?:Y(7Y-G#D= (08+>EU-SS(AIZ&24\&NE.6KD!++'O9!DN?/V6Y?=XMGW_:)8WO$CGTW"6(8>#X< M3*>V(W11HQ:#\^V*7($.IE3>4 _9:GLDQGC6ME7"2_&D.R;'M$ELG$BQOHSU MM%Z7.+=1%/A25;[.<+_4)TGD.R@F*;*\-(0><:#;FX:QY0KMFF@QN 3EDTKZ MZ:%;3?N,,6U ^V;)%O(0)Z%^4KPO6_WD7.)4/P6^5-7O4U'F'W?Y8[,*O-1Q M81@$;I3Z,$UIW.D/=D,?"VUCJ%N;LPZ&H00M3$V:)T"RFN"9X5>;VO%1.ZG2 MC8Q)R)PXV\O6. E_. 5.EBGN2IGMMOJ147MI5>-J?[N[VV^'[>/#EL[*1U'B M^HX?Q0'T[=##=IP.QGTWB(1J8O28-*QS(\KVWJ4!)QB @@-2P8H8383SR=T, M7(MIG@::S52^GT;"'#5TW267* 45M&-:Z]N@,&/+\!W"")_FD&>34L@G($Q2OMRIU M!5I0\Y3IO6*&HP)/ELN%R)&J%V?JYM18X16<[I'JZ[O^QKWR_EM^W[TZ%3@. M2M(TC.(X=@*(K3@<%[))$GE\NZOJ=HSOMAX>5&='6';Y?;$&M_N&QKQ- _9E M(?KNI@*E?!HT#9=B*G0@<40%!EC3ZM!9=BXHD3JCR] B#7Y4NOL:?W5'9ZNZ M8\O-IKI+^C&X<@(_M5V,H&.QD,MU_ -EI"5(-ZJ.MG/-QSX](S2^?NIJAG% M5P >;N7]6-(UR6-W'W-V6^UW@)2[8M?=%,C^H*U6?7>HZ2/[LD9-Q;.L.K68 MV!<#J@D8XR\IF8(YN>(2&09Y2DK.>'RFN$25G_G+3)0]J/3U%K%($67- RPW M['_8VX;?LRT3'+A#65T_4]7Z1[;=YRO7#A&!Q$D3WXLCNCX.W&BP;=-_BD6- M>FP:CR 9OO;H^YI]D1^03AOY<+%U(0K2R_8R(B+-/E4F^R=_I-2% /\L-CF[ M-7U;-?LZORY_RZO[.GMZ*-:PSC.Z@/R>E_N<=O5RMTH=$D>A!X/(L2(<>D%H)^.JT[(X5X'+PFQ<#WH@ M[%6,WJ'N)\9%^S;^YW["$F\,7K'@=OV<-KO;]@=!CT'O^4/88_-EX.://1]@U[.K47$5; MW:;&Z\ZW_BW5XW?:0'7H+-FAL^PJD&VW;$^K[3#KP4^U(O#)VN',&F!Y_6#^ M5<4".:F6/'+-15KL8N.ZS+9HW^RJQ[SF@NVEL8>\D/@6C*!O17$4#0>E8(Q] M8B[(,@)WLOB*2F,OBN!^#*&J"4(H,ZVL/WJ:O7FG"9P&-\'HY_PQDYDN8BY< MFKVK&(N4\J%WK,?>P1$D31HCR9"O*3PRVNX_7V1DE@Z%H&B"=N+?H[N^^U:4 M]]M\!'/SD.WZPH5\0]'WI_5JX/?2^&)' 2QP]MQR-D M."($@]3F?DEH&C2&]_\.6RL'@6H?WLP&%]JR1-OZ/]GO/%+\;Y1.=!/+>/OQ M;A(NJ>FDMA2O[T#GP5'LP7P HQ/MD[G4C2'D -/$)-(@HFEW3#L3=0]& ?)NS'_X-_/JKAOU/1>8N M[I9.U2KSS_43^_MF)W9:IGGW;=G&U.[Y]WSW4&W8)>C-KJT4@>7F?U5%N?L' M_0<-/0X7.+MIY+*7EXAC01R0T+/=[KT2+W1C%[VW3#5EUN"JLT4*.JC@"&N[ MI=NB!0/^J:;JWEK%]0Y>\"67E7RN0$IJ:Z9E=,EK=\>'7QV_HAW^RW-, Z,OJQI!H -]_9V:[FIH)W=\6VR'9Y<_*WV[YYP&FY MGNM C B.O0 2UXTMTN/T$(X%Z]JFQV=<>8\']L>R#9T&7UB.]> -Z.^ ?EG; M+":K,[0OGPXONV'%A'M Q[)-QZU;7&K=*W#NS^96>^U-=FT$26L:]JCVRQ]\GSXE2_9,_L6_)'5FVYU\K%L=G6;ZF^N MV;/H-P]9>?W4UIS]@\X!.5VX]*_4HSCU(VBG86K3E0J=!3QH==*/8X>XEL@M M#(L!;7AW\^NW/QKPO84$-ON:95_8?<3/>58+QOQ+(8QW*; 4O 97" S_K[?, M 7#L)#CR$MP^@^/?ZST%K:M70V[MR%O0NLMVP$O0.WP%.I?9TJ-S>N*EPT1- M>6E%L;3>M(PI;GFTO%Y_+ X@=ZF/.>BHHJNK^@5ZD@0!=I #D4/74QA;3C"@ M]Q*^YPZ7AGF*B74]H'H]MUZ!,F\K(AOF;@-^%+N'AWS;E1+MLK]XKU5:&JD< ME45+@FMX[@7)Y;DWZ>?>_O=>S+WGI]Z;HZD7C#ZSK.X[D^^R>PY_.=.28$]3 M0ET>[D#J].(#E8FJ"\38NY_T!WGKVR]4&0[9O/U4L)ML;%A6A3= 1?IJX#?3];V"CJTS_M^M_BXSS)NB'DT1_ MHW:]B?X.:@9H;^X_:%R?_C21W^F&FC\>5.Q _ZVB1%6NYHD=M;0P[Y[9QW)= M/>:?JJ9AAPM1=]T"'="'^Q:2G)V)[7ZO1?)[459UZU-74@O+S3EN# XN?AP:@>N<3X?;[:><%<4_5]5V278,ZW5\ELXH\%X8^BAS'@59D MAY[OC1-'X/A<5[1, ,.P2M/P]-=)E)J;=F-";8+Q*76ZQ[]XF>YQZE5IT<;[ M:45:V%%UC9;CEOO%OZ;)=U_S75&WZ<3KVVUQWP+Y2I?$U#3+)<(RVSXW17/T MK57B^,B"'HF0'P2VZZ4D)?0_M!6PYT"^1W%,8S LSBUL<, -#L"O ,,)>J!@ M _^//ZV8 ;+6$OQ2?H2&DE,S\VUCYD'#.4(OB#DIIML&2INW,O7#R1.PJJR M?J]2&T,/.R1UJ,F0(-OWX&"/N'&\ZO9-O^VR>J>HT^_:$AGDKV%QC_S\B/H1=CRK,")@HC^'TZ#U+))'(:6XP=YE/9R86(WJUX*;CD;^4M@)Z92K4U6@E:?"]++_9\H_-9$V?VVF M+DU#UT=< M1P#U6S4='0]X0-X!TB2-XNPJ"J-18C7*XH%P\@[ATXKB:_YD)%&Z#18NB/)^ M\L=:7;%(XVT5LA*G2CR4]]S_#1T(CM(O0&!A6Q-F^_B M=@T+(GI@IY[8+5QYCV@#UEGS .ZVU0_.0Z1&Z%;=03?+M,Y=\QXI.Y(Y8%V( M2+XE46IG7+XI%BZ4*IYQ[X"KLJ>^ZVT3/\*NZP;MA1=.Z*4V&NPA3&"_ZTW* MC>J>]WN6Q/>\!U#<8Y7^ <]V]T^P8IHDMQVX$$]HM>5TU)N&]4,UY3-HC/?U;?( 3CHD%\!AKU[CVDA\OD> MQU+Y,%WMMG#YU>IZ[E^ZCG$8Q!A*T+"FJ&]66HIB'?7K_'8)!!7G4L*%=.$CB1XQ W)1B['K02SQ^,0\].1&11D\EI])"&/^Q!E2.< MA]-MX,\.JJ!&ZJ*<3QQG8%M*%=6(-J*4?-1=D$C-W"]#&W4[51GMKY)J.)K[ M/6?W[:TG9/E8[FQ@ZB1$"?8QU[0 M&PQQW_JXNQK@62;KUD&[[>\'&*R@J7T;O=M"4B;U*._WQ8/?\YW?^]N2/V6 M;?.5XUH!@58<1ZX7N3A-[ .*"V$X]6NVF7;RS(V%S8A[1O=X!ZX% W(>_3@ M?H3?+HHV1SZ K'6B_7XE=D1AEA:]K*4_0V.*"?#@3?\:*WSQ&NO@$3BX!(Y] MZK=:VK_JSO2P;O'WX0)XYMK"FYO_&,O2FUWVCO:B8>.X;>XZ?Z*_VE[[O\Z> M"JH)Q7^Q/$?7R.LM_:*X*]KO@*?Q&=^G\1G??.PX9;7K1ON/HLG!)K\KRNZ- M17:I^R[[JRJKQ^?Q49]L3:'W0<"&85@7_>Y>4:ZW^TWWIV75'=ECQCI$]$^I MU*R[FW;ZA,SX^D5#"0:W^X9:IK^M^#Z0@<8_$5/,W^[^@ +VZW><9N=&W'WMN?=4C;]^=77LJ>"8WA1-WC!U*7SX]<6+#B@;87FX,O;G_?3XI^M M0P)G6Z=JT/>#G 6VI5A<\]^A&06>HUE><\K%*Q,V*]?K,5IX/1,*3-QH\\_^ M4SM['^F>MZ7 MF. D(!%.(S\,2!CZ5I#:]H "8X@U*:F4[5G5].K%@&:H)2OAM+>(LJP:;PR= MTBK3#E/KZRE"Y316J6D6K[-JWO%KK086.3>/_R-?[W#^/=]6;:+W:W'_0,UW M87),W(1@Y$4D\*S4H:&Q0T:#-%+FS9 JFC&LHCTZL#G W6+3V@33XE(KNW7 MJ3@4WDEMZ3M"!CIH@B5!.G@4VM>VORIM] M%Q@YOV^G@\;YDPRZ'*FT=S&!C;&,=A;$?&W8G06#H="R8HBADX16BAP+HPBY M@R'HL'(>SHTNN8\WO7'%4('U 9; AH4D7QS[2.:I$MP7:EDZ0B0ASK)T">S7 MF*=-18QW)]2X>=W]U$3X- /G=DK4Z)I?=%4=J+1U';$.-CXVD KL8?USW>U9F]_F; !(CWX6>@SV$K-"U MG#"-_''7%05<#XHJ?+QAH3F@$EZ-R_+U?EPW 55BJG+$DO2B6Y8N_KAN MK4 M%]GTU_;;W1C8/;[N?VJ!W6D*S@1VBGS-']BI.E!IZSO\*DL>BS9TA-MM]8/= M/C>8\KW CI&'XA032"P28B<>8T@?*_3^U=*DTN%[M)D\:WA#;)EICH MBC!DYHCT2RHN+)5E25O&$ED:_>L3T$HL<&?A]LVN>LSK82$^2A.B!H@5!#@* MD8\\+W2BP9H//:&G-61M3)2%$TVZR3+&F72;@"S!I%N/"(R0YDJZG:;F4M)- MDJN+#EQ,G06&;K T049TL'L,F1(BR>5_GXG)D/O M'!-]T)0Z^:6\! M/HF;DWPQV5/GW8C^"1)X01---<4R=-*8=]4T'5JKGIX\'T(7O3BRK#@(D1>[ ML8.M-!V0D,CA.JYATO[LNJKM1)R1UM&BM\8;1K?F+N9TG 2Q\EJLU$P_A1ZK M>2BFR1K8Y"D0^6=&5>GEOD;L>)Y%7&@[U(3K$YN,)Z #['!7X(E_LF$M;0$) MU]U)$'19],QS(R9GQ[1(E'U(\,-?[V&6)]5"C^[NRM?5'C]:/O=-KJ7$[@T# M9VH\Y)F:O[A# 7NEHZ^(1;$W=;;)'[/Z7^QRR/8?3* 'FP&$! 8I0K%M!8'C M)VD\EO!922JT@Z)FR;":CN#^1_L5*"DTL8!3D4B^T'(Z#L54]X"KO>.NX["% M-E/*\B)1%X)"/00O(_S3Y$MEH@ORAW1]HO1R=#DWP?\-_/JK4A3*3\^9\-0 O_/' MK2:%([7-HXY@N'YZ!7<&J18-9(0,Q)U870 M6#?9RPB2M7M5F>VB@IK763AA>WC]DT;KGA6GH9/X%K2])*&".YX1"80NN54V M-HO*2>TNJ?/**7!34JI#V6;9%WJ/I4NBIHO@A:B9-G=>RYA>G@3U"Q^]I32^ MUS=$BRCR<>1$OAM: 571B"![/+EBIYAKAT>G/<,J=HSM\#"E8'FW%EZ%)&PR M2L54[ R;,V4M.;AZ7\NT,+TH.=/CT6E%T\C6) ]C?2K*_".-*)N5[?A^FH1^ MF#BQ@SPWI&OF 5QBVUSKU(DA&99&G4_P,*= Z]64SRL)M.[[N=>%-JR80/^W M:M,)G\TRT[9R&>#CAFFSO?]N;VF-9)_))\_0FO/GF^=P6N>[6K*<:WAEXW.^ M@[=->ZYS93EIY$:AZ_F^FZ81@E$\'JL-;&1I>EQ#Q*3A:?Z]MQS82\]_#F#U M/:0A1#K?VF@&OL5F7TU43_U6QA%Y%]9+FME?QI))MU/\#V+(,CQIT"VXI@NF_3;;Y1OX6-6[XK^ZM9]% M(80!)"Z, VC%@>_Y8SH]CB*\*O-[]D?*6B8+@&MHQMW0/,;*/4*/@(%C9-JD M3IIZ9?$SRKD1.11NC*D5\@REM;,*[HL1PB[CA>$ MD)#(BFT<#D;#U*+Q8;7+MCK6RN^:$HH.1U3< YHMS'3'AEP,ZECX:B5/^X)W M,9I'L4BO;KDI7KR6"3DCM)H5Y$C3O0'DK_5VORG*^]^J:O.CV&Y7*('8\SPW M0 0&H0/=(!X?E73"0.>E >+&#:]R.3+\'T;08$#]B]:[ B1:A$\%9VT,,5W4 MW0YSW _PAL\+ZFFL:9:AI^;<$[L60)5'?LT]L=I_:SQ,/.2&?NR[*+*QY22V M/1X\L%-;J!I6DTGC^BJ8^C)*+Z]L3LZLJ%B>)G41$LG#W45AU$K^4N10KU-O M1- 9[+21P/;MZ8#*[*($Y H2%*;P-#WX'ALU[%]*+(PUF+0\/)X"2L['IX$ M!J(2S3!K87 MD<3W4.H%B1]%ON?8"?'CP')@$'&_7*5JQW"<0>&! 1]@ ,& $#"(0H<-M=!Z M.=28FE&Q^&)Q9/+7+4Y)ZL]R'/T=3L[4#.IB5/K[F9#0UVD MHB!TO= +7-M-B.-"Z 3I8#.(+2(@]8J6S(M]?4F>A(Y<:N*62^\GI%58\1?' MJ)#H3\CL3R3[EUDY+_R:V%R$].ORI3+1W_CE_Q]97;"3!E^S76NT/T'F!$X0 M1$D2QCB!/O9A MW!$$Y(PJOYDA]O6.@'5(#!:H6)7X%D"7M?R"?@2DR]W](D M<9.4+%_\,CT!;S^+-I^FXHP@*_(VOPJK.E!IZT/\>IL6?^6;5U:P[Z1!0)"# M@B#PO0B'0=A;<6.4VKQB*_/9AI6VA20CLU(\O:^QIBD2$]A7[$BHJQ1-_-)J MFJZ?15=/\'!&5%48FU]1E=!7>OJ-=(XZ>1[3)"1$*/8Q3+ ?!!Z.[!#AP185 M6C1$;J!X2XGDOG@CB!&*;$3P9;R$E%M@\E+4R=2]:3\!2A M4#AU;(@]Q93Q],1)9X@-$?@3B?-I-O@RPA+L+4*<57TXGP&69H2WR.ISM+#P9X7$5_H@6=Y*X9%FD$!VRH3 MO890@;;+HCPM8Z+"3#&!'A385:"%-=.-@V<)NE!YID[J,LK--/A1Z>YN8K+S MB0VYWEYO* R2Q H-QBRH"-T'9#$QQN/!MG885=_W5;E1E!M M9-CBDQG#1(GI2PMFU)=Y9.4M(1?T1(&]90B)B@.5MI[$OYS\G3WPQXYDU]GV M*+$8)IZ#0\_SPBCPG9@0RW-'C;(CKL?>%#[>L'2T:R ZVWZ@T?K]/JNS>?P&/1X"O:%3_5-4[L*[S3;$#V7U>KMG5YO3/-OGW?%L]L1@?W#)QYU]% MR5+^_MIS K;%].<8D.QVC"Q=_"O."6C[69:;IZDXL]94Y&W^A::J Y6V/L0O MV.W;2:_6M+TQ.R2N"RV8QB$,O!0'%D&#,1?:7.M+11.&A5OF?3M)KMY7VXEH M$E/<[OVZ-PD_R=?J)+D3?)W./(<_B_R>I^.,!&O@;WX9UN'$Z]?E='#"N_3N M"DN;7=WVD*'$E&W5D[N[G+V.DG_):1>CO><^7]D!#+%CD\B-+3=$$;)#.&#P M/23TCK)>RX;%^Y\Y>\*:W1KVG0COS?CATGH\)R!EOYPH6$H<1W8FUJ- M%I9TB08G8UP[IV;)$MXTG8,GZ2H6_7S)14T4UJ]C\+EAO-$ JL,ZQ\RTT0@E'JV784PS#&<"B\]'T;D^%. MWANIFDA>*UR#^>7%NS=293>_OEQ-]OC []EN7['\.)%FY+VA M4I3?::O3)4U=?,]8N/&Y8J%3MH6/U9Y:H\UJ88\D5N!Y4>J'@8N'U8L?Q(3K M3CE5&\:WU@9<5W28=,A UD+CBYR5.;R\T)B2/K'UQC%S R@ +S-W(3="(^Z_ MW5??_T?G,,N,N/W73&'$*?)&!JDL1WS3M?Z+1O6 MI3'76+.3@0V%? 7NVJ."CQW PZ1=7\I&3M$&[Z=*YJ5?3-=>9'E!BQ:T<,'U MW@QWTX2K_E^2:^#N $$Q]O&VB=^ S0;WSBZS#/ MV@9&)CX#;:$P\?7]_M]NXNO\4I_X!%OKIYKX1'V3F_BD&)1(Q/X]WV[2JOZ6 M;?/K&A<-VS9?V?].48(^L=M^_Y#G!5LJ!,6V3>8RK7B@WK?E M7TW6OS^_.:)@W%J\D/F=I&F%-]VG;E75+7F&%U# @"$&US4XQ@P.H.=M!ND] M_:F;0WY2[5*\;&B\'6+K;=8TQ5U!6R1K7@RP;57>_TI']J/^\26QL\+!-M^6 MB\YFFW]V->G<^4T:_1SREG-2%'V'7;=VKO>[Z[NCMRO;^E)6#5+G#WG9%-_S MC^6Z>LQO6*BX\B",F/4(83=R"(0V]*P4!K$%TP1"H4.79I$8GGU?@P>LMH8. M[>/W8[MJ]1<>@,X%\&?K!&?!^D1-=WDZ75ZKBAX-NQ ));M07?U/:]O*UZQUVQ<1">.<7++Q?$3SDPF-AUH<-NA!D^L MU>B/LO5NS_(H6QKM-BA@QX[Z,&#$3WXU(YX]@"Y^ %$@PWU?EID&6TD%K_]VS0/?[ID&1B#^*8^-BS GNU>Q.L-_RLJ_W_)I_S\M]OK*)X\0HPLB.8ALYV(]<=[ 8$ >*E=VH M6#)>8]-=/G/?ZT7=P9I6#R[P-5BR>5_CXG-IY0U="!?5-G9?-8 M-&P?<478 X2.D\3TO^+$MR']],&0XR$H<(69@A6N(:1\A=G7<0RM*40V#[-S M!=R'!_2,I+?L7!A "E0N8]RH.%!IZU9RL\Z7NMKLUVQ4DK]8&6.^LF(8)ZD7 M6&$,=4-\-M8;F!&W;E2+.KV\N1!JO$#AV?D!@[:10B.TUA2@:K8>IQW4BDRY;A MM7\/KSW.EKT R!X:8@@G'EGO\'5A?.EB>AFC3)LWE9G^*#;BAO/H@Q4[A '$ M@>.FOA-!Z/HP&N9*V\(XEIB[1$U,,V.-=VKTHVG:P?2*DPN#1Y:]90P6:?25 MGCXD-AC:!$:7LU@%5NJF48P1L8GGA1XD@3U:L /!Q('()QM/%'2IQ'=V#HUT M^R,:+G1Y&;*6T=VED%?J747TT>FRZLY%E_>_9479L.K@O%E9:1#;CN^$0>C3 M59)EXS@=K*6IYXEU>5DKQKL_ \,N[&EO"Z"K%/'[ 70]H7R2H L#0Y7290P2 M92_>/)ZL@Q7>P9-6=5[<]W="KY_;1$/6+HV8;68ZR>_H[]QD?ZU(G/HN=",K M2JPPL0,_L;P!00"C5&Q Z;1L?)#U8/L+/-;/8'> "^Y9*X$/V[:=?IEVU FP M>&$DFFB+98Q.(YY5YGNRZ+*GW9BBEE+* .JN"Z'Z<;@OI$,P'"/_*V]^+\JJ M+G;/0RA*%VHO/X7\YY[^^/=\]U#1G[#KG=L;W59!2D-4%X5QG(9^@B%!03AX M8/N^4-)B2;@-)T#ZS>WV)J[UZ"BH1D_!;>LJV#$OVSQ)WGK"+N;*L[JDO]U> M#Y3=W17;@MVW-O4:;[*VNKA^7%Z/68;2+9*9-^O>!6)44-ISMN,PI@OXP MB MSR>.'[M6,*[G28A]L4A)CTWS&_;Y;M&2I2HVJL0O42:4?;HXP/4PIB\(^MC> M=4F_]84=-:Y*N-O5Q>U^QZ[5N:GHPJM]>Z_:4B/W@]ZL4BOTDC2 ,,4814E M;'1(5'NN4%'_3!#G#FV6%JC(D*P4DQAMU27JRO0D"$<:$[0)KW)]J:N[8L? MKH@=V6ED1XZ#8B^U I\$\2B-5"Y79;[CTQJ!#Q7;HMJ)AP5S).R"]F12^QUW_*%4^,M_HN;J]]O"J6966-++T,8IG59 M>-;5SC?W+F&^.Z!;I4D('1@[OI/X:1AY,$R&2F,G"2W,/\V*?:[QF;;H8O'7 MHYU=4P[)-X"J^JGJFF+BW<%CFB[M"4K1N8RA)XG]]?Z? @.\@^';CLXW[9F7 MNV_L&?J':DNY:;KU.KQMV@?H5W:2>)'KL>5Y1(=B@*VP"W8]@E"*>>^$UF-, M9 V[%1HV(SZ6JCI&^'^##B/X >G F-\ MDF66+#%Y$N/)T.F=5W1E+B8?NGU!:744A(Z@8ARR'R^8>T8('6C0DPTI.CBDPW33(D)QTN29I*. M$Y1<$ \5 I5/JZDW )[8EL]W /O>T[MD>7(*Y#?#^QH] /!Y.1@X4V MP)0,&1:5E]C&5THGKZ(]2]#E4EIU7IU-PA<6S-D:8B&#@88PM6T@PNCE'0(C;;,,+37FW=N\ MOT$6^;.:KVU*[?'[#HJQPZJS/1)"Y*C":Q^X)2+)[XN25?:!)*,_6$^\JZ^'RHLYTTG;:ADZ,;73;[*N,W#.K2H/ M&?WTCTVSSS?\ERO9\VP^@17Q$ M/!*%28R29-@1(M2LT.)-X&--9T3&@H)EE^[QTK2,[BT#_'SIGICO0E='G+K[ MDIJ$W[-BRR;B_HGR;_EZ7[>OUQ_NTJ0]Y_J.G7>$<>0D 8P)2KT(^X%K)4.^ MDG@>%!H8DX$RO7M1[;(M6#_0[^5L>7V7%37XGFWW[?G];/#DU[NJ_K4]U=^, MSK1/R++?ZNM\=ME?8I/R= W+-Z$OLDW%@H$+5QE_8&[\<@7@VS8].'-T4W+W M("5MWIL+[6KN*A,-[7!!L"=OZF7(_?1NG[J!97K>=4PUYT_6PW+3_FO[ZA+G M$:Q/8[[ 2UT_\0/'L9!C6V/(YT%;J'9F)HB33$-W)V^VZ#"#[$B9^">>R05* MO@TDY6J"1E^^>$U!@H"43=8F.H0-YW7QO;T/L?G?^VQ;W#T7Y3UL_IYO[O-F MQ)4Z'DZ")/&\T,>.31+;M@9IMP M^>*CV5\!G3'!M Y)&=[(+KN'*[Y4S:[.=T7=EC,/[VC3$74RLDL"._1I,(#MFI2XU)E%P"]/+(G8P$/74N' 5'0LORR65'@7)),9JB MD9EWMV<'!^R\U'4[%TY;Z M\*7=S+J^@YOJB05Q*]]WHS"P"4GMF/B>'SH1&@#1Z(T('8TP!\-P3'1 #CKH M3(,H>'! #T;X+&CJ'&@?X^I=$#QQ8;#%^!*&"VDLL12AR78R<^)#FN4+4\8$ M3;>,66$*1U\?-IF*V_>T/V^NA MBO%ZJ!5*0QA87AP&!&,WBCPO&G>TG! E/-)N'H5A91]*+UKTX#5\T.-G1[NS ML]^L_V\GZ2]7F!>2+N]FI,I M8>U$:SO]-*O,X(E9=KI6F7>2G=#/:NK^SC_%HNRIV&5;=L5*6QC)[E9A=ZZ< M+HUL5FX2VDGHQVELI\@. Y]@;YSDHYCKUF83=DTOD(YQ=M5>9[K%B.[_7]W<,1(88$LU?A!FCGROK_WIT+6*6^ M9R$[06D<0]M-+10Y>( 78AB*[5%,!LOXIL0+M%(W^\W<;GQYOV4UF-34>&;^ MNP*#+YTDOVG0,W\'>H^FS0SJ:H<+><+)FWH96)_? M5!3A4]44#.#U73(^@K;R$<*^12>S) JPZT4I]N-Q6L-^RC=O& 8QQ2PQ .-\ M)&[2-GA_!30W^3H5_R#X%#>XJ-IL620JM,>&/7.\1>6/V8;:AE+'4,^\AU^9=>1J4NZ_P' M*UF'Z__<%W6^016[D(QM'*UB%(>)E81V9&$O\MP$XZ$B(W6#(!%+=6DQ:7R! M\H5^_X$-:QI&[8:;*QO%ZSVE">;3U.F8U7 !Z!7X1W="8L!X!1A*T,&<\5;0 M,\1=D$BMO"]#$?6Z=.DB43U\"=W)U=W"@?8X=N#+'O.E84!HDUW,>8(B^&8J]GFD @,F:EWM)D>-MU9OL.\%]Y MO2XZ:6P5\==;AABLCR"#VZZ &SRQ"N[W;^PQ=SF7&-471KG)AEO&H#?JX:D[ MMHRRJ2@)K2Z= >)AZ(66A_S0CZ/0\F-BC]J$;.B(K%$-F#>\0%44 ^4[0TPT M&%^ -7-;B85;W37K'5K0P>WK^,?0J\7<-]@QZO'>C[2J[_)BMZ^G?BI9G&EQ MY=;1;(L6;BT.\NFV/BZE5J[=M#%$D2L"Z3HY07;B.E+CG@7HI+, M+D/1M'AR:=FIQ Y/B<#% /?%\=9R0_H@JG_EZ_JI>YNRW/PSJ^N,/5$?.+9G M$10DD'C0#<( 6=&X&D8!EZ)-CVJJ0)35E';/4G72MR]I]WRU!#T9K(+NS-FI MF%10/V=H\O>+%);;VKI"V5ZF0>\,:+T!%#48_&$%#-W?]RZU/QV<6FSC\M1YV-NPY9Z]A-(.TZY]QP%;=)U@TW6"'?W=[F+IXR-2;P<^^[VS@[_] MC1\] :,24 E0*YK0VBYGZBCF:?OY2RMF\KN:>]2)+9%P\;W8Y.6F.7KZ#V7- MPPJY,/2Q'8=18,,8^99CC^92UW,D'K&7MB6QDR?Q,/T(#VS8:3D:\@$:+1P' M#6++)'EJ^=9(9NF4FH1'2&RC[O &*/T7Q37MZN@<.Q>61LJ$+F-=I.Y&I;FC MZ3M^\S7?Y(^=-JX2!\:1'Y$(AIX% \?RW>&$:NI%5JSO=(V(5>-5!Z\R.LW^ MMBDV1<9R.ET<)'=D=/*3%T>D2AZLD&F690Q1[5X)'(N09VWB1ZTPPHG=/KAE MNTZ:)@$)QZV\U,9^_W -*3E'^$2P1&;7EQYP2P#]@___-2M-S;0,09C::3.O M68EQ+O6:E1U@'!$G8?4]+K0)(GY_H7MJQ8'K"HN"R(=//K3G*HJ1>*^)E[N% MC#:Q+SG[?O=X/Q\,1!__RO1V 468EM>]BE%NTX):D?>"0)0B]-4DNL MW$S2B/&*,B2]]):EC6_A/0%?8LON_GG;H_=9_NPP3?S&[6EB+BB((I/+T!)5 M)RJMO4M&7](]7=SW=M(@QBB&#DS#(';3R(7([NWX 29T"$(9)1%"&B1,3$%$=2.M*"F55"CNAX5SUDJ%N2<$CA/ZD9\DSP/Q_)WA'( MWYJ+2.#83DIL!!/71B&.$F\P9Z>.)_:8I*01P^+1X^JO5A23#WGB^%1D$L[$ MQ&2@:P&B&KAA5=P_O@V5&3!-$CN/[3@I3EF) EC/8=.P@%5$=-4N&I>> !VSRV]W1ZYIB,J1()Y\63<>D MF"#]\0V,!9RLG..(U'EDZ2)1%[1)#\'+$"A-OE0FNJ#@RR!5_5355!LQ':%O MEV]^Y-A1D(:.@PA*J3Q&[F 36ZY0@*1FR;!4C>#4E$J133ZEFHY(,:4Z<,B MS9_7N]]-;M"T_]!#! M'HQ3%+H$$6?(,OE6*/9\HXH=TR)U!(T546PZ<((2I<(CIT!-1*&@/+UBK\8S!_E&V4D&^H"-(HC9TD'6RYT$[2Q/(= MF#@.#BWH)H.M)+:YHB8U"X:%: 3&HJ4>&?]Y P7B+NO/=)P)+N%&N@Z@WI<= MG;SQG[F8AC^Y\Q,?QW<^&O"0;]D#,6!_HBNJG6XXR\ )7=;#V/RG#C3X4.GL M0V*A8?\@^6'%?#(LIWW$:;AFK72[B+H26>HE?1I"IV:?*9%<5E+SBKWS3O3A\O)WA.2CP M YNNP)$-$V1%]/_'*)?X0H_U2II8;"V$+&6+4&A8H! AVC6;2S6[1M0AS7\?&X74K<-!+1%WDK MAB6F!:86,BDPR"ZS[@SZ/*ISEJ +PJ-.ZC*T1X,? ME>[N)J9 7_-L2YI=MLM[,\@EKHUC0I>.4>CX!"$']6:"..5[JEKZPPWK#<,# M\A:0F,J(L\0G+D8)$M.4EIL.RTQ"\IJ,"_HAS=LR9$,>?J6I_PCN"&;- RPW M[']88=?W;,LR@[U)XGF>[WA^3*+45UYO#NKC MAV=WL(V8V#4Y1YL6@QJF08"\&'E!:MM6FD8PP8,QU_.XDC2*)B9901V>91?8 M'%3A[?W=P8DHDUDW,53@>(=+?(-0A3O^'<*).)3;(GS3\T!9[4#%OON#W9"V MWF9-4]P5^49MD_ \"6=V"36P-O\VH0XG*JT]B5^0OV3UKE@73UFY^U1E96\' M^X[OQ&'LQ7X:+$Q/>8 M(P9(0G8EN>)77/.7OHP M$IL%L.T$O1W+H6M\WT91Z)* 2K@#QU*[P',A$MXD$/KT24+;KM-+[ F($26P M%V",(YE8M@,S9^;_F([W,OY2U"UCI:R _U2&7X$)[L*%K*C;)S5^;T\ZY6W0 M-W[S[T5>TT]Z>,;58U:4*Q>YJ8<3RT]AX""Z+"=H./,4P!@CL1MC]-H6&412 M%\DP9-U[-F#$!O[LT$V]AR_"W*6M?2,ML(RQ:,BWUX4 !AGDOGTYORO*?'-T M%_0(X/J._;/3D95GN5$:!A%&7NK!$(960@;K(?9\D4! ETW#X<%-M_7Z9FW\]1 MS42YX+;ES\$V?Y9K)M9ECR+=5?5C]P9H=EOM=R#/U@^ _5WW9M/8..NCQJD. MWJBEQ?BY.I,K,T#V_ DT$TY51CNHOIFG#_@C*\8V7;C;*(Q2G]!ICSTDW!F. M8HOK_5Z-YN:?<=Y=+QMC6GV>,4"R]CEF/G[US2P&>)9\((QW^C [>YQ-XQ@@ M<_FSAJA# C.&%%>\69K?]AE[@BL?2[7=)')"%-./]OT@MK$3^V0PX\3($TNF M"G^\\7SI 9%8TD6<*+[LBE&&Q(3\ &6F39G77%S(B4C3MHSDASS\2E/WX0\J M#R:RYU[,QUROU2@8,3VH=)K;V[%")1=!RE/%% MT<;9$IMG7A,U4SQ]BI4+,;42BGO8[B52T$,%UV(JI)5I MCJSM#!0+IFUYN)4(?+61+)"ZG8%LN= 6@N'OV"Y@L;ACX=B_0"R]8Y&Q/0_X'X(A=@4\Y0]=Q]8T9__97\;A_)'\]5:P8 ML:U^6R$WQ&X2Q '$+IM"'9RF@T486%R7!.FP8SAD/MX%>^SP@;P'2 <:@RAP M=%.5T_?GK2GI%)NOCIGLH8$!&[B9F$B!@[ 3$BJYG]A6HPZ=\ZG:T4]@$U#V M6.WI1$'GC+L]NYYUF#H:\&%?;HIFS7[,TBYL@OF2U=T&\.-35C[3F6._I3-: M#FIVV02[>)?.3H_9OW) _Y2NC-B?'#8JV4355L;,K:3@]!1*34^& MJ92;G#Z?Z(F]OG>+HA.3ST/6&*^MO,C;^Z*OP/6B)%_%C]."K\R,Z.*D*-D$ M\Y%&--^+#>TCPU33?,J;YN8A*[^Q.\HVL(V&5G%@VT[L(\>E0%S;1XDS8D$P MY#JM9!;!=-/$%>BA@P/V,227$SO=K2&VX)FO(:3GFF],48"MRJY/U,I+A6BY+=H(-[ER9 M"I/+FETT^',Q;Z;.E%A!U+BO=+W?-;N,6B_O^\D*QG9H^]"Q(;$]._9])XG' M.JPPM<6+HQ2,35(HU3X@NN[VT:L#1)FJ*15>+\\'LU J-AT[Q1KYJ5R4H\.^&Z G=Y#FJ&$/1A+G_0I?#XK2[W6K;0E/8'^R1!(6*VL]I94[M[R JRQ8OG]+:;X!*?=H_,8G* MVF^ 3 7M[Y,3/Y'V=XC%M%^0\\5JOZ@?[VN_%#,\VO\UO]]O&7_/W9UPM&-\ M*K+;8MN>)[O);K?Y3?[7+J$>_VN54-N)D[+W>:$?V9&7>J&=$)_.0D$2V]R% MJUJ-&IX9#EB'6YO9P)V6@6FS7>91C\V6(%#"QHT0J/Y)Q8Q;E>&N*98R_[9^R#?[;7Y]]QK, MP;+C^"BV2>PE81HF'@PP='O+[,;U4.PZ'AT618:AU*&_ 22+U=Z.R-MG]DTZ MJL72Z%JXYLND3TVRV$1SF5UY?=.35^?@[D)J72?SR\BN:_6H,M=/^6-M]JSB M[OG;CG[ZU_R)=M*'K,D;>-NT-;HK#!%Q;6)97@1AY"$'>FX:1,A*7$(2KL>C M%"V8&WH=,/ !M-C $;A?P)\#/H&H3I5*_CAN0DKE(C=%:GEBMZ<2? Z:/>UX?7=3MP]C=-;;.6_ENLAEAL+0CUQ*C^=;HSV,0J'Z M!'DKAA?R+3 V]0_0^@'3S?N<&NPO1D\LL(@33P2$MOSPL .XSCJ[:6I9W,= M.%2W,I46]0-(X/T!#0QRKN4F(4]2@;AX,[-,.T?+I<69,I7+T!T-?KQ>B&EB M1C &:LWTETO'.$1THBS#]2/6M608J] M,''C%(>1C^S(BATR6 X\1$1$18<]PRK30;P"9U<(#"EHH0I*CQ:R^;1H:IYE M,FB*%!M1+ [>+DB83M:7H6E:/:K,]5'^Q#6[;+BZ:QXRVC]OGTM* [M7HMK2 M7[\O2JH7>;/[UOYTY<4PQ1&Q(]NU4A<'J1W[HW%(N*^^UVC2L/:UMW.S>YM: M-&R3[B5:,,"] AU@_BRW3M[?WSR8B7+!/;R?@VW^_8696)?;:]#'/L^V S\U M9[8@#' [_W:$":9__Z MGAT@XH<13MA]G+UY'' =C=5NU/ L]"KU,""] CU6P, "BK:+ L4R/OJ8YTO[ MS$*ZV 2DBV\CZ1]>_B[D@+0WP3(20?K=J@QW706-_$>VW><#!F;\]WSW4&U6 MOF5%*'1)"+T(NLAS4B<93">)SW5\5*O!2;7Q"K0PKX[&;#M6.ZPS#M0S[/$. M4E7R%SA E5VZ-#CU\"5<77-]QU[!2+?5CT-Q8>K%?A"&5FC'D6^%V(9)9'D> MA,C%(71Y=TN4;!A_&:+D0R=M\V7.^*[^T)JA&(1U :!TX* M/1_A*$A<'Y(.B(A1LIW4#7)8>^< 0@Z+\!8R@P0'U;((H3NP%F3382LL03Y,. M5I/U>#&AA9O_V#>[]O[[F^IKSI@JMCF%][%<5X_YIZJAWQ>%&L:^G02T"7S+ MA<2S(#E =?S4$Y'B60 :%NLCG]A[1255E*+U1E"QYVD\/DU??+N)J?ZK)AL= M FPZZ%P"'YA3O[ ?_RSS@XE&NC"#S-HGEC''S$M!M: Q*C9/X?RISM=%NXT% M2W8Q?;WKGUAC%PW'H1L@%Z'(M3%!@1,/%F%(N-Y*T6''\*QQ#*V],"0[ C>M M;EQ@Z<+PU\'M,D:Q%D\J_3U/;$S]EA4E&^/7)=L#O+Y+]DU1YDVSPHD',?(\ M['L!L1")@P .YA(G#59E?L^>A[CA'U?2MK@&5=P-JC>PN,<6@P?HL&KZC>_; M'AY_496>@76.I@NC2IG990PI=37[LQ)Z#46(1/\48)L0> M4QT!Q&*74:E:$QD_4A=1#0#[) #897_QEE)K8Y1O43\EE6+K\Y'#?BU.L8$> M'/C0PSO_1)*A(/DB61<#93TT+T.IM'GS)F#6R1+W^S,TI$##HZ_K9[A>U_ML MB[*Z?J;?:K>>O^1U43%8;%,ZQWGWOZLXL@FQ?3M*_<2VPAB'-AKPN+[%=:&K M>12&HX4/7W.JD33,9L?J?CEZ';U]97U\37?-?=?K!.W"IXW+:!(QU628P1%H MT*.^ AU4,& %'P:T$XNH-*L7Y-5\2RU#>"?P\_5;.A,Q*Y[AP$7S5#4%RZ9< MWW6W#]JKQ/:L*$C2)'0B%'J^XR)_,(HP1DIY#BF+TV0[/C"4OX M&_U'28^L M!2DFNZH,\VGK%*Q*"6B;-^KW?2B31^@8H? RH88S2*>HXLHC*7&\#.G3Y&)V$0HJ)XZ=>%3<][NYR]F),C33@5_:ST1-0 M#:Z(KMFG;E?.-?X2&U0N)W#<2B.^*W LVDPZP. 1T^QS?W3;NG647I@XF:"W M52XE'V9J_V5,'+-Y_SJY,6LK\$Y-U[N'O/Y,FA9&*?N8 _;CBTVRGN;6*B\SIW<%2.A+*G8I=MQUHD/XUP&B9^:#EQ[)(P M3I*C6J18Z&8XC68-YUC1 WO&K &LI&&L-LP.#PUM#^_/"!:3\IF8EU, MVTYD21GYAU+/'NIL=9[\+%Y00 --L0Q)-.%89;P;JXHF7*_9>Y3-UWR=%]_; MZ\<=:B@.[#B)G2"RW30,TG''C/X_% O:M)@T'K]]&&#^ C8]4#9VLQXJJ$>L MJE(I0[BL2)IB6J<\#AC!U_E<#E?F25[^/Y?>\ MI%33&&AE$2JX+I61V(F([Z<)Q-Y8Y.0Z1%7V1&S-I7=%C_%95>6$B)65-^V, MZM2U(W!SZ]D1%"$AD^%WJ0HFY*(A"B.(<(^'#?2_0AC53'3 F(NE7OJP(^%RNURN&HS4^L]=:?< M26V"FVHJ67FBS;9&W390WGV$>78U5(9;4VTU+E5Z^3[^JR 4X5 M\I+,YN&L9&<\AH&3(CI=("_P;8)AXD:#<2_TE05:RNA<@MQIKQ[-E6-;.@UI MC&:M*52P%[&*K"0,$$$H3MPP3F*2I&/FD^!(<;=&"P3#.S>'4;PY'L5C,O*IPWXB M;#W:T]&5IU1K*]7,Y63-I#>7^>6HA7K@X!-'VTRQ"GDAQ]^= 0/],O>U#-YWRW"IS(QDYHN8&7)B$DMA>/<;0'W9CW M40C]EN?1Z#7A__C/_9 @--2+^Y>WXY@/)#(-0-+W9VY?'U=FU7VDM_O:U^V>\>JKI5SK\I/50A MW @G9E.SC3G_DQ4&?:NF& YZTS['DW8:V"Y['=6A1CV$0BLZW(WEHP0JUJ-) MVYUGNNP&M,:5BP+Q>M) IC@WD@M:T++D+(L*62&9MECJ D2#9X+Y(7GV]%_Q MO;+K*B/R7A/,+7^L7\M M]6,)[^[HXHE*"PO!W"!U,+9LVPE"Y**$C$FG"(>QHDZJ S"NERW2[JJ49LS7 MM@N;K'^C;>9A_"Z'(L-97X,L=%AK=/"]X:V;2^YA7E?K/-^T]RQTET?3[VSV M+ K+^\(9AZ146D@8N2[V/)*$R=$ETC!-1#*Y&LP93N ."/L]E8><]\XP,P/X M7;XN#5A]9"]D@&ITZ/6 U,V5_ #\]E#5NYN\?NP61:U.K& <^@$U%4 WA5[H MI7XX&D=1:*L-0BF3A@?BMW[8-0S;K_0#'MN36STZP56()I(Y5R#3\RNX^GBA M<0/1WPY$?^0@>B*].T6=D.8I<;]4W5-SZEWMT\"9]#KCI.W =Y$3)B0*?3] M?D"B:+R<'\=$\+B^'IO&5Q-?Z/1%9I M2KPO1/_T^O3>6DP#8_(5-5^IQ;I84[%@>?*5#WW;3V-DN<@. R?!.!E%U_9P MI'J$2M"<<1(.4M*KAYGM&.:!B,:1F5K&;IH$/V:-!Q$Y]Q[4P.@J, M?(F[U=4,2HQ2B:O51SP@ZR!VXR^G&KI[5H]2)+D6BTX,\JL6E; G0GID;80R M8)LG&#E)$T<0HD;O,K1,DR]G@@X=#,FDFMC3%75QNV=;%1]+6&RN[^BWJ)2R ME%=5K@@K>',]!SJAB_PP0@D<+_H(+21T0%&GW4FSO_?5][PNV_?^[NML&)9M M:,'>[QE1RR>CE)M!/",U90NHI*6.<;;G#HOVO 3BX=UX;NH=$CD35+J:8B%" M:<*S"ZDJO>Q)A(+'8-J2XA-53"L[=#&*D$/LR(^]P$T3:PQ(76BGZ2OQB@"8="NKA6C@XG(YD]7#QPPO]_*4_!#$"!G"F*FI!.OG"2JT-LQ#] M-.7=^=#3 (N*E=5I4=)@^'0A*$IA1$)" NR[%HJCR'-'(#1&%MH#-6#><&B: M?OP,/R/>JNK)..>3U)GI%E-5=AJ%H05?CDZC?&"( 7M+;@1]I*BS77M\4^Q6D0M3[,$PH&;M M)$"$?CG:ACB47>_+6S0LITE5U]4/VA -V)>TVX$Z_UYMO[-AO6X!@KML/8ZO0O8^!J]NG"JE(78[S#\[P]"[E^DEHQ_9\4AC@D_N'<2QS$EL2V M@KRQ:;84#O@4!J5NFODB',/42@4R1W16=Z!%U:;06ES3BIJ,D*E3N@SQTN!' MI;NS"=R5U31[MC]Q??QC9?;W>K-(U@B.AZ,$1A8J5)8+OCJ1/HVB[W MA5AR'V\X.AA0L>%2][C:F@.!"Y0D>;LL-Q-1)J8S(UO7=V" !/ D; G<*66> M-;F+H]JE9E'>;:L?#=M[W22D!-ZK(&]!=S4 MI.A I:TG\4OOLF MP)4,XT6M3!S)*\P-2ER*!?1&2-00T\MKOQ)Y:9?X",1PQOBR5 M\TNZ%B_.1/IJK(B6?%[?C;OWJ&IVS0K'EA='";']V$H"@F+OD&Q''A9\35?: MC'$!?U%F>#>6O]SEX/G; M0U;G#]66$M>L8NQ8/DEL[":)0R!.R.' 2VQ!3_9\OY0QX^,)%\U8N=X>0*=3 MS9I5LU?;+1M817__D_3Y?CF.^3:ZIR!7^43_YY>$?GR74,-G^4]1Q2%:BAPO M2[I4G3E[;%\#1S+%="?-!C&)D!V2,$[H\M%!H>..UP3X#N)Z)TJ;,<.;Y,<' MB*1I<^="):(&GF1D[7AW M>Y/GC^Q-H2]U_\CTMUVU_MCAQ6ZBHX_'.TP$L&-&"%NY\6OD^ ME9S*J;%-EJ>C.IV[H*K:.13/(N&"'0DI-PVJ'A^KLC-*[3@A3" *4\M-4VC[ M]E@]1.@"7#:7)&5L@A5PCPH\9>Q]44WVE0^=9'-4;$S(LEH&BB($ T0P/*)"9J57H&9C>II- M;.;U#^YVSK#0\&)_!Q\.S\T-CU:SSVYV&?T5MME!F_2^SNGGU_2CLQ+$%MAD MS\TOBL4?7&2?J_[0VU+S[Q7J=J@RUJO%RP7O^MN5J[OK'R5=>3X43V,>9^6' MM@>QA4AJXS2,<.J'_F 6IB[7:[G:C$VZAF;KYXM[(.,[*KLZ*YNLO=N'1HH" MV:^+55>7F'JGZ$H+R0L8=%K=.5%RI9$GF836T[2@9I?Q=E\W+*?"KLJ>=CR+$'AA M,!MIAV6,9#.N51/T8_Z0M[_[!K6V6=:G89%=4>[S#;7_]WR[H9K"(H+#JV4*1IPC4#F[)M>"0/EYF##\5X^7W1C5XVO#='+H#; M$35_"L%(<[R?KIF[)<1R-^.E7QU>5FM]C!A0R(!A;G,[[9-)R5*:@C^U,W>3 MR.5YON9/[(6'MK3K89C@QA'"[IQOO\@/FM9F:UZ,FSZ[TQ:J5'7[.?0[1;51 M2]]($'IF46FR:>9?8QKUKIJF@PMG MMAF9%IO5!J#@PP#U$%HP'?S[XL@7N-!EOD:0F\>T-P;7+2]"+)V9G Q1/?^\ M9,JQRG@W%Y'QP8;9+G54YOY!9 MFZPYEY%MF\[=:J9A(WCK?@?GNOZ2U;O^'[AHL;'];_A8[E7S%_S M=4Y_96.OL!?$,;%BU[6B&!(K0H$WSDT^C(0NX#>*Q/ ,T+T(SZY_:O& _1,K M6QP>+)>N^C;<.GR"OYR&$4S@]1)/ VF&?)3\(^Q7H$,_O",UX@># Q-?WJ]" M]061GZ8)EZ'P$_GZ^G;_"1E6T?;V1>.F8.;_D6WW^?5=)UW]2\<4"_("RW5# M!Q%L8=^";NP>=G!#'ZMJNCJ":;0\Z_& W4-=[>\?QBK!;;MD/[PLO"VR6ZDK MR VUC[RJ3]LT>M3\"/,5:%$S,>_;< ^OXJ_2ZV@>NMKJN6JMD8?.=1:-Z.\ M*CT>@?C251FC?5WGY8ZN"QBP[A\K._)]G" _"!+D.K9'9G6[T;T#9;4#S_FN/2,DIK5Z6.:3ULD)%E/2 [<]OFG5D8>= M"V*HE=QE:)]>ERJ#G5%,V;ZM'_+-?DN5]+>JVOPHMML;AF"%,<$NBEP'DCAQ M8M\*4AKM^G[B!9$7PT!$S&1MF,X(][!8+#( W^VT,ZG#O62R*=54_ G)D]2 MU!E1JC/<7! G53:7H4?*7E1Z^QA_G05^VGX;DFW/O^>/MWF]LN(H=E" 0VA[ M@0]1Z+JHLQ*&(4$A_[W;,I\N,DZD;MG&7SZ! RKP9X>+>Z2B9?6 5 M2N;?[%5"7^GI&&)3ZC" /A5E_G&7/S8K'SMT&$56C$AJ>=B!,/(&.Y[C"TVF MXI]N>!H]Z#^#!%I,@O.G!&-\,Z=9LL3F3#&>C$R6;^BX,$W*4[>,"5(!?Z6K M$\GIQC_K8K?+R^N[NZ_YMGV3L6+%C]=W0_GC'V7!E@,T_HF,H(J92AR71S0 *##)Z>0[SWNV3*WN_EF4FR]U M]1_Y>M>LPB2F4NA3FZZ-;?K??D(&XS[&7(M)S28-*U>'B444/R@J\-3#XC_N MH)/=R](U([&2J]$#2L!@7H$#VPPJ^#(KV_P'2V9B7>Y0B3[V>5*%_-2J/V>K+/53E>X=I>Z=GD MR3.J'I^JLHV8_MHEV_9V=V@[7I18;NABWXH=-X;0]]L,(57- ,F5(VF%,&&U M4G?[WS%PT"._ K?/8 3?E^0 Y@1HO9 N;-+;6GRBN("&$M-+TVUDN()*A&6N M BLCS;8,-3;MY-GR+(.<']U0YX-73+[FV98TNVR7]V:( MY8<.)A&B2SABRTMA* M^<\/*!@Q/AY:;$H[@>>].[/SIX&.^7?Z=#A1:>TBHE'D75'FFR0OZ1<[9ODF MJ^_S]JOV_#/(6!;Z*R!5L.&H\X.&3A" M)!IXZB29-R"=B5_10+6%"7J<@,&[ CWA[!_=50Y*O^9%_=O<$30"RV;&2>N98<6PC@<<'@X$"J, MT&_=L&A^R>GWRQU%QE+6AZ&LK)W*K,L*Z)2$ZU!1N-[MZ2IGF2KZ#IE"4JJK M89:JI]K\>U=4]3)I(@C]RB[R_[THB\?]XPKA-"1Q$, XP2G5?#OVQI@X]$EH M*B 5 C%Y<'H%>FCFHE2Q5M ?L1IK ./1*VBAO]M"L\>RQPQKBFNE&FVIFJS; M385X5X%7+&3V#9.@RAR(C=$ QPGL82NB3<&8@Z%[J"95FC> M5C"ET 8:8#*%?J>%%J+0'4JM"BW8:#^K0HNZJ:S04KS**W3WYM7'H?6;U9);[C0QRC_X^]=VV.',>R!/\*S'9V)M-,D]5N_H M2<76Q*V\9K\+9.'"@! ?QJ9I(3^D*((@ZJT[],\7[ M@^26AWA[MH9U_T?6_9,&WAFX2>^R/&<;H!\GN!^!DT6A[CXL#G/MVP.].MF1 M5; FWVO;B?;+M-Z4^46^ W!59^LU>]5M82(2A3'V"(P(1 ZR[,#MD6"(C&$E MUG#[FFNK%AI['V?='E>HBZX+@XIA;-[\9&]_ENEC43:_L3JV,VN\N,A67>.& M1.%J40L9%/F+.JN!W;Q'.;7"GB162&W5A6FNRJO0PY,JK)I->47^2IO^?5*E M%;L'K$+YZBJMZW7:[*=:!+%GVC@*@L"R; /1L;@9=R!,+R;N,#$>9%KWFGR/ M[:QYG*QJ7K&I=OC.0)X*7F>HFGM9P1V-=A5:NQ>'!NY9$X@]Q%.K[#$VA016 M25CFJJUJG#LIJPHY'+#>4R9Y=4LE)TSK[VF:_YHF["@W _$Y?4K7M-IVB&-" M8EB!8YDX0I$76CT2:%H#976X?F"EH8<-.MQ@#SAHD0]>!!H>&NGUGU&C MHF3I9TA QEKS.<6JV'*/LAC-58<5>GAZD4[R]D&?Y3/YL6QF M,R_IP+F=UZSVID*@@4T+^@AZT \=GV8,,]B"BDVAEWHU0]<^3V-ETV+[[> MMJC!LH,-T@XW*"EPT/[S8'56&R99H9XL0BHTNP,/>O2@AP\8_FZAB!;1/)N, MQYH(%N!;;'Y81R#G*NQZG#T]FZR/8]5+0Q#'A@?CD":6B/BQ8]#_WULG)@R[ MI2&2K]0N#)VR*[XPU$-4L2R4YJL__YH0;PAFV[F'>26Y)B3&FH*KQ\[S9?'P M_A4Z)O*0 WT?VZ[GVK1@A'XK'70<[^%(:%5(#P+=>VYZ1-7N6JL6K;*[Q(;0 MSU=L3<^\6(UUXB:Q%O/'N4CL,,='-%9OS.:AN)I]Y+]%3!FCDFI\T0/!1<4> MOCUVJYGGQJ[K6''HPY@][@TMS^\!(=\>(LDJ84R@RQW<0<*L-!)2ZCQ5$(9* M]!8W8,";Y:(/<>6C -_\H>=?TWT7#,LSU M]W3]E/Y*4\]]M; H%6%)O8(;%EQ!VJV$'>P/,6:K%HUG;6-P?+M5KR MI55[,M['$>^F;F]] *T3D^NU".-BLJTEEK-5;SW>GA9QC2QKTG)6NEQ_+Q80 M0]LG81"XCA<$H>,2>PO+!IPRT0-"OW(/G8M10K46P=; \CDXWU36%/FMU M[NA5)\JB\?J06BSLY# )EN-4I_+2%ILN0@_:-@HLQXZ)CT/7WTW1Q [T=9;/ M_"#TJR_4K[Y\=.O37^5,CZG #/S\-9BA5*S"0E'[N#HLYJ8")9;@5:,6Q[37 M+.*(V#[-#L2RC"#$EAF&5H\F].*!I^K48-"OQ+YV)>8C6YL0*^=Y1!UFV&TH7MA_"( P,WS7,,,+("&W2HPEP/'2% M4 D&_1(48(I]_A),02J68)&0?5P)%O)2@02+LZI)@AF2 MW^"WX"H:!'O<0(RUOZ-IW1_$T<%=N[,6N /!D&=X@^/\X=, 0K<'I835/$N M?GSGOS9)2>VLG^,L3_)EEJS/\]NB?&AN56\..NPVHQL6BF/;MIS8]US;<2P[ M:B]"1&X7FQA+'I(R^X,=.;W=9J]L+WLU MEWG3L4Q=@+S(/VV#LV+!675^_3+H37D^VM[)2!HXG_ZM>=4.%=K:)W]BV;,1 M/E]M;JILE27E,_J150O/1#"P QA9L1L$V(MBC_36+.PZO-EDB W-*61?R$#X M#';HP&\,GX"H#6+R=*X8BT31:99Y\,>?"<;B44[^HSWM9O<*5%N PX3\B-<' MU%L%3]-+MA(O"K6M1Z#JWQJ(BHQZX9N["$W\FR(L>D08VLBA$',7=^+ M?EAW);\G&RTBD6I2F"6.REPG08(U^+C<"-34.CF2D\_K^W1/,EEE_/T^6]Z# MFO[YVQHYR[=2V];20ZOE5X09M>3N6A%PK:#;]P_DI'3O4?R:_IPTU: M+AS;BXEO>*X3>W'D8^2[7O]];%@VKVJ*?56S9'9@P$_A9GU'_SGY>5#;?>'; M@88KY__TK582=S$T\B*)?KWK%9T5:(0N)*X=VP[M$[$!72ONK$0!B8S%4UK> M%'S97OSK(JUW'XA 6EN_&"VTN(12FP1G/)E?+UFBR7\*ED1J +UL24ZB";+& ME]S?>'HPO\MS,KU8#D)?J&D9_,+YU^0I*?->F*,(!H%M&TY$_Q(AU_8,:_M] MFQ#>1"_V557GA\0 SE6)E>!B5Q%T/;@T#-6-R565[]WAD(0Q29CLL6 M"$(+0A]"P^@-6"3D>F!&XK.Z)X8Z-#*5CR _'*6A/FH$J\+Q6!$H!?6Q(UD% M.08%T]IGN3UW_K6T-79Q$$&_;_(=VS' M"F.+^&0[I^H%-O?BINSW-4QI+6O*I(&DM29"%Z>>!55 M%T52%>FC=8VXKO=*UVFX#ZIP$V: MYB#9-MXL9Q,4^3)[3-9G]-]H9TBK^@Q4%'MS2G&3K\[8Q^FWTX?'1MH?R^(I MJ]@S5,U/&)";,DVH&>K$MKBN[Y.ZS0(4<5(W\QMIONHG0-IGY)LW-]E.AO2? M&XIX_=Q@S(NZQ4F]2U?*#LFT3!]-%C)-8RZ90@K[^\=@I!C@O8FD?3/^2UHO ML&5A[,6>XSM^Y!!B(]3/;Q/#];G.(HI_57-NH!!87Z5@Q"X$$:#E>#K0RXA8 M*F!DH.-D:+F$8^O[.[U=GI]Y7)8A@;L8VC+XJ\"O:=F<9J>N7-7%\O=O>597 M?Z<)Z]>D_#VM<4'S6_.$83?0-P(O=F)H6:'I8-LEQ#6AX?FQ[1$OK;Q5@\$"+#^P \M=*RKD^76=.2;.8].PA!0U4T& ]0+K$O*IR]OGK MV"FC(%?EBD5C4,4G2,Z!>E 7Q=-7B]H\*_0WT(%YB V<]GZPA=&AL&S7A[9C M(M,-7,^T<8!PC\(,'3PH%PVT/48^:L:5^SUU"W*@*@[E73(OC4BYFMQT. "J M\M/02 S,42-&1&V>&A(9Z:1UG"V1Q*6(]YDF+U7>G4I@2EF43F*=-2] =FAA MPT?(0G$80,NW>FO0@MZ@9,5I8X2D-%#O>,F2S# :>%*3212E"U[Z!J8%#32J ME7]]&B^NY8)DS52S1;TXIW; M[B95OD[(N, YPXF8E]_6G6SJ^Z+,_DA777NGC;S:ZPM5NP#ZD#R#F[3M&/17 M;Y[W3VJ?L4Z2['<3]L.V$ZV2.GW1:P9>8\5/\(%ANVX,,/ M]TF9ADF5KEBK2_.J:>NHI&CNFFT"X?/N5[K7*=#WI%PU?_E;6M59?O>U6:TW M%\1V(:2I-' ,;+NN$49QT$/TG5CH#>-1@6G.@@TD\-1BZO8V"+X',6J8^%:0 M9QLAP83),'ZZ82#!OB-@SQ.FS/N_UWD#&D_.VK^!SB/P]7A\]3PKH3 61Q;% M)PGY/-;5IW']]=L4T_$OE%!N3D.\.0;Q,KN[K_LTF-RE"^)Z"'G(A!@1,PIB M*PY0C]4U3;&7AB9!.&J**1MT?>E(X4EDF_%C*)!V9AV^B?-/Z]L9^'HZ^OIR MD>H G4I*DS6(&66GZ3AX+TU-'!'M^8K\>,S*YI?;A+KP,$(80C=TB&F''O&Q MWR_P8&0%7+1LI*XI'2G(FT!FGT[+/S9KJA MCXHHZ$@QTI'^X&E%WF]5J60@\]KGS[YLV(K4Q6WSTPH])=F:O?<4%V4S$[@@ M#G8,FN<<$E+(['1%M(7K^#'7Q;:3@]1]F**!U\RM-P!!TB-L#CU\5SFEZEY5.V3-]'_Z7(V513V@[8JNNB3M;[/\=%57\IZG^D]66Z M+.YRMA"Z<&SB1)[K>B:V#6A!8D?;!2S;,[FVI$V/4G-*ZQT#G6?@D#R>@:U[ MK0Q69R_EDWE'?Z<&SVD-=@Z*Y<,)6P-?0OP8#4$L(T[7!K3D0FTA.I(,IV\6 M\\B&,^"AF%N'G4D^;(>E-)MW?\1^SUR$,8%>!!T[##QD>]#"VUWB.+0@UQ[! MF4+_Z)GSK)O>:L84>Y[/)*-*MJ>)TZS^IC2SW"O MO0>2,U9*5Q%#KDW\[R(F59T]L!N5*(#;-&/W,U_2?Z6.7-S>4C_+:A&8861: M'O$(-%$0>[%E1#T4S_/Y7^#1!4!WSNT1,C7K((*2_H' EG)MW!_/;+.A76*V M%(1O9TMWH=C!!@PWRU.@1SZ'N CL^Y]#?.0. >S"P;H#FYIF/21+F[ DCX_K MC/YH_T0 2'\P#]/N3LPF;)\ZA\!C\;CI;GA^=9 )(V<#MO]+TGSH:, NJ,V M@W,!VETL1NP%_(E26Z:_;!YC7UT7>%.6M+-U?_M'FK23W=7"81<[.Y$?AZ9O MPB!$V.J=B:+(Y+[T?L8N:$[6S8 D[P8DY18W_<<&>'/W>8N9_D;2+9\*9(P9 M,\M1"\P8_=BCW??*B]>#7=#X?F#$^X\7(U[0,4#_$] YO_T[8Z%=G_V3-#3^ MXF;&7HQT1O+NKDSO6'6TR??D:,E:$:URTG]NLOJYFWEIJQSPD*R:-QK2CKL* MK#9E_SQ.+U[=W;&;G!8 +[^RW&^MW2>;%GL;V$689 MJ+_L7Q;$-",2NWY@Q;'E.0;U)>Q]\J'!G6OF[XGV.8>]BGLI-0'!ZOGFWS_" M )&[ 8WA9EVOP!3O(;=J/P4UI27^JB/1.RL!WD6X$#B1\A'Q.3F([? M0PXCA_]&R:F!CC.A?EL*](4=C0(YMW)E# M.YB^AIH/%:\W LT"E/X*B#1#HO.\JLNFNU<7[)'2^C[)V^M2^XN!OK]]-6@! M0R-V(V+'3NQB*XYLH]_W%-M&B*#VJD@G>,V54B=V_:7#S<,FW3W#2_'G?F;) MH,Z::2Z1'[V.:AT'>YZ#QG6VOR+OKB/?W4G7MJO7#[M]]'8U0L4UE_8U616F MM9UIKV%K8%KO V"-!''N.&82^ MZ]N]+SBRHED5?%(>3%#U/>X]=C37TD^N-$#Y$$?CUO5<3_Q3-;&;E MH/;F]J%J0K%F-YO"\+T@3ED=#FI4_X>4B,,X&KM.5!#1:8O%_OKPS3K]-4VJ M3=E\KKL$UO)L&Q/ZO]#&/BUS8].%VZH7^<[TE>(@^/J74;>BV1Y"WC3O7VZ? MG:"@P<,.M=!31S.F==**<;0&,==R M)DHWMVF+Q&/Q&[U"5-*8_LSEH1J"1JD-%<9RVL*P70I/GHM-?LY[3&=*XU7-MP M6J_!Y<=M.'.HU+0VH+E79P(-:=IZ['641J_!I)O)G[GNDB=EE%IK8,RT/UKT MO@/7.P?:$Q7GW9M+?T_9H>%TA9[2,KE+FQ]&29W&25;^+5EOTH5O.[[GF%9@ MV%]G>.1O=+1)+W*>!6Y!XBZ#"VAQD!0PD8 M3-#@'.EQI/&;S?$"[^,Y]&>H ;OCM%G_3. 9&-A(Y_5RD^HV\4[!,#N,W.UV M'O=I?T#>5#TF-7'DIYWY:7W+>'WK5D.+V^;QVJ]EMDP7Q#-,#QFV$Q&,X\CQ M$2)](>;3GTP_5S2"DYIGEW8)XK%+$-_[!)%T":*Y$@2L6(*X90GBB;FRW;>V MO1OYD;DSAQF&,5K>E)-9,VMT?[;29[MGB3UMV;3LK_\GM>PYS+;-K(7/?7YN MK)8^[>3>\$8Q^G3@B.WXSSR!.":-HTPYCMXNM X%SO-EF=(_S/*WT+/;5V=@ MJB]%C=JG.!;L<80P1A:*K3 RHQ Y;#C3^> @K+V^UX9<<]'>XV:2_WYUGMV^ M.4'1JAX M9]&N)BMC-;8OK26I;-14UYG:6\\'+A[UWE^E3 MFF_2*J;1(#]H*9(G:[RIZN*!5B4H7WTN\KO/V1,M3JLJK:OKY&:=+ESL1P&V MHB (D(4]._8]T\ &=KW "B'F>A9J)"B:"[$>/1M!]_@!:]F@]P!L70!)O@+, MB4^-%Z!U _S6./+_":X*:PX@YU+N?&(G6#/I#YN>==)!A!];W!PGDC-9D1S) MV=?+B&-R?"H3+(M-7I?/BV]7"]L+7 ?;L6,X$.&((+:HV'W8U M[\/YEF=L[O.*5KK\EP+N]] J7?YR5SS]/YU3K(/:_;^POFGO]58P(X$(ZYOQ5 M#+[/V('.IN?[KA&Z7HP#V_$C:!G$#_L:R79MW^4M8$2^J;F7-E#XD[(0&Z>K M%5U$B'77!H5$A2)$!G]QHHL4N;J$DQR>@F//L0.UAHSKTY<94JB+80$7*RZN M_K9 5A [$ :.B_T (,CRC#TB=)D^;F[6V5*LP_*0PM=A M%;,AUF&CBU_/OYQC] 5*Q^&UT?11$<"%=-3%^NA?PH5#K, V'*2A"I RCX8J KB0;@#\*81.8%GVZ$9.!;:=@7L^+SS3:+?U=QTMW#XIUJ$F3D]]Z23 M%+%LLT4B,03%\-CS:]W7 M^VR=/3YF>=JOJSFA;R%JQ;8(@A8T7(.XO0WD$9NOAI;[MO9R>@\2?^>6X.BT M[NDE1TSY]K!(:)\$/?SJIY>FC[)'X T+!]12GJWI]7( ]D)%>Q$;R/SZWXLH M0!&!MD^(A7UL.5;L>/V' R.R1 8R')_37 W^2MONLA";9N A@6^:0;'_8O+W M*_GO8S<1P(5TS/GKF7"SODO*K"^8+#,RPC!$.$"> M UW#=>-^ZZ]CF;[).W03_*SFOMJCX<_1HK2WL@$I6+*"O\98M& M=CY*S?*2@@,%BR1/TUKF(#-NR L\*3,NU#0LYR'3Z#\>N M$8C4*1R?TZQ]7S=I61?@4KA8X6&"KUA13(+@6.T;N;R^ )U]MT0RJ]_8=.E#M2?D\?:TG![L8 M&&O^%OK7Y(_D]_NJWIH( ^QX*/9#9/J&%7D0;H?5CD="KDVF4A_67/LQ//>_ M,SS\8SQQ"[R,6N[89H]V'?][@>U!7XG&8]O+H\!Y_1E[\>KC2E M>> KLA53("9]I[U77&=__NN1.EN BGG4V2* "^FP\U&O[,+GU3Q)W,;1]\.M?<]/[_@4OQ'"19WH!_2 M,ZW8C%!_2LQ!1A3R M2J#PAS6K8/L.A?@]5>($G=9#K=R(2>*6%KE[JL39X9=&K2Q]%'5\3<(!@93F M:GJ-E(=>*&@K8O<0"UZ$^9E6KN=U^E M#!1X) AC'%+KH1'$Q.SAN AAKLMS MM(/0K,"R%]"EP_JB=5SB9Q4HL72@,T9:;AB6Y?@='1TM;/.X55B_ MF\7(W4%.RQ>.&40V"IW(\ -HTW\CMK/]?&0(W0[/_=%QM%9.+T\S(J9_2LF0 MT[-I1(E#9+BYF9=H\,,^( *"?O-VZJ]E\9B6]?-7V@IJJBGL9;-'5HA_2>N% M[5F6Y;H(^XYONA[T/-+?7>H&7HCYMA$I,:5]:U&/[@P\,GQ-WDY[A&<@3^MQ MN\0QMHYT$R4DSZ/KJ'&ET- (Q;K8>;ZD&?LZ^4%^L!=ETC#-T]N,O0939_DF MR^\N**)F4%RAFZHNDV6],*,@@"XV8Q*S*2PCH,B,.(XL:,30-SR1%*O#ON9L MW$(&%#/H0(.?.M@_GX$=K2$AR_?3QT9L=) 4U"TJ*<$LT=$ M56>JFUY7$?G5=G2K+8=/#&Q'*YGGHFS)O"CV-44RIHO0VI797QR5TX2$? M62@TH>\1(_)=P_3#WKA%$->[9HI-:M:M'J68<*FBDT^_)F!23,9Z@("G#!Q7 MSOBX.Z)JBLF?A[BI=JK0VF %GY=F#V\V*Y!+N5H1(N+!"!(?>98#+<-W/*^' M10S"=6YB-#":Y;'!+SB$UA\ /MF<%?=B@MI [[9G+#_8L'HH[4>T>+2(SD.E MQW/W]6/1X_(L.-Q^@>YM5L$V],PP)*[OQ[;CH- P26\[-F.AV4\U%F<\]![* MI= ?$0:Y8;AKV5W!O4K%W6G!^6*J)^'+BKVZ?T!NE+&1(?I/ *\,*P0F8&+ M;!^ZM%X.' \;/03'LX6$3JGA60_9U5 K-G ?G57)X;M(V3G-,)Z'28[!O-* MS$,4];AV8&"O@3_N=?&B3+.[7*8J103[ ?%LTPF(!0FVD(U[0(;I<=TV/@(, MW>OB+7+1=7&-M'.NB\^#<<%U\1;TAQK RQ-];%UZ#)60^RA](IN"X^'I.RZ^(<9>!$Z^)'N>-9%U=#_CS$3;53A];% M57(V\*C/P@TM(T3(">@H'2+;,E$4]-9L:GI1%W6RYM,V61M"8K:%P]T/K]E_ M,HM#'DA' M5BULVXH"[!#+#$,/>K06<3&)B6%8/@D-2^AL^3!+FI/_%A%H(('?&"C!HVL# MJ>2<$QJ-1;'$+TB@GFF<8]P,.:$4BI6Z3H=4]B4X=!(V'X.89O.GN+4A9Q9PN MQ(*J^R&B*SAA/RRP>I5<%]\\V6#R6,\LHTS/QZ&L-#TRP2FX,GNB9I_2.,L3 M"H*M*%=UV=S'6+UPIKD,D Z&?2-R;6A$R#9@[)@N[%#$#K:%\I1JV]HGY7JX M8(L7[ $^ WN0!2\ U18.WKF\Z2(A.JFG- B:9O>$V#PZS:O9GX MT\FB&J5M+^KK )@&,1S#<7&(;2\D?AS%7@L@<(D5"6V546AV)(%7ST \YZ._N'9'R_^3#A]VG%VB][LS0,JT;$&,O\AP[" +#Q98;$M/Q M@MZ4'4.NB^ '&="L"102V&$2G-8 M./O/*Q[AXQW=4$+?Q$\P*G&A4-BD$V90':4@S@YJ%+2N,98'\LJ!E<['!JA&IBQ#1!AA/UND Y.*8# M(A3-I-\+07[=S\7]Y:\3+J\6 <*.9SJAA9#KP"B*(?:[3WO(]KEF3X0^J+L. M*.]2=H@@.0-?Z6\=OH!_ "6\"5\Q&X()GI<(#9G]\@TO+]*@ "\SZ<%"D-]D M:F%_>1[0VZZA[>8<^O=+AJZI-6,3A"$Q2&B;@1.%GD$1^_W\!#8,DROASP'G M>+LK]B8'NUG _=65WD=PD8.MEZ!Q$^S["1I'P4M/A68ZYL ZQV.$4T,<96/& MO]K$7IO@?X)Q:J@B;4/N1LIS^6UV FQ0\EL53MJ+_REZ#?-R4CT5%&QG] M4-DS0%O737J7Y3G[I^9IEGS5_&%"P2W;7[YEK?>I:;T/+<7-Y#7[T6K7FI.V M-;-OK/=:]*9BGZNRNSR[S9;L 9C-?CO.6#PJ\-/G](DV3OOG7\#5AGI6OHC0 M&:C2QZ1,ZG3]##IBV%>7]Y1 :F.U:;I)?4\]IH"*U1E(:DHK]-_ 3^;/H-F'#^[H$+EBQ*V+BA'3OIG9?P3\5*;).ON#TL>5IWM-%/TG]/EK3A M;-;43QK.YCG49?% _;U/\XI1G+4G<'YB)GYN0-'_B.)@_TE1/A\(P;^#GZR? M6?2IY8H-WZIDS?Z65=6FB?%9\U_0_[1>=Y']B2+[^=^;/_[)IFR525[=LD?W M&$CZA[L_**@*T7;0A0_\Q"A,?R0/C^OT;._75K3MT":YYSOC>=OO:9H?\/SPX[H\#YYJEIQW"N(Y"=WTS['.AHEB?FEH%J.";H[1 MA-")0\NU0@L'01!')B8]Y@!Y7'O:YH'T3S(R$%KIF ?STXX.-#2/>8X//F++ MF,4804,+43!*Z,K["MRE>7-U.4W6Z5W!)NGYBG-6K;5#"5:.O5_GLR]U_[E@ M+4_KRE>%//L6LW1TR"%<[=-BORZSFTW=H*!E9N-,L5X7W^DO_JO@_U?!/WG! M?W U>UZZ]:M$V19O4$/QI;8$\0##(GD3*D'B'ML@*64O:0X\E/>M)OUB/4S(HF^ST]Z%974[:VVL&(O0!'7A %5D0")\:> MX_2K]*QW2ZX/3[PH :1^0[S21K2'--5M9 M-20W$<(5YC1-Q ]+90H"H"0A[W^=?.<(!""+'C1R8T+=>R(V,WD>)&)G>>461._PN*]=[1^(9P]5#/,GC@F8ELL9.\;_9_+P^._=\H?D MT"3[NS^L22# 6WONBR.YX.UE:P& ?,=B##'YCH$F;?@:HX".POF2 $TKM% M/@C[$GLX)HB"7"+[] E\*?+T%_I7\.(+(/V1576_R6"W;>,7\.F3FG5J/HY. MK3HK9GKZQ*3-L_=6A+6P)WRQ;HN", S/N$QIZKRDI='"L0+#]V(78]=Q+!); M/NQ'8<0/?21U+:ZDK;%3TAEH(8(6(V @)>^TE67W>-*9@MB!B4:(4[W7R;Y/ MUI&E=%4TSV,]79DWARYB5<(23\G][2HJUNND/*?#NA^-:I[GVZ/*"]/'R U) M;,;T+Y"6]U0]6WO(QLB'?-M4AMO1ODOEU3)L78!OOUS] EK,>XN$/]HM=>UF MEN26*B4PP7.:",S[#&3\="D]'M5B>O8-7/6$[J#1?]PNER:CD;KA\N3OSS3;. MYI,+$F 88F@80>@Y"$+?-+L[;)%#HM 1GM>9 N1X%?>>=X"Y]\Y9E.KU8937 MQU?>.>W2?%QBVF*2%B$PPS3WQB ]2OA7.W!DYKKFWA[47FC #L&_.' MT\>%^R;I@E9V.:WBP[8S7+$R_(J*0@/^FB%>F#%!06@'7FC'T L]&,:1$2// MQ[YM0XL(73"MP)[V[1<=1-!A! U(L$4)?FMPBMY(K8)IOLG'L4D6W98QE%\] M-UN?)NW(1*1*RN53AY9()<[=9XXL!U_- W86#Z$0YC MWW5@#\,*35^=^$D8GUH)JS/0@Y98E=87$Q4RJ3D#:(8;ZZ8C1RQ6H("JMEKP,&.F1G MW1&?>N17S(ZP=$2@E) [#YU2X\KKM\G4\<.K6E_+]#')5N3'(RLT^MW=+W23 MCN8"Y'C("L*(D# *',_96C:);8ME>A46M>?]#B1(6Y2MGG470G4E03M-+J9@ M2MCF$[*Q:1;3LY[?#EY#;WNFIT4XD:YQD'9$WE12/@^54^I1H:^!BE["])16 M=3.$.L_1[6TSE9]65WN%"851+)L_I<#^L\CR^F_TUS>T12\LR[2A3XW3NC$P M+1B@N*\>D1U[@N,>O5BTZ^0.?G\Q7;)Z:N\IKXL7I5[[PZV#8U_U-(#E(SU^ MG.C-0PM&\O7-G5+C,/#BQ&F[UM>X)IF@ -( M/(1,B_1VL1T+K;H-MZ9YS'=!H[),P1;7R+,D)_DYFK%5<3N//JK0GS?96BU3 M@_M:4RTLL DC)_"H9=\(0VR;1KPU:J(P%AV:##*F?S:RJ$8OB(\Q(M.SQ*B< M>;<2=(:W3\EPQ-NA]JKL;=<-8VP[)':# 6VZR'3A%YOR0MBKI>'AWQ?=X+: M&U@>3D[JV.(;H.LF2FQ OL\1^*T'-/(2Y#N4')&8(03.0U<&>5"H:TZ""QWI M;4J'YZLXR]E(CR6EZ@MUN!VS?TFI7=?'V/$-9+"G4X(X1![N[3J$".G)<&N: MU:4'"&X;A,W%^ QD.5',E*@67B<_6NVEIG9V%TY@A@&R4&"YB$JO$;E6/W\9!H;+=?>9 M(E-CJ6#W0D:=_!A[DN\X01S=;""S\^IC0YTYT,&4<"0Q5MFS95O0M'S+(#C& M00Q#$SEF;XOV<*[WT(=9&'&\,ED!SM5SAM$WCPXST(?#9;@T([S=8^^8"[2##\@SZ5]^Q+-,,C* W'T>B2U;*S&J?+_M\ MCL+SS^?7Y^0*H"\1N+J^P'_]CXO/$;F\^E^ _->W\^M_C-O!>+D[TN>4TS^/ M;JC>K4)SLY7NK*_W(X8F'::;GFLX<>QB"%U6I6X-6H+[:P88&FT[[1[&D5>+ M#K/#U^5D*9U=)Y-VY'"W&L:-P#[;Z^+]+7)N[+)%)]V7W;M#8N3C,X?.0F"$.%,H:DO0@?#<[MQVO M4$-^[#9W%MB>"1TK@G9OTXN"2'H<+F%+_]Q8D=]]8A<_SF,P_I8BOO'X &KG MT8T4^7)X5#Z8(;&,S=K5-6U636]>A!AZQ$30M",80#/R$-G6!KZ+H'C*%OO^ M!#E;)CL+DB:2GO7Q-20_[QKE%"GZ!2O)NEA[ Q8(IO;S$- M1GY,*P ;1K1$@- W8MOJ;486WQ,_:BS]>2;Z1.B5GNO3Q*R:Z;ZI%.DH3V*3 M?A+\SD.E%/ER>NI/FB&A'2OO%E^+V(>V&R,3Q]"A0QGH^[;1&S2Q+33]-\#, M*'M7UMO!Q62S?X+"FZXQQ.'E^A)#(GAP9#=6>^Z MA$1N?]8LL+ 1":Z8#S"D?9B^C^U_@;1!-_(H76J7B@).Y]&35#CRNI!6Q0W_ MQ9D/#T7>F&WO(XX-'P7$H+T6^3:V/3^*^PD "X:!8/\1_KS^?28-(E Q2&/? MHOB2BR-=1)JV>70,>?AO;CDF!3=(JWI!SI%@,8G$?'&.) MH:PU"=9:R_MTM5FG%[=QEF=U^CE[2E?G>4U;4':S3ML-S>W=SI8%G(_("(W6VAT*SNF=X.*3NTUV+]U( %.[3;T[,R-\RK# #G M]/ TW O.&JNC74]MS$WBL5I9?23FH80Z''M=2^OBCOO%W\-F/V_O98Y<)W \ MW[>0XX78#ES#)+WIV'8]H6=_51C4K):GNNIGV>OFU;#-)Y"C$RTFC2HXUO,B M, =O1]10*>WST$&U+KU^(%@]7PJT+]ZP&]C0WG4'_46/_52'Y9N8RBYV32MB MKX/$OF7WD(B'A.I(K4 FUKI_27XN\OJ\6"'LX-B D$)H8HL@Q(.Y!V082.N*O&8KF[$![JJ=,QY50 M/UC)QV9=K9:_+^/, =!Z %H79J/<''3+:;?*.,Y>O94ZRZ_?ZCG6H^"L?KG^ M7BS\R'0<".W0-^(@0 XQ';/'@D)+Z,(C/0CTZS74J=?<1.N0:1T.48U:BWM+&F"S<.4.BYD4&U'EIN&)D$]6A, M$L2:%9<+@W[-];5K+A_9VE17.<_CZ2Z#/GOE92#5:J]0Q#ZL^HIY.5Q_)5C5 MI\ Q[2X+F@$"U[1CR_>@SRYV\YV@!^/:EM!Q%$T0].MOH%M_^:C6);_*61Y- M?1GRN8LOPZA4>X7"]5&E5\S)P,)+_YO9"R_]7;7"*Q*N#RN\0DX.%UYQ M3@7N*NM?IM@W?G&[.]OUWL7Z"Y\X3D@B"/THAK9!* 1HAL0-3!N[+A%:GM.% M0;/T'GKUX^S@HB$GU'N*7LES<[IWM!N^_$3+ZQ70RY!Y1 M:MWAFH=4:_?R[95W([#*?X@O7[&,ZO&; ZMCL\U]OV%1511=3F[86Q$7HP#GW?]>)(I%Z7-*&Y'&>HP M8&@LDCS(:LJG80%OF%$L1>:*+"0&1D. M-=$;\QUH#M$53A/C*\O 2D:,0#EUT<#=8'V9N([9)T9 8P29G*?*B#IQ0F>D M.)&>X0V?O[!K ]*+V]T?/S=2QPR%-JV7YAN7V ,*8A(-F?>7-CCL3 M_ Q:G'(5CT*R)6>(Q^%YT*PQ+\7CS!P?)$QD-GDXZS-1.@V.G9IU5L6=G")V MQCL-CGW/CF+";L>$00R#,"1;#48V$3J;,<3.R)IWMNV1H?+8 M&@PLZ,7^H J-W\P$:_.?92^ ',*F9 FFA\CA"_4\'(Y3P'0>S1O[@&\ETGMB"T6@ $ M>\@5>L%1H5G-FK6'M'E][076,]"B!;]U?^?95:@]#GSJ-E$(Q-1./?O:WOK@ MX_+HUDWE 9F'3NIP[)V70[1PQU_;M8]A?J4-^3ZITAV@[LIQ/PP=UT;0-^/8 MBYT0(]_ !B9F%$21(22>0VUIK_+Z)]]Z@&"'4'8SYD!V>0N^\8@5K?J&<*JI M]CM*UM$"4 W-\U W9=Z\*055LC1$ 1K M16G^1];'HP1*Z:::D,Q=3Q5YR:VS*ED=KK\'L'0SE@@2FY@0V\2*/-\-L!VC M'@TVB2+]'89ARKKS#!R3!\G%$4VA&BK0XT5)81$[+$ C*_A1AJ447$W,YJ[@ MBKSD5G"5K)Y2\"2M%F2=+NLR6V;U\PY,WCRO4/V:/MRD);LS-H0AL@B[,]8R MXAA#W!NU7)/K 3!%IC3K\1["_0[?8>336E6D'I?4"?@44\[C5(+?6H"<^4L5 MIZMBN6&=K-GP-B=N7P#CYOC3)W8[3/H+_2MX\060TG*/LGQ;E*"^SRJ0KE/V MPU_ IT^\"8FRT&09T^IR#!\M[Z02Q7Q.FS%4.U-H:7/\^A]OTO4A:\2U44#3 MC(E<1&*$;-OKLPTR3,@U SS4AF;%9] &2?T@_DYK_%C4B8G[ =8D5'T0??QR M/A:-'T7'C_!Q0,!5,#B]V/, M?E\?W"'P67Z;K0*JA\YHZV%9Z18,'H)'GJ7^S+495QWGZ99EBV> M2O6P5?10;.A?E_4F62]\UR.^8: @BBP;NR1T@K W',6>QW>EJT*#(GU1ZL;6 M'E\%ON6T50&&&S0:*%',JF+Y=%D[ ;WB4@<.YI(6)&A1CL\O?]$[ <]RY>_U M?0J2!@R[)YZ12TLJ0#_#YOL?MZN@FZ:1LQ^MM[FH_RE8;IT;5!?S<7:@0E9, M^/2ULFJ'"FV-4T4V^7M&AUCY1=X\-K&(0YN6[6: W!#[<> $!!N]91QC5T4Z M$;.H/9_$F^:,Y_ZA _Y7UY5R.R2)Z"-5919I40(*LWDE9P*.5202?5S+9Y*' M+,\>-@_OI)+DKDQI'JD+4#VF.7=".0/?[[/E/7A,GKN3.+23K#8I^-[&L* Q M?&8O'16WS<=NDG7SH$9UGZ8U6"4U]_-'@BGI!?O".4DN=G-.2I(><66E(6RI M2$O7WPMFN5HX%G1A@#QJVX46,GW7-'O3IN4@=7F)V^1$B8GS>7FU[ [/3%IH MU9":*,XF-2D90XK2K"XY::'[(V0G&D+V'UZ)H@3_6! MD$Q4PG&I6^,P(+$1VJ$5F(;AQ2']?W9O/"8.5IBM M^(U.E*]\A4(JP+""C*6'6ATYBR%5GK4$R%:8M_20_H$R%V6AG$7BVD9"-G6) MA_(#)"\)IT32ERQG*A(8>^*[2YX^#F(WMHEC-[MC"<1D:]NT G7YB]_F1.DK M4*>H OP.SUYZB-60O!A0U;E+@&EUJ4L/XQ\H<]U2-/7]#%+7-A*2F4L\DO-/ M7!(^">0M6<:4I*WLJ4N9!$>N&7@NQC9T'),X@;,=\\6.:RA,6]PVITE;EJ%0 M3/GY59"VM!"K(VU1H,K3%C_3"M.6%L8_4-J*L]MY9*T^$+)92SB0'R!KB?LD MDK4D&1N6M6@C+]/DEC;71>3Y<>1'V'9M)_2@:?J^MYVD]%Q31<(2,#=%KMK! M4Z&C(MP.25::2%69IZ8C5D5NTD3P1TA+C=?M@&KRS+0+@W!2DHC@G/.1C#M< MJ4B:IV%9:.$8H67[H8==C*(PL'S#=GIC,(3AHB[J9#TD\YPT(=)S=V@&91OV M%15Z>)J^(>E%*7,*D\HXS*G('TH9E,\:3:M5GSLTJ;VPQG.S/&=EYW>"2\\% M.>%3\:JZR*^2=8KR5915CT65K"]N456E=;4PZ8>A&4/;,TR3!!%V'-<,B1NX M@1<'/M?KM<.M"&FYY",B10XHI+2Y$W[5 63;3Y,&HH@X#>*31]G'HE)4W"F+ M%SE@R "%!GILX.(6H'%9%%'YL=B4$_KN:!1MB.NNE38[T!C'1?E.0_UEH'P? M8>.@@JM@< XBKL2/0G7;$I#R]"Y9TV_7[8T&"]>-HRAR/#.*7)<]B10%H14ZMH-CSS%,1'J+ MT(NY'BM684>S+O:00+W#)'AOT! 23VOEF/R):6=[_U('#7S:'O8'UY-0*7@+ MTTB4RNGM2VK+=)W4[:1$LQ]U![4I8<&R)YY6L\4R:WZ7G0EDMS;5@(G3Z[+W M9E-E>4I+8_I?94]9S9XOI+]"$=7E9EEORBR_J]@\1[5)V/Q(0:T\4H3#[WHZ M3/N!/* J6-/G!66>O+[T21D[O/<^-59Q4=6T1.^,7SRF9<)>^UJ$,,(6=BTW M=C *8A,[7M2;C) ?BUSX-,B0YLS18!.[Q&D8;\=SQ>B4R20+AJN9+.J0G8$M MMG%O:SK&TCM"I)3<>=S/I,:50D/CD]"BSE:U"!!&L1L@0B"ME@V(? _W-K - M?9XU-+DO:UXZ:];)0-'THK3%-$&/Z=DXU46$69M1GQ#'_EXGD&2 9^06I;>T M>%N%:4[_H?Y*FPFJJLW#(TOXU16UFC4UW?-U@>]I$THK=%,UA<$"Q0X,:$GF M6G80(L-R,/8:+('IN00&O&,Z?0@TY^P...B0 P8=[&$'>^#!=0$Z^."WW@&! M.V4UANGTJ'$>$1(K$?XDP>$?A\XC2!_EJF!IM@X,+/6S/_V0=YE%5+MF1XF=3I1?Z502WR+H4O8 2= MP(5N" ,2M;YLH='-@-,@_78!:T;)=*?)C7X7FS6*S:_NUEW,\));9%\9F690:>X=@4DHE[<''HN'KF& 9! MFF2.87<(IU$7^K.R00\Z"1$^>3!F#%7//HP6OE%F']H2XA:T_HPX_3 LJ+JF M'T8+[JR*B=?3#WS]?695!E\0EH,E0[+3V7H9!SWJVTB-UHQ*XQBHLR M*C8W]>UFC9;-C$IUF2[3["FY6:=X4Y;L2)KA1:YI6L@CED5"Q\=&%#88[,@W M'(-K,Z$>RYIKAAX8%8D>V1E(>@]:9>A\ $GWNV+G!!0'XGA%,'T,Q!(_>L%T MCQ1LHW*Y%Y4.[;@[I86(/+*36D] YK'36I-OQ1A-6DQ4XRS/ZO1S]I2NSFD- MDM]EU&1[FP&%LGG8-&?[T$-1UMD?;7EGA]@EIN>Y;AAY<1 B!\<=D #'KI"R M:C _QKDJ6IGU8+O!UAG3TAXON[AI"WC MW3Q5Y%=UL?S]:U)>E%%?J: MJ+3L-68JM*GOBS+[(UTMH(L-UW2@;?F6;V++)+'9642>0[B6MU78&57F&C&K M0+*%U\A=^Z?R&B?.K;"V::5UB*:UP, .V60Z]IHB/OV2)G9VNB7OR6&]&LB. MM$Z=5]6&6G,<$ADQL8W0]+%M1TYL.KTU&_I@A36Q(+4@1,1(D,V9"I&H%Z=$2(H5:0&ZV-05';"NV"49412Y#JW( ML(\-9,0.=/VM2<_U\" 5$C$TA105.WP*]4B(7DE1TL6L"F7:PS:Q/.TA$=$H M&7)G*E12KIQ2*WE^>"7KFBU*;LKG/:,+8IENX+M>9, @(-0JLF!OR<)0J%Z2 M^;YF@>HAO9(H:5F2HI!/C72S)R9"6^)>R-"XRO,.(T<$9PA_\]"901X4ZEJ3 MF*I<+>_3U6:=7MS^+2DSMA1WGM.>FE8U88]Q9&EUS?YPX?B^A9'A8C/R(APY MCHV,WCIT(ZX+&%3;U*P^/4RV5:T'"GJDH(<*?FO )U65W6;+9@7SXK;YR3/Z MD54+*LE&Y/FV';N(1'%DD.Y(/(42.@X4D4DM #1KYI&N&SZ#E[B9KK;(P6\, MNZ"$ZHD/GYY.'AHQ<3TFJ,>9UZ*G,NP=$5>MP9B'TNIUL1BQ<0M.T[TR^"ZT MYZAX2+)\$1$'V8Y-O( $84ALP[=V2Q4!\86F[50:UCV-]T95#_1WJK,M8D&E M51L%SMF]J0*@1%F?SU[GNI/,ZYG]$V#QV&R@CF#,0UGUN/9ZME ??X.JV>>O M9?:0E,_M<8AE1O_QU_3A)BT7 3)"QP^1#4UB6R'V#'];4A/H6(/K6'G3VA=% M\JI89ZMNR];APJF%JZ)H'1"& >7J.!%0):<=6+"']G0(QJM>#Y(I6K<.C\H\ M=%67ZOH&'IHN)CRVYIF M_$_[*H,(&HQ*)%. W2$:J8=8-:+(Q^F(&K@E2UCTQ&F>L\I)>,,E:[(L\=QP M\:7(+],E;8)5&J4W=7\>RXF@X6/3#GQVD88?AJ:%>D/(L+EOJY#\O&:UHJ@^ ME1TLL**XP">P;*&!FV3=''!,:O#4=\"L[X!I5P4..F#^/B?O]!T%!$Y_\'NH M X6RQB1X('OOL-+%[>M338LPMN+ )Q&,0Q.&MA'8MFLX5A0XEHUAS'7-K")3 MFCO+/CJV2K?#)_1(NBI>^;+ZB)2*)75Y-O6:1S5&Y@0CHJ\I"!C2CR;=YZ M6?K[&O<0;"&!%A//LT1Z=@P<(.?8%H&A?,ZC"PUWX_4F #6\\':;J'NA]R]E ML7FLSO/E>L/V=#:WVM*B+]^DJ^XUQ2*OOB0/:3=K2Z(@B WD8VBX/C:(Z?E^ MCR; R%\\I>5-P5L)Z$(ATO?V 7-WP1XX:) #!FVBI0])"H_T4-U!F4<'UNYE M,6Y3YQ\"GW_]ZG3SA$X8.[%G!RZ*36*Q\[C^5EN\,.9^;DK@DYJK=X9$<,U" ME)/C=8-&.L2JA!&8X+\I4!,CE#) MW]F" 79M9)F1:T1.$+N&%UN]+<]WQNO2?M-P_N?(WC,1YU D# M?3A>Y4LQ,N @%5K^![=28DGIT\12;+#G8&8II]L6[%0EM+U)E4W,!WL $.YR@ WJV M=Y4*:+$*'B52Q3GGO-\$= M. RI@6D^9P$?=L<)!,?GST#[E7KTN+K2P-DP3 M+U,VBY'E=SL8N]_I <6F$<# @RZR;,.* M\QMR(=04MH<5$CC,F4$:N.55=?*CIG8W M677/YMDN;ME&E-;BPH4H-((XLA!$MF=;EFEZVU&K X7NE1U@1K,JOT3&MC P M;&>3=.?#+!WIK@JHG4=W5.%(H;S9B76GR_2.W0U=E,_-IHCF2"&)8FB8D>O% M]/N!@1P?&K'G8P,3.G2U')%^)/-]S1UH!ZG=\2-U"%J*-[XR1#=E8O6%*%M: M=.8=2HX(S! "YZ$L@SPHU#6G05K2K1=CTS4]SW9BQX*!Y1)JR^YL>79LV0/4 MA-/"Z'HB==A7DCTI3=% W%!5F62ORKNT\"N+((VSU!91'XZKBQ0C/'M$PC+Y M(UM?)V5V>\OVH#^E9996)$_+N^>OW<"C:B!T2UB>:6(C"(/(-V(?FB2BA5,/ MP:/_Q[N31+EAS6K4X@4M8+!##%K(8(NY[7C\^S#41^#TOI5)R1=3-$'>)3;" MJ \ _W:920,AMZGFTR?PIG %AUM7$^_D4>?:\4(;75HMKHND[QZR"KVF"4N*O8,6Y\\XY1"RE?- M\U_[T$A,(#:CV#%\SPMBVS-=TD,COLEU(_:H@*;*;ONN@,87L%=C,F\ =0>T M[ZLIR7PZHBF;$2<.I*),*1Y#95E41S"'9M>)@_JQLZXX>4+96&-LYIJE=;I\ M,GMKYYLGJY/U5;)^2E9%^1I>9S)RW-KFF^S33]0]%PS#AR+/99M$26D"/K%0/8F\=BQ1 '"F4M2> H:[XL M'M+KY$=:=3+%[B^*J5]X4]7T1V5GNT,0HCB,(],P(8$0(8,=KND16!B%W.== M%=O5+#4M7-#@!7N 4,,MI %#HFJYOUT93DEY6*RQMTC=K"\:I_/6Y($02UX2,9#(7WJ"P9_$)@_*1\ED,D0=2&=:.9\^ MI^EUKQBI[?)GMV8!X-5VM-Z:[0=F&-F!X<:6Z?C4K-/O=_5BS^%ZH6:H#+O=-H9BSJQ['* -8D,,H@^_D0Q%HT?)1\. [*M@<'IU M5^)%H;9=R9X6^)PE-]FZ?] L"J$1D@ 2Q\78<(/ )?UN+.C1Y"!W7D#,AF:M MWM.;+:Z!IY $.>2;?!^#/C&]EF%.\\F!%]0W'P_, 05@9H M3G=B 0:^Z2$,0]_U'?9_@=W/MD [=KFV;@RW,HGN##RM),RDM/9H(%&%^DQ\ M<%+5V0-[\.Z2_@7?T[:6;@%TQ9<9$(M8 M<>31\;+EV5X0;S4V_RK@OO3P]X) M:1?3-B'&!^Z[5D&]W.[JD4,@-XJ^OD]!TESZP&[W*'=)9[WEOTS7373J B1T M<-UYQ7[]=E-ORA34;1Q+]J?+QL\*9#EHN?A%V8;KTWP>&(5K"LKT W-=CAW8 M(JV<.ZZ-T+?L=<Y&Q'WEI9!1C2G MIQVV_KHMT=6_812>SCNCL2>690X1)[/=>1"# EN=QV+RHTRY'B/D@-HKX7!Z M;5?C1J&X;8D./5[-\H;LRK;5_]Y4]!>!^;!';A0Z)B.7[!@D"J[>-+)/[ M^4EU%L<9<+RYER1L;DK<@A6M=Y5PS3O*&)MFJ0'&*8:EAQ9*J!8=58Q-N5R. M4$8]__" @YBC(P.5Q$Z?.#3X]&8\H)XQ9??RO!Z10,\,,'&('X?8MVW'MNUM M9K,PY%KBTV9\U)FM8_?$#)S?4A<-L5FN20(Q9*Z+*P:Z[NL1#H;B.WMT!N6C M#&ADB.*8UE+.^5SRF"[W1._P&<:C]GM\7L.+HCB,/MM+-Z$; M>NXH=_F(@IHJ&PK=!:,L4^J*K&P&G4%0%656N7B.?;^/<&!'NN-'9X _=I:6 M(U H>VN.T5RSNFZW5=WY,XQWWIUCS9CZ,JVSLFG-%S?K[*YI[_LSM@'"H6GB M((Q#._!B#&D9TIGVC8AP[=50:E!S]FYGD78@P0ZES"T2:C@^GFLGHUAR@Y6DH/YG$NQ?%P1]Z4NXJXD3@:VU?,NQO4+-_UC2 R;6S;=F2& MH<=JZ-9D0$+N/5N##6G6]#?'/?<02A_UE*#SM*Z/RJ28LA\C'6N'#Y1.Y0?R4>X*KPI2]I*%K9O0]/%IF7$A@-A MB VCOW#!CX,P6CREY4TA^1 7MQ61_K,/B+O[7!FL>6G4%BQZX9H\#Q M"8XLQ_)\Z/8&7<^PAZF/@*&1!.@+FZ?3(T(BK,KID"8Z!TO1#M>T:K3#(2!( M$J3.4Y-D'#DA2]+\\,E/M*DSDV&Y!TY?2N&'#<#I&FO-#!A&/F!$WD8N3@T/(2C?KXD M\+"-!JN3@*UIAQ$J14J$8&F=TL2L"JF:?E#Q#DMB@B7![FPU2\:7T[(ES1#/ MZEK351_3,BM6MT69;,]<5;1VOT_?.9:UB V+6)9!B[DX="&*B8?[I^GHP,?C MOM-'O67-ZV^MJK6(FX6,/_0(584B M=,ZU&A3RX605*,X(3_7WM>FMQ2W*\TW2G6'8G;M?A AC'-@8>0[R'=\(XFAG M$%N$M]0;:$9S7=>B8]?/)0V^_OJY1.+BE*&$GJ[21N12K"3;T=A"Z\_1R=P_ M,Y1&_D)K1#KEJJH!M/*43\?]/U K*2)M^L)(E2.%\@8E-8*G-+8'T(J21GR3 MKY;LI 4KQAHPK:[M9&T163ZQ@RB&+H-D^($!^\,7@>4$W&-KJ0 L?-/C;XT*>D7N@/@SVT5<%Y]+8NG;)6N%KYCV+;E1+X36M V M G:9V7:JPPL-OO6_N:#5OH+8'M/HECWV;Q%/VB?.ZOND!JML!?*B!FE2YB!I MKPMO[AQGWO*+_AP(Y4C?B]_6 MA+]^F -<_87&KL7<)/0'RZ;O'U8,5F]\;UI, M7G02 8H<9+L6LVI;3-FWF*P"CYV[O]"6!2KV#OV2W=UUQM2FMP >DF=6[SQD M=?.<04Z'(8]E5J6L^LGRY7JS2NGOLZS6RM;W8K->@9OF:8/RKGT'(?WQF.;T M/[EY9M_8Y-W7Z0_WOI=4[(?)>EU\9Z]OMY]LBJND+[@H!77VT'[GH2CK[ _F M4F.V^6W& M/)3P_)[^PGCYORL6@\NMG4S0K-SJ]5D5:-OO9.L!\S: T_%%KW MS$.6M_\AD]\;2L^P!QI&:+P'ZKPY=9OI"\)9L5',4]R&E)B[71T*@6,+.D;L M1,1U(AQA+PQ0#QQ%+N8\J3(CP",5FOG6M]%KS6G:@4RY.?L&H*#BW/DXPZ)S MFJ8RI.ZU9!_59]C59^*BT\=+9B[_IRT^\RQ!)V6D*-5Z QBQ5>( MOK.SY/4J)<6Q9*)XEZ*V&U,HGHDLAY@D#I'MN<0.+=0O7*(XAMRW[&@#H'NE M\/4BQ1E3O0YE+W=B^5U7)'B*NQD$0;1<>^\$R=G;[1!G8 <^%#M"*$=-O&SLRCP:LAUT M[.CJ3]0C1'F2]"T1;9V)_7V:%:?[@;'\N$7 4,<5E 9*N.<]6'2UO$]7FW5Z M<8N+A\')@A<0,G) []G]CY?YU(M"^YM#"I0OP '5 VBXZ+O,[R#9L6O*!5 M@LAEY:/$YWC&GUM@Q%)\CYI-X.YPLW][)U8_=>A_!K\U#@#F 6A<&/D]AP%D M'SF--D8(YW%F;11/B_$[B*RJD]O;=%EG3^D6SF52IVQR-E_2E-1(TFM(B)@& M])W0"$(<(A@;OMU#\CW?E95U#5"TZ_I+=&PU]=L5B%/:B)/UOI P3]H'TQ"Y M EM/MS]KUEFO[]/M]C_VJ]??"_"US.A/_I$FI71BT!%BTF7 M]HTX#GW/CNG0PZ$ [[&\5XN)%N=A!;\1[!YY_SD;\CI1DW M96V0ZB9(CUV0V.^4NR E[9:7-&\WSC2[7Q[9O ;;&=/L!!@T9R9$YX$I,3TA MF7[&2Y-?A>[&+#NRB=+;E-;2*XJGW9-"P;R8:'N!)L#8MS#"1F0'MN5[&'M6 MCR:V#"@[J%&+0G]BVSP\).4SRVL]\B:S=;M!F>1*WV6I+32B@Y'I8B(_#GDO M&LG+:,QH""+$,-?H0T_,YC;PT.3EP3&'3E;%%;O-'V%Z6Y2[05!$_U;5V9(B MB^F?9W>O!T&NY\(01H87862%H1V;CM&AB@W/DE9N/6C&6FEH<8/]POD,=) ; M&>\]D=5P3<$2U?+IHR2OZ5UP;EZ'ZFP;G$;B^ZC-1]ZE2.>2>;WAG)O<:_;V MH.R/P3*W_+<5YXOUD.0AR]O%T+WD8]HACCUD&SZ$IFE[R.P70F+B61;/=C/5 M-K7O)?O1SOR#KT5-A^I9LEX_@ZO-S?].ES6X+L >ZD;3_W-39M4J6\JL(ZL* M Z> 3Q !0:'N1D*O%X1W**<79#X2CPFOXC#,1&!5>_5:2+6P)B^8[3:2NS1? MLII]:]XR71,:$6'[AUT'Q8'K]^5Z'$)L"A;&JLQJKX"_-0?F[O)F;Q[KM-W* M^F!%E.595A)'(%B%)KZ .4-1?)]&(54<&(FYRN)0MT[JHA+>>-8M_[))RB2O MT[3ZG-:LU+JXQ66ZRFIT4]5ELJP71N0BRR P]%&$K)A =GMTLSW2I<#BF )N3Z]$CDNKF.S-D5'^)<9QF95;5OST MB=U"D?["+IEX\060_LCZFS/K^ZP"Z3IE/_P%?/HT:*7P)"L'5@?5L3G]BJ!" M7PH=[4U8_HORXF:=W;5U./GQF+5;JB.V^>YS\3TM/V\3*[)M8ON0F#;& MN+R?V !M MDZSWL*"J*I89NQGO[UE]3X?I;'9]0Q4^2F]8MHPLVS,]V_("T\0V#OIK8ZW_ MG[UO;8X;Q[+\*XC8V-VJ"+N6;X*SGT@\JK4M6QY)51TS]2&#RJ0D=J62:C+3 MMOK7+\!'9NJ1F0 (D)2[9V=K;-GF/?=4I3$T^!THJ66%O>B-M^+6B'6[YH)1-;%\I)O MGKAIE@2[0PC+;+7@T[HO>R?_LU<]E/^C:G-3Y8N<+X;=;*I\E5555O6[!+Y7 M? YDY6%B/GZ6'LC/8NC>))[%]\^8'T=6K\_.'$HC)[*<(+0]"\>.&_JD0X!8 MC2$ZRM1MU_ X<__@GD ::!:S)59VM(?A=!8>,P*2VP?>&_GBR77,(*BETVTP MJGK5OKNV^F7B_-]5G6V/)]Y^B4^2NP.ISE0$QD]NQCPKS+=?N:UMNZ7#3]G# M35;. L?V"'));(6!XUBA'75W6G'+$9+9]"O]\>'V::3U"Y$/;'S/^_'A?6I& M-DR]Y.7(QBAE"J>Q 4H=?J&I*8G7<_5QK*MTF5UF]:L$9VR \K"J3V5U-A&, M'(^&D<\L0I?]-^QF@@(G"H37"?I;,MQ1:H"@8@A!V4 $^0ZC>'F@@=+3U=BP M;,K57PV1'!QHT8$]>."/!J!$P:6!4?$2:UAFU8JJO@R+E$LG>3A0(.GC;_R2 M2*,OA8D6)C'[GE;WJ%AR>V6ZY%O67^R::BV[5F@E%-E6&,<(H=!#%MEF&(_X MHFJORYYAS>F(IL%#HQ].W0MKI^&;F)HPO29V_[#!@PZ>YZU%^E:WX MQ8)5-M_P6R7:/[]-^55CZZ=A1R!OL7=D%-*+[&F,1/JY4&AL?/K6B<_S57:V MSAY8'B41M2FQ$4Z"(,+00S!I;8=V(/XRA#Z+IK.5P&0F!PMJM!(%MD;.^R_G MFJ%;^]+MZ$SK6Y(UP[C:T*9F->=@^)5M["_R&-SFJW0USUD$6N&KNJ<+ZQ=. M4K#FLX6_\)MMJVSW=](R YNJ>8=QD5?S)4MM[45P]>'!?'5;E _-7J>72[*+ M@K]"!QYJF:O (F,8&FM\HWK]."3?9L'OH&-?YZFNP6!T;78;*,5U6/E 3Z!@ MU.^3Q/JJ*F,BF6[/S*?T>_ZP>2#?'XN*%4K7Q3I=S@)6I :1';$"U7<#FEAX M9]'Q;2J^YZFO)>,E9//48Z^^<\+' SU&%S/C]Q-MGA3ZVXU2G_B\X=)[<1O? ME5E]&*^:X="-, G#!'LDH9&/@RCJ[ 5)E"CU" 4[QOM#@XF/J':H=/6.U_Z> M[AL].)I4S^CCQ]O]HC/@*$ PB!+L!S[=@O M MVNMX1T_3AD=)+3K0P0,UOF>'K,!/V3]X/<\J-U;);<\@]CSYZIF\%$A_/\E+Q3F%Y*7,H4CR M>KX81K/&Y*=\Q6',_"BR(7(2#]I!@JTP2HBWG2NT R0^3]'/SD!+OWO75#&$ M3><#+<9>_>ZH]P>ZF![&QN]-FOPH=+>EWGVDZ:HS#\;8H0Z&KD-964F(C=RM M/0(E9K?[V1FUCS083?21YLMR?422LNE*DZ/BP9@B6Y M<8<$04;V2+U@XLCV*%7.IK$S2AE]H:?ER.R'>G@HF!8][4Q5\?>\FMFNC^W$ M\3TK#D+L65%"O,/ 'AR:UX4:5OM,S&H,P)ZS5/SN=T/MX 8[+Z; ME-X.W,$]23WC/'Z9V=^%0F.[[Y4Z<+VM;6;1)+ 0LOV &;$<3%T?=K9<8DEL MG56U,$+R '\TV/H)H2B#2NG# 'G]\\>PO/7*( ;X4TPA"_Z0TFT^;[)(>_\/ M_V?U,8DW,H9V46ZX$%=E2>XF*!6^9U$7(TE/VM8@FLTX-/?[L5E0Y:7TQIKD!(Y8=VRH7#^6986 M<0DU2(^:;I)EQA]^G[^HIO?JV(JS9/7N_+OTX[=TO0;W_-*K?A+ZG(L# MNJE(V/ABJ0J\Z-U89.K5=/DIX^&_YFMZC1F;>KY'W,"S;(@\V_9PM)U1\:-0 M>".CTL>-5ZEL@-> M?";RFJ4R52DQIF2;8R0( P<[6V,VI$+W,_8T,=B24STMU@"3FA'M2Z'L&I0Q]E27HB2( M,[PHM4^-T-J4$I=36Z)2<^+@2E4/3N35YG/ZT(VC4AX&//)PX-O:W MX^B8N&I:(V%@0*7AJ"3GS?IQ)RLRAFA3EQ@QQ@SKRXX5(751('%JVJ+BPD%E M4>9#7E?.MP>S/>1:KA [96HJ21$U6Q+\_X):9<]DK)WKQ)BLI M9BA3510QM@SKR?F1"QMT$#@U-5'PX*"8J+)Q2DORU=>L6N^K5K%Z*%;9.BV? M/A=\D)TNF_L(9I&/ MNQXSARDM -HP#Y;FBD0CN4>DH<'M$IZIL_LM=\?7_-#QPE7+;7W-]?^- O7S_9,Q)3&#A6Z$.($FA1*XAH M9QE;GC-C>&6K)G5K0ETO:KI>!TRE*D@;A*#L((*'%J-J1=6#8=D*RS"]O96M MQ0>V ,&G4^0:+L .,B94D/7G>VH%F@:/#A9LNM@262K"P M3(FO&1IG;)!]SV^O+KZ]\7E_>_(/L ?ZK0 >6.OL%>OQUSK[P2\TM7GUQ-!. M1P8X"J(H=%P:!G$26@'VDLX0M2/APS**GQ\A.4COV55E3CY!&""M?XH8C"_U M-&& -[5$\38PK8IZ=/=R3V*FIZJR#AS1524NA';GW>?++%W]MLH7Z0)GM.#M MID#+VW;?BA/Y7FS9D(2VY2),'62[6RV/D- ZC X[IO?L-?! @P_@#+0( 3JG M$MO2^K)Y6G:')%).?X]RJ++'KR^9$MO]!B15<>??FO%L M2U+5Y3X^D)1S4$QYOD@+CB15PI)MCB4UG>X(4I=F2::D]=@<8_U$N&:.Z>X7 MD[K[S/GC8JO&TV045A'^:UGMPX.(EB9E^L]\F:>KRRQ=)N6R-13&-L:06DD8 M1MAV/1SZ3F<(^;%PC:SX><-ZND4%."R07)Z+ZX0J8:RH4%!+ M24[$1=(<-XKGISE'/S&2C"CB,V\/"*$:(^/KGR+NHF];D#D>O2P>;O*V>"VZ MXC5QDQC"B%F(7 JIF_A!MX9&41@ZX@>DE3YO>HS>H6H'H1:Y MDARIOZ))Z:BT&E\RAZ6-\Z9Z7/H9?S\Q LV,V-\DX-"8O1];XVMJ7P<*;2U' M7&7CDK\&F:\R;B@NNU/9. B2T'9(Q.0<)E80V@1UAJ 74E&55?R\897=HFJ: M?WQY):X:JH2=5MD!N))3V=H6G1-]P_."O:AZKQI;4G_D)7HQ$7UK^F_TS_O.<;M?/K;'67_?6?Z]86 M3'!"/$(38GFV%R+D.\%6Q'$D=/U&/PN&!78/&*B1B6M&#]9.B^PPA,D)[2NN MP%__^UI!;'L0)RZXPQ"H)KJOB?R),6E$> _2<$!\^],VO@!K\*'0V9#$A9@6 M99;?KLA%$9>$J$DB2D-&[NAE5A8 M>%I!CS7# MV"!!U*T, $#"=H@8HKCR9^3\OW\-3*2;D JPK"KHE><9$?GF8U MP=="MXC<"Q%R0/KUDCE^&M#L3V&JV+;+$[PD%S9GN>I\NSW4G& M%D* TP("FT24!I1GS\[UT&('5?J53BMADUO@&BQ[C](L44+]N#*W=^@E_OC M661TVN42BC#CTCJGYW8'&1K?T$>CT9C&?0]F7"L&:,WZK[D)? KC$'M.2'WH MNG[@0+^U;%O(PV+OS.JT*--SE5Z&^FW=Z)8LH[=/HHEH]4KB218XM MT0Y9/Z*SNEH7\S\QO[PA6RVJ+UEY=9^6&<[F2_9_%C,?QZ'G88O8D6-3ZA'7 M\VK3D1W[B1W)]4@M)LUWR0X:6+28^"T8]3M0*U!Q\."GQZP$%8<-TOINL)^' M[:$B1![IHEKC,(T^JM>EPF"[E>NE%^O[K"3?'[-5E>&\FB\+_AS$YV)5L";( M=&-U%]^P!)[.US,2^=BS70Q#QPX3:(>!YY$$D=#&7A*Z0IL+#9@U/.:HD8(6 M:GUAXQ8B^*,#*7D%KT[2Q88;(_$M-]CH2;41)10G[H@>&F!_&JIHPK'">,L5 MG[B_FM]GB\TR*VYK&/M6SU8L8V 2>0'$8%N@* 74]N'G?W82X1W M7^NU:E@?.[#\[JVF S_KMPU@\%,+^>>33]F;CL'I2?[QZ)>3R_?&O/C\_W@1 M4%L'T!T)D24!*8X.+ V8X7G\)0)#?A6F6ZC^Q'2^O3@_(#Z)(N+8V/)1C!,* M=QC",/9T)R=QRU-+4.>R+VL8"HB^3&4F%H:SU53"H#]MF0F'6NK:I[F^:G7* MN>S\R!,J9@/P?G*:@F\*>4V50:&3_/_8Y.NG3]GZOEB ML /\ 6PA@QUFP$'W._ M0\^!#FJ&XO$[IR&_"M.-4V&N>%\26C&8^2CR+-_' M%%%DXS".4(([F M%OOS(KS%Z\TN7,VH9_NA&\4.MJW0<=AO7:NSAC#RY=9 5:V,EJ\.;]8RLV/H M;7Z.;0[JR>@T>D]O+UYN^='"2L^^0].\_#U=;O96!F:Q0^PD(4F L _]T/8M M+^D 1%8@MSE2GUG36R,/]:X/@*,%-5RPPRNY0U(C_6(+EB,Q+S>GH8WT(97N M#0KEQ:]/'":MA[T<$Y/(_MR)JF8WFK^X/0"EF9[&(;:00P-J)780Q:X=$_Z# MV+,MZM- ZM5D328'G!,^V(GE%LQT##IYCEWIM MSW24Q!1U @&24UA3L3&BN6KL'M%@P^&:AB:;=K(8M N8UNSVU2LOM-G_TLC! M%/MQ[+@)=5HX01*[0J^5& @+/?*Q,:;>!, VEWJZ\:+NMF;Q57XE5D1?]3OBKX43.^7+G86>]NQX:QXQ"/$"NP4.#YV,%A9\]+ MB/"S4OVL&%;B#ER].+_8Z]?B>YMZLGAZ.]EP!,IIY$'N%.XRZ4FB^&:PX06R959?6 4^?NRU@>0H(PCT4!#1^,0$D-/\2=BH;W(U%"PP6,JRI;5VA3ELS:#+/,&"0$ M6Q8):$0BOM6ZLX'8KV7$4>[+AO6O ?,!M'"&[67/F#C2D=08FT9?4<1>Z&@S M*BV>E9CSUDSHAU8,*8PB3"C"4>C@K1D;4EN^T4M\?*!VOT,DE]?ER1++WD9Y MDLO1$A095(>=]9,"H<#:E#1"!?Z;,J',@ZA2G.?I#1N]K/-L*TF4A+'OQD[B M!CC"O@^MQ.L,^3Y",EJA\'G#:K&':*14^9J3(]VA!X'3Z!!]'"BT-2;E3K'? M 4/?BQTKP%88(@)C@AS:V8I6N?A:&[!ICI8HWF1'K( I,3JZ/J/APN)LH M,R+:4[K%C+,5:V]L/#=S8I:7 M?R72?@3W&$$4VV]2P*A-["4/ZXZ0DF?L_C M?;%DK:'ZW]U<1[Q>E_G-9LUWO_*-'YSR8K5F-I;-M0L-]F$[T4OFCO0?99*G MT774X1>:&IOD+.Y>&VI:T,R.HYCX#K$2G$0LH5%*MM/%+D528S.%ST^ATWQ) MAT\TKZDZ-O^GSNLT^DD?!U[.Y_7E0F35^K?5(J^:1I(M2%KRBZ^KB]L#B^=G MJ_ERL\@69ZO+;)WFJ]T_F4&&PG<#FX28NH[CTR1RM]TXCGW1!>[! !GNC\_\ M !TJ<'$+#N_6Z;QAOP"=/]M_*K[\.UQ,3R^W3S*<[!'H=?-!(240BF9[[88-9_5G>$$'&'#$A[.!N-[KC\/I##UJ".0R M\;MC7SRKCAH%'=ES\2PV91<;KK]'\V>O#"G+VH%,:(S\\3.>.=>* 1JO> 9+ MTBJO<'Y[FY49(R7)UM^R;(72LGSB+R#4S31>[>V&F4&/(B_P+(H)1*[C>B[Q M.PP$4J'->V8L&\YA-6"P0PQ:R*###!K0@*'>VULFKJ,&8G$ZC8T;!KD\]AXC M()[*QHW$>]DH+LW2@=QECNWQDY=!WXHAVJOD9K)ES76VJ)\U8ZBR!2H>^(6; M=4OL[M[T'$0C2**0),BG;A+Y,*B?.?-M#T>>W!8S/28-)ZPO?%KE.W\ <(N, M=.))8_6V5WW,5KF=??!T$FU,FCII._G!0?S\ 'K+6CV8N97QYUD/_$?D>.+[3D/>AG7[U0/T(G.NM MC#]GZXM;!G$&7<=R/8^$U'>LV',2ASH=B,B/R&Q=K-.ES@I9V+14I;Q%*2[P M_)]TM?$'L,KJJ5E6/)NHD\7YUEDO&Z':5-W\ 7QN0G!]) 0CUM =F;UK:>FH M3$-T33FG5%LK]^U[A=Q_T!( M@SPK6H-!Z!I<[L7 M&GZ(9B;Q3.5DG1AF4;\N/,$M#_]6=[+:M;;42;FSS9K(M_M\?@^8F^".T;-F M8]JM.('%IN1K6?P/R^RQ*.LWP1Z;)L:O\IS/68+G5RZ";_FZ^0@3R(=ZRQW_ M3;IC_)=^SV>.%= #:S;3;V#CK_V\ XZ*]R09DL=GC/GS>U8==L9&"?4\"WN^ MZX8PC%D-[+7.^(D?R5VH-$T7!BD7GVMW73-^K4%+WL0T30I%;W6:)GK#)>-; MLQ'[)>/-T[-9BV-ZKV;\ !H">!)O*/@@4BR:.5TV2I"/G6";=JN; MQKS+U$EZ>1)OXG#%]_EG-VO,CQ,LVV>$4&!YEAVP+SH61#&EQ*&UB]E9^!+$@YM6E?E M:ORQG3KT0D-;D9/+3^EZP[>P)T__E:5E\XZ/&UO0AC1$R Y]%"'JVZTA+X@M MX?<8%#\_A'1VL/@,(P?VA]1#97VX$U-2P[0IZ.EXC,G)JV'FWI/(OJ;BB-3V MX&T:@MO'@4);&U(37VZF>WS'CTE$73\@ 4:$^+:%8&0[R]1^'=42$@O J\34MX51PX(+S*7*@([\4J MZQ[-0=#W4)2X+G2Q$WJ^A?W.EN-YGJKVBELP++^\M:KKA@11\E)KAJ/>:LM@ M*3Q0TX,Y==$UP^![U=TM&X+2*\_>]-17P8%3BNZU'H M0>PCQ_9BQ^ML81H*7?S9SX)Y#0[4E42"*'D--L-1;PUFL#1HL 1SZAILAL'W MJL%;-@0U6)Z]Z6FP@@]'-%B5$24-9I'M%!_&L0<#'P8A2B!R+!*8+BNSHJ+,E#6HKA1GIFSBPB".2.(E88"@U1F#E$AM:% T85Z7H;JNR% E M+\N&6.JMRAR7!E&6(4]=DPV1^%XE>4>'H"(K\#<]059QXH@>*W.B),?YUT[[ M+4338#(GO5HZW=(C*L3Q_$Y1C!2>.R;$J)[)R?'V?E5EZRW2M-8=11"P8(0<2 M)PH#W[:=K3G"?J8BR-)&#$OR#H^:MLB3)B?-1OGJ(\X[8#W569Y!-7TVRN1[ M5.B7A AHM#*'TU)I=3<.Z'1/7D24FC64RVS.6E*5<>$+DY:,WZ '>$;,Y0^;EB9&2;0@0*U]M2P>C7_M_P\T.Q[43)^<^\'O]#4 M-"0?KBR^UBIWMN)GFIIS4\ME\8T?^Z_BU>(RJ[+R:U9=%LLE+4I^:&H6N9Y- M2 ")1VC AJD0(K=!@D*^MU_J;4L#]@UWD@XR/UZY!0UVJ$&Z6H .-_B#(P*Z0$7%WX'HKKJU'3N$,+ <&S+[3*.I9W58F%(+;88WB\!PG2K0>5OD_.EI MCKW^TU-W5@\9(ATJ.D1TM*NJ2F!&4-H#W"HK;]]8O0[_U(" ".\PZQ5@F M"CKT5S?SIB17@.T1%':'2EE4%0+P'G14Q2TIZ53F38]:QHN_;YKWS*J9'4"( M$PL[5H "VZ8X\/W./@ZHT)J#?JOCUZ][:'5*I!3U.C32%.O:15*$\!%4<@^6 MLDRJQ. ]Z*227U)"JN9&L>LF/G2MA-@D=B*+-.^F,+& -! ZT*##CL'M6BV\9KZF!@CV$((_ M.HPR^[:T4"NQ?VMHBM_-/BX!8@[MY]+)Z?@;7?2Z4QAJ>V+JM#'G\%UPOO+T:Z*6_;RB#,B7C*H Z[*)G4Q#OT3'[ M]H)_GR[3NQG!(238=R&-73MP_9BT]0[[OI6XOFB7EONJX3Z]!0,X&O%.+4G- MZ5YMCA6Y;BU(B(9^_[8B[J)O>Y#/UE^ZP3).U]D,$IL&06C9 M(0R(;R;X4DSNHE1IS/// M.#B1\-7X&E\?>N)_HP3HPX2,7M"\FJ?+YK3U?%/-'#^)$@H#-LX+$SN.8\>% MK2480=^650S9[P^E&0VN[J(%ADQ>-:2I$]<-DZPI*HR!V\H2#\VY#6D4:S&5H@"UPUCAP9A:)$(6X%G=[:([0L=ANEG86 =:?-J M+R61(E!62TQQUT]-A&C3KB=[7 @IB@IW4],4)1\.JHHZ(R*Z* MG#(($J)!"YYY?*#_J[$R?I]7Q%WT;0_B?;M9P;C,[G*^<+%:?TX?LEF"73_T M8("#A+@QAM )MF8L[ I=#ZW\<<,]O5WPW($"')5XCU,'!4;%0 MY6LJ:J&,_Y5<]&-"1"_0IBR?37ATTZ:V0QT[@C:FF)& H./$6VGRO5AX&D+9 M@&'5:'$]FYN37P51I^^T> S"G)Q^*)&F04,.47% 1GHS-[Z2]'>AT-B29.L/ MFB^S$C$+=T7Y-/-CF#B^9R$G\GWH> @2LJUR0AC*51]RWQZF]J@Q@0Z4;.$A MR99HV6&.**6B0Y C;17',_>/UAMJ1(VO$;W0OZHU^K @,3(I'AZ*U=6ZF/]Y M=9^R5G.Q65?K=,4G3F9)$KDP(*&;6(Z+2$Q(O"UOO# 6GJ[48&J@,4L-$=08 M/X &)=B#*3V$Z<6N\'AF*&+5!C>JG.H;ZQSAY_C 1P>Q4]$E/J5F9!BEFK>5 M?]FA U4-3UJA%)D4UB;S)*JI4LO?%ABX.LZ?/C5ZDY'C.M2/Q,DH4$\W7FN/ M#E[$5>?W8KE9K=.R*\0E[J.9T.,W3AR7!ON5HL#L:>.U+\^C,Y\[5"! MVQJ6K+Y(U0QO]*-/HQ(:X6?\N6 MR[^NBF^KJRRMBE6V.*NJ35;.$F@[H9>@("$.&[DYF&]AZ]0)NI&<:JA:&48] M.#I0PP,=/M E-41939%]60((I5TA0/[^*<4A]H4Y@ I1Y6F+Y%349S>?KQ2 M'CW,B"O0E\W-,I_399&N9_P6(X?&CH4=SPKC)/&3SD;D!;[0!4-J7QY&:1I$ MH(8DJRU2/(GJB2F*E#1$B!UMJK'G^E&E4*%H*NJ@A/V5(J@S('JQ#LU7^3H[ MS[\RM6%5S^HNOUEF<55EZ]^J[':S/,]OLQGVXR (2$A=BI#EQ!&,H]JT!Z&; M^%CF]C$M!@UK1H/Q8PT2[%""&N8'T %'*GEPJ#K51.^1!WGV_7X7>+7.;5GSBOYLNBVI39=?9]G3 . M_IQAS[,2VW5I&-&$A$'B^6%CVB*()D*[=;4:-*Q\EV=7?[T"\6<,?ON,R.5U M?/;Y^HQWR:;*5UE5Q?-_;/(JKR^V39[V?G>=,O&=$6Q! M2&'D($1B)KPH@('E\5O!,?&M0.BN%&/&#/Q][R: M!1X;P;LP<)R L)J6$.S1SAJVL=2K-*HV#*OH6_T5_,&12>JD,H=BI+YC14JK<7A=XFUE]S^"_++,/%0YJO9K9%21"%%@JBA.D< M26+J=';=*))ZN;6_M1%TZ /H,((_&I0:-$F28W5U,D=O?YV2878PS7I&F*1Z MJ9$]71U3]$= T?HPU4/;SMD/SM;90S6C?&&$\C<&(Q3YR+,LF"743)'1> M5HNA42HK#@_4^/IKF02GRC)FADX=E98(DT-IUY8E.=F2)W>RBJ7@RFFQ4N5' M5J=0\7"3K^H)/\3&G3FCK_[-=9FNJMNL++.%/4MH8+L46SA)$/6@#6W/[B!X MT)%:7M!J>"@=VP/[ 3R#"_;PJJF:G@C(J=S@Y"NJ7D_>C6J@"(<"FJ@U%-/2 M2+VN'=!, _R):NB7]*E^3.JZ:$O+#E-6_5H6537SPM"/8I*$,4)>[-,XC&AG MUH:>U#"VMS'#6MGAXT\!MPC!#N('4(.44\C^_(JIXJ#4RBEA/U:-Z-\IMHYH MGC:BIZ%S^MPI##5(8S7AQ?H^*^T99L+JAK:-$@I=V[5HF) .1^*Z0I?9F[,^ MK>KP ZAA&RL214.BO5(T$ VCY>*I0(Q=-39\ZBD=)6,S#5TUZ)]Z$:G$9 _E MOV.%NP7)#?YFFWY[!JL\(B7BW.V8_S9;[.LXK]V>8A6Z"TNN?O MDK&_\C5=\C0R\PDF'L0Q3B($$^@$GN5TH)'K*2WFC@1U%$W?.0CV/6QV 5== M8;:H7U/<\Q*T;C(M8HXV;RWN7.V=" 9M(*&;9=#)67-$9,+HF- MT50FF_%&(>-T>APO1B+/^^XV5;$TSJ]28';XK_A[G)MT>7&SS.]J-ZIZ3]5N M4ZOG6([CN;X7APP5CB)$FM/3G@NQ[;FSKUEY4YS*D48AR(C;/EJ93> M7K ' M&.PA%G\,V%P@CB>BR41 +KULMY%>W(+386CWD *1;?D#1D;\Z>9)1$CM.>;E-_%G66@V(L:S_/+;,VK4KY=>,Z4 M,F?_FA^>9J5 48(LG=^#N[+8//(_K_*'?)F6^Y_XP&S-EYOZ508V' $/Z??\ M8?, 'HLUUV+62M*'8L,@L7]^NUGSLQN/W03B3YO5(J_F_(^SQ<_U/V]A,LOL MQ\L%N,E F;4ER[I@7_\S ^Q?9>7^W\ZR7WJ]3JT:^S=*B4&:TOBO6)MWL1BP M:\H-C..O*>L$S! MRBM6-EQE\TU9EQ4XNUE_2M?M[_Z6K^_SU<4JX]?0Q@_\ M'B56HJ"B6L^(97G4M5F983LA]2!R XLZGHV(9SLV$KK>:$ XA@>X6P\^,M'Z M6#$?P,Z)#X"[ 79^? "?>8ZY_I8MOV;@$VL']^QG6X< ]P@D:95+CF:'"*O8 MB'5B$94K&P8/II$A:/\0'!EF#AC?:0PEAW2X&*TOF8PP9USOG#$2?A9,8T-V20DD]E$6X/6E-:C(8R4T?1%122OC= &)I;= MQF#@4(X;+1K"VZ;+8IYEBXHR/GDVOK@]G)]G(0Z](.*C0"N*PR2TO!T$Y 5" M%WX:,6PX-]5! X\M8L#;'N!AK9<.8GH%JBU4R4W56MD7RQ:C$2^7!KX\8YO# MJLD^EAP&WGHMP>.Q;=@FPC$-13;CVLOMV>;X$]70G4I?W)ZMOF;5NE%L1 -( M@R2D%B:^3YW8LZ.=8B=2)XQ5;1A6QA,EU[9(VX,LIY#*W(J)X1"TRNF>3D:- MZ-X!RHY(7%^2IZ%FO;TH]#8]7;/N=7'SVZKWZ?E75;IVDS^-@LG-XWW)&]*F\/[NO+F)G M_(AH M/$FK=9*M%OC+^:?LX28K9Y$5PRA!%K$L&#IA@/C\1&TC@7YH"Y6Q:E\VK.+X MR_]*'Q[_[SFK2%.^\XEA$RZ5WNP%KSP\T.S5F1B_G?? 7NAH"^(M.[I<9D^=$4)*54X.EUJ M&*9'KKAXQ@SXH\$C44RH4"1>/ABF2JU@^/@1?"Y6V2_LO^#9%T#V/:_6%;@M M^#)%7H%LF?$__ 5\_-A+.5_3<$ Z>_ UOG;V 5]H:3/BZHE8 ZB^YLS&3J/= MV$/8NZZ!05^ZFH#P6DI9<9.BZEI MJN34=(^C;?DDKZE*5(F+JFG*U%15B3H1\7S#W0/JV8>8\>6S%_I"3_,0%]"S M=7I37*6K\Z+,5O\L6CL.] ,;TO$G6 >7M1^SX MRML3?Z&KBESYV M3&\/K/O'7E?(FH6883=7'"'HR+8*';1.8T.%%D\*_8U.KCOA[#9?98LD6[%? MK+^P=G:5K=?-7&K%?]O):O(?I,BW4VZ*FM[U"*;Y$UZ %+5S 7X >X@_U#]J+WJ5VT*F+0C'*ZA1 MB%>JJS21;43W!-D[HH&Z^9^&'FKWJC#;:OOJ)-/EU5UVMFI_M+L&[[)8+FE1 M?DO+Q0S'5AB'3I00V_8<*[9]GW9@/-^1JD@,03!#L,_AR>?'_ M"+HF&"3D,Z%GU^ B.3_[-;X^N_C\'WT%4T\T5/5S\$#HD-,&-,A7VY_O<(,_ M.'+00A_X24DU?J4$5VO IJJ_>IT\*<<&.%57YU<@9LB/0T(@HB&V8$ "-PS0 M+B_$S+5H^:E%_+G-]LZMN8 MDR?^HR],+?)Y_ICR4[T)@2ZKB,,@M&T&),"^O:V-21Q'/88^7G#SU(S@]R&/K9$G&)4K,#5%9ZKZJ8GC(5HOF@@27Q($7>Q8.DY#]CT=)$G5F,?9Z2JFD,1P\W&- ZVU1W"5,NZL[S98=:%Z>'12YOJRI:YUM"BS_&Z%-F69K>9/Y/N\ M7C^Y9%K1K*14K^<1[8@2!UHD\;%/&," ^G&'S?5BJ;L\AT%D>D[O]I9O$.6/ M&S;@P;Q%#[(6/B@9?M#\NK=X&@F:JKR.'2\= MSZ #HG0.<%X&Y,2945V);2 M;9/1G*JR&_7YI/:;9USG^G68)# (2&@G+OM?UZ+,[G8-*4&H7;\FJ[Y#=PF; M\JO7';Q>:]?9:B&PFR\MLO2E7%ZN][8:6 MY[MV#+$?TP!#Z+E!8G4 $COJN<-/V:SANJO!!;B%.L:9>)$7:-["[ID(XMBP<( M[+.91#H(4Q7%WG[);AY19,[3C6XB=H^5.?LR MW5CIIBO)37D_X$XPT1"\DTZL[E_OG6!R3&K:3V%'%OM_U+'M@% +(6S[V^(J M#FU;RP*EE,5AUB;%=E:\JYT HL1.M2>J.2.W$T".HQZK8YO5(N-G7=:;ZN*6 M_V26N*%+(NS&(81N:(6(>-N-GC#$T6Q=K-.E\N*7O$&I$<06FW /:Q"!JH8$ MTOJ93YS-Z\LU@&OW7LI28%AYI#1(95<4T'PU3%W-(1&#X^SGZ+=9I"R]9Z$/+1=BU:6#'T/5];'N6YP?0)L0.;2)Z4Z/"IPW/.?]VU>OR MN]<.O=$[>GH^_K5W?< 76J(OWGIC5H^\MD-C.X$>]&/?B1P+QLB/86_65/FYZ47M3%H_"]XR^_3+9&VX=:,V] M&!B_-?>#7VAJ"1+%1I6_-A,2[$8P8@D@@IYGA]AW_,X,2L3?*5/ZN.E2@V'J M5VF\X=2A0J./_^.WY7[P"TWM0&Z2[=>B6'S+E\O]Z\<0C (K0H&#',^F3APZ M;(S96L*!*U1H]/F^X1;=01*]OD\?;V+S7*8IDYO,DF7+R'35&Y05#H:TYJ6M)$&>D^ MG\16*+-90_BCAC=D?,[6X"9E/YH/_-1&1X! EQ'F:%H]0ASV@08OZ;=H>_Z4 ME7SJC-_M?@7BSQC@LZLO%^T/ MY&H 4S$0*P@F0+]<== "YB7!#C)(5PNP#QKLH09_<-R@!C[PZ$>-W2,Z:#A< MTU!-TTX6@W8!.47^?T6^6B^?+KZMLL5OZWR9K^N-X.NS%5.IK%I7U^G-,IO9 M*'8CFWB!1WT<60[%CET;#QSH0AK(*+ FDX85MT4):IB@Q5EOT%F#+5+6U3E6 MR1DA79R+*>X(=,LIK!ZFC>BI&'=']%,S^=/02]U.%48;K!X]C+_GU2QR;$(# MVW9<*_ 1=1#%26>2#?FD3M[V,C2B]OW! 6H2/#%2^\F<=C[UB=L)*@=5- Y% M0<>DV)VV>LFY(JA9"OST52I4&U"*TLQ.&2'@?N=K7#6O4#A3@J( G M_J*](EO'-6@8HN1DYQ5'X(\&DZ!Z]R!K4LP&-9+#;S^@W*#2>UN&5__O=6X(M:X#>MP/,[Q]:_]-K! M]28[![9P]6-R_#UVS\E14%HEEL1UUC1;[UEEW^#F M@,;V87%\A>V%OM#3EB1.XN3I0TZ+N& MF#!S$8519R4.8Z$I4]5O&U;H!I)\+:Q$TVE%-LV0G!8_)T=!@958$M=>TVR] M9]5]@YL#>MN'Q?&5MA?Z0D];$E?7_\X?'K+RN16;6EX28,MU8F@3!)'M;34\ M\)'0XKGJMPVK:P-)7EV5:#JMKJ89DE/7Y^0HJ*L22^+J:IJM]ZRN;W!S0%W[ ML#B^NO9"7^AI2^JK_V29S==E/F=!OR[35?605Q6SWVPJW5[Q>_54K;.'%E02 MN]!/H.U8U$UP @,2;*<_'(B%%ML&@F)8N_=AJN\2,!&"XT(_0?;E\L+S709[ MT,$^]FZG_18]:."?SB/&-R+(LRVX4<%@&*>WD<&DLT>'78C\/3 MQ?1@],FIYT'F% KL?A2*5]J#4=F[Y%[?9Z ^T5KQAW!?U-<:ZNIC3!PHL+60 M-WZEK<>-0G.CTGQFZCQ?96D6Q+L=D3U:I M<$DN;E&1+BF?R]K=6T;3.0>39]4^PEE"'1>&-O3\( CMA+^RZ'88 M8$R%KW[4;]FP?C: ^=P>A_RQQ@QVH,$.]8?G):!XS6<@&J=KZ7$#(2>F[S,& MXL7XN+%0J]#UQT2D6)=FZD %;X[Q\.A\" MC^&4MX\,<&BL8@4,W#P[,'I-VH8*R[:AA,?P-8%T/C0B/++&.9U#&M' MIC'4D&!>80QB(J[3'IP8\5APU&*.[;YY@)E]+$H.(UUG6YA7]VF9S6P]CW[#.;]'H$?5>3/<3\:%(UBC:SR#O27@->AH" M?815!4'6$:-I"[ 6#P4%5Q^;?07VU[*HJE?ZW\YE767EUWR>S8A/HR@(48!" M&B4D#KWMM1LQPH$6I=4"Q+#DUABWT\"@1:5'?_4$HI\0#QX#C8KZT4X AGU6G330R+IH4_I,?0LK*Y1/-5^F*V5J>K6Z+ M\J&VN;ORV HCZ'LA2:@;HHAX'DR:JZ=\"R>![?8X_H[/X'.#X.@8__?8Y_@V?L;_SLYS6Z^)<3,Q'H%M.K;< MP18AV(,XXB7N8M0=T5K-W$]#3'4[51AMKW)RV-S]GBY9F;YYK,Y6\^5FD:_N M^#7PQ6J=KS;9XN*Q7>C0X$,801=2G5A+$%@DHX3,. MQK"$XK,K=/'Y^NSS;TQ&+[Z0RWCW:L9?R#G^2"\N/U[%YP0DOUV=?2975T3R M!0WSX1+3V$E%2DY].^B@P?X!;-&#??A@A__#WA,;(XIS7\Z/R/9@X9R&H _G M;C%2MY%+ F>KK]F*!>3I+9.!@R *8!10&L*(8!^BYK)[W[5Q%'JSKUEY4XA* M?"]3,J*PCTI8&\X^_TX^7U]<_I><*O?C3TQQ!R-.3DVWL*:AD<=8.J)_6LB= MAK;I<:4PT/CD-*E>VTO2*EN@XN$Q6U6U*,9ER5I?QO=O)D^[O_(E?>(_BOF[ ML1>/M7J2[UDYSZN,J>R7K,R+17U:YVRU+O-5E<]_3Y>;;!;RASNPZ]J1ZT8P M<+";-%O-/0H] J7>%IH$8,,%;G/T+^\P@:\<%)]/+!H?0-8Z(;@5>5+<"0KQ M)+":$_0:^\<;#A[L.PCV/ 0W3V#_[[5>@MK-#Z!U] /8NEKOQJN=Y>5VUWIJ M5X?-#T,$[TB>F53;F4:^FA8EQ83[NL0-@SUA_YY5_+UPCI6F>=G M .",?9< M)W$\BUB$^@YL84862H2ODAT%W"!Y\9;!>9T2O]9X)6[T&R5XQW/?NXB;0IX# MR?$\E[1YKOU[S_),JR=G/6V\A16MU?9O,L_YHM**.\JW0N;J_6Q?S/%O4LB2S;#=S$L6(8VEX4 M!U'<(70=6^HIN"%Q&:X7.$I0MC !;[*UMG2C9ZY %8?;Z9#<:'K0 (H-FJ<: M.[F:H?.BVQC[;!"\[\D'4$?X\EF$R5YT:X>Z"F+8(;#&4!P9Z8X1\&D,:$?Q MO!B_NPTTO4O^L-CQJ=PBUL3 &U\6^W+U6P5^VEV!4#M7_?P? TWR M&@JYX>G>\6,]^,1OXS+8\QG43K/B)EWMIH6WCK-?OFA3X ].!FC9&'CQ<-A0 MFY@F-MOFII%?ITJ.KJGC(6(XH2S=*, L"(. >(X?6OSXCQ6B!-(./PFH.VOF M7:[6:;F>3)(6Q"ZCV2_=%);O+2B0,IG.[O+5BD]9,65M/CFY7"T:^,FD:0/1 M?C<9^H=+Q(U;X^9@R0;U+Y-^97D9/O,J16[\I-M,(G=KT;,H=&,KCL,HB)"' M \^GA'3PP]#W9ZMZ:61Q/< F*-W8A50X:E3XE9O"BOS[\;7==R:.SRD>11L5 MH_RC2Z,J+8,I8Z^XC2^,;!1UF^7['G@)=; =)"%"H86MA$(:=AXD7H0GI8WR M\(>1QRVN^BF=[/LCOSAS*@,1A9B//10Q%.>)#T9VK6B[B_1'R;BO CI*TE5O M5C]ZWNW!S&"IMV_TQL^^O[)/K+=;9&>V90?8"NP@A&%$"*$TVHZJ;"^R!CF4 MH1NTX0TE-9KIY%;9B(Z=6 T&C)5I66P3-HK M;N.GT9>SDU[H>B3V$@)CER16:%LNZO"CT'/:)36R6HR=2V61RR^H=4ZJ+:=E M;/1Z>B'MG0GE%)="1 /_HTNE,B^C+87(1<[H(3;!RY4@#6B%7\197>$I7ZZN (_\3>- ML^_IP^,R^P >F8?KXJ$]Z\+_QH?VU^GC[B)04.9W]ZQI-7]>9E^S%3^D5X+' MLKC-UR"=W^?LAW6[;/]UW3KYW_\9?+O/Y_?@/OV:@5U!QP_;W*3LS^<9J.ZS M; T6Z3H;Z5"?5/1U'_,ST_3>\<$_0X3H. IH,E93J,CBU8)\?\SF]4%'_J/6 MDPA3&$56S/S@GM#8QMN]K3Y)HJF4:*KX!ZK9FB78&AY8%[4:3KB04VX,XU=V M0[2#29=ZC #0,0"NB_K'DZO_E!O8= K"(1K:OV*%R/XE[P=OJ>5[K!P/-).1 M2LF^C?;'KRU[,S1@L:DGFA-://E;QK6$.?8U*].[K%X3PJR+;V_=V#]UA:#G MHRBPL,7<=6/+PO'62\N/I=X&>F^^&:Y:.ZR@!=LL6 ,.=^^2)?!3O@(+ACHM M*U[",DUF%$WP9++>9C7V?HGQ6]14MU7LG9P2;,%_Q#?LD^E\_>.==I9I'>.N M/QIIQ_\RJY1FV!M^+=-@*WA/%<[,BOT8N21P@L@*L9/ A-BM:SX)K&D>QN[O MUK_/:1MJ+N^G7-':1GZ8&N5?KS"9>#4BW$S_78+(4S;!ND,RWN,7&\_/@Y[V MSXL2;"70]R"&#O78+V*K\\\)0ZE7Y-Z/5X,L_$VEH-#>),:N*L9L#5,M+=H% MP+WG/OZU*@S)-C&!.Q;TM=L?O=8PQMM(MS3HCOSX54=[%';#I%# .>H@)[(2 M&P86]),$$V_KG(LQGD;)H=4EP_7&>[CN05/;&+OV&*U93+7PV"/D7ZWFD&D+ M8]XOH;>Q_NC5AAG2AKZ5PD3,QZ\SGA\4/NV?Z]IN#!/H$9P0:$)0D 8X# M KT@C&R$D+M-5C%K=Q.\5J&_4_^^<>'?RX\*S>5'%W83E$UR^5$JWE,X2WC: MI\1E:RK M\Y4"OAD5O/I OD M-^_?>&]5LXEF.YTR>N3F:ZRN;@OJKT>4\M_%]IC-:"JW?NAK[S]^.6Z2O#'O M"M'=!L9?1[S8W73TPKG+["'-^5%/5*SJX_Z;='F=E0_5##MQ$$1AXB"*,0RL MR UPYZ-OA7 :NT-,>&:X7#^\HOCA=1HK.R_J),7_+[/X,)7=JT;:U=B;6,=N M4E/=R[K'RQM[6;?<@#UR0,W.C[)0KM P1EDQ-]F ?_2EN+*J/!M MT]JX#TFBUZNP)""+A@F2%,9]-."/!H^,-*J0)"&.ALE2E$G-/B:)07.67<05&017ENQ#71*$=J@BC#E8@:OG3Q@!0J,S&^ M#JI#+S2T!+EE@7@^+]DHG1;E,]4]+ZJ*#^+96#Y;S?.LPGDU7Q;5ILRZJWMG MQ$\"2"V<(-]S,(*.QTK8%A!!#I&9PS<(8\@"%#P#*S>1;C(28K/>$PF"G)2W MH %?,W\>"X[[>4# #OEH5U"KDWQDNG> R$UC;G8(1XO!>X49R9Y9KN,2XL(@ ML>W8@[9+ ]*:1Q:)/1,"?=*H\6(WO4XU$O. M0FCCW(A>"E-X1##UAV$:BFG K\)T ^ZEF=N:-@R(1<+0L0ET[20*D!?XG37/ M1TBFJ%2U,=B$:9_QO#*!2@)GA+M^(R)4WF)$5)WHOC$J3(BJK@ M-"5CO$9I63ZQ'S:;HPD* ^RYQ',"XH8PQC8.MP6B[[A]Y$?-HF$QBN_NRNR. M'UAB?RDKOV95/;2:+]/\H0*+C ]@P4VQON=CW)N4UPS\!$J9I56Q8K]] GQK M[P/_@W[ZI1@/-34S'XJ>VM8B'%?8WF1)0N;ZL3Q-T>OITPD)U,&8QE%KOJHK M0!+2!$*'B7$0$0R#D,:XLV]C3VJB3Y]5P\+8P@"/Q3IC<-,E6#)PVH>EHA1K M&Y8:8-?8L+3!.KEA:0.KW[!4,@R3%$,=?LD/2Y68$]FQ;N>1HQ/TG78P,4MJ-'M=]->FS(. M>WU@>X8&FL;?J*'#B4)KTY&K$$A:\M,6U9>LK,]R7&??UPES[L^9%UB)[82A M1VP:42NT_/;2%]<)8B>B,A6!NA736R_BR\]GGW^] E_();CZ2WQ)Y+)_#_K$ MLOTPS,EE]PX3?ZRJO7OC#XX+U, &GJDY2-"1W-V?U&GD:@U^%+J;FYS\X.PV M7V6+)%NQ7ZR_L&;VXCQ87%6;A^;0V&\5?X0)I)O=B2T:Z1(!H6OA88V"'[#SGE&RMR8K+Y M#H(FI[FM0Z"+VY?Z4I97IYSWW +<+_ZDX)YGX'781YMB-Q.B(ZH_X8-KZWK]BLUI?I.IMA!V&,(@:2( 0#Z(51V.%S,12Z1'MX M5(934H<%E R,Y"S<@*%134!3B(J.G/,JQ1S/+Q_ -J[HYNAL%H.)=P9!5?;ICO7SF4M^@&S"U]PCA IADH@J/D'>X;;P+/;ITZ.]4$ MII>'#L?(5%;2T"I^@!RE@P6=&4M;5 :9G/NL;Q@&FZP:,X"AS=LP_ M\&8[>)]3=\?#96K^3E,CF6I:&X$)G3-Y6J-C8GCV-L!G8TB'AHEO(\OR/(_& M#&H4VML<[#K&1F4:H TYL6=N[*4C1OJ'7 .'Q_A(ZV V>C<3?:UXY(PF/$V-YD=)@;KHT)X4M<9I MN#1Y9%H4$6KYMF4[CAUZMALE$,8=9$S=>-@4V0/H *ME(RR6Z8_G4'EPH%". MF0/?Z>J9;+R,9CX-S>1'R7HZJ-">\;3%1^3HV6NXKU;XKC8W5;[(T_+IMXJ! MODJ7[)=)NEI4,^IXEDVMV'A>F)Q%;A;EJE:EZF M['Y7[/8T5UL7P(;[ *K:"7!3,"_$KVDV'++CV6I:T>J?BM[:>[X##VKTH($/ M:OR3B9/XW=O3B9?:1=V7V2._(H2_L+:^S][J63_QG^^NPGS]-SZ ;_?Y_![D MS2?J%YQ*?K2^_7+[YFU:[\Y*P:(M,]+ELOM8!=+UNLQO-K6!I_HS7*"Y^<[> M;5$^,&GGC^-F#X_+XBG+ +_:))_S2TY6+!WR%W*9X)?\KZSOTW5MZ>?&Z)X\ M-& W559M-8+'@O^K1<9'_BR>X':SYO?]=L;K6S[Y!-+V#;IT.YTD5T*+G*OM MU:;>*&^&:Z?CG\X=R,]B: 7H4W7L@.RZ09TD]YMNUW)G-$)1$ :VP\;X"0XB MALJU?!2%A-C(<7K4'7IQ#%1Y/$MH%T<*CAY#Z4'"IE)[C!PY6GP)D MO*"IE2"&@Z>6<:5(%,ZY9D(SQ:QKR-.C>=,@US6U!P",V]G M2Y%Y9&[74%2F,5MKRKF7ST.;Y%!D;+.ST^S:B+_GU0S9#O4=&J+ 8UG=M]C_ MV)V9**9"VV*4/VY8)?-=+TS;7LAA23P\IT;9Z<&"<;;DM&PLHL0+=>.$J57? MKXCK54B_Y>2!ZK@7'^.7O/W@%YK:A;ITMF])$X?$B>4Z-H0X"I/$@U;2&?(2 M)'0O18_/#R^?TF^]JQ(G+Z$&..LMHH/1I2ZD!FA3D]*.K/JN=;.ZVE@25%9) M@J:GK;(.'%%7)2Y$]/6"KPV=*(O;1UG#.'$0JXU1@BET;>A[>&L\M%SA@E6C M2<,Z7"/=&V."@V-,'8\%B_-RH ,9(';\3F7"J<)H8Y2;>>,WY_*S@TE:';1, MH>/X,*$N3%R?V @%R&\L$TAM2^KU81WV#'>[#J+DZ08M3(K-E0U-HEP]U*'[ M6,/3(%=ZYL0$2#LR$::3\FG,?FGUJ##70&4NK5]EW_@<&EEEY=T3RLIU?IO/ M^15'K4T,[1A'B1W:./:A&UAV3#N;29 (+1SHL61ZIWH'$#0(P3[$TQW0!+6G M1W;#LBHG:A,D5'SL-RRQO;?4O1Y0LS_9+.N=^%S'0#K_QR8O^6_+;5BR)BSS M/=]^Z?E.PPG2#I3!^L@>O_K5Z$MAHCG*U;HGZNSDZ5/Z]Z)$2];HSO-5=K;. M'JH9*Z\]["#H^SYUXP2'H1=V4&#@09GBUP@ PYED;XES>6CXR<&"&JWD4K.9 MB(@5T:,'0RX!Z8J#D=I:AK:P M9\C#*,)V9%M1[&*20#_>#@U"QPID-%>+0<,:2X_WZPZGG+;J85I,2PX6BZF7EVY-B.2]T$.9[O84*# M;84=)X'4W)03M,E0*+[N-AR5:FMNRI0*[R<[Y/RQ+62]"1M_W4R3'R\W MBFEB1GBN-LW+W_DM)&V&6"W.\_0F7^;KG*_4I=6&V;Y876;S3QCDYB#!W0:M=X(?K^<#AV)>?%]J>5CP2\+ MPMG-^HJ;;9'5^P/LR(4)QK[M4\="GHMA#%N;4>@3.F,C_9M"?$]J'ULR4K$/ M2WP_Y?Y.H^(6X.RQJ/+U:-LHCY!U= .E#I*GT7TU^?)JTZ0^AD2&9;\6K#FN M>/99,(/5UF![V -;U":=%@QO# ;(<.<'A@AT_A M%%=?1D\/S@8D4ZZLF12/XB.T ?E4&Z+UX55DE':<@ /#-$VLC3].T^5(H;U% MR55+A(T#UT]TLUIL=]<[3A02RW$CQV,?AI20KBJ+(ALY-5T4-)%!C M&JD4>L7*D?)'G<%IE#P]\!>ZVI+D"*(LJ@JQX4JVFC^=K5AMD#4W67>'4UKK MA+K,FA<&;A1Y#B)^$D:==8]")#F6T&35_*B" P7S%BE++F7^E:6FK]G 3[8( M$G9L9*&9\FET..U>O1QM&&%-.&$M\WH>DV\UO2A_+8O-(RW*[:3$17TY?7VG M!T70"5$2VAYF=0L-H!V'G7T_25R917)]5@V/2CJ@]69NUM9 C;6^(6%O_K#! M*W5ECP'^Q:9NQZ%>;@RCDW4S!8V!F(9>&O#K9>%BB#GIY9C&TAMP MVC$&*Z*0QRBTB.TD3H \WR6M^=B'D2.U?5Z74<.*N>N@']H>^@$-6EK/ZH+"*/"<(+2H"^,()Q&V.K.!'V"I;?5]C1G6QBV^CPS@1XX07.U- M(TJ=7=='L)@,#LJMG/SUI-7,)O83=!U1.FU,3T/A]+GS;"5Q9X9 G\H]VBGY<<.*M<.C*$_R;(G)D5&BY.1'AB-# MSTT^Y^*(MBC3-@TM48?_ZBG&7CR(:L5UF2[XGIWYO-BLUL]N74*1QV MBX/ #ESB>5N#'I(Z6MW#C&']:)'U+W/Z,"FF* .1**!J=2Y,O+^<]-#(TY#[]\^V]+]BWW03: MONO0T(U=W[-@M]$P"0B5>EQI6&0#3C&W)RCY3OT]C[H=_0M0K([MYZ_]ZG%M MUL !EYRPGERLU6>U!POS9$]PG M21<;QWIO6-/?\O7 M][^MBAO^)#6?4CM;/6[6%8/)R&?HZZVRE\]0U@[6GYGA*$"1'V$OB7P<60GR M;-S!Q!@+/<(R&K@!<]6>2^ ;\PGL.P4:K\!SM_9/H]6>M5+8?%(Q60T6=\E\ M-<60JZ>LX:)M-F=IBHI(VAJZ 4PLOZO)%FFT2\U.#U7%C MVZ5.%#IL+ A#XMF0MEA1[&&IMS7&03CM3%:](6Y;!X=,9SV;@=F<-EP+Q M]0G^I++;T?@82'%ZVL/[SG.:.-"4['1&9,AYQ?BFJB= 9S;TB4,MB"T_00Y" M5F1W^[Q0@@*I[0J# ALLOVVO93LTVW2Q>BEGH/-B^/E#\< .-WUH)*8CSQYV M/KW#N<,.NN&I0^FH3RPO#>JZ@8E#1?ZEM_+2HKQZMM]N:SB&?AQ%7FA1*T#( M\>TP<;:&'4]J)E"#.=/;>7^/S\[CY)Q\I!>7'Z_B<_(?BGMW>S J)NH#DRDG MU2?V[XXDO*/5Q97(G3LOC3Z_ZF=KV/,PCFP+.22A MK* /G "BSK ;)E!L6XQ&@\;WQN#GEYO\QT_VS^+WQ>AB];BHC42GHJ@!AA!P MB*"F5D[9C#$L?C//"$RKW=#S\2.OV[-?V'_!LR^ ['M>L?J?GQ]>W[-:/EO6 MP_U?P,>/O>[L$:/FC31A@-?Q[_#1[5!AK VJIXGFSI2W3-L!,XM]._)CA!'+ M5VZW9Q,%H2]XS8]6D\9317OSSUZR4-.9 Y-?$D> 'K+7NS;'J(.']HX#@WX'72=O1!% M0K=Z]K=B>(;D^C+&9Y]_E9P6Z4&:V&S(,'S)98"W3OJ,-/-QD)XC$Q[]*9W& M/(<&/]X^Z-.;&9%R]96M1NZV%F$8VS#P@HA98;9)EYY"4OI=J\P0G!XI,74R.7UMJ\Z30W\Y4 MKYUH5P@[<]C!L>V1,$YB*XXLR.SXG3G;"HC_Q]=GOY$JR MGE2G3JR<'(0S.1'?NY.BV4$^5BUYB)LCI61O.J=12?9WX^"=%;UX$16!%R;$Q\K[N#%L61'GE0Z&M)JFGX+9O$#W#DQ<1R<4@2#T4NW*Y3,Z-2=R3WLV1X8D=',E8B4#8C MF^9..2WOMK^/GYKEI$V M\, .'_B#(P0UQ($%38"T([*FD_)IB)M6CPIS#52V KO-5]DBR5;L%^LOK&'& M#_P*K?J,),"5! M*'7$TQP*PZ(8?[KX[?/U%;@DZ.+7SV?_33"X^ RN_T( NOA\=7%^AN-K]K,D M/H\_(P*N_D+(]95LB6SVK1HN2_:7]>?69\UK?TK6>V3QR2 MQ)A&B&*;0&)#VN& 221YS[)NZX9E>X<$-$_.]Y;DOFPK2_& 1&N1X.;P(%^: MXS_H_K3Z ':@1Q?>XYS*":ZF^$Q6:'7Y=UI@M3(I*JQ?LE7%WS]:+2[6]UGY MI6 RGJWSYH3[:Y#MTW/KO9F*&8(XII#5[99OA;&+0B^..F"V;=/9*KM+U]GB M6EQP!T E) Q1(PRO'!"OG^?S__@=T;.?_GE*$T6(FIM=3 MB9.2@+?@ZR/<-7SP'#]X2^&9D+=.@-'6?OJS?D3B!PSI-#1_2(>+T;J/V:RP MAV@O8R'B.AAA*X$1C3")?2_:#@58TW:[Q& F)ZAA4D@+>C/":J0R40N]&G6E M7_C>I[3T]+FGNNA@W-BT["Q$/@Z)DP2^:\<.L=VXG1X.B!53+YRMBW6Z-#0= M>]*ZU'A^"U1\/)^Q@7P-$92[N;UT#3)6NQ2WX"E+2\.SKJ<#8&BV52OW \VR MCC["/TZISBE5X?!,0Y(-^M=W"E6225&I_925=VS@&L__L/ M1?O;W6I@78VXHJU&\A$Q,!RU:2B":2>+07N"G#;4A2$J'A[+[)Y7BU^S ML]6\>,C:YW!0^^+1=9 MFSBVE\2AZ]'0=I&;6'YSHZ7W_]E[T^;(<2Q+]*_ [-E['6FFR.*^]/L$DF"6 M9B(EC:3(FK;\X$:Y0Q*[7*2*I"M"_>L'X.8NR1< !$@J>\9ZLB(D#\>YYP+G MWHM5#TUD<)9\H\-37OU]>$NJVF('R>H_-V5%LW,B.&EM*:B2G^.*B&S.C\C+ M9.Z=A_!,9WX^DV$F1ZR^9P5.UC2?ZF!=9ML]E8F#$H:T[MA]%2/-X-K+, K#BO2_-4MX;(\&7QLQ? #7T#)Q<^7NWXD>GWZY( M5RK #2Y>TB4F7U]6X$M8X%5:_7(&;N>B@S(=*2"/D_2C>:OF-)0PBNF$_AJJ ML7L6,,@P_9XE3W2+^4YX.! 10C>&;A3$T/(]S=#\R([=)B(8AA'HAL"NE:F@ MCK.5I>TG9R"CBQ'+:I,4:;(&#P0[^+(FZ']I+Z3 X+F&/K\L<: C! 1Q+-?/ M6P-'8X%1]L;U"LM53"VB^MWI]&Y#:VP*ZV)#WY_.[VN("UUS3"^,+1W%(0H, M%)NNJ=F&[9M$>'6#:4NSM,849W'=TMMR!R1XKM??LAHG7?:D?V?X"6=R.EO<))K M3JZHPPV."_!'4JS^P&75AZ6%:X6>']N:$]#Y#,V)3#WLVHYU%PX,#@(M3A+V$7=;A$E-06?AWO1; M\)2L,%C5$QD[.V+$S?=:4 M09=-&;3=O[9 CFU:,(QL:&MNJ(60Q*ZN;6AZ3'>HR&UQI"C2G>[9.V,%5CU> M;MF303IS3!F9;[' LKM6V\VJ7+:S*CL;FJS0I.([2'HLYIUD\ M'G@D>F$VT4>F31]#D'3&6.+0]U]O?LWR;).1SMM-Q!T(B>4B#O1 -PP3A5&H MA[9IVJ[>-1_:*& -15(;51R-*%9Z[\C7[Q3MSI3SP:2<(P^7R_[IF#09\7QA MJ>:$@Y$&^4\#I]R%%C5JZX/[('GJN$ M'HVF&PN2[/5D^T:@ZW'DQ3[2/1@&2+?LJ%\5,KR(-?+(;55QZ&G @A:M9!F4 MS/_IV#,=]7S!YS.QSAY]IF-?+/S(] )+(.+BYT D4L/Q]*%(D5VYZM[)'HS. MK[YUK9)4O\[T#[;NVM /3=.(21EFPTA'R.U:=SP+.:RA2&:;B@,1@;HS K?% M$-W[_UTT/53KA-/Q:"K^^:+1(>IG1SA[*)J*>+% )-$!+'&(@YP#44@%O=/' M("56Y6H[)<=J$$?KFJ7KT'8"0PN\P$%NX"&[:]V*#?9-:A+;5+TBI% $I5+/ ML"HT$>NF&9G1-&P@RK_M(:W#4>*-$^@82SA5HQN-Z2)29(\U"X64\ MNF7$EK'BRL"@(H?4644422;M#RQ:8>^!PU78YHO&]:"XFAQC9#P@C,UHE,,*A,K?YVY;: M._UAMMJY=-O37.CY@>:[>J@%OAZ&@56W[G@$16#P7;XJJU6>L21TVRI<+INK ME>GD?)971)2>DU>J3G2?>M&.LV=!:9+#/+-8C4XYOWP14J<6+Q:6CLN95)YG M(W!RK?HH>0I88RG;P\\J$N \#S\'=/\;V%[=JQYR/6< MT(B@'4)70\@( ]W775U^#8->P4[ MX,"?%!ZC1DDAE"W!'8M+/M47IE%)>GN$HR,IK0QFYY'&2K$DE]_OI*A3E#\1 MM5QHGN<[MJ6;=H L)S @[!4QBAUD2M GQI:F4Z@&H!R-8J5UD$HI8%2:3ITB MI.8%X^8YK 90\W^*%^563A^*X=FA;2 MZ7\\W;)0Y&JA%D:DFD>:X?*HE7@KBI5JNS[80P,=MG&'U4&*C@RIX;3.8SA) ML".7W>'$AM$U)H5016>A^P:UF S;R$!!;"-3(_\715K7H.5$3/=:2&AFM(&T MQ79Z)$GGDBW4CT0C7YP78U"I%GWDAT&,!I Z+S4:8L@!.1K,#:L>M5_?M$?O MALO7Z?*U^>_VH;C(]=T(!9%/FK;K/YLDNPAC*[9LS>:3)CDM*E:I%B3H49Z! M!B'XL_W?R1YD9.+OR/"3R_\\1J)DFW*5/99O?+XY"-A.F(:>'1 !<(+ <'0G M1KYM!WI]93Q]/]MT^!;R15I0OFC_[K0K[UR_I-?K/S)S9%P-X7$>HVB0!>_? MB1_,!LO*[\WR$:\V:TP#YI+TI1)'^*Z*<)6DZUL:/;?#,]1,,PPMS8 &&9MZ M:.M!K&LZ"ET2/2V#:4Y-&)>!?"C1**IP\W:LS*%7=-D;(GWE0D!?H](?]-Z8[;MQ'P'9 @ M#&S7#&T8Q);A:WIL&W8')$ ^8ILW4 A ^;1"@Q9LX387:-U5(KFY7.YYZJ+) M2!>OD3XR_Z%PDE,QR?6*2/4TF7=D5%*T)KIO?/7T9I2\+;$FKJUX*#Y99RGQ MU_1!4+6!>^LOA5RR;ZWK3Y_".]HSE]7",VUDZDY@(.0%]/0=^4$AKSSB_^KU:YWVM[S/;/#L_H>[P^,')T9YIZMTIKS>O NPL@Q8LL)#4?7 MO$@+-?+?#B!TK9!K)7@\6"-.M?>V@*TQ9Z S!VSM.0.-1: U"?0VM:D0Y^;7 M,;W,II$2!%!KVS4LS?28C^A*:4UQQ-@!24_,[Q.6DNN8 MED2>3T]%C$\QGV;/F5V.H[JCLRQX6%<"VTR'=5GX.%#NR^5R^NI>LCVYJEXG M,4BTQUNB0(^1I>LHBJ(8ZF% @E/7LJ[;S"^?R&IO%H&"Z[2<5+8E! L%1*L( M%]-Q+#%D*.!:+&AT=()[4A/-)H(*)(T)LG8HD]5U?Q>LB M_'T1VI&A^3I$1A20*D:/C*@/4;ZF,YU+Y/@ZU7$ _HZN+R\OV.2'AX;C"JZ( M 4Z!/F7\D4F3$B]_?F2K;%[)$" B6E'N C@7-CK M_-L7\GUS%>6W-,/G%7XJ%] -/;HYS]>,$.JQ%KL6ZG/,F.V:%IGM33R)3"(@ MQ0IJL )KXX/I9M^B,";39?\?!F&2+Y7J22.?9(W""E!.; F11.GV& M)]VB/!&\9.X-N:;0:.[T4HA$Z?[^HNUPX'H09&DY'=T5%#&Z0F MC.P)Z8E\XF0HRG'.QM"4&@&[JO#1.$M=X33AN+*(\,%2X'9OCL1Y1N\^?<)/ M\*' N+G'0[C+S([YK3?)OY"-B@1A1KS/:*FBTZL(7'7E8- M8_)TP3H:B7QZ,Q/^V&O1T7@4*T!%^62I.(^9?J#,E,+6]+6E'#-RR;V(7:;W M-!/FZS6N+U.\PD6:KQ9!$(4(ZBY"D>%8 ;2AYG:M!H&AL:JUC+94)X9[AL89 M6/8HP7,-DUU\I/![6L/'II8S==S+ZA8@N)J"579E'YM=,8$?RC*+T#,P<4#O M97(XO>Q+M297T]/DY.K_2*M'2)I_P5L@)!!!&.BQ%NA>X&J1$YNFW6&P'#5+K D#Q@@;PCOA-ZP$Y181Z M3RBI++@],K3BV,N30!DRC._I@Y1"VQ@+%AD,LDYD(P)CM<*KB$3)EX2V&2=I M\4>RWN#+^X^_A&6)JX7G6JZM!P@A"QK0#H+ Z@HJVPL<8Y'ABFV:6TGS3&/7 M;\9NAY1YV&[!@!I-*30#KH9VMAGRZ3@7BEP=(K"%= 8H8E!#I@*ZYR.-<\:= M8AC"W#RU# #B3Q0T8SEGNGKF]$LS21903QD^)L4#+K>W#/EQ M@'PMCCQ;=PR([#BT-9(*V+Z!0HLTR[.?9VA;BJ,IO+E!M^#\]RMX?OT[NK@% MZ']?H8L;Q%?5#":4K8 9DTN^&%DKI MBKY$DFE0'_5RN-Z3PB0ECJ/M0ADMB0DF?+*%[*&/+"3P+!EH4Q:8? MQ:X;1%'D!7X,3<^- AXAG!=RU44*O<#P"[4,E[^ K76 _!@E1490DL1IQT;0 M&LFGN_/BE%'%YP5:74S8F9/:,?0,;/O&^Y[1&+RW7X D6X'&:M"9#:C8@3>& M@];R"?:NC^K6(]%KGMUK'K%PIMSDGT$@.!_APEG9(+FL'G%QE1-#<)46]4)/ M0##]T'9T*XXLTS)@$!AUVJ!KNF= FR?D*@.A.'H&Z +% MY[?@ZAN\N.&+B.IX9PMNLZ"<+TZUD.L(4X,&;U&##C;8N?=YNKI&E.$C(4.Y MT^:A_NK-?/^BVSB\,M]IN[DK\;\VI&WT0D/*3JT6F(851(&G0\?R+%2O.'IMTCD,O,=X 8,N,/W.4DPTCJW!U7R M<^1I4R;*CLV>RN5\'N-/ME'OYU)5<,:<%NQM$Q8%Z:%-IO*Z_KRN=Z@AW[B8IF6N#QOMYS?YE6R/J=7F9'T9UGO,UD8L188A@Y=GZYCZ2B& M#NJ@(]O0^<;U+" K5X4:%'CI-GL1D2@!Z:_DNTA/&3GVCD#XL3 ^)W_/0Y'F M1[IOM:W4O=2PQUVM94"Q@[LHYG4.=-OKIG6_'PF@X1=:K9S_,%KN"GH M(W"_)S_3I\U3?5NL>UT'-J-X1F9G MA3!X!2T^T +D?FQ@**6G]Z".R*;P4NL,B&3?&SHBH6);/TG*@$KCN7L&RY3LOP%-+>5(OOPU[N_$X.0?"D"1&IP\HL@S)I?_K %UT7;I_XW:/R?1!0*_='7UB0QN><)9_7%";1%^*' MZ5F>IIF+MG?\7K_CO- -\O]B/PP#QW;#&,4>#+MV[-!DNFE7_-L5"WRG01TJ MCA=?Q,@ZK=_J>>(3[?<4@3\;2#ROXXAQQ?$6CG+.!)]+:[G;EX G%;A+R*>7 M&)2/&),/D51]F!3OI>& _@ZC;'K1'8@_E]5YV.7U6WJ7%]_+5=N YGH^#%!@ MZ"YR71.&KM>#^PJ[*J)-09L@_],V@4)7,VP]\&'H.%:DN:8/NR9T.BHEAD\?=S@14$A^BYA-XB>H@4ON B><#7F$X%I-G#[TE%(%2O.FG9CB++ MC3W;BFW'T4S7=+J6'3_VQ8Y^BK>G6%7_@=.'1]+=O[8(00\1W.+B::JC= ?Y M.K)92";;\]CK(]6B@X?-9+'%?D2,=$4BW@_X\C["=]7?\>H!KX+7;LWMFLCO M%EVYL)#A:TX0!UH8!9H1^1[L4=BNZ_"=#)/;MN+1^?_226B*LYOL7[^"!C)= M?SS/5O@G^&(<#E'C\'\\99H#]7Q9U19I3_\NZ6WV0/'NW+\W\NLVG&P>D4U5 M?IF'A"JS[L.1+Y4LLDKK+7YZSHND>$7_VA %#U[#=5*6E_5,OA5HH^G63LBB1(IGX<*RC0H5]8]V2>]SI_7]!Q; MNDI)PVW)"$F*&AH6J1B-V-,"Y)"BL6W%]:TX9IWW$OENQ2IV?O4-;#&Q3_ ( MT71Z DPU0WP2])8<@6DP(9;89\)4LR4V&?;U*[C(,_PK^2]X\PT _TS+JJQO MM*P>TQ+@=;U]^E?P]>N@J; ]/!R8#1O"V/038H/0YW+ZS:"L\5O_&K43^ @% MKA^@6#-"RW=-+VZ;\[38A0-R1?9&1LX0!1ZU'\ZC4":HAL)A^9_0Z_1*,KYO M1]ZOET;H++,[ 3..YW2BO+#JS_>LP,F:7FW5779UF9UG]!A8\YRA89NZ QT8 MNG:$O! :0=RIGA=:3L0C0T/;4JQ&6WAOKLO+Z1UY/4@^51K,+ILXC4DLGT8- MXU2)5IT@ZXADR:)Y'LHES9I<36<%25&\IME#4:OY"-_[>[JJZHB MO=M4M$*^S4DN3BBK"'?D^Q^Z2<-R0016MV 0!G&LF9;IAXX>=4"=P(CYKD^8 M "#/L!8[1MQG(+C)0):M5>WF_$$IW"@N%$K^YN:[H=.&G3WM7:_T+MC6I/XF MV%VC0)6#MV;U"S,C2[E\O[ GK&-V@GD$C"D).)XDC^\+GB=;KTB/QT6!5_6T M[ TN4O)+EZ[BZY;KDJ;T$.INY&EM<^3'D/EAI4&-*$ZHMX]./G?H0%DO2Y0U M/O[W/L6H/#VK.AJ+?%*]); 'UJ[KW(Q*(/_;J,J)'/H,*B>A/.^=[K/]P&RK M%+JFGW:58\:>!TLE\,*BU._""8Y"1E?;LN/6A^I%^?@:3LSJ/+/O3(2MB!\"&= M[^E#B7R3D1_07GM5I$M\A8OZDJR%&"%#R3M*VD6 ?-*0E3+C1/- ;;0^=^MAA! M#1(0E.#F*-%C3.4F8H][.<K E* M LHP?5./D!T;EN>ZFM^AM$*VPT-381MM(F:Y-0K\J[4*_&C, L_$KCX%*NDT M;UJ;!NZH;?2?KSKKZ,ZDVCQ0$/OXYR%&=3S[_,]U#)[E&=C_/))E$RD_,K4WAW.GK MJ$FMWS.3-YT7>/*1#EJX>=JLZ]-"/;)S>I\Q3@HVB*X=Z*YM0,M$MF:2BC$P MHSYE,GRFQYTF 39:)M)G'\O>I)W<(\U TEBE- T9S]_L.<@L72V:@/119VO- M3LPYST!KD-+L8SPO\Z<>L_3VT+QC3*_S)!VRR#Z1<8SNT_FD&^.;OB?7F(A_ MUFG@G$4@7-[O?'K[7%QDZRBPD!_J MON^YCJ?IIEV_C6#Y#H'&=2W#"' 4)Q7G%W^@F]O?T<7M#3B_ / B C#Z UZ$ MZ ;<7@(8Q^??SN$MXGS6=PP_L ,=#;0 M.+#[SZ9[_W(X\T>FK$=TZSRFL\BU6F#_6M9["D%U?4FQ*[%^C; MHX>A9<>1K5G0AZ86A%&H.7KS7'P XB8MIW(;$^QGF\ATJ7W%B38HN23<2D$ ML^GTV-SR"?$I6D\?WU9T\=A)THYHJ$S*YR&24BWZKTENQ=8$T'?C U3LU$8ZKH9F(Y9"ZQMQ*&&;/97^V2UJ/P$S;NC M%W5V1._^JW<<$2N^=F;45V%Q3'W(HIQAWFH"KCFGH^@:@&VQZ:";S=,3W6E"5YW;IP1H[U[GV<-7DA0\O3\L5O^VZOH^W6U' M'Q-,LM=_*T%&1D+1>7!U;"0P30>Q<7AHED>R!V8P>2/;HEQ=?Q6..NW-FBDN MK_%S\P1E+;3O<&C(,[T0V7%HH2AV8* '88?#TTU7. 9):E]Y1.IK\#@O0'<= M:?T7>>%(EB^X@],$3A@:JK:008^Y31$DABY9'A$.9!-X1BRL[:0.-$RE3S2" MD3^U.\;IUO$6?W./D]+0Q<8:6R"3[('9A379]AT.[<@(#]D M*\A81J 800=&I&*VIQ^AJ@W,1^NY?,N5>^_TVC8:A)KEV99MQ9J'--NQH*[7 MC>J:Z6E0XUFI'-B4XI%Y5>"OM\G/^EJ[$D 2+RE6,B@O,P!?DG1=!VPZ;W*3 MD#_0#]P627VIT@U>M@[D6\DOV(U=-D0]_),6J M_L\?!":]@ H7:;[2%XX)?4_S?L&,0?=AB]W.M4: VZ*SY'] :!AK+QAW_,EUR1"TF\?P\M&4: MT_,9C+R1=.NR/OA=7FZJLB+5/P%ZG:_7)'^AOUQ$GA?$00 ]Z#JD- PBQ]#J M32&6Y4>&R9773011<3[8@@-?ML<@:BO*7_Z=+\N;RH-LV>$GF\,>N'9$*R%2AQ_2+&L7 MM9\_4RY]B.9Q=(O3I7\YR>*U7YU:"7F"6:CH1:3G9;G!JVA3].E\D^K5OVP! MH9^X6*8$["+R-5O3"(K01=#40U]W8 L$FB9T%QE^J%=@.%)H^2B8M,9OM.8# M8&:QZ?%PYL0*6&?,=R=B>O)BY H-?"_5JKD< M*VDD*>T]3NF26@FS%?KYG!;U-Y3G66/2(HX-._!"/T".ZX<. >NX'6[7#4(1 MZ9X<]#A*W^)L]Y)@BI-;]2>G:J1)D9%\.GE,V;&S[A4[EDX6952[3F'U(:_; MS"2&S83_SMPK=.5?0Y@&V*]\YI[/$V/)$]V^@U=-^HZ7=%(DIS_Z"-_T M/#ORH(^@&P6V986!:?;PH<7U?LML0"O.GQN#D>W>WYR46/U@$*M MD]X)_AH2*)\6RRN]M>( MQBH)4C?EIL:7,XOG"^AX.K01U!S#\J/(=,.N0+8U*]3]20\##$(^]R,"\W;[ MK**T5%]_CM#\EXS'TP=AYI[TWRKRLK,R3;CE])JT&%NR%?>XWS]PU @+1;X> M&I[C>@9$H6O#V.V,\&S7EEHOCPM=]02PX-F8>9$D*Z;.U[7R0VLYX%#.9XNQ M4OTZ)-1.T\$^2<2=B!S>P#NE#V=S2NFH38'N(Q1&M@DUJ(>N'FIV;Y/I!%Q/ MA\W;$L71^3.<9QK6$\8IAN?3":8KD9G.07VVP*[2[U,>HI+2'S])V)\'5V,? MOI+HX=&*\K<[^H]/*UB^[GNV%6JN;=K(#C7H=18XR&6Z07N.N#_ED:XQ_3I2 M)3Z12R!OM1U46X KZU2<)PU,P([OT5N:]N:TM6U"/' \YT P< M+X)&Y/I6BU[W74>;\)#:(-S_]^C:7W)ID-7MGT0JQV9EHJ5!/J_-YTC<4:-< MI)L:B/_\J[?H;Y?M)CG5(ZY5\C$1B+K-&/@$KT\00'0X^BUR !3S"'EF?ZT'4" M4SF"^IL#IW^IN,WHQW'.ITKI27^- M2"R=%75G625ZC2NVWIU&?\<]H7"-GY*4GMH(\ZP^#;=)UO19>F,1>R&QQ(^0 MKCLH0IKCZMW\JVXX'N2.LS/#KSCFOBE]?G02FK026G2PP7*+&Y!FGNK#KZ\X M*) BUW#LR/7,7TOB/L9@AB:QIBQ?T2SIIN/_QPI MPI@];)S,8::=ZU-.Y_]5L@UY?4)A$C)!Q_UKY"93$"&?XHE@L^1E2CI+>.D'U-WE+FN,/Q5 M4@D!_RK,&53VMK]&&Z(,Y9@K#6D'#;Q0;)/=P,7KR'%6\FJ^(@U"&R],@R MD>>Y1F38_?Z!V/#]>>U^%[5BRHGV22.DPHXQESWO8_2)SS _WO/PN0.QL,,G MW>,^M!/^-0+Y"#R-OK-=CF6%.,R\]/(A/Y-31YY55^G,FT\?3QU>@T#9-TS==4D5'IA,'L1DC\B>-;2%5\*L5QY(M M'/!G#>CPRR]2B#JN]2-PQ*?/'/0<4=(2+W]]R%_^UIA'==1L_TP5U-Q1T/T$ M[%&]@4Q-JU1#P>=2>HN@(GQ+,WQ>X:=RX1A1&(6F9="3+0%T]-@QVH9B(]*8 M;F48\/4C*@,%!6I4HO+ P1JG1*@A3%PF6+A2HQ4]$RQZP4_;S#1#P(!#NB'* M!6O%?)XM\R=\F_RD%7Q6X@!G^#ZMZ%)TFFU( 7_YC/N;-MN/7F-*2+I.FU2I M?9=M8>C0M&W-\&*=@#)Y)MK)XID[DTT\5_E-2V/'A5H88**R _Q,N<KH=QI[?00I,S9(=!X2!C! ,!5]7)Z!#%?T_J?=4'#7) 'RHX&X M9^2%@5&[\O,H_7!3!21>$K\RM3W. M"YP^9&\^$:7D'Q:DXZ?)>N&;$0Q\.]().@.YIN9IJ(,& [YGS48!I%CK:X>! M/*.;)RA0@)."G@LIY:O[<-_(4_E1W:)*[5LC/GQNUY 9J_XI'PQ4?VDN_CQ1 M0)[) M% ,M\RHT+X2#=6G&<1)F@*O"(?@F6)JY)NFFBJE?4Z_Y%D]$V1V-"0 MYD\3.D? M+^^#39EFN"P7MFT;EA6:NFW9GAFY1A0%#1Y+\RQ;>G@10Z$XD'PGGBFJA(@/ MG4[J\"DH.01]("]LJ*=?58#804[G_SKL,PX#>[D>*/C#_/=YI'V@G0(B+H/9 M4W*=X)()RS_2ZO$Q7].S0_7Z]0N1M&1=+KPHA&YL0"MRG-B*8\\UPPY-[!@: MBUBKQJ!8JH-D!5;XKB+_66V6%"B;2BNG_KA&SXEU-0H-=J WG^G S\1!JWRY MH;L)ZV_Y%(YZ@YA]!O41DQ2FZ )E1?ZZ:J<]EACH'QEG]8]R[-FUC^;GJT^,=.5Z@_U-'S*VN4)FZH M0Z]NM(%WH%_VA-VQ/#UMT!W-RGS<\2._/KK&SPGIQDF3 ;2SAZA=?5B8*')< M% :QI5LA"B#Y,^P3@1C%LNND86@4!^'M9 T=W>ODA_Q*:: WY%5,XSE"5>6T M:T&]=:)=INF,F'$)=93\@:64',=^GI)*DKT"I95,IF656-'S^K<\7_U(U^OS MI^_^__\0S=^/\SK&"G,C_C\BHDI62K*HIJT& ']8RKH/<$#RQ\A/WU M>6H=<1,%RIN!? X3WGTG'Q>>Y^AF& 6AZ;NVIR$K]'KE#W1/7U1YE:R'R*U0 MLUPBVR,4&/S5J?.!(P[E?4QQ#^!!=,]YV XSC&FP2N".9=(AS)^>\XR,__R^ M/JF49^T.]FX#>YFL<7Z?9B1]H!5 ]GM2IAE$-U<5_E:M?EWHOA$YOJMYMA.X M.O+,*'8[2(3OD'7N03D0U9/+'?ZZSAIV'& G)B53_A2*C9WG %J ?U( M9P-=':BM ,0,0.P U) YN8U]XF)6[A.;OQC)C2QS#D/9/##U,)J3II^!&,_4 M?()!P'G=\?(1KS9K?'E_@:MXDZWPJC[A7=:WS=WBGU5 :/OG NG(U4P=&IYA M.($=V+%AZP&R?<^)78-M[Y3L-A5'T@XF'<\$*&B0-C")2:-<#"-*90L< M;)'3)*C%#FKPHN(IV2^\8CJ=2\3%E<$;,Y);+H:9Y%>-S^8FQXJL/"C/*ED5 MD.LE*>DVZZ1Y1^2JR/^S?DBDO=SN\FZ=/C3S5N]PA2'!H_LH]C37(?]%O@-[ M7$CGNB!(/9HQ)7QK0KWJWAL!6BO CAG"8J[*:]RR/@.'#1!X'E_-2>K%6&<3 M?<4>G9W\J[;W<" 8A6F!D%"6FZ?F=8WO)3U2_#8@12$T8Q^&QA- MZZ2L@$AP,F-8FV/*^Q8HH$B%%7P8R=PZ/1J_ ]3X';5S$MQC]+')JA0'S$X\ MY5AU6"(ELL:RDKIMN5G0O;R_S'"[.2=YP%=YFE7=E0MA+[CQEX4 MNV9@^=#6/=.)]0Z>[>K>X@47=SG+NNJHL'@&^ZX%S&.>[A-;.?G/XM 7F&OS[WMGU]KGV>9LL")V6SOYSI M7ZQP^R](_^AN/DEV^DF> 7J[/MWKCIM[]@(NPF7&NJ M!>(A+ LL$(]$\+ %XC?[KF_JNF/;-NI 6:'#=0>"8B@C"V=GP)M1 M#H@-X)7\=FO% $U5X"X!J9W64\,4F-5)\Q)G;L99-5N=*VDFE6!Y?J^Y;B_39XDK]MU5I\'Y84[KD7 M\\>F?<":_B'&9U3IL-#)ML8OTR]SJV3D&G=XQ5\^AWR5RGX [09A4^('>+O4W M\ V_$,*_M%;\(I+^2O4+3WDRE4/$"Y-W->*.5[K[-^54)%)=(E*+3.4:657( M4_*?I+Q8-N,DI>>B[_MST=MZI/[QFYJ#UBU_(_\RKV\2PD_/Z_P5XVU]0C_S M*[A]3$N0TJ.R3TUG>$KJF][6FQ4^ W>;"I#?9WD%UNE32C<]5_F_ORF.WL3N M'3QG]:?NZ=A_J<<^^35.EH]O[7G]\*^Z30+K6@WH3=UI]OZK'E-<$,%^I$C! MC\>4?.N[3SSAA')8WW=#?KY>#SL2+M2;3A9?*GKFG,HN)?;M+;C4,*% SK/G354V>P[*\^Q@^N+:#M1,+[0=S?:(HWE0D8:*7D=67^M(Y M2IAUYXRNDM)17NIV9JQ( M75L^@GB=_ZCK*8":]+L ;PRJEX4Z@T%C<;_ZW]DHM 5:I5-YZN*Y>%.\3G[O MGH\.?.\P6=O85?I0:/_Z3'PI5EB_J:MQYU3%?4;[QSV]#_2>@$O6X!4G1=-V6_(F#P\%?J#7 ],5 MQKK$_?!QVB!.[DD6+6L/O+B;3V]^'Z$+S:D"'L7>_=O=1V.:M4*.F@7RKFF: MZVS/-M=W%-,;W K\2,=5=T=J@.E4%WVP^*ZLBF19+:+0@"AV8\V. QWZ3N#H M<0U.=W53-[CNE!@)DN)J>/>"@N;:\#>HNZO&OWS+RY)Q5GULG['5N#-T%U]> MT>W$HA+?>.HJ)Z!PE393E=M4@L:+,\#EV3,2;:BI]9WR?W;6CESMRG'1D1IW MY#XPC\IV;*/S2"IX8&RP4!*A/$)5.>U)VF)+8=SYQW)+)@HQ )MTKJB/;;TF:E71(XG(+ M,0IU^J"$8SF.9Z#0MK3 ZB"&IFLOLGJB8:4VH E!8])#O]'#72N89?%[5FP/ M5V5T4P/=MENDR1H\T*L'OJQ'JIR$G:[>(G-".D6YKE@T1C(PP#HT.%#2BD.?%+\50N(HF M_E? ;ND_&7,6[C3W8\R^2:5]5O'B4\4&9=& W]&?6/\%C)4ZI<;)\0"-;ZXA MOWU,JG^DZW6 R0^*BN;),6&2 3(=(^?9!?Y9Q?6BY7_@I.@G! /DZ(YC.&8 M3=TU@RAJ3V@0*UPOM =.L4V*7?6:3_OJ0+](W:Q-DSIFG91E>I\V/^J>/J(+ MRNUR<[]T/#@&3=LWA(/6I^D6?%&NM?1-,#MK7Z=H>T=O*: ZR!?G #48-!8# M:O*!XX!\;N9N='"[T[&[%W(G-A.Z%CAH9K M&;8>.[J-' 1;2(9'JL9A@5@BD$^WH"73":(1;R+^982O=L_E+O;ZB/CA1::I M8Q$[V5R!18$/YQHE5)AZ4O*5\2M7O^F$'PTNB]C3 FB;4#,#P[==T_-"MP,1 M!F;0+>?3BA,G=T#M9B M;K]\)O7E-TY(;P4Y'#J[=9N+)?AOT_M%[&M1%#N!:?I.Y&BZJ9M!!]IW W/@ M"L>84#_%"LBHOALVV31#M\U[;FGJ4"'3;0+S1R/WE[F&HFG(8)P=FL1'K*'N M&WT\I;Q\Q@4)K=E#/_7DVGZ,W !:AF<&IJ-9D=^\$VM8IFLA@V>>1[0-Q5,X M#:PST -CF:>62R);L!B#/SZ5%Z).B2(?X.:(E YE-FM>9%FY@:![1.@W!,(HD4.P!__:8GTCO> M-D5!\_6\:/KKJKM)KKG^C3K@?E-D:3VQ4Y^(_]4Y)4WU@@;9O(B\,7/+EL04=5S."MBW+U1RNP]EB+8R2 M7H(6U<#24':0JSRG>\G,PI17F<4T8I;,/>?'(8(ZP"T[92 M-[EJ;L7ZK:"SPZ%K!WZ$HM Q/.0;,()FWYP# Z[-"L*-*):9;JB\B W@&?CM*GA+%.43.$=$9S.<\=&>X&;GD?B9R M-]X%KIJ9.U@UU^?4]^3D5PFMZDBB=5LD67E/AO=M3J< +P@W]**=?$V^^>$\ M(P,??WPZ,0AU7[>MV$6Q%6J1Y_BP>3K1"*W8@TR3<#. J5@!WS^.URX8[%I( M5QX:&^L2L;<2W.: V@G>&@IZ2\&? Z]FFZ9?G"[I/U&7X)/TW0OY#O6&6_'> M(..ZOFGZA,@]?K/O&V+S&RK[B*2K]50P?V#"9";NGG["92Y$[+VE;P:^$7A+ MC&VE\QTJRS5BZ&IA;'FQ[\>![;3'DHW0)H"YRC;56%17=P1DGM57Q=+7KYBV M2@@_/J;&66S%X9S\))AP,#NHV\LRG_OFA3@_4IJ.Y,!J4]#9#_K>P-&+(M3DKR.Q?2S1G9O#YR%M\Z/E?>H\.X#L:T[*H(=Y M1K1@%[WE:;:M&;[O^5I@$WT/HKA#[WI!R/%JTXQ0*Q?'&CA])Z8!]EXES^KC MIR3]*ZG%9?URZ2->-_OKJN0G'CB)/![5AV:49^CL&4POSY&5?-Y#E"]K/']Z M3M*"0KB\_Y9G#]](TMKN /@[&5]Q7GPO\2+08L=S/-\T7 <:H>,ZNJ>%H1Y" M+XC-$/',+,AI4?'$P18D%1T*\VN-LWOWDB+]2K3GZX9UO[1DPMEF <;GFJ_( MET*SDD29B;DC6:Y1HDJV*5?95_E4L'W1FK3_!WW@?/M,_$5.K\#8%#09 M63AA:.BN:^B>8P<:LEW/"YNV?0+/#51Z%6F-M:E_MFCK^[NN M(/L6*XFDG]Y!-PW??"E)334!V3TX"SJ8]4O#.T#I3JBIJ&;?F#8-Y6)[S*11 MSU+R,Q-SH&"73^STY;8"FW*579$OR:M+[#JX;5/-D%3G#P2;9>NV@4(SMC1H MQ+JO68;;M:C'IL.7V@UI27E"URR:UNC 3OW5XALWN3M"U)&43@:]\TCDI%B2 MR^]\[$G;Q>;I#A?Y_7.1_R=>5F66KTGM1OHE)DGB\Z8H-WBU<#7/AX[EFEZ@ M.YYN6X[6CV?+US76?$U*8XI3M:S&2/.P#B7(;DBCH*YK!G% 2F?;-#4/]J6TY3'=#2;\Y:IG1=^O%_*MQ/)SQ;;HJI0FSLE, M9H:4E/?OF3A2TPN3-H]"7AQ^+JGSL*=FUWA)^DN)(WQ7U;=%+X@402O43-\( M(!&DT'.#9L>=&3LN9'NA1NR;%2M$!PA01.#XU=@LP?"#@0>BH#@1TX>_ =AS M&5V!<]?[YJ[$_]J0\8)>R'_JG?8+.[ -/PP#9$$M-DU;LWU/"\G@B8T@LFVN MIP^%&E#80 VJ/>W">4V:&'5L,5 Y:WQQD)LP-9OO]Y!R)"0.XG >87&8 M">\WH _G0U!5OJ49/J_P4[EP/;KSTG:@'\M.SPZXY_(3.4G<$S#BN/:*\,%_/F#\] MY=E-E2__&:4OZ0IGJ_(*%_5>\C I'Z^2=+4@B9,+(?)#U]9#)W!C$\*N:0,A MKDW94AI4K$L-1E"#/ ,]S#- @((:*;T%M7P$%"SG/8Y2^&;3K-&IYM,O.2RK MN?"1@;DCVB:5^'GHG%R3WE\**9\OIL-ZM,$"/Y/^^9B4^+G('XKD*5FM4CH? MGJR33?68%_1AF*1^*V8!75=S#$<+8L?38]]R0J3W$JS')O.5C[(;5IVG4;Q@ M"QBTB,_ %C/8@@8-:H[;]Z0[XO3BU*0^X$ST/AW]'-<93ND&P0L*Y;J#Z=0H M)TL')@N5D3W]7*(ZT_(1.BM?SM[N:RWCO+CNP5S>[T3116RZ7N#8ED>*!@P/J.PQ4B7J'>3S'%SR-.T'I7F-7Z@]_+DQ6NSE@:SU;8- M%\HQO1 MNS&EL<\X%3@I\9RIX\[]EUNTW:%G^AC4#F"V^]05WW;)R.FQF45E_IF'E"JT M[^ =EFJ89!7:.,V2;)EF#\U1'KH<;3"]VYT>8L^S*B5_7;4O^N595-\Q=54G MIINJN68GP*1:Z:]M_+EPS< R'-VW=4BC\0VOJ2""_(.>_U.00+N-F6:X;($R^X! _ %_URN-_6UQO0C MV2MX2-(,T"=E<_)!XOE56C[G9;(^HS]\+O*7M*0=@AX!K:W_9?B=])T=%]T<#MD8.]='!#Y7C^GW[:=%1K\VE&&5^ML1?.]I;^ M08ACVT:A&4#7M) ;1Y:ANW&'V-?Y*I4I<2H._]U#'.OZ(8X]$K;:#4Z=FM&G M:>^:,)0V7U"QAJ$Y<,I86WT6M_.E'ONSC;-W3[+<,R8F7_,^,>F[!$-FHJ3& M4^BO(Q7B''K)/.K+63"1SV\,2PB*I#ET?X^7U>6](/B%[5AZ'" S<$.#GE , M+2?JT+I:$"XR_$"?.Q@0$D= R:2+?J.+NP;Q!D02SP#^22__'?EF1$7$\@K8 MB*ZVS)"[I[WTVN7]W@_VX& (D:>'R(*6KY'T!#D$6@O.< V-[Q["D4#QB)?0 ME87TP>EZQK-6KFZJLMXHD?9WW'TZ'>-V!*]RJ?/TC+5*H=$LZJ2:<^;=J 4- M\-7K%1E(]*UK^N#(,QTF.V^9QH$-H:59KAW8>ASY%C2:72%0=PV'\:4BB0TJ MUY$.XQF@*%>U@/0XZS>%P/<2WV_6X%MZCT'XYK$_ODE+&?RSS3V.3#S?%.); MQJMWC$_]2.=IZHYM!I;'^SSD5*9![S<#R^:*9?M'F#RGI%*B&__/,Q+]<5DU MB6&$7_ ZK]LG6,*\?H5IV53-;Q[J-$W?"4/'U'2-J'04&(%I=IB0:[CL;[FI MQZ)6;H)_QPI S "[=K#O.1C!8:=WB\S+4WQJN^N9WET,+N(1XBF\ MQKY/9%[>$]LETGMNN>/.=AO':L>+-)8N=[U(ZI]_;6GZO1PCVII/,0YXMF,^-,]DDX8O\JS_Z^'DX"VB&"(K#"+#\^-( M@ZZE^U;0(?),S62/QJJ1C#(ATKS@4#_11-]#Z8VHU9U8]77G)\W!$OJ+G=?* M24AX+O RY:AN1G$CRX[.^?B/=S?G.R_M^*U#WY9*4+14&M]C//LXY^,YP7/F MFZ>GI'BEP;;H74=#<4:&W/8G#SCK-L'07ZY2HK/IW:;^P7VR[,YV/??U\7-? M'^/>Z?4<15GF=(S25G;&[HIE[++MV1SDD8/[-C!V_"1 MOG]\GM5QYQI7:5$_AGQYMTX?DCVY!K1"+_+C4(\LVW%\Z&JVWN'1_< 1.X K M&X7B_96[AT(;Z"#-VBB_10^V\$4/YDKW#ML\Y3PNN7TR^92F,,M'9CK5 M>VX>$Z CV'GP**]:9ODE_'_D:5:M7R]_9'CUO:+I2A-5=@[L68X1Q[YK6(8. M]2"VD*W['83(<0156T+#(PIUBQ;4<$&+MTG@.5\CD$L]KR2/S+JX"A\C?$;B M>YI/)KV5Z):Y2:Q,TPZJJG3^>+8#-8]FUU?>T-W!M8I?XSI1#_.R*NN+%(.D M)'E[>U?.%E5DFY&CQW[DFY:&?-UT-%BC,A"TM"CF/9.D$HMJN?T[O$9? WB# M(A!>_GZ%+F[@[?GE!?\A(J4.85/<.?F"3X2WR-L+O'KLH 4/:O1GS26Q7^^H M :"_ VRZ^QP&4GYBT]48SIR'=(]F[9YM5N.QS"SP^!X7!5[=)C]WKMR!=V55 M),MJ$7@^TIW CEPG1#",39Y7.\$#&Q*L3QWZ.@AOMUKJ_Z=4Y\' M\LDHO^-1R:FN!U@\ [\5=./KGQW&L<7S*&''M%$.TS.1/DG&O%;;;H0B0ZW(>!I3<.M.(''+(+TKO"6),NDD)[G#U M ^,,W.7Y/^NU&7KTC^0Y:=D^E%P;(4/W!KACB! J]H-D93RZMW0.,GF03F[= M'.Z8.0NI!.N8E%46B\.D]I)>SK.P/#?63&CZ;F2ZEF^;>@#;%E%,_BQ#5ME: M4BZA-0RJE?7D7(6?GO."KJ"OMM(J0S,9>1VBCQ()E:R%-;(Y:%X-A%O?^(B= MLY9Q6L*D6R+L\&I4?U?%3KL+3S>@Y:,@BCS-,37/L;N[G SD(3_B.E8]I"&N M&I;_>/2)ZDM,G<08Y9,GY61*K6*GT:=]'#$(U"!JYZ50PTPY(%$2^!'(HYJ= MK!>XVE;)D:-[8:!Y=NPYNF^9T#>Z)O5(8WK]24I#8\ZS->C$I]@$:.3.F]0R M.$"8&F!G@&ZBGL&\V@>>V+(G<7KG)4[#3#FV0,]!AXF1?%Z MGQ<_DF)5+GQH:X8//5-S-0/:T//=L$- K[L>I%4#VE4L73VRYA*'Y2ZV@1(V MA&Q!11N)9PD"M^6=0@4A$^_CR-UA$GG43X(K9BJ&,BP[I8W2V!.6RO:4VI[V M \^U7"O0?61$?A2Y,-"[]DU=Y]O^(JU5Q3+9XI(ODN(T"TKD* Q+$,B.\=G) MXR$"><1QL!-F*HW#[3HEC)*8$Y9%\H?N9ZBY6/0:E[AXP?2!)[A<%IMD72Y" MUX/0T1 ,3<=Q-1=&2.LUFJCT((V4 T&Q8 8)/0=WUZS\Y?4J0[TTV[^#,%0X M)3E"4$7']X$$2:5_[G_1PCX#'?#:4QWTB366B5X>P97KKYFJKV0C3TFQ"DXE MZO+N?D0"*, 9OD\K BBTD6>0"!&1@!':&G2<;:" #M>+H@IA*-;GG1-R2[I+ M4[H:"],O39''8%Z9*K_9Q$V5N8,_.V4^0/,P=1[JNT^CT(,-Y5=I.=RRW"JS M#TQ(_IY6;W+W>@%RH1L60K$6>*;NFZZ#K-#KYC5B&)B(]34_J8TJ5F$Z]I2=D=K+3U'QNH;^<3>#82R*><_7Z6R:@7NXSE]K%]?Z-^Z@ D M]49<^M3=74(^M\2@?,2X JNDPMUODJ=\0Q(2\K?[345/,]%_O\*KYA(L4J$4 MI'3,'IJKII/U&FRR#3W)5!T81OU;1D7W'8#\%23@)5EOVM"Z7N<_*)Q?!]W4 MPN.;/9%1F7NGOX-%C5FYXF$Q=)VQWA5&2A[/A]! %K)=7XM"%/>-67'H#5M2 M9&I"]>IA/;'3CE#Y.TBYR!1=,I3.HXS5P4FWC.X0P[7BQ\7D3#-T3B-.KN,) M<"*L.HW$::'G.%A@B&T,YFU"\)?26_A/P4!^^6W7# MA^8 ];6J ]6&D41!M9'/GP2UF7 #Z%MB>-2&C\F9J@VG$:?41H038;7YH\NA M89="+YS(\SW+@K89:)Z/; OZ4==R;.AQ=W#F=D#>(] LTW!Z>XKFEC\7^H;+ M\M_W5183CZR/A/$,LP%TSW3,#;'HU !S:R8]OI MBYO($#H2PM7 *'$_HY,&LJ,^$WV",5\VG=^#OKL".!.Q(L XMU@S M4SM3.>(R@6%+-22$ M90VQ>2$TOZ<'1=*'QXI\#+=/>A/_6MN^$4 K-"/7=6,8("O6' ]% M+FD2L6U)EM66XAG7!B(-WAW(KQ1E]\KY&:"='A"D_\:QHB6%X]-KAV/3RZ=0 M+,Q:DS#+OD0X-L-B*X,RF&99E&-@X\!:G$P>IU^"DVI-KJ:W<=Z%W=\I^&8S M2U'0B[IIAPQ>/UP[".DR(+U6IGH]KU]6JN\BK"?H;Q^3[/*Y7F.^R+,77)+D M\#I?K^-F[7 1.5;D:9IN($/S=,LCUCB=$8ZN<=T8.#/HJK<9DCX OEQLGNYP M00=\;5KYR^'3T6KN?AZ5\R.9Y$R=/X\,=:[DO+_!>J8P^02TRI?_?,S7Q*5E M@^LBK_#V.M?M%:UVI$>N%KB1I7LN >+YOJD%#M1-,_)0P+5=6EZKBF6K Y$K@\O3LPBT(%?LTJR>,S$UYN>.17KW6GM ;8YX]1!ORGYO-79FNTJ1X;=M"KN7 R/(,HMJ1 1VDZ:AO MR_"9E^#$6U LIQ08J)&!+;1!7?V@J0>Z^W!JIN_R$FS(9786]JX/LX?D*2_; M[_<\PZ5/%SD:BJ#M1,A!;OO]KA=:(6MWY_M6Q5V\!<,>^S@Y.9T?J*.#+R]H M<0BD YR4L*]QNPA08Z;.P# M?@AYIP5Q)-[XU'$_90)B.80[=N4]B4>$GO/BA>%U>0?+%G>RY$R(B1;CN:9NE6]\6^'D0LJLOQ=:JW+,(+^#L4 M6=@K\?+7A_SE;ZTM=%W/[/Y"N[NYLZ2WM7=/YQ8@8]J.+ (X%W8\>ZIPF^(* M?ZBV?,LR##<.7#,.;-U!H0F=KATW,GW6+$'LVQ5WWQH42\TOBZS368%ZGO@2 M@O<4":0"@ERQ9P'J.1-EQ9'N1%@5Q8#A&UQ34V#::#FI L99VN(3D5)RUTXHZ"F%\HKJ' M*P%=%2>-75I'(4],785(9!'80S8?T-C!%$TOL\--R"5V&7:QO=FL/[3B.+KF M!KJI01-"([+\0(==*[J!F&[F$OUNQ1)+(,E:H-ICW8'N/82'Z7OV(/2YG-[ MT9_S3?5(7+YJ6X"AXR$;NE[DZZ&GF4X0=DM=KLF1,_!^K^I^W,%ACW7M%^O^X:ONY896J9K.1%)%IQNWM5SW=AAKI)XOE1U951CXT\1@YP.]SK'@_C__ MD6:K"_SC/L7K3C2CT(X<(XH=ES1@H,!SO4XT/0AM;_&"B[N<:;%=Y.MY^NXN M$O:5SO\)**QA*YI[+#NTECF$A.F[\##XN:3.P-ZE_Y$419H7UYNL;<*,XRCT M7 W&;F@APXW"OO A37C,09K[BQ4'ZA8/((#8HQ,_.Z/<(KXOBN" IB#T'#<$UZ MABGR'9T^*GC!0^X1N)#YY=PHIX$=TD MS,8/VQ[AK6D')$[(^NGE30QV/M#K[+)V7B5W^4V2?% MENV;;@2#*.K:B3579Z]7Q+Y?><%2PP)?"##0(OM%3D_>:^^!+CV,F^G[]D#\ MN:Q>PG<]3O-^4)PLZXM=X<^T7!B1:QEVZ,(P>[!$?AZ MU=./S>M9'23P)P7%&,^&D'8\TH_$%^<4)1]52NZM^4C('OF0P-X\;J(98D N MK2<-49 H?TK2;.%XFFUXR-(C:&NA[D.K/[KCF0[?75I"#8RM(@VL03K"2IV( MDBA@;:"6G")L!#5I(##K"2>'W!]9/67[+DZS+^6,4 MQT81A[:A6EMV8($:%Z>JB%+'*"PCL,:I+1\( MXZY>),G+?FJ.**\S4EAAVY^^TU*:XR>^JUX47(^[P)]T<$'=QU^L&P-X-G$IP_[A\$_SA,P')3%.0;UZ\@>4G2=7W5XB8CHOYNM*6X!$D%RFYK M+OW[C[1ZW/U]^^]V.\>7]OOW-;W&9?GNQ?+^4R7(-U59)1D]*OP+J')P3[[] M[7?3W8EY_79R@=?T*2+RZ[(:]MJ!N*,/;?Y1WW.FGY\<\LT(7N/GYHF1\O+^6YX]W.+BB5X! MNO!\"T;(UDR2," _]G4;>EUS%G29[N08W(CBB+S%18?_FB#[2K[EJ1ZPX\YQ M'6+HR"378%+G,K\PM>0 MJ<6NK?LHC,+8]LS8;YOU+=TV6#->*8TI'U =1A+]RLR MH]/+E[SN,$OQ 0*PN36[A0BN)V*6/3D=G6'!"W5(3E@_+M^EGG4OSHB:=7_M M$\;B77>GL;LB_Y_\O4E1TPPDRR714/HT>C-IM,0%_0C)[5YPEK2A!_],RXIF M?/5@21X*7+\$-FQ"AX7O UF>5%=-G];)-2=7U*5%XLX%KIJ7VQ=Z;!NN8YH! M1!#2BP0]V^U;,2R+/\RP?_=X427#9'C4H$1TCH,MGH"AABCA^$#@ #@&1R+2 MKX8K<:7?BOFV:]4O"^_.(^SH?*/K+^3G^:8$:US_E0:(!Z+G15:#6(/G(G]) M2_HF(Z@>DZK_@F;"X:Z9<2*MT+^^::G*054D67E/OG4'$/TQ^>AS4@>@9?[T MG&3#[F;9XY&3L8#?=W.2?@'T>Y5>E 76BKR>&[C(L_RYOC4V>SC/B,,Q"2ZH M>1MY^\Z1ZQN^A2S?1S:,8&3;EF/5[QP9,7$VY-I3++%9U?/HMW]'U^#B\N+K MY16ZAK?G%[\!]+^OT,4-XMO2(Y-IMET^$Y$L,D^^BQ(T,&N=:X%.^.@F.XE' M9D\4>&(>\RDJ#,N5]V(^B8QPD;Z0EE_PSFO(I/F_X]4#@0.7Y%?UBL"^MT!] M4[/M2(?T4633,FP'!GX-2?-C)X9,YRI' :)81B-T??X'4<\_$#B_N+F]_OX[ MNKB] ? B G]'T6]456%(?GU^>XYN^(15K7_8I'8VKN$3WRULL(.[5MX6.=A" MG\T8*&3: M/SHB'.4S)[L6T(JSMP$T1H OU(Q? .V4H+.$UIN[MK0/$7.>PQG#FVRQ8&:. MY)W9&<>'BM8UAS)_= 5T-+?.(TZ,:?"'5=61N6:>+NF =$UW+SAZGA/H>FQ: MFA99NAO[KM>U%AJ6QG:]P-!6>&1!Z)*!K19TR#CG0$3I8YSP&($WSMF-#X1- M=*SI #7'YBP&DCD/$1MLQ?O9""FLL,K->5:G875+:)T^I5DMB&V;1A#H*# = M*XA)0AQ8=N1;O<29,=8B3)%MR%3V0Y_QE\9P34<3U3"VIZ>O_W>UBW=-$D#1@&F%L1GH$ MO=!R-7^;DJ& _0XF:4TJSYAZI/6D6@USX+DI-LL/+*]*)V[Z-5?Y)N4*.QI? M_&^3C&M,M_J3I*.OB[*'\PH_Q7EQO#)Z6QA]2S-,_UFY,'R+[D[5 D>WO# , M7-LP.K0D=V':)3HU1L4Y1XL.]':=@1W+ ,58']5@F1[Y.#M"S:R_@_?:JLEZ M!%OV\QDZ U_>-'T_4))^*7+4D<1MZJXQCY1O0U8WB6;%YQM2%QV7,M$ M?JC;Y'M#Z$)DZGVXM2*?,97D_EKEZ6*'9.QY\Z;5H[/?G!3-8[CQP_XP$RUD M-]/]VZO_W)1DT%Q52WA75D6RK$\-F9KEV7%@^R9$OHO\H&LE0M!A+Y%$OEUY M]^Y @:O;D./Z:1&BCNS]D8<#M?80QJ8OJP>AS^7T M&XYG)M^E,><9 MSLGG-3;0.G1I;;7/3>S'J0Q\D7T$--+BG^0?W'W6O^+Y6.*[\%V MC_\*+^LC2^ I^2"'S3HIUJ_- 2?:?'LRZ?B7G0&: MLU-+LKQZ!SVI3F/_==@+K-*ZW(&T8H(^/7TV,H71^:0Z,N)>UCXO,RS30A'4 M;/)_D6W9"&K]VJ!M^9RWL(R!:-P=K;=Y=S:ICI?4V6FVH0K46D>7TP-,^@8& MI#.P7H\PLA/99O+GYS^^;$C:1M;3I?C\]K(>J4RG\>]<9@-'M5GFIE9!QIG> M]\T*G*S3_\*K[2&-\KC'BA ]D)H.)NGR]51B>23W;T!56_P^4#@\! M0Z@5"0,C4?SY0L%A8DZ& PFM+G1D>XX-]2"((?1UW4&6UK7G6J[.&A.&M:(X&.R ^UNR!<>;_0]D\G0 M&(]$/N7?Q05V""Q'9I!=Y\=C\K,(_%%&#BB['!:GEW1)=N2R^Q?'N^=/STE: MT([0Q@DKT@/=#:%'"@@S#C7D17V<\%W/763XH3XOS2;?W-_/-$3\9HA\@,(\ M3+:PN)-V?L9.Z[,:EL1._(W)#+ON*F7HLTCM>Q(.J*LP5],+JCCT7$)?X:(?!SR7U'7;!_;A19A&;41@ZCJF[MAU& ;)AW)^M\%S(=)&%X%(3U/$)8A=3Q41]%BG]2,,!(1W U_0R.@1\+J7/<)3Z M]28TNEEDNP5MNP.MV8!6[S^#50.#[OJ]S4F_J8=9OE[7>QB)GF'28Q:^AYPH M\LPX0,B/M""PK%[C710;["<>1@;&,]H$SZNM_KW;\E=O$UMNM_SEVRU_=\V6 MOXI:=@:2'=OH=K+LC74@[] MDAXINX)+H?ATS!V;7;Y NB6V 4C2)M!!I"^@PZF(98]W8Q,L^HX8/9!'KQTJ M\#-]X;0^M;!]7&R%5YOZ\; ZI]E[5)#D+46[&;U.8OB2H/HFNU.CAS2PKL]/ MM$?V"$KR^7\KZ5F[^A!5GM%+\-_4)_ MD5)KT^R%J"6NL?]X3)>/31,-I"=J=;D:H8@WPDZ$KY7]#6A53,8;LBHK%/ YC9QTXV0"8,0VJ[N M^X8?FJX>![$9AX9FVU[$%<=GE"\F#B!3 MR9FRHSSMT2VY_,[C#)@D6W(5/5".8I5A\EQ'[6_];6R6[UNQ:<2V;R#;L=S8 M#U$+0#=TUY8A7P+-3J9EY1GHT ZXBU.F X8)G6+N9:D>-^VCJN!'$@4D<8 G MYJV/0PQC%,O!W'%>(TEG;:Z;,N4J*>CC8PL'Q;83TXTUEN=XE@8M7^O;@P;G M#0BBK2C6Q1984^^]>1":5G8,,R J+Z'\2->143BN:YS ](BV[3<7##>V=*A$9 M=VJ9/ST#.17I?/G'_OG'7:2 0!6:D)3*-_O$Y%2\BTU07K^=EGQ."EKPDDC_ MG&1T!G#_U.&1\3!LRHZ#O -3=RKHGWX*3XE5N=I.R_MZ%DTONWM5#J_/-9^K M5^G0SZI(".UIEA2O=0JZ?Z5N$1O0L:W(CTS?#)PXA+H;M(@-#=K&HLJK9,V6 M*$Z)DROV]2;Q;J]HY^_;581V4K_BOR%K4H^RE>B?Q9E"VV1V;\S:?_M9Z^+V M\[?-IIDW!C8U_QEX:R/HC!S[%3)EWCI2MLRAC\RC\)D%$Q_>3YL!)H% 1Y"@ MG\]T8B7 &;Y/JT7H6::)C,B%<1A P_",J&_-C&R?XQC3T*:8I&GX8= ^LA A MJH%-(2)\SFD8#[!B[Q M""P)>5\R.QE[9,2F$2+'=ST4N9.(MZJA!HWD>@M120O^ZBGY!#6\922)Z?"^JKL*_(&RMIEU7/ M2$W@[04G-"?(W_;D,\,"EZ=H(V3DKY1SU*HZ?J%',=]\K/CI\<9B>JO6<9%N MTQT]:W2AR%W+1&Z(/,_Q2;H2H6G0XG7"2<";#(R+4G9O1DT.BI8= M?"?TABQ+HA*(D:?%QXG%_'T,^L\Z28 MI\62/,"!(7J.[4]FSLQWP]! ANW&#*+G>]P7>"@'=E>E$'*4#G3!(]P4[ZM[ MR:VH1B)+Z3'+)8!) 68%2]U%5EQ'D27V\*R$/>P/!2FKY'O^W.-^:RH=%626 M5X:(/7YF,AYUT467X>.O+/]X)-TH\R+?I.FV7$W=*$*&9R'7-,QIA +;LAE( M'SD3I1E(/VCWE8/0)B#R%"\EI]B?>FJN* V1)_>HB0BE!?.[4%IQ+B)/\>'9 MR&5@UCU:)*H3;%M2#GNR4J?$Y$(2F:G),.U_D.1D('G1Z(ZEXG#G]FI15N M14TU]95+>/'X:\B"1"SMN7Y(ZOJJI.0\2Z5V5Y(S+:?/^&F;GL.2:Q[V(FM1 ML^Q[MDWWVP7FM@I0&%B![\5F9'EV$+M>%#$ $YQZBJLS]?JS6M20M@UB6@\7 M62_HIX"(JH^TP9=1T6%@83'JN(NLP4@;_QN\?K^ODM?+2:[.H/L-V>#ZQZ!Q M']\D91'K5;>X8>S$&%64[W;Y?GG,-W_7'RSQ'%^0F;Z:3,U),/4-WS*], B< MT/8-!L?W8^X:@U006IC8AN*'DA!H/DT8 'WT3^3B>HM:(BQ.D5 R#*^&#A0[ MG,'#0B>-1-JA(JT$-&B2K]+[?#NAT\;"T0DN^CUD1[LJ0+$ MNP>'%4&SE]\*&U>)[CLOLDW:=E+8IN4X#C+"*8;DNF9LQ5,&"UGDTA"I+MP/ MC-9N?"!4Y/1"BM!1FC_+DU"E3U,6WUW5PT(,_C/;W0[X_8UH9 M:.)Y5NR'"(4S%!NSP&DS#MOW7%YKE_+')5MY@[E>,,K.A7_GP&]/M"J,O+.@ M\"_]=C/FD&&\8IE2%1G?(N72RQ7-;)&[W6]TTCX\ M_58E!;$,5OPNOR:G,)TUGU_-;,M&YF3J189MNE%@((\]NQC'4Y_K/G6E@+38 M]9Y7A'\:-NVQ4XF7C1.L24-)_3V1FR=1HHK8_HZ@IXPM<$V#=(DQ(NUQ;0F8 M"H2DY4Q?*47NA4>0=/A^^/_NW,;B\24Y=@*RUX-_[Z(7LB9?. M%C^8(ATMTLD/?V:+SS_\,4GG__CAILCO?O@C+_Z1?1G]]-.ZT ^K'Z;9[!^? M1O/TAZ_S[#_FX\_IW>A-/AXM5J_]O%C<_\8UZM\\^1]?RP^^>?Y/O'H: M2BE_67V[?72>O?1@J!;^\G]_>_-AI>)/V6R^&,W&Z8__\W_\\,-_%ODT?9_> M_%#^^_O[JV_*C]+YS^/\[I?RNU_4^)_+;)Z5Z,R?_AQ>7LKP'Y^+].8O/X8B M06-((5KK^_\?*K9XN$__\N,\N[N?!I5_.5:FU8\V78RR:7/)7BK X.>?S='%U=S_*BK+[<5_OT]FJ MY>Z5;6^A#N1Y_.#ZYDT^NWV3?4DGJT?G?TVGDX#/[_-THA]6']7$M_47=:#W MVU%1A-[\2WJ,3KLJZ4#>>MU"C:)'R:;367J3+=Y-1P>[@9<>;>W=:AS&].6T M',XW'U]_FF:WJ^&YGD$C:^M"@^O%Y[0P^=U]D7X.]@ITN@H>S5WZ)I_7[-&. MK[@]O>[RY6PQ?Y^.\]M9]J]T]H6KH7'SZGH=U'*!=?>VL: M/OWYCS2[_1Q>K()'.KI-0_M;WMTW&(J.KKZ)>+99%6WXP>RGXD M0IDFU;6F@P_]WM]&TV5Z?5/^OAYIYK69"Y[ZW$8$J]GZ;L\FRW,Y]'L M-K33HZC4O-+6]'F3?DFG^'T^G?J\^'-43)I+?ZB*UF1MZ /4*=J>;.G"+V>3 M=/)A,5HL(SBPOX(VY7R7%EF8@(\W'YM\7M-1;%Q/:U)OV[6:3C>S^@B(:]32 MFL2U_+_=!8Z2([@0=]EBU74?$."%)]MZ\YMT-$_GZ_'DMVR6W2WOMN/)LF8+ MCJVN-1W"O.=C6MR]6Q;CS^']3[YJKD#MNMJ2OF%W6:-D6Y+5:AP[GS]2BAWN MYT%I#I3K1JIWHR( \#E=9./1-%;$%RMI3=YRO$I79KJ^,:/Y9S_-_VR"YM[R MW4BY(B5]>5:^I XEA5-J^Q&E^\GN+$J[*ZI+\E;L43-:CO1 MZ?H^+49UEHGK5]"QG&U ?J"V8S589*%IS<99C3'NA6?;>_LWO[P+0#05:6\% M[]+6]*1VECA*$IM^6AQX]=-'CG[7VWQ6KB0N MBWE:_FJ"E_H0]-HL,JK9I/2O:]HKNKZVM?@MS/:+, "7&[J3Y;2FL]Z\HK;E M;CB[:%##T9+N-FISCC2NJU7I(T#N'>%R):C(0M]R/YINFDZ8D5]_20L?WOSW M=%1$PMV\XJ/U^K#\-,\FV:AX>,;5JYE-;T;+Z>*Z4.-Q.BW=A[3F6NGQ%1^M M5ZUAXOL'CW]O:"!A] DF6V2AXH_%/@D^RF.) MMF&I\8J>="W2(,;[;/Z/]^EJ=W_KA2]\6KIJ[:O>^(W](%'[07=SDY:_I._R MHIRZP7Z_]HG[TOEXNRL#KR0KWJDPP4.#P:+I=.M /'X,T+2-Q MQ*O[P:;F9".JMN,TR.;CU9"X3">/*\"KET[+!O5A-$WU MY6^Z=M!*Y3WJ5ZUS7=^L(\)'TU^+?'D?1I7Q=+EJ'2]6UP4:[8C2(W;UFN@1 M51ZGR^8$4'B5"^]?/%S-;O+B;O7^0S+7*'J4;&Y4S()!Y^_2XL/G47%HZW+7 MXZW*\/SWFCL]3:MI5>:&O5/=XJW*^-BLGW^C1_-LO#J+,EW67@=LJ_I6=:S5 M$^PO=)P\=4(P6HRP6%>U-^B^?AQ_7&4MR+_^VP87:9+.)HVDW5^T-=G>IHO' MPPMJL2BR3\M%29N/N2I7:8K[O&AP_*.-JEO3[<,B'__C?7J_B>2+@/] #2U( M^CX=3T?S>7:3;0)=P[3A^D;EXVD3:6O7TH+$]7JB%QYMX]W%:#8?C5I#H\;),>/ MXQV\JE/=ZWEHC2HY2M[UBOO'T=>#0KWP9%MO+G=6\MGZ"-^3C^M1H'$];4EM MTYNT"!U:^&4;M/ODLV_B=QLJ$EUU6[IM0R.WG\6LG,97V)8>CQM*OLCOUH&S MR^#3/<8]Z/0F+QZE:JS8L6]H5]/PX[O1PZI[")1YBG6SY:;C*VY+KX8#7HV2 M;4E6JRO?^7Q;4OQ>KI1OLK"%#S:I9YJ;N5X]1TK])?3->7$H+."[Y]IY:UU( M7GZ\'1EJ*SF7=CB?K M7=GK/\-SB@;\F9Q?C1MO*/5^GMZ MTOIAY>E_)\SUS=,'-V#/;+9V2,M*W5JKNO67:E^9M/LO7KGT9[5-^ M5\_R<96U+__JPT:KM$VK:5_F6CRM4?)XR8+!KBN#/47BA<_KB!M172@Z(=K!<-U*MUF;>IXML'3CSF*V\YFAP M?,7=Z/5T'>U=W8-ND;5UHX%-[\-T-GNZ8_0AOUG\.2K2IYM)*U?]/EN,INLD MYFL'_DA]VWQW-^ALIRQEDKK1U)?;,GXT;K1:V4[EW>CW/KU=Q^V'#U=Y63:_ MKG=\-^#;;+X.,0^_'D_R%E[9#1:UNO::I8^2\'TZ2=.[E>M81LE?WSR="!V0 MKU;9[J1KN 8955=WTN_]LA8]VJK^2!U732HO'EY*D7)0@SJ%.Y2O+G,:U-&A MM/N_U0_OT_LPD*VG@;?K,>]X]8Y]:8=XU&PE]:LX4M;5T/)N5'Q['.6@?/N+ M=2+3XP;\TR>>;!M5NTIU&=3N:WK4^>D372B[I_Y.M*S9)NH4[D:^9P>UGL3V MK0Z[?LZGD[1N#L-V7W*C^>[7G5 M$C7Y[^6\7)PI$YA]+2/PJSVV>77&8'/(H#H5\BPBO[;S-C0Y3XKZYNC4XUYW M.0]\<7][M0D>9D7UMGV='B]%!3>H4[E"^NMQK4$>'TM8T-=V5,4"W79F^A#N39YE]J?.U]='T=:-$P7*-9)1W(^VZ^W.1% MK]N]-ZRF&YF?_MHHH/B(&KO19/ZW=+X.W=I<1E4W!\(1-7:@R?MV>+2[FFYD M;IE'M6KL1I.6>52KQ@XT6<=QK7KK-OATN+IN=6B97XUJ[D"S>GY-C:+'R;;\ M-$__N0R>LRL/JS[[]:!X]4IW*6%-"C2JY"AY/^9A.KKKC$4]:9M4T536KY^* MZ<]YT) M^39=M"OG\PK;$_5=6F3YQ,U:!O;E:ML6^\,B3*2Z$/S[BML3_6-:S--VA?Z^ MRA;%+9MYR^)^5V4KXD8P8?&]A(?-?E^D\] ?KP:Y-^&AS:-EE;L[W%5"LGFV MFI0^_?G;%Z5?%^ELDDY^+%\47C7-QR^ILU+E9C3_M-)G.?_I=C2Z_Z7LG7]) MIXMY],UI_*O?V53)_FBV(TWL:234L4_O)C$""I M4RQ!D"B"/+/<8VZP4= 1:Q0CS$JMO/U6SU!M&;N\0;0S17]+B]O0-+[!?G4P MYC[?_%I>3S3-RV34\X\!?!WD^,<>".(J3"C3BCHK,3%"."Z98+ "1P;,#H#S ME'"J&/^0%Y.T^,N/\,Q-ML][O7I/+;:JZR1_FF527. B&\D,@8 MIQ1C)G"O H0"=@B0MEK\XCO'H-?V7IL6>:]P/[;T ]R;I^.?;_,OOTS2K*0= M*7\HV4:>L"U\E+P)?LW4K:Z*4U^S^0M$>N&IA!+'#=?>"0 %M(Q+LQ7:,:XO MAB/=F3-O"]W6*;&6Q.9WHVRV@P]/'TF@,$9)*BF@ K/05*3&E;B*$G+V9#C* M1GDKJ.TU\G?K&^&#Y+?PDM"7I>GB/O\S+7Y+[SZEQ0OFW/ELHHR'D#"F='!U MH&24"5Y)*)E5%V'7.)OD[6)7NPD?[SH]Z;!V]/<'2H21$0&+!4.(.>:X*!+VE,JH4)BS*Q76D'(-1(*F;6* M+@S2BL6Q!P^//;UU2^VA?3I"'>R6]I9+H ?"*T(YLAPQ[BU!M%*30 TNIDMJ MQ=;U^!,%;0\,V@IJRBM?KV]6^]<'.J2=91)%#''2&0TL#1AAI!EY5$_@..:0 MX3&GM^ZH+:Q[H-)3"0_V0-\_G# '%:6"^3#!)-P'>"RO%%*$7\X27 LVS5M& M\S1N])OPP56 HN&$;%LL\<@KY(-20!I)#0% R$I)K$WDBAP=(&5.."N+A?LT MG'J7%N/2IK?E&;5\\?36[>J.J69LJU%A8BGS'BE 98";Z0"2 MMVBV5?^X4G MF<1%T.,PY]H'O4^#;N]'#ZG#2QWS3)BIUTOFO13[?-ZH>*IH0SJE4 M3G-E#%'4*RY]I2P4)')9:H +"YWPJF5XA]5WK4)(6^K UG4E-K0MS"$TV@L, M,0A.JZO@T!BCBYDWGKH7B\+[-/1[O[UPZFH2D,UNLM%WMX5^FT1S=8PLG919 M8#99BK^,ID\CQNMQM<47)]191X155DLCM$!A.HX 2E+V*?SC@] MM(+MS9[59;C+HKQA>A7AO(?#^XHE&L!R.Q=Q"B# S$B 1*4D(S+2062OA($M M0MMKN.)+9WFVT8JMA45_&])Y*;&1G$BKE/)>.2\=Q]AS";6CDGA#N.6O.C+: M&(X0])I"2IQ"A&/O*G#*J*"+6^DXCB+MQ$4W [V'CN:9S)<5&XUE>)D7"!-! M#2>$&&,\$R8,&4H3:D[2_I]M*S[-/;NZA&^R,L5H^H0_^F%MI-$TS#F7]^55 MO=/E) Q?Y3/KFXC#A&";0?-02'5/$B2*"B^T%M:Y,C($4&O !GZM/>UK&^CD M9R]JTW#_!O1 [-2#]_R-#JL=L56N]1H1-@=*)@8RPATP&% .O P=,-FJ2I&^ MG,#OP7$G[])0I^7DP2WR@V43(IS!D#KA,.%(4& DK-156)Y_K'+K=J_/IRB( M^V;4^I?0OF[TPX?1-'V;+UYN=CL#X=NH-B'$AGFP-L)(R2AGD!I;@10^._^S M$!WP91\3N\6_;Y+^-9U.;O)BWAX_Z]>8, 0,T5;28!:L$,!4TBTTEEW._FA/ MU.P,^L8'NK+5S=,E)_'FYY*-^ D;UY\FCU=4[W #7WPN08HY #AV!BAMG'0. MHRU[1Z9=CR9&6T2%H1(99(G6EI+'T1@H M>7GF;6J8O%4$^S]GT4$7V>P,4$<") A)AI4.B-O0(SNOG:B&;". <1<3]3/4 M,6_0]NY[XG!(A;>CN\,G,"-K3(BB1$#HC6<,,.C8XY*"\5X>V@4/)$0@#WB! 7I.),&>X@8I4T"L#(7?0!SBW[ M-'P\P!&MWWUXJZ_W-_HGCR2$:(X5!I81[@4 UHEJ[F,X=)$[2 -TK'IMZ?$( M?V/Q\PD?[A/=KF=F+[:KCT4VRR:CR:_I;*/&[[-I=IQG:P7$*-U($4 M&G.IF6#,(K&%@(2?+R82MT^.M U[1$>249TK%K_/QU,^!8F"]B/>]-C:/M/4J1*&FQ@UY*)CD)C<K-G[.+-:Y.,TGV*CWD-TKW'5@^7 M3JC5P .J$?:B3%[MC*TF A93?4G+*H-DTO.CL*V;K+F#\,U[K_\,ONK\_(FGZ]:C5DC$V!ZA.:@5[&O<(*Y%I) +35DQ$/(J;!;A9GM*VO@:V=I M9Q:+Z2$?C_.,9I--E%<9>_C83>\Y5].TBD00 #A0 EG&-0P30@IUI0\U.C(L M;X K=D/F7\=6BV7A1N]=X85/NO)U1J /^?2ET]''59AHB*"@V#KO.$."A#&" M;L'4%[$[UYW]OR-8#R9H3K?*-2T1*37.;[Z3XZ6!MF[11$LG&6!8<1<^Y!.8.]4*@#L/L.9=E%_%]'V:P<^*]GU>-U0UGJUY@X12F76C@$ MC2N]!>VKY3?K%8K,RCJ@SNISYOAE&1V]*".6<"PN]@81Y00E3U<$$2Y")#+4: MD#/84R]Y:LO$\C9;^THD$@F%J;( 0HNPA9RI M[02(R-@)Q("VIWLA1'L(1X2%_G.Y>M_BTV\RUJB4KHES7F/= N>8$VZ6:H((;9[S#FFML.-*ZZI,=];'! M\1"\0CZU _')V/,^#3[^O]))HU6RIE4E6& E.;4X:.X(M!K8ZMBJ,S;V$A$X MH*->)^9;:]AWM*/T-ET\[WB/V4]ZH;H$8TL?1/%6+Z_N5%C>;C->[8ND[>%,"G2)" M(R&E,!!HZ@"MUNO"CR0V\^>@@I2'0]1.C=.2V.WQM MZ_F=(__(JE;SI9=7DEP%T;,R'T$0\3Z(F'[[YGYRI#\*<5U4(\/US%;?U M+E X4#*17CL)O!44,J0<]8:"2EWB8L\6#FA5H2\ZY%WBWF?C?P+4S9M\=OLF M^Y).UOB4W:::37Z?IQ/]L/KHA)'/ ?+\K]#OY=%QS4*98X:[26P HI& \#":;& M5;)[(B^G-;=EP[PS<&LO1USF%6@FYO1-+\=W5]=7>VUY0M/)M!Y::&7 M(#B40'MOK-:5=-SSR%V6 :55:\6BQR/7W*[K9%(V_9).\_MR$*FB\G9VNS5* M)18K%*81T!!BC2K=?K8>?#A7C(/S3U?;BKW;13$B!JY1:D2/I'#8>57NB%B' MK="\TA!X&+D6.Z## *W8-!ZQV+;[-OWS)@NSU!KYT+]]-,'&,N.),H8:8" ) MT_*-BZ@%1['C[( 6UUMLI4=!%]$T1_.%3D/G\.[-_@;Z_+E$ B6D-L !$"3A MS&CN*\DHCVVF UK;;J>9'HE;A .5CKZDQ=]&TVGZL-]_^N[!I+R1@4I$ \^T M!QYCPG EFU;V_,/-VW&?C@4N9A=KELZ_9.&-AQKJ"T\F6!%C"2(([48?O_*]MGWQV00)RJ#Q$I(@ MIL<*2,PJ";'0D7>O#2CXNA7;MH%=<^NNUU*W"V=[K?OBLX%_82XF)/5&0RL\ M\]#R2D(2>IGSCX5NQ;QM@-='2H#TT^)J-E\4RU+*-S521.XHD7#FN1 6"4*- MAT@IX;:JT>!2G/U*1R>+S^VBV@-A5KQ^>,-:-&S-1OG78':YY;SVU%11OM]24^XG3R4^!-N"3=62D\<]AYJ MHAP"QD"C!&9*BB%O/WM+G$#&W!>SG^OHB_;-MF6;@9Z#\.! M#U*&B>3>X M]DF;=?/Y+1V5;6=R/7N?CI=%DS7^?Y9_F:?&EA.5J=K]T_6=F:4ZGYRWK M8ZAGQR"Z[_&$*6:U6QV"H1!CQK B&SFE]['Q_>*=W!K? 6$ZHA0 2'E"K&H,2'D6FT!Q0)%1?<[D6 MT.V32(]+(>7JIKHK+[UM,#O;4SS!6@07CFI.%<(."FZ!JI0F"$=N+ ZH3VO= M^KM8U1[*/5#K75ZL3+;8BO^"'COG71&U)!HY8!"TWF I 02<&UU!(*F*/?8_ M8**U0HCGJ<,Z0[R/]$_S178W6H2>_2C6-:DFP19HKH@I@^L4HX)1CRL0F(A. MR3,\VG7"C.>)G[I#?B#'O1"B1 MJ+9?>0F9I$+D2.B@429@:I46*84\&6V M0VW+P^<;B4+EY[^%&F^#G<>]FF'6]=$0AX3CRB 4)++>""1@:P# M6G!MQ8+QB/5_-$0JRIASILR\K5?GR)6MY$-41UIT0,L6K5BT!>CZ/!H"-25 M4N^41(YS0!B#6\ET[#4& _*4VFFF1^+6[]$0X1'#!D*%B,/6$DTLVG8D7D=N MNP_Y#%>,38\&KN^C(4Y!(%A@FV188FRUD5OI.(J]&:SQ*:Y>CX;$&/9X[$YQ M-,2AP#5,-*/,AMX$$T3HXQ 1>QGUD,]SQ=BV#>SZ3G00!G_K!086!14IY%90 M7DD')8\<8@=TR4<[W?'1R TET0%33E$G#3VWI /><7[ MR6VA>%;G@33%NKRX ;,PY3/:4XRVLP$*=.0BU8#\LT[W?]M!M0?"',@@Z//B M]_E+9PP:E4]T>6LX$Q(CSA0RC#-8K?IHC\WEQ-@>;?>\>WA[8-5:PA?V:YX& M]NQA5:WR"3,&0C*@9<&VB=(EO&=YS)502)$SV!.@D(<2$,0K%:''?>W6GF-GTQZLS;N8 M=4=G1D7Q$'JT=6!,[>&H606)Y98&=(A7I6OH89APT$H7$WVDLK'+?$X4Z13A MYFRI;OJ]WTSS9ODT.%T!SS2\_7Y9S)?IH7N8]Q5-.!!2,<*QT) )&&848-M/ M$AF[8SR@'%==\*,#9..9D:UZL'12"7. #<\?3YRG4DL7ZN8$8<80\;"2DX/8 ML.H!K:!VR8 CT>S![PB]5=E7!8W7O=H>9^/YHPG % G.L?8Z.$T48R#4UHDB M(G)Q?4!+L%WY%T&(-8!"K+F4H%]T^FZ! MMD^[=-/%Z'26WF2+=]/1["1=2GF/5NC4UN2:3=ZGBVQ]TJ51/]*@ED1Y ;3V M&'#G@$4FV)RL40?0&M8TX4Y+YUO6-X4%V5<3W7=Y$':KQ,9&3ZA;I]>(K3(I M#\X+0QDDWA), CLUJ@ 2Z().OG3"FN<'8/JQ0O>=@QJ/EW?+Z6@1.K+UQ]>? MIMGMJL(3IO$Z0?]AH=>.N?"'.*:T1 8#;R"$3&&,3G-AW.,FI VFF6UMM#+= MHQ+S7>F^HNI)-)+&82$ )A@&ASE,EU$%!9('K\ZZT)ZB+C_R_J ?R&DEX[6' MY7EZ(JU!&ENH>"6T\2CVSN_A\:4C6^XYOM0,VI,?7V($8X$YU$AKS:@12-)* M7.9QY#K%@)APE(UV'5]JAEI$=/TT'2^*_'ZTG.Z/[/S^P4102ARWHCR'98FG MRD%9R0:(/O^T5?'6R%L$KI?XKWU=U@O?'L@2$E5?XJQD9;IS2"DC2H4I\>,P M"JV,W&T?T+&J?L:*/HUP(FX>RBNRLTPBP^1*4R><<]9A(C (D[NM>O304L#P M^ZR>K%^#:S& ]\"GWV=9F-!^"#9,YYNI^DK>ZYO?/VPZ^V^4.9CL(:["Q"A. M7>C[M2#(HC"@A*E#!0PQ!%TT$QMR(S\!XGUD3\J+-+N=/56A(?=JUI!HP+$+ MMO-2"\0%$5#YKV3K1N(3S)P/@X V]W31H/H"^43KX4&VAA>7C8 MA180B$IMH5SD3M, 0R1/Y;0=#_I)N+9O\;@1Z?95E @EN(*,,ZT1A<99PFT% MA*:Q ;IG,8@>Q8N#K&L1]9/0[VEW_4>V^+Q/G_G5S'T=I_/@/ZQ47^WBUMA" MZ/"MB0?6. ZE@@ XY W%9.NK.,$B5\O.8L#NEMBG,M&9MH+;VR(-WZ>;$XS' M=N9]")103KR$B$N$D&(208BVAF%"G7^BK$&QNX<6U[K-S[PQMN9;]2-2(K44 MRD+#O**$8<:HVDZ]@.&12QUG,9A==H-LT>IGWB2W9R*??GNBMOBB+(FAP&AJ M82 -USK\*2\+W/:0*/*2A@%.U%];(VS#W*=I?97N7<[(XMZ14$0EUAP:Q!V M&%&"M_!) R)]R+-H+1W/OWHQR%GPN6K 1_IP;;TUH9IB@#3Q1EI(&28<;@=L MX?0E[XUVSLK6VT5;9CRKEM*"E]7FFQ/IA.2.!X"9U@%I3Q[=@?#7^=^\=HDM MI@U3]AI\OSI&4,8C%^GGTFO\DE[-0IGT33Z?OZHX?(H1";XL(19B#+1G&,CU M 0GFK3:' @XO*0X?A/^$0Y A"C67FA@LUE!P8-3SF][/>*SNA!]'Q>$W@_[5 M1&\R:9##F!$AK-+ NO(ZQ TLV)'+2=;6$5M:B=YL9H2SB][$6A.-J>1 H?)D MC<0,5^IY*2\[9JY%Z]>.WFP&^"N*WB2B3 O!F*!>6G/7ZH-.;T+;^CCZ&K4O$_."Q!JD MG.<>4*]A& LT@UO@,$2O+=JS-H^:1'MV98VATOAMNGA79'GQ(2V^9./4Y/.% M"43(%EN%V^;UX3C=4K&-EM"Z_0;< M-'X-OM>\7&=.YUVVAY=>$XP:L#*6D>#S(VDT?%XE MOYY__#Q:_)%-ISH-'Q2+[%_IQ =CU-Q)O)J]3;\N?/ S1]._IZ,BSJWO4I)$ M.P890PQKA2''VEH$*U-P82YY':1C_W] 9CM)"_++1;F1N-:ZNJ'B12>O47.H M7VU"F6'8($X0A9Y!ZIA3&Y"0""/G);O\PV#?P5;2F34'0_G2H2O!/)KD545) MF4-34:P UDA2CH4PO +":*S[=>(__IO=?9CQA$[0QSP.X&_AC?!YVGEQXB6P MUC.-L626@>#88ET!+;F.W%<\CTG!F324$]J[A[##M1'>I^/\=E:J=C4S^6R> M3[/)ZFC**#PT3C]\3LN\ZJ\I]M 8B1'2IDS_IR#5U-+UB,ZL0]P<:IB7%'NH MD%'": .A9%!"X!PT%12>PO//Y-DI/XZ*/6P&_:N)/:36 ,'"K)=CI2"3@$E8 MP<*HOIRLU!VQI978PV9&.+O80P>T#4W;$P.)5!YJ+"HPO?;TDO?D6K5^[=C# M9H"_HMA#)1%CG"M%2+"N%\1Y4@$C@;ODI:+&W&@G]K 9XA<5>\@T)$!I(IQ0 MWCL+L+"5ZL;%7F![%FONQY*M&X@O)O804R6=UE:7N%K!I%>\4ANHV#O*!LBL M4SEMQX-^RMW,ITL03Y<=CMF7/%1G>8),$AQ:NB7EO0W>< PJ>!SCEW.(J66V MU-UA;-D I^'GZL!PZ-S+7S:?SQ\O$VW&R_UU)9 ZY+0*7H;Q%CKAH/ 5'$++ M2YYTM,Z8PQQMU1@]<'/O37,OC#5FK6*$55Y(C0 % M7&'#B9(58!#"2/:>X>9?9R3NW4@#9/4396KUPJW4GP3''%EC@1;22^L4)7)K ML:!8YQMUIXU.'1BMVS#1$'W=-GW?0Z>BOJ3%Z+:\1'MY=[_*J_.J=GR!M=2%,5!X MP "$1$)*P2I]47D8T)_FUNC3[/AR#"TQ/+B]@!@L&9/.;J% XG(.WG7"CZ-V M?)M!_VIV?+$C 09GA#'2A;\\%A7XFD#T6G=\:[.EE1W?9D8XNQU?CIPDE&!I M'(5 ,Z?-5CTOW24O!K9J_=H[OLT ?T4[O@"Q,+YH1+@NS]8I;(6N@*$N-G?W MF3"Q(3?:V?%MAOA%[?@:HCVR2&#*(4&6:^M'63Q":QS MJHWDIXKM4ZL$O%Q0?!_MSX+< M_=*OSJYT#Q8<>@,H5;J^>;H\=S4;%^EHWEESV/W&1$BO,)728RDE\L'(8.N^ M4<\N)W+MDAI':_87!]*[]I/UO33Q5*O1'B!#LO*=( M$V:W,ZK@^UYPDQF,L]2JB08V8+RL6P=NT^$7)K2W3?Y+/;CVEQ]SY=+(O9=]Z%H/$)32<5JU[%DVI\UE)T]RLOH0FU9MF]S6>4SE=M J)-BP@?O"#\=U.H#\M/\VR2C8J' MW^=!A0^C:?A1CV:3ET:-H^M,/"( >J HDAA Z2"D9COV2G')-Q:W,6?HVP!M M4.[)'7Y;L9:E6.,G32+;W<>V4&OBI9&,,XAT>?2)R: Y!M1(7I[$0[&;[=(J[X9/921@:\K*%93+@7R1&$+C+&>5Q5A]DYET0X*A2Q%3"K8HLD_+U5K*\W37 MS5RZF#V& 6)($K79XU=-(:><'#[E%,.NSP]6".DS#YF5[/EL^B M I/J59D@;*@T5DHDJ='<:@YY!8Y%L7F!!]BW]LW53O _#3GW+>V6;>WCG^GT M2_I;:(2?FPWVC6I.$ F6"4V8(^NA"6,= GX#E2M=A43;.( -E:GA_ ML^B9>E4FFG&,P[R28.^$T50\.DJ>?+9K.N6C4F MWKK@K''L$ )2ES>.:E1!HYF//']U%D$(PV-KA$4&2M;L2\M]:UEC@H7F4DL@ M*(#:&@4TKM9JRERID=,L^F^R]F21X9&U5.)QD6/^\7-:I*.;Q=ZE_+9>D82I M,:>26@BX(]8J2EEE+._#=W%T9O^F\ZE,U'V F!]EQ=]&TV5Z?;,)^WUM]^-A M(J&79LW4 1IF?P M=0:&U>;'<=D2&T'_>@+#$%"$:0P8,Q!:J 6MP,?9&ES5VYG+0DSVEGGA(9 PS#?%=RX"@+,8U?8!LBR M4SEP;4'? _M>$/2@V[:S3,(P@$);"H0"F%KBI%>5>H2XRTFDWHG-G]];TQ+, M/;#(_7,91O,/Z7A9K.[-.3@@OEP@(4X)$5 *73/6'D/IG:\4\]KW%;?R)2T^ MY1TSJ 7KYAU@VAM9_'(VJQC."JR+T'=)A395201CB&(O(-&:0P-M\&SK)2#/C8!T !C--IG2DN8 M]K%,\.%C>37//33D! QUPIS58FZW+ M;'9*(V0Y4%A7DFH9N^/++YD ;0+:WX+RX^C8Z#*ZBKLAMW.SC))N>=,#?662N@M MVX'7P)BV4.V!-._3T=3-R_W<@UQY_FABL,/02A>&8<$1=<8@LU&&!8_L4$C? M+HH,<&^@?8H<"68?TZ#1_'.8[Y?_E(M&7T;3,N3V\#QH3['$!4PH(E0ZX0F2 M@$BX5=(P';L9\"J6>EL$MOE4:-6CE3I=S;ZD\\7=7BKL+Y 8SY@ATA#F(01E M.+:N-F49#@A$DN"B5W%;A;2Y^=^-PBQ\G-V/9HLW^6BVU_(O/IM8BBB27!)9 MWJ.#RF7"K83!B<*11K_H]=>VT.S+]UR?:JCG)-^2:<'(J'J59"4@642 M4.*1=LHX'J;LU:(0LYJQB]D=["<(JA/4^Z3;;ZM-JW1]5.P[#0[&1#6J)\$& M>V*#]^X50R8X8&Y[?H4I:?O*-ME'G$O;Q-C%NPYP[Y-^5[/[Y6*^P@,>7K;; M72KQG(0!03@)(#8&8JWUMD,'#EY.ZI^.++^+7T=#?2(VH2@V;4HE4IDP/8!: M ;01?Y;@:0C@#A!H()0*F"9VDYGN(]<91[@PL&ICC8< M#_I)N/9B2H5&;'NQAH0 +#QGPAKBB>*A8>DJMI]Q2R[Y9ONCF'"09VW W7VF MCJN[^]%X<7US/4O?Y=EL83Z/9K>A.WYR4]_KRMN!@GF4LEA#S"$FV"$#@XFD MA$PJ>2BQ?:WEY;WW(GXHC_\MLB_9XN%COK;&OIS 1]67*$^X#*)1A&5PVQ Q MAE7:4L\-;-R9HOI?Q0HZAFYNT:O)I,0X@5)=J7LV>7O9\71U% M+9,2S1K<+QC[@H1;3B3E5'-I-#642(XJ+)1EL5MEPZ%C3U392\R>K-,-4VW: M,5/KO2#15'),K'**N3 9$4:(+1:2LO//]3M,IG9BG:[[U/4EQM7MWQWTJ?M> MD#", ASE-"Y(PJQ< !@4X MIXYQ8#@'&RPX8C(R8]* 5CZ&R=1.K-/]Q'6]5O@^GTY]7OPY*B:O:IHJ#= : M4PZHUIIB HT7*VL@[J& ASSE;F X37I):J46W !IE85(0,,IK:"P$EW.+:^= M\..H])+-H#_)LNDITDL"A+UDW#&!O/ TS)8LK&"16%Q.PK6.V-)*>LEF1C@1 M-^/32V*I) '6$<"#RV@4QQI4ZHE_IY>L;?W:Z26; =[?$

49T%9ZIR WR&CJJ5JK M+0 P,'(+:D +^Z>>91X/^DFX5D7PO!A_]&2]M!$!ZU:::(JHLM)0!9C%!A&_ MV= ( '%YT?/2H_ARD(T=6>"B8ADIE\X)[B%$2N@ @92V4IV$SWLBWWU:9'EY M:T"QZ)F"[9,D,LRQF25.0D(U7BQ'T^UNUU;V#XML.OUK.FW601ZL+8'*6>T- M<]PZKHA"6-(*$L-5Y-&! 31/YQ]&TW2N9I,/Z6(Q M7;O8C=BYKZ)$>@9Q>7NA1 @#122"?@,$9-Z=?X3(H(C9HBE.PLF/1?"Z@UGG M.EW\F::S)].^U:RL&3$/UI90X@CD#B!)$#3!J6<:59!PB"[YYN<3L+-M>YS& MO5PONIMEL.YL_."^CE= EN$MFZ":6*^S0<4)#_X]XD)QQH4F(C1K*+= >1@9 MES# )!^#(&Z'IKFH*1(W'I1W X>F:LOD62#\J51W\."]M&WE9EY/D=QL\@J8 MV8(=N@^G>SLJBE#Z2_JJPN@4""8.-L:8(" 5 9I $"PO,24"V==T2[,!T!AF MO9>^3/#J$06H@@)X>#D77W7"CZ/"Z)I!_VK"Z+@S"@"$A)?A)\^ L+:"A3IW M.5MH';&EE3"Z9D8XNS ZX+ C2&KJI/30>T4LK]3#8<9],1SKV/JUP^B: =X# MGX9R2[,&&CG-PY3$J[*)A[9L*F D+LLF9ZO)IXO M,:=NT00"AH4)4U3GC0O-QF..*_DM1)?<.QUESN_/XK6)6:Q]_2^2*; MW;Y;+ J:1E*)<1(';WC4TIT.)5,ZGF^F=,4>#W1IMGO[> ML'OYIFB"$<>(<>FD\5H))4J_LY)?JY;/E+%BC M&@]W\'E7-].DBL1KJ"%"V!EKH*$84[Y=UC/4Q=[D,QSR=&3>O!>\F_/GW0J, MYK/?2ZT;.5-DP0=_YYJ7MA4'>(1S@_1_.G M00T)(! J&AQ^H(5FCFOAJA&?$8\BYU<#5VA<"2Y3V4"&) M@\=K2!@!@'=&8B#+*?$K"O8(;I0!&AH#O) >8<:0J*" 3+S.O+^U^7%4L$B1FR5CT" U'L-4)GPL2& MW&@GV*,9XA>5OHL2RK$42@-C%-'2>+D=0PRRD7OW UIIZHYLW4!\,:%$B'$M ML?? MIMGMRLS'YKO95V%B%>"*(ZD=A 0!!2GU%3"$HL@[D ?8_?7-PP[0/PDMOY._ M$0>_*YT8JKASPGAN@6".8<[,8TM4?:4Z/WU^FW:(<9"'QUK@1(-O\24;IR:? M[ULXWUNNO,G7 VHAT,@*RH &6%5J*L0N)ROKR2D6C_I)R'4U"S9)YXO&['I: M,$&82H3*1:8P6PK>!>)!Z8VB@I+(LZ8#VKL>#+V.@/TTCMS3<%7]4'[T+@PS MV3B['S5->G2@KD0[@8,WRQF','3FS%*X]6N=4I%;#F<10MHS"]NUQ&E2<97S MH3 SFD0DW_JF:(*=8D018+GFX3_BG99;-]F22-J=1?A%S[0["OA33ACF[T99 ML_GJTX()Y11SZB0WP@A+PGQ=DDI1R7"D]U8_Q\NWRR27S;$C@#\)PU9Y$8ML M-/UUE,W>Y/-F7=EWI1-23GP\Q,0;5.JKO&+;KMO$;B[P,UJ2ZYEPQYI@H!G9 MCELJB:@_@=([)(#3U%(7L&.>;F=;F,2&08I_C\,GL,Y%K.YQK8/OZSC4./P? M Q\4WJXM:1.YG"S/+37;R=;VFN%_TGV.T^3VAX9XRJ#%1B!AB*1,;A<_-:21 M1U;.8MFFG_V.EBUPFJ&^H\25P F!$;'"8:HLAIPRL/6M">_K$KK3[WVT1Y+( MU)7-+'&Z6J"0!A&*HA*7*,RL$P4R#1X#E)>_[GH"$+9EA",O9 M[NY^FC_L#>JK74>B [A ":Z!]00 ;0C9+C8X"2+G+VU880@D['1/ MA2K))/=E7A&E"'1"*_ZX%H$C2=EX3Z6/&Q6'2,LC[7'&:]XP^-] >@0AS-^/==\41CCIVT6'$A, ?<.+(- !$\]O1O\U"SM-=2S<:;C\N0R5>5'\41Q2@"PCGFL0:"VEU<2 >5HH,.!]M -#*?)CZ*) M44Y#3)@6P@)F&0<5%!BROC8;AI4?I38_CLJ/T@SZ5Y,?Q5!"*?>APX1:"T\H M9WX+"Q6O]3*>&DT(:H"AM'8NU//A(D-N=%.?I1FB%]4?A2$ MF",,*Z> Q 25%WU6[=J'3R-7OLYB._]8LG4#\>7D1Z&(,\JU(IQ[C(5T>MNH MH#*7PZQ3.6W'@WX2KKV\V%!C.M^TJD1XB+V2" HL.018"K1MV$3)\[_IH"-N M'&1>J[B?;9X HLL;99PB)'3O.@PB\A%/(N@E9U1LBP"-,@0TP_N,,P0XXQ$3 M2&*HO)9 .&T?'0;L(^_7&.#(>4)B'0'X29CEOMZGXS"W.3*L=WF@3 M;)PUZ_?J5)AX;8TUDDAI*%'(< _L&I@P"J"+SE71&R\[,,0 &%H>$YZ7YX33 MAJ_Y-0\'TZSF]GV;_2 M2<"K.JANE^G'_$E0 &S$QWI5)MIHABRQRE+D)37065.! Z"(3"T5F_OB%$$= MO3&T$XL,:#VFA768A)37JBJ+G0,"6FHI![I2GA,;N6W;.*KRHL?M5J#O/L)H MZ^:JZA M)E H:S7%%117P['.K9^[?BB9H"_HO@B M;Y1F'$$-"-.(:B<%J8!AV%TV$QMRHYWXHF:(7U1\$5;26!8@A0XQ02C6Q&R1 MUC"2;&>QEW4LV;J!^#3'W!^V$T 3VLYM7F1IT'0@V[;SC*)10Y1SBVGC!&'H'IL7)XQ0R]XL&S! MYGDW,/? (O?/91C-/Z3C99$M@IP'!\27"R3,2*<$E< XK)"%6.*J"7I U>4< M*VC!MGD'B/8RW'U:-"#*2X\GPE"DK56&6^0)E.565J64=_AR0G[:ITD+>/9 MDO?I:.KFY<3A($&>/YHX0#FR3AA$A)+4"J)9I8QSL=Y-XV1G?>25:I\>1Z*Y MEQJC=+ZR-T0;:X>+U4;@3IOO+Y!(@RG! F-GG9%:&^+6 MVSCEQ5L21&;+&61&L?8LWRJFEW,<0R(N,1,"."9"G^@$D)7:#J!(*@TP8^*I MIDC'@WX2KGT<%;?IXJ7]V4:4VUU-8AG@1'!(/)5&4>*=A=L&9V%D8.D 7>"6 M.7&0<:UA?A+B_9%FMY\7Z42%T65TFQ[%O@-U)2+,5P$L,7 80 Z,M;R"@U@6 M>51C@.YUWQ1L%_B!=8#ORZQHOV6S[&YYUU)G^+3*Q%C/G61,26U]:*]0DJTG MPFGL1LP A^3A=(Q'X#](;((&YJWAH2!QT'&"HD$&*::NH1K=3G"$6>W!^@P]X))W8& MZ+4)>@^#T:/@ZBY?SA;SQY#WJYD>A3YAG'[XG*:+"/XUJC'QREB )46V! A3 M138;Z $:X'5DP.@ O?=^^=BE$?KEYWB\O%M.RS,G ;5W1?[?JR.6W^7=C.DI M(^M.C DP0>F\ )R%OX.?J;9P.1AY3FR OGW/G.W%'/VR=SY?WMVOA/Y]GDYB M.+JOAL1;HW"8Z#A.%8#>2*[16O4PWD1G>!J@(]\S$UL$O?DFTZ,<[N8F-('K MF^M9^BXMQJ6I;M-W>39;5%G=35HL1MGLB< '.=;V*Q+)N!=ANHTUD8I"@9F' M%1Z4Q^:T:WSO>Q\;65W2\,1VZ;5?#.[RDQ-MD;.[IX])'C:-BXXC)IH+6&"\^Y M#)X+HY2Z"J@R.T@<.P=X=K9W=G9MBV,&\_7:8(!A?>_C2XN$#JMMF7TKCGF-KX:_K*&Z:S/T.V/9"OWT\IZ8B4N-BA)*&94< M!HR9M\%UY@(]NBB*1X8/-+X9_M)ZP@ZP/Z;G>UF@[H2%1H6XBPX M(<2QU>RHKK"=5R6<,@6P,(1!+* $?+N+P"'0.C8GZ:O?NSF)>8Y: M%MKD&?3+14#BFYMR UK5QN[H8149VW0]*+[NA&ECD)>8&H*1D5!V$;3Q9LYE];?]6:2;0(. U%VVCM(^481!]?H 5PE?%AKR;%S&H#>,,:A? M3X(LH(YCJ(VS4##)A-[D!N-4&W0H_*MS*!Y%KC.4[2^8 ,^M),)[I P%BEGF M8*6L\S;R#$OC<:FG9M\%"_(.\>Z\5;])1_-TONZ>-N%W57=DE^EI,X&=H.D' MMQ88[0RQ6DA/L;16>NT) ,AZ<'#MN2,H1O=9>07L7E/5@:))/0E Y74$R#)J M?)A@0FA=!86S6D>>?!RFP]H%0YYW"QV"W\/SCW_F?T]'Q;YS*@UK2J3S MG&+L( @@V##V>V$J*,*<,7)N-,RIT7"(&&V 7$QO#-MBXW;NA+O,?(N^)%2 M"LPYY>7]>%73-"QRAWR0Y\Z'Q<=8$PR'D3Y?%BT1 M5$S;H.@8:8&AT/'CY[1(1S>+O4E@&M:4,&,5"E@KJZSD7@''<04%421R&MTX MFNV5D3': $/AXK$,3+"6"B"&F*1A,, ,IY:6HKX1U#4$? M!->J^_:N9N/I-:J^.8J"NZL-#3)XSN6M*P@0 940D.KM9$Z!R-/UPXQC M&P@W6[/&("C[;LV OXVFRW7DZ+/OCR+NH]O9J.M:6+=(#A:_OTV)4[B(N<8A\ QM)T'&A\9 M-3?,$[D];-IT"_]PF'AXXZ9918EP,K1(& :6$GAE#%7;Y3'I8&22DD%NW73& MD3@NQEE@.%2LM8'3N*X$,R6ATHJRX-9(*BAFU2S0>^LC]Q('N84S,$)&&V%0 MG*RSD1-16\(5#HXWEH9S8XEFQJ-J9\M+ZB\IA?#P>!EKAB$QL\Z&3O/*$NRI M%]!X1H.'A"$RDF\!$5)'+A\-M*H#?!DP%$"*,M0]080+9N36B[ M%[3%,S!21AMA.)P\GHF)8%HX'/YF"%,%"(7<;D<)&[O?/<"MGH&QKR'PW1'AM@?S" PN$+E/">JZ$H"B,4088!ZW4G!TZG-X- M%+L-=.@B[P,E$R2T)A0K+F#H[#S11HE*76MC]]3./EB_-@OR+N'N8;#9+;!^ MV-S;\G!]4V9,KIZ8'+CE,;+&Q 87D!#/K,%"2&(\1*R"AJ#8C/X#9&)K'*G- MO3:!/RDG=ZAQ\#;(R!H3Q1UVD!OLD&6"2H.]JJ QT+T&3K;$G=I<;=,@S8_; MNVDZ7A39.%L\/(HV6XT)^Z_\.EPP$19JKA5R I1!$]X;;BK9$;V@6W,Z-V[> M(>[-.>.7Z;096?:42%SH^670'JIRWTTIC%D%@@*07\[UVGVRI#W F]-C?7%= M(W[L*Y*$R:)TSD*#PZS4>B2UV,I+<.S]LP/,0]TG05I$_*0.TIL:MPO6*)TH M99"1F#!B'7?(4"LK'U0IYR+#,,ZJ%^K*&8\%N7G/LUN&]44!Z\R%._J@>H43 M05D85X$*8"!LJ--$ZDH'ZP\NEYQ3O$ZK)LT[1KI-MOR1+3YGL^O9:A.G,5V^ M*9UXC4-'"J6BV@@OB70&5%H8__Q:^+,.I^F?+\= W3YA]H1C-2F>$,0IEXH% M12A'"@97#59Z0$0B)^&#C'0Y%64BL>Z ,_O"I9I5D'#I/-!8(PD!* ^U:H\K M7;PCD1%2@XQ$.1EO8M%NGSG[PID:E4^(,-)3CQW!JY4"QXW;:@)19)*$08:* MG(HWL6!W0)L]X4:-RB?.V#!/9-08S F!CDBR[3H]H9&W\@PRF.-DM(D$NTW: M[ T%JELTL:Q,NV -IIAHQB$4@FW'649A3Y$7ETF6:)S;Y$EC=B0$:(2%9H8: M9;5$ F!2RWRO0=K#(MDW+/YB^%6QTNE'"-@/ 2 *>, MMF^.9I>NQ]Y]GRBJ,1.&,V#'IXHQ@'2 M&[4(!ZRO,X>7U8L=VL%$^+)(93+:VSAB'A)%)6X:UR M3.F^DK/WU=E$VW9/3HDC\.SJ^AIUPHCZ&Q4%8@"*TCUPP&V*8[XL;^ MLQKM(1^_BO!B,-LW\0B'KO2)J"GQP&N@(&-4*(&@P8:12CNI8_?7!KDEVRVS M^C% 5X/+;)Y/L\EHD4[T:#J:C=,/G]/T-+?W? C"KZY5NK[QV2S(DHVF[_)Y MMJ+8X;&E3O'$*J,9D42@8%HL"0,<0X#"[U!HI0[UIMTHOG8Y:JCX[8.)%4)S MSHG6R FNK#!XJPSAL4&C QP:VC5MWB*H/4P0UO)M\O34)LFSYQ-G'* (*N=I MF"1K#;38JH6IBSST.4"NQ)KS158(R080&$K)4)KN*1(P':I<02* M/5#!;L#_./JZ5KM6%[*G5 *U@UHH;[ERP$A,&4/;<92R2[JKHUVBM =J#[QY M5Z3WHVRRV7P^S)@7GT^XQU(J0#CUWF%CPW345&H91B-/P#1/NG1FHTT;8/:1 MO*L\2/J-YOLV?[Y[.$%AH/3&,$8Q<\88X6C562KF66]!@&?&CJ.1[&WY[OK& M9O/[?#Z:_EKDR_OUQ1IA0E;N/ZSV(Y;I9+,UE<]J.+;1E29",<"1(H1;Q32" M-'AK%4!6@LC]Q.;W49P9U7I#O.\5Y;HKR0D+L@JI<) ?$D"M17K;LBCED;)O/Q@UW&+XODDB+*1V MR7 TD+TXP7GHUA8/[Z:C(.9L4JXNWI>+1<%SK\&8.L43+5EH%I((#AS73 I# MMDH3(B*/4@UVE^$8LW_G);<.;Q]1LZ/99 ]GRJ\3*BU!2#I+!"Y/!OK@\U=" M&PDN)Q5;NR9\'@K;',I3]BDKMSZF-UD53(3Q& 4=%064*Z2%E%5OK*USD:F2 M!C@*=;><[U=N_ MG=#**Q)*PDR42N2918@:!#VHFJ)ARG2^5R77#)VEMZ4NY\O1$QFDC[B.?!:P M68Y+L:]*P6^#S0\?#-A=*I$ <8,H[:,AM)(:B3;)1D:7SH$P^7GT:&L/_SK/9XF_A\661[AOMCJHW$8IC[R'3CCJE,;!6 M;X=\J6WDELL 9Y8ML>6%O?Z^P&]^M,:FGQ8?TN)+-D[?!SL57U8RK) (SF$9 M.;XK\T^-DHFVRE*)-0QB.T2)P;IJMP9PEJGTH&95W*45QOB+F:-U-2:UCO&)XM(>06D8 MFO98,)&&,Z&PTQ8ZSK22R)!*48-T7S.U7JX9[(1.K>+;W(?9#),FO#&=STLK MK(38X;?L>#K!6(*B3^:QF%4EH-MHJ1(SWV*K0;UJ%GY ]DC,#7&/I-+=!1W#WR[7ZJ0]V%TK0 M_V/O2Y?P!_V)6+^8+4UHZO62+(=,W\0O-W5:H[9I(:+[I6??@"2 M5;VH662A%A8I.\*ZK5:A"CAY &0F,A.*<$.((LR;N()*)V"U#2.5F]0U0G=O M]R(_S*EV( ^8-_IQ\B-E*IZ>,?JR0< B#@ HK&@6@,EB8?[@3DJ1.99U;C9 MDRW< PFCK2 =QL%71#FM3^;*VPT",5$Y P1 Q%,VDK$2EL>WSD)R/3M7#USI M!-)AUI7E)@KB)P3JEY:WVP0,A3**"4E!5!FQ4HR4.0$.,SI4Z8)!K@7H97WI M!-?FIO>G(JYL<9:E0ZW#\C_P9( 2&4SB"FBDC/J<)DJ6QUP.B-S"CN.\J*@[ MJ7>#9G-91TO]='&__7#@2'H>&6@C_9R.FKOGU9:GHZUX11[YCB7>":##6BT= M9WRV?',P"AI'*3,FVI+ ZEL>>SE!%69WMT1G@/TL,,,B_U9C.M&1G7@%B@! MH=$, 0QCK:C+@>$F,H,S*#_.VMZ)5,>G,/RHU' 9VV[0" VDM )"36 M(,XM+<_-O (XLSK]N VCWETPK7%NK0I]J-N^:I\/'F@"O=>68L^XAFDBE#WU M.C?>99S72'R>H](_T$?GJ$U9],YSX!CU@))RS?.$DLR2HJ,L M/]Z]Z#O!=-C0IC=!."VXZ&YH9F&$L?N2.N199]B.V*UT$LG:OSR0"#Z7C /FE-#6:HLKP)S( M/?(:MW.I0RH.+H%SN1":N@X"M-!88)07RA. A1!^;\D@8#7*=!F,V]'4#[&R M01VDV,'!^YEJ&%/3*@A <G.V)GFD>^QK1#)^Y&L95K##I+P,03VFN)0:AN6\+EC!8/*Z8$H=TM$* MY^6A,P),L$S%;-SJ?S_4&P#^ 3CY,S#5IOXQE::)8EZOE]/?-^OM]7"+M\=Z MTOUG77XH& ,4EX@[";2PR$M'? FDX-=J8/3#Y+.*YBP);:QP<:QR8400K'1=DA1S&PBE]%W-H7C\7[Q2H5$KBY_S+YLSY:O,F;@L.>"2*M8PP0I!#U M.?/.J)AFIG M8#D@(G(UH].MO0$KTO9 G]: GL5&:V2;!2J()0IJZ VRUAA&K"P'Y+.O2VQ^ MQM.[*[X'?K2& "@Y2ME9I,0%&DHS M4UDN1%\^B\7>4@07X_?LW=\9F(R33V(E&,'(60*=KR:B-3XSM7>$Q2E&PMRS MB&T$Q3%.._M^LVG@6EEDO %&>&V)1X#9:K D]QA\A'OOD)'S74#]Q*O__E_/ M47X?']G^]O4O]ZU_ FU2K/X2K8P=SJG(_&(VO4NJL)[,)O/;XO-#4:04^@3B M0[&>WC[YM78]*?Y<%_.[XNZ_];RH'R]64KMDGU#K1&HIM""*.2RA0)([Z*%V M5&(KK#GJ->G)L)_-%G\D0?C%TBXVOZ_O-[.?;\(^(0F\R7M"Y!Z%$$4H$'*: M" .L+J$ !%Q/T9)NB?':N.\1\P$VE@C(=%V\GWXO[EX7.'WFMGA^STD-_YJ_ M+&!MJ(.,4:HM\U*KN.CN 9'&TTP2CC!MJU<2]@[\L$=O<2>Z66X!N]OZ.SX6 MR\\/$>733N,.M0Y6>V+BEAO-&.*]HHI(5PZ9 I,9.S_"N*U>N=8]TL.2:]O# ME=JL'Z*-^^^B[I+ FE:!4P,H)!PC@00T*)H(<#]$Q8C+]&F.,!)K*#*U1/@< M)'JW6FV:$6C7(A#B+/ . PU3V<9H"4!2#@USD>G2:G[/T961)PO= MQ6TZN26:L.=9LV"MI20NK";JD JDZS9%-4A&V6!6^Y51*!_BH<_A=OT]]2!N M]W1P"%(I*+. 2^GB\!3BY9"0X9D+3_.4A\MF37MDAW"1WSX4=YM9<7/_C\ER MFHS0*K1YOM[ZJ+ZD7]8Y5$Y[0R!"(*, -= R:RPA6(%RZ)S:3"=W\T+=ETVJ M?M >@&B'NJM_F-EDM9K>3V^WLKVYW_[+#_7GM&[9RGE=B',-6"8P]E0YZRUP M')6@:$(R\_7'Z,OJFB6+P=$?0N%ZU=LOSQ6_'X>^VE M],U>%*0"F@@=K1WH,-*& 5'-?L=)9CC-"+G8#SU.61.[ O]L+'P_G1?OHCK3 M>"]^:AF4-]!IK"$SE"/%>$H,WP_5\-QTQ#%Z[\^Q[68#W;SH5A<%:(GE0!B( MI0 D_J$U1*KLHP(XT[8HMA?)39##D D/O?-"8%)N M\)H)>3WU%P>0?C:L_4>,5";PZN;>3%8/?K;X8_6R$X,'BU3]:!8D\E.SX(FD MC'/ H104< N5CO..*&6PY0H?K7167+XNTC\UOI[,B@O.4V_1ET=T:UL?G I<4:A8Y0 %6C@#EGN2" MJ,^\)66$ZLN G!V!H 9@ORVBB*/]O][5E3PQ5*ZF5E[F9WYY==B74=2&6*73^&D[QZ_3:;+A)UY MF"R_UL8?O-T@0(=2Y7 J/) R6K60>U0.3 "1>:WS"*,P1\6S3H0QR&ZZD^$. MHR^3/]V?WXKYJM@79:[=46M;!D(ED@19HX&CWEJE':RT&*8R>3?*&@:C8EZW M0UD*JX2N,IHI+A_DQ#VDQ7#SM'5_(V']$9 M:]L&R*QW%G&*'>#(1)V%5[,WCC>3GJ>'H0Y8VF-4!.U:,H/:++LJY-/=D?TN M30F>9+F\U3!H2(!@VFN.A.&$(FQH-5!K>R_C_1_[I2O9#*%?OE7JOAR$CUB7 M%?*WM?)_?E07]XME4>DR=?IHMU\*.MTKC D1$%DOG:)EP.ST*4&04B M_T/3(S3M2B(#$.ZUSOP,D'TUSQ-.@4Y_2:!>6,\UY0!)B1U/P7]/D,K!BO!< MT]E.;_"?A7\_%VQHQ+R?FP<4AR@9E%HB)B#VG/E*^X[_SXR,//T,9\!EL \J M'&5;:\C/PK-W\^\1T,6R_NZ9VG8!N @ACA*62#A*O5:65"Y;C#)7L]SCFNMC M5C[69Z'4QV7Q;3*]*[VL^TV_O.!P9XX^Z1_-V?C6"X)446,Q<5X:PBAT5FDLRH$33GL_RKEV M]G4 ^EG5N(^3'TDC2%$X.RLR M-^01GM"<5='K4 3-TR3>TA+V_IQR38X_[KN8"KD?2)]H_)[ D( 6<8 9\9HK M!XFLUGBB<&9]M!&6^>B17$,@/X+=-7>1._B6X!G$BDN.XJB),1R()^< -3K3 MB!UAM9 1[++YN ] O=,=2YWDG@2 M>(<1SB%98I*JT5U;,1 [A5)S8NK]5Z2 M>$"/76_PGX]_R51?=94#5?.R@*3E!+J4QXTYPYH#4KG0L4"95Y"/] J"X;*@ MNH-\B"RHR8_]48^Z_7^;Z;*(HXES9_WCXVPR7TYU'U)8!S,+ ,%M^6FR_SD:/)='\? M-8DHM=I\O<8OB]L"9AY9"R!$C!MLM*LT8F%Y[[6:?Q%&=BV(83)$;XOB;A\. ML<5HO5D^2V=X,9;5J13-?VLP1 +J32IR3:PTW!M9:4F:@,S5\W+.?'MAZF#R M&)BRN]2;^)N[34*K..JG/MXX(.?CQN&X2 5HB=-PZ0B_T M6?G6 ?3G4!2;4NZ4]H%1;!#73G!*F:',"5'ECEGI,KV#HPS]/Z;!NODR"U@[ F2D!FM/408?Z4MAJ-^LQL MSE'>F'S6@[:&0)^/:?N;-KHYY*UY63!>"<>=8Y9B8*00J7AS&76!NYJZ1/2M0H?5TA/P#A'C 8*H]D/$_7G'+'7W242238-CSV;-9LGWP MJRO0,T*/5ZM-LIQO[I]7"#\47_SFP\%[H;B)ZB0W7 .O&<15)(/",#-\Z7(. M0[MD1&0(9#CP?#XC@MAQSHR%JKF,%/X:4 9<9QC#)]9B!"= 1U M>6/EA,5\>Y\=);8-%T0:%&&"#D<$:R6@OE"/P(K=<8^-SQ2%"'PW0'M!M6=V+.?]J M%JN3SIA?-PE6 B*%=I!*H)F+^^F30F5([FVBEW3:UXN!U W<@P8O_#:=+Y;3 M]8_M#;L/BUD4Y&E1"V\U#-(B0)V&%FN-G++:/1TW2: R*_R/LG[6&7C5">@# MNWB:\NM(TY#N$#20IYRPN&$CPQ%&3QB:S$WP%<5C M2B[]6 IS>WOXB7P[_J+@&29,28>9519:RY6K$$9&Y%Z_=_H!WK73KW,9#*J8 MV6D":WZW,HO'Q\7\*/EJ&X8X-L255H9[@+U7T;BH7!TNZ@^99+ND[*1^M;0. M4,_P)CP=5N]&ER+!MNG/VP(T=]MP_[>VR-,;!RB @LQ)[ AG F.#-B-@1I@ M;.XR=4E91)T[%/I ?MA@EVCM;I:W#Y-5D2)TFBQ0AQL'H)$5).H AD/LC./0 M\6K 0F>ZO>$HJU2=89'J#/E\M^?]/C!_<7_SQSSJ'0_3;U7ZT1&O9UW30#DD MR@+C/+2>"^LIIV7_E<>YU1M'& LPL,^S0]0'5N6?L7X;O/4&0B?J\B>\*2 M M29PW0$M+XD)M*3?5!-(N-]467DXZ3]_*?/="&%6$5">148%"BQERU@D*%=

+($>PNKKM)#WC*'#^@KF6\*0!&-%)6 :R%PPA0CV4Y.N]UYN8YPK)E MG1)I&+0S J!>Y:E-MU<JS\4VM7UPUV)AHK]H'HZ@GA'.*(%9, 2;*7 ]JA">YM<0: MGPU]VTHETF"YOA:BM8/Z:A@F*+'4$6&E]T82"["K?#>0V-STP<99#3N&N7F_ MWM8S\JL9T /PZ_/FV[?9%HQT0>H.C'?SN-4_[J1Y/%?KQ#<$I"T&EG-CHIII M05R_(:G\@R)WGVQP='29:EF_, ]26V3G(?XXF=Z]75O]P)-!,^@\)4P8)+B. M^&A;>?"4 ;FKT@@)T[5L?RH6T@;88>K/[*JY%ZM3:/+ZX<"-I4(R#8"'F!"/ M'<>5%6MQ9D##&)>6WIG2$MN!5*(T[NJZQ#([>G[WAG4%FB]5F69RPE[5] M=6"&>N4,AU "3"SC2JC*0O$PT_70X-#ZLC>Y@?$?XM!G-Y*;Y<=H->W_\JSZ MIGI,UZ/LZII,[_9WSNYNQ2ONZF[5;O7>8 F3T@&),1!2.2 ,JY8'0E5F3:X1 M[JS#$>KU\=& \CD3C;<5[G97AF^-F_+>\'WEN\;T/?J^8 @#&'-DG 66 H4E M?CK2S;XY;(3;_*AHV[5UO7_]RW_HGL";% MZB]1#][AFY;HQ6QZEX( *R12!8'M,=OJW3RY>]8_7G:E^',=QU;<_;=^G3=/ M@ME&[NVS*G8=.L5UVL7C9%I7*_3-YX-,X8U":,I-_"^TQ*D2K!0=FUG'9\PD:2?=UY%0'8 Z MA!/J*5[^M^+Q]V)9YU5Z_6R<4,0QHFDT\*R45AB-63D<)+)UQ_%QI*4T7[N' M6@(Y "^^I$B%S?+':<88S3'=_.E4JWF<3-+WHIM:DP:_[)X*.:KZ?=B=[QW?+DY]1U!88,H M99XY$U%,5]O:I_W7\$PRC3#1J>.EIR> !SH)2'7Y%[/XZJ]E9,%12M4U"Q)2 M!(E$%",7S08H..7E( 7*S2H?8>Y(MRSJ$-,A73+OXS+Z+OYXDA^F>CAX%%5] M[SRW/JKZ(.K[5E0S@;I,DHQ0+^[:^9(+X3!Q/Z]N,?K95_DITMLOEG],EGG?C3)IY7Q9O+["URU87'PBI\I5%@&M('%>&>L/Q'CCGHN$Z M$#F'BO?OC5<_K8AGD,X0M$X5U5:IP%51MT0^?RP *K"'UOF(%T:&I7K7Y2"0 M9$-%3%X=Q?(Q'J8BQOUT_7ZQ.E+L8O]0H) R!1PUCCC!M31:ESX0%X=U/8ZE MH>B1C>T Y#ADB*;>JN^3Z2PMBOL$XL_%[6:Y*^MQ]W\WNVM-/Q3KF_LODS]K MJ-75)X*2 NE4JL]XDI1B#'3IV'6$J$QBCM"'-10QSR29,],Z#JB8?IWO0H]N M?WQ93N:KR?9N036_V_YMMN-(5R3/_V"@<3=AQ&.J*4,(& 1!M9D0E7L+R @] M;6.@_&!R.O,$L%']^AY'\KU8_:_-9#:]3YF*:O6WXNYKL6K)]9/>G6Q1JYG6 MA'!J$70:0E#"A9',O$YKA*Z_,="Z#Y&,PTX.T,[H<-* ^LV1<\\HYO=UO6)?M0_*%N;U/.4G*6+:?SV^FW61S+KE#+S;VZ6WP[IZ+EH?BI:#R:)YP3 ]F:4:V*N'HHB+]>ULLEI-[Z>W6^$M MB^V1^7HQF1=;+!Z+]G]3N#\5PQ0"1GSEHL!"&B\M0@;@8K MOW/Y]!M:%LW9MX\!,\GMGPX"8J>V!6??/@HX5*^NX5L"UAQJ3J67T!O(&775 M$:^#0N8FI8SP-'((AO6+_@#;;WE33MG%$JPT"#M=/8WJT!'5WX[>AM35)X*G M!!BHC9=2I0M3C4"V!(];E7L=]B@OA!AJ=SZ3<)JOEF]_O>RNW11?%K&_WQ:[ MY.&;^^/U8K-?&*@QEH(X=[5@%A/A+975++8TMUC0**^+&&(5'4P49XM9+%%, MTZKL?335?I_.)T=,F:SW!0"UQT@"*%+ (<&6+^'Q3.#,JL7C#%A?*B%<@@Y M#)TSM"VQ4)962)=\_K;5@4]-(CK0/$@CN091TQ' $D&PMK8TVSQF+->(.?W\ MZ(J6QQZ!'RH(;A>A8C?+9.WO8G"VD2O;/W7$["XYK8KYZMA2F/&VH&+/(,=2 M68H1$)QI4(8F>T-D[OT\C0]]AKB5?-#8ME[E<#YJ;J=65\RL>5D@5A$.B*'1 M&A0<4.E@-5<-5+EQER.\>^#,M.Q."$-OS[L)5:[SI^[*+UL%IZ+VH:-E1I!! M6$1CC)81I-X9DKL CO"&@K-LQ:W0;FX%URZ]+TX9YW?NSV)Y.TT7[FU;W6Q] MZND?_CE9+B=O7\?3^3<"0Y 9YA6CBC,.#- 5#J)8;G\^P4/5,XMFR%KJ3VK MOI#*@-6L?8>:!(,5IQ9*+AA4TE" 8#4XCW,OB4*G'Z6\M$*^7#S_.D9\%+Z8 M%&-Z<_]QBV^9IG$T\Z;-:Z/*(1E@2E /H=3$4\O+)%NO%69I*V<:;0,/?'7%B^8C/AC#1?$3)KA4,Z M^4RQ@LXXNL\K\4 RG)G^@!H?GEP9P_(A?N+)&8KM[I2&AV(]O9W,7O;KFBKO MBDLX9M8(;XA2 !$/MJ)10$4R.!5?T%!SZ9&$\U7 NEELJV1305>\7.Z5Y MH#;NP,0"!R6"WA.'"2D'3C4;[O.I&N M>ONY:\UF_BEO"M!P(+<"!TJGHVJ.(# @+LY>2VF/10V,(Y$\9;MC3#51<8OB M*M4CLN4@@).9>2]CG\_=RO=P*GDS=,^8JI*?5OGVA; G3+>ANQ*P,Q)+'@6! ML 0N==U+_4)J17QZE=/R)+'D M;50WYMVG8C*;_KNX^_NWJ)DG'_CR_31J^W?;QP1.-! M$VU0*4*&::ZW>K3G>1<_?\=/D@N9YV.H"8,]8=HQ'E4IKI+I#J0O@47:959? M;EZ?J_=T[5]JVK46]!EGT$D51CHWYCKX:B!>(,JY5)QI92R#0E008YP; S#" M6G?GMMN&%]89Y\/?Y\O]%EDJQ#?S9P!T:Y'E?RPX 8QG"3^,M>00&J\J0 $8 MRD%W/@-L4%:>.%,&D^>95:[C>N:+<;?4MS*_%H!5RANB490DT0 XI40%J<*] MUY\?BZDSQIDRG%Q_^8)]"'*6RA@+23VD"J!4O6@/%X@:ZM7;'&/E?Q_B.ZLE M<9^N6ZJOTM:#)='ZJP$X22BBWG+(%>0<:D9+B#G F:FV(TSS/K\E,;2P1C4? MX@@_QK$M/Q?+[]/;(N4#LM9XSZF FDN.A>#(5$X,QJ_G MTM-1\#5[#@TAW%'-H[0Y_GT^>4PAM<]LK;XG4?//!BLL5%"E.WNPH M9(L R0V"_<\,ZG8&]2[9T=OK)Q?>]8MEQ*!$J'?+OF6_ F=".L8$8919A#!7 MJ-2>+4,^LX1/;HVI<_H QCG_$F( M2\:S\L89A[SV!!!H3)3@69(:FP29'DURZ"ZGYI1/!:P1))'TF'@.HS:@ ?4E MH-BAWL]61KR[GU'!Q$/%$6^/L!@$T0"5BGJC!7446UC"B*04PYZ-7/4$&4) MHS]C?#'DP<*!MQLY0@);0@22&ED$K<=\!R2"2*/,2.#L@XI?8C_H74R7L.%@D1@QPS4R!L*&8U&O0.9N\ ( MKZD?PZ0XD]0N-'IK^,"MM H9[A6WVBLB!4! 6NK+50@A#3-+7I]^AO*K;1;# MRFOT6E)FO,L(@["2<'R4![2*$4>$.41%905 Y64YRI?XXP MR:"UM!<]XCK MECV=S)[?B7NOMLG\.?-=D%9*@G#%BM&'?12>P[+8>*XB%X- M?;H2]P$6=8'NH"3Z:]RFEI.F%/JI57 0*N,4@51PX)@7*=ER/T2J2.;Z,\(4 MC=X)U!;; >GS$H/&FU>(Z@_14>.QP@-/=)P9@I4#4QX-5GNF]RB1GDG3"M9! MXHM649/_ZV)QM_J\F-V5W3Y!ZSG2,EBE.<1QAX= QJ$J8\!>CY;609R9E3_" M9:=KM:=;8 ?CT/8$]'&Z2G;74=H\?SA0#1BWR#,9_W!.,2OW0"F$ .U=01[P MF*XSV;[)F1:H#K@U?5PN[C;;^'AJEDQ^+\NLZ7[%V_ MZ7?%:8OO -3YZS(=2VVO)JBAR[.G E=,2YKNYF6 6(2A];8<@N* 78WNV[7F MD@_B$#S8&F\S-;]3=X_3>?(%; _FCV]"1UH&C+35C&+*4$2+2P%*CW$5!)((1)CDI!P*-SC3CW=Z&,(% MLZ0=E(.PXGNQ.X#:#?V$Y+%#30(CVYU2"$XCVZ7"Q*!R< #93&NH>8;CQ=G- M'2$ZQ%8TFJZ@<:QN0!%C%04H&F33. M.EP&F444=*[CY?03Z8LE4-?0#A6)L5\6ZRX^>_%<$ (B1%/0H<6240244>4P MK,V-B#L]!?""MZ(V0 [%A]V8C[%A]U1P'BJKN7"66PV1HQ@\:5@V-WY%7O]J MD0_B #SXL)@O=K$B\Z_/EK4:3AQH$7B$Q&L*&;>4$\.HL-62IS1PF+NC^EL]N[QVV2Z3&,_NT-- G;82"^59$(2)ZATK!H< M@MDA>+^$A[KMIO(^G^(HJ7]J$9A3F''J;+K2T B#$2MC5 CG M+C?R)S<5[0(IV!;3P=?5MBOBH5G"H7"6&JGBUL$<@(3BTD@B.M^"^ 7'0CKV089IK)VQ"D4L73GU*((B4U%% MS1,Z+VZ_SP9Q,&U4/2XV45D^1'SSU5 ANN4Q>6D*D MI.4I-26"9<8UHU\@)>L,\(_"@JH;JHN/KW^TLI>.OSYP %$$#3*@C$TQ-<:6 M$UW%WV4&LXTR-VQ8DC6VI3H7UN ,?U.Q6'5T&437GPK".@.L !Q03! BQ%%7 M@FF1RPS,&O&)^"B8/[C@A@@&*]9/@VQ)\\;O"L);J(U14E@(/:6"*%S"H;WH M_7;VH1/NSDKFOL4S-%M/96*05DI,##94,F>0P<27@&D/2*YN^PLD[;7!\;R& MU:?B6W+KENI'9Q;5\?<&#SG30D/@-$"$$6%9F>6JJ4&YF_/I$2'7:$IUCOLH M;*A6%E)P'"JD$351IT"2,\)8F6&@@=:9Z]H(JW\-Q(O&9D]#"8S:J'D%9"_6 MS*MO!&4(]9)$P] K(YR02;LH-Q1->[^IY)L'S2ZMX,+201JYBN]^E@L/S]$&/5D=5(%L-IVP1I-F9)Q3!AC:!&*8RN'J63NW=EHA'7W.Z][ MVB&NHU"!XD"V8]B.II4^].)-01/M%&!0(L$I8!PQ4YX%&@=T9B'[QLK1]V+Y M^Z+OVI;=<**Q^M,&\)'I0GDL;/#. !S"R%#(.?9<8N \*6/DC!2D]YID5\;' M_J _UZ;:=#,- BB.HH[@'*'2. (D*8-YC:'J>DI1]<.G+D ] U?L=+99%W<9 M*MBKEH%HS9GET7;%T72-R[8S)7 &B-Q+6-$O4$VF6V3'HH;M1]&)(O;\78$+ M(9UQREL,F)/$:LA*.+S/CN^\A*TOFQDYRE@+T,>GCF6QL=%;@\((4N:ICWL& M118B0\K#6&.S,XPN0B7KAY=]PG^^K;;Y%AL0D[SRW5W8>W()?IZ2?#"Z0E?:VF0 MF N#+=',&1T) 020#/NN1','HTV[0>*M*6\Z/B7%$=3,^:W&P1*B:4$4FR= MAT)!S+3?#DX+09F_'HVV)YDO>D!Y #553V:3^6WQ^:$HUN\7^WN\_YS6A M:A($H,APRS2U%!J-C;:@')QD)+>.V?@HU%:XBUX /1-;[.)Q,JVS4 XW"LHS M+-)>YKT%!CNM7868DE=T)W=[$9_ F2Q0!SN.JFRM$Y>9FE9!8\!=-,Z\X]3: MB!L1M!RBP"+S]K@1FJD=KS3=87H^VAQ=;VK;!>"I811"()S!<4?'#L%RF-R: MZUER.I'U:?S)@G8 !KV?KJ=?MSTTDU5Q9+WY^>% O4NWMJ:[&275@FIF23D@ MXG+#=D98LKKC9:8UE(-SXTO\[-&%Y5"30 G%S#$G,! 1,,R-8>7@G#778SNU M$6PM1[+!')0I:>';K$Y>1YX>#U1*@8"$*%WDRY 7CNE*S1,N1Y@R % -8S#95$*AW"Q^%4VS+A5V1 MQ+K$8YD@3D$2UY/#?WC M0^SOLKBY?_KUCV.KR\DO"6F@&L<5E"&.C64"H$K)TSZW,&P]4XQ8;CT7&KMJFFDL,N]=.,"6-2!V&N9U0;GC*=_4)'SPANX]ND]]PC)J*&#%R4B $&40C L03$UU!$9+?C@V@_NOB+\-?- M9#F9KXM(KF*=*!TWOC@#IG5AJ">U"\!2A8#C6BBKD'<<:ECVGAAX/=5S>A+J MHC^P:S>%.IHLEC>_S_9VU\K]^6VZ#\ZZUBP/].E%Z![H<[?OWUK39VG=P2@C1 .68P=%MQ! M;(PI1Z2MO?QXUK-2)QOHYM2IUM)U^BD-:C.9/>N96JT6M].4VO'/Z?KAPV*^ M+&X7FXBZ+7X_1*56[XR3Q2+,($L7>T%HTBV*J!RQR@Z8:GPXU&=*8W_D&A+Z MYF3[?/M0W&UFSRW_ _T\%&R7\9: O)=( L0X)" BB3FMU &C$# 4%#.K8+J#PV,FN2&5%BE IIMW9-I1;P)NL"9E M8]X]?PYZ=$]O'*T/Q>.NS36F5!+GO.'5CBT,&JIJ5[^\Z4.F#2B3!?4 ?KJG M5?BWXO'W8EGCIWC]:& ($F>P4X SA "'4MC]8.)LDY=_(-"'8!>=@MI\08GZ M5+'^/)D5GXI9TJK>S>^*Q_ET/:UAP$GM C-"(N*YI+'? L<_*P@8RJ\O^4O0 MH0^$,S:;R>K!+&;IZ\O);/KOB/A+U:R6(2>V#AA$:+R!@"L5;4-.3.7L8IRX MS*)\(XJEZYDG_> \Q#GBMIM'N53W>)#0<*0$A1Q"BRRF2N!R4%K8H4RCOFWM MGG>=#J ]F2^KXO8O7Q??_^NNF":JD/1#8@AYQI#XJ]BGKY.9VY9Z/F .O?%4 M (1C[XTEEGN$B7:>Z++3@-%,'61DFT[?-D][8#MGPZXG!ZV;UX\$PRV1'@NB M$5-QU K(TE? &'>9>2 CTD5;R6C1"6H#;!&[NCMF\?AM,O]Q=(=XX^G@H692 M0VP),00[JA2F^R%QSM'E)ZKG"_'U[:VMT>O>G5$76=2H?5!.>N@=-%8S)JT@ M1I1S@T/F,NM?CDS+'(,S+!?RYN1Y]M'?)G].'S>/[L]ONTH)J>3> \7FHY$H\P0XZ(OD%M1X\,FK60W]^KKLM@5=CM. MC)_;!,M3Y2C.M25.>TDMVT8^;7O,M.S]ML]KHT5KB _3 M)$*0%?E4_Z*@E7 (6H=]?X8E1405?^B MX+QU#E@@),("&BHTYN78,,OUQ8XH,V@\C,I&O3FC7KKW?+'KP&_3>>K4 ?+4 MMDD9>5 8I(F 3%O I7:D @:R3#=;XY2-R]:&NH2X,U+LF-J,%+LV@0AED4=6 M8.3C\N@B&KCJL4][EOEIM?^:H3R MX=M]72XHB)?&)749Q@T-&2O%?HA*.W]%!0Q:BKA!7:YFF)Z/-BWKLD^< M-I9* 9$QD-)RF!;"3"MWA-3I1-:-ZG(U@[:YCOFI^+K9QBY]*KX7\TU1&R_T M]L-1Y1'8>N28IZFLJHH+KBG[R!"Y_)/!_F%*"" <]-7-$(D!:"LKO27D'.0BL9'8KW:89:\_W? MS8KU.66O0YYYLEATA]L09Z@# MUS;C@*HX)[ EACL:K73#*AB= YF%7T9TKMJ3H=D;Q(-SK)/:9EIB%*=0G(W" M$<4\(?L8.JA3;.7%+S]]BKU);;-&.&=L0//OT^5BGM3DR:S6^GSCR6#A]G8O MS;F.+R;,$L;+WF%!+G\3ZE1$BR[!S#C/JHI]ULKY]6-!&D40$IYS(R&&SA!9 M[IA: IHIY-$;"^V%W!+)<^@>[]L5*@2>*JY85,_BD"QCR*@*)2MUYFG(B.)M MAM(MHB MISZ#B<[(PK[D,#P-3]A]#[0(G#G@.$?0"1PU5&8(*T]*#*'F\G.%>]Q:N\'T M#'39S36U-I/E\D?\Y3\FL\WI@5$'V@=G>#1HL2.(.\X]L*#T=6-WQ'MKE0*'N&4C.NL8-RK,MPL3EJ2J8^-?J'JG%V=0?R" M89=0K_., (]5C]@'QRR6/]Y/)[]/9]O"2C73]=835)\W"AI4JZFZ':?.Z0!! B&!*%*?.6BF-@^58+21#*>Y#S.">2)!? M;#E7"OU,^>?EX(>,_YZ?-)MQ;OH \_^IMR'Q?S3LPK^I=V_ MJ]Z0%JHOQ?+QG%F%7X=_/8PTW: M%XXE";[Q=+ @U8=D'C-*F;($ ,7*84EV!8&W78GUC7G9#LOFIL^KN59&_!^Y M<>!(J^ 9),+I%'M,F(YJ.R5HWVN4+JV\*@9DBVS1%Z!9-%@>^'YME/;1=D$P MC@DG#$.L'<)*(>;+GC,)+C]8H5/Q+?J#MCDI_C%93A.C/TW6VR[4!M&]_7! M##$FM.;2:D4M55KALH]6Y]XK/3[Q=R6J1<>(-I>ZG_Y9W)TD\C>>#)8BSY@S MR##&*!&6,[[O'98F-ZE[1.<2_1IYGK_(@$W_.6GPUEZ\V^Z2;_C.:>,NKJ_7>:HFOCVPX%K@BPGA'#!*)+. 8(K^D(QU)6H MER+MSI!L+NV;]4.Q?#626HD?;A @=Q@KH+SDBA%O&7"F["M6N;>[CRA?IGNI M=X;F %O 2^7X_0FY50=:!"8<'+NV);L$E M 9V,7W=_7]RNI]^+C\7R-DGPZ^G'#T?>$R!3W&X#VB3 W @#N2IAH,1D?$UEU[Y< MS-SO#-+68H]_;23YI^<#8]812;2GV#MD85R'*H):H*XG/;M'J6?#>;(>458 MF\Z_QVTE:1%X_W/B!GZF/^Q^&T>[G'Z?I&WGPR+)9C([>/O*D18A$@^DRV4 M(T1XRAFVY69%F729\;HCNMZ@:X9T"VCSQ>&Y]O'YC\FWU3[#X/GO5]NSE/K; M#!J_)W@O,9=,8\TQ=81)KZMESTLH\ZC2^(:#RZ'*$##W2J#:FP\:OR<8B:US M6G <-29D#+>L# .@1)',XY+&MR%<+8&R8&ZMGORMF-WYQ3)=RWZS3.%@VT#G M37%W\ZU8[F*;3]-;3GA1 $AB 3$! @EEF8%2N')L"(),$U9<-X5ZQWFP6-C? M4H6FZ?I'&59_!4&PF!.*D.( 464%Y<*9O4 IEMQUDEJR_?0.JD,!K6\]%DPZ M+X%,QK?OAP+ " M @K/C8&<&FD\A?L^$J; Y5>4;R>91<< MA-R^FAMP,K;#P="T^U+F#+'K'&. M0E"QF40E4UR-D-O(YX"HLV%L+^J;>?TE$0>?#\8(2HS4& ML45S+@*5E3Q') M+9(P8H'G2*E&X+E(MI?YES\6C61>/1\(8 ACX@41EAH$B4*D[*GU///&N9$% MD?0H\UPD.Y!Y?+;93'_6(@BEB&!4,&ZT,"@=I[NRM]#KZ[@\N4^Y9V/97O(^ MVC>-!/_4()C84YAJXBGI--&<&0'*O@KO,E7T$7GX>Y9[-I0=B'WZO=E\?VH0 M@''1."'&&PA=M/R5,U5?C4:9NMR(W/9]BST7RG9B__)0+(O)?83M9,&_;A*L MD0X(:9!P2'(6]5A4]=?%WUV\&[Y'T;<$,T_X>YOS?4TTV*%'@[.*.:VY,PII MJ[T&3TH(&.4$1SB:>N6PG/*7GYK=E5A/J-/0#,M!DG'F7R.RCV4 ^M'K MM'Y^/,1EA !M@--.8LOCHJ)Y.2ANKZB$;2N)_I2.TQK),]#CA*NQWFH0B(;> M2F.-D!HX:2 7JAQ85%:OYS;X=F(]PI$L,%LG_M::8&\GG%#"$+/:,*$8%$I+ MK&C90P%?7TM_1>)N*J'#&;]92#8.I>SG%MUT+1>0'F!BO7)<^6@X5IW&N0%, M([+&NMP0V@/8N=1=PRMTJ?-QR%8KJSE&%CC/3:4A07;Y"3.M9'3H"MUFJ&5D MW\:UR6[B'Y\WOZ^F=]/)\D=] NZAYX/C)*67">0HM2@:I"!Y /=#13+SL&QD M\LV3S:)[_)I+6LV_3AX7AZLN_/1,$"(Y .)(@+,JVO^.N5(CX<)F]N7(I&_K:9(2LC.L[L M1-+=(=A96I5IPW)9#Y93B M3.&.Z)RR$^&V!B[C3/+;[,3=^(TG@TSKBQ% 8QDU/*E@_'O9.V>YRA/KB))X M.A%K>^0:&[^W*?UP^6.7/KK_R^O\T?VOPT?UAL2?_C&N*X(*KIQ#WD'* ""P MZJJ$^O+3;%H+.1NLYO/UR[18%R?.V#>?#9(0A+B/(_.:0N8,5JS2"2S.S-R4 M5R3.KK!K+EVSN'U83N:G"OC0XX$8):F WE)A03I01ZQTVW %0&:D" 17)N2. M\&LNY\^;4W?=-YX,<3R :XB!2L5T+9$:EHYW#I'+S=VX-E=5>^@R!+O8K!]F MD_E=O5!?/A648<)1Q865,.H$F&E3NLXXSI^NU^:I:@=;QFK\,/V^J _.?/Y( M@%&5@YQ@0W#4U&U:UD7S\6L/?6" Y4'!AQ*-K4U380^R5R9^JU.9M:XI9SQG,7H3URQ//T2%#: M"Z>B2HY1U,RM9("7IQ4"$I8;M7=M?J46F&6< :PGOR\^3^;O%W%<_Z[W%+[Y M;%#,"N-@5+4)E^@!SU6'&KN51K_F=@'? /%U)@(^7?O);;K#^%"( MS>&'0RKHC*CARFC&@+50LS(V53 $,\N2C4BMZB/TLC6.@Q/C:-CE6X\')@!% MPA%H%04&2D6J VL1+8++OU2I"X'6::$4)TPIB M",JAV>PLD!%%'/2QTW0#9HZS_!D_XU=O[E_2_U.1Z#^=?]6+Y7+Q1_S!3+[% M?UO_..A.SWUA$*D6; 2)0X8-%T@37 ;6",/TY==,ZDS8BS/@W9Q;VWLF.B%5 MQIN"4IQ H6R<@%I#(KP1Z&F%O8+ Q3[8U#_0@V]E<03%P6+.QYH$ ZW3UJ1K M5B"!7E +JGU?2W;Y56"Z9E''B Y ET_%M\F/U,G5S7W*TOFRS]*IH!YQ1*9](* M*K O(Y$E@?3R"]7TH=+T@&P;9GPHUBI2='V<"-63 7J*.,-Q\$ZI%) L**]Z MAW++3HXH0K1?N><"F7%L,[]=%I.4EKO[[W1>%I5W?WXKYKM\W4/'.*>TC41% M0".. 4LW(P'"J*U&0..P+CZ.M \J] 'M$SFZKGOSXH*DR7+Y(VYD.]TY+EY) M+UI=004<:;3@Q%#').:4,:<%=!8AHH6D<5,^PN,A#,><"C@\:A8*<2-3+*L6 M A)KRF$!=F47 K81ZPD5<)IAF;,G/[^#_>GK-<7>ZYH$SK%GC$C&(PI6:*HX M*_OKP)75]L\6UJ(7--M)_^G3M57@ZYJ$="NV=<@+YS&5*&Y*5)7]]9I=1^&Y M;B1V@ (M('V\9/(R_\LHK MX:!'&(-4_&'?>TYRKR,?,2'RY;?H$]EN>4&S>4'+WB-HL(L*I6&&:P>ME*Y: M*;W,C+48T;G$X+S(0[837LBR#ZPI+UZW##8MGMPBQRSCQCL#4Q+CKO=*Y89A MCNBD82A>M$2V$UX( '9]X$UY\;IEL 8"KZ&16FAM#$#(V++WFJC+/U(8BA==#Y+AG@* WK_3-Y\^SC8K5-)4G$"14U\2#'(H_A(J B4%F"M.03DF M W)WEQ'%Y/?(EIY [F1!V7;F6^P,OMMV139=5PZ\( !B"05,2:.(IQ@BI75E ML1.6:;6.Z$QAJ.6E&X [W7T0R-U]RI9!2BWC9ND-U=HKC#ET%3B$P,PCIQ$= M/0R]^V0BVXT5@_ H(@+CIVNM"J;>RC5^"2BS_R2 MP2R9EN!V0@XBRD[@IN3XJ6DZ2_',>:6))P9PR:.17O8?*909QM"X/L8UD*,M MN!D)A/0O%+S1DUTOZCUC)[4-@BEM@?"6(QUW16DYK.CMN,ZT:<946J,7=O0! M;B8]JN^OMMV9QUZLMGH/HK4^]-,:A\AN1CT@!H%HO1L.!$-I# 930!G-O2C@ MVKVGO:#;G"')@C*+>5Q]U]/?9\67Y6:UWAI7T_6T6+%R/:NW89J])$!C"7- MLVV91D*EY+YBO;>Y5[->NU^U5Y0S*DW,)X^+V)5_%W?I=#D%/1RIA7FP0:#* M(V!DJB]EL+&<8U9MDXR#S+IZ8ZHDT@LC.D.TE?0_+HO'S?3Q5-F_>#S0E+?M M!49*((T5<''@E6//'0TNZ:S>R.5*O@V> \1@=W$7$=/60J8I$EA1%FUOK:KC M:NMTYLTC(]HON@S7Z!#),] C]RXB#X"-"QQ-!I>7U#*OT%,TD[G\Z]Z[$>MI M=Q$U [-=0$_MMO'S@X%KIXB&6AKLG: B+G#54#W-70LN0-!-97,@="<+Q@$6 M@G],EM.TWGV:K(_M$:\?#4H)"SQEG!M&XUKII!.5LB-]IH]B1-IC'_M#2Q0' MIL31?>'GAX/2' HE( 4:1,W*"P(K"TA%<*YFJ<@790TGLD <1F.X6^RR GZ? MS/]U< \4L "I5 0Y*M'54:#&(K<.XKBYTU3D M/VL3G2,[> [Z^Q;E5(2%%D)*(,-><2>X(U7T4KI@_>+C?_K8A[H!E&E) MB=XN,OTVW7?]L5C>)@E^/3T9YABQN)J7,& , MZXP)M0B8)QS*N^X)@*"L? M%!*Y=[N.WL/2-<,R$DT8Z["26,>_5"%,RF3JLZ>K M)B^+57RYF'G>#9[MI/UA,3]=X$\/!Z($II@Z@ZTC&,?U!U5G 1*+3/MW1 '& M?0L[&\MA,LX_3);I8KSOQ34DF4N&B$(JFA#;^AXB@NVU)P 0:;P]%H4VA :6 MDV3NA,#$RVA$(^.QUL!Z7@Y+&95;VGN<4["-6$](,F^&Y0 *^EN%BXZXK@\U M"8Y(;9$40%-)L8:"1WSV@[,(Y(;9C9,HV9)=](+FF:ARTG%G?<.0*N<+'R'R MUECLG3?(5\CE!\Z,CS;M17T"=[*!'8!!5:A@[:%IS=,!48&C,L2$XDI'%8;K MN"#OAR0\S[Q6X$*XDB/:1=>8#GM2[D#LE5$F&E^<$2Q5W(?+OC%,,[>4$?IT M.I9W)W!>2&25 =03"1"A5F!N)):25/QU['HXTJ7:T0&2%Q1912U7D%JB/7#: M,0T(LN7 .)*Y=TZ-CR+MQ'I:9%4S, =@R2Y%)66F'+]NY*=G T#688,Y-X99 MI\'VN'@W'.5!]@V0X^=&4W$NND7R!3$N9Q'N",5+V:!?[CE'MN>?'PX0$AMU M2J29(19R@PPH31OE#,@L2W4A86VYFW-K' 7@M#77ZCAJ)MA:CF2#V=R<\RGD8#&=K],/_Z=8+O;Q!\_V WM"9F;3 MUP3+J04&,>VILCY.+>:K<2%$K\L-W4ZRB\%@SDCGY7_A]/77C]0_K&T3J.:3C'"**5 8E'NF@M)>?H6[7HC1):8]+B+UQ&CZFB"X0\1;[*BD7&$6]56X M'U=4V>RUJB-#+2)Y,&^JVL2>+H;&P!C"62&(60)P&5_%ND1%6XXSJRF._O:> M[GG1$MEN%%P$ZDM=U30)TD$FM#,.(T&)Y(H+_K2^\1;7]_O M6O7;Q_&6 5$>USMD'$,86<^UXZPRKRS.K5MR]:[6SJ&]J(QR9"RA%$LB8%P0 M!71:E+YDK2W,#+X9O7.MRR/@7#";+R#]7RG*!-642^:X((Q[SIPOHT2T@?KR M+ZKJ3(2-KQ1M!NVYLDNV=XO6K".'&P7OD5>.>:(9MQ%')%@9R6:\ 9GAWXWW MGW,6$FC*GLY1/6N5BL_KE'K;LD3%ZY<$K2RW41F#GBKM"+:&E)B:.)NNM?96 M>U+UAO'@)/.3V^+HRG2H28!4IZQ'&T;N $" *4 X JAJW4NAPN\2SS HO33PQ? MEC:X* IU#>[@2T^_57&( "ANZQ!(X5+-3<"@J08O1&9EE-$?'W:]-'6&<'.3 M[)4O8K&>WA9F,INM%Y^*]72Y.PL_8)*=U#9@19VAW'@H-9,4*5H=FQO,^.7? MNM6'2=8'M&W)\2EJ7\OIMBJ867POYI/Y>E53SZ+9"P*2RHIH5&K!#%8"(<9 MI<)1DQEH.?KCQ"YITB&^;;GRI)LO[LWDVW0]F7U>+V[_M;CWBV4Q_3K_O/E] M-;V;QK6N6.WNZ)A_O?E]-OVZE>!I*T[;CP1O,"7$(,Z]M8@!CI#88V*U0)=? M_[8OCARDX, BZ6-)^SR9Q<[_=3-9QK\MEHOEN_B[9[U^/L2/R\5M4=RM_KXJ M[M+2_&WRH\:%.8X.4X@I3*(%3OG3V6^!(9KS.B(Y1!B?U."0U4JZ_ MVYI!ZX69K![\;/''=/6^6*W6#Y,Y/>FR- ^3Y=<3 MK:@N/A0DEMX 1J@P!CK!X5/1%4M8;EW_$7D,1T'PGL72"V4G?S[K\LO)E4_/ MFI<&!3SA5G%BN+4::25]&>-J'829B94CRE88!Q6[$\$3[7JMS%FL/T;5_W;Z M;3+;.>53X,K-]V*9LL#^=S%9KJZ@9J=WR&DD!(S"U1RYJ.=IJ!V5V,=?F&,G M-R=/^CU4A^IOOO58P%QR9A3GSAOMF*?,@[)OW,OKN2:JK6P6G8&8MZ+_-EFG M&TQ_Z!]I6APHDG'XX6"M,0IJ$ZWI./Q YMMDXT92?VH1 -;6\/%-<,O_X-4>V$ $PXH#ZW%^X1";K2V MQRR-D^;5Y]N'XFXS*V[N(ZK+9ZCN,:UU8Y_6.#C)'836^ZCM :\H,@*5X^ D M]V:'$(D.O MPR_:M>1^VGF[P#:C?%'UN5J/^.O'XO9!-?5,49O\>@82!ZI^:2XS]:J1R;P3 MP2PZ0[&Y='^;1*7]WY-:6^G%,X%@YIT C*:T&BN,$I25/3( 7<=!5KX<%MW@ MEC-/9T^]KB\K]O.3@0--N:/88Q)'YP&GY>5#W$IG,V.51I5UW9E;7#+F*>+K\OI M?/6O^BGZXJ&@M;(PZ@91<]"(<\$Y &6?D-.]WXI].;)L!5QS8:;;8789J'LM MH$9!?O/9 +APA!A/H-8( @Y56<^#6P?TY=]LUK-JW 6J'/V3D%3+346Y)XHCDR5:BF@.E%GP=APFXIHT360PQ\HP-@]21@! AOM);:&JK)_QH!6HK?]?!$C%O/A;<_J*(HJUE'WS4E+Y*O3MZ=>;.'[ M$@'3\3W_.K!PGM@Z8*L&ZEE+TXXC^)/J-M0 MQ6_BXE8\+7$O.]>0-DU>%CP37CI!2/R!E=P*0WA"F+5O#8>3VOR7Y M_&,RV\35J$].]OK-P#!R3#LAJ!0$8^.XJA"C&F2>.HW(8]4#5\_!S/!A"AB0!&5%:QH[EL=W3\7Y"T&)*YC3-U)"4J]2__@5();5QR00SDTG:TS'= M+A>0!)[SX. .(N/6$[BA$:SFUK[Q0[R]CF$($#"T3-,,:9,0(>U>L+3QV-Y MYAW\^9Q3&1P8*H>&XWIIH3 MB&LZCW0#"KH]B2X] N(N:&/*'S_*V2H7];KA(HIKE2\OFT2[/QD 1T!Q"25& M0BM%-9&PFJ^4/E./#;3F06^4:@WPW@AV/9_<%$80[B);S MJ0 =$ )[J9W3UGEH%=TL+"+%9=5V;XE8/0#=A0;[])"\7*]N_^MA-$]X5SOX MXH_1HXZ6Y+I]MA:K]_E@XQ'*(<"%@00QHZ 3U964]USFAFX/M%I\;ZJL$_2[ M>KV:3WZ.4G[CYZ3'"S4;_]]B?#>9W:F4^OC5B;7?UZN:@VOXQ)7]U< HE)ZC MN-EX8E*X$GWB"Y >"'#(O7\P,.U[^F[CLT%B0*F%2@ ,4&4J:>T(A$HYE7F M(_@@G\IZ8-.[@G:]2>;$6F?M11S_S^KV3 M/KL/37%Q(FD4K\>$42^)2N>VM:<$UA:H0Z4!NH')CR;SU1/;XGEJ"SV:IANR M+]^+8ODQC2,22S\^-XA;[VI**0A)/S[-W1:+R=ULU7971ION?S1H1U(M9.J% M -[%Q2P$JT#VV&:^9%V8TJO-Q'*@;3!FKWAQ[N:!P I]YQ8SGP""M: M9>&-XR12GK\IUHJ0]@H\"\F<$.0UAU/IKO\I(I?++=,Z$)9<^PL!&J:M=M$. M3*E,XLD78?$T&T.TO8Q0Y>-E6?:!;@\!CR]TZ4;!?MP3^5RK7^ 1*J"!8%81 MK5+R#KF9IB?B_ M@#G!3ZD(RO1)P?:I[.L?5HMZK'D&E3+960&(,T!1)#VD% MF)'$G_^.UK*$=_+F&%A[9U# M\60C>RK=TY _6WL&YX6Q4C')#"7("@J4JZ8J.,CT5QFD.VEO&B@;WEZ9M$$A M)4]ZM11JT6EW]R!H2D&;\G18#ZSB M%J^5B/:68\?&-?SG[BF[ME56LHGYY: MU0)YS*?7YA/!,!)GSQAQ7B8=+2&PU>2QTYG%A1M[;EXLQ7*1SDFX\'8;7E[= MWL8__6,69;+E2F/'95/C[P1 #(<\ZF2OL/-*:@%X-3-!;.85]B!=-=MD4!]@ M'T.C5QOQL5QJ\K$ @8?"*."($\@([QC9S-%1D+GO#=(5LSM"=8CXZ?? U6I9 M)Z';3$[=C2:SQ=*4T^DHBFYKM:$V/Q\< X80 !5TUD%#C2%PLQ01S7P8'J1C MYZF,LY9E<'KB;NR![LA;^R>"]518AK%B,/Z?<][YZFK02G&P5M%9.8J>TO9K M61 GN&)K<+$6,(J["8>>& KC^#7&L#JJ6X-DYETL;'Z1G^),SYI568">ZA:M MZ=U94(I@#8V05!K+4OYG5;W56L)1KN=+\TO[L^=)/JK-SPO/EY-_%>#);EFXTGT6C<]=!X/?7/&;;;1UEG7PI>#0LQ@2QD"F#(+B0!L MHYR=U+G9HR[^XO\T^ _0\;UR'"G&R?=]^?R/3[U_^[YO]S@&4B+*.92&&!;W M.X(8M%9HZ;6,?]\T;?9OW_=M3DR2*RVMLBES$ !"6.!]!;)"*O,F;M ^.1TR ML3_?]V9RZ_7(\(SOY\GB7SL\YNMT"T@3;S37"CL9ST@8 MBK6)4B-8+5,PO;+O)2H['>_K= O&",N0,<1J9'RT0HBGFU5/[66KQN:BWLF? MHZ'M@3\?HDT:Y;5,F7BJ\>[TV#_<*3",;5QI&AM"4"J5*.!FU3')+ZFX>AMB M+CL"M@?FF'FY>/*DO'G,HE'-+P2OK6 MT1Y(\OX <>#HMKU#8,PC+#D %A(CO73<;=BO.+J<#.8#/+2U(I*3<.W@46U7 ME[AA:YU2&DID0/+MU5P7]V8J\6[._.#VUF- MWB$:=MY20)14&&AC#=A<\"FMW.5D #E>Z.^.^6VCVP.A/I6S\6;:V$R:"]:7X73ZR*#: MTL\*/FN$\NFIU6KPF7!2>\EMW"64@IPX[9\G;TFF!^! Z_V>@&*Y2)_82V:5 MZ7D7LXP.-5+S+?J2)RP,[)=O9^\>Y)B[BK>8"8 M6J@1)4"QJ*% U%^D&BC=\BD:"B@LG446Y'VWG2&.]L'X#4#)EI#+ X1 MH!1Y+ZJ18@?./_M3.W+:+_0L+)M+_;K\LYC_\>?WO4D+7S<*TC-.%0.<*:8U M0UB*S0R1OESY-A5)V1*".6MY-/VC6,XG-U_+V:&$E.^;!N@))0XS J!(49C$ MRHWBHO%@?O:77NU+N 4<>ST2ZL=/J81[4=MK\V6'X)BT7BD4SS;$,$OT4,E;TMO%<=>"?)I]*.)6^5S\V!4I+U'5G!&5R_HT-+-\E'N_//6MB74 MG1S)!K,/-[A*;=9W>]O>(SAA,4K!1DA0DUX#%'4;G#B^Q,-BCF#?NK>U@F;/ MH<5-'E2>[]*(P0 3:2Q@@ DL6#PQ;R"2^I(*C[>]R^2"6)L7B^+F;W?ES_^8 MS.+!9YE8@9_^G/B 7_!A_;$%<3U8A+**7)*CKF MDFW%]KY8&7N_7S)>WFH[IJ624'J!C86 :*J?:K]"(YP\%$35#4Q? M;KX7XX=I<76[%N>+R[I#3QN'N@8C(FL=,A) )BA7V NRF3"FN>D"AKS?=,B* MLE/T&YLUXV*26$;2'Q*YR MRQ;\*'XN[T=1%A;!\W'&#LJ55L)YY"J0#2CGA MXV;*H:@&3;'(] L:(&7:$U_9%IJM4V ]DIU7)&^;A!1$H!4'VE!J4L4&86@U M7"G%^4>9'B6CLA74FE^5V_OIEX=OB\EX$BW?O3?E6UH&ASVUWD#"XD'>Q:.: MI;(:'<+^_*^Z\N51MHE<+^&=;Q15G5N+W9T"HU)C(P"!B%NG#3%V Q1P\OS? M4#K3]:V#V^^]>3RT5HPWP K]%MG0(< _:2(W'D_7M M\0NV-U%%]3X0.'0:2TXYL<1&(\)R)#83QYSD,6N 8>H=Z*%.(#[Q;6WMAN[V MMDC_4%RG%)3E+%JM<;'Y:?EG:OK[3O?5[1W!$E.$#?148\6D].0I18J2T/M3 M>Z>_F-#?X]GT8[E8;.+)5I?V4;Z+[Y-[_?AA%BE5?(GL6U7)V!:5]CHC5GW' M]ZX'$03AEA!EB"+&&Q2- B.?A* $OJ"0Y5Z86B/YW2#DV.N9M>[<,U(\'OY@ MB(("4$J+ <%0 *F%4Q4P#-#<*@-G0O 3D^WH]9 APO[RCKP<:-W$(^_[)$L+ M L92!GYNM;*<:5!-+YW/?F&&-A/_]LPD1R/>QS7+"RLQ.34<='KE,ER(C3T@E_9DJ''# . C+.*$00G+'*<:.*N:IEKHJM*$T5/YRL@.> MP7&N/3F=CHH'CW-[^P6 ./.$89$R$@ ;]W997(*(99!@"Y126 MFXFRW,R2]-()U FZ_5WY5;>5M5FTMU\0W"!.);9@I2"2Y$M,V8-59BXS;7"RXNBXNQ=,[@RJ\3D9V:JY^+F_)N-OEW,?XP M>[I6_Q&Y\3U:A:L.">&WH0^?:E86:>_G HE"PYY8SX5$$J8M8;,=" $O,15X M.R1KPN%^A#, QD]'B\7D=K*.C%,W-P\_'E:9FJ[,AP^S9=D%ZW-_,L"X][EH M_2@HC#4&B;B/5N RGAL*.<#[L!,SORO!C+CD6YVB.+VVA0?QW]E8[T M-\NTAF_FQ6A1V&+]OY^*OY9?_RRF/XL_RMGR^ZX8W:Y^+@"'O.%&2XLHAT(X MO_&XU M_NM\-%N,;E+#ZWGY+=EZ5[>?RN55!&T^C];C'O7=Q<\%;B#AF@)OC!":>4!H M)6$C"<]\[CHWX_UXU3T X>2E2MB,[CER^N7 (FKE>(<:KML]$,P9=T)3"#A/ M);V\JI[_C- \,Y/4 *\R.U2K'8%]+J'M'V;%[^#V^B'#5$.17E0I85YPZK"U ME2A9RH//E33 T$H( EUX,$GK3#U=<'LS.9[Z M[J#'X':/,37)=94(@S26['D?@Y:[2\Q*/QRRM1/U:8@2]H$Q3C2W"1J/JA1#B2\J2T()D M:P6W-P/T+&,AB-)"2F/BE)B'#GH%JC>'E7[_-:[%A[$]MB>GLXV%4$))QW!< M:CK76BJP;Q4(T@_9L8B'BA*@!"B$G,!,:$K#1T2C?J?E\ M&--4NK5B(9J!.D1?=VN4!,:*N)88M0Y SBH77(2@NYQ]K5U:= 7PV3JG2NR= M\28J8!"M2F>QMM5--=(>9^:Y'>!K:S?JI4UPSS1Y%&,^%6#PVFM F(M_W.SF MR%)RB44T!VMAMRBH,TT>Q33QC'-."8:.&@,UIIM):G0Y!G8[HFZ2/*H9M&>8 M/,HK[KS02)FX[V-BG?15F@F$ ;Q$[APCYOK)HYH!>[:Y?9250&"$XY:O"%3> M*5FE%D%0LTP7BP':Y)WPITUL+RK_F/34I/4C/$0.,.T,K():$($@DU:#-K!: MI%4W*)_Z@?EC>Z%#6&)A<:KZXRDRGG."JN+YW)%.S\;H:?%3_TX?QVKM^XT4_*Q:+KW'91O&T%%/4QCB")TRG^R%@KV6$1;*?GW1[-I[8YZ"PF1 M52!:6)40*"69^>7/15&VS=33.6$VDV-_CFJ5-CSL*K*]0^ 8":L!!Y Y)[P4 M'K!J8@3[RTE1.$2R;'=K.TY$)^%>71_)=UU""A3Q D1YQO.MP@@YY:O),8 N M1T$>*]R#7,D"M >V?"JC]579; >OAK:T#MPJ2U4JV>M("BHR#-NG*6G$Q.4X M@APOU+)M-,_T:59:"Y1D#@/!$97*:K29I-'X$BL7#'9;:U%09_HTJX4F3DK' M"-28(8OH9OEJ#2[X-Q*!WPA;YTR:V/5#H^+(K MP#)NC,)*0):R 6!C>#4E;'/I9UO:@23-8:[L].9UMJ!%E3-AXF%6$:TLLE8BPS<[N\>68VZW(NE&H43-H MSR;4"#@0/X\-ETHBRI0SIEIL!C-\.49V2]*M%6K4#-0AAAHA:KREWCN%O5$4 M(,Q5-0./9&;\_@!MYW9IT17 9QMJ!)&/&SER0B+MA =8 5U-$T&769MW@/91 M-^JE37![X%#S//A>&,&,Q-A8(;TS%AE834%PEVD_#] 1L1M^Y$/9?-/Y7-RM MLXM^+GX6LX?])7JV-PZ$:>E2JG_((826>^&KTZ5Q7&>>L0>8D+#];:451/OP MD3^JPAMUPEI(9*K^'$TESA$G&Q)KFDF0LZN;DJL/C@7T"*U01^[[.P3C&0!Q M?LH0 9R!%CBWX3+)C6\_NZ(H1VF'8U%MSH#GU-+) _?JOIBOKX"N;I^S\A9C M_;"8)*?>8A?@34]X'WJ0(2/[07- M4"&AA4H09T5<1$AC)9\F;JU3F40;H*UZ!G>]G8CL5%Q]Y=NO%D_X;IE81B!, MDV\'(;5 E$D"T]NP3[&[E3$958J[')?$MNE3AYT=2J(/XK[8$#8;137B50+^ M^W(QFK[>.38-XY2N;K^._MK'WE9^(&@/O",J52O%FJ9#,*JV0[K1T"M#9!X+%),8 Z2JX/ WJEXMEE/QTF*+WS+:UOF._?!'+";'T6? M?T\_)I^6'8X=NYH&1IPFP #%>,R_;=PF_$)?8G)8!H*IFP5P>,EO--?8G?C MP*QD4G*$/6=*<\ LT=48/93G'U1QO'3VB#D+Q.:"-G%JQ6CVC]ED/!K;PI=) M7Y5F>KOW NE KX D)0I X3@$V%B/#'SFN33G'[W?AL3*KO#,9L%UL8@_>E]' M]*^:!D.%$M 0YY2&AKGDCK@9'X&=GP;.5-['@-A^&QIJPR2KSA/+.(\8!\ MK6T6W V%S4:GY7I(N>(OVLFN]_R-O>.%C& M-(?(R4A'H0'CT)EJC(+P\W_=;UG4K<"8LR%/EI/%]^OR83;^^[?]BWIKVR"M MP=YZ KQP5D(JC935"*D&F6Y_ WK);WT[/A[%YG+^S]&_1__ZOEB.9I.OQ>RN M^,]_[XZP$+SL$@;0%$CIK"!V^@4=]BHDQ7!(MC=;*>U[-0 -[B8\R.?(KN\6U!]WAXK#&XV+\ MC(.?Q&'?3$;3%Z]4!_V(FWPF[M?,.F>BT$ +111%<1^O[+(X)8\R ^(&=,'8G?F2"V)M7BR* MF[_=E3__8S+[62R6B17XZ<^)#_@%']9_^W)EE"M%.5VG$M["B0,]@@9(4]8;Z6J&X)8C[N+HP94@\N59P" SI*] VCN];>08,Z@[:$WN?73TLTW7 M>)4$\>WR2#V^%O,?BZ>+A]_^:"]\DZ2CVEFO!4.0,\Z3Q;'R,8S_XPYNS$/S M1Q, 0Z"CZI,:2@P]9OPIBE,!&?_N O>3#F5^P!^M&=C'>2NM_4J7?XS^FOQX M^%'3,^U]IZ LQ9A$-08A9MY&8YZXS9CI!7@O'2VL'O?[3:U_<_EV]K&R"* M_^>E,9I1;KSSZY*/JQ%2DUN[]VQ$WU1.9;MX]N^2+*"AT'@!O6-$I0S6DE?C MLPA<3B*>MM5])H*G<4D6E#.(9;)G' 5 )$I68R0BUP=FP*NZN70.NR0W [&Y MH#].OI7S?RSV/W"\;A0 %U)IIZ.9ZCC'RG!1J1\]:M?- .T!\;T5U4>,(@H!H9;2RGURA*^ M0=,JELFE 9FMG7"I&W3/PNM%4L;CKBT8<()JAQFA&P.-47>)*:_:LF-R03P+ MKQ?)"8=,&,TY@M80I+BOID0@/?]KC5;D6=/KI1F8%^'UX@RU43VF+(*>,@8P MQVP#H?29B38&O1'E\Z<[8'O@TG4QOTFBNBNN;FWQ;;FJ6S_6K_;1YXGMVY\: M?BD0AR1@T;0#QFJ K!1J P7E/'/O&O09_'B.=0ORB7VL5EO[;[>IE0N-!E(@ MZS32 BD7;9RH-R"(=H-Q# #?-(W7CLS 6TFSOE9<">-KA%_';_UKQX5L@R\$ MJAA!UBA) ?<(:06=JV9D+.GK6J5?3\H.!5_V(8;LZ*,M:?H:\*K91X*'#%@3 M#W7&&NDAMIZ3ISEQ[&'F=>[ G73[H5:GDLA):/'C1SF.IE0>K^IV#Y91S[GE M1'FC+-$""UW- TG35[')2V141S(XQC%$+1;%GIQ-2=SE?SWPTS=W#S\6!>;>"KZ^B.*]'LQ6ZP 3&G@ M(W:;TF!GYU^U\/H^GD]C'^:S-:?/?3\L_5,6-1B^O]#R1@ MR[$5W@(//;6"217/-T_82@PR;[L:9RBZQ*4P>&D>LU*>!_MA5G2U"MKXD;@5 M H<5%L8S1Q1C%&I:8<(ASZR\,Z#$3*?G]PGDU YW/Y6S][4*LDE:XVM!(("= M!([&5BR MAM\+FIO$Z!(46%U>OG,8'*+@>GB@__+P;5'\[T.D[G7M,-D']'R_101-?^GH%JI2P$6'EJE"$RZN$-< *; MRTD?.?1=KEU!G9:3AP/)#O4-1@!#B9>&>8D$4,PSNU'^2ES4E48[?Q'Y.#^?85=W"_S/QB2%E=K8 1' :ID@)!)BMH-)2_!/N:LF0? M_SJ#OF]6KO\A#OM6/WYICYH-/QLL=, @@ 7$SBE!&4*P LD3?/X)&WKF9[?X M]W&0N/E>C!^FQ=6M^]^'R?+QCV+YO1Q_6(7J)'/G_=\6JUC"0W(VY MP1$CR"(F'""E4042H!>4-6#HIF6/4NR!ZKM&>]#HW-\Q.*:\] A;91 4DG.M M0351ZDRF3AW@GM\/'=XFW&\3_.:>(&H>9S89_9$B%./O':CVMJ5MP$XA@#Q$ MEAGC@" FN?;*)*IS09(C[8D5;:+:(;S>QSTO"SW"_MUH\"8XLK:N+-C%H]= M/++]:6.W@&&46?EK@(95!U(^"LKFXOU2SHK]*4=?M C>>RJ,=Q 9@#1AC#A6 MC89S>OXU>(Z10-D&9LTE^)_SR;?)_A)]SRV"E)AAZ)WG%%FN)4]%IIY&0Q7) ME." EF9+$LS'+",F9/)M]./;:*\,7[4)WD@O,0720*<%PH8K68W(&73^AX*6 MI'@,:CT8X2_/.!_+6B\1N[H$S''<^CTW!)IH7#J+D*DFI[S+?+X:8%:6H9\3 M6Y+0B>AW\/RWNU-0&E/+&-88,N@1Y#Q:HT\3M$QDFGT#L@[:$W$-SF2!VGSS M^53.;M9)T%=Q9WLWH:UM@^8B#DD!12@AUE -Q6;2&I#+<;%H0TIENVCVH"4^ MI]J1!W:E39O@XU:JF$$622LQ5P:2S?")8IF62>.PN-_;4*Y(^F+4P:>=%ZT" M2^\#/-I\'#,F):$<;5/Q.54-\J27=D>='TP8%VRY3 #7K8+2AJAF " :>8M!%!5 M3HSQ("YA9BCJ@&XM6F7 $=#UP(#N-\X#QDH_ P@6&2J]$I!0+%E4Y:E\9:7 M*'IE O%P-P28]1X*F+_QLM&X'H$S0PHG0Y MC\)#H]HQ 9G9\LNX +^?%ON+[;QH$0RDUF,N*%%Q]I81PE$U&NSHY3CJ=RZN ML@V ,UZLBK@LXDI8+/:_>;QK%ZP6'@CKI?32*2>]V;P!0$9,9OZI =J!?8K^ M6)A?$6#X3TNG@+CO1_W1PWRT^+Z<[U]?;YL%RX4U$BODA3$"8:)X=>< *3:9 MI2 &^(;4I^R/1+FY]/_QY9^3V?AZ7OY/<;/<[4*]JVG #DEMX_PX48 #XY'2 MF_%!GWG=,L KW#Y9T +2=?3L@*R8XV=]>;U]0"O OI<42VAG6&^3HJ?\9<_3W[.=K]B;&\8A!82"2J< M4P @Z@4#SQ/U+O,D/,0L9GT:L,?BG,>!@[*O7G3C1J\-TI#$_9YIBP2L^!B) MB3,SUPU,TQ\C@[(%V)J+\/#Z?3D9:H!UDDM-G<72&2+B$>EI- ;E9CX>T,FS M12'FXW81SP\?:]15ZW$4 1JI,<14 @8=XU'#PDJ$*)XW,NWY >XYOQ\B

MX[.W5G[,HW.^3^P^SE ID,IZ,YH]/58-V^C/7[!^8<@RF',P& M8\VI),)5QV5$/+B<6J>#I$?9O<@R?!8?TMY2/D7>585H%E_*9WC?>B[N[A&H MLM0Y:3D03%%/H=75:PKR-/=T-J"M_5P(UIZ0^GY=W0^+B27E3%..%CW)XI?S? MI]3>PN8:O8,F4C!I$ 8&2&VI%%IO5K7#?=63^4W<;@268U;67CS)?7[UEW<1 MT%RHQ4N#&L^JH6 M\VL3?8"2[B.IS<./']$VO[I]SDVQ6!73^?I]-'OQ=Q]FGXM5I9WKT3R5ES"C M^3S5'ME9#[S='PA"6*P!E!9Z:+C#VMHJA 93IS*O20?X2#+D)7)2F3;?+CX6 MRV4Z,9@HWK 6N76 M^/PEK\Z.4]L=2*L'U;N*Z_OPXSYN%VF YOMH?K?79M[>(7C/+>5$,:&(10A3 M(JHH#AP/Q9GI9<40:\T-F8BM2JFYLMM8'1^C+6[*Q7+QM?Q23*<[%-RNYL$A MPH3Q@C/!& $$FRHKC<5QV62&:D+NEZM!R;,W?[D5TME_/)MX=E\NI:ED_W_5$F MTU7AX_4@=] V_X.!"Z@51%00Z[QR1@A3O:%A9DAF,@OX^S&H,6=[$V(F8=]< MIS_#% GP=Z!\.]Y=![9RW@0"#/4)48&%NMA-ZV"L%1#:PSUR@"%+,6;+*#8@M#2E?A2;V:]?PC&,\ '(P>VMW;OWSJ_0[YN%S^%L>V%M>.I%.S<:H] MZ,MY.K*_4,6;&DB-T+3%&J6EC=N-UQY[ZSTS!Z. ZX6T%C^+.)ZUP;9E>/8A'1RN M5Y?%FI[;WVA;^G+@6!/$H*20 80%M5SP%0*1YEK3BRH' MV@TURE,*Y%1N!J\U9XN\[N%7X_F(.H.UXIBX:+(2!+FO();9)7 '^)[7->>' M)ZQ3K8A(TCBD@0M:UC$;8GX!!'F2EY&[]H]G'9<%*" M=RV9(5PJK'*L_&*7 P)H)612,49&4],1Y 74CDJI.:/J4(J>C@('\VYW,F[C MOD;YZCB)?^V+,NQ_- %!!XS!R&D)C,*4,+H1"U4TUU/C_$]OM?GZ-JQP\$+L M2 .6-P]IY'&T+LXN)3>)1\\?KQ*"U--TVU_J]WQ^C[:JVS5@J3#65&"@'70* M2>#0"D($F(B[V&G44T6'U8:Q3W.\:AB(QT@K+2A P#I(K86NFHRBN:'X UK4 M[8OU[2H^!M#:5O.BN/G;7?GS/\;%))&"I#\D+I 77(A_%3[&,_UT/9/KWC8<41\EH[(5U/K(8U$1>?,86T?G/[_< D$XP402 M;3SF"EE/-X@8:')?Q(=#@Y96?&L0MK[PJTWM:_S\CH7_LDDP*0T\B^:?=DYZ M ;Q K!HN$BHS+=J %GX;HBI; :]U6:LXD'$:C)^.MKDXOVL3G.7")<<>KS!D MF"JG5#5@H''F%>N0U_=QTCX&OA MQM::YPW/7DX.Q)87^S$H=D8#'P_RH^G_5XSF/O[-+IM^1^N J)8Z92J'E&NH ME$)8/$U"2$$S$UX/,":L92H=$"(?R=8I\74^2K>$7QY_?"NWY;UYUR8(:X&*IQ?,"?42$D<@ MK@:L<6Z&T0%FE6M)],>@U]%)_W-QEP(!1K-EJA.S]\3_NFG0%E-.!+-,.ZRL MB";L9OC 8I\G_ &&%+4D_!9 [(@#)LYM/II^F(V+O_ZS>-Q+@C=M@]&&4FJ@ ME#)J*X4M@+:: ,013=E9O M(\!&(*0V;*9$99H" XS0:8D,+0'9D5KPDVDQ-W$X=^5\OU)XU3)0)32B!!@D M*16(&.'<1J=QD>N*WC@ZYFQH<#R(76T,Y8\?Y>S+LKSYUY?O$9'%U<-RL1S- MQMLCX^MU#%I+' _ '&N L''*.;51=H2KW->AR[TZ;!W3KNBR5F>?B_MRGC)[ MI^GO/%#NZQ*/[8!8T<\^&<8F'IPB&0#9=I57$%EAF\N)R+R/;A+,C M?EP_?)M.;ORT'&WSJMK:+G")HL6L$+"( *YTRD?Y-'!)6':.G^TX0KP=0PU_Y%U= L4$,$D\%C3NN\YZHM=7_"F+ MOB:'#D+]3+".>_#./H$PH*/2X,1!+SW@@$I835$AF7D).$!3_G@AE]U@VL]2 M?/O/UV74')/31!*TN42UP @XZ1PV&J&H0@VAC$6MB2VQB![B;S\37(']F+-0 MW_0,V %/I7&$0:R$!980MIHNH012D&LPG=%RK2WP \OU.&3[6;2?1O/DX_^S M.&%.D%;W4R0PBW@Z(YA(B2$U=)X) P2'U(G3+-;GJ L5C:KQ9/J0$/^2$@E. M4M$F]U>*OBC&Z\PT/^X?UD*]NGVW 1SRM&_UAX)CTEJEXUG0>3B^'3J<3_MD[2$>CWX5">9JA'BV*<,"AFBR?)SD>SN]4!=J$?G]M< MCQY7 35I3L\3FXVOIZ-9>B??&8_0Y<\%YSF#SD(NF>8,.^LBP$^@LFCQ7PRE M,[GT5B^>7@8]$/MSD?)FWBR+\>HIYA^SR7+Q^VCYPCQ41A GM MG&760V%H-2U'0.9&/<2GM6%LU&U(H0]R/8WN'[/%?7$SN9T4X\.[[JX^<0]! M3FKD5=Q%E"(2*@NJZ2&8?2,_0)(=)]UW1XMV .V!+]?STJ>@YX,;W^N& 4 # M2(J7(]8IPYQC!%<3H81R5PY'ER99+K>/NH:X!8Z9XRH5E/$5>.Z.M MJB8;K=G,**T!:ME!,*86B[.ETP,533G[6EX!56#,J-YN4 _IR'HC;$WK9)<*OR'0^9[G.T#VS*X CU=W'&MD]VOJ) M( 56"EI'O.<<>N@MJ=0G1DQGQ@$,T3GO(HRG7,'UP/K#]3WB)/1H,;EYY3>6 M5=SEU9<"$I(IIZ@76 )+*5,IL^@:"FE)9N[5L]F^NB1/XQHNQTAF+TFWIOT[ M/!Z;X-I9OJIV_Z"19=@"3@QPP -KA>;53)S.+;-[-IMX#QSK4A[#W_37=2Z[ MV_'7WP]<$Z443DY/R;O*",?%!C9!,H^< [PK.;FJ/(6\AN RL.ME<%T+^V4\ MW+K2X3'^ DU_*W!#N10*6VF(5!0Z G4%IW$B,ZIQ@-;NR>E_:MF=P5+X[WBJ M+<8I/^U?]T4ZW'XMTU_UN4+J#B%0"X AEFO&+'0,0@U9!3Z7*O.I<)#E#>?2Z<=___E>Z=VS13H'KRH(K(XL%^+?'W&F5E)""*:. M,\LY6I=,--):BPY%_7?MW[^BE7XTT]%B4=]9_UVOD*Z4D93IPL(P!RQ#7%;3 M])9?CF_,\8+>Z7E_+*K-[X-L7;^$W8V#1%IH#ZF(>Z)BQ&H,;35&H/SEA%^U M(JBR93S;D/G.E_E]S0.2"@KH)%?86R:8(?1YRNQ@B8_AR[T-&>T5=Q:09^L- M+B401DEH.8!Q=3 C^08SBD5?/G)='HG:$7.CQ]QFJ/9U)EF?K X2YEW; !1F M%,4)<698_ 5L?#4=9S3/O' :T+-!)Q0Y%L?!QM]1@K77@C*,G1#&,FET-0UJ M=>;U^X#HT(5MT0:40[@./(-@.NR1TR2J7B@9A-1%6$T%JES:1CT M>)L;HR6)=.*;^,M)X\R,X-7N_;27UW%/W-H^>.H=$1A;RE)U%13W?_HT+8^R M<\H.T/F@"^NG#4C[L(M7?@NINNW;,\$+Q9/JZE8K(+79+(%]AO11'PY,2TU3 MT5[&E20,4VIP!912%^0C>"1/WMKJQ5!86#.)-O _28ZUNA'0-S/XR;KTY%H^E338/54E'+N,M_>U@F4_9K:4;3 MZ;,)\,^4R7"VUX@[XJL!,&*P%@1+@H&/@@$,/4,D,E.B##!]=.M,[ GRH;#R M_2'^Q1G_6'+N_7C@DCIAH+-6,2VDP@H^+V/!,SDZ0/>Q$W"T3>2''&GD!(.: M"6>4T(0+E4+;JYE ;S-=$)N7["NC-,Z 0UV">[I3Q--XZQ1TROQ28 Y119P@ MFC.-35PSE7)70#J8J:N:%P4\$Y[U _-0SA(OIW/L:>+EMX+6GAFE)>'$"@TY MA-94<& -,KVL!EA]\ 3GB2. [L=7>G4#?O8>T!P8Q!$4R +"I#0($[XJ_0"= MEMR=V@/Z@!OZ2@9URA1D?C$PS85TU/_W8;)\/,G27OURG07]JF&P%#'NN!,N*EZEJ'$: [Z=R6=C)XF9:+A[J%0*J_8U ;7IBUMP2*+@ 0$B)*PB$NR!W MGUS1;_-+[ #9+I>DNKEY^/$P'46U<;7\7LR3\\.\^%[,%I.?*X/BE'%)F4M7 M"660M-QI2"E4S #@)0=_3RO0_H9_OM4%!2D\\$"K!C+%IWADD. M!2$N:V0*H?;AV/:^?K_/1;#%="VS\/P^+9<+DH%-PO0\$ M#CW7@#J#G<*6>D2@KB8.LB\F!\BF(^6^>V]K#]U^:?6I6/X]0E!=<]EB,;F; MK?3U_+\>1M/)[6,\%)O1XKN?EG_^WV)\5R/W;1N?#X)HHXRSW%"&%&8.:%6! M9@7,C 8?H%M79Y3L"_M^"6N+V\FL&.MB%O^P3+[ABSQ]6.-# 5A,%)8::L2= M%Y1;RBL@%)29*0@'Z/K5&0G;1[E?NNTR6YLP;?\W@D2G9&L58"'P:^DM3_6R4K=\%-!*Z2!!9#KY*Y!''745V P("^G MS%4O9\^.X1\.%WTY+Z+Y8!ZBA&?W:D':WM\5-BPOBN-\/' $K.8#,*DZI 8Q(\@R[RTRI+;<)9(>Y3?0(%1V(U8./Z_;DZ.B^>'RW58GU./I+N MM;X=/$#:"0-2*5%D?#Q8N.KU'K.(9$]!6[\,L[N0RHE)O/<@N_UI]$AJ'_&+ M 3@998D]1Y^?C-:/05>WZZ>C M#[.(=4H0F,HWS2>SF\G]M*AF7NSS%&GYEP+P3 N702188J=Q-8"Q1UDD"!# M,WWCX/EZDG3'[GY$-)Q7D0$[FVA, "0"0$D%PPAI938*A&F?F5 79KX0NMGX M,IA_>E$-A_UG[FLB';2<"A%5#?%$,R9\]8Q ,,:YL229#Y"_V@KI57C#63-G MZ&IB$46>2&:YLD03P0RHWH>) BHW$T#CU\]?68VO\V/EK,CA3#%TFOEC_MYW\G(R+V?@: I^,48[:*2 M\AA30*6H)F8IS;V+&MYA/5>@;Y,*' ]B'^DIWHSR<'&\'3VBLK(I.Z?WV"$= M-S>+-*ZFIJV\G.++QPGV $ORT#P-40Z7N]O5)VA+A"9&42*MD,9#K=UZ>AA@ MW5M!L?[)TEB^A_F2!6G_C#EMOO9D@5I_TSY6"-J=5>7P 7UTE"FI/?>(2I E,33Y)RR%U2MM<-M M*!?.'KABUKGF4U*_S3&ARKB9+J:N1Y-MZ=R;= \2>ZZ4DX93:)CF'BM531HY MEWM%/W@.98C];<&[]N$],:=L;RT1T*1[ ,;%O9Y+81&W48-;0RH5#BTC M?050GF ?ZY95F0#O9=768A*KGY\7]P_SF^^C17$_+^_FHQ^C\7B29#*:CAZ6 MW\OYY-_%>+2JO[>%,#F?"8ISP! #VC,!O23,.+@!#?K,U,P#S"#3&FUZ@+D' MI?1U7HP6#_/'U4S^>S1]*-3-_SY,YJD4[B*:Y!.P,AY>DRT5&, MO & 5I,F.O?^=8")8UI721W VP.GGHKPI%?PSYNU<77[0K_N8=3ASL%C+C2C M1$14F7,\FI\;':R4SO3H&6 X7NM\:AW!1]SI:HH^VR5W@+%OW>JCHU#MFSC5,)]J\R3U6=EV=5FTYQ.!2B2$BYLZ MD8IZ8[#6F\L.2E1F/H;FE;G.G%+M0=S'?5(:\;,:O5X;?Y^+=)>60H$VMM]S MFW7-;+B'X+@1IAF:/Q1*($ MP@!BA6TU=:9!;L*[ 88^]:21CH6X>Y^:3\7RV?/G=62+*A:FG-^7ZZ)T9^AS MXZWS1"@4+3V7R*8 GS($;*K2^79HIQ.QFN1%8O%U^^CV3^_E]/I MX]6?LV*+[Y/[#+"Z+8K%<.]8NJE"-Y*YUR'&GL]\, M0%$##$0&.P:5UIYRN($89L?J#$]AY%+KW97U,"31Q[;U7 %OA=WZ\NO#[&>Q M#J=X_[=%\6GTXZ"?T1&?#[2Z(V+7< M>B#WKM'6++JSJV/@D$'N@6%"$02AH$;R:J),ZLLA:#]TV%JUUFU%FUI5S MW@EJD37*$^2XE-:+:EK&9J=5&1[?6I)NK;IRS4#M(V9LXTF17+H^S,SH?K(< M30\7M=G7+PC%".<1,XUU_!,12#F@(-.<:L)S2XL,D#M'2OEMO%>+H/; G<_I MABDJY*I@^D'2;.\0 (5.*T:9!YQ(+CP#3V%K1#%@+LFEKEV^M()G+WZ9[>_H M'VLXEW?ZN\%0K026$'-D%>$:0[J!&1F5^8HS0(>^X1ED0Q)L#^OGU9W_'KZ_ M:A<(M)0"R2 @Y.RH_LZ_E M'Y-9.8^S7[V&QB40I;2H\?32_&.! ^LAC-8'<8XC:80RK@)$\-P3P0 57DMT MZASB/E1/&1?$;!G!BY^^J]1G7"7I(;Y(,_LR2I>":SV[!JYJM4]3'?'9H$24 MB,9*4P"HH4I*)BN0TM*\F--%EP1ZJ_KZ$T@/K*T@JD9HB^=Y?"[&Q8_[5<&+ M/02M^86 @<%< @R!T9ZGK+MD@W>TNS.C.NIOLGVG2.Z1DMV(H/DK0+)64WJY M*(XXU?3KVQ?+-CHUZA\@L)\$I!:B&7]"DK(M$*HDR/Z@$&>;3 MMA.#W[U;V1MWN+R,35N7Q_;O[SFA'.X4;-Q",'0 1#DJ00Q2!'LF#-#8N2C& MTSB*I>)$5[>O7%0/.GKMZA,P-CC-C7,J<"0]B=2LIFA-;[6,NUN=;8KY[?50 M2ZCV^5;\-.9UD$;-=^*W?8( G/EH9W$'">$L:A4IGJ;G/8&YF22'0YH6);SK MC?=(4/NX3G\QPH./N^\;!VFY,1("9Q67G$#JJ*PF%$VD"_)9.EZFVS5+/IK] M9L$X^"+WKFT@7!!G4#28!0 NZ5E*J^D@@2Y.A62)BRP4^]AGTLG\?;C# M@8UF9Z< %10^'K@)DLPS93Q0SPN( G0YWDCM[S1MH7HRVAQ.&+BG6\#(46^0 M%-0)R@QP\6!>31)S<#G.(6T(NA9WLH#-R)R3?OQ=+A;SP7Q[>/PVVF.+U.\< M"'3IU8TKK9BSPJ4JK=4<+,69EQ)G0XZFDBP[!K@_;\4M:K:.BT>-WH%YFU[Q MI;=<4 ,%D,A54V;$9*:!&^"[9?M[5?OP9JB=T;0H;Q>K8-]OC[-7%VJ3IPNU MG6'8S3X0B%0^+@HH( 8>6^;A\\)CRF4^YPQ0_;0JV+('K+OAS7UR"]J>H:3I M)P*S5$J,E 6*&"44=,2NYT. R[3'VQ )G$'-W8=@WR6R9,H@4 I;01@\11) MK*/*5U.$W&9F2A[0=M7AS6][N%Y8^J2X]6M.<<2 &4>YL-J#S;JQ++-V^8"> MEOLB57L@]\VPCG)/4@"$X=AQE1Y5#4$>Z6K26N=F%!C0,W)?S&H'X"Z?BC^G M'+V+Q>1VH;)1BAU&D.AK 8B[@U0.> 5TP"%8_>[I![ M=%0(6ME M1).F=YK5Q#6 !&:>F0;(IB/EOKMJ97OH]DNK-X62;;&8W,U6NGK^7P^CZ>3V M<3*[>UT^N0GILC\?%.( $4RY%X)YS2$0N@)-Z=R[H0'=,79.R;ZP[Y>P;XH8 MISK%>?JPQH>"--ICIN,Y5 HEG$($JN>5J_JJ9'*Z>/T6:-@^SLT?2-2/CZ5.=X;W)K[*_%Q#0(AZSL-%Q15%CF-"HFBG5N5G4 M!G0[V2Z?^@2[ESPB>0>D \?/8SX; '!<,:,PMI @QIE%L@(I%8.YF(WV-*?3 M'F4S8 (?/.4>]^$HG:@\#+9$10N;6@(8W*QT3/WE!$KW0Z>6.)PEG &SN$;: MIV,^'!A&R4<):^:T\<)[".%FO_+L_".A^B942SS.$L\)>/QL5]>=V<<:CHO]CW'KBG5X .I2P-UD AH4&6"HRK*3*'+JE2^TF8\?;2O351]!); MME@F?]'1;/%CLDB'S#TD>]\X.*P514C+^%]24ZB8V^Q1B)C.[R_[3IM=CUO!P_W"2DW%_W$88Z.NQ=GP"DDMH3!KCD,E6U,\P\30\B3CO?3W]% MEK4EC1[(MM:S4S4;J_&/R6R2O#V6$8K#E#O0,SC($75.6N0%-]![Y5TU5>Y) M9O32 .\QA\"X=H71 ^\VR4K9[J/2B56# 8R^D-0XZ0CA1CL'-%"#+W!<;EV7^52S[?.A[ M8,^GKXX;L[OT(+Y(CT1[*YGNZ!& 9Q(BBCCC-)J2 %I9.7)$I4LRX[D; M5V;^55C5CAAZ8)@OY\7D;F8>H@AG-X^K \AH91E6#ABZN(UMOH[^VL.Z!E\) M3GJ*%1;),8-KR*@&I(* *9&9/[%Q?>9?A8G=B:878ZQ*])W<@$PYB^OI(2ZI MJ_NG.YBGP5<7D'\5B[<)2:/E^?HKVRNC[=.I/8XB,(]2_ B7TG.JK7*&\4H$ MD-),(W* 5:>'L#:&*]C>UE:?7X2VQ\JA=_5]K.+=M;(DE_&0QPB3A#I$)09L<^9SW.;6 M0/O]%E)+:[8CE4'8$K'%]&$<_^HZ>>U%<%^E#]Z>)/@HLR'G!T.J%Z4]4\I; M:X1F#IKG&S."U@==K*X64\NHEG-K3HA7,WBO[XO%Z/I MU>W6AI^*]'BU]XC8S@\$J1UWA"&)*:).&(S4Y@ -),NMSYOQ;+2\>.Z?1&0] MC7XASV; /PH+8 MI_M=;+Y\/,I>./SYD-+8&J^UC*O-2D2(T]45#E(D^RSV^Q7J.".A=!X%N='=]=^O?B%E>0SR7::@67F"GE6>&4L( MQD1HKITB7A)K.(7:48D,H5(?RG-1*Y+OR\WW8OR0ZK/M+5"C9N-ZY6E6*'^- MN.KX\__:,M?N?S1H R6DQ'/GB0%6,*E,A9L7*C/#^ #=_G/Y4@Y4%'UDI-G, MMXXRC!KL(*%;^G(@''G%@?%$>"F]IDR3)ZAH1#'32!K@#Z>6U/-S_>*?D^7W'5O! M&6;V0TQ9':U3'/D%2%"6JHY MEQ!*(O5F:HRZS%3VPS>*:HOT0 W9'!3/-L.>!EXJ"8VS/$[. HP,VH!&W.58 MT$=*N5'FO&:@GDWF/$HPHPIQ1"FS!!+B&:BFI?+O5H;'E9:D6RMS7C-0^\@8 M-1Y/DHA&T^O19/QA9D;WD^5H>CA!U+Y^ 1(3K1='&&?2&NR9KEYA+ 12]A4P M>JKL/;6E_#8;5(N@]G*PB8;@K!B[T7P6#<3#">^V=PC2.LFPUM1"[)7E'%11 MW#9N[C8S7_A@3\AML:45-/N)*]ARC#A(EGW=@E .($MX-/V4E]Q Z' U2<38 MY2>=["=6;2HP'J MEXZLWB/ [.7F=SVZ?\P6]\7-Y'92C ]7H]S5)TBDM=&8(6&9\I08+V U/8-4 MKOO%\+ARI'3?7=JV VA&RLIU>8S1QG1:EXU:?I^7#W??8W.V/T-ES>[!0FN1 M%,8AY+P7\12 -^< :R\H]7,+HBP[Q_=HGKP:ABUN5H/ ,'5KPI>#GPG*&4P- M0PH1!)4TF%?/[7&I<9$98S/ S:=3WK2-<]MZYM60CM$XVSX4E'4P@D<1H8 P M!ZP5F[E1E/OP/<"7F3YU3PM(9[#(??G'E^?(A0^SF[\]'_J?__[J?NW(M=W: MS?M08$!S295F1,IHYW/@?&4'(J^=OA@6M6,&]X)RUPS:6X [YU,!8Z13%5@J M!0?"$8.$VXM S8S\#"(93;QV1<;=' MD#M -)255)UQF8E$!I@]J]V;FT%*IY^XLOI3^#2JD6X]\XL!.XNI58PJX0$R ME$"\V0V@L)=3'W%H5'L?5=:#_)I;<:M,=5\>OBTFX\EH_KCWP+BU;>#0$"29 MBX.QD "(C-ML>)C@R\GDW[D(RW:A;DZ&_Q?!'\WV08SLQD4%80\OYV#?)Q_: [PY/>*P)[/)S6B6*HM_FTYN]E)C1^M@ MD/0^'E"$8XH[2"FH,K18K$UN9< !&L]]TJ(=L)M3XH_18C*++6O:#+N:!PV( MPU3C1%YGI;7.57X#F%F:^8Q5/V+W(DG1$MJ]ADEM3Z7S_F^+(H%SR._BB,\& M(1BQAB&;DH%39K%TU9T[1MIUGLKX3 _Y/6+>F\_R^]'6=%[>U3$X@:PF7DFC M*8/>6*$V*Q 9DVD;#?"8U \=MCHYMP1^*V\A^Y]>=[4//!KXS@B -;8$,VFP MJ0Q^3!W.=$$=($W:DMC^5XPL5.L\50SPD-H!HEW8$^=SRNL T)X.[\N=_C(M)V@5)^D/28.3%YA?_*GPL[D;3=5:6'4;6EE8A%8%BA%$3L>!& MNG0OL2&"S$U#V3AO_[G83,=#V+K/LDWDSLRR: 6U4UU4556_XNBKZH6SN^O5"%(,RVCV^''R8[(LQGLM M]89?"R"IRA6!C,Z^U!F0 9)F_ILM'XA]I-9 M>CHVY?R^7%_+[7\0J=,W&$<(>HEPU PUM9IS8@.[ 6^%%%U@V M9X,9W7P?W3V,]HK]=:/@*!54,$X0ED 1YZ70U9BXEIG7.P.Z.VQ%OD>!5F?S M'-#!H17 3N,'\&[+?O9,G&RN5\J#KN%-/Q,,\4QS3SU&C%LCO3&524 8IF; M9^-R7>=RF.P!XVZYL_>/5)I&[I1+JRWG?;D&ZVXKQ'@UIWV$-^SV93-3%D_'3/^RA4^XG M@Z$>&*5N!0VUNP>@![7S=\:TGS$_BK+,*R/LS'IH7WR?WU\7\ M)@GY;E\VT]K?")1XYQCGB!)')69<(K]9CQ9<3O1[^Y3K"N03F%1;!JT?7V>S M6C=I8'+5_F:03FOC-'#*Q>7G-22PND1BT-+,W-@#ND?NCH-]@=X#)Z_GY4U1 MC%>%=^PD+:=)-!R*JUO]L(@XI:+K>]A7HW>P$GA$@ /"8\F]B'^NEB$SBATJ M#3+\^^SN>-8^O#D/6F^BTT?I<+M8'6SO]^V*]3L'"JS1QA-@H, (4P$WU@ C M--=I8$ W^.U3I#-TFS/DRVA:+$9W\V(=+OOP6,S75RC+\OYA?O-]M"C*2D%. MGB9>_!7'-UD4XQW$.>J;07-KD&** NSC8K!2;(X[C,;3S\7>_A_'ISY!SZ.9 M>C6X->N_EM=/@]MLPQ4G&;^(6VQVW/*;L;U[7'VJL%J6<2_*9;/]4;2(?C'_;18 M[B)?![\4$#38$$HYAI)I(I6R&VN 29])27GIE#R]*)H3-142+I^*"*^V_/+V MR[*\^==D]OS*_[FX22(<+TMU_<'LX&'S#P5I".,80<$@Y\HP8"BKYJ84RO1! M@N#2>=8YU,?8]Q]FZO8VN:0NBRT'VB_E=)>QUN03 0)M#&%=Z< M@#U1N4D^+OIZOV.0,UPSG@^CY>8P6NW>U?]&2O]/<;-\+NRZRSWC_V?O7;?; MN)6TX7OY+F!OG ]K?7]PS'B]3IS73F:O^87%B"V9LV520U)./%?_ J2Z)4L\ M=(/=8)/./L2RTN@&GGH 5!4*55DO"T1(!JBR@A-!A1,2P!I$QIW)O=]VU7[[ M8G#W1*FH]"V63Z<'*; W=N3WARBO"%CU=:,_+FY-M4Q%([X[]7)Q@MS,JGG\ M_]Z0LJ&^%X7"L28, H8X%QP#A>H5FR-O<\N77;5W?TP2*>!UW:UIOIO?+*LX M^9*[+UD\'VZW%6VW1Q[U4P?\-FCL,:8I*,4##9@D0/@&) -SU]/.!P(E M"I#T[ZHM"'WIX_E?%NN=)[I)F4W%:C_,Z\?;GLZW?V/0PL?]1F)EJ;> 6 CM M,S30Y[*R\_'!9;*R#.IC.3K=SJU3#TNW;PDT&N],BL.MHJZ^C3.YA>C/<#K;B\*$CNC<#(PD758(R-]L_L MQS)39,.K/E@I G59SCUO%A]NFQU$5[>+9=69=NW>%9P!D,"(+Y264^.L(K#1 M>Z)>GLF\JSX_*87V",BG;M<92UZK5P7E"70BY4(BFC%K%<:UCR+EA,B,>D=7 M?:12".P"S-M3)CGJ&E^BFI$&=H!KQQO'J4:LT-P[+13'2 O#ZQ@@89W)O,^( MKOK493!X"_ IV?0?EENK_L7L>/?BG/$ H5JT#B!5YT5"\+AZ.\^DUJZ90@G> M3$9=]?'+T< V]#<39?PJ<_\* #076$H8Q]E0(I0WBS5B!RJV6_@.< MF!2"?"!ZU1E[%FE-G:0S[OS>_??W+I]9O@(M=_L?-XLL6:S^9+?]S1L7SP(9[J%D !GH(I%)*L*A5"(F0A]K1"*KG MC!_;:(L;X_K*L>;!<4HS#M>E()J)@F@%-8#S7J5+E'Y^.;KOT(?#$< MM@//S7?S=%:?CN^3"_3G:I(Z.U7KYR%4Z\GL?G4M;17\VO]ND+F@SX /-@Y+4>XZ=H\@A3B637M8# MQU1DWOZZM!G=6OS[9G1_$!

:9D2U'":BL\R"Q5T M1GG;X&AL=FC5B-G4B^#WLZH'E$L2ZGEN)=U6?5D\Q@WD:#V--LV#$(@13QUG M!D!%! /F&4R+KG"A.E7ZQ[6/4U$N.DT0IRYX#Q"$C@:A!\5&$R77(_)@,'1+ZLG=#\^!^S:AD__?G;^^IK M==_>7#CP@N"I5P)"8)QA&% L!0=/ [=*V^NA7"FKH3^P2[+LA;:[>CN"]E9$ MF_I.N=CB.L>#U$K;.O7H^86/U*?A^_3H;Z3&Q"66QZ:A4\4D(2 M2!WPD-B4**]12:T4ZGIR7YZ/37E0GXE-.(M-N)XPV-I4QA%@3RF")FJ9K!ZB M$R9S;1IA&,?YV)0'=48:G$W)G-GD_NA)W;MT-7>ZN<*0(LX7][-IM$BF+Q70 M51.-L">^8Z"O!>>(CUJNL901CD1T0C4L'T))AW^C,&N++KZ4X"H(-1O9,.9:(-E^M#I-Z]X.!21F7 M"LXQAH!88[@TIAZ(9_[RO<=C(,'KZ/-31%""2S$6P0BTI/[@WL\;#M5!&_9DJO>);)@I+NS3Y& M?&WUQY'$)B^?#%9A+H5 !#(".2!.>157>0:!<]'(RCRL'Y'9.L*%Z#09%*#3 M^]GDC]G];#UK%:ZWX^D K6&&:99J4D@"@*1-Z$,TV&FFTW9$YL((:76Z'+H; M!R]Y_-MBO3-QS<[G K$ZVO!"6\6UIHP"RNLS-,>]*;4GE8P65 L+ 8+< %=J1-(3^S^!)% M]SDNE7' [^9QV:C>)]DF,1X.C&G3/$ J4[W15(1( 4DP4A34@W94Y2:#&MF^ M-!KJ["K5V*^(1L#+HU$T[5X0 "&:4\R0CJ-%T=1D0-<#!_&?%\_-86C0D6-9 M8'1C6O'A[^.-L]>\C^MNA9D$))BA5PB)E M 8H NW2K8#M(R',3=8^(::/6VWH435'^I?SYR0#[+7[ZJ)9VJ%EP2#"E&)/1 M? ,6"&X];@8IS/5<8.M'U'OYJM M1"M'*"3(R:>A*>;@Y<<.]"O@UU?->D&U1%#I=JMV?]U\GLSOJM:T.=@N&*6( ML, :;*6#BD"K:@-(00URTQ?^(.3I$]L"%*I36'V((4L\_QE1*>Z@Y*G-V!+[%;+Q6IEGJR$+!JU?$-PEL>I BCW!+.X M!#-(?#UTC63F@C2B,[UA=[-!4,X($A[.R'A_+.*]P*=#*M*F;4KS* T&"K"H MHC[A9Q!UF2P=T%WR[MW\YOYQ6DW?S=UD M.8^M6V4;*=JA@+3C2@O!"=9:.&65,;5@*/.92ES[.2>WW:4PO=_*764< M"=^'G(Y#L>#JIN?^0\?5>*;LH4X&9H"AF@EK!(3I/J+A#=\P'SX)T=_3^#J8 M4?30\$5IV.9W$; 6L<"MWQ'U(F6I2BG)HT6!!).P.<(PSH'K<<^.?$8,);$3 M_ XOLVO\:[;^?&SB?8_9Q^KN\3Z1Y=L;]?V8#V*P#PO%]@;8F6;>CIX$[;'V MS,8UV5'&/8P+L:A%P0G,=)S3O]6R$4V]T^5^+5/PP^/ZP^TXYN"+K@2@ 5"$ M: BYD1P!Q.Q3A(7&%*#,>B?L[VUPQ',Q7_XCGXR[E?.!IMONCP7$J$"(DJB] M1^$[X8"WS2%,U/'S)A3_>UW(Y\JQU>+7^+[%]-W\9AE?4-EJ^^>9 MMJ[=G0F>84FIL89:#F4T\('C3< P)F'Q>+ON3:B7:L7T0^<7..7Q7Q9#^JE ML^C*$FPHC)@6!EDJ$;7I&F;*,"TYAD)11X]-MX$'.F")24$(ET(!1##PV@-B MTHW3[<"A\U=8N>TD\>>4F.P&<3-Y=<^QIY7)B6.]...L9BO9_/'.+R':KGI^.H_JOMIU"X_ M3>ZK#\OXR,-B%?_UK?Z6?G/TKDSV.P,2E.,(1+I#*P'6* +T!(\&BAW+!7:! ME#T;P5X?\A>260%*N_]YW!@NZ\_) /E:K=8;K?YXM<)#[8+#D,@H:&0(2:>_ MSF%>#U.IW/)*([QI.CIJ]BF7[C$G[Q?SN_?1+)YNX4@S0LVGO\=Y<#!MS+%F M03D0]R4"*-.<*T*I%RGQ6+ZY^S^_NCR]?V# MP1@3S3Z+G-&"<6:@]*0>B,8\,ZQTA!=11\.O7@11UD3>5>>]G:&\LT*\=I9; M')4 R3SR)&[_7#9#U;D.ES'OD0.;RSV@7))0!^JY=W->OBT''^<.U-9 ) F% MP"NAA6@&+<7EESSJ7?K[6-4?R@6HU:%6]@&&=:FXC;647G+J/!9>$2L1?EZN M+;Z>XC+]$F)1"O$2V4(FR^6WN(Q_K![B,**NN($DAW@=WQ1,TCH]9E)PG3+. M&Y9N?&RA$$A=C[]Y$'Z\3B8R*/@E'!FK]>S+9%U]N#UI]>ORFL 3W".T)%'AM*K^,A.CM@&O@+P:G + "&P]Y-*ZAIA2# M&BTN;&8,[(@VRWZXLHMX9Y?&=]R],$F<$[PSN3+;>L:?SHJZ>L:_:Q:<5"*I M7)(@":V-%JZMEU2#ET!8&ECB%IK8*8+:D1'-V.C8N\R::/>C.C&XUCE4>8D;57=_.-N\?6? MTVJ6YCQ)/Z2I3EY,]?BK\+ZZF]R[N%JMO^VQFW<\%>+ N8?6>4&21\ERY6%- M'&6/1E^/?S(/:BZ?CFCO--CV9*_5^_J1( 0U&'!CG6486B\QK\EO063PQ9NI M)\EHT0MJW=5--UFM=36?VE_?']0EWSP75%R[$%+4.Z&LM,I(7ZL?EDE<2IY# M)FK)E\:B/^0R9/K'X_JP[?GBB<"!QL(IX@P3T%-FI'9U;R3QF>ZC$9F9_4@Q M&['N\OO]__QK-I_^4OUY.XOJ_T%![GHT< H\<4)#Q+UBBM"XS30ZFG"9,0(C M,N%ZD6@/T.6*UJ;+ZXN'%-#PZW+QW]7-@>B0%JV"!YC*2$K*(<-6&*5$0TCA M:.91Q(ATJQX%WA>*W67_?V;WR\5B?XF--\\$!CUDCA.)==(B8"IFVBPTT%Q^ MBIE>Y'H*9MVEJ!]O;R?WB[O)P[MW[P[*3 1H&G44:>RT(,]IJ7_NBG78X M,S*P?;Z2RY#HZ<@5\'9M4I:JV]N-O7_ $WOP^1"M ,,,A@! 1'A<;Q2H=4$G M0&YRSQ'EVSB9$'WBUWVZ?UK<3Y:?'F+'#\[UUX\%*5T<(]4&NOA*(Q@$M8'O M@%&92MW.6BC!S>/!:0D?R43^ M[7'Y1SIJ/NQYVOEPD)IQ!!7PB"HC,!=(UI?%?-+9,V5[=%1V99"I:JF=;\,HKD9A*[-PW0B;AGRG-U'#?_C M;'I7_;KX\\ANNOOAP(%"0@FAF*:,DKB2N-KEF8Z58:9L.WN9QF^J](%?QJK\ M[V7L,:\R9"F"G=:W(B]81==]G^G.Y:Q1[_ MYZSZ\Z!DWSX8!+8"*Q8M+\\9-4"5O)6O_[6_/@?LVH9/_WYVR8- M>?ML$0=>$-(5=H09EEX2!#2.!ETS<(!19N#UB [[2B>-Z _LDBQ[F8#W[0C: M)Y%H\YY@6-SW&/7&20J]87&"JBT,$FB"+C\F;RA:[&/= *B7)-\V@_4&#WCT M0/- JT %-])P2RW"% #'%0#U$#U6N=[:$1.K7\GOX]?)4)^)32B+3:@^Y+4$ M*H$Q,A;I-#).2#U$$'6]BP]1/#^;\J ^$YMP%IMPK6'Z: UHHRVBB'E*N;2X M&2(2F2[J$7FHS\^F/*B[VV$G7-99O9_--XE^CB9^..7=05A%G7220PVYMTC& M%;E&@$F;Z5T=D>.M7):(@G(XF8EJ/GU1*/5 GP\4M>CCM0''*4%\/)K/YR!(OO).;1\"NRWVX'L2,_S<@P'=MY6[8.4!B.!#9=<((P@ M;K)V2!AMK\O/R5^6'(OA95"*>N^^/,1^)U7%?)XL[W:6(C_<()"(DC#248,$ M$X!Y)ET],&%,YKWQSN;"D >:YZ?7J;"7BM".PU]L,RK,[]Q?#]7\8!6X?4T" M T9CP("F1$5PA#:@Q@H"#DL9#5?+J9Z +\"J^C+^\P1XOU@=6J5V-PA:<(@) MM 8AHK!2W%A?#\Q2FLFH$874G)5/O8#^S*;!Z^Z]54ROK/H>A=9*;JA)=YP- MHQ!2'DU J!A3AP-P![<';"OTEXO[PU&66&-5 PP:QA$"GM1CUY"DWL,/)[) MWB\'>C+_<[ OL(.DX6Q+6ES_WG@I\;XFP2"GM%&(0 ^I BHJ7KX>G!&Y-\E'1*F^ MA'N4*UF %F#+NWE41"KU\+!<3&X^O^WWT:.5=B\(SEG"M(7(*\&BW@:QAO7 MO1;7L^.=+OI% 8#+!DKU4'+66\")XEA"!;"E2DJ &O2X+>7$N=;-K2_@2_+J M"FK1:ND9]53J:,I"IR%"OM& N>"YUZ/&P^H>^56J%FTWF70_&ARJTP@1IPC35.ATY/0Q729:J((PKD M&HV*V /\)9DV8/U%'V>L9D8!3S3G5D"A:C"Y@U=4F:PWZ>?47^R&<@%JE:^_ M:%VD"9P)QP3)U2CG+P//#"$U9+#JB)"K#S $-+Z\-R M826XR@LA [*H)^KV)*[N=-X41(SV?S4UD]5G?[\XG#QIW^.!NG2Z:)C5V$&( M.22^ OGNNO-+^'49R]/%4$"_^SB9WQV+NFR>"9XY@H0A@%")61R\]JKN MOM>Y47$CNL1[7@LU%^A2/#FJ][]X*FA)- 96Q*5:.<00]:8.RQ*47%&$1X;4 M=LD]"[8"DO]Y-I]]>?QR5/;?/1>,0=%N\5XH3Q5D@@M?![<(0WUNRKZ12K^K M[!;]05>" 9._VC'@Y7-!2F)!FA$8$G,)W?XGO:>&I>/1[B@A5UY;A:N:@P;;//$*9:<]&E(AW!!Z8TS O MZEG)B$ >N@2YT,Q3XP5T&D@B4AEB\#POW>6'%?3#E7[\)SU+XSON7I@DS@G> ME47O5BU"/O8V"I91Z)6-_$>*&8 \:.*V),/B\O73L=&N=YFT)MVJNOG'W>+K M/Z?5+/&-I!\2S<@+FNTH6K^#5[M*VTLL#,?1T#=$F=A[@FP=OBP-4YE5ID>4 MG/X\NL[I4/?.CY?9W?>0X[L$\ Q)#("1T#*BI,!*XZ:[P.C<^E[C8<9),EKT M@EIW/;9[^6F"H\6E7%SI(+6< V*:B#2I/+A\5V:^#/:6G^Z&67YRS:TSC!D#F%#N@7)8"FNU)?Z\\?)^E!ZQ;:O"#ZBC SE2E+G+-02 M<-I81,K\';>1P9,C$90]R>(\1(R"^O+KLOIM\M>'.H'DSY/EW6S^:[6\B6+H MQLEC;PN.:\4(M@XSS!%EAK[8@W1N/=01Z5&CI&?/8BG/U#H^JMLJ^;)5X Y# M!!23V$B),;-*U+$6"KGL'HQ$^GKRZ_4CTD6/8):],5FG.?[6,0O:VW8!8V3CXN40 MU)IQ1K&DIAZF!DQ_Y/[=_.X M<3QN+A)^A\.14_".;PH4<@$L38N.PH![ BE_@L(3@Z^0J^=GU:*DR,JJ #TD M0574>6BHABPN&5"Q5*.G'IZG'%R\GV&XK?\D)$L2Y0JRFB)LN'>>"0>\\33^ MH)YFH23:X2NL]IO/KU)93;O)Y.S[>CW\D[;TER\)$#B0KB09;3#33GCKG]80 M21VREQ^%,AX*==K$3Q!2 9::B%@UO]D7"+?KL<"IX5H)1AQ0*79/4P3K02CF M+O\,ON==^@3P.L>VW3Q]:QO@5O_M=91;_?N@[N^?>A=US+T;ZJ''@V&6$2RE M!-0@JATD3-8#PIY?3P:U/#$N>H=P:$ZXWS\>XD#\UP$S8KEF*D( 1>HY%;;N ML,$Z';O#Y__'3P?G^\5.0RA &B49*4<*M]=R(IPXSA<7E MQ] -(^ONT!7529\5E(^SU;^/[/Z'F@4'&-=8$DNB2F,1 J+>%>,@."A=H%X:5,Z1B9\7%NE@I37FRBC MEEQ/VHE^A/W:!],CM@4H]&X><:Y6FX"4UOS9WR@X;JPB-&KLAC)/$?*P-O.9 MCBK9Q2LT@Y*G-V!+.#>6B]6J-MNR:-3R#4%I&8=IC&4(2P[3==I&T[,JUP@> MH4MD$$X-@W()@BV^?%E,TUE@:T+M;A$ C>NN%U@(Y"7W$A *ZJ$)!#-/OD:H M10]#H%Y0/>':R_.HMN[>TP^:VZ1C&>:K01GN@-,81N4TVC;1;!6U% P ,-.B M&U%>W9XLNO')8E0,;I?S9:CO!L@Y\7$101H9*:6WT+@:.:G8Y4>WC(I^9:9$ MEF@OT$2Q+NV!A#K(%8NC=0JA>H",^U)GN5^KY1^+RV1O5Z:TMW*ZR29C1=Y: MY[4Z[.)'I]-J^@*BY5W$=3:O?JU6BX.WIW->%3R34<&65B+K)/&&$5+;_PD[ MF,>]$9G'XV1>(7D-P$?WN#R1AL]O"%A(";%6F'@'*3(\3K5Z-)K[3.?,B SI M"V9?MIBZDZXQZ-1\^F']N5H^]V+SUX-\:]4:0LC!84)8JDD-GM$"#PEY]X] 2I'C.J5 2= 5X !/>7%!SQNA"F9@G'&0FKCZM@0V[K,6R,C,FWZ9$0? M$)[@#=^FPMB3<.)]VX1E[=X2@*";E0W#.!J!$1.FCB5VW!F31XP19=$?XKQE M$&S+I\C9IOHS44:S36C8H9"HPRT#01*(E*O94$*BXH4$KVUR)[2X_*"H0>5_ M."G.B6"7Y-4OU?J5K=_<6-YGZ/]KMO[\-K-0&RKV]K' $%7(F"0@SS7CPO-& M4$2#S$5P1/K26=A[+OF<^2#Z4!*FX3X6C!#19C&."JP4,7TK/K!XDRV/3XQ4 MK%4Q9QQ@DBB'':^K)G@!D3CF'!QXH%N6J/GT\.H;'WB3G_18>LC>OA&HUT " M@H6"6!.>(AUT Z%G+GMG',;UT0\=#B=3*8;FQ>65DA)Y[KVFPCO""$,"LGIX M3.?FE1J1:^2,C&B=DJJ;$/Y.2=4M=XV1%AC(@2;(*L\15D_5I+TD1F6Z3\;, M\'Q^%4M)U4DF!0C_%&KSQ_I3&EF[I))[VP0JD:74PFA4$0F1E8+X>GC2J?P= M>+24.QM!%L/(Y*)NR!FKN-:&: ZCBJ2Y@M[40T-*9!Z?CLA!/%JZ]2.1(F1; M/BR6DW75<8T[V"Y B86VED+J$3 $6Z%$/4Q.7:D2%$/ZX$9,O?XDT]T;]],B M@CY/#HAI_/RJ^?S!FVV'&P4+/'5">N^YQ5H3D9;HISY[GQL7-"*/V.BXU+M0 MBJ3=Z;2 [9P=W#L+H4 T93-DF)H<3THH4EF#.((K_&.AFD]BJ, Q[8%NOWC M?'J<8&^>#1XAR1U 6"(B4\DTYW2C:4*3>46Q9+IX.UL4:2PG#W',&\#<+6["P-[F44 #O9W>SA,BZ^O)A M^=-R\?@05_8&T@\/!Y)<=7Y'\$8@;C2'Q"(,/1-0\7KX5.?6F1R_<_@,![Q# M":7D@>^VDSM&TOX ]\@K0C3##(GR!0XBC9@A%+NGP2LJY/648QF #_L.:/O% MO #AU-?)[#[-MMO%:!FVX9 0Q#GR#0EW$/5R'27>H(%4/AE"N#)/QGU)H2130JAZ,$[D5U<>\50[%FQ.A+<"3 MWY:3:5(";C85W5O6'-O?*&J9("(DH(38,@89=H0T R0FTQLWH@LNQ;C3&\AE M8S&;'_]C5BWCIS]_>U]]K>[;!V8>>$%0!BDOD78*$J"H\A[!>N!>ZE('[3^" M$C^(1$I2\>7E@+8X5I@2( MVHK0+%JGUWK?XYSN\S,([DQ>]LQD0_LR3PWUJ6 E,Y)*2[2D5H*H5L%FB;+6 M7J&OOBP'6[CT"\IOQ)-A]?$5U$]Y-X>:$0>_%Q".2YQ'DJ.XNPKN"!1U8@"C MB,U,UC!FW_!%3HL^A7@ABE*77&H]?"9 01WR0%A M4'& EKU[W1AOT=93#0 M3"@ONQ(!GMM!':?P]P\&@[0@Q"LF !' BUE[?(QGE[CP6]1\;\.\#P%_))A MPM%._O1= &H;9AUM')2@2DK"@0?,&$0AUZC![9KB5W(%O2\@N"](NZ<>>=V% M[U,*'$EOWJYQ(,1:"8%!3ONH3[!-;O>G,6"N2QV2E/!J]2G1QW M.])E7_- ((MCB)J I,I8$P'#=62J89QFWFD9Y6%%(<+T!'6Y4/).6]/>-H$H M"HGQ*&$8C1F6DN[4P^-&7D]UM)YVI+Z0[+ZVO/GREK)'EI0CK8+@"@I&F(P] MC?W%%.#Z9-H +DNE*RVQDO0@NL50P!:-[FAM*^UK$BRR"A+'E59 22#BJ.K8 M*P-!;L[O49[J]K1N] 1E 9Z\, M;4&3'TX')5)#<4ZN)- A:1XELO&,29E;? M&:5V,@JK^G09%%U^NA'L8+N4A<:F3/T 6YY*U4HL&M4OCC,S'F"$!O5),MZ[ M%IT.Z3-S!JE!LCD=OIIJ(P1YZ1QV1O,H-XY$U#J@=E0R%M=Z?JPPY# #_73S MN9H^WEC8O4-5,WO]3N""&V>=@EX1"IS&#(@:2@?E%5ZZ M/XE0B_'(HKOETVM1LN^/^8ZRM^CW XM6@Y+$CUE*)_#]>9J^/:[NQMSV;PJ<2Z>5C:/AGC)ID4:V'AT0.-,C,$K;;C@. M#H9W^5B"YSGS-G:OQ;:?\;:HV"(CJ(W@,^.5,G&:T1H2Y4GF>[U/6&_0F, MBSKN;#Z)F_GD_OEF5NS9VDQBOZJI6G]O;;8F7?:+@XPK/5&,,>P=)A0RSQL% MPEB9&?DT[I3MO?.N%/P#>3BV?9_?14VSFGT]FYOCQ>=;>#=V/!T0EU!Q9P$0 M3A%D$.=^@R;P0BD(CY!Y(!UF![RMM)5#[8(AD&"$L$8&0F.Y0I340S4L=[\8 MH=/A)#F_5D=ZA+3<7#QCG>/3IZ3 U&'(=*IJ':T)(>,OO(<(" 8$/U-5XQ<^ MI[=X)WL[SH;IN_G7:K5.*[F)LV&V_K^/DQ1U_6X^G6TZ>:RL<7\?"<8RY DS MB,%T)&,B[VT-HN+D>@IYGL2@_8[%LOAW5Q W=Q]G?SRNJ^EZL6L)V)-CHW7; M !",RYN'P'KB$8]C4>!I!(@ ?#VY#\XA]<6PTAB 3P>+U;5L':R&WA$(G;76 M*VAT1*<>!83T\L\]!A!H%ZIDP9P1*+J\BQC$[^^]#[_CJ0#3 :]1REDH#4>$ M;^HL/XV8J\NOGCZ(B!9] 5K ]_HI2F=S1^VG:G&WG#Q\CFOCL:2N>]N$N%-C MA(V,W[*&8PRPQ/7PXK9^[+SY$UUWE4IW/792#]):G(C>H((V M/Q\0M/DY&&H1D% Y9'5<%Z%%MM&W(O4SO5]CW$UZ%W1G] 85].^?#@CZ]T_! M606=@\Q[YU)::8T@2EVUTG'&:*::.<*+V?T+NC-Z@PI:'UJZ]<<0K23,@77" M8 \M!L8J5X\225HJF]8E"KHS>MUMQ%JI7>Q2:@^FM>K0.BAN1+2A883 *!@W M($Z:41 /,J\2CG&RG]=)-8P\"E@+ORS6U>JYJ[]4ATXCWCX<)*3.(84(XH8@ MZTB<&HUR+,SE9U@81+J+GG$M3Y2?4N;*]E39/!XT-YYI20'%FDEAG5<9(@ MSS0F1J1CGH$L.4P>M3BDQ7P6%]$OU1=UMZRV.=SW;%&'FH1H2F.D M/%(LZLMQ7W;"RKJ_0-)25PPODPD]HYL1??7VHV9Q?U_=)'G\6BUGB^D>4K1H M&;2VQBG(G;.($:VH HW;5FN4::",2&\=FAO]@]SO@I$RM*F;;>[;NELYJ\C. M]P2H5$K&KJ'047]G'F-:CXPR0#+-GA'E9SWGTM('Y 64%1=',(T*__-ED1>! MA6__Y2:4^H RD_.Z(#CA*7AO%I?' L+ MXEZ C'5>]W?SF\67ZL/Z\\$,Z3N>#@I0H91 <5OGVE/.&*SC=2B4_E@0YAXJ M\1]C2>L/V+,L7#]-9O,/\[>_[[1<[7M)B#H X!9+HU T,JVUT.EFY?8ZT^LO M?BQF#89W=[7KIVI>+3?B,).'RWGZF[RK\EZO4IE468;Y]?M8ND?UX_+ MZLTS>Y2P$]\:$!&I,@CA2AM//%.B<<-29T$FR^2/P;+R B@7AWV^!!"GAV%K MQB4DCG*B=-1VB0!T>\4)8F*D.U:DNYVAO0^SH]>8CC8,WC LO*,I*18A"#(. M=-U_I7+-[!%Y;GL1WF) 3(>99]NUXE[-IY\>OWR9++]]N/TTNYO/;FP\L^]M+]IDX-W;*&B!4D*V"#.%0'"KB 3;.U].>,VZSL5^ M!OEA>3>9S_YWNVQ',SEV>KKYR^9V[H?;7U](5S^NX@:Q6MEJ=;.Z3GIO\-&"4H(!:;S#PD53WN,:*F7]]5S:'(9 K\\6"\JB1"CTY\5R_5NU M_)(2AJ?Z>L=B[7<]'PR#7#IIG$^IL Q,\5_ (X2198R[ZZ%8(>F_#I/N ?1S M<.EX4/WN%H%K2Z)5X(4#&F//E9<^#@U#3>-DO:*B)"=*]AA/LN LP)3DZOEP MNXTP.UH0]>W#@3*.#;<0RS@<9#"!$"6 M 260G0]Z\W)$GV3*?=$+ N00T_N M)W%1_?2YJM;OD^B2E [O2ON:!.F-\=!;2SCAB!N$+*A77.Q\9J*9$853G7=C MZ@GW,Y'JZ/:TOU$P7&B .$7I]HK0V$)IZP%29Z]G!3I=Q"TXDP5J =9LCD"W MQKH :U5#'&2-$(B13//E&.7'Q$\-&]ZP;4 ==3TOQ^W5R]6?K$\ ML*$?488ZO2<8K-(5'N\U],HR*H1O_" H.NY_G(>#6E(813@9#(Y/MQN7,Q1 MP$?7L5V/!P:05)YCSAE0E!@%%:L'102_GBQ \GZ=0&NTS$NOI@=F%Z=%K,C M[PDIDYY00!*E@& 8 (F:?2(JJM>3-WD,BUF_PBC R0,=/KJR'6T;XJ@7GYAJ8!8LA@6\9.ZB3S?5?+*<+=KF+7KY?.!*(VT LUX) M":%G<3#UL+C/K0H_HLL99SY+Z0'T$EQZZMWO\]5#=3.[G573XZ/,R?3^0!:%WMX=!$3"2?&FPF*O,C@3X9X]ASF<>]4Z**)3 MG64'N/9,Q^V#.)G.;-.HD1:9QND(';GCHMUI8CCKUGT0+7=[6]VLGSU!__=Q M$A](,:3I;UG;^0G?"RB:>8PY[PQUR"&*'-3/(L.9B^H5^9%/9_<8!#>.B.BW MHW6K]>Q+U/U_L##H=/QIA:(X;J,&H!3%:F'\4T 2]U-&SQ(&_9QH;+^Q M./*.Q%^L@#-$4JH,MYQ'H^P) FE]9IZ<$6ISPQ!C;_V*?G'O?D_W8_R2>GA8 M+B8WGP]4HGC]6/!Q"150 8362_D/[5T%>@;Y!(>(MC0MCW57E:>89>>?-HD36AOY%W1F_(DD%;Q?+ M+]L\$=^:4MG-,E?[8X]H%QW>$CA''#.&(X9",<'9-8CLW_"K M/ZB[&\2ZFE>WL_7F?/*@&?SVP:"I9M!BXY7B@"*+M#00, PD4%A<42Q73R): M](AFD;5CFX/5_?50S5?' Y-W/A\\1APYPH WSL0Y0:"1-3K:B"'>U?BG0FE_94)^57^];1">W M:+U).HHH=P8#10#@DKO:#>%)]OG@".]4G',)RX5[_"%VVT<^S#\\;%),I_2V MJ\?[G;G !_YB8-)!(027@&!K,0,NRHVT+@E!747M']U4&(D1]'UPGW*[$I.3-QN%1+[Z A'C-$63UH3X]F([\< ML@W @QR;LAO>5V)32ND1QSU']_U2(,>F[ ;U5=B4 M+EKE1%N*#*68*Z:L=O60)>.9<>>7'5S4^Q*6"W>1&_HM8&E1BZ+3>P*"C FA MH6"2"8J0!T0D&&R$ _LK*"8^""=RE+-,R,=AU?G9?):0^EI-W\5OS>]F<7YN MT]^-XH94/S5M/-64(Z,M3$6Z"++;V_)4$L&L1,>.0H=>%PX(H;W9=NPEP2KD M*63.$BRAYSH:**(&(:7%O)H5H0\B[%T(>H:YP/[S,:U<1VRQYIG '?7*0N*@ MX YPR-@3]WGDJKK8S9+?H#[H2#)C\U8X!+Y\+4%$H@'46<\_B'XQP7 \#,)49LSI",[87!IP M70$&'-CQVG@]VC0/''$.O$&84&V B"8^A/6@/8'74U&C@"(Q .!G9=GOJ^KV M\?[][/:0:=.F>;!4,18GJ8\&M@$HSE0EGP8ML*;7JUGV4T*Y[MZ<_22U]Y60?EH'')K M-;:.4H9H_ 70EFKO/+3P>K:B0DQH=Q$G _J+O=@%$'00,9@\F(!:*#FEVV%Z M@+"[_*6L5UEWNLC5#=K.]X^GU2R1AZ0?$F?("\[$7X7WU=WDWL7ILOZV9P7: M\53 W%!A)>/2.& -LTBF3B/M+6 &E[J\KI=,DTAIA[9@2&#&?>FH@8=Z+4KK&D-?V\J6SZ!_! BI#G]5L!99< M>>L@5B#!I$R"ZDG'A^SO6FVGJ:(]X7XF4IU2S99K1JGA"L<98[R--J1J$//* M7,_MN]-%W+Z:;3=0"["F_]JD<5121- K (Y2H](S1WAB?1 MJ> 68-)YJMSJY%PPB'@N.6&<4(5(L[P+>#TY#,ZC.0TIC *<[*/*+4;&>@[B M%*-.<^>T)0UTS)GKR$T<;J87Y9?OONE'>HM!8>V#%JNF%QC"CKS8T39( M;[WTTE+,'5,ZPF2;PSM%B^6>O&ABG(YK<>VG5%EL"HU14F$/*146.8.E:":( M-9DY;$>8_F0,VD^_PCC+55YAF%! MY[+8W0 O<5&RE[+8SBC.)"(\[1)IGX>H,6191#./1U=70C9W#>L#]"*7;OLL MB^V<9=Q*EA)5,VBCXJ":22@C>E>S-ITHW=9EL;L!>M;$7V,HBZVA4(A1*P5" MQA&.C6H,%X=R SWX^/AWGC6MM("Z6Y;[>SA_3)OYXG;>^':G3R)=3_Z:;,X* M%LO[9W=OY]CCKA\(7"GIO81<<*>A9\+@.+>M\Y)88N3UG!$6I,UB!)+*8.U3 MAZ;5_>QKM=PDBDM9VB=WRVK3XWUD/-8N6(LA@E$?QE9K88SE?A.]H1U'DKGK MN8QV)H[U+("S;N '<7JJ-?]K%=64J9VM;NX7J\?(CH_5UVK^6'VL;A9W\]G_ M5E/U)37-VN7[[$# *&6(M%Y#AB%SJ6".VT9!(91$\L.']N0S?]22'.\4&EE] M>8P=UP1AQ1U13JM( -ZX#7O.%'$40>-%7($P$[:&'*#2*_/UGW$P& M$V.I*#"S^!)I\+F:K^(HMK=O]HUJ)P1Q@!]N?YO\M=-F'>A+ 4*I)'74"QH].-&#==_M8FQ^:A9@$31HRGT%EEH*" "P7J@:KL M^D8C=&SU(>S7QY'] 5M@__I]57VXK1-\'MI^OG\P,,KCYJN@Y,(9Y83T#3J: M6WP]=<0'8,A)4';W328#?9%&\%A-G^ISI'3^\VFTT^\GJU5CEZR.KQXGO2\" M1CWA$ANMB9<$6[4YX=^,E#J0&=;>V:-3H@1?C[0IB7F)7$F3V?(_)_>/VRQ2 MVT*F[^81F\>-2K;M_X&%J%7[X'E4E%)*=VVE%L@:MU&5-L,F%F;&V'3VC5P8 MU8;$N$38UF3U.R';].[E-O?Y^GJI7+VEYO#\Z/)VV&;.(GR^"1^B)5J"(2+)!C[&O%:++^U M]VWM:Q*(-()A1#3#$"K$M3>D66^AS@RFD3\$?7H"M0!C?ETNHHF\_O;K??)( MSZ=IWWU(ADM[!K5]10" 6LL99REI-B-,"-BLPU"KS#+*20H_ *4&0KG(HO1] M8N(7:86/[G1'VP:40A01MNE,!Z2;F\;6/AMCL?5C^-_[AK<$F[X\3&;+ M[4FYG:T>%JO)_8?;]XOYW:;;VW%TV/XR7A=7<8>U8 ABH3@Q1GM;.W.,!R8W M;\V/X=$O@'@!&MHG.9G/D^5=U8%PAQL&)RVP DK.E,50 VAT,]\T,9E:%QQA M).< U.H5VP(DV@;M_%RM/R^F265\NO]Y=%<\V"YH11S'PFKF%4 >4$>:80JD MW4M0YGU]CN[$Z_,*=G0_X@]_'W=FG+M&@:"47+\6HB$ MM12(5'*M'B@S/E>7^E$\ZKVB6X)&*6PTBNII(ORZB..OUK/E)GPUN4V.*U9M M7Q&00/XZ;7/\Z[.Q@O]#5J2=<2R3M2AK>QX;@'^*J>O"R'BSP)C?Y[8_A4N\9W8R;\(MYBE2,*,0G[Z)- M4*5(G98Z=[O&@3$0#08I+:5.,VTIEO4:ZBQSF:? :%1%(0;2L =!N$34Z&)9 MS>[FVYO'L:?+N*-&#)ZB8#=_O6\;Q'SR.X.5E$@=I0D$,TB:B)9HUF,B,D_] MT(_A+"\%>P%6?G_AO=L%G*-M@] LCE,IJ>,P%:;6$UP/%P/),UGV8_C-^X:W M1":WSQ$L/5E5TW1G,!H4&]%]V-P@W_C7;B*4LZ]5.[LOXVT!,0R@]X)%_0 # M;KUB] D2KS3(- '1CQ(V/SSD)5A8;52#YWN>:OIE-I\E:#8W5O]* ^OBT9KKET8_AEB^">9$CZ>7LZZ;+G8ZC]S4*7#FG ML+7 HDD4$H 4P\0LMSTENC'"'7O#=>RQ/EP>QMMXH1$+I5E$ MJ6TMFS;K5J?W!(@,XE!+%5=L"YDEEL)FK;8^]P;VC^&N'Q+J(JO;ZF8YV^B5 M'VX/Y#?Y9;'^KVJ]R4)530^N%LL&GPY7-5JU#X!"8S6TCA!EM8L:AGR*_]9 2IV;"K+S MD<"EVJ4#@%PBE'"RG,?>KGZMEAO+NCVKCK0,GC$MB#$,S.Y_H,6#"R8U ML!QAY4'<+AB+?Q( B+1"NZ-9O@92.6\^5]/'^VUNFOIJU^O!;,ID'-([6[\D M(!3-/H"!5M)9Z"5FDM0@2.>OIUS70-QX4RIG(.1+1"'L[['^]O/DOQ=+D[)Q M':GFU>$M 1MK*;9>"6\B% HB!6H(H&*Y]XO'1[XA:/$Z\& PW,]+O>>N_S+Y M4ATM_M7Q38$;[R6P$E#N 64&4R!J*(QVUY,,=!!^M.=@#^"7R%_UN%HOOE3+ MC]53D,[GV%',_:V"X) QZCB7PA&EB/%QN$]#1 #]$/PZ3?:O4U+U!G;W M\,]/D_MJ91;SFVJ5XN'W,V/_PT&Q^%(F&( 26R< (]PTFH56N5$H/QXA>L.X MQ+J2HE*C7ODXN?\XN_N\;K&F[&X1/,,.0(T!8I'DE'#N4#TT)7.S9XPP:J[8 M>M(+T 4XM-.>/\JC ZV"0]B9=%E5Q%FAK8:&PWJ(1,G,S(@CO'9>BDO]@7U> MG?M]BVJH;9H'2XE,"8V0(DP;+"F KAZTQS0W(FE\##NO@9<+^'E9YA_7R>7R MUA/9PM-WRFL#$M!$I$U4[JRWP'N!< V28[DJV&7IY!F4:<_'OD5P7I[N&,Z13 M>P[W+YS1L?B_JLGRMS\7O9'WZ7U!6$BBOHRU %Y*11PDC:JC-+J>JKX7P-D\ MF8R3JO'SATZ],M\8J)=*,VI!G+,<49TN"#3>3B=]'ETORZ0>%5TSI#)*POK% MXR'3/.^%(4Y>22'V2# NH")0D,;)23&ZGL*X%T+7#*&,DZWQV7[9&I\-%#K# MN:*"$,61<,8*W;@]J,D\_QCA/;=+86MWH9PG4JG^]Q\7]_=^L?QSLIS^HIA/]8:-'! M=@%[:MGFP"8B!K2 ,JZD3\,D &8FE!AE^.O)DG[-G!Z!+7;R4U+">]Z- <;68#*36;F&MM M,&Y&RIG-W,E'Z) [7< ]X-==ONY+-6DIWUV/!NJ<( Y!(2PA(OFA!:O[YZ4] M=FOK"I(19U1VFJ"+6>&NU1F\:G3B)/&,4PX WC%F9\DHT4OJ&5LSW\\KJO#N_+S$\%$W8!B*0%0 M3&OKB-;-9@*)O_P[6/GX+_I K( _I%Z'WK<(VWSS;*#2 9^N+$L(M9:22/OL M$-!'G5_,/M[>;:S/5]+=%NCKQX;9V$?T^G[4Y MMFCUGF 1LT9 !96'"/F4T=_5,&ANK\+W'.%V??M6'+T'8%[ MHA$AG'&NH]5,J$*-CY-PE%O$H#6#Y)9!\V@\I%7\(HG4-\H%2=:"0P$B*! 0 MA$6U#WJE71Q"LXLJ4$SQ7:PG]Q?'C8[H%5]?.B\F#:?X]0G8, M);=%KP"?3H"])V;['PX..:4!WISB2ZXU$> Y!E^;RS]W.5TZ!\2Y>_"DK?T+ E<:F3@#C+9>Q#62$MN,A0-\^:M"'W)<%(#VO+>S!DJU29SU M$J7T#A%.;PQ.T2E-EH=4Q_Q*_.L#[SG#8W]>^@V<;M,C+K"4BDL,J<-QN@NZ MA<()G7W8/*)%;E!^G)ANLQOX!7A8YU[;5)7LG-JL1>O@!4)41)M#:$P=-(:9 M9L@>YM;\O"R^G<:%/>GR^@.] ,^.[ 0=MMR.;PK642PH0DA3H# W$7!70R$E MSU3J1AU<,^BV.RS^YZ=BQ^TWXVT!I!L]W'MM@(Y3$UK#60V)8SA3$QSADC@8 M5[IQL@JRTY9SP&A3!2*:V,<:[?J-3@'.%4,P!=;\S;]'3 3H\P,0VS8,AUD@+)012 M8>MTNN]<#YHC<#WY'H:EQ$Z?4Z_0%^!;W;4#7I)_56DMKZ8J;E.3NRHN[K>/ M]^]GMX>B DYY;4#.(TX<$,I)) FR&.EGD'+ML,O3[/KE9T&1%-W!#\ZX5IOV MP3<$ B6*%J3'VB!"B76>-7@KG9M48X2.JJ)L' ;]S'/LV:NSU\E^]AQM$\TC M[2%%!*09PP E&C9*,\?R>O2Z(GSI&^]QQ$+^<#&0@+JHWHAH3=*HTFNOG# M>Z<4L%2[8XMHJZE'N-SG7"K'3_)*="!@2Y&6($H=*<:] M(LK@&GCMQ;$BT^.?"N<@Z1LM:X2B+#"'.@VAU7EBYAM#U$0T9<9J*S7G3B7E MI%G9I+NF0Z%Q46UQ#OEUMS]^742_+A?_7=TL^O!!;GH'>WNK#"QW\O%D0QSWS\4N$.".JA?)T!T\QS![$&GE"NL# 0->37/#>=^(C4,X5I(/O6!<\++%JT+W+2Y8O&H1-. 4 M2D U],SB9)&21L%D&F329X1GA4/3IU^@NZ\E/T_FD[NJY1ZS^^%@#<6*($N, M 1P#Q./P&]W/L,Q4;2,\""RQEO2"<7<>N"^SS=JE[N\7?R:'UF$F['L\4,*@ M-,1(;YURP'&+9+/F474]B=]+<*$GE,<=F0PX9%8KXZ!!V$OD<+/ 6\SFUT$-VMPC4Q-$XP)@5W%!#"$>B<70IDLD> M_N,M-_T"79!#FR3)2>G^/'MHSZ,=K0*1*4D=<(X2J+R$7N)G=1V[3)^*^)M+ MIX-=@$\[PYF.\NE JZ"4U]0R[("V5"JNL6B&:(G*C#Z7/RZ?^@-[7#=O>KYP MCI35PG@H&82:*,@Q?G8_9>=Y&9%M/H)CBV%E9;7D0:$I9WWM]-S\:Q(IW,)Y]^:Y8"4B M!#BL((H#3%><77->QBS*]-N-\ R@A/C[@+C NO_;44\\9(&$U$1+67C7<2:)]I.HU(Y3C'0M(GY)GWA0KEO=3 4"VE M-!![2 T42=KQ@)]YF6!S@<(U[(3#8I^@36JB:U]BFV;WZF;]>SK;#VKZD+V M1TRFEF\(EF HH75>8D41Q1&))L@-4Y'I/AS1R=4(3*5A9%&"AMO.[>CV47OH M6-. XMI-@/1\DVD*$JWCS&L.<-CU),'L7?JOV=4OTN5HM3N&]Z@>UJ)U,(): M@03%'+"(JW &-A8']/9Z2J?U)_S=K.H1Y8PHKU.7[?<'$OKT^X$ $:5><\HU MDL@0S*-"T41>0GCYA6_.N(^>553G#:+^I5JWN*#=[@4!("^PX)A0BKT71@G9 MG& R:#*KTX]H53P74=I'4^>+X[P\/%:Y]%C3D!(L0ZNE@D)2BQQ3NK'@).&9 M45$CXMY0PF_/K1R@S\NJ%S4UU9?%":F BKI-@(: &*J+IGCT#N?>$1G8*-AI$#B.,, M/(Q+^BDLW-4\,"" 0\P)ICUTBE.BFF-!!&FQ$XW!=N*19577SC[O%UW]. MJUDB#TD_),Z0%YR)OPKOHV%][^;KV?K;GC/Q'4\%3C".QB@6 @$)/+'>JKK3 MPJG,Z[LCY,;)4EOT!6+ODM_V9.]1].M'@E/06R,Q0 @@IHAFL=]/W6647;[, M3Y+1HA?4NI_RZ/!8:1U419S[AV5FD.':_[I:B^_*22 M^9)8] 9;=W':A_MJ>5"2+YX(1%#@4C5B#:6EP#BG;=T;%W7%BW=A]"+$?,1R MTB',YE%1J*KUP^+/(Y+<^6P @ADNE) IW\>FCC5I] LG8*9,1^0$Z$6F?6"7 MD>3@C\=U=3BOP?,3@7@ND'0 (FE4*ATNK:M[P['-=&J/*#BP%TGF(Y:UNGYZ M_&,UF\XFRV_'5MG73P8@133QF>4*$D:5X1B;;>\XY\YDNN4!9GQ MK^5LO:[F'VYO-_?/J^EOBY2GZ\.M?ES%WJ]6O\]G;9Q)K=X3H+"2*:F<]CIB MP(1&O(:!L2NJ,GX" _9P:0B "_+LW9>'R6R9PD7?'XX2VMT@4".TM,!S1B@D M&#(,:3TP*G.C=4>X%O7/G).0+$B1%J2(.[7FQDO/N4IEQP2FJN$WQ2PS?_Z( M[(;A:- 1NP*"KU>N376OU:8@P*_5\B8)Z"XN;/^Y2-'J[^81[&K5JH9;W@N# M!,H9QH&C2%@'C4*U^RLBRW@FJ49DPO1/JB)(%UQ[ZA[:QV7L>!S*;'&(:(>: M!<*CA6?X M?5GN88\9W?X%@6L9]3 :AX"AA?&?5+MF#;:Y%<8[Y_&[!&X,BFP&2ZKYT]4F M,WF8W,S6T>B_F_QKLMY/B_TM @%::F6=!L))YXC0H-F+H:>97I819N3KB0>] M05EP3SEV'^*[YX*U!'.ML-/60RBH(L_#4$1GAB2-,*]>_[M&#H %>>#CTO6? MD_O'ZCG.H@4K=K0*&A(-(6+6\^1GE-2J!BC ;.9QY@ASY?7/D=/A_'_LO>MV M&S>3-GI'[^!\^(ECMF< M-E&!4UV7O*_KH+0#JCH^3JVND6")EQ)*BR"RUOAD]H $@L2."TS0U3E36^;& MWM"UEI$_[XVECJI^I3M;JYQ*PGC"@$90N@H"+U'F ?X R=<%+4ZH[M4,]_-2 MK^/J7E0@CBCA5J%HZ M L*W@E@[51B9?#@4[X<>)U;V:@=\##TTY6Y33R9#J)IR#[Z72 M18!P2CFQ-MJI'$BX%9-R=3TGFSW,.VTBW0>A-GFTCLR7MQD7'DI/-<$40 ^) M1T*G(-^U&-"Y3(?A ">:EK2Y)WE9#I@]<.)S' Y%S82R?280RY!DAC(?^^HY M3U@8IP4R'&0JE@QKU.>XXW0&LM,"V2 <0OG=>GD M MX#RUZF9?IX^[KC!_AU^,6@/?)2.,O3!D!C('&*X(B"$H0-STU\/\!9J%VU MEQV"?)[3K-6@^H7.J:BBQFFNF382:YAJ$7"H'4U'%!377G/K^IQJ>]LAZD#' M+_OKJ(.I-V\%A)CG0L955U@)(*%"X4I,"=#E7[/M6/OU210RH6X>YK0S:"*X(42VZE"@'+,C/4#M!!VRW9SJ60?$I^O*W"0P^= M@C1B8DZ300K/''1 IV 4IP2.LE?R>E ;?' YGKK^"-B#'OKPXQU.N+46R#\N M$VHO;#GWST,Q6Q2UQ.WB:X(C).H,62A=M!D5B[_("D2@>&:^DP%ZCOI=NL^@ MFVXL^G>S^&/LV#_G,=NW7]_(2#_P5B!QJ=*><9YW?E< M;V(>,Q,<>BU(8IB/0FJ4(J%XY))SE: ^_DU/1GD_Y<):T/>;U(6M8=OYR#3E M_4,Y2TD,]MAS<3 MN"YFT7!>FG4YG,GL[KD>3A/QCV\M0"LEIP9ZMZ(WD RA"I;(^>L)-VB%&_O& M>&> ]W$T4$25C:;M4C&_T> DED)QYG5*XBH,X@A7 $E!KL?9VRE[7I\G]*6/ M/J*M'N<)WHU(;X0Y%'1U^,U G!&,8<>QCI)I&]?][3R $;L>/V0?='@=G]4J M]CW0S&Y4=ABK VP[KH' E%!(:<@%2XXP"J#0E>#(J]UN50\]KM['X';$&GY,,P$@ MG2*]%!:=]IKD7)VVGO>#$IJ:R3%$G.@&"?6 M0[L6%0(/Y?6X'?N@PYZ==CO8][G3/HC5,3OM@PW$;9[B2O@XGCTG7GE (:\$ MAQY=S_I\!M)UHH(>N-><;/M$HQH!K12)JX;G"B.HK*Q$PU'.OB(A.J_.VN=J MV@[8G1^@5NR/OVQJ%<]N7GSV?C+Z-IE.EI,K.U.-4X(1%$D+J# 0&BJD\-IC M[Y#5!M1-J-VN)C_C?H2DAU\,.LZ+D&EJ>2JY:CP&6%?" B&NYW"@%8WO61Y: MP;9'D^3G_GZ:EW%J6SY]FHYFRSC$W?]]G#RD6Z"-6;6WI< %4M;&Z9$I1SS3 M0E"^1=CQS/P1Q].LQU+R;9'B**ZUA?C9R+>Z$-.8:*NW A'< ZRPY!9S$FU_ MJ-5&1.=A;G+(XRW?:R55#KH]$F@[D[_H\A$,VO5:$!!%<\MI:Z.YAH%@5%2C MQ DG,S=/S9U%G9NW'1.H!7#[G8*VE9>;F5!O7@O:,BB,!H)ZP: D6$E4"0DM MN)X2'!T;4*P[Z;+:$L[M40L2,YO.GVW+^]VA^<\Q\=$0K02H*D%0" PZ0 MHDI(;BH(%*+D:JSS=HA0QZ[6D#X'V3[A./T1K">=ST"Q-\)O/-MZISU&W\Q]%\OZH\7C^.)HVXMQ1#894 MNU,Q$&T/S!@'7%D'MN,OCL"K.;7KAX!=@#X,-J9;'?'/M:9G-QO7Z8F,W--H M,(8Z$WI7UTS\?;+\:;[>5ZRB M:1,!(N).$ LPBU2J2.83[+EN%X?]>+%T*Y2[*SR^^M+/#O:O5S+YG STF3RE#3VD@HU/L\+W#LL$:4*,DFH8MS:2K"X.NM<1R?( MG6HNGC/YX'8>5N1N;XOQPD\@PYY\ZCN? M"Q!S:P !5@NJC/#6X,V9+G8ISN3BJ7"JVO9I/P.]/I2_M[S"GB>#IPX)+HDV MF"!/.=Z>8&"G'TC)P![!X8N:^WM;5^#K\8A/02 M.4J(T49*J_0JZ^YF#,=]U,5/7OW2H>P0_.8KV^^CQ606G_SR^&TQN9F,YD\' M5[=]CP?(()4$4:(T,DAZA#2M^LELKG-\@"1I2U]EZZ#V8=B^/U 9O_#@2%K M;#(!K"$B0@(]V[A>L$<67'[!N:[V-[D0GN\VY*ZK?7M<4NVFJ:SYDH"@PI0" M)#Q,/CJNI*L&D\=$9H84#VB&:H,\^4DKVX6_#W/IK<-TM"Q>];[*09>2B#Q& M/CS]]/ AF^KTU@, VCJ;Z@V"!!83E&ZU%FV*ZZFZ> Z:O3;#>M?70"B^.SW. MP=.F4YH-7 G$F$T9?9 2D!HO*@/):PPR=Q,#VJ->&*E;4M1 V/PZI41ZPD[B MBTECD]'T1%;7-1\DCB:_I!9&W)#C& A0[0*]TOKR#=T+8W?+"AL(R\WW5#_T MW>RT6*66ORDHCX #TOJX]$EL7%P.M\L?02[3!3# L.X+X7YWNAO(,+"3Q4.Y MF*QK5%8%NT\D_,XV XV6'"$&0TJHP)8C:S<7>0D0A&92>X"!YA="[3:TU-Q7 M>DS/_IPLOW\OIS<1JA4T/Z+*=E_M.K'%(*Q1W"-%+&.>>"\X-I6T<7N?67-G M@,'K9^1DOSH:R+3ZN7@8+>?KGS_>;BPH-YK/HG2G3J\'VP[86<:=T9Y 8IQ6 M\6>U'<#>949&-X^POV9*GTM;W4RW]F%:%=M[=_\PFLSW9%@ZJ;W $4Z2(JD% MX'%3S*FWVV&,<\O 'A^Q_ROPLD\-#62B7=V74C?_\[AVUY\ZM[YN+DA&O !8 M8DF(,X IBD$%"H]V?E]7!:Z9MCTJZ&RLW85C8Z[N:B0(P2 V5ALL.14@W2S= M#EL-L_,D'G]!88B)4/NE: MZ:;ZT;XM(EK?+Y&PN9[=KXZ+8&!?1>B[*V\DL MSAW%(O9O%2*AW)=/R^+]\N9?>U;X4YL-4"++) >",LVABYM(SRNYH\[-Q1]. MM'A&? ; FQ/M6=!W,W5[NQI+Q<>_9Q'@[Y.'3\5\G/1U5WPIG]%Z1:HF302J M 45 ,XPI XK$C1_"&WD@$YKF$6A _O^6"=0AN,W)\N$Q15V5MW_\Z[_^]3($ M^0 Y#KT2! 96"LVB*:J<)DC&GE?]I?P*\IRT3(86P>S\NMWZQY2*RDLV9(7U%M39" 0;?XBFW;C=L5"U&BAT<6OL).0,,FO?$CU1(">=H_QQT^CIW11 M:+$59.WV+28_5A]?UZ81Q!F0>PDAQ )QE5+:>R8,$,XC#\]3 >J%4IYQ/T; ME\^G0@_ 8D6\AQ@*X5QR4VQ$8P3^(ANO8_6[[Y+1"9#V>=^M&4]>B(2PX0Q# MK#6.$Z99)1I[!DAFAA$T-^SZ.^SJ@B79@/; D54.\!=U6XK%IL#J :;L?2<8 MAID5<8/$B<&(4, =J,23F&5N! 9TF- E7]J"]2RL^5#.QAG$>7XM3I_0&BX% M,0+$F10*K;;3IT,R?/]B7X['@\\'Z#'!ACE+*:/:BY@RAA.I?R -LXHY)C6E1B*N\M/KM22%LOV0.R3 M"[6YMUX]&1"R O)4%91)KYQ0GII*%*3P]>1\R-3@/AYDP=<\1$BE3Y;?Y^7C MW??XHSB8+&OWPT%(*!51CB-+B&'02;3M(X#V>DXTLY53MHQAGI[E]FL17W]M MK;;WO1*P5#+E,V94$N$%X^AY[8N&8F8H_@#/]-K2>4M(9FD>B='LYEOQ5,YN MCM/[GA<"-8)1#J"R&D,@J4"LZJMD5&3>9QN@ Z#8P_K^RII2CI9^JTH M[^:CA^^3\6A:E]EUWSO!$,:($00C[ RBEAG'*_&\ 9>?MK4;&[ M0/O@2W'W MNJ.UEN'>=X*34EDAK0+2:^8C?@A6XAEZ30E93]?P:\ZT!&KC7)OC\G&VG#^M MDVUN?GF=;7/SE>' TT%@#QES(LZ%T<9U#',KJUX212[_[*?=-:$] M*$]0^,O2F<]]L"GEU+[)OM'[ 6$;"8LUIAXHRD64H#*KG+;D\MV(K:AQ%R5: MAK8Y2?Y/,9K'#_FRC&8N.;BAV/5H4!1!HK'F-"YZ!#I*S';68@Y>F>K;4U?9 M*JX9=\K*Y_X?U/K;!T/L '6,N24%@ XBS2M^N:0R;Q,.+!]0;-026$MALS:2CRO;.85Y@$=_'=VH- *H.?BRU&%/FK> M#- 9HJ63UC/E#$0DP.N5"6[CV&1RO M'I??5U=T:@S8W2\$*(@0DEGDB7< $&L4J02SQ&2&R \HT6XWUFLK:)Z%)K4V MZ[Y70K3'F!"6&F49A9 8;MEVC52N[CK1Y9@>IRJWEBM9@/;"EM4J.$WY=&>/ MQ9=B_F,R+MY]_E)KK-:\&;AC4$%,I-48"Q9'G-FNH4K7YB^Y9.XT5?8;]K2) M;%]']55]DY=K:2V):MX,6DN*4^01!A9XBP#QH!(56)H9W3% 0[=U$K6+; \D MVIAB9GV*6,N<78\'Q2$P$$L')6<*.>I%=63IN;C&VUQMT:4%.)MO@W89:>\/ M5+^L?2=$V3&%7% *X@8 >*8),"?YI-R MGHZBCKNOE=MDP(Q'> @D+HXQR0V7>+-%Y$ X5OD1T8NYQ8P/QLAN\OG MK*5TU BLL5;F72*@^,^B'"/_%9$ MZ-3E5Y/K;GIK#]8>F/.VSN+K4HQ5B<9:.C5M*FB&+&'*:*R$\BI=FJ$5&$YP M=K6;S=,YUC'6/1#OM+JPQ]0+15Q1HKR5U#"%#"'*J4ID;F0FO1I7:OM1S+^5 M%T>P]@'."EK?E*!9;!?I^-FJLOWBX^W+:C1KO]ND6'QY_);R\7\M/Z3R2[!U8Z"=40=]'B?_7%3IF-/D MG]\(+D[=T=XTU - TV'J-J""TR1J'KV.+Y4FU_2:%7=)1Q="L'9!/>\<]JF8 M?_D>\>MA+JN^*CAIN-/ :B$YDR+"1/W68 4B]TY'\^IGO_"DEJF,'B:W/V;S M[=[XA<3/J8.+V6BZG&QR!V_R(:^SD1V16ZN%U@/S$F&%HW'"$3("0P/9U@_) M')9LA,FAZ/[6@@#I2-E;P!C0DEO$[2:/4!S4 MS&;Z\0;$R+/PYUCNMJ:804VO^43=TU1 FC#F((&>*0R<(L17AA'C42<7?TPV M:):VHY5!4?09O8T)WI$%\*KU0!1 A')MXA)(#;=$R\KER@@GF2%P<$!,'I8% M0I9DC3 MZPE$W=-4H!9B*Z2Q5G.J%;6,@ H,QVUFA,. YLU!L[0=K31W6/TQ&Q?SY6@R M2U]>+B8K)X6ZN5G],)J^6%X.K-]Y#05N>$10$H>5AR1*2,U6-BUE[F;]JH-J M>H'Z?#-=\PDM@*@/)!"V1@(?]W&.\6?1!+^.J-(N57[<%-40Y_-1Z.OWT?+/ M\G%Z\^[^(>*P#6+;,ZRFP8 \0,YZ*RCWPD)O&/#;M0"9S-R' UHXAT' M=M60LU+F=.M3.4\(_3E9?E?+Y7SR[7%9+/Y,]2]2%.V=?YQ.CXJ$Z+D'@6 I M,#;:42&I,8X@S;=V1[25KR+>M0=2#UMOK8T"%?LTGCRL#[X^%XO'Z?+=[$.Q MM,5X7HP6QC1-:>=W0,3(<7,%)&_PQII*Q[$V3;IU\ "BZ]UI&3I\'FD=%0];'5W\TIJAF&7ZA 8;IUF M1%#L^:90-='6>5=G9G4CYI?Q]^+F<1J)8\K[AW*6RE5_O-T34K72QM>(OXZ= M^>L #">T&KC@&A!*G0 "0,@)\W(#DR/QGY[V^%W&]K;*EM?)#7J#OH_L&5MA MCKD4FT'/YLV&:$= P 71($Z/6G$/1*48)YCH*RWNY?.S<^Q/R+I0+#Z-GM)W MJ]G-<\7G6H(U;B, [[5@V&/L2!3)6&M-)1$T*K-0;N.]]Z6QJ6N@>YW;WES( M2+EI)J-O<1"DXZ&,::U1BT$:(Y!1!E@L,1+,&(8J:#P"F8' C7>XE\;!?F'O ME9%KF'1Q6\Z?9V<;_UC$[4<4:I,2)X.962T'RBC7W )FC4):X[B- ANH/& H MDZ&-=Y:7S] ^X.^#J8_W]Z/YTT]V[>A^,EO'W1_%R.-:"!)B;581>8)S"#%3 ML#*)(^ H\\1Q0!=9.^5=)R"?A5_K3"AW131-BTR"[6XBH&B#I MOF EO.8F,V'UH.ZR]LNQ5G#NW+.UQT]GB^5H,KT2CQ<14!H8#6U!E3&62T V MXUHA:5C=K=ENQ/QY@[G78>K^&4\?;R*/UK?LTTVMY/6-'WPMU[/8^A97L7R< MSQ:?R^G4K]-!',"JZZ\.FE -C5'2>R\1D09)4@$.!<@-B+ZLU>IHUI6#ULY% M!69)Q#G5*14T\L *+0&%E6B*P+Z(]["J OQE.9HO.Z7?<*AR9$!7,_V<-?IY M=8ZU6)]MI=B'"+YYG">MK&L\OSQWRXJ);O(%(96Z@#C^IRP#VB,/@=L AXF5 MF3?S!Q3P=:F4[E:10QL!JWR?W?%_3_-QXZ\@@]Y'R!R%UBNLJVD#8\8S]R8# MB@R[+O:WH\;S<;^*8NB(^XV:#\;I.%L0H:EVSDN12EU4H E ,V]R'>\5_SDG MR]=_#X$>M=E:!-AVG&Y[^Z%8_M3A*KO\:N$:/WV=CV:+Z4H%S:*[3OFF(+WA M7F(I.8,6(XB9%Q4Z5/E,*V= D5N#)?DP-#JT*?]+L5Q.B_L4NY("U^+S21>; M>@Z3@QGK6_V>0+CD !%%B!;2<84]>#EM9(8T'N_^__CAQ3JJ1X>II-Q.JI;Y9Y:QH_>3^XGR]J4^AU\6] (.6>5)$PYZT2T-@6M M( 5&92XAQQ]C_'ND#$:Y%^6Y3,5[N-#"<&0@$(1;OSD64L1@D;G%;9S9<^VY M=+-NDB]>*FD;:J>K0[L?\9UR_G2>0[G-ES<\E-O[5I"4.Z0E,()3Y3S%6J[' M,L6025PW4?"PP989B0S'L>5WE+A8&5H%;RZPHD;T'?;]*JMH9M MQ^/RK&?F;0]/;22UCG"-C%,"IYOX:S\U@XAK67>2UK&8GT=__Q[MJ_ED-$V[ MT8^WT9@HYC\.[LCJ7PX>9#GUBUH?M] ;0O? M7E)G;_K\Y3%9GD5S,NU\,0"F/)'0I43AA@BA'-]B2#RXGM2&G1*I#6S[)%'L MYS&4B8\% P3$QD.'"2("$:LUV@B!E3ZN#WK'D!-*X%%\S+2 ME"BJM2(02>YW*7W&>T>W^[^-D^?1[L?Q>WKSH8^SA?Y:3V?*_XR\U^?(R6PJ(V[B] MHC0NN4Y;#Y&Q=NWYD$S&W=?9]@%U:OJ9>INGC]W,G]9XL!0Z35P<(U(*S@2 MF%:@@>Q,1@.<,SICTXX5OU>=G&]ZV5Y'7F/[\>]9U.+WR<,V,?CL9E7U;S*[ M2[F8BKQ0_3W7CK?=F\Q&S]U;ONA>34K.)DT$8;2UV$03$'NF)6 42T"M2M<0 MH:GUC)UO;EFM7"=.(>MR\#)N>RGD%DO&$.646V,K")2RF;?X!S13=$>*C"DB M!_,>-I";\CV?1O/E.GABM#XATT\O_T;],SGDD3B^D<" 4]@Z9*+(4F@*I585 M )R0S+3+ R)=AYQX37:%>^Q\.'A)ON20 $48LXS9NV[)0%;_-0P=^*:%E\>?RVF-Q,1O-HQ-U_*^9[EO6=SP9 L7!* M.V\=919)K%[T$)#+3X//CZDF,'UR7UZ9G4/]K&X>:Y(5[.4]=.!X FCT'NL*-9<6&MP"KI: M V^C%7)53OINE\%!:JR'H=)(A ^C^Z)VG@29XZ!L'6;#90 M7$_)MZ%1[755ZU[T=S2U%\7X7W?EC_^8K*: 1&R\^3E1&K^@]/K3%W/%GDEZ MYW.!:XL(P!9:#KTSG%-AMG!AVMMYU@7/I6T VPYX,P$+D,.+8<0(< M%91X5XF ,W-P5 MG\J_B_G!?=3NAP,0CGL,!2.4Q/5&L[CX;"=_Q#+O^ W($FU3S:U@F*'G]Z-FAMD"7<:P@YTUICE"K"KWO(",KTEPQHC6Q5RRU V%S) M.IVL;!?R@SK>]6A 5$9CC4@OM3 $(.$$WKI_7.UIZ?"+-+2IXA80;*YA-UTL M1P<5^^*)$(UQ YF7#"FJ'. NY:3>]@9??BF!-O69#UR&&F?+XJ_#:GQ^(J2M M%5702N.1), 0(WG5&P]RZ[4USI[890A^JXK,AB[#"_TX&I?3F]%QD^Z>IP/& MC"H@K892:N84963K=B<\M]QMX^2%ES%.VP&QN:H_/MR-CU/SCB<#5UQ@QYR$ MDG"$I61Z:]\AHC.GXL87Y"Y#Q:<#V(/S]./R>S%_]IKL9<3!YP,TTECJ*# 6 M8!\EC!AM)RCH,KT+\OIXT2:,C?U,XW2!<_ZT=C1M?GGM:=I\'+Y^WD&"Y[\, MSB"OJ;?1KC#,:\>$)]N=GC.96;@AN#Z59X/6?'+_/?9OL9P7Q?*AU@NR\]G@ M*9+6@KAO-P0#9(RBL.HAE3BW9/V5.KO:P+"GNS%U[O+W567J$R/JMNV$5)1% M2@HA%1Y+IPFR6Z.56]]YSJPK.(WH _@>^/?[9):2K3Q5T;/;<-I/Q7R<='Q7 MZ*=/*ZP/L*]!*T$!K+3D.EI;T>(BC"*E 8U;7NV4$>9Z@F(Z8D;9%_2]SW[/ MD>K5&<6D6*C%HARO(V!?!/QZ>Y '$73=[/;,:")8G63WS0$,F%8;*5<)[ZEEF&?0!FE>= ML6)_(;MM5Y,#BM&:J##$XS MG&*FD18" )=,,,19)8(FN66O!D2,$S57$YS6#+ZNC^NCZ<*T\\X#Q(EF<1?H M>=4;84QF%.J0E=E4#7N.ZYL!-Q"_H8G_NRNC;;A66-V=DIP& ], B=@#3DSQC"IC5):2$9,U6/@P\I7:R </!H[#JD0#CN"-08&_C.%0D)8,D5><%DYFA]P-0Y,VTM1YX? M#9QRH(074EKGC943T;>X44O5V^KGD[5NA\4VTJV#+R?#VRY>CII>=SP?.*5$(, LX M-TZH%,Q?B25QKIMN0-?;SL.:;(3/$+C<(#HY(!7G288!Q8@1YS677F_75\/J M:O<,_ZIBWQ=MPHE9OI>D"W]GK@V1DUTIR9 MMNKFNMKKN)C\*&Y2L=<]7=W#P*;-!,>EPX@ KHA.!3J=()41R+T3N9[@7\L5 MW /RS1FE1XO)PDYNHQ**V;C0Q?+OHIA5Y1#656+5[ 4 >RC5N)T@B#>$$>"M M$P8C3'"Z*KV6S F?&S\ZP#/0CCG5-?3GOJGP]/%VUT6%C[>[;P9=;O$.121R M6A-+)(_K!:,X\B!:-@Y)R[&L(=G%&%'<2"2"@HB21-1[)K" "Z M@NB9[DB17;RC&>:];+\VF8C7TZ4I[Q_*V>JFQN& U(/O12"YQ-0DS+S$$B!J M?26FU_3RP]([U/R;/5E[0/=V_W+;R]KPT9W/!P64,-0S3@F@5% F.*G$2DZ+ MJ^%/2]K=>8_R-%#[./!>052;..GE8T$[!:FR'G%JF.+2(."VPTCAZRG^ZT >C7NO:?MZ2<#FOK7%CW9.\J\?J18+743B($I5\E6 717*NZ M:S&[_/0D)^FH; 6UYHZ-*B7C4Q-2FXJ/H$S14DFLG7 MPHYDEUF@92CRY*):!#E,C&$ ,,F9UQJS+5"\@QJ3&W,L5*8B]3NI>J7XS!S*5W0(&&K>CT1-@&EW, &X.) MU4* &LD,!1EBX,K460 MP%Q^&I,3-5>3=J 9?(T9T&:V6DL@80(#+0TUEAHI0>42=5;PRZ\%?[*.WB:K M;899QCK>0LV>*)O QEF$O6?>&JU8Y0-P#HO+OQ39EEY;P_ D/;];CJ:'S?'= M#P<$')>K$E)6"*4]4+XR0IR6-/.09T"K>$=ZSL?P=#V/9C='6.D'7PK$,(>A MY\Y9XR6WT8#E59^ARBUN/*#K'UWJ_20L<^)"3BO;1+DW!@AA%$0$:8ZMH%7_ ME)"9 ;,#NL/1IJY;0+"YAIOE@5(8"YDN 6A $(0 .ESM/AWGN6-W0+#Y:+.>/XY3)^=-HODQIV@\?&=:^&#B,,X;&TCI!!!,I=7P5X.(M MM-?#ODL&[?E"S=^W7MF*2( 82.$K %'#K:=,;UFF M<.;H'I"GHD\SJ3O@^\A9,AX_WC].8R]O5A4=4Z#CO/A>S!:3'\5Z74[9>#X4 MRX^W7T?_'&!@PY924@ZK!6/ <0S2N@Q(Y=PM];Q'I? M%8,BI@(@*:5.1I6$SN*M^$*KS(WB@,[=^F5?5\#WO@(/I;H:P!Y2KVC*5629 M1Y;SK:&C$8Z4\E.F@!4?#!XEJ(ZP PSCS6L^%>LGRR=4Q[CW,?;_%/56R"C[.OHS2 M76W]N(AH'$Q\N>^5H*0SQ$ 0-VA.:F.UP;82CF.8F2_A0O<4I\]8+>'[=NK>W)N[?(YA[IJEV M&@\8*A+-5$ZM%YA 0B"5%088@,Q[K0,ZF>UO CN+1IJS\MW]PV@R3UTH;U.7 MWZMUSKR\EG&_WFG;B7[^/9E^+^X=R/IH_/8OM)UG?6_6Q[&LB8 ;?=>+&#V;'#_E(^P[1S*K0LUP(1^/'>2WJ IW4!D5*-X["8%Y4INMHI5QDM M7VZK#TQMS1L+%GH!J+0XI5:EW/-MV*<"$?+<_#@#3/G7S]S6N0KZX.2\'!?% MS2*ED;.3A-HDN6J>MTD_R;(XEISYK08&G$?>0.\8<1*+E%E\ Q'TU.=>Q?IE MSS/ZTT4/=*WZO!IPBU4TR_.L__'VO\OUEFHCRV98[EK%3VLPKBU&0$NX )( M@96C"E7 6 MSLZ?^LL<>O:BAM_#0M*-/PVU/QL;:Z,Z:]T.TBBV+4D8S!FB@ MJ&005V*S*''K]N(""FM<':&FHEO8M(:,V]_4\$QYS1!U$DDF:28 M(U\9SI +FIM$NO&I2!\Q?>=D86LJ:.Z7^30OEJ-_IO%+R]N;U9<6-]^V-JK[ M9Q/:>!=[5LYN-KV:;/*IQS_7\8[QB7(;\+C'?=/!-P7*,4*&ZV@A8QPMD:CV MZC0I?F)R\PK\DD-K5(:.W_A7<_FWKP;KN76*8!B%9D !A2BO M!%8^-VZDL8NCC\6L,RX!DQ@K,ST@@[QCT1>%SZVD'A:]WT?SO^+:'COYI1@_SE=1$N=8 MZUYT:A66,=N:HXGT^JY5W^KHXR+@D3*I MVZC"*-+7[_/R\>Z[G_Q82;=HF\I'?4]@2"1/C=!Q=H[ZTRE+< 6C\KE'2L,^ MSSPWJ[O03)\$ORWGBY_$^VU>+A:5!SEYCU\XZPZ%_!TZH^K@VP)QT"LH,3/0 M4VL5THZ26M\BV3_&CPR+JFLF<,L)DVDU U)QS0%Y M!L&0W&QKPSYT[8JD'0+?1U#)=FC\Y.LYM ?8_48PGHFX >,>6$>I3T4[Y?/ MTIDG^<.^6M85I]K!^*P&Z6J&_F,V?S%'9QF<.]H)W&#*4M$/;Q W$4>): 4# M(#+SB&/8QZ']&Y2G(]\# 3=^H>=>OPXR.$"ZVG>#):D0B8?$$@4M@I2G/),; M<17(+- S[&MD71&M;;3/Y,([WQEZWQX\1+C0%%#N4+23O8&:Z95'%0*,2&WN MGVY >(X=:GAN?OC%H T@@A)*/! .4!89""MA!<1V:FQ#XYZ&8+8IS#.J='3EF(!]^,3#IF5+2(8J@!1%:H>CZ.(1)K77= MF54?PJY^VW2\V4E?HW8"IMY2(Q# 1JJ(!$6255!8;*]G:+=%B;(_M'L;@ ME5%6>_6E\QX$$I?HJ8]XO4KD MWXKR;CYZ^#X9CZ8UV?KWOA,H<"PB+BQ3$#--A-"N$L]!=SUUWP?'E]=1=RVI MJ \&%G>O.UJ;,W_O.T$!1DD4!2(DXDY>(N]()9[WV3<6AL? %C3\FC,M@7HT M9W(J8:I#E3#5YX"-T)!;;#PVQ@BE$<>;KAK"7W]E M&N4XP=)H:SS7!!$@':^ I_&7*XI4&?;".4A]]S#0AE/7!J0S'JD\, Y*X3 W MSW.0HKF9I08X@P^-:BW5M6FFO^8W:E6Q,*-Y2J$Q.URL\>V#@4I)F&12IIP' M!E#&)*CZACF['NN@<^65+>)\%7;$^Z/*L/36BV Q 1!8R26G&GF)(-UJDF%X M3>& O[I%D:OTYG/O"^_;*K7O:+Q,V8$GLU5']LS#AU\*UD0\+?=6Q\4(8F.] M,9L^6X!I;MZ?7Y&H&40H.])3/KU],)@X&+4C0)"X1F&! M4>Q0):[0N;40?\GMTVD<.EDW/=@"*YZ_/92K._MZ^T:(D@$-&9?1MJ8)),RW MHAG',K"A MX1(2CK3#R?H&B.IJCN6*7U-X_' )U:J.\M;!%,14SMP_Z4L?)XOOZR3X7T?_ MC#9Q$"_J,1Q8)9LT$X"P&,!T1P5H+(QAPE=^ JL5Z:M"2S^YR(;-OHYUU]<: M^['9 OOJ\2"UX8A2HJ$%'DG*+:XV7!8)F%FTH'&P_:].R!9UU!?QCN/;1@3L M*&:8*4L'VA?")=J["" M\[AM$X 8A,0ZTU/\-T+?-)1O3QFQJG99[$'%L9I]_\%W G30LV\%)F%EP;H1FI+>V4WR#8W>%<6=ORFY?10"J4TN9[<#EWH^R0L,]W&FYXW]!OO?RM$.]"SJ"@PQ%U!.CI$_WX&TEI%4B9ZKD@E5&>2N4B$(0!K@0SE1@&\][JUG:^.^B2(YEH M]FC2G^]R;5=6O+("0&4[ONL=;KY],>?]0SJ)6 MFV4 ;M!>@(HIPH5(*04H!DAR(2MHF/EU[N4=39&]*7V[0[W75-4_N[9^7M%. M8V2#1@.CGE*"O!;<3N:EFC9'?0=KDMQ+&W[_=+;M./S M:UJLJ*#&*T"9HA!CI9AEZ^T&\I "56=E]1HG\,)H./;&^%&-!"Z1)(Y(Z:BR M*N[$"2,5""B.@E]E63J:#,<% )P.=;_C_?I,48H$5((@8A6$R&,*+*$46BR\ M)0ZFTM]O-DL(T:28H1!CSEGFF )/">65@!42DXC4526J1%6\SGW:% M>,\C?77$]KE83N:KDYB/WZ:3N_59^AD/EKN="C3V3 .@E"/Q/Z"]4][Y5>DZ M(JR29YD*]NKA>Z!%IKS.+-H+]'TDN=TG2 [O@H=6$9O2/D<)N3.01E@WXCDLZP9> M6\R*2I^4-U^6H_FR4WYUSH)C6=<0^'/RZD5,:;34'Y-..RM M5U1"+(2G%0@^^R!M@-[-P?#N="UD7,[>UYG5YFQ/H,?AEP(5*D[W@ "&!!/Q M'^N9!]!)GF+O669NC '&>?3%G-8Q'\B4]645T73JC+5I)6 -I$268!>Q, YR MJ*NA(CVIW;*>'!TBU[2;%;&'Q#POT@^O3FF:D/%U&RF: MFEO'$& ..&@8FLQL\ .L<#$8#IZH@G,R\'/Q8[)($_FM6RPG]W'R MR-JEOFDE&."1$-13@JCG2$#F204!,#!S9SK XA>#8>')2KBX/2IT5%B,,2-6 M$HTX\=!4XAGK^JI[L=ZCNMG-K\&SAK"?U=Q+H>O3I\_%8CF?C*-AM+ZDX$>3 M^7^/IH]933VZGKL&9_#)M0Q^S_[[[GSDJI9;M5=[Z:C M=8"5XA@*)*T%3$I:B8ML;D+A 1*K-;T?SZ];Y(MH^VNHW%4&23B?YH15(D,N+V>W!*MZO]8;F4#W0.WW+08)[_$;\5L,\]^G8]F MB_O)(OEEU]DRXM]_>UR=%502U:ZKIS0;/.,8$&H\(9):$T=YG/(W('D'KJ?$ M3:N,*<^F@1YHJA\CD)/97>QW]>.[^X=Y^6/E;*NW\XYZ/Y H'U 0$B YB>:, M8W)K6D!%,@/(!KC.=DF\+J#N@6'^<3Z;+!_GZ>Z&G_R3?JJGU?Z7@M08.@8= MY,HCHJC": L?92HSNF* 03U=62PAI7X5N;2:X"I7;JD5U=P]\"VSZ/97=W63Q[GP#F8MI7Y2HG6)>/!4 (M *I8FT0B#B(KG!1@02!LV#K0?._3V:3^\?[6MW_]%QP$EDO>(JH\)[A. @K\3P&F:&H@Q5^TUU M5[8'71\,&/US' ->/A>XP0 ;2[@!6"AD(4=;,:S,'?\#W.^TPH 3H#NG^?G^ MB+I=]2\'$FUJRI"6'"#CHZ4EO:T$9@!FQ@<,T. \GP\Z%^RS;VZR=S2!R0B4 M7!4=4/T_SF&0> MC!R_0OY\1^92&7HF=9Q]7OQ09 4E5N^FM-54)]^[!U:G6VIDZX8G#.:F !_@ MMOULLV-SE'L@E1D]3):CZ>1_BYL4?OL8\?]2WB[_CE >9M3A%T.T=7DJZR1I MW+LH[F4<-)6@0*/,0B #-.$ZI%.K$)]S@OIC4=P^3M]/;@]%#Q_Q=E!"*B<@ M=@31M*VR6&[M"Z=X9B#> ._NG6.2RL:YYVL"+Y?US8W":EB\7-GC*R\&T+M9 M5%JQ6%[MI0++/40&8*8\I8XI;>6ZL BV !A SW*IX*6J#D5&OG@L(.(@\U0Q M#KW$QIMT564M".0:9!82N*1M6G.=O@YWS,?SO";'R_&;9WN\;"$ #H7"4%+N M&*0 <^-4);HG.)-* _0Y=D>E;J#N@675A)\25F]3MKR0Y@"]ZEX-VBBL*02* M*V"M D1S70DKL,S5HZB=1QWXTWN2'N5[36# E'8_K$T MZDI(0VAFG< !TJEMI1_)J0R0S\BDV@M!AU\,#FE,A8X 0L2X%L8K50EJ,;J> MNT#MJ/M(#F6!V]R"-N6L6/R83*?%'[/)DNR-!]K[;.!4^SB D*3"R&B]>>!\ MU4,>=Y!7K_ZFFBK;1;2YSO\K?>'LRQKS@QK?\6003G/I'#62&4J-D Y7O9-Q M2W<]_I@.]'TZGLVU_?MD=#_Q<!9=':QMRZV$WI-S4*8^\4 M5YF+^P#]$QWH_'0\FVO[_YOS7:@[=/Q['D/4%WXC;(?N.G[Y6FQ+.KCQ$]K.&B%!=4"(N"QMEHPQ[:+ M8(0\TX@<8";5EHEW%OB;STI?4['NEWUCKT2MQLH?@-@F(+$2<(*8"W MX\I:G7D/H7%2U(NC2\O GM%IL?7@O#_BML+QC00 ,3&">8Z=%1X;[M%V?086 M7<\-ES.YQDZ&O/GD\^$Q4;M\/BUYSG#Q?&[RLK][9J3&[03M$18<"D(9XU!K M$*?72C*A?&;\Y 6Y1D[1=MD?\F>>J^?(R_1AEG<9%^'"?A_BSG?[U+ MT>UW$<2<":Y!Z\$82C7CW!-%$',4,,0VD"FE>&8R^TN<^?+)>CY]G)'"Z VNEBC8IX4(2@BI(M-"95PHOR '5 T7; MP[_Y2OT\K9O1PRAM8'XO[D9_CI;+?4$Y!]X()C9O)%=Q'4!<&&V]!U5OJ:L- MIKU\UU5+JV][&)]QDOIM7BX6;Z;?#4Q?BOF/R3AGMCJFV>"HEY)QPR+<4CO% MR?9H4)GL3.D7Y%7K8=KJ0!%#L@K7Y\R[P]G:L L/M1^ EH((S!R"%G.L/$HV M]1HV@'*]+1?DG#N'9=BB1GH.4/QN2*ON4R(U$HQ M3B3R!G#+"%9"4QJUI@#ES)_G1D^?94(P=4XI( S'S @,"46V @"@W #G ?I M6N1";IF09ECW<9GT\=MT,M[,<]N)X./\C]F\^B4=F#TNZG*>-VDG0.TQP=03 MY A"@D)HP!8&0Z\G6K9]8KR^9MHA[GTDN'NQ$KWH\K9"0&WDXW$-!*09$@@Y M[)VUF"B@":T$5P1>3SQM1WQXG3JO"]3[I-NVI_7)%?>\$I!1AEH E8V8>00E M):82CE)U/=6UVE;V/BZ=!G /[-DE?"U_]K\4D"4(8(E,%(I;;:DE;",@PX1D M'CX-T)_?,8-:@_@*%=/_,*2"EP$1@ZS5DJD('&)M9DJ;Y&7F*,KPTJ@Y#)SV[ MZU=VS!5ZW@%@D&OJ"*%$0J%\^F-U1A)1I[4E+'H6^6N$7,?O_"M'YNW+@7A- M4^9 PJFFT%M)U"9"0T&.6&805V-3ZDW=]^- ..KLN7B7/&M=P=2>\> MYY/9G2U^%--R+>?LYF7XV&H<'Z)1*^T&C"4SAF$ @3+*:J0QKB1W'&6>YS3> M EXFP\ZA@N;DVW> >W@)J:/>B:T&KQPQVB*14F0J3J DNI):8-!7OJ[+)5Z_ M"NAA#_GLI#'?4[V.=VLK['/<3LQ7M0,_?IM.[D9'38XGMQD4,<)*;Z!-0>=2 M<4!A!0^4.M,W-L!PP^X6WK[ [Y6;^R)^%LWH6-],( QY+SDB""JH/7$45K!# MRU@F P<89]@' UO'NYMMW>?BIBCNTV#XLHQ]^GC[Y?';8G(S&-@%%4FO <.(,M0AQPQH%GTCH:OQLW#9W:G1RA0NMI M!5_)Q7FO-U+\8N$" &@:TY$(S%IE(0-5_!WRF)V:0>[&355AVB.P9 M!MZ'T3RYB'Z<,ZZQO8&HN.04$@4$U\XS)FC2HF(RSK*>P?.D7GS56?UDIJ/% M(JHA::,N>K'^Y6"](B1*BQ#$!&A@*'65T-+E[G,'>"AULM;+CK'MPUJ+BEH9 MF.L^IR39Y2S^6A>7>/"]0!&DRA/@,4JW4*E$=BNFQ?QJ*722RE\;9"TBW .1 M7O6R-L!PY_/!&<6P(,@ B341%CA&*K$P\9F)M@9(G):T6[8/:A]'X#3FW6SC&*R-^3KX7C">4N.=H)YS2I1@ +&-F%Q#=#V!@R=J^?7I=(N@ M]NI>6,/P>['\7L9N_R@6R^?Q]/+3HO@PNJ\K ']*LX%K)&C<74LED&-<$P:V M(%G+,TMS#C XK,OEKC\%]+8:ONWMDO1S2_PH MO"_N1M/8L[1AW;VD[7@J**6HP@IR Y57@BKEY'9$^-SBT0/,']+!"G4ZGJV3 M8-V3O8O)ZT>"8% 1ZJ3AAD;:0NM()3+WW%]^IO*3=%2V@EK&?/\P?7;Y'I[G MWSX9E*?,("*505X [1C@N.J=)/[RY_=\?91M(M=YX,F"%//(LMLFA MD]YHJRLIHS63NVX/:#/1BEY/1ZZ/:Y'I*+]FX[E])LY7D!@+62IL*;5G7EE8 M==\"GIEL9(!A%!WN(G/1[(L,]==BGY\*FD$O'+<2 XJU $1&L#&#@$AXDQW7=IO MJKNR/>CZ8,#HG^,8\/*YH B/_R*.(=50<8&@J>P4H;B[GKRDK3#@!.AZ8,"K M->_]$;>2][T2F)8NE<[1S@-DB.185!X- 7RNNWF T6X=&@HM@=M3=H1UT/QO MT5A^GY+]S9[]H(<(5/-F0!1#II@RG*:*+ IIOQTDAC![-2O,ZD1FA/63[ M.#4;)5?Z:MRDZQ63F\U%OL_%N)C\*&X^%?-5Q8S1N":O8K.& E!,8",94UYP M'W\DAFQG<\TSKRX,< EKG6*= MU+2J J2O!#.1N7LV4$,W[)777S9W.(/9K/ MG^*GZ]R/A_9%&>Q MK] HR*VHME+Q8Y49A3G\?4(^>5J&M#D%7H#0-D"8NSMI2$,T[CY(BY!=A7H?-2:YJY8@VP/%W7ZU4[ .>O06G/ M48P?TTV>_S?5@.O*7Q.1>/!-73+]A:"*?IU5'S3K# M5KIX5O7S7=3AO!C-VR!I6U^3*MQ#3I$BV%&0$B)I;+?C%\E,AXC\11AZ)C6< MX1[EP;\\7^*J5UI]OJ+:_)+EVW<#1S2N;G%3%7EA@+ 2,>TICVN=M 3;N@W+ M>1Q91R?8:-90D! JI2 %D!//$8\_RPT8CG-[M=[Y4WC1T(MU$N)=30JKW#3E M_&F;5^_]9/1M4^GS'$/^;1[QQ1&#_'>H&[G., M]#.F3VA_P"M$(<;8"F&)@)H2++EGP@ 3K2](F@[XW?E,-B0HWY!@]#,)]B1( M:-Q& !XXB;VAS/!HRQKAH*JDD@9<3_+N5E1;]@-S+R>;/W6Z+K[W[=/!V;@[ MAI8R#W3<_AES;/&EGY\/)LYX+%WE)HA+ M1%T4"V_$8MBC3-?!@%C3BDX/\R,+RN;>*3T?_>]D^C5NUF\C^\?EC]7ID9L5 M\[NG3X_S\??1HEBL.G3P>DC39@)+A::DEE8 +SATUJ)J%#'F^/A[<.!,0J]) @P2Y$CWAE0;2F8Q+GE MVP9X#ZX=DK2&9,8%YMFXO"^^COY)YQ4K6B9;WD=!S>-B&?]JONG)XQ6+Z;W10/ MR;,U6WXIYC\FXV+M:2CGAR>1W*:"H0[%61, I9#1W""H?24?,2+3=3/ \*?V M*-0#SLUYM#*,7KL7#M+EP!L!"PFUQ7)5%96(V&U2[3&99R0S@=P @Y?:8T5[ M:_>"5P*F.Z':4$%2?])7*VP<=31OE*D]SG79.JWGB]9D)[FF'&+Y>0^'8E\ MCO];E^S8=N=H]TM](P%*AQSREL5U%#$<]_K;S1TWUY33M 6U[G&TM(YRACOE M]G8RGA2S\=.G>7DW']W7F[6'7@D< 0S24JT14]819M3SV $V;8I@)G4!I'G/#:"(P)QG@[%)#)O38[: =(>@PBE,Q@)IMSWDYU2RSXOB@G7O=<:\7'?2P]=I;"^^X M,X9C7@]2&0VAD=IK+)DW/ ['C= "6)=I:0_:)7@J\3K$-W>B^_)0C">CZ7,7 M#EO9AU\*U #IL&.(:$T,DCYE#-WT&2*5&4XQ:(=@>Y-12ZB>[!1^X:EJXAE^ M\UI $0(@+<0IO86%6K,T3:[[+9W.W'4-\')ANVQH&=?F?#C6C_G^0$ZVK':" M[=Q'T WW\$Z,(\SN>[TSC4O!&PP!Q2 M Q%(]\"YCICYK6A2]W4MK,N<,!WK_'"$:";09^!0NM/6F$;/+P479VSHE23" M&8L(8H+32D#*'1?N.6;8216O#> M'(SE3R=IWU;WW4\GPTO&?^.?Q2T,H8([%1C"A!!)#>/O?9H,RZ; -R*?8WV;2* M]$D+5I1O?0)71@7'G&#O+$M:M%IHS[G.17/+;E,:+C[<;D_\U'KZ<__E],O[^H?Q< M+!_GLY>E"NSC/+:P.3%^6H^A=XM/\S)E5;O90\T>OCD( C!&Q JB$<= IIB; MK27 =&YR#?#K&?3#U%@;?'_>CYR!\EU\>3"($^")=9188PW34E48*DM-;HJ' M7]"[/UBEY1!_A[G[VL")O1HGU=\54=CY,I6FV4OEO.8"@PH1!YW7"C/JL$:J M,J&4]SPW1]F PH[[I&8O2NB/;.]F'XI_ED?NBMK]DH"Q0RKN^@A3R&KGL-CN M_!2&+K>Z]86>LY^'F*VHYIFN_27:._RW^NES\1!%7"7B+>Y6J\$U9>;#5#B( M )):0&>@9-A[0"@CW*RRR]<,G5;C;]K+S >%X9!)R23$GD3::V(KJ;@3F:EI MAGMKZC359F?F:P9S#][:+U%GJQ!4_;B(L^!BL1FRBYIKO@??"\13X!BC2" , M"/( ,U6)28GH*ZG64&SRAKI_G:NU1:C[8-1FSJ^[Z/O3U(R9JGD3''XB@LVU_,?B2 V_?3 XXQ!7GE)N,#%> RMEU3?B0>:= MI$$%RK6GWY/Q:Z[;W\>C\9':W?5HH H+JR/GG&96(IA* %3] S#WFD?C[>-E MZ+<%!"\IA%]QBPD#W#JEG:0BLA=6DBGI,D/X+]3GE6?Z]0'\P"-FL:)4200X MX)I*"+QEVQE09=FF5]\RI5>45Q!D#M:4/&IYA M[%W$#E7Q:=I$T,Y3C;R6E"DJH"">\$HF+>'5)6DZ3;$[#QM:1[D/W]#>LD.G MU8AZ%ADA:F3$E&CNN2:*684W(G/L6&8![T%N/-ND5G<0=S7[KR3_-)HOGU8I M.T:K0I5GFO%W]^6H:?_PJX$;K:6@."VV#AM(J$7KJEN0*B;KPJ#[%?BY#.%Q MM1V/;B6P:%\X3J@DF'+G,4#&;&!@3MAK.IUJBQ!O#+FNT.YW@+^'87$T*%1!XQS+O&-[B9/$T20YL/IWA7LO MGH1C.E^;Q_K81H)2AA/-7(IE5$P;1J6I (AV]Q4=977+CR.7K),UT#,%CTAY M_?KA(%,:N;AO4YAQCJ)X@CP+9*\J'*=])1_@41:\?:3KN[V-6_C433=;'LH> M>?B%8#VVFB(LD0%,&(0Q)I5@GJMK*K":K]37N?C:@/)\R]JA [QC7PW>>Z D M U2LDO,RY/566(S ]52F&\02EHM[#R2SCZL:1R\Z?O@49N?S@2%J."0662$= M1]I+Y5=B21&!!-=45+,M!9?MX]H/7;Z6/W=R'T^-B4#MC4+*F[RK#WI1!M.P6)098(X9! 2FI3"O_-=O: M0OQLE*J_W7#@M4 TCMM4)&#\0V!GO .R$A(C>D67'5I0]%'VEQ_,N!*8(8E 0HI(0V0!*]'520@NL)C6E'DV7' M /\\VS@9L($07>6ZBD9-AIY"MQC+.95[FOQG63NT:= M"G0/O-ET[M-T=,1UN[,>Q^5K.YF9 M3WCD*E99-U626XL[[E]_ 4E4K9)(B(0H)=,9+V6"!-[SXN .(O1SD&.A(9$ M\S,;7L9^/42>K'L Z31,<*?%H+W J_7N:3(&,*LE5): MRJGQ9 N X)G\&E"JDM,L<+U)X RNUP$GD")@B77>:ZT-X[5UJ;B#E[,!ZT/( MAZ_7V\%[1M?K!""4CMLY]EI@9:A!J!Z8HQ<4M'Z,4)M=K[>#\LROUR'32@D1 M!TN$M (X;FMS4TG,,J_7!U@>=A!+6"[N14CVHYJTO&+?V28XPED<"8T0,0LQ M-E34I_U*Q#U-W^I(KFDUJ1:GO0]M+.97_.D&V;+:*?9OG9WSW:I:Z-7MY]'] M 0(=:!NH(DP!0ZG#0BDK$*1J"R#SF?<< SQ#ZI%*W6)<@%+O)A'O:AZ[>3U] MJ)XBLX=+NQL%@+W ! 'G$=3&0.\PJP<(M,X,O1O@/JTW$G4&;D'VN#^_5Y-Y M6_J\T2I *K213F#-#*0,*(H>=:[WA^*4\;K]QBL122Q M-EJTTA+&(]12R%4@'58(('PHA\FI7'8.AOOGOBI0R*%@!DDITUFF(R*9]VM MI#.7XT_1'35:.^HN$5Y,,#3 MQ$38(@68]; >)"/NTOT!VPFZC;-H.V"'Z2Q*+2=Q$V\)' &WC<$ M LZD"6Z,M/U'.,D ][W[2#M_VZ9KZ-)_$[=:D_,YU]GZX= M&*/VW)M*OD'+$$?O@7 \G5E918WBVPF5JE1G%OX>.#G:2F[:)Z:G6\3R5JW5 M_)&(HE0V!7L! *4( 8$V0[1.@LSP\ %>/@YBF9/G_9LF[&GRQHS]P'$!/E.;;6 PR4H$QI_3A8B#*W:A?C M ]BQALK%O0#)OLRJT7PY^_EY,;W^0UW_][\IM9ZW"D)0 M%S_=][8(!WNFXM2;>&@FIB+-X[0Y!@'7T1!F:S'22 M"H^OCP12_]MEZ6_2/%A"@(88>RZ]=IQ%@O'-P)WQ^H+.;+J1_[1WC O.WU-Z MT/0RC>,^5$/*O:%:.2XHM<(F)PD&)3(&G\9WYK?)>7\T>^WW01V9O MNX"8H/&# E%A6%P?O.9P,U1.T"6=;70C\9?9(#H$MT04[/5U"DN9?Y@NJOG[ M:;1 (B)^/!E-KL>3NT=W/_W$]>]+[-R!8]EC7ALB1 QKQ3"#"#!$(T"N!DE% MO7DQ#.R(*R^#:\MA7^3X[6D?&YS;OGX\>$3B?@FZ5)R7:R",@=M!&7O0\_%\ M"%5&]*].VXZ&O/V%X\?1?'&SK&:/_LA[;QEW/1Z 0I0[!BS'4 (!J)?;209M M;FW0 5+C."E-.X>RL>J85]?_<3?]\7]NJG'2&B3](?&!/%$6\4?A?74WNE^G M$]BQ.+WQ5*! 4F(8,((X26VJ<07J3CM$,JV= ;JR=+O6' ]EY_)?]V3G O'R MD2"X=B[NS1Q%D&H&5+OVD?WX8+9:S0QN. M)LT#A=0A2!R4%*?(!D:HJ@?M(F( MJ)'.&T!\-)8=4G@S:"4!OOP=:QX%&O+K"*A/R*\F#B('VP9&/,**,X:%3[E! MHKZF]7 YM:42(%R:RLH%N,2)W/W]]%]QPU[YZE__N(G;=_;6 MZ 6!&J$QC8!*IBCDQ$+IZX%3S"XGAJA##KP\:>L#Z8*'OH]]_&4VG3E$;H@KCW%N^,]H^=T"B3J MP)H/R[1SN+J]^K[*33RY M^US=)??R?;S9V28PA(SVG@LI)6+* LFWZ[C6(G-A:VV+E_ ;ZH\[7<';?I^^ M_O+T-HUA/KW5RWGZPUM4V/-T7-;COA-;HQ!(&A(CRDS=2P/TY>3 [)X"W<%: M0'68T?R;FMRDW]P_EU'+W2>2JH49S68_(VU7#DK[/$Z:M \8F^A?2Z7T 75[];(^[?KO\4WUZ/=R-?FE2@&YW[^-KU5R;WN2 MJC,]-8UMXE]O-LHP9;58+&;CK\M%=?-E&DVT:GPW,6FMG8VK^<=JEAQL=BBL M8M\/'J4\&T0Q@8"PG# .]7:9!R!S'61_#=(.653]D][]&1>NR>C>+.>+Z4-< MP\KQ/>?3@7A)#.%1I$HH"H04 FZ/;BS-C';A?U/]A%+*M1RO;C_'Q>2^VG;M MR[?18K,5JFYBW[Y4DTV/KF:_QJY>W7Z9+B*BZ]'MM3./?'? 5,5533F&-*(< M(N)MO3/3R4W*G5K[THSNWTUNI[.'U>NN M;C^.GA:T+NGMVJAC9OKP?33Y>36Y__FH-QJXQ![_\B ]M%8KRA'TS@F0JH< M#XE6A$ OP*G(,4E)CR33VG&G&M;?UL#'/C4@?X*U028KL MTCN=R6$@SI11_WH)J>'&(0QBUXU4=:<18!=(GBXDN,>ELAV@)W>I=)9S(J " M<;]@C>5&>%9WE\8_G+W\CY+1+I?*=J@5.*U_IOL.EL5[X^E@#'=&X71 AKVP M0D,DZR$!AB^#"'E"?%E2^FCT2ES?[%5W+QU/95P4M*A!:02RBL MT5Y0LEUDD8:E\DN;5H$L?[_,% 1=H82D6<9A 9"HRIYR7Q M#ATJMS)\3=2_B%_ZJQP#<#&FF.4LH=:8,"^>#P0HK1'@7$DL-([;?%.OZH1' M]7Y!)S"Y GV3%\?A>#&N"%P(2 7P&%F@,"8$&KH9M@307XY#^)%2SW(^: =N MD1CE..[Q]:*Z.99=+=\41)RJ3+FHQ;W5TD1DO*FA0"PW\&" UE&W/.L7Y@*, MLV]5J-V@LX=>^YH%SR&#G&/'(0(4.0LLK@=)C#UT5W,^T5'=+.[53!>"V)8JM7.N=?><2*WVAC@3-H,LD1GQ\3I#-029T*S MZOMH?+.I(1HUYM7B6S5[!LB^,Z+#K>/>5J9JR$AJZYRVDC"RG2K0X4ROBT%Z M;W;+H^[!+;U+:[H["WCE7\J=9 )[Q06*:W$]#(Q 9KA):V?)17)4.2.&' -B M 2Z\VU8JF+^;J-O;\?TX+J7SS\NO\_'->)2KGT9^_V,ZGBQ^CX\O M9WMKW!_UWH 0Q%S$N1%AEA#%';&OP5;8L\P3@$$FMNWH!* DWD66O.GW:K;X M^?%^%.?@Y";M#[X_-#M4.M@V$"$0DQ1":21W3"F(7#U<@WWF7>E@K>VCR=4U MHJ)SJYXV7SKEFJ"3ZBZ-Y4P)>B)IG%(OQ@UPCE:,S0)/A1;B"*$4 M $/E&*.U4:L$-9DZL?URVOO.X 0:L3V^!4CT9)/;P!Y[X^F@O<'$>2IEW$Y1 MIB#DM26BF/29X:(###[NR (['L."YYMKK\Y5-9;YA^GD>KWWW:]@#K8-F@IC MB * *>Q]%JQ^AX@PNDNIW3.4;+><<[9%:PG.B5_['++@_+'AH%(J*5"2B*J M(GC 4E0?PVD)Z.5D&^V#/YU@6G9E:L29-Y\/&'&(!$J%'(ST7$-%8#VL.%R.F=[NW"YH4P;C8Y] J42HI2Z+NG( MA:TE; 7D_7X\^CJ^'Z_JDTQN5B6]ODWOHS#FB:2+GPTV0$U?$1@F"B &XJ^" M(!1WD4!N!V\OZMJCF,ML3^"795YSC]K=C8*&46-#1E.,+C6(2A47 M*L&N[H6^FU7'P5SF]'J5Y/#CZ&<*9&AP[_]F@R#C3/-:(TPIBFN]THIL B D M0''G>#$;\"Z$NR/1Y%&0EO%M_#+-\&SH!$\LP, M6P/<=/? F#^8O;? M_6B:3E M0)K/U60\G:WJ91UFR^N'@Z 4 \]I58YRJC&V-0#0L1=?V*QCR;ZY*AT#:0&6_&.9.OEY^35*9SQ9 M>3DU9,R!EH&M;F$-5 S)J&"I);6REA PGQG.,^S=4H?LZ1;>T^RVF]UT[VL7 MN!4^FFN8VVC/<;X*UJV':9')/$4>]NZI0Q9U"6ZI&^\WD3AT[?UFH^ %Q]0K M:#PGT?SG0N"ME1=MR>$H]0Y2VM'68D,L)F748,L M0=3[+JLSF$ND@)D^/$PGJQX?S/;RXM'@@5#2@:A%E< &,V%]/<40U_*2+C"[ M$.FK/&1'P5GB$N'F9IR$,[K_.!K?O)N8T?=Q5.K[KA#>;A$X]08I;@PF7#"" M%*/UO1HBEER2(T4/3.D&U2*Y?U+-A.K&C6:3\>1N_BQLYW9\/=ZW.!UN' !$ MR40S$L3-(O<($E&OPD@"E7F /,A%J@<:=0YPV4B_E26?DH/.JF_59#[^4;V; M7$\?JO?3>?*"OKK],OIS_^UFFS<%H;A"UB)LH64<**M0?3B!A%"EG$G/E&O] MHEV >%]2^:#E[&PDR#QX;KX+>Q[V^:7W MW7L/'#H:U9-LPUIMOX)V<4A 6I!QYI!>V6]Q9#G4>3 29QZ8$?1\,Y &_E M([R4 X5$&\@9AD) [QC'!F[W"T9G1L4,,-RAY+5H%U _\FH8E6W6/_E6+<;7 MH_N_R]SLK&%B(>&6H*@J# #"0JT=A]I1";&B\& 0=$\KS$;L5[>O1_CHGW^H MW$V+MP1BA?$PA?5 S&URZE=P X/V3%S.G7E)RKQ06!L=!! M57?7 57JC+AL&9S&,MI5!J<=:B72U!Q=!B="RG0ZXJ;1))=$QU]K36DXYN>_ MJN0+L4$9G';H%;DWVJWLLFK@-'E/$!HKK;CPAEG#F(B[0U3# *" %^.0U>>J M4@+ZLD?#3W-_7=T^7MN_E6VEV1%QFS<&X0C1J>B5L)YCX 2AV\E)J2M5H?84 M!G,GC-E]=MRC&(:P2;?C'^/XU,T\)S&>AGOHCU!O%>HJ(9PAJZY?E:#::+*J5 MGGI?+9)DHZ$2B3#^NXKV;FX9RH&VVA/$.39,*6,=\$Q:BX$F[%#UQDLY7L0P M3BIKE)4F&JM( Q;_?P.#@/"2K:7^*'/$\6([>;3/"!9[L!A/[E9CG:R&M1S= M7WV]']^M@)CKGU_BFW<<+;9[0?".6Q/_(UH; 6TR1.,=A+> BM]D_U]NF@"GKK\>"]0T!9C@171GG"D-S.%P)MIJ_J@"),"RBA M#H#-L&U&\V]F>I\X.QO=C_]=O=Q.[]4\#5L'*AEP5F&&1+0%!>4";SD?MQ>9 MJF90KLP]*YM^D!Z(JX:1S&,E,6)-=JB=AZL&(5)1:BWP KHJK$ M]9 B5)D9EP9&A#PA-G'5:(5>B:B\45P4=ZP'KYX)DD*NH,=4RA1K8:U2ONZ^ ME#K33V= MF2)U>!86$NQXJ!Z>/)44#S.$B"4=0+&<1 A%=P2F]/+N4?,D-I; M, M)80#I0S!5'&/S!8&Z#)MBP'FLBIA6_0)??N3K"?G+!OJNS^_KRZSOTS?SAG2 MH%4PF%NLF63*XG3TAJS?SINH3#-5S@ 7G9Z$.>T+ZJ,(\F&9E.+5K;J;5>LA M'J;'ZS9!Q)G"%:#.6FF!@=2)[;)*&<\,,1K@>E24'$<#?9SN6!M.[R8WR9EN M.;JO23I_7\WG7[Z-)JNA)\?@Y<[2<=GO"Y)%A1N7:83C,#&D1J/M2$U<[B]F M\UM6W_0IA"Z6JC=ZUGC!>J-MP%C&A5PCIB@%RFILR'8$Z6+[8NR<4RQ;QP-> M[%9W>SUTM5S,%Z-)*JVX4W,U;1J4A!Q2A:!RJ08YI4C+[14V]YE!4.T3?)XY MNWK"N[T^>G[S[*MJO?]<*\T=>FAOFZ UH=(QS TP5B+.E21;#1I_EL>0]EEE MSIPA70/=&376BK =-=9M B+4.T^1\B NLM)#*6G=8Z=-YA:<_TV-XX >0EA' MRZ=K-*]NK[Y7LXV+Q=_1'SLCBUPZZE-8><SZ"M M4_)M97HHWF-ONX"Y=5AIHRB/K$?28 [KH5(JSO_^^!2TV'7ZUX$$!N*'I(G1 M'E%#!*8XU9AA"&\Z#:DU[/)HM8/R])Y'1FLLA$"2.ZN@EMS40X;* MY]XL#4CR1\EHI^=1*]3.PO.(68*H0\(Z"E(POX? ;H>$5&;MBH$1(4^(#3R/ MVJ%7\I;QA:++NV(\^)) I"0>(T\ED2[@S M53^JR;)*B32>UXK:Y]RTJTVTRCQE/J51)H() A218#L\A3(/< >DA_H4^:NT M\]V@W/[T9)V\]=VD3GA_=;LSQ\J.LY06;P@J14IJPYC4P!)O!3.D'@T0+/-D MY8R43P>1'-5\D--;@O)M$><2?[-%"NYH$KA 'SD&,I(**4$>% MK <'_075#2R@A#H"N40X(AUH&1!F M1 L!L8(R[CT<0(^317&5Z2_1_%;R>4F"O)4,-!* MDI*J$>BX3^4U]78_X:3(5$!#OFCLCR[YN):BQH:X^PSF9\]%AAMEJ)?2.JFD MY9S1[=854YRYVVI^RWA9^N08;$LL2Z-Q'.5T'CMW-7%_ID#;Y7C^;7T!9*NO M^RR<@VV#)8P"A84CQE "J#>LW@D@)W+]/(=\*]GCPM0QVD6LYK4U=MC&>?%D MB+UV3 K'@#5">0RA0?50./"9H>WB+ZJ#CD.W"%'JRF'I.&$=\+^,!'^\@=;5 M[72VJ3#V9?1G-8\S8#9:%Z"?_5S!D]+(I@0!T_O8O[M&.[3>OAI\JMI(K+18 M8LV\49#7]W\(*)J9>4H.KXA/$?H.14[%ID(]@)!ENKKA@5C\6Z (T^5(O':;.'/,^>"X)*RFSP_ENEOGY=?UUHU M3NC5O_SM&;;3!8@XX(#1PEC!D8U_2D& %*UJ2!EW,#]W/Z"5SPNLD'!4&@J) M4DJJN, *6\. _055C"I)F2/R K>3QT!\R(CS0,3^.>6)Q2G,.M5?6G<:4GG^ MY:9ZE>0>C[)VP)[ M9=HPI W!TC*"->5Q'[?%1"&2:ZD.BPAY0FS@4=8.O1)Q==/)7<3R(9UC[DD; MO^_Q$&>(Q$AH2X5D!CK,J=P.2N;F,1J@HT:?:T2'")^ -CL7DOT-@N54"44% MPU)Y:ID&YHF&)>=?Q+ ;L1[@2!:8[=V_/E77TV4$*GUV;Q[=UP^&% O&/2$$ M,&JYY)#SQ[XI<3G9KHZ5S;1#&(\3L?OS^GZ9PG9?GT"T8D"C]P2F*544* "@ M8$Q1:Q2N1Z8%SXQQ&N BTA-!^D"YP$+R^V@V3NOEI]C1 [;'RT<#X!@+XX6$ M3%(JG6>/FW:$P%\SLV:NW7$DNH6I>/UP\$"1."8B<)Q=3'(&%:L'!+"\ M'%LC7Y1[.)$%8AE+]&8Z65TK?AU-_KBZC:*H;E*/W[_35Y\.UW]HTCX(YCPW M3!CA@4:+V3*IRSWUT?8U"18P M9!ED,'90< % *N6TZ:^3,C.H=H"IB/I<=#I&^3A6/'YZ;^6S?4V"P,A@:F#L MJ]*<*"0EK_O+#I>B'+Y^Z$YB.RAP)*3M*;"^9?TM\OIZ.5M?JG).[;)*I^5[ M-S<-6@8//0""Q:T:UMYI39 5VPLEJ\]_P>A.?M,^D>V6%S2;%[3>@!'O)<(D M=AAH ZD&8KO<"2@R?8,&M,TMSHL\9#OAA:S[P-KRXF7+0"3''!-LM<(T*E!M M^=;((I2>_UZV%"^.1+837L35;]T'WI87+UL&0(&Q5"L.$!(T;N2X!G7O+$"'(T M=L%1XGS=DT*)0*NJ4J/-!H*^/PMJNGA4!G MYDQN'B=6J 1JD9W,D>!V0@XBZD[@MN1XU30P(.,FS&'(4N8DYSV@]0IIK;.9 MFYG6,5B70(YCP6U/#D7_@X(W>K+NQ?Z3L49M ]4AA.ENDHMXITB*E_)_OU1J[&P2(A8U& M$XC+GJ>$:*Q3?H]U7R4SN6[GEWY>VAFB!2[P3U,YCYM4EU@9* G$&%(2M6,- M S&,G/U)24G?H3ZA+\# Y].NCE!/C@KN]K:Z3DFH/E:SZR3ONWW!>:W>$R1# MF#,#N-4^E=F!1I#M0LU$J>S3)83:*Q#HFU7A++,,)H M.T;C4>9Q;/-;P.>)(SY4BPN2?Q[&QS'@PW32G 2/#P?%M(E*"4-A$+"*.D"W M!T#C0?SS]':8UNKB9/?3)A8_MC]RLBCAX1ZK 3TL8Q M.P']XQY YY8S&Z#Q>PK#HS/<3VKYK@N('FGVOGQ)$-)H9SUBD#L1YYX'S&S/ M+I7-C (;T'7C4"S>(Y$O0+W784HI,"K=OJ_2V^SAVX&605-L*4,60V0(3%8^ MAH^SS/]5*_+EDJQ;N O%)G_9!-CIG[^.%LM92NAP./70_H:!6Z64 <@H%L<+ M'(R?W^X806YY]-97GI?"JT[1+DRK36_'U?Q3]7WTW'V3BB]3VE'_I0 M_;GX\J_J_D?UZW2R^'8HI4+V>X/BU#'NB)):TPB-8VQ[&XBQR$QW.:";DJ[I MLH>%?:,_-)+^;S6:??G7M"MN;EX7+%7$&@'XJ@)L7!BDWRX(V/K,.YL!7=D, MB9)YH ^2B?'K^[89>2\,2"FJHX%"J>0N2L)"M;T/%PIE!N(,R+%^<&S,@'V( M?/33Y8&XX?;O"UI":5#<^E..+>3*/.;OL%S#S WP _VAL+&#-0'2<;QCTYU M8WI?\$Q02X1'Q"/AB:5$;2UWK%RF:AS@,>!@R-@>]6&14=U&877+QV>O#$!' M46A./'"88R4!>MQ, @@SXZ@'>$!X>DH> _PC*T^8);L^D[BZ-:/Y-W\__=?? M2;%W9S@6W$G($"*"&$^Y5L2+51IT[; E!W=E/8-62_!YX=TFB+S=,D!(L3!8 M&2$) YH9)U4]7,1R:VD-\%RD)#5VN7UU(H/&*UV_":^U<4385,/2>^DPE0R8 MNM-"T\S EB$3YUCI[4ERW0[,SAG@6B:Y%I !0./.53@B-1)("[_I+B&"G7^5 MZJ-DM"O)=3O4"ABTQR>YMM1S*S7FP'LG@$MYP.LA >0RXZ@'1H0\(39(8/7!,@51P8*K(V%CF$!'D$PPF2Z< WP%+SK=:0 V@4H]Z%: MI'Y_G$U_C./>0__\;57R:%,Y;7*GDC_R:G.VAW#-7Q*45X!0JPQG$C!.H06H M!H KYLY>8_5+B]<5I/H!_G3,6Q=L?];W!AO/]B\+<;6@T#G-/,"4<0ZE(UO, MB?HK*+[^F=B= $K88[/I=57=K(I(?AZE4*3XDYOE*B)#S>?58I\./-PXI"LE M1BE@RCN&)'? ;P>LE2BU92L12=,G'5Y:=ET#W]Z5_N/FU-)/9^L1KO[V;J(F M-^KFQVAR73=)+\?;P[5FM/BV @BF8MPDXYAYD"0$%9 M]Y8RF^D=.$ _@U)\Z0SK BO&"2US'V!QD/H8 0&VD81TR1[5$@88[T[A!P6:M>7[B?@F9Z.8];F=C;5)&X M#C2)B_?M[?A^/-H?K]'^94%J ;V)0&M#O$$"IE)Y:T HX+EQL,W= "Y8Y_4N MC4$=<71RM!&HA)YYQ CD&$EOK)=X"P#4F?&2[6V[RA7GA,=S MO1%ESY%=5_(H3,-W\_DR'0;%3C]Q96S(P;<;!X@] A8XIIRC0B# MW!JI=7E ME)8<$/TZ$44![CV;)LT8MZM) (PIQ8 0&'NBO>50U%>!FIG'Z>3S8GK]1X.3E]V- Y208"XD$\QXB22FBM8# M%AIE!J2=TY%?L=6Q:V&>2[2/#?0 M0 Z62^N\3J11E'9;A,QTWNA6[6638*&&2".NG5?* ZX]?!P=3_S8+N]XHQE.ABTM_@N^B+M M>. +,&^=DOWJUOT9]T&3NU6"U*M)&HZ:K$!S_UR.?XSN$V)[N-?F-<%PQB&7 MJ9"&<(9R#O%V)?"$9SIUMDX,>3'JKT?P2P2%O=G/C]5L/+UYZ1BVAX%M7A,8 M9$@8! E7@E@/E#3;XV^&8.8)A_WJ$_F3\4U&ESV8_H_;^?72_;$^\ M%^V#U=&*UDQ:&V>?8%X 64\[0YW(/-]K78KO^THHD02S0B4%RO/N..0OAG > MZW2$+I'26&!D-1/;8<==?NYM?^OB?FO&N4F_9\H#XEL[X OP[?/R^_?[%1:C M^QJ>)[E)&CA#-7Q#8!9*:Q3$ECH('262UL>7)OY#IF$WI'J!1?G6#^Q%PC#6 MWJL?1^-4O&9OU,6S)X,1DAN&'7+G) M8FE>*W.?U=*BXB9G7&L.//"20Q;79$I9#0-"]@+3=A2@S$MSIC=Y#"1E'8,& MH9165B(I,&.(4%AWVCJ9>:TS0!+U(LD]Z>O: 7OR]'66H#@_*,1*,DTY1\)M MN^N=/'\C]B@9[4I?UPZULTA?YPFAF" -N*9(,^4L%/60 (:Y5=.'180\(39( M7]<.O9+IZXI62$=(1?.=8D:@E9P2IA%YA!1G9M49XD:GQU6E!/1E_ 36.YKW MT_D!5X#'YX+%1 &GD+-:0( HXHS6PXAS])*-VTZD^_JZ/QO< AQ9>;V\L0GV MTUDUOML4WKW^^64VFLRC.9^$.KE9_>U^+>*;_[=<9P6* [VZ_3+Z\^V;O ;[ MT])="8A)KHRAG (CI5<>"U<+0QN1F:]@@+JR#-,'+K\SF$R_1*,HJ0DU&\_' MDSN[G,5?UR#4D/0X?QI\/40#C7IF/;:0:8\4]>31RO(@TQ5LD%'!PZ5SQ_.N M>[F?<*JE@30=^*?J^GXTGX]OQ]?>I&MV/_UW=_/9].EEE4YR] M'_]S.;Y9/7[$E#Q!+X.W'$C$I1.*NY56A[7I0:0QO:]V!6/&SG[J#I\?9S+% M7TNRY]GZ^H/!(B:4!0XC"3@F5% J:V Q\9>3A^@O->V.%O0)9Y"-L/X8I51V M\_^[C+KA-ODCJ?E_5C=WU;RW?5P'7PU,"NB)QE SI**F\L+6)X8$.)B9%&2 M^5I/NV4K+ZH3SH;?)K/- EE;PE>3)P!TNQG+_UC0W"$!A0*.6H(,3BZ#-:". MLTM*F#X(7C:<*\4D>F*3Z["=^6S<1]I;F5\+6E($9,IKSY3VT**4:G,#*02Y M!Q1GM WZQ]3D]6A]NH] M'Z,6F56+\6QE'3Q%RD]G$8,:H=ZW]4?V*W#B/>$0:$F\Y$!CH.Q&3-2P_JL^ M_+V,G8WP3SQ'&P^VLTO,([X8J*3642" ],Y1EG+1FQI:AWCFTI9=T.R$IPO# MG%SE9'OB:7/D'-@.FC%C4Y2 @HQIXC%%MCY\I]JXS(6B=5J]@EE]3G(*< 3F M18(T7G6X[FS\V_WR)MF!R4B,0EXL9N.ORT6**/@R_3"-#T\640RQ3W=U_/S> M,(Y.OQ0(581P2J6!Q"(OKCN64NR\[FZ3-#7MWA005AJFO1ZS#D^'%$H'L[\ NLGZ^M8?TS_;HJ MD6IBY^^FJ4+'CK#XC+<$I*)&%PX93IFW#C((50U!W/BAR^%?'[R8E@*^1,3U MZX[NC+H_V"901@1CG#%)4BH;;;VD]?"DT9D9@@;(JUYD_C) NR.83Z+!YH]9 M3.9O[?;;ZK(&[PN&GU;H7P8F8>4B_[6P3 M&(J0$6^\0 X:X841?#,\S#R_9/W6J?0;<"T'\ )\VD0V; X*UUU]UON#64L: MOB$XIG@J3@25,SC5.:=QYFZ&[K#)3%]\)EQK*?UI"8A+L<GJU2VNJ?VS_^ MY[B:Q4]_^_F^^E'='U@XF[T@$ &E0H@)@803V@E#=#UP;E@Q]\:+6"E[P;PD MV7ZM1DFMKVNXO!K!P>6RU7N",4"DRK>8,<$L(L[I[9S3<19>C%KKFA:[6-<# MZB7)]V[R?;F8K_# A]?.W:V"B_N@:'*D6AO, 6XL<+X>(I#@I+\+GX= M#?5 4D5ZQ9&*??71J' @F@\8F*TQ8=#E5!GN<\T['MB3IXHD,)794YJG1*E)XZZ&.-'=,8RZ4 MIMM1A&F1$, M R-"GA ;I(ILA][%IHH$D&%K.?<28F\CG#8.O]Y"$ENJKN1YKRHEH!]8YK*# M6:.Z2U/6Y%.!1G4@&>3(.F,0\P1)]CB=0>:)0&[@2O\E>WNBVA%9Q7H0TYGD M%SHR^=+@LX>M(H>@0X@3IRVW&C C/-TNO5J+S!OWW)#Z2Y]?@Q;N665I*96@ M915X0!DR.FHXC8##3@L@MYN4J/8RD^OE1IU<^API(:/!!W ]&W*Q1"L)2*.I M<'$WSHEA@%,LK:5;G8%TYO5>=BC(A9.]B)#.)13JR9_?Q3=-?ZR>B.-=5[7N M.R[JP.<#2$6RE?6 &R2H9E)1#2BUP!EG#Y,X^/+A\8G M500M@)A%87O'K#%$J% S)/>V$*"NHP5M(F='$ XQN3\(A M4F $&:%:@<@-'/^WO6V7 F0>U_*_UY9S$.<0 L16!^1_ET5]H\:EU4H(HYB7 MB%MA4%2C'@+H#$_W2P=#B5^"%F6T0@*B#0[Q!\%67Q>;N+M=X5QO/18(%-YP MA6TT9R 6A M$8M^\,<)HAR['[[>D'*>= 3X0#Q..M,$&>N 8%YZ[N&%,]:D MLXQ*<@%1?<>):H\+23OD3N]"(HRW1C*$H-)8Q T/67?7.<65O S/@6P9[70A M:87:6;B0F+C)!0XSK1&#S#M)J4Y#DE:F.C^ERL[VF:HL7XP-G$C:X;>7$H?6 M^WVN'[L>#=P3"IG""CKB)3!>$U;KMKB>91[2#BBBK!.-WA%\[<7[Z),2=QG3 MY2QE":J[L1K*EVA:Z_BJ/W8(O?D+@@$8Q]T\0 I);J&A4-=F#6$$]9X3_=)- MP-Y$T9Y6_UA.4F;0Y=+<35_SOR6^JO-RX(V MFG)LJ-+)@2@B2!&MQZB=+.4*7R+#ZLFU68^"Z?D\:YS"/T8;AYDGR?:O8_WO48-SJF8O"%)Y*S0&$#&C',82<@"UB_LE-(=)SG\:8,&L4Q!(#AE;B8/%'96&I]$G_OI[-_C68W>Y#(>%N(EA1TC@E'G&=,R;B@XAH6B'+OW*B'C8P-C,U;6O* M?5\Y!GQ>C&:+7HG7*S.F_0O@Y+PSWT:SNY04.]4"B3]W?WY/&X=L'NYX7X ( M1W8CBY RUT E@A?G;3\<.F8+X>0,?'3>R:?@DW<$R(2P&E@$F&$0>LLH MK8=OF<_<0 XP)\-PR)W!)C7#2YA;9.FCCO-L-&"F?Z:;2. MV5Y;AF[2KS/M<)B7!_]I3RR:GLRH6^)\50W25M&3'YI9K>S4;?OXVOG]P8G6*&;[KTJ?J> M A"BB!J49=C1)*[X4=TBYAVW''+&&=K8FT"A%--VFHN-%[UM>8%QN'7 Q!G! MK=1(40]!-&T8KX?M,;F<7*K'"_[EU43GZ)YDWIZRV$J'TU=*0I 5P'#"!! ^ M_H\ XSU7L?MXJ&+^WX&^&&9?/FN;J^B03M*W=UT?]\6<6>;P"2G)C(*IE\$ M),197@_1@0MRM3]>R--^,"VPSZN[NAY\L@):<.9UHP"\9-0BISUU&,3_K 7U M G+]: :X)EJ;Z0Y&M23J/73;;NZU.I*""Z4Y\ 9J3VB2A '-%,0L72S?Z@J M:-_>)B_[_01__7/SC\V+8S5^6U"$.Y&<[K@$'C.#J8% J[C[\ Q(>SF9HH\G MQDY_DK[0+I//<3Z]WV196OF3'\A]_W:#(#RT##,&,30Z&KY$*;8=&+K(6E<] M2/UUIL;CL3X)B0ZFL]_5)'@+&+!&*@D(QYAC0T@]. [QY5BFQPKW(%>R "W MEFULO%[.QY-J/J]MH0.:9V^[@(WV$&,MXS333%+H#:V'"5WN1>L0C=.""JA+ MR$LP:]V[@\KGV7.!&(]7@7:&$/AN0 ML9;'&60)D)@)1[U0]7 ,%)FKT!!U2:X<=_,A"\*RC&B]6SK8-D"KH>=Q"@&& M, &$:(4>)Q+-9,P G7-.I&4Z@?W4+&NCB79N!%)I/T"8<11PP2%UUHIZR$+" MRXDCZE#Z;7B5!7,YJ_BMZ?:^0:6.)LV#%]%$Y*GJ"<;0,2RC_M\":G++: ZZ M0$[^#-@8ED+"@1MRX",N*<3\6^UV>W6IE2 M^2)*Q%AW=GY]&NS[9M[:X[:Z^3B+_?PS:N?%;/QUN;V^ZI:,33\6"'+<&L@5 M5RS%GF&@98V1ERISS6V]A[QP?O8DC@)K<\I2,+D>WX\WF1+4?%XMYBEG9[V" M3!\-C12_<=A3*_>5(:X6$0C%&;=2&3^=W+T?_ZANUC-/_WST9!G=JUDU.NS. MWO]' Q4,.V@0XIPAR2%*,;L;@2HB:!ZEFZ>7/V<5.QBQ].J#-=_EA'7 1VNW M"32OUZ;MXK1.&ZZKV'B30CPVJ4Z9-Z1+/R]"/178$^6U,"32RWH("&744F:D M/>2)4L;.VWJ/?IQ-;\>+526U1V-A_L):..#V=?S+ S5.LI06RW+J'354R2UH MR)D+NKP3\CIS#&#:26*P&8(E98PY"O!Z8U/?]4W:<@03,?L7;0 MGYF/&(+(6\UQG*S"4&^=!&:+%;B@FXQCA=O41ZP=H 78\BJZXF#B\!TM@A." M:0@])@!8 KF77&SU.B*E5K9"63B/%._+BC.=8%J +N\FJ[FXZJ2['S^D_+,1 M@X.DV=LN(*VATY@1[966FE ;=\$U;-AG!BD/T*6P<^)TB>O9>J0:!"2U2&", M%"?0 X&VLX3BW 08@[R;.J']TZ4,!NNB*HUE $,HB""&> 840O4PF&*78_!T M),V]+JKMP&Q_;_G;_)=JLN+_GA7H[0<#<#Y5YZ"(> (H 48+7/?-:EDJ^J'@ M 6%;H4P[Q*^];-7DIFHJWC>?#5XKH21V*1T>BB0F4MJZAUZ)S(29@UP5CI=P M%Q"V%[*>C?X]OF\HY;+0U" M=D7<4-<>-7N=#-:/!,8)=M) &GMM%%<.P^V<)K986=Y3^# 5E_\K7X,L&638 M5;4WT>)ZCRO.CB>#D"1:>8)Z32563G(G]?80QN4ZO0_YB./D#.E&%!DQ&KO] M2W=[I+WIM[>#7]U](!#$O23(&THY=UAC:;>WYM'RR72^')3B.IH&TP$@?X*P MBU8V10/GQ$[>'Q#!Q%D%:/S/4D*= MM[4DIR'> '=/_<%5U/"7O&_=!D5HWN MQ_^N;FPU&_^('?Q1S7^)>[%YZN";1EB39D$)9(FA9)4N*NZT%-#;PQ:C.\$L%<0"++C:VAV* MB1'<^_3^?CU5F-NO[G8$WXYV9).QYPN!=">,N\>OH_&LS2FO6KFY6.!6*@A-TI$A8B] M 4[8+94E%YDN#6 M1G6'M7_TYS% 9Q9I;'[!]M>A1@?PMZ?'Z^WA#G*\?C!X;(UA#$-.J;':4>6W M)UQQ,L(:MHPS2>]-GQ9!G'N1EP'-4Z(G$5BZ@6ZTZM MXC2G'R)"J9O3^]7!6G(NKN9O5C'H_B-!"L>L%3B:8TY:H#4AVUG"7>Y%RR!O M!D^X=)U29NUY_+Z:SS]4"Q=ML,7/=Q,WFDWB]^=7M^KV=@7?SG6P0Z$"X88\)[(-@V_B1*(#.MG&P] M$Z:+T?T%SH3ABW28N196:25L%;]]O198?%(]I&N2?]=_-:/OXTB:50WTF_%B M.;N8_ J82PI5JE@KM'? &ALWE:N"1=IXY0ZEW.MI@">OH\,Y%I+IN*F$ %C/ MJ4YUHM:P4$,NJ #*T<3HH(Y..[3/-H302PX,,T83H.(6'0J-?#U,SDEF%,&@ MKJR+L*!5S& [T <;,QAGH.1QA:4>8JHQ 4+Q>AA0%W-W.'7,8&-I[HT9; =F MV9A!3!A V I' ((T;E, A>N^&<2YOD"'O+9"V1\SV Z_4\0,$DV0ATI!#"2E M/(X4JKJ'%M,+=*@[0L)=0'B:F$% -< \#A;$_[Q,E#1U'[W)K:\ZP"O4XX7< M"8+E8P8YYLQ;ZH#&6"+E)':N[A\3NO>[T+.:R!T@6#YFD#H/+)3.(&50<0F U$MY"3@4D;+/--1B)7'^&,X@9S%J, MCT>PP ;+CN?7ZT//ZN;QS/,_J_ODHO5Y%#>EL[7O3?SGV[@'C3\YF%HJ^YW! M"B0X-X1RII1$U#('@"$:,VA0=MCQ("\N=0LZ"Q M!=XI8@'C"#%@ :A704RXRBQ[TOJ&9[)BO:W96>P?^@)TQ-$,/=1S0MC!Z21!#@M)'106"?J05NH2U55&F8UK^Q# MY^Z1+T"WM<[<0ZCU X$0R;T5G%!D&=0,(J.W.M3BS+.+(1]"=B3(:0=PEC"1 M=]]V[S."=[<*7&F0? J]E()R)1E[HED-S_3M&/*A9C^,Z0[C' ?PQV^/GG\[ MF5EQE/-H9M7W,GNEI1W'>R%0 M >0S;.77?C-?DO?5+MMXQ^,!*6B<9R2NS=%B4Q"(1YL>4) 96C#$LLI]4:,C M:(OX1=;N96L7M-HG;:\3X]M-@HH++6<>,XF;*,:@652_S M=Y-'__!4"WQ\,Q[-QM4\6NW3Z]5/HP7VC^EXLO@]/IY49B,=E/'>()&6/EUW M(L/U*/ITE7MTQS@2WK+/ZO,VM!3_F6;0+#V4@#K+,>, 2F(VPY/ M*5;*2[[D=46_--CE+G\D\N5NQYYVM*G;_.LV(:[J-BZT5G#K,4 \+O&F'IXC M+/.(>HC$.E[";]]V'0UJ8\[,J^O_N)O^^#_7:_LB40;7?TELP4_8LOEQ^.WS M&[1X_,> F:3$8$\ X2H:8XH:4'>5D=P]UI OM8Z1U_1(_-H?%J_.(S],)[_M M=Z!X^5C0--+:4!9D*BP""L2.**@IL5!];&L+< ,5!1;UT M*MW6D/4J7;-/NN8J<,@;*.J@;TTZEVQJR7J7[B]XC MW5]T( Y)# E"V#K'8303];:K$.:>]@_HCK-3V;8&+"-\:797I5B'T?[(I>=/ M17/?(, @L$0RC#649!U4M6*<(:5B2@8NQN.1:R_/CW$\X^_?DW_57HF^>BX0 M+9"*?*'4S$M7!O_[/'AW\Z_\$&P?I.!;. M(2,,(G&4K.ZJ!#8SM=" XCHZU<&M WXUFX_TJ^/E# <&4AU(K(Q4C MG )*?7V02A 4F4D=(;@P*1Z-7*\S]>.^4Z:/GX(%&"')D(2(8H 449#47?44 M9%9L@9=ZS-0:L7Z%J_8)5P7$(8:1>Y(32X"TA#!9=]5!G)MG9U 1"]V*MRUF M[37Q/R**H_U!_$\?"1)P98Q*.:$X,8PQY^H+>&)I;O ^;'W.-'@9'HE<>TG^ MU^C?HS^^S1<'I/GRL:"E(4QYH144 %G&^7:M)\SIW,"S 7GZ=R;/(['K5?F^ M_Z\]RO?]?P7'(OVPEX(J:BBF6CUV50B6>Q7;^IAIX&+.1BPG4N>AFDT/9%!Y M_E"P%GM/K((4">JXUM;7FVG""B_Q5.D8X-J+\O=QM9B,'O:*\MDS*=Z8 M.**0P=H[(5TZE=ZN!-[DJME*N\%(==7%X^%AR@BD$F8R_B M"H \M*J^0"(*V-S-RJ4=&G6 74EWV4Z32VLNM#"",Z0LM48!"&J+GN87;9EGFEF6=1\#G)F!&/4*J%K1R&*G%>9FF8XBJ9C:>[-,]T. MS(*<>#/%VL$D> U:I^/=N#=1EEC'!-&& E)/+LJ-OIRRQ9F2WL&7[B MP**6 M6O=]@T16N:\,0$GFI/9&Q\5< ^D=K%=WJI3)="4]0H(IR-H&+ P$ M2HN5)A8(R7'\F\-DVWD++B>VK7_Q[N!32X@+\./C;!HU[^+GQ_O1*@(VQ?%^ M3\KY0[4OF'1?LX 90HA29001D#+.F*LW,%0RG>EO-4BCO#B3.@3^I,'6.__] MX_1^?#VNSCZJ6G#G$ >.0(RPX41C@:DVGGA,XXIT:&=:9H KL'^N?_T2,=;Q MLW^T&.V;[8/EDENGK:0.T]6?\6;HA *:6P-B@.O(\<(_D%^S"WS[FN;WU?6B MNOF_R]$L GW_TX\GH\GU>'1O1XO1*2;OZYX\T2IIJW$_G2]G58,YW?)- 3$! M'5'8.ZF45U(98Z%V5%)@F>6'UKL3P-%DKC=[00!<"DJXTQYS(QTAZ29V,WC- MX.64Z.J-%=,"N)]""9PP/Z[G ML_>#R5&>/1B44Q @C2W!BD#N"&"H'DPT*.U?=FXWEO*NP_09C6 MKBOK/[_T7%G_]$D.L1V7,6\^%Y1WC#"MF>?1](C&#B%;%*A %W3JF2FV:7?H ME1#^SDN3'4\&)!E&DFIAXKBUY11@60\!*E\JMT1_!#A2G@0 MZ-S D0$3)5_"C3--M0.U5_=FM2]P2'T*-!6@LG%?FNH-<6>=MZ[N*M8J,\1O MB/(_7EK3(]$KH!S6^5T?'49&]W%G5'W^5E7IWD'=W(Q7!1?N'[='<_US7:-N M=/_+;+K\/H^ON%_>C"=W;]_T'UB2RG0@("N!<% Q")@#5$BMMC*+?\M46T.\ M2^]F?1ND6 K,AU9#^#!ZJ XNI9EO#(HZ0:6#7E >S5:*F8?;54;YW B$X3%V M:%1[7;.S@/S:[_M^'3FXVSZ_ZKKQ7Y/_+<>#2INA2E.->@15EY8(^VC M;8-R*W,.3>(6V0W)UTLB!IL5[@HCKM"":2@F9XC[=O-2("N0N,9MU!@5> M'2[TAW !HKG4^]GX^K?%^'Z\^+GQN-O#J+<;A#B2N+K&Y141S"BSF&[O[*14 M!V]FSRL1=B\2G_: *5MA@ :0W$R87U@;\F-SR(AZ+R/NORT5:Y+],/TPG MR3",H-^O:BPU*-S8QP>#1M)0RZ%%EMA4< YSO9UXCF=>X TJ+4Q9U@Y"3L4G MP(Y]3K6XNOTR^K,QK?>_)E (#5+"<\X04Y)!#;8@> RSQ8&E4_YE&3M%/TR M82AQ;4B]WT.PQX<"TD*E339.%5>QI-K8&B5)*TSZ:38_0L@3S:R!:@1 M2?O([3WL>/9<<,)#B%RD-??$8(2 M._]8S3Y_B[#IT7Q\W>#P86^[0+D$$EG%B7 VCE8#N[54A="92F:8VX#NCANZ MQ'00UG\U,@QCA#N/0&QC\:!CRM_:?OC4!:@GX(H=WR^C*9IA>+UH&0B$ M%'%GN972:*N,!*H>JD/RHLZR^C.]CD-U*,;79A2=F%]/WQ4D8MQCCB&Q0', M!<)@.Y\X[/TR\40&6#8KC2_O3GSE;,'C-O[@[Y[^#X:SY+AZ?[\7DWFU<=9%77B*AWQ#K_0?4U" MROSHH".6_?(.]8S!+1S]\F+Z=N_.7T7B25MZK M2?UXT^B'YF],6!L.<9QHTAAA!9>N=K/5&L-+J-7:P]:P#-I%3/:U&\7:SEOE M/=]KBK]Z.DCBD!48Q0]P&'^QAM9W8%JZW.2I0[P:[(X^Q^-8PEI^^%K=W%0W MMIJ-?T3Y_*@2H:\FKW^^SX!N_)* O>+60&;3O.!*@+BIK0%P<:+D$6E I4/Z M.*+J"][BIP4I\^;BYZ_5XMOTYC&GQ.& U@/M@_%>M]=4#XEE8X?C6>_C^Z7E9K/ MEP_?5Q.:DFUG>90 M64D5V+*O^Q:_=B#7U+/G@M7,$249(,IZYY W&^&@9"^I"CS\I*?=@=\B2P' MV; \#FQRDXJU-,H(UF.9--S5@!%N,R^5!^AV=_H5 MO[BTADSOMS;144&L+RVF]].[GTU2*/7_]2 P1YI3[H&$0!,!D,0UY$HX\=?1 M\!W2LZN9T9L+&N=34>?OKT1"E!F >-^0>2204 M-)[7D'O-+^?X8E#\[7-N=2+H4VAIN M*G%F=:HAVFQ_M7EUA)A+S:JOAX?\ME,"+2H _]'DT!/F>V[+T:3S_P\^JJO90+;DLO?7MH 3BR@MF(5+$,CBU_B^Q;V M[3ESBFX$!;R@4!'N5;2DA?. DQI7REBF^VO[S&Y_R>ES!A(OZ>+R832;K7S1 M__9K>>5LX(1 T1*G"MJXU:76_%L<5T]9Z!A'1G&LE M#*HA9!3VG@#L7/Q:&E.M-[^6=I(:K%]+M/V!9YYP)+T0FAA$9#T,(_WE%/0Y M@>3W^K6T WX(6[ S\&L1F#' G(NFC/&<"AG_6H,JB;X<]9G)I1)^+>UD<'9^ M+93&Z4]PM%"55@2!:$=OL28&9V9-&2#%3DN.QGXM[>11@&Z?JGDJ@9(R"*7. M_C89+^:?/O]VD')[VP41MSZ>"FNPD(XA#:UDFV$RY-SEE%H;%.VZE$G[\YZ/ MU6P5>)8*7&X__]_CQ;=?1[,_JH693M;5+O=7[FOYE@!D7$FB/1W'$^ MBC.'C?K'IX*62D&$G,*4<(BH%=S60_".7D[038;4WI)[%FP%)/_K>#)^6#X< ME/VSYP("U$*)M&$H17:D+8.NA\&@NC#IMY7=M#OH2C!@]&(ZRQ!I*B>L'E MUN-2Q1+^"C9*<6EE. X]GIJN?"P^SL;7E4KYA:]C9ZYNU^<,JY_N\OEI_H;@ M"6;$(.P,1P 9)+PFF]$8 H6^F)6NI.2G)60Q9,6Y^N7W:KY(I76KV7AZ<] W MNJ//!(@ "&W)\P-/1?4I^<_4T']T= M=&GN^GO!4:844Y ;Y:"5'GE9.]T8"F%FTL$A&A4GG@S MM9FK'Z/Q?=JJ^.EL9?CU8?\<^&1PQ! 0=0AQ.@(, .=V"RX1/C/!^3G>I S0 M%NI6>"5=LZK9C[A=V>%R/UUEZJ[62]Q\50WEZ;\G7^$/T\7_5HM/U?7T;C+^ M]_YR6'U],Q#LB&64,F@PX(@[;+>;+;&4*1WSI-CO4Y&K;#Y M47INWV:Z;$>"]HXSRPG6DBG,.#);UP*C$<\\/QIB#8T+G$9=B+2KR$@7-T,/ M*9HD=N>V&B^6LRK%:<9A7=W>QE'/WCJ$/^9U04)M(6(NH@^5],PC4-]V&,9$ MIN]<\T(=ETS=@H)I3\#>YM,F'NK+U"QG23";W_ZW&JUMNET4/EV'0JIDCHD5 M7J>"+5(K@VJLK;4PTU59_CT)SDVT65Y_*X-4?#_MW>MO6TCR?;[_3&[_7X %Q>H?BV"NYL,DNP.[B="<>A$ M6(^4E>3LS/[ZVY1%VHFM!ULBV:25 69BCT1VUZE37=U57<49(!&T($2&.AO% M<2D2S_&KAG=7S>P(A#%9XCC[ZH?L#/)N7(7'V/G E28A$,%0E'B=1N.41*GJ M?PW,CA7B1#_[T"'MISV'M ^6P92WRU6Y_86=+3Y52>7?RU6^!K\'1&J MF;+FI5M*0U+GI?$4E%29*,+K$ 3#VBBN:"UIZTAB95)\C2&/#=J<2%2GB]S? ME7\K9U4QGNIC>Q,KAAM,002EUL<_AEH5+5/ 7#:&"E1B[CR^QIU'A6M.W'GP M3F=_+.\WV_L.O?/EYP$46%)GF",H@$!0;?ZPKF5II$\MY72-/V>/9/CW!].,-[LLK=^J@[9E(1LRD1VD?1TZ3$6BC(5?0&B"07!N;/<(B0@>M2* M>"E2^SNTCF'' 7Y:3H^,8P<\IW7L8:;S4V>ZO#&4\Y,(+A 4@ MRIRW-CBF 'QM7Q5.[DYWC=1/$/T>V?IF<;.*/G(Y7SR?R/SVYW) ;Y<;^/;M M;OYBNN,@XRBJQ I3M7T+Q#CL##"+&LDR2"W > W^CP72/FMQ_[*^AYO-_'NT M%]=JW,]*)%M%C1)&&#">!LT"H@_="(0ADKAC2UQ'VXA15>.FRCM>A529%M1A M7!U1[$1(A>:)EQTR#)CWI6J=5>-NAU2VU;BQ=$HR0C2->WP;E*=:U].07EZ[ MS)^!_,%JW.T$G\-YRPBJ<4?W@#DN'&"M*2)C$1U.[=^8H<8,B_6)=1K;H9)RXZA)R5"FL M)+:"$%;M['38"8S%[5/B[C?'+++!E^_>T9S=)I^^7=W=AN:J^-$@@ MY:6!%-(RA@WQ06+B));$8U(#X0COR^L=2;#D9+7M+5AR 5"GP:Z'^_?#$NMA M#(600GA&N$3&@T32&M5HB1>AKS8EW[:']!\VL]4F3UYUK-S];\YL2!0#T,HM*2 *06VC(G& _>U\*7DB=N?$_W _4#^1;EE]E#R^=<5[6I ML.\L_$=-OMV5ZX'Y]VP4!3.!."R,M%8BATQ045MV$!BF$T\23K^N<*5@SQ0\ M5P5&S<(?TY4R2)$K,,+"(8&%5%)[[Y_N4C#3B9=-IW3=82K$.POX4;,NQWT? MDY1Y8,8KH-X@B1&UM?BM9(DU6EO?DWC8]_G%YROW\D7_4G66+N=![R52?R\O M.+%"N( $)\@JRS7!K)$AXM;1G-(5V M06F-(,JXDG( [!H%X-XD=D":4EV_Z1#K,CHP#>_P:(IZ-D&Y-B,MK&+<:A%W MUA%3"@@Y:*!$'!(]S1R#W9..V76(^2NA;^:<+1!PL-0+(C22CAAE/-Z!QKU MUU!@)IS)D/LM=6?4A/\QAI,GZUN.L6#:.&049\HI$IBJJB[6\!$I)]2J. .R MY$WZ;E5GU,Q_+!N]SI/V;098L.A/$HT,5@(I;HSSK &..M=YY//*^6PXWZ'> MC)KP4RPY0BFFH(QBWAFOL):*U'?PN*8Z<:E_G0'7D=.^6]49-?,GM*NWQ@@' MPBLFI,;66MJ8:R"IU;Q?;Z!WY)SO3'/RBW:E4#>+<16&1N/*#9,8JG*A&'G= MG*8$Z1/S@E]G:+E3OHY17?(CZK,@8*[,;3_0(CI,""'C'0K(<,&QL+41%5JD M]L)^G<'LT5.Y<_T9M<_][GZSWLP6G^>++S_)Y7U9W5N/O[?+Q;:2S/WL[F.Y MZN::=A?C+!P!(;0TQ ;GE$":BOK*O>!()C;\F])A6\Y!\.X1[[D':T3_.U,EIG$$ MSM4B#$*E]A++S^[UI6K=549KA52VE=$D"&"&&VL#A1" !J4:02(WG5)\ R!_ ML#):.\'GX*B.H#*:0Y0XBS%S2@OM.6C6"-4%-QWSF:A+?51&:X?!T)71 L> M*/;:6- \>%ZE>>]&BXU,/&_(4&.&Q?K$RFCMT,C!* Y<&8T*J9WWTF)7E;H6 M"G9W%&BPT1Q,*!%M\.6[=[3Z\!GOMBI1?GYYM/"D_LX?9[^;SC8H2Z^E-L/S0^:H\"&+9&-RWY>;=;9S=V8:W?E#! M* **5#!2:7G5EGZK.=@I)SK[N[M3?_UZN;N;KLLF0 M^UBA_6:Q6\^Q5 Q[&P(C#M7RH1XGJGKK1,:)JGHFL/4< M!WW,R[!5DLDJ_OT:!WT6G&(D>IS>,6Z)4H$8D'Q7>]US)\6QW>XU#AKWJ*"8 M!L6YMTJ*P"1"H1:A%#"=%B=]J5IG<=!V2&4;!^7."LLP 3 ,&V 8[0+*P@MF M_'0B1P,@?S .VD[P.6R#1A '-1AIRJ@3%@4I"-8!BUJH/'@S&6U.U*4^XJ#M M,!@Z#BJ-X4*%X()5F-/ +:X7$J%U:MYUAAHS+-8GQD';H9)PX#JH"K?K" M:^I=7)48#XBX6F#>J\0 TZ3CH*G+=^]HY:S>(VRB01@C/ J>>R^-QQQDT(WP MDU/KIQJ+/5E5A^J)T0[.G"ZS-4=(!]C1\P@*IA#GB&BM-#(\:&M<;12%5*:O M3H,3)4?>:&;-C>USUK_.-U^_EG>?PW+U@,4CE4MO08GRL(Q"0:#9I@ZZ3RI4DEK$4H\H;/BOE2ML^!$.Z2R#4Y@ M$_T.*VW\C]? B,52U=-0FO:U91O3Z<;)R!\,3K03? X'%2,(3B"'9=R:$L$U M@+6(\L!KH5(E$Q-3,M3F1%WJ(SC1#H,>%/M]&1>->57IX_$P_/V'O^^-9YST MO<(!LX8!H6!U$,12(T4]3:Q18LW6#%5M6"59=H=)#C9UX-B&ELK3N#ET&&R4 M&26*ZEI@"./$8.ZD8QNIJW_O:"6%?>.F?'E;^=A5:97X^;)\2"V/GV619_M. MA4[X9D$"UL1$AD:Y21G >!;JT3./$Z^XC-%@7A#I99<8Y'(_JZDZMI72>IO5 M^O3_5YO%M\O-_Y6;]^7-\LMB_I\HUZTTPG*U^U7U.7S F/8[D$)P"%'JA#.* ML?"< FG6/T]3JPGD:'C[)\,H(,W9^4CJ:3=(_/G%YGI.,*<0PL03I#!3T=HU M7J# *'$3.,T 02JWLH9T&MS*J$.U\N"]U$%Y8S!S51T]5HL_!)58"N(UMR-+ M4N[!>E2WPW_4],LOJ2I$O; ^_E$!$.AHGDT3ZA!Q)]JUJSB:T@!38=]9^(^: M?+OF1P/S[]DH"G#4JP*A9^&,O MHD$H^.,0"L:8PN"E!ZQ$0 H%@6KA:^H3V]"_SD99>1/O+.!'S;H<]WV.,*ZX M%8("!P#+O,=-7)GJQ*LOK[=A5=[<.P_]G%*<_W&82/V]O#"$":19$-)0P(YK M^N@V&&43TZNFM'*=%_3*$L;\J/"LV\V@W-@SFD)0RHV3"#&J V?".?(H99;: M:ZWU$ XI1:%&<>26Z(W MC2U.F^YQPVZ$6O6Y4W%'*H4WQ BM/64<:=^DAC&4Z.Q-J<'@* +/'6+^2NB; M.6<+[YG!0"6A1$.(X"'NFC0X[/NJ&3^A>'8WG,F0^RUU9]2$_S$0F2?K6XZQ M,-YR1ZD%X0155::4>/EJ2-^MZHR:^;OXYWUU.S]+VK<98,&# M"8$Q+K"VTFE7I>8VF;E6)(8/IY00^FHXWZ'>C)KP/\9=\^1\RS$6 0FCG;$" M<-#@#"6X29S2!A+[CTXI]O)J:-^MZHR:^=/9U1OB4< 4<:VQ,LX32\2CN4:) MR_SKS588.><[TYS\PKLIU,UB7 7QP, SK1CR3&@F"322MY@FAGS5A-;HO$.^ MET8X/VX]"VKG2K;V RT"EL)YYA57!#N@QKC&S;%.)P:L])5]4X%\U)[MN_O- M>C-;?)XOOOPDE_=E580F_MXN%]MZSNX_EJIMJ*UV,L] L.,:9$9@RIX3W MCC3N%F,T,><#HRMU)P)YSU51G_ZXZT9Z+9#ZK&JED!*$T81)9(6UBL1_MH5M M.:84AV,UPZX%4LM"(DP-($&Y1M113*R!6H2.A6,U9L=31:@O5>NN>ULKI+(M MD$I%H#8*T6*EF 7*A=6[:3 4U(3*5O6/_,$"J>T$GX.G.H("J4!$P*R2'[<( M,8$,:X1JN9Q.?>E$7>JC0&H[#$9;(!4<%Q*KP)S&' .33+!ZFHR("566'E1) M6A5(;8=)#C9UZ.9OGLAH,+A@' 0-E"*%:H$19R>4+C;XZM\[6GVXG'=;E2@_ MOSRYW4[YD"]ZT@,*1FS0RNOJ$(\':C17HIZXTVPZ=<_[5)*?O=,NH,CELMO' MV>^F7)2W\TV(,F^GHY=Y04&9BNN:%B \"F!=T*Y9\;Q!B:' "=:Y.E^5!T$L M&W/[MMR\NXVS.]OLU@\J%"6(,N9EX 0!(X8$4@M"T4 MDIS"SL^ZI&WOD0X773XRGD)34?4)159JA;TD#"%>2UHY+:YIENG*/R9D<]XM MMKP+$ZL1[O- MEI*XWHX"VYRCO8]I) M8SJN4=YGH3?L +2FSE$D ..H>>9A!\BMD<1)KD@4 M7BU"+_PURMM6U3J+\K9#*MLH+[@HR3@+RR6F%C$6.]AA#='1X:LV 9F4[.0J(N]1'E;8?!:*.\W&C.+59: M&B1Q2^V^O>.5L[J/<)N-#:*70$.,F! 0 DP0+7PB:?322#K4U&':BW3#LRL M@R3#AT4*ZXT0CE@"EFCDG4.D@9N9U([@.:XB_5,C;RRS9L;V.>M?YYNO7\N[ MJFOIQ]GOY;Y&SH./JY!.>&*TPEQZZ:C35M:;.,V%2;S9-J5B3:-AT440[C/$ ML=U,/GC&:,!>?,$89>XQME MX2GFBE..XMY<(VF5,5"+T",RG>/FOE2ML_A&.Z3RC6\PC!F'$)SWQC%#P=-Z M&L[8Q-I(&2K< ,@?CF^T$GP.AQ4CB&^0N&EU0(R 8 .1AH/#M5"UIXGG=1EJ MGK'U%-RHZ58Y] MB>EGXI&#'1TXIB&M]R[N!AT31@HOG&.Z%A@%<VW]5 MY\SSQ9>'8P#K3+*36?O?R]7-?'VP36C[AQ5.(XY0E(:5'BBV M&HO:;05*(?$VT 0O3G>DX5TC-@(+_Z2MRD--VOEJ^X1UEZE+I[Z["(%PHZPV M7DAM192QD+6XI4Q-[SL]I/S:"9(9P"/@TX_]2CHDSX\O*C B5C%-# V288M( M %X+4F%RO).@?8@G>&,64-I(WQ@B3?3IIG=-]2Q5$=@CH!) MNQU:%0SJG#+/WE58 T+$8<&IXV$'2* $$B,?TRR.DT'DHQM8I\.S MX5-IZG>>(6=Q77'V$$92+*_

M-:["8.V]=9P" FPEMH@W,%%A$O,OIW32D2%3,]*('(A[S'#]&'88:@4]?10% M,(VUXLPBR2GWW")0-03"R\1"W5,Z8LF0E(/AGP,%)[.)9("=4%X -4(Y($YJ MMA,]UE+T=2PSNB#:X/0;!/\14.]XF&0@1IXWL$)Z3)&7S@ 71&!EHL=2 ^6H M371 1F(TN MK^S*'LN^:/3I^,0_M5[+][6E)\]HBJ!LA$0[C['PSJ.JVV4-"1$JL7J4 MNM)K5+B.@&JM5_!]LCEZNS:+018@33 H2**XDX)J94+C<@2@B76B]9684X![ M!'S=[Q,,0BYY+'5 1C,7B&':->*4D.A"=FELVI8R6X=G5%[SC\@-_ MG&I/[MY/+XV+OW?6>*R"1(9:(ZQ^/(.*^^1$_DPISR0KK^X\_ 8JAOWTU[M& MV]>ZV,^*%0,F(7"!@'HA, = ;-<2)TC'X%B9@8[LW:CJ8N.X1F#+N L::RX M6QYJ$6)RM+3X>*IN]J5JG=7%;H=4MG6Q$0>NE#)>,0G.0C3%I)E&T-,IQ#X M\@?K8K<3? [;LC'4Q08FO5-...F *!!2V%JH<=I3[?MYLB[U4A>[%0:CJXMM MN","!2N8#21(+K'1]?1 L6N_S\LHQ\EUL=OAD8,=';@N-G<0%.$848>XU\%R MY6N!"8DG5!AU\!6_=[3Z<#/OMBI1?GYYID7%"X$@8C17 8=I<<1CP+;"0YIDW@V.<'"I.>K\B"(96-NWY:;=[=Q=F>; MW?I!A65,,L2TYD9670D#$KSAO,"]W=Y<;F9W4]793B')V=/==^W[8X5V;S'; M4UY?2$ M?JX[Y:6\IC$:8"FH(@KC)9QJ$KCU9T30AX$J6-2Z31$"RC%!E"E*7F05\H1HQXETU"P%-U?ZIME95] MH,EZ??_;P^^V,'^,P)HXOG^VS I(?U%!F%;*!1L$ME@K(I%WM3"IA&/"',^! M6%]*=T)J0&]P)?B;1TZW/]S_]MML]<>[VS!?S!8W\]G=APC^UM!7'ULN*J$] MG=-1O>[AK876B''K-";6!^40X%U>!\48\3"=X$3/2IX?=GV<3QR;\).YP,UF M_GV^^>,LZ][NX04@YXSE@:#H5Y$ <4=J:X')8!)#R1EFKF9DT3N%:" K_CYN M#5?S*BU].Z._+^:;]:_SS=?E_>9OL]4_R_C1Q>=YST8^>5"%P 8'<#+N:85Q MU()']G4XN1G[P@]/+>0G B!?*$.>>TQ)8STD@. M.<(F[[2B&4%@*#==)H+R@ D1P9 <@B%]C1[-U^)GC24?6^ M[Q3:4,*,,PJ#8)HA;CVKIQ@WK!.Z_7DVR#^?+5](IH,P<\#:!9PN^OSEAZ]EN8GF'#X_V/?9W>/: MM#9_Q!^^+=>SN[^LEO??UO$1=_=549GJ,\O%9KZX+S^_^U;N>JT%7#&@O5 M(*#.V4;3D$@NT/7=[\\@O;6Y#AQP\4S 06!-4< O:$ M(RM4,W=A0F+_L@P-:^=@+2\@W_98_V\9.1%IL%[/#D+^['.%MU8P10.15M@X M,Q?=KGIDAO/$]-<\,P-[0_Y<,?>]DMF[V7H]OYW?/.!XV-<[\LU"6L>,A$"0 M)(''"7/=;-01L8G%@C+4J-R=M,L"-:Q.MO.C7OIN4?4T!NR]50XA;%W@_)'( MTDYG7WTQW$_7IR01]ZU1#S]$?MV:/S[,[LJWR\W+M#M:QNJ%JYR3U?*Y@60L2) M8N[B7SQ!"D(]24IA.F4C+P'T2;J3)-@^M.?'H_P3RN7N^4:!,3?&NCBW8*U4 M3FCSN"2XU"ZQ&=Y2R-YX702@873ON-G:]YT"!U)4FDO5YU]?^ZGV_^^%NY^;K\_&;QO5QO*JO]_+=E69T='EO\SGAL M@;3G5EC+C.881+3KI!$2]CK10F5X92G[%;(_%/LH,;1GM$?7TL-?+'QT5..6 M&VMLI;384:-QH#"1>$QGI[5; M]'I0Y8^K8H_4J WH7UL[+(-;'^E^-]GF$ZCZ.=C7_3_D9?EO>+S8'>PV?]H0B M3AQ[Z:R'(&3SN_F46J-S_'H MB'Q8WKUD+=L^HL"!,U4=HDCOG.9$,,#U?"R>4%FGG)6P8]3Z7MQK,P_13XLC MKJQ]'/_6/SEU@3_PB**JY>FJ8QKK;!R-4%8W&<+$L<3 ]ZL\)[CP(G\YU 9; MZ-^7U>%B%-BCZ7_\3.K:?\I#BX"1EEI(#G';2)Q6[!$!)TFB[YIAA:0QJ'5O M./81K_H]RN?+_7S]M1+WNUM7?MH\#/90K&KOEPHNP2 =' $)5%!",!9-[)G) MQ+3<#,L7C4%1+X93#XH86713EI_757,--Z_+G0 6 M7W;M[P:L5;(=T@/0$=/=>$ZI6'+XBP575#F!I5>&1\-@"?+8&^LE=LQC=>R" M3X>3K67>*&T$9%D#\K8F<3.&AWGOAKFO<$WK9Q1$**.YT%Y1816#@+FJ9P0LM7-"KLIS891? MJ%;7A=1/]FC6Y/F,HL>QA1DK3(:++RPFV#[W8FPNXYY.%#5('SAD-V#!# M PC46&$N16+WRXQTXTSD]N&?)+[V*XQ?;,I_'DS8>_*)0@H+1"),@$:=1EA3 MS9Z,9OS5E\Z&87D)P24X"O.[N#=[/__\I?QE^>]R=1#1ES]<&"F]T-PP38E! M)DCK0CW&8%UB]>:,JC9<$MR+R#"!KG?KS>'Z+D\^43 9][3!,>= $2VP9[(Q M0EZ;WEK-CP+1=,%UY]?_]4 F:])S"N&YUW%9P@YQ"\X$]>B72 F)8=&,2-Z] MJ]:'X/./KX.*[@VR%#MK7=Q@!T]MX^!@,_Y+'1W#G!HA;R?WA!7FQ9LKOS3Q MHOE-"5]6Y?9L=M\2U.(1!(F.!6QE :BF0D@W[%$[<'XS4()VG1QW*O;T> M_:5<[,[;[>S;[&8[L"^S7V>;S;[%[, WBF"EX%H9*8AB+(I <5Z/5GN3>(4B M(T^F/RVYG)@'N9*XC096XOGX=;;X6/[V;;F:K?YX\]NWV7RUQR:E/ZP0F",, MT9EWDI-*&I7!K06,:&+%L(Q2&?O1N]X0N-1ZU\YQ:O6,@O% /:(V*.4I(,$# M:H3'2.J)6.O,Q"YCN4.O>9<1_6#V[6VYJ2[IK.LP+"^%L[YF#'SI1Z#^KV3"X[B1P+/+_PE8+;J@4+=\$&BYT$;4US M1H(4)"Z-&:7U]:M2%Y+S8#:KO9&*[B;#7%(-Q&$D"8D_4E1/S3K;5[_ \:^$ MEQ7T<#H4HM>WO5#U&)%OKU8O/*0 XK$QW@CKN.(R^I3,-!L;)/K*GYN*L>I, M\H?3X/[[S]5'JY:"__-?_P]02P$"% ,4 " #6DE=(-;;50-R/!P#@X9\ M$ @ $ 865S+3(P,34Q,C,Q+GAM;%!+ 0(4 Q0 ( M -:25T@524/@]$< +F2 P 0 " 0J0!P!A97,M,C Q-3$R M,S$N>'-D4$L! A0#% @ UY)72*_T&M7N6P /N<# !0 M ( !+-@' &%E&UL4$L! A0#% @ UY)72$UW M:R]BI@$ 0"H5 !0 ( !3#0( &%E&UL4$L! A0#% @ UY)72,Q4\T67$ , !JTH !0 ( ! MX-H) &%E&UL4$L! A0#% @ UY)72,?(+W^@ M$P( *S\; !0 ( !J>L, &%E&UL 64$L%!@ & 8 A $ 'O_#@ $! end

P9XEIT9!>.*_O%XW^J-\*Y ^)O^[RVP6'VNG# M4/D&,'HHG!S$6\I+/M7E^_]@@@)[8/PIULZ.'3OT+-=U!*/PL8_T\!O>]^F"[!&648%IM2?'X^1UVL5S<2]'9]DLC>DL'9Y()1>P9L M(V.,1@^SU0P;,HPW(')"8N1B"8ID!DH"S")&(KS!9Z F>E0H7ZZIM-68E.;I MS!"\+&4,RZJ^O412M.;X(6-LWF=%\,;%J7=;?Z,/AHR(RIP,XIKZ6O7AX%HO MMDT*H:H>S2S+$RQ"]IXH_;"L#(8L9F'PT.!F>\%YF<*YL#((!OTXMGQLD0Y6 MW?$]*W#]8Q)5A'C--$O%!^2V+(KR/O\J6@IEKCQ?W/B$9J>33Y_RBPE78_;Y M#Q);&/O+.$2RR; +DBKRYHPV$S(ZW^W7[A!+,D8B-\GA?%/;*:;SQ4U5*5[7 M(!=C0 AZJ]"U[XNRI*K/1S8,&TDI-QARUP]+N=GE!W&.YA^NGFX1.---^;Z_ M-^!],U_?5D.= 9]CW+V@/=8N/8D/BZS_@>J_TCAP4NPX;D3+=JR;JFTT4M&9PL-?C$5VEXAL8.HF[(CQ829M.JM/DK[RBQ# M2;F>EV:V;;DALH+3:1KZZ23'#-Q1V@D]$W<$+XPZ+HKULFAO0-W_\>D=6>PY M46Y9?N+ CK7#288A8&:[T\1U$_>(#6K_S,D,",NCTZ3G(9,!NA[J>:_\%S7,/#H"=V?C#-78^S6/, M3OENF.>Y=906PYKN<;6NYIML#VFCE4NOWHMB?E^4V%*L%R!M1#^J.1^*3B(! M3?+8?I+1F(Z[IPT&.=1_K!9DR@ZS6P6?6@PT0S_!( MWF%%V:\6:A[@!+0W]1WNGW^NBQGHFP*E@O0-[6ACFRYJ0 _1VR@(W[['V[C5 MK3;F7;[IM+L>G]^.?.LM'E+U^+'1,H&+L?%Z<-JD,?[PF. !KOMV_P7(?/!D MG=RU0SO.TBQR\Q0[&X7Q) PFTR-4T@0G9])JL".K#?5 ' O/G[J\F#5N!KQU MA\@\(C?*M-QA,FPE09G1Y5"":HAFJU:LDYBN>LN=UEIEK*FHBD0][OB(TI44 MR\&;YLM[C).Q"4RS1$>D:[/#3BC6Q3.MCFH<^L/9>RGS*+ F3IA/_2R([<3U MK!344@I!FQO'\5$*NM\$T4:*U#ZUN]8 5T91/?H-ZX4T59%&?E0\#8+Z_##C]"=/!^ M 8H:3'-D[7UK M<]LXLNCW\RMX\^%63M4FL9UD,IF[LZ?D5U:SCJ7U8^;L^7(*)D&)&PK0@*1M MS:^_:( /D 1)D)(B>*2JJ8E, (UN=*/1: #=?_VOYT7H/&(6!93\_.KX[=$K M!Q.7>@&9_?SJ_O;-Z/9L/'[U7W_[C[_^GS=O_OOTYLHYIVZRP"1VSAA&,?:< MIR">.[]Y./KF^(PNG-\H^Q8\HC=O9"-'_'B.O)\B=XX7R$%QS(*'),:7E"W. ML8^2,/[Y54)^3U 8^ 'V. HAABY*%93B&+$9CJ_1 D=+Y.*?7\WC>/G3NW=/ M3T]O$8[>NG3Q[N3H^./QR?OC5PZGD$0_\>]&]<* ?"M5?'Y@X5O*9KSFT?MW M4/R (IQ5)Y209*%OX,7L7;Q:XG>\TAM>"[/ S=MU-RHW@ I>G+=1L?KX3A:J M58,6&@(2Q8BX.0W/-9J?WHO:QY\_?WXG2O.JD:>KR,$>O_OOKU>W@L.O_O8? MCB,X'BR6E,4.J7'*1]&#:)E$;V8(+04;WAP=OP%&2#FYHBZ*A52J)&L;OL-A M'&5?WA2@WG(<7CGO^J'#:(BC#>$C8*V+$$C#IA 2L(8@U"9%#>C4F\!?;[)V M;^#3F^.3]; HYF,_++)VF\#B\SO$7& U9YL;O\'/RQ 1%%.VNN1_FV$6,E:" MOU\;6J-Q*\A"TP)7$ > M<13W%A"E6?I[;?$@*'#%XGOEB3<)2& O22%ZZ$L2;X)#.ZE9,MR7&MXDXOOD M05(' .YX!2?@6[J1^WL21(+5D?K[E0/5[F_&VKVSP*&Q:=9=UF$A37\[.3[Y M>'QTY+QQSH/(#6F4,,S_4)N7_OCKNRJ$"NPDPMZ$_$W\K@Y*VCBMTM*P,H6- MVY6GB;99^C$;\UZ<$#_/<8R"+Q8HH"!]_WB>8D)6"S=_-$W;)\UQ[I9 M X"< I*3@MI[)A0?)OX5);.KX!%[HFKT=QQZ?%+<\_Y.5^)3CXFUN<[:)^"Q MSJYH8+;S6OE&?0=0>"-PD$TB![ 04Q;PCO+(=9,%8,07%OEY\A &,X&AN0[K"[%5F1WSS?#'5EXYKY5. M\J*BF_U4:PU,F,1SS,[H@A,WYWJ%:_TQX8S#5S3JL158 W@GLS_W8+;HT"GU MZ,@NG=?0Z7\>>#]:P!%==(-=.B/!']@;DS.^M:)AX(E)B4*X!G [Q]RD&R@ M WKHE((/75(@.W6*7IV .%P<'+5O)^W0$KO!20G?<. MP'92X >V#7#GM3;OG')=;-ISSUUI<'%\F1 />[>CAP,3<31V&8WD$< M./7:('4N9^V^7.=U86PZ"O@#^XP/.32-6H\VCG679"I,V;_SC#.Z6 2QV+<: MC+E:N_TTX[WF-$-IO9\C?(51A"/I-OC*>U@DB]P[D?2PX'J#;-=6[S56G=(% MF-[0R5\RAT?:3^[P<'A/^ZFX5$90,KO#;#%-F#OGPZ44#6-L-[Q.KM9LP#)7 MX?8$=.%D?:CE>\_0 3NKMM:=S*J=+I28M>?;*F4LC V$>IMV^^"]QCXH\6 ? MK8.&,S.CX6]JV\(&;C7P_\!R@$VI>.HON-!X?'9@1AQ-$>-4S7$<<#S7X4P9 M4 >;/HK98L@FOM]18>_K',I'*YKX9RB:7X;TJ>]Q@ M82_%6?2QW^HR#KC!1]S T+VEUF\_C=&]0RZUW]=Q+OTQY>(Y9/#U0-HX[*",#;E4TPI!%.)X: M11N:[=E@7E,"#ZH2%F'X\PPQMN(2ECZV&A$/CK![**/^,-L5TXGF]@0 =5[S M7MYDW-8?7R<;:4TO) MQE9]>E"G918,G(+KS;_:U74=XPYSKSS*.)ZR@-O,2Q2FIL%Y@B>/F%WR,?H7 M1FR-B=@#>"=S:P_NM,R%QPE9C[FIP_MTH%,'>G5$M_O+_-OD(0J\ +%59;T; MDW.9UF3"1JZ+0W",XAYO\=8 WLG\VOY;,K_HSJG;1P%QTCX=RAREU_WEO?&. M7*G$?"=HH-]G28L>!3VP9A$,1-9I6!;_G?LS<"D='F1&!XC)IK":G7' M'/V@=<=DL!T%N#!#4_!. ?_ O_J8RV@+O.0J0 ]!*+Z=B809\:\17TUD\HQ8 M"Z_///Z.Z+2J@J,?M#N;'E+DO$Y#74*Q@B;X7B5VSF/TUBF05<$'!?B#8NDM M">EV-QK=G74*DN;:1B]!2E%P,AP.NPYC M[DV2&+)W>V+>9VWX#.1HH#"_4G6Z LA;$)XAW7>*D^9>5R]Q4I!2F^9H%?<5 M(%4-H'80LE8N]S@ZZP>Q]7SMZ ?M^5HO4=C#@S@^6F+/G?#V^0,?P8,0C(5; M%.+3) H(CB(SGO8#V'J:\DS?0BU-TMZOQ$%PYK",/W/A13/RYEUV(GODRBB,(OC"9+OJMUPT2LUEIPVQ*:-='I M%+&ZQ3!(Q#(T8;^<(>I(3/_BY+@V 3_(9;<@F%L20\"VFA,GND!CP^1D#ZT* MZ@I+BS/@@@]7O!H3OJ]?"*Q,N-G6O(5K1WET]V^R4! )&Q' -GC(:_^W>,QLS&H-A:=G/R@>=)< M9Y'NTUX^;JZ.\@"#N1-$N[VB.Y_7<6?/#=[J*!1\=HU>RLE__%$9VG&=%%]P>!@($QMB4;&K9;BS]H7EGKF+=_MJ!Q M1,;N@(LGQ\=:"V/?8BE*@EO3I_;+RMH38*L>.]8N6&EHQ*X4K"+UZGZJ*S%" M\O_GP6/@8>+UYF!#\TY^U2X[I_S*V)9#//#F&L=%:N)1'+/@(8E!J=_1$5S# M9$LJO0+#>-<;?"=OZS9%B;=OQ$/ 4NIC1^W7B:ES-\?.Z.+64;K?>SFXC:G[ M[08OTZ0, Z=J$Y1.KM8NNE5FK #L*)#W>>;>8#=$413X09K :9+$$W]$W; O MU[HA=7*N=G,_8UD-ML.!@Y$_FIQ='=C7,NBF@2][@3LP?XT"&SG!*IOF#.^ M*1TY3[PGI]R5D_>UG[,I3[=MP+JB;NO&^D@7?+1(O+V/@UN^0OL5(Q@5;Q3G M%GD M8FUSIG(QSZ5=@KWG7.,K 8.X"XRO ZE8]WS+:PRJDWLU"U#EG@K=4<$?&)B/ MRSVA#Q%FCV"GCYD3B[6/,\J%U7@ZAV0/>?>S8;T:2N<3L[5=@,JYVX.FK3.-^/M=+5%ZX[Z MZ(-F1ZWR8O]VU9[)^:^H()9B@<$>\V62P06TW\ MVV!&A!^:Q,5SVAZ7#GN#;%=OQQKUEG8A+BREG8"O7.E&>0GL9!T=V-K( ^4+ MHX3_=''F7?:Z];;5[MLU\+'&GA\F+J5O);2$?XPCYJ28[:4R[\MC MF?1T3(J2BR@.^&:JAT]T\WUV"E-MBS]0F"0J$#57*^8 M9(-G;$%LN,-VJ^-8<[ESH.A(/(K$P2)O<"XY!YNEBX^7T#6^"AZQ-^9$DQG$ MXY7!#+>G>@PZ[=0]-4__0 %Z+9%Q!#9.@8XC\=E/ETA?AE[CIR8S9>OVD7G? MG3)5.W\8*%,:]UU#5"_ITTDX/K-=QI_KWR/T]"5@O&V_-'CJ%H.[F,A*"^J>LYX,D MF/!I>Q)@S/GZOG 8YP\,U[%EP'/]WB [65QW.QJQ>,\?]'?QH7A]OQF?T":[ MZQ2)VNU=(Y%07_Y++-XTN($.$J-AH;ESV0Q0J]/X^$AS5&TV\??/"RR?G]ZA M9R/VJ+5;M](GNN3LZ5-7T7P_AQB>W%,"OKV)KWPVUY7FL%H5X8DN*;O*'I%9 M)@4/.D\MV\]%L33$/F;O:\Z.,J\SZ/!WI@M% M%!OUN]+O00+ZLLCTG>SZ?1QDX3O+0IZ*)O\V]&'3 *"=W*YM],KP&\4PYJGDZM'( "R'H4BK^L&+)> M]Y[W _Q;;:T[N5?+357FWIZ[K)2A-?8UU-NTNA5.=%GDRTS8:_?!/;S3I#,2 M_"'LTU-,>$=]_(#FL#HG2\W)5^:3"EXHMJR#?9T\CQQYRDQ"119U6_T_1WK_ M3]IV'\>VSSRH-&F_C:9WY:0@]EN>>RP%Y1:M"\&1?B'(1WP?5X%'',7BSN*8 M<#-UY#TBXO)EE8Y\7^PCC;G0":9=[?S8H'92L/RWL&DSR,X==0K8!XZ5ACKW M#[(Q;G2N^313ODWLM]5OLOEU=_MB@+HTD!")EY1Z3 M-&96CE@>&TL R'"3;[?W\UC0A,WR5BQ88NEK4A0.BF.QN;XZY4>SD3:7GP(' M)T="C8AQ$)16YJW$+8 :[R:^6O$A"KR #_*F5=):*'2*E<95VU>L5NG]!(U8 M01#,HL'_18OE_W-4- ]RU\#T7D:D(;!V^_+'!OO23!;VW?[\BM@W+ )HWT+H M&G%(U9=[6ACMEN?';LNS@.H48 ]L*L9BH+9N ]6N=3]V&X-:IAV4I6[,AVG* M%DCM:O)CMYIL8-[^:S]Z,P;5 MR"EK:]U^G*B[I=S,J#U=LKBBF62*1IT2FN^FS.H# MLMWD_]RXT'%8;W)@.1-;R@Y\[3GEF@&T&XV?&V>=GF=[./&F#-;V>#4-D4P$ M_7L2+,&D-N!-<]OVJ?1>,Y4R6(X )M5A!N[ #OX;+N?>X#B0,7DG#V$PDU?U MS(V.-8"W[ZS?:RX:9YW]1<=1Y[7HTBGZ=)1.]],T:>2.^O9CNNQA9/:%V,GD MVJ:A@\GE9R73J7!$7QS86V+&.>:$N8$:U^*6^O$38E@-.R%.0)=!C$(X3LI. M'S<@#!OIOU-T:MN4#M%1LQ<%L!THOA0(I>G="Y0. MBYB>M\;[N2X([1NZ]YH-70>C]V]+=X,]C!?BC 6RTTY\]>3?@$7M[5NW=LF?2#UZI$CS]K[/LNUNW]4Y16!K06&FO,M;MH M5:G'.A]9)]N[Y6(?U:ZP'RA;Y2^XE9?31HQN!="N>'4I'PJ ZMMN!>:!.[TW M/V9PVC7ML5;3=O!J3]5KVVBWEYZN;O"2LO2RR4RZ.C;#YL$==\I%S4W2+1?= M-=XX#RNGP,E)D3I(5(UU/19E S#M"^^Q=N'MU +[N+"*;?D4L7)N=",V-31M MO]2D>UB4@G($+$<%=F"%$K5/K:%$$,B"#/31P!OJJOT&C>XJ?C.KG==J;,!R M/34K6H;#OFZ*^K!.K;$M\=#UT2D7&AO-3"Y88[V#/*BCT6.U;070?O5*]\"B MC9.'!38?7N7W;T$\5Q)9W,X1PW,:>IAM8-+V[*ASYM8. UKX7?KCB7=>RM>A M=K^?(OH%U>T]9<6_/VF?3I M@T9S"GZ,JOS8R[F1K?GC,TH\N*"@?6D\\;G6,;M0UQ-@ZVQZ_T'.IMPP47Z. M^1]Y%\U/2&4W!X8VC/\I"N%)YNTI?7[:)VT[S](PW5MMCNOT[X=T?E^ M6J[#F26_S'',[8CP>TB'ML-.47F_!5%Q2J@;C^?!8\!K>2(:J'J.!@_+ M\\?>VY*B?KUWBM3GS8A4CI6,4EHZ710/XG/,#A+6S>,O">+[G!@+IE[A..;[ MF8E_QK 7;&WM,NFS2YJ.-V+".*\+7*1'76(C+@P*? XRU,W/GK7YH,C7!'X1 M5GA;HK9!U#KUVX>-2.100*8,_;D8K2J0[[#_(D=P."L7]GO#D[ @A1 MF[VV^F>"PL"'R+4CUZ4)B7MQM@M4^_G$QY;S"6!G#EQ8I@5X)X-_X%YMR ?H M>$.([2K[8\NA@Q$O]UOS=O"@N-/47J^_;MYLQ^W:^V.+]C:3$?6.E8%$[:&2 MEQ>[.8^^8#IC:#D/7&4%-)&,#@BM*OU8=X$CNVP.;"I@J@OS@4'] Z ; FK5 MVL>?-'=?N]FUGZJZ?;S--:\1G%9%>OSI??UJJ@';]E@A1DWCW<&.D??O)((+ MBPPR54&BQ"P.0)2ES4SS9F99F2MI&WOYDZW!M5-KU.Y79KBWR9^)9LF(<#@5 M;R!75XF.-)!]A1PE8W4M:>7>.J[7E"7Q]D@-P0-7 ;3!@$1H'B^(N1Q\1UE? M#[].^:X%,]N8? O$_^*4HAN)VPP-\8P<%7_G(,P#A.4&/V*20,!6.?JGJS/8 M(/1)TK9M##H%LA82:5,"F:(F95"^.'Q8.2EZ!W%K879C^92&@6MV27YC7;4) MT,GQIY/Z/>X> M1:YW6&PWZ)2(A=;J;\,T$LQBQ0W]R$2:CM+3GAJC6DX,B!1G"*B+C\=US=C( MQST/#:]O78^M'\#AR9%?2FYAU M=F!R,4PWFU/%&E"=4[;NTVMDY\U!%3<-^Q94<3O43K[6#P]:^7I0Q9T\WH(J M;H?:R>-/O7A\4,5=3);!B\5&;U,JN05D)WOKY]N-[)7ACV4_!QW=SH$$W#Q",]URG\: M,:<#0OMQU8G.;YN#< 2,VH>]NMS?/KP]5*09H/83JQ--T*]N=NVESKNC,0J; M$I2:L\T(3"O3CG2Y.P38]G2G?VZ>_?7=<^3]A);+@/@4/J4?"*$2>_$-/N%0 MOA)$#U',D!O__"IF"7XEF,Q9];^CDZ/CC_&$$I(L?O+H M @5DS N GE>.K,@Y&%#O3E3T$I8>M[WK11'OK%Z MP"M*O :*FFO81\_'MQ^/9&"&>SY)73Z917"(\P1S.CY42#.L;">5.MYP+[*M1XM[*/WLVXB_2 1 MKK#2J*I]%%[@XBA;+^+#/Z9(Z3FV!+O#E9W^#D^#:G[K4+HD/9KT!YG8#9 M?K*0::@%WIJ(2E+8%?\CPR2\+2G",V*HZ> \RJO3/KUP1HU4WI@&)N#S'_>;-[TG B'_&RV7C")W7J&DO8Y] M-"GOE"?^.7CFL7>*"?\13Z75/G+C!+$ A;"07..X0O : .P;#>+AZ M'7C:M M4-I0:",57+O5D%>_68CS#"UH#>GR1_NP9EQC<2.\JLYJGZW%'$]Q1$>L.O!- MI1;2P8L#]!7V"!Q\E0Q]H7U41 %J5#OZLMUO[""ZP"7E0\S"5;I+PQ[?9J ( MG7-8C^*I4$P?<+I$<).?Q/0",<)MBV(#LS:8+>Y3//S0>YM2&I_Q8HD"D,+X MC)N<,QR-8AG^!C".Z37E.S02,QJ&8&]QRL$L+0W-4 B[&)5AHE\B,KW*4)T" MK77LF HW..8[#.$;? B#F32(8$M>HJ*MUDXVW(-Y=HM"G*;A''/+:$&$%T;# MN(Z*=G /]A],A,!<@ 8J+M[P"<;@C DV1"6R3%O8K)XB4!\<4S&IW##AJG4V M992#BE=3W@E$P+G@.^(Z/@U#%$4B]R^T2_-XQQ01+"A8 MX'A.N>AFAR 9O>L">3&:_!1T6)YYK:R\&\IVKJ]/411$YX'OS4M*HI^K:RFFZ(*LL5'[=.+OBTFZVF"7/G M7"XC(:'-E!NV>YFT&W"^1]L7,@9W#)%H$41P%B&6D4);7,I"'?6:4@OIX-NV:#[E%J_WY6%9)4-?:!\5B>^C MD'Y!50+JWVW%?8:6X_%8BWZER$(*PAFT6PQ@VM2 MB*RX)H(N%,_Y'6:+@I8!+8=O&#-B-LVH,\01GR451M6^6B=@9QQ/1JM;J=K7 MG0M8&MF]E-G@DM&%_F@F*@CIV\PZKU)E!-30]N*Q:H547;GM-,%Y8\:#\P0< ME.?X$8=TF<:'Y^SCTINX0DD );4+K)L 9,--5D@(?,:%DN\'&>(;?A<'C]@# MB171Y3%;(A:+,.D9W<;U7\CA0)DB8.@5COGO:.*?"5FK:BK3ZA:H,)ER^N_8 MF^'BN8,PW)$0R:F J))F6']WZV%.G/!>C,DUCN6%:/4$G2_L(H7H><)_"OQ] MSJ$[:J+ -P_7.FW8.!7F05@Y+BA_LL^: /00@0M-9^%2@WJ]S%8:[DG@(>\< M7U*HS5'VM>2T5+.1,H**([0SRI940CD;G]6H,ZAJ(X6/E-5(4;_9AS-%X5?, ME9I[5W.*-Y192(,[Y^H70X2;P NXBJS2T5AN(2TA73P$J::B52W65&HA'8L% MY:O1*G/]%1?]Q)]5N@QKVTMG@7'YL6E;A9= 3>D1<4OY[I\*MQ%QNH+V#;LW M\_I6;-)2[Q1X%0*2\ &;/!%N>,Z#969G7CS'JN2O"6<0_SGS.^'0E.'KD2.'SZ555H^J*+%0X&9K[_4OD MBM.MW'%\2AFC3_S'&5KRLGBED#8<@FT7EI1A@=?JPF(G@MU)Z3+%*(HH)-#$ MWF]!/)=W:&G"(G&I4AF9M8#8-C@MDM]*IUR!RHMOCQ:[7XZ'$EXUGPQKVZC: M6C&':0]]&O-7;6#;;>,,XXCOL?Z-W?B.7N,8J!DQ!BXT:%S;7?9I8B5[A2L0 M[@FG>>7(3/K 1;SBZM0UJ6SWK&VEH#YMS:I;R%CI;9([SVQ#>A$&"TZ&YNI@ MC_H6TOJ(.6_B7P,::NZT-A?;1XE\J')-Y3%%A8Z&PMT;DA*Q&^QAF3)/I-"; M^'#1($TZ$7 $IPS[F-?TBN<8XRA*L'>Z2J^L3A,NA!$^3?B.!4?1'4N*-X;; M[F2-39&(^=XVB"96)\>"+O@V]A:S1UQL=FN?AZ^9L"6<8380T2:1K>W9K-BI M*=A=)X ,];F1S3=@E*21']3K#/ .+%+P[]%D5^S0$-B7.NM)XULACAY*PE@^ M>\' P(3^^?-*Z]2^]D.]=$ MR/K:AJ>AS+:]C8*F&'(-^MEW8Q&;K\ EF#S@;8K86/B8%JGEX^(S%(8QE<_3 M1:A9E1*3RK:I"CVQ4^EL13-,_?1FED@ 1/U+Z>_--0,W<:2Q0V;*/EL_*AN MND7O\4!]6I!W@T'N(!<6SJS^VA/A7BUV_4BX&]FOZ#E8)(L; $5]J!_3[-:3 M.X](?LN5C=2N.A[XDB/&_ M**/<2HO42:]JB"FC+L9>=!^! ^0&+]%*=7)_K\YVHW&^ZY".*W,NB*[XWC2> M(_+QNXYV.Q[VJ?ZO*(9=_NIT]2^,6-6*UI;NWH V(>ANSM4*\N/J'9...M9Y MM%1\@0EE!VMCJ?5T7/*)U\R96@W[Z:%)BZ35:EA/SX1TL$>M8#TU=W.&.^@I M5[&?HB?:08]28?=N1(Y<$1 -HL.6C4A-F6UA[512P)G,-\?PRL*T%8BOQSHP] M>--Q#A<#8_&V;>)GAR"J-/=I8MTSD"KE=^A91H'C/^3=)!%%R:?L"3)1<"2C M&NF&;5Z.W*N!KGD/G+A$'J%%MV#@RLSA=U0^$]+X2X8#V+W[I(I[^K-P:14. M]OL(DI1P'K#5*2)>U#P _8#8ZV^LTG7A^]B-)_X$XBF++5N6=6-,(&PDG+5 MF)T)20.FIP%.FT=J#8CV+J!]B!3$^=P^2!C9S+!U0'S)PY;E>MF>H]\<7I=A$#MWE4FAOL_F"\BJMR0I.O1&"GS5RZ %:)HB!E M:C/)?<%8OK)5+S6,P'[[53R*F)7?E/1IL/NG) W8E@)T=%!6K6OY/*ZBGUUA M*5]M,:N[^]F[9' 13=SB(YZ:EN;O.(2$ O""1[* M+U' Q-V^:QR?KM( Q[<0X/BL%-ZXZ9K)-D#;\&*N2MDUY4NVSW_=$P\SS:WS MIB$Q:?AB-K<9::>K]()H>I)=/@KJJ&7SD5 3ZM6#E,YZ%KJ$"YP!2A/+E+*7 MP2B TLR>4JD%+L(,,T53#E M/5O;9CDVLC5X0(N'2D2ZZD?[9E80)L 4)>^! M.K>:2BV>7364*_.KN=Q"YD3((#]C=S4;*7/EHWSLI5>EX*DK\< ^31-R%/9I MC=PA;7>O/YOPOJEDXVA*&[T. "NO2J=^-KX12^\0:1BM+[>!F4O*=U&BMS%) MLP5I.92&1LM?ND:!EY;DFPSY-@$2PF4Q!94QV'8_EAGPVA'FAH*6YB+]1#7@ MP/#F.]_UFV">7295LQAEX7Q'L0SP._'3%-&LUZ#T!KWC2YT]]AT 'H!TE&CX):&>@W<%X(-Q,OL\&*^IK^_ M\ 4P*M/77,FZBQLMYD1.")+6H%^U!FLW%OJUV?DEA2 J?/%J^.&O :%P'0[D MT,OSFZD\[MO..K878Z!<,5+F77&Q(CV9+(@W;[#K^9IC2O/;4]G2F_V;1@\I M4E%IZ.S7VEH#4$,/YGL;)@RVW-2]7U(R$C<6#],N MN&R[ 29NH,Z*[77P8KQ6U!6/1""U*:^,:[L,AN+[?.:5%%%>9CR(G@PE=?M2FZ\_NTL=O#U(*;B^AO2TCXA M6(9-<7_U13924'NK5/ID'<87*(I/,?%J$4QT!?9A#V&I*GB7/NWA;2QF6/!> \S=RI9#85ZVL:?_DJ6'!LO"JI?9O93'F122V-\=A(;'-- M2^FC2Y2$5$=/I<1&_#,DRX:@KL!"[/EFKCKLZB?[,%Y@U)0MO*',0AID3M=1 M&-(GV&]79W)S^>ZMJ,4RI"N,TY>&(M8@9"WWSI0[V==4;'6P)VXLRYQU:CFL MI-.8?&9$T7""!1&"*[Q,#6TYC=#[\,#]%GBX>' R(5\PF,/+>>".X.4%F/DD MP?)EKO;R2)Q%+;ZC:5@ODO7Q-H#-TG&5QS/ MJ3?._:3Y05H1*DH]->_;:+<';WIL\[,SOG/#HQG#N.1RZM?&-NND<68*LD2D M1W"32VIJY^:=M6P[!+I(N)*D[*(:NDCSW;X]2<*H#G%J-=;%I4/QE(BK.^7B M_U>^J/&%SIL0F="&&XR0^P=%04W4-@#'-F&LD-1"Q#VA#Q!.!] ?DV42EYVZ MIRL!03Q)*[LXMMN%[<+6A]S22>D&X-A[:F^5HV9L M/OP MVML8)F@G'\]B=TZ"WQ.\,=W5!MM>I97J6("D54;U\A>@9%J>5Q<FS%&G' M9FO=[.40-TS$+79D[ZS'O]['Z%_EZ#6GN.^#T[ MM/'YXD;I;][V;AJZMVQKXG=N%FFSA#3K%I*:5*H2K@BD-2 P__@17]XX MHR%<=^<-IZ5(P&95=Q\#.+L4)BYENJO"GQ#)"(,-NJ9O*ROU3IF("RYEGH<] MQ:7"X(%W -',H\H;AX%M[9N#773 39*>I)>:V$KQQ;,KLHS(B$6(0&PXN-.L MI;6SLJU4_I*P(/("H70B+6GZ&O;1D^"PXQE5>Y7=KQT)A))(P[ QOA2 <9C& M \IO/CZL2*D"A0+^!7-J2(0$E^#F]&(9XKCP@FT%]&XO74* ((9^0[$BGJU5 M!J_Y]&GMR*8MF/&%=Q&(%Q0^9=+:&4*@(9A=#$*C'(;T ;R:/D-9.#$\12P& MHZXBE"8U=R^AM1@K=]Q(S5+K_!802!@*,>@*?O9IL:OHO(WL@P =XK6:AQ_B MJ"'J?&.$G/*E 1Z M%\_+0+8\A[>@5[#(B. W%7*-&^W>YVR \?URV9_,4B,[R4R3*7'$Q5ON&_ J MFK&TLZ5M047[#H,9RSM;VC8,33IN/!U=G4T@;@1;LB#"T9BX;\N*K+W*SK75 M>'J5F6'7E-P3F(;ZU(E105&?)K99<^/I]$.50U,+#I=S_'(3.4VL.V40[D]$ M:;K_ CUK"N M/P!K!T5XT2%TB8RHG7!KLH@'!3(1#E.K/.@JIV#14Z_Q6Y?$# MV6^B5J0T*U(&]6E@'=6-BKE$5$'*Q%?C#&5!W"LJ?%A;ZS:$>737(E)0_9Y< M5R7;-H(Z?$N/N-HJV//Z*L<21U.T J1D7K;TFI[^D*AO(QNOV"@TI-%J 46A M>;((57)&Z>9DGV:[M[W2;/;G6/X[)CD1H_1HB_],&1E=XUBAM7=#BU?S$BU! MGBXL-3;A.E\3X4V57PZQ+HKFW+10LJ@_U+*O]VYE&_G-4YUOIV8!1Q7)4#S* M>_R&,GL?T5<1+OOK&TLMT$)R!LFKLT97.?LUL>'^@8KQ[1-:1L()-/'5[Y&X M09PZBW2DFC;<[2VH'AC+MS0#2,T;[H;4EBDHWPE!!A;YM@&?4;:DN@#2II4M MF*!9+, QR3?I'=$2>[;9M<3FX1QEKAQ49 UNH;5F$T@+O"(3-&WF/ M(MQW3(NHG=6#N)YMK-N*-6<6TA?M?JY%40(C/!&9,A)6,3^;2E^,P16C!WJ+ MR!5EF/Q1N:3?5&B=V^(7RCQ4T>:5;SL7I%\2>%3%19SCQ:=N+$XK^*8T!A.0 M2PVO"WZ'[/*Y!P_DU83 02YJ=Y@ME+93AGW,&/9N\SL?^1A\WSYM.S5K'GKQ MMBW=#NLMVIYM;/2;_ ,](F[/E*=%]:-U<_D?Z _T;0X\K2)>^VXQ[L$=YJ;R M/_Z(FXBH5["/&LPG'Y_;4525(4V!?=@'^+&"MOK%2GRY07<3/!)@@G/IT\XMGRL\0V&$XS@L1;>O?[;- M:"X(B,!G7D^V4$_(8%;57D+AJJ9 4- M-$4OO70:4[B!6DL285C75ML\>ZJUNJ1L@5FX&KDNY);!<(Z!(E1XDV/Z@$<+ M>.GW!^^/Q#2;7/E(; 24;0/5I/>O(*G$?52YMES[:MUZ=<4-QYG&2-!\MP_W M\H4I.&T;$>\^JEX>-ZCW$FCC\PC42"=MU7J[MS@XCN"QT"9%S9YOZ??]PYK: M<**58:X\?N4LHBX8'<*S Z[)?$FXP5$2QN*&&EQ;XDNAO+16'8>UH=FF3ZO# M5>=N=0BT-5X>67S!XXOAR(T35.-R9VUK+=9& N[FF&'DQV7-95#WY7$6IF- M((@7I,",NNFM-WBQ1-.$]2-::?!2B9X0K"9=-:_^4@F^F_-UIA>;2RU>+-E/ MM!_117U[2>;6@0ALP0UB&?+4 ;ES4-3H76[H:_HWY1QVQ]NR"A) M5*O4M%>RD"J"9M)@#V;S:NRSQE(+Z>##_@>JHE_^:"'644#X3J_I!DQ+^])$$>?^.KZ8X60E@H64D,,='1')?NHXD;> M><+_UZ@F6BI82$U"8@[WUP _58;JQ=.?Z^AK'$ 'Q M3$:<+;U"Y)-:<=J>UAZ7#&OZ4LS3CL/9,G]-*]O [CN(P.KSU?..PM6]CL?- M?1J\F!>\G"CP08\8 ]&%JN4G-RWEUBF>.JZEQU#-Q;M_#U60\)2>P')@4T8) M_^F**B0-WP'!A$4$\-A+[Y/&Z%D^AZ*\QUKPSXU"W&I@D&$L;Z(N&GET&7/] M6WD-T*N%;6\!KFD1>:FB=G4E]LU0D: LO_0OW[J5YFA+!8MF:1E+&9$_;J"A M*+75P5A!N'C1KS_N-:]NPQ%O!5O%%ILPU4XK E TT&G6TC8>&\[$S';IF(^: M:M;.RJ\H3I]9W."E]!:#B[@A,OC0QA:*./^S72.5*M@FL U$E6)I-9193(IF MFY %(CA/\!U5PGE/?,W^Z"6I6V\9G1=>YB2T.Y*JF MF[[01NN--2P&E4VC047;J:OQ2%MH.Q6=O+&#)SGV8DLZ\6_Y% ]Q'G/H;H[B M_&*R..HEZ>O["?M*&;RUA"7@!C]B HBGE&X(V*ZB898'A?IG%$(L\(6H.#:Y M1&ZZ.?\%TAED \=KAY_L\$,8B?#1"=!X^!AXD7 MW=$Q>:3?\"E%S*/^.:?2C2F++M*$?S=)B.O#L4G0M@Q8YG1-UT4UCD5[%5L( MT"1NC*H4--39F5O*A :0K9%(N53DH30BK*FA-=1" ,.(YL9FE:9ZL2VB-H6+ M--Q@S@,?%_:R;MYT5[>&L#S& %P3N.5 <(TM#75L(2%3R6()H>KK M0I.*UNCP0,2VQMZR@0F:670*Q\'ZW!'YZ]\[VHB/& /?EV2#< M?0&\@$')=N9U0[^KTJYU3WK60V97X'@5<:%)+'@"@7-S*KIJV>J2+1"G472& M&%OY,N%V),4K?2I_1X7M*$,'GF,OD7N3.WJ*BX0(W*I:!FY]2#8(>1?#.."L M;;*+ZRG%+&Z)/(8RYSRY8([=W4-CNJ ME?&0U$O'WO)W.]>5UH.WUAIVT@-9U)28PQIZFFI82D_^=%8J2"U%C77LI.D& MS\ +2-FJ43,V5K&=(B7\2"M9NGIVTN:J%F,@5NLB,%6+I=FOG1U+7%#)<2$" ML[/"H]55R3:K,B,N?\2X1&25N>6ZTE;V;;0K]T"3]$(>^, -./;Q%:U&YVTJ MM&X.3E$4>PEF>0JLJ$I(8_G.YU0:)R#B.\PT/87';;P@\\9P,TQU/!K7MFY; MH*%7L3#&9%3D/;BC^2O(0$NZ<4/K1J%1@C'S*5L :.%?$D]U*T+<6L6^.:E# M%VX,?$7L&^8J$X15^(^[J6QM]C(H?X(H_$5!3H?[(^_?250*O=99:_ALW51B]@Q%8"R$RPCY.HZEB^SDZ/C#]/8^JE+37M5Z MDF[,2;K9-4F-$V[.=PG+)=QXJ4PG38%]ZH+R%<53[Q)4B&@NMY 6" #T-*]2 M4/FZ>X4ELCRK!GJ.JZ[$.C-"H2-&SW+C2'U/O+# 7I$E\N+9#1,O(+,9'S18 M-V38+=Z ?X8HR6Z>YIG6GI=M"[CEHQG2*-K26&X:M+5;:27=4)%-J^(D+8;& MK/)+(!:VR>*'=@-C4/$E$'F#^2:33/QTXZDCKU[%=L)\X 4*N:++\R?6XFL8 MUK6-U,;%6IH3Y_@1AW39%$"NLY8%BSDHQ7@%/K9X1#QX12 0S<)]%Z]*U#O2 MTFF>9=*^QNK[:87X+8"V[%9(YSAR B;^R'7EQ63LG>,EU\V!#.5 63Q#,^Q- M0^SQ?R:07@T$YHY>!5A= +<#W+*Q;)IKD%5WM%PRBMRY^GQ=\WWW[]5-B"B_ MV=.66+<[*0?N&$/0T@0:E!C27F?WS-$14WE-_S*">YAP*3>,ZYD;ZR?Q0QI: M+:.%]%5F6WL=JVEJ9MGN>:+#MQZKXL4%JFB,4O&20E2DMP)$N$(172/]L]&N MT$=161^,C=$;%\M#=TJND$PFZW.N/$0^(%; M#S=L4M&"A2N-(10X)%4-S:E M3SM?%$K9ID^3%6;RU>L=S1Y3U(Z_Q+YRRJ=E?H*R+A#K^#E@=%+;?<"0%"VW M:-.;4DM]F8/G845*H2Z#C&^B5*72N,4VTP)MBKPEL(17Z$.@TF8-!HIAVO#% M?S')N.IT<135;^$VEEJAE")4FCU4S)Z8+M/90[/9DW$!/_-)$$3%9F9=(+99 M&<0AQ8FPC$I3$3QN\:>I5;YI=Y0WNG43L-#;/%K-'N)T4W^>UO65IX;][0 M7MX;/.3I2[@]O*^3^XC"1%3G*/_.C:/ 7W'X2.8M[=2 /5M;85DVNS2;/;YP M,'3Q'&-&4)@G>,V'8Y,0K;LHV3ACL'B1C=V$@X50+AYGZL7%GJV\JZ1XV2@GN1VI73<$UC_.''%.^3]SIJ.^N^!!H_O<_P/NZD M45?W1="8B=^';A+K55\4A1_-*?SXHBC\\>A(HOVIDT)-U9=$X=,]'[HI%!3]250*%:\)5_QWGL"^\^=A#:WV/V57_D,K;AG7G[AU5QLZ6LU MO5]UQ!C<+Q0WS5=%E?0JW0A2S&5YS[-0+I'8$D+JQ-35FI^0C8E\T)6/T7?M M-> =,J"&P=QHH M/ZS/[@G?4?@D4YYLGR-=W6]S,M@X[K]A",+)"R!_]PQ_X1W%YRC&WW&2K('9 MCM["?2]N?=])L2]SP!J1_S-+>$Z#\@JF0F]1)[S9'>JAE4DJD- M6SCML&T+4-T^E!<VKX]%@BL(-WL-3QM]OC]D'5:Y4?O=ALP2B#^T M\/EA553IUEAQH;%$+=Z")O$- "L-U??J\<\ZN$(-14&Z1^A<%M)GA]07EZC* M43+LQO'/RL"4VJ?ZI--W$7ONT^3-ICT,7$9IP@'I*Y- []Z ?F:QJ/E,@SP^F.^1LZ^& M#(4:Y$Q\.$/D >=>O)A60A-MOQ_[DN0)U!C.XMLL&9TQM#@;GSTDJP?D?BN' MF#>N;=^A61!R;MP$WHQO[5!8R;K=6&H]'8AXMTO>3SL]M5HVTR7S C;14RZU MCPX^([A.^U;!O_K50KQ#Q,383F^NKLZJZ.L+[:1"-Q_JWRW$G>"PBK;ZR4*, MDW@.64BK6%<_[_Y* 6Q;(8L@]M(XJ,HA:A;$AJ, G"0O<*P*E+=HY4^[0 9A^#!&3<$5CYEPF_VO S2J.T<_;)BZ]/ .FV=(U\@K&99;"ZV)\'B'5XL M*>-S2CHW1WRT4'@>0)X2XMU@$5\6&N0TF=>WU/\&SVI29Q8\/YTR[&/&V21> MW8@':6=TP3$02Y6L" P05E]M5F\&UH[O40RDX@:$:\V1R&#L./![-_:YB"OW M0'JWVNV.H1M=N?L[7=TN(3=Q.$W8DD;X-(D"@J/HCB51;$Z[&;#A2@)"EL\P MLV%0IHCUUPR]X5JO)0PH$K=TL@SS&QVK*F1;K_]T$RNO.D[\?\*.E:O)3(E$ M7]'J%)^G]KN9BHWE5)DVPN2#KA^P59>5U4.]6]IF5OE,1S\<[I,J0B@H*\X,4W!)RB7Q*B>2FU$4CVC4^ 8]RT+V\JM(\*4%B_ M0&CV< 6I<#R1E;="3'L=.VFZIN0^TM!1_KY[3PG@)!OQ;2?*4XM&,8WGN!*R M NY;EHCIV7#W5S\4K#ER,C,EY8K?3XCGTBB.@!:QFXM%KE54R^"Z%@3[K@K< M<=9QU5F.-JV>4]U9S;9@+7<<:. A[PLFJ5/IGH3!@G=?.=DRJ6B?BN$M M)[X2A[WD<6DHW+V_Q9BEK7&TIVO X 9 M!Y@07D^:RI0/N,^1]-2(-.+H4Z6F1QO;#.O[?P KSO$C#NE27%%D%#S-45GX MNJO9)X0"Y6O\Y Y;+-1DQ2,T4 M$)0CWU%I^#19)AM/'7A_6RR+?Z25TBO]!K5[EL #[G P 4 865S M+3(P,34Q,C,Q7V-A;"YX;6SLO5MS&SF2*/Q^?D5_\SUC&O?+QLXY(*DJ5A7IGHF)<8LDD$@D$HG,1"+S MW__/[[>3'[[$:E[.IG_Y$_DS_M,/<>IGH9Q>_^5/OWY"%Y\NW[W[T__YW__K MW_\_A/[OJX_O?W@]\\O;.%W\<%E%NXCAAZ_EXN:'OX4X_^V'5,UN?_C;K/JM M_&(16G7ZH?YC4DY_?_A]7O[;W-_$6_M^YNVB'O9FL;C[MQ]__/KUZY]_ M=]7DS[/J^D>*,?OQH=?.%OD3NF^&\E>(4,3(GW^?AS_] ).;SAO 7[?\M]_S M%T_:?V5U:V*,^;'^]:'IO-S6$,"2'__OS^\_U5-$Y72^L%,?__2__];?,'C&X=]NJIC^ M\B?H C,F@M#5?/__0]T6W^[B7_XT+V_O)C#E'X_%J?[S=5S8LVV=A\#O MLW63V!&]IWW[PVX:7I?SNUF'1=W>PTSO0:&[C^]F\H40[ M'G!_\[J=+:>+^@F"=3[0>YOA MYM]_B^7U#0Q\ 1JIO8ZP_Y:W=RV.HJ/A]C:K+"L\C/AVN5A6\?X7^RW+D0Z3 M:0.NMSF\!;GW5SM9QJN4/Z\.E_:X-P'3&\Y96GLX$J^F\<.LG"XN;^ST&O;I M4:S4'FAO\WD?O\0)^SB;3-[.JJ^V"NVQ/P2B-UQ;Z@!-NO:'6UR\74Y##)\6 M=K'LP /[ ?2)YX=8E6" ^_77E[-Y0T6Q-9S>L'[8UQ>3R=JJ[T#B!E!ZP[B1 M_K>[PU%X@ IQ6RYJT7T @2TM^QKY?;3S.%^=)S^7T_)V>?MPGBP;[N"NX'J; M ]@]GV-U^V%9^1L8?^.G]A-H#*LO[%N*RP8]^\*LT>;8V?Y(+':HGP>Q.=!O M&*P^V H(3KBAN!=(;OOF\BO4R7:5+.[]Y.YE];4/-O?V'P;)6K^;O MIF_^OBP7W[KBNAW*&!AWY8JV((>9RTL#M^L4=D,:"_->5J(AV$'F='47*]O$ M3=P EZ]3>8U]HM>C$-V2)HN%Z=X?4]BY\M&&&@,N0KZ+"<-#0OV@/J M&^^6]E +"$=CNGM1V_-(:UB]8M^!R*-3./NNJA)DRYV=K+?.ZV6\^A*KMS#R M?T=;=21W>\!'S^O3TLW+4-KJVS->?3=]'9-=3A97U87W<9+5A]C0NWL\X*/G MU>B8>-GP^'%A@\#I TNV* 'PYVHY7WR*/LNIQB=K:SA'8EV57^H]\VXZ7U1U M[%0^"OXCANN\]3W\5 ]Z$.N6<,;!>G6= [^\+ZTK)_5WE\LJZ\!_G0-K^M7? M6^$U7:[Q43D=[5['>7D]S5LVX[QX_+CN/2[YNF,S#@6S$W(60$=Y[-$W61H, M,=)!NSJM;_U%N/. XE&C=\DU+,'^*'696-\T[8"FX(:O2#RHBT:[9%CP!YW%S6;Y9@ MJ#V&H*"SK_$*M/-[8Z=-FZJWFO.#S_W/"F MIRV87G%N*9V:=N\5Q\=M_?R75W9>^OKUS&39V _8%_A>Y]A($NSO=!P^38)& M>HP)68':^TR@^;S[")[::J[6=7BP4H?H'N;VZ?%S/_V,=ZM8P\[D/\ A!XP_1C]Q,[G92K7 MH;E@-EREBYF?M,&V,90Q,&X2JM(%5 ^X-Y.B6YKV,79EIW/KZWG^K5S<9-QBO.F[N=C0!XUEX=G)P<0?-&NGU&?NEE^CG:^K&*X6#PT:$:^ MSO#ZF<7Z[4B$Q?+EI&PA7]N Z =7X*DJW^!5P%%K^K2X)FD+IG^]6QZ%^4%@_>#_7TN;C:*UV^7!,&J)>#,H_6#\L0<6:0*C'VP;'0,[ M6A^'03FUL%^GUS#76'YIA,:>+KWCTG#%#O?L';-F2W:PXU%X_12GL;(3,/@^ M+6]O;?7M*GTJKZ>U^C)=/'KX&]KU7<&-.H>-;ZK9%/[T\?ZT_.^XN BSN\9V M]1A#CTJ;AP>K#[^\F2]*D+(-M9#!QAN5"JM;U_NG%>^F]S@UVK'###;J_$'H ME(M8)PH!C1O0RI%/;5YU#S?@J'3X)7[=M6,'%1.MQQV5*@.=!?V>";-9^%I. M\NBU8^PY5QW"O6'W07&\3^5P<9LC%/Y1:[KKS#(-V:ZW 0:=Y_WO']OF+C@> M\*#S>OZY3G]5-989_4 ?=8;#S&S,&;6\&^H*;M Y/%[N''^.#S#4H'-OIJ&U M G(4OJO;@L_V]X-(;6G9U\CY5F@V73T_W/BZ&0NTAM,7UJ]CBA4(-/CP$'"\ M\=V3V..6$^D,^F1S:W(!T1O\OF;Y$+SZ\%T7_W!W@'W-X_'*[VTUNUV%-B]! M,!]S:OEL=Z@9U^8 M-3JP=K;O"XM?\WW .K,??+%.9]1^F9O!.1+K+W "S:I#@1LOVO4S:E.2;&_> M#PX->69KZZ,QF*\R^;R;P@Z^"%]R&W39Z4DQV(W2O^^MT__V/PRF\Y6JGV.:AZ/&2S8U?V";5)BR_=-T.T ;I Y-"?PPA MRMMA\2UG8ZU?8X"&=9=%SP'4#O8;!JO:0?,Q+LI5>-!C!OR&I\'Q@(>9UZ:W M\$/3IX@=H0TS@]?Q#LS9[-,L+;[:*FY>F=6J^EVYL)-58OR5 G_D?/L< M>QCJ/)@L.?&AG;S-ET]OK6_ED^T'^##S^QBO5R\KX,LZ<\[ZX^I>>TW\U^5\ M]0@ /A[/Y#T,.0PM&HGVAKV/PO!C##'>UJIC?L=PE38-H0/X->H[''8M?9"= M8 V'_=X?&[%'7^"/G&.]I6;5MVU); [.H$GG ?%KRCDM8 R([?Y?7WW[&._@ M(%N9@=>K,^_XZ1T[Z(#T:+A+FH,X$M?Z:/E@JZ>/;@[BM[_;(#@]AAELMMBX M-KJ_56K*0?T.,^*<-UL,,=D]\ >99<,]T:3S,/@]>XZV$<%8/T>^F4U";)IE MLM]!CIMO.?\MRY9?IQY4-EM.FQQ_^_KTCTU#FC;H>A1N]_ODW>5L&K(9MO6> M HS2.IOW 6R[ 1L1_\UR$\T6H#?X)YKEDRSL0T]YWV CSO_A"7Z.-MG4M/-% MSDR^,R/10- M&H0,A\OX'1SP;2@Q^.G1X^5.P^&^2G.KBM[ M=U/ZYLG[&O8>$L.&K-8*R)#X-F.8-C#ZP':^:Z@#F%R$_UG.LW,FIYC[/4?@ MW]^QS>_?&*P?&=R_?7D6D=]8>3LW/$]*]?4#L<>[[FP';KW?KB_!P2IJGKW^ M+' [)74_QB]QNLR!3*NYO/IVF:5NTR#VD48?@T([?V_XEKWO88Z<\Z1^M@W' M:;6(U>3;@Y[WVB[LP9DTZ3P@?DUYKP6, ;%M>,@U!W$$LPP.&]^ M;!50? 3$868R_VNN:O5I 'F%DSO:9!U^-P6[IY_/L2-.T@,&[) *R!'X?MY!N;HKC<6S;!M V(;KMY.? YA U9Y#VW6+3-V MN]&NDQ?-RUJUV_S[Z3CQ]P68V3'T.])N?7+ \;9MHMZ'JV/%[V;CT/+I8,/1 M,_L2WMW>@4V0+>ZM[YJ&&^?QBZOT?C:]KO,=K=P;N3)-CD,":?EJ%;LY,@WV MVQK#C3L4*Z^31^37! -#WZBBL?[Z\:W48,3<@<#+,AZ/N6'VXY(Q 5PF,_]$ MOJ_'_]U5DS\G.W=_GE77/R[GZ-K:NQ^SX/\Q3A;S^V_JHP!A@M:'P?KKXC7@ M.GT@3T:Z ZO7B_=>1%L579\5GV*U9?2Q\O9?+$*!1J,DH='+!ASTG$O MD8H^(J5R(M ,68_KEO\.,^I$C)$5"[B[7W_5,UN3\=@LW-=$2#:N3+\3[:< MSK-TB_,AN7S;,(5-U& -BTLMQ8@):A&AFB#+F&=$$6FQ[<3:])&UT;]X>X!U M. U#W^8+K,^S5_=/<&/(8:P-3^]?X*1^6\Z!8?X[VJH=B_KM%TXMB)G<["%Q-@DGP@")C0H M<241[(V$N-?*S;'W@ I%&?%1 M4!2$MTASXI%07B/%$[.1FV!"-P7M=*?8]\6D1ZS$(UO^^X_/K,A^+,N:DG5H MT"HKX[OIY6PZGTW*4)N[&V]3SLR\?(GX)K(=CL^=L HC0<.@.B"8IT &) @2 M0F-D!-=6@+;-93B3$W'E:WH[J_*'^_2:N49>79R^)5GVPRJHCLPIP4&^:HND MP: >&F,0CL)8S8(V(7V'9U]/?'!8'^Z=O".<81^R,*U#VVH)^P&.W.HA@]#+ M.#[P(S@OC. %#A6GD"D034HXXYRAW^=9-PQ3GH3@ M9\BE&Q-J)"M[@5\HZUS2V",I5$(Z.MCED6I$*5!.$.ZL[B8_V;]XM3^:#ZV! M;?[]MWK58KCX$BM[?3">K>]KAOMZ/RL=]OX7^VUW5.'63E=/!2>&WD-UD5N#U0DZGO4X>\&GXP6%V^7&6!^7+<\+[MB M$[$5$[8TQ)]W+U30TL7LK02]#3G!,0HX^^638-$2ES"59V(]O+C=;#7W%[T+ MY;Q4,L!M@CZ(>!I?UC;1W6[O M;(, 9I 1%,N !'<1*6,=PLD3E(Q-03!K@CBT?0YJ]'\L%NJ+CD-K/ODF,U;E M+)1^_77VX(YR CW0Y6)2<\MHQ_M0P3"7L]O;]#%>?PW_7. .9[]OL>674\\$):344$T\=9)U#@ M42%&C4-,D("U$!1DP$FT@,-S@X4]BC;0OV!)"7,=1= SXB\8,_;%80^P"L(#44%YI!6.2&NA41 J MTX43@JV-BG6+.V/_9#QV#$G/A\O>SI953TSV *J((3@1O44L^HBX9@P9*FRV M.3EGAM* N]V4\7\N'CN&HF?$8N67ON38 Z@"R"VI5Q1I+#W"+!A$;-! ?2D] M"9%1W$WI%_]D+'8$1<^%Q3[?Q"K:M(C[(EM;0BI\C?UDV7(U\Z].'5V@RT4EY+Q*)%4 MVH.8EP&VI ](AJBHXD9&<=9Q)F?OT.B5]B,PZ<-#Z,Z.M(80"DDUC=QCY+ + MR'C-D4N<(2V4]9@ZH]-IXO,;3N"PLZ<=H$);+ UU''DG,"(Q.D3R1R*PP<9H M3IPZ8W?/(.L^&YFBY[/#&CE]6L,JN-?$8"!$ LH@31(%0><\(IHF0@*AG/,S M=ON<$9,=1=2SXK,FSI\.T IG(VCRUB+G(D71!H9(4AI9C<&4I-8H2\_8_7-> MO'8,6<^)VYHX@=H#*T1DG'I"$%?,(4X41D&"@6F8L,&GX+@\9S?06?':,50] M*U9KX QJ#ZSP7"?);$0Q/Z\"PS4BH0PH&5[9* DSGG:[.1G''71>K'8$5<^' MU1HYA5K# LLT@.+J#$I.YC#S&)&VPB$:%1B*1&E%S]DM=$:,=A11AX@?VPQ% MFDVO/\?J]L.R\C(.%A%'ZG&Y)"=>B3.N7A@.;V:QAT9!EKT+E2RA%/B4!0!1([ #&''5#V; M@"V53'8SB(:UNOM/T'$WB$W' $60;@ 7VF:[M !2&"D>T!=,=YP0QCG.DHI:K^3CJ@83=+(AA MK=53L<$QA.N?$?99E:WZ%]A[)D)RR'(JD58>K!WK]6HVAHLL^<[0D#P1&QQ# MMP&X8(_!UZI_H5/D(HF$A"<<61G@I#/&KF83F!'ZH(YS"AOO5%QP!-WZY(*] M=EC3KD7,B75THDAY(U&0W"/'E5_-03NN?<=<2,.:7:.O_5$D&]BH&OXAZ,9@ MPSV&V9'!I@># M4,$8G]9OG M\YFOO\U%9O,+Z[]"\UP0:X_KYRBX1=+&J$04TEJ":L691"PYC&RPEH5 DL"' MTO:T0^80<@Y3J*#"!0* MG^WO#Z@WS:>WIV/!"1,&E'RD2-#($$F0PR)[@(02,'6J.LJ9X0WED7FG=T*V MUSX>$LR")3&OLU#MRFZQIW41P8BW7%/0DUQ$7N37;M[S%1$$832);KZ1X>WC M$;6,_J@WQCUW5GZ>$V??7?:V]H5Q1D>I#8K9[\.BR-=#GB'&*$\I.1X[)M)4 M?Q3&Z)M^([#&1OXYF'Y=S^UF-H%EF6=2++[MX9)#70MN67Z1$9"7R2+A$T78 M10(65U!<<="W3E359 /SPV'>+QL7)$0P%IT'T-9DME H:990(%'E50R)=(O< M&">4N]^%FPU KA$8_\+[.@OD!_LM^_<.\\'V#@6E'LB2#!@3G.4J)C##R P* MG@O-*'-"=8N"'9T7.BW7;" BC6-[U6]W&G/ ]@Z%\R#6H[(@S1F<#P9;9&0B MR BIF<7<>M7M_>@X,?<]"=1^(9NOXC8,%6&1X0!2QRB"A)8L MN_O#2HGGP>X"/$4\9R][B$_5!G7(/D*JUJL=K)3]5L>;=Z8PM&&WSK9]-% M.07YLHX0GDU;*?)=(!=&86]"4L@J29 6.B!!7@4Q8Y6 M"7[9)S+VMB^\3J"V"HXP#@H)!:P$FLS:-02[B')]CC?V/2[!;MW@*#(=IQX< M7-$=>&+CK-#6(B9!>3$1Q)%@PJY=MMA9T]&"'WV[]K"O MHC/L75Q;-MO=J5!)>.530*!WP6:CQB,0S Y1*0/(:IG?<7T?)FY/O-,KK<[8 MX&UKH'0$7JC($_$F(FK 2!3>"Z1TR.$+7./@I?.Z6V6+TGACL)#0=@1$W M0MY!\%[6^%_'J=]?#7%/KT*PP D1"7D&DY,Q[[=$&4J!<.ZHPK)C.OW1E:C^ M#>%^Z38">WR,(<;;?*>3&1GP!5K"(-?W%SXKFES:JOH&WZYJ[.WAFR[@"A#; M4M+HD*Y"[.A!U M))5J-JVQK3/4'M"C-IL6/G)L&< T3CIDDF?()2=12,[IY$.BIIMT.167M%NB M+>K2D>09(Z DA#+3QDX^V#*\FZX3".\+)]G>HS!$:*^!.(1H@RB7'!G/"1*" M16DIG-:RV\WU.$[IGE>_/RJ-HB@O;'90O;'5% 3>_,+[Y6U>B!BRZ\J7^]7B M0YT+$H04/F 4E$LH1)@Y#RZ""-4<8^5(BMVB3\>QJGIFC4$(-D[LV3V>M<<* M!-Q=%6^RX_-+A -U=AO?S^;Y%YO[%BV#4V\$9OI<13M?5M\::1HO&Q?84'"*?75'CBKKQP$IU2[ M>ME@PS^O/Z5#M0<2#?N*_)3WL$<*F8'>6Y_B07*/[/(=/33>^=(:.'Q?@-6> M;H7RD2AM.:)< /VL@O-%VNS^H1(;*Y40W1SI^GMA@)[),T:XBYV&/>N=?RY$ M(H0YQ0'3 &Q+=0!KFW&$G:7 R!*T\G.^(.EO49Y'GG0CSBEW=RVANNSONF.1 M)(D6@Q6O3 *[RBN+P"[SR(.ZI+0+@K%S=H,/Q@F]DVU MQ,4JVO/B-MON_ZB_;Y.ILN\A"J=!"Q4*(X9M $6=6429 )3[VNE\42U]1OU=1OX:3/OY3]5LOC\$;F5;'L?H&XZ-^:3::'ZU!?H#-=@4ST48G*5AHD:T* M:7"= +[. 5<)BRBZ+;_Y7C348^DQQJZW\YL<@PG_R?S]Q4[JJ,S%?:S)QW>V,Q MYK5"'VS0,Y5&8(?,KU-8B6_[7:";S0J@CS+< X58!'L^@,44DV/(&$M3(HER MWRUX9\PKDCZ6^TBJC/L\_>$NY_!FW].K"-;9D*Q&"M@560KJD(.S+5=D<3I: MYV/';,QC7@'UL?C]$FD4_VB\LV5X\_M=G,X;I!K"NLZ69"C'GAUL=Y[-W4>O&Q<,$:5CCRAH(A'AG*+$M' MTZ#36$NU#KC;,X Q[[CZ6/->:#.:HZCGW&7=@1;68**B2$A9IY%T-.646_!7 MXH(ZSCWIF,ED3!=4+PKBF#1\9+0^"Z#M*!CVP68L;^*B](^/388I5/9I ?_6 M)M95RI;WV\GL:\N"94,Z[3[$JIP%6-0[[_^>FQ4B*2-SB88*. <$1PP6-@,%#(LE6086R*[6:?C\,50R_7R\KX[ MP48Q7!\O=I_=Y^XU7'?V OOB#>B8 ML),G][VM#<#.,(N$$^&,&,2<)<@K;!#GL+DT-IH;)HCIF/YG'&_\2(PV)GU' M4GGF>4X1CN WO^=I+V=V[=9^V?153+,J M/ASR^]2J?D(0]YFU .-B(DG8$1643"DEYJ:7&KF-5-/.'8LK3DWVL.]#\ M0!$(ND)UK6T>N@K=UJ?0UB27#.Q13SCBH B 5@JR/2=](DQ:$U*WC-<$_Z%8 MJT\*CA(-]53_>S=]&=&U-TKJ<'<@9X =('(^&*F1XC)[T0AL%HH9#HR%*#HF MN2!_*-89B)@GX:+[0+']EU][^Q7"&*X( W62&X&8(1&9"!^!CC&EZ)PV'1^D MTC\XWQQ'Q9,PS#JXZ-Y#LA::]RE-#N;3Z0:P //6X/K^1SF,')@I*-H(Q(DY MG263V>72C<7^6 [PTVP:@D(K"H0[GO=.*(RN31$&9E%_5 M%:A_ 0D@LA4D<.1P-2M2* MG*'7("5Q\)Y8(GW'H_(/Y7\?C;I[66]K3;UMA_C:O+P7JO#G&LWY]K<+G> 4 MB@6:K 5#Q/J$6*Y%2VGPJX+"0?KH.F8F)7\(E_I81#V#DZ^KB-H)!10 QP+6 M&!'%#<):!)0+[0""5'NL E"AV[4@&2=X_DR.P.-(.@)G[:#3ZFW@D:&06X 4 M0EOA I69SCPGETY($J)!SR1,,4:X=MV<[^.$-ITZ%+(?DHX1"FF_U6'/GV<7 M'@A5Q2[Y:9H#*9B6U-"4$!'"(\SR[:<0%M&<;8$9 5NOVUNOTWJJCE[OY[&4 M0U+T%&QU']!5)U&]3RV\F8^V#7L=!%8X[ @.$FBOF$+1.8&8EQXQI4&7C,Q@ MU2U!R6D=6X.SV1"4'2>@V\<8UC=+-8UR^N+'.,(G\YDWY;ON4'--SL0MSGD^ MJ$'!68IP2$).,5H'$CK5OQTEC,!;_C4KAD1EQ%^6M M@>#9VB]740"9RC7R < E")RP9,'TT%S21&H@CD)8\ H>F^("(XKTNV=PS@) M)$Z@!/5/T7$%T>9<:O=_.^]Y2T@%3DGJJ$P.T5=(A\" '$ =XF@DE!GXJ>/5 MS&D#.@>45@/1]73W,V_+*8C?(^]GM@ IK%3:4QQRM<^<%4Y:I#&VB+L@I,1* M!-U->1K'OW3J^YE^2#KRN?@QWJVWRE5ZG]UC('^K&/8^*VW4O] D8!M9RDY= MV+0R.42)-R@$+"V/R72M"W#2!!='+_*>L[!/6H[ 1EU89_<455!:IY1%KH/C M7>=*3#01I*4V1"8>O>S&+J>]7>F;7_HD8/MXI\W1/T8_6U99I&Y]R;FO>8&Q M4RG7JTO)&M#E@)\%D6Q=X] G&IZ7(FM_TGS'B]TS[=JO\Z94>C>?+[.Y=Y5^ MF4VKPXO>J&\A9-1>*# 3C77()R61-!RO9\&LB1TMI9->.O3) $/1<60%X[[T M[Z<;6\5U%>*&NL6VKH67R2J?7RHS%9"" Q%Q0Q/BG-N@!4F8= O0/ND]PY!J M14]D/.ZT:"8[]O0HK"*4NQ20,: #!88E$B:F%:=;1HGIN/"GO1@8ZLPXGGPC M.E*NT@,9+F?S1K=(S[L43GH10\XY:D$S%IEH&(,)'YETF ?&6?H>$T+T+AGZ MH]^H=XYMSY&]'0N2WS*E*)$G6"&<&$>"2P$:LX^"$$5XZ,8LIW7Z#\4LO5%Q M9.7C46_Z&$.,MSG2_T.U?OWV:3'SOS5410X#*HBABIA(8>LD@;B@'A%*X8 E M/)+ I=7FG.N7G4 Q&82HHYY:K\M,K&F87\YN;V?3@QRUMV/AL/+&"8N\ C7> MJJ01=GE/69=4(H$1W]%C=EKG_G!'6$]D[& @/]XOK&:7[\WORH6=U&]J0QUR MN.U\:MZY "'JO&#J>-:^_52!Z*E./>(H+B MOJS\C9W'?/W91I3L[EQP3Z-6$<0F"1@Y)AR2 0R R*P3C@JF<+=,H"?.Q#"4 M..F5E-U];FD=&CA+5U^GH&7=E'J)221U/%P^4/X87NEW ARY V8\7YQE=[\#J??]#I^M(MX-=T>4;%' MB+0!4W"F/7'8(),$!@-/1.2D34@K;XG&RA+;K=K2. )DM'"3@8G:7GZL]\YE MC8IAV00HL+?*DX$YQJ8LC; M2VK>&$G?O*:7^!7(X6/OC+YW7AF4G(\L,DQMMR?EEGN=TQ^+#%YEZB =+H*NU/J;RG5R$Y!I'DX4C3 M6"+I8D)@@'%DO%>&&JZ3.A0L-/I4'VHE?LB%B4!T+%91[MG%_7F6,\WFN/?9 M!'"ZOCC$):;(6.<1 ?$.8L)2)),T#$NK5%?C;1RYV!>WS,Z- MS..X#/Z9"M6==$V_LVIVM5=B"\'J!.NS"A9K7>;5?_MG<^G7]M?K3>H'# M_RQ7ST\;B/UA!BP26.8^OQ+"QEMD)2A%R02!E$J).BN)C=T2*XZ4:.J,6/9L M5NB$[-]TGO>U""ZJ475Y?O/D8[ M*?\1PZ]WLU45Q^I]"496J)N/=,#TA&5!M'#46(D$UB"&?0I(>$%1XCX9CK4) M]JSSAWU'N^_[6-X3[]+7(&6^V)R_:/Y?2YAA^E;G[?Z/&*[K=+C'[*U&L O% M.7/:8\2$U:"8"(E4S,55HB(N.!]!/>FT(T9ZE!NE MRAZGV:\&UGVP0JBDB'82!2X9L@0HJQ((-\TTP4FZV+D T\D5K@&XJB%/C[H> M)Q;2AT^G)W,_4FQW'*V0PKMDI$1$)8)DOH!(.1H\,&F#C9HSV\U'= :JS>GX M?-P5.3&C?\A?U+I9W>K#;+ZHXJ*LZNN-=:GEG*AXWIN#Z8@1"ZN3E5XFT%=# M0!@3T/-RJN2H:?+48DEIM]CZ(&BVAD#@D[PC" M"F))?*18?2 ZG'S2>I?+2:N< M25YR9'/> H^Y(<%QBFW'4EHGUWV[S?&[<*V?\N+CI"0?Q4H^:=:2DY+W5"?Y M"'%'+R=\HA"@AU+7\QUC#IVN[G&Y]QP>3]H545(?-? ;YP"2PE(B+7*^ZR@Y M5UQ$(PZ%HOPK3J*?@/BNJ_*=13ELG++K!*3E= FR_G'W]!R]-IY,)*<1#W+#CW54R@.3[4.8SS^[P- M]Q.K2Y]L0EG%K/X<%SWS[&+W&ZW%=X8'N'0I @ MI6462>\-G'13U^7\(6%] ML*8P125\BAWKF8[CQ1N4+?J@UBC7///% M5?II-@OS3[-)N,=_[_7-UAZ%A\FEX(!8WC-@?!UA3)"U0CAM+296B[.^6N_K MM.B//J,M?^VGORWGV>]Y<.4W&Q?$$\RR1A^9C$C45_@*K&(IG>>.*FOM.9OV MO:S5UO4_DDHC'@?WU2%GTSH3U;S)8?"B3\&<AFZ%RT8Z&;X;N[3W=1C%5;BBT&$V>]:RT(%9RRVH M4BY:9**SB(N\-P-SFCG+G.^6*VRD6\[OA:V.I_LH;'0_V15!&MUV;.]2)$Y2 M\HJBF!-:"644B@240:8-,R$PI0^^XS]EOI_OAZ]ZH_\8QZ,MI_-,CCB_@H,\ MEV5;EO.;C/Y5VI&6K''? B9IJ<4"1L^E#JS)80W2(26,P%Q2H]TY%Z7^7EAN MB(48*PAN+7[W77@]:5=PFC07AB*J+9#':HLPF!M@A A+A&,DIFYIRT:J0_&] M,-6Q5!^+@9ZFVMG%/JM6!5<CSOSKJ!N$_&.=>1? ^XM';"]O;'5]6(7:WJL()#AII$(.$X^8 M %&M$PTYN)IX)U2DI&,JX9'*7GPO;-;O(HS :[M?0=P__%T1=O]CE190"A7 M'L'2(QNQ1$W&$H.;2L%A1^NN+H7B$D1] M!#EOA,MEM!PHIP;D?.(RA*1,2!V9[E^>_*%68+1H7Z#6&LOU(YF#D;DO>A1. MAWSC1D U90'4!QURDN"$(@W42..T26?]M/-LPVC[(/7H<>/'1GSOVIE.$:=E MTL@&A_/+;X(\LR:G*2-1*L>#['8?.4XVG[-ELO[I/@++;::E!X&'PA8]2!XLC[$,J4+1. MP-G )0I!Y#K2PCK6T0@>__ET_YS2^A'?(!0?G56WBNYY3PF3^AZJB"D1DHNZ M@51Q*!D@K9*&(F=MD)09H^0YZXNG9.&34'^,:'!;30')7+/ITXVMXNMRLES$ ML(Q(115"8B9BW)<=3SZVGS?D, M:L&##IHK#,P(ZR]$LD@XEI"VE#*;I/?\G!^-]\(!1^RVX\EY%BI-5UYK *N@ M"BCO0=(ID#HH2 OV O99ZH ]"\2)472K03C2"[W!.6P8(IY 8+^R\[W/]K:V M+PC7R0F-D8Z1H&BP1D+;A"(+)*; A:*'^.,LA'4]FYY%]2/, G.GN:02:4DT MBHXP6'R1$*8DY-R(D>%N'N/3".H.:W^L%=:T[>OWG+,%7N%+^7YIL,[S$!';=_#E E8:.8=0X0!]U-J M':+6:N2T P+A*(/H&"9V@OQZ_?)!Z[T^!+7/VCGT,=[E.]O6SLPCQCA,8^VI MX\D3I$#O!MTW1S<%II"RQ"DOL(RQF\OS!/ZB,3GZS!;E- ??\"EF,]7BU)=Q M5S;9OL _^? !ICW"F*_CPI:3H4?)''N"83]GWA]@D,WWF/U"_:6NPS9;5KD. MO5M:QN#U!OQ]$#8]7G":'KTR07O7\VWN?9XG$3;1P* MNYH6(4A/):>(41!A%I. /.<&*6I9,C$P2MH:^$WP7,7+;KO4V-VXD$8P)X1! M*8 ( MXZ"04* G<1K8:O)2"LKU.1JV0R_F410:X@#?(M1^MHME#GG^Y&]B6$[B8&?! MEK%_ 8%:)RT9=-#=(KQ_"=Y4?+]D.4J4$48ZQ!UHHS9F5UD"5EDS2" DMC6Q M#V*X?[MO$TL*#"^&@T71*(*$SN7J@@TK++E1B:9S+-7< \EG?1.FO;QN):QW MR"%LG!7:@OD@X30Q40*R3-@5G@([:U2WQY/#2^IA%O HV@PEHT\K),%F_5"5 MH+/?VEFY>AM-6W9^?%N^GKF.QRLKBJ M+KR/DVQUQC H+D,:+?GL 0L)Z+HHLUN@6LX7GZ+/Q_&01MEC2:%WT_FB6M9& M/!R%N:90/AH]_%1C<,*AZ_>@^9?WI74Y86LVR%?;]*_S'&JS^GLKO$ZG>4^Q MV@_X;."]+_1Z6_N"1:^EX0Q%G1C"!H:R/H%8T_ERVBFJR*$"U$-/[ZTMJ[_: M"4B%]'(.^QR934$4*@5I=8[%EP9G!R]&0;"$P"[R#@L10L><).,XUGM8V>>1 MY<-1KKTJLG5ZO\P65RG!QOT5=EH%ITCV_5S Z36]CKL>7R<:T,B2R=<[A+?QPR*@W'>/'2D--7NLG#)"^N5L BN: MJQ3QT38X[QZ.9V8&H"RH[+F M2D-IQ&*KID4*)"KE(C(^N_28 QO#6X,93';;9&N!#OF%%_-ZO@#O"&< MPE$9Z\QGR42'G'46><'7[A(!:.)X=/V 'L2AW^A.[GMMPIW4C\$4DE$?% M,9(\FIRU!:@'QP@B/@IJI6*)="MK,_9)/9($&H"@P[C+CG IO([S\GJ:G4C9 MJ[!X_+CNW=BK,(9/Y')V>SL+H#IMU(0^ ZRJ"#A]+.>_?8R9,\+#G?_B; 9..&;U**^4-<)].X2I=V?O-V,ONZJKC]'4WEW31^GY-YLA'?SJH:V0OO MLSB"WJ?'^EF:L+/:CE?+Q7QAIZ$FU'T?H"@,9B]:VQ M>#4&D\Q2G^PDOEK.RVG/68:V@[N ME'[W?^7U^3Z(^RSCWD@T?C9JX9SR03B*I&<21<8U"DP(%**0"IODXL$XN9,Z M(T[.?@,F8SI^K4Z5DRFGW:LUKJO4<>YMM\/Q(Q9@I6F:'$M459QW^V:;:2L.M_'7CC)0@UB;;=2) 93[V:^UBEAW-4#BG=3$!HK?NE_ MM.?/'H%7T^8B/RN;6YZ6PQ.OG^2=4+_]6"[(8+KX QU_' M7Y:W+E99.W[,&[!I>.T1XRTA%=X:%UWDB&/%D%,4MKY3 A&+L9;"L" .O44? M[-%;57ND[:3V2TU7N#]]YG2_C#%\L-_J#;O_+J$_X 7FW'"N0(1S()<342%M M:"[/'63 E!K-#\70G%+%&Y1/7CYC&Y_:X[S+/#RO2SN97-W=GV)_R^*O!][< M#K70CE A,$9,>X\L3P91PP#QB"/7SA%&NZ4 &N?6Z^R8LCL89"L(F)*.F*$BV?IUD:7#8G";B=.C\#M]I^H8!5[=]UH9C MDC+T9YD^MQZ&LCU7^>Z'@GOAP;)=UO>H=5D0./ONJG@3I_,<.P>K,)Q=5H^_ M^O=U^:4, '&SO7%^L/'L_A!_YX&GH/)23>EE,+'#N] MAGG%\LN(HPQ'LRV##46^G^(TQ_^!Q?TIJZG5-S"2RNMI?9),%X^!.L-YK=MB ML/%--9O"GS[>"\[_CHN+,+L;\AEI6VPO;[)C[=WT\9WTXD=X6Q?O+ MK'M4[Q$\%Y:#[0"&TWN0DP%.>\ QOZ]=!8">#0U_B5]W\>6Y<>2 .WE=8QA0 M65='?[I:XX^8*^?Y[ :ZS4&3_ZB!KZOI#;<>!W"Z__TC*+!O9]576YWR-NP> MFSV>E_LFA2-8!XDY(CEP@TR^AD28^(IL\1I02*:FVU.-N5XTCA=#TRA5#D&L(=^$AD?O\ M\X7_^S+/ZV1G0#L]9F"G_%-4?HF+-[^O0X,;' Y-NA?:<$NH3H"#U"A0J1") M+"+)O6$!QR#\:0Z.%V=S%H/'3'\[@,+97&H"!*LE@2+LB$-!.XMLC%9$0JCG MW]%?G$Q,1 91SB?]I@G&W)S4P/=PT_M@14BV:"TMH@QIY&T(((] M\QR!7"8^F"19///*VP,SUR@T/2VC_;+W3?_^CD4@22H*2D(T3J#$O4?*X80D M%BH1RP)11[_F'Y*!^IS>/Q_K'+*9#G4ML)/2&D.0U$!?SD RUQ?(/%KXQEGJ MU#F7)#P-]W0EW2FTY^'#B ]A\!A6?!)?X 'LAO*3/CR;&1AX#DN835?)_S>^ M/JE-LL9B[:M[%:J!GX5Q,R5 !2G*NJX<5V.76I2R[@E%4",6ZI<88R];H M825G0Y-LE#0L*0+:88UU^SW1#$"!+38F88]TDCG"DBN4G$PHF)"\MT[:@X4$ M3WE^#\$O@U%N!+99\WI=T27G1X&UZB)>]O:0$EKEB%F=DP["7\D( M%S!)SG7+/#U.*/* 0J9WPHTH:I[@WEW@- %38.)"3>"4:$*$BNRD]@XLIA04 M(4J"R1PQ 08V$IY MXVVW TI^M_PR&.6&<$H\,417>.?">_=IWS:^>Y(![H3)XKYCS7;L2F/I-.(DOL!TT.>X^T="AN5=-@"H2(%(1-T M6BDN7A,M0X!IAW-^S'W\@AWB@*YD.@4/K%^.3:_K,I2Y'E=:A;2U8HS=4 K* MM'9)!>0L*#'Y\@2I:#&2T:3HG(03L%LQNA-Q2X?%/<0OO5+O%$QT:>_*A9T< MQ4*[8!2&!)N8EL@3YQ!SH--0 6*:9/ROWUA@,U"/M3L$^\,?] M=VM5]F/,KWEB5A0OO*^6=M**EQH!++@W A1EBJB*!/$ EA5V#*QP+P0#+3E) M>M[%(H9GK*$(>1Y,(&T6![DBH4W!!?DN[6HG)9/;53A]S5S9AB9>]"\XX-8P3 M9%720$FJD6:XK@-!4HQ))WO6#QZ&M\=[(=J(O/+@.FWGB-S6K6"1\"1Y0(&" M0&0I!&2Y"4@I:FDD-@>P?1_64]\.NY[(-:X,V<#U0S6[B]7BVX>)7>5>_?NR MO+O=7H*Z(Z0B\DBI32HK]0Y%JP/0Q"G8*UXY86&OJ+-.S=W;4N\6,0/1\61L MU4)+>=ZKH-Q'[+1#2FJ&K \2.682D-1P#(JY56<=B30RNW2EV;G=U@V4FF@# MI827PFO/@\RB>W>%U"QQPS5NZMT-D'^$(9)R@W#,7 M78Z+ID@$FU D1E.J1)0==?]QKD?.B#<'(/69\.A]QJGCO%P]CU38R(0D$?9X MY P)9C72B@0D,)Q"G%C*9+>\,.-97NR^4GJP1-)VAE1_!(8\)9V'$76O[R9/DXWMN($X"EY1UT8P@B#.<01Q#O]( MA\5J(Q+)L+7=-#K]1^"JL6E[)D*N]I]?A/]9SA>'2IAU 55<$^>7*,%KG'^ IE5:GAY[BXF<$O7^+A+34B%D7"T9*LUP.[*)0XL*;4FB+N MO17)@G%J#U5J.YNE> U_S!=[BXH= ;6(VAN6 FPE(T Y2-8CPB1\#)9H)6S" MO)O^-6;RD#/DJM:%F/I)(5%J+B'TG/AXSJM"XYS?:%LI)X(B+" M)D@D;;9M24Y''9(31CJJ+#O[X^N(%=NZ/8\GT@@'2/T::"-V:N^E^;$ M:PO&)Y4A/U C'H'EP9$@0DMN';;^4)C[6!-;Y^UH-;]UGR)@ZJU+#'D>#")2 M)D192-GR\8H([Z(Z^@7]@ Q^[,+-AJ/327@\U[+KP V/W0J3?(#-[)'@.:E4 M3E+*')'(@(;('?=!\G-6= 9GB*-(-;#&,7QBU8W!1LA2^FNNJ#>[GI;_J*]Z M[Y_;#3B[+["NLVJ JX/H$^J[:UQV)]I9;-9$6U4AGN*%(L>^6 (BLDQ4+(M M38DDRD]T##Y@^=%^_=F"B5+:27ZJ+.SH4$J:XM5\C("/_D%,T^ MRP\=:<+&>VG".1^,W1?QA9ACD;UT@.=U@]^#W>Y1?A%^%+ M#CZ:?YY=I%1?-YQJU(=[D)6;YNKK-%;SF_)NPYU3OUPNI]=U.=5A3]5#V*XJ M#>9S?EVK- ?-#E_#MCEJW^I4\2\PNTJ;#=V\#"5,X\3$'(79?[;5;[$NQ/XI MU_]]\BATQ"''(?2VD8>B\KHD0%:"\YN]5>*)D88!XV9VG_QI]=L)U=4-#/<< MUQNM"JYD=$$IY*D(*((1AN!S1,(*3Z*RVIE#81F- E$VQLPNZLKZQ>=8W8)\ MR$NP(]ID?Z>"4H&=S!XY21@U>$07 ,*\IRS['=>AMF %&H?8O23 M+:=7TT\VEP9Y6F/VV6J^;%@H(9.("2-)' 9F#A:9Y.@*/P%*#_9'U\TZ\Q7L MA2KM5^T^0O(JO8_7=K*Z-KJ.4_]MQ^KM[E#DZ@R>:@TFC 8LA1?(4F777&:B M2JF;_VN<9R9]K&*OU.FV!_,-8*ZLG =>EO.;? [/TF?[NUW7S-F?BJ(+F$(+ M^)\6'ED;&;)$,["&F%T%GCEF2>IXUS/.,XV^]N_ -!O!]*^QO'JJQQS2()XU M+R3'$29&$3&4H%RP!7D+C,YSVA[*&%.D6X3G.$\CCF6&GFDSUJ*_U%\/K?O+ M'@63,L48E0@8%&QVN6[RL= M+2?2J-\MY:-^K[:[MT\1I,/&<8NL2 (%+W+0C54KI4!J&U/JEDIR1-.EVS+, MAB-1>[VI5M9@M,4D[GGT\*Q5P3TQC%@'4U48I0#S5;"]5R>X9=8+=<[IC'M: MO*.)TGZY-C%OZ478W:N@FBE) %4PM\ ^YB*7 35Q;6YAHQGMIK>,:+X9R5GOF[\^S^Z/WT"&RHUMAL196@U).C,K9Z!@HZD9IX&-.K<,QN/,W M:8[BAH&H-)I&,ZB3&92[!R)L:E!;OA\/@Z%F?# ]X0A#UNT_S=+BJZWB9OWS^IZR M+B>0;P?O;R_'1_?A O4J7<[LY&V9"U]9WZA0U!#X?(S7ZV+QT_!+?IV[_OA3 MG*Y#Y5=ZZ*(JW3)_/+C(;927G6B]F40/0_I'-#9Q>$C@M]K]8?",\!(A3&$6U"[$<,ANZZ413Y&M\[/+9Q5!X->A]$!=G/?@2R8^SL6";0= MB\%25R8Q,#]@PL()C^#X5$J[(!CKYM0>UD([B_6?#4SI<>*$E['O M25Q+BDV1VR63;U]#%$YST.; ZF+8!L0CLX@R0Y!14MF<#ENDH^W1(=*'GR.O MGG!1AM"0=^(WE,[X,888;^NPC\7,_W:5-D-\1AYN^-CNO"3W*CX@U2\&_M7WAHP2KF2OD9$S(4.,1298@XH7GG@>AXVE* M@;Y$]]OA-TV[.Q6>:(RE=R N&ZS M$/9A,IP54%NP'RR8?I\K.YU;7_O,QQOID[^)89F#6C=;;*3PN,_P,2#EVV"V MV6)TE,9F@\V_<^+43^7UM$REM]/%IQM;Q9Q(-58#TJ&<_Y9WPJ]3'V$;EM.! M;--MPPPVJ7N^>G$W[!NUH;* MVU-UA)EH8TZQKV)D.=\E0UPG@*\]#2EA$<5IM-)+.[^I;]_F-]G3]L5.\FWA MQ>+)L\$]TVS4O_"!\9 K;0KF)(K8&D1U 'RL49QX[G ZYP1Q1ZSE;!QRC:*\ M9F>V!^E\+,^TA%1@(97D6J'@*4/)V@"JF\RZ(;&1^N"=/>ML);UQS_"$&X&/ M7B]C3ONV<=*73;(;[>M6: YJ?'(8<:H%2H8ZQ+ARR-&$J0=#,'6L<3!.0%Q_ M'-(SE<9@ARV5>!MPP^Y>1;#.AF0U4I1'9"D(3@>[ 7)G8[6^2BZ59\=)QZN M1V;HE4@C\,*'*M[9\CXL[OZNM*G&U:!WD8B6@BF/+'8<&6\52L)89(2V1"=" M2.Q6CF^<%S_]\<8PQ!HCS.&01WCM2XHI><)#0BDHBF+T&L4032ZVC;$BSA!W MSD[2+K,XA:YY>L7J*!J-K%&=7LDXBEI#:A>G/W*/(\UP9^WI#YRC*//=GC1/ ML_!LS0 $LYCY^EN8UW_.RNGBK]!\61W,/=89;I&T,2H1A;26'"F>$V3D76># MM2P$D@3N=N@"%.4!*>Z<<0X!:UZ/*7[I-&)?"2-8@?V=RPX8<)$[I$B02.3 M\S.R:^A9_+XO?%V':/PM_/NB;W_UDF2N!MGF5T0U0P1S!$@PR M1*362/- D03E>_4NVBK"#3Z4@N)4SX2&GNW8I\4IG"0!M3::00DFSA *)*D\H)'*: M?YYUN+K>T:EP3$G-P JUEM7I,A.RT07D:-14J$1H/.?0AIXYH5="C?/D-A>. M:27O=O8IHDV&)D= =P5E@GHI4'[YB8B5S#)I5.+=,FR-<[_0OU3HC4XCL,*G M."UGU2^S11,>>-FXD$$Z00A%R0=0"#2?%[(="X MFDXC4WQK^R(I*JRW'CD?)$HC7.'HE1*9"-WRE8VN\_3$ M$_T3[#2:<#.7]+Y^A4\N&LHMDCI9%*V7R$ICD9#>2V533DCQ?>A /?%&W^0: MRS_=]F3@$RDC":3>>&%TUZHDG>J75N%K2 MQ334J476[[569:N:*4Q;NQ;<,L(3#G!LP@X0'F0C=I$@&X+B*FN(:>]ATM_[ MSNZOF5;?W,1%">.>R6NOU^67$EJ%ND3[D]"*:7B,N3@39']:VLI.%['&[GU< M+( _KM)E%4,YW#O9=BBV;+T ZM;YQM(Z=>;!1YZ#[N!?XF*5M#0GP-ZS79^T M*Z*D/FJ7M5D 224%O448C5B4'/:FB$;$D]@UCSAF[EZ5/EF6T^M'6K^*L"9Q MHTKMF]\7E5WI9]6W=[ XM=3-:8=GDTF=-W^5LW)OW-=@HQ;4:R^]-LB R$/. M:0+: 6B&ZNX 1EI3+<',./864?PS=;B]>="Y%&>Y7V)TVUQN7LX<6>?(G)" MN201,2\U$B9DWQK12!/AE)9@B?AN;JBQ"N*>R>J_"#/OC^#MHPU6JM*[Z1M; M36%&\Z=YW9X,2T828$IK0ZYVN2<^.O >@] M D.M&VXH M&-0T=$M5L.%M&"(U[;GS5_]T'\N5-79UVE.^]SE7[CF.Q&-QRBG*@1U\S/// M*&R.I?(8)Y@MI_-,N3B_>E:(\RJ]CFZ?;G2P;P''M*46"QC=Y<*-8#V;(!U2 MP@C,)37:'7*]G/+QS[GRU1"$'T7]7LW]L';TK&6A [.6@]X77+3(@ J(N%!@ MJ ;F-'.6.=\M7X+^YQ90Q]-Y%+99$V6-Y2M0X5)YV,7YHD?A=/"@WA&$-0M( M4QV0F2 4]UA;41IY6>V+Z(8ZE_Z*T?T M,?K9LLI%7]WB\VQA)SN<52_:%90H(PQ(80Z[%-E(&$HIW!?FE(&0>)J+B/LX MCXSJSW:QK-:Y8._LM_I],U"Z*H'\=YG^OP#5/G^-DR_Q9Y!&-_NTS*/@%@[( M'KQP*,G_U]VU_L9M(_'O][\0QX?X$' XP&F:0X"T=@.W0#\)?"8ZV"M7ZW7K M^^MO1EJGFV2?VA6EY(N-M9?D<.9'1I"@BT9C4P3C)')_C)? % M9-],R\8<;_&G3.GW:-O;/YM+ 6W=724D*-X::"N+8(@77)!":4R*P6PHL!8. M'_98-7[DU(3X&LZ]6<(*1M^GB [KL#*@8A=>* P'3<0['8@OL?PK%9PJ;YDO MA]D]X\>330VM@?R;([C> ",OB2WLKXJE\F"_%809%TB!560C[NZ615>:LDB4 M#BLL,JX;V@R@-9!]LT16_73170O[JT3@5AJ6""RP1*B#'\'(@LB4O%52PH8^ M+*7/N'?&.FC)H47^=R< ;6^=\^A)C4\,U=\^?$+H1(QDW;H&-I>/7\ZQ(K/??/ MSO7BPY5_K)\.E;P[OI-*&BM=X(I$F0H2HH']@3%#$F9F$((5QDT31 [$8X6M MWK'68E4/^$M8(>7Q8'+3PXVK:+CS05#B"Z])-*#')6 $B3H9(;PJ=!IV99O- M%7 4$7^=&^SRC#S=->MFO?.\:=K/T]KA,_D3>H@O;YMM!4F_+*!]:C^5$DE* M3F$ZTFE28B8TP=FZY*RV5CDU[*$ZWY7LF#C)Q=0!D-E [OL(A]@"-_B'>O>% MZ)X6%>/,!&> -U' >>82)]PJW5-,19%2,2P8+X\W50X47)1[>9YMVFA19^I_ MOUU\GN5X__O-WJ:5\64H@XR$RE* ]D4C*3'?C/.@B DGF-)GQV)]P[O&B'S, M )R7_>ZVN?)_K.HVGJ*8'&I;Q;+DI4F&&"E*PKT,1(/MCYFT?0FK* %'S[5R MOP/HC,'(*;#S:K6L%Q$])>"X?'GNWLS7>PJ8#G96.>H8#0I8K@4H:\Y)]*CW M1&C#E(^BI'K8[5PF3ZJIT#4&9S/ ;0>[UO;P>=;DEDXJ.-2-YS006Z";1U*6 M&$HM*5R02E$M@SET[HUO36Y>9+Q#J;[$0!YI4.YL7QD6J(TB(08 :"IA9($O M20A4V2*F4J9A-Y23VI1G"WJ/37E)7N;8OC=(?[M526V2,CX.5!/%I ?YI:%R0?Z==P7QKK&+KY($''$1 ML;5=Q;SF3I<1+&CC"8N,$A?+M4$=.6B\=-@^D2?7Q\C"'XN'&>V#-TT+T%VU M_B.8Q7 F-O?WS:++ZW&$/;"[<87N549'20HX7HD3TA$54B!16"<=ET+3L^-N MOH-M8Q1.3J:?'(F>0VTKXQ4U6 DF4>U)!(N&6 L,=@E865I#+3L[#.<[P,X( M?,RX\URG3SEM3MMUMC<$NUA[T+PL\5HK8G4RA#I1$&E=THD%P?PPFTA_ESO. MQ;B8%3*?N-$E_S\*+)\WJ9SR,@9GB+)@Y$GD':6\A.U4.5H$ 6K\,(_$3!$T MV6%R-O\R'T<;1VH7=GC:'=2)/554.,H<9Z040O1YCP/&Y7NC*?>%K^&V2Q@6?T]+9C+38MQ6;%]JM+UJ ML69)A"^%,UA]H9$K*J,5SL%*E$I@449.(J<*S%@=?1%-J>VP!^8\-\VS0.*V M8/A9B2Q7/H:C)HW5B'Y=V/NF?:S_%P.&>*.TQEX>IP];698$"U& KAPIL;($ M&YU:A\&G3)71P;$US+,OD\O6M[TXL@ALPI6!DWD?_9U=+NM4^QXCGYB-FM35 M]0]OCY83J%O AQ%:(P?=V3^+G>->X"L M?D>-X:;%;".8^::MW:I+>8-!5;"@[]#!JUO+_?[R52:<">\0!N3M^:E>-&V7 M)K5W8NO\V39[Z;.H_A0?/S9APY]_OSMT+BJJ1*-E3BEBRX3>'=P390SFC? 6 MKY]2/&CX'OEV_R4>=C[6?_G%*BGKN+&", %*+:58Z3::V,?>F2[=Q9RSC,]6 MG,V%N7ZZ1T<_J?ULZ1AR]=@3AIO>;;,],]8N]X_+#E()7M" =0"IM)((S321 M^(C4\44*:;P;IK+/-M%T=C1.+K'3D?PN=D; URFS#R8Y/Z)EQ1@W6JB2&$TI M$3%JXKP(_0S*F)PJSPZ7FED^O.R@&T<.HUAW9ZIH73S'ZPB&GJ]?%/BK_H+I MY>,ZTJS+%A?JQU4[9M&=\Z:S+G* <^@F]NKY!S1 VN>I"=[Y_YOFKO;U.,K[ M7<1@+S#'6E@V=\^?C.C7]M'F'F]$ >P;=C3+Z*-MXRN[C %O2>)B.9;!N76< M-[9NT>+&<*S5_4.W:8['X*TD_&S;/GEZYG%OEJOUH_F(:WK7R)L?U\DS\Q.Q M_"VB48T;#\'&;R?@PPZU[7K;NE/)(L-"DZ6R:@7-U=W MG<(;PW:ZUP0>\1QT6D=5#%):H37H@D"48BP1CRGL:'*1%]:Q:*=)]W+^@?B1#8.66\8\5F'@_/N'SZ>&UL[+U;E]LXDB[ZOG]%G3[/587[9=;TW@O7 M;I]Q.3VVJVO/$Q>=8J8UK11S*,GE[%]_0$E4IFU=2 BDF%G5O=JME @PXHL/ M0 (!/[]_WRYF_WPN:@6TW+^U[_ G\!??BCFU^5D.K_]ZU]^??^C>F]>O?K+ M__G?_^O?_Y\??_R_^MWK'VQYO;HKYLL?3%7DRV+RP^_3Y:K?/OEO]:^3Y:[ TX?ISYL?=X_69;^J^G>\?A9**7]>_[I[=#'= M]V"H%/[\?W]Y_7Z-QH_3^6*9SZ^+O_SO__7##_]>E;/B77'S0_W_O[Y[]57Y MO%C\=%W>_5S_]K.Z_I_5=#&M@5P\_1Q>7LOP;Y^JXN:O?PE% CB00K2!YO\] M56SY<%_\]2^+Z=W]+*#S\[DRK3_:8IE/9]TEVU>X#_D^Y!]G1:1X7Y=-)]U\ M8J>+^S+"J/M+]B59A&V/5G">G(M%L7QU=Y]/J[JGSJ"1M?6AP=7R4U&9\NZ^*CX%>P4ZO0K.SUWQNERT[-'.KSB=7G?E:KY< MO"NNR]OY]%_%Y-7U>O/]4A'8?H5Q\[95G5?<1W>Z%?+554TO^0/=3\2H4R7ZI+IX$._ M]X]\MBJN;NJ_-X-+=]G;5)-,YKJWO@Y#XM6\>%M.YTOS*9_?AG9Z%I6Z5YI, MG]?%YV*&WY6SF2^KW_-JTEWZ4U4DD[6C#]"F:#K9BJ5?S2?%Y/TR7ZXB.'"\ M@I1ROBVJ:9BK7V^_-N6BI:/8N9YD4N_:M9K-M@L $1"WJ"69Q*W\O\,%SI(C MN!!WT^6ZZSXAP)XG4[WY=9$OBL5F//EE.I_>K>YVX\FJ90N.K2Z9#F'>\Z&H M[MZNJNM/X?U/?NJN0.NZ4DG?L;ML43*59*T:Q\'GSY3B@/MY4IH3Y?J1ZFU> M!0 ^%K8FVFJQN3+S[Y6?E[%S2/EN]'RK5[M7@U=_^S MFBX?8F7=7\L0$L>RHFN5_>CR_00W5H7#-0TE>1)+M*RV%YVN[HLJ;[-,W+Z" MGN5, ?F)VL[58#D-36M^/6TQQNUY-MW;O_KC;0"BJTA'*T@G9UL'Y7"1=++4 MBVWG"G>JCG32MO2D#I8X2Q);?%R>>/731\Y^UYMR7J\DKJI%4?]I@I?Z$/3: M+C*J^:3VKUO:*[J^U%K\$F;[51B ZPW=R6K6TEGO7E%JN3O.+CK4<+:DAXW: MG2.=ZTHJ?03(@R-S;=,),_*KST7EPYO_J\BK2+B[5WRV7N]7 M'Q?3R32O'K[AZJNY+6[RU6QY5:GKZV)6NP]%R[72\RL^6Z]6P\3W#Y[_WM! MPN@33+:!_+ (UKS>?]];7UES# MBW(Y[&RQF-[.ZR9;R[Q\_'-;>ECXXJ49!L%Z2:^[8KV[O_/"E[ZH7;7TJG=^XS!(M'[0W=P4]1_%V[*J)^>/ZX'UH\GQ MZDNND:'Z:EZ,%-?.DET0V:^Z4U]6:_F"QU:[I:'T$!!V$V$8K((819!H,VY? M]]BOMW[1,'I?K99UX/5DC7M3)A@H<#B?[98.],.'($UB),YX]3#8M)QL1-5V MG@;3Q?5Z2%P5D\<5X/5+9W6#>I_/"KU:3.=%\*U.*A!5V8#R=UT[2%+Y@/HU MZUQ7-YN(\'SVMZI.O=7U@48:40;$KET3/:/*\W39'A8*KW+A M_5(9O_VZYT].U MFJ0R=^R=VA9/*N-CL_[V%YTOIM?KLRBS5>MUP%35)]6Q54]PO-!Y\K0)P4@8 M8;&IZFC0??LX_KC*$LB_^=<&%VE2S">=I#U>-)EL;XKEX^$%M5Q6TX^K94V; M#Z6J5VFJ^[+JI&E=>S+M*VKB6!Q.UZHCV/IGAWE<\7^?5:Q=^FRT_U\G-P?<(3L_6R MZ;*HBD7;)=QSJCQ+E]U!B!,"?O=]79TE^LK(T\O_G*J\G%MNEB]WDHJ/@[6I)(_&[!!1I4T<::5L- P>>/D^" MZ3P/[75^&W0MII];B7&D2')96EKL=,GDDK4SV5/DL3)K>K^[N M\NKAZN;]]':^]ESFR\=5\I9SX]CJ!M7AR3=5.0\?KXMFM/RO8JDFY7WKN>D0 MKQX4F]T1RMTO;K&,.8M710UW.&??WPD%Q>%/\?JC%]MI-='[OH*CT-!:D'1/*LGBO,C;)!=1=O M]?KV[W5"IJIUGY&F]D$U[$>S(37JN+\26UVO.CQND)P_CO?PJEYU;^>A=:KD M+'DW*^X?\B\GA=KS9*HWUSLKY7QSA._)U^THT+F>5%+;XJ:H0H<6_M@%[3[Y M[JOXW8Z*1%>=2K==:.3NNYB5T_@*4^GQN*'DJ_)N$SB["C[=8]R#+F[*ZE&J MSHJ=^X:TFH:/;_.'=?<0*/,4ZV[+3>=7G$JOC@->BY*I)&O5E1]\/I44O]8K MY=LL;.&+;>J9[F9N5\^94G\.?7-9G0H+^.ZY-&]M"\G^Q]/(T)(S>Y\^6X+% M)NO*JWEHP6KRN4XDLOA0JIN;=2?<2JRV5?0NZVX\V>S*7OT>YO*+3]/[9@,V M%&N.=:XW%%HWB/Y?W3LVF^6,NB%O%^?S6><=K>3O&4CKA[6G_YTP5S=/']R> MV>S@F0WS^MXQ:MW]=*LHG=R_Y-4_BW70S^,QT"[B'BO?KY013&I13;\R=Z?# MZ5K.DG@[VZV=DCK2MU6J[J-ETDOSIIR7&]>^CO:I?VMG^;C*TLN__K+3*FW7 M:M++W(JG+4J>+UDPV%5CL*=([/F^C;@1U?6B0WN 3Q8^2[ZW5=T$:"?+]2/5>FWF7;&<;@)G'K.5MQP-SJ^X'[V>KJ.];7O0+;*V M?C2PQ7V8SDZ?[AB]+V^6O^=5\70S:>VJWT^7^6R3Q'SCP)^I;\IW]X/.;LI2 M)ZG+9[[>EO'Y=:?5RC25]Z/?N^)V$[Q+D7)2@S:%>Y2O+7,ZU-&CM,=_U0_OBOLPD&VF@;>; M,>]\]I'I<0/^Z1-/MHV:7:6V M#$K[F@%U?OI$'\H>J;\7+5NVB3:%^Y'OFX-:3V+[UH==/Y6S2=$VAV':EYRG M[W3QS[IO^75^'5RV?#IO,_P=*Y->FI:8MBAZEFQ-.WEEROFDGH;MW:<(D])U MKN@3TL95-J#\3Z\&:&> 9/5?2,NO8!D?G;*@^=\;)8"_2Z6"Y#OWMULTF>UP<>'=XW( H=GVYRYS]-G=\' M6.G%&A+38CXMJS?EM?>D$MXL5#XO)HIMT%+[W M=H3I4D<*:1>'7G5"$C7Y[]6B7IRI$YA]J2/P MFSVV17/&8'O(H#D5\DU$?FOG;6QR7A3U[=&IQ[WN>AZX=W][O0D>9D7M9>&1X>KZ4?FQ#QJ56,_FB3F4:L:>]!D M$\>U[JU3\.ET=?WJD)A?G6KN0;-V?DV+HN?)MOJX*/YG%3QG5Q]6_>;/D^*U M*]VGA"TIT*F2L^3]4(;IZ*$S%NVD[5+%/EGSZKH1=_OQJ<1?/E:SG\KJ]N?I M?/GS9'KW\_:9G_/9-_=U/U%Q5P@!0-=53)8_UI_7 C\IF5">\+G>"2CG/TXV M=W!&2G>PGGYD+>_RZ?Q\4;^J)J6DZXI_O"ON/A95K)C[ZD@HXZ=0576]^EC\ MN ,D4M(C->V3-Q"DSB\4GGH='MD^6(MTN+VO\V$MUF463S]__9KBR[*83XI) MTA<=GH?M7E>_++QN5E[OPV^-W4V^^+@&<+7X\3;/[W^N^Z*?B]ERT7RS[IU^ M!/#';?^T_3IK;I=Y(EG0IGBU+.YV\LSRC\7LKW\) F1MBF4>>84\,QQ((ZDA M @)2/B;.8^UT5_K&:JM(W6WJ/:FZ.-FRA[9%_KAR5_KL?F(\EVKRIP%0G@A MD3%.*<8,$VP#B'44,'H"D$>BJ>KZA[*:%-5?_P*;0ML&UVELN*G*NSX,6@X* M5% L?+'N+?[M>E8&#^NO?UE6ZYS[VR_+^3(T(S=;[TV'CF*SP-B.:HOB^J?; M\O//DV):LXS4'VIRD2?D"E]EKXO;?.;6-R&I+]-]C6;/4QDECANNO1, "F@9 MEV:GJ6/\5!M)1(DC7>OW%.G/FF4JG-:,2&G@U_1HW+,P+Y.B,'KC#6ZTKR2_L,TZV.J[R5#X M(OLEO&2QK(IB>5_^7E2_?.5W/K'*P6);U2ST$:U//3,1\.T MF%V(#IM$P\7!/KAUV0P"[YCDP#"I W1.*X\:=;&48G0C:S+[M>!#"JA>/$/& M,GR/EQB#$V(33[6+'GY=;N[ .S&*'"F542$Q9M8KK2#D&@F%3#-5=4*Q&!+@ M%S*2I,/MXR/$X$38"6KJ&U2O;M;;P2?&CH-E,D4,<=(9#2P-&&&D&7E43^ 8 I 7 M,G*D0FT 4CR5\&27\/W#&7-042J8Y]H3[@,\EC<**<+I:$>(!#8J>T+G!9A] M;-W_**P]A@GDV]!=!ACRV_J85+E\>O%S<\U1MUEEBPHS2YGW2 $J0T?*M$)> M@1W&6-I1+$7VNK4W"' #,LJ4=Q_KD]SK4++0!"?;L^[KK#*;VUY@"QZUJ2;3 MGD'L+;!:&T\$%)# '0@"^6%6.\? GA[@&H S;_.']3F5#^66UXTZQ>)O5;DX MYGZ>*IH1SJE43G-E#%'4*RY]HRP4)&H1J_OZQ26YD1BBX$A!F&P=@T<&F,4PYCN\Y9GTIM$8789"KW;W0'T:A+:P_1FFG]W M@>/7>0W7)WN*29V88YLX]G,^>QK$VXYO"5^<46<=$599+8W0 @57%#5 &QRW MI4Z?.SDO!_ 3-Y=F-C<,;JJZHM[BVI:'G/$CQ7+-(#UICGB%$" F9$ B49) M1F24P\2>%8L2PO/(@7__^>L0UL11K?N..*2.H5TG\KXO!XG7_?I=%XS9_6:9 M]FEJO/4=09.UA/DLB%N'1=;GZ?7#1O9\%GRHU7U]D^!L-0D4JI_97)08!L== M@J\=8=LOI_"1-:CS6"F8M$%/V#DV4S(IS!D#KA M,.%(4& D;-156*K1;B(ELV-[?IP%V8MGRMCVG<9+D,L28_-'Z%!O],/[,#=_ M4R[W][,' ]]35)L18L-,4!MA@G=".8/4V :D\-U01QC:S903VOP8F_K%<&BB M_;V836[*:I&.8^UKS!@"AF@K:3 +5@A@*ND.&LO&M7,U$+UZ@Z_S>:CI^GK8 MFE=X^[EF%'["J,VWV>,]L@<\Z;W/94@Q!P#'S@"EC9/.8;2#B]JH$+F>3VF, MU6]. ? 0_#CHX1QX,A,2"*B%1M!*KKE0W,E&!6O<^ )LS[3$(7N>!<>SM.Q8 M/-7+&K2#(?<>D_SU/WZ;SB=OJ_*_B^OEX8'\T*.9T1918:A$!EFBM:7DT7D! M2H[" 3P;W#(I"L/'K/6&GO6<4N%-?G?Z"&%DC1E1E @(O?&, 08=>US3,-Y+/CJ?9JS4.3:- MZMT>?U+V"41C<=;^X$P]UUM454!KFO]2IX0/[SOJ+NY]-L-,,6H4PL)#HQC3 MFC:>DC&*C".IQF!F*-/"U=V@[N-J61PUXY,G,@*X1X2X(!5GRG '$6ND40#" M&.,-LQS7L_'B08IH@^[]&WUUO.D]>20C1'.L,+",<"\ L$XT,U'#H8O:?>XM MPGO0%A>/TO#S;(\D4-1!8:DD6A)#M&KD T!'G0#J+>IZ2"LF0*N[-3]4 M\-KV;+HO)4=.>+)=1(W4@G\9<:B88LTCL("#A\Z@"F(>T8F'RJCYO-L^/=[_?/9@9*H0R022+%,;0:K+;XS.$D2BS]A91/&@G?"Y6 MW>WX'T5P]@.8B\5Q,W[W7&:IQ][6A]J5L\&OYP+R1C*DXS:D^$NPXKE0#7&( MKBJOBV)SA;6=U@O!ZYN_'E,9%$?/T9TNG5&K@0=4(^R%(L@[8QL7PF*JQS6U M>0[QJ^E![]Y9?/7>J]_#V+/X-+U_-=_=@OZP/89\H!-I73X3@F I+& ><:2) MTU[X1A.D3)2'U]OD:LSTZ1/VP;9N7I>+->_-!ID TR,T)[==CA7.,-="$JBE MAHQX"#D5=JZO&@4#Z?;$.$ZN"SQZY2?5PLJ_SZ<$?5 MOHI,$ X4 )9QC4,#AJ%NM&'&AT5E]7;;'3,'.H9^5@F;?4^%%_VI$/=)-QX M7\[V';8\K\),0P0%Q=9YQQD2)/34= >F'LE:<7\6_(XB X#8G3"-DU8C4FM< MWGPGQ[X!JVW13$LGPSP$*\Z9)YA( 4DCO^7HU%&\8=RB04C0 UQ#[U$>HN[? M KCU 'HU;QYONT?9OL;,*4JYU,(A:%P]ZFK?3$FM5R@JX5YRQZ=W)@V+8DQ_ M4BSS+V$<7I0WDVTD_<>=VN[+=B"^#9*5\\E6JNEZ?"["#]<[]ZL\YB_W]*:, M4,ZYL- ;2)@7E##51'A;@DS4/GARQVB@WNK2Z,9R;[KV%X=A7^)W950J;KVS M-@S[QBD17-%=ZZ121R7G2;Y],"#_+HMO=P:^6=60E3>__O0?/SW=USKB8!\K MD@&AB%7..DLDJ)=SC12-O)*H<>P[#,*'A#!U-^OCII7)[_/KZ?+AE^(V_RU? M'O2-CY3()!(*4V4!A!9A"SE3.Y>>R#B7./DVQ"!&38=21.C,_ZS6[UM^*B>/ MD>4[E_PQ.^61MMNICHQ#"X#G3AEM-'=6<6EVJTB81<7:BV=I]SYQ&W@OJD;E MZF:_0FUWI([6D1EAG+=>> T9QT!!"IK.S2'$HZ*VY+.C3=^X#4";[B0YI)J@ M@AMGO,.::VPXTKKI&QWU<8%\$#Q;3J2!Z6(,>%<$O_5?Q:33*DK7JC(LL)*< M6APT=P1:#6QS6,H9>_*6W?V<>7[+L0/AU]/*_9MB^6T'>,ZZ_9[J,HPM<S^F2B+ZNWJ^KZ4[XHU/+J?JW% MS3;1Z*%8O![>E$&GB-!(2"D,!)HZ0)NUG/"1Q&49?)Z+M9>'MSOY].JAJ#9O M_5 V%36H3ZZ$^%!4=P>XU;VB#'".B"=(.X(X@Q (@W9CN8^\ M&OAYKK/VCEYW9C1O?Q**\VTOZ>K$N?5)P8.)HN,JR@CFS'B%P_]0Z&2M-'+G MY0&)HS89X?-<<>T=O4=F),LL7>=$?Q7$GM:G\8)X]T&\XNNWIDCSO/OIY^+R29+>VT<-9_\NB@F^F']U0730=OBX_)5?5_X:GUI7XO4S0=* M9)QY+H1%@E#C(5)*. Z<911K034_%4;6JC-XO+/N.\ /I3MN4RQS8L#E\ ME;TN;O.9"[W3\N% .I,]3]67&EJGA&9&T= )N5LK:&W$AR,+O!MX]D7 K,B7:08:Z0P/I-)">O0=F.@\AB:6B/62,0B#\4E7Q:. MQ[%,HW?,_/;F)I^5M_G]JU>OCMICSY-A]NVEA5X"H1W0WANK=2,=]SQJ%3;Y M(FP2JYRO?>QI?EM\+F;E?3V@-M$D!WNQ%J4RBQ5"2D-#B#5*.PG89B#F7+'@ MH8TB0#6)S=(B$1&[T2GMB4=2..R\JE=-;9B6"LT;#8&'4:L]R=<)D]@E7NO8 M-O2F^/UF&F:W+3)B?/UHAHUEQA-E##7 0 (9S.HY[,L"+&$D00YL@@3(5ANI$.(#B.R+XDICE?^^ZV>;7,/Y;O M\_GKLBKF_RJ/6F?OLQD2E$'C)21!3(\5D)@U$F*AHZZY2!Y"E\0^*?3O;J'U M-;F/RU-'+;3WV<"AX.4+2;W1T K//+2[-4T2VOHX(MJ2F"@% /$JJW%_&:G MPWS*J]NCB5:.E,I4<&N"T\,HDAA)((F0H%'141 U@/67.S+1XGMZ8(;:-GN3 M5W7@P.?B1>Q5Z0!F'?.)F4/":$]Q -T8:)30%.A3(;,7W:ORECB!C.V#:L''717;+>'UE4,GTO(?+),A M91BGEC#I)=&*:,/ %A,BB!]H53W=KE9K&Y?](#3 "+L3=1,D\$N1U\E+)E?U MA>^KJKZP6^>+Z>+7>?EQ452?:UA>S>]7R_H^^/GU=#9=AW4]U?-D?O"^7IE1 M110$6DMIL3:8.L%E ZZ5THUN1RXA7PXQ-#J.> BW7L M\8PI9K5;QS]3B#%C6)&MG-+[N+#0GJXR[,6[2@C.&4;\EM)ORGF5?(3I^8V9 M4M*;>F?.UM?#&@2T%PU:VFLS.D\IC>WW$6DTZ/[)R>.HC<7I>5%4'*N[(\. M[!F"E%D.!#5:>-[(;:D9A[LS&N-U\7:Z(3ODQ$T_;-';9%@-D+5?B-I7,K/" M&T L)]1" D/J#6-40F/HA*I]72QXU#+40EP&H 2;\MJ#?MR)_GNPV."W9,7 MQG>H)=/( 8.@]09+"2#@W.@& DD5'9U#E-RVWZ8XZ1V\(;N61Y'K'0%U5U^0 MUF%]YTCQ#&L19IY4Z^'/,DE%&7/.U&F*-:I#-]4NR@U1'665_D_^Q5@E@?I#GF6" MFA(@J7=*(LY9)>,2P@5 AXK"U1!.+=@W: MZZ@HF_X/_\78Y6SEAS[+Y!0$@@7&2(8EQE8;N9..H[AK=OH__A=CFO.UO\19 M)H<"6S#1C#(;VC0FB-#'SC;NGM'^CP'&V">%_A'=VEEY&\)0:+W P**@(H7< M"MIL\6DH>=2 T_])P*B.[6SM8_VTU'D;F'**.FD8AA91+H'ES61-6VJC]BK[ M/QT8[[VE0F* I=X3.?5\6?VZV'>LIE/Y3-=W?#(A,>),(<,X@\T43WMLAHKY M/>]@6M>3-GU"- S-A+N67)^&OQQA!FMRF?,& 0Y1U PJH&C7(AM@Y Q:U M8Y1\NMT7,_J *"+,:75W_WYU]S9_V"3HORYJ@@9:UKEHI_--%NV;M_?YH7BG MMN4S1KVT1@H88))880F@VVH"G611V\F]W:R=\L!=7Q ]RU/*A$**G,&> (4\ ME( @WJ@(/1YHV^="33X=,-T;^J:[,7E5/81^9;//W;I;[U9!9KFE 1WB5;WS MY6'PI6BCBXD\49M\_:&/IMX;1MWMW=SH=[_U0>?E++@?1?6Q"&^_7U6+57'J MSL1C13,.A%2,.9\U1JZ4+=G"#,&"(>-G)R$!=(FGRYHT\KGHG( &-PZ#7J/B-HO.E=C@R\ MWSZ: 4R1X!QKKX,#03$&0NT<"B*B5K.2KY?T-=J>B<:C:?M-!+(.'SF4_B,^ MB[XNYJ'0\NTLG_=;N;J^7MVM9OFRF&R_OOHXF]ZNW=J+YC8)6NU$JB5]'(A? MM\ITTJ)\YK700!O#ZZPR4&@!@0#>0 B9$LJ=&@7[4?TQ5NE[)1:/6BP.94V) MJB?32!J'A0"88!B:6ACP4 ,%DBIJ*$F>1B6I3*H7T\\J-,-[!\MD$A*OJ1/..>LP$1@X]Z@> M%:,;EP>R9@ONG /@B^/)6%R YT:/P6GQ:S!#,7F_S)?%XNWVMLA:WJN;7]]O M1^FOE#EY;B^NPLPH3ET8M+4@R*+@"1#'&F"((6@4KDM"^Y870&V(<^5E54QO MYT]5Z,B?EC5D&G#L$ !>:H&X( (JOW/WF!O(K[D88?J!Z2+CT+$%X$Z#T[&* M,J$$5Y!QIC6BT#A+N&V T#0N?&3 #B;E0F.OR%V$0D^;P6_3Y:=C^BQ>S=V7 MZV(1^M:UZNN]G>8JYDY\2_;6S -K'(=200 <\H9BLNO'G6!1*RH#=F;]DO-2 M,#]3)M_>5D7XO=@&#Y_;J0XA4$8Y\1(B+A%"BDD$(=H9A@DUU&'B6/Y?@*$# MM)KD=GOF#2J9GS*,2)G44B@+#?.*$H89HVKG6@+#HZ94 PXJ+[M1);3<,V]6 MNPCVI[]>J#WME24S%!A-+0RDX5J'_]4W NUZ.125?[7'R/,_5D-*8;++M*!& M]SYG*''OR"BB$FL.#>(.0(PHP3OXI %1_MB C.]Y/C((J,^"DTTC/-,?2O76 MC&J* =+$&VDA99APN!LXA=-#;4M$]]1],RLYMU.9XEFQ/8''DO+-F71"@ZR_^@*Q/88[T8>('@JO7A\=,>7=?%9]J[^MS\6H>RA2O MR\7BQ<=9 XN98Y92BJUVFB#F/=2.2LAAG;;J#Q1G#<)_A$.0(0HUEYH8++90 M *.&NN%6?=#:Y^XZR?>RP:DP8YC!D1PBH-K*OO MEBB1T9*)-# MC[%HK(&F"XD5'SJ0O$HK6V;YI8M&ZHO:A8 M-"@DML8X[ S3U#N@F6P\42O V/(0I29,/S!=.A;MT'Q9%S=!WP_YEZ@5^9@7 M9-8@Y3SW@'H-0QO3#.YF.ABBYQB[%CMYNPBB8Z7BFV+YMIJ6U?NB^CR]+DRY M6)JJF$R7.X53<_/T&[/@GVBLN#&26:$EIX[:!EJ(F1\Y6?NE4PHV)[?!B.G] MMV#$1;U"62SZY/2^UP2C!JR,923X-,@92H F#8@&\[&/ZL^"R F 'RM[>^/K M$Z"8"6X4I(!0Y91%QAO4 *60'7M@RO@9&@OU93BYN7ONPZ=\^=MT-M-%^*): M3O]53'PP1LN=H%?S-\67I0\>6S[[KR*OXISF\6&0UM:^>H!O-LHC8595X K2A6 &LD*<="&-X 8336 M(^\ZGS,U(VUP04_B0QD'\-?P1C@.:5Z<>0FL]4QC'&;!# 3O$.L&:,EUU#+^ MD-[Q,R'[!6W6<^S4Q@#OBNOR=EZK]6INROFBG$TGZSCU/#QT7;S_5!3+EQ] MA:F23FNKB8'$"B:]VO1:S'J@[!\I4:5"1@FC#82200F!<]!LH7">PH'2GR4( MH&IMT[,"J+K!]6< U;$@ &H-$"S,"3E6"C()F(0-EHSJ@7*D]AA U9HL20*H MNL'Y[ )C'-"60^7KYBV5AQJ+!DRO/?4O+("JM35;1\C$ ?CB>/(R JB&I\MLWS0!5-U0>U$!5$Q# I0FP@GEO;, M"]NH;ESS-QR# M!A['^-@NBNQSBC84B)?AV.;FP[*J_]A^OWB\K:4;MX[7E4'JD-,J],#&6^B$ M@\(W< @M1Q_-E-KJIWF6%- !^+7M==5\LT[YM@R0%,MIM5Y?V-/7FXTBKZ?Y MQ^DLF/;H58;G5YX989474B- 5?8<*)D QB$,(J!P^_9],; P1$>(26?*-.J M&TQ2?Q8\#F2-!5I(+ZU3E,B=Q8)BSV1_933$3 'R&%V^E*Y>Q@VUW"'-*(8* M.8@5V_I##@2_.VH!M,?K7T??PL3HD]A%JT^%U5^6P2O8G5W MO\[(\.*WVKC0S"/L*5:2$6ZT)F%DJI-=8!VL'!4P3$8,F8 M#)/>#10"(C'0P9<$6VVM;7K65ELWN/[<:CNV7(P="=@Y(XR1+OSCL:"-Q0B, MN]EV5%MMK2XD# M\,7QY&5LM0U/CS_L5AM #!*I$>&Z/C.EL!6Z 8:ZN-RT%]AJ:VW?-%MMW5![ M45MMAFB/+!*8GR+\NUL&J^>RZ M#L"=SF^WI1[S&D;MPZ5X868)=99J2JFD&EM-T>/8H(@Z%4AZZ0XKY>1N% A? M:@?OJ6+'U*H!KY>PWH4NONO.7LP[,HN,M48&#)TQ@@G")6_@"^-$U/'" 0DZ M+(7:; <.8(6QD[A6Z>JF/@(1QIWU-Z_FUU61+WJC].$W9D)ZA:F4'DLID0]& M!KNAC7H6U0,/Z $\7X(GL\G8W8TZ0TE13 T=@=Y0LPZHR^.KD]G@6QW9?[]<5NK\OY[8>BNGM7+%?5_"KF1H.T MK\XC=-'&2WYDUKH632'WKWTKJ_-C/. 0@ 1 M@IQ ++40J@'9>ARU6#=@B-5+: ;)K'.T">3%8LUKB+:L#E_L$?Z[*<7[ULCOBAN MHVK R+W^J-,GC/W&ZS4>PB;=3?-+_E '";W\,#V&A2&(<@F8D$)I1!7QVF/O MN:/:GKHC\26%Z4$AA ;&.6,=$1:9^NSB!@H+0JMX-F%ZK6UZ5IA>-[C^#-,[ M%FJBO/1:"ZT\TRKTNA)BT%@,*S'0C8\]ANFU)DN2,+UN<#Z[\"LBM<2TUBL M&F84SAK=J&?"3/:%A>FUMF;K.*PX %\<3UY&F-[P]/C#ANDQ6Q\LU$B3^OYI M1X4BM@&&4_9I?OYLGN[GY6/M0),>?+:OIQM;UF^(RLJ5%OR+PBC'CCO+'! MK402N'HXV$ GK9$C[Y)23M\N ^E%V/B-7M\LVD2%:+2K,D/84&FLE$A2H[G5 M'/(&'(OB./XB'=]ZP? R!#NV*%BWEP^_%[//Q2^A(7WJMAS0J>8,D6"9 MT PYLAZ:,&=&P&^A\D3%1;D-V+VE)L1I!O:([OB(6'?7'WXOT_%O6V'&# 4.ECTH./& O-R[:Q8$Z4K:%]W>+(VA79:89QSCXO@1[)XRF MXM'I\(2+J(YNP#W9$3(N M9Q!6[O@8%X'J2 DW_9RXCZMKS+#07&H)! 506Z. QLT>2)U&+FKJ0/_0 MA.N.ZO@(5ROQ./E>?/A45$5^LSRZ_);J%5F8[G$JJ86 .V*MHI0UQO(^_!9# M2?9'I60JF/L-=_'YM/I'/EL55S?;0,(_PL4O DE' '&"0 6A5, R11EQP3]B M)-CB#Q3FP@ER0M6>H"%: ^RX_@QS.;I5BX B M3&/ F('00BTH:K#DYF2PV?C#7%J3)4V82R3%Q+F,C@]_K!A+@@X9.N]>&R%U$I9YDD#C*84 M#42H5)@+%)(2:IBTD%B$>%"]&?:)E';LYSS/)4P_,%UD M'-(/NTFQ"?R_+:MIT=T7/EA+QHQVUCFA(=#06B6X<0T$F,>M 79GRK/P@%.! M. "/]@AZTI\Y6"9C&$"A+05" 4PM<=(W\UI"B.//R.]-8,-O[R-(#-N+8\?X MO=TQD6)P,KC_604'ZGUQO:K6EV2<]$'V%\B(4T($E,)(BK7'4'KG&\6\]N,* M#$I@G[('5 8SMU_-)VTM_>39S+,ZWE(AY3F3V-?.-=RJ0YEU4<&MO?F5?1DY M'I A^O9J^CFHV\7,AXIDPC$$D7?0*(VAX3:XXXURT,=EB^DM!":]M1/A,L0Z MQ?L/]3'V5?6@YI._E9^+:EZOX9]>CCA6+N,>(8%0F"E[%;HM#PUH%G@H@BSJ MM%9O\2CIS9\2G $X8,KJOJR"\K;XN.PPG!\MEQ$J$!3,@L12<^!E. ,P8&B6DYOIM?U0ED].[XO%RT6E8Z4RB"@G!AGB9+U;5G. M.-3X+Q1P.:YXC![LGPR:[OEF?ITO:L(5D\"]T._4*QH'37GT^0QB!;6OTX@I MC9#E0&'=2*IEW 8['[\14X(RW.KPXTC3L2-O53X+)',2UK?04>4A 1QJN1NW MPOPDA@MB_%SH$Z0AN#']4B=VNR[OBG8^_?X"&4&&40;#P&6@T@:(\+]=G^5H MU#TY\AE9/P4J YA[?;-IQ^9_L$Q6;\920[VE$CJ', J(->JY,&>-6ID!S\?J MJ9 9P/#OBGSF%O5&YTE[?_MH9K##T$H7AC3!$77&(--$GP4/Y51$X7XS/Z,5 MN#,!&<(]SQ>?PERR_K]Z4>%S/JNC=$_[YT>*92Y@0A&AT@E/D 1$PIV2ANFX M9==GM"27$)SN+OKF!NJ@TZOYYV*QO#MJSN,%,N,9,T0:PCR$H(["ULT^)<,! M@2A#/H/5MJ2P=#?AVSS,\*ZG]_E\^;K,YT>MM_?9S%)$D>22R/JB"50O!>TD M#$Y%U'WM\!FLDZ5"9"A_:G.PH)T?]?39#* P>E!H1)CDL\!$I'83?4:PBDLR M](P6P7A>?B]F)D)EV%61U!)($E'BDG3*. MA^E@LVC K&8LA@K=^^@11LOT@M^0Q/EEO=1?;,Y-?:?!R?"(3O5DV&!/;/!+ MO6+(!+?$F6;S@"EIS6@#:E*;^1"+>D3Q#TNJL<7A/"LN78Y#K^;WJ^5BC0<\ MO>QWN%3F.0F#OG 20&P,Q%KKW: -'!Q7@$Y/UCO$D;/ANA C4!0CMJ4RJ4R8 M3D&M .5,\^#$*;*;6V$>YE-5-9"SCEHS] M.M^4Q[?[@2SO->G"J[O[_'IY=7,U+]Z6 57S*9_?!HH_N<;I> J&K6AGBK%I M3>_*V]Y-7GQ>1^49T!;Z9V"W*#@VWJJ8."!1 ( T\ELNM']U_%:DR5)WH=N<%[$#SKG/#^62A)@@W/ &31&<:Q! MHYYX>7D?6ENS]<'^. !?'$_&M@+W7.AQJ5#, 0[J$^L11< )2A14U#$/=ZIC M9@;*?77V0?W6%HP\J-\-IA>TX:BY$4(Y1 C%'%A+O"&-XD3%.2JC.IX?ZZCT M@M^+W1NB&G",/'50 (P$T8C+!@;N1WQ!6VHSG[5)%(?B'Y948W-WGA677L!F M@C,,6 0(],!21KTQ6#XA1$KH M (&4ME&=A.]'3J#T)H[KH)3D"^*Q?M\ M5BS4?/*^6"XW.RK=.JQC%672,XCKZP(D0A@H(A'T6R @\RYJKWW JX@N0*Z$ M<%Z$5Q^J?+ZX*:J%+I:_%\7\B5.Z]AF[D>MD;1DECD#N )($06.591HUD'"( MQG[UT 48EAK3RSA:F^57LZJJ8G[]X+Y1@5!S#@-427<,OZ@[??L*,W>57ER^GGXL7'^6@OJ/82((@P MYH );R@(!)"8$H1.CMDO*<[' &@,L]Y+7^=7\(@"U$ !/!PH06B".)_6-CTK MSJ<;7'_&^1S;J^;.* 0$EZ&3YX!86V#)77N^T4L;]3#868PVEVRGJW9.I C#L 7QY.Q;7P]%WH,3HNQW.^B@49. M\^"A>U7WZ*'K-@TPDKFQ+TQWMF^:^UVZH7:43GM3@VQ?:H(#54T_KI9;L=ZL MZK>7ZTG>/H^E;=$, H:%\00Z;UQ0Q6..&_DM1&.W>@H/N2>LDME:U1/W?Q2+ MY71^^[:HIN6^?8-.Y3-.C)"> J:1E*)>"8 [U@:'38U\IZ!GJY\-6#+3/_V[ M8S/_JFB&$<>(<>FD\5H))>IQM9%?J7%E41_3E?S0.F MS=AR@).'FGN7*C*OH88(86>L@89B3#EL]#'4Q:5C3$V GDQ4#H)9=PZ\S:MB MOC3EW7T^?X@D0:0D&AC':0T-TDRB)QZKCG<"SHQT[E,+AU9\*K MMZ\;&=Z4\U]KK3ORH$,-&:=*&HR1#VV'*@N=XXTV3! WCD0;@["@/]0BG(&S M.="AA@P0"!4-3BS00C/'M7#-Z,F(1U%^?W(W=.Z6-;9XC3%>P-9UF(!I MB;VWT&O))9#,.^"=D1A*B\RI..N7M'4=7! #-#0&>"$]PHPAL8$"2,A$U&T9 M%]FZ;FW3L[:NN\'UY];UL>T7;8GBP5H**1.Z5F:0(@V6Q-B!J-?CUG5KLB39 MNNX&Y_/;DC068X>H9D$MCIAE&#?JX?#E"]NZ;FW-]GN340"^.)Z\C*WKX>GQ MA]VZ)DI@13R&84:.&;)6/0(#45S&R$ML7;>U;YJMZVZH#7'Z=[",)Y10CJ50 M&ABCB);&R]VP;Y"-VO4>A%K?R=^)1]^5S@Q5W#E1W^@,!',, M6Y,:*#'IV0>2TICU)(O.Q>]"8U?U>7I=F'*Q[#AB[ ]H!8"C:R@ M#&B 5:.F0FR@W%S/A2;QR%V$(*_FRR+,,)>=&?*T8(8PE0C5<]#@Q(4Q&O&@ M]%9104G4T:<+G-P>B")G0'<9E^9I[)I^J+]Z-U?X1%V9=@('OXXS#F'H M5)FE<.?A.:6BEH,O<$)[(":E1?,RJ25J[S[X^9.(9!)?%BSEG@7=+]7;S-I]UF4$\+9I13S*F3W @C+ DS2$D: M127#4=X,>[$L.0.ZR^5#JJ;Y[&\!WM?EHEN'\EWIC-2NO(>8>(-J?957;->! MFKA5//YBV7(N?B--#G+>O#NB_@Q*[Y 3E-+7<".>;J;.& 2%T8E7BSM^D?X MHBN)E\E""0WQE$&+C4#"$$F9W"UN:$@'N@)XY"N*B5&\3/_74Q9*X(3 B%CA M,%460TX9V'D+A(\]Y7]Z$T=FH>R&X^6\KCTY#KL[7WLJR0"A&"IAJ?+,"D$P MT^ 18#GVO8T+$"D1E&-8;')W][/RX>B.?.LZ,AW !4IP#:PG &A#R&X"XR2( M6&(4?! M_N"]# ^?G*G8H->-;=\5SS3FV$F+%0^> 0?<.+);U14\+F3ZPF>NT[GF9^-U MZ1BC\U8;CE54I^%7U%K/!81!<:\ WNTU.0['OD(^6,31NKW] MNMY(?/G'M2CBC'*M".<>8R&=WMPA 92'RIR*P'U)Q[4T,\:D)9SQB DD,E=<2"*?M8V>*?532Q ''G,'( M<09H%V&'^W)?7 ?_Z\R B,/59%:$L9Q:1! DAGDKH-PU$0WQV(.S!F-.,@@O M$U9S5U;+Z;_6.Q!7-V\#8-63?M)4Q63:K?=I4V'FM3762")EF*\J9+@'FUMO M0>B+T>A/X S&K1[ ' '+ZLCM11VZ772,WCI42T:YDH11!I%A1E-' 7<-!%*A MJ,V* 3<=+\2G> 0O0J)WQ75Y.Y_^JY@$O)KH?[LJ/I1/ME5A)T:UJS+31C-D MB566(B^I@>($V%R! MRPQPX.1-2R\I1(+[0$$%'(2:0*&LU11OH-".2S/0!D"*$(FV-CTK1*(;7'^& M2!R]4!!*RPSB3@*K-*GCH4&#)7%VH'N >PR1:$V6-)>Q=H+SV6U]"ZT^!Q +XXGKR,$(GAZ?&'#9'P1FG&$=2 ,(VH M=E*0!AB&W5"$.G?'N[5]TX1(=$/M185(8"6-90%2Z! 3A&)-S YI#:,(V%\>. M\7N[8R+%X&1P_[,*#M3[XGI5!2L4BY,^R/X"&3/2*4$E, XK9"&6N.EG/:!J MJ+CP=BY' ON4/: RB(?Q<=G!V/L>SX2A2%NK#+?($RCKC_PN(*ATILZ M 28#&/I=D<_/NO?+S:OFIJ#;AE$E@-T4&=@.$J"Y5^2$VQ392:U=$0B#:'UP29(8&X:<) &45%C MET['-!C!HC#L-W1LO<1[*$IL^]J(5YCR[FZZ_.J6@S[J?EWDBV+A5\M@T&WS M?9L_K'^RJ^)X"%P: BNGN[JJX_!5F>_'3! +S#4NU8?Z1O:%$Z4\H@ M(S%AQ#H>YF_42@$,, Y:I<*$[B+!=X<%/Q5N=Z)DAH36A-8YU:#WS!-M5*.N MM!8,M'U\-, NJ=7*/N$9:T#=82WUPW9V_7!U4R/9/#$YL8T866.8NGM.B&?6 M8"$D,1XBUN!)T% 7.G?:4DQ&D=;42PGA $[<844.J'%R0RFRQDQQAQWD!CMD MF0@3QN3K936]GBX? M'D6;KX_<'%]O/UTP$Q9JKA4*\R\O$?#><-/(CNC(%E=[-U#9(W;=[>Y7Q:R; MP8^4R%QP!&30'BJJG%<*8]: H #DXPJN&]+2Z4"+W4+K9.-C13)"H73.0H.! M8]:C.D5Y(R_!<>$,O2U%#FGDA*AUM_)A1=5=N0K_KF_3.&#O=H4S05GHAX * MCCW"ACI-I&YTL)X]EXX\?M[<&U8I[?W;=/EI.K^:%_]5Y(<:>,O2F=U]N:K.,?VN?$:$D9YZ[ A>SS <-VZG"43CNE3C4I:/ MA:L'PT\_G]7F=^4S9VSP3!DU!G-"H".2[+HO3VA4RMC>,L]6+Q?1F>KW-(KG!]T1(1DQU&>(0A'$>8T^5L]X"5R=%V""I"1EWDJ-$)"D' MQW& #?%O9=W?9$_N@G>I)K..*$RP8]))K1T& NV:??A.C#;\HE^3EX-#^@?E MU]A"*YXOK0:GTWYIWU;3N[QZV$1U7T_#QY/G5;M5E$D%-!%:80X=1MHP(':# MA.-DH'L06\X;^S%QF^$O%8#=%PG>E.N4QZMJ4=1GJS?7B1]:(-C_<$8L!\) M'&;0)/RC-42JD;&^ 7A41D[M6R?#Y6S;A3\[F>_Q^2RX:P35]W8*#[WS0F#2 M=(J:"3E0)J+Q6# :FCY6=AY7*-9IV-8++U!7TJ K;0"^-!?$V<1=:=ZJIZ5.KG" M\=6#61ATI-1<,06%I8Q1:)Z\[X7'2*M>X@D"7 9+/_3 M3LJ3L[F]SP<743@NA*;:SD[8^6BX+^A'A/> ,8VPP ,ZY M1DW*1W9595JKIP1F /N_J\,JYL7$Y=5\.K\]G<=Q?X$L=%E>.$P$(4PY) Q$ ML%&,*#VN4-BT%D^"R!!-_?IZ=;>:U0LAZZ,WM?Y5\:GV<3X7K^;7Y=WI!(^M MZ\@4-HA2YIDS 47C);./8YGA483H+4(V<1?0$T@#<.1-.:\7#P)VH>K;9DWR M)"V.%!55\6?V>5Y,C?.A84X:S( M<\)EP'YQ&H RWXL;5)JM)H'M;^N;;8-%ELMJ^G&UK%?"/I3[&\31M<$4+PA^ MEY$6 :XA<5P9Z@W'6^"<"X[WJ C6&RN^6U^\ +9#D/)3'@1[M5BLBF.=U-/' M,D %]M Z'_#"R#"O6>.M.219U(75O,_/A0 M1B%E"CAJ''&":VFT;N9>+J@UKDGI4":.QF< Q]RGFMIU>=\.JN[I0# ^WQ6 M/*;15Y/_7FU2=K\IEEI$P6CEM][FZ6/@;:#87UA$MNBFGY>'[Q:_.),OK:JNYY36ELV& ,U^X#UPBS?$JA=@JNG\>GI?QP6_#?UZ.;FZ49/R?ODD M[FQ??$5TI1FE6' &G0OP.THH1\(T 5')8I:\KE3:S \NX?+;\]W+^KSW55Q M_=5ACZI8;SXMRWQ>K+&X*Y:?RLET=YG5'@J=76=F/%<,$,F9LQ8+08C8K1\@ M;J*R*D#P7"DT-)[=&;2-3%AG7JP7>>O[.7S :?\R[Z'4.1UKR;#F4',JO83> M0,ZHVP7#.BAD7)SWLUV*[Q_! 8:R7Z;SLEKO'FQ$;,"JE;#3Q:-6A[80_KZ! M\\C ENH5F:<$&*B-ES),N3TP MD&/&Y5W!'V9[_0?R%XHPZ)[7E[(ZY=%1_* M(.]]N9AN#CWJU6(Z+Q:+XE#W%5]A1HVQ%(36IP6SF AOJ=RU0TNC[L>$SW9# M85 P+Q8)TZ!8-XQ&^C#U^#B=YR=<\ZCZ,@"UQT@"*.I-50X-L'X+BV<&15V0 M#)_]OL(06 X=7?V/?+8JU'7 J"HFIJRCA&I_L&VX]8'BF322:Q \!@$L$01K M:YMIB,>,Q3GESWZ%OP?HA@JVV>S&VU55SS_7D\[-+OWZ7UVG9*^70HKYXE2' M%%%;IH)DD&.I+,4(A/FM!DW(FC=$QEU7\NP7Y?M'\G+D6C>.5-PZ4EE&;'V? M+3$TS&P$!U0ZN&MM!JJX"*UGOWK>.Y!##W.;1M'TMFU'MZ]+94Z%45R'>09! M!F$1IA:TB3CSSL1E7(?/?AT\'6+=YV5'N\"O=G+F$_>EJ*ZGB^+J9EWJ:KU> M6O_P6YWK,,P/$;G0WD7<+/ML%[TOC.T W9*>? MIY-B/ED\.7=9IQTYT@<=*I(97"<%A)(+!I4T%""X4\[CN$10Z-DN=2>&:Q23 M^SHD[>IFDS>WB8T^&:Q^3K5AW)8,,"6HAU!JXJGES5D@KQ6(ZI#0LUT8OP"D M%UXI?U=,BKM-/QJY$/ZDADPC)0453BA.@&((4-QL'GDB0-0V"WK1Z]SQZ#T2 MI_'JOJCRKQKK@*_L7>4ZN*&87T_[R8;_ M6/M7?[P-2A]Y9<\W B^^%N9UBY1LAPME!IK0)T%AZZAU))@3&@/-N-<2<>9/ M)9\=2,E3*=KV%\@H)9822+%U044%,=-^HYP0E/FX38G.0\O15&TI3//=5<0) MP,A'FKKMZ6T1K\M-A,J)K&V'BF0"4&2X99I:"HW&1EO0("(9&2B!:J>$;>?: MMNP%F@$UVR&F)!YO4O?S3=:" V>!] +9 M,#@+3N1Q&Q,)!C?^QIM^3&[0;A0X4BH+XRIW! GO.+4VX$8$;5046$2E\>L^ M!;WD0) .G-FMR:\8X(26S7C@]G0?5B MF3&VT6%\A!B<"*\#WK=K"4V^*$X,#=\_G%'OI$7>*LTEU8)J9DFC$'$HZKAQ M]XC)2XX(9X,RN)4_A->>;.F'BF244,Q6$,&%LW/P;#7]#@]5BT.I6Q?]_C&952(" AXDA8AKQP3.\F2<)%=>[= M0Y7'T;E'PW(!6W=HVD\+9%( 8#W34$FDH 4DJ+/S>0B'SZ!KCS'3"9N?!JJAW4INO3UT5V[Z2K%94XS"@,<2QL4P M)L& M:>^B3AMT/VQPT2&@+[ &9\M6[M/]P^%2F1<,6^\4$X9+S^NK!7<-0F%GQCM$ M]&#&HTQ)@=N+I,CHQI%Q,V-P1M2QGM-UPH(Z_/?[@(Z'#\67I0[O_N<1@K2O M)#-"2L_"/Q0H08E'G*,- ,XP10>Z@[QE7%L/80B]0=5+%-NC<+:^)6'6,;AG M?]Z*IMKE.F5"?KU5-H\7U)^2ZU"T3D0M&?)>(@D0XY JQ#FU&TUHT8/M?:^-X2G)Q.5 M0X&5/L0GJA7HAWJ]Z8!KWZV"#$-!,;/U=;_&>LPD-Z0! (;A9T01/;W:MQP MO8@\/B=$.>B>M2^<(:@XT(8'=X;6*1F\X:;101B$1N?(]V6C#A0X"[KG28.Q M..O/Q_J#^^M_6^7U ;VB.'W5U[>/KL_T.8.= KS.8,RA%':K3.@[A[J*]X3O MW8=QRJ3 =&_;:K$HEO5!IW>;K'&O@M-\-U]G2S]HQ5;E,A8F"8B$B20-<@L< M_MU!P)",.P:;_)A0CR;M Z6(OCM??#+EK'Y[E<^F_RHFKXME^%R?>*F*R?3P M#5P=2F<8!&B\@8 K98SAQ "W8REQ-,;6R?-5]6SK?K :8N5M+>9)/AQ[/)/0 M<*0$A1Q"BRRF2N!&*2ULU*PO>3*I ?KO!."TMOBBN/[IMOS\\Z28UL8F]8?: MQN2)C<-70:;;?.:"VLM#^S%[GLH X=A[8XGE'F&BG2?-])8 MF9T/47*[;B0YZ'Q_^TAFN"728T$T8BIHK8"$C;B,'[K:_8(SK;,P+Y.B,'KC MC65^=!&;#3YD;H[)UD>&\_G#R1%SS].9AYI)#;$EQ!#LJ%*8-JN+G*.H6^&2 M3WCB#?'M76!G(]#=\WW2Y?^2?YG>K>[M .Z^!?5P5#E/ZN-2LEW!TSEOH3@O36<9]LZI!N+I1MU6Q.=!^VK3? ME\DLQ](ZSK4E3GM)+5MO<:TE9EI&K41?9+J:S+!G@S38W&4WQ;I:+1?+?%[? M,ZKNZJL43LYC#A?-..*>6LVE!,8$-UTZM.N@B#112Y(7F=3&,Z(GK+JW]^VZ M6%D=[GC>U0E,7I>_%]7KZ=WTT$44W2O*M!(.(2N9$6' LI11OR-]?3'0LYG; MGM*\J* S21$"F+>!2.[(#!K*HM9#DN8G[MW5* MD)*9=<.U;F;=E,F(4!9Y9 5&/G12+J"!=Q([$>7+)\\+?#&S1H'4EG7]& MZ9U:6[A#5H]NZ#S;W V:.TNTT\92*2 R!E+:J&DA5*/;I4AJNTY)'.*@>K', M&,L6R'@)<:X+_JZX7:WC6-X5GXOYJC@:.[+_X>!/"FP]*J]$\Q2LB,II6(@:U["/SL?C8L'$#"G !4, M>&Y"_T* M! TXDH[PCC[LS _%$D0A\+HC3<6U^SET=/ M,GSW7,:!YA9#+YPDTE.+%6&-9$[9H?T8*#J@*O,:6 M&.XHQ,ZP'8S.@:CCPI?).!>[6M$;6,\SW8"6&(7&$-J5<$0Q3\AND;".>QO= M -NG&;OD'8C"[4529"S#^#-AQMD#__SSM"KG]60OGQU=R]CS9&8AE<@YS;D. M%1-F">.-=%C$W=0V4+J(2)C+E(!$; #O4F,=M=6WCV72*(*0\)P;"3%TALC& M4]$2T+@K]9Z+H>P8!I" M103$GFU/%$$#G!I'1/^01H[D54<@AW<$U^$Q5S=OP[?3,'VJ?ST'O6%Y/!$:C&.'2B1<>: XQQ!)W 8MYDA MK-F-,(2:@4YG7FZ02H/+!4R^:2]J:?*J>@A?_B.?K=K'4QTHGSG#@[N-'4', M82Z4A9;ONDPZV,0RRL7M;KL37$@!T3A&E8,ARYWKR-PZCV.83FDFG15A9J9L MHSZT),H[&6H2E)HAR6 :@"7;>(&R>G@]S3].9^O<(4<8L??Y#$B#)*4."4P- M(O+_9^]=M^/&D731=]D/T(/[Y:RS?^#:4[M=EH_MZEZS_V"E)4K.:3GIR4RY MROWT!\@4J5M>F"#(I%3=M;I*E@$2\7U!(!"("! (4".69'FV:?%4I@&7BQ*H MY(3+_*B6J]GMQ?7F3.R1!NX-F=G7(1B-I,"*"N$D@0F''/9>>C-2E82@?4+]S]G_V=35Q M8$=JIQ[I%3R#1#B=8B@(TW'>BYOG>U%1*MT]#N,GG3KW8JP>"IK3E_/X_N6> M]Q^,&SG:+T0[$Q-.&(98.X250LPW(V<2N,D='1>EHQX>JM=$]E0.@:?+<5]N M_SY;SM,L]'&VW@SAX''B[L8!,<28T)I+JQ6U5&F%FS%:G7/WH\/2Y.67#5+B91C.^D.2-8T^ MGD".EH[?VSXX;HRD5J64&4:L@-S89J11U[*FS8&#SPZH1+]J E$W5XLEAJ!X&E%%. ME6:+9JC'2SF_:!PXTQK$=2@E"$@"%8>$- (!A:81?3 ,R[W1.'U"_C5.ZO/[ MBN%'3=K=C0/7!%E.".&"422= P2W*@A%UBW8@Y2I*\=8,31.9^QB_;5:/I/D M(&O[.P3('<8**"^Y8L1;!IQIQHH5S)I1!RDL5Y:Y8HB,,)T^->&;C5C:1+GK MZ^IR/?]1?8@;@A3T=-/=>7_D.0$RQ>WFE%L"S(TPD*L&!DI&N]B^VV'?L [^ MLE#UWL >*AV\JVD0ADHJO!4*:P$X-M30^_%1KOFT@L]+45D(C=YLF;OELMI9 M!'9_XT"C[6^,$IY **3BTJK&)4(IM%F.AL%B)09D+ ^/WIS%/YY$VT/[P)AU M1!+M*?8.61@G@E:[+%!91<8&BY$8D+EL2$[.'9[=[ZS$=ZA*@\()6?!HP0X2EGV#8S/F72947"%"^\ M6IKELJ"<_I$^7H8__3[[OKJ/H7O\^]7&P7RXSNK)SPG>2\PETUAS3!UATNMV M^O$2RARZB]=>'>*C'AJJ097@8%76DY\3C,36.2TXCJ8#,H9;UIPS4J)(EKNQ M>*76,RM!%E2]E^O_K&ZO?+U,=]Q=+%.6QR8@[JZZNO@>=^:;ZK3=UO$.#PH M22P@)D @H2PS4 K7R(8@R-H7B=>@!H-C53XR X:\IF76^_MG W3OYZ,$.7WL9/C4,1ZZ;_UYLV"2KQ$R M&9\&A%$^VG'W1[TT3O1VI*.6O1>J]\.S+B;X2%%]C_58__RO:K8\<)J]NW%@ M6 $!A>?&0$Z--)["!AVFP$@E$#M?K9=/3%T8BM-7J\>O32\]>-RYNW$@-%55 MQY0Y9HUS% (CFC%&$TM,\NBZ+]Y[J.L-RS0IG-)Q]?F9*\W8Q>)PI=B][8,Q M@A(C-<8"6\0)!9:VZPC)RUH;Y,RY+]('2,M%HS]OGW^O3^*M;1\(8 ACX@41 MEAH$B7I8_ZWG63=K#'**/"!ON6@4X"VV/>V+>]0C"*6(8%0P;K0P*)WCN6:T MT.NL$XM!SI.'Y"X;C_[L^;A?.HF\AP[!Q)'"5#I#2:>)YLP(T(Q5>)>U5QCD M1'E [K+A*$#=_,=IW]U#AP",PYP0XPV$#A"HG&G':C3*,E$&N4]L2.IRX>A' MW>>OU;*:7:^K[M_=\R[!&NF D 8)AR1GT39#[7A=_-TDW-0#TM<3D/$/YBV$ M ,35U^DXOS.".+;WD2LTE>"?3CAC,0=+ 1A&<1.^GRV7FS.N-Y%Y[+%6F+.X M_*BX4=,*X@@XX=A)+E*\U(FNQ:ED'AOB/ %Q-T*,[&8.R[6.3./ M.S/2(?/X-!C*^RA+!0TO;N+,_:T)[CM:)/ME\Q G#0*T 4X[B2V/4XCF#1+< MCE6"J'=^3F="7P0/]\9DE.CPIZ/L4,UX5X= -/16&FN$U,!) [E0C6#1DJ"3 MD(Y[W >4/L3\6;.B72"YB[G4/.=\=6Q[4.,:L-$XI!H;3$BC8C%'"L M*S@[5Q#JA_+^A*TL-$X.C!OF J941QM(#S"Q7CFN?-Q>M8/&>6$P9\B!/76- M[0]%F.^[R2B(IEU MZ#3\;4R=\:W+8W Z6VIQ,_M6[T\C?M$F")%\2E$2X*RBS#KF&CN+"S/6FC4& M*WWD/IV)OU:+:MGQF]G9-C!C@-?2&B*E3.D=BC8F4+K<:QJ)+D68*2%_1KCT M!_7.7+@4J?M].5]5JU\6EW\YR-.!'L%X1Q".0V7>24E4'*UL1LLYS J%*'ZT M5X2MWO$#3&F'F2PGL5H7*65L^7.;MG?_A^=Y>_>_#A_4#M8>_C)^WX(*KIQ#WD'* ""P':J$ M>AHI&;V)RA;X]._F\[Q:5QV_G)UM@R0$(>ZC9%Y3R)S!BK5KI,59&7-R$CUFS-N0(@JQPA!),DJA &IW/U MZ:[K*K2C98CR *XA!BI56+1$:MBXFSE$+B]L?)HNA?[B9Y!3WZV_WLX65X>) M>=HJ*,.$HXH+*V%<(S'3IG%Q<)S[V4S3H]!/](R9[>O\1WTX".YQDP"C>0(Y MP8;@:$':^!FSQK@7G/N\&*IINA!ZR)VQ"_W;/^:+J_?5[]?SZO;PU[&K:;"& M6H:L9SR.#*5D8-'HB5"*YLU;TW06%)#_='[^,5LNY_7RX]WAFVB?-PO8>VL$ M!RH*1AR*.ZYV0HWC$GG?RS1= CUES_%,7RVK8X[IAR9!:2^M)(! MWOAG!20L+X!MFKO_'G)G>#W7LR_UI]GB7;VL%O\Z[)/9V38H9H5Q,!J A,KD MG=#6-B/T@.;"6>+#>R-R.@4'XT,V]4\, $H$HY JR@P4"K2'GF):*OJ MR04YE"#H(->]@'DCK$\E.F(J9(]/1FIQO'1NM![>@0?ESCDX_H& M.# 2,2QL,P$*A^585=^[A1#V(^"/0@_9/)+9G"(T8'JP1UH6G@$0) MJKTU.8]U"09:IZU)Y< A@5Y0"]IY54LVC:(!XR2&9:,R N4?J^^SGVF0JXOK M%&+_^3[$_@#E^[H$(8FRC@(<)S/HU79S*2^$R@B4_S7" MLTH7,E>KBX7[(]U6?#=??4UCO[@^POW1OH$*9K'U0"(!)%1$6VU:#<=Y(32C M%^/-58+2\)R^_'^LHC3SRW5U96:KKVIQE=[ZJ5K^F%]6\>_B#SLOB^_:-4C@ M,/"<0NE,FL<$]DVXG2203J.JP1 +_ #H]&'W?;564(,1^&= M4BGJ3E#>C@[EUB\NE]4L99AM_SM?-!5ZW1_?J\4V]6R? M%[Q+WZAL"&C$,6#IS@1 &+6M!#2*-8E JR'H' *>!X)+UK%X$ MK248)Y!D(:S>1$4+8:&%D)*XI?6*.\$=X>$\IA+%Q82J9KQ>,S:Y$Z=R#.RAM!!$TZ=V*L=*TV.T+Y.?JL6\7OX6+:O+ MNV4THNMUQ3FU=U5*I3X@YR;NN08-=-+<-,UP[:*5T[7KD9=91\"!E?T?E-@^=(MS*9@SL M5&Z?]PPV36+<(L0W 0IP.#=+_KBXX?;NQ5J M5$UTH+GK0X+9W%I.H2)04H"YXA0T,AF0-U,/4FUX(,8' JK(A[T9S/\X B"44,"6-(IYBB)36C2R4L*Q=[R UBL?XS,N 5'0F1R!W)F]Z M!BFUC N/-U1KKS#FT+7@$ )1#L7%G?YCS^29Z)2QKO']C(+@R>;U\Z[!,LHL MX-Q#0%#$!<=!MU:&S3O2*7X&,)I]W1.>(O02T0P"GTKOBZ[I#,,SYY4FGAC M)8_;OV;\2*&LP_3BB=MCT=L7GHP,(OH7"G:,9#N*PYZ/3GV#8$I;(+SE2,?5 M15H.6P5U7&?9V>4SO@=A> B ,BENW[_:#&<11[':V "('G17=NL% ,)1D,)@"RFA>(>S7X>$:!*'364Y6O:D7/ZKE>O[EMOJ\O%NM-P9_ MA+5:L69>.6Q7G_:0 (TES '--I6I")62^U9SOQU^+X&12HC>7HQ^U;' MH?RKNMI])\T!3"J47&"F!-%; 1<%;QXT#>=_DZ_!K%<)DA/C4$G=/ M,&TM9)HB@15E<4^G57O$9IW.*FU^^MP[^G%^04S.0'3N[0,^[NKC=$/3=L!+ M:IE7J'70&$,F=^9?AJ9NUQ#D@?.&V)]*6,"42"\9VG%P)7[9,'#M%-%02X.] M$U3$]:85U=.\J7GL6RVET95<71&4(JGJUF3 M$I.&[:($E^G^U ]Q;8Q_-[OIG@IQY#G!84@08,1X$JT@C%C\TAH8,(9Y#K&A ME&38=(FR4(VN,7JVFJ\^?5]6LZN+Q>//"796EOV/"#!Y")DD',OX10J"H6Q] M5DCD738W>F6(,GI2#*5^&[=#%V3ON!::<+[FP]- Y$"4PQ=09;1S".$P!J'? 2BRQ+>_2*"7T)R\9C^,3=MW7[ M/#*64(HE$1 !)*#30GGM"0!$:PM?Z^WS3@A,O(Q6/C(>:PVLY_=B26547HG8 MDS^BK%S=SHQTR-4]#8;RN;IEU&%7Y90C[LA]78(C4ELD!=!44JRAX-(TB%@$ M\B*LQG=+=B:V'@27$38CNT;:Z5SH<,>0*B\+'R'RUECLG3?(M\AQH";KMNQ/ M70==Z W4&]:,J;DXIZ80HRM"&TAX\-SQ0.N J,#12F5"<:6C;:M*T5.7QF7< V,'XJB,,@#$C03!4BG4V$>289JU@@_F.2K,61%(7DG, ME@'4$PD0H59@;B26DK0ZZ-A(/)_-4BN R2N*VJ&6*T@MT1XX[9@&!-E&,(ZD MFZQ5UH^F;N$[>>"\(?:G9GE-@?31R=[FYJ24G./W [QH&P"R#AO,N3',.@TV M)[!;<90'F3?!C1SFU9F2NBP:X]I75!H''042>.H8L@H@W8R-0SZMD[E"3!6! M8O03VB-6UFZHW(Z!2_GWT[ MOJKNZQ(HXE@C90GB'@KD-;:H$4Y;(R=K5?4AZB#GO<%Y8QHP-O[F)]'9H#MD$U\ZF."Y=0"@YCV5%D?YTCF6[D0HB.=>64= M'.>P4X\&U>DJH/A?.'W^]B.U$0_V"=1SFFK^248XQ10H#!H7CX+23J-RWB#D MEL1EP(_Y,+FG/B8([A#Q%CLJ*5>8Q>T";$Z! ;$C66J3_ICSH,KXF,5?P O] M.UQ3[U"7P-,%QP 82R S#"%+ &[&JU#>)7DC163U_93+P7(ZC9_CWS7AM^I+ M_:/:_.+7>K'^NHGC]K?U+#GK4^1E,[S_<[[5 MZ:D0@P*52_Y0]9 IHD3%D7K$C!1"16/&MDM7G MS:![I"IXB-)=$IPBW!>LA M8P8I9ER3"(Z3)%HBND%%6XZS*BV.=!]/>6Y[HE/&:$/@*"/\PS/.O\HGCIO=&,MDQ8;0D""0 >:A!:X 2D5>7K7CQO8$X'@BE4JZ3PTOMP3XA[BL,$0<9QQ!&UG/M.&O- M?HOS"H>\$I=8<7A.)W?X"PV9H)IRR1P7A''/F?/-(;DV4$_C(IC2V1Q#P7.F MN.RC%X;O[Q2\1UXYYHEFW$8(IR;S5,,E]$/+!^GO7]: MQW]=]2PS\/PA02O+;5RNH*=*.X*M(0VF)GX/(Y46.I-B#(;3Z(KB9Y?5T?EA M7Y< J4XII0PQ2P074!K8?@7 TJS98?2\YC)*D(W*")0/>[L\-T H!0 '$#% ML)6Z"= RQ+/7<;M\KA*4AF?T"6#8"B-$ !072 BD<*DX'V#0M,(+D56A8O2K MZK[Z($9]^7ZP-NMK,_L^7\]N/ZWK MRW_6U[Y>5O.;Q:>[+ZOYU3S..=5J6_-_<7/QY79^,TL\=/OR^[XD>(,I(09Q M[JU%#'"$Q#TF5@LT5O'"XV7>A^!YKQJ-#.L04\NGV6T<_%_O9LOXIWI9+W^) MOWLTZL8X-4HHK3*$$3OG&26>! M(UGGOX/<"3*J8DX#[8GJZR\;TWY=F]GJJ[^M?Y^OWE6KU?KK;$'/J2KV(''AH4\(1;Q8GAUFJDE?1-[))U$&8E8PQR?_+Y MU:DWS_M MW8$2?_N:!J$--$88CRQSE@$(((;:48D]2Q?<'M'!4\>XKT[?KF8!<\F949P[ M;[1CGC(/[L=&N)B&2.!>'JW9)7 >P]UO6&9)H6C4[2D>0S,@ M?3T!.9W _ MY/)6*&(!EM*/C(XW@6C8CXPIF'24.9E06<:WTQ6 8;V%[7//S M?;UX>FV[W6X=+Y;J\K*Z36[S5'1Y*MY"J$ T Q@! AOM);:&WL>E< N +^(M M_'3YM;JZNZTNKB,XRT?@W$-ST(?8K7-PDCL(K?=Q=01>463$?4(--YSDU8<> MVK/8&?MZ8#A&]#?>#U/_?/ABCC@=]_0(#"HNL>06Q0E &F8]SPK67U)^G46C=%_S0[:\4_:!(*9=P(PFL+\K3!*4-:,R TTF%, M!VLP'\NZC.PYG\SMPZ@/EPEYV3)P$'?NCF*/293. TZ;*Q^XE>"-!T MV],Z8$FCMF)LH8ER>Z>@:3]\"^#T+L(K /@AZGK!,E42IV2&GY^[OIPU,8M_ MG]>WFQR8@XO:GM;!I:)V"EA!,$':(R=<:_^PN!1/QC;O#7-=&HR\$Y%&W?;5 M&MC9+F""-3 8&BQUU$3 .6NV$P9,<;0ZQ+&#T6%$;<>Y>C1X/;N= M+2ZK3U^K:OTNC2,JA_[YT"#J^B81(ZW+^N<]Z[9:S6\6F[;[#L^&?VG0CJ3B M0M0+ ;RC& C![D'6'N==3U'HT*VPEM03Q72DD[NXK*1D+[5^%H$](,$]D)FNDQ.R04Q"0+[>R&VDTK*#/_O M*DXN]0ZQCG@F.C\A0,.TU4X D,YJH,<(MPLCT78ZWHK^?-1C(#3")OEA_=EN M!.Y-_TX6]),>0:4T."L@,09HBJ2'M%F9C"1^K&^[:\&E(0R\,M",ROK+75\G MZE]V"Q)*PHR)Y@B&DF/FTQ')O9 *D:S::@.6X!V6_][XG.'3?]CLG_#U/W0* MS O,A26 ((8M11Q8U AH-.1L5_YBM(^XA@&(G2,T:%B#P4!@%''$"&>$=(ZV, MCN9=\C%@2=_AE&) U,Z_FFPT?AM3T JG;E+]^K6I;V]GZVJY,]6QY..#8\ 0 M J""SCIHJ#$$MI\3HEEG5 ->X7KV<.(UO67=*/2"7.V?-@.$2H;(_8SB:BJ+I*X9WKAS_>]W[+ MX9T68,V!A89Y!#120$%FK=#2:P40/99/^^_PSBX1:I(K+:V*VSW" !#" N_O M098*J2POS:CAG9VU9+SPSM,P+1_>6?JC?E3E?;[ZYYZ@T"[= M+$&\VUPD[& M#0"&7)D&&<+%2+7!IQ(=VEE/]MK7O2$>=5_U&)6]$8E=N@5CA&7(&&(U,CXN M\,331DA*+9]3"5B=;KJ,+H:/+[GNAGOWA#7XYT"P]C& MB51C0PA*11L$;"=5)O-*RH[@:^M#53T0.".P;Y;UZC[F[O)GEBIT?$+PVGHF MXSJKXC?E&/5,VT9T0VA6Y9$1_'(%]6(8I$90DOM+*]T?EU_306EGU3C8+T ' MTV7JVO(H)#=($"O:C8.U6;;H"(ZY@@I1$I\1U.!B_;5:=B9_1^N ,,(.&PTE MP,HS:QQIIC^E*.N MU6#%4=:)[$#5C":\VRP"[EFTYNA>8E^7N 1J'6UN(9$!*:)3*]N8WHHA,KW* MI:7(.LI]+X#>F!9,;3;RD@2BH,M+$& M,-BND3?_G2GL:R ER<7JC!$9IO[VK;Z* M0WX$V"3"+$X+KGB@EA@,,)'& @:8P((1Y*Q1C%B5"@$>,V.&%NM8',2SEL$Y M$S>QD",C!-4 0QWUZ%XPX(4,%O9^8#GBEX\SV%/#Y.4W8&3PSIOLOFIB^.14WOFQ8L/5@W:VSX KQDP MT1A@J2 E2DFPHE5O!Z99 *H_[H=)[(7-E-F]#_7NU_/7WKP7G>G&L M$M?+I@%Z0HG#C H4FX=L;)=$>*>>J03B=%9*H#%J-M%_?-]NB:TZASJ^+A# M<$Q:KQ2*NR;B&&?(HE8P*/Q(D0:C6BY%$1F5ZO>S;Z?$G#TT#T9%!?;("L[H MYAP66MI^",KAR9DYI4C:RWEO<-X(\U,QB:9$^/B19/X(3%*&4O M(4%-\GHKVF[7(<1E.=NWED/,\8JP((IW)7E67?[FI?T31H]V^3E3C^Y\3 MR?@1R=O?/A:V7GRK%]5ZQU+@G-.KOZSBG);"[#]6J=[$59K=8HO8WE>;Y?&<3O[MZ!XY M,+KX^O=W"HQ*C8T !")NG3;$6+I)?V70 ">/;3F'$?+AXKX7(S]V!G"L:S B MZIM#1@+(!.4*>T$:@06F>3G390\%2M!5#PK+L$F)S4)_5=X'\CE;!>N8ID XHY82/2Q.'HI&48I%U#^_ )P?EV*M+ MX7*RU7:,S.U(]NZXGC<)*:99*PZTH=2DTMO"M%^"E&)Z.7Z],*^+HC!Y\J:R M13X+9WV]T/9[UVO*=[0,#GMJO8$D;OB%HQI8*IO1(>RG<>U#/J9U2>G'=4A5 MZS9&YD.]VF)\<[.,ZKE^"*GIYJSJ]*A A+E:DKFJ=ME-;M*@T]ANJ>H3>=G!(4%%!YZ ##26&@(G;\7WPJN M1KH>_'SZ,A12&0>1L]77A]%\K"ZK*.&5CR"837VDY??96V+@-L1R)5G#,LV[A'2R?"<\*LL1(;=Y]6H;33XICM M= ;AV]30C=LSLK;Z.O^N?_ZRB(I2?5I'E4W-W^U(,'U:G*1[E.[0@PB"<$N( M,D01XPV*RZV1]R0H@<=*R^H8 %Q&G3K4@IH$V,-Z$,?\1#(*GAU_8+#6 BBE MQ8!@*(#4PJD&309H7E'HL:*$IJ-KO3^'##+&2V-^/-"N>#JF/QK\M*M] M< IQ@I!7GB*H(/2F2>J.8FDYEAO_I SH/NP\]_<4 &54%W*Y2JT<<*$(@(CX MS7T,@EO<+L""9R4]CQ;$_*K,DTS(1]6K ME2ER.G6GE.K,@^J-ZL5KL#S.JPZCJT'IRJU60<8(=L+J^(^0DF/=6F4,32.% MK2Q5W2NWG@;.& ;F:)5;H<<, X",LXH1SKB1I!'=89Y5J/,\E5MS]6(8I$90 MDF$JMU(N.'*,<2ZD=89Y#UPC)E!'0UHG5+DU5R%*XC."&O2OW)IJBW%",?1$ M*>*IP7$G=^\>UT1G;43/4[DUE_+^J(QB$NS<3AW9B![H%:20W'&*L:.*>:JE M5NVY"%0^*YCW]&_]K>U#RR%^/J4ZNM\XV"\ Q)DG#(N4:PYL7"UEXQ/21"(V MV8UH$>ZZZ4,OJ-ZL9DQM*SH]A3C;5M3]\3V"5G7>A3YI'YQ1 D(H),*,,@@1 M1(W=I $%(V4.=30R"C&T9P?:!YA1PEY7ZXOK3[/;:G\1EKUM Y2 8VXB+@(Z MECX))5JSB8FL#WRP#>4P//<%Y?2(U??5VOW/W7P=39WF:LZ+:W5]/;^=1]$. MU]+IU#=((IEVG!-'O8@['J=1XW73 O&LBG&#;0O+TCH42*?3O"D%^\NW[[/Y M,LEU;$(^UB7@N$L"7DDKA7$2LVCI-D>U6O*\8CJ#;?S*DUH0FQ&FY32?Q%FE MS;EI-CU'Y^C#'0-%2'N!B&:080B44UBV@K*\6I#T=2C!( B-Y_EKG):=->%@ MOR"X09Q*;,%FOK+0,M^:L]AGN8'8ZU*$D@"--"5T^_X;$9S@J6(]C_\(#*6/ M%F;CQ-88Z*P9G[\NCO/A.%.T2>O>^EA=UC>+= ?[+XM[C^6W[\OJ:]K*I@X) MK>?) ^\[EN@O][I !.'8$^MYW--(F#Z5]C,1<:LSJ9W>.2/(QP%X EI[.UNM MYM?S;7Z7NKR\^W:WJ0US87Z)>^)Z",W-?66 <4YP<6974!AK#!)Q?FG 93PO M*6^$ ]&S:.]((&=LE!Z-9<^'M3DOJ*[C@O]Y]DW?ZH?JT7ZZ_[,CZ'>ET #GG#C98640Z%<+Z-AM3*Y^4$CW 86U09 M)P3P"%-I$N-B8>>KRTW=K+O9C@Q >U=]KI.I>CE+&=*?E[/%:G:9&GY8UE_2 MV=7%]?MZ?1%!6R[GBYL#T^@0KPO<0,(U!=X8(33S@-"&82,)SW+UCG">/,@4 M.@& \Q+@V]$]Y.$^'EA$K;[:,QUV[1X(YHP[H2D$G*=[:KQJ7-]&:)Y5+64P MU\. T]M @+V&9.=?%M6_TYVQQ,+B5+K"4V1\5!W4Z PF^NB$>0;AWV"Z,W=: M*0\E2Y5\(Q4&F/M;GZ.5BL8*DBZ1[MQ9G&3O9 MT*ZAZ>RKT:_1@_(*A(NG.Z)QEZ09FF&EN$C4;->0W$XZ6_ M]TUW[LQ.IW3GTT!YE4'F1&DAI3%1).:A@UZ!YK1BLR:/XU!_:\9).<1?;2BQ M$DHZAN,W QSE ((H72,F%%1.UA(IPMU),<5Y4+U9S9B:Z3$]A3B#(I0(,H\" M40,40DY@)C0DH%U.46Z4ZIF"S#LSU"G(_#1@IAB ;(V2P%@1OP=&K0.0LR8> M$R'H1C(CSD+M4""]VDA%B;TSWL2)$$1#W%FL;7,,@K3'6:5QSQ2,GON9EP3H M3!%"?:LH,>;3S2U>>PT(<_''=F5$EI*L#>7;R5XMZ?7,A/R55LMAFGC&.:<$ M0T>-@1K35DB-IKNO*$/=*65S\J!ZHWHQM5W%]-3A;+N*4E64O.+."XV4B486 M)M9)W]270!C J5Y9VH>J[E643@/GU1;(458"@1&.]I4B4'FG9%,7!$'-LH*6 MSE,Q*5<'2N(SQO'%:,6TI*V6L4U($7DQ^5@&[AZ>9FD MC[W_!"&;5$AHH1+$66&!0QI'?=.>Q%%9Z]2Q,A=3B4=[W2&;DL0 M.2>\%!ZP!@V"_4AUK*;J?.RL*[N#HOJ!/5ZDW*-Q=@V4>]$EI&0.+P .%K; M"B/DE&^$8P#YR;H;^Y)UE/M> +TQ+9B:!6 M6:K2[;6.I"PNP["]%TDC)J85I-"?F+HT(J_TN%):"Y1D#@/!$97*:M0*:30> MJ=+Z6[,8"D+^2H^EM-#$2>D8@1HS9!%M/T2M@9]NK=TRU)UR/I4'U1O5BZE9 M%--3AU=_7)DL,2JI4:H<"Z=6F6D'DH\6$G)!(.^$!5D W8B+HLNZ-/5.J5>YG7A*@ M$?3@]*+P7AC!C,386"&],Q89V(@@N,O:-ISI&I!W[&X<"-/2I;KWD$,(+??"-QMCX[C.VN*?Z=*.G"FZ""ICA)[WNDJ+ M.F$M)#+=+AQ-!\X1)ZTB:II%\IDNY,C]+ON"TN/K[,+=X0[!> 9 E$\9(H S MT +G6GTD>3GK9[IMH]=7VA>9TUE\J F>@K OOE?+K?_HXOJA%'-UI>]6\Q27 M?9#?G$<%HZ-D<63GF9MB\7K87X$S,Z5$_(D]%VM[AV4.YR7 M&7D>ISP["*E%W%]* M,1ED]I=\UB%VER8T6,%?;'(0TL\H*@/?".J'1='M8T&2K8;G@/2,N4'/=L8/_:91M/W=2>D^#_1[CH3G#&BAB*)(8(\8U"ZN M?!PHCX[YOX86JWL"SO;<*QI9B@G,03H_C<(X%2VEC3C,28JGE263P<+>M2!' M_/)Y*SOMTX=!ZI_IO'O/H>^^IH$1IPDPP$#%N$S_%JX52NAI5_P^D9>Z*!:G M[R6>OW3OB=G^QH%9R:3D"$>-5IH#9HENQNBAA),[0.V/]@':>H$R30*G*WQ?QJ=F4K7Z<)MC:WUP?WZ4=Z!23CSA) X3@$..XOD8$/ M\XTTT\AU+X%Z/10FV4Q^J%;QI=^[T/>D:3!4* $-<4YI:)A+ 5SM^ BGE[D*K=C0-7Z>H\#S3GTD),+*>H&:.A:J1Z M?..2502*T^ER=\LZ_O\@2T_:!,,%LAA !PWD7C,(9#LB)^0TSO@*D],'@8RY MKKZMOWV9WW^Y]9'9;F?C$/?[2@@9!R>Q%S[N_EFS2'O#>=;EL\6/]4K/=R6@ M.)TNM;RID@>F2J]5R\-G +L;!\N8YA Y&55*:, X=*89HR!\&@=TA>DJ D7. M A6!6GW]4-\MKO[ZY?#'M;-MD-9@;ST!7C@K(95&RF:$5(.L2);BAW'%EZ?^ M2)S.U=]F_YK]\^MJ/5O,/U>+F^IO_]J?QW"P?1#::D>&YPWPOQ4O&=3(KSO*OPL[?'B>\)OMDCE^GZ?+?>7+NG<-_"XM&%B#)=$ M2Z.U\IXW$FA@IQJ!D,-!/2PV(WS&+@[KZJJZ>L#!S^.P+^>SVT>GO$>C%$]Y M3#1_F'7.Q+T \SZ%\ @#6GA17G+0"+$!/11D!)@ZZ\JJNOS+3?TCXO&C6JV3 MIN#[GY..X$+ M&%.&!+T7&0)#II5&-$P$0BEPSACC[WM<< M]2,IXU)#P8 35#O,XIR_C;I2D%%W[HJ^IT;]"( AT'&BB3))##UF_#Z+10$9 M?S?1J)_.+!R)^CE-_#-$_6R#YM:_SOZ8?[O[UC'^YV6GH"S%F,29 T+,O(W6 M"G&MH'2LP(1>OI/.7.T)3>B-2K^0DJ>O[QQI[49(35YEU .'D_4#^NZ+";](_E.#9L5T%!HO(#>,:)2V5G)F_%9!$;: MDIQUL%<[ P81QBO M)\,"=<;(I\W>>%\PT_V8SQ67UZ6M5K>.PU=75?+M&)OQ9@(7>5#_0J5;;_[LJK^ MYRZ^R?V(_SH0W7"D1R#80F@($9(QF"XEV%QTM,7#4)H5Y#!P1.#D5.5Y>?@B M4(]@_^X8Z%&GY]X^@4/KA!$.8J12\BI$\ MC-?U,OXQG2OMGF*/FBN93PPID=X*&,%AD"HI$&2R@49#.982=?3/EV/ZD X- M!M_8FK7]0QSVM?[YJ9QZG?C88*$#!@$L('9."*_XOB-ED7>T#=@I M!)"'R#)C'! $0//@8R59B]-@EG8IM.NRJ&1D,L5!+^OZ,&%/&P7&%%?61F,+ ML[@CY5%C[VTM"QA&6>5U![-7!V"J%QRG4_2I7E2'*PT\:A&\]U08[R R &G" M&'&L&0WG>;?_#I*:F8MB74+NTUGXVW+^97ZX'O5#BR E9AAZYSE%EFO)4PG0 M^]%01;)8&"0+LP +^7)G))?/O\R^?9D=Y.%)F^"-]!)3( UT6B!LN)+-B)Q! M(^UYQF&BC^0CV(>/-V_OZD[G3?NZ!,QQ7 H]-P2::# YBY!IA%/>91TTGGXQ MR9O:RA;"^DR*='23L;]34!I3RQC6&#+H$>0\VEGW EHF\&2WI_TIZZ #O4!Z M@]HPM>WFE)2@[_K^OEY<;DM$J=6J.GS_Q\ZV07,1AZ2 (I00:ZB&HA5: S*M MY*L22-=E$1GA@_V8"J ?6?C;-L%':T4Q@RR25F*N#"3M\(EB60;'@UDCAF3DE".VHV?4=I.=O'.8&$7C[U@>)6,3FT! M'I?(T0G\-:+Y[>[;40J?M L,6\. X''0D& 1H0"XW;\2,=;-Q]W6X2S\ZW+B MC\'BMG;G<18?MPM*&J&8 (!IYBT$4#6!SQ9X"44.BX.Y>HNPV$/\4>J5#&U9 M'+'+QAE L,A0Z96 A&+)XI2:+D]H)E)*LXKGG'Y%YILR^B;)W-@17\=$Z%;N M*>^) ;@T(U'@J8O_C;:"0$U&)(PH33<*8FJJ4J"B]981PU(P&.SJM)*_!(:]+@)1Q'EU%U4[7 M-*\.GX:^:!>L%AX(ZZ7TTBDGO6E/%B$C)NL.B7'"C0>FKR]4XT3?8(&P0Y)C M@:%FPFEIFYT-I,)DF<;#50P:D;Y>.&6$Y M&!/'2!0W[;BPR2H)>/K)]03YZXG4Z0S^]ND?\\75AV7]W]7E@3M,]S4-2;VT MC?)QH@ 'QB.EV_%!G^7B.OUD8H),%D#K'!&H@E EN99>"T"DD(A8T8PP_FH: MN5[]\3T:JEB0]F1: MGJ@I:^'(3(R@IG'?<5E55RL?>7@R";\L4;VKB/KQWD''G2F3!F%@0-SW4BFT M;K],A[.LG<'<:*]!^5=O;)];U ME^IC=5E%D?8MM4._-G")/392Q.7#"N2YA[[E)&[$LX+2!_,43EE9)\C6"+/I MI[MOWZ*M>G']4$-@=;'^6BT_?YTM'OWNE\7'ZC;2=O5AMDQ7$9C9FBXP]K:)FR7 &#.>2FK.9GY>7T:?M=M5XG"]HL MJXC:_5#6=:K;I&Z65?5M_\:X2]<031MH/$:,&,F5A%BPQ@K'6L&L%)#!7(-3 MUJN!$!]A"MPD-/WR[7N6\J)8D(1BQ"F1#1QV3AN M]+(*U(H_HRH5Q?GT*:==O]]%R]34<;_^N?Y4/=Q]\6R:V=<\.$28,%YP)A@C M@U/^P."I^5K*G_#/J0T&4QW&CO)3^KY&#=_5J=;%H,+NXWFU65NN+Z\^S M/PX[50J\($AN9?IRK!(<60$X1QS%CYL& M"0&SA#I-M79"06]A4X@%*^SS+B/ZTYXC%(#X=!7X:[5HG'VS[[/+316KF]D_ M9NN]FG"@1Z"2(L AQD19QP"RQ#0''!@@FJ<0?]HS@W)(YP0>/K+4]=W/:GGQ M/8WD<_WA;GGY=;:JVI.NPX>2IS\H (TMXE8X!;7DABO=EI38R)NE17]*G_\H M! RJ7,U)6>JR^K"<7^ZZA*_W,X/0BE%$E=6"L/AM*8C;K2@T-B\J[T_IZ1^; MBXP8SIV;2;5>+^=?[M8I_7%=W_MT(RGQ:3?-(/<%>F8_,' !M8*("F*=5\X( M89JS#LP,R4I]AG]:I_UH1&0JW3.7Z0-,<5#+*E75B7]W2,DZ/2 P)B3ASDA, MB=(:&D>;K"",?*85]J=TD0\*?,;)975=+9?55=[!]XE/")YR#Z$G2FE@+;.< MRM8*4-SE%;GZTWK$AT,^?]__H?Z]6D9AM_-CE/%A#!UBQH[T#H9[RZ'WSEK M@4">H:8T*+9:Y96X^U.ZP8=#/2.;\&ZUCD M5Y^JY?Y@AV>M@K!40VL,]+6/=TY5AR&G#'!! MF6$I1M(UKGY"CZ..@/6O;__L<#WG&@_]S\[NFO[GL^0?WWWW__ M2U3VO\1Q_<<&[3VE$A97Z:HP7R_3%O+19-C>CW$2DK9:S^:WJZ>R5'^LJ\55 MFNS^8YS!;XKP##"(^O(N:6!\K8MC27'(U_7RVY/8W6,SCQ.?C/*@=E0AP \VQ:6!@H38D=A%H6W*)>(RTTH("!*R# MU%KH[H5ABN:%[YU^EC)[.-W><>=,#PJ>!QWU$7XSMR01KM;_3YHQJZO__;_6 MR[OJX9?Q4XLJ[&XWK_C?_VM5W6S#@[I0OZHN_W)3_XBSUCRQ3M(/B6SRB.SX MJ_"NNIG=;K^C/?7,=K0*+!I3U#C(B41Q5Z@,\2U@TN4E4)U.\TE%QW*YJDNA MT-EBZ4K==B1["QH];Q*P5,A#ICQ"6%.###&@&2[SADVNJ%8OS.NB*$R>O-%) MVU->ZBR<#(%8,UPD5%:VSV !!066 MPYX %.=+Q8%1[O^RD89CWQK3]H&X:!G<:\(N6".0HVM-0^3C)U6BEWACZX/$H-1 MZ>-F<7;[7]5LZ>-O]EF6>UH'1+74*;D=4JZA4@IA<2^$D()F50P:["B[,)W] ML!B8T*VN=:?T4?O #<,)#,\X!TZF^MZP$23:X%D'Q8.=$P]":CX:Q6G]O)PE M#]*GG]^^U+N"P5^T"<):H*+UA3FA7D+B",3-@#7.2R0=[$2V$'U]$!AHT_"Q MNDDG)[/%.I7+.;AY>-HT:(LI)X)9IAU65D2SK!T^L#CKKL7!SD(+$5@ B(%X M-%&VY>SVE\55](/((ID=9; + 1"*E6(RE164OC8$>+A0@M!,9 MGZ>?WU9+$X=S4R\/?YQ/6@:JA$:4 (,DI0(1(YQKYQ8N\J(P!SO6*_IM]@%B MJ$FV_O:M7GQ:UY?__/1UMJQ6%W?KU7JVN-H=I-:M8]!:XKBYXE@#A(U3SJEV MTB%I"NMR.]\<9O99VT"1PQXC J,ICY5$&(J' M31?+3!.#]P25AF^/?4?45]82@?KN1FRT6<_5S?/\!<___*&. M6,P'""-Z_J+WLV6*9_I1'0Z>&K9T1^3_:GY[EX;Q*07DSU.)&O='"O:JKK8Q M;=^^WZTWL4X7U\]%>-<^BAM\1Y)DS:=2.FCVUS!@I; M:N/E>LIY-.RIZ(N"8]):I>-*['DTH*GU!-Z#"0TW(]WC>C!L:GS%>1YL=4[( MAPW6ZC%C_#Y;7J4S]R.743YI%S!)U:.E\0@RS "AV)![V9&)B]84P[?.Q/[S M&CX]8WAJ_P*?+:C%;SNLC9MK.]H%[K(@@3&CG++,> M"D,;L1P!6>;:Z5[HUVBNEG_<.R]BF#\:A5\;1A M - DC*8B'7*,.<8P8T@E)"1O$9=S8C^?+R\AB$?C1%H[;GRZ9^['W#,TS/< M6P.QD"FL&$<6.(^8%*IQW2&):);"G7YV^AH-D>FP+J(5%ZM:X_QQQD M'I!HXTH>_R ];$\_O459@?N#110.I@PE,1I!%8[7%8J3J9ZMYI=/@F2RRD(] M>5) 0C+E%/4"2V I9((0+#HGM0T7:6F3L^'IO@VEN KG/_ MH)%EV ).#'# VN%YHTD3N>5?AYY6AE!3X;$=/H.A:-WVQ5Y?N":**4P8] X MAXT1CHL6-D&RS.?! JS//F6= _,IG.OO.S/@(U VY7,WL]U^M68 M6MYU"(%: RQ7#-FH6,0ZFB,WX//IA3GU]3! M$1X^_>3A-.>%%S/MZN)G=&^\GS&)P]S.5JN+ZPW<[SID9.QL'SSUC@B,+66I MCA.RWE"O/?9&>G0\PWCH](K-:/7/S=B[YTJ\Z!52O!:2,FV\#7/ ,L3EO9C6 M6SY2C,+!Q(>>_.S-8N@+1OF4A-W7=70]@-[?.$BDA?:0BKAR*4:LQM V@@'E M\Q(SQSHW[L%371B9TSU0+U^[]WSL4/. I((".LD5]I8)9@A]$)DQ,[ECUQ*8 M'Z2O%S#3)7(JAYM3X>^-'#M)"811$EH.8)RMF)&\Q8QB,8U0L3)$G734=!HN M8^VJMGO#HY2_:!N PHRB*!!GAL4W8.,;<9S1/,MQ5?P88!":^V(QAOL^*U>3 M$JR]%I1A[(0PEDFC&S&HU5GN]-&"__O;3B5 F8*#\!7DL6&/G"9Q(H2204A= MA-4TH'JE]>1LO)ZZ,49"6QZF_U;8(N!.Q99] WHZNGZZ;]]OZY]5=8H]M+=/ M@"1*!BQ$UF *B%!<-*N. XA.*P3OO 37PV#Z:G=.@@L(+;/"6NAM%%8"USKZ MH,^Z5V"X$H!34IV2N(YAGF]"*=)->\^W)H]T/UUVU\B5VK2"';+G>STX,"TU M%4 KQI4D#%-J< .44A,+ 2SK+!\5N4G$D?8*'0V6 4. I-Y2"IE3@+)FR^LY M9M,*+BZK*L71&4$=_E'-;[ZFT_\?<8PWU?:@/R+RO*SNYFSS@&:<])P A09Q MZ1;4,J6I$@(PWL! ,J:3P:+SRNK)$,"-8GI8Z@P=$"DP\8#SJRE,"[86*L& M"@=QELX,%A W]L32!ZIQM&:YL?UFM_>UNS?JKM;;R]>35^YS;6:WMP_+Z3]2 M+4B/M8 MH5(Z:R-)W'MFQ0D.=NU1&3T8$J#S6<;WX^URD4?FDP)SB"KB!-&<:6RBWC>3 MK +2P:PY8["+E4:QC@M!-17[^+$X?2WDQ\\*6GMFE):$$RLTY!!:T\"!-??M[G860;U8?ZV6R>6[ MK+ZFPZ@?&S+.6U.5=EXKU)SXJ:(4TL !RG2P6XJB+IK*4'&F$&)#' MIO"S G(LEOJ4QP0*L&,L?EV&21XW"(1C=DA0T!!# IQC+/0SW^TJ- M%D!MC//UIZ,\&L"QLWVPS@F+HJV'E8/(&ZQE*Y;#4$XV9*@06\\/RPN"]&9T M8&I1.%.B?OQ#[H>I\/-RMEC=;@,$KO[[;K5.F!P-ENCV@,"AYQI09[!3<3OA M$8&Z$1QD;J,'.[3NR=U^2Z,<0N.JQOMJ_=<(0;.AL]5J?K/8+)_+_^]N=CN_ M_AGW3F:V^NIOZ]__L[JZZ5 EK<3C@R#:*.,L-Y0AA9D#6C6@60&ST@4'.^ > M3*W&PF] *&@S*J7 M--@A^&"*5!ZI<55FGS5_BK8C(9O:LEU6<.K=W'5_^W+EV6[XU6+; MYT.]6B^K]7P;][ Q9LHI>^Z;HR)0)1F4$"BF*%..L@9J[&5>Z8OAJB%.3,U' M0GTZ"EY.85LHD$MY&M)S0:V"7D+:VN^8"R\F9P;?0;EZ/#5(:J%GV,2EQ0ABF<.JV69@Q$16\L%P=0/'4K3Q M$!TEP^[I4).AT0')K1V^WM:;ZZ"%)5\3H$,(48485T(!2CVWH@'1:)NEEL,5 M"1Q++<\(\9DGQUU[P]GE>FM8Y'H AGEA ( *@Y25PLJX]O!HQN &6!G7H4D% MKDYB2AT-[#-KL8U?X(_-!G#UX/)7J^UNKZ?"=GIV\ !I)PQ(5[8@XZ.![9KS M*\PBDI,*E)V$;@Z!ZYG5\."6;/>Q0D_E[/'& )R,7&)/$3/2,NIQNF%F RVA M%F=-IX-%Z$Y"9<=#^\R*W%,K'SQK'&K.F4$8>NZXPY+01FBD(,U1,0C>M(YE M8C<1A?E0+S=T/4FL^C!;5@=O6NGYY$"A(()X$#\OP;@14JO&OT6(1'EJ]OJ/ MA\:%]8P:^.#_WWKV+ZZWYP"_+"+6J69&*N^^G"\NY]]OJT;RZE#0;^$WA72# M,^#211 9IMA);"U0W$$&"3(T*\ "OO[SG?/"/$ >S2;B8/MO._\QOZH65^?, M._ET]V55_<]=BN[\$?_UKD-^R;XN@0OJI:%,2>^]0U0 !("1%'L,G;+'S,51 M!#Q:>W]'\T!3G(8QVA$%/,844"FV@B%M*4) ^7$>R"'0,]7H)S M7Y^@+1&:&$6)M$(:#[5V]]\4P)KZZ69Q].7K./^]('ISFC"Y7([)*,"YB3]> M+'Y7^X"!YD1##2&R4"HCB!+-&2DO5;([O) M7$^!7A]F\UU54D[I'B3V7"DG#:?0,,T]5JH1&CF7=77 6)K0WSP< *(SZX5- M)[S+G=5S3ND>@'%Q%N526,1M_+*L(QN_;5>SO]57 M$F8<;$&#/JMNTF"QB\6H'P&J$::&S\MJMKI;_MQ(\O?9[5VE+O_G;KY,E:%7 M<:&+XS\T-73I'K0S$%*>'%Z.8N0- +01FFB<-34,%EI8?&H8 *(1].*^TEL* ME/C8ZO?%]:-Y[H!6'.\ M*>[+!-XK= M[#GV+XR.1,F]IMRMV=URXO7T!^P6J5M?2)!$0W+F)9%E@@2^^@!4%0I53@O/ MC.;17I+, JAA,UF0(6G7LR<+Z*%V\(U C+'(U:MA(( M X@5MLW0F09I=Z8G"[[*M#(,A6G:F(%?J\U#>,73F!Q5KK]9?Y M[;O%IHI3KZ,[9]&[QK=K%8+_\;575!=U.A84,>&UPQD%L. = (6XPXQ3Z!MEHY&8J M4]8K=J0 FCW?PO-)((/F=ZBW'1--'FH8.&20>V"84 1!**B1O!DHDQJ4&Z^2 M1;Q[,U..#.8;9D]Q,2ZOD#1#3SS??53OS0=7+[.WJ_FZSF]S\=/!$)<3+8*' M1%&%&4#"4X/K11DUO=4:E57]=RSDEU-@D\5=,$76U\,[LYG1/V6+L@%".<1\PTUO$G M(I!R0$&F.=6$GRPJ4T)"\\Z2>IXK:T1@LB0IVLSJK'%-B:>3@M_?( *G5:, M,@\XD5QX!EKG%0.FK,#'<24^"B+3'AP\.^PXYYW#>^QW%=6>',EU\?)W:!V8 MM[7W5'K+H\(/HPQ1'2!@XISSC)A3L=D3^>KW=/FDK_U0FX"CZ:&4B$L)%1@! M0"C ]T-TUN3*=WS45SZJI)Y[O$<"IEB/=:.1/"X\V-6B>]XF","9U\1Q!PGA MT2"64C0H>P*3+N!#UMA >'+<4WC4PY,J^,N'@[3<& E!5%JYY 12 M1V4S(*IIP0[?X3+:OU ,1^<-B+U8L^NOEQ]I%C!RU!LD!8VF*3.@+K#7#!)S M0,K=RD<07"T8W#N*-)83@Q2@J!G-]7R:KT-%?_C^V*YJ/T! M$9C8[GI^?VYX,!"_WPL"D"L-;&J:R(BLJ@,)H1 M*H!73 (-HHI_*K%*'AB[#NN46W?0>P.)>C2@**)DL4!.J8C/#BKEM5*9S/RC MKM^S,.-$R88I02[>C3QJ".8UAT#H!C2E;5)*QLQQ M1R/0*A=^>4GWK*#IT\HI?>C5X45!&NTQT\@C*91P"A&H'F:?*BM]VV1$&A^I M_EXW];4N.O$_.TW]:G]5VXO-W6PUG]WMDE^7T! 2V$LMCH.">H,4QH MU(R4ZK3+3Y.E;!N'$SD!RQ+>FF;YG;"0A[PV ."X8D9A;"%!C#.+9 -2G?^N MP)/=\QC0&5$NF(HGC;!A+X[2B!=>JU/U;=J<7?LC.](JVT!<&F$-5!(:)"E M N-FB,RALJI(E'"6-QZ860)\UW6]N=K/]W6^?JQ6[XWP??YP<%@KBI"6\1]2 M4ZB8:^<=(J8LAU8)[!B,8<9%Y.-J>7FW+;#N_KJ-,'190EZT"4 JJ3UA@$LN MZP2XAIG[X4'$:1)%)G-5E4"1L:#,P)3="G>C%I?J\FL4TWJSVA6Z/,F7$RV# M@QQ1YZ1%7G #O5?>-4/EGB1%%$[FS"J!->,"FH$[;2J3DUQY]F2 T>RH,ZW7 M]<>%4I@JT2R8$%B;Q(W)ZA"4P(UA &;@PG;HN]$>X<&CIP(#'GLAK7'0$<*) M<@RV0X!IQ7-='@^O:47\T8?B!%G719 D1 M19QQ&E4I *ULCJ7CFD>2;AM,5HB@!%Z, V0&COCEJII?+\S=:E4M+KYO5>C9 M5CUJ#I-U=16?^6WVUQ'>]'A+<-)3K+"H#YFYAHQJ0!H(F!))N>4F*T90 I>F M S>+/M+D*J^#$LRRKLM^%R?%A]M[(_Z^\\U9T5_5^I?Y8KF:;[XW^VM4OIZ^ M97]6QV/K6L9>!.;C[H\-E])SJJURAO%&!)#2)#UJL@(+)?"[7.%DFQ]Q4/=: MY/T1^TDNOV@1M(O61S1EK;$ 6 Z1YJK=6H1."ZZ;K)9#.<0;BF3V173H\G=H M;D@NH\'"").$.D0E!JRU7QRW:3G[WK13>@IG"\$IQW%O6D_>1&"R,!P.U]? M[ 87T6S&UFC+'Q;QKV^7Z]G-AZN]#_Y:U8<)1PV><3X0I';<$88DIH@Z83!2 MK3D()$O+L_VFW?AG 3X#8S^NEE'UJ =QA'4/#X7ZTK,74"!D)/& 4<=DNZG$ MC2:).6_:E9\,7A$[\K%UV,7'-]\'[;^G7Q_J!$O&:RWCG+$2$>)TXUI BB3: M%V_\@" [[#F\RH\+T!WS)3]^+OAH0R$E$46:>BZ(XKJ)T8CF%4B[#_BFCQ:& MX#=5JHMM+/>A?!;W'TQ_^8-C<_W/^>;+?F7SG'F+G[N=WG=(D7&P3; $J+IX M!$0*$ZN,0.Z>&)8B8TXE\LLSQ%.)+/8^'Y!6A AIJ>9<0BB)U/<>% OC;GLJ M_7*.!!4CR&4Y/A0_5AH)#;Q4,AJ+ED=$+,#(H 8;05Q2?L.)TT@,%'*O]!#] MX'DUJ0$HP8PJQ!&ES!)(B&>@&9:*6UFQETU&DE:G' %I(+T9#F27_:#T$'E% MGUWDT]2'@<0@0QUAG$EKL&>Z<<'8NK9662'P R75JSY,/V"R7,49ISZ,M$XR MK#6U$'ME.0?-'5 +*;%)U9TSYVE(E?@HB.0)&=MC0U:%5+&/B$L&X;>;W.>+:C%;S9==E?O'SP=DD:"2"\'K=0L" M0KEYV QUTFW-B:^V3Z34#X EA[3O>_?[8GU;7$N,%;(9GD'H%11_3I/6B'/FX +TY'A2KV)]9_#W$OC]ASD72\%]'0P:VI8VUA*=Q&$,=RT$AG6S/C(_^9J@G,'4,*0005!)@WESDA&G"Q=)D:V3Z>^3RGYL MK,:>[T^Z-&3F[WM14-;!"!Y%A +"'+!6M&.C<<1%*?0YUX 1T$I@@OO\^^>' M>,.Z4OV#?^'A]Q]N=R?.^U7ZM!<%!C275&E&I(S&# ?.-RHR\MHEU:+JSX0S MZ/I9\)J:"T=KE*2\*F",=%WR@4K!@7#$(&':\3$LB[,"II9C,ET& ?KVB%.* MV?#:^?):S S$!,9$82FKA#J8F*H'!\_$C0#2@,=>0P)K^M">BH?W& P*21X,N=Q3O$-0*F_U-Y]5._- M!U>K>[>K^;JJQ_;342$>:1$518Z=U]XK KV#&-DV[@UA#S.Y_PJ4Z7B@]1=Q M['9$]6*VJ(OQ_G$SOS@JW@-/!X.D]Q9:X9CB#FXK[-[W$FN35E-GLNN%.44[ M#F#]Q?K+;#U?Q"<[[J&''@\:$(>IQC4!G976.M>$,F%F:=(![F2W^'(*=B3$ MLD1L?*DN[VZJ#U?[4TZ\_&U5U>"<"N<:\-H@!"/6,&3K'*J462S;2S,8:9^0YH[[RH9N@R"/>O?<# M1@;S#;.G-%_!:R3-!">)QX^$#CT?>+1]G!$ :VP)9M)@T]A"F#J<=%U@X@LB MPU$_?@"8A,SY=,UHOV(+=#1W@(%:"F-D<[T!V\=7WTNP^2>0X$C G-O,]](P MJRCVWG,!F#*2VJ:W@OBDRWH37^ 858SC8=-Y[UU7%S]=+[_]X[*:U]LNJ7^H MQ4P>[;;Q5^%]=3V[V64*.:#=[WDJU.52&&'41"RXD:YV+K46C4S+]-<_%\<9 ME/7A8(PNP5U/#FI&SQ\)SD0+ED;-P"(#J).@SEC5$)C#\D*L!F&^'!6%XH57 MB@)[%IF-H'GJ5=QQ;^:SQ>Q4B-KS)P/70$(N>%2X.<5:*(\:=9LX)W.)YO@F MEX[I MVW=8&D $8D)Y23SQE#>)Y2*:(JE>RNCND_.18WP(,X1:;/./?XJ=7MU=;.Y6 M\\5U70O]6)C7@18!>&.UXL8ZH9PR7K6)YBV54.<*KNAVRC=^]N9Q8,E]=>=X M2*2)\V-^>?^'(Y1(?64PU /CE"7"((M)G>:^72VI3:L7/-D!__B6_XPF^?K+_/9CM!+CGV?7QU+!=WY'H,0[QSA'E#@J,>,2M:NHM*"L!#+C MTV8JH#+PY#D8>SJMOS_->KE[Y AODM\9I-/:. V<0T);-Q,#$9]K0C? MP_C^- @37: M> (,%!AA*F"[LS)"TX[Q)RLS-)Z8)T.HOY0_SVZJ]>QZ5>WN1]]]KU8[4RU: M;'>KBR^S=;5L%JKY_<"KOV+_YNNZB-!>X0]Z9]#<&J28H@#[2&@K1:O",QHU M^CR^]K-P(B=P:5113SJW8^YORX_WG6NWM :.[8 ^KN87A]:)0>\,G-07QZR/ M"I?14LO8W>:\/9K\)BDR4KP>JN0"KC]5_%V]7>W/I][VZX_OBR!^,I&5K)#4[8?/O2,O_KBXV#^5! M#YWR)KTL$"$9J//W<2*H<$("V(#(N#-I-^!>@7\U&V0CT2(J0W#NB, M'?G]-J)^\65>?=OJ4\LK4ZWJ$D!/3AA<)/G%O%K$_Q\,+)KJ>U$H'&O"(&"( M<\$Q4*A9.3GR-JU&YROPPI:$:@;/VG[-Z]WB8E7%"52[@VHM_L/5Q]FJO9'< M/'7$Y3;DM4%CCS&M#U8]T(!) H1O03(P;5U[18[;C.#E/I#\=;G9>_Y5JW9U M(>L/B^;QKN>1W=\8M/!QU9=86>HM(!9"^P -]&F\>D5.WCRXE7+,M)L=0P^6 M=F\)-!J43')FE6>8^SK:K'%U<>556N#4*W <3X]5!KHT.[A9?OUCOKN!\;FZ MG46^5S=;@_%Z,?^?ZO)Q@?F]B3K?K==WNUL;Z\TZSA_WUVVUV.^5SO7I0*7! M!%)JI?9*".TM:G(]<.Y TADG? 7>ZT(!SL#FW=Z_=7P\B1J)@ZVBWGH99^2C MT1[A9K\7!8F=4;@VF)!U6",C?;L+ ,>2\I?#5^#\S@)77MX\+-H?KMJ57%=7 MRU75FSK=WA6< 9# B"^4EE/CK"*PU2&BEIK$GE?@X\Z%6 $$4E>;A*6GTZN" M\@0Z42=:))HQ:Q7&C=U#* ,G:EOSPVIG;3YB^+M'YSE' M2-&A=0!U)6XD!(^KJ/-,:NW::5##F\2*5^ BGPZC%)]X![?#R^"!PR=FZ2\, MV%!@+6$88T^%4-K418_NQPI4D@L(O1JO=B;8)J)(DQ%C6:]MLSI'QA!^O'Q; MD ABRHC$4!H@$-$*F79]M&FV-'H%?N=\F#TPX__]QP-?_VO[NZ:_N6SX! M[<\___PI=O>GB^77?VS!\K/YZO_,;NZJIQ^J_MI4B\O:-?./P6]^MZA/<^H# MGMHQ\$LUJQT&EVK3/F"KS6Q^LS[0@UYA3-NT(/.Z--R);[ZKCZ$NMRZ*VAI= MWLPO9YOJ\G&]F77+B$.A3--\+3A'/'+(V$@,C@3"RF'";*0>M1K)4_-H&EVC M'8O^_KC;6[[/%]?;; 5'E(TNS8.2U'N.G:-Q^)Q*)KV\'SC#5"0%D?=706=?F__U<<:O7PR[BHQ:GI;K8GMO_[?ZVK MZUU@1C;VW<.]JPZUGI^J3GBB95U)G-.Z3"BS4$%GE+>ZP.6XV[*+*G@T^QXVEM8_??"N=\);@A8:2J^59?EW=QG3^96[]+\R $8B0.FC,#H"*" ?,P M*2W*M,%US[ _%6$F .N'7&DR\:6;036N4"=<8K(3Q\Q6J^]Q9_Y4W<9A1$UQ M"TD*>7J^*2B$# 222*0YBP:E)*"!V[AH;Q9%H$EDO,P)8(Y4 NO-_&L=N'TU M:!7J\YK G''2: 6Y<\!X!"1P#0@^:I9)CIW7S*()TCO[8__,:]6\=-? MOK^OOE4WW6VJ(R\(GGHE( 3&&88!Q5)PT-BU2MM,M"G2M!H/MIQ\>:0#KE^. MH+N*W.4] 2&,N;#"Q-DC"""$,M' 4&>A>@U6UBAB/L2B"5'\84E5L %6/I?. MQZ%WB]N[S7J+!SRI^AQI%224"EIBO*BOOCF.L.*M*U8G7@^=W. :5WJ'.#(8 MKC,Q B4Q C45J) 2DD#J@(?$UHFB6@/ 2J'*RL%V/D:DP74F1N D1N"&]-C: MNE8QP)Y2!$W4Z5DS1"=,TAHQ60C$^1B1!E?_V(=Q3^74'_$ELXM#-XVG^5C M6JL(C$,T0@^T9-BW^[>&N(SJ2"4=@18CBQR1G^OU<6+N?S P*:-!RCG&$!!K M#)?&- /QS)?A^RM!D,\C08? F(,/%Q=;C_KNXD3MD?BUVM1W7N]6)V[LG6@9 MF'5Q4,BPJ-$QBGE$L$4L+MYEI#K=66K/TY<(G_\ M9+ *Y ;E7B:Y!<97:RO\#[FXF_+S=ZK M_GN?"\3JJ-<+;177FC(**&].(ASWIJSU?1"TR_%@R#!_MWQ5EY?5Y6^SOQYM M1%WV])-M@Z!&2ND$M,I#%4=,/6V&:[%-NOLU>E1V@7-[;&0G#-[>&=PUTR-^ M=5ZO^)81HZH? K57$8/-_%NU4[X>3=%&2!_JK3+",U]<;\.$?E\L_UA7JRUR M6^? TTZ^/Q5BG>'3HY_AL M4%I*Q>*_:0[:+XLRQ6,*7&?6_+QM2E>U?5E_K([%L< M<%S^JOI7I\\@.[V@@ (T9QBAG0<+8HF) .Z&3B(_RPVG&%$\,%D(#C^*.7 MT?)HQL6,!YFXT,V*'UM6RVS )1)BSUC]<_B+*L37(K[<4LIA"W"[YN+,/F S+#]/%#]P67R:;[^UPFU^%BS MH 03E"IAD;( 18!='0"_&R3D:=EC)XK:+5H='A'DK$RJTS/7?K/?XJ=/JB_' MF@6'!%.*1:L8*6"!X-;C=I#"E'M/3#:%"]45Z4ILR61X?L--BFP;J, M.V'3V=,WU?:W"-2+N)I&19]HY0B%!#EY/S3%'$1%::_C".GY%;11D,D1.KG3 MB]Q?%U]FB^NJL^B/M@M&*2(LL 9;Z: BT*K&ZE-0@[1$ M-$JB0L$ZH:%QHEF5C/6\#,V[!.(=NMQ2DGA> MV[Q8/QUX4R7GW>+BYNZRNGRW<+/5(K;NE'8@:X="-.FYTD)P@K463EEE3",8 MRGR27C+]G=!"R#KE7)I*A&]N;AT^4UF7,]^.=3(P PS53%@C(*SOAQG>\@WS M7*E$_IZ#9Q5K5G?WHSIN[>\B8!WN5W1^1]1(E*4*JCJB/0Z?2=AZ_(QSH"Q/ M2.&LG@KU =;SXRO7_YQOOIR:/$\Q^U1=W]W4 O_^0OD]94E/]N% A1*D/@>% M-!J."BG0.BRBB\^EDSSJ0: : 4]- M7'T4MM!R;3#901__0KFD,\K)G)&%+\UERNR53Y=ML:JK:A55K5\GJQ3\ T^?X;)[*]/HP]WFPU49\^A1 M5P+0 "A"-(3<2(X 8O;^/%!C"E!2>8+)ZB;_/9&&"*_PF;1?M9UHKNS_6$", M"H0HB;IO%+X3#GC;NO"CAIPR&R8KUOR&9\,HXBF<[Z=F_,?XON7EN\7%*KZ@ MLM7NWV?:._9W)GB&):7&&FHYE-'$!8ZWQ[X )QWY359R^@W/ERSBFS"_P*_+ MQ:H9T&-WQP0Y!G9>D <@'W_Z );ONR81&/+N(*RB3CK)H8:\KF*/552+)<=0 M B;MVZW*)@CA4BB " 9>>T!,?6VJ'KA0T/EBKOCGD6Y*#;9^")9Z%__14+=0 MFYO9ND?UM:=M G*4"\]0G>U1(U-[.DV#"7 DK:#]-->,II'U82(-0BJG5O5\ MQO7:DQ^/LWN6]Y$_&:25E$OEF7;80PK+KW^C^KF,AHYVS+UJUT]ZOC75_I[_9N34?K)[PQ(4(XC M$/5-. FP1A&@>W@T4(QF8EY/(_-L)'D>MY )]PRT=/^^V]K FR^U+?NM6F^V M1N+I6F3'V@6'(9$@6KN&D/HXW#G,FV$JE5:28_K0KU+H-2:V_4-AWB\7U^_G MWZK+'1PUJ]7B\O?(Y:,9+TXU"\J!N#\00)GF7!%*K6BI#Y5,,DFG#YPZ-RZN$JH6CN"8& &O#-3(7Z89:RF] MY-1Y++PB5B+\,#LL-J_!B3!,M@.J-:>!EW.)F; @?%Q-H;8&(DDH!%X)+40[ M>"ER%?X9K2!\*F$F .N'7&G*M+5'$>J$2TQVXIRO(+RIU7J/F11S%(3G7#.EF8AKO %US=EFF3?11"C+ M)Y.#11.B-^ "TKT]6&D'!,-?$7@U, 6(&-AQPY S6EH<6%=<9;2.++?1Z1BT/V; MD\=1*\4&>U-4+/5DP9$ZXA(@)2! 7!H45;VFWS9"681^7(SP^APL]$-V%$;< MGZ#V9<239L')V..HVTN")+16 V4;;<%@54@!^%?"B"'(]F?$_J/UR,I'7=%W MZ_FBBAT\?$R=^JJ@&92:8*)\'"9@FH+6M6& YDEY]ZUX!-O)Y$!%F]/>9'0 MTCH/FX$X#I,.$T:_=%TJ009AV9D4Z^KBI^OEMW]<5O.:#Z3^H:8!>42#^*OP MOKJ>W;BX!&Z^'_#<['DJQ(%S#V-7!:G]DI:KATXK2Y.N>_5?(<[OL!F.S>@" MW?7DH(W[_)$@!#48<&.=91A:+S%O:&R!]*0X1\D@S)>CHE"\\$KQ*)Q%9D.U M>C=;;W2UN+0?WQ]5V5\\%U3<"1!2U#NAK+3*2-]HB)9)7,;95SJ>R_'&GB"5 M/^XVQPWM1T\$#C063A%GF(">,B.U:WHCB4]RN8UN4X\CB>11]Y?![__YS_GB M\M?JSZMYM).."F/?HX%3X(D3&B+N%5.$Q@VW582%2](?1[=71Y'*",-/%8^M M4X,L;^NPF8^KY7]7%T="B3JT"AY@*B.Q*(<,6V&4$BVIA*-)AW2C6X4C"FTL M)/K+[S_G-ZOE\G"]BQ?/! 8]9(X3B76]I\*ZK&D[X:$I(PO6*+(9,N[^DM!W M5U>SF^7U[/;=NW='Y;'GR0 -@\XBC;T6A!EMM6\BW)UV."G =_242J-(9?CH M,W@[M@F"U=75UJ8_XH8]^GR(NJEA!D, ("(\SGL%&OW&"9"62G?TS$"#A3HF M!OVGW>?ES6SU^39V_.B<>_Y8D-+%,5)MH(NO-()!T)CO#AB5=*8V>A::42;< MP*'W%XF9?:WBPGM<($\?"EP:BPPCVBH%XO"0-4WXD8-(BA1QR"+%,6C@"3;0 M8E/]Z[@-]/!$T)0[+"#&V'%D%5)QNVQZXTW:O48(BI1#^K 3#OUN;ZK5\;.\ MAR<"M(0:99"VT!FC:?Q7HS,Z[DC27(!E^@32AYVLH/T\N^VBG;6/!:0GQ_T#>Q\.4C.. MH (>464$Y@+)YC:AKS7))/D4ZB(8 X$$'6MVMYJMOVQ6L^,ZUK/'@I.,DVAQ M$1Y50"E4742RZ9=!-"U)5YE^@(%C3Y#)_.9;M?HTO[RN/B[_/+&[['\X<*"0 M4$(HIBFC),YHUSB7ZINTI[+'[9=/F;Z 41!(6-_^M8H]KG[?M!7BCJUO>Q\. MB!B/H<;Q_QII1!CTS7#CA$],=5>F;V 4!!*D]+E>5!O/W7$9[7DT",,UYG%Z M$\YEI UGK?O"&P#2M.;R#/V1QM]?/K_4MY]BC__/O/KSJ'1>/A@$M@(K%G5Z MSQDUP%H V[V1IV5GAF4:^H-'GV#8G#CO?#CK0]'(M=OY:@40)%+$-@FTO)0D MR1<&R[3P4P>=P:_Y*+*E_?$_YM4J?OK+]VV"^.Z)*HZ\(-27K!%F6'I)$- X MF@KMP %&25&F_16+\P?]3 I;3KX\3K#\<@3=\PYT>4\P+.XDC'KC)(7>L#C5 MU X&"31!Y<49327F0RR:$,4?EE39R=0]JT7Y7#H?A^YS9M=XP)/'=$=:!2JX MD89;:A&F #BN &B&Z+%*\[J.K9],++U#'!D,UYD8@9(8@9JC2TN@$A@C8Y&N M1\8):88(HF:=PHCIDSQF9T0:7&=B!$YB!&[T>1_M)VVT110Q3RF7%K=#1"+) MU3Q]BL?LC$B#J[_U^>S*AEIN0"QY%ZR6.\-N X4(J)BO]%T?YVV'+3 MC-M"F*DXQ;1W7@:4J3@#QAE6F]U ]B18>3R&(^M.I_9!2H.1P(9++A!&$+=7 MZB6,&F 9M8[S"G@Y/8ZYZ//NZVWL=[U0FR^SU?7>HMK'&P0241)&.FJ08 (P MSZ1K!B:,2;J0F>-F>&:"# 4N5PQB'/YR=]EX<>W^NHVVX['228>:! :,QH ! M38F*X AM0(,5!!R6H;B!%\VET <*UU7DC[!B?X.@!8>80&L0(@HK MQ8WUS< LI4F6N"AQ8S(N+D32+SV M!$ CN5>G3I'4B\>;Q"$IDA"[06WSC&IZM1>#1J0 MF[2 H6F.]3*+?SD!?AETB9?]/'GJ$)RSA&D+ MD5>"1=T;8@V;@7LM,BDG'7WFP\6WS !2WD"A$>KJ>@LX41Q+J "V5$D)4(L> MMYF<4J] ;Q@+PIP,>0-U2K7TC'HJM< ..@T1\KP!EPONBU5=1N!+KH*E:1C_ M3>1102Y-^WI#_!UZF#U5\FB$G72$0 & %%0:PBEK-5F65I;R]57"[2R]/MFC M^T&;82F;IM@M]-Y1#3'%U-3W/JT ]GZ8'(NT<(;IXZ#.S: IL,VK^(]L]T,5TB49 1-5;BG&"!@!R R!IY6H66BA/G%Z,GCX?EF[S\J M8#C"5 CM#=486XA:&)SR^C6HS*.(>=!%R#04?UA2%:Q-E\^E\W%HM MSRDDN MN:*801:!](*1=H@6X5QE+*>X,-=9>CTNS/6#:_"%N5Y[=9=BS8FO#2 FFAT. \P MM+2)\1%6 EZ6VO.C=8E-=FMGZB[]9 M'L]T=^CQ0%T=*&&8U=A!B#DDO@7,<5I&/:GS2^EY8=?A4&;0SS_-%M>G;FZT MSP3/'$'"$$"HQ"P.7GO5=-_KM$CL_FE#"U:JAD*62^(G+;!'3P4MB<; BKAP M*H<8HMXTD<2"DH)#&1.DL$^.@V!XE1(M9;\_CR"S"_"7B.;7NZ\G1?CDN6 , M,MQY+Y2G"C+!A6_"&86A/BT-[52.D"3\E^,-/X<49W]UD^+CYX*4Q(*:U1@1 MS@VK-=!F&)#+).5JLDBX4:0X8/@9I/C/:G[])2INZENUFG585O<^'QP$T@'* MN122$Z A0>VP#$P[XI\LJ]<84AT#A@%V]WUPY6_Q/5V#W'AB*I]7#5< MU.\YA-(\F(0>H:1$C?V3K1>LUXZ(7E;O2L*%BHF_&(1FGAHOH-- $E&7FP8/ M,\R5%V2H(-NP71JF9 H9^E?)*5BI'@[:Z))^7*CF@)B?U+)A2&( MC(26$24%5AJWW05&H^*4V4&8+T=%H7CAE:+UG45F0[6S_YS?K);+S5%5[,DS M@6#*N7)QWX#4<@Z(::/3I?(@EU.^9S6KSC@NQQEW?TG<5Z"]GMV^>_>N2YW> MQT^&:$H@3R6PGC@DM +V8>LEV"5-DNDK]:9(9?CH^\OF>2'Y X)Y46\>,P8P MH=P#Y; 4UFK;9FXT4>TJPK\ZBE0&#OT,(;[1"OJM6GW]5'VK%G?5SZOEGYLO MGV:;8TFFN[XB^*A1(4.YDM0Y"[4$G+:*L#)O(Q3E?7*"THGQ/ ^9-K'G'U?5 M;[._/C2)M'^9K:[GBX]1L=]F.NW#JU-O"XYKQ0BV#C/,$66&/IJD.JW"=&DV M[#04&QG:_&QKPK;ZK5:/6P7NHHT.%)/82(DQLTHT\0D*N;0,Z#FRXI^7/0,@ M?&#)Z+G0_^MN5N_>D4PS$S_'#F]OQQQ*:[[_P2"(PAQ8[:UFP%FMO&.[ MP0@GD]I3EZYMYZ.N#N5U:G^G8@!' % >(* M6^2=@!Z!5HA*E7)F88#_S?.)82_%R?S6Z9V=UK9:S;]M-1T_7\QB M_V'$@7//-P4*N0"6UGNDPH![ BF_A\(3@\LH:%@@,Y8Y M8<^YL(Z2<%Y1YZ&A&K(X[:%B=7W'9GB>> M"0>\\33^H.[GDR3:8?$:-,14ON3*P)V&\=]$'A7D@E7 U\[?PK2^9OB#%+[' M+PD0.%!?!C3:8*:=\-;?[VF2.F1SQ;"<.9%X9QKT4O$& )V!:28B5BTN#D4D M[GLL<&JX5H(1!U0=1*DI:MRK5#&7*6S@'#K< !AZQZE=W']K%ZS6_.EYQ%KS M^Z!N;NY[%VV)@[O4L<>#8981+*4$U""J'21,-@/"GM-B5:4TL2PG@^0-R+HT M;>)\(LXK6O?[IV.BC'\=,".6:Z8B!%#4/:?"-ATV6"'2VRU7*\;>S.)"AW?$)26<9C&6(:PY+ N5]FJQE:E&>&3Y3>:A!?3 M()6#),NO7Y>7=8Q 9U+L;Q$ C>N?%U@(Y"7W$A *FJ$)!)-.Q/N;#F)ZF^R M=T>P%)O_;XYWD] K-#:MJS4P0AWDBL71.H50,T#&?1FQ'(7)NKNUV@_=A*5Q MYREI3"(7/WIY65T^@FAU'16E^:+Z6*V71],]I+PJ>":CD26M1-9)X@TCI/'% MU-C!%/9,>V^[&/9DPGP"3KF[U4 J/;PA8"$EQ%IAXAVDR/ X79K1:.Z3G%W3 MWMU^70Q*AKH_<5K#7"TN/VR^5*N'7FS_>)0SW1H'J33GA@@+.8Q(80L>,*(6 M)M%E=/='N729!.4,6D^_BCD))U4PGJI@S\O%Z M*@:Y1-BK8(J%Q'I%D;(P6@:4*%*'@N^& ($O+VGW "DT*"-:*&=6IG$!R\F-7ZO-,V.Q32UPR%+\YWSSY66JN"YT&NUC@2&J MD#&U@#S7C O/6T$1#4ZE-CN##S 7 \^%\9F/V-;JC_76"9[C7*W]6#!"1(W, M."JP4L0XB]B]S:PP\**,],0Y>%@,QOUY^/MGN[RYF:W>+2ZKO[8PO%LT/O#9 M 3H=;1.@,(IJYV%=J(@;%_\CFAX;)T5V[\L/G6+ M/H7D!7;;5YY:D2;X9'#2<&TX %(SHC@7L(E85<19G90^>UJ7=8YUZ?Q(/S!S M]"2V;6\?C7*=E,)VDL0F:G%Y?%&)#[S(2/S^2$;<2;X3+(58"T@Q\APK3 D0 M]Z5]O(YKV"E'4[E0GDJW.]HW O4:2$"P4!%*PNOC87T/H8">N3R[W]Y,O6?F MS/%D,=D@GY6?!GB$-&Y21G%XKZGPCC#"D("LP83IM#1N$Z?_/0,A.F> ZP=G M3A?&6TB<9:0%!G*@";+*-*I3%KCV?.[=17R MQL^O MV\\?O5EUO%&PP%,GI/>>6ZPU$?5">=]G[]-B4R:[XUP,'T8'-DLBG5[+R%Z& M<^\LA (!1.LTK!1#BYM!"4V2XM'ZWV!^;6P9$=(,/''_OHN[H[];7)XFR8MG M@T=(<@<0EHC(NOJF<[K5NZ!)NN/6/Q[\M3)D*)[9Z-%C(=G?(%B%A,)" 4P) M5@)0H-J!00R2RI#R'XPH T'-X>29)&V7HXQP#2%D'L?Y +E1[=XJ&4H*-! _ M#'?&Q/9-)7UR'L?90CC#4A)D'-53%DS\,K:9!^15>\X_X21(U?JRT M5#Z"Z!5K-7\,TYS!X(?AT6C(YE"&;N;7\QJ13?7UP^KGU?+N-JZN+:0?;H]D MG.K]CN"-0-QH#HE%&'HFH.+-\*E.JP4\<86N\Q_M3@5OSA.R72?WC*3[B=>) M5X1H7!@" 8.(HV8(12[^\$K*B0J]BAV OD>.MJ:!L,?C$BE'86^(OYDYXWZ M-IO?U*OOU7*UGMU4/:S^4TV#-EPR@A@'/J[ITNJH+32#993ENI_<4TD:383+ M2>'*XDYN0N=[E#MK!D,H5X;)^$\IM"0*:-4,Q@F:= @U_0GF5+(?"$\&6?^V MFEW6RMG%Q?)NL>E8Y.YPHZC'@XB0@!)BRQADV!'2#I"8)-_?](>04\E_-*!R M:A+Z>_OC?\RK5?STE^_OJV_53?? U2,O",H@Y2723D$"%%7>(]@,W$N=Z9CZ ME9DZDV";DU2/KW"\'$%W';7+>P+2PD#DL 2,*X@\MH V,"!$RJVI-[:8#[%H M0A1_6%*59OV\*BZ=CT.[:W);/.#ILZO#K8+2 @I-E,=24PL))JWS6RFMDBXH M3F_UC"N]XTDD!L!U)D:@)$:@1MFG#@E/$7&U9X$A9FFK-0J?RZE;/"/2X#H3 M(W 2(W"C]".BJ584"8&B_8=='8S?D![KLFK/G(\1:7!E]8R,5\62*P0T]("I M:&-ZYC5DC?M'>YCF+9NXBN7Y[:$1$ID'U1GE1FIE2'AWRAT&-=G](22\EID(9 Z6(F D*6[Q,6E[O M\Q2]["RDCG> ^B'S"D.3J-46?GD%]GP5V*E8?_5Y 6$'LD>0HKA"".P)%DX; *&*3 MTCODNJO_RJ@]IB!R\GL V$>2_T[QF0 %=<@#80'5!AD#)&R4'Z,-*SIYP+G9 MG!__' &BNT&=IN'3!X-!6A#B%1. "&"!EK))MF$\+?48-*L(GP>(#@$P9ZAP MU)L_/PE@[<*.DXV#$E1)23CP@!F#*.0:M;CE"ZSHQIA481T*"AX+EJ,\V)MR MY'D7GJ8P.)%\OEOC0(BU$@*#G/9Q;V;;S/OW8\!4^"'F@<"61Q#W%,E5<::"!ANXEH-X[0L/V0FD8\$5KYP\%Y+_,$V@2@* MB?&HQC JYZQ.EM,,CQM95G6LD5;VL=#H/\-??'E'NQ,3^T2K(+B"@A$F8T]C M?S$%N#F",X#+7/DON\EP!/"74T&3]3RYL_9^J$FPR"I('%=: 26!B*-JCDP, M!&DYSR:NR.!D4'2C\R4#D+>\W1@LJYA[:G51!H$K:-$MEX3"9/J_!3M MOAILIPU',>L2T(\B1]O5F6.L),H!;'E=M%-BT2I!<9QEQ14,DM/!%6$X+ _2 M'[U2RC:8[E!-E/MOIKQ_OI@M+N($BA.KFG_+]Y&D(B][E:+/%U^JR[N;:GFU M[SOOCU1CZ=$Z*&Z$AP!*@(R"'OBZ&**'"$0[CGAPRNB99BEH.O]A7^=K!WN< MAY?O%M^J]:9VQ.^*._[7W:SVK+];7,ZWG3Q59&6\CP1C&?(D&D0,UHNS ?&? M]R "Q4DF37-OE95)N+ L!,G9Z,53]L[$[3'[_(^[376Y6>Z#\$ 0=>>V 2!H M"(S86T\\XA$ !5KD <[D;>H527T.H2^GQ;6_X7JR%T>S('=L':R&WA$(G;76 M*VAT1*<9!834%A

/;BMBXQ MQJ/V%?&#C5MZRHQ?:,TA1'TNOR:2\9"',Z!JJVLF#S9M[HDPS*_Y\*;U1G\F MIGO%YR46N0F&A)"OXIY]ET.^X&T)0K=!9 K)LU067QC7KK^Y#_QT0%>3(7*! MH@8-^2@19\4?/\UKRK3--MOWU2\F:%-[]QT_<= MUJ2;+NAF7OB\R:,5Z(]GQQ M)=*6\A$A2%O/4VO#7(4NY!;HJ1&MKIG3K/V.[TVWA)!4DG;@H M0(UU<-=9+PG\@,?JL.9B\ZGCGY@7"S^@AXUBP?WGG*H&X%42$:YL^Z177 ZR M?W+R=N]$_3_;.=P_Z+RM7N :F(_C[.9)]I#R6<:"ZL&\+(Y%Y(T?SQC!*+C& M(3KG[ /\P#ZP#Z)P-8C"/:NON)G=_.WU <[C6Q&E0238-Y%()_O5V\K,INSM MVCG%^88@5I-&^FZ*M]JHY+?]ZWUVH=+4X\FPCHD?^7XG:K:%\7XJ8M9F8X)H M ZV[Q;!T) #5/MX_;+,]UCWIT0FQ4Z MER\-6K[JH?3KSU^6J[W-S.'#IG).?%9?3'E!HU8!\,Y8ZRZ(0Z&@^%< M&[]"X[8^9O1K2C]A5/,*I*M@[?(V'#K9E-@TN 3[P#YN:#'Z.5L;=M%'H6 T M\MK#..R46Z'QFK#NLF-OV24V X?$(5(%PS7 < CQK=GUK M]QDSFXFK?:!MVOJ3SGU-U&%_:B]PWJ.&?7+[\'3 4T8F\?7I?S.7JT, LRA+ M,AZR8#CB7JJN,<)ZI/ TU MCQJDJ1#[[+.,J0REW5%*FY8GN_KE_;EEF[-7!)$7"YY0A7=\D?_YKJ@\/308 MTD.3XJA">C,Q0*6,R/MH;G4ZNY=9Z+/B*6RG>/0[?>N=VKJT>$ZI".I=?'), MXIB-9!*HG<]-W2P4OGBG:U;ZD6R>==NL9?2F),GIK?'.^ MICI3Z%B(XG*'0]"L^<]C^.Q>AK7NV;N MLR<.0QCR?Q&M/'K,K52[32CC/W!<- FK0V!N,E6*PR19].(_ F?,(.MTUSR,X:&UX^_S3 MFIPK<%R3V-!=@!=JO#K@/8 7:;AYVU)3?;#KM:I\)7DC.Z''_G M>BK<%NH>KOV/FV/HD&ST25UE(5Y\^Y7"4ZH?LM,U: M5GK0I/40 \-$'.SSVO99V?5LHX+472/ MZCWT_GL0QE(^9SF$,X&=NE&T+H:K<">UULG[#OUK,8?9(;O5"W OL<_6;&I8 M_ST+VSBKMXG:#(V!QCBC,:5-I* UT!IH#;0&6@.M@=9 :VJM-<&95 ZR?'UGW29J/6;_/0\E^YB-V=77UFAH##:[KU,OI^V[+ZM0+ MX%/M(6^O>*!FIVOMQ*.F>"&P86O94$'L":P *\ *L *L:!@KVNT3L %L !MR M-AR!#1:B6=N1B_S;_M_WV3^"R&<[%VJW.3G2AP1\B^6_A)U(F4-V MQDZ+=:T=VM04QP,R;"T9D$<$5H 5"QG8UJ)M( /(4',RP$6 %6#%8G(=R& A M?+5BF+/F1VQ<_ID%Z9@-13J0/@NB.Y&D*KLN80O&7?WIE@_7Z%9RN ;F F X M&,X5PZV\3S6.B +B@#@@#H@#XH X( Z(<\IP0-Q+#(?\FFL9\IA=CW@0(<2Y M&1E[U2P;ZXOS.N];I]C&"A'RE2913Q$A!QE !DRB@A5@!5@!5H 5Z#B!#" # M7 02;JH-=/TLI7\?A.&"*5=_EN7TFD.DU[@4EH/A8#A,R[AB.&>,!<0!<4 < M$ ?$N6,X( Z( ^+<-QS2:RZ^::NI_WU!:',S.M:H_)IVZWVKC?P:1,97VL>F M;6UKM:9$Q,&&K64#YHG "K "K KP JP JP *S">6)L-I9#6^Y3W0K'T^M+? MI7HM)(4\MOOM;)%+3YG!D$K*T4\)(F*"^5Q^323C(0]G8-96UTP>K.O /!&& M^34?WK3>Z,_40%[Q>8F1;X*A2-A7<<^^RR%?(.&0Q[=!9 K)LU067QC&ZV_N M S\=T-5DB)Z,?1&KB&G(1XDX*_[X:1X*TW+'2_G77V7WC?Z8;?]]+[CFM23M0/]7.YG&[7;_T)F^WL ,(^C]MG4O0GSS@Q M'8'<$NW1#Y;(,/#9?[7T/]9LN7('=*%?=OPR ZK;]*=[TS'KR= WS_E%\"2+ MA3Y:]X*G K"K9-;>-0B^-NP^\3@>4YG8^5!F9,P*R+P9LKJ+NG;[%:#VC'"! MS1-7EH/L,P]B]CL/,Z@:5&T3@/L6BY3_>-28KU6T+S)9^2RBFO3#'P[467=7 M_Q0\9I>1+WQV(3PQ[(F8==N[K--J'T!;,)!Q+@]T0P,9AYS]%W$GPJE5K>V& M#]@!=JO#SMI1;H =8+PW\5J,R .B /B@#@@#H@#XH XEPP'Q%4? 7C=R:\\[;K=I9NM M#/;SJ4)5D^!.^(SK83X;B)#^CGR6)<(_6[#DZN^PO(=ANY(]#"$=L _LLQG7 MLXT>!O@!?H ?X ?X<=8^P _P _PX,<)>?8Z]2;OUL9U+GJ3LHXC\=XB5(XE]GG0V&Z(VU\V!JI55R>]XJZ:U3.L*1N> M0&(@,9"8Y]NB@AW%H#70&F@-M&;A-FMK7J P4!@H#!0&O1EH#;0&6O,ZP1ET M9U8UP/,G 5>(5\#! ,! /!0# 0K.$$ZQZ! M5^ 5>&4]>^X0O*HL_MBH,.-O^W_?9_\((I_M?!7W_4"$]G8Z@/*X9I]JD^GH M7R3381ILH]G=37%#(,/6D@%I0V %6 %6@!5@!5@!5H 5&$YL-JKE7@BYPG,U M+H+$HV^#*!,^DR,1\S204>+0>1J=2L[3<*AUG1-&& Z&>R57C%.A@#@@SF7# M.6,L( Z( ^* ."#.'<,!<2\QW)8GW7SB0Q%+&;%>E@212!*1(,JY&2UK5LZ- M];-" )_&!LF[QXB2@PU@ R92P0JPX@$?T;76DP ;P(::LP$^ JP *Q9\Q G( ML$XTR[V@:H7)-I=_9D$Z9D.1#J3/@NA.).F0WI.P!>.N_G3+Z38'2+=Q*4(' MP\%PF*9QQ7#.& N( ^* ." .B'/'<$ <$ ?$N6^X%P4H9@W5>HV,FPH#$]=! M2-5FWP/_5K!O\E[$"'UN1MZ:E8&#(^00.5\YZ"#6 #V*!O.T BOXT UXHAPJ9%OBZC5/QA"T"(5=??<-4> M+-Z=W#4!,@ ,E0V"@(KP JP JP *\ * ML *L:#@K,)QX))CU/N6]4"R]OO1WJ5Z/K+9:MZ'^WV/_/%HW70GFB3#,H??A M3>N-_DPMY!6?\]*4T7HPRM>]Y:6["88B85_%/?LNASSZB3UD_F5!P/O 3P=G M!ZU5A& 6=:M?_.PXY',P^TC;'E/E9WC?UM5\?FL?VUW8UYY=V&#*AZU+)$M(>Z!IT M;55=ZT+7UF/UXN#315F[*AW1?14Q'OGLW+_CD2>T:ISW^T$8\%2L=8#WI#KH M;T&7UM2E V=UR5$=.JV%#OVJ->&KC/;ROE5TNY&1WJ*)(3V0GI7VDH+T//6P M=JL6VE/L6J9[/T:(KJ*41[>!8O:Y&6HYW?UY#!OEJ/<)\:B\_5NW,RIO_[;^ M!,7-0)",A:&\5P)NI#')AD,>TW74HZ2?$T)\T"?TT].S2/82$=_IZX)HE)&A MLX1&KT&DK_TB[D3(NFPH>)+%0L?_E@Z$5Y-S2_QA;^L*3)AIPIF9DC"'&@L=,D)5]=B$\,>Q1DW?;NZS36G(H MY$LL??8H:%8.LFY M@B?5A?GPIG/X]IE./+^QO>'[3FM2SO;QAE_8.=AT#9_7%#79FM2YU C8YW'[ MK+R+4:ZUN27:HQ\LD6'@L\*3VLTD6?!K:V0HZ$_WQK'U9.B;YZC(_-1BOZL0 M/6"U&=JM"J5763]3/?(4UG1OD]T(;Q %?P)YKB%O51%S"5:_E8=B5VHH!E2Y MA:J&ZMEW'MT*MO,/_;WPI_8])W/Q6_'N!=$1]'%!WLWW<2NPU3/)N4;T=SDY M=X)H:C.Z.U0Y+RLS$N""?6 ?V ?V@7W6[WG:=VY_4?-,S_9J56U.W=ZTA2UO M%?-E:7JJGII3X._ST(8RDQB^+P6-4-H/S%M@GLU]CVSAS'BXG!6[XS!^A?-_O88X-> M6ISI5;L>3P9,6;V^=@%N-H6;\RC*>,AB<2>B3##JA-ZG@_H:!L!Y-7^\=W+R M5BWW/7K+=O:.WU:;[B@6*?_!Y&1G M +.LKX&F ^8<[!P?'^C.<;M%O>-6Q9UC0 [VL=7518\6^(%]8)]FVZ>ZB;EB M21++5R*Q3S+1^X]\XB.U?TQ];09,O5IO\NAM-?W'U?.,ZYY84<&1E X-9)RC MYLJG@S3F=-RVM7-#&G\Z+HC5_-"*/695F>C@D,& M%='6J6I$0Y9#%!SKX>_ MUS'AXM.W;*>+3P\H<:R_1/9M!2.\ MSN)YY4B^!:\02[$MY$C&!?)>!WE(S@7T7BW#HJOS*["5P^L##O9!!!GX@7U@ M']AG0UU.Y.IN+Z*L]R3;IBMY>(1478(AM3NMMS,-HS*Z M=:\@B'RUQ*Y]1%]8,J3YJ"X_4\ML \]\C+D""LYO,T:-0T7Z+K3Y6D!X0!55+7UN-Q/%;7\:%* M?=QE?660.VT0'OGECX- Q#SV!F,5&C&6&A*-QG]-6']B:YXD9"A]:QCP7A & M:2#4J\C6/!;:_L.2_4O/?]K^]'3U[H5F>*:5\B!"'JG7;>$+3ZH)4!F=*2KD M^:#"$\.>B*>L[;9W6:?5/ERW!/KQVDB;J@N5^L!*J7=9+Z-FDS&['P3>8*8! M$^8'B1?*1/C[+^9*:33A$61%_" Y2D^9<1.M.8:IS^771#(>\G"&E&UUS>3! MAC.>",/\F@]O6F_T9_(;7O%YB>%N@B&!_:NX9]_ED"_X#C.W;@K)LU067QA' MI;^Y#_QT<'9ZNG_2.FP=G70Z1V24D\.WQ803M7?(1XDX*_[X:7[T-:U%.30T M73717CIWM$)T21?MPYN#P[=/NM-9!Y_?V-[P?2( ^* ." .B /B@#@@SB7# 7$O,=S6KAQ[8*Y09RLBBK)Y5FXC^8 ?X ?X M 7Z 'V?M _P /\"/$X,/]\; ,RO:NJ,?3H*K!WA['K- WZN( 4%U M5E>=FHG+X:[%72N;HB'@P];RX6#WZ/0(? ?P(>J(B=@!5A1"?Z]PE,*45_F9"HN'7B.HBKUX73&<,\8"XH X( Z( ^+<,1P0!\0! M<>X;#LN:<::"$ZS<1O(!/\ /\ /\ #_.V@?X 7Z 'R<&'^Z-@7&F@GH*SE1H MCOIB\[YG)AN\XOZ@AU@9 8V!QD!C*M28 VNI?M 8: PT!AJSB01*: VT!EH# MK8'60&N@-= :C)T%P!4S%-6-)O "-?IYN-(!NTA_2'](?TI]7EP_IC],9"!57H+#1:^?*J$N>S]9A MXZA)]6X)6X0M]]@Z:C2;)X0MPA9AB]83"6 $L!T"6*O=..R0\2)L$;:<8ZO3 MZ![3G*N\ %&MXD!47('2HCY'7PX;[4-G=KLN'$)XV&,\'!XZ*Q)&>" \[#@> M2HB<$"H(%3N."K(2A ?" UF)Y\4C?HXQ/)=]+6W&!?U8B'O[!5 MXE\6QWF0?CS\T.ZNPPBS6K?^Q<\.)3U'9Q\9VV/H_ P!-+&7SQ_LXZ(0G:<- M,C>Z&?"-:/U(A= MG/W^^]7M68/%0WB./Y*AU''$8Q4QU3=?/@Q5(#2'1XI >'$D/1E/V(A'WT3, M9,C.HH$(8QGR!N.ASW@DX%LO2'SAX\\+TGY>+^TGO/J#C$'\7KY]+$U3Q;A) MK3N3Q.HSM#MZX8O-:[ #1C @X!$,\ 14G%VH4*M ^B!2GYWS@(>>8+=# :TX M8# @K,]EQ.YY #*V,EPQ1.*[$9.VU[X'!,$#8_X=[W+1^A_:QPRN":0*G0@# MA]=)NSI';ML5.VG6RG(YB\5<7U-Z2^OW;/"_'[[N7YZRV[P\/#T_:I^U3UOG5]W3Z_.KRZ/3HS?_,0EU7T2,LR ]D#A!HH5K M5>2+*)@TV' R5O 28W7M#3"^P!?PDOA!B#"S/V..EAG,'%(KM 0;-A(<50U5 MAR%)-_#EXKN,;9,M1U]8/F=\/ ZDL#TJ\';Q&2EU(_4/$J!]I'OH1C_3U,P" M(<"#Z0E+[)(O8A&A385[XP7+(,-[H6.CXGBQ[9*Q#+@89IXG_DY0.EJ M3-/ M;J,X'@6$;F50SCPO2N - M*$)E^EKDB+=.>UO^. 4*K1O"/7CD+/DF;7\V+1>Y&-3F23I.QBISYH%4M33F M!%B8LUZB@2BU1CL!B@!^QE]):,W-@XR'"T8%;\KL6@0V*ONZ![-#;A^+Q@TL M&$Z,H$42.B4COK*_%9X) M[3'C$AC3FW:_\,3'?;N-_9FV.W\FF\OFXS_BWV#(H"O):(P2A;][*@%/ ]V- M9;;?NB#F!IQ_&GU!N14=D*FWT>,:))7J0P_,%MP"@AW9T>/W7 9HAXU.:M1 M#R;$.J,+5+>QB,P-."21U-_86WR4^F46R<]+7W)HPE[VU@4#9 MC^#1\,1[&"QXA$IT'D'0"#CHKHBRQAGO4D39Y&2)5-1#[E+EHYM#-1_F'='[ M6=A*9N$P@[K$5<"_ M$I3,<.-?B3_ /VR RQ>#2)C'/PRE-\1.V9X:&@VS.0U" D E0IAU&H@"D *< M04P.V%E**#_I&4J!C^;]1@U3S[Q@N(921#SRAI.9(3;:JAZ0?^S-9E( 765: M#D(<-("+F3*M-(.-5!T^XOW3R$4KFZ4-0:GQ^=B-N6LZV36V"5:Z\1 %E(H2 M-<(78%F-60$2".!2_6%GPNW=DSJ&VTWO9Q?G^NVC2H7'7TZN"[@H M!C62T-HX4.^_$X7_22D6HQ'6]ECJU>B* >E(U.W>))UW6^N*IE$B@9A8Q=3[ M*AAM8(VYIQF^5MJX*I:*"G98YT[>$M=%>3!EL,9.)WV@"(GP;^4U 83\3. MSL%[#S,VF/6[BL&"!5JQ($9'$SLO'/Z:7H?\@"Z MO3$W$\G ,@],( )F)N&I9[Q($YEGELU8EG;(/!T,M/B2/ M9>II7XU3:DBPP>9)=^;IC6PXS%2@( L4'@@#I8RO@/ZC7Q/APB9RWD0*F " M-][C,X !@>32F3^T$+P8G@3VCC#HF9L!7.>2T++ :M9J,T610$6@_TONP5AC/&0Q]MB*J\^5-5(%T$OY40*$P5\>$2H,0GN]G M:Z%B&BR,Q!@T $$)^BR5_X2OOWHU_[%%^IE5?7M5./B:;WF9+O^OL9K?/#UN M-:^:%R<7G:/KH_9Y^^3RS*[FGUT=7W:VNYK?&?D']O3CA2'IQNLR- M2CL 'HLSCUR%@DT$CV8Y13M+H&1]AA _:@,$_&\\VJR-@74,3 M) 1/$F;,<\R:;Y'SP BCL?@(?EW(SD8@!0]:-+T?6MY3OO&7@4.!M$!<,SOC MTM":X;0>L.8#7 '72I[8XI;?W,!*0V0:FFZ+:8 MUF8>X>%6@,>C=)LX"85[%G9[%K4+/QH>]AN=UO'[1]_Z9E])GB@/.!C+3YD?_PROS%[N2><.UVG2[>PK^'( MFI;]^N;HY,=G^M#IC:UMW]?9E896NX,;%:;=_CF4+::DSS9=LDZK\>+Y$1W< M6:"HIW*RIE282J(U_L[,9C+VOYOFGRWE;"THG"=PCE&FRBW=T4NJ1JI6BJHM M[M7>?M'R74\2DSO2KF!+^:JHME1^&F5K2K4#M:4Z5/N;.(8XACBF1(XYIKR; MY?B$M4L.>,%'(E+J16XN*[MIAD7T! Q6* M6JXI?X3FU-)MC#OW:&Y6(\7]D0/.' M5R"=$A9G7[,&R:DSRGE",'5A'@(3@6EE%54"4S4F\UO!G3O%N5.X-WJ:,VCI MWF::>[SR>NLL*#L 2E\EN"/[)72U-PNR3PFO#BNVIT>O+ZZZF :B,:(QHK%7 MF1,ZW-RV]S1&92(RI2\ANX(YGUF[[ H+92*.BH< UQ_LO2D3L1K_+RT;\57D M!U !^N_Q#"Z,"AZ%S;(0V!PFL9K)ZBU#3(=_-,V,8,I"I"=0\\U:63I5>VP5 MCT MI FE[F+5X(,PDWS]@MT*P3RH6K-U9&)3G==Y^ MPJMG$@,=:SSVH7!K[4-/*+XLB/6\RD]'B!Z*>- MO% !ILA(4^_&,UE",>U$GM?'9D?48O84M,9L2)@O!#7SGD<2$XGFZ7LQA:I- M*)F$Z:'M-!%[FNRT =?&)A51($=F6T&L&FD2$,SP:+._8LJ$;."QE6/U .HX M#FR>69/G*<]PX7$]-/F0QGR2GBSO+S8<2RT,D@"KJDR8-^0 M?2@N6?2UF(N M7\\F;(BA829MK9_6:L$'>KG4M"VR(D!'U4AZ"%=?VH/KBP?.\V2Z*I0F86O: M,".F0@98['^:A!:/N _R0^79\T3QL#R*B/V=\"C&5/TV;YPY98^(UZDT37OS ME'5+1#*7[MDDR=9/#+\RV9Z'>9X+F[,65 W4C=ML CU3&T#$,X__21S/*J6$6RI6XP_6:(>;MRI3/I_C"?03^)DRA3 M$DR=F8ZW+_M8_R"C4>AFWJ@G4IM4D47,?6[2CB\FQ?C\Z>;3GU>_7_W.SO+L M#;LIH3-0.,PT@6G( !'(((.\CE(D,"]C:C";70-R,'[-!CN[NIWBFID3BS9' MF7JQR-.923IE,9WW 5F6^3[@G,"VW.2$=4+_Q10<>;[F92R#C D0B6RN)VYI M9:DR-/ "DT1$ B:%R;L>%0R,C);67C("Y(!0$#3R]S0TG>:$PL0VN:$"\] S M:4R\B1?8?',#KM_W)3;06H8LM=), A1#:U-6RQ(KI6QD/2I@YWAH$H9HL,%! M:D5 $&XL;JMI\J8X*@11H.# %!PQG0=R'$A,=C7UE]@-4*IO;=.\$J?^I#;I M1Q\ !WHHQU,IR8S[0_& !B:1@)C4_!9-0"[F*?-C9D0L=X:E9K;%I*X3 RWZ M8T7%OS%*='/C9CB=D/:C_K2;=M[-C?BT1 ) 4+^H_-?T+?&# MUMPJ\ !XL,N I4UR2@&_%7S2;%K5M" S;M>4N)9X7LM%AVG@BBQ:=,<"K0KY MZ(;J ?U2D:8?+7BCME-#J<&]Q)DOPM569_*%3:(,YL36K(B.L?\B#<2,?ED[']6_0JI'Z+"=@143Y(/XP&Z NZ+!9&":;BP18;P",ZFS MN$KQ5$2A[8,IU@)&&3QP$-4X4CV38G WG4\]K++32 M=E:#3?MN=>N/@]L#=HG)L2+=2 4?34-''#TGZ'F8UISR)H5"2S )TB\L9#GM M5BFE&1W734KWDK^H../T06E!UCP$8&S=G+3?9SA=*#>&_U& ;?PQ)]Z"7BQ/ M,F=K^6$UB;0R::$>BPV/\YY"ON<^COU,+3LGG?ZA?=IV4!FTC(']H=T\<=JT MYY3?K*PE7)BOVRIAVYZJN\[)BE8-D-QIL*]Y9DCV21VPT\.?\7OV]DWAA]/# M-^]24X>\DF^87H7S_B(_&@HK1,5%[G3)F4KVEA*V2D]6L,45^,.&OS17<3T20YV7.0Z/&:A8FS=&KD@C&*PV08M?0)C16QU/'2-F^C0UE*C4; MTE!)C!4 3+!V1N_F4H2:B$8<)3JV18%ZD[F)-_IOZ/?).'4>T['(9^K@#.:# M8IYG%GDF.A:C@ZQ4N%4(:T%$.J)9Y4^68-+]?S)?L-CP&5<$=6P $H+A%MMR MM5R/]^>0_5<"$QX,TJ$G\O00SY%)]Z2-;'(XRR;P;4XGR=A6=5,'#7HAWLM:EM>;, RT[657Q+!@+W@%>_Q[^[P1] M1+/3P>K*?1J=P7L+3)7%OV9US;PN):T[$8T4?&&:H?2SL]DY_:NE,7J3=U5RC -$5TOH[)L5I+6.1PB1?#5- MA/Q$F8BH0+:;A>KC- MU'O1C\C&5-+*^N2OT6Z8_T=8Q'*NW<;5@9DMEAC &542948L;^Z4$&9*8]I5 MP&EIH+//%Q\/V&\< ^)&K,ILA5!I]01O6C9L=NH\4P LST(^W3R/Q,O->B(^ M=:I>6=#$5QC_4+%Y39B68(]CL]:13Q^U$+;TAEF9;-@2$AAM*90.6-V'M%52 MIYG19V3(^D&"RYYIW8MPMD-SD8?56KM,S>=%7*PZ&F(-T1"DBA$'STM&B=6$ MY?)=,7[0^^FN%*PGG#_4%ATQM2G =@9&0*:2L-WZ$MD/>:1IH5Y3_DL@_\82 MOL4P6\%O,B+)FHP6-"WAA&#(N_28UGD\LE4P;-'&I1O%9H1I. 1CM(3ASP6;?BFIKEHWU%]/X+B?@YO MIJ7IGV/$P9!>-Z];%U?GG%%?8QX'CJT%3X-\QF:T,D( MRQG\DU;B'D18O=H48!5^6J$KVP)V=GT+?.-E]1N*!0NR:H9F'9+96@S;6KLN M.7+8V%I''$86748[7[(C;_J@S8M5/);.>\W^[4C)CMTZJT7RH;()5**T2JN8L M%26I&JG:XZJV.%NJ8P*1\LX[_[8B *$7(Q"N0%TAN58.[<[9<&^.V^_^:?IN MX[39+ET>=3DN3RQ#+$,LLPG+'!ZY2^5(+$,L0RQ#++/(,MVFNQ1G=6>99Z?^ M65S??WQI?F817RD?=R";WU17U'0[L\YO#;Y\^7_[KY^)&=?;IDG^_^ M\^HKN_ET=_;IMYOSCU?L[/;VZN[VT7'?='M"ZZC,0WJ2;K>;VXV!\8I VK\%ZYHRRBM('B8'9HU/&-HD]/3U5W'ZR^?9RVEO@>&]! MN_O"O06=[I;7F$]V9"V<^D?]V\;[VC7O7SW'C_:PT&JFZ]7,/QZ?-]"R.2F: M&T4[PW.#I&ND:UO0M=\OSBY(U4C5MJ!J5TFDQHM9%4G92-E*L*%:EU-SM&6RV%>\U@T[5D(2S?=:[LYVZ MW3@Z/''5[;KLFJ:P*C' WC# R:FS0UN$?\(_X7_'\-_J$OX)_X3_O<7_29/P M3_@G_.\I_H]H^D_P)_CO*_P[C=-#9UD5Z\( I>UUV_&E@F+1CD+%"EMRY!E* M-#UE_,)-F4[7L9ZQ-],U"M^V&ZU#=RG:7BJUJ=[M#'6_.=HMV/"GT3,>O80=!F W3'<';I+3KTO=HW,5VW10'N+"0V$!MII M2V@@-&PAA$"H(%3L."IH-R:!@<"0.4R-H[:S&%9=\$![$YO@[^T:+.-19N:H*Z,55-:%26 $< (8 0P A@!C !& ". $< (8 0P MBGQ4>=O;5N#VZF4_GJ-J:R?O+4&.NT!5M I$^D/Z0_I#^E--^9#^D/Z0_I#^ MD/Y44#ZT:\19\8N]"YDXK1%!T4B*1A*T2C@@1< B8!&P2CAK1< B8!&PXY((9"C>#X5I>JO=_+'PH,-QG"[!:A M=?O'R0BLU0$K6<'7QE6G<7+J+-%+[:&UYP5V*YQ9%S-'J")4$:H(582JK>WE=QB,)+>0H$90(P-&!HQ0M<7(1K?C M+D1/)JRT?8Z4I7T_XOI=6MTN70!D\/8/6+31D8!%P**-C@0L M9N (LR\1# M"&"T-Y%P1;C:*5RU&ETZKKFVANSYWL2M9,W?,0"][;2.7>%G'V+NM,"UMU I M89)4%\-"J"!4$"H(%80*0@6A@E!!J"!4$"IH"KY3V]YV/;R5I?=CW/L[D9'P MF9]$T% 6#P6; "^5@;7:!)+IA'OI B ;MG^XHIT%!# "& &, $8 (X 1P A@ M!# "& &, $:QC0KBB@H]KE'H\7 3L%&AFN?#CG9=1N'!UW*2Y"\4:*-U+^(P(6 6L'@$7YCPA8!*PR M@$6%'@E8!"S*>T2X(ESM JXZC=,6F:SRXH2U"@=23<87'M!L-XXZ'6=HH\H% MM/!#8*/B.Y1#@%!%J")4$:IV%554DY'<0H(:&3 R8(2JG435VW;C^/ YQWG( MA#D/-5)-1B?JU@%U\U72"\2+P%AR+/RE8OQA:\)[4BW=8]8UNW5;KR^M?7$B M:'626(Q8K.J[:8G&B,:(QHC&=GSO,M$8T1C1&-%8'>/01&=$9T1G1&<[MS^? M6(Q8C%B,6.PUYI:-UJ&S$CI$9(4US)]C#EU?=OW6&E806B!#\7XH#.6UVLT? M"R\YWDQH^6W_[[%_-F[?##%UYX@)/\^KP2R3Y5?($%@Z_O"^=0+?N.LTWJ:3 M\2.+TX](_' D*$+!)^XL&=O0EST>8?#D\87!-( M%;IX''N0((-0F8YY,5.AZ4THX@5Q]%5D?DN[>,#NAE)#]U PFL6*7?626#38 MPU!Z0Q" S_I)$$Q2D8$$!EGE*!!9%46!X_W -6XG@8$.,0=M]^#%H$0,GBS! M8!%QG?8,X%[$S?8C7OY!QO ^SS[I\HOQF/#?CZP07GC)2$S;>3DM =97200J M]7?"HUA$.-:8R[=A?KM0H OAA(W!+U2 HA1?89CP8*H>!8R!9@$.8R9CS69Z M$(FQ AJ!=R:AC-G;-\5?W[PS8QD)3PU":*C/^-*GB^]C$6H!;7S$F]Q$'#]T M6L<.5'/Z0 2;F.]TG\L ^G8;BS%K839EE!)\&;%['B3"Z'(@@-CB(0_-CW.0 MSK"*%XXC.>(1M(/Y<"N@F3-?>)'@(!_ @R7\+A&"O1Y](WI,?SDFT?'[$%$ M@OF1O >Z YK+[M-XXSA2?PD/[X-'//#(9V,%U^/[/*$;9J "\XUI)0Z)N3H2 M\+0$GM&/U @:$XH'=L&!HV0\85^L_I@LTF_?7'R! 8?W ,_&5E %(:3T/"FH$*CF&YW$03:*-N)@OM8]R1A>CWX5\X8\&F2BQ"M![9&;V-7ME\8JD5LS M $+_DLG6#M8X +S"U2*\EY$*$4@ 7@,E:%<2"7TP1=--:-6SW9@"<$[VH&K& M6***CL:!A*]",0 !W,^,(^_'Z1 -)V.PV\+X$&R<1- [T%$K#AX$RK/"FXXI MV&\4#'9XD$C?: T:LQX.+N(#A-J3H;E-_X*W1 +U'?IK3%B1,G)U&G$9FB=F MW4JWG;W0N)7((4;P4TX\F"548\H1(\+8/NSD'[?L]OR/]&NC2)GIKXM1_!T& M$10T$N#N?$$2&$2ML:FG4V95:M9K-']WT M,H6"8:00[E;>-_QN0:99YQKL)O0L1\81#S6XF]BQG!=3U73:VQ]:1VXQ! W+ MTEX>L%LAV"<5"S=M;2_ND-X\,+9\Z<@-:LZF:KEXKG\CJ2(;(S/@(X'496BL M.WZJ#=6<)_T^#Q3[C8_+=;^7D$QWEF2*?G'H"FB[YH8VG0X4 M!3KKW65NK326'1P##3UUQ2CQ$)C-D3V6Z$Y9_]CXRG?B.]<'[*G)5-?!9&JU M]-:9:H3IGVT[=9@V0+$1>/[@!,XYI$N:<\ *SN$+O+M(!.+>.-N+;IX55.96 MSLX*9OS1S.,\8&<:O#YP8I,@7N'_.0IC%,'3+-?1*P[V*_IY&=DVMQ#L^'CU MU=YH$[0)K@V_1X Z\4 :)S% F-X"?B.(Q$9"OP\E,KPRPW>HJ2V M=+3LK4;-):H43+=1RIKU!/[X!IH*I/_M3;$R_5(F[12FJG>6*;+1 64%"HH5 M-(M'"BBHQXT9"=-N%9T4QN^A7P8Y$1!)9.;6X-XB$7/+\6.%=VL>V(CQ(]+2 MN?FR+3#1JV)0P1<>X@VEE8<*]$Q7E^EF];%L[LML0BN;7JP CH7:<^,\H&T] M\7A,++4LO6QI(!WM/""4+0IL(5"T*M8#W97J4EF+M%],\P9S,Y05H7@=L-DQBN,UT'Z M[?/S!FTLHU&>&:QS^X?(D<9".X^:P1+U2F?7+:/F[;EXX5*JU17[SV M@;3Z(; M:LZ*7-X.!5[_%FY(]4R_2RM?VDA\))6OI\;^P\9#6PAP> )):.58%IXRLQ.@ M.:<0^+GXFA =GF!&AUIX3?Y@*U8/W+WTFE_?--^8SQI7;M+/2T;Q3HY [I_$ M _NJP(#-MQQ&:2!#VTB>Q"K[PFY+,]\\2#\>?L#H9K:UQH/1YF,M/F1_+(2 MINTNGJ&?9FGH+LV9L,8Q?-,8>,#QCT]NUIG=,I3>V-KPOI,MOV_K][5WI:$T M@'O9/U)0)^][7GH32C"T8+I:K6IG&%IP4%ZP-W>Y8^FDK#CI&^G;2_5M[>I_ M1'HEURXM0P>?D.4SM?(%.ZV7:^5O9F/SN=N,6*1SI'./Z%RQ#L39"&->_YB( M'ZD?J=\6U ]3 !+AD<:1D26=JZ_.D9$E]=LM(_O2ZFC;T,%2#MHOE^!MTL-] MG[CROR%^U];/[>A?Y?!+_$;Z0_I#^D/Z4TWYD/Z0_I#^D/Z0_E10/ALM1E8H M]9R3F9NY[8L]H,=\W,ZNQF8+LFG32\Z^'KG.C63:LBHUTA8Y8F_RW>U^.KNU M-R9L+(NZ9*K;(=ZKEA4AAMEKAGGKKC+64\*H<[$_HA^B'Z*?Y\NB0PX.,0PQ M##%,:0S3=E?7@"B&*(8HABB&YE TAR+Z(?JI"/VTW14\J;N'L[<;'.U^1I/: MS%.80$4OS0R[QDILNX25V&?LFW4-GF-GMKLN&*%M"7L+AKWDB,! 8" P6!^JZVQ&03X4(:7&2.DZ2_-5%[-!.[JSVR[@ MJRA-SS_FDTKNZ&YONJ-[;4 ['=I71/J1,P>Q]A'J'4+[[AK*NN#J;;=\8)$3 M2J CT!676YMDS A7A"OG3J*SM2?"%>&*<#5U$LLW6.0D$N@(=$4GD8Q9.4'/ MNNW)^YV'?" >BV_NW\) VUG:@[I@A%;)]A8,;UO.W#?RT@@I-4;*^F5\R&P0 M&&H.AHZSS H$!@+#CH/A;'YZJ4""X/#+YR$.? M)5J4&+6J32R8,M"4+@ R2?N'*RNEDW:K7;Y^$< (8'L',#)&J$J[V>U=;=GR7=K.YW I:%VS0^M+>@N%MRUGB+%J) M):34&"DM9UE]R6P0&'8<#!W*,$=@(#!D/A1EZ24?BI!"/M2>[69S&)]*-#1) M1%@,P0:J&.YGBT3 8RR,,)1CS19DNOZ+'&>:ZU"FN34'EA+-E2X LI?[!ZNW ME&>.4H@0YK:*.=K-0$:- %:FKTC%QPE7A"OWSF*G_.17Y"T2Z ATI>3,JKTQ MVZC*QBY'.S_'\%-UHIG==ZST<*:*?!%E8]$:?V=:!=)G_[MI_MDU<+?<[;M] M0C!UP7CUX+S#)K)>8'KK;MJWIF#VV4DEH.TMT-QM]26K16#:GOJSH[1BC:!CD"W5CD/VLQ/P")@E7"8VETLD8!%P")@Y0>S#\O/ MF$M^(J&.4#=3LH2V/I877=P^HDKA'_/IP>Y+[*G M\^Y"7W1EZ&,Q?N/\E[X M[":,>3B0O4"P,ZW%9OD+.R4D47A"I+M 3+1&1/I#^D/Z0_I33?F0_I#^D/Z0 M_I#^5% ^.YVWBZI05B!,TJ%B7A1^I/ CI>DA@!' =@E@9+@(5X2K$G!5_IY& MPA7A:N]P10XA 8P 1H:K"KC:V_T>YK9_\5A$)88&=PPW5 WCN?TDZU);,)3@ MI1$J"!4[C@HR$00& D.^L9S 0& @,)"_1*@@5)")H(UJFRO*\A3L6T@85I>@ M;VMK69MK'Q2FQ99M++;L"2[+6.TD@!) ":!D. F7A,O:XM+=U)%P2;@D7))# M2P E@.X!0,EP5F9[(.64WUBW=@QT1^X.8>U)(0=:%20P57UQU831:6-S<;R :(QK;7%@N2Z*^ M6%Q4"XLHCBB.*,[Q1I.6N\)BY*D1C1&-$8V] HUU.Z>O+RZB,:(QHC&BL1=, M.%T65Z89)W$<<1QQ7,4XKGU":P-EK';^''/H^M+K"W\7^A7(4+P?VG+1K7;S M1X=C_/\>^^?1OIE.,$\$0:K!O[YIOC&?882\['/:FJ+2=T'#BZV[DR.AV2?Q MP+ZJ$0]_8:O$OVR5^$'Z\?!#I[D.:F;U=?V+G[U0_1R=?61LCZ'S,QQ\A+U\ M_F ?%X6HD_$C*^R/M.9P'*>>CS7=\"#'=@D;\"+1K<;_\68PR6]K-UM=UN,! M#SW!9.@%B0\Z^\?!?Q^P?\G09VHL(AY+%>H#=A.RLV20Z)B9N^*AT()Q4[^= M/8A(X'8.O\%Z2#VW@+%:L)U@DQBJ*A0^WP[7:@X;) M,!'%]S&L.0BWR@BNUDD +^$1WMD/A(>W/LAX*$.6W@NZ--/86R'8)Q4+MC!Z MFTAI,4*YB98^LC_M>8^SG_#J#S(&O?#L"RZE'BLMI^+[3Q'X[_LJ>G_+@=+. M$PV*!>.UF*5]@]X FT6LGT28<0LT!SZ-C.P/%B7^7,OQ+ 8FQMU=QFWO(>-^ M%6/@,P'W!6+ @[1N O)B)#PA[X%&)SH6(_@82-Z3@8PG;,PG([A%LWZD1H90 M(S%( AZKZ(#@1G!;#VZ=/83;<@?G\LO'JZ_L82B](9,:?0@M81X'7L4P,YD: M32:X)ZK/+@&8HQZ8N4ZK@;[/(;D7Y%X0WU6>[[I[R'H#&=I&\B16V1=V:<-\8[FVU01!I %:P&? QUI\R/Y8 M@.!R\I[BNKGT#,X:Y&L:\^N;SO&/S^3]],;6AO=M^WT;WW=:^Q=VGG7C\ZPX MG=!;P.IIM4_H+1#R"]8ZS*<'R\@]%?BIIYY.6*9BS&8N&QAETL%-=+#S"CKX MA"R?J94O\$27:^792"4@PY/]1W@N?U)'4<0OJ^"_S!:6=[R$@K22L?M\A3)?Q=Q$.U-A_N=)(#)ZZWN>T"OHJX]ZS"Y\X1NS=[ M$VNP];!=NC#JLK&0]D>79?2J(SAWP%KA[]=09J1L+W>M7-/ZVG&U'1(7Z5GU M].P6G$U\Y'MY[=;<= MFIGN%L572'#NGW5]=0QF1Z)=5D7B*4??'.R7J1?$@^)!^2#\FGBO)QFEZ/3@73J6 Z%5R5%]*IX&U8 M%SH5_.2IX+7KKY .TJG@!G[TZ\K3H6_*AX7ZNQ=%:9,/(* M:C=_5KF2V*#STX245T?*VAN&7ZN!>W2FN[R5R*^/95)\3::A<]\[LW+K[,@- M;:>L#N7LF*VNCN#*XYSIE*F&8B-]V^E];SLD,-*TG=:T7=AAZ4XP6SCA_N$'WMEH4DP9'@2' D.!+<'@INK8-%6S/WCYU:5.6_: MMLM.3JM.:E- 4NA8CDSE2%[<#R>^CT6H!1:FG"]$F5>J- 5V%SJ^23O;S27Q MY$T>!%T"I Z&KIK57CPNO\F#J IG9<[;M5]\WNYHVZ>\FKMRX(XZ2!VL>$.K MW<$=.1U72NUQ\VEA^_';8C'K9WCT=%YNM4R7>EL[LT12K3D0J=I3JG9,JD:J MMAU5.R%5(U7;CJHY6YPC52-5>U35EH2@:-O&LS;?\4!H>'OH":UQ'K&):CZY MO;6NTIZ ZV*HNXQ.L"%8$*X(5P8I@1; B6!&L"%8$J[V'U2ZO(:;,8#WU7+3MUVK*I8<.$?Y@TT)3(90+T MRU&3+X4G1CT135_5:358N]DZK-*00WL6]_6\[EA#DQ:7=#<3423T6'BQO!?! MY.!QUDS__O>?$_U^P/GXPV]*^0^@A/V6',R0'?2FU%RB=1.(.2.D\4-ZW M__BW__7O:]SY1072F^1WX1%NY+6OHO_KF^M+5([_T_V?N\LW3/KP!??B]R?= MT^-FY^KZZ.R\?7IT?GA^WKIHG5]U3Z]/NV>'E^=O_F..6XO2>2)=X3)[MI*: MR^9A\W$A6D7THMJDU94PD-D- *Y,; I'/\7)CQ@/:ZE-@]Z&(I0@#,#+X*K-(.;O"$\ M"5XH0^;)R$M&&A[MP1>A,&?_8V@./BMM&EJKV7<=%'OPD\Y>6FA,C/E2PP'S M\5'0DL]>K&9XJ_4X="JC/.;R#R 2P%BJ/=DP;5LM"N+EL;$OD1BC1P%R3D!3 M6 !#'#1@Q*4W9&;XV>WY'^RM/! '^$&-1<3-Y5H,[',T,VIF],L\,OME^FCN M>>#.FC\'B?114]XU4(TX,,UH#'X:7&[> =^&PK:"]01,'Y>^]-T!NPGAM;&( M1J#@\(,$M9SMBFZ8QF3" /V,X)H'&0_-Q4 [?"#FVJGC*/%BX,\#]GG^G2"+ M"/00543V)2;Q!63 &Q O/)C\ ]_$*OM],NV73H4YXM\$2\9X"[AL"UW2 (@' MA3(!#T\4;^?V8R\5,;R$,PUW!@N#)_OX](FY0P"%JQ'./@+HO 0EXM$!LVQO MFAY(WI.!C*6PKX +E6>R$YLW+'UT1AM&EWKPDM$X4!.XI3>QHYD]= +W!T;U MX&%X8]I?%0)[])7\G$@@**0D5',AJ$-I>+S8+$S<#4(Q MOZ/)MA?V@ _[T&CS3*/R$RPVCJ),>U=X"[0&2Y'C0#28X* *9U>WK)? & )3 M6HWD4XCV>(#X,$*(99R@$!>&@^OI2(N;Q@P)J%V-CJ!@?CR.%@^L+F)1A!]&:]L%5LO*=M9*@)?-C MV@#Q>D%B[C39PK^C(<4KIXK-,*C&/!Y%$T.K(V35C'8##LV8FMM9(YVKFPCO M9:1":X)O^C,<6>@VD$:&+WQ C/(SQ!3(;_@CP"(T^F+P@0\IMG*Q=WC_(!(@ M_B]B:ZTAC5JQSK@ ^(0FM>\&C"3 T#MJ#U*)1L&^/C#)*8+ XI80_PSPHZEM\U7#WM9>Z&4Z1/,M*SYJ MMH$_%=N#(C4-1F8%C$ED>#96,5JI67<+E31M0\IAN50+3APHN5%+B>86*"Z5 M0JXKV.OB:-@79-92L9'@.#^Q')D+N= ,F+\8HQ&! 1N$ .8&/A*T\X#]"XWM M5$RYD!I+] _[>B]]="GY3\U>YNZ0"'3:H3R1P(<\0G:)_", MK;>#%@EA#D*.?/-I4D"@'1?]#J%HN53UM(CN;6T E40I$Q2'"XC=,,DXDC!2 M*X=?%:2M.9K4<]#+=6_1%4_V2F,,NQ+E5 MX@\RI<2'@WJAP\K]OQ*=41>^9M'ST3^A0B>CL553?( /TWX<(!S2U*E'E$-+ M(@'.;#A%Z@IO:F8NEGM?FO5 :[/+[802F$^\M^J?&3SKXTT) @3K4)>MM[D?.]+8PKJ ?0]:WTR&8;,#$O/KH M6S'WO9E&)3Z:SA=BW.GTI,Q9\4]ZG;@(T"]6;@DFJ5.&&C13M]S&18P[8[\P M"@0_(Y&@6['H?RP)KN"DIY38RFJS82 UMZA0M"#K6HZB^VR7(5(#[0N8<_A% M*S;+G(E.2?-Q)WOJC"\)'J LYT)=\R,XPTD@9&-_;8GW-]E,BWX/C@-F5AKC KO8)37F@:MF3CYC7@ M2M9/(B,AF*^D$^.8?Q.AI<5E(P"C"_Y5.I3IF.',>#+F^M'QS4S;8I-"\_T8 M$*VLOVB<34.$R-K8+X4_PQ-&F03A)="P]"US,X:#12+9.+0^%R OAM5O\K=^ MCBZE'BO-@\_]CRH<&'[;-,!^W;WJ'%Y<= X/NU>'I\W3\\NSK@VP7QZV.MW+ M>@78E]B) G/V&8HS9>NRC(1AK\=H8 6C!M.FI=SSUBHTKN&/W[&A"/SWH+/& M>N , H'9$X9/@?A37V)IW+80:WC)6#\!X8*/, M/"P"#A0! --XXM $]-Y0:# J(K;QPM2C1&#@9Y"(Q[$P5SS)FC"()!!J++QA MJ (U0'<76XO",%'>!C"X%]B@91R)T-F+4C M!JV'$>N9Z8NU?:&?35# ;[Z7*M'!I%"7#D:^GP3PDOZC4\^"6A;C$*MTS>A2 M>AWJ]^QL:?JPQMQT--O>,.M[9 OCJ6/RY'1U"3Q1K>Q]<\V9VJ8\>C!_>SHB MT^"!T2J,JRI\:H@J@CID>]V')^)JQ34\.-7.:3MLW"F%PB2OIV<\)WQ?9#A MXEBIGJ6)Y0+RLL Y6//$L_.\M. @W";U,&-17H2(:85MFHU.+#0PG9V"HH7O MYW]L%!NR+*XPZQ4NCL)(B)12@9R!H+D-K#,OP)"\76'14_($^A'9DLNJH6!:@V!N8V6AX$6U*\92'!Y2W724_#G!W:@O!<'37$I:5 +'L"-!U0 M#60P(\"&U>[%GA;8H-#CC$TB8>C6+_0Y,-R9MAXH%&23/2L5T[0/J<2>N]%A M$[]JQB\S<^D[_GW)MH@U_*_6]='IY=7%V?5UMW5YU6RVKP^OT?\Z:S:[9V?7 MAUOWOTK=SW#SZ>+S[U?L[NS_7MWN8&1A1:>,!C!0 ?8%IRM8DJ"Q"IWI*=& MY:RDS/WYFSR[A\]=E8 M_8'BRD]0DGI$8AA:LTP+HTX M<0UQ#7$-<2GZ N:8_B9A MIZ?J-&PBIU>LP_#V\,BU::HSKQ"%["]26FUG&6<)*@256D/%74+ ?8 *K<4L M%^"M.1"Q($5:B:GL2LS>U5)WEX2>0H*50=3N.@H$*X(5P8I@1;!Z(:PH@$P! M9 H@KQ5 IID^!<4H*+8]VUL7$TM8("P0%B@"_.AN?!4)>"[%@"D&7%TV.VPZ M\X%K/Z^F\;,_&=39V+9]5MK6$%HE:^6Y&6 N=Q8NI$?<43RE\%ENR5@;1ER18ZO3G53HNH]%4 I"ZQ,MI\)15; M,:[0@+3RT!\'MP=3QM9YF_MIBMMIQ15;$SFM7C2M!2OR3F?7V!K<6'$%LQGS M05I.W#S'E,A;7K4EJ[)F:KM0V98=*-O2?&'9EN--R[9L6KWC9$>JC% [=W!S M!55#V?E9R*NN;3TAR\UP_MOICKT8R65B-"WH>!2VVQB2JZV7^X+-,N0'>&6 M<$NX)=P^'[?/GT;4;;:0+O(T6"AB7!LJSAMZ(A1]^:J%_?:)ZW9X(D!)Q>"V M=\[@12*B"\_PV6V,*D0=S&9S&2"1R$T5%=R MAKI/U%3+@'@U)^_5@"+%U0A\Y;K6SG8JU!%^[IQN0ET5!%<5U!'H7LE_KY.; M_B MB@K-)\N3Y!_@TD8QEZ'96C%66IJCMI6<6NX35=5Q3EX"A]5QL$/8(>P0 M=@@[M'>:]DZ[+B4\Y.% L#1D'?"'2LXR]XF2ZC@]IR@91 C M\.W\]JPZHH]"U.O)Z3>E_ <9!$R.QEQ&(Q%2[@Z*%3Q9YME9+REA?QWE[2:7N M-A#>?M A@9? 6^F%)X(QP9A@O%48.YM9$'@IQOZDP*X62JQ2].,UN,U1Y?&* M<%C7W?K?NE+:#[(BT!'H5CH.QP0Z AV!;KL1LY)"9GL/NH);_K.I;;_L^HWT M&^[K1_;767[$[:Y$D,*^W:8CS+ MTI6SL8BP!"L?",9[P&=,:L;'XTA]ER.8A0031QTZ<=6?2 30+I_%R@A>V09;<;Z"Y_8#TX&H1"W9G>@ M.5X21=#I@G#A35'>!-."L6T!XQ&>YYE2XDL;M"B M"=/):,0CD(^ESG6Z JT'$0>&5KA&OKF$"T>];"L ^DN=5L,-RL <+^8->365 MS9JTN/-LDP=]>#'IIAYSSKO6"UZH$3]+O(4'S\Q@FG/LC9^+;PY5-.+!#.&W M\)K\P5:C/!$$Z36_OFF^,9_!>_>RSTN$="='H&Z?Q /[JD9\85X("CJ0H6TD M3V*5?6%G%.:;!^G'0[@:9)-.2&#.$/"Q%A^R/WZ9GR=,VUV,G^=SC=.9.<@S M(O"F+;^^.3[Y\7[=J6=U>[?\]9C* 1#\EE//GES.V\>E]53 MZZ8ER/+Q8,R"&7I!.&:YK[_4.2!5(U4K1=76/FY NX67WG:S?&Y1F$>G\QUG MH>GJ2+5R6-\ZOE<.1C64\X=MR>Y)I:S^XE'KJ*0EVV=(RXW6. !?L,&R#'$8 M<1AQV.ON.FD1A[GBL!=N16WMN%][IV(>K(JC^=3?K[ :M/R*CZM-W M:2[H$JG4A::)8HABB&)>WT.L,<50Y//IR&>ZC8+"GI4C> H)O$"I=H#0C\I/ MKEH7(B>.V06.2?T*O+4TIZ(6#%2*H)SST^EIZ;+:AL:\/GOM]]GX)[S-Z<9E M"APXX_R\N>U7V#KSC(TRSL\1NBOJ^(1@ZL)-!"8"TVNGT*D+ELH*-]5P13+S M VC^5\-%A+T)0CTEO#I$J1S. C<65UT,!-$8T1C1V*M,#)O;RZ56>QJCI#+S M]]F/>/GCV2 N15]$D?#9-"U$&?D?\M?,[0+L!\*+S<'Z4,0VWX9)7&E.S;_E M[Z;$'(O16$4\FC!?PB61"#UX0D_$#T+8(_X>CR)SO)^/0-7M(_@T:4 PS1& M66M87X8\]"3, R(!3X[QSG$2C95.LV&8M 'IHQ(-;<>["IE!9BY^VRNT58U% MQ,T# Z73A\$-'@A QK:=\*P''ODVWX 63$+_M$F"H&.3EH!;L8B0>R8[39K% M$[,0P$]X(68F\=+,-3V3=<#*CCT,19A*&*^#!R0\""8PQ8$I+O0A$AX:4^%7 M/ZF)N>]L9W(H-(HIL9[-3 M.'D@JJ&,L%.@@!.@2"1#.4I&!2F4UO%#M_TV'&Y&C&6Z]2#CH4IB*Q*. MRC*K#*@'QC0\324[E'.FI.$Z.>B63W*MHTQ%@>1V1N1+3%2:PN])O=H5BV30 M949,H!MU#\2B$B!+DT2G)P8R#-.A-(.(]*+1J8/^V41Y3R&S,>?2 >3NN0RR MY$^90/]*(JE]F5J&LJ37=DI-CM3UAW;7N86V8Y..JQD\,!+.DE;]X-BTS2K3 M(RR_&S[XGSQ(3'O! @?J@9O9ER] _SE.C1RY%\V.VT'P$T/:U6)@M!J.5/;4 M,J9>)-JX2.@DB!&(>9+:[]Z0AP-AC%LZ<;]? M5&ST\_&9&N7AB2CFP#;P&)5$[#SB_\C W/FG%''(1TPG/2U]"2\6FM \U<[3 M:H/938I"=V ^/74\J2T=S&XD^%PP+P,L)O&]E_%D-6"+(,VC>RG.5SYU ,_1 M,?OCX/8@GZ\O^L4[@OGB9+(G BGNLV"BC#%)]PA(D@7RFS 2YS ?4+']/0N- M^%D0%SW?++*JF1ZJAQ ?J1X*X0\;T+#AC7X2)Y$)FJ8NLHFAPCMM0,.$5(:1 M2@;#=%CN1:1!UC NXKO49CZ2W;P\#HPCFH5F39?T?'AT^JK>) ^@9!(88O+G M0.%0B&C$/!!?Q$T4.F*<@7K&"EX(S4F?4FR0?>WL9!T?(,,$'Z] L*&,,;H' M%R2Q!+E818/'X=1A4:HVT P_H>)-H>L5L]8^,5F#&6F GB9(=,1#/A C3).; M#_O3(RZ7-FQA>+-AR^1BNZ63?E]Z$E\Y-^8 :I2$*CC 6?!M$5@->! XT/9E M]EHD"F@DM";9G?@U:D9?(:U8O5F25G@IM.86+0IIA1N[%..I8UYAU)ONF)(* M4U+A:B?=K7O_**EP18[@U4P^E.F5D@J3JE5!U2BI\,OV&5XNV2W54^I;OH35 MXUJ:R<0XP@EE/'&%[0J)MW*@=TZ*>[,U>/=W_KYM-]K=YM8$LH-E)=\1!1$% M$0652D&=+23[V0<*VN]4&K82WZ-K,S15=#]5W+-S_V]+._.Y6C1UYBR"&D%M M%=0ZS:UEV=@'J%%4:NEM-@''S*IWMM1-\:==HC>G0GY5%Z-QV-F:D['7,R;" M+>'6)6Z/CHX(MY5T9>KDL7Q^Y&0&@[ M6X"H"QXH6+#TMHN51V]HRE$A!JK+E,+A=*+N>=<(5X2K]4M2=MS5BZL[L/9[ MKGW.?>:+7FSVJ"JSQ(J 1" ^I:6ZTCVGJ3U/_=73EH]#ZP[(:$S2IJ! ![V?)]12G."Q.,'RO>T8B[4:IZ=;2S!6EUD5X8GP MM/H<_8FSG?W[@B>*4BR][=.\T7^;Y^2C*<\6..P9V.P -GV5X"Z2EQ#7WJ1L M?TIX==.#A M'::R>0^+OD4";\.2[#+&HMH:RZ-C&TR1[;S1T%C[ ER>M-?:FNR!N.<@,/PQ M"4TBS$$B[56F7GE:?1W?>L!NARH)?'-G_F13-WPD8^PH,:ASLB\]>-@(- $/F6NX8^87+\W[9B&!7Q^P M @!_T@6E@P$) 4;F<0''$8"FX;#@;SKF<:)3)&E1[""/1*X!?HK(A1';1* _ MM%M9N78GSW-4UOV'SHG39KFK[O[#<=-MRY"54 ,F@$7-@&E@@"^%)T8]$4U) MI--R)-FE97%?<:27UDY]W2&&)BUN9]Y,1*G]DO=@-2TK *:9'AH\]_O(33G< MHF&UFCC5OTI11SR$9#3@(?&'Q*1)\';F?6^ M4,4.V)D&;S,RE(8\-E8/P&/C)/*&'/C-L!GXM%-O/7OX .,_(7I.ULG.&_ MAG;.S<;?^PJ=:&3%S*LK>%C&N?O@1BV:/[JS\7V51!;QC;0#T.[>Q$U##QTV M%"8$HK2&MER*U,[X1N#VHRX$LI]/0W-= Z,Y@GF>$#"S$B.VN ;YS)?;CWCY M!W3ZI6>;<^#00IRT6^W%.(.;=IZGR-J1YGX&R'R.@'GD/^F.9"#\6S&P,S(G MG4 ]*DR@90A?C.S+IC,^5*D5;+8X\I5E^-3!+$X]D9-FF3SC9)@]ES/A=#RQ M*_I2;\O VG#0D Q*^=> M<%NJO<8XDAM?4S?^P\:0*2R*> +U9B5&"D^963!LS@$-/Q=?$Z*!"F:PV<)K M\@=;Z'@B"-)K?GW3?&,^ZS'WLL]+)'(G1P" 3^*!?54COK ,"T@Q MRKZP"TSFFP?IQT.X&@21+EQY@"$^UN)#]LMK;%/ MRC3FUS='QS\^N:HUNR"7WMC:\GTG.]).ZM]K]N]YNP)IZRW)9SWYY,WMO,+6 MY"=DN41^C]G9%VP_,)\>K*'MJ9G;Z.$)KA016.1@[I[F]V6Y;@]VT1RUW1S'W>;,L$1 1$!'0!@1T>-0D M B("(@(B GHE MI"N9Q](*#]SIGS287O74Y8B97W-I]'JW'.48!V5= M*5-X-8B2M!JM=DDY.Y\CL+I8 R(R(C(BLMB2[:QV-G9T;M1_Q\NS8N/EF8:?K'V&6'NR.?V=?E);VO/-"!S82DUXPE:9JF,\X-E8@C$F:\2X]OHRG+,.'-\!JE MD\AF3S-9TSPU"*&_JQYCDJC![6-H29@=J6;C2-U+C6?HYW/N8:-M'KW0!-%, M&VYC^(\]TP\/^)P?X]V1@\MGIMF[=% MR5QVEU1M/U90M MGC-8G%#U@B8YS%51654O4]-WP_),X8C^0:@%>YOF,GDW:_L+UCX)E6N9K F_%AMQA3LGX"9Y?.JU;3?3[ M0@:5=5W>=DHE@]UP7OXE3%KSL8KA\9('P:28Y[,PC^ )YL;'.4.8C$2D$LW^ M2B*I?>GE:>N*M0>LVQ-RF](/'HN% *;.'\\#M*<^B;;>FPR1@9R).,T!1X M3$98&^!N^N;>!&^6$8-G)I%MMNK'PB1$'0?B>YH''E,&_IW [4R+>Q$!7"T; M0W?LA;&P4ZAIFC.)\1.;Y6QBHB?P5GO3"KF([R!9V[>LWUH"R/O0+1@#(R]H M3)Y"=4%2MCC 0Y9>7E"JJ\JDNGIIIJOCPRUG/&IWZYBZJ)35(_-I(3#]7P5T MKKL,4#V![?*RY58R?:RO<.5G_4"[]C_&PMQ.K13,O9:FV)OAX^:[_%)7SI6L>')X]6G)MP=J>PWL)4%3MRT.YYM@VZ+#TY MSDZ1@A23 -.L@!Q"$3-?>)'@6CQ^PO1!QD.XI=6>6KP1M&RX,]80J5[H6([X M-.E23\0/F,+)C;ZW*NMKM=VVK,'&$<@Q@NOL\610?)3HT@.8S!R>#'%:[\,\#/60H@52-5>YFJ M.2L42*I&JO:XJJU=\XNV!BV]+#29:FG+%8PK),G*X=LY_^U- M/87=+Y?0.2V_RG==:B$0QQ#'$,=LPC'N2N01QQ#'$,<0Q\S?UCTF/Z:\>6B= MIIMGT*PX7\K,*B%A_MO9^DD40'(?0'JJ(OPFLGK%BN_."F;6A5D("WN+!6&E'F>%YKG;J/FYAA*]-908*'U2(C9P*\15IJD5A M.<(5X-MUK(F/:CN;?^ML.K\X MX.4ML#F&%"4!(J \"11G\TD""@&ESD!9>\LX 86"QZNRP)O$/\:?!2=7P!O2 MS0S>A,41#W7PK-**-!.GF?@KN,1/2J3.S$:8(\R]@M- F"/,$>;6T2HKI9-V MJUW^B@:%GNO@E=].TT91(( " 4_9]-8I10(H9$9(H=@R 86 X@0H1\ZS+-49 M*11<7GK;1TP[B:'EI0E3:3MRE0CJJ:Q+=9F,.PPZOU1B=69$PBQAUN$$U]T9 M P(M@99 NY65)@)M-><>=9IB%-(^+BO.0:$.9P3W#(1V *&^2K 8PDN2ME9# MP]SE1UI71M7/D]0Y=K>-X"FIU&5%DRB&*(8HYE52RA+%$,40Q1#%+%!,23/4 M&E/,[I57SZ(&\W#=2O'*"S6"<9Z86GD>: Z7II >EL/324]+7_)(8M' 2&1) M)(,)2Z!%D2D@*$-;?*\W,>7R(A&(>ZSL&?/O$NON)?%0P?OQ$7A&^1Z>IA)M MSBJ;@\FV/'36BD@,DH!'\ :NM<#_V2)\*H;W2AXPE<2>&HFTUI\6Q3:8 GZ" M>\.L$F#:AK^22&I?IB>E'X8B9+Z(103WX<]X)??%WPGW)MF=3Q?S-,4' 5+^ M ?O74 *.I"E*J/HQ/E[V^]+#VIZQ8N-(X,MM951H:J$3ML1@+$?8#GA9)+0* MDJR8(0IDS!',*!-H238^Q8/>#?: )0\#*>X%_CGD\%\^'D=J'$D>"Q2EYT4) MM![EKY+Y!V75#P_8?ZH'>$C4@$'SH3=I*]-ZD3/MM!<42D>::_I)G("6P#/" MV3K>$@;7B\V[01CWJ "F7J45X*/U4NV;(QX.A!7)M("J#&VU5(URS$JG&AUX MY('0/E#KOX1GAD8#@TD8*5387"KQY(#=F,$$&6N)'&GZ@@V!(35E2XMZF*56 MA59D$BCJY(A/X M/0%.L -2]U#C"Q;2LC]:DS&I7FE9X6:U=; :,<-!@O02^ MYF&H8OQ^6EEU=^JC'[#/()IE)=Y! ; R+HPU2AN% : 8P#5A)FQ;H#.5"XQ1 M)/"86%%"H&M6 P&LCUN1].]__SG1[P>\>^74GN!TO#".V#D\T!Y MW_[CW_[7OR]<]T4%TIODUT"S0J3PKZ+_ZYOK2Q38_^G^S]WE&R9]^ +:]/ZX MV[GL'IY=79P<75Z*OYN%!8Z.;3Q>??K]C=V?^]NG6CE87-[*#\?0$(LYA"DY*22B!Y3P;6+"$G M%-"7%7Y-U0MOA$'48!\$,(3."UJ;2JK (@B5(/L)<-321,!\/!CE1!_F.I-Z"M_>^A$GH!# Q8-VL)P%_-C$U!;XHX M2,( /"[01=2OO##WF$L_*SD.+J]QVN:'=6Q(SXA68B$R4#TS-F,! V*>;6I3 MVV<6W@ZO,I2J405-/?1TF%8]AJ,JP^UC:(EUSXQW.&-2I\^WSD!LFAJ:]3C3 MAMMLS W\/H/]L)9Z8]LPQ_FS=B$&UP5]B#.#[&MP.6/Q$=#KV[O6,!#M]O%9 M^_3T\OKZ].2D=7U\UCKLI ;BJ-L\JYF!,)=_D#$0B)=:B%R&S J1W4X]N+,1 MHO8?2VW.S8<=KOL76&.I8,(+"+G8;@WX;ZP-);PPC3L,".:X2+^6#+?H,QC%<]'E0!31F2 M;7'<:I^?[CY__9_=L.PL'UPTBZE2P61^Q".)H1>=!RV ;7-\TWYK.&:6+V^?FJ#T(>R- VDB>QRKZP*Q/F&U/7':X&0:01 M60\&"W>A?\C^^&4^NCIM=W'W3!ZA/5VZA6J-_3=IC?GC[12G?_E]N]+.:O?O M>;NQ7FU=KI2%IN7V(8N0L4ZK00N9SA8R\^92.>UEY;2='U\C52-56ZYJ:^=I MIU."2V^[3D1@YHH*UQ=@*O^0KRW0$<'7WA*SB7RHX.GN;('IEI\/K"Y;7XAC MB&.(8S;@F,/R\WS6A6/V^S#7[1@#_;@IRRX>Z&0\#J2@'&@ES.5>>DQUQTZC M=K9W&K4N7$1H(C2MG#:4=#BGOFBBX,_2V^Y4S .:@=7QX-/>3-&>$EX-YG!' MQ]L[C5G[21[1&-$8T=AKT-AQA M >8,D3FSP+WT!,;![,Y//"PD[7[BP#P%SQKB5D\5P?.C;R(^8!?X6=IMG3H9 MY2OI:260I6_/Y$"30-M-#VVCC'RG=Q:V1S^RDY7-[&3]S0@M""8-^[W$ M8R1^XF421@G8AS)INSWSW>QI'J\=D#GKCK.Y[,W-W M8R38<1BWL=(@P?18"1"L#'F$2I5$-H]P#SLEM&[,G8?RT$_!E@^!< =#^ 8> M#JT$9L,FF7,!^,B"IF !9QSWYV\D7TY%\W2E8W,(YB8\"_TS_]YL_[U39_T^ M2 W^]YZ0Q!W(#[W"U<_A]C:[;-FY_RDW3DY;':/CD^OFYWT9./YX>75Z4G] M=IG?WOT.7';+;CZQLT^7[.SRS[-/%U>W[.XS.[N^OOEXG!7_)T8]#R %NNA',\>Y,J//QJ$ZORHY>R&]%33LL,=Z9D] M>SS0'):T[[ T4=BA;@\"%_:H;WZ2C_:H.]ZCWCIZX2;U[L:;L0]I]WJK&K$>J6)%5+&D0V85G%(XEUX>JC1<8-XPF9(;=<]]Q MM;>1;D&WTACV5(Q_FN6FF;PII'GN->]PWS7O<[:H,I7C3;JZ,OWFQW*L\-[L M]KU5F&KYBUEO__+5F3W>!]%]2:#OBGV5GJJAW"I'C'1@=7\/K!8V.94NE;IL M!B2N(:XAKGF^+-SM1R:&(89Y?<%5!%;;-.&+NE*>G!PS\=KS60(?@6]MK5J2 MFYPP]WS,[/N5P')N'O&W90#,\ M:*F;LDF[*C$[J&J$ZP_,R.]/9?3?T$A?C7975)6S1&NOL9<R('.&*<%4!P55D M0D3KFK27@#!'F-M!S.U"71EW8KG,,D *GUV%(AKLSJZ"G0G#EKT/@-W&F"9Q M=P54.=M1UW7.EK/R8OLRJR$PU!8,M.A/J*"ES/G;3ITGC:KS9(& LK= *<%\ M[ -B:.W?W/9;PN%5?H66_]NES+8K-'CE*?_%4 ;N4F951V*5LR5[MS[9Z=(" M)0&+@.4^F<")NXRE!"P"UNL+KB+3HD[Y.]7V89I$F"/,K8^Y\FW9/F!NOU;^ M/W_Y[:(ZT8<.K?4_,5XWH2\7PT4[(YC*68FZ+FNV3IU9@WV9P! ::HP&9P$T M0L/>H*&N:Y;=4]="J/-\@(!"0"&@E#)QKE#XJCSY?<8SX8SG=>PK&<*JJO#^ MY)%421UE5CD27W_Q[XG*-G59'&PYT[I-!;8OWYTYV*>"]T/!)AK.%OQD.?AY[0+%8E MS$T)KB0?=ZY9!UPS7R6]0+BKGEJ#6E[KRJCZ<=:CEKND)4])95^<=Z(8HABB MF$+J3&=)+XABB&*>/2G;Q[D7Z0_ICZ.Y^\\Q!X9==OW6B-&T@'DB"%*Y_OJF M^<9\!H%ZV>>T)<71Z8+@BRV[DR.8=W\2#^RK&O'P%[:JB"G:A1M#&"1NJP->,LWL>28,-&<8" M[HI9+XF9U"Q4L;EA',D1CR:L)T+1EYZ$OP]>S '/@B/!;W?AU]Y#^-U-8?:3 M9NHA%)$>RC'B,$L9@@ ;BL 'A$4J&0S9V=4M^PT0%C4 DPO"V: 11\>+6[\V M>,Q[;#YZ.J%97N68JE(G/2U]0P33=F,_M9.6'S:=M)RI?B[N!@-F2X(8P&%# MZ*;=HM\77BSOQ8HQ@@>X:$BGXZ0_(.N870I/C'H@[4ZKP=K-5K=A>F('R<5; MCEO.A%]0Z=>4_J$;Z9/)(Y.WT3'(O3!Y>!"5#3E8NQ!T7$&3^S("2A+?H7E: MJA#<2/47X)TEH0_TY8M[$:@Q+FH>L#OC9=J?==H(M+KT$P4;#>X2!PF)*$7":[ATNQ[<*UB_IWUN)9FE#T "X?_!@J% M+J(1XUJ+6)OVY*V#N\3?B8PGA65UU$!X1AR!JG*K<0^@RI'H!U:O'F0\A">G M-W([+\K;%Z N-\RT"6_#>1/>P!2(8@2-,5?K(8\$SKFP^]8X@D'W/!6AD@23 MAKD*FPE(&*O(M *NPV^G?;_G08*?LZ;89GIJ$,)P^?A#*(RLU$@<3)GG3%L! M@PTN#A3>&?DO1$=,$ M?F13CB\&$1A1ZY ,1XH M!=H7"P\;N- I4\3,E[Z!X3@2]W@ 6P$^)@SWB4JC1M-.&Z?N%4%Y"LM1P!6 M'@K;>IA[V;X67>4T7 /B 3)UV:%.TVF'K($OLBM0W+U$G&+##5?BE!*Z:Z8# M8XY>CQQS,V$PX6\],W8@H,:4W'B1W(H1+G AX E)NDL*J#:!MJ.8I'E>QOXS MCTZT3 D[I9V1B(?*-XQCGP"_FYE8J%@,CCGSK<&*YRT(ZF"Q-:G*0EM#%;[' MMD4*9&RF1'8DK9P\KH<@ K@[XS5SIY;6$RJ:)6CX2P=HA?-P-GTE(!%9& 1@ M6I8ASYVJQWFG(^4)X0.A1VIDC28')K1&4"_3?9TI_Y;$\F5E"WNH. +\C3EQ M(7#=B H&WZI3(1!C:H88'8;W7>#[K@.8'>2: UZP!.5=;A.[.V1,RAI0IY5S MBLV==9>O12]*,(;>.LG02.UX#A#[ D1 EI#/K(SML4Q M,+V93XA:64>W\=^ MMS*XATY^E?Y I,-1QBSPOQ)P37+O#D7Z)4&W#E[L*:0^\,A.VV'AS+CXX@FHZOX"Y$H(.A8/\)1&OF M!G@I_H9/GAUYXRCX8+R\>,ZZ%Z>"N=_:/EV&5?!*O:&9B^&WD1B!ZJ$1/VS^ MN H;2SIN6ABJAV)<75LUAT9 RPYR^;:+\LT9(U!9$S(+A$Z-DT%^6?B]2!6+ MOBJ2Q%?KJ_)!6C)Y3S3^*D#G?>B6NI35!ILN9732F%:I0J+ M1@#!!=.,]$)G^M5MNYWO >>=)8,$>HIT4QQ/\5U$GD2D([J7C&A!4]!!3!\S M#7ID_K4A"63$J:L!EW_V8E6(X3V^Q%%1"VCNNPD+'%F8-!2@6BW=7DV-6>CB M[P3,>7]BC9;IDM'O? Z*.C!62"%T#X"_@W?3RUE8>;=XP$>8W(' MS8YC:$8BX.G"PCQ-9] Z^WSQT7U'NFY#, Q\#_16O(!K+?O2=JFD295-F1*J M,%VA2>/PY4V#SU/IWPYA^I'KLI/W99/FJ;7,9L^.7 L;_8BB"4+#AO?S@$=Q M$I/'ZLN+;I0Z;FA\'"TS=-U&)W?1ZJV:]TW=Q)D0A!-!S2S[M;M/!S(R0UQT M7@M&8\G M+LNF"PI%1\M._9:X6O;\]DQ@PK+]S!N!+;$9QI!% N8R@!&P=7-+QGP+AFXQ M$3$9NJT8NG]$I*IGX;9LT3#2=XY:PS[&RV*TF\BC:!GOAHL[XJL6<5\Z5\P% M,P6LD=#;-^;;-^]P'[&OHA&NH-N88C;_^^/@OP_L4KDO]=@$$M/X82&L@BRE M#$Y2Z@+46I@@&<0"4-[#9PDCH"E(@F$U9> MU(;B/#!X/0$W^,*L :O$[JOI\?";_LD$;\Q#YTVJKX3=9).NH5HQ9%[_>97H#S) M>^TJ2M'J[29314NTKQ);TDCRS9./(- D<0T"#!;)S*]_S](K"&HS*%-2IV82 M2P(:W:?/OO*'R02(!6(J^:( P,@2AN3DP#I(2J(B52L+$F <24&:630)BS%I M'N$,+(WO"?(KT/FZ09^W':./F]ZWZ4@K.^UO[4(_E.W8"SI+2=KKUJ;IZ;(; M!-UBPJ6T4'6^H4*[QY$QL8QB07OXMA**M=P""WYCD^&;V9I"60\IW9L8HV!B MO$1=H>FW_Y"'!>DGAQ2CRHNRAR^5(DWI\EH\T*@:T6$W034H.=3!&03F^SIK M"]W3"7SAWS7FG1?XI<5#V(QF@IR'@LL9R\P---U!9DXQ2;/ AR.\?:5MC8#U M&'O'VO*"_\/9._&N-N^!Q>[?Y>F>E:CO?[8KCWSO[G>=O4H(= MIEBR8B>"=Q697Z@DY!@(]T00Z M4 3:"4 OE .W4#7I'=%JYREM=EJ'(5BI?,*_+NKBF^#$')U**?/Y)..R?=0R M0X?3WFS2"8WT<8#J^@G<\E5WBY.95M<3J7 MRKR.;;\G)][US[\"OFT2U#:VWJK$0!*H<3Z3.6!.>I^;:-9P@8+ _*6AP=&> M?U$,"]:ET*>5';P\CY;$Z8G9L[0YK'BZ'3,?.&E!]H7V]":DU*8_-@L\4-AW M%Q=;6Z-ZI^.=V?4^Y;+D9MH__&.WYZ1+K3::L5H%_KR>3L."M,&/VKEV9"3' M#Y\,C_&Z:9CL=!R408$PRM,TOR+"05K 9!%Y-,MM:,O$!18-ENI&7FQ@Z$QV M*+ *PO#JI^$?.6QA+O]:9^T=#!(AJX:02302A9>4@@ _D.AV#E)-A7>7J%]S'BG[# M1>DHP54[O@@P(IR5XKWZQT*ML65>JT&5A@]\]W+)"7+V[? M][VMA_Z@/Z _H#^@/V#W'[Q;!Y G.-C[7ET^S&:W?W ZT(J' "VH*#\ +OKI MBG6489[&.O*@]+G@A#2VOA]KL,*&I1[COB@#@='MJV,@&.">6Y;";0']G+EA M.[#_U6*J.QD:]\'AW9^ PG=ORON@2-V:HN+9Y0^S2X]J;:BVF'KD4CFD.32>RYRR-6(O:R?T/(]YOCSFW>RW@NX[F,YS(KXS([G?G!/(OQ+,:S&,]B%EF,YS">PW@.XSF,YS _ MG*DW,[]S+L=T8\3X5&?,#_V5+#SM9K M3PV>&CPU,#6\ZRP?SU.#IX9'3@W;G:65>&+PQ/#(B>&Z]EB>*CQ5>*KP5.%3 MFV_&&)RZDF11/A7!2^Q3]FH55-0I)'^F/;*]U159/7E'KP\E/8!X>BJ$M>_S MS#Q=>;KJGJXZ*YWV=.7IRM.5+O'R9.7)RI/5(W!?> +S!.8)S!/80SD.U\;' M+CN![\^Z[>"^VO8<*P#;(P.5QRJ/51ZK/%8]!E!YK/)8Y;'*8]5C )7'*H]5 M'8/JD1B&#]CIW7=W7QUL?7-:WS'4-Z=]TJCV!%'I*>IJCP>AGB?O\F+2HYH7 MDT\7U9X@*JW:^'PVY0P'=5' ;05A68KJIPX/]-U[[I@)\?.Z]^R^\?E\#X8. MSUC">1[S?'G,WKXO'?,\9HVTZ(<$XF, W-H Z[%AG)=JSU>J[7BAYEF,9S&> MQ?B2!<]KG@:O\0KTP[BCGY+7^3C/HOLZGI]J*ZJ=WO:N[^S\ +K,4^6_3XP> MMGMO]CJ;V>CIX?G1PWJ$Q=<./AY_GB<_W?'MD#TU>&I0VH5OE.^)P:L6/]6C ML49>M=4GV*5).$S2I$K$2IP=3Z7ASMYN9XS9>ZW7A[[6BU4]1\+:\:/I/6&M MDX[DPT$>XSPKOY\GQW-R3U>>KGSFC">P)T%@7E7RF3.WY%%6YLR*/4J/C'EO M][;V.JLN?R['[4X"-<'G\\-[72!3H;#.:YJ:>&1TX- MK]]X8O#$X%4+GSSS -X.^&V1IREL+TBPK9@H5U,NY+W8WHN]#@[81\O7GPN! M;7>F_7BZ\G3EHT,^D69- /?L.+E7E3Q+]P3F"[MWM9.9Q4CSX4W>Q;\9.GAW9X/>GEJ\$$O MGT_CN>F/<]-]STP],7ABX-=>[G?6]W'QQN]Z])]FA[WRE.+5C@=V=_RE"H>I M:'O^P42 !:8TR<2&G-:^O;/U9^,WF>A7E"(*@1(Q0& .0/PE$&216D=PV\Z^<*?=O;V G@J3?*LDP5A MQVE8P?:J/*@F(JBS."FK(AG6E7V*?$1_/@(.MMO.P5.1_CU MIYVNMQ5F7>'3ZVZQ:907A"ASP)PR$!DB_N.@W*[VLUCG]Y.O&/:T6!]P7^Y6 MSD14 2VG\\V@3VSA<=PNXF0X'A=B#"PGB,*BF&/29CC-:U@.CI'7!;#J2U%6 M4Y!@R+:EN]WF5.)[) 2BM.24HDAI&?DDO -_2(H@$ZIW?#"<=\7:7N]T2JJ; MUZLD\M]__4M=;HS#@8$SW,1U065$,,?#T!%!,EZ482H M=?0)N"!EHC0OZT+H;P28D@L_G(G1WUY\/$0,^K^]?UTO]EYM[VS_6&P]^[CQ[W##^_>O?C?ANIC0_0BF0(>'(NK MX"R?ALNUQ;MH3ATI2O3CPC#BH^/?!^<77P;'%^?!T7'PI7_VC\%%_\/G07 ^ M./AZ=G1Q-#A_'#K@A:-_-&AUJG$GB &;B'M*JBPU&@%-(JG_*/G(H*R8-MW/&SIA:)Q+BMF?I3+ A0Y0W,@=K!+@DG0-^FPH0*\%5 M4DV8CP:C$%CI99C6(I@DH@B+:#(/)N&E"(9"9$',U _<&)X_SBMQC;5UGYUV M<][KLDSN0^#T^/ND DLYXB]\1##]CF#J1BX$2&CN%2'I%$A9E2BF9-X,0P1\ MSA>5A17P8+K'(BF_(8V%9@7\-;X-G+D$LP"[0^ E!Y/\RK8I@(2S<"S*7C#- MLZ3*"T:,J0B1P0.1 Z%;5&ZH6BDB3X2LN[(Y]CK6%^A6+\,D1?!O@)Z_489P M#R]?]#^>OWC%7-=BM9,0/6%D64X1/?BWDKH!EF0A=&C'=&QB+=G_4%17R'OP M +CWZBIG4VC)-I(4(;B MOPC[@ JJ21YO!A];S"N/]S]+EJVGD39#']1WL-5 1/P'\&/<1$S+XP.TRWC, M:K5-P%UZ93IF1$6 ;J<>6&#+#PE$@X=K'HC\5=4DS-;R:(Q00."PT^[@G^4= MP1TWMH' VZC$= :$58#-"\([*9"M(9-K%=#H_\O'&=T3FM7:IU@$)P='K&^, M\C3-KX@-\MOU%-:"5TKB=^,";A4P.T?[NV0_HF*LC6M&8X"OI&SU1GEVZ=FE M6>C]O6U?*]@8":S]O8TOP EI;34L9OS9_DR6%],P=8SL;7Q&+\RD$HDTE<_\ M[<76"_JYG(61^OGN7@R@O'&2\2;#NLK5+SBH1K^Y2N)J D\#((9Y$0-? '1* MPUDIWJM__-H,QYI]VXF\)GJYVQJJNT4N,&WF;R_>[/[YQL"H&XJ4+VX_\'NO M'\D^_?E^YOGNEOGN\PL\?&X'G]O7H3!CEY#8GGT/RCQ-XD"I# ^3GW&=G/V! MM![Z:<%;WJJ>>53SJ+825.NL):Q'-8]JUZ/:K3L$^F9/K:]]6N* *!<]$%T1 M]1K!=>VHO7-NN.+*[1]%OS\]&%)UGXK=^12^WKNMSG+2?<6^YS*>RW@NT\)E M]E_[H82>RW@NX[G,*KG,WM9KSV7N;ILN+XZZ0Q9SAWG'=FZS6<^L=)JG232_ M17;RA\-WNUO;K_?[KP_W/QZ^.=S;>[?/VUV$IB:"9MS8H$TQ+2>5!G9/&+&#/?X.^8H]@+(B1,RMIBST L M9GF95+U@C&(GHS2)9J8<93D"+1?&OGB%I#@/)63F#H)RP!8[(1^2?>97 KJ]YUQHCF/.IMC M0A7V:L+_E7":<^8KYM "6F"17!E,1!K#(3?,(RI!-BP*>J;"NA1 )$R8B?*R MV@Q.,/5F27;-PG[C''Z;Y15O,;[EMEIR.S%[1B:&M>S1I&=O!OW%EYND8QZG MMW'#N#G (A%&B&(S/#)\:@:7EL?!%65!<:%-(\T+$\!RG95FT)RMJ%?:?LY* ].WGMJ:5=Y;A>^US0()=K=XX.*(JQ*,I^!(P$!0;0 M!RB3H#BR_( ?C1)9WJ5Z;>_=SO[.A\/][9W=#]OO#C^\/=R2U6N#_NNWNZ\? M3#^4QM3*"]ALF/TPAEF;=I!LJ^-3+))W'W-DDS#X@@6G80=L;T&)/@ MFAG" M@YN 2U4C*J;7[S"!_'7'/0]DEK6&CI6@'*K\>50U%(OLHKQ(EJET7,2+M4\+ MJ*45P*D0+.DC6 6"5$''%KB%_4^*J2#M9,,58-80=@1IU6345+EO'( MMU \Z-=*605]6YUA\!W;8R@)8P.]MW"P7TIU.2PF08_A+A.D$F,Y QB'5W"F MCK!N+7M)O%G;5A(=$^EUK22"7I+ /L ;02 M/>4XOV0RWME2!'QW986VUPNN)@F8K[K+$C[5R9;?[?^Y&XQW%"P04,?)F$3Q MAQ!,A.!S,DU($F<=[AWK,AYB\Q:AR7,@QUVU-MBQ#G6]-KB.J@1[L>SZ8M4Q M(:^+:A+\NPY!EA5(-$AS5 =F64XG<:H@R_QKZ]6K Z^W'GSJGO$ MZVIO[SK>VVVTK[V[J%V,@&VZUJ N $F6ZEOWEJ /+"Z_;OYC,_@G6LLO)1H# MZIZRX0S(N0HYVJ_'-?#FG9TV*5JBSW_-Q$E#C)==^'^EBE87'6U1WYWM^2B! M 46A;2# ;6\&%SD@ +7[6KT39'N_XQ87/\\+\J;;DY" X[:2[IW%^:V%7;NH M*WNRH]M/]8-0W-%Q?%PC\"3C!EC$Y#D5%CPZ%(;;;]=6&.ZNI214+*$7W" H MB&7<348^CLC+HL@\ #TU'(NL(S6[*1UG19*:E+R=USUY0PM2DO59E>-@VSQZ MA^@*'X?EQBC!G _XC23=8(CQ,".6+.ZB"8A M_C2C-XW-RD_#YG:8T8;C0A";L*+@"QN>AG_D!;>=-/O%)]6.EGGG[5WASW([ MA'?A#)[_GDR!3:5==:[<^6G>^\Z\]EO=GB"N"^TE@LW#>5R3;;=5@S;4TK46 MO81=V.=94>AP1>F&].-"*+%_\']?C\Z/+HY.CG^\YZ5UB%8N:AWJ@0V1+XC[ MYU6!6L]I#F3=D>?6Y:X?Q;"HL0/0]MN; XZAB8-W1I6=6B6D'>;3*>I<.',/ M?[< 1W6X7G"419ND&*R$7^YW'.(!P5/6(;PIU1!,[>!,$.0]'%IG$16+$LL:!HF7G]KL+USV'_[ M<>?CZ[=O]W9WWW#FU&%_]^#CX,EDUM-[R)Q9!1R*-+]"O;BD*R8TJ*EA[Q1X M_;2>!JD@>E!(0(WM+3\8"8IPABH&/\J-]=J]'E4^%I3)2(GCTG.!7S9H1RV# M0:9>^_G&!\-',VN 8-/5EA9K@^ZU)97+V]&V=K8Z->0*$8Y )>G9K1M]7[ZU MZ[SW,!WT#NA]L1?3F)[0B6JO&0Q])SS! !/MY MFG"5@?DER,O; O>18.1*:J?;(=RJ$=T'5WW;K 78'D@5E(V/.P!US=!Q?1FD M1[H%I#,1P;NAG>_;UOI:JPWE>W'X7AR+KW77CO/)-^+P[7[N+_P\BWF^+.;- M&\]B5J;//#&UY2ZHHK>YYKV= M\+@+JMR:7CH%WL^4*MM>"_.&WOK(H:="5V]\OV1OW=Q20-T%59ZJ0K>]F$;S MS!4Z;]T\6V)XZXG!6S>W$QXMZ8=>"UN!5'GR6IBW;KQUXZV;=9!<3TE 7>B, M]I60T\_-&>V:JMYU)ZUN ,Q3(2YO(WEB6F9#O>LL1/1TR#/M:>6WP MNF1!G\KCS:R?G"WH,NE=8-)Q7F/IX8_(KV>33G@3\)Y ON%V;^===\'N>P/L MJ3"RYVW78N^%]\'1=%9S7PAN.N;5AOW)]JX-]70/4R-W'K!QUMUK:^= M+G1BH?;%[7U8O)+JE=0'$8_[W5G2SUY#]:;V TC4AP3BV@.N@YGLM^_RYO2& M*\9AEOR'VHZ9'NOPPX>P3& 1*>SX5[(C\J$HHR*A=L?]+.Y'$8X @P_3_,[D M;H,X][??'1STW[[^N+?S>F_G8&?GS6";V\F]V]O=WW_X0>T=X0']N-"6X-/@ M>'#6_QSTCP^#\Z]?OO3/_A6?@M.3 MST<'1X,?;[+[8*WRL'/^05[,:PAZ-1DB8X%+X7O,0^7*H_?"]X 5]^@1.M M7UC='%ZN(VSEPWU%[>ZZY!G32- W%(,+?P+$0 PFP#6VG612E4.\H9@U(-%T^ B*G7K/SSXDJ;P9>\ MI G=L,ZR+^G=TF"'5 [84IN>ZX=5PT]ZPCG8'+]03F QA 1 FYO=ZH41/<8* M2S21]+C?X%QG)X='1\ CCN<2!T&RNQ=&80J E@0H MD*(R-2TGLH4SKF,FC6-S677FQ4D'>$ZZ%$F3P!7TZ((2]#$:0)[AV(,1V+/P M]1ZPMHHFOLCM]V@[\E)A-]B:TXPS%_^N<5F>7D[]K[5"T,'GA/[X M_Y][Q!.!Q:<\%"(XF21YCZ!8,W>VW+8$^Q'V^;8DQ2B,=--EN-.LG@H0:B7? M]C0I2_5 M1YJ<2TW.F\$!:.G8JEU\GXFL1()DU ;@!:-:I+ &;DG-<5$'!BRH,R!FB22I M&O DA0]M/\#-%Z731SHI EQA/ =4"L>"18.9'F)VD;B83EO!WV557H"\G:6( MO-@Y'@@Y99 ;B5;6LUFJ;D(UPT74DC1WXY;ABPCD(D:ZU-UX>921G$\C'YTD M,W-S7<^W[6:\[?_7W1A:_A$?=X8FG.+TC**">SFE>T&P#X!!S/#^.CD#SPN0 M-PB7&0O VO2&KMKKP&G:!?O7\P%*],'YQ=&7_@7(R95(\UDA0$D,5?-U'FQU M(T^08@>']2(O).0WS!W9 [PQ T7-TN+@[V)F#WC+$CVQB_2!/G!#$#@@G#_U M^Z<@G M!??5+1V@!*4[#;R!LK%#<#KH=9\)=(TD/*W;9.% #Y6 M"_J@XGCV6!M^AX -4,OCS: /FC-\1PU2@\M(\4 AT*-)LI+"VZ@*<"&2-7" MP5@(V+(&36@Y8*4B]YZ/&1;%'+_/F^:-RE=![2[%J$X!5)<,R31'MPW\%$M( M_LK_"]NMX(II#$8^3),Q=SG_-4C@MI."?V]:[_<6%^(/.YJ&)1=^)5^\U"V! MG5^Q$H6< F=))Y>HX3.%Q];"I"1&T% M5# 8I1J7)O94+J/ 3>:S'/Z77'3P1?A*+$%9!<,\_R9W]O+%;Y\__ X$*^%/ MS>NES@#VI[@B-=K2@X#C5%(PRG,"KP:U7>ZV8=S)R8A+MELJDP^'H["H'@KK MM23;0&.B(BE="#B((%(,7F++^QE/4(&7PDQAD:5[O_HU0-+#/3EW*+++I,@S MA"1!QOH37@Y #=5N^E,E<3J(TC"14V'@%JM4:E>/5#H='IV#K7EQ=/QU=2T_EZ#B-EN M&],*:J^9%PCZ04Y"R/@F40)E<5C$9?!U1HS\Y8O^^5= Y^-\D];;V'K[XT,0 MEJI%QHN*Z-IJ4+^\R&=)!'O9Y^DM#5VJYRI3ZO'=UUNOW@=G6E X$SBMR>+X M\J$K^'B&""K-\ ,",L^490]T,D"3NT;W$/"-W4JZ'=\HC1LTCDM4\9U4"1*V,ZX;HH8); M&0-T@7F-*GX +<"7><'#7=!) +?$TP,#P6H(>3;DHK^4]C@/!+[A_^X4U!N' MIX+0GX(\1(<=,4LYC.;] =CEZ:64F85\NW%_-.8*(T9RO@\Z2(:. MEX;T+[BI/'&'N9"CB2]=S@>36&D+(1=L:H(8LXOEB*'M('0]\[9!DT.K_3^6 MIAD6>GZ,-<1R5[/-F*K4NJ2E(P'0M4H=$) @2$CG9.NZ MS)6*C^JK2ZM&^;] M%_[P!3]& T^OGV@K^3_-?S=L[8H, /)9J@TLHVJ]%5S'>H]\G7#7%FF2QP.^ MCJ-WNW5D["RV!UY/3X8]8(L@YM[K!QW]ZP6V M:+VFACX6B3KL4CE$<&(7 ,E6^ Q%-DOD'"!&)R+NF=?9/Y,QC&QM1/L8Z@(A M#)Q?#SDF4]&]G5 B7'WLM'Q24C'^B=.46\Y9^U+UMYPA,Y2T[>(/Z$P.-8@LD\0;=? M.!YC,+52$IN48+T;\VR"F#I"1\UPKN?*P3X+2F6$8\="_AL]@KA 4Z1>!R2E M_<-7C!)"#*!DKZ0P2H/2*IWPHQMT/,#O?\0#/);PTC\Q=!AF%O]+KN5=KF6K MYW*7MKM,>@L!*="2 >5/^BAO\DL&@&@B5;%65,XD/I9+72^;P6_Y%;Q5H 8R MES/!BP!4M%+IDG),L23_)0IN4MHSQLE(4\$DPT868RF@HY%AL)R_X"Z6>P:R MG-R)@GR!(;J2'&ZDC#%%K< ,;)UI^2T!UR;G;JNS#C;I&C<6ST FX*X;U44A M)0;L?,[17Y)0-G?2TD\QCBN1HMH'=S9YM!ZFL\'!Y_[Y.64_M4\4OY(T4/ M4A2/L[!.$/+M%"MW< M)W[B84_)!^K\($A^>H[PBD[T\@RYM?1ZO4+7*.A4Q,[,P-FQR*).#Z5$0;OD M=@6WYOND&(L,M:'F\.W=IG=#4:Q%."K\X.31S/B7%-W(E\<3'IZ<#G ?,GM0 MVA9+=M?AK:P6TTZ+/!(BEJ=!05=>!_0>*99H3MA^+TPK>7 \'"W@8;D$$?>( M^1!&KD;&;JU:QG[L'YT%O_<_?QUT'YOY:$*7)B$N$M(#K4Q3CL(RT984$\]D M9!@E1H6WT1%L<U+QEC=EWB-KC:',&VJ$9^TUVKSD< RC/2S1#1-C?*H0 MK!L ;F0\\9%(TL9B6-FA\%* Q)59N$W'O$, 'SBQ,#B?H'_4\M&NB#&<3_*B MVL!#VJ=9>UW@A*/1?&\OD8VQ0O.JDYW_"O=7))N->8[LV6;%P/:W,B. M*>S(6>LF]$A>#!W1I" 4*LY_U!F+&^WN;63;:+G6FO&$"X56WHCESU'>%+T MEL;-\ 65%67Y&MLDCU)EW)2JQ40J:\7U]QGHPB)U_Y@46#KI:N$0 ]I7J&ZT MR7Y60>@%\EXBOK 'U2@@1MNP$Y1!I2@K.Q83A)=ADJ(<5BG;(U ^\D*GS"&Z M@?5!+U >4E)^XVHG^IF!MRI@7HYR MAV/P.SHY$9/""P2$?)(O_Y5+3.20S2?),-'1:SX)J25-%9T3!9$&XS]JI9[@ MVD,L]0O'-C@ M@$I^I54J?;N:5/4U/Q*\=U5KC9KYL!0%931JA$?U5><\&"3]IPI_S67V1F7^ MV@L0C!C4LG(GJ42*+[H2T21+_EVK0@/BNY@^.0,KB?(;,B8ZW)IPKSE6]-&^ MWC3\GDSAJ'0I=4GW:!TJR6:UQ#9JJ=!XLLX6GE5H!;9H6:JH7(FE/92Z2AYO M3!88%T)P1J(,5?!)B8UFRJ9!DJ!BNVBN$TY2M"#F MFT%?,I1?2H>EP(_2XVZB/9;@FB2B"(MH,G>NF+ UOT+^PR^340!'=2*1TK1O M%X,J&^0SOF\B/=O*2IL 4N/Z>(S&,[OJ&=X"0[>:(( D*!$C*+^"W=>C''-N MR_?7DA4;,!$8?Y*(_O9BZP7]#""-U,^21&PZVU-DM:3H-UA&K]%UA2X_1N\3S"KH-*]K<[.Z]_O'D"-HCI\J@_ M=+ %NK"=&G7&,@[0^]]UCO\C62QYOTGV,.NE9"%@.@GBMHR=*NE*J4O(0,A7 M8;0O2VA3.K^S&O'KG .MLF31]FTJ):]%=-,,%*\RM@ MC*@& >,@GW#,SAIVT1DUA[50E<=&96372\S;]#'PY._)?WW)?\Z:X@:MWV#BL I[LJ()12M8CA%F2,OD1_63>8]BT%SO M@(:DK)X' R(-R B7FO$BFU":F;)86@]$JX/BE89%.]_J+7_/<+S%1;0OLS1G M):64F& O:#)=9_6>N@Y.RC*P0.!Q35-8FO(62BM!GC=/,&@/O/$2U[C$U@@Z M2(^)+:,0TW*Y282U*B563:>4I2"W0VM?4E2M4)LA!Y)._6V]6)0+45Y0V$KZ M !BC0%O+;LIA\:S5L];'S5IWKV.MF@TX5ITDIC^DF5_F=1$)RM5N,1,Q41^) MM"Y-!3=8Y>QX:WDZ^Z5:=.3(/V/Q.0>4.24$2UE5J8B.$RWU180M#BAB02J1 MT79;H5Z:907I,32QM9/+%3%VFX 4@G1159GF-R09\PM/U8:"+K4O(T'R<<%I:U M@<*RPW\IVL//$!>3?"=5GX[]0'2>!*S)9M:U^2[E#(3]A]M+NW1,>#JQ1?B>4?'P9?^V3\&%_T/GP> T =? MSXXNCE;57\3D;UO\RDYCX0I$U4ZHS@AK*)XPA+]CJ=]2CM@+QMB8(>.\'<8C MS0@I2I!G8JYT@E&=Q=A]IS7_A)DU5[18&UU(II&=(MQ/+>6YU#,IDNWJ'.Y+ MKYB>1BZ?9KX\(5<;9Z ]EGJ&+XV$) M(.L9I=Q^C\DA2F*F@[I*;K:F.A:8M M&78)Y)K2BEG*8J8\)=57^89Y1.JD*+L2UF] >@$BH;*#6NYF<&+IV4U!NK#? M.*=*B(JW&-]R6UH#-0G_Z*DMPEA5ZS3V:,=$^XLO-TG'BJTU-#@11I,%%8%6:6%ILN.#K>SAY3D',7?VII5SEDMV+N"'-\@@W,S@8' S"] M4.W 7_8_?S[Y9_\8M.F/)V?!XP];/6*TC4QYE,];1IR=@3GQFBU6:&#,.D7U*+$ M7KD'YGP)KY$_734\SKE%(YR &A.0GW\LEFQBL38'SZ)]0X+83&1U-7,_S]XK M; 904L:4ZJU%KGZ<"E!A_R_]716>M#J$96K;M!G91$P:DJ 0PD.F\Z3L1VRI MYM$D+,96;]8\:SVD+!7G!+E%ZT%W]*#EG"Y8U* ZJ@'(W,159?S-< 5*"C_* M^,ZB4':C=#CC0E$C@0E3.^'K'#H-_JDZQUHWJ"QK>R.H=6@7'6$^[MBK]&?X+XS@T- M$)9QHF)HU+252BL/<@E?\R:"2ZIKEM6I97&(C?[&T@LN!;#=PSV2QX2]U9&" M,)F7,AV/C^W\SOD^6CVQB%+.D*)NUS+;A,(JH:C0)5F9FIU-:F *K$?8\5L+^?'+\:>/ST>\# MT#G.SP>K4"T^+V13*P_>3/=JF^F^MT*U:NNIIZ6 DFV(:5!4*:FE"K,QRTA^ MU.K7*744OJ67R:;8[ 74VTC(O2R\_>J1W.%U_8-;X-C]A5[_.9Z"0'H,I0.4 ME2Y@M$WE&#O'18GD1N1(E],5N"VFS(!-IIAT):P&;12FC%5R*W=2'1%97XM. M4H5LZ(DIBG393CA@JN (_O;B?7Y!BCMWKO..VP+]%3>7-S2]8)K M'ZE9%^JOXL^HRAHWXRR!*'W:C$/RP\]Y!@KBQ&=B8!>B[H6_7&:>@@JE2 MX5!C7JY5EB0SOI(-7.S*'%(/PECF>5:E=!B2S0][^F2.+B,SB+6JNRYB6C@- MQZR,2UDMB_/-V6. Y%P)"%+]L6DQUX68P&X1JW8ZI*[0FYSA>1T+,6D)[$AJ M=KVR>@U9W84>!:,YM/AQ3[;=4J:X0?\PO405D)4WV0-[::?J'I>CR*&];2HE MM@S%\VY0;:T:AG$I%@SB1LMLG:;G#$"Q/$@TU('\JT0W=DLK96!^L:)H?+%8 M B:9&^G:C/',?3A-CC5OH!VIC%@FADW212Y=YO:?G2Y6&/VX/2F!S2&+=O2" MC4H?JRU<3ZK-6L *"5)$?UMB\AT3 Y8+ LY'O#D9=%SR8<6E\4=BL ;2M.&> ML^K"1I04X#?L+:&^S7R#JV.H=1 WO=(;>"3TY ;X/A3A?[ E:-8ZO4?IPQ3R MN0X=> 0.O2EG=!GW#674TS/,[.WA)*9M?2&MI_\P=FN2C-#)5HVK5$=0VPQ[Z;EH"RUERVAZS_+UI=+-\O80$KGA-$ELPNPSE3O M%&)]["TS'5;4)Z?A_/KA A?7[P;M42M/B7H%RY2# [/# M?E%@_^3N&A*L/QDO 'Z^U7SF#4;OF%:M-"I