American Funds Insurance Series®
Prospectus
Class 1 shares
May
1, 2022
SEC. File Nos. 002-86838
811-03857
UNITED STATES
SECURITIES AND EXCHANGE COMMISSION
Washington, D.C. 20549
FORM N-1A
Registration Statement
Under
the Securities Act of 1933
Post-Effective Amendment No. 100
and
Registration Statement
Under
the Investment Company Act of 1940
Amendment No. 100
AMERICAN FUNDS INSURANCE SERIES
(Exact Name of Registrant as Specified in Charter)
333 South Hope Street
Los Angeles, California 90071-1406
(Address of Principal Executive Offices)
Registrant's telephone number, including area code:
(213) 486-9200
Steven I. Koszalka, Secretary
American Funds Insurance Series
333 South Hope Street
Los Angeles, California 90071-1406
(Name and Address of Agent for Service)
Copies to:
Lea Anne Copenhefer
Morgan, Lewis & Bockius LLP
One Federal Street
Boston, MA 02110-1726
(Counsel for the Registrant)
Approximate date of proposed public offering:
It is proposed that this filing become effective on May 1, 2022, pursuant to paragraph (a) of Rule 485.
American Funds Insurance Series® Prospectus May
1, 2022 |
|
American Funds Global Balanced Fund
Table of contents
| American Funds Global Balanced Fund 1 | Investment objectives, strategies and risks 6 Management and organization 10 Purchases and redemptions of shares 15 |
|||
| The U.S. Securities and Exchange Commission has not approved or disapproved of these securities. Further, it has not determined that this prospectus is accurate or complete. Any representation to the contrary is a criminal offense. |
American Funds Global Balanced Fund
Investment objectives This fund seeks the balanced accomplishment of three objectives: long-term growth of capital, conservation of principal and current income.
Fees and expenses of the fund This table describes the fees and expenses that you may pay if you buy, hold and sell an interest in Class 1 shares of the fund. You may pay other fees, such as insurance contract fees and expenses, which are not reflected in the tables and examples below. If insurance contract fees and expenses were reflected, expenses shown would be higher.
| Annual fund operating expenses (expenses that you pay each year as a percentage of the value of your investment) | Class 1 |
| Management fee | 0.66% |
| Other expenses | 0.07 |
| Total annual fund operating expenses | 0.73 |
| Fee waiver* | 0.22 |
| Total annual fund operating expenses after fee waiver | 0.51 |
* The investment adviser is currently waiving a portion of its management fee equal to .22% of the fund’s net assets. This waiver will be in effect through at least May 1, 2023. The waiver may only be modified or terminated with the approval of the fund’s board.
Example This example is intended to help you compare the cost of investing in Class 1 shares of the fund with the cost of investing in other mutual funds.
The example assumes that you invest $10,000 in the fund for the time periods indicated and then redeem all of your shares at the end of those periods. The example also assumes that your investment has a 5% return each year and that the fund’s operating expenses remain the same. The example does not reflect insurance contract expenses. If insurance contract expenses were reflected, expenses shown would be higher. The example reflects the fee waiver described above through the expiration date of such waiver and total annual fund operating expenses thereafter. No sales charge (load) or other fees are charged by the fund upon redemption, so you would incur these hypothetical costs whether or not you were to redeem your shares at the end of the given period. Although your actual costs may be higher or lower, based on these assumptions your costs would be:
| 1 year | 3 years | 5 years | 10 years | |
| Class 1 | $52 | $211 | $384 | $886 |
Portfolio turnover The fund pays transaction costs, such as commissions, when it buys and sells securities (or “turns over” its portfolio). A higher portfolio turnover rate may indicate higher transaction costs. These costs, which are not reflected in annual fund operating expenses or in the example, affect the fund’s investment results. During the most recent fiscal year, the fund’s portfolio turnover rate was 39% of the average value of its portfolio.
1 American Funds Insurance Series / Prospectus
Principal investment strategies As a balanced fund with global scope, the fund seeks to invest in equity and debt securities around the world that offer the opportunity for growth and/or provide dividend income, while also constructing the portfolio to protect principal and limit volatility.
Normally the fund will maintain at least 45% of the value of its assets in common stocks and other equity investments. Although the fund’s equity investments focus on medium to larger capitalization companies, the fund’s investments are not limited to a particular capitalization size.
Normally the fund will invest at least 25% of the value of its assets in bonds and other debt securities (including money market instruments). These will consist of investment-grade securities (rated Baa3 or better or BBB– or better by Nationally Recognized Statistical Rating Organizations designated by the fund’s investment adviser or unrated but determined to be of equivalent quality by the fund’s investment adviser).
The fund will allocate its assets among various countries, including the United States (but in no fewer than three countries). Under normal market conditions, the fund will invest at least 40% of its net assets in issuers outside the United States, unless market conditions are not deemed favorable by the fund’s investment adviser, in which case the fund would invest at least 30% of its net assets in issuers outside the United States.
The fund’s ability to invest in issuers outside the United States includes investing in emerging markets.
The fund may invest in bonds and other debt securities, including securities issued and guaranteed by the U.S. government, securities issued by federal agencies and instrumentalities and securities backed by mortgages or other assets. The fund may also invest in securities of governments, agencies, corporations and other entities domiciled outside the United States. These investments will typically be denominated in currencies other than U.S. dollars.
The investment adviser uses a system of multiple portfolio managers in managing the fund’s assets. Under this approach, the portfolio of the fund is divided into segments managed by individual managers.
The fund relies on the professional judgment of its investment adviser to make decisions about the fund’s portfolio investments. The basic investment philosophy of the investment adviser is to seek to invest in attractively valued securities that, in its opinion, represent good, long-term investment opportunities. Securities may be sold when the investment adviser believes that they no longer represent relatively attractive investment opportunities.
Principal risks
This section describes the principal risks associated with investing in the fund. You may lose money by investing in the fund. The likelihood of loss may be greater if you invest for a shorter period of time. Investors in the fund should have a long-term perspective and be able to tolerate potentially sharp declines in value.
Market conditions — The prices of, and the income generated by, the common stocks, bonds and other securities held by the fund may decline – sometimes rapidly or unpredictably – due to various factors, including events or conditions affecting the general economy or particular industries; overall market changes; local, regional or global political, social or economic instability; governmental, governmental agency or central bank responses to economic conditions; and currency exchange rate, interest rate and commodity price fluctuations.
Economies and financial markets throughout the world are highly interconnected. Economic, financial or political events, trading and tariff arrangements, wars, terrorism, cybersecurity events, natural disasters, public health emergencies (such as the spread of infectious disease) and other circumstances in one country or region, including actions taken by governmental or quasi-governmental authorities in response to any of the foregoing, could have impacts on global economies or markets. As a result, whether or not the fund invests in securities of issuers located in or with significant exposure to the countries affected, the value and liquidity of the fund’s investments may be negatively affected by developments in other countries and regions.
Issuer risks — The prices of, and the income generated by, securities held by the fund may decline in response to various factors directly related to the issuers of such securities, including reduced demand for an issuer’s goods or services, poor management performance, major litigation, investigations or other controversies related to the issuer, changes in government regulations affecting the issuer or its competitive environment and strategic initiatives such as mergers, acquisitions or dispositions and the market response to any such initiatives.
Investing in growth-oriented stocks — Growth-oriented common stocks and other equity-type securities (such as preferred stocks, convertible preferred stocks and convertible bonds) may involve larger price swings and greater potential for loss than other types of investments.
Investing in income-oriented stocks — The value of the fund’s securities and income provided by the fund may be reduced by changes in the dividend policies of, and the capital resources available for dividend payments at, the companies in which the fund invests.
Investing outside the United States — Securities of issuers domiciled outside the United States, or with significant operations or revenues outside the United States, may lose value because of adverse political, social, economic or market developments (including social instability, regional conflicts, terrorism and war) in the countries or regions in which the issuers operate or generate revenue. These securities may also lose value due to changes in foreign currency exchange rates against the U.S. dollar and/or currencies of other countries. Issuers of these securities may be more susceptible to actions of foreign governments, such as nationalization, currency blockage or the imposition of price controls or punitive taxes, each of which could adversely impact the value of these securities. Securities markets in certain countries may be more volatile and/or less liquid than those in the United States. Investments outside the United States may also be subject to different accounting and auditing practices and standards and different regulatory, legal and reporting
American Funds Insurance Series / Prospectus 2
requirements, and may be more difficult to value, than those in the United States. In addition, the value of investments outside the United States may be reduced by foreign taxes, including foreign withholding taxes on interest and dividends. Further, there may be increased risks of delayed settlement of securities purchased or sold by the fund. The risks of investing outside the United States may be heightened in connection with investments in emerging markets.
Investing in emerging markets — Investing in emerging markets may involve risks in addition to and greater than those generally associated with investing in the securities markets of developed countries. For instance, emerging market countries tend to have less developed political, economic and legal systems and accounting and auditing practices and standards than those in developed countries. Accordingly, the governments of these countries may be less stable and more likely to intervene in the market economy, for example, by imposing capital controls, nationalizing a company or industry, placing restrictions on foreign ownership and on withdrawing sale proceeds of securities from the country, and/or imposing punitive taxes that could adversely affect the prices of securities. Information regarding issuers in emerging markets may be limited, incomplete or inaccurate, and there may be fewer rights and remedies available to the fund and its shareholders. In addition, the economies of these countries may be dependent on relatively few industries, may have limited access to capital and may be more susceptible to changes in local and global trade conditions and downturns in the world economy. Securities markets in these countries can also be relatively small and have substantially lower trading volumes. As a result, securities issued in these countries may be more volatile and less liquid, and may be more difficult to value, than securities issued in countries with more developed economies and/or markets. Less certainty with respect to security valuations may lead to additional challenges and risks in calculating the fund’s net asset value. Additionally, emerging markets are more likely to experience problems with the clearing and settling of trades and the holding of securities by banks, agents and depositories that are less established than those in developed countries.
Investing in debt instruments — The prices of, and the income generated by, bonds and other debt securities held by the fund may be affected by factors such as the interest rates, maturities and credit ratings of these securities.
Rising interest rates will generally cause the prices of bonds and other debt securities to fall. A general rise in interest rates may cause investors to sell debt securities on a large scale, which could also adversely affect the price and liquidity of debt securities and could also result in increased redemptions from the fund. Falling interest rates may cause an issuer to redeem, call or refinance a debt security before its stated maturity, which may result in the fund failing to recoup the full amount of its initial investment and having to reinvest the proceeds in lower yielding securities. Longer maturity debt securities generally have greater sensitivity to changes in interest rates and may be subject to greater price fluctuations than shorter maturity debt securities.
Bonds and other debt securities are also subject to credit risk, which is the possibility that the credit strength of an issuer or guarantor will weaken or be perceived to be weaker, and/or an issuer of a debt security will fail to make timely payments of principal or interest and the security will go into default. A downgrade or default affecting any of the fund’s securities could cause the value of the fund’s shares to decrease. Lower quality debt securities generally have higher rates of interest and may be subject to greater price fluctuations than higher quality debt securities. Credit risk is gauged, in part, by the credit ratings of the debt securities in which the fund invests. However, ratings are only the opinions of the rating agencies issuing them and are not guarantees as to credit quality or an evaluation of market risk. The fund’s investment adviser relies on its own credit analysts to research issuers and issues in seeking to assess credit and default risks.
Investing in mortgage-related and other asset-backed securities — Mortgage-related securities, such as mortgage-backed securities, and other asset-backed securities, include debt obligations that represent interests in pools of mortgages or other income-bearing assets, such as consumer loans or receivables. While such securities are subject to the risks associated with investments in debt instruments generally (for example, credit, extension and interest rate risks), they are also subject to other and different risks. Mortgage-backed and other asset-backed securities are subject to changes in the payment patterns of borrowers of the underlying debt, potentially increasing the volatility of the securities and the fund’s net asset value. When interest rates fall, borrowers are more likely to refinance or prepay their debt before its stated maturity. This may result in the fund having to reinvest the proceeds in lower yielding securities, effectively reducing the fund’s income. Conversely, if interest rates rise and borrowers repay their debt more slowly than expected, the time in which the mortgage-backed and other asset-backed securities are paid off could be extended, reducing the fund’s cash available for reinvestment in higher yielding securities. Mortgage-backed securities are also subject to the risk that underlying borrowers will be unable to meet their obligations and the value of property that secures the mortgages may decline in value and be insufficient, upon foreclosure, to repay the associated loans. Investments in asset-backed securities are subject to similar risks.
Liquidity risk — Certain fund holdings may be or may become difficult or impossible to sell, particularly during times of market turmoil. Liquidity may be impacted by the lack of an active market for a holding, legal or contractual restrictions on resale, or the reduced number and capacity of market participants to make a market in such holding. Market prices for less liquid or illiquid holdings may be volatile, and reduced liquidity may have an adverse impact on the market price of such holdings. Additionally, the sale of less liquid or illiquid holdings may involve substantial delays (including delays in settlement) and additional costs and the fund may be unable to sell such holdings when necessary to meet its liquidity needs or may be forced to sell at a loss.
Management — The investment adviser to the fund actively manages the fund’s investments. Consequently, the fund is subject to the risk that the methods and analyses, including models, tools and data, employed by the investment adviser in this process may be flawed or incorrect and may not produce the desired results. This could cause the fund to lose value or its investment results to lag relevant benchmarks or other funds with similar objectives.
Your investment in the fund is not a bank deposit and is not insured or guaranteed by the Federal Deposit Insurance Corporation or any other governmental agency, entity or person. You should consider how this fund fits into your overall investment program.
3 American Funds Insurance Series / Prospectus
Investment results The following bar chart shows how the investment results of the Class 1 shares of the fund have varied from year to year, and the following table shows how the fund’s average annual total returns for various periods compare with a broad measure of securities market results and other applicable measures of market results. This information provides some indication of the risks of investing in the fund. The 60%/40% MSCI All Country World Index/Bloomberg Global Aggregate Index blends the MSCI All Country World Index, which measures global equity markets, with the Bloomberg Global Aggregate Index, which measures investment-grade bonds (rated BBB-/Baa3 and above), by weighting their total returns at 60% and 40% respectively. This assumes the blend is rebalanced monthly. Past investment results (before and after taxes) are not predictive of future investment results. Past investment results (before and after taxes) are not predictive of future investment results. Figures shown reflect fees and expenses associated with an investment in the fund, but do not reflect insurance contract fees and expenses. If insurance contract fees and expenses were included, results would have been lower. Updated information on the fund’s investment results can be obtained by visiting capitalgroup.com/afis.
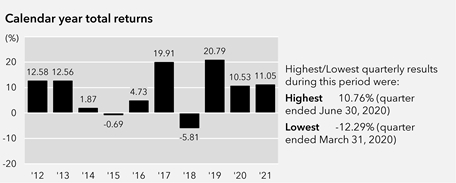
| Average annual total returns For the periods ended December 31, 2021: | 1 year | 5 years | 10 years | Lifetime |
| Fund (inception date — 5/2/11) | 11.05% | 10.86% | 8.44% | 7.28% |
| 60%/40% MSCI All Country World Index/Bloomberg Global Aggregate Index (reflects no deduction for sales charges, account fees, expenses or U.S. federal income taxes) | 8.78 | 10.11 | 7.91 | 6.50 |
| MSCI All Country World Index (reflects no deduction for sales charges, account fees, expenses or U.S. federal income taxes) | 18.54 | 14.40 | 11.85 | 9.40 |
| Bloomberg Global Aggregate Index (reflects no deduction for sales charges, account fees, expenses or U.S. federal income taxes) | –4.71 | 3.36 | 1.77 | 1.76 |
American Funds Insurance Series / Prospectus 4
Management
Investment
adviser Capital Research and Management CompanySM
Portfolio managers The individuals primarily responsible for the portfolio management of the
fund are:
| Portfolio
manager/ Series title (if applicable) |
Portfolio
manager experience in this fund |
Primary
title with investment adviser |
| Alfonso Barroso | Less than 1 year | Partner – Capital Research Global Investors |
| Andrew A. Cormack | 1 year | Partner – Capital Fixed Income Investors |
| Bradford F. Freer | Less than 1 year | Partner – Capital Research Global Investors |
| Thomas H. Høgh | 3 years | Partner – Capital Fixed Income Investors |
| Winnie Kwan | Less than 1 year | Partner – Capital Research Global Investors |
Purchase and sale of fund shares Shares of the fund are not sold directly to the general public. The fund is offered only as an underlying investment option for variable insurance contracts, and insurance company separate accounts and qualified feeder funds — and not the holders of variable insurance contracts — are the shareholders of the fund. Although the fund does not require a minimum amount for initial or subsequent purchases from insurance companies, your insurance company may impose investment minimums for your purchase of the fund.
You may sell (redeem) shares on any business day. You must sell (redeem) shares through your insurance company.
Tax information See your variable insurance contract prospectus for information regarding the federal income tax treatment of your variable insurance contract and related distributions.
Payments to broker-dealers and other financial intermediaries The fund is not sold directly to the general public but instead is offered as an underlying investment option for variable insurance contracts. The fund and its related companies may make payments to the sponsoring insurance company (or its affiliates) for distribution and/or other services. These payments may be a factor that the insurance company considers in including the fund as an underlying investment option in the variable insurance contract. The prospectus (or other offering document) for your variable insurance contract may contain additional information about these payments.
5 American Funds Insurance Series / Prospectus
Investment objectives, strategies and risks
American Funds Global Balanced Fund This fund seeks the balanced accomplishment of three objectives: long-term growth of capital, conservation of principal and current income. While it has no present intention to do so, the fund’s board may change the fund’s investment objectives without shareholder approval upon 60 days’ written notice to shareholders.
Normally, the fund will maintain at least 45% of the value of its assets in common stocks and other equity investments under normal market conditions. Although the fund’s equity investments focus on medium to larger capitalization companies, the fund’s investments are not limited to a particular capitalization size.
Normally the fund will invest at least 25% of the value of its assets in bonds and other debt securities (including money market instruments). These will consist of investment-grade securities (rated Baa3 or better or BBB– or better by Nationally Recognized Statistical Rating Organizations designated by the fund’s investment adviser or unrated but determined to be of equivalent quality by the fund’s investment adviser).
Under normal market conditions, the fund will invest at least 40% of its net assets in issuers outside the United States, unless market conditions are not deemed favorable by the fund’s investment adviser, in which case the fund would invest at least 30% of its net assets in issuers outside the United States.
The fund’s ability to invest in issuers outside the United States includes investing in emerging markets.
The fund may also invest to a limited extent in lower quality, higher yielding debt securities including those convertible into common stocks (rated Ba1 or below or BB+ or below by Nationally Recognized Statistical Rating Organizations designated by the fund’s investment adviser or unrated but determined to be of equivalent quality by the fund’s investment adviser). Such securities are sometimes referred to as “junk bonds.”
The fund may invest in bonds and other debt securities, including securities issued and guaranteed by the U.S. government, securities issued by federal agencies and instrumentalities and securities backed by mortgages or other assets. The fund may also invest in securities of governments, agencies, corporations and other entities domiciled outside the United States. These investments will typically be denominated in currencies other than U.S. dollars.
There are no restrictions on the maturity or duration of the bonds and other debt securities in the fund’s portfolio.
The fund may enter into currency transactions to provide for the purchase or sale of a currency needed to purchase a security denominated in such currency. In addition, the fund may enter into agreements, known as forward currency contracts, to purchase or sell a specific currency at a future date at a fixed price. The fund may enter into forward currency contracts to protect against changes in currency exchange rates, to increase exposure to a particular foreign currency, to shift exposure to currency fluctuations from one currency to another or to seek to increase returns.
The fund may also hold cash or cash equivalents, including commercial paper and short-term securities issued by the U.S. government, its agencies and instrumentalities. The percentage of the fund invested in such holdings varies and depends on various factors, including market conditions and purchases and redemptions of fund shares. The investment adviser may determine that it is appropriate to invest a substantial portion of the fund’s assets in such instruments in response to certain circumstances, such as periods of market turmoil. For temporary defensive purposes, the fund may invest without limitation in such instruments. A larger percentage of such holdings could moderate the fund’s investment results in a period of rising market prices. Alternatively, a larger percentage of such holdings could reduce the magnitude of the fund’s loss in a period of falling market prices and provide liquidity to make additional investments or to meet redemptions.
The fund may invest in other funds managed by the investment adviser or its affiliates (“Central Funds”) to more effectively invest in a diversified set of securities in a specific asset class such as money market instruments, bonds and other securities. Shares of Central Funds are only offered for purchase to the fund’s investment adviser and its affiliates and other funds, investment vehicles and accounts managed by the fund’s investment adviser and its affiliates. When investing in Central Funds, the fund bears its proportionate share of the expenses of the Central Funds in which it invests but does not bear additional management fees through its investment in such Central Funds. The investment results of the portions of the fund’s assets invested in the Central Funds will be based upon the investment results of the Central Funds.
The fund may also lend portfolio securities to brokers, dealers and other institutions that provide cash or U.S. Treasury securities as collateral in an amount at least equal to the value of the securities loaned.
The fund relies on the professional judgment of its investment adviser to make decisions about the fund’s portfolio investments. The basic investment philosophy of the investment adviser is to seek to invest in attractively valued securities that, in its opinion, represent good, long-term investment opportunities. The investment adviser believes that an important way to accomplish this is through fundamental analysis, which may include meeting with company executives and employees, suppliers, customers and competitors. Securities may be sold when the investment adviser believes that they no longer represent relatively attractive investment opportunities.
The following are principal risks associated with investing in the fund.
Market conditions — The prices of, and the income generated by, the common stocks, bonds and other securities held by the fund may decline – sometimes rapidly or unpredictably – due to various factors, including events or conditions affecting the general economy or particular industries; overall market changes; local, regional or global political, social or economic instability; governmental, governmental agency or central bank responses to economic conditions; and currency exchange rate, interest rate and commodity price fluctuations.
American Funds Insurance Series / Prospectus 6
Economies and financial markets throughout the world are highly interconnected. Economic, financial or political events, trading and tariff arrangements, wars, terrorism, cybersecurity events, natural disasters, public health emergencies (such as the spread of infectious disease) and other circumstances in one country or region, including actions taken by governmental or quasi-governmental authorities in response to any of the foregoing, could have impacts on global economies or markets. As a result, whether or not the fund invests in securities of issuers located in or with significant exposure to the countries affected, the value and liquidity of the fund’s investments may be negatively affected by developments in other countries and regions.
Issuer risks — The prices of, and the income generated by, securities held by the fund may decline in response to various factors directly related to the issuers of such securities, including reduced demand for an issuer’s goods or services, poor management performance, major litigation, investigations or other controversies related to the issuer, changes in government regulations affecting the issuer or its competitive environment and strategic initiatives such as mergers, acquisitions or dispositions and the market response to any such initiatives.
Investing in growth-oriented stocks — Growth-oriented common stocks and other equity-type securities (such as preferred stocks, convertible preferred stocks and convertible bonds) may involve larger price swings and greater potential for loss than other types of investments.
Investing in income-oriented stocks — The value of the fund’s securities and income provided by the fund may be reduced by changes in the dividend policies of, and the capital resources available for dividend payments at, the companies in which the fund invests.
Investing outside the United States — Securities of issuers domiciled outside the United States, or with significant operations or revenues outside the United States, may lose value because of adverse political, social, economic or market developments (including social instability, regional conflicts, terrorism and war) in the countries or regions in which the issuers operate or generate revenue. These securities may also lose value due to changes in foreign currency exchange rates against the U.S. dollar and/or currencies of other countries. Issuers of these securities may be more susceptible to actions of foreign governments, such as nationalization, currency blockage or the imposition of price controls or punitive taxes, each of which could adversely impact the value of these securities. Securities markets in certain countries may be more volatile and/or less liquid than those in the United States. Investments outside the United States may also be subject to different accounting and auditing practices and standards and different regulatory, legal and reporting requirements, and may be more difficult to value, than those in the United States. In addition, the value of investments outside the United States may be reduced by foreign taxes, including foreign withholding taxes on interest and dividends. Further, there may be increased risks of delayed settlement of securities purchased or sold by the fund. The risks of investing outside the United States may be heightened in connection with investments in emerging markets.
Investing in emerging markets — Investing in emerging markets may involve risks in addition to and greater than those generally associated with investing in the securities markets of developed countries. For instance, emerging market countries tend to have less developed political, economic and legal systems and accounting and auditing practices and standards than those in developed countries. Accordingly, the governments of these countries may be less stable and more likely to intervene in the market economy, for example, by imposing capital controls, nationalizing a company or industry, placing restrictions on foreign ownership and on withdrawing sale proceeds of securities from the country, and/or imposing punitive taxes that could adversely affect the prices of securities. Information regarding issuers in emerging markets may be limited, incomplete or inaccurate, and there may be fewer rights and remedies available to the fund and its shareholders. In addition, the economies of these countries may be dependent on relatively few industries, may have limited access to capital and may be more susceptible to changes in local and global trade conditions and downturns in the world economy. Securities markets in these countries can also be relatively small and have substantially lower trading volumes. As a result, securities issued in these countries may be more volatile and less liquid, and may be more difficult to value, than securities issued in countries with more developed economies and/or markets. Less certainty with respect to security valuations may lead to additional challenges and risks in calculating the fund’s net asset value. Additionally, emerging markets are more likely to experience problems with the clearing and settling of trades and the holding of securities by banks, agents and depositories that are less established than those in developed countries.
Investing in debt instruments — The prices of, and the income generated by, bonds and other debt securities held by the fund may be affected by factors such as the interest rates, maturities and credit ratings of these securities.
Rising interest rates will generally cause the prices of bonds and other debt securities to fall. A general rise in interest rates may cause investors to sell debt securities on a large scale, which could also adversely affect the price and liquidity of debt securities and could also result in increased redemptions from the fund. Falling interest rates may cause an issuer to redeem, call or refinance a debt security before its stated maturity, which may result in the fund failing to recoup the full amount of its initial investment and having to reinvest the proceeds in lower yielding securities. Longer maturity debt securities generally have greater sensitivity to changes in interest rates and may be subject to greater price fluctuations than shorter maturity debt securities.
Bonds and other debt securities are also subject to credit risk, which is the possibility that the credit strength of an issuer or guarantor will weaken or be perceived to be weaker, and/or an issuer of a debt security will fail to make timely payments of principal or interest and the security will go into default. A downgrade or default affecting any of the fund’s securities could cause the value of the fund’s shares to decrease. Lower quality debt securities generally have higher rates of interest and may be subject to greater price fluctuations than higher quality debt securities. Credit risk is gauged, in part, by the credit ratings of the debt securities in which the fund invests. However, ratings are only the opinions of the rating agencies issuing them and are not guarantees as to credit quality or an evaluation of market risk. The fund’s investment adviser relies on its own credit analysts to research issuers and issues in seeking to assess credit and default risks.
Investing in mortgage-related and other asset-backed securities — Mortgage-related securities, such as mortgage-backed securities, and other asset-backed securities, include debt obligations that represent interests in pools of mortgages or other income-bearing assets, such
7 American Funds Insurance Series / Prospectus
as residential mortgage loans, home equity loans, mortgages on commercial buildings, consumer loans and equipment leases. While such securities are subject to the risks associated with investments in debt instruments generally (for example, credit, extension and interest rate risks), they are also subject to other and different risks. Mortgage-backed and other asset-backed securities are subject to changes in the payment patterns of borrowers of the underlying debt, potentially increasing the volatility of the securities and the fund’s net asset value. When interest rates fall, borrowers are more likely to refinance or prepay their debt before its stated maturity. This may result in the fund having to reinvest the proceeds in lower yielding securities, effectively reducing the fund’s income. Conversely, if interest rates rise and borrowers repay their debt more slowly than expected, the time in which the mortgage-backed and other asset-backed securities are paid off could be extended, reducing the fund’s cash available for reinvestment in higher yielding securities. Mortgage-backed securities are also subject to the risk that underlying borrowers will be unable to meet their obligations and the value of property that secures the mortgages may decline in value and be insufficient, upon foreclosure, to repay the associated loans. Investments in asset-backed securities are subject to similar risks, as well as additional risks associated with the assets underlying those securities.
Liquidity risk — Certain fund holdings may be or may become difficult or impossible to sell, particularly during times of market turmoil. Liquidity may be impacted by the lack of an active market for a holding, legal or contractual restrictions on resale, or the reduced number and capacity of market participants to make a market in such holding. Market prices for less liquid or illiquid holdings may be volatile, and reduced liquidity may have an adverse impact on the market price of such holdings. Additionally, the sale of less liquid or illiquid holdings may involve substantial delays (including delays in settlement) and additional costs and the fund may be unable to sell such holdings when necessary to meet its liquidity needs or may be forced to sell at a loss.
Management — The investment adviser to the fund actively manages the fund’s investments. Consequently, the fund is subject to the risk that the methods and analyses, including models, tools and data, employed by the investment adviser in this process may be flawed or incorrect and may not produce the desired results. This could cause the fund to lose value or its investment results to lag relevant benchmarks or other funds with similar objectives.
The following are additional risks associated with investing in the fund.
Interest rate risk — The values and liquidity of the securities held by the fund may be affected by changing interest rates. For example, the values of debt securities may decline when interest rates rise and increase when interest rates fall. Longer maturity debt securities generally have greater sensitivity to changes in interest rates and may be subject to greater price fluctuations than shorter maturity debt securities. The fund may invest in variable and floating rate securities. When the fund holds variable or floating rate securities, a decrease in market interest rates will adversely affect the income received from such securities and the net asset value of the fund’s shares. Although the values of such securities are generally less sensitive to interest rate changes than those of other debt securities, the value of variable and floating rate securities may decline if their interest rates do not rise as quickly, or as much, as market interest rates. Conversely, floating rate securities will not generally increase in value if interest rates decline. During periods of extremely low short-term interest rates, certain of the fund’s debt securities may not be able to maintain a positive yield and, given the current low interest rate environment, risks associated with rising rates are currently heightened.
Investing in securities backed by the U.S. government — Securities backed by the U.S. Treasury or the full faith and credit of the U.S. government are guaranteed only as to the timely payment of interest and principal when held to maturity. Accordingly, the current market values for these securities will fluctuate with changes in interest rates and the credit rating of the U.S. government. Securities issued by U.S. government-sponsored entities and federal agencies and instrumentalities that are not backed by the full faith and credit of the U.S. government are neither issued nor guaranteed by the U.S. government.
Investing in lower rated debt instruments — Lower rated bonds and other lower rated debt securities generally have higher rates of interest and involve greater risk of default or price declines due to changes in the issuer’s creditworthiness than those of higher quality debt securities. The market prices of these securities may fluctuate more than the prices of higher quality debt securities and may decline significantly in periods of general economic difficulty. These risks may be increased with respect to investments in junk bonds.
Currency transactions — In addition to the risks generally associated with investing in derivative instruments, the use of forward currency contracts involves the risk that currency movements will not be accurately predicted by the investment adviser, which could result in losses to the fund. While entering into forward currency contracts could minimize the risk of loss due to a decline in the value of the hedged currency, it could also limit any potential gain that may result from an increase in the value of the currency. Additionally, the adviser may use forward currency contracts to increase exposure to a certain currency or to shift exposure to currency fluctuations from one country to another. Forward currency contracts may expose the fund to potential gains and losses in excess of the initial amount invested.
Exposure to country, region, industry or sector — Subject to the fund’s investment limitations, the fund may have significant exposure to a particular country, region, industry or sector. Such exposure may cause the fund to be more impacted by risks relating to and developments affecting the country, region, industry or sector, and thus its net asset value may be more volatile, than a fund without such levels of exposure. For example, if the fund has significant exposure in a particular country, then social, economic, regulatory or other issues that negatively affect that country may have a greater impact on the fund than on a fund that is more geographically diversified.
Investing in derivatives — The use of derivatives involves a variety of risks, which may be different from, or greater than, the risks associated with investing in traditional securities, such as stocks and bonds. Changes in the value of a derivative may not correlate perfectly with, and may be more sensitive to market events than, the underlying asset, rate or index, and a derivative instrument may expose the fund to losses in excess of its initial investment. Derivatives may be difficult to value, difficult for the fund to buy or sell at an opportune time or price and difficult to terminate or otherwise offset. The fund’s use of derivatives may result in losses to the fund, and investing in derivatives may reduce the fund’s returns and increase the fund’s price volatility. The fund’s counterparty to a derivative transaction (including, if applicable, the fund’s clearing broker, the derivatives exchange or the clearinghouse) may be unable or unwilling to honor its financial obligations in respect of the transaction.
American Funds Insurance Series / Prospectus 8
Lending of portfolio securities — Securities lending involves risks, including the risk that the loaned securities may not be returned in a timely manner or at all and/or the risk of a loss of rights in the collateral if a borrower or the lending agent defaults. These risks could be greater for non-U.S. securities. Additionally, the fund may lose money from the reinvestment of collateral received on loaned securities in investments that decline in value, default or do not perform as expected.
Cybersecurity breaches — The fund may be subject to operational and information security risks through breaches in cybersecurity. Cybersecurity breaches can result from deliberate attacks or unintentional events, including “ransomware” attacks, the injection of computer viruses or malicious software code, the use of vulnerabilities in code to gain unauthorized access to digital information systems, networks or devices, or external attacks such as denial-of-service attacks on the investment adviser’s or an affiliate’s website that could render the fund’s network services unavailable to intended end-users. These breaches may, among other things, lead to the unauthorized release of confidential information, misuse of the fund’s assets or sensitive information, the disruption of the fund’s operational capacity, the inability of fund shareholders to transact business, or the destruction of the fund’s physical infrastructure, equipment or operating systems. As a result of these potential outcomes, the fund could incur violations of applicable privacy and other laws, reputational damage, additional costs associated with corrective measures and/or financial loss. The fund may also be subject to additional risks if its third-party service providers, such as the fund’s investment adviser, transfer agent, custodian, administrators and other financial intermediaries, experience similar cybersecurity breaches and potential outcomes. Cybersecurity risks may also impact issuers of securities in which the fund invests, which may cause the fund’s investments in such issuers to lose value.
In addition to the principal investment strategies described above, the fund has other investment practices that are described in the statement of additional information, which includes a description of other risks related to the fund’s principal investment strategies and other investment practices. The fund’s investment results will depend on the ability of the fund’s investment adviser to navigate the risks discussed above as well as those described in the statement of additional information.
Fund comparative indexes — The 60%/40% MSCI All Country World Index/Bloomberg Global Aggregate Index blends the MSCI All Country World Index with the Bloomberg Global Aggregate Index by weighting their cumulative total returns at 60% and 40%, respectively. This assumes the blend is rebalanced monthly. The MSCI All Country World Index is a free float-adjusted market capitalization-weighted index that is designed to measure equity market results in the global developed and emerging markets, consisting of more than 40 developed and emerging market country indexes. Results reflect dividends gross of withholding taxes through December 31, 2000, and dividends net of withholding taxes thereafter. This index is unmanaged, and its results include reinvested dividends and/or distributions but do not reflect the effect of sales charges, commissions, account fees, expenses or U.S. federal income taxes. The Bloomberg Global Aggregate Index represents the global investment-grade fixed income markets. This index is unmanaged, and its results include reinvested distributions but do not reflect the effect of sales charges, commissions, account fees, expenses or U.S. federal income taxes.
Portfolio holdings A description of the fund’s policies and procedures regarding disclosure of information about its portfolio holdings is available in the statement of additional information.
9 American Funds Insurance Series / Prospectus
Management and organization
Investment adviser Capital Research and Management Company, an experienced investment management organization founded in 1931, serves as the investment adviser to the Series and other funds, including the American Funds. Capital Research and Management Company is a wholly owned subsidiary of The Capital Group Companies, Inc. and is located at 333 South Hope Street, Los Angeles, California 90071. Capital Research and Management Company manages the investment portfolios and business affairs of the Series. The total management fee paid by each fund to its investment adviser for the most recent fiscal year, including any amounts waived, in each case expressed as a percentage of average net assets of that fund, appears in the Annual Fund Operating Expenses table for each fund. Please see the statement of additional information for further details. A discussion regarding the basis for the approval of the Series’ Investment Advisory and Service Agreement by the Series’ board of trustees is contained in the Series’ annual report to shareholders for the fiscal year ended December 31, 2021.
Capital Research and Management Company manages equity assets through three equity investment divisions and fixed income assets through its fixed income investment division, Capital Fixed Income Investors. The three equity investment divisions — Capital International Investors, Capital Research Global Investors and Capital World Investors — make investment decisions independently of one another.
The equity investment divisions may, in the future, be incorporated as wholly owned subsidiaries of Capital Research and Management Company. In that event, Capital Research and Management Company would continue to be the investment adviser, and day-to-day investment management of equity assets would continue to be carried out through one or more of these subsidiaries. Although not currently contemplated, Capital Research and Management Company could incorporate its fixed income investment division in the future and engage it to provide day-to-day investment management of fixed income assets. Capital Research and Management Company and each of the funds it advises have received an exemptive order from the U.S. Securities and Exchange Commission that allows Capital Research and Management Company to use, upon approval of the funds’ boards, its management subsidiaries and affiliates to provide day-to-day investment management services to the funds, including making changes to the management subsidiaries and affiliates providing such services. The Series’ shareholders approved this arrangement; however, there is no assurance that Capital Research and Management Company will incorporate its investment divisions or exercise any authority granted to it under the exemptive order.
In addition, shareholders of the Series have approved a proposal to reorganize the Series into a Delaware statutory trust. However, the Series reserved the right to delay implementing the reorganization and has elected to do so.
The Capital SystemSM Capital Research and Management Company uses a system of multiple portfolio managers in managing mutual fund assets. Under this approach, the portfolio of a fund is divided into segments managed by individual managers. In addition, Capital Research and Management Company’s investment analysts may make investment decisions with respect to a portion of a fund’s portfolio. Investment decisions are subject to a fund’s objective(s), policies and restrictions and the oversight of the appropriate investment-related committees of Capital Research and Management Company and its investment divisions.
Certain senior members of Capital Fixed Income Investors, the investment adviser’s fixed income investment division, serve on the Portfolio Strategy Group. The group utilizes a research-driven process with input from the investment adviser’s analysts, portfolio managers and economists to define investment themes on a range of macroeconomic factors, including duration, yield curve and sector allocation. Where applicable, the investment decisions made by a fund’s fixed income portfolio managers are informed by the investment themes discussed by the group.
American Funds Insurance Series / Prospectus 10
The primary individual portfolio managers for each of the funds are:
| Portfolio
manager for the Series/Title (if applicable) |
Primary title with investment adviser (or affiliate) and investment experience | Portfolio
manager’s role in management of, and experience in, the fund(s) |
| Donald D. O’Neal Co-President and Trustee | Partner – Capital International Investors Investment professional for 36 years, all with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: Growth-Income Fund — 16 years |
| Alan N. Berro Co-President | Partner – Capital World Investors Investment professional for 37 years in total; 31 years with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: Washington Mutual Investors Fund — 5 years Asset Allocation Fund — 22 years |
| Carl M. Kawaja Vice President | Partner – Capital World Investors Investment professional for 35 years in total; 31 years with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: New World Fund — 23 years |
| Sung Lee Vice President | Partner – Capital Research Global Investors Investment professional for 28 years, all with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: Capital
World Growth and Income Fund — 1 year |
| Keiko McKibben Vice President | Partner – Capital Research Global Investors Investment professional for 28 years in total; 24 years with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: Growth-Income Fund — 8 years (plus 10 years of prior experience as an investment analyst for the fund) |
| Renaud H. Samyn Vice President | Partner – Capital Research Global Investors Investment professional for 21 years, all with Capital Research and Management Company or affiliate |
Serves as an equity portfolio manager for: Global Small Capitalization Fund — 3 years (plus
15 years of prior experience as an investment analyst for the fund) |
| Pramod Atluri | Partner – Capital Fixed Income Investors Investment professional for 24 years in total; 6 years with Capital Research and Management Company or affiliate |
Serves
as a fixed income portfolio manager for: The Bond Fund of America — 6 years |
| Aline Avzaradel | Partner – Capital International Investors Investment professional for 19 years in total; 18 years with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: Capital Income Builder — 2 years |
| Alfonso Barroso | Partner – Capital Research Global Investors Investment professional for 28 years, all with Capital Research and Management Company or affiliate |
Serves as an equity portfolio manager for: Capital
World Growth and Income Fund — 1 year |
| Michael Beckwith | Vice President – Capital Research Global Investors Investment professional for 20 years in total; 3 years with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: Global Small Capitalization Fund — 3 years |
| Paul Benjamin | Partner – Capital World Investors Investment professional for 17 years, all with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: Growth Fund — 4 years (plus 12 years of prior experience as an investment analyst for the fund) |
| David J. Betanzos | Partner – Capital Fixed Income Investors Investment professional for 22 years in total; 20 years with Capital Research and Management Company or affiliate |
Serves
as a fixed income portfolio manager for: The Bond Fund of America — 1 year American Funds Mortgage Fund — 8 years U.S. Government Securities Fund — 7 years |
| Jeremy Burge | Partner – Capital World Investors Investment professional for 40 years in total; 20 years with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: Capital World Growth and Income Fund — 1 year (plus 1 year of prior experience as an investment analyst for the fund) |
| Grant L. Cambridge | Partner – Capital International Investors Investment professional for 29 years in total; 25 years with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: Capital Income Builder — 2 years |
| Mark L. Casey | Partner – Capital International Investors Investment professional for 22 years, all with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: Growth Fund — 5 years (plus 11 years of prior experience as an investment analyst for the fund) Washington Mutual Investors Fund — 1 year |
| Philip Chitty | Partner – Capital Fixed Income Investors Investment professional for 28 years in total; 18 years with Capital Research and Management Company or affiliate |
Serves
as a fixed income portfolio manager for: Capital World Bond Fund — 1 year |
| Tom Chow | Partner – Capital Fixed Income Investors Investment professional for 33 years in total; 7 years with Capital Research and Management Company or affiliate |
Serves
as a fixed income portfolio manager for: American High-Income Trust— 7 years |
11 American Funds Insurance Series / Prospectus
| Portfolio
manager for the Series/Title (if applicable) |
Primary title with investment adviser (or affiliate) and investment experience | Portfolio
manager’s role in management of, and experience in, the fund(s) |
| Michael Cohen | Partner – Capital World Investors Investment professional for 31 years in total; 22 years with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: Capital World Growth and Income Fund — 4 years International Growth and Income Fund — Less than 1 year |
| Patrice Collette | Partner – Capital World Investors Investment professional for 28 years in total; 22 years with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: Global Growth Fund — 7 years (plus 14 years of prior experience as an investment analyst for the fund) International Growth and Income Fund — Less than 1 year |
| Andrew A. Cormack | Vice President – Capital Fixed Income Investors Investment professional for 18 years in total; 4 years with Capital Research and Management Company or affiliate |
Serves
as a fixed income portfolio manager for: Capital World Bond Fund — 3 years |
| David A. Daigle | Partner – Capital Fixed Income Investors Investment professional for 28 years, all with Capital Research and Management Company or affiliate |
Serves
as a fixed income portfolio manager for: Asset Allocation Fund — 13 years American High-Income Trust— 13 years (plus 9 years of prior experience as an investment analyst for the fund) |
| Oliver V. Edmonds | Vice President – Capital Fixed Income Investors Investment professional for 19 years, all with Capital Research and Management Company or affiliate |
Serves
as a fixed income portfolio manager for: American Funds Mortgage Fund - 1 year |
| Peter Eliot | Partner – Capital International Investors Investment professional for 27 years in total; 18 years with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: Asset Allocation Fund — 6 years |
| Charles E. Ellwein | Partner – Capital Research Global Investors Investment professional for 26 years in total; 16 years with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: Growth-Income Fund — 7 years (plus 8 years of prior experience as an investment analyst for the fund) |
| Brady L. Enright | Partner – Capital World Investors Investment professional for 31 years in total; 25 years with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: Washington Mutual Investors Fund — 1 year |
| Paul Flynn | Partner – Capital World Investors Investment professional for 26 years in total; 24 years with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: Global Growth Fund — 5 years International Growth and Income Fund — Less than 1 year |
| J. Blair Frank | Partner – Capital Research Global Investors Investment professional for 29 years in total; 28 years with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: Growth-Income Fund — 16 years |
| Bradford F. Freer | Partner – Capital Research Global Investors Investment professional for 30 years in total; 28 years with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: Global Small Capitalization Fund — 4 years New World Fund — 5 years (plus 13 years of prior experience as an investment analyst for the fund) American Funds Global Balanced Fund – Less than 1 year |
| Irfan M. Furniturewala | Partner – Capital International Investors Investment
professional for |
Serves
as an equity portfolio manager for: (plus
1 year of prior experience as an investment analyst for the fund) |
| Nicholas J. Grace | Partner – Capital Research Global Investors Investment professional for 32 years in total; 28 years with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: New World Fund — 10 years (plus 8 years of prior experience as an investment analyst for the fund) |
| Leo Hee | Partner – Capital World Investors Investment
professional for 28 years in total; |
Serves
as an equity portfolio manager for: Capital World Growth and Income Fund — 1 year (plus 10 years of prior experience as an investment analyst for the fund) International Growth and Income Fund — Less than 1 year |
| David A. Hoag | Partner – Capital Fixed Income Investors Investment professional for 34 years in total; 31 years with Capital Research and Management Company or affiliate |
Serves
as a fixed income portfolio manager for: Capital Income Builder — 2 years The Bond Fund of America — 15 years |
| Thomas H. Høgh | Partner – Capital Fixed Income Investors Investment professional for 35 years in total; 32 years with Capital Research and Management Company or affiliate |
Serves
as a fixed income portfolio manager for: American Funds Global Balanced Fund —3 years Capital World Bond Fund — 16 years |
| Roz Hongsaranagon | Partner – Capital World Investors Investment professional for 20 years, all with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: Global Growth Fund — 4 years |
| Dawid Justus | Partner – Capital World Investors Investment professional for 23 in total years; 17 years with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: New World Fund — 2 years (plus 14 years of prior experience as an investment analyst for the fund) |
American Funds Insurance Series / Prospectus 12
| Portfolio
manager for the Series/Title (if applicable) |
Primary title with investment adviser (or affiliate) and investment experience | Portfolio
manager’s role in management of, and experience in, the fund(s) |
| Jonathan Knowles | Partner – Capital World Investors Investment professional for 30 years, all with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: Global Growth Fund — 9 years (plus 10 years of prior experience as an investment analyst for the fund) New World Fund — 2 years (plus 8 years of prior experience as an investment analyst for the fund) |
| Winnie Kwan | Partner – Capital Research Global Investors Investment professional for 26 years in total; 22 years with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: New World Fund — 2 years (plus 2 years of prior experience as an investment analyst for the fund) Capital Income Builder — 2 years American Funds Global Balanced Fund –Less than 1 year |
| Harold H. La | Partner – Capital Research Global Investors Investment professional for 24 years in total; 23 years with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: Global Small Capitalization Fund — 14 years (plus 4 years of prior experience as an investment analyst for the fund) |
| Jeffrey T. Lager | Partner – Capital International Investors Investment professional for 27 years in total; 26 years with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: Washington Mutual Investors Fund — 1 year Asset Allocation Fund — 15 years |
| Jin Lee | Partner – Capital World Investors Investment professional for 26 years in total; 25 years with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: Washington Mutual Investors Fund — 1 year Capital World Growth and Income Fund— 1 year Asset Allocation Fund — 4 years |
| Steven D. Lotwin | Partner – Capital Fixed Income Investors Investment professional for 21 years, all with Capital Research and Management Company or affiliate |
Serves
as a fixed income portfolio manager for: Ultra-Short Bond Fund — 4 years |
| James B. Lovelace | Partner – Capital Research Global Investors Investment professional for 40 years, all with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: Capital Income Builder — 2 years |
| Robert W. Lovelace | Partner – Capital International Investors Investment professional for 37 years, all with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: New World Fund — 2 years |
| Fergus N. MacDonald | Partner – Capital Fixed Income Investors Investment professional for 30 years in total; 19 years with Capital Research and Management Company or affiliate |
Serves
as a fixed income portfolio manager for: Capital Income Builder — 2 years The Bond Fund of America — 1 year American Funds Mortgage Fund — 11 years U.S. Government Securities Fund — 12 years |
| Aidan O’Connell | Partner – Capital Research Global Investors Investment professional for 24 years in total; 18 years with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: Global Small Capitalization Fund — 8 years (plus 9 years of prior experience as an investment analyst for the fund) |
| Lara Pellini | Partner – Capital World Investors Investment professional for 21 years, all with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: Capital World Growth and Income Fund — 1 year (plus 10 years of prior experience as an investment analyst for the fund) |
| Piyada Phanaphat | Partner – Capital World Investors Investment professional for 19 years in total; 15 years with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: New World Fund — 5 years (plus 9 years of prior experience as an investment analyst for the fund) |
| Anne-Marie Peterson | Partner – Capital World Investors Investment professional for 28 years in total; 17 years with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: Growth Fund — 4 years (plus 11 years of prior experience as an investment analyst for the fund) |
| John R. Queen | Partner – Capital Fixed Income Investors Investment professional for 32 years in total; 20 years with Capital Research and Management Company or affiliate |
Serves
as a fixed income portfolio manager for: Asset Allocation Fund — 6 years |
| Caroline Randall | Partner – Capital Research Global Investors Investment professional for 25 years in total; 17 years with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: Capital Income Builder — 2 years |
| Andraz Razen | Partner – Capital World Investors Investment professional for 24 years in total; 18 years with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: Growth Fund — 9 years (plus 3 years of prior experience as an investment analyst for the fund) |
| William L. Robbins | Partner – Capital International Investors Investment professional for 30 years in total; 27 years with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: Growth-Income Fund — 10 years (plus 12 years of prior experience as an investment analyst for the fund) |
| Carlos A. Schonfeld | Partner – Capital International Investors Investment professional for 24 years, all with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: Growth-Income Fund — 8 years |
13 American Funds Insurance Series / Prospectus
| Portfolio
manager for the Series/Title (if applicable) |
Primary title with investment adviser (or affiliate) and investment experience | Portfolio
manager’s role in management of, and experience in, the fund(s) |
| Akira Shiraishi | Partner – Capital International Investors Investment professional for 25 years in total; 19 years with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: New World Fund — 2 years |
| Kirstie Spence | Partner – Capital Fixed Income Investors Investment professional for 27 years, all with Capital Research and Management Company or affiliate |
Serves
as a fixed income portfolio manager for: New World Fund — 2 years (plus 9 years of prior experience as an investment analyst for the fund) |
| Eric H. Stern | Partner – Capital International Investors Investment
professional for |
Serves
as an equity portfolio manager for: Washington Mutual Investors Fund — 1 year |
| Andrew B. Suzman | Partner – Capital World Investors Investment professional for 29 years, all with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: International Growth and Income Fund — Less than 1 year |
| Tomonori Tani | Partner – Capital World Investors Investment professional for 24 years in total; 18 years with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: New World Fund — 4 years |
| Lisa Thompson | Partner – Capital International Investors Investment professional for 34 years in total; 28 years with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: New World Fund — 2 years International Growth and Income Fund — Less than 1 year |
| Christopher Thomsen | Partner – Capital Research Global Investors Investment professional for 25 years, all with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: International Fund — 16 years New World Fund — 2 years |
| Tara L. Torrens | Partner – Capital Fixed Income Investors Investment professional for 19 years, all with Capital Research and Management Company or affiliate |
Serves
as a fixed income portfolio manager for: American High-Income Trust —4 years |
| Ritchie Tuazon | Partner – Capital Fixed Income Investors Investment professional for 22 years in total; 11 years with Capital Research and Management Company or affiliate |
Serves
as a fixed income portfolio manager for: U.S. Government Securities Fund — 7 years |
| Bradley J. Vogt | Partner – Capital Research Global Investors Investment professional for 35 years, all with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: Capital Income Builder — 2 years |
| Diana Wagner | Partner – Capital World Investors Investment
professional for |
Serves
as an equity portfolio manager for: Washington Mutual Investors Fund — 1 year |
| Shannon Ward | Partner – Capital Fixed Income Investors Investment professional for 30 years in total; 5 years with Capital Research and Management Company or affiliate |
Serves
as a fixed income portfolio manager for: American High-Income Trust — 5 years |
| Steven T. Watson | Partner – Capital International Investors Investment professional for 35 years in total; 32 years with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: Capital Income Builder — 4 years International Growth and Income Fund — Less than 1 year |
| Gregory W. Wendt | Partner – Capital Research Global Investors Investment professional for 35 years, all with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: Global Small Capitalization Fund — 10 years (plus 14 years of prior experience as an investment analyst for the fund) |
| Alan J. Wilson | Partner – Capital World Investors Investment
professional for |
Serves
as an equity portfolio manager for: Growth Fund — 8 years Washington Mutual Investors Fund — 1 year |
| Philip Winston | Partner – Capital International Investors Investment professional for 37 years in total; 25 years with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: Capital Income Builder — 8 years |
Information regarding the portfolio managers’ compensation, their ownership of securities in the Series and other accounts they manage is in the statement of additional information.
American Funds Insurance Series / Prospectus 14
Purchases and redemptions of shares Shares of the Series are currently offered only to insurance company separate accounts as well as so-called “feeder funds” under master-feeder arrangements sponsored by insurance companies as underlying investments for such insurance companies’ variable annuity contracts and variable life insurance policies. All such shares may be purchased or redeemed by the insurance company separate accounts (or feeder funds) at net asset value without any sales or redemption charges. These purchases and redemptions are made at the price next determined after such purchases and redemptions of units of the separate accounts (or feeder funds). The Series typically expects to remit redemption proceeds one business day following receipt and acceptance of a redemption order, regardless of the method the Series uses to make such payment (e.g., check, wire or automated clearing house transfer). However, payment may take longer than one business day and may take up to seven days as generally permitted by the Investment Company Act of 1940, as amended (the “1940 Act”). Under the 1940 Act, the Series may be permitted to pay redemption proceeds beyond seven days under certain limited circumstances.
Under normal conditions, the Series typically expects to meet shareholder redemptions by monitoring the Series’ portfolio and redemption activities and by regularly holding a reserve of highly liquid assets, such as cash or cash equivalents. The Series may use additional methods to meet shareholder redemptions, if they become necessary. These methods may include, but are not limited to, the sale of portfolio assets, the use of overdraft protection afforded by the Series’ custodian bank, borrowing from a line of credit and making payment with fund securities or other fund assets rather than in cash (as further discussed in the following paragraph).
Although payment of redemptions normally will be in cash, the Series may pay the redemption price wholly or partly with portfolio securities or other fund assets under conditions and circumstances determined by the Series’ board of trustees. On the same redemption date, some shareholders may be paid in whole or in part in securities (which may differ among those shareholders), while other shareholders may be paid entirely in cash. In general, in-kind redemptions to affiliated shareholders will as closely as practicable represent the affiliated shareholder’s pro rata share of the Series’ securities, subject to certain exceptions. Securities distributed in-kind to unaffiliated shareholders will be selected by the investment adviser in a manner the investment adviser deems to be fair and reasonable to the Series’ shareholders. The disposal of the securities received in-kind may be subject to brokerage costs and, until sold, such securities remain subject to market risk and liquidity risk, including the risk that such securities are or become difficult to sell. If the Series pays your redemption with illiquid or less liquid securities, you will bear the risk of not being able to sell such securities.
15 American Funds Insurance Series / Prospectus
Frequent trading of fund shares The Series and American Funds Distributors, Inc., the Series’ distributor, reserve the right to reject any purchase order for any reason. The funds are not designed to serve as vehicles for frequent trading. Frequent trading of fund shares may lead to increased costs to the funds and less efficient management of the funds’ portfolios, potentially resulting in dilution of the value of the shares held by long-term shareholders. Accordingly, purchases, including those that are part of exchange activity, that the Series or American Funds Distributors has determined could involve actual or potential harm to a fund may be rejected.
The Series, through its transfer agent, American Funds Service Company, has agreements with the Series’ insurance relationships to maintain its surveillance procedures that are designed to detect frequent trading in fund shares. The agreements generally require the insurance companies to (i) provide, upon request from a fund, the Series or their agent, certain identifying and account information regarding contract owners who invest in fund shares through an insurance company account and (ii) execute instructions from a fund, the Series or their agent to restrict further purchases or exchanges of fund shares by a contract owner who the Series has identified as having engaged in potentially harmful market timing or frequent trading. Under these procedures, various analytics are used to evaluate factors that may be indicative of frequent trading. For example, transactions in fund shares that exceed certain monetary thresholds may be scrutinized. American Funds Service Company may work with the insurance company separate accounts or feeder funds to apply their procedures that American Funds Service Company believes are reasonably designed to enforce the frequent trading policies of the Series. You should refer to disclosures provided by the insurance company with which you have a contract to determine the specific trading restrictions that apply to you.
Under the Series’ frequent trading policy, certain trading activity will not be treated as frequent trading, such as:
· retirement plan contributions, loans and distributions (including hardship withdrawals) identified as such on the retirement plan recordkeeper’s system;
· purchase transactions involving in-kind transfers of fund shares, if the entity maintaining the contract owner’s account is able to identify the transaction as one of these types of transactions; and
· systematic redemptions and purchases if the entity maintaining the contract owner’s account is able to identify the transaction as a systematic redemption or purchase.
Generally, purchases and redemptions will not be considered “systematic” unless the transaction is prescheduled for a specific date.
American Funds Service Company will monitor for other types of activity that could potentially be harmful to the Series – for example short-term trading activity in multiple funds. If American Funds Service Company identifies any activity that may constitute frequent trading, it reserves the right to contact the insurance company separate account or feeder fund and request that the separate account or feeder fund either provide information regarding an account owner’s transactions or restrict the account owner’s trading. If American Funds Service Company is not satisfied that insurance company separate account or feeder fund has taken appropriate action, American Funds Service Company may terminate the separate account’s or feeder fund’s ability to transact in fund shares.
There is no guarantee that all instances of frequent trading in fund shares will be prevented.
Notwithstanding the Series’ surveillance procedures described above, all transactions in fund shares remain subject to the right of the Series, American Funds Distributors and American Funds Service Company to restrict potentially abusive trading generally, including the types of transactions described above that will not be prevented.
American Funds Insurance Series / Prospectus 16
Valuing shares The net asset value of each share class of a fund is the value of a single share of that class. The net asset value per share is calculated once daily as of the close of regular trading on the New York Stock Exchange, normally 4 p.m. New York time, each day the New York Stock Exchange is open. If the New York Stock Exchange makes a scheduled (e.g. the day after Thanksgiving) or an unscheduled close prior to 4 p.m. New York time, the net asset value of each fund will be determined at approximately the time the New York Stock Exchange closes on that day. If on such a day market quotations and prices from third-party pricing services are not based as of the time of the early close of the New York Stock Exchange but are as of a later time (up to approximately 4 p.m. New York time), for example because the market remains open after the close of the New York Stock Exchange, those later market quotations and prices will be used in determining the funds’ net asset value.
Equity securities are valued primarily on the basis of market quotations, and debt securities are valued primarily on the basis of prices from third-party pricing services. Futures contracts are valued primarily on the basis of settlement prices. The funds have adopted procedures for making fair value determinations if market quotations or prices from third-party pricing services, as applicable, are not readily available or are not considered reliable. For example, if events occur between the close of markets outside the United States and the close of regular trading on the New York Stock Exchange that, in the opinion of the investment adviser, materially affect the value of any of the funds’ equity securities that trade principally in those international markets, those securities will be valued in accordance with fair value procedures. Similarly, fair value procedures may be employed if an issuer defaults on its debt securities and there is no market for its securities. Use of these procedures is intended to result in more appropriate net asset values and, where applicable, to reduce potential arbitrage opportunities otherwise available to short-term investors.
Because certain of the funds may hold securities that are listed primarily on foreign exchanges that trade on weekends or days when the funds do not price their shares, the values of securities held in the funds may change on days when you will not be able to purchase or redeem fund shares.
Shares of the funds will be purchased or sold at the net asset value next determined after receipt of requests from the appropriate insurance company. Requests received by the appropriate insurance company prior to 4 p.m. New York time and communicated by the insurance company to the Series or its agent will be purchased or sold at that day’s net asset value. Orders in good order received after the New York Stock Exchange closes (scheduled or unscheduled) will be processed at the net asset value (plus any applicable sales charge) calculated on the following business day.
17 American Funds Insurance Series / Prospectus
Plan of distribution The Series has not adopted (and does not presently intend to adopt) a plan of distribution or “12b-1 plan” for Class 1 shares.
Other compensation to dealers American Funds Distributors, at its expense, provides additional compensation to insurance companies. These payments may be made, at the discretion of American Funds Distributors, to insurance companies (or their affiliates) that have sold shares of the funds of the American Funds Insurance Series and American Funds as the exclusive underlying investments to their variable contracts. A number of factors will be considered in determining payments, including the sales, assets, and the quality of the company’s relationship with American Funds Distributors. The payment will be determined using a formula applied consistently to insurance companies based on the relevant facts and circumstances. The level of payments made to a qualifying firm in any given year will vary and (excluding payments for meetings as described below) will represent the sum of (a) up to .14% of the current year’s American Funds Insurance Series new deposits in the contracts, (b) up to .07% of the current and previous year’s American Funds Insurance Series new deposits in the contracts, and (c) up to .0084% of American Funds Insurance Series assets attributable to the contracts, with an adjustment made for the quality of the company’s relationship with American Funds Distributors. Aggregate payments made by American Funds Distributors to insurance companies may also change from year to year. Only assets and deposits in variable annuity contracts that offer exclusively shares of the American Funds Insurance Series and American Funds are included in the formula. Further, assets for which the insurance company, or an affiliated broker-dealer, acts as an ERISA investment fiduciary are generally excluded from the formula. American Funds Distributors makes these payments to help defray the costs incurred by qualifying insurance companies in connection with efforts to educate its sales force about the American Funds Insurance Series so that they help financial advisers make recommendations and provide services that are suitable and meet contractholders needs. These payments may also be made to help defray the costs associated with the insurance company’s provision of account related services and activities and support the insurance company’s distribution activities. American Funds Distributors will, on an annual basis, determine the advisability of continuing these payments.
Firms receiving additional compensation payments must sign a letter acknowledging the purpose of the payment and American Funds Distributors’ goal that the payment will help facilitate education of the firm’s sales force about the American Funds Insurance Series and American Funds to help financial professionals make suitable recommendations and better serve their clients who invest in the funds as underlying investments to variable contracts. The letters generally require the firms to (1) have significant assets invested in the American Funds, (2) provide American Funds Distributors broad access to their sales force and product platforms and develop a business plan to achieve such access, and (3) agree to maintain American Funds within their existing products.
American Funds Distributors may also pay expenses associated with meetings and other training and educational opportunities conducted by insurance companies, selling dealers, advisory platform providers and other intermediaries to facilitate educating financial professionals and shareholders about the American Funds. For example, some of these expenses may include, but not be limited to, meeting sponsor fees, meeting location fees, and fees to obtain lists of financial professionals to better tailor training and education opportunities.
If investment advisers, distributors or other affiliates of mutual funds pay additional compensation or other incentives to insurance companies in differing amounts, insurance companies and the financial professionals with which they interact may have financial incentives for recommending a particular mutual fund over other mutual funds or investments, creating a potential conflict of interest. You should consult with your financial professional and review carefully any disclosure by your financial professional’s firm as to compensation received.
American Funds Insurance Series / Prospectus 18
Fund expenses In periods of market volatility, assets of the funds may decline significantly, causing total annual fund operating expenses (as a percentage of the value of your investment) to become higher than the numbers shown in the Annual Fund Operating Expenses tables in this prospectus.
The “Other expenses” items in the Annual Fund Operating Expenses tables in this prospectus are based on expenses as of each fund’s most recently completed fiscal year. These items include third-party expenses, such as custodial, legal, audit, accounting, regulatory reporting and pricing vendor services, and an administrative services fee payable to the Series’ investment adviser for administrative services provided by the Series’ investment adviser and its affiliates.
For all share classes, “Other expenses” items in the Annual Fund Operating Expenses table in this prospectus include fees for administrative services provided by the fund’s investment adviser and its affiliates. Administrative services are provided by the investment adviser and its affiliates to help assist third parties providing non-distribution services to fund shareholders. These services include providing in-depth information on the fund and market developments that impact fund investments. Administrative services also include, but are not limited to, coordinating, monitoring and overseeing third parties that provide services to fund shareholders.
The Administrative Services Agreement between the fund and the investment adviser provides the fund the ability to charge an administrative services fee of .05% for all share classes. The fund's investment adviser receives an administrative services fee at the annual rate of .03% of the average daily net assets of the fund attributable to all share classes (which could be increased as noted above) for its provision of administrative services.
Investment results All fund results in the “Investment results” section of this prospectus reflect the reinvestment of dividends and capital gains distributions, if any. Unless otherwise noted, fund results reflect any fee waivers and/or expense reimbursements in effect during the period presented.
Distributions and taxes Each fund of the Series intends to qualify as a “regulated investment company” under the Internal Revenue Code. In any fiscal year in which a fund so qualifies and distributes to shareholders its investment company taxable income and net realized capital gain, the fund itself is relieved of federal income tax.
It is the Series’ policy to distribute to the shareholders (the insurance company separate accounts) all of its investment company taxable income and capital gain for each fiscal year.
See the applicable contract prospectus for information regarding the federal income tax treatment of the contracts and distributions to the separate accounts.
19 American Funds Insurance Series / Prospectus
Financial highlights The Financial Highlights table is intended to help you understand a fund’s results for the past five fiscal years. . Certain information reflects financial results for a single share of a particular class. The total returns in the table represent the rate that an investor would have earned or lost on an investment in a fund (assuming reinvestment of all dividends and capital gain distributions). Where indicated, figures in the table reflect the impact, if any, of certain waivers from Capital Research and Management Company. For more information about these waivers, see the fund's statement of additional information and annual report. The information in the Financial Highlights table has been audited by PricewaterhouseCoopers LLP, whose current report, along with the funds’ financial statements, is included in the statement of additional information, which is available upon request. Figures shown do not reflect insurance contract fees and expenses. If insurance contract fees and expenses were reflected, results would be lower.
| Income
(loss) from investment operations1 |
Dividends and distributions | |||||||||||||||||||||||||
| Period ended | Net
asset value, beginning of period |
Net investment income |
Net
gains (losses) on securities (both realized and unrealized) |
Total
from investment operations |
Dividends (from net investment income) |
Distributions (from capital gains) |
Total dividends and distributions |
Net
asset value, end of period |
Total return2 |
Net
assets, end of period (in millions) |
Ratio
of expenses to average net assets before waivers3 |
Ratio
of expenses to average net assets after waivers2,3 |
Ratio
of net income to average net assets2 | |||||||||||||
| Global Growth Fund | ||||||||||||||||||||||||||
| Class 1: | ||||||||||||||||||||||||||
| 12/31/2021 | $41.16 | $.25 | $6.48 | $6.73 | $(.26 | ) | $(2.17 | ) | $(2.43 | ) | $45.46 | 16.72 | % | $4,270 | .55 | % | .54 | % | .56 | % | ||||||
| 12/31/2020 | 32.57 | .20 | 9.56 | 9.76 | (.21 | ) | (.96 | ) | (1.17 | ) | 41.16 | 30.79 | 3,309 | .56 | .56 | .59 | ||||||||||
| 12/31/2019 | 25.74 | .32 | 8.60 | 8.92 | (.41 | ) | (1.68 | ) | (2.09 | ) | 32.57 | 35.61 | 2,515 | .56 | .56 | 1.07 | ||||||||||
| 12/31/2018 | 30.51 | .29 | (2.65 | ) | (2.36 | ) | (.28 | ) | (2.13 | ) | (2.41 | ) | 25.74 | (8.81 | ) | 1,942 | .55 | .55 | .98 | |||||||
| 12/31/2017 | 24.05 | .26 | 7.30 | 7.56 | (.26 | ) | (.84 | ) | (1.10 | ) | 30.51 | 31.80 | 2,010 | .55 | .55 | .94 | ||||||||||
| Class 1A: | ||||||||||||||||||||||||||
| 12/31/2021 | 41.02 | .14 | 6.46 | 6.60 | (.17 | ) | (2.17 | ) | (2.34 | ) | 45.28 | 16.45 | 18 | .80 | .79 | .33 | ||||||||||
| 12/31/2020 | 32.47 | .12 | 9.52 | 9.64 | (.13 | ) | (.96 | ) | (1.09 | ) | 41.02 | 30.49 | 12 | .81 | .81 | .34 | ||||||||||
| 12/31/2019 | 25.69 | .25 | 8.55 | 8.80 | (.34 | ) | (1.68 | ) | (2.02 | ) | 32.47 | 35.22 | 8 | .81 | .81 | .83 | ||||||||||
| 12/31/2018 | 30.46 | .23 | (2.66 | ) | (2.43 | ) | (.21 | ) | (2.13 | ) | (2.34 | ) | 25.69 | (9.02 | ) | 5 | .80 | .80 | .77 | |||||||
| 12/31/20174,5 | 24.50 | .11 | 6.94 | 7.05 | (.25 | ) | (.84 | ) | (1.09 | ) | 30.46 | 29.13 | 6 | 2 | .80 | 7 | .80 | 7 | .39 | 7 | ||||||
| Class 2: | ||||||||||||||||||||||||||
| 12/31/2021 | 40.72 | .13 | 6.41 | 6.54 | (.15 | ) | (2.17 | ) | (2.32 | ) | 44.94 | 16.42 | 4,559 | .80 | .80 | .30 | ||||||||||
| 12/31/2020 | 32.24 | .12 | 9.44 | 9.56 | (.12 | ) | (.96 | ) | (1.08 | ) | 40.72 | 30.47 | 4,387 | .81 | .81 | .34 | ||||||||||
| 12/31/2019 | 25.50 | .24 | 8.51 | 8.75 | (.33 | ) | (1.68 | ) | (2.01 | ) | 32.24 | 35.28 | 3,895 | .81 | .81 | .83 | ||||||||||
| 12/31/2018 | 30.24 | .22 | (2.63 | ) | (2.41 | ) | (.20 | ) | (2.13 | ) | (2.33 | ) | 25.50 | (9.04 | ) | 3,306 | .80 | .80 | .73 | |||||||
| 12/31/2017 | 23.85 | .19 | 7.23 | 7.42 | (.19 | ) | (.84 | ) | (1.03 | ) | 30.24 | 31.47 | 4,012 | .80 | .80 | .69 | ||||||||||
| Class 4: | ||||||||||||||||||||||||||
| 12/31/2021 | 40.45 | .03 | 6.35 | 6.38 | (.09 | ) | (2.17 | ) | (2.26 | ) | 44.57 | 16.14 | 744 | 1.05 | 1.04 | .07 | ||||||||||
| 12/31/2020 | 32.05 | .03 | 9.38 | 9.41 | (.05 | ) | (.96 | ) | (1.01 | ) | 40.45 | 30.17 | 533 | 1.06 | 1.06 | .09 | ||||||||||
| 12/31/2019 | 25.39 | .17 | 8.45 | 8.62 | (.28 | ) | (1.68 | ) | (1.96 | ) | 32.05 | 34.87 | 382 | 1.06 | 1.06 | .57 | ||||||||||
| 12/31/2018 | 30.13 | .14 | (2.60 | ) | (2.46 | ) | (.15 | ) | (2.13 | ) | (2.28 | ) | 25.39 | (9.24 | ) | 249 | 1.05 | 1.05 | .47 | |||||||
| 12/31/2017 | 23.81 | .10 | 7.22 | 7.32 | (.16 | ) | (.84 | ) | (1.00 | ) | 30.13 | 31.11 | 211 | 1.05 | 1.05 | .37 | ||||||||||
American Funds Insurance Series / Prospectus 20
| Income
(loss) from investment operations1 |
Dividends and distributions | |||||||||||||||||||||||
| Period ended | Net
asset value, beginning of period |
Net investment (loss) income |
Net
gains (losses) on securities (both realized and unrealized) |
Total
from investment operations |
Dividends (from net investment income) |
Distributions (from capital gains) |
Total dividends and distributions |
Net
asset value, end of period |
Total return |
Net
assets, end of period (in millions) |
Ratio
of expenses to average net assets3 |
Ratio
of net (loss) income to average net assets | ||||||||||||
| Global Small Capitalization Fund | ||||||||||||||||||||||||
| Class 1: | ||||||||||||||||||||||||
| 12/31/2021 | $32.64 | $(.02 | ) | $2.32 | $2.30 | $— | $(.77 | ) | $(.77 | ) | $34.17 | 6.98 | % | $1,707 | .74 | % | (.07 | )% | ||||||
| 12/31/2020 | 26.80 | (.01 | ) | 7.49 | 7.48 | (.05 | ) | (1.59 | ) | (1.64 | ) | 32.64 | 30.04 | 2,391 | .75 | (.06 | ) | |||||||
| 12/31/2019 | 21.75 | .12 | 6.61 | 6.73 | (.10 | ) | (1.58 | ) | (1.68 | ) | 26.80 | 31.84 | 2,050 | .75 | .48 | |||||||||
| 12/31/2018 | 25.38 | .11 | (2.51 | ) | (2.40 | ) | (.09 | ) | (1.14 | ) | (1.23 | ) | 21.75 | (10.31 | ) | 1,453 | .73 | .42 | ||||||
| 12/31/2017 | 20.24 | .12 | 5.17 | 5.29 | (.15 | ) | — | (.15 | ) | 25.38 | 26.22 | 1,639 | .73 | .54 | ||||||||||
| Class 1A: | ||||||||||||||||||||||||
| 12/31/2021 | 32.49 | (.07 | ) | 2.28 | 2.21 | — | (.77 | ) | (.77 | ) | 33.93 | 6.73 | 5 | .99 | (.21 | ) | ||||||||
| 12/31/2020 | 26.74 | (.09 | ) | 7.48 | 7.39 | (.05 | ) | (1.59 | ) | (1.64 | ) | 32.49 | 29.72 | 1 | .99 | (.33 | ) | |||||||
| 12/31/2019 | 21.71 | .05 | 6.61 | 6.66 | (.05 | ) | (1.58 | ) | (1.63 | ) | 26.74 | 31.56 | 1 | .99 | .22 | |||||||||
| 12/31/2018 | 25.36 | .05 | (2.52 | ) | (2.47 | ) | (.04 | ) | (1.14 | ) | (1.18 | ) | 21.71 | (10.56 | ) | — | 8 | .98 | .21 | |||||
| 12/31/20174,5 | 20.70 | .08 | 4.71 | 4.79 | (.13 | ) | — | (.13 | ) | 25.36 | 23.19 | 6 | — | 8 | .96 | 7 | .35 | 7 | ||||||
| Class 2: | ||||||||||||||||||||||||
| 12/31/2021 | 31.56 | (.10 | ) | 2.25 | 2.15 | — | (.77 | ) | (.77 | ) | 32.94 | 6.74 | 2,521 | .99 | (.30 | ) | ||||||||
| 12/31/2020 | 26.02 | (.08 | ) | 7.25 | 7.17 | (.04 | ) | (1.59 | ) | (1.63 | ) | 31.56 | 29.72 | 2,653 | 1.00 | (.31 | ) | |||||||
| 12/31/2019 | 21.16 | .05 | 6.43 | 6.48 | (.04 | ) | (1.58 | ) | (1.62 | ) | 26.02 | 31.52 | 2,363 | 1.00 | .22 | |||||||||
| 12/31/2018 | 24.72 | .04 | (2.44 | ) | (2.40 | ) | (.02 | ) | (1.14 | ) | (1.16 | ) | 21.16 | (10.55 | ) | 2,056 | .98 | .17 | ||||||
| 12/31/2017 | 19.72 | .06 | 5.04 | 5.10 | (.10 | ) | — | (.10 | ) | 24.72 | 25.89 | 2,551 | .98 | .27 | ||||||||||
| Class 4: | ||||||||||||||||||||||||
| 12/31/2021 | 31.67 | (.18 | ) | 2.24 | 2.06 | — | (.77 | ) | (.77 | ) | 32.96 | 6.43 | 344 | 1.24 | (.53 | ) | ||||||||
| 12/31/2020 | 26.16 | (.14 | ) | 7.27 | 7.13 | (.03 | ) | (1.59 | ) | (1.62 | ) | 31.67 | 29.39 | 268 | 1.25 | (.56 | ) | |||||||
| 12/31/2019 | 21.28 | (.01 | ) | 6.47 | 6.46 | — | 9 | (1.58 | ) | (1.58 | ) | 26.16 | 31.24 | 206 | 1.25 | (.04 | ) | |||||||
| 12/31/2018 | 24.91 | (.02 | ) | (2.46 | ) | (2.48 | ) | (.01 | ) | (1.14 | ) | (1.15 | ) | 21.28 | (10.80 | ) | 146 | 1.24 | (.08 | ) | ||||
| 12/31/2017 | 19.91 | — | 9 | 5.09 | 5.09 | (.09 | ) | — | (.09 | ) | 24.91 | 25.62 | 125 | 1.23 | — | 10 | ||||||||
| Income
from investment operations1 |
Dividends and distributions | |||||||||||||||||||||||
| Period ended | Net
asset value, beginning of period |
Net investment income (loss) |
Net
gains on securities (both realized and unrealized) |
Total
from investment operations |
Dividends (from net investment income) |
Distributions (from capital gains) |
Total dividends and distributions |
Net
asset value, end of period |
Total return |
Net
assets, end of period (in millions) |
Ratio
of expenses to average net assets3 |
Ratio
of net income (loss) to average net assets | ||||||||||||
| Growth Fund | ||||||||||||||||||||||||
| Class 1: | ||||||||||||||||||||||||
| 12/31/2021 | $120.22 | $.46 | $24.29 | $24.75 | $(.58 | ) | $(16.81 | ) | $(17.39 | ) | $127.58 | 22.30 | % | $19,783 | .34 | % | .37 | % | ||||||
| 12/31/2020 | 81.22 | .43 | 41.28 | 41.71 | (.53 | ) | (2.18 | ) | (2.71 | ) | 120.22 | 52.45 | 15,644 | .35 | .46 | |||||||||
| 12/31/2019 | 69.96 | .83 | 19.63 | 20.46 | (.76 | ) | (8.44 | ) | (9.20 | ) | 81.22 | 31.11 | 10,841 | .35 | 1.09 | |||||||||
| 12/31/2018 | 77.85 | .64 | .25 | .89 | (.54 | ) | (8.24 | ) | (8.78 | ) | 69.96 | (.01 | ) | 8,474 | .34 | .81 | ||||||||
| 12/31/2017 | 67.29 | .55 | 17.89 | 18.44 | (.55 | ) | (7.33 | ) | (7.88 | ) | 77.85 | 28.62 | 8,100 | .35 | .75 | |||||||||
| Class 1A: | ||||||||||||||||||||||||
| 12/31/2021 | 119.59 | .16 | 24.11 | 24.27 | (.35 | ) | (16.81 | ) | (17.16 | ) | 126.70 | 21.97 | 121 | .59 | .13 | |||||||||
| 12/31/2020 | 80.92 | .20 | 41.05 | 41.25 | (.40 | ) | (2.18 | ) | (2.58 | ) | 119.59 | 52.07 | 60 | .60 | .21 | |||||||||
| 12/31/2019 | 69.77 | .65 | 19.55 | 20.20 | (.61 | ) | (8.44 | ) | (9.05 | ) | 80.92 | 30.79 | 18 | .60 | .85 | |||||||||
| 12/31/2018 | 77.74 | .47 | .24 | .71 | (.44 | ) | (8.24 | ) | (8.68 | ) | 69.77 | (.26 | ) | 10 | .59 | .60 | ||||||||
| 12/31/20174,5 | 68.84 | .35 | 16.38 | 16.73 | (.50 | ) | (7.33 | ) | (7.83 | ) | 77.74 | 25.47 | 6 | 3 | .59 | 7 | .47 | 7 | ||||||
| Class 2: | ||||||||||||||||||||||||
| 12/31/2021 | 119.18 | .15 | 24.03 | 24.18 | (.27 | ) | (16.81 | ) | (17.08 | ) | 126.28 | 21.97 | 21,986 | .59 | .12 | |||||||||
| 12/31/2020 | 80.57 | .19 | 40.89 | 41.08 | (.29 | ) | (2.18 | ) | (2.47 | ) | 119.18 | 52.10 | 20,594 | .60 | .21 | |||||||||
| 12/31/2019 | 69.48 | .63 | 19.47 | 20.10 | (.57 | ) | (8.44 | ) | (9.01 | ) | 80.57 | 30.77 | 15,885 | .60 | .83 | |||||||||
| 12/31/2018 | 77.35 | .44 | .27 | .71 | (.34 | ) | (8.24 | ) | (8.58 | ) | 69.48 | (.25 | ) | 13,701 | .59 | .55 | ||||||||
| 12/31/2017 | 66.92 | .37 | 17.76 | 18.13 | (.37 | ) | (7.33 | ) | (7.70 | ) | 77.35 | 28.28 | 15,716 | .60 | .50 | |||||||||
| Class 3: | ||||||||||||||||||||||||
| 12/31/2021 | 121.13 | .24 | 24.47 | 24.71 | (.35 | ) | (16.81 | ) | (17.16 | ) | 128.68 | 22.07 | 302 | .52 | .19 | |||||||||
| 12/31/2020 | 81.84 | .26 | 41.56 | 41.82 | (.35 | ) | (2.18 | ) | (2.53 | ) | 121.13 | 52.20 | 279 | .53 | .28 | |||||||||
| 12/31/2019 | 70.44 | .69 | 19.77 | 20.46 | (.62 | ) | (8.44 | ) | (9.06 | ) | 81.84 | 30.86 | 213 | .53 | .90 | |||||||||
| 12/31/2018 | 78.32 | .50 | .26 | .76 | (.40 | ) | (8.24 | ) | (8.64 | ) | 70.44 | (.18 | ) | 187 | .52 | .62 | ||||||||
| 12/31/2017 | 67.67 | .42 | 17.98 | 18.40 | (.42 | ) | (7.33 | ) | (7.75 | ) | 78.32 | 28.39 | 212 | .53 | .57 | |||||||||
| Class 4: | ||||||||||||||||||||||||
| 12/31/2021 | 117.24 | (.15 | ) | 23.59 | 23.44 | (.08 | ) | (16.81 | ) | (16.89 | ) | 123.79 | 21.69 | 3,214 | .84 | (.13 | ) | |||||||
| 12/31/2020 | 79.41 | (.04 | ) | 40.24 | 40.20 | (.19 | ) | (2.18 | ) | (2.37 | ) | 117.24 | 51.71 | 2,347 | .85 | (.04 | ) | |||||||
| 12/31/2019 | 68.64 | .44 | 19.19 | 19.63 | (.42 | ) | (8.44 | ) | (8.86 | ) | 79.41 | 30.44 | 1,513 | .85 | .59 | |||||||||
| 12/31/2018 | 76.56 | .24 | .28 | .52 | (.20 | ) | (8.24 | ) | (8.44 | ) | 68.64 | (.50 | ) | 1,076 | .84 | .31 | ||||||||
| 12/31/2017 | 66.41 | .18 | 17.61 | 17.79 | (.31 | ) | (7.33 | ) | (7.64 | ) | 76.56 | 27.99 | 954 | .85 | .25 | |||||||||
21 American Funds Insurance Series / Prospectus
| (Loss)
income from investment operations1 |
Dividends and distributions | |||||||||||||||||||||||
| Period ended | Net
asset value, beginning of period |
Net investment income |
Net
(losses) gains on securities (both realized and unrealized) |
Total
from investment operations |
Dividends (from net investment income) |
Distributions (from capital gains) |
Total dividends and distributions |
Net
asset value, end of period |
Total return |
Net
assets, end of period (in millions) |
Ratio
of expenses to average net assets3 |
Ratio
of net income to average net assets | ||||||||||||
| International Fund | ||||||||||||||||||||||||
| Class 1: | ||||||||||||||||||||||||
| 12/31/2021 | $23.64 | $.38 | $(.67 | ) | $(.29 | ) | $(.65 | ) | $— | $(.65 | ) | $22.70 | (1.23 | )% | $4,747 | .55 | % | 1.57 | % | |||||
| 12/31/2020 | 20.86 | .14 | 2.82 | 2.96 | (.18 | ) | — | (.18 | ) | 23.64 | 14.28 | 5,652 | .55 | .71 | ||||||||||
| 12/31/2019 | 17.66 | .30 | 3.74 | 4.04 | (.34 | ) | (.50 | ) | (.84 | ) | 20.86 | 23.21 | 5,353 | .54 | 1.54 | |||||||||
| 12/31/2018 | 21.71 | .34 | (2.97 | ) | (2.63 | ) | (.40 | ) | (1.02 | ) | (1.42 | ) | 17.66 | (12.94 | ) | 4,811 | .53 | 1.62 | ||||||
| 12/31/2017 | 16.82 | .26 | 5.16 | 5.42 | (.30 | ) | (.23 | ) | (.53 | ) | 21.71 | 32.46 | 5,014 | .53 | 1.33 | |||||||||
| Class 1A: | ||||||||||||||||||||||||
| 12/31/2021 | 23.55 | .33 | (.67 | ) | (.34 | ) | (.60 | ) | — | (.60 | ) | 22.61 | (1.47 | ) | 12 | .80 | 1.39 | |||||||
| 12/31/2020 | 20.80 | .08 | 2.81 | 2.89 | (.14 | ) | — | (.14 | ) | 23.55 | 13.96 | 10 | .80 | .43 | ||||||||||
| 12/31/2019 | 17.62 | .25 | 3.72 | 3.97 | (.29 | ) | (.50 | ) | (.79 | ) | 20.80 | 22.90 | 7 | .79 | 1.27 | |||||||||
| 12/31/2018 | 21.67 | .27 | (2.93 | ) | (2.66 | ) | (.37 | ) | (1.02 | ) | (1.39 | ) | 17.62 | (13.11 | ) | 5 | .78 | 1.32 | ||||||
| 12/31/20174,5 | 17.17 | .09 | 4.93 | 5.02 | (.29 | ) | (.23 | ) | (.52 | ) | 21.67 | 29.46 | 6 | 2 | .77 | 7 | .43 | 7 | ||||||
| Class 2: | ||||||||||||||||||||||||
| 12/31/2021 | 23.54 | .33 | (.68 | ) | (.35 | ) | (.59 | ) | — | (.59 | ) | 22.60 | (1.49 | ) | 4,190 | .80 | 1.35 | |||||||
| 12/31/2020 | 20.78 | .09 | 2.80 | 2.89 | (.13 | ) | — | (.13 | ) | 23.54 | 13.97 | 4,481 | .80 | .46 | ||||||||||
| 12/31/2019 | 17.60 | .25 | 3.72 | 3.97 | (.29 | ) | (.50 | ) | (.79 | ) | 20.78 | 22.88 | 4,311 | .79 | 1.29 | |||||||||
| 12/31/2018 | 21.63 | .29 | (2.95 | ) | (2.66 | ) | (.35 | ) | (1.02 | ) | (1.37 | ) | 17.60 | (13.13 | ) | 3,875 | .78 | 1.40 | ||||||
| 12/31/2017 | 16.76 | .22 | 5.13 | 5.35 | (.25 | ) | (.23 | ) | (.48 | ) | 21.63 | 32.14 | 4,422 | .78 | 1.10 | |||||||||
| Class 3: | ||||||||||||||||||||||||
| 12/31/2021 | 23.69 | .34 | (.67 | ) | (.33 | ) | (.60 | ) | — | (.60 | ) | 22.76 | (1.39 | ) | 21 | .73 | 1.41 | |||||||
| 12/31/2020 | 20.92 | .10 | 2.81 | 2.91 | (.14 | ) | — | (.14 | ) | 23.69 | 14.00 | 25 | .73 | .53 | ||||||||||
| 12/31/2019 | 17.70 | .27 | 3.75 | 4.02 | (.30 | ) | (.50 | ) | (.80 | ) | 20.92 | 23.05 | 25 | .72 | 1.37 | |||||||||
| 12/31/2018 | 21.75 | .31 | (2.98 | ) | (2.67 | ) | (.36 | ) | (1.02 | ) | (1.38 | ) | 17.70 | (13.10 | ) | 24 | .71 | 1.48 | ||||||
| 12/31/2017 | 16.85 | .23 | 5.17 | 5.40 | (.27 | ) | (.23 | ) | (.50 | ) | 21.75 | 32.23 | 31 | .71 | 1.17 | |||||||||
| Class 4: | ||||||||||||||||||||||||
| 12/31/2021 | 23.25 | .27 | (.67 | ) | (.40 | ) | (.54 | ) | — | (.54 | ) | 22.31 | (1.71 | ) | 459 | 1.05 | 1.13 | |||||||
| 12/31/2020 | 20.54 | .04 | 2.76 | 2.80 | (.09 | ) | — | (.09 | ) | 23.25 | 13.66 | 423 | 1.05 | .21 | ||||||||||
| 12/31/2019 | 17.40 | .20 | 3.69 | 3.89 | (.25 | ) | (.50 | ) | (.75 | ) | 20.54 | 22.67 | 379 | 1.04 | 1.03 | |||||||||
| 12/31/2018 | 21.42 | .23 | (2.93 | ) | (2.70 | ) | (.30 | ) | (1.02 | ) | (1.32 | ) | 17.40 | (13.41 | ) | 295 | 1.03 | 1.13 | ||||||
| 12/31/2017 | 16.64 | .11 | 5.16 | 5.27 | (.26 | ) | (.23 | ) | (.49 | ) | 21.42 | 31.89 | 289 | 1.03 | .55 | |||||||||
| Income
(loss) from investment operations1 |
Dividends and distributions | |||||||||||||||||||||||||
| Period ended | Net
asset value, beginning of period |
Net investment income |
Net
gains (losses) on securities (both realized and unrealized) |
Total
from investment operations |
Dividends (from net investment income) |
Distributions (from capital gains) |
Total dividends and distributions |
Net
asset value, end of period |
Total return2 |
Net
assets, end of period (in millions) |
Ratio
of expenses to average net assets before waivers3 |
Ratio
of expenses to average net assets after waivers2,3 |
Ratio
of net income to average net assets2 | |||||||||||||
| New World Fund | ||||||||||||||||||||||||||
| Class 1: | ||||||||||||||||||||||||||
| 12/31/2021 | $31.59 | $.29 | $1.38 | $1.67 | $(.36 | ) | $(1.07 | ) | $(1.43 | ) | $31.83 | 5.16 | % | $2,443 | .74 | % | .56 | % | .88 | % | ||||||
| 12/31/2020 | 25.84 | .15 | 5.93 | 6.08 | (.06 | ) | (.27 | ) | (.33 | ) | 31.59 | 23.89 | 2,309 | .76 | .64 | .58 | ||||||||||
| 12/31/2019 | 20.98 | .28 | 5.79 | 6.07 | (.29 | ) | (.92 | ) | (1.21 | ) | 25.84 | 29.47 | 2,129 | .76 | .76 | 1.18 | ||||||||||
| 12/31/2018 | 25.30 | .27 | (3.65 | ) | (3.38 | ) | (.27 | ) | (.67 | ) | (.94 | ) | 20.98 | (13.83 | ) | 1,702 | .77 | .77 | 1.11 | |||||||
| 12/31/2017 | 19.72 | .26 | 5.59 | 5.85 | (.27 | ) | — | (.27 | ) | 25.30 | 29.73 | 2,050 | .77 | .77 | 1.14 | |||||||||||
| Class 1A: | ||||||||||||||||||||||||||
| 12/31/2021 | 31.43 | .17 | 1.41 | 1.58 | (.24 | ) | (1.07 | ) | (1.31 | ) | 31.70 | 4.90 | 12 | .99 | .81 | .54 | ||||||||||
| 12/31/2020 | 25.74 | .07 | 5.92 | 5.99 | (.03 | ) | (.27 | ) | (.30 | ) | 31.43 | 23.63 | 18 | 1.01 | .87 | .26 | ||||||||||
| 12/31/2019 | 20.92 | .22 | 5.76 | 5.98 | (.24 | ) | (.92 | ) | (1.16 | ) | 25.74 | 29.11 | 4 | 1.01 | 1.01 | .92 | ||||||||||
| 12/31/2018 | 25.25 | .21 | (3.64 | ) | (3.43 | ) | (.23 | ) | (.67 | ) | (.90 | ) | 20.92 | (14.02 | ) | 2 | 1.02 | 1.02 | .91 | |||||||
| 12/31/20174,5 | 20.14 | .13 | 5.24 | 5.37 | (.26 | ) | — | (.26 | ) | 25.25 | 26.72 | 6 | 1 | 1.00 | 7 | 1.00 | 7 | .53 | 7 | |||||||
| Class 2: | ||||||||||||||||||||||||||
| 12/31/2021 | 31.25 | .20 | 1.38 | 1.58 | (.28 | ) | (1.07 | ) | (1.35 | ) | 31.48 | 4.92 | 1,086 | .99 | .81 | .63 | ||||||||||
| 12/31/2020 | 25.59 | .08 | 5.87 | 5.95 | (.02 | ) | (.27 | ) | (.29 | ) | 31.25 | 23.58 | 1,109 | 1.01 | .89 | .34 | ||||||||||
| 12/31/2019 | 20.79 | .22 | 5.73 | 5.95 | (.23 | ) | (.92 | ) | (1.15 | ) | 25.59 | 29.15 | 981 | 1.01 | 1.01 | .93 | ||||||||||
| 12/31/2018 | 25.07 | .20 | (3.61 | ) | (3.41 | ) | (.20 | ) | (.67 | ) | (.87 | ) | 20.79 | (14.04 | ) | 843 | 1.02 | 1.02 | .85 | |||||||
| 12/31/2017 | 19.54 | .20 | 5.55 | 5.75 | (.22 | ) | — | (.22 | ) | 25.07 | 29.44 | 1,055 | 1.02 | 1.02 | .89 | |||||||||||
| Class 4: | ||||||||||||||||||||||||||
| 12/31/2021 | 31.04 | .12 | 1.36 | 1.48 | (.21 | ) | (1.07 | ) | (1.28 | ) | 31.24 | 4.63 | 906 | 1.24 | 1.06 | .38 | ||||||||||
| 12/31/2020 | 25.47 | .02 | 5.83 | 5.85 | (.01 | ) | (.27 | ) | (.28 | ) | 31.04 | 23.29 | 807 | 1.26 | 1.14 | .08 | ||||||||||
| 12/31/2019 | 20.71 | .16 | 5.70 | 5.86 | (.18 | ) | (.92 | ) | (1.10 | ) | 25.47 | 28.82 | 646 | 1.26 | 1.26 | .67 | ||||||||||
| 12/31/2018 | 24.99 | .14 | (3.59 | ) | (3.45 | ) | (.16 | ) | (.67 | ) | (.83 | ) | 20.71 | (14.25 | ) | 464 | 1.27 | 1.27 | .61 | |||||||
| 12/31/2017 | 19.51 | .14 | 5.52 | 5.66 | (.18 | ) | — | (.18 | ) | 24.99 | 29.06 | 427 | 1.27 | 1.27 | .61 | |||||||||||
American Funds Insurance Series / Prospectus 22
| Income
(loss) from investment operations1 |
Dividends and distributions | |||||||||||||||||||||||||
| Period ended | Net
asset value, beginning of period |
Net investment income |
Net
gains (losses) on securities (both realized and unrealized) |
Total
from investment operations |
Dividends (from net investment income) |
Distributions (from capital gains) |
Total dividends and distributions |
Net
asset value, end of period |
Total return2 |
Net
assets, end of period (in millions) |
Ratio
of expenses to average net assets before waivers3 |
Ratio
of expenses to average net assets after waivers2,3 |
Ratio
of net income to average net assets2 | |||||||||||||
| Capital World Growth and Income Fund | ||||||||||||||||||||||||||
| Class 1: | ||||||||||||||||||||||||||
| 12/31/2021 | $16.67 | $.38 | $2.10 | $2.48 | $(.33 | ) | $(.40 | ) | $(.73 | ) | $18.42 | 15.03 | % | $812 | .63 | % | .47 | % | 2.14 | % | ||||||
| 12/31/2020 | 15.92 | .22 | 1.14 | 1.36 | (.23 | ) | (.38 | ) | (.61 | ) | 16.67 | 9.03 | 657 | .66 | .66 | 1.49 | ||||||||||
| 12/31/2019 | 13.02 | .31 | 3.67 | 3.98 | (.32 | ) | (.76 | ) | (1.08 | ) | 15.92 | 31.39 | 625 | .65 | .65 | 2.08 | ||||||||||
| 12/31/2018 | 15.81 | .29 | (1.62 | ) | (1.33 | ) | (.28 | ) | (1.18 | ) | (1.46 | ) | 13.02 | (9.36 | ) | 492 | .63 | .63 | 1.94 | |||||||
| 12/31/2017 | 13.02 | .35 | 3.06 | 3.41 | (.36 | ) | (.26 | ) | (.62 | ) | 15.81 | 26.40 | 485 | .63 | .63 | 2.43 | ||||||||||
| Class 1A: | ||||||||||||||||||||||||||
| 12/31/2021 | 16.62 | .37 | 2.06 | 2.43 | (.31 | ) | (.40 | ) | (.71 | ) | 18.34 | 14.71 | 7 | .88 | .70 | 2.08 | ||||||||||
| 12/31/2020 | 15.88 | .18 | 1.13 | 1.31 | (.19 | ) | (.38 | ) | (.57 | ) | 16.62 | 8.78 | 2 | .90 | .90 | 1.23 | ||||||||||
| 12/31/2019 | 13.00 | .26 | 3.68 | 3.94 | (.30 | ) | (.76 | ) | (1.06 | ) | 15.88 | 31.04 | 2 | .90 | .90 | 1.77 | ||||||||||
| 12/31/2018 | 15.81 | .26 | (1.63 | ) | (1.37 | ) | (.26 | ) | (1.18 | ) | (1.44 | ) | 13.00 | (9.62 | ) | 1 | .88 | .88 | 1.74 | |||||||
| 12/31/20174,5 | 13.21 | .18 | 3.03 | 3.21 | (.35 | ) | (.26 | ) | (.61 | ) | 15.81 | 24.54 | 6 | — | 8 | .84 | 7 | .84 | 7 | 1.20 | 7 | |||||
| Class 2: | ||||||||||||||||||||||||||
| 12/31/2021 | 16.63 | .33 | 2.11 | 2.44 | (.29 | ) | (.40 | ) | (.69 | ) | 18.38 | 14.78 | 1,340 | .88 | .73 | 1.85 | ||||||||||
| 12/31/2020 | 15.89 | .18 | 1.13 | 1.31 | (.19 | ) | (.38 | ) | (.57 | ) | 16.63 | 8.73 | 1,349 | .91 | .91 | 1.23 | ||||||||||
| 12/31/2019 | 12.99 | .27 | 3.68 | 3.95 | (.29 | ) | (.76 | ) | (1.05 | ) | 15.89 | 31.14 | 1,366 | .90 | .90 | 1.84 | ||||||||||
| 12/31/2018 | 15.78 | .26 | (1.63 | ) | (1.37 | ) | (.24 | ) | (1.18 | ) | (1.42 | ) | 12.99 | (9.63 | ) | 1,228 | .88 | .88 | 1.70 | |||||||
| 12/31/2017 | 13.00 | .31 | 3.05 | 3.36 | (.32 | ) | (.26 | ) | (.58 | ) | 15.78 | 26.06 | 1,538 | .88 | .88 | 2.11 | ||||||||||
| Class 4: | ||||||||||||||||||||||||||
| 12/31/2021 | 16.35 | .29 | 2.06 | 2.35 | (.26 | ) | (.40 | ) | (.66 | ) | 18.04 | 14.46 | 225 | 1.13 | .97 | 1.65 | ||||||||||
| 12/31/2020 | 15.63 | .14 | 1.12 | 1.26 | (.16 | ) | (.38 | ) | (.54 | ) | 16.35 | 8.55 | 166 | 1.16 | 1.16 | .97 | ||||||||||
| 12/31/2019 | 12.81 | .23 | 3.61 | 3.84 | (.26 | ) | (.76 | ) | (1.02 | ) | 15.63 | 30.73 | 145 | 1.15 | 1.15 | 1.56 | ||||||||||
| 12/31/2018 | 15.60 | .21 | (1.60 | ) | (1.39 | ) | (.22 | ) | (1.18 | ) | (1.40 | ) | 12.81 | (9.89 | ) | 95 | 1.13 | 1.13 | 1.43 | |||||||
| 12/31/2017 | 12.89 | .22 | 3.08 | 3.30 | (.33 | ) | (.26 | ) | (.59 | ) | 15.60 | 25.83 | 79 | 1.14 | 1.14 | 1.49 | ||||||||||
| Income
(loss) from investment operations1 |
Dividends and distributions | |||||||||||||||||||||||
| Period ended | Net
asset value, beginning of period |
Net investment income |
Net
gains (losses) on securities (both realized and unrealized) |
Total
from investment operations |
Dividends (from net investment income) |
Distributions (from capital gains) |
Total dividends and distributions |
Net
asset value, end of period |
Total return |
Net
assets, end of period (in millions) |
Ratio
of expenses to average net assets3 |
Ratio
of net income to average net assets | ||||||||||||
| Growth-Income Fund | ||||||||||||||||||||||||
| Class 1: | ||||||||||||||||||||||||
| 12/31/2021 | $55.38 | $.79 | $12.64 | $13.43 | $(.86 | ) | $(.60 | ) | $(1.46 | ) | $67.35 | 24.42 | % | $25,507 | .29 | % | 1.28 | % | ||||||
| 12/31/2020 | 50.71 | .75 | 6.02 | 6.77 | (.80 | ) | (1.30 | ) | (2.10 | ) | 55.38 | 13.81 | 22,903 | .29 | 1.52 | |||||||||
| 12/31/2019 | 45.39 | 1.00 | 10.40 | 11.40 | (.92 | ) | (5.16 | ) | (6.08 | ) | 50.71 | 26.46 | 21,057 | .29 | 2.05 | |||||||||
| 12/31/2018 | 50.22 | .84 | (1.25 | ) | (.41 | ) | (.84 | ) | (3.58 | ) | (4.42 | ) | 45.39 | (1.55 | ) | 16,783 | .28 | 1.65 | ||||||
| 12/31/2017 | 44.41 | .81 | 8.89 | 9.70 | (.78 | ) | (3.11 | ) | (3.89 | ) | 50.22 | 22.68 | 15,765 | .28 | 1.69 | |||||||||
| Class 1A: | ||||||||||||||||||||||||
| 12/31/2021 | 55.16 | .65 | 12.55 | 13.20 | (.74 | ) | (.60 | ) | (1.34 | ) | 67.02 | 24.08 | 32 | .53 | 1.04 | |||||||||
| 12/31/2020 | 50.54 | .63 | 5.99 | 6.62 | (.70 | ) | (1.30 | ) | (2.00 | ) | 55.16 | 13.55 | 16 | .54 | 1.28 | |||||||||
| 12/31/2019 | 45.28 | .89 | 10.36 | 11.25 | (.83 | ) | (5.16 | ) | (5.99 | ) | 50.54 | 26.14 | 11 | .54 | 1.82 | |||||||||
| 12/31/2018 | 50.15 | .72 | (1.25 | ) | (.53 | ) | (.76 | ) | (3.58 | ) | (4.34 | ) | 45.28 | (1.78 | ) | 7 | .53 | 1.43 | ||||||
| 12/31/20174,5 | 45.39 | .67 | 7.96 | 8.63 | (.76 | ) | (3.11 | ) | (3.87 | ) | 50.15 | 19.83 | 6 | 2 | .52 | 7 | 1.41 | 7 | ||||||
| Class 2: | ||||||||||||||||||||||||
| 12/31/2021 | 54.66 | .63 | 12.45 | 13.08 | (.70 | ) | (.60 | ) | (1.30 | ) | 66.44 | 24.10 | 15,319 | .54 | 1.03 | |||||||||
| 12/31/2020 | 50.08 | .62 | 5.93 | 6.55 | (.67 | ) | (1.30 | ) | (1.97 | ) | 54.66 | 13.54 | 14,012 | .54 | 1.27 | |||||||||
| 12/31/2019 | 44.90 | .87 | 10.27 | 11.14 | (.80 | ) | (5.16 | ) | (5.96 | ) | 50.08 | 26.14 | 13,586 | .53 | 1.80 | |||||||||
| 12/31/2018 | 49.71 | .71 | (1.23 | ) | (.52 | ) | (.71 | ) | (3.58 | ) | (4.29 | ) | 44.90 | (1.79 | ) | 12,035 | .53 | 1.40 | ||||||
| 12/31/2017 | 44.00 | .68 | 8.80 | 9.48 | (.66 | ) | (3.11 | ) | (3.77 | ) | 49.71 | 22.38 | 13,930 | .53 | 1.45 | |||||||||
| Class 3: | ||||||||||||||||||||||||
| 12/31/2021 | 55.49 | .68 | 12.65 | 13.33 | (.74 | ) | (.60 | ) | (1.34 | ) | 67.48 | 24.18 | 166 | .47 | 1.10 | |||||||||
| 12/31/2020 | 50.81 | .66 | 6.02 | 6.68 | (.70 | ) | (1.30 | ) | (2.00 | ) | 55.49 | 13.60 | 154 | .47 | 1.34 | |||||||||
| 12/31/2019 | 45.47 | .91 | 10.43 | 11.34 | (.84 | ) | (5.16 | ) | (6.00 | ) | 50.81 | 26.24 | 156 | .46 | 1.87 | |||||||||
| 12/31/2018 | 50.29 | .75 | (1.25 | ) | (.50 | ) | (.74 | ) | (3.58 | ) | (4.32 | ) | 45.47 | (1.72 | ) | 140 | .46 | 1.47 | ||||||
| 12/31/2017 | 44.47 | .72 | 8.90 | 9.62 | (.69 | ) | (3.11 | ) | (3.80 | ) | 50.29 | 22.47 | 168 | .46 | 1.52 | |||||||||
| Class 4: | ||||||||||||||||||||||||
| 12/31/2021 | 53.99 | .48 | 12.28 | 12.76 | (.58 | ) | (.60 | ) | (1.18 | ) | 65.57 | 23.80 | 1,928 | .79 | .79 | |||||||||
| 12/31/2020 | 49.52 | .49 | 5.85 | 6.34 | (.57 | ) | (1.30 | ) | (1.87 | ) | 53.99 | 13.25 | 1,407 | .79 | 1.02 | |||||||||
| 12/31/2019 | 44.47 | .74 | 10.18 | 10.92 | (.71 | ) | (5.16 | ) | (5.87 | ) | 49.52 | 25.86 | 1,216 | .79 | 1.56 | |||||||||
| 12/31/2018 | 49.31 | .58 | (1.23 | ) | (.65 | ) | (.61 | ) | (3.58 | ) | (4.19 | ) | 44.47 | (2.05 | ) | 899 | .78 | 1.15 | ||||||
| 12/31/2017 | 43.73 | .56 | 8.73 | 9.29 | (.60 | ) | (3.11 | ) | (3.71 | ) | 49.31 | 22.08 | 827 | .78 | 1.19 | |||||||||
23 American Funds Insurance Series / Prospectus
| Income
(loss) from investment operations1 |
Dividends and distributions | |||||||||||||||||||||||||
| Period ended | Net
asset value, beginning of period |
Net investment income |
Net
gains (losses) on securities (both realized and unrealized) |
Total
from investment operations |
Dividends (from net investment income) |
Distributions (from capital gains) |
Total dividends and distributions |
Net
asset value, end of period |
Total return2 |
Net
assets, end of period (in millions) |
Ratio
of expenses to average net assets before waivers3 |
Ratio
of expenses to average net assets after waivers2,3 |
Ratio
of net income to average net assets2 | |||||||||||||
| Washington Mutual Investors Fund | ||||||||||||||||||||||||||
| Class 1: | ||||||||||||||||||||||||||
| 12/31/2021 | $14.35 | $.29 | $3.73 | $4.02 | $(.28 | ) | $— | $(.28 | ) | $18.09 | 28.12 | % | $6,766 | .42 | % | .31 | % | 1.79 | % | |||||||
| 12/31/2020 | 13.56 | .25 | .95 | 1.20 | (.26 | ) | (.15 | ) | (.41 | ) | 14.35 | 9.04 | 5,684 | .43 | .43 | 2.00 | ||||||||||
| 12/31/2019 | 12.38 | .30 | 2.25 | 2.55 | (.30 | ) | (1.07 | ) | (1.37 | ) | 13.56 | 21.66 | 5,559 | .42 | .42 | 2.28 | ||||||||||
| 12/31/2018 | 14.96 | .31 | (1.44 | ) | (1.13 | ) | (.31 | ) | (1.14 | ) | (1.45 | ) | 12.38 | (8.45 | ) | 4,810 | .41 | .41 | 2.13 | |||||||
| 12/31/2017 | 13.53 | .32 | 1.96 | 2.28 | (.32 | ) | (.53 | ) | (.85 | ) | 14.96 | 17.30 | 5,581 | .41 | .41 | 2.27 | ||||||||||
| Class 1A: | ||||||||||||||||||||||||||
| 12/31/2021 | 14.28 | .27 | 3.67 | 3.94 | (.26 | ) | — | (.26 | ) | 17.96 | 27.70 | 169 | .67 | .53 | 1.62 | |||||||||||
| 12/31/2020 | 13.51 | .23 | .93 | 1.16 | (.24 | ) | (.15 | ) | (.39 | ) | 14.28 | 8.79 | 25 | .67 | .67 | 1.78 | ||||||||||
| 12/31/2019 | 12.35 | .26 | 2.24 | 2.50 | (.27 | ) | (1.07 | ) | (1.34 | ) | 13.51 | 21.35 | 9 | .67 | .67 | 2.03 | ||||||||||
| 12/31/2018 | 14.94 | .26 | (1.42 | ) | (1.16 | ) | (.29 | ) | (1.14 | ) | (1.43 | ) | 12.35 | (8.67 | ) | 3 | .66 | .66 | 1.84 | |||||||
| 12/31/20174,5 | 13.75 | .28 | 1.75 | 2.03 | (.31 | ) | (.53 | ) | (.84 | ) | 14.94 | 15.21 | 6 | 1 | .65 | 7 | .65 | 7 | 2.01 | 7 | ||||||
| Class 2: | ||||||||||||||||||||||||||
| 12/31/2021 | 14.15 | .25 | 3.67 | 3.92 | (.24 | ) | — | (.24 | ) | 17.83 | 27.78 | 3,426 | .67 | .56 | 1.54 | |||||||||||
| 12/31/2020 | 13.39 | .22 | .91 | 1.13 | (.22 | ) | (.15 | ) | (.37 | ) | 14.15 | 8.68 | 3,082 | .68 | .68 | 1.75 | ||||||||||
| 12/31/2019 | 12.24 | .26 | 2.22 | 2.48 | (.26 | ) | (1.07 | ) | (1.33 | ) | 13.39 | 21.38 | 3,093 | .67 | .67 | 2.03 | ||||||||||
| 12/31/2018 | 14.80 | .27 | (1.42 | ) | (1.15 | ) | (.27 | ) | (1.14 | ) | (1.41 | ) | 12.24 | (8.66 | ) | 2,850 | .66 | .66 | 1.88 | |||||||
| 12/31/2017 | 13.39 | .28 | 1.94 | 2.22 | (.28 | ) | (.53 | ) | (.81 | ) | 14.80 | 17.04 | 3,551 | .66 | .66 | 2.02 | ||||||||||
| Class 4: | ||||||||||||||||||||||||||
| 12/31/2021 | 14.06 | .21 | 3.65 | 3.86 | (.21 | ) | — | (.21 | ) | 17.71 | 27.51 | 1,104 | .92 | .81 | 1.30 | |||||||||||
| 12/31/2020 | 13.31 | .19 | .91 | 1.10 | (.20 | ) | (.15 | ) | (.35 | ) | 14.06 | 8.47 | 788 | .93 | .93 | 1.51 | ||||||||||
| 12/31/2019 | 12.19 | .23 | 2.20 | 2.43 | (.24 | ) | (1.07 | ) | (1.31 | ) | 13.31 | 21.03 | 621 | .92 | .92 | 1.78 | ||||||||||
| 12/31/2018 | 14.77 | .23 | (1.42 | ) | (1.19 | ) | (.25 | ) | (1.14 | ) | (1.39 | ) | 12.19 | (8.92 | ) | 368 | .91 | .91 | 1.62 | |||||||
| 12/31/2017 | 13.39 | .25 | 1.93 | 2.18 | (.27 | ) | (.53 | ) | (.80 | ) | 14.77 | 16.70 | 247 | .91 | .91 | 1.76 | ||||||||||
| Income
(loss) from investment operations1 |
Dividends and distributions | |||||||||||||||||||||||||
| Period ended | Net
asset value, beginning of period |
Net investment income |
Net
gains (losses) on securities (both realized and unrealized) |
Total
from investment operations |
Dividends (from net investment income) |
Distributions (from capital gains) |
Total dividends and distributions |
Net
asset value, end of period |
Total return2 |
Net
assets, end of period (in millions) |
Ratio
of expenses to average net assets before waivers3 |
Ratio
of expenses to average net assets after waivers2,3 |
Ratio
of net income to average net assets2 | |||||||||||||
| Capital Income Builder | ||||||||||||||||||||||||||
| Class 1: | ||||||||||||||||||||||||||
| 12/31/2021 | $10.87 | $.37 | $1.28 | $1.65 | $(.35 | ) | $— | $(.35 | ) | $12.17 | 15.31 | % | $563 | .53 | % | .27 | % | 3.19 | % | |||||||
| 12/31/2020 | 10.73 | .31 | .15 | .46 | (.32 | ) | — | (.32 | ) | 10.87 | 4.64 | 621 | .53 | .35 | 3.07 | |||||||||||
| 12/31/2019 | 9.37 | .32 | 1.36 | 1.68 | (.32 | ) | — | (.32 | ) | 10.73 | 18.16 | 533 | .53 | .53 | 3.17 | |||||||||||
| 12/31/2018 | 10.40 | .31 | (1.00 | ) | (.69 | ) | (.32 | ) | (.02 | ) | (.34 | ) | 9.37 | (6.77 | ) | 317 | .54 | .54 | 3.08 | |||||||
| 12/31/2017 | 9.46 | .32 | .93 | 1.25 | (.31 | ) | — | (.31 | ) | 10.40 | 13.29 | 254 | .54 | .54 | 3.21 | |||||||||||
| Class 1A: | ||||||||||||||||||||||||||
| 12/31/2021 | 10.86 | .34 | 1.27 | 1.61 | (.32 | ) | — | (.32 | ) | 12.15 | 14.95 | 10 | .78 | .52 | 2.94 | |||||||||||
| 12/31/2020 | 10.72 | .28 | .16 | .44 | (.30 | ) | — | (.30 | ) | 10.86 | 4.38 | 6 | .78 | .60 | 2.81 | |||||||||||
| 12/31/2019 | 9.36 | .29 | 1.37 | 1.66 | (.30 | ) | — | (.30 | ) | 10.72 | 17.90 | 6 | .78 | .78 | 2.84 | |||||||||||
| 12/31/2018 | 10.39 | .28 | (.99 | ) | (.71 | ) | (.30 | ) | (.02 | ) | (.32 | ) | 9.36 | (7.01 | ) | 2 | .79 | .79 | 2.82 | |||||||
| 12/31/20174,5 | 9.57 | .27 | .84 | 1.11 | (.29 | ) | — | (.29 | ) | 10.39 | 11.72 | 6 | 1 | .79 | 7 | .79 | 7 | 2.63 | 7 | |||||||
| Class 2: | ||||||||||||||||||||||||||
| 12/31/2021 | 10.87 | .34 | 1.27 | 1.61 | (.32 | ) | — | (.32 | ) | 12.16 | 14.94 | 13 | .78 | .52 | 2.93 | |||||||||||
| 12/31/2020 | 10.72 | .29 | .16 | .45 | (.30 | ) | — | (.30 | ) | 10.87 | 4.48 | 8 | .78 | .60 | 2.83 | |||||||||||
| 12/31/2019 | 9.36 | .30 | 1.35 | 1.65 | (.29 | ) | — | (.29 | ) | 10.72 | 17.89 | 6 | .78 | .78 | 2.91 | |||||||||||
| 12/31/2018 | 10.40 | .28 | (1.00 | ) | (.72 | ) | (.30 | ) | (.02 | ) | (.32 | ) | 9.36 | (7.08 | ) | 4 | .79 | .79 | 2.83 | |||||||
| 12/31/2017 | 9.46 | .29 | .93 | 1.22 | (.28 | ) | — | (.28 | ) | 10.40 | 13.04 | 1 | .79 | .79 | 2.82 | |||||||||||
| Class 4: | ||||||||||||||||||||||||||
| 12/31/2021 | 10.85 | .31 | 1.27 | 1.58 | (.29 | ) | — | (.29 | ) | 12.14 | 14.68 | 559 | 1.03 | .77 | 2.69 | |||||||||||
| 12/31/2020 | 10.71 | .26 | .15 | .41 | (.27 | ) | — | (.27 | ) | 10.85 | 4.11 | 462 | 1.03 | .85 | 2.55 | |||||||||||
| 12/31/2019 | 9.35 | .27 | 1.36 | 1.63 | (.27 | ) | — | (.27 | ) | 10.71 | 17.62 | 454 | 1.03 | 1.03 | 2.68 | |||||||||||
| 12/31/2018 | 10.38 | .26 | (1.00 | ) | (.74 | ) | (.27 | ) | (.02 | ) | (.29 | ) | 9.35 | (7.25 | ) | 352 | 1.04 | 1.04 | 2.58 | |||||||
| 12/31/2017 | 9.45 | .27 | .92 | 1.19 | (.26 | ) | — | (.26 | ) | 10.38 | 12.65 | 338 | 1.04 | 1.04 | 2.72 | |||||||||||
American Funds Insurance Series / Prospectus 24
| Income
(loss) from investment operations1 |
Dividends and distributions | |||||||||||||||||||||||
| Period ended | Net
asset value, beginning of period |
Net investment income |
Net
gains (losses) on securities (both realized and unrealized) |
Total
from investment operations |
Dividends (from net investment income) |
Distributions (from capital gains) |
Total dividends and distributions |
Net
asset value, end of period |
Total return |
Net
assets, end of period (in millions) |
Ratio
of expenses to average net assets3 |
Ratio
of net income to average net assets | ||||||||||||
| Asset Allocation Fund | ||||||||||||||||||||||||
| Class 1: | ||||||||||||||||||||||||
| 12/31/2021 | $26.50 | $.48 | $3.54 | $4.02 | $(.50 | ) | $(.94 | ) | $(1.44 | ) | $29.08 | 15.40 | % | $18,836 | .30 | % | 1.71 | % | ||||||
| 12/31/2020 | 24.05 | .43 | 2.59 | 3.02 | (.46 | ) | (.11 | ) | (.57 | ) | 26.50 | 12.71 | 19,238 | .30 | 1.80 | |||||||||
| 12/31/2019 | 21.29 | .51 | 3.94 | 4.45 | (.50 | ) | (1.19 | ) | (1.69 | ) | 24.05 | 21.54 | 17,730 | .29 | 2.21 | |||||||||
| 12/31/2018 | 23.71 | .48 | (1.43 | ) | (.95 | ) | (.44 | ) | (1.03 | ) | (1.47 | ) | 21.29 | (4.35 | ) | 14,627 | .28 | 2.04 | ||||||
| 12/31/2017 | 21.68 | .44 | 3.06 | 3.50 | (.41 | ) | (1.06 | ) | (1.47 | ) | 23.71 | 16.51 | 16,556 | .29 | 1.90 | |||||||||
| Class 1A: | ||||||||||||||||||||||||
| 12/31/2021 | 26.42 | .42 | 3.52 | 3.94 | (.45 | ) | (.94 | ) | (1.39 | ) | 28.97 | 15.13 | 24 | .55 | 1.49 | |||||||||
| 12/31/2020 | 23.99 | .37 | 2.58 | 2.95 | (.41 | ) | (.11 | ) | (.52 | ) | 26.42 | 12.43 | 14 | .55 | 1.56 | |||||||||
| 12/31/2019 | 21.26 | .45 | 3.92 | 4.37 | (.45 | ) | (1.19 | ) | (1.64 | ) | 23.99 | 21.19 | 11 | .54 | 1.95 | |||||||||
| 12/31/2018 | 23.69 | .42 | (1.42 | ) | (1.00 | ) | (.40 | ) | (1.03 | ) | (1.43 | ) | 21.26 | (4.58 | ) | 7 | .53 | 1.82 | ||||||
| 12/31/20174,5 | 21.97 | .39 | 2.78 | 3.17 | (.39 | ) | (1.06 | ) | (1.45 | ) | 23.69 | 14.78 | 6 | 4 | .53 | 7 | 1.69 | 7 | ||||||
| Class 2: | ||||||||||||||||||||||||
| 12/31/2021 | 26.21 | .41 | 3.49 | 3.90 | (.43 | ) | (.94 | ) | (1.37 | ) | 28.74 | 15.10 | 5,473 | .55 | 1.46 | |||||||||
| 12/31/2020 | 23.79 | .37 | 2.56 | 2.93 | (.40 | ) | (.11 | ) | (.51 | ) | 26.21 | 12.46 | 5,242 | .55 | 1.55 | |||||||||
| 12/31/2019 | 21.08 | .45 | 3.89 | 4.34 | (.44 | ) | (1.19 | ) | (1.63 | ) | 23.79 | 21.23 | 5,154 | .54 | 1.96 | |||||||||
| 12/31/2018 | 23.49 | .41 | (1.41 | ) | (1.00 | ) | (.38 | ) | (1.03 | ) | (1.41 | ) | 21.08 | (4.60 | ) | 4,668 | .53 | 1.78 | ||||||
| 12/31/2017 | 21.49 | .37 | 3.04 | 3.41 | (.35 | ) | (1.06 | ) | (1.41 | ) | 23.49 | 16.23 | 5,480 | .54 | 1.64 | |||||||||
| Class 3: | ||||||||||||||||||||||||
| 12/31/2021 | 26.53 | .43 | 3.55 | 3.98 | (.45 | ) | (.94 | ) | (1.39 | ) | 29.12 | 15.22 | 36 | .48 | 1.53 | |||||||||
| 12/31/2020 | 24.08 | .39 | 2.59 | 2.98 | (.42 | ) | (.11 | ) | (.53 | ) | 26.53 | 12.50 | 33 | .48 | 1.62 | |||||||||
| 12/31/2019 | 21.32 | .47 | 3.93 | 4.40 | (.45 | ) | (1.19 | ) | (1.64 | ) | 24.08 | 21.30 | 32 | .47 | 2.02 | |||||||||
| 12/31/2018 | 23.73 | .43 | (1.41 | ) | (.98 | ) | (.40 | ) | (1.03 | ) | (1.43 | ) | 21.32 | (4.49 | ) | 29 | .46 | 1.85 | ||||||
| 12/31/2017 | 21.70 | .39 | 3.07 | 3.46 | (.37 | ) | (1.06 | ) | (1.43 | ) | 23.73 | 16.29 | 38 | .47 | 1.72 | |||||||||
| Class 4: | ||||||||||||||||||||||||
| 12/31/2021 | 26.06 | .34 | 3.47 | 3.81 | (.37 | ) | (.94 | ) | (1.31 | ) | 28.56 | 14.84 | 6,337 | .80 | 1.22 | |||||||||
| 12/31/2020 | 23.67 | .31 | 2.54 | 2.85 | (.35 | ) | (.11 | ) | (.46 | ) | 26.06 | 12.16 | 5,131 | .80 | 1.30 | |||||||||
| 12/31/2019 | 20.99 | .39 | 3.87 | 4.26 | (.39 | ) | (1.19 | ) | (1.58 | ) | 23.67 | 20.92 | 4,493 | .79 | 1.71 | |||||||||
| 12/31/2018 | 23.40 | .35 | (1.40 | ) | (1.05 | ) | (.33 | ) | (1.03 | ) | (1.36 | ) | 20.99 | (4.83 | ) | 3,594 | .78 | 1.54 | ||||||
| 12/31/2017 | 21.43 | .32 | 3.02 | 3.34 | (.31 | ) | (1.06 | ) | (1.37 | ) | 23.40 | 15.91 | 3,582 | .79 | 1.40 | |||||||||
| Income
(loss) from investment operations1 |
Dividends and distributions | |||||||||||||||||||||||
| Period ended | Net
asset value, beginning of period |
Net investment income |
Net
gains (losses) on securities (both realized and unrealized) |
Total
from investment operations |
Dividends (from net investment income) |
Distributions (from capital gains) |
Total dividends and distributions |
Net
asset value, end of period |
Total return |
Net
assets, end of period (in millions) |
Ratio
of expenses to average net assets3 |
Ratio
of net income to average net assets | ||||||||||||
| American Funds Global Balanced Fund | ||||||||||||||||||||||||
| Class 1: | ||||||||||||||||||||||||
| 12/31/2021 | $14.19 | $.18 | $1.37 | $1.55 | $(.19 | ) | $(.82 | ) | $(1.01 | ) | $14.73 | 11.05 | % | $120 | .73 | % | 1.24 | % | ||||||
| 12/31/2020 | 13.51 | .17 | 1.24 | 1.41 | (.19 | ) | (.54 | ) | (.73 | ) | 14.19 | 10.53 | 139 | .72 | 1.29 | |||||||||
| 12/31/2019 | 11.67 | .24 | 2.17 | 2.41 | (.20 | ) | (.37 | ) | (.57 | ) | 13.51 | 20.79 | 134 | .72 | 1.88 | |||||||||
| 12/31/2018 | 12.75 | .23 | (.96 | ) | (.73 | ) | (.20 | ) | (.15 | ) | (.35 | ) | 11.67 | (5.81 | ) | 110 | .72 | 1.82 | ||||||
| 12/31/2017 | 11.08 | .21 | 1.99 | 2.20 | (.15 | ) | (.38 | ) | (.53 | ) | 12.75 | 19.91 | 93 | .72 | 1.68 | |||||||||
| Class 1A: | ||||||||||||||||||||||||
| 12/31/2021 | 14.16 | .15 | 1.36 | 1.51 | (.15 | ) | (.82 | ) | (.97 | ) | 14.70 | 10.83 | 4 | .98 | 1.02 | |||||||||
| 12/31/2020 | 13.49 | .14 | 1.23 | 1.37 | (.16 | ) | (.54 | ) | (.70 | ) | 14.16 | 10.25 | 3 | .97 | 1.03 | |||||||||
| 12/31/2019 | 11.65 | .21 | 2.17 | 2.38 | (.17 | ) | (.37 | ) | (.54 | ) | 13.49 | 20.54 | 2 | .97 | 1.63 | |||||||||
| 12/31/2018 | 12.74 | .18 | (.94 | ) | (.76 | ) | (.18 | ) | (.15 | ) | (.33 | ) | 11.65 | (6.03 | ) | 2 | .98 | 1.44 | ||||||
| 12/31/20174,5 | 11.18 | .16 | 1.92 | 2.08 | (.14 | ) | (.38 | ) | (.52 | ) | 12.74 | 18.71 | 6 | — | 8 | .94 | 7 | 1.27 | 7 | |||||
| Class 2: | ||||||||||||||||||||||||
| 12/31/2021 | 14.16 | .15 | 1.36 | 1.51 | (.15 | ) | (.82 | ) | (.97 | ) | 14.70 | 10.79 | 208 | .98 | 1.01 | |||||||||
| 12/31/2020 | 13.48 | .14 | 1.23 | 1.37 | (.15 | ) | (.54 | ) | (.69 | ) | 14.16 | 10.30 | 208 | .97 | 1.03 | |||||||||
| 12/31/2019 | 11.65 | .21 | 2.16 | 2.37 | (.17 | ) | (.37 | ) | (.54 | ) | 13.48 | 20.44 | 207 | .97 | 1.64 | |||||||||
| 12/31/2018 | 12.72 | .20 | (.96 | ) | (.76 | ) | (.16 | ) | (.15 | ) | (.31 | ) | 11.65 | (6.01 | ) | 185 | .97 | 1.57 | ||||||
| 12/31/2017 | 11.06 | .18 | 1.98 | 2.16 | (.12 | ) | (.38 | ) | (.50 | ) | 12.72 | 19.57 | 210 | .96 | 1.43 | |||||||||
| Class 4: | ||||||||||||||||||||||||
| 12/31/2021 | 14.02 | .11 | 1.34 | 1.45 | (.12 | ) | (.82 | ) | (.94 | ) | 14.53 | 10.46 | 135 | 1.23 | .77 | |||||||||
| 12/31/2020 | 13.36 | .10 | 1.22 | 1.32 | (.12 | ) | (.54 | ) | (.66 | ) | 14.02 | 10.00 | 105 | 1.22 | .78 | |||||||||
| 12/31/2019 | 11.55 | .18 | 2.14 | 2.32 | (.14 | ) | (.37 | ) | (.51 | ) | 13.36 | 20.21 | 94 | 1.22 | 1.37 | |||||||||
| 12/31/2018 | 12.63 | .17 | (.96 | ) | (.79 | ) | (.14 | ) | (.15 | ) | (.29 | ) | 11.55 | (6.31 | ) | 69 | 1.22 | 1.34 | ||||||
| 12/31/2017 | 11.00 | .13 | 1.99 | 2.12 | (.11 | ) | (.38 | ) | (.49 | ) | 12.63 | 19.38 | 51 | 1.22 | 1.07 | |||||||||
25 American Funds Insurance Series / Prospectus
| Income
(loss) from investment operations1 |
Dividends and distributions | |||||||||||||||||||||||||
| Period ended | Net
asset value, beginning of year |
Net investment income (loss) |
Net
gains (losses) on securities (both realized and unrealized) |
Total
from investment operations |
Dividends (from net investment income) |
Distributions (from capital gains) |
Total dividends and distributions |
Net
asset value, end of year |
Total return2 |
Net
assets, end of year (in millions) |
Ratio
of expenses to average net assets before reimbursements |
Ratio
of expenses to average net assets after reimbursements2 |
Ratio
of net income (loss) to average net assets2 | |||||||||||||
| American Funds Mortgage Fund | ||||||||||||||||||||||||||
| Class 1: | ||||||||||||||||||||||||||
| 12/31/2021 | $11.11 | $.06 | $(.09 | ) | $(.03 | ) | $(.08 | ) | $(.37 | ) | $(.45 | ) | $10.63 | (.32 | )% | $231 | .49 | % | .29 | % | .58 | % | ||||
| 12/31/2020 | 10.56 | .10 | .64 | .74 | (.17 | ) | (.02 | ) | (.19 | ) | 11.11 | 6.98 | 224 | .48 | .36 | .93 | ||||||||||
| 12/31/2019 | 10.30 | .24 | .30 | .54 | (.28 | ) | — | (.28 | ) | 10.56 | 5.30 | 210 | .47 | .47 | 2.26 | |||||||||||
| 12/31/2018 | 10.47 | .20 | (.14 | ) | .06 | (.23 | ) | — | (.23 | ) | 10.30 | .58 | 209 | .48 | .48 | 1.97 | ||||||||||
| 12/31/2017 | 10.56 | .16 | — | 9 | .16 | (.18 | ) | (.07 | ) | (.25 | ) | 10.47 | 1.47 | 265 | .47 | .47 | 1.52 | |||||||||
| Class 1A: | ||||||||||||||||||||||||||
| 12/31/2021 | 11.08 | .04 | (.10 | ) | (.06 | ) | (.06 | ) | (.37 | ) | (.43 | ) | 10.59 | (.47 | ) | 2 | .74 | .54 | .33 | |||||||
| 12/31/2020 | 10.55 | .07 | .63 | .70 | (.15 | ) | (.02 | ) | (.17 | ) | 11.08 | 6.63 | 1 | .73 | .59 | .61 | ||||||||||
| 12/31/2019 | 10.28 | .22 | .30 | .52 | (.25 | ) | — | (.25 | ) | 10.55 | 5.09 | 1 | .71 | .71 | 2.04 | |||||||||||
| 12/31/2018 | 10.46 | .18 | (.14 | ) | .04 | (.22 | ) | — | (.22 | ) | 10.28 | .36 | 1 | .73 | .73 | 1.77 | ||||||||||
| 12/31/20175 | 10.55 | .14 | — | 9 | .14 | (.16 | ) | (.07 | ) | (.23 | ) | 10.46 | 1.31 | 6 | — | 8 | .70 | 7 | .70 | 7 | 1.38 | 7 | ||||
| Class 2: | ||||||||||||||||||||||||||
| 12/31/2021 | 11.09 | .04 | (.10 | ) | (.06 | ) | (.05 | ) | (.37 | ) | (.42 | ) | 10.61 | (.57 | ) | 58 | .74 | .54 | .33 | |||||||
| 12/31/2020 | 10.54 | .08 | .63 | .71 | (.14 | ) | (.02 | ) | (.16 | ) | 11.09 | 6.72 | 58 | .73 | .60 | .68 | ||||||||||
| 12/31/2019 | 10.28 | .21 | .31 | .52 | (.26 | ) | — | (.26 | ) | 10.54 | 5.04 | 56 | .72 | .72 | 2.01 | |||||||||||
| 12/31/2018 | 10.45 | .18 | (.15 | ) | .03 | (.20 | ) | — | (.20 | ) | 10.28 | .32 | 57 | .73 | .73 | 1.72 | ||||||||||
| 12/31/2017 | 10.54 | .14 | (.01 | ) | .13 | (.15 | ) | (.07 | ) | (.22 | ) | 10.45 | 1.22 | 63 | .72 | .72 | 1.27 | |||||||||
| Class 4: | ||||||||||||||||||||||||||
| 12/31/2021 | 10.97 | .01 | (.09 | ) | (.08 | ) | (.03 | ) | (.37 | ) | (.40 | ) | 10.49 | (.78 | ) | 43 | .99 | .79 | .08 | |||||||
| 12/31/2020 | 10.44 | .04 | .63 | .67 | (.12 | ) | (.02 | ) | (.14 | ) | 10.97 | 6.38 | 37 | .98 | .85 | .41 | ||||||||||
| 12/31/2019 | 10.19 | .18 | .31 | .49 | (.24 | ) | — | (.24 | ) | 10.44 | 4.80 | 28 | .97 | .97 | 1.71 | |||||||||||
| 12/31/2018 | 10.38 | .15 | (.15 | ) | — | 9 | (.19 | ) | — | (.19 | ) | 10.19 | .07 | 24 | .98 | .98 | 1.49 | |||||||||
| 12/31/2017 | 10.48 | .11 | — | 9 | .11 | (.14 | ) | (.07 | ) | (.21 | ) | 10.38 | .97 | 12 | .97 | .97 | 1.03 | |||||||||
| Income
(loss) from investment operations1 |
Dividends and distributions | |||||||||||||||||||||||||
| Period ended | Net
asset value, beginning of period |
Net investment income |
Net
gains (losses) on securities (both realized and unrealized) |
Total
from investment operations |
Dividends (from net investment income) |
Distributions (from capital gains) |
Total dividends and distributions |
Net
asset value, end of period |
Total return2 |
Net
assets, end of period (in millions) |
Ratio
of expenses to average net assets before waivers3 |
Ratio
of expenses to average net assets after waivers2,3 |
Ratio
of net income to average net assets2 | |||||||||||||
| American High-Income Trust | ||||||||||||||||||||||||||
| Class 1: | ||||||||||||||||||||||||||
| 12/31/2021 | $9.80 | $.51 | $.34 | $.85 | $(.46 | ) | $— | $(.46 | ) | $10.19 | 8.74 | % | $278 | .53 | % | .37 | % | 4.95 | % | |||||||
| 12/31/2020 | 9.87 | .61 | .17 | .78 | (.85 | ) | — | (.85 | ) | 9.80 | 8.21 | 123 | .52 | .52 | 6.46 | |||||||||||
| 12/31/2019 | 9.34 | .67 | .52 | 1.19 | (.66 | ) | — | (.66 | ) | 9.87 | 12.85 | 525 | .51 | .51 | 6.71 | |||||||||||
| 12/31/2018 | 10.19 | .64 | (.84 | ) | (.20 | ) | (.65 | ) | — | (.65 | ) | 9.34 | (2.15 | ) | 501 | .50 | .50 | 6.32 | ||||||||
| 12/31/2017 | 10.18 | .63 | .10 | .73 | (.72 | ) | — | (.72 | ) | 10.19 | 7.25 | 632 | .49 | .49 | 5.98 | |||||||||||
| Class 1A: | ||||||||||||||||||||||||||
| 12/31/2021 | 9.78 | .49 | .33 | .82 | (.44 | ) | — | (.44 | ) | 10.16 | 8.42 | 1 | .78 | .64 | 4.75 | |||||||||||
| 12/31/2020 | 9.86 | .56 | .20 | .76 | (.84 | ) | — | (.84 | ) | 9.78 | 7.94 | 1 | .78 | .78 | 5.85 | |||||||||||
| 12/31/2019 | 9.33 | .65 | .51 | 1.16 | (.63 | ) | — | (.63 | ) | 9.86 | 12.61 | 1 | .75 | .75 | 6.47 | |||||||||||
| 12/31/2018 | 10.18 | .62 | (.84 | ) | (.22 | ) | (.63 | ) | — | (.63 | ) | 9.33 | (2.35 | ) | 1 | .75 | .75 | 6.11 | ||||||||
| 12/31/20174,5 | 10.28 | .60 | .02 | .62 | (.72 | ) | — | (.72 | ) | 10.18 | 6.02 | 6 | — | 8 | .72 | 7 | .72 | 7 | 5.74 | 7 | ||||||
| Class 2: | ||||||||||||||||||||||||||
| 12/31/2021 | 9.61 | .48 | .33 | .81 | (.44 | ) | — | (.44 | ) | 9.98 | 8.42 | 673 | .78 | .65 | 4.80 | |||||||||||
| 12/31/2020 | 9.70 | .55 | .19 | .74 | (.83 | ) | — | (.83 | ) | 9.61 | 7.94 | 665 | .78 | .78 | 5.88 | |||||||||||
| 12/31/2019 | 9.19 | .64 | .50 | 1.14 | (.63 | ) | — | (.63 | ) | 9.70 | 12.55 | 667 | .76 | .76 | 6.45 | |||||||||||
| 12/31/2018 | 10.03 | .61 | (.83 | ) | (.22 | ) | (.62 | ) | — | (.62 | ) | 9.19 | (2.34 | ) | 661 | .75 | .75 | 6.07 | ||||||||
| 12/31/2017 | 10.04 | .59 | .10 | .69 | (.70 | ) | — | (.70 | ) | 10.03 | 6.89 | 776 | .74 | .74 | 5.72 | |||||||||||
| Class 3: | ||||||||||||||||||||||||||
| 12/31/2021 | 9.84 | .50 | .34 | .84 | (.44 | ) | — | (.44 | ) | 10.24 | 8.60 | 10 | .71 | .58 | 4.86 | |||||||||||
| 12/31/2020 | 9.92 | .57 | .19 | .76 | (.84 | ) | — | (.84 | ) | 9.84 | 7.93 | 10 | .71 | .71 | 5.94 | |||||||||||
| 12/31/2019 | 9.38 | .66 | .52 | 1.18 | (.64 | ) | — | (.64 | ) | 9.92 | 12.70 | 10 | .69 | .69 | 6.52 | |||||||||||
| 12/31/2018 | 10.23 | .63 | (.85 | ) | (.22 | ) | (.63 | ) | — | (.63 | ) | 9.38 | (2.33 | ) | 10 | .68 | .68 | 6.14 | ||||||||
| 12/31/2017 | 10.22 | .61 | .10 | .71 | (.70 | ) | — | (.70 | ) | 10.23 | 7.02 | 12 | .67 | .67 | 5.79 | |||||||||||
| Class 4: | ||||||||||||||||||||||||||
| 12/31/2021 | 10.54 | .50 | .36 | .86 | (.41 | ) | — | (.41 | ) | 10.99 | 8.18 | 90 | 1.03 | .89 | 4.52 | |||||||||||
| 12/31/2020 | 10.56 | .57 | .22 | .79 | (.81 | ) | — | (.81 | ) | 10.54 | 7.74 | 69 | 1.03 | 1.03 | 5.58 | |||||||||||
| 12/31/2019 | 9.96 | .67 | .54 | 1.21 | (.61 | ) | — | (.61 | ) | 10.56 | 12.27 | 63 | 1.01 | 1.01 | 6.21 | |||||||||||
| 12/31/2018 | 10.82 | .63 | (.90 | ) | (.27 | ) | (.59 | ) | — | (.59 | ) | 9.96 | (2.64 | ) | 31 | 1.00 | 1.00 | 5.83 | ||||||||
| 12/31/2017 | 10.79 | .61 | .10 | .71 | (.68 | ) | — | (.68 | ) | 10.82 | 6.63 | 34 | .99 | .99 | 5.46 | |||||||||||
American Funds Insurance Series / Prospectus 26
| (Loss)
income from investment operations1 |
Dividends and distributions | |||||||||||||||||||||||||
| Period ended | Net
asset value, beginning of period |
Net investment income |
Net
(losses) gains on securities (both realized and unrealized) |
Total
from investment operations |
Dividends (from net investment income) |
Distributions (from capital gains) |
Total dividends and distributions |
Net
asset value, end of period |
Total return2 |
Net
assets, end of period (in millions) |
Ratio
of expenses to average net assets before waivers3 |
Ratio
of expenses to average net assets after waivers2,3 |
Ratio
of net income to average net assets2 | |||||||||||||
| Capital World Bond Fund | ||||||||||||||||||||||||||
| Class 1: | ||||||||||||||||||||||||||
| 12/31/2021 | $12.94 | $.25 | $(.85 | ) | $(.60 | ) | $(.24 | ) | $(.31 | ) | $(.55 | ) | $11.79 | (4.73 | )% | $988 | .60 | % | .50 | % | 2.06 | % | ||||
| 12/31/2020 | 12.12 | .26 | .95 | 1.21 | (.18 | ) | (.21 | ) | (.39 | ) | 12.94 | 10.17 | 1,219 | .59 | .52 | 2.08 | ||||||||||
| 12/31/2019 | 11.42 | .31 | .61 | .92 | (.22 | ) | — | (.22 | ) | 12.12 | 8.08 | 1,077 | .58 | .58 | 2.60 | |||||||||||
| 12/31/2018 | 11.88 | .30 | (.44 | ) | (.14 | ) | (.28 | ) | (.04 | ) | (.32 | ) | 11.42 | (1.14 | ) | 1,015 | .57 | .57 | 2.56 | |||||||
| 12/31/2017 | 11.22 | .28 | .52 | .80 | (.07 | ) | (.07 | ) | (.14 | ) | 11.88 | 7.11 | 1,273 | .56 | .56 | 2.37 | ||||||||||
| Class 1A: | ||||||||||||||||||||||||||
| 12/31/2021 | 12.91 | .23 | (.85 | ) | (.62 | ) | (.22 | ) | (.31 | ) | (.53 | ) | 11.76 | (4.88 | ) | 1 | .85 | .75 | 1.85 | |||||||
| 12/31/2020 | 12.10 | .23 | .95 | 1.18 | (.16 | ) | (.21 | ) | (.37 | ) | 12.91 | 9.89 | 1 | .83 | .76 | 1.83 | ||||||||||
| 12/31/2019 | 11.41 | .28 | .60 | .88 | (.19 | ) | — | (.19 | ) | 12.10 | 7.75 | 1 | .83 | .83 | 2.35 | |||||||||||
| 12/31/2018 | 11.87 | .27 | (.43 | ) | (.16 | ) | (.26 | ) | (.04 | ) | (.30 | ) | 11.41 | (1.29 | ) | 1 | .82 | .82 | 2.36 | |||||||
| 12/31/20174,5 | 11.22 | .26 | .52 | .78 | (.06 | ) | (.07 | ) | (.13 | ) | 11.87 | 7.00 | 6 | — | 8 | .72 | 7 | .72 | 7 | 2.27 | 7 | |||||
| Class 2: | ||||||||||||||||||||||||||
| 12/31/2021 | 12.84 | .22 | (.84 | ) | (.62 | ) | (.21 | ) | (.31 | ) | (.52 | ) | 11.70 | (4.92 | ) | 1,030 | .85 | .75 | 1.82 | |||||||
| 12/31/2020 | 12.03 | .22 | .95 | 1.17 | (.15 | ) | (.21 | ) | (.36 | ) | 12.84 | 9.90 | 1,058 | .84 | .77 | 1.83 | ||||||||||
| 12/31/2019 | 11.34 | .28 | .60 | .88 | (.19 | ) | — | (.19 | ) | 12.03 | 7.77 | 1,002 | .83 | .83 | 2.35 | |||||||||||
| 12/31/2018 | 11.79 | .27 | (.43 | ) | (.16 | ) | (.25 | ) | (.04 | ) | (.29 | ) | 11.34 | (1.33 | ) | 1,032 | .82 | .82 | 2.32 | |||||||
| 12/31/2017 | 11.14 | .25 | .51 | .76 | (.04 | ) | (.07 | ) | (.11 | ) | 11.79 | 6.86 | 1,164 | .81 | .81 | 2.12 | ||||||||||
| Class 4: | ||||||||||||||||||||||||||
| 12/31/2021 | 12.71 | .19 | (.84 | ) | (.65 | ) | (.18 | ) | (.31 | ) | (.49 | ) | 11.57 | (5.18 | ) | 66 | 1.10 | 1.00 | 1.57 | |||||||
| 12/31/2020 | 11.92 | .19 | .94 | 1.13 | (.13 | ) | (.21 | ) | (.34 | ) | 12.71 | 9.62 | 61 | 1.09 | 1.02 | 1.58 | ||||||||||
| 12/31/2019 | 11.24 | .24 | .60 | .84 | (.16 | ) | — | (.16 | ) | 11.92 | 7.54 | 49 | 1.08 | 1.08 | 2.09 | |||||||||||
| 12/31/2018 | 11.70 | .24 | (.43 | ) | (.19 | ) | (.23 | ) | (.04 | ) | (.27 | ) | 11.24 | (1.61 | ) | 40 | 1.07 | 1.07 | 2.09 | |||||||
| 12/31/2017 | 11.08 | .22 | .51 | .73 | (.04 | ) | (.07 | ) | (.11 | ) | 11.70 | 6.63 | 31 | 1.06 | 1.06 | 1.89 | ||||||||||
| (Loss)
income from investment operations1 |
Dividends and distributions | |||||||||||||||||||||||||
| Period ended | Net
asset value, beginning of period |
Net investment income |
Net
(losses) gains on securities (both realized and unrealized) |
Total
from investment operations |
Dividends (from net investment income) |
Distributions (from capital gains) |
Total dividends and distributions |
Net
asset value, end of period |
Total return2 |
Net
assets, end of period (in millions) |
Ratio
of expenses to average net assets before waivers3 |
Ratio
of expenses to average net assets after waivers2,3 |
Ratio
of net income to average net assets2 | |||||||||||||
| The Bond Fund of America | ||||||||||||||||||||||||||
| Class 1: | ||||||||||||||||||||||||||
| 12/31/2021 | $11.89 | $.21 | $(.23 | ) | $(.02 | ) | $(.19 | ) | $(.47 | ) | $(.66 | ) | $11.21 | (.14 | )% | $8,555 | .39 | % | .26 | % | 1.84 | % | ||||
| 12/31/2020 | 11.17 | .23 | .87 | 1.10 | (.27 | ) | (.11 | ) | (.38 | ) | 11.89 | 9.96 | 6,844 | .40 | .40 | 2.00 | ||||||||||
| 12/31/2019 | 10.47 | .30 | .71 | 1.01 | (.31 | ) | — | (.31 | ) | 11.17 | 9.70 | 6,481 | .39 | .39 | 2.76 | |||||||||||
| 12/31/2018 | 10.82 | .29 | (.35 | ) | (.06 | ) | (.28 | ) | (.01 | ) | (.29 | ) | 10.47 | (.45 | ) | 5,962 | .38 | .38 | 2.70 | |||||||
| 12/31/2017 | 10.80 | .24 | .18 | .42 | (.24 | ) | (.16 | ) | (.40 | ) | 10.82 | 3.88 | 6,434 | .38 | .38 | 2.19 | ||||||||||
| Class 1A: | ||||||||||||||||||||||||||
| 12/31/2021 | 11.84 | .18 | (.23 | ) | (.05 | ) | (.16 | ) | (.47 | ) | (.63 | ) | 11.16 | (.36 | ) | 12 | .64 | .51 | 1.59 | |||||||
| 12/31/2020 | 11.13 | .20 | .87 | 1.07 | (.25 | ) | (.11 | ) | (.36 | ) | 11.84 | 9.68 | 9 | .65 | .65 | 1.74 | ||||||||||
| 12/31/2019 | 10.45 | .27 | .71 | .98 | (.30 | ) | — | (.30 | ) | 11.13 | 9.36 | 7 | .64 | .64 | 2.48 | |||||||||||
| 12/31/2018 | 10.80 | .26 | (.33 | ) | (.07 | ) | (.27 | ) | (.01 | ) | (.28 | ) | 10.45 | (.60 | ) | 3 | .63 | .63 | 2.50 | |||||||
| 12/31/20174,5 | 10.82 | .22 | .15 | .37 | (.23 | ) | (.16 | ) | (.39 | ) | 10.80 | 3.46 | 6 | 1 | .62 | 7 | .62 | 7 | 2.01 | 7 | ||||||
| Class 2: | ||||||||||||||||||||||||||
| 12/31/2021 | 11.73 | .18 | (.22 | ) | (.04 | ) | (.16 | ) | (.47 | ) | (.63 | ) | 11.06 | (.31 | ) | 3,729 | .64 | .52 | 1.57 | |||||||
| 12/31/2020 | 11.02 | .20 | .86 | 1.06 | (.24 | ) | (.11 | ) | (.35 | ) | 11.73 | 9.73 | 3,840 | .65 | .65 | 1.75 | ||||||||||
| 12/31/2019 | 10.34 | .27 | .70 | .97 | (.29 | ) | — | (.29 | ) | 11.02 | 9.36 | 3,561 | .64 | .64 | 2.51 | |||||||||||
| 12/31/2018 | 10.69 | .26 | (.34 | ) | (.08 | ) | (.26 | ) | (.01 | ) | (.27 | ) | 10.34 | (.71 | ) | 3,524 | .63 | .63 | 2.45 | |||||||
| 12/31/2017 | 10.67 | .21 | .18 | .39 | (.21 | ) | (.16 | ) | (.37 | ) | 10.69 | 3.67 | 3,966 | .63 | .63 | 1.94 | ||||||||||
| Class 4: | ||||||||||||||||||||||||||
| 12/31/2021 | 11.69 | .15 | (.22 | ) | (.07 | ) | (.14 | ) | (.47 | ) | (.61 | ) | 11.01 | (.59 | ) | 891 | .89 | .76 | 1.34 | |||||||
| 12/31/2020 | 11.00 | .17 | .85 | 1.02 | (.22 | ) | (.11 | ) | (.33 | ) | 11.69 | 9.38 | 714 | .90 | .90 | 1.48 | ||||||||||
| 12/31/2019 | 10.33 | .24 | .70 | .94 | (.27 | ) | — | (.27 | ) | 11.00 | 9.08 | 502 | .89 | .89 | 2.25 | |||||||||||
| 12/31/2018 | 10.68 | .23 | (.33 | ) | (.10 | ) | (.24 | ) | (.01 | ) | (.25 | ) | 10.33 | (.89 | ) | 366 | .88 | .88 | 2.22 | |||||||
| 12/31/2017 | 10.70 | .19 | .16 | .35 | (.21 | ) | (.16 | ) | (.37 | ) | 10.68 | 3.29 | 297 | .88 | .88 | 1.72 | ||||||||||
27 American Funds Insurance Series / Prospectus
| (Loss)
income from investment operations1 |
Dividends and distributions | |||||||||||||||||||||||||
| Period ended | Net
asset value, beginning of period |
Net investment income |
Net
(losses) gains on securities (both realized and unrealized) |
Total
from investment operations |
Dividends (from net investment income) |
Distributions (from capital gains) |
Total dividends and distributions |
Net
asset value, end of period |
Total return2 |
Net
assets, end of period (in millions) |
Ratio
of expenses to average net assets before waivers |
Ratio
of expenses to average net assets after waivers2 |
Ratio
of net income to average net assets2 | |||||||||||||
| U.S. Government Securities Fund | ||||||||||||||||||||||||||
| Class 1: | ||||||||||||||||||||||||||
| 12/31/2021 | $13.04 | $.18 | $(.26 | ) | $(.08 | ) | $(.18 | ) | $(1.11 | ) | $(1.29 | ) | $11.67 | (.44 | )% | $522 | .39 | % | .29 | % | 1.50 | % | ||||
| 12/31/2020 | 12.34 | .16 | 1.07 | 1.23 | (.26 | ) | (.27 | ) | (.53 | ) | 13.04 | 10.09 | 429 | .38 | .38 | 1.21 | ||||||||||
| 12/31/2019 | 11.94 | .25 | .43 | .68 | (.28 | ) | — | (.28 | ) | 12.34 | 5.69 | 1,418 | .37 | .37 | 2.07 | |||||||||||
| 12/31/2018 | 12.08 | .24 | (.13 | ) | .11 | (.25 | ) | — | (.25 | ) | 11.94 | .91 | 1,445 | .36 | .36 | 2.02 | ||||||||||
| 12/31/2017 | 12.05 | .21 | .01 | .22 | (.19 | ) | — | (.19 | ) | 12.08 | 1.83 | 1,558 | .36 | .36 | 1.68 | |||||||||||
| Class 1A: | ||||||||||||||||||||||||||
| 12/31/2021 | 13.00 | .16 | (.26 | ) | (.10 | ) | (.16 | ) | (1.11 | ) | (1.27 | ) | 11.63 | (.65 | ) | 5 | .64 | .53 | 1.28 | |||||||
| 12/31/2020 | 12.32 | .09 | 1.10 | 1.19 | (.24 | ) | (.27 | ) | (.51 | ) | 13.00 | 9.75 | 4 | .64 | .64 | .69 | ||||||||||
| 12/31/2019 | 11.93 | .22 | .43 | .65 | (.26 | ) | — | (.26 | ) | 12.32 | 5.42 | 2 | .62 | .62 | 1.82 | |||||||||||
| 12/31/2018 | 12.08 | .22 | (.14 | ) | .08 | (.23 | ) | — | (.23 | ) | 11.93 | .70 | 1 | .61 | .61 | 1.82 | ||||||||||
| 12/31/20174,5 | 12.05 | .18 | .03 | .21 | (.18 | ) | — | (.18 | ) | 12.08 | 1.73 | 6 | — | 8 | .58 | 7 | .58 | 7 | 1.53 | 7 | ||||||
| Class 2: | ||||||||||||||||||||||||||
| 12/31/2021 | 12.89 | .15 | (.25 | ) | (.10 | ) | (.15 | ) | (1.11 | ) | (1.26 | ) | 11.53 | (.62 | ) | 1,391 | .64 | .54 | 1.24 | |||||||
| 12/31/2020 | 12.21 | .09 | 1.10 | 1.19 | (.24 | ) | (.27 | ) | (.51 | ) | 12.89 | 9.80 | 1,439 | .64 | .64 | .73 | ||||||||||
| 12/31/2019 | 11.82 | .22 | .42 | .64 | (.25 | ) | — | (.25 | ) | 12.21 | 5.31 | 1,343 | .62 | .62 | 1.82 | |||||||||||
| 12/31/2018 | 11.96 | .21 | (.14 | ) | .07 | (.21 | ) | — | (.21 | ) | 11.82 | .73 | 1,323 | .61 | .61 | 1.77 | ||||||||||
| 12/31/2017 | 11.93 | .17 | .02 | .19 | (.16 | ) | — | (.16 | ) | 11.96 | 1.59 | 1,473 | .61 | .61 | 1.43 | |||||||||||
| Class 3: | ||||||||||||||||||||||||||
| 12/31/2021 | 13.07 | .16 | (.26 | ) | (.10 | ) | (.16 | ) | (1.11 | ) | (1.27 | ) | 11.70 | (.62 | ) | 9 | .57 | .47 | 1.31 | |||||||
| 12/31/2020 | 12.37 | .10 | 1.12 | 1.22 | (.25 | ) | (.27 | ) | (.52 | ) | 13.07 | 9.91 | 10 | .57 | .57 | .78 | ||||||||||
| 12/31/2019 | 11.97 | .23 | .43 | .66 | (.26 | ) | — | (.26 | ) | 12.37 | 5.49 | 9 | .55 | .55 | 1.88 | |||||||||||
| 12/31/2018 | 12.11 | .22 | (.14 | ) | .08 | (.22 | ) | — | (.22 | ) | 11.97 | .71 | 9 | .54 | .54 | 1.84 | ||||||||||
| 12/31/2017 | 12.07 | .18 | .03 | .21 | (.17 | ) | — | (.17 | ) | 12.11 | 1.72 | 10 | .54 | .54 | 1.50 | |||||||||||
| Class 4: | ||||||||||||||||||||||||||
| 12/31/2021 | 12.88 | .12 | (.25 | ) | (.13 | ) | (.12 | ) | (1.11 | ) | (1.23 | ) | 11.52 | (.88 | ) | 238 | .89 | .79 | .98 | |||||||
| 12/31/2020 | 12.22 | .05 | 1.10 | 1.15 | (.22 | ) | (.27 | ) | (.49 | ) | 12.88 | 9.48 | 272 | .89 | .89 | .42 | ||||||||||
| 12/31/2019 | 11.84 | .19 | .42 | .61 | (.23 | ) | — | (.23 | ) | 12.22 | 5.14 | 124 | .87 | .87 | 1.56 | |||||||||||
| 12/31/2018 | 11.98 | .18 | (.12 | ) | .06 | (.20 | ) | — | (.20 | ) | 11.84 | .50 | 91 | .86 | .86 | 1.53 | ||||||||||
| 12/31/2017 | 11.96 | .14 | .01 | .15 | (.13 | ) | — | (.13 | ) | 11.98 | 1.28 | 62 | .86 | .86 | 1.18 | |||||||||||
American Funds Insurance Series / Prospectus 28
| (Loss)
income from investment operations1 |
Dividends and distributions | |||||||||||||||||||||||
| Period ended | Net
asset value, beginning of period |
Net investment (loss) income |
Net
(losses) gains on securities (both realized and unrealized) |
Total
from investment operations |
Dividends (from net investment income) |
Distributions (from capital gains) |
Total dividends and distributions |
Net
asset value, end of period |
Total return |
Net
assets, end of period (in millions) |
Ratio
of expenses to average net assets |
Ratio
of net (loss) income to average net assets | ||||||||||||
| Ultra-Short Bond Fund | ||||||||||||||||||||||||
| Class 1: | ||||||||||||||||||||||||
| 12/31/2021 | $11.31 | $(.03 | ) | $(.01 | ) | $(.04 | ) | $— | $— | $— | $11.27 | (.35 | )% | $37 | .37 | % | (.28 | )% | ||||||
| 12/31/2020 | 11.30 | .02 | .02 | .04 | (.03 | ) | — | (.03 | ) | 11.31 | .34 | 44 | .37 | .16 | ||||||||||
| 12/31/2019 | 11.31 | .22 | — | 9 | .22 | (.23 | ) | — | (.23 | ) | 11.30 | 1.92 | 30 | .36 | 1.92 | |||||||||
| 12/31/2018 | 11.29 | .18 | — | 9 | .18 | (.16 | ) | — | (.16 | ) | 11.31 | 1.58 | 37 | .35 | 1.60 | |||||||||
| 12/31/2017 | 11.27 | .08 | (.01 | ) | .07 | (.05 | ) | — | (.05 | ) | 11.29 | .66 | 37 | .35 | .68 | |||||||||
| Class 1A: | ||||||||||||||||||||||||
| 12/31/2021 | 11.31 | (.03 | ) | — | 9 | (.03 | ) | — | — | — | 11.28 | (.27 | ) | — | 8 | .36 | (.28 | ) | ||||||
| 12/31/2020 | 11.30 | .03 | .01 | .04 | (.03 | ) | — | (.03 | ) | 11.31 | .32 | — | 8 | .35 | .26 | |||||||||
| 12/31/2019 | 11.31 | .22 | — | 9 | .22 | (.23 | ) | — | (.23 | ) | 11.30 | 1.92 | — | 8 | .37 | 1.90 | ||||||||
| 12/31/2018 | 11.29 | .18 | — | 9 | .18 | (.16 | ) | — | (.16 | ) | 11.31 | 1.58 | — | 8 | .35 | 1.60 | ||||||||
| 12/31/20174,5 | 11.27 | .08 | — | 9 | .08 | (.06 | ) | — | (.06 | ) | 11.29 | .67 | 6 | — | 8 | .34 | 7 | .69 | 7 | |||||
| Class 2: | ||||||||||||||||||||||||
| 12/31/2021 | 10.99 | (.06 | ) | — | 9 | (.06 | ) | — | — | — | 10.93 | (.55 | ) | 245 | .62 | (.53 | ) | |||||||
| 12/31/2020 | 11.01 | — | 9 | — | 9 | — | 9 | (.02 | ) | — | (.02 | ) | 10.99 | .03 | 288 | .62 | (.05 | ) | ||||||
| 12/31/2019 | 11.03 | .18 | — | 9 | .18 | (.20 | ) | — | (.20 | ) | 11.01 | 1.62 | 230 | .61 | 1.66 | |||||||||
| 12/31/2018 | 11.01 | .15 | — | 9 | .15 | (.13 | ) | — | (.13 | ) | 11.03 | 1.36 | 247 | .60 | 1.34 | |||||||||
| 12/31/2017 | 10.99 | .05 | — | 9 | .05 | (.03 | ) | — | (.03 | ) | 11.01 | .46 | 249 | .60 | .42 | |||||||||
| Class 3: | ||||||||||||||||||||||||
| 12/31/2021 | 11.12 | (.05 | ) | — | 9 | (.05 | ) | — | — | — | 11.07 | (.45 | ) | 5 | .55 | (.46 | ) | |||||||
| 12/31/2020 | 11.13 | — | 9 | .02 | .02 | (.03 | ) | — | (.03 | ) | 11.12 | .13 | 4 | .55 | .03 | |||||||||
| 12/31/2019 | 11.14 | .20 | — | 9 | .20 | (.21 | ) | — | (.21 | ) | 11.13 | 1.76 | 3 | .54 | 1.74 | |||||||||
| 12/31/2018 | 11.12 | .16 | (.01 | ) | .15 | (.13 | ) | — | (.13 | ) | 11.14 | 1.38 | 4 | .53 | 1.42 | |||||||||
| 12/31/2017 | 11.10 | .06 | — | 9 | .06 | (.04 | ) | — | (.04 | ) | 11.12 | .54 | 4 | .53 | .50 | |||||||||
| Class 4: | ||||||||||||||||||||||||
| 12/31/2021 | 11.08 | (.09 | ) | .01 | (.08 | ) | — | — | — | 11.00 | (.72 | ) | 46 | .87 | (.79 | ) | ||||||||
| 12/31/2020 | 11.13 | (.04 | ) | .01 | (.03 | ) | (.02 | ) | — | (.02 | ) | 11.08 | (.25 | ) | 40 | .87 | (.35 | ) | ||||||
| 12/31/2019 | 11.15 | .16 | — | 9 | .16 | (.18 | ) | — | (.18 | ) | 11.13 | 1.40 | 22 | .86 | 1.40 | |||||||||
| 12/31/2018 | 11.13 | .12 | .01 | .13 | (.11 | ) | — | (.11 | ) | 11.15 | 1.14 | 18 | .86 | 1.11 | ||||||||||
| 12/31/2017 | 11.12 | .02 | — | 9 | .02 | (.01 | ) | — | (.01 | ) | 11.13 | .16 | 15 | .85 | .19 | |||||||||
29 American Funds Insurance Series / Prospectus
| Year ended December 31, | |||||
Portfolio turnover rate for all share classes excluding mortgage dollar roll transactions11 |
2021 | 2020 | 2019 | 2018 | 2017 |
| Capital Income Builder | 60% | 110% | 44% | 42% | 59% |
| Asset Allocation Fund | 45 | 49 | 47 | 34 | 39 |
| American Funds Mortgage Fund | 38 | 123 | 84 | 60 | 98 |
| American Funds Global Balanced Fund | 36 | 68 | 60 | 30 | 28 |
| Capital World Bond Fund | 64 | 88 | 110 | 78 | 74 |
| The Bond Fund of America | 87 | 72 | 146 | 98 | 153 |
| U.S. Government Securities Fund | 126 | 112 | 103 | 76 | 120 |
| Year ended December 31, | |||||
Portfolio turnover rate for all share classes including mortgage dollar roll transactions, if applicable11 |
2021 | 2020 | 2019 | 2018 | 2017 |
| Global Growth Fund | 18% | 17% | 14% | 25% | 31% |
| Global Small Capitalization Fund | 29 | 38 | 50 | 43 | 33 |
| Growth Fund | 25 | 32 | 21 | 35 | 24 |
| International Fund | 44 | 40 | 32 | 29 | 29 |
| New World Fund | 43 | 70 | 38 | 58 | 56 |
| Capital World Growth and Income Fund | 85 | 36 | 29 | 49 | 41 |
| Growth-Income Fund | 24 | 33 | 27 | 39 | 27 |
| International Growth and Income Fund | 41 | 56 | 28 | 38 | 51 |
| Washington Mutual Investors Fund | 90 | 40 | 37 | 49 | 34 |
| Capital Income Builder | 93 | 184 | 72 | 98 | 88 |
| Asset Allocation Fund | 124 | 145 | 79 | 86 | 85 |
| American Funds Global Balanced Fund | 39 | 86 | 74 | 51 | 41 |
| American Funds Mortgage Fund | 975 | 1,143 | 350 | 811 | 680 |
| American High-Income Trust | 56 | 78 | 58 | 67 | 78 |
| Capital World Bond Fund | 91 | 145 | 159 | 125 | 105 |
| The Bond Fund of America | 456 | 461 | 373 | 514 | 502 |
| U.S. Government Securities Fund | 433 | 867 | 277 | 446 | 551 |
| Ultra-Short Bond Fund | —12 | —12 | —12 | —12 | —12 |
1 Based on average shares outstanding.
2 This column reflects the impact of certain waivers/reimbursements from Capital Research and Management Company. During some of the periods shown, Capital Research and Management Company waived a portion of investment advisory services fees on some funds.
3 Ratios do not include expenses of any Central Funds. The fund indirectly bears its proportionate share of the expenses of any Central Funds, if applicable.
4 Based on operations for a period that is less than a full year.
5 Class 1A shares began investment operations on January 6, 2017.
6 Not annualized.
7 Annualized.
8 Amount less than $1 million.
9 Amount less than $.01.
10 Amount less than .01%.
11Rates do not include the fund’s portfolio activity with respect to any Central Funds, if applicable.
12Amount is either less than 1% or there is no turnover.
American Funds Insurance Series / Prospectus 30
Other fund information Shares of the Series are currently offered to insurance company separate accounts funding both variable annuity contracts and variable life insurance policies. Interests of various contract owners participating in the Series may be in conflict. The board of trustees of the Series will monitor for the existence of any material conflicts and determine what action, if any, should be taken. Shares may be purchased or redeemed by the separate accounts without any sales or redemption charges at net asset value.
Annual/Semi-annual report to shareholders The shareholder reports contain additional information about the Series, including financial statements, investment results, portfolio holdings, a discussion of market conditions and the Series’ investment strategies, and the independent registered public accounting firm’s report (in the annual report).
Statement of additional information (SAI) and codes of ethics The current SAI, as amended from time to time, contains more detailed information about the Series, including the funds’ financial statements, and is incorporated by reference into this prospectus. This means that the current SAI, for legal purposes, is part of this prospectus. The codes of ethics describe the personal investing policies adopted by the Series, the Series’ investment adviser and its affiliated companies.
The codes of ethics and current SAI are on file with the U.S. Securities and Exchange Commission (SEC). These and other related materials about the Series are available for review on the EDGAR database on the SEC’s website at sec.gov or, after payment of a duplicating fee, via email request to publicinfo@sec.gov.
The current SAI and annual/semi-annual reports to shareholders can be found online at capitalgroup.com/afis and may be available on the website of the company that issued your insurance contract. You also may request a free copy of these documents or the codes of ethics by calling Capital Group at (800) 421-9900, ext. 65413 or writing to the Secretary at 333 South Hope Street, Los Angeles, California 90071.
| INA1PRX-054-0522P Printed in USA CGD/AFD/8024 | Investment Company File No. 811-03857 |
American Funds Insurance Series® Prospectus May
1, 2022 |
 |
American Funds Global Balanced Fund
Table of contents
| American Funds Global Balanced Fund 1 | Investment objectives, strategies and risks 6 Management and organization 10 Purchases and redemptions of shares 15 |
|||
| The U.S. Securities and Exchange Commission has not approved or disapproved of these securities. Further, it has not determined that this prospectus is accurate or complete. Any representation to the contrary is a criminal offense. |
American Funds Global Balanced Fund
Investment objectives This fund seeks the balanced accomplishment of three objectives: long-term growth of capital, conservation of principal and current income.
Fees and expenses of the fund This table describes the fees and expenses that you may pay if you buy, hold and sell an interest in Class 1A shares of the fund. You may pay other fees, such as insurance contract fees and expenses, which are not reflected in the tables and examples below. If insurance contract fees and expenses were reflected, expenses shown would be higher.
| Annual fund operating expenses (expenses that you pay each year as a percentage of the value of your investment) | Class 1A |
| Management fee | 0.66% |
| Other expenses | 0.32 |
| Total annual fund operating expenses | 0.98 |
| Fee waiver* | 0.22 |
| Total annual fund operating expenses after fee waiver | 0.76 |
* The investment adviser is currently waiving a portion of its management fee equal to .22% of the fund’s net assets. This waiver will be in effect through at least May 1, 2023. The waiver may only be modified or terminated with the approval of the fund’s board.
Example This example is intended to help you compare the cost of investing in Class 1A shares of the fund with the cost of investing in other mutual funds.
The example assumes that you invest $10,000 in the fund for the time periods indicated and then redeem all of your shares at the end of those periods. The example also assumes that your investment has a 5% return each year and that the fund’s operating expenses remain the same. The example does not reflect insurance contract expenses. If insurance contract expenses were reflected, expenses shown would be higher. The example reflects the fee waiver described above through the expiration date of such waiver and total annual fund operating expenses thereafter. No sales charge (load) or other fees are charged by the fund upon redemption, so you would incur these hypothetical costs whether or not you were to redeem your shares at the end of the given period. Although your actual costs may be higher or lower, based on these assumptions your costs would be:
| 1 year | 3 years | 5 years | 10 years | |
| Class 1A | $78 | $290 | $520 | $1,181 |
Portfolio turnover The fund pays transaction costs, such as commissions, when it buys and sells securities (or “turns over” its portfolio). A higher portfolio turnover rate may indicate higher transaction costs. These costs, which are not reflected in annual fund operating expenses or in the example, affect the fund’s investment results. During the most recent fiscal year, the fund’s portfolio turnover rate was 39% of the average value of its portfolio.
Principal investment strategies As a balanced fund with global scope, the fund seeks to invest in equity and debt securities around the world that offer the opportunity for growth and/or provide dividend income, while also constructing the portfolio to protect principal and limit volatility.
Normally the fund will maintain at least 45% of the value of its assets in common stocks and other equity investments. Although the fund’s equity investments focus on medium to larger capitalization companies, the fund’s investments are not limited to a particular capitalization size.
Normally the fund will invest at least 25% of the value of its assets in bonds and other debt securities (including money market instruments). These will consist of investment-grade securities (rated Baa3 or better or BBB– or better by Nationally Recognized Statistical Rating Organizations designated by the fund’s investment adviser or unrated but determined to be of equivalent quality by the fund’s investment adviser).
The fund will allocate its assets among various countries, including the United States (but in no fewer than three countries). Under normal market conditions, the fund will invest at least 40% of its net assets in issuers outside the United States, unless market conditions are not deemed favorable by the fund’s investment adviser, in which case the fund would invest at least 30% of its net assets in issuers outside the United States.
The fund’s ability to invest in issuers outside the United States includes investing in emerging markets.
The fund may invest in bonds and other debt securities, including securities issued and guaranteed by the U.S. government, securities issued by federal agencies and instrumentalities and securities backed by mortgages or other assets. The fund may also invest in securities of governments, agencies, corporations and other entities domiciled outside the United States. These investments will typically be denominated in currencies other than U.S. dollars.
The investment adviser uses a system of multiple portfolio managers in managing the fund’s assets. Under this approach, the portfolio of the fund is divided into segments managed by individual managers.
The fund relies on the professional judgment of its investment adviser to make decisions about the fund’s portfolio investments. The basic investment philosophy of the investment adviser is to seek to invest in attractively valued securities that, in its opinion, represent good, long-term investment opportunities. Securities may be sold when the investment adviser believes that they no longer represent relatively attractive investment opportunities.
1 American Funds Insurance Series / Prospectus
Principal risks
This section describes the principal risks associated with investing in the fund. You may lose money by investing in the fund. The likelihood of loss may be greater if you invest for a shorter period of time. Investors in the fund should have a long-term perspective and be able to tolerate potentially sharp declines in value.
Market conditions — The prices of, and the income generated by, the common stocks, bonds and other securities held by the fund may decline – sometimes rapidly or unpredictably – due to various factors, including events or conditions affecting the general economy or particular industries; overall market changes; local, regional or global political, social or economic instability; governmental, governmental agency or central bank responses to economic conditions; and currency exchange rate, interest rate and commodity price fluctuations.
Economies and financial markets throughout the world are highly interconnected. Economic, financial or political events, trading and tariff arrangements, wars, terrorism, cybersecurity events, natural disasters, public health emergencies (such as the spread of infectious disease) and other circumstances in one country or region, including actions taken by governmental or quasi-governmental authorities in response to any of the foregoing, could have impacts on global economies or markets. As a result, whether or not the fund invests in securities of issuers located in or with significant exposure to the countries affected, the value and liquidity of the fund’s investments may be negatively affected by developments in other countries and regions.
Issuer risks — The prices of, and the income generated by, securities held by the fund may decline in response to various factors directly related to the issuers of such securities, including reduced demand for an issuer’s goods or services, poor management performance, major litigation, investigations or other controversies related to the issuer, changes in government regulations affecting the issuer or its competitive environment and strategic initiatives such as mergers, acquisitions or dispositions and the market response to any such initiatives.
Investing in growth-oriented stocks — Growth-oriented common stocks and other equity-type securities (such as preferred stocks, convertible preferred stocks and convertible bonds) may involve larger price swings and greater potential for loss than other types of investments.
Investing in income-oriented stocks — The value of the fund’s securities and income provided by the fund may be reduced by changes in the dividend policies of, and the capital resources available for dividend payments at, the companies in which the fund invests.
Investing outside the United States — Securities of issuers domiciled outside the United States, or with significant operations or revenues outside the United States, may lose value because of adverse political, social, economic or market developments (including social instability, regional conflicts, terrorism and war) in the countries or regions in which the issuers operate or generate revenue. These securities may also lose value due to changes in foreign currency exchange rates against the U.S. dollar and/or currencies of other countries. Issuers of these securities may be more susceptible to actions of foreign governments, such as nationalization, currency blockage or the imposition of price controls or punitive taxes, each of which could adversely impact the value of these securities. Securities markets in certain countries may be more volatile and/or less liquid than those in the United States. Investments outside the United States may also be subject to different accounting and auditing practices and standards and different regulatory, legal and reporting requirements, and may be more difficult to value, than those in the United States. In addition, the value of investments outside the United States may be reduced by foreign taxes, including foreign withholding taxes on interest and dividends. Further, there may be increased risks of delayed settlement of securities purchased or sold by the fund. The risks of investing outside the United States may be heightened in connection with investments in emerging markets.
Investing in emerging markets — Investing in emerging markets may involve risks in addition to and greater than those generally associated with investing in the securities markets of developed countries. For instance, emerging market countries tend to have less developed political, economic and legal systems and accounting and auditing practices and standards than those in developed countries. Accordingly, the governments of these countries may be less stable and more likely to intervene in the market economy, for example, by imposing capital controls, nationalizing a company or industry, placing restrictions on foreign ownership and on withdrawing sale proceeds of securities from the country, and/or imposing punitive taxes that could adversely affect the prices of securities. Information regarding issuers in emerging markets may be limited, incomplete or inaccurate, and there may be fewer rights and remedies available to the fund and its shareholders. In addition, the economies of these countries may be dependent on relatively few industries, may have limited access to capital and may be more susceptible to changes in local and global trade conditions and downturns in the world economy. Securities markets in these countries can also be relatively small and have substantially lower trading volumes. As a result, securities issued in these countries may be more volatile and less liquid, and may be more difficult to value, than securities issued in countries with more developed economies and/or markets. Less certainty with respect to security valuations may lead to additional challenges and risks in calculating the fund’s net asset value. Additionally, emerging markets are more likely to experience problems with the clearing and settling of trades and the holding of securities by banks, agents and depositories that are less established than those in developed countries.
Investing in debt instruments — The prices of, and the income generated by, bonds and other debt securities held by the fund may be affected by factors such as the interest rates, maturities and credit ratings of these securities.
Rising interest rates will generally cause the prices of bonds and other debt securities to fall. A general rise in interest rates may cause investors to sell debt securities on a large scale, which could also adversely affect the price and liquidity of debt securities and could also result in increased redemptions from the fund. Falling interest rates may cause an issuer to redeem, call or refinance a debt security before its stated maturity, which may result in the fund failing to recoup the full amount of its initial investment and having to reinvest the proceeds in lower yielding securities. Longer maturity debt securities generally have greater sensitivity to changes in interest rates and may be subject to greater price fluctuations than shorter maturity debt securities.
American Funds Insurance Series / Prospectus 2
Bonds and other debt securities are also subject to credit risk, which is the possibility that the credit strength of an issuer or guarantor will weaken or be perceived to be weaker, and/or an issuer of a debt security will fail to make timely payments of principal or interest and the security will go into default. A downgrade or default affecting any of the fund’s securities could cause the value of the fund’s shares to decrease. Lower quality debt securities generally have higher rates of interest and may be subject to greater price fluctuations than higher quality debt securities. Credit risk is gauged, in part, by the credit ratings of the debt securities in which the fund invests. However, ratings are only the opinions of the rating agencies issuing them and are not guarantees as to credit quality or an evaluation of market risk. The fund’s investment adviser relies on its own credit analysts to research issuers and issues in seeking to assess credit and default risks.
Investing in mortgage-related and other asset-backed securities — Mortgage-related securities, such as mortgage-backed securities, and other asset-backed securities, include debt obligations that represent interests in pools of mortgages or other income-bearing assets, such as consumer loans or receivables. While such securities are subject to the risks associated with investments in debt instruments generally (for example, credit, extension and interest rate risks), they are also subject to other and different risks. Mortgage-backed and other asset-backed securities are subject to changes in the payment patterns of borrowers of the underlying debt, potentially increasing the volatility of the securities and the fund’s net asset value. When interest rates fall, borrowers are more likely to refinance or prepay their debt before its stated maturity. This may result in the fund having to reinvest the proceeds in lower yielding securities, effectively reducing the fund’s income. Conversely, if interest rates rise and borrowers repay their debt more slowly than expected, the time in which the mortgage-backed and other asset-backed securities are paid off could be extended, reducing the fund’s cash available for reinvestment in higher yielding securities. Mortgage-backed securities are also subject to the risk that underlying borrowers will be unable to meet their obligations and the value of property that secures the mortgages may decline in value and be insufficient, upon foreclosure, to repay the associated loans. Investments in asset-backed securities are subject to similar risks.
Liquidity risk — Certain fund holdings may be or may become difficult or impossible to sell, particularly during times of market turmoil. Liquidity may be impacted by the lack of an active market for a holding, legal or contractual restrictions on resale, or the reduced number and capacity of market participants to make a market in such holding. Market prices for less liquid or illiquid holdings may be volatile, and reduced liquidity may have an adverse impact on the market price of such holdings. Additionally, the sale of less liquid or illiquid holdings may involve substantial delays (including delays in settlement) and additional costs and the fund may be unable to sell such holdings when necessary to meet its liquidity needs or may be forced to sell at a loss.
Management — The investment adviser to the fund actively manages the fund’s investments. Consequently, the fund is subject to the risk that the methods and analyses, including models, tools and data, employed by the investment adviser in this process may be flawed or incorrect and may not produce the desired results. This could cause the fund to lose value or its investment results to lag relevant benchmarks or other funds with similar objectives.
Your investment in the fund is not a bank deposit and is not insured or guaranteed by the Federal Deposit Insurance Corporation or any other governmental agency, entity or person. You should consider how this fund fits into your overall investment program.
3 American Funds Insurance Series / Prospectus
Investment results The following bar chart shows how the investment results of the Class 1A shares of the fund have varied from year to year, and the following table shows how the fund’s average annual total returns for various periods compare with a broad measure of securities market results and other applicable measures of market results. This information provides some indication of the risks of investing in the fund. The 60%/40% MSCI All Country World Index/Bloomberg Global Aggregate Index blends the MSCI All Country World Index, which measures global equity markets, with the Bloomberg Global Aggregate Index, which measures investment-grade bonds (rated BBB-/Baa3 and above), by weighting their total returns at 60% and 40% respectively. This assumes the blend is rebalanced monthly. Past investment results (before and after taxes) are not predictive of future investment results. Past investment results (before and after taxes) are not predictive of future investment results. Figures shown reflect fees and expenses associated with an investment in the fund, but do not reflect insurance contract fees and expenses. If insurance contract fees and expenses were included, results would have been lower. Updated information on the fund’s investment results can be obtained by visiting capitalgroup.com/afis.
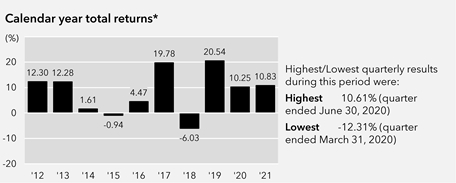
| Average annual total returns For the periods ended December 31, 2021: | 1 year | 5 years* | 10 years* | Lifetime* |
| Fund | 10.83% | 10.64% | 8.19% | 10.47% |
| 60%/40% MSCI All Country World Index/Bloomberg Global Aggregate Index (reflects no deduction for sales charges, account fees, expenses or U.S. federal income taxes) | 8.78 | 10.11 | 7.91 | 6.50 |
| MSCI All Country World Index (reflects no deduction for sales charges, account fees, expenses or U.S. federal income taxes) | 18.54 | 14.40 | 11.85 | 9.40 |
| Bloomberg Global Aggregate Index (reflects no deduction for sales charges, account fees, expenses or U.S. federal income taxes) | -4.71 | 3.36 | 1.77 | 1.76 |
* Lifetime returns are from May 2, 2011, the date the fund began investment operations. Class 1A shares began investment operations on January 6, 2017; therefore, returns for the fund prior to that date assume a hypothetical investment in Class 1 shares, but reflect the .25% annual expense that applies to Class 1A shares and is described in the “Fund expenses” section of the prospectus. Returns for Class 1 shares are comparable to those of Class 1A shares because both classes invest in the same portfolio of securities.
American Funds Insurance Series / Prospectus 4
Management
Investment
adviser Capital Research and Management CompanySM
Portfolio managers The individuals primarily responsible for the portfolio management of the
fund are:
| Portfolio
manager/ Series title (if applicable) |
Portfolio
manager experience in this fund |
Primary
title with investment adviser |
| Alfonso Barroso | Less than 1 year | Partner – Capital Research Global Investors |
| Andrew A. Cormack | 1 year | Partner – Capital Fixed Income Investors |
| Bradford F. Freer | Less than 1 year | Partner – Capital Research Global Investors |
| Thomas H. Høgh | 3 years | Partner – Capital Fixed Income Investors |
| Winnie Kwan | Less than 1 year | Partner – Capital Research Global Investors |
Purchase and sale of fund shares Shares of the fund are not sold directly to the general public. The fund is offered only as an underlying investment option for variable insurance contracts, and insurance company separate accounts and qualified feeder funds — and not the holders of variable insurance contracts — are the shareholders of the fund. Although the fund does not require a minimum amount for initial or subsequent purchases from insurance companies, your insurance company may impose investment minimums for your purchase of the fund.
You may sell (redeem) shares on any business day. You must sell (redeem) shares through your insurance company.
Tax information See your variable insurance contract prospectus for information regarding the federal income tax treatment of your variable insurance contract and related distributions.
Payments to broker-dealers and other financial intermediaries The fund is not sold directly to the general public but instead is offered as an underlying investment option for variable insurance contracts. The fund and its related companies may make payments to the sponsoring insurance company (or its affiliates) for distribution and/or other services. These payments may be a factor that the insurance company considers in including the fund as an underlying investment option in the variable insurance contract. The prospectus (or other offering document) for your variable insurance contract may contain additional information about these payments.
5 American Funds Insurance Series / Prospectus
Investment objectives, strategies and risks
American Funds Global Balanced Fund This fund seeks the balanced accomplishment of three objectives: long-term growth of capital, conservation of principal and current income. While it has no present intention to do so, the fund’s board may change the fund’s investment objectives without shareholder approval upon 60 days’ written notice to shareholders.
Normally, the fund will maintain at least 45% of the value of its assets in common stocks and other equity investments under normal market conditions. Although the fund’s equity investments focus on medium to larger capitalization companies, the fund’s investments are not limited to a particular capitalization size.
Normally the fund will invest at least 25% of the value of its assets in bonds and other debt securities (including money market instruments). These will consist of investment-grade securities (rated Baa3 or better or BBB– or better by Nationally Recognized Statistical Rating Organizations designated by the fund’s investment adviser or unrated but determined to be of equivalent quality by the fund’s investment adviser).
Under normal market conditions, the fund will invest at least 40% of its net assets in issuers outside the United States, unless market conditions are not deemed favorable by the fund’s investment adviser, in which case the fund would invest at least 30% of its net assets in issuers outside the United States.
The fund’s ability to invest in issuers outside the United States includes investing in emerging markets.
The fund may also invest to a limited extent in lower quality, higher yielding debt securities including those convertible into common stocks (rated Ba1 or below or BB+ or below by Nationally Recognized Statistical Rating Organizations designated by the fund’s investment adviser or unrated but determined to be of equivalent quality by the fund’s investment adviser). Such securities are sometimes referred to as “junk bonds.”
The fund may invest in bonds and other debt securities, including securities issued and guaranteed by the U.S. government, securities issued by federal agencies and instrumentalities and securities backed by mortgages or other assets. The fund may also invest in securities of governments, agencies, corporations and other entities domiciled outside the United States. These investments will typically be denominated in currencies other than U.S. dollars.
There are no restrictions on the maturity or duration of the bonds and other debt securities in the fund’s portfolio.
The fund may enter into currency transactions to provide for the purchase or sale of a currency needed to purchase a security denominated in such currency. In addition, the fund may enter into agreements, known as forward currency contracts, to purchase or sell a specific currency at a future date at a fixed price. The fund may enter into forward currency contracts to protect against changes in currency exchange rates, to increase exposure to a particular foreign currency, to shift exposure to currency fluctuations from one currency to another or to seek to increase returns.
The fund may also hold cash or cash equivalents, including commercial paper and short-term securities issued by the U.S. government, its agencies and instrumentalities. The percentage of the fund invested in such holdings varies and depends on various factors, including market conditions and purchases and redemptions of fund shares. The investment adviser may determine that it is appropriate to invest a substantial portion of the fund’s assets in such instruments in response to certain circumstances, such as periods of market turmoil. For temporary defensive purposes, the fund may invest without limitation in such instruments. A larger percentage of such holdings could moderate the fund’s investment results in a period of rising market prices. Alternatively, a larger percentage of such holdings could reduce the magnitude of the fund’s loss in a period of falling market prices and provide liquidity to make additional investments or to meet redemptions.
The fund may invest in other funds managed by the investment adviser or its affiliates (“Central Funds”) to more effectively invest in a diversified set of securities in a specific asset class such as money market instruments, bonds and other securities. Shares of Central Funds are only offered for purchase to the fund’s investment adviser and its affiliates and other funds, investment vehicles and accounts managed by the fund’s investment adviser and its affiliates. When investing in Central Funds, the fund bears its proportionate share of the expenses of the Central Funds in which it invests but does not bear additional management fees through its investment in such Central Funds. The investment results of the portions of the fund’s assets invested in the Central Funds will be based upon the investment results of the Central Funds.
The fund may also lend portfolio securities to brokers, dealers and other institutions that provide cash or U.S. Treasury securities as collateral in an amount at least equal to the value of the securities loaned.
The fund relies on the professional judgment of its investment adviser to make decisions about the fund’s portfolio investments. The basic investment philosophy of the investment adviser is to seek to invest in attractively valued securities that, in its opinion, represent good, long-term investment opportunities. The investment adviser believes that an important way to accomplish this is through fundamental analysis, which may include meeting with company executives and employees, suppliers, customers and competitors. Securities may be sold when the investment adviser believes that they no longer represent relatively attractive investment opportunities.
The following are principal risks associated with investing in the fund.
Market conditions — The prices of, and the income generated by, the common stocks, bonds and other securities held by the fund may decline – sometimes rapidly or unpredictably – due to various factors, including events or conditions affecting the general economy or particular industries; overall market changes; local, regional or global political, social or economic instability; governmental, governmental agency or central bank responses to economic conditions; and currency exchange rate, interest rate and commodity price fluctuations.
American Funds Insurance Series / Prospectus 6
Economies and financial markets throughout the world are highly interconnected. Economic, financial or political events, trading and tariff arrangements, wars, terrorism, cybersecurity events, natural disasters, public health emergencies (such as the spread of infectious disease) and other circumstances in one country or region, including actions taken by governmental or quasi-governmental authorities in response to any of the foregoing, could have impacts on global economies or markets. As a result, whether or not the fund invests in securities of issuers located in or with significant exposure to the countries affected, the value and liquidity of the fund’s investments may be negatively affected by developments in other countries and regions.
Issuer risks — The prices of, and the income generated by, securities held by the fund may decline in response to various factors directly related to the issuers of such securities, including reduced demand for an issuer’s goods or services, poor management performance, major litigation, investigations or other controversies related to the issuer, changes in government regulations affecting the issuer or its competitive environment and strategic initiatives such as mergers, acquisitions or dispositions and the market response to any such initiatives.
Investing in growth-oriented stocks — Growth-oriented common stocks and other equity-type securities (such as preferred stocks, convertible preferred stocks and convertible bonds) may involve larger price swings and greater potential for loss than other types of investments.
Investing in income-oriented stocks — The value of the fund’s securities and income provided by the fund may be reduced by changes in the dividend policies of, and the capital resources available for dividend payments at, the companies in which the fund invests.
Investing outside the United States — Securities of issuers domiciled outside the United States, or with significant operations or revenues outside the United States, may lose value because of adverse political, social, economic or market developments (including social instability, regional conflicts, terrorism and war) in the countries or regions in which the issuers operate or generate revenue. These securities may also lose value due to changes in foreign currency exchange rates against the U.S. dollar and/or currencies of other countries. Issuers of these securities may be more susceptible to actions of foreign governments, such as nationalization, currency blockage or the imposition of price controls or punitive taxes, each of which could adversely impact the value of these securities. Securities markets in certain countries may be more volatile and/or less liquid than those in the United States. Investments outside the United States may also be subject to different accounting and auditing practices and standards and different regulatory, legal and reporting requirements, and may be more difficult to value, than those in the United States. In addition, the value of investments outside the United States may be reduced by foreign taxes, including foreign withholding taxes on interest and dividends. Further, there may be increased risks of delayed settlement of securities purchased or sold by the fund. The risks of investing outside the United States may be heightened in connection with investments in emerging markets.
Investing in emerging markets — Investing in emerging markets may involve risks in addition to and greater than those generally associated with investing in the securities markets of developed countries. For instance, emerging market countries tend to have less developed political, economic and legal systems and accounting and auditing practices and standards than those in developed countries. Accordingly, the governments of these countries may be less stable and more likely to intervene in the market economy, for example, by imposing capital controls, nationalizing a company or industry, placing restrictions on foreign ownership and on withdrawing sale proceeds of securities from the country, and/or imposing punitive taxes that could adversely affect the prices of securities. Information regarding issuers in emerging markets may be limited, incomplete or inaccurate, and there may be fewer rights and remedies available to the fund and its shareholders. In addition, the economies of these countries may be dependent on relatively few industries, may have limited access to capital and may be more susceptible to changes in local and global trade conditions and downturns in the world economy. Securities markets in these countries can also be relatively small and have substantially lower trading volumes. As a result, securities issued in these countries may be more volatile and less liquid, and may be more difficult to value, than securities issued in countries with more developed economies and/or markets. Less certainty with respect to security valuations may lead to additional challenges and risks in calculating the fund’s net asset value. Additionally, emerging markets are more likely to experience problems with the clearing and settling of trades and the holding of securities by banks, agents and depositories that are less established than those in developed countries.
Investing in debt instruments — The prices of, and the income generated by, bonds and other debt securities held by the fund may be affected by factors such as the interest rates, maturities and credit ratings of these securities.
Rising interest rates will generally cause the prices of bonds and other debt securities to fall. A general rise in interest rates may cause investors to sell debt securities on a large scale, which could also adversely affect the price and liquidity of debt securities and could also result in increased redemptions from the fund. Falling interest rates may cause an issuer to redeem, call or refinance a debt security before its stated maturity, which may result in the fund failing to recoup the full amount of its initial investment and having to reinvest the proceeds in lower yielding securities. Longer maturity debt securities generally have greater sensitivity to changes in interest rates and may be subject to greater price fluctuations than shorter maturity debt securities.
Bonds and other debt securities are also subject to credit risk, which is the possibility that the credit strength of an issuer or guarantor will weaken or be perceived to be weaker, and/or an issuer of a debt security will fail to make timely payments of principal or interest and the security will go into default. A downgrade or default affecting any of the fund’s securities could cause the value of the fund’s shares to decrease. Lower quality debt securities generally have higher rates of interest and may be subject to greater price fluctuations than higher quality debt securities. Credit risk is gauged, in part, by the credit ratings of the debt securities in which the fund invests. However, ratings are only the opinions of the rating agencies issuing them and are not guarantees as to credit quality or an evaluation of market risk. The fund’s investment adviser relies on its own credit analysts to research issuers and issues in seeking to assess credit and default risks.
Investing in mortgage-related and other asset-backed securities — Mortgage-related securities, such as mortgage-backed securities, and other asset-backed securities, include debt obligations that represent interests in pools of mortgages or other income-bearing assets, such
7 American Funds Insurance Series / Prospectus
as residential mortgage loans, home equity loans, mortgages on commercial buildings, consumer loans and equipment leases. While such securities are subject to the risks associated with investments in debt instruments generally (for example, credit, extension and interest rate risks), they are also subject to other and different risks. Mortgage-backed and other asset-backed securities are subject to changes in the payment patterns of borrowers of the underlying debt, potentially increasing the volatility of the securities and the fund’s net asset value. When interest rates fall, borrowers are more likely to refinance or prepay their debt before its stated maturity. This may result in the fund having to reinvest the proceeds in lower yielding securities, effectively reducing the fund’s income. Conversely, if interest rates rise and borrowers repay their debt more slowly than expected, the time in which the mortgage-backed and other asset-backed securities are paid off could be extended, reducing the fund’s cash available for reinvestment in higher yielding securities. Mortgage-backed securities are also subject to the risk that underlying borrowers will be unable to meet their obligations and the value of property that secures the mortgages may decline in value and be insufficient, upon foreclosure, to repay the associated loans. Investments in asset-backed securities are subject to similar risks, as well as additional risks associated with the assets underlying those securities.
Liquidity risk — Certain fund holdings may be or may become difficult or impossible to sell, particularly during times of market turmoil. Liquidity may be impacted by the lack of an active market for a holding, legal or contractual restrictions on resale, or the reduced number and capacity of market participants to make a market in such holding. Market prices for less liquid or illiquid holdings may be volatile, and reduced liquidity may have an adverse impact on the market price of such holdings. Additionally, the sale of less liquid or illiquid holdings may involve substantial delays (including delays in settlement) and additional costs and the fund may be unable to sell such holdings when necessary to meet its liquidity needs or may be forced to sell at a loss.
Management — The investment adviser to the fund actively manages the fund’s investments. Consequently, the fund is subject to the risk that the methods and analyses, including models, tools and data, employed by the investment adviser in this process may be flawed or incorrect and may not produce the desired results. This could cause the fund to lose value or its investment results to lag relevant benchmarks or other funds with similar objectives.
The following are additional risks associated with investing in the fund.
Interest rate risk — The values and liquidity of the securities held by the fund may be affected by changing interest rates. For example, the values of debt securities may decline when interest rates rise and increase when interest rates fall. Longer maturity debt securities generally have greater sensitivity to changes in interest rates and may be subject to greater price fluctuations than shorter maturity debt securities. The fund may invest in variable and floating rate securities. When the fund holds variable or floating rate securities, a decrease in market interest rates will adversely affect the income received from such securities and the net asset value of the fund’s shares. Although the values of such securities are generally less sensitive to interest rate changes than those of other debt securities, the value of variable and floating rate securities may decline if their interest rates do not rise as quickly, or as much, as market interest rates. Conversely, floating rate securities will not generally increase in value if interest rates decline. During periods of extremely low short-term interest rates, certain of the fund’s debt securities may not be able to maintain a positive yield and, given the current low interest rate environment, risks associated with rising rates are currently heightened.
Investing in securities backed by the U.S. government — Securities backed by the U.S. Treasury or the full faith and credit of the U.S. government are guaranteed only as to the timely payment of interest and principal when held to maturity. Accordingly, the current market values for these securities will fluctuate with changes in interest rates and the credit rating of the U.S. government. Securities issued by U.S. government-sponsored entities and federal agencies and instrumentalities that are not backed by the full faith and credit of the U.S. government are neither issued nor guaranteed by the U.S. government.
Investing in lower rated debt instruments — Lower rated bonds and other lower rated debt securities generally have higher rates of interest and involve greater risk of default or price declines due to changes in the issuer’s creditworthiness than those of higher quality debt securities. The market prices of these securities may fluctuate more than the prices of higher quality debt securities and may decline significantly in periods of general economic difficulty. These risks may be increased with respect to investments in junk bonds.
Currency transactions — In addition to the risks generally associated with investing in derivative instruments, the use of forward currency contracts involves the risk that currency movements will not be accurately predicted by the investment adviser, which could result in losses to the fund. While entering into forward currency contracts could minimize the risk of loss due to a decline in the value of the hedged currency, it could also limit any potential gain that may result from an increase in the value of the currency. Additionally, the adviser may use forward currency contracts to increase exposure to a certain currency or to shift exposure to currency fluctuations from one country to another. Forward currency contracts may expose the fund to potential gains and losses in excess of the initial amount invested.
Exposure to country, region, industry or sector — Subject to the fund’s investment limitations, the fund may have significant exposure to a particular country, region, industry or sector. Such exposure may cause the fund to be more impacted by risks relating to and developments affecting the country, region, industry or sector, and thus its net asset value may be more volatile, than a fund without such levels of exposure. For example, if the fund has significant exposure in a particular country, then social, economic, regulatory or other issues that negatively affect that country may have a greater impact on the fund than on a fund that is more geographically diversified.
Investing in derivatives — The use of derivatives involves a variety of risks, which may be different from, or greater than, the risks associated with investing in traditional securities, such as stocks and bonds. Changes in the value of a derivative may not correlate perfectly with, and may be more sensitive to market events than, the underlying asset, rate or index, and a derivative instrument may expose the fund to losses in excess of its initial investment. Derivatives may be difficult to value, difficult for the fund to buy or sell at an opportune time or price and difficult to terminate or otherwise offset. The fund’s use of derivatives may result in losses to the fund, and investing in derivatives may reduce the fund’s returns and increase the fund’s price volatility. The fund’s counterparty to a derivative transaction (including, if applicable, the fund’s clearing broker, the derivatives exchange or the clearinghouse) may be unable or unwilling to honor its financial obligations in respect of the transaction.
American Funds Insurance Series / Prospectus 8
Lending of portfolio securities — Securities lending involves risks, including the risk that the loaned securities may not be returned in a timely manner or at all and/or the risk of a loss of rights in the collateral if a borrower or the lending agent defaults. These risks could be greater for non-U.S. securities. Additionally, the fund may lose money from the reinvestment of collateral received on loaned securities in investments that decline in value, default or do not perform as expected.
Cybersecurity breaches — The fund may be subject to operational and information security risks through breaches in cybersecurity. Cybersecurity breaches can result from deliberate attacks or unintentional events, including “ransomware” attacks, the injection of computer viruses or malicious software code, the use of vulnerabilities in code to gain unauthorized access to digital information systems, networks or devices, or external attacks such as denial-of-service attacks on the investment adviser’s or an affiliate’s website that could render the fund’s network services unavailable to intended end-users. These breaches may, among other things, lead to the unauthorized release of confidential information, misuse of the fund’s assets or sensitive information, the disruption of the fund’s operational capacity, the inability of fund shareholders to transact business, or the destruction of the fund’s physical infrastructure, equipment or operating systems. As a result of these potential outcomes, the fund could incur violations of applicable privacy and other laws, reputational damage, additional costs associated with corrective measures and/or financial loss. The fund may also be subject to additional risks if its third-party service providers, such as the fund’s investment adviser, transfer agent, custodian, administrators and other financial intermediaries, experience similar cybersecurity breaches and potential outcomes. Cybersecurity risks may also impact issuers of securities in which the fund invests, which may cause the fund’s investments in such issuers to lose value.
In addition to the principal investment strategies described above, the fund has other investment practices that are described in the statement of additional information, which includes a description of other risks related to the fund’s principal investment strategies and other investment practices. The fund’s investment results will depend on the ability of the fund’s investment adviser to navigate the risks discussed above as well as those described in the statement of additional information.
Fund comparative indexes — The 60%/40% MSCI All Country World Index/Bloomberg Global Aggregate Index blends the MSCI All Country World Index with the Bloomberg Global Aggregate Index by weighting their cumulative total returns at 60% and 40%, respectively. This assumes the blend is rebalanced monthly. The MSCI All Country World Index is a free float-adjusted market capitalization-weighted index that is designed to measure equity market results in the global developed and emerging markets, consisting of more than 40 developed and emerging market country indexes. Results reflect dividends gross of withholding taxes through December 31, 2000, and dividends net of withholding taxes thereafter. This index is unmanaged, and its results include reinvested dividends and/or distributions but do not reflect the effect of sales charges, commissions, account fees, expenses or U.S. federal income taxes. The Bloomberg Global Aggregate Index represents the global investment-grade fixed income markets. This index is unmanaged, and its results include reinvested distributions but do not reflect the effect of sales charges, commissions, account fees, expenses or U.S. federal income taxes.
Portfolio holdings A description of the fund’s policies and procedures regarding disclosure of information about its portfolio holdings is available in the statement of additional information.
9 American Funds Insurance Series / Prospectus
Management and organization
Investment adviser Capital Research and Management Company, an experienced investment management organization founded in 1931, serves as the investment adviser to the Series and other funds, including the American Funds. Capital Research and Management Company is a wholly owned subsidiary of The Capital Group Companies, Inc. and is located at 333 South Hope Street, Los Angeles, California 90071. Capital Research and Management Company manages the investment portfolios and business affairs of the Series. The total management fee paid by each fund to its investment adviser for the most recent fiscal year, including any amounts waived, in each case expressed as a percentage of average net assets of that fund, appears in the Annual Fund Operating Expenses table for each fund. Please see the statement of additional information for further details. A discussion regarding the basis for the approval of the Series’ Investment Advisory and Service Agreement by the Series’ board of trustees is contained in the Series’ annual report to shareholders for the fiscal year ended December 31, 2021.
Capital Research and Management Company manages equity assets through three equity investment divisions and fixed income assets through its fixed income investment division, Capital Fixed Income Investors. The three equity investment divisions — Capital International Investors, Capital Research Global Investors and Capital World Investors — make investment decisions independently of one another.
The equity investment divisions may, in the future, be incorporated as wholly owned subsidiaries of Capital Research and Management Company. In that event, Capital Research and Management Company would continue to be the investment adviser, and day-to-day investment management of equity assets would continue to be carried out through one or more of these subsidiaries. Although not currently contemplated, Capital Research and Management Company could incorporate its fixed income investment division in the future and engage it to provide day-to-day investment management of fixed income assets. Capital Research and Management Company and each of the funds it advises have received an exemptive order from the U.S. Securities and Exchange Commission that allows Capital Research and Management Company to use, upon approval of the funds’ boards, its management subsidiaries and affiliates to provide day-to-day investment management services to the funds, including making changes to the management subsidiaries and affiliates providing such services. The Series’ shareholders approved this arrangement; however, there is no assurance that Capital Research and Management Company will incorporate its investment divisions or exercise any authority granted to it under the exemptive order.
In addition, shareholders of the Series have approved a proposal to reorganize the Series into a Delaware statutory trust. However, the Series reserved the right to delay implementing the reorganization and has elected to do so.
The Capital SystemSM Capital Research and Management Company uses a system of multiple portfolio managers in managing mutual fund assets. Under this approach, the portfolio of a fund is divided into segments managed by individual managers. In addition, Capital Research and Management Company’s investment analysts may make investment decisions with respect to a portion of a fund’s portfolio. Investment decisions are subject to a fund’s objective(s), policies and restrictions and the oversight of the appropriate investment-related committees of Capital Research and Management Company and its investment divisions.
Certain senior members of Capital Fixed Income Investors, the investment adviser’s fixed income investment division, serve on the Portfolio Strategy Group. The group utilizes a research-driven process with input from the investment adviser’s analysts, portfolio managers and economists to define investment themes on a range of macroeconomic factors, including duration, yield curve and sector allocation. Where applicable, the investment decisions made by a fund’s fixed income portfolio managers are informed by the investment themes discussed by the group.
American Funds Insurance Series / Prospectus 10
The primary individual portfolio managers for each of the funds are:
| Portfolio
manager for the Series/Title (if applicable) |
Primary title with investment adviser (or affiliate) and investment experience | Portfolio
manager’s role in management of, and experience in, the fund(s) |
| Donald D. O’Neal Co-President and Trustee | Partner – Capital International Investors Investment professional for 36 years, all with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: Growth-Income Fund — 16 years |
| Alan N. Berro Co-President | Partner – Capital World Investors Investment professional for 37 years in total; 31 years with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: Washington Mutual Investors Fund — 5 years Asset Allocation Fund — 22 years |
| Carl M. Kawaja Vice President | Partner – Capital World Investors Investment professional for 35 years in total; 31 years with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: New World Fund — 23 years |
| Sung Lee Vice President | Partner – Capital Research Global Investors Investment professional for 28 years, all with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: Capital
World Growth and Income Fund — 1 year |
| Keiko McKibben Vice President | Partner – Capital Research Global Investors Investment professional for 28 years in total; 24 years with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: Growth-Income Fund — 8 years (plus 10 years of prior experience as an investment analyst for the fund) |
| Renaud H. Samyn Vice President | Partner – Capital Research Global Investors Investment professional for 21 years, all with Capital Research and Management Company or affiliate |
Serves as an equity portfolio manager for: Global Small Capitalization Fund — 3 years (plus
15 years of prior experience as an investment analyst for the fund) |
| Pramod Atluri | Partner – Capital Fixed Income Investors Investment professional for 24 years in total; 6 years with Capital Research and Management Company or affiliate |
Serves
as a fixed income portfolio manager for: The Bond Fund of America — 6 years |
| Aline Avzaradel | Partner – Capital International Investors Investment professional for 19 years in total; 18 years with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: Capital Income Builder — 2 years |
| Alfonso Barroso | Partner – Capital Research Global Investors Investment professional for 28 years, all with Capital Research and Management Company or affiliate |
Serves as an equity portfolio manager for: Capital
World Growth and Income Fund — 1 year |
| Michael Beckwith | Vice President – Capital Research Global Investors Investment professional for 20 years in total; 3 years with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: Global Small Capitalization Fund — 3 years |
| Paul Benjamin | Partner – Capital World Investors Investment professional for 17 years, all with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: Growth Fund — 4 years (plus 12 years of prior experience as an investment analyst for the fund) |
| David J. Betanzos | Partner – Capital Fixed Income Investors Investment professional for 22 years in total; 20 years with Capital Research and Management Company or affiliate |
Serves
as a fixed income portfolio manager for: The Bond Fund of America — 1 year American Funds Mortgage Fund — 8 years U.S. Government Securities Fund — 7 years |
| Jeremy Burge | Partner – Capital World Investors Investment professional for 40 years in total; 20 years with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: Capital World Growth and Income Fund — 1 year (plus 1 year of prior experience as an investment analyst for the fund) |
| Grant L. Cambridge | Partner – Capital International Investors Investment professional for 29 years in total; 25 years with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: Capital Income Builder — 2 years |
| Mark L. Casey | Partner – Capital International Investors Investment professional for 22 years, all with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: Growth Fund — 5 years (plus 11 years of prior experience as an investment analyst for the fund) Washington Mutual Investors Fund — 1 year |
| Philip Chitty | Partner – Capital Fixed Income Investors Investment professional for 28 years in total; 18 years with Capital Research and Management Company or affiliate |
Serves
as a fixed income portfolio manager for: Capital World Bond Fund — 1 year |
| Tom Chow | Partner – Capital Fixed Income Investors Investment professional for 33 years in total; 7 years with Capital Research and Management Company or affiliate |
Serves
as a fixed income portfolio manager for: American High-Income Trust— 7 years |
11 American Funds Insurance Series / Prospectus
| Portfolio
manager for the Series/Title (if applicable) |
Primary title with investment adviser (or affiliate) and investment experience | Portfolio
manager’s role in management of, and experience in, the fund(s) |
| Michael Cohen | Partner – Capital World Investors Investment professional for 31 years in total; 22 years with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: Capital World Growth and Income Fund — 4 years International Growth and Income Fund — Less than 1 year |
| Patrice Collette | Partner – Capital World Investors Investment professional for 28 years in total; 22 years with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: Global Growth Fund — 7 years (plus 14 years of prior experience as an investment analyst for the fund) International Growth and Income Fund — Less than 1 year |
| Andrew A. Cormack | Vice President – Capital Fixed Income Investors Investment professional for 18 years in total; 4 years with Capital Research and Management Company or affiliate |
Serves
as a fixed income portfolio manager for: Capital World Bond Fund — 3 years |
| David A. Daigle | Partner – Capital Fixed Income Investors Investment professional for 28 years, all with Capital Research and Management Company or affiliate |
Serves
as a fixed income portfolio manager for: Asset Allocation Fund — 13 years American High-Income Trust— 13 years (plus 9 years of prior experience as an investment analyst for the fund) |
| Oliver V. Edmonds | Vice President – Capital Fixed Income Investors Investment professional for 19 years, all with Capital Research and Management Company or affiliate |
Serves
as a fixed income portfolio manager for: American Funds Mortgage Fund - 1 year |
| Peter Eliot | Partner – Capital International Investors Investment professional for 27 years in total; 18 years with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: Asset Allocation Fund — 6 years |
| Charles E. Ellwein | Partner – Capital Research Global Investors Investment professional for 26 years in total; 16 years with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: Growth-Income Fund — 7 years (plus 8 years of prior experience as an investment analyst for the fund) |
| Brady L. Enright | Partner – Capital World Investors Investment professional for 31 years in total; 25 years with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: Washington Mutual Investors Fund — 1 year |
| Paul Flynn | Partner – Capital World Investors Investment professional for 26 years in total; 24 years with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: Global Growth Fund — 5 years International Growth and Income Fund — Less than 1 year |
| J. Blair Frank | Partner – Capital Research Global Investors Investment professional for 29 years in total; 28 years with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: Growth-Income Fund — 16 years |
| Bradford F. Freer | Partner – Capital Research Global Investors Investment professional for 30 years in total; 28 years with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: Global Small Capitalization Fund — 4 years New World Fund — 5 years (plus 13 years of prior experience as an investment analyst for the fund) American Funds Global Balanced Fund – Less than 1 year |
| Irfan M. Furniturewala | Partner – Capital International Investors Investment
professional for |
Serves
as an equity portfolio manager for: (plus
1 year of prior experience as an investment analyst for the fund) |
| Nicholas J. Grace | Partner – Capital Research Global Investors Investment professional for 32 years in total; 28 years with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: New World Fund — 10 years (plus 8 years of prior experience as an investment analyst for the fund) |
| Leo Hee | Partner – Capital World Investors Investment
professional for 28 years in total; |
Serves
as an equity portfolio manager for: Capital World Growth and Income Fund — 1 year (plus 10 years of prior experience as an investment analyst for the fund) International Growth and Income Fund — Less than 1 year |
| David A. Hoag | Partner – Capital Fixed Income Investors Investment professional for 34 years in total; 31 years with Capital Research and Management Company or affiliate |
Serves
as a fixed income portfolio manager for: Capital Income Builder — 2 years The Bond Fund of America — 15 years |
| Thomas H. Høgh | Partner – Capital Fixed Income Investors Investment professional for 35 years in total; 32 years with Capital Research and Management Company or affiliate |
Serves
as a fixed income portfolio manager for: American Funds Global Balanced Fund — 3 years Capital World Bond Fund — 16 years |
| Roz Hongsaranagon | Partner – Capital World Investors Investment professional for 20 years, all with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: Global Growth Fund — 4 years |
| Dawid Justus | Partner – Capital World Investors Investment professional for 23 in total years; 17 years with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: New World Fund — 2 years (plus 14 years of prior experience as an investment analyst for the fund) |
American Funds Insurance Series / Prospectus 12
| Portfolio
manager for the Series/Title (if applicable) |
Primary title with investment adviser (or affiliate) and investment experience | Portfolio
manager’s role in management of, and experience in, the fund(s) |
| Jonathan Knowles | Partner – Capital World Investors Investment professional for 30 years, all with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: Global Growth Fund — 9 years (plus 10 years of prior experience as an investment analyst for the fund) New World Fund — 2 years (plus 8 years of prior experience as an investment analyst for the fund) |
| Winnie Kwan | Partner – Capital Research Global Investors Investment professional for 26 years in total; 22 years with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: New World Fund — 2 years (plus 2 years of prior experience as an investment analyst for the fund) Capital Income Builder — 2 years American Funds Global Balanced Fund –Less than 1 year |
| Harold H. La | Partner – Capital Research Global Investors Investment professional for 24 years in total; 23 years with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: Global Small Capitalization Fund — 14 years (plus 4 years of prior experience as an investment analyst for the fund) |
| Jeffrey T. Lager | Partner – Capital International Investors Investment professional for 27 years in total; 26 years with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: Washington Mutual Investors Fund — 1 year Asset Allocation Fund — 15 years |
| Jin Lee | Partner – Capital World Investors Investment professional for 26 years in total; 25 years with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: Washington Mutual Investors Fund — 1 year Capital World Growth and Income Fund— 1 year Asset Allocation Fund — 4 years |
| Steven D. Lotwin | Partner – Capital Fixed Income Investors Investment professional for 21 years, all with Capital Research and Management Company or affiliate |
Serves
as a fixed income portfolio manager for: Ultra-Short Bond Fund — 4 years |
| James B. Lovelace | Partner – Capital Research Global Investors Investment professional for 40 years, all with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: Capital Income Builder — 2 years |
| Robert W. Lovelace | Partner – Capital International Investors Investment professional for 37 years, all with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: New World Fund — 2 years |
| Fergus N. MacDonald | Partner – Capital Fixed Income Investors Investment professional for 30 years in total; 19 years with Capital Research and Management Company or affiliate |
Serves
as a fixed income portfolio manager for: Capital Income Builder — 2 years The Bond Fund of America — 1 year American Funds Mortgage Fund — 11 years U.S. Government Securities Fund — 12 years |
| Aidan O’Connell | Partner – Capital Research Global Investors Investment professional for 24 years in total; 18 years with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: Global Small Capitalization Fund — 8 years (plus 9 years of prior experience as an investment analyst for the fund) |
| Lara Pellini | Partner – Capital World Investors Investment professional for 21 years, all with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: Capital World Growth and Income Fund — 1 year (plus 10 years of prior experience as an investment analyst for the fund) |
| Piyada Phanaphat | Partner – Capital World Investors Investment professional for 19 years in total; 15 years with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: New World Fund — 5 years (plus 9 years of prior experience as an investment analyst for the fund) |
| Anne-Marie Peterson | Partner – Capital World Investors Investment professional for 28 years in total; 17 years with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: Growth Fund — 4 years (plus 11 years of prior experience as an investment analyst for the fund) |
| John R. Queen | Partner – Capital Fixed Income Investors Investment professional for 32 years in total; 20 years with Capital Research and Management Company or affiliate |
Serves
as a fixed income portfolio manager for: Asset Allocation Fund — 6 years |
| Caroline Randall | Partner – Capital Research Global Investors Investment professional for 25 years in total; 17 years with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: Capital Income Builder — 2 years |
| Andraz Razen | Partner – Capital World Investors Investment professional for 24 years in total; 18 years with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: Growth Fund — 9 years (plus 3 years of prior experience as an investment analyst for the fund) |
| William L. Robbins | Partner – Capital International Investors Investment professional for 30 years in total; 27 years with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: Growth-Income Fund — 10 years (plus 12 years of prior experience as an investment analyst for the fund) |
| Carlos A. Schonfeld | Partner – Capital International Investors Investment professional for 24 years, all with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: Growth-Income Fund — 8 years |
13 American Funds Insurance Series / Prospectus
| Portfolio
manager for the Series/Title (if applicable) |
Primary title with investment adviser (or affiliate) and investment experience | Portfolio
manager’s role in management of, and experience in, the fund(s) |
| Akira Shiraishi | Partner – Capital International Investors Investment professional for 25 years in total; 19 years with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: New World Fund — 2 years |
| Kirstie Spence | Partner – Capital Fixed Income Investors Investment professional for 27 years, all with Capital Research and Management Company or affiliate |
Serves
as a fixed income portfolio manager for: New World Fund — 2 years (plus 9 years of prior experience as an investment analyst for the fund) |
| Eric H. Stern | Partner – Capital International Investors Investment
professional for |
Serves
as an equity portfolio manager for: Washington Mutual Investors Fund — 1 year |
| Andrew B. Suzman | Partner – Capital World Investors Investment professional for 29 years, all with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: International Growth and Income Fund — Less than 1 year |
| Tomonori Tani | Partner – Capital World Investors Investment professional for 24 years in total; 18 years with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: New World Fund — 4 years |
| Lisa Thompson | Partner – Capital International Investors Investment professional for 34 years in total; 28 years with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: New World Fund — 2 years International Growth and Income Fund — Less than 1 year |
| Christopher Thomsen | Partner – Capital Research Global Investors Investment professional for 25 years, all with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: International Fund — 16 years New World Fund — 2 years |
| Tara L. Torrens | Partner – Capital Fixed Income Investors Investment professional for 19 years, all with Capital Research and Management Company or affiliate |
Serves
as a fixed income portfolio manager for: American High-Income Trust —4 years |
| Ritchie Tuazon | Partner – Capital Fixed Income Investors Investment professional for 22 years in total; 11 years with Capital Research and Management Company or affiliate |
Serves
as a fixed income portfolio manager for: U.S. Government Securities Fund — 7 years |
| Bradley J. Vogt | Partner – Capital Research Global Investors Investment professional for 35 years, all with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: Capital Income Builder — 2 years |
| Diana Wagner | Partner – Capital World Investors Investment
professional for |
Serves
as an equity portfolio manager for: Washington Mutual Investors Fund — 1 year |
| Shannon Ward | Partner – Capital Fixed Income Investors Investment professional for 30 years in total; 5 years with Capital Research and Management Company or affiliate |
Serves
as a fixed income portfolio manager for: American High-Income Trust — 5 years |
| Steven T. Watson | Partner – Capital International Investors Investment professional for 35 years in total; 32 years with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: Capital Income Builder — 4 years International Growth and Income Fund — Less than 1 year |
| Gregory W. Wendt | Partner – Capital Research Global Investors Investment professional for 35 years, all with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: Global Small Capitalization Fund — 10 years (plus 14 years of prior experience as an investment analyst for the fund) |
| Alan J. Wilson | Partner – Capital World Investors Investment
professional for |
Serves
as an equity portfolio manager for: Growth Fund — 8 years Washington Mutual Investors Fund — 1 year |
| Philip Winston | Partner – Capital International Investors Investment professional for 37 years in total; 25 years with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: Capital Income Builder — 8 years |
Information regarding the portfolio managers’ compensation, their ownership of securities in the Series and other accounts they manage is in the statement of additional information.
American Funds Insurance Series / Prospectus 14
Purchases and redemptions of shares Shares of the Series are currently offered only to insurance company separate accounts as well as so-called “feeder funds” under master-feeder arrangements sponsored by insurance companies as underlying investments for such insurance companies’ variable annuity contracts and variable life insurance policies. All such shares may be purchased or redeemed by the insurance company separate accounts (or feeder funds) at net asset value without any sales or redemption charges. These purchases and redemptions are made at the price next determined after such purchases and redemptions of units of the separate accounts (or feeder funds). The Series typically expects to remit redemption proceeds one business day following receipt and acceptance of a redemption order, regardless of the method the Series uses to make such payment (e.g., check, wire or automated clearing house transfer). However, payment may take longer than one business day and may take up to seven days as generally permitted by the Investment Company Act of 1940, as amended (the “1940 Act”). Under the 1940 Act, the Series may be permitted to pay redemption proceeds beyond seven days under certain limited circumstances.
Under normal conditions, the Series typically expects to meet shareholder redemptions by monitoring the Series’ portfolio and redemption activities and by regularly holding a reserve of highly liquid assets, such as cash or cash equivalents. The Series may use additional methods to meet shareholder redemptions, if they become necessary. These methods may include, but are not limited to, the sale of portfolio assets, the use of overdraft protection afforded by the Series’ custodian bank, borrowing from a line of credit and making payment with fund securities or other fund assets rather than in cash (as further discussed in the following paragraph).
Although payment of redemptions normally will be in cash, the Series may pay the redemption price wholly or partly with portfolio securities or other fund assets under conditions and circumstances determined by the Series’ board of trustees. On the same redemption date, some shareholders may be paid in whole or in part in securities (which may differ among those shareholders), while other shareholders may be paid entirely in cash. In general, in-kind redemptions to affiliated shareholders will as closely as practicable represent the affiliated shareholder’s pro rata share of the Series’ securities, subject to certain exceptions. Securities distributed in-kind to unaffiliated shareholders will be selected by the investment adviser in a manner the investment adviser deems to be fair and reasonable to the Series’ shareholders. The disposal of the securities received in-kind may be subject to brokerage costs and, until sold, such securities remain subject to market risk and liquidity risk, including the risk that such securities are or become difficult to sell. If the Series pays your redemption with illiquid or less liquid securities, you will bear the risk of not being able to sell such securities.
15 American Funds Insurance Series / Prospectus
Frequent trading of fund shares The Series and American Funds Distributors, Inc., the Series’ distributor, reserve the right to reject any purchase order for any reason. The funds are not designed to serve as vehicles for frequent trading. Frequent trading of fund shares may lead to increased costs to the funds and less efficient management of the funds’ portfolios, potentially resulting in dilution of the value of the shares held by long-term shareholders. Accordingly, purchases, including those that are part of exchange activity, that the Series or American Funds Distributors has determined could involve actual or potential harm to a fund may be rejected.
The Series, through its transfer agent, American Funds Service Company, has agreements with the Series’ insurance relationships to maintain its surveillance procedures that are designed to detect frequent trading in fund shares. The agreements generally require the insurance companies to (i) provide, upon request from a fund, the Series or their agent, certain identifying and account information regarding contract owners who invest in fund shares through an insurance company account and (ii) execute instructions from a fund, the Series or their agent to restrict further purchases or exchanges of fund shares by a contract owner who the Series has identified as having engaged in potentially harmful market timing or frequent trading. Under these procedures, various analytics are used to evaluate factors that may be indicative of frequent trading. For example, transactions in fund shares that exceed certain monetary thresholds may be scrutinized. American Funds Service Company may work with the insurance company separate accounts or feeder funds to apply their procedures that American Funds Service Company believes are reasonably designed to enforce the frequent trading policies of the Series. You should refer to disclosures provided by the insurance company with which you have a contract to determine the specific trading restrictions that apply to you.
Under the Series’ frequent trading policy, certain trading activity will not be treated as frequent trading, such as:
· retirement plan contributions, loans and distributions (including hardship withdrawals) identified as such on the retirement plan recordkeeper’s system;
· purchase transactions involving in-kind transfers of fund shares, if the entity maintaining the contract owner’s account is able to identify the transaction as one of these types of transactions; and
· systematic redemptions and purchases if the entity maintaining the contract owner’s account is able to identify the transaction as a systematic redemption or purchase.
Generally, purchases and redemptions will not be considered “systematic” unless the transaction is prescheduled for a specific date.
American Funds Service Company will monitor for other types of activity that could potentially be harmful to the Series – for example short-term trading activity in multiple funds. If American Funds Service Company identifies any activity that may constitute frequent trading, it reserves the right to contact the insurance company separate account or feeder fund and request that the separate account or feeder fund either provide information regarding an account owner’s transactions or restrict the account owner’s trading. If American Funds Service Company is not satisfied that insurance company separate account or feeder fund has taken appropriate action, American Funds Service Company may terminate the separate account’s or feeder fund’s ability to transact in fund shares.
There is no guarantee that all instances of frequent trading in fund shares will be prevented.
Notwithstanding the Series’ surveillance procedures described above, all transactions in fund shares remain subject to the right of the Series, American Funds Distributors and American Funds Service Company to restrict potentially abusive trading generally, including the types of transactions described above that will not be prevented.
American Funds Insurance Series / Prospectus 16
Valuing shares The net asset value of each share class of a fund is the value of a single share of that class. The net asset value per share is calculated once daily as of the close of regular trading on the New York Stock Exchange, normally 4 p.m. New York time, each day the New York Stock Exchange is open. If the New York Stock Exchange makes a scheduled (e.g. the day after Thanksgiving) or an unscheduled close prior to 4 p.m. New York time, the net asset value of each fund will be determined at approximately the time the New York Stock Exchange closes on that day. If on such a day market quotations and prices from third-party pricing services are not based as of the time of the early close of the New York Stock Exchange but are as of a later time (up to approximately 4 p.m. New York time), for example because the market remains open after the close of the New York Stock Exchange, those later market quotations and prices will be used in determining the funds’ net asset value.
Equity securities are valued primarily on the basis of market quotations, and debt securities are valued primarily on the basis of prices from third-party pricing services. Futures contracts are valued primarily on the basis of settlement prices. The funds have adopted procedures for making fair value determinations if market quotations or prices from third-party pricing services, as applicable, are not readily available or are not considered reliable. For example, if events occur between the close of markets outside the United States and the close of regular trading on the New York Stock Exchange that, in the opinion of the investment adviser, materially affect the value of any of the funds’ equity securities that trade principally in those international markets, those securities will be valued in accordance with fair value procedures. Similarly, fair value procedures may be employed if an issuer defaults on its debt securities and there is no market for its securities. Use of these procedures is intended to result in more appropriate net asset values and, where applicable, to reduce potential arbitrage opportunities otherwise available to short-term investors.
Because certain of the funds may hold securities that are listed primarily on foreign exchanges that trade on weekends or days when the funds do not price their shares, the values of securities held in the funds may change on days when you will not be able to purchase or redeem fund shares.
Shares of the funds will be purchased or sold at the net asset value next determined after receipt of requests from the appropriate insurance company. Requests received by the appropriate insurance company prior to 4 p.m. New York time and communicated by the insurance company to the Series or its agent will be purchased or sold at that day’s net asset value. Orders in good order received after the New York Stock Exchange closes (scheduled or unscheduled) will be processed at the net asset value (plus any applicable sales charge) calculated on the following business day.
17 American Funds Insurance Series / Prospectus
Plan of distribution The Series has adopted a plan of distribution or “12b-1 plan” for Class 1A shares under which it may finance activities intended primarily to sell shares, provided that the categories of expenses are approved in advance by the Series' board of trustees. The plan provides for annual expenses of .25% for Class 1A shares; however, the Series' board of trustees has not authorized any payments under the plan.
Other compensation to dealers American Funds Distributors, at its expense, provides additional compensation to insurance companies. These payments may be made, at the discretion of American Funds Distributors, to insurance companies (or their affiliates) that have sold shares of the funds of the American Funds Insurance Series and American Funds as the exclusive underlying investments to their variable contracts. A number of factors will be considered in determining payments, including the sales, assets, and the quality of the company’s relationship with American Funds Distributors. The payment will be determined using a formula applied consistently to insurance companies based on the relevant facts and circumstances. The level of payments made to a qualifying firm in any given year will vary and (excluding payments for meetings as described below) will represent the sum of (a) up to .14% of the current year’s American Funds Insurance Series new deposits in the contracts, (b) up to .07% of the current and previous year’s American Funds Insurance Series new deposits in the contracts, and (c) up to .0084% of American Funds Insurance Series assets attributable to the contracts, with an adjustment made for the quality of the company’s relationship with American Funds Distributors. Aggregate payments made by American Funds Distributors to insurance companies may also change from year to year. Only assets and deposits in variable annuity contracts that offer exclusively shares of the American Funds Insurance Series and American Funds are included in the formula. Further, assets for which the insurance company, or an affiliated broker-dealer, acts as an ERISA investment fiduciary are generally excluded from the formula. American Funds Distributors makes these payments to help defray the costs incurred by qualifying insurance companies in connection with efforts to educate its sales force about the American Funds Insurance Series so that they help financial advisers make recommendations and provide services that are suitable and meet contractholders needs. These payments may also be made to help defray the costs associated with the insurance company’s provision of account related services and activities and support the insurance company’s distribution activities. American Funds Distributors will, on an annual basis, determine the advisability of continuing these payments.
Firms receiving additional compensation payments must sign a letter acknowledging the purpose of the payment and American Funds Distributors’ goal that the payment will help facilitate education of the firm’s sales force about the American Funds Insurance Series and American Funds to help financial professionals make suitable recommendations and better serve their clients who invest in the funds as underlying investments to variable contracts. The letters generally require the firms to (1) have significant assets invested in the American Funds, (2) provide American Funds Distributors broad access to their sales force and product platforms and develop a business plan to achieve such access, and (3) agree to maintain American Funds within their existing products.
American Funds Distributors may also pay expenses associated with meetings and other training and educational opportunities conducted by insurance companies, selling dealers, advisory platform providers and other intermediaries to facilitate educating financial professionals and shareholders about the American Funds. For example, some of these expenses may include, but not be limited to, meeting sponsor fees, meeting location fees, and fees to obtain lists of financial professionals to better tailor training and education opportunities.
If investment advisers, distributors or other affiliates of mutual funds pay additional compensation or other incentives to insurance companies in differing amounts, insurance companies and the financial professionals with which they interact may have financial incentives for recommending a particular mutual fund over other mutual funds or investments, creating a potential conflict of interest. You should consult with your financial professional and review carefully any disclosure by your financial professional’s firm as to compensation received.
American Funds Insurance Series / Prospectus 18
Fund expenses In periods of market volatility, assets of the funds may decline significantly, causing total annual fund operating expenses (as a percentage of the value of your investment) to become higher than the numbers shown in the Annual Fund Operating Expenses tables in this prospectus.
The “Other expenses” items in the Annual Fund Operating Expenses tables in this prospectus are based on expenses as of each fund’s most recently completed fiscal year. These items include third-party expenses, such as custodial, legal, audit, accounting, regulatory reporting and pricing vendor services, and an administrative services fee payable to the Series’ investment adviser for administrative services provided by the Series’ investment adviser and its affiliates. In addition, the “Other expenses” items for Class 1A shares include fees for administrative services provided by the insurance companies that include Class 1A shares of any of the funds as underlying investments in their variable contracts. Each fund will pay an insurance administration fee of .25% of Class 1A share assets to these insurance companies for providing certain services pursuant to an insurance administrative services plan adopted by the Series.
For all share classes, “Other expenses” items in the Annual Fund Operating Expenses table in this prospectus include fees for administrative services provided by the fund’s investment adviser and its affiliates. Administrative services are provided by the investment adviser and its affiliates to help assist third parties providing non-distribution services to fund shareholders. These services include providing in-depth information on the fund and market developments that impact fund investments. Administrative services also include, but are not limited to, coordinating, monitoring and overseeing third parties that provide services to fund shareholders.
The Administrative Services Agreement between the fund and the investment adviser provides the fund the ability to charge an administrative services fee of .05% for all share classes. The fund's investment adviser receives an administrative services fee at the annual rate of .03% of the average daily net assets of the fund attributable to all share classes (which could be increased as noted above) for its provision of administrative services.
Investment results All fund results in the “Investment results” section of this prospectus reflect the reinvestment of dividends and capital gains distributions, if any. Unless otherwise noted, fund results reflect any fee waivers and/or expense reimbursements in effect during the period presented.
Distributions and taxes Each fund of the Series intends to qualify as a “regulated investment company” under the Internal Revenue Code. In any fiscal year in which a fund so qualifies and distributes to shareholders its investment company taxable income and net realized capital gain, the fund itself is relieved of federal income tax.
It is the Series’ policy to distribute to the shareholders (the insurance company separate accounts) all of its investment company taxable income and capital gain for each fiscal year.
See the applicable contract prospectus for information regarding the federal income tax treatment of the contracts and distributions to the separate accounts.
19 American Funds Insurance Series / Prospectus
Financial highlights The Financial Highlights table is intended to help you understand a fund’s results for the past five fiscal years. . Certain information reflects financial results for a single share of a particular class. The total returns in the table represent the rate that an investor would have earned or lost on an investment in a fund (assuming reinvestment of all dividends and capital gain distributions). Where indicated, figures in the table reflect the impact, if any, of certain waivers from Capital Research and Management Company. For more information about these waivers, see the fund's statement of additional information and annual report. The information in the Financial Highlights table has been audited by PricewaterhouseCoopers LLP, whose current report, along with the funds’ financial statements, is included in the statement of additional information, which is available upon request. Figures shown do not reflect insurance contract fees and expenses. If insurance contract fees and expenses were reflected, results would be lower.
| Income
(loss) from investment operations1 |
Dividends and distributions | |||||||||||||||||||||||||
| Period ended | Net
asset value, beginning of period |
Net investment income |
Net
gains (losses) on securities (both realized and unrealized) |
Total
from investment operations |
Dividends (from net investment income) |
Distributions (from capital gains) |
Total dividends and distributions |
Net
asset value, end of period |
Total return2 |
Net
assets, end of period (in millions) |
Ratio
of expenses to average net assets before waivers3 |
Ratio
of expenses to average net assets after waivers2,3 |
Ratio
of net income to average net assets2 | |||||||||||||
| Global Growth Fund | ||||||||||||||||||||||||||
| Class 1: | ||||||||||||||||||||||||||
| 12/31/2021 | $41.16 | $.25 | $6.48 | $6.73 | $(.26 | ) | $(2.17 | ) | $(2.43 | ) | $45.46 | 16.72 | % | $4,270 | .55 | % | .54 | % | .56 | % | ||||||
| 12/31/2020 | 32.57 | .20 | 9.56 | 9.76 | (.21 | ) | (.96 | ) | (1.17 | ) | 41.16 | 30.79 | 3,309 | .56 | .56 | .59 | ||||||||||
| 12/31/2019 | 25.74 | .32 | 8.60 | 8.92 | (.41 | ) | (1.68 | ) | (2.09 | ) | 32.57 | 35.61 | 2,515 | .56 | .56 | 1.07 | ||||||||||
| 12/31/2018 | 30.51 | .29 | (2.65 | ) | (2.36 | ) | (.28 | ) | (2.13 | ) | (2.41 | ) | 25.74 | (8.81 | ) | 1,942 | .55 | .55 | .98 | |||||||
| 12/31/2017 | 24.05 | .26 | 7.30 | 7.56 | (.26 | ) | (.84 | ) | (1.10 | ) | 30.51 | 31.80 | 2,010 | .55 | .55 | .94 | ||||||||||
| Class 1A: | ||||||||||||||||||||||||||
| 12/31/2021 | 41.02 | .14 | 6.46 | 6.60 | (.17 | ) | (2.17 | ) | (2.34 | ) | 45.28 | 16.45 | 18 | .80 | .79 | .33 | ||||||||||
| 12/31/2020 | 32.47 | .12 | 9.52 | 9.64 | (.13 | ) | (.96 | ) | (1.09 | ) | 41.02 | 30.49 | 12 | .81 | .81 | .34 | ||||||||||
| 12/31/2019 | 25.69 | .25 | 8.55 | 8.80 | (.34 | ) | (1.68 | ) | (2.02 | ) | 32.47 | 35.22 | 8 | .81 | .81 | .83 | ||||||||||
| 12/31/2018 | 30.46 | .23 | (2.66 | ) | (2.43 | ) | (.21 | ) | (2.13 | ) | (2.34 | ) | 25.69 | (9.02 | ) | 5 | .80 | .80 | .77 | |||||||
| 12/31/20174,5 | 24.50 | .11 | 6.94 | 7.05 | (.25 | ) | (.84 | ) | (1.09 | ) | 30.46 | 29.13 | 6 | 2 | .80 | 7 | .80 | 7 | .39 | 7 | ||||||
| Class 2: | ||||||||||||||||||||||||||
| 12/31/2021 | 40.72 | .13 | 6.41 | 6.54 | (.15 | ) | (2.17 | ) | (2.32 | ) | 44.94 | 16.42 | 4,559 | .80 | .80 | .30 | ||||||||||
| 12/31/2020 | 32.24 | .12 | 9.44 | 9.56 | (.12 | ) | (.96 | ) | (1.08 | ) | 40.72 | 30.47 | 4,387 | .81 | .81 | .34 | ||||||||||
| 12/31/2019 | 25.50 | .24 | 8.51 | 8.75 | (.33 | ) | (1.68 | ) | (2.01 | ) | 32.24 | 35.28 | 3,895 | .81 | .81 | .83 | ||||||||||
| 12/31/2018 | 30.24 | .22 | (2.63 | ) | (2.41 | ) | (.20 | ) | (2.13 | ) | (2.33 | ) | 25.50 | (9.04 | ) | 3,306 | .80 | .80 | .73 | |||||||
| 12/31/2017 | 23.85 | .19 | 7.23 | 7.42 | (.19 | ) | (.84 | ) | (1.03 | ) | 30.24 | 31.47 | 4,012 | .80 | .80 | .69 | ||||||||||
| Class 4: | ||||||||||||||||||||||||||
| 12/31/2021 | 40.45 | .03 | 6.35 | 6.38 | (.09 | ) | (2.17 | ) | (2.26 | ) | 44.57 | 16.14 | 744 | 1.05 | 1.04 | .07 | ||||||||||
| 12/31/2020 | 32.05 | .03 | 9.38 | 9.41 | (.05 | ) | (.96 | ) | (1.01 | ) | 40.45 | 30.17 | 533 | 1.06 | 1.06 | .09 | ||||||||||
| 12/31/2019 | 25.39 | .17 | 8.45 | 8.62 | (.28 | ) | (1.68 | ) | (1.96 | ) | 32.05 | 34.87 | 382 | 1.06 | 1.06 | .57 | ||||||||||
| 12/31/2018 | 30.13 | .14 | (2.60 | ) | (2.46 | ) | (.15 | ) | (2.13 | ) | (2.28 | ) | 25.39 | (9.24 | ) | 249 | 1.05 | 1.05 | .47 | |||||||
| 12/31/2017 | 23.81 | .10 | 7.22 | 7.32 | (.16 | ) | (.84 | ) | (1.00 | ) | 30.13 | 31.11 | 211 | 1.05 | 1.05 | .37 | ||||||||||
American Funds Insurance Series / Prospectus 20
| Income
(loss) from investment operations1 |
Dividends and distributions | |||||||||||||||||||||||
| Period ended | Net
asset value, beginning of period |
Net investment (loss) income |
Net
gains (losses) on securities (both realized and unrealized) |
Total
from investment operations |
Dividends (from net investment income) |
Distributions (from capital gains) |
Total dividends and distributions |
Net
asset value, end of period |
Total return |
Net
assets, end of period (in millions) |
Ratio
of expenses to average net assets3 |
Ratio
of net (loss) income to average net assets | ||||||||||||
| Global Small Capitalization Fund | ||||||||||||||||||||||||
| Class 1: | ||||||||||||||||||||||||
| 12/31/2021 | $32.64 | $(.02 | ) | $2.32 | $2.30 | $— | $(.77 | ) | $(.77 | ) | $34.17 | 6.98 | % | $1,707 | .74 | % | (.07 | )% | ||||||
| 12/31/2020 | 26.80 | (.01 | ) | 7.49 | 7.48 | (.05 | ) | (1.59 | ) | (1.64 | ) | 32.64 | 30.04 | 2,391 | .75 | (.06 | ) | |||||||
| 12/31/2019 | 21.75 | .12 | 6.61 | 6.73 | (.10 | ) | (1.58 | ) | (1.68 | ) | 26.80 | 31.84 | 2,050 | .75 | .48 | |||||||||
| 12/31/2018 | 25.38 | .11 | (2.51 | ) | (2.40 | ) | (.09 | ) | (1.14 | ) | (1.23 | ) | 21.75 | (10.31 | ) | 1,453 | .73 | .42 | ||||||
| 12/31/2017 | 20.24 | .12 | 5.17 | 5.29 | (.15 | ) | — | (.15 | ) | 25.38 | 26.22 | 1,639 | .73 | .54 | ||||||||||
| Class 1A: | ||||||||||||||||||||||||
| 12/31/2021 | 32.49 | (.07 | ) | 2.28 | 2.21 | — | (.77 | ) | (.77 | ) | 33.93 | 6.73 | 5 | .99 | (.21 | ) | ||||||||
| 12/31/2020 | 26.74 | (.09 | ) | 7.48 | 7.39 | (.05 | ) | (1.59 | ) | (1.64 | ) | 32.49 | 29.72 | 1 | .99 | (.33 | ) | |||||||
| 12/31/2019 | 21.71 | .05 | 6.61 | 6.66 | (.05 | ) | (1.58 | ) | (1.63 | ) | 26.74 | 31.56 | 1 | .99 | .22 | |||||||||
| 12/31/2018 | 25.36 | .05 | (2.52 | ) | (2.47 | ) | (.04 | ) | (1.14 | ) | (1.18 | ) | 21.71 | (10.56 | ) | — | 8 | .98 | .21 | |||||
| 12/31/20174,5 | 20.70 | .08 | 4.71 | 4.79 | (.13 | ) | — | (.13 | ) | 25.36 | 23.19 | 6 | — | 8 | .96 | 7 | .35 | 7 | ||||||
| Class 2: | ||||||||||||||||||||||||
| 12/31/2021 | 31.56 | (.10 | ) | 2.25 | 2.15 | — | (.77 | ) | (.77 | ) | 32.94 | 6.74 | 2,521 | .99 | (.30 | ) | ||||||||
| 12/31/2020 | 26.02 | (.08 | ) | 7.25 | 7.17 | (.04 | ) | (1.59 | ) | (1.63 | ) | 31.56 | 29.72 | 2,653 | 1.00 | (.31 | ) | |||||||
| 12/31/2019 | 21.16 | .05 | 6.43 | 6.48 | (.04 | ) | (1.58 | ) | (1.62 | ) | 26.02 | 31.52 | 2,363 | 1.00 | .22 | |||||||||
| 12/31/2018 | 24.72 | .04 | (2.44 | ) | (2.40 | ) | (.02 | ) | (1.14 | ) | (1.16 | ) | 21.16 | (10.55 | ) | 2,056 | .98 | .17 | ||||||
| 12/31/2017 | 19.72 | .06 | 5.04 | 5.10 | (.10 | ) | — | (.10 | ) | 24.72 | 25.89 | 2,551 | .98 | .27 | ||||||||||
| Class 4: | ||||||||||||||||||||||||
| 12/31/2021 | 31.67 | (.18 | ) | 2.24 | 2.06 | — | (.77 | ) | (.77 | ) | 32.96 | 6.43 | 344 | 1.24 | (.53 | ) | ||||||||
| 12/31/2020 | 26.16 | (.14 | ) | 7.27 | 7.13 | (.03 | ) | (1.59 | ) | (1.62 | ) | 31.67 | 29.39 | 268 | 1.25 | (.56 | ) | |||||||
| 12/31/2019 | 21.28 | (.01 | ) | 6.47 | 6.46 | — | 9 | (1.58 | ) | (1.58 | ) | 26.16 | 31.24 | 206 | 1.25 | (.04 | ) | |||||||
| 12/31/2018 | 24.91 | (.02 | ) | (2.46 | ) | (2.48 | ) | (.01 | ) | (1.14 | ) | (1.15 | ) | 21.28 | (10.80 | ) | 146 | 1.24 | (.08 | ) | ||||
| 12/31/2017 | 19.91 | — | 9 | 5.09 | 5.09 | (.09 | ) | — | (.09 | ) | 24.91 | 25.62 | 125 | 1.23 | — | 10 | ||||||||
| Income
from investment operations1 |
Dividends and distributions | |||||||||||||||||||||||
| Period ended | Net
asset value, beginning of period |
Net investment income (loss) |
Net
gains on securities (both realized and unrealized) |
Total
from investment operations |
Dividends (from net investment income) |
Distributions (from capital gains) |
Total dividends and distributions |
Net
asset value, end of period |
Total return |
Net
assets, end of period (in millions) |
Ratio
of expenses to average net assets3 |
Ratio
of net income (loss) to average net assets | ||||||||||||
| Growth Fund | ||||||||||||||||||||||||
| Class 1: | ||||||||||||||||||||||||
| 12/31/2021 | $120.22 | $.46 | $24.29 | $24.75 | $(.58 | ) | $(16.81 | ) | $(17.39 | ) | $127.58 | 22.30 | % | $19,783 | .34 | % | .37 | % | ||||||
| 12/31/2020 | 81.22 | .43 | 41.28 | 41.71 | (.53 | ) | (2.18 | ) | (2.71 | ) | 120.22 | 52.45 | 15,644 | .35 | .46 | |||||||||
| 12/31/2019 | 69.96 | .83 | 19.63 | 20.46 | (.76 | ) | (8.44 | ) | (9.20 | ) | 81.22 | 31.11 | 10,841 | .35 | 1.09 | |||||||||
| 12/31/2018 | 77.85 | .64 | .25 | .89 | (.54 | ) | (8.24 | ) | (8.78 | ) | 69.96 | (.01 | ) | 8,474 | .34 | .81 | ||||||||
| 12/31/2017 | 67.29 | .55 | 17.89 | 18.44 | (.55 | ) | (7.33 | ) | (7.88 | ) | 77.85 | 28.62 | 8,100 | .35 | .75 | |||||||||
| Class 1A: | ||||||||||||||||||||||||
| 12/31/2021 | 119.59 | .16 | 24.11 | 24.27 | (.35 | ) | (16.81 | ) | (17.16 | ) | 126.70 | 21.97 | 121 | .59 | .13 | |||||||||
| 12/31/2020 | 80.92 | .20 | 41.05 | 41.25 | (.40 | ) | (2.18 | ) | (2.58 | ) | 119.59 | 52.07 | 60 | .60 | .21 | |||||||||
| 12/31/2019 | 69.77 | .65 | 19.55 | 20.20 | (.61 | ) | (8.44 | ) | (9.05 | ) | 80.92 | 30.79 | 18 | .60 | .85 | |||||||||
| 12/31/2018 | 77.74 | .47 | .24 | .71 | (.44 | ) | (8.24 | ) | (8.68 | ) | 69.77 | (.26 | ) | 10 | .59 | .60 | ||||||||
| 12/31/20174,5 | 68.84 | .35 | 16.38 | 16.73 | (.50 | ) | (7.33 | ) | (7.83 | ) | 77.74 | 25.47 | 6 | 3 | .59 | 7 | .47 | 7 | ||||||
| Class 2: | ||||||||||||||||||||||||
| 12/31/2021 | 119.18 | .15 | 24.03 | 24.18 | (.27 | ) | (16.81 | ) | (17.08 | ) | 126.28 | 21.97 | 21,986 | .59 | .12 | |||||||||
| 12/31/2020 | 80.57 | .19 | 40.89 | 41.08 | (.29 | ) | (2.18 | ) | (2.47 | ) | 119.18 | 52.10 | 20,594 | .60 | .21 | |||||||||
| 12/31/2019 | 69.48 | .63 | 19.47 | 20.10 | (.57 | ) | (8.44 | ) | (9.01 | ) | 80.57 | 30.77 | 15,885 | .60 | .83 | |||||||||
| 12/31/2018 | 77.35 | .44 | .27 | .71 | (.34 | ) | (8.24 | ) | (8.58 | ) | 69.48 | (.25 | ) | 13,701 | .59 | .55 | ||||||||
| 12/31/2017 | 66.92 | .37 | 17.76 | 18.13 | (.37 | ) | (7.33 | ) | (7.70 | ) | 77.35 | 28.28 | 15,716 | .60 | .50 | |||||||||
| Class 3: | ||||||||||||||||||||||||
| 12/31/2021 | 121.13 | .24 | 24.47 | 24.71 | (.35 | ) | (16.81 | ) | (17.16 | ) | 128.68 | 22.07 | 302 | .52 | .19 | |||||||||
| 12/31/2020 | 81.84 | .26 | 41.56 | 41.82 | (.35 | ) | (2.18 | ) | (2.53 | ) | 121.13 | 52.20 | 279 | .53 | .28 | |||||||||
| 12/31/2019 | 70.44 | .69 | 19.77 | 20.46 | (.62 | ) | (8.44 | ) | (9.06 | ) | 81.84 | 30.86 | 213 | .53 | .90 | |||||||||
| 12/31/2018 | 78.32 | .50 | .26 | .76 | (.40 | ) | (8.24 | ) | (8.64 | ) | 70.44 | (.18 | ) | 187 | .52 | .62 | ||||||||
| 12/31/2017 | 67.67 | .42 | 17.98 | 18.40 | (.42 | ) | (7.33 | ) | (7.75 | ) | 78.32 | 28.39 | 212 | .53 | .57 | |||||||||
| Class 4: | ||||||||||||||||||||||||
| 12/31/2021 | 117.24 | (.15 | ) | 23.59 | 23.44 | (.08 | ) | (16.81 | ) | (16.89 | ) | 123.79 | 21.69 | 3,214 | .84 | (.13 | ) | |||||||
| 12/31/2020 | 79.41 | (.04 | ) | 40.24 | 40.20 | (.19 | ) | (2.18 | ) | (2.37 | ) | 117.24 | 51.71 | 2,347 | .85 | (.04 | ) | |||||||
| 12/31/2019 | 68.64 | .44 | 19.19 | 19.63 | (.42 | ) | (8.44 | ) | (8.86 | ) | 79.41 | 30.44 | 1,513 | .85 | .59 | |||||||||
| 12/31/2018 | 76.56 | .24 | .28 | .52 | (.20 | ) | (8.24 | ) | (8.44 | ) | 68.64 | (.50 | ) | 1,076 | .84 | .31 | ||||||||
| 12/31/2017 | 66.41 | .18 | 17.61 | 17.79 | (.31 | ) | (7.33 | ) | (7.64 | ) | 76.56 | 27.99 | 954 | .85 | .25 | |||||||||
21 American Funds Insurance Series / Prospectus
| (Loss)
income from investment operations1 |
Dividends and distributions | |||||||||||||||||||||||
| Period ended | Net
asset value, beginning of period |
Net investment income |
Net
(losses) gains on securities (both realized and unrealized) |
Total
from investment operations |
Dividends (from net investment income) |
Distributions (from capital gains) |
Total dividends and distributions |
Net
asset value, end of period |
Total return |
Net
assets, end of period (in millions) |
Ratio
of expenses to average net assets3 |
Ratio
of net income to average net assets | ||||||||||||
| International Fund | ||||||||||||||||||||||||
| Class 1: | ||||||||||||||||||||||||
| 12/31/2021 | $23.64 | $.38 | $(.67 | ) | $(.29 | ) | $(.65 | ) | $— | $(.65 | ) | $22.70 | (1.23 | )% | $4,747 | .55 | % | 1.57 | % | |||||
| 12/31/2020 | 20.86 | .14 | 2.82 | 2.96 | (.18 | ) | — | (.18 | ) | 23.64 | 14.28 | 5,652 | .55 | .71 | ||||||||||
| 12/31/2019 | 17.66 | .30 | 3.74 | 4.04 | (.34 | ) | (.50 | ) | (.84 | ) | 20.86 | 23.21 | 5,353 | .54 | 1.54 | |||||||||
| 12/31/2018 | 21.71 | .34 | (2.97 | ) | (2.63 | ) | (.40 | ) | (1.02 | ) | (1.42 | ) | 17.66 | (12.94 | ) | 4,811 | .53 | 1.62 | ||||||
| 12/31/2017 | 16.82 | .26 | 5.16 | 5.42 | (.30 | ) | (.23 | ) | (.53 | ) | 21.71 | 32.46 | 5,014 | .53 | 1.33 | |||||||||
| Class 1A: | ||||||||||||||||||||||||
| 12/31/2021 | 23.55 | .33 | (.67 | ) | (.34 | ) | (.60 | ) | — | (.60 | ) | 22.61 | (1.47 | ) | 12 | .80 | 1.39 | |||||||
| 12/31/2020 | 20.80 | .08 | 2.81 | 2.89 | (.14 | ) | — | (.14 | ) | 23.55 | 13.96 | 10 | .80 | .43 | ||||||||||
| 12/31/2019 | 17.62 | .25 | 3.72 | 3.97 | (.29 | ) | (.50 | ) | (.79 | ) | 20.80 | 22.90 | 7 | .79 | 1.27 | |||||||||
| 12/31/2018 | 21.67 | .27 | (2.93 | ) | (2.66 | ) | (.37 | ) | (1.02 | ) | (1.39 | ) | 17.62 | (13.11 | ) | 5 | .78 | 1.32 | ||||||
| 12/31/20174,5 | 17.17 | .09 | 4.93 | 5.02 | (.29 | ) | (.23 | ) | (.52 | ) | 21.67 | 29.46 | 6 | 2 | .77 | 7 | .43 | 7 | ||||||
| Class 2: | ||||||||||||||||||||||||
| 12/31/2021 | 23.54 | .33 | (.68 | ) | (.35 | ) | (.59 | ) | — | (.59 | ) | 22.60 | (1.49 | ) | 4,190 | .80 | 1.35 | |||||||
| 12/31/2020 | 20.78 | .09 | 2.80 | 2.89 | (.13 | ) | — | (.13 | ) | 23.54 | 13.97 | 4,481 | .80 | .46 | ||||||||||
| 12/31/2019 | 17.60 | .25 | 3.72 | 3.97 | (.29 | ) | (.50 | ) | (.79 | ) | 20.78 | 22.88 | 4,311 | .79 | 1.29 | |||||||||
| 12/31/2018 | 21.63 | .29 | (2.95 | ) | (2.66 | ) | (.35 | ) | (1.02 | ) | (1.37 | ) | 17.60 | (13.13 | ) | 3,875 | .78 | 1.40 | ||||||
| 12/31/2017 | 16.76 | .22 | 5.13 | 5.35 | (.25 | ) | (.23 | ) | (.48 | ) | 21.63 | 32.14 | 4,422 | .78 | 1.10 | |||||||||
| Class 3: | ||||||||||||||||||||||||
| 12/31/2021 | 23.69 | .34 | (.67 | ) | (.33 | ) | (.60 | ) | — | (.60 | ) | 22.76 | (1.39 | ) | 21 | .73 | 1.41 | |||||||
| 12/31/2020 | 20.92 | .10 | 2.81 | 2.91 | (.14 | ) | — | (.14 | ) | 23.69 | 14.00 | 25 | .73 | .53 | ||||||||||
| 12/31/2019 | 17.70 | .27 | 3.75 | 4.02 | (.30 | ) | (.50 | ) | (.80 | ) | 20.92 | 23.05 | 25 | .72 | 1.37 | |||||||||
| 12/31/2018 | 21.75 | .31 | (2.98 | ) | (2.67 | ) | (.36 | ) | (1.02 | ) | (1.38 | ) | 17.70 | (13.10 | ) | 24 | .71 | 1.48 | ||||||
| 12/31/2017 | 16.85 | .23 | 5.17 | 5.40 | (.27 | ) | (.23 | ) | (.50 | ) | 21.75 | 32.23 | 31 | .71 | 1.17 | |||||||||
| Class 4: | ||||||||||||||||||||||||
| 12/31/2021 | 23.25 | .27 | (.67 | ) | (.40 | ) | (.54 | ) | — | (.54 | ) | 22.31 | (1.71 | ) | 459 | 1.05 | 1.13 | |||||||
| 12/31/2020 | 20.54 | .04 | 2.76 | 2.80 | (.09 | ) | — | (.09 | ) | 23.25 | 13.66 | 423 | 1.05 | .21 | ||||||||||
| 12/31/2019 | 17.40 | .20 | 3.69 | 3.89 | (.25 | ) | (.50 | ) | (.75 | ) | 20.54 | 22.67 | 379 | 1.04 | 1.03 | |||||||||
| 12/31/2018 | 21.42 | .23 | (2.93 | ) | (2.70 | ) | (.30 | ) | (1.02 | ) | (1.32 | ) | 17.40 | (13.41 | ) | 295 | 1.03 | 1.13 | ||||||
| 12/31/2017 | 16.64 | .11 | 5.16 | 5.27 | (.26 | ) | (.23 | ) | (.49 | ) | 21.42 | 31.89 | 289 | 1.03 | .55 | |||||||||
| Income
(loss) from investment operations1 |
Dividends and distributions | |||||||||||||||||||||||||
| Period ended | Net
asset value, beginning of period |
Net investment income |
Net
gains (losses) on securities (both realized and unrealized) |
Total
from investment operations |
Dividends (from net investment income) |
Distributions (from capital gains) |
Total dividends and distributions |
Net
asset value, end of period |
Total return2 |
Net
assets, end of period (in millions) |
Ratio
of expenses to average net assets before waivers3 |
Ratio
of expenses to average net assets after waivers2,3 |
Ratio
of net income to average net assets2 | |||||||||||||
| New World Fund | ||||||||||||||||||||||||||
| Class 1: | ||||||||||||||||||||||||||
| 12/31/2021 | $31.59 | $.29 | $1.38 | $1.67 | $(.36 | ) | $(1.07 | ) | $(1.43 | ) | $31.83 | 5.16 | % | $2,443 | .74 | % | .56 | % | .88 | % | ||||||
| 12/31/2020 | 25.84 | .15 | 5.93 | 6.08 | (.06 | ) | (.27 | ) | (.33 | ) | 31.59 | 23.89 | 2,309 | .76 | .64 | .58 | ||||||||||
| 12/31/2019 | 20.98 | .28 | 5.79 | 6.07 | (.29 | ) | (.92 | ) | (1.21 | ) | 25.84 | 29.47 | 2,129 | .76 | .76 | 1.18 | ||||||||||
| 12/31/2018 | 25.30 | .27 | (3.65 | ) | (3.38 | ) | (.27 | ) | (.67 | ) | (.94 | ) | 20.98 | (13.83 | ) | 1,702 | .77 | .77 | 1.11 | |||||||
| 12/31/2017 | 19.72 | .26 | 5.59 | 5.85 | (.27 | ) | — | (.27 | ) | 25.30 | 29.73 | 2,050 | .77 | .77 | 1.14 | |||||||||||
| Class 1A: | ||||||||||||||||||||||||||
| 12/31/2021 | 31.43 | .17 | 1.41 | 1.58 | (.24 | ) | (1.07 | ) | (1.31 | ) | 31.70 | 4.90 | 12 | .99 | .81 | .54 | ||||||||||
| 12/31/2020 | 25.74 | .07 | 5.92 | 5.99 | (.03 | ) | (.27 | ) | (.30 | ) | 31.43 | 23.63 | 18 | 1.01 | .87 | .26 | ||||||||||
| 12/31/2019 | 20.92 | .22 | 5.76 | 5.98 | (.24 | ) | (.92 | ) | (1.16 | ) | 25.74 | 29.11 | 4 | 1.01 | 1.01 | .92 | ||||||||||
| 12/31/2018 | 25.25 | .21 | (3.64 | ) | (3.43 | ) | (.23 | ) | (.67 | ) | (.90 | ) | 20.92 | (14.02 | ) | 2 | 1.02 | 1.02 | .91 | |||||||
| 12/31/20174,5 | 20.14 | .13 | 5.24 | 5.37 | (.26 | ) | — | (.26 | ) | 25.25 | 26.72 | 6 | 1 | 1.00 | 7 | 1.00 | 7 | .53 | 7 | |||||||
| Class 2: | ||||||||||||||||||||||||||
| 12/31/2021 | 31.25 | .20 | 1.38 | 1.58 | (.28 | ) | (1.07 | ) | (1.35 | ) | 31.48 | 4.92 | 1,086 | .99 | .81 | .63 | ||||||||||
| 12/31/2020 | 25.59 | .08 | 5.87 | 5.95 | (.02 | ) | (.27 | ) | (.29 | ) | 31.25 | 23.58 | 1,109 | 1.01 | .89 | .34 | ||||||||||
| 12/31/2019 | 20.79 | .22 | 5.73 | 5.95 | (.23 | ) | (.92 | ) | (1.15 | ) | 25.59 | 29.15 | 981 | 1.01 | 1.01 | .93 | ||||||||||
| 12/31/2018 | 25.07 | .20 | (3.61 | ) | (3.41 | ) | (.20 | ) | (.67 | ) | (.87 | ) | 20.79 | (14.04 | ) | 843 | 1.02 | 1.02 | .85 | |||||||
| 12/31/2017 | 19.54 | .20 | 5.55 | 5.75 | (.22 | ) | — | (.22 | ) | 25.07 | 29.44 | 1,055 | 1.02 | 1.02 | .89 | |||||||||||
| Class 4: | ||||||||||||||||||||||||||
| 12/31/2021 | 31.04 | .12 | 1.36 | 1.48 | (.21 | ) | (1.07 | ) | (1.28 | ) | 31.24 | 4.63 | 906 | 1.24 | 1.06 | .38 | ||||||||||
| 12/31/2020 | 25.47 | .02 | 5.83 | 5.85 | (.01 | ) | (.27 | ) | (.28 | ) | 31.04 | 23.29 | 807 | 1.26 | 1.14 | .08 | ||||||||||
| 12/31/2019 | 20.71 | .16 | 5.70 | 5.86 | (.18 | ) | (.92 | ) | (1.10 | ) | 25.47 | 28.82 | 646 | 1.26 | 1.26 | .67 | ||||||||||
| 12/31/2018 | 24.99 | .14 | (3.59 | ) | (3.45 | ) | (.16 | ) | (.67 | ) | (.83 | ) | 20.71 | (14.25 | ) | 464 | 1.27 | 1.27 | .61 | |||||||
| 12/31/2017 | 19.51 | .14 | 5.52 | 5.66 | (.18 | ) | — | (.18 | ) | 24.99 | 29.06 | 427 | 1.27 | 1.27 | .61 | |||||||||||
American Funds Insurance Series / Prospectus 22
| Income
(loss) from investment operations1 |
Dividends and distributions | |||||||||||||||||||||||||
| Period ended | Net
asset value, beginning of period |
Net investment income |
Net
gains (losses) on securities (both realized and unrealized) |
Total
from investment operations |
Dividends (from net investment income) |
Distributions (from capital gains) |
Total dividends and distributions |
Net
asset value, end of period |
Total return2 |
Net
assets, end of period (in millions) |
Ratio
of expenses to average net assets before waivers3 |
Ratio
of expenses to average net assets after waivers2,3 |
Ratio
of net income to average net assets2 | |||||||||||||
| Capital World Growth and Income Fund | ||||||||||||||||||||||||||
| Class 1: | ||||||||||||||||||||||||||
| 12/31/2021 | $16.67 | $.38 | $2.10 | $2.48 | $(.33 | ) | $(.40 | ) | $(.73 | ) | $18.42 | 15.03 | % | $812 | .63 | % | .47 | % | 2.14 | % | ||||||
| 12/31/2020 | 15.92 | .22 | 1.14 | 1.36 | (.23 | ) | (.38 | ) | (.61 | ) | 16.67 | 9.03 | 657 | .66 | .66 | 1.49 | ||||||||||
| 12/31/2019 | 13.02 | .31 | 3.67 | 3.98 | (.32 | ) | (.76 | ) | (1.08 | ) | 15.92 | 31.39 | 625 | .65 | .65 | 2.08 | ||||||||||
| 12/31/2018 | 15.81 | .29 | (1.62 | ) | (1.33 | ) | (.28 | ) | (1.18 | ) | (1.46 | ) | 13.02 | (9.36 | ) | 492 | .63 | .63 | 1.94 | |||||||
| 12/31/2017 | 13.02 | .35 | 3.06 | 3.41 | (.36 | ) | (.26 | ) | (.62 | ) | 15.81 | 26.40 | 485 | .63 | .63 | 2.43 | ||||||||||
| Class 1A: | ||||||||||||||||||||||||||
| 12/31/2021 | 16.62 | .37 | 2.06 | 2.43 | (.31 | ) | (.40 | ) | (.71 | ) | 18.34 | 14.71 | 7 | .88 | .70 | 2.08 | ||||||||||
| 12/31/2020 | 15.88 | .18 | 1.13 | 1.31 | (.19 | ) | (.38 | ) | (.57 | ) | 16.62 | 8.78 | 2 | .90 | .90 | 1.23 | ||||||||||
| 12/31/2019 | 13.00 | .26 | 3.68 | 3.94 | (.30 | ) | (.76 | ) | (1.06 | ) | 15.88 | 31.04 | 2 | .90 | .90 | 1.77 | ||||||||||
| 12/31/2018 | 15.81 | .26 | (1.63 | ) | (1.37 | ) | (.26 | ) | (1.18 | ) | (1.44 | ) | 13.00 | (9.62 | ) | 1 | .88 | .88 | 1.74 | |||||||
| 12/31/20174,5 | 13.21 | .18 | 3.03 | 3.21 | (.35 | ) | (.26 | ) | (.61 | ) | 15.81 | 24.54 | 6 | — | 8 | .84 | 7 | .84 | 7 | 1.20 | 7 | |||||
| Class 2: | ||||||||||||||||||||||||||
| 12/31/2021 | 16.63 | .33 | 2.11 | 2.44 | (.29 | ) | (.40 | ) | (.69 | ) | 18.38 | 14.78 | 1,340 | .88 | .73 | 1.85 | ||||||||||
| 12/31/2020 | 15.89 | .18 | 1.13 | 1.31 | (.19 | ) | (.38 | ) | (.57 | ) | 16.63 | 8.73 | 1,349 | .91 | .91 | 1.23 | ||||||||||
| 12/31/2019 | 12.99 | .27 | 3.68 | 3.95 | (.29 | ) | (.76 | ) | (1.05 | ) | 15.89 | 31.14 | 1,366 | .90 | .90 | 1.84 | ||||||||||
| 12/31/2018 | 15.78 | .26 | (1.63 | ) | (1.37 | ) | (.24 | ) | (1.18 | ) | (1.42 | ) | 12.99 | (9.63 | ) | 1,228 | .88 | .88 | 1.70 | |||||||
| 12/31/2017 | 13.00 | .31 | 3.05 | 3.36 | (.32 | ) | (.26 | ) | (.58 | ) | 15.78 | 26.06 | 1,538 | .88 | .88 | 2.11 | ||||||||||
| Class 4: | ||||||||||||||||||||||||||
| 12/31/2021 | 16.35 | .29 | 2.06 | 2.35 | (.26 | ) | (.40 | ) | (.66 | ) | 18.04 | 14.46 | 225 | 1.13 | .97 | 1.65 | ||||||||||
| 12/31/2020 | 15.63 | .14 | 1.12 | 1.26 | (.16 | ) | (.38 | ) | (.54 | ) | 16.35 | 8.55 | 166 | 1.16 | 1.16 | .97 | ||||||||||
| 12/31/2019 | 12.81 | .23 | 3.61 | 3.84 | (.26 | ) | (.76 | ) | (1.02 | ) | 15.63 | 30.73 | 145 | 1.15 | 1.15 | 1.56 | ||||||||||
| 12/31/2018 | 15.60 | .21 | (1.60 | ) | (1.39 | ) | (.22 | ) | (1.18 | ) | (1.40 | ) | 12.81 | (9.89 | ) | 95 | 1.13 | 1.13 | 1.43 | |||||||
| 12/31/2017 | 12.89 | .22 | 3.08 | 3.30 | (.33 | ) | (.26 | ) | (.59 | ) | 15.60 | 25.83 | 79 | 1.14 | 1.14 | 1.49 | ||||||||||
| Income
(loss) from investment operations1 |
Dividends and distributions | |||||||||||||||||||||||
| Period ended | Net
asset value, beginning of period |
Net investment income |
Net
gains (losses) on securities (both realized and unrealized) |
Total
from investment operations |
Dividends (from net investment income) |
Distributions (from capital gains) |
Total dividends and distributions |
Net
asset value, end of period |
Total return |
Net
assets, end of period (in millions) |
Ratio
of expenses to average net assets3 |
Ratio
of net income to average net assets | ||||||||||||
| Growth-Income Fund | ||||||||||||||||||||||||
| Class 1: | ||||||||||||||||||||||||
| 12/31/2021 | $55.38 | $.79 | $12.64 | $13.43 | $(.86 | ) | $(.60 | ) | $(1.46 | ) | $67.35 | 24.42 | % | $25,507 | .29 | % | 1.28 | % | ||||||
| 12/31/2020 | 50.71 | .75 | 6.02 | 6.77 | (.80 | ) | (1.30 | ) | (2.10 | ) | 55.38 | 13.81 | 22,903 | .29 | 1.52 | |||||||||
| 12/31/2019 | 45.39 | 1.00 | 10.40 | 11.40 | (.92 | ) | (5.16 | ) | (6.08 | ) | 50.71 | 26.46 | 21,057 | .29 | 2.05 | |||||||||
| 12/31/2018 | 50.22 | .84 | (1.25 | ) | (.41 | ) | (.84 | ) | (3.58 | ) | (4.42 | ) | 45.39 | (1.55 | ) | 16,783 | .28 | 1.65 | ||||||
| 12/31/2017 | 44.41 | .81 | 8.89 | 9.70 | (.78 | ) | (3.11 | ) | (3.89 | ) | 50.22 | 22.68 | 15,765 | .28 | 1.69 | |||||||||
| Class 1A: | ||||||||||||||||||||||||
| 12/31/2021 | 55.16 | .65 | 12.55 | 13.20 | (.74 | ) | (.60 | ) | (1.34 | ) | 67.02 | 24.08 | 32 | .53 | 1.04 | |||||||||
| 12/31/2020 | 50.54 | .63 | 5.99 | 6.62 | (.70 | ) | (1.30 | ) | (2.00 | ) | 55.16 | 13.55 | 16 | .54 | 1.28 | |||||||||
| 12/31/2019 | 45.28 | .89 | 10.36 | 11.25 | (.83 | ) | (5.16 | ) | (5.99 | ) | 50.54 | 26.14 | 11 | .54 | 1.82 | |||||||||
| 12/31/2018 | 50.15 | .72 | (1.25 | ) | (.53 | ) | (.76 | ) | (3.58 | ) | (4.34 | ) | 45.28 | (1.78 | ) | 7 | .53 | 1.43 | ||||||
| 12/31/20174,5 | 45.39 | .67 | 7.96 | 8.63 | (.76 | ) | (3.11 | ) | (3.87 | ) | 50.15 | 19.83 | 6 | 2 | .52 | 7 | 1.41 | 7 | ||||||
| Class 2: | ||||||||||||||||||||||||
| 12/31/2021 | 54.66 | .63 | 12.45 | 13.08 | (.70 | ) | (.60 | ) | (1.30 | ) | 66.44 | 24.10 | 15,319 | .54 | 1.03 | |||||||||
| 12/31/2020 | 50.08 | .62 | 5.93 | 6.55 | (.67 | ) | (1.30 | ) | (1.97 | ) | 54.66 | 13.54 | 14,012 | .54 | 1.27 | |||||||||
| 12/31/2019 | 44.90 | .87 | 10.27 | 11.14 | (.80 | ) | (5.16 | ) | (5.96 | ) | 50.08 | 26.14 | 13,586 | .53 | 1.80 | |||||||||
| 12/31/2018 | 49.71 | .71 | (1.23 | ) | (.52 | ) | (.71 | ) | (3.58 | ) | (4.29 | ) | 44.90 | (1.79 | ) | 12,035 | .53 | 1.40 | ||||||
| 12/31/2017 | 44.00 | .68 | 8.80 | 9.48 | (.66 | ) | (3.11 | ) | (3.77 | ) | 49.71 | 22.38 | 13,930 | .53 | 1.45 | |||||||||
| Class 3: | ||||||||||||||||||||||||
| 12/31/2021 | 55.49 | .68 | 12.65 | 13.33 | (.74 | ) | (.60 | ) | (1.34 | ) | 67.48 | 24.18 | 166 | .47 | 1.10 | |||||||||
| 12/31/2020 | 50.81 | .66 | 6.02 | 6.68 | (.70 | ) | (1.30 | ) | (2.00 | ) | 55.49 | 13.60 | 154 | .47 | 1.34 | |||||||||
| 12/31/2019 | 45.47 | .91 | 10.43 | 11.34 | (.84 | ) | (5.16 | ) | (6.00 | ) | 50.81 | 26.24 | 156 | .46 | 1.87 | |||||||||
| 12/31/2018 | 50.29 | .75 | (1.25 | ) | (.50 | ) | (.74 | ) | (3.58 | ) | (4.32 | ) | 45.47 | (1.72 | ) | 140 | .46 | 1.47 | ||||||
| 12/31/2017 | 44.47 | .72 | 8.90 | 9.62 | (.69 | ) | (3.11 | ) | (3.80 | ) | 50.29 | 22.47 | 168 | .46 | 1.52 | |||||||||
| Class 4: | ||||||||||||||||||||||||
| 12/31/2021 | 53.99 | .48 | 12.28 | 12.76 | (.58 | ) | (.60 | ) | (1.18 | ) | 65.57 | 23.80 | 1,928 | .79 | .79 | |||||||||
| 12/31/2020 | 49.52 | .49 | 5.85 | 6.34 | (.57 | ) | (1.30 | ) | (1.87 | ) | 53.99 | 13.25 | 1,407 | .79 | 1.02 | |||||||||
| 12/31/2019 | 44.47 | .74 | 10.18 | 10.92 | (.71 | ) | (5.16 | ) | (5.87 | ) | 49.52 | 25.86 | 1,216 | .79 | 1.56 | |||||||||
| 12/31/2018 | 49.31 | .58 | (1.23 | ) | (.65 | ) | (.61 | ) | (3.58 | ) | (4.19 | ) | 44.47 | (2.05 | ) | 899 | .78 | 1.15 | ||||||
| 12/31/2017 | 43.73 | .56 | 8.73 | 9.29 | (.60 | ) | (3.11 | ) | (3.71 | ) | 49.31 | 22.08 | 827 | .78 | 1.19 | |||||||||
23 American Funds Insurance Series / Prospectus
| Income
(loss) from investment operations1 |
Dividends and distributions | |||||||||||||||||||||||||
| Period ended | Net
asset value, beginning of period |
Net investment income |
Net
gains (losses) on securities (both realized and unrealized) |
Total
from investment operations |
Dividends (from net investment income) |
Distributions (from capital gains) |
Total dividends and distributions |
Net
asset value, end of period |
Total return2 |
Net
assets, end of period (in millions) |
Ratio
of expenses to average net assets before waivers3 |
Ratio
of expenses to average net assets after waivers2,3 |
Ratio
of net income to average net assets2 | |||||||||||||
| Washington Mutual Investors Fund | ||||||||||||||||||||||||||
| Class 1: | ||||||||||||||||||||||||||
| 12/31/2021 | $14.35 | $.29 | $3.73 | $4.02 | $(.28 | ) | $— | $(.28 | ) | $18.09 | 28.12 | % | $6,766 | .42 | % | .31 | % | 1.79 | % | |||||||
| 12/31/2020 | 13.56 | .25 | .95 | 1.20 | (.26 | ) | (.15 | ) | (.41 | ) | 14.35 | 9.04 | 5,684 | .43 | .43 | 2.00 | ||||||||||
| 12/31/2019 | 12.38 | .30 | 2.25 | 2.55 | (.30 | ) | (1.07 | ) | (1.37 | ) | 13.56 | 21.66 | 5,559 | .42 | .42 | 2.28 | ||||||||||
| 12/31/2018 | 14.96 | .31 | (1.44 | ) | (1.13 | ) | (.31 | ) | (1.14 | ) | (1.45 | ) | 12.38 | (8.45 | ) | 4,810 | .41 | .41 | 2.13 | |||||||
| 12/31/2017 | 13.53 | .32 | 1.96 | 2.28 | (.32 | ) | (.53 | ) | (.85 | ) | 14.96 | 17.30 | 5,581 | .41 | .41 | 2.27 | ||||||||||
| Class 1A: | ||||||||||||||||||||||||||
| 12/31/2021 | 14.28 | .27 | 3.67 | 3.94 | (.26 | ) | — | (.26 | ) | 17.96 | 27.70 | 169 | .67 | .53 | 1.62 | |||||||||||
| 12/31/2020 | 13.51 | .23 | .93 | 1.16 | (.24 | ) | (.15 | ) | (.39 | ) | 14.28 | 8.79 | 25 | .67 | .67 | 1.78 | ||||||||||
| 12/31/2019 | 12.35 | .26 | 2.24 | 2.50 | (.27 | ) | (1.07 | ) | (1.34 | ) | 13.51 | 21.35 | 9 | .67 | .67 | 2.03 | ||||||||||
| 12/31/2018 | 14.94 | .26 | (1.42 | ) | (1.16 | ) | (.29 | ) | (1.14 | ) | (1.43 | ) | 12.35 | (8.67 | ) | 3 | .66 | .66 | 1.84 | |||||||
| 12/31/20174,5 | 13.75 | .28 | 1.75 | 2.03 | (.31 | ) | (.53 | ) | (.84 | ) | 14.94 | 15.21 | 6 | 1 | .65 | 7 | .65 | 7 | 2.01 | 7 | ||||||
| Class 2: | ||||||||||||||||||||||||||
| 12/31/2021 | 14.15 | .25 | 3.67 | 3.92 | (.24 | ) | — | (.24 | ) | 17.83 | 27.78 | 3,426 | .67 | .56 | 1.54 | |||||||||||
| 12/31/2020 | 13.39 | .22 | .91 | 1.13 | (.22 | ) | (.15 | ) | (.37 | ) | 14.15 | 8.68 | 3,082 | .68 | .68 | 1.75 | ||||||||||
| 12/31/2019 | 12.24 | .26 | 2.22 | 2.48 | (.26 | ) | (1.07 | ) | (1.33 | ) | 13.39 | 21.38 | 3,093 | .67 | .67 | 2.03 | ||||||||||
| 12/31/2018 | 14.80 | .27 | (1.42 | ) | (1.15 | ) | (.27 | ) | (1.14 | ) | (1.41 | ) | 12.24 | (8.66 | ) | 2,850 | .66 | .66 | 1.88 | |||||||
| 12/31/2017 | 13.39 | .28 | 1.94 | 2.22 | (.28 | ) | (.53 | ) | (.81 | ) | 14.80 | 17.04 | 3,551 | .66 | .66 | 2.02 | ||||||||||
| Class 4: | ||||||||||||||||||||||||||
| 12/31/2021 | 14.06 | .21 | 3.65 | 3.86 | (.21 | ) | — | (.21 | ) | 17.71 | 27.51 | 1,104 | .92 | .81 | 1.30 | |||||||||||
| 12/31/2020 | 13.31 | .19 | .91 | 1.10 | (.20 | ) | (.15 | ) | (.35 | ) | 14.06 | 8.47 | 788 | .93 | .93 | 1.51 | ||||||||||
| 12/31/2019 | 12.19 | .23 | 2.20 | 2.43 | (.24 | ) | (1.07 | ) | (1.31 | ) | 13.31 | 21.03 | 621 | .92 | .92 | 1.78 | ||||||||||
| 12/31/2018 | 14.77 | .23 | (1.42 | ) | (1.19 | ) | (.25 | ) | (1.14 | ) | (1.39 | ) | 12.19 | (8.92 | ) | 368 | .91 | .91 | 1.62 | |||||||
| 12/31/2017 | 13.39 | .25 | 1.93 | 2.18 | (.27 | ) | (.53 | ) | (.80 | ) | 14.77 | 16.70 | 247 | .91 | .91 | 1.76 | ||||||||||
| Income
(loss) from investment operations1 |
Dividends and distributions | |||||||||||||||||||||||||
| Period ended | Net
asset value, beginning of period |
Net investment income |
Net
gains (losses) on securities (both realized and unrealized) |
Total
from investment operations |
Dividends (from net investment income) |
Distributions (from capital gains) |
Total dividends and distributions |
Net
asset value, end of period |
Total return2 |
Net
assets, end of period (in millions) |
Ratio
of expenses to average net assets before waivers3 |
Ratio
of expenses to average net assets after waivers2,3 |
Ratio
of net income to average net assets2 | |||||||||||||
| Capital Income Builder | ||||||||||||||||||||||||||
| Class 1: | ||||||||||||||||||||||||||
| 12/31/2021 | $10.87 | $.37 | $1.28 | $1.65 | $(.35 | ) | $— | $(.35 | ) | $12.17 | 15.31 | % | $563 | .53 | % | .27 | % | 3.19 | % | |||||||
| 12/31/2020 | 10.73 | .31 | .15 | .46 | (.32 | ) | — | (.32 | ) | 10.87 | 4.64 | 621 | .53 | .35 | 3.07 | |||||||||||
| 12/31/2019 | 9.37 | .32 | 1.36 | 1.68 | (.32 | ) | — | (.32 | ) | 10.73 | 18.16 | 533 | .53 | .53 | 3.17 | |||||||||||
| 12/31/2018 | 10.40 | .31 | (1.00 | ) | (.69 | ) | (.32 | ) | (.02 | ) | (.34 | ) | 9.37 | (6.77 | ) | 317 | .54 | .54 | 3.08 | |||||||
| 12/31/2017 | 9.46 | .32 | .93 | 1.25 | (.31 | ) | — | (.31 | ) | 10.40 | 13.29 | 254 | .54 | .54 | 3.21 | |||||||||||
| Class 1A: | ||||||||||||||||||||||||||
| 12/31/2021 | 10.86 | .34 | 1.27 | 1.61 | (.32 | ) | — | (.32 | ) | 12.15 | 14.95 | 10 | .78 | .52 | 2.94 | |||||||||||
| 12/31/2020 | 10.72 | .28 | .16 | .44 | (.30 | ) | — | (.30 | ) | 10.86 | 4.38 | 6 | .78 | .60 | 2.81 | |||||||||||
| 12/31/2019 | 9.36 | .29 | 1.37 | 1.66 | (.30 | ) | — | (.30 | ) | 10.72 | 17.90 | 6 | .78 | .78 | 2.84 | |||||||||||
| 12/31/2018 | 10.39 | .28 | (.99 | ) | (.71 | ) | (.30 | ) | (.02 | ) | (.32 | ) | 9.36 | (7.01 | ) | 2 | .79 | .79 | 2.82 | |||||||
| 12/31/20174,5 | 9.57 | .27 | .84 | 1.11 | (.29 | ) | — | (.29 | ) | 10.39 | 11.72 | 6 | 1 | .79 | 7 | .79 | 7 | 2.63 | 7 | |||||||
| Class 2: | ||||||||||||||||||||||||||
| 12/31/2021 | 10.87 | .34 | 1.27 | 1.61 | (.32 | ) | — | (.32 | ) | 12.16 | 14.94 | 13 | .78 | .52 | 2.93 | |||||||||||
| 12/31/2020 | 10.72 | .29 | .16 | .45 | (.30 | ) | — | (.30 | ) | 10.87 | 4.48 | 8 | .78 | .60 | 2.83 | |||||||||||
| 12/31/2019 | 9.36 | .30 | 1.35 | 1.65 | (.29 | ) | — | (.29 | ) | 10.72 | 17.89 | 6 | .78 | .78 | 2.91 | |||||||||||
| 12/31/2018 | 10.40 | .28 | (1.00 | ) | (.72 | ) | (.30 | ) | (.02 | ) | (.32 | ) | 9.36 | (7.08 | ) | 4 | .79 | .79 | 2.83 | |||||||
| 12/31/2017 | 9.46 | .29 | .93 | 1.22 | (.28 | ) | — | (.28 | ) | 10.40 | 13.04 | 1 | .79 | .79 | 2.82 | |||||||||||
| Class 4: | ||||||||||||||||||||||||||
| 12/31/2021 | 10.85 | .31 | 1.27 | 1.58 | (.29 | ) | — | (.29 | ) | 12.14 | 14.68 | 559 | 1.03 | .77 | 2.69 | |||||||||||
| 12/31/2020 | 10.71 | .26 | .15 | .41 | (.27 | ) | — | (.27 | ) | 10.85 | 4.11 | 462 | 1.03 | .85 | 2.55 | |||||||||||
| 12/31/2019 | 9.35 | .27 | 1.36 | 1.63 | (.27 | ) | — | (.27 | ) | 10.71 | 17.62 | 454 | 1.03 | 1.03 | 2.68 | |||||||||||
| 12/31/2018 | 10.38 | .26 | (1.00 | ) | (.74 | ) | (.27 | ) | (.02 | ) | (.29 | ) | 9.35 | (7.25 | ) | 352 | 1.04 | 1.04 | 2.58 | |||||||
| 12/31/2017 | 9.45 | .27 | .92 | 1.19 | (.26 | ) | — | (.26 | ) | 10.38 | 12.65 | 338 | 1.04 | 1.04 | 2.72 | |||||||||||
American Funds Insurance Series / Prospectus 24
| Income
(loss) from investment operations1 |
Dividends and distributions | |||||||||||||||||||||||
| Period ended | Net
asset value, beginning of period |
Net investment income |
Net
gains (losses) on securities (both realized and unrealized) |
Total
from investment operations |
Dividends (from net investment income) |
Distributions (from capital gains) |
Total dividends and distributions |
Net
asset value, end of period |
Total return |
Net
assets, end of period (in millions) |
Ratio
of expenses to average net assets3 |
Ratio
of net income to average net assets | ||||||||||||
| Asset Allocation Fund | ||||||||||||||||||||||||
| Class 1: | ||||||||||||||||||||||||
| 12/31/2021 | $26.50 | $.48 | $3.54 | $4.02 | $(.50 | ) | $(.94 | ) | $(1.44 | ) | $29.08 | 15.40 | % | $18,836 | .30 | % | 1.71 | % | ||||||
| 12/31/2020 | 24.05 | .43 | 2.59 | 3.02 | (.46 | ) | (.11 | ) | (.57 | ) | 26.50 | 12.71 | 19,238 | .30 | 1.80 | |||||||||
| 12/31/2019 | 21.29 | .51 | 3.94 | 4.45 | (.50 | ) | (1.19 | ) | (1.69 | ) | 24.05 | 21.54 | 17,730 | .29 | 2.21 | |||||||||
| 12/31/2018 | 23.71 | .48 | (1.43 | ) | (.95 | ) | (.44 | ) | (1.03 | ) | (1.47 | ) | 21.29 | (4.35 | ) | 14,627 | .28 | 2.04 | ||||||
| 12/31/2017 | 21.68 | .44 | 3.06 | 3.50 | (.41 | ) | (1.06 | ) | (1.47 | ) | 23.71 | 16.51 | 16,556 | .29 | 1.90 | |||||||||
| Class 1A: | ||||||||||||||||||||||||
| 12/31/2021 | 26.42 | .42 | 3.52 | 3.94 | (.45 | ) | (.94 | ) | (1.39 | ) | 28.97 | 15.13 | 24 | .55 | 1.49 | |||||||||
| 12/31/2020 | 23.99 | .37 | 2.58 | 2.95 | (.41 | ) | (.11 | ) | (.52 | ) | 26.42 | 12.43 | 14 | .55 | 1.56 | |||||||||
| 12/31/2019 | 21.26 | .45 | 3.92 | 4.37 | (.45 | ) | (1.19 | ) | (1.64 | ) | 23.99 | 21.19 | 11 | .54 | 1.95 | |||||||||
| 12/31/2018 | 23.69 | .42 | (1.42 | ) | (1.00 | ) | (.40 | ) | (1.03 | ) | (1.43 | ) | 21.26 | (4.58 | ) | 7 | .53 | 1.82 | ||||||
| 12/31/20174,5 | 21.97 | .39 | 2.78 | 3.17 | (.39 | ) | (1.06 | ) | (1.45 | ) | 23.69 | 14.78 | 6 | 4 | .53 | 7 | 1.69 | 7 | ||||||
| Class 2: | ||||||||||||||||||||||||
| 12/31/2021 | 26.21 | .41 | 3.49 | 3.90 | (.43 | ) | (.94 | ) | (1.37 | ) | 28.74 | 15.10 | 5,473 | .55 | 1.46 | |||||||||
| 12/31/2020 | 23.79 | .37 | 2.56 | 2.93 | (.40 | ) | (.11 | ) | (.51 | ) | 26.21 | 12.46 | 5,242 | .55 | 1.55 | |||||||||
| 12/31/2019 | 21.08 | .45 | 3.89 | 4.34 | (.44 | ) | (1.19 | ) | (1.63 | ) | 23.79 | 21.23 | 5,154 | .54 | 1.96 | |||||||||
| 12/31/2018 | 23.49 | .41 | (1.41 | ) | (1.00 | ) | (.38 | ) | (1.03 | ) | (1.41 | ) | 21.08 | (4.60 | ) | 4,668 | .53 | 1.78 | ||||||
| 12/31/2017 | 21.49 | .37 | 3.04 | 3.41 | (.35 | ) | (1.06 | ) | (1.41 | ) | 23.49 | 16.23 | 5,480 | .54 | 1.64 | |||||||||
| Class 3: | ||||||||||||||||||||||||
| 12/31/2021 | 26.53 | .43 | 3.55 | 3.98 | (.45 | ) | (.94 | ) | (1.39 | ) | 29.12 | 15.22 | 36 | .48 | 1.53 | |||||||||
| 12/31/2020 | 24.08 | .39 | 2.59 | 2.98 | (.42 | ) | (.11 | ) | (.53 | ) | 26.53 | 12.50 | 33 | .48 | 1.62 | |||||||||
| 12/31/2019 | 21.32 | .47 | 3.93 | 4.40 | (.45 | ) | (1.19 | ) | (1.64 | ) | 24.08 | 21.30 | 32 | .47 | 2.02 | |||||||||
| 12/31/2018 | 23.73 | .43 | (1.41 | ) | (.98 | ) | (.40 | ) | (1.03 | ) | (1.43 | ) | 21.32 | (4.49 | ) | 29 | .46 | 1.85 | ||||||
| 12/31/2017 | 21.70 | .39 | 3.07 | 3.46 | (.37 | ) | (1.06 | ) | (1.43 | ) | 23.73 | 16.29 | 38 | .47 | 1.72 | |||||||||
| Class 4: | ||||||||||||||||||||||||
| 12/31/2021 | 26.06 | .34 | 3.47 | 3.81 | (.37 | ) | (.94 | ) | (1.31 | ) | 28.56 | 14.84 | 6,337 | .80 | 1.22 | |||||||||
| 12/31/2020 | 23.67 | .31 | 2.54 | 2.85 | (.35 | ) | (.11 | ) | (.46 | ) | 26.06 | 12.16 | 5,131 | .80 | 1.30 | |||||||||
| 12/31/2019 | 20.99 | .39 | 3.87 | 4.26 | (.39 | ) | (1.19 | ) | (1.58 | ) | 23.67 | 20.92 | 4,493 | .79 | 1.71 | |||||||||
| 12/31/2018 | 23.40 | .35 | (1.40 | ) | (1.05 | ) | (.33 | ) | (1.03 | ) | (1.36 | ) | 20.99 | (4.83 | ) | 3,594 | .78 | 1.54 | ||||||
| 12/31/2017 | 21.43 | .32 | 3.02 | 3.34 | (.31 | ) | (1.06 | ) | (1.37 | ) | 23.40 | 15.91 | 3,582 | .79 | 1.40 | |||||||||
| Income
(loss) from investment operations1 |
Dividends and distributions | |||||||||||||||||||||||
| Period ended | Net
asset value, beginning of period |
Net investment income |
Net
gains (losses) on securities (both realized and unrealized) |
Total
from investment operations |
Dividends (from net investment income) |
Distributions (from capital gains) |
Total dividends and distributions |
Net
asset value, end of period |
Total return |
Net
assets, end of period (in millions) |
Ratio
of expenses to average net assets3 |
Ratio
of net income to average net assets | ||||||||||||
| American Funds Global Balanced Fund | ||||||||||||||||||||||||
| Class 1: | ||||||||||||||||||||||||
| 12/31/2021 | $14.19 | $.18 | $1.37 | $1.55 | $(.19 | ) | $(.82 | ) | $(1.01 | ) | $14.73 | 11.05 | % | $120 | .73 | % | 1.24 | % | ||||||
| 12/31/2020 | 13.51 | .17 | 1.24 | 1.41 | (.19 | ) | (.54 | ) | (.73 | ) | 14.19 | 10.53 | 139 | .72 | 1.29 | |||||||||
| 12/31/2019 | 11.67 | .24 | 2.17 | 2.41 | (.20 | ) | (.37 | ) | (.57 | ) | 13.51 | 20.79 | 134 | .72 | 1.88 | |||||||||
| 12/31/2018 | 12.75 | .23 | (.96 | ) | (.73 | ) | (.20 | ) | (.15 | ) | (.35 | ) | 11.67 | (5.81 | ) | 110 | .72 | 1.82 | ||||||
| 12/31/2017 | 11.08 | .21 | 1.99 | 2.20 | (.15 | ) | (.38 | ) | (.53 | ) | 12.75 | 19.91 | 93 | .72 | 1.68 | |||||||||
| Class 1A: | ||||||||||||||||||||||||
| 12/31/2021 | 14.16 | .15 | 1.36 | 1.51 | (.15 | ) | (.82 | ) | (.97 | ) | 14.70 | 10.83 | 4 | .98 | 1.02 | |||||||||
| 12/31/2020 | 13.49 | .14 | 1.23 | 1.37 | (.16 | ) | (.54 | ) | (.70 | ) | 14.16 | 10.25 | 3 | .97 | 1.03 | |||||||||
| 12/31/2019 | 11.65 | .21 | 2.17 | 2.38 | (.17 | ) | (.37 | ) | (.54 | ) | 13.49 | 20.54 | 2 | .97 | 1.63 | |||||||||
| 12/31/2018 | 12.74 | .18 | (.94 | ) | (.76 | ) | (.18 | ) | (.15 | ) | (.33 | ) | 11.65 | (6.03 | ) | 2 | .98 | 1.44 | ||||||
| 12/31/20174,5 | 11.18 | .16 | 1.92 | 2.08 | (.14 | ) | (.38 | ) | (.52 | ) | 12.74 | 18.71 | 6 | — | 8 | .94 | 7 | 1.27 | 7 | |||||
| Class 2: | ||||||||||||||||||||||||
| 12/31/2021 | 14.16 | .15 | 1.36 | 1.51 | (.15 | ) | (.82 | ) | (.97 | ) | 14.70 | 10.79 | 208 | .98 | 1.01 | |||||||||
| 12/31/2020 | 13.48 | .14 | 1.23 | 1.37 | (.15 | ) | (.54 | ) | (.69 | ) | 14.16 | 10.30 | 208 | .97 | 1.03 | |||||||||
| 12/31/2019 | 11.65 | .21 | 2.16 | 2.37 | (.17 | ) | (.37 | ) | (.54 | ) | 13.48 | 20.44 | 207 | .97 | 1.64 | |||||||||
| 12/31/2018 | 12.72 | .20 | (.96 | ) | (.76 | ) | (.16 | ) | (.15 | ) | (.31 | ) | 11.65 | (6.01 | ) | 185 | .97 | 1.57 | ||||||
| 12/31/2017 | 11.06 | .18 | 1.98 | 2.16 | (.12 | ) | (.38 | ) | (.50 | ) | 12.72 | 19.57 | 210 | .96 | 1.43 | |||||||||
| Class 4: | ||||||||||||||||||||||||
| 12/31/2021 | 14.02 | .11 | 1.34 | 1.45 | (.12 | ) | (.82 | ) | (.94 | ) | 14.53 | 10.46 | 135 | 1.23 | .77 | |||||||||
| 12/31/2020 | 13.36 | .10 | 1.22 | 1.32 | (.12 | ) | (.54 | ) | (.66 | ) | 14.02 | 10.00 | 105 | 1.22 | .78 | |||||||||
| 12/31/2019 | 11.55 | .18 | 2.14 | 2.32 | (.14 | ) | (.37 | ) | (.51 | ) | 13.36 | 20.21 | 94 | 1.22 | 1.37 | |||||||||
| 12/31/2018 | 12.63 | .17 | (.96 | ) | (.79 | ) | (.14 | ) | (.15 | ) | (.29 | ) | 11.55 | (6.31 | ) | 69 | 1.22 | 1.34 | ||||||
| 12/31/2017 | 11.00 | .13 | 1.99 | 2.12 | (.11 | ) | (.38 | ) | (.49 | ) | 12.63 | 19.38 | 51 | 1.22 | 1.07 | |||||||||
25 American Funds Insurance Series / Prospectus
| Income
(loss) from investment operations1 |
Dividends and distributions | |||||||||||||||||||||||||
| Period ended | Net
asset value, beginning of year |
Net investment income (loss) |
Net
gains (losses) on securities (both realized and unrealized) |
Total
from investment operations |
Dividends (from net investment income) |
Distributions (from capital gains) |
Total dividends and distributions |
Net
asset value, end of year |
Total return2 |
Net
assets, end of year (in millions) |
Ratio
of expenses to average net assets before reimbursements |
Ratio
of expenses to average net assets after reimbursements2 |
Ratio
of net income (loss) to average net assets2 | |||||||||||||
| American Funds Mortgage Fund | ||||||||||||||||||||||||||
| Class 1: | ||||||||||||||||||||||||||
| 12/31/2021 | $11.11 | $.06 | $(.09 | ) | $(.03 | ) | $(.08 | ) | $(.37 | ) | $(.45 | ) | $10.63 | (.32 | )% | $231 | .49 | % | .29 | % | .58 | % | ||||
| 12/31/2020 | 10.56 | .10 | .64 | .74 | (.17 | ) | (.02 | ) | (.19 | ) | 11.11 | 6.98 | 224 | .48 | .36 | .93 | ||||||||||
| 12/31/2019 | 10.30 | .24 | .30 | .54 | (.28 | ) | — | (.28 | ) | 10.56 | 5.30 | 210 | .47 | .47 | 2.26 | |||||||||||
| 12/31/2018 | 10.47 | .20 | (.14 | ) | .06 | (.23 | ) | — | (.23 | ) | 10.30 | .58 | 209 | .48 | .48 | 1.97 | ||||||||||
| 12/31/2017 | 10.56 | .16 | — | 9 | .16 | (.18 | ) | (.07 | ) | (.25 | ) | 10.47 | 1.47 | 265 | .47 | .47 | 1.52 | |||||||||
| Class 1A: | ||||||||||||||||||||||||||
| 12/31/2021 | 11.08 | .04 | (.10 | ) | (.06 | ) | (.06 | ) | (.37 | ) | (.43 | ) | 10.59 | (.47 | ) | 2 | .74 | .54 | .33 | |||||||
| 12/31/2020 | 10.55 | .07 | .63 | .70 | (.15 | ) | (.02 | ) | (.17 | ) | 11.08 | 6.63 | 1 | .73 | .59 | .61 | ||||||||||
| 12/31/2019 | 10.28 | .22 | .30 | .52 | (.25 | ) | — | (.25 | ) | 10.55 | 5.09 | 1 | .71 | .71 | 2.04 | |||||||||||
| 12/31/2018 | 10.46 | .18 | (.14 | ) | .04 | (.22 | ) | — | (.22 | ) | 10.28 | .36 | 1 | .73 | .73 | 1.77 | ||||||||||
| 12/31/20175 | 10.55 | .14 | — | 9 | .14 | (.16 | ) | (.07 | ) | (.23 | ) | 10.46 | 1.31 | 6 | — | 8 | .70 | 7 | .70 | 7 | 1.38 | 7 | ||||
| Class 2: | ||||||||||||||||||||||||||
| 12/31/2021 | 11.09 | .04 | (.10 | ) | (.06 | ) | (.05 | ) | (.37 | ) | (.42 | ) | 10.61 | (.57 | ) | 58 | .74 | .54 | .33 | |||||||
| 12/31/2020 | 10.54 | .08 | .63 | .71 | (.14 | ) | (.02 | ) | (.16 | ) | 11.09 | 6.72 | 58 | .73 | .60 | .68 | ||||||||||
| 12/31/2019 | 10.28 | .21 | .31 | .52 | (.26 | ) | — | (.26 | ) | 10.54 | 5.04 | 56 | .72 | .72 | 2.01 | |||||||||||
| 12/31/2018 | 10.45 | .18 | (.15 | ) | .03 | (.20 | ) | — | (.20 | ) | 10.28 | .32 | 57 | .73 | .73 | 1.72 | ||||||||||
| 12/31/2017 | 10.54 | .14 | (.01 | ) | .13 | (.15 | ) | (.07 | ) | (.22 | ) | 10.45 | 1.22 | 63 | .72 | .72 | 1.27 | |||||||||
| Class 4: | ||||||||||||||||||||||||||
| 12/31/2021 | 10.97 | .01 | (.09 | ) | (.08 | ) | (.03 | ) | (.37 | ) | (.40 | ) | 10.49 | (.78 | ) | 43 | .99 | .79 | .08 | |||||||
| 12/31/2020 | 10.44 | .04 | .63 | .67 | (.12 | ) | (.02 | ) | (.14 | ) | 10.97 | 6.38 | 37 | .98 | .85 | .41 | ||||||||||
| 12/31/2019 | 10.19 | .18 | .31 | .49 | (.24 | ) | — | (.24 | ) | 10.44 | 4.80 | 28 | .97 | .97 | 1.71 | |||||||||||
| 12/31/2018 | 10.38 | .15 | (.15 | ) | — | 9 | (.19 | ) | — | (.19 | ) | 10.19 | .07 | 24 | .98 | .98 | 1.49 | |||||||||
| 12/31/2017 | 10.48 | .11 | — | 9 | .11 | (.14 | ) | (.07 | ) | (.21 | ) | 10.38 | .97 | 12 | .97 | .97 | 1.03 | |||||||||
| Income
(loss) from investment operations1 |
Dividends and distributions | |||||||||||||||||||||||||
| Period ended | Net
asset value, beginning of period |
Net investment income |
Net
gains (losses) on securities (both realized and unrealized) |
Total
from investment operations |
Dividends (from net investment income) |
Distributions (from capital gains) |
Total dividends and distributions |
Net
asset value, end of period |
Total return2 |
Net
assets, end of period (in millions) |
Ratio
of expenses to average net assets before waivers3 |
Ratio
of expenses to average net assets after waivers2,3 |
Ratio
of net income to average net assets2 | |||||||||||||
| American High-Income Trust | ||||||||||||||||||||||||||
| Class 1: | ||||||||||||||||||||||||||
| 12/31/2021 | $9.80 | $.51 | $.34 | $.85 | $(.46 | ) | $— | $(.46 | ) | $10.19 | 8.74 | % | $278 | .53 | % | .37 | % | 4.95 | % | |||||||
| 12/31/2020 | 9.87 | .61 | .17 | .78 | (.85 | ) | — | (.85 | ) | 9.80 | 8.21 | 123 | .52 | .52 | 6.46 | |||||||||||
| 12/31/2019 | 9.34 | .67 | .52 | 1.19 | (.66 | ) | — | (.66 | ) | 9.87 | 12.85 | 525 | .51 | .51 | 6.71 | |||||||||||
| 12/31/2018 | 10.19 | .64 | (.84 | ) | (.20 | ) | (.65 | ) | — | (.65 | ) | 9.34 | (2.15 | ) | 501 | .50 | .50 | 6.32 | ||||||||
| 12/31/2017 | 10.18 | .63 | .10 | .73 | (.72 | ) | — | (.72 | ) | 10.19 | 7.25 | 632 | .49 | .49 | 5.98 | |||||||||||
| Class 1A: | ||||||||||||||||||||||||||
| 12/31/2021 | 9.78 | .49 | .33 | .82 | (.44 | ) | — | (.44 | ) | 10.16 | 8.42 | 1 | .78 | .64 | 4.75 | |||||||||||
| 12/31/2020 | 9.86 | .56 | .20 | .76 | (.84 | ) | — | (.84 | ) | 9.78 | 7.94 | 1 | .78 | .78 | 5.85 | |||||||||||
| 12/31/2019 | 9.33 | .65 | .51 | 1.16 | (.63 | ) | — | (.63 | ) | 9.86 | 12.61 | 1 | .75 | .75 | 6.47 | |||||||||||
| 12/31/2018 | 10.18 | .62 | (.84 | ) | (.22 | ) | (.63 | ) | — | (.63 | ) | 9.33 | (2.35 | ) | 1 | .75 | .75 | 6.11 | ||||||||
| 12/31/20174,5 | 10.28 | .60 | .02 | .62 | (.72 | ) | — | (.72 | ) | 10.18 | 6.02 | 6 | — | 8 | .72 | 7 | .72 | 7 | 5.74 | 7 | ||||||
| Class 2: | ||||||||||||||||||||||||||
| 12/31/2021 | 9.61 | .48 | .33 | .81 | (.44 | ) | — | (.44 | ) | 9.98 | 8.42 | 673 | .78 | .65 | 4.80 | |||||||||||
| 12/31/2020 | 9.70 | .55 | .19 | .74 | (.83 | ) | — | (.83 | ) | 9.61 | 7.94 | 665 | .78 | .78 | 5.88 | |||||||||||
| 12/31/2019 | 9.19 | .64 | .50 | 1.14 | (.63 | ) | — | (.63 | ) | 9.70 | 12.55 | 667 | .76 | .76 | 6.45 | |||||||||||
| 12/31/2018 | 10.03 | .61 | (.83 | ) | (.22 | ) | (.62 | ) | — | (.62 | ) | 9.19 | (2.34 | ) | 661 | .75 | .75 | 6.07 | ||||||||
| 12/31/2017 | 10.04 | .59 | .10 | .69 | (.70 | ) | — | (.70 | ) | 10.03 | 6.89 | 776 | .74 | .74 | 5.72 | |||||||||||
| Class 3: | ||||||||||||||||||||||||||
| 12/31/2021 | 9.84 | .50 | .34 | .84 | (.44 | ) | — | (.44 | ) | 10.24 | 8.60 | 10 | .71 | .58 | 4.86 | |||||||||||
| 12/31/2020 | 9.92 | .57 | .19 | .76 | (.84 | ) | — | (.84 | ) | 9.84 | 7.93 | 10 | .71 | .71 | 5.94 | |||||||||||
| 12/31/2019 | 9.38 | .66 | .52 | 1.18 | (.64 | ) | — | (.64 | ) | 9.92 | 12.70 | 10 | .69 | .69 | 6.52 | |||||||||||
| 12/31/2018 | 10.23 | .63 | (.85 | ) | (.22 | ) | (.63 | ) | — | (.63 | ) | 9.38 | (2.33 | ) | 10 | .68 | .68 | 6.14 | ||||||||
| 12/31/2017 | 10.22 | .61 | .10 | .71 | (.70 | ) | — | (.70 | ) | 10.23 | 7.02 | 12 | .67 | .67 | 5.79 | |||||||||||
| Class 4: | ||||||||||||||||||||||||||
| 12/31/2021 | 10.54 | .50 | .36 | .86 | (.41 | ) | — | (.41 | ) | 10.99 | 8.18 | 90 | 1.03 | .89 | 4.52 | |||||||||||
| 12/31/2020 | 10.56 | .57 | .22 | .79 | (.81 | ) | — | (.81 | ) | 10.54 | 7.74 | 69 | 1.03 | 1.03 | 5.58 | |||||||||||
| 12/31/2019 | 9.96 | .67 | .54 | 1.21 | (.61 | ) | — | (.61 | ) | 10.56 | 12.27 | 63 | 1.01 | 1.01 | 6.21 | |||||||||||
| 12/31/2018 | 10.82 | .63 | (.90 | ) | (.27 | ) | (.59 | ) | — | (.59 | ) | 9.96 | (2.64 | ) | 31 | 1.00 | 1.00 | 5.83 | ||||||||
| 12/31/2017 | 10.79 | .61 | .10 | .71 | (.68 | ) | — | (.68 | ) | 10.82 | 6.63 | 34 | .99 | .99 | 5.46 | |||||||||||
American Funds Insurance Series / Prospectus 26
| (Loss)
income from investment operations1 |
Dividends and distributions | |||||||||||||||||||||||||
| Period ended | Net
asset value, beginning of period |
Net investment income |
Net
(losses) gains on securities (both realized and unrealized) |
Total
from investment operations |
Dividends (from net investment income) |
Distributions (from capital gains) |
Total dividends and distributions |
Net
asset value, end of period |
Total return2 |
Net
assets, end of period (in millions) |
Ratio
of expenses to average net assets before waivers3 |
Ratio
of expenses to average net assets after waivers2,3 |
Ratio
of net income to average net assets2 | |||||||||||||
| Capital World Bond Fund | ||||||||||||||||||||||||||
| Class 1: | ||||||||||||||||||||||||||
| 12/31/2021 | $12.94 | $.25 | $(.85 | ) | $(.60 | ) | $(.24 | ) | $(.31 | ) | $(.55 | ) | $11.79 | (4.73 | )% | $988 | .60 | % | .50 | % | 2.06 | % | ||||
| 12/31/2020 | 12.12 | .26 | .95 | 1.21 | (.18 | ) | (.21 | ) | (.39 | ) | 12.94 | 10.17 | 1,219 | .59 | .52 | 2.08 | ||||||||||
| 12/31/2019 | 11.42 | .31 | .61 | .92 | (.22 | ) | — | (.22 | ) | 12.12 | 8.08 | 1,077 | .58 | .58 | 2.60 | |||||||||||
| 12/31/2018 | 11.88 | .30 | (.44 | ) | (.14 | ) | (.28 | ) | (.04 | ) | (.32 | ) | 11.42 | (1.14 | ) | 1,015 | .57 | .57 | 2.56 | |||||||
| 12/31/2017 | 11.22 | .28 | .52 | .80 | (.07 | ) | (.07 | ) | (.14 | ) | 11.88 | 7.11 | 1,273 | .56 | .56 | 2.37 | ||||||||||
| Class 1A: | ||||||||||||||||||||||||||
| 12/31/2021 | 12.91 | .23 | (.85 | ) | (.62 | ) | (.22 | ) | (.31 | ) | (.53 | ) | 11.76 | (4.88 | ) | 1 | .85 | .75 | 1.85 | |||||||
| 12/31/2020 | 12.10 | .23 | .95 | 1.18 | (.16 | ) | (.21 | ) | (.37 | ) | 12.91 | 9.89 | 1 | .83 | .76 | 1.83 | ||||||||||
| 12/31/2019 | 11.41 | .28 | .60 | .88 | (.19 | ) | — | (.19 | ) | 12.10 | 7.75 | 1 | .83 | .83 | 2.35 | |||||||||||
| 12/31/2018 | 11.87 | .27 | (.43 | ) | (.16 | ) | (.26 | ) | (.04 | ) | (.30 | ) | 11.41 | (1.29 | ) | 1 | .82 | .82 | 2.36 | |||||||
| 12/31/20174,5 | 11.22 | .26 | .52 | .78 | (.06 | ) | (.07 | ) | (.13 | ) | 11.87 | 7.00 | 6 | — | 8 | .72 | 7 | .72 | 7 | 2.27 | 7 | |||||
| Class 2: | ||||||||||||||||||||||||||
| 12/31/2021 | 12.84 | .22 | (.84 | ) | (.62 | ) | (.21 | ) | (.31 | ) | (.52 | ) | 11.70 | (4.92 | ) | 1,030 | .85 | .75 | 1.82 | |||||||
| 12/31/2020 | 12.03 | .22 | .95 | 1.17 | (.15 | ) | (.21 | ) | (.36 | ) | 12.84 | 9.90 | 1,058 | .84 | .77 | 1.83 | ||||||||||
| 12/31/2019 | 11.34 | .28 | .60 | .88 | (.19 | ) | — | (.19 | ) | 12.03 | 7.77 | 1,002 | .83 | .83 | 2.35 | |||||||||||
| 12/31/2018 | 11.79 | .27 | (.43 | ) | (.16 | ) | (.25 | ) | (.04 | ) | (.29 | ) | 11.34 | (1.33 | ) | 1,032 | .82 | .82 | 2.32 | |||||||
| 12/31/2017 | 11.14 | .25 | .51 | .76 | (.04 | ) | (.07 | ) | (.11 | ) | 11.79 | 6.86 | 1,164 | .81 | .81 | 2.12 | ||||||||||
| Class 4: | ||||||||||||||||||||||||||
| 12/31/2021 | 12.71 | .19 | (.84 | ) | (.65 | ) | (.18 | ) | (.31 | ) | (.49 | ) | 11.57 | (5.18 | ) | 66 | 1.10 | 1.00 | 1.57 | |||||||
| 12/31/2020 | 11.92 | .19 | .94 | 1.13 | (.13 | ) | (.21 | ) | (.34 | ) | 12.71 | 9.62 | 61 | 1.09 | 1.02 | 1.58 | ||||||||||
| 12/31/2019 | 11.24 | .24 | .60 | .84 | (.16 | ) | — | (.16 | ) | 11.92 | 7.54 | 49 | 1.08 | 1.08 | 2.09 | |||||||||||
| 12/31/2018 | 11.70 | .24 | (.43 | ) | (.19 | ) | (.23 | ) | (.04 | ) | (.27 | ) | 11.24 | (1.61 | ) | 40 | 1.07 | 1.07 | 2.09 | |||||||
| 12/31/2017 | 11.08 | .22 | .51 | .73 | (.04 | ) | (.07 | ) | (.11 | ) | 11.70 | 6.63 | 31 | 1.06 | 1.06 | 1.89 | ||||||||||
| (Loss)
income from investment operations1 |
Dividends and distributions | |||||||||||||||||||||||||
| Period ended | Net
asset value, beginning of period |
Net investment income |
Net
(losses) gains on securities (both realized and unrealized) |
Total
from investment operations |
Dividends (from net investment income) |
Distributions (from capital gains) |
Total dividends and distributions |
Net
asset value, end of period |
Total return2 |
Net
assets, end of period (in millions) |
Ratio
of expenses to average net assets before waivers3 |
Ratio
of expenses to average net assets after waivers2,3 |
Ratio
of net income to average net assets2 | |||||||||||||
| The Bond Fund of America | ||||||||||||||||||||||||||
| Class 1: | ||||||||||||||||||||||||||
| 12/31/2021 | $11.89 | $.21 | $(.23 | ) | $(.02 | ) | $(.19 | ) | $(.47 | ) | $(.66 | ) | $11.21 | (.14 | )% | $8,555 | .39 | % | .26 | % | 1.84 | % | ||||
| 12/31/2020 | 11.17 | .23 | .87 | 1.10 | (.27 | ) | (.11 | ) | (.38 | ) | 11.89 | 9.96 | 6,844 | .40 | .40 | 2.00 | ||||||||||
| 12/31/2019 | 10.47 | .30 | .71 | 1.01 | (.31 | ) | — | (.31 | ) | 11.17 | 9.70 | 6,481 | .39 | .39 | 2.76 | |||||||||||
| 12/31/2018 | 10.82 | .29 | (.35 | ) | (.06 | ) | (.28 | ) | (.01 | ) | (.29 | ) | 10.47 | (.45 | ) | 5,962 | .38 | .38 | 2.70 | |||||||
| 12/31/2017 | 10.80 | .24 | .18 | .42 | (.24 | ) | (.16 | ) | (.40 | ) | 10.82 | 3.88 | 6,434 | .38 | .38 | 2.19 | ||||||||||
| Class 1A: | ||||||||||||||||||||||||||
| 12/31/2021 | 11.84 | .18 | (.23 | ) | (.05 | ) | (.16 | ) | (.47 | ) | (.63 | ) | 11.16 | (.36 | ) | 12 | .64 | .51 | 1.59 | |||||||
| 12/31/2020 | 11.13 | .20 | .87 | 1.07 | (.25 | ) | (.11 | ) | (.36 | ) | 11.84 | 9.68 | 9 | .65 | .65 | 1.74 | ||||||||||
| 12/31/2019 | 10.45 | .27 | .71 | .98 | (.30 | ) | — | (.30 | ) | 11.13 | 9.36 | 7 | .64 | .64 | 2.48 | |||||||||||
| 12/31/2018 | 10.80 | .26 | (.33 | ) | (.07 | ) | (.27 | ) | (.01 | ) | (.28 | ) | 10.45 | (.60 | ) | 3 | .63 | .63 | 2.50 | |||||||
| 12/31/20174,5 | 10.82 | .22 | .15 | .37 | (.23 | ) | (.16 | ) | (.39 | ) | 10.80 | 3.46 | 6 | 1 | .62 | 7 | .62 | 7 | 2.01 | 7 | ||||||
| Class 2: | ||||||||||||||||||||||||||
| 12/31/2021 | 11.73 | .18 | (.22 | ) | (.04 | ) | (.16 | ) | (.47 | ) | (.63 | ) | 11.06 | (.31 | ) | 3,729 | .64 | .52 | 1.57 | |||||||
| 12/31/2020 | 11.02 | .20 | .86 | 1.06 | (.24 | ) | (.11 | ) | (.35 | ) | 11.73 | 9.73 | 3,840 | .65 | .65 | 1.75 | ||||||||||
| 12/31/2019 | 10.34 | .27 | .70 | .97 | (.29 | ) | — | (.29 | ) | 11.02 | 9.36 | 3,561 | .64 | .64 | 2.51 | |||||||||||
| 12/31/2018 | 10.69 | .26 | (.34 | ) | (.08 | ) | (.26 | ) | (.01 | ) | (.27 | ) | 10.34 | (.71 | ) | 3,524 | .63 | .63 | 2.45 | |||||||
| 12/31/2017 | 10.67 | .21 | .18 | .39 | (.21 | ) | (.16 | ) | (.37 | ) | 10.69 | 3.67 | 3,966 | .63 | .63 | 1.94 | ||||||||||
| Class 4: | ||||||||||||||||||||||||||
| 12/31/2021 | 11.69 | .15 | (.22 | ) | (.07 | ) | (.14 | ) | (.47 | ) | (.61 | ) | 11.01 | (.59 | ) | 891 | .89 | .76 | 1.34 | |||||||
| 12/31/2020 | 11.00 | .17 | .85 | 1.02 | (.22 | ) | (.11 | ) | (.33 | ) | 11.69 | 9.38 | 714 | .90 | .90 | 1.48 | ||||||||||
| 12/31/2019 | 10.33 | .24 | .70 | .94 | (.27 | ) | — | (.27 | ) | 11.00 | 9.08 | 502 | .89 | .89 | 2.25 | |||||||||||
| 12/31/2018 | 10.68 | .23 | (.33 | ) | (.10 | ) | (.24 | ) | (.01 | ) | (.25 | ) | 10.33 | (.89 | ) | 366 | .88 | .88 | 2.22 | |||||||
| 12/31/2017 | 10.70 | .19 | .16 | .35 | (.21 | ) | (.16 | ) | (.37 | ) | 10.68 | 3.29 | 297 | .88 | .88 | 1.72 | ||||||||||
27 American Funds Insurance Series / Prospectus
| (Loss)
income from investment operations1 |
Dividends and distributions | |||||||||||||||||||||||||
| Period ended | Net
asset value, beginning of period |
Net investment income |
Net
(losses) gains on securities (both realized and unrealized) |
Total
from investment operations |
Dividends (from net investment income) |
Distributions (from capital gains) |
Total dividends and distributions |
Net
asset value, end of period |
Total return2 |
Net
assets, end of period (in millions) |
Ratio
of expenses to average net assets before waivers |
Ratio
of expenses to average net assets after waivers2 |
Ratio
of net income to average net assets2 | |||||||||||||
| U.S. Government Securities Fund | ||||||||||||||||||||||||||
| Class 1: | ||||||||||||||||||||||||||
| 12/31/2021 | $13.04 | $.18 | $(.26 | ) | $(.08 | ) | $(.18 | ) | $(1.11 | ) | $(1.29 | ) | $11.67 | (.44 | )% | $522 | .39 | % | .29 | % | 1.50 | % | ||||
| 12/31/2020 | 12.34 | .16 | 1.07 | 1.23 | (.26 | ) | (.27 | ) | (.53 | ) | 13.04 | 10.09 | 429 | .38 | .38 | 1.21 | ||||||||||
| 12/31/2019 | 11.94 | .25 | .43 | .68 | (.28 | ) | — | (.28 | ) | 12.34 | 5.69 | 1,418 | .37 | .37 | 2.07 | |||||||||||
| 12/31/2018 | 12.08 | .24 | (.13 | ) | .11 | (.25 | ) | — | (.25 | ) | 11.94 | .91 | 1,445 | .36 | .36 | 2.02 | ||||||||||
| 12/31/2017 | 12.05 | .21 | .01 | .22 | (.19 | ) | — | (.19 | ) | 12.08 | 1.83 | 1,558 | .36 | .36 | 1.68 | |||||||||||
| Class 1A: | ||||||||||||||||||||||||||
| 12/31/2021 | 13.00 | .16 | (.26 | ) | (.10 | ) | (.16 | ) | (1.11 | ) | (1.27 | ) | 11.63 | (.65 | ) | 5 | .64 | .53 | 1.28 | |||||||
| 12/31/2020 | 12.32 | .09 | 1.10 | 1.19 | (.24 | ) | (.27 | ) | (.51 | ) | 13.00 | 9.75 | 4 | .64 | .64 | .69 | ||||||||||
| 12/31/2019 | 11.93 | .22 | .43 | .65 | (.26 | ) | — | (.26 | ) | 12.32 | 5.42 | 2 | .62 | .62 | 1.82 | |||||||||||
| 12/31/2018 | 12.08 | .22 | (.14 | ) | .08 | (.23 | ) | — | (.23 | ) | 11.93 | .70 | 1 | .61 | .61 | 1.82 | ||||||||||
| 12/31/20174,5 | 12.05 | .18 | .03 | .21 | (.18 | ) | — | (.18 | ) | 12.08 | 1.73 | 6 | — | 8 | .58 | 7 | .58 | 7 | 1.53 | 7 | ||||||
| Class 2: | ||||||||||||||||||||||||||
| 12/31/2021 | 12.89 | .15 | (.25 | ) | (.10 | ) | (.15 | ) | (1.11 | ) | (1.26 | ) | 11.53 | (.62 | ) | 1,391 | .64 | .54 | 1.24 | |||||||
| 12/31/2020 | 12.21 | .09 | 1.10 | 1.19 | (.24 | ) | (.27 | ) | (.51 | ) | 12.89 | 9.80 | 1,439 | .64 | .64 | .73 | ||||||||||
| 12/31/2019 | 11.82 | .22 | .42 | .64 | (.25 | ) | — | (.25 | ) | 12.21 | 5.31 | 1,343 | .62 | .62 | 1.82 | |||||||||||
| 12/31/2018 | 11.96 | .21 | (.14 | ) | .07 | (.21 | ) | — | (.21 | ) | 11.82 | .73 | 1,323 | .61 | .61 | 1.77 | ||||||||||
| 12/31/2017 | 11.93 | .17 | .02 | .19 | (.16 | ) | — | (.16 | ) | 11.96 | 1.59 | 1,473 | .61 | .61 | 1.43 | |||||||||||
| Class 3: | ||||||||||||||||||||||||||
| 12/31/2021 | 13.07 | .16 | (.26 | ) | (.10 | ) | (.16 | ) | (1.11 | ) | (1.27 | ) | 11.70 | (.62 | ) | 9 | .57 | .47 | 1.31 | |||||||
| 12/31/2020 | 12.37 | .10 | 1.12 | 1.22 | (.25 | ) | (.27 | ) | (.52 | ) | 13.07 | 9.91 | 10 | .57 | .57 | .78 | ||||||||||
| 12/31/2019 | 11.97 | .23 | .43 | .66 | (.26 | ) | — | (.26 | ) | 12.37 | 5.49 | 9 | .55 | .55 | 1.88 | |||||||||||
| 12/31/2018 | 12.11 | .22 | (.14 | ) | .08 | (.22 | ) | — | (.22 | ) | 11.97 | .71 | 9 | .54 | .54 | 1.84 | ||||||||||
| 12/31/2017 | 12.07 | .18 | .03 | .21 | (.17 | ) | — | (.17 | ) | 12.11 | 1.72 | 10 | .54 | .54 | 1.50 | |||||||||||
| Class 4: | ||||||||||||||||||||||||||
| 12/31/2021 | 12.88 | .12 | (.25 | ) | (.13 | ) | (.12 | ) | (1.11 | ) | (1.23 | ) | 11.52 | (.88 | ) | 238 | .89 | .79 | .98 | |||||||
| 12/31/2020 | 12.22 | .05 | 1.10 | 1.15 | (.22 | ) | (.27 | ) | (.49 | ) | 12.88 | 9.48 | 272 | .89 | .89 | .42 | ||||||||||
| 12/31/2019 | 11.84 | .19 | .42 | .61 | (.23 | ) | — | (.23 | ) | 12.22 | 5.14 | 124 | .87 | .87 | 1.56 | |||||||||||
| 12/31/2018 | 11.98 | .18 | (.12 | ) | .06 | (.20 | ) | — | (.20 | ) | 11.84 | .50 | 91 | .86 | .86 | 1.53 | ||||||||||
| 12/31/2017 | 11.96 | .14 | .01 | .15 | (.13 | ) | — | (.13 | ) | 11.98 | 1.28 | 62 | .86 | .86 | 1.18 | |||||||||||
American Funds Insurance Series / Prospectus 28
| (Loss)
income from investment operations1 |
Dividends and distributions | |||||||||||||||||||||||
| Period ended | Net
asset value, beginning of period |
Net investment (loss) income |
Net
(losses) gains on securities (both realized and unrealized) |
Total
from investment operations |
Dividends (from net investment income) |
Distributions (from capital gains) |
Total dividends and distributions |
Net
asset value, end of period |
Total return |
Net
assets, end of period (in millions) |
Ratio
of expenses to average net assets |
Ratio
of net (loss) income to average net assets | ||||||||||||
| Ultra-Short Bond Fund | ||||||||||||||||||||||||
| Class 1: | ||||||||||||||||||||||||
| 12/31/2021 | $11.31 | $(.03 | ) | $(.01 | ) | $(.04 | ) | $— | $— | $— | $11.27 | (.35 | )% | $37 | .37 | % | (.28 | )% | ||||||
| 12/31/2020 | 11.30 | .02 | .02 | .04 | (.03 | ) | — | (.03 | ) | 11.31 | .34 | 44 | .37 | .16 | ||||||||||
| 12/31/2019 | 11.31 | .22 | — | 9 | .22 | (.23 | ) | — | (.23 | ) | 11.30 | 1.92 | 30 | .36 | 1.92 | |||||||||
| 12/31/2018 | 11.29 | .18 | — | 9 | .18 | (.16 | ) | — | (.16 | ) | 11.31 | 1.58 | 37 | .35 | 1.60 | |||||||||
| 12/31/2017 | 11.27 | .08 | (.01 | ) | .07 | (.05 | ) | — | (.05 | ) | 11.29 | .66 | 37 | .35 | .68 | |||||||||
| Class 1A: | ||||||||||||||||||||||||
| 12/31/2021 | 11.31 | (.03 | ) | — | 9 | (.03 | ) | — | — | — | 11.28 | (.27 | ) | — | 8 | .36 | (.28 | ) | ||||||
| 12/31/2020 | 11.30 | .03 | .01 | .04 | (.03 | ) | — | (.03 | ) | 11.31 | .32 | — | 8 | .35 | .26 | |||||||||
| 12/31/2019 | 11.31 | .22 | — | 9 | .22 | (.23 | ) | — | (.23 | ) | 11.30 | 1.92 | — | 8 | .37 | 1.90 | ||||||||
| 12/31/2018 | 11.29 | .18 | — | 9 | .18 | (.16 | ) | — | (.16 | ) | 11.31 | 1.58 | — | 8 | .35 | 1.60 | ||||||||
| 12/31/20174,5 | 11.27 | .08 | — | 9 | .08 | (.06 | ) | — | (.06 | ) | 11.29 | .67 | 6 | — | 8 | .34 | 7 | .69 | 7 | |||||
| Class 2: | ||||||||||||||||||||||||
| 12/31/2021 | 10.99 | (.06 | ) | — | 9 | (.06 | ) | — | — | — | 10.93 | (.55 | ) | 245 | .62 | (.53 | ) | |||||||
| 12/31/2020 | 11.01 | — | 9 | — | 9 | — | 9 | (.02 | ) | — | (.02 | ) | 10.99 | .03 | 288 | .62 | (.05 | ) | ||||||
| 12/31/2019 | 11.03 | .18 | — | 9 | .18 | (.20 | ) | — | (.20 | ) | 11.01 | 1.62 | 230 | .61 | 1.66 | |||||||||
| 12/31/2018 | 11.01 | .15 | — | 9 | .15 | (.13 | ) | — | (.13 | ) | 11.03 | 1.36 | 247 | .60 | 1.34 | |||||||||
| 12/31/2017 | 10.99 | .05 | — | 9 | .05 | (.03 | ) | — | (.03 | ) | 11.01 | .46 | 249 | .60 | .42 | |||||||||
| Class 3: | ||||||||||||||||||||||||
| 12/31/2021 | 11.12 | (.05 | ) | — | 9 | (.05 | ) | — | — | — | 11.07 | (.45 | ) | 5 | .55 | (.46 | ) | |||||||
| 12/31/2020 | 11.13 | — | 9 | .02 | .02 | (.03 | ) | — | (.03 | ) | 11.12 | .13 | 4 | .55 | .03 | |||||||||
| 12/31/2019 | 11.14 | .20 | — | 9 | .20 | (.21 | ) | — | (.21 | ) | 11.13 | 1.76 | 3 | .54 | 1.74 | |||||||||
| 12/31/2018 | 11.12 | .16 | (.01 | ) | .15 | (.13 | ) | — | (.13 | ) | 11.14 | 1.38 | 4 | .53 | 1.42 | |||||||||
| 12/31/2017 | 11.10 | .06 | — | 9 | .06 | (.04 | ) | — | (.04 | ) | 11.12 | .54 | 4 | .53 | .50 | |||||||||
| Class 4: | ||||||||||||||||||||||||
| 12/31/2021 | 11.08 | (.09 | ) | .01 | (.08 | ) | — | — | — | 11.00 | (.72 | ) | 46 | .87 | (.79 | ) | ||||||||
| 12/31/2020 | 11.13 | (.04 | ) | .01 | (.03 | ) | (.02 | ) | — | (.02 | ) | 11.08 | (.25 | ) | 40 | .87 | (.35 | ) | ||||||
| 12/31/2019 | 11.15 | .16 | — | 9 | .16 | (.18 | ) | — | (.18 | ) | 11.13 | 1.40 | 22 | .86 | 1.40 | |||||||||
| 12/31/2018 | 11.13 | .12 | .01 | .13 | (.11 | ) | — | (.11 | ) | 11.15 | 1.14 | 18 | .86 | 1.11 | ||||||||||
| 12/31/2017 | 11.12 | .02 | — | 9 | .02 | (.01 | ) | — | (.01 | ) | 11.13 | .16 | 15 | .85 | .19 | |||||||||
29 American Funds Insurance Series / Prospectus
| Year ended December 31, | |||||
Portfolio turnover rate for all share classes excluding mortgage dollar roll transactions11 |
2021 | 2020 | 2019 | 2018 | 2017 |
| Capital Income Builder | 60% | 110% | 44% | 42% | 59% |
| Asset Allocation Fund | 45 | 49 | 47 | 34 | 39 |
| American Funds Mortgage Fund | 38 | 123 | 84 | 60 | 98 |
| American Funds Global Balanced Fund | 36 | 68 | 60 | 30 | 28 |
| Capital World Bond Fund | 64 | 88 | 110 | 78 | 74 |
| The Bond Fund of America | 87 | 72 | 146 | 98 | 153 |
| U.S. Government Securities Fund | 126 | 112 | 103 | 76 | 120 |
| Year ended December 31, | |||||
Portfolio turnover rate for all share classes including mortgage dollar roll transactions, if applicable11 |
2021 | 2020 | 2019 | 2018 | 2017 |
| Global Growth Fund | 18% | 17% | 14% | 25% | 31% |
| Global Small Capitalization Fund | 29 | 38 | 50 | 43 | 33 |
| Growth Fund | 25 | 32 | 21 | 35 | 24 |
| International Fund | 44 | 40 | 32 | 29 | 29 |
| New World Fund | 43 | 70 | 38 | 58 | 56 |
| Capital World Growth and Income Fund | 85 | 36 | 29 | 49 | 41 |
| Growth-Income Fund | 24 | 33 | 27 | 39 | 27 |
| International Growth and Income Fund | 41 | 56 | 28 | 38 | 51 |
| Washington Mutual Investors Fund | 90 | 40 | 37 | 49 | 34 |
| Capital Income Builder | 93 | 184 | 72 | 98 | 88 |
| Asset Allocation Fund | 124 | 145 | 79 | 86 | 85 |
| American Funds Global Balanced Fund | 39 | 86 | 74 | 51 | 41 |
| American Funds Mortgage Fund | 975 | 1,143 | 350 | 811 | 680 |
| American High-Income Trust | 56 | 78 | 58 | 67 | 78 |
| Capital World Bond Fund | 91 | 145 | 159 | 125 | 105 |
| The Bond Fund of America | 456 | 461 | 373 | 514 | 502 |
| U.S. Government Securities Fund | 433 | 867 | 277 | 446 | 551 |
| Ultra-Short Bond Fund | —12 | —12 | —12 | —12 | —12 |
1 Based on average shares outstanding.
2 This column reflects the impact of certain waivers/reimbursements from Capital Research and Management Company. During some of the periods shown, Capital Research and Management Company waived a portion of investment advisory services fees on some funds.
3 Ratios do not include expenses of any Central Funds. The fund indirectly bears its proportionate share of the expenses of any Central Funds, if applicable.
4 Based on operations for a period that is less than a full year.
5 Class 1A shares began investment operations on January 6, 2017.
6 Not annualized.
7 Annualized.
8 Amount less than $1 million.
9 Amount less than $.01.
10 Amount less than .01%.
11Rates do not include the fund’s portfolio activity with respect to any Central Funds, if applicable.
12Amount is either less than 1% or there is no turnover.
American Funds Insurance Series / Prospectus 30
Other fund information Shares of the Series are currently offered to insurance company separate accounts funding both variable annuity contracts and variable life insurance policies. Interests of various contract owners participating in the Series may be in conflict. The board of trustees of the Series will monitor for the existence of any material conflicts and determine what action, if any, should be taken. Shares may be purchased or redeemed by the separate accounts without any sales or redemption charges at net asset value.
Annual/Semi-annual report to shareholders The shareholder reports contain additional information about the Series, including financial statements, investment results, portfolio holdings, a discussion of market conditions and the Series’ investment strategies, and the independent registered public accounting firm’s report (in the annual report).
Statement of additional information (SAI) and codes of ethics The current SAI, as amended from time to time, contains more detailed information about the Series, including the funds’ financial statements, and is incorporated by reference into this prospectus. This means that the current SAI, for legal purposes, is part of this prospectus. The codes of ethics describe the personal investing policies adopted by the Series, the Series’ investment adviser and its affiliated companies.
The codes of ethics and current SAI are on file with the U.S. Securities and Exchange Commission (SEC). These and other related materials about the Series are available for review on the EDGAR database on the SEC’s website at sec.gov or, after payment of a duplicating fee, via email request to publicinfo@sec.gov.
The current SAI and annual/semi-annual reports to shareholders can be found online at capitalgroup.com/afis and may be available on the website of the company that issued your insurance contract. You also may request a free copy of these documents or the codes of ethics by calling Capital Group at (800) 421-9900, ext. 65413 or writing to the Secretary at 333 South Hope Street, Los Angeles, California 90071.
| INA5PRX-054-0522P Printed in USA CGD/AFD/8024 | Investment Company File No. 811-03857 |
American Funds Insurance Series® Prospectus May
1, 2022 |
 |
American Funds Global Balanced Fund
Table of contents
| American Funds Global Balanced Fund 1 | Investment objectives, strategies and risks 6 Management and organization 10 Purchases and redemptions of shares 15 |
|||
| The U.S. Securities and Exchange Commission has not approved or disapproved of these securities. Further, it has not determined that this prospectus is accurate or complete. Any representation to the contrary is a criminal offense. |
American Funds Global Balanced Fund
Investment objectives This fund seeks the balanced accomplishment of three objectives: long-term growth of capital, conservation of principal and current income.
Fees and expenses of the fund This table describes the fees and expenses that you may pay if you buy, hold and sell an interest in Class 2 shares of the fund. You may pay other fees, such as insurance contract fees and expenses, which are not reflected in the tables and examples below. If insurance contract fees and expenses were reflected, expenses shown would be higher.
| Annual fund operating expenses (expenses that you pay each year as a percentage of the value of your investment) | Class 2 |
| Management fee | 0.66% |
| Distribution and/or service (12b-1) fees | 0.25 |
| Other expenses | 0.07 |
| Total annual fund operating expenses | 0.98 |
| Fee waiver* | 0.22 |
| Total annual fund operating expenses after fee waiver | 0.76 |
* The investment adviser is currently waiving a portion of its management fee equal to .22% of the fund’s net assets. This waiver will be in effect through at least May 1, 2023. The waiver may only be modified or terminated with the approval of the fund’s board.
Example This example is intended to help you compare the cost of investing in Class 2 shares of the fund with the cost of investing in other mutual funds.
The example assumes that you invest $10,000 in the fund for the time periods indicated and then redeem all of your shares at the end of those periods. The example also assumes that your investment has a 5% return each year and that the fund’s operating expenses remain the same. The example does not reflect insurance contract expenses. If insurance contract expenses were reflected, expenses shown would be higher. The example reflects the fee waiver described above through the expiration date of such waiver and total annual fund operating expenses thereafter. No sales charge (load) or other fees are charged by the fund upon redemption, so you would incur these hypothetical costs whether or not you were to redeem your shares at the end of the given period. Although your actual costs may be higher or lower, based on these assumptions your costs would be:
| 1 year | 3 years | 5 years | 10 years | |
| Class 2 | $78 | $290 | $520 | $1,181 |
Portfolio turnover The fund pays transaction costs, such as commissions, when it buys and sells securities (or “turns over” its portfolio). A higher portfolio turnover rate may indicate higher transaction costs. These costs, which are not reflected in annual fund operating expenses or in the example, affect the fund’s investment results. During the most recent fiscal year, the fund’s portfolio turnover rate was 39% of the average value of its portfolio.
Principal investment strategies As a balanced fund with global scope, the fund seeks to invest in equity and debt securities around the world that offer the opportunity for growth and/or provide dividend income, while also constructing the portfolio to protect principal and limit volatility.
Normally the fund will maintain at least 45% of the value of its assets in common stocks and other equity investments. Although the fund’s equity investments focus on medium to larger capitalization companies, the fund’s investments are not limited to a particular capitalization size.
Normally the fund will invest at least 25% of the value of its assets in bonds and other debt securities (including money market instruments). These will consist of investment-grade securities (rated Baa3 or better or BBB– or better by Nationally Recognized Statistical Rating Organizations designated by the fund’s investment adviser or unrated but determined to be of equivalent quality by the fund’s investment adviser).
The fund will allocate its assets among various countries, including the United States (but in no fewer than three countries). Under normal market conditions, the fund will invest at least 40% of its net assets in issuers outside the United States, unless market conditions are not deemed favorable by the fund’s investment adviser, in which case the fund would invest at least 30% of its net assets in issuers outside the United States.
The fund’s ability to invest in issuers outside the United States includes investing in emerging markets.
The fund may invest in bonds and other debt securities, including securities issued and guaranteed by the U.S. government, securities issued by federal agencies and instrumentalities and securities backed by mortgages or other assets. The fund may also invest in securities of governments, agencies, corporations and other entities domiciled outside the United States. These investments will typically be denominated in currencies other than U.S. dollars.
The investment adviser uses a system of multiple portfolio managers in managing the fund’s assets. Under this approach, the portfolio of the fund is divided into segments managed by individual managers.
The fund relies on the professional judgment of its investment adviser to make decisions about the fund’s portfolio investments. The basic investment philosophy of the investment adviser is to seek to invest in attractively valued securities that, in its opinion, represent good,
1 American Funds Insurance Series / Prospectus
long-term investment opportunities. Securities may be sold when the investment adviser believes that they no longer represent relatively attractive investment opportunities.
Principal risks
This section describes the principal risks associated with investing in the fund. You may lose money by investing in the fund. The likelihood of loss may be greater if you invest for a shorter period of time. Investors in the fund should have a long-term perspective and be able to tolerate potentially sharp declines in value.
Market conditions — The prices of, and the income generated by, the common stocks, bonds and other securities held by the fund may decline – sometimes rapidly or unpredictably – due to various factors, including events or conditions affecting the general economy or particular industries; overall market changes; local, regional or global political, social or economic instability; governmental, governmental agency or central bank responses to economic conditions; and currency exchange rate, interest rate and commodity price fluctuations.
Economies and financial markets throughout the world are highly interconnected. Economic, financial or political events, trading and tariff arrangements, wars, terrorism, cybersecurity events, natural disasters, public health emergencies (such as the spread of infectious disease) and other circumstances in one country or region, including actions taken by governmental or quasi-governmental authorities in response to any of the foregoing, could have impacts on global economies or markets. As a result, whether or not the fund invests in securities of issuers located in or with significant exposure to the countries affected, the value and liquidity of the fund’s investments may be negatively affected by developments in other countries and regions.
Issuer risks — The prices of, and the income generated by, securities held by the fund may decline in response to various factors directly related to the issuers of such securities, including reduced demand for an issuer’s goods or services, poor management performance, major litigation, investigations or other controversies related to the issuer, changes in government regulations affecting the issuer or its competitive environment and strategic initiatives such as mergers, acquisitions or dispositions and the market response to any such initiatives.
Investing in growth-oriented stocks — Growth-oriented common stocks and other equity-type securities (such as preferred stocks, convertible preferred stocks and convertible bonds) may involve larger price swings and greater potential for loss than other types of investments.
Investing in income-oriented stocks — The value of the fund’s securities and income provided by the fund may be reduced by changes in the dividend policies of, and the capital resources available for dividend payments at, the companies in which the fund invests.
Investing outside the United States — Securities of issuers domiciled outside the United States, or with significant operations or revenues outside the United States, may lose value because of adverse political, social, economic or market developments (including social instability, regional conflicts, terrorism and war) in the countries or regions in which the issuers operate or generate revenue. These securities may also lose value due to changes in foreign currency exchange rates against the U.S. dollar and/or currencies of other countries. Issuers of these securities may be more susceptible to actions of foreign governments, such as nationalization, currency blockage or the imposition of price controls or punitive taxes, each of which could adversely impact the value of these securities. Securities markets in certain countries may be more volatile and/or less liquid than those in the United States. Investments outside the United States may also be subject to different accounting and auditing practices and standards and different regulatory, legal and reporting requirements, and may be more difficult to value, than those in the United States. In addition, the value of investments outside the United States may be reduced by foreign taxes, including foreign withholding taxes on interest and dividends. Further, there may be increased risks of delayed settlement of securities purchased or sold by the fund. The risks of investing outside the United States may be heightened in connection with investments in emerging markets.
Investing in emerging markets — Investing in emerging markets may involve risks in addition to and greater than those generally associated with investing in the securities markets of developed countries. For instance, emerging market countries tend to have less developed political, economic and legal systems and accounting and auditing practices and standards than those in developed countries. Accordingly, the governments of these countries may be less stable and more likely to intervene in the market economy, for example, by imposing capital controls, nationalizing a company or industry, placing restrictions on foreign ownership and on withdrawing sale proceeds of securities from the country, and/or imposing punitive taxes that could adversely affect the prices of securities. Information regarding issuers in emerging markets may be limited, incomplete or inaccurate, and there may be fewer rights and remedies available to the fund and its shareholders. In addition, the economies of these countries may be dependent on relatively few industries, may have limited access to capital and may be more susceptible to changes in local and global trade conditions and downturns in the world economy. Securities markets in these countries can also be relatively small and have substantially lower trading volumes. As a result, securities issued in these countries may be more volatile and less liquid, and may be more difficult to value, than securities issued in countries with more developed economies and/or markets. Less certainty with respect to security valuations may lead to additional challenges and risks in calculating the fund’s net asset value. Additionally, emerging markets are more likely to experience problems with the clearing and settling of trades and the holding of securities by banks, agents and depositories that are less established than those in developed countries.
American Funds Insurance Series / Prospectus 2
Investing in debt instruments — The prices of, and the income generated by, bonds and other debt securities held by the fund may be affected by factors such as the interest rates, maturities and credit ratings of these securities.
Rising interest rates will generally cause the prices of bonds and other debt securities to fall. A general rise in interest rates may cause investors to sell debt securities on a large scale, which could also adversely affect the price and liquidity of debt securities and could also result in increased redemptions from the fund. Falling interest rates may cause an issuer to redeem, call or refinance a debt security before its stated maturity, which may result in the fund failing to recoup the full amount of its initial investment and having to reinvest the proceeds in lower yielding securities. Longer maturity debt securities generally have greater sensitivity to changes in interest rates and may be subject to greater price fluctuations than shorter maturity debt securities.
Bonds and other debt securities are also subject to credit risk, which is the possibility that the credit strength of an issuer or guarantor will weaken or be perceived to be weaker, and/or an issuer of a debt security will fail to make timely payments of principal or interest and the security will go into default. A downgrade or default affecting any of the fund’s securities could cause the value of the fund’s shares to decrease. Lower quality debt securities generally have higher rates of interest and may be subject to greater price fluctuations than higher quality debt securities. Credit risk is gauged, in part, by the credit ratings of the debt securities in which the fund invests. However, ratings are only the opinions of the rating agencies issuing them and are not guarantees as to credit quality or an evaluation of market risk. The fund’s investment adviser relies on its own credit analysts to research issuers and issues in seeking to assess credit and default risks.
Investing in mortgage-related and other asset-backed securities — Mortgage-related securities, such as mortgage-backed securities, and other asset-backed securities, include debt obligations that represent interests in pools of mortgages or other income-bearing assets, such as consumer loans or receivables. While such securities are subject to the risks associated with investments in debt instruments generally (for example, credit, extension and interest rate risks), they are also subject to other and different risks. Mortgage-backed and other asset-backed securities are subject to changes in the payment patterns of borrowers of the underlying debt, potentially increasing the volatility of the securities and the fund’s net asset value. When interest rates fall, borrowers are more likely to refinance or prepay their debt before its stated maturity. This may result in the fund having to reinvest the proceeds in lower yielding securities, effectively reducing the fund’s income. Conversely, if interest rates rise and borrowers repay their debt more slowly than expected, the time in which the mortgage-backed and other asset-backed securities are paid off could be extended, reducing the fund’s cash available for reinvestment in higher yielding securities. Mortgage-backed securities are also subject to the risk that underlying borrowers will be unable to meet their obligations and the value of property that secures the mortgages may decline in value and be insufficient, upon foreclosure, to repay the associated loans. Investments in asset-backed securities are subject to similar risks.
Liquidity risk — Certain fund holdings may be or may become difficult or impossible to sell, particularly during times of market turmoil. Liquidity may be impacted by the lack of an active market for a holding, legal or contractual restrictions on resale, or the reduced number and capacity of market participants to make a market in such holding. Market prices for less liquid or illiquid holdings may be volatile, and reduced liquidity may have an adverse impact on the market price of such holdings. Additionally, the sale of less liquid or illiquid holdings may involve substantial delays (including delays in settlement) and additional costs and the fund may be unable to sell such holdings when necessary to meet its liquidity needs or may be forced to sell at a loss.
Management — The investment adviser to the fund actively manages the fund’s investments. Consequently, the fund is subject to the risk that the methods and analyses, including models, tools and data, employed by the investment adviser in this process may be flawed or incorrect and may not produce the desired results. This could cause the fund to lose value or its investment results to lag relevant benchmarks or other funds with similar objectives.
Your investment in the fund is not a bank deposit and is not insured or guaranteed by the Federal Deposit Insurance Corporation or any other governmental agency, entity or person. You should consider how this fund fits into your overall investment program.
Investment results The following bar chart shows how the investment results of the Class 2 shares of the fund have varied from year to year, and the following table shows how the fund’s average annual total returns for various periods compare with a broad measure of securities market results and other applicable measures of market results. This information provides some indication of the risks of investing in the fund. The 60%/40% MSCI All Country World Index/Bloomberg Global Aggregate Index blends the MSCI All Country World Index, which measures global equity markets, with the Bloomberg Global Aggregate Index, which measures investment-grade bonds (rated BBB-/Baa3 and above), by weighting their total returns at 60% and 40% respectively. This assumes the blend is rebalanced monthly. Past investment results (before and after taxes) are not predictive of future investment results. Past investment results (before and after taxes) are not predictive of future investment results. Figures shown reflect fees and expenses associated with an investment in the fund, but do not reflect insurance contract fees and expenses. If insurance contract fees and expenses were included, results would have been lower. Updated information on the fund’s investment results can be obtained by visiting capitalgroup.com/afis.
3 American Funds Insurance Series / Prospectus
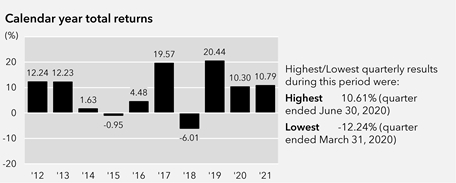
| Average annual total returns For the periods ended December 31, 2021: | 1 year | 5 years | 10 years | Lifetime |
| Fund (inception date — 5/2/11) | 10.79% | 10.59% | 8.16% | 7.01% |
| 60%/40% MSCI All Country World Index/Bloomberg Global Aggregate Index (reflects no deduction for sales charges, account fees, expenses or U.S. federal income taxes) | 8.78 | 10.11 | 7.91 | 6.50 |
| MSCI All Country World Index (reflects no deduction for sales charges, account fees, expenses or U.S. federal income taxes) | 18.54 | 14.40 | 11.85 | 9.40 |
| Bloomberg Global Aggregate Index (reflects no deduction for sales charges, account fees, expenses or U.S. federal income taxes) | -4.71 | 3.36 | 1.77 | 1.76 |
American Funds Insurance Series / Prospectus 4
Management
Investment
adviser Capital Research and Management CompanySM
Portfolio managers The individuals primarily responsible for the portfolio management of the
fund are:
| Portfolio
manager/ Series title (if applicable) |
Portfolio
manager experience in this fund |
Primary
title with investment adviser |
| Alfonso Barroso | Less than 1 year | Partner – Capital Research Global Investors |
| Andrew A. Cormack | 1 year | Partner – Capital Fixed Income Investors |
| Bradford F. Freer | Less than 1 year | Partner – Capital Research Global Investors |
| Thomas H. Høgh | 3 years | Partner – Capital Fixed Income Investors |
| Winnie Kwan | Less than 1 year | Partner – Capital Research Global Investors |
Purchase and sale of fund shares Shares of the fund are not sold directly to the general public. The fund is offered only as an underlying investment option for variable insurance contracts, and insurance company separate accounts and qualified feeder funds — and not the holders of variable insurance contracts — are the shareholders of the fund. Although the fund does not require a minimum amount for initial or subsequent purchases from insurance companies, your insurance company may impose investment minimums for your purchase of the fund.
You may sell (redeem) shares on any business day. You must sell (redeem) shares through your insurance company.
Tax information See your variable insurance contract prospectus for information regarding the federal income tax treatment of your variable insurance contract and related distributions.
Payments to broker-dealers and other financial intermediaries The fund is not sold directly to the general public but instead is offered as an underlying investment option for variable insurance contracts. The fund and its related companies may make payments to the sponsoring insurance company (or its affiliates) for distribution and/or other services. These payments may be a factor that the insurance company considers in including the fund as an underlying investment option in the variable insurance contract. The prospectus (or other offering document) for your variable insurance contract may contain additional information about these payments.
5 American Funds Insurance Series / Prospectus
Investment objectives, strategies and risks
American Funds Global Balanced Fund This fund seeks the balanced accomplishment of three objectives: long-term growth of capital, conservation of principal and current income. While it has no present intention to do so, the fund’s board may change the fund’s investment objectives without shareholder approval upon 60 days’ written notice to shareholders.
Normally, the fund will maintain at least 45% of the value of its assets in common stocks and other equity investments under normal market conditions. Although the fund’s equity investments focus on medium to larger capitalization companies, the fund’s investments are not limited to a particular capitalization size.
Normally the fund will invest at least 25% of the value of its assets in bonds and other debt securities (including money market instruments). These will consist of investment-grade securities (rated Baa3 or better or BBB– or better by Nationally Recognized Statistical Rating Organizations designated by the fund’s investment adviser or unrated but determined to be of equivalent quality by the fund’s investment adviser).
Under normal market conditions, the fund will invest at least 40% of its net assets in issuers outside the United States, unless market conditions are not deemed favorable by the fund’s investment adviser, in which case the fund would invest at least 30% of its net assets in issuers outside the United States.
The fund’s ability to invest in issuers outside the United States includes investing in emerging markets.
The fund may also invest to a limited extent in lower quality, higher yielding debt securities including those convertible into common stocks (rated Ba1 or below or BB+ or below by Nationally Recognized Statistical Rating Organizations designated by the fund’s investment adviser or unrated but determined to be of equivalent quality by the fund’s investment adviser). Such securities are sometimes referred to as “junk bonds.”
The fund may invest in bonds and other debt securities, including securities issued and guaranteed by the U.S. government, securities issued by federal agencies and instrumentalities and securities backed by mortgages or other assets. The fund may also invest in securities of governments, agencies, corporations and other entities domiciled outside the United States. These investments will typically be denominated in currencies other than U.S. dollars.
There are no restrictions on the maturity or duration of the bonds and other debt securities in the fund’s portfolio.
The fund may enter into currency transactions to provide for the purchase or sale of a currency needed to purchase a security denominated in such currency. In addition, the fund may enter into agreements, known as forward currency contracts, to purchase or sell a specific currency at a future date at a fixed price. The fund may enter into forward currency contracts to protect against changes in currency exchange rates, to increase exposure to a particular foreign currency, to shift exposure to currency fluctuations from one currency to another or to seek to increase returns.
The fund may also hold cash or cash equivalents, including commercial paper and short-term securities issued by the U.S. government, its agencies and instrumentalities. The percentage of the fund invested in such holdings varies and depends on various factors, including market conditions and purchases and redemptions of fund shares. The investment adviser may determine that it is appropriate to invest a substantial portion of the fund’s assets in such instruments in response to certain circumstances, such as periods of market turmoil. For temporary defensive purposes, the fund may invest without limitation in such instruments. A larger percentage of such holdings could moderate the fund’s investment results in a period of rising market prices. Alternatively, a larger percentage of such holdings could reduce the magnitude of the fund’s loss in a period of falling market prices and provide liquidity to make additional investments or to meet redemptions.
The fund may invest in other funds managed by the investment adviser or its affiliates (“Central Funds”) to more effectively invest in a diversified set of securities in a specific asset class such as money market instruments, bonds and other securities. Shares of Central Funds are only offered for purchase to the fund’s investment adviser and its affiliates and other funds, investment vehicles and accounts managed by the fund’s investment adviser and its affiliates. When investing in Central Funds, the fund bears its proportionate share of the expenses of the Central Funds in which it invests but does not bear additional management fees through its investment in such Central Funds. The investment results of the portions of the fund’s assets invested in the Central Funds will be based upon the investment results of the Central Funds.
The fund may also lend portfolio securities to brokers, dealers and other institutions that provide cash or U.S. Treasury securities as collateral in an amount at least equal to the value of the securities loaned.
The fund relies on the professional judgment of its investment adviser to make decisions about the fund’s portfolio investments. The basic investment philosophy of the investment adviser is to seek to invest in attractively valued securities that, in its opinion, represent good, long-term investment opportunities. The investment adviser believes that an important way to accomplish this is through fundamental analysis, which may include meeting with company executives and employees, suppliers, customers and competitors. Securities may be sold when the investment adviser believes that they no longer represent relatively attractive investment opportunities.
The following are principal risks associated with investing in the fund.
Market conditions — The prices of, and the income generated by, the common stocks, bonds and other securities held by the fund may decline – sometimes rapidly or unpredictably – due to various factors, including events or conditions affecting the general economy or particular industries; overall market changes; local, regional or global political, social or economic instability; governmental, governmental agency or central bank responses to economic conditions; and currency exchange rate, interest rate and commodity price fluctuations.
American Funds Insurance Series / Prospectus 6
Economies and financial markets throughout the world are highly interconnected. Economic, financial or political events, trading and tariff arrangements, wars, terrorism, cybersecurity events, natural disasters, public health emergencies (such as the spread of infectious disease) and other circumstances in one country or region, including actions taken by governmental or quasi-governmental authorities in response to any of the foregoing, could have impacts on global economies or markets. As a result, whether or not the fund invests in securities of issuers located in or with significant exposure to the countries affected, the value and liquidity of the fund’s investments may be negatively affected by developments in other countries and regions.
Issuer risks — The prices of, and the income generated by, securities held by the fund may decline in response to various factors directly related to the issuers of such securities, including reduced demand for an issuer’s goods or services, poor management performance, major litigation, investigations or other controversies related to the issuer, changes in government regulations affecting the issuer or its competitive environment and strategic initiatives such as mergers, acquisitions or dispositions and the market response to any such initiatives.
Investing in growth-oriented stocks — Growth-oriented common stocks and other equity-type securities (such as preferred stocks, convertible preferred stocks and convertible bonds) may involve larger price swings and greater potential for loss than other types of investments.
Investing in income-oriented stocks — The value of the fund’s securities and income provided by the fund may be reduced by changes in the dividend policies of, and the capital resources available for dividend payments at, the companies in which the fund invests.
Investing outside the United States — Securities of issuers domiciled outside the United States, or with significant operations or revenues outside the United States, may lose value because of adverse political, social, economic or market developments (including social instability, regional conflicts, terrorism and war) in the countries or regions in which the issuers operate or generate revenue. These securities may also lose value due to changes in foreign currency exchange rates against the U.S. dollar and/or currencies of other countries. Issuers of these securities may be more susceptible to actions of foreign governments, such as nationalization, currency blockage or the imposition of price controls or punitive taxes, each of which could adversely impact the value of these securities. Securities markets in certain countries may be more volatile and/or less liquid than those in the United States. Investments outside the United States may also be subject to different accounting and auditing practices and standards and different regulatory, legal and reporting requirements, and may be more difficult to value, than those in the United States. In addition, the value of investments outside the United States may be reduced by foreign taxes, including foreign withholding taxes on interest and dividends. Further, there may be increased risks of delayed settlement of securities purchased or sold by the fund. The risks of investing outside the United States may be heightened in connection with investments in emerging markets.
Investing in emerging markets — Investing in emerging markets may involve risks in addition to and greater than those generally associated with investing in the securities markets of developed countries. For instance, emerging market countries tend to have less developed political, economic and legal systems and accounting and auditing practices and standards than those in developed countries. Accordingly, the governments of these countries may be less stable and more likely to intervene in the market economy, for example, by imposing capital controls, nationalizing a company or industry, placing restrictions on foreign ownership and on withdrawing sale proceeds of securities from the country, and/or imposing punitive taxes that could adversely affect the prices of securities. Information regarding issuers in emerging markets may be limited, incomplete or inaccurate, and there may be fewer rights and remedies available to the fund and its shareholders. In addition, the economies of these countries may be dependent on relatively few industries, may have limited access to capital and may be more susceptible to changes in local and global trade conditions and downturns in the world economy. Securities markets in these countries can also be relatively small and have substantially lower trading volumes. As a result, securities issued in these countries may be more volatile and less liquid, and may be more difficult to value, than securities issued in countries with more developed economies and/or markets. Less certainty with respect to security valuations may lead to additional challenges and risks in calculating the fund’s net asset value. Additionally, emerging markets are more likely to experience problems with the clearing and settling of trades and the holding of securities by banks, agents and depositories that are less established than those in developed countries.
Investing in debt instruments — The prices of, and the income generated by, bonds and other debt securities held by the fund may be affected by factors such as the interest rates, maturities and credit ratings of these securities.
Rising interest rates will generally cause the prices of bonds and other debt securities to fall. A general rise in interest rates may cause investors to sell debt securities on a large scale, which could also adversely affect the price and liquidity of debt securities and could also result in increased redemptions from the fund. Falling interest rates may cause an issuer to redeem, call or refinance a debt security before its stated maturity, which may result in the fund failing to recoup the full amount of its initial investment and having to reinvest the proceeds in lower yielding securities. Longer maturity debt securities generally have greater sensitivity to changes in interest rates and may be subject to greater price fluctuations than shorter maturity debt securities.
Bonds and other debt securities are also subject to credit risk, which is the possibility that the credit strength of an issuer or guarantor will weaken or be perceived to be weaker, and/or an issuer of a debt security will fail to make timely payments of principal or interest and the security will go into default. A downgrade or default affecting any of the fund’s securities could cause the value of the fund’s shares to decrease. Lower quality debt securities generally have higher rates of interest and may be subject to greater price fluctuations than higher quality debt securities. Credit risk is gauged, in part, by the credit ratings of the debt securities in which the fund invests. However, ratings are only the opinions of the rating agencies issuing them and are not guarantees as to credit quality or an evaluation of market risk. The fund’s investment adviser relies on its own credit analysts to research issuers and issues in seeking to assess credit and default risks.
Investing in mortgage-related and other asset-backed securities — Mortgage-related securities, such as mortgage-backed securities, and other asset-backed securities, include debt obligations that represent interests in pools of mortgages or other income-bearing assets, such
7 American Funds Insurance Series / Prospectus
as residential mortgage loans, home equity loans, mortgages on commercial buildings, consumer loans and equipment leases. While such securities are subject to the risks associated with investments in debt instruments generally (for example, credit, extension and interest rate risks), they are also subject to other and different risks. Mortgage-backed and other asset-backed securities are subject to changes in the payment patterns of borrowers of the underlying debt, potentially increasing the volatility of the securities and the fund’s net asset value. When interest rates fall, borrowers are more likely to refinance or prepay their debt before its stated maturity. This may result in the fund having to reinvest the proceeds in lower yielding securities, effectively reducing the fund’s income. Conversely, if interest rates rise and borrowers repay their debt more slowly than expected, the time in which the mortgage-backed and other asset-backed securities are paid off could be extended, reducing the fund’s cash available for reinvestment in higher yielding securities. Mortgage-backed securities are also subject to the risk that underlying borrowers will be unable to meet their obligations and the value of property that secures the mortgages may decline in value and be insufficient, upon foreclosure, to repay the associated loans. Investments in asset-backed securities are subject to similar risks, as well as additional risks associated with the assets underlying those securities.
Liquidity risk — Certain fund holdings may be or may become difficult or impossible to sell, particularly during times of market turmoil. Liquidity may be impacted by the lack of an active market for a holding, legal or contractual restrictions on resale, or the reduced number and capacity of market participants to make a market in such holding. Market prices for less liquid or illiquid holdings may be volatile, and reduced liquidity may have an adverse impact on the market price of such holdings. Additionally, the sale of less liquid or illiquid holdings may involve substantial delays (including delays in settlement) and additional costs and the fund may be unable to sell such holdings when necessary to meet its liquidity needs or may be forced to sell at a loss.
Management — The investment adviser to the fund actively manages the fund’s investments. Consequently, the fund is subject to the risk that the methods and analyses, including models, tools and data, employed by the investment adviser in this process may be flawed or incorrect and may not produce the desired results. This could cause the fund to lose value or its investment results to lag relevant benchmarks or other funds with similar objectives.
The following are additional risks associated with investing in the fund.
Interest rate risk — The values and liquidity of the securities held by the fund may be affected by changing interest rates. For example, the values of debt securities may decline when interest rates rise and increase when interest rates fall. Longer maturity debt securities generally have greater sensitivity to changes in interest rates and may be subject to greater price fluctuations than shorter maturity debt securities. The fund may invest in variable and floating rate securities. When the fund holds variable or floating rate securities, a decrease in market interest rates will adversely affect the income received from such securities and the net asset value of the fund’s shares. Although the values of such securities are generally less sensitive to interest rate changes than those of other debt securities, the value of variable and floating rate securities may decline if their interest rates do not rise as quickly, or as much, as market interest rates. Conversely, floating rate securities will not generally increase in value if interest rates decline. During periods of extremely low short-term interest rates, certain of the fund’s debt securities may not be able to maintain a positive yield and, given the current low interest rate environment, risks associated with rising rates are currently heightened.
Investing in securities backed by the U.S. government — Securities backed by the U.S. Treasury or the full faith and credit of the U.S. government are guaranteed only as to the timely payment of interest and principal when held to maturity. Accordingly, the current market values for these securities will fluctuate with changes in interest rates and the credit rating of the U.S. government. Securities issued by U.S. government-sponsored entities and federal agencies and instrumentalities that are not backed by the full faith and credit of the U.S. government are neither issued nor guaranteed by the U.S. government.
Investing in lower rated debt instruments — Lower rated bonds and other lower rated debt securities generally have higher rates of interest and involve greater risk of default or price declines due to changes in the issuer’s creditworthiness than those of higher quality debt securities. The market prices of these securities may fluctuate more than the prices of higher quality debt securities and may decline significantly in periods of general economic difficulty. These risks may be increased with respect to investments in junk bonds.
Currency transactions — In addition to the risks generally associated with investing in derivative instruments, the use of forward currency contracts involves the risk that currency movements will not be accurately predicted by the investment adviser, which could result in losses to the fund. While entering into forward currency contracts could minimize the risk of loss due to a decline in the value of the hedged currency, it could also limit any potential gain that may result from an increase in the value of the currency. Additionally, the adviser may use forward currency contracts to increase exposure to a certain currency or to shift exposure to currency fluctuations from one country to another. Forward currency contracts may expose the fund to potential gains and losses in excess of the initial amount invested.
Exposure to country, region, industry or sector — Subject to the fund’s investment limitations, the fund may have significant exposure to a particular country, region, industry or sector. Such exposure may cause the fund to be more impacted by risks relating to and developments affecting the country, region, industry or sector, and thus its net asset value may be more volatile, than a fund without such levels of exposure. For example, if the fund has significant exposure in a particular country, then social, economic, regulatory or other issues that negatively affect that country may have a greater impact on the fund than on a fund that is more geographically diversified.
Investing in derivatives — The use of derivatives involves a variety of risks, which may be different from, or greater than, the risks associated with investing in traditional securities, such as stocks and bonds. Changes in the value of a derivative may not correlate perfectly with, and may be more sensitive to market events than, the underlying asset, rate or index, and a derivative instrument may expose the fund to losses in excess of its initial investment. Derivatives may be difficult to value, difficult for the fund to buy or sell at an opportune time or price and difficult to terminate or otherwise offset. The fund’s use of derivatives may result in losses to the fund, and investing in derivatives may reduce the fund’s returns and increase the fund’s price volatility. The fund’s counterparty to a derivative transaction (including, if applicable, the fund’s clearing broker, the derivatives exchange or the clearinghouse) may be unable or unwilling to honor its financial obligations in respect of the transaction.
American Funds Insurance Series / Prospectus 8
Lending of portfolio securities — Securities lending involves risks, including the risk that the loaned securities may not be returned in a timely manner or at all and/or the risk of a loss of rights in the collateral if a borrower or the lending agent defaults. These risks could be greater for non-U.S. securities. Additionally, the fund may lose money from the reinvestment of collateral received on loaned securities in investments that decline in value, default or do not perform as expected.
Cybersecurity breaches — The fund may be subject to operational and information security risks through breaches in cybersecurity. Cybersecurity breaches can result from deliberate attacks or unintentional events, including “ransomware” attacks, the injection of computer viruses or malicious software code, the use of vulnerabilities in code to gain unauthorized access to digital information systems, networks or devices, or external attacks such as denial-of-service attacks on the investment adviser’s or an affiliate’s website that could render the fund’s network services unavailable to intended end-users. These breaches may, among other things, lead to the unauthorized release of confidential information, misuse of the fund’s assets or sensitive information, the disruption of the fund’s operational capacity, the inability of fund shareholders to transact business, or the destruction of the fund’s physical infrastructure, equipment or operating systems. As a result of these potential outcomes, the fund could incur violations of applicable privacy and other laws, reputational damage, additional costs associated with corrective measures and/or financial loss. The fund may also be subject to additional risks if its third-party service providers, such as the fund’s investment adviser, transfer agent, custodian, administrators and other financial intermediaries, experience similar cybersecurity breaches and potential outcomes. Cybersecurity risks may also impact issuers of securities in which the fund invests, which may cause the fund’s investments in such issuers to lose value.
In addition to the principal investment strategies described above, the fund has other investment practices that are described in the statement of additional information, which includes a description of other risks related to the fund’s principal investment strategies and other investment practices. The fund’s investment results will depend on the ability of the fund’s investment adviser to navigate the risks discussed above as well as those described in the statement of additional information.
Fund comparative indexes — The 60%/40% MSCI All Country World Index/Bloomberg Global Aggregate Index blends the MSCI All Country World Index with the Bloomberg Global Aggregate Index by weighting their cumulative total returns at 60% and 40%, respectively. This assumes the blend is rebalanced monthly. The MSCI All Country World Index is a free float-adjusted market capitalization-weighted index that is designed to measure equity market results in the global developed and emerging markets, consisting of more than 40 developed and emerging market country indexes. Results reflect dividends gross of withholding taxes through December 31, 2000, and dividends net of withholding taxes thereafter. This index is unmanaged, and its results include reinvested dividends and/or distributions but do not reflect the effect of sales charges, commissions, account fees, expenses or U.S. federal income taxes. The Bloomberg Global Aggregate Index represents the global investment-grade fixed income markets. This index is unmanaged, and its results include reinvested distributions but do not reflect the effect of sales charges, commissions, account fees, expenses or U.S. federal income taxes.
Portfolio holdings A description of the fund’s policies and procedures regarding disclosure of information about its portfolio holdings is available in the statement of additional information.
9 American Funds Insurance Series / Prospectus
Management and organization
Investment adviser Capital Research and Management Company, an experienced investment management organization founded in 1931, serves as the investment adviser to the Series and other funds, including the American Funds. Capital Research and Management Company is a wholly owned subsidiary of The Capital Group Companies, Inc. and is located at 333 South Hope Street, Los Angeles, California 90071. Capital Research and Management Company manages the investment portfolios and business affairs of the Series. The total management fee paid by each fund to its investment adviser for the most recent fiscal year, including any amounts waived, in each case expressed as a percentage of average net assets of that fund, appears in the Annual Fund Operating Expenses table for each fund. Please see the statement of additional information for further details. A discussion regarding the basis for the approval of the Series’ Investment Advisory and Service Agreement by the Series’ board of trustees is contained in the Series’ annual report to shareholders for the fiscal year ended December 31, 2021.
Capital Research and Management Company manages equity assets through three equity investment divisions and fixed income assets through its fixed income investment division, Capital Fixed Income Investors. The three equity investment divisions — Capital International Investors, Capital Research Global Investors and Capital World Investors — make investment decisions independently of one another.
The equity investment divisions may, in the future, be incorporated as wholly owned subsidiaries of Capital Research and Management Company. In that event, Capital Research and Management Company would continue to be the investment adviser, and day-to-day investment management of equity assets would continue to be carried out through one or more of these subsidiaries. Although not currently contemplated, Capital Research and Management Company could incorporate its fixed income investment division in the future and engage it to provide day-to-day investment management of fixed income assets. Capital Research and Management Company and each of the funds it advises have received an exemptive order from the U.S. Securities and Exchange Commission that allows Capital Research and Management Company to use, upon approval of the funds’ boards, its management subsidiaries and affiliates to provide day-to-day investment management services to the funds, including making changes to the management subsidiaries and affiliates providing such services. The Series’ shareholders approved this arrangement; however, there is no assurance that Capital Research and Management Company will incorporate its investment divisions or exercise any authority granted to it under the exemptive order.
In addition, shareholders of the Series have approved a proposal to reorganize the Series into a Delaware statutory trust. However, the Series reserved the right to delay implementing the reorganization and has elected to do so.
The Capital SystemSM Capital Research and Management Company uses a system of multiple portfolio managers in managing mutual fund assets. Under this approach, the portfolio of a fund is divided into segments managed by individual managers. In addition, Capital Research and Management Company’s investment analysts may make investment decisions with respect to a portion of a fund’s portfolio. Investment decisions are subject to a fund’s objective(s), policies and restrictions and the oversight of the appropriate investment-related committees of Capital Research and Management Company and its investment divisions.
Certain senior members of Capital Fixed Income Investors, the investment adviser’s fixed income investment division, serve on the Portfolio Strategy Group. The group utilizes a research-driven process with input from the investment adviser’s analysts, portfolio managers and economists to define investment themes on a range of macroeconomic factors, including duration, yield curve and sector allocation. Where applicable, the investment decisions made by a fund’s fixed income portfolio managers are informed by the investment themes discussed by the group.
American Funds Insurance Series / Prospectus 10
The primary individual portfolio managers for each of the funds are:
| Portfolio
manager for the Series/Title (if applicable) |
Primary title with investment adviser (or affiliate) and investment experience | Portfolio
manager’s role in management of, and experience in, the fund(s) |
| Donald D. O’Neal Co-President and Trustee | Partner – Capital International Investors Investment professional for 36 years, all with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: Growth-Income Fund — 16 years |
| Alan N. Berro Co-President | Partner – Capital World Investors Investment professional for 37 years in total; 31 years with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: Washington Mutual Investors Fund — 5 years Asset Allocation Fund — 22 years |
| Carl M. Kawaja Vice President | Partner – Capital World Investors Investment professional for 35 years in total; 31 years with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: New World Fund — 23 years |
| Sung Lee Vice President | Partner – Capital Research Global Investors Investment professional for 28 years, all with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: Capital
World Growth and Income Fund — 1 year |
| Keiko McKibben Vice President | Partner – Capital Research Global Investors Investment professional for 28 years in total; 24 years with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: Growth-Income Fund — 8 years (plus 10 years of prior experience as an investment analyst for the fund) |
| Renaud H. Samyn Vice President | Partner – Capital Research Global Investors Investment professional for 21 years, all with Capital Research and Management Company or affiliate |
Serves as an equity portfolio manager for: Global Small Capitalization Fund — 3 years (plus
15 years of prior experience as an investment analyst for the fund) |
| Pramod Atluri | Partner – Capital Fixed Income Investors Investment professional for 24 years in total; 6 years with Capital Research and Management Company or affiliate |
Serves
as a fixed income portfolio manager for: The Bond Fund of America — 6 years |
| Aline Avzaradel | Partner – Capital International Investors Investment professional for 19 years in total; 18 years with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: Capital Income Builder — 2 years |
| Alfonso Barroso | Partner – Capital Research Global Investors Investment professional for 28 years, all with Capital Research and Management Company or affiliate |
Serves as an equity portfolio manager for: Capital
World Growth and Income Fund — 1 year |
| Michael Beckwith | Vice President – Capital Research Global Investors Investment professional for 20 years in total; 3 years with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: Global Small Capitalization Fund — 3 years |
| Paul Benjamin | Partner – Capital World Investors Investment professional for 17 years, all with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: Growth Fund — 4 years (plus 12 years of prior experience as an investment analyst for the fund) |
| David J. Betanzos | Partner – Capital Fixed Income Investors Investment professional for 22 years in total; 20 years with Capital Research and Management Company or affiliate |
Serves
as a fixed income portfolio manager for: The Bond Fund of America — 1 year American Funds Mortgage Fund — 8 years U.S. Government Securities Fund — 7 years |
| Jeremy Burge | Partner – Capital World Investors Investment professional for 40 years in total; 20 years with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: Capital World Growth and Income Fund — 1 year (plus 1 year of prior experience as an investment analyst for the fund) |
| Grant L. Cambridge | Partner – Capital International Investors Investment professional for 29 years in total; 25 years with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: Capital Income Builder — 2 years |
| Mark L. Casey | Partner – Capital International Investors Investment professional for 22 years, all with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: Growth Fund — 5 years (plus 11 years of prior experience as an investment analyst for the fund) Washington Mutual Investors Fund — 1 year |
| Philip Chitty | Partner – Capital Fixed Income Investors Investment professional for 28 years in total; 18 years with Capital Research and Management Company or affiliate |
Serves
as a fixed income portfolio manager for: Capital World Bond Fund — 1 year |
| Tom Chow | Partner – Capital Fixed Income Investors Investment professional for 33 years in total; 7 years with Capital Research and Management Company or affiliate |
Serves
as a fixed income portfolio manager for: American High-Income Trust— 7 years |
11 American Funds Insurance Series / Prospectus
| Portfolio
manager for the Series/Title (if applicable) |
Primary title with investment adviser (or affiliate) and investment experience | Portfolio
manager’s role in management of, and experience in, the fund(s) |
| Michael Cohen | Partner – Capital World Investors Investment professional for 31 years in total; 22 years with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: Capital World Growth and Income Fund — 4 years International Growth and Income Fund — Less than 1 year |
| Patrice Collette | Partner – Capital World Investors Investment professional for 28 years in total; 22 years with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: Global Growth Fund — 7 years (plus 14 years of prior experience as an investment analyst for the fund) International Growth and Income Fund — Less than 1 year |
| Andrew A. Cormack | Vice President – Capital Fixed Income Investors Investment professional for 18 years in total; 4 years with Capital Research and Management Company or affiliate |
Serves
as a fixed income portfolio manager for: Capital World Bond Fund — 3 years |
| David A. Daigle | Partner – Capital Fixed Income Investors Investment professional for 28 years, all with Capital Research and Management Company or affiliate |
Serves
as a fixed income portfolio manager for: Asset Allocation Fund — 13 years American High-Income Trust— 13 years (plus 9 years of prior experience as an investment analyst for the fund) |
| Oliver V. Edmonds | Vice President – Capital Fixed Income Investors Investment professional for 19 years, all with Capital Research and Management Company or affiliate |
Serves
as a fixed income portfolio manager for: American Funds Mortgage Fund - 1 year |
| Peter Eliot | Partner – Capital International Investors Investment professional for 27 years in total; 18 years with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: Asset Allocation Fund — 6 years |
| Charles E. Ellwein | Partner – Capital Research Global Investors Investment professional for 26 years in total; 16 years with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: Growth-Income Fund — 7 years (plus 8 years of prior experience as an investment analyst for the fund) |
| Brady L. Enright | Partner – Capital World Investors Investment professional for 31 years in total; 25 years with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: Washington Mutual Investors Fund — 1 year |
| Paul Flynn | Partner – Capital World Investors Investment professional for 26 years in total; 24 years with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: Global Growth Fund — 5 years International Growth and Income Fund — Less than 1 year |
| J. Blair Frank | Partner – Capital Research Global Investors Investment professional for 29 years in total; 28 years with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: Growth-Income Fund — 16 years |
| Bradford F. Freer | Partner – Capital Research Global Investors Investment professional for 30 years in total; 28 years with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: Global Small Capitalization Fund — 4 years New World Fund — 5 years (plus 13 years of prior experience as an investment analyst for the fund) American Funds Global Balanced Fund – Less than 1 year |
| Irfan M. Furniturewala | Partner – Capital International Investors Investment
professional for |
Serves
as an equity portfolio manager for: (plus
1 year of prior experience as an investment analyst for the fund) |
| Nicholas J. Grace | Partner – Capital Research Global Investors Investment professional for 32 years in total; 28 years with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: New World Fund — 10 years (plus 8 years of prior experience as an investment analyst for the fund) |
| Leo Hee | Partner – Capital World Investors Investment
professional for 28 years in total; |
Serves
as an equity portfolio manager for: Capital World Growth and Income Fund — 1 year (plus 10 years of prior experience as an investment analyst for the fund) International Growth and Income Fund — Less than 1 year |
| David A. Hoag | Partner – Capital Fixed Income Investors Investment professional for 34 years in total; 31 years with Capital Research and Management Company or affiliate |
Serves
as a fixed income portfolio manager for: Capital Income Builder — 2 years The Bond Fund of America — 15 years |
| Thomas H. Høgh | Partner – Capital Fixed Income Investors Investment professional for 35 years in total; 32 years with Capital Research and Management Company or affiliate |
Serves
as a fixed income portfolio manager for: American Funds Global Balanced Fund — 3 years Capital World Bond Fund — 16 years |
| Roz Hongsaranagon | Partner – Capital World Investors Investment professional for 20 years, all with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: Global Growth Fund — 4 years |
| Dawid Justus | Partner – Capital World Investors Investment professional for 23 in total years; 17 years with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: New World Fund — 2 years (plus 14 years of prior experience as an investment analyst for the fund) |
American Funds Insurance Series / Prospectus 12
| Portfolio
manager for the Series/Title (if applicable) |
Primary title with investment adviser (or affiliate) and investment experience | Portfolio
manager’s role in management of, and experience in, the fund(s) |
| Jonathan Knowles | Partner – Capital World Investors Investment professional for 30 years, all with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: Global Growth Fund — 9 years (plus 10 years of prior experience as an investment analyst for the fund) New World Fund — 2 years (plus 8 years of prior experience as an investment analyst for the fund) |
| Winnie Kwan | Partner – Capital Research Global Investors Investment professional for 26 years in total; 22 years with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: New World Fund — 2 years (plus 2 years of prior experience as an investment analyst for the fund) Capital Income Builder — 2 years American Funds Global Balanced Fund –Less than 1 year |
| Harold H. La | Partner – Capital Research Global Investors Investment professional for 24 years in total; 23 years with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: Global Small Capitalization Fund — 14 years (plus 4 years of prior experience as an investment analyst for the fund) |
| Jeffrey T. Lager | Partner – Capital International Investors Investment professional for 27 years in total; 26 years with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: Washington Mutual Investors Fund — 1 year Asset Allocation Fund — 15 years |
| Jin Lee | Partner – Capital World Investors Investment professional for 26 years in total; 25 years with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: Washington Mutual Investors Fund — 1 year Capital World Growth and Income Fund— 1 year Asset Allocation Fund — 4 years |
| Steven D. Lotwin | Partner – Capital Fixed Income Investors Investment professional for 21 years, all with Capital Research and Management Company or affiliate |
Serves
as a fixed income portfolio manager for: Ultra-Short Bond Fund — 4 years |
| James B. Lovelace | Partner – Capital Research Global Investors Investment professional for 40 years, all with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: Capital Income Builder — 2 years |
| Robert W. Lovelace | Partner – Capital International Investors Investment professional for 37 years, all with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: New World Fund — 2 years |
| Fergus N. MacDonald | Partner – Capital Fixed Income Investors Investment professional for 30 years in total; 19 years with Capital Research and Management Company or affiliate |
Serves
as a fixed income portfolio manager for: Capital Income Builder — 2 years The Bond Fund of America — 1 year American Funds Mortgage Fund — 11 years U.S. Government Securities Fund — 12 years |
| Aidan O’Connell | Partner – Capital Research Global Investors Investment professional for 24 years in total; 18 years with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: Global Small Capitalization Fund — 8 years (plus 9 years of prior experience as an investment analyst for the fund) |
| Lara Pellini | Partner – Capital World Investors Investment professional for 21 years, all with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: Capital World Growth and Income Fund — 1 year (plus 10 years of prior experience as an investment analyst for the fund) |
| Piyada Phanaphat | Partner – Capital World Investors Investment professional for 19 years in total; 15 years with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: New World Fund — 5 years (plus 9 years of prior experience as an investment analyst for the fund) |
| Anne-Marie Peterson | Partner – Capital World Investors Investment professional for 28 years in total; 17 years with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: Growth Fund — 4 years (plus 11 years of prior experience as an investment analyst for the fund) |
| John R. Queen | Partner – Capital Fixed Income Investors Investment professional for 32 years in total; 20 years with Capital Research and Management Company or affiliate |
Serves
as a fixed income portfolio manager for: Asset Allocation Fund — 6 years |
| Caroline Randall | Partner – Capital Research Global Investors Investment professional for 25 years in total; 17 years with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: Capital Income Builder — 2 years |
| Andraz Razen | Partner – Capital World Investors Investment professional for 24 years in total; 18 years with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: Growth Fund — 9 years (plus 3 years of prior experience as an investment analyst for the fund) |
| William L. Robbins | Partner – Capital International Investors Investment professional for 30 years in total; 27 years with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: Growth-Income Fund — 10 years (plus 12 years of prior experience as an investment analyst for the fund) |
| Carlos A. Schonfeld | Partner – Capital International Investors Investment professional for 24 years, all with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: Growth-Income Fund — 8 years |
13 American Funds Insurance Series / Prospectus
| Portfolio
manager for the Series/Title (if applicable) |
Primary title with investment adviser (or affiliate) and investment experience | Portfolio
manager’s role in management of, and experience in, the fund(s) |
| Akira Shiraishi | Partner – Capital International Investors Investment professional for 25 years in total; 19 years with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: New World Fund — 2 years |
| Kirstie Spence | Partner – Capital Fixed Income Investors Investment professional for 27 years, all with Capital Research and Management Company or affiliate |
Serves
as a fixed income portfolio manager for: New World Fund — 2 years (plus 9 years of prior experience as an investment analyst for the fund) |
| Eric H. Stern | Partner – Capital International Investors Investment
professional for |
Serves
as an equity portfolio manager for: Washington Mutual Investors Fund — 1 year |
| Andrew B. Suzman | Partner – Capital World Investors Investment professional for 29 years, all with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: International Growth and Income Fund — Less than 1 year |
| Tomonori Tani | Partner – Capital World Investors Investment professional for 24 years in total; 18 years with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: New World Fund — 4 years |
| Lisa Thompson | Partner – Capital International Investors Investment professional for 34 years in total; 28 years with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: New World Fund — 2 years International Growth and Income Fund — Less than 1 year |
| Christopher Thomsen | Partner – Capital Research Global Investors Investment professional for 25 years, all with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: International Fund — 16 years New World Fund — 2 years |
| Tara L. Torrens | Partner – Capital Fixed Income Investors Investment professional for 19 years, all with Capital Research and Management Company or affiliate |
Serves
as a fixed income portfolio manager for: American High-Income Trust —4 years |
| Ritchie Tuazon | Partner – Capital Fixed Income Investors Investment professional for 22 years in total; 11 years with Capital Research and Management Company or affiliate |
Serves
as a fixed income portfolio manager for: U.S. Government Securities Fund — 7 years |
| Bradley J. Vogt | Partner – Capital Research Global Investors Investment professional for 35 years, all with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: Capital Income Builder — 2 years |
| Diana Wagner | Partner – Capital World Investors Investment
professional for |
Serves
as an equity portfolio manager for: Washington Mutual Investors Fund — 1 year |
| Shannon Ward | Partner – Capital Fixed Income Investors Investment professional for 30 years in total; 5 years with Capital Research and Management Company or affiliate |
Serves
as a fixed income portfolio manager for: American High-Income Trust — 5 years |
| Steven T. Watson | Partner – Capital International Investors Investment professional for 35 years in total; 32 years with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: Capital Income Builder — 4 years International Growth and Income Fund — Less than 1 year |
| Gregory W. Wendt | Partner – Capital Research Global Investors Investment professional for 35 years, all with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: Global Small Capitalization Fund — 10 years (plus 14 years of prior experience as an investment analyst for the fund) |
| Alan J. Wilson | Partner – Capital World Investors Investment
professional for |
Serves
as an equity portfolio manager for: Growth Fund — 8 years Washington Mutual Investors Fund — 1 year |
| Philip Winston | Partner – Capital International Investors Investment professional for 37 years in total; 25 years with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: Capital Income Builder — 8 years |
Information regarding the portfolio managers’ compensation, their ownership of securities in the Series and other accounts they manage is in the statement of additional information.
American Funds Insurance Series / Prospectus 14
Purchases and redemptions of shares Shares of the Series are currently offered only to insurance company separate accounts as well as so-called “feeder funds” under master-feeder arrangements sponsored by insurance companies as underlying investments for such insurance companies’ variable annuity contracts and variable life insurance policies. All such shares may be purchased or redeemed by the insurance company separate accounts (or feeder funds) at net asset value without any sales or redemption charges. These purchases and redemptions are made at the price next determined after such purchases and redemptions of units of the separate accounts (or feeder funds). The Series typically expects to remit redemption proceeds one business day following receipt and acceptance of a redemption order, regardless of the method the Series uses to make such payment (e.g., check, wire or automated clearing house transfer). However, payment may take longer than one business day and may take up to seven days as generally permitted by the Investment Company Act of 1940, as amended (the “1940 Act”). Under the 1940 Act, the Series may be permitted to pay redemption proceeds beyond seven days under certain limited circumstances.
Under normal conditions, the Series typically expects to meet shareholder redemptions by monitoring the Series’ portfolio and redemption activities and by regularly holding a reserve of highly liquid assets, such as cash or cash equivalents. The Series may use additional methods to meet shareholder redemptions, if they become necessary. These methods may include, but are not limited to, the sale of portfolio assets, the use of overdraft protection afforded by the Series’ custodian bank, borrowing from a line of credit and making payment with fund securities or other fund assets rather than in cash (as further discussed in the following paragraph).
Although payment of redemptions normally will be in cash, the Series may pay the redemption price wholly or partly with portfolio securities or other fund assets under conditions and circumstances determined by the Series’ board of trustees. On the same redemption date, some shareholders may be paid in whole or in part in securities (which may differ among those shareholders), while other shareholders may be paid entirely in cash. In general, in-kind redemptions to affiliated shareholders will as closely as practicable represent the affiliated shareholder’s pro rata share of the Series’ securities, subject to certain exceptions. Securities distributed in-kind to unaffiliated shareholders will be selected by the investment adviser in a manner the investment adviser deems to be fair and reasonable to the Series’ shareholders. The disposal of the securities received in-kind may be subject to brokerage costs and, until sold, such securities remain subject to market risk and liquidity risk, including the risk that such securities are or become difficult to sell. If the Series pays your redemption with illiquid or less liquid securities, you will bear the risk of not being able to sell such securities.
15 American Funds Insurance Series / Prospectus
Frequent trading of fund shares The Series and American Funds Distributors, Inc., the Series’ distributor, reserve the right to reject any purchase order for any reason. The funds are not designed to serve as vehicles for frequent trading. Frequent trading of fund shares may lead to increased costs to the funds and less efficient management of the funds’ portfolios, potentially resulting in dilution of the value of the shares held by long-term shareholders. Accordingly, purchases, including those that are part of exchange activity, that the Series or American Funds Distributors has determined could involve actual or potential harm to a fund may be rejected.
The Series, through its transfer agent, American Funds Service Company, has agreements with the Series’ insurance relationships to maintain its surveillance procedures that are designed to detect frequent trading in fund shares. The agreements generally require the insurance companies to (i) provide, upon request from a fund, the Series or their agent, certain identifying and account information regarding contract owners who invest in fund shares through an insurance company account and (ii) execute instructions from a fund, the Series or their agent to restrict further purchases or exchanges of fund shares by a contract owner who the Series has identified as having engaged in potentially harmful market timing or frequent trading. Under these procedures, various analytics are used to evaluate factors that may be indicative of frequent trading. For example, transactions in fund shares that exceed certain monetary thresholds may be scrutinized. American Funds Service Company may work with the insurance company separate accounts or feeder funds to apply their procedures that American Funds Service Company believes are reasonably designed to enforce the frequent trading policies of the Series. You should refer to disclosures provided by the insurance company with which you have a contract to determine the specific trading restrictions that apply to you.
Under the Series’ frequent trading policy, certain trading activity will not be treated as frequent trading, such as:
· retirement plan contributions, loans and distributions (including hardship withdrawals) identified as such on the retirement plan recordkeeper’s system;
· purchase transactions involving in-kind transfers of fund shares, if the entity maintaining the contract owner’s account is able to identify the transaction as one of these types of transactions; and
· systematic redemptions and purchases if the entity maintaining the contract owner’s account is able to identify the transaction as a systematic redemption or purchase.
Generally, purchases and redemptions will not be considered “systematic” unless the transaction is prescheduled for a specific date.
American Funds Service Company will monitor for other types of activity that could potentially be harmful to the Series – for example short-term trading activity in multiple funds. If American Funds Service Company identifies any activity that may constitute frequent trading, it reserves the right to contact the insurance company separate account or feeder fund and request that the separate account or feeder fund either provide information regarding an account owner’s transactions or restrict the account owner’s trading. If American Funds Service Company is not satisfied that insurance company separate account or feeder fund has taken appropriate action, American Funds Service Company may terminate the separate account’s or feeder fund’s ability to transact in fund shares.
There is no guarantee that all instances of frequent trading in fund shares will be prevented.
Notwithstanding the Series’ surveillance procedures described above, all transactions in fund shares remain subject to the right of the Series, American Funds Distributors and American Funds Service Company to restrict potentially abusive trading generally, including the types of transactions described above that will not be prevented.
American Funds Insurance Series / Prospectus 16
Valuing shares The net asset value of each share class of a fund is the value of a single share of that class. The net asset value per share is calculated once daily as of the close of regular trading on the New York Stock Exchange, normally 4 p.m. New York time, each day the New York Stock Exchange is open. If the New York Stock Exchange makes a scheduled (e.g. the day after Thanksgiving) or an unscheduled close prior to 4 p.m. New York time, the net asset value of each fund will be determined at approximately the time the New York Stock Exchange closes on that day. If on such a day market quotations and prices from third-party pricing services are not based as of the time of the early close of the New York Stock Exchange but are as of a later time (up to approximately 4 p.m. New York time), for example because the market remains open after the close of the New York Stock Exchange, those later market quotations and prices will be used in determining the funds’ net asset value.
Equity securities are valued primarily on the basis of market quotations, and debt securities are valued primarily on the basis of prices from third-party pricing services. Futures contracts are valued primarily on the basis of settlement prices. The funds have adopted procedures for making fair value determinations if market quotations or prices from third-party pricing services, as applicable, are not readily available or are not considered reliable. For example, if events occur between the close of markets outside the United States and the close of regular trading on the New York Stock Exchange that, in the opinion of the investment adviser, materially affect the value of any of the funds’ equity securities that trade principally in those international markets, those securities will be valued in accordance with fair value procedures. Similarly, fair value procedures may be employed if an issuer defaults on its debt securities and there is no market for its securities. Use of these procedures is intended to result in more appropriate net asset values and, where applicable, to reduce potential arbitrage opportunities otherwise available to short-term investors.
Because certain of the funds may hold securities that are listed primarily on foreign exchanges that trade on weekends or days when the funds do not price their shares, the values of securities held in the funds may change on days when you will not be able to purchase or redeem fund shares.
Shares of the funds will be purchased or sold at the net asset value next determined after receipt of requests from the appropriate insurance company. Requests received by the appropriate insurance company prior to 4 p.m. New York time and communicated by the insurance company to the Series or its agent will be purchased or sold at that day’s net asset value. Orders in good order received after the New York Stock Exchange closes (scheduled or unscheduled) will be processed at the net asset value (plus any applicable sales charge) calculated on the following business day.
17 American Funds Insurance Series / Prospectus
Plan of distribution The Series has adopted a plan of distribution or “12b-1 plan” for Class 2 shares. Under the plan, the Series may finance activities primarily intended to sell shares, provided the categories of expenses are approved in advance by the Series’ board of trustees. The plan provides for annual expenses of .25% for Class 2 shares. Amounts paid under the 12b-1 plan are used by insurance company contract issuers to cover distribution expenses and/or the expenses of certain contract owner services. The 12b-1 fees paid by the Series, as a percentage of average net assets, for the most recent fiscal year, are indicated in the prospectus in the Annual Fund Operating Expenses table for each fund. Since these fees are paid out of the Series’ assets on an ongoing basis, over time they may cost you more than paying other types of sales charges or service fees and reduce the return of an investment in Class 2 shares.
Other compensation to dealers American Funds Distributors, at its expense, provides additional compensation to insurance companies. These payments may be made, at the discretion of American Funds Distributors, to insurance companies (or their affiliates) that have sold shares of the funds of the American Funds Insurance Series and American Funds as the exclusive underlying investments to their variable contracts. A number of factors will be considered in determining payments, including the sales, assets, and the quality of the company’s relationship with American Funds Distributors. The payment will be determined using a formula applied consistently to insurance companies based on the relevant facts and circumstances. The level of payments made to a qualifying firm in any given year will vary and (excluding payments for meetings as described below) will represent the sum of (a) up to .14% of the current year’s American Funds Insurance Series new deposits in the contracts, (b) up to .07% of the current and previous year’s American Funds Insurance Series new deposits in the contracts, and (c) up to .0084% of American Funds Insurance Series assets attributable to the contracts, with an adjustment made for the quality of the company’s relationship with American Funds Distributors. Aggregate payments made by American Funds Distributors to insurance companies may also change from year to year. Only assets and deposits in variable annuity contracts that offer exclusively shares of the American Funds Insurance Series and American Funds are included in the formula. Further, assets for which the insurance company, or an affiliated broker-dealer, acts as an ERISA investment fiduciary are generally excluded from the formula. American Funds Distributors makes these payments to help defray the costs incurred by qualifying insurance companies in connection with efforts to educate its sales force about the American Funds Insurance Series so that they help financial advisers make recommendations and provide services that are suitable and meet contractholders needs. These payments may also be made to help defray the costs associated with the insurance company’s provision of account related services and activities and support the insurance company’s distribution activities. American Funds Distributors will, on an annual basis, determine the advisability of continuing these payments.
Firms receiving additional compensation payments must sign a letter acknowledging the purpose of the payment and American Funds Distributors’ goal that the payment will help facilitate education of the firm’s sales force about the American Funds Insurance Series and American Funds to help financial professionals make suitable recommendations and better serve their clients who invest in the funds as underlying investments to variable contracts. The letters generally require the firms to (1) have significant assets invested in the American Funds, (2) provide American Funds Distributors broad access to their sales force and product platforms and develop a business plan to achieve such access, and (3) agree to maintain American Funds within their existing products.
American Funds Distributors may also pay expenses associated with meetings and other training and educational opportunities conducted by insurance companies, selling dealers, advisory platform providers and other intermediaries to facilitate educating financial professionals and shareholders about the American Funds. For example, some of these expenses may include, but not be limited to, meeting sponsor fees, meeting location fees, and fees to obtain lists of financial professionals to better tailor training and education opportunities.
If investment advisers, distributors or other affiliates of mutual funds pay additional compensation or other incentives to insurance companies in differing amounts, insurance companies and the financial professionals with which they interact may have financial incentives for recommending a particular mutual fund over other mutual funds or investments, creating a potential conflict of interest. You should consult with your financial professional and review carefully any disclosure by your financial professional’s firm as to compensation received.
American Funds Insurance Series / Prospectus 18
Fund expenses In periods of market volatility, assets of the funds may decline significantly, causing total annual fund operating expenses (as a percentage of the value of your investment) to become higher than the numbers shown in the Annual Fund Operating Expenses tables in this prospectus.
The “Other expenses” items in the Annual Fund Operating Expenses tables in this prospectus are based on expenses as of each fund’s most recently completed fiscal year. These items include third-party expenses, such as custodial, legal, audit, accounting, regulatory reporting and pricing vendor services, and an administrative services fee payable to the Series’ investment adviser for administrative services provided by the Series’ investment adviser and its affiliates.
For all share classes, “Other expenses” items in the Annual Fund Operating Expenses table in this prospectus include fees for administrative services provided by the fund’s investment adviser and its affiliates. Administrative services are provided by the investment adviser and its affiliates to help assist third parties providing non-distribution services to fund shareholders. These services include providing in-depth information on the fund and market developments that impact fund investments. Administrative services also include, but are not limited to, coordinating, monitoring and overseeing third parties that provide services to fund shareholders.
The Administrative Services Agreement between the fund and the investment adviser provides the fund the ability to charge an administrative services fee of .05% for all share classes. The fund's investment adviser receives an administrative services fee at the annual rate of .03% of the average daily net assets of the fund attributable to all share classes (which could be increased as noted above) for its provision of administrative services.
Investment results All fund results in the “Investment results” section of this prospectus reflect the reinvestment of dividends and capital gains distributions, if any. Unless otherwise noted, fund results reflect any fee waivers and/or expense reimbursements in effect during the period presented.
Distributions and taxes Each fund of the Series intends to qualify as a “regulated investment company” under the Internal Revenue Code. In any fiscal year in which a fund so qualifies and distributes to shareholders its investment company taxable income and net realized capital gain, the fund itself is relieved of federal income tax.
It is the Series’ policy to distribute to the shareholders (the insurance company separate accounts) all of its investment company taxable income and capital gain for each fiscal year.
See the applicable contract prospectus for information regarding the federal income tax treatment of the contracts and distributions to the separate accounts.
19 American Funds Insurance Series / Prospectus
Financial highlights The Financial Highlights table is intended to help you understand a fund’s results for the past five fiscal years. . Certain information reflects financial results for a single share of a particular class. The total returns in the table represent the rate that an investor would have earned or lost on an investment in a fund (assuming reinvestment of all dividends and capital gain distributions). Where indicated, figures in the table reflect the impact, if any, of certain waivers from Capital Research and Management Company. For more information about these waivers, see the fund's statement of additional information and annual report. The information in the Financial Highlights table has been audited by PricewaterhouseCoopers LLP, whose current report, along with the funds’ financial statements, is included in the statement of additional information, which is available upon request. Figures shown do not reflect insurance contract fees and expenses. If insurance contract fees and expenses were reflected, results would be lower.
| Income
(loss) from investment operations1 |
Dividends and distributions | |||||||||||||||||||||||||
| Period ended | Net
asset value, beginning of period |
Net investment income |
Net
gains (losses) on securities (both realized and unrealized) |
Total
from investment operations |
Dividends (from net investment income) |
Distributions (from capital gains) |
Total dividends and distributions |
Net
asset value, end of period |
Total return2 |
Net
assets, end of period (in millions) |
Ratio
of expenses to average net assets before waivers3 |
Ratio
of expenses to average net assets after waivers2,3 |
Ratio
of net income to average net assets2 | |||||||||||||
| Global Growth Fund | ||||||||||||||||||||||||||
| Class 1: | ||||||||||||||||||||||||||
| 12/31/2021 | $41.16 | $.25 | $6.48 | $6.73 | $(.26 | ) | $(2.17 | ) | $(2.43 | ) | $45.46 | 16.72 | % | $4,270 | .55 | % | .54 | % | .56 | % | ||||||
| 12/31/2020 | 32.57 | .20 | 9.56 | 9.76 | (.21 | ) | (.96 | ) | (1.17 | ) | 41.16 | 30.79 | 3,309 | .56 | .56 | .59 | ||||||||||
| 12/31/2019 | 25.74 | .32 | 8.60 | 8.92 | (.41 | ) | (1.68 | ) | (2.09 | ) | 32.57 | 35.61 | 2,515 | .56 | .56 | 1.07 | ||||||||||
| 12/31/2018 | 30.51 | .29 | (2.65 | ) | (2.36 | ) | (.28 | ) | (2.13 | ) | (2.41 | ) | 25.74 | (8.81 | ) | 1,942 | .55 | .55 | .98 | |||||||
| 12/31/2017 | 24.05 | .26 | 7.30 | 7.56 | (.26 | ) | (.84 | ) | (1.10 | ) | 30.51 | 31.80 | 2,010 | .55 | .55 | .94 | ||||||||||
| Class 1A: | ||||||||||||||||||||||||||
| 12/31/2021 | 41.02 | .14 | 6.46 | 6.60 | (.17 | ) | (2.17 | ) | (2.34 | ) | 45.28 | 16.45 | 18 | .80 | .79 | .33 | ||||||||||
| 12/31/2020 | 32.47 | .12 | 9.52 | 9.64 | (.13 | ) | (.96 | ) | (1.09 | ) | 41.02 | 30.49 | 12 | .81 | .81 | .34 | ||||||||||
| 12/31/2019 | 25.69 | .25 | 8.55 | 8.80 | (.34 | ) | (1.68 | ) | (2.02 | ) | 32.47 | 35.22 | 8 | .81 | .81 | .83 | ||||||||||
| 12/31/2018 | 30.46 | .23 | (2.66 | ) | (2.43 | ) | (.21 | ) | (2.13 | ) | (2.34 | ) | 25.69 | (9.02 | ) | 5 | .80 | .80 | .77 | |||||||
| 12/31/20174,5 | 24.50 | .11 | 6.94 | 7.05 | (.25 | ) | (.84 | ) | (1.09 | ) | 30.46 | 29.13 | 6 | 2 | .80 | 7 | .80 | 7 | .39 | 7 | ||||||
| Class 2: | ||||||||||||||||||||||||||
| 12/31/2021 | 40.72 | .13 | 6.41 | 6.54 | (.15 | ) | (2.17 | ) | (2.32 | ) | 44.94 | 16.42 | 4,559 | .80 | .80 | .30 | ||||||||||
| 12/31/2020 | 32.24 | .12 | 9.44 | 9.56 | (.12 | ) | (.96 | ) | (1.08 | ) | 40.72 | 30.47 | 4,387 | .81 | .81 | .34 | ||||||||||
| 12/31/2019 | 25.50 | .24 | 8.51 | 8.75 | (.33 | ) | (1.68 | ) | (2.01 | ) | 32.24 | 35.28 | 3,895 | .81 | .81 | .83 | ||||||||||
| 12/31/2018 | 30.24 | .22 | (2.63 | ) | (2.41 | ) | (.20 | ) | (2.13 | ) | (2.33 | ) | 25.50 | (9.04 | ) | 3,306 | .80 | .80 | .73 | |||||||
| 12/31/2017 | 23.85 | .19 | 7.23 | 7.42 | (.19 | ) | (.84 | ) | (1.03 | ) | 30.24 | 31.47 | 4,012 | .80 | .80 | .69 | ||||||||||
| Class 4: | ||||||||||||||||||||||||||
| 12/31/2021 | 40.45 | .03 | 6.35 | 6.38 | (.09 | ) | (2.17 | ) | (2.26 | ) | 44.57 | 16.14 | 744 | 1.05 | 1.04 | .07 | ||||||||||
| 12/31/2020 | 32.05 | .03 | 9.38 | 9.41 | (.05 | ) | (.96 | ) | (1.01 | ) | 40.45 | 30.17 | 533 | 1.06 | 1.06 | .09 | ||||||||||
| 12/31/2019 | 25.39 | .17 | 8.45 | 8.62 | (.28 | ) | (1.68 | ) | (1.96 | ) | 32.05 | 34.87 | 382 | 1.06 | 1.06 | .57 | ||||||||||
| 12/31/2018 | 30.13 | .14 | (2.60 | ) | (2.46 | ) | (.15 | ) | (2.13 | ) | (2.28 | ) | 25.39 | (9.24 | ) | 249 | 1.05 | 1.05 | .47 | |||||||
| 12/31/2017 | 23.81 | .10 | 7.22 | 7.32 | (.16 | ) | (.84 | ) | (1.00 | ) | 30.13 | 31.11 | 211 | 1.05 | 1.05 | .37 | ||||||||||
American Funds Insurance Series / Prospectus 20
| Income
(loss) from investment operations1 |
Dividends and distributions | |||||||||||||||||||||||
| Period ended | Net
asset value, beginning of period |
Net investment (loss) income |
Net
gains (losses) on securities (both realized and unrealized) |
Total
from investment operations |
Dividends (from net investment income) |
Distributions (from capital gains) |
Total dividends and distributions |
Net
asset value, end of period |
Total return |
Net
assets, end of period (in millions) |
Ratio
of expenses to average net assets3 |
Ratio
of net (loss) income to average net assets | ||||||||||||
| Global Small Capitalization Fund | ||||||||||||||||||||||||
| Class 1: | ||||||||||||||||||||||||
| 12/31/2021 | $32.64 | $(.02 | ) | $2.32 | $2.30 | $— | $(.77 | ) | $(.77 | ) | $34.17 | 6.98 | % | $1,707 | .74 | % | (.07 | )% | ||||||
| 12/31/2020 | 26.80 | (.01 | ) | 7.49 | 7.48 | (.05 | ) | (1.59 | ) | (1.64 | ) | 32.64 | 30.04 | 2,391 | .75 | (.06 | ) | |||||||
| 12/31/2019 | 21.75 | .12 | 6.61 | 6.73 | (.10 | ) | (1.58 | ) | (1.68 | ) | 26.80 | 31.84 | 2,050 | .75 | .48 | |||||||||
| 12/31/2018 | 25.38 | .11 | (2.51 | ) | (2.40 | ) | (.09 | ) | (1.14 | ) | (1.23 | ) | 21.75 | (10.31 | ) | 1,453 | .73 | .42 | ||||||
| 12/31/2017 | 20.24 | .12 | 5.17 | 5.29 | (.15 | ) | — | (.15 | ) | 25.38 | 26.22 | 1,639 | .73 | .54 | ||||||||||
| Class 1A: | ||||||||||||||||||||||||
| 12/31/2021 | 32.49 | (.07 | ) | 2.28 | 2.21 | — | (.77 | ) | (.77 | ) | 33.93 | 6.73 | 5 | .99 | (.21 | ) | ||||||||
| 12/31/2020 | 26.74 | (.09 | ) | 7.48 | 7.39 | (.05 | ) | (1.59 | ) | (1.64 | ) | 32.49 | 29.72 | 1 | .99 | (.33 | ) | |||||||
| 12/31/2019 | 21.71 | .05 | 6.61 | 6.66 | (.05 | ) | (1.58 | ) | (1.63 | ) | 26.74 | 31.56 | 1 | .99 | .22 | |||||||||
| 12/31/2018 | 25.36 | .05 | (2.52 | ) | (2.47 | ) | (.04 | ) | (1.14 | ) | (1.18 | ) | 21.71 | (10.56 | ) | — | 8 | .98 | .21 | |||||
| 12/31/20174,5 | 20.70 | .08 | 4.71 | 4.79 | (.13 | ) | — | (.13 | ) | 25.36 | 23.19 | 6 | — | 8 | .96 | 7 | .35 | 7 | ||||||
| Class 2: | ||||||||||||||||||||||||
| 12/31/2021 | 31.56 | (.10 | ) | 2.25 | 2.15 | — | (.77 | ) | (.77 | ) | 32.94 | 6.74 | 2,521 | .99 | (.30 | ) | ||||||||
| 12/31/2020 | 26.02 | (.08 | ) | 7.25 | 7.17 | (.04 | ) | (1.59 | ) | (1.63 | ) | 31.56 | 29.72 | 2,653 | 1.00 | (.31 | ) | |||||||
| 12/31/2019 | 21.16 | .05 | 6.43 | 6.48 | (.04 | ) | (1.58 | ) | (1.62 | ) | 26.02 | 31.52 | 2,363 | 1.00 | .22 | |||||||||
| 12/31/2018 | 24.72 | .04 | (2.44 | ) | (2.40 | ) | (.02 | ) | (1.14 | ) | (1.16 | ) | 21.16 | (10.55 | ) | 2,056 | .98 | .17 | ||||||
| 12/31/2017 | 19.72 | .06 | 5.04 | 5.10 | (.10 | ) | — | (.10 | ) | 24.72 | 25.89 | 2,551 | .98 | .27 | ||||||||||
| Class 4: | ||||||||||||||||||||||||
| 12/31/2021 | 31.67 | (.18 | ) | 2.24 | 2.06 | — | (.77 | ) | (.77 | ) | 32.96 | 6.43 | 344 | 1.24 | (.53 | ) | ||||||||
| 12/31/2020 | 26.16 | (.14 | ) | 7.27 | 7.13 | (.03 | ) | (1.59 | ) | (1.62 | ) | 31.67 | 29.39 | 268 | 1.25 | (.56 | ) | |||||||
| 12/31/2019 | 21.28 | (.01 | ) | 6.47 | 6.46 | — | 9 | (1.58 | ) | (1.58 | ) | 26.16 | 31.24 | 206 | 1.25 | (.04 | ) | |||||||
| 12/31/2018 | 24.91 | (.02 | ) | (2.46 | ) | (2.48 | ) | (.01 | ) | (1.14 | ) | (1.15 | ) | 21.28 | (10.80 | ) | 146 | 1.24 | (.08 | ) | ||||
| 12/31/2017 | 19.91 | — | 9 | 5.09 | 5.09 | (.09 | ) | — | (.09 | ) | 24.91 | 25.62 | 125 | 1.23 | — | 10 | ||||||||
| Income
from investment operations1 |
Dividends and distributions | |||||||||||||||||||||||
| Period ended | Net
asset value, beginning of period |
Net investment income (loss) |
Net
gains on securities (both realized and unrealized) |
Total
from investment operations |
Dividends (from net investment income) |
Distributions (from capital gains) |
Total dividends and distributions |
Net
asset value, end of period |
Total return |
Net
assets, end of period (in millions) |
Ratio
of expenses to average net assets3 |
Ratio
of net income (loss) to average net assets | ||||||||||||
| Growth Fund | ||||||||||||||||||||||||
| Class 1: | ||||||||||||||||||||||||
| 12/31/2021 | $120.22 | $.46 | $24.29 | $24.75 | $(.58 | ) | $(16.81 | ) | $(17.39 | ) | $127.58 | 22.30 | % | $19,783 | .34 | % | .37 | % | ||||||
| 12/31/2020 | 81.22 | .43 | 41.28 | 41.71 | (.53 | ) | (2.18 | ) | (2.71 | ) | 120.22 | 52.45 | 15,644 | .35 | .46 | |||||||||
| 12/31/2019 | 69.96 | .83 | 19.63 | 20.46 | (.76 | ) | (8.44 | ) | (9.20 | ) | 81.22 | 31.11 | 10,841 | .35 | 1.09 | |||||||||
| 12/31/2018 | 77.85 | .64 | .25 | .89 | (.54 | ) | (8.24 | ) | (8.78 | ) | 69.96 | (.01 | ) | 8,474 | .34 | .81 | ||||||||
| 12/31/2017 | 67.29 | .55 | 17.89 | 18.44 | (.55 | ) | (7.33 | ) | (7.88 | ) | 77.85 | 28.62 | 8,100 | .35 | .75 | |||||||||
| Class 1A: | ||||||||||||||||||||||||
| 12/31/2021 | 119.59 | .16 | 24.11 | 24.27 | (.35 | ) | (16.81 | ) | (17.16 | ) | 126.70 | 21.97 | 121 | .59 | .13 | |||||||||
| 12/31/2020 | 80.92 | .20 | 41.05 | 41.25 | (.40 | ) | (2.18 | ) | (2.58 | ) | 119.59 | 52.07 | 60 | .60 | .21 | |||||||||
| 12/31/2019 | 69.77 | .65 | 19.55 | 20.20 | (.61 | ) | (8.44 | ) | (9.05 | ) | 80.92 | 30.79 | 18 | .60 | .85 | |||||||||
| 12/31/2018 | 77.74 | .47 | .24 | .71 | (.44 | ) | (8.24 | ) | (8.68 | ) | 69.77 | (.26 | ) | 10 | .59 | .60 | ||||||||
| 12/31/20174,5 | 68.84 | .35 | 16.38 | 16.73 | (.50 | ) | (7.33 | ) | (7.83 | ) | 77.74 | 25.47 | 6 | 3 | .59 | 7 | .47 | 7 | ||||||
| Class 2: | ||||||||||||||||||||||||
| 12/31/2021 | 119.18 | .15 | 24.03 | 24.18 | (.27 | ) | (16.81 | ) | (17.08 | ) | 126.28 | 21.97 | 21,986 | .59 | .12 | |||||||||
| 12/31/2020 | 80.57 | .19 | 40.89 | 41.08 | (.29 | ) | (2.18 | ) | (2.47 | ) | 119.18 | 52.10 | 20,594 | .60 | .21 | |||||||||
| 12/31/2019 | 69.48 | .63 | 19.47 | 20.10 | (.57 | ) | (8.44 | ) | (9.01 | ) | 80.57 | 30.77 | 15,885 | .60 | .83 | |||||||||
| 12/31/2018 | 77.35 | .44 | .27 | .71 | (.34 | ) | (8.24 | ) | (8.58 | ) | 69.48 | (.25 | ) | 13,701 | .59 | .55 | ||||||||
| 12/31/2017 | 66.92 | .37 | 17.76 | 18.13 | (.37 | ) | (7.33 | ) | (7.70 | ) | 77.35 | 28.28 | 15,716 | .60 | .50 | |||||||||
| Class 3: | ||||||||||||||||||||||||
| 12/31/2021 | 121.13 | .24 | 24.47 | 24.71 | (.35 | ) | (16.81 | ) | (17.16 | ) | 128.68 | 22.07 | 302 | .52 | .19 | |||||||||
| 12/31/2020 | 81.84 | .26 | 41.56 | 41.82 | (.35 | ) | (2.18 | ) | (2.53 | ) | 121.13 | 52.20 | 279 | .53 | .28 | |||||||||
| 12/31/2019 | 70.44 | .69 | 19.77 | 20.46 | (.62 | ) | (8.44 | ) | (9.06 | ) | 81.84 | 30.86 | 213 | .53 | .90 | |||||||||
| 12/31/2018 | 78.32 | .50 | .26 | .76 | (.40 | ) | (8.24 | ) | (8.64 | ) | 70.44 | (.18 | ) | 187 | .52 | .62 | ||||||||
| 12/31/2017 | 67.67 | .42 | 17.98 | 18.40 | (.42 | ) | (7.33 | ) | (7.75 | ) | 78.32 | 28.39 | 212 | .53 | .57 | |||||||||
| Class 4: | ||||||||||||||||||||||||
| 12/31/2021 | 117.24 | (.15 | ) | 23.59 | 23.44 | (.08 | ) | (16.81 | ) | (16.89 | ) | 123.79 | 21.69 | 3,214 | .84 | (.13 | ) | |||||||
| 12/31/2020 | 79.41 | (.04 | ) | 40.24 | 40.20 | (.19 | ) | (2.18 | ) | (2.37 | ) | 117.24 | 51.71 | 2,347 | .85 | (.04 | ) | |||||||
| 12/31/2019 | 68.64 | .44 | 19.19 | 19.63 | (.42 | ) | (8.44 | ) | (8.86 | ) | 79.41 | 30.44 | 1,513 | .85 | .59 | |||||||||
| 12/31/2018 | 76.56 | .24 | .28 | .52 | (.20 | ) | (8.24 | ) | (8.44 | ) | 68.64 | (.50 | ) | 1,076 | .84 | .31 | ||||||||
| 12/31/2017 | 66.41 | .18 | 17.61 | 17.79 | (.31 | ) | (7.33 | ) | (7.64 | ) | 76.56 | 27.99 | 954 | .85 | .25 | |||||||||
21 American Funds Insurance Series / Prospectus
| (Loss)
income from investment operations1 |
Dividends and distributions | |||||||||||||||||||||||
| Period ended | Net
asset value, beginning of period |
Net investment income |
Net
(losses) gains on securities (both realized and unrealized) |
Total
from investment operations |
Dividends (from net investment income) |
Distributions (from capital gains) |
Total dividends and distributions |
Net
asset value, end of period |
Total return |
Net
assets, end of period (in millions) |
Ratio
of expenses to average net assets3 |
Ratio
of net income to average net assets | ||||||||||||
| International Fund | ||||||||||||||||||||||||
| Class 1: | ||||||||||||||||||||||||
| 12/31/2021 | $23.64 | $.38 | $(.67 | ) | $(.29 | ) | $(.65 | ) | $— | $(.65 | ) | $22.70 | (1.23 | )% | $4,747 | .55 | % | 1.57 | % | |||||
| 12/31/2020 | 20.86 | .14 | 2.82 | 2.96 | (.18 | ) | — | (.18 | ) | 23.64 | 14.28 | 5,652 | .55 | .71 | ||||||||||
| 12/31/2019 | 17.66 | .30 | 3.74 | 4.04 | (.34 | ) | (.50 | ) | (.84 | ) | 20.86 | 23.21 | 5,353 | .54 | 1.54 | |||||||||
| 12/31/2018 | 21.71 | .34 | (2.97 | ) | (2.63 | ) | (.40 | ) | (1.02 | ) | (1.42 | ) | 17.66 | (12.94 | ) | 4,811 | .53 | 1.62 | ||||||
| 12/31/2017 | 16.82 | .26 | 5.16 | 5.42 | (.30 | ) | (.23 | ) | (.53 | ) | 21.71 | 32.46 | 5,014 | .53 | 1.33 | |||||||||
| Class 1A: | ||||||||||||||||||||||||
| 12/31/2021 | 23.55 | .33 | (.67 | ) | (.34 | ) | (.60 | ) | — | (.60 | ) | 22.61 | (1.47 | ) | 12 | .80 | 1.39 | |||||||
| 12/31/2020 | 20.80 | .08 | 2.81 | 2.89 | (.14 | ) | — | (.14 | ) | 23.55 | 13.96 | 10 | .80 | .43 | ||||||||||
| 12/31/2019 | 17.62 | .25 | 3.72 | 3.97 | (.29 | ) | (.50 | ) | (.79 | ) | 20.80 | 22.90 | 7 | .79 | 1.27 | |||||||||
| 12/31/2018 | 21.67 | .27 | (2.93 | ) | (2.66 | ) | (.37 | ) | (1.02 | ) | (1.39 | ) | 17.62 | (13.11 | ) | 5 | .78 | 1.32 | ||||||
| 12/31/20174,5 | 17.17 | .09 | 4.93 | 5.02 | (.29 | ) | (.23 | ) | (.52 | ) | 21.67 | 29.46 | 6 | 2 | .77 | 7 | .43 | 7 | ||||||
| Class 2: | ||||||||||||||||||||||||
| 12/31/2021 | 23.54 | .33 | (.68 | ) | (.35 | ) | (.59 | ) | — | (.59 | ) | 22.60 | (1.49 | ) | 4,190 | .80 | 1.35 | |||||||
| 12/31/2020 | 20.78 | .09 | 2.80 | 2.89 | (.13 | ) | — | (.13 | ) | 23.54 | 13.97 | 4,481 | .80 | .46 | ||||||||||
| 12/31/2019 | 17.60 | .25 | 3.72 | 3.97 | (.29 | ) | (.50 | ) | (.79 | ) | 20.78 | 22.88 | 4,311 | .79 | 1.29 | |||||||||
| 12/31/2018 | 21.63 | .29 | (2.95 | ) | (2.66 | ) | (.35 | ) | (1.02 | ) | (1.37 | ) | 17.60 | (13.13 | ) | 3,875 | .78 | 1.40 | ||||||
| 12/31/2017 | 16.76 | .22 | 5.13 | 5.35 | (.25 | ) | (.23 | ) | (.48 | ) | 21.63 | 32.14 | 4,422 | .78 | 1.10 | |||||||||
| Class 3: | ||||||||||||||||||||||||
| 12/31/2021 | 23.69 | .34 | (.67 | ) | (.33 | ) | (.60 | ) | — | (.60 | ) | 22.76 | (1.39 | ) | 21 | .73 | 1.41 | |||||||
| 12/31/2020 | 20.92 | .10 | 2.81 | 2.91 | (.14 | ) | — | (.14 | ) | 23.69 | 14.00 | 25 | .73 | .53 | ||||||||||
| 12/31/2019 | 17.70 | .27 | 3.75 | 4.02 | (.30 | ) | (.50 | ) | (.80 | ) | 20.92 | 23.05 | 25 | .72 | 1.37 | |||||||||
| 12/31/2018 | 21.75 | .31 | (2.98 | ) | (2.67 | ) | (.36 | ) | (1.02 | ) | (1.38 | ) | 17.70 | (13.10 | ) | 24 | .71 | 1.48 | ||||||
| 12/31/2017 | 16.85 | .23 | 5.17 | 5.40 | (.27 | ) | (.23 | ) | (.50 | ) | 21.75 | 32.23 | 31 | .71 | 1.17 | |||||||||
| Class 4: | ||||||||||||||||||||||||
| 12/31/2021 | 23.25 | .27 | (.67 | ) | (.40 | ) | (.54 | ) | — | (.54 | ) | 22.31 | (1.71 | ) | 459 | 1.05 | 1.13 | |||||||
| 12/31/2020 | 20.54 | .04 | 2.76 | 2.80 | (.09 | ) | — | (.09 | ) | 23.25 | 13.66 | 423 | 1.05 | .21 | ||||||||||
| 12/31/2019 | 17.40 | .20 | 3.69 | 3.89 | (.25 | ) | (.50 | ) | (.75 | ) | 20.54 | 22.67 | 379 | 1.04 | 1.03 | |||||||||
| 12/31/2018 | 21.42 | .23 | (2.93 | ) | (2.70 | ) | (.30 | ) | (1.02 | ) | (1.32 | ) | 17.40 | (13.41 | ) | 295 | 1.03 | 1.13 | ||||||
| 12/31/2017 | 16.64 | .11 | 5.16 | 5.27 | (.26 | ) | (.23 | ) | (.49 | ) | 21.42 | 31.89 | 289 | 1.03 | .55 | |||||||||
| Income
(loss) from investment operations1 |
Dividends and distributions | |||||||||||||||||||||||||
| Period ended | Net
asset value, beginning of period |
Net investment income |
Net
gains (losses) on securities (both realized and unrealized) |
Total
from investment operations |
Dividends (from net investment income) |
Distributions (from capital gains) |
Total dividends and distributions |
Net
asset value, end of period |
Total return2 |
Net
assets, end of period (in millions) |
Ratio
of expenses to average net assets before waivers3 |
Ratio
of expenses to average net assets after waivers2,3 |
Ratio
of net income to average net assets2 | |||||||||||||
| New World Fund | ||||||||||||||||||||||||||
| Class 1: | ||||||||||||||||||||||||||
| 12/31/2021 | $31.59 | $.29 | $1.38 | $1.67 | $(.36 | ) | $(1.07 | ) | $(1.43 | ) | $31.83 | 5.16 | % | $2,443 | .74 | % | .56 | % | .88 | % | ||||||
| 12/31/2020 | 25.84 | .15 | 5.93 | 6.08 | (.06 | ) | (.27 | ) | (.33 | ) | 31.59 | 23.89 | 2,309 | .76 | .64 | .58 | ||||||||||
| 12/31/2019 | 20.98 | .28 | 5.79 | 6.07 | (.29 | ) | (.92 | ) | (1.21 | ) | 25.84 | 29.47 | 2,129 | .76 | .76 | 1.18 | ||||||||||
| 12/31/2018 | 25.30 | .27 | (3.65 | ) | (3.38 | ) | (.27 | ) | (.67 | ) | (.94 | ) | 20.98 | (13.83 | ) | 1,702 | .77 | .77 | 1.11 | |||||||
| 12/31/2017 | 19.72 | .26 | 5.59 | 5.85 | (.27 | ) | — | (.27 | ) | 25.30 | 29.73 | 2,050 | .77 | .77 | 1.14 | |||||||||||
| Class 1A: | ||||||||||||||||||||||||||
| 12/31/2021 | 31.43 | .17 | 1.41 | 1.58 | (.24 | ) | (1.07 | ) | (1.31 | ) | 31.70 | 4.90 | 12 | .99 | .81 | .54 | ||||||||||
| 12/31/2020 | 25.74 | .07 | 5.92 | 5.99 | (.03 | ) | (.27 | ) | (.30 | ) | 31.43 | 23.63 | 18 | 1.01 | .87 | .26 | ||||||||||
| 12/31/2019 | 20.92 | .22 | 5.76 | 5.98 | (.24 | ) | (.92 | ) | (1.16 | ) | 25.74 | 29.11 | 4 | 1.01 | 1.01 | .92 | ||||||||||
| 12/31/2018 | 25.25 | .21 | (3.64 | ) | (3.43 | ) | (.23 | ) | (.67 | ) | (.90 | ) | 20.92 | (14.02 | ) | 2 | 1.02 | 1.02 | .91 | |||||||
| 12/31/20174,5 | 20.14 | .13 | 5.24 | 5.37 | (.26 | ) | — | (.26 | ) | 25.25 | 26.72 | 6 | 1 | 1.00 | 7 | 1.00 | 7 | .53 | 7 | |||||||
| Class 2: | ||||||||||||||||||||||||||
| 12/31/2021 | 31.25 | .20 | 1.38 | 1.58 | (.28 | ) | (1.07 | ) | (1.35 | ) | 31.48 | 4.92 | 1,086 | .99 | .81 | .63 | ||||||||||
| 12/31/2020 | 25.59 | .08 | 5.87 | 5.95 | (.02 | ) | (.27 | ) | (.29 | ) | 31.25 | 23.58 | 1,109 | 1.01 | .89 | .34 | ||||||||||
| 12/31/2019 | 20.79 | .22 | 5.73 | 5.95 | (.23 | ) | (.92 | ) | (1.15 | ) | 25.59 | 29.15 | 981 | 1.01 | 1.01 | .93 | ||||||||||
| 12/31/2018 | 25.07 | .20 | (3.61 | ) | (3.41 | ) | (.20 | ) | (.67 | ) | (.87 | ) | 20.79 | (14.04 | ) | 843 | 1.02 | 1.02 | .85 | |||||||
| 12/31/2017 | 19.54 | .20 | 5.55 | 5.75 | (.22 | ) | — | (.22 | ) | 25.07 | 29.44 | 1,055 | 1.02 | 1.02 | .89 | |||||||||||
| Class 4: | ||||||||||||||||||||||||||
| 12/31/2021 | 31.04 | .12 | 1.36 | 1.48 | (.21 | ) | (1.07 | ) | (1.28 | ) | 31.24 | 4.63 | 906 | 1.24 | 1.06 | .38 | ||||||||||
| 12/31/2020 | 25.47 | .02 | 5.83 | 5.85 | (.01 | ) | (.27 | ) | (.28 | ) | 31.04 | 23.29 | 807 | 1.26 | 1.14 | .08 | ||||||||||
| 12/31/2019 | 20.71 | .16 | 5.70 | 5.86 | (.18 | ) | (.92 | ) | (1.10 | ) | 25.47 | 28.82 | 646 | 1.26 | 1.26 | .67 | ||||||||||
| 12/31/2018 | 24.99 | .14 | (3.59 | ) | (3.45 | ) | (.16 | ) | (.67 | ) | (.83 | ) | 20.71 | (14.25 | ) | 464 | 1.27 | 1.27 | .61 | |||||||
| 12/31/2017 | 19.51 | .14 | 5.52 | 5.66 | (.18 | ) | — | (.18 | ) | 24.99 | 29.06 | 427 | 1.27 | 1.27 | .61 | |||||||||||
American Funds Insurance Series / Prospectus 22
| Income
(loss) from investment operations1 |
Dividends and distributions | |||||||||||||||||||||||||
| Period ended | Net
asset value, beginning of period |
Net investment income |
Net
gains (losses) on securities (both realized and unrealized) |
Total
from investment operations |
Dividends (from net investment income) |
Distributions (from capital gains) |
Total dividends and distributions |
Net
asset value, end of period |
Total return2 |
Net
assets, end of period (in millions) |
Ratio
of expenses to average net assets before waivers3 |
Ratio
of expenses to average net assets after waivers2,3 |
Ratio
of net income to average net assets2 | |||||||||||||
| Capital World Growth and Income Fund | ||||||||||||||||||||||||||
| Class 1: | ||||||||||||||||||||||||||
| 12/31/2021 | $16.67 | $.38 | $2.10 | $2.48 | $(.33 | ) | $(.40 | ) | $(.73 | ) | $18.42 | 15.03 | % | $812 | .63 | % | .47 | % | 2.14 | % | ||||||
| 12/31/2020 | 15.92 | .22 | 1.14 | 1.36 | (.23 | ) | (.38 | ) | (.61 | ) | 16.67 | 9.03 | 657 | .66 | .66 | 1.49 | ||||||||||
| 12/31/2019 | 13.02 | .31 | 3.67 | 3.98 | (.32 | ) | (.76 | ) | (1.08 | ) | 15.92 | 31.39 | 625 | .65 | .65 | 2.08 | ||||||||||
| 12/31/2018 | 15.81 | .29 | (1.62 | ) | (1.33 | ) | (.28 | ) | (1.18 | ) | (1.46 | ) | 13.02 | (9.36 | ) | 492 | .63 | .63 | 1.94 | |||||||
| 12/31/2017 | 13.02 | .35 | 3.06 | 3.41 | (.36 | ) | (.26 | ) | (.62 | ) | 15.81 | 26.40 | 485 | .63 | .63 | 2.43 | ||||||||||
| Class 1A: | ||||||||||||||||||||||||||
| 12/31/2021 | 16.62 | .37 | 2.06 | 2.43 | (.31 | ) | (.40 | ) | (.71 | ) | 18.34 | 14.71 | 7 | .88 | .70 | 2.08 | ||||||||||
| 12/31/2020 | 15.88 | .18 | 1.13 | 1.31 | (.19 | ) | (.38 | ) | (.57 | ) | 16.62 | 8.78 | 2 | .90 | .90 | 1.23 | ||||||||||
| 12/31/2019 | 13.00 | .26 | 3.68 | 3.94 | (.30 | ) | (.76 | ) | (1.06 | ) | 15.88 | 31.04 | 2 | .90 | .90 | 1.77 | ||||||||||
| 12/31/2018 | 15.81 | .26 | (1.63 | ) | (1.37 | ) | (.26 | ) | (1.18 | ) | (1.44 | ) | 13.00 | (9.62 | ) | 1 | .88 | .88 | 1.74 | |||||||
| 12/31/20174,5 | 13.21 | .18 | 3.03 | 3.21 | (.35 | ) | (.26 | ) | (.61 | ) | 15.81 | 24.54 | 6 | — | 8 | .84 | 7 | .84 | 7 | 1.20 | 7 | |||||
| Class 2: | ||||||||||||||||||||||||||
| 12/31/2021 | 16.63 | .33 | 2.11 | 2.44 | (.29 | ) | (.40 | ) | (.69 | ) | 18.38 | 14.78 | 1,340 | .88 | .73 | 1.85 | ||||||||||
| 12/31/2020 | 15.89 | .18 | 1.13 | 1.31 | (.19 | ) | (.38 | ) | (.57 | ) | 16.63 | 8.73 | 1,349 | .91 | .91 | 1.23 | ||||||||||
| 12/31/2019 | 12.99 | .27 | 3.68 | 3.95 | (.29 | ) | (.76 | ) | (1.05 | ) | 15.89 | 31.14 | 1,366 | .90 | .90 | 1.84 | ||||||||||
| 12/31/2018 | 15.78 | .26 | (1.63 | ) | (1.37 | ) | (.24 | ) | (1.18 | ) | (1.42 | ) | 12.99 | (9.63 | ) | 1,228 | .88 | .88 | 1.70 | |||||||
| 12/31/2017 | 13.00 | .31 | 3.05 | 3.36 | (.32 | ) | (.26 | ) | (.58 | ) | 15.78 | 26.06 | 1,538 | .88 | .88 | 2.11 | ||||||||||
| Class 4: | ||||||||||||||||||||||||||
| 12/31/2021 | 16.35 | .29 | 2.06 | 2.35 | (.26 | ) | (.40 | ) | (.66 | ) | 18.04 | 14.46 | 225 | 1.13 | .97 | 1.65 | ||||||||||
| 12/31/2020 | 15.63 | .14 | 1.12 | 1.26 | (.16 | ) | (.38 | ) | (.54 | ) | 16.35 | 8.55 | 166 | 1.16 | 1.16 | .97 | ||||||||||
| 12/31/2019 | 12.81 | .23 | 3.61 | 3.84 | (.26 | ) | (.76 | ) | (1.02 | ) | 15.63 | 30.73 | 145 | 1.15 | 1.15 | 1.56 | ||||||||||
| 12/31/2018 | 15.60 | .21 | (1.60 | ) | (1.39 | ) | (.22 | ) | (1.18 | ) | (1.40 | ) | 12.81 | (9.89 | ) | 95 | 1.13 | 1.13 | 1.43 | |||||||
| 12/31/2017 | 12.89 | .22 | 3.08 | 3.30 | (.33 | ) | (.26 | ) | (.59 | ) | 15.60 | 25.83 | 79 | 1.14 | 1.14 | 1.49 | ||||||||||
| Income
(loss) from investment operations1 |
Dividends and distributions | |||||||||||||||||||||||
| Period ended | Net
asset value, beginning of period |
Net investment income |
Net
gains (losses) on securities (both realized and unrealized) |
Total
from investment operations |
Dividends (from net investment income) |
Distributions (from capital gains) |
Total dividends and distributions |
Net
asset value, end of period |
Total return |
Net
assets, end of period (in millions) |
Ratio
of expenses to average net assets3 |
Ratio
of net income to average net assets | ||||||||||||
| Growth-Income Fund | ||||||||||||||||||||||||
| Class 1: | ||||||||||||||||||||||||
| 12/31/2021 | $55.38 | $.79 | $12.64 | $13.43 | $(.86 | ) | $(.60 | ) | $(1.46 | ) | $67.35 | 24.42 | % | $25,507 | .29 | % | 1.28 | % | ||||||
| 12/31/2020 | 50.71 | .75 | 6.02 | 6.77 | (.80 | ) | (1.30 | ) | (2.10 | ) | 55.38 | 13.81 | 22,903 | .29 | 1.52 | |||||||||
| 12/31/2019 | 45.39 | 1.00 | 10.40 | 11.40 | (.92 | ) | (5.16 | ) | (6.08 | ) | 50.71 | 26.46 | 21,057 | .29 | 2.05 | |||||||||
| 12/31/2018 | 50.22 | .84 | (1.25 | ) | (.41 | ) | (.84 | ) | (3.58 | ) | (4.42 | ) | 45.39 | (1.55 | ) | 16,783 | .28 | 1.65 | ||||||
| 12/31/2017 | 44.41 | .81 | 8.89 | 9.70 | (.78 | ) | (3.11 | ) | (3.89 | ) | 50.22 | 22.68 | 15,765 | .28 | 1.69 | |||||||||
| Class 1A: | ||||||||||||||||||||||||
| 12/31/2021 | 55.16 | .65 | 12.55 | 13.20 | (.74 | ) | (.60 | ) | (1.34 | ) | 67.02 | 24.08 | 32 | .53 | 1.04 | |||||||||
| 12/31/2020 | 50.54 | .63 | 5.99 | 6.62 | (.70 | ) | (1.30 | ) | (2.00 | ) | 55.16 | 13.55 | 16 | .54 | 1.28 | |||||||||
| 12/31/2019 | 45.28 | .89 | 10.36 | 11.25 | (.83 | ) | (5.16 | ) | (5.99 | ) | 50.54 | 26.14 | 11 | .54 | 1.82 | |||||||||
| 12/31/2018 | 50.15 | .72 | (1.25 | ) | (.53 | ) | (.76 | ) | (3.58 | ) | (4.34 | ) | 45.28 | (1.78 | ) | 7 | .53 | 1.43 | ||||||
| 12/31/20174,5 | 45.39 | .67 | 7.96 | 8.63 | (.76 | ) | (3.11 | ) | (3.87 | ) | 50.15 | 19.83 | 6 | 2 | .52 | 7 | 1.41 | 7 | ||||||
| Class 2: | ||||||||||||||||||||||||
| 12/31/2021 | 54.66 | .63 | 12.45 | 13.08 | (.70 | ) | (.60 | ) | (1.30 | ) | 66.44 | 24.10 | 15,319 | .54 | 1.03 | |||||||||
| 12/31/2020 | 50.08 | .62 | 5.93 | 6.55 | (.67 | ) | (1.30 | ) | (1.97 | ) | 54.66 | 13.54 | 14,012 | .54 | 1.27 | |||||||||
| 12/31/2019 | 44.90 | .87 | 10.27 | 11.14 | (.80 | ) | (5.16 | ) | (5.96 | ) | 50.08 | 26.14 | 13,586 | .53 | 1.80 | |||||||||
| 12/31/2018 | 49.71 | .71 | (1.23 | ) | (.52 | ) | (.71 | ) | (3.58 | ) | (4.29 | ) | 44.90 | (1.79 | ) | 12,035 | .53 | 1.40 | ||||||
| 12/31/2017 | 44.00 | .68 | 8.80 | 9.48 | (.66 | ) | (3.11 | ) | (3.77 | ) | 49.71 | 22.38 | 13,930 | .53 | 1.45 | |||||||||
| Class 3: | ||||||||||||||||||||||||
| 12/31/2021 | 55.49 | .68 | 12.65 | 13.33 | (.74 | ) | (.60 | ) | (1.34 | ) | 67.48 | 24.18 | 166 | .47 | 1.10 | |||||||||
| 12/31/2020 | 50.81 | .66 | 6.02 | 6.68 | (.70 | ) | (1.30 | ) | (2.00 | ) | 55.49 | 13.60 | 154 | .47 | 1.34 | |||||||||
| 12/31/2019 | 45.47 | .91 | 10.43 | 11.34 | (.84 | ) | (5.16 | ) | (6.00 | ) | 50.81 | 26.24 | 156 | .46 | 1.87 | |||||||||
| 12/31/2018 | 50.29 | .75 | (1.25 | ) | (.50 | ) | (.74 | ) | (3.58 | ) | (4.32 | ) | 45.47 | (1.72 | ) | 140 | .46 | 1.47 | ||||||
| 12/31/2017 | 44.47 | .72 | 8.90 | 9.62 | (.69 | ) | (3.11 | ) | (3.80 | ) | 50.29 | 22.47 | 168 | .46 | 1.52 | |||||||||
| Class 4: | ||||||||||||||||||||||||
| 12/31/2021 | 53.99 | .48 | 12.28 | 12.76 | (.58 | ) | (.60 | ) | (1.18 | ) | 65.57 | 23.80 | 1,928 | .79 | .79 | |||||||||
| 12/31/2020 | 49.52 | .49 | 5.85 | 6.34 | (.57 | ) | (1.30 | ) | (1.87 | ) | 53.99 | 13.25 | 1,407 | .79 | 1.02 | |||||||||
| 12/31/2019 | 44.47 | .74 | 10.18 | 10.92 | (.71 | ) | (5.16 | ) | (5.87 | ) | 49.52 | 25.86 | 1,216 | .79 | 1.56 | |||||||||
| 12/31/2018 | 49.31 | .58 | (1.23 | ) | (.65 | ) | (.61 | ) | (3.58 | ) | (4.19 | ) | 44.47 | (2.05 | ) | 899 | .78 | 1.15 | ||||||
| 12/31/2017 | 43.73 | .56 | 8.73 | 9.29 | (.60 | ) | (3.11 | ) | (3.71 | ) | 49.31 | 22.08 | 827 | .78 | 1.19 | |||||||||
23 American Funds Insurance Series / Prospectus
| Income
(loss) from investment operations1 |
Dividends and distributions | |||||||||||||||||||||||||
| Period ended | Net
asset value, beginning of period |
Net investment income |
Net
gains (losses) on securities (both realized and unrealized) |
Total
from investment operations |
Dividends (from net investment income) |
Distributions (from capital gains) |
Total dividends and distributions |
Net
asset value, end of period |
Total return2 |
Net
assets, end of period (in millions) |
Ratio
of expenses to average net assets before waivers3 |
Ratio
of expenses to average net assets after waivers2,3 |
Ratio
of net income to average net assets2 | |||||||||||||
| Washington Mutual Investors Fund | ||||||||||||||||||||||||||
| Class 1: | ||||||||||||||||||||||||||
| 12/31/2021 | $14.35 | $.29 | $3.73 | $4.02 | $(.28 | ) | $— | $(.28 | ) | $18.09 | 28.12 | % | $6,766 | .42 | % | .31 | % | 1.79 | % | |||||||
| 12/31/2020 | 13.56 | .25 | .95 | 1.20 | (.26 | ) | (.15 | ) | (.41 | ) | 14.35 | 9.04 | 5,684 | .43 | .43 | 2.00 | ||||||||||
| 12/31/2019 | 12.38 | .30 | 2.25 | 2.55 | (.30 | ) | (1.07 | ) | (1.37 | ) | 13.56 | 21.66 | 5,559 | .42 | .42 | 2.28 | ||||||||||
| 12/31/2018 | 14.96 | .31 | (1.44 | ) | (1.13 | ) | (.31 | ) | (1.14 | ) | (1.45 | ) | 12.38 | (8.45 | ) | 4,810 | .41 | .41 | 2.13 | |||||||
| 12/31/2017 | 13.53 | .32 | 1.96 | 2.28 | (.32 | ) | (.53 | ) | (.85 | ) | 14.96 | 17.30 | 5,581 | .41 | .41 | 2.27 | ||||||||||
| Class 1A: | ||||||||||||||||||||||||||
| 12/31/2021 | 14.28 | .27 | 3.67 | 3.94 | (.26 | ) | — | (.26 | ) | 17.96 | 27.70 | 169 | .67 | .53 | 1.62 | |||||||||||
| 12/31/2020 | 13.51 | .23 | .93 | 1.16 | (.24 | ) | (.15 | ) | (.39 | ) | 14.28 | 8.79 | 25 | .67 | .67 | 1.78 | ||||||||||
| 12/31/2019 | 12.35 | .26 | 2.24 | 2.50 | (.27 | ) | (1.07 | ) | (1.34 | ) | 13.51 | 21.35 | 9 | .67 | .67 | 2.03 | ||||||||||
| 12/31/2018 | 14.94 | .26 | (1.42 | ) | (1.16 | ) | (.29 | ) | (1.14 | ) | (1.43 | ) | 12.35 | (8.67 | ) | 3 | .66 | .66 | 1.84 | |||||||
| 12/31/20174,5 | 13.75 | .28 | 1.75 | 2.03 | (.31 | ) | (.53 | ) | (.84 | ) | 14.94 | 15.21 | 6 | 1 | .65 | 7 | .65 | 7 | 2.01 | 7 | ||||||
| Class 2: | ||||||||||||||||||||||||||
| 12/31/2021 | 14.15 | .25 | 3.67 | 3.92 | (.24 | ) | — | (.24 | ) | 17.83 | 27.78 | 3,426 | .67 | .56 | 1.54 | |||||||||||
| 12/31/2020 | 13.39 | .22 | .91 | 1.13 | (.22 | ) | (.15 | ) | (.37 | ) | 14.15 | 8.68 | 3,082 | .68 | .68 | 1.75 | ||||||||||
| 12/31/2019 | 12.24 | .26 | 2.22 | 2.48 | (.26 | ) | (1.07 | ) | (1.33 | ) | 13.39 | 21.38 | 3,093 | .67 | .67 | 2.03 | ||||||||||
| 12/31/2018 | 14.80 | .27 | (1.42 | ) | (1.15 | ) | (.27 | ) | (1.14 | ) | (1.41 | ) | 12.24 | (8.66 | ) | 2,850 | .66 | .66 | 1.88 | |||||||
| 12/31/2017 | 13.39 | .28 | 1.94 | 2.22 | (.28 | ) | (.53 | ) | (.81 | ) | 14.80 | 17.04 | 3,551 | .66 | .66 | 2.02 | ||||||||||
| Class 4: | ||||||||||||||||||||||||||
| 12/31/2021 | 14.06 | .21 | 3.65 | 3.86 | (.21 | ) | — | (.21 | ) | 17.71 | 27.51 | 1,104 | .92 | .81 | 1.30 | |||||||||||
| 12/31/2020 | 13.31 | .19 | .91 | 1.10 | (.20 | ) | (.15 | ) | (.35 | ) | 14.06 | 8.47 | 788 | .93 | .93 | 1.51 | ||||||||||
| 12/31/2019 | 12.19 | .23 | 2.20 | 2.43 | (.24 | ) | (1.07 | ) | (1.31 | ) | 13.31 | 21.03 | 621 | .92 | .92 | 1.78 | ||||||||||
| 12/31/2018 | 14.77 | .23 | (1.42 | ) | (1.19 | ) | (.25 | ) | (1.14 | ) | (1.39 | ) | 12.19 | (8.92 | ) | 368 | .91 | .91 | 1.62 | |||||||
| 12/31/2017 | 13.39 | .25 | 1.93 | 2.18 | (.27 | ) | (.53 | ) | (.80 | ) | 14.77 | 16.70 | 247 | .91 | .91 | 1.76 | ||||||||||
| Income
(loss) from investment operations1 |
Dividends and distributions | |||||||||||||||||||||||||
| Period ended | Net
asset value, beginning of period |
Net investment income |
Net
gains (losses) on securities (both realized and unrealized) |
Total
from investment operations |
Dividends (from net investment income) |
Distributions (from capital gains) |
Total dividends and distributions |
Net
asset value, end of period |
Total return2 |
Net
assets, end of period (in millions) |
Ratio
of expenses to average net assets before waivers3 |
Ratio
of expenses to average net assets after waivers2,3 |
Ratio
of net income to average net assets2 | |||||||||||||
| Capital Income Builder | ||||||||||||||||||||||||||
| Class 1: | ||||||||||||||||||||||||||
| 12/31/2021 | $10.87 | $.37 | $1.28 | $1.65 | $(.35 | ) | $— | $(.35 | ) | $12.17 | 15.31 | % | $563 | .53 | % | .27 | % | 3.19 | % | |||||||
| 12/31/2020 | 10.73 | .31 | .15 | .46 | (.32 | ) | — | (.32 | ) | 10.87 | 4.64 | 621 | .53 | .35 | 3.07 | |||||||||||
| 12/31/2019 | 9.37 | .32 | 1.36 | 1.68 | (.32 | ) | — | (.32 | ) | 10.73 | 18.16 | 533 | .53 | .53 | 3.17 | |||||||||||
| 12/31/2018 | 10.40 | .31 | (1.00 | ) | (.69 | ) | (.32 | ) | (.02 | ) | (.34 | ) | 9.37 | (6.77 | ) | 317 | .54 | .54 | 3.08 | |||||||
| 12/31/2017 | 9.46 | .32 | .93 | 1.25 | (.31 | ) | — | (.31 | ) | 10.40 | 13.29 | 254 | .54 | .54 | 3.21 | |||||||||||
| Class 1A: | ||||||||||||||||||||||||||
| 12/31/2021 | 10.86 | .34 | 1.27 | 1.61 | (.32 | ) | — | (.32 | ) | 12.15 | 14.95 | 10 | .78 | .52 | 2.94 | |||||||||||
| 12/31/2020 | 10.72 | .28 | .16 | .44 | (.30 | ) | — | (.30 | ) | 10.86 | 4.38 | 6 | .78 | .60 | 2.81 | |||||||||||
| 12/31/2019 | 9.36 | .29 | 1.37 | 1.66 | (.30 | ) | — | (.30 | ) | 10.72 | 17.90 | 6 | .78 | .78 | 2.84 | |||||||||||
| 12/31/2018 | 10.39 | .28 | (.99 | ) | (.71 | ) | (.30 | ) | (.02 | ) | (.32 | ) | 9.36 | (7.01 | ) | 2 | .79 | .79 | 2.82 | |||||||
| 12/31/20174,5 | 9.57 | .27 | .84 | 1.11 | (.29 | ) | — | (.29 | ) | 10.39 | 11.72 | 6 | 1 | .79 | 7 | .79 | 7 | 2.63 | 7 | |||||||
| Class 2: | ||||||||||||||||||||||||||
| 12/31/2021 | 10.87 | .34 | 1.27 | 1.61 | (.32 | ) | — | (.32 | ) | 12.16 | 14.94 | 13 | .78 | .52 | 2.93 | |||||||||||
| 12/31/2020 | 10.72 | .29 | .16 | .45 | (.30 | ) | — | (.30 | ) | 10.87 | 4.48 | 8 | .78 | .60 | 2.83 | |||||||||||
| 12/31/2019 | 9.36 | .30 | 1.35 | 1.65 | (.29 | ) | — | (.29 | ) | 10.72 | 17.89 | 6 | .78 | .78 | 2.91 | |||||||||||
| 12/31/2018 | 10.40 | .28 | (1.00 | ) | (.72 | ) | (.30 | ) | (.02 | ) | (.32 | ) | 9.36 | (7.08 | ) | 4 | .79 | .79 | 2.83 | |||||||
| 12/31/2017 | 9.46 | .29 | .93 | 1.22 | (.28 | ) | — | (.28 | ) | 10.40 | 13.04 | 1 | .79 | .79 | 2.82 | |||||||||||
| Class 4: | ||||||||||||||||||||||||||
| 12/31/2021 | 10.85 | .31 | 1.27 | 1.58 | (.29 | ) | — | (.29 | ) | 12.14 | 14.68 | 559 | 1.03 | .77 | 2.69 | |||||||||||
| 12/31/2020 | 10.71 | .26 | .15 | .41 | (.27 | ) | — | (.27 | ) | 10.85 | 4.11 | 462 | 1.03 | .85 | 2.55 | |||||||||||
| 12/31/2019 | 9.35 | .27 | 1.36 | 1.63 | (.27 | ) | — | (.27 | ) | 10.71 | 17.62 | 454 | 1.03 | 1.03 | 2.68 | |||||||||||
| 12/31/2018 | 10.38 | .26 | (1.00 | ) | (.74 | ) | (.27 | ) | (.02 | ) | (.29 | ) | 9.35 | (7.25 | ) | 352 | 1.04 | 1.04 | 2.58 | |||||||
| 12/31/2017 | 9.45 | .27 | .92 | 1.19 | (.26 | ) | — | (.26 | ) | 10.38 | 12.65 | 338 | 1.04 | 1.04 | 2.72 | |||||||||||
American Funds Insurance Series / Prospectus 24
| Income
(loss) from investment operations1 |
Dividends and distributions | |||||||||||||||||||||||
| Period ended | Net
asset value, beginning of period |
Net investment income |
Net
gains (losses) on securities (both realized and unrealized) |
Total
from investment operations |
Dividends (from net investment income) |
Distributions (from capital gains) |
Total dividends and distributions |
Net
asset value, end of period |
Total return |
Net
assets, end of period (in millions) |
Ratio
of expenses to average net assets3 |
Ratio
of net income to average net assets | ||||||||||||
| Asset Allocation Fund | ||||||||||||||||||||||||
| Class 1: | ||||||||||||||||||||||||
| 12/31/2021 | $26.50 | $.48 | $3.54 | $4.02 | $(.50 | ) | $(.94 | ) | $(1.44 | ) | $29.08 | 15.40 | % | $18,836 | .30 | % | 1.71 | % | ||||||
| 12/31/2020 | 24.05 | .43 | 2.59 | 3.02 | (.46 | ) | (.11 | ) | (.57 | ) | 26.50 | 12.71 | 19,238 | .30 | 1.80 | |||||||||
| 12/31/2019 | 21.29 | .51 | 3.94 | 4.45 | (.50 | ) | (1.19 | ) | (1.69 | ) | 24.05 | 21.54 | 17,730 | .29 | 2.21 | |||||||||
| 12/31/2018 | 23.71 | .48 | (1.43 | ) | (.95 | ) | (.44 | ) | (1.03 | ) | (1.47 | ) | 21.29 | (4.35 | ) | 14,627 | .28 | 2.04 | ||||||
| 12/31/2017 | 21.68 | .44 | 3.06 | 3.50 | (.41 | ) | (1.06 | ) | (1.47 | ) | 23.71 | 16.51 | 16,556 | .29 | 1.90 | |||||||||
| Class 1A: | ||||||||||||||||||||||||
| 12/31/2021 | 26.42 | .42 | 3.52 | 3.94 | (.45 | ) | (.94 | ) | (1.39 | ) | 28.97 | 15.13 | 24 | .55 | 1.49 | |||||||||
| 12/31/2020 | 23.99 | .37 | 2.58 | 2.95 | (.41 | ) | (.11 | ) | (.52 | ) | 26.42 | 12.43 | 14 | .55 | 1.56 | |||||||||
| 12/31/2019 | 21.26 | .45 | 3.92 | 4.37 | (.45 | ) | (1.19 | ) | (1.64 | ) | 23.99 | 21.19 | 11 | .54 | 1.95 | |||||||||
| 12/31/2018 | 23.69 | .42 | (1.42 | ) | (1.00 | ) | (.40 | ) | (1.03 | ) | (1.43 | ) | 21.26 | (4.58 | ) | 7 | .53 | 1.82 | ||||||
| 12/31/20174,5 | 21.97 | .39 | 2.78 | 3.17 | (.39 | ) | (1.06 | ) | (1.45 | ) | 23.69 | 14.78 | 6 | 4 | .53 | 7 | 1.69 | 7 | ||||||
| Class 2: | ||||||||||||||||||||||||
| 12/31/2021 | 26.21 | .41 | 3.49 | 3.90 | (.43 | ) | (.94 | ) | (1.37 | ) | 28.74 | 15.10 | 5,473 | .55 | 1.46 | |||||||||
| 12/31/2020 | 23.79 | .37 | 2.56 | 2.93 | (.40 | ) | (.11 | ) | (.51 | ) | 26.21 | 12.46 | 5,242 | .55 | 1.55 | |||||||||
| 12/31/2019 | 21.08 | .45 | 3.89 | 4.34 | (.44 | ) | (1.19 | ) | (1.63 | ) | 23.79 | 21.23 | 5,154 | .54 | 1.96 | |||||||||
| 12/31/2018 | 23.49 | .41 | (1.41 | ) | (1.00 | ) | (.38 | ) | (1.03 | ) | (1.41 | ) | 21.08 | (4.60 | ) | 4,668 | .53 | 1.78 | ||||||
| 12/31/2017 | 21.49 | .37 | 3.04 | 3.41 | (.35 | ) | (1.06 | ) | (1.41 | ) | 23.49 | 16.23 | 5,480 | .54 | 1.64 | |||||||||
| Class 3: | ||||||||||||||||||||||||
| 12/31/2021 | 26.53 | .43 | 3.55 | 3.98 | (.45 | ) | (.94 | ) | (1.39 | ) | 29.12 | 15.22 | 36 | .48 | 1.53 | |||||||||
| 12/31/2020 | 24.08 | .39 | 2.59 | 2.98 | (.42 | ) | (.11 | ) | (.53 | ) | 26.53 | 12.50 | 33 | .48 | 1.62 | |||||||||
| 12/31/2019 | 21.32 | .47 | 3.93 | 4.40 | (.45 | ) | (1.19 | ) | (1.64 | ) | 24.08 | 21.30 | 32 | .47 | 2.02 | |||||||||
| 12/31/2018 | 23.73 | .43 | (1.41 | ) | (.98 | ) | (.40 | ) | (1.03 | ) | (1.43 | ) | 21.32 | (4.49 | ) | 29 | .46 | 1.85 | ||||||
| 12/31/2017 | 21.70 | .39 | 3.07 | 3.46 | (.37 | ) | (1.06 | ) | (1.43 | ) | 23.73 | 16.29 | 38 | .47 | 1.72 | |||||||||
| Class 4: | ||||||||||||||||||||||||
| 12/31/2021 | 26.06 | .34 | 3.47 | 3.81 | (.37 | ) | (.94 | ) | (1.31 | ) | 28.56 | 14.84 | 6,337 | .80 | 1.22 | |||||||||
| 12/31/2020 | 23.67 | .31 | 2.54 | 2.85 | (.35 | ) | (.11 | ) | (.46 | ) | 26.06 | 12.16 | 5,131 | .80 | 1.30 | |||||||||
| 12/31/2019 | 20.99 | .39 | 3.87 | 4.26 | (.39 | ) | (1.19 | ) | (1.58 | ) | 23.67 | 20.92 | 4,493 | .79 | 1.71 | |||||||||
| 12/31/2018 | 23.40 | .35 | (1.40 | ) | (1.05 | ) | (.33 | ) | (1.03 | ) | (1.36 | ) | 20.99 | (4.83 | ) | 3,594 | .78 | 1.54 | ||||||
| 12/31/2017 | 21.43 | .32 | 3.02 | 3.34 | (.31 | ) | (1.06 | ) | (1.37 | ) | 23.40 | 15.91 | 3,582 | .79 | 1.40 | |||||||||
| Income
(loss) from investment operations1 |
Dividends and distributions | |||||||||||||||||||||||
| Period ended | Net
asset value, beginning of period |
Net investment income |
Net
gains (losses) on securities (both realized and unrealized) |
Total
from investment operations |
Dividends (from net investment income) |
Distributions (from capital gains) |
Total dividends and distributions |
Net
asset value, end of period |
Total return |
Net
assets, end of period (in millions) |
Ratio
of expenses to average net assets3 |
Ratio
of net income to average net assets | ||||||||||||
| American Funds Global Balanced Fund | ||||||||||||||||||||||||
| Class 1: | ||||||||||||||||||||||||
| 12/31/2021 | $14.19 | $.18 | $1.37 | $1.55 | $(.19 | ) | $(.82 | ) | $(1.01 | ) | $14.73 | 11.05 | % | $120 | .73 | % | 1.24 | % | ||||||
| 12/31/2020 | 13.51 | .17 | 1.24 | 1.41 | (.19 | ) | (.54 | ) | (.73 | ) | 14.19 | 10.53 | 139 | .72 | 1.29 | |||||||||
| 12/31/2019 | 11.67 | .24 | 2.17 | 2.41 | (.20 | ) | (.37 | ) | (.57 | ) | 13.51 | 20.79 | 134 | .72 | 1.88 | |||||||||
| 12/31/2018 | 12.75 | .23 | (.96 | ) | (.73 | ) | (.20 | ) | (.15 | ) | (.35 | ) | 11.67 | (5.81 | ) | 110 | .72 | 1.82 | ||||||
| 12/31/2017 | 11.08 | .21 | 1.99 | 2.20 | (.15 | ) | (.38 | ) | (.53 | ) | 12.75 | 19.91 | 93 | .72 | 1.68 | |||||||||
| Class 1A: | ||||||||||||||||||||||||
| 12/31/2021 | 14.16 | .15 | 1.36 | 1.51 | (.15 | ) | (.82 | ) | (.97 | ) | 14.70 | 10.83 | 4 | .98 | 1.02 | |||||||||
| 12/31/2020 | 13.49 | .14 | 1.23 | 1.37 | (.16 | ) | (.54 | ) | (.70 | ) | 14.16 | 10.25 | 3 | .97 | 1.03 | |||||||||
| 12/31/2019 | 11.65 | .21 | 2.17 | 2.38 | (.17 | ) | (.37 | ) | (.54 | ) | 13.49 | 20.54 | 2 | .97 | 1.63 | |||||||||
| 12/31/2018 | 12.74 | .18 | (.94 | ) | (.76 | ) | (.18 | ) | (.15 | ) | (.33 | ) | 11.65 | (6.03 | ) | 2 | .98 | 1.44 | ||||||
| 12/31/20174,5 | 11.18 | .16 | 1.92 | 2.08 | (.14 | ) | (.38 | ) | (.52 | ) | 12.74 | 18.71 | 6 | — | 8 | .94 | 7 | 1.27 | 7 | |||||
| Class 2: | ||||||||||||||||||||||||
| 12/31/2021 | 14.16 | .15 | 1.36 | 1.51 | (.15 | ) | (.82 | ) | (.97 | ) | 14.70 | 10.79 | 208 | .98 | 1.01 | |||||||||
| 12/31/2020 | 13.48 | .14 | 1.23 | 1.37 | (.15 | ) | (.54 | ) | (.69 | ) | 14.16 | 10.30 | 208 | .97 | 1.03 | |||||||||
| 12/31/2019 | 11.65 | .21 | 2.16 | 2.37 | (.17 | ) | (.37 | ) | (.54 | ) | 13.48 | 20.44 | 207 | .97 | 1.64 | |||||||||
| 12/31/2018 | 12.72 | .20 | (.96 | ) | (.76 | ) | (.16 | ) | (.15 | ) | (.31 | ) | 11.65 | (6.01 | ) | 185 | .97 | 1.57 | ||||||
| 12/31/2017 | 11.06 | .18 | 1.98 | 2.16 | (.12 | ) | (.38 | ) | (.50 | ) | 12.72 | 19.57 | 210 | .96 | 1.43 | |||||||||
| Class 4: | ||||||||||||||||||||||||
| 12/31/2021 | 14.02 | .11 | 1.34 | 1.45 | (.12 | ) | (.82 | ) | (.94 | ) | 14.53 | 10.46 | 135 | 1.23 | .77 | |||||||||
| 12/31/2020 | 13.36 | .10 | 1.22 | 1.32 | (.12 | ) | (.54 | ) | (.66 | ) | 14.02 | 10.00 | 105 | 1.22 | .78 | |||||||||
| 12/31/2019 | 11.55 | .18 | 2.14 | 2.32 | (.14 | ) | (.37 | ) | (.51 | ) | 13.36 | 20.21 | 94 | 1.22 | 1.37 | |||||||||
| 12/31/2018 | 12.63 | .17 | (.96 | ) | (.79 | ) | (.14 | ) | (.15 | ) | (.29 | ) | 11.55 | (6.31 | ) | 69 | 1.22 | 1.34 | ||||||
| 12/31/2017 | 11.00 | .13 | 1.99 | 2.12 | (.11 | ) | (.38 | ) | (.49 | ) | 12.63 | 19.38 | 51 | 1.22 | 1.07 | |||||||||
25 American Funds Insurance Series / Prospectus
| Income
(loss) from investment operations1 |
Dividends and distributions | |||||||||||||||||||||||||
| Period ended | Net
asset value, beginning of year |
Net investment income (loss) |
Net
gains (losses) on securities (both realized and unrealized) |
Total
from investment operations |
Dividends (from net investment income) |
Distributions (from capital gains) |
Total dividends and distributions |
Net
asset value, end of year |
Total return2 |
Net
assets, end of year (in millions) |
Ratio
of expenses to average net assets before reimbursements |
Ratio
of expenses to average net assets after reimbursements2 |
Ratio
of net income (loss) to average net assets2 | |||||||||||||
| American Funds Mortgage Fund | ||||||||||||||||||||||||||
| Class 1: | ||||||||||||||||||||||||||
| 12/31/2021 | $11.11 | $.06 | $(.09 | ) | $(.03 | ) | $(.08 | ) | $(.37 | ) | $(.45 | ) | $10.63 | (.32 | )% | $231 | .49 | % | .29 | % | .58 | % | ||||
| 12/31/2020 | 10.56 | .10 | .64 | .74 | (.17 | ) | (.02 | ) | (.19 | ) | 11.11 | 6.98 | 224 | .48 | .36 | .93 | ||||||||||
| 12/31/2019 | 10.30 | .24 | .30 | .54 | (.28 | ) | — | (.28 | ) | 10.56 | 5.30 | 210 | .47 | .47 | 2.26 | |||||||||||
| 12/31/2018 | 10.47 | .20 | (.14 | ) | .06 | (.23 | ) | — | (.23 | ) | 10.30 | .58 | 209 | .48 | .48 | 1.97 | ||||||||||
| 12/31/2017 | 10.56 | .16 | — | 9 | .16 | (.18 | ) | (.07 | ) | (.25 | ) | 10.47 | 1.47 | 265 | .47 | .47 | 1.52 | |||||||||
| Class 1A: | ||||||||||||||||||||||||||
| 12/31/2021 | 11.08 | .04 | (.10 | ) | (.06 | ) | (.06 | ) | (.37 | ) | (.43 | ) | 10.59 | (.47 | ) | 2 | .74 | .54 | .33 | |||||||
| 12/31/2020 | 10.55 | .07 | .63 | .70 | (.15 | ) | (.02 | ) | (.17 | ) | 11.08 | 6.63 | 1 | .73 | .59 | .61 | ||||||||||
| 12/31/2019 | 10.28 | .22 | .30 | .52 | (.25 | ) | — | (.25 | ) | 10.55 | 5.09 | 1 | .71 | .71 | 2.04 | |||||||||||
| 12/31/2018 | 10.46 | .18 | (.14 | ) | .04 | (.22 | ) | — | (.22 | ) | 10.28 | .36 | 1 | .73 | .73 | 1.77 | ||||||||||
| 12/31/20175 | 10.55 | .14 | — | 9 | .14 | (.16 | ) | (.07 | ) | (.23 | ) | 10.46 | 1.31 | 6 | — | 8 | .70 | 7 | .70 | 7 | 1.38 | 7 | ||||
| Class 2: | ||||||||||||||||||||||||||
| 12/31/2021 | 11.09 | .04 | (.10 | ) | (.06 | ) | (.05 | ) | (.37 | ) | (.42 | ) | 10.61 | (.57 | ) | 58 | .74 | .54 | .33 | |||||||
| 12/31/2020 | 10.54 | .08 | .63 | .71 | (.14 | ) | (.02 | ) | (.16 | ) | 11.09 | 6.72 | 58 | .73 | .60 | .68 | ||||||||||
| 12/31/2019 | 10.28 | .21 | .31 | .52 | (.26 | ) | — | (.26 | ) | 10.54 | 5.04 | 56 | .72 | .72 | 2.01 | |||||||||||
| 12/31/2018 | 10.45 | .18 | (.15 | ) | .03 | (.20 | ) | — | (.20 | ) | 10.28 | .32 | 57 | .73 | .73 | 1.72 | ||||||||||
| 12/31/2017 | 10.54 | .14 | (.01 | ) | .13 | (.15 | ) | (.07 | ) | (.22 | ) | 10.45 | 1.22 | 63 | .72 | .72 | 1.27 | |||||||||
| Class 4: | ||||||||||||||||||||||||||
| 12/31/2021 | 10.97 | .01 | (.09 | ) | (.08 | ) | (.03 | ) | (.37 | ) | (.40 | ) | 10.49 | (.78 | ) | 43 | .99 | .79 | .08 | |||||||
| 12/31/2020 | 10.44 | .04 | .63 | .67 | (.12 | ) | (.02 | ) | (.14 | ) | 10.97 | 6.38 | 37 | .98 | .85 | .41 | ||||||||||
| 12/31/2019 | 10.19 | .18 | .31 | .49 | (.24 | ) | — | (.24 | ) | 10.44 | 4.80 | 28 | .97 | .97 | 1.71 | |||||||||||
| 12/31/2018 | 10.38 | .15 | (.15 | ) | — | 9 | (.19 | ) | — | (.19 | ) | 10.19 | .07 | 24 | .98 | .98 | 1.49 | |||||||||
| 12/31/2017 | 10.48 | .11 | — | 9 | .11 | (.14 | ) | (.07 | ) | (.21 | ) | 10.38 | .97 | 12 | .97 | .97 | 1.03 | |||||||||
| Income
(loss) from investment operations1 |
Dividends and distributions | |||||||||||||||||||||||||
| Period ended | Net
asset value, beginning of period |
Net investment income |
Net
gains (losses) on securities (both realized and unrealized) |
Total
from investment operations |
Dividends (from net investment income) |
Distributions (from capital gains) |
Total dividends and distributions |
Net
asset value, end of period |
Total return2 |
Net
assets, end of period (in millions) |
Ratio
of expenses to average net assets before waivers3 |
Ratio
of expenses to average net assets after waivers2,3 |
Ratio
of net income to average net assets2 | |||||||||||||
| American High-Income Trust | ||||||||||||||||||||||||||
| Class 1: | ||||||||||||||||||||||||||
| 12/31/2021 | $9.80 | $.51 | $.34 | $.85 | $(.46 | ) | $— | $(.46 | ) | $10.19 | 8.74 | % | $278 | .53 | % | .37 | % | 4.95 | % | |||||||
| 12/31/2020 | 9.87 | .61 | .17 | .78 | (.85 | ) | — | (.85 | ) | 9.80 | 8.21 | 123 | .52 | .52 | 6.46 | |||||||||||
| 12/31/2019 | 9.34 | .67 | .52 | 1.19 | (.66 | ) | — | (.66 | ) | 9.87 | 12.85 | 525 | .51 | .51 | 6.71 | |||||||||||
| 12/31/2018 | 10.19 | .64 | (.84 | ) | (.20 | ) | (.65 | ) | — | (.65 | ) | 9.34 | (2.15 | ) | 501 | .50 | .50 | 6.32 | ||||||||
| 12/31/2017 | 10.18 | .63 | .10 | .73 | (.72 | ) | — | (.72 | ) | 10.19 | 7.25 | 632 | .49 | .49 | 5.98 | |||||||||||
| Class 1A: | ||||||||||||||||||||||||||
| 12/31/2021 | 9.78 | .49 | .33 | .82 | (.44 | ) | — | (.44 | ) | 10.16 | 8.42 | 1 | .78 | .64 | 4.75 | |||||||||||
| 12/31/2020 | 9.86 | .56 | .20 | .76 | (.84 | ) | — | (.84 | ) | 9.78 | 7.94 | 1 | .78 | .78 | 5.85 | |||||||||||
| 12/31/2019 | 9.33 | .65 | .51 | 1.16 | (.63 | ) | — | (.63 | ) | 9.86 | 12.61 | 1 | .75 | .75 | 6.47 | |||||||||||
| 12/31/2018 | 10.18 | .62 | (.84 | ) | (.22 | ) | (.63 | ) | — | (.63 | ) | 9.33 | (2.35 | ) | 1 | .75 | .75 | 6.11 | ||||||||
| 12/31/20174,5 | 10.28 | .60 | .02 | .62 | (.72 | ) | — | (.72 | ) | 10.18 | 6.02 | 6 | — | 8 | .72 | 7 | .72 | 7 | 5.74 | 7 | ||||||
| Class 2: | ||||||||||||||||||||||||||
| 12/31/2021 | 9.61 | .48 | .33 | .81 | (.44 | ) | — | (.44 | ) | 9.98 | 8.42 | 673 | .78 | .65 | 4.80 | |||||||||||
| 12/31/2020 | 9.70 | .55 | .19 | .74 | (.83 | ) | — | (.83 | ) | 9.61 | 7.94 | 665 | .78 | .78 | 5.88 | |||||||||||
| 12/31/2019 | 9.19 | .64 | .50 | 1.14 | (.63 | ) | — | (.63 | ) | 9.70 | 12.55 | 667 | .76 | .76 | 6.45 | |||||||||||
| 12/31/2018 | 10.03 | .61 | (.83 | ) | (.22 | ) | (.62 | ) | — | (.62 | ) | 9.19 | (2.34 | ) | 661 | .75 | .75 | 6.07 | ||||||||
| 12/31/2017 | 10.04 | .59 | .10 | .69 | (.70 | ) | — | (.70 | ) | 10.03 | 6.89 | 776 | .74 | .74 | 5.72 | |||||||||||
| Class 3: | ||||||||||||||||||||||||||
| 12/31/2021 | 9.84 | .50 | .34 | .84 | (.44 | ) | — | (.44 | ) | 10.24 | 8.60 | 10 | .71 | .58 | 4.86 | |||||||||||
| 12/31/2020 | 9.92 | .57 | .19 | .76 | (.84 | ) | — | (.84 | ) | 9.84 | 7.93 | 10 | .71 | .71 | 5.94 | |||||||||||
| 12/31/2019 | 9.38 | .66 | .52 | 1.18 | (.64 | ) | — | (.64 | ) | 9.92 | 12.70 | 10 | .69 | .69 | 6.52 | |||||||||||
| 12/31/2018 | 10.23 | .63 | (.85 | ) | (.22 | ) | (.63 | ) | — | (.63 | ) | 9.38 | (2.33 | ) | 10 | .68 | .68 | 6.14 | ||||||||
| 12/31/2017 | 10.22 | .61 | .10 | .71 | (.70 | ) | — | (.70 | ) | 10.23 | 7.02 | 12 | .67 | .67 | 5.79 | |||||||||||
| Class 4: | ||||||||||||||||||||||||||
| 12/31/2021 | 10.54 | .50 | .36 | .86 | (.41 | ) | — | (.41 | ) | 10.99 | 8.18 | 90 | 1.03 | .89 | 4.52 | |||||||||||
| 12/31/2020 | 10.56 | .57 | .22 | .79 | (.81 | ) | — | (.81 | ) | 10.54 | 7.74 | 69 | 1.03 | 1.03 | 5.58 | |||||||||||
| 12/31/2019 | 9.96 | .67 | .54 | 1.21 | (.61 | ) | — | (.61 | ) | 10.56 | 12.27 | 63 | 1.01 | 1.01 | 6.21 | |||||||||||
| 12/31/2018 | 10.82 | .63 | (.90 | ) | (.27 | ) | (.59 | ) | — | (.59 | ) | 9.96 | (2.64 | ) | 31 | 1.00 | 1.00 | 5.83 | ||||||||
| 12/31/2017 | 10.79 | .61 | .10 | .71 | (.68 | ) | — | (.68 | ) | 10.82 | 6.63 | 34 | .99 | .99 | 5.46 | |||||||||||
American Funds Insurance Series / Prospectus 26
| (Loss)
income from investment operations1 |
Dividends and distributions | |||||||||||||||||||||||||
| Period ended | Net
asset value, beginning of period |
Net investment income |
Net
(losses) gains on securities (both realized and unrealized) |
Total
from investment operations |
Dividends (from net investment income) |
Distributions (from capital gains) |
Total dividends and distributions |
Net
asset value, end of period |
Total return2 |
Net
assets, end of period (in millions) |
Ratio
of expenses to average net assets before waivers3 |
Ratio
of expenses to average net assets after waivers2,3 |
Ratio
of net income to average net assets2 | |||||||||||||
| Capital World Bond Fund | ||||||||||||||||||||||||||
| Class 1: | ||||||||||||||||||||||||||
| 12/31/2021 | $12.94 | $.25 | $(.85 | ) | $(.60 | ) | $(.24 | ) | $(.31 | ) | $(.55 | ) | $11.79 | (4.73 | )% | $988 | .60 | % | .50 | % | 2.06 | % | ||||
| 12/31/2020 | 12.12 | .26 | .95 | 1.21 | (.18 | ) | (.21 | ) | (.39 | ) | 12.94 | 10.17 | 1,219 | .59 | .52 | 2.08 | ||||||||||
| 12/31/2019 | 11.42 | .31 | .61 | .92 | (.22 | ) | — | (.22 | ) | 12.12 | 8.08 | 1,077 | .58 | .58 | 2.60 | |||||||||||
| 12/31/2018 | 11.88 | .30 | (.44 | ) | (.14 | ) | (.28 | ) | (.04 | ) | (.32 | ) | 11.42 | (1.14 | ) | 1,015 | .57 | .57 | 2.56 | |||||||
| 12/31/2017 | 11.22 | .28 | .52 | .80 | (.07 | ) | (.07 | ) | (.14 | ) | 11.88 | 7.11 | 1,273 | .56 | .56 | 2.37 | ||||||||||
| Class 1A: | ||||||||||||||||||||||||||
| 12/31/2021 | 12.91 | .23 | (.85 | ) | (.62 | ) | (.22 | ) | (.31 | ) | (.53 | ) | 11.76 | (4.88 | ) | 1 | .85 | .75 | 1.85 | |||||||
| 12/31/2020 | 12.10 | .23 | .95 | 1.18 | (.16 | ) | (.21 | ) | (.37 | ) | 12.91 | 9.89 | 1 | .83 | .76 | 1.83 | ||||||||||
| 12/31/2019 | 11.41 | .28 | .60 | .88 | (.19 | ) | — | (.19 | ) | 12.10 | 7.75 | 1 | .83 | .83 | 2.35 | |||||||||||
| 12/31/2018 | 11.87 | .27 | (.43 | ) | (.16 | ) | (.26 | ) | (.04 | ) | (.30 | ) | 11.41 | (1.29 | ) | 1 | .82 | .82 | 2.36 | |||||||
| 12/31/20174,5 | 11.22 | .26 | .52 | .78 | (.06 | ) | (.07 | ) | (.13 | ) | 11.87 | 7.00 | 6 | — | 8 | .72 | 7 | .72 | 7 | 2.27 | 7 | |||||
| Class 2: | ||||||||||||||||||||||||||
| 12/31/2021 | 12.84 | .22 | (.84 | ) | (.62 | ) | (.21 | ) | (.31 | ) | (.52 | ) | 11.70 | (4.92 | ) | 1,030 | .85 | .75 | 1.82 | |||||||
| 12/31/2020 | 12.03 | .22 | .95 | 1.17 | (.15 | ) | (.21 | ) | (.36 | ) | 12.84 | 9.90 | 1,058 | .84 | .77 | 1.83 | ||||||||||
| 12/31/2019 | 11.34 | .28 | .60 | .88 | (.19 | ) | — | (.19 | ) | 12.03 | 7.77 | 1,002 | .83 | .83 | 2.35 | |||||||||||
| 12/31/2018 | 11.79 | .27 | (.43 | ) | (.16 | ) | (.25 | ) | (.04 | ) | (.29 | ) | 11.34 | (1.33 | ) | 1,032 | .82 | .82 | 2.32 | |||||||
| 12/31/2017 | 11.14 | .25 | .51 | .76 | (.04 | ) | (.07 | ) | (.11 | ) | 11.79 | 6.86 | 1,164 | .81 | .81 | 2.12 | ||||||||||
| Class 4: | ||||||||||||||||||||||||||
| 12/31/2021 | 12.71 | .19 | (.84 | ) | (.65 | ) | (.18 | ) | (.31 | ) | (.49 | ) | 11.57 | (5.18 | ) | 66 | 1.10 | 1.00 | 1.57 | |||||||
| 12/31/2020 | 11.92 | .19 | .94 | 1.13 | (.13 | ) | (.21 | ) | (.34 | ) | 12.71 | 9.62 | 61 | 1.09 | 1.02 | 1.58 | ||||||||||
| 12/31/2019 | 11.24 | .24 | .60 | .84 | (.16 | ) | — | (.16 | ) | 11.92 | 7.54 | 49 | 1.08 | 1.08 | 2.09 | |||||||||||
| 12/31/2018 | 11.70 | .24 | (.43 | ) | (.19 | ) | (.23 | ) | (.04 | ) | (.27 | ) | 11.24 | (1.61 | ) | 40 | 1.07 | 1.07 | 2.09 | |||||||
| 12/31/2017 | 11.08 | .22 | .51 | .73 | (.04 | ) | (.07 | ) | (.11 | ) | 11.70 | 6.63 | 31 | 1.06 | 1.06 | 1.89 | ||||||||||
| (Loss)
income from investment operations1 |
Dividends and distributions | |||||||||||||||||||||||||
| Period ended | Net
asset value, beginning of period |
Net investment income |
Net
(losses) gains on securities (both realized and unrealized) |
Total
from investment operations |
Dividends (from net investment income) |
Distributions (from capital gains) |
Total dividends and distributions |
Net
asset value, end of period |
Total return2 |
Net
assets, end of period (in millions) |
Ratio
of expenses to average net assets before waivers3 |
Ratio
of expenses to average net assets after waivers2,3 |
Ratio
of net income to average net assets2 | |||||||||||||
| The Bond Fund of America | ||||||||||||||||||||||||||
| Class 1: | ||||||||||||||||||||||||||
| 12/31/2021 | $11.89 | $.21 | $(.23 | ) | $(.02 | ) | $(.19 | ) | $(.47 | ) | $(.66 | ) | $11.21 | (.14 | )% | $8,555 | .39 | % | .26 | % | 1.84 | % | ||||
| 12/31/2020 | 11.17 | .23 | .87 | 1.10 | (.27 | ) | (.11 | ) | (.38 | ) | 11.89 | 9.96 | 6,844 | .40 | .40 | 2.00 | ||||||||||
| 12/31/2019 | 10.47 | .30 | .71 | 1.01 | (.31 | ) | — | (.31 | ) | 11.17 | 9.70 | 6,481 | .39 | .39 | 2.76 | |||||||||||
| 12/31/2018 | 10.82 | .29 | (.35 | ) | (.06 | ) | (.28 | ) | (.01 | ) | (.29 | ) | 10.47 | (.45 | ) | 5,962 | .38 | .38 | 2.70 | |||||||
| 12/31/2017 | 10.80 | .24 | .18 | .42 | (.24 | ) | (.16 | ) | (.40 | ) | 10.82 | 3.88 | 6,434 | .38 | .38 | 2.19 | ||||||||||
| Class 1A: | ||||||||||||||||||||||||||
| 12/31/2021 | 11.84 | .18 | (.23 | ) | (.05 | ) | (.16 | ) | (.47 | ) | (.63 | ) | 11.16 | (.36 | ) | 12 | .64 | .51 | 1.59 | |||||||
| 12/31/2020 | 11.13 | .20 | .87 | 1.07 | (.25 | ) | (.11 | ) | (.36 | ) | 11.84 | 9.68 | 9 | .65 | .65 | 1.74 | ||||||||||
| 12/31/2019 | 10.45 | .27 | .71 | .98 | (.30 | ) | — | (.30 | ) | 11.13 | 9.36 | 7 | .64 | .64 | 2.48 | |||||||||||
| 12/31/2018 | 10.80 | .26 | (.33 | ) | (.07 | ) | (.27 | ) | (.01 | ) | (.28 | ) | 10.45 | (.60 | ) | 3 | .63 | .63 | 2.50 | |||||||
| 12/31/20174,5 | 10.82 | .22 | .15 | .37 | (.23 | ) | (.16 | ) | (.39 | ) | 10.80 | 3.46 | 6 | 1 | .62 | 7 | .62 | 7 | 2.01 | 7 | ||||||
| Class 2: | ||||||||||||||||||||||||||
| 12/31/2021 | 11.73 | .18 | (.22 | ) | (.04 | ) | (.16 | ) | (.47 | ) | (.63 | ) | 11.06 | (.31 | ) | 3,729 | .64 | .52 | 1.57 | |||||||
| 12/31/2020 | 11.02 | .20 | .86 | 1.06 | (.24 | ) | (.11 | ) | (.35 | ) | 11.73 | 9.73 | 3,840 | .65 | .65 | 1.75 | ||||||||||
| 12/31/2019 | 10.34 | .27 | .70 | .97 | (.29 | ) | — | (.29 | ) | 11.02 | 9.36 | 3,561 | .64 | .64 | 2.51 | |||||||||||
| 12/31/2018 | 10.69 | .26 | (.34 | ) | (.08 | ) | (.26 | ) | (.01 | ) | (.27 | ) | 10.34 | (.71 | ) | 3,524 | .63 | .63 | 2.45 | |||||||
| 12/31/2017 | 10.67 | .21 | .18 | .39 | (.21 | ) | (.16 | ) | (.37 | ) | 10.69 | 3.67 | 3,966 | .63 | .63 | 1.94 | ||||||||||
| Class 4: | ||||||||||||||||||||||||||
| 12/31/2021 | 11.69 | .15 | (.22 | ) | (.07 | ) | (.14 | ) | (.47 | ) | (.61 | ) | 11.01 | (.59 | ) | 891 | .89 | .76 | 1.34 | |||||||
| 12/31/2020 | 11.00 | .17 | .85 | 1.02 | (.22 | ) | (.11 | ) | (.33 | ) | 11.69 | 9.38 | 714 | .90 | .90 | 1.48 | ||||||||||
| 12/31/2019 | 10.33 | .24 | .70 | .94 | (.27 | ) | — | (.27 | ) | 11.00 | 9.08 | 502 | .89 | .89 | 2.25 | |||||||||||
| 12/31/2018 | 10.68 | .23 | (.33 | ) | (.10 | ) | (.24 | ) | (.01 | ) | (.25 | ) | 10.33 | (.89 | ) | 366 | .88 | .88 | 2.22 | |||||||
| 12/31/2017 | 10.70 | .19 | .16 | .35 | (.21 | ) | (.16 | ) | (.37 | ) | 10.68 | 3.29 | 297 | .88 | .88 | 1.72 | ||||||||||
27 American Funds Insurance Series / Prospectus
| (Loss)
income from investment operations1 |
Dividends and distributions | |||||||||||||||||||||||||
| Period ended | Net
asset value, beginning of period |
Net investment income |
Net
(losses) gains on securities (both realized and unrealized) |
Total
from investment operations |
Dividends (from net investment income) |
Distributions (from capital gains) |
Total dividends and distributions |
Net
asset value, end of period |
Total return2 |
Net
assets, end of period (in millions) |
Ratio
of expenses to average net assets before waivers |
Ratio
of expenses to average net assets after waivers2 |
Ratio
of net income to average net assets2 | |||||||||||||
| U.S. Government Securities Fund | ||||||||||||||||||||||||||
| Class 1: | ||||||||||||||||||||||||||
| 12/31/2021 | $13.04 | $.18 | $(.26 | ) | $(.08 | ) | $(.18 | ) | $(1.11 | ) | $(1.29 | ) | $11.67 | (.44 | )% | $522 | .39 | % | .29 | % | 1.50 | % | ||||
| 12/31/2020 | 12.34 | .16 | 1.07 | 1.23 | (.26 | ) | (.27 | ) | (.53 | ) | 13.04 | 10.09 | 429 | .38 | .38 | 1.21 | ||||||||||
| 12/31/2019 | 11.94 | .25 | .43 | .68 | (.28 | ) | — | (.28 | ) | 12.34 | 5.69 | 1,418 | .37 | .37 | 2.07 | |||||||||||
| 12/31/2018 | 12.08 | .24 | (.13 | ) | .11 | (.25 | ) | — | (.25 | ) | 11.94 | .91 | 1,445 | .36 | .36 | 2.02 | ||||||||||
| 12/31/2017 | 12.05 | .21 | .01 | .22 | (.19 | ) | — | (.19 | ) | 12.08 | 1.83 | 1,558 | .36 | .36 | 1.68 | |||||||||||
| Class 1A: | ||||||||||||||||||||||||||
| 12/31/2021 | 13.00 | .16 | (.26 | ) | (.10 | ) | (.16 | ) | (1.11 | ) | (1.27 | ) | 11.63 | (.65 | ) | 5 | .64 | .53 | 1.28 | |||||||
| 12/31/2020 | 12.32 | .09 | 1.10 | 1.19 | (.24 | ) | (.27 | ) | (.51 | ) | 13.00 | 9.75 | 4 | .64 | .64 | .69 | ||||||||||
| 12/31/2019 | 11.93 | .22 | .43 | .65 | (.26 | ) | — | (.26 | ) | 12.32 | 5.42 | 2 | .62 | .62 | 1.82 | |||||||||||
| 12/31/2018 | 12.08 | .22 | (.14 | ) | .08 | (.23 | ) | — | (.23 | ) | 11.93 | .70 | 1 | .61 | .61 | 1.82 | ||||||||||
| 12/31/20174,5 | 12.05 | .18 | .03 | .21 | (.18 | ) | — | (.18 | ) | 12.08 | 1.73 | 6 | — | 8 | .58 | 7 | .58 | 7 | 1.53 | 7 | ||||||
| Class 2: | ||||||||||||||||||||||||||
| 12/31/2021 | 12.89 | .15 | (.25 | ) | (.10 | ) | (.15 | ) | (1.11 | ) | (1.26 | ) | 11.53 | (.62 | ) | 1,391 | .64 | .54 | 1.24 | |||||||
| 12/31/2020 | 12.21 | .09 | 1.10 | 1.19 | (.24 | ) | (.27 | ) | (.51 | ) | 12.89 | 9.80 | 1,439 | .64 | .64 | .73 | ||||||||||
| 12/31/2019 | 11.82 | .22 | .42 | .64 | (.25 | ) | — | (.25 | ) | 12.21 | 5.31 | 1,343 | .62 | .62 | 1.82 | |||||||||||
| 12/31/2018 | 11.96 | .21 | (.14 | ) | .07 | (.21 | ) | — | (.21 | ) | 11.82 | .73 | 1,323 | .61 | .61 | 1.77 | ||||||||||
| 12/31/2017 | 11.93 | .17 | .02 | .19 | (.16 | ) | — | (.16 | ) | 11.96 | 1.59 | 1,473 | .61 | .61 | 1.43 | |||||||||||
| Class 3: | ||||||||||||||||||||||||||
| 12/31/2021 | 13.07 | .16 | (.26 | ) | (.10 | ) | (.16 | ) | (1.11 | ) | (1.27 | ) | 11.70 | (.62 | ) | 9 | .57 | .47 | 1.31 | |||||||
| 12/31/2020 | 12.37 | .10 | 1.12 | 1.22 | (.25 | ) | (.27 | ) | (.52 | ) | 13.07 | 9.91 | 10 | .57 | .57 | .78 | ||||||||||
| 12/31/2019 | 11.97 | .23 | .43 | .66 | (.26 | ) | — | (.26 | ) | 12.37 | 5.49 | 9 | .55 | .55 | 1.88 | |||||||||||
| 12/31/2018 | 12.11 | .22 | (.14 | ) | .08 | (.22 | ) | — | (.22 | ) | 11.97 | .71 | 9 | .54 | .54 | 1.84 | ||||||||||
| 12/31/2017 | 12.07 | .18 | .03 | .21 | (.17 | ) | — | (.17 | ) | 12.11 | 1.72 | 10 | .54 | .54 | 1.50 | |||||||||||
| Class 4: | ||||||||||||||||||||||||||
| 12/31/2021 | 12.88 | .12 | (.25 | ) | (.13 | ) | (.12 | ) | (1.11 | ) | (1.23 | ) | 11.52 | (.88 | ) | 238 | .89 | .79 | .98 | |||||||
| 12/31/2020 | 12.22 | .05 | 1.10 | 1.15 | (.22 | ) | (.27 | ) | (.49 | ) | 12.88 | 9.48 | 272 | .89 | .89 | .42 | ||||||||||
| 12/31/2019 | 11.84 | .19 | .42 | .61 | (.23 | ) | — | (.23 | ) | 12.22 | 5.14 | 124 | .87 | .87 | 1.56 | |||||||||||
| 12/31/2018 | 11.98 | .18 | (.12 | ) | .06 | (.20 | ) | — | (.20 | ) | 11.84 | .50 | 91 | .86 | .86 | 1.53 | ||||||||||
| 12/31/2017 | 11.96 | .14 | .01 | .15 | (.13 | ) | — | (.13 | ) | 11.98 | 1.28 | 62 | .86 | .86 | 1.18 | |||||||||||
American Funds Insurance Series / Prospectus 28
| (Loss)
income from investment operations1 |
Dividends and distributions | |||||||||||||||||||||||
| Period ended | Net
asset value, beginning of period |
Net investment (loss) income |
Net
(losses) gains on securities (both realized and unrealized) |
Total
from investment operations |
Dividends (from net investment income) |
Distributions (from capital gains) |
Total dividends and distributions |
Net
asset value, end of period |
Total return |
Net
assets, end of period (in millions) |
Ratio
of expenses to average net assets |
Ratio
of net (loss) income to average net assets | ||||||||||||
| Ultra-Short Bond Fund | ||||||||||||||||||||||||
| Class 1: | ||||||||||||||||||||||||
| 12/31/2021 | $11.31 | $(.03 | ) | $(.01 | ) | $(.04 | ) | $— | $— | $— | $11.27 | (.35 | )% | $37 | .37 | % | (.28 | )% | ||||||
| 12/31/2020 | 11.30 | .02 | .02 | .04 | (.03 | ) | — | (.03 | ) | 11.31 | .34 | 44 | .37 | .16 | ||||||||||
| 12/31/2019 | 11.31 | .22 | — | 9 | .22 | (.23 | ) | — | (.23 | ) | 11.30 | 1.92 | 30 | .36 | 1.92 | |||||||||
| 12/31/2018 | 11.29 | .18 | — | 9 | .18 | (.16 | ) | — | (.16 | ) | 11.31 | 1.58 | 37 | .35 | 1.60 | |||||||||
| 12/31/2017 | 11.27 | .08 | (.01 | ) | .07 | (.05 | ) | — | (.05 | ) | 11.29 | .66 | 37 | .35 | .68 | |||||||||
| Class 1A: | ||||||||||||||||||||||||
| 12/31/2021 | 11.31 | (.03 | ) | — | 9 | (.03 | ) | — | — | — | 11.28 | (.27 | ) | — | 8 | .36 | (.28 | ) | ||||||
| 12/31/2020 | 11.30 | .03 | .01 | .04 | (.03 | ) | — | (.03 | ) | 11.31 | .32 | — | 8 | .35 | .26 | |||||||||
| 12/31/2019 | 11.31 | .22 | — | 9 | .22 | (.23 | ) | — | (.23 | ) | 11.30 | 1.92 | — | 8 | .37 | 1.90 | ||||||||
| 12/31/2018 | 11.29 | .18 | — | 9 | .18 | (.16 | ) | — | (.16 | ) | 11.31 | 1.58 | — | 8 | .35 | 1.60 | ||||||||
| 12/31/20174,5 | 11.27 | .08 | — | 9 | .08 | (.06 | ) | — | (.06 | ) | 11.29 | .67 | 6 | — | 8 | .34 | 7 | .69 | 7 | |||||
| Class 2: | ||||||||||||||||||||||||
| 12/31/2021 | 10.99 | (.06 | ) | — | 9 | (.06 | ) | — | — | — | 10.93 | (.55 | ) | 245 | .62 | (.53 | ) | |||||||
| 12/31/2020 | 11.01 | — | 9 | — | 9 | — | 9 | (.02 | ) | — | (.02 | ) | 10.99 | .03 | 288 | .62 | (.05 | ) | ||||||
| 12/31/2019 | 11.03 | .18 | — | 9 | .18 | (.20 | ) | — | (.20 | ) | 11.01 | 1.62 | 230 | .61 | 1.66 | |||||||||
| 12/31/2018 | 11.01 | .15 | — | 9 | .15 | (.13 | ) | — | (.13 | ) | 11.03 | 1.36 | 247 | .60 | 1.34 | |||||||||
| 12/31/2017 | 10.99 | .05 | — | 9 | .05 | (.03 | ) | — | (.03 | ) | 11.01 | .46 | 249 | .60 | .42 | |||||||||
| Class 3: | ||||||||||||||||||||||||
| 12/31/2021 | 11.12 | (.05 | ) | — | 9 | (.05 | ) | — | — | — | 11.07 | (.45 | ) | 5 | .55 | (.46 | ) | |||||||
| 12/31/2020 | 11.13 | — | 9 | .02 | .02 | (.03 | ) | — | (.03 | ) | 11.12 | .13 | 4 | .55 | .03 | |||||||||
| 12/31/2019 | 11.14 | .20 | — | 9 | .20 | (.21 | ) | — | (.21 | ) | 11.13 | 1.76 | 3 | .54 | 1.74 | |||||||||
| 12/31/2018 | 11.12 | .16 | (.01 | ) | .15 | (.13 | ) | — | (.13 | ) | 11.14 | 1.38 | 4 | .53 | 1.42 | |||||||||
| 12/31/2017 | 11.10 | .06 | — | 9 | .06 | (.04 | ) | — | (.04 | ) | 11.12 | .54 | 4 | .53 | .50 | |||||||||
| Class 4: | ||||||||||||||||||||||||
| 12/31/2021 | 11.08 | (.09 | ) | .01 | (.08 | ) | — | — | — | 11.00 | (.72 | ) | 46 | .87 | (.79 | ) | ||||||||
| 12/31/2020 | 11.13 | (.04 | ) | .01 | (.03 | ) | (.02 | ) | — | (.02 | ) | 11.08 | (.25 | ) | 40 | .87 | (.35 | ) | ||||||
| 12/31/2019 | 11.15 | .16 | — | 9 | .16 | (.18 | ) | — | (.18 | ) | 11.13 | 1.40 | 22 | .86 | 1.40 | |||||||||
| 12/31/2018 | 11.13 | .12 | .01 | .13 | (.11 | ) | — | (.11 | ) | 11.15 | 1.14 | 18 | .86 | 1.11 | ||||||||||
| 12/31/2017 | 11.12 | .02 | — | 9 | .02 | (.01 | ) | — | (.01 | ) | 11.13 | .16 | 15 | .85 | .19 | |||||||||
29 American Funds Insurance Series / Prospectus
| Year ended December 31, | |||||
Portfolio turnover rate for all share classes excluding mortgage dollar roll transactions11 |
2021 | 2020 | 2019 | 2018 | 2017 |
| Capital Income Builder | 60% | 110% | 44% | 42% | 59% |
| Asset Allocation Fund | 45 | 49 | 47 | 34 | 39 |
| American Funds Mortgage Fund | 38 | 123 | 84 | 60 | 98 |
| American Funds Global Balanced Fund | 36 | 68 | 60 | 30 | 28 |
| Capital World Bond Fund | 64 | 88 | 110 | 78 | 74 |
| The Bond Fund of America | 87 | 72 | 146 | 98 | 153 |
| U.S. Government Securities Fund | 126 | 112 | 103 | 76 | 120 |
| Year ended December 31, | |||||
Portfolio turnover rate for all share classes including mortgage dollar roll transactions, if applicable11 |
2021 | 2020 | 2019 | 2018 | 2017 |
| Global Growth Fund | 18% | 17% | 14% | 25% | 31% |
| Global Small Capitalization Fund | 29 | 38 | 50 | 43 | 33 |
| Growth Fund | 25 | 32 | 21 | 35 | 24 |
| International Fund | 44 | 40 | 32 | 29 | 29 |
| New World Fund | 43 | 70 | 38 | 58 | 56 |
| Capital World Growth and Income Fund | 85 | 36 | 29 | 49 | 41 |
| Growth-Income Fund | 24 | 33 | 27 | 39 | 27 |
| International Growth and Income Fund | 41 | 56 | 28 | 38 | 51 |
| Washington Mutual Investors Fund | 90 | 40 | 37 | 49 | 34 |
| Capital Income Builder | 93 | 184 | 72 | 98 | 88 |
| Asset Allocation Fund | 124 | 145 | 79 | 86 | 85 |
| American Funds Global Balanced Fund | 39 | 86 | 74 | 51 | 41 |
| American Funds Mortgage Fund | 975 | 1,143 | 350 | 811 | 680 |
| American High-Income Trust | 56 | 78 | 58 | 67 | 78 |
| Capital World Bond Fund | 91 | 145 | 159 | 125 | 105 |
| The Bond Fund of America | 456 | 461 | 373 | 514 | 502 |
| U.S. Government Securities Fund | 433 | 867 | 277 | 446 | 551 |
| Ultra-Short Bond Fund | —12 | —12 | —12 | —12 | —12 |
1 Based on average shares outstanding.
2 This column reflects the impact of certain waivers/reimbursements from Capital Research and Management Company. During some of the periods shown, Capital Research and Management Company waived a portion of investment advisory services fees on some funds.
3 Ratios do not include expenses of any Central Funds. The fund indirectly bears its proportionate share of the expenses of any Central Funds, if applicable.
4 Based on operations for a period that is less than a full year.
5 Class 1A shares began investment operations on January 6, 2017.
6 Not annualized.
7 Annualized.
8 Amount less than $1 million.
9 Amount less than $.01.
10 Amount less than .01%.
11Rates do not include the fund’s portfolio activity with respect to any Central Funds, if applicable.
12Amount is either less than 1% or there is no turnover.
American Funds Insurance Series / Prospectus 30
Other fund information Shares of the Series are currently offered to insurance company separate accounts funding both variable annuity contracts and variable life insurance policies. Interests of various contract owners participating in the Series may be in conflict. The board of trustees of the Series will monitor for the existence of any material conflicts and determine what action, if any, should be taken. Shares may be purchased or redeemed by the separate accounts without any sales or redemption charges at net asset value.
Annual/Semi-annual report to shareholders The shareholder reports contain additional information about the Series, including financial statements, investment results, portfolio holdings, a discussion of market conditions and the Series’ investment strategies, and the independent registered public accounting firm’s report (in the annual report).
Statement of additional information (SAI) and codes of ethics The current SAI, as amended from time to time, contains more detailed information about the Series, including the funds’ financial statements, and is incorporated by reference into this prospectus. This means that the current SAI, for legal purposes, is part of this prospectus. The codes of ethics describe the personal investing policies adopted by the Series, the Series’ investment adviser and its affiliated companies.
The codes of ethics and current SAI are on file with the U.S. Securities and Exchange Commission (SEC). These and other related materials about the Series are available for review on the EDGAR database on the SEC’s website at sec.gov or, after payment of a duplicating fee, via email request to publicinfo@sec.gov.
The current SAI and annual/semi-annual reports to shareholders can be found online at capitalgroup.com/afis and may be available on the website of the company that issued your insurance contract. You also may request a free copy of these documents or the codes of ethics by calling Capital Group at (800) 421-9900, ext. 65413 or writing to the Secretary at 333 South Hope Street, Los Angeles, California 90071.
| INA2PRX-054-0522P Printed in USA CGD/AFD/8024 | Investment Company File No. 811-03857 |
American Funds Insurance Series® Prospectus May
1, 2022 |
 |
American Funds Global Balanced Fund
Table of contents
| American Funds Global Balanced Fund 1 | Investment objectives, strategies and risks 6 Management and organization 10 Purchases and redemptions of shares 15 |
|||
| The U.S. Securities and Exchange Commission has not approved or disapproved of these securities. Further, it has not determined that this prospectus is accurate or complete. Any representation to the contrary is a criminal offense. |
American Funds Global Balanced Fund
Investment objectives This fund seeks the balanced accomplishment of three objectives: long-term growth of capital, conservation of principal and current income.
Fees and expenses of the fund This table describes the fees and expenses that you may pay if you buy, hold and sell an interest in Class 4 shares of the fund. You may pay other fees, such as insurance contract fees and expenses, which are not reflected in the tables and examples below. If insurance contract fees and expenses were reflected, expenses shown would be higher.
| Annual fund operating expenses (expenses that you pay each year as a percentage of the value of your investment) | Class 4 |
| Management fee | 0.66% |
| Distribution (12b-1) fees | 0.25 |
| Other expenses | 0.32 |
| Total annual fund operating expenses | 1.23 |
| Fee waiver* | 0.22 |
| Total annual fund operating expenses after fee waiver | 1.01 |
* The investment adviser is currently waiving a portion of its management fee equal to .22% of the fund’s net assets. This waiver will be in effect through at least May 1, 2023. The waiver may only be modified or terminated with the approval of the fund’s board.
Example This example is intended to help you compare the cost of investing in Class 4 shares of the fund with the cost of investing in other mutual funds.
The example assumes that you invest $10,000 in the fund for the time periods indicated and then redeem all of your shares at the end of those periods. The example also assumes that your investment has a 5% return each year and that the fund’s operating expenses remain the same. The example does not reflect insurance contract expenses. If insurance contract expenses were reflected, expenses shown would be higher. The example reflects the fee waiver described above through the expiration date of such waiver and total annual fund operating expenses thereafter. No sales charge (load) or other fees are charged by the fund upon redemption, so you would incur these hypothetical costs whether or not you were to redeem your shares at the end of the given period. Although your actual costs may be higher or lower, based on these assumptions your costs would be:
| 1 year | 3 years | 5 years | 10 years | |
| Class 4 | $103 | $369 | $655 | $1,469 |
Portfolio turnover The fund pays transaction costs, such as commissions, when it buys and sells securities (or “turns over” its portfolio). A higher portfolio turnover rate may indicate higher transaction costs. These costs, which are not reflected in annual fund operating expenses or in the example, affect the fund’s investment results. During the most recent fiscal year, the fund’s portfolio turnover rate was 39% of the average value of its portfolio.
1 American Funds Insurance Series / Prospectus
Principal investment strategies As a balanced fund with global scope, the fund seeks to invest in equity and debt securities around the world that offer the opportunity for growth and/or provide dividend income, while also constructing the portfolio to protect principal and limit volatility.
Normally the fund will maintain at least 45% of the value of its assets in common stocks and other equity investments. Although the fund’s equity investments focus on medium to larger capitalization companies, the fund’s investments are not limited to a particular capitalization size.
Normally the fund will invest at least 25% of the value of its assets in bonds and other debt securities (including money market instruments). These will consist of investment-grade securities (rated Baa3 or better or BBB– or better by Nationally Recognized Statistical Rating Organizations designated by the fund’s investment adviser or unrated but determined to be of equivalent quality by the fund’s investment adviser).
The fund will allocate its assets among various countries, including the United States (but in no fewer than three countries). Under normal market conditions, the fund will invest at least 40% of its net assets in issuers outside the United States, unless market conditions are not deemed favorable by the fund’s investment adviser, in which case the fund would invest at least 30% of its net assets in issuers outside the United States.
The fund’s ability to invest in issuers outside the United States includes investing in emerging markets.
The fund may invest in bonds and other debt securities, including securities issued and guaranteed by the U.S. government, securities issued by federal agencies and instrumentalities and securities backed by mortgages or other assets. The fund may also invest in securities of governments, agencies, corporations and other entities domiciled outside the United States. These investments will typically be denominated in currencies other than U.S. dollars.
The investment adviser uses a system of multiple portfolio managers in managing the fund’s assets. Under this approach, the portfolio of the fund is divided into segments managed by individual managers.
The fund relies on the professional judgment of its investment adviser to make decisions about the fund’s portfolio investments. The basic investment philosophy of the investment adviser is to seek to invest in attractively valued securities that, in its opinion, represent good, long-term investment opportunities. Securities may be sold when the investment adviser believes that they no longer represent relatively attractive investment opportunities.
Principal risks
This section describes the principal risks associated with investing in the fund. You may lose money by investing in the fund. The likelihood of loss may be greater if you invest for a shorter period of time. Investors in the fund should have a long-term perspective and be able to tolerate potentially sharp declines in value.
Market conditions — The prices of, and the income generated by, the common stocks, bonds and other securities held by the fund may decline – sometimes rapidly or unpredictably – due to various factors, including events or conditions affecting the general economy or particular industries; overall market changes; local, regional or global political, social or economic instability; governmental, governmental agency or central bank responses to economic conditions; and currency exchange rate, interest rate and commodity price fluctuations.
Economies and financial markets throughout the world are highly interconnected. Economic, financial or political events, trading and tariff arrangements, wars, terrorism, cybersecurity events, natural disasters, public health emergencies (such as the spread of infectious disease) and other circumstances in one country or region, including actions taken by governmental or quasi-governmental authorities in response to any of the foregoing, could have impacts on global economies or markets. As a result, whether or not the fund invests in securities of issuers located in or with significant exposure to the countries affected, the value and liquidity of the fund’s investments may be negatively affected by developments in other countries and regions.
Issuer risks — The prices of, and the income generated by, securities held by the fund may decline in response to various factors directly related to the issuers of such securities, including reduced demand for an issuer’s goods or services, poor management performance, major litigation, investigations or other controversies related to the issuer, changes in government regulations affecting the issuer or its competitive environment and strategic initiatives such as mergers, acquisitions or dispositions and the market response to any such initiatives.
Investing in growth-oriented stocks — Growth-oriented common stocks and other equity-type securities (such as preferred stocks, convertible preferred stocks and convertible bonds) may involve larger price swings and greater potential for loss than other types of investments.
Investing in income-oriented stocks — The value of the fund’s securities and income provided by the fund may be reduced by changes in the dividend policies of, and the capital resources available for dividend payments at, the companies in which the fund invests.
Investing outside the United States — Securities of issuers domiciled outside the United States, or with significant operations or revenues outside the United States, may lose value because of adverse political, social, economic or market developments (including social instability, regional conflicts, terrorism and war) in the countries or regions in which the issuers operate or generate revenue. These securities may also lose value due to changes in foreign currency exchange rates against the U.S. dollar and/or currencies of other countries. Issuers of these securities may be more susceptible to actions of foreign governments, such as nationalization, currency blockage or the imposition of price controls or punitive taxes, each of which could adversely impact the value of these securities. Securities markets in certain countries may be more volatile and/or less liquid than those in the United States. Investments outside the United States may also be subject to different accounting and auditing practices and standards and different regulatory, legal and reporting
American Funds Insurance Series / Prospectus 2
requirements, and may be more difficult to value, than those in the United States. In addition, the value of investments outside the United States may be reduced by foreign taxes, including foreign withholding taxes on interest and dividends. Further, there may be increased risks of delayed settlement of securities purchased or sold by the fund. The risks of investing outside the United States may be heightened in connection with investments in emerging markets.
Investing in emerging markets — Investing in emerging markets may involve risks in addition to and greater than those generally associated with investing in the securities markets of developed countries. For instance, emerging market countries tend to have less developed political, economic and legal systems and accounting and auditing practices and standards than those in developed countries. Accordingly, the governments of these countries may be less stable and more likely to intervene in the market economy, for example, by imposing capital controls, nationalizing a company or industry, placing restrictions on foreign ownership and on withdrawing sale proceeds of securities from the country, and/or imposing punitive taxes that could adversely affect the prices of securities. Information regarding issuers in emerging markets may be limited, incomplete or inaccurate, and there may be fewer rights and remedies available to the fund and its shareholders. In addition, the economies of these countries may be dependent on relatively few industries, may have limited access to capital and may be more susceptible to changes in local and global trade conditions and downturns in the world economy. Securities markets in these countries can also be relatively small and have substantially lower trading volumes. As a result, securities issued in these countries may be more volatile and less liquid, and may be more difficult to value, than securities issued in countries with more developed economies and/or markets. Less certainty with respect to security valuations may lead to additional challenges and risks in calculating the fund’s net asset value. Additionally, emerging markets are more likely to experience problems with the clearing and settling of trades and the holding of securities by banks, agents and depositories that are less established than those in developed countries.
Investing in debt instruments — The prices of, and the income generated by, bonds and other debt securities held by the fund may be affected by factors such as the interest rates, maturities and credit ratings of these securities.
Rising interest rates will generally cause the prices of bonds and other debt securities to fall. A general rise in interest rates may cause investors to sell debt securities on a large scale, which could also adversely affect the price and liquidity of debt securities and could also result in increased redemptions from the fund. Falling interest rates may cause an issuer to redeem, call or refinance a debt security before its stated maturity, which may result in the fund failing to recoup the full amount of its initial investment and having to reinvest the proceeds in lower yielding securities. Longer maturity debt securities generally have greater sensitivity to changes in interest rates and may be subject to greater price fluctuations than shorter maturity debt securities.
Bonds and other debt securities are also subject to credit risk, which is the possibility that the credit strength of an issuer or guarantor will weaken or be perceived to be weaker, and/or an issuer of a debt security will fail to make timely payments of principal or interest and the security will go into default. A downgrade or default affecting any of the fund’s securities could cause the value of the fund’s shares to decrease. Lower quality debt securities generally have higher rates of interest and may be subject to greater price fluctuations than higher quality debt securities. Credit risk is gauged, in part, by the credit ratings of the debt securities in which the fund invests. However, ratings are only the opinions of the rating agencies issuing them and are not guarantees as to credit quality or an evaluation of market risk. The fund’s investment adviser relies on its own credit analysts to research issuers and issues in seeking to assess credit and default risks.
Investing in mortgage-related and other asset-backed securities — Mortgage-related securities, such as mortgage-backed securities, and other asset-backed securities, include debt obligations that represent interests in pools of mortgages or other income-bearing assets, such as consumer loans or receivables. While such securities are subject to the risks associated with investments in debt instruments generally (for example, credit, extension and interest rate risks), they are also subject to other and different risks. Mortgage-backed and other asset-backed securities are subject to changes in the payment patterns of borrowers of the underlying debt, potentially increasing the volatility of the securities and the fund’s net asset value. When interest rates fall, borrowers are more likely to refinance or prepay their debt before its stated maturity. This may result in the fund having to reinvest the proceeds in lower yielding securities, effectively reducing the fund’s income. Conversely, if interest rates rise and borrowers repay their debt more slowly than expected, the time in which the mortgage-backed and other asset-backed securities are paid off could be extended, reducing the fund’s cash available for reinvestment in higher yielding securities. Mortgage-backed securities are also subject to the risk that underlying borrowers will be unable to meet their obligations and the value of property that secures the mortgages may decline in value and be insufficient, upon foreclosure, to repay the associated loans. Investments in asset-backed securities are subject to similar risks.
Liquidity risk — Certain fund holdings may be or may become difficult or impossible to sell, particularly during times of market turmoil. Liquidity may be impacted by the lack of an active market for a holding, legal or contractual restrictions on resale, or the reduced number and capacity of market participants to make a market in such holding. Market prices for less liquid or illiquid holdings may be volatile, and reduced liquidity may have an adverse impact on the market price of such holdings. Additionally, the sale of less liquid or illiquid holdings may involve substantial delays (including delays in settlement) and additional costs and the fund may be unable to sell such holdings when necessary to meet its liquidity needs or may be forced to sell at a loss.
Management — The investment adviser to the fund actively manages the fund’s investments. Consequently, the fund is subject to the risk that the methods and analyses, including models, tools and data, employed by the investment adviser in this process may be flawed or incorrect and may not produce the desired results. This could cause the fund to lose value or its investment results to lag relevant benchmarks or other funds with similar objectives.
Your investment in the fund is not a bank deposit and is not insured or guaranteed by the Federal Deposit Insurance Corporation or any other governmental agency, entity or person. You should consider how this fund fits into your overall investment program.
3 American Funds Insurance Series / Prospectus
Investment results The following bar chart shows how the investment results of the Class 4 shares of the fund have varied from year to year, and the following table shows how the fund’s average annual total returns for various periods compare with a broad measure of securities market results and other applicable measures of market results. This information provides some indication of the risks of investing in the fund.The fund has selected the 60%/40% MSCI All Country World Index/Bloomberg Global Aggregate Index to replace the MSCI All Country World Index as its broad-based securities market index. The fund's investment adviser believes that the 60%/40% MSCI All Country World Index/Bloomberg Global Aggregate Index better reflects the market sectors and securities in which the fund primarily invests and the investment strategies employed by the adviser in seeking to achieve the fund's investment objective. MSCI All Country World Index is a free float-adjusted market capitalization weighted index that is designed to measure equity market results in the global developed and emerging markets, consisting of more than 40 developed and emerging market country indexes. Results reflect dividends gross of withholding taxes through December 31, 2000, and dividends net of withholding taxes thereafter. Bloomberg Global Aggregate Index represents the global investment-grade fixed income markets. Past investment results (before and after taxes) are not predictive of future investment results. Figures shown reflect fees and expenses associated with an investment in the fund, but do not reflect insurance contract fees and expenses. If insurance contract fees and expenses were included, results would have been lower. Updated information on the fund’s investment results can be obtained by visiting capitalgroup.com/afis.
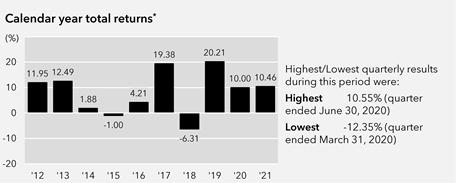
| Average annual total returns For the periods ended December 31, 2021: | 1 year | 5 years | 10 years | Lifetime* |
| Fund | 10.46% | 10.31% | 8.02% | 7.59% |
| 60%/40% MSCI All Country World Index/Bloomberg Global Aggregate Index (reflects no deduction for sales charges, account fees, expenses or U.S. federal income taxes) | 8.78 | 10.11 | 7.91 | 6.50 |
| MSCI All Country World Index (reflects no deduction for sales charges, account fees, expenses or U.S. federal income taxes) | 18.54 | 14.40 | 11.85 | 9.40 |
| Bloomberg Global Aggregate Index (reflects no deduction for sales charges, account fees, expenses or U.S. federal income taxes) | –4.71 | 3.36 | 1.77 | 1.76 |
* Lifetime returns are from May 2, 2011, the date the fund began investment operations. Class 4 shares began investment operations on December 14, 2012; therefore, returns for the fund prior to that date assume a hypothetical investment in Class 1 shares, but reflect the .50% annual expense that applies to Class 4 shares, .25% of which is described in the “Plan of distribution” section of this prospectus and .25% of which is described in the “Fund expenses” section of this prospectus. Returns for Class 1 shares are comparable to those of Class 4 shares because both classes invest in the same portfolio of securities.
American Funds Insurance Series / Prospectus 4
Management
Investment
adviser Capital Research and Management CompanySM
Portfolio managers The individuals primarily responsible for the portfolio management of the
fund are:
| Portfolio
manager/ Series title (if applicable) |
Portfolio
manager experience in this fund |
Primary
title with investment adviser |
| Alfonso Barroso | Less than 1 year | Partner – Capital Research Global Investors |
| Andrew A. Cormack | 1 year | Partner – Capital Fixed Income Investors |
| Bradford F. Freer | Less than 1 year | Partner – Capital Research Global Investors |
| Thomas H. Høgh | 3 years | Partner – Capital Fixed Income Investors |
| Winnie Kwan | Less than 1 year | Partner – Capital Research Global Investors |
Purchase and sale of fund shares Shares of the fund are not sold directly to the general public. The fund is offered only as an underlying investment option for variable insurance contracts, and insurance company separate accounts and qualified feeder funds — and not the holders of variable insurance contracts — are the shareholders of the fund. Although the fund does not require a minimum amount for initial or subsequent purchases from insurance companies, your insurance company may impose investment minimums for your purchase of the fund.
You may sell (redeem) shares on any business day. You must sell (redeem) shares through your insurance company.
Tax information See your variable insurance contract prospectus for information regarding the federal income tax treatment of your variable insurance contract and related distributions.
Payments to broker-dealers and other financial intermediaries The fund is not sold directly to the general public but instead is offered as an underlying investment option for variable insurance contracts. The fund and its related companies may make payments to the sponsoring insurance company (or its affiliates) for distribution and/or other services. These payments may be a factor that the insurance company considers in including the fund as an underlying investment option in the variable insurance contract. The prospectus (or other offering document) for your variable insurance contract may contain additional information about these payments.
5 American Funds Insurance Series / Prospectus
Investment objectives, strategies and risks
American Funds Global Balanced Fund This fund seeks the balanced accomplishment of three objectives: long-term growth of capital, conservation of principal and current income. While it has no present intention to do so, the fund’s board may change the fund’s investment objectives without shareholder approval upon 60 days’ written notice to shareholders.
Normally, the fund will maintain at least 45% of the value of its assets in common stocks and other equity investments under normal market conditions. Although the fund’s equity investments focus on medium to larger capitalization companies, the fund’s investments are not limited to a particular capitalization size.
Normally the fund will invest at least 25% of the value of its assets in bonds and other debt securities (including money market instruments). These will consist of investment-grade securities (rated Baa3 or better or BBB– or better by Nationally Recognized Statistical Rating Organizations designated by the fund’s investment adviser or unrated but determined to be of equivalent quality by the fund’s investment adviser).
Under normal market conditions, the fund will invest at least 40% of its net assets in issuers outside the United States, unless market conditions are not deemed favorable by the fund’s investment adviser, in which case the fund would invest at least 30% of its net assets in issuers outside the United States.
The fund’s ability to invest in issuers outside the United States includes investing in emerging markets.
The fund may also invest to a limited extent in lower quality, higher yielding debt securities including those convertible into common stocks (rated Ba1 or below or BB+ or below by Nationally Recognized Statistical Rating Organizations designated by the fund’s investment adviser or unrated but determined to be of equivalent quality by the fund’s investment adviser). Such securities are sometimes referred to as “junk bonds.”
The fund may invest in bonds and other debt securities, including securities issued and guaranteed by the U.S. government, securities issued by federal agencies and instrumentalities and securities backed by mortgages or other assets. The fund may also invest in securities of governments, agencies, corporations and other entities domiciled outside the United States. These investments will typically be denominated in currencies other than U.S. dollars.
There are no restrictions on the maturity or duration of the bonds and other debt securities in the fund’s portfolio.
The fund may enter into currency transactions to provide for the purchase or sale of a currency needed to purchase a security denominated in such currency. In addition, the fund may enter into agreements, known as forward currency contracts, to purchase or sell a specific currency at a future date at a fixed price. The fund may enter into forward currency contracts to protect against changes in currency exchange rates, to increase exposure to a particular foreign currency, to shift exposure to currency fluctuations from one currency to another or to seek to increase returns.
The fund may also hold cash or cash equivalents, including commercial paper and short-term securities issued by the U.S. government, its agencies and instrumentalities. The percentage of the fund invested in such holdings varies and depends on various factors, including market conditions and purchases and redemptions of fund shares. The investment adviser may determine that it is appropriate to invest a substantial portion of the fund’s assets in such instruments in response to certain circumstances, such as periods of market turmoil. For temporary defensive purposes, the fund may invest without limitation in such instruments. A larger percentage of such holdings could moderate the fund’s investment results in a period of rising market prices. Alternatively, a larger percentage of such holdings could reduce the magnitude of the fund’s loss in a period of falling market prices and provide liquidity to make additional investments or to meet redemptions.
The fund may invest in other funds managed by the investment adviser or its affiliates (“Central Funds”) to more effectively invest in a diversified set of securities in a specific asset class such as money market instruments, bonds and other securities. Shares of Central Funds are only offered for purchase to the fund’s investment adviser and its affiliates and other funds, investment vehicles and accounts managed by the fund’s investment adviser and its affiliates. When investing in Central Funds, the fund bears its proportionate share of the expenses of the Central Funds in which it invests but does not bear additional management fees through its investment in such Central Funds. The investment results of the portions of the fund’s assets invested in the Central Funds will be based upon the investment results of the Central Funds.
The fund may also lend portfolio securities to brokers, dealers and other institutions that provide cash or U.S. Treasury securities as collateral in an amount at least equal to the value of the securities loaned.
The fund relies on the professional judgment of its investment adviser to make decisions about the fund’s portfolio investments. The basic investment philosophy of the investment adviser is to seek to invest in attractively valued securities that, in its opinion, represent good, long-term investment opportunities. The investment adviser believes that an important way to accomplish this is through fundamental analysis, which may include meeting with company executives and employees, suppliers, customers and competitors. Securities may be sold when the investment adviser believes that they no longer represent relatively attractive investment opportunities.
The following are principal risks associated with investing in the fund.
Market conditions — The prices of, and the income generated by, the common stocks, bonds and other securities held by the fund may decline – sometimes rapidly or unpredictably – due to various factors, including events or conditions affecting the general economy or particular industries; overall market changes; local, regional or global political, social or economic instability; governmental, governmental agency or central bank responses to economic conditions; and currency exchange rate, interest rate and commodity price fluctuations.
American Funds Insurance Series / Prospectus 6
Economies and financial markets throughout the world are highly interconnected. Economic, financial or political events, trading and tariff arrangements, wars, terrorism, cybersecurity events, natural disasters, public health emergencies (such as the spread of infectious disease) and other circumstances in one country or region, including actions taken by governmental or quasi-governmental authorities in response to any of the foregoing, could have impacts on global economies or markets. As a result, whether or not the fund invests in securities of issuers located in or with significant exposure to the countries affected, the value and liquidity of the fund’s investments may be negatively affected by developments in other countries and regions.
Issuer risks — The prices of, and the income generated by, securities held by the fund may decline in response to various factors directly related to the issuers of such securities, including reduced demand for an issuer’s goods or services, poor management performance, major litigation, investigations or other controversies related to the issuer, changes in government regulations affecting the issuer or its competitive environment and strategic initiatives such as mergers, acquisitions or dispositions and the market response to any such initiatives.
Investing in growth-oriented stocks — Growth-oriented common stocks and other equity-type securities (such as preferred stocks, convertible preferred stocks and convertible bonds) may involve larger price swings and greater potential for loss than other types of investments.
Investing in income-oriented stocks — The value of the fund’s securities and income provided by the fund may be reduced by changes in the dividend policies of, and the capital resources available for dividend payments at, the companies in which the fund invests.
Investing outside the United States — Securities of issuers domiciled outside the United States, or with significant operations or revenues outside the United States, may lose value because of adverse political, social, economic or market developments (including social instability, regional conflicts, terrorism and war) in the countries or regions in which the issuers operate or generate revenue. These securities may also lose value due to changes in foreign currency exchange rates against the U.S. dollar and/or currencies of other countries. Issuers of these securities may be more susceptible to actions of foreign governments, such as nationalization, currency blockage or the imposition of price controls or punitive taxes, each of which could adversely impact the value of these securities. Securities markets in certain countries may be more volatile and/or less liquid than those in the United States. Investments outside the United States may also be subject to different accounting and auditing practices and standards and different regulatory, legal and reporting requirements, and may be more difficult to value, than those in the United States. In addition, the value of investments outside the United States may be reduced by foreign taxes, including foreign withholding taxes on interest and dividends. Further, there may be increased risks of delayed settlement of securities purchased or sold by the fund. The risks of investing outside the United States may be heightened in connection with investments in emerging markets.
Investing in emerging markets — Investing in emerging markets may involve risks in addition to and greater than those generally associated with investing in the securities markets of developed countries. For instance, emerging market countries tend to have less developed political, economic and legal systems and accounting and auditing practices and standards than those in developed countries. Accordingly, the governments of these countries may be less stable and more likely to intervene in the market economy, for example, by imposing capital controls, nationalizing a company or industry, placing restrictions on foreign ownership and on withdrawing sale proceeds of securities from the country, and/or imposing punitive taxes that could adversely affect the prices of securities. Information regarding issuers in emerging markets may be limited, incomplete or inaccurate, and there may be fewer rights and remedies available to the fund and its shareholders. In addition, the economies of these countries may be dependent on relatively few industries, may have limited access to capital and may be more susceptible to changes in local and global trade conditions and downturns in the world economy. Securities markets in these countries can also be relatively small and have substantially lower trading volumes. As a result, securities issued in these countries may be more volatile and less liquid, and may be more difficult to value, than securities issued in countries with more developed economies and/or markets. Less certainty with respect to security valuations may lead to additional challenges and risks in calculating the fund’s net asset value. Additionally, emerging markets are more likely to experience problems with the clearing and settling of trades and the holding of securities by banks, agents and depositories that are less established than those in developed countries.
Investing in debt instruments — The prices of, and the income generated by, bonds and other debt securities held by the fund may be affected by factors such as the interest rates, maturities and credit ratings of these securities.
Rising interest rates will generally cause the prices of bonds and other debt securities to fall. A general rise in interest rates may cause investors to sell debt securities on a large scale, which could also adversely affect the price and liquidity of debt securities and could also result in increased redemptions from the fund. Falling interest rates may cause an issuer to redeem, call or refinance a debt security before its stated maturity, which may result in the fund failing to recoup the full amount of its initial investment and having to reinvest the proceeds in lower yielding securities. Longer maturity debt securities generally have greater sensitivity to changes in interest rates and may be subject to greater price fluctuations than shorter maturity debt securities.
Bonds and other debt securities are also subject to credit risk, which is the possibility that the credit strength of an issuer or guarantor will weaken or be perceived to be weaker, and/or an issuer of a debt security will fail to make timely payments of principal or interest and the security will go into default. A downgrade or default affecting any of the fund’s securities could cause the value of the fund’s shares to decrease. Lower quality debt securities generally have higher rates of interest and may be subject to greater price fluctuations than higher quality debt securities. Credit risk is gauged, in part, by the credit ratings of the debt securities in which the fund invests. However, ratings are only the opinions of the rating agencies issuing them and are not guarantees as to credit quality or an evaluation of market risk. The fund’s investment adviser relies on its own credit analysts to research issuers and issues in seeking to assess credit and default risks.
Investing in mortgage-related and other asset-backed securities — Mortgage-related securities, such as mortgage-backed securities, and other asset-backed securities, include debt obligations that represent interests in pools of mortgages or other income-bearing assets, such
7 American Funds Insurance Series / Prospectus
as residential mortgage loans, home equity loans, mortgages on commercial buildings, consumer loans and equipment leases. While such securities are subject to the risks associated with investments in debt instruments generally (for example, credit, extension and interest rate risks), they are also subject to other and different risks. Mortgage-backed and other asset-backed securities are subject to changes in the payment patterns of borrowers of the underlying debt, potentially increasing the volatility of the securities and the fund’s net asset value. When interest rates fall, borrowers are more likely to refinance or prepay their debt before its stated maturity. This may result in the fund having to reinvest the proceeds in lower yielding securities, effectively reducing the fund’s income. Conversely, if interest rates rise and borrowers repay their debt more slowly than expected, the time in which the mortgage-backed and other asset-backed securities are paid off could be extended, reducing the fund’s cash available for reinvestment in higher yielding securities. Mortgage-backed securities are also subject to the risk that underlying borrowers will be unable to meet their obligations and the value of property that secures the mortgages may decline in value and be insufficient, upon foreclosure, to repay the associated loans. Investments in asset-backed securities are subject to similar risks, as well as additional risks associated with the assets underlying those securities.
Liquidity risk — Certain fund holdings may be or may become difficult or impossible to sell, particularly during times of market turmoil. Liquidity may be impacted by the lack of an active market for a holding, legal or contractual restrictions on resale, or the reduced number and capacity of market participants to make a market in such holding. Market prices for less liquid or illiquid holdings may be volatile, and reduced liquidity may have an adverse impact on the market price of such holdings. Additionally, the sale of less liquid or illiquid holdings may involve substantial delays (including delays in settlement) and additional costs and the fund may be unable to sell such holdings when necessary to meet its liquidity needs or may be forced to sell at a loss.
Management — The investment adviser to the fund actively manages the fund’s investments. Consequently, the fund is subject to the risk that the methods and analyses, including models, tools and data, employed by the investment adviser in this process may be flawed or incorrect and may not produce the desired results. This could cause the fund to lose value or its investment results to lag relevant benchmarks or other funds with similar objectives.
The following are additional risks associated with investing in the fund.
Interest rate risk — The values and liquidity of the securities held by the fund may be affected by changing interest rates. For example, the values of debt securities may decline when interest rates rise and increase when interest rates fall. Longer maturity debt securities generally have greater sensitivity to changes in interest rates and may be subject to greater price fluctuations than shorter maturity debt securities. The fund may invest in variable and floating rate securities. When the fund holds variable or floating rate securities, a decrease in market interest rates will adversely affect the income received from such securities and the net asset value of the fund’s shares. Although the values of such securities are generally less sensitive to interest rate changes than those of other debt securities, the value of variable and floating rate securities may decline if their interest rates do not rise as quickly, or as much, as market interest rates. Conversely, floating rate securities will not generally increase in value if interest rates decline. During periods of extremely low short-term interest rates, certain of the fund’s debt securities may not be able to maintain a positive yield and, given the current low interest rate environment, risks associated with rising rates are currently heightened.
Investing in securities backed by the U.S. government — Securities backed by the U.S. Treasury or the full faith and credit of the U.S. government are guaranteed only as to the timely payment of interest and principal when held to maturity. Accordingly, the current market values for these securities will fluctuate with changes in interest rates and the credit rating of the U.S. government. Securities issued by U.S. government-sponsored entities and federal agencies and instrumentalities that are not backed by the full faith and credit of the U.S. government are neither issued nor guaranteed by the U.S. government.
Investing in lower rated debt instruments — Lower rated bonds and other lower rated debt securities generally have higher rates of interest and involve greater risk of default or price declines due to changes in the issuer’s creditworthiness than those of higher quality debt securities. The market prices of these securities may fluctuate more than the prices of higher quality debt securities and may decline significantly in periods of general economic difficulty. These risks may be increased with respect to investments in junk bonds.
Currency transactions — In addition to the risks generally associated with investing in derivative instruments, the use of forward currency contracts involves the risk that currency movements will not be accurately predicted by the investment adviser, which could result in losses to the fund. While entering into forward currency contracts could minimize the risk of loss due to a decline in the value of the hedged currency, it could also limit any potential gain that may result from an increase in the value of the currency. Additionally, the adviser may use forward currency contracts to increase exposure to a certain currency or to shift exposure to currency fluctuations from one country to another. Forward currency contracts may expose the fund to potential gains and losses in excess of the initial amount invested.
Exposure to country, region, industry or sector — Subject to the fund’s investment limitations, the fund may have significant exposure to a particular country, region, industry or sector. Such exposure may cause the fund to be more impacted by risks relating to and developments affecting the country, region, industry or sector, and thus its net asset value may be more volatile, than a fund without such levels of exposure. For example, if the fund has significant exposure in a particular country, then social, economic, regulatory or other issues that negatively affect that country may have a greater impact on the fund than on a fund that is more geographically diversified.
Investing in derivatives — The use of derivatives involves a variety of risks, which may be different from, or greater than, the risks associated with investing in traditional securities, such as stocks and bonds. Changes in the value of a derivative may not correlate perfectly with, and may be more sensitive to market events than, the underlying asset, rate or index, and a derivative instrument may expose the fund to losses in excess of its initial investment. Derivatives may be difficult to value, difficult for the fund to buy or sell at an opportune time or price and difficult to terminate or otherwise offset. The fund’s use of derivatives may result in losses to the fund, and investing in derivatives may reduce the fund’s returns and increase the fund’s price volatility. The fund’s counterparty to a derivative transaction (including, if applicable, the fund’s clearing broker, the derivatives exchange or the clearinghouse) may be unable or unwilling to honor its financial obligations in respect of the transaction.
American Funds Insurance Series / Prospectus 8
Lending of portfolio securities — Securities lending involves risks, including the risk that the loaned securities may not be returned in a timely manner or at all and/or the risk of a loss of rights in the collateral if a borrower or the lending agent defaults. These risks could be greater for non-U.S. securities. Additionally, the fund may lose money from the reinvestment of collateral received on loaned securities in investments that decline in value, default or do not perform as expected.
Cybersecurity breaches — The fund may be subject to operational and information security risks through breaches in cybersecurity. Cybersecurity breaches can result from deliberate attacks or unintentional events, including “ransomware” attacks, the injection of computer viruses or malicious software code, the use of vulnerabilities in code to gain unauthorized access to digital information systems, networks or devices, or external attacks such as denial-of-service attacks on the investment adviser’s or an affiliate’s website that could render the fund’s network services unavailable to intended end-users. These breaches may, among other things, lead to the unauthorized release of confidential information, misuse of the fund’s assets or sensitive information, the disruption of the fund’s operational capacity, the inability of fund shareholders to transact business, or the destruction of the fund’s physical infrastructure, equipment or operating systems. As a result of these potential outcomes, the fund could incur violations of applicable privacy and other laws, reputational damage, additional costs associated with corrective measures and/or financial loss. The fund may also be subject to additional risks if its third-party service providers, such as the fund’s investment adviser, transfer agent, custodian, administrators and other financial intermediaries, experience similar cybersecurity breaches and potential outcomes. Cybersecurity risks may also impact issuers of securities in which the fund invests, which may cause the fund’s investments in such issuers to lose value.
In addition to the principal investment strategies described above, the fund has other investment practices that are described in the statement of additional information, which includes a description of other risks related to the fund’s principal investment strategies and other investment practices. The fund’s investment results will depend on the ability of the fund’s investment adviser to navigate the risks discussed above as well as those described in the statement of additional information.
Fund comparative indexes — The 60%/40% MSCI All Country World Index/Bloomberg Global Aggregate Index blends the MSCI All Country World Index with the Bloomberg Global Aggregate Index by weighting their cumulative total returns at 60% and 40%, respectively. This assumes the blend is rebalanced monthly. The MSCI All Country World Index is a free float-adjusted market capitalization-weighted index that is designed to measure equity market results in the global developed and emerging markets, consisting of more than 40 developed and emerging market country indexes. Results reflect dividends gross of withholding taxes through December 31, 2000, and dividends net of withholding taxes thereafter. This index is unmanaged, and its results include reinvested dividends and/or distributions but do not reflect the effect of sales charges, commissions, account fees, expenses or U.S. federal income taxes. The Bloomberg Global Aggregate Index represents the global investment-grade fixed income markets. This index is unmanaged, and its results include reinvested distributions but do not reflect the effect of sales charges, commissions, account fees, expenses or U.S. federal income taxes.
Portfolio holdings A description of the fund’s policies and procedures regarding disclosure of information about its portfolio holdings is available in the statement of additional information.
9 American Funds Insurance Series / Prospectus
Management and organization
Investment adviser Capital Research and Management Company, an experienced investment management organization founded in 1931, serves as the investment adviser to the Series and other funds, including the American Funds. Capital Research and Management Company is a wholly owned subsidiary of The Capital Group Companies, Inc. and is located at 333 South Hope Street, Los Angeles, California 90071. Capital Research and Management Company manages the investment portfolios and business affairs of the Series. The total management fee paid by each fund to its investment adviser for the most recent fiscal year, including any amounts waived, in each case expressed as a percentage of average net assets of that fund, appears in the Annual Fund Operating Expenses table for each fund. Please see the statement of additional information for further details. A discussion regarding the basis for the approval of the Series’ Investment Advisory and Service Agreement by the Series’ board of trustees is contained in the Series’ annual report to shareholders for the fiscal year ended December 31, 2021.
Capital Research and Management Company manages equity assets through three equity investment divisions and fixed income assets through its fixed income investment division, Capital Fixed Income Investors. The three equity investment divisions — Capital International Investors, Capital Research Global Investors and Capital World Investors — make investment decisions independently of one another.
The equity investment divisions may, in the future, be incorporated as wholly owned subsidiaries of Capital Research and Management Company. In that event, Capital Research and Management Company would continue to be the investment adviser, and day-to-day investment management of equity assets would continue to be carried out through one or more of these subsidiaries. Although not currently contemplated, Capital Research and Management Company could incorporate its fixed income investment division in the future and engage it to provide day-to-day investment management of fixed income assets. Capital Research and Management Company and each of the funds it advises have received an exemptive order from the U.S. Securities and Exchange Commission that allows Capital Research and Management Company to use, upon approval of the funds’ boards, its management subsidiaries and affiliates to provide day-to-day investment management services to the funds, including making changes to the management subsidiaries and affiliates providing such services. The Series’ shareholders approved this arrangement; however, there is no assurance that Capital Research and Management Company will incorporate its investment divisions or exercise any authority granted to it under the exemptive order.
In addition, shareholders of the Series have approved a proposal to reorganize the Series into a Delaware statutory trust. However, the Series reserved the right to delay implementing the reorganization and has elected to do so.
The Capital SystemSM Capital Research and Management Company uses a system of multiple portfolio managers in managing mutual fund assets. Under this approach, the portfolio of a fund is divided into segments managed by individual managers. In addition, Capital Research and Management Company’s investment analysts may make investment decisions with respect to a portion of a fund’s portfolio. Investment decisions are subject to a fund’s objective(s), policies and restrictions and the oversight of the appropriate investment-related committees of Capital Research and Management Company and its investment divisions.
Certain senior members of Capital Fixed Income Investors, the investment adviser’s fixed income investment division, serve on the Portfolio Strategy Group. The group utilizes a research-driven process with input from the investment adviser’s analysts, portfolio managers and economists to define investment themes on a range of macroeconomic factors, including duration, yield curve and sector allocation. Where applicable, the investment decisions made by a fund’s fixed income portfolio managers are informed by the investment themes discussed by the group.
American Funds Insurance Series / Prospectus 10
The primary individual portfolio managers for each of the funds are:
| Portfolio
manager for the Series/Title (if applicable) |
Primary title with investment adviser (or affiliate) and investment experience | Portfolio
manager’s role in management of, and experience in, the fund(s) |
| Donald D. O’Neal Co-President and Trustee | Partner – Capital International Investors Investment professional for 36 years, all with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: Growth-Income Fund — 16 years |
| Alan N. Berro Co-President | Partner – Capital World Investors Investment professional for 37 years in total; 31 years with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: Washington Mutual Investors Fund — 5 years Asset Allocation Fund — 22 years |
| Carl M. Kawaja Vice President | Partner – Capital World Investors Investment professional for 35 years in total; 31 years with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: New World Fund — 23 years |
| Sung Lee Vice President | Partner – Capital Research Global Investors Investment professional for 28 years, all with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: Capital
World Growth and Income Fund — 1 year |
| Keiko McKibben Vice President | Partner – Capital Research Global Investors Investment professional for 28 years in total; 24 years with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: Growth-Income Fund — 8 years (plus 10 years of prior experience as an investment analyst for the fund) |
| Renaud H. Samyn Vice President | Partner – Capital Research Global Investors Investment professional for 21 years, all with Capital Research and Management Company or affiliate |
Serves as an equity portfolio manager for: Global Small Capitalization Fund — 3 years (plus
15 years of prior experience as an investment analyst for the fund) |
| Pramod Atluri | Partner – Capital Fixed Income Investors Investment professional for 24 years in total; 6 years with Capital Research and Management Company or affiliate |
Serves
as a fixed income portfolio manager for: The Bond Fund of America — 6 years |
| Aline Avzaradel | Partner – Capital International Investors Investment professional for 19 years in total; 18 years with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: Capital Income Builder — 2 years |
| Alfonso Barroso | Partner – Capital Research Global Investors Investment professional for 28 years, all with Capital Research and Management Company or affiliate |
Serves as an equity portfolio manager for: Capital
World Growth and Income Fund — 1 year |
| Michael Beckwith | Vice President – Capital Research Global Investors Investment professional for 20 years in total; 3 years with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: Global Small Capitalization Fund — 3 years |
| Paul Benjamin | Partner – Capital World Investors Investment professional for 17 years, all with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: Growth Fund — 4 years (plus 12 years of prior experience as an investment analyst for the fund) |
| David J. Betanzos | Partner – Capital Fixed Income Investors Investment professional for 22 years in total; 20 years with Capital Research and Management Company or affiliate |
Serves
as a fixed income portfolio manager for: The Bond Fund of America — 1 year American Funds Mortgage Fund — 8 years U.S. Government Securities Fund — 7 years |
| Jeremy Burge | Partner – Capital World Investors Investment professional for 40 years in total; 20 years with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: Capital World Growth and Income Fund — 1 year (plus 1 year of prior experience as an investment analyst for the fund) |
| Grant L. Cambridge | Partner – Capital International Investors Investment professional for 29 years in total; 25 years with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: Capital Income Builder — 2 years |
| Mark L. Casey | Partner – Capital International Investors Investment professional for 22 years, all with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: Growth Fund — 5 years (plus 11 years of prior experience as an investment analyst for the fund) Washington Mutual Investors Fund — 1 year |
| Philip Chitty | Partner – Capital Fixed Income Investors Investment professional for 28 years in total; 18 years with Capital Research and Management Company or affiliate |
Serves
as a fixed income portfolio manager for: Capital World Bond Fund — 1 year |
| Tom Chow | Partner – Capital Fixed Income Investors Investment professional for 33 years in total; 7 years with Capital Research and Management Company or affiliate |
Serves
as a fixed income portfolio manager for: American High-Income Trust— 7 years |
11 American Funds Insurance Series / Prospectus
| Portfolio
manager for the Series/Title (if applicable) |
Primary title with investment adviser (or affiliate) and investment experience | Portfolio
manager’s role in management of, and experience in, the fund(s) |
| Michael Cohen | Partner – Capital World Investors Investment professional for 31 years in total; 22 years with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: Capital World Growth and Income Fund — 4 years International Growth and Income Fund — Less than 1 year |
| Patrice Collette | Partner – Capital World Investors Investment professional for 28 years in total; 22 years with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: Global Growth Fund — 7 years (plus 14 years of prior experience as an investment analyst for the fund) International Growth and Income Fund — Less than 1 year |
| Andrew A. Cormack | Vice President – Capital Fixed Income Investors Investment professional for 18 years in total; 4 years with Capital Research and Management Company or affiliate |
Serves
as a fixed income portfolio manager for: Capital World Bond Fund — 3 years |
| David A. Daigle | Partner – Capital Fixed Income Investors Investment professional for 28 years, all with Capital Research and Management Company or affiliate |
Serves
as a fixed income portfolio manager for: Asset Allocation Fund — 13 years American High-Income Trust— 13 years (plus 9 years of prior experience as an investment analyst for the fund) |
| Oliver V. Edmonds | Vice President – Capital Fixed Income Investors Investment professional for 19 years, all with Capital Research and Management Company or affiliate |
Serves
as a fixed income portfolio manager for: American Funds Mortgage Fund - 1 year |
| Peter Eliot | Partner – Capital International Investors Investment professional for 27 years in total; 18 years with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: Asset Allocation Fund — 6 years |
| Charles E. Ellwein | Partner – Capital Research Global Investors Investment professional for 26 years in total; 16 years with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: Growth-Income Fund — 7 years (plus 8 years of prior experience as an investment analyst for the fund) |
| Brady L. Enright | Partner – Capital World Investors Investment professional for 31 years in total; 25 years with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: Washington Mutual Investors Fund — 1 year |
| Paul Flynn | Partner – Capital World Investors Investment professional for 26 years in total; 24 years with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: Global Growth Fund — 5 years International Growth and Income Fund — Less than 1 year |
| J. Blair Frank | Partner – Capital Research Global Investors Investment professional for 29 years in total; 28 years with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: Growth-Income Fund — 16 years |
| Bradford F. Freer | Partner – Capital Research Global Investors Investment professional for 30 years in total; 28 years with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: Global Small Capitalization Fund — 4 years New World Fund — 5 years (plus 13 years of prior experience as an investment analyst for the fund) American Funds Global Balanced Fund – Less than 1 year |
| Irfan M. Furniturewala | Partner – Capital International Investors Investment
professional for |
Serves
as an equity portfolio manager for: (plus
1 year of prior experience as an investment analyst for the fund) |
| Nicholas J. Grace | Partner – Capital Research Global Investors Investment professional for 32 years in total; 28 years with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: New World Fund — 10 years (plus 8 years of prior experience as an investment analyst for the fund) |
| Leo Hee | Partner – Capital World Investors Investment
professional for 28 years in total; |
Serves
as an equity portfolio manager for: Capital World Growth and Income Fund — 1 year (plus 10 years of prior experience as an investment analyst for the fund) International Growth and Income Fund — Less than 1 year |
| David A. Hoag | Partner – Capital Fixed Income Investors Investment professional for 34 years in total; 31 years with Capital Research and Management Company or affiliate |
Serves
as a fixed income portfolio manager for: Capital Income Builder — 2 years The Bond Fund of America — 15 years |
| Thomas H. Høgh | Partner – Capital Fixed Income Investors Investment professional for 35 years in total; 32 years with Capital Research and Management Company or affiliate |
Serves
as a fixed income portfolio manager for: American Funds Global Balanced Fund —3 years Capital World Bond Fund — 16 years |
| Roz Hongsaranagon | Partner – Capital World Investors Investment professional for 20 years, all with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: Global Growth Fund — 4 years |
| Dawid Justus | Partner – Capital World Investors Investment professional for 23 in total years; 17 years with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: New World Fund — 2 years (plus 14 years of prior experience as an investment analyst for the fund) |
American Funds Insurance Series / Prospectus 12
| Portfolio
manager for the Series/Title (if applicable) |
Primary title with investment adviser (or affiliate) and investment experience | Portfolio
manager’s role in management of, and experience in, the fund(s) |
| Jonathan Knowles | Partner – Capital World Investors Investment professional for 30 years, all with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: Global Growth Fund — 9 years (plus 10 years of prior experience as an investment analyst for the fund) New World Fund — 2 years (plus 8 years of prior experience as an investment analyst for the fund) |
| Winnie Kwan | Partner – Capital Research Global Investors Investment professional for 26 years in total; 22 years with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: New World Fund — 2 years (plus 2 years of prior experience as an investment analyst for the fund) Capital Income Builder — 2 years American Funds Global Balanced Fund –Less than 1 year |
| Harold H. La | Partner – Capital Research Global Investors Investment professional for 24 years in total; 23 years with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: Global Small Capitalization Fund — 14 years (plus 4 years of prior experience as an investment analyst for the fund) |
| Jeffrey T. Lager | Partner – Capital International Investors Investment professional for 27 years in total; 26 years with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: Washington Mutual Investors Fund — 1 year Asset Allocation Fund — 15 years |
| Jin Lee | Partner – Capital World Investors Investment professional for 26 years in total; 25 years with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: Washington Mutual Investors Fund — 1 year Capital World Growth and Income Fund— 1 year Asset Allocation Fund — 4 years |
| Steven D. Lotwin | Partner – Capital Fixed Income Investors Investment professional for 21 years, all with Capital Research and Management Company or affiliate |
Serves
as a fixed income portfolio manager for: Ultra-Short Bond Fund — 4 years |
| James B. Lovelace | Partner – Capital Research Global Investors Investment professional for 40 years, all with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: Capital Income Builder — 2 years |
| Robert W. Lovelace | Partner – Capital International Investors Investment professional for 37 years, all with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: New World Fund — 2 years |
| Fergus N. MacDonald | Partner – Capital Fixed Income Investors Investment professional for 30 years in total; 19 years with Capital Research and Management Company or affiliate |
Serves
as a fixed income portfolio manager for: Capital Income Builder — 2 years The Bond Fund of America — 1 year American Funds Mortgage Fund — 11 years U.S. Government Securities Fund — 12 years |
| Aidan O’Connell | Partner – Capital Research Global Investors Investment professional for 24 years in total; 18 years with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: Global Small Capitalization Fund — 8 years (plus 9 years of prior experience as an investment analyst for the fund) |
| Lara Pellini | Partner – Capital World Investors Investment professional for 21 years, all with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: Capital World Growth and Income Fund — 1 year (plus 10 years of prior experience as an investment analyst for the fund) |
| Piyada Phanaphat | Partner – Capital World Investors Investment professional for 19 years in total; 15 years with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: New World Fund — 5 years (plus 9 years of prior experience as an investment analyst for the fund) |
| Anne-Marie Peterson | Partner – Capital World Investors Investment professional for 28 years in total; 17 years with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: Growth Fund — 4 years (plus 11 years of prior experience as an investment analyst for the fund) |
| John R. Queen | Partner – Capital Fixed Income Investors Investment professional for 32 years in total; 20 years with Capital Research and Management Company or affiliate |
Serves
as a fixed income portfolio manager for: Asset Allocation Fund — 6 years |
| Caroline Randall | Partner – Capital Research Global Investors Investment professional for 25 years in total; 17 years with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: Capital Income Builder — 2 years |
| Andraz Razen | Partner – Capital World Investors Investment professional for 24 years in total; 18 years with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: Growth Fund — 9 years (plus 3 years of prior experience as an investment analyst for the fund) |
| William L. Robbins | Partner – Capital International Investors Investment professional for 30 years in total; 27 years with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: Growth-Income Fund — 10 years (plus 12 years of prior experience as an investment analyst for the fund) |
| Carlos A. Schonfeld | Partner – Capital International Investors Investment professional for 24 years, all with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: Growth-Income Fund — 8 years |
13 American Funds Insurance Series / Prospectus
| Portfolio
manager for the Series/Title (if applicable) |
Primary title with investment adviser (or affiliate) and investment experience | Portfolio
manager’s role in management of, and experience in, the fund(s) |
| Akira Shiraishi | Partner – Capital International Investors Investment professional for 25 years in total; 19 years with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: New World Fund — 2 years |
| Kirstie Spence | Partner – Capital Fixed Income Investors Investment professional for 27 years, all with Capital Research and Management Company or affiliate |
Serves
as a fixed income portfolio manager for: New World Fund — 2 years (plus 9 years of prior experience as an investment analyst for the fund) |
| Eric H. Stern | Partner – Capital International Investors Investment
professional for |
Serves
as an equity portfolio manager for: Washington Mutual Investors Fund — 1 year |
| Andrew B. Suzman | Partner – Capital World Investors Investment professional for 29 years, all with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: International Growth and Income Fund — Less than 1 year |
| Tomonori Tani | Partner – Capital World Investors Investment professional for 24 years in total; 18 years with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: New World Fund — 4 years |
| Lisa Thompson | Partner – Capital International Investors Investment professional for 34 years in total; 28 years with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: New World Fund — 2 years International Growth and Income Fund — Less than 1 year |
| Christopher Thomsen | Partner – Capital Research Global Investors Investment professional for 25 years, all with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: International Fund — 16 years New World Fund — 2 years |
| Tara L. Torrens | Partner – Capital Fixed Income Investors Investment professional for 19 years, all with Capital Research and Management Company or affiliate |
Serves
as a fixed income portfolio manager for: American High-Income Trust —4 years |
| Ritchie Tuazon | Partner – Capital Fixed Income Investors Investment professional for 22 years in total; 11 years with Capital Research and Management Company or affiliate |
Serves
as a fixed income portfolio manager for: U.S. Government Securities Fund — 7 years |
| Bradley J. Vogt | Partner – Capital Research Global Investors Investment professional for 35 years, all with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: Capital Income Builder — 2 years |
| Diana Wagner | Partner – Capital World Investors Investment
professional for |
Serves
as an equity portfolio manager for: Washington Mutual Investors Fund — 1 year |
| Shannon Ward | Partner – Capital Fixed Income Investors Investment professional for 30 years in total; 5 years with Capital Research and Management Company or affiliate |
Serves
as a fixed income portfolio manager for: American High-Income Trust — 5 years |
| Steven T. Watson | Partner – Capital International Investors Investment professional for 35 years in total; 32 years with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: Capital Income Builder — 4 years International Growth and Income Fund — Less than 1 year |
| Gregory W. Wendt | Partner – Capital Research Global Investors Investment professional for 35 years, all with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: Global Small Capitalization Fund — 10 years (plus 14 years of prior experience as an investment analyst for the fund) |
| Alan J. Wilson | Partner – Capital World Investors Investment
professional for |
Serves
as an equity portfolio manager for: Growth Fund — 8 years Washington Mutual Investors Fund — 1 year |
| Philip Winston | Partner – Capital International Investors Investment professional for 37 years in total; 25 years with Capital Research and Management Company or affiliate |
Serves
as an equity portfolio manager for: Capital Income Builder — 8 years |
Information regarding the portfolio managers’ compensation, their ownership of securities in the Series and other accounts they manage is in the statement of additional information.
American Funds Insurance Series / Prospectus 14
Purchases and redemptions of shares Shares of the Series are currently offered only to insurance company separate accounts as well as so-called “feeder funds” under master-feeder arrangements sponsored by insurance companies as underlying investments for such insurance companies’ variable annuity contracts and variable life insurance policies. All such shares may be purchased or redeemed by the insurance company separate accounts (or feeder funds) at net asset value without any sales or redemption charges. These purchases and redemptions are made at the price next determined after such purchases and redemptions of units of the separate accounts (or feeder funds). The Series typically expects to remit redemption proceeds one business day following receipt and acceptance of a redemption order, regardless of the method the Series uses to make such payment (e.g., check, wire or automated clearing house transfer). However, payment may take longer than one business day and may take up to seven days as generally permitted by the Investment Company Act of 1940, as amended (the “1940 Act”). Under the 1940 Act, the Series may be permitted to pay redemption proceeds beyond seven days under certain limited circumstances.
Under normal conditions, the Series typically expects to meet shareholder redemptions by monitoring the Series’ portfolio and redemption activities and by regularly holding a reserve of highly liquid assets, such as cash or cash equivalents. The Series may use additional methods to meet shareholder redemptions, if they become necessary. These methods may include, but are not limited to, the sale of portfolio assets, the use of overdraft protection afforded by the Series’ custodian bank, borrowing from a line of credit and making payment with fund securities or other fund assets rather than in cash (as further discussed in the following paragraph).
Although payment of redemptions normally will be in cash, the Series may pay the redemption price wholly or partly with portfolio securities or other fund assets under conditions and circumstances determined by the Series’ board of trustees. On the same redemption date, some shareholders may be paid in whole or in part in securities (which may differ among those shareholders), while other shareholders may be paid entirely in cash. In general, in-kind redemptions to affiliated shareholders will as closely as practicable represent the affiliated shareholder’s pro rata share of the Series’ securities, subject to certain exceptions. Securities distributed in-kind to unaffiliated shareholders will be selected by the investment adviser in a manner the investment adviser deems to be fair and reasonable to the Series’ shareholders. The disposal of the securities received in-kind may be subject to brokerage costs and, until sold, such securities remain subject to market risk and liquidity risk, including the risk that such securities are or become difficult to sell. If the Series pays your redemption with illiquid or less liquid securities, you will bear the risk of not being able to sell such securities.
15 American Funds Insurance Series / Prospectus
Frequent trading of fund shares The Series and American Funds Distributors, Inc., the Series’ distributor, reserve the right to reject any purchase order for any reason. The funds are not designed to serve as vehicles for frequent trading. Frequent trading of fund shares may lead to increased costs to the funds and less efficient management of the funds’ portfolios, potentially resulting in dilution of the value of the shares held by long-term shareholders. Accordingly, purchases, including those that are part of exchange activity, that the Series or American Funds Distributors has determined could involve actual or potential harm to a fund may be rejected.
The Series, through its transfer agent, American Funds Service Company, has agreements with the Series’ insurance relationships to maintain its surveillance procedures that are designed to detect frequent trading in fund shares. The agreements generally require the insurance companies to (i) provide, upon request from a fund, the Series or their agent, certain identifying and account information regarding contract owners who invest in fund shares through an insurance company account and (ii) execute instructions from a fund, the Series or their agent to restrict further purchases or exchanges of fund shares by a contract owner who the Series has identified as having engaged in potentially harmful market timing or frequent trading. Under these procedures, various analytics are used to evaluate factors that may be indicative of frequent trading. For example, transactions in fund shares that exceed certain monetary thresholds may be scrutinized. American Funds Service Company may work with the insurance company separate accounts or feeder funds to apply their procedures that American Funds Service Company believes are reasonably designed to enforce the frequent trading policies of the Series. You should refer to disclosures provided by the insurance company with which you have a contract to determine the specific trading restrictions that apply to you.
Under the Series’ frequent trading policy, certain trading activity will not be treated as frequent trading, such as:
· retirement plan contributions, loans and distributions (including hardship withdrawals) identified as such on the retirement plan recordkeeper’s system;
· purchase transactions involving in-kind transfers of fund shares, if the entity maintaining the contract owner’s account is able to identify the transaction as one of these types of transactions; and
· systematic redemptions and purchases if the entity maintaining the contract owner’s account is able to identify the transaction as a systematic redemption or purchase.
Generally, purchases and redemptions will not be considered “systematic” unless the transaction is prescheduled for a specific date.
American Funds Service Company will monitor for other types of activity that could potentially be harmful to the Series – for example short-term trading activity in multiple funds. If American Funds Service Company identifies any activity that may constitute frequent trading, it reserves the right to contact the insurance company separate account or feeder fund and request that the separate account or feeder fund either provide information regarding an account owner’s transactions or restrict the account owner’s trading. If American Funds Service Company is not satisfied that insurance company separate account or feeder fund has taken appropriate action, American Funds Service Company may terminate the separate account’s or feeder fund’s ability to transact in fund shares.
There is no guarantee that all instances of frequent trading in fund shares will be prevented.
Notwithstanding the Series’ surveillance procedures described above, all transactions in fund shares remain subject to the right of the Series, American Funds Distributors and American Funds Service Company to restrict potentially abusive trading generally, including the types of transactions described above that will not be prevented.
American Funds Insurance Series / Prospectus 16
Valuing shares The net asset value of each share class of a fund is the value of a single share of that class. The net asset value per share is calculated once daily as of the close of regular trading on the New York Stock Exchange, normally 4 p.m. New York time, each day the New York Stock Exchange is open. If the New York Stock Exchange makes a scheduled (e.g. the day after Thanksgiving) or an unscheduled close prior to 4 p.m. New York time, the net asset value of each fund will be determined at approximately the time the New York Stock Exchange closes on that day. If on such a day market quotations and prices from third-party pricing services are not based as of the time of the early close of the New York Stock Exchange but are as of a later time (up to approximately 4 p.m. New York time), for example because the market remains open after the close of the New York Stock Exchange, those later market quotations and prices will be used in determining the funds’ net asset value.
Equity securities are valued primarily on the basis of market quotations, and debt securities are valued primarily on the basis of prices from third-party pricing services. Futures contracts are valued primarily on the basis of settlement prices. The funds have adopted procedures for making fair value determinations if market quotations or prices from third-party pricing services, as applicable, are not readily available or are not considered reliable. For example, if events occur between the close of markets outside the United States and the close of regular trading on the New York Stock Exchange that, in the opinion of the investment adviser, materially affect the value of any of the funds’ equity securities that trade principally in those international markets, those securities will be valued in accordance with fair value procedures. Similarly, fair value procedures may be employed if an issuer defaults on its debt securities and there is no market for its securities. Use of these procedures is intended to result in more appropriate net asset values and, where applicable, to reduce potential arbitrage opportunities otherwise available to short-term investors.
Because certain of the funds may hold securities that are listed primarily on foreign exchanges that trade on weekends or days when the funds do not price their shares, the values of securities held in the funds may change on days when you will not be able to purchase or redeem fund shares.
Shares of the funds will be purchased or sold at the net asset value next determined after receipt of requests from the appropriate insurance company. Requests received by the appropriate insurance company prior to 4 p.m. New York time and communicated by the insurance company to the Series or its agent will be purchased or sold at that day’s net asset value. Orders in good order received after the New York Stock Exchange closes (scheduled or unscheduled) will be processed at the net asset value (plus any applicable sales charge) calculated on the following business day.
Plan of distribution The Series has adopted a plan of distribution or “12b-1 plan” for Class 4 shares. Under the plan, the Series may finance activities primarily intended to sell shares, provided the categories of expenses are approved in advance by the Series’ board of trustees. The plan provides for annual expenses of .25% for Class 4 shares. Amounts paid under the 12b-1 plan are used by insurance company contract issuers to cover distribution expenses and/or the expenses of certain contract owner services. The 12b-1 fees paid by the Series, as a percentage of average net assets, for the most recent fiscal year, are indicated in the prospectus in the Annual Fund Operating Expenses table for each fund. Since these fees are paid out of the Series’ assets on an ongoing basis, over time they may cost you more than paying other types of sales charges or service fees and reduce the return of an investment in Class 4 shares.
17 American Funds Insurance Series / Prospectus
Other compensation to dealers American Funds Distributors, at its expense, provides additional compensation to insurance companies. These payments may be made, at the discretion of American Funds Distributors, to insurance companies (or their affiliates) that have sold shares of the funds of the American Funds Insurance Series and American Funds as the exclusive underlying investments to their variable contracts. A number of factors will be considered in determining payments, including the sales, assets, and the quality of the company’s relationship with American Funds Distributors. The payment will be determined using a formula applied consistently to insurance companies based on the relevant facts and circumstances. The level of payments made to a qualifying firm in any given year will vary and (excluding payments for meetings as described below) will represent the sum of (a) up to .14% of the current year’s American Funds Insurance Series new deposits in the contracts, (b) up to .07% of the current and previous year’s American Funds Insurance Series new deposits in the contracts, and (c) up to .0084% of American Funds Insurance Series assets attributable to the contracts, with an adjustment made for the quality of the company’s relationship with American Funds Distributors. Aggregate payments made by American Funds Distributors to insurance companies may also change from year to year. Only assets and deposits in variable annuity contracts that offer exclusively shares of the American Funds Insurance Series and American Funds are included in the formula. Further, assets for which the insurance company, or an affiliated broker-dealer, acts as an ERISA investment fiduciary are generally excluded from the formula. American Funds Distributors makes these payments to help defray the costs incurred by qualifying insurance companies in connection with efforts to educate its sales force about the American Funds Insurance Series so that they help financial advisers make recommendations and provide services that are suitable and meet contractholders needs. These payments may also be made to help defray the costs associated with the insurance company’s provision of account related services and activities and support the insurance company’s distribution activities. American Funds Distributors will, on an annual basis, determine the advisability of continuing these payments.
Firms receiving additional compensation payments must sign a letter acknowledging the purpose of the payment and American Funds Distributors’ goal that the payment will help facilitate education of the firm’s sales force about the American Funds Insurance Series and American Funds to help financial professionals make suitable recommendations and better serve their clients who invest in the funds as underlying investments to variable contracts. The letters generally require the firms to (1) have significant assets invested in the American Funds, (2) provide American Funds Distributors broad access to their sales force and product platforms and develop a business plan to achieve such access, and (3) agree to maintain American Funds within their existing products.
American Funds Distributors may also pay expenses associated with meetings and other training and educational opportunities conducted by insurance companies, selling dealers, advisory platform providers and other intermediaries to facilitate educating financial professionals and shareholders about the American Funds. For example, some of these expenses may include, but not be limited to, meeting sponsor fees, meeting location fees, and fees to obtain lists of financial professionals to better tailor training and education opportunities.
If investment advisers, distributors or other affiliates of mutual funds pay additional compensation or other incentives to insurance companies in differing amounts, insurance companies and the financial professionals with which they interact may have financial incentives for recommending a particular mutual fund over other mutual funds or investments, creating a potential conflict of interest. You should consult with your financial professional and review carefully any disclosure by your financial professional’s firm as to compensation received.
American Funds Insurance Series / Prospectus 18
Fund expenses In periods of market volatility, assets of the funds may decline significantly, causing total annual fund operating expenses (as a percentage of the value of your investment) to become higher than the numbers shown in the Annual Fund Operating Expenses tables in this prospectus.
The “Other expenses” items in the Annual Fund Operating Expenses tables in this prospectus are based on expenses as of each fund’s most recently completed fiscal year. These items include third-party expenses, such as custodial, legal, audit, accounting, regulatory reporting and pricing vendor services, and an administrative services fee payable to the Series’ investment adviser for administrative services provided by the Series’ investment adviser and its affiliates. In addition, the “Other expenses” items for Class 4 shares include fees for administrative services provided by the insurance companies that include Class 4 shares of any of the funds as underlying investments in their variable contracts. Each fund will pay an insurance administration fee of .25% of Class 4 share assets to these insurance companies for providing certain services pursuant to an insurance administrative services plan adopted by the Series.
For all share classes, “Other expenses” items in the Annual Fund Operating Expenses table in this prospectus include fees for administrative services provided by the fund’s investment adviser and its affiliates. Administrative services are provided by the investment adviser and its affiliates to help assist third parties providing non-distribution services to fund shareholders. These services include providing in-depth information on the fund and market developments that impact fund investments. Administrative services also include, but are not limited to, coordinating, monitoring and overseeing third parties that provide services to fund shareholders.
The Administrative Services Agreement between the fund and the investment adviser provides the fund the ability to charge an administrative services fee of .05% for all share classes. The fund's investment adviser receives an administrative services fee at the annual rate of .03% of the average daily net assets of the fund attributable to all share classes (which could be increased as noted above) for its provision of administrative services.
Investment results All fund results in the “Investment results” section of this prospectus reflect the reinvestment of dividends and capital gains distributions, if any. Unless otherwise noted, fund results reflect any fee waivers and/or expense reimbursements in effect during the period presented.
Distributions and taxes Each fund of the Series intends to qualify as a “regulated investment company” under the Internal Revenue Code. In any fiscal year in which a fund so qualifies and distributes to shareholders its investment company taxable income and net realized capital gain, the fund itself is relieved of federal income tax.
It is the Series’ policy to distribute to the shareholders (the insurance company separate accounts) all of its investment company taxable income and capital gain for each fiscal year.
See the applicable contract prospectus for information regarding the federal income tax treatment of the contracts and distributions to the separate accounts.
19 American Funds Insurance Series / Prospectus
Financial highlights The Financial Highlights table is intended to help you understand a fund’s results for the past five fiscal years. . Certain information reflects financial results for a single share of a particular class. The total returns in the table represent the rate that an investor would have earned or lost on an investment in a fund (assuming reinvestment of all dividends and capital gain distributions). Where indicated, figures in the table reflect the impact, if any, of certain waivers from Capital Research and Management Company. For more information about these waivers, see the fund's statement of additional information and annual report. The information in the Financial Highlights table has been audited by PricewaterhouseCoopers LLP, whose current report, along with the fund’s financial statements, is included in the statement of additional information, which is available upon request. Figures shown do not reflect insurance contract fees and expenses. If insurance contract fees and expenses were reflected, results would be lower.
| Income
(loss) from investment operations1 |
Dividends and distributions | |||||||||||||||||||||||||
| Period ended | Net
asset value, beginning of period |
Net investment income |
Net
gains (losses) on securities (both realized and unrealized) |
Total
from investment operations |
Dividends (from net investment income) |
Distributions (from capital gains) |
Total dividends and distributions |
Net
asset value, end of period |
Total return2 |
Net
assets, end of period (in millions) |
Ratio
of expenses to average net assets before waivers3 |
Ratio
of expenses to average net assets after waivers2,3 |
Ratio
of net income to average net assets2 | |||||||||||||
| Global Growth Fund | ||||||||||||||||||||||||||
| Class 1: | ||||||||||||||||||||||||||
| 12/31/2021 | $41.16 | $.25 | $6.48 | $6.73 | $(.26 | ) | $(2.17 | ) | $(2.43 | ) | $45.46 | 16.72 | % | $4,270 | .55 | % | .54 | % | .56 | % | ||||||
| 12/31/2020 | 32.57 | .20 | 9.56 | 9.76 | (.21 | ) | (.96 | ) | (1.17 | ) | 41.16 | 30.79 | 3,309 | .56 | .56 | .59 | ||||||||||
| 12/31/2019 | 25.74 | .32 | 8.60 | 8.92 | (.41 | ) | (1.68 | ) | (2.09 | ) | 32.57 | 35.61 | 2,515 | .56 | .56 | 1.07 | ||||||||||
| 12/31/2018 | 30.51 | .29 | (2.65 | ) | (2.36 | ) | (.28 | ) | (2.13 | ) | (2.41 | ) | 25.74 | (8.81 | ) | 1,942 | .55 | .55 | .98 | |||||||
| 12/31/2017 | 24.05 | .26 | 7.30 | 7.56 | (.26 | ) | (.84 | ) | (1.10 | ) | 30.51 | 31.80 | 2,010 | .55 | .55 | .94 | ||||||||||
| Class 1A: | ||||||||||||||||||||||||||
| 12/31/2021 | 41.02 | .14 | 6.46 | 6.60 | (.17 | ) | (2.17 | ) | (2.34 | ) | 45.28 | 16.45 | 18 | .80 | .79 | .33 | ||||||||||
| 12/31/2020 | 32.47 | .12 | 9.52 | 9.64 | (.13 | ) | (.96 | ) | (1.09 | ) | 41.02 | 30.49 | 12 | .81 | .81 | .34 | ||||||||||
| 12/31/2019 | 25.69 | .25 | 8.55 | 8.80 | (.34 | ) | (1.68 | ) | (2.02 | ) | 32.47 | 35.22 | 8 | .81 | .81 | .83 | ||||||||||
| 12/31/2018 | 30.46 | .23 | (2.66 | ) | (2.43 | ) | (.21 | ) | (2.13 | ) | (2.34 | ) | 25.69 | (9.02 | ) | 5 | .80 | .80 | .77 | |||||||
| 12/31/20174,5 | 24.50 | .11 | 6.94 | 7.05 | (.25 | ) | (.84 | ) | (1.09 | ) | 30.46 | 29.13 | 6 | 2 | .80 | 7 | .80 | 7 | .39 | 7 | ||||||
| Class 2: | ||||||||||||||||||||||||||
| 12/31/2021 | 40.72 | .13 | 6.41 | 6.54 | (.15 | ) | (2.17 | ) | (2.32 | ) | 44.94 | 16.42 | 4,559 | .80 | .80 | .30 | ||||||||||
| 12/31/2020 | 32.24 | .12 | 9.44 | 9.56 | (.12 | ) | (.96 | ) | (1.08 | ) | 40.72 | 30.47 | 4,387 | .81 | .81 | .34 | ||||||||||
| 12/31/2019 | 25.50 | .24 | 8.51 | 8.75 | (.33 | ) | (1.68 | ) | (2.01 | ) | 32.24 | 35.28 | 3,895 | .81 | .81 | .83 | ||||||||||
| 12/31/2018 | 30.24 | .22 | (2.63 | ) | (2.41 | ) | (.20 | ) | (2.13 | ) | (2.33 | ) | 25.50 | (9.04 | ) | 3,306 | .80 | .80 | .73 | |||||||
| 12/31/2017 | 23.85 | .19 | 7.23 | 7.42 | (.19 | ) | (.84 | ) | (1.03 | ) | 30.24 | 31.47 | 4,012 | .80 | .80 | .69 | ||||||||||
| Class 4: | ||||||||||||||||||||||||||
| 12/31/2021 | 40.45 | .03 | 6.35 | 6.38 | (.09 | ) | (2.17 | ) | (2.26 | ) | 44.57 | 16.14 | 744 | 1.05 | 1.04 | .07 | ||||||||||
| 12/31/2020 | 32.05 | .03 | 9.38 | 9.41 | (.05 | ) | (.96 | ) | (1.01 | ) | 40.45 | 30.17 | 533 | 1.06 | 1.06 | .09 | ||||||||||
| 12/31/2019 | 25.39 | .17 | 8.45 | 8.62 | (.28 | ) | (1.68 | ) | (1.96 | ) | 32.05 | 34.87 | 382 | 1.06 | 1.06 | .57 | ||||||||||
| 12/31/2018 | 30.13 | .14 | (2.60 | ) | (2.46 | ) | (.15 | ) | (2.13 | ) | (2.28 | ) | 25.39 | (9.24 | ) | 249 | 1.05 | 1.05 | .47 | |||||||
| 12/31/2017 | 23.81 | .10 | 7.22 | 7.32 | (.16 | ) | (.84 | ) | (1.00 | ) | 30.13 | 31.11 | 211 | 1.05 | 1.05 | .37 | ||||||||||
American Funds Insurance Series / Prospectus 20
| Income
(loss) from investment operations1 |
Dividends and distributions | |||||||||||||||||||||||
| Period ended | Net
asset value, beginning of period |
Net investment (loss) income |
Net
gains (losses) on securities (both realized and unrealized) |
Total
from investment operations |
Dividends (from net investment income) |
Distributions (from capital gains) |
Total dividends and distributions |
Net
asset value, end of period |
Total return |
Net
assets, end of period (in millions) |
Ratio
of expenses to average net assets3 |
Ratio
of net (loss) income to average net assets | ||||||||||||
| Global Small Capitalization Fund | ||||||||||||||||||||||||
| Class 1: | ||||||||||||||||||||||||
| 12/31/2021 | $32.64 | $(.02 | ) | $2.32 | $2.30 | $— | $(.77 | ) | $(.77 | ) | $34.17 | 6.98 | % | $1,707 | .74 | % | (.07 | )% | ||||||
| 12/31/2020 | 26.80 | (.01 | ) | 7.49 | 7.48 | (.05 | ) | (1.59 | ) | (1.64 | ) | 32.64 | 30.04 | 2,391 | .75 | (.06 | ) | |||||||
| 12/31/2019 | 21.75 | .12 | 6.61 | 6.73 | (.10 | ) | (1.58 | ) | (1.68 | ) | 26.80 | 31.84 | 2,050 | .75 | .48 | |||||||||
| 12/31/2018 | 25.38 | .11 | (2.51 | ) | (2.40 | ) | (.09 | ) | (1.14 | ) | (1.23 | ) | 21.75 | (10.31 | ) | 1,453 | .73 | .42 | ||||||
| 12/31/2017 | 20.24 | .12 | 5.17 | 5.29 | (.15 | ) | — | (.15 | ) | 25.38 | 26.22 | 1,639 | .73 | .54 | ||||||||||
| Class 1A: | ||||||||||||||||||||||||
| 12/31/2021 | 32.49 | (.07 | ) | 2.28 | 2.21 | — | (.77 | ) | (.77 | ) | 33.93 | 6.73 | 5 | .99 | (.21 | ) | ||||||||
| 12/31/2020 | 26.74 | (.09 | ) | 7.48 | 7.39 | (.05 | ) | (1.59 | ) | (1.64 | ) | 32.49 | 29.72 | 1 | .99 | (.33 | ) | |||||||
| 12/31/2019 | 21.71 | .05 | 6.61 | 6.66 | (.05 | ) | (1.58 | ) | (1.63 | ) | 26.74 | 31.56 | 1 | .99 | .22 | |||||||||
| 12/31/2018 | 25.36 | .05 | (2.52 | ) | (2.47 | ) | (.04 | ) | (1.14 | ) | (1.18 | ) | 21.71 | (10.56 | ) | — | 8 | .98 | .21 | |||||
| 12/31/20174,5 | 20.70 | .08 | 4.71 | 4.79 | (.13 | ) | — | (.13 | ) | 25.36 | 23.19 | 6 | — | 8 | .96 | 7 | .35 | 7 | ||||||
| Class 2: | ||||||||||||||||||||||||
| 12/31/2021 | 31.56 | (.10 | ) | 2.25 | 2.15 | — | (.77 | ) | (.77 | ) | 32.94 | 6.74 | 2,521 | .99 | (.30 | ) | ||||||||
| 12/31/2020 | 26.02 | (.08 | ) | 7.25 | 7.17 | (.04 | ) | (1.59 | ) | (1.63 | ) | 31.56 | 29.72 | 2,653 | 1.00 | (.31 | ) | |||||||
| 12/31/2019 | 21.16 | .05 | 6.43 | 6.48 | (.04 | ) | (1.58 | ) | (1.62 | ) | 26.02 | 31.52 | 2,363 | 1.00 | .22 | |||||||||
| 12/31/2018 | 24.72 | .04 | (2.44 | ) | (2.40 | ) | (.02 | ) | (1.14 | ) | (1.16 | ) | 21.16 | (10.55 | ) | 2,056 | .98 | .17 | ||||||
| 12/31/2017 | 19.72 | .06 | 5.04 | 5.10 | (.10 | ) | — | (.10 | ) | 24.72 | 25.89 | 2,551 | .98 | .27 | ||||||||||
| Class 4: | ||||||||||||||||||||||||
| 12/31/2021 | 31.67 | (.18 | ) | 2.24 | 2.06 | — | (.77 | ) | (.77 | ) | 32.96 | 6.43 | 344 | 1.24 | (.53 | ) | ||||||||
| 12/31/2020 | 26.16 | (.14 | ) | 7.27 | 7.13 | (.03 | ) | (1.59 | ) | (1.62 | ) | 31.67 | 29.39 | 268 | 1.25 | (.56 | ) | |||||||
| 12/31/2019 | 21.28 | (.01 | ) | 6.47 | 6.46 | — | 9 | (1.58 | ) | (1.58 | ) | 26.16 | 31.24 | 206 | 1.25 | (.04 | ) | |||||||
| 12/31/2018 | 24.91 | (.02 | ) | (2.46 | ) | (2.48 | ) | (.01 | ) | (1.14 | ) | (1.15 | ) | 21.28 | (10.80 | ) | 146 | 1.24 | (.08 | ) | ||||
| 12/31/2017 | 19.91 | — | 9 | 5.09 | 5.09 | (.09 | ) | — | (.09 | ) | 24.91 | 25.62 | 125 | 1.23 | — | 10 | ||||||||
| Income
from investment operations1 |
Dividends and distributions | |||||||||||||||||||||||
| Period ended | Net
asset value, beginning of period |
Net investment income (loss) |
Net
gains on securities (both realized and unrealized) |
Total
from investment operations |
Dividends (from net investment income) |
Distributions (from capital gains) |
Total dividends and distributions |
Net
asset value, end of period |
Total return |
Net
assets, end of period (in millions) |
Ratio
of expenses to average net assets3 |
Ratio
of net income (loss) to average net assets | ||||||||||||
| Growth Fund | ||||||||||||||||||||||||
| Class 1: | ||||||||||||||||||||||||
| 12/31/2021 | $120.22 | $.46 | $24.29 | $24.75 | $(.58 | ) | $(16.81 | ) | $(17.39 | ) | $127.58 | 22.30 | % | $19,783 | .34 | % | .37 | % | ||||||
| 12/31/2020 | 81.22 | .43 | 41.28 | 41.71 | (.53 | ) | (2.18 | ) | (2.71 | ) | 120.22 | 52.45 | 15,644 | .35 | .46 | |||||||||
| 12/31/2019 | 69.96 | .83 | 19.63 | 20.46 | (.76 | ) | (8.44 | ) | (9.20 | ) | 81.22 | 31.11 | 10,841 | .35 | 1.09 | |||||||||
| 12/31/2018 | 77.85 | .64 | .25 | .89 | (.54 | ) | (8.24 | ) | (8.78 | ) | 69.96 | (.01 | ) | 8,474 | .34 | .81 | ||||||||
| 12/31/2017 | 67.29 | .55 | 17.89 | 18.44 | (.55 | ) | (7.33 | ) | (7.88 | ) | 77.85 | 28.62 | 8,100 | .35 | .75 | |||||||||
| Class 1A: | ||||||||||||||||||||||||
| 12/31/2021 | 119.59 | .16 | 24.11 | 24.27 | (.35 | ) | (16.81 | ) | (17.16 | ) | 126.70 | 21.97 | 121 | .59 | .13 | |||||||||
| 12/31/2020 | 80.92 | .20 | 41.05 | 41.25 | (.40 | ) | (2.18 | ) | (2.58 | ) | 119.59 | 52.07 | 60 | .60 | .21 | |||||||||
| 12/31/2019 | 69.77 | .65 | 19.55 | 20.20 | (.61 | ) | (8.44 | ) | (9.05 | ) | 80.92 | 30.79 | 18 | .60 | .85 | |||||||||
| 12/31/2018 | 77.74 | .47 | .24 | .71 | (.44 | ) | (8.24 | ) | (8.68 | ) | 69.77 | (.26 | ) | 10 | .59 | .60 | ||||||||
| 12/31/20174,5 | 68.84 | .35 | 16.38 | 16.73 | (.50 | ) | (7.33 | ) | (7.83 | ) | 77.74 | 25.47 | 6 | 3 | .59 | 7 | .47 | 7 | ||||||
| Class 2: | ||||||||||||||||||||||||
| 12/31/2021 | 119.18 | .15 | 24.03 | 24.18 | (.27 | ) | (16.81 | ) | (17.08 | ) | 126.28 | 21.97 | 21,986 | .59 | .12 | |||||||||
| 12/31/2020 | 80.57 | .19 | 40.89 | 41.08 | (.29 | ) | (2.18 | ) | (2.47 | ) | 119.18 | 52.10 | 20,594 | .60 | .21 | |||||||||
| 12/31/2019 | 69.48 | .63 | 19.47 | 20.10 | (.57 | ) | (8.44 | ) | (9.01 | ) | 80.57 | 30.77 | 15,885 | .60 | .83 | |||||||||
| 12/31/2018 | 77.35 | .44 | .27 | .71 | (.34 | ) | (8.24 | ) | (8.58 | ) | 69.48 | (.25 | ) | 13,701 | .59 | .55 | ||||||||
| 12/31/2017 | 66.92 | .37 | 17.76 | 18.13 | (.37 | ) | (7.33 | ) | (7.70 | ) | 77.35 | 28.28 | 15,716 | .60 | .50 | |||||||||
| Class 3: | ||||||||||||||||||||||||
| 12/31/2021 | 121.13 | .24 | 24.47 | 24.71 | (.35 | ) | (16.81 | ) | (17.16 | ) | 128.68 | 22.07 | 302 | .52 | .19 | |||||||||
| 12/31/2020 | 81.84 | .26 | 41.56 | 41.82 | (.35 | ) | (2.18 | ) | (2.53 | ) | 121.13 | 52.20 | 279 | .53 | .28 | |||||||||
| 12/31/2019 | 70.44 | .69 | 19.77 | 20.46 | (.62 | ) | (8.44 | ) | (9.06 | ) | 81.84 | 30.86 | 213 | .53 | .90 | |||||||||
| 12/31/2018 | 78.32 | .50 | .26 | .76 | (.40 | ) | (8.24 | ) | (8.64 | ) | 70.44 | (.18 | ) | 187 | .52 | .62 | ||||||||
| 12/31/2017 | 67.67 | .42 | 17.98 | 18.40 | (.42 | ) | (7.33 | ) | (7.75 | ) | 78.32 | 28.39 | 212 | .53 | .57 | |||||||||
| Class 4: | ||||||||||||||||||||||||
| 12/31/2021 | 117.24 | (.15 | ) | 23.59 | 23.44 | (.08 | ) | (16.81 | ) | (16.89 | ) | 123.79 | 21.69 | 3,214 | .84 | (.13 | ) | |||||||
| 12/31/2020 | 79.41 | (.04 | ) | 40.24 | 40.20 | (.19 | ) | (2.18 | ) | (2.37 | ) | 117.24 | 51.71 | 2,347 | .85 | (.04 | ) | |||||||
| 12/31/2019 | 68.64 | .44 | 19.19 | 19.63 | (.42 | ) | (8.44 | ) | (8.86 | ) | 79.41 | 30.44 | 1,513 | .85 | .59 | |||||||||
| 12/31/2018 | 76.56 | .24 | .28 | .52 | (.20 | ) | (8.24 | ) | (8.44 | ) | 68.64 | (.50 | ) | 1,076 | .84 | .31 | ||||||||
| 12/31/2017 | 66.41 | .18 | 17.61 | 17.79 | (.31 | ) | (7.33 | ) | (7.64 | ) | 76.56 | 27.99 | 954 | .85 | .25 | |||||||||
21 American Funds Insurance Series / Prospectus
| (Loss)
income from investment operations1 |
Dividends and distributions | |||||||||||||||||||||||
| Period ended | Net
asset value, beginning of period |
Net investment income |
Net
(losses) gains on securities (both realized and unrealized) |
Total
from investment operations |
Dividends (from net investment income) |
Distributions (from capital gains) |
Total dividends and distributions |
Net
asset value, end of period |
Total return |
Net
assets, end of period (in millions) |
Ratio
of expenses to average net assets3 |
Ratio
of net income to average net assets | ||||||||||||
| International Fund | ||||||||||||||||||||||||
| Class 1: | ||||||||||||||||||||||||
| 12/31/2021 | $23.64 | $.38 | $(.67 | ) | $(.29 | ) | $(.65 | ) | $— | $(.65 | ) | $22.70 | (1.23 | )% | $4,747 | .55 | % | 1.57 | % | |||||
| 12/31/2020 | 20.86 | .14 | 2.82 | 2.96 | (.18 | ) | — | (.18 | ) | 23.64 | 14.28 | 5,652 | .55 | .71 | ||||||||||
| 12/31/2019 | 17.66 | .30 | 3.74 | 4.04 | (.34 | ) | (.50 | ) | (.84 | ) | 20.86 | 23.21 | 5,353 | .54 | 1.54 | |||||||||
| 12/31/2018 | 21.71 | .34 | (2.97 | ) | (2.63 | ) | (.40 | ) | (1.02 | ) | (1.42 | ) | 17.66 | (12.94 | ) | 4,811 | .53 | 1.62 | ||||||
| 12/31/2017 | 16.82 | .26 | 5.16 | 5.42 | (.30 | ) | (.23 | ) | (.53 | ) | 21.71 | 32.46 | 5,014 | .53 | 1.33 | |||||||||
| Class 1A: | ||||||||||||||||||||||||
| 12/31/2021 | 23.55 | .33 | (.67 | ) | (.34 | ) | (.60 | ) | — | (.60 | ) | 22.61 | (1.47 | ) | 12 | .80 | 1.39 | |||||||
| 12/31/2020 | 20.80 | .08 | 2.81 | 2.89 | (.14 | ) | — | (.14 | ) | 23.55 | 13.96 | 10 | .80 | .43 | ||||||||||
| 12/31/2019 | 17.62 | .25 | 3.72 | 3.97 | (.29 | ) | (.50 | ) | (.79 | ) | 20.80 | 22.90 | 7 | .79 | 1.27 | |||||||||
| 12/31/2018 | 21.67 | .27 | (2.93 | ) | (2.66 | ) | (.37 | ) | (1.02 | ) | (1.39 | ) | 17.62 | (13.11 | ) | 5 | .78 | 1.32 | ||||||
| 12/31/20174,5 | 17.17 | .09 | 4.93 | 5.02 | (.29 | ) | (.23 | ) | (.52 | ) | 21.67 | 29.46 | 6 | 2 | .77 | 7 | .43 | 7 | ||||||
| Class 2: | ||||||||||||||||||||||||
| 12/31/2021 | 23.54 | .33 | (.68 | ) | (.35 | ) | (.59 | ) | — | (.59 | ) | 22.60 | (1.49 | ) | 4,190 | .80 | 1.35 | |||||||
| 12/31/2020 | 20.78 | .09 | 2.80 | 2.89 | (.13 | ) | — | (.13 | ) | 23.54 | 13.97 | 4,481 | .80 | .46 | ||||||||||
| 12/31/2019 | 17.60 | .25 | 3.72 | 3.97 | (.29 | ) | (.50 | ) | (.79 | ) | 20.78 | 22.88 | 4,311 | .79 | 1.29 | |||||||||
| 12/31/2018 | 21.63 | .29 | (2.95 | ) | (2.66 | ) | (.35 | ) | (1.02 | ) | (1.37 | ) | 17.60 | (13.13 | ) | 3,875 | .78 | 1.40 | ||||||
| 12/31/2017 | 16.76 | .22 | 5.13 | 5.35 | (.25 | ) | (.23 | ) | (.48 | ) | 21.63 | 32.14 | 4,422 | .78 | 1.10 | |||||||||
| Class 3: | ||||||||||||||||||||||||
| 12/31/2021 | 23.69 | .34 | (.67 | ) | (.33 | ) | (.60 | ) | — | (.60 | ) | 22.76 | (1.39 | ) | 21 | .73 | 1.41 | |||||||
| 12/31/2020 | 20.92 | .10 | 2.81 | 2.91 | (.14 | ) | — | (.14 | ) | 23.69 | 14.00 | 25 | .73 | .53 | ||||||||||
| 12/31/2019 | 17.70 | .27 | 3.75 | 4.02 | (.30 | ) | (.50 | ) | (.80 | ) | 20.92 | 23.05 | 25 | .72 | 1.37 | |||||||||
| 12/31/2018 | 21.75 | .31 | (2.98 | ) | (2.67 | ) | (.36 | ) | (1.02 | ) | (1.38 | ) | 17.70 | (13.10 | ) | 24 | .71 | 1.48 | ||||||
| 12/31/2017 | 16.85 | .23 | 5.17 | 5.40 | (.27 | ) | (.23 | ) | (.50 | ) | 21.75 | 32.23 | 31 | .71 | 1.17 | |||||||||
| Class 4: | ||||||||||||||||||||||||
| 12/31/2021 | 23.25 | .27 | (.67 | ) | (.40 | ) | (.54 | ) | — | (.54 | ) | 22.31 | (1.71 | ) | 459 | 1.05 | 1.13 | |||||||
| 12/31/2020 | 20.54 | .04 | 2.76 | 2.80 | (.09 | ) | — | (.09 | ) | 23.25 | 13.66 | 423 | 1.05 | .21 | ||||||||||
| 12/31/2019 | 17.40 | .20 | 3.69 | 3.89 | (.25 | ) | (.50 | ) | (.75 | ) | 20.54 | 22.67 | 379 | 1.04 | 1.03 | |||||||||
| 12/31/2018 | 21.42 | .23 | (2.93 | ) | (2.70 | ) | (.30 | ) | (1.02 | ) | (1.32 | ) | 17.40 | (13.41 | ) | 295 | 1.03 | 1.13 | ||||||
| 12/31/2017 | 16.64 | .11 | 5.16 | 5.27 | (.26 | ) | (.23 | ) | (.49 | ) | 21.42 | 31.89 | 289 | 1.03 | .55 | |||||||||
| Income
(loss) from investment operations1 |
Dividends and distributions | |||||||||||||||||||||||||
| Period ended | Net
asset value, beginning of period |
Net investment income |
Net
gains (losses) on securities (both realized and unrealized) |
Total
from investment operations |
Dividends (from net investment income) |
Distributions (from capital gains) |
Total dividends and distributions |
Net
asset value, end of period |
Total return2 |
Net
assets, end of period (in millions) |
Ratio
of expenses to average net assets before waivers3 |
Ratio
of expenses to average net assets after waivers2,3 |
Ratio
of net income to average net assets2 | |||||||||||||
| New World Fund | ||||||||||||||||||||||||||
| Class 1: | ||||||||||||||||||||||||||
| 12/31/2021 | $31.59 | $.29 | $1.38 | $1.67 | $(.36 | ) | $(1.07 | ) | $(1.43 | ) | $31.83 | 5.16 | % | $2,443 | .74 | % | .56 | % | .88 | % | ||||||
| 12/31/2020 | 25.84 | .15 | 5.93 | 6.08 | (.06 | ) | (.27 | ) | (.33 | ) | 31.59 | 23.89 | 2,309 | .76 | .64 | .58 | ||||||||||
| 12/31/2019 | 20.98 | .28 | 5.79 | 6.07 | (.29 | ) | (.92 | ) | (1.21 | ) | 25.84 | 29.47 | 2,129 | .76 | .76 | 1.18 | ||||||||||
| 12/31/2018 | 25.30 | .27 | (3.65 | ) | (3.38 | ) | (.27 | ) | (.67 | ) | (.94 | ) | 20.98 | (13.83 | ) | 1,702 | .77 | .77 | 1.11 | |||||||
| 12/31/2017 | 19.72 | .26 | 5.59 | 5.85 | (.27 | ) | — | (.27 | ) | 25.30 | 29.73 | 2,050 | .77 | .77 | 1.14 | |||||||||||
| Class 1A: | ||||||||||||||||||||||||||
| 12/31/2021 | 31.43 | .17 | 1.41 | 1.58 | (.24 | ) | (1.07 | ) | (1.31 | ) | 31.70 | 4.90 | 12 | .99 | .81 | .54 | ||||||||||
| 12/31/2020 | 25.74 | .07 | 5.92 | 5.99 | (.03 | ) | (.27 | ) | (.30 | ) | 31.43 | 23.63 | 18 | 1.01 | .87 | .26 | ||||||||||
| 12/31/2019 | 20.92 | .22 | 5.76 | 5.98 | (.24 | ) | (.92 | ) | (1.16 | ) | 25.74 | 29.11 | 4 | 1.01 | 1.01 | .92 | ||||||||||
| 12/31/2018 | 25.25 | .21 | (3.64 | ) | (3.43 | ) | (.23 | ) | (.67 | ) | (.90 | ) | 20.92 | (14.02 | ) | 2 | 1.02 | 1.02 | .91 | |||||||
| 12/31/20174,5 | 20.14 | .13 | 5.24 | 5.37 | (.26 | ) | — | (.26 | ) | 25.25 | 26.72 | 6 | 1 | 1.00 | 7 | 1.00 | 7 | .53 | 7 | |||||||
| Class 2: | ||||||||||||||||||||||||||
| 12/31/2021 | 31.25 | .20 | 1.38 | 1.58 | (.28 | ) | (1.07 | ) | (1.35 | ) | 31.48 | 4.92 | 1,086 | .99 | .81 | .63 | ||||||||||
| 12/31/2020 | 25.59 | .08 | 5.87 | 5.95 | (.02 | ) | (.27 | ) | (.29 | ) | 31.25 | 23.58 | 1,109 | 1.01 | .89 | .34 | ||||||||||
| 12/31/2019 | 20.79 | .22 | 5.73 | 5.95 | (.23 | ) | (.92 | ) | (1.15 | ) | 25.59 | 29.15 | 981 | 1.01 | 1.01 | .93 | ||||||||||
| 12/31/2018 | 25.07 | .20 | (3.61 | ) | (3.41 | ) | (.20 | ) | (.67 | ) | (.87 | ) | 20.79 | (14.04 | ) | 843 | 1.02 | 1.02 | .85 | |||||||
| 12/31/2017 | 19.54 | .20 | 5.55 | 5.75 | (.22 | ) | — | (.22 | ) | 25.07 | 29.44 | 1,055 | 1.02 | 1.02 | .89 | |||||||||||
| Class 4: | ||||||||||||||||||||||||||
| 12/31/2021 | 31.04 | .12 | 1.36 | 1.48 | (.21 | ) | (1.07 | ) | (1.28 | ) | 31.24 | 4.63 | 906 | 1.24 | 1.06 | .38 | ||||||||||
| 12/31/2020 | 25.47 | .02 | 5.83 | 5.85 | (.01 | ) | (.27 | ) | (.28 | ) | 31.04 | 23.29 | 807 | 1.26 | 1.14 | .08 | ||||||||||
| 12/31/2019 | 20.71 | .16 | 5.70 | 5.86 | (.18 | ) | (.92 | ) | (1.10 | ) | 25.47 | 28.82 | 646 | 1.26 | 1.26 | .67 | ||||||||||
| 12/31/2018 | 24.99 | .14 | (3.59 | ) | (3.45 | ) | (.16 | ) | (.67 | ) | (.83 | ) | 20.71 | (14.25 | ) | 464 | 1.27 | 1.27 | .61 | |||||||
| 12/31/2017 | 19.51 | .14 | 5.52 | 5.66 | (.18 | ) | — | (.18 | ) | 24.99 | 29.06 | 427 | 1.27 | 1.27 | .61 | |||||||||||
American Funds Insurance Series / Prospectus 22
| Income
(loss) from investment operations1 |
Dividends and distributions | |||||||||||||||||||||||||
| Period ended | Net
asset value, beginning of period |
Net investment income |
Net
gains (losses) on securities (both realized and unrealized) |
Total
from investment operations |
Dividends (from net investment income) |
Distributions (from capital gains) |
Total dividends and distributions |
Net
asset value, end of period |
Total return2 |
Net
assets, end of period (in millions) |
Ratio
of expenses to average net assets before waivers3 |
Ratio
of expenses to average net assets after waivers2,3 |
Ratio
of net income to average net assets2 | |||||||||||||
| Capital World Growth and Income Fund | ||||||||||||||||||||||||||
| Class 1: | ||||||||||||||||||||||||||
| 12/31/2021 | $16.67 | $.38 | $2.10 | $2.48 | $(.33 | ) | $(.40 | ) | $(.73 | ) | $18.42 | 15.03 | % | $812 | .63 | % | .47 | % | 2.14 | % | ||||||
| 12/31/2020 | 15.92 | .22 | 1.14 | 1.36 | (.23 | ) | (.38 | ) | (.61 | ) | 16.67 | 9.03 | 657 | .66 | .66 | 1.49 | ||||||||||
| 12/31/2019 | 13.02 | .31 | 3.67 | 3.98 | (.32 | ) | (.76 | ) | (1.08 | ) | 15.92 | 31.39 | 625 | .65 | .65 | 2.08 | ||||||||||
| 12/31/2018 | 15.81 | .29 | (1.62 | ) | (1.33 | ) | (.28 | ) | (1.18 | ) | (1.46 | ) | 13.02 | (9.36 | ) | 492 | .63 | .63 | 1.94 | |||||||
| 12/31/2017 | 13.02 | .35 | 3.06 | 3.41 | (.36 | ) | (.26 | ) | (.62 | ) | 15.81 | 26.40 | 485 | .63 | .63 | 2.43 | ||||||||||
| Class 1A: | ||||||||||||||||||||||||||
| 12/31/2021 | 16.62 | .37 | 2.06 | 2.43 | (.31 | ) | (.40 | ) | (.71 | ) | 18.34 | 14.71 | 7 | .88 | .70 | 2.08 | ||||||||||
| 12/31/2020 | 15.88 | .18 | 1.13 | 1.31 | (.19 | ) | (.38 | ) | (.57 | ) | 16.62 | 8.78 | 2 | .90 | .90 | 1.23 | ||||||||||
| 12/31/2019 | 13.00 | .26 | 3.68 | 3.94 | (.30 | ) | (.76 | ) | (1.06 | ) | 15.88 | 31.04 | 2 | .90 | .90 | 1.77 | ||||||||||
| 12/31/2018 | 15.81 | .26 | (1.63 | ) | (1.37 | ) | (.26 | ) | (1.18 | ) | (1.44 | ) | 13.00 | (9.62 | ) | 1 | .88 | .88 | 1.74 | |||||||
| 12/31/20174,5 | 13.21 | .18 | 3.03 | 3.21 | (.35 | ) | (.26 | ) | (.61 | ) | 15.81 | 24.54 | 6 | — | 8 | .84 | 7 | .84 | 7 | 1.20 | 7 | |||||
| Class 2: | ||||||||||||||||||||||||||
| 12/31/2021 | 16.63 | .33 | 2.11 | 2.44 | (.29 | ) | (.40 | ) | (.69 | ) | 18.38 | 14.78 | 1,340 | .88 | .73 | 1.85 | ||||||||||
| 12/31/2020 | 15.89 | .18 | 1.13 | 1.31 | (.19 | ) | (.38 | ) | (.57 | ) | 16.63 | 8.73 | 1,349 | .91 | .91 | 1.23 | ||||||||||
| 12/31/2019 | 12.99 | .27 | 3.68 | 3.95 | (.29 | ) | (.76 | ) | (1.05 | ) | 15.89 | 31.14 | 1,366 | .90 | .90 | 1.84 | ||||||||||
| 12/31/2018 | 15.78 | .26 | (1.63 | ) | (1.37 | ) | (.24 | ) | (1.18 | ) | (1.42 | ) | 12.99 | (9.63 | ) | 1,228 | .88 | .88 | 1.70 | |||||||
| 12/31/2017 | 13.00 | .31 | 3.05 | 3.36 | (.32 | ) | (.26 | ) | (.58 | ) | 15.78 | 26.06 | 1,538 | .88 | .88 | 2.11 | ||||||||||
| Class 4: | ||||||||||||||||||||||||||
| 12/31/2021 | 16.35 | .29 | 2.06 | 2.35 | (.26 | ) | (.40 | ) | (.66 | ) | 18.04 | 14.46 | 225 | 1.13 | .97 | 1.65 | ||||||||||
| 12/31/2020 | 15.63 | .14 | 1.12 | 1.26 | (.16 | ) | (.38 | ) | (.54 | ) | 16.35 | 8.55 | 166 | 1.16 | 1.16 | .97 | ||||||||||
| 12/31/2019 | 12.81 | .23 | 3.61 | 3.84 | (.26 | ) | (.76 | ) | (1.02 | ) | 15.63 | 30.73 | 145 | 1.15 | 1.15 | 1.56 | ||||||||||
| 12/31/2018 | 15.60 | .21 | (1.60 | ) | (1.39 | ) | (.22 | ) | (1.18 | ) | (1.40 | ) | 12.81 | (9.89 | ) | 95 | 1.13 | 1.13 | 1.43 | |||||||
| 12/31/2017 | 12.89 | .22 | 3.08 | 3.30 | (.33 | ) | (.26 | ) | (.59 | ) | 15.60 | 25.83 | 79 | 1.14 | 1.14 | 1.49 | ||||||||||
| Income
(loss) from investment operations1 |
Dividends and distributions | |||||||||||||||||||||||
| Period ended | Net
asset value, beginning of period |
Net investment income |
Net
gains (losses) on securities (both realized and unrealized) |
Total
from investment operations |
Dividends (from net investment income) |
Distributions (from capital gains) |
Total dividends and distributions |
Net
asset value, end of period |
Total return |
Net
assets, end of period (in millions) |
Ratio
of expenses to average net assets3 |
Ratio
of net income to average net assets | ||||||||||||
| Growth-Income Fund | ||||||||||||||||||||||||
| Class 1: | ||||||||||||||||||||||||
| 12/31/2021 | $55.38 | $.79 | $12.64 | $13.43 | $(.86 | ) | $(.60 | ) | $(1.46 | ) | $67.35 | 24.42 | % | $25,507 | .29 | % | 1.28 | % | ||||||
| 12/31/2020 | 50.71 | .75 | 6.02 | 6.77 | (.80 | ) | (1.30 | ) | (2.10 | ) | 55.38 | 13.81 | 22,903 | .29 | 1.52 | |||||||||
| 12/31/2019 | 45.39 | 1.00 | 10.40 | 11.40 | (.92 | ) | (5.16 | ) | (6.08 | ) | 50.71 | 26.46 | 21,057 | .29 | 2.05 | |||||||||
| 12/31/2018 | 50.22 | .84 | (1.25 | ) | (.41 | ) | (.84 | ) | (3.58 | ) | (4.42 | ) | 45.39 | (1.55 | ) | 16,783 | .28 | 1.65 | ||||||
| 12/31/2017 | 44.41 | .81 | 8.89 | 9.70 | (.78 | ) | (3.11 | ) | (3.89 | ) | 50.22 | 22.68 | 15,765 | .28 | 1.69 | |||||||||
| Class 1A: | ||||||||||||||||||||||||
| 12/31/2021 | 55.16 | .65 | 12.55 | 13.20 | (.74 | ) | (.60 | ) | (1.34 | ) | 67.02 | 24.08 | 32 | .53 | 1.04 | |||||||||
| 12/31/2020 | 50.54 | .63 | 5.99 | 6.62 | (.70 | ) | (1.30 | ) | (2.00 | ) | 55.16 | 13.55 | 16 | .54 | 1.28 | |||||||||
| 12/31/2019 | 45.28 | .89 | 10.36 | 11.25 | (.83 | ) | (5.16 | ) | (5.99 | ) | 50.54 | 26.14 | 11 | .54 | 1.82 | |||||||||
| 12/31/2018 | 50.15 | .72 | (1.25 | ) | (.53 | ) | (.76 | ) | (3.58 | ) | (4.34 | ) | 45.28 | (1.78 | ) | 7 | .53 | 1.43 | ||||||
| 12/31/20174,5 | 45.39 | .67 | 7.96 | 8.63 | (.76 | ) | (3.11 | ) | (3.87 | ) | 50.15 | 19.83 | 6 | 2 | .52 | 7 | 1.41 | 7 | ||||||
| Class 2: | ||||||||||||||||||||||||
| 12/31/2021 | 54.66 | .63 | 12.45 | 13.08 | (.70 | ) | (.60 | ) | (1.30 | ) | 66.44 | 24.10 | 15,319 | .54 | 1.03 | |||||||||
| 12/31/2020 | 50.08 | .62 | 5.93 | 6.55 | (.67 | ) | (1.30 | ) | (1.97 | ) | 54.66 | 13.54 | 14,012 | .54 | 1.27 | |||||||||
| 12/31/2019 | 44.90 | .87 | 10.27 | 11.14 | (.80 | ) | (5.16 | ) | (5.96 | ) | 50.08 | 26.14 | 13,586 | .53 | 1.80 | |||||||||
| 12/31/2018 | 49.71 | .71 | (1.23 | ) | (.52 | ) | (.71 | ) | (3.58 | ) | (4.29 | ) | 44.90 | (1.79 | ) | 12,035 | .53 | 1.40 | ||||||
| 12/31/2017 | 44.00 | .68 | 8.80 | 9.48 | (.66 | ) | (3.11 | ) | (3.77 | ) | 49.71 | 22.38 | 13,930 | .53 | 1.45 | |||||||||
| Class 3: | ||||||||||||||||||||||||
| 12/31/2021 | 55.49 | .68 | 12.65 | 13.33 | (.74 | ) | (.60 | ) | (1.34 | ) | 67.48 | 24.18 | 166 | .47 | 1.10 | |||||||||
| 12/31/2020 | 50.81 | .66 | 6.02 | 6.68 | (.70 | ) | (1.30 | ) | (2.00 | ) | 55.49 | 13.60 | 154 | .47 | 1.34 | |||||||||
| 12/31/2019 | 45.47 | .91 | 10.43 | 11.34 | (.84 | ) | (5.16 | ) | (6.00 | ) | 50.81 | 26.24 | 156 | .46 | 1.87 | |||||||||
| 12/31/2018 | 50.29 | .75 | (1.25 | ) | (.50 | ) | (.74 | ) | (3.58 | ) | (4.32 | ) | 45.47 | (1.72 | ) | 140 | .46 | 1.47 | ||||||
| 12/31/2017 | 44.47 | .72 | 8.90 | 9.62 | (.69 | ) | (3.11 | ) | (3.80 | ) | 50.29 | 22.47 | 168 | .46 | 1.52 | |||||||||
| Class 4: | ||||||||||||||||||||||||
| 12/31/2021 | 53.99 | .48 | 12.28 | 12.76 | (.58 | ) | (.60 | ) | (1.18 | ) | 65.57 | 23.80 | 1,928 | .79 | .79 | |||||||||
| 12/31/2020 | 49.52 | .49 | 5.85 | 6.34 | (.57 | ) | (1.30 | ) | (1.87 | ) | 53.99 | 13.25 | 1,407 | .79 | 1.02 | |||||||||
| 12/31/2019 | 44.47 | .74 | 10.18 | 10.92 | (.71 | ) | (5.16 | ) | (5.87 | ) | 49.52 | 25.86 | 1,216 | .79 | 1.56 | |||||||||
| 12/31/2018 | 49.31 | .58 | (1.23 | ) | (.65 | ) | (.61 | ) | (3.58 | ) | (4.19 | ) | 44.47 | (2.05 | ) | 899 | .78 | 1.15 | ||||||
| 12/31/2017 | 43.73 | .56 | 8.73 | 9.29 | (.60 | ) | (3.11 | ) | (3.71 | ) | 49.31 | 22.08 | 827 | .78 | 1.19 | |||||||||
23 American Funds Insurance Series / Prospectus
| Income
(loss) from investment operations1 |
Dividends and distributions | |||||||||||||||||||||||||
| Period ended | Net
asset value, beginning of period |
Net investment income |
Net
gains (losses) on securities (both realized and unrealized) |
Total
from investment operations |
Dividends (from net investment income) |
Distributions (from capital gains) |
Total dividends and distributions |
Net
asset value, end of period |
Total return2 |
Net
assets, end of period (in millions) |
Ratio
of expenses to average net assets before waivers3 |
Ratio
of expenses to average net assets after waivers2,3 |
Ratio
of net income to average net assets2 | |||||||||||||
| Washington Mutual Investors Fund | ||||||||||||||||||||||||||
| Class 1: | ||||||||||||||||||||||||||
| 12/31/2021 | $14.35 | $.29 | $3.73 | $4.02 | $(.28 | ) | $— | $(.28 | ) | $18.09 | 28.12 | % | $6,766 | .42 | % | .31 | % | 1.79 | % | |||||||
| 12/31/2020 | 13.56 | .25 | .95 | 1.20 | (.26 | ) | (.15 | ) | (.41 | ) | 14.35 | 9.04 | 5,684 | .43 | .43 | 2.00 | ||||||||||
| 12/31/2019 | 12.38 | .30 | 2.25 | 2.55 | (.30 | ) | (1.07 | ) | (1.37 | ) | 13.56 | 21.66 | 5,559 | .42 | .42 | 2.28 | ||||||||||
| 12/31/2018 | 14.96 | .31 | (1.44 | ) | (1.13 | ) | (.31 | ) | (1.14 | ) | (1.45 | ) | 12.38 | (8.45 | ) | 4,810 | .41 | .41 | 2.13 | |||||||
| 12/31/2017 | 13.53 | .32 | 1.96 | 2.28 | (.32 | ) | (.53 | ) | (.85 | ) | 14.96 | 17.30 | 5,581 | .41 | .41 | 2.27 | ||||||||||
| Class 1A: | ||||||||||||||||||||||||||
| 12/31/2021 | 14.28 | .27 | 3.67 | 3.94 | (.26 | ) | — | (.26 | ) | 17.96 | 27.70 | 169 | .67 | .53 | 1.62 | |||||||||||
| 12/31/2020 | 13.51 | .23 | .93 | 1.16 | (.24 | ) | (.15 | ) | (.39 | ) | 14.28 | 8.79 | 25 | .67 | .67 | 1.78 | ||||||||||
| 12/31/2019 | 12.35 | .26 | 2.24 | 2.50 | (.27 | ) | (1.07 | ) | (1.34 | ) | 13.51 | 21.35 | 9 | .67 | .67 | 2.03 | ||||||||||
| 12/31/2018 | 14.94 | .26 | (1.42 | ) | (1.16 | ) | (.29 | ) | (1.14 | ) | (1.43 | ) | 12.35 | (8.67 | ) | 3 | .66 | .66 | 1.84 | |||||||
| 12/31/20174,5 | 13.75 | .28 | 1.75 | 2.03 | (.31 | ) | (.53 | ) | (.84 | ) | 14.94 | 15.21 | 6 | 1 | .65 | 7 | .65 | 7 | 2.01 | 7 | ||||||
| Class 2: | ||||||||||||||||||||||||||
| 12/31/2021 | 14.15 | .25 | 3.67 | 3.92 | (.24 | ) | — | (.24 | ) | 17.83 | 27.78 | 3,426 | .67 | .56 | 1.54 | |||||||||||
| 12/31/2020 | 13.39 | .22 | .91 | 1.13 | (.22 | ) | (.15 | ) | (.37 | ) | 14.15 | 8.68 | 3,082 | .68 | .68 | 1.75 | ||||||||||
| 12/31/2019 | 12.24 | .26 | 2.22 | 2.48 | (.26 | ) | (1.07 | ) | (1.33 | ) | 13.39 | 21.38 | 3,093 | .67 | .67 | 2.03 | ||||||||||
| 12/31/2018 | 14.80 | .27 | (1.42 | ) | (1.15 | ) | (.27 | ) | (1.14 | ) | (1.41 | ) | 12.24 | (8.66 | ) | 2,850 | .66 | .66 | 1.88 | |||||||
| 12/31/2017 | 13.39 | .28 | 1.94 | 2.22 | (.28 | ) | (.53 | ) | (.81 | ) | 14.80 | 17.04 | 3,551 | .66 | .66 | 2.02 | ||||||||||
| Class 4: | ||||||||||||||||||||||||||
| 12/31/2021 | 14.06 | .21 | 3.65 | 3.86 | (.21 | ) | — | (.21 | ) | 17.71 | 27.51 | 1,104 | .92 | .81 | 1.30 | |||||||||||
| 12/31/2020 | 13.31 | .19 | .91 | 1.10 | (.20 | ) | (.15 | ) | (.35 | ) | 14.06 | 8.47 | 788 | .93 | .93 | 1.51 | ||||||||||
| 12/31/2019 | 12.19 | .23 | 2.20 | 2.43 | (.24 | ) | (1.07 | ) | (1.31 | ) | 13.31 | 21.03 | 621 | .92 | .92 | 1.78 | ||||||||||
| 12/31/2018 | 14.77 | .23 | (1.42 | ) | (1.19 | ) | (.25 | ) | (1.14 | ) | (1.39 | ) | 12.19 | (8.92 | ) | 368 | .91 | .91 | 1.62 | |||||||
| 12/31/2017 | 13.39 | .25 | 1.93 | 2.18 | (.27 | ) | (.53 | ) | (.80 | ) | 14.77 | 16.70 | 247 | .91 | .91 | 1.76 | ||||||||||
| Income
(loss) from investment operations1 |
Dividends and distributions | |||||||||||||||||||||||||
| Period ended | Net
asset value, beginning of period |
Net investment income |
Net
gains (losses) on securities (both realized and unrealized) |
Total
from investment operations |
Dividends (from net investment income) |
Distributions (from capital gains) |
Total dividends and distributions |
Net
asset value, end of period |
Total return2 |
Net
assets, end of period (in millions) |
Ratio
of expenses to average net assets before waivers3 |
Ratio
of expenses to average net assets after waivers2,3 |
Ratio
of net income to average net assets2 | |||||||||||||
| Capital Income Builder | ||||||||||||||||||||||||||
| Class 1: | ||||||||||||||||||||||||||
| 12/31/2021 | $10.87 | $.37 | $1.28 | $1.65 | $(.35 | ) | $— | $(.35 | ) | $12.17 | 15.31 | % | $563 | .53 | % | .27 | % | 3.19 | % | |||||||
| 12/31/2020 | 10.73 | .31 | .15 | .46 | (.32 | ) | — | (.32 | ) | 10.87 | 4.64 | 621 | .53 | .35 | 3.07 | |||||||||||
| 12/31/2019 | 9.37 | .32 | 1.36 | 1.68 | (.32 | ) | — | (.32 | ) | 10.73 | 18.16 | 533 | .53 | .53 | 3.17 | |||||||||||
| 12/31/2018 | 10.40 | .31 | (1.00 | ) | (.69 | ) | (.32 | ) | (.02 | ) | (.34 | ) | 9.37 | (6.77 | ) | 317 | .54 | .54 | 3.08 | |||||||
| 12/31/2017 | 9.46 | .32 | .93 | 1.25 | (.31 | ) | — | (.31 | ) | 10.40 | 13.29 | 254 | .54 | .54 | 3.21 | |||||||||||
| Class 1A: | ||||||||||||||||||||||||||
| 12/31/2021 | 10.86 | .34 | 1.27 | 1.61 | (.32 | ) | — | (.32 | ) | 12.15 | 14.95 | 10 | .78 | .52 | 2.94 | |||||||||||
| 12/31/2020 | 10.72 | .28 | .16 | .44 | (.30 | ) | — | (.30 | ) | 10.86 | 4.38 | 6 | .78 | .60 | 2.81 | |||||||||||
| 12/31/2019 | 9.36 | .29 | 1.37 | 1.66 | (.30 | ) | — | (.30 | ) | 10.72 | 17.90 | 6 | .78 | .78 | 2.84 | |||||||||||
| 12/31/2018 | 10.39 | .28 | (.99 | ) | (.71 | ) | (.30 | ) | (.02 | ) | (.32 | ) | 9.36 | (7.01 | ) | 2 | .79 | .79 | 2.82 | |||||||
| 12/31/20174,5 | 9.57 | .27 | .84 | 1.11 | (.29 | ) | — | (.29 | ) | 10.39 | 11.72 | 6 | 1 | .79 | 7 | .79 | 7 | 2.63 | 7 | |||||||
| Class 2: | ||||||||||||||||||||||||||
| 12/31/2021 | 10.87 | .34 | 1.27 | 1.61 | (.32 | ) | — | (.32 | ) | 12.16 | 14.94 | 13 | .78 | .52 | 2.93 | |||||||||||
| 12/31/2020 | 10.72 | .29 | .16 | .45 | (.30 | ) | — | (.30 | ) | 10.87 | 4.48 | 8 | .78 | .60 | 2.83 | |||||||||||
| 12/31/2019 | 9.36 | .30 | 1.35 | 1.65 | (.29 | ) | — | (.29 | ) | 10.72 | 17.89 | 6 | .78 | .78 | 2.91 | |||||||||||
| 12/31/2018 | 10.40 | .28 | (1.00 | ) | (.72 | ) | (.30 | ) | (.02 | ) | (.32 | ) | 9.36 | (7.08 | ) | 4 | .79 | .79 | 2.83 | |||||||
| 12/31/2017 | 9.46 | .29 | .93 | 1.22 | (.28 | ) | — | (.28 | ) | 10.40 | 13.04 | 1 | .79 | .79 | 2.82 | |||||||||||
| Class 4: | ||||||||||||||||||||||||||
| 12/31/2021 | 10.85 | .31 | 1.27 | 1.58 | (.29 | ) | — | (.29 | ) | 12.14 | 14.68 | 559 | 1.03 | .77 | 2.69 | |||||||||||
| 12/31/2020 | 10.71 | .26 | .15 | .41 | (.27 | ) | — | (.27 | ) | 10.85 | 4.11 | 462 | 1.03 | .85 | 2.55 | |||||||||||
| 12/31/2019 | 9.35 | .27 | 1.36 | 1.63 | (.27 | ) | — | (.27 | ) | 10.71 | 17.62 | 454 | 1.03 | 1.03 | 2.68 | |||||||||||
| 12/31/2018 | 10.38 | .26 | (1.00 | ) | (.74 | ) | (.27 | ) | (.02 | ) | (.29 | ) | 9.35 | (7.25 | ) | 352 | 1.04 | 1.04 | 2.58 | |||||||
| 12/31/2017 | 9.45 | .27 | .92 | 1.19 | (.26 | ) | — | (.26 | ) | 10.38 | 12.65 | 338 | 1.04 | 1.04 | 2.72 | |||||||||||
American Funds Insurance Series / Prospectus 24
| Income
(loss) from investment operations1 |
Dividends and distributions | |||||||||||||||||||||||
| Period ended | Net
asset value, beginning of period |
Net investment income |
Net
gains (losses) on securities (both realized and unrealized) |
Total
from investment operations |
Dividends (from net investment income) |
Distributions (from capital gains) |
Total dividends and distributions |
Net
asset value, end of period |
Total return |
Net
assets, end of period (in millions) |
Ratio
of expenses to average net assets3 |
Ratio
of net income to average net assets | ||||||||||||
| Asset Allocation Fund | ||||||||||||||||||||||||
| Class 1: | ||||||||||||||||||||||||
| 12/31/2021 | $26.50 | $.48 | $3.54 | $4.02 | $(.50 | ) | $(.94 | ) | $(1.44 | ) | $29.08 | 15.40 | % | $18,836 | .30 | % | 1.71 | % | ||||||
| 12/31/2020 | 24.05 | .43 | 2.59 | 3.02 | (.46 | ) | (.11 | ) | (.57 | ) | 26.50 | 12.71 | 19,238 | .30 | 1.80 | |||||||||
| 12/31/2019 | 21.29 | .51 | 3.94 | 4.45 | (.50 | ) | (1.19 | ) | (1.69 | ) | 24.05 | 21.54 | 17,730 | .29 | 2.21 | |||||||||
| 12/31/2018 | 23.71 | .48 | (1.43 | ) | (.95 | ) | (.44 | ) | (1.03 | ) | (1.47 | ) | 21.29 | (4.35 | ) | 14,627 | .28 | 2.04 | ||||||
| 12/31/2017 | 21.68 | .44 | 3.06 | 3.50 | (.41 | ) | (1.06 | ) | (1.47 | ) | 23.71 | 16.51 | 16,556 | .29 | 1.90 | |||||||||
| Class 1A: | ||||||||||||||||||||||||
| 12/31/2021 | 26.42 | .42 | 3.52 | 3.94 | (.45 | ) | (.94 | ) | (1.39 | ) | 28.97 | 15.13 | 24 | .55 | 1.49 | |||||||||
| 12/31/2020 | 23.99 | .37 | 2.58 | 2.95 | (.41 | ) | (.11 | ) | (.52 | ) | 26.42 | 12.43 | 14 | .55 | 1.56 | |||||||||
| 12/31/2019 | 21.26 | .45 | 3.92 | 4.37 | (.45 | ) | (1.19 | ) | (1.64 | ) | 23.99 | 21.19 | 11 | .54 | 1.95 | |||||||||
| 12/31/2018 | 23.69 | .42 | (1.42 | ) | (1.00 | ) | (.40 | ) | (1.03 | ) | (1.43 | ) | 21.26 | (4.58 | ) | 7 | .53 | 1.82 | ||||||
| 12/31/20174,5 | 21.97 | .39 | 2.78 | 3.17 | (.39 | ) | (1.06 | ) | (1.45 | ) | 23.69 | 14.78 | 6 | 4 | .53 | 7 | 1.69 | 7 | ||||||
| Class 2: | ||||||||||||||||||||||||
| 12/31/2021 | 26.21 | .41 | 3.49 | 3.90 | (.43 | ) | (.94 | ) | (1.37 | ) | 28.74 | 15.10 | 5,473 | .55 | 1.46 | |||||||||
| 12/31/2020 | 23.79 | .37 | 2.56 | 2.93 | (.40 | ) | (.11 | ) | (.51 | ) | 26.21 | 12.46 | 5,242 | .55 | 1.55 | |||||||||
| 12/31/2019 | 21.08 | .45 | 3.89 | 4.34 | (.44 | ) | (1.19 | ) | (1.63 | ) | 23.79 | 21.23 | 5,154 | .54 | 1.96 | |||||||||
| 12/31/2018 | 23.49 | .41 | (1.41 | ) | (1.00 | ) | (.38 | ) | (1.03 | ) | (1.41 | ) | 21.08 | (4.60 | ) | 4,668 | .53 | 1.78 | ||||||
| 12/31/2017 | 21.49 | .37 | 3.04 | 3.41 | (.35 | ) | (1.06 | ) | (1.41 | ) | 23.49 | 16.23 | 5,480 | .54 | 1.64 | |||||||||
| Class 3: | ||||||||||||||||||||||||
| 12/31/2021 | 26.53 | .43 | 3.55 | 3.98 | (.45 | ) | (.94 | ) | (1.39 | ) | 29.12 | 15.22 | 36 | .48 | 1.53 | |||||||||
| 12/31/2020 | 24.08 | .39 | 2.59 | 2.98 | (.42 | ) | (.11 | ) | (.53 | ) | 26.53 | 12.50 | 33 | .48 | 1.62 | |||||||||
| 12/31/2019 | 21.32 | .47 | 3.93 | 4.40 | (.45 | ) | (1.19 | ) | (1.64 | ) | 24.08 | 21.30 | 32 | .47 | 2.02 | |||||||||
| 12/31/2018 | 23.73 | .43 | (1.41 | ) | (.98 | ) | (.40 | ) | (1.03 | ) | (1.43 | ) | 21.32 | (4.49 | ) | 29 | .46 | 1.85 | ||||||
| 12/31/2017 | 21.70 | .39 | 3.07 | 3.46 | (.37 | ) | (1.06 | ) | (1.43 | ) | 23.73 | 16.29 | 38 | .47 | 1.72 | |||||||||
| Class 4: | ||||||||||||||||||||||||
| 12/31/2021 | 26.06 | .34 | 3.47 | 3.81 | (.37 | ) | (.94 | ) | (1.31 | ) | 28.56 | 14.84 | 6,337 | .80 | 1.22 | |||||||||
| 12/31/2020 | 23.67 | .31 | 2.54 | 2.85 | (.35 | ) | (.11 | ) | (.46 | ) | 26.06 | 12.16 | 5,131 | .80 | 1.30 | |||||||||
| 12/31/2019 | 20.99 | .39 | 3.87 | 4.26 | (.39 | ) | (1.19 | ) | (1.58 | ) | 23.67 | 20.92 | 4,493 | .79 | 1.71 | |||||||||
| 12/31/2018 | 23.40 | .35 | (1.40 | ) | (1.05 | ) | (.33 | ) | (1.03 | ) | (1.36 | ) | 20.99 | (4.83 | ) | 3,594 | .78 | 1.54 | ||||||
| 12/31/2017 | 21.43 | .32 | 3.02 | 3.34 | (.31 | ) | (1.06 | ) | (1.37 | ) | 23.40 | 15.91 | 3,582 | .79 | 1.40 | |||||||||
| Income
(loss) from investment operations1 |
Dividends and distributions | |||||||||||||||||||||||
| Period ended | Net
asset value, beginning of period |
Net investment income |
Net
gains (losses) on securities (both realized and unrealized) |
Total
from investment operations |
Dividends (from net investment income) |
Distributions (from capital gains) |
Total dividends and distributions |
Net
asset value, end of period |
Total return |
Net
assets, end of period (in millions) |
Ratio
of expenses to average net assets3 |
Ratio
of net income to average net assets | ||||||||||||
| American Funds Global Balanced Fund | ||||||||||||||||||||||||
| Class 1: | ||||||||||||||||||||||||
| 12/31/2021 | $14.19 | $.18 | $1.37 | $1.55 | $(.19 | ) | $(.82 | ) | $(1.01 | ) | $14.73 | 11.05 | % | $120 | .73 | % | 1.24 | % | ||||||
| 12/31/2020 | 13.51 | .17 | 1.24 | 1.41 | (.19 | ) | (.54 | ) | (.73 | ) | 14.19 | 10.53 | 139 | .72 | 1.29 | |||||||||
| 12/31/2019 | 11.67 | .24 | 2.17 | 2.41 | (.20 | ) | (.37 | ) | (.57 | ) | 13.51 | 20.79 | 134 | .72 | 1.88 | |||||||||
| 12/31/2018 | 12.75 | .23 | (.96 | ) | (.73 | ) | (.20 | ) | (.15 | ) | (.35 | ) | 11.67 | (5.81 | ) | 110 | .72 | 1.82 | ||||||
| 12/31/2017 | 11.08 | .21 | 1.99 | 2.20 | (.15 | ) | (.38 | ) | (.53 | ) | 12.75 | 19.91 | 93 | .72 | 1.68 | |||||||||
| Class 1A: | ||||||||||||||||||||||||
| 12/31/2021 | 14.16 | .15 | 1.36 | 1.51 | (.15 | ) | (.82 | ) | (.97 | ) | 14.70 | 10.83 | 4 | .98 | 1.02 | |||||||||
| 12/31/2020 | 13.49 | .14 | 1.23 | 1.37 | (.16 | ) | (.54 | ) | (.70 | ) | 14.16 | 10.25 | 3 | .97 | 1.03 | |||||||||
| 12/31/2019 | 11.65 | .21 | 2.17 | 2.38 | (.17 | ) | (.37 | ) | (.54 | ) | 13.49 | 20.54 | 2 | .97 | 1.63 | |||||||||
| 12/31/2018 | 12.74 | .18 | (.94 | ) | (.76 | ) | (.18 | ) | (.15 | ) | (.33 | ) | 11.65 | (6.03 | ) | 2 | .98 | 1.44 | ||||||
| 12/31/20174,5 | 11.18 | .16 | 1.92 | 2.08 | (.14 | ) | (.38 | ) | (.52 | ) | 12.74 | 18.71 | 6 | — | 8 | .94 | 7 | 1.27 | 7 | |||||
| Class 2: | ||||||||||||||||||||||||
| 12/31/2021 | 14.16 | .15 | 1.36 | 1.51 | (.15 | ) | (.82 | ) | (.97 | ) | 14.70 | 10.79 | 208 | .98 | 1.01 | |||||||||
| 12/31/2020 | 13.48 | .14 | 1.23 | 1.37 | (.15 | ) | (.54 | ) | (.69 | ) | 14.16 | 10.30 | 208 | .97 | 1.03 | |||||||||
| 12/31/2019 | 11.65 | .21 | 2.16 | 2.37 | (.17 | ) | (.37 | ) | (.54 | ) | 13.48 | 20.44 | 207 | .97 | 1.64 | |||||||||
| 12/31/2018 | 12.72 | .20 | (.96 | ) | (.76 | ) | (.16 | ) | (.15 | ) | (.31 | ) | 11.65 | (6.01 | ) | 185 | .97 | 1.57 | ||||||
| 12/31/2017 | 11.06 | .18 | 1.98 | 2.16 | (.12 | ) | (.38 | ) | (.50 | ) | 12.72 | 19.57 | 210 | .96 | 1.43 | |||||||||
| Class 4: | ||||||||||||||||||||||||
| 12/31/2021 | 14.02 | .11 | 1.34 | 1.45 | (.12 | ) | (.82 | ) | (.94 | ) | 14.53 | 10.46 | 135 | 1.23 | .77 | |||||||||
| 12/31/2020 | 13.36 | .10 | 1.22 | 1.32 | (.12 | ) | (.54 | ) | (.66 | ) | 14.02 | 10.00 | 105 | 1.22 | .78 | |||||||||
| 12/31/2019 | 11.55 | .18 | 2.14 | 2.32 | (.14 | ) | (.37 | ) | (.51 | ) | 13.36 | 20.21 | 94 | 1.22 | 1.37 | |||||||||
| 12/31/2018 | 12.63 | .17 | (.96 | ) | (.79 | ) | (.14 | ) | (.15 | ) | (.29 | ) | 11.55 | (6.31 | ) | 69 | 1.22 | 1.34 | ||||||
| 12/31/2017 | 11.00 | .13 | 1.99 | 2.12 | (.11 | ) | (.38 | ) | (.49 | ) | 12.63 | 19.38 | 51 | 1.22 | 1.07 | |||||||||
25 American Funds Insurance Series / Prospectus
| Income
(loss) from investment operations1 |
Dividends and distributions | |||||||||||||||||||||||||
| Period ended | Net
asset value, beginning of year |
Net investment income (loss) |
Net
gains (losses) on securities (both realized and unrealized) |
Total
from investment operations |
Dividends (from net investment income) |
Distributions (from capital gains) |
Total dividends and distributions |
Net
asset value, end of year |
Total return2 |
Net
assets, end of year (in millions) |
Ratio
of expenses to average net assets before reimbursements |
Ratio
of expenses to average net assets after reimbursements2 |
Ratio
of net income (loss) to average net assets2 | |||||||||||||
| American Funds Mortgage Fund | ||||||||||||||||||||||||||
| Class 1: | ||||||||||||||||||||||||||
| 12/31/2021 | $11.11 | $.06 | $(.09 | ) | $(.03 | ) | $(.08 | ) | $(.37 | ) | $(.45 | ) | $10.63 | (.32 | )% | $231 | .49 | % | .29 | % | .58 | % | ||||
| 12/31/2020 | 10.56 | .10 | .64 | .74 | (.17 | ) | (.02 | ) | (.19 | ) | 11.11 | 6.98 | 224 | .48 | .36 | .93 | ||||||||||
| 12/31/2019 | 10.30 | .24 | .30 | .54 | (.28 | ) | — | (.28 | ) | 10.56 | 5.30 | 210 | .47 | .47 | 2.26 | |||||||||||
| 12/31/2018 | 10.47 | .20 | (.14 | ) | .06 | (.23 | ) | — | (.23 | ) | 10.30 | .58 | 209 | .48 | .48 | 1.97 | ||||||||||
| 12/31/2017 | 10.56 | .16 | — | 9 | .16 | (.18 | ) | (.07 | ) | (.25 | ) | 10.47 | 1.47 | 265 | .47 | .47 | 1.52 | |||||||||
| Class 1A: | ||||||||||||||||||||||||||
| 12/31/2021 | 11.08 | .04 | (.10 | ) | (.06 | ) | (.06 | ) | (.37 | ) | (.43 | ) | 10.59 | (.47 | ) | 2 | .74 | .54 | .33 | |||||||
| 12/31/2020 | 10.55 | .07 | .63 | .70 | (.15 | ) | (.02 | ) | (.17 | ) | 11.08 | 6.63 | 1 | .73 | .59 | .61 | ||||||||||
| 12/31/2019 | 10.28 | .22 | .30 | .52 | (.25 | ) | — | (.25 | ) | 10.55 | 5.09 | 1 | .71 | .71 | 2.04 | |||||||||||
| 12/31/2018 | 10.46 | .18 | (.14 | ) | .04 | (.22 | ) | — | (.22 | ) | 10.28 | .36 | 1 | .73 | .73 | 1.77 | ||||||||||
| 12/31/20175 | 10.55 | .14 | — | 9 | .14 | (.16 | ) | (.07 | ) | (.23 | ) | 10.46 | 1.31 | 6 | — | 8 | .70 | 7 | .70 | 7 | 1.38 | 7 | ||||
| Class 2: | ||||||||||||||||||||||||||
| 12/31/2021 | 11.09 | .04 | (.10 | ) | (.06 | ) | (.05 | ) | (.37 | ) | (.42 | ) | 10.61 | (.57 | ) | 58 | .74 | .54 | .33 | |||||||
| 12/31/2020 | 10.54 | .08 | .63 | .71 | (.14 | ) | (.02 | ) | (.16 | ) | 11.09 | 6.72 | 58 | .73 | .60 | .68 | ||||||||||
| 12/31/2019 | 10.28 | .21 | .31 | .52 | (.26 | ) | — | (.26 | ) | 10.54 | 5.04 | 56 | .72 | .72 | 2.01 | |||||||||||
| 12/31/2018 | 10.45 | .18 | (.15 | ) | .03 | (.20 | ) | — | (.20 | ) | 10.28 | .32 | 57 | .73 | .73 | 1.72 | ||||||||||
| 12/31/2017 | 10.54 | .14 | (.01 | ) | .13 | (.15 | ) | (.07 | ) | (.22 | ) | 10.45 | 1.22 | 63 | .72 | .72 | 1.27 | |||||||||
| Class 4: | ||||||||||||||||||||||||||
| 12/31/2021 | 10.97 | .01 | (.09 | ) | (.08 | ) | (.03 | ) | (.37 | ) | (.40 | ) | 10.49 | (.78 | ) | 43 | .99 | .79 | .08 | |||||||
| 12/31/2020 | 10.44 | .04 | .63 | .67 | (.12 | ) | (.02 | ) | (.14 | ) | 10.97 | 6.38 | 37 | .98 | .85 | .41 | ||||||||||
| 12/31/2019 | 10.19 | .18 | .31 | .49 | (.24 | ) | — | (.24 | ) | 10.44 | 4.80 | 28 | .97 | .97 | 1.71 | |||||||||||
| 12/31/2018 | 10.38 | .15 | (.15 | ) | — | 9 | (.19 | ) | — | (.19 | ) | 10.19 | .07 | 24 | .98 | .98 | 1.49 | |||||||||
| 12/31/2017 | 10.48 | .11 | — | 9 | .11 | (.14 | ) | (.07 | ) | (.21 | ) | 10.38 | .97 | 12 | .97 | .97 | 1.03 | |||||||||
| Income
(loss) from investment operations1 |
Dividends and distributions | |||||||||||||||||||||||||
| Period ended | Net
asset value, beginning of period |
Net investment income |
Net
gains (losses) on securities (both realized and unrealized) |
Total
from investment operations |
Dividends (from net investment income) |
Distributions (from capital gains) |
Total dividends and distributions |
Net
asset value, end of period |
Total return2 |
Net
assets, end of period (in millions) |
Ratio
of expenses to average net assets before waivers3 |
Ratio
of expenses to average net assets after waivers2,3 |
Ratio
of net income to average net assets2 | |||||||||||||
| American High-Income Trust | ||||||||||||||||||||||||||
| Class 1: | ||||||||||||||||||||||||||
| 12/31/2021 | $9.80 | $.51 | $.34 | $.85 | $(.46 | ) | $— | $(.46 | ) | $10.19 | 8.74 | % | $278 | .53 | % | .37 | % | 4.95 | % | |||||||
| 12/31/2020 | 9.87 | .61 | .17 | .78 | (.85 | ) | — | (.85 | ) | 9.80 | 8.21 | 123 | .52 | .52 | 6.46 | |||||||||||
| 12/31/2019 | 9.34 | .67 | .52 | 1.19 | (.66 | ) | — | (.66 | ) | 9.87 | 12.85 | 525 | .51 | .51 | 6.71 | |||||||||||
| 12/31/2018 | 10.19 | .64 | (.84 | ) | (.20 | ) | (.65 | ) | — | (.65 | ) | 9.34 | (2.15 | ) | 501 | .50 | .50 | 6.32 | ||||||||
| 12/31/2017 | 10.18 | .63 | .10 | .73 | (.72 | ) | — | (.72 | ) | 10.19 | 7.25 | 632 | .49 | .49 | 5.98 | |||||||||||
| Class 1A: | ||||||||||||||||||||||||||
| 12/31/2021 | 9.78 | .49 | .33 | .82 | (.44 | ) | — | (.44 | ) | 10.16 | 8.42 | 1 | .78 | .64 | 4.75 | |||||||||||
| 12/31/2020 | 9.86 | .56 | .20 | .76 | (.84 | ) | — | (.84 | ) | 9.78 | 7.94 | 1 | .78 | .78 | 5.85 | |||||||||||
| 12/31/2019 | 9.33 | .65 | .51 | 1.16 | (.63 | ) | — | (.63 | ) | 9.86 | 12.61 | 1 | .75 | .75 | 6.47 | |||||||||||
| 12/31/2018 | 10.18 | .62 | (.84 | ) | (.22 | ) | (.63 | ) | — | (.63 | ) | 9.33 | (2.35 | ) | 1 | .75 | .75 | 6.11 | ||||||||
| 12/31/20174,5 | 10.28 | .60 | .02 | .62 | (.72 | ) | — | (.72 | ) | 10.18 | 6.02 | 6 | — | 8 | .72 | 7 | .72 | 7 | 5.74 | 7 | ||||||
| Class 2: | ||||||||||||||||||||||||||
| 12/31/2021 | 9.61 | .48 | .33 | .81 | (.44 | ) | — | (.44 | ) | 9.98 | 8.42 | 673 | .78 | .65 | 4.80 | |||||||||||
| 12/31/2020 | 9.70 | .55 | .19 | .74 | (.83 | ) | — | (.83 | ) | 9.61 | 7.94 | 665 | .78 | .78 | 5.88 | |||||||||||
| 12/31/2019 | 9.19 | .64 | .50 | 1.14 | (.63 | ) | — | (.63 | ) | 9.70 | 12.55 | 667 | .76 | .76 | 6.45 | |||||||||||
| 12/31/2018 | 10.03 | .61 | (.83 | ) | (.22 | ) | (.62 | ) | — | (.62 | ) | 9.19 | (2.34 | ) | 661 | .75 | .75 | 6.07 | ||||||||
| 12/31/2017 | 10.04 | .59 | .10 | .69 | (.70 | ) | — | (.70 | ) | 10.03 | 6.89 | 776 | .74 | .74 | 5.72 | |||||||||||
| Class 3: | ||||||||||||||||||||||||||
| 12/31/2021 | 9.84 | .50 | .34 | .84 | (.44 | ) | — | (.44 | ) | 10.24 | 8.60 | 10 | .71 | .58 | 4.86 | |||||||||||
| 12/31/2020 | 9.92 | .57 | .19 | .76 | (.84 | ) | — | (.84 | ) | 9.84 | 7.93 | 10 | .71 | .71 | 5.94 | |||||||||||
| 12/31/2019 | 9.38 | .66 | .52 | 1.18 | (.64 | ) | — | (.64 | ) | 9.92 | 12.70 | 10 | .69 | .69 | 6.52 | |||||||||||
| 12/31/2018 | 10.23 | .63 | (.85 | ) | (.22 | ) | (.63 | ) | — | (.63 | ) | 9.38 | (2.33 | ) | 10 | .68 | .68 | 6.14 | ||||||||
| 12/31/2017 | 10.22 | .61 | .10 | .71 | (.70 | ) | — | (.70 | ) | 10.23 | 7.02 | 12 | .67 | .67 | 5.79 | |||||||||||
| Class 4: | ||||||||||||||||||||||||||
| 12/31/2021 | 10.54 | .50 | .36 | .86 | (.41 | ) | — | (.41 | ) | 10.99 | 8.18 | 90 | 1.03 | .89 | 4.52 | |||||||||||
| 12/31/2020 | 10.56 | .57 | .22 | .79 | (.81 | ) | — | (.81 | ) | 10.54 | 7.74 | 69 | 1.03 | 1.03 | 5.58 | |||||||||||
| 12/31/2019 | 9.96 | .67 | .54 | 1.21 | (.61 | ) | — | (.61 | ) | 10.56 | 12.27 | 63 | 1.01 | 1.01 | 6.21 | |||||||||||
| 12/31/2018 | 10.82 | .63 | (.90 | ) | (.27 | ) | (.59 | ) | — | (.59 | ) | 9.96 | (2.64 | ) | 31 | 1.00 | 1.00 | 5.83 | ||||||||
| 12/31/2017 | 10.79 | .61 | .10 | .71 | (.68 | ) | — | (.68 | ) | 10.82 | 6.63 | 34 | .99 | .99 | 5.46 | |||||||||||
American Funds Insurance Series / Prospectus 26
| (Loss)
income from investment operations1 |
Dividends and distributions | |||||||||||||||||||||||||
| Period ended | Net
asset value, beginning of period |
Net investment income |
Net
(losses) gains on securities (both realized and unrealized) |
Total
from investment operations |
Dividends (from net investment income) |
Distributions (from capital gains) |
Total dividends and distributions |
Net
asset value, end of period |
Total return2 |
Net
assets, end of period (in millions) |
Ratio
of expenses to average net assets before waivers3 |
Ratio
of expenses to average net assets after waivers2,3 |
Ratio
of net income to average net assets2 | |||||||||||||
| Capital World Bond Fund | ||||||||||||||||||||||||||
| Class 1: | ||||||||||||||||||||||||||
| 12/31/2021 | $12.94 | $.25 | $(.85 | ) | $(.60 | ) | $(.24 | ) | $(.31 | ) | $(.55 | ) | $11.79 | (4.73 | )% | $988 | .60 | % | .50 | % | 2.06 | % | ||||
| 12/31/2020 | 12.12 | .26 | .95 | 1.21 | (.18 | ) | (.21 | ) | (.39 | ) | 12.94 | 10.17 | 1,219 | .59 | .52 | 2.08 | ||||||||||
| 12/31/2019 | 11.42 | .31 | .61 | .92 | (.22 | ) | — | (.22 | ) | 12.12 | 8.08 | 1,077 | .58 | .58 | 2.60 | |||||||||||
| 12/31/2018 | 11.88 | .30 | (.44 | ) | (.14 | ) | (.28 | ) | (.04 | ) | (.32 | ) | 11.42 | (1.14 | ) | 1,015 | .57 | .57 | 2.56 | |||||||
| 12/31/2017 | 11.22 | .28 | .52 | .80 | (.07 | ) | (.07 | ) | (.14 | ) | 11.88 | 7.11 | 1,273 | .56 | .56 | 2.37 | ||||||||||
| Class 1A: | ||||||||||||||||||||||||||
| 12/31/2021 | 12.91 | .23 | (.85 | ) | (.62 | ) | (.22 | ) | (.31 | ) | (.53 | ) | 11.76 | (4.88 | ) | 1 | .85 | .75 | 1.85 | |||||||
| 12/31/2020 | 12.10 | .23 | .95 | 1.18 | (.16 | ) | (.21 | ) | (.37 | ) | 12.91 | 9.89 | 1 | .83 | .76 | 1.83 | ||||||||||
| 12/31/2019 | 11.41 | .28 | .60 | .88 | (.19 | ) | — | (.19 | ) | 12.10 | 7.75 | 1 | .83 | .83 | 2.35 | |||||||||||
| 12/31/2018 | 11.87 | .27 | (.43 | ) | (.16 | ) | (.26 | ) | (.04 | ) | (.30 | ) | 11.41 | (1.29 | ) | 1 | .82 | .82 | 2.36 | |||||||
| 12/31/20174,5 | 11.22 | .26 | .52 | .78 | (.06 | ) | (.07 | ) | (.13 | ) | 11.87 | 7.00 | 6 | — | 8 | .72 | 7 | .72 | 7 | 2.27 | 7 | |||||
| Class 2: | ||||||||||||||||||||||||||
| 12/31/2021 | 12.84 | .22 | (.84 | ) | (.62 | ) | (.21 | ) | (.31 | ) | (.52 | ) | 11.70 | (4.92 | ) | 1,030 | .85 | .75 | 1.82 | |||||||
| 12/31/2020 | 12.03 | .22 | .95 | 1.17 | (.15 | ) | (.21 | ) | (.36 | ) | 12.84 | 9.90 | 1,058 | .84 | .77 | 1.83 | ||||||||||
| 12/31/2019 | 11.34 | .28 | .60 | .88 | (.19 | ) | — | (.19 | ) | 12.03 | 7.77 | 1,002 | .83 | .83 | 2.35 | |||||||||||
| 12/31/2018 | 11.79 | .27 | (.43 | ) | (.16 | ) | (.25 | ) | (.04 | ) | (.29 | ) | 11.34 | (1.33 | ) | 1,032 | .82 | .82 | 2.32 | |||||||
| 12/31/2017 | 11.14 | .25 | .51 | .76 | (.04 | ) | (.07 | ) | (.11 | ) | 11.79 | 6.86 | 1,164 | .81 | .81 | 2.12 | ||||||||||
| Class 4: | ||||||||||||||||||||||||||
| 12/31/2021 | 12.71 | .19 | (.84 | ) | (.65 | ) | (.18 | ) | (.31 | ) | (.49 | ) | 11.57 | (5.18 | ) | 66 | 1.10 | 1.00 | 1.57 | |||||||
| 12/31/2020 | 11.92 | .19 | .94 | 1.13 | (.13 | ) | (.21 | ) | (.34 | ) | 12.71 | 9.62 | 61 | 1.09 | 1.02 | 1.58 | ||||||||||
| 12/31/2019 | 11.24 | .24 | .60 | .84 | (.16 | ) | — | (.16 | ) | 11.92 | 7.54 | 49 | 1.08 | 1.08 | 2.09 | |||||||||||
| 12/31/2018 | 11.70 | .24 | (.43 | ) | (.19 | ) | (.23 | ) | (.04 | ) | (.27 | ) | 11.24 | (1.61 | ) | 40 | 1.07 | 1.07 | 2.09 | |||||||
| 12/31/2017 | 11.08 | .22 | .51 | .73 | (.04 | ) | (.07 | ) | (.11 | ) | 11.70 | 6.63 | 31 | 1.06 | 1.06 | 1.89 | ||||||||||
| (Loss)
income from investment operations1 |
Dividends and distributions | |||||||||||||||||||||||||
| Period ended | Net
asset value, beginning of period |
Net investment income |
Net
(losses) gains on securities (both realized and unrealized) |
Total
from investment operations |
Dividends (from net investment income) |
Distributions (from capital gains) |
Total dividends and distributions |
Net
asset value, end of period |
Total return2 |
Net
assets, end of period (in millions) |
Ratio
of expenses to average net assets before waivers3 |
Ratio
of expenses to average net assets after waivers2,3 |
Ratio
of net income to average net assets2 | |||||||||||||
| The Bond Fund of America | ||||||||||||||||||||||||||
| Class 1: | ||||||||||||||||||||||||||
| 12/31/2021 | $11.89 | $.21 | $(.23 | ) | $(.02 | ) | $(.19 | ) | $(.47 | ) | $(.66 | ) | $11.21 | (.14 | )% | $8,555 | .39 | % | .26 | % | 1.84 | % | ||||
| 12/31/2020 | 11.17 | .23 | .87 | 1.10 | (.27 | ) | (.11 | ) | (.38 | ) | 11.89 | 9.96 | 6,844 | .40 | .40 | 2.00 | ||||||||||
| 12/31/2019 | 10.47 | .30 | .71 | 1.01 | (.31 | ) | — | (.31 | ) | 11.17 | 9.70 | 6,481 | .39 | .39 | 2.76 | |||||||||||
| 12/31/2018 | 10.82 | .29 | (.35 | ) | (.06 | ) | (.28 | ) | (.01 | ) | (.29 | ) | 10.47 | (.45 | ) | 5,962 | .38 | .38 | 2.70 | |||||||
| 12/31/2017 | 10.80 | .24 | .18 | .42 | (.24 | ) | (.16 | ) | (.40 | ) | 10.82 | 3.88 | 6,434 | .38 | .38 | 2.19 | ||||||||||
| Class 1A: | ||||||||||||||||||||||||||
| 12/31/2021 | 11.84 | .18 | (.23 | ) | (.05 | ) | (.16 | ) | (.47 | ) | (.63 | ) | 11.16 | (.36 | ) | 12 | .64 | .51 | 1.59 | |||||||
| 12/31/2020 | 11.13 | .20 | .87 | 1.07 | (.25 | ) | (.11 | ) | (.36 | ) | 11.84 | 9.68 | 9 | .65 | .65 | 1.74 | ||||||||||
| 12/31/2019 | 10.45 | .27 | .71 | .98 | (.30 | ) | — | (.30 | ) | 11.13 | 9.36 | 7 | .64 | .64 | 2.48 | |||||||||||
| 12/31/2018 | 10.80 | .26 | (.33 | ) | (.07 | ) | (.27 | ) | (.01 | ) | (.28 | ) | 10.45 | (.60 | ) | 3 | .63 | .63 | 2.50 | |||||||
| 12/31/20174,5 | 10.82 | .22 | .15 | .37 | (.23 | ) | (.16 | ) | (.39 | ) | 10.80 | 3.46 | 6 | 1 | .62 | 7 | .62 | 7 | 2.01 | 7 | ||||||
| Class 2: | ||||||||||||||||||||||||||
| 12/31/2021 | 11.73 | .18 | (.22 | ) | (.04 | ) | (.16 | ) | (.47 | ) | (.63 | ) | 11.06 | (.31 | ) | 3,729 | .64 | .52 | 1.57 | |||||||
| 12/31/2020 | 11.02 | .20 | .86 | 1.06 | (.24 | ) | (.11 | ) | (.35 | ) | 11.73 | 9.73 | 3,840 | .65 | .65 | 1.75 | ||||||||||
| 12/31/2019 | 10.34 | .27 | .70 | .97 | (.29 | ) | — | (.29 | ) | 11.02 | 9.36 | 3,561 | .64 | .64 | 2.51 | |||||||||||
| 12/31/2018 | 10.69 | .26 | (.34 | ) | (.08 | ) | (.26 | ) | (.01 | ) | (.27 | ) | 10.34 | (.71 | ) | 3,524 | .63 | .63 | 2.45 | |||||||
| 12/31/2017 | 10.67 | .21 | .18 | .39 | (.21 | ) | (.16 | ) | (.37 | ) | 10.69 | 3.67 | 3,966 | .63 | .63 | 1.94 | ||||||||||
| Class 4: | ||||||||||||||||||||||||||
| 12/31/2021 | 11.69 | .15 | (.22 | ) | (.07 | ) | (.14 | ) | (.47 | ) | (.61 | ) | 11.01 | (.59 | ) | 891 | .89 | .76 | 1.34 | |||||||
| 12/31/2020 | 11.00 | .17 | .85 | 1.02 | (.22 | ) | (.11 | ) | (.33 | ) | 11.69 | 9.38 | 714 | .90 | .90 | 1.48 | ||||||||||
| 12/31/2019 | 10.33 | .24 | .70 | .94 | (.27 | ) | — | (.27 | ) | 11.00 | 9.08 | 502 | .89 | .89 | 2.25 | |||||||||||
| 12/31/2018 | 10.68 | .23 | (.33 | ) | (.10 | ) | (.24 | ) | (.01 | ) | (.25 | ) | 10.33 | (.89 | ) | 366 | .88 | .88 | 2.22 | |||||||
| 12/31/2017 | 10.70 | .19 | .16 | .35 | (.21 | ) | (.16 | ) | (.37 | ) | 10.68 | 3.29 | 297 | .88 | .88 | 1.72 | ||||||||||
27 American Funds Insurance Series / Prospectus
| (Loss)
income from investment operations1 |
Dividends and distributions | |||||||||||||||||||||||||
| Period ended | Net
asset value, beginning of period |
Net investment income |
Net
(losses) gains on securities (both realized and unrealized) |
Total
from investment operations |
Dividends (from net investment income) |
Distributions (from capital gains) |
Total dividends and distributions |
Net
asset value, end of period |
Total return2 |
Net
assets, end of period (in millions) |
Ratio
of expenses to average net assets before waivers |
Ratio
of expenses to average net assets after waivers2 |
Ratio
of net income to average net assets2 | |||||||||||||
| U.S. Government Securities Fund | ||||||||||||||||||||||||||
| Class 1: | ||||||||||||||||||||||||||
| 12/31/2021 | $13.04 | $.18 | $(.26 | ) | $(.08 | ) | $(.18 | ) | $(1.11 | ) | $(1.29 | ) | $11.67 | (.44 | )% | $522 | .39 | % | .29 | % | 1.50 | % | ||||
| 12/31/2020 | 12.34 | .16 | 1.07 | 1.23 | (.26 | ) | (.27 | ) | (.53 | ) | 13.04 | 10.09 | 429 | .38 | .38 | 1.21 | ||||||||||
| 12/31/2019 | 11.94 | .25 | .43 | .68 | (.28 | ) | — | (.28 | ) | 12.34 | 5.69 | 1,418 | .37 | .37 | 2.07 | |||||||||||
| 12/31/2018 | 12.08 | .24 | (.13 | ) | .11 | (.25 | ) | — | (.25 | ) | 11.94 | .91 | 1,445 | .36 | .36 | 2.02 | ||||||||||
| 12/31/2017 | 12.05 | .21 | .01 | .22 | (.19 | ) | — | (.19 | ) | 12.08 | 1.83 | 1,558 | .36 | .36 | 1.68 | |||||||||||
| Class 1A: | ||||||||||||||||||||||||||
| 12/31/2021 | 13.00 | .16 | (.26 | ) | (.10 | ) | (.16 | ) | (1.11 | ) | (1.27 | ) | 11.63 | (.65 | ) | 5 | .64 | .53 | 1.28 | |||||||
| 12/31/2020 | 12.32 | .09 | 1.10 | 1.19 | (.24 | ) | (.27 | ) | (.51 | ) | 13.00 | 9.75 | 4 | .64 | .64 | .69 | ||||||||||
| 12/31/2019 | 11.93 | .22 | .43 | .65 | (.26 | ) | — | (.26 | ) | 12.32 | 5.42 | 2 | .62 | .62 | 1.82 | |||||||||||
| 12/31/2018 | 12.08 | .22 | (.14 | ) | .08 | (.23 | ) | — | (.23 | ) | 11.93 | .70 | 1 | .61 | .61 | 1.82 | ||||||||||
| 12/31/20174,5 | 12.05 | .18 | .03 | .21 | (.18 | ) | — | (.18 | ) | 12.08 | 1.73 | 6 | — | 8 | .58 | 7 | .58 | 7 | 1.53 | 7 | ||||||
| Class 2: | ||||||||||||||||||||||||||
| 12/31/2021 | 12.89 | .15 | (.25 | ) | (.10 | ) | (.15 | ) | (1.11 | ) | (1.26 | ) | 11.53 | (.62 | ) | 1,391 | .64 | .54 | 1.24 | |||||||
| 12/31/2020 | 12.21 | .09 | 1.10 | 1.19 | (.24 | ) | (.27 | ) | (.51 | ) | 12.89 | 9.80 | 1,439 | .64 | .64 | .73 | ||||||||||
| 12/31/2019 | 11.82 | .22 | .42 | .64 | (.25 | ) | — | (.25 | ) | 12.21 | 5.31 | 1,343 | .62 | .62 | 1.82 | |||||||||||
| 12/31/2018 | 11.96 | .21 | (.14 | ) | .07 | (.21 | ) | — | (.21 | ) | 11.82 | .73 | 1,323 | .61 | .61 | 1.77 | ||||||||||
| 12/31/2017 | 11.93 | .17 | .02 | .19 | (.16 | ) | — | (.16 | ) | 11.96 | 1.59 | 1,473 | .61 | .61 | 1.43 | |||||||||||
| Class 3: | ||||||||||||||||||||||||||
| 12/31/2021 | 13.07 | .16 | (.26 | ) | (.10 | ) | (.16 | ) | (1.11 | ) | (1.27 | ) | 11.70 | (.62 | ) | 9 | .57 | .47 | 1.31 | |||||||
| 12/31/2020 | 12.37 | .10 | 1.12 | 1.22 | (.25 | ) | (.27 | ) | (.52 | ) | 13.07 | 9.91 | 10 | .57 | .57 | .78 | ||||||||||
| 12/31/2019 | 11.97 | .23 | .43 | .66 | (.26 | ) | — | (.26 | ) | 12.37 | 5.49 | 9 | .55 | .55 | 1.88 | |||||||||||
| 12/31/2018 | 12.11 | .22 | (.14 | ) | .08 | (.22 | ) | — | (.22 | ) | 11.97 | .71 | 9 | .54 | .54 | 1.84 | ||||||||||
| 12/31/2017 | 12.07 | .18 | .03 | .21 | (.17 | ) | — | (.17 | ) | 12.11 | 1.72 | 10 | .54 | .54 | 1.50 | |||||||||||
| Class 4: | ||||||||||||||||||||||||||
| 12/31/2021 | 12.88 | .12 | (.25 | ) | (.13 | ) | (.12 | ) | (1.11 | ) | (1.23 | ) | 11.52 | (.88 | ) | 238 | .89 | .79 | .98 | |||||||
| 12/31/2020 | 12.22 | .05 | 1.10 | 1.15 | (.22 | ) | (.27 | ) | (.49 | ) | 12.88 | 9.48 | 272 | .89 | .89 | .42 | ||||||||||
| 12/31/2019 | 11.84 | .19 | .42 | .61 | (.23 | ) | — | (.23 | ) | 12.22 | 5.14 | 124 | .87 | .87 | 1.56 | |||||||||||
| 12/31/2018 | 11.98 | .18 | (.12 | ) | .06 | (.20 | ) | — | (.20 | ) | 11.84 | .50 | 91 | .86 | .86 | 1.53 | ||||||||||
| 12/31/2017 | 11.96 | .14 | .01 | .15 | (.13 | ) | — | (.13 | ) | 11.98 | 1.28 | 62 | .86 | .86 | 1.18 | |||||||||||
American Funds Insurance Series / Prospectus 28
| (Loss)
income from investment operations1 |
Dividends and distributions | |||||||||||||||||||||||
| Period ended | Net
asset value, beginning of period |
Net investment (loss) income |
Net
(losses) gains on securities (both realized and unrealized) |
Total
from investment operations |
Dividends (from net investment income) |
Distributions (from capital gains) |
Total dividends and distributions |
Net
asset value, end of period |
Total return |
Net
assets, end of period (in millions) |
Ratio
of expenses to average net assets |
Ratio
of net (loss) income to average net assets | ||||||||||||
| Ultra-Short Bond Fund | ||||||||||||||||||||||||
| Class 1: | ||||||||||||||||||||||||
| 12/31/2021 | $11.31 | $(.03 | ) | $(.01 | ) | $(.04 | ) | $— | $— | $— | $11.27 | (.35 | )% | $37 | .37 | % | (.28 | )% | ||||||
| 12/31/2020 | 11.30 | .02 | .02 | .04 | (.03 | ) | — | (.03 | ) | 11.31 | .34 | 44 | .37 | .16 | ||||||||||
| 12/31/2019 | 11.31 | .22 | — | 9 | .22 | (.23 | ) | — | (.23 | ) | 11.30 | 1.92 | 30 | .36 | 1.92 | |||||||||
| 12/31/2018 | 11.29 | .18 | — | 9 | .18 | (.16 | ) | — | (.16 | ) | 11.31 | 1.58 | 37 | .35 | 1.60 | |||||||||
| 12/31/2017 | 11.27 | .08 | (.01 | ) | .07 | (.05 | ) | — | (.05 | ) | 11.29 | .66 | 37 | .35 | .68 | |||||||||
| Class 1A: | ||||||||||||||||||||||||
| 12/31/2021 | 11.31 | (.03 | ) | — | 9 | (.03 | ) | — | — | — | 11.28 | (.27 | ) | — | 8 | .36 | (.28 | ) | ||||||
| 12/31/2020 | 11.30 | .03 | .01 | .04 | (.03 | ) | — | (.03 | ) | 11.31 | .32 | — | 8 | .35 | .26 | |||||||||
| 12/31/2019 | 11.31 | .22 | — | 9 | .22 | (.23 | ) | — | (.23 | ) | 11.30 | 1.92 | — | 8 | .37 | 1.90 | ||||||||
| 12/31/2018 | 11.29 | .18 | — | 9 | .18 | (.16 | ) | — | (.16 | ) | 11.31 | 1.58 | — | 8 | .35 | 1.60 | ||||||||
| 12/31/20174,5 | 11.27 | .08 | — | 9 | .08 | (.06 | ) | — | (.06 | ) | 11.29 | .67 | 6 | — | 8 | .34 | 7 | .69 | 7 | |||||
| Class 2: | ||||||||||||||||||||||||
| 12/31/2021 | 10.99 | (.06 | ) | — | 9 | (.06 | ) | — | — | — | 10.93 | (.55 | ) | 245 | .62 | (.53 | ) | |||||||
| 12/31/2020 | 11.01 | — | 9 | — | 9 | — | 9 | (.02 | ) | — | (.02 | ) | 10.99 | .03 | 288 | .62 | (.05 | ) | ||||||
| 12/31/2019 | 11.03 | .18 | — | 9 | .18 | (.20 | ) | — | (.20 | ) | 11.01 | 1.62 | 230 | .61 | 1.66 | |||||||||
| 12/31/2018 | 11.01 | .15 | — | 9 | .15 | (.13 | ) | — | (.13 | ) | 11.03 | 1.36 | 247 | .60 | 1.34 | |||||||||
| 12/31/2017 | 10.99 | .05 | — | 9 | .05 | (.03 | ) | — | (.03 | ) | 11.01 | .46 | 249 | .60 | .42 | |||||||||
| Class 3: | ||||||||||||||||||||||||
| 12/31/2021 | 11.12 | (.05 | ) | — | 9 | (.05 | ) | — | — | — | 11.07 | (.45 | ) | 5 | .55 | (.46 | ) | |||||||
| 12/31/2020 | 11.13 | — | 9 | .02 | .02 | (.03 | ) | — | (.03 | ) | 11.12 | .13 | 4 | .55 | .03 | |||||||||
| 12/31/2019 | 11.14 | .20 | — | 9 | .20 | (.21 | ) | — | (.21 | ) | 11.13 | 1.76 | 3 | .54 | 1.74 | |||||||||
| 12/31/2018 | 11.12 | .16 | (.01 | ) | .15 | (.13 | ) | — | (.13 | ) | 11.14 | 1.38 | 4 | .53 | 1.42 | |||||||||
| 12/31/2017 | 11.10 | .06 | — | 9 | .06 | (.04 | ) | — | (.04 | ) | 11.12 | .54 | 4 | .53 | .50 | |||||||||
| Class 4: | ||||||||||||||||||||||||
| 12/31/2021 | 11.08 | (.09 | ) | .01 | (.08 | ) | — | — | — | 11.00 | (.72 | ) | 46 | .87 | (.79 | ) | ||||||||
| 12/31/2020 | 11.13 | (.04 | ) | .01 | (.03 | ) | (.02 | ) | — | (.02 | ) | 11.08 | (.25 | ) | 40 | .87 | (.35 | ) | ||||||
| 12/31/2019 | 11.15 | .16 | — | 9 | .16 | (.18 | ) | — | (.18 | ) | 11.13 | 1.40 | 22 | .86 | 1.40 | |||||||||
| 12/31/2018 | 11.13 | .12 | .01 | .13 | (.11 | ) | — | (.11 | ) | 11.15 | 1.14 | 18 | .86 | 1.11 | ||||||||||
| 12/31/2017 | 11.12 | .02 | — | 9 | .02 | (.01 | ) | — | (.01 | ) | 11.13 | .16 | 15 | .85 | .19 | |||||||||
29 American Funds Insurance Series / Prospectus
| Year ended December 31, | |||||
Portfolio turnover rate for all share classes excluding mortgage dollar roll transactions11 |
2021 | 2020 | 2019 | 2018 | 2017 |
| Capital Income Builder | 60% | 110% | 44% | 42% | 59% |
| Asset Allocation Fund | 45 | 49 | 47 | 34 | 39 |
| American Funds Mortgage Fund | 38 | 123 | 84 | 60 | 98 |
| American Funds Global Balanced Fund | 36 | 68 | 60 | 30 | 28 |
| Capital World Bond Fund | 64 | 88 | 110 | 78 | 74 |
| The Bond Fund of America | 87 | 72 | 146 | 98 | 153 |
| U.S. Government Securities Fund | 126 | 112 | 103 | 76 | 120 |
| Year ended December 31, | |||||
Portfolio turnover rate for all share classes including mortgage dollar roll transactions, if applicable11 |
2021 | 2020 | 2019 | 2018 | 2017 |
| Global Growth Fund | 18% | 17% | 14% | 25% | 31% |
| Global Small Capitalization Fund | 29 | 38 | 50 | 43 | 33 |
| Growth Fund | 25 | 32 | 21 | 35 | 24 |
| International Fund | 44 | 40 | 32 | 29 | 29 |
| New World Fund | 43 | 70 | 38 | 58 | 56 |
| Capital World Growth and Income Fund | 85 | 36 | 29 | 49 | 41 |
| Growth-Income Fund | 24 | 33 | 27 | 39 | 27 |
| International Growth and Income Fund | 41 | 56 | 28 | 38 | 51 |
| Washington Mutual Investors Fund | 90 | 40 | 37 | 49 | 34 |
| Capital Income Builder | 93 | 184 | 72 | 98 | 88 |
| Asset Allocation Fund | 124 | 145 | 79 | 86 | 85 |
| American Funds Global Balanced Fund | 39 | 86 | 74 | 51 | 41 |
| American Funds Mortgage Fund | 975 | 1,143 | 350 | 811 | 680 |
| American High-Income Trust | 56 | 78 | 58 | 67 | 78 |
| Capital World Bond Fund | 91 | 145 | 159 | 125 | 105 |
| The Bond Fund of America | 456 | 461 | 373 | 514 | 502 |
| U.S. Government Securities Fund | 433 | 867 | 277 | 446 | 551 |
| Ultra-Short Bond Fund | —12 | —12 | —12 | —12 | —12 |
1 Based on average shares outstanding.
2 This column reflects the impact of certain waivers/reimbursements from Capital Research and Management Company. During some of the periods shown, Capital Research and Management Company waived a portion of investment advisory services fees on some funds.
3 Ratios do not include expenses of any Central Funds. The fund indirectly bears its proportionate share of the expenses of any Central Funds, if applicable.
4 Based on operations for a period that is less than a full year.
5 Class 1A shares began investment operations on January 6, 2017.
6 Not annualized.
7 Annualized.
8 Amount less than $1 million.
9 Amount less than $.01.
10 Amount less than .01%.
11Rates do not include the fund’s portfolio activity with respect to any Central Funds, if applicable.
12Amount is either less than 1% or there is no turnover.
American Funds Insurance Series / Prospectus 30
Other fund information Shares of the Series are currently offered to insurance company separate accounts funding both variable annuity contracts and variable life insurance policies. Interests of various contract owners participating in the Series may be in conflict. The board of trustees of the Series will monitor for the existence of any material conflicts and determine what action, if any, should be taken. Shares may be purchased or redeemed by the separate accounts without any sales or redemption charges at net asset value.
Annual/Semi-annual report to shareholders The shareholder reports contain additional information about the Series, including financial statements, investment results, portfolio holdings, a discussion of market conditions and the Series’ investment strategies, and the independent registered public accounting firm’s report (in the annual report).
Statement of additional information (SAI) and codes of ethics The current SAI, as amended from time to time, contains more detailed information about the Series, including the funds’ financial statements, and is incorporated by reference into this prospectus. This means that the current SAI, for legal purposes, is part of this prospectus. The codes of ethics describe the personal investing policies adopted by the Series, the Series’ investment adviser and its affiliated companies.
The codes of ethics and current SAI are on file with the U.S. Securities and Exchange Commission (SEC). These and other related materials about the Series are available for review on the EDGAR database on the SEC’s website at sec.gov or, after payment of a duplicating fee, via email request to publicinfo@sec.gov.
The current SAI and annual/semi-annual reports to shareholders can be found online at capitalgroup.com/afis and may be available on the website of the company that issued your insurance contract. You also may request a free copy of these documents or the codes of ethics by calling Capital Group at (800) 421-9900, ext. 65413 or writing to the Secretary at 333 South Hope Street, Los Angeles, California 90071.
| INA4PRX-054-0522P Printed in USA CGD/AFD/8024 | Investment Company File No. 811-03857 |
American Funds Insurance Series®
Part
B
Statement of Additional Information
May 1, 2022
This document is not a prospectus but should be read in conjunction with the current prospectus of American Funds Insurance Series (the “Series”), dated May 1, 2022, for the funds listed below. Except where the context indicates otherwise, all references herein to the “fund“ apply to each of the funds listed below. You may obtain a prospectus from your financial professional, by calling American Funds Service Company® at (800) 421-4225 or by writing to the Series at the following address:
American
Funds Insurance Series
Attention: Secretary
333
South Hope Street
Los Angeles, California 90071
| Class 1, Class 1A, Class 2 and Class 4 shares of: |
| American Funds Global Balanced FundSM |
Table of Contents
| Item | Page no. |
American Funds Insurance Series — Page 1
Certain investment limitations and guidelines
The following limitations and guidelines are considered at the time of purchase, under normal circumstances, and are based on a percentage of each fund’s net assets (excluding, for the avoidance of doubt, collateral held in connection with securities lending activities) unless otherwise noted. This summary is not intended to reflect all of the funds’ investment limitations.
American Funds Global Balanced Fund
· The fund will invest at least 45% of the value of its assets in equity investments.
· The fund will invest a portion of its assets in issuers domiciled outside of the United States, including issuers domiciled in emerging markets.
· The fund will invest at least 25% of the value of its assets in debt securities (including money market instruments). These will consist of investment-grade securities (rated Baa3 or better or BBB– or better by Nationally Recognized Statistical Rating Organizations designated by the fund’s investment adviser or unrated but determined to be of equivalent quality by the fund’s investment adviser). The fund currently intends to look to the ratings from Moody’s Investors Service, Standard & Poor’s Ratings Services and Fitch Ratings. If rating agencies differ, securities will be considered to have received the highest of these ratings, consistent with the fund's investment policies.
· The fund may also invest up to 5% of its assets in lower quality, higher yielding debt securities including those convertible into common stocks (rated Ba1 or below and BB+ or below by Nationally Recognized Statistical Rating Organizations designated by the fund’s investment adviser or unrated but determined to be of equivalent quality by the fund’s investment adviser). Such securities are sometimes referred to as “junk bonds.”
· In determining the domicile of an issuer, the fund's investment adviser will generally look to the domicile determination of a leading provider of global indexes, such as Morgan Stanley Capital International. However, the adviser in its discretion also may take into account such factors as where the issuer's securities are listed and where the issuer is legally organized, maintains principal corporate offices, conducts its principal operations, generates revenues and/or has credit risk exposure.
* * * * * *
The funds may experience difficulty liquidating certain portfolio securities during significant market declines or periods of heavy redemptions.
American Funds Insurance Series — Page 2
Description of certain securities, investment techniques and risks
The descriptions below are intended to supplement the material in the prospectus under “Investment objectives, strategies and risks.” With respect to all funds, portfolio changes will be made without regard to the length of time a particular investment may have been held.
Market conditions – The value of, and the income generated by, the securities in which the fund invests may decline, sometimes rapidly or unpredictably, due to factors affecting certain issuers, particular industries or sectors, or the overall markets. Rapid or unexpected changes in market conditions could cause the fund to liquidate its holdings at inopportune times or at a loss or depressed value. The value of a particular holding may decrease due to developments related to that issuer, but also due to general market conditions, including real or perceived economic developments such as changes in interest rates, credit quality, inflation, or currency rates, or generally adverse investor sentiment. The value of a holding may also decline due to factors that negatively affect a particular industry or sector, such as labor shortages, increased production costs, or competitive conditions.
Global economies and financial markets are highly interconnected, and conditions and events in one country, region or financial market may adversely impact issuers in a different country, region or financial market. Furthermore, local, regional and global events such as war, acts of terrorism, social unrest, natural disasters, the spread of infectious illness or other public health threats could also adversely impact issuers, markets and economies, including in ways that cannot necessarily be foreseen. The fund could be negatively impacted if the value of a portfolio holding were harmed by such conditions or events.
Significant market disruptions, such as those caused by pandemics, natural or environmental disasters, war, acts of terrorism, or other events, can adversely affect local and global markets and normal market operations. Market disruptions may exacerbate political, social, and economic risks. Additionally, market disruptions may result in increased market volatility; regulatory trading halts; closure of domestic or foreign exchanges, markets, or governments; or market participants operating pursuant to business continuity plans for indeterminate periods of time. Such events can be highly disruptive to economies and markets and significantly impact individual companies, sectors, industries, markets, currencies, interest and inflation rates, credit ratings, investor sentiment, and other factors affecting the value of the fund’s investments and operation of the fund. These events could disrupt businesses that are integral to the fund’s operations or impair the ability of employees of fund service providers to perform essential tasks on behalf of the fund.
Governmental and quasi-governmental authorities may take a number of actions designed to support local and global economies and the financial markets in response to economic disruptions. Such actions may include a variety of significant fiscal and monetary policy changes, including, for example, direct capital infusions into companies, new monetary programs and significantly lower interest rates. These actions may result in significant expansion of public debt and may result in greater market risk. Additionally, an unexpected or quick reversal of these policies, or the ineffectiveness of these policies, could negatively impact overall investor sentiment and further increase volatility in securities markets.
Equity securities — Certain funds may invest in equity securities. Equity securities represent an ownership position in a company. Equity securities held by the fund typically consist of common stocks. The prices of equity securities fluctuate based on, among other things, events specific to their issuers and market, economic and other conditions. For example, prices of these securities can be affected by financial contracts held by the issuer or third parties (such as derivatives) relating to the security or other assets or indices. Holders of equity securities are not creditors of the issuer. If an issuer liquidates, holders of equity securities are entitled to their pro rata share of the issuer’s assets, if any, after creditors (including the holders of fixed income securities and senior equity securities) are paid.
American Funds Insurance Series — Page 3
There may be little trading in the secondary market for particular equity securities, which may adversely affect the fund’s ability to value accurately or dispose of such equity securities. Adverse publicity and investor perceptions, whether or not based on fundamental analysis, may decrease the value and/or liquidity of equity securities.
The growth-oriented, equity-type securities generally purchased by certain of the funds may involve large price swings and potential for loss. To the extent the fund invests in income-oriented, equity-type securities, income provided by the fund may be reduced by changes in the dividend policies of, and the capital resources available at, the companies in which the fund invests.
Debt instruments — Debt securities, also known as “fixed income securities,” are used by issuers to borrow money. Bonds, notes, debentures, asset-backed securities (including those backed by mortgages), and loan participations and assignments are common types of debt securities. Generally, issuers pay investors periodic interest and repay the amount borrowed either periodically during the life of the security and/or at maturity. Some debt securities, such as zero coupon bonds, do not pay current interest, but are purchased at a discount from their face values and their values accrete over time to face value at maturity. Some debt securities bear interest at rates that are not fixed, but that vary with changes in specified market rates or indices. The market prices of debt securities fluctuate depending on such factors as interest rates, credit quality and maturity. In general, market prices of debt securities decline when interest rates rise and increase when interest rates fall. These fluctuations will generally be greater for longer-term debt securities than for shorter-term debt securities. Prices of these securities can also be affected by financial contracts held by the issuer or third parties (such as derivatives) relating to the security or other assets or indices. Borrowers that are in bankruptcy or restructuring may never pay off their indebtedness, or they may pay only a small fraction of the amount owed. Direct indebtedness of countries, particularly developing countries, also involves a risk that the governmental entities responsible for the repayment of the debt may be unable, or unwilling, to pay interest and repay principal when due.
Lower rated debt securities, rated Ba1/BB+ or below by Nationally Recognized Statistical Rating Organizations, are described by the rating agencies as speculative and involve greater risk of default or price changes due to changes in the issuer’s creditworthiness than higher rated debt securities, or they may already be in default. Such securities are sometimes referred to as “junk bonds” or high yield bonds. The market prices of these securities may fluctuate more than higher quality securities and may decline significantly in periods of general economic difficulty. It may be more difficult to dispose of, and to determine the value of, lower rated debt securities. Investment grade bonds in the ratings categories A or Baa/BBB also may be more susceptible to changes in market or economic conditions than bonds rated in the highest rating categories.
American Funds Insurance Series — Page 4
Certain additional risk factors relating to debt securities are discussed below:
Sensitivity to interest rate and economic changes — Debt securities may be sensitive to economic changes, political and corporate developments, and interest rate changes. In addition, during an economic downturn or a period of rising interest rates, issuers that are highly leveraged may experience increased financial stress that could adversely affect their ability to meet projected business goals, to obtain additional financing and to service their principal and interest payment obligations. Periods of economic change and uncertainty also can be expected to result in increased volatility of market prices and yields of certain debt securities and derivative instruments. As discussed under “Market conditions” above in this statement of additional information, governments and quasi-governmental authorities may take actions to support local and global economies and financial markets during periods of economic crisis, including direct capital infusions into companies, new monetary programs and significantly lower interest rates. Such actions may expose fixed income markets to heightened volatility and may reduce liquidity for certain investments, which could cause the value of the funds’ portfolio to decline.
Payment expectations — Debt securities may contain redemption or call provisions. If an issuer exercises these provisions in a lower interest rate market, the funds may have to replace the security with a lower yielding security, resulting in decreased income to investors. If the issuer of a debt security defaults on its obligations to pay interest or principal or is the subject of bankruptcy proceedings, the funds may incur losses or expenses in seeking recovery of amounts owed to them.
Liquidity and valuation — There may be little trading in the secondary market for particular debt securities, which may affect adversely the funds’ ability to value accurately or dispose of such debt securities. Adverse publicity and investor perceptions, whether or not based on fundamental analysis, may decrease the value and/or liquidity of debt securities.
Credit ratings for debt securities provided by rating agencies reflect an evaluation of the safety of principal and interest payments, not market value risk. The rating of an issuer is a rating agency’s view of past and future potential developments related to the issuer and may not necessarily reflect actual outcomes. There can be a lag between the time of developments relating to an issuer and the time a rating is assigned and updated. The investment adviser considers these ratings of securities as one of many criteria in making its investment decisions.
Bond rating agencies may assign modifiers (such as +/–) to ratings categories to signify the relative position of a credit within the rating category. Investment policies that are based on ratings categories should be read to include any security within that category, without giving consideration to the modifier except where otherwise provided. See the Appendix to this statement of additional information for more information about credit ratings.
American Funds Insurance Series — Page 5
Securities with equity and debt characteristics — Certain securities have a combination of equity and debt characteristics. Such securities may at times behave more like equity than debt or vice versa.
Preferred stock — Preferred stock represents an equity interest in an issuer that generally entitles the holder to receive, in preference to common stockholders and the holders of certain other stocks, dividends and a fixed share of the proceeds resulting from a liquidation of the issuer. Preferred stocks may pay fixed or adjustable rates of return, and preferred stock dividends may be cumulative or non-cumulative and participating or non-participating. Cumulative dividend provisions require all or a portion of prior unpaid dividends to be paid before dividends can be paid to the issuer’s common stockholders, while prior unpaid dividends on non-cumulative preferred stock are forfeited. Participating preferred stock may be entitled to a dividend exceeding the issuer’s declared dividend in certain cases, while non-participating preferred stock is entitled only to the stipulated dividend. Preferred stock is subject to issuer-specific and market risks applicable generally to equity securities. As with debt securities, the prices and yields of preferred stocks often move with changes in interest rates and the issuer’s credit quality. Additionally, a company’s preferred stock typically pays dividends only after the company makes required payments to holders of its bonds and other debt. Accordingly, the price of preferred stock will usually react more strongly than bonds and other debt to actual or perceived changes in the issuing company’s financial condition or prospects. Preferred stock of smaller companies may be more vulnerable to adverse developments than preferred stock of larger companies.
Convertible securities — A convertible security is a debt obligation, preferred stock or other security that may be converted, within a specified period of time and at a stated conversion rate, into common stock or other equity securities of the same or a different issuer. The conversion may occur automatically upon the occurrence of a predetermined event or at the option of either the issuer or the security holder. Under certain circumstances, a convertible security may also be called for redemption or conversion by the issuer after a particular date and at predetermined price specified upon issue. If a convertible security held by a certain fund is called for redemption or conversion, the fund could be required to tender the security for redemption, convert it into the underlying common stock, or sell it to a third party.
The holder of a convertible security is generally entitled to participate in the capital appreciation resulting from a market price increase in the issuer’s common stock and to receive interest paid or accrued until the convertible security matures or is redeemed, converted or exchanged. Before conversion, convertible securities have characteristics similar to non-convertible debt or preferred securities, as applicable. Convertible securities rank senior to common stock in an issuer’s capital structure and, therefore, normally entail less risk than the issuer’s common stock. However, convertible securities may also be subordinate to any senior debt obligations of the issuer, and, therefore, an issuer’s convertible securities may entail more risk than such senior debt obligations. Convertible securities usually offer lower interest or dividend yields than non-convertible debt securities of similar credit quality because of the potential for capital appreciation. In addition, convertible securities are often lower-rated securities.
Because of the conversion feature, the price of a convertible security will normally fluctuate in some proportion to changes in the price of the underlying asset, and, accordingly, convertible securities are subject to risks relating to the activities of the issuer and/or general market and economic conditions. The income component of a convertible security may cushion the security against declines in the price of the underlying asset but may also cause the price of the security to fluctuate based upon changes in interest rates and the credit quality of the issuer. As with a straight fixed income security, the price of a convertible security tends to increase when interest rates decline and decrease when interest rates rise. Like the price of a common
American Funds Insurance Series — Page 6
stock, the price of a convertible security also tends to increase as the price of the underlying stock rises and to decrease as the price of the underlying stock declines.
Hybrid securities — A hybrid security is a type of security that also has equity and debt characteristics. Like equities, which have no final maturity, a hybrid security may be perpetual. On the other hand, like debt securities, a hybrid security may be callable at the option of the issuer on a date specified at issue. Additionally, like common equities, which may stop paying dividends at virtually any time without violating any contractual terms or conditions, hybrids typically allow for issuers to withhold payment of interest until a later date or to suspend coupon payments entirely without triggering an event of default. Hybrid securities are normally at the bottom of an issuer’s debt capital structure because holders of an issuer’s hybrid securities are structurally subordinated to the issuer’s senior creditors. In bankruptcy, hybrid security holders should only get paid after all senior creditors of the issuer have been paid but before any disbursements are made to the issuer’s equity holders. Accordingly, hybrid securities may be more sensitive to economic changes than more senior debt securities. Such securities may also be viewed as more equity-like by the market when the issuer or its parent company experiences financial difficulties.
Contingent convertible securities, which are also known as contingent capital securities, are a form of hybrid security that are intended to either convert into equity or have their principal written down upon the occurrence of certain trigger events. One type of contingent convertible security has characteristics designed to absorb losses, by providing that the liquidation value of the security may be adjusted downward to below the original par value or written off entirely under certain circumstances. For instance, if losses have eroded the issuer’s capital level below a specified threshold, the liquidation value of the security may be reduced in whole or in part. The write-down of the security’s par value may occur automatically and would not entitle holders to institute bankruptcy proceedings against the issuer. In addition, an automatic write-down could result in a reduced income rate if the dividend or interest payment associated with the security is based on the security’s par value. Such securities may, but are not required to, provide for circumstances under which the liquidation value of the security may be adjusted back up to par, such as an improvement in capitalization or earnings. Another type of contingent convertible security provides for mandatory conversion of the security into common shares of the issuer under certain circumstances. The mandatory conversion might relate, for example, to the issuer’s failure to maintain a capital minimum. Since the common stock of the issuer may not pay a dividend, investors in such instruments could experience reduced yields (or no yields at all) and conversion would deepen the subordination of the investor, effectively worsening the investor’s standing in the case of the issuer’s insolvency. An automatic write-down or conversion event with respect to a contingent convertible security will typically be triggered by a reduction in the issuer’s capital level, but may also be triggered by regulatory actions, such as a change in regulatory capital requirements, or by other factors.
Investing in smaller capitalization stocks — Certain funds may invest in the stocks of smaller capitalization companies. Investing in smaller capitalization stocks can involve greater risk than is customarily associated with investing in stocks of larger, more established companies. For example, smaller companies often have limited product lines, limited operating histories, limited markets or financial resources, may be dependent on one or a few key persons for management and can be more susceptible to losses. Also, their securities may be less liquid or illiquid (and therefore have to be sold at a discount from current prices or sold in small lots over an extended period of time), may be followed by fewer investment research analysts and may be subject to wider price swings, thus creating a greater chance of loss than securities of larger capitalization companies. Because Global Small Capitalization Fund in particular emphasizes the stocks of issuers with smaller market capitalizations (by U.S. standards), it can be expected to have more difficulty obtaining information about the issuers or valuing or disposing of its securities than if it were to concentrate on larger capitalization stocks. The funds determine relative market capitalizations using U.S. standards.
American Funds Insurance Series — Page 7
Accordingly, the funds' investments in certain countries outside the United States may have larger market capitalizations relative to other companies within those countries.
Investing in private companies — Certain funds may invest in companies that have not publicly offered their securities. Investing in private companies can involve greater risks than those associated with investing in publicly traded companies. For example, the securities of a private company may be subject to the risk that market conditions, developments within the company, investor perception, or regulatory decisions may delay or prevent the company from ultimately offering its securities to the public. Furthermore, these investments are generally considered to be illiquid until a company’s public offering and are often subject to additional contractual restrictions on resale that would prevent the fund from selling their company shares for a period of time following the public offering.
Investments in private companies can offer the fund significant growth opportunities at attractive prices. However, these investments can pose greater risk, and, consequently, there is no guarantee that positive results can be achieved in the future.
Investing outside the U.S. — Certain funds may invest in securities of issuers domiciled outside the United States and which may be denominated in currencies other than the U.S. dollar. Securities of issuers domiciled outside the United States, or with significant operations or revenues outside the United States, may lose value because of adverse political, social, economic or market developments (including social instability, regional conflicts, terrorism and war) in the countries or regions in which the issuers are domiciled, operate or generate revenue. These issuers may also be more susceptible to actions of foreign governments such as the imposition of price controls or punitive taxes that could adversely impact the value of these securities. To the extent the fund invests in securities that are denominated in currencies other than the U.S. dollar, these securities may also lose value due to changes in foreign currency exchange rates against the U.S. dollar and/or currencies of other countries. Securities markets in certain countries may be more volatile or less liquid than those in the United States. Investments outside the United States may also be subject to different accounting and auditing practices and standards and different regulatory, legal and reporting requirements, and may be more difficult to value, than those in the United States. In addition, the value of investments outside the United States may be reduced by foreign taxes, including foreign withholding taxes on interest and dividends. Further, there may be increased risks of delayed settlement of securities purchased or sold by the fund. The risks of investing outside the United States may be heightened in connection with investments in emerging markets.
Additional costs could be incurred in connection with the fund’s investment activities outside the United States. Brokerage commissions may be higher outside the United States, and the fund will bear certain expenses in connection with its currency transactions. Furthermore, increased custodian costs may be associated with maintaining assets in certain jurisdictions.
Investing in emerging markets — Investing in emerging markets may involve risks in addition to and greater than those generally associated with investing in the securities markets of developed countries. For instance, emerging market countries tend to have less developed political, economic and legal systems and accounting and auditing practices and standards than those in developed countries. Accordingly, the governments of these countries may be less stable and more likely to intervene in the market economy, for example, by imposing capital controls, nationalizing a company or industry, placing restrictions on foreign ownership and on withdrawing sale proceeds of securities from the country, and/or imposing punitive taxes that could adversely affect the prices of securities. Information regarding issuers in emerging markets may be limited, incomplete or inaccurate, and there may be fewer rights and remedies available to the fund and its shareholders. In addition, the economies of these countries may be dependent on relatively few industries, may have limited access to capital and may be more susceptible to changes in local and global trade conditions and downturns in the world economy. Securities markets in these countries can also be relatively small and have substantially lower trading volumes. As a result, securities issued in these countries may be more
American Funds Insurance Series — Page 8
volatile and less liquid, and may be more difficult to value, than securities issued in countries with more developed economies and/or markets. Less certainty with respect to security valuations may lead to additional challenges and risks in calculating the fund’s net asset value. Additionally, emerging markets are more likely to experience problems with the clearing and settling of trades and the holding of securities by banks, agents and depositories that are less established than those in developed countries.
In countries where direct foreign investment is limited or prohibited, the fund may invest in operating companies based in such countries through an offshore intermediary entity that, based on contractual agreements, seeks to replicate the rights and obligations of direct equity ownership in such operating company. Because the contractual arrangements do not in fact bestow the fund with actual equity ownership in the operating company, these investment structures may limit the fund’s rights as an investor and create significant additional risks. For example, local government authorities may determine that such structures do not comply with applicable laws and regulations, including those relating to restrictions on foreign ownership. In such event, the intermediary entity and/or the operating company may be subject to penalties, revocation of business and operating licenses or forfeiture of foreign ownership interests, and the fund’s economic interests in the underlying operating company and its rights as an investor may not be recognized, resulting in a loss to the fund and its shareholders. In addition, exerting control through contractual arrangements may be less effective than direct equity ownership, and a company may incur substantial costs to enforce the terms of such arrangements, including those relating to the distribution of the funds among the entities. These special investment structures may also be disregarded for tax purposes by local tax authorities, resulting in increased tax liabilities, and the fund’s control over – and distributions due from – such structures may be jeopardized if the individuals who hold the equity interest in such structures breach the terms of the agreements. While these structures may be widely used to circumvent limits on foreign ownership in certain jurisdictions, there is no assurance that they will be upheld by local regulatory authorities or that disputes regarding the same will be resolved consistently.
Although there is no universally accepted definition, the investment adviser generally considers an emerging market to be a market that is in the earlier stages of its industrialization cycle with a low per capita gross domestic product (“GDP”) and a low market capitalization to GDP ratio relative to those in the United States and the European Union, and would include markets commonly referred to as “frontier markets.”
Certain risk factors related to emerging markets
Currency fluctuations — Certain emerging markets’ currencies have experienced and in the future may experience significant declines against the U.S. dollar. For example, if the U.S. dollar appreciates against foreign currencies, the value of the fund’s emerging markets securities holdings would generally depreciate and vice versa. Further, the fund may lose money due to losses and other expenses incurred in converting various currencies to purchase and sell securities valued in currencies other than the U.S. dollar, as well as from currency restrictions, exchange control regulation and currency devaluations.
Government regulation — Certain developing countries lack uniform accounting, auditing and financial reporting and disclosure standards, have less governmental supervision of financial markets than in the United States, and may not honor legal rights or protections enjoyed by investors in the United States. Certain governments may be more unstable and present greater risks of nationalization or restrictions on foreign ownership of local companies. Repatriation of investment income, capital and the proceeds of sales by foreign investors may require governmental registration and/or approval in some developing countries. While the fund will only invest in markets where these restrictions are considered acceptable by the investment adviser, a country could impose new or additional repatriation restrictions after the fund’s investment. If this happened, the fund’s response might include, among other things, applying
American Funds Insurance Series — Page 9
to the appropriate authorities for a waiver of the restrictions or engaging in transactions in other markets designed to offset the risks of decline in that country. Such restrictions will be considered in relation to the fund’s liquidity needs and other factors. Further, some attractive equity securities may not be available to the fund if foreign shareholders already hold the maximum amount legally permissible.
While government involvement in the private sector varies in degree among developing countries, such involvement may in some cases include government ownership of companies in certain sectors, wage and price controls or imposition of trade barriers and other protectionist measures. With respect to any developing country, there is no guarantee that some future economic or political crisis will not lead to price controls, forced mergers of companies, expropriation, or creation of government monopolies to the possible detriment of the fund’s investments.
Fluctuations in inflation rates — Rapid fluctuations in inflation rates may have negative impacts on the economies and securities markets of certain emerging market countries.
Less developed securities markets — Emerging markets may be less well-developed and regulated than other markets. These markets have lower trading volumes than the securities markets of more developed countries and may be unable to respond effectively to increases in trading volume. Consequently, these markets may be substantially less liquid than those of more developed countries, and the securities of issuers located in these markets may have limited marketability. These factors may make prompt liquidation of substantial portfolio holdings difficult or impossible at times.
Settlement risks — Settlement systems in developing countries are generally less well organized than those of developed markets. Supervisory authorities may also be unable to apply standards comparable to those in developed markets. Thus, there may be risks that settlement may be delayed and that cash or securities belonging to the fund may be in jeopardy because of failures of or defects in the systems. In particular, market practice may require that payment be made before receipt of the security being purchased or that delivery of a security be made before payment is received. In such cases, default by a broker or bank (the “counterparty”) through whom the transaction is effected might cause the fund to suffer a loss. The fund will seek, where possible, to use counterparties whose financial status is such that this risk is reduced. However, there can be no certainty that the fund will be successful in eliminating this risk, particularly as counterparties operating in developing countries frequently lack the standing or financial resources of those in developed countries. There may also be a danger that, because of uncertainties in the operation of settlement systems in individual markets, competing claims may arise with respect to securities held by or to be transferred to the fund.
Limited market information — The fund may encounter problems assessing investment opportunities in certain emerging markets in light of limitations on available information and different accounting, auditing and financial reporting standards. For example, due to jurisdictional limitations, the Public Company Accounting Oversight Board (“PCAOB”), which regulates auditors of U.S. reporting companies, may be unable to inspect the audit work and practices of PCAOB-registered auditing firms in certain developing countries. As a result, there is greater risk that financial records and information relating to an issuer’s operations in developing countries will be incomplete or misleading, which may negatively impact the fund’s investments in such company. When faced with limited market information, the fund’s investment adviser will seek alternative sources of information, and to the extent the investment adviser is not satisfied with the sufficiency or accuracy of the information obtained with respect to a particular market or security, the fund will not invest in such market or security.
American Funds Insurance Series — Page 10
Taxation — Taxation of dividends, interest and capital gains received by the fund varies among developing countries and, in some cases, is comparatively high. In addition, developing countries typically have less well-defined tax laws and procedures and such laws may permit retroactive taxation so that the fund could become subject in the future to local tax liability that it had not reasonably anticipated in conducting its investment activities or valuing its assets.
Fraudulent securities — Securities purchased by the fund may subsequently be found to be fraudulent or counterfeit, resulting in a loss to the fund.
Remedies — Developing countries may offer less protection to investors than U.S. markets and, in the event of investor harm, there may be substantially less recourse available to the fund and its shareholders. In addition, as a matter of law or practicality, the fund and its shareholders - as well as U.S. regulators - may encounter substantial difficulties in obtaining and enforcing judgments and other actions against non-U.S. individuals and companies.
Investing through Stock Connect — The fund may invest in China A-shares of certain Chinese companies listed and traded on the Shanghai Stock Exchange (“SSE”) and on the Shenzhen Stock Exchange (“SZSE”, and together, the “Exchanges”) through the Shanghai-Hong Kong Stock Connect Program and the Shenzhen-Hong Kong Stock Connect Program, respectively (together, “Stock Connect”). Stock Connect is a securities trading and clearing program developed by the Exchange of Hong Kong, the Exchanges and the China Securities Depository and Clearing Corporation Limited. Stock Connect facilitates foreign investment in the People’s Republic of China (“PRC”) via brokers in Hong Kong. Persons investing through Stock Connect are subject to PRC regulations and Exchange listing rules, among others. These could include limitations on or suspension of trading. These regulations are relatively new and subject to changes which could adversely impact the fund’s rights with respect to the securities. For example, a stock may be recalled from the scope of securities traded on the SSE or SZSE eligible for trading via Stock Connect for various reasons, and in such event the stock can be sold but is restricted from being bought. In such event, the investment adviser’s ability to implement the fund’s investment strategies may be adversely affected. As Stock Connect is still relatively new, investments made through Stock Connect are subject to relatively new trading, clearance and settlement procedures and there are no assurances that the necessary systems to run the program will function properly. In addition, Stock Connect is subject to aggregate and daily quota limitations on purchases and permitted price fluctuations. As a result, the fund may experience delays in transacting via Stock Connect and there can be no assurance that a liquid market on the Exchanges will exist. Since Stock Connect only operates on days when both the Chinese and Hong Kong markets are open for trading, and banking services are available in both markets on the corresponding settlement days, the fund’s ownership interest in securities traded through Stock Connect may not be reflected directly and the fund may be subject to the risk of price fluctuations in China A-shares when Stock Connect is not open to trading. Changes in Chinese tax rules may also adversely affect the fund’s performance. The fund’s shares are held in an omnibus account and registered in nominee name. Please also see the sections on risks relating to investing outside the U.S. and investing in emerging markets.
Investing through Bond Connect — The fund may invest in onshore China bonds via Bond Connect, the opening up of China’s Interbank Bond Market (CIBM) to global investors through the China-Hong Kong mutual access program. The program allows foreign and mainland China investors the ability to trade in each other’s bond market through a connection between the mainland and Hong Kong based financial infrastructure institutions. Bond Connect aims to enhance the efficiency and flexibility of investing in the CIBM. This is accomplished by easing the access requirements to enter the market and using the Hong Kong trading infrastructure to connect to China Foreign Exchange Trading System (CFETS). Market volatility and potential lack of liquidity due to low trading volume of certain debt securities in CIBM may result in prices of certain debt securities traded on such market fluctuating significantly. The bid and offer spreads of the prices of such securities may be large, and the fund may therefore incur significant trading, settlement and realization costs and may face counterparty default,
American Funds Insurance Series — Page 11
liquidity, and volatility risks, resulting in significant losses for the funds and their investors. Bond Connect is a novel concept and, as such, the current regulations are untested and there is no certainty as to how they will be applied. In addition, the current regulations are subject to change which may have potential retrospective effects and there can be no assurance that Bond Connect will not be abolished. New regulations may be issued from time to time by the regulators in the PRC and Hong Kong in connection with operations, legal enforcement and cross-border trades under Bond Connect. The fund may be adversely affected as a result of such changes.
Synthetic local access instruments — Participation notes, market access warrants and other similar structured investment vehicles (collectively, “synthetic local access instruments”) are instruments used by investors to obtain exposure to equity investments in local markets where direct ownership by foreign investors is not permitted or is otherwise restricted by local law. Synthetic local access instruments, which are generally structured and sold over-the-counter by a local branch of a bank or broker-dealer that is permitted to purchase equity securities in the local market, are designed to replicate exposure to one or more underlying equity securities. The price and performance of a synthetic local access instrument are normally intended to track the price and performance of the underlying equity assets as closely as possible. However, there can be no assurance that the results of synthetic local access instruments will replicate exactly the performance of the underlying securities due to transaction costs, taxes and other fees and expenses. The holder of a synthetic local access instrument may also be entitled to receive any dividends paid in connection with the underlying equity assets, but usually does not receive voting rights as it would if such holder directly owned the underlying assets.
Investments in synthetic local access instruments involve the same risks associated with a direct investment in the shares of the companies the instruments seek to replicate, including, in particular, the risks associated with investing outside the United States. Synthetic local access instruments also involve risks that are in addition to the risks normally associated with a direct investment in the underlying equity securities. For instance, synthetic local access instruments represent unsecured, unsubordinated contractual obligations of the banks or broker-dealers that issue them. Consequently, a purchaser of a synthetic local access instrument relies on the creditworthiness of such a bank or broker-dealer counterparty and has no rights under the instrument against the issuer of the underlying equity securities. Additionally, there is no guarantee that a liquid market for a synthetic local access instrument will exist or that the issuer of the instrument will be willing to repurchase the instrument when an investor wishes to sell it.
Currency transactions — Certain funds may enter into currency transactions on a spot (i.e., cash) basis at the prevailing rate in the currency exchange market to provide for the purchase or sale of a currency needed to purchase a security denominated in such currency. In addition, certain funds may enter into forward currency contracts to protect against changes in currency exchange rates, to increase exposure to a particular foreign currency, to shift exposure to currency fluctuations from one currency to another or to seek to increase returns. A forward currency contract is an obligation to purchase or sell a specific currency at a future date, which may be any fixed number of days from the date of the contract agreed upon by the parties, at a price set at the time of the contract. Some forward currency contracts, called non-deliverable forwards or NDFs, do not call for physical delivery of the currency and are instead settled through cash payments. Forward currency contracts are typically privately negotiated and traded in the interbank market between large commercial banks (or other currency traders) and their customers. Although forward contracts entered into by the fund will typically involve the purchase or sale of a currency against the U.S. dollar, the fund also may purchase or sell a non-U.S. currency against another non-U.S. currency.
Currency exchange rates generally are determined by forces of supply and demand in the foreign exchange markets and the relative merits of investment in different countries as viewed from an international perspective. Currency exchange rates, as well as foreign currency transactions, can also be affected unpredictably by intervention by U.S. or foreign governments or central banks or by
American Funds Insurance Series — Page 12
currency controls or political developments in the United States or abroad. Such intervention or other events could prevent the fund from entering into foreign currency transactions, force the fund to exit such transactions at an unfavorable time or price or result in penalties to the fund, any of which may result in losses to the fund.
Generally, a fund will not attempt to protect against all potential changes in exchange rates and the use of forward contracts does not eliminate the risk of fluctuations in the prices of the underlying securities. If the value of the underlying securities declines or the amount of the fund’s commitment increases because of changes in exchange rates, the fund may need to provide additional cash or securities to satisfy its commitment under the forward contract. The fund is also subject to the risk that it may be delayed or prevented from obtaining payments owed to it under the forward contract as a result of the insolvency or bankruptcy of the counterparty with which it entered into the forward contract or the failure of the counterparty to comply with the terms of the contract.
The realization of gains or losses on foreign currency transactions will usually be a function of the investment adviser’s ability to accurately estimate currency market movements. Entering into forward currency transactions may change the fund’s exposure to currency exchange rates and could result in losses to the fund if currencies do not perform as expected by the fund’s investment adviser. For example, if the fund’s investment adviser increases a fund’s exposure to a foreign currency using forward contracts and that foreign currency’s value declines, the fund may incur a loss. In addition, while entering into forward currency transactions could minimize the risk of loss due to a decline in the value of the hedged currency, it could also limit any potential gain that may result from an increase in the value of the currency. See also the “Derivatives” section under "Description of certain securities, investment techniques and risks" for a general description of investment techniques and risks relating to derivatives, including certain currency forwards.
Forward currency contracts may give rise to leverage, or exposure to potential gains and losses in excess of the initial amount invested. Leverage magnifies gains and losses and could cause a fund to be subject to more volatility than if it had not been leveraged, thereby resulting in a heightened risk of loss. Under current regulatory requirements, the fund will segregate liquid assets that will be marked to market daily to meet its forward contract commitments to the extent required by the U.S. Securities and Exchange Commission.
Forward currency transactions also may affect the character and timing of income, gain, or loss recognized by the fund for U.S. tax purposes. The use of forward currency contracts could result in the application of the mark-to-market provisions of the Internal Revenue Code of 1986, as amended (the “Code”) and may cause an increase (or decrease) in the amount of taxable dividends paid by the fund.
Indirect exposure to cryptocurrencies – Cryptocurrencies are currencies which exist in a digital form and may act as a store of wealth, a medium of exchange or an investment asset. There are thousands of cryptocurrencies, such as bitcoin. Although the fund has no current intention of directly investing in cryptocurrencies, some issuers have begun to accept cryptocurrency for payment of services, use cryptocurrencies as reserve assets or invest in cryptocurrencies, and certain funds may invest in securities of such issuers. Certain funds may also invest in securities of issuers which provide cryptocurrency-related services.
Cryptocurrencies are subject to fluctuations in value. Cryptocurrencies are not backed by any government, corporation or other identified body. Rather, the value of a cryptocurrency is determined by other factors, such as the perceived future prospects or the supply and demand for such cryptocurrency in the global market for the trading of cryptocurrency. Such trading markets are unregulated and may be more exposed to operational or technical issues as well as fraud or manipulation in comparison to established, regulated exchanges for securities, derivatives and traditional currencies. The value of a cryptocurrency may decline precipitously (including to zero) for a
American Funds Insurance Series — Page 13
variety of reasons, including, but not limited to, regulatory changes, a loss of confidence in its network or a change in user preference to other cryptocurrencies. An issuer that owns cryptocurrencies may experience custody issues, and may lose its cryptocurrency holdings through theft, hacking, or technical glitches in the applicable blockchain. Certain funds may experience losses as a result of the decline in value of its securities of issuers that own cryptocurrencies or which provide cryptocurrency-related services. If an issuer that owns cryptocurrencies intends to pay a dividend using such holdings or to otherwise make a distribution of such holdings to its stockholders, such dividends or distributions may face regulatory, operational and technical issues.
Factors affecting the further development of cryptocurrency include, but are not limited to: continued worldwide growth of, or possible cessation of or reversal in, the adoption and use of cryptocurrencies and other digital assets; the developing regulatory environment relating to cryptocurrencies, including the characterization of cryptocurrencies as currencies, commodities, or securities, the tax treatment of cryptocurrencies, and government and quasi-government regulation or restrictions on, or regulation of access to and operation of, cryptocurrency networks and the exchanges on which cryptocurrencies trade, including anti-money laundering regulations and requirements; perceptions regarding the environmental impact of a cryptocurrency; changes in consumer demographics and public preferences; general economic conditions; maintenance and development of open-source software protocols; the availability and popularity of other forms or methods of buying and selling goods and services; the use of the networks supporting digital assets, such as those for developing smart contracts and distributed applications; and general risks tied to the use of information technologies, including cyber risks. A hack or failure of one cryptocurrency may lead to a loss in confidence in, and thus decreased usage and/or value of, other cryptocurrencies.
Forward commitment, when issued and delayed delivery transactions — Certain funds may enter into commitments to purchase or sell securities at a future date. When a fund agrees to purchase such securities, it assumes the risk of any decline in value of the security from the date of the agreement. If the other party to such a transaction fails to deliver or pay for the securities, the fund could miss a favorable price or yield opportunity, or could experience a loss.
Certain funds may enter into roll transactions, such as a mortgage dollar roll where a fund sells mortgage-backed securities for delivery in the current month and simultaneously contracts to repurchase substantially similar (same type, coupon, and maturity) securities on a specified future date, at a pre-determined price. During the period between the sale and repurchase (the “roll period”), a fund forgoes principal and interest paid on the mortgage-backed securities. The fund is compensated by the difference between the current sales price and the lower forward price for the future purchase (often referred to as the “drop”), if any, as well as by the interest earned on the cash proceeds of the initial sale. The fund could suffer a loss if the contracting party fails to perform the future transaction and a fund is therefore unable to buy back the mortgage-backed securities it initially sold. The fund also takes the risk that the mortgage-backed securities that it repurchases at a later date will have less favorable market characteristics than the securities originally sold (e.g., greater prepayment risk). These transactions are accounted for as purchase and sale transactions, which contribute to a fund’s portfolio turnover rate.
With to be announced (TBA) transactions, the particular securities (i.e., specified mortgage pools) to be delivered or received are not identified at the trade date, but are “to be announced” at a later settlement date. However, securities to be delivered must meet specified criteria, including face value, coupon rate and maturity, and be within industry-accepted “good delivery” standards.
The fund will not use any of these transactions for the purpose of leveraging and will segregate liquid assets that will be marked to market daily in an amount sufficient to meet their payment obligations in these transactions. Although these transactions will not be entered into for leveraging purposes, to the extent the fund’s aggregate commitments in connection with these transactions exceed its segregated assets, the fund temporarily could be in a leveraged position (because it may have an amount greater
American Funds Insurance Series — Page 14
than its net assets subject to market risk). Should market values of the fund’s portfolio securities decline while the fund is in a leveraged position, greater depreciation of its net assets would likely occur than if it were not in such a position. The fund will not borrow money to settle these transactions and, therefore, will liquidate other portfolio securities in advance of settlement if necessary to generate additional cash to meet their obligations. After a transaction is entered into, the fund may still dispose of or renegotiate the transaction. Additionally, prior to receiving delivery of securities as part of a transaction, the fund may sell such securities.
Obligations backed by the “full faith and credit” of the U.S. government — U.S. government obligations include the following types of securities:
U.S. Treasury securities — U.S. Treasury securities include direct obligations of the U.S. Treasury, such as Treasury bills, notes and bonds. For these securities, the payment of principal and interest is unconditionally guaranteed by the U.S. government, and thus they are of high credit quality. Such securities are subject to variations in market value due to fluctuations in interest rates and in government policies, but, if held to maturity, are expected to be paid in full (either at maturity or thereafter).
Federal agency securities — The securities of certain U.S. government agencies and government-sponsored entities are guaranteed as to the timely payment of principal and interest by the full faith and credit of the U.S. government. Such agencies and entities include, but are not limited to, the Federal Financing Bank (“FFB”), the Government National Mortgage Association (“Ginnie Mae”), the U.S. Department of Veterans Affairs (“VA”), the Federal Housing Administration (“FHA”), the Export-Import Bank of the United States (“Exim Bank”), the U.S. International Development Finance Corporation (“DFC”), the Commodity Credit Corporation (“CCC”) and the U.S. Small Business Administration (“SBA”).
Other federal agency obligations — Additional federal agency securities are neither direct obligations of, nor guaranteed by, the U.S. government. These obligations include securities issued by certain U.S. government agencies and government-sponsored entities. However, they generally involve some form of federal sponsorship: some operate under a congressional charter; some are backed by collateral consisting of “full faith and credit” obligations as described above; some are supported by the issuer’s right to borrow from the Treasury; and others are supported only by the credit of the issuing government agency or entity. These agencies and entities include, but are not limited to: the Federal Home Loan Banks, the Federal Home Loan Mortgage Corporation (“Freddie Mac”), the Federal National Mortgage Association (“Fannie Mae”), the Tennessee Valley Authority and the Federal Farm Credit Bank System.
In 2008, Freddie Mac and Fannie Mae were placed into conservatorship by their new regulator, the Federal Housing Finance Agency (“FHFA”). Simultaneously, the U.S. Treasury made a commitment of indefinite duration to maintain the positive net worth of both firms. As conservator, the FHFA has the authority to repudiate any contract either firm has entered into prior to the FHFA’s appointment as conservator (or receiver should either firm go into default) if the FHFA, in its sole discretion determines that performance of the contract is burdensome and repudiation would promote the orderly administration of Fannie Mae’s or Freddie Mac’s affairs. While the FHFA has indicated that it does not intend to repudiate the guaranty obligations of either entity, doing so could adversely affect holders of their mortgage-backed securities. For example, if a contract were repudiated, the liability for any direct compensatory damages would accrue to the entity’s conservatorship estate and could only be satisfied to the extent the estate had available assets. As a result, if interest payments on Fannie Mae or Freddie Mac mortgage-backed securities held by the fund were reduced because underlying borrowers failed to make payments or such payments were not advanced by a loan servicer, the fund’s only recourse might be against the conservatorship estate, which might not have sufficient assets to offset any shortfalls.
American Funds Insurance Series — Page 15
The FHFA, in its capacity as conservator, has the power to transfer or sell any asset or liability of Fannie Mae or Freddie Mac. The FHFA has indicated it has no current intention to do this; however, should it do so a holder of a Fannie Mae or Freddie Mac mortgage-backed security would have to rely on another party for satisfaction of the guaranty obligations and would be exposed to the credit risk of that party.
Certain rights provided to holders of mortgage-backed securities issued by Fannie Mae or Freddie Mac under their operative documents may not be enforceable against the FHFA, or enforcement may be delayed during the course of the conservatorship or any future receivership. For example, the operative documents may provide that upon the occurrence of an event of default by Fannie Mae or Freddie Mac, holders of a requisite percentage of the mortgage-backed security may replace the entity as trustee. However, under the Federal Housing Finance Regulatory Reform Act of 2008, holders may not enforce this right if the event of default arises solely because a conservator or receiver has been appointed.
Pass-through securities — Certain funds may invest in various debt obligations backed by pools of mortgages, corporate loans or other assets including, but not limited to, residential mortgage loans, home equity loans, mortgages on commercial buildings, consumer loans and equipment leases. Principal and interest payments made on the underlying asset pools backing these obligations are typically passed through to investors, net of any fees paid to any insurer or any guarantor of the securities. Pass-through securities may have either fixed or adjustable coupons. The risks of an investment in these obligations depend in part on the type of the collateral securing the obligations and the class of the instrument in which the fund invests. These securities include:
Mortgage-backed securities — These securities may be issued by U.S. government agencies and government-sponsored entities, such as Ginnie Mae, Fannie Mae and Freddie Mac, and by private entities. The payment of interest and principal on mortgage-backed obligations issued by U.S. government agencies may be guaranteed by the full faith and credit of the U.S. government (in the case of Ginnie Mae), or may be guaranteed by the issuer (in the case of Fannie Mae and Freddie Mac). However, these guarantees do not apply to the market prices and yields of these securities, which vary with changes in interest rates.
Mortgage-backed securities issued by private entities are structured similarly to those issued by U.S. government agencies. However, these securities and the underlying mortgages are not guaranteed by any government agencies and the underlying mortgages are not subject to the same underwriting requirements. These securities generally are structured with one or more types of credit enhancements such as insurance or letters of credit issued by private companies. Borrowers on the underlying mortgages are usually permitted to prepay their underlying mortgages. Prepayments can alter the effective maturity of these instruments. In addition, delinquencies, losses or defaults by borrowers can adversely affect the prices and volatility of these securities. Such delinquencies and losses can be exacerbated by declining or flattening housing and property values. This, along with other outside pressures, such as bankruptcies and financial difficulties experienced by mortgage loan originators, decreased investor demand for mortgage loans and mortgage-related securities and increased investor demand for yield, can adversely affect the value and liquidity of mortgage-backed securities.
Adjustable rate mortgage-backed securities — Adjustable rate mortgage-backed securities (“ARMS”) have interest rates that reset at periodic intervals. Acquiring ARMS permits the fund to participate in increases in prevailing current interest rates through periodic adjustments in the coupons of mortgages underlying the pool on which ARMS are based. Such ARMS generally have higher current yield and lower price fluctuations than is the case with more traditional fixed income debt securities of comparable rating and maturity. In addition, when prepayments of principal are made on the underlying mortgages during periods of rising interest rates, the fund can reinvest the proceeds of such prepayments at rates higher than
American Funds Insurance Series — Page 16
those at which they were previously invested. Mortgages underlying most ARMS, however, have limits on the allowable annual or lifetime increases that can be made in the interest rate that the mortgagor pays. Therefore, if current interest rates rise above such limits over the period of the limitation, the fund, when holding an ARMS, does not benefit from further increases in interest rates. Moreover, when interest rates are in excess of coupon rates (i.e., the rates being paid by mortgagors) of the mortgages, ARMS behave more like fixed income securities and less like adjustable rate securities and are subject to the risks associated with fixed income securities. In addition, during periods of rising interest rates, increases in the coupon rate of adjustable rate mortgages generally lag current market interest rates slightly, thereby creating the potential for capital depreciation on such securities.
Collateralized mortgage obligations (CMOs) — CMOs are also backed by a pool of mortgages or mortgage loans, which are divided into two or more separate bond issues. CMOs issued by U.S. government agencies are backed by agency mortgages, while privately issued CMOs may be backed by either government agency mortgages or private mortgages. Payments of principal and interest are passed through to each bond issue at varying schedules resulting in bonds with different coupons, effective maturities and sensitivities to interest rates. Some CMOs may be structured in a way that when interest rates change, the impact of changing prepayment rates on the effective maturities of certain issues of these securities is magnified. CMOs may be less liquid or may exhibit greater price volatility than other types of mortgage or asset-backed securities.
Commercial mortgage-backed securities — These securities are backed by mortgages on commercial property, such as hotels, office buildings, retail stores, hospitals and other commercial buildings. These securities may have a lower prepayment uncertainty than other mortgage-related securities because commercial mortgage loans generally prohibit or impose penalties on prepayments of principal. In addition, commercial mortgage-related securities often are structured with some form of credit enhancement to protect against potential losses on the underlying mortgage loans. Many of the risks of investing in commercial mortgage-backed securities reflect the risks of investing in the real estate securing the underlying mortgage loans, including the effects of local and other economic conditions on real estate markets, the ability of tenants to make rental payments and the ability of a property to attract and retain tenants. Commercial mortgage-backed securities may be less liquid or exhibit greater price volatility than other types of mortgage or asset-backed securities and may be more difficult to value.
Asset-backed securities — These securities are backed by other assets such as credit card, automobile or consumer loan receivables, retail installment loans or participations in pools of leases. Credit support for these securities may be based on the underlying assets and/or provided through credit enhancements by a third party. The values of these securities are sensitive to changes in the credit quality of the underlying collateral, the credit strength of the credit enhancement, changes in interest rates and at times the financial condition of the issuer. Obligors of the underlying assets also may make prepayments that can change effective maturities of the asset-backed securities. These securities may be less liquid and more difficult to value than other securities.
Collateralized bond obligations (CBOs) and collateralized loan obligations (CLOs) — A CBO is a trust typically backed by a diversified pool of fixed-income securities, which may include high risk, lower rated securities. A CLO is a trust typically collateralized by a pool of loans, which may include, among others, senior secured loans, senior unsecured loans, and subordinate corporate loans, including lower rated loans. CBOs and CLOs may charge management fees and administrative expenses.
American Funds Insurance Series — Page 17
For both CBOs and CLOs, the cash flows from the trust are split into two or more portions, called tranches, varying in risk and yield. The riskiest and highest yielding portion is the “equity” tranche which bears the bulk of any default by the bonds or loans in the trust and is constructed to protect the other, more senior tranches from default. Since they are partially protected from defaults, the more senior tranches typically have higher ratings and lower yields than the underlying securities in the trust and can be rated investment grade. Despite the protection from the equity tranche, the more senior tranches can still experience substantial losses due to actual defaults of the underlying assets, increased sensitivity to defaults due to impairment of the collateral or the more junior tranches, market anticipation of defaults, as well as potential general aversions to CBO or CLO securities as a class. Normally, these securities are privately offered and sold, and thus, are not registered under the securities laws. CBOs and CLOs may be less liquid, may exhibit greater price volatility and may be more difficult to value than other securities.
“IOs” and “POs” are issued in portions or tranches with varying maturities and characteristics. Some tranches may only receive the interest paid on the underlying mortgages (IOs) and others may only receive the principal payments (POs). The values of IOs and POs are extremely sensitive to interest rate fluctuations and prepayment rates, and IOs are also subject to the risk of early repayment of the underlying mortgages that will substantially reduce or eliminate interest payments.
Warrants and rights — Warrants and rights may be acquired by certain funds in connection with other securities or separately. Warrants generally entitle, but do not obligate, their holder to purchase other equity or fixed income securities at a specified price at a later date. Rights are similar to warrants but typically have a shorter duration and are issued by a company to existing holders of its stock to provide those holders the right to purchase additional shares of stock at a later date. Warrants and rights do not carry with them the right to dividends or voting rights with respect to the securities that they entitle their holder to purchase, and they do not represent any rights in the assets of the issuing company. Additionally, a warrant or right ceases to have value if it is not exercised prior to its expiration date. As a result, warrants and rights may be considered more speculative than certain other types of investments. Changes in the value of a warrant or right do not necessarily correspond to changes in the value of its underlying security. The price of a warrant or right may be more volatile than the price of its underlying security, and they therefore present greater potential for capital appreciation and capital loss. The effective price paid for warrants or rights added to the subscription price of the related security may exceed the value of the subscribed security’s market price, such as when there is no movement in the price of the underlying security. The market for warrants or rights may be very limited and it may be difficult to sell them promptly at an acceptable price.
Depositary receipts — Depositary receipts are securities that evidence ownership interests in, and represent the right to receive, a security or a pool of securities that have been deposited with a bank or trust depository. Certain funds may invest in American Depositary Receipts (“ADRs”), European Depositary Receipts (“EDRs”), Global Depositary Receipts (“GDRs”), and other similar securities. For ADRs, the depository is typically a U.S. financial institution and the underlying securities are issued by a non-U.S. entity. For other depositary receipts, the depository may be a non-U.S. or a U.S. entity, and the underlying securities may be issued by a non-U.S. or a U.S. entity. Depositary receipts will not necessarily be denominated in the same currency as their underlying securities. Generally, ADRs are issued in registered form, denominated in U.S. dollars, and designed for use in the U.S. securities markets. Other depositary receipts, such as EDRs and GDRs, may be issued in bearer form, may be denominated in either U.S. dollars or in non-U.S. currencies, and are primarily designed for use in securities markets outside the United States. ADRs, EDRs and GDRs can be sponsored by the issuing bank or trust company or the issuer of the underlying securities. Although the issuing bank or trust company may impose charges for the collection of dividends and the conversion of such securities into the underlying securities, generally no fees are imposed on the purchase or sale of these securities other than transaction fees ordinarily involved with trading stock. Such securities may be less liquid or may trade at a lower price than the underlying securities of the issuer. Additionally, the issuers of
American Funds Insurance Series — Page 18
securities underlying depositary receipts may not be obligated to timely disclose information that is considered material under the securities laws of the United States. Therefore, less information may be available regarding these issuers than about the issuers of other securities and there may not be a correlation between such information and the market value of the depositary receipts.
Inflation-linked bonds — Certain funds may invest in inflation-linked bonds issued by governments, their agencies or instrumentalities and corporations.
The principal amount of an inflation-linked bond is adjusted in response to changes in the level of an inflation index, such as the Consumer Price Index for Urban Consumers (“CPURNSA”). If the index measuring inflation falls, the principal value or coupon of these securities will be adjusted downward. Consequently, the interest payable on these securities will be reduced. Also, if the principal value of these securities is adjusted according to the rate of inflation, the adjusted principal value repaid at maturity may be less than the original principal. In the case of U.S. Treasury Inflation-Protected Securities (“TIPS”), currently the only inflation-linked security that is issued by the U.S Treasury, the principal amounts are adjusted daily based upon changes in the rate of inflation (as currently represented by the non-seasonally adjusted CPURNSA, calculated with a three-month lag). TIPS may pay interest semi-annually, equal to a fixed percentage of the inflation-adjusted principal amount. The interest rate on these bonds is fixed at issuance, but over the life of the bond this interest may be paid on an increasing or decreasing principal amount that has been adjusted for inflation. The current market value of TIPS is not guaranteed and will fluctuate. However, the U.S. government guarantees that, at maturity, principal will be repaid at the higher of the original face value of the security (in the event of deflation) or the inflation adjusted value.
Other non-U.S. sovereign governments also issue inflation-linked securities that are tied to their own local consumer price indexes and that offer similar deflationary protection. In certain of these non-U.S. jurisdictions, the repayment of the original bond principal upon the maturity of an inflation-linked bond is not guaranteed, allowing for the amount of the bond repaid at maturity to be less than par. Corporations also periodically issue inflation-linked securities tied to CPURNSA or similar inflationary indexes. While TIPS and non-U.S. sovereign inflation-linked securities are currently the largest part of the inflation-linked market, the fund may invest in corporate inflation-linked securities.
The value of inflation-linked securities is expected to change in response to the changes in real interest rates. Real interest rates, in turn, are tied to the relationship between nominal interest rates and the rate of inflation. If inflation were to rise at a faster rate than nominal interest rates, real interest rates would decline, leading to an increase in value of the inflation-linked securities. In contrast, if nominal interest rates were to increase at a faster rate than inflation, real interest rates might rise, leading to a decrease in value of inflation-linked securities. There can be no assurance, however, that the value of inflation-linked securities will be directly correlated to the changes in interest rates. If interest rates rise due to reasons other than inflation, investors in these securities may not be protected to the extent that the increase is not reflected in the security’s inflation measure.
The interest rate for inflation-linked bonds is fixed at issuance as a percentage of this adjustable principal. Accordingly, the actual interest income may both rise and fall as the principal amount of the bonds adjusts in response to movements of the consumer price index. For example, typically interest income would rise during a period of inflation and fall during a period of deflation.
The market for inflation-linked securities may be less developed or liquid, and more volatile, than certain other securities markets. There is a limited number of inflation-linked securities currently available for the fund to purchase, making the market less liquid and more volatile than the U.S. Treasury and agency markets.
American Funds Insurance Series — Page 19
Municipal bonds — Municipal bonds are debt obligations that are exempt from federal, state and/or local income taxes. Opinions relating to the validity of municipal bonds, exclusion of municipal bond interest from an investor’s gross income for federal income tax purposes and, where applicable, state and local income tax, are rendered by bond counsel to the issuing authorities at the time of issuance.
The two principal classifications of municipal bonds are general obligation bonds and limited obligation or revenue bonds. General obligation bonds are secured by the issuer’s pledge of its full faith and credit including, if available, its taxing power for the payment of principal and interest. Issuers of general obligation bonds include states, counties, cities, towns and various regional or special districts. The proceeds of these obligations are used to fund a wide range of public facilities, such as the construction or improvement of schools, highways and roads, water and sewer systems and facilities for a variety of other public purposes. Lease revenue bonds or certificates of participation in leases are payable from annual lease rental payments from a state or locality. Annual rental payments are payable to the extent such rental payments are appropriated annually.
Typically, the only security for a limited obligation or revenue bond is the net revenue derived from a particular facility or class of facilities financed thereby or, in some cases, from the proceeds of a special tax or other special revenues. Revenue bonds have been issued to fund a wide variety of revenue-producing public capital projects including: electric, gas, water and sewer systems; highways, bridges and tunnels; port and airport facilities; colleges and universities; hospitals; and convention, recreational, tribal gaming and housing facilities. Although the security behind these bonds varies widely, many provide additional security in the form of a debt service reserve fund which may also be used to make principal and interest payments on the issuer's obligations. In addition, some revenue obligations (as well as general obligations) are insured by a bond insurance company or backed by a letter of credit issued by a banking institution.
Revenue bonds also include, for example, pollution control, health care and housing bonds, which, although nominally issued by municipal authorities, are generally not secured by the taxing power of the municipality but by the revenues of the authority derived from payments by the private entity which owns or operates the facility financed with the proceeds of the bonds. Obligations of housing finance authorities have a wide range of security features, including reserve funds and insured or subsidized mortgages, as well as the net revenues from housing or other public projects. Many of these bonds do not generally constitute the pledge of the credit of the issuer of such bonds. The credit quality of such revenue bonds is usually directly related to the credit standing of the user of the facility being financed or of an institution which provides a guarantee, letter of credit or other credit enhancement for the bond issue.
Insured municipal bonds — The fund may invest in municipal bonds that are insured generally as to the timely payment of interest and repayment of principal. The insurance for such bonds may be purchased by the bond issuer, the fund or any other party, and is usually purchased from private, non-governmental insurance companies. Insurance that covers a municipal bond is expected to protect the fund against losses caused by a bond issuer’s failure to make interest or principal payments. However, insurance does not guarantee the market value of the bond or the prices of the fund’s shares. Also, the investment adviser cannot be certain that the insurance company will make payments it guarantees. The market value of the bond could drop if a bond's insurer fails to fulfill its obligations. Market conditions or changes to ratings criteria could adversely impact the ratings of municipal bond insurers. When rating agencies lower or withdraw the credit rating of the insurer, the insurance may be providing little or no enhancement of credit or resale value to the municipal bond.
Real estate investment trusts — Real estate investment trusts ("REITs"), which primarily invest in real estate or real estate-related loans, may issue equity or debt securities. Equity REITs own real estate properties, while mortgage REITs hold construction, development and/or long-term mortgage loans. The values of REITs may be affected by changes in the value of the underlying property of the trusts, the creditworthiness of the issuer, property taxes, interest rates, tax laws and regulatory requirements,
American Funds Insurance Series — Page 20
such as those relating to the environment. Both types of REITs are dependent upon management skill and the cash flows generated by their holdings, the real estate market in general and the possibility of failing to qualify for any applicable pass-through tax treatment or failing to maintain any applicable exemptive status afforded under relevant laws.
Variable and floating rate obligations — The interest rates payable on certain securities and other instruments in which certain of the funds may invest may not be fixed but may fluctuate based upon changes in market interest rates or credit ratings. Variable and floating rate obligations bear coupon rates that are adjusted at designated intervals, based on the then current market interest rates or credit ratings. The rate adjustment features tend to limit the extent to which the market value of the obligations will fluctuate. When the fund holds variable or floating rate securities, a decrease in market interest rates will adversely affect the income received from such securities and the net asset value of the fund’s shares.
The London Interbank Offered Rate (“LIBOR”) is one of the most widely used interest rate benchmarks and is intended to represent the rate at which contributing banks may obtain short-term borrowings from each other in the London interbank market. On July 27, 2017, the U.K. Financial Conduct Authority (“FCA”), which regulates LIBOR, announced that the FCA will no longer persuade or compel banks to submit rates for the calculation of LIBOR after 2021. On March 5, 2021, the FCA and ICE Benchmark Administration, Limited (IBA), the administrator of LIBOR, announced that the publication of the one-week and two-month USD LIBOR maturities and non-USD LIBOR maturities will cease immediately after December 31, 2021, with the remaining USD LIBOR maturities ceasing immediately after June 30, 2023. As a result, LIBOR may no longer be available or may no longer be deemed an appropriate reference rate upon which to determine the interest rate on certain loans, bonds, derivatives and other instruments in the fund’s portfolio.
Public and private sector industry initiatives have been underway to identify new or alternative reference rates to be used in place of LIBOR. In the US, the Alternative Reference Rates Committee (ARCC), a group of market participants convened to help ensure a successful transition away from USD LIBOR, has identified the Secured Overnight Financing Rate (“SOFR”), which is intended to be a broad measure of secured overnight U.S. Treasury repo rates, as its preferred alternative rate. Working groups and regulators in other countries have suggested other alternative rates for their markets. There is no assurance that the composition or characteristics of any such alternative reference rate will be similar to or produce the same value or economic equivalence as LIBOR or that instruments using an alternative rate will have the same volume or liquidity. This, in turn, may affect the value or return on certain of the fund’s investments, result in costs incurred in connection with closing out positions and entering into new trades and reduce the effectiveness of related fund transactions such as hedges. Relatedly, there are outstanding contracts governing bonds and other instruments which reference LIBOR that are due to mature beyond the LIBOR cessation date. These “legacy contracts” will need to be transitioned to an alternative reference rate, and a failure to do so may adversely impact the security (for example, under existing contract language the instrument could fall back to a fixed rate or have no fallback rate) and create contractual uncertainty, as well as market and litigation risk. Although there are ongoing efforts among certain government entities and other organizations to address these uncertainties, the ultimate effectiveness of such efforts is not yet known. These risks may also apply with respect to potential changes in connection with other interbank offering rates (e.g., Euribor) and other indices, rates and values that may be used as “benchmarks” and are the subject of recent regulatory reform.
Cash and cash equivalents — The fund may hold cash or invest in cash equivalents. Cash equivalents include, but are not limited to: (a) shares of money market or similar funds managed by the investment adviser or its affiliates; (b) shares of other money market funds; (c) commercial paper; (d) short-term bank obligations (for example, certificates of deposit, bankers’ acceptances (time drafts on a commercial bank where the bank accepts an irrevocable obligation to pay at maturity)) or bank notes; (e) savings association and savings bank obligations (for example, bank notes and certificates of
American Funds Insurance Series — Page 21
deposit issued by savings banks or savings associations); (f) securities of the U.S. government, its agencies or instrumentalities that mature, or that may be redeemed, in one year or less; and (g) higher quality corporate bonds and notes that mature, or that may be redeemed, in one year or less.
Commercial paper — The fund may purchase commercial paper. Commercial paper refers to short-term promissory notes issued by a corporation to finance its current operations. Such securities normally have maturities of thirteen months or less and, though commercial paper is often unsecured, commercial paper may be supported by letters of credit, surety bonds or other forms of collateral. Maturing commercial paper issuances are usually repaid by the issuer from the proceeds of new commercial paper issuances. As a result, investment in commercial paper is subject to rollover risk, or the risk that the issuer cannot issue enough new commercial paper to satisfy its outstanding commercial paper. Like all fixed income securities, commercial paper prices are susceptible to fluctuations in interest rates. If interest rates rise, commercial paper prices will decline and vice versa. However, the short-term nature of a commercial paper investment makes it less susceptible to volatility than many other fixed income securities because interest rate risk typically increases as maturity lengths increase. Commercial paper tends to yield smaller returns than longer-term corporate debt because securities with shorter maturities typically have lower effective yields than those with longer maturities. As with all fixed income securities, there is a chance that the issuer will default on its commercial paper obligations and commercial paper may become illiquid or suffer from reduced liquidity in these or other situations.
Commercial paper in which the fund may invest includes commercial paper issued in reliance on the exemption from registration afforded by Section 4(a)(2) of the 1933 Act. Section 4(a)(2) commercial paper has substantially the same price and liquidity characteristics as commercial paper generally, except that the resale of Section 4(a)(2) commercial paper is limited to institutional investors who agree that they are purchasing the paper for investment purposes and not with a view to public distribution. Technically, such a restriction on resale renders Section 4(a)(2) commercial paper a restricted security under the 1933 Act. In practice, however, Section 4(a)(2) commercial paper typically can be resold as easily as any other unrestricted security held by the fund. Accordingly, Section 4(a)(2) commercial paper has been generally determined to be liquid under procedures adopted by the fund’s board of trustees.
Restricted or illiquid securities — Certain funds may purchase securities subject to restrictions on resale. Restricted securities may only be sold pursuant to an exemption from registration under the Securities Act of 1933, as amended (the “1933 Act”), or in a registered public offering. Restricted securities held by the fund are often eligible for resale under Rule 144A, an exemption under the 1933 Act allowing for resales to “Qualified Institutional Buyers.” Where registration is required, the holder of a registered security may be obligated to pay all or part of the registration expense and a considerable period may elapse between the time it decides to seek registration and the time it may be permitted to sell a security under an effective registration statement. Difficulty in selling such securities may result in a loss to the fund or cause it to incur additional administrative costs.
Some fund holdings (including some restricted securities) may be deemed illiquid if the fund expects that a reasonable portion of the holding cannot be sold in seven calendar days or less without the sale significantly changing the market value of the investment. The determination of whether a holding is considered illiquid is made by the Series’ adviser under a liquidity risk management program adopted by the Series’ board and administered by the Series’ adviser. The fund may incur significant additional costs in disposing of illiquid securities.
Loan assignments and participations — Certain funds may invest in loans or other forms of indebtedness that represent interests in amounts owed by corporations or other borrowers (collectively "borrowers"). Loans may be originated by the borrower in order to address its working capital needs, as a result of a reorganization of the borrower’s assets and liabilities (recapitalizations), to merge with or acquire another company (mergers and acquisitions), to take control of another
American Funds Insurance Series — Page 22
company (leveraged buy-outs), to provide temporary financing (bridge loans), or for other corporate purposes.
Some loans may be secured in whole or in part by assets or other collateral. The greater the value of the assets securing the loan the more the lender is protected against loss in the case of nonpayment of principal or interest. Loans made to highly leveraged borrowers may be especially vulnerable to adverse changes in economic or market conditions and may involve a greater risk of default.
Some loans may represent revolving credit facilities or delayed funding loans, in which a lender agrees to make loans up to a maximum amount upon demand by the borrower during a specified term. These commitments may have the effect of requiring the fund to increase its investment in a company at a time when it might not otherwise decide to do so (including at a time when the company’s financial condition makes it unlikely that such amounts will be repaid). To the extent that the fund is committed to advance additional funds, the fund will segregate assets determined to be liquid in an amount sufficient to meet such commitments.
Some loans may represent debtor-in-possession financings (commonly known as “DIP financings”). DIP financings are arranged when an entity seeks the protections of the bankruptcy court under Chapter 11 of the U.S. Bankruptcy Code. These financings allow the entity to continue its business operations while reorganizing under Chapter 11. Such financings constitute senior liens on unencumbered collateral (i.e., collateral not subject to other creditors’ claims). There is a risk that the entity will not emerge from Chapter 11 and will be forced to liquidate its assets under Chapter 7 of the U.S. Bankruptcy Code. In the event of liquidation, the fund’s only recourse will be against the collateral securing the DIP financing.
The investment adviser generally makes investment decisions based on publicly available information, but may rely on non-public information if necessary. Borrowers may offer to provide lenders with material, non-public information regarding a specific loan or the borrower in general. The investment adviser generally chooses not to receive this information. As a result, the investment adviser may be at a disadvantage compared to other investors that may receive such information. The investment adviser’s decision not to receive material, non-public information may impact the investment adviser’s ability to assess a borrower’s requests for amendments or waivers of provisions in the loan agreement. However, the investment adviser may on a case-by-case basis decide to receive such information when it deems prudent. In these situations the investment adviser may be restricted from trading the loan or buying or selling other debt and equity securities of the borrower while it is in possession of such material, non-public information, even if such loan or other security is declining in value.
The fund normally acquires loan obligations through an assignment from another lender, but also may acquire loan obligations by purchasing participation interests from lenders or other holders of the interests. When the fund purchases assignments, it acquires direct contractual rights against the borrower on the loan. The fund acquires the right to receive principal and interest payments directly from the borrower and to enforce their rights as a lender directly against the borrower. However, because assignments are arranged through private negotiations between potential assignees and potential assignors, the rights and obligations acquired by the fund as the purchaser of an assignment may differ from, and be more limited than, those held by the assigning lender. Loan assignments are often administered by a financial institution that acts as agent for the holders of the loan, and the fund may be required to receive approval from the agent and/or borrower prior to the purchase of a loan. Risks may also arise due to the inability of the agent to meet its obligations under the loan agreement.
Loan participations are loans or other direct debt instruments that are interests in amounts owed by the borrower to another party. They may represent amounts owed to lenders or lending syndicates, to suppliers of goods or services, or to other parties. The fund will have the right to receive payments of principal, interest and any fees to which it is entitled only from the lender selling the participation and
American Funds Insurance Series — Page 23
only upon receipt by the lender of the payments from the borrower. In connection with purchasing participations, the fund generally will have no right to enforce compliance by the borrower with the terms of the loan agreement relating to the loan, nor any rights of set-off against the borrower. In addition, the fund may not directly benefit from any collateral supporting the loan in which it has purchased the participation and the fund will have to rely on the agent bank or other financial intermediary to apply appropriate credit remedies. As a result, the fund will be subject to the credit risk of both the borrower and the lender that is selling the participation. In the event of the insolvency of the lender selling a participation, the fund may be treated as a general creditor of the lender and may not benefit from any set-off between the lender and the borrower.
Loan assignments and participations are generally subject to legal or contractual restrictions on resale and are not currently listed on any securities exchange or automatic quotation system. Risks may arise due to delayed settlements of loan assignments and participations. The investment adviser expects that most loan assignments and participations purchased for the fund will trade on a secondary market. However, although secondary markets for investments in loans are growing among institutional investors, a limited number of investors may be interested in a specific loan. It is possible that loan participations, in particular, could be sold only to a limited number of institutional investors. If there is no active secondary market for a particular loan, it may be difficult for the investment adviser to sell the fund’s interest in such loan at a price that is acceptable to it and to obtain pricing information on such loan.
Investments in loan participations and assignments present the possibility that the fund could be held liable as a co-lender under emerging legal theories of lender liability. In addition, if the loan is foreclosed, the fund could be part owner of any collateral and could bear the costs and liabilities of owning and disposing of the collateral. The fund anticipates that loan participations could be sold only to a limited number of institutional investors. In addition, some loan participations and assignments may not be rated by major rating agencies and may not be protected by securities laws.
Inverse floating rate notes — Certain funds may invest in inverse floating rate notes (a type of derivative instrument). These notes have rates that move in the opposite direction of prevailing interest rates. A change in prevailing interest rates will often result in a greater change in these instruments’ interest rates. As a result, these instruments may have a greater degree of volatility than other types of interest-bearing securities.
Reinsurance related notes and bonds — American High-Income Trust may invest in reinsurance related notes and bonds. These instruments, which are typically issued by special purpose reinsurance companies, transfer an element of insurance risk to the note or bond holders. For example, such a note or bond could provide that the reinsurance company would not be required to repay all or a portion of the principal value of the note or bond if losses due to a catastrophic event under the policy (such as a major hurricane) exceed certain dollar thresholds. Consequently, the fund may lose the entire amount of its investment in such bonds or notes if such an event occurs and losses exceed certain dollar thresholds. In this instance, investors would have no recourse against the insurance company. These instruments may be issued with fixed or variable interest rates and rated in a variety of credit quality categories by the rating agencies.
Repurchase agreements — Certain funds may enter into repurchase agreements, or “repos”, under which the fund buys a security and obtains a simultaneous commitment from the seller to repurchase the security at a specified time and price. Because the security purchased constitutes collateral for the repurchase obligation, a repo may be considered a loan by the fund that is collateralized by the security purchased. Repos permit the fund to maintain liquidity and earn income over periods of time as short as overnight.
American Funds Insurance Series — Page 24
The seller must maintain with a custodian collateral equal to at least the repurchase price, including accrued interest. In tri-party repos, a third party custodian, called a clearing bank, facilitates repo clearing and settlement, including by providing collateral management services. However, as an alternative to tri-party repos, the fund could enter into bilateral repos, where the parties themselves are responsible for settling transactions.
The fund will only enter into repos involving securities of the type (excluding any maturity limitations) in which they could otherwise invest. If the seller under the repo defaults, the fund may incur a loss if the value of the collateral securing the repo has declined and may incur disposition costs and delays in connection with liquidating the collateral. If bankruptcy proceedings are commenced with respect to the seller, realization of the collateral by the fund may be delayed or limited.
Maturity — There are no restrictions on the maturity compositions of the portfolios of certain funds. Certain funds invest in debt securities with a wide range of maturities. Under normal market conditions, longer term securities yield more than shorter term securities, but are subject to greater price fluctuations.
Adjustment of maturities — The investment adviser seeks to anticipate movements in interest rates and may adjust the maturity distribution of the portfolio accordingly, keeping in mind the fund’s objectives.
Derivatives — In pursuing its investment objective, the fund may invest in derivative instruments. A derivative is a financial instrument, the value of which depends on, or is otherwise derived from, another underlying variable. Most often, the variable underlying a derivative is the price of a traded asset, such as a traditional cash security (e.g., a stock or bond), a currency or a commodity; however, the value of a derivative can be dependent on almost any variable, from the level of an index or a specified rate to the occurrence (or non-occurrence) of a credit event with respect to a specified reference asset. In addition to investing in forward currency contracts, as described above under “Currency transactions,” the fund may take positions in futures contracts and swaps, each of which is a derivative instrument described in greater detail below.
Derivative instruments may be distinguished by the manner in which they trade: some are standardized instruments that trade on an organized exchange while others are individually negotiated and traded in the over-the-counter (OTC) market. Derivatives also range broadly in complexity, from simple derivatives to more complex instruments. As a general matter, however, all derivatives — regardless of the manner in which they trade or their relative complexities — entail certain risks, some of which are different from, and potentially greater than, the risks associated with investing directly in traditional cash securities.
As is the case with traditional cash securities, derivative instruments are generally subject to counterparty credit risk; however, in some cases, derivatives may pose counterparty risks greater than those posed by cash securities. The use of derivatives involves the risk that a loss may be sustained by the fund as a result of the failure of the fund’s counterparty to make required payments or otherwise to comply with its contractual obligations. For some derivatives, though, the value of — and, in effect, the return on — the instrument may be dependent on both the individual credit of the fund’s counterparty and on the credit of one or more issuers of any underlying assets. If the fund does not correctly evaluate the creditworthiness of its counterparty and, where applicable, of issuers of any underlying reference assets, the fund’s investment in a derivative instrument may result in losses. Further, if a fund’s counterparty were to default on its obligations, the fund’s contractual remedies against such counterparty may be subject to applicable bankruptcy and insolvency laws, which could affect the fund’s rights as a creditor and delay or impede the fund’s ability to receive the net amount of payments that it is contractually entitled to receive.
American Funds Insurance Series — Page 25
The value of some derivative instruments in which the fund invests may be particularly sensitive to changes in prevailing interest rates, currency exchange rates or other market conditions. Like the fund’s other investments, the ability of the fund to successfully utilize such derivative instruments may depend in part upon the ability of the fund’s investment adviser to accurately forecast interest rates and other economic factors. The success of the fund’s derivative investment strategy will also depend on the investment adviser’s ability to assess and predict the impact of market or economic developments on the derivative instruments in which the fund invests, in some cases without having had the benefit of observing the performance of a derivative under all possible market conditions. If the investment adviser incorrectly forecasts such factors and has taken positions in derivative instruments contrary to prevailing market trends, or if the investment adviser incorrectly predicts the impact of developments on a derivative instrument, the fund could be exposed to the risk of loss.
Certain derivatives may also be subject to liquidity and valuation risks. The potential lack of a liquid secondary market for a derivative (and, particularly, for an OTC derivative) may cause difficulty in valuing or selling the instrument. If a derivative transaction is particularly large or if the relevant market is illiquid, as is often the case with many privately-negotiated OTC derivatives, the fund may not be able to initiate a transaction or to liquidate a position at an advantageous time or price. Particularly when there is no liquid secondary market for the fund’s derivative positions, the fund may encounter difficulty in valuing such illiquid positions. The value of a derivative instrument does not always correlate perfectly with its underlying asset, rate or index, and many derivatives, and OTC derivatives in particular, are complex and often valued subjectively. Improper valuations can result in increased cash payment requirements to counterparties or a loss of value to the fund.
Because certain derivative instruments may obligate the fund to make one or more potential future payments, which could significantly exceed the value of the fund’s initial investments in such instruments, derivative instruments may also have a leveraging effect on the fund’s portfolio. Certain derivatives have the potential for unlimited loss, irrespective of the size of the fund’s investment in the instrument. When a fund leverages its portfolio, investments in that fund will tend to be more volatile, resulting in larger gains or losses in response to market changes. In accordance with currently applicable regulatory requirements, the fund will generally segregate or earmark liquid assets, or enter into offsetting financial positions, to cover its obligations under derivative instruments, effectively limiting the risk of leveraging the fund’s portfolio. Because the fund is legally required to maintain asset coverage or offsetting positions in connection with leveraging derivative instruments, the fund’s investments in such derivatives may also require the fund to buy or sell portfolio securities at disadvantageous times or prices in order to comply with applicable requirements.
In October 2020, the SEC adopted a new rule applicable to the fund’s use of derivatives. The new rule, among other things, generally requires a fund to adopt a derivatives risk management program, appoint a derivatives risk manager and comply with an outer limit on fund leverage risk based on value at risk, or “VaR”. However, subject to certain conditions, if a fund uses derivatives only in a limited manner, it may be deemed a limited derivatives user and would not be subject to the full requirements of the new rule. The SEC also eliminated the asset segregation and cover framework, described above, arising from prior SEC guidance for covering derivatives and certain financial instruments effective at the time that a fund complies with the new rule. Compliance with the new rule will be required beginning in August 2022. The implementation of these requirements may limit the ability of the fund to use derivatives as part of its investment strategy.
Futures — The fund may enter into futures contracts to seek to manage the fund’s interest rate sensitivity by increasing or decreasing the duration of the fund or a portion of the fund’s portfolio. A futures contract is an agreement to buy or sell a security or other financial instrument (the “reference asset”) for a set price on a future date. Futures contracts are standardized, exchange-traded contracts, and, when a futures contract is bought or sold, the fund will incur brokerage fees and will be required to maintain margin deposits.
American Funds Insurance Series — Page 26
Unlike when the fund purchases or sells a security, such as a stock or bond, no price is paid or received by the fund upon the purchase or sale of a futures contract. When the fund enters into a futures contract, the fund is required to deposit with its futures broker, known as a futures commission merchant (FCM), a specified amount of liquid assets in a segregated account in the name of the FCM at the applicable derivatives clearinghouse or exchange. This amount, known as initial margin, is set by the futures exchange on which the contract is traded and may be significantly modified during the term of the contract. The initial margin is in the nature of a performance bond or good faith deposit on the futures contract, which is returned to the fund upon termination of the contract, assuming all contractual obligations have been satisfied. Additionally, on a daily basis, the fund pays or receives cash, or variation margin, equal to the daily change in value of the futures contract. Variation margin does not represent a borrowing or loan by the fund but is instead a settlement between the fund and the FCM of the amount one party would owe the other if the futures contract expired. In computing daily net asset value, the fund will mark-to-market its open futures positions. In the event of the bankruptcy or insolvency of an FCM that holds margin on behalf of the fund, the fund may be entitled to return of margin owed to it only in proportion to the amount received by the FCM’s other customers, potentially resulting in losses to the fund. An event of bankruptcy or insolvency at a clearinghouse or exchange holding initial margin could also result in losses for the fund.
When the fund invests in futures contracts and deposits margin with an FCM, the fund becomes subject to so-called “fellow customer” risk – that is, the risk that one or more customers of the FCM will default on their obligations and that the resulting losses will be so great that the FCM will default on its obligations and margin posted by one customer, such as the fund, will be used to cover a loss caused by a different defaulting customer. Applicable rules generally prohibit the use of one customer’s funds to meet the obligations of another customer and limit the ability of an FCM to use margin posed by non-defaulting customers to satisfy losses caused by defaulting customers. As a general matter, an FCM is required to use its own funds to meet a defaulting customer’s obligations. While a customer’s loss would likely need to be substantial before non-defaulting customers would be exposed to loss on account of fellow customer risk, applicable rules nevertheless permit the commingling of margin and do not limit the mutualization of customer losses from investment losses, custodial failures, fraud or other causes. If the loss is so great that, notwithstanding the application of an FCM’s own funds, there is a shortfall in the amount of customer funds required to be held in segregation, the FCM could default and be placed into bankruptcy. Under these circumstances, bankruptcy law provides that non-defaulting customers will share pro rata in any shortfall. A shortfall in customer segregated funds may also make the transfer of the accounts of non-defaulting customers to another FCM more difficult.
Although certain futures contracts, by their terms, require actual future delivery of and payment for the reference asset, in practice, most futures contracts are usually closed out before the delivery date by offsetting purchases or sales of matching futures contracts. Closing out an open futures contract purchase or sale is effected by entering into an offsetting futures contract sale or purchase, respectively, for the same aggregate amount of the identical reference asset and the same delivery date with the same FCM. If the offsetting purchase price is less than the original sale price (in each case taking into account transaction costs, including brokerage fees), the fund realizes a gain; if it is more, the fund realizes a loss. Conversely, if the offsetting sale price is more than the original purchase price (in each case taking into account transaction costs, including brokerage fees), the fund realizes a gain; if it is less, the fund realizes a loss.
Under current regulations, the fund is generally required to segregate liquid assets equivalent to the fund’s outstanding obligations under each futures contract. With respect to long positions in futures contracts that are not legally required to cash settle, the fund will segregate
American Funds Insurance Series — Page 27
or earmark liquid assets in an amount equal to the contract price the fund will be required to pay on settlement less the amount of margin deposited with an FCM. For short positions in futures contracts that are not legally required to cash settle, the fund will segregate or earmark liquid assets in an amount that, when added to the amounts deposited with an FCM as margin, equals the market value of the reference asset underlying the futures contract. With respect to futures contracts that are required to cash settle, however, the fund is permitted to segregate or earmark liquid assets in an amount that, when added to the amounts deposited with an FCM as margin, equals the fund’s daily marked-to-market (net) obligation under the contract (i.e., the daily market value of the contract itself), if any; in other words, the fund may set aside its daily net liability, if any, rather than the notional value of the futures contract. By segregating or earmarking assets equal only to its net obligation under cash-settled futures, the fund may be able to utilize these contracts to a greater extent than if the fund were required to segregate or earmark assets equal to the full contract price or current market value of the futures contract. Such segregation of assets is intended to ensure that the fund has assets available to satisfy its obligations with respect to futures contracts and to limit any potential leveraging of the fund’s portfolio. However, segregation of liquid assets will not limit the fund’s exposure to loss. To maintain a sufficient amount of segregated assets, the fund may also have to sell less liquid portfolio securities at disadvantageous prices, and the earmarking of liquid assets will have the effect of limiting the fund’s ability to otherwise invest those assets in other securities or instruments.
The value of a futures contract tends to increase and decrease in tandem with the value of its underlying reference asset. Purchasing futures contracts will, therefore, tend to increase the fund’s exposure to positive and negative price fluctuations in the reference asset, much as if the fund had purchased the reference asset directly. When the fund sells a futures contract, by contrast, the value of its futures position will tend to move in a direction contrary to the market for the reference asset. Accordingly, selling futures contracts will tend to offset both positive and negative market price changes, much as if the reference asset had been sold.
There is no assurance that a liquid market will exist for any particular futures contract at any particular time. Futures exchanges may establish daily price fluctuation limits for futures contracts and may halt trading if a contract’s price moves upward or downward more than the limit in a given day. On volatile trading days, when the price fluctuation limit is reached and a trading halt is imposed, it may be impossible to enter into new positions or close out existing positions. If the market for a futures contract is not liquid because of price fluctuation limits or other market conditions, the fund may be prevented from promptly liquidating unfavorable futures positions and the fund could be required to continue to hold a position until delivery or expiration regardless of changes in its value, potentially subjecting the fund to substantial losses. Additionally, the fund may not be able to take other actions or enter into other transactions to limit or reduce its exposure to the position. Under such circumstances, the fund would remain obligated to meet margin requirements until the position is cleared. As a result, the fund’s access to other assets held to cover its futures positions could also be impaired.
Although futures exchanges generally operate similarly in the United States and abroad, foreign futures exchanges may follow trading, settlement and margin procedures that are different than those followed by futures exchanges in the United States. Futures contracts traded outside the United States may not involve a clearing mechanism or related guarantees and may involve greater risk of loss than U.S.-traded contracts, including potentially greater risk of losses due to insolvency of a futures broker, exchange member, or other party that may owe initial or variation margin to the fund. Margin requirements on foreign futures exchanges may be different than those of futures exchanges in the United States, and, because initial and variation margin payments may be measured in foreign currency, a futures contract traded outside the United States may also involve the risk of foreign currency fluctuations.
American Funds Insurance Series — Page 28
Swaps — The fund may enter into swap agreements, which are two-party contracts entered into primarily by institutional investors for a specified time period. In a typical swap transaction, two parties agree to exchange the returns earned or realized from one or more underlying assets or rates of return.
Swap agreements can be traded on a swap execution facility (SEF) and cleared through a central clearinghouse (cleared), traded over-the-counter (OTC) and cleared, or traded bilaterally and not cleared. For example, standardized interest rate swaps and credit default swap indices are traded on SEFs and cleared. Other forms of swap agreements, such as total return swaps, are entered into on a bilateral basis. Because clearing interposes a central clearinghouse as the ultimate counterparty to each participant’s swap, and margin is required to be exchanged under the rules of the clearinghouse, central clearing is intended to decrease (but not eliminate) counterparty risk relative to uncleared bilateral swaps. To the extent the fund enters into bilaterally negotiated swap transactions, the fund will enter into swap agreements only with counterparties that meet certain credit standards and subject to agreed collateralization procedures; however, if the counterparty’s creditworthiness deteriorates rapidly and the counterparty defaults on its obligations under the swap agreement or declares bankruptcy, the fund may lose any amount it expected to receive from the counterparty. In addition, bilateral swaps are subject to certain regulatory margin requirements that mandate the posting and collection of minimum margin amounts, which may result in the fund and its counterparties posting higher margin amounts for bilateral swaps than would otherwise be the case.
The term of a swap can be days, months or years and certain swaps may be less liquid than others. If a swap transaction is particularly large or if the relevant market is illiquid, it may not be possible to initiate a transaction or liquidate a position at an advantageous time or price, which may result in significant losses.
Swap agreements can take different forms. The fund may enter into the following types of swap agreements:
Interest rate swaps — The fund may enter into interest rate swaps to seek to manage the interest rate sensitivity of the fund by increasing or decreasing the duration of the fund or a portion of the fund’s portfolio. An interest rate swap is an agreement between two parties to exchange or swap payments based on changes in an interest rate or rates. Typically, one interest rate is fixed and the other is variable based on a designated short-term interest rate such as the Secured Overnight Financing Rate (SOFR), prime rate or other benchmark. In other types of interest rate swaps, known as basis swaps, the parties agree to swap variable interest rates based on different designated short-term interest rates. Interest rate swaps generally do not involve the delivery of securities or other principal amounts. Rather, cash payments are exchanged by the parties based on the application of the designated interest rates to a notional amount, which is the predetermined dollar principal of the trade upon which payment obligations are computed. Accordingly, the fund’s current obligation or right under the swap agreement is generally equal to the net amount to be paid or received under the swap agreement based on the relative value of the position held by each party. Under current regulations, the fund will generally segregate assets with a daily value at least equal to the excess, if any, of the fund’s accrued obligations under the swap agreement over the accrued amount the fund is entitled to receive under the agreement, less the value of any posted margin or collateral on deposit with respect to the position.
In addition to the risks of entering into swaps discussed above, the use of interest rate swaps involves the risk of losses if interest rates change.
American Funds Insurance Series — Page 29
Credit default swap indices — In order to assume exposure to a diversified portfolio of credits or to hedge against existing credit risks, the fund may invest in credit default swap indices, including CDX and iTraxx indices (collectively referred to as “CDSIs”). A CDSI is based on a portfolio of credit default swaps with similar characteristics, such as credit default swaps on high-yield bonds. In a typical CDSI transaction, one party — the protection buyer — is obligated to pay the other party — the protection seller — a stream of periodic payments over the term of the contract. If a credit event, such as a default or restructuring, occurs with respect to any of the underlying reference obligations, the protection seller must pay the protection buyer the loss on those credits. Also, if a restructuring credit event occurs in an iTraxx index, the fund as protection buyer may receive a single name credit default swap (CDS) contract representing the relevant constituent.
The fund may enter into a CDSI transaction as either protection buyer or protection seller. If the fund is a protection buyer, it would pay the counterparty a periodic stream of payments over the term of the contract and would not recover any of those payments if no credit events were to occur with respect to any of the underlying reference obligations. However, if a credit event did occur, the fund, as a protection buyer, would have the right to deliver the referenced debt obligations or a specified amount of cash, depending on the terms of the applicable agreement, and to receive the par value of such debt obligations from the counterparty protection seller. As a protection seller, the fund would receive fixed payments throughout the term of the contract if no credit events were to occur with respect to any of the underlying reference obligations. If a credit event were to occur, however, the value of any deliverable obligation received by the fund, coupled with the periodic payments previously received by the fund, may be less than the full notional value that the fund, as a protection seller, pays to the counterparty protection buyer, effectively resulting in a loss of value to the fund. Furthermore, as a protection seller, the fund would effectively add leverage to its portfolio because it would have investment exposure to the notional amount of the swap transaction.
The use of CDSI, like all other swap agreements, is subject to certain risks, including the risk that the fund’s counterparty will default on its obligations. If such a default were to occur, any contractual remedies that the fund might have may be subject to applicable bankruptcy laws, which could delay or limit the fund’s recovery. Thus, if the fund’s counterparty to a CDSI transaction defaults on its obligation to make payments thereunder, the fund may lose such payments altogether or collect only a portion thereof, which collection could involve substantial costs or delays.
Additionally, when the fund invests in a CDSI as a protection seller, the fund will be indirectly exposed to the creditworthiness of issuers of the underlying reference obligations in the index. If the investment adviser to the fund does not correctly evaluate the creditworthiness of issuers of the underlying instruments on which the CDSI is based, the investment could result in losses to the fund.
Pursuant to current regulations and published positions of the U.S. Securities and Exchange Commission, the fund’s obligations under a CDSI agreement will be accrued daily and, where applicable, offset against any amounts owing to the fund. In connection with CDSI transactions in which the fund acts as protection buyer, the fund will segregate liquid assets with a value at least equal to the fund’s exposure (i.e., any accrued but unpaid net amounts owed by the fund to any counterparty), on a marked-to-market basis, less the value of any posted margin. When the fund acts as protection seller, the fund will segregate liquid assets with a value at least equal to the full notional amount of the swap, less the value of any posted margin. Such segregation is
American Funds Insurance Series — Page 30
intended to ensure that the fund has assets available to satisfy its obligations with respect to CDSI transactions and to limit any potential leveraging of the fund’s portfolio. However, segregation of liquid assets will not limit the fund’s exposure to loss. To maintain this required margin, the fund may also have to sell portfolio securities at disadvantageous prices, and the earmarking of liquid assets will have the effect of limiting the fund’s ability to otherwise invest those assets in other securities or instruments.
Equity-linked notes — A fund may purchase equity-linked notes to enhance the current income of its portfolio. Equity-linked notes are hybrid instruments that are specially designed to combine the characteristics of one or more reference securities — usually a single stock, a stock index or a basket of stocks — and a related equity derivative, such as a put or call option, in a single note form. For example, an equity-linked note that refers to the stock of an issuer may be the economic equivalent of holding a position in that stock and simultaneously selling a call option on that stock with a strike price greater than the current stock price. The holder of the note would be exposed to decreases in the price of the equity to the same extent as if it held the equity directly. However, if the stock appreciated in value, the noteholder would only benefit from stock price increases up to the strike price (i.e., the point at which the holder of the call option would be expected to exercise its right to buy the underlying stock). Additionally, the terms of an equity-linked note may provide for periodic interest payments to holders at either a fixed or floating rate.
As described in the example above, the return on an equity-linked note is generally tied to the performance of the underlying reference security or securities. In addition to any interest payments made during the term of the note, at maturity, the noteholder usually receives a return of principal based on the capital appreciation of the linked securities. Depending on the terms of the issuance, the maximum principal amount to be repaid on the equity-linked note may be capped. For example, in consideration for greater current income or yield, a noteholder may forego its participation in the capital appreciation of the underlying equity assets above a predetermined price limit. Alternatively, if the linked securities have depreciated in value, or if their price fluctuates outside of a preset range, the noteholder may receive only the principal amount of the note, or may lose the principal invested in the equity-linked note entirely.
The price of an equity-linked note is derived from the value of the underlying linked securities. The level and type of risk involved in the purchase of an equity-linked note by the fund is similar to the risk involved in the purchase of the underlying linked securities. However, the value of an equity-linked note is also dependent on the individual credit of the issuer of the note, which, in the case of an unsecured note, will generally be a major financial institution, and, in the case of a collateralized note, will generally be a trust or other special purpose vehicle or finance subsidiary established by a major financial institution for the limited purpose of issuing the note. An investment in an equity-linked note bears the risk that the issuer of the note will default or become bankrupt. In such an event, the fund may have difficulty being repaid, or may fail to be repaid, the principal amount of, or income from, its investment. Like other structured products, equity-linked notes are frequently secured by collateral consisting of a combination of debt or related equity securities to which payments under the notes are linked. If so secured, the fund would look to this underlying collateral for satisfaction of claims in the event that the issuer of an equity-linked note defaulted under the terms of the note. However, depending on the law of the jurisdictions in which an issuer is organized and in which the note is issued, in the event of default, the fund may incur substantial expenses in seeking recovery under an equity-linked note, and may have limited legal recourse in attempting to do so.
Equity-linked notes are often privately placed and may not be rated, in which case the fund will be more dependent than would otherwise be the case on the ability of the investment adviser to evaluate the creditworthiness of the issuer, the underlying security, any collateral features of the note, and the potential for loss due to market and other factors. Ratings of issuers of equity-linked notes refer only to the creditworthiness of the issuer and strength of related collateral arrangements or other credit
American Funds Insurance Series — Page 31
supports, and do not take into account, or attempt to rate, any potential risks of the underlying equity securities. The fund’s successful use of equity-linked notes will usually depend on the investment adviser’s ability to accurately forecast movements in the prices of the underlying securities. Should the prices of the underlying securities move in an unexpected manner, or should the structure of a note respond to market conditions differently than anticipated, the fund may not achieve the anticipated benefits of the investment in the equity-linked note, and the fund may realize losses, which could be significant and could include the fund’s entire principal investment in the note.
Equity-linked notes are generally designed for the over-the-counter institutional investment market, and the secondary market for equity-linked notes may be limited. The lack of a liquid secondary market may have an adverse effect on the ability of the fund to accurately value and/or sell the equity-linked notes in its portfolio.
Diversification — Capital World Bond Fund is a nondiversified investment company which allows the fund to invest a greater percentage of its assets in any one issuer than a diversified investment company. For the fund to be considered a “diversified” investment company under the Investment Company Act of 1940, as amended, the fund with respect to 75% of its total assets, would be required to limit its investment in any one issuer (other than the U.S. government) to 5% of the market value of the total assets of the fund or to 10% of the outstanding voting securities of such issuer. However, such a diversification limitation would reduce the extent to which the fund could concentrate its investments in securities of governmental issuers outside the United States, which are generally considered to be of higher credit quality than are securities of private issuers domiciled outside the United States. Accordingly, such a diversification limitation might increase the fund's investment risk. Although Capital World Bond Fund is nondiversified, it has no current intention of investing more than 5% of its assets in securities of any one corporate issuer. In addition, the fund intends to comply with the diversification and other requirements of the U.S. Internal Revenue Code of 1986, as amended, applicable to regulated investment companies so that the fund will not be subject to U.S. taxes on the net investment income and net capital gains that it distributes to its shareholders. (See “Taxes and Distributions.”)
Washington Mutual Investors Fund and its investment policies — Washington Mutual Investors Fund has an Eligible List of investments considered appropriate for a prudent investor seeking opportunities for income and growth of principal consistent with common stock investing. Numerous criteria govern which securities may be included on the fund’s Eligible List. Currently, those criteria include, for example: (a) a security shall be listed on the New York Stock Exchange (“NYSE”) or meet the financial listing requirements of the NYSE (the applicable listing requirements are set forth in Section 1 of the Listed Company Manual of the NYSE); (b) most companies must have fully earned their dividends in at least four of the past five years (with the exception of certain banking institutions) and paid a dividend in at least eight of the past ten years; (c) issuing companies must meet both initial and ongoing market capitalization requirements; (d) the ratio of current assets to liabilities for most individual companies must be at least 1.5 to 1, or their bonds must be rated at least investment grade by Standard & Poor’s Ratings Services; and (e) companies must not derive the majority of their revenues from alcohol or tobacco products. The investment adviser generates and maintains the Eligible List and selects the fund’s investments exclusively from the issuers on the Eligible List.
Although the fund generally invests in U.S. companies, the fund may invest up to 10% of its assets in securities of certain companies domiciled outside the United States. The fund may also hold securities of companies domiciled outside the U.S. when such companies have merged with or otherwise acquired a company in which the fund held shares at the time of the merger.
It is believed that in applying the above disciplines and procedures, the fund makes available to pension and profit-sharing trustees and other fiduciaries a prudent stock investment and a continuity of investment quality which it has always been the policy of the fund to provide. However, fiduciary investment responsibility and the Prudent Investor Rule, pursuant to which a fiduciary is generally
American Funds Insurance Series — Page 32
required to invest and manage trust assets as a prudent investor would, involve a mixed question of law and fact which cannot be conclusively determined in advance. Moreover, recent changes to the Prudent Investor Rule in some jurisdictions speak to an allocation of funds among a variety of investments. Therefore, each fiduciary should examine the common stock portfolio of the fund to see that it, along with other investments, meets the requirements of the specific trust.
Cybersecurity risks — With the increased use of technologies such as the Internet to conduct business, the fund has become potentially more susceptible to operational and information security risks through breaches in cybersecurity. In general, a breach in cybersecurity can result from either a deliberate attack or an unintentional event. Cybersecurity breaches may involve, among other things, “ransomware” attacks, injection of computer viruses or malicious software code, or the use of vulnerabilities in code to gain unauthorized access to digital information systems, networks or devices that are used directly or indirectly by the fund or its service providers through “hacking” or other means. Cybersecurity risks also include the risk of losses of service resulting from external attacks that do not require unauthorized access to the fund’s systems, networks or devices. For example, denial-of-service attacks on the investment adviser’s or an affiliate’s website could effectively render the fund’s network services unavailable to fund shareholders and other intended end-users. Any such cybersecurity breaches or losses of service may, among other things, cause the fund to lose proprietary information, suffer data corruption or lose operational capacity, or may result in the misappropriation, unauthorized release or other misuse of the fund’s assets or sensitive information (including shareholder personal information or other confidential information), the inability of fund shareholders to transact business, or the destruction of the fund’s physical infrastructure, equipment or operating systems. These, in turn, could cause the fund to incur violations of applicable privacy and other laws and subsequent regulatory penalties, reputational damage, additional costs (including compliance costs) associated with corrective measures and/or financial loss. While the fund and its investment adviser have established business continuity plans and risk management systems designed to prevent or reduce the impact of cybersecurity attacks, there are inherent limitations in such plans and systems due in part to the ever-changing nature of technology and cybersecurity attack tactics, and there is a possibility that certain risks have not been adequately identified or prepared for.
In addition, cybersecurity failures by or breaches of the fund’s third-party service providers (including, but not limited to, the fund’s investment adviser, transfer agent, custodian, administrators and other financial intermediaries) may disrupt the business operations of the service providers and of the fund, potentially resulting in financial losses, the inability of fund shareholders to transact business with the fund and of the fund to process transactions, the inability of the fund to calculate its net asset value, violations of applicable privacy and other laws, rules and regulations, regulatory fines, penalties, reputational damage, reimbursement or other compensatory costs and/or additional compliance costs associated with implementation of any corrective measures. The fund and its shareholders could be negatively impacted as a result of any such cybersecurity breaches, and there can be no assurance that the fund will not suffer losses relating to cybersecurity attacks or other informational security breaches affecting the fund’s third-party service providers in the future, particularly as the fund cannot control any cybersecurity plans or systems implemented by such service providers.
Cybersecurity risks may also impact issuers of securities in which the fund invests, which may cause the fund’s investments in such issuers to lose value.
Interfund borrowing and lending — Pursuant to an exemptive order issued by the U.S. Securities and Exchange Commission, certain funds may lend money to, and borrow money from, other funds advised by Capital Research and Management Company or its affiliates. Such funds will borrow through the program only when the costs are equal to or lower than the costs of bank loans. Such funds will lend through the program only when the returns are higher than those available from an investment in repurchase agreements. Interfund loans and borrowings normally extend overnight, but can have a maximum duration of seven days. Loans may be called on one day's notice. A fund may have to borrow from a bank at a higher interest rate if an interfund loan is called or not renewed. Any
American Funds Insurance Series — Page 33
delay in repayment to a lending fund could result in a lost investment opportunity or additional borrowing costs.
Affiliated investment companies — Certain funds may purchase shares of another investment company managed by the investment adviser or its affiliates. The risks of owning another investment company are similar to the risks of investing directly in the securities in which that investment company invests. When investing in another investment company managed by the investment adviser or its affiliates, a fund bears its proportionate share of the expenses of any such investment company in which it invests but will not bear additional management fees through its investment in such investment company. Investments in other investment companies could allow a fund to obtain the benefits of a more diversified portfolio than might otherwise be available through direct investments in a particular asset class, and will subject the fund to the risks associated with the particular asset class or asset classes in which an underlying fund invests. However, an investment company may not achieve its investment objective or execute its investment strategy effectively, which may adversely affect the fund’s performance. Any investment in another investment company will be consistent with the fund’s objective(s) and applicable regulatory limitations.
American Funds Insurance Series — Page 34
Securities lending activities – Certain funds may lend portfolio securities to brokers, dealers or other institutions that provide cash or U.S. Treasury securities as collateral in an amount at least equal to the value of the securities loaned. While portfolio securities are on loan, the fund will continue to receive the equivalent of the interest and the dividends or other distributions paid by the issuer on the securities, as well as a portion of the interest on the investment of the collateral. Additionally, although the fund will not have the right to vote on securities while they are on loan, the fund has a right to consent on corporate actions and a right to recall each loan to vote on proposals, including proposals involving material events affecting securities loaned. The fund has delegated the decision to lend portfolio securities to the investment adviser. The adviser also has the discretion to consent on corporate actions and to recall securities on loan to vote. In the event the adviser deems a corporate action or proxy vote material, as determined by the adviser based on factors relevant to the fund, it will use reasonable efforts to recall the securities and consent to or vote on the matter.
Securities lending involves risks, including the risk that the loaned securities may not be returned in a timely manner or at all and/or the risk of a loss of rights in the collateral if a borrower or the lending agent defaults. These risks could be greater for non-U.S. securities. Additionally, the fund may lose money from the reinvestment of collateral received on loaned securities in investments that decline in value, default or do not perform as expected. The fund will make loans only to parties deemed by the fund’s adviser to be in good standing and when, in the adviser’s judgment, the income earned would justify the risks.
Citibank, N.A. (“Citibank”) serves as securities lending agent for the funds that may lend portfolio securities. As the securities lending agent, Citibank administers each such fund’s securities lending program pursuant to the terms of a securities lending agent agreement entered into between the fund and Citibank. Under the terms of the agreement, Citibank is responsible for making available to approved borrowers securities from the fund’s portfolio. Citibank is also responsible for the administration and management of the fund’s securities lending program, including the preparation and execution of an agreement with each borrower governing the terms and conditions of any securities loan, ensuring that securities loans are properly coordinated and documented, ensuring that loaned securities are valued daily and that the corresponding required collateral is delivered by the borrowers, arranging for the investment of collateral received from borrowers, and arranging for the return of loaned securities to the fund in accordance with the fund’s instructions or at loan termination. As compensation for its services, Citibank receives a portion of the amount earned by the funds for lending securities.
American Funds Insurance Series — Page 35
The following table sets forth, for the fund’s most recently completed fiscal year, the fund’s dollar amount of income and fees and/or other compensation related to its securities lending activities. Net income from securities lending activities may differ from the amount reported in the fund’s annual report, which reflects estimated accruals.
Global Growth Fund
| Gross income from securities lending activities | $872,637 |
| Fees paid to securities lending agent from a revenue split | 43,629 |
| Fees paid for any cash collateral management service (including fees deducted from a pooled cash collateral reinvestment vehicle) not included in the revenue split | 0 |
| Administrative fees not included in the revenue split | 0 |
| Indemnification fees not included in the revenue split | 0 |
| Rebates (paid to borrower) | 0 |
| Other fees not included in the revenue split | 0 |
| Aggregate fees/compensation for securities lending activities | 43,629 |
| Net income from securities lending activities | 828,952 |
Global Small Capitalization Fund
| Gross income from securities lending activities | $1,140,345 |
| Fees paid to securities lending agent from a revenue split | 56,968 |
| Fees paid for any cash collateral management service (including fees deducted from a pooled cash collateral reinvestment vehicle) not included in the revenue split | 0 |
| Administrative fees not included in the revenue split | 0 |
| Indemnification fees not included in the revenue split | 0 |
| Rebates (paid to borrower) | 0 |
| Other fees not included in the revenue split | 0 |
| Aggregate fees/compensation for securities lending activities | 56,968 |
| Net income from securities lending activities | 1,082,419 |
Growth Fund
| Gross income from securities lending activities | $768,167 |
| Fees paid to securities lending agent from a revenue split | 38,409 |
| Fees paid for any cash collateral management service (including fees deducted from a pooled cash collateral reinvestment vehicle) not included in the revenue split | 0 |
| Administrative fees not included in the revenue split | 0 |
| Indemnification fees not included in the revenue split | 0 |
| Rebates (paid to borrower) | 0 |
| Other fees not included in the revenue split | 0 |
| Aggregate fees/compensation for securities lending activities | 38,409 |
| Net income from securities lending activities | 729,758 |
American Funds Insurance Series — Page 36
International Fund
| Gross income from securities lending activities | $781,631 |
| Fees paid to securities lending agent from a revenue split | 39,082 |
| Fees paid for any cash collateral management service (including fees deducted from a pooled cash collateral reinvestment vehicle) not included in the revenue split | 0 |
| Administrative fees not included in the revenue split | 0 |
| Indemnification fees not included in the revenue split | 0 |
| Rebates (paid to borrower) | 0 |
| Other fees not included in the revenue split | 0 |
| Aggregate fees/compensation for securities lending activities | 39,082 |
| Net income from securities lending activities | 742,550 |
New World Fund
| Gross income from securities lending activities | $321,106 |
| Fees paid to securities lending agent from a revenue split | 16,055 |
| Fees paid for any cash collateral management service (including fees deducted from a pooled cash collateral reinvestment vehicle) not included in the revenue split | 0 |
| Administrative fees not included in the revenue split | 0 |
| Indemnification fees not included in the revenue split | 0 |
| Rebates (paid to borrower) | 0 |
| Other fees not included in the revenue split | 0 |
| Aggregate fees/compensation for securities lending activities | 16,055 |
| Net income from securities lending activities | 305,051 |
Capital World Growth and Income Fund
| Gross income from securities lending activities | $596,224 |
| Fees paid to securities lending agent from a revenue split | 29,811 |
| Fees paid for any cash collateral management service (including fees deducted from a pooled cash collateral reinvestment vehicle) not included in the revenue split | 0 |
| Administrative fees not included in the revenue split | 0 |
| Indemnification fees not included in the revenue split | 0 |
| Rebates (paid to borrower) | 0 |
| Other fees not included in the revenue split | 0 |
| Aggregate fees/compensation for securities lending activities | 29,811 |
| Net income from securities lending activities | 566,413 |
American Funds Insurance Series — Page 37
Growth and Income Fund
| Gross income from securities lending activities | $777,382 |
| Fees paid to securities lending agent from a revenue split | 38,869 |
| Fees paid for any cash collateral management service (including fees deducted from a pooled cash collateral reinvestment vehicle) not included in the revenue split | 0 |
| Administrative fees not included in the revenue split | 0 |
| Indemnification fees not included in the revenue split | 0 |
| Rebates (paid to borrower) | 0 |
| Other fees not included in the revenue split | 0 |
| Aggregate fees/compensation for securities lending activities | 38,869 |
| Net income from securities lending activities | 738,513 |
International Growth and Income Fund
| Gross income from securities lending activities | $255,541 |
| Fees paid to securities lending agent from a revenue split | 12,777 |
| Fees paid for any cash collateral management service (including fees deducted from a pooled cash collateral reinvestment vehicle) not included in the revenue split | 0 |
| Administrative fees not included in the revenue split | 0 |
| Indemnification fees not included in the revenue split | 0 |
| Rebates (paid to borrower) | 0 |
| Other fees not included in the revenue split | 0 |
| Aggregate fees/compensation for securities lending activities | 12,777 |
| Net income from securities lending activities | 242,764 |
Washington Mutual Investors Fund
| Gross income from securities lending activities | $116,292 |
| Fees paid to securities lending agent from a revenue split | 5,815 |
| Fees paid for any cash collateral management service (including fees deducted from a pooled cash collateral reinvestment vehicle) not included in the revenue split | 0 |
| Administrative fees not included in the revenue split | 0 |
| Indemnification fees not included in the revenue split | 0 |
| Rebates (paid to borrower) | 0 |
| Other fees not included in the revenue split | 0 |
| Aggregate fees/compensation for securities lending activities | 5,815 |
| Net income from securities lending activities | 110,477 |
American Funds Insurance Series — Page 38
Capital Income Builder
| Gross income from securities lending activities | $59,821 |
| Fees paid to securities lending agent from a revenue split | 2,991 |
| Fees paid for any cash collateral management service (including fees deducted from a pooled cash collateral reinvestment vehicle) not included in the revenue split | 0 |
| Administrative fees not included in the revenue split | 0 |
| Indemnification fees not included in the revenue split | 0 |
| Rebates (paid to borrower) | 0 |
| Other fees not included in the revenue split | 0 |
| Aggregate fees/compensation for securities lending activities | 2,991 |
| Net income from securities lending activities | 56,830 |
Asset Allocation Fund
| Gross income from securities lending activities | $1,180,363 |
| Fees paid to securities lending agent from a revenue split | 59,019 |
| Fees paid for any cash collateral management service (including fees deducted from a pooled cash collateral reinvestment vehicle) not included in the revenue split | 0 |
| Administrative fees not included in the revenue split | 0 |
| Indemnification fees not included in the revenue split | 0 |
| Rebates (paid to borrower) | 0 |
| Other fees not included in the revenue split | 0 |
| Aggregate fees/compensation for securities lending activities | 59,019 |
| Net income from securities lending activities | 1,121,344 |
American Funds Global Balanced Fund
| Gross income from securities lending activities | $4,303 |
| Fees paid to securities lending agent from a revenue split | 215 |
| Fees paid for any cash collateral management service (including fees deducted from a pooled cash collateral reinvestment vehicle) not included in the revenue split | 0 |
| Administrative fees not included in the revenue split | 0 |
| Indemnification fees not included in the revenue split | 0 |
| Rebates (paid to borrower) | 0 |
| Other fees not included in the revenue split | 0 |
| Aggregate fees/compensation for securities lending activities | 215 |
| Net income from securities lending activities | 4,088 |
* * * * * *
American Funds Insurance Series — Page 39
Portfolio turnover — Portfolio changes will be made without regard to the length of time particular investments may have been held. Short-term trading profits are not the funds’ objective, and changes in their investments are generally accomplished gradually, though short-term transactions may occasionally be made. Higher portfolio turnover may involve correspondingly greater transaction costs in the form of dealer spreads or brokerage commissions. It may also result in the realization of net capital gains, which are taxable when distributed to shareholders, unless the shareholder is exempt from taxation or his or her account is tax-favored.
Fixed income securities are generally traded on a net basis and usually neither brokerage commissions nor transfer taxes are involved. Transaction costs are usually reflected in the spread between the bid and asked price.
A fund’s portfolio turnover rate would equal 100% if each security in the fund’s portfolio was replaced once per year. The following table sets forth the portfolio turnover rates for each fund for the fiscal years ended December 31, 2021 and 2020, and the portfolio turnover rates excluding mortgage dollar roll transactions for certain funds for the fiscal years ended December 31, 2021 and 2020. See “Forward commitment, when issued and delayed delivery transactions” above for more information on mortgage dollar rolls.
| Fiscal year | Portfolio turnover rate* | Portfolio turnover rate (excluding mortgage dollar roll transactions) | |
| American Funds Global Balanced Fund | 2021 2020 |
39% 86 |
36% 68% |
* Increases (or decreases) in turnover were due to increased (or decreased) trading activity during the period.
See “Financial highlights” in the prospectus for each fund’s annual portfolio turnover rates for each of the last five fiscal years.
American Funds Insurance Series — Page 40
Fund policies
All percentage limitations in the following fund policies are considered at the time securities are purchased and are based on a fund’s net assets (excluding, for the avoidance of doubt, collateral held in connection with securities lending activities) unless otherwise indicated. None of the following policies involving a maximum percentage of assets will be considered violated unless the excess occurs immediately after, and is caused by, an acquisition by a fund. In managing a fund, a fund’s investment adviser may apply more restrictive policies than those listed below.
Fundamental policies — The Series has adopted the following policies, which may not be changed without approval by holders of a majority of its outstanding shares. Such majority is currently defined in the Investment Company Act of 1940, as amended (the “1940 Act”), as the vote of the lesser of (a) 67% or more of the voting securities present at a shareholder meeting, if the holders of more than 50% of the outstanding voting securities are present in person or by proxy, or (b) more than 50% of the outstanding voting securities.
Except where otherwise indicated, the following policies apply to each fund in the Series (please also see “Additional information about fundamental policies” below):
1. Except as permitted by (i) the 1940 Act and the rules and regulations thereunder, or other successor law governing the regulation of registered investment companies, or interpretations or modifications thereof by the U.S. Securities and Exchange Commission (“SEC”), SEC staff or other authority of competent jurisdiction, or (ii) exemptive or other relief or permission from the SEC, SEC staff or other authority of competent jurisdiction, a fund may not:
a. Borrow money;
b. Issue senior securities;
c. Underwrite the securities of other issuers;
d. Purchase or sell real estate or commodities;
e. Make loans; or
f. Purchase the securities of any issuer if, as a result of such purchase, a fund’s investments would be concentrated in any particular industry.
2. The fund may not invest in companies for the purpose of exercising control or management.
3. For Washington Mutual Investors Fund, the fund may not invest more than 5% of net assets in money market instruments, after allowing for sales of portfolio securities and fund shares within 30 days and the accumulation of cash balances representing undistributed net investment income and realized capital gains, in order to maintain a fully invested portfolio.
Nonfundamental policies — The following policy may be changed without shareholder approval:
The fund may not acquire securities of open-end investment companies or unit investment trusts registered under the 1940 Act in reliance on Sections 12(d)(1)(F) or 12(d)(1)(G) of the 1940 Act.
American Funds Insurance Series — Page 41
Additional information about fundamental policies — The information below is not part of the Series’ fundamental policies. This information is intended to provide a summary of what is currently required or permitted by the 1940 Act and the rules and regulations thereunder, or by the interpretive guidance thereof by the SEC or SEC staff, for particular fundamental policies of the Series. Information is also provided regarding the fund’s current intention with respect to certain investment practices permitted by the 1940 Act.
For purposes of fundamental policy 1a, the fund may borrow money in amounts of up to 33-1/3% of its total assets from banks for any purpose. Additionally, the fund may borrow up to 5% of its total assets from banks or other lenders for temporary purposes (a loan is presumed to be for temporary purposes if it is repaid within 60 days and is not extended or renewed). The percentage limitations in this policy are considered at the time of borrowing and thereafter. See "General information - Credit facility" in this statement of additional information for more information.
For purposes of fundamental policies 1a and 1e, certain funds may borrow money from, or loan money to, other funds managed by Capital Research and Management Company or its affiliates to the extent permitted by applicable law and an exemptive order issued by the SEC.
For purposes of fundamental policy 1b, a senior security does not include any promissory note or evidence of indebtedness if such loan is for temporary purposes only and in an amount not exceeding 5% of the value of the total assets of the fund at the time the loan is made (a loan is presumed to be for temporary purposes if it is repaid within 60 days and is not extended or renewed). Further, to the extent the fund covers its commitments under certain types of agreements and transactions, including derivatives, mortgage-dollar-roll transactions, sale-buybacks, when-issued, delayed-delivery, or forward commitment transactions, and other similar trading practices, by segregating or earmarking liquid assets equal in value to the amount of the fund’s commitment (in accordance with applicable SEC or SEC staff guidance), such agreement or transaction will not be considered a senior security by the fund.
For purposes of fundamental policy 1c, the policy will not apply to the fund to the extent the fund may be deemed an underwriter within the meaning of the 1933 Act in connection with the purchase and sale of fund portfolio securities in the ordinary course of pursuing its investment objectives and strategies.
For purposes of fundamental policy 1e, the fund may not lend more than 33-1/3% of its total assets, provided that this limitation shall not apply to the fund’s purchase of debt obligations, money market instruments and repurchase agreements.
For purposes of fundamental policy 1f, the fund may not invest more than 25% of its total assets in the securities of issuers in a particular industry. This policy does not apply to investments in securities of the United States government, its agencies or instrumentalities or government sponsored entities or repurchase agreements with respect thereto. Additionally, for purposes of fundamental policy 1f, Capital World Bond Fund considers the sovereign debt of each country as one separate industry.
For purposes of fundamental policy 3, money market instruments include one or more money market or similar funds managed by the investment adviser or its affiliates.
American Funds Insurance Series — Page 42
Management of the Series
Board of trustees and officers
Independent trustees1
The Series’ nominating and governance committee and board select independent trustees with a view toward constituting a board that, as a body, possesses the qualifications, skills, attributes and experience to appropriately oversee the actions of the Series’ service providers, decide upon matters of general policy and represent the long-term interests of fund shareholders. In doing so, they consider the qualifications, skills, attributes and experience of the current board members, with a view toward maintaining a board that is diverse in viewpoint, experience, education and skills.
The Series seeks independent trustees who have high ethical standards and the highest levels of integrity and commitment, who have inquiring and independent minds, mature judgment, good communication skills, and other complementary personal qualifications and skills that enable them to function effectively in the context of the Series’ board and committee structure and who have the ability and willingness to dedicate sufficient time to effectively fulfill their duties and responsibilities.
Each independent trustee has a significant record of accomplishments in governance, business, not-for-profit organizations, government service, academia, law, accounting or other professions. Although no single list could identify all experience upon which the Series’ independent trustees draw in connection with their service, the following table summarizes key experience for each independent trustee. These references to the qualifications, attributes and skills of the trustees are pursuant to the disclosure requirements of the SEC, and shall not be deemed to impose any greater responsibility or liability on any trustee or the board as a whole. Notwithstanding the accomplishments listed below, none of the independent trustees is considered an “expert” within the meaning of the federal securities laws with respect to information in the Series’ registration statement.
American Funds Insurance Series — Page 43
| Name, year of birth and position with Series (year first elected as a trustee2) | Principal
occupation(s) during the past five years |
Number
of portfolios in fund complex overseen by trustee |
Other
directorships3 held by trustee during the past five years |
Other relevant experience |
| Francisco
G. Cigarroa, MD, 1957 Trustee (2021) |
Professor of Surgery, University of Texas Health San Antonio; Trustee, Ford Foundation; Clayton Research Scholar, Clayton Foundation for Biomedical Research | 86 | None | · Corporate board experience · Service on boards of community and nonprofit organizations · MD |
| James
G. Ellis, 1947 Trustee (2010) |
Former Dean and Professor of Marketing, Marshall School of Business, University of Southern California | 99 | Advanced Merger Partners; EVe Mobility Acquisition Corp (acquisitions of companies in the electric vehicle market); J. G. Boswell (agricultural production); Mercury General Corporation | · Service as chief executive officer for multiple companies · Corporate board experience · Service on advisory and trustee boards for charitable, municipal and nonprofit organizations · MBA |
American Funds Insurance Series — Page 44
| Name, year of birth and position with Series (year first elected as a trustee2) | Principal
occupation(s) during the past five years |
Number
of portfolios in fund complex overseen by trustee |
Other
directorships3 held by trustee during the past five years |
Other relevant experience |
| Nariman
Farvardin, 1956 Trustee (2018) |
President, Stevens Institute of Technology | 91 | None | · Senior management experience, educational institution · Corporate board experience · Professor, electrical and computer engineering · Service on advisory boards and councils for educational, nonprofit and governmental organizations · MS, PhD, electrical engineering |
| Mary
Davis Holt, 1950 Trustee (2015-2016; 2017) |
Principal, Mary Davis Holt Enterprises, LLC (leadership development consulting); former Partner, Flynn Heath Holt Leadership, LLC (leadership consulting); former COO, Time Life Inc. (1993–2003) | 87 | None | · Service as chief operations officer, global media company · Senior corporate management experience · Corporate board experience · Service on advisory and trustee boards for educational, business and nonprofit organizations · MBA |
American Funds Insurance Series — Page 45
| Name, year of birth and position with Series (year first elected as a trustee2) | Principal
occupation(s) during the past five years |
Number
of portfolios in fund complex overseen by trustee |
Other
directorships3 held by trustee during the past five years |
Other relevant experience |
| Merit
E. Janow, 1958 Trustee (2007) |
Former Dean and Professor of Practice, International Economic Law & International Affairs, Columbia University, School of International and Public Affairs | 93 | Aptiv (autonomous and green vehicle technology); Mastercard Incorporated Former director of Trimble Inc. (software, hardware and services technology) (until 2021) |
· Service with Office of the U.S. Trade Representative and U.S. Department of Justice · Corporate board experience · Service on advisory and trustee boards for charitable, educational and nonprofit organizations · Experience as corporate lawyer · JD |
| Margaret
Spellings, 1957 Chair of the Board (Independent and Non-Executive) (2010) |
President and CEO, Texas 2036; former President, Margaret Spellings & Company (public policy and strategic consulting); former President, The University of North Carolina; former President, George W. Bush Presidential Center | 91 | Former director of ClubCorp Holdings, Inc. (until 2017) | · Former U.S. Secretary of Education, U.S. Department of Education · Former Assistant to the President for Domestic Policy, The White House · Former senior advisor to the Governor of Texas · Service on advisory and trustee boards for charitable and nonprofit organizations |
American Funds Insurance Series — Page 46
| Name, year of birth and position with Series (year first elected as a trustee2) | Principal
occupation(s) during the past five years |
Number
of portfolios in fund complex overseen by trustee |
Other
directorships3 held by trustee during the past five years |
Other relevant experience |
| Alexandra
Trower, 1964 Trustee (2018) |
Former Executive Vice President, Global Communications and Corporate Officer, The Estée Lauder Companies | 86 | None | · Service on trustee boards for charitable and nonprofit organizations · Senior corporate management experience · Branding |
| Paul
S. Williams, 1959 Trustee (2020) |
Former Partner/Managing Director, Major, Lindsey & Africa (executive recruiting firm) | 86 | Air Transport Services Group, Inc. (aircraft leasing and air cargo transportation); Compass Minerals, Inc. (producer of salt and specialty fertilizers); Public Storage, Inc.; Romeo Power, Inc. (manufacturer of batteries for electric vehicles) Former director of Bob Evans Farms, Inc. (restaurant company) (until 2017); Essendant, Inc. (business products wholesaler) (until 2019) |
· Senior corporate management experience · Corporate board experience · Corporate governance experience · Service on trustee boards for charitable and educational nonprofit organizations · Securities law expertise · JD |
American Funds Insurance Series — Page 47
Interested trustee(s)4,5
Interested trustees have similar qualifications, skills and attributes as the independent trustees. Interested trustees are senior executive officers and/or directors of Capital Research and Management Company or its affiliates. Such management roles with the Series’ service providers also permit the interested trustees to make a significant contribution to the Series’ board.
| Name,
year of birth and position with Series (year first elected as a trustee2) |
Principal
occupation(s) during the past five years and positions held with affiliated entities or the Principal Underwriter of the Series during the past five years |
Number
of portfolios in fund complex overseen by trustee |
Other directorships3 held by trustee during the past five years |
| Donald
D. O’Neal, 1960 Co-President and Trustee (1998) |
Partner – Capital International Investors, Capital Research and Management Company; Partner – Capital International Investors, Capital Bank and Trust Company* | 35 | None |
| Michael
C. Gitlin, 1970 Trustee (2019) |
Partner – Capital Fixed Income Investors, Capital Research and Management Company; Vice Chairman and Director, Capital Research and Management Company; Director, The Capital Group Companies, Inc.*; served as Head of Fixed Income at a large investment management firm prior to joining Capital Research and Management Company in 2015 | 86 | None |
Other officers5
| Name,
year of birth and position with Series (year first elected as an officer2) |
Principal
occupation(s) during the past five years and positions held with affiliated entities or the Principal Underwriter of the Series |
| Alan
N. Berro, 1960 Co-President (1998) |
Partner – Capital World Investors, Capital Research and Management Company; Partner – Capital World Investors, Capital Bank and Trust Company*; Director, The Capital Group Companies, Inc.* |
| Maria
Manotok, 1974 Principal Executive Officer (2012) |
Senior Vice President and Senior Counsel – Fund Business Management Group, Capital Research and Management Company; Chair, Senior Vice President, Senior Counsel and Director, Capital International, Inc.*; Senior Vice President and Director, Capital Group International, Inc.*; Director, Capital Group Investment Management Limited* |
| Michael
W. Stockton, 1967 Executive Vice President (2021) |
Senior Vice President – Fund Business Management Group, Capital Research and Management Company |
| Martin
Jacobs, 1962 Vice President (2016) |
Partner – Capital Research Global Investors, Capital Research and Management Company; Director, The Capital Group Companies, Inc.* |
American Funds Insurance Series — Page 48
| Name,
year of birth and position with Series (year first elected as an officer2) |
Principal
occupation(s) during the past five years and positions held with affiliated entities or the Principal Underwriter of the Series |
| Carl
M. Kawaja, 1964 Vice President (2008) |
Partner – Capital World Investors, Capital Research and Management Company; Partner – Capital World Investors, Capital Bank and Trust Company*; Chairman and Director, Capital Research and Management Company |
| Sung
Lee, 1966 Vice President (2008) |
Partner – Capital Research Global Investors, Capital International, Inc.*; Director, The Capital Group Companies, Inc.* |
| Keiko
McKibben, 1969 Vice President (2010) |
Partner – Capital Research Global Investors, Capital Research and Management Company |
| Renaud
H. Samyn, 1974 Vice President (2010) |
Partner – Capital Research Global Investors, Capital International, Inc.* |
| Steven
I. Koszalka, 1964 Secretary (2003) |
Vice President – Fund Business Management Group, Capital Research and Management Company |
| Gregory
F. Niland, 1971 Treasurer (2008) |
Vice President - Investment Operations, Capital Research and Management Company |
| Susan
K. Countess, 1966 Assistant Secretary (2014) |
Associate – Fund Business Management Group, Capital Research and Management Company |
| Sandra
Chuon, 1972 Assistant Treasurer (2019) |
Assistant Vice President – Investment Operations, Capital Research and Management Company |
| Brian
C. Janssen, 1972 Assistant Treasurer (2015) |
Senior Vice President – Investment Operations, Capital Research and Management Company |
* Company affiliated with Capital Research and Management Company.
1 The term independent trustee refers to a trustee who is not an “interested person” of the funds within the meaning of the 1940 Act.
2 Trustees and officers of the Series serve until their resignation, removal or retirement.
3 This includes all directorships/trusteeships (other than those in the American Funds or other funds managed by Capital Research and Management Company or its affiliates) that are held by each trustee as a director/trustee of a public company or a registered investment company. Unless otherwise noted, all directorships/trusteeships are current.
4 The term interested trustee refers to a trustee who is an “interested person” of the funds within the meaning of the 1940 Act, on the basis of his or her affiliation with the Series’ investment adviser, Capital Research and Management Company, or affiliated entities.
5 All of the trustees and/or officers listed are officers and/or directors/trustees of one or more of the other funds for which Capital Research and Management Company serves as investment adviser.
The address for all trustees and officers of the Series is 333 South Hope Street, 55th Floor, Los Angeles, California 90071, Attention: Secretary.
American Funds Insurance Series — Page 49
Fund shares owned by trustees as of December 31, 2021:
| Name | Dollar
range1,2 of fund shares owned3 |
Aggregate dollar range1 of shares owned in all funds overseen by trustee in the same family of investment companies as the fund |
Dollar range1 of independent trustees deferred compensation4 allocated to fund |
Aggregate dollar range1,2 of independent trustees deferred compensation4 allocated to all funds overseen by trustee in the same family of investment companies as the fund |
| Independent trustees | ||||
| Francisco G. Cigarroa | None | None | N/A5 | Over $100,000 |
| James G. Ellis | None | Over $100,000 | N/A5 | N/A |
| Nariman Farvardin | None | Over $100,000 | N/A5 | Over $100,000 |
| Mary Davis Holt | None | Over $100,000 | N/A5 | N/A |
| Merit E. Janow | None | Over $100,000 | N/A5 | $50,001 – $100,000 |
| Margaret Spellings | None | Over $100,000 | N/A5 | Over $100,000 |
| Alexandra Trower | None | Over $100,000 | N/A5 | Over $100,000 |
| Paul S. Williams | None | Over $100,000 | N/A5 | Over $100,000 |
| Name | Dollar
range1,2 of fund shares owned |
Aggregate dollar range1 of shares owned in all funds overseen by trustee in the same family of investment companies as the fund |
| Interested trustees | ||
| Donald D. O’Neal | None | None |
| Michael C. Gitlin | None | Over $100,000 |
1 Ownership disclosure is made using the following ranges: None; $1 – $10,000; $10,001 – $50,000; $50,001 – $100,000; and Over $100,000. The amounts listed for interested trustees include shares owned through The Capital Group Companies, Inc. retirement plan and 401(k) plan.
2 N/A indicates that the listed individual, as of December 31, 2021, was not a trustee of a particular fund, did not allocate deferred compensation to the fund or did not participate in the deferred compensation plan.
3 Shares of the funds may only be owned by purchasing variable annuity and variable life insurance contracts. Each trustee’s need for variable annuity or variable life contracts and the role those contracts would play in his or her comprehensive investment portfolio will vary and depend on a number of factors including tax, estate planning, life insurance, alternative retirement plans or other considerations.
4 Eligible trustees may defer their compensation under a nonqualified deferred compensation plan. Amounts deferred by the trustee accumulate at an earnings rate determined by the total return of one or more American Funds as designated by the trustee.
5 The funds in the Series are not available for investment in the independent trustees deferred compensation plan.
American Funds Insurance Series — Page 50
Trustee compensation — No compensation is paid by the Series to any officer or trustee who is a director, officer or employee of the investment adviser or its affiliates. Except for the independent trustees listed in the “Board of trustees and officers — Independent trustees” table under the “Management of the Series” section in this statement of additional information, all other officers and trustees of the Series are directors, officers or employees of the investment adviser or its affiliates. The boards of funds advised by the investment adviser typically meet either individually or jointly with the boards of one or more other such funds with substantially overlapping board membership (in each case referred to as a “board cluster”). The Series typically pays each independent trustee an annual retainer fee based primarily on the total number of board clusters on which that independent trustee serves.
In addition, the Series generally pays independent trustees attendance and other fees for meetings of the board and its committees. Board and committee chairs receive additional fees for their services.
Independent trustees also receive attendance fees for certain special joint meetings and information sessions with directors and trustees of other groupings of funds advised by the investment adviser. The Series and the other funds served by each independent trustee each pay a portion of these attendance fees.
No pension or retirement benefits are accrued as part of Series expenses. Independent trustees may elect, on a voluntary basis, to defer all or a portion of their fees through a deferred compensation plan in effect for the Series. The Series also reimburses certain expenses of the independent trustees.
Trustee compensation earned during the fiscal year ended December 31, 2021:
| Name | Aggregate
compensation (including voluntarily deferred compensation1) from the series |
Total
compensation (including voluntarily deferred compensation1) from all funds managed by Capital Research and Management Company or its affiliates |
| Francisco
G. Cigarroa2 (service began January 2, 2021) |
$63,902 | $318,000 |
| James G. Ellis | 49,534 | 502,000 |
| Nariman Farvardin2 | 46,669 | 400,500 |
| Mary Davis Holt | 48,680 | 375,000 |
| R.
Clark Hooper2 (retired December 31, 2021) |
41,163 | 418,676 |
| Merit E. Janow2 | 43,953 | 443,476 |
| Margaret Spellings2 | 53,512 | 513,476 |
| Alexandra Trower2 | 63,900 | 318,000 |
| Paul S. Williams2 | 64,003 | 318,500 |
1 Amounts may be deferred by eligible trustees under a nonqualified deferred compensation plan adopted by the Series in 1993. Deferred amounts accumulate at an earnings rate determined by the total return of one or more American Funds as designated by the trustees. Compensation shown in this table for the fiscal year ended December 31, 2021 does not include earnings on amounts deferred in previous fiscal years. See footnote 2 to this table for more information.
2 Since the deferred compensation plan’s adoption, the total amount of deferred compensation accrued by the Series (plus earnings thereon) through the end of the 2021 fiscal year for participating trustees is as follows: Francisco G. Cigarroa ($30,289), Nariman Farvardin ($346,859), R. Clark Hooper ($194,344), Merit E. Janow ($11,787), Margaret Spellings ($357,139), Alexandra Trower ($403,562) and Paul S. Williams ($49,254). Amounts deferred and accumulated earnings thereon are not funded and are general unsecured liabilities of the Series until paid to the trustees.
American Funds Insurance Series — Page 51
Series organization and the board of trustees — The Series, an open-end investment company, was organized as a Massachusetts business trust on September 13, 1983. At a meeting of the Series’ shareholders on November 24, 2009, shareholders approved the reorganization of the Series to a Delaware statutory trust. However, the Series reserved the right to delay implementing the reorganization and has elected to do so. A summary comparison of the governing documents and state laws affecting the Delaware statutory trust and the current form of organization of the Series can be found in the proxy statement for the Series dated August 28, 2009, which is available on the SEC’s website at sec.gov.
All Series operations are supervised by its board of trustees, which meets periodically and performs duties required by applicable state and federal laws. Independent board members are paid certain fees for services rendered to the Series as described above. They may elect to defer all or a portion of these fees through a deferred compensation plan in effect for the Series.
Massachusetts common law provides that a trustee of a Massachusetts business trust owes a fiduciary duty to the trust and must carry out his or her responsibilities as a trustee in accordance with that fiduciary duty. Generally, a trustee will satisfy his or her duties if he or she acts in good faith and uses ordinary prudence.
The Series currently consists of separate funds which have separate assets and liabilities, and invest in separate investment portfolios. The board of trustees may create additional funds in the future. Income, direct liabilities and direct operating expenses of a fund will be allocated directly to that fund and general liabilities and expenses of the Series will be allocated among the funds in proportion to the total net assets of each fund.
Each fund has Class 1, Class 1A, Class 2 and Class 4 shares. In addition, Growth Fund, International Fund, Growth-Income Fund, Asset Allocation Fund, American High-Income Trust, Ultra-Short Bond Fund and U.S. Government Securities Fund have Class 3 shares. Other funds in the series have Class P1 and/or Class P2 shares. The shares of each class represent an interest in the same investment portfolio. Each class has equal rights as to voting, redemption, dividends and liquidation, except that each class bears different distribution expenses and other expenses properly attributable to the particular class as approved by the board of trustees and set forth in the Series’ amended and restated rule 18f-3 Plan. Class 1A, Class 2, Class 3 and Class 4 shareholders have exclusive voting rights with respect to their respective rule 12b-1 Plans adopted in connection with the distribution of Class 1A, Class 2, Class 3 and Class 4 shares. Class 1A and Class 4 shareholders have exclusive voting rights with respect to their Insurance Administrative Services Plans. Shares of each Class of the Series vote together on matters that affect all classes in substantially the same manner. Each class votes as a class on matters that affect that class alone.
The Series does not hold annual meetings of shareholders. However, significant matters that require shareholder approval, such as certain elections of board members or a change in a fundamental investment policy, will be presented to shareholders at a meeting called for such purpose. Shareholders have one vote per share owned. At the request of the holders of at least 10% of the shares, the Series will hold a meeting at which any member of the board could be removed by a majority vote.
The Series’ declaration of trust and by-laws, as well as separate indemnification agreements that the Series has entered into with independent trustees, provide in effect that, subject to certain conditions, the Series will indemnify its officers and trustees against liabilities or expenses actually and reasonably incurred by them relating to their service to the Series. However, trustees are not protected from liability by reason of their willful misfeasance, bad faith, gross negligence or reckless disregard of the duties involved in the conduct of their office.
American Funds Insurance Series — Page 52
Leadership structure — The board’s chair is currently an independent trustee who is not an “interested person” of the Series within the meaning of the 1940 Act. The board has determined that an independent chair facilitates oversight and enhances the effectiveness of the board. The independent chair’s duties include, without limitation, generally presiding at meetings of the board, approving board meeting schedules and agendas, leading meetings of the independent trustees in executive session, facilitating communication with committee chairs, and serving as the principal independent trustee contact for Series management and counsel to the independent trustees and the fund.
Risk oversight — Day-to-day management of the Series, including risk management, is the responsibility of the Series’ contractual service providers, including the Series’ investment adviser, principal underwriter/distributor and transfer agent. Each of these entities is responsible for specific portions of the Series’ operations, including the processes and associated risks relating to the funds’ investments, integrity of cash movements, financial reporting, operations and compliance. The board of trustees oversees the service providers’ discharge of their responsibilities, including the processes they use to manage relevant risks. In that regard, the board receives reports regarding the operations of the Series’ service providers, including risks. For example, the board receives reports from investment professionals regarding risks related to the funds’ investments and trading. The board also receives compliance reports from the Series and the investment adviser’s chief compliance officers addressing certain areas of risk.
Committees of the Series board, which are comprised of independent board members, none of whom is an “interested person” of the fund within the meaning of the 1940 Act, as well as joint committees of independent board members of funds managed by Capital Research and Management Company, also explore risk management procedures in particular areas and then report back to the full board. For example, the Series’ audit committee oversees the processes and certain attendant risks relating to financial reporting, valuation of fund assets, and related controls. Similarly, a joint review and advisory committee oversees certain risk controls relating to the fund’s transfer agency services.
Not all risks that may affect the Series can be identified or processes and controls developed to eliminate or mitigate their effect. Moreover, it is necessary to bear certain risks (such as investment-related risks) to achieve each fund’s objectives. As a result of the foregoing and other factors, the ability of the Series’ service providers to eliminate or mitigate risks is subject to limitations.
Committees of the board of trustees — The Series has an audit committee comprised of Francisco G. Cigarroa, James G. Ellis and Paul S. Williams. The committee provides oversight regarding the Series’ accounting and financial reporting policies and practices, its internal controls and the internal controls of the Series’ principal service providers. The committee acts as a liaison between the Series’ independent registered public accounting firm and the full board of trustees. The audit committee held five meetings during the 2021 fiscal year.
The Series has a contracts committee comprised of all of its independent board members. The committee’s principal function is to request, review and consider the information deemed necessary to evaluate the terms of certain agreements between the Series and its investment adviser or the investment adviser’s affiliates, such as the Investment Advisory and Service Agreement and plan of distribution adopted pursuant to rule 12b-1 under the 1940 Act, that the Series may enter into, renew or continue, and to make its recommendations to the full board of trustees on these matters. The contracts committee held one meeting during the 2021 fiscal year.
The Series has a nominating and governance committee comprised of Nariman Farvardin, Mary Davis Holt, Merit E. Janow, Margaret Spellings and Alexandra Trower. The committee periodically reviews such issues as the board’s composition, responsibilities, committees, compensation and other relevant issues, and recommends any appropriate changes to the full board of trustees. The committee also coordinates annual self-assessments of the board and evaluates, selects and
American Funds Insurance Series — Page 53
nominates independent trustee candidates to the full board of trustees. While the committee normally is able to identify from its own and other resources an ample number of qualified candidates, it will consider shareholder suggestions of persons to be considered as nominees to fill future vacancies on the board. Such suggestions must be sent in writing to the nominating and governance committee of the Series, addressed to the Series’ secretary, and must be accompanied by complete biographical and occupational data on the prospective nominee, along with a written consent of the prospective nominee for consideration of his or her name by the committee. The nominating and governance committee held two meetings during the 2021 fiscal year.
The independent board members of the Series have oversight responsibility for the Series and certain other funds managed by the investment adviser. As part of their oversight responsibility for these funds, each independent board member sits on one of three fund review committees comprised solely of independent board members. The three committees are divided by portfolio type. Each committee functions independently and is not a decision making body. The purpose of the committees is to assist the board of each series in the oversight of the investment management services provided by the investment adviser. In addition to regularly monitoring and reviewing investment results, investment activities and strategies used to manage the funds’ assets, the committees also receive reports from the investment adviser’s Principal Investment Officers for the funds, portfolio managers and other investment personnel concerning efforts to achieve the funds’ investment objectives. Each committee reports to the full board of the Series.
Proxy voting procedures and principles — The funds’ investment adviser, in consultation with the Series’ board, has adopted Proxy Voting Procedures and Principles (the “Principles”) with respect to voting proxies of securities held by the funds and other American Funds. The complete text of these principles is available at capitalgroup.com. Proxies are voted by a committee of the appropriate equity investment division of the investment adviser under authority delegated by the Series’ board. Therefore, if more than one fund invests in the same company, they may vote differently on the same proposal. The boards of American Funds have established a Joint Proxy Committee (“JPC”) composed of independent board members from each American Funds board. The JPC’s role is to facilitate appropriate oversight of the proxy voting process and provide valuable input on corporate governance and related matters.
The Principles, which have been in effect in substantially their current form for many years, provide an important framework for analysis and decision-making by all funds. However, they are not exhaustive and do not address all potential issues. The Principles provide a certain amount of flexibility so that all relevant facts and circumstances can be considered in connection with every vote. As a result, each proxy received is voted on a case-by-case basis considering the specific circumstances of each proposal. The voting process reflects the funds’ understanding of the company’s business, its management and its relationship with shareholders over time.
The investment adviser seeks to vote all U.S. proxies; however, in certain circumstances it may be impracticable or impossible to do so. Proxies for companies outside the U.S. also are voted, provided there is sufficient time and information available. Certain regulators have granted investment limit relief to the investment adviser and its affiliates, conditioned upon limiting its voting power to specific voting ceilings. To comply with these voting ceilings, the investment adviser will scale back its votes across all funds and clients on a pro-rata basis based on assets. After a proxy statement is received, the investment adviser prepares a summary of the proposals contained in the proxy statement. A notation of any potential conflicts of interest also is included in the summary (see below for a description of Capital Research and Management Company’s special review procedures).
For proxies of securities managed by a particular equity investment division of the investment adviser, the initial voting recommendation is made by one or more of the division’s investment analysts familiar with the company and industry. A second recommendation is made by a proxy coordinator (an investment analyst or other individual with experience in corporate governance and proxy voting
American Funds Insurance Series — Page 54
matters) within the appropriate investment division, based on knowledge of these Principles and familiarity with proxy-related issues. The proxy summary and voting recommendations are made available to the appropriate proxy voting committee for a final voting decision. In cases where a fund is co-managed and a security is held by more than one of the investment adviser’s equity investment divisions, the divisions may develop different voting recommendations for individual ballot proposals. If this occurs, and if permitted by local market conventions, the fund’s position will generally be voted proportionally by divisional holding, according to their respective decisions. Otherwise, the outcome will be determined by the equity investment division or divisions with the larger position in the security as of the record date for the shareholder meeting.
In addition to our proprietary proxy voting, governance and executive compensation research, Capital Research and Management Company may utilize research provided by Institutional Shareholder Services, Glass-Lewis & Co. or other third-party advisory firms on a case-by-case basis. It does not, as a policy, follow the voting recommendations provided by these firms. It periodically assesses the information provided by the advisory firms and reports to the JPC, as appropriate.
From time to time the investment adviser may vote proxies issued by, or on proposals sponsored or publicly supported by (a) a client with substantial assets managed by the investment adviser or its affiliates, (b) an entity with a significant business relationship with Capital Group, or (c) a company with a director of an American Fund on its board (each referred to as an “Interested Party”). Other persons or entities may also be deemed an Interested Party if facts or circumstances appear to give rise to a potential conflict. The investment adviser analyzes these proxies and proposals on their merits and does not consider these relationships when casting its vote.
The investment adviser has developed procedures to identify and address instances where a vote could appear to be influenced by such a relationship. Under the procedures, prior to a final vote being cast by the investment adviser, the relevant proxy committees’ voting results for proxies issued by Interested Parties are reviewed by a Special Review Committee (“SRC”) of the investment division voting the proxy if the vote was in favor of the Interested Party.
If a potential conflict is identified according to the procedure above, the SRC will be provided with a summary of any relevant communications with the Interested Party, the rationale for the voting decision, information on the organization’s relationship with the party and any other pertinent information. The SRC will evaluate the information and determine whether the decision was in the best interest of fund shareholders. It will then accept or override the voting decision or determine alternative action. The SRC includes senior investment professionals and legal and compliance professionals.
Information regarding how the funds voted proxies relating to portfolio securities during the 12-month period ended June 30 of each year will be available on or about September 1 of such year (a) without charge, upon request by calling American Funds Service Company at (800) 421-4225, (b) on the Capital Group website and (c) on the SEC’s website at sec.gov.
The following summary sets forth the general positions of American Funds, the Series and the investment adviser on various proposals. A copy of the full Principles is available upon request, free of charge, by calling American Funds Service Company or visiting the Capital Group website.
Director matters — The election of a company’s slate of nominees for director generally is supported. Votes may be withheld for some or all of the nominees if this is determined to be in the best interest of shareholders or if, in the opinion of the investment adviser, such nominee has not fulfilled his or her fiduciary duty. Separation of the chairman and CEO positions also may be supported.
American Funds Insurance Series — Page 55
Governance provisions — Typically, proposals to declassify a board (elect all directors annually) are supported based on the belief that this increases the directors’ sense of accountability to shareholders. Proposals for cumulative voting generally are supported in order to promote management and board accountability and an opportunity for leadership change. Proposals designed to make director elections more meaningful, either by requiring a majority vote or by requiring any director receiving more withhold votes than affirmative votes to tender his or her resignation, generally are supported.
Shareholder rights — Proposals to repeal an existing poison pill generally are supported. (There may be certain circumstances, however, when a proxy voting committee of a fund or an investment division of the investment adviser believes that a company needs to maintain anti-takeover protection.) Proposals to eliminate the right of shareholders to act by written consent or to take away a shareholder’s right to call a special meeting typically are not supported.
Compensation and benefit plans — Option plans are complicated, and many factors are considered in evaluating a plan. Each plan is evaluated based on protecting shareholder interests and a knowledge of the company and its management. Considerations include the pricing (or repricing) of options awarded under the plan and the impact of dilution on existing shareholders from past and future equity awards. Compensation packages should be structured to attract, motivate and retain existing employees and qualified directors; however, they should not be excessive.
Routine matters — The ratification of auditors, procedural matters relating to the annual meeting and changes to company name are examples of items considered routine. Such items generally are voted in favor of management’s recommendations unless circumstances indicate otherwise.
American Funds Insurance Series — Page 56
Principal fund shareholders — The following tables identify those investors who own of record, or are known by the Series to own beneficially, 5% or more of any class of a fund’s shares as of the opening of business on April 1, 2022. Unless otherwise indicated, the ownership percentages below represent ownership of record rather than beneficial ownership.
American Funds Global Balanced Fund
| NAME AND ADDRESS | OWNERSHIP | OWNERSHIP PERCENTAGE | |
| Information to come | |||
As of April 1, 2022, the officers and trustees of the Series, as a group, owned beneficially or of record less than 1% of the outstanding shares of each fund.
American Funds Insurance Series — Page 57
Investment adviser — Capital Research and Management Company, the Series’ investment adviser, founded in 1931, maintains research facilities in the United States and abroad (Beijing, Geneva, Hong Kong, London, Los Angeles, Mumbai, New York, San Francisco, Singapore, Tokyo and Washington, D.C.). These facilities are staffed with experienced investment professionals. The investment adviser is located at 333 South Hope Street, Los Angeles, CA 90071. It is a wholly owned subsidiary of The Capital Group Companies, Inc., a holding company for several investment management subsidiaries. Capital Research and Management Company manages equity assets through three equity investment divisions and fixed income assets through its fixed income investment division, Capital Fixed Income Investors. The three equity investment divisions — Capital World Investors, Capital Research Global Investors and Capital International Investors — make investment decisions independently of one another. Portfolio managers in Capital International Investors rely on a research team that also provides investment services to institutional clients and other accounts advised by affiliates of Capital Research and Management Company. The investment adviser, which is deemed under the Commodity Exchange Act (the “CEA”) to be the operator of certain funds, has claimed an exclusion from the definition of the term commodity pool operator under the CEA with respect to each fund and, therefore, is not subject to registration or regulation as such under the CEA with respect to the funds.
The investment adviser has adopted policies and procedures that address issues that may arise as a result of an investment professional’s management of the funds and other funds and accounts. Potential issues could involve allocation of investment opportunities and trades among funds and accounts, use of information regarding the timing of fund trades, investment professional compensation and voting relating to portfolio securities. The investment adviser believes that its policies and procedures are reasonably designed to address these issues.
Compensation of investment professionals — As described in the prospectus, the investment adviser uses a system of multiple portfolio managers in managing fund assets. In addition, Capital Research and Management Company’s investment analysts may make investment decisions with respect to a portion of a fund’s portfolio within their research coverage.
Portfolio managers and investment analysts are paid competitive salaries by Capital Research and Management Company. In addition, they may receive bonuses based on their individual portfolio results. Investment professionals also may participate in profit-sharing plans. The relative mix of compensation represented by bonuses, salary and profit-sharing plans will vary depending on the individual’s portfolio results, contributions to the organization and other factors.
To encourage a long-term focus, bonuses based on investment results are calculated by comparing pretax total investment returns to relevant benchmarks over the most recent one-, three-, five- and eight-year periods, with increasing weight placed on each succeeding measurement period. For portfolio managers, benchmarks may include measures of the marketplaces in which the fund invests and measures of the results of comparable mutual funds. For investment analysts, benchmarks may include relevant market measures and appropriate industry or sector indexes reflecting their areas of expertise. Capital Research and Management Company makes periodic subjective assessments of analysts’ contributions to the investment process and this is an element of their overall compensation. The investment results of each of the funds’ portfolio managers may be measured against one or more benchmarks, depending on his or her investment focus, such as:
American Funds Insurance Series — Page 58
Global Growth Fund — MSCI All Country World Index and a custom average consisting of funds that disclose investment objectives and strategies comparable to those of the fund;
Global Small Capitalization Fund —MSCI USA Small Cap Index, MSCI All Country World ex USA Small Cap Index and a custom average consisting of funds that disclose investment objectives and strategies comparable to those of the fund;
Growth Fund — S&P 500 Index, Russell 1000 Growth Index with 6.5% Issuer Cap and a custom average consisting of funds that disclose investment objectives and strategies comparable to those of the fund;
International Fund — MSCI All Country World ex USA Index and a custom average consisting of funds that disclose investment objectives and strategies comparable to those of the fund;
New World Fund — MSCI All Country World Index, MSCI Emerging Markets Index and a custom average consisting of funds that disclose investment objectives and strategies comparable to those of the fund;
Capital World Growth and Income Fund — MSCI All Country World Index and a custom average consisting of funds that disclose investment objectives and strategies comparable to those of the fund;
Growth-Income Fund — S&P 500 Index and a custom average consisting of funds that disclose investment objectives and strategies comparable to those of the fund;
International Growth and Income Fund — MSCI All Country World ex USA Index and a custom average consisting of funds that disclose investment objectives and strategies comparable to those of the fund;
Washington Mutual Investors Fund — S&P 500 Index, securities that are eligible to be purchased by the fund;
Capital Income Builder — [a custom index of U.S., international and global funds that have an explicit income objective or focus, a custom index of global securities screened by yield that aligns to the investment objectives and strategies of the fund];
Asset Allocation Fund — S&P 500 Index, Bloomberg U.S. Aggregate Index, Bloomberg U.S. Corporate High Yield Index 2% Issuer Cap and a custom average consisting of funds that disclose investment objectives and strategies comparable to those of the fund;
American Funds Global Balanced Fund — Bloomberg Global Aggregate Index Cap and a custom average consisting of funds that disclose investment objectives and strategies comparable to those of the fund;
American Funds Mortgage Fund — Bloomberg U.S. Mortgage Securities Index and a custom average consisting of funds that disclose investment objectives and strategies comparable to those of the fund;
American Funds Insurance Series — Page 59
American High-Income Trust — Bloomberg U.S. Corporate High Yield Index 2% Issuer Cap and a custom average consisting of funds that disclose investment objectives and strategies comparable to those of the fund;
Capital World Bond Fund — Bloomberg U.S. Corporate High Yield Index 2% Issuer Cap and a custom average consisting of funds that disclose investment objectives and strategies comparable to those of the fund;
The Bond Fund of America — Bloomberg U.S. Aggregate Index and a custom average consisting of funds that disclose investment objectives and strategies comparable to those of the fund;
Corporate Bond Fund — Bloomberg U.S. Corporate Bond Index and a custom average consisting of funds that disclose investment objectives and strategies comparable to those of the fund; and
U.S. Government Securities Fund — Bloomberg U.S. Government/Mortgage Backed Securities Index and a custom average consisting of funds that disclose investment objectives and strategies comparable to those of the fund.
From time to time, Capital Research and Management Company may adjust or customize these benchmarks to better reflect the universe of comparably managed funds of competitive investment management firms.
Portfolio manager fund holdings and management of other accounts — Shares of the funds may only be owned by purchasing variable annuity and variable life insurance contracts. Each portfolio manager’s need for variable annuity or variable life insurance contracts and the role those contracts would play in his or her comprehensive investment portfolio will vary and depend on a number of factors including tax, estate planning, life insurance, alternative retirement plans or other considerations. The portfolio managers have determined that variable insurance or annuity contracts do not meet their current needs. Consequently, they do not hold shares of the funds.
Portfolio managers may also manage assets in other funds advised by Capital Research and Management Company or its affiliates. Other managed accounts as of the end of American Funds Insurance Series’ most recently completed fiscal year are listed as follows:
American Funds Insurance Series — Page 60
The following table reflects information as of December 31, 2021:
| Portfolio
manager/ Investment professional |
Number of other registered investment companies (RICs) for which portfolio manager or investment professional manages (assets of RICs in billions)1 |
Number of other pooled investment vehicles (PIVs) for which portfolio manager or investment professional manages (assets of PIVs in billions)1 |
Number of other accounts for which portfolio manager or investment professional manages (assets of other accounts in billions)1,2 | ||
| Global Growth Fund | |||||
| Patrice Collette | 3 | $166.5 | 3 | $19.37 | None |
| Paul Flynn | 3 | $148.5 | 1 | $0.09 | None |
| Jonathan Knowles | 5 | $481.8 | 4 | $22.18 | None |
| Roz Hongsaranagon | 1 | $82.2 | None | None | |
| Global Small Capitalization Fund | |||||
| Renaud H. Samyn | 4 | $221.3 | 2 | $1.24 | None |
| Michael Beckwith | 1 | $82.2 | None | None | |
| Bradford F. Freer | 5 | $174.0 | 1 | $0.55 | None |
| Harold H. La | 2 | $117.4 | 2 | $1.11 | None |
| Aidan O’Connell | 2 | $176.0 | 2 | $0.96 | None |
| Gregory W. Wendt | 2 | $176.0 | 2 | $0.96 | None |
| Growth Fund | |||||
| Paul Benjamin | 2 | $360.4 | 3 | $3.49 | None |
| Mark L. Casey | 5 | $834.3 | 4 | $6.92 | None |
| Irfan M. Furniturewala | Info to come | ||||
| Anne-Marie Peterson | 2 | $516.8 | 3 | $5.21 | None |
| Andraz Razen | 3 | $523.2 | 3 | $21.80 | None |
| Alan J. Wilson | 4 | $698.6 | 4 | $6.12 | None |
| International Fund | |||||
| Sung Lee | 3 | $316.0 | 3 | $3.60 | None |
| Renaud H. Samyn | 4 | $216.5 | 2 | $1.24 | None |
| Nicholas J. Grace | 3 | $250.7 | 3 | $3.10 | None |
| Christopher Thomsen | Info to come | ||||
American Funds Insurance Series — Page 61
| Portfolio
manager/ Investment professional |
Number of other registered investment companies (RICs) for which portfolio manager or investment professional manages (assets of RICs in billions)1 |
Number of other pooled investment vehicles (PIVs) for which portfolio manager or investment professional manages (assets of PIVs in billions)1 |
Number of other accounts for which portfolio manager or investment professional manages (assets of other accounts in billions)1,2 | |||||
| New World Fund | ||||||||
| Carl M. Kawaja | 3 | $538.4 | 4 | $17.00 | None | |||
| Bradford F. Freer | 5 | $174.2 | 1 | $0.55 | None | |||
| Nicholas J. Grace | 3 | $255.7 | 3 | $3.10 | None | |||
| Dawid Justus | 1 | $60.0 | 1 | $0.55 | None | |||
| Jonathan Knowles | 5 | $487.0 | 4 | $22.18 | None | |||
| Winnie Kwan | 5 | $201.0 | 3 | $1.19 | None | |||
| Robert W. Lovelace | Info to come | |||||||
| Piyada Phanaphat | 1 | $60.0 | 1 | $0.55 | None | |||
| Akira Shiraishi | Info to come | |||||||
| Kirstie Spence | 3 | $64.8 | 5 | $4.89 | 5 | $2.37 | ||
| Tomonori Tani | Info to come | |||||||
| Lisa Thompson | Info to come | |||||||
| Christopher Thomsen | Info to come | |||||||
| Capital World Growth and Income Fund | ||||||||
| Sung Lee | 3 | $323.0 | 3 | $3.60 | None | |||
| Alfonso Barroso | 4 | $267.8 | 5 | $2.08 | None | |||
| Jeremy Burge | 1 | $127.3 | 3 | $12.82 | None | |||
| Michael Cohen | Info to come | |||||||
| Leo Hee | 4 | $227.1 | 4 | $12.91 | None | |||
| Jin Lee | 4 | $339.8 | 3 | $1.30 | None | |||
| Lara Pellini | 3 | $348.8 | 5 | $4.70 | None | |||
| Renaud H. Samyn | 4 | $223.5 | 2 | $1.24 | None | |||
| Growth-Income Fund | ||||||||
| Donald D. O’Neal | 2 | $417.8 | 4 | $3.56 | None | |||
| Keiko McKibben | None | None | None | |||||
| Charles Ellwein | 1 | $88.0 | 1 | $0.63 | None | |||
| J. Blair Frank | 1 | $292.1 | 1 | $2.52 | None | |||
| William L. Robbins | Info to come | |||||||
| Carlos Schonfeld | None | None | None | |||||
American Funds Insurance Series — Page 62
| Portfolio
manager/ Investment professional |
Number of other registered investment companies (RICs) for which portfolio manager or investment professional manages (assets of RICs in billions)1 |
Number of other pooled investment vehicles (PIVs) for which portfolio manager or investment professional manages (assets of PIVs in billions)1 |
Number of other accounts for which portfolio manager or investment professional manages (assets of other accounts in billions)1,2 | |||
| International Growth and Income Fund | ||||||
| Michael Cohen | Info to come | |||||
| Patrice Collette | Info to come | |||||
| Paul Flynn | 3 | $157.7 | 1 | $0.09 | None | |
| Leo Hee | 4 | $229.1 | 4 | $12.91 | None | |
| Andrew B. Suzman | 20 | $414.6 | 2 | $2.44 | None | |
| Lisa Thompson | Info to come | |||||
| Steven T. Watson | Info to come | |||||
| Washington Mutual Investors Fund | ||||||
| Alan N. Berro | 24 | $510.2 | 3 | $3.59 | None | |
| Mark L. Casey | 5 | $868.2 | 5 | $6.92 | None | |
| Brady L. Enright | 4 | $537.1 | 4 | $20.99 | None | |
| Irfan M. Furniturewala | Info to come | |||||
| Jeffrey T. Lager | 3 | $425.7 | 3 | $3.59 | None | |
| Jin Lee | 4 | $330.7 | 3 | $2.15 | None | |
| Eric H. Stern | Info to come | |||||
| Diana Wagner | 2 | $330.7 | 2 | $1.71 | None | |
| Alan J. Wilson | 4 | $732.5 | 4 | $6.12 | None | |
| Capital Income Builder | ||||||
| Aline Avzaradel | 2 | $238.2 | 5 | $1.68 | None | |
| Alfonso Barroso | 5 | $269.6 | 5 | $2.08 | None | |
| Grant L. Cambridge | Info to come | |||||
| David A. Hoag | 8 | $483.9 | 5 | $9.79 | None | |
| Winnie Kwan | Info to come | |||||
| James B. Lovelace | 3 | $326.2 | 6 | $2.30 | None | |
| Fergus N. MacDonald | 8 | $272.5 | 5 | $1.65 | None | |
| Caroline Randall | 2 | $243.4 | 3 | $0.84 | None | |
| Bradley J. Vogt | 6 | $586.2 | 4 | $9.98 | None | |
| Steven T. Watson | Info to come | |||||
| Philip Winston | Info to come | |||||
American Funds Insurance Series — Page 63
| Portfolio
manager/ Investment professional |
Number of other registered investment companies (RICs) for which portfolio manager or investment professional manages (assets of RICs in billions)1 |
Number of other pooled investment vehicles (PIVs) for which portfolio manager or investment professional manages (assets of PIVs in billions)1 |
Number of other accounts for which portfolio manager or investment professional manages (assets of other accounts in billions)1,2 | |||||||||||
| Asset Allocation Fund | ||||||||||||||
| Alan N. Berro | 24 | $491.0 | 3 | $3.59 | None | |||||||||
| David A. Daigle | 3 | $152.3 | 2 | $1.81 | 23 | $0.79 | ||||||||
| Peter Eliot | 1 | $82.2 | None | None | ||||||||||
| Jeffrey T. Lager | 3 | $406.5 | 3 | $3.59 | None | |||||||||
| Jin Lee | 4 | $311.5 | 3 | $2.15 | None | |||||||||
| John R. Queen | 21 | $477.6 | 3 | $2.94 | 97 | $0.57 | ||||||||
| American Funds Global Balanced Fund | ||||||||||||||
| Alfonso Barroso | 5 | $270.2 | 5 | $2.08 | None | |||||||||
| Andrew A. Cormack | 3 | $44.9 | 2 | $2.71 | 1 | $1.00 | ||||||||
| Bradford F. Freer | 5 | $178.1 | 1 | $0.55 | None | |||||||||
| Thomas H. Høgh | 3 | $44.9 | 3 | $3.98 | 1 | $1.00 | ||||||||
| Winnie Kwan | Info to come | |||||||||||||
| American Funds Mortgage Fund | ||||||||||||||
| David J. Betanzos | 6 | $159.7 | 2 | $0.50 | None | |||||||||
| Oliver V. Edmonds | 1 | $9.3 | None | None | ||||||||||
| Fergus N. MacDonald | 8 | $273.3 | 4 | $1.13 | None | |||||||||
| American High-Income Trust | ||||||||||||||
| Tom Chow | 1 | $20.3 | None | None | ||||||||||
| David A. Daigle | 3 | $181.9 | 2 | $1.81 | 23 | $0.79 | ||||||||
| Tara L. Torrens | 1 | $20.3 | None | None | ||||||||||
| Shannon Ward | 6 | $409.3 | 4 | $10.58 | 14 | $0.29 | ||||||||
| Capital World Bond Fund | ||||||||||||||
| Phillip Chitty | 1 | $15.9 | 3 | $2.71 | 1 | $1.00 | ||||||||
| Andrew A. Cormack | 3 | $43.3 | 3 | $2.71 | 1 | $1.00 | ||||||||
| Thomas H. Høgh | 3 | $43.3 | 4 | $3.98 | 1 | $1.00 | ||||||||
American Funds Insurance Series — Page 64
| Portfolio
manager/ Investment professional |
Number of other registered investment companies (RICs) for which portfolio manager or investment professional manages (assets of RICs in billions)1 |
Number of other pooled investment vehicles (PIVs) for which portfolio manager or investment professional manages (assets of PIVs in billions)1 |
Number of other accounts for which portfolio manager or investment professional manages (assets of other accounts in billions)1,2 | |||
| The Bond Fund of America | ||||||
| Pramod Atluri | 3 | $435.2 | 3 | $2.86 | None | |
| David J. Betanzos | 6 | $146.8 | 2 | $0.50 | None | |
| David A. Hoag | 8 | $471.8 | 5 | $9.79 | None | |
| Fergus N. Macdonald | 8 | $260.4 | 4 | $1.13 | None | |
| Ultra-Short Bond Fund | ||||||
| Steven D. Lotwin | None | None | None | |||
| Corporate Bond Fund | ||||||
| Scott Sykes | 3 | $21.8 | 1 | $1.24 | 12 | $12.31 |
| U.S. Government Securities Fund | ||||||
| David J. Betanzos | 6 | $157.8 | 2 | $0.50 | None | |
| Fergus N. MacDonald | 8 | $271.4 | 4 | $1.13 | None | |
| Ritchie Tuazon | 4 | $271.9 | 3 | $2.94 | None | |
1 Indicates other RIC(s), PIV(s) or other accounts managed by Capital Research and Management Company or its affiliates for which the portfolio manager also has significant day to day management responsibilities. Assets noted are the total net assets of the RIC(s), PIV(s) or other accounts and are not the total assets managed by the individual, which is a substantially lower amount. No RIC, PIV or other account has an advisory fee that is based on the performance of the RIC, PIV or other account, unless otherwise noted.
2 Personal brokerage accounts of portfolio managers and their families are not reflected.
3 The advisory fee of one of these accounts (representing $0.29 billion in total assets) is based partially on its investment results.
4 The advisory fee of one of these accounts (representing $0.29 billion in total assets) is based partially on its investment results.
The fund’s investment adviser has adopted policies and procedures to mitigate material conflicts of interest that may arise in connection with a portfolio manager’s management of the fund, on the one hand, and investments in the other pooled investment vehicles and other accounts, on the other hand, such as material conflicts relating to the allocation of investment opportunities that may be suitable for both the fund and such other accounts.
American Funds Insurance Series — Page 65
Investment Advisory and Service Agreement — The Investment Advisory and Service Agreement (the “Agreement”) between the Series and the investment adviser will continue in effect until April 30, 2023, unless sooner terminated, and may be renewed from year to year thereafter, provided that any such renewal has been specifically approved at least annually by (a) the board of trustees, or by the vote of a majority (as defined in the 1940 Act) of the outstanding voting securities of the applicable Series, and (b) the vote of a majority of trustees who are not parties to the Agreement or interested persons (as defined in the 1940 Act) of any such party, in accordance with applicable laws and regulations. The Agreement provides that the investment adviser has no liability to the Series for its acts or omissions in the performance of its obligations to the Series not involving willful misconduct, bad faith, gross negligence or reckless disregard of its obligations under the Agreement. The Agreement also provides that either party has the right to terminate it, without penalty, upon 60 days’ written notice to the other party, and that the Agreement automatically terminates in the event of its assignment (as defined in the 1940 Act). In addition, the Agreement provides that the investment adviser may delegate all, or a portion of, its investment management responsibilities to one or more subsidiary advisers approved by the Series’ board, pursuant to an agreement between the investment adviser and such subsidiary. Any such subsidiary adviser will be paid solely by the investment adviser out of its fees.
American Funds Insurance Series — Page 66
Under the Agreement, the investment adviser receives a management fee based on the following annualized rates and daily net asset levels:
Global Growth Fund
| Rate | Net asset level | |
| In excess of | Up to | |
| 0.690% | $ 0 | $ 600,000,000 |
| 0.590 | 600,000,000 | 1,200,000,000 |
| 0.530 | 1,200,000,000 | 2,000,000,000 |
| 0.500 | 2,000,000,000 | 3,000,000,000 |
| 0.480 | 3,000,000,000 | 5,000,000,000 |
| 0.460 | 5,000,000,000 | 8,000,000,000 |
| 0.445 | 8,000,000,000 | |
Or, if net assets of Global Growth Fund are less than $1 billion
| Rate | Net asset level | |
| In excess of | Up to | |
| 0.580% | $ 0 | $ 500,000,000 |
| 0.480 | 500,000,000 | 1,000,000,000 |
Global Small Capitalization Fund
| Rate | Net asset level | |
| In excess of | Up to | |
| 0.800% | $ 0 | $ 600,000,000 |
| 0.740 | 600,000,000 | 1,000,000,000 |
| 0.700 | 1,000,000,000 | 2,000,000,000 |
| 0.670 | 2,000,000,000 | 3,000,000,000 |
| 0.650 | 3,000,000,000 | 5,000,000,000 |
| 0.635 | 5,000,000,000 | |
American Funds Insurance Series — Page 67
Growth Fund
| Rate | Net asset level | |
| In excess of | Up to | |
| 0.500% | $ 0 | $ 600,000,000 |
| 0.450 | 600,000,000 | 1,000,000,000 |
| 0.420 | 1,000,000,000 | 2,000,000,000 |
| 0.370 | 2,000,000,000 | 3,000,000,000 |
| 0.350 | 3,000,000,000 | 5,000,000,000 |
| 0.330 | 5,000,000,000 | 8,000,000,000 |
| 0.315 | 8,000,000,000 | 13,000,000,000 |
| 0.300 | 13,000,000,000 | 21,000,000,000 |
| 0.290 | 21,000,000,000 | 27,000,000,000 |
| 0.285 | 27,000,000,000 | 34,000,000,000 |
| 0.280 | 34,000,000,000 | |
International Fund
| Rate | Net asset level | |
| In excess of | Up to | |
| 0.690% | $ 0 | $ 500,000,000 |
| 0.590 | 500,000,000 | 1,000,000,000 |
| 0.530 | 1,000,000,000 | 1,500,000,000 |
| 0.500 | 1,500,000,000 | 2,500,000,000 |
| 0.480 | 2,500,000,000 | 4,000,000,000 |
| 0.470 | 4,000,000,000 | 6,500,000,000 |
| 0.460 | 6,500,000,000 | 10,500,000,000 |
| 0.450 | 10,500,000,000 | 17,000,000,000 |
| 0.440 | 17,000,000,000 | 21,000,000,000 |
| 0.430 | 21,000,000,000 | |
New World Fund
| Rate | Net asset level | |
| In excess of | Up to | |
| 0.850% | $ 0 | $ 500,000,000 |
| 0.770 | 500,000,000 | 1,000,000,000 |
| 0.710 | 1,000,000,000 | 1,500,000,000 |
| 0.660 | 1,500,000,000 | 2,500,000,000 |
| 0.620 | 2,500,000,000 | 4,000,000,000 |
| 0.580 | 4,000,000,000 | |
American Funds Insurance Series — Page 68
Capital World Growth and Income Fund
| Rate | Net asset level | |
| In excess of | Up to | |
| 0.690% | $ 0 | $ 600,000,000 |
| 0.590 | 600,000,000 | 1,200,000,000 |
| 0.530 | 1,200,000,000 | 2,000,000,000 |
| 0.500 | 2,000,000,000 | 3,000,000,000 |
| 0.480 | 3,000,000,000 | |
Growth-Income Fund
| Rate | Net asset level | |
| In excess of | Up to | |
| 0.500% | $ 0 | $ 600,000,000 |
| 0.450 | 600,000,000 | 1,500,000,000 |
| 0.400 | 1,500,000,000 | 2,500,000,000 |
| 0.320 | 2,500,000,000 | 4,000,000,000 |
| 0.285 | 4,000,000,000 | 6,500,000,000 |
| 0.256 | 6,500,000,000 | 10,500,000,000 |
| 0.242 | 10,500,000,000 | 13,000,000,000 |
| 0.235 | 13,000,000,000 | 17,000,000,000 |
| 0.230 | 17,000,000,000 | 21,000,000,000 |
| 0.225 | 21,000,000,000 | 27,000,000,000 |
| 0.222 | 27,000,000,000 | 34,000,000,000 |
| 0.219 | 34,000,000,000 | |
American Funds Insurance Series — Page 69
International Growth and Income Fund
| Rate | Net asset level | |
| In excess of | Up to | |
| 0.690% | $ 0 | $ 500,000,000 |
| 0.590 | 500,000,000 | 1,000,000,000 |
| 0.530 | 1,000,000,000 | 1,500,000,000 |
| 0.500 | 1,500,000,000 | |
Washington Mutual Investors Fund
| Rate | Net asset level | |
| In excess of | Up to | |
| 0.500% | $ 0 | $ 600,000,000 |
| 0.450 | 600,000,000 | 1,500,000,000 |
| 0.400 | 1,500,000,000 | 2,500,000,000 |
| 0.380 | 2,500,000,000 | 4,000,000,000 |
| 0.370 | 4,000,000,000 | 6,500,000,000 |
| 0.360 | 6,500,000,000 | 10,500,000,000 |
| 0.350 | 10,500,000,000 | |
Capital Income Builder
| Rate | Net asset level | |
| In excess of | Up to | |
| 0.500% | $ 0 | $ 600,000,000 |
| 0.450 | 600,000,000 | 1,000,000,000 |
| 0.410 | 1,000,000,000 | |
Asset Allocation Fund
American Funds Insurance Series — Page 70
| Rate | Net asset level | |
| In excess of | Up to | |
| Rate | Net asset level | |
| In excess of | Up to | |
| 0.500% | $ 0 | $ 600,000,000 |
| 0.420 | 600,000,000 | 1,200,000,000 |
| 0.360 | 1,200,000,000 | 2,000,000,000 |
| 0.320 | 2,000,000,000 | 3,000,000,000 |
| 0.280 | 3,000,000,000 | 5,000,000,000 |
| 0.260 | 5,000,000,000 | 8,000,000,000 |
| 0.250 | 8,000,000,000 | 13,000,000,000 |
| 0.244 | 13,000,000,000 | 21,000,000,000 |
| 0.240 | 21,000,000,000 | |
American Funds Global Balanced Fund
| Rate | Net asset level | |
| In excess of | Up to | |
| 0.660% | $ 0 | $ 500,000,000 |
| 0.570 | 500,000,000 | 1,000,000,000 |
| 0.510 | 1,000,000,000 | |
American Funds Mortgage Fund
| Rate | Net asset level | |
| In excess of | Up to | |
| 0.420% | $ 0 | $ 600,000,000 |
| 0.360 | 600,000,000 | 1,000,000,000 |
| 0.320 | 1,000,000,000 | 2,000,000,000 |
| 0.300 | 2,000,000,000 | 3,000,000,000 |
| 0.290 | 3,000,000,000 | |
Corporate Bond Fund
| Rate | Net asset level | |
| In excess of | Up to | |
| 0.460% | $ 0 | |
American Funds Insurance Series — Page 71
American High-Income Trust
| Rate | Net asset level | |
| In excess of | Up to | |
| 0.500% | $ 0 | $ 600,000,000 |
| 0.460 | 600,000,000 | 1,000,000,000 |
| 0.440 | 1,000,000,000 | 2,000,000,000 |
| 0.420 | 2,000,000,000 | |
Capital World Bond Fund
| Rate | Net asset level | |
| In excess of | Up to | |
| 0.570% | $ 0 | $1,000,000,000 |
| 0.500 | 1,000,000,000 | 3,000,000,000 |
| 0.450 | 3,000,000,000 | |
The Bond Fund of America
| Rate | Net asset level | |
| In excess of | Up to | |
| 0.480% | $ 0 | $ 600,000,000 |
| 0.440 | 600,000,000 | 1,000,000,000 |
| 0.400 | 1,000,000,000 | 2,000,000,000 |
| 0.380 | 2,000,000,000 | 3,000,000,000 |
| 0.360 | 3,000,000,000 | 5,000,000,000 |
| 0.340 | 5,000,000,000 | 8,000,000,000 |
| 0.330 | 8,000,000,000 | 13,000,000,000 |
| 0.320 | 13,000,000,000 | |
U.S. Government Securities Fund
| Rate | Net asset level | |
| In excess of | Up to | |
| 0.420% | $ 0 | $ 600,000,000 |
| 0.360 | 600,000,000 | 1,000,000,000 |
| 0.320 | 1,000,000,000 | 2,000,000,000 |
| 0.300 | 2,000,000,000 | 3,000,000,000 |
| 0.290 | 3,000,000,000 | |
American Funds Insurance Series — Page 72
Ultra-Short Bond Fund
| Rate | Net asset level | |
| In excess of | Up to | |
| 0.320% | $ 0 | $1,000,000,000 |
| 0.290 | 1,000,000,000 | 2,000,000,000 |
| 0.270 | 2,000,000,000 | |
Management fees are paid monthly and accrued daily.
In addition to providing investment advisory services, the investment adviser furnishes the services and pays the compensation and travel expenses of qualified persons to perform the executive and related administrative functions of the Series, and provides necessary office space, office equipment and utilities, and general purpose accounting forms, supplies and postage used at the office of the Series relating to the services furnished by the investment adviser. Subject to the expense agreement described below, the Series will pay all expenses not expressly assumed by the investment adviser, including, but not limited to: registration and filing fees of federal and state agencies; blue sky expenses (if any); expenses of shareholders' meetings; the expense of reports to existing shareholders; expenses of printing proxies and prospectuses; insurance premiums; legal and auditing fees; dividend disbursement expenses; the expense of the issuance, transfer and redemption of its shares; custodian fees; printing and preparation of registration statements; taxes; compensation, fees and expenses paid to trustees unaffiliated with the investment adviser; association dues; and costs of stationary and forms prepared exclusively for the Series.
American Funds Insurance Series — Page 73
For the fiscal years ended December 31, 2021, 2020 and 2019, the investment adviser earned from the Series management fees, as follows:
| Fiscal year ended | |||||
| 2021 | 2020 | 2019 | |||
| Global Growth Fund | $45,364,000 | $35,225,000 | $32,238,000 | ||
| Global Small Capitalization Fund | 36,199,000 | 30,652,000 | 29,892,000 | ||
| Growth Fund | 129,405,000 | 98,281,000 | 84,702,000 | ||
| International Fund | 49,637,000 | 45,293,000 | 47,450,000 | ||
| New World Fund | 30,185,000 | 24,693,000 | 23,766,000 | ||
| Capital World Growth and Income Fund | 13,427,000 | 11,651,000 | 11,970,000 | ||
| Growth-Income Fund | 102,401,000 | 87,809,000 | 85,788,000 | ||
| International Growth and Income Fund | 8,064,000 | 8,128,000 | 8,588,000 | ||
| Washington Mutual Investors Fund | 39,958,000 | 33,547,000 | 34,092,000 | ||
| Capital Income Builder | 5,244,000 | 4,711,000 | 4,075,000 | ||
| Asset Allocation Fund | 82,192,000 | 71,046,000 | 67,563,000 | ||
| American Funds Global Balanced Fund | 3,005,000 | 2,767,000 | 2,697,000 | ||
| American Funds Mortgage Fund | 1,392,000 | 1,248,000 | 1,231,000 | ||
| American High-Income Trust | 4,750,000 | 4,534,000 | 6,009,000 | ||
| Corporate Bond Fund | N/A | N/A | N/A | ||
| Capital World Bond Fund | 11,735,000 | 11,401,000 | 11,276,000 | ||
| The Bond Fund of America | 44,686,000 | 38,894,000 | 37,299,000 | ||
| U.S. Government Securities Fund | 7,451,000 | 8,276,000 | 9,824,000 | ||
| Ultra-Short Bond Fund | 1,128,000 | 1,098,000 | 925,000 | ||
The Series’ board of trustees approved an amended Investment Advisory and Service Agreement, pursuant to which the annualized rate payable to the investment adviser on daily net assets of Global Growth Fund, International Growth and Income Fund and Capital Income Builder in excess of certain levels would be decreased. The investment adviser voluntarily waived management fees to give effect to the approved rates in advance of the effective date of the amended Agreement. Accordingly, after giving effect to the voluntary fee waivers described above, the funds paid the investment adviser management fees of $35,224,000 (a reduction of $1,000) for Global Growth Fund for the fiscal year ended in 2020.
American Funds Insurance Series — Page 74
Beginning May 1, 2020 and May 1, 2021, as applicable, the investment adviser has agreed to waive a portion of the management fee for funds that have aligned their objectives, investment strategies and portfolio management teams with that of an American Fund of the same name. The waiver is intended to align the management fee of the Series fund with that of the American Fund as of the date of the Series' prospectus. The funds subject to this waiver since May 1, 2020, are New World Fund, Capital Income Builder, American Funds Mortgage Fund and Capital World Bond Fund. The funds subject to this waiver since May 1, 2021, are Capital World Growth and Income Fund, Washington Mutual Investors Fund, American High-Income Trust, The Bond Fund of America and U.S. Government Securities Fund. Accordingly, after giving effect to the waivers described above, the funds paid the investment adviser management fees of $20,311,000 (a reduction of $4,382,000) for New World Fund, $2,976,000 (a reduction of $1,735,000) for Capital Income Builder, $888,000 (a reduction of $360,000) for American Funds Mortgage Fund and $9,943,000 (a reduction of $1,458,000) for Capital World Bond Fund for the fiscal year ended in December 31, 2020.
The funds subject to this waiver since May 1, 2022, are Global Growth Fund, Global Small Capitalization Fund, New World Fund, Capital World Growth and Income Fund, International Growth and Income Fund, Washington Mutual Investors Fund, Capital Income Builder, American Funds Global Balanced Fund, American Funds Mortgage Fund, American High-Income Trust, Capital World Bond Fund, The Bond Fund of America and U.S. Government Securities Fund. Accordingly, after giving effect to the waivers described above, the funds paid the investment adviser management fees of $xx (a reduction of $28,000) for Global Growth Fund, $xx for (a reduction of $xx) for Global Small Capitalization Fund, $xx (a reduction of $8,018,000) for New World Fund, $xx (a reduction of $3,624,000) for Capital World Growth and Income Fund, $xx (a reduction of $48,000) for International Growth and Income Fund, $xx (a reduction of $11,310,000) for Washington Mutual Investors Fund, $xx (a reduction of $2,808,000) for Capital Income Builder, $xx (a reduction of 664,000) for American Funds Mortgage Fund, $xx (a reduction of $1,313,000) for American High-Income Trust, $xx (a reduction of $2,207,000) for Capital World Bond Fund, $xx (a reduction of 16,515,000) for The Bond Fund of America, and $xx (a reduction of 2,236,000) for U.S. Government Securities Fund for the fiscal year ended in December 31, 2021.
American Funds Insurance Series — Page 75
Administrative services — The investment adviser and its affiliates provide certain administrative services for shareholders of the Series’ Class 1, 1A, 2, 3 and 4 shares. Administrative services are provided by the investment adviser and its affiliates to help assist third parties providing non-distribution services to fund shareholders. These services include providing in-depth information on the fund and market developments that impact fund investments. Administrative services also include, but are not limited to, coordinating, monitoring and overseeing third parties that provide services to Series shareholders.
These services are provided pursuant to an Administrative Services Agreement (the “Administrative Agreement”) between the Series and the investment adviser relating to the Series’ Class 1, 1A, 2, 3 and 4 shares. The Administrative Agreement will continue in effect until April 30, 2023, unless sooner renewed or terminated, and may be renewed from year to year thereafter, provided that any such renewal has been specifically approved by the vote of a majority of the members of the Series’ board who are not parties to the Administrative Agreement or interested persons (as defined in the 1940 Act) of any such party. The Series may terminate the Administrative Agreement at any time by vote of a majority of independent board members. The investment adviser has the right to terminate the Administrative Agreement upon 60 days’ written notice to the Series. The Administrative Agreement automatically terminates in the event of its assignment (as defined in the 1940 Act).
The Administrative Services Agreement between the fund and the investment adviser provides the fund the ability to charge an administrative services fee of .05% for all share classes. The investment adviser receives an administrative services fee at the annual rate of .03% of the average daily net assets of the fund (which could be increased as noted above) for its provision of administrative services. Administrative services fees are paid monthly and accrued daily.
American Funds Insurance Series — Page 76
During the 2021 fiscal year, the administrative services fees were:
| Administrative services fee | ||||||
| Class 1 | Class 1A | Class 2 | Class 3 | Class 4 | ||
| Global Growth Fund | $1,173,000 | $ 4,000 | $1,368,000 | N/A | $ 193,000 | |
| Global Small Capitalization Fund | 684,000 | 1,000 | 801,000 | N/A | 97,000 | |
| Growth Fund | 5,245,000 | 26,000 | 6,433,000 | $88,000 | 839,000 | |
| International Fund | 1,572,000 | 3,000 | 1,319,000 | 7,000 | 134,000 | |
| New World Fund | 732,000 | 4,000 | 337,000 | N/A | 263,000 | |
| Capital World Growth and Income Fund | 223,000 | 1,000 | 406,000 | N/A | 60,000 | |
| Growth-Income Fund | 7,308,000 | 7,000 | 4,456,000 | 49,000 | 503,000 | |
| International
Growth and Income Fund |
293,000 | 1,000 | 66,000 | N/A | 37,000 | |
| Washington
Mutual Investors Fund |
1,816,000 | 29,000 | 985,000 | N/A | 284,000 | |
| Capital Income Builder | 172,000 | 2,000 | 3,000 | N/A | 155,000 | |
| Asset Allocation Fund | 6,070,000 | 5,000 | 1,628,000 | 10,000 | 1,732,000 | |
| American Funds Global Balanced Fund | 36,000 | 1,000 | 63,000 | N/A | 37,000 | |
| American
Funds Mortgage Fund |
69,000 | -* | 18,000 | N/A | 12,000 | |
| American High-Income Trust | 61,000 | -* | 204,000 | 3,000 | 26,000 | |
| Corporate Bond Fund | N/A | N/A | N/A | N/A | N/A | |
| Capital World Bond Fund | 327,000 | -* | 316,000 | N/A | 19,000 | |
| The Bond Fund of America | 2,361,000 | 3,000 | 1,143,000 | N/A | 243,000 | |
| U.S.
Government Securities Fund |
122,000 | 1,000 | 429,000 | 3,000 | 74,000 | |
| Ultra-Short Bond Fund | 12,000 | -* | 80,000 | 1,000 | 13,000 | |
* Amount less than $1,000.
American Funds Insurance Series — Page 77
Plans of distribution — The Series has adopted plans of distribution (the “Plans”) for its Class 1A, Class 2 , Class 3 and Class 4 shares, pursuant to rule 12b-1 under the 1940 Act. As required by rule 12b-1, the Plans have been approved by a majority of the entire board of trustees, and separately by a majority of the trustees who are not “interested persons” of the Series and who have no direct or indirect financial interest in the operation of the Plans. Potential benefits of the Plans to the Series include benefits to the investment process from growth or stability of assets and maintenance of a financially healthy management organization. The selection and nomination of trustees who are not “interested persons” of the Series is committed to the discretion of the trustees who are not “interested persons” during the existence of the Plans. The Plans are reviewed quarterly and must be renewed annually by the board of trustees.
Under the Plans, the Series will pay to insurance company contract issuers .25% of each fund’s average net assets annually (Class 2 and Class 4 shares) or .18% of each fund’s average net assets annually (Class 3 shares) to finance any distribution activity which is primarily intended to benefit the Class 2, Class 3 and/or Class 4 shares of the Series, respectively, provided that the board of trustees of the Series has approved the categories of expenses for which payment is being made. Under the Plan for Class 1A shares, the Series may expend up to .25% of the assets of Class 1A shares; however, the board of trustees has not authorized any payments on Class 1A assets pursuant to the Plan for Class 1A shares. Payments made pursuant to the Plans will be used by insurance company contract issuers to pay a continuing annual service or distribution fee to dealers on the value of all variable annuity and variable life insurance contract payments for account-related services provided to existing shareholders. During the fiscal year ended December 31, 2021, the Series incurred distribution expenses for Class 2 shares of $167,118,000, for Class 3 shares of $973,000 and for Class 4 shares of $39,343,000 payable to certain life insurance companies under the respective Plans. Accrued and unpaid distribution expenses were $14,027,000 for Class 2 shares, $83,000 for Class 3 shares and $3,536,000 for Class 4 shares.
Insurance administration fee — The insurance companies for which the fund’s Class 1A and Class 4 shares are available provide certain administrative services for the separate accounts that hold the shares of the fund and the contractholders for which the shares of the fund are beneficially owned as underlying investments of such contractholders annuities. These services include, but are not limited to, record maintenance, shareholder communications and transactional services.
These services are provided pursuant to Insurance Administrative Services Plans adopted by the Series relating to the fund’s Class 1A and Class 4 shares. Under these plans, the insurance company receives .25% of the fund’s average daily net assets attributable to Class 1A and Class 4 shares, respectively. During the fiscal year ended December 31, 2021, the Series incurred insurance administration fees of $767,000 for Class 1A shares and $39,343,000 for Class 4 shares.
American Funds Insurance Series — Page 78
Compensation to insurance companies — American Funds Distributors, Inc., at its expense, currently makes payments to certain of the insurance companies listed below that use the Series as the underlying investment in insurance contracts. These payments generally cover additional compensation (as described in the prospectus) and/or expenses associated with education and training meetings sponsored by American Funds Distributors, Inc. for insurance company sales forces.
AEGON N.V.
American International Group, Inc.
American Fidelity Assurance Co.
Ameritas Life Insurance Corp.
AXA Equitable Life Insurance Company
Brighthouse Financial, Inc. (formerly MetLife)
Delaware Life Holdings, LLC
Farmers Insurance & Financial Solutions
Global Atlantic Financial Group (fka Forethought)
Great-West Life & Annuity Company
Guardian Insurance & Annuity Company, Inc.
Horace Mann Life Insurance Company
Jackson National Life Insurance Co
John Hancock Life Insurance Co
Kansas City Life Insurance Co
Lincoln National Life Insurance Co
Lombard International Life Assurance Company
Massachusetts Mutual Life Insurance Company
| Matrix |
MEMBERS Life Insurance Company (aka CUNA Mutual Group)
Merrill Lynch Bank of America
Midland National Life Insurance Company
Minnesota Life Insurance Company (aka Securian Financial Group, Inc.)
Modern Woodmen of America
Mutual of America Life Insurance Company
National Life Group
Nationwide Advisory Solutions (formerly Jefferson National)
Nationwide Life Insurance Company
New York Life Insurance & Annuity Corporation
Pacific Life Insurance Company
Principal Life Insurance Co
Protective Life Insurance Company
Prudential Financial
Sammons Financial Group Inc
Security Benefit Life Insurance Company
Symetra Life Insurance Company
Talcott Resolution Life Insurance Company
Thrivent Financial
Venerable Insurance And Annuity Company
(formerly Voya Financial)
Western & Southern Financial Group
Woodmen Financial Services, Inc.
American Funds Insurance Series — Page 79
Execution of portfolio transactions
The investment adviser places orders with broker-dealers for the fund’s portfolio transactions. Purchases and sales of equity securities on a securities exchange or an over-the-counter market are effected through broker-dealers who receive commissions for their services. Generally, commissions relating to securities traded on foreign exchanges will be higher than commissions relating to securities traded on U.S. exchanges and may not be subject to negotiation. Equity securities may also be purchased from underwriters at prices that include underwriting fees. Purchases and sales of fixed income securities are generally made with an issuer or a primary market maker acting as principal with no stated brokerage commission. The price paid to an underwriter for fixed income securities includes underwriting fees. Prices for fixed income securities in secondary trades usually include undisclosed compensation to the market maker reflecting the spread between the bid and ask prices for the securities.
In selecting broker-dealers, the investment adviser strives to obtain “best execution” (the most favorable total price reasonably attainable under the circumstances) for the fund’s portfolio transactions, taking into account a variety of factors. These factors include the size and type of transaction, the nature and character of the markets for the security to be purchased or sold, the cost, quality, likely speed and reliability of execution and settlement, the broker-dealer’s or execution venue’s ability to offer liquidity and anonymity and the trade-off between market impact and opportunity costs. The investment adviser considers these factors, which involve qualitative judgments, when selecting broker-dealers and execution venues for fund portfolio transactions. The investment adviser views best execution as a process that should be evaluated over time as part of an overall relationship with particular broker-dealer firms. The investment adviser and its affiliates negotiate commission rates with broker-dealers based on what they believe is reasonably necessary to obtain best execution. They seek, on an ongoing basis, to determine what the reasonable levels of commission rates for execution services are in the marketplace, taking various considerations into account, including the extent to which a broker-dealer has put its own capital at risk, historical commission rates and commission rates that other institutional investors are paying. The fund does not consider the investment adviser as having an obligation to obtain the lowest commission rate available for a portfolio transaction to the exclusion of price, service and qualitative considerations. Brokerage commissions are only a small part of total execution costs and other factors, such as market impact and speed of execution, contribute significantly to overall transaction costs.
The investment adviser may execute portfolio transactions with broker-dealers who provide certain brokerage and/or investment research services to it but only when in the investment adviser’s judgment the broker-dealer is capable of providing best execution for that transaction. The investment adviser makes decisions for procurement of research separately and distinctly from decisions on the choice of brokerage and execution services. The receipt of these research services permits the investment adviser to supplement its own research and analysis and makes available the views of, and information from, individuals and the research staffs of other firms. Such views and information may be provided in the form of written reports, telephone contacts and meetings with securities analysts. These services may include, among other things, reports and other communications with respect to individual companies, industries, countries and regions, economic, political and legal developments, as well as scheduling meetings with corporate executives and seminars and conferences related to relevant subject matters. Research services that the investment adviser receives from broker-dealers may be used by the investment adviser in servicing the fund and other funds and accounts that it advises; however, not all such services will necessarily benefit the fund.
The investment adviser bears the cost of all third-party investment research services for all client accounts it advises. However, in order to compensate certain U.S. broker-dealers for research consumed, and valued, by the investment adviser’s investment professionals, the investment adviser continues to operate a limited commission sharing arrangement with commissions on equity trades for certain registered investment companies it advises. The investment adviser voluntarily reimburses such
American Funds Insurance Series — Page 80
registered investment companies for all amounts collected into the commission sharing arrangement. In order to operate the commission sharing arrangement, the investment adviser may cause such registered investment companies to pay commissions in excess of what other broker-dealers might have charged for certain portfolio transactions in recognition of brokerage and/or investment research services. In this regard, the investment adviser has adopted a brokerage allocation procedure consistent with the requirements of Section 28(e) of the Securities Exchange Act of 1934. Section 28(e) permits the investment adviser and its affiliates to cause an account to pay a higher commission to a broker-dealer to compensate the broker-dealer or another service provider for certain brokerage and/or investment research services provided to the investment adviser and its affiliates, if the investment adviser and each affiliate makes a good faith determination that such commissions are reasonable in relation to the value of the services provided by such broker-dealer to the investment adviser and its affiliates in terms of that particular transaction or the investment adviser’s overall responsibility to the fund and other accounts that it advises. Certain brokerage and/or investment research services may not necessarily benefit all accounts paying commissions to each such broker-dealer; therefore, the investment adviser and its affiliates assess the reasonableness of commissions in light of the total brokerage and investment research services provided to the investment adviser and its affiliates. Further, investment research services may be used by all investment associates of the investment adviser and its affiliates, regardless of whether they advise accounts with trading activity that generates eligible commissions.
In accordance with their internal brokerage allocation procedure, the investment adviser and its affiliates periodically assess the brokerage and investment research services provided by each broker-dealer and each other service provider from which they receive such services. As part of its ongoing relationships, the investment adviser and its affiliates routinely meet with firms to discuss the level and quality of the brokerage and research services provided, as well as the value and cost of such services. In valuing the brokerage and investment research services the investment adviser and its affiliates receive from broker-dealers and other research providers in connection with its good faith determination of reasonableness, the investment adviser and its affiliates take various factors into consideration, including the quantity, quality and usefulness of the services to the investment adviser and its affiliates. Based on this information and applying their judgment, the investment adviser and its affiliates set an annual research budget.
Research analysts and portfolio managers periodically participate in a research poll to determine the usefulness and value of the research provided by individual broker-dealers and research providers. Based on the results of this research poll, the investment adviser and its affiliates may, through commission sharing arrangements with certain broker-dealers, direct a portion of commissions paid to a broker-dealer by the fund and other registered investment companies managed by the investment adviser or its affiliates to be used to compensate the broker-dealer and/or other research providers for research services they provide. While the investment adviser and its affiliates may negotiate commission rates and enter into commission sharing arrangements with certain broker-dealers with the expectation that such broker-dealers will be providing brokerage and research services, none of the investment adviser, any of its affiliates or any of their clients incurs any obligation to any broker-dealer to pay for research by generating trading commissions. The investment adviser and its affiliates negotiate prices for certain research that may be paid through commission sharing arrangements or by themselves with cash.
When executing portfolio transactions in the same equity security for the funds and accounts, or portions of funds and accounts, over which the investment adviser, through its equity investment divisions, has investment discretion, each investment division within the adviser and its affiliates normally aggregates its respective purchases or sales and executes them as part of the same transaction or series of transactions. When executing portfolio transactions in the same fixed income security for the fund and the other funds or accounts over which it or one of its affiliated companies has investment discretion, the investment adviser normally aggregates such purchases or sales and executes them as part of the same transaction or series of transactions. The objective of aggregating
American Funds Insurance Series — Page 81
purchases and sales of a security is to allocate executions in an equitable manner among the funds and other accounts that have concurrently authorized a transaction in such security. The investment adviser and its affiliates serve as investment adviser for certain accounts that are designed to be substantially similar to another account. This type of account will often generate a large number of relatively small trades when it is rebalanced to its reference fund due to differing cash flows or when the account is initially started up. The investment adviser may not aggregate program trades or electronic list trades executed as part of this process. Non-aggregated trades performed for these accounts will be allocated entirely to that account. This is done only when the investment adviser believes doing so will not have a material impact on the price or quality of other transactions.
The investment adviser currently owns an interest in IEX Group and Luminex Trading and Analytics. The investment adviser may place orders on these or other exchanges or alternative trading systems in which it, or one of its affiliates, has an ownership interest, provided such ownership interest is less than five percent of the total ownership interests in the entity. The investment adviser is subject to the same best execution obligations when trading on any such exchange or alternative trading system.
Purchase and sale transactions may be effected directly among and between certain funds or accounts advised by the investment adviser or its affiliates, including the fund. The investment adviser maintains cross-trade policies and procedures and places a cross-trade only when such a trade is in the best interest of all participating clients and is not prohibited by the participating funds’ or accounts’ investment management agreement or applicable law.
The investment adviser may place orders for the fund’s portfolio transactions with broker-dealers who have sold shares of the funds managed by the investment adviser or its affiliated companies; however, it does not consider whether a broker-dealer has sold shares of the funds managed by the investment adviser or its affiliated companies when placing any such orders for the fund’s portfolio transactions.
Purchases and sales of futures contracts for the fund will be effected through executing brokers and FCMs that specialize in the types of futures contracts that the fund expects to hold. The investment adviser will use reasonable efforts to choose executing brokers and FCMs capable of providing the services necessary to obtain the most favorable price and execution available. The full range and quality of services available will be considered in making these determinations. The investment adviser will monitor the executing brokers and FCMs used for purchases and sales of futures contracts for their ability to execute trades based on many factors, such as the sizes of the orders, the difficulty of executions, the operational facilities of the firm involved and other factors.
Forward currency contracts are traded directly between currency traders (usually large commercial banks) and their customers. The cost to the fund of engaging in such contracts varies with factors such as the currency involved, the length of the contract period and the market conditions then prevailing. Because such contracts are entered into on a principal basis, their prices usually include undisclosed compensation to the market maker reflecting the spread between the bid and ask prices for the contracts. The fund may incur additional fees in connection with the purchase or sale of certain contracts.
American Funds Insurance Series — Page 82
Brokerage commissions paid (net of any reimbursements described below) by each fund for the fiscal years ended December 31, 2021, 2020 and 2019 were:
| Fiscal year ended | ||||
| 2021 | 2020 | 2019 | ||
| Global Growth Fund | $ 990,000 | $1,030,000 | $818,000 | |
| Global Small Capitalization Fund | 2,015,000 | 1,992,000 | 2,164,000 | |
| Growth Fund | 3,472,000 | 4,577,000 | 2,070,000 | |
| International Fund | 5,918,000 | 4,384,000 | 3,488,000 | |
| New World Fund | 1,857,000 | 2,794,000 | 1,508,000 | |
| Capital World Growth and Income Fund | 1,417,000 | 929,000 | 575,000 | |
| Growth-Income Fund | 5,274,000 | 5,268,000 | 4,193,000 | |
| International Growth and Income Fund | 1,020,000 | 818,000 | 493,000 | |
| Washington Mutual Investors Fund | 3,410,000 | 1,980,000 | 1,692,000 | |
| Capital Income Builder | 272,000 | 368,000 | 147,000 | |
| Asset Allocation Fund | 3,162,000 | 2,588,000 | 2,271,000 | |
| American Funds Global Balanced Fund | 57,000 | 63,000 | 90,000 | |
| American Funds Mortgage Fund | — | — | — | |
| American High-Income Trust | 3,000 | 3,000 | 6,000 | |
| Corporate Bond Fund | N/A | N/A | N/A | |
| Capital World Bond Fund | 1,000 | — | — | |
| The Bond Fund of America | — | — | — | |
| U.S. Government Securities Fund | — | — | — | |
| Ultra-Short Bond Fund | — | — | — | |
Increases (or decreases) in the dollar amount of brokerage commissions borne by each fund over the last three fiscal years resulted from increases (or decreases) in the volume of trading activity and/or the amount of commissions used to pay for research services through a commission sharing arrangement.
American Funds Insurance Series — Page 83
The investment adviser is reimbursing the fund for all amounts collected into the commission sharing arrangement. For the fiscal years ended December 31, 2021, 2020 and 2019, the investment adviser reimbursed the following for commissions paid to broker-dealers through a commission sharing arrangement to compensate such broker-dealers for research services:
| Fiscal year ended | Fiscal year ended | Fiscal year ended | ||
| 2021 | 2020 | 2019 | ||
| Global Growth Fund | $19,600 | $25,000 | $55,000 | |
| Global Small Capitalization Fund | 50,700 | 92,000 | 172,000 | |
| Growth Fund | 374,200 | 468,000 | 462,000 | |
| International Fund | 19,800 | 29,000 | 30,000 | |
| New World Fund | 51,200 | 55,000 | 30,000 | |
| Capital World Growth and Income Fund | 28,400 | 11,000 | 15,000 | |
| Growth-Income Fund | 440,300 | 497,000 | 406,000 | |
| International Growth and Income Fund | 600 | 2,000 | 6,000 | |
| Washington Mutual Investors Fund | 156,700 | 268,000 | 390,000 | |
| Capital Income Builder | 14,100 | 9,000 | 10,000 | |
| Asset Allocation Fund | 178,100 | 197,000 | 322,000 | |
| American Funds Global Balanced Fund | 3,500 | 3,000 | 3,000 | |
| American Funds Mortgage Fund | — | — | — | |
| American High-Income Trust | — | — | — | |
| Corporate Bond Fund | — | — | — | |
| Capital World Bond Fund | — | — | — | |
| The Bond Fund of America | — | — | — | |
| U.S. Government Securities Fund | — | — | — | |
| Ultra-Short Bond Fund | — | — | — | |
American Funds Insurance Series — Page 84
The Series is required to disclose information regarding investments in the securities of its “regular” broker-dealers (or parent companies of its regular broker-dealers) that derive more than 15% of their revenue from broker-dealer, underwriter or investment adviser activities. A regular broker-dealer is (a) one of the 10 broker-dealers that received from the Series the largest amount of brokerage commissions by participating, directly or indirectly, in the Series’ portfolio transactions during the Series’ most recently completed fiscal year; (b) one of the 10 broker-dealers that engaged as principal in the largest dollar amount of portfolio transactions of the Series during the Series’ most recently completed fiscal year; or (c) one of the 10 broker-dealers that sold the largest amount of securities of the Series during the Series’ most recently completed fiscal year. At the end of the Series’ most recently completed fiscal year, the Series’ regular broker-dealers included Citigroup Inc., Credit Suisse Group AG, Deutsche Bank A.G., Goldman Sachs Group, Inc., J.P. Morgan Securities LLC, Macquarie Group Limited, Morgan Stanley & Co. LLC, RBC Capital Markets LLC, UBS Group AG and Wells Fargo Securities, LLC. At the end of the Series’ most recently completed fiscal year, the following funds held debt and/or equity securities of an affiliated company of such regular broker-dealers:
| Affiliated company of regular broker-dealer | Type
of security |
Amount | |
| Global Growth Fund | J.P. Morgan Securities LLC | equity | $67,584,000 |
| Macquarie Group Limited | equity | 14,316,000 | |
| Capital World Growth and Income Fund | Citigroup Inc. | equity | 4,116,000 |
| J.P. Morgan Securities LLC | equity | 14,696,000 | |
| Morgan Stanley & Co. LLC | equity | 1,870,000 | |
| Wells Fargo Securities, LLC | equity | 6,836,000 | |
| Growth-Income Fund | J.P. Morgan Securities LLC | equity | 746,562,000 |
| Morgan Stanley & Co. LLC | equity | 42,333,000 | |
| International Growth and Income Fund | Macquarie Group Limited | equity | 627,000 |
| Washington Mutual Investors Fund | Citigroup Inc. | equity | 24,274,000 |
| Wells Fargo Securities, LLC | equity | 20,704,000 | |
| Capital Income Builder | Citigroup Inc. | equity | 908,000 |
| Goldman Sachs Group, Inc. | debt | 76,000 | |
| J.P. Morgan Securities LLC | debt/equity | 13,417,000 | |
| Morgan Stanley & Co. LLC | equity | 3,542,000 | |
| UBS Group AG | equity | 628,000 | |
| Wells Fargo Securities, LLC | equity | 441,000 |
American Funds Insurance Series — Page 85
| Affiliated company of regular broker-dealer | Type
of security |
Amount | |
| Asset Allocation Fund | Citigroup Inc. | debt/equity | $75,851,000 |
| Credit Suisse Group AG | debt | 2,541,000 | |
| Goldman Sachs Group, Inc. | debt | 19,270,000 | |
| J.P. Morgan Securities LLC | debt/equity | 251,914,000 | |
| Morgan Stanley & Co. LLC | debt | 18,869,000 | |
| RBC Capital Markets LLC | debt | 4,674,000 | |
| Wells Fargo Securities, LLC | debt | 8,883,000 | |
| American Funds Global Balanced Fund | Citigroup, Inc. | debt | 591,000 |
| Goldman Sachs Group, Inc. | debt | 806,000 | |
| J.P. Morgan Securities LLC | debt/equity | 8,066,000 | |
| Morgan Stanley & Co. LLC | debt | 510,000 | |
| Capital World Bond Fund | Citigroup Inc. | debt | 5,523,000 |
| Credit Suisse Group AG | debt | 1,936,000 | |
| Deutsche Bank A.G. | debt | 849,000 | |
| Goldman Sachs Group, Inc. | debt | 15,700,000 | |
| J.P. Morgan Securities LLC | debt | 11,873,000 | |
| Morgan Stanley & Co. LLC | debt | 3,479,000 | |
| RBC Capital Markets LLC | debt | 6,701,000 | |
| The Bond Fund of America | Citigroup Inc. | debt | 10,582,000 |
| Credit Suisse Group AG | debt | 54,282,000 | |
| Goldman Sachs Group, Inc. | debt | 91,184,000 | |
| J.P. Morgan Securities LLC | debt | 68,568,000 | |
| Morgan Stanley & Co. LLC | debt | 55,737,000 | |
| Wells Fargo Securities, LLC | debt | 21,005,000 |
American Funds Insurance Series — Page 86
Disclosure of portfolio holdings
The Series’ investment adviser, on behalf of the funds, has adopted policies and procedures with respect to the disclosure of information about the funds’ portfolio securities. These policies and procedures have been reviewed by the Series’ board of trustees, and compliance will be periodically assessed by the board in connection with reporting from the Series’ Chief Compliance Officer.
Under these policies and procedures a complete list of portfolio holdings of each fund available for public disclosure, dated as of the end of each calendar quarter, is permitted to be posted on the Capital Group website (capitalgroup.com/afis) no earlier than the 10th day after such calendar quarter. In practice, the publicly disclosed portfolio is typically posted on the Capital Group website within 30 days after the end of the calendar quarter. The publicly disclosed portfolio may exclude certain securities when deemed to be in the best interest of the fund as permitted by applicable regulations. Such portfolio holdings information may be disclosed to any person pursuant to an ongoing arrangement to disclose portfolio holdings information to such person no earlier than one day after the day on which the information is posted on the Capital Group website.
Certain intermediaries are provided additional information about the fund’s management team, including information on the fund’s portfolio securities they have selected. This information is provided to larger intermediaries that require the information to make the fund available for investment on the firm’s platform. Intermediaries receiving the information are required to keep it confidential and use it only to analyze the fund.
The Series’ custodian, outside counsel, auditor, financial printers, proxy voting service providers, pricing information vendors, consultants or agents operating under a contract with the investment adviser or its affiliates, co-litigants (such as in connection with a bankruptcy proceeding related to a fund holding) and certain other third parties described below, each of which requires portfolio holdings information for legitimate business and fund oversight purposes, may receive fund portfolio holdings information earlier. See the “General information” section in this statement of additional information for further information about the Series’ custodian, outside counsel and auditor.
Each fund’s portfolio holdings, dated as of the end of each calendar month, are made available to insurance companies that use the funds as underlying investments in their variable annuity contracts and variable life insurance policies. Monthly holdings are made available to help the insurance companies evaluate the funds for inclusion in the contracts and life insurance policies they offer and to evaluate and manage the insurance guarantees offered under their insurance contracts. Monthly holdings may be provided to insurance companies no earlier than the 10th day after the end of the calendar month. In practice, monthly holdings are provided within 30 days after the end of the calendar month. Monthly holdings may also be provided to the sub-adviser of the American Funds Insurance Series Managed Risk Funds. Holdings may also be disclosed more frequently to certain statistical and data collection agencies including Morningstar, Lipper, Inc., Value Line, Vickers Stock Research, Bloomberg and Thomson Financial Research. Information on certain portfolio characteristics of the funds are also provided to the insurance companies and the sub-adviser of the American Funds Insurance Series Managed Risk Funds each business day.
Affiliated persons of the Series, including officers of the Series and employees of the investment adviser and its affiliates, who receive portfolio holdings information are subject to restrictions and limitations on the use and handling of such information pursuant to applicable codes of ethics, including requirements not to trade in securities based on confidential and proprietary investment information, to maintain the confidentiality of such information, and to pre-clear securities trades and report securities transactions activity, as applicable. For more information on these restrictions and limitations, please see the “Code of ethics” section in this statement of additional information and the Code of Ethics. Third-party service providers of the Series and other entities, as described in this
American Funds Insurance Series — Page 87
statement of additional information, receiving such information are subject to confidentiality obligations and obligations that would prohibit them from trading in securities based on such information. When portfolio holdings information is disclosed other than through the Capital Group website to persons not affiliated with the Series, such persons will be bound by agreements (including confidentiality agreements) or fiduciary or other obligations that restrict and limit their use of the information to legitimate business uses only. None of the Series, its investment adviser or any of their affiliates receives compensation or other consideration in connection with the disclosure of information about portfolio securities.
Subject to board policies, the authority to disclose a fund’s portfolio holdings, and to establish policies with respect to such disclosure, resides with the appropriate investment-related committees of the Series’ investment adviser. In exercising their authority, the committees determine whether disclosure of information about the funds’ portfolio securities is appropriate and in the best interest of fund shareholders. The investment adviser has implemented policies and procedures to address conflicts of interest that may arise from the disclosure of fund holdings. For example, the investment adviser’s code of ethics specifically requires, among other things, the safeguarding of information about fund holdings and contains prohibitions designed to prevent the personal use of confidential, proprietary investment information in a way that would conflict with fund transactions. In addition, the investment adviser believes that its current policy of not selling portfolio holdings information and not disclosing such information to unaffiliated third parties until such holdings have been made public on the Capital Group website (other than to certain Series service providers and other third parties for legitimate business and fund oversight purposes) helps reduce potential conflicts of interest between fund shareholders and the investment adviser and its affiliates.
The Series’ investment adviser and its affiliates provide investment advice to clients other than the Series that have investment objectives that may be substantially similar to those of the funds. These clients also may have portfolios consisting of holdings substantially similar to those of the funds and generally have access to current portfolio holdings information for their accounts. These clients do not owe the Series’ investment adviser or the funds a duty of confidentiality with respect to disclosure of their portfolio holdings.
American Funds Insurance Series — Page 88
Price of shares
Shares are purchased at the offering price or sold at the net asset value price next determined after the purchase or sell order is received and accepted by the Series or its designee. Orders received by the Series or authorized designee after the time of the determination of the net asset value will be entered at the next calculated offering price.
The price you pay for shares, the offering price, is based on the net asset value per share, which is calculated once daily as of the close of regular trading on the New York Stock Exchange, normally 4 p.m. New York time, each day the New York Stock Exchange is open. If the New York Stock Exchange makes a scheduled (e.g. the day after Thanksgiving) or an unscheduled close prior to 4 p.m. New York time, the net asset value of the fund will be determined at approximately the time the New York Stock Exchange closes on that day. If on such a day market quotations and prices from third-party pricing services are not based as of the time of the early close of the New York Stock Exchange but are as of a later time (up to approximately 4 p.m. New York time), for example because the market remains open after the close of the New York Stock Exchange, those later market quotations and prices will be used in determining the fund’s net asset value.
Orders in good order received after the New York Stock Exchange closes (scheduled or unscheduled) will be processed at the net asset value (plus any applicable sales charge) calculated on the following business day. The New York Stock Exchange is currently closed on weekends and on the following holidays: New Year’s Day; Martin Luther King Jr. Day; Presidents’ Day; Good Friday; Memorial Day; Juneteenth National Independence Day; Independence Day; Labor Day; Thanksgiving Day; and Christmas Day. Each share class of the fund has a separately calculated net asset value (and share price). The fund’s investment adviser delivers the net asset value every day it is calculated to each insurance company that offers such fund as an underlying investment to its variable contracts by, for example, email, direct electronic transmission or facsimile or through the systems of the National Securities Clearing Corporation.
All portfolio securities of funds managed by Capital Research and Management Company (other than American Funds U.S. Government Money Market Fund) are valued, and the net asset values per share for each share class are determined, as indicated below. The fund follows standard industry practice by typically reflecting changes in its holdings of portfolio securities on the first business day following a portfolio trade.
Equity securities, including depositary receipts, are generally valued at the official closing price of, or the last reported sale price on, the exchange or market on which such securities are traded, as of the close of business on the day the securities are being valued or, lacking any sales, at the last available bid price. Prices for each security are taken from the principal exchange or market on which the security trades.
Fixed income securities, including short-term securities, are generally valued at prices obtained from one or more pricing vendors. The pricing vendors base prices on, among other things, benchmark yields, transactions, bids, offers, quotations from dealers and trading systems, new issues, underlying equity of the issuer, interest rate volatilities, spreads and other relationships observed in the markets among comparable securities and proprietary pricing models such as yield measures calculated using factors such as cash flows, prepayment information, default rates, delinquency and loss assumptions, financial or collateral characteristics or performance, credit enhancements, liquidation value calculations, specific deal information and other reference data. The fund’s investment adviser performs certain checks on vendor prices prior to calculation of the fund’s net asset value. When the investment adviser deems it appropriate to do so (such as when vendor prices are unavailable or not deemed to be representative), fixed income securities will be valued in good faith at the mean quoted
American Funds Insurance Series — Page 89
bid and ask prices that are reasonably and timely available (or bid prices, if ask prices are not available) or at prices for securities of comparable maturity, quality and type.
Securities with both fixed income and equity characteristics (e.g., convertible bonds, preferred stocks, units comprised of more than one type of security, etc.), or equity securities traded principally among fixed income dealers, are generally valued in the manner described above for either equity or fixed income securities, depending on which method is deemed most appropriate by the investment adviser.
Forward currency contracts are valued at the mean of representative quoted bid and ask prices, generally based on prices supplied by one or more pricing vendors.
Futures contracts are generally valued at the official settlement price of, or the last reported sale price on, the principal exchange or market on which such instruments are traded, as of the close of business on the day the contracts are being valued or, lacking any sales, at the last available bid price.
Swaps, including both interest rate swaps and positions in credit default swap indices, are valued using market quotations or valuations provided by one or more pricing vendors.
Assets or liabilities initially expressed in terms of currencies other than U.S. dollars are translated prior to the next determination of the net asset value of the fund’s shares into U.S. dollars at the prevailing market rates.
Securities and other assets for which representative market quotations are not readily available or are considered unreliable by the investment adviser are valued at fair value as determined in good faith under fair value guidelines adopted by authority of the Series’ board. Subject to board oversight, the Series’ board has appointed the fund’s investment adviser to make fair valuation determinations, which are directed by a valuation committee established by the fund’s investment adviser. The board receives regular reports describing fair-valued securities and the valuation methods used.
The valuation committee has adopted guidelines and procedures (consistent with SEC rules and guidance) to consider certain relevant principles and factors when making fair value determinations. As a general principle, securities lacking readily available market quotations, or that have quotations that are considered unreliable by the investment adviser, are valued in good faith by the valuation committee based upon what the fund might reasonably expect to receive upon their current sale. Fair valuations and valuations of investments that are not actively trading involve judgment and may differ materially from valuations that would have been used had greater market activity occurred. The valuation committee considers relevant indications of value that are reasonably and timely available to it in determining the fair value to be assigned to a particular security, such as the type and cost of the security, contractual or legal restrictions on resale of the security, relevant financial or business developments of the issuer, actively traded similar or related securities, conversion or exchange rights on the security, related corporate actions, significant events occurring after the close of trading in the security and changes in overall market conditions. The valuation committee employs additional fair value procedures to address issues related to equity securities that trade principally in markets outside the United States. Such securities may trade in markets that open and close at different times, reflecting time zone differences. If significant events occur after the close of a market (and before the fund’s net asset values are next determined) which affect the value of equity securities held in the fund’s portfolio, appropriate adjustments from closing market prices may be made to reflect these events. Events of this type could include, for example, earthquakes and other natural disasters or significant price changes in other markets (e.g., U.S. stock markets).
Each class of shares represents interests in the same portfolio of investments and is identical in all respects to each other class, except for differences relating to distribution, service and other charges
American Funds Insurance Series — Page 90
and expenses, certain voting rights, differences relating to eligible investors, the designation of each class of shares, conversion features and exchange privileges. Expenses attributable to the fund, but not to a particular class of shares, are borne by each class pro rata based on relative aggregate net assets of the classes. Expenses directly attributable to a class of shares are borne by that class of shares. Liabilities attributable to particular share classes, such as liabilities for repurchases of fund shares, are deducted from total assets attributable to such share classes.
Net assets so obtained for each share class are then divided by the total number of shares outstanding of that share class, and the result, rounded to the nearest cent, is the net asset value per share for that class.
American Funds Insurance Series — Page 91
Taxes and distributions
Taxation as a regulated investment company — The Series intends to qualify each year as a “regulated investment company” under Subchapter M of the Internal Revenue Code (“Code”) so that it will not be liable for federal tax on income and capital gains distributed to shareholders. In order to qualify as a regulated investment company, and avoid being subject to federal income taxes, the Series intends to distribute substantially all of its net investment income and realized net capital gains on a fiscal year basis, and intends to comply with other tests applicable to regulated investment companies under Subchapter M, including the asset diversification test. The asset diversification test requires that at the close of each quarter of the Series’ taxable year that (i) at least 50% of the Series’ assets be invested in cash and cash items, government securities, securities of other funds and other securities which, with respect to any one issuer, represent neither more than 5% of the assets of the Series nor more than 10% of the voting securities of the issuer, and (ii) no more than 25% of the Series’ assets be invested in the securities of any one issuer (other than government securities or the securities of other funds), the securities (other than the securities of other funds) of two or more issuers that the Series controls and are engaged in similar trades or businesses, or the securities of one or more qualified publicly traded partnerships.
The Code includes savings provisions allowing the Series to cure inadvertent failures of certain qualification tests required under Subchapter M. However, should the Series fail to qualify under Subchapter M, the Series would be subject to federal, and possibly state, corporate taxes on its taxable income and gains.
The Series is subject to a set of asset diversification requirements applicable to insurance company separate accounts and their underlying funding vehicles. To satisfy these diversification requirements, as of the end of each calendar quarter or within 30 days thereafter, the Series must (a) be qualified as a "regulated investment company"; and (b) have either (i) no more than 55% of the total value of its assets in cash and cash equivalents, government securities and securities of other regulated investment companies; or (ii) no more than 55% of its total assets represented by any one investment, no more than 70% by any two investments, no more than 80% by any three investments, and no more than 90% by any four investments. For this purpose all securities of the same issuer are considered a single investment, and each agency or instrumentality of the U.S. government is treated as a separate issuer of securities. The Series intends to comply with these regulations. If the Series should fail to comply with these regulations, Contracts invested in the Series will not be treated as annuity, endowment or life insurance contracts under the Code.
The Series may declare a capital gain distribution consisting of the excess of net realized long-term capital gains over net realized short-term capital losses. Net capital gains for a fiscal year are computed by taking into account any capital loss carryforward of the Series.
Certain distributions reported by the Series as Section 163(j) interest dividends may be treated as interest income by shareholders for purposes of the tax rules applicable to interest expense limitations under Section 163(j) of the Code. Such treatment by the shareholder is generally subject to holding period requirements and other potential limitations, although the holding period requirements are generally not applicable to dividends declared by money market funds and certain other funds that declare dividends daily and pay such dividends on a monthly or more frequent basis. The amount that the Series is eligible to report as a Section 163(j) dividend for a tax year is generally limited to the excess of the Series’ business interest income over the sum of the Series’ (i) business interest expense and (ii) other deductions properly allocable to the Series’ business interest income.
Tax consequences of investing in non-U.S. securities — Dividend and interest income received by the Series from sources outside the United States may be subject to withholding and other taxes imposed by such foreign jurisdictions. Tax conventions between certain countries and the United States,
American Funds Insurance Series — Page 92
however, may reduce or eliminate these foreign taxes. Some foreign countries impose taxes on capital gains with respect to investments by foreign investors.
Foreign currency gains and losses, including the portion of gain or loss on the sale of debt securities attributable to fluctuations in foreign exchange rates, are generally taxable as ordinary income or loss. These gains or losses may increase or decrease the amount of dividends payable by the Series to shareholders. The Series may elect to treat gain and loss on certain foreign currency contracts as capital gain and loss instead of ordinary income or loss.
If the fund invests in stock of certain passive foreign investment companies (PFICs), the fund intends to mark-to-market these securities and recognize any gains at the end of its fiscal and excise tax years. Deductions for losses are allowable only to the extent of any previously recognized gains. Both gains and losses will be treated as ordinary income or loss, and the fund is required to distribute any resulting income. If the fund is unable to identify an investment as a PFIC security and thus does not make a timely mark-to-market election, the fund may be subject to adverse tax consequences.
Tax consequences of investing in derivatives — The Series may enter into transactions involving derivatives, such as futures, swaps and forward contracts. Special tax rules may apply to these types of transactions that could defer losses to the Series, accelerate the Series’ income, alter the holding period of certain securities or change the classification of capital gains. These tax rules may therefore impact the amount, timing and character of fund distributions.
American Funds Insurance Series — Page 93
General information
Custodian of assets — Securities and cash owned by all funds, including proceeds from the sale of shares of the funds and of securities in the funds’ portfolios, are held by State Street Bank and Trust Company, One Lincoln Street, Boston, MA 02111, as custodian. Non-U.S. securities may be held by the custodian in non-U.S. banks or securities depositories or foreign branches of U.S. banks.
Transfer agent services — American Funds Service Company, a wholly owned subsidiary of the investment adviser, maintains the records of each insurance company’s separate account, processes purchases and redemptions of the funds’ shares, acts as dividend and capital gain distribution disbursing agent, and performs other related shareholder service functions. The principal office of American Funds Service Company is located at 6455 Irvine Center Drive, Irvine, CA 92618. Transfer agent fees are paid according to a fee schedule, based on the number of accounts serviced, contained in a Shareholder Services Agreement between the fund and American Funds Service Company. American Funds Service Company was paid a fee of $12,000 for Class 1 shares, less than $1,000 for Class 1A shares, $9,000 for Class 2 shares, less than $1,000 for Class 3 shares and $1,000 for Class 4 shares for the 2021 fiscal year.
Independent registered public accounting firm — PricewaterhouseCoopers LLP, 601 South Figueroa Street, Los Angeles, CA 90017, serves as the Series’ independent registered public accounting firm, providing audit services, preparation of tax returns and review of certain documents to be filed with the SEC. The financial statements included in this statement of additional information that are from the Series' annual report have been audited by PricewaterhouseCoopers LLP, an independent registered public accounting firm, as stated in their report appearing herein. Such financial statements have been so included in reliance upon the report of such firm given upon their authority as experts in accounting and auditing. The selection of the Series’ independent registered public accounting firm is reviewed and determined annually by the board of trustees.
Independent legal counsel — Morgan, Lewis & Bockius LLP, One Federal Street, Boston, MA 02110-1726, serves as independent legal counsel (“counsel”) for the Series and for trustees who are not interested persons (as defined by the 1940 Act) of the Series. A determination with respect to the independence of the Series’ counsel will be made at least annually by the independent trustees of the Series, as prescribed by applicable 1940 Act rules.
Prospectuses and reports to shareholders — The Series’ fiscal year ends on December 31. Contract owners are provided updated prospectuses or summary prospectuses by their insurance provider annually and at least semiannually with reports showing the funds’ investment portfolios or summary investment portfolios, financial statements and other information. The Series’ annual financial statements are audited by the independent registered public accounting firm of PricewaterhouseCoopers LLP.
Code of ethics — The Series, Capital Research and Management Company and its affiliated companies have adopted codes of ethics that allow for personal investments, including securities in which the funds of the Series may invest from time to time. These codes include a ban on acquisitions of securities pursuant to an initial public offering; restrictions on acquisitions of private placement securities; pre-clearance and reporting requirements; review of duplicate confirmation statements; annual recertification of compliance with codes of ethics; blackout periods on personal investing for certain investment personnel; a ban on short-term trading profits for investment personnel; limitations on service as a director of publicly traded companies; disclosure of personal securities transactions; and policies regarding political contributions.
Shareholder and trustee responsibility — Under the laws of certain states, including Massachusetts, where the Series was organized, and California, where the Series’ principal office is located,
American Funds Insurance Series — Page 94
shareholders of a Massachusetts business trust may, under certain circumstances, be held personally liable as partners for the obligations of the Series. However, the risk of a shareholder incurring any financial loss on account of shareholder liability is limited to circumstances in which the Series itself would be unable to meet its obligations. The declaration of trust contains an express disclaimer of shareholder liability for acts or obligations of the Series and provides that notice of the disclaimer may be given in each agreement, obligation, or instrument which is entered into or executed by the Series or trustees. The declaration of trust provides for indemnification out of Series property of any shareholder personally liable for the obligations of the Series and also provides for the Series to reimburse such shareholder for all legal and other expenses reasonably incurred in connection with any such claim or liability.
Under the declaration of trust, the trustees or officers are not liable for actions or failure to act; however, they are not protected from liability by reason of their willful misfeasance, bad faith, gross negligence, or reckless disregard of the duties involved in the conduct of their office. The Series will provide indemnification to its trustees and officers as authorized by its by-laws and by the 1940 Act and the rules and regulations thereunder.
Registration statement — A registration statement has been filed with the Securities and Exchange Commission under the Securities Act of 1933 and the 1940 Act with respect to the Series. The prospectus and this statement of additional information do not contain all information set forth in the registration statement, its amendments and exhibits, to which reference is made for further information concerning the Series. Statements contained in the prospectus and this statement of additional information as to the content of the contracts issued through the separate accounts and other legal instruments are summaries. For a complete statement of the terms thereof, reference is made to the registration statements of the separate accounts and contracts as filed with the Securities and Exchange Commission.
Authorized shares — The Series was organized as a Massachusetts business trust which permits each fund of the Series to issue an unlimited number of shares of beneficial interest of one or more classes.
Redemption of shares — While payment of redemptions normally will be in cash, the Series’ declaration of trust permits payment of the redemption price wholly or partly with portfolio securities or other fund assets under conditions and circumstances determined by the Series’ board of trustees. For example, redemptions could be made in this manner if the board determined that making payments wholly in cash over a particular period would be unfair and/or harmful to other Series shareholders.
Voting rights — Shareholders have one vote per share owned. In accordance with current laws, it is anticipated that an insurance company issuing a variable contract that participates in a fund will request voting instructions from variable contract owners and will vote shares or other voting interests in the separate account in accordance with voting instructions received, and will vote shares or other voting interests not received in proportion to the voting instructions received by all separate accounts. In addition, fund shares held directly by an insurance company, if any, will be voted in proportion to the voting instructions received by all separate accounts. As a result of proportional voting, the vote of a small number of contract holders could determine the outcome of a shareholder vote.
Credit facility — Global Small Capitalization Fund, New World Fund and American High-Income Trust, together with other U.S. registered investment funds managed by Capital Research and Management Company, have entered into a committed line of credit facility pursuant to which the funds may borrow up to $1.5 billion as a source of temporary liquidity on a first-come, first-served basis. Under the credit facility, loans are generally unsecured; however, a borrowing fund must collateralize any borrowings under the facility on an equivalent basis if it has certain other collateralized borrowings.
American Funds Insurance Series — Page 95
Financial statements — The fund’s audited financial statements for the fiscal year ended December 31, 2021, including the related notes thereto, are incorporated into the statement of additional information by reference to the fund’s Form N-CSR dated as of December 31, 2021.
American Funds Insurance Series — Page 96
Appendix
The following descriptions of debt security ratings are based on information provided by Moody’s Investors Service, Standard & Poor’s Ratings Services and Fitch Ratings, Inc.
Description of bond ratings
Moody’s
Long-term rating scale
Aaa
Obligations rated Aaa are judged to be of the highest quality, subject to the lowest level of credit
risk.
Aa
Obligations rated Aa are judged to be of high quality and are subject to very low credit risk.
A
Obligations rated A are considered upper-medium grade and are subject to low credit risk.
Baa
Obligations rated Baa are judged to be medium-grade and subject to moderate credit risk and as such
may possess certain speculative characteristics.
Ba
Obligations rated Ba are judged to be speculative and are subject to substantial credit risk.
B
Obligations rated B are considered speculative and are subject to high credit risk.
Caa
Obligations rated Caa are judged to be speculative and of poor standing and are subject to very high
credit risk.
Ca
Obligations rated Ca are highly speculative and are likely in, or very near, default, with some prospect
of recovery of principal and interest.
C
Obligations rated C are the lowest rated and are typically in default, with little prospect for recovery
of principal or interest.
Note: Moody’s appends numerical modifiers 1, 2, and 3 to each generic rating classification from Aa through Caa. The modifier 1 indicates that the obligation ranks in the higher end of its generic rating category; the modifier 2 indicates a mid-range ranking; and the modifier 3 indicates a ranking in the lower end of that generic rating category. Additionally, a “(hyb)” indicator is appended to all ratings of hybrid securities issued by banks, insurers, finance companies and securities firms.
American Funds Insurance Series — Page 97
Standard
& Poor’s
Long-term issue credit ratings
AAA
An obligation rated AAA has the highest rating assigned by Standard & Poor’s. The obligor’s
capacity to meet its financial commitment on the obligation is extremely strong.
AA
An obligation rated AA differs from the highest-rated obligations only to a small degree. The obligor’s
capacity to meet its financial commitment on the obligation is very strong.
A
An obligation rated A is somewhat more susceptible to the adverse effects of changes in circumstances
and economic conditions than obligations in higher-rated categories. However, the obligor’s capacity to meet its financial commitment
on the obligation is still strong.
BBB
An obligation rated BBB exhibits adequate protection parameters. However, adverse economic conditions
or changing circumstances are more likely to lead to a weakened capacity of the obligor to meet its financial commitment on the obligation.
BB, B, CCC, CC, and C
Obligations rated BB, B, CCC, CC, and C are regarded as having significant speculative characteristics. BB indicates the least degree of speculation and C the highest. While such obligations will likely have some quality and protective characteristics, these may be outweighed by large uncertainties or major exposures to adverse conditions.
BB
An obligation rated BB is less vulnerable to nonpayment than other speculative issues. However, it
faces major ongoing uncertainties or exposure to adverse business, financial, or economic conditions which could lead to the obligor’s
inadequate capacity to meet its financial commitment on the obligation.
B
An obligation rated B is more vulnerable to nonpayment than obligations rated BB, but the obligor currently
has the capacity to meet its financial commitment on the obligation. Adverse business, financial, or economic conditions will likely
impair the obligor’s capacity or willingness to meet its financial commitment on the obligation.
CCC
An obligation rated CCC is currently vulnerable to nonpayment and is dependent upon favorable business,
financial, and economic conditions for the obligor to meet its financial commitment on the obligation. In the event of adverse business,
financial, or economic conditions, the obligor is not likely to have the capacity to meet its financial commitment on the obligation.
CC
An obligation rated CC is currently highly vulnerable to nonpayment. The CC rating is used when a default
has not occurred, but Standard & Poor’s expects default to be a virtual certainty, regardless of the anticipated time to default.
American Funds Insurance Series — Page 98
C
An obligation rated C is currently highly vulnerable to nonpayment, and the obligation is expected
to have lower relative seniority or lower ultimate recovery compared to obligations that are rated higher.
D
An obligation rated D is in default or in breach of an imputed promise. For non-hybrid capital instruments,
the D rating category is used when payments on an obligation are not made on the date due, unless Standard & Poor’s believes
that such payments will be made within five business days in the absence of a stated grace period or within the earlier of the stated
grace period or 30 calendar days. The D rating also will be used upon the filing of a bankruptcy petition or the taking of similar action
and where default on an obligation is a virtual certainty, for example due to automatic stay provisions. An obligation’s rating
is lowered to D if it is subject to a distressed exchange offer.
Plus (+) or minus (–)
The ratings from AA to CCC may be modified by the addition of a plus or minus sign to show relative standing within the major rating categories.
NR
This indicates that no rating has been requested, that there is insufficient information on which to base a rating, or that Standard & Poor’s does not rate a particular obligation as a matter of policy.
American Funds Insurance Series — Page 99
Fitch
Ratings, Inc.
Long-term credit ratings
AAA
Highest credit quality. AAA ratings denote the lowest expectation of default risk. They are assigned
only in case of exceptionally strong capacity for payment of financial commitments. This capacity is highly unlikely to be adversely
affected by foreseeable events.
AA
Very high credit quality. AA ratings denote expectations of very low default risk. They indicate very
strong capacity for payment of financial commitments. This capacity is not significantly vulnerable to foreseeable events.
A
High credit quality. A ratings denote expectations of low default risk. The capacity for payment of
financial commitments is considered strong. This capacity may, nevertheless, be more vulnerable to changes in circumstances or in economic
conditions than is the case for higher ratings.
BBB
Good credit quality. BBB ratings indicate that expectations of default risk are low. The capacity for
payment of financial commitments is considered adequate but adverse changes in circumstances and economic conditions are more likely
to impair this capacity.
BB
Speculative. BB ratings indicate an elevated vulnerability to default risk, particularly in the event
of adverse changes in business or economic conditions over time; however, business or financial flexibility exists which supports the
servicing of financial commitments.
B
Highly speculative. B ratings indicate that material default risk is present, but a limited margin
of safety remains. Financial commitments are currently being met; however, capacity for continued payment is vulnerable to deterioration
in the business and economic environment.
CCC
Substantial credit risk. Default is a real possibility.
CC
Very high levels of credit risk. Default of some kind appears probable.
C
Exceptionally high levels of credit risk. Default is imminent or inevitable, or the issuer is in standstill.
Conditions that are indicative of a C category rating for an issuer include:
· The issuer has entered into a grace or cure period following nonpayment of a material financial obligation;
· The issuer has entered into a temporary negotiated waiver or standstill agreement following a payment default on a material financial obligation; or
· Fitch Ratings otherwise believes a condition of RD or D to be imminent or inevitable, including through the formal announcement of a distressed debt exchange.
American Funds Insurance Series — Page 100
RD
Restricted default. RD ratings indicate an issuer that in Fitch Ratings’ opinion has experienced
an uncured payment default on a bond, loan or other material financial obligation but which has not entered into bankruptcy filings,
administration, receivership, liquidation or other formal winding up procedure, and which has not otherwise ceased operating. This would
include:
· The selective payment default on a specific class or currency of debt;
· The uncured expiry of any applicable grace period, cure period or default forbearance period following a payment default on a bank loan, capital markets security or other material financial obligation;
· The extension of multiple waivers or forbearance periods upon a payment default on one or more material financial obligations, either in series or in parallel; or
· Execution of a distressed debt exchange on one or more material financial obligations.
D
Default. D ratings indicate an issuer that in Fitch Ratings’ opinion has entered into bankruptcy
filings, administration, receivership, liquidation or other formal winding up procedure, or which has otherwise ceased business.
Default ratings are not assigned prospectively to entities or their obligations; within this context, nonpayment on an instrument that contains a deferral feature or grace period will generally not be considered a default until after the expiration of the deferral or grace period, unless a default is otherwise driven by bankruptcy or other similar circumstance, or by a distressed debt exchange.
Imminent default typically refers to the occasion where a payment default has been intimated by the issuer, and is all but inevitable. This may, for example, be where an issuer has missed a scheduled payment, but (as is typical) has a grace period during which it may cure the payment default. Another alternative would be where an issuer has formally announced a distressed debt exchange, but the date of the exchange still lies several days or weeks in the immediate future.
In all cases, the assignment of a default rating reflects the agency’s opinion as to the most appropriate rating category consistent with the rest of its universe of ratings, and may differ from the definition of default under the terms of an issuer’s financial obligations or local commercial practice.
Note: The modifiers “+” or “–” may be appended to a rating to denote relative status within major rating categories. Such suffixes are not added to the AAA long-term rating category, or to categories below B.
American Funds Insurance Series — Page 101
Description of commercial paper ratings
Moody’s
Global short-term rating scale
P-1
Issuers (or supporting institutions) rated Prime-1 have a superior ability to repay short-term debt obligations.
P-2
Issuers (or supporting institutions) rated Prime-2 have a strong ability to repay short-term debt obligations.
P-3
Issuers (or supporting institutions) rated Prime-3 have an acceptable ability to repay short-term obligations.
NP
Issuers (or supporting institutions) rated Not Prime do not fall within any of the Prime rating categories.
Standard & Poor’s
Commercial paper ratings (highest three ratings)
A-1
A short-term obligation rated A-1 is rated in the highest category by Standard & Poor’s. The obligor’s capacity to meet its financial commitment on the obligation is strong. Within this category, certain obligations are designated with a plus sign (+). This indicates that the obligor’s capacity to meet its financial commitment on these obligations is extremely strong.
A-2
A short-term obligation rated A-2 is somewhat more susceptible to the adverse effects of changes in circumstances and economic conditions than obligations in higher rating categories. However, the obligor’s capacity to meet its financial commitment on the obligation is satisfactory.
A-3
A short-term obligation rated A-3 exhibits adequate protection parameters. However, adverse economic conditions or changing circumstances are more likely to lead to a weakened capacity of the obligor to meet its financial commitment on the obligation.
American Funds Insurance Series — Page 102
American Funds Insurance Series
Part C
Other Information
Item 28. Exhibits for Registration Statement (1940 Act No. 811-03857 and 1933 Act No. 002-86838)
| (a-1) | Articles of Incorporation – Declaration of Trust dated 9/9/83 – previously filed (see Post-Effective (“P/E”) Amendment No. 24 filed 3/31/97); Certificate of Amendment of Declaration of Trust dated 10/19/88 - previously filed (see P/E Amendment No. 24 filed 3/31/97); Redesignation of an Existing Series of Shares of Beneficial Interest without Par Value dated 3/19/02 – previously filed (see P/E Amendment No. 33 filed 4/30/02); Establishment and Designation of Additional Class of Shares of Beneficial Interest Without Par Value dated 9/16/02 – previously filed (see P/E Amendment No. 35 filed 10/30/03); Establishment and Designation of Additional Series of Shares of Beneficial Interest Without Par Value dated 3/14/06 – previously filed (see P/E Amendment No. 40 filed 4/28/06); Establishment and Designation of Additional Series of Shares of Beneficial Interest Without Par Value dated 9/19/06 – previously filed (see P/E Amendment No. 44 filed 10/2/06); and Establishment and Designation of Additional Series of Shares of Beneficial Interest Without Par Value dated 6/18/08 – previously filed (see P/E Amendment No. 47 filed 7/14/08); Establishment and Designation of Additional Series of Shares of Beneficial Interest Without Par Value dated 12/1/10 – previously filed (see P/E Amendment No. 53 filed 4/29/11); Establishment and Designation of Additional Series of Shares of Beneficial Interest Without Par Value dated 6/13/12 – previously filed (see P/E Amendment No. 58 filed 9/17/12); Establishment and Designation of Additional Series of Shares of Beneficial Interest Without Par Value dated 9/12/12 – previously filed (see P/E Amendment No. 61 filed 12/14/12); Establishment and Designation of Additional Series of Shares of Beneficial Interest Without Par Value Dated 12/5/12 – previously filed (see P/E Amendment No. 64 filed 4/30/13); Establishment and Designation of Additional Series of Shares of Beneficial Interest Without Par Value Dated 1/16/13 – previously filed (see P/E Amendment No. 64 filed 4/30/13); Redesignation of Existing Series of Shares of Beneficial Interest Without Par Value dated 4/15/13 – previously filed (see P/E Amendment No. 64 filed 4/30/13); Establishment and Designation of Additional Series of Shares of Beneficial Interest Without Par Value dated 1/23/14 – previously filed (see P/E Amendment No. 67 filed 4/30/14); Amendment to Declaration of Trust dated 12/8/14 – previously filed (see P/E Amendment No. 70 filed 4/30/15); Establishment and Designation of Additional Series of Shares of Beneficial Interest Without Par Value dated 1/9/15 – previously filed (see P/E Amendment No. 70 filed 4/30/15); Redesignation of Existing Series of Shares of Beneficial Interest Without Par Value dated 12/4/15 – previously filed (see P/E Amendment No. 73 filed 4/29/16); Establishment and Designation of Additional Class of Shares of Beneficial Interest Without Par Value dated 9/14/16 – previously filed (see P/E Amendment No. 76 filed 12/23/16); Establishment and Designation of Additional Series of Shares of Beneficial Interest Without Par Value dated 6/13/19 – previously filed (see P/E Amendment No. 91 filed 12/6/19); Certificate of Amendment of Declaration of Trust dated 12/9/19 – previously filed (see P/E Amendment No. 94 filed 4/30/20); and Certificate of Amendment of Declaration of Trust dated 12/8/20 – previously filed (see P/E Amendment No. 97 filed 4/30/21) |
| (a-2) | Certificate of Amendment of Declaration of Trust dated 1/28/21 - to be provided by amendment |
| (b) | By-Laws - By-Laws as amended 8/29/18 – previously filed (see P/E Amendment No. 86 filed 9/28/18) |
| (c) | Instruments Defining Rights of Security Holders – See Items 28(a) (Articles 2,6 and 7 of Declaration of Trust) and 28(b) (Article 1 and Section 5.04) |
| (d-1) | Investment Advisory Contracts – Sub-Advisory Agreement with Milliman Financial Risk Management LLC – previously filed (see P/E Amendment No. 58 filed 9/17/12); First Amendment to Subadvisory Agreement with Milliman Financial Risk Management LLC dated 3/3/13 – previously filed (see P/E Amendment No. 64 filed 4/30/13); Investment Advisory and Service Agreement (Portfolio Series Funds) dated 5/1/15 – previously filed (see P/E Amendment No. 70 filed 4/30/15); Second Amendment to Subadvisory Agreement with Milliman Financial Risk Management LLC dated 5/1/15 – previously filed (see P/E Amendment No. 70 filed 4/30/15); Amendment to Investment Advisory and Service Agreement (Portfolio Series Funds) dated 1/1/16 – previously filed (see P/E Amendment No. 73 filed 4/29/16); Third Amendment to Subadvisory Agreement with Milliman Financial Risk Management LLC dated 3/4/19; (see P/E Amendment 88 filed 4/30/19); Investment Advisory and Service Agreement (Target Date Series) dated 9/18/19 – previously filed (see P/E Amendment No. 91 filed 12/6/19); Exhibit A to the Subadvisory Agreement with Milliman Financial Risk Management LLC dated 5/1/15 – previously filed (see P/E Amendment No. 97 filed 4/30/21); Amended and Restated Investment Advisory and Service Agreement dated 5/1/21 – previously filed (see P/E Amendment No. 97 filed 4/30/21); and Amended and Restated Investment Advisory and Service Agreement (Managed Risk Funds) dated 5/1/21 – previously filed (see P/E Amendment No. 97 filed 4/30/21) |
| (d-2) | Amended and Restated Investment Advisory and Service Agreement dated 5/1/22 - to be provided by amendment |
| (e) | Underwriting Contracts – Form of Fund Participation Agreement - previously filed (see P/E Amendment No. 23 filed 1/15/97); Principal Underwriting Agreement dated 7/12/89 – previously filed (see P/E Amendment No. 24 filed 3/31/97); Amendment to Principal Underwriting Agreement dated 2/7/92 – previously filed (see P/E Amendment No. 24 filed 3/31/97); and Fund Participation Agreement dated 9/30/02 – previously filed (see P/E Amendment No. 35 filed 10/30/03) |
| (f) | Bonus or Profit Sharing Contracts – Deferred Compensation Plan effective 1/1/20 – previously filed (see P/E Amendment No. 94 filed 4/30/20) |
| (g-1) | Custodian Agreements – Global Custody Agreement with State Street Bank and Trust Company dated 12/14/06 – previously filed (see P/E Amendment No. 45 filed 5/1/07); and Amendment to Global Custody Agreement with State Street Bank and Trust Company effective 5/1/21 – previously filed (see P/E Amendment No. 97 filed 4/30/21) |
| (g-2) | Amendment to Global Custody Agreement with State Street Bank and Trust Company effective 12/10/21- to be provided by amendment; and Amendment to Global Custody Agreement with State Street Bank and Trust Company effective 5/1/22- to be provided by amendment |
| (h-1) | Other Material Contracts – Form of Indemnification Agreement dated 7/1/04 - previously filed (see P/E Amendment No. 38 filed 4/29/05); Sub-Administration Agreement – previously filed (see P/E Amendment No. 58 filed 9/17/12); Agreement and Plan of Reorganization and Liquidation dated 12/5/12 – previously filed (see P/E Amendment No. 64 filed 4/30/13); Insurance Administrative Services Plan for Classes P1 and P2 shares dated 9/17/12, as amended 4/26/13 – previously filed (see P/E Amendment No. 64 filed 4/30/13); Amended and Restated Insurance Administrative Services Plan for Classes 1A and 4 shares dated 1/6/17 – previously filed (see P/E Amendment No. 76 filed 12/23/16); American Funds Insurance Series – Portfolio Series Amended and Restated Administrative Services Agreement dated 1/6/17 – previously filed (see P/E Amendment No. 76 filed 12/23/16); Amended and Restated Administrative Services Agreement dated 1/1/18 – previously filed (see P/E Amendment No. 83 filed 4/30/18); Administrative Services Agreement (Target Date Series) dated 9/18/19 – previously filed (see P/E Amendment No. 91 filed 12/6/19); Amendment to Sub-Administration Agreement with Bank of New York Mellon dated 4/1/21 – previously filed (see P/E Amendment No. 97 filed 4/30/21); Exhibit A to the Insurance Administrative Services Plan for Classes 1A and 4 shares as dated 5/1/21 – previously filed (see P/E Amendment No. 97 filed 4/30/21); Exhibit A to the Insurance Administrative Services Plan for Classes P1 and P2 shares as dated 5/1/21 – previously filed (see P/E Amendment No. 97 filed 4/30/21); Amended and Restated Shareholder Services Agreement dated 1/1/21 – previously filed (see P/E Amendment No. 97 filed 4/30/21); Exhibit A to the Amended and Restated Shareholder Services Agreement dated 5/1/21 – previously filed (see P/E Amendment No. 97 filed 4/30/21); and Exhibit A to the Amended and Restated Administrative Services Agreement dated 5/1/21 – previously filed (see P/E Amendment No. 97 filed 4/30/21) |
| (h-2) | Exhibit A to the Insurance Administrative Services Plan for Classes 1A and 4 shares as dated 5/1/22 – to be provided by amendment; Exhibit A to the Amended and Restated Shareholder Services Agreement dated 5/1/22 – to be provided by amendment; Exhibit A to the Amended and Restated Administrative Services Agreement dated 5/1/22 – to be provided by amendment; and Form of Fund of Funds Investment Agreement – American Funds/American Funds Insurance Series (Rule 12d1-4) |
| (i) | Legal Opinion – Legal Opinion – previously filed (see P/E Amendment No. 24 filed 3/31/97; P/E Amendment No. 36 filed 1/15/04; P/E Amendment No. 58 filed 9/17/12; P/E Amendment No. 61 filed 12/14/12; P/E Amendment No. 67 filed 4/30/14; P/E Amendment No. 70 filed 4/30/15; P/E Amendment No. 76 filed 12/23/16; and P/E Amendment No. 91 filed 12/6/19) |
| (j) | Other Opinions – Consent of Independent Registered Public Accounting Firm – to be provided by amendment |
| (k) | Omitted Financial Statements - none |
| (l) | Initial Capital Agreements – Investment Letter from Investment Adviser relating to initial shares dated December 1983 – previously filed (see P/E Amendment No. 24 filed 3/31/97); Mixed and Shared Funding Order - previously filed (see P/E Amendment No. 36 filed 1/15/04) |
| (m-1) | Rule 12b-1 Plan – Amended and Restated Class 1A Plan of Distribution dated 5/1/21 – previously filed (see P/E Amendment No. 97 filed 4/30/21); Amended and Restated Class 2 Plan of Distribution dated 5/1/21 – previously filed (see P/E Amendment No. 97 filed 4/30/21); Amended and Restated Class 3 Plan of Distribution dated 5/1/21 – previously filed (see P/E Amendment No. 97 filed 4/30/21); Amended and Restated Class 4 Plan of Distribution dated 5/1/21 – previously filed (see P/E Amendment No. 97 filed 4/30/21); Amended and Restated Class P1 Plan of Distribution dated 5/1/21 – previously filed (see P/E Amendment No. 97 filed 4/30/21); and Amended and Restated Class P2 Plan of Distribution dated 5/1/21 – previously filed (see P/E Amendment No. 97 filed 4/30/21) |
| (m-2) | Exhibit A to the Amended and Restated Class 1A Plan of Distribution dated 5/1/22 – to be provided by amendment; Exhibit A to the Amended and Restated Class 2 Plan of Distribution dated 5/1/22 – to be provided by amendment; and Exhibit A to the Amended and Restated Class 4 Plan of Distribution dated 5/1/22 – to be provided by amendment |
| (n-1) | Rule 18f-3 – Amended and Restated Multiple Class Plan effective 9/18/19 – previously filed (see P/E Amendment No. 91 filed 12/6/19); and Exhibit A to the Amended and Restated Multiple Class Plan dated 5/1/21 – previously filed (see P/E Amendment No. 97 filed 4/30/21) |
| (n-2) | Exhibit A to the Amended and Restated Multiple Class Plan dated 5/1/22 – to be provided by amendment |
| (o) | Reserved |
| (p) | Code of Ethics – Code of Ethics for The Capital Group Companies dated July 2021; and Code of Ethics for the Registrant – to be provided by amendment |
| Item 29. | Persons Controlled by or Under Common Control with the Fund |
| None. |
| Item 30. | Indemnification |
The Registrant is a joint-insured under Investment Adviser/Mutual Fund Errors and Omissions Policies, which insure its officers and trustees against certain liabilities. However, in no event will Registrant maintain insurance to indemnify any such person for any act for which Registrant itself is not permitted to indemnify the individual.
Article V of the Registrant’s Declaration of Trust and Article VI of the Registrant’s By-Laws as well as the indemnification agreements that the Registrant has entered into with each of its trustees who is not an "interested person" of the Registrant (as defined under the Investment Company Act of 1940, as amended), provide in effect that the Registrant will indemnify its officers and trustees against any liability or expenses actually and reasonably
incurred by such person in any proceeding arising out of or in connection with his or her service to the Registrant, to the fullest extent permitted by applicable law, subject to certain conditions. In accordance with Section 17(h) and 17(i) of the Investment Company Act of 1940, as amended, and their respective terms, these provisions do not protect any person against any liability to the Registrant or its shareholders to which such person would otherwise be subject by reason of willful misfeasance, bad faith, gross negligence, or reckless disregard of the duties involved in the conduct of his or her office.
Insofar as indemnification for liability arising under the Securities Act of 1933 may be permitted to trustees, officers and controlling persons of the Registrant pursuant to the foregoing provisions, or otherwise, the Registrant has been advised that in the opinion of the U.S. Securities and Exchange Commission such indemnification is against public policy as expressed in the Act and is, therefore, unenforceable. In the event that a claim for indemnification against such liabilities (other than the payment by the Registrant of expenses incurred or paid by a trustee, officer or controlling person of the Registrant in the successful defense of any action, suit or proceeding) is asserted by such trustee, officer or controlling person in connection with the securities being registered, the Registrant will, unless in the opinion of its counsel the matter has been settled by controlling precedent, submit to a court of appropriate jurisdiction the question whether such indemnification by it is against public policy as expressed in the Act and will be governed by the final adjudication of such issue.
Registrant will comply with the indemnification requirements contained in the Investment Company Act of 1940, as amended, and Release Nos. 7221 (June 9, 1972) and 11330 (September 4, 1980).
| Item 31. | Business and Other Connections of the Investment Adviser |
None.
| Item 32. | Principal Underwriters |
Not applicable.
| Item 33. | Location of Accounts and Records |
Accounts, books and other records required to be maintained by Rules 31a-1 and 31a-2 under the Investment Company Act of 1940, as amended, are maintained and kept in the offices of the Series and the Registrant’s investment adviser, Capital Research and Management Company, 333 South Hope Street, Los Angeles, California 90071. Certain accounting records are maintained and kept in the offices of the investment adviser's accounting department, 6455 Irvine Center Drive, Irvine, California 92618; and/or 5300 Robin Hood Road, Norfolk, Virginia 23513.
Records covering portfolio transactions are also maintained and kept by State Street Bank and Trust Company, One Lincoln Street, Boston, Massachusetts 02111.
Certain other books and records required to be maintained by the Registrant’s investment adviser under Section 4.23 under the Commodity Exchange Act and the rules and regulations promulgated thereunder, including records relating to certain portfolio transactions, are maintained and kept in the offices of Bank of New York Mellon, One Wall Street, New York, New York 10286 and/or Milliman Financial Risk Management LLC, 71 South Wacker Drive, 31st Floor, Chicago, Illinois 60606.
| Item 34. | Management Services |
None.
| Item 35. | Undertakings |
None.
SIGNATURES
Pursuant to the requirements of the Securities Act of 1933 and the Investment Company Act of 1940, the Registrant has duly caused this registration statement to be signed on its behalf by the undersigned, thereunto duly authorized, in the City of Los Angeles, and State of California on the 11th day of February 2022.
American Funds Insurance Series
By: /s/ Maria Manotok
(Maria Manotok, Principal Executive Officer)
Pursuant to the requirements of the Securities Act of 1933, this amendment to registration statement has been signed below on February 11, 2022, by the following persons in the capacities indicated.
| Signature | Title | |
| (1) | Principal Executive Officer: | |
/s/ Maria Manotok |
Principal Executive Officer | |
| Maria Manotok | ||
| (2) | Principal Financial Officer and Principal Accounting Officer: | |
/s/ Gregory F. Niland |
Treasurer | |
| Gregory F. Niland | ||
| (3) | Trustees: | |
| Francisco G. Cigarroa* | Trustee | |
| James G. Ellis* | Trustee | |
| Nariman Farvardin* | Trustee | |
| Michael C. Gitlin* | Trustee | |
| Mary Davis Holt* | Trustee | |
| Merit E. Janow* | Trustee | |
| Donald D. O’Neal* | Co-President and Trustee | |
| Margaret Spellings* | Chair (Independent and Non-Executive) | |
| Alexandra Trower* | Trustee | |
| Paul S. Williams* | Trustee | |
*By: /s/ Steven I. Koszalka |
||
| (Steven I. Koszalka, pursuant to a power of attorney filed herewith) | ||
POWER OF ATTORNEY
I, Francisco G. Cigarroa, the undersigned Board member of the following registered investment companies (collectively, the “Funds”):
| - | American Funds College Target Date Series (File No. 333-180729, File No. 811-22692) |
| - | American Funds Corporate Bond Fund (File No. 333-183929, File No. 811-22744) |
| - | American Funds Emerging Markets Bond Fund (File No. 333-208636; File No. 811-23122) |
| - | The American Funds Income Series – U.S. Government Securities Fund (File No. 002-98199, File No. 811-04318) |
| - | American Funds Inflation Linked Bond Fund (File No. 333-183931, File No. 811-22746) |
| - | American Funds Insurance Series (File No. 002-86838, File No. 811-03857) |
| - | American Funds Insurance Series |
| - | American Funds Mortgage Fund (File No. 333-168595, File No. 811-22449) |
| - | American Funds Multi-Sector Income Fund (File No. 333-228995, File No. 811-23409) |
| - | American Funds Portfolio Series (File No. 333-178936, File No. 811-22656) |
| - | American Funds Retirement Income Portfolio Series (File No. 333-203797, File No. 811-23053) |
| - | American Funds Short-Term Tax-Exempt Bond Fund (File No. 033-26431, File No. 811-05750) |
| - | American Funds Strategic Bond Fund (File No. 333-207474, File No. 811-23101) |
| - | American Funds Target Date Retirement Series (File No. 333-138648, File No. 811-21981) |
| - | American Funds Tax-Exempt Fund of New York (File No. 333-168594, File No. 811-22448) |
| - | The American Funds Tax-Exempt Series II – The Tax-Exempt Fund of California (File No. 033-06180, File No. 811-04694) |
| - | American Funds U.S. Government Money Market Fund (File No. 333-157162, File No. 811-22277) |
| - | American High-Income Municipal Bond Fund (File No. 033-80630, File No. 811-08576) |
| - | American High-Income Trust (File No. 033-17917, File No. 811-05364) |
| - | The Bond Fund of America (File No. 002-50700, File No. 811-02444) |
| - | Capital Group Central Fund Series – Capital Group Central Cash Fund (File No. 811-23391) |
| - | Capital Group Central Fund Series II (File No. 811-23633) |
| - | Capital World Bond Fund (File No. 033-12447, File No. 811-05104) |
| - | Intermediate Bond Fund of America (File No. 033-19514, File No. 811-05446) |
| - | Limited Term Tax-Exempt Bond Fund of America (File No. 033-66214, File No. 811-07888) |
| - | Short-Term Bond Fund of America (File No. 333-135770, File No. 811-21928) |
| - | The Tax-Exempt Bond Fund of America (File No. 002-49291, File No. 811-02421) |
hereby revoke all previous powers of attorney I have signed and otherwise act in my name and behalf in matters involving the Funds and do hereby constitute and appoint
Jennifer L. Butler Steven I. Koszalka Julie E. Lawton Michael W. Stockton Courtney R. Taylor Timothy W. McHale Zarouhi M. Chavdarian Jane Y. Chung Susan K. Countess Marilyn Paramo Lovelyn C. Sims Michael R. Tom |
Brian D. Bullard Sandra Chuon Kyle J. Ilsley Brian C. Janssen Hong T. Le Gregory F. Niland W. Michael Pattie |
each of them singularly, my true and lawful attorneys-in-fact, with full power of substitution, and with full power to each of them, to sign for me and in my name in the appropriate capacities, all Registration Statements of the Funds on Form N-1A, any and all subsequent Amendments, or Post-Effective Amendments to said Registration Statement on Form N-1A or any successor thereto, and any supplements or other instruments in connection therewith, and generally to do all such things in my name and behalf in connection therewith as said attorneys-in-fact deem necessary or appropriate, to comply with the provisions of the Securities Act of 1933 and the Investment Company Act of 1940 as amended, and all related requirements of the U. S. Securities and Exchange Commission. I hereby ratify and confirm all that said attorneys-in-fact or their substitutes may do or cause to be done by virtue hereof.
EXECUTED at San Antonio, Texas, on March 10, 2021.
(City, State)
/s/ Francisco G. Cigarroa
Francisco G. Cigarroa, Board member
POWER OF ATTORNEY
I, James G. Ellis, the undersigned Board member of the following registered investment companies (collectively, the “Funds”):
| - | AMCAP Fund (File No. 002-26516, File No. 811-01435) |
| - | American Funds College Target Date Series (File No. 333-180729, File No. 811-22692) |
| - | American Funds Corporate Bond Fund (File No. 333-183929, File No. 811-22744) |
| - | American Funds Emerging Markets Bond Fund (File No. 333-208636; File No. 811-23122) |
| - | American Funds Global Balanced Fund (File No. 333-170605, File No. 811-22496) |
| - | American Funds Global Insight Fund (File No. 333-233375, File No. 811-23468) |
| - | The American Funds Income Series – U.S. Government Securities Fund (File No. 002-98199, File No. 811-04318) |
| - | American Funds Inflation Linked Bond Fund (File No. 333-183931, File No. 811-22746) |
| - | American Funds Insurance Series (File No. 002-86838, File No. 811-03857) |
| - | American Funds Insurance Series |
| - | American Funds International Vantage Fund (File No. 333-233374, File No. 811-23467) |
| - | American Funds Mortgage Fund (File No. 333-168595, File No. 811-22449) |
| - | American Funds Multi-Sector Income Fund (File No. 333-228995, File No. 811-23409) |
| - | American Funds Portfolio Series (File No. 333-178936, File No. 811-22656) |
| - | American Funds Retirement Income Portfolio Series (File No. 333-203797, File No. 811-23053) |
| - | American Funds Short-Term Tax-Exempt Bond Fund (File No. 033-26431, File No. 811-05750) |
| - | American Funds Strategic Bond Fund (File No. 333-207474, File No. 811-23101) |
| - | American Funds Target Date Retirement Series (File No. 333-138648, File No. 811-21981) |
| - | American Funds Tax-Exempt Fund of New York (File No. 333-168594, File No. 811-22448) |
| - | The American Funds Tax-Exempt Series II – The Tax-Exempt Fund of California (File No. 033-06180, File No. 811-04694) |
| - | American Funds U.S. Government Money Market Fund (File No. 333-157162, File No. 811-22277) |
| - | American High-Income Municipal Bond Fund (File No. 033-80630, File No. 811-08576) |
| - | American High-Income Trust (File No. 033-17917, File No. 811-05364) |
| - | American Mutual Fund (File No. 002-10607, File No. 811-00572) |
| - | The Bond Fund of America (File No. 002-50700, File No. 811-02444) |
| - | Capital Group Central Fund Series – Capital Group Central Cash Fund (File No. 811-23391) |
| - | Capital Group Central Fund Series II (File No. 811-23633) |
| - | Capital Group Private Client Services Funds (File No. 333-163115, File No. 811-22349) |
| - | Capital Group U.S. Equity Fund (File No. 333-233376, File No. 811-23469) |
| - | Capital World Bond Fund (File No. 033-12447, File No. 811-05104) |
| - | Emerging Markets Growth Fund, Inc. (File No. 333-74995, File No. 811-04692) |
| - | Intermediate Bond Fund of America (File No. 033-19514, File No. 811-05446) |
| - | The Investment Company of America (File No. 002-10811, File No. 811-00116) |
| - | Limited Term Tax-Exempt Bond Fund of America (File No. 033-66214, File No. 811-07888) |
| - | Short-Term Bond Fund of America (File No. 333-135770, File No. 811-21928) |
| - | The Tax-Exempt Bond Fund of America (File No. 002-49291, File No. 811-02421) |
hereby revoke all previous powers of attorney I have signed and otherwise act in my name and behalf in matters involving the Funds and do hereby constitute and appoint
Jennifer L. Butler Steven I. Koszalka Julie E. Lawton Michael W. Stockton Courtney R. Taylor Timothy W. McHale Zarouhi M. Chavdarian Jane Y. Chung Susan K. Countess Marilyn Paramo Lovelyn C. Sims Michael R. Tom |
Brian D. Bullard Sandra Chuon Kyle J. Ilsley Brian C. Janssen Hong T. Le Gregory F. Niland W. Michael Pattie |
each of them singularly, my true and lawful attorneys-in-fact, with full power of substitution, and with full power to each of them, to sign for me and in my name in the appropriate capacities, all Registration Statements of the Funds on Form N-1A, any and all subsequent Amendments, or Post-Effective Amendments to said Registration Statement on Form N-1A or any successor thereto, and any supplements or other instruments in connection therewith, and generally to do all such things in my name and behalf in connection therewith as said attorneys-in-fact deem necessary or appropriate, to comply with the provisions of the Securities Act of 1933 and the Investment Company Act of 1940 as amended, and all related requirements of the U. S. Securities and Exchange Commission. I hereby ratify and confirm all that said attorneys-in-fact or their substitutes may do or cause to be done by virtue hereof.
EXECUTED at San Marino, CA, on March 10, 2021.
(City, State)
/s/ James G. Ellis
James G. Ellis, Board member
POWER OF ATTORNEY
I, Nariman Farvardin, the undersigned Board member of the following registered investment companies (collectively, the “Funds”):
| - | American Balanced Fund (File No. 002-10758, File No. 811-00066) |
| - | American Funds College Target Date Series (File No. 333-180729, File No. 811-22692) |
| - | American Funds Corporate Bond Fund (File No. 333-183929, File No. 811-22744) |
| - | American Funds Developing World Growth and Income Fund (File No. 333-190913, File No. 811-22881) |
| - | American Funds Emerging Markets Bond Fund (File No. 333-208636; File No. 811-23122) |
| - | The American Funds Income Series – U.S. Government Securities Fund (File No. 002-98199, File No. 811-04318) |
| - | American Funds Inflation Linked Bond Fund (File No. 333-183931, File No. 811-22746) |
| - | American Funds Insurance Series (File No. 002-86838, File No. 811-03857) |
| - | American Funds Insurance Series |
| - | American Funds Mortgage Fund (File No. 333-168595, File No. 811-22449) |
| - | American Funds Multi-Sector Income Fund (File No. 333-228995, File No. 811-23409) |
| - | American Funds Portfolio Series (File No. 333-178936, File No. 811-22656) |
| - | American Funds Retirement Income Portfolio Series (File No. 333-203797, File No. 811-23053) |
| - | American Funds Short-Term Tax-Exempt Bond Fund (File No. 033-26431, File No. 811-05750) |
| - | American Funds Strategic Bond Fund (File No. 333-207474, File No. 811-23101) |
| - | American Funds Target Date Retirement Series (File No. 333-138648, File No. 811-21981) |
| - | American Funds Tax-Exempt Fund of New York (File No. 333-168594, File No. 811-22448) |
| - | The American Funds Tax-Exempt Series II – The Tax-Exempt Fund of California (File No. 033-06180, File No. 811-04694) |
| - | American Funds U.S. Government Money Market Fund (File No. 333-157162, File No. 811-22277) |
| - | American High-Income Municipal Bond Fund (File No. 033-80630, File No. 811-08576) |
| - | American High-Income Trust (File No. 033-17917, File No. 811-05364) |
| - | The Bond Fund of America (File No. 002-50700, File No. 811-02444) |
| - | Capital Group Central Fund Series – Capital Group Central Cash Fund (File No. 811-23391) |
| - | Capital Group Central Fund Series II (File No. 811-23633) |
| - | Capital World Bond Fund (File No. 033-12447, File No. 811-05104) |
| - | The Income Fund of America (File No. 002-33371, File No. 811-01880) |
| - | Intermediate Bond Fund of America (File No. 033-19514, File No. 811-05446) |
| - | International Growth and Income Fund (File No. 333-152323, File No. 811-22215) |
| - | Limited Term Tax-Exempt Bond Fund of America (File No. 033-66214, File No. 811-07888) |
| - | Short-Term Bond Fund of America (File No. 333-135770, File No. 811-21928) |
| - | The Tax-Exempt Bond Fund of America (File No. 002-49291, File No. 811-02421) |
| - | Washington Mutual Investors Fund (File No. 002-11051, File No. 811-00604) |
hereby revoke all previous powers of attorney I have signed and otherwise act in my name and behalf in matters involving the Funds and do hereby constitute and appoint
Jennifer L. Butler Steven I. Koszalka Julie E. Lawton Michael W. Stockton Courtney R. Taylor Timothy W. McHale Jane Y. Chung Susan K. Countess Marilyn Paramo Lovelyn C. Sims Michael R. Tom |
Sandra Chuon Kyle J. Ilsley Brian C. Janssen Hong T. Le Gregory F. Niland Becky L. Park W. Michael Pattie Troy S. Tanner |
each of them singularly, my true and lawful attorneys-in-fact, with full power of substitution, and with full power to each of them, to sign for me and in my name in the appropriate capacities, all Registration Statements of the Funds on Form N-1A, any and all subsequent Amendments, or Post-Effective Amendments to said Registration Statement on Form N-1A or any successor thereto, and any supplements or other instruments in connection therewith, and generally to do all such things in my name and behalf in connection therewith as said attorneys-in-fact deem necessary or appropriate, to comply with the provisions of the Securities Act of 1933 and the Investment Company Act of 1940 as amended, and all related requirements of the U. S. Securities and Exchange Commission. I hereby ratify and confirm all that said attorneys-in-fact or their substitutes may do or cause to be done by virtue hereof.
EXECUTED at Hoboken, NJ, on January 1, 2022.
(City, State)
/s/ Nariman Farvardin
Nariman Farvardin, Board member
POWER OF ATTORNEY
I, Michael C. Gitlin, the undersigned Board member of the following registered investment companies (collectively, the “Funds”):
| - | American Funds College Target Date Series (File No. 333-180729, File No. 811-22692) |
| - | American Funds Corporate Bond Fund (File No. 333-183929, File No. 811-22744) |
| - | American Funds Emerging Markets Bond Fund (File No. 333-208636; File No. 811-23122) |
| - | The American Funds Income Series – U.S. Government Securities Fund (File No. 002-98199, File No. 811-04318) |
| - | American Funds Inflation Linked Bond Fund (File No. 333-183931, File No. 811-22746) |
| - | American Funds Insurance Series (File No. 002-86838, File No. 811-03857) |
| - | American Funds Insurance Series |
| - | American Funds Mortgage Fund (File No. 333-168595, File No. 811-22449) |
| - | American Funds Multi-Sector Income Fund (File No. 333-228995, File No. 811-23409) |
| - | American Funds Portfolio Series (File No. 333-178936, File No. 811-22656) |
| - | American Funds Retirement Income Portfolio Series (File No. 333-203797, File No. 811-23053) |
| - | American Funds Short-Term Tax-Exempt Bond Fund (File No. 033-26431, File No. 811-05750) |
| - | American Funds Strategic Bond Fund (File No. 333-207474, File No. 811-23101) |
| - | American Funds Target Date Retirement Series (File No. 333-138648, File No. 811-21981) |
| - | American Funds Tax-Exempt Fund of New York (File No. 333-168594, File No. 811-22448) |
| - | The American Funds Tax-Exempt Series II – The Tax-Exempt Fund of California (File No. 033-06180, File No. 811-04694) |
| - | American Funds U.S. Government Money Market Fund (File No. 333-157162, File No. 811-22277) |
| - | American High-Income Municipal Bond Fund (File No. 033-80630, File No. 811-08576) |
| - | American High-Income Trust (File No. 033-17917, File No. 811-05364) |
| - | The Bond Fund of America (File No. 002-50700, File No. 811-02444) |
| - | Capital Group Central Fund Series – Capital Group Central Cash Fund (File No. 811-23391) |
| - | Capital Group Central Fund Series II (File No. 811-23633) |
| - | Capital World Bond Fund (File No. 033-12447, File No. 811-05104) |
| - | Intermediate Bond Fund of America (File No. 033-19514, File No. 811-05446) |
| - | Limited Term Tax-Exempt Bond Fund of America (File No. 033-66214, File No. 811-07888) |
| - | Short-Term Bond Fund of America (File No. 333-135770, File No. 811-21928) |
| - | The Tax-Exempt Bond Fund of America (File No. 002-49291, File No. 811-02421) |
hereby revoke all previous powers of attorney I have signed and otherwise act in my name and behalf in matters involving the Funds and do hereby constitute and appoint
Jennifer L. Butler Steven I. Koszalka Julie E. Lawton Michael W. Stockton Courtney R. Taylor Timothy W. McHale Zarouhi M. Chavdarian Jane Y. Chung Susan K. Countess Marilyn Paramo Lovelyn C. Sims Michael R. Tom |
Brian D. Bullard Sandra Chuon Kyle J. Ilsley Brian C. Janssen Hong T. Le Gregory F. Niland W. Michael Pattie |
each of them singularly, my true and lawful attorneys-in-fact, with full power of substitution, and with full power to each of them, to sign for me and in my name in the appropriate capacities, all Registration Statements of the Funds on Form N-1A, any and all subsequent Amendments, or Post-Effective Amendments to said Registration Statement on Form N-1A or any successor thereto, and any supplements or other instruments in connection therewith, and generally to do all such things in my name and behalf in connection therewith as said attorneys-in-fact deem necessary or appropriate, to comply with the provisions of the Securities Act of 1933 and the Investment Company Act of 1940 as amended, and all related requirements of the U. S. Securities and Exchange Commission. I hereby ratify and confirm all that said attorneys-in-fact or their substitutes may do or cause to be done by virtue hereof.
EXECUTED at Los Angeles, CA, on March 10, 2021.
(City, State)
/s/ Michael C. Gitlin
Michael C. Gitlin, Board member
POWER OF ATTORNEY
I, Mary Davis Holt, the undersigned Board member of the following registered investment companies (collectively, the “Funds”):
| - | American Funds College Target Date Series (File No. 333-180729, File No. 811-22692) |
| - | American Funds Corporate Bond Fund (File No. 333-183929, File No. 811-22744) |
| - | American Funds Emerging Markets Bond Fund (File No. 333-208636; File No. 811-23122) |
| - | The American Funds Income Series – U.S. Government Securities Fund (File No. 002-98199, File No. 811-04318) |
| - | American Funds Inflation Linked Bond Fund (File No. 333-183931, File No. 811-22746) |
| - | American Funds Insurance Series (File No. 002-86838, File No. 811-03857) |
| - | American Funds Insurance Series |
| - | American Funds Mortgage Fund (File No. 333-168595, File No. 811-22449) |
| - | American Funds Multi-Sector Income Fund (File No. 333-228995, File No. 811-23409) |
| - | American Funds Portfolio Series (File No. 333-178936, File No. 811-22656) |
| - | American Funds Retirement Income Portfolio Series (File No. 333-203797, File No. 811-23053) |
| - | American Funds Short-Term Tax-Exempt Bond Fund (File No. 033-26431, File No. 811-05750) |
| - | American Funds Strategic Bond Fund (File No. 333-207474, File No. 811-23101) |
| - | American Funds Target Date Retirement Series (File No. 333-138648, File No. 811-21981) |
| - | American Funds Tax-Exempt Fund of New York (File No. 333-168594, File No. 811-22448) |
| - | The American Funds Tax-Exempt Series II – The Tax-Exempt Fund of California (File No. 033-06180, File No. 811-04694) |
| - | American Funds U.S. Government Money Market Fund (File No. 333-157162, File No. 811-22277) |
| - | American High-Income Municipal Bond Fund (File No. 033-80630, File No. 811-08576) |
| - | American High-Income Trust (File No. 033-17917, File No. 811-05364) |
| - | The Bond Fund of America (File No. 002-50700, File No. 811-02444) |
| - | Capital Group Central Fund Series – Capital Group Central Cash Fund (File No. 811-23391) |
| - | Capital Group Central Fund Series II (File No. 811-23633) |
| - | Capital World Bond Fund (File No. 033-12447, File No. 811-05104) |
| - | Intermediate Bond Fund of America (File No. 033-19514, File No. 811-05446) |
| - | Limited Term Tax-Exempt Bond Fund of America (File No. 033-66214, File No. 811-07888) |
| - | Short-Term Bond Fund of America (File No. 333-135770, File No. 811-21928) |
| - | The Tax-Exempt Bond Fund of America (File No. 002-49291, File No. 811-02421) |
| - | Washington Mutual Investors Fund (File No. 002-11051, File No. 811-00604) |
hereby revoke all previous powers of attorney I have signed and otherwise act in my name and behalf in matters involving the Funds and do hereby constitute and appoint
Jennifer L. Butler Steven I. Koszalka Julie E. Lawton Michael W. Stockton Courtney R. Taylor Timothy W. McHale Zarouhi M. Chavdarian Jane Y. Chung Susan K. Countess Marilyn Paramo Lovelyn C. Sims Michael R. Tom |
Brian D. Bullard Sandra Chuon Kyle J. Ilsley Brian C. Janssen Hong T. Le Gregory F. Niland W. Michael Pattie |
each of them singularly, my true and lawful attorneys-in-fact, with full power of substitution, and with full power to each of them, to sign for me and in my name in the appropriate capacities, all Registration Statements of the Funds on Form N-1A, any and all subsequent Amendments, or Post-Effective Amendments to said Registration Statement on Form N-1A or any successor thereto, and any supplements or other instruments in connection therewith, and generally to do all such things in my name and behalf in connection therewith as said attorneys-in-fact deem necessary or appropriate, to comply with the provisions of the Securities Act of 1933 and the Investment Company Act of 1940 as amended, and all related requirements of the U. S. Securities and Exchange Commission. I hereby ratify and confirm all that said attorneys-in-fact or their substitutes may do or cause to be done by virtue hereof.
EXECUTED at Alexandria, Virginia, on March 10, 2021.
(City, State)
/s/ Mary Davis Holt
Mary Davis Holt, Board member
POWER OF ATTORNEY
I, Merit E. Janow, the undersigned Board member of the following registered investment companies (collectively, the “Funds”):
| - | AMCAP Fund (File No. 002-26516, File No. 811-01435) |
| - | American Funds College Target Date Series (File No. 333-180729, File No. 811-22692) |
| - | American Funds Corporate Bond Fund (File No. 333-183929, File No. 811-22744) |
| - | American Funds Emerging Markets Bond Fund (File No. 333-208636; File No. 811-23122) |
| - | American Funds Global Balanced Fund (File No. 333-170605, File No. 811-22496) |
| - | The American Funds Income Series – U.S. Government Securities Fund (File No. 002-98199, File No. 811-04318) |
| - | American Funds Inflation Linked Bond Fund (File No. 333-183931, File No. 811-22746) |
| - | American Funds Insurance Series (File No. 002-86838, File No. 811-03857) |
| - | American Funds Insurance Series |
| - | American Funds Mortgage Fund (File No. 333-168595, File No. 811-22449) |
| - | American Funds Multi-Sector Income Fund (File No. 333-228995, File No. 811-23409) |
| - | American Funds Portfolio Series (File No. 333-178936, File No. 811-22656) |
| - | American Funds Retirement Income Portfolio Series (File No. 333-203797, File No. 811-23053) |
| - | American Funds Short-Term Tax-Exempt Bond Fund (File No. 033-26431, File No. 811-05750) |
| - | American Funds Strategic Bond Fund (File No. 333-207474, File No. 811-23101) |
| - | American Funds Target Date Retirement Series (File No. 333-138648, File No. 811-21981) |
| - | American Funds Tax-Exempt Fund of New York (File No. 333-168594, File No. 811-22448) |
| - | The American Funds Tax-Exempt Series II – The Tax-Exempt Fund of California (File No. 033-06180, File No. 811-04694) |
| - | American Funds U.S. Government Money Market Fund (File No. 333-157162, File No. 811-22277) |
| - | American High-Income Municipal Bond Fund (File No. 033-80630, File No. 811-08576) |
| - | American High-Income Trust (File No. 033-17917, File No. 811-05364) |
| - | American Mutual Fund (File No. 002-10607, File No. 811-00572) |
| - | The Bond Fund of America (File No. 002-50700, File No. 811-02444) |
| - | Capital Group Central Fund Series – Capital Group Central Cash Fund (File No. 811-23391) |
| - | Capital Group Central Fund Series II (File No. 811-23633) |
| - | Capital Income Builder (File No. 033-12967, File No. 811-05085) |
| - | Capital World Bond Fund (File No. 033-12447, File No. 811-05104) |
| - | Capital World Growth and Income Fund (File No. 033-54444, File No. 811-07338) |
| - | Intermediate Bond Fund of America (File No. 033-19514, File No. 811-05446) |
| - | The Investment Company of America (File No. 002-10811, File No. 811-00116) |
| - | Limited Term Tax-Exempt Bond Fund of America (File No. 033-66214, File No. 811-07888) |
| - | The New Economy Fund (File No. 002-83848, File No. 811-03735) |
| - | Short-Term Bond Fund of America (File No. 333-135770, File No. 811-21928) |
| - | The Tax-Exempt Bond Fund of America (File No. 002-49291, File No. 811-02421) |
hereby revoke all previous powers of attorney I have signed and otherwise act in my name and behalf in matters involving the Funds and do hereby constitute and appoint
Jennifer L. Butler Steven I. Koszalka Julie E. Lawton Michael W. Stockton Courtney R. Taylor Timothy W. McHale Zarouhi M. Chavdarian Jane Y. Chung Susan K. Countess Marilyn Paramo Lovelyn C. Sims Michael R. Tom |
Brian D. Bullard Sandra Chuon Kyle J. Ilsley Brian C. Janssen Hong T. Le Gregory F. Niland W. Michael Pattie |
each of them singularly, my true and lawful attorneys-in-fact, with full power of substitution, and with full power to each of them, to sign for me and in my name in the appropriate capacities, all Registration Statements of the Funds on Form N-1A, any and all subsequent Amendments, or Post-Effective Amendments to said Registration Statement on Form N-1A or any successor thereto, and any supplements or other instruments in connection therewith, and generally to do all such things in my name and behalf in connection therewith as said attorneys-in-fact deem necessary or appropriate, to comply with the provisions of the Securities Act of 1933 and the Investment Company Act of 1940 as amended, and all related requirements of the U. S. Securities and Exchange Commission. I hereby ratify and confirm all that said attorneys-in-fact or their substitutes may do or cause to be done by virtue hereof.
EXECUTED at New York, NY, on March 10, 2021.
(City, State)
/s/ Merit E. Janow
Merit E. Janow, Board member
POWER OF ATTORNEY
I, Donald D. O’Neal, the undersigned Board member of the following registered investment companies (collectively, the “Funds”):
| - | American Funds Insurance Series (File No. 002-86838, File No. 811-03857) |
| - | American Funds Insurance Series |
hereby revoke all previous powers of attorney I have signed and otherwise act in my name and behalf in matters involving the Funds and do hereby constitute and appoint
Jennifer L. Butler Steven I. Koszalka Michael W. Stockton Courtney R. Taylor Timothy W. McHale Jane Y. Chung Susan K. Countess Julie E. Lawton |
Brian D. Bullard Sandra Chuon Kyle J. Ilsley Brian C. Janssen Hong T. Le Gregory F. Niland W. Michael Pattie |
each of them singularly, my true and lawful attorneys-in-fact, with full power of substitution, and with full power to each of them, to sign for me and in my name in the appropriate capacities, all Registration Statements of the Funds on Form N-1A, any and all subsequent Amendments, or Post-Effective Amendments to said Registration Statement on Form N-1A or any successor thereto, and any supplements or other instruments in connection therewith, and generally to do all such things in my name and behalf in connection therewith as said attorneys-in-fact deem necessary or appropriate, to comply with the provisions of the Securities Act of 1933 and the Investment Company Act of 1940 as amended, and all related requirements of the U. S. Securities and Exchange Commission. I hereby ratify and confirm all that said attorneys-in-fact or their substitutes may do or cause to be done by virtue hereof.
EXECUTED at San Francisco, CA, on 10/27/2020.
(City, State) (Date)
/s/ Donald D. O’Neal
Donald D. O’Neal, Board member
POWER OF ATTORNEY
I, Margaret Spellings, the undersigned Board member of the following registered investment companies (collectively, the “Funds”):
| - | American Balanced Fund (File No. 002-10758, File No. 811-00066) |
| - | American Funds College Target Date Series (File No. 333-180729, File No. 811-22692) |
| - | American Funds Corporate Bond Fund (File No. 333-183929, File No. 811-22744) |
| - | American Funds Developing World Growth and Income Fund (File No. 333-190913, File No. 811-22881) |
| - | American Funds Emerging Markets Bond Fund (File No. 333-208636; File No. 811-23122) |
| - | The American Funds Income Series – U.S. Government Securities Fund (File No. 002-98199, File No. 811-04318) |
| - | American Funds Inflation Linked Bond Fund (File No. 333-183931, File No. 811-22746) |
| - | American Funds Insurance Series (File No. 002-86838, File No. 811-03857) |
| - | American Funds Insurance Series |
| - | American Funds Mortgage Fund (File No. 333-168595, File No. 811-22449) |
| - | American Funds Multi-Sector Income Fund (File No. 333-228995, File No. 811-23409) |
| - | American Funds Portfolio Series (File No. 333-178936, File No. 811-22656) |
| - | American Funds Retirement Income Portfolio Series (File No. 333-203797, File No. 811-23053) |
| - | American Funds Short-Term Tax-Exempt Bond Fund (File No. 033-26431, File No. 811-05750) |
| - | American Funds Strategic Bond Fund (File No. 333-207474, File No. 811-23101) |
| - | American Funds Target Date Retirement Series (File No. 333-138648, File No. 811-21981) |
| - | American Funds Tax-Exempt Fund of New York (File No. 333-168594, File No. 811-22448) |
| - | The American Funds Tax-Exempt Series II – The Tax-Exempt Fund of California (File No. 033-06180, File No. 811-04694) |
| - | American Funds U.S. Government Money Market Fund (File No. 333-157162, File No. 811-22277) |
| - | American High-Income Municipal Bond Fund (File No. 033-80630, File No. 811-08576) |
| - | American High-Income Trust (File No. 033-17917, File No. 811-05364) |
| - | The Bond Fund of America (File No. 002-50700, File No. 811-02444) |
| - | Capital Group Central Fund Series – Capital Group Central Cash Fund (File No. 811-23391) |
| - | Capital Group Central Fund Series II (File No. 811-23633) |
| - | Capital World Bond Fund (File No. 033-12447, File No. 811-05104) |
| - | The Income Fund of America (File No. 002-33371, File No. 811-01880) |
| - | Intermediate Bond Fund of America (File No. 033-19514, File No. 811-05446) |
| - | International Growth and Income Fund (File No. 333-152323, File No. 811-22215) |
| - | Limited Term Tax-Exempt Bond Fund of America (File No. 033-66214, File No. 811-07888) |
| - | Short-Term Bond Fund of America (File No. 333-135770, File No. 811-21928) |
| - | The Tax-Exempt Bond Fund of America (File No. 002-49291, File No. 811-02421) |
| - | Washington Mutual Investors Fund (File No. 002-11051, File No. 811-00604) |
hereby revoke all previous powers of attorney I have signed and otherwise act in my name and behalf in matters involving the Funds and do hereby constitute and appoint
Jennifer L. Butler Steven I. Koszalka Julie E. Lawton Michael W. Stockton Courtney R. Taylor Timothy W. McHale Zarouhi M. Chavdarian Jane Y. Chung Susan K. Countess Marilyn Paramo Lovelyn C. Sims Michael R. Tom |
Brian D. Bullard Sandra Chuon Kyle J. Ilsley Brian C. Janssen Hong T. Le Gregory F. Niland W. Michael Pattie |
each of them singularly, my true and lawful attorneys-in-fact, with full power of substitution, and with full power to each of them, to sign for me and in my name in the appropriate capacities, all Registration Statements of the Funds on Form N-1A, any and all subsequent Amendments, or Post-Effective Amendments to said Registration Statement on Form N-1A or any successor thereto, and any supplements or other instruments in connection therewith, and generally to do all such things in my name and behalf in connection therewith as said attorneys-in-fact deem necessary or appropriate, to comply with the provisions of the Securities Act of 1933 and the Investment Company Act of 1940 as amended, and all related requirements of the U. S. Securities and Exchange Commission. I hereby ratify and confirm all that said attorneys-in-fact or their substitutes may do or cause to be done by virtue hereof.
EXECUTED at Dallas, Texas, on March 10, 2021.
(City, State)
/s/ Margaret Spellings
Margaret Spellings, Board member
POWER OF ATTORNEY
I, Alexandra Trower, the undersigned Board member of the following registered investment companies (collectively, the “Funds”):
| - | American Funds College Target Date Series (File No. 333-180729, File No. 811-22692) |
| - | American Funds Corporate Bond Fund (File No. 333-183929, File No. 811-22744) |
| - | American Funds Emerging Markets Bond Fund (File No. 333-208636; File No. 811-23122) |
| - | The American Funds Income Series – U.S. Government Securities Fund (File No. 002-98199, File No. 811-04318) |
| - | American Funds Inflation Linked Bond Fund (File No. 333-183931, File No. 811-22746) |
| - | American Funds Insurance Series (File No. 002-86838, File No. 811-03857) |
| - | American Funds Insurance Series |
| - | American Funds Mortgage Fund (File No. 333-168595, File No. 811-22449) |
| - | American Funds Multi-Sector Income Fund (File No. 333-228995, File No. 811-23409) |
| - | American Funds Portfolio Series (File No. 333-178936, File No. 811-22656) |
| - | American Funds Retirement Income Portfolio Series (File No. 333-203797, File No. 811-23053) |
| - | American Funds Short-Term Tax-Exempt Bond Fund (File No. 033-26431, File No. 811-05750) |
| - | American Funds Strategic Bond Fund (File No. 333-207474, File No. 811-23101) |
| - | American Funds Target Date Retirement Series (File No. 333-138648, File No. 811-21981) |
| - | American Funds Tax-Exempt Fund of New York (File No. 333-168594, File No. 811-22448) |
| - | The American Funds Tax-Exempt Series II – The Tax-Exempt Fund of California (File No. 033-06180, File No. 811-04694) |
| - | American Funds U.S. Government Money Market Fund (File No. 333-157162, File No. 811-22277) |
| - | American High-Income Municipal Bond Fund (File No. 033-80630, File No. 811-08576) |
| - | American High-Income Trust (File No. 033-17917, File No. 811-05364) |
| - | The Bond Fund of America (File No. 002-50700, File No. 811-02444) |
| - | Capital Group Central Fund Series – Capital Group Central Cash Fund (File No. 811-23391) |
| - | Capital Group Central Fund Series II (File No. 811-23633) |
| - | Capital World Bond Fund (File No. 033-12447, File No. 811-05104) |
| - | Intermediate Bond Fund of America (File No. 033-19514, File No. 811-05446) |
| - | Limited Term Tax-Exempt Bond Fund of America (File No. 033-66214, File No. 811-07888) |
| - | Short-Term Bond Fund of America (File No. 333-135770, File No. 811-21928) |
| - | The Tax-Exempt Bond Fund of America (File No. 002-49291, File No. 811-02421) |
hereby revoke all previous powers of attorney I have signed and otherwise act in my name and behalf in matters involving the Funds and do hereby constitute and appoint
Jennifer L. Butler Steven I. Koszalka Julie E. Lawton Michael W. Stockton Courtney R. Taylor Timothy W. McHale Zarouhi M. Chavdarian Jane Y. Chung Susan K. Countess Marilyn Paramo Lovelyn C. Sims Michael R. Tom |
Brian D. Bullard Sandra Chuon Kyle J. Ilsley Brian C. Janssen Hong T. Le Gregory F. Niland W. Michael Pattie |
each of them singularly, my true and lawful attorneys-in-fact, with full power of substitution, and with full power to each of them, to sign for me and in my name in the appropriate capacities, all Registration Statements of the Funds on Form N-1A, any and all subsequent Amendments, or Post-Effective Amendments to said Registration Statement on Form N-1A or any successor thereto, and any supplements or other instruments in connection therewith, and generally to do all such things in my name and behalf in connection therewith as said attorneys-in-fact deem necessary or appropriate, to comply with the provisions of the Securities Act of 1933 and the Investment Company Act of 1940 as amended, and all related requirements of the U. S. Securities and Exchange Commission. I hereby ratify and confirm all that said attorneys-in-fact or their substitutes may do or cause to be done by virtue hereof.
EXECUTED at New York, NY, on March 10, 2021.
(City, State)
/s/ Alexandra Trower
Alexandra Trower, Board member
POWER OF ATTORNEY
I, Paul S. Williams, the undersigned Board member of the following registered investment companies (collectively, the “Funds”):
| - | American Funds College Target Date Series (File No. 333-180729, File No. 811-22692) |
| - | American Funds Corporate Bond Fund (File No. 333-183929, File No. 811-22744) |
| - | American Funds Emerging Markets Bond Fund (File No. 333-208636; File No. 811-23122) |
| - | The American Funds Income Series – U.S. Government Securities Fund (File No. 002-98199, File No. 811-04318) |
| - | American Funds Inflation Linked Bond Fund (File No. 333-183931, File No. 811-22746) |
| - | American Funds Insurance Series (File No. 002-86838, File No. 811-03857) |
| - | American Funds Insurance Series |
| - | American Funds Mortgage Fund (File No. 333-168595, File No. 811-22449) |
| - | American Funds Multi-Sector Income Fund (File No. 333-228995, File No. 811-23409) |
| - | American Funds Portfolio Series (File No. 333-178936, File No. 811-22656) |
| - | American Funds Retirement Income Portfolio Series (File No. 333-203797, File No. 811-23053) |
| - | American Funds Short-Term Tax-Exempt Bond Fund (File No. 033-26431, File No. 811-05750) |
| - | American Funds Strategic Bond Fund (File No. 333-207474, File No. 811-23101) |
| - | American Funds Target Date Retirement Series (File No. 333-138648, File No. 811-21981) |
| - | American Funds Tax-Exempt Fund of New York (File No. 333-168594, File No. 811-22448) |
| - | The American Funds Tax-Exempt Series II – The Tax-Exempt Fund of California (File No. 033-06180, File No. 811-04694) |
| - | American Funds U.S. Government Money Market Fund (File No. 333-157162, File No. 811-22277) |
| - | American High-Income Municipal Bond Fund (File No. 033-80630, File No. 811-08576) |
| - | American High-Income Trust (File No. 033-17917, File No. 811-05364) |
| - | The Bond Fund of America (File No. 002-50700, File No. 811-02444) |
| - | Capital Group Central Fund Series – Capital Group Central Cash Fund (File No. 811-23391) |
| - | Capital Group Central Fund Series II (File No. 811-23633) |
| - | Capital World Bond Fund (File No. 033-12447, File No. 811-05104) |
| - | Intermediate Bond Fund of America (File No. 033-19514, File No. 811-05446) |
| - | Limited Term Tax-Exempt Bond Fund of America (File No. 033-66214, File No. 811-07888) |
| - | Short-Term Bond Fund of America (File No. 333-135770, File No. 811-21928) |
| - | The Tax-Exempt Bond Fund of America (File No. 002-49291, File No. 811-02421) |
hereby revoke all previous powers of attorney I have signed and otherwise act in my name and behalf in matters involving the Funds and do hereby constitute and appoint
Jennifer L. Butler Steven I. Koszalka Julie E. Lawton Michael W. Stockton Courtney R. Taylor Timothy W. McHale Zarouhi M. Chavdarian Jane Y. Chung Susan K. Countess Marilyn Paramo Lovelyn C. Sims Michael R. Tom |
Brian D. Bullard Sandra Chuon Kyle J. Ilsley Brian C. Janssen Hong T. Le Gregory F. Niland W. Michael Pattie |
each of them singularly, my true and lawful attorneys-in-fact, with full power of substitution, and with full power to each of them, to sign for me and in my name in the appropriate capacities, all Registration Statements of the Funds on Form N-1A, any and all subsequent Amendments, or Post-Effective Amendments to said Registration Statement on Form N-1A or any successor thereto, and any supplements or other instruments in connection therewith, and generally to do all such things in my name and behalf in connection therewith as said attorneys-in-fact deem necessary or appropriate, to comply with the provisions of the Securities Act of 1933 and the Investment Company Act of 1940 as amended, and all related requirements of the U. S. Securities and Exchange Commission. I hereby ratify and confirm all that said attorneys-in-fact or their substitutes may do or cause to be done by virtue hereof.
EXECUTED at Columbus, Ohio, on March 10, 2021.
(City, State)
/s/ Paul S. Williams
Paul S. Williams, Board member