The fund’s investment objective is to provide a high level of current income consistent with prudent investment risk and preservation of capital.
This table describes the fees and expenses that you may pay if you buy, hold and sell shares of the fund. You may pay other fees, such as brokerage commissions and other fees to financial intermediaries, which are not reflected in the tables and examples below. For example, in addition to the fees and expenses described below, you may also be required to pay brokerage commissions on purchases and sales of Class F-2, F-3, 529-F-2 or 529-F-3 shares of the fund. You may qualify for sales charge discounts if you and your family invest, or agree to invest in the future, at least $100,000 in American Funds. More information about these and other discounts is available from your financial professional, in the “Sales charge reductions and waivers” sections on page 38 of the prospectus and on page 70 of the fund’s statement of additional information, and in the sales charge waiver appendix to the prospectus.
Shareholder Fees - U.S. Government Securities Fund® |
Class A |
Class 529-A |
Class C |
Class 529-C |
Class 529-E |
Class 529-T |
Class T |
Class F-1 |
Class F-2 |
Class F-3 |
Class 529-F-1 |
Class 529-F-2 |
Class 529-F-3 |
Class R-1 |
Class R-2 |
Class R-3 |
Class R-4 |
Class R-5 |
Class R-6 |
Class R-2E |
Class R-5E |
||
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Maximum sales charge (load) imposed on purchases (as a percentage of offering price) | 3.75% | 3.50% | none | none | none | 2.50% | 2.50% | none | none | none | none | none | none | none | none | none | none | none | none | none | none | ||
| Maximum deferred sales charge (load) (as a percentage of the amount redeemed) | 1.00% | [1] | 1.00% | [1] | 1.00% | 1.00% | none | none | none | none | none | none | none | none | none | none | none | none | none | none | none | none | none |
| Maximum sales charge (load) imposed on reinvested dividends | none | none | none | none | none | none | none | none | none | none | none | none | none | none | none | none | none | none | none | none | none | ||
| Redemption or exchange fees | none | none | none | none | none | none | none | none | none | none | none | none | none | none | none | none | none | none | none | none | none | ||
| [1] | A contingent deferred sales charge of 1.00% applies on certain redemptions made within 18 months following purchases of $1 million or more made without an initial sales charge. Contingent deferred sales charge is calculated based on the lesser of the offering price and market value of shares being sold. |
Annual Fund Operating Expenses - U.S. Government Securities Fund® |
Class A |
Class C |
Class T |
Class F-1 |
Class F-2 |
Class F-3 |
Class 529-A |
Class 529-C |
Class 529-E |
Class 529-T |
Class 529-F-1 |
Class 529-F-2 |
Class 529-F-3 |
Class R-1 |
Class R-2 |
Class R-2E |
Class R-3 |
Class R-4 |
Class R-5E |
Class R-5 |
Class R-6 |
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Management fees | 0.20% | 0.20% | 0.20% | 0.20% | 0.20% | 0.20% | 0.20% | 0.20% | 0.20% | 0.20% | 0.20% | 0.20% | 0.20% | 0.20% | 0.20% | 0.20% | 0.20% | 0.20% | 0.20% | 0.20% | 0.20% |
| Distribution and/or service (12b-1) fees | 0.25% | 1.00% | 0.25% | 0.25% | none | none | 0.23% | 1.00% | 0.50% | 0.25% | 0.25% | none | none | 1.00% | 0.75% | 0.60% | 0.50% | 0.25% | none | none | none |
| Other expenses | 0.15% | 0.15% | 0.15% | 0.19% | 0.14% | 0.04% | 0.20% | 0.20% | 0.15% | 0.20% | 0.25% | 0.16% | 0.09% | 0.11% | 0.37% | 0.24% | 0.19% | 0.14% | 0.19% | 0.09% | 0.04% |
| Total annual fund operating expenses | 0.60% | 1.35% | 0.60% | 0.64% | 0.34% | 0.24% | 0.63% | 1.40% | 0.85% | 0.65% | 0.70% | 0.36% | 0.29% | 1.31% | 1.32% | 1.04% | 0.89% | 0.59% | 0.39% | 0.29% | 0.24% |
This example is intended to help you compare the cost of investing in the fund with the cost of investing in other mutual funds.
The example assumes that you invest $10,000 in the fund for the time periods indicated and then redeem all of your shares at the end of those periods. The example also assumes that your investment has a 5% return each year and that the fund’s operating expenses remain the same. You may be required to pay brokerage commissions on your purchases and sales of Class F-2, F-3, 529-F-2 or 529-F-3 shares of the fund, which are not reflected in the example.
Expense Example - U.S. Government Securities Fund® - USD ($) |
Class A |
Class C |
Class T |
Class F-1 |
Class F-2 |
Class F-3 |
Class 529-A |
Class 529-C |
Class 529-E |
Class 529-T |
Class 529-F-1 |
Class 529-F-2 |
Class 529-F-3 |
Class R-1 |
Class R-2 |
Class R-2E |
Class R-3 |
Class R-4 |
Class R-5E |
Class R-5 |
Class R-6 |
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| 1 year | $ 434 | $ 237 | $ 310 | $ 65 | $ 35 | $ 25 | $ 412 | $ 243 | $ 87 | $ 315 | $ 72 | $ 37 | $ 30 | $ 133 | $ 134 | $ 106 | $ 91 | $ 60 | $ 40 | $ 30 | $ 25 |
| 3 years | 560 | 428 | 437 | 205 | 109 | 77 | 545 | 443 | 271 | 453 | 224 | 116 | 93 | 415 | 418 | 331 | 284 | 189 | 125 | 93 | 77 |
| 5 years | 697 | 739 | 576 | 357 | 191 | 135 | 689 | 766 | 471 | 603 | 390 | 202 | 163 | 718 | 723 | 574 | 493 | 329 | 219 | 163 | 135 |
| 10 years | $ 1,097 | $ 1,418 | $ 981 | $ 798 | $ 431 | $ 306 | $ 1,109 | $ 1,185 | $ 1,049 | $ 1,040 | $ 871 | $ 456 | $ 368 | $ 1,579 | $ 1,590 | $ 1,271 | $ 1,096 | $ 738 | $ 493 | $ 368 | $ 306 |
Expense Example No Redemption - U.S. Government Securities Fund® - USD ($) |
Class C |
Class 529-C |
|---|---|---|
| 1 year | $ 137 | $ 143 |
| 3 years | 428 | 443 |
| 5 years | 739 | 766 |
| 10 years | $ 1,418 | $ 1,185 |
The fund pays transaction costs, such as commissions, when it buys and sells securities (or “turns over” its portfolio). A higher portfolio turnover rate may indicate higher transaction costs and may result in higher taxes when fund shares are held in a taxable account. These costs, which are not reflected in annual fund operating expenses or in the example, affect the fund’s investment results. During the most recent fiscal year, the fund’s portfolio turnover rate was 488% of the average value of its portfolio.
Normally at least 80% of the fund’s assets will be invested in securities that are guaranteed or sponsored by the U.S. government, its agencies and instrumentalities, including bonds and other debt securities denominated in U.S. dollars, which may be represented by derivatives. The fund may also invest in mortgage-backed securities issued by federal agencies and instrumentalities that are not backed by the full faith and credit of the U.S. government.
The fund may invest in inflation-linked bonds issued by U.S. and non-U.S. governments, their agencies or instrumentalities, and corporations. Inflation-linked bonds are structured to protect against inflation by linking the bond’s principal and interest payments to an inflation index, such as the Consumer Price Index for Urban Consumers, so that principal and interest adjust to reflect changes in the index.
The fund may invest in futures contracts and swaps, which are types of derivatives. A derivative is a financial contract, the value of which is based on the value of an underlying financial asset (such as a stock, bond or currency), a reference rate or a market index.
The investment adviser uses a system of multiple portfolio managers in managing the fund’s assets. Under this approach, the portfolio of the fund is divided into segments managed by individual managers.
The fund relies on the professional judgment of its investment adviser to make decisions about the fund’s portfolio investments. The basic investment philosophy of the investment adviser is to seek to invest in attractively priced securities that, in its opinion, represent good, long-term investment opportunities. Securities may be sold when the investment adviser believes that they no longer represent relatively attractive investment opportunities.
This section describes the principal risks associated with investing in the fund. You may lose money by investing in the fund. The likelihood of loss may be greater if you invest for a shorter period of time.
Market conditions — The prices of, and the income generated by, the securities held by the fund may decline – sometimes rapidly or unpredictably – due to various factors, including events or conditions affecting the general economy or particular industries or companies; overall market changes; local, regional or global political, social or economic instability; governmental, governmental agency or central bank responses to economic conditions; and currency exchange rate, interest rate and commodity price fluctuations.
Economies and financial markets throughout the world are highly interconnected. Economic, financial or political events, trading and tariff arrangements, wars, terrorism, cybersecurity events, natural disasters, public health emergencies (such as the spread of infectious disease) and other circumstances in one country or region, including actions taken by governmental or quasi-governmental authorities in response to any of the foregoing, could have impacts on global economies or markets. As a result, whether or not the fund invests in securities of issuers located in or with significant exposure to the countries affected, the value and liquidity of the fund’s investments may be negatively affected by developments in other countries and regions.
Issuer risks — The prices of, and the income generated by, securities held by the fund may decline in response to various factors directly related to the issuers of such securities, including reduced demand for an issuer’s goods or services, poor management performance, major litigation, investigations or other controversies related to the issuer, changes in financial condition or credit rating, changes in government regulations affecting the issuer or its competitive environment and strategic initiatives such as mergers, acquisitions or dispositions and the market response to any such initiatives.
Investing in debt instruments — The prices of, and the income generated by, bonds and other debt securities held by the fund may be affected by factors such as the interest rates, maturities and credit quality of these securities.
Rising interest rates will generally cause the prices of bonds and other debt securities to fall. Also, when interest rates rise, issuers are less likely to refinance existing debt securities in order to enjoy lower interest rates in a higher interest rate environment, causing the market prices of such securities to decline. A general rise in interest rates may cause investors to sell debt securities on a large scale, which could also adversely affect the price and liquidity of debt securities and could also result in increased redemptions from the fund. Falling interest rates may cause an issuer to redeem, call or refinance a debt security before its stated maturity, which may result in the fund failing to recoup the full amount of its initial investment and having to reinvest the proceeds in lower yielding securities. Longer maturity debt securities generally have greater sensitivity to changes in interest rates and may be subject to greater price fluctuations than shorter maturity debt securities.
Bonds and other debt securities are also subject to credit risk, which is the possibility that the credit strength of an issuer or guarantor will weaken or be perceived to be weaker, and/or an issuer of a debt security will fail to make timely payments of principal or interest and the security will go into default. Changes in actual or perceived creditworthiness may occur quickly. A downgrade or default affecting any of the fund’s
securities could cause the value of the fund’s shares to decrease. Credit risk is gauged, in part, by the credit ratings of the debt securities in which the fund invests. However, ratings are only the opinions of the rating agencies issuing them and are not guarantees as to credit quality or an evaluation of market risk. The fund’s investment adviser relies on its own credit analysts to research issuers and issues in assessing credit and default risks.
Investing in securities backed by the U.S. government — Securities backed by the U.S. Treasury or the full faith and credit of the U.S. government are guaranteed only as to the timely payment of interest and principal when held to maturity. Accordingly, the current market values for these securities will fluctuate with changes in interest rates and the credit rating of the U.S. government. Securities issued by U.S. government-sponsored entities and federal agencies and instrumentalities that are not backed by the full faith and credit of the U.S. government are neither issued nor guaranteed by the U.S. government. U.S. government securities are subject to market risk, interest rate risk and credit risk.
Investing in mortgage-related and other asset-backed securities — Mortgage-related securities, such as mortgage-backed securities, and other asset-backed securities, include debt obligations that represent interests in pools of mortgages or other income-bearing assets, such as consumer loans or receivables. While such securities are subject to the risks associated with investments in debt instruments generally (for example, credit, extension and interest rate risks), they are also subject to other and different risks. Mortgage-backed and other asset-backed securities are subject to changes in the payment patterns of borrowers of the underlying debt, potentially increasing the volatility of the securities and the fund’s net asset value. When interest rates fall, borrowers are more likely to refinance or prepay their debt before its stated maturity. This may result in the fund having to reinvest the proceeds in lower yielding securities, effectively reducing the fund’s income. Conversely, if interest rates rise and borrowers repay their debt more slowly than expected, the time in which the mortgage-backed and other asset-backed securities are paid off could be extended, reducing the fund’s cash available for reinvestment in higher yielding securities. Mortgage-backed securities are also subject to the risk that underlying borrowers will be unable to meet their obligations and the value of property that secures the mortgages may decline in value and be insufficient, upon foreclosure, to repay the associated loans. Investments in asset-backed securities are subject to similar risks.
Investing in future delivery contracts — The fund may enter into contracts, such as to-be-announced contracts and mortgage dollar rolls, that involve the fund selling mortgage-related securities and simultaneously contracting to repurchase similar securities for delivery at a future date at a predetermined price. This can increase the fund’s market exposure, and the market price of the securities that the fund contracts to repurchase could drop below their purchase price. While the fund can preserve and generate capital through the use of such contracts by, for example, realizing the difference between the sale price and the future purchase price, the income generated by the fund may be reduced by engaging in such transactions. In addition, these transactions increase the turnover rate of the fund.
Investing in inflation-linked bonds — The values of inflation-linked bonds generally fluctuate in response to changes in real interest rates — i.e., rates of interest after factoring in inflation. A rise in real interest rates may cause the prices of inflation-linked securities to fall, while a decline in real interest rates may cause the prices to increase.
Inflation-linked bonds may experience greater losses than other debt securities with similar durations when real interest rates rise faster than nominal interest rates. There can be no assurance that the value of an inflation-linked security will be directly correlated to changes in interest rates; for example, if interest rates rise for reasons other than inflation, the increase may not be reflected in the security’s inflation measure.
Investing in inflation-linked bonds may also reduce the fund’s distributable income during periods of deflation. If prices for goods and services decline throughout the economy, the principal and income on inflation-linked securities may decline and result in losses to the fund.
Investing in derivatives — The use of derivatives involves a variety of risks, which may be different from, or greater than, the risks associated with investing in traditional securities, such as stocks and bonds. Changes in the value of a derivative may not correlate perfectly with, and may be more sensitive to market events than, the underlying asset, rate or index, and a derivative instrument may cause the fund to lose significantly more than its initial investment. Derivatives may be difficult to value, difficult for the fund to buy or sell at an opportune time or price and difficult, or even impossible, to terminate or otherwise offset. The fund’s use of derivatives may result in losses to the fund, and investing in derivatives may reduce the fund’s returns and increase the fund’s price volatility. The fund’s counterparty to a derivative transaction (including, if applicable, the fund’s clearing broker, the derivatives exchange or the clearinghouse) may be unable or unwilling to honor its financial obligations in respect of the transaction. In certain cases, the fund may be hindered or delayed in exercising remedies against or closing out derivative instruments with a counterparty, which may result in additional losses. Derivatives are subject to additional risks, including operational risk (such as documentation issues, settlement issues and systems failures) and legal risk (such as insufficient documentation, insufficient capacity or authority of a counterparty, and issues with the legality or enforceability of a contract).
Management — The investment adviser to the fund actively manages the fund’s investments. Consequently, the fund is subject to the risk that the methods and analyses, including models, tools and data, employed by the investment adviser in this process may be flawed or incorrect and may not produce the desired results. This could cause the fund to lose value or its investment results to lag relevant benchmarks or other funds with similar objectives.
It is important to note that neither your investment in the fund nor the fund’s yield is guaranteed by the U.S. government.
Your investment in the fund is not a bank deposit and is not insured or guaranteed by the Federal Deposit Insurance Corporation or any other governmental agency, entity or person. You should consider how this fund fits into your overall investment program.
The following bar chart shows how the fund’s investment results have varied from year to year, and the following table shows how the fund’s average annual total returns for various periods compare with a broad measure of securities market results and other applicable measures of market results. This information provides some indication of the risks of investing in the fund. The Lipper General U.S. Government Funds Average includes the fund and other funds that disclose investment objectives and/or strategies reasonably comparable to those of the fund. The Consumer Price Index provides a comparison of the fund’s results to inflation. Past investment results (before and after taxes) are not predictive of future investment results. Prior to October 30, 2020, certain fees, such as 12b-1 fees, were not charged on Class 529-F-1 shares. If these expenses had been deducted, results would have been lower. Updated information on the fund’s investment results can be obtained by visiting capitalgroup.com.
The following bar chart shows how the fund’s investment results have varied from year to year, and the following table shows how the fund’s average annual total returns for various periods compare with a broad measure of securities market results and other applicable measures of market results.
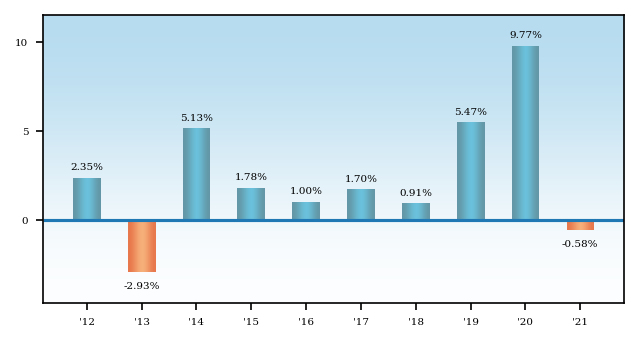
Highest/Lowest quarterly results during this period were:
Highest 7.84% (quarter ended March 31, 2020)
Lowest -2.74% (quarter ended March 31, 2021)
The fund's total return for the nine months ended September 30, 2022, was -11.93%.
Average Annual Returns - U.S. Government Securities Fund® |
Average Annual Returns, 1 Year |
Average Annual Returns, 5 Years |
Average Annual Returns, 10 Years |
Average Annual Returns, Since Inception |
Average Annual Returns, Inception Date |
|---|---|---|---|---|---|
| Class F-2 | (0.58%) | 3.39% | 2.41% | 3.48% | Aug. 07, 2008 |
| Class A | (4.56%) | 2.32% | 1.75% | 5.21% | Oct. 17, 1985 |
| Class C | (2.54%) | 2.35% | 1.51% | 3.24% | Mar. 15, 2001 |
| Class F-1 | (0.88%) | 3.10% | 2.14% | 3.55% | Mar. 15, 2001 |
| Class F-3 | (0.47%) | 3.49% | Jan. 27, 2017 | ||
| Class 529-A | (4.31%) | 2.35% | 1.72% | 3.23% | Feb. 20, 2002 |
| Class 529-C | (2.56%) | 2.33% | 1.69% | 3.19% | Feb. 19, 2002 |
| Class 529-E | (1.06%) | 2.86% | 1.85% | 3.19% | Mar. 07, 2002 |
| Class 529-F-1 | (0.69%) | 3.30% | 2.31% | 3.38% | Oct. 11, 2002 |
| Class 529-F-2 | (0.56%) | none | Oct. 30, 2020 | ||
| Class 529-F-3 | (0.48%) | 0.08% | Oct. 30, 2020 | ||
| Class R-1 | (1.47%) | 2.38% | 1.39% | 2.65% | Jun. 13, 2002 |
| Class R-2 | (1.56%) | 2.38% | 1.39% | 2.69% | May 31, 2002 |
| Class R-2E | (1.29%) | 2.66% | 2.16% | Aug. 29, 2014 | |
| Class R-3 | (1.03%) | 2.81% | 1.83% | 3.11% | Jun. 06, 2002 |
| Class R-4 | (0.75%) | 3.16% | 2.17% | 3.48% | May 28, 2002 |
| Class R-5E | (0.61%) | 3.37% | 2.90% | Nov. 20, 2015 | |
| Class R-5 | (0.45%) | 3.46% | 2.47% | 3.82% | May 15, 2002 |
| Class R-6 | (0.47%) | 3.50% | 2.52% | 3.24% | May 01, 2009 |
| After Taxes on Distributions | Class F-2 | (1.11%) | 2.35% | 1.43% | ||
| After Taxes on Distributions and Sale of Fund Shares | Class F-2 | (0.34%) | 2.19% | 1.47% | ||
| Bloomberg U.S. Government/Mortgage-Backed Securities Index (reflects no deductions for sales charges, account fees, expenses or U.S. federal income taxes) | (1.77%) | 2.85% | 2.21% | 3.36% | Aug. 07, 2008 |
| Lipper General U.S. Government Funds Average (reflects no deductions for sales charges, account fees or U.S. federal income taxes) | (2.18%) | 2.68% | 1.90% | 3.07% | Aug. 07, 2008 |
| Consumer Price Index | 7.04% | 2.92% | 2.14% | 1.78% | Aug. 07, 2008 |
After-tax returns are shown only for Class F-2 shares; after-tax returns for other share classes will vary. After-tax returns are calculated using the highest individual federal income tax rates in effect during each year of the periods shown and do not reflect the impact of state and local taxes. Your actual after-tax returns depend on your individual tax situation and likely will differ from the results shown above. In addition, after-tax returns are not relevant if you hold your fund shares through a tax-favored arrangement, such as a 401(k) plan, individual retirement account (IRA) or 529 college savings plan.