The Portfolio seeks maximum total return from a combination of capital appreciation and current income.
This table describes the fees and expenses that you may pay if you buy, hold and sell shares of the Portfolio, a series of The Lazard Funds, Inc. (the “Fund”). You may pay other fees, such as brokerage commissions and other fees to financial intermediaries, which are not reflected in the table and the Example below.
Annual Fund Operating Expenses - Lazard US Corporate Income Portfolio |
Institutional |
Open |
R6 |
|
|---|---|---|---|---|
| Management Fees | 0.55% | 0.55% | 0.55% | |
| Distribution and Service (12b-1) Fees | none | 0.25% | none | |
| Other Expenses | 0.15% | 0.28% | 37.75% | |
| Acquired Fund Fees and Expenses | 0.03% | 0.03% | 0.03% | |
| Total Annual Portfolio Operating Expenses | 0.73% | 1.11% | 38.33% | |
| Fee Waiver and/or Expense Reimbursement | [1] | 0.15% | 0.28% | 37.75% |
| Total Annual Portfolio Operating Expenses After Fee Waiver and/or Expense Reimbursement | [2] | 0.58% | 0.83% | 0.58% |
| [1] | Reflects a contractual agreement by Lazard Asset Management LLC (the “Investment Manager”) to waive its fee and, if necessary, reimburse the Portfolio until May 1, 2025 for Institutional Shares and Open Shares, and until May 1, 2034 for R6 Shares, to the extent Total Annual Portfolio Operating Expenses exceed .55%, .80% and .55% of the average daily net assets of the Portfolio’s Institutional Shares, Open Shares and R6 Shares, respectively, exclusive of taxes, brokerage, interest on borrowings, fees and expenses of “Acquired Funds,” fees and expenses related to filing foreign tax reclaims and extraordinary expenses. This expense limitation agreement can only be amended by agreement of the Fund, upon approval by the Fund’s Board of Directors, and the Investment Manager to lower the net amount shown and will terminate automatically in the event of termination of the Management Agreement between the Investment Manager and the Fund, on behalf of the Portfolio. |
| [2] | Excluding Acquired Fund Fees and Expenses, the Total Annual Portfolio Operating Expenses After Fee Waiver and/or Expense Reimbursement are .55%, .80% and .55% of the Portfolio’s Institutional Shares, Open Shares and R6 Shares, respectively. |
This Example is intended to help you compare the cost of investing in the Portfolio with the cost of investing in other mutual funds.
The Example assumes that you invest $10,000 in the Portfolio for the time periods indicated and then hold or redeem all of your shares at the end of those periods. The Example also assumes that your investment has a 5% return each year and that the Portfolio’s operating expenses remain the same, giving effect to the expense limitation agreement described above. Although your actual costs may be higher or lower, based on these assumptions your costs would be:
Expense Example - Lazard US Corporate Income Portfolio - USD ($) |
Institutional |
Open |
R6 |
|---|---|---|---|
| 1 Year | $ 59 | $ 85 | $ 59 |
| 3 Years | 218 | 325 | 5,618 |
| 5 Years | 391 | 584 | 8,089 |
| 10 Years | $ 892 | $ 1,327 | $ 9,806 |
The Portfolio pays transaction costs, such as commissions, when it buys and sells securities (or “turns over” its portfolio). A higher portfolio turnover rate may indicate higher transaction costs and may result in higher taxes when Portfolio shares are held in a taxable account. These costs, which are not reflected in annual portfolio
operating expenses or in the Example, affect the Portfolio’s performance. During the most recent fiscal year, the Portfolio’s portfolio turnover rate was 26% of the average value of its portfolio.
Under normal circumstances, the Portfolio invests at least 80% of its assets in high yield fixed-income securities issued by corporations or other non-governmental issuers similar to corporations, which securities are tied economically to the US. The Portfolio considers “high yield” fixed income securities to be those rated, at the time of purchase, below investment grade by S&P Global Ratings (“S&P”) or Moody’s Investors Service, Inc. (“Moody’s”) and as low as C or Ca by S&P or Moody’s, respectively, or the unrated equivalent as determined by the Investment Manager (“junk bonds”). The Portfolio may invest in dollar-denominated securities of non-US companies, including, to a limited extent, in emerging market companies.
Although the Portfolio may invest in fixed-income securities without regard to their maturity, the Portfolio’s average weighted maturity is expected to range between two and ten years.
Securities are evaluated based on their fundamental and structural characteristics. Valuation analysis is tailored to the specific asset class, but may include credit research, prepayment or call options, maturity, duration, coupon, currency and country risks. The Portfolio is constructed using a bottom-up discipline in which the Investment Manager follows a systematic process to seek out undervalued opportunities within each sector.
The Portfolio may invest up to 20% of its assets in other securities which need not be fixed-income securities as described above and need not be tied economically to the US.
Risk Table - Lazard US Corporate Income Portfolio |
Risk [Text Block] |
|---|---|
| Risk Lose Money [Member] |
The value of your investment in the Portfolio will fluctuate, which means you could lose money. |
| Market Risk |
Market Risk: The Portfolio may incur losses due to declines in one or more markets in which it invests. These declines may be the result of, among other things, political, regulatory, market, economic or social developments affecting the relevant market(s). To the extent that such developments impact specific industries, market sectors, countries or geographic regions, the Portfolio’s investments in such industries, market sectors, countries and/or geographic regions can be expected to be particularly affected, especially if such investments are a significant portion of its investment portfolio. In addition, turbulence in financial markets and reduced liquidity in equity, credit and/or fixed income markets may negatively affect many issuers, which could adversely affect the Portfolio. Global economies and financial markets are increasingly interconnected, and conditions and events in one country, region or financial market may adversely impact issuers worldwide. As a result, local, regional or global events such as war or military conflict, acts of terrorism, the spread of infectious illness or other public health issues, social unrest, supply chain disruptions, government defaults, government shutdowns, the imposition of sanctions and other similar measures, recessions or other events could have a significant negative impact on global economic and market conditions. For example, a public health or other emergency and aggressive responses taken by many governments or voluntarily imposed by private parties, including closing borders, restricting travel and imposing prolonged quarantines or similar restrictions, as well as the closure of, or operational changes to, many retail and other businesses, may have severe negative impacts on markets worldwide. Additionally, general market conditions may affect the value of a Portfolio’s securities, including changes in interest rates, currency rates or monetary policies. |
| Issuer Risk |
Issuer Risk: The value of a security may decline for a number of reasons which directly relate to the issuer, such as management performance, financial leverage and reduced demand for the issuer’s goods or services, as well as the historical and prospective earnings of the issuer and the value of its assets or factors unrelated to the issuer’s value, such as investor perception. |
| Fixed-Income and Debt Securities Risk |
Fixed-Income and Debt Securities Risk: The market value of a debt security may decline due to general market conditions that are not specifically related to a particular company, such as real or perceived adverse economic conditions, changes in the outlook for corporate earnings, changes in interest or currency rates or adverse investor sentiment generally. The debt securities market can be susceptible to increases in volatility and decreases in liquidity. Liquidity can decline unpredictably in response to overall economic conditions or credit tightening. Prices of bonds and other debt securities tend to move inversely with changes in interest rates. Interest rate risk is usually greater for fixed-income securities with longer maturities or durations. A rise in interest rates (or the expectation of a rise in interest rates) may result in periods of volatility, decreased liquidity and increased redemptions, and, as a result, the Portfolio may have to liquidate portfolio securities at disadvantageous prices. The Portfolio may be subject to heightened interest rate risk because the Federal Reserve has raised, and may continue to raise, interest rates. The Portfolio’s investments in lower-rated, higher-yielding securities (“junk bonds”) are subject to greater credit risk than its higher rated investments. Credit risk is the risk that the issuer will not make interest or principal payments, or will not make payments on a timely basis. Non-investment grade securities tend to be more volatile, less liquid and are considered speculative. If there is a decline, or perceived decline, in the credit quality of a debt security (or any guarantor of payment on such security), the security’s value could fall, potentially lowering the Portfolio’s share price. The prices of non-investment grade securities, unlike investment grade debt securities, may fluctuate unpredictably and not necessarily inversely with changes in interest rates. The market for these securities may be less liquid and therefore these securities may be harder to value or sell at an acceptable price, especially during times of market volatility or decline. |
| Non-US Securities Risk |
Non-US Securities Risk: The Portfolio’s performance will be influenced by political, social and economic factors affecting the non-US countries and companies in which the Portfolio invests. Non-US securities carry special risks, such as less developed or less efficient trading markets, political instability, a lack of company information, differing auditing and legal standards, and, potentially, less liquidity. Non-US securities may be subject to economic sanctions or other similar governmental actions or developments, which could, among other things, effectively restrict or eliminate the Portfolio’s ability to purchase or sell certain foreign securities. To the extent the Portfolio holds securities subject to such actions, the securities may become difficult to value and/or less liquid (or illiquid). In some cases, the securities may become worthless. In addition, investments denominated in currencies other than US dollars may experience a decline in value, in US dollar terms, due solely to fluctuations in currency exchange rates. Emerging market countries can generally have economic structures that are less diverse and mature, and political systems that are less stable, than those of developed countries. |
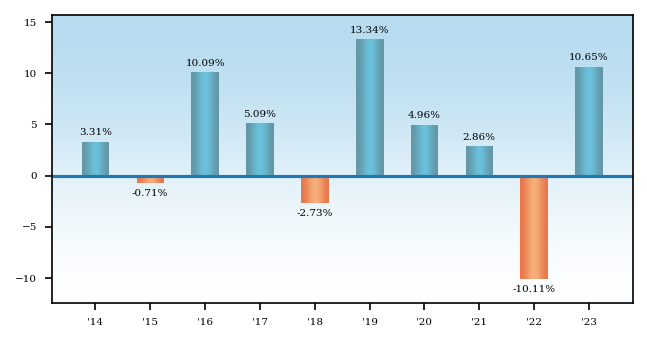
The accompanying bar chart and table provide some indication of the risks of investing in Lazard US High Yield Portfolio by showing the Portfolio’s year-by-year performance and its average annual performance compared to that of a broad measure of market performance. The bar chart shows how the performance of the Portfolio’s Institutional Shares has varied from year to year over the past 10 calendar years. Updated performance information is available at www.lazardassetmanagement.com or by calling (800) 823-6300. The Portfolio’s past performance (before and after taxes) is not necessarily an indication of how the Portfolio will perform in the future.
|
Best Quarter: | |
|
2020, Q2 |
7.80% |
|
|
|
|
Worst Quarter: | |
|
2020, Q1 |
-9.80% |
After-tax returns are shown only for Institutional Shares. After-tax returns of the Portfolio’s other share classes will vary. After-tax returns are calculated using the historical highest individual marginal income tax rates and do not reflect the impact of state and local taxes. Actual after-tax returns depend on the investor’s tax situation and may differ from those shown. The after-tax returns shown are not relevant to investors who hold their shares through tax-deferred arrangements such as 401(k) plans or individual retirement accounts.
Effective as of February 1, 2024, the ICE BofA US High Yield Index replaced the ICE BofAML BB-B US Cash Pay Non-Distressed High Yield Index as the Portfolio’s primary index. The Investment Manager believes that the new index provides a more appropriate comparison of Portfolio performance than the prior index.
Effective as of May 1, 2024, the US Universal Index replaced the ICE BofA US High Yield Index as the Portfolio’s broad-based securities market index. The US Universal Index was selected in connection with certain regulatory requirements to provide a broad measure of market performance.
| [1] | Life of Portfolio return not available since the index has not been in existence as long as the Portfolio. |