The Navigator Tactical Fixed Income Fund (the “Fund”) investment objective is to seek total return
with a secondary goal of current income.
The following table describes the fees and expenses that you may pay if you buy, hold and sell shares of the Fund. You may pay other fees, such as brokerage commissions and other fees to financial intermediaries, which are not reflected in the tables and examples below. More information about these and other discounts is available from your financial intermediary and in How to Purchase Shares on page [47] of the Fund’s Prospectus and in Purchase, Redemption and Pricing of Shares on page [62] of the Statement of Additional Information.
Shareholder Fees - Navigator Tactical Fixed Income Fund |
Navigator Tactical Fixed Income Fund Class A Shares |
Navigator Tactical Fixed Income Fund Class C Shares |
Navigator Tactical Fixed Income Fund Class I Shares |
|---|---|---|---|
| Maximum Sales Charge (Load) Imposed on Purchases (as a % of offering price) | 3.75% | none | none |
| Maximum Deferred Sales Charge (Load) (as a % of the lower of original purchase price or redemption proceeds) | none | none | none |
| Maximum Sales Charge (Load) Imposed on Reinvested Dividends and Other Distributions | none | none | none |
| Redemption Fee | none | none | none |
Annual Fund Operating Expenses - Navigator Tactical Fixed Income Fund |
Navigator Tactical Fixed Income Fund Class A Shares |
Navigator Tactical Fixed Income Fund Class C Shares |
Navigator Tactical Fixed Income Fund Class I Shares |
|
|---|---|---|---|---|
| Management Fees | 0.82% | 0.82% | 0.82% | |
| Distribution and Service (12b-1) Fees | 0.25% | 1.00% | none | |
| Other Expenses | 0.16% | 0.16% | 0.16% | |
| Acquired Fund Fees and Expenses | [1] | 0.11% | 0.11% | 0.11% |
| Total Annual Fund Operating Expenses | 1.34% | 2.09% | 1.09% | |
| Fee Waiver and/or Expense Reimbursement | (0.02%) | (0.02%) | (0.02%) | |
| Total Annual Fund Operating Expenses After Fee Waiver and/or Expense Reimbursement | 1.32% | 2.07% | 1.07% | |
| [1] | Acquired Fund Fees and Expenses are the indirect costs of investing in other investment companies. |
This Example is intended to help you compare the cost of investing in the Fund with the cost of investing in other mutual funds.
Expense Example - Navigator Tactical Fixed Income Fund - USD ($) |
Expense Example, with Redemption, 1 Year |
Expense Example, with Redemption, 3 Years |
Expense Example, with Redemption, 5 Years |
Expense Example, with Redemption, 10 Years |
|---|---|---|---|---|
| Navigator Tactical Fixed Income Fund Class A Shares | 504 | 782 | 1,080 | 1,926 |
| Navigator Tactical Fixed Income Fund Class C Shares | 210 | 653 | 1,122 | 2,419 |
| Navigator Tactical Fixed Income Fund Class I Shares | 109 | 345 | 599 | 1,327 |
The Fund pays transaction costs, such as commissions, when it buys and sells securities (or “turns over” its portfolio). A higher portfolio turnover may indicate higher transaction costs and may result in higher taxes when Fund shares are held in a taxable account. These costs, which are not reflected in annual fund operating expenses or in the Example, affect the Fund’s performance. During the most recent fiscal year, the Fund’s portfolio turnover rate was 34%.
In seeking to achieve its investment objective, the Fund will invest, under normal circumstances, at least 80% of its assets, defined as net assets plus the amount of any borrowings for investment purposes, in long and/or short positions in fixed income securities (“80% investment policy”). For purposes of the 80% investment policy, the Fund defines fixed income securities as including (i) bills, (ii) notes, (iii) structured notes, (iv) bonds, (v) preferred stocks, (vi) any other debt or debt-related securities of any maturities, whether issued by U.S. or non-U.S. governments, agencies or instrumentalities thereof or corporate entities, and having fixed, variable, floating or inverse floating rates, (vii) fixed income derivatives including options, financial futures, options on futures and swaps, and (viii) underlying funds (defined below) that invest primarily in fixed income securities, or (ix) other evidences of indebtedness. The Fund may invest in debt securities of any maturity or credit quality, including those rated below investment grade (“high yield securities”). Below investment grade debt securities are those rated below Baa3 by Moody’s Investors Service or equivalently by another nationally recognized statistical rating organization (“NRSRO”). The Fund may invest in affiliated mutual funds, and affiliated mutual funds (including money market funds), exchange traded funds (“ETFs”) and inverse ETFs (collectively, “Underlying Funds”).
The Fund may invest up to 20% of its net assets in equity index futures or equities. Equity index futures are utilized by the Fund when Clark Capital Management Group, Inc. (the “Adviser”) believes that doing so is attractive from a risk/reward analysis perspective. The Fund may invest in equity index futures when doing so provides greater efficiency and lower cost than investing directly in equity securities and when such futures are attractively priced. The Fund may also purchase or write (sell) credit default swaps (“CDS”) or credit default swap indexes (“CDX”), which are credit derivatives used to hedge credit risk and/or take a position on a basket of credit entities. Unlike a credit default swap, which is an over the counter derivative, a CDX may be exchange traded, or sold over the counter. Each CDX is designed to track a basket of credit entities, which may be standard or customized. This means that it may be more liquid than a credit default swap, and it may be cheaper to hedge the Fund’s portfolio with a CDX than it would be to buy many single name credit default swaps to achieve a similar effect. The Fund may also purchase or write (sell) CDX swaptions, which are options to sell or buy credit protection on a specific reference by entering into a pre-defined swap agreement by some specified date in the future. The Fund may also purchase or sell total return swaps or invest in inverse ETFs to hedge its long positions. The Fund may also use derivative transactions to create investment leverage. For example, the Fund may use total return swaps or CDX to take indirect long or short positions on equity or fixed income indices, equity or fixed income securities, or currencies.
The Fund’s investment strategy is primarily driven by a modeling process which measures the relative strength or momentum of various asset classes against one another. Specifically, using this momentum-based strategy, the Fund will tactically shift its asset class exposure across high yield U.S. treasuries, and cash. Under normal conditions, the Fund expects to invest in fixed income securities and derivatives. When the high yield asset class is favored, the Fund will normally use a combination of fixed income securities and derivatives designed to create an investment return that tracks the return of the Fund’s primary benchmark index, currently the Barclays U.S. Corporate High Yield Index. Specifically, the Fund may purchase securities, such as high yield ETFs or corporate bonds, and also enter into swaps or futures where the reference asset is a high yield index, high yield corporate bond ETFs or basket of high yield securities to seek to approximate the return of the Fund’s primary benchmark. When the treasury asset class is favored, the Fund will normally sell and/or hedge a portion of its high yield exposure using derivatives such as listed commodities, S&P 500 futures contracts, or CDX to hedge its high yield exposure, and increase the Fund’s exposure to treasuries through securities and derivatives. When the cash asset class is favored, the Fund will normally sell and/or hedge its high yield and/or treasury exposure and increase the Fund’s exposure to cash equivalents through securities and derivatives.
Due to the structure of the derivatives the Fund expects to use, the Fund will hold a portion of its assets in highly liquid securities as collateral for its derivatives transactions and still have excess cash to invest regardless of whether the favored asset class is high yield, treasuries or cash (or a combination of these asset classes). The Fund will normally invest this excess cash in a mix of investment grade corporate bonds, treasury bills and notes, municipal bonds and other instruments for diversification, risk management and to seek to obtain additional return. As a result, when the high yield asset class is favored, a portion of the Fund’s assets will be invested in non-high yield investments. Similarly, when the treasury asset class is favored, the Fund will hold a portion of its assets in non-treasury investments, and when the cash asset class is favored, the Fund will hold a portion of its assets in non-cash investments.
As with all mutual funds, there is the risk that you could lose money through your investment in the Fund. The Fund is not intended to be a complete investment program. Many factors affect the Fund’s net asset value and performance.
| ● | CDS Risk – CDS are a type of derivative instrument, involve special risks and may result in losses to the Fund. CDS are typically two-party financial contracts that transfer credit exposure between the two parties. Under a typical CDS, one party (the “seller”) receives pre-determined periodic payments from the other party (the “buyer”). The seller agrees to make compensating specific payments to the buyer if a negative credit event occurs, such as the bankruptcy or default by the issuer of the underlying debt instrument. The use of CDS involve investment techniques and risks different from those associated with ordinary portfolio security transactions, such as potentially heightened counterparty, concentration and exposure risks. Counterparty risk refers to the risk that the counterparty to the swap will default on its obligation to pay. CDS may in some cases be illiquid, and they increase credit risk since the Fund has exposure to the issuer of the referenced obligation and either the counterparty to the credit default swap or, if it is a cleared transaction, the brokerage firm through which the trade was cleared and the clearing organization that is the counterparty to that trade. In addition, for cleared trades, the brokerage firm would impose margin requirements and would be able to require termination of those trades in certain circumstances. Certain CDS will be required to be traded on a regulated execution facility or contract market that makes them available for trading. The transition to trading these swaps on such a facility or contract market may not result in swaps being easier to trade or value and may present certain execution risks if such a facility or contract market does not operate properly. Swaps may be difficult to unwind or terminate. |
| ● | CDX Risk – A CDX is subject to the risks of the underlying credit default swap obligations, which include risks such as concentration risk and counterparty risk. Concentration risk refers to the certain large institutional buyers that may take large positions in credit default swaps. The failure of such a buyer could materially and adversely affect the credit default swap market as a whole. Counterparty risk refers to the risk that the counterparty to the swap will default on its obligation to pay. |
| ● | Credit Risk – The issuer of a fixed income security may not be able to make interest or principal payments when due. Generally, the lower the credit rating of a security, the greater the risk is that the issuer will default on its obligation. |
| ● | Derivatives Risk – The Fund may execute an investment strategy or hedge by entering into derivative contracts such as futures, options and swaps, which can be riskier than traditional investments because they may involve leverage, be illiquid, suffer counterparty default and limit gains. Equity market-related swap contracts (including total return swaps and CDS) and options involve leverage risk, tracking risk and counterparty default risk. Option positions may expire worthless exposing the Fund to potentially significant losses. There is a risk that adverse price movements in a swap instrument can result in a loss substantially greater than the Fund’s initial investment in that instrument (in some cases, the potential loss is unlimited). |
| ● | Equity Securities Risk – Common and preferred stocks are susceptible to general stock market fluctuations and to volatile increases and decreases in value as market confidence in, and perceptions of their issuers, change. Warrants and rights may expire worthless if the price of a common stock is below the conversion price of the warrant or right. Convertible bonds may decline in value if the price of a common stock falls below the conversion price. Investor perceptions are based on various and unpredictable factors including expectations regarding government, economic, monetary and fiscal policies; inflation and interest rates; economic expansion or contraction and global or regional political, economic and banking crises. |
| ● | Fixed Income Risk – Typically, a rise in interest rates causes a decline in the value of fixed income securities. In general, the market price of fixed income securities with longer maturities will decrease more in response to rising interest rates than shorter-term securities. Other risk factors include credit risk (the debtor may default), extension risk (an issuer may exercise its right to repay principal on a fixed rate obligation held by the Fund later than expected), and prepayment risk (the debtor may pay its obligation early, reducing the amount of interest payments). A rise in interest rates may result in a decline in the value of the fixed income investments held by the Fund. |
| ● | Foreign Investment Risk – Foreign investing involves risks not typically associated with U.S. investments, including adverse fluctuations in foreign currency values, adverse political, social and economic developments, less liquidity, greater volatility, less developed or less efficient trading markets, political instability and differing auditing and legal standards. Investing in emerging markets imposes risks different from, or greater than, risks of investing in foreign developed countries. |
| ● | Foreign Currency Risk – Currency market risk results from the price movement of foreign currency values in response to shifting market supply and demand. Interest rate risk arises whenever a country changes its stated interest rate target associated with its currency. Country risk arises because virtually every country has interfered with international transactions in its currency. Interference has taken the form of regulation of the local exchange market, restrictions on foreign investment by residents or limits on inflows of investment funds from abroad. Restrictions on the exchange market or on international transactions are intended to affect the level or movement of the exchange rate. This risk could include the country issuing a new currency, effectively making the “old” currency worthless. |
| ● | Futures Risk – The Fund’s use of futures contracts involves risks different from, or possibly greater than, the risks associated with investing directly in securities and other traditional investments. These risks include (i) leverage risk; (ii) correlation or tracking risk and (iii) liquidity risk. Because futures require only a small initial investment in the form of a deposit or margin, they involve a high degree of leverage. Accordingly, the fluctuation of the value of futures in relation to the underlying assets upon which they are based is magnified. Thus, the Fund may experience losses that exceed losses experienced by funds that do not use futures contracts. |
| ● | Government-Sponsored Entities Risk – The Fund invests in securities issued or guaranteed by government-sponsored entities, but these securities may not be guaranteed or insured by the U.S. government and may only be supported by the credit of the issuing agency. |
| ● | Hedging Risk – When the Adviser believes market conditions are unfavorable, the Adviser may attempt to “hedge” with defensive positions and strategies including, for example, holding substantial positions in lower-yield fixed-income securities and/or cash equivalents, which may limit potential gains when compared to unhedged funds. There can be no assurance that the Fund’s hedging strategy will reduce the risk of the Fund’s investments. |
| ● | High-Yield Bond Risk – Lower-quality bonds, known as high-yield bonds or “junk bonds,” present a significant risk for loss of principal and interest. These bonds offer the potential for higher return, but also involve greater risk than bonds of higher quality, including an increased possibility that the bond’s issuer, obligor or guarantor may not be able to make its payments of interest and principal (credit quality risk). |
| ● | Interest Rate Risk – The value of the Fund may fluctuate based on changes in interest rates and market conditions. As interest rates rise, the value of income producing instruments may decrease. This risk increases as the term of the note increases. |
| ● | Issuer-Specific Risk – The value of a specific security can be more volatile than the market as a whole and can perform differently from the value of the market as a whole, and the risk that the value of a security may decline for a reason directly related to the issuer, such as management performance, changes in financial condition or credit rating, reputation or reduced demand for the issuer’s goods or services. |
| ● | Leverage/Volatility Risk – The use of leverage by the Fund, such as borrowing money to purchase securities or the use of options, will cause the Fund to incur additional expenses and magnify the Fund’s gains or losses. |
| ● | Management Style Risk – The Adviser’s judgments about the potential appreciation of a particular security in which the Fund invests may prove to be incorrect. The Adviser’s proprietary modeling process may incorrectly measure or predict the relative strength or momentum of various fixed income asset classes, and the Fund may hold a high percentage of either high-yield bonds or cash equivalents during certain periods, or for an extended period. |
| ● | Market and Geopolitical Risk – The increasing interconnectivity between global economies and financial markets increases the likelihood that events or conditions in one region or financial market may adversely impact issuers in a different country, region or financial market. Securities in the Fund may underperform due to inflation (or expectations for inflation), interest rates, global demand for particular products or resources, natural disasters, pandemics, epidemics, terrorism, international conflicts, regulatory events and governmental or quasi-governmental actions. The occurrence of global events similar to those in recent years, such as a worldwide pandemic, terrorist attacks, natural disasters, social and political discord or debt crises and downgrades, among others, may result in market volatility and may have long term effects on both the U.S. and global financial markets. It is difficult to predict when similar events affecting the U.S. or global financial markets may occur, the effects that such events may have and the duration of those effects. Any such event(s) could have a significant adverse impact on the value and risk profile of the Fund. For example, the COVID-19 global pandemic had negative impacts, and in many cases severe negative impacts, on markets worldwide. It is not known how long any future impacts of other significant events described above will last, but there could be a prolonged period of global economic slowdown, which may impact your investment. Therefore, the Fund could lose money over short periods due to short-term market movements and over longer periods during more prolonged market downturns. During a general market downturn, multiple asset classes may be negatively affected. Changes in market conditions and interest rates can have the same impact on all types of securities and instruments. In times of severe market disruptions, you could lose your entire investment. |
| ● | Options Risk – The Fund may lose the entire put or call option premium paid if the reference asset or index does not decrease below or rise above the respective strike price before expiration. Options may not be an effective hedge because they may have imperfect correlation to the value of the Fund’s assets. |
| ● | Portfolio Turnover Risk – A higher portfolio turnover may result in higher transactional and brokerage costs. |
| ● | Preferred Stock Risk – Typically, a rise in interest rates causes a decline in the value of preferred stock. Preferred stocks are also subject to credit and default risk, which is the possibility that an issuer of preferred stock will fail to make its dividend payments. |
| ● | Sector Risk – The Fund may focus its investments in securities of a particular sector. Economic, legislative or regulatory developments may occur that significantly affect the sector. This may cause the Fund’s net asset value to fluctuate more than that of a fund that does not focus in a particular sector. |
| ● | Short Selling and Short Position Risk – The Fund may engage in short selling and short position derivative activities, which are significantly different from the investment activities commonly associated with conservative stock or bond funds. Positions in shorted securities and derivatives are speculative and riskier than “long” positions (purchases) because the cost of the replacement security or derivative is unknown. Therefore, the potential loss on an uncovered short is unlimited, whereas the potential loss on long positions is limited to the original purchase price. You should be aware that any strategy that includes selling securities short could suffer significant losses. Shorting will also result in higher transaction costs (such as interest and dividends), which reduce the Fund’s return, and may result in higher taxes. When the Fund is selling a security short, it must maintain a segregated account of cash or high-grade securities equal to the margin requirement. As a result, the Fund may maintain high levels of cash or other liquid assets (such as U.S. Treasury bills, money market instruments, certificates of deposit, high quality commercial paper and long equity positions). The need to maintain cash or other liquid assets in segregated accounts could limit the Fund’s ability to pursue other opportunities as they arise. |
| ● | Small and Medium Company Credit Risk – Small and mid-sized companies may have limited product lines, markets or financial resources, and they may be dependent on a limited management group. Therefore, equity or fixed income securities issued by smaller companies may pose greater credit risk than is generally associated with the securities of larger, more established companies. |
| ● | Stock Market Risk – Equity prices can fall rapidly in response to developments affecting a specific company or industry, or to changing economic, political or market conditions. |
| ● | Structured Notes Risk – Structured notes involve leverage risk, tracking risk and issuer default risk. |
| ● | Swap Risk – Swap agreements are subject to the risk that the counterparty to the swap will default on its obligation to pay the Fund and the risk that the Fund will not be able to meet its obligations to pay the counterparty to the swap. Swap agreements may also involve fees, commissions or other costs that may reduce the Fund’s gains from a swap agreement or may cause the Fund to lose money. |
| ● | Swaption Risk – A swaption is an option contract that gives the holder the right (but not the obligation) to enter into a swap at a predetermined rate at expiration in exchange for a premium payment. Swaptions enable the Fund to purchase exposure that is significantly greater than the premium paid. Consequently, the value of swaptions can be volatile, and a small investment in swaptions can have a large impact on the performance of the Fund. The Fund risks losing all or part of the cash paid (premium) for purchasing swaptions. Additionally, the value of the underlying interest rate swap changes unfavorably with respect to the Fund. The Fund’s loss may exceed the option premium received by the Fund. |
| ● | Underlying Funds Risk – Underlying Funds in which the Fund invests are subject to investment advisory and other expenses, which will be indirectly paid by the Fund. As a result, the cost of investing in the Fund will be higher than the cost of investing directly in the Underlying Funds and may be higher than other mutual funds that invest directly in stocks and bonds. Each of the Underlying Funds is subject to specific risks, depending on the nature of the fund. |
| ◌ | Inverse ETF Risk – Investing in inverse ETFs may result in increased volatility and will magnify the Fund’s losses or gains. During periods of market volatility, inverse ETFs may not perform as expected. |
The bar chart and performance table below show the variability of the Fund’s returns, which is some indication of the risks of investing in the Fund. The bar chart shows performance of the Fund’s Class I shares for each full calendar year for the past ten years. Returns for Class A and Class C shares, which are not presented, would be different than the returns for Class I shares. The performance table compares the performance of the Fund over time to the performance of a broad-based securities market index. You should be aware that the Fund’s past performance (before and after taxes) may not be an indication of how the Fund will perform in the future. Updated performance information is available at no cost by calling 1-877-766-2264 or visiting www.navigatorfunds.com.
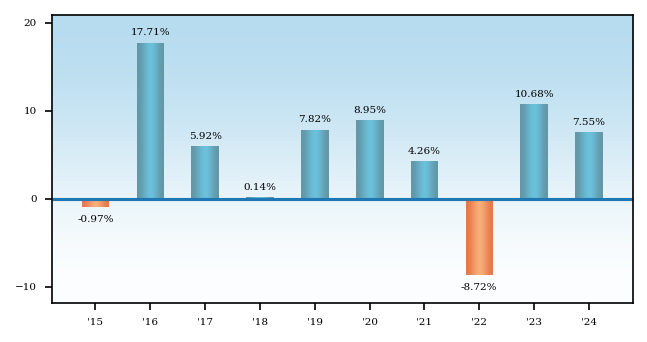
| Best Quarter: | First Quarter 2016 | 7.10% |
| Worst Quarter: | Second Quarter 2022 | (6.13)% |
Average Annual Total Returns - Navigator Tactical Fixed Income Fund |
Label |
1 Year |
5 Years |
10 Years |
|
|---|---|---|---|---|---|
| Navigator Tactical Fixed Income Fund Class I Shares | Return before taxes | 7.55% | 4.30% | 5.11% | |
| Navigator Tactical Fixed Income Fund Class I Shares | Return after taxes on distributions | 4.85% | 2.26% | 3.18% | ||
| Navigator Tactical Fixed Income Fund Class I Shares | Return after taxes on distributions and sale of Fund shares | 4.44% | 2.49% | 3.15% | ||
| Navigator Tactical Fixed Income Fund Class A Shares | Return before taxes with sales charge | 3.36% | 3.27% | 4.45% | |
| Navigator Tactical Fixed Income Fund Class C Shares | Return before taxes | 6.61% | 3.29% | 4.07% | |
| Bloomberg U.S. Corporate High Yield Bond Index | [1] | 8.19% | 4.21% | 5.17% | |
| Bloomberg U.S. Aggregate Bond Index | [2] | 1.25% | (0.33%) | 1.35% | |
| [1] | The Bloomberg U.S. Corporate High Yield Bond Index is a market value-weighted index which covers the U.S. non-investment grade fixed-rate debt market. Investors cannot invest directly in an index or benchmark. |
| [2] | Bloomberg U.S. Aggregate Bond Index is an unmanaged index comprised of U.S. investment grade, fixed rate bond market securities, including government, government agency, corporate and mortgage-backed securities. Investors cannot invest directly in an index or benchmark. |
After-tax returns are calculated using the highest historical individual federal marginal income tax rate and do not reflect the impact of state and local taxes. Actual after-tax returns depend on a shareholder’s tax situation and may differ from those shown. The after-tax returns are not relevant if you hold your Fund shares in tax-deferred arrangements, such as 401(k) plans or individual retirement accounts (“IRA”). The after-tax returns for Class A and Class C shares are not shown and would differ from those of Class I Shares.
| ● | CDS Risk – CDS are a type of derivative instrument, involve special risks and may result in losses to the Fund. CDS are typically two-party financial contracts that transfer credit exposure between the two parties. Under a typical CDS, one party (the “seller”) receives pre-determined periodic payments from the other party (the “buyer”). The seller agrees to make compensating specific payments to the buyer if a negative credit event occurs, such as the bankruptcy or default by the issuer of the underlying debt instrument. The use of CDS involve investment techniques and risks different from those associated with ordinary portfolio security transactions, such as potentially heightened counterparty, concentration and exposure risks. Counterparty risk refers to the risk that the counterparty to the swap will default on its obligation to pay. CDS may in some cases be illiquid, and they increase credit risk since the Fund has exposure to the issuer of the referenced obligation and either the counterparty to the credit default swap or, if it is a cleared transaction, the brokerage firm through which the trade was cleared and the clearing organization that is the counterparty to that trade. In addition, for cleared trades, the brokerage firm would impose margin requirements and would be able to require termination of those trades in certain circumstances. Certain CDS will be required to be traded on a regulated execution facility or contract market that makes them available for trading. The transition to trading these swaps on such a facility or contract market may not result in swaps being easier to trade or value and may present certain execution risks if such a facility or contract market does not operate properly. Swaps may be difficult to unwind or terminate. |
| ● | CDX Risk – A CDX is subject to the risks of the underlying credit default swap obligations, which include risks such as concentration risk and counterparty risk. Concentration risk refers to the certain large institutional buyers that may take large positions in credit default swaps. The failure of such a buyer could materially and adversely affect the credit default swap market as a whole. Counterparty risk refers to the risk that the counterparty to the swap will default on its obligation to pay. |
| ● | Credit Risk – The issuer of a fixed income security may not be able to make interest or principal payments when due. Generally, the lower the credit rating of a security, the greater the risk is that the issuer will default on its obligation. |
| ● | Derivatives Risk – The Fund may execute an investment strategy or hedge by entering into derivative contracts such as futures, options and swaps, which can be riskier than traditional investments because they may involve leverage, be illiquid, suffer counterparty default and limit gains. Equity market-related swap contracts (including total return swaps and CDS) and options involve leverage risk, tracking risk and counterparty default risk. Option positions may expire worthless exposing the Fund to potentially significant losses. There is a risk that adverse price movements in a swap instrument can result in a loss substantially greater than the Fund’s initial investment in that instrument (in some cases, the potential loss is unlimited). |
| ● | Equity Securities Risk – Common and preferred stocks are susceptible to general stock market fluctuations and to volatile increases and decreases in value as market confidence in, and perceptions of their issuers, change. Warrants and rights may expire worthless if the price of a common stock is below the conversion price of the warrant or right. Convertible bonds may decline in value if the price of a common stock falls below the conversion price. Investor perceptions are based on various and unpredictable factors including expectations regarding government, economic, monetary and fiscal policies; inflation and interest rates; economic expansion or contraction and global or regional political, economic and banking crises. |
| ● | Fixed Income Risk – Typically, a rise in interest rates causes a decline in the value of fixed income securities. In general, the market price of fixed income securities with longer maturities will decrease more in response to rising interest rates than shorter-term securities. Other risk factors include credit risk (the debtor may default), extension risk (an issuer may exercise its right to repay principal on a fixed rate obligation held by the Fund later than expected), and prepayment risk (the debtor may pay its obligation early, reducing the amount of interest payments). A rise in interest rates may result in a decline in the value of the fixed income investments held by the Fund. |
| ● | Foreign Investment Risk – Foreign investing involves risks not typically associated with U.S. investments, including adverse fluctuations in foreign currency values, adverse political, social and economic developments, less liquidity, greater volatility, less developed or less efficient trading markets, political instability and differing auditing and legal standards. Investing in emerging markets imposes risks different from, or greater than, risks of investing in foreign developed countries. |
| ● | Foreign Currency Risk – Currency market risk results from the price movement of foreign currency values in response to shifting market supply and demand. Interest rate risk arises whenever a country changes its stated interest rate target associated with its currency. Country risk arises because virtually every country has interfered with international transactions in its currency. Interference has taken the form of regulation of the local exchange market, restrictions on foreign investment by residents or limits on inflows of investment funds from abroad. Restrictions on the exchange market or on international transactions are intended to affect the level or movement of the exchange rate. This risk could include the country issuing a new currency, effectively making the “old” currency worthless. |
| ● | Futures Risk – The Fund’s use of futures contracts involves risks different from, or possibly greater than, the risks associated with investing directly in securities and other traditional investments. These risks include (i) leverage risk; (ii) correlation or tracking risk and (iii) liquidity risk. Because futures require only a small initial investment in the form of a deposit or margin, they involve a high degree of leverage. Accordingly, the fluctuation of the value of futures in relation to the underlying assets upon which they are based is magnified. Thus, the Fund may experience losses that exceed losses experienced by funds that do not use futures contracts. |
| ● | Government-Sponsored Entities Risk – The Fund invests in securities issued or guaranteed by government-sponsored entities, but these securities may not be guaranteed or insured by the U.S. government and may only be supported by the credit of the issuing agency. |
| ● | Hedging Risk – When the Adviser believes market conditions are unfavorable, the Adviser may attempt to “hedge” with defensive positions and strategies including, for example, holding substantial positions in lower-yield fixed-income securities and/or cash equivalents, which may limit potential gains when compared to unhedged funds. There can be no assurance that the Fund’s hedging strategy will reduce the risk of the Fund’s investments. |
| ● | High-Yield Bond Risk – Lower-quality bonds, known as high-yield bonds or “junk bonds,” present a significant risk for loss of principal and interest. These bonds offer the potential for higher return, but also involve greater risk than bonds of higher quality, including an increased possibility that the bond’s issuer, obligor or guarantor may not be able to make its payments of interest and principal (credit quality risk). |
| ● | Interest Rate Risk – The value of the Fund may fluctuate based on changes in interest rates and market conditions. As interest rates rise, the value of income producing instruments may decrease. This risk increases as the term of the note increases. |
| ● | Issuer-Specific Risk – The value of a specific security can be more volatile than the market as a whole and can perform differently from the value of the market as a whole, and the risk that the value of a security may decline for a reason directly related to the issuer, such as management performance, changes in financial condition or credit rating, reputation or reduced demand for the issuer’s goods or services. |
| ● | Leverage/Volatility Risk – The use of leverage by the Fund, such as borrowing money to purchase securities or the use of options, will cause the Fund to incur additional expenses and magnify the Fund’s gains or losses. |
| ● | Management Style Risk – The Adviser’s judgments about the potential appreciation of a particular security in which the Fund invests may prove to be incorrect. The Adviser’s proprietary modeling process may incorrectly measure or predict the relative strength or momentum of various fixed income asset classes, and the Fund may hold a high percentage of either high-yield bonds or cash equivalents during certain periods, or for an extended period. |
| ● | Market and Geopolitical Risk – The increasing interconnectivity between global economies and financial markets increases the likelihood that events or conditions in one region or financial market may adversely impact issuers in a different country, region or financial market. Securities in the Fund may underperform due to inflation (or expectations for inflation), interest rates, global demand for particular products or resources, natural disasters, pandemics, epidemics, terrorism, international conflicts, regulatory events and governmental or quasi-governmental actions. The occurrence of global events similar to those in recent years, such as a worldwide pandemic, terrorist attacks, natural disasters, social and political discord or debt crises and downgrades, among others, may result in market volatility and may have long term effects on both the U.S. and global financial markets. It is difficult to predict when similar events affecting the U.S. or global financial markets may occur, the effects that such events may have and the duration of those effects. Any such event(s) could have a significant adverse impact on the value and risk profile of the Fund. For example, the COVID-19 global pandemic had negative impacts, and in many cases severe negative impacts, on markets worldwide. It is not known how long any future impacts of other significant events described above will last, but there could be a prolonged period of global economic slowdown, which may impact your investment. Therefore, the Fund could lose money over short periods due to short-term market movements and over longer periods during more prolonged market downturns. During a general market downturn, multiple asset classes may be negatively affected. Changes in market conditions and interest rates can have the same impact on all types of securities and instruments. In times of severe market disruptions, you could lose your entire investment. |
| ● | Options Risk – The Fund may lose the entire put or call option premium paid if the reference asset or index does not decrease below or rise above the respective strike price before expiration. Options may not be an effective hedge because they may have imperfect correlation to the value of the Fund’s assets. |
| ● | Portfolio Turnover Risk – A higher portfolio turnover may result in higher transactional and brokerage costs. |
| ● | Preferred Stock Risk – Typically, a rise in interest rates causes a decline in the value of preferred stock. Preferred stocks are also subject to credit and default risk, which is the possibility that an issuer of preferred stock will fail to make its dividend payments. |
| ● | Sector Risk – The Fund may focus its investments in securities of a particular sector. Economic, legislative or regulatory developments may occur that significantly affect the sector. This may cause the Fund’s net asset value to fluctuate more than that of a fund that does not focus in a particular sector. |
| ● | Short Selling and Short Position Risk – The Fund may engage in short selling and short position derivative activities, which are significantly different from the investment activities commonly associated with conservative stock or bond funds. Positions in shorted securities and derivatives are speculative and riskier than “long” positions (purchases) because the cost of the replacement security or derivative is unknown. Therefore, the potential loss on an uncovered short is unlimited, whereas the potential loss on long positions is limited to the original purchase price. You should be aware that any strategy that includes selling securities short could suffer significant losses. Shorting will also result in higher transaction costs (such as interest and dividends), which reduce the Fund’s return, and may result in higher taxes. When the Fund is selling a security short, it must maintain a segregated account of cash or high-grade securities equal to the margin requirement. As a result, the Fund may maintain high levels of cash or other liquid assets (such as U.S. Treasury bills, money market instruments, certificates of deposit, high quality commercial paper and long equity positions). The need to maintain cash or other liquid assets in segregated accounts could limit the Fund’s ability to pursue other opportunities as they arise. |
| ● | Small and Medium Company Credit Risk – Small and mid-sized companies may have limited product lines, markets or financial resources, and they may be dependent on a limited management group. Therefore, equity or fixed income securities issued by smaller companies may pose greater credit risk than is generally associated with the securities of larger, more established companies. |
| ● | Stock Market Risk – Equity prices can fall rapidly in response to developments affecting a specific company or industry, or to changing economic, political or market conditions. |
| ● | Structured Notes Risk – Structured notes involve leverage risk, tracking risk and issuer default risk. |
| ● | Swap Risk – Swap agreements are subject to the risk that the counterparty to the swap will default on its obligation to pay the Fund and the risk that the Fund will not be able to meet its obligations to pay the counterparty to the swap. Swap agreements may also involve fees, commissions or other costs that may reduce the Fund’s gains from a swap agreement or may cause the Fund to lose money. |
| ● | Swaption Risk – A swaption is an option contract that gives the holder the right (but not the obligation) to enter into a swap at a predetermined rate at expiration in exchange for a premium payment. Swaptions enable the Fund to purchase exposure that is significantly greater than the premium paid. Consequently, the value of swaptions can be volatile, and a small investment in swaptions can have a large impact on the performance of the Fund. The Fund risks losing all or part of the cash paid (premium) for purchasing swaptions. Additionally, the value of the underlying interest rate swap changes unfavorably with respect to the Fund. The Fund’s loss may exceed the option premium received by the Fund. |
| ● | Underlying Funds Risk – Underlying Funds in which the Fund invests are subject to investment advisory and other expenses, which will be indirectly paid by the Fund. As a result, the cost of investing in the Fund will be higher than the cost of investing directly in the Underlying Funds and may be higher than other mutual funds that invest directly in stocks and bonds. Each of the Underlying Funds is subject to specific risks, depending on the nature of the fund. |
| ◌ | Inverse ETF Risk – Investing in inverse ETFs may result in increased volatility and will magnify the Fund’s losses or gains. During periods of market volatility, inverse ETFs may not perform as expected. |
| ◌ | Inverse ETF Risk – Investing in inverse ETFs may result in increased volatility and will magnify the Fund’s losses or gains. During periods of market volatility, inverse ETFs may not perform as expected. |
The Navigator Ultra Short Bond Fund (the “Fund”) seeks current income consistent with the preservation of capital.
The following table describes the fees and expenses that you may pay if you buy, hold and sell shares of the Fund. More information about these and other discounts is available from your financial professional and in How to Purchase Shares on page [47] of the Fund’s Prospectus and in Purchase, Redemption and Pricing of Shares on page [62] of the Statement of Additional Information.
Shareholder Fees - Navigator Ultra Short Bond Fund |
Navigator Ultra Short Bond Fund Class A |
Navigator Ultra Short Bond Fund Class I |
|---|---|---|
| Maximum Sales Charge (Load) Imposed on Purchases (as a % of offering price) | 3.75% | none |
| Maximum Deferred Sales Charge (Load) (as a % of the lower of original purchase price or redemption proceeds) | none | none |
| Maximum Sales Charge (Load) Imposed on Reinvested Dividends and Other Distributions | none | none |
| Redemption Fee | none | none |
Annual Fund Operating Expenses - Navigator Ultra Short Bond Fund |
Navigator Ultra Short Bond Fund Class A |
Navigator Ultra Short Bond Fund Class I |
|
|---|---|---|---|
| Management Fees | 0.30% | 0.30% | |
| Distribution and Service (12b-1) Fees | 0.25% | none | |
| Other Expenses | 0.35% | 0.35% | |
| Acquired Fund Fees and Expenses | [1] | 0.01% | 0.01% |
| Total Annual Fund Operating Expenses | 0.91% | 0.66% | |
| Fee Waiver and/or Expense Reimbursement | [2] | (0.25%) | (0.25%) |
| Total Annual Fund Operating Expenses After Fee Waiver and/or Expense Reimbursement | 0.66% | 0.41% | |
| [1] | Acquired Fund Fees and Expenses are the indirect costs of investing in other investment companies. |
| [2] | Clark Capital Management Group, Inc. (the “Adviser”) has contractually agreed to reduce its fees and to reimburse expenses, at least until February 28, 2026, to ensure that total annual fund operating expenses after fee waiver and/or reimbursement (excluding any front-end or contingent deferred loads, brokerage fees and commissions, acquired fund fees and expenses, fees and expenses associated with investments in other collective investment vehicles or derivative instruments (including for example options and swap fees and expenses), borrowing costs (such as interest and dividend expense on securities sold short), taxes, expenses incurred in connection with any merger or reorganization, and extraordinary expenses, such as litigation expenses (which may include indemnification of Fund officers and Trustees and contractual indemnification of Fund service providers (other than the Adviser)) will not exceed 0.65%, and 0.40% of average daily net assets attributable to Class A and Class I shares, respectively. These fee waivers and expense reimbursements are subject to possible recoupment from the Fund in future years on a rolling three-year basis (within the three years after the fees have been waived or reimbursed) if such recoupment can be achieved within the foregoing expense limits. This agreement may be terminated only by the Board, on 60 days written notice to the Adviser. |
This Example is intended to help you compare the cost of investing in the Fund with the cost of investing in other mutual funds.
Expense Example - Navigator Ultra Short Bond Fund - USD ($) |
Expense Example, with Redemption, 1 Year |
Expense Example, with Redemption, 3 Years |
Expense Example, with Redemption, 5 Years |
Expense Example, with Redemption, 10 Years |
|---|---|---|---|---|
| Navigator Ultra Short Bond Fund Class A | 440 | 630 | 836 | 1,430 |
| Navigator Ultra Short Bond Fund Class I | 42 | 186 | 343 | 799 |
The Fund pays transaction costs, such as commissions, when it buys and sells securities (or “turns over” its portfolio). A higher portfolio turnover may indicate higher transaction costs and may result in higher taxes when Fund shares are held in a taxable account. These costs, which are not reflected in annual fund operating expenses or in the Example, affect the Fund’s performance. During the most recent fiscal period, the Fund’s portfolio turnover rate was 21% of the average value of its portfolio.
In seeking to achieve its investment objective, the Fund invests primarily in various types of short duration, investment grade debt (or fixed income) securities. Under normal circumstances, the Fund invests at least 80% of its assets, defined as net assets plus the amount of any borrowings for investment purposes, in fixed income securities (“80% investment policy”). For purposes of the 80% investment policy, the Fund defines fixed income securities as including (i) bills, (ii) notes, (iii) corporate bonds of domestic, foreign and emerging market issuers, (iv) fixed income securities issued by the U.S. government, its agencies or instrumentalities, (v) fixed income derivatives including options, financial futures, options on futures and swaps, (vi) exchange traded funds and mutual funds that invest primarily in fixed income securities (“Underlying Funds”), or (vii) asset-backed and mortgage backed-securities. The Fund defines emerging market issuers as those found in the MSCI Emerging Markets Index. Fixed income securities in which the Fund may invest may have fixed, floating or inverse interest rates. The Fund may invest in affiliated mutual funds, and unaffiliated mutual funds (including money market funds), ETFs and inverse ETFs (collectively, “Underlying Funds”).
The Fund may invest in debt securities of any maturity or credit quality, including those rated below investment grade (commonly known as junk bonds or high yield securities). Below investment grade debt securities are those rated below Baa3 by Moody’s Investors Service or equivalently by another nationally recognized statistical rating organization (NRSRO). The Fund will not invest more than 15% of its assets in high yield securities. Mortgage backed securities in which the Fund may invest include those issued by non-governmental agencies (“non-agency MBS”).
The Adviser expects that the investment portfolio for the Fund will have an average duration of one year or less. Duration is a measure of the expected life of a fixed income security that is used to determine the sensitivity of a security’s price to changes in interest rates. For example, the value of a portfolio of fixed income securities with an average duration of one year would generally be expected to decline by approximately 1% if interest rates rose by one percentage point. The average duration of the Fund’s investment portfolio may vary from time to time, and there is no assurance that the duration of the Fund’s investment portfolio will not exceed one year but will also not typically exceed two years.
The Fund may also purchase or write (sell) credit default swaps (“CDS”) or credit default swap indexes (“CDX”), which are credit derivatives used to hedge credit risk and/or take a position on a basket of credit entities. Unlike a credit default swap, which is an over the counter derivative, a CDX may be exchange traded, or sold over the counter. Each CDX is designed to track a basket of credit entities, which may be standard or customized. This means that it may be more liquid than a credit default swap, and it may be cheaper to hedge the Fund’s portfolio with a CDX than it would be to buy many single name credit default swaps to achieve a similar effect. The Fund may also purchase or sell total return swaps or invest in inverse ETFs to hedge its long positions.
The Fund engages in active and frequent trading of its portfolio securities.
As with all mutual funds, there is the risk that you could lose money through your investment in the Fund. The Fund is not intended to be a complete investment program. Many factors affect the Fund’s net asset value and performance.
| ● | Asset-Backed Securities Risk – Asset-backed securities are subject to credit risk because underlying loan borrowers may default. Additionally, these securities are subject to prepayment risk because the underlying loans held by the issuers may be paid off prior to maturity. The value of these securities may go down as a result of changes in prepayment rates on the underlying mortgages or loans. During periods of declining interest rates, prepayment rates usually increase, and the Fund may have to reinvest prepayment proceeds at a lower interest rate. |
| ● | CDS Risk – CDS are a type of derivative instrument, involve special risks and may result in losses to the Fund. CDS are typically two-party financial contracts that transfer credit exposure between the two parties. Under a typical CDS, one party (the “seller”) receives pre-determined periodic payments from the other party (the “buyer”). The seller agrees to make compensating specific payments to the buyer if a negative credit event occurs, such as the bankruptcy or default by the issuer of the underlying debt instrument. The use of CDS involves investment techniques and risks different from those associated with ordinary portfolio security transactions, such as potentially heightened counterparty, concentration and exposure risks. CDS may in some cases be illiquid, and they increase credit risk since the Fund has exposure to the issuer of the referenced obligation and either the counterparty to the credit default swap or, if it is a cleared transaction, the brokerage firm through which the trade was cleared and the clearing organization that is the counterparty to that trade. In addition, for cleared trades, the brokerage firm would impose margin requirements and would be able to require termination of those trades in certain circumstances. Certain CDS will be required to be traded on a regulated execution facility or contract market that makes them available for trading. The transition to trading these swaps on such a facility or contract market may not result in swaps being easier to trade or value and may present certain execution risks if such a facility or contract market does not operate properly. Swaps may be difficult to unwind or terminate. |
| ● | CDX Risk – A CDX is subject to the risks of the underlying credit default swap obligations, which include risks such as concentration risk and counterparty risk. Concentration risk refers to the certain large institutional buyers may take large positions in credit default swaps, and the failure of such a buyer could materially adversely affect the credit default swap market as a whole. Counterparty risk refers to the risk that the counterparty to the swap will default on its obligation to pay. |
| ● | Credit Risk – The issuer of a fixed income security may not be able to make interest or principal payments when due. Generally, the lower the credit rating of a security, the greater the risk is that the issuer will default on its obligation. |
| ● | Derivatives Risk – The Fund may execute an investment strategy or hedge by entering into derivative contracts such as futures, options and swaps, which can be riskier than traditional investments because they may involve leverage, be illiquid, suffer counterparty default and limit gains. Equity market-related swap contracts (including total return swaps and CDS) and options involve leverage risk, tracking risk and counterparty default risk. Option positions may expire worthless exposing the Fund to potentially significant losses. There is a risk that adverse price movements in a swap instrument can result in a loss substantially greater than the Fund’s initial investment in that instrument (in some cases, the potential loss is unlimited). |
| ● | Emerging Market Risk – Investing in emerging markets involves not only the risks described below with respect to investing in foreign securities, but also other risks, including exposure to economic structures that are generally less diverse and mature, limited availability and reliability of information material to an investment decision, and exposure to political systems that can be expected to have less stability than those of developed countries. The market for the securities of issuers in emerging market typically is small, and a low or nonexistent trading volume in those securities may result in a lack of liquidity and price volatility. |
| ● | Fixed Income Risk – The value of the Fund’s investments in fixed income securities and derivatives will fluctuate with changes in interest rates. Typically, a rise in interest rates causes a decline in the value of fixed income securities and derivatives owned by the Fund. On the other hand, if rates fall, the value of the fixed income securities and derivatives generally increases. Your investment will decline in value if the value of the Fund’s investments decreases. |
| ● | Floating Rate Risk – Changes in short-term market interest rates will directly affect the yield on investments in floating rate debt. If short-term market interest rates fall, the yield on the Fund’s shares will also fall. Conversely, when short-term market interest rates rise, because of the lag between changes in such short-term rates and the resetting of the floating rates on the floating rate debt in the Fund’s portfolio, the impact of rising rates will be delayed to the extent of such lag. This contrasts with the Fund’s investments in fixed rate instruments, where a rise in interest rates generally causes values to fall |
| ● | Foreign Investment Risk – Foreign investing involves risks not typically associated with U.S. investments, including adverse fluctuations in foreign currency values, adverse political, social and economic developments, less liquidity, greater volatility, less developed or less efficient trading markets, political instability and differing auditing and legal standards. Investing in emerging markets imposes risks different from, or greater than, risks of investing in foreign developed countries. |
| ◌ | Foreign Currency Risk – Currency market risk results from the price movement of foreign currency values in response to shifting market supply and demand. Interest rate risk arises whenever a country changes its stated interest rate target associated with its currency. Country risk arises because virtually every country has interfered with international transactions in its currency. Interference has taken the form of regulation of the local exchange market, restrictions on foreign investment by residents or limits on inflows of investment funds from abroad. Restrictions on the exchange market or on international transactions are intended to affect the level or movement of the exchange rate. This risk could include the country issuing a new currency, effectively making the “old” currency worthless. |
| ● | Government-Sponsored Entities Risk – The Fund invests in securities issued or guaranteed by government-sponsored entities, but these securities may not be guaranteed or insured by the U.S. government and may only be supported by the credit of the issuing agency. |
| ● | Hedging Risk – When the Adviser believes market conditions are unfavorable, the Adviser may attempt to “hedge” with defensive positions and strategies including, for example, holding substantial positions in lower-yield fixed-income securities and/or cash equivalents, which may limit potential gains when compared to unhedged funds. |
| ● | High Yield Bond Risk – Lower-quality bonds, known as “high yield” or “junk” bonds, are speculative and present greater risk than bonds of higher quality, including an increased risk of default. An economic downturn or period of rising interest rates could adversely affect the market for these bonds and reduce the Fund’s ability to sell its bonds. The lack of a liquid market for these bonds could decrease the Fund’s share price. |
| ● | Interest Rate Risk – The value of the Fund may fluctuate based on changes in interest rates and market conditions. As interest rates rise, the value of income producing instruments may decrease. This risk increases as the term of the note increases. |
| ● | Issuer-Specific Risk – The value of a specific security can be more volatile than the market as a whole and can perform differently from the value of the market as a whole, and the risk that the value of a security may decline for a reason directly related to the issuer, such as management performance, changes in financial condition or credit rating, reputation or reduced demand for the issuer’s goods or services. |
| ● | Leverage/Volatility Risk – The use of leverage by the Fund, such as borrowing money to purchase securities or the use of options, will cause the Fund to incur additional expenses and magnify the Fund’s gains or losses. |
| ● | Management Style Risk – The Adviser’s judgments about the potential appreciation of a particular security in which the Fund invests may prove to be incorrect. The Adviser’s proprietary modeling process may incorrectly measure or predict the relative strength or momentum of various fixed income asset classes, and the Fund may hold a high percentage of either high-yield bonds or cash equivalents during certain periods, or for an extended period. |
| ● | Market and Geopolitical Risk – The increasing interconnectivity between global economies and financial markets increases the likelihood that events or conditions in one region or financial market may adversely impact issuers in a different country, region or financial market. Securities in the Fund may underperform due to inflation (or expectations for inflation), interest rates, global demand for particular products or resources, natural disasters, pandemics, epidemics, terrorism, international conflicts, regulatory events and governmental or quasi-governmental actions. The occurrence of global events similar to those in recent years, such as a worldwide pandemic, terrorist attacks, natural disasters, social and political discord or debt crises and downgrades, among others, may result in market volatility and may have long term effects on both the U.S. and global financial markets. It is difficult to predict when similar events affecting the U.S. or global financial markets may occur, the effects that such events may have and the duration of those effects. Any such event(s) could have a significant adverse impact on the value and risk profile of the Fund. For example, the COVID-19 global pandemic had negative impacts, and in many cases severe negative impacts, on markets worldwide. It is not known how long any future impacts of other significant events described above would last, but there could be a prolonged period of global economic slowdown, which may impact your investment. Therefore, the Fund could lose money over short periods due to short-term market movements and over longer periods during more prolonged market downturns. During a general market downturn, multiple asset classes may be negatively affected. Changes in market conditions and interest rates can have the same impact on all types of securities and instruments. In times of severe market disruptions, you could lose your entire investment. |
| ● | Mortgage-Backed Security Risk – When the Fund invests in residential mortgage-backed securities (“RMBS”) and commercial mortgage-backed securities (“CMBS”), the Fund is subject to the risk that, if the underlying borrowers fail to pay interest or repay principal, the assets backing these securities may not be sufficient to support payments on the securities. The value of these securities may be significantly affected by changes in interest rates, the market’s perception of issuers, and the creditworthiness of the parties involved. RMBS default rates tend to be sensitive to these conditions and to home prices. CMBS default rates tend to be sensitive to overall economic conditions and to localized commercial property vacancy rates and prices. Any unrealized losses the Fund experiences with respect to its RMBS and CMBS investments may be an indication of future realized losses. Mortgage-backed securities issued or guaranteed by private issuers are also known as “non-agency MBS”. Non-agency MBS generally are a greater credit risk than MBS issued by the U.S. government, and the market for non-agency MBS is smaller and less liquid than the market for government issued MBS. |
| ● | Options Risk – The Fund may lose the entire put or call option premium paid if the reference asset or index does not decrease below or rise above the respective strike price before expiration. Options may not be an effective hedge because they may have imperfect correlation to the value of the Fund’s assets. |
| ● | Portfolio Turnover Risk – A higher portfolio turnover may result in higher transactional and brokerage costs. |
| ● | Sector Risk – The Fund may focus its investments in securities of a particular sector. Economic, legislative or regulatory developments may occur that significantly affect the sector. This may cause the Fund’s net asset value to fluctuate more than that of a fund that does not focus in a particular sector. |
| ● | Swap Risk – Swap agreements are subject to the risk that the counterparty to the swap will default on its obligation to pay the Fund and the risk that the Fund will not be able to meet its obligations to pay the counterparty to the swap. Swap agreements may also involve fees, commissions or other costs that may reduce the Fund’s gains from a swap agreement or may cause the Fund to lose money. |
| ● | Underlying Funds Risk – Underlying Funds in which the Fund invests are subject to investment advisory and other expenses, which will be indirectly paid by the Fund. As a result, the cost of investing in the Fund will be higher than the cost of investing directly in the Underlying Funds and may be higher than other mutual funds that invest directly in stocks and bonds. Each of the Underlying Funds is subject to specific risks, depending on the nature of the fund. |
.
| ◌ | Inverse Fund Risk – Inverse ETFs are designed to rise in price when stock prices are falling. Inverse ETFs tend to limit the Fund’s participation in overall market-wide gains. Accordingly, their performance over longer terms can perform very differently than underlying assets and benchmarks, and volatile markets can amplify this effect. |
| ● | U.S. Government Securities Risk – The Fund may invest in obligations issued by agencies and instrumentalities of the U.S. Government. The U.S. Government may choose not to provide financial support to U.S. Government sponsored agencies or instrumentalities if it is not legally obligated to do so, in which case, if the issuer defaulted, the Fund might not be able to recover its investment. |
The bar chart and performance table below show the variability of the Fund’s returns, which is some indication of the risks of investing in the Fund. The bar chart shows performance of the Fund’s Class I shares for each full calendar year since the Fund’s inception. Returns for Class A shares, which are not presented, would be different than the returns for Class I shares. The performance table compares the performance of the Fund over time to the performance of a broad-based securities market index and a supplemental index. You should be aware that the Fund’s past performance (before and after taxes) may not be an indication of how the Fund will perform in the future. Updated performance information is available at no cost by calling 1-877-766-2264 or visiting www.navigatorfunds.com.
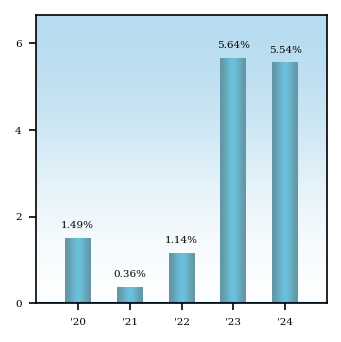
| Best Quarter: | Second Quarter 2020 | 2.94% |
| Worst Quarter: | First Quarter 2020 | (2.11)% |
Average Annual Total Returns - Navigator Ultra Short Bond Fund |
Label |
1 Year |
5 Years |
Since Inception |
Inception Date |
|
|---|---|---|---|---|---|---|
| Navigator Ultra Short Bond Fund Class I | Return before taxes | 5.54% | 2.81% | 2.78% | Mar. 25, 2019 | |
| Navigator Ultra Short Bond Fund Class I | Return after taxes on distributions | 3.34% | 1.68% | 1.66% | |||
| Navigator Ultra Short Bond Fund Class I | Return after taxes on distributions and sale of Fund shares | 3.25% | 1.67% | 1.65% | |||
| Navigator Ultra Short Bond Fund Class A | Return before taxes with sales charge | 1.35% | 1.89% | 2.15% | Mar. 25, 2019 | |
| Bloomberg U.S. Aggregate Bond Index | [1] | 1.25% | (0.33%) | 0.68% | ||
| Bloomberg U.S. Treasury Bellwethers: 1 Year Index | [2] | 5.03% | 2.35% | 2.42% | ||
| [1] | Bloomberg U.S. Aggregate Bond Index is an unmanaged index comprised of U.S. investment grade, fixed rate bond market securities, including government, government agency, corporate and mortgage-backed securities. Investors cannot invest directly in an index or benchmark. |
| [2] | Bloomberg U.S. Treasury Bellwethers: 1 Year Index measures the performance of the U.S. government bond market and includes public obligations of the U.S. Treasury with a maturity of up to a year. Investors cannot invest directly in an index or benchmark. |
After-tax returns are calculated using the highest historical individual federal marginal income tax rate and do not reflect the impact of state and local taxes. Actual after-tax returns depend on a shareholder’s tax situation and may differ from those shown. The after-tax returns are not relevant if you hold your Fund shares in tax-deferred arrangements, such as 401(k) plans or individual retirement accounts (“IRA”). The after-tax returns for Class A and Class C shares are not shown and would differ from those of Class I Shares.
| ● | CDS Risk – CDS are a type of derivative instrument, involve special risks and may result in losses to the Fund. CDS are typically two-party financial contracts that transfer credit exposure between the two parties. Under a typical CDS, one party (the “seller”) receives pre-determined periodic payments from the other party (the “buyer”). The seller agrees to make compensating specific payments to the buyer if a negative credit event occurs, such as the bankruptcy or default by the issuer of the underlying debt instrument. The use of CDS involves investment techniques and risks different from those associated with ordinary portfolio security transactions, such as potentially heightened counterparty, concentration and exposure risks. CDS may in some cases be illiquid, and they increase credit risk since the Fund has exposure to the issuer of the referenced obligation and either the counterparty to the credit default swap or, if it is a cleared transaction, the brokerage firm through which the trade was cleared and the clearing organization that is the counterparty to that trade. In addition, for cleared trades, the brokerage firm would impose margin requirements and would be able to require termination of those trades in certain circumstances. Certain CDS will be required to be traded on a regulated execution facility or contract market that makes them available for trading. The transition to trading these swaps on such a facility or contract market may not result in swaps being easier to trade or value and may present certain execution risks if such a facility or contract market does not operate properly. Swaps may be difficult to unwind or terminate. |
| ● | CDX Risk – A CDX is subject to the risks of the underlying credit default swap obligations, which include risks such as concentration risk and counterparty risk. Concentration risk refers to the certain large institutional buyers may take large positions in credit default swaps, and the failure of such a buyer could materially adversely affect the credit default swap market as a whole. Counterparty risk refers to the risk that the counterparty to the swap will default on its obligation to pay. |
| ● | Credit Risk – The issuer of a fixed income security may not be able to make interest or principal payments when due. Generally, the lower the credit rating of a security, the greater the risk is that the issuer will default on its obligation. |
| ● | Derivatives Risk – The Fund may execute an investment strategy or hedge by entering into derivative contracts such as futures, options and swaps, which can be riskier than traditional investments because they may involve leverage, be illiquid, suffer counterparty default and limit gains. Equity market-related swap contracts (including total return swaps and CDS) and options involve leverage risk, tracking risk and counterparty default risk. Option positions may expire worthless exposing the Fund to potentially significant losses. There is a risk that adverse price movements in a swap instrument can result in a loss substantially greater than the Fund’s initial investment in that instrument (in some cases, the potential loss is unlimited). |
| ● | Fixed Income Risk – The value of the Fund’s investments in fixed income securities and derivatives will fluctuate with changes in interest rates. Typically, a rise in interest rates causes a decline in the value of fixed income securities and derivatives owned by the Fund. On the other hand, if rates fall, the value of the fixed income securities and derivatives generally increases. Your investment will decline in value if the value of the Fund’s investments decreases. |
| ● | Foreign Investment Risk – Foreign investing involves risks not typically associated with U.S. investments, including adverse fluctuations in foreign currency values, adverse political, social and economic developments, less liquidity, greater volatility, less developed or less efficient trading markets, political instability and differing auditing and legal standards. Investing in emerging markets imposes risks different from, or greater than, risks of investing in foreign developed countries. |
| ◌ | Foreign Currency Risk – Currency market risk results from the price movement of foreign currency values in response to shifting market supply and demand. Interest rate risk arises whenever a country changes its stated interest rate target associated with its currency. Country risk arises because virtually every country has interfered with international transactions in its currency. Interference has taken the form of regulation of the local exchange market, restrictions on foreign investment by residents or limits on inflows of investment funds from abroad. Restrictions on the exchange market or on international transactions are intended to affect the level or movement of the exchange rate. This risk could include the country issuing a new currency, effectively making the “old” currency worthless. |
| ◌ | Foreign Currency Risk – Currency market risk results from the price movement of foreign currency values in response to shifting market supply and demand. Interest rate risk arises whenever a country changes its stated interest rate target associated with its currency. Country risk arises because virtually every country has interfered with international transactions in its currency. Interference has taken the form of regulation of the local exchange market, restrictions on foreign investment by residents or limits on inflows of investment funds from abroad. Restrictions on the exchange market or on international transactions are intended to affect the level or movement of the exchange rate. This risk could include the country issuing a new currency, effectively making the “old” currency worthless. |
| ● | Government-Sponsored Entities Risk – The Fund invests in securities issued or guaranteed by government-sponsored entities, but these securities may not be guaranteed or insured by the U.S. government and may only be supported by the credit of the issuing agency. |
| ● | Hedging Risk – When the Adviser believes market conditions are unfavorable, the Adviser may attempt to “hedge” with defensive positions and strategies including, for example, holding substantial positions in lower-yield fixed-income securities and/or cash equivalents, which may limit potential gains when compared to unhedged funds. |
| ● | High Yield Bond Risk – Lower-quality bonds, known as “high yield” or “junk” bonds, are speculative and present greater risk than bonds of higher quality, including an increased risk of default. An economic downturn or period of rising interest rates could adversely affect the market for these bonds and reduce the Fund’s ability to sell its bonds. The lack of a liquid market for these bonds could decrease the Fund’s share price. |
| ● | Interest Rate Risk – The value of the Fund may fluctuate based on changes in interest rates and market conditions. As interest rates rise, the value of income producing instruments may decrease. This risk increases as the term of the note increases. |
| ● | Issuer-Specific Risk – The value of a specific security can be more volatile than the market as a whole and can perform differently from the value of the market as a whole, and the risk that the value of a security may decline for a reason directly related to the issuer, such as management performance, changes in financial condition or credit rating, reputation or reduced demand for the issuer’s goods or services. |
| ● | Leverage/Volatility Risk – The use of leverage by the Fund, such as borrowing money to purchase securities or the use of options, will cause the Fund to incur additional expenses and magnify the Fund’s gains or losses. |
| ● | Management Style Risk – The Adviser’s judgments about the potential appreciation of a particular security in which the Fund invests may prove to be incorrect. The Adviser’s proprietary modeling process may incorrectly measure or predict the relative strength or momentum of various fixed income asset classes, and the Fund may hold a high percentage of either high-yield bonds or cash equivalents during certain periods, or for an extended period. |
| ● | Market and Geopolitical Risk – The increasing interconnectivity between global economies and financial markets increases the likelihood that events or conditions in one region or financial market may adversely impact issuers in a different country, region or financial market. Securities in the Fund may underperform due to inflation (or expectations for inflation), interest rates, global demand for particular products or resources, natural disasters, pandemics, epidemics, terrorism, international conflicts, regulatory events and governmental or quasi-governmental actions. The occurrence of global events similar to those in recent years, such as a worldwide pandemic, terrorist attacks, natural disasters, social and political discord or debt crises and downgrades, among others, may result in market volatility and may have long term effects on both the U.S. and global financial markets. It is difficult to predict when similar events affecting the U.S. or global financial markets may occur, the effects that such events may have and the duration of those effects. Any such event(s) could have a significant adverse impact on the value and risk profile of the Fund. For example, the COVID-19 global pandemic had negative impacts, and in many cases severe negative impacts, on markets worldwide. It is not known how long any future impacts of other significant events described above would last, but there could be a prolonged period of global economic slowdown, which may impact your investment. Therefore, the Fund could lose money over short periods due to short-term market movements and over longer periods during more prolonged market downturns. During a general market downturn, multiple asset classes may be negatively affected. Changes in market conditions and interest rates can have the same impact on all types of securities and instruments. In times of severe market disruptions, you could lose your entire investment. |
| ● | Options Risk – The Fund may lose the entire put or call option premium paid if the reference asset or index does not decrease below or rise above the respective strike price before expiration. Options may not be an effective hedge because they may have imperfect correlation to the value of the Fund’s assets. |
| ● | Portfolio Turnover Risk – A higher portfolio turnover may result in higher transactional and brokerage costs. |
| ● | Sector Risk – The Fund may focus its investments in securities of a particular sector. Economic, legislative or regulatory developments may occur that significantly affect the sector. This may cause the Fund’s net asset value to fluctuate more than that of a fund that does not focus in a particular sector. |
| ● | Swap Risk – Swap agreements are subject to the risk that the counterparty to the swap will default on its obligation to pay the Fund and the risk that the Fund will not be able to meet its obligations to pay the counterparty to the swap. Swap agreements may also involve fees, commissions or other costs that may reduce the Fund’s gains from a swap agreement or may cause the Fund to lose money. |
| ● | Underlying Funds Risk – Underlying Funds in which the Fund invests are subject to investment advisory and other expenses, which will be indirectly paid by the Fund. As a result, the cost of investing in the Fund will be higher than the cost of investing directly in the Underlying Funds and may be higher than other mutual funds that invest directly in stocks and bonds. Each of the Underlying Funds is subject to specific risks, depending on the nature of the fund. |
.
| ◌ | Inverse Fund Risk – Inverse ETFs are designed to rise in price when stock prices are falling. Inverse ETFs tend to limit the Fund’s participation in overall market-wide gains. Accordingly, their performance over longer terms can perform very differently than underlying assets and benchmarks, and volatile markets can amplify this effect. |
| ● | Asset-Backed Securities Risk – Asset-backed securities are subject to credit risk because underlying loan borrowers may default. Additionally, these securities are subject to prepayment risk because the underlying loans held by the issuers may be paid off prior to maturity. The value of these securities may go down as a result of changes in prepayment rates on the underlying mortgages or loans. During periods of declining interest rates, prepayment rates usually increase, and the Fund may have to reinvest prepayment proceeds at a lower interest rate. |
| ● | Emerging Market Risk – Investing in emerging markets involves not only the risks described below with respect to investing in foreign securities, but also other risks, including exposure to economic structures that are generally less diverse and mature, limited availability and reliability of information material to an investment decision, and exposure to political systems that can be expected to have less stability than those of developed countries. The market for the securities of issuers in emerging market typically is small, and a low or nonexistent trading volume in those securities may result in a lack of liquidity and price volatility. |
| ● | Floating Rate Risk – Changes in short-term market interest rates will directly affect the yield on investments in floating rate debt. If short-term market interest rates fall, the yield on the Fund’s shares will also fall. Conversely, when short-term market interest rates rise, because of the lag between changes in such short-term rates and the resetting of the floating rates on the floating rate debt in the Fund’s portfolio, the impact of rising rates will be delayed to the extent of such lag. This contrasts with the Fund’s investments in fixed rate instruments, where a rise in interest rates generally causes values to fall |
| ● | Mortgage-Backed Security Risk – When the Fund invests in residential mortgage-backed securities (“RMBS”) and commercial mortgage-backed securities (“CMBS”), the Fund is subject to the risk that, if the underlying borrowers fail to pay interest or repay principal, the assets backing these securities may not be sufficient to support payments on the securities. The value of these securities may be significantly affected by changes in interest rates, the market’s perception of issuers, and the creditworthiness of the parties involved. RMBS default rates tend to be sensitive to these conditions and to home prices. CMBS default rates tend to be sensitive to overall economic conditions and to localized commercial property vacancy rates and prices. Any unrealized losses the Fund experiences with respect to its RMBS and CMBS investments may be an indication of future realized losses. Mortgage-backed securities issued or guaranteed by private issuers are also known as “non-agency MBS”. Non-agency MBS generally are a greater credit risk than MBS issued by the U.S. government, and the market for non-agency MBS is smaller and less liquid than the market for government issued MBS. |
.
| ◌ | Inverse Fund Risk – Inverse ETFs are designed to rise in price when stock prices are falling. Inverse ETFs tend to limit the Fund’s participation in overall market-wide gains. Accordingly, their performance over longer terms can perform very differently than underlying assets and benchmarks, and volatile markets can amplify this effect. |
| ● | U.S. Government Securities Risk – The Fund may invest in obligations issued by agencies and instrumentalities of the U.S. Government. The U.S. Government may choose not to provide financial support to U.S. Government sponsored agencies or instrumentalities if it is not legally obligated to do so, in which case, if the issuer defaulted, the Fund might not be able to recover its investment. |
The Navigator Tactical Investment Grade Bond Fund (the “Fund”) seeks total return
with a secondary goal of current income.
This table describes the fees and expenses that you may pay if you buy, hold and shares of the Fund. More information about these and other discounts is available from your financial professional and in How to Purchase Shares on page [47] of the Fund’s Prospectus and in Purchase, Redemption and Pricing of Shares on page [62] of the Statement of Additional Information.
Shareholder Fees - Navigator Tactical Investment Grade Bond Fund |
Navigator Tactical Investment Grade Bond Fund Class A |
Navigator Tactical Investment Grade Bond Fund Class I |
|---|---|---|
| Maximum Sales Charge (Load) Imposed on Purchases (as a % of offering price) | 3.75% | none |
| Maximum Deferred Sales Charge (Load) (as a % of the lower of original purchase price or redemption proceeds) | none | none |
| Maximum Sales Charge (Load) Imposed on Reinvested Dividends and Other Distributions | none | none |
| Redemption Fee | none | none |
Annual Fund Operating Expenses - Navigator Tactical Investment Grade Bond Fund |
Navigator Tactical Investment Grade Bond Fund Class A |
Navigator Tactical Investment Grade Bond Fund Class I |
|
|---|---|---|---|
| Management Fees | 0.85% | 0.85% | |
| Distribution and Service (12b-1) Fees | 0.25% | none | |
| Other Expenses | 0.24% | 0.24% | |
| Acquired Fund Fees and Expenses | [1] | 0.08% | 0.08% |
| Total Annual Fund Operating Expenses | 1.42% | 1.17% | |
| Fee Waiver and/or Expense Reimbursement | [2] | (0.08%) | (0.08%) |
| Total Annual Fund Operating Expenses After Fee Waiver and/or Expense Reimbursement | 1.34% | 1.09% | |
| [1] | Acquired Fund Fees and Expenses are the indirect costs of investing in other investment companies. |
| [2] | Clark Capital Management Group, Inc. (the “Adviser”) has contractually agreed to waive management fees and/or to make payments to limit Fund expenses, at least until February 28, 2026, so that the total annual operating expenses (exclusive of any front-end or contingent deferred loads; brokerage fees and commissions, acquired fund fees and expenses; fees and expenses associated with investments in other collective investment vehicles or derivative instruments (including for example option and swap fees and expenses); borrowing costs (such as interest and dividend expense on securities sold short); taxes; and extraordinary expenses, such as litigation expenses (which may include indemnification of Fund officers and Trustees, contractual indemnification of Fund service providers (other than the adviser)) of the Fund do not exceed will not exceed 1.26% and 1.01% of average daily net assets attributable to Class A and Class I shares, respectively. Fee waivers and expense reimbursements are subject to possible recoupment from the Fund in future years on a rolling three-year basis (within the three years from the date in which the fees were waived or reimbursed) if such recoupment can be achieved within the foregoing expense limit and any expense limitation in place at the time of recoupment. This agreement may be terminated only by the Board of Trustees on 60 days written notice to the Adviser. |
This Example is intended to help you compare the cost of investing in the Fund with the cost of investing in other mutual funds.
Expense Example - Navigator Tactical Investment Grade Bond Fund - USD ($) |
Expense Example, with Redemption, 1 Year |
Expense Example, with Redemption, 3 Years |
Expense Example, with Redemption, 5 Years |
Expense Example, with Redemption, 10 Years |
|---|---|---|---|---|
| Navigator Tactical Investment Grade Bond Fund Class A | 506 | 800 | 1,115 | 2,007 |
| Navigator Tactical Investment Grade Bond Fund Class I | 111 | 364 | 636 | 1,413 |
The Fund pays transaction costs, such as commissions, when it buys and sells securities (or “turns over” its portfolio). A higher portfolio turnover may indicate higher transaction costs and may result in higher taxes when Fund shares are held in a taxable account. These costs, which are not reflected in annual fund operating expenses or in the Example, affect the Fund’s performance. During the most recent fiscal period, the Fund’s portfolio turnover rate was 360%.
In seeking to achieve its investment objective, the Fund will invest, under normal circumstances, at least 80% of its assets, defined as net assets plus the amount of any borrowings for investment purposes, in long and/or short positions in investment grade bonds or fixed income securities (“80% investment policy”). For purposes of the 80% investment policy, the Fund defines bonds or fixed income securities as including (i) bills, (ii) notes, (iii) structured notes, (iv) bonds, (v) preferred stocks, (vi) any other debt or debt-related securities of any maturities, whether issued by U.S. or non-U.S. governments, agencies or instrumentalities thereof or corporate entities, and having fixed, variable, floating or inverse floating rates, (vii) fixed income derivatives including options, financial futures, options on futures and swaps, and (viii) underlying funds (defined below) that invest primarily in fixed income securities, or (ix) other evidences of indebtedness. The Fund will invest primarily in investment grade bonds, rated by at least one nationally recognized statistical rating organization (NRSRO) as investment grade, at the time of purchase. From time to time, the Fund may also invest up to 20% of its assets directly or have exposure to high yield bonds (“junk bonds”) that are rated as below investment grade. The Fund may invest in underlying funds such as mutual funds (including money market funds), exchange traded funds (“ETFs”) and inverse ETFs (collectively, “Underlying Funds”).
The Fund may also purchase or write (sell) credit default swaps (“CDS”) or credit default swap indexes (“CDX”), which are credit derivatives used to hedge credit risk and/or take a position on a basket of credit entities. Unlike a credit default swap, which is an over the counter derivative, a CDX may be exchange traded, or sold over the counter. Each CDX is designed to track a basket of credit entities, which may be standard or customized. This means that it may be more liquid than a credit default swap, and it may be more efficient to hedge the Fund’s portfolio with a CDX than it would be to buy many single name credit default swaps to achieve a similar effect. The Fund may also purchase or sell total return swaps or invest in inverse ETFs to hedge its long positions.
The Fund’s investment strategy is primarily driven by a modeling process which measures the relative strength or momentum of various asset classes against one another. Specifically, using this momentum-based strategy, the Fund will tactically shift its asset class exposure across investment grade securities, intermediate to long-term Treasuries, and T bills and cash. That analysis assists the adviser to determine the preferred asset class, which in turn drives the underlying investment exposure. Under normal conditions, the Fund expects to invest in fixed income securities and derivatives. When the investment grade asset class is favored, the Fund will seek exposure to investment grade securities. When the treasury asset class is favored, the Fund will normally sell and/or hedge the Fund’s investment grade exposure by short-selling common stocks, entering into puts or put spreads on individual stocks, equity indices, and/or futures, selected to replicate the credit component of investment grade corporate bonds and increase the Fund’s exposure to Treasuries through bonds, notes, and money market funds which invest primarily in T-bills and/or ETFs. When the cash asset class is favored, the Fund will normally sell and/or hedge its investment grade security and/or treasury exposure and increase the Fund’s exposure to cash equivalents through securities and derivatives. The Fund may also use swaps or credit default swaps on individual securities or equity and fixed income indices for hedging purposes. The Fund may invest in affiliated mutual funds, and unaffiliated mutual funds (including money market funds), exchange traded funds (“ETFs”) and inverse ETFs (collectively, “Underlying Funds”).
Due to the structure of the derivatives the Fund expects to use, the Fund will hold a portion of its assets in highly liquid securities as collateral for its derivatives transactions and still have excess cash to invest regardless of whether the favored asset class is investment grade securities, intermediate to long-term treasuries and T-Bills or cash (or a combination of these asset classes). The Fund will normally invest this excess cash in a mix of investment grade corporate bonds, treasury bills and notes, municipal bonds and other instruments for diversification, risk management, and to seek to obtain additional return. As a result, when the investment grade security asset class is favored, a portion of the Fund’s assets may be invested in non-investment grade investments. Similarly, when the treasury asset class is favored, the Fund may hold a portion of its assets in non-treasury investments, and when the cash asset class is favored, the Fund may hold a portion of its assets in non-cash investments.
The Adviser may engage in frequent buying and selling of securities to achieve the Fund’s investment objective.
As with all mutual funds, there is the risk that you could lose money through your investment in the Fund. The Fund is not intended to be a complete investment program. Many factors affect the Fund’s net asset value and performance.
| ● | CDS Risk – CDS are a type of derivative instrument, involve special risks and may result in losses to the Fund. CDS are typically two-party financial contracts that transfer credit exposure between the two parties. Under a typical CDS, one party (the “seller”) receives pre-determined periodic payments from the other party (the “buyer”). The seller agrees to make compensating specific payments to the buyer if a negative credit event occurs, such as the bankruptcy or default by the issuer of the underlying debt instrument. The use of CDS involves investment techniques and risks different from those associated with ordinary portfolio security transactions, such as potentially heightened counterparty, concentration and exposure risks. Counterparty risk refers to the risk that the counterparty to the swap will default on its obligation to pay. CDS may in some cases be illiquid, and they increase credit risk since the Fund has exposure to the issuer of the referenced obligation and either the counterparty to the credit default swap or, if it is a cleared transaction, the brokerage firm through which the trade was cleared and the clearing organization that is the counterparty to that trade. In addition, for cleared trades, the brokerage firm would impose margin requirements and would be able to require termination of those trades in certain circumstances. Certain CDS will be required to be traded on a regulated execution facility or contract market that makes them available for trading. The transition to trading these swaps on such a facility or contract market may not result in swaps being easier to trade or value and may present certain execution risks if such a facility or contract market does not operate properly. Swaps may be difficult to unwind or terminate. |
| ● | CDX Risk – A CDX is subject to the risks of the underlying credit default swap obligations, which include risks such as concentration risk and counterparty risk. Concentration risk refers to the certain large institutional buyers may take large positions in credit default swaps, and the failure of such a buyer could materially adversely affect the credit default swap market as a whole. Counterparty risk refers to the risk that the counterparty to the swap will default on its obligation to pay. |
| ● | Credit Risk – The issuer of a fixed income security may not be able to make interest or principal payments when due. Generally, the lower the credit rating of a security, the greater the risk is that the issuer will default on its obligation. |
| ● | Derivatives Risk – The Fund may execute an investment strategy or hedge by entering into derivative contracts such as futures, options and swaps, which can be riskier than traditional investments because they may involve leverage, be illiquid, suffer counterparty default and limit gains. Equity market-related swap contracts (including total return swaps and CDS) and options involve leverage risk, tracking risk and counterparty default risk. Option positions may expire worthless exposing the Fund to potentially significant losses. There is a risk that adverse price movements in a swap instrument can result in a loss substantially greater than the Fund’s initial investment in that instrument (in some cases, the potential loss is unlimited). |
| ● | Equity Securities Risk – Common stocks are susceptible to general stock market fluctuations and to volatile increases and decreases in value as market confidence in and perceptions of their issuers change. Warrants and rights may expire worthless if the price of a common stock is below the conversion price of the warrant or right. Convertible bonds may decline in value if the price of a common stock falls below the conversion price. Investor perceptions are based on various and unpredictable factors including expectations regarding government, economic, monetary and fiscal policies; inflation and interest rates; economic expansion or contraction and global or regional political, economic and banking crises. |
| ● | Fixed Income Risk – The value of the Fund’s investments in fixed income securities will fluctuate with changes in interest rates. Typically, a rise in interest rates causes a decline in the value of fixed income securities. During periods of sustained rising rates, fixed income risks may be amplified. Rising rates may decrease liquidity and increase volatility, which may make portfolio management more difficult and costly to the Fund and its shareholders. |
| ● | Futures Risk – The Fund’s use of futures contracts involves risks different from, or possibly greater than, the risks associated with investing directly in securities and other traditional investments. These risks include (i) leverage risk; (ii) correlation or tracking risk and (iii) liquidity risk. Because futures require only a small initial investment in the form of a deposit or margin, they involve a high degree of leverage. Accordingly, the fluctuation of the value of futures in relation to the underlying assets upon which they are based is magnified. Thus, the Fund may experience losses that exceed losses experienced by funds that do not use futures contracts. |
| ● | Government-Sponsored Entities Risk – The Fund invests in securities issued or guaranteed by government-sponsored entities, but these securities may not be guaranteed or insured by the U.S. Government and may only be supported by the credit of the issuing agency. |
| ● | Hedging Risk – When the adviser believes market conditions are unfavorable, the adviser may attempt to “hedge” with defensive positions and strategies including, for example, holding substantial positions in lower-yield fixed-income securities and/or cash equivalents, which may limit potential gains when compared to unhedged funds. There can be no assurance that the Fund’s hedging strategy will reduce the risk of the Fund’s investments. |
| ● | High-Yield Bond Risk – Lower-quality bonds, known as high-yield bonds or “junk bonds,” present a significant risk for loss of principal and interest. These bonds offer the potential for higher return, but also involve greater risk than bonds of higher quality, including an increased possibility that the bond’s issuer, obligor or guarantor may not be able to make its payments of interest and principal (credit quality risk). |
| ● | Interest Rate Risk – The value of the Funds may fluctuate based on changes in interest rates and market conditions. As interest rates rise, the value of income producing instruments may decrease. This risk increases as the term of the note increases. |
| ● | Issuer-Specific Risk – The value of a specific security can be more volatile than the market as a whole and can perform differently from the value of the market as a whole, , and the risk that the value of a security may decline for a reason directly related to the issuer, such as management performance, changes in financial condition or credit rating, reputation or reduced demand for the issuer’s goods or services. |
| ● | Leverage/Volatility Risk – The use of leverage by the Fund, such as borrowing money to purchase securities or the use of options, will cause the Fund to incur additional expenses and magnify the Fund’s gains or losses. |
| ● | Management Style Risk – The adviser’s judgments about the potential appreciation of a particular security in which the Fund invests may prove to be incorrect. The adviser’s proprietary modeling process may incorrectly measure or predict the relative strength or momentum of various fixed income asset classes, and the Fund may hold a high percentage of either high-yield bonds or cash equivalents during certain periods, or for an extended period. |
| ● | Market and Geopolitical Risk – The increasing interconnectivity between global economies and financial markets increases the likelihood that events or conditions in one region or financial market may adversely impact issuers in a different country, region or financial market. Securities in the Fund may underperform due to inflation (or expectations for inflation), interest rates, global demand for particular products or resources, natural disasters, pandemics, epidemics, terrorism, international conflicts, regulatory events and governmental or quasi-governmental actions. The occurrence of global events similar to those in recent years, such as terrorist attacks, a worldwide pandemic, natural disasters, social and political discord or debt crises and downgrades, among others, may result in market volatility and may have long term effects on both the U.S. and global financial markets. It is difficult to predict when similar events affecting the U.S. or global financial markets may occur, the effects that such events may have and the duration of those effects. Any such event(s) could have a significant adverse impact on the value and risk profile of the Fund. For example, the COVID-19 global pandemic had negative impacts, and in many cases severe negative impacts, on markets worldwide. It is not known how long any future impacts of other significant events described above or would last, but there could be a prolonged period of global economic slowdown, which may impact your investment. Therefore, the Fund could lose money over short periods due to short-term market movements and over longer periods during more prolonged market downturns. During a general market downturn, multiple asset classes may be negatively affected. Changes in market conditions and interest rates can have the same impact on all types of securities and instruments. In times of severe market disruptions you could lose your entire investment. |
| ● | Non-U.S. Issuers Risk – The Fund may have exposure to U.S. dollar-denominated bonds of non-U.S. corporate issuers as a result of its investment in other ETFs and mutual funds. Securities issued by non-U.S. issuers have different risks from securities issued by U.S. issuers. These risks include differences in accounting, auditing and financial reporting standards, the possibility of expropriation or confiscatory taxation, adverse changes in investment or exchange control regulations, political instability which could affect U.S. investments in non-U.S. countries, uncertainties of transnational litigation, and potential restrictions on the flow of international capital, including the possible seizure or nationalization of the securities issued by non-U.S. issuers held by the Fund. Non-U.S. issuers may be subject to less governmental regulation than U.S. issuers. Moreover, individual non-U.S. economies may differ favorably or unfavorably from the U.S. economy in such respects as growth of gross domestic product, rate of inflation, capital reinvestment, resource self-sufficiency and balance of payment positions. Unfavorable political, economic or governmental developments in non-U.S. countries could affect the payment of a security’s principal and interest. Securities issued by non-U.S. issuers may also be less liquid than, and more difficult to value than, securities of U.S. issuers. In addition, the value of these securities may fluctuate due to changes in the exchange rate of the issuer’s local currency against the U.S. dollar. |
| ● | Options Risk – The Fund may lose the entire put or call option premium paid if the reference asset or index does not decrease below or rise above the respective strike price before expiration. Options may not be an effective hedge because they may have imperfect correlation to the value of the Fund’s assets. |
| ● | Portfolio Turnover Risk – A higher portfolio turnover may result in higher transactional and brokerage costs. |
| ● | Preferred Stock Risk – Typically, a rise in interest rates causes a decline in the value of preferred stock. Preferred stocks are also subject to credit and default risk, which is the possibility that an issuer of preferred stock will fail to make its dividend payments. |
| ● | Sector Risk – The Fund may focus its investments in securities of a particular sector. Economic, legislative or regulatory developments may occur that significantly affect the sector. This may cause the Fund’s net asset value to fluctuate more than that of a fund that does not focus in a particular sector. |
| ● | Short Selling and Short Position Risk – The Fund may engage in short selling and short position derivative activities, which are significantly different from the investment activities commonly associated with conservative stock or bond funds. Positions in shorted securities and derivatives are speculative and more-risky than “long” positions (purchases) because the cost of the replacement security or derivative is unknown. Therefore, the potential loss on an uncovered short is unlimited, whereas the potential loss on long positions is limited to the original purchase price. You should be aware that any strategy that includes selling securities short could suffer significant losses. Shorting will also result in higher transaction costs (such as interest and dividends), which reduce the Fund’s return, and may result in higher taxes. When the Fund is selling a security short, it must maintain a segregated account of cash or high-grade securities equal to the margin requirement. As a result, the Fund may maintain high levels of cash or other liquid assets (such as U.S. Treasury bills, money market instruments, certificates of deposit, high quality commercial paper and long equity positions). The need to maintain cash or other liquid assets in segregated accounts could limit the Fund’s ability to pursue other opportunities as they arise. |
| ● | Stock Market Risk – Equity prices can fall rapidly in response to developments affecting a specific company or industry, or to changing economic, political or market conditions. |
| ● | Structured Notes Risk – Structured notes involve leverage risk, tracking risk and issuer default risk. |
| ● | Swap Risk – Swap agreements are subject to the risk that the counterparty to the swap will default on its obligation to pay the Fund and the risk that the Fund will not be able to meet its obligations to pay the counterparty to the swap. Swap agreements may also involve fees, commissions or other costs that may reduce the Fund’s gains from a swap agreement or may cause the Fund to lose money. |
| ● | Underlying Funds Risk – Underlying Funds in which the Fund invests are subject to investment advisory and other expenses, which will be indirectly paid by the Fund. As a result, the cost of investing in the Fund will be higher than the cost of investing directly in the Underlying Funds and may be higher than other mutual funds that invest directly in stocks and bonds. Each of the Underlying Funds is subject to specific risks, depending on the nature of the fund. |
| ◌ | Inverse ETF Risk – Investing in inverse ETFs may result in increased volatility and will magnify the Fund’s losses or gains. During periods of market volatility, inverse ETFs may not perform as expected. |
The bar chart and performance table below show the variability of the Fund’s returns, which is some indication of the risks of investing in the Fund. The bar chart shows performance of the Fund’s Class I shares for each full calendar year since the Fund’s inception. Returns for Class A shares, which are not presented, would be different than the returns for Class I shares. The performance table compares the performance of the Fund over time to the performance of a broad-based securities market index. You should be aware that the Fund’s past performance (before and after taxes) may not be an indication of how the Fund will perform in the future. Updated performance information is available at no cost by calling 1-877-766-2264 or visiting www.navigatorfunds.com.
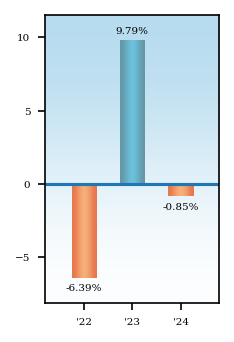
| Best Quarter: | Fourth Quarter 2023 | 9.03% |
| Worst Quarter: | Second Quarter 2022 | (5.50)% |
Average Annual Total Returns - Navigator Tactical Investment Grade Bond Fund |
Label |
1 Year |
Since Inception |
Inception Date |
|
|---|---|---|---|---|---|
| Navigator Tactical Investment Grade Bond Fund Class I | Return before taxes | (0.85%) | (0.13%) | Aug. 31, 2021 | |
| Navigator Tactical Investment Grade Bond Fund Class I | Return after taxes on distributions | (2.50%) | (1.35%) | |||
| Navigator Tactical Investment Grade Bond Fund Class I | Return after taxes on distributions and sale of Fund shares | (0.49%) | (0.61%) | |||
| Bloomberg U.S. Aggregate Bond Index | [1] | 1.25% | (2.42%) | ||
| [1] | The Bloomberg U.S. Aggregate Bond Index is an unmanaged index comprised of U.S. investment grade, fixed rate bond market securities, including government, government agency, corporate and mortgage-backed securities. Investors cannot invest directly in an index or benchmark. |
After-tax returns are calculated using the highest historical individual federal marginal income tax rate and do not reflect the impact of state and local taxes. Actual after-tax returns depend on a shareholder’s tax situation and may differ from those shown. The after-tax returns are not relevant if you hold your Fund shares in tax-deferred arrangements, such as 401(k) plans or individual retirement accounts (“IRA”). The after-tax returns for Class A and Class C shares are not shown and would differ from those of Class I Shares.
| ● | CDS Risk – CDS are a type of derivative instrument, involve special risks and may result in losses to the Fund. CDS are typically two-party financial contracts that transfer credit exposure between the two parties. Under a typical CDS, one party (the “seller”) receives pre-determined periodic payments from the other party (the “buyer”). The seller agrees to make compensating specific payments to the buyer if a negative credit event occurs, such as the bankruptcy or default by the issuer of the underlying debt instrument. The use of CDS involves investment techniques and risks different from those associated with ordinary portfolio security transactions, such as potentially heightened counterparty, concentration and exposure risks. Counterparty risk refers to the risk that the counterparty to the swap will default on its obligation to pay. CDS may in some cases be illiquid, and they increase credit risk since the Fund has exposure to the issuer of the referenced obligation and either the counterparty to the credit default swap or, if it is a cleared transaction, the brokerage firm through which the trade was cleared and the clearing organization that is the counterparty to that trade. In addition, for cleared trades, the brokerage firm would impose margin requirements and would be able to require termination of those trades in certain circumstances. Certain CDS will be required to be traded on a regulated execution facility or contract market that makes them available for trading. The transition to trading these swaps on such a facility or contract market may not result in swaps being easier to trade or value and may present certain execution risks if such a facility or contract market does not operate properly. Swaps may be difficult to unwind or terminate. |
| ● | CDX Risk – A CDX is subject to the risks of the underlying credit default swap obligations, which include risks such as concentration risk and counterparty risk. Concentration risk refers to the certain large institutional buyers may take large positions in credit default swaps, and the failure of such a buyer could materially adversely affect the credit default swap market as a whole. Counterparty risk refers to the risk that the counterparty to the swap will default on its obligation to pay. |
| ● | Credit Risk – The issuer of a fixed income security may not be able to make interest or principal payments when due. Generally, the lower the credit rating of a security, the greater the risk is that the issuer will default on its obligation. |
| ● | Derivatives Risk – The Fund may execute an investment strategy or hedge by entering into derivative contracts such as futures, options and swaps, which can be riskier than traditional investments because they may involve leverage, be illiquid, suffer counterparty default and limit gains. Equity market-related swap contracts (including total return swaps and CDS) and options involve leverage risk, tracking risk and counterparty default risk. Option positions may expire worthless exposing the Fund to potentially significant losses. There is a risk that adverse price movements in a swap instrument can result in a loss substantially greater than the Fund’s initial investment in that instrument (in some cases, the potential loss is unlimited). |
| ● | Equity Securities Risk – Common stocks are susceptible to general stock market fluctuations and to volatile increases and decreases in value as market confidence in and perceptions of their issuers change. Warrants and rights may expire worthless if the price of a common stock is below the conversion price of the warrant or right. Convertible bonds may decline in value if the price of a common stock falls below the conversion price. Investor perceptions are based on various and unpredictable factors including expectations regarding government, economic, monetary and fiscal policies; inflation and interest rates; economic expansion or contraction and global or regional political, economic and banking crises. |
| ● | Fixed Income Risk – The value of the Fund’s investments in fixed income securities will fluctuate with changes in interest rates. Typically, a rise in interest rates causes a decline in the value of fixed income securities. During periods of sustained rising rates, fixed income risks may be amplified. Rising rates may decrease liquidity and increase volatility, which may make portfolio management more difficult and costly to the Fund and its shareholders. |
| ● | Futures Risk – The Fund’s use of futures contracts involves risks different from, or possibly greater than, the risks associated with investing directly in securities and other traditional investments. These risks include (i) leverage risk; (ii) correlation or tracking risk and (iii) liquidity risk. Because futures require only a small initial investment in the form of a deposit or margin, they involve a high degree of leverage. Accordingly, the fluctuation of the value of futures in relation to the underlying assets upon which they are based is magnified. Thus, the Fund may experience losses that exceed losses experienced by funds that do not use futures contracts. |
| ● | Government-Sponsored Entities Risk – The Fund invests in securities issued or guaranteed by government-sponsored entities, but these securities may not be guaranteed or insured by the U.S. Government and may only be supported by the credit of the issuing agency. |
| ● | Hedging Risk – When the adviser believes market conditions are unfavorable, the adviser may attempt to “hedge” with defensive positions and strategies including, for example, holding substantial positions in lower-yield fixed-income securities and/or cash equivalents, which may limit potential gains when compared to unhedged funds. There can be no assurance that the Fund’s hedging strategy will reduce the risk of the Fund’s investments. |
| ● | High-Yield Bond Risk – Lower-quality bonds, known as high-yield bonds or “junk bonds,” present a significant risk for loss of principal and interest. These bonds offer the potential for higher return, but also involve greater risk than bonds of higher quality, including an increased possibility that the bond’s issuer, obligor or guarantor may not be able to make its payments of interest and principal (credit quality risk). |
| ● | Interest Rate Risk – The value of the Funds may fluctuate based on changes in interest rates and market conditions. As interest rates rise, the value of income producing instruments may decrease. This risk increases as the term of the note increases. |
| ● | Issuer-Specific Risk – The value of a specific security can be more volatile than the market as a whole and can perform differently from the value of the market as a whole, , and the risk that the value of a security may decline for a reason directly related to the issuer, such as management performance, changes in financial condition or credit rating, reputation or reduced demand for the issuer’s goods or services. |
| ● | Leverage/Volatility Risk – The use of leverage by the Fund, such as borrowing money to purchase securities or the use of options, will cause the Fund to incur additional expenses and magnify the Fund’s gains or losses. |
| ● | Management Style Risk – The adviser’s judgments about the potential appreciation of a particular security in which the Fund invests may prove to be incorrect. The adviser’s proprietary modeling process may incorrectly measure or predict the relative strength or momentum of various fixed income asset classes, and the Fund may hold a high percentage of either high-yield bonds or cash equivalents during certain periods, or for an extended period. |
| ● | Market and Geopolitical Risk – The increasing interconnectivity between global economies and financial markets increases the likelihood that events or conditions in one region or financial market may adversely impact issuers in a different country, region or financial market. Securities in the Fund may underperform due to inflation (or expectations for inflation), interest rates, global demand for particular products or resources, natural disasters, pandemics, epidemics, terrorism, international conflicts, regulatory events and governmental or quasi-governmental actions. The occurrence of global events similar to those in recent years, such as terrorist attacks, a worldwide pandemic, natural disasters, social and political discord or debt crises and downgrades, among others, may result in market volatility and may have long term effects on both the U.S. and global financial markets. It is difficult to predict when similar events affecting the U.S. or global financial markets may occur, the effects that such events may have and the duration of those effects. Any such event(s) could have a significant adverse impact on the value and risk profile of the Fund. For example, the COVID-19 global pandemic had negative impacts, and in many cases severe negative impacts, on markets worldwide. It is not known how long any future impacts of other significant events described above or would last, but there could be a prolonged period of global economic slowdown, which may impact your investment. Therefore, the Fund could lose money over short periods due to short-term market movements and over longer periods during more prolonged market downturns. During a general market downturn, multiple asset classes may be negatively affected. Changes in market conditions and interest rates can have the same impact on all types of securities and instruments. In times of severe market disruptions you could lose your entire investment. |
| ● | Options Risk – The Fund may lose the entire put or call option premium paid if the reference asset or index does not decrease below or rise above the respective strike price before expiration. Options may not be an effective hedge because they may have imperfect correlation to the value of the Fund’s assets. |
| ● | Portfolio Turnover Risk – A higher portfolio turnover may result in higher transactional and brokerage costs. |
| ● | Preferred Stock Risk – Typically, a rise in interest rates causes a decline in the value of preferred stock. Preferred stocks are also subject to credit and default risk, which is the possibility that an issuer of preferred stock will fail to make its dividend payments. |
| ● | Sector Risk – The Fund may focus its investments in securities of a particular sector. Economic, legislative or regulatory developments may occur that significantly affect the sector. This may cause the Fund’s net asset value to fluctuate more than that of a fund that does not focus in a particular sector. |
| ● | Short Selling and Short Position Risk – The Fund may engage in short selling and short position derivative activities, which are significantly different from the investment activities commonly associated with conservative stock or bond funds. Positions in shorted securities and derivatives are speculative and more-risky than “long” positions (purchases) because the cost of the replacement security or derivative is unknown. Therefore, the potential loss on an uncovered short is unlimited, whereas the potential loss on long positions is limited to the original purchase price. You should be aware that any strategy that includes selling securities short could suffer significant losses. Shorting will also result in higher transaction costs (such as interest and dividends), which reduce the Fund’s return, and may result in higher taxes. When the Fund is selling a security short, it must maintain a segregated account of cash or high-grade securities equal to the margin requirement. As a result, the Fund may maintain high levels of cash or other liquid assets (such as U.S. Treasury bills, money market instruments, certificates of deposit, high quality commercial paper and long equity positions). The need to maintain cash or other liquid assets in segregated accounts could limit the Fund’s ability to pursue other opportunities as they arise. |
| ● | Stock Market Risk – Equity prices can fall rapidly in response to developments affecting a specific company or industry, or to changing economic, political or market conditions. |
| ● | Structured Notes Risk – Structured notes involve leverage risk, tracking risk and issuer default risk. |
| ● | Swap Risk – Swap agreements are subject to the risk that the counterparty to the swap will default on its obligation to pay the Fund and the risk that the Fund will not be able to meet its obligations to pay the counterparty to the swap. Swap agreements may also involve fees, commissions or other costs that may reduce the Fund’s gains from a swap agreement or may cause the Fund to lose money. |
| ● | Underlying Funds Risk – Underlying Funds in which the Fund invests are subject to investment advisory and other expenses, which will be indirectly paid by the Fund. As a result, the cost of investing in the Fund will be higher than the cost of investing directly in the Underlying Funds and may be higher than other mutual funds that invest directly in stocks and bonds. Each of the Underlying Funds is subject to specific risks, depending on the nature of the fund. |
| ◌ | Inverse ETF Risk – Investing in inverse ETFs may result in increased volatility and will magnify the Fund’s losses or gains. During periods of market volatility, inverse ETFs may not perform as expected. |
| ◌ | Inverse ETF Risk – Investing in inverse ETFs may result in increased volatility and will magnify the Fund’s losses or gains. During periods of market volatility, inverse ETFs may not perform as expected. |
| ● | Non-U.S. Issuers Risk – The Fund may have exposure to U.S. dollar-denominated bonds of non-U.S. corporate issuers as a result of its investment in other ETFs and mutual funds. Securities issued by non-U.S. issuers have different risks from securities issued by U.S. issuers. These risks include differences in accounting, auditing and financial reporting standards, the possibility of expropriation or confiscatory taxation, adverse changes in investment or exchange control regulations, political instability which could affect U.S. investments in non-U.S. countries, uncertainties of transnational litigation, and potential restrictions on the flow of international capital, including the possible seizure or nationalization of the securities issued by non-U.S. issuers held by the Fund. Non-U.S. issuers may be subject to less governmental regulation than U.S. issuers. Moreover, individual non-U.S. economies may differ favorably or unfavorably from the U.S. economy in such respects as growth of gross domestic product, rate of inflation, capital reinvestment, resource self-sufficiency and balance of payment positions. Unfavorable political, economic or governmental developments in non-U.S. countries could affect the payment of a security’s principal and interest. Securities issued by non-U.S. issuers may also be less liquid than, and more difficult to value than, securities of U.S. issuers. In addition, the value of these securities may fluctuate due to changes in the exchange rate of the issuer’s local currency against the U.S. dollar. |
The Navigator Tactical U.S. Allocation Fund (the “Fund”) seeks long-term capital appreciation.
The following table describes the fees and expenses that you may pay if you buy, hold and sell shares of the Fund. More information about these and other discounts is available from your financial professional and in How to Purchase Shares on page 47 of the Fund’s Prospectus and in Purchase, Redemption and Pricing of Shares on page 62 of the Statement of Additional Information.
Shareholder Fees - Navigator Tactical U.S. Allocation Fund |
Navigator Tactical U.S. Allocation Fund Class A |
Navigator Tactical U.S. Allocation Fund Class I |
|---|---|---|
| Maximum Sales Charge (Load) Imposed on Purchases (as a % of offering price) | 3.75% | none |
| Maximum Deferred Sales Charge (Load) (as a % of the lower of original purchase price or redemption proceeds) | none | none |
| Maximum Sales Charge (Load) Imposed on Reinvested Dividends and Other Distributions | none | none |
| Redemption Fee | none | none |
Annual Fund Operating Expenses - Navigator Tactical U.S. Allocation Fund |
Navigator Tactical U.S. Allocation Fund Class A |
Navigator Tactical U.S. Allocation Fund Class I |
|
|---|---|---|---|
| Management Fees | 0.85% | 0.85% | |
| Distribution and Service (12b-1) Fees | 0.25% | none | |
| Other Expenses | 0.33% | 0.33% | |
| Acquired Fund Fees and Expenses | [1] | 0.03% | 0.03% |
| Total Annual Fund Operating Expenses | 1.46% | 1.21% | |
| Fee Waiver and/or Expense Reimbursement | [2] | (0.17%) | (0.17%) |
| Total Annual Fund Operating Expenses After Fee Waiver and/or Expense Reimbursement | 1.29% | 1.04% | |
| [1] | Acquired Fund Fees and Expenses are the indirect costs of investing in other investment companies. |
| [2] | Clark Capital Management Group, Inc. (the “Adviser”) has contractually agreed to waive management fees and/or to make payments to limit Fund expenses, at least until February 28, 2026, so that the total annual operating expenses (exclusive of any front-end or contingent deferred loads; brokerage fees and commissions, acquired fund fees and expenses; fees and expenses associated with investments in other collective investment vehicles or derivative instruments (including for example option and swap fees and expenses); borrowing costs (such as interest and dividend expense on securities sold short); taxes; and extraordinary expenses, such as litigation expenses (which may include indemnification of Fund officers and Trustees, contractual indemnification of Fund service providers (other than the adviser)) of the Fund do not exceed will not exceed 1.26%, and 1.01% of average daily net assets attributable to Class A and Class I shares, respectively. Fee waivers and expense reimbursements are subject to possible recoupment from the Fund in future years on a rolling three-year basis (within the three years from the date in which the fees were waived or reimbursed) if such recoupment can be achieved within the foregoing expense limit and any expense limitation in place at the time of recoupment. This agreement may be terminated only by the Board of Trustees on 60 days written notice to the Adviser. |
This Example is intended to help you compare the cost of investing in the Fund with the cost of investing in other mutual funds.
Expense Example - Navigator Tactical U.S. Allocation Fund - USD ($) |
Expense Example, with Redemption, 1 Year |
Expense Example, with Redemption, 3 Years |
Expense Example, with Redemption, 5 Years |
Expense Example, with Redemption, 10 Years |
|---|---|---|---|---|
| Navigator Tactical U.S. Allocation Fund Class A | 501 | 803 | 1,127 | 2,042 |
| Navigator Tactical U.S. Allocation Fund Class I | 106 | 367 | 649 | 1,451 |
The Fund pays transaction costs, such as commissions, when it buys and sells securities (or “turns over” its portfolio). A higher portfolio turnover may indicate higher transaction costs and may result in higher taxes when Fund shares are held in a taxable account. These costs, which are not reflected in annual fund operating expenses or in the Example, affect the Fund’s performance. During the most recent fiscal period, the Fund’s portfolio turnover rate was 4%.
Under normal circumstances, the Fund invests at least 80% of its net assets (plus borrowings for investment purposes, if any) in U.S. equity and fixed income securities. The Adviser uses a relative strength modeling process (as described below) to determine the Fund’s long and/or short positions in equity securities and/or fixed income securities. Depending on the adviser’s modeling process, the Fund may be fully invested in equity securities or fixed income securities at a given time.
The Fund defines equity securities as including individual U.S. stocks of any market capitalization, exchange traded funds and mutual funds (“Underlying Funds”) that primarily invest in equity securities, and futures, options, and swaps on equity securities and indices. The Fund defines fixed income securities as including (i) bills, (ii) notes, (iii) structured notes, (iv) bonds, (v) preferred stocks, (vi) any other debt or debt-related securities of any maturities, whether issued by U.S. or non-U.S. governments, agencies or instrumentalities thereof or corporate entities, and having fixed, variable, floating or inverse floating rates, (vii) fixed income derivatives including options, financial futures, options on futures and swaps, and (viii) Underlying Funds that invest primarily in fixed income securities, or (ix) other evidences of indebtedness. The Fund may invest in debt securities of any maturity or credit quality, including those rated below investment grade (“high yield securities” or “junk bonds”). Below investment grade debt securities are those rated below Baa3 by Moody’s Investors Service or equivalently by another nationally recognized statistical rating organization (NRSRO).
The Fund’s investment strategy is primarily driven by a modeling process which measures the relative strength or momentum of various asset classes against one another. Specifically using this momentum-based strategy, the Fund will tactically shift its asset class exposure across U.S. equity securities, U.S. Treasuries, and cash. Under normal conditions, the Fund expects to invest in securities and derivatives. When the equity asset class is favored, the Fund will normally use a combination of securities and derivatives designed to create an investment return that tracks the return of the Fund’s primary benchmark index, currently the S&P 500 Index. Specifically, the Fund typically will purchase E-Mini S&P 500 futures contracts and invest in equity and fixed income securities in seeking to approximate the return of the Fund’s primary benchmark. When the treasury asset class is favored, the Fund will normally sell and/or hedge a portion of its equity exposure using derivatives such as E-Mini S&P 500 futures contracts and increase the Fund’s exposure to cash equivalents through securities and derivatives. When the cash asset class is favored, the Fund will normally sell and/or hedge its equity and/or treasury exposure and increase the Fund’s exposure to cash equivalents through securities and derivatives. The Fund may invest in affiliated mutual funds, and unaffiliated mutual funds (including money market funds), ETF and inverse ETFs (collectively, “Underlying Funds”).
Due to the structure of the derivatives the Fund expects to use, the Fund will hold a portion of its assets in highly liquid securities, including investment grade bonds, as collateral for its derivatives transactions and still have excess cash to invest regardless of whether the favored asset class is U.S. equity securities, treasuries, or cash (or a combination of these asset classes). The Fund will normally invest this excess cash in a mix of investment grade corporate bonds, treasury bills and notes, municipal bonds and other instruments for diversification, risk management, and to seek to obtain additional return. As a result, when U.S. equity securities are favored, a portion of the Fund’s assets may be invested in non-equity investments. Similarly, when the treasury asset class is favored, the Fund may hold a portion of its assets in non-treasury investments, and when the cash asset class is favored, the fund may hold a portion of its assets in non-cash investments.
The Adviser may engage in frequent buying and selling of securities to achieve the Fund’s investment objective.
As with all mutual funds, there is the risk that you could lose money through your investment in the Fund. The Fund is not intended to be a complete investment program. Many factors affect the Fund’s net asset value and performance.
| ● | CDS Risk – CDS are a type of derivative instrument, involve special risks and may result in losses to the Fund. CDS are typically two-party financial contracts that transfer credit exposure between the two parties. Under a typical CDS, one party (the “seller”) receives pre-determined periodic payments from the other party (the “buyer”). The seller agrees to make compensating specific payments to the buyer if a negative credit event occurs, such as the bankruptcy or default by the issuer of the underlying debt instrument. The use of CDS involves investment techniques and risks different from those associated with ordinary portfolio security transactions, such as potentially heightened counterparty, concentration and exposure risks. Counterparty risk refers to the risk that the counterparty to the swap will default on its obligation to pay. CDS may in some cases be illiquid, and they increase credit risk since the Fund has exposure to the issuer of the referenced obligation and either the counterparty to the credit default swap or, if it is a cleared transaction, the brokerage firm through which the trade was cleared and the clearing organization that is the counterparty to that trade. In addition, for cleared trades, the brokerage firm would impose margin requirements and would be able to require termination of those trades in certain circumstances. Certain CDS will be required to be traded on a regulated execution facility or contract market that makes them available for trading. The transition to trading these swaps on such a facility or contract market may not result in swaps being easier to trade or value and may present certain execution risks if such a facility or contract market does not operate properly. Swaps may be difficult to unwind or terminate. |
| ● | Credit Risk – The issuer of a fixed income security may not be able to make interest or principal payments when due. Generally, the lower the credit rating of a security, the greater the risk is that the issuer will default on its obligation. |
| ● | Derivatives Risk – The Fund may execute an investment strategy or hedge by entering into derivative contracts such as futures, options and swaps, which can be riskier than traditional investments because they may involve leverage, be illiquid, suffer counterparty default and limit gains. Equity market-related swap contracts (including total return swaps and CDS) and options involve leverage risk, tracking risk and counterparty default risk. Option positions may expire worthless exposing the Fund to potentially significant losses. There is a risk that adverse price movements in a swap instrument can result in a loss substantially greater than the Fund’s initial investment in that instrument (in some cases, the potential loss is unlimited). |
| ● | Equity Securities Risk – Common and preferred stocks are susceptible to general stock market fluctuations and to volatile increases and decreases in value as market confidence in and perceptions of their issuers change. Warrants and rights may expire worthless if the price of a common stock is below the conversion price of the warrant or right. Convertible bonds may decline in value if the price of a common stock falls below the conversion price. Investor perceptions are based on various and unpredictable factors including expectations regarding government, economic, monetary and fiscal policies; inflation and interest rates; economic expansion or contraction and global or regional political, economic and banking crises. |
| ● | Fixed Income Risk – The value of the Fund’s investments in fixed income securities will fluctuate with changes in interest rates. Typically, a rise in interest rates causes a decline in the value of fixed income securities. During periods of sustained rising rates, fixed income risks may be amplified. Rising rates may decrease liquidity and increase volatility, which may make portfolio management more difficult and costly to the Fund and its shareholders. |
| ● | Futures Risk – The Fund’s use of futures contracts involves risks different from, or possibly greater than, the risks associated with investing directly in securities and other traditional investments. These risks include (i) leverage risk; (ii) correlation or tracking risk and (iii) liquidity risk. Because futures require only a small initial investment in the form of a deposit or margin, they involve a high degree of leverage. Accordingly, the fluctuation of the value of futures in relation to the underlying assets upon which they are based is magnified. Thus, the Fund may experience losses that exceed losses experienced by funds that do not use futures contracts. |
| ● | Government-Sponsored Entities Risk – The Fund invests in securities issued or guaranteed by government-sponsored entities, but these securities may not be guaranteed or insured by the U.S. Government and may only be supported by the credit of the issuing agency. |
| ● | Hedging Risk – When the adviser believes market conditions are unfavorable, the adviser may attempt to “hedge” with defensive positions and strategies including, for example, holding substantial positions in lower-yield fixed-income securities and/or cash equivalents, which may limit potential gains when compared to unhedged funds. There can be no assurance that the Fund’s hedging strategy will reduce the risk of the Fund’s investments. |
| ● | High-Yield Bond Risk – Lower-quality bonds, known as high-yield bonds or “junk bonds,” present a significant risk for loss of principal and interest. These bonds offer the potential for higher return, but also involve greater risk than bonds of higher quality, including an increased possibility that the bond’s issuer, obligor or guarantor may not be able to make its payments of interest and principal (credit quality risk). |
| ● | Interest Rate Risk – Fixed income securities are subject to the risk that securities could lose value because of interest rate changes. Fixed income securities with longer maturities are subject to greater price shifts as a result of interest rate changes than fixed income securities with shorter maturities. Floating or adjustable rate securities (such as most loans) typically have less exposure to interest rate fluctuations than other fixed income securities and their exposure will generally be limited to the period of time until the interest rate on the security is reset. |
| ● | Issuer-Specific Risk – The value of a specific security can be more volatile than the market as a whole and can perform differently from the value of the market as a whole, and the risk that the value of a security may decline for a reason directly related to the issuer, such as management performance, changes in financial condition or credit rating, reputation or reduced demand for the issuer’s goods or services. |
| ● | Leverage/Volatility Risk – The use of leverage by the Fund, such as borrowing money to purchase securities or the use of options, will cause the Fund to incur additional expenses and magnify the Fund’s gains or losses. |
| ● | Large Capitalization Stock Risk – Large-capitalization companies may be less able than smaller capitalization companies to adapt to changing market conditions. Large-capitalization companies may be more mature and subject to more limited growth potential compared with smaller capitalization companies. During different market cycles, the performance of large capitalization companies has trailed the overall performance of the broader securities markets. |
| ● | Market and Geopolitical Risk – The increasing interconnectivity between global economies and financial markets increases the likelihood that events or conditions in one region or financial market may adversely impact issuers in a different country, region or financial market. Securities in the Fund may underperform due to inflation (or expectations for inflation), interest rates, global demand for particular products or resources, natural disasters, pandemics, epidemics, terrorism, international conflicts, regulatory events and governmental or quasi-governmental actions. The occurrence of global events similar to those in recent years, such as terrorist attacks, a worldwide pandemic, natural disasters, social and political discord or debt crises and downgrades, among others, may result in market volatility and may have long term effects on both the U.S. and global financial markets. It is difficult to predict when similar events affecting the U.S. or global financial markets may occur, the effects that such events may have and the duration of those effects. Any such event(s) could have a significant adverse impact on the value and risk profile of the Fund. For example, the COVID-19 global pandemic had negative impacts, and in many cases severe negative impacts, on markets worldwide. It is not known how long any future impacts of other significant events described above would last, but there could be a prolonged period of global economic slowdown, which may impact your investment. Therefore, the Fund could lose money over short periods due to short-term market movements and over longer periods during more prolonged market downturns. During a general market downturn, multiple asset classes may be negatively affected. Changes in market conditions and interest rates can have the same impact on all types of securities and instruments. In times of severe market disruptions you could lose your entire investment. |
| ● | Management Style Risk – The Adviser’s judgments about the potential appreciation of a particular security in which the Fund invests may prove to be incorrect. The adviser’s proprietary modeling process may incorrectly measure or predict the relative strength or momentum of various fixed income asset classes, and the Fund may hold a high percentage of either high-yield bonds or cash equivalents during certain periods, or for an extended period. |
| ● | Options Risk – The Fund may lose the entire put or call option premium paid if the reference asset or index does not decrease below or rise above the respective strike price before expiration. Options may not be an effective hedge because they may have imperfect correlation to the value of the Fund’s assets. |
| ● | Portfolio Turnover Risk – A higher portfolio turnover may result in higher transactional and brokerage costs. |
| ● | Preferred Stock Risk – Typically, a rise in interest rates causes a decline in the value of preferred stock. Preferred stocks are also subject to credit and default risk, which is the possibility that an issuer of preferred stock will fail to make its dividend payments. |
| ● | Sector Risk – The Fund may focus its investments in securities of a particular sector. Economic, legislative or regulatory developments may occur that significantly affect the sector. This may cause the Fund’s net asset value to fluctuate more than that of a fund that does not focus in a particular sector. |
| ● | Short Selling and Short Position Risk – The Fund may engage in short selling and short position derivative activities, which are significantly different from the investment activities commonly associated with conservative stock or bond funds. Positions in shorted securities and derivatives are speculative and more-risky than “long” positions (purchases) because the cost of the replacement security or derivative is unknown. Therefore, the potential loss on an uncovered short is unlimited, whereas the potential loss on long positions is limited to the original purchase price. You should be aware that any strategy that includes selling securities short could suffer significant losses. Shorting will also result in higher transaction costs (such as interest and dividends), which reduce the Fund’s return, and may result in higher taxes. When the Fund is selling a security short, it must maintain a segregated account of cash or high-grade securities equal to the margin requirement. As a result, the Fund may maintain high levels of cash or other liquid assets (such as U.S. Treasury bills, money market instruments, certificates of deposit, high quality commercial paper and long equity positions). The need to maintain cash or other liquid assets in segregated accounts could limit the Fund’s ability to pursue other opportunities as they arise. |
| ● | Small and Medium Company Credit Risk – Small and mid-sized companies may have limited product lines, markets or financial resources, and they may be dependent on a limited management group. Therefore, equity or fixed income securities issued by smaller companies may pose greater credit risk than is generally associated with the securities of larger, more established companies. |
| ● | Stock Market Risk – Equity prices can fall rapidly in response to developments affecting a specific company or industry, or to changing economic, political or market conditions. |
| ● | Structured Notes Risk – Structured notes involve leverage risk, tracking risk and issuer default risk. |
| ● | Swap Risk – Swap agreements are subject to the risk that the counterparty to the swap will default on its obligation to pay the Fund and the risk that the Fund will not be able to meet its obligations to pay the counterparty to the swap. Swap agreements may also involve fees, commissions or other costs that may reduce the Fund’s gains from a swap agreement or may cause the Fund to lose money. |
| ● | Underlying Funds Risk – Underlying Funds in which the Fund invests are subject to investment advisory and other expenses, which will be indirectly paid by the Fund. As a result, the cost of investing in the Fund will be higher than the cost of investing directly in the Underlying Funds and may be higher than other mutual funds that invest directly in stocks and bonds. Each of the Underlying Funds is subject to specific risks, depending on the nature of the fund. |
The bar chart and performance table below show the variability of the Fund’s returns, which is some indication of the risks of investing in the Fund. The bar chart shows performance of the Fund’s Class I shares for each full calendar year since the Fund’s inception. Returns for Class A shares, which are not presented, would be different than the returns for Class I shares. The performance table compares the performance of the Fund over time to the performance of a broad-based securities market index. You should be aware that the Fund’s past performance (before and after taxes) may not be an indication of how the Fund will perform in the future. Updated performance information is available at no cost by calling 1-877-766-2264 or visiting www.navigatorfunds.com.
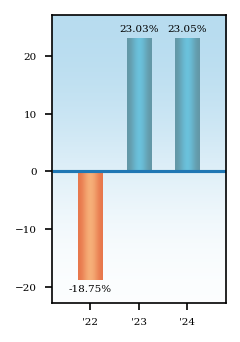
| Best Quarter: | First Quarter 2024 | 10.10% |
| Worst Quarter: | Second Quarter 2022 | (14.08)% |
Average Annual Total Returns - Navigator Tactical U.S. Allocation Fund |
Label |
1 Year |
Since Inception |
Inception Date |
|
|---|---|---|---|---|---|
| Navigator Tactical U.S. Allocation Fund Class I | Return before taxes | 23.05% | 9.53% | Jun. 11, 2021 | |
| Navigator Tactical U.S. Allocation Fund Class I | Return after taxes on distributions | 17.60% | 6.83% | |||
| Navigator Tactical U.S. Allocation Fund Class I | Return after taxes on distributions and sale of Fund shares | 14.83% | 6.49% | |||
| S&P 500 Index | [1] | 25.02% | 11.27% | ||
| [1] | The S&P 500 Index is widely regarded as the best single gauge of large-cap U.S. equities. The index includes 500 leading companies and covers approximately 80% of available market capitalization. |
After-tax returns are calculated using the highest historical individual federal marginal income tax rate and do not reflect the impact of state and local taxes. Actual after-tax returns depend on a shareholder’s tax situation and may differ from those shown. The after-tax returns are not relevant if you hold your Fund shares in tax-deferred arrangements, such as 401(k) plans or individual retirement accounts (“IRA”). The after-tax returns for Class A and Class C shares are not shown and would differ from those of Class I Shares.
| ● | CDS Risk – CDS are a type of derivative instrument, involve special risks and may result in losses to the Fund. CDS are typically two-party financial contracts that transfer credit exposure between the two parties. Under a typical CDS, one party (the “seller”) receives pre-determined periodic payments from the other party (the “buyer”). The seller agrees to make compensating specific payments to the buyer if a negative credit event occurs, such as the bankruptcy or default by the issuer of the underlying debt instrument. The use of CDS involves investment techniques and risks different from those associated with ordinary portfolio security transactions, such as potentially heightened counterparty, concentration and exposure risks. Counterparty risk refers to the risk that the counterparty to the swap will default on its obligation to pay. CDS may in some cases be illiquid, and they increase credit risk since the Fund has exposure to the issuer of the referenced obligation and either the counterparty to the credit default swap or, if it is a cleared transaction, the brokerage firm through which the trade was cleared and the clearing organization that is the counterparty to that trade. In addition, for cleared trades, the brokerage firm would impose margin requirements and would be able to require termination of those trades in certain circumstances. Certain CDS will be required to be traded on a regulated execution facility or contract market that makes them available for trading. The transition to trading these swaps on such a facility or contract market may not result in swaps being easier to trade or value and may present certain execution risks if such a facility or contract market does not operate properly. Swaps may be difficult to unwind or terminate. |
| ● | Credit Risk – The issuer of a fixed income security may not be able to make interest or principal payments when due. Generally, the lower the credit rating of a security, the greater the risk is that the issuer will default on its obligation. |
| ● | Derivatives Risk – The Fund may execute an investment strategy or hedge by entering into derivative contracts such as futures, options and swaps, which can be riskier than traditional investments because they may involve leverage, be illiquid, suffer counterparty default and limit gains. Equity market-related swap contracts (including total return swaps and CDS) and options involve leverage risk, tracking risk and counterparty default risk. Option positions may expire worthless exposing the Fund to potentially significant losses. There is a risk that adverse price movements in a swap instrument can result in a loss substantially greater than the Fund’s initial investment in that instrument (in some cases, the potential loss is unlimited). |
| ● | Equity Securities Risk – Common and preferred stocks are susceptible to general stock market fluctuations and to volatile increases and decreases in value as market confidence in and perceptions of their issuers change. Warrants and rights may expire worthless if the price of a common stock is below the conversion price of the warrant or right. Convertible bonds may decline in value if the price of a common stock falls below the conversion price. Investor perceptions are based on various and unpredictable factors including expectations regarding government, economic, monetary and fiscal policies; inflation and interest rates; economic expansion or contraction and global or regional political, economic and banking crises. |
| ● | Fixed Income Risk – The value of the Fund’s investments in fixed income securities will fluctuate with changes in interest rates. Typically, a rise in interest rates causes a decline in the value of fixed income securities. During periods of sustained rising rates, fixed income risks may be amplified. Rising rates may decrease liquidity and increase volatility, which may make portfolio management more difficult and costly to the Fund and its shareholders. |
| ● | Futures Risk – The Fund’s use of futures contracts involves risks different from, or possibly greater than, the risks associated with investing directly in securities and other traditional investments. These risks include (i) leverage risk; (ii) correlation or tracking risk and (iii) liquidity risk. Because futures require only a small initial investment in the form of a deposit or margin, they involve a high degree of leverage. Accordingly, the fluctuation of the value of futures in relation to the underlying assets upon which they are based is magnified. Thus, the Fund may experience losses that exceed losses experienced by funds that do not use futures contracts. |
| ● | Government-Sponsored Entities Risk – The Fund invests in securities issued or guaranteed by government-sponsored entities, but these securities may not be guaranteed or insured by the U.S. Government and may only be supported by the credit of the issuing agency. |
| ● | Hedging Risk – When the adviser believes market conditions are unfavorable, the adviser may attempt to “hedge” with defensive positions and strategies including, for example, holding substantial positions in lower-yield fixed-income securities and/or cash equivalents, which may limit potential gains when compared to unhedged funds. There can be no assurance that the Fund’s hedging strategy will reduce the risk of the Fund’s investments. |
| ● | High-Yield Bond Risk – Lower-quality bonds, known as high-yield bonds or “junk bonds,” present a significant risk for loss of principal and interest. These bonds offer the potential for higher return, but also involve greater risk than bonds of higher quality, including an increased possibility that the bond’s issuer, obligor or guarantor may not be able to make its payments of interest and principal (credit quality risk). |
| ● | Interest Rate Risk – Fixed income securities are subject to the risk that securities could lose value because of interest rate changes. Fixed income securities with longer maturities are subject to greater price shifts as a result of interest rate changes than fixed income securities with shorter maturities. Floating or adjustable rate securities (such as most loans) typically have less exposure to interest rate fluctuations than other fixed income securities and their exposure will generally be limited to the period of time until the interest rate on the security is reset. |
| ● | Issuer-Specific Risk – The value of a specific security can be more volatile than the market as a whole and can perform differently from the value of the market as a whole, and the risk that the value of a security may decline for a reason directly related to the issuer, such as management performance, changes in financial condition or credit rating, reputation or reduced demand for the issuer’s goods or services. |
| ● | Leverage/Volatility Risk – The use of leverage by the Fund, such as borrowing money to purchase securities or the use of options, will cause the Fund to incur additional expenses and magnify the Fund’s gains or losses. |
| ● | Management Style Risk – The Adviser’s judgments about the potential appreciation of a particular security in which the Fund invests may prove to be incorrect. The adviser’s proprietary modeling process may incorrectly measure or predict the relative strength or momentum of various fixed income asset classes, and the Fund may hold a high percentage of either high-yield bonds or cash equivalents during certain periods, or for an extended period. |
| ● | Market and Geopolitical Risk – The increasing interconnectivity between global economies and financial markets increases the likelihood that events or conditions in one region or financial market may adversely impact issuers in a different country, region or financial market. Securities in the Fund may underperform due to inflation (or expectations for inflation), interest rates, global demand for particular products or resources, natural disasters, pandemics, epidemics, terrorism, international conflicts, regulatory events and governmental or quasi-governmental actions. The occurrence of global events similar to those in recent years, such as terrorist attacks, a worldwide pandemic, natural disasters, social and political discord or debt crises and downgrades, among others, may result in market volatility and may have long term effects on both the U.S. and global financial markets. It is difficult to predict when similar events affecting the U.S. or global financial markets may occur, the effects that such events may have and the duration of those effects. Any such event(s) could have a significant adverse impact on the value and risk profile of the Fund. For example, the COVID-19 global pandemic had negative impacts, and in many cases severe negative impacts, on markets worldwide. It is not known how long any future impacts of other significant events described above would last, but there could be a prolonged period of global economic slowdown, which may impact your investment. Therefore, the Fund could lose money over short periods due to short-term market movements and over longer periods during more prolonged market downturns. During a general market downturn, multiple asset classes may be negatively affected. Changes in market conditions and interest rates can have the same impact on all types of securities and instruments. In times of severe market disruptions you could lose your entire investment. |
| ● | Options Risk – The Fund may lose the entire put or call option premium paid if the reference asset or index does not decrease below or rise above the respective strike price before expiration. Options may not be an effective hedge because they may have imperfect correlation to the value of the Fund’s assets. |
| ● | Portfolio Turnover Risk – A higher portfolio turnover may result in higher transactional and brokerage costs. |
| ● | Preferred Stock Risk – Typically, a rise in interest rates causes a decline in the value of preferred stock. Preferred stocks are also subject to credit and default risk, which is the possibility that an issuer of preferred stock will fail to make its dividend payments. |
| ● | Sector Risk – The Fund may focus its investments in securities of a particular sector. Economic, legislative or regulatory developments may occur that significantly affect the sector. This may cause the Fund’s net asset value to fluctuate more than that of a fund that does not focus in a particular sector. |
| ● | Short Selling and Short Position Risk – The Fund may engage in short selling and short position derivative activities, which are significantly different from the investment activities commonly associated with conservative stock or bond funds. Positions in shorted securities and derivatives are speculative and more-risky than “long” positions (purchases) because the cost of the replacement security or derivative is unknown. Therefore, the potential loss on an uncovered short is unlimited, whereas the potential loss on long positions is limited to the original purchase price. You should be aware that any strategy that includes selling securities short could suffer significant losses. Shorting will also result in higher transaction costs (such as interest and dividends), which reduce the Fund’s return, and may result in higher taxes. When the Fund is selling a security short, it must maintain a segregated account of cash or high-grade securities equal to the margin requirement. As a result, the Fund may maintain high levels of cash or other liquid assets (such as U.S. Treasury bills, money market instruments, certificates of deposit, high quality commercial paper and long equity positions). The need to maintain cash or other liquid assets in segregated accounts could limit the Fund’s ability to pursue other opportunities as they arise. |
| ● | Small and Medium Company Credit Risk – Small and mid-sized companies may have limited product lines, markets or financial resources, and they may be dependent on a limited management group. Therefore, equity or fixed income securities issued by smaller companies may pose greater credit risk than is generally associated with the securities of larger, more established companies. |
| ● | Stock Market Risk – Equity prices can fall rapidly in response to developments affecting a specific company or industry, or to changing economic, political or market conditions. |
| ● | Structured Notes Risk – Structured notes involve leverage risk, tracking risk and issuer default risk. |
| ● | Swap Risk – Swap agreements are subject to the risk that the counterparty to the swap will default on its obligation to pay the Fund and the risk that the Fund will not be able to meet its obligations to pay the counterparty to the swap. Swap agreements may also involve fees, commissions or other costs that may reduce the Fund’s gains from a swap agreement or may cause the Fund to lose money. |
| ● | Underlying Funds Risk – Underlying Funds in which the Fund invests are subject to investment advisory and other expenses, which will be indirectly paid by the Fund. As a result, the cost of investing in the Fund will be higher than the cost of investing directly in the Underlying Funds and may be higher than other mutual funds that invest directly in stocks and bonds. Each of the Underlying Funds is subject to specific risks, depending on the nature of the fund. |
| ● | Large Capitalization Stock Risk – Large-capitalization companies may be less able than smaller capitalization companies to adapt to changing market conditions. Large-capitalization companies may be more mature and subject to more limited growth potential compared with smaller capitalization companies. During different market cycles, the performance of large capitalization companies has trailed the overall performance of the broader securities markets. |