The Portfolio seeks long-term capital appreciation.
This table describes the fees and expenses that you may pay if you buy, hold and sell shares of the Portfolio, a series of The Lazard Funds, Inc. (the “Fund”). You may pay other fees, such as brokerage commissions and other fees to financial intermediaries, which are not reflected in the table and the Example below.
Annual Fund Operating Expenses - Lazard US Convertibles Portfolio |
Institutional |
Open |
R6 |
||
|---|---|---|---|---|---|
| Management Fees | 0.60% | 0.60% | 0.60% | ||
| Distribution and Service (12b-1) Fees | none | 0.25% | none | ||
| Other Expenses | 1.26% | 4.12% | 1.26% | [1] | |
| Total Annual Portfolio Operating Expenses | 1.86% | 4.97% | 1.86% | ||
| Fee Waiver and/or Expense Reimbursement | [2] | 1.11% | 3.97% | 1.16% | |
| Total Annual Portfolio Operating Expenses After Fee Waiver and/or Expense Reimbursement | 0.75% | 1.00% | 0.70% | ||
| [1] | Based on estimated amounts for the current fiscal year, using amounts for Institutional Shares from the last fiscal year. |
| [2] | Reflects a contractual agreement by Lazard Asset Management LLC (the “Investment Manager”) to waive its fee and, if necessary, reimburse the Portfolio until May 1, 2026, to the extent Total Annual Portfolio Operating Expenses exceed .75%, 1.00% and .70% of the average daily net assets of the Portfolio’s Institutional Shares, Open Shares and R6 Shares, respectively, exclusive of taxes, brokerage, interest on borrowings, fees and expenses of “Acquired Funds,” fees and expenses related to filing foreign tax reclaims and extraordinary expenses. This expense limitation agreement can only be amended by agreement of the Fund, upon approval by the Fund’s Board of Directors, and the Investment Manager to lower the net amount shown and will terminate automatically in the event of termination of the Management Agreement between the Investment Manager and the Fund, on behalf of the Portfolio. |
This Example is intended to help you compare the cost of investing in the Portfolio with the cost of investing in other mutual funds.
The Example assumes that you invest $10,000 in the Portfolio for the time periods indicated and then hold or redeem all of your shares at the end of those periods. The Example also assumes that your investment has a 5% return each year and that the Portfolio’s operating expenses remain the same, giving effect to the expense limitation agreement in year one only. Although your actual costs may be higher or lower, based on these assumptions your costs would be:
Expense Example - Lazard US Convertibles Portfolio - USD ($) |
Institutional |
Open |
R6 |
|---|---|---|---|
| 1 Year | $ 77 | $ 102 | $ 72 |
| 3 Years | 477 | 1,136 | 472 |
| 5 Years | 902 | 2,171 | 898 |
| 10 Years | $ 2,089 | $ 4,760 | $ 2,085 |
The Portfolio pays transaction costs, such as commissions, when it buys and sells securities (or “turns over” its portfolio). A higher portfolio turnover rate may indicate higher transaction costs and may result in higher taxes when Portfolio shares are held in a taxable account. These costs, which are not reflected in annual portfolio operating expenses or in the Example, affect the Portfolio’s performance. During the most recent fiscal year, the Portfolio’s portfolio turnover rate was 38% of the average value of its portfolio.
Under normal circumstances, the Portfolio invests at least 80% of its assets (including borrowing for investment purposes) in convertible securities that are economically tied to the US. The convertible securities may be issued by corporations, or other non-governmental issuers similar to corporations; issued or guaranteed by governments or their subdivisions, agencies, authorities, instrumentalities or sponsored enterprises; or issued by a supranational organization.
The Investment Manager seeks to achieve the Portfolio’s investment objective primarily through actively managing a portfolio of convertible securities economically tied to the US. As part of its investment process, the Investment Manager undertakes the following analysis of the convertible securities in which the Portfolio may invest:
· proprietary quantitative analysis to assess each convertible security’s exposure or sensitivity to factors such as equity market performance, interest rates and credit spreads and its implied volatility, in order to assist the Investment Manager in forming a view regarding the relative value of the convertible security when assessed against: (i) comparable convertible securities; (ii) its historical price-to-book ratios (a measure of the security’s issuer’s market capitalization (or valuation) to its book value); (iii) the creditworthiness of the issuer; and/or (iv) what the Investment Manager assesses to be the future growth outlook or valuation prospects of the equity into which the security is convertible;
· credit analysis, which will look at the credit quality of the issuers of the convertible securities (i.e., the capacity of an issuer to meet its obligations), the potential for credit quality improvement, the duration of the convertible securities, etc.; and
· fundamental, bottom-up analysis of the equity securities into which the convertible securities are convertible in order to form a view as to the growth outlook for the issuer, and the potential for improving valuations, in the underlying equity securities.
The Portfolio may invest without limitation in securities rated below investment grade (i.e., lower than Baa by Moody’s Investors Service, Inc. (“Moody’s”) or lower than BBB by S&P Global Ratings (“S&P”)) (“junk bonds”) or equivalent unrated securities as determined by the Investment Manager. Additionally, the Portfolio is not restricted to investments in securities of any particular maturity or duration, and there are no restrictions on the Portfolio’s average maturity or duration. Duration is an estimate of the sensitivity of the price of a fixed income or convertible security to a change in interest rates. Generally, the longer the duration, the higher the expected volatility. For example, the market price of a fixed income or convertible security with a duration of three years would be expected to decline 3% if interest rates rose 1%. Conversely, the market price of the same security would be expected to increase 3% if interest rates fell 1%.
The Portfolio may invest up to 20% of its assets in securities and other assets which need not be convertible securities as described below and need not be economically tied to the US as described above, including securities of emerging markets issuers.
“Convertible securities” are fixed-income and preferred equity securities that pay a fixed or floating rate of interest or dividends and that convert into: (1) underlying shares of common stock or other equity securities of the issuer of the convertible securities or of another issuer; (2) cash; or (3) a combination of cash and common stock or other equity securities of the issuer of the convertible securities or of another issuer; in each case, the form and amount of payment upon conversion is determined by the terms of the governing documents of the convertible securities. As a result, convertible securities have characteristics similar to both fixed-income and equity securities.
The Portfolio may, but is not required to, (1) enter into interest rate, bond and equity index futures contracts and interest rate and credit default swap agreements; and (2) purchase put and call options on securities (including
shares of exchange-traded open-end management investment companies (“ETFs”)) and indexes, in each case for hedging purposes or to seek to increase returns.
Although the Portfolio is classified as “diversified” under the Investment Company Act of 1940, as amended (the “1940 Act”), it may invest in a smaller number of issuers than other, more diversified investment portfolios. In addition, implementation of the Portfolio’s investment strategy may, during certain periods, result in the investment of a significant portion of the Portfolio’s assets in a particular market sector.
Risk Table - Lazard US Convertibles Portfolio |
Risk [Text Block] |
|---|---|
| Principal Investment Risks | Principal Investment Risks The value of your investment in the Portfolio will fluctuate, which means you could lose money. |
| Risk Lose Money [Member] | The value of your investment in the Portfolio will fluctuate, which means you could lose money. |
| Market Risk | Market Risk: The Portfolio may incur losses due to declines in one or more markets in which it invests. These declines may be the result of, among other things, political, regulatory, market, economic or social developments affecting the relevant market(s). To the extent that such developments impact specific industries, market sectors, countries or geographic regions, the Portfolio’s investments in such industries, market sectors, countries and/or geographic regions can be expected to be particularly affected, especially if such investments are a significant portion of its investment portfolio. In addition, turbulence in financial markets and reduced liquidity in equity, credit and/or fixed income markets may negatively affect many issuers, which could adversely affect the Portfolio. Global economies and financial markets are increasingly interconnected, and conditions and events in one country, region or financial market may adversely impact issuers worldwide. As a result, local, regional or global events such as war or military conflict, acts of terrorism, the spread of infectious illness or other public health issues, social unrest, natural disasters, extreme weather, other geological events, man-made disasters, supply chain disruptions, deflation, inflation, government defaults, government shutdowns, the imposition of sanctions or other similar measures, recessions or other events could have a significant negative impact on global economic and market conditions. For example, a public health or other emergency and aggressive responses taken by many governments or voluntarily imposed by private parties, including closing borders, restricting travel and imposing prolonged quarantines or similar restrictions, as well as the closure of, or operational changes to, many retail and other businesses, may have severe negative impacts on markets worldwide. Additionally, general market conditions may affect the value of a Portfolio’s securities, including changes in interest rates, currency rates or monetary policies. Furthermore, the imposition of tariffs, trade restrictions, currency restrictions or similar actions (or retaliatory measures taken in response to such actions), or the threat or potential of one or more such events and developments, could lead to price volatility and overall declines in the US and global investment markets. |
| Issuer Risk | Issuer Risk: The value of a security may decline for a number of reasons which directly relate to the issuer, such as management performance, financial leverage and reduced demand for the issuer’s goods or services, as well as the historical and prospective earnings of the issuer and the value of its assets or factors unrelated to the issuer’s value, such as investor perception. |
| Convertible Securities Risk | Convertible Securities Risk: The market value of convertible securities may perform like that of non-convertible fixed income securities; that is, their prices move inversely with changes in interest rates (i.e., as interest rates go up, prices go down). In addition, convertible securities are subject to the risk that the issuer will not make interest or principal payments, or will not make payments on a timely basis. Since it derives a portion of its value from the common stock into which it may be converted, a convertible security also is subject to the same types of market and issuer risks that apply to the underlying common stock. |
| Fixed-Income and Debt Securities Risk | Fixed-Income and Debt Securities Risk: The market value of a debt security may decline due to general market conditions that are not specifically related to a particular company, such as real or perceived adverse economic conditions, changes in the outlook for corporate earnings, changes in interest or currency rates or adverse investor sentiment generally. The debt securities market can be susceptible to increases in volatility and decreases in liquidity. Liquidity can decline unpredictably in response to overall economic conditions or credit tightening. Prices of bonds and other debt securities tend to move inversely with changes in interest rates. Interest rate risk is usually greater for fixed-income securities with longer maturities or durations. A rise in interest rates (or the expectation of a rise in interest rates) may result in periods of volatility, decreased liquidity and increased redemptions, and, as a result, the Portfolio may have to liquidate portfolio securities at disadvantageous prices. The Portfolio may be subject to heightened interest rate risk because the Federal Reserve has raised, and may continue to raise, interest rates. The Portfolio’s investments in lower-rated, higher-yielding securities (“junk bonds”) are subject to greater credit risk than its higher rated investments. Credit risk is the risk that the issuer will not make interest or principal payments, or will not make payments on a timely basis. Non-investment grade securities tend to be more volatile, less liquid and are considered speculative. If there is a decline, or perceived decline, in the credit quality of a debt security (or any guarantor of payment on such security), the security’s value could fall, potentially lowering the Portfolio’s share price. The prices of non-investment grade securities, unlike investment grade debt securities, may fluctuate unpredictably and not necessarily inversely with changes in interest rates. The market for these securities may be less liquid and therefore these securities may be harder to value or sell at an acceptable price, especially during times of market volatility or decline. Some debt securities may give the issuer the option to call, or redeem, the securities before their maturity, and, during a time of declining interest rates, the Portfolio may have to reinvest the proceeds of called or redeemed securities in an investment offering a lower yield (and the Portfolio may not fully benefit from any increase in the value of its portfolio holdings as a result of declining interest rates). Adjustable rate securities provide the Portfolio with a certain degree of protection against rises in interest rates, although adjustable rate securities will participate in any declines in interest rates. Certain adjustable rate securities, such as those with interest rates that fluctuate directly or indirectly based on multiples of a stated index, are designed to be highly sensitive to changes in interest rates and can subject the holders thereof to extreme reductions of yield and possibly loss of principal. Certain fixed-income securities may be issued at a discount from their face value (such as zero coupon securities) or purchased at a price less than their stated face amount or at a price less than their issue price plus the portion of “original issue discount” previously accrued thereon, i.e., purchased at a “market discount.” The amount of original issue discount and/or market discount on certain obligations may be significant, and accretion of market discount together with original issue discount will cause the Portfolio to realize income prior to the receipt of cash payments with respect to these securities. |
| Preferred Securities Risk | Preferred Securities Risk: There are various risks associated with investing in preferred securities. In addition, unlike common stock, participation in the growth of an issuer may be limited. · Credit risk is the risk that a security held by the Portfolio will decline in price or the issuer of the security will fail to make dividend, interest or principal payments when due because the issuer experiences a decline in its financial status. · Interest rate risk is the risk that securities will decline in value because of changes in market interest rates. When market interest rates rise, the market value of such securities generally will fall. · Preferred securities may include provisions that permit the issuer, at its discretion, to defer or omit distributions for a stated period without any adverse consequences to the issuer. · Preferred securities are generally subordinated to bonds and other debt instruments in an issuer’s capital structure in terms of having priority to corporate income, claims to corporate assets and liquidation payments, and therefore will be subject to greater credit risk than more senior debt instruments. · During periods of declining interest rates, an issuer may be able to exercise an option to call, or redeem its issue at par earlier than the scheduled maturity. If this occurs during a time of lower or declining interest rates, the Portfolio may have to reinvest the proceeds in lower yielding securities (and the Portfolio may not benefit from any increase in the value of its portfolio holdings as a result of declining interest rates). · Certain preferred securities may be substantially less liquid than many other securities, such as common stocks or US government securities. Illiquid securities involve the risk that the securities will not be able to be sold at the time desired by the Portfolio or at prices approximating the value at which the Portfolio is carrying the securities on its books. |
| Depositary Receipts Risk | Depositary Receipts Risk: American Depositary Receipts (“ADRs”) and similar depositary receipts typically will be subject to certain of the risks associated with direct investments in the securities of non-US companies, because their values depend on the performance of the underlying non-US securities. However, currency fluctuations will impact investments in depositary receipts differently than direct investments in non-US dollar-denominated non-US securities, because a depositary receipt will not appreciate in value solely as a result of appreciation in the currency in which the underlying non-US dollar security is denominated. |
| Government Securities Risk | Government Securities Risk: Not all obligations of the US government, its agencies and instrumentalities are backed by the full faith and credit of the US Treasury. Some obligations are backed only by the credit of the issuing agency or instrumentality, and in some cases there may be some risk of default by the issuer. Any guarantee by the US government or its agencies or instrumentalities of a security held by the Portfolio does not apply to the market value of such security or to shares of the Portfolio itself. A security backed by the US Treasury or the full faith and credit of the United States is guaranteed only as to the timely payment of interest and principal when held to maturity. |
| Quantitative Model Risk | Quantitative Model Risk: A quantitative model, such as the risk and other models used by the Investment Manager requires adherence to a systematic, disciplined process. The Investment Manager’s ability to monitor and, if necessary, adjust its quantitative model could be adversely affected by various factors including incorrect or outdated market and other data inputs. Factors that affect a security’s value can change over time, and these changes may not be reflected in the quantitative model. In addition, factors used in quantitative analysis and the weight placed on those factors may not be predictive of a security’s value. |
| Derivatives and Hedging Risk | Derivatives and Hedging Risk: Derivatives and other similar transactions, including those entered into for hedging purposes (i.e., seeking to protect Portfolio investments), may increase volatility, reduce returns, limit gains or magnify losses, perhaps substantially, particularly since most derivatives have a leverage component that provides investment exposure in excess of the amount invested. Swap agreements and other over-the-counter derivatives transactions are subject to the risks of the creditworthiness of and default by the counterparty and consequently may lose all or a portion of their value due solely to the creditworthiness of or default by the counterparty. Over-the-counter derivatives frequently may be illiquid and difficult to value. Changes in liquidity may result in significant, rapid and unpredictable changes in the prices for derivatives. These derivatives transactions, as well as the exchange-traded futures and options in which the Portfolio may invest, are subject to many of the risks of, and can be highly sensitive to changes in the value of the related reference asset, index or rate. As such, a small investment could have a potentially large impact on the Portfolio’s performance. In fact, many derivatives may be subject to greater risks than those associated with investing directly in the underlying or other reference asset. Derivatives transactions incur costs, either explicitly or implicitly, which reduce returns, and costs of engaging in such transactions may outweigh any gains or any losses averted from hedging activities. Successful use of derivatives, whether for hedging or for other investment purposes, is subject to the Investment Manager’s ability to predict correctly movements in the direction of the relevant reference asset or market and, for hedging activities, correlation of the derivative instruments used with the investments seeking to be hedged. Use of derivatives transactions, even if entered into for hedging purposes, may cause the Portfolio to experience losses greater than if the Portfolio had not engaged in such transactions. When the Portfolio enters into derivatives transactions, it may be required to post margin and make settlement payments while the positions are open, and the Portfolio may have to sell a security at a disadvantageous time or price to meet such obligations. Derivatives transactions are also subject to operational and legal risk. |
| Securities Selection Risk | Securities Selection Risk: Securities and other investments selected by the Investment Manager for the Portfolio may not perform to expectations. This could result in the Portfolio’s underperformance compared to other funds with similar investment objectives or strategies. |
| Focused Investing Risk | Focused Investing Risk: The Portfolio’s net asset value may be more vulnerable to changes in the market value of a single issuer or group of issuers and may be relatively more susceptible to adverse effects from any single corporate, industry, economic, market, political or regulatory occurrence than if the Portfolio’s investments consisted of securities issued by a larger number of issuers. |
| Liquidity Risk | Liquidity Risk: The lack of a readily available market may limit the ability of the Portfolio to sell certain securities and other investments at the time and price it would like. The size of certain securities offerings of emerging markets issuers may be relatively smaller in size than offerings in more developed markets and, in some cases, the Portfolio, by itself or together with other Portfolios or other accounts managed by the Investment Manager, may hold a position in a security that is large relative to the typical trading volume for that security; these factors can make it difficult for the Portfolio to dispose of the position at the desired time or price. |
The accompanying bar chart and table provide some indication of the risks of investing in Lazard US Convertibles Portfolio by showing the Portfolio’s year-by-year performance and its average annual performance compared to that of a broad measure of market performance and an index that is generally more representative of the types of the market sectors and/or types of investments in which the Portfolio invests. The bar chart shows how the performance of the Portfolio’s Institutional Shares has varied from year to year. Updated performance information is available at www.lazardassetmanagement.com or by calling (800) 823-6300. The Portfolio’s past performance (before and after taxes) is not necessarily an indication of how the Portfolio will perform in the future.
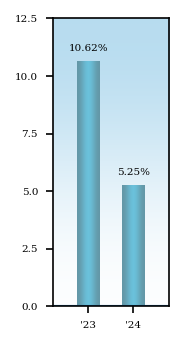
Best Quarter: | |
2023, Q4 | 5.70% |
|
|
Worst Quarter: | |
2023, Q3 | -4.06% |
After-tax returns are shown only for Institutional Shares. After-tax returns of the Portfolio’s other share classes will vary. After-tax returns are calculated using the historical highest individual marginal income tax rates and do not reflect the impact of state and local taxes. Actual after-tax returns depend on the investor’s tax situation and may differ from those shown. The after-tax returns shown are not relevant to investors who hold their shares through tax-deferred arrangements such as 401(k) plans or individual retirement accounts. Returns shown below for the Portfolio’s R6 Shares (which were not operational as of December 31, 2024) reflect the performance of the Portfolio’s Institutional Shares. R6 Shares would have had substantially similar returns as Institutional Shares because the share classes are invested in the same portfolio of securities, and the returns would differ only to the extent that the classes do not have the same expenses.
Average Annual Total Returns - Lazard US Convertibles Portfolio |
Label |
1 Year |
Since Inception |
Inception Date |
|---|---|---|---|---|
| Institutional | 5.25% | 7.89% | Dec. 30, 2022 | |
| Institutional | After Taxes on Distributions | 4.39% | 6.68% | ||
| Institutional | After Taxes on Distributions and Sales | 3.19% | 5.59% | ||
| Open | 5.08% | 7.67% | Dec. 30, 2022 | |
| R6 | 5.25% | 7.88% | Dec. 30, 2022 | |
| US Universal Index | US Universal Index | 2.04% | 4.09% | |
| ICE BofAML US Convertible Index | ICE BofAML US Convertible Index | 11.14% | 12.00% |