The Portfolio seeks long-term capital appreciation.
This table describes the fees and expenses that you may pay if you buy, hold and sell shares of the Portfolio, a series of The Lazard Funds, Inc. (the “Fund”). You may pay other fees, such as brokerage commissions and other fees to financial intermediaries, which are not reflected in the table and the Example below.
Annual Fund Operating Expenses - Lazard US Sustainable Equity Portfolio |
Institutional |
Open |
R6 |
||
|---|---|---|---|---|---|
| Management Fees | 0.60% | 0.60% | 0.60% | ||
| Distribution and Service (12b-1) Fees | none | 0.25% | none | ||
| Other Expenses | 1.10% | 1.77% | 1.10% | [1] | |
| Total Annual Portfolio Operating Expenses | 1.70% | 2.62% | 1.70% | ||
| Fee Waiver and/or Expense Reimbursement | [2] | 0.95% | 1.62% | 1.00% | |
| Total Annual Portfolio Operating Expenses After Fee Waiver and/or Expense Reimbursement | 0.75% | 1.00% | 0.70% | ||
| [1] | Based on estimated amounts for the current fiscal year, using amounts for Institutional Shares from the last fiscal year. |
| [2] | Reflects a contractual agreement by Lazard Asset Management LLC (the “Investment Manager”) to waive its fee and, if necessary, reimburse the Portfolio until May 1, 2026, to the extent Total Annual Portfolio Operating Expenses exceed .75%, 1.00% and .70% of the average daily net assets of the Portfolio’s Institutional Shares, Open Shares and R6 Shares, respectively, exclusive of taxes, brokerage, interest on borrowings, fees and expenses of “Acquired Funds,” fees and expenses related to filing foreign tax reclaims and extraordinary expenses. This expense limitation agreement can only be amended by agreement of the Fund, upon approval by the Fund’s Board of Directors, and the Investment Manager to lower the net amount shown and will terminate automatically in the event of termination of the Management Agreement between the Investment Manager and the Fund, on behalf of the Portfolio. |
This Example is intended to help you compare the cost of investing in the Portfolio with the cost of investing in other mutual funds.
The Example assumes that you invest $10,000 in the Portfolio for the time periods indicated and then hold or redeem all of your shares at the end of those periods. The Example also assumes that your investment has a 5% return each year and that the Portfolio’s operating expenses remain the same, giving effect to the expense limitation agreement in year one only. Although your actual costs may be higher or lower, based on these assumptions your costs would be:
Expense Example - Lazard US Sustainable Equity Portfolio - USD ($) |
Institutional |
Open |
R6 |
|---|---|---|---|
| 1 Year | $ 77 | $ 102 | $ 72 |
| 3 Years | 433 | 660 | 438 |
| 5 Years | 834 | 1,245 | 829 |
| 10 Years | $ 1,929 | $ 2,833 | $ 1,925 |
The Portfolio pays transaction costs, such as commissions, when it buys and sells securities (or “turns over” its portfolio). A higher portfolio turnover rate may indicate higher transaction costs and may result in higher taxes when Portfolio shares are held in a taxable account. These costs, which are not reflected in annual portfolio operating expenses or in the Example, affect the Portfolio’s performance. During the most recent fiscal year, the Portfolio’s portfolio turnover rate was 28% of the average value of its portfolio.
The Portfolio invests primarily in equity securities, principally common stocks, of US companies selected using the Investment Manager’s process employed in implementing the Portfolio’s investment strategy, described below. The market capitalization of companies in which the Portfolio invests may vary with market conditions, but typically the Portfolio invests in companies with market capitalizations over $1 billion.
The Investment Manager’s process first identifies companies within the investable universe, which are companies that the Investment Manager believes are capable of (1) generating and maintaining high financial productivity (i.e., the return a company generates) for periods in excess of market expectations, or (2) capable of improving financial productivity to a greater extent or more expeditiously than the market expects (i.e., are undervalued) and which exhibit good expectations for future cash flows and profitability. Next, the Investment Manager reduces the investable universe using fundamental analysis and research on the companies identified.
In further narrowing the investable universe to select companies for investment by the Portfolio, the Investment Manager considers both (a) the financial sustainability of the company as a business—a company whose financial productivity is likely to be supported or enhanced in the future as a result of the move toward a more sustainable world (such as by considering the nature of the products and/or services that the company provides, from the perspective of environmental and social factors that impact financial productivity)—and (b) how the company counters potential risks arising as a result of environmental and social concerns that may be material to the particular companies or the industries or sectors in which they operate (collectively, “Sustainable Companies”). The Investment Manager uses its proprietary sustainability analysis methodology to assess each company considered for investment, to the extent relevant to the company or its industry or sector, against the specific sustainability factors listed below (and other factors that may be considered relevant to the company or its industry), divided into the three categories of Human Capital, Natural Capital and Corporate Governance.
Human Capital: the extent to which the company
· follows best practices in managing its workforce in a responsible manner, such as health and safety considerations and diversity and inclusion policies;
· acts responsibly in terms of the impact its business operations, products and services have on the broader community;
· aims to ensure its suppliers act responsibly; and
· endeavors to treat its customers fairly and responsibly, for example by having appropriate product safety and data privacy and security standards.
Natural Capital: the extent to which the company, and its supply chains,
· are reliant on using resources which generate significant environmental impact; and
· actively seek to reduce the impact they have on the environment.
Corporate Governance: the extent to which the company’s board composition and policies, executive management composition and compensation, and the exercise of shareholder rights and voting powers are in line with current best practices.
Companies considered by the Investment Manager to be significantly involved in the manufacture of products or the provision of services that are broadly recognized as unsustainable by society (e.g., the production of tobacco, the generation, extraction and/or refining of certain fossil fuels or the production of unconventional weapons) generally will not fall within the investable universe for the Portfolio. However, it is possible that the Investment Manager may determine, after a combined consideration of its assessment of such a company’s financial productivity potential as described above and the results of the Investment Manager’s sustainability analysis
methodology, that such a company is an appropriate investment for the Portfolio. The Portfolio may, however, invest in companies that provide equipment and services to the energy and mining sectors.
Under normal circumstances, the Portfolio invests at least 80% of its assets in equity securities of US Sustainable Companies. The Portfolio may invest up to 20% of its assets in securities of non-US companies, including those in emerging markets.
Although the Portfolio is classified as “diversified” under the Investment Company Act of 1940, as amended, it may invest in a smaller number of issuers than other, more diversified, investment portfolios.
Risk Table - Lazard US Sustainable Equity Portfolio |
Risk [Text Block] |
|---|---|
| Principal Investment Risks | Principal Investment Risks The value of your investment in the Portfolio will fluctuate, which means you could lose money. |
| Risk Lose Money [Member] | The value of your investment in the Portfolio will fluctuate, which means you could lose money. |
| Market Risk | Market Risk: The Portfolio may incur losses due to declines in one or more markets in which it invests. These declines may be the result of, among other things, political, regulatory, market, economic or social developments affecting the relevant market(s). To the extent that such developments impact specific industries, market sectors, countries or geographic regions, the Portfolio’s investments in such industries, market sectors, countries and/or geographic regions can be expected to be particularly affected, especially if such investments are a significant portion of its investment portfolio. In addition, turbulence in financial markets and reduced liquidity in equity, credit and/or fixed income markets may negatively affect many issuers, which could adversely affect the Portfolio. Global economies and financial markets are increasingly interconnected, and conditions and events in one country, region or financial market may adversely impact issuers worldwide. As a result, local, regional or global events such as war or military conflict, acts of terrorism, the spread of infectious illness or other public health issues, social unrest, natural disasters, extreme weather, other geological events, man-made disasters, supply chain disruptions, deflation, inflation, government defaults, government shutdowns, the imposition of sanctions or other similar measures, recessions or other events could have a significant negative impact on global economic and market conditions. For example, a public health or other emergency and aggressive responses taken by many governments or voluntarily imposed by private parties, including closing borders, restricting travel and imposing prolonged quarantines or similar restrictions, as well as the closure of, or operational changes to, many retail and other businesses, may have severe negative impacts on markets worldwide. Additionally, general market conditions may affect the value of a Portfolio’s securities, including changes in interest rates, currency rates or monetary policies. Furthermore, the imposition of tariffs, trade restrictions, currency restrictions or similar actions (or retaliatory measures taken in response to such actions), or the threat or potential of one or more such events and developments, could lead to price volatility and overall declines in the US and global investment markets. |
| Issuer Risk | Issuer Risk: The value of a security may decline for a number of reasons which directly relate to the issuer, such as management performance, financial leverage and reduced demand for the issuer’s goods or services, as well as the historical and prospective earnings of the issuer and the value of its assets or factors unrelated to the issuer’s value, such as investor perception. |
| Focused Investing Risk | Focused Investing Risk: The Portfolio’s net asset value may be more vulnerable to changes in the market value of a single issuer or group of issuers and may be relatively more susceptible to adverse effects from any single corporate, industry, economic, market, political or regulatory occurrence than if the Portfolio’s investments consisted of securities issued by a larger number of issuers. |
| Large Cap Companies Risk | Large Cap Companies Risk: Investments in large cap companies may underperform other segments of the market when such other segments are in favor or because such companies may be less responsive to competitive challenges and opportunities and may be unable to attain high growth rates during periods of economic expansion. |
| Small and Mid Cap Companies Risk | Small and Mid Cap Companies Risk: Small and mid cap companies carry additional risks because their earnings tend to be less predictable, their share prices more volatile and their securities less liquid than larger, more established companies. The shares of small and mid cap companies tend to trade less frequently than those of larger companies, which can have an adverse effect on the pricing of these securities and on the ability to sell these securities when the Investment Manager deems it appropriate. |
| Non-US Securities Risk | Non-US Securities Risk: The Portfolio’s performance will be influenced by political, social and economic factors affecting the non-US countries and companies in which the Portfolio invests. Non-US securities carry special risks, such as less developed or less efficient trading markets, political instability, a lack of company information, differing auditing and legal standards, and, potentially, less liquidity. Non-US securities may be subject to economic sanctions or other governmental actions or developments, exchange controls (including repatriation restrictions), confiscations, trade restrictions (including tariffs) or problems related to share registration, trade settlement or asset custody, which could, among other things, effectively restrict or eliminate the Portfolio’s ability to purchase or sell certain foreign securities. To the extent the Portfolio holds securities subject to such actions, the securities may become difficult to value and/or less liquid (or illiquid). In some cases, the securities may become worthless. |
| Emerging Market Risk | Emerging Market Risk: Emerging market countries generally have economic structures that are less diverse and mature, and political systems that are less stable, than those of developed countries. The economies of countries with emerging markets may be based predominantly on only a few industries, may be highly vulnerable to changes in local or global trade conditions, and may suffer from extreme debt burdens or volatile inflation rates. Further, investments in securities of issuers located in certain emerging countries involve the risk of loss resulting from problems in share registration, settlement or custody, substantial economic, political and social disruptions and the imposition of sanctions or exchange controls (including repatriation restrictions). The securities markets of emerging market countries have historically been extremely volatile and less liquid than more developed markets. These market conditions may continue or worsen. Investments in these countries may be subject to political, economic, legal, market and currency risks. Significant devaluation of emerging market currencies against the US dollar may occur subsequent to acquisition of investments denominated in emerging market currencies. |
| Foreign Currency Risk | Foreign Currency Risk: Investments denominated in currencies other than US dollars may experience a decline in value, in US dollar terms, due solely to fluctuations in currency exchange rates. The Portfolio’s investments denominated in such currencies (particularly currencies of emerging markets countries), as well as any investments in currencies themselves, could be adversely affected by delays in, or a refusal to grant, repatriation of funds or conversion of currencies. Irrespective of any foreign currency exposure hedging, the Portfolio may experience a decline in the value of its portfolio securities, in US dollar terms, due solely to fluctuations in currency exchange rates. The Investment Manager does not intend to actively hedge the Portfolio’s foreign currency exposure. |
| Sustainable Investing Risk | Sustainable Investing Risk: The Portfolio’s performance is dependent upon, among other things, the success of its investment strategy as implemented by the Investment Manager (i.e., the performance of the investments purchased pursuant to the investment strategy). The Portfolio’s investment strategy focuses on investing in companies that satisfy the criteria for being considered a Sustainable Company (as described above), which may cause the Investment Manager to forgo investments for the Portfolio that the Investment Manager otherwise believes may be attractive but that are not considered to be Sustainable Companies. |
| Sector Risk | Sector Risk: Implementation of the Portfolio’s investment strategy may, during certain periods, result in the investment of a significant portion of the Portfolio’s assets in a particular market sector, such as information technology companies, and the Portfolio would be expected to be affected by developments in that sector. Information technology companies generally operate in intensely competitive markets on a worldwide basis. Also, because technological development in many areas increases at a rapid rate, these companies often produce products with very short life cycles and face the risk of product obsolescence. |
| Securities Selection Risk | Securities Selection Risk: Securities and other investments selected by the Investment Manager for the Portfolio may not perform to expectations. This could result in the Portfolio’s underperformance compared to other funds with similar investment objectives or strategies. |
The accompanying bar chart and table provide some indication of the risks of investing in Lazard US Sustainable Equity Portfolio by showing the Portfolio’s year-by-year performance and its average annual performance compared to that of a broad measure of market performance. The bar chart shows how the performance of the Portfolio’s Institutional Shares has varied from year to year. Updated performance information is available at www.lazardassetmanagement.com or by calling (800) 823-6300. The Portfolio’s past performance (before and after taxes) is not necessarily an indication of how the Portfolio will perform in the future.
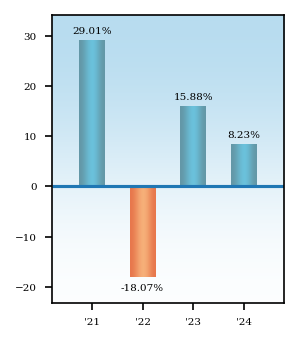
Best Quarter: | |
2023, Q4 | 12.73% |
|
|
Worst Quarter: | |
2022, Q2 | -14.00% |
After-tax returns are shown only for Institutional Shares. After-tax returns of the Portfolio’s other share classes will vary. After-tax returns are calculated using the historical highest individual marginal income tax rates and do not reflect the impact of state and local taxes. Actual after-tax returns depend on the investor’s tax situation and may differ from those shown. The after-tax returns shown are not relevant to investors who hold their shares through tax-deferred arrangements such as 401(k) plans or individual retirement accounts.
Average Annual Total Returns - Lazard US Sustainable Equity Portfolio |
Label |
1 Year |
Since Inception |
Inception Date |
|---|---|---|---|---|
| Institutional | 8.23% | 11.40% | Jun. 30, 2020 | |
| Institutional | After Taxes on Distributions | 6.92% | 10.70% | ||
| Institutional | After Taxes on Distributions and Sales | 5.81% | 8.99% | ||
| Open | 7.96% | 11.10% | Jun. 30, 2020 | |
| R6 | 8.23% | 11.40% | Jun. 30, 2020 | |
| S&P 500 Index | S&P 500 Index | 25.02% | 17.02% |