Exhibit 3
OPERATING AND FINANCIAL REVIEW
You should read the following discussion of our operating and financial condition and prospects in conjunction
with the financial statements and the notes thereto included elsewhere in this 6-K, as well as in our Annual Report on Form 20-F filed on March 31, 2025 (the “Annual Report”).
On January 30, 2025, we effected a change in the ratio of our ADSs to ordinary shares from one ADS representing
15 ordinary shares to a new ratio of one ADS representing 600 ordinary shares. For ADS holders, the ratio change had the same effect as a one-for-forty reverse ADS split. All ADS and related option and warrant information presented in this report
have been retroactively adjusted to reflect the reduced number of ADSs and the increase in the ADS price which resulted from this action. Unless otherwise indicated, in this report fractional ADSs have been rounded to the nearest whole number.
Forward Looking Statements
The following discussion contains “forward-looking
statements,” including statements regarding expectations, beliefs, intentions or strategies for the future. These include statements regarding management's expectations, beliefs and intentions regarding, among other things, the potential benefits
of motixafortide, the potential success of our out-licensing agreements, expectations and commercial potential of motixafortide, as well as its potential investigational uses, expectations with regard to clinical trials of motixafortide, the
plans and objectives of management for future operations, and statements as to results of operations or of financial condition, expected capital needs and expenses. These statements involve known and unknown risks, uncertainties and other factors
that may cause our actual results, performance or achievements to be materially different from any future results, performance or achievements expressed or implied by the forward-looking statements. In some cases, you can identify forward-looking
statements by terms including “anticipates,” “believes,” “could,” “estimates,” “expects,” “intends,” “may,” “plans,” “potential,” “predicts,” “projects,” “should,” “will,” “would,” and similar expressions intended to identify forward-looking
statements. Forward-looking statements reflect our current views with respect to future events and are based on assumptions, and are subject to risks and uncertainties. You should not put undue reliance on any forward-looking statements. Our
actual results could differ materially from those discussed in the forward-looking statements. Factors
that could cause or contribute to these differences include those listed below as well as those discussed in our Annual Report (particularly those in “Item 3. Key Information – Risk Factors”). Unless we are required to do so under U.S. federal
securities laws or other applicable laws, we do not intend to update or revise any forward-looking statements. Readers are encouraged to consult the Company’s filings made on Form 6-K, which are periodically filed with or furnished to the SEC.
Factors that could cause our actual results to differ materially from those expressed or implied in such
forward-looking statements include, but are not limited to:
| • |
the clinical development, commercialization and market acceptance of our therapeutic candidates, including the degree and pace of market uptake of APHEXDA for the mobilization of hematopoietic stem cells for
autologous transplantation in multiple myeloma patients;
|
| • |
the initiation, timing, progress and results of our preclinical studies, clinical trials and other therapeutic candidate development efforts;
|
| • |
our ability to advance our therapeutic candidates into clinical trials or to successfully complete our preclinical studies or clinical trials;
|
| • |
whether the clinical trial results for APHEXDA will be predictive of real-world results;
|
| • |
our receipt of regulatory approvals for our therapeutic candidates, and the timing of other regulatory filings and approvals;
|
| • |
whether access to APHEXDA is achieved in a commercially viable manner and whether APHEXDA receives adequate reimbursement from third-party payors;
|
| • |
our ability to establish, manage, and maintain corporate collaborations, as well as the ability of our collaborators to execute on their development and commercialization plans;
|
| • |
our ability to integrate new therapeutic candidates and new personnel, as well as new collaborations;
|
| • |
the interpretation of the properties and characteristics of our therapeutic candidates and of the results obtained with our therapeutic candidates in preclinical studies or clinical trials;
|
| • |
the implementation of our business model and strategic plans for our business and therapeutic candidates;
|
| • |
the scope of protection that we are able to establish and maintain for intellectual property rights covering our therapeutic candidates and our ability to operate our business without infringing the
intellectual property rights of others;
|
| • |
estimates of our expenses, future revenues, capital requirements and our need for and ability to access sufficient additional financing;
|
| • |
risks related to changes in healthcare laws, rules and regulations in the United States or elsewhere;
|
| • |
competitive companies, technologies and our industry;
|
| • |
our ability to maintain the listing of our ADSs on Nasdaq;
|
| • |
statements as to the impact of the political and security situation in Israel on our business, including the impact of Israel’s war with Hamas and other militant groups, which may exacerbate the magnitude of
the factors discussed above; and
|
| • |
those factors referred to in “Risk Factors” in our Annual Report.
|
Overview
General
We are a biopharmaceutical company pursuing life-changing therapies in oncology and rare diseases. Our first approved product,
APHEXDA® (motixafortide), a novel peptide for the treatment of stem-cell mobilization and solid tumors, with an indication in the United States for stem cell mobilization for autologous transplantation in multiple myeloma, is being developed and
commercialized by Ayrmid Pharma Ltd., or Ayrmid, (globally, excluding Asia) and Guangzhou Gloria Biosciences Co., Ltd., or Gloria, (in Asia). We are also advancing the development of motixafortide for patients with pancreatic cancer and other
solid tumors.
In October 2023, we out-licensed the rights to motixafortide for all indications in substantially all of Asia to Gloria, and in
November 2024, we out-licensed the global rights (other than in Asia) to motixafortide for all indications, other than solid tumors, to Ayrmid. As a result of the November 2024 transaction, we shut down our independent commercialization activities
in the United States and refocused our operations on development activities in Israel in the fields of oncology (including solid tumors) and rare diseases, at a significantly reduced annual cash burn rate.
We have retained the rights to develop motixafortide across all solid tumor indications, in all territories other than Asia, including in PDAC, for which an
investigator-initiated Phase 2b trial, sponsored by Columbia University, and supported equally by us and Regeneron, is ongoing at a relatively minimal cost to us. We expect this program to continue to advance without any significant expense to us.
A key component of our strategy moving forward is to in-license additional assets in oncology and/or rare diseases that exhibit distinct advantages over currently available
therapies or address unmet medical needs that we can advance through clinical development. We have generated our pipeline by systematically identifying, rigorously validating and in-licensing therapeutic candidates that we believe exhibit a high
probability of therapeutic and commercial success. We have substantial experience in scouting and assessing assets in transactions with back-ended, success-based consideration, which can be acquired or licensed for a modest upfront payment, and
with relatively modest and affordable clinical development programs. We are actively working on this initiative and are being presented with many promising opportunities that meet these criteria.
2
Our longer-term vision is to develop innovative assets with significant potential value whose development costs have been offset by the royalties and milestones from our
existing motixafortide partnerships. We aim to continue pursuing new partnerships on these programs to create additional value for our shareholders.
We use “APHEXDA” when referring to our FDA approved drug and “motixafortide” when referring to our development of APHEXDA for additional indications. We refer to the license
agreements with Ayrmid and Gloria as the Ayrmid License Agreement and Gloria License Agreement, respectively.
Our Product Pipeline
The table below summarizes key information about our products and our clinical programs:
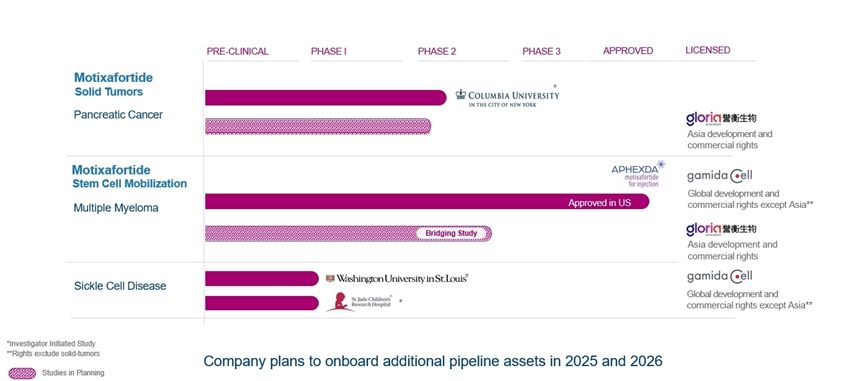
Motixafortide
Motixafortide, is a novel, short peptide that functions as a high-affinity antagonist for CXCR4, for the treatment of stem cell
mobilization and solid tumors. CXCR4 is expressed by normal hematopoietic cells and overexpressed in various human cancers where its expression correlates with disease severity. CXCR4 is a chemokine receptor that mediates the homing and retention
of hematopoietic stem cells, or HSCs, in the bone marrow, and also mediates tumor progression, angiogenesis (growth of new blood vessels in the tumor), metastasis (spread of tumor to other organs) and survival. Before “motixafortide” was approved
by the World Health Organization, or WHO, in 2019 as an International Nonproprietary Name, this therapeutic candidate was known as “BL-8040.” In October 2021, we received WHO approval of the United States Adopted Name, or USAN, “motixafortide.” The
FDA-approved trade or brand name of motixafortide is APHEXDA.
Inhibition of CXCR4 by motixafortide leads to the mobilization of HSCs from the bone marrow to the peripheral blood, enabling their
collection for subsequent autologous or allogeneic transplantation in cancer patients. Clinical data has demonstrated the ability of motixafortide to mobilize higher numbers of long-term engrafting HSCs (CD34+CD38-CD45RA-CD90+CD49f+) as compared to
G-CSF.
Motixafortide also mobilizes cancer cells from the bone marrow, detaching them from their survival signals and sensitizing them to
chemotherapy. In addition, motixafortide has demonstrated a direct anti-cancer effect by inducing apoptosis (cell death) and inhibiting proliferation in various cancer cell models (multiple myeloma, non-Hodgkin’s lymphoma, leukemia, non-small-cell
lung carcinoma, neuroblastoma and melanoma).
3
In the field of immuno-oncology, motixafortide mediates infiltration of T-cells while reducing immune regulatory cells in the tumor
microenvironment, or TME. In clinical studies, the combination of motixafortide with immune checkpoint inhibitors, such as anti PD-1, has shown T-cell activation and a reduction in tumor cell numbers.
The following is a summary of our motixafortide principal development activities.
Stem cell mobilization
Multiple Myeloma
In September 2023, the FDA approved motixafortide in combination with G-CSF to mobilize hematopoietic stem cells to the peripheral
blood for collection and subsequent autologous transplantation in patients with multiple myeloma. In March 2025, marketing authorization with the FDA was transferred to Ayrmid.
In November 2023, we initiated pivotal bridging study preparation activities with Gloria, our Asia partner, to support potential
approval and commercialization of motixafortide in stem-cell mobilization in China. In February 2024, an IND was filed with the Center for Drug Evaluation of the National Medical Products Administration, which was approved in May 2024. The study in
China was originally planned to commence in the first half of 2025, with data approximately 18 months later. Gloria is not currently advancing this study according to schedule and it is unclear when such study will be initiated, if at all. There
can be no assurance that Gloria will meet its obligations under the Gloria License Agreement.
Sickle Cell Disease
In March 2023, we entered into a clinical collaboration with Washington University School of Medicine in St. Louis to advance a Phase 1 clinical trial in which motixafortide
will be evaluated as a monotherapy and in combination with natalizumab (VLA-4 inhibitor), as novel regimens to mobilize CD34+ hematopoietic stem cells (HSC) for gene therapies in Sickle Cell Disease. The proof-of-concept investigator-initiated
study plans to enroll five adults with a diagnosis of SCD who are receiving automated red blood cell exchanges via apheresis. The trial’s primary objective is to assess the safety and tolerability of motixafortide alone and in combination with
natalizumab in SCD patients, defined by dose-limiting toxicities. Secondary objectives include determining the number of CD34+ hematopoietic stem and progenitor cells (HSPCs) mobilized via leukapheresis; and determining the pharmacokinetics of
CD34+ HSPCs mobilization to peripheral blood in response to motixafortide alone and motixafortide plus natalizumab in SCD patients. As anticipated, the study began enrolling in 2023, with first patient dosed in December 2023, and is
ongoing. Initial data from this study was presented at an oral presentation at the 66th American Society of Hematology (ASH) Annual Meeting. Five patients completed mobilization and apheresis with motixafortide alone, and four of five with
motixafortide in combination with natalizumab. Motixafortide alone, and in combination with natalizumab, were found to be safe and well-tolerated in the trial. Common adverse events were transient and included Grade 1-2 injection site (pruritis,
tingling/pain) and systemic reactions (pruritis, hives). No grade 4 adverse events or vaso-occlusive events occurred. Motixafortide alone, and in combination with natalizumab, resulted in robust CD34+ HSC mobilization to peripheral blood.
Motixafortide alone mobilized a median of 198 CD34+ cells/μl (range 77-690) to PB with median 3.49x10⁶ CD34+ cells/kg as part of a single blood volume collection, projecting the collection of 13.9x10⁶ HSCs in a normal,
single-day four-blood-volume apheresis collection session. Motixafortide in combination with natalizumab mobilized a median of 231 CD34+ cells/μl (range 117-408), with median 4.64x10⁶ CD34+ cells/kg collected as part of a single blood
volume collection, projecting the collection of 18.6x10⁶ CD34+ HSCs in a single day four blood volume apheresis collection session. Following the out-licensing of motixafortide to Ayrmid, the study is being continued under the Ayrmid
License Agreement.
In May 2024, we announced that we entered into a multi-center Phase 1 clinical trial sponsored by St. Jude Children’s Research Hospital, Inc. to evaluate motixafortide for the
mobilization of CD34+ hematopoietic stem cells (HSCs) used in the development of gene therapies for patients with SCD. Investigators in the trial from St. Jude Children’s Research Hospital, Inc. and two other clinical sites have extensive SCD gene
therapy clinical development experience and are recognized leaders in the field. Following the out-licensing of motixafortide to Ayrmid, the study is being continued under the Ayrmid License Agreement. The first patient in the study was dosed in
February 2025.
4
Pancreatic Cancer
In January 2016, we entered into a clinical collaboration with MSD (a tradename of
Merck & Co., Inc., Kenilworth, New Jersey) in the field of cancer immunotherapy. Based on this collaboration, in September 2016 we initiated a Phase 2a study, known as the COMBAT/KEYNOTE-202 study, focusing on evaluating the mechanism of
action and safety of motixafortide in combination with KEYTRUDA® (pembrolizumab), MSD’s anti-PD-1 therapy, in 37 patients with metastatic PDAC. The study was an open-label, multicenter, single-arm trial designed to evaluate the
mechanism of action, safety and tolerability, and clinical response of the combination of these therapies. The mechanistic evaluation consisted of multiple pharmacodynamic parameters, including the ability to improve infiltration of T-cells into
the tumor and their reactivity. Top-line results showed that the dual combination demonstrated encouraging disease control and overall survival in patients with metastatic pancreatic cancer. In addition, assessment of patient biopsies supported
motixafortide’s ability to induce infiltration of tumor-reactive T-cells into the tumor, while reducing the number of immune regulatory cells.
In July 2018, we announced the expansion of the COMBAT/KEYNOTE-202 study under the
collaboration to include a triple combination arm investigating the safety, tolerability and efficacy of motixafortide, KEYTRUDA® and chemotherapy. We initiated this arm of the trial in December 2018. In December 2019, we announced
that preliminary data from the study indicated that the triple combination therapy showed a high level of disease control, including seven partial responders and 10 patients with stable disease out of 22 evaluable patients. In February 2020, we
completed the recruiting of a total of 43 patients for the study and in December 2020, we announced the final results of the study. The results of the study showed substantial improvement as compared to comparable historical results of other
pancreatic cancer studies across all study endpoints. Of the 38 evaluable patients, median overall survival was 6.5 months, median progression free survival was 4.0 months, confirmed overall response rate was 13.2%, overall response rate was
21.2% and disease control rate was 63.2%. The combination was generally well tolerated, with a safety profile consistent with the individual safety profile of each component alone; adverse event and severe adverse event profiles were as expected
with chemotherapy-based treatment regimens.
In October 2020, we announced that motixafortide will be tested in combination with the anti-PD-1 cemiplimab (LIBTAYO®) and
standard-of-care chemotherapy (gemcitabine and nab-paclitaxel) in first-line PDAC. This investigator-initiated Phase 2, single-arm study (CheMo4METPANC), led by Columbia University and supported equally by BioLineRx and Regeneron, initially
enrolled 11 PDAC patients in a pilot phase. In September 2023, we reported data from the pilot phase of the study. As of July 2023, of those 11 patients, seven patients (64%) experienced a partial response (PR), of which six (55%) are now confirmed
PRs, with one patient experiencing resolution of the hepatic (liver) metastatic lesion. Three patients (27%) experienced stable disease, resulting in a disease control rate of 91%. These findings compare favorably to historic partial response and
disease control rates of 23% and 48%, respectively, reported with the chemotherapy combination of gemcitabine and nab-paclitaxel. Additionally, analysis of paired pre- and on-treatment biopsy samples demonstrated an increase in CD8+ T-cell density
in tumors from all 11 patients treated (P = 0.007).
Based on the preliminary data from this pilot phase, the planned single-arm study was amended to a significantly larger, randomized
multi-center study, with a new planned total of 108 patients. The amended Phase 2b study is evaluating the combination of motixafortide, PD-1 inhibitor cemiplimab, and standard of care chemotherapies gemcitabine and nab-paclitaxel, versus
gemcitabine and nab-paclitaxel alone. The trial's primary endpoint is progression free survival, and a pre-specified interim futility analysis will be conducted when 40% of progression free survival events are observed, which is expected in 2026.
Secondary objectives include safety, response rate, disease control rate, duration of clinical benefit and overall survival. In February 2024, the first patient was dosed, with full enrollment projected for 2027.
We have also been advancing plans in collaboration with Gloria, our Asia partner, for a Phase 2b randomized study assessing motixafortide in combination with the PD-1 inhibitor
zimberelimab and standard-of-care chemotherapy as first-line treatment in patients with metastatic pancreatic cancer. IND submission and protocol finalization was planned for the first half of 2025, with study initiation expected during 2025.
However, Gloria is not currently advancing this study according to schedule and it is unclear when such study will be initiated, if at all. There can be no assurance that Gloria will meet its obligations under the Gloria License Agreement.
Other Studies
In addition to the above, from time to time a number of Company-sponsored and investigator-initiated studies may be conducted in a
variety of indications, to support the interest of the scientific and medical communities in exploring additional uses for motixafortide. These studies serve to potentially further elucidate the mechanism of action for motixafortide, generate data
about motixafortide’s potential use in other indications, and inform the life-cycle management process of motixafortide. The results of studies such as these are presented from time to time at relevant professional conferences.
5
Orphan Drug Designations
Motixafortide has been granted three Orphan Drug Designations by the FDA: for use to mobilize HSCs from the bone marrow to peripheral blood for collection in autologous or
allogeneic transplantation (granted in July 2012); for the treatment of AML (granted in September 2013); and for the treatment of pancreatic cancer (granted in February 2019). Orphan Drug Designation is granted to therapeutics intended to treat
rare diseases or conditions that affect not more than 200,000 people in the United States (or diseases or conditions that affect more than 200,000 people but where there is no reasonable expectation that the product development cost will be
recovered from product sales in the United States). If an Orphan Drug-Designated product subsequently receives FDA approval for the disease or condition for which it was designated, the product is entitled to a seven-year marketing exclusivity
period, which means that the FDA may not approve any other applications to market the same drug for the same indication, except in very limited circumstances (such as a showing of clinical superiority to the product with orphan exclusivity by means
of greater effectiveness, greater safety or providing a major contribution to patient care or in instances of drug supply issues), for seven years. In addition, Orphan Drug Designation enables sponsors to apply for certain federal grants and tax
credits for clinical trials and provides an exemption from the Prescription Drug User Fee so long, as the sponsor’s annual revenue is below $50,000,000.
In January 2020, the EMA granted an Orphan Drug Designation to motixafortide for the treatment of pancreatic cancer. In addition, in December 2023, the EMA granted Orphan Drug
Designation to motixafortide for treatment of patients undergoing hematopoietic stem cell transplantation. The EMA grants orphan medicinal product designation to investigational drugs intended to treat, prevent or diagnose a life-threatening or
chronically debilitating disease affecting fewer than five in 10,000 people in the EU and for which no satisfactory treatment is available or, if such treatment exists, the medicine must be of significant benefit to those affected by the condition.
Orphan medicinal product designation provides regulatory and financial incentives for companies to develop and market therapies, including ten years of market exclusivity, protocol assistance, fee reductions and EU-funded research.
BL-5010
Our commercialized, legacy therapeutic product, BL-5010, is a customized, proprietary pen-like applicator containing a novel, acidic, aqueous solution for the non-surgical
removal of skin lesions. It offers an alternative to painful, invasive and expensive removal treatments including cryotherapy, laser treatment and surgery. Since the treatment is non-invasive, it poses minimal infection risk and eliminates the need
for anesthesia, antiseptic precautions and bandaging. The pre-filled device controls and standardizes the volume of solution applied to a lesion, ensuring accurate administration directly on the lesion and preventing both accidental exposure of the
healthy surrounding tissue and unintentional dripping. It has an ergonomic design, making it easy to handle, and has been designed with a childproof cap. BL-5010 is applied topically on a skin lesion in a treatment lasting a few minutes with the
pen-like applicator and causes the lesion to gradually dry out and fall off within one to four weeks.
In December 2014, we entered into an exclusive out-licensing arrangement with Perrigo Company plc, or Perrigo, for the rights to
BL-5010 for over-the-counter, or OTC, indications in Europe, Australia and additional selected countries. In March 2016, Perrigo received CE Mark approval for BL-5010 as a novel OTC treatment for the non-surgical removal of warts. The commercial
launch of products for treatment of this first OTC indication (warts/verrucas) commenced in Europe in the second quarter of 2016. Since then, Perrigo has invested in improving the product and during 2019 launched an improved version of the product
in several European countries. In March 2020, we agreed that Perrigo could relinquish its license rights for certain countries that had been included in its territory according to the original license agreement, and was also no longer obligated to
develop, obtain regulatory approval for, and commercialize products for a second OTC indication. In turn, in March 2020, we agreed with our licensor of the rights to BL-5010, Innovative Pharmaceutical Concepts (IPC) Inc., or IPC, to return to IPC
those license rights no longer out-licensed to Perrigo as a result of the agreement described in the preceding sentence, in consideration of the payment to us of royalties or fees on sublicense receipts.
6
Expanding our Product Portfolio
Following entry into the Gloria License Agreement and the Ayrmid License Agreement as well as the shutdown of our U.S. commercial operations, we have refocused our operations
on development activities in Israel in the fields of oncology and rare diseases, at a significantly reduced annual cash burn rate.
We are continuing to advance the development of motixafortide for patients with pancreatic cancer and other solid tumors.
In addition, as part of our growth strategy, we are actively pursuing in-licensing opportunities as well as other strategic
transactions such as co-development agreements, acquisitions, and technology partnerships, to expand and diversify our product pipeline. We are specifically targeting innovative therapeutic candidates that complement our existing portfolio and
align with our core expertise in oncology and rare disease. Our business development team is evaluating potential assets across various stages of development, from preclinical to late-stage clinical programs. We maintain a disciplined approach to
asset acquisition, focusing on opportunities that offer significant market potential, address unmet medical needs, and can leverage our established development and commercialization capabilities. Through these strategic in-licensing efforts, we aim
to enhance shareholder value while advancing our mission of bringing novel therapies to patients in need.
Israel-Hamas war
In October 2023, Hamas terrorists infiltrated Israel’s southern border from the Gaza Strip and conducted a series of attacks on
civilian and military targets. Hamas also launched extensive rocket attacks on Israeli population and industrial centers located along Israel’s border with the Gaza Strip and in other areas within the State of Israel. These attacks resulted in
extensive deaths, injuries and kidnapping of civilians and soldiers. Following the attack, Israel’s security cabinet declared war against Hamas and a military campaign against these terrorist organizations commenced in parallel to their continued
rocket and terror attacks. In addition, since the commencement of these events, there have been continued hostilities along Israel’s northern border with Lebanon (with the Hezbollah terror organization), which have escalated into a military
campaign against Hezbollah, and maritime and air attacks from the Houthi movement in Yemen. It is possible that other terrorist organizations, including Palestinian military organizations in the West Bank as well as other hostile countries will
join the hostilities. In addition, Iran launched two direct attacks on Israel in April and October 2024, involving hundreds of drones and ballistic missiles and has threatened to continue to attack Israel and is widely believed to be developing
nuclear weapons. Iran is also believed to have a strong influence among extremist groups in the region, such as Hamas in Gaza, Hezbollah in Lebanon, the Houthi movement in Yemen and various rebel militia groups in Syria and Iraq. Such clashes may
escalate in the future into a greater regional conflict. We cannot currently predict the intensity or duration of Israel’s war on all fronts, nor can we predict how this war will ultimately affect our business and operations or Israel’s economy in
general.
Funding
We have funded our operations primarily through the sale of equity securities (both in public and private offerings), payments
received under our strategic licensing and collaboration arrangements, funding received from the Israel Innovation Authority, or IIA, debt financing and interest earned on investments. We expect to continue to fund our operations over the next
several years through our existing cash resources, potential future milestone and royalty payments that we may receive from our existing out-licensing agreements, primarily royalties from the commercialization of APHEXDA by Ayrmid, potential future
upfront, milestone or royalty payments that we may receive from Gloria and any other out-licensing transaction, interest earned on our investments, and additional capital to be raised through public or private equity offerings or debt financings.
As of March 31, 2025, we had $26.4 million of cash, cash equivalents and short-term bank deposits.
Revenues
Our revenues to date have been generated primarily from upfront and milestone payments under out-licensing agreements and between
the fourth quarter of 2023 and November 2024, revenues from product sales of APHEXDA.
We expect our revenues, if any, for the next several years to be derived primarily from future royalties on product sales, primarily
royalties paid by Ayrmid from the commercialization of APHEXDA in stem cell mobilization in the U.S. and potential milestone payments from the license agreements with Ayrmid and Gloria.
7
Cost of Revenues
Our cost of revenues to date have consisted of sub-license payments to the licensors in respect of upfront and milestone payments
associated with out-licensing agreements, costs associated with the manufacture of APHEXDA, and royalty payments to the licensor with respect to direct product sales of APHEXDA. Prior to receiving FDA approval for APHEXDA in September 2023, we
expensed all manufacturing and material costs as research and development expenses.
We expect our cost of revenues, if any, for the next several years to be derived primarily from sub-license payments to the
licensors in respect of out-licensing agreements and other potential collaboration arrangements, including future royalties on product sales from such out-licensing agreements.
Research and Development
Our research and development expenses consist primarily of salaries and related personnel expenses, fees paid to external service
providers, up-front and milestone payments under our license agreements, patent-related legal fees, costs of preclinical studies and clinical trials, drug and laboratory supplies and costs for facilities and equipment. We primarily use external
service providers to manufacture our therapeutic candidates for clinical trials and for the majority of our preclinical and clinical development work. We charge all research and development expenses to operations as they are incurred. We expect our
research and development expenses to remain one of our primary expenses in the near future as we continue to develop motixafortide and additional assets we may in license.
The following table identifies our current major research and development projects:
|
Project
|
Status
|
Expected Near Term Milestones
|
||
|
motixafortide
|
1.
|
FDA approval received on September 8, 2023 for stem-cell mobilization in multiple myeloma patients.
|
1.
|
Out-licensed to Ayrmid in November 2024; five-year long-term follow-up of GENESIS patients ongoing
|
|
2.
|
Reported data from single-arm pilot phase of the investigator-initiated Phase 2 combination trial in first-line PDAC. Of 11 patients with metastatic pancreatic cancer enrolled, 7 patients
(64%) experienced partial response (PR), of which 6 (55%) were confirmed PRs with one patient experiencing resolution of the hepatic (liver) metastatic lesion. 3 patients (27%) experienced stable disease, resulting in a disease control rate
of 91%. Based on these encouraging results, study was substantially revised to a multi-institution, randomized Phase 2b trial of 108 patients
|
2.
|
First patient dosed in February 2024. Interim data expected in 2026 and full enrollment projected for 2027*
|
|
|
3.
|
Phase 1 study for gene therapies in SCD (with Washington University School of Medicine in St. Louis)**
|
3.
|
First patient dosed in December 2023 and initial data from the study released in November 2024. Final data planned in 2025*
|
|
|
4.
|
Phase 1 study for gene therapies in SCD (with St. Jude Children’s Research Hospital, Inc.)**
|
4.
|
First patient dosed in February 2025, with data planned in 2025/2026*
|
|
|
5.
|
IND approved in China for initiation of pivotal bridging study in SCM under license agreement with Gloria
|
5.
|
Initiation of the study is currently delayed***
|
|
|
6.
|
Phase 2b randomized study in first-line PDAC in China under license agreement with Gloria
|
6.
|
IND submission and protocol finalization is currently delayed***
|
|
| * |
These studies are investigator-initiated studies; therefore, the timelines are ultimately controlled by the independent investigators and are subject to change.
|
| ** |
Study to be continued under the Ayrmid License Agreement
|
| *** |
Under the Gloria License Agreement, Gloria is late in the payment of $2.4 million to us for the achievement of a specific milestone under the Gloria License Agreement and for certain product supply, which was
due during 2024. In addition, the planned studies of motixafortide in China under the Gloria License Agreement are currently not advancing according to schedule and it is unclear when such studies will be initiated, if at all. There can be
no assurance that Gloria will meet its payment obligations or any other obligations under the Gloria License Agreement.
|
8
We expect that a large percentage of our research and development expenses in the future will be incurred in support of our current
and future preclinical and clinical development projects. Due to the inherently unpredictable nature of preclinical and clinical development processes, we are unable to estimate with any certainty the costs we will incur in the continued
development of motixafortide in our pipeline for commercialization. Clinical development timelines, the probability of success and development costs can differ materially from expectations. We expect to continue to test motixafortide and any other
therapeutic candidates in preclinical studies for toxicology, safety and efficacy, and to conduct additional clinical trials for each such candidate. If we are not able to enter into an out-licensing arrangement with respect to any therapeutic
candidate prior to the commencement of later stage clinical trials, we may fund the trials for the therapeutic candidate ourselves.
Our future research and development expenses will depend on the clinical success of motixafortide in solid tumor indications and on other potential therapeutic candidates, as
well as ongoing assessments of each therapeutic candidate’s commercial potential. In addition, we cannot forecast with any degree of certainty which therapeutic candidates may be subject to future out-licensing arrangements, when such out-licensing
arrangements will be secured, if at all, and to what degree such arrangements would affect our development plans and capital requirements.
As we obtain results from clinical trials, we may elect to discontinue or delay clinical trials for certain therapeutic candidates or projects in order to focus our resources
on more promising therapeutic candidates or projects. Completion of clinical trials by us or our licensees may take several years or more, but the length of time generally varies according to the type, complexity, novelty and intended use of a
therapeutic candidate.
The cost of clinical trials may vary significantly over the life of a project as a result of differences arising during clinical development, including, among others:
|
|
•
|
the number of sites included in the clinical trials;
|
|
|
•
|
the length of time required to enroll suitable patients;
|
|
|
|
|
|
|
•
|
the number of patients that participate, and are eligible to participate, in the clinical trials;
|
|
|
•
|
the duration of patient follow-up;
|
|
|
|
|
|
|
•
|
whether the patients require hospitalization or can be treated on an outpatient basis;
|
|
|
•
|
the development stage of the therapeutic candidate; and
|
|
|
•
|
the efficacy and safety profile of the therapeutic candidate.
|
The lengthy process of completing clinical trials and seeking regulatory approval for our therapeutic candidates requires expenditure of substantial resources. Any failure or
delay in completing clinical trials, or in obtaining regulatory approvals, could cause a delay in generating product revenue and cause our research and development expenses to increase and, in turn, have a material adverse effect on our operations.
Due to the factors set forth above, we are not able to estimate with any certainty when we would recognize any net cash inflows from our projects.
9
Sales and Marketing Expenses
Sales and marketing expenses consisted primarily of compensation for employees in commercialization, marketing and business
development functions. Other significant costs included marketing and communication materials, market access activities, professional fees for outside market research and consulting, and legal services related to compliance and to potential business
development transactions.
Following the license agreement with Ayrmid and the termination of our commercialization activities in the U.S., we experienced a
significant reduction in sales and marketing expenses and, during the first quarter of 2025, we did not incur any sales and marketing expenses. We expect that any future sales and marketing expenses will be primarily related to business
development.
General and Administrative Expenses
General and administrative expenses consist primarily of compensation for employees in executive and operational functions,
including accounting, finance, legal, investor relations, information technology and human resources. Other significant general and administration costs include facilities costs, professional fees for outside accounting and legal services, travel
costs, insurance premiums and depreciation.
Non-Operating Expense and Income
Non-operating expense and income includes fair-value adjustments of liabilities on account of the warrants issued in equity financings
we carried out in February 2019, September 2022 April 2024, November 2024 and January 2025. These fair-value adjustments are highly influenced by our share price at each period end (revaluation date). Non-operating expense and income also includes
issuance expenses under the “at-the-market” offering agreement, or ATM Agreement, between us and HCW entered into in September 2021, and the pro-rata share of issuance expenses from the placements related to the warrants. Net sales-based royalties
from the license agreement with Perrigo have also been included as part of non-operating income, as the out-licensed product is not an integral part of our strategy, and the amounts are not material.
Financial Expense and Income
Financial expense and income consist of interest earned on our cash, cash equivalents and short-term bank deposits; interest expense
related to our loans from BlackRock, bank fees and other transactional costs. In addition, it may also include gains/losses on foreign exchange hedging transactions, which we carry out from time to time to protect against a portion of our
NIS-denominated expenses (primarily compensation) in relation to the dollar.
Critical Accounting Policies and Estimates
We describe our significant accounting policies more fully in Note 2 to our consolidated financial statements for the year ended
December 31, 2024. We believe that the accounting policies below are critical for one to fully understand and evaluate our financial condition and results of operations.
Our consolidated financial statements are prepared in conformity with International Financial Reporting Standards, or IFRS, as
issued by the International Accounting Standards Board, or IASB. In preparing our consolidated financial statements, we make judgements, estimates and assumptions about the application of our accounting policies which affect the reported amounts of
assets, liabilities, revenue and expenses. Our critical accounting judgements and sources of estimation uncertainty are described in Note 4 to the consolidated financial statements included in our Annual Report.
10
Results of Operations
Comparison of the three-month period ended March 31, 2025 to the three-month period ended March 31, 2024
Revenues
|
Three months ended
March 31,
|
||||||||||||
|
2024
|
2025
|
Increase
(decrease)
|
||||||||||
|
(in thousands of U.S. dollars)
|
||||||||||||
|
License revenues
|
5,931
|
255
|
(5,676
|
)
|
||||||||
|
Product sales, net
|
924
|
-
|
(924
|
)
|
||||||||
|
Total revenues
|
6,855
|
255
|
(6,600
|
)
|
||||||||
Revenues for the three-month period ended March 31, 2025 were $0.3 million, a decrease of $6.6 million, compared to revenues of $6.9 million for the three-month period ended
March 31, 2024. The significant decrease in revenues from 2024 to 2025 reflects the one-time revenues recorded in 2024 relating to the out-licensing transaction with Gloria during the fourth quarter of 2023, as well as the change in our operations
following the out-licensing of APHEXDA to Ayrmid during the fourth quarter of 2024. The revenues in 2025 reflect the royalties paid by Ayrmid from the commercialization of APHEXDA in stem cell mobilization in the U.S. The revenues in 2024 primarily
reflect a portion of the up-front payment received by us under the Gloria License Agreement and a milestone payment achieved under the Gloria License Agreement, which collectively amounted to $5.9 million, as well as $0.9 million of net revenues
from product sales of APHEXDA in the United States.
Cost of revenues
|
Three months ended
March 31, |
||||||||||||
|
2024
|
2025
|
Increase
(decrease)
|
||||||||||
|
(in thousands of U.S. dollars)
|
||||||||||||
|
Cost related to license revenues
|
741
|
-
|
(741
|
)
|
||||||||
|
Amortization of intangible asset in respect of license revenues
|
646
|
-
|
(646
|
)
|
||||||||
|
Cost of product sales
|
68
|
34
|
(34
|
)
|
||||||||
|
Total cost of revenues
|
1,455
|
34
|
(1,421
|
)
|
||||||||
Cost of revenues for the three-month period ended March 31, 2025 was immaterial, compared to cost of revenues of $1.5 million for the three-month period ended March 31, 2024.
The cost of revenues in 2025 reflects sub-license fees on royalties paid by Ayrmid from the commercialization of APHEXDA in stem cell mobilization in the U.S. The cost of revenues in 2024 primarily reflects sub-license fees on a milestone payment
received under the Gloria Biosciences License Agreement and royalties on net product sales of APHEXDA in the U.S., as well as amortization of intangible assets and cost of goods sold on product sales.
Research and development expenses
|
Three months ended
March 31,
|
||||||||||||
|
2024
|
2025
|
Increase
(decrease)
|
||||||||||
|
(in thousands of U.S. dollars)
|
||||||||||||
|
Research and development expenses
|
2,494
|
1,623
|
(871
|
)
|
||||||||
Research and development expenses for the three months ended March 31, 2025 were $1.6 million, a decrease of $0.9 million, or 34.9%, compared to $2.5 million for the three
months ended March 31, 2024. The decrease resulted primarily from lower expenses related to motixafortide due to the out-licensing of U.S. rights to Ayrmid, as well as a decrease in payroll and share-based compensation, primarily due to a decrease
in headcount.
11
Sales and marketing expenses
|
Three months ended
March 31,
|
||||||||||||
|
2024
|
2025
|
Increase
(decrease)
|
||||||||||
|
(in thousands of U.S. dollars)
|
||||||||||||
|
Sales and marketing expenses
|
6,342
|
-
|
(6,342
|
)
|
||||||||
There were no sales and marketing expenses for the three months ended March 31, 2025, compared to $6.3 million for the three months
ended March 31, 2024. The decrease resulted primarily from the shutdown of U.S. commercial operations in the fourth quarter of 2024 following the Ayrmid out-licensing transaction.
General and administrative expenses
|
Three months ended
March 31,
|
||||||||||||
|
2024
|
2025
|
Increase
(decrease)
|
||||||||||
|
(in thousands of U.S. dollars)
|
||||||||||||
|
General and administrative expenses
|
1,386
|
989
|
(397
|
)
|
||||||||
General and administrative expenses for the three months ended March 31, 2025 were $1.0 million, a decrease of $0.4 million, or 28.6%, compared to $1.4 million for the three
months ended March 31, 2024. The decrease resulted primarily from a decrease in payroll and share-based compensation, primarily due to a decrease in headcount, as well as small decreases in a number of general and administrative expenses.
Non-operating income (expenses), net
|
Three months ended
March 31,
|
||||||||||||
|
2024
|
2025
|
Increase
(decrease)
|
||||||||||
|
(in thousands of U.S. dollars)
|
||||||||||||
|
Non-operating income (expenses), net
|
4,490
|
7,644
|
(3,154
|
)
|
||||||||
We recognized net non-operating income of $7.6 million for the three months
ended March 31, 2025, compared to net non-operating income of $4.5 million for the three months ended March 31, 2024. Non-operating income for both periods primarily relates to
fair-value adjustments of warrant liabilities on our balance sheet, as a result of changes in our share price.
12
Financial income (expenses), net
|
Three months ended
March 31,
|
||||||||||||
|
2024
|
2025
|
Increase
(decrease)
|
||||||||||
|
(in thousands of U.S. dollars)
|
||||||||||||
|
Financial income
|
565
|
294
|
(271
|
)
|
||||||||
|
Financial expenses
|
(929
|
)
|
(420
|
)
|
509
|
|||||||
|
Net financial income (expenses)
|
(364
|
)
|
(126
|
)
|
238
|
|||||||
Net financial expenses for the three months ended March 31, 2025 were $0.1 million compared to net financial expenses of $0.4 million for the three months ended March 31, 2024.
Net financial expenses for both periods primarily relate to loan interest paid, partially offset by investment income earned on our bank deposits.
Liquidity and Capital Resources
Since our inception, we have funded our operations primarily through public and private offerings of our equity securities, payments received under our strategic licensing and
collaboration arrangements, interest earned on investments, debt financing and funding previously received from the IIA. As of March 31, 2025, we held $26.4 million of cash, cash equivalents and short-term bank deposits. We have invested
substantially all our available cash funds in short-term bank deposits.
In September 2021, we entered into the ATM Agreement with HCW pursuant to which we may offer and sell, at our option, up to $25.0
million of our ADSs through an at-the-market equity program under which HCW agreed to act as sales agent. As of the issuance date of this report, we have sold 194,656 of our ADSs for total gross proceeds of approximately $6.0 million under the ATM
program. Under General Instruction I.B.5 to Form F-3 (also known as the baby shelf rule), we may currently sell up to $4.8 million under the ATM program.
Loan Agreements with BlackRock
In September 2022, we entered into a secured Loan Agreement with BlackRock EMEA Venture and Growth Lending (previously Kreos Capital VII Aggregator SCSP), or BlackRock, under
which BlackRock agreed to provide us with access to term loans in an aggregate principal amount of up to $40 million in three tranches, or the Loans. We drew down the initial tranche of $10 million following execution of the agreement in September
2022 and we drew down the second tranche of $20 million in April 2024, following fulfilment of the requisite milestones. The third tranche was available for draw down until October 1, 2024, upon achievement of certain milestones was not drawn down.
In November 2024, in connection with the Ayrmid License Agreement, we entered into the Loan Amendment to the Loan Agreement with
BlackRock, pursuant to which, (i) we agreed to make aggregate payments of $16.5 million, as partial repayment of the Loans and in lieu of future revenue-based payments, which were fully cancelled, (ii) effective December 1, 2024, we agreed to pay
the remaining amounts outstanding under the Loans (in principal and interest) over a three year period ending December 1, 2027, and (iii) our minimum cash balance requirement under the Loan Agreement was reduced from $10 million to $4 million. In
addition, pursuant to the Loan Amendment, 10% of any future milestone payments received by us from the out-licensing agreements through December 1, 2027 will be used to repay principal of the Loans, and the repayments in (ii) above will be adjusted
accordingly. All other terms of the Loan Agreement remain the same.
Interest on each tranche of the Loans accrues at a fixed rate of 9.5% per annum from the drawdown date until repayment in full of
the tranche.
We may prepay all, but not less than all, of the outstanding balance of any of the Loans. In connection with any prepayment, we will also pay an end of loan payment equal to 5%
of the amount of each tranche drawn down upon the final repayment of each such tranche, or the End of Loan Payment, and any other unpaid fees or costs, if any.
13
The Loans are subject to mandatory accelerated repayment provisions that require repayment of the outstanding principal amount of the Loans, and all accrued and unpaid interest
thereon, upon the occurrence of an event of default, subject to certain limitations and cure rights. In addition, in the event of acceleration upon an event of default (a) we will be required to pay the aggregate of the monthly interest payments
scheduled to be paid by the Company for the period from the date of acceleration to the expiry of the applicable Loan, in each case discounted from the applicable monthly repayment date to the date of prepayment at the rate of 2% per annum and (b)
the End of Loan Payment.
Outstanding borrowings under the Loan Agreement are secured by (a) a first priority fixed charge over certain assets and intellectual property of the Company as well as all
shares held by the Company in BioLineRx USA, Inc, or the Fixed Charge, (b) a first priority floating charge over all our assets as of the date of the Loan Agreement or thereafter acquired, other than the assets charged under the Fixed Charge or as
otherwise specifically excluded pursuant to the terms of the floating charge, and (c) subject to the provisions of the Fixed Charge, a security interest in our intellectual property.
The Loan Agreement contains customary representations and warranties, indemnification provisions in favor of the Lender, events of
default and affirmative and negative covenants, including, among others, covenants that limit or restrict the Company’s ability to, among other things, incur additional indebtedness, merge or consolidate, make acquisitions, pay dividends or other
distributions or repurchase equity, and dispose of assets, in each case subject to certain exceptions. The Company has also granted BlackRock certain information rights.
Cash Flows
Net cash used in operating activities was $2.6 million for the three months
ended March 31, 2025, compared to net cash used in operating activities of $14.1 million for the three months ended March 31, 2024. The $11.5 million decrease in net cash used in operating activities in 2025 was primarily the result of a decrease in contract liabilities in the 2024 period, resulting from deferred revenues as of December 31, 2023 that were recognized during 2024, as
well as a decrease in accounts receivables and a decrease in sales and marketing expenses as described above.
Net cash used in investing activities was $8.2 million for the three months ended March 31, 2025, compared to net cash provided by
investing activities of $16.7 million for the three months ended March 31, 2024. The changes in cash flows from investing activities relate primarily to investments in, and maturities of, short-term bank deposits.
Net cash provided by financing activities was $9.5 million for the three months
ended March 31, 2025, compared to net cash used in financing activities of $0.9 million for the three months ended March 31, 2024. The net cash provided by financing activities in 2025 primarily reflects the net proceeds of the registered direct
offering and net proceeds from the ATM facility, offset by repayments of the loan from BlackRock and the repayments of lease liabilities. Net
cash used in financing activities in 2024 primarily reflects repayments of the loan from BlackRock and the repayments of lease liabilities.
Funding Requirements
We have incurred accumulated losses in the amount of $395 million through March 31, 2025, and we expect to continue incurring losses and negative cash flows from operations
until the cash flows from our strategic partnerships reach a level to offset our ongoing development costs. In this regard, management monitors rolling forecasts of our liquidity reserves on the basis of anticipated cash flows and seeks to maintain
liquidity balances at levels that are sufficient to meet its needs. Our cash flow projections are subject to various risks and uncertainties concerning their fulfilment, and these factors and the risk inherent in our operations, which management
has concluded indicate that a material uncertainty exists, may cast significant doubt on our ability to continue as a going concern. Similarly, our independent registered public accounting firm included a “going concern” explanatory paragraph in
its report on our financial statements as of and for the year ended December 31, 2024.
14
Developing drugs and conducting clinical trials is expensive and we will need to raise substantial additional funds to achieve our
strategic objectives. Based on our current projected cash requirements, we believe that our existing cash and investment balances and other sources of liquidity, including royalties received from Ayrmid from product sales of APHEXDA and milestone
payments from our license agreements with Ayrmid and Gloria, will be sufficient to meet our capital requirements through the second half of 2026. We expect to also continue to seek to finance our operations through other sources, including
out-licensing arrangements for the development and commercialization of our therapeutic candidates or other partnerships or joint ventures, public and private offerings of our equity securities, as well as grants from government agencies and
foundations. Our future capital requirements will depend on many factors, including:
| • |
the progress and costs of our preclinical studies, clinical trials and other research and development activities;
|
| • |
the scope, prioritization and number of our clinical trials and other research and development programs;
|
| • |
the amount of revenues we receive, if any, under our collaboration or licensing arrangements;
|
| • |
the costs of the development and expansion of our operational infrastructure;
|
| • |
the costs and timing of obtaining regulatory approval of our therapeutic candidates;
|
| • |
our success in effecting out-licensing arrangements with third parties;
|
| • |
the ability of our collaborators and licensees to achieve development milestones, marketing approval and other events or developments under our collaboration and out-licensing agreements;
|
| • |
the costs of filing, prosecuting, enforcing and defending patent claims and other intellectual property rights;
|
| • |
the costs and timing of securing manufacturing arrangements for clinical or commercial production;
|
| • |
the costs of establishing sales and marketing capabilities or contracting with third parties to provide these capabilities for us;
|
| • |
the costs of acquiring or undertaking development and commercialization efforts for any future therapeutic candidates;
|
| • |
the magnitude of our general and administrative expenses;
|
| • |
interest and principal payments on the loan from BlackRock;
|
| • |
any cost that we may incur under current and future licensing arrangements relating to our therapeutic candidates; and
|
| • |
market conditions.
|
If funds are not available, we may be required to delay, reduce the scope of, or eliminate one or more of our research or development programs.
Off-Balance Sheet Arrangements
Since inception, we have not entered into any transactions with unconsolidated entities whereby we have financial guarantees, subordinated retained interests, derivative
instruments or other contingent arrangements that expose us to material continuing risks, contingent liabilities, or any other obligations under a variable interest in an unconsolidated entity that provides us with financing, liquidity, market risk
or credit risk support.
15
Share and per-share information in ADSs
Share and per-share information in ADSs are presented in the tables below. Each ADS represents 600 ordinary shares.
|
Three months ended
March 31,
|
||||||||
|
2024
|
2025
|
|||||||
|
(in U.S. dollars)
|
||||||||
|
Earnings (loss) per ADS – basic and diluted
|
(0.38
|
)
|
1.40
|
|||||
|
Loss per ordinary share – basic and diluted
|
(0.00
|
)
|
0.00
|
|||||
|
December 31,
2024
|
March 31,
2025
|
|||||||
|
(in number of ADSs)
|
||||||||
|
Authorized share capital
|
8,333,333
|
8,333,333
|
||||||
|
Issued and paid-up capital
|
2,227,784
|
3,721,003
|
||||||
16