Exhibit 99.44
BLUE MOON METALS INC.
ANNUAL INFORMATION FORM
FOR THE FINANCIAL YEAR ENDED DECEMBER 31, 2024
September 12, 2025
TABLE OF CONTENTS
| INTRODUCTORY NOTES | 1 |
| Cautionary Statement Regarding Forward- | |
| Looking Information | 1 |
| Currency and Exchange Rate Information | 2 |
| Technical Abbreviations | 3 |
| CORPORATE STRUCTURE | 6 |
| The Corporation | 6 |
| Intercorporate Relationships | 6 |
| DESCRIPTION OF THE BUSINESS | 7 |
| General | 7 |
| Business Strategy | 7 |
| Specialized Skills and Knowledge | 8 |
| Competitive Conditions | 8 |
| Economic Dependence and Components | 8 |
| Business Cycles | 8 |
| Environmental Protection | 8 |
| Employees | 9 |
| Foreign Operations | 9 |
| GENERAL DEVELOPMENT OF THE BUSINESS | 9 |
| Three Year History | 9 |
| MINERAL PROJECTS | 16 |
| The Nussir Property | 16 |
| The Blue Moon Property | 46 |
| RISK FACTORS | 80 |
| Permits, Licences and Approvals | 80 |
| Governmental Regulation | 80 |
| Volatility of Commodity Prices | 81 |
| Liquidity and Additional Financing | 81 |
| Nature of Mineral Exploration and Development | 82 |
| No Earnings and History of Losses | 82 |
| Third-Party Approvals | 82 |
| Exploration, Development and Operations | 83 |
| Information Systems and Cyber Security Threats | 83 |
| Global Financial Conditions | 83 |
| Market Price of the Common Shares | 83 |
| Foreign Operations Risks | 83 |
| Foreign Currency Risk | 84 |
| Enforcing Judgments | 84 |
| Dependence on Key Personnel | 85 |
| Reliability of Mineral Resources Estimates | 85 |
| Uncertainty Relating to Inferred Mineral Resources | 85 |
| Acquiring Title | 85 |
| Title Matters | 86 |
| Uncertainty and Inherent Sample Variability | 86 |
| Term and Extension of Concession Contracts | 86 |
| Surface Rights | 86 |
| Climate Change | 86 |
| Uninsurable Risks | 87 |
| Competition | 87 |
| Local Communities, Indigenous Peoples and First | |
| Nations | 87 |
| Conflicts of Interest | 88 |
| Infrastructure | 88 |
| Pre-existing Environmental Liabilities | 88 |
| Outbreaks of Diseases and Public Health Crises | 88 |
| Potential Impact of Tariffs and Trade Restrictions | 89 |
| International Conflict, Geopolitical Instability and War | 89 |
| The Outstanding Common Shares Could be | |
| Subject to Dilution | 89 |
| No Dividends Policy | 89 |
| DIVIDENDS OR DISTRIBUTIONS | 90 |
| DESCRIPTION OF CAPITAL STRUCTURE | 90 |
| Common Shares | 90 |
| Preferred Shares | 90 |
| Equity Incentive Plans | 91 |
| Convertible Securities | 91 |
| MARKET FOR SECURITIES | 91 |
| Trading Price and Volume of Securities | 91 |
| Prior Sales – Securities Not Listed or Quoted on a Marketplace | 92 |
| DIRECTORS AND OFFICERS | 93 |
| Cease Trade Orders, Bankruptcies, Penalties or Sanctions | 97 |
| Conflicts of Interest | 98 |
| AUDIT COMMITTEE | 98 |
| The Audit Committee's Charter | 98 |
| Composition of the Audit Committee | 99 |
| Relevant Education and Experience | 99 |
| Pre-Approval Policies and Procedures | 100 |
| External Auditor Service Fees | 100 |
| LEGAL PROCEEDINGS AND REGULATORY ACTIONS | 100 |
| INTERESTS OF MANAGEMENT AND | |
| OTHERS IN MATERIAL TRANSACTIONS | 100 |
| TRANSFER AGENT AND REGISTRAR | 100 |
| MATERIAL CONTRACTS | 101 |
| INTERESTS OF EXPERTS | 101 |
| ADDITIONAL INFORMATION | 102 |
| SCHEDULE "A" AUDIT COMMITTEE CHARTER | A-1 |
- ii -
INTRODUCTORY NOTES
Cautionary Statement Regarding Forward-Looking Information
This annual information form (this "AIF") of Blue Moon Metals Inc. (the "Corporation" or "Blue Moon") contains or incorporates by reference forward-looking statements and forward-looking information within the meaning of applicable Canadian securities laws, which are based on expectations, estimates and projections as of the date hereof. This forward-looking information includes, or may be based upon, without limitation, estimates, forecasts and statements as to management's expectations with respect to, among other things, the Corporation's historical trends, current conditions, future operations, proposed exploration activities or other development plans at the Corporation's properties; the ability and timing of the Corporation to undertake anticipated exploration, drilling, development, construction and other activities of the Corporation and the result of such activities; the timing and amount of funding required to execute the Corporation's exploration, development and business plans; anticipated capital and exploration expenditures; the ability of exploration work (including drilling and drilling results) to accurately predict mineralization; the type of drilling included in the Corporation's drill program; the ability to generate additional drill targets; expansions of previously known mineralized zones and the discovery of new mineralized zones; the results and assumptions underlying the mineral resource estimates on the Blue Moon Property (as defined herein) and the Nussir Property (as defined herein); the timing and ability (if at all) for the Corporation to complete the recommended work program in the Blue Moon Technical Report (as defined herein) and the Nussir Technical Report (as defined herein); the timing and ability (if at all) for Blue Moon to complete a feasibility study on the Nussir Property and Blue Moon Property; the Corporation's ability to sustain and enhance shareholder value; potential mineralization; the ability to realize upon any mineralization in a manner that is economic; the capital resources available to Blue Moon; the ability for further work to define, expand or upgrade mineral resources at the Corporation's properties; category conversion; the expected ability and timing of the Corporation to advance the Nussir Property and the Blue Moon Property to final investment decision and construction (if at all) and the costs relating to same; the effect on the Corporation of any changes to existing legislation or policy; government regulation of exploration, development and mining operations; the ability of the Corporation and the length of time required to obtain permits, certifications and approvals; the ability for the Corporation to obtain consent or third-party approvals in order to enter into or complete agreements or transactions; the potential impact of the Corporation's projects in local communities and the social acceptability of the Corporation's properties; the success of exploration, development and mining activities; the geology of the Corporation's properties; sustainability and environmental impacts of operations at the Corporation's properties; environmental risks; the availability of labour; the focus of the Corporation in the future; the future payment by the Corporation of dividends; progress in development of mineral properties; the ability of the Corporation to complete its exploration and development objectives for the Corporation's properties; the Corporation's ability to raise funding privately or on a public market in the future; the Corporation's future growth; results of operations and performance; and business prospects and opportunities.
Wherever possible, words such as "anticipate", "believe", "expect", "intend", "may", "plan" and similar expressions have been used to identify such forward-looking information. Forward-looking information is based on the opinions and estimates of management at the date the information is given, and on information available to management at such time. Forward-looking information involves significant risks, uncertainties, assumptions and other factors that could cause actual results, performance or achievements to differ materially from the results discussed or implied in the forward-looking information. These factors, including, but not limited to: errors in management's geological modelling; the inability of the Corporation to capitalize on mineralization on its properties in a manner that is economic; lack of adequate drill density; the timing and ability (if at all) to complete further exploration activities, including drilling; risks relating to costs, timing and ability (if at all) to advance the properties of the Corporation or to reach a construction decision in respect of the Blue Moon Property and the Nussir Property, or other properties of the Corporation differing materially from estimates; the inability to obtain all authorizations and permits needed to continue advancing the Corporation's properties in a timely manner (or at all); failure of the Corporation to complete any further studies for the Blue Moon Property and the Nussir Property in the timing contemplated (or at all); risks relating to the key assumptions, parameters, limitations and methods used in the Blue Moon Technical Report (as defined herein) and the Nussir Technical Report (as defined herein), including the mineral resources estimates contained therein; the prospects, if any, of the Blue Moon Property and the Nussir Property mineral deposits; the amount and type of drilling to be completed and the timing to complete such drilling; the potential to extend mineralization down-plunge and at depth; the ability of exploration work (including drilling) to accurately predict mineralization; upgrading an inferred mineral resource to a measured mineral resource or indicated mineral resource category; future drilling and advancement at the properties of the Corporation; the results of exploration activities; risks relating to mining activities; the global economic climate; metal prices; dilution; environmental risks; community and non-governmental actions; fluctuations in currency markets; social acceptability or the Corporation's projects; fluctuations in commodity prices; risks relating to capital market conditions and the ability of the Corporation to access sufficient capital on favourable terms or at all; changes in law, rules and regulations applicable to the Corporation and its operations; taxation, controls and regulations; risks relating to outbreaks of diseases and public health crises; risks relating to international conflict, geopolitical instability of war; risks relating to any imposition of tariffs or other trade restrictions; political or economic developments in Canada, the United States, Norway or in other countries in which the Corporation does business or may carry on business in the future; risks relating to foreign operations and enforcement of judgments; operating or technical difficulties in connection with exploration or development activities; employee relations; information systems security threats; the speculative nature of mineral exploration and development; obtaining necessary licenses and permits; contests over title to properties, especially title to undeveloped properties; the inherent risks involved in the exploration and development of mineral properties; the uncertainties involved in interpreting drill results and other geological data; environmental hazards; industrial accidents; unusual or unexpected formations, pressures, cave-ins and flooding; limitations of insurance coverage and the possibility of cost overruns or unanticipated costs and expenses; factors discussed under the heading "Risk Factors"; and other risks, including those risks set out in the continuous disclosure documents of the Corporation, which are available on SEDAR+ (www.sedarplus.ca) under the Corporation's issuer profile.
Many of these uncertainties and contingencies can affect the Corporation's actual results and could cause actual results to differ materially from those expressed or implied in any forward-looking statements made by, or on behalf of, the Corporation. Prospective investors should not place undue reliance on any forward-looking information. Although the forward-looking information contained in this AIF is based upon what management believes, or believed at the time, to be reasonable assumptions, there can be no assurance that actual results will be consistent with such forward-looking information, as there may be other factors that cause results not to be as anticipated, estimated or intended. Neither the Corporation nor any other person assumes responsibility for the accuracy and completeness of any such forward-looking information. The Corporation does not undertake, and assumes no obligation, to update or revise any such forward-looking statements or forward-looking information contained herein to reflect new events or circumstances, except as may be required by securities laws.
Currency and Exchange Rate Information
In this AIF, unless otherwise indicated, all references to "$", "dollars" or "CAD" refer to Canadian dollars, all references to "US$" or "USD" refer to United States dollars, and all references to "NOK" refer to Norwegian Krone.
The following table sets forth: (i) the rates of exchange for U.S. dollars and Norwegian Krone expressed in Canadian dollars in effect at the end of the periods indicated; (ii) the average exchange rates in effect during such periods; (iii) the high rate of exchange in effect during such periods; and (iv) the low rate of exchange in effect during such periods, such rates, in each case, based on the noon or daily average exchange rate, as applicable, for conversion of one U.S. dollar or one Norwegian Krone (as applicable) to Canadian dollars as reported by the Bank of Canada.
| U.S. Dollars | Norwegian Krone | |||||
| Year Ended | Year Ended | Year Ended | Year Ended | Year Ended | Year Ended | |
| December 31, | December 31, | December 31, | December 31, | December 31, | December 31, | |
| 2024(1) | 2023(1) | 2022(1) | 2024(1) | 2023(1) | 2022(1) | |
| Period End | 1.4389 | 1.3226 | 1.3544 | 0.1268 | 0.1304 | 0.1375 |
| Average | 1.3698 | 1.3497 | 1.3013 | 0.1274 | 0.1278 | 0.1357 |
| High | 1.4416 | 1.3875 | 1.3856 | 0.1302 | 0.1361 | 0.1452 |
| Low | 1.3316 | 1.3128 | 1.2451 | 0.1240 | 0.1209 | 0.1269 |
Notes:
| (1) | Exchange rate based on the daily average rate of exchange as reported by the Bank of Canada. |
- 2 -
On September 11, 2025, the daily average rate of exchange as reported by the Bank of Canada was US$1.00 = $1.3844 and NOK1.00 = $0.1401.
Technical Abbreviations
Unless the context otherwise requires, technical terms or abbreviations not otherwise defined in this AIF shall have the following meanings:
| List of Abbreviations | |
| Abbreviation | Definition |
| 3 D | Three dimensional |
| AES | Atomic Emission Spectrometry |
| Ag | Silver |
| AI | Bond Abrasion Index |
| Al | Aluminium |
| ALS | ALS Chemex Laboratory |
| As | Arsenic |
| Au | Gold |
| AuAg | Copper-mineralisation Electrum |
| Aup | Administrative Use Permit |
| Ba | Barium |
| Bh | Bore Hole |
| Bi | Bismuth |
| BLM | US Bureau of Land Management |
| BWI | Bond Ball Mill Work Index |
| CEQA | California Environmental Quality Act |
| CIM | Canadian Institute of Mining, Metallurgy and Petroleum |
| Cr | Chromium |
| CRM | Certified reference material |
| Cu | Copper |
| DFS | Definitive Feasibility Study |
| EM | Electromagnetic |
| ENE | East-northeast |
| F | Fluorine |
| GIIP | Good International Industry Practice |
| GPS | Global Positioning System |
| ICP | Inductively Coupled Plasma |
| ID | Identification |
| ID3 | Inverse Distance Cubed |
| IP | Induced Polarization |
| IRR | Internal Rate of Return |
| ISO | International Organization for Standardization |
- 3 -
| List of Abbreviations | |
| Abbreviation | Definition |
| IW | Intersected Width |
| K | Potassium |
| LiDAR | Light Detection and Ranging |
| Micon | Micon International Limited |
| Mo | Molybdenum |
| MRE | Mineral Resource Estimate |
| MSO | Mineable Shape Optimizer |
| Na | Sodium |
| NE | Northeast |
| NEPA | National Environmental Policy Act |
| NGU | Norwegian Geological Survey |
| Ni | Nickel |
| NNE | North-northeast |
| No. | Number |
| NOI | Notice of Intent |
| NPV, NPV8 | Net present value, at 8% discount |
| NS | North South |
| NSR | Net smelter return |
| NW | Northwest |
| OES | Optical Emission Spectroscopy |
| OMAC | OMAC Laboratories |
| Pb | Lead |
| PFS | Pre-Feasibility Study |
| PLT | Point load testing |
| Pt | Platinum |
| QA/QC | Quality Assurance / Quality Control |
| RDA | Resource Development Associates Inc. |
| RMR | Rock Mass Rating |
| RQD | Rock quality designation |
| Sb | Antimony |
| Se | Selenium |
| SE | Southeast |
| SPI | SAG Power Index test |
| Sn | Tin |
| Sr | Strontium |
| SW | Southwest |
| Ta | Tantalum |
| Te | Tellurium |
| Ti | Titanium |
| TMF | Tailings Management Facility |
- 4 -
| List of Abbreviations | |
| Abbreviation | Definition |
| UCS | Uniaxial Compressive Strength |
| V | Vanadium |
| VMS | Volcanogenic Massive Sulphide |
| W | Tungsten |
| WSW | West-southwest |
| XRF | X-ray fluorescence |
| XRT | X-ray Transmission |
| Zn | Zinc |
| ZnEq | Zinz Equivalent – polymetallic rock value expressed in terms of zinc content |
| Units of Measurement | |
| Abbreviation | Definition |
| ± | Plus / minus |
| $ , US$, CAD, NOK | Dollar(s) US, Canadian, Norwegian Krone |
| > , < | Greater than, less than |
| $ /t | Dollars per tonne |
| o | Degree(s) |
| oC | Degrees Celsius |
| % | Percent(age) |
| cm | Centimetre(s) |
| d | Day (24 hours) |
| ft | Foot, feet (linear) |
| g | Gram(s) |
| g/cm3 | Gram(s) per cubic centimetre |
| g/t | Gram(s) per metric tonne |
| gal | Gallons (US) |
| h | Hour (s) |
| in | Inch(es) |
| kg | Kilogram(s) |
| kWh | Kilowatt-hour |
| km | Kilometre(s) |
| km2 | Square kilometre(s) |
| L | Litre(s) |
| Lb, Lbs | Pound(s) avoirdupoids |
| m | Metre(s) |
| M | Million(s) |
| m2 | Square metre(s) |
| m3 | Cubic metre(s) |
- 5 -
| Units of Measurement | |
| Abbreviation | Definition |
| mg | Milligram(s) |
| mm | Millimetre(s) |
| Moz | Million ounces |
| Mt | Million tonnes |
| opt | Ounces per short ton |
| oz | Ounces (troy) |
| oz/y | Ounces per year |
| s | Second |
| t | Tonne (metric) |
| T | Short ton (2,000 lbs) |
| y | Year |
CORPORATE STRUCTURE
The Corporation
The Corporation is an exploration and development stage company which is focused on the exploration and development of mineral resource properties. The Corporation was registered and incorporated under the Business Corporations Act (British Columbia) ("BCBCA") on January 15, 2007 under the name "Savant Explorations Ltd." as a spin-out entity in connection with a spin-out transaction by the Corporation's then parent company, Pacifica Resources Ltd. (now, EDM Resources Inc.) ("Pacifica") of certain assets including, among other things, Pacifica's interest in the Yava polymetallic suphide property in Nunavut, the Blue Moon Property, the Tillex copper prospect in Ontario and various copper projects in Chile (the "Spin Out Transaction"). The Spin Out Transaction, which was effected by way of a plan of arrangement under section 288 of the BCBCA, was completed on June 6, 2007. On June 7, 2007, common shares of the Corporation (the "Common Shares") commenced trading on the TSX Venture Exchange (the "TSXV") under the symbol "SVT". On July 4, 2017, the Corporation changed its name to "Blue Moon Zinc Corp." and in connection with the name change, the Common Shares commenced trading under a new symbol "MOON" on July 5, 2017.
On April 14, 2021, the Corporation further changed its name to "Blue Moon Metals Inc." On March 7, 2023, the Corporation consolidated its Common Shares on the basis of one post-consolidation Common Share for each ten pre-consolidation Common Shares (the "2023 Consolidation").
On March 13, 2025, the Corporation further consolidated its Common Shares on the basis of ten pre-consolidation Common Shares to one post-consolidation Common Share (the "2025 Consolidation", together with the 2023 Consolidation, the "Consolidation"). Unless otherwise noted, all figures set out in this AIF, relating to a number, value or price of Common Shares are presented on a post-Consolidation basis.
The Common Shares are listed for trading on the TSXV under the symbol "MOON", the Frankfurt Stock Exchange under the symbol "8SX0", and the OTCQX Best Market under the symbol "BMOOF". See "Market For Securities".
The Corporation's registered office is located at 2700-1133 Melville Street, Vancouver, British Columbia, Canada, V6E 4E5 and its head office is located at 220 Bay Street, Suite 550, Toronto, Ontario, Canada, M5J 2W4.
Intercorporate Relationships
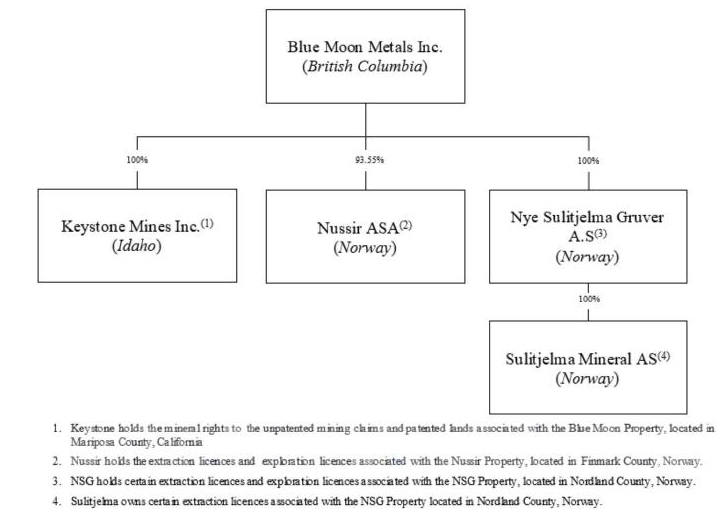
As of the date of this AIF, the Corporation has four material subsidiaries, Keystone Mines Inc. ("Keystone"), Nussir ASA ("Nussir"), Nye Sulitjelma Gruver AS ("NSG") and Sulitjelma Mineral AS ("Sulitjelma").
- 6 -
DESCRIPTION OF THE BUSINESS
General
Blue Moon is a Canadian mineral exploration and development company focused on advancing its three polymetallic brownfield projects, being the Nussir copper-gold-silver property in Norway (the "Nussir Property"), the Blue Moon zinc-copper-gold-silver property in California, USA (the "Blue Moon Property"), and the NSG copper-zinc-gold-silver property in Norway (the "NSG Property").
As of the date of this AIF, the Corporation considers the Blue Moon Property and the Nussir Property to be its only material mineral properties for the purposes of National Instrument 43-101 – Standards for Disclosure for Mineral Projects ("NI 43-101"). The Corporation holds a 100% interest in Keystone which holds the mineral rights to the unpatented mining claims and patented lands associated with the Blue Moon Property, located in Mariposa County, California. The Corporation also holds a 93.55% interest in Nussir which holds the extraction licences and exploration licences associated with the Nussir Property, located in Finmark county, Norway. For additional information on the Blue Moon Property and the Nussir Property, please see "Mineral Projects".
Business Strategy
The Corporation's long-term strategy is to focus on the advancement of its material properties, the Nussir Property and the Blue Moon Property with the aim of taking these properties into production. This will be complemented by continuing to explore and develop the NSG Property. In the near-term, the Corporation intends to focus its efforts on optimizing and advancing the Nussir Property, which is fully permitted, towards an optimized feasibility study, and further advancing the Blue Moon Property towards feasibility. The Corporation intends to engage in continued drilling and exploration activities to expand and further define mineral resources on its properties. In addition, the Corporation will evaluate further critical metals mergers and acquisition opportunities.
- 7 -
Specialized Skills and Knowledge
All aspects of the Corporation's business require specialized skills and knowledge. Such skills and knowledge include the areas of finance, operations, geology, drilling, mining, construction, engineering, metallurgy, accounting and natural resources. The Corporation retains executive officers, skilled personnel and consultants with experience in these areas in Canada, the United States and Norway, generally.
In order to attract and retain personnel with the specialized skills and knowledge required for its operations the Corporation maintains remuneration and compensation packages that it believes to be competitive. The Corporation has been successful to date in identifying and retaining personnel with such skills and knowledge. See "Directors and Officers" for details as to the specific skills and knowledge of the Corporation's directors and management.
Competitive Conditions
The mineral exploration and mining business is a competitive business. The Corporation competes with numerous other companies and individuals in the search for and the acquisition, development and advancement of attractive mineral properties, and to retain qualified personnel, suitable contractors for drilling and bulk sampling operations, technical and engineering resources, and necessary exploration and mining equipment. The Corporation has put in place experienced management personnel and will continue to evaluate the required expertise and skill to carry out its operations.
Economic Dependence and Components
The Corporation's business is not dependent on any contract to sell a major part of its products or to purchase a major part of its requirements for goods, services or raw materials, or on any franchise or license or other agreement to use a patent, formula, trade secret, process or trade name upon which its business depends. It is not expected that the Corporation's business will be affected in the current financial year by the renegotiation, amendment or termination of contracts or subcontracts.
Business Cycles
The Corporation's business, at its current exploration and development phase, is not cyclical, and may be conducted year-round.
Environmental Protection
The Corporation's exploration activities are subject to, and any future development and production operations will be subject to, environmental laws and regulations in the jurisdictions in which its exploration activities and operations are carried out. See "Risk Factors".
Exploration activities have a limited impact on the environment while mining is an extractive industry that has environmental impacts. The Corporation's goal is to constantly evaluate ways to minimize that impact. The Corporation has strived to meet or exceed environmental standards at the Blue Moon Property and the Nussir Property, and the Corporation expects to continue this approach during its transition from the exploration stage towards the development stage through effective engagement with affected stakeholders, including local communities, government and regulatory agencies.
The Corporation's environmental performance is overseen at the Board level and environmental performance is the responsibility of the Corporation. In common with other natural resources and mineral processing companies, the Corporation's operations generate hazardous and non-hazardous waste, effluent, emissions into the atmosphere and contaminated soils that are all managed in compliance with local and international regulations and standards. There are numerous federal, state, and local laws that apply to the Corporation's operations, exploration, development projects and land holdings. These laws address such matters as protection of the natural environment, air and water quality, emissions standards and disposal of waste.
- 8 -
The Corporation recognizes environmental management as a corporate priority and places a strong emphasis on preserving the environment for future generations, while also providing for safe, responsible and profitable operations by developing natural resources for the benefit of its employees, stakeholders and local communities. The Corporation strives to comply with all applicable environmental laws and regulations and to promote environmental stewardship in its activities. Employees are expected to maintain compliance with applicable laws governing the jurisdictions in which they perform their duties.
Employees
As of December 31, 2024, the Corporation had two full-time employees. As of the date of this AIF, the Corporation had twenty-seven full-time employees.
On an ongoing basis, the Corporation evaluates the required expertise and skills to execute its business strategy and will seek to attract and retain the individuals required to meet the Corporation's goals.
The Corporation believes its success is dependent on the performance of its management team and key individuals, many of whom have specialized skills in exploration, development and production in the mining industry. Substantially all / a majority of site personnel and/or consultants have been active at the Blue Moon Property and the Nussir Property for several years or otherwise have extensive experience with similar projects and are knowledgeable as to operations, geology, engineering, construction, environment, mining, metallurgy and infrastructure related to mining development.
The Corporation believes it has adequate personnel with the specialized skills required to carry out its operations and anticipates making ongoing efforts to match its workforce capabilities with its business strategy for its operations as it evolves.
Foreign Operations
As the Corporation's material mineral properties are located in the United States and Norway, the Corporation's business is dependent on foreign operations and as such, a substantial portion of the Corporation's business is exposed to various degrees of political, economic and other risks and uncertainties.
The Corporation's operations and investments may be affected by local political and economic developments, including expropriation, invalidation of government orders, permits or agreements pertaining to property rights, political unrest, labour disputes, limitations on repatriation of earnings, limitations on mineral exports, limitations on foreign ownership, inability to obtain or delays in obtaining necessary mining permits, opposition to mining from local, environmental or other non-governmental organizations, government participation, royalties, duties, rates of exchange, high rates of inflation, price controls, exchange controls, currency fluctuations, taxation and changes in laws, regulations or policies as well as by laws and policies of Canada affecting foreign trade, investment and taxation. For more information, please see "Risk Factors – Foreign Operations Risks".
GENERAL DEVELOPMENT OF THE BUSINESS
Three Year History
The Corporation was incorporated on January 15, 2007, and its primary focus has been to acquire, explore, and if appropriate, develop polymetallic properties in the United States and in Norway. The following is a summary of the Corporation's development over the three most recently completed financial years.
Unless otherwise noted, all figures set out in this AIF, relating to a number, value or price of Common Shares are presented on a post-Consolidation basis.
- 9 -
2022
On March 1, 2022, the Corporation announced results of its 2021 fall exploration program at the Blue Moon Property, including the discovery of an additional massive sulphide zone and extension of the American Eagle Zone from surface to a depth of 700 metres.
2023
Financings
On March 3, 2023, the Corporation completed a non-brokered private placement (the "March 2023 Offering") of 1 20,000 Common Shares for aggregate gross proceeds of $120,000. In connection with the closing of the March 2023 Offering, the Corporation completed the 2023 Consolidation. The March 2023 Offering was priced at $1.00 per Common Share. The proceeds from the March 2023 Offering were used for the Corporation's continuing costs to maintain the Blue Moon Project, regulatory fees, audited financials and other general working capital.
On May 8, 2023, the Corporation completed a non-brokered private placement of an aggregate of 270,000 Common Shares at a price of $0.65 per Common Share for aggregate gross proceeds of $175,500. The proceeds of the financing were used for the Corporation's working capital, regulatory costs, shareholder meeting costs and costs associated with the Blue Moon Project.
On June 15, 2023, the Corporation completed a non-brokered private placement of an aggregate of 769,600 Common Shares at a price of $0.65 per Common Share, for aggregate gross proceeds of $500,240. The proceeds of the financing were used for the Corporation's mineral resource report and other work to advance and maintain the Blue Moon Project, as well as general working capital.
Exploration and Technical Study Updates
On August 21, 2023, the Corporation announced it commenced work on an updated mineral resource estimate ("MRE") for its Blue Moon Project. The Corporation further announced the appointment of Enrique Correa as a director to the Board. In addition to this board change, Douglas Urch stepped down as a director to the Board.
On November 27, 2023, the Corporation filed a technical report for the Blue Moon Project, entitled the "Technical Report for the Blue Moon Mine, Township 4 South, Range 16 East MDB&M, Mariposa County, California", dated November 19, 2023, with an effective date of October 27, 2023, in respect of an updated MRE for the Blue Moon Project. This technical report has been superseded by the Blue Moon Technical Report.
2024
Board Updates
On July 3, 2024, the Corporation announced the appointment of Pedro Fonseca as an independent director to the Board. In addition to this board change, Enrique Correa stepped down as a director of the Board.
Non-Brokered Private Placement
On August 30, 2024, the Corporation completed a non-brokered private placement of 2,640,000 Common Shares at a price of $0.35 per Common Share for aggregate gross proceeds of $924,000, pursuant to the minimum pricing exception under the policies of the TSXV. The net proceeds from the private placement were used for further permitting and exploration activities at the Corporation's Blue Moon Project, as well as general working capital and corporate purposes.
- 10 -
Sale of Yava Project
On October 2, 2024, the Corporation announced that it entered into a definitive agreement with Honey Badger Silver Inc. ("Honey Badger") to sell its Yava Project, located in Nunavut. Pursuant to the definitive agreement dated October 1 , 2024, the Corporation received 4,250,000 common shares of Honey Badger, with an approximate value of $340,000, representing a price of $0.08 per Honey Badger share.
Shareholder Meeting and Board and Management Updates
On October 17, 2024, the Corporation announced the results of its 2024 annual general meeting, including the key additions to its Board as follows: (i) Maryse Bélanger as independent Chairman to the Board, (ii) Christian Kargl-Simard as independent director, and (iii) Haytham Hodaly as independent director.
On November 1, 2024, the Corporation announced key management changes with the following appointments: (i) Christian Kargl-Simard as President and Chief Executive Officer ("CEO"); and (ii) Frances Kwong as Chief Financial Officer ("CFO") and Corporate Secretary. In addition, the Corporation added Garfield MacVeigh and Christian Aramayo, two non-executive advisors, to its Board. The Corporation further announced it granted 177,500 RSUs and DSUs to certain of its directors, advisors and consultants under the Corporation's Omnibus Plan. The RSUs will vest annually over three years from the grant date and the DSUs will vest upon the departure of the grantees from the Corporation. An additional 115,000 Options were granted to certain officers and advisors of the Corporation, pursuant to its Omnibus Plan, with an exercise price of $3.40 per Option, exercisable for a period of five years from the date of grant and vesting over a three-year period.
Acquisition of Nussir and NSG and Concurrent Financing
On November 27, 2024, the Corporation announced the entering into two separate binding letters of intent with Nussir and NSG, pursuant to which the Corporation agreed to acquire all of the issued and outstanding shares of Nussir and NSG (the "Nussir Shares" and the "NSG Shares", respectively). Subsequently on December 19, 2024, the Corporation announced it entered into two share purchase agreements (the "Nussir Share Purchase Agreement" and the "NSG Share Purchase Agreement", respectively) with Nussir and NSG, pursuant to which the Corporation agreed to acquire 99.55% of the Nussir Shares and 100% of the NSG Shares, in exchange for the issuance of an aggregate of up to 31,314,283 Common Shares to Nussir and NSG shareholders, at a deemed price of C$3.00 per Common Share. Under the NSG Share Purchase Agreement, the Corporation agreed to pay US$3,000,000 in cash milestone payments, of which US$1,500,000 will be paid upon receipt by NSG of the discharge permit for the NSG Property and the remaining US$1,500,000 upon receipt by NSG of the operating permit for the NSG Property. The summary of the terms of the Nussir Share Purchase Agreement and the NSG Share Purchase Agreement are qualified entirely by the full text of these agreements, copies of which are available on SEDAR + (www.sedarplus.ca) under the Corporation's issuer profile.
In connection with, and to finance, the Nussir and NSG Transaction, on December 19, 2024, the Corporation completed a brokered private placement of 10,000,031 units of the Corporation at a price of C$3.00 per unit for aggregate gross proceeds of C$30,000,093 (the "Concurrent Financing") pursuant to the terms of the agency agreement dated December 19, 2024 among the Corporation and the Agents (as defined below) (the "Agency Agreement"). The Concurrent Financing was co-led by Cormark Securities Inc. and Scotia Capital Inc., on behalf of a syndicate which includes National Bank Financial Inc., Haywood Securities Inc., Raymond James Ltd., and CIBC World Markets Inc. (collectively, the "Agents"). Each unit consists of 0.1 post-Consolidation Common Share (one (1) pre-2025 Consolidation Common Share) and nine (9) subscription receipts (each, a "Subscription Receipt"). Each Subscription Receipt entitled the holder thereof to receive, upon the satisfaction or waiver the Escrow Release Conditions (as defined below) 0.1 post-Consolidation Common Share (one (1) pre-2025 Consolidation Common Share). The "Escrow Release Conditions" in respect of the Subscription Receipts includes the following events: (i) satisfaction or waiver of all condition precedents to each of the Nussir Transaction and the NSG Transaction (other than the issuance of the consideration shares); (ii) receipt of regulatory, shareholder and third party approvals for the Nussir and NSG Transaction; and (ii) delivery of the escrow release notice by the Corporation and the co-lead agents under the subscription receipt agreement dated December 19, 2024 governing the Subscription Receipts.
- 11 -
Pursuant to the Concurrent Financing and the terms of the Agency Agreement, the Agents were paid a commission equal to 6% of the gross proceeds of the Concurrent Financing (reduced in connection with subscriptions by certain strategic, institutional or retail investors, and by insiders of Blue Moon and shareholders of Nussir and NSG).
Hartree Partners LP ("Hartree") subscribed for C$7,250,000 under the Concurrent Financing. In connection with this subscription, Hartree was granted, among other things, the right to further subscribe for between C$5,250,000 and C$7,750,000 in Common Shares (the "Subscription Option") as well as pro rata pre-emptive rights in respect of future equity issuances of the Corporation, the right to appoint a person to the Board by the end of 2025, and to have representation on a technical committee. The Corporation also agreed to enter into an offtake agreement with Hartree (the "Offtake Agreement") for concentrate production at the Nussir Property and right of last offer for a portion of the offtake volumes at the Blue Moon Property and the NSG Property. In addition, Hartree and the Corporation entered into a memorandum of understanding for up to US$20 million secured bridge loan.
In addition, as Wheaton Precious Metals Corp. ("Wheaton") subscribed for C$4,950,000, the Corporation granted Wheaton a right of first refusal on any precious metals streams from the Corporation's properties for a payment of C$50,000.
As part of the Concurrent Financing, Leonard Nilsen & Sønner AS ("LNS") subscribed for C$4,200,000 worth of units and agreed to subscribe for an additional C$2,300,000 worth of Common Shares upon two milestones, the first being the start of decline construction at the Nussir Property (the "First Milestone") and the second 10 months after the start of the decline construction. The Corporation also agreed to grant LNS the right to appoint one member to the Board by the end of June 2025 if it holds 5% of the Common Shares, which LNS has not yet exercised as of the date hereof.
The trading of the Common Shares was halted pending the approval of the TSXV of the Nussir and NSG Transaction. Trading resumed on March 14, 2025. See "General Development of the Business – Three Year History – 2024 – TSXV Graduation, 2025 Consolidation and Resumption of Trading".
Events Subsequent to 2024
Completion of Nussir and NSG Transaction
On February 27, 2025, the Corporation announced the closing of its acquisition of Nussir and NSG (the "Nussir Transaction" and the "NSG Transaction", respectively, and collectively, the "NSG and Nussir Transaction"). As consideration for the NSG and Nussir Transaction, the Corporation issued an aggregate of 29,776,149 Common Shares, comprised of: (i) 24,168,149 Common Shares to former shareholders of Nussir, and (ii) 5,608,000 Common Shares to former shareholders of NSG, in exchange for a 93.55% interest in Nussir and a 100% interest in NSG, respectively. The aggregate consideration for the NSG and Nussir Transaction of 31,314,283 Common Shares, previously announced by the Corporation on December 19, 2024, was reduced by 1,538,134 Common Shares, as the 9 9.5% interest initially contemplated by the Nussir Share Purchase Agreement was reduced to 93.55%. In connection with the closing of the NSG and Nussir Transaction, the Escrow Release Conditions were met and the Subscription Receipts were automatically converted into Common Shares.
In connection with the Nussir Transaction, Nussir was granted the right to appoint two nominees to the Board. Baker Steel Resources Trust Limited ("BSRT"), one of the former shareholders of Nussir, acquired 5,572,888 Common Shares as part of the consideration it received pursuant to the Nussir Transaction. In addition, BSRT held 1,950,003 subscription receipts which were automatically converted into 195,000 Common Shares. As a result, BSRT holds 5 ,789,555 Common Shares, representing approximately 12.8% immediately after the completion of the Nussir Transaction and approximately 11.2% of the issued and outstanding Common Shares as of the date hereof. For additional details, please refer to the early warning report filed by BSRT dated February 27, 2025.
Concurrently with the closing of the NSG and Nussir Transaction, the Corporation appointed Nussir's nominees, Karin Thorburn and Francis Johnstone, an investment advisor at BSRT, to the Board.
- 12 -
Nussir Technical Report
On February 27, 2025, the Corporation filed a technical report for the Nussir Property entitled the "Report NI 43-101 Technical Report on the Mineral Resources of the Nussir and Ulveryggen Projects, Norway", dated January 24, 2025, with an effective date as at January 20, 2025. This technical report has been superseded by the Nussir Technical Report.
Corporate Updates
On February 27, 2025, the Corporation also announced key management changes as follows: (i) Skott Mealer as President and Chief Operating Officer ("COO"); and (ii) Theodore Veligrakis as Vice President, Exploration.
Blue Moon Technical Report
On March 3, 2025, the Corporation announced an updated MRE and the results of a preliminary economic assessment ("PEA") for the Blue Moon Project (as defined herein). Subsequently on April 15, 2025, the Corporation filed a technical report in respect of the updated MRE for the Blue Moon Project entitled the "NI 43-101 Technical Report for the Preliminary Economic Assessment of the Blue Moon Mine, Mariposa County, California", dated April 14, 2025, with an effective date as at March 3, 2025. This technical report has been superseded by the Blue Moon Technical Report.
Hartree Subscription and Investor Rights Agreement
On March 7, 2025, Hartree exercised its Subscription Option to purchase an additional 1,750,000 Common Shares at a price of C$3.00 per Common Share for aggregate proceeds of C$5,250,000. In connection with this subscription, the Corporation and Hartree entered into an investor rights agreement dated March 7, 2025 (the "Hartree Investor Rights Agreement") which provides for, among other things, the right to nominate a board member, participation right and top-up rights in respect of future equity issuances and right to appoint a representative or observer to the technical committee, demand registration rights and piggy registration rights. The summary of the terms of the Hartree Investor Rights Agreement is qualified entirely by the full text of the Hartree Investor Rights Agreement, a copy of which is available on SEDAR+ (www.sedarplus.ca) under the Corporation's issuer profile.
In connection with this subscription, the Corporation and Hartree also entered into the Offtake Agreement.
REAS Acquisition
On March 10, 2025, the Corporation announced the acquisition of Repparfjord Eiendom AS (the "REAS Acquisition") from Wergeland Eigedom AS ("WG"), which included the ship loading equipment and infrastructure related to aggregate mining, port area and adjacent properties to the Corporation's Nussir Project, pursuant to the terms of the share purchase agreement dated March 6, 2025 between the Corporation and WG (the "REAS Share Purchase Agreement"). Pursuant to the terms of the REAS Share Purchase Agreement, as consideration in respect of the REAS Acquisition, the Corporation paid 180,000,000 NOK (approximately US$16,000,000), comprised of 4,210,000 Common Shares and approximately US$7.2 million in cash.
TSXV Graduation, 2025 Consolidation and Resumption of Trading
On March 13, 2025, the Corporation announced its graduation to a tier 1 issuer on the TSXV. In addition, the Corporation announced the 2025 Consolidation will be effective as of March 14, 2025 upon the resumption of trading of the Common Shares on the TSXV. The Common Shares had been halted in connection with the Nussir Transaction and NSG Transaction. See "General Development of the Business – Three Year History – 2024 – Acquisition of Nussir and NSG and Concurrent Financing".
- 13 -
Norwegian License Updates
On March 18, 2025, the Corporation announced that the Norwegian Ministry of Trade, Industry and Fisheries upheld the Corporation's operating license and the extended deadline for start-up of operations for the Nussir Property. The license will remain in place as long as mining activities on the Nussir Property have commenced by September 2027.
NSG MRE
On April 10, 2025, the Corporation announced a maiden MRE for the NSG Property, highlighting 17 Mt grading 1 .06% Cu and 0.21% Zn in the inferred category over three deposits.
BLM Approval
On April 15, 2025, the Corporation announced it received the approval of the Bureau of Land Management for a portal and tunnel to enable underground mineral exploration activities at the Corporation's Blue Moon Property. The Corporation expects to complete a feasibility study within 24 months following the start of construction of the decline in Q3 2025.
Uplist to OTCQX Best Market
On April 14, 2025, the Corporation announced the reinstatement of quotation on the OTCQB, trading under the symbol " BMOOF", following a halt in the trading of the Common Shares on the TSXV as part of its acquisition of the Nussir Property and the NSG Property. Subsequently, on April 15, 2025, the Corporation announced that its Common Shares started trading on the OTCQX under the ticker symbol "BMOOF", representing an upgrade from the OTCQB Venture Market.
Corporate Updates
On April 21, 2025, the Corporation announced the appointment of Boi Linh Doig as Vice President, Mining.
Change of Auditors
On April 21, 2025, the Corporation filed a notice of change of auditor, along with letters from its former and successor auditors, changing its auditor from Davidson & Company LLP, Chartered Professional Accountants to MNP LLP, Chartered Professional Accountants. See "Interest of Experts".
LNS Investment & Engagement of Red Cloud Securities
On May 8, 2025, the Corporation announced that LNS has been mobilized in preparation for the underground development of the exploration decline and underground mining parameter confirmation at the Nussir Project. In addition, as the Corporation achieved the First Milestone, LNS subscribed for 376,833 Common Shares at a price of C$3.00 per Common Share for aggregate proceeds of C$1,130,499. See "General Development of the Business – Three Year History – 2024 – Acquisition of Nussir and NSG and Concurrent Financing". In addition, the Corporation retained Red Cloud Securities Inc. as a market maker for the Corporation.
Sulitjelma Technical Report
On May 20, 2025, the Corporation filed a technical report for the Sulitjelma project entitled the "Report NI 43-101 Technical Report on the Mineral Resources of the Sulitjelma Project, Norway", dated May 20, 2025, with an effective date as at February 20, 2025. This technical report has been superseded by the Sulitjelma Technical Report.
Corporate Updates
On July 3, 2025, the Corporation announced the appointment of Stephen Eddy as Senior Vice-President, Corporate Development.
- 14 -
The Corporation granted 200,000 Options to Stephen Eddy, pursuant to its Omnibus Plan, with an exercise price of $3.37 per Option, exercisable for a period of five years from the date of grant and vesting over a three-year period.
Strategic Project Status for the Nussir Project
On June 5, 2025, the Corporation announced that, on June 4, 2025, the Nussir Project was designated by the European Union Commission as a Strategic Critical Raw Material Project.
Norwegian Environmental Permit
On July 9, 2025, the Corporation announced that it received environmental permits for its planned activities from the Norwegian Environmental Agency and awarded a contract to Fauskebygg AS for the extension of its Rupsi tunnel at NSG.
Loan and Investment by Hartree and Oaktree
On August 19, 2025, the Corporation announced that it entered into a memorandum of understanding (the "MOU") with Hartree and funds managed by Oaktree Capital Management, L.P. ("Oaktree", together with Hartree, the " Lenders", and each a "Lender") in respect of an investment package which consists of (i) a previously agreed to bridge loan (the "Bridge Loan") and (ii) a project financing package (the "Project Finance Package"), which provides for up to US$140 million of support for the continued development and construction of the Corporation's flagship, fully permitted Nussir Project. The Project Finance Package includes a US$50 million senior secured term loan (the "Term Loan"), a US$70 million precious metals stream (the "Stream"), and an equity investment of up to US$20 million (subject to a 19.9% Oaktree / Hartree combined ownership limitation) (the "Equity Investment").
The Corporation and its subsidiaries, Nussir and Keystone, as borrowers, and Blue Moon Norway AS and Repparfjord Eiendom AS, each a wholly-owned subsidiary of the Corporation, as guarantors, entered into the loan agreement dated August 19, 2025 (as amended on September 2, 2025) (the "Bridge Loan Agreement") with the Lenders and related documents relating to the Bridge Loan on August 19, 2025. Pursuant to the Bridge Loan Agreement the Lenders shall provide a bridge facility of up to US$25,000,000 with a maturity of June 30, 2027, available from the closing date to and including March 31, 2026 with interest equal to the base rate (the "Base Rate") plus 8.0% per annum, where the Base Rate is the 3-month Term SOFR plus 0.10% per annum, subject to a minimum Base Rate of 3.00% per annum. In connection with the Bridge Loan, the Corporation has agreed to grant Hartree, as a loan bonus, 1,045,000 Common Shares which was issued upon the initial draw of funds under the Bridge Loan of US$12.5 million which was completed on September 4, 2025. The Bridge Loan is expected to be used to fund early works, pre-construction activities, development, construction, operation and working capital requirements of the Nussir Project, advancing the Blue Moon Project, and for general corporate and working capital purposes. In addition, the Corporation also entered into a non-binding letter agreement on August 19, 2025 in respect of the Term Loan and Stream.
Further, in relation to the Equity Investment, the Corporation executed a subscription agreement dated August 19, 2 025 with Oaktree to purchase 2,092,173 Common Shares at a price of C$3.30 per Common Share for aggregate gross proceeds of approximately US$5 million (the "Initial Equity Offering"). The Initial Equity Offering was subsequently closed on September 4, 2025 and represents the first tranche of the Equity Investment. The remainder of which will be subscribed to by both Oaktree and Hartree. The Corporation intends to use the proceeds of the Initial Equity Offering for general corporate and working capital purposes.
Nussir Technical Report
On September 12, 2025, the Corporation filed an amended and restated technical report for the Nussir Property entitled the " NI 43-101 Technical Report on the Mineral Resources of the Nussir and Ulveryggen Projects, Norway", dated January 24, 2025 (as amended and restated on September 12, 2025), with an effective date as at January 20, 2025 (the "Nussir Technical Report"). This is the current NI 43-101 technical report in respect of the Nussir Property.
- 15 -
Blue Moon Technical Report
On September 12, 2025, the Corporation filed an amended and restated technical report in respect of the updated MRE for the Blue Moon Project entitled the "NI 43-101 Technical Report for the Preliminary Economic Assessment of the Blue Moon Mine, Mariposa County, California", dated April 14, 2025 (as amended and restated on September 12, 2 025), with an effective date as at March 3, 2025 (the "Blue Moon Technical Report"). This is the current NI 43-1 01 technical report in respect of the Blue Moon Property.
Sulitjelma Technical Report
On September 12, 2025, the Corporation filed an amended and restated technical report for the Sulitjelma project entitled the "NI 43-101 Technical Report on the Mineral Resources of the Sulitjelma Project, Norway", dated May 20, 2025 (as amended and restated on September 12, 2025), with an effective date as at February 20, 2025 (the "Sulitjelma Technical Report"). This is the current NI 43-101 technical report in respect of the Sulitjelma project.
MINERAL PROJECTS
The Nussir Property
Technical Report
Scientific and technical information relating to the Nussir Property provided in this AIF is supported by and qualified in its entirety by the full text of the most recent technical report on the Nussir Property filed in accordance with NI 43-101 entitled "NI 43-101 Technical Report On The Mineral Resources Of The Nussir And Ulveryggen Projects, Norway" dated January 24, 2025 (as amended and restated on 12, 2025) with an effective date of January 20, 2025, being the Nussir Technical Report, which was prepared, reviewed, and approved by Adam Wheeler, B.Sc., M.Sc., C. Eng., Eur Ing., FIMMM who is a "qualified person" for purposes of NI 43-101. Reference should be made to the full text of the Nussir Technical Report, which is available electronically on SEDAR + (www.sedarplus.ca) under Blue Moon's issuer profile.
Scientific or technical information in respect of the Nussir Property provided subsequent to the date of the Nussir Technical Report were prepared by or under the supervision of Dustin Small, who is a consultant to the Corporation and a non-independent qualified person for the purposes of NI 43-101.
Property Description, Location and Access
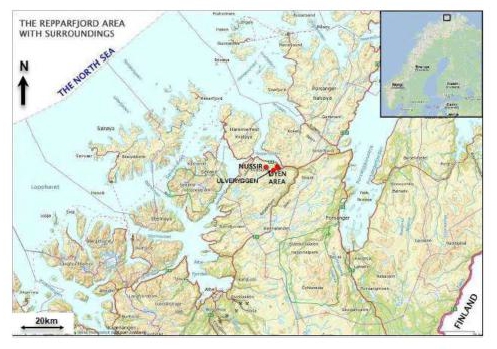
The Nussir deposit is located about 1.5 km north of the Øyen Industrial area and 1.5 km south of the Markoppnes Industrial area, in Repparfjord, Kvalsund, Hammerfest Municipality, in the western part of Finnmark county, northern Norway. The Ulveryggen deposit is located approximately 3 km south of Nussir. It is envisaged that an industrial area with mineral processing plant and related facilities could be located either at the established industrial area at Øyen, subject to a deal with the current operator, or at the Markoppnes industrial area. The zoned area for mining and industrial activity in the Repparfjord area is about 5000 acres.
For exploration activities, access is year-round for the underground, however, for surface exploration, only the legislated window of May 1 to June 15 each year is unavailable. This means that all work that is planned and budgeted can be undertaken on tenure for the Nussir and Ulveryggen projects.
- 16 -
Figure 2.1: Area Map of West Finnmark
Accessibility
The Øyen area and nearby Markoppnes, which are on the coast just to the north-west of each deposit, are situated along National Highway 94 (R94). The R94 highway continues to the north-west, up to the city of Hammerfest with its major oil installations. The E6 major road is just a few kilometres away at the site of Skaidi; this road connects the previous mining area to the biggest city in Finnmark, Alta, to the south. Alta is approximately 70km south-west of the deposit areas and has an international airport.
The Repparfjord is ice-free during winter, making sea transport of supplies and export of concentrate directly to and from the site possible year-round.
Site Description
The topography overlying and around the area of the Nussir deposit is an unspoiled Arctic environment, extending westwards from the port area at Øyen. The area immediately overlying Nussir is relatively flat for most of the first 8 km from the coast, passing various small shallow post-glacial lakes, at an elevation generally of approximately 200 m. Almost immediately north of the Nussir outcrop, hill rise up steeply, up to a height of approximately 500 m. Approximately 800m south-east of the Nussir deposit the land again rises up to 400-500 m. The most westward part of the Nussir deposit passes under the rising hills. The vegetation of the projects is predominantly described as alpine and rare, but variable. It ranges from areas of birch trees close to the fjord to more like alpine tundra, at altitude, with very sparse and limited vegetation. Near bog ecosystems, dwarf birch trees are present.
The Ulveryggen deposit is approximately 3km south-east from the Nussir deposit and 2km south-west from the coastline. There are four old open pits at the Ulveryggen deposit, which were mined from 1972 to 1979. There is some surface infrastructure which connects to a 2.5 km 36 m2 (6x6 meter) historical underground haulage tunnel which is in good condition, as well as existing 4.5 km of surface haul roads from the Øyen industrial area all the way up to the open pits at 450 meter above sea level. Next to the tunnel portal there is an existing workshop building for trucks and other vehicles. The current strike of the Ulveryggen deposit is much smaller than Nussir, extending approximately 2 km from west to east.
- 17 -
Licenses
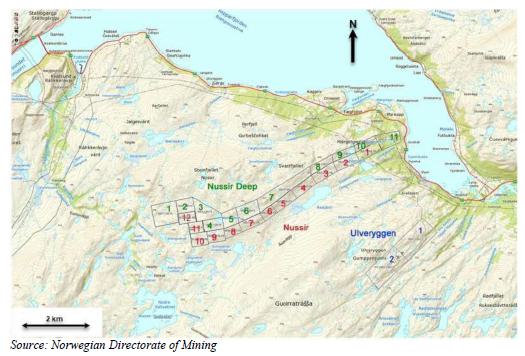
The main license areas held by Nussir, are shown in Figure 2.2, and are summarized in Table 2.1 for Nussir and in Table 2.2 for Ulveryggen. These areas all have valid extraction status and are held by Nussir. These extraction licences areas do not expire as the operating licence on top of these is valid and are held by Nussir. Nussir applied for an operating license for the area covered by the 25 extraction licences, and the operating licence was awarded in 2019. In 2024 it applied for extension of the operating licence for a further 3 years according to the Minerals Act of Norway. The extension was granted by the Mining Directorate of Norway in 2024 and then objected to by third parties. The Mining Directorate upheld its decision and then sent the objections to be finally decided by the Ministry of Trade, Industry and Fisheries and a decision is expected within Q1 2025. As long as the objections regarding the extension is under processing, the permit still remains valid. Other than the fees described below, under the heading "Fees and Royalties", there are no other obligations that must be met to retain the permit.
Nussir, a Norwegian public limited liability company, holds various mineral extraction and exploration permits necessary for its mining operations. According to the title and legal opinion provided by Simonsen Vogt Wiig AS, Nussir is duly incorporated and in good standing under Norwegian law, with no ongoing bankruptcy proceedings as of December 19th, 2024, and has valid title to all licences listed in Tables 2.1 and 2.2. The company does not own or lease any real property, meaning it must enter into an agreement with the public landowner Finnmark Estate for mining activities. Nussir is given access by the state to the land covered by the extraction permits which allows Nussir to access the surface rights both for the Nussir and Ulveryggen properties, and to carry out the required exploration and development activities. In addition, Nussir needs to submit an application to the Municipality for the use of vehicles for such activities, typically once a year. Nussir will need to reach an agreement to acquire and/or lease additional industrial area to construct a full mine and milling operation. Two options exist at the Markoppnes or the Oyen industrial areas next to the project. Both are being evaluated by Nussir, with a further decision to come in due course, but at this time Nussir is in good legal standing with all of its licenses and access arrangements with the different governing entities for the current stage of project.
The title opinion confirms that Nussir holds a 100% interest in all its registered mining permits, which remain in good standing. These include an operating license, extraction permits named for copper, gold, palladium, platinum, and silver (but will in fact also include all other state-owned minerals (i.e metals with a specific gravity of 5 grams/cm3 or higher) within the license areas) and 4 exploration permits. The company's operating license, initially issued in 2 019, was extended until 2027 by the Norwegian Directorate of Mining, although this decision has been appealed and is currently under review by the Ministry of Trade, Industry, and Fisheries. If the extension is overturned, a new application process could take up to two years. The opinion also notes that the permits are not subject to any registered security interests and that no legal or regulatory issues outside Norway have been identified that would affect Nussir's ability to hold these rights.
Table 2.1: Summary of License Areas – Nussir
| License Code | NAME | AREA (m2) |
| G.UTV 0001/2006-FB | Nussir 1 | 291,172 |
| G.UTV 0002/2006-FB | Nussir 2 | 292,251 |
| G.UTV 0003/2006-FB | Nussir 3 | 299,109 |
| G.UTV 0004/2006-FB | Nussir 4 | 298,875 |
| G.UTV 0005/2006-FB | Nussir 5 | 296,036 |
| G.UTV 0006/2006-FB | Nussir 6 | 174,865 |
| G.UTV 0007/2006-FB | Nussir 7 | 287,282 |
| G.UTV 0008/2006-FB | Nussir 8 | 205,676 |
| G.UTV 0009/2006-FB | Nussir 9 | 242,878 |
| G.UTV 0010/2006-FB | Nussir 10 | 255,072 |
| G.UTV 0011/2006-FB | Nussir 11 | 199,900 |
| G.UTV 0012/2006-FB | Nussir 12 | 215,893 |
| G.UTV 0001-1/2015 | Nussir Deep 1 | 644,623 |
| G.UTV 0002-1/2015 | Nussir Deep 2 | 288,715 |
- 18 -
| License Code | NAME | AREA (m2) |
| G.UTV 0003-1/2015 | Nussir Deep 3 | 433,512 |
| G.UTV 0004-1/2015 | Nussir Deep4 | 269,706 |
| G.UTV 0005-1/2015 | Nussir Deep 5 | 283,553 |
| G.UTV 0006-1/2015 | Nussir Deep 6 | 399,766 |
| G.UTV 0007-1/2015 | Nussir Deep 7 | 806,227 |
| G.UTV 0008-1/2015 | Nussir Deep 8 | 233,762 |
| G.UTV 0009-1/2015 | Nussir Deep 9 | 207,267 |
| G.UTV 0010-1/2015 | Nussir Deep 10 | 184,362 |
| G.UTV 0011-1/2015 | Nussir Deep 11 | 369,850 |
| Table 2.2: Summary of License Areas – Ulveryggen | ||
| License Code | NAME | AREA (m2) |
| G.UTV 001-1/2013 | Ulveryggen 1 | 991,269 |
| G.UTV 002-1/2013 | Ulveryggen 2 | 988,113 |
Figure 2.2: Plan of License Areas
Fees and Royalties
Under the Norwegian Minerals Act, metals with a specific gravity of 5 g/cm³ or higher, including copper, silver, and gold, are classified as state-owned minerals. These metals, which are of primary economic interest at both Nussir and Ulveryggen, require compensation to the state through payment of yearly fees in order to uphold the extraction and exploration permits. These fees are calculated based on the size of the areas in question and must be paid within the 15th of January each year. Nussir has made payment of NOK 107,000 in total for all extraction and exploration permits for 2025.
- 19 -
Further, all extraction of state-owned minerals requires payment of a 0.5% net smelter royalty of the sales value of the extracted minerals to the landowner, who is Finnmarkseiendommen (FeFo). In addition, an increased landowner royalty of 0.25% net smelter royalty is mandated for projects in Finnmark as is the case for Nussir, which is also paid to FeFo.
Blue Moon must therefore pay a 0.75% net smelter royalty on all extracted minerals. This royalty will be due for payment by March 31 of the following year. There are no back-in rights, payments or other encumbrances to which both Nussir and Ulveryggen permits are subject to.
Environmental Liabilities
The Nussir and Ulveryggen projects have negligible environmental liability, since any impact from historical mining operations, notably at Ulveryggen deposit, rest with the Norwegian Government.
History
Nussir
Initial Exploration
Copper ore deposits in the Repparfjord area were discovered at the turn of the last century. In 1903, the Swedish company Nordiska Grufaktiebolag began to explore the ore field. Sydvaranger AS, a large Norwegian mining company with an iron ore mine in Finnmark, was prospecting west of Ulveryggen and found some Cu-enriched sites, which were later identified to be the Nussir orebody. AS Prospektering was established from Sydvaranger as an independent company, and worked on building their geological database, including the Nussir project.
In 2000, Terra Holding bought AS Prospektering and took over the Nussir deposit rights. Further analyses on the deposit showed promising results, and plans were made to further study and develop the project. In December 2004, Terra Holding created Nussir AS to focus on developing the Nussir deposit.
Geophysical surveys
Ground IP and Resistivity
Three ground geophysical surveys campaigns have been done by the Norwegian Geological Survey (NGU) using surveying equipment comprising a Terrameter ABEM-LS unit and multielectrode cables.
Induced polarisation and resistivity were measured in the ground above drillhole intersections for correlation purposes and in target exploration areas. Results indicated strong correlations between copper mineralisation, strong IP anomalies and low resistivity anomalies, as exemplified in Figure 2.4. Other mineralisation suffers from a low signal-to-noise ratio. Large parts of the regions are characterized by "negative" in phase data, typical for regions with high susceptibility and/or high resistivity. All collected data have a significant higher quality and resolution than earlier airborne data collected by the NGU in the same area in the 1970s.
A GPS system from Seatex (SEAPOS 100E) was used for helicopter positioning.
- 20 -
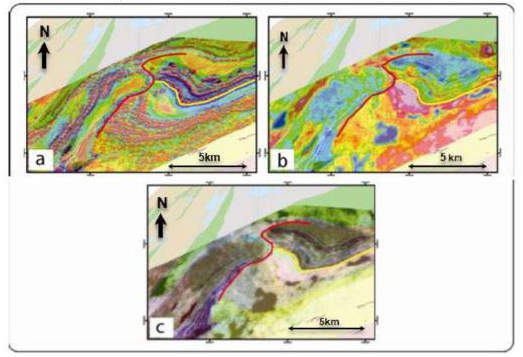
Progressing from the (eastern) Nussir I mineralised body, detailed field observations allowed the establishment of its potential Nussir II continuation towards west. Figure 2.3 shows its magnetic and radiometric signatures, with a red line highlighting a possible thrust discontinuity. The vertical derivative of the total magnetic field (Figure 2.3a) shows that the Nussir greenstones to the east of the red line are characterised by two very prominent, parallel high anomalies. A third, weaker and less continuous anomaly parallels these two anomalies further to the north. These features are the most prominent elements of the magnetic signature in the greenstones of the Nussir Mountain. They are folded about a NE-SW trending axis and can be readily traced eastward, where they strike ENE-WSW. The same fold geometry is shown by the anomalies generated by the Saltvatn Group lithologies, south of the yellow line. The Nussir mineralisation is folded by this structure, which generated local thickening and duplication of the deposit. It is obvious from Figure 2.3 that these high anomalies do not continue simply to the west of the red line, where a single, yet extremely irregular and laterally stepped magnetic anomaly has instead been observed. The radiometric dataset is less conclusive with regard to the detailed internal architecture of the greenstone bodies exposed to the east and west of the discontinuity, but on the other hand, highlights significant compositional similarities between the two greenstone bodies, expressed by a similar total count signature (Figure 2.3b) and, above all, the ternary radiometric information of Figure 6-1c.
Figure 2.3: Geophysical Signature of the Nussir West Area
[Source: NGU]
Geological information is drawn on top of:
a) The vertical gradient of the magnetic total field.
b) The radiometric total count.
c) The ternary radiometry.
The red line traces possible thrust discontinuity (Pharaoh et al., 1983). The yellow line shows
the boundary between the Nussir (to the north) and Saltvatn Groups (to the south).
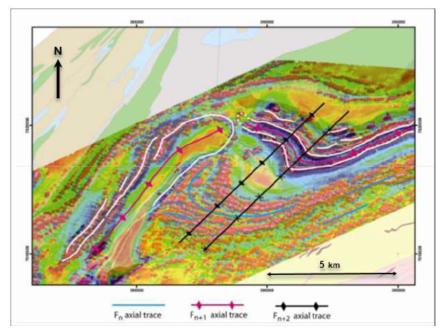
The current interpretation of the local structural framework is shown in Figure 2.4. White lines are used to trace the main anomalies within the greenstones. These interpretations are supported by the results from structural investigations: the Skinnfjellet greenstone body is interpreted as being folded by a Fn+1 antiform, with an undulating axial trace trending generally SW-NE. The fold nose has been traced, however, not by following the curved map pattern of the dolomites, but instead by joining the high magnetic anomalies of the underlying greenstones, which are the likely source of the magnetic signature from underneath a presumably very thin dolomite occurrence. The south-eastern limb of the antiform is easily identified and corresponds to the top-to-the-NW sheared contact between dolomites and greenstones and the Dypelv conglomerates.
The conglomerates contain also early Fn folds, which are the oldest structural feature recognised by Nussir within the Repparfjord Window. Later Fn+2 shortening generated the prominent folds that refold Fn+1 and Fn folds. Fn+2 are the folds that caused the current folded pattern of the Nussir and Saltvatn Group lithologies in the Nussir West area.
- 21 -
Figure 2.4: Structural Interpretation of Nussir West Area.
[Source: NGU]
[Interpretation superimposed on the vertical gradient of the total magnetic field]
Key to the understanding of a possible existence of a south-westward continuation of Nussir I, into the postulated Nussir II towards the west, was the geological and structural evolution in the Nussir West area. The currently preferred interpretation, i.e. the Nussir Group greenstones occupying the hanging wall of a thrust with top-to-the-SE transport direction, calls for a possible continuation of Nussir I below this thrust plane on the south-eastern side of Skinnfjellet. The dip of the thrust plane is, however, an important factor. Although there is a lack of direct field constraints on the geometry of the structure, it can be argued that the dip of this thrust is probably steep, as indicated by the abrupt termination of the magnetic anomalies of the highly magnetic Djupelv Formation conglomerate. If the conglomerate continued at shallow depth beneath the greenstones of Steinfjellet, then the magnetic signature of this formation should be encountered as deeply seated magnetic anomalies, which is not the case, thus, suggesting a sharp truncation by the thrust plane.
Detailed studies of the highest frequency of apparent resistivity, give a clear indication of an anomaly which fits with the mapped Nussir mineralisation in the eastern part. In this part the geophysical profiles are perpendicular to the mineralisation. In the western part the outline of the mineralisation is swinging north, and the geophysical profiles are parallel. In this area the geophysical anomalies are not easy to interpret.
The geophysical study shows that lakes and strong faults also give the same anomaly as the mineralised zone, and it is not easy to distinguish the three. There are a lot of lakes and faults in the area.
Ulveryggen
Initial Exploration and Historical Open Pit Mining
The Repparfjord deposit was identified around 1900. The first trenches and shafts were opened in 1903 by the Swedish company "Nordiska Grufaktiebolaget". In 1905, the company was granted a mining permit.
In 1955, 2,358 m of drilling was carried out by the Canadian company "Invex Corporation Ltd". In 1963, a Norwegian company acquired the rights to the deposit. In the 1960s, the Norwegian company "AS National Industri" drilled around 10,000 m. Based on the geological work from this period, the deposit was estimated at 10 million tons averaging 0.72% Cu. Folldal Verk AS acquired the rights to the deposit in 1970, and at the same time construction of mining and flotation facilities began. 2 years later in May 1972 the test production started, and full open pit production later the same year.
Mine development included 700 m of crosscuts, shafts and about 1,700 m of trenches, however, the grade of ore was found to be too low to allow for a profitable operation at that time. The Ulveryggen ore was mined and processed by Folldal Verk AS from 1972 until 1979.
- 22 -
The Repparfjord deposit produced 2 Mt of waste rock and 3 Mt of ore averaging 0.66% Cu from four small open pits. The deposit was opened by 4 open pits each 100-400 m long, 30-120 m wide and with 2-5 benches of 10 m height. For wintertime transport, a 2,500 m long haulage tunnel was driven 200 m under the open pit level. Ore was dumped through an ore pass down to the tunnel from where trucks hauled the ore to an ore pass leading to and feeding the primary crusher. An underground conveyor took the primary crushed ore to further crushing, milling and separation in the nearby processing plant.
The deposit outcrops at around 425 meter above sea level, and due to the climatic conditions the crushing and processing facilities were placed at sea level around 4 km from the deposit. The ore was crushed and milled in 4 operations down to 80% under 0.074 mm in size. From the crude ore, 50,903 tons of concentrate with an average content of 35.5% Cu were processed. The copper mill recovery was 91.3% on average.
Since the closure of the mine, one of the pits has been used for disposal of cleaned drilling cuttings from the offshore oil activities. The filling is cement stabilized.
In 2011, Nussir purchased the rights to the old Ulveryggen mine with all its existing facilities and access to complement the Nussir project.
Geophysical Survey
In October 2007 a helicopter-borne geophysical survey was completed around Ulveryggen. Measurements taken included magnetic, frequency-domain EM, and spectral gamma ray radiometry data. These measurements were a small part (~40 km2) of a larger survey carried out south of Vargsundet.
This survey showed that the delineation of EM and magnetic anomalies are related to overall district-scale structures.
Structural Mapping and Field XRF Analyses
Reconnaissance structural geological mapping and field XRF-analyses were carried out in the Ulveryggen area in
August 2007. The preliminary conclusions from this work suggest a structural control of at least part of the mineralisation.
Observations at Hovedfelt suggest a relatively constant dip direction of the bedding to the NE. There appears to be a large antiform to the south of the studies area, with Ulveryggen being located on its north-western limb. At Hovedfelt and Vestfelt there is a significant brittle/ductile shear zone, seemingly associated with the high copper values within the meta-sediments.
XRF analyses were carried out by using a Thermo Scientific NITON XLp Analyzer. The analyses were mostly carried out along across-strike profiles in NE facing walls within the open pits, three profiles in the 'Hovedfelt' and 'Vestfelt', and a final profile in the NE-wall of the northeasternmost Erik pit. The analyses commonly show strong variation along each profile, but there are also examples of rather homogeneous values.
The intimate spatial association of the locally very high Cu values and sheared volumes of the Ulveryggen Formation suggests a structural control on at least part of the mineralisation. The brittle/ductile shear zones are generally characterized by complex internal architectures, with irregular distribution of highly sheared and practically undeformed domains, separated by irregular fracture networks.
Stream Sediment Sampling
Target areas in the Repparfjord District were identified, based on interpretation of geophysics, geochemistry, known geology and the stream sediment grades. Other targets exist in presumed sub-parallel structural zones.
- 23 -
Historical Mineral Resources
There have been several historical mineral resources for the Nussir and Ulveryggen projects, which are summarized in this section. Blue Moon is not treating the historical estimates as current mineral resources or mineral reserves.
The author of the Nussir Technical Report has not done sufficient work to classify any of the historical estimates discussed in this section as current mineral reserves or mineral resources. The author has referred to these estimates as "historical estimates" and the reader is cautioned not to treat them, or any part of them, as current mineral resources. The historical estimates summarized below are included simply to provide the reader with a complete history of the property. The author of the Nussir Technical Report has reviewed the information in this section, as well as that within the cited references, and have determined that it is suitable for disclosure. All stakeholders are cautioned that none are considered current and therefore should not rely on them due to being superseded by the Nussir Technical Report.
In 2012, the author was commissioned by Nussir for a mineral resource estimate that incorporated drilling from 1985 to 2011 (17,761 m in 90 core drill holes). The mineral resource estimate report was completed, titled "Nussir Report Estimation Updated May 2012" (Wheeler, 2012) and it is historical in nature and should not be relied upon. Subsequently in 2013, the author was re-engaged for a mineral resource estimate update to include an additional 3,222 metres of drilling from 21 core drill holes. A report titled, "Nussir Report Estimation Updated March 2014" was completed (Wheeler, 2013). The report is considered historical in nature and should not be relied upon.
In April 2016, Nussir commissioned a PFS for the Nussir project. For the PFS, an updated mineral resource estimate report was completed, titled "Nussir Report Estimation Updated October 2016" that incorporated additional drilling results from 67 core drill holes totalling 19,880 metres. Both the PFS and the mineral resource are historical in nature and should not be relied upon.
The author was commissioned by Nussir in 2018 to update the mineral resource estimate to incorporate an additional 7 ,947 metres of drilling in 20 core drill holes. A report titled "Nussir Report Estimation Updated January 2018" was completed (Wheeler, 2018). This mineral resource is historical in nature, and it should not be relied upon.
In 2019, Nussir commissioned a DFS for the Nussir project. The DFS, titled, "Nussir Feasibility Study 2023", was supported by a mineral resource estimate that incorporated a further 3,912 metres of additional drilling in 13 core drill holes. Both the DFS and the mineral resource are historical in nature and should not be relied upon.
Geographical Setting, Mineralization and Deposit Type
Regional Geology – Nussir
The Nussir project area is situated within the Repparfjord-Komagfjord (Pharaoh et al. 1983) Precambrian tectonic window which was uplifted and exposed due to erosion of the overlying Caledonian nappes. The first detailed bedrock mapping of the region was carried out by Reitan (1963). Revised mapping of the northern part was done in the 1970's by Pharaoh et al (1983). Later, more detailed mapping of the area was conducted by Nilsen & Nilsson (1996). Geochemical studies of the metavolcanic rocks were performed by Jensen (1996).
The bedrock of the window consists predominantly of metavolcanic and metasedimentary rock. The rocks are intruded by mafic, ultramafic and felsic intrusive rocks. Although geochronological constraints are generally scarce, the meta-supracrustal rocks are assumed to be primarily of Early Proterozoic age, even though the lowermost stratigraphic sequences might represent Archaean rocks, as suggested by the comparison to correlative sequences in inner Finnmark. The oldest metavolcanic unit within the Kautokeino Greenstone Belt has revealed an Archaean Age (~2780 Ma, A. Solli pers. comm. 2008). The Paleoproterozoic rocks are overlain by thin sequences of Neoproterozoic sediments. The basement rocks are overthrust by allochthonous rocks of the Caledonian Nappe Complex and have undergone multiphase deformation during the Svecokarelian and Caledonian orogenies.
- 24 -
Mineralisation – Nussir
The Nussir deposit mineralisation is hosted by yellowish to greenish grey, banded, fine-grained sandstones and siltstones with common carbonate-rich layers. Studies of thin sections show that the rocks have strong variations in deformation, from well-preserved primary layering to strong ductile deformation (Sandstad, 2010). These show that the major ore minerals in the eastern part of Nussir are bornite and chalcocite. They mainly comprise cement of clastic grains of the sandstone and suggest a diagenetic origin for their deposition rather than strictly epigenetic formation, related to deformation of the host rock. Accessory sulphide minerals include chalcopyrite, covelite, wittichenite, carrollite, and cinnabar.
Gold (Au) and Silver (Ag) are closely associated with the Cu-mineralisation. Electrum (AuAg) has been identified at the contact and as inclusions and cracks in bornite. Ag also occurs in minerals associated with Tellurium (Te), Lead (Pb), Selenium (Se) and Bismuth (Bi). Platinum (Pt) most frequently occurs as microscopic grains of sperrylite that form clusters of inclusions in bornite and disseminated, interstitial grains in the silicate matrix of the sandstone.
Other sulphides are rare, although pyrite and molybdenite occur locally. Malachite is observed on surface outcrops. The mineralisation occurs as fine-grained impregnation fracture fillings. The thickness of the mineralised zone varies from zero to more than 4 meters.
Regional Geology – Ulveryggen
The prospect area is comprised of folded Precambrian metasedimentary rocks of the Ulveryggen Formation, part of the Saltvatn Group, that are exposed in the Komagfjord tectonic window, within the Caledonian mountain belt of western Finnmark. Sediments in the general prospect area are typically sandstones and quartzites, trending to what have been previously described as conglomerates in the immediate area of the old Ulveryggen Mine (Nilsen, K. 2019). Evidence of ENE-trending faulting, roughly parallel to the regional trend of bedding, is strong, as is the presence of NNE-trending faulting, particularly obvious in the mine area. Occasional small mafic dikes are also present in the mine area. The Ulveryggen sedimentary units are fault-bounded to the south by older greenstones and to the north by probably younger sedimentary units.
Mineralisation – Ulveryggen
The mineralization occurs along a 2-kilometer trend between the two main faults and along a fan of smaller faults located in between. NNE-trending strike slip faults offset mineralization along the order of 10's to several 100's of meters. Copper mineralization, typically in the form of chalcopyrite, bornite, lesser chalcocite, and secondary malachite, is present as disseminations in conglomerates (partly interpreted as mylonites), on shears, along bedding, in cracks and fractures, and in small, sometimes cross-cutting, quartz veins and veinlets. The thickness of the mineralization appears to diminish with depth as the two main faults coalesce. However, there is strong mineral potential for more to be discovered, heretofore undiscovered, copper mineralization along strike of the main system, both to the east and west.
Clay alteration is apparent in narrow ENE-trending shear zones that have been previously described as thin argillite partings. Although extremely difficult to ascertain in hand samples, mass silicification of the quartzites is probable along the main ENE-trending fault zones.
In section the mineralisation is SE-dipping (from about 60o to vertical), often significantly widening to the top and narrowing to the bottom. Generally, the horizontal length of the mineralised zone is about 2.6 km, with widths up to 2 00 m, and a vertical extent of approximately 150 m.
Host rocks of the deposit are notably bedded and foliated with the foliation in many cases. The foliation is not necessarily parallel to the bedding, mostly dipping NW or SE with the angles of 22˚ to 40˚, marking gentle, almost symmetrical folds. It appears that NW-dipping predominates.
Mineralized metasedimentary rocks appear to be significantly silicified. Sometimes mineralization occurs as a set of mesothermal quartz veins with rich chalcopyrite-bornite mineralization. The main part of the economic mineralization in the mined-out John open pit is bounded between to two antithetic NE-striking, NW- and SE-dipping shear zones.
- 25 -
Striations observed in the Erik pit appear flatter than striations in the Hovedfelt pit, which implies that the vertical component of the shear zone movement is progressively increasing in the SW direction, while the horizontal component is getting weaker. Kinematics of the shear zone appear to be dextral–normal (SE block uplifted), which is shown by observed shear zone fabrics, as well as by porphyroblast (pebbles) rotation.
Numerous ductile shear zones with NW orientation cut and displace mineralization, while being mineralized themselves. The shear zone offsets on a larger scale affect the major ore bodies, as shown by the position of the existing pits. Some of the faults also demonstrate the presence of vertical movement component. The faults appear to be reverse in the mineralized faults and normal in the non-mineralized.
The appearance of the dextral shear zones suggests a model of a contractional imbricate fan. of a dextral (and of course reverse) shear zone. The northern (SE-dipping) shear zone appears to be the main structure, while the southern (NW-dipping) structures are in the form of a set of splays (shears). Vertically the shears are reverse, as would result from NW orientated compression, which is supported by the presence of NW-oriented tension gashes observed in the field.
Opening of both NW- and SE-dipping foliation planes due to more recent NE-orientated stresses is also suggested, as suggested by northern tension gashes. It appears that the higher-grade mineralization is related to the intersection of the NW-striking cross-faults with the main structure. Superposition of all or some of these factors caused the formation of the Ulveryggen mineralization, characterized by disseminated and fracture filling texture.
Impressions from the 2017 logging of drill cores indicate that parts of the conglomeratic zones may have been formed by alteration (silicification- carbonatization) of exhalitic volcanics, possibly in combination with larger scale alteration, mobilization and eventually Cumineralization by precipitation in the pressure shadows within shear zones. Chlorite in the "conglomerate" matrix and relatively higher Ni- and Cr- background levels in correlation with Cu, may indicate a possible mafic volcanic source for the Ulveryggen mineralisation. Further studies of the Cu-genesis, high Cu-background data from old stream samples, as well as shearzones, could help define possible promising exploration targets in vicinity of Ulveryggen area.
Deposit Type
The two Cu-deposits, Nussir and Ulveryggen, have a similar composition of Cu-bearing sulphides. They are probably the result of a similar geological system. They represent examples of sedimentary-associated type of deposits, with many common features found in the Copperbelt in central Africa and Kupferschiefer in Poland and Germany, which include a continental rift environment, hot sub-aquatic conditions, shale/dolomite/conglomerate sequences, stratabound disseminated veinlets of Cu minerals, partly extensive alteration, syngenetic-diagenetic settings and epigenetic events.
Nussir
The Nussir deposit is considered to be a stratabound sediment hosted copper deposit, and the mineralisation is interpreted as post-diagenetic. The Nussir deposit is a generally homogenous, Cu-ore zone with Ag, Au, some Pt and Pd. It was primarily deposited as a continuous dolomiteschist layer on the sea floor, with relatively little deviation in grade, thickness and other factors. Later events with folding, shearing and alterations have partly affected primary features.
Description of the Copperbelt deposits has many similarities with the mineralisation in the Repparfjord area, in particular with the Nussir deposit. They both have a base of conglomerates overlaid by dolomites and siltstones. Both are interpreted to be associated with deposition in rift basins.
Similar stratigraphy can also be seen in the Kupferschiefer in Poland. At the base there are clastic materials lying in a series of basins, mainly red sandstones and conglomerates, and the uppermost sections are composed of arenites and carbonates.
- 26 -
Ulveryggen
The Ulveryggen deposit is also considered to be a stratabound sediment hosted copper deposit, with a similar composition of copper-bearing sulphides to Nussir, but the general mineralogy and genetic setting is different. The Ulveryggen deposit constitutes a more complex orebody, described as sedimentary deposition of copper minerals within layers in sandstone-conglomeratic sequences. The Ulveryggen mineralisation has a different setting, interpreted as syngenetic shear-zones. The Au- Ag and Pt- Pd content is considerably lower at Ulveryggen than at Nussir.
The main Ulveryggen deposit area is dominated by two sub-parallel ENE-trending faults, dipping steeply towards each other. Known mineralization occurs in several pods along a 2-kilometer trend between the two main faults and along a fan of smaller faults located in between. The thickness of mineralization appears to diminish with depth as the two main faults coalesce. However, there is potential for more, heretofore undiscovered, copper mineralization along strike of the main system, both to the east and west.
Exploration
Blue Moon has not carried out any exploration work on the property. For a description of historical exploration work, including that completed by Nussir and its predecessor companies (AS Prospektering and Terra Holdings), refer to the History section of this summary.
Drilling
Blue Moon has not carried out any drilling activities on either Nussir or Ulveryggen deposits, and all drilling on these properties and for the mineral resource estimation exercises were completed by prior operators.
Historical Drilling – Nussir
A total of 211 exploration diamond drillholes, covering over 52,700 m, have been drilled on the Nussir project up to 2 019. One drillhole (no.212) was delayed out of the 2019 resource estimation and was drilled in 2020 and confirmed the modelled grade and width. A few additional drillholes were performed in 2024, however, these were solely for metallurgical and processing test work, in order to achieve enough core material to perform material sorting tests and were not intended or used for mineral resource estimation, because they were all twin drill holes of older, successfully completed drillholes. In addition, ten channel samples have been collected from mineralized surface outcropping. A total of approximately 2,600 samples have been assayed.
In 1984, ten channel samples were collected from mineralized surface outcrops. The drilling started in 1985 with six relatively short diamond drill holes, all less than 80 m in length and a dip varying between 50 to 70 degrees. In 1986, further two diamond drillholes were drilled to check the continuity of the mineralization at depth. One of the drillholes confirmed the vertical extension of the mineralization to more than 250 m below surface. The laboratory Mercury Analytical Ltd. was used to analyse the core from the first eight drillholes.
In 1988, six diamond drill holes were drilled. The core was analyzed by Caleb Brett Laboratories. A total of 35 diamond drill holes were drilled in the period between 1990 and 1996. Between 1985 and 1996, a total of 600 samples were analyzed from 43 drill holes. All samples were analyzed for Cu, and partly for Ag and Au. The samples were analyzed by different laboratories with unknown analytical methods. For verification purposes, 69 samples from 1990 were assayed in 2008. The older samples were not independently used to define blocks defined as Indicated Resources in the current study.
In 2002, 63 samples from nine diamond drillholes were analyzed by OMAC Laboratories, Ireland for 47 elements using Aqua Regia digestion and ICP. Ag was the only precious metal analyzed. However, only a few meters of each of the drill holes were analyzed. Typically, the analyzed core section analyzed was one meter per sample.
The drilling continued in 2006 with the drilling of seven diamond holes. A total of 32 samples from four holes were analyzed by OMAC Laboratories, Ireland using 46 elements by Aqua Regia digestion and ICP-OES. In addition, Au was analyzed by Fire Assay/AA on 30 g samples.
- 27 -
4 07 samples from 9 holes were analyzed in 2008 for 46 elements by Aqua Regia digestion and ICP-OES by OMAC Laboratories, Ireland. The digestion is partial for some elements especially Al, Ba, Cr, K, Na, Sn, Sr, Ta, Ti, V and W. In addition, Au, Pt and Pd were analyzed by Fire Assay/AA on 30 g samples. The whole cores from drill holes Bh 3 9 (117.6 m), 40 (43.2 m) and 60 (120 m) were analyzed, whereas parts of Bh 19, 20, 54, 55, 57 and 90 were analyzed. The analyzed core lengths were 1-2 m.
In 2011, a total of six diamond drillholes (1996 m) were drilled on the Nussir deposit. Five of the drill holes (1,432 m) were drilled as infill holes in the eastern part of the deposit to decrease the drill spacing from 250 m to 125 m. In addition, one deep diamond drill hole (564 m) was drilled in the central part of the Nussir deposit to confirm the extension of the mineralization in this previous undrilled zone. The drill hole successfully confirmed an 8.6 m intersection zone (7m true width) averaging 0.69% Cu (including 3.6 m averaging 1,09% Cu) from 541 m downhole. From the 2011 drill campaign, a total of 164 samples (including standards and blanks) were submitted to ALS Chemex laboratory in Piteå. All samples were analyzed by 33 element four acid ICP-AES and Au, Pt and Pd 30 g Fire Assay ICP. In the mineralized zone the core were normally analyzed on one meter intervals. However, additional samples of varying length were sampled in zones of interest.
All pre-2011 drill hole collar locations were originally surveyed using a DPOS GPS (TOPCON) with an accuracy of 1 -2 dm. The 2011 drill holes were surveyed using a handheld GPS with and later surveyed by DPOS GPS (TOPCON) in 2012. Downhole surveys have been done for all intact drillholes in 2012 using a pee-wee magnetic survey tool. The registered azimuth values in the upper part of some holes were influenced by magnetic rocks and had to be corrected. Gyro based downhole surveying was chosen during 2013 campaign to avoid this problem.
In 2017, 89 drillhole collars were re-measured using a more accurate (within 1-2cm) CPOS GPS instrument, in a re-survey program completed by the company GeoNord. The collar database used in the resource estimation covered in the Nussir Technical Report is summarized in Table 2.3, with respect to the positioning system used.
Table 2.3: Summary of Collar Positioning Systems – Nussir
| Method | Number | Proportion |
| Unknown (Channels) | 10 | 5% |
| Hand GPS | 15 | 7% |
| DPOS | 107 | 48% |
| CPOS | 89 | 40% |
| TOTAL | 221 | 100% |
Most of the drill holes have been drilled with success. However, in the central parts of the 9 km long mineralized horizon, four drill holes were abandoned before they reached the mineralization. This was due to strongly fractured rocks in an interpreted fault zone.
All cores were transported down to a warehouse with logging facilities and logged for geological, sampling and geotechnical purposes by in-house personnel.
Geotechnical data have been collected from some pre-2011 drill holes, including RQD, core recovery, fracture density and orientation, hardness and joint data. All core drilled from 2008 have been photographed. Data collected on the six diamond drillholes drilled from 2011, includes geology, down hole survey, sample, RQD, core recovery and assay data.
A summary of the current database, with relation to the different diamond drilling campaigns, to date is shown in Table 2.4.
- 28 -
Table 2.4: Nussir Diamond Drilling Summary
| Average | |||||||
| Hole | Core | ||||||
| Number | Length | Length | Hole | Diameter | Drilling | ||
| Year | of Holes | (m) | (m) | Size | (mm) | Company | Drill Rig |
| 1985 | 6 | 264 | 44 | AQ | 27 | - | - |
| 1986 | 2 | 496 | 248 | AQ | 27 | - | - |
| 1988 | 6 | 1,325 | 221 | AQ | 27 | - | - |
| 1990 | 24 | 1,893 | 78 | AQ | 27 | - | - |
| 1995 | 4 | 724 | 181 | AQ | 27 | - | - |
| 1996 | 4 | 1,182 | 296 | AQ | 27 | - | - |
| 2006 | 7 | 2,687 | 384 | - | 18 | Diamantboring | Diamec 262 |
| Nord AS | |||||||
| 2007 | 1 | 78 | 78 | AQ | 27 | - | - |
| 2008 | 30 | 7,116 | 233 | BQTK | 36.5 | Arctic Drilling AS | Diamec 252 |
| 2011 | 6 | 1,996 | 333 | BQTK | 40.7 | Arctic Drilling AS | Diamec 252 |
| 2013 | 21 | 3,222 | 153 | BQTK | 40.7 | ADC Ltd. Oy | K1 with Sandvik drill |
| 2014 | 34 | 9,308 | 274 | NQ/BQ | 47.6/36.5 | Arctic Drilling AS | Atlas U6 and 264 |
| 2015 | 33 | 10,572 | 320 | NQ | 47.6 | Arctic Drilling AS | Atlas U6/264 |
| 2017 | 20 | 7,947 | 397 | NQ | 47.6 | Arctic Drilling | Atlas U6/264, |
| AS/Rockma | Sandvik DE 140 MT | ||||||
| 2019 | 13 | 3,912 | 301 | NQ | 47.6 | Arctic Drilling | Atlas U6/264, |
| AS/Rockma | Sandvik DE 140 MT | ||||||
| Total | 211 | 52,722 | 250 |
The 10 lines of channel samples that were taken in 1985 covered an average sampled length of 35 m/line. In 2006, 20 air percussive holes were also drilled, with an average length of 20 m, but samples from these percussive holes were not used in the current resource estimate. Selected core material including intersections from 2013 campaigns are stored in Skaidi, nearby the deposit. Core from 35 older holes are stored at the Norwegian Geological Survey in Løkken.
Historical Drilling – Ulveryggen
Complete sets of data from 134 diamond drillholes have now been collated, as summarized in Table 2.5.
All the 2014 and 2017 drillholes are of NQ (47.6 mm) diameter. For the drilling since 2010, all remaining core is stored in the National core-storage facility at Løkken, except for core lengths near or inside the mineralised zones, which is kept at Blue Moon's facility in Skaidi.
- 29 -
Table 2.5: Ulveryggen Drilling Summary
| Avg. | |||||
| Length/Hole | |||||
| Sample Type | YEAR | Holes/Channels | Length (m) | (m) | Cu Samples |
| pre-2010 | 83 | 11,141 | 134 | 3,988 | |
| Surface | 2014 | 1 | 412 | 412 | 24 |
| Drillholes | 2017 | 7 | 967 | 138 | 88 |
| Sub-total | 91 | 12,520 | 138 | 4,100 | |
| pre-2010 | 22 | 2,754 | 125 | 325 | |
| U/g Drillholes | 2010 | 21 | 1,464 | 70 | 455 |
| Sub-total | 43 | 4,219 | 98 | 780 | |
| Total | 134 | 16,738 | 125 | 4,880 |
Sampling, Analysis and Data Verification
Sample Preparation, Analysis and Security
Nussir
1984 to 1996
Descriptions of historical sampling methods, preparation and analysis by ASPRO have been recorded. The sample intervals are well defined. The sample intervals were picked based on mineralized or geological boundaries. Chemical analysis was normally made for one-meter intervals.
No cores before 1986 are available. Cores from 1986 to 1996 are stored at the central Norwegian core facility at the Norwegian Geological Survey, Løkken in Trondheim. Sampling and splitting of the cores were done by the company at the site, and sample preparation such as crushing and pulverizing was done by the laboratories.
Mercury Analytical Ltd. was responsible for assay analysis from 1984 to 1985. In 1988, six diamond drill holes were drilled. The holes were analyzed by Caleb Brett Laboratories, England. In both cases, the analytical methods are not known, and the analyzed core lengths are usually one meter or shorter.
These pre-2000 samples were analyzed for Cu, Ag and Au. Cu-oxide mineralization is confined typically to the upper level of the deposit and, historically, non-sulphide Cu was not universally quantified by analysis of soluble Cu.
In 2002, 63 samples from nine holes were re-analyzed for 47 elements by Aqua Regia digestion and ICP by OMAC Laboratories, Ireland. Only Ag among the precious metals was analyzed.
Terra Control/Nussir ASA 2006 to 2019
From 2006 to 2008, TerraControl (now Nussir ASA) and Nussir drilled 43 (five were abandoned) diamond drill holes on the Nussir Property.
Most of the core samples from 2006 and 2007 were marked on core boxes, and cut in half by the on-site geologist, Kjell Nilsen. The samples were placed in boxes and shipped to OMAC, Ireland, for analysis. The drill core boxes from the 2008 drilling campaign were shipped to ALS Chemex in Sweden, which did all the sample preparation based on the marked intervals made by Nussir`s on-site geologist.
Between 2006 and 2008, samples from 20 percussion drillholes and nine diamond drill holes were analyzed for 46 elements using Aqua Regia digestion and ICP-OES by OMAC Laboratories, Ireland.
In 2008, 199 samples from four diamond drillholes (Bh 19, 20, 39, 40) were re-analyzed for 46 elements, using four-acid ICP-AES and Pt, Pd, Au 30g Fire Acid ICP. Samples from 30 diamond drillholes were analyzed in 2008 by 46 elements four-acid ICP-AES and Pt, Pd, Au 30g Fire Acid ICP.
- 30 -
In 2011, six diamond drillholes were analyzed by ALS Chemex laboratory in Sweden by 33 element four acid ICP-AES and Au, Pt and Pd 30 g Fire Assay ICP. In this campaign, intersections for assaying were identified by initial assaying using handheld XRF. In 2011 and 2013, external check samples were sent to SGS.
For the drilling campaigns in 2015, 2017 and 2019, ALS Chemex was used as the primary laboratory, and Labtium as the external check laboratory.
Sample preparation work has been done using ALS Chemex in Piteå, under instructions from Nussir's geologists, using the following steps:
1 . Sawing of core into two halves.
2 . Crushing of one-half sample, 70% < 2mm.
3 . Riffle splitting of crushed sample.
4 . Pulverising to 85% < 75 μm.
5 . Taking of sample for analysis.
Quality Assurance/Quality Control
2008
During 2008, 1443 assay measurements were made by OMAC, from core stemming from the 1990 drilling campaigns.
Most of these were taken to provide measurements of previously unassayed core, but 69 overlapped with previous assays, measured in either Mercury Analytical or Caleb Brett laboratories. A diagram depicting these reassayed duplicates and a check analysis study of the data is shown in the Nussir Technical Report.
2009-2011
This combined set of 110 check samples was analyzed for the 2009 campaign. The Cu grades are displayed diagrammatically in the Nussir Technical Report, along with results of an additional 2011 check analysis study.
For the samples associated with the 2011 drilling campaign, the following quality control measures were taken:
| · | Standards (certified by Geostat Pty. Ltd.) and blanks were inserted for every ten samples, and at the start of every batch. | |
| · | ALS inserted their own internal duplicates in the laboratory. Of the 141 samples assayed for the 2011 campaign, 4 internal duplicates were taken. |
2013
For the 2013 campaign, 6-7 internal coarse duplicates were taken, out of 152 primary assays. The results are shown in the Nussir Technical Report.
During the 2013 campaign one blank was inserted for approximately every 10 samples. These blanks were prepared from local gabbro source. Of these 26 samples, only 2 showed any Cu grades above expected blank levels, representing 8% of the samples analyzed. The cause of the 2 error values is not known.
During 2013, 27 external duplicates were assayed at SGS, stemming from pulp material returned by ALS from the 2011 and spring 2013 campaigns. Results are summarized in the Nussir Technical Report.
Additionally, three external standard samples were purchased from Geostat. The results of assays on two of these standards are also shown in the Nussir Technical Report. These cover both 2011 and 2013 results. The results from these 2 standards are acceptable, with no check assays outside of 2 x standard deviation limits. Another lower grade standard was also assayed, and produced consistent results, but there appears to have been a misallocation of the standard ID, and so these results have not been used.
- 31 -
2017
A summary of the QA/QC samples taken through the 2017 drilling campaign is shown in Table 2.6.
Table 2.6: Summary of QAQC Samples – 2017
| Type of Control | Number of Samples | Number | Frequency | |
| Twin Samples | TS | 265 | 24 | 9% |
| Coarse Duplicates | CD | 265 | 2 | 0.8% |
| Fine Duplicates | PD | 265 | 19 | 7% |
| Standards | STD | 265 | 16 | 6% |
| Coarse Blanks | CB | 265 | 16 | 6% |
| Fine Blanks | FB | 265 | 21 | 8% |
| External Controls | EC | 265 | 30 | 11% |
| Total | 48% |
Precision analysis results for field duplicates are summarized in the Nussir Technical Report. The proportion of errors is greater than the usual 10% error threshold for acceptability. However, one of the error pairs is almost directly on the error limit failure line. If this one error was removed, the proportion of errors would be reduced to 13%.
Coarse duplicate measurements were very limited. Precision analysis results for pulp duplicates were quite acceptable. Additionally, results for standards' analysis were consistently acceptable. Coarse blanks' results were also consistently acceptable, showing no relationship with previous assays, indicating no contamination during sample preparation.
All fine blanks' Cu assays were below the level of detection, indicating no contamination during analysis. The lack of coarse duplicates results means there is no direct measure of the precision of sample preparation. That withstanding, it may be concluded that overall, the 2017 QA/QC results are generally acceptable.
2019
A summary of the QA/QC samples taken through the 2019 drilling campaign is shown in Table 2.7.
Table 2.7: Summary of QAQC Samples – 2019
| Type of Control | Number of Samples | Number | Frequency | |
| Twin Samples | TS | 100 | 9 | 9% |
| Coarse Duplicates | CD | 100 | 11 | 11% |
| Fine Duplicates | PD | 100 | 11 | 11% |
| Standards | STD | 100 | 5 | 5% |
| Coarse Blanks | CB | 100 | 9 | 9% |
| Fine Blanks | FB | 100 | 0 | 0% |
| External Controls | EC | 100 | 10 | 10% |
| Total | 55% |
Precision analysis results for all forms of duplicates are shown in the Nussir Technical Report: no errors were apparent.
- 32 -
Standards' results are summarized in the Nussir Technical Report as well; no errors were apparent. Coarse blanks' results are included as well.Although of the assays are rather high, there appears to be no relationship with the previous assays.
The proportion of errors is greater than the usual 10% error threshold for acceptability. However, one of the error pairs is almost directly on the error limit failure line. If this one error was removed, the proportion of errors would be reduced to 13%.
Results for the external check Cu samples, which were sent to Labtium, show very low bias results, and those check samples which were outliers had extremely low grades, of less than 0.005% Cu.
Density Measurements
Density measurements were done by Promin. Selected drill core billets were accurately cut and then polished to have a cut that was as close to 90° as possible (at SINTEF). The length was then measured four times around the circumference of the drill core and averaged.
The same was done with the diameter of the core; measured 4 times and averaged. The resulting volume was then used as the volume for the core billet. Along with the dry weight, the density was then calculated. The drill cores were also inspected for any chippings or other damage to the cylinder shape, to check the volume calculation was not affected.
Ulveryggen
In 2014 and 2017, the diamond drillhole samples were analyzed by ALS Chemex laboratory in Sweden by four acid
ICP-AES. The selection of intersections for assaying was also assisted by initial assaying using handheld XRF.
Sample preparation work has been done using ALS Chemex in Piteå, under instructions from Nussir's geologists, using the following steps:
1 . Sawing of core into two halves.
2 . Crushing of one-half sample, 70% < 2mm.
3 . Riffle splitting of crushed sample.
4 . Pulverising to 85% < 75 μm.
5 . Taking of sample for analysis.
2014
In terms of sample preparation and QA/QC, the Ulveryggen drillholes completed in 2014 were part of the drilling campaign for the neighbouring Nussir deposit.
A summary of the QA/QC samples taken through the 2014 and 2015 campaigns for Nussir is shown below in Table 2.8.
Table 2.8: Summary of QAQC Samples – 2014 and 2015
| 2014 | 2015 | Combined | ||||
| Number | Proportion | Number | Proportion | Number | Proportion | |
| Primary Samples | 324 | 247 | 571 | |||
| Field Duplicates | 0 | 0.0% | 23 | 9.3% | 23 | 4.0% |
| Pulp Duplicates | 4 | 1.2% | 21 | 8.5% | 25 | 4.4% |
| External Duplicates | 14 | 4.3% | 13 | 5.3% | 27 | 4.7% |
| Blanks | 4 | 1.2% | 12 | 4.9% | 16 | 2.8% |
| Standards | 14 | 4.3% | 18 | 7.3% | 32 | 5.6% |
| Total | 11.1% | 35.2% | 21.5% | |||
- 33 -
Asummary of the 2015 field duplicates' results is included in the Nussir Technical Report. The results show a relatively high proportion of errors. The 2014 and 2015 pulp duplicates' results are also presented. Both sets of results are acceptable.
In the 2014 campaign, primary samples were assayed at Labtium, with external assaying done at ALS. In the 2015 campaign, primary samples were assayed at ALS, with external assaying done at Labtium.
Standards' results were acceptable, although there were not sufficient of them for the same standard ID to present graphically.
External duplicates' and coarse blanks' results are also presented in the Nussir Technical Report. These results are acceptable.
2017
In terms of sample preparation and QA/QC, the seven Ulveryggen drillholes completed in 2017 were part of the drilling campaign for the neighbouring Nussir deposit. A summary of the QA/QC samples taken through the 2017 campaign for Nussir is shown below in Table 2.9. Of the 265 total primary samples assayed, 177 came from the Nussir drilling, 88 came from Ulveryggen.
Table 2.9: Summary of QA/QC Samples – 2017
| Type of Control | Number of Samples | Number | Frequency | |
| Twin Samples | TS | 265 | 24 | 9% |
| Coarse Duplicates | CD | 265 | ||
| Fine Duplicates | PD | 265 | 19 | 7% |
| Standards | STD | 265 | 16 | 6% |
| Coarse Blanks | CB | 265 | 16 | 6% |
| Fine Blanks | FB | 265 | 21 | 8% |
| External Controls | EC | 265 | 30 | 11% |
| Total | 48% |
Precision analysis results for field duplicates are summarized in the Nussir Technical Report. The proportion of errors is greater than the usual 10% error threshold for acceptability. However, one of the error pairs is almost directly on the error limit failure line. If this one error was removed, the proportion of errors would be reduced to 13%.
Precision analysis results for pulp duplicates are also summarized in the Nussir Technical Report. These results were quite acceptable.
Additionally, results for standards' analysis are shown in the Nussir Technical Report. These results are consistently acceptable.
Coarse blanks' results are also summarized in the Nussir Technical Report, showing consistently acceptable results, as well as no relationship with previous assays, indicating no contamination during sample preparation.
- 34 -
All fine blanks' Cu assays were below the level of detection, indicating no contamination during analysis. The absence of coarse duplicates results means there is no direct measure of the precision of sample preparation. That withstanding, it may be concluded that overall the 2017 QA/QC results are generally acceptable.
Core and Sample Storage
Drill core is stored at Blue Moon's facility at Skaidi and at the NGU national archive in Løkken. Both are secure lockable facilities. The author has visited them both.
Rejects and pulp material from 29 Nussir holes (all from 2014) and 1 Ulveryggen hole are stored at Løkken, stemming from the preparation of 289 samples. There is also reject and pulp material at the core shack in Skaidi, but there is no inventory available for this at the current time.
Overview
There have been five laboratories associated with the Nussir and Ulveryggen project over the year (Table 11-20).
Three of the five laboratories have ISO 17025 accreditation. It should be noted that none of the laboratories involved in either project have or have had interests in the project or the operators, which includes Nussir.
In the opinion of the author, the QA/QC results overall are acceptable and support the use of the available samples for resource estimation purposes on the Nussir and Ulveryggen deposits.
Data Verification
Data verification steps completed by the author include:
| · | Site visits to Nussir, before, during, and after exploration drilling campaigns. |
| · | Site visit to Ulveryggen, including open pits and exploration adit. |
| · | Check review of example Nussir drill core, at Skaidi and the NGU core storage in Lokken. |
| · | Check of collar positions relative to surface maps. |
| · | Check of data base integrity through drillhole data processing, statistical analysis, visualisation and plotting. |
| · | Additional checking of Ulveryggen sample data relative to underground adit model. |
Site Visit
In 2007, the author walked the entire strike length of the Nussir deposit outcrop and project area. In 2014, the author visited Nussir during that year's drilling campaign. The author most recently visited Nussir between January 14 and 6, 2025. The author has also done check review work of example Nussir and Ulveryggen drill core, at Skaidi and the NGU core storage in Løkken. The author also visited the Ulveryggen site in 2010, which included the old open pit areas and the underground drilling locations. He also visited Ulveryggen between January 14 to 16, 2025.
Drill Hole Data
Collar Data
The author did his own GPS verifications of 5 historic and recent drillhole collar positions at Nussir during his 2014 site visit. Any XY errors were within 2 m accuracy of the information in the databases, and the author found no anomalies that would be material to any mineral resource estimate.
The drillhole collars for both Nussir and Ulveryggen, which have been measured by DPOS or CPOS, have been checked for elevation against LiDAR topographical data. Histograms comparing LiDAR elevation differences, and the DPOS/CPOS systems are shown in the Nussir Technical Report. A summary of the elevation differences from this check exercise for Nussir is shown in Table 2.11, and elevation differences have been plotted as histograms available in the Nussir Technical Report. A summary of the elevation differences for Ulveryggen is shown in Table 2.12, and elevation differences have been plotted as histograms which can be found in the Nussir Technical Report.
- 35 -
In 2019 Nussir also completed their own check exercise on azimuths of drillhole collars. For the original survey file, 65 holes only had one measurement, i.e. 156 had a proper series of downhole measurements. Of these 65, 33 hole-collars' azimuths were remeasured in 2019 using Devico equipment. The results of the horizontal displacements, at end of these holes due to the azimuth differences, is shown in Table 2.10.
Table 2.10: Summary of Horizontal Displacements - Azimuth Differences – Nussir
| Parameter | Value |
| Number of Collars | 30 |
| Mean | 4.90 |
| Median | 37.76 |
| Prop'n exceeding 0.5m | 33% |
| Prop'n exceeding 1m | 23.3% |
| Prop'n exceeding 5m | 10.0% |
For these check data, observations include:
| · | For Nussir deposit, there does not appear to be an appreciable difference in elevation accuracy between DPOS and CPOS measurements as verified by the author. |
| · | The azimuth validation review by the author has identified 3 of the holes with high differences. Two of these three holes did not intersection mineralisation, and the remaining hole has negligible effect of the zones' interpretation. |
| · | In general, the elevation differences seem worse for Ulveryggen deposit than Nussir deposit. However, this might be due to difficult type of topography at Ulveryggen deposit, with many very steep faces and slopes left by the open pit mining, making the LiDAR pick-up more difficult without more detailed DPOS or CPOS measurements for calibration. |
| · | The distribution of LiDAR errors is near normal, not indicating any positive or negative bias in the opinion of the author. |
| · | The proportion of +2m and +5m LiDAR errors are rather high, and efforts in the future to reduce these should be made to increase precision. |
| · | There does not appear to be any relationship between higher elevation differences and XY positioning. |
| · | It is considered the errors encountered from this validation exercise do not have any appreciable effect on the current MRE. |
- 36 -
Table 2.11: Summary of Collars' Elevation Differences with LiDAR – Nussir
| Parameter | All Holes | Mineralised Holes |
| Number of Collars | 221 | 178 |
| Mean Absolute Difference (m) | 1.66 | 1.42 |
| Median Absolute Difference (m) | 0.83 | 0.80 |
| Prop'n exceeding Mean+3SD | 2.7% | 2.2% |
| Prop'n exceeding 2m | 21.7% | 18.5% |
| Prop'n exceeding 5m | 7.2% | 5.1% |
| Prop'n exceeding 10m | 2.7% | 1.7% |
Table 2.12: Summary of Collars' Elevation Differences with LiDAR – Ulveryggen
| Parameter | All Holes | Mineralised Holes |
| Number of Collars | 93 | 67 |
| Mean Absolute Difference (m) | 2.48 | 2.76 |
| Median Absolute Difference (m) | 1.77 | 2.11 |
| Prop'n exceeding Mean+3SD | 0.1% | 0.0% |
| Prop'n exceeding 2m | 46.2% | 50.7% |
| Prop'n exceeding 5m | 14.0% | 16.4% |
| Prop'n exceeding 10m | 2.2% | 3.0% |
Drillhole Core
The site visits included a review of selected Nussir and Ulveryggen deposit drill core, at Skaidi and the NGU core storage in Lokken, in order to validate and verify the information in the databases against data entry. The items reviewed during this work included:
| · | Correspondence between logged/database lithologies and actual lithologies in the core boxes. |
| · | Correspondence between mineralisation and marked sample limits with the database. |
| · | Any notable aspects of copper mineralisation. |
In these reviews the mineralisation and lithologies observed correspond well with the database information.
Database
Check of database integrity was through operations including:
| · | Range checks. |
| · | Checks of tabulated data against original logged data. |
| · | Drillhole data processing. |
| · | Statistical analysis. |
| · | Visualisation and plotting. |
Any discrepancies found were discussed and resolved through communication with Nussir geologists.
- 37 -
The author completed all of the above verification steps. In the case of Ulveryggen, there was additional checking of Ulveryggen sample data relative to the underground adit model and the old open pit workings.
Overview
Please note that the author was not able to verify surface drillhole collar locations at Ulveryggen deposit, owing to surface mining activities after drilling, as well as extensive snow cover at the time of the Author’s visits. However, the additional validation step of comparison drill collar locations with LIDAR data, as well as analysis of sections of the pit workings relative to drillhole data, have led the Author to believe that the Ulveryggen deposit, surface drillhole collar data are valid and therefore verified for resource estimation purposes.
In the author's opinion, the geological data in the databases are also adequate for the Nussir and Ulveryggen deposit resource estimation work, and that this technical information was collected in line with industry best practices as defined in the CIM Mineral Resources and Mineral Reserves Best Practice Guidelines.
Mineral Processing and Metallurgical Testing
Overview
Several metallurgical test work programs have been executed under Nussir project development on the Nussir and Ulveryggen copper deposits. Three major test work programs were performed between 2010/11 and 2019:
| · | "An Investigation into RECOVERY OF COPPER FROM THE KVALSUND DEPOSIT" prepared for NUSSIR ASA, SGS Project 12527-001 – Final report, dated May 9, 2011. |
| · | For a historical PFS in 2016; "SGS Lakefield – An Investigation into PRE-FEASIBILITY LEVEL METALLURGICAL TESTING ON SAMPLES FROM NUSSIR AND ULVERYGGEN COPPER DEPOSITS" prepared for NUSSIR ASA, SGS Project 12527-003 – Final Report, dated Aug 17, 2016. |
All test work has been done by SGS Lakefield, Canada, and are documented in separate reports. Canadian consultant and flotation provider, Woodgrove Technologies, took part in coordinating the test programs. The Ulveryggen deposit was in production from 1972 to 1979, with documented process plant performance.
The two deposits yield copper concentrate grades and copper recoveries that are very high compared to most copper deposits in the world. The reason for the high concentrate grade is due to the high amount of bornite and chalcocite in the deposits. The high copper recovery is due to the clean ore with practically no other sulphides, no oxidised ore and beneficial grind size for efficient flotation.
The following types of metallurgical samples were taken in the historical 2019 DFS testwork and sent to SGS for different metallurgical tests, including but not limited to grindability and flotation testing.
1. Composite Samples. Three different spatial composites from Nussir were prepared.
2. Variability Samples. 15 were taken from Nussir, and 3 from Ulveryggen.
The spatial composites from Nussir are summarized in Table 2.13. QEMSCAN analysis verified their original assay results, as well as providing additional metallurgical data on the mineralogical makeup of the composites. All three composites were dominated by bornite, with lesser chalcopyrite (Composite 3) and chalcocite (Composite 1).
Table 2.13: Summary of Nussir Composite Metallurgical Samples
| Element | Unit | Comp 1 | Comp 2 | Comp 3 |
| Cu | % | 1.10 | 1.53 | 1.18 |
| Au | g/t | 0.19 | 0.16 | 0.11 |
- 38 -
| Element | Unit | Comp 1 | Comp 2 | Comp 3 |
| Ag | g/t | 17.6 | 20.1 | 12.4 |
| S | % | 0.36 | 0.67 | 0.61 |
| Total Weight | kg | 10.43 | 28.42 | 47.07 |
| Number of Holes | 3 | 5 | 6 |
A more detailed breakdown of the assays from the three prepared composites is shown in Table 2.14.
Table 2.14: Assay Breakdown of Nussir Composite Metallurgical Samples
Sample ID |
Comp 1 | Comp 2 | Comp 3 |
| Au g/t | 0.19 | 0.16 | 0.11 |
| Ag g/t | 17.6 | 20.1 | 12.4 |
| Pt g/t | 0.13 | 0.16 | <0.02 |
| S % | 0.36 | 0.67 | 0.61 |
| Cu seq H2SO4 % | 0.024 | 0.025 | 0.016 |
| Cu seq. NaCN % | 0.99 | 1.4 | 0.86 |
| Cu seq. A/R % | 0.037 | 0.14 | 0.3 |
| Cu % | 1.10 | 1.53 | 1.18 |
| Ag g/t | 17 | 21 | 11 |
| Al g/t | 46200 | 46300 | 40400 |
| As g/t | <30 | <30 | <30 |
| Be g/t | 0.8 | 0.76 | 0.7 |
| Bi g/t | <20 | <20 | <20 |
| Ca g/t | 130000 | 126000 | 125000 |
| Cd g/t | <2 | <2 | <2 |
| Co g/t | 11 | 13 | 14 |
| Cr g/t | 31 | 30 | 27 |
| Fe g/t | 12800 | 13600 | 16500 |
| K g/t | 26200 | 24400 | 19500 |
| Li g/t | <20 | <20 | <20 |
| Mg g/t | 10700 | 13300 | 36800 |
| Mn g/t | 3500 | 3110 | 4380 |
| Mo g/t | <20 | <20 | <20 |
| Na g/t | 12700 | 16300 | 13800 |
| Ni g/t | <20 | 30 | 24 |
| P g/t | 352 | 417 | 284 |
| Pb g/t | <20 | <20 | <20 |
| Sb g/t | <10 | <10 | <10 |
| Se g/t | <40 | <40 | <40 |
- 39 -
| Sample ID | Comp 1 | Comp 2 | Comp 3 |
| Sn g/t | <40 | <40 | <40 |
| Sr g/t | 196 | 178 | 123 |
| Ti g/t | 1530 | 1510 | 1320 |
| T1 g/t | <30 | <30 | <30 |
| U g/t | <20 | <20 | <20 |
| V g/t | 46 | 45 | 42 |
| Y g/t | 11.2 | 10.9 | 9.2 |
| Zn g/t | <40 | <40 | <40 |
Figure 2.5: Nussir Long Section – Drillholes Used for Variability Metallurgical Samples
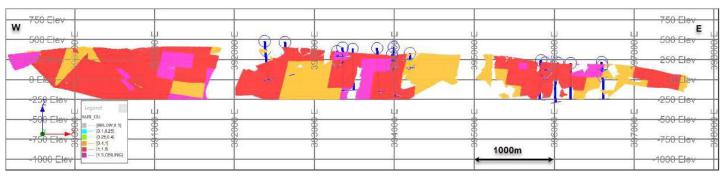
Variability and Hardness Testing
The drillholes used for providing the variability samples from Nussir are depicted in long section in Figure 2.5. The grades of all the variability samples are summarized in Table 2.15. The variability samples were submitted for comminution testwork, including SAG Power Index test (SPI®), Bond Ball Mill Work Index (BWI), ModBond test, and Bond Abrasion Index (AI) test. These results are summarized in Table 2.16.
Table 2.15: Variability Samples Head Assays
| Sample ID | Bore Hold ID | Cu, % | Au, g/t | Ag, g/t | S, % |
| Nussir Deposit | |||||
| VAR 1 | NUS-DD-188 | 1.84 | 0.16 | 34.2 | 0.51 |
| VAR 2 | NUS-DD-189 | 0.31 | < 0.02 | 1.3 | 0.19 |
| VAR 3 | NUS-DD-190 | 1.11 | 0.05 | 3.8 | 0.69 |
| VAR 4 | NUS-DD-191 | 0.49 | 0.03 | 5.2 | 0.22 |
| VAR 5 | NUS-DD-192 | 1.48 | 0.19 | 14.8 | 0.64 |
| VAR 6 | NUS-DD-195 | 1.03 | 0.17 | 23.3 | 0.42 |
| VAR 7 | NUS-DD-196 | 0.12 | < 0.02 | < 0.5 | 0.10 |
| VAR 10 | NUS-DD-193 | 0.61 | 0.11 | 8.0 | 0.25 |
| VAR 11 | NUS-DD-194 | 0.77 | 0.12 | 7.0 | 0.42 |
| VAR 12 | NUS-DD-198 | 1.63 | 0.14 | 12.4 | 0.65 |
| VAR 14 | NUS-DD-179 | 1.51 | 0.93 | 20.0 | 0.50 |
| VAR 15 | NUS-DD-181 | 1.31 | 0.38 | 18.5 | 0.51 |
- 40 -
| Sample ID | Bore Hold ID | Cu, % | Au, g/t | Ag, g/t | S, % |
| VAR 16 | NUS-DD-183 | 0.83 | 0.30 | 25.4 | 0.28 |
| VAR 17 | NUS-DD-185 | 0.45 | 0.06 | 3.9 | 0.16 |
| VAR 18 | NUS-DD-186 | 0.54 | 0.18 | 8.8 | 0.27 |
| Ulveryggen Deposit | |||||
| VAR 8 | ULV-DD-17-01 | 0.84 | < 0.02 | 1.4 | 0.31 |
| VAR 9 | ULV-DD-17-04 | 0.50 | < 0.02 | 0.7 | 0.13 |
| VAR 13 | ULV-DD-17-05 | 0.95 | 0.02 | 2.1 | 0.28 |
Table 2.16: Nussir Deposit Grindability Statistics
| BWI (kWh/t) | ||||
| Statistic | SPI
(Min) |
Full Bond | Mod Bond | Al
(g) |
| Number of Samples | 21 | 4 | 23 | 3 |
| Maximum | 112 | 12.6 | 15.1 | 0.27 |
| Minimum | 34.1 | 11.6 | 9.13 | 0.13 |
| Average | 77.4 | 12.0 | 11.5 | 0.18 |
| Relative Std Dev, % | 25.0 | 3.76 | 12.5 | 44.4 |
| 75th Percentile | 87.1 | 12.2 | 12.3 | 0.20 |
| 25th Percentile | 66.6 | 11.7 | 10.7 | 0.13 |
Based on statistical analysis of the results, the SPI and BWI results indicate the Nussir material as being soft to moderately hard, and slightly abrasive. The Ulveryggen sample results were categorised as moderately hard to hard, and very abrasive.
Locked-Cycle Testing
A series of locked cycle tests and comparable open-circuit batch tests for each of the spatial composites were conducted. The batch and locked cycle test results compared well, with concentrate grades slightly higher in the batch tests and recoveries approximately 2-4% higher in the locked cycle tests. The two ore bodies gave similar results under the conditions tested.
The results of the locked cycle tests and the comparable open-circuit batch tests for each composite, as well as two of the variability samples were also selected for locked cycle testing along with the comparable open-circuit batch test. The results are provided in Table 2.17.
Table 2.17: Locked Cycle and Open Circuit Test Results Summary
| Composite | Test No. | Product | Assays,
% Cu |
% Distribution Cu |
| Comp 1 | LCT2 | Cu Conc | 59.5 | 97.0 |
| F27 | Cu Conc | 63.9 | 93.4 | |
| Comp 2 | LCT 3 | Cu Conc | 50.1 | 95.3 |
| F26 | Cu Conc | 53.1 | 92.7 | |
| Comp 3 | LCT1 | Cu Conc | 36.9 | 96.7 |
| F25 | Cu Conc | 41.4 | 92.3 |
- 41 -
| Bore Hole ID | Composite | Test No. | Product | Assays,
% Cu |
% Distribution Cu |
| NUS-DD-188 | VAR 1 | LCT 4 | Cu Conc | 62.6 | 95.6 |
| F28 | Cu Conc | 62.8 | 91.8 | ||
| ULV-DD-17-01 | VAR 8 | LCT 5 | Cu Conc | 53.6 | 95.9 |
| F35R | Cu Conc | 54.8 | 93.6 |
The average copper grade of the final concentrates was 53.3% Cu and recovery was 92.5%. The average copper grade of the final concentrates for the three Ulveryggen samples was 60.8% Cu and recovery was 90.4%.
There was no evidence of a relationship between the copper head grade and copper recovery. Overall, the test results indicated that high copper grades and recoveries are feasible for all samples under the conditions applied.
Material Sorting Studies
A sorting study on Nussir copper mineralization was conducted by Comex and it was completed on December 19, 2 024. The objective of the study was to evaluate the potential of employing a multi-sensor sorting technology, utilizing X-ray Transmission (XRT) and X-ray Fluorescence (XRF) sensors. Drill core samples containing copper minerals were provided by Nussir and crushed to optimize grain shape and element release before testing. The XRT sensor classified the material into three categories: high-grade, low-grade, and waste. Initial results indicated that a significant portion of the waste fraction still contained copper, necessitating an additional refinement step using XRF to further separate copper-rich particles.
The combined sorting process achieved a pre-concentration of the feed material from 0.57% Cu to 1.28% Cu while reducing the waste fraction by 31.1% of the total input. The final waste contained only 0.11% Cu, resulting in a metal recovery efficiency of 94.4% with minimal copper losses. The study confirmed that sorting technology is a viable method for pre-concentration, allowing for the removal of low-grade material early in processing. However, Comex is recommending larger-scale tests to account for variability in the copper mineralization and therefore further optimize the sorting parameters to maximize effectiveness.
Mineral Resource Estimate
The MRE work was carried out and prepared in compliance with NI 43-101, and the mineral resources in this estimate were calculated using the CIM Standards on Mineral Resources and Reserves, Definitions and Guidelines prepared by the CIM Standing Committee on Reserve Definitions and adopted by CIM Council May, 2014.
Conforming with guidelines for "reasonable prospects for eventual economic extraction", constrained evaluations were completed using a Mineable Shape Optimiser (MSO) to generate wireframes.
The updated mineral resource estimate of the Nussir deposit is summarized in Table 2.18, related to a cut-off grade of 0.3%Cu and a minimum width of 2.0 m.
Table 2.18: Nussir Resource Estimation Summary (Effective Date: January 20, 2025)
| Category | Tonnes
Mt |
Cu % |
Ag
g/t |
Au
g/t |
Cu Eq % |
Cu
Metal Kt |
Ag
Metal Koz |
Au
Metal Koz |
| Measured | 2.69 | 1.08 | 12.8 | 0.18 | 1.31 | 29 | 1,103 | 16 |
- 42 -
| Category | Tonnes
Mt |
Cu % |
Ag
g/t |
Au
g/t |
Cu Eq % |
Cu
Metal Kt |
Ag
Metal Koz |
Au
Metal Koz |
| Indicated | 26.03 | 1.01 | 12.3 | 0.11 | 1.19 | 263 | 10,288 | 92 |
| Meas + Ind | 28.72 | 1.02 | 12.3 | 0.12 | 1.20 | 292 | 11,391 | 108 |
| Inferred | 31.99 | 1.01 | 14.6 | 0.14 | 1.23 | 324 | 14,972 | 143 |
Notes:
| (1) | CIM definitions were followed for MRE. | |
| (2) | A minimum mining width of 2.0 m was applied in making the MRE constraint wireframes. These wireframes were generated using a preliminary MSO. | |
| (3) | Density values for Nussir were estimated from density sample values or assigned default average values where insufficient samples occur nearby. | |
| (4) | MRE constraint wireframes were generated for a cut-off grade of 0.30% Cu, related to potential underground mining. | |
| (5) | Metal prices assumed for the MRE were US$4.20 lb Cu, US$27.00/Oz Ag and US$2,200oz Au, which represent reasonable long-term consensus metal pricing. | |
| (6) | Metallurgy recovery assumptions were 96% Cu, 80% Ag and 93% Au, which stem from SGS metallurgical testwork completed in 2022. | |
| (7) | The cut-off grade of 0.30% Cu was derived from the price and recovery values above, as well as a smelter payability of 97.3% and an assumed total operating cost $26.20/t of ore. | |
| (8) | Rounding may result in apparent summation differences between tonnes, grades and metal content; not considered material. | |
| (9) | Mineral Resources are not Mineral Reserves and do not have demonstrated economic viability. |
The updated resource estimate of the Ulveryggen deposit is summarized in Table 2.19.
Table 2.19: Ulveryggen Resource Estimation Summary (Effective Date: January 20, 2025)
| Resource Category | Tonnes
Mt |
Cu % |
Cu
Metal Kt |
| Indicated | 4.05 | 0.65 | 26.3 |
| Inferred | 3.70 | 0.68 | 25.0 |
Notes:
| (1) | CIM definitions were followed for MRE. | |
| (2) | A minimum mining width of 2.0 m was applied in making the MRE constraint wireframes. These wireframes were generated using a preliminary MSO. | |
| (3) | A global density value was assigned for Ulveryggen, based on analysis of density measurements. | |
| (4) | MRE constraint wireframes generated for a cut-off grade of 0.30% Cu, related to potential underground mining. | |
| (5) | The assumed metal price assumed for the MRE was 4.20 $/lb Cu, which represents a reasonable long-term value. | |
| (6) | The assumed metallurgical recovery was 96% Cu, which stems from SGS metallurgical testwork completed in 2022. | |
| (7) | The cut-off grade of 0.30% Cu was derived from the price and recovery values above, as well as a smelter payability of 97.3% and an assumed total operating cost $26.20/t of ore. | |
| (8) | Rounding may result in apparent summation differences between tonnes, grades and metal content; not considered material. | |
| (9) | Mineral Resources are not Mineral Reserves and do not have demonstrated economic viability. |
Exploration, Development and Production
Exploration Status
The Nussir and Ulveryggen projects are at the Mineral Resource development stage. Drilling was carried out between 1 985 and 2019, during which operators completed 345 core drill holes for a total of 69,440 m. Other exploration work has included surficial geochemistry sampling, ground and airborne geophysical studies, geological mapping, surface chip and grab sampling (including trenching), and regional lithogeochemical rock sampling for rocktype fingerprinting. In addition to the two deposits that have been identified, there are a number of mineralized occurrences both around the deposits and regionally that are either untested or supported by limited drilling. This means that additional infill and exploration drilling is warranted to more fully test favourable stratigraphy both around the deposits and regionally.
- 43 -
Additionally, there are several opportunities to improve the current results that should be investigated further as part of the ongoing development of the Nussir and Ulveryggen projects.
Exploration Targets – Nussir
The Nussir deposit is open to the west and to depth. In particular, the current limit of Inferred category resources excludes the influence of the deep drillhole intersections, because they are excessively distant to the grid of holes above. The exploration target potential was derived by modelling the identified mineralization. The volume of the modelled areas determines the potential tonnage statement in the exploration target. The grade range given in the exploration target is determined with consideration to the drill results within the modelled exploration target area and consideration of the geological setting in an established mineral resource estimate area. The potential tonnages and grades are therefore conceptual in nature and are based on previous drill results that defined the approximate length, thickness, depth and grade of the portion of the mineral resource estimate. There has been insufficient exploration and data collection to define a current mineral resource for the exploration target and the Corporation cautions that there is a risk that further exploration will not result in the delineation of a mineral resource. The exploration target around these deeper intersections therefore represents a tonnage between 8.5 Mt and 16.5Mt, and a Cu grade between 0.7 and 1 .3% Cu, between 9 and 17 g/t silver, and 0.1 and 0.15g/t gold.
There are also a number of mineralized targets that occur both downdip and along strike of the mineralized exploration target that has been defined. This mineral potential has not been properly tested by drilling. Additionally, a number of mineral targets currently outside of the resource area of the Nussir and Ulveryggen deposits are supported by geological mapping and limited drilling. This means that additional infill and exploration drilling is warranted to more fully test favourable stratigraphy both regionally and directly at Nussir and Ulveryggen deposits.
Exploration Targets – Ulveryggen
The Ulveryggen deposit is open to depth, and based on geochemical sampling and geophysics, there are drilling targets both along strike and down-dip.
Double Mineralized Intersections – Nussir Deposit
There are some instances at Nussir, mainly in the more folded west end, of single drillholes picking up two mineralised intersections. This could be due to reverse faulting, and when drilled sufficiently in the future, could lead to an improved interpretation with more mineralised material that is currently modelled. These potentially repeated strata are only known to occur over 2.5 of the 10 km strike length of known mineralization. Limited drilling has been done to date to fully test the mineral potential of this possible extension. Given the presence of a mineral resource adjacent to this parallel zone of favourable strata, it means additional drilling is warranted but there is no guarantee that additional drilling will result in the delineation of a mineral resource in these areas.
Inferred Resource Conversion – Nussir Deposit
The Nussir deposit is open to depth over much of its strike length, as well as westwards. If the project progresses and the proposed underground development commences, this could allow much closer and offset access for drilling of deeper zones. This would provide an opportunity to significantly extend Indicated resources to depth and westwards. Additional drilling should be designed in order to enable a significant proportion of the deposit to be reclassified into a higher category of confidence, such as Indicated category, as well as provide a more accurate interrelation and structural geology and mineralised zones. Stakeholders should be cautioned that additional drilling is not a guarantee for upgrading the resource category.
Inferred Resource Conversion – Ulveryggen Deposit
There are numerous areas currently modelled at the Ulveryggen deposit, where the current drilling density does not support an Indicated resource categorisation. Additional drilling should be designed to enable a significant proportion of the deposit to be reclassified into a higher category of confidence, such as Indicated category, as well as provide a more accurate interrelation and structural geology and mineralised zones. Stakeholders should be cautioned that additional drilling is not a guarantee for upgrading the resource category.
- 44 -
Recommendations
The author of the Nussir Technical Report made the following recommendations for future exploration, development and production activities.
Sample Preparation, Analyses and Security
| · | Develop rigorous quality control and quality assurance ("QA/QC") policy for standards, blanks and duplicate sample when drilling that is monitored on a batch-by-batch basis when data is received from the accredited laboratory. |
| · | Consider the use of prep- and or reject duplicate samples to enhance the QA/QC. |
| · | Select certified reference material (CRM) that are more aligned to the grades of the Nussir and Ulveryggen deposits for copper, gold and silver; being mindful that if geochemically testing for platinum and or palladium, it might require a different CRM. |
| · | Develop an umpire or secondary independent laboratory, remitting approximately 10 to 15% of the total samples, and select analysis methodologies that are similar to the primary laboratory. This will provide future assurances that the range of grades seen in the analytical certificates are valid and respected. |
| · | Consider centralizing all pulp and reject storage |
Data Verification
| · | Finish the drill collar validations done in 2019, referencing the Devisight system from Devico for the X and Y coordinates, and then validating elevation (or Z) data between the surveys for each of the drill collar locations against the LiDAR survey. Having a valid elevation data strengthens the respect of the mineral resource modelling. |
| · | Consider a more rigorous check analysis program, if the analytical pulps are available from prior drilling program results. At a minimum, select approximately 100 to 200 pulps from each round of drilling that would be re-run at both the primary and secondary laboratory. |
| · | Consider moving point and vector data from drilling into a proper database management system such as MX Deposit. This includes but is not limited to drill collar information, lithological data, structural data, sample data, and analytical results. The advantage of such a cloud-based database management system is that it negates expensive software purchasing and it can be linked to major 3D modelling programs such as Seequent's Leapfrog Geo and other programs. |
Further Studies
| · | An optimization and or trade-off study should be done to assess a conventional tailings facility approach for any future engineering studies. |
| · | Consider building a Leapfrog Geo model of all lithological units and structures that is maintained and updated regularly when new surficial mapping and or drilling is completed. This will help better guide future studies and mineral resource estimation processes. |
| · | Consider adding RMR to the geomechanical (rock mechanics) data collection in addition to the RQD work already part of the core logging process. This methodology is typically done for deposits that potentially could be extracted through an underground. |
- 45 -
| · | Consider adding point load testing ("PLT") to the geomechanical data collection process in the coreshack. The addition of this process will provide rock quality and strength information that will be invaluable when assessing ground stability in future engineering studies. It will also provide a large dataset that can be used in conjunction with any analytical program carried out at a rock mechanics laboratory. |
| · | Consider a regular analytical process at a rock mechanics laboratory to backstop geomechanical data collection. Testing could include UCS, BTS, and Triaxial measurements. |
| · | Consider taking a coreshack measurement of specific gravity for each sample marked for collection or add an analytical pulp or reject measurement at the primary laboratory. The addition of a larger number of specific gravity measurements will greatly enhance the estimation of the tonnes on a block by block basis in the mineral resource model, as currently the estimations are using average values for lithologies. |
Exploration Program and Budget
| · | For further development of the project, the author recommends a work program at the Nussir and Ulveryggen projects that includes the preparation of the development of an exploration decline (including logistics and support), exploration drilling and optimization studies including engineering. A summary breakdown of this work program is presented below along with associated estimated costs expected to cost C$13.0 million (Table 2.20). |
Table 2.20: Proposed Budget
| Item | (C$000) |
| Underground access (decline) preparation, exploration logistics and support | 4,000 |
| Exploration – drilling 25,000 to 30,000 m | 6,000 |
| Optimization studies including engineering studies | 3,000 |
| Total | 13,000 |
The Blue Moon Property
Technical Report
Scientific and technical information relating to the Blue Moon Property provided in this AIF is supported by and qualified in its entirety by the full text of the Blue Moon Technical Report on the Blue Moon Property filed in accordance with NI 43-101 entitled "NI 43-101 Technical Report for the Preliminary Economic Assessment of the Blue Moon Mine, Mariposa County, California" dated April 14, 2025 (as amended and restated on September 12, 2025) with an effective date of March 3, 2025, being the Blue Moon Technical Report, which was prepared, reviewed, and approved by Scott Wilson, C.P.G. SME-RM, Peter Szkilnyk, P.Eng., Alan J. San Martin, P.Eng., Richard Gowans, P.Eng., Justin Taylor, P.Eng., and Christopher Jacobs, C.Eng., MIMMM., each of whom is a "qualified person" ("QP") for purposes of NI 43-101. Reference should be made to the full text of the Blue Moon Technical Report, which is available electronically on SEDAR+ (www.sedarplus.ca) under Blue Moon's issuer profile. Development of the Blue Moon Property is referred to as the "Blue Moon Project".
Scientific or technical information in respect of the Blue Moon Property provided subsequent to the date of the Blue Moon Technical Report were prepared by or under the supervision of Dustin Small, who is a consultant to the Corporation and a non-independent qualified person for the purposes of NI 43-101.
Property Description, Location and Access
The Blue Moon Property is located in Mariposa County, California, approximately 120 miles southeast of San Francisco. The town of Mariposa, located sixteen miles east of the Blue Moon Project, has a population of around 2 ,000 and a tourist-based economy. The town of Merced, with a population of around 80,000 inhabitants, is twenty-two miles to the southwest of Blue Moon and has a diverse economy related to large scale agriculture. The local community of Hornitos with a population of about 75, is situated about 4.5 miles south of the Blue Moon Property. Figure 1.1 shows the location of the Blue Moon Property.
- 46 -
Access to the Blue Moon Property is via California County Route J16 also known as Hornitos Rd. and Bear Valley Rd., a paved secondary highway between the communities of Hornitos and Bear Valley. From a point two miles north of Hornitos, at the intersection of J16 and Exchequer Rd., the Blue Moon Property is accessible via a 3.4-mile route traversing a combination of public and private gravel roads.
Four distinct lenses of massive sulphide mineralization have been identified on the Blue Moon Property: the West, Main, East and American Eagle zones. The American Eagle Zone appears to occur in the same stratigraphic position as the West Zone.
Figure 1.1: Blue Moon Location Map
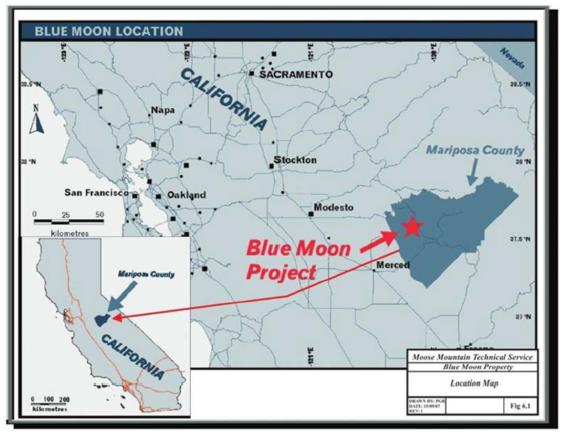
Source: Meade (2002)
Mineral Tenure
As of the date of the Blue Moon Technical Report, the Blue Moon Property consisted of three distinct land tenure components that covered 494.25 acres. These include:
1. Two patented mineral claims (American Eagle, and Blue Bell & Bonanza) owned 100% by Keystone; Blue Moon owns the surface and subsurface rights here.
2. Eight federal lode claims (Red Cloud 1-8) held 100% by Keystone, Blue Moon's wholly owned US subsidiary which has the mineral rights pursuant to Bureau of Land Management (BLM) claims.
3. 100% interest in the mineral rights from two Spanish land grants of the James Gann Jr. Trust of 1991, owned by Keystone in conjunction with a surface rights lease agreement for 40 acres, pursuant to an option purchase agreement completed in 2001.
- 47 -
Table 1.1 lists the Blue Moon Property mineral claims and surface rights on private land as of the date of the Blue Moon Technical Report. For updated information regarding Blue Moon Property mineral claims and surface rights on private lands, please see "The Blue Moon Property – Subsequent Events".
Table 1.1: Blue Moon Claims
| # | Claim Type | Status | Claim
Reference # |
Claim
Name |
Claim
Size (Acres) |
Parcel (APN) |
Claim
Owner |
Notes |
Patented Claims | ||||||||
| 1. | Patented Mineral Claim | Active | MS 5719 | American Eagle | 20.67 | 007-120-005-0 | Keystone Mines Inc. | Patent No. 973403 dated January 28, 1926, covering Mineral Survey No. 5719, for the American Eagle lode mining claim, covering portions of Section 30, Township 4 South, Range 16 East, MDM. |
| 2. | Patented Mineral Claim | Active | M5718 | Blue Bell and Bonanza | 22.4 | 007-120-002-0 | Keystone Mines Inc. | Patent No. 959494, dated May 18, 1925, covering Mineral Survey No. 5718, for the Blue Bell and Bonanza lode mining claims, covering portions of Section 30, Township 4 South, Range 16 East, MDM. |
| BLM Land | ||||||||
| 3. | Unpatented Mining Claim (Federal Lode Claim) | Active | CA101349794 | Red Cloud #1 | 20.32 | 007-100-010-0 | Keystone Mines Inc. | Land administered by Bureau of Land Management (Federal Land) |
| 4. | Unpatented Mining Claim (Federal Lode Claim) | Active | CA101303528 | Red Cloud #2 | 20.66 | 007-100-010-0 | Keystone Mines Inc. | Land administered by Bureau of Land Management (Federal Land) |
| 5. | Unpatented Mining Claim (Federal Lode Claim) | Active | CA101300462 | Red Cloud #3 | 6.89 | 007-100-010-0 | Keystone Mines Inc. | Land administered by Bureau of Land Management (Federal Land) |
| 6. | Unpatented Mining Claim (Federal Lode Claim) | Active | CA101301850 | Red Cloud #4 | 20.66 | 007-120-003-0 | Keystone Mines Inc. | Land administered by Bureau of Land Management (Federal Land) |
| 7. | Unpatented Mining Claim (Federal Lode Claim) | Active | CA101452189 | Red Cloud #5 | 20.66 | 007-120-003-0 | Keystone Mines Inc. | Land administered by Bureau of Land Management (Federal Land) |
- 48 -
| # | Claim Type | Status | Claim
Reference # |
Claim
Name |
Claim
Size (Acres) |
Parcel (APN) |
Claim
Owner |
Notes |
| 8. | Unpatented Mining Claim (Federal Lode Claim) | Active | CA101379487 | Red Cloud #6 | 20.66 | 007-120-003-0 | Keystone Mines Inc. | Land administered by Bureau of Land Management (Federal Land) |
| 9. | Unpatented Mining Claim (Federal Lode Claim) | Active | CA101347731 | Red Cloud #7 | 3.16 | 007-120-004-0 | Keystone Mines Inc. | Land administered by Bureau of Land Management (Federal Land) |
| 10 | Unpatented Mining Claim (Federal Lode Claim) | Active | CA101378594 | Red Cloud #8 | 6.89 | 007-100-010-0 | Keystone Mines Inc. | Land administered by Bureau of Land Management (Federal Land) |
| Private Land | ||||||||
| 11 | GANN Lands | Active | Letter dated 1 September 2001 | Spanish Land Grant (J. GANN) | 331.28 | 007-120-007-0 | Keystone Mines Inc. | Includes 40 acre surface rights, flexible location within total 320 acre area |
Unpatented mining claim maintenance fees are current and paid through August 31, 2025.
The Blue Moon Property was previously owned by Westmin Mines, Inc., an Idaho corporation and subsidiary of Westmin Resources, Inc. On September 12, 2002, Westmin Resources was acquired by Expatriate, now Yukon Zinc Corporation. The acquisition was subject to a purchase agreement with Boliden Westmin, whereby Expatriate Resources Ltd. ("Expatriate") acquired 100% interest in Westmin Resources, Inc. in return for the issuance of 3 million common shares and the granting of a 0.5% net smelter return royalty capped at US$500,000 to Boliden
Westmin.
The subsidiary Westmin Mines, Inc. changed names to Keystone Mines, Inc, on October 25, 2002. In 2004, Expatriate transferred Keystone to Pacifica Resources Ltd., now EDM Resources Inc., through a Plan of Arrangement. Subsequently, in 2007, Pacifica through the Pacifica arrangement, transferred Keystone to Savant Explorations Ltd. Savant Explorations Ltd. changed names to Blue Moon Zinc Corp. on June 5, 2017 and changed its name to Blue Moon Metals Inc. on April 13, 2021. Currently, the Blue Moon Property is controlled by Blue Moon through its 100% ownership of the US subsidiary, Keystone, an Idaho corporation.
In 2017, Northern Empire Resources Corp. (NM) through an agreement with Imperial Metals Corporation, acquired a 10% net profits interest (NPI) in the Blue Moon Property through the takeover of Imperial's Sterling Mines subsidiary. The NPI is only to be paid after deducting all operating expenses, all pre-production expenditures dating back to May 14, 1996, and all post-production expenditures. A finance charge of prime plus one-half of one percent is also to be deducted before any NPI is paid. The NPI was repurchased and extinguished by Keystones in January 2018 through the issuance of 300,000 Common Shares and the payment of US$20,000 cash to NM.
A mineral deed dated effective September 1, 2001, and recorded March 4, 2008, as Document No. 2080941, reserved to the James W. Gann, Jr. Trust of 1991, a 3% Net Smelter Returns (as defined in the deed) that in the aggregate was not to exceed US$200,000 on the lands included in the Gann Land.
In September 2020, Blue Moon repurchased two separate 1% Net Smelter Returns (NSR) on the Blue Moon Project by paying each 1% NSR holder US$12,000 or US$24,000 in total.
- 49 -
The Blue Moon Project is located within the boundaries of the County of Mariposa in the state of California. Mariposa County is the lead agent for all county, state and federal permitting jurisdictions. Exploration permits are issued by Mariposa County through an Administrative Use Permit (AUP). The Corporation's existing AUP expired on June 26, 2023 and the Corporation will need to apply for a new AUP before commencing any future drilling activities. The Corporation must file a Notice of Intent to Operate (NOI) with the Bureau of Land Management. The Corporation has a current NOI in place through to August 27, 2026.
To the extent known, there are no other royalties, back-in rights, payments or other encumbrances to which the Blue Moon Property is subject. The author knows of no known environmental liabilities for which the Blue Moon Property is subject. The author of the Blue Moon Technical Report knows of no other significant factors and risks that may affect access, title or the right or ability to perform work on the Blue Moon Property.
History
Background
Extending along the foothills of the west slope of the Sierra Nevada from Butte County on the north to Fresno County on the south is a discontinuous belt of copper and zinc mineralization. This belt also has been the source of substantial amounts of gold. Gold-bearing gossans in the oxidized zones overlying the copper-zinc deposits were mined during the gold rush. Later, during the copper "booms" of the Civil War and World Wars I and II, considerable amounts of gold were recovered as a by-product. During the 1930s a few gossan deposits in this belt were again mined for gold.
The primary copper and zinc deposits consist of lenticular sulphide bodies in zones of alteration in greenstones and various types of schists. Mineralization contains abundant pyrite with associated chalcopyrite, sphalerite and some gold and silver. Most of the mineralization contains only a small fraction of an ounce of gold per ton, but some deposits have yielded as much as one ounce of gold per ton. Also present are galena, bornite, tetrahedrite, covellite, and chalcocite.
The most important mines in the foothill belt have been the Big Bend mine, Butte County; Spencerville and Boss mines, Nevada County; Dairy Farm and Valley View mines, Placer County; Copper Hill and Newton mines, Amador County; Penn, Quail Hill, Napoleon, Collier, Keystone-Union, and North Keystone mines, Calaveras County; Blue Moon, Pocahontas, Green Mountain and La Victoria mines, Mariposa County; Buchanan, Jessie Belle, and Daulton mines, Madera County; and Fresno Copper and Copper King mines, Fresno County.
Considerable by-product gold has been recovered from copper mines in the Moonlight District of northeastern Plumas County, the principal sources having been the Walker, Engels, and Superior mines. However, few production figures are available, so the total gold output of these mines is unknown. In 1931, the Walker mine was the source of 432,000 tons of copper ore that had an average gold content of 0.05 ounces per ton. At the Walker mine, the mineral bodies consist of wide chalcopyrite-bearing quartz veins in schist and hornfels near granitic rocks. At the Engels and Superior mines, the deposits are bands of chalcopyrite and bornite in sheared granitic rocks.
The Blue Moon deposit is the largest known volcanogenic massive sulphide deposit of its type within the Foothills Massive Sulphide Belt.
A few miles to the south of the Blue Moon Property in Mariposa County is the nearby town of Hornitos. a formerly rollicking Mexican village that sprang up in the 1850s from the newly rich gold diggings at Quartzburg. Situated on Burns Creek, "Hornitos" means "little ovens" in Spanish and was named for the above ground rock and adobe graves of Mexican settlers found in the area. These gravestones were built like little square bake ovens. The population is less than 75 residents today.
1890 – 1945
Although copper was discovered in Mariposa County during mid-1800s gold rush, initial exploration on the Blue Moon Property did not begin until the 1890's. Approximately 50 prospect pits, trenches, and shafts were developed by gold prospectors at that time, mainly on quartz outcrops and pyritic/gossanous outcrops. In 1899, the American Eagle adit was driven 300 ft into an alteration zone and an "appreciable quantity" of gold was produced from one of six known mineralized zones. This zone is now covered but was reported to be about 4 ft wide and consisted of oxidized sphalerite, pyrite, tetrahedrite, galena, chalcopyrite, silver, and gold, with grades of roughly 3% to 8% zinc, 2 % to 11% copper, 1% lead, 1 opt to 3 opt silver, and 0.01 opt to 0.22 opt Au. This mine was worked until 1912, and then was idle until 1942 when, during WWII, a small block of ground was stoped. By 1943, production from the American Eagle was suspended and it has remained inactive since then. No reliable figures for the total production at the American Eagle are available.
- 50 -
In the early 1930's prospecting in the Blue Moon area, just north of the American Eagle was begun. In 1935 a small amount of Au-Ag-Cu oxide ore was mined, probably representing the surface expression of the Blue Moon Main Zone. In 1940, Red Cloud Mines, Inc. (Red Cloud), began developing shallow workings which intersected zinc, probably in the Main Zone in the area Blue Moon Shaft #1. The Federal Bureau of Mines had initiated a diamond-drilling program at the American Eagle mine based on an examination by one of its engineers in June 1943; drilling was done from January to March 1944. The results of this drilling by the government are unknown.
Exploratory drilling at that time verified continuity of the mineralization at depth. In 1943, Red Cloud was acquired by Hecla Mining Co. Production at a rate of 200 tons per day yielded ore with an average content of 14% zinc and minor copper, lead, silver and gold. Cutoff grade was defined as 7% zinc over a minimum stope width of four feet. Ore was milled and concentrated by flotation at the Jenny Lind gold mine and mill site located four miles to the southeast. Zinc concentrates were sold to Metals Reserve Co. at Merced Falls and later at Merced; copper concentrates were trucked to the ASARCO smelter at Selby, California.
In 1945, the "hanging wall fault breccia" caved twice, once in the summer and again in November. Following the second cave-in, all work at the Blue Moon mine was suspended. At that time the mine had been developed to a depth of 490 ft and along strike for 320 ft, with a total of 2,370 ft of workings. Total reported production amounted to 55,655 tons containing about 12.3% zinc, 0.37% copper, 0.48% lead, 3.76 opt silver, and 0.062 opt Au.
At the time of its closing, the consolidated Blue Moon mine was ranked as the eleventh largest producing mine, and by far the largest productive base metal mine, in Mariposa County.
1945 – 1975
Exploration and mining activities on the Blue Moon Property were paused during this period.
1976 – 1990
In 1976, Amselco acquired the Blue Moon Property from prospectors Tom Evans and Norm Stevens, and conducted soil geochemical and electromagnetic surveys and 4,161 feet of percussion drilling between 1976 and 1979. Between 1981 and 1984, Colony Pacific Explorations Ltd. (an Imperial Metals Corporation subsidiary) conducted geological mapping, soil geochemical sampling, induced polarization and downhole EM geophysical surveys, and 33,385 ft of diamond drilling. This drilling was focused on testing the down dip extension of the mine area. Mr. Evans supervised this work and defined the steep plunge of the lenses to the south, still recognized today.
American Mine Services optioned the Blue Moon Property from Colony Pacific in 1983 and calculated a geological and mineable reserve, as per 1983 criteria, as well as undertaking preliminary metallurgical studies, mine engineering and design studies and site facilities planning but subsequently defaulted on their option agreement in 1983. Westmin Resources Limited concluded an option on the Blue Moon Property and conducted several exploration programs in the period 1984-1987 and completed 56,853 ft of diamond drilling expanding the resource base of the deposit and discovering the American Eagle lens and East lenses. The exploration work included recalculation of the mineral resource, and commencing engineering studies and conducting metallurgical, hydrological, and environmental baseline studies. In October 1987, Westmin terminated its option and converted its interest into an equity position in Colony Pacific. The latter continued with permitting of an underground exploration permit and made application for a permit for an underground development and exploration program. More than US$5 million in exploration was completed in the period (Thompson, 1995).
- 51 -
1991 – 2001
In 1991 Lac Minerals (eventually Barrick) optioned the Blue Moon Property from Colony Pacific and carried out 19,654 ft of drilling in 15 holes. Lac Minerals also completed soil and rock geochemical surveys, and HLEM and magnetic surveys. Westmin re-acquired the Blue Moon Property in May 1996 at a cost of US$1.45 million.
Following the repurchase in May of 1996, Westmin resumed evaluation of the development of the Blue Moon Property, however as budgetary priorities were being focused on the company's discovery at the Wolverine deposit in the Yukon, exploration and development efforts were diverted away from Blue Moon. In February 1998, Westmin granted Augusta Metals Corporation an option on the Blue Moon Property. Augusta completed 2,470 ft of drilling in five holes on the Lone Oak barite-gold prospect southeast of the main VMS zone. Subsequently Augusta failed to fulfill its work commitments, and the option was forfeited during 2000/2001.
2002 - Present
In 2002, Expatriate (Harlan Meade) purchased Westmin from Boliden Westmin. In 2004, the Blue Moon Property was spun out into Selwyn Resources Ltd. Subsequently, in 2007, Savant Explorations Ltd. was spun out from Selwyn Resources and issued a NI 43-101 resource estimate based on previous well-documented work programs in 2008 (Morris, R.J. and Giroux, G. 2008).
In 2017, Savant was renamed Blue Moon Zinc Corp., and an updated mineral resource estimate was issued. Between 2 018 and 2021, a multi-year drilling program was carried out by Blue Moon and under a JV with Platina Resources, and a 10% NPI and two 1% NSR royalties were bought back.
In April, 2021, the Corporation was renamed Blue Moon Metals Inc.
In 2023, a geophysical (gravity) survey was conducted on the Blue Moon Property (Carpenter, T., 2023) and a revised resource estimate was published, including the 2018-2021 drilling data (Hendricksen, A.H. and Wilson, S., 2023).
Geology and Mineralization
The Blue Moon deposit is hosted by the Upper Jurassic Gopher Ridge Formation of the Western Block of the Sierra Foothills Metamorphic Belt. This belt extends for 186 miles along the western foothills of the Sierra Nevada Mountains and is approximately 9.5 miles wide. Along the length of the belt, clusters of Zn-Cu rich, polymetallic, massive sulphide deposits occur at approximately 25-mile intervals. Many mines were developed between 1860 and the mid 1900s along the belt. One of the largest was the Penn mine in Calaveras County north of Mariposa County, which produced 883,402 tons of Cu-Zn-Pb (Au-Ag) ore (Martin, 1988).
Regional Geology
Rocks in the Sierra foothills consist of north trending tectonostratigraphic belts of metamorphosed sedimentary, volcanic, and intrusive rocks ranging in age from late Paleozoic to Mesozoic. These belts represent rock sequences, largely of island-arc affinity, that were accreted to the continent. They extend about 235 miles along the western side of the Sierra and are flanked to the east by the Sierra Nevada Batholith and to the west by sedimentary rocks of the Cretaceous and Jurassic Great Valley sequence.
The structural belts are internally bounded by the Melones and Bear Mountains fault zones, and are characterized by extensive faulting, shearing, and folding (Earhart, 1988). Historically, three belts have been identified in the southern Sierran foothills based on lithologic differences and the nature of gold mineralization - the West Gold Belt, the Mother Lode Belt, and the East Gold Belt. The Mother Lode Belt is responsible for most of the gold produced. However, substantial gold has been produced from the East Belt, as well as gold, copper, and other base metals from rocks of the West Belt.
- 52 -
The West Belt consists of an eastern component composed of an ophiolitic melange and a Jurassic age western component composed of the Copper Hill Volcanics, the Salt Springs slate, and Gopher Ridge Volcanics. The Bear Mountains fault zone separates the melange from the Copper Hill Volcanics. The West Belt contains widely scattered gold deposits occurring in quartz veins and stringers in schist, slate, granitic rocks, altered mafic rocks, and as gray ore in greenstone. The West Belt also hosts the Foothill Copper-Zinc Belt and the massive sulphide deposits of the Penn Mine and other VMS deposits.
The Mother Lode Belt traverses western Calaveras County and consists of the upper Jurassic Logtown Ridge and Mariposa formations. The Logtown Ridge Formation consists of about 6,500 ft of volcanic and volcanic-sedimentary rocks of island arc affinity. The overlying Mariposa Formation contains a distal turbidite, hemipelagic sequence of black slate, schist, amphibolite and chlorite schist, fine-grained tuffaceous rocks, and subvolcanic intrusive rocks. The thickness of the Mariposa Formation is estimated to be about 2,600 ft thick at the Consumnes River (Earhart, 1988).
Mother Lode mineralization is characterized by steeply dipping gold-bearing mesothermal quartz veins and bodies of mineralized country rock adjacent to veins. Mother Lode mineral production is generally low to moderate grade (1/3 ounce of gold or less per ton), but mineral occurrences may be considered large in volume. Mother Lode veins are characteristically enclosed in Mariposa Formation slate with associated greenstone. The Mother Lode belt vein system ranges from a few hundred feet to a mile or more in width. Mother Lode type veins fill voids created within faults and fracture zones and consist of quartz, gold and associated sulphides, ankerite, calcite, chlorite, limonite, talc, and sericite. The Melones Fault zone separates the Mother Lode Belt from the East Belt.
The Eastern Belt is dominantly argillite, phyllite plus phyllonite, chert, and metavolcanic rocks of Paleozoic-Mesozoic age. The phyllite and phyllonite are dark to silvery gray. The chert is mostly thinbedded with phyllite partings.
The Paleozoic-Mesozoic metasedimentary and metavolcanic rocks of the Eastern Belt have been assigned to the Calaveras Complex by most investigators (Earhart, 1988). Older Paleozoic metamorphic rocks have been assigned to the Shoo Fly Complex. The metamorphic complexes have been intruded in places by Mesozoic plutonic rocks. Lode deposits of the East Belt consist of many individual gold-bearing quartz veins enclosed in metamorphic rocks of possible Jurassic age, metamorphic rocks of the Calaveras Complex, metamorphic rocks of the Shoo Fly complex, or in granitic rocks. Most of the veins trend northward and dip steeply. An east-west set of intersecting faults may be a controlling factor in controlling deposition of metals. Mineral deposits of the East Belt are smaller and narrower than those of the Mother Lode, but commonly are more chemically complex, and richer in grade. Gold is usually associated with appreciable amounts of pyrite, chalcopyrite, pyrrhotite, galena, sphalerite, and arsenopyrite.
Local Geology
The Foothill Copper-Zinc Belt forms part of a complex litho-tectonic belt of Jurassic age island arc metavolcanic, metasedimentary, and meta-plutonic rocks. It lies west of, and roughly parallel to the Mother Lode gold belt. The metallic deposits, which form lenticular bodies in the metavolcanic rocks, are primarily composed of massive pyrite and various amounts of chalcopyrite, sphalerite, gold and silver. Some deposits, however, contain small amounts of pyrrhotite, galena, tetrahedrite, orbornite.
Until the early 1970s, the massive sulphide deposits at the Penn Mine were thought to be epigenetic replacement deposits formed along shear zones (Heyl, et al, 1948; Clark and Lydon, 1962). The reinterpretation of massive sulphide deposits in Japan as being of volcanogenic origin rather than replacement deposits resulted in a re-evaluation of many massive sulphide deposits in the western US. As a result, more recent studies of specific deposits, including those of the Penn Mine, have proposed a syngenetic origin of these deposits (Peterson, 1985).
Kemp (1982) defined the island-arc setting in which the Foothill Copper-Zinc Belt deposits are situated. Schmidt (1978) defined the textural and structural attributes, stratigraphic framework, and the sulphide mineralogy at the Penn Mine and concluded these deposits are more indicative of Kuroko-type syngenetic volcanogenic sulphides. Bedrock at the Penn Mine consists primarily of greenschist-facies metavolcanic rocks of the Gopher Ridge Volcanics that strike N30°W and dip steeply to the east (generally greater than 70°).
- 53 -
Despite the regional metamorphism and eastward tilting there is little evidence of major folding or faulting in the area (Peterson, 1985). The metavolcanic rocks have a weak to intense foliation paralleling the strike. Peterson (1985) subdivided the Gopher Ridge Volcanics at the Penn Mine into one intrusive and five volcanic sub-units based on prominent lithologic features: 1) felsic quartz porphyry intrusive unit, 2) siliceous tuff unit, 3) basalt unit, 4) mafic to intermediate tuff unit, 5) heterogeneous tuff unit, and 6) vent complex unit.
Most of the copper-zinc deposits are intimately associated with sills and lenses of the felsic quartz porphyry unit which occur within the lower three volcanic units. Also associated with the deposits are large areas of sericitic and silicic alteration that produced a quartz sericite schist, and chloritic, hematitic, and pyritic alteration halos around the mineralization. Mineralization occurs in two distinct zones; a western ore zone lying to the east of quartz porphyry schist and along which Shaft Nos. 1, 2, 6 were sunk, and an eastern ore zone just west of chloritic quartz porphyry, which was mined in shafts Nos. 3 and 4. Twelve separate zones were differentiated during underground mining. Heyl et al (1948) provides numerous cross sections through many of these areas within the mine.
Schmidt (1978) identified several zoned mineralization types including massive sulphides, stringer veins and disseminated mineralization. The principal domains consist of massive mixtures of sphalerite, pyrite, bornite, and chalcopyrite with minor gangue comprised of barite, quartz, calcite and/or mica schist, and rare to minor galena and tetrahedrite/tennantite. Quartz, selenite, and some native copper are also present (Clark and Lydon, 1962).
Many of the massive zones are banded with alternating layers of chalcopyrite, pyrite, or sphalerite, whereas others are a fine-grained heterogeneous mixture of up to 60% sphalerite, 50% pyrite, and varying proportions (up to 30%) of copper and accessory minerals. Many of the banded mineral bodies show kinks, swirls, and folds indicative of post-deposition deformation (Schmidt, 1978). The mineralization shapes are lenticular in form, and the long axes plunge down dip or steeply to the north or south. Mineralization shows pronounced elongation with length-to-width ratios ranging from 2:1 to 5:1 and averaging 3:1 (Schmidt, 1978). They varied considerably in size, some having been mined along the pitch length of as much as 1,000 ft (Heyl et al, 1948). Thickness of mineralization varies from 4 ft to 30 ft. Stringers are pyrite, chalcopyrite, sphalerite, bornite, calcite, barite, and quartz. Gangue of finemedium- grained aggregates of quartz, calcite, and barite occur interstitial to the stringers.
Disseminated mineralization consists of disseminated pyrite, chalcopyrite, and sphalerite, and are associated with extensive wall-rock alteration (Schmidt, 1978). Fine-grained pyrite comprises between 1% to 10% of the rock. Mineralization displays a strong asymmetric zonation both in mineralogy and mode of mineral occurrence, which was not consistent with a replacement origin.
A typical mineral body in the Western zone consists of: 1) a hanging wall layer of massive to banded mineralization rich in sphalerite, barite, chalcopyrite, pyrite, and galena, and tetrahedrite-tennantite, with sphalerite-barite rich mineralization being more abundant towards the hanging wall, and copper minerals more abundant towards the footwall; 2) a zone of stringer mineralization with copper minerals (bornite and chalcopyrite), pyrite, quartz, and minor tetrahedrite; and 3) quartz-pyrite veinlets and disseminated pyrite mineralization with quartz porphyry or rhyolitic tuffs.
In the Eastern zone, the above sequence is reversed, occurring from footwall to hanging wall. The zoning was attributed to a syngenetic process where gravity would contribute to the asymmetry of both the mineral types and alteration effects (Schmidt, 1978). Mineralized zones are conformable with the volcanic section. Mineralization lies along bedding and schistosity planes rather than along fault planes or fractures zones as would be expected by a hydrothermal origin. These zones also exhibit stratigraphic selectivity, occurring only within or to one side of a felsic quartz porphyry.
Mineralization commonly occurs at the contact of a felsic porphyry with more mafic rocks. The felsic quartz porphyry intrusive units and parts of the volcanic units are altered to sericite and silicified in the stratigraphic horizons of the deposits (Peterson, 1985). Similar associations of felsic rocks and alteration are characteristic of Kuroko-type deposits massive sulphide deposits (Franklin et al, 1981). The fluids affecting the felsic quartz porphyry intrusive and responsible for the mineralization are thought to have had a common origin, with alteration occurring contemporaneously with deposition of the metallic mineralization. First the volcanic units were deposited in an island arc environment. Contemporaneous with or shortly after their deposition, felsic quartz porphyry bodies intruded the volcanic rocks along bedding planes to form a number of sills, the massive sulphide bodies were deposited, and the adjacent country rock was altered.
- 54 -
Property Geology
The Gopher Ridge Formation in the area of the Blue Moon deposit consists of a basal sequence of basalt and andesite overlain by a rhyolite, Figure 1.2. The rhyolite strata are up to 300m thick and host the Blue Moon deposit(s). The sulphide-sulphate mineralized lenses are hosted in the lower part of the felsic sequence. The felsic volcanic rocks are succeeded to the east by volcaniclastic rocks and ultimately by deep-water argillaceous, sedimentary rocks (Meade,
1996).
Strata at the Blue Moon Property strike approximately 20° west of north, dip near vertically, face to the east and are tightly folded. Minor fold features suggest a steep, north plunge of the regional structure. All lithologies have undergone low grade metamorphism and the prefix "meta" is not applied to lithologic names for the sake brevity in writing. Lithologies observed at Blue Moon exhibit metamorphic characteristics of the lower greenschist facies. The rhyolite strata have been subdivided on the basis of phenocryst mineralogy into three distinct units: aphyric rhyolite, feldspar porphyry rhyolite and quartz-feldspar porphyry rhyolite. The distinction of these different types of rhyolite allows the modeling of the depositional environment of the volcanic rocks at the time of the sulphide mineralization and the identification of stratigraphic horizons within the felsic rocks. More massive phases of aphyric rhyolite define rhyolite dome features that are flanked by clastic, fragmental facies. The thinning of the aphyric rhyolite proximal to the domes defines favorable environments for deposition of massive sulphide mineralization. Further up the stratigraphic sequence, massive feldspar porphyry rhyolite appears to define sill or dyke features that locally truncate sulphide mineralization.
Sericitic alteration and bleaching of the rhyolite strata cause wide ranges in the appearance of the various rhyolite rocks, and careful distinction of alteration changes versus changes in lithology is important to defining the volcanic stratigraphy.
Lateral to the sulphide mineralization, chemical sedimentary rocks containing hematite, magnetite, barite, silica and manganese minerals, helped define mineralized horizons. Sulphide-barite mineralization on the edges of massive sulphide mineralization grades laterally into hematite-jasper iron formation, which, in turn, grades into manganese-bearing siliceous tuffaceous rock.
- 55 -
Figure 1.2: Property Geology (Meade, 2002)
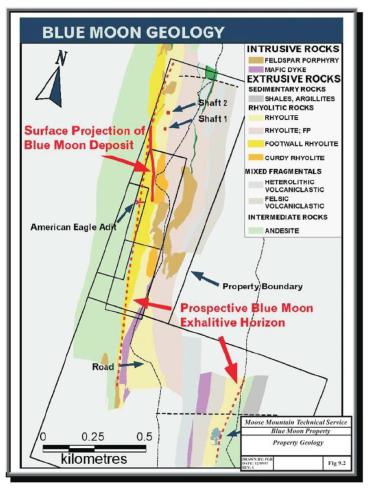
Mineralization
Probably the best local surface geology maps displaying mineralization at the Blue Moon deposits were those during Harlan Meade's leadership time with both Western Mines and Expatriate (Figure 1.2). Several geologists, including Paul Wodjak and Garfield McVeigh are mentioned in the references. Several subsequent geologists have mapped offset faults in the Main Zone and more work is necessary to clarify these differences.
The Blue Moon deposit is a Kuroko-type volcanogenic massive sulphide deposit. The deposit is shown to have some similarities with the Lynx and Myra deposits at Myra Falls, Vancouver Island. Stacked sulphide-sulphate lenses occur in two or more horizons within a 50 ft to 180 ft stratigraphic interval. Four distinct lenses of massive sulphide mineralization have been identified; the West, Main, East and American Eagle zones. The American Eagle Zone appears to occur in the same stratigraphic position as the West Zone.
The West Zone occupies the lowest stratigraphic position and occurs near the base of the aphyric rhyolite sequence. The Main Zone lies stratigraphically above the West Zone and occurs with the first appearance of quartz and feldspar porphyry rhyolite. The East Zone lies stratigraphically above the Main Zone, although several authors have included it as part of the Main Zone. It is hosted entirely within feldspar porphyry rhyolite.
Massive sulphide mineralization consists of pyrite, sphalerite, chalcopyrite, galena, and minor tetrahedrite and bornite. Massive and semi-massive sulphides may be accompanied by purple anhydrite, gypsum or barite. Textures include massive, banded and clastic mineralization.
Metal zoning in base or precious metal is poorly understood although there is a strong tendency for narrower mineralized zones to be relatively richer in gold and silver and to have barite gangue. The potential mineral horizons are enveloped by sericite-silica-pyrite alteration that extends laterally in the rhyolite stratigraphy at least 3,000 ft, as far as known mineralization is recognized, and more than 490 ft into the footwall andesite. A stockwork sulphide feeder zone is not clearly identified within the footwall alteration zone. This discordant sericite altered zone is linked to a lower strata-bound sericite altered zone in the footwall andesite which extends at least 0.7 miles to the south from the deposit and may be an important exploration tool to identify other mineralized centres.
- 56 -
The lower mineralized horizon (West and American Eagle zones) generally contains more pyrite, chalcopyrite, sphalerite, anhydrite and gypsum than the upper mineralized horizon (Main and East zones) which is comparatively enriched in galena, tetrahedrite and barite. The South Zone has not been studied. Gold and silver grades can be significant in the lower horizon lenses but are on average three times greater in the upper horizon lenses.
A database of some 1,540 samples is available for the deposit. All the samples are from drill core. Table 1.2 lists some of the general statistics.
Table 1.2: Blue Moon Summary Statistics from Drill Core
| Parameter | Minimum | Maximum | Mean | Stand. Dev. | C.V. |
| Sample length (ft) | 0.4 | 21.3 | 3.78 | 1.78 | 0.47 |
| Copper (%) | 0.0 | 10.7 | 0.35 | 0.85 | 2.44 |
| Zinc (%) | 0.0 | 46.0 | 2.37 | 5.09 | 2.15 |
| Lead (%) | 0.0 | 6.4 | 0.14 | 0.47 | 3.48 |
| Silver (oz/ton) | 0.0 | 40.3 | 0.69 | 2.44 | 3.55 |
| Gold (oz/ton) | 0.0 | 1.04 | 0.019 | 0.06 | 3.19 |
Deposit Types
The Blue Moon deposit is a Kuroko-type, polymetallic, volcanogenic, massive sulphide deposit, or VMS deposit. The sulphide-sulphate deposit is hosted in rhyolite. Anomalous metalliferous mineralization includes pyrite, sphalerite, chalcopyrite, galena, and minor tetrahedrite and bornite. The associated sulphate minerals are barite, gypsum and purple anhydrite. To date, four lenses of mineralization have been identified within at least two, possibly three, horizons. The lenses are enveloped by sericite-silicapyrite alteration. Gold and silver grades are significant in the lower horizon lenses but are, on average, three times greater in the upper horizon lenses.
The volcanogenic massive sulphide deposit type and model for Blue Moon is considered appropriate, and the proposed exploration program is planned accordingly.
Exploration
Exploration of the Blue Moon Property, mostly historical in nature, was carried out by earlier owners and includes geological mapping, soil geochemical surveys and geophysical surveys, including an induced polarization survey, down-hole EM surveys and, in 2023, a gravity survey.
Drilling
Most of the drilling on the Blue Moon Property was completed by previous owners, starting in 1942, and by Blue Moon in 2018, 2019, and 2021.
Drilling has occurred on the Blue Moon Property since 1942 with a total of 136,416 ft of drilling in 124 drill holes. Most of the holes were drilled in the Blue Moon deposit area. A few holes were drilled in the Amselco Hill and Lone Oak areas, targeting the favorable stratigraphic horizon. Figure 1.3 shows the location of all drill holes on the Blue Moon prospect through 2023 (Shum, Kevin 2023).
- 57 -
Figure 1.3: Location of All Drill Holes on the Blue Moon Prospect through 2023 (Shum, Kevin 2023)
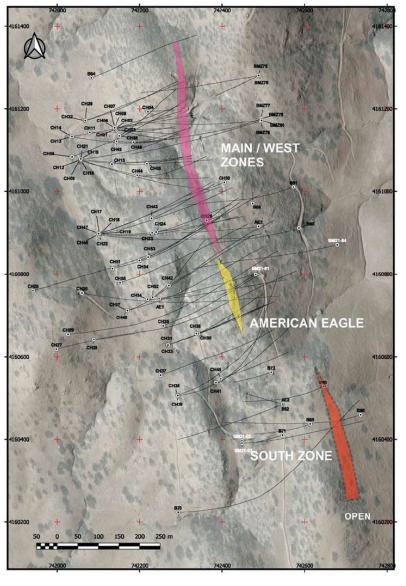
Most of the holes drilled on the Blue Moon Property have been diamond drill holes of BQ and NQ core, except for nine percussion holes drilled in 1979 by Amselco. As well, with the exception of the Amselco holes, all the holes have down-hole surveys. Only core holes drilled since 1979 were used in the resource calculation.
Table 1.3 and Table 1.4 list the footage drilled by others and by Blue Moon, respectively.
Table 1.3: Summary of Drilling on the Blue Moon Property, Prior to the Formation of Blue Moon
| Year | Operator | No
of Holes |
Hole Numbers | Drilled Length |
| 1942 | Red Cloud Mines Inc. | 10 | RC2 - RC8, 101-103 | 4,516.5 |
| 1944 | US Bureau of Mines | 7 | 1-7 | 2,800.0 |
| 1979 | Amselco | 9 | 79-1 – 79-9 | 4,161.0 |
| 1981 | Colony Pacific | 2 | B1, B2 | 1,584.0 |
| 1982 | Colony Pacific | 12 | AE1 -AE3, B3-82 - B11-82 | 11,054.1 |
- 58 -
| Year | Operator | No
of Holes |
Hole Numbers | Drilled Length (ft) |
| 1983 | Colony Pacific | 6 | B12-83 - B17-83 | 9,856.6 |
| 1984 | Westmin | 5 | B18 - B22 | 10,891.7 |
| 1985 | Westmin | 10 | CH13-14,17-18,23-28 | 10,307.5 |
| 1986 | Westmin | 15 | AE 86 CH 1,B 86 CH 29 - B 86CH 42 | 22,129.8 |
| 1987 | Westmin | 7 | B 87 CH 43 - B 86 CH49 | 6,872.0 |
| 1988 | Westmin | 10 | B 88 CH 50 - B 88 CH59 | 16,447.0 |
| 1991 | Lac Minerals | 15 | B 91 CH 60 - B 91 CH74 | 19,639.0 |
| 1999 | Augusta | 5 | LO 99 CH 01- LO 99CH 05 | 2,471.0 |
| Totals | 113 | - | 122,730.2 | |
Table 1.4: Drilling by Blue Moon Since 2018 at Blue Moon Project
| Hole | Drilled Length |
| BMZ75 (2018) | 1,180 |
| BMZ76 (2018) | 950 |
| BMZ77 (2018) | 180 |
| BMZ78 (2018) | 1,789 |
| BMZ79 (2019) | 1,837 |
| BMZ80 (2019) | 1,877 |
| BMZ81 (2021) | 719 |
| BMZ82 (2021) | 577 |
| BMZ83 (2021) | 2,809 |
| BMZ84 (2021) | 1,768 |
| Total | 13,686 |
Table 1.5 details significant Intercepts from the Blue Moon Drill Program.
Table 1.5: Significant Intercepts from the Blue Moon Drill Program
| Hole | From
(ft) |
To
(ft) |
Length
(ft) |
Zinc (%) |
Gold
(g/t) |
Silver
(g/t) |
Lead (%) |
Copper (%) |
ZnEq (%) |
| BMZ75 | 1,022.0 | 1,038.0 | 16.0 | 1.2 | 0.08 | 0.7 | 0 | 0.04 | 1.4 |
| Inc | 1,027.0 | 1,029.0 | 2.0 | 2.9 | 0.05 | 1.5 | 0 | 0.08 | 3.2 |
| BMZ78 | 1,425.0 | 1,545.7 | 120.7 | 9.45 | 1.10 | 42.93 | 0.15 | 0.58 | 12.61 |
| Inc | 1,436.0 | 1,441.0 | 5.0 | 1.90 | 4.98 | 32.60 | 0.47 | 0.11 | 8.08 |
| Inc | 1,459.0 | 1,464.0 | 5.0 | 2.60 | 5.01 | 18.50 | 0.01 | 0.33 | 8.77 |
| Inc | 1,468.5 | 1,453.3 | 15.2 | 5.98 | 2.30 | 15.44 | 0.03 | 0.38 | 9.40 |
| Inc | 1,508.0 | 1,538.0 | 30.0 | 30.30 | 1.67 | 71.07 | 0.05 | 1.70 | 36.80 |
- 59 -
| Hole | From
(ft) |
To
(ft) |
Length
(ft) |
Zinc (%) |
Gold
(g/t) |
Silver
(g/t) |
Lead (%) |
Copper (%) |
ZnEq (%) |
| Inc | 1,508.0 | 1,511.0 | 3.0 | 46.50 | 3.14 | 130.00 | 0.13 | 2.20 | 56.51 |
| BMZ79 | 412.8 | 420.3 | 7.5 | 25.6 | 0.68 | 17.39 | 0.02 | 0.87 | 28.46 |
| Inc | 414.7 | 417.7 | 3.0 | 49.6 | 0.91 | 30.32 | 0.05 | 1.39 | 54.11 |
| BMZ79 | 450.4 | 461.3 | 10.9 | 3.1 | 0.16 | 4.49 | 0.27 | 0.47 | 4.62 |
| Inc | 457.2 | 459.2 | 2.0 | 4.2 | 0.08 | 3.30 | 0.33 | 0.24 | 5.24 |
| BM21- 83 | 504.0 | 514.0 | 10.0 | 3.8 | 0.07 | 5.10 | 0.17 | 0.12 | 4.40 |
| Inc | 509.0 | 514.0 | 5.0 | 5.0 | 0.07 | 5.10 | 0.22 | 0.08 | 5.50 |
| BM21- 83 | 1,829.0 | 1839.0 | 10.0 | 1.1 | 3.62 | 11.3 | 0.30 | 0.04 | 5.30 |
| Inc | 1,839.0 | 1839.0 | 5.0 | 1.2 | 6.96 | 15.2 | 0.30 | 0.03 | 8.80 |
| BM21- 83 | 2,408.0 | 2,458.0 | 50.0 | 2.4 | 0.31 | 4.5 | 0.06 | 0.12 | 3.13 |
| Inc | 2,413.0 | 2,423.0 | 10.0 | 3.4 | 0.17 | 5.8 | 0.05 | 0.09 | 3.90 |
| Inc | 2,443.0 | 2,453.0 | 10.0 | 4.3 | 0.31 | 4.5 | 0.01 | 0.34 | 5.46 |
Figure 1.4 presents a longitudinal section showing the drill hole intercepts to date.
Drill hole BMZ-78 cut 30 ft (9.35 m) of massive sulphide mineralization grading 30.3% zinc, 1.7% copper, 1.67 g/t gold and 71 g/t silver for a zinc equivalent grade of 36.8% within a broader interval of 120.7 ft (36.5 m) that returned 9 .45% zinc, 0.58% copper, 1.1 g/t gold and 42.9 g/t silver for a zinc equivalent grade of 12.61%.
BMZ-78 was drilled into a previously untested area (200 ft x 500 ft) within the West and Main Zones at a vertical depth of approximately 1,200 ft (374 m).
Blue Moon's 2018 drill program demonstrated that the massive sulphide lenses are now traceable for approximately 3 ,000 ft (900 m) along plunge and remain open to surface and depth.
Hole BMZ79 intersected significant zones of high-grade sphalerite including the following intervals. Note that stated dimensions are intersected width (IW); true width is approximately 55% of IW.
| · | 7.47 m (24.5 ft) at 25.55% zinc, 0.87% copper, 0.68 g/t gold and 17 g/t silver for a zinc equivalence ("ZnEq") of 28.46% from 412.81 m, including: |
| ○ | 3.05 m (10.0 ft) at 49.60% zinc, 1.39% copper, 0.91 g/t gold and 30 g/t silver for a ZnEq of 54.11% from 414.65 m. |
- 60 -
Figure 1.4: Long Section Showing Latest Drilling through 2021
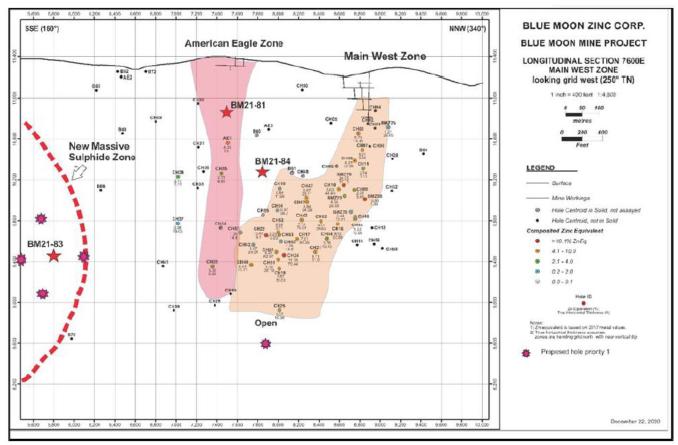
Source: Hendricksen and Wilson (2023)
A second zone of zinc mineralization in the same hole from 450 m, included:
| · | 10.96 m (36.0 ft) at 3.11% zinc, 0.47% copper and 0.27 % lead for a ZnEq of 4.62% from 450.37 m, including: |
| ○ | 2.08 m (6.8 ft) at 4.2% zinc for a ZnEq of 5.24% from 457.16 m. |
The high-grade zone of BMZ79 includes the highest zinc interval ever intercepted in the Blue Moon Project to date, 1.71 m (5.6 ft) at 51.9% zinc, 1.49% copper, 0.05% lead, 0.85 g/t gold and 31.9 g/t silver from 414.65 m.
The high-grade mineralized intercept in Hole BMZ79 is 50 m (164 ft) above and 8 m (26 ft) south of the high-grade mineralization intercepted by the 2018 diamond hole BMZ78. The intercept extends the size of the high-grade zone of mineralization within the Main mineralized horizon. The Main mineralized horizon also intersected some interesting anomalies of gold and silver (Table 1.5).
The stage 1 drilling program totaled 1,132 m (3,714 ft) and tested the northern border of the mineral resource as well as extend the zone of high-grade mineralization near hole BMZ78 which was drilled by Blue Moon in 2018.
A new drill discovery was made in 2021 testing a geophysical conductor target, located west of the three previously discovered Blue Moon mineralized zones and south of the American Eagle workings, as shown in Table 1.6. This new zone was discovered deep and lateral to the previously known mineral system. Sphalerite encountered in this new discovery has a different hue from the other zones which may indicate a separate emplacement pulse, with slightly different timing, which could add the currently known zones.
- 61 -
Table 1.6: Assay Highlights New South Zone (Drill Hole BM21-83)
| Drill
Hole |
From
(ft) |
To
(ft) |
Thickness
(ft) |
Zinc
(Zn%) |
Copper
(Cu%) |
Lead
(Pb %) |
Silver |
Gold opt) |
ZnEq %(*) |
| BM21- 83 | 2408 | 2458 | 50 | 2.4 | 0.12 | 0.06 | 0.13 Ag) |
0.009 (0.31 g/t Au) |
3.13 |
| including | 2413 | 2423 | 10 | 3.4 | 0.09 | .05 | 0.17 Ag) |
0.005 (0.17 g/t Au) |
3.90 |
| and | 2443 | 2453 | 10 | 4.3 | 0.34 | 0.01 | 0.13 Ag) |
0.009 (0.31 g/t Au) |
5.46 |
Notes:
| * | The above thicknesses are core lengths and are not true thicknesses. The estimated true thicknesses are approximately 50% of the core length. These results are also reported in Table 1.5. |
Stringers and blebs of sulphides were encountered starting at a core depth of 2,363 ft that continued until the banded and massive interval from 2,400 ft to 2,452 ft (52 ft interval at a vertical depth from surface of approximately 800 ft). Mineralization then tapered off into another stringer zone down to 2,461 ft core depth. The mineral-rich zone comprised nearly 100 ft core length (not true thickness). Higher up in the hole, several smaller zones were encountered. Mineralization is hosted in rhyolite and rhyolite tuffs of the Gopher Ridge Formation. The stringer and main zone of sulphides are composed of sphalerite, chalcopyrite, galena tetrahedrite and pyrite.
Sample Preparation, Analyses and Security
Core from the drill holes through 2021 was collected at the drilling rig by a company geologist and brought to the core logging facility on the Blue Moon Property. The core was cleaned, logged for rock type, structures and mineralization prior to a geologist marking out specific intervals for sampling based on sulphide content. Sampling of the core was done either by a hydraulic splitter if visually lower grade or sawn if deemed to be potentially higher grade. The core was sampled lengthwise with one half placed into a plastic sample bag with a sample tag. The other half was returned to the core box with a duplicate sample tag number for a permanent record. Standards and blank samples were not inserted into the stream of core samples prior to Blue Moon as this was not practiced by the majority of mining companies at that time. Core with visual mineralization was stored in locked shipping containers which remain on site, with saved mineralized sections of core available for inspection.
Samples for analysis were sent by truck to independent laboratories. Some of the earlier samples were sent to a Mineral Assay Office Inc., Nevada; however, the majority of the core samples were analyzed by Chemex Labs (now ALS Laboratories) in Vancouver, Canada. Both laboratories were certified assayers within their respective jurisdictions and independent of the owners of the Blue Moon Property. All assay data used in the resource calculation was generated via standard, industry accepted assaying techniques. Gold assaying used a 30g sample size for a fire assay with an atomic absorption spectrometry finish (FA-AAS). Silver and lead assays were generated with atomic absorption spectrometry (AAS). All other elements were assayed by inductively coupled plasma atomic emission spectroscopy (ICP-AES), including barium which required an additional, final gravimetric procedure. Known standards and blank samples were inserted into the sample stream by the laboratory for quality control.
One set of check assays carried out by Giroux (2018) included 55 samples that were assayed by both Chemex Labs in Vancouver (Chemex) and Mineral Assay Office Inc. in Nevada (Mineral). At that time, Chemex and Mineral were independent facilities with no relation to the issuer. Chemex was an ISO 9001:2015 certified laboratory. Chemex and Mineral are no longer in business as of the effective date of the Blue Moon Technical Report. Table 1.7 summarizes the results of those check assays.
- 62 -
Table 1.7: Summary Statistics, Check Assays
| Parameter | Copper
(Cu %) |
Zinc
(Zn %) |
Silver
(opt Ag) |
Gold
(opt Au) |
| Mean, Chemex | 0.918 | 5.385 | 2.554 | 0.035 |
| Mean, Mineral | 0.970 | 5.500 | 2.433 | 0.038 |
| Stand. Dev, Chemex | 0.997 | 6.622 | 7.037 | 0.082 |
| Stand. Dev, Mineral | 1.066 | 6.653 | 7.009 | 0.094 |
| CV, Chemex | 1.09 | 1.23 | 2.76 | 2.31 |
| CV, Mineral | 1.10 | 1.21 | 2.88 | 2.44 |
A paired t-test was performed and previously reported on the data to check bias between the laboratories. In all cases the difference between the laboratories is considered insignificant. Table 1.8 summarizes the results.
No documentation exists for sample preparation, analyses and security from previous operators. It is the opinion of the QP that the sample preparation, security and analytical procedures followed can be relied upon for the purposes of the Blue Moon Technical Report.
Table 1.8: Paired t-test, Check Assays
| Element | Results |
| Cu | Mineral reports 0.05% higher than Chemex |
| Zn | No bias found between laboratories |
| Ag | Chemex reports 0.12 oz/ton higher than Mineral |
| Au | No bias found between laboratories |
Data Verification
The QP conducted a personal inspection of Blue Moon on November 5 and 6, 2024. The QP had access to the complete database of the Blue Moon Project including all original assay certificates from the Corporation and previous operators, the original drill logs of the Corporation, and down-hole, directional survey results for all drilling. As well as the original surveyor's report on drill hole locations, the QP was provided with a report of a 2018 survey commissioned by Blue Moon and completed by Jones Snyder and Associates, a registered land surveyor in the state of California. The 2018 survey included resurveying of 29 of the holes used for the Blue Moon Project as well as monuments established by the surveys of 1984 and 1991, established decades prior to the involvement of Blue Moon.
There is no documentation of data verification procedures from previous operators.
All mineralized intersections are preserved in a secured storage facility on the Blue Moon Property. As part of the verification process, the author completed cross checks of the assay sample numbers recorded in the original assay certificates with drill logs and the sample tags in the core boxes for 30 of the mineralized intercepts. No discrepancies or errors were noted between the sample numbers on the tags in the core boxes and those recorded in the assay certificates. The author did not note any visual discrepancies between what was observed in the core with what was recorded in the drill logs. No assay with high zinc, copper or lead were noted to be at odds with what was observed in the drill core for the comparable interval.
The QP reviewed the results of the 2018 drill hole survey and compared these with the original surveys of 1984 and 1 991. In addition, the surveys of the 2019 program were also compared for drilling in those years. The results of the surveys compare, and no material difference was found. As a check of the professional surveys, the author also checked the collar locations with a handheld GPS unit (Garmin). The co-ordinates noted matched those of the earlier surveys.
- 63 -
As a check on core recoveries reported in the historical logs, the QP carried out spot checks of key mineralized sections in 25 holes used in the resource calculation of the Blue Moon Technical Report. The core recovery noted by the author matched those reported in the historical logs. The author also checked the thicknesses of mineralization by measuring the angle between the core axis and the contact of massive sulphide zones with the bounding rhyolite host rocks. Spot checking of 25 holes used in the resource calculation with respect to drill hole length, azimuth and grid location found no material differences.
During the November 2024 site visit, the QP collected a random interval of core from Drill Hole CH7. The sample was submitted to ALS Reno USA for sample preparation. The assaying was performed at ALS Vancouver BC. ALS Reno USA and ALS Vancouver BC are both subsidiaries of ALS Global. ALS Global is independent of the issuer. ALS Global Quality complies with ISO/EIC 176025:2017. Table 1.9 shows the original assay which is used in the drilling database versus the check sample submitted by the author. The results confirm the occurrence of mineralization for that sample at the encountered drilling depth.
Table 1.9: Independent QP's Data Verification, November 5, 2024
| Parameter | Hole ID | Sample
ID |
From | To | Silver Ag) |
Gold Au) |
Copper
(Cu %) |
Lead
(Pb %) |
Zinc
(Zn %) |
| Original | CH47 | 73860 | 1495.4 | 1496.5 | 1.9 | 0.01 | 0.9 | 0.005 | 10.7 |
| Check | - | - | - | - | 0.91 | 0.001 | 0.411 | 0.001 | 5.3 |
QPs Christoper Jacobs and Alan San Martin were also present during the site visit on 5-6 November 2024. At that time, Mr. San Martin was able to examine drill core from the mineralized zone and its host rock and was thus able to verify the RQD values recorded in drill logs that informed the preliminary estimate of stope spans for the proposed underground mine. Also, Mr. San Martin and Mr. Jacobs were able to verify the condition of the site access road, the availability of suitable terrain for construction of a mine portal, process plant and tailings storage facility, and confirm the proximity of power lines at the nearby hydro-electric dam and distance to the settlement at Hornitos.
Mr. Gowans examined metallurgical testwork reports prepared on behalf of previous operators of the Project and, based on the level of detail provided, determined their suitability for inclusion.
No limitations were placed on the QP during the site visit. In the opinion of the QP, the data used to estimate mineral resources for the Blue Moon Property is adequate for purposes used in the Blue Moon Technical Report.
Further details on the sampling methods, analyses and data verification are available in the Blue Moon Technical Report, which is available on SEDAR+ (www.sedarplus.ca) under the Corporation's issuer profile.
Mineral Processing and Metallurgical Testing
A program of metallurgical testwork was undertaken using two mineralized samples (identified as Sample 1 and Sample 2) by Lakefield Research (now SGS Mineral Services), Ontario, Canada, in 1988, under the direction of Wright Engineers Limited on behalf of Westmin Resources Limited. This preliminary testwork program comprised chemical and mineralogical analyses, hardness testing, batch and locked cycle flotation, flotation concentrate analyses, gravity separation and preliminary settling tests on samples of zinc concentrate and zinc rougher tailings.
Sample 1 was reported by Lakefield Research to comprise relatively coarse high-sulphide mineralization with active pyrite and sphalerite. Sample 2 was reported to contain less sulphides and be more complex and finer grained than Sample 1.
- 64 -
The results of preliminary mineralogical characterization study by Lakefield Research showed that the samples were similar with respect to sulphide mineral species but there were differences in the amounts of each sulphide and mineral associations. In general, Sample 1 contained more sulphides and was relatively coarse grained (> 100 microns) while Sample 2 contained more non-opaque minerals and sulphide particles were smaller in size.
The work indices derived from standard bond grinding testing of around 9 kWh/t are considered relatively low compared with most copper and zinc ores (between 11 and 14 kWh/t), although the elevated content of barite and gypsum could explain the perceived discrepancy.
Lakefield Research completed 26 separate bench scale batch flotation tests and one locked cycle test primarily to investigate the sequential flotation of copper and zinc from the two samples.
The results of the cycle test using Sample 1 show a 93% copper recovery into a concentrate containing 26.5% Cu, 8 .42 g/t Au, 484 g/t Ag, 2.35% Pb and 7.0% Zn. Lead recovery to the copper concentrate was also 93% while the recoveries of gold and silver were around 68%. A zinc recovery of 95.2% Zn was achieved into a high quality zinc concentrate containing 62.3% Zn.
Although preliminary mineralogical studies suggested that Sample 2 was more complex and fine grained than Sample 1 , the results from batch rougher and cleaner flotation tests were similar to Sample 1. A simple batch pyrite recovery test was completed using Sample 2 following sequential flotation of Cu/Pb and Zn. Approximately 20% of the original mass was recovered to a pyrite rougher concentrate.
The conclusions from the 1988 testwork program are as follows:
| · | Good recoveries of copper and zinc into high grade concentrates were achieved using conventional sequential flotation technology. Typically, most of the gold and silver in the samples tended to report to the copper/lead concentrate. Net recoveries of gold and silver to both the zinc and copper concentrates were 86.2% and 94.3% respectively. |
| · | The copper/lead concentrate produced contained minor amounts of deleterious elements which may incur penalties when sold to smelters. Conversely, this product also contained gold and silver in payable quantities. |
| · | The zinc concentrate produced was of high grade with relatively low iron and contained no significant amount of penalty elements. |
| · | Flotation of pyrite from zinc tailings was successful and additional work to improve the product quality is recommended. |
| · | Separation of copper and lead into separate products was challenging but further work to improve selectivity is warranted. |
| · | The work indices calculated from standard bond ball mill tests were relatively low and need to be confirmed using fresh samples that represent the main ore types at Blue Moon. |
| · | The samples contained interesting amounts of barite and gypsum. More work is required to quantify the distribution of these minerals within the deposit, the quality of these minerals, and the potential to recover these minerals as valuable by-products. |
| · | The samples appeared to contain a certain amount of free or nuggetty gold which should be investigated further. Deportment studies on the gold and silver are recommended. |
| · | Elements of particular interest that should be investigated in the next phase of metallurgical testwork include germanium and gallium. The economic potential of these elements as well as indium should be considered during the next geo-metallurgical testwork program. |
- 65 -
| · | Based on the limited amount of testing undertaken so far, there are no processing factors or other deleterious elements that that could have a significant effect on the potential economic extraction of the deposit. |
Mineral Resource Estimate
The MRE for the Blue Moon Technical Report was determined by using inverse distance cubed (ID3) techniques for the Main, Western and Eastern Zones of the Blue Moon Massive Sulphide Deposit. Assay data was derived from the current drilling database, including drill holes completed after 2018. Mineralized domain solids were created from the coding of drill data in a three-dimensional (3D) geological modeling program. Drilling intercept assay values were capped for each mineralized domain using statistical analysis and subsequently composited forming the sample set used for the MRE grade estimates. The MRE has been determined according to the CIM Estimation of Mineral Resources and Mineral Reserves Best Practice Guidelines (November 29, 2019). Mineral Resources have been reported in accordance with the disclosure requirements under NI 43-101.
The MRE is subdivided into three zones: Main Zone (vm1), East Zone (ve) and West Zone (vw). Using compiled and modeled 3D drill data there are distinct, separate, continuous lenses of mineralization, generally striking north. The Main Zone represents the largest occurrence of mineralization. Mineralization has been identified over a strike length of 2,500 ft as well as a plunge of nearly 2,500 ft of depth. The West and East Zones display less continuity as compared to the Main Zone. These were modeled independently and subsequently appended together to form a combined east and west zone triangulation domains. In addition to the dominant mineralized lenses numerous prominent mineralized intervals exist along many drill holes throughout the deposit. Individual mineralized domain solids were developed for these intervals which were subsequently labeled east lenses (vle) and west lenses (vlw) based upon their respective relationships to the Main Zone. The "vle" and "vlw" lenses were compiled and added to the overall "ve" and "vw" domain triangulations.
Reasonable prospects of eventual economic extraction assume underground mining of the deposit, surface mill processing and production of zinc concentrates and copper concentrates. Mineral Resources are reported at a Zinc Equivalent Percent (ZnEq %) cutoff grade of 2.9%. Cutoff grade sensitivities can be found in the Blue Moon Technical Report.
ZnEq % is calculated by each assayed metal being assigned a metal price, assumed recovery percentage and overall value factor based on the metal's price and recovery. Notwithstanding its potential for eventual economic extraction, for the purposes of this preliminary economic assessment lead was assumed not payable and so makes no contribution to ZnEq % grade. Parameters forming the basis for the ZnEq % formula are detailed in the Blue Moon Technical Report.
The formula used to estimate ZnEq % is:
ZnEq = Zn% + ((Cu% * 78.20)+(Pb% * 0)+(Ag opt * 25.46)+(Au opt * 1896.40))/23.83.
Table 1.10 and Table 1.11, respectively, present the Indicated and Inferred Mineral Resource Estimates. Resources are not Mineral Reserves and do not have demonstrated economic viability. There is no certainty that all or any part of the Mineral Resources will be converted into Mineral Reserves.
Figure 1.5 shows the location of drill holes on the Blue Moon Property, as well as a plan projection of the three mineralized zones. Figure 1.6 and Figure 1.7 show the mineralized domains on long-section 7500E looking West and East, respectively.
Table 1.10: Blue Moon Indicated Mineral Resource Estimate Effective Date December 24, 2024
| Domain
(Vein) |
ZnEq
Cutoff |
Tons | ZnEq (%) |
Copper
(Cu %) |
Lead
(Pb %) |
Zinc
(Zn %) |
Gold
(opt Au) |
Silver
(opt Ag) |
| Main | 2.9% | 3,073,000 | 12.66 | 0.78 | 0.16 | 5.90 | 0.04 | 1.14 |
| East | 2.9% | 498,000 | 18.99 | 0.47 | 0.63 | 6.64 | 0.09 | 3.72 |
- 66 -
| Domain
(Vein) |
ZnEq
Cutoff |
Tons | ZnEq (%) |
Copper
(Cu %) |
Lead
(Pb %) |
Zinc
(Zn %) |
Gold
(opt Au) |
Silver
(opt Ag) |
| West | 2.9% | 78,000 | 9.50 | 0.62 | 0.33 | 4.41 | 0.03 | 0.93 |
| Total | 3,650,000 | 13.46 | 0.73 | 0.23 | 5.97 | 0.04 | 1.49 | |
| Metal | Cu Mlbs | Pb Mlbs | Zn Mlbs | Au Moz | Ag Moz | |||
| Main | 47.94 | 10.08 | 362.76 | 0.11 | 3.51 | |||
| East | 4.67 | 6.29 | 66.15 | 0.04 | 1.85 | |||
| West | 0.97 | 0.52 | 6.91 | 0.00 | 0.07 | |||
| Total | 53.59 | 16.90 | 435.83 | 0.16 | 5.43 | |||
Table 1.11: Blue Moon Inferred Mineral Resource Estimate Effective Date December 24, 2024
| Domain
(Vein) |
ZnEq
Cutoff |
Tons | ZnEq (%) |
Copper
(Cu %) |
Lead
(Pb %) |
Zinc
(Zn %) |
Gold
(opt Au) |
Silver
(opt Ag) |
| Main | 2.9% | 3,261,000 | 11.41 | 0.52 | 0.23 | 5.68 | 0.04 | 1.15 |
| East | 2.9% | 994,000 | 15.49 | 0.59 | 0.56 | 5.04 | 0.07 | 2.43 |
| West | 2.9% | 173,000 | 6.28 | 0.73 | 0.22 | 1.98 | 0.02 | 0.40 |
| Total | 4,428,000 | 12.12 | 0.54 | 0.30 | 5.39 | 0.04 | 1.41 | |
| Metal | Cu Mlbs | Pb Mlbs | Zn Mlbs | Au Moz | Ag Moz | |||
| Main | 33.65 | 14.74 | 370.27 | 0.11 | 3.76 | |||
| East | 11.80 | 11.20 | 100.11 | 0.07 | 2.42 | |||
| West | 2.52 | 0.74 | 6.84 | 0.00 | 0.07 | |||
| Total | 47.97 | 26.68 | 477.22 | 0.19 | 6.25 | |||
Notes:
| (1) | Scott Wilson, CPG, President of RDA is responsible for this mineral resource estimate and is an independent Qualified Person as such term is defined by NI 43-101. |
| (2) | Reasonable prospects of eventual economic extraction were assessed by enclosing the mineralized material in the block model estimate in 3 D wireframe shapes that were constructed based upon geological interpretations as well as adherence to a minimum mining unit with geometry appropriate for underground mining. |
| (3) | The cutoff grade of 2.9% ZnEq considered parameters of: |
| (a) | Metal selling prices: Au-US$2,200/oz, Ag-US$27/oz, Cu-US$4.25/lb., Pb-US$0.90/lb., Zn-US$1.25/lb. | |
| (b) | Recoveries of Au 86.2%, Ag 94.3%, Cu 93.1%, Pb 0%, Zn 95.3%. | |
| (c) | Costs including mining, processing, general and administrative (G&A). |
| (4) | Zinc Equivalent Grade ("ZnEq") is estimated by the formula: |
ZnEq = Zn% + ((Cu% * 78.20)+(Pb% * 0)+(Ag opt * 25.46)+(Au opt * 1896.40))/23.83
| (5) | Mineral resources are not mineral reserves and do not have demonstrated economic viability. |
| (6) | Figures may not add up due to rounding. |
| (7) | Tonnages shown in Table 1.10 and Table 1.11 are short tons. |
| (8) | The QP knows of no other legal, political, environmental, or other risks that could materially affect the potential development of the mineral resources for the Blue Moon Project. |
- 67 -
Figure 1.5: Plan View of Mineralized Domains and Drilling
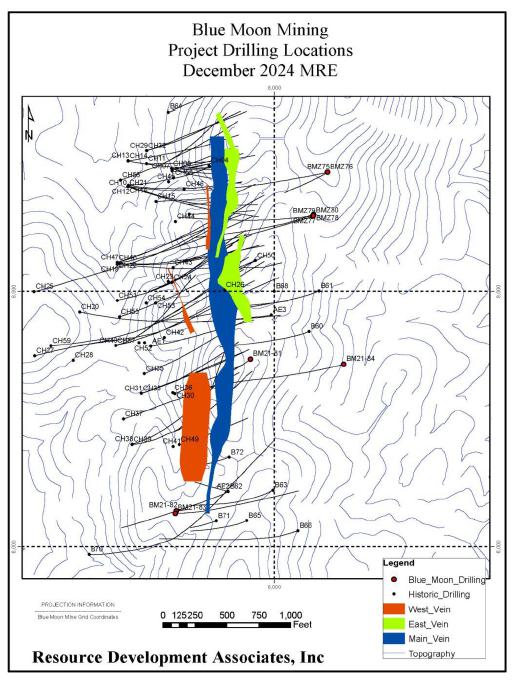
- 68 -
Figure 1.6: Long-Section View - 7500E Looking West - Mineralized Domains
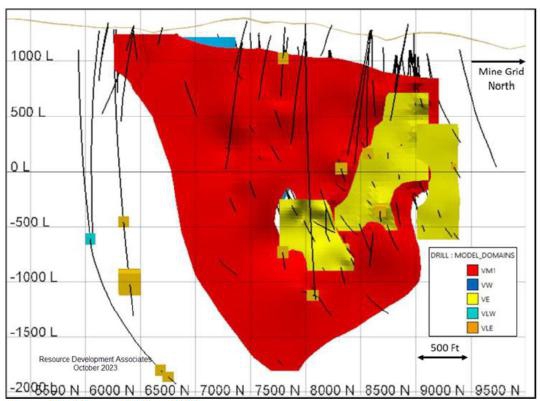
Source: Henricksen and Wilson (2023)
Figure 1.7: Long Section View - 7500E Looking East - Mineralized Domains
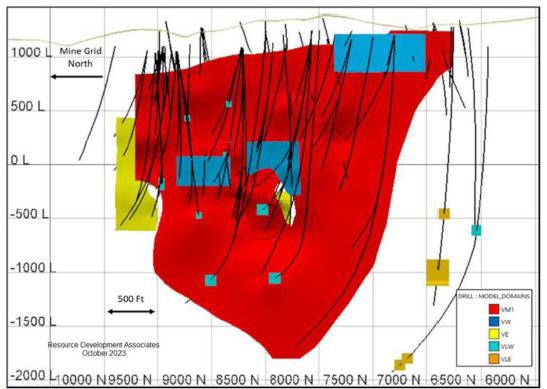
Source: Henricksen and Wilson (2023)
The QP knows of no other legal, political, environmental, or other risks that could materially affect the potential development of the mineral resources for the Blue Moon Project.
- 69 -
Mineral Reserve Estimate
No current mineral reserve estimate has been established on the Blue Moon Property.
Mining Operations
The PEA is preliminary in nature. It includes Inferred Mineral Resources that are considered too speculative geologically to have the economic considerations applied to them that would enable them to be categorized as mineral reserves, and there is no certainty that the PEA will be realized. Mineral Resources that are not Mineral Reserves do not have demonstrated economic viability.
The PEA utilizes the Mineral Resources described in the Blue Moon Technical Report and only those portions of the Mineral Resource that fall within the constraints defined by underground parameters of the PEA are used to inform the Blue Moon Project economics.
The mining method selection was largely guided by the results of the Mineable Shape Optimizer (MSO) analysis, which evaluated various stoping methods and sizes based on economic and operational parameters. The MSO process assessed multiple configurations, including longhole stoping and cut and fill methods. As a result of this analysis, a stope height of 80 ft, using a $75/ton NSR cutoff, was selected as the basis for the mine design as this maximises resource recovery, limits excessive sustaining capital requirements (level development), and provides the highest relative operating margin compared to the other cases considered.
The mine will be accessed through a ramp system designed with a nominal grade of 13%, reaching a maximum of 1 5% in some sections. The initial portal and decline will provide access for exploration drilling and be utilized once the mine moves into production as the main haulage route. The layout separates the deposit into North and South mining zones to minimize level development and provide additional mine sequencing flexibility. The decline is positioned to first access the North Zone, prioritizing thicker, higher-grade levels in the mine.
Mining levels will be spaced at 80-ft vertical intervals, with mining fronts consisting of 5 or 6 levels grouped together. Each level will include essential infrastructure such as truck load-out areas, electrical substations, and dewatering sumps. The primary decline will serve as the main haulage route, with additional accesses developed as mining advances. Allowances were added (5% for ramp, 20% for level development) to account for remucks and infrastructure cutouts (Figure 1.8).
The production schedule was created in Datamine's Enhanced Production Scheduler (EPS) software, using benchmark development rates observed on recent projects. The initial decline advances to the main fresh air intake raise, before continuing to the north and beginning the north spiral ramp to the first mining front.
Separate level development crews are assigned to handle level and ventilation accesses, as well as ore sill drives. Stopes are scheduled by linking dependencies between designed stope shapes, in a Primary- Primary retreat sequence to the level access. Additional dependencies were added to the schedule to ensure ventilation breakthroughs are complete in advance of production on a level. The dedicated ramp resource crew advances to the next mining front. Overall production is targeted at 2,000 tons per day. Mining fronts were prioritized by grade and size to aid in early revenue generation.
The underground mining fleet will include a combination of development and production equipment. The development fleet will consist of jumbo drills, bolters, load-haul-dump (LHD) machines, and scissor decks for support infrastructure installation. The production fleet will include 42 tonne haul trucks, longhole drills, and 6-yard LHDs for material movement.
Workforce estimates were created based on the mine schedule, assuming 2-12 h shifts, with a 4-shift rotation. Mine technical and administrative staff and certain fixed plant maintenance personnel were assumed to work 5-d weeks, day shift only. Peak salaried and hourly-waged personnel requirements are 61 and 160 people, respectively.
- 70 -
Provision has been made in the design for mine services including dewatering, electrical distribution, communications and safety, refuge chambers, and compressed air.
Figure 1.8: Mine Design Model View Looking West
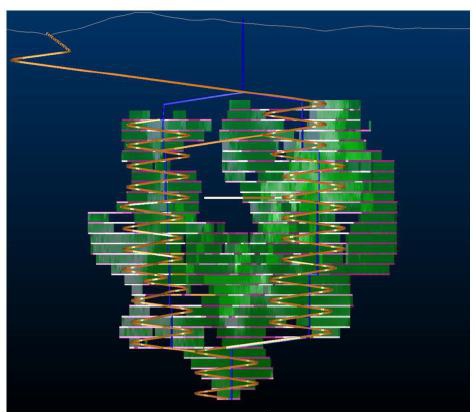
Not to scale.
Processing and Recovery Operations
The processing facility has been designed to treat 657,000 tonnes per year. Mineralization will be received from the underground mine at the process site which comprises the following areas:
| · | Crushing Plant. | |
| · | Crushed Ore Handling and Storage. | |
| · | SAG and Ball Mill Grinding Circuit. | |
| · | Flotation Circuits: |
| ○ | Copper Flotation. | |
| ○ | Zinc Flotation. | |
| ○ | Pyrite Flotation. |
| · | Concentrate Handling by means of thickening, filtration and loading for copper, zinc and pyrite concentrates. | |
| · | Tailings Handling by means of thickening, filtration and preparing for paste and dry stack storage. | |
| · | Paste Backfill Plant. | |
| · | Reagents Handling and Storage. | |
| · | Plant Services. |
The mineral processing operation shall begin when the haul trucks from the underground mine deliver the ore to the primary crusher station. The ore will be crushed and conveyed to a stockpile where it will be reclaimed and transported to the main mill building. The crushed ore will be sufficiently reduced in size in the grinding circuit to liberate the desired minerals. Downstream, the flotation circuits shall selectively recover the target minerals for each type of concentrate. Dedicated thickeners shall densify each slurry stream and recover the overflow water for re-use in the process, while the thickened slurry will be further dewatered through dedicated filter presses. Concentrates and tailings shall all be handled as filter cakes.
- 71 -
Copper and zinc concentrates shall be collected from the storage stockpile located below the filter presses and loaded onto a hopper and conveyor system which will be used to load the concentrate within a lined rectangular shipping container. Pyrite and tailings filter cake will be conveyed by means of conveyors to a paste backfill mixer. The mixer shall blend the filtered tailings with additional water and a binder into a paste which will then be pumped to the underground mine by means of a piping network.
Infrastructure, Permitting and Compliance Activities
Project Infrastructure
The infrastructure of the Blue Moon Property is designed to support the operation of a processing plant and production from the underground operation. The mine and processing plant will operate on a nominal 24 h/day, 7 days/week schedule to achieve an average throughput of 1,800 tonne/day. The proposed general arrangement for the mine site is presented in Figure 1.9.
Figure 1.9: Blue Moon General Arrangement
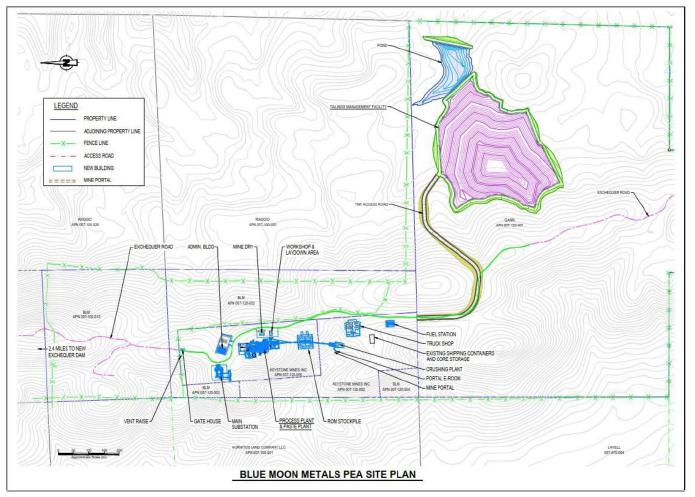
Infrastructural elements considered in the PEA include access roads, on-site haulage and service roads, power supply from the neighbouring hydro-electric dam, process- , fresh-, and potable water supplies, fuel storage facilities and on-site workshops, mine dry (change-house) and gatehouse and offices for administration, technical services, etc.
The average daily requirement for make-up water will be 75,529 gallons. To the extent possible, this will likely be obtained from wells sunk in the area of the mine. However, additional hydrogeological studies will be required to confirm the adequacy of borehole supply capacity.
- 72 -
Tailings from the flotation plant will be thickened using a conventional underflow system and then be further dewatered using a filter press to produce a "dry" cake comprising approximately 90% solids by weight. The daily production of tailings will be approximately 1,800 tonnes, dry mass. In due course, a proportion of the filter cake tailings will be combined with a suitable binder and water to form a paste for backfilling completed underground workings. A tailings management facility comprising a dry stack, water pond and access routes, will be located on 40 acres of the Gann land. Within this area, the dry stack area will occupy 31 acres, with the remaining land accommodating the pond and access road. The stack and pond will be located in a shallow valley on the eastern side of the Bullion Hill ridge, as indicated in Figure 1.10.
Figure 1.10: TMF General Arrangement
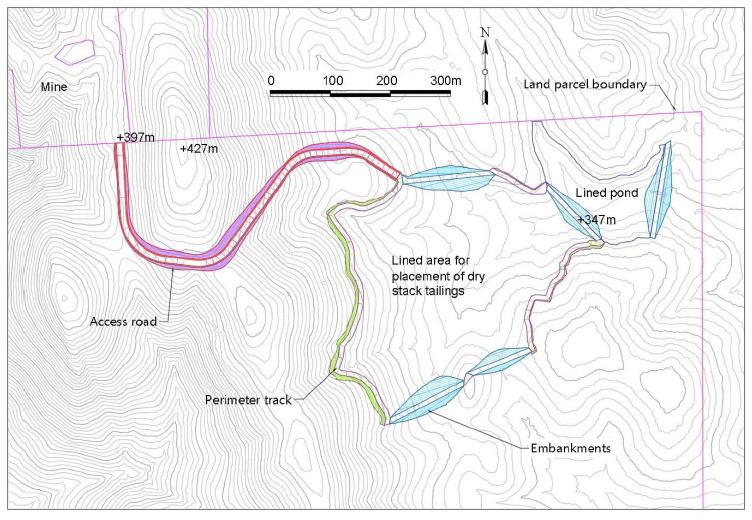
Environmental Studies, Permitting and Social or Community Impact
Development activities on the Blue Moon Property are subject to various federal, state, and local laws and regulations. The environmental effects of proposed development activities will be evaluated by the US Bureau of Land Management and the Mariposa County Planning Department in accordance with the National Environmental Policy Act (NEPA) and the California Environmental Quality Act (CEQA). Various federal and state environmental laws and regulations will also apply to proposed development activities on the Blue Moon Property. In addition to compliance with all applicable Federal, State and County legal requirements, Blue Moon intends to develop the Blue Moon Property in general alignment with good international industry practice (GIIP).
The legal framework surrounding mining activities in California is comprehensive and environmental standards are high. The associated environmental permitting process, which is yet to commence, can therefore be extensive and time-consuming.
Blue Moon holds the mineral rights to the Blue Moon VMS deposit through its wholly owned subsidiary, Keystone. As of the date of the Blue Moon Technical Report, the mineral and property rights covered a total land area of 494.25 acres and comprise three distinct land tenure components. For updated information regarding Blue Moon Property mineral claims and surface rights, please see "The Blue Moon Property – Subsequent Events".
- 73 -
Technical studies were undertaken in the 1980s and 1990s under previous management of the Blue Moon Property. These studies provide an indication of baseline conditions in the Blue Moon Project area at the time and can be used to inform the approach to future studies. The previous baseline studies did not identify any significant barriers to Blue Moon Project development. However, it is important to note that they were undertaken on a different project design (e.g., a vertical shaft instead of a ramp decline) and will require updating.
The Blue Moon Project is situated within the lower western foothills of the Sierra Nevada mountain range within the watershed of the Merced River. Previous studies indicated that the types of wildlife likely to be present were considered typical of the region and not at significant risk from mining activities. None of the sites of archaeological interest found during previous studies correspond with the footprint of the current Blue Moon Project design.
The nearest settlement to the Blue Moon Project is the small town of Hornitos, located approximately 4.5 miles south.The Blue Moon Project site was historically mined as part of the Californian Gold Rush. There are active mining operations in the region, and good transport connections.
A full review of the potential environmental and social impacts will be undertaken as the Blue Moon Project advances. Based on the current Blue Moon Project design, location, and an understanding of metal mining operations in similar environments, the main potential risks associated with operations of this nature include natural hazards, disturbance from air quality, noise, vibration and artificial lighting, impacts on water flow and water quality, impacts on biodiversity mainly through loss of habitat, and risks to groundwater from tailings. However, socio-economic impacts are considered to be positive. Potential environmental and social risks and impacts are considered typical of similar exploration and mining operations in North America, and any potential impacts can be managed appropriately.
Responsible closure planning will be integrated into all phases of the Blue Moon Property and undertaken in compliance with Federal and California State legislative requirements and GIIP. A detailed closure plan and cost estimate has not yet been developed but an indicative amount of US$15 million has been budgeted.
Capital and Operating Costs
The PEA is preliminary in nature. It includes Inferred Mineral Resources that are considered too speculative geologically to have the economic considerations applied to them that would enable them to be categorized as mineral reserves, and there is no certainty that the PEA will be realized. Mineral Resources that are not Mineral Reserves do not have demonstrated economic viability.
Micon’s QP prepared the economic analysis of the Blue Moon Project on the basis of a discounted cash flow model, from which Net Present Value (NPV), Internal Rate of Return (IRR) and payback period can be determined. Assessments of NPV are generally accepted within the mining industry as representing the economic value of a project after allowing for the cost of capital invested.
All results are expressed in United States dollars ($ or US$) except where stated otherwise. Conservatively, an exchange rate of CAD 1.35/US$ has been applied where required for conversion of cost inputs whereas, at the effective date of the Blue Moon Technical Report, the spot rate was approximately CAD 1.45/US$.
Cost estimates and other inputs to the cash flow model for the Blue Moon Project have been prepared using constant, first quarter 2025 money terms, i.e., without provision for escalation or inflation.
Blue Moon Project revenues will be generated from the sale of zinc and copper concentrates, with credits for gold and silver content. The Blue Moon Project has been evaluated using constant metal prices of US$4.20/lb copper, US$1.25/lb zinc, US$2,200/oz Au and US$27/oz Ag. No credit or penalty has been applied for lead or any other by-product content in concentrates. These price assumptions are supported by the 10-year price history of each metal presented in Section 19. The sensitivity of the Blue Moon Project to changes in price assumptions has been tested 1 0% above and below base case values and using both spot (February 2025 market average prices) and consensus price forecasts.
- 74 -
Figure 1.11 shows the relative contribution of each metal to NSR value of the saleable concentrates.
Figure 1.11: NSR Value by Metal
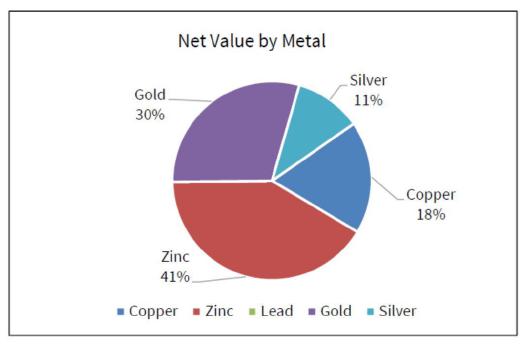
The capital expenditure (CAPEX) estimate for the PEA has been developed using a combination of budgetary quotes from vendors, historical pricing from comparable projects, and parametric calculations based on similar equipment and infrastructure. Cost elements have been refined and itemized to enhance confidence in the estimate. However, the overall accuracy remains within the expected range for a PEA-level study. The approach ensures a robust and well supported cost estimate while maintaining alignment with the early-stage nature of the assessment.
Table 1.12 summarizes the initial, sustaining and total LOM capital costs for the Blue Moon Project, in addition to which a provision of US$15 million has been made for mine closure and rehabilitation costs.
Table 1.12: LOM Capital Cost Estimate
| Area | Initial
US$ M |
Sustaining
US$ M |
LOM
Total US$ M |
| Mining | 18.4 | 10.0 | 28.4 |
| Processing | 55.0 | 42.8 | 97.7 |
| Infrastructure | 26.7 | 11.7 | 38.4 |
| Sub-Total Direct Costs | 100.1 | 64.5 | 164.5 |
| Indirect | 15.9 | 0.0 | 15.9 |
| Contingency | 28.5 | 0.0 | 28.5 |
| Total Capital Costs | 144.5 | 64.5 | 209.0 |
The operating costs have been estimated from first principals and in each area of the operating cost estimate, labour costs are based on the proposed headcount, estimated salary and burden for each position.
- 75 -
Table 1.13 provides a summary of the estimated life-of-mine (LOM) PEA operating costs.
Table 1.13: LOM Operating Cost Estimate
| Area | LOM
Average (US$/0 |
LOM
Cost US$’000 |
| Mining | 75.02 | 503,709 |
| Processing | 36.11 | 242,453 |
| E/S and G&A | 5.10 | 34,239 |
| Total Direct Costs | 116.24 | 780,401 |
| Selling Costs | 22.30 | 149,740 |
| Royalties | 0.35 | 2,350 |
| Total Operating Costs | 138.89 | 931,991 |
Table 1.14 presents some key statistics for the Blue Moon mine base case economic assessment.
Table 1.14: Base Case – Key Statistics
| Item | Units | Value | |
| Nominal Processing Capacity | tonnes per day | 1,800 | |
| LOM Total Processed | ’000 tonnes | 6,714 | |
| Zinc Equivalent Grade Processed | % ZnEq | 12.55 | |
| Net Smelter Return | US$/tonne treated | 246.00 | |
| Average Annual Payable Production (LOM) | Copper | 000‘lbs | 7,237 |
| Zinc | 000‘lbs | 62,260 | |
| Gold | oz | 22,566 | |
| Silver | oz | 681,784 | |
| ZnEq | 000‘lbs | 151,046 | |
The average C1 cash cost over the LOM is estimated at US$0.60/lb zinc equivalent. Including sustaining and mine closure expenses, the average All-in Sustaining Cost (AISC) over the LOM is estimated at US$0.66/lb zinc equivalent and, including initial capital, the average All-in Cost (AIC) over the LOM is estimated at US$0.77/lb zinc equivalent.
- 76 -
A chart summarizing the LOM annual cash flow projection for the base case is given in Figure 1.12.
Figure 1.12: Annual Cash Flow Projection
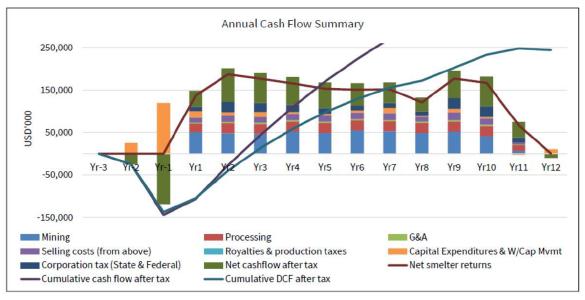
The base case cash flow equates to a pre-tax IRR of 48% and a net present value at an 8% annual discount rate (NPV8) of US$354 million before tax. After-tax base-case cash flows provide an IRR of 38% and evaluate to NPV8 of US$244 million. After-tax undiscounted payback is achieved in approximately 2.8 years.
Micon has tested the sensitivity of the base case NPV8 and IRR to changes in prices (which may also be used as a proxy for ore grades and recoveries), as well as operating costs and capital expenditures. The Blue Moon Project is most sensitive to changes in product prices with a 30% reduction resulting in a near-zero NPV8. A 30% increase in operating and capital costs reduce NPV8 to US$144 million and US$155 million, respectively, showing the Blue Moon Project to be relatively insensitive to either factor alone.
Table 1.15 compares the key economic results for metal prices 10% lower and higher than the base case, as well as at long-term consensus prices forecast in 2024 and average spot prices observed in February, 2025.
Table 1.15: Detailed Metal Price Sensitivity
| Parameters | PEA
Base Case |
-10%
Pricing |
+10%
Pricing |
Long-Term
Consensus Forecast |
Spot
Prices 2025-02 | |
| Metal Prices Assumed |
Copper US$/lb | 4.20 | 3.78 | 4.62 | 4.75 | 4.23 |
| Zinc US$/lb | 1.25 | 1.13 | 1.38 | 1.26 | 1.27 | |
| Gold US$/oz | 2,200 | 1,980 | 2,420 | 2,181 | 2,895 | |
| Silver US $/oz | 27.00 | 24.30 | 29.70 | 26.16 | 32.18 | |
| After-Tax NPV (US$ M, 8% Discount Rate) | $244 | $163 | $324 | $260 | $340 | |
| After-Tax IRR (%) | 38% | 29% | 46% | 39% | 48% | |
| First 6 Years of After-Tax Cashflow (US$ M) | $367 | $293 | $442 | $382 | $458 | |
| Payback Period (Years) | 2.4 | 2.9 | 2.0 | 2.3 | 1.9 | |
- 77 -
| Parameters | PEA
Base Case |
-10%
Pricing |
+10%
Pricing |
Long-Term
Consensus Forecast |
Spot
Prices 2025-02 |
| Cl Cost (US$/lb ZnEq) | $0.60 | $0.60 | $0.61 | $0.60 | $0.55 |
| LOM Average Head Grade (ZnEq %) | 12.55 | 12.66 | 12.47 | 12.72 | 13.83 |
Recommendations
The following recommended work program adopts a two-phased approach to the further development of the Blue Moon Property. Blue Moon intends to construct an exploration decline to access a broader portion of the mineral deposit. Drilling of the deposit from underground offers technical and cost benefits over surface drilling; therefore, development of an exploration decline is recommended. Blue Moon must obtain permits prior to construction of the decline. Phase 1 of the work program includes the steps necessary to obtain the required permitting for construction. Phase 1 culminates with the decision to advance to Phase 2; the construction of the exploration decline. The following sections describe the work program phases.
Phase 1: Planning, Hiring and Permitting
Following the completion of the PEA, Blue Moon plans to initiate permitting for the development of an exploration decline which, by providing underground access, will allow more efficient exploration core drilling as well as facilitating the geotechnical, hydrogeological, and metallurgical studies which are to be carried out in Phase 2.
Concurrently, Blue Moon intends to expand its team by recruiting additional California-based staff to manage the project’s continued development.
It is recommended that Blue Moon complete the ongoing collation and digitization of paper records from previous work on the Blue Moon Property as a guide to future exploration and development work.
To the extent possible, core from earlier drill programs not already stored securely should also be preserved and examined to provide geological and geotechnical data relevant to the Blue Moon Project.
Phase 2: Exploration Decline Development and Further Studies
Exploration Decline Development
Upon finalizing the permitting process for the exploration decline, Blue Moon intends to tender and award a construction contract for its development. The decline’s construction is anticipated to take around one year and will support underground exploration and geotechnical drilling, reducing both surface disturbance and drilling costs. Additionally, the decline will be designed for dual functionality, serving as the primary access and haulage way once the mine is in operation. It is projected to extend to a depth of approximately 1,000 feet below the surface.
Geology and Exploration
The Blue Moon mineralization remains open along strike to the south and at depth. A program of exploration drilling is suggested in order to improve confidence in the resource estimate, aimed at bringing at least part of the Inferred Resource into the Indicated category. That drilling would permit geotechnical logging of the core and generate fresh samples on which to conduct metallurgical testwork. As proposed, therefore, Phase 2 includes an exploration drilling program comprising 13 holes totaling 10,650 m, to be conducted from the decline described above. Beyond mineral resource expansion, the program aims to improve understanding of underground geotechnical conditions to refine assumptions regarding stope spans, backfill strength and mining dilution, providing critical data for future mine planning efforts.
- 78 -
Hydrogeological Framework
Pump-testing of existing boreholes should be used to confirm their adequacy as a source of make-up water for the proposed process plant. Additional hydrogeological field work will be conducted to better define mine dewatering requirements during mine operation.
Metallurgical Testwork
Metallurgical testwork on representative composite samples of fresh core should be undertaken to (a) confirm the process design criteria currently based on results of earlier testwork; (b) establish whether barite, gypsum, and/or pyrite can be recovered economically; (c) investigate the occurrence of gallium, germanium and indium in the concentrates. Drill core from the exploration drilling program will be used for this purpose, and the testwork should include:
| · | Pre concentration amenability tests to investigate upgrading of the mineralization and the potential to extract barite and /or gypsum before grinding. | |
| · | Detailed mineralogical characterization studies. | |
| · | Deportment studies for gold, silver and potential critical metals, such as gallium, germanium and indium. | |
| · | Hardness and comminution tests. | |
| · | Additional gravity testwork. | |
| · | Further flotation optimization batch tests followed by locked cycle tests. | |
| · | Tailings characterization studies. |
Based on the additional testwork described above, the process flowsheet and equipment sizing may be refined, and the location of the plant and ancillary services may be optimized to minimize capital and operating costs and improve the quality of concentrates produced.
Environmental and Social
Recommendations considered important for ongoing development of the Blue Moon Project include the following:
1. Update all baseline studies and undertake additional surveys and testwork to ensure comprehensive understanding of environmental and social conditions. Particular attention should be paid to geochemical properties, seasonal differences in water bodies and biodiversity (migratory birds and mammals), potential nesting sites for birds of prey, and socio-economic conditions.
2. Demarcate any known cultural heritage sites and design infrastructure and access routes to avoid them, in collaboration with regulatory authorities.
3. Communicate with regulatory authorities and other relevant stakeholders to better determine the presence/absence of threatened/protected species and potential migration routes for mammals and birds.
4. Consider installing basic monitoring infrastructure, such as a weather station and groundwater monitoring boreholes to support ongoing baseline data collection.
5. Ensure all stakeholder interactions, including informal meetings, are documented and filed to assist the community relations and communications teams in future should the Blue Moon Project proceed to an operational mine.
6. Integrate sensitive/protected areas into the GIS used by the exploration team, to minimize the risk for damage, for example cultural heritage sites and known wildlife habitats.
7. Ensure all future exploration drill holes are properly closed up, to minimize land disturbance and avoid future problems with water connectivity. Establish a formal procedure for this and ensure the closure of all drill sites is properly documented.
- 79 -
8. Regularly review the project design, to adapt to emerging environmental and social risks and incorporate the latest available technologies for energy efficiency and environmental protection.
Feasibility Study
The results of the Phase 2 field work programs will inform a Feasibility Study (“FS”) undertaken to refine the Blue
Moon Project’s economic and technical parameters, reduce project risks, and enhance resource confidence, while supporting permitting efforts. Upon completion of a FS, a formal construction decision will be made by the Board.
Work Program
A provisional budget estimate for the proposed work program is outlined in the Blue Moon Technical Report.
Subsequent Events
Subsequent to the date of the Blue Moon Technical Report, the Corporation acquired one additional federal lode claim (CA106727777) which is held by Keystone, Blue Moon’s wholly owned US subsidiary. This added approximately 6 .89 acres to the size of the Blue Moon Property. As of the date of this AIF, the Blue Moon Property covers 501.14 acres.
RISK FACTORS
The Corporation’s business, being the acquisition, exploration, and development of polymetallic properties in the United States and Norway, is speculative and involves a high degree of risk. The risk factors listed below could materially affect the Corporation’s financial condition and/or future operating results and could cause actual events to differ materially from those described in forward-looking statements made by or relating to the Corporation. Additional risks or uncertainties not presently known to us or that we consider immaterial may also impair our business operations.
Permits, Licences and Approvals
The operations of the Corporation require licenses and permits from various governmental authorities. The Corporation believes it holds or is in the process of obtaining all necessary licences and permits to carry on the activities, which it is currently conducting under applicable laws and regulations. Such licences and permits are subject to changes in regulations and in various operating circumstances. The Corporation will use its best efforts to obtain all necessary licenses and permits to carry on the activities which it intends to conduct, and it intends to comply in all material respects with the terms of such licenses and permits. However, there can be no guarantee that the Corporation will be able to obtain and maintain, at all times, all necessary licenses and permits required to undertake its proposed exploration and development, or to place its properties into commercial production and to operate mining facilities thereon. In the event of commercial production, the cost of compliance with changes in governmental regulations has the potential to reduce the imposition of fines or penalties as well as criminal charges against the Corporation for violations of applicable laws or regulations.
Governmental Regulation
The mineral exploration and development activities of the Corporation are subject to various laws governing prospecting, development, production, taxes, labour standards and occupational health, mine safety, toxic substances, land use, water use, land claims of local people, and other matters in local areas of operation. Although the Corporation’s exploration and development activities are currently carried out in accordance with all applicable rules and regulations, no assurance can be given that new rules and regulations will not be enacted or that existing rules and regulations will not be applied in a manner, which could limit or curtail exploration, development, or production. Amendments to current laws and regulations governing the Corporation’s operations, or more stringent implementation thereof, could have an adverse impact on the Corporation’s business and financial condition.
- 80 -
The Corporation’s operations may be subject to environmental regulations promulgated by government agencies from time to time. Environmental legislation provides for restrictions and prohibitions on spills, releases, or emissions of various substances produced in association with certain mining operations, such as seepage from tailings disposal areas, which would result in environmental degradation. A breach of such legislation may result in the imposition of fines, and penalties. Environmental legislation is evolving in a manner that means standards are stricter, and enforcement, fines, and penalties for non-compliance are more stringent. Environmental assessments of proposed projects carry a heightened degree of responsibility for companies and their directors, officers, and employees. The cost of compliance with changes in governmental regulations has the potential to reduce the profitability of the Corporation’s future operations. Compensation projects are also imposed by the governmental authorities to alleviate the impacts of mining activities.
Failure to comply with applicable laws, regulations, and permitting requirements may result in enforcement actions, including orders issued by regulatory or judicial authorities that could cause operations to cease or be curtailed. Other enforcement actions may include corrective measures requiring capital expenditures, the installation of additional equipment or remedial actions. Parties engaged in mining operations may be required to compensate those suffering loss or damage by reason of such mining activities and may have civil or criminal fines or penalties imposed upon them for violations of applicable laws or regulations.
Volatility of Commodity Prices
The development of the Corporation’s properties is dependent on the future prices of minerals and metals. As well, should any of the Corporation’s properties eventually enter commercial production, the Corporation’s profitability will be significantly affected by changes in the market prices of minerals and metals.
Metal prices are subject to volatile price movements, which can be material and occur over short periods of time and which are affected by numerous factors, all of which are beyond the Corporation’s control. Such factors include, but are not limited to, interest and exchange rates, inflation or deflation, fluctuations in the value of the U.S. dollar and foreign currencies, global and regional supply and demand, speculative trading, the costs of and levels of metals production, and political and economic conditions. Such external economic factors are in turn influenced by changes in international investment patterns, monetary systems, the strength of and confidence in the U.S. dollar (the currency in which the prices of metals are generally quoted), and political developments.
The effect of these factors on the prices of metals, and therefore the economic viability of any of the Corporation’s exploration projects, cannot be accurately determined. The prices of commodities have historically fluctuated widely, and future price declines could cause the development of (and any future commercial production from) the Corporation’s properties to be impracticable or uneconomical. As such, the Corporation may determine that it is not economically feasible to commence commercial production at some or all of its properties, which could have a material adverse impact on the Corporation’s financial performance and results of operations. In such a circumstance, the Corporation may also curtail or suspend some or all of its exploration activities.
Liquidity and Additional Financing
The Corporation’s ability to continue its business operations is dependent on management’s ability to secure additional financing. The Corporation’s only source of liquidity is its cash and cash equivalent balances. Liquidity requirements are managed based upon forecasted cash flows to ensure that there is sufficient working capital to meet the Corporation’s obligations.
The advancement, exploration, and development of the Corporation’s properties, including continuing exploration and development projects, and, if warranted, construction of mining facilities and the commencement of mining operations, will require substantial additional financing. As a result, the Corporation may be required to seek additional sources of equity financing in the near future. While the Corporation has been successful in raising such financing in the past, its ability to raise additional equity financing may be affected by numerous factors beyond its control including, but not limited to, adverse market conditions, commodity price changes, and economic downturns. There can be no assurance that the Corporation will be successful in obtaining any additional financing required to continue its business operations and/or to maintain its property interests, or that such financing will be sufficient to meet the Corporation’s objectives or obtained on terms favourable to the Corporation. Failure to obtain sufficient financing as and when required may result in the delay or indefinite postponement of exploration and/or development on any or all of the Corporation’s properties, or even a loss of property interest, which would have a material adverse effect on the Corporation’s business, financial condition, and results of operations.
- 81 -
Nature of Mineral Exploration and Development
The Corporation’s future is dependent on its exploration and development programs. The exploration and development of mineral deposits involve significant financial risks over a prolonged period of time, which may not be eliminated even through a combination of careful evaluation, experience and knowledge. Few properties that are explored are ultimately developed into economically viable operating mines. Major expenditures on the Corporation’s exploration properties may be required to construct mining and processing facilities at a site, and it is possible that even preliminary due diligence will show adverse results, leading to the abandonment of projects. It is impossible to ensure that preliminary or full feasibility studies on the Corporation’s projects, or the current or proposed exploration programs on any of the properties in which the Corporation has exploration rights, will result in any profitable commercial mining operations. The Corporation cannot give any assurance that its current and future exploration activities will result in a discovery of mineral deposits containing mineral reserves.
Estimates of mineral resources and any potential determination as to whether a mineral deposit will be commercially viable can also be affected by such factors as: the particular attributes of the deposit, such as its size and grade; unusual or unexpected geological formations and metallurgy; proximity to infrastructure; financing costs; metal prices, which are highly volatile; and governmental regulations, including those relating to prices, taxes, royalties, infrastructure, land use, importing and exporting of metal concentrates, exchange controls and environmental protection. The effect of these factors cannot be accurately predicted, but the combination of any or all of these factors may result in the Corporation not receiving an adequate return on its invested capital or suffering material adverse effects to its business and financial condition. Exploration and development projects also face significant operational risks including but not limited to an inability to obtain access rights to properties, accidents, equipment breakdowns, labour disputes (including work stoppages and strikes), and other unanticipated interruptions.
No Earnings and History of Losses
The business of developing and exploring resource properties involves a high degree of risk and, therefore, there is no assurance that current exploration programs will result in profitable operations. The Corporation has not determined whether any of its properties contain economically recoverable reserves of mineralized material and currently has not earned any revenue from its projects; therefore, the Corporation does not generate cash flow from its operations. There can be no assurance that significant additional losses will not occur in the future. The Corporation’s operating expenses and capital expenditures may increase in future years with advancing exploration, development, and/or production from the Corporation’s properties. The Corporation does not expect to receive revenues from operations in the foreseeable future and expects to incur losses until such time as one or more of its properties enters into commercial production and generates sufficient revenue to fund continuing operations. There is no assurance that any of the Corporation’s properties will eventually enter commercial operation. There is also no assurance that new capital will become available, and if it is not, the Corporation may be forced to substantially curtail or cease operations.
Third-Party Approvals
The Corporation may require the consent or approval of third parties in order to enter into or complete certain agreements or transactions necessary in the course of its operations. There can be no assurance that such third parties, which may include shareholders, regulatory bodies or entities with an interest in the applicable property or others (including water supply management and availability), will provide the required approval or consent or enter into such agreement in a timely manner, or at all. Failure to obtain such third party approval may result in a material adverse effect on the Corporation’s operations and financial condition.
- 82 -
Exploration, Development and Operations
The long-term profitability of the Corporation’s operations will be in part directly related to the cost and success of its exploration programs, which may be affected by a number of factors, including the Corporation’s ability to extend the permitted term of exploration granted by the underlying concession contracts. Substantial expenditures are required to establish reserves through drilling, to develop processes to extract the resources, and in the case of new properties, to develop the extraction and processing facilities and infrastructure at any site chosen for extraction. Although substantial benefits may be derived from the discovery of a major deposit, no assurance can be given that any such deposit will be commercially viable or that the funds required for development can be obtained on a timely basis.
Information Systems and Cyber Security Threats
The Corporation’s operations depend upon information technology systems in the conduct of its operations. The Corporation could be adversely affected by network disruptions from a variety of sources, including, without limitation, computer viruses, security breaches, cyber-attacks, natural disasters and defects in design. Cybersecurity threats include attempts to gain unauthorized access to data or automated network systems and the manipulation or improper use of information technology systems.
A failure of any part of the Corporation’s information technology systems could, depending on the nature of such failure, materially adversely impact the Corporation’s reputation, financial condition and results of operations. The Corporation is subject to cybersecurity attacks and related threats from time to time. Although to date the Corporation has not experienced any material losses relating to cyber attacks or other information security breaches, there can be no assurance that the Corporation will not incur such losses in the future. The Corporation’s risk and exposure to these matters cannot be fully mitigated because of, among other things, the evolving nature of these threats. As a result, cyber security and the continued development and enhancement of controls, processes, and practices designed to protect systems, computers, software, data and networks from attack, damage, or unauthorized access remain a priority. As cyber threats continue to evolve, the Corporation may be required to expend additional resources to continue to modify or enhance protective measures or to investigate and remediate any security vulnerabilities.
Global Financial Conditions
Current global financial conditions have been subject to increased volatility, and access to public financing, particularly for junior resource companies, has been negatively impacted. These factors may impact the ability of the Corporation to obtain equity or debt financing in the future and, if obtained, such financing may not be on terms favourable to the Corporation. If increased levels of volatility and market turmoil continue, the Corporation’s operations could be adversely impacted, and the value and price of the Common Shares could be adversely affected.
Market Price of the Common Shares
The Common Shares trade on the TSXV under the symbol “MOON”, the Frankfurt Stock Exchange under the symbol “8SX0”, and the OTCQX Best Market under the symbol “BMOOF”. The market price of securities of many companies, particularly exploration and development stage mining companies, experience wide fluctuations that are not necessarily related to the operating performance, underlying asset values or prospects of such companies. There can be no assurance that an active market for the Common Shares will be sustained, or that fluctuations in the price of the Common Shares will not occur. The market price of the Common Shares at any given point in time may not accurately reflect the Corporation’s long-term value. Securities class action litigation has often been brought against companies following periods of volatility in the market price of their securities. The Corporation may in the future be the target of similar litigation. Securities litigation could result in substantial costs and damages and divert management’s attention and resources.
Foreign Operations Risks
The Corporation’s material properties are located in the United States and Norway. Such properties and operations are subject to various levels of political, economic and other risks and certainties that are different from those encountered in Canada. These risks vary from country to country and may include: political unrest, labour disputes, invalidation of governmental orders and permits, corruption, war, civil disturbances and terrorist actions, arbitrary changes in law or policies of particular countries, foreign taxation, price controls, delays in obtaining or the inability to obtain necessary governmental permits, opposition to mining from environmental or other non-governmental organizations, limitations on foreign ownership, limitations on the repatriation of earnings, import and export controls and increased financing costs. These risks may limit, delay or disrupt the Corporation’s projects, restrict the movement of funds or result in the deprivation of contract rights or the taking of property by nationalization or expropriation without fair compensation.
- 83 -
There can be no assurance that there will be no changes in the laws of the jurisdiction or changes in the regulatory environment for mining companies in the local jurisdiction that would adversely affect the Corporation. It is difficult for the Corporation to predict the effect of any constitutional or political changes on the Corporation’s business and operations, and it is also possible that future social unrest in the United States or Norway will adversely affect the Corporation’s operations.
In the future, the Corporation may choose to acquire properties or operate in foreign jurisdictions other than the U.S. and Norway.
For additional risks relating to foreign operations, please see “Risk Factors – Foreign Currency Risk” and “Risk Factors – Potential Impact of Tariffs and Trade Restrictions”.
Foreign Currency Risk
The Corporation is subject to currency risks. The Corporation’s functional currency is the Canadian dollar, which is exposed to fluctuations against other currencies. The Corporation’s activities are located in Canada, the United States and Norway, and as such many of its expenditures and obligations are denominated in U.S. dollars and Norwegian Krone. The Corporation maintains its principal office in Canada, and maintains cash accounts in Canadian dollars, U.S. dollars and Norwegian Krone and has monetary assets and liabilities in Canadian dollars, U.S. dollars and Norwegian Krone.
The Corporation’s assets and liquidities are significantly affected by changes in the Canadian/U.S. dollar and Canadian/Norwegian Krone exchange rates. Most expenses are currently denominated in Canadian dollars, U.S. dollars and Norwegian Krone. Exchange rate movements can therefore have a significant impact on the Corporation’s costs. The appreciation of non-Canadian dollar currencies against the Canadian dollar can increase the costs of the Corporation’s activities.
Additionally, the imposition of tariffs and other trade restrictions between Canada, Norway and the United States may further contribute to currency fluctuations. For more details, see “Potential Impact of Tariffs and Trade Restrictions” above.
Enforcing Judgments
Some of the Corporation’s mineral assets, including the Corporation’s material properties, the Nussir Property and the Blue Moon Property, are located outside of Canada and are held indirectly through foreign affiliates. As a result, it may be difficult or impossible for Canadian investors to initiate a lawsuit within Canada against these persons or to enforce judgments in Canada against such assets. In addition, it may not be possible for Canadian investors to collect from these persons or assets judgments obtained in courts in Canada predicated on the civil liability provisions of securities legislation of certain of the provinces and territories of Canada. It may also be difficult or impossible for Canadian investors to succeed in a lawsuit in the United States or in Norway based solely on violations of Canadian Securities Laws.
In addition, in the event of a dispute involving the foreign operations of the Corporation, the Corporation may be subject to the exclusive jurisdiction of foreign courts or may not be successful in subjecting foreign persons to the jurisdiction of courts in Canada. The Corporation’s ability to enforce its rights could have a material adverse effect on its future cash flows, earnings, results of operations and fmancial condition.
- 84 -
Dependence on Key Personnel
The Corporation’s future growth and its ability to develop depend, to a significant extent, on its ability to attract and retain highly qualified personnel. The Corporation relies on a limited number of key employees, consultants, and members of senior management and competes with mining and other companies to attract and retain key executives and other employees and third-party contractors with appropriate technical skills and managerial experience necessary to operate its business. While the Corporation maintains policies, procedures and frameworks in place to mitigate this risk, there can be no assurance that the Corporation will be able to attract and retain skilled and experienced personnel. Although the Corporation believes it will be able to replace key employees, consultants or members of senior management within reasonable time should the need arise, the loss of such key personnel, if not replaced in a timely manner, could have a material adverse effect on the Corporation’s business, financial condition, and prospects.
To operate successfully and manage its potential future growth, the Corporation must attract and retain highly qualified engineering, managerial and financial personnel. The Corporation faces intense competition for qualified personnel in these areas, and there can be no certainty that the Corporation will be able to attract and retain qualified personnel. If the Corporation is unable to hire and retain additional qualified personnel in the future to develop its properties, its business, financial condition, and operating results could be adversely affected.
Reliability of Mineral Resources Estimates
Mineral resources are estimates only, and no assurance can be given that the anticipated tonnages and grades will be achieved or that the indicated level of recovery will be realized. MREs may be materially affected by environmental, permitting, legal, title, taxation, socio-political, marketing and other relevant issues. There are numerous uncertainties inherent in estimating mineral resources, including many factors beyond the Corporation’s control. Such estimation is a subjective process, and the accuracy of any MRE is a function of the quantity and quality of available data, the nature of the mineralized body, and the assumptions made and judgments used in engineering and geological interpretation. These estimates may require adjustments or downward revisions based upon further exploration or development work or actual production experience.
Fluctuations in commodity prices, results of drilling, metallurgical testing and production, the evaluation of mine plans after the date of any estimate, permitting requirements or unforeseen technical or operational difficulties, may require revision of MREs. Should reductions in mineral resources occur, the Corporation may be required to take a material write-down of its investment in mining properties, reduce the carrying value of one or more of its assets or delay or discontinue production or the development of new projects, resulting in increased net losses and reduced cash flow. Mineral resources should not be interpreted as assurances of mine life or the profitability of current or future operations. Any material reductions in estimates of mineral resources could have a material adverse effect on the Corporation’s results of operations and financial condition.
Mineral resources are not mineral reserves and have a greater degree of uncertainty as to their existence and feasibility. There is no assurance that mineral resources will be upgraded to proven or probable mineral reserves.
Uncertainty Relating to Inferred Mineral Resources
Inferred mineral resources are not mineral reserves and do not have demonstrated economic viability. However, it is reasonably expected that the majority of inferred mineral resources could be upgraded to indicated mineral resources with continued exploration.
Acquiring Title
The acquisition of title to mineral properties is a very detailed and time-consuming process. The Corporation may not be the registered holder of some or all of the claims and concessions comprising the Blue Moon Property, the Nussir Property or any of the mineral projects of the Corporation. These claims or concessions may currently be registered in the names of other individuals or entities, which may make it difficult for the Corporation to enforce its rights with respect to such claims or concessions. There can be no assurance that proposed or pending transfers will be effected as contemplated. Failure to acquire title to any of the claims or concessions at one or more of the Corporation’s projects may have a material adverse impact on the financial condition and results of operation of the Corporation.
- 85 -
Title Matters
Once acquired, title to, and the area of, mineral properties may be disputed. There is no guarantee that title to one or more claims or concessions at the Corporation’s projects will not be challenged or impugned. There may be challenges to any of the Corporation’s titles which, if successful, could result in the loss or reduction of the Corporation’s interest in such titles. The Corporation’s properties may be subject to prior unregistered liens, agreements, transfers or claims, and title may be affected by, among other things, undetected defects. In addition, the Corporation may be unable to operate its properties as permitted or to enforce its rights with respect to its properties. The failure to comply with all applicable laws and regulations, including a failure to pay taxes or to carry out and file assessment work, can lead to the unilateral termination of concessions by mining authorities or other governmental entities.
Uncertainty and Inherent Sample Variability
Although the Corporation believes that the estimated mineral resources at the Blue Moon Property and the Nussir Property have been delineated with appropriately spaced drilling, there exists inherent variability between duplicate samples taken adjacent to each other and between sampling points that cannot be reasonably eliminated. There also may be unknown geologic details that have not been identified or correctly appreciated at the current level of delineation. This results in uncertainties that cannot be reasonably eliminated from the estimation process. Some of the resulting variances can have a positive effect and others can have a negative effect on mining and processing operations.
Term and Extension of Concession Contracts
Non-compliance with concession contracts may lead to their early termination by the relevant mining authorities or other governmental entities. A corporation whose concession contracts were subject to termination could be prevented from being issued new concessions or from keeping the concessions that it already held. The Corporation is not aware of any cause for termination or any investigation or procedure aimed at the termination of any of its concession contracts.
Surface Rights
The Corporation does not own all of the surface rights at its properties and there is no assurance that surface rights owned by the government or third parties will be granted, nor that they will be on reasonable terms if granted. Failure to acquire surface rights may impact the Corporation’s ability to access its properties, as well as its ability to commence and/or complete construction or production, any of which would have a material adverse effect on the profitability of the Corporation’s future operations.
Climate Change
The Corporation’s activities are subject to risks related to climate change. While it is widely recognized that continued emission of greenhouse gases will cause further warming of the planet and this warming could lead to damaging economic and social consequences for the Corporation, the exact timing and severity of physical effects are difficult to estimate. There exists a common misperception regarding the long-term nature of climate change implications, leading some to believe they may not be immediately relevant to present decision-making. Natural catastrophes are more and more present, and the Corporation must continue to assess its vulnerabilities and implement corrective measures to secure its infrastructure.
Yet, the potential repercussions of climate change on the Corporation extend beyond physical impacts and are not exclusively relegated to the distant future. Mitigating the effects of climate change necessitates a reduction in greenhouse gas emissions and an expedited transition to a lower-carbon economy. This reduction involves a shift away from fossil fuel energy and related physical assets. While the changes associated with transitioning to a lower-carbon economy pose substantial risks, they also present significant opportunities for the Corporation to focus more on climate change mitigation and adaptative solutions.
- 86 -
Uninsurable Risks
Mining operations generally involve a high degree of risk. Exploration, development, and production operations on mineral properties involve numerous risks, including but not limited to unexpected or unusual geological operating conditions, seismic activity, rock bursts, cave-ins, fires, floods, landslides, earthquakes, and other environmental occurrences, risks relating to the shipment of metal concentrates or ore bars, and political and social instability, any of which could result in damage to, or destruction of, the mine and other producing facilities, damage to life or property, environmental damage and possible legal liability. Although the Corporation believes that appropriate precautions to mitigate these risks are being taken, operations are subject to hazards such as equipment failure or failure of structures, which may result in environmental pollution and consequent liability. It is not always possible to obtain insurance against all such risks and the Corporation may decide not to insure against certain risks because of high premiums or other reasons. Should such liabilities arise, they could reduce or eliminate the Corporation’s future profitability and result in increasing costs and a decline in the value of the Common Shares. The Corporation does not maintain insurance against title, political or environmental risks.
While the Corporation may obtain insurance against certain risks in such amounts as it considers adequate, the nature of these risks is such that liabilities could exceed policy limits or be excluded from coverage. The potential costs that could be associated with any liabilities not covered by insurance or in excess of insurance coverage may cause substantial delays and require significant capital outlays, thereby adversely affecting the Corporation’s business and financial condition.
Competition
The mineral exploration and mining business is competitive in all of its phases. In the search for and acquisition of attractive mineral properties, the Corporation competes with numerous other companies and individuals, including competitors with greater financial, technical, and other resources. The Corporation’s ability to acquire properties in the future will depend on its ability to select and acquire suitable producing properties or prospects for mineral exploration. There is no assurance that the Corporation will continue to be able to compete successfully with its competitors in acquiring such properties or prospects, nor that it will be able to develop any market for the raw materials that may be produced from its properties. Any such inability could have a material adverse effect on the Corporation’s business and financial condition.
Local Communities, Indigenous Peoples and First Nations
Indigenous title claims, rights to consultation/accommodation and the Corporation’s relationship with local communities may affect the Corporation’s existing exploration and development projects. Governments in many jurisdictions must consult with first nations, indigenous communities or tribal nations with respect to grants of mineral rights or surface rights and the issuance or amendment of project authorizations. Consultation and other rights of Certain stakeholders may require accommodations, including undertakings regarding employment, royalty payments and other matters. This may affect the Corporation’s ability to acquire, within a reasonable time frame, effective mineral titles or surface rights in these jurisdictions in which first nations, indigenous communities, tribal nations or local communities’ titles are claimed, and may affect the timetable and costs of development of mineral properties in these jurisdictions. The risk of such unforeseen title claims also could affect exploration and development projects. These legal requirements may also affect the Corporation’s ability to transfer existing projects or to develop new projects.
The Corporation’s relationship with the communities in which it conducts activities are critical to ensure the future success of its existing activities and the exploration and development of its projects. There is an increasing level of public concern relating to the perceived effect of mining activities on the environment and on communities impacted by such activities. Adverse publicity relating to the mining industry generated by non-governmental organizations and others could have an adverse effect on the Corporation’s reputation or financial condition and may impact its relationship with the communities in which it conducts activities. While the Corporation is committed to working in a socially responsible manner, there is no guarantee that the Corporation’s efforts in this regard will mitigate this potential risk.
- 87 -
The inability of the Corporation to maintain positive relationships with local communities may result in additional obstacles to permitting, increased legal challenges, or other disruptive operational issues at any of the Corporation’s projects, and could have a significant adverse impact on the Corporation’s share price and financial condition.
Conflicts of Interest
Certain of the directors and officers of the Corporation also serve as directors and/or officers of other companies involved in natural resource exploration, development and mining operations. Consequently, there exists the possibility for such directors and officers to be in a position of conflict. The directors of the Corporation are required by law to act honestly and in good faith with a view to the best interests of the Corporation, and to disclose any interest they may have in any project or opportunity of the Corporation. In addition, each of the directors is required by law to declare his or her interest in and refrain from voting on any matter in which he or she may have a conflict of interest, in accordance with applicable laws.
Infrastructure
Mining, processing, development, and exploration activities depend, to one degree or another, on adequate infrastructure. Reliable roads, bridges, power sources, and water supplies, as well as the location of population centres and pools of labour, are important determinants, which affect capital and operating costs. Unusual or infrequent weather phenomena, sabotage, government or other interference in the maintenance or provision of such infrastructure could impact the Corporation’s ability to explore its properties, thereby adversely affecting its business and financial condition.
Pre-existing Environmental Liabilities
Pre-existing environmental liabilities may exist on the properties in which the Corporation hold an interest or on properties that may be subsequently acquired by the Corporation which are unknown, and which have been caused by previous or existing owners or operators of the properties. In such event, the Corporation may be required to remediate these properties and the costs of remediation could be substantial. Further, in such circumstances, the Corporation may not be able to claim indemnification or contribution from other parties. In the event the Corporation were required to undertake and fund significant remediation work, such event could have a material adverse effect upon the Corporation and the value of its securities.
Outbreaks of Diseases and Public Health Crises
The Corporation faces risks related to health epidemics and other outbreaks of communicable diseases, which could significantly disrupt its operations and may materially and adversely affect its business and financial conditions.
Although the Corporation’s current operations are not being materially impacted by any public health crises, the Corporation continues to monitor the developments and impact of any health crises and pandemic diseases as they may arise. The Corporation cannot estimate whether, or to what extent, any future outbreak of epidemics oar pandemics or other health crises may have an impact on the business, operations and financial condition of the Corporation. The outbreak of epidemics, pandemics or other public health crises, such as the Coronavirus pandemic, may result in volatility and disruptions in the supply and demand for copper, zinc and other critical metals and minerals, global supply chains and financial markets, as well as declining trade and market sentiment and reduced mobility of people, all of which could affect commodity prices, interest rates, credit ratings, credit risk, share prices and inflation. The risks to the Corporation of such public health crises also include risks to employee health and safety, a slowdown or temporary suspension of operations in geographic locations impacted by an outbreak, increased labor and fuel costs, regulatory changes, political or economic instabilities or civil unrest as well as the Corporation’s ability to service its debt obligations. As such, the impacts of such crises may have a material adverse effect on the Corporation’s business, results of operations and financial condition and the market price of the Common Shares. There can be no assurance that the Corporation’s personnel or its contractors’ personnel will not be impacted by these pandemic diseases and ultimately see its workforce productivity reduced or incur increased safety and medical costs / insurance premiums as a result of these health risks.
- 88 -
Potential Impact of Tariffs and Trade Restrictions
The imposition of tariffs and trade restrictions between Canada and the United States presents a risk to the Corporation and the global economy, which may have adverse effects on supply chains, capital expenditures, and operational costs. Since February 2025, the United States announced broad-based tariffs on goods exported out of a number of countries including Canada and Norway, into the United States. In response, the Canadian government and a number of other governments imposed, or announced they would impose, retaliatory tariffs. The introduction of protectionist or retaliatory international trade tariffs, sanctions or other barriers to international commerce by the United States, Canada or other countries may impact the Corporation’s current or proposed mineral exploration and development objectives or otherwise negatively impact the Corporation. The timing, implementation and extent of such tariffs and other measures is uncertain. Any change to tariffs and/or international trade regulations, and related impact to global economic conditions, may have a material adverse effect on the Canadian economy and the mining industry as well as global economic conditions and the stability of global financial markets, and may, as a result, have a material adverse effect on the Corporation’s business, financial conditions and results of operations. Furthermore, there is a risk that the tariffs imposed by the United States on other countries could trigger a broader global trade war which could have a material adverse effect on the Canadian, United States and global economies, and by extension the mining industry and the Corporation.
Higher capital and operating costs resulting from tariffs may negatively impact project economics, profitability, and production efficiency. The impact of tariffs may also increase the cost of certain materials originating from the United States. Supply chain disruptions and delays in procuring essential equipment could also affect project timelines and operational efficiency. In addition, the imposition of tariffs and other trade restrictions may also exacerbate other risk factors such as currency fluctuations and general economic volatility. Tariffs could impact trade flows, investor sentiment, and monetary policy decisions, leading to greater fluctuations in the exchange rates. Since a certain portion of the Corporation’s equipment, supplies, and operational expenses are denominated in U.S. dollars, a weaker Canadian dollar vis-à-vis the U.S. dollar and the Norwegian Krone would increase costs in Canadian dollar terms, potentially reducing the profitability of the Corporation’s operations and projects. See also “Foreign Currency Risks” above. These impacts may have a material adverse effect on the Corporation’s business, results of operations and financial condition.
International Conflict, Geopolitical Instability and War
International conflict and other geopolitical tensions and events, including war, military action, terrorism, trade disputes, and international responses thereto have historically led to, and may in the future lead to, uncertainty or volatility in global commodity and financial markets and supply chains. International conflicts (such as the Russian invasion of Ukraine and the Israel-Hamas conflict) including any related sanctions or other international action, may have a destabilizing effect on commodity prices, supply chains, and global economies more broadly. Volatility in commodity prices and supply chain disruptions may adversely affect the Corporation’s business, financial condition, and results of operations. The extent and duration of the international conflicts and related international action cannot be accurately predicted at this time and the effects of such conflict may magnify the impact of the other risks identified in this AIF, the financial statements of the Corporation and the management’s discussion and analysis, including those relating to commodity price volatility and global financial conditions. International conflicts may result in unforeseeable impacts, including on shareholders of the Corporation, and third parties with which the Corporation relies on or transacts, and may have an adverse effect on the Corporation’s business, results of operation, and financial condition.
The Outstanding Common Shares Could be Subject to Dilution
The exercise of Options, DSUs and RSUs (as defined herein) already issued by the Corporation and the issuance of additional equity securities in the future could result in dilution in the equity interests of holders of Common Shares.
No Dividends Policy
The Corporation has not declared a dividend since incorporation and does not anticipate doing so in the foreseeable future. Any future determination as to the payment of dividends will be at the discretion of the Board and will depend on the availability of profit, operating results, the financial position of the Corporation, future capital requirements and general business and other factors considered relevant by the directors of the Corporation. No assurances in relation to the payment of dividends can be given.
- 89 -
DIVIDENDS OR DISTRIBUTIONS
There are no restrictions in the Corporation’s articles or by-laws or pursuant to any agreement or understanding which could prevent the Corporation from paying dividends. The Corporation has never declared or paid any dividends on any class of securities. The Corporation currently intends to retain future earnings, if any, to fund the development and growth of its business, and does not intend to pay any cash dividends on the Common Shares for the foreseeable future. Any decision to pay dividends on the Common Shares in the future will be made by the Board on the basis of earnings, financial requirements and other conditions existing at the time.
DESCRIPTION OF CAPITAL STRUCTURE
Common Shares
The Corporation is authorized to issue an unlimited number of Common Shares without par value, of which 5 4,623,262 Common Shares were issued and outstanding as at September 11, 2025.
All Common Shares rank equally as to dividends, voting powers and participation in the distribution of assets. All holders of Common Shares are entitled to receive notice of any meetings of shareholders of the Corporation, and to attend and cast one vote per Common Share at all such meetings. Holders of Common Shares do not have cumulative voting rights with respect to the election of directors. Holders of Common Shares are entitled to receive on a pro rata basis such dividends, if any, as and when declared by the Board at its discretion from funds legally available therefor, and upon the liquidation, dissolution or winding up of the Corporation are entitled to receive on a pro rata basis the net assets of the Corporation after payment of liabilities, in each case subject to the rights, privileges, restrictions and conditions attaching to any other series or class of shares ranking senior in priority to or on a pro rata basis with the holders of Common Shares with respect to dividends or liquidation. The Common Shares do not carry any pre-emptive, subscription, redemption or conversion rights, nor do they contain any sinking or purchase fund provisions.
Preferred Shares
The Corporation is authorized to issue an unlimited number of Class “A” preferred shares (the “Class A Preferred Shares”) with par value of $10 per share and an unlimited Class “B” preferred shares (the “Class B Preferred Shares”, and together with the Class A Preferred Shares the “Preferred Shares”) without par value. As at September 12, 2025, no Preferred Shares are issued and outstanding.
The holders of Class A Preferred Shares are entitled, on the liquidation or dissolution of the Corporation, whether voluntary or involuntary, or on any other distribution of its assets among its Shareholders for the purpose of winding up its affairs, to receive, before any distribution is made to the holders of Common Shares or any other shares of the Corporation ranking junior to the Class A Preferred Shares with respect to repayment of capital on the liquidation or dissolution of the Corporation, whether voluntary or involuntary, or on any other distribution of its assets among its Shareholders for the purpose of winding up its affairs, the amount paid up with respect to each Class A Preferred Share held by them, together with the fixed premium (if any) thereon, all accrued and unpaid cumulative dividends (if any and if preferential) thereon, which for such purpose will be calculated as if such dividends were accruing on a day-to-day basis up to the date of such distribution, whether or not earned or declared, and all declared and unpaid noncumulative dividends (if any and if preferential) thereon. After payment to the holders of Class A Preferred Shares of the amounts so payable to them, they will not be entitled to share in any further distribution of the property or assets of the Corporation except as specifically provided in the special rights and restrictions attached to any particular series. Holders of Class A Preferred Shares are not entitled to receive notice of, or to attend or vote at, any general meeting of Shareholders of the Corporation.
- 90 -
The holders of Class B Preferred Shares are entitled, on the liquidation or dissolution of the Corporation, whether voluntary or involuntary, or on any other distribution of its assets among its Shareholders for the purpose of winding up its affairs, to receive, before any distribution is made to the holders of Common Shares or any other shares of the Corporation ranking junior to the Class B Preferred Shares with respect to repayment of capital on the liquidation or dissolution of the Corporation, whether voluntary or involuntary, or on any other distribution of its assets among its Shareholders for the purpose of winding up its affairs, the amount paid up with respect to each Class B Preferred Share held by them, together with the fixed premium (if any) thereon, all accrued and unpaid cumulative dividends (if any and if preferential) thereon, which for such purpose will be calculated as if such dividends were accruing on a day-to-day basis up to the date of such distribution, whether or not earned or declared, and all declared and unpaid noncumulative dividends (if any and if preferential) thereon. After payment to the holders of Class B Preferred Shares of the amounts so payable to them, they will not be entitled to share in any further distribution of the property or assets of the Corporation except as specifically provided in the special rights and restrictions attached to any particular series. Holders of Class B Preferred Shares are not entitled to receive notice of, or to attend or vote at, any general meeting of Shareholders of the Corporation.
Equity Incentive Plans
The Corporation’s omnibus share compensation plan (the “Omnibus Plan”) has been established for the benefit of its directors, officers, employees and consultants. The Omnibus Plan was adopted by the Board on September 12, 2024 and approved by shareholders of the Corporation on October 17, 2024. The Omnibus Plan provides for the grant of Options, RSUs and DSUs with an aggregate maximum number of Common Shares that may be reserved for issuance under the Omnibus Plan and all other share-based compensation arrangements of the Corporation equal to 10% of the outstanding Common Shares.
Convertible Securities
As of the date of this AIF, the following convertible securities are issued and outstanding:
| · | 774,500 options to acquire Common Shares (“Options”) issued pursuant to the Omnibus Plan; |
| · | 62,500 restricted share units (“RSUs”) outstanding pursuant to the Omnibus Plan; and |
| · | 224,506 deferred share units (“DSUs”) outstanding pursuant to the Omnibus Plan. |
MARKET FOR SECURITIES
Trading Price and Volume of Securities
Common Shares
The Common Shares trade on the TSXV under the symbol “MOON”, the Frankfurt Stock Exchange under the symbol “8SX0”, and the OTCQX Best Market under the symbol “BMOOF”. The following table sets out the high and low trading prices, as well as the trading volume, for the Common Shares on the TSXV for each month of the fiscal year ended December 31, 2024 (being presented on a post-Consolidation basis).
| Date | High | Low | Trading Volume |
| January, 2024 | $0.75 | $0.55 | 10,227 |
| February, 2024 | $0.70 | $0.55 | 2,435 |
| March, 2024 | $0.65 | $0.55 | 11,604 |
| April, 2024 | $0.60 | $0.40 | 19,352 |
| May, 2024 | $0.50 | $0.35 | 24,167 |
| June, 2024 | $0.55 | $0.35 | 69,546 |
| July, 2024 | $0.35 | $0.30 | 50,505 |
| August, 2024 | $1.75 | $0.25 | 913,480 |
| September, 2024 | $3.00 | $1.40 | 289,250 |
- 91 -
| Date | High | Low | Trading Volume |
| October, 2024 | $3.90 | $2.80 | 135,709 |
| November, 2024 | $4.30 | $3.30 | 73,562 |
| December, 2024 | $3.55 | $3.55 | – |
Prior Sales – Securities Not Listed or Quoted on a Marketplace
During the financial year ended December 31, 2024, other than issuances of Common Shares, the Corporation issued Options, RSUs, DSUs and Subscription Receipts.
Options
During the financial year ended December 31, 2024, the Corporation issued the following Options to purchase Common Shares (being presented on a post-Consolidation basis).
| Date of Grant | Number of Options | Exercise Price | Expiry Date |
| January 10, 2024 | 120,000(1) | $1.00 | January 10, 2029 |
| November 1, 2024 | 115,000(2) | $3.40 | November 1, 2029 |
Notes
| (1) | Vesting over 18 months, with a third of the Options vesting every six months. | |
| (2) | Vesting over a three-year period. |
RSUs
During the financial year ended December 31, 2024, the Corporation issued the following RSUs (being presented on a post-Consolidation basis), which may be settled in Common Shares, cash or a combination of Common Shares and cash, at the Corporation’s discretion:
| Date of Grant | Number of RSUs | |
| November 1, 2024 | 37,500 (1) | |
Notes
(1) Vesting annually over three years from the date of grant.
DSUs
During the financial year ended December 31, 2024, the Corporation issued the following DSUs (being presented on a post-Consolidation basis), which may be settled in Common Shares, cash or a combination of Common Shares and cash, at the Corporation’s discretion:
| Date of Grant | Number of RSUs |
| November 1, 2024(1) | 140,000(1) |
Notes
(1) Vesting annually over three years from the date of grant.
Subscription Receipts
In connection with the Concurrent Financing, the Corporation issued 90,000,279 Subscription Receipts which were automatically converted to 9,000,035 Common Shares (on a post-Consolidation basis, rounded) in accordance with their terms on February 27, 2025, in connection with the completion of the Nussir and NSG Transaction. See “General Development of the Business – Three Year History – 2024 – Acquisition of Nussir and NSG and Concurrent Financing”.
- 92 -
PRINCIPAL HOLDERS OF VOTING SECURITIES
To the best of knowledge of the directors and senior officers of the Corporation, as of the date of this AIF, no other person owns, directs, or controls, directly or indirectly, 10% or more of the issued and outstanding Common Shares, other than as disclosed below:
| Name of Shareholder | Number of Common Shares | Percentage
of Issued and Outstanding |
| Baker Steel Resources Trust Ltd. | 5,789,555 | 10.6% |
| Monial AS | 8,292,206 | 15.2% |
DIRECTORS AND OFFICERS
The following table sets forth the name and residence of each director and executive officer of the Corporation, as well as such individual’s position with the Corporation, period of service as a director (if applicable), and principal occupation(s) within the five preceding years. Each of the directors of the Corporation will hold office until the close of the next annual meeting of shareholders or until the director’s successor is elected or appointed.
| Name,
Province and Country of Residence) |
Position(s)
with Corporation |
Date
of Appointment as Director |
Principal
Occupation(s) for Five Preceding Years |
|
Maryse Belanger British Columbia, Canada |
Director | October 17, 2024 |
Director and Chair of Environment, Social and Governance Committee at Equinox Gold Corp since June 2020. Formerly, Director and Chair of the board of directors of Adventus Mining Corporation from March 28, 2024 to July 2024; Interim Chief Executive Officer of IAMGOLD Corporation from May 2022 to April 2023 and board chair of IAMGOLD Corporation from February 2022 to September 2023. Former Director and CEO of Bullfrog Gold Corp. (now, Augusta Gold Corp.) from September 2020 to April 2021. |
|
Christian Kargl-Simard Ontario, Canada |
Director, CEO | October 17, 2024 | Non-executive Chairman of Surge Copper Corp. since September 2020 and board member of NorthX Nickel Corp. since November 2022. Formerly CEO of Adventus Mining Corporation from December 2016 until July 2024. |
|
Haytham Hodaly(2) British Columbia, Canada
|
Director | October 17, 2024 |
President Of Wheaton Precious Metal Corp since September 2025. Senior Vice President, Corporate Development of Wheaton Precious Metals Corp from January 2012 to September 2025. Director of NEXE Innovations Inc. since 2020. Formerly, a Director of Goldsource Mines Inc. from 2017 until 2024 and a Director of the Denver Gold Group from 2019 until 2024. |
Karin Thorburn(2) Bergen, Norway |
Director | February 26, 2025 | Research Chair Professor of Finance at NHH Norwegian School of Economics since 2009 and Adjunct Full Professor of Finance at The Wharton School of University of Pennsylvania, USA since 2016. Director of the Board of Argentum Asset Management AS since 2022, Maritime & Merchant Bank ASA since 2016, and Nussir ASA from 2023-2025. |
| Francis Johnstone(2) | Director | February 26, 2025 | Investment Advisor to Baker Steel Resources Trust Ltd since 2010. |
- 93 -
| Name,
Province and Country of Residence) |
Position(s)
with Corporation |
Date
of Appointment as Director |
Principal Occupation(s) for Five Preceding Years
|
| London, United Kingdom | |||
| Skott Mealer Florida, USA |
President and COO | – |
Formerly Vice President of Adventus Mining Corporation and General Manager of Curimining, concession holder of the Curipamba - El Domo Project, from February 2022 until July 2024. |
| Frances Kwong Ontario, Canada |
CFO and Corporate Secretary | – | Formerly CFO of Adventus Mining Corporation from October 2017 until July 2024. |
|
Theodore Veligrakis Paleochori Chalkidikis, Macedonia, Greece |
Vice President, Exploration | – |
Mineral Exploration Consultant at Physis Corp since September 2024. Formerly Exploration Manager of Adriatic Metals plc from May 2021 until May 2024, previously Senior Exploration Geologist at Tethyan Resources from May 2019 until May 2021 and Exploration Geologist at Eldorado Gold from May 2012 until April 2019. |
| Boi Linh Doig Ontario, Canada |
Vice President, Mining | – | Formerly Principal Projects Engineer at Evolution Mining Limited from May 2020 until April 2025. |
| Stephen Eddy Ontario, Canada |
Senior Vice President, Corporate Development | Formerly SVP, Business Development of Iamgold Corporation from 2023 to 2025 and Vice President, Business Development of Iamgold Corporation from 2014 to 2023, Stephen has guided transformative projects such as the turnaround of the Cote Gold project. |
Notes:
| (1) | The information as to province and country of residence and principal occupation, not being within the knowledge of the Corporation, has been furnished by the respective directors individually. | |
| (2) | Member of the Audit Committee. Karin Thorburn is the Chair. |
Based on the disclosure available on the System for Electronic Disclosure by Insiders, as of the date of this AIF, the directors and executive officers of the Corporation (as listed in this AIF) as a group, beneficially owned, or controlled or directed, directly or indirectly, a total of 1,757,303 Common Shares, representing approximately 3.41% of the total issued and outstanding Common Shares as of the date hereof.
Set forth below is a brief description of the background of the directors and executive officers of the Corporation.
Maryse Bélanger, Director
Ms. Bélanger currently serves as Director of the Corporation. Ms. Bélanger also currently serves on the board of directors of Equinox Gold Corp., where she is chair of its Environment, Social and Governance Committee and is a member of its Compensation and Nomination Committee. She has over 35 years of experience globally, with proven strengths in operational excellence and efficiency, technical studies and services. She has provided oversight and project management support through some of the mining industry’s key strategic acquisitions. Ms. Bélanger was appointed Chair of Adventus Mining Corporation’s board of directors in March 2024, prior to its sale to Silvercorp Metals Inc. in July 2024 for $235M. She was Interim CEO and Board Chair of IAMGOLD Corporation from 2022-2 023, successfully overcoming financing and construction issues to advance the company’s flagship Côté Mine toward production. From 2016 to 2020, Ms. Bélanger was President, COO and Director of Atlantic Gold, where she guided the company’s Touquoy Mine through construction to production, and the eventual acquisition of Atlantic Gold by St. Barbara for C$722 million. She was recognized twice by the Women in Mining UK “WIM (UK)” 100 Global Inspirational Women in Mining Project as one the most inspirational Global Women in Mining. She holds a Bachelor of Science degree in Geology, a graduate certificate in Geostatistics and ICD.D designation.
- 94 -
Christian Kargl-Simard, CEO & Director
Mr. Kargl-Simard currently serves as CEO and Director of the Corporation. He has over 20 years of experience in the mining industry, having worked both in technical and finance roles. He recently sold Adventus Mining Corporation to Silvercorp Metals Inc. for $235M after starting with a $2M exploration focused asset base in December 2016. Prior to starting Adventus Mining, he worked for 10 years in investment banking roles at Raymond James Ltd. and Haywood Securities Inc. During his tenure in investment banking, Christian was involved in financings raising more than $7 billion, and he assisted in completing over 35 M&A transactions. Christian also worked for Dynatec up to its sale to Sherritt International Corp. in 2007, both in metallurgical engineering and corporate development roles. Christian holds a B.A.Sc. degree in Metallurgical Engineering from the University of British Columbia. Christian is also non-executive chairman of Surge Copper Corp.
Haytham Hodaly, Director
Mr. Hodaly currently serves as a director of the Corporation and Senior Vice President, Corporate Development of -Wheaton Precious Metals. Mr. Hodaly has almost 30 years of experience in analyzing mining opportunities. He joined Wheaton Precious Metals in 2012 and has since been involved with more than US$10 billion worth of streaming transactions. Prior to joining Wheaton Precious Metals, Mr. Hodaly had spent more than 16 years in the North American securities industry, most recently as Director and Mining Analyst, Global Mining Research, at RBC Capital Markets. Prior to this, Mr. Hodaly held the position of Co-Director of Research and Senior Mining Analyst at Salman Partners Inc., in addition to holding the titles of Vice President and Director of the firm. Mr. Hodaly is an engineer with a Bachelor of Applied Science in Mining and Mineral Processing Engineering and a Master of Engineering, specializing in Mineral economics, both obtained from the University of British Columbia. Mr. Hodaly currently serves as a director of NEXE Innovations Inc. since 2020 and a Director of Blue Moon Metals Inc. since October 2024 and was formerly a director of Goldsource Mines Inc. from 2017 until 2024 and a Director of Gold Denver Gold Group from 2019 until 2024.
Karin Thorburn, Director
Dr. Thorburn is Research Chair Professor of Finance at NHH Norwegian School of Economics and Adjunct Full Professor of Finance at The Wharton School of University of Pennsylvania, USA. Before joining NHH in 2009, she was a faculty member at the Tuck School of Business at Dartmouth College, USA. Her research focuses on M&A, restructuring, raising capital, and corporate governance, and is regularly published in leading academic journals. Dr. Thorburn is a Research Associate of the Center for Economic Policy Research (CEPR) in London and a Research Affiliate of the European Corporate Governance Institute (ECGI) in Brussels. She is a Director of the Board of Argentum Asset Management AS, Maritime & Merchant Bank ASA, Preferred Global Health AS, Green LNG Services AS, and Horus of Norway AS, and previously of Nussir ASA, SEB Investment Management AB, and Nordea Bank Norway ASA. She has served on several government-appointed committees on topics related to banking regulation and the investment strategy of Norway’s Government Pension Fund Global. Dr. Thorburn holds a PhD in financial economics from the Stockholm School of Economics .
Francis Johnstone, Director
Mr. Johnstone has been an Investment Advisor to Baker Steel Resources Trust Ltd since its inception and is based in London. Mr. Johnstone has trained in corporate finance and M&A at Citibank, Francis entered the mining business in 1989 with Cluff Resources plc and became Group Projects and Operations Manager. Prior to Cluff’s takeover by Ashanti Goldfields in 1996, Mr. Johnstone was a key member of the team who built Freda Rebecca the largest gold mine in Zimbabwe, the Ayanfuri Gold Mine in Ghana and negotiated for and discovered the Geita Gold Mine in Tanzania. In 2003, he joined Ridge Mining plc as Commercial Director, and was an integral member of the team that undertook a feasibility study, financed and developed the Blue Ridge Platinum Mine in South Africa prior to the acquisition of Ridge Mining Plc by Aquarius Platinum Limited in 2009.
- 95 -
Skott Mealer, President and COO
Mr. Mealer currently serves as President and COO of the Corporation. Mr. Mealer is a seasoned mining professional with over 20 years of experience in project development and construction. He most recently led the advancement of the El Domo Project for Adventus Mining in Ecuador resulting in granting of all required permits for construction and operation of the mine – only the third in Ecuador and first since 2016. Prior to that he worked for Kinross Gold Corporation for 10 years on various projects including successfully leading the La Coipa restart in Chile and Round Mountain Phase W in Nevada, and also held key roles on other projects in Chile, Brazil and Ecuador including FDN and Mirador. He is fluent in Spanish and English and has extensive experience building and leading multidisciplinary, multicultural teams in both engineering and construction with consistent performance in safety, cost reduction and schedule adherence.
Frances Kwong, CFO and Corporate Secretary
Ms. Kwong currently serves as CFO and Corporate Secretary of the Corporation. Ms. Kwong is a financial professional with over 40 years of international experience from finance and strategy planning to management of financial systems implementation in mining and other industries. She has close to 20 years of experience in the global mining sector, ensuring compliance with financial and regulatory requirements and has been involved in numerous financing as well as transactions both at asset and corporate level, serving as Chief Financial Officer of Adventus Mining for 7 years up to its $235M sale to Silvercorp Metals in the summer of 2024, Vaaldiam Mining Inc., and as senior consultant for a major mining-focused equity and royalty fund. Prior to the mining sector, Frances worked in the telecommunications and information technology industries. Frances is a fellow of the Institute of Chartered Accountants in England and Wales, a Canadian CPA, and holds a B. Soc. Sc. (Hons) degree from the University of Hong Kong.
Theodore Veligrakis, Vice President, Exploration
Mr. Veligrakis currently serves as Vice President of Exploration of the Corporation. Mr. Veligrakis is a professional geologist with over 13 years of experience in mineral exploration across world-class Au-Ag epithermal, Au-Pb-Zn-Ag carbonate replacement, Cu-Au porphyry, skarn and VMS deposits across the Western Tethyan Mineral Belt and West Africa. Previously, he was the Exploration Manager of Adriatic Metals (ASX: ADT) in Bosnia & Herzegovina, where he was involved in the discovery of Rupice NW polymetallic deposit, doubling the existing life of mine to 20 years. Before Adriatic Metals, Theo was the Senior Exploration Geologist for Tethyan Resources (TSX-V: TETH) in Serbia and a Generative Exploration Geologist for Eldorado Gold (TSX: ELD / NYSE: EGO) in Greece and Balkans. Throughout his career, Mr. Veligrakis has demonstrated strong leadership in exploration strategy, team management, and technical excellence. As Exploration Manager at Adriatic Metals, he led a team of 13 geologists, streamlining exploration processes and implementing successful near mine and regional drilling programs. His expertise spans project generation, surface mapping, and geochemical and geophysical data integration. He has also conducted technical due diligence on multi-commodity projects across Europe, Africa, and Central Asia, contributing to strategic investment decisions. Passionate about early- to mid-stage exploration, he is committed to unlocking new mineral discoveries through innovative and systematic exploration approaches.
Boi Linh Doig, Vice President, Mining
Mrs. Doig currently serves as Vice President of Mining of the Corporation. Mrs. Doig has over 20 years of underground experience in the mining industry. Most recently, she served as Principal Projects Engineer at Evolution Mining – Red Lake Operations, where she led a team in delivering several key projects resulting in significant cost savings and operational improvements. She has previously held several leadership roles, including Chief Mine Engineer with Newmont Goldcorp’s Red Lake Gold Mines, and Engineering Team Leader with Goldcorp at Musselwhite Mine. Throughout her career, she has demonstrated exceptional skills in managing multi-disciplinary engineering teams, optimizing mine operations, driving strategic initiatives, and executing projects that enhance safety, efficiency, and productivity. Mrs. Doig holds a Bachelor of Applied Sciences in Mineral Engineering from the University of Toronto and is a licensed Professional Engineer with Professional Engineers of Ontario.
- 96 -
Stephen Eddy, Senior Vice President, Corporate Development
Mr. Eddy is a strategic financial executive with over two decades of experience leading capital markets transactions, risk management, and corporate development in the mining sector. As Senior Vice President of Business Development at IAMGOLD, he spearheaded $900M in acquisitions and $2.4B in divestitures, including landmark deals such as the $ 500M sale of Niobec and a $195M strategic investment by Sumitomo. Known for his sharp financial acumen, collaborative leadership, and ability to unlock value in complex, high-stakes environments, Stephen has guided transformative projects such as the turnaround of the Cote Gold project. A Chartered Professional Accountant, Master of Management and Professional Accounting (MMPA) graduate from Rotman School of Management and holds a honours BA in Economics from the University of Western Ontario, he brings a rigorous analytical approach, a passion for growth, and a commitment to operational excellence. Stephen excels in aligning strategy with execution to drive shareholder value and position organizations for long-term success.
Cease Trade Orders, Bankruptcies, Penalties or Sanctions
Other than as set out below, no individual set forth in the above table is, as at the date hereof, or was, within 10 years before the date hereof, a director, chief executive officer or chief financial officer of any company (including the Corporation) that:
| (a) | was subject to a cease trade order, an order similar to a cease trade order or an order that denied the relevant company access to any exemption under securities legislation, that was in effect for a period of more than 30 consecutive days and that was issued while such individual was acting in the capacity as director, chief executive officer or chief financial officer; or |
| (b) | was subject to a cease trade order, an order similar to a cease trade order or an order that denied the relevant company access to any exemption under securities legislation, that was in effect for a period of more than 30 consecutive days, that was issued after such individual ceased to be a director, chief executive officer or chief financial officer, and which resulted from an event that occurred while such individual was acting in the capacity as director, chief executive officer or chief financial officer. |
Other than as set out below, no individual set forth in the above table or shareholder holding a sufficient number of securities of the Corporation to affect materially the control of the Corporation, nor any personal holding company of any such individual:
| (a) | is, as of the date hereof, or has been within 10 years before the date hereof, a director or executive officer of any company (including the Corporation) that, while such individual was acting in that capacity, or within a year of such individual ceasing to act in that capacity, became bankrupt, made a proposal under any legislation relating to bankruptcy or insolvency, was subject to or instituted any proceedings, arrangement or compromise with creditors, or had a receiver, receiver manager or trustee appointed to hold its assets; or |
| (b) | has, within the 10 years before the date hereof, become bankrupt, made a proposal under any legislation relating to bankruptcy or insolvency, become subject to or instituted any proceedings, arrangement or compromise with creditors, or had a receiver, receiver manager or trustee appointed to hold the assets of such individual; or |
| (c) | has been subject to (i) any penalties or sanctions imposed by a court relating to securities legislation or by a securities regulatory authority, or has entered into a settlement agreement with a securities regulatory authority, or (ii) any other penalties or sanctions imposed by a court or regulatory body that would likely be considered important to a reasonable investor in making an investment decision. |
Ms. Bélanger was a director of Mirabela Nickel Limited (“MBN”) from July 2014 to June 2016. On September 24, 2015, the board of directors of MBN elected to place the company into voluntary administration under the relevant provisions of the Australian Corporations Act 2001 to progress discussions with financiers to put in place funding arrangements or other restructuring options that would alleviate the liquidity challenges facing MBN’s operations at the time. Such discussions were unsuccessful and on June 13, 2016 the creditors of MBN voted to place MBN in liquidation. On September 21, 2015, an order was issued by the British Columbia Securities Commission that all trading in the securities of MBN be ceased due to its failure to file financial statements for the period ended June 30, 2015. On September 25, 2015 and October 7, 2015, orders were issued by the Ontario Securities Commission that all trading in the securities of MBN be ceased due to its failure to file financial statements for the period ended June 30, 2015.
- 97 -
Ms. Bélanger was a director of Pure Gold Mining Inc. (“Pure Gold”) from February 2020 until March 30, 2023. Pure Gold owned the Madsen Mining property, located near Red Lake Ontario. After redeveloping the property and processing facilities, Pure Gold experienced significant start up and operational difficulties. Consequently, on October 31, 2022, Pure Gold applied for and received an initial order for creditor protection from the Supreme Court of British Columbia (“Court”) under the Companies’ Creditors Arrangement Act (“CCAA”). KSV Restructuring Inc. was appointed as the monitor. On November 10, 2022, the Court approved a Sales and Investment Solicitation Process Order, among other relief. On March 30, 2023, the Court approved Pure Gold’s appointment of a Chief Administrative Officer and all members of the Pure Gold board of directors resigned immediately. Pure Gold’s common shares were suspended from trading on the NEX Board of the TSXV. Pure Gold was subsequently acquired by West Lake Gold Mines on June 16, 2023 under the CCAA proceedings.
Ms. Bélanger was a director of Plateau Energy Metals Inc. (“Plateau”) from May 2016 to May 2021. On May 3, 2021, Plateau and two of its officers (Alexander Holmes and Philip Gibbs) received a Notice of Hearing together with a Statement of Allegations from staff of the Ontario Securities Commission (the “OSC”) announcing the commencement of regulatory proceedings on the basis that Plateau misled investors about a decision by a Peruvian mining regulator that threatened their mining rights over certain properties in Peru. In October of 2022, Plateau, Alexander Holmes and Philip Gibbs entered into a Settlement Agreement with the OSC and paid $210,000, $60,000 and $30,000 respectively on account of costs to the OSC in accordance with the terms of the Settlement Agreement. Plateau, Alexander Holmes and Philip Gibbs also made payments of $500,000, $175,000 and $75,000 respectively on account of administrative penalties.
Dr. Thorburn has been a director of Preferred Global Health AS (“PGH”) since October 2020. She is also a director of Preferred Global Health Ltd. (“PGH Bermuda”), a wholly-owned subsidiary of PGH, since October 7, 2022. PGH petitioned to have a receiver appointed in respect of PGH Bermuda, which entered a voluntary receivership process. On December 1, 2023, the Supreme Court of Bermuda appointed an Official Receiver as the Provisional Liquidator of PGH Bermuda. On December 16, 2024, the Supreme Court of Bermuda ordered that Elizabeth Cava and Marcin Czarnocki, both of Deloitte Financial Advisory Ltd., replace the Official Receiver and appointed them as Joint Provisional Liquidators (the “JPLs”) of PGH Bermuda. On June 19, 2025, the directors of PGH Bermuda received notice of the appointment of the JPLs and provided all relevant documentation.
Conflicts of Interest
Certain of the directors and officers of Blue Moon are directors and officers of other companies, some of which are in the same business as Blue Moon. See “Risk Factors”. Certain of the officers and directors of the Corporation also serve as directors and/or officers of other companies involved in the mineral exploration and development business, and consequently there exists the possibility for such officers or directors to be in a position of conflict. Any decision made by any such officers or directors involving the Corporation will be made in accordance with their duties and obligations under the laws of the Province of British Columbia and Canada.
AUDIT COMMITTEE
The Audit Committee’s Charter
The Board has adopted a Charter for the Audit Committee, which sets out the Audit Committee’s mandate, organization, powers and responsibilities. The full text of the Audit Committee Charter is attached hereto as Schedule “A”.
- 98 -
Composition of the Audit Committee
The members of the Audit Committee are Karin Thorburn, Haytham Hodaly and Francis Johnstone, all of whom are ” independent” and “financially literate” (as such terms are defined in National Instrument 52-110 – Audit Committees).
| Name of Member | Independent(1) | Financially Literate(2) |
| Karin Thorburn | Yes | Yes |
| Haytham Hodaly | Yes | Yes |
| Francis Johnstone | Yes | Yes |
Notes:
| (1) | To be considered independent, a member of the Audit Committee must not have any direct or indirect “material relationship” with the Corporation. A “material relationship” is a relationship which could, in the view of the Board, be reasonably expected to interfere with the exercise of a member’s independent judgment. |
| (2) | To be considered financially literate, a member of the Audit Committee must have the ability to read and understand a set of financial statements that present a breadth and level of complexity of accounting issues that are generally comparable to the breadth and complexity of issues that can reasonably be expected to be raised by the Corporation’s financial statements. |
Relevant Education and Experience
The following is a summary of the Audit Committee members’ education and experience which is relevant to the performance of their responsibilities as an Audit Committee member:
Karin Thorburn
Dr. Thorburn is Research Chair Professor of Finance at NHH Norwegian School of Economics and Adjunct Full Professor of Finance at The Wharton School of University of Pennsylvania, USA. She is a Research Associate of the Center for Economic Policy Research (CEPR) in London and a Research Affiliate of the European Corporate Governance Institute (ECGI) in Brussels. Dr. Thorburn is a Director of the Board of Argentum Asset Management AS, Maritime & Merchant Bank ASA, Preferred Global Health AS, Green LNG Services AS, and Horus AS, and previously of Nussir ASA, SEB Investment Management AB, and Nordea Bank Norway ASA. She has served on several government-appointed committees on topics related to banking regulation and the investment strategy of Norway’s Government Pension Fund Global. Dr. Thorburn holds a PhD in financial economics from the Stockholm School of Economics.
Haytham Hodaly
Mr. Hodaly is the Senior Vice President, Corporate Development of Wheaton Precious Metals and brings with him almost 30 years of experience in analyzing mining opportunities. Mr. Hodaly is an engineer with a Bachelor of Applied Science in Mining and Mineral Processing Engineering and a Master of Engineering, specializing in Mineral Economics, both obtained from the University of British Columbia.
Francis Johnstone
Mr. Johnstone is an Investment Advisor to Baker Steel Resources Trust Ltd and has trained in corporate finance and M&A at Citibank. Since then, he has been involved in the financial side of the mining business for over 35 years and has served on the audit committees of a number of publicly listed mining companies.
In these positions, each member has been responsible for receiving information relating to companies and obtaining an understanding of the balance sheet, income statements, statements of cash flows and assessing the financial condition of the Corporation and its operating results. Each member has an understanding of the mineral exploration and mining business in which the Corporation is engaged and has an appreciation of the financial issues and accounting principles that are relevant in assessing the Corporation’s financial disclosures and internal controls.
For more information see “Directors and Officers”.
- 99 -
Pre-Approval Policies and Procedures
The Audit Committee has adopted specific policies and procedures for the engagement of non-audit services as described below under the heading “Responsibilities of the Committee” of the Audit Committee Charter.
External Auditor Service Fees
The following table discloses the aggregate fees charged to the Corporation by its external auditor during the last two financial years:
| Financial Year Ending | Audit Fees(1) | Audit-Related
Fees(2) |
Tax Fees(3) | All Other Fees(4) |
| December 31, 2024 | $19,232 | Nil | $8,250 | Nil |
| December 31, 2023 | $19,000 | Nil | Nil | Nil |
Notes:
| (1) | The aggregate audit fees billed. |
| (2) | The aggregate fees billed for assurance and related services that are reasonably related to the performance of the audit or review of the Corporation’s fmancial statements that are not included under the heading “Audit Fees”. |
| (3) | The aggregate fees billed for professional services rendered for tax compliance, tax advice and tax planning. |
| (4) | The aggregate fees billed for products and services other than as set out under the headings “Audit Fees”, “Audit Related Fees” and “Tax Fees”. |
LEGAL PROCEEDINGS AND REGULATORY ACTIONS
The Corporation is not and was not a party to, and none of its property is or was the subject of, any legal proceedings during the Corporation’s most recently completed financial year, nor does the Corporation contemplate any such legal proceedings.
No penalties or sanctions have been imposed against the Corporation (i) by a court relating to securities legislation or (ii) by a securities regulatory authority, nor has the Corporation entered into any settlement agreements (a) before a court relating to securities legislation or (b) with a securities regulatory authority, during the Corporation’s most recently completed financial year, nor has a court or regulatory body imposed any other penalties or sanctions against the Corporation.
INTERESTS OF MANAGEMENT AND OTHERS IN MATERIAL TRANSACTIONS
Except as disclosed elsewhere in this AIF, no (a) director or executive officer, (b) person or Corporation that beneficially owns, controls or directs, directly or indirectly, more than 10% of the Common Shares, nor (c) associate or affiliate of any of the persons or companies referred to in (a) or (b) has, or has had within the three most recently completed financial years before the date hereof, any material interest, direct or indirect, in any transaction that has materially affected or is reasonably expected to materially affect the Corporation or any of its subsidiaries.
TRANSFER AGENT AND REGISTRAR
The transfer agent and registrar of the Corporation is Odyssey Trust Company, and the register of Common Shares and registers of transfers are maintained at its Toronto office.
- 100 -
MATERIAL CONTRACTS
The only material contracts that the Corporation has entered into (i) since the beginning of its most recently completed financial year, or (ii) before the beginning of its most recently completed fmancial year and that are still in effect, other than contracts entered into in the ordinary course of business, are as follows (copies of which are available on SEDAR+ (www.sedarplus.ca) under the Corporation’s issuer profile):
| (a) | the Agency Agreement (see “General Development of the Business – Three Year History – 2024 –Acquisition of Nussir and NSG and Concurrent Financing”); | |
| (b) | the subscription receipt agreement dated December 19, 2024 among the Corporation, Cormark Securities Inc., Scotia Capital Inc. and Odyssey Trust Company, relating to the Concurrent Financing (see “General Development of the Business – Three Year History – 2024 – Acquisition of Nussir and NSG and Concurrent Financing”); | |
| (c) | the Nussir Share Purchase Agreement dated December 19, 2024, between the Corporation, Nussir ASA, Monial AS, Baker Steel Resources Trust Limited, Antaeus AS, and Nils Christian Thrane (see “General Development of the Business – Three Year History – 2024 – Acquisition of Nussir and NSG and Concurrent Financing”); | |
| (d) | the NSG Share Purchase Agreement dated December 19, 2024, between the Corporation, NSG, Starker Bjornstad, Fauskebygg Holding AS, Fauskebygg Invest AS, Orjan Grotnes Valla, Morten Grotnes Valla, and Leif Roar Stavnes (see “General Development of the Business – Three Year History – 2024 – Acquisition of Nussir and NSG and Concurrent Financing”); | |
| (e) | Hartree Investor Rights Agreement (see “General Development of the Business – Three Year History – 2024 – Acquisition of Nussir and NSG and Concurrent Financing”); | |
| (f) | the REAS Share Purchase Agreement (see “General Development of the Business – Three Year History – Events Subsequent to 2024 – REAS Acquisition”); and | |
| (g) | the Bridge Loan Agreement (see “General Development of the Business – Three Year History –Events Subsequent to 2024 – Loan and Investment by Hartree and Oaktree”. |
INTERESTS OF EXPERTS
The authors of: (i) the Blue Moon Technical Report are Scott Wilson, C.P.G. SME-RM from Resource Development Associates Inc., Peter Szkilnyk, P. Eng. from Micon International Limited, Alan J. San Martin, P.Eng. from Micon International Limited, Richard Gowans, P.Eng. from Micon International Limited, Justin Taylor, P. Eng. from Micon International Limited and Christopher Jacobs, C. Eng., MIMMM from Micon International Limited; and (ii) the Nussir Technical Report is Adam Wheeler, B.Sc, M.Sc, C. Eng., Eur Ing., FIMMM. To the knowledge of the Corporation, each of these experts holds less than 1% of the outstanding securities of the Corporation or of any associate or affiliate thereof as of the date hereof. None of the aforementioned firms or persons received, or will receive, any direct or indirect interest in any securities of the Corporation or of any associate or affiliate thereof in connection with the preparation of the report prepared by such person. None of the aforementioned firms or persons, nor any directors, officers or employees of such firms, are currently, or are expected to be elected, appointed or employed as, a director, officer or employee of the Corporation, or of any associate or affiliate of the Corporation.
Davidson & Company LLP, the former auditors of the Corporation (until April 21, 2025), prepared an auditors’ report to the shareholders of the Corporation on the statement of financial position of the Corporation for the years ended December 31, 2024 and 2023, and the statements of loss and comprehensive loss, cash flows and changes in shareholders’ equity for the years ended December 31, 2024 and 2023. Davidson & Company LLP has advised that it is independent with respect to the Corporation within the meaning of the rules of Professional Conduct of Chartered Professional Accountants of Ontario. Davidson & Company LLP resigned effective on April 21, 2025 and succeeded by MNP LLP, as the current auditors of the Corporation.
- 101 -
ADDITIONAL INFORMATION
Additional information, including directors’ and officers’ remuneration and indebtedness, principal holders of the Corporation’s securities and securities authorized for issuance under equity compensation plans, as applicable, is contained in the Corporation’s management information circular dated September 17, 2024, which is available on SEDAR+ (www.sedarplus.ca) under Blue Moon’s issuer profile. Additional financial information is provided in the Corporation’s financial statements and management’s discussion and analysis for the Corporation’s most recently completed financial year. Additional information relating to the Corporation may also be found on SEDAR+ (www.sedarplus.ca) under Blue Moon’s issuer profile.
- 102 -
SCHEDULE “A”
AUDIT COMMITTEE CHARTER
1.0 PURPOSE
| 1.1 | The Audit Committee (the “Committee”) is a standing committee of the board of directors (the “Board”) of Blue Moon Metals Inc. (the “Corporation”) charged with assisting the Board in fulfilling its fmancial oversight responsibilities by reviewing the financial reports and other fmancial information provided by the Corporation to regulatory authorities and shareholders, the Corporation’s systems of internal controls regarding fmance and accounting and the Corporation’s auditing, accounting and financial reporting processes. Consistent with this function, the Committee will encourage continuous improvement of, and should foster adherence to, the Corporation’s policies, procedures and practices at all levels. The Committee’s primary duties and responsibilities are to: |
| (a) | serve as an independent and objective party to monitor the Corporation’s financial reporting and internal control system and review the Corporation’s fmancial statements; |
| (b) | review and appraise the performance of the Corporation’s external auditors; and |
| (c) | provide an open avenue of communication among the Corporation’s auditors, financial and senior management and the Board. |
2.0 COMMITTEE MEMBERSHIP
| 2.1 | The Board shall annually elect a minimum of three (3) directors to the Committee, a majority of whom shall be fmancially literate, independent of management and free from any material relationship with the Corporation, that in the opinion of the Board, would interfere with the director’s exercise of independent judgment as a member of the Committee. Unless a chair of the Committee (“Chair”) is elected by the full Board, the members of the Committee may designate a Chair by a majority vote of the full Committee membership. |
| 2.2 | If the Corporation ceases to be a “venture issuer” (as that term is defmed in National Instrument 52-110 –Audit Committees (“NI 52-110”)), then all of the members of the Committee shall be independent (as that term is defmed in NI 52-110). |
| 2.3 | If the Corporation ceases to be a “venture issuer” (as that term is defined in NI 52-110), then all members of the Committee shall be financially literate. All members of the Committee that are not financially literate will work towards becoming fmancially literate to obtain a working familiarity with basic finance and accounting practices. For the purposes of this Charter of the Audit Committee (the “Charter”), the defmition of “fmancially literate” is the ability to read and understand a set of financial statements that present a breadth and level of complexity of accounting issues that are generally comparable to the breadth and complexity of the issues that can presumably be expected to be raised by the Corporation’s fmancial statements. |
3.0 MEETINGS
| 3.1 | The Committee shall meet a least four (4) times annually, or more frequently as circumstances dictate. As part of its job to foster open communication, the Committee will meet at least annually with the external auditors. |
| 3.2 | A quorum for the transaction of business at any meeting of the Committee shall be two (2) members. |
A-1
4.0 RESPONSIBILITIES AND DUTIES
To fulfill its responsibilities and duties, the Committee shall:
4.1 Documents/Reports Review
| (a) | review this Charter annually and recommend any changes to the Board; and |
| (b) | review the Corporation’s financial statements, management discussion and analysis and any annual and interim earnings press releases before the Corporation publicly discloses this information, and any reports or other financial information (including quarterly fmancial statements), which are submitted to any governmental body, or to the public, including any certification, report, opinion, or review rendered by the external auditors. |
4.2 External Auditors
| (a) | annually review the performance of the external auditors who shall be ultimately accountable to the Board and the Committee as representatives of the shareholders of the Corporation; |
| (b) | annually obtain a formal written statement of external auditors setting forth all relationships between the external auditors and the Corporation, consistent with Independence Standards Board Standard No. 1 - Independence Discussions with Audit Committees; |
| (c) | review and discuss with the external auditors any disclosed relationships or services that may impact the objectivity and independence of the external auditors; |
| (d) | take appropriate action to oversee the independence of the external auditors, including the resolution of disagreements between management and the external auditor regarding fmancial reporting; |
| (e) | recommend to the Board the selection and, where applicable, the replacement of the external auditors nominated annually for shareholder approval; |
| (f) | recommend to the Board the compensation to be paid to the external auditors; |
| (g) | at least once per year, consult with the external auditors, without the presence of management, about the quality of the Corporation’s accounting principles, internal controls and the completeness and accuracy of the Corporation’s financial statements; |
| (h) | review and approve the Corporation’s hiring policies regarding partners, employees and former partners and employees of the present and former external auditors of the Corporation; |
| (i) | review with management and the external auditors the audit plan for the year-end financial statements and intended template for such statements; and |
| (i) | review and pre-approve all audit and audit-related services and the fees and other compensation related thereto; |
| (k) | review and pre-approve any non-audit services provided by the Corporation’s external auditors, subject to the following: |
| (i) | the pre-approval requirement shall be satisfied with respect to the provision of non-audit services if the following criteria (as set forth in Section 2.4 of NI 52-110) are met: |
| (A) | the aggregate amount of all such non-audit services provided to the Corporation constitutes not more than five percent of the total amount of fees paid by the Corporation (and its subsidiary entities) to its external auditors during the fiscal year in which the non-audit services are provided; |
A-2
| (B) | such services were not recognized by the Corporation (or the subsidiary entity) at the time of the engagement to be non-audit services; |
| (C) | such services are promptly brought to the attention of the Committee and approved, prior to the completion of the audit, by the Committee or by one or more members of the Committee who are members of the Board to whom authority to grant such approvals has been delegated by the Committee (with such delegation being in compliance with Section 2.5 of NI 52-110); and |
| (ii) | the Committee may delegate to the Chair or any other independent member of the Committee the authority to pre-approve non-audit services, provided such pre-approved non-audit services are presented to the Committee at the next scheduled Committee meeting following such pre-approval. |
4.3 Financial Reporting Processes
| (a) | in consultation with the external auditors, review with management the integrity of the Corporation’s financial reporting process, both internal and external; |
| (b) | consider the external auditors’ judgments about the quality and appropriateness of the Corporation’s accounting principles as applied in its financial reporting; |
| (c) | consider and approve, if appropriate, changes to the Corporation’s auditing and accounting principles and practices as suggested by the external auditors and management; |
| (d) | review significant judgments made by management in the preparation of the financial statements and the view of the external auditors as to the appropriateness of such judgments; |
| (e) | following completion of the annual audit, review separately with management and the external auditors any significant difficulties encountered during the course of the audit, including any restrictions on the scope of work or access to required information; |
| (f) | review any significant disagreement among management and the external auditors in connection with the preparation of the financial statements; |
| (g) | review with the external auditors and management the extent to which changes and improvements in financial or accounting practices have been implemented; |
| (h) | review any complaints or concerns about any questionable accounting, internal accounting controls or auditing matters; |
| (i) | establish a procedure for the receipt, retention and treatment of complaints received by the Corporation regarding accounting, internal accounting controls or auditing matters; and |
| (j) | establish a procedure for the confidential, anonymous submission by employees of the Corporation of concerns regarding questionable accounting or auditing matters. |
4.4 Internal Control
| (a) | consider the effectiveness of the Corporation’s internal control system; |
| (b) | understand the scope of external auditors’ review of internal control over financial reporting, and obtain reports on significant findings and recommendations, together with management’s responses; |
A-3
| (c) | review external auditors’ management letters and management’s responses to such letters; |
| (d) | as requested by the Board, discuss with management and the external auditors the Corporation’s major risk exposures (whether financial, operational or otherwise), the adequacy and effectiveness of the accounting and financial controls, and the steps management has taken to monitor and control such exposures; |
| (e) | annually review the Corporation’s disclosure controls and procedures, including any significant deficiencies in, or material non-compliance with, such controls and procedures; and |
| (f) | discuss with the Chief Financial Officer and, as is in the Committee’s opinion appropriate, the Chief Executive Officer, all elements of the certification required pursuant to National Instrument 5 2-109 - Certification of Disclosure in Issuers’ Annual and Interim Filings. |
4.5 Other
| (a) | review any related-party transactions; |
| (b) | engage independent counsel and other advisors as it determines necessary to carry out its duties; |
| (c) | set and pay compensation for any independent counsel and other advisors employed by the Committee; and |
| (d) | communicate directly with the internal and external auditors. |
Approved by the Board of Directors on October 17, 2024
A-4