| Class | Costs of a $10,000 Investment | Costs Paid as a Percentage of a $10,000 Investment |
|---|---|---|
| Institutional Class Shares | $231 | 2.21% |
Our portfolio hasn't changed much over the past few years; we think we have very good allocation of conventional value shares along with a couple of names that we purchased as conventional value stocks but have become very popular and rewarding for the Fund. Examples of those are Apple Inc. (APPL) and Microsoft Corporation (MSFT). Both are riding high in part due to the new artificial intelligence (AI) boom. Apple seems likely as a very profitable distributor of the service through its very large ecosystem and Microsoft more directly by developing their own models and data centers. Time will tell. The world is changing, again and fast!
It's hard for "little brains" like us to fathom how the many hundreds and hundreds of billions of dollars in investment in AI is going to pay off for the investors. It seems to us as a testosterone based race, not for profitably, but more importantly not to be in second place.
The media says that many of the companies in America will get real profit increases by using AI, and we hope to own many of them. We are happy with our indirect method of profiting from this new technology. AI and what it means is quite scary, not just from an investment point of view, but as a human being.
Our positions in large banks have treated the Fund very well this past year. Bank of America Corporation (BAC), JPMorgan Chase & Co. (JPM) and Wells Fargo & Company (WFC) have done very well. They have reported good earnings and have become popular no doubt due to their dividends and perhaps being largely USA centric.
Our position in Mitsubishi UFJ Financial Group (MUFG), one of Japan's' largest banks, has been particularity interesting. The Japanese central bank has started to increase local interest rates after many years of keeping them near zero. This has caused, we think, the locals to sell off some of their US Treasuries (perhaps causing rates to rise for us here) and reinvest the proceeds locally and that is good for Mitsubishi UFJ Financial Group (MUFG). This strategy was suggested by some of Warren Buffett's holdings over the past years. The bank has been increasing its earnings and buying its own stock back.
The current political administration policies regarding investing in this country and hiring our people must be good for our banks and likely many of our industries.
Inflation seems a concern, as an economy that is doing as well as ours seems to be, could generate some price gains and that could spook the markets. Perhaps the changes that are being made in our immigration policies (rents lower?) as well as perhaps the de-inflationary nature of AI will come to the rescue.
We are happy with the positions we have and look forward to a new year.
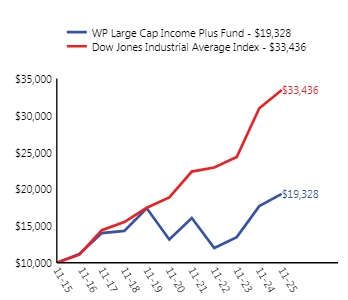
| One Year | Five Years | Ten Years | |
|---|---|---|---|
| WP Large Cap Income Plus Fund | 9.32% | 8.10% | 6.81% |
| Dow Jones Industrial Average Index |
| Net Assets ($) | $24,760,367 |
|---|---|
| Number of Portfolio Holdings | |
| Portfolio Turnover Rate (%) | 4% |
| Total Advisory Fees Paid ($) | $317,417 |
| Apple Inc. | |
| Microsoft Corporation | |
| JPMorgan Chase & Co. | |
| Bank of America Corporation | |
| Wells Fargo & Company | |
| Mitsubishi UFJ Financial Group, Inc. - ADR | |
| ImmunityBio, Inc. | |
| Berkshire Hathaway Inc. - Class B | |
| Exxon Mobil Corporation | |
| UBS Group AG (Switzerland) |
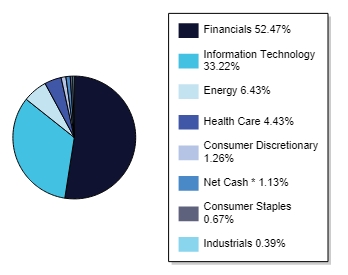
* | Net Assets represents cash, cash equivalents and liabilities, including options written, in excess of other assets. |
| Apple Inc. | |
| Microsoft Corporation | |
| JPMorgan Chase & Co. | |
| Bank of America Corporation | |
| Wells Fargo & Company | |
| Mitsubishi UFJ Financial Group, Inc. - ADR | |
| ImmunityBio, Inc. | |
| Berkshire Hathaway Inc. - Class B | |
| Exxon Mobil Corporation | |
| UBS Group AG (Switzerland) |