ASX:ELV • NASDAQ:ELVR Elevra Lithium FY26 Half Year Results 25 FEBRUARY 2026
Agenda ELEVRA LITHIUM 2 01 FY26 Half Year Highlights 02 Operational Performance 03 Merger Update 04 Financial Performance 05 Lithium
Market and Guidance
01FY26 Half Year Highlights
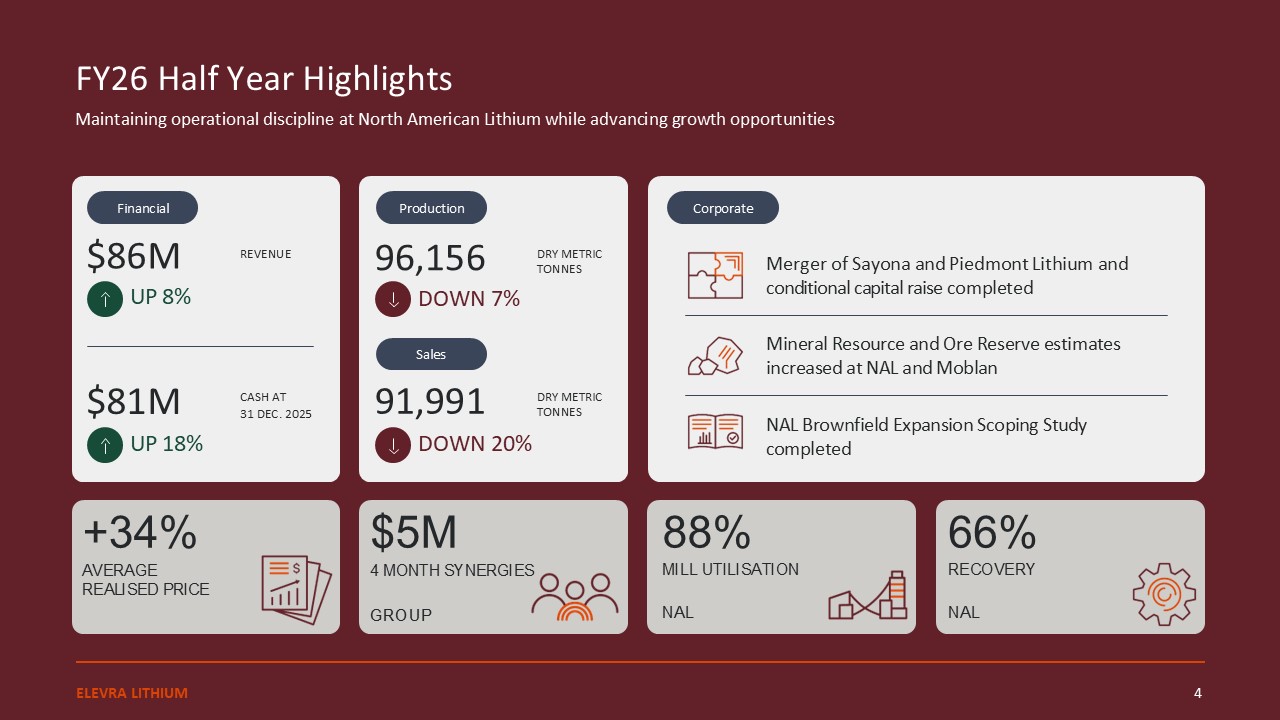
FY26 Half Year Highlights Maintaining operational discipline at North American Lithium while advancing growth opportunities ELEVRA
LITHIUM 4 Production Sales DRY METRIC TONNES DRY METRIC TONNES 96,156 DOWN 7% 91,991 DOWN 20% Corporate Merger of Sayona and Piedmont Lithium and conditional capital raise completed Mineral Resource and Ore Reserve estimates
increased at NAL and Moblan +34% AVERAGE REALISED PRICE 88% MILL UTILISATION NAL 66% RECOVERY NAL $5M 4 MONTH SYNERGIES GROUP Financial REVENUE CASH AT 31 DEC. 2025 $86M UP 8% $81M UP 18% NAL Brownfield Expansion Scoping
Study completed
02Operational Performance
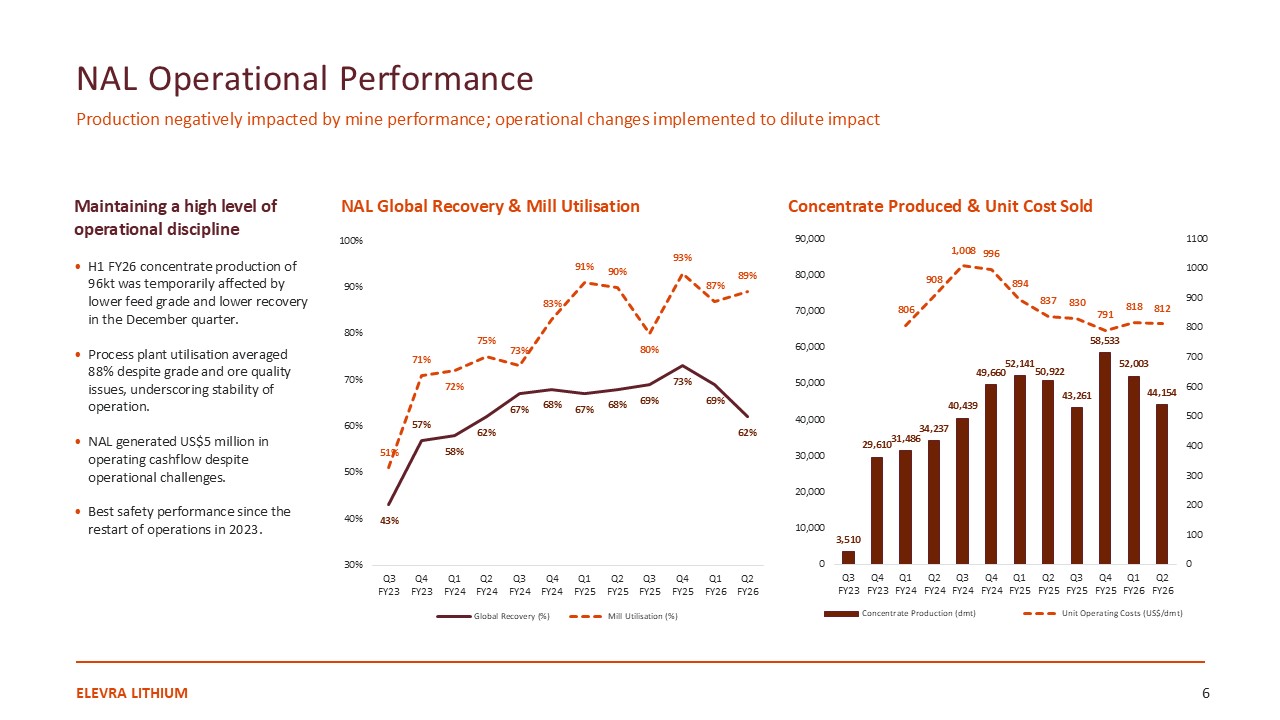
NAL Operational Performance Production negatively impacted by mine performance; operational changes implemented to dilute impact ELEVRA
LITHIUM 6 NAL Global Recovery & Mill Utilisation Concentrate Produced & Unit Cost Sold Maintaining a high level of operational discipline H1 FY26 concentrate production of 96kt was temporarily affected by lower feed grade and lower
recovery in the December quarter. Process plant utilisation averaged 88% despite grade and ore quality issues, underscoring stability of operation. NAL generated US$5 million in operating cashflow despite operational challenges. Best safety
performance since the restart of operations in 2023.
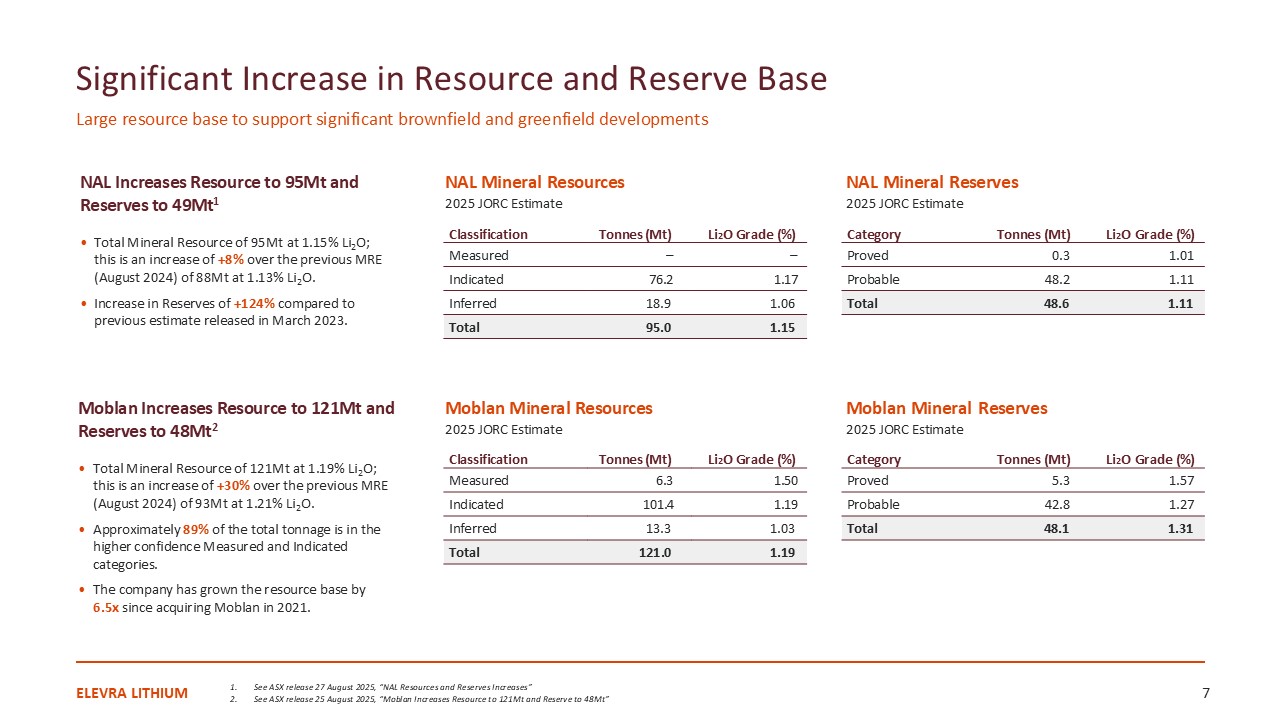
Significant Increase in Resource and Reserve Base Large resource base to support significant brownfield and greenfield developments ELEVRA
LITHIUM 7 NAL Increases Resource to 95Mt and Reserves to 49Mt1 Total Mineral Resource of 95Mt at 1.15% Li2O; this is an increase of +8% over the previous MRE (August 2024) of 88Mt at 1.13% Li2O. Increase in Reserves of +124% compared to
previous estimate released in March 2023. NAL Mineral Resources 2025 JORC Estimate Moblan Mineral Resources 2025 JORC Estimate Classification Tonnes (Mt) Li2O Grade
(%) Measured – – Indicated 76.2 1.17 Inferred 18.9 1.06 Total 95.0 1.15 Category Tonnes (Mt) Li2O Grade (%) Proved 0.3 1.01 Probable 48.2 1.11 Total 48.6 1.11 NAL Mineral Reserves 2025 JORC Estimate Moblan Mineral
Reserves 2025 JORC Estimate Classification Tonnes (Mt) Li2O Grade (%) Measured 6.3 1.50 Indicated 101.4 1.19 Inferred 13.3 1.03 Total 121.0 1.19 Category Tonnes (Mt) Li2O Grade
(%) Proved 5.3 1.57 Probable 42.8 1.27 Total 48.1 1.31 Moblan Increases Resource to 121Mt and Reserves to 48Mt2 Total Mineral Resource of 121Mt at 1.19% Li2O; this is an increase of +30% over the previous MRE (August 2024) of 93Mt at
1.21% Li2O. Approximately 89% of the total tonnage is in the higher confidence Measured and Indicated categories. The company has grown the resource base by 6.5x since acquiring Moblan in 2021. See ASX release 27 August 2025, “NAL Resources
and Reserves Increases” See ASX release 25 August 2025, “Moblan Increases Resource to 121Mt and Reserve to 48Mt”
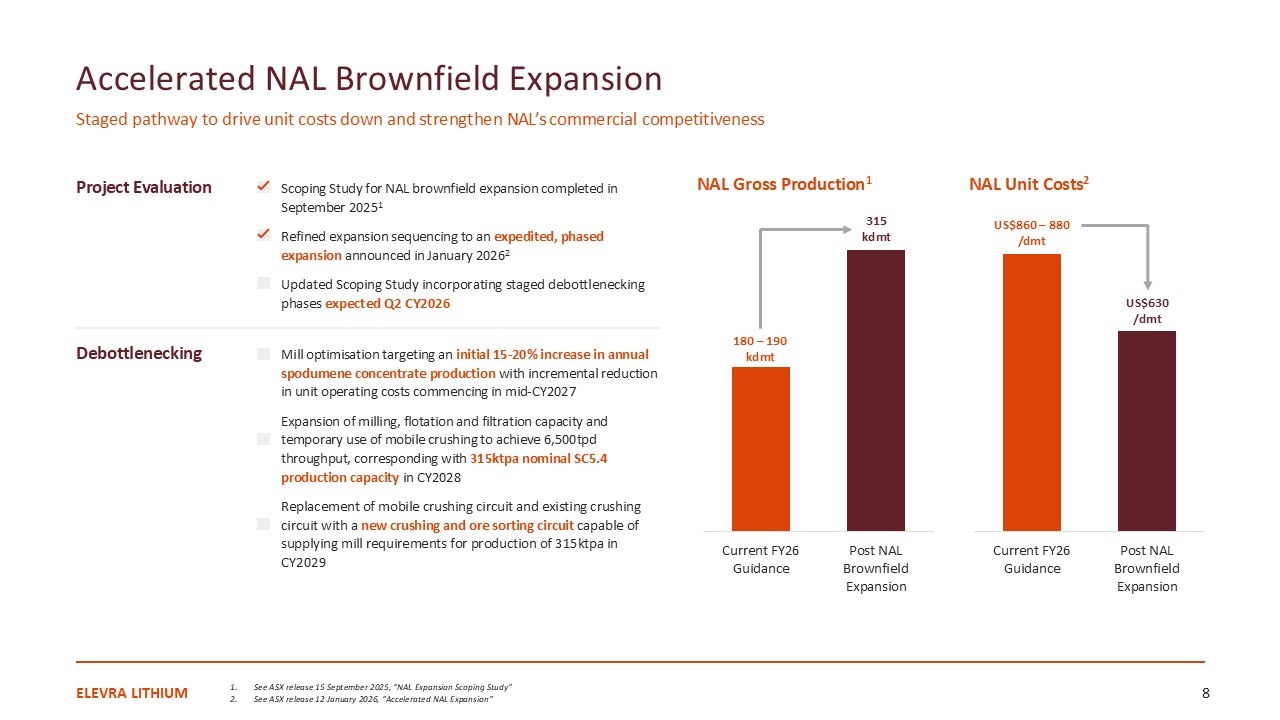
Accelerated NAL Brownfield Expansion Staged pathway to drive unit costs down and strengthen NAL’s commercial competitiveness ELEVRA LITHIUM 8 See
ASX release 15 September 2025, “NAL Expansion Scoping Study” See ASX release 12 January 2026, “Accelerated NAL Expansion” Project Evaluation Debottlenecking Scoping Study for NAL brownfield expansion completed in September 20251 Refined
expansion sequencing to an expedited, phased expansion announced in January 20262 Updated Scoping Study incorporating staged debottlenecking phases expected Q2 CY2026 Mill optimisation targeting an initial 15-20% increase in annual spodumene
concentrate production with incremental reduction in unit operating costs commencing in mid-CY2027 Expansion of milling, flotation and filtration capacity and temporary use of mobile crushing to achieve 6,500tpd throughput, corresponding with
315ktpa nominal SC5.4 production capacity in CY2028 Replacement of mobile crushing circuit and existing crushing circuit with a new crushing and ore sorting circuit capable of supplying mill requirements for production of 315ktpa in
CY2029 NAL Gross Production1 180 – 190 kdmt 315 kdmt NAL Unit Costs2 US$860 – 880 /dmt US$630 /dmt
03Merger Update
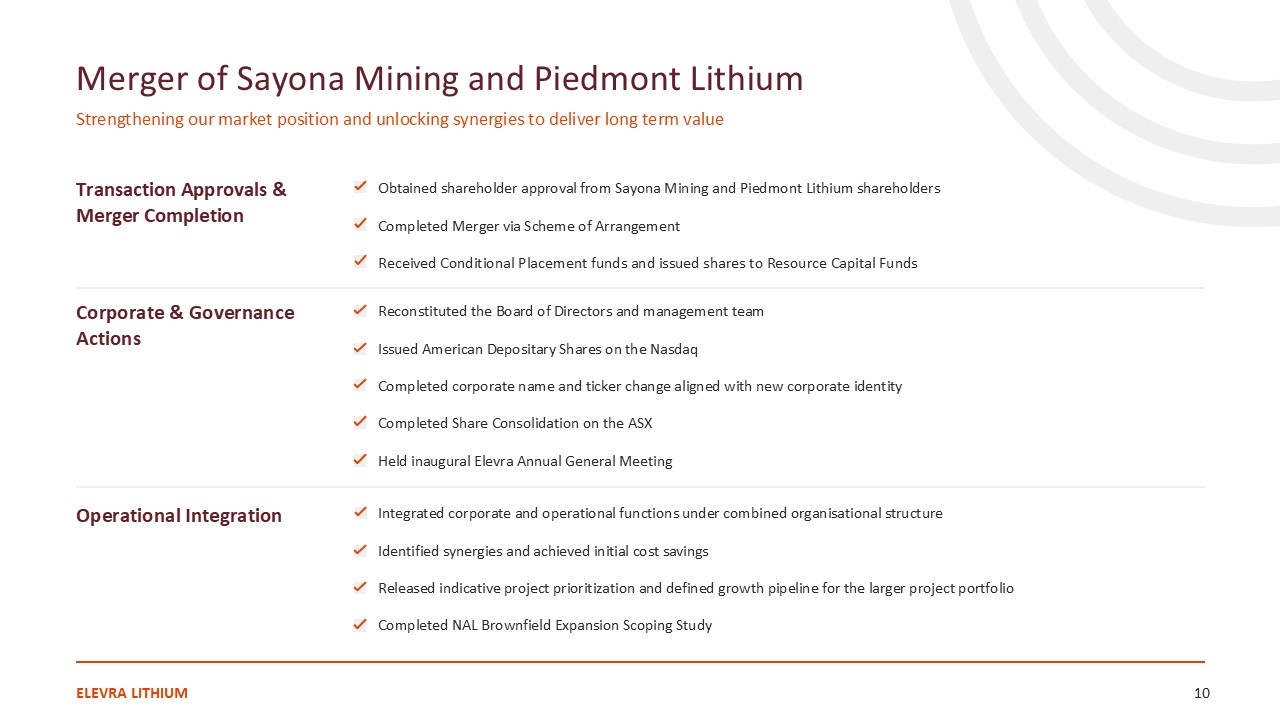
Merger of Sayona Mining and Piedmont Lithium Strengthening our market position and unlocking synergies to deliver long term value ELEVRA
LITHIUM 10 Transaction Approvals & Merger Completion Corporate & Governance Actions Obtained shareholder approval from Sayona Mining and Piedmont Lithium shareholders Completed Merger via Scheme of Arrangement Received Conditional
Placement funds and issued shares to Resource Capital Funds Reconstituted the Board of Directors and management team Issued American Depositary Shares on the Nasdaq Completed corporate name and ticker change aligned with new corporate
identity Completed Share Consolidation on the ASX Held inaugural Elevra Annual General Meeting Operational Integration Integrated corporate and operational functions under combined organisational structure Identified synergies and achieved
initial cost savings Released indicative project prioritization and defined growth pipeline for the larger project portfolio Completed NAL Brownfield Expansion Scoping Study
04Financial Performance
ELEVRA LITHIUM 12 Operational and Financial Overview Merger completion and improved pricing delivered positive financial performance, offsetting
temporary operational challenges All figures are reported in 100% terms and USD unless noted otherwise. Numbers presented may not add up precisely to the totals provided due to rounding. Average realised sales price is calculated on an
accruals basis and reported in $/dmt sold, FOB Port of Québec. Unit operating cost produced is calculated on an accruals basis and includes mining, processing, transport, port charges, site-based general and administration costs, and excludes
inventory movements, depreciation and amortisation charges, freight and royalties. It is reported in $/dmt produced, FOB Port of Québec. Unit operating cost sold is calculated on an accruals basis and includes mining, processing, transport,
port charges, site-based general and administration costs and cash based inventory movements, and excludes depreciation and amortisation charges, freight and royalties. It is reported in $/dmt sold, FOB Port of Québec. UOM1 H1 FY26 H1
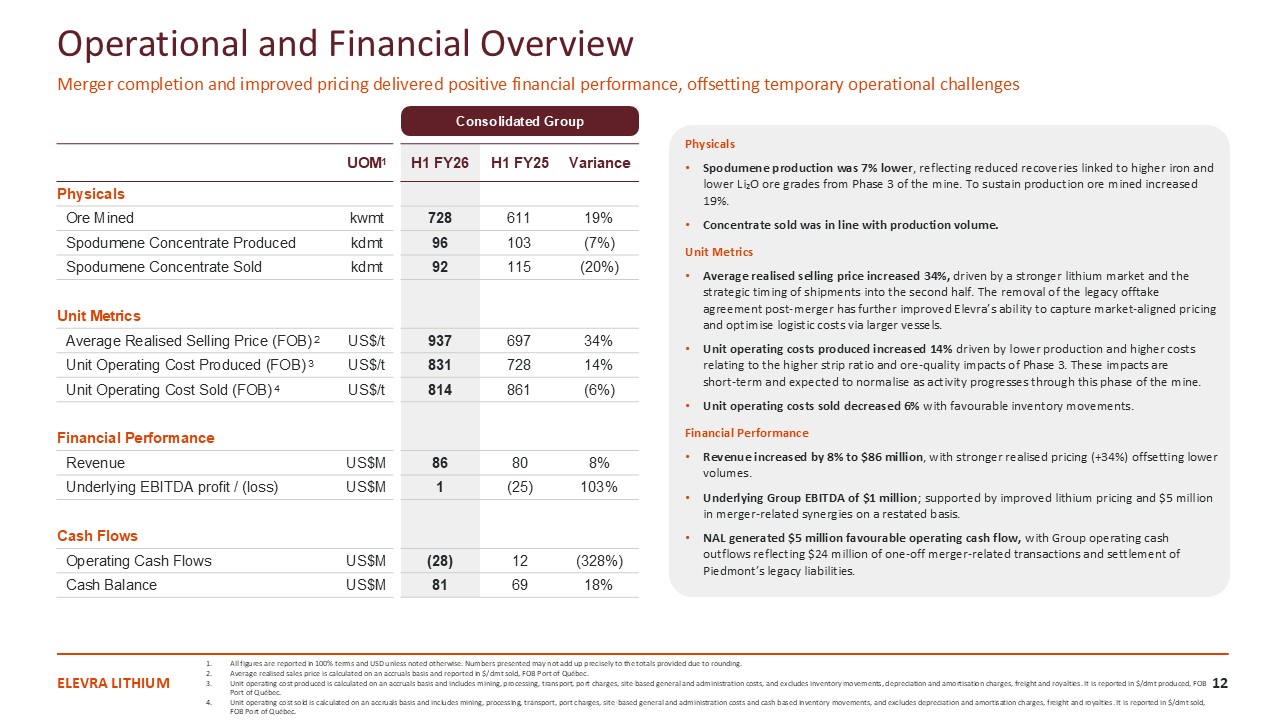
FY25 Variance Physicals Ore Mined kwmt 728 611 19% Spodumene Concentrate Produced kdmt 96 103 (7%) Spodumene Concentrate Sold kdmt 92 115 (20%) Unit Metrics Average Realised Selling Price (FOB) 2 US$/t 937 697 34% Unit
Operating Cost Produced (FOB) 3 US$/t 831 728 14% Unit Operating Cost Sold (FOB) 4 US$/t 814 861 (6%) Financial Performance Revenue US$M 86 80 8% Underlying EBITDA profit / (loss) US$M 1 (25) 103% Cash Flows Operating Cash
Flows US$M (28) 12 (328%) Cash Balance US$M 81 69 18% Physicals Spodumene production was 7% lower, reflecting reduced recoveries linked to higher iron and lower Li₂O ore grades from Phase 3 of the mine. To sustain production ore
mined increased 19%. Concentrate sold was in line with production volume. Unit Metrics Average realised selling price increased 34%, driven by a stronger lithium market and the strategic timing of shipments into the second half. The removal
of the legacy offtake agreement post‑merger has further improved Elevra’s ability to capture market‑aligned pricing and optimise logistic costs via larger vessels. Unit operating costs produced increased 14% driven by lower production and
higher costs relating to the higher strip ratio and ore‑quality impacts of Phase 3. These impacts are short‑term and expected to normalise as activity progresses through this phase of the mine. Unit operating costs sold decreased 6% with
favourable inventory movements. Financial Performance Revenue increased by 8% to $86 million, with stronger realised pricing (+34%) offsetting lower volumes. Underlying Group EBITDA of $1 million; supported by improved lithium pricing and
$5 million in merger‑related synergies on a restated basis. NAL generated $5 million favourable operating cash flow, with Group operating cash outflows reflecting $24 million of one-off merger‑related transactions and settlement of Piedmont’s
legacy liabilities. Consolidated Group
ELEVRA LITHIUM 13 Financial Performance NAL delivered record profit, while corporate costs were contained through early synergies All figures are
reported in 100% terms and USD unless noted otherwise. Numbers presented may not add up precisely to the totals provided due to rounding. Underlying Depreciation and Amortisation includes depreciation and amortisation and non-cash inventory
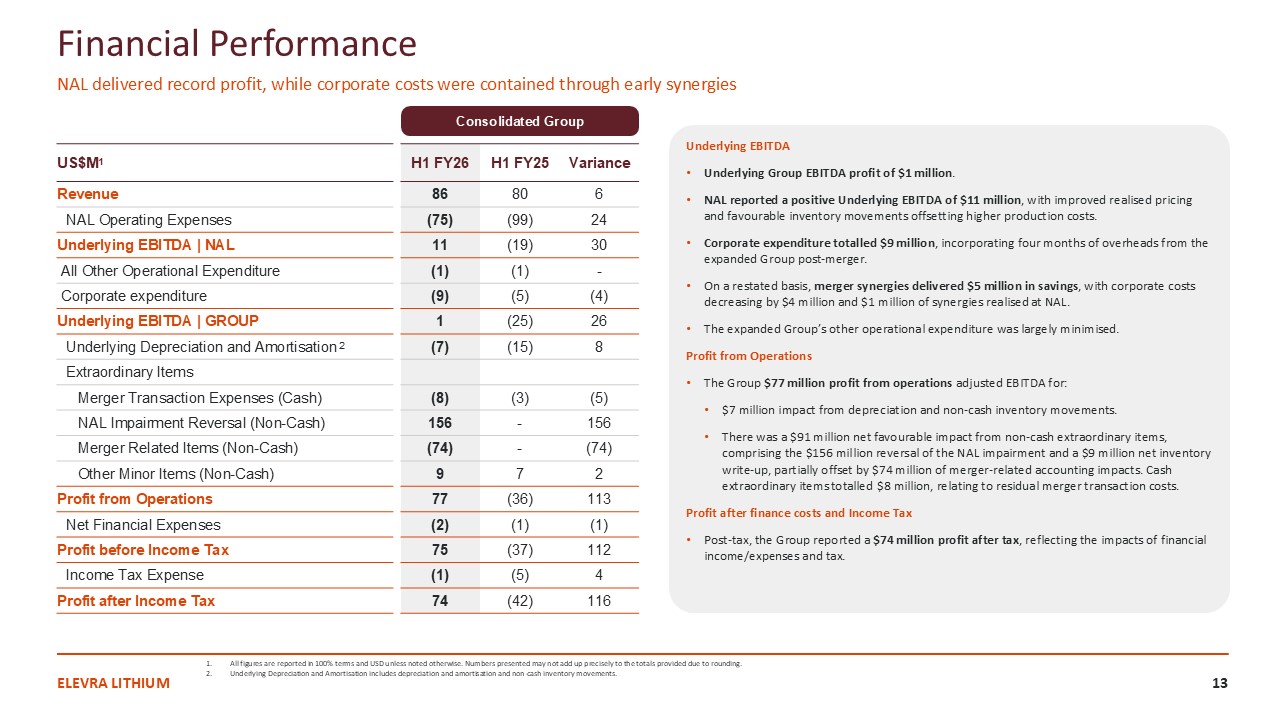
movements. US$M1 H1 FY26 H1 FY25 Variance Revenue 86 80 6 NAL Operating Expenses (75) (99) 24 Underlying EBITDA | NAL 11 (19) 30 All Other Operational Expenditure (1) (1) - Corporate expenditure (9) (5) (4) Underlying
EBITDA | GROUP 1 (25) 26 Underlying Depreciation and Amortisation 2 (7) (15) 8 Extraordinary Items Merger Transaction Expenses (Cash) (8) (3) (5) NAL Impairment Reversal (Non-Cash) 156 - 156 Merger Related
Items (Non-Cash) (74) - (74) Other Minor Items (Non-Cash) 9 7 2 Profit from Operations 77 (36) 113 Net Financial Expenses (2) (1) (1) Profit before Income Tax 75 (37) 112 Income Tax Expense (1) (5) 4 Profit after Income
Tax 74 (42) 116 Underlying EBITDA Underlying Group EBITDA profit of $1 million. NAL reported a positive Underlying EBITDA of $11 million, with improved realised pricing and favourable inventory movements offsetting higher production
costs. Corporate expenditure totalled $9 million, incorporating four months of overheads from the expanded Group post-merger. On a restated basis, merger synergies delivered $5 million in savings, with corporate costs decreasing by $4
million and $1 million of synergies realised at NAL. The expanded Group’s other operational expenditure was largely minimised. Profit from Operations The Group $77 million profit from operations adjusted EBITDA for: $7 million impact from
depreciation and non‑cash inventory movements. There was a $91 million net favourable impact from non‑cash extraordinary items, comprising the $156 million reversal of the NAL impairment and a $9 million net inventory write‑up, partially
offset by $74 million of merger‑related accounting impacts. Cash extraordinary items totalled $8 million, relating to residual merger transaction costs. Profit after finance costs and Income Tax Post‑tax, the Group reported a $74 million
profit after tax, reflecting the impacts of financial income/expenses and tax. Consolidated Group
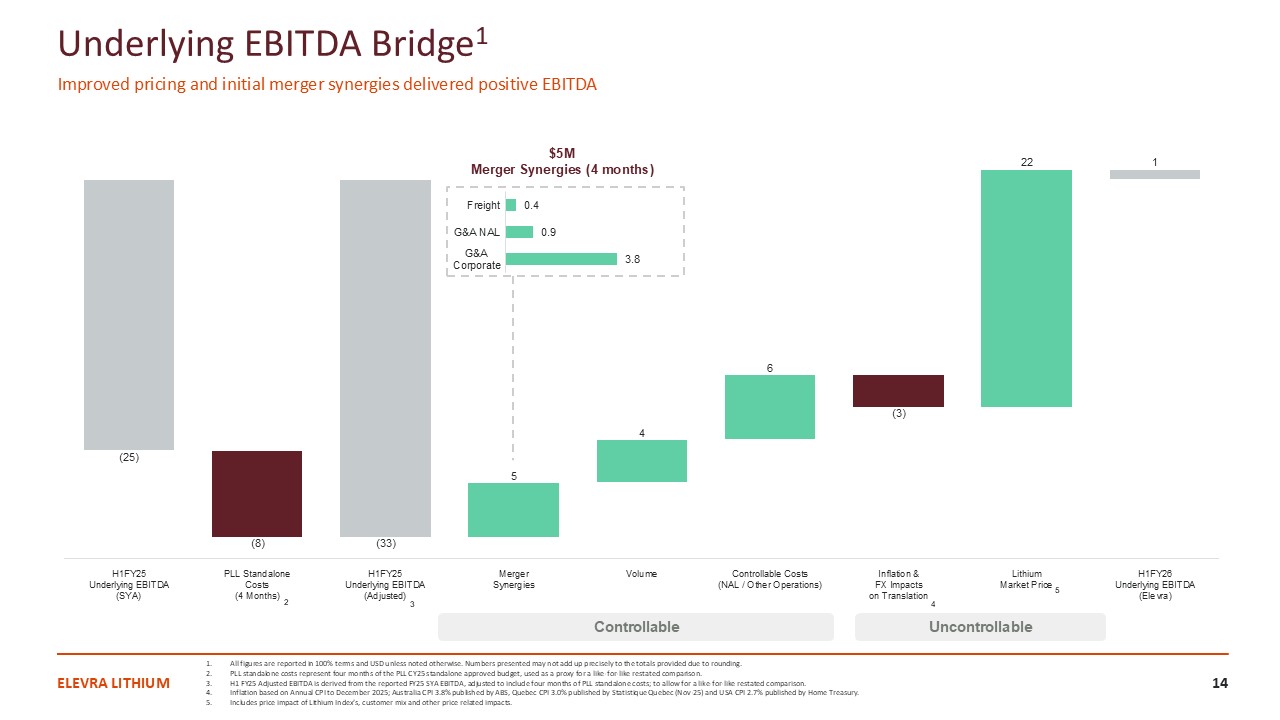
ELEVRA LITHIUM 14 Underlying EBITDA Bridge1 Improved pricing and initial merger synergies delivered positive EBITDA All figures are reported in
100% terms and USD unless noted otherwise. Numbers presented may not add up precisely to the totals provided due to rounding. PLL standalone costs represent four months of the PLL CY25 standalone approved budget, used as a proxy for a
like‑for‑like restated comparison. H1 FY25 Adjusted EBITDA is derived from the reported FY25 SYA EBITDA, adjusted to include four months of PLL standalone costs; to allow for a like‑for‑like restated comparison. Inflation based on Annual CPI
to December 2025; Australia CPI 3.8% published by ABS, Quebec CPI 3.0% published by Statistique Quebec (Nov-25) and USA CPI 2.7% published by Home Treasury. Includes price impact of Lithium Index’s, customer mix and other price related
impacts. $5M Merger Synergies (4 months) 4 5 3 2 Controllable Uncontrollable
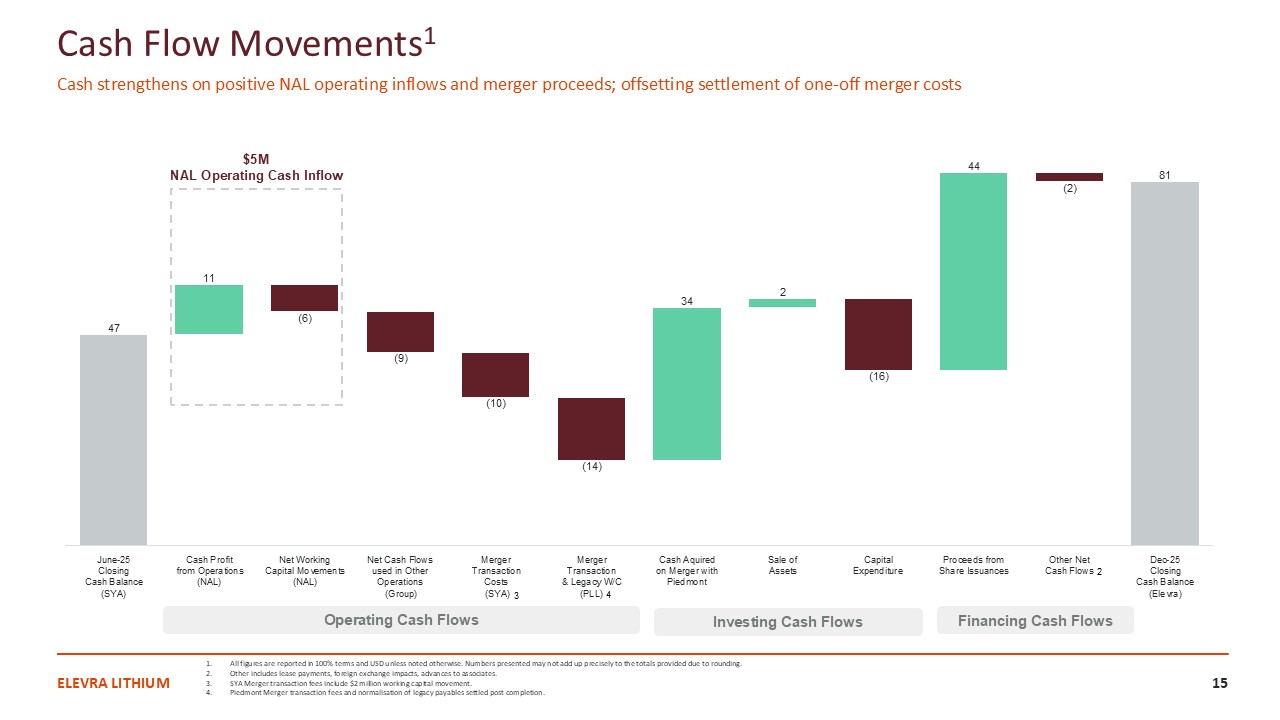
ELEVRA LITHIUM 15 Cash strengthens on positive NAL operating inflows and merger proceeds; offsetting settlement of one‑off merger costs All
figures are reported in 100% terms and USD unless noted otherwise. Numbers presented may not add up precisely to the totals provided due to rounding. Other includes lease payments, foreign exchange impacts, advances to associates. SYA Merger
transaction fees include $2 million working capital movement. Piedmont Merger transaction fees and normalisation of legacy payables settled post completion. Cash Flow Movements1 3 Operating Cash Flows Investing Cash Flows Financing Cash
Flows 4 $5M NAL Operating Cash Inflow 2
ELEVRA LITHIUM 16 Financial Position Stronger balance sheet post merger with wider portfolio and reversal of impairment at NAL All figures are
reported in 100% terms and USD unless noted otherwise. Numbers presented may not add up precisely to the totals provided due to rounding. Interest bearing liabilities include non-convertible redeemable cumulative preference shares, contract
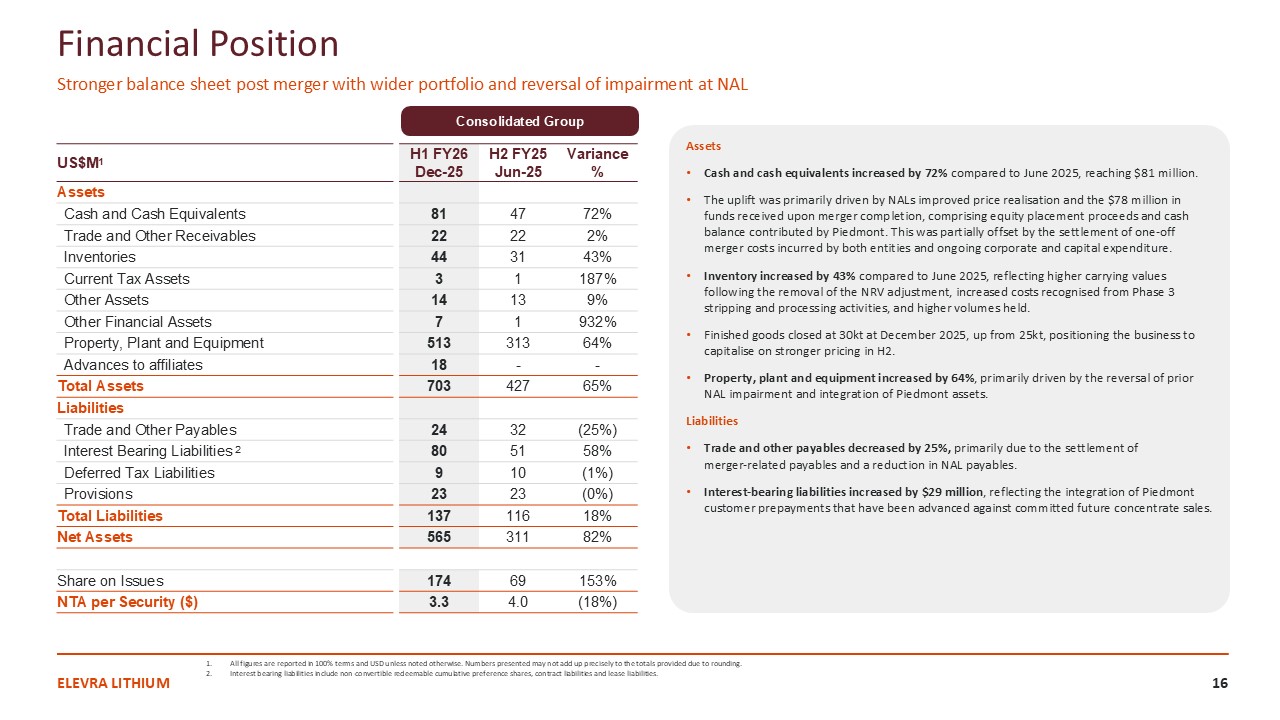
liabilities and lease liabilities. Assets Cash and cash equivalents increased by 72% compared to June 2025, reaching $81 million. The uplift was primarily driven by NALs improved price realisation and the $78 million in funds received upon
merger completion, comprising equity placement proceeds and cash balance contributed by Piedmont. This was partially offset by the settlement of one‑off merger costs incurred by both entities and ongoing corporate and capital
expenditure. Inventory increased by 43% compared to June 2025, reflecting higher carrying values following the removal of the NRV adjustment, increased costs recognised from Phase 3 stripping and processing activities, and higher volumes
held. Finished goods closed at 30kt at December 2025, up from 25kt, positioning the business to capitalise on stronger pricing in H2. Property, plant and equipment increased by 64%, primarily driven by the reversal of prior NAL impairment and
integration of Piedmont assets. Liabilities Trade and other payables decreased by 25%, primarily due to the settlement of merger‑related payables and a reduction in NAL payables. Interest‑bearing liabilities increased by $29 million,
reflecting the integration of Piedmont customer prepayments that have been advanced against committed future concentrate sales. US$M1 H1 FY26 Dec-25 H2 FY25 Jun-25 Variance % Assets Cash and Cash Equivalents 81 47 72% Trade and
Other Receivables 22 22 2% Inventories 44 31 43% Current Tax Assets 3 1 187% Other Assets 14 13 9% Other Financial Assets 7 1 932% Property, Plant and Equipment 513 313 64% Advances to affiliates 18 - - Total
Assets 703 427 65% Liabilities Trade and Other Payables 24 32 (25%) Interest Bearing Liabilities 2 80 51 58% Deferred Tax Liabilities 9 10 (1%) Provisions 23 23 (0%) Total Liabilities 137 116 18% Net
Assets 565 311 82% Share on Issues 174 69 153% NTA per Security ($) 3.3 4.0 (18%) Consolidated Group
05Lithium Market and Guidance
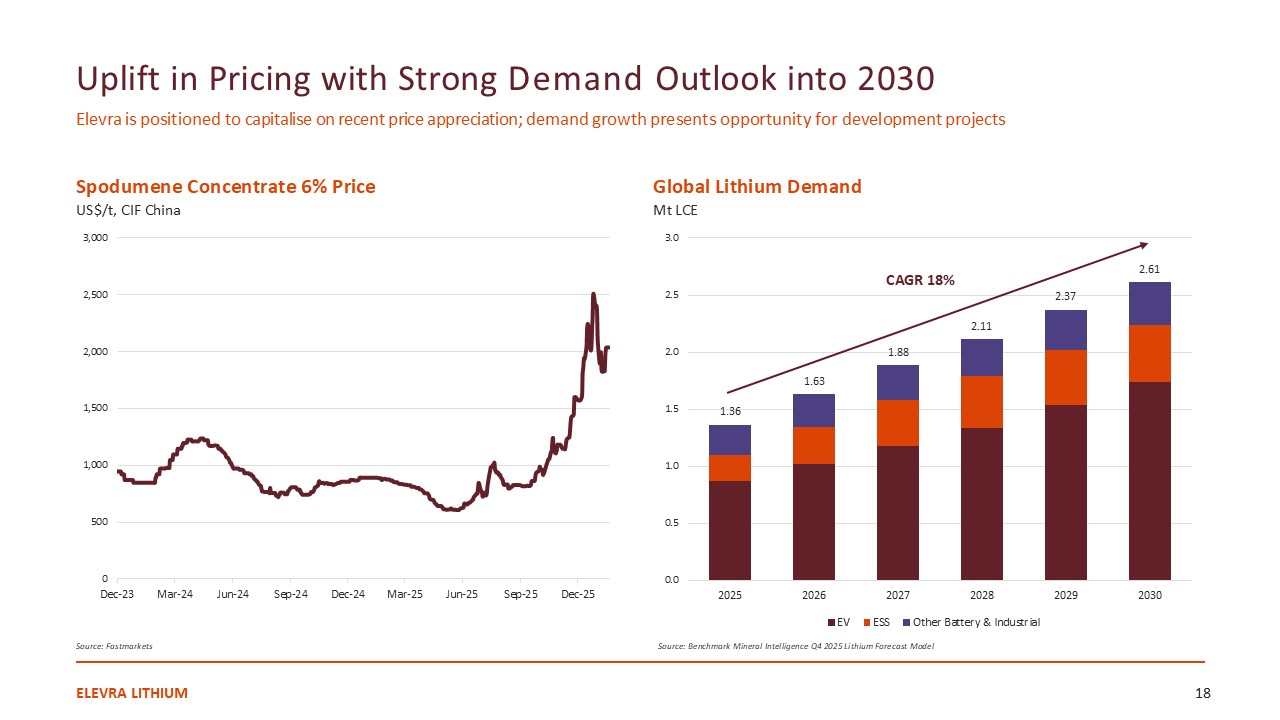
Uplift in Pricing with Strong Demand Outlook into 2030 Elevra is positioned to capitalise on recent price appreciation; demand growth presents
opportunity for development projects Spodumene Concentrate 6% Price US$/t, CIF China Global Lithium Demand Mt LCE ELEVRA LITHIUM 18 Source: Benchmark Mineral Intelligence Q4 2025 Lithium Forecast Model CAGR 18% Source: Fastmarkets
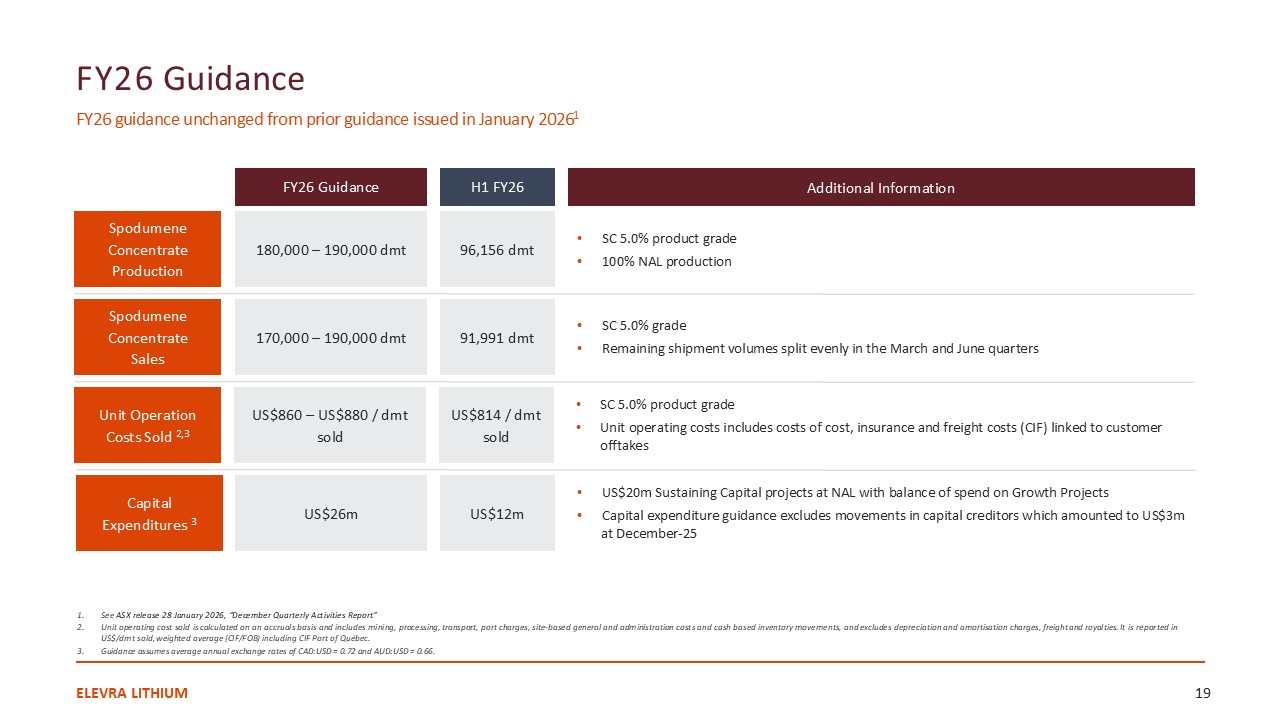
FY26 Guidance FY26 guidance unchanged from prior guidance issued in January 20261 See ASX release 28 January 2026, “December Quarterly Activities
Report” Unit operating cost sold is calculated on an accruals basis and includes mining, processing, transport, port charges, site-based general and administration costs and cash based inventory movements, and excludes depreciation and
amortisation charges, freight and royalties. It is reported in US$/dmt sold, weighted average (CIF/FOB) including CIF Port of Québec. Guidance assumes average annual exchange rates of CAD:USD = 0.72 and AUD:USD = 0.66. ELEVRA
LITHIUM 19 Spodumene Concentrate Production Spodumene Concentrate Sales Unit Operation Costs Sold 2,3 SC 5.0% product grade 100% NAL production SC 5.0% grade Remaining shipment volumes split evenly in the March and June quarters SC
5.0% product grade Unit operating costs includes costs of cost, insurance and freight costs (CIF) linked to customer offtakes 180,000 – 190,000 dmt Additional Information FY26 Guidance Capital Expenditures 3 US$20m Sustaining Capital
projects at NAL with balance of spend on Growth Projects Capital expenditure guidance excludes movements in capital creditors which amounted to US$3m at December-25 170,000 – 190,000 dmt US$860 – US$880 / dmt sold US$26m 96,156 dmt H1
FY26 91,991 dmt US$814 / dmt sold US$12m
Appendix
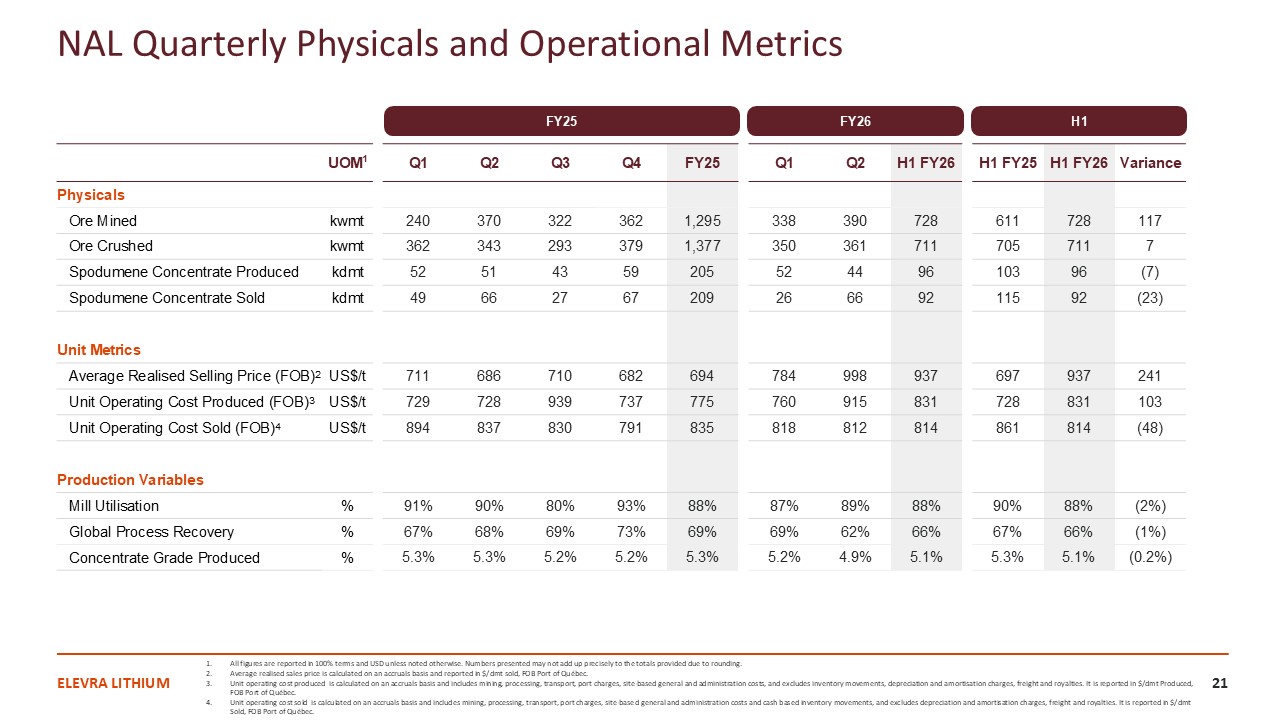
ELEVRA LITHIUM 21 NAL Quarterly Physicals and Operational Metrics All figures are reported in 100% terms and USD unless noted otherwise. Numbers
presented may not add up precisely to the totals provided due to rounding. Average realised sales price is calculated on an accruals basis and reported in $/dmt sold, FOB Port of Québec. Unit operating cost produced is calculated on an
accruals basis and includes mining, processing, transport, port charges, site-based general and administration costs, and excludes inventory movements, depreciation and amortisation charges, freight and royalties. It is reported in $/dmt
Produced, FOB Port of Québec. Unit operating cost sold is calculated on an accruals basis and includes mining, processing, transport, port charges, site-based general and administration costs and cash based inventory movements, and excludes
depreciation and amortisation charges, freight and royalties. It is reported in $/dmt Sold, FOB Port of Québec. FY25 FY26 H1 UOM1 Q1 Q2 Q3 Q4 FY25 Q1 Q2 H1 FY26 H1 FY25 H1 FY26 Variance Physicals Ore
Mined kwmt 240 370 322 362 1,295 338 390 728 611 728 117 Ore Crushed kwmt 362 343 293 379 1,377 350 361 711 705 711 7 Spodumene Concentrate Produced kdmt 52 51 43 59 205 52 44 96 103 96 (7) Spodumene
Concentrate Sold kdmt 49 66 27 67 209 26 66 92 115 92 (23) Unit Metrics Average Realised Selling Price (FOB)2 US$/t 711 686 710 682 694 784 998 937 697 937 241 Unit Operating Cost Produced
(FOB)3 US$/t 729 728 939 737 775 760 915 831 728 831 103 Unit Operating Cost Sold (FOB)4 US$/t 894 837 830 791 835 818 812 814 861 814 (48) Production Variables Mill
Utilisation % 91% 90% 80% 93% 88% 87% 89% 88% 90% 88% (2%) Global Process Recovery % 67% 68% 69% 73% 69% 69% 62% 66% 67% 66% (1%) Concentrate Grade
Produced % 5.3% 5.3% 5.2% 5.2% 5.3% 5.2% 4.9% 5.1% 5.3% 5.1% (0.2%)
ELEVRA LITHIUM 22 NAL Operating Costs NAL operating costs temporarily impacted by reduced lower production and the phase 3 ore profile All
figures are reported in 100% terms and USD unless noted otherwise. Numbers presented may not add up precisely to the totals provided due to rounding. Unit operating cost produced is calculated on an accruals basis and includes mining,
processing, transport, port charges, site-based general and administration costs, and excludes inventory movements, depreciation and amortisation charges, freight and royalties. It is reported in $/dmt produced, FOB Port of Québec. Unit
operating cost sold is calculated on an accruals basis and includes mining, processing, transport, port charges, site-based general and administration costs and cash based inventory movements, and excludes depreciation and amortisation charges,
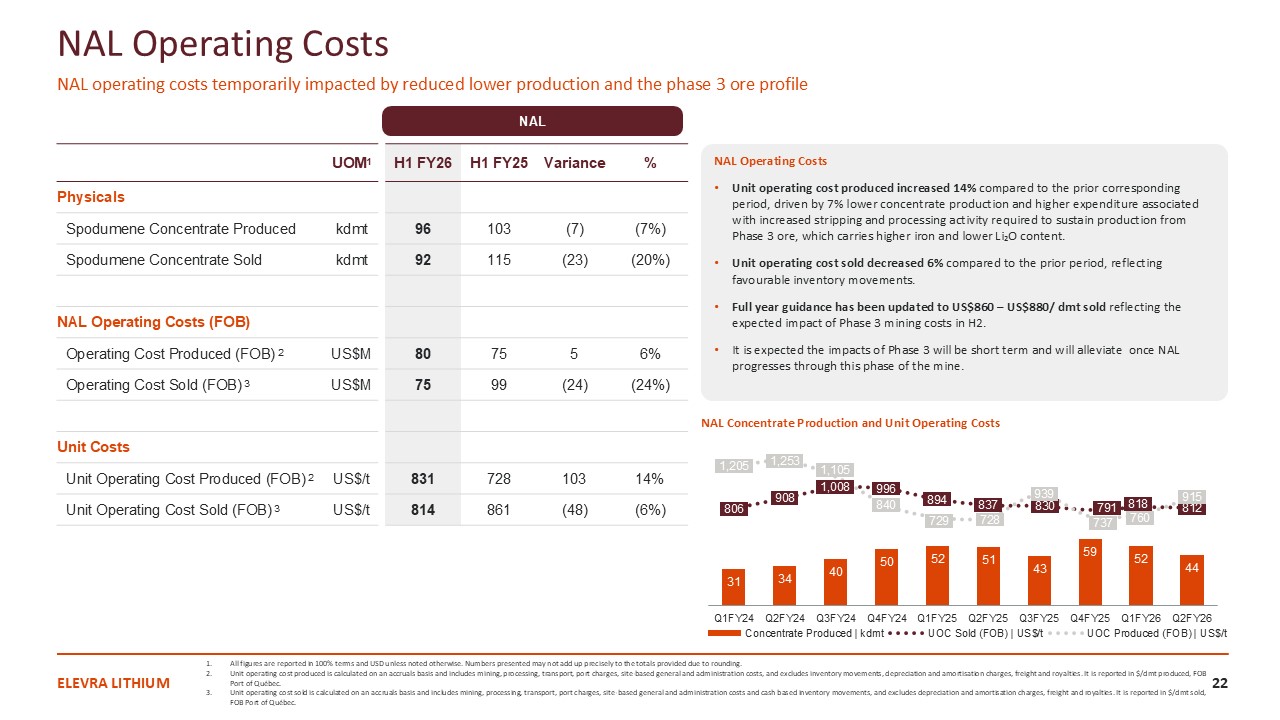
freight and royalties. It is reported in $/dmt sold, FOB Port of Québec. NAL UOM1 H1 FY26 H1 FY25 Variance % Physicals Spodumene Concentrate Produced kdmt 96 103 (7) (7%) Spodumene Concentrate
Sold kdmt 92 115 (23) (20%) NAL Operating Costs (FOB) Operating Cost Produced (FOB) 2 US$M 80 75 5 6% Operating Cost Sold (FOB) 3 US$M 75 99 (24) (24%) Unit Costs Unit Operating Cost Produced (FOB)
2 US$/t 831 728 103 14% Unit Operating Cost Sold (FOB) 3 US$/t 814 861 (48) (6%) NAL Operating Costs Unit operating cost produced increased 14% compared to the prior corresponding period, driven by 7% lower concentrate production
and higher expenditure associated with increased stripping and processing activity required to sustain production from Phase 3 ore, which carries higher iron and lower Li₂O content. Unit operating cost sold decreased 6% compared to the prior
period, reflecting favourable inventory movements. Full year guidance has been updated to US$860 – US$880/ dmt sold reflecting the expected impact of Phase 3 mining costs in H2. It is expected the impacts of Phase 3 will be short term and
will alleviate once NAL progresses through this phase of the mine. NAL Concentrate Production and Unit Operating Costs
ELEVRA LITHIUM 23 Underlying EBITDA Reconciliation All figures are reported in 100% terms and USD unless noted otherwise. Numbers presented may
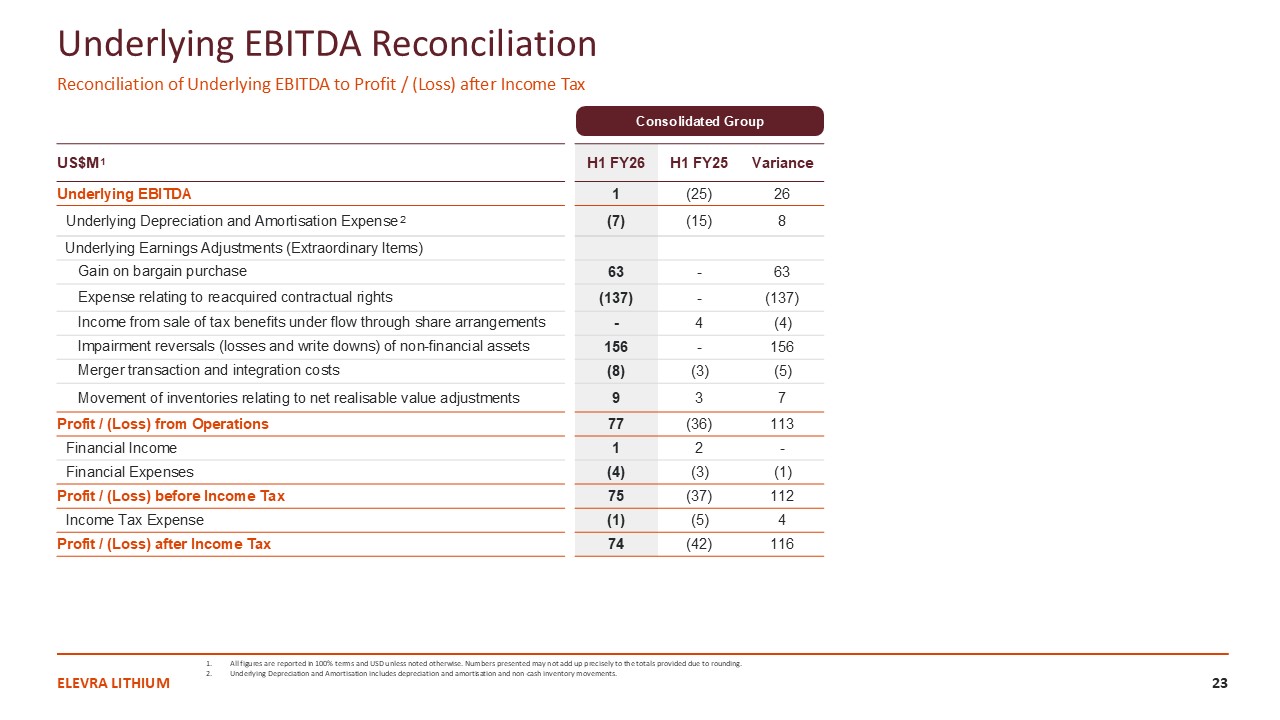
not add up precisely to the totals provided due to rounding. Underlying Depreciation and Amortisation includes depreciation and amortisation and non-cash inventory movements. US$M 1 H1 FY26 H1 FY25 Variance Underlying
EBITDA 1 (25) 26 Underlying Depreciation and Amortisation Expense 2 (7) (15) 8 Underlying Earnings Adjustments (Extraordinary Items) Gain on bargain purchase 63 - 63 Expense relating to reacquired contractual
rights (137) - (137) Income from sale of tax benefits under flow through share arrangements - 4 (4) Impairment reversals (losses and write downs) of non-financial assets 156 - 156 Merger transaction and integration
costs (8) (3) (5) Movement of inventories relating to net realisable value adjustments 9 3 7 Profit / (Loss) from Operations 77 (36) 113 Financial Income 1 2 - Financial Expenses (4) (3) (1) Profit / (Loss) before Income
Tax 75 (37) 112 Income Tax Expense (1) (5) 4 Profit / (Loss) after Income Tax 74 (42) 116 Consolidated Group Reconciliation of Underlying EBITDA to Profit / (Loss) after Income Tax
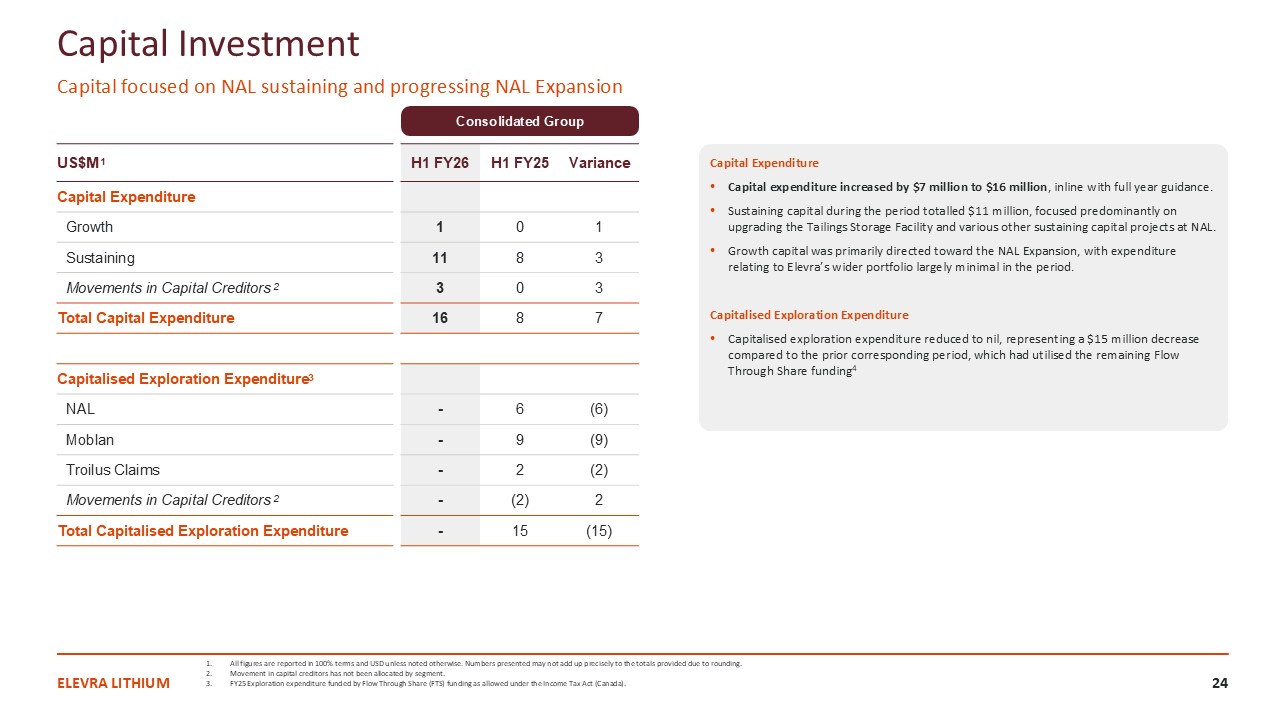
ELEVRA LITHIUM 24 Capital Investment Capital focused on NAL sustaining and progressing NAL Expansion Capital Expenditure Capital expenditure
increased by $7 million to $16 million, inline with full year guidance. Sustaining capital during the period totalled $11 million, focused predominantly on upgrading the Tailings Storage Facility and various other sustaining capital projects
at NAL. Growth capital was primarily directed toward the NAL Expansion, with expenditure relating to Elevra’s wider portfolio largely minimal in the period. Capitalised Exploration Expenditure Capitalised exploration expenditure reduced to
nil, representing a $15 million decrease compared to the prior corresponding period, which had utilised the remaining Flow Through Share funding4 All figures are reported in 100% terms and USD unless noted otherwise. Numbers presented may not
add up precisely to the totals provided due to rounding. Movement in capital creditors has not been allocated by segment. FY25 Exploration expenditure funded by Flow Through Share (FTS) funding as allowed under the Income Tax Act
(Canada). US$M 1 H1 FY26 H1 FY25 Variance Capital Expenditure Growth 1 0 1 Sustaining 11 8 3 Movements in Capital Creditors 2 3 0 3 Total Capital Expenditure 16 8 7 Capitalised Exploration
Expenditure3 NAL - 6 (6) Moblan - 9 (9) Troilus Claims - 2 (2) Movements in Capital Creditors 2 - (2) 2 Total Capitalised Exploration Expenditure - 15 (15) Consolidated Group