Exhibit 99.3
Management’s Discussion and Analysis
Year Ended December 31, 2025
REPORT DATED: March 18, 2026
Management’s Discussion and Analysis
Year Ended December 31, 2025
Dated: March 18, 2026
(in 000’s of Canadian Dollars, unless otherwise noted)
Contents
| 1. | Introduction | 2 |
| 2. | Business Overview | 2 |
| 3. | Recent Developments | 2 |
| 4. | Overall Performance and Discussion of Operations | 5 |
| 5. | Selected Annual Information | 13 |
| 6. | Summary of Quarterly Results | 14 |
| 7. | Outstanding Share Data | 15 |
| 8. | Liquidity and Capital Resources | 20 |
| 9. | Off-Balance Sheet Arrangements | 22 |
| 10. | Related Party Transactions | 22 |
| 11. | Proposed Material Transactions | 23 |
| 12. | Critical Accounting Estimates | 23 |
| 13. | Changes in Accounting Policies | 23 |
| 14. | Financial Instruments and Risk Management | 23 |
| 15. | Disclosure Controls and Procedures and Internal Control of Financial Reporting | 24 |
| 16. | Risks and Uncertainties | 26 |
| 17. | Restoration Provision | 26 |
| 18. | Emerging Market Issuer Disclosure | 27 |
| 19. | Forward-looking Information | 31 |
| 20. | General | 34 |
| 21. | Additional Information | 34 |
| 22. | Management’s Responsibility for Financial Statements | 34 |
| Glossary of Terms | 35 | |
| Page | 1 |
Management’s Discussion and Analysis
Year Ended December 31, 2025
Dated: March 18, 2026
(in 000’s of Canadian Dollars, unless otherwise noted)
| 1. | Introduction |
This management’s discussion and analysis (“MD&A”), dated March 18, 2026, provides a review of, and discusses the financial position and results of operations of, Almonty Industries Inc. (Nasdaq: ALM; TSX: AII; ASX: AII; Frankfurt: ALI1) (“Almonty” or the “Company”) for the three and twelve months ended December 31, 2025. It should be read in conjunction with the audited annual consolidated financial statements of the Company and notes thereto for the year ended December 31, 2025 (the “Annual Financial Statements”).
A glossary of terms is affixed to the last page of this MD&A. Capitalized terms used but not otherwise defined herein have their respective meanings ascribed thereto in the glossary of terms. All currency figures in this MD&A appear in thousands of Canadian dollars, except per common share amounts, unless otherwise stated. All per common share amounts and figures relating to the price and number of common shares reflect the Share Consolidation, as such term is defined in Section 3 of this MD&A.
| 2. | Business Overview |
Almonty is a diversified and experienced global producer of tungsten concentrate. The Company is primarily engaged in the development of the Sangdong tungsten mine project (the “Sangdong Mine”) located in Gangwon Province, the Republic of Korea (“Korea” or “South Korea”), and is currently mining, processing and shipping tungsten concentrate from the Panasqueira tin and tungsten mine in Covilha, Castelo Branco, Portugal (the “Panasqueira Mine”). Additionally, the Company is evaluating its molybdenum project with inferred mineral resources on a separate property adjacent to the tungsten orebody at the Sangdong Mine (the “Sangdong Molybdenum Project”) and its Valtreixal tin and tungsten mine project located in Western Spain in the province of Zamora (the “Valtreixal Mine”). The Company also owns the Los Santos tungsten mine located near Salamanca, Spain (the “Los Santos Mine”), which is currently under care and maintenance, and is evaluating its newly-acquired unpatented tungsten mining claims located in Beaverhead County, Montana in the United States (the “Gentung Tungsten Project”).
| 3. | Recent Developments |
During the year ended December 31, 2025:
| ● | On January 9, 2025, Almonty announced that it received its final drawdown of US$906,000 of the US$75.1 million KfW IPEX-Bank GmbH (“KfW”) project loan facility (the “KfW Facility”) related to the construction of the Sangdong Mine, a milestone that marked the culmination of a strong and collaborative partnership with KfW. | |
| ● | On January 20, 2025, Almonty announced its intention to change its jurisdiction of incorporation from Canada to the State of Delaware (the “U.S. Domestication”) while maintaining its listings for now on the Toronto Stock Exchange and the ASX. The U.S. Domestication reflects the growing importance of the United States in Almonty’s strategic positioning, and with its robust regulatory framework for critical materials like tungsten and molybdenum and the evolving global economic landscape, the United States presents a compelling jurisdiction for Almonty. The U.S. Domestication was approved by Almonty’s shareholders at a special meeting held on February 27, 2025 and remains under consideration as of the date of this MD&A. It is possible that, if the Board of Directors is, among other factors, not satisfied that the U.S. Domestication is in Almonty’s best interest due to anticipated Canadian tax or other consequences, Almonty may not proceed with the U.S. Domestication, |
| Page | 2 |
Management’s Discussion and Analysis
Year Ended December 31, 2025
Dated: March 18, 2026
(in 000’s of Canadian Dollars, unless otherwise noted)
| ● | On January 29, 2025 Almonty announced that it entered into an exclusive offtake agreement with SeAH M&S Corp. (“SeAH”), the largest processor of molybdenum products in South Korea and the second largest molybdenum oxide smelter in the world, pursuant to which SeAH has agreed to purchase 100% of the material produced from the Sangdong Molybdenum Project for life of mine. SeAH is building a US$110 million metals and fabrication facility in Temple, Texas, that is slated to provide fabricated metal products to Space Exploration Technologies Corp. and to the U.S. defense and civilian aerospace sectors. | |
| ● | On March 20, 2025, General Gustave F. Perna (U.S. Army, Retired) was appointed to the Board of Directors. | |
| ● | On May 30, 2025, Mr. Alan Estevez, former United States Under Secretary of Commerce for Industry and Security, was appointed to the Board of Directors. | |
| ● | On June 2, 2025, Almonty announced it had received bipartisan recognition from the U.S. House Select Committee on the Strategic Competition Between the United States and the Chinese Communist Party (the “Committee”). The Committee acknowledged Almonty’s role in supporting U.S. efforts to strengthen domestic supply chains for critical minerals, highlighting the strategic relevance of the Sangdong Mine and the Company’s contemplated U.S. Domestication. The Committee also expressed interest in ongoing engagement and potential collaboration with Almonty to support the U.S. defense industrial base, including supply chain integration with American defense contractors and potential contributions to the U.S. National Defense Stockpile. | |
| ● | On June 30, 2025, Almonty announced that its common shares had been added to the S&P/TSX Global Mining Index, effective as of market open on June 23, 2025. The S&P/TSX Global Mining Index serves as a benchmark for globally traded mining companies. Management believes Almonty’s inclusion in the S&P/TSX Global Mining Index reflects Almonty’s growing profile in the global mining sector and ongoing momentum in the tungsten industry. | |
| ● | On July 3, 2025, Almonty effected a 1.5-to-1 consolidation of its common shares (the “Share Consolidation”) and its common shares commenced trading on a post-consolidated basis on July 7, 2025. | |
| ● | On July 3, 2025, the Company announced that, following a reassessment of its mining portfolio conducted by the Company, the Company concluded that, on the basis of its current strategy, including management’s focus and the deployment of resources on the Sangdong Mine and the expected economic importance to the Company of the expected production at Phase I relative to its other properties, as well as the expected timing and significant potential production increase of Phase II, the Sangdong Mine is the only mineral project on a property that is material to the Company for the purposes of NI 43-101. In connection with the reassessment, the Company voluntarily filed an updated NI 43-101 technical report related to the Sangdong Mine. The technical report is available on SEDAR+ at www.sedarplus.ca under Almonty’s profile. On July 11, 2025 the Company also filed an updated technical report for the Sangdong Mine with the ASX which was prepared in accordance with the Australasian Code for Reporting of Exploration Results, Minerals Resources and Ore Reserves (2012) (the “JORC Code”). There were no material changes between the technical reports filed under NI 43-101 and the JORC Code. |
| Page | 3 |
Management’s Discussion and Analysis
Year Ended December 31, 2025
Dated: March 18, 2026
(in 000’s of Canadian Dollars, unless otherwise noted)
| ● | On July 15, 2025, the Company closed its initial public offering of 20,000,000 common shares in the United States at a price of US$4.50 per common share for gross proceeds of US$90 million, which common shares commenced trading on the Nasdaq on July 14, 2025 under the ticker symbol “ALM” (the “Nasdaq IPO”). The Company intends to use up to approximately 1% of the net proceeds of the offering to fund remaining early-stage development activities for a nano tungsten oxide downstream processing plant in Korea, near the Sangdong Mine (the “Tungsten Oxide Facility”) and up to approximately 84% of the net proceeds of the offering toward the development of the Tungsten Oxide Facility, with the remaining net proceeds to be used primarily for working capital, corporate expenses, business development, potential future acquisitions and other purposes. | |
| ● | On July 29, 2025, Almonty announced the appointment of Mr. Brian Fox, CPA as Chief Financial Officer. | |
| ● | On November 17, 2025, the Company completed a share purchase transaction involving U.S. Tungsten Inc., a U.S.-based privately-owned minerals explorer, to acquire the exclusive right to explore, develop and mine the Gentung Tungsten Project for aggregate consideration of US$9.75 million, payable in US$750 of cash and US$9 million of common shares of Almonty issued at a price per common share determined on the day of signing and converted into U.S. dollars at the noon rate published by the Bank of Canada on the business day immediately preceding the date of the agreement (the “Consideration Shares”). The Consideration Shares are subject to restrictions under applicable securities laws in addition to a one-year contractual lock-up from the date of closing. The Company also acquired, in a separate transaction, pursuant to a share purchase agreement, the shares of a privately held Montana corporation holding a number of assets including, but not limited to, a plant permit, water rights and tungsten mining equipment for use in the processing of tungsten from the Gentung Tungsten Project for US$250 in cash. | |
| ● | On December 1, 2025, Almonty announced the appointment of Brigadier General (Retired) Steven L. Allen as Chief Operating Officer to optimize tungsten deliveries at the Sangdong Mine and Panasqueira Mine, as well as accelerate the development of the Sangdong Molybdenum Project and the Gentung Tungsten Project. | |
| ● | On December 10, 2025, the Company closed an additional public offering of 20,700,000 Common Shares in the United States (the “December 2025 Offering”) at a price of US$6.25 per common share for gross proceeds of US$129.375 million. The Company intends to use approximately 26.4% of the net proceeds of the offering to fund exploration and development work at the Gentung Tungsten Project, approximately 26.4% to fund expansion work at the Panasqueira Mine, 26.4% to fund expansion work at the Sangdong Molybdenum Project, with the remaining net proceeds to be used primarily for working capital, corporate expenses, business development, potential future acquisitions and other purposes. |
| Page | 4 |
Management’s Discussion and Analysis
Year Ended December 31, 2025
Dated: March 18, 2026
(in 000’s of Canadian Dollars, unless otherwise noted)
| ● | On December 15, 2025, Almonty announced the voluntary withdrawal of its short form base shelf prospectus dated October 31, 2025 (the “Shelf Prospectus”) and the corresponding registration statement on Form F-10 (the “Registration Statement”) because, following the successful completion of the December 2025 Offering, Almonty did not intend to complete further offerings under the Base Prospectus or Registration Statement. | |
| ● | On December 16, 2025, Almonty announced the first truckload of ore has been successfully delivered to the ROM (Run-of-Mine) pad at the Sangdong Mine, a pivotal transition from early-stage mine development to active mining operations and the final step before commencement of commercial production. The ROM pad functions as a staging area for ore that has just been brought out of the ground. Ore is first obtained inside the mine gallery through controlled blasting, then collected and transported through the haulage system. From there, a truck delivers it to the ROM pad, where it is stockpiled by grade before processing begins. |
During 2026 to the date of this MD&A:
| ● | On January 6, 2026, Almonty announced the appointment of Guillaume Wiesenbach de Lamaziere, CFA as Chief Development Officer to spearhead key corporate development strategy and execution. |
| 4. | Overall Performance and Discussion of Operations |
Financial Information
The following financial information is for the years ended December 31, 2025 and 2024:
| Year ended | ||||||||
| 31-Dec-25 | 31-Dec-24 | |||||||
| $’000 | $’000 | |||||||
| Gross revenue | 32,514 | 28,836 | ||||||
| Mine production costs | 27,928 | 24,679 | ||||||
| Care and maintenance | 1,168 | 1,067 | ||||||
| Depreciation and amortization | 1,043 | 1,120 | ||||||
| Income from mining operations | 2,375 | 1,970 | ||||||
| General and administrative costs | 20,521 | 6,155 | ||||||
| Non-cash compensation costs | 11,085 | 2,734 | ||||||
| Loss before the under noted items | (29,231 | ) | (6,919 | ) | ||||
| Interest income | (1,539 | ) | (2 | ) | ||||
| Interest expense | 4,033 | 4,568 | ||||||
| Loss on valuation of embedded derivative liability | 97,408 | 630 | ||||||
| Loss (gain) on valuation of warrant liabilities | 29,337 | 2,032 | ||||||
| Foreign exchange loss | 2,973 | 1,779 | ||||||
| Tax provision | 470 | 372 | ||||||
Net loss for the year | (161,913 | ) | (16,298 | ) | ||||
| Income (loss) per share – basic and diluted | $ | (0.78 | ) | $ | (0.10 | ) | ||
| Dividends | - | - | ||||||
| Cash flows provided by (used in): | ||||||||
| Operating activities | (19,136 | ) | (7,498 | ) | ||||
| Investing activities | (62,271 | ) | (36,231 | ) | ||||
| Financing activities | 342,004 | 29,371 | ||||||
| Page | 5 |
Management’s Discussion and Analysis
Year Ended December 31, 2025
Dated: March 18, 2026
(in 000’s of Canadian Dollars, unless otherwise noted)
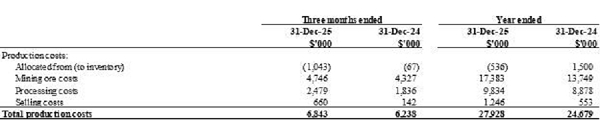
The following table sets forth a summary of the Company’s consolidated mine production costs for the years presented:
The following table sets forth a summary of the Company’s consolidated financial position as of the dates presented:
| 31-Dec-25 | 31-Dec-24 | |||||||
| $’000 | $’000 | |||||||
| Cash | 268,409 | 7,830 | ||||||
| Total assets | 589,732 | 256,349 | ||||||
| Long-term debt | 162,113 | 158,022 | ||||||
| Shareholders’ equity | 357,811 | 39,073 | ||||||
| Other | ||||||||
| Outstanding common shares (’000) | 262,776 | 176,947 | ||||||
| Basic and fully diluted weighted average outstanding common shares (’000) | 208,031 | 169,357 | ||||||
| Closing common share price | $ | 12.07 | $ | 1.36 | ||||
Analysis of Financial Information
Gross revenue for the three months ended December 31, 2025 was $8,719 ($6,280 for the three months ended December 31, 2024) and $32,514 for the year ended December 31, 2025 ($28,836 for the year ended December 31, 2024).
| Page | 6 |
Management’s Discussion and Analysis
Year Ended December 31, 2025
Dated: March 18, 2026
(in 000’s of Canadian Dollars, unless otherwise noted)
Production at the Panasqueira Mine during the three months ended December 31, 2025 decreased by 9.9% compared to the three months ended December 31, 2024. Production at the Panasqueira Mine decreased 10.3% for the year ended December 31, 2025 compared to the year ended December 31, 2024.
Decreased overall production at the Panasqueira Mine was a result of a lower amount of ore mined and processed during the three and twelve months ended December 31, 2025 when compared to the three and twelve months ended December 31, 2024. In addition, during the second quarter of fiscal 2025, fewer underground faces were worked on, yielding lower-grade material, as a result of temporarily diverting resources to Level 4 during the second quarter. Shipment volumes from the Panasqueira Mine decreased by 26.6% overall in the three months ended December 31, 2025, and decreased 19.5% overall in the year ended December 31, 2025, when compared to the three and twelve months ended December 31, 2024. Overall revenue at the Panasqueira Mine increased by $2,439 or 38.8% for the three months ended December 31, 2025, or $3,678 or 12.7% for the twelve months ended December 31, 2025, when compared to the three and twelve months ended December 31, 2024, as a result of a significant increase in the spot price of APT. As at December 31, 2025, the Company recorded deferred revenue of $3,071 (December 31, 2024 - $74) relating to two shipments of concentrate that occurred during December 2025 but were not received by the customers until early January 2026. As a result, this amount will be included in revenue for the three months ending March 31, 2026.
Mine production costs for the three months ended December 31, 2025 (including direct mining costs, milling costs and tailings costs associated with current production) were $9,487, compared to $6,238 for the three months ended December 31, 2024, and $27,928 (or 85.9% of revenue) for the year ended December 31, 2025, compared to $24,679 (or 85.6% of revenue) for the year ended December 31, 2024.
The Company carries out a quarterly assessment of its ore and in-process ore and finished goods inventory as well as its stockpiles of long-term tailings inventory to ensure that the carrying is recorded at the lower of cost and net realizable value. Any adjustments to the carrying value of ore, in-process ore and finished goods inventory are included in cost of goods sold (mine production costs). No write-downs of finished goods inventory were recognized during the three or twelve months ended December 31, 2025 or December 31, 2024. Any adjustment to long-term tailings inventory that is recognized as an impairment amount is expensed through the statement of operations as an addition to mine production costs. Conversely, any adjustment to long-term tailings inventory that is recognized as a reversal of prior period impairment charges is recorded as a reduction in mine production costs. Reversals may occur in future periods as a result of continued increases in the expected price of an MTU of APT in future periods.
Income from mining operations during the three months ended December 31, 2025 was $1,313, compared to a loss from mining operations in the three months ended December 31, 2024 of ($503), and $2,375 for the year ended December 31, 2025, compared to income of $1,970 for the year ended December 31, 2024.
General and administrative costs of $9,352 incurred during the three months ended December 31, 2025, or $20,521 for the year ended December 31, 2025, were significantly higher than the $1,806 recorded during the three months ended December 31, 2024, or $6,155 for the year ended December 31, 2024, as a result of additional legal fees and shareholder communication costs incurred relating to the U.S. Domestication, the Nasdaq IPO, including regulatory and legal follow-on expenses, Almonty’s special meeting held on September 29, 2025, and the December 2025 Offering. General and administrative costs include employee salaries and employment-related expenses of all non-mining/processing personnel as well as corporate overhead costs, business development and corporate development costs, listing and transfer agent fees, accounting, legal and other professional fees and travel.
| Page | 7 |
Management’s Discussion and Analysis
Year Ended December 31, 2025
Dated: March 18, 2026
(in 000’s of Canadian Dollars, unless otherwise noted)
A foreign exchange gain on the revaluation of interest-bearing long-term debt and non-interest-bearing trade payables denominated in $US and in Euro, of $4,897 was recorded during the three months ended December 31, 2025, or $2,973 for the year ended December 31, 2025, due to the appreciation of the Canadian dollar versus the United States dollar and Euro. This compared to a foreign exchange gain of $220 recorded for the three months ended December 31, 2024 or a loss of $1,779 for the year ended December 31, 2024.
A loss on valuation of embedded derivative liabilities of $87,269 was recorded during the three months ended December 31, 2025, or $97,408 for the year ended December 31, 2025, in conjunction with various convertible debentures, compared to a loss of $294 during the three months ended December 31, 2024, or a loss of $630 during the year ended December 31, 2024 (see Note 11 of the Company’s 2025 Annual Financial Statements for further details).
A gain on valuation of share purchase warrant (“warrant”) liabilities of $44 was recorded during the three months ended December 31, 2025, or a loss of $29,337 for the year ended December 31, 2025 compared to a loss of $1,728 during the three months ended December 31, 2024 or a loss of $2,032 for the year ended December 31, 2024. The Company uses the Black-Scholes Option Pricing Model to measure the fair value of warrant liabilities, wherein the Company’s trading price is the main driver for calculating the resulting amount. The revaluation of this derivative non-cash liability, arising from an increase in the Company’s common share price during the year ended December 31, 2025, resulted in the recognition of a loss of $97,408 (2024 – $630) in the statements of operations and comprehensive loss during the year ended December 31, 2025. (See “Loss on Valuation of Warrant Liabilities” below.)
Net income (loss) for the three months ended December 31, 2025 was ($102,273) or ($0.50) per common share, or ($161,913) or ($0.78) per common share for the year ended December 31, 2025. This compares to net loss of ($5,404), or ($0.02) per common share for the three months ended December 31, 2024, or ($16,298) or ($0.06) per common share for the year ended December 31, 2024.
Mineral Projects
Sangdong Mine
The Company is primarily engaged in the development of the Sangdong Mine. The current mine and processing plant construction at the Sangdong Mine (Phase I) began commercial mining in December 2025. The processing plant is in commissioning and expected to be complected in due course. Once fully operational, the targeted ore throughput capacity is expected to reach around 640,000 tonnes per year. The Company expects to increase its throughput capacity up to 1.2 million tonnes through the Phase II planned expansion. This expansion is fully permitted under existing Phase I approvals, and during the development of Phase I, some components have been built which may support a higher throughput or expansion. It is expected that, subject to positive operating results from Phase I and prevailing market conditions, Phase II could be completed in 2027, and first ore production under Phase II could commence that same year.
| Page | 8 |
Management’s Discussion and Analysis
Year Ended December 31, 2025
Dated: March 18, 2026
(in 000’s of Canadian Dollars, unless otherwise noted)
Tungsten Oxide Facility
The Company is also intending the development of the Tungsten Oxide Facility to process the tungsten oxide from the Sangdong Mine and to supply the South Korean battery anode and cathode manufacturing industry, reducing the costs of such processing by avoiding the need to export tungsten oxide outside of South Korea for processing and reimporting it for sale to local customers. To date, the Company has completed a pre-basic engineering study in March 2025 with UTG Universaltechnik GmbH, forming the basis for current design and cost planning. The Tungsten Oxide Facility is to be located in Yeongwol County on a greenfield site, secured under a memorandum of understanding with the local government, as announced on July 11, 2024. The Company expects to source feedstock for the Tungsten Oxide Facility from other tungsten producers as well as its existing and future mining operations. This includes the planned Phase II expansion of the Sangdong Mine, which is currently expected to serve as the primary initial source. The Company may also evaluate the use of concentrate from the Panasqueira Mine, whether from current output or potential future expansion, as well as material from other Company-owned assets in Spain, subject to further technical and economic assessment. As of the date hereof, no final sourcing decisions have been made beyond the expected production from Phase II. The plant is expected to process scheelite and wolframite concentrates into high-purity WO₃, with an initial nameplate production capacity of 4,000 tonnes per year and the option to scale up to 6,000 tonnes per year. As of the date hereof, the Tungsten Oxide Facility remains in the pre-construction stage and is not yet material to the Company’s current operations. No significant capital expenditure has been incurred to date.
Panasqueira Mine
The Company is currently mining, processing and shipping tungsten concentrate from the Panasqueira Mine. The Company is also planning an extension of the Panasqueira Mine, with the potential to extend the life of the mine and significantly increase production capacity. Key objectives of this extension include increased ore throughput and improved average head grade, while continuing to serve customers who rely on the mine’s concentrate. Initial indications suggest that the extension expected may increase production to ~124,000 MTUs of WO₃ concentrate.
Between the third quarter of fiscal 2019 and the second quarter of fiscal 2021, management at the Panasqueira Mine determined that it would mine certain ore with a lower grade so as to enable work to be done to ensure that access to ore with the usual higher grade would be accessible in the future. Tungsten recovery rates for the three- and 12-month periods ended December 31, 2025, remained generally stable compared to the corresponding periods in fiscal 2024 and were consistent with the expected average recovery rate for the life of mine, subject to minor deviations observed over the longer term.
Mined grades in the three- and twelve-month periods ended December 31, 2025 were generally consistent with the levels achieved under the revised mine plan implemented by Almonty since its acquisition of the Panasqueira Mine in January 2016. Production of by-product metals, namely copper and tin, provided additional revenue streams that supported and improved the cash flow profile of the Panasqueira mining operation.
| Page | 9 |
Management’s Discussion and Analysis
Year Ended December 31, 2025
Dated: March 18, 2026
(in 000’s of Canadian Dollars, unless otherwise noted)
Los Santos Mine
In February 2020, as a result of additional testing work, Almonty placed the Los Santos Mine into care and maintenance. The Company is considering reopening operations in the near future once it has finalized plans to modify the plant’s infrastructure, through an approximately €1 million capital expenditure, which is expected to result in improved recovery rates from the future processing of its tailings inventory.
Valtreixal Mine
The Company is evaluating its Valtreixal Mine, a potential open pit operation located in Western Spain in the province of Zamora. The principal potential products are tungsten and tin.
Gentung Tungsten Project
On November 17, 2025, the Company completed its acquisitions of U.S. Tungsten Inc., a U.S.-based privately-owned minerals explorer with the exclusive right to explore, develop and mine the Gentung Tungsten Project, and a privately held Montana corporation holding a number of assets including, but not limited to, a plant permit, water rights and tungsten mining equipment for use in the processing of tungsten from the Gentung Tungsten Project.
The Gentung Tungsten Project is among the most advanced undeveloped tungsten assets in the U.S. and is positioned for near-term production. Significant work was completed by the previous owners of the project over the years to prepare the site for production. The project is located in a historic U.S. tungsten district that once supplied the U.S. national strategic stockpile and offers existing road access and infrastructure, supporting a relatively expeditious path to initial production.
Market for Tungsten Concentrate
The tungsten market is characterized by its critical importance to various high-tech and industrial applications and is deemed a critical material by the European Union, the United States, Australia, Canada, and South Korea due to its supply risks and economic value. The global tungsten market is relatively small in volume but highly concentrated in supply, with China dominating around 80% of the market in 2025 (Source: U.S. Department of the Interior – U.S. Geological Survey, Mineral Commodity Summaries, 2026). This concentration has led to increased market tension and supply chain vulnerabilities, particularly as geopolitical tensions rise and China limits exports of tungsten. The market’s tight supply conditions and the strategic importance of tungsten in critical industries are expected to support sustained price strength over the medium to long term.
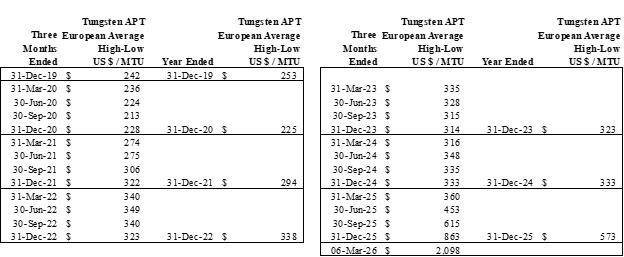
APT pricing increased significantly during fiscal 2025, with mid-market prices rising from US$330 per MTU in January 2025 to US$862.5 per MTU by the end of fiscal 2025. In February 2025, China implemented export controls on certain rare metal products, including tungsten, contributing to tightening market supply conditions. Around the same time, increased military spending in the United States, Germany, France, Japan, the United Kingdom and among NATO member states has been associated with increased demand for tungsten in defense applications.
| Page | 10 |
Management’s Discussion and Analysis
Year Ended December 31, 2025
Dated: March 18, 2026
(in 000’s of Canadian Dollars, unless otherwise noted)
Near the end of fiscal 2025 and into the first quarter of fiscal 2026, APT prices increased significantly, with average mid-prices rising from US$862.5 per MTU in early January 2026 to approximately US$2,250 per MTU as at March 13, 2026, based on market quotations. APT prices have shown an upward trend since the fourth quarter of 2024. The upward trend continued into fiscal 2026. There can be no assurance that this pricing trend will continue in the future. See “RISK FACTORS – Financial Risks – Price of Metals” in the AIF (as defined herein).
The average of the high and low weekly quoted price for European APT according to the Metal Bulletin (“MB”) European weekly quotation for APT (from which Almonty’s concentrate prices are derived by the formulae under its supply agreements) averaged the following:
Source: Metal Bulletin, ammonium para tungstate (APT), European (US$/MTU).
Almonty prices its tungsten concentrate product (on volumes of material that are not subject to a fixed-price contract) in relation to the prior month’s average weekly quoted price for APT on the MB European weekly quotation service and the Metal Pages pricing service.
Financing
During the year ended December 31, 2025, the Company closed the Nasdaq IPO on July 15, 2025 for gross proceeds of US$90 million and for net proceeds, after deducting underwriting discounts and offering expenses, of approximately US$80.3 million.
In addition, during December 2025, Almonty closed the December 2025 Offering for gross proceeds of US$129.375 million and for net proceeds, after deducting underwriting discounts and offering expenses, of approximately US$121,493 million.
| Page | 11 |
Management’s Discussion and Analysis
Year Ended December 31, 2025
Dated: March 18, 2026
(in 000’s of Canadian Dollars, unless otherwise noted)
The table below sets out, as at December 31, 2025, the particulars of how the Company is, and has been, using the proceeds, as well as variations, if any, from the Company’s anticipated use of proceeds, from the Company’s prior financing during the Company’s financial year ended December 31, 2024 and the year ended December 31, 2025.
| Financing | Anticipated
Use of Proceeds |
Allocated Proceeds (1) | Actual Use of Proceeds (as at December 31, 2025) | Variation from Anticipated Use of Proceeds | Explanation and Impact | |||||
Initial public offering of common shares in the United States for gross proceeds of US$90 million (July 15, 2025) |
(I) Development of the Tungsten Oxide Facility | US$68.3 million | US$Nil | The Company has not yet spent the proceeds of the financing. | N/A | |||||
| 1. Early-stage development activities | US$0.8 million | US$Nil | The Company has not yet spent the proceeds of the financing. | N/A | ||||||
| 2. Development and construction of the Tungsten Oxide Facility | US$67.5 million | US$Nil | The Company has not yet spent the proceeds of the financing. | N/A | ||||||
| (II) Working capital and general corporate purposes (2) | US$12.0 million | US$9.2 million | US$2.8 million not yet spent. | N/A | ||||||
Offering of common shares in the United States for gross proceeds of US$129.375 million (December 10, 2025) |
(I) Exploration and development work at the Gentung Tungsten Project | US$32.1 million | US$Nil | The Company has not yet spent the proceeds of the financing. | N/A | |||||
| (II) Expansion work at the Panasqueira Mine | US$32.1 million | US$Nil | The Company has not yet spent the proceeds of the financing. | N/A | ||||||
| (III) Exploration work at the Sangdong Molybdenum Project | US$32.1 million | US$Nil | The Company has not yet spent the proceeds of the financing. | N/A | ||||||
| (IV) Working capital and general corporate purposes (2) | US$25.2 million | US$Nil | The Company has not yet spent the proceeds of the financing. | N/A |
(1) Represents allocated net proceeds of the financing, after deducting underwriting discounts and offering expenses.
(2) Funds included in general corporate purposes may be allocated to corporate expenses, business development, potential future acquisitions, and to other purposes.
| Page | 12 |
Management’s Discussion and Analysis
Year Ended December 31, 2025
Dated: March 18, 2026
(in 000’s of Canadian Dollars, unless otherwise noted)
| 5. | Selected Annual Information |
| Year ended | Year ended | Year ended | ||||||||||
| December 31, 2025 | December 31, 2024 | December 31, 2023 | ||||||||||
| Total Revenue | 32,514 | 28,836 | 22,510 | |||||||||
| Net loss | (161,913 | ) | (16,298 | ) | (8,837 | ) | ||||||
| Basic and diluted loss per common share | $ | (0.78 | ) | $ | (0.10 | ) | $ | (0.04 | ) | |||
| Total assets | 589,732 | 256,349 | 235,334 | |||||||||
| Total non-current financial liabilities | 158,176 | 159,887 | 120,128 | |||||||||
| Dividends | - | - | - | |||||||||
The Company’s audited annual consolidated financial statements for the years ended December 31, 2025, 2024 and 2023 have been prepared in compliance with IFRS Accounting Standards as issued by the International Accounting Standards Board (“IASB”). The material accounting policies applied in these consolidated financial statements have been applied consistently to all years presented.
During the year ended December 31, 2025, the Company recorded a loss on valuation of warrant liabilities of $29,337 (2024 - $2,032; 2023 – gain of 1,227) and a loss on valuation of embedded derivative liabilities of $97,408 (2024 - $630; 2023 – gain of $432).
As at December 31, 2025, the Company had a cash balance of $268,409 (December 31, 2024 - $7,830; December 31, 2023 - $22,019).
| Page | 13 |
Management’s Discussion and Analysis
Year Ended December 31, 2025
Dated: March 18, 2026
(in 000’s of Canadian Dollars, unless otherwise noted)
| 6. | Summary of Quarterly Results |
4th Quarter (2025) | 3rd Quarter (2025) | 2nd Quarter (2025) | 1st Quarter (2025) (“Q1-2025”) | |||||||||||||
| Period Ended | December 31, 2025 | September 30, 2025 | June 30, 2025 | March 31, 2025 | ||||||||||||
| Total Revenue | 8,719 | 8,695 | 7,192 | 7,908 | ||||||||||||
| Net income (loss) | (102,273 | ) | 33,191 | (58,209 | ) | (34,622 | ) | |||||||||
| Basic gain (loss per common share) | $ | (0.50 | ) | $ | 0.15 | $ | (0.30 | ) | $ | (0.13 | ) | |||||
| Diluted gain (loss) per common share | $ | (0.50 | ) | $ | 0.13 | $ | (0.30 | ) | $ | (0.13 | ) | |||||
| Total assets | 589,732 | 433,138 | 315,597 | 279,041 | ||||||||||||
| Total long-term debt | 162,113 | 197,263 | 192,690 | 171,612 | ||||||||||||
| Dividends | - | - | - | - | ||||||||||||
4th Quarter (2024) (“Q4-2024”) | 3rd Quarter (2024) (“Q3-2024”) | 2nd Quarter (2024) (“Q2-2024”) | 1st Quarter (2024) (“Q1-2024”) | |||||||||||||
| Period Ended | December 31, 2024 | September 30, 2024 | June 30, 2024 | March 31, 2024 | ||||||||||||
| Total Revenue | 6,280 | 6,794 | 7,938 | 7,824 | ||||||||||||
| Net income (loss) | (5,404 | ) | (5,319 | ) | (1,793 | ) | (3,782 | ) | ||||||||
| Basic loss per common share | $ | (0.02 | ) | $ | (0.02 | ) | $ | (0.01 | ) | $ | (0.01 | ) | ||||
| Diluted loss per common share | $ | (0.02 | ) | $ | (0.02 | ) | $ | (0.01 | ) | $ | (0.01 | ) | ||||
| Total assets | 256,349 | 255,280 | 231,163 | 233,638 | ||||||||||||
| Total long-term debt | 156,901 | 149,748 | 132,779 | 128,576 | ||||||||||||
| Dividends | - | - | - | - |
During the quarters discussed below, the Company received planned drawdowns on its KfW Facility, the funds from which were used for the development of the Sangdong Mine.
Revenues recorded in Q4-2025 were $8,719 compared to $8,695 in Q3-2025. The Company sold 26.6% fewer MTUs of WO3 in Q4-2025 compared to Q3-2025 as a result of the fact that certain December 2025 shipments were not received by our customers until January 2026. As a result, $3,071 was included in deferred revenue as at December 31, 2025 (2024 - $74) and will be included in Q1 2026 revenue. The Company also recorded a gain on revaluation of warrant liabilities totalling $44, as well as a non-cash loss on the revaluation of derivative liabilities totalling $87,269.
Revenues recorded in Q3-2025 were $8,695 compared to $7,192 in Q2-2025. The Company sold 9.6% fewer MTUs of WO3 in Q3-2025 compared to Q2-2025. During Q3-2025, the Company also recorded a gain on revaluation of warrant liabilities totalling $34,513, as well as a non-cash loss on the revaluation of derivative liabilities totalling $288.
Revenues in Q2-2025 were $7,192 compared to $7,908 in Q1-2025. The Company sold 10.5% fewer MTUs of WO3 in Q2-2025 compared to Q1-2025. The production costs increased primarily due to the fact that fewer underground faces were worked on, yielding lower-grade material, as a result of temporarily diverting resources to Level 4 during the quarter. During Q2-2025, the Company also recorded a non-cash loss on revaluation of warrant liabilities totalling $38,084 as well as a non-cash loss on the revaluation of derivative liabilities totalling $6,942.
| Page | 14 |
Management’s Discussion and Analysis
Year Ended December 31, 2025
Dated: March 18, 2026
(in 000’s of Canadian Dollars, unless otherwise noted)
Revenues in Q1-2025 were $7,908 compared to $6,280 in Q4-2024. The Company sold 24.7% more MTUs of WO3 and produced 15.1% more MTUs of WO3 in Q1-2025 compared to Q4-2024. During Q1-2025, the Company also recorded a non-cash loss on revaluation of warrant liabilities totalling $25,810 as well as a non-cash loss on the revaluation of derivative liabilities totalling $2,909.
Revenues in Q4-2024 were $6,280 compared to $6,794 in Q3-2024. The Company sold 1.0% more MTUs of WO3 at a higher average selling price per MTU and produced 7.3% more MTUs of WO3 in Q4-2024 compared to Q3-2024.
Revenues in Q3-2024 were $6,794 compared to $7,938 in Q2-2024. The Company sold 27.2% fewer MTUs of WO3 and produced 21.4% fewer MTUs of WO3 in Q3-2024 compared to Q2-2024. During Q3-2024, the Company also recorded non-cash losses totalling $1,044 on revaluation of warrant liabilities and derivative liabilities totalling as well as recording $1,464 for share-based compensation expense on granting of stock options.
Revenues in Q2-2024 were $7,938 compared to $7,824 in Q1-2024. The Company sold 20.7% fewer MTUs of WO3 and produced 1.3% more MTUs of WO3 in Q2-2024 compared to Q1-2024.
Revenues in Q1-2024 were $7,824 compared to $5,421 in Q4-2023. The Company sold 8.1% more MTUs of WO3 and produced 9.4% more MTUs of WO3 in Q1-2024 compared to Q4-2023. As at the end of Q4-2023, the Company recorded deferred revenue totalling $1,062 which was recognized as revenue in Q1-2024.
| 7. | Outstanding Share Data |
Common Shares
The Company’s authorized share capital consists of an unlimited number of common shares. The common shares do not have a par value. As of the date of this MD&A, there were 281,938,231 common shares outstanding (including CDIs), 6,997,979 stock options outstanding, with each option entitling the holder thereof to acquire one common share of Almonty at a weighted average price of $1.74 per common share, and 1,381,514 warrants (which include CDI options) enabling the holders to acquire one common share (or CDI, as applicable) at prices between C$0.98 and C$1.71 (or at A$1.88 in the case of CDI options) expiring between April 2026 and Feb 2028.
| Page | 15 |
Management’s Discussion and Analysis
Year Ended December 31, 2025
Dated: March 18, 2026
(in 000’s of Canadian Dollars, unless otherwise noted)
As at December 31, 2025, the Company had common shares outstanding as follows:
| Number of Shares | Amount | |||||||
| Authorized – Unlimited number of common shares | ||||||||
| Issued and outstanding | ||||||||
| Outstanding at December 31, 2023 | 155,925,779 | $ | 127,359 | |||||
| Shares issued for cash | 12,259,413 | 8,320 | ||||||
| Shares issued for settlement of debt | 1,875,857 | 1,572 | ||||||
| Shares issued for conversion of debt | 6,886,167 | 9,265 | ||||||
| Outstanding at December 31, 2024 | 176,947,216 | $ | 146,516 | |||||
| Shares issued for cash | 49,606,881 | 285,425 | ||||||
| Shares issued for exercise of stock options | 8,054,911 | 6,599 | ||||||
| Shares issued for exercise of CDI options | 14,672,241 | 55,402 | ||||||
| Shares issued for exercise of warrants | 5,580,798 | 8,961 | ||||||
| Shares issued for settlement of RSUs | 786,089 | 2,837 | ||||||
| Shares issued for settlement of debt | 66,667 | 90 | ||||||
| Shares issued for conversion of debt | 5,714,120 | 11,607 | ||||||
| Shares issued on acquisition of 100% of US Tungsten Inc. | 1,347,305 | 12,463 | ||||||
| Outstanding at December 31, 2025 | 262,776,228 | $ | 529,900 | |||||
Stock Options
The Company’s omnibus equity incentive plan (the “Omnibus Plan”) was approved by the Company’s shareholders at the Company’s Annual and Special Meeting of Shareholders held on April 30, 2025, pursuant to which the Company may grant its directors, officers, employees and consultants stock options to acquire common shares, subject to a 10% insider participation limit and the maximum number of common shares reserved for issuance under the Omnibus Plan.
As of the date of this MD&A, there are 6,997,979 stock options outstanding, all of which were granted under the Omnibus Plan or the Company’s third amended and restated incentive stock option plan (which was superseded and replaced by the Omnibus Plan). The Company’s stock options do not include CDI options.
| Page | 16 |
Management’s Discussion and Analysis
Year Ended December 31, 2025
Dated: March 18, 2026
(in 000’s of Canadian Dollars, unless otherwise noted)
As at December 31, 2025, the Company had outstanding stock options, all of which are exercisable, as follows:
Number of Stock Options | ||||
| Options outstanding at December 31, 2023 | 11,383,334 | |||
| Options granted | 3,803,334 | |||
| Options expired | (666,667 | ) | ||
| Options outstanding at December 31, 2024 | 14,520,001 | |||
| Options granted | 2,564,667 | |||
| Options exercised | (9,886,690 | ) | ||
| Options expired | (66,666 | ) | ||
| Options outstanding at December 31, 2025 | 7,131,312 | |||
The following table discloses the average exercise price, number of options and contractual life as at December 31, 2025:
Range of Exercise Prices | Number Outstanding | Number Exercisable | Weighted Average Remaining Contractual Life | Weighted Average Exercise Price | ||||||||||||
| $0.78 - $ 1.79 | 4,866,648 | 4,866,648 | 2.77 | $ | 1.03 | |||||||||||
| $2.43 - $ 3.86 | 2,064,664 | 1,878,262 | 4.29 | $ | 3.55 | |||||||||||
| $8.93 | 200,000 | 200,000 | 4.91 | $ | 8.93 | |||||||||||
| Total Options | 7,131,312 | 6,944,910 | 3.27 | $ | 1.98 | |||||||||||
Warrants and CDI options
For the years ended December 31, 2025 and 2024, the outstanding warrants and CDI options, all of which are exercisable, are summarized as follows:
| Number of CDI Options | Number of Warrants | Total Number Outstanding | ||||||||||
| Warrants outstanding at December 31, 2023 | 5,626,363 | 5,325,114 | 10,951,477 | |||||||||
| Warrants issued | 7,356,632 | 4,902,782 | 12,259,414 | |||||||||
| Warrants expired | (4,907,408 | ) | (476,190 | ) | (5,383,598 | ) | ||||||
| Warrants outstanding at December 31, 2024 | 8,075,587 | 9,751,706 | 17,827,293 | |||||||||
| Warrants issued | 7,222,222 | 1,684,667 | 8,906,889 | |||||||||
| Warrants exercised | (13,931,517 | ) | (6,321,546 | ) | (20,253,063 | ) | ||||||
| Warrants expired | - | (1,197,083 | ) | (1,197,083 | ) | |||||||
| Warrants outstanding at December 31, 2025 | 1,366,292 | 3,917,744 | 5,284,036 | |||||||||
| Page | 17 |
Management’s Discussion and Analysis
Year Ended December 31, 2025
Dated: March 18, 2026
(in 000’s of Canadian Dollars, unless otherwise noted)
The following table discloses the average exercise price, number of CDI options and contractual life as at December 31, 2025:
Range of Exercise Prices | Number Outstanding and Exercisable | Weighted Average Remaining Contractual Life | Weighted Average Exercise Price | |||||||||
| $ 1.68 (AUD $1.88) | 1,366,292 | 2.04 | $ | 1.68 | ||||||||
| Total CDI Options | 1,366,292 | 2.04 | $ | 1.68 | ||||||||
The following table discloses the average exercise price, number of warrants and contractual life as at December 31, 2025:
Range of Exercise Prices | Number Outstanding and Exercisable | Weighted Average Remaining Contractual Life | Weighted Average Exercise Price | |||||||||
| $ 0.68 - $ 0.90 | 1,481,480 | 0.82 | $ | 0.79 | ||||||||
| $ 1.11 - $ 1.13 | 1,984,931 | 0.21 | $ | 1.11 | ||||||||
| $ 1.71 - $ 1.85 | 451,333 | 2.08 | $ | 1.71 | ||||||||
| Total Warrants | 3,917,744 | 0.66 | $ | 1.06 | ||||||||
Loss on Valuation of Warrant Liabilities
Under International Financial Reporting Standards (“IFRS”), certain warrants are treated as a derivative liability because these were denominated in currencies other than the Company’s functional currency of Canadian dollars and, accordingly, the Company was not able to demonstrate that it met the “fixed for fixed” criterion per IAS 32, Financial Instruments: Presentation (“IAS 32”). As a result, at the balance sheet date, these warrants issued as part of a unit private placement must be recorded at their fair value.
On September 29, 2025, the Company obtained shareholder approval for the amendment to the exercise prices of various CDI options from AUD to CAD, with the effective date being January 2, 2025. No changes were made to the number of instruments, expiry dates, or other terms. As a result of the amendment, the “fixed for fixed” criteria per IAS 32 would be met, therefore certain CDI options were fair valued using the value of the equity instrument at January 2, 2025 as required by IFRIC 19, Extinguishing Financial Liabilities with Equity Instruments and transferred to equity.
The Company uses the Black-Scholes Option Pricing Model to measure the fair value of warrant liabilities, wherein the Company’s trading price is the main driver for calculating the resulting amount. The revaluation of this derivative liability arising from an increase in share price from $1.36 per common share at December 31, 2024, to $12.07 per common share at December 31, 2025, has resulted in the recognition of loss of $29,337 (2024 – $2,032) in the statement of operations and comprehensive loss for the year ended December 31, 2025.
| Page | 18 |
Management’s Discussion and Analysis
Year Ended December 31, 2025
Dated: March 18, 2026
(in 000’s of Canadian Dollars, unless otherwise noted)
Changes in the balance of the warrant liabilities for the years ended December 31, 2025 and 2024 are summarized as follows:
| December 31, 2025 | December 31, 2024 | |||||||
| Balance, beginning of year | $ | 5,154 | $ | 958 | ||||
| CDI options issued | 2,500 | 2,164 | ||||||
| CDI options exercised | (31,251 | ) | - | |||||
| CDI options reclassified to equity | (3,802 | ) | - | |||||
| Fair value revaluation on exercise of CDI options | 8,336 | - | ||||||
| Fair value revaluation on CDI options at end of year | 57,829 | 2,032 | ||||||
| Fair value revaluation on amendment of exercise price | (36,828 | ) | - | |||||
| Balance, end of year | $ | 1,938 | $ | 5,154 | ||||
The fair value of the warrants outstanding was estimated using the Black-Scholes Option Pricing Model with the following weighted average assumptions:
| December 31, 2025 | December 31, 2024 | |||||||
| Stock price | $ | 12.07 | $ | 01.36 | ||||
| Exercise price | $ | 1.72 | $ | 0.72 | ||||
| Expected life | 2.07 yrs | 1.99 yrs | ||||||
| Risk-free interest rate | 2.58 | % | 2.93 | % | ||||
| Expected volatility | 89.07 | % | 53.23 | % | ||||
| Expected dividends | nil | nil | ||||||
Restricted Share Units
Restricted share units (“RSUs”) granted to employees under the Company’s restricted share unit plan (“RSU Plan”) or Omnibus Plan vest in accordance with the conditions determined at the time of grant.
Between December 31, 2023 and December 31, 2025, the Company had RSUs outstanding as follows:
| Number of RSUs | ||||
| RSUs outstanding at December 31, 2023 | 1,166,667 | |||
| RSUs granted | 1,400,000 | |||
| RSUs outstanding at December 31, 2024 | 2,566,667 | |||
| RSUs granted | 1,497,204 | |||
| RSUs settled | (786,098 | ) | ||
| RSUs outstanding at December 31, 2025 | 3,277,773 | |||
| Page | 19 |
Management’s Discussion and Analysis
Year Ended December 31, 2025
Dated: March 18, 2026
(in 000’s of Canadian Dollars, unless otherwise noted)
During the year ended December 31, 2025, the Company granted 1,497,195 RSUs to directors of the Company pursuant to the RSU Plan. The value of the RSUs granted was based on the value of the underlying shares at the date of issuance. The grant resulted in the recording of share-based compensation of $5,028 during the year ended December 31, 2025.
Convertible Debentures
Changes in the balances of the convertible debentures for the years ended December 31, 2025 and 2024 are summarized as follows:
| December 31, 2025 | December 31, 2024 | |||||||
| Balance, beginning of year | $ | 27,872 | $ | 32,620 | ||||
| Debentures converted for shares | (19,456 | ) | (5,963 | ) | ||||
| Debentures revalued, derivative liability component | (623 | ) | - | |||||
| Interest accrued | 720 | 240 | ||||||
| Translation adjustment | 790 | 975 | ||||||
| Balance, end of year | $ | 9,303 | $ | 27,872 | ||||
| 8. | Liquidity and Capital Resources |
As at December 31, 2025, the Company held cash and receivables of $271,494 (compared to $10,757 as at December 31, 2024) (of which $2,461 ($2,170 as at December 31, 2024) represented cash restricted for use for the development of the Sangdong Mine). Based on the Company’s currently available non-contingent financial resources and its expected rate of cash burn, the Company expects to be able to continue operations for a minimum of 15 months.
Capital Resources
Loan and Credit Facility
KfW IPEX-Bank Loan
In conjunction with the closing of the KfW Facility in July 2022, and the additional US$20 million loan availability, the Company received the first drawdown of US$12.80 million and a second drawdown of US$4.10 million in August 2022, with a third drawdown of US$9.80 million received during November 2022, a fourth drawdown of US$5.60 million received during April 2023, a fifth drawdown of US$9.80 million received during August 2023, a sixth drawdown of US$13.68 million received in November 2023, a seventh drawdown of US$5.01 million received in July 2024, an eighth drawdown of US$5.63 million received in July 2024, a ninth drawdown of US$0.91 million received in January 2025, a tenth drawdown of US$5.00 million received in February 2025, an eleventh drawdown of US$8.87 million received in April 2025, and a final drawdown of US$6.13 million received in June 2025.
| Page | 20 |
Management’s Discussion and Analysis
Year Ended December 31, 2025
Dated: March 18, 2026
(in 000’s of Canadian Dollars, unless otherwise noted)
Deutsche Rohstoff AG Debt
During November 2024, the Company negotiated the extension of the maturity dates of the debt owed to Deutsche Rohstoff AG (“DRAG”) totalling $24,258, including accrued interest of $6,482, from September 30, 2025 to October 31, 2026.
Equity, Options and Other Financings
Issuance of Common Shares
During the year ended December 31, 2025, the Company closed the Nasdaq IPO on July 15, 2025. The net proceeds from this offering, after deducting underwriting discounts and offering expenses, were approximately US$80.3 million. In addition, during December 2025, the Company closed an additional financing for net proceeds of approximately US$121,493.
Warrants and CDI Options
During the year ended December 31, 2025, the Company issued 20,253,063 common shares in conjunction with exercise of warrants and CDI options for proceeds totalling $29,030.
Subsequent to December 31, 2025, the Company issued 3,902,522 common shares in conjunction with the exercise of warrants and CDI options for proceeds totalling $4,913.
Stock Options
During the year ended December 31, 2025, the Company issued 9,886,690 common shares in conjunction with the exercise of stock options, mainly on a cashless basis, for proceeds totalling $177.
Subsequent to December 31, 2025, the Company issued 125,418 common shares in conjunction with the exercise of stock options on a cashless basis.
Other Financings
During January and February 2025, the Company secured additional financings totalling $10,847.
Long-Term Debt
The Company had $162,113 in long-term debt as at December 31, 2025 ($156,740 as at December 31, 2024), of which $27,267 is the current portion ($21,894 as at December 31, 2024), comprised of individual facilities with Spanish-domiciled banks, one facility with an Austrian bank, promissory notes owed to a shareholder, convertible loans and drawdowns on the KfW loan facility as at December 31, 2025. (See Note 11 of the Company’s 2025 Annual Financial Statements for additional details regarding each component of long-term debt.)
Sources of Financing:
On July 15, 2025, the Company received gross proceeds of US$90,000,000 in conjunction with the completion of the Nasdaq IPO.
| Page | 21 |
Management’s Discussion and Analysis
Year Ended December 31, 2025
Dated: March 18, 2026
(in 000’s of Canadian Dollars, unless otherwise noted)
During December 2025, the Company received gross proceeds of US$129,375,000 in conjunction with the completion of an additional equity raise in the U.S.
The Company expects to use the net proceeds of the offerings primarily to fund the development of the Tungsten Oxide Facility, as well as to fund the development of the Sangdong Molybdenum Project, the Montana property and the Panasqueira Level 4 development and for working capital and other general corporate purposes.
Summary of Long-Term Debt
| Note | December 31, 2025 | December 31, 2024 | ||||||||
| Term and other loans – Euro | $ | 25,707 | $ | 24,486 | ||||||
| Term and other loans – U.S. dollar | 8,224 | 8,634 | ||||||||
| Promissory note | 250 | 250 | ||||||||
| Convertible debentures | 9,303 | 27,872 | ||||||||
| Lease liabilities | 489 | 210 | ||||||||
| Mine construction loan facility | 130,656 | 106,876 | ||||||||
| 174,629 | 168,328 | |||||||||
| Deferred financing costs | (12,516 | ) | (11,427 | ) | ||||||
162,113 | 156,901 | |||||||||
| Less: current portion | (27,267 | ) | (21,894 | ) | ||||||
| $ | 134,846 | $ | 135,007 | |||||||
Summary of Contractual Obligations
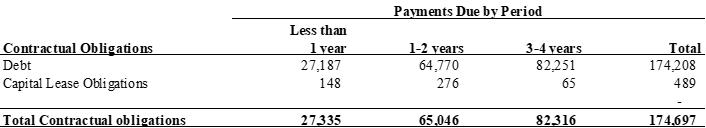
| 9. | Off-Balance Sheet Arrangements |
The Company has no off-balance sheet arrangements as at the date of this MD&A.
| 10. | Related Party Transactions |
For the year ended December 31, 2025, the Company paid or accrued compensation to key management personnel, which includes the Company’s chief executive officer (“CEO”), chief financial officer (“CFO”) and members of the Board of Directors, totalling $16,778 (2024 - $1,354).
| Page | 22 |
Management’s Discussion and Analysis
Year Ended December 31, 2025
Dated: March 18, 2026
(in 000’s of Canadian Dollars, unless otherwise noted)
The Company has long-term debt owing to DRAG, a company that is an existing shareholder of Almonty, and whose former chief executive officer is a member of the Board of Directors. In addition to the transactions disclosed in Notes 11(b) and 11(c) of the Annual Financial Statements, interest of $772 was accrued on the DRAG loans during the year ended December 31, 2025 ($856 for the year ended December 31, 2024). As at December 31, 2025, there is $6,482 ($5,139 as at December 31, 2024) of unpaid interest on these loans included in accounts payable and accrued liabilities.
| 11. | Proposed Material Transactions |
The Company has not entered into any undisclosed material proposed transactions as at the date of this MD&A.
| 12. | Critical Accounting Estimates |
The preparation of Almonty’s consolidated financial statements in conformity with IFRS requires management to make judgments, estimates and assumptions that affect the reported amounts of assets, liabilities and contingent liabilities at the date of the consolidated financial statements and reported amounts of revenues and expenses during the reporting period. Estimates and assumptions are continuously evaluated and are based on management’s experience and other factors, including expectations of future events that are believed to be reasonable under the circumstances. However, actual outcomes can differ from these estimates. In particular, information about significant areas of estimation uncertainty considered by management in preparing the consolidated financial statements is described in more detail in Note 2 and Note 11 of the Company’s 2025 Annual Consolidated Financial Statements.
New and Pending Accounting Standards
Other accounting standards or amendments to existing accounting standards that have been issued but have future effective dates have now been assessed by the Company and are not expected to have any impact on the Company’s consolidated financial statements. The Company has not early adopted these standards.
| 13. | Changes in Accounting Policies |
There have been no changes in the Company’s accounting policies during the year ended December 31, 2025.
| 14. | Financial Instruments and Risk Management |
The Company’s principal financial instruments comprise cash deposits and long-term debt.
The main purpose of these instruments is to provide cash flow funding for the operations of Almonty and its subsidiaries.
The main risks arising from the Company’s financial instruments are interest rate risk, foreign currency risk, credit risk and liquidity risk, which are described in Section 15 of this MD&A.
| Page | 23 |
Management’s Discussion and Analysis
Year Ended December 31, 2025
Dated: March 18, 2026
(in 000’s of Canadian Dollars, unless otherwise noted)
| 15. | Disclosure Controls and Procedures and Internal Control of Financial Reporting |
Disclosure Controls and Procedures
The Company’s CEO and CFO are responsible for establishing and maintaining the Company’s disclosure controls and procedures (“DC&P”) as well as its internal control over financial reporting (“ICFR”), as those terms are defined in NI 52-109.
The CEO and the CFO have designed DC&P, or caused them to be designed under their supervision, to provide reasonable assurance that:
| ● | material information relating to the Company is made known to them by others, particularly during the period in which the interim filings are being prepared; and | |
| ● | information required to be disclosed by the Company in its annual filings, interim filings or other reports filed or submitted by it under securities legislation is recorded, processed, summarized and reported within the time periods specified in securities legislation. |
As of December 31, 2025, the Company’s management, including the CEO and CFO, evaluated the effectiveness of the Company’s disclosure controls and procedures, as defined in Rules 13a-15(e) and 15d-15(e) under the U.S. Securities Exchange Act of 1934, as amended, and National Instrument 52-109 – Certification of Disclosure in Issuers’ Annual and Interim Filings. Based on this evaluation, management concluded that the Company’s disclosure controls and procedures were not effective as of December 31, 2025, due to the continuing impact of previously identified material weakness in ICFR, as described below under the heading “Internal Control over Financial Reporting”.
A material weakness is a significant deficiency, or combination of significant deficiencies, that results in more than a remote likelihood that a material misstatement of the annual or interim financial statements will occur and not be detected by management before the financial statements are published. Controls can potentially be circumvented by the individual acts of some persons, by collusion of two or more people or by management override of the control. The design of any system of controls is also based in part upon certain assumptions about the likelihood of future events, and there can be no assurance that any design will succeed in achieving its stated goals under all potential future conditions. Over time, control may become inadequate because of changes in conditions, or the degree of compliance with the policies or procedures may deteriorate. Because of the inherent limitations in a cost-effective control system, misstatements due to error or fraud may occur and not be detected.
Internal Control over Financial Reporting
The CEO and CFO have also designed ICFR, or caused it to be designed under their supervision, to provide reasonable assurance regarding the reliability of financial reporting and the preparation of financial statements for external purposes in accordance with IFRS.
| Page | 24 |
Management’s Discussion and Analysis
Year Ended December 31, 2025
Dated: March 18, 2026
(in 000’s of Canadian Dollars, unless otherwise noted)
As of December 31, 2025, management, including the CEO and CFO, also evaluated the effectiveness of the Company’s ICFR based upon the Internal Control – Integrated Framework (2013) issued by the Committee of Sponsoring Organizations of the Treadway Commission.
In its assessment of the effectiveness in ICFR as of December 31, 2025, the Company determined it had ineffective design and implementation of internal controls over the financial statement close and related disclosure processes, including segregation of duties within transaction processing and control over system data integrity. The cumulative impact of such deficiencies increases the reliance on management review procedures which may not be designed at a level of precision to detect material misstatements regarding assertions about the completeness, existence, and accuracy of the financial information.
Remediation Plan
During 2025, the Company continued to implement measures to strengthen its internal control environment, including increased segregation of duties within the financial reporting and close process. These measures also included the ongoing expansion of the Company’s internal accounting and financial reporting team, and the engagement of an external firm to assist management with ongoing assessments of the design and operating effectiveness of ICFR. This assessment remains in progress as of the date of this MD&A. Management expects the assessment to be substantially completed in the second quarter of 2026 with any existing material weaknesses subsequently addressed by management to further strengthen the Company’s ICFR.
While these initiatives represent meaningful progress toward remediation of control weaknesses, management has determined that additional work remains to be completed during 2026, including increased scope of ICFR effectiveness testing to fully document and assess the impact of ongoing control remediation with respect to segregation of duties and information technology general controls. Accordingly, management concludes that the Company’s internal control over financial reporting was not effective as of December 31, 2025.
In light of the aforementioned material weakness, management, with the assistance of an external firm, continues to assess ICFR effectiveness and work to address material weaknesses and deficiencies as necessary. While remediation efforts are ongoing, management continues to monitor and enhance internal processes and controls designed to ensure the reliability of the Company’s financial reporting. Accordingly, management has conducted a thorough review of all significant or non-routine adjustments for the year ended December 31, 2025. As a result of this review, management believes that there were no material inaccuracies or omissions of material fact and, to the best of its knowledge, believes that the consolidated financial statements for the year ended December 31, 2025 fairly present in all material respects the financial condition and results of operations for the Company in conformity with International Financial Reporting Standards.
Other than the measures noted above, there have been no changes in the Company’s ICFR that occurred during the year ended December 31, 2025, that have materially affected, or are reasonably likely to materially affect, the Company’s ICFR.
Please also refer to the section entitled “RISK FACTORS – Financial Risks – Weaknesses in Disclosure Control and Procedures and Financial Disclosure” in the Company’s Annual Information Form dated March 18, 2026 (the “AIF”) for a discussion of the limitations of DC&P and ICFR and efforts by management to improve DC&P and ICFR (including with respect to the material weakness in ICFR for past financial years) and the section of this MD&A entitled “Emerging Market Issuer Disclosure” for a discussion of how the Company’s operations in South Korea impacted the design of ICFR.
| Page | 25 |
Management’s Discussion and Analysis
Year Ended December 31, 2025
Dated: March 18, 2026
(in 000’s of Canadian Dollars, unless otherwise noted)
| 16. | Risks and Uncertainties |
The Company operates in the mining industry, which presents a variety of risks and uncertainties, many of which could materially and adversely affect the Company’s business, financial condition and results of operations and could cause actual events to differ materially from those described in the Company’s forward-looking statements. While some exposures may be reduced by the Company’s risk management strategies, many risks are driven by external factors beyond the Company’s control or are of a nature which cannot be eliminated.
For a comprehensive discussion and description of the risks and uncertainties related to the Company and its activities, please refer to the section entitled “RISK FACTORS” in the Company’s AIF, which is available on the Company’s website at www.almonty.com and on SEDAR+ at www.sedarplus.ca under the Company’s profile. The section entitled “RISK FACTORS” in the AIF is incorporated by reference into this MD&A.
The Company’s view of risks and uncertainties that could affect the Company is not static. Readers are cautioned that there can be no assurance that all risks and uncertainties with respect to the Company, at any point in time, can be accurately identified, assessed as to significance or impact, managed or effectively controlled, or mitigated. There can be additional new or elevated risks or uncertainties with respect to the Company that are not described herein or in the AIF.
| 17. | Restoration Provision |
Included in other long-term liabilities are provisions for the future restoration of the Company’s mining properties, in accordance with local requirements, as follows:
| Balance at December 31, 2023 | $ | 22,821 | ||
| Revisions in estimated cash flows and changes in assumptions | 579 | |||
| Accretion expense | 495 | |||
| Translation adjustment | 396 | |||
| Balance, at December 31, 2024 | $ | 24,291 | ||
| Revisions in estimated cash flows and changes in assumptions | (3,884 | ) | ||
| Acquisitions | 250 | |||
| Accretion expense | 402 | |||
| Translation adjustment | 1,595 | |||
| Balance, at December 31, 2025 | $ | 22,654 |
As at December 31, 2025, there is a restoration provision of $18,026 (December 31, 2024 - $20,122) with respect to the Panasqueira Mine, representing management’s estimate of the present value of the rehabilitation costs relating to the mine site totaling $21,499 and are to be incurred after the mine ceases production subsequent to 2045. BTW has assumed an inflation rate of 2.0% per year in calculating its estimates and a discount rate of 3.48%.
| Page | 26 |
Management’s Discussion and Analysis
Year Ended December 31, 2025
Dated: March 18, 2026
(in 000’s of Canadian Dollars, unless otherwise noted)
There is a restoration provision of $942 (December 31, 2024 - $1,008) with respect to Daytal’s future obligation to restore and reclaim the Los Santos Mine once it has ceased the processing of tungsten from the Los Santos Mine. The restoration provision represents management’s estimate of the present value of the rehabilitation costs relating to the mine site totalling $1,282 and are to be incurred beginning in 2027 after Daytal ceases processing operations. Daytal has used a 5.5% discount rate and assumes an inflation rate of 2.0% per year in calculating its estimates. The Company has filed, and is awaiting final approval of its mine plan and restoration provision by the relevant authorities in Spain. Banco Popular has posted a bank warranty of $294 (€180) on behalf of Daytal with the Region of Castilla y Leon, Trade and Industry Department as a form of deposit to cover the expected costs of restoring the mining property as required by Daytal’s Environmental Impact Statement that forms a part of its mining and exploitation license on the Los Santos Mine.
There is a restoration provision of $3,436 (December 31, 2024 - $3,161) with respect to the Sangdong Mine. The provision was determined based on a levy imposed by the relevant local government authority.
There is a restoration provision of $250 (December 31, 2024 – nil) with respect to the Gentung Tungsten Project. The provision represents management’s estimate of the present value of the rehabilitation costs relating to the property.
| 18. | Emerging Market Issuer Disclosure |
Asset Verification
The Company’s title to the Sangdong Mine is held through its wholly-owned subsidiary, Almonty Korea Tungsten Corporation (“AKTC”), which holds the relevant mining rights and permits as required under the laws of Korea.
The Company is satisfied as to its ownership of its property interests in the Sangdong Mine through: (a) the receipt and review of title opinion dated July 15, 2025 regarding the Company’s mineral rights to the mine provided by the Company’s Korean legal counsel, which is a law firm recognized as having expertise in energy and natural resources law matters; (b) searches conducted in the mining registry of the relevant Korean government authorities, in which all applications, grants, transfers and assignments of exploration permits, mining concessions and other evidence of mineral rights to conduct exploration and mining activities are registered and recorded; (c) correspondence with the relevant authorities pursuant to which exploration and mining plans, as well as detailed reports of work performed and geological and technological studies, are required to be submitted; and (d) review, negotiation and execution of various agreements relating to the acquisition or transfer of certain mining titles. As of the date of this report, the Company has obtained and maintains all material title opinions and supporting documentation in respect of the mineral rights of the Sangdong Mine.
AKTC holds exclusive real property rights over the Sangdong Mine during the validity period of its mining rights (excavation rights). However, if the Minister of Trade, Industry and Energy (the “Minister”) deems the mining operation to be detrimental to the public interest or interfering with projects of national importance, the Minister has the power to revoke the mining rights or order a reduction of the mining area in accordance with Article 34 of the Mining Industry Act.
| Page | 27 |
Management’s Discussion and Analysis
Year Ended December 31, 2025
Dated: March 18, 2026
(in 000’s of Canadian Dollars, unless otherwise noted)
Legal Right to Conduct Operations
Korea has an established Mining Industry Act which defines the mining rights guaranteed by the government of Korea. As a result, the Company and other foreign mining companies are generally able to operate predictably and stably in that country.
Except for relatively small areas in the south in the main river valley and a few small areas of vegetable farms, the Sangdong Mine is on government land. On government (i.e., non-private) land, an environmental security bond must be lodged. On private land, access must be negotiated with the individual landowner(s). In the case of mining, there is no formal mediated process for land disturbance, and the purchase or lease of the surface rights would have to be negotiated with the landowner(s).
AKTC has obtained all permits required for the conduct of its business as presently conducted, including the grant of the extraction right and authorization of extraction plan by the Ministry of Economy and Finance of Korea in relation to the Sangdong Mine. AKTC holds, or may be required to obtain in the future, certain customary or routine permits, licenses, or other regulatory approvals in the ordinary course of its operations.
The Company has retained reputable legal counsel in Korea to provide necessary or prudent advice, guidance and/or opinions relating to the Company, including as to the Company’s (and its subsidiaries’) legal right to conduct business in Korea.
The Company is not aware of, and has not received notice of, any non-compliance with any requirements with respect to permits, licenses or other regulatory approvals required to carry on its business in Korea as currently conducted. Further, the Company is not aware of any material restrictions against foreign investment in Korean companies, nor any material legal requirements imposed on foreign ownership of Korean mining companies. To the best knowledge of the Company, the Company and AKTC are in compliance with all foreign investment regulations in Korea.
Foreign Operating Entity
The Company has incorporated and maintains subsidiaries as they are relevant to the jurisdictions in which the Company undertakes its operations and enables the Company’s compliance with its corporate and commercial obligations within each of the legal frameworks of those countries. The Company maintains the subsidiaries as separate operating entities to limit the Company’s liability for its operations and business across multiple jurisdictions, to diversify risk and to allow for increased efficiencies. The Company has implemented a system of corporate governance, ICFR and DC&P that apply at all levels of the Company and its subsidiaries. These systems are overseen by the Board of Directors and implemented by the Company’s senior management.
The Company’s corporate structure has been designed to ensure that the Company controls, or has a measure of direct oversight over, the operations of its subsidiaries. Almonty owns a 100% indirect ownership interest in the Sangdong Mine through its subsidiaries. Almonty’s interest in the Sangdong Mine is held by AKTC, which owns a 100% direct interest in the Sangdong Mine. AKTC is a wholly-owned direct subsidiary of Woulfe Mining Corp., itself a wholly-owned direct subsidiary of Almonty.
| Page | 28 |
Management’s Discussion and Analysis
Year Ended December 31, 2025
Dated: March 18, 2026
(in 000’s of Canadian Dollars, unless otherwise noted)
The Company, as the direct or indirect controlling shareholder of its subsidiaries, has visibility into and effective control of the operations and assets of its subsidiaries. For example, the Company, directly or indirectly, has the power to appoint and dismiss any of its subsidiaries’ directors at any time. The directors of each subsidiary then have the power to appoint and dismiss such subsidiaries’ officers at any time, give instructions to such officers, and require such officers to comply with their fiduciary and other obligations. As the direct or indirect controlling shareholder of its subsidiaries, the Company’s approval will be required for any fundamental changes requiring shareholder approval. The Company, as shareholder, can also enforce its rights by way of various shareholder remedies available to it under local laws. In addition, as the direct or indirect controlling shareholder of its subsidiaries, the Company is able to cause each subsidiary to transfer funds, by way of dividend, capital reduction or other right as a shareholder under the applicable law, to the Company to fund the expenses of the Company, including the salary of its officers, director fees, legal fees or the costs of any investigation that the Board of Directors or the Audit Committee (as defined herein) may need to undertake in order to comply with their fiduciary obligations to the Company.
The current members of the board of directors of AKTC are Antonio Correa de sa, Daniel D’Amato and Lewis Black, and the representative director of AKTC is Lewis Black. Pursuant to the Articles of Incorporation of AKTC, the term of office of a director shall be three years; provided, however, that such term shall be extended until the conclusion of the ordinary general meeting of shareholders for the final settlement of accounts within the term. According to Article 385 of the Korean Commercial Code, a director may be removed at any time by a resolution of the general meeting of shareholders passed by the affirmative votes of not less than two-thirds of the voting rights of the shareholders present and not less than one-third of the total number of issued shares. However, if the director is removed before the expiration of his or her term without just cause, the director may claim compensation for damages resulting from such dismissal against AKTC. In the case of removing a representative director while retaining his or her position as a director, as AKTC’s Articles of Incorporation stipulate that the representative director be appointed by a resolution of the general meeting of shareholders, with the approval of a majority of the shareholders present and at least one-quarter of the total issued shares, the removal and replacement of a representative director may also be carried out according to the same procedure, and Article 385 of the Korean Commercial Code would not apply.
The Company’s books and records are located at the principal office of the Company. The minute books, corporate seal (if applicable) and records of AKTC are held in Seoul, Korea. There are no restrictions on the Board of Directors from accessing the books and records of the Company.
The Company confirms that there are no material agreements that involve AKTC that have not been identified as a material contract of the Company and that could reasonably be considered a material contract if the Company itself were a party to the agreement. A “material change” in the business, operations or capital of AKTC would be regarded as a material change for the Company.
| Page | 29 |
Management’s Discussion and Analysis
Year Ended December 31, 2025
Dated: March 18, 2026
(in 000’s of Canadian Dollars, unless otherwise noted)
Shareholder Rights
The Company is a corporation existing under the Canada Business Corporations Act (the “CBCA”) and is a reporting issuer in the provinces of Ontario, Alberta and British Columbia. Shareholders of the Company have all rights and remedies available to them under the CBCA and applicable securities laws.
The fact that the Sangdong Mine is located in Korea and that title to the mine is held by AKTC, which is incorporated under Korean law, does not affect a shareholder’s ability to exercise statutory rights and remedies against the Company under applicable securities laws. However, the enforcement of a judgment obtained in a Canadian court could be adversely affected by the fact that certain of the Company’s assets are located outside of Canada, including the Sangdong Mine. Further, certain directors and officers are resident outside of Canada. The enforcement of judgments obtained in a Canadian court against such directors or officers of the Company may be adversely affected by the fact that they reside outside of Canada.
Management Experience in Foreign Jurisdiction
The Board of Directors and officers of Almonty have some but generally limited experience conducting business in Korea.
For directors and officers with limited experience conducting business in Korea, in order to facilitate such individuals familiarizing themselves with: (i) the laws and legal/operational requirements of Korea; (ii) the role the government of Korea has in the Company’s Korean operations; and (iii) the local business culture and practices in Korea, including differences in banking systems and controls as between Korea and the jurisdiction(s) they are familiar with, the Company has taken the following measures:
| ● | the Company has facilitated visits of such individuals to Korea as well as the material projects of the Company; | |
| ● | the Company has engaged English-speaking local legal counsel in Korea; | |
| ● | there is active communication among and between directors and officers with experience conducting business in Korea and those with more limited experience in Korea; and | |
| ● | regular updates on current events and business in Korea are shared among directors and officers. |
Of the current members of the Board of Directors, a majority have visited Korea and the Sangdong Mine. The members of the Board of Directors receive regular updates regarding the Company’s operations in Korea and are able to discuss with local management in Korea on a regular basis via teleconference/telephone.
Internal Control over Financial Reporting
The Company maintains ICFR with respect to its operations in emerging jurisdictions by taking various measures. Certain of the Company’s key employees have the relevant language proficiency (Korean in Korea), local cultural understanding, and relevant work experience in each of the Company’s operating jurisdictions, which facilitates better understanding and oversight of the Company’s operations in the foreign jurisdictions in the context of internal controls over financial reporting.
Differences in banking systems and controls between Canada and Korea are addressed by having stringent controls over cash in all locations, especially over access to cash, cash disbursements, appropriate authorization levels, performing and reviewing bank reconciliations in Korea on a regular basis, and the segregation of duties.
| Page | 30 |
Management’s Discussion and Analysis
Year Ended December 31, 2025
Dated: March 18, 2026
(in 000’s of Canadian Dollars, unless otherwise noted)
The difference in cultures and practices between Canada and Korea is addressed by employing competent staff in Canada and Korea who are familiar with the local laws, business culture, and standard practices, have local language proficiency, are experienced in working in the jurisdiction and in dealing with the relevant governmental authorities, and have experience and knowledge of the local banking systems and treasury requirements.
The foreign subsidiaries also have established practices, protocols, and routines in place for the distribution of their excess cash to the Company. Furthermore, the opening and closing of bank accounts in the name of a foreign subsidiary is controlled, overseen, and approved by the Company.
The Company will ensure the flow of funds between Canada and Korea functions as intended by:
| ● | controlling the Company’s treasury management and control over bank accounts; | |
| ● | appointing common directors and/or officers of the Company and the foreign subsidiary; | |
| ● | closely monitoring the finance departments in Korea; and | |
| ● | by regular personal visits by the CEO, CFO, other key executives and members of the Board of Directors to Korea. |
| 19. | Forward-looking Information |
This MD&A contains “forward-looking statements” and “forward-looking information” within the meaning of applicable securities laws.
All statements, other than statements of present or historical facts, are forward-looking statements. Forward-looking statements involve known and unknown risks, uncertainties and assumptions and accordingly, actual results could differ materially from those expressed or implied in such statements.
You are hence cautioned not to place undue reliance on forward-looking statements. Forward-looking statements are typically identified by words such as “plan”, “development”, “growth”, “continued”, “intentions”, “expectations”, “emerging”, “evolving”, “strategy”, “opportunities”, “anticipated”, “trends”, “potential”, “outlook”, “ability”, “additional”, “on track”, “prospects”, “viability”, “estimated”, “reaches”, “enhancing”, “strengthen”, “target”, “believes”, “next steps” or variations of such words and phrases or statements that certain actions, events or results “may”, “could”, “would”, “might” or “will” be taken, occur or be achieved. Forward-looking statements in this MD&A include, but are not limited to, statements with respect to: demand for tungsten; tungsten prices; tungsten recovery and production; reductions in operating and unit production costs; currency and interest rate fluctuations; expectations regarding impairments of the Company’s mineral properties; improvements in efficiencies or reduction in dilution; future remediation and reclamation activities; expectations regarding the further exploration, development and life of mine of the Company’s mineral projects, including the Sangdong Mine, the Panasqueira Mine and the Gentung Tungsten Project; plans and expectations regarding the Company’s mineral projects, including the re-opening of the Los Santos Mine, the potential of the Sangdong Molybdenum Project, the potential production profile of the Gentung Tungsten Project and the development of and production at the Gentung Tungsten Project; the estimation of mineral reserves and mineral resources; the realization of mineral reserve and mineral resource estimates; the timing of activities; the amount of estimated revenues and expenses; the success of exploration activities; permitting timelines; the success of mine development and construction activities; the success of future mine operations; the success of other future business operations; the U.S. Domestication, litigation risks; changes to governmental laws and regulations; and requirements for additional capital and sources and uses of funds.
| Page | 31 |
Management’s Discussion and Analysis
Year Ended December 31, 2025
Dated: March 18, 2026
(in 000’s of Canadian Dollars, unless otherwise noted)
Forward-looking statements are based upon certain assumptions and other important factors that, if untrue, could cause actual results to be materially different from future results expressed or implied by such statements. There can be no assurance that forward-looking statements will prove to be accurate. Key assumptions upon which the Company’s forward-looking information is based include, without limitation: the absence of material adverse changes in the Company’s industry or the global economy including interest rate fluctuations, inflationary pressures, supply chain disruptions, and commodity market volatility; trends in the Company’s industry and markets, including the competitive environment; the ability of the Company to maintain its interests in its mineral projects, including with respect to title, access, and permitting matters; the Company’s ability to manage risks normally incidental to the exploration, development and operation of mineral properties; the performance and results of Phase I operations at the Sangdong Mine; the Company’s ability to proceed with Phase II expansion of the Sangdong Mine; the Company’s ability to maintain good business relationships with key stakeholders, including customers, suppliers, lenders, regulators, and local communities; the Company’s ability to manage its growth effectively, both organically and through acquisitions; the Company’s ability to effectively integrate acquisitions and realize anticipated benefits; the Company’s ability to manage potential uncertainties in the interpretation of geological data, drill results and market data, including data related to pricing trends, demand forecasts, and competitive positioning; the Company’s ability to manage the possibility that future exploration, development or mining results may not be consistent with its expectations; the accuracy of the Company’s mineral resource and reserve estimates and their underlying assumptions, including with respect to cut-off grades, recovery rates, and long-term commodity prices; the adequacy and availability of infrastructure (including power, water, roads, and processing capacity) at or near the mineral properties; the timely receipt and maintenance of necessary governmental and third-party approvals, permits, licenses, authorizations and regulatory compliance obligations; the Company’s ability to comply with current and future environmental, health and safety, and other regulatory requirements and to timely obtain and maintain required regulatory approvals, licenses and permits; the Company’s expectation that its operations will not be significantly disrupted as a result of political instability, pandemics and communicable diseases, nationalization, terrorism, sabotage, social or political activism, breakdown, natural disasters, governmental or political actions, litigation or arbitration proceedings, equipment or infrastructure failure, labour shortages, transportation disruptions or accidents, or other development or exploration risks; the Company’s ability to execute construction and development activities on schedule and within budget; the Company’s ability to recruit, retain and engage qualified personnel and contractors in all required jurisdictions; the Company’s ability to raise sufficient debt or equity financing to support its continued growth; the Company’s ability to continue to have sufficient working capital to fund its operations; the performance of counterparties under offtake agreements, supply arrangements, financing agreements, and other material contracts; that input costs, including energy, labour, equipment, and materials, will not increase materially beyond current expectations; that the price of tungsten and other metals and commodities will not decline significantly or for a protracted period of time; that the global financial markets and general economic conditions (including trade and monetary policies, currency exchange rates and rates of inflation) will be stable and conducive to business in the future; the Company’s ability to maintain the security and integrity of its information technology systems and mitigate the impact of any potential cybersecurity threats; and the Company’s ability to meet increasing expectations regarding environmental, social and governance (“ESG”) matters from regulators, investors, and other stakeholders.
| Page | 32 |
Management’s Discussion and Analysis
Year Ended December 31, 2025
Dated: March 18, 2026
(in 000’s of Canadian Dollars, unless otherwise noted)
Forward-looking statements are also subject to risks and uncertainties facing the Company’s business, including, without limitation: the negative cash flow from the Company’s operations; the adequacy of the Company’s disclosure control and procedures and internal controls over financial reporting; the price of metals; the Company’s economic dependency on few customers; fluctuation in foreign currency; fluctuation in interest rates; inflation; tax-related risks; the risk of default under any of the Company’s credit agreements; future financing; the Company’s liquidity and level of indebtedness; risks associated with the Company’s business being carried on through foreign subsidiaries; credit risk; the Company’s ability to continue as a going concern; risks relating to the development of the Sangdong Mine, including risks relating to the start-up of commercial production, commissioning, ramp-up and process performance risk, financing risk, construction risks, risk relating to the offtake agreements for the Sangdong Mine, availability of infrastructure and skilled labour, and risks related to the implementation of technological innovations at the Sangdong Mine; risks relating to the Tungsten Oxide Facility, including project financing and capital cost overrun risk, execution and construction risk, and permitting and regulatory risk; the Company’s production; the Company’s mineral reserve and mineral resource estimates; the Company’s dependence on key personnel; the Company’s competition; trade risks and supply chain disruptions (including as a result of geopolitical tensions); the cost of raw materials; energy supply and power grid reliability; water supply and management; infrastructure and operational risks; the Company’s impairment of assets; risks related to property title; laws and regulations; licenses and permits; mining risks and insurance limitations; legal systems; mineral reserve and mineral resource depletion; risks related to underground stope stability; reputational risks; geopolitical risks in key operating regions; public allegations, regulatory investigations, or litigation; capital market structure and dilution risk; environmental and global climate change risks; risks related to costs of land reclamation; technological obsolescence; management of growth; cybersecurity and data protection; opposition to mining; costs and compliance risks as a result of being a public company; acquisitions and synergies; anti-corruption and anti-bribery laws; Canada’s Extractive Sector Transparency Measures Act; health and pandemic risks; and risks related to the Company’s proposed redomiciling to the United States, including disruptions to the Company’s business, Canadian corporate tax risk.
Any of these risks could have a material adverse effect on the Company’s business, financial condition, results of operations and growth prospects. Readers should consider reviewing the detailed risk discussion under the heading “RISK FACTORS” of the AIF for a fuller understanding of the risks and uncertainties that affect the Company’s business and operations and that could cause the Company’s actual results, performance or achievements to be materially different from any anticipated results, performance or achievements expressed or implied by forward-looking statements.
Although Almonty has attempted to identify important factors that could cause actual results, level of activity, performance or achievements to differ materially from those contained in forward-looking statements, there may be other factors that cause results, level of activity, performance or achievements not to be as anticipated, estimated or intended. There can be no assurance that forward-looking statements will prove to be accurate and even if events or results described in the forward-looking statements are realized or substantially realized, there can be no assurance that they will have the expected consequences to, or effects on, Almonty. Accordingly, readers should not place undue reliance on forward-looking statements and are cautioned that actual outcomes may vary.
| Page | 33 |
Management’s Discussion and Analysis
Year Ended December 31, 2025
Dated: March 18, 2026
(in 000’s of Canadian Dollars, unless otherwise noted)
Investors are cautioned against attributing undue certainty to forward-looking statements. Almonty cautions that the foregoing list of material factors is not exhaustive. When relying on Almonty’s forward- looking statements and information to make decisions, investors and others should carefully consider the foregoing factors and other uncertainties and potential events. Almonty has also assumed that material factors will not cause any forward-looking statements and information to differ materially from actual results or events. However, the list of these factors is not exhaustive and is subject to change and there can be no assurance that such assumptions will reflect the actual outcome of such items or factors.
THE FORWARD-LOOKING INFORMATION CONTAINED IN THIS MD&A REPRESENTS THE EXPECTATIONS OF ALMONTY AS OF THE DATE OF THIS MD&A AND, ACCORDINGLY, IS SUBJECT TO CHANGE AFTER SUCH DATE. READERS SHOULD NOT PLACE UNDUE IMPORTANCE ON FORWARD-LOOKING INFORMATION AND SHOULD NOT RELY UPON THIS INFORMATION AS OF ANY OTHER DATE. WHILE ALMONTY MAY ELECT TO, IT DOES NOT UNDERTAKE TO UPDATE THIS INFORMATION AT ANY PARTICULAR TIME, WHETHER AS A RESULT OF NEW INFORMATION, FUTURE EVENTS OR OTHERWISE, EXCEPT AS REQUIRED IN ACCORDANCE WITH APPLICABLE LAWS.
| 20. | General |
The Company’s management is responsible for the preparation of the Company’s unaudited interim condensed consolidated financial statements as well as other information contained in this MD&A. The Board of Directors is required to ensure that management assumes its responsibility in regard to the preparation of the Company’s financial statements. To facilitate this process, the Board of Directors has created an audit committee (the “Audit Committee”). The Audit Committee met with members of the management team to discuss the operating results and the financial results of the Company, before making their recommendations and submitting the Annual Financial Statements and MD&A to the Board of Directors for review and approval. Following the recommendation of the Audit Committee, the Board of Directors approved the Annual Financial Statements and this MD&A on March 12, 2026.
The Annual Financial Statements have been prepared in accordance with IFRS.
Adam Wheeler, B.Sc, M.Sc, C. Eng., an independent qualified person pursuant to NI 43-101, reviewed, prepared or supervised the preparation of, and approved, the information upon which the scientific and technical information relating to the Company’s mineral properties contained in this MD&A is based.
| 21. | Additional Information |
Additional information relating to the Company, including the Annual Financial Statements and the AIF, is available on the Company’s website at www.almonty.com and on SEDAR+ at www.sedarplus.ca under the Company’s profile.
| 22. | Management’s Responsibility for Financial Statements |
The information provided in this MD&A, including the Company’s financial statements, is the responsibility of management. In the preparation of these statements, estimates are sometimes necessary to make a determination of future values for certain assets or liabilities. Management believes such estimates have been based on careful judgements and have been properly reflected in the accompanying financial statements.
March 18, 2026
On behalf of the Company’s management and the Board of Directors,
“Lewis Black”
___________________________________
Chairman, President and Chief Executive Officer
| Page | 34 |
Management’s Discussion and Analysis
Year Ended December 31, 2025
Dated: March 18, 2026
(in 000’s of Canadian Dollars, unless otherwise noted)
Glossary of Terms
| A$ | Australian dollars | |
| APT | ammonium para tungstate is an intermediate product which is one of the principal chemical forms in which tungsten is traded | |
| ASX | Australian Securities Exchange | |
| Board of Directors | the board of directors of the Company | |
| C$ | Canadian dollars | |
| CDI | CHESS Depositary Interests, the form under which the Company’s common shares trade on the ASX, with each CDI representing a single common share | |
| concentrate | the valuable fraction of an ore that is left after waste material is removed in processing | |
| € | Euros | |
| Frankfurt | Frankfurt Stock Exchange | |
| KRW | Korean Won | |
| MTU | metric tonne unit, equal to 1 percent of a metric tonne or 10 kg (22.046 pounds) of contained WO3 | |
| Nasdaq | Nasdaq Capital Market | |
| NI 43-101 | National Instrument 43-101 – Standards of Disclosure for Mineral Projects | |
| NI 52-109 | National Instrument 52-109 – Certification of Disclosure in Issuers’ Annual and Interim Filings | |
| scheelite | a brown tetragonal mineral, CaWO4. It is found in pneumatolytic veins associated with quartz and fluoresces to show a blue colour. Scheelite is a mineral of tungsten | |
| tonne | a metric unit equal to 1,000 kg (2,204.6 pounds) | |
| TSX | Toronto Stock Exchange | |
| tungsten concentrates | concentrates generally containing between 40 and 75 percent WO3 | |
| US$ | United States dollars | |
| WO3 | tungsten tri-oxide, a compound of tungsten and oxygen |
| Page | 35 |