N-4
Apr. 17, 2026
USD ($)
Index Options.
You may allocate your Purchase Payments to any or all of the Index Options available under your Contract. The
Contract currently offers Index Options with different types of Crediting Methods, including the Index Protection Strategy with Trigger,
Index Protection Strategy with Cap, Index Precision Strategy, Index Dual Precision Strategy, Index Guard Strategy, and Index Performance
Strategy.
We credit positive, zero, or negative
Performance Credits (i.e.,
positive, zero, or negative interest) at the end of a Term for amounts allocated to an Index Option based, in part, on the performance
of the applicable Index (the Index Return).
Other Index Options include a feature, either a Buffer or
Floor, that provides limited protection from negative Index Returns. Under these other Index Options, you may lose a significant amount
of money if an Index declines in value.
Each Index Option offers a certain
level of protection from negative Index Returns.
Each Index Option offers a certain
level of protection from negative Index Returns.
−
The Index Protection Strategy with Trigger and Index Protection
Strategy with Cap offer complete (or 100%) protection from negative Index Returns. For example, if at the end of a Term, the Index Return
is -25%, we will apply a 0% Performance Credit to your investment (i.e.,
no loss due to the negative Index Return).
−
Other Index Options include a feature, either a Buffer or
Floor, that provides limited protection from negative Index Returns. Under these other Index Options, you may lose a significant amount
of money if an Index declines in value.
○
Buffer – A Buffer is the maximum amount of negative
Index Return that we
absorb before applying a negative Performance Credit. For example, if at the end of a Term, the Index Return is -25% and the Buffer is
10%, we apply a Performance Credit of -15%, meaning your Contract Value allocated to that Index Option will decrease by 15% since the
Term Start Date. This reflects the negative Index Return that exceeds the protection of the 10% Buffer. The Index Precision Strategy,
Index Dual Precision Strategy, and Index Performance Strategy offer Index Options with Buffers.
○
Floor – A Floor, on the other hand, is the maximum
amount of negative Index Return you
absorb as a negative Performance Credit. We absorb any negative Index Return beyond the Floor. For example, if the Index Return is -25%
and the Floor is -10%, we apply a Performance Credit of -10%, meaning your Contract Value allocated to that Index Option will decrease
by 10% since the Term Start Date. This reflects the negative Index Return down to the -10% Floor and no further reduction in Index Option
Value occurring as a result. The Index Guard Strategy offers Index Options with a Floor.
−
The current limit on Index loss for an Index Option will
not change for the life of that Index Option. However, we reserve the right to add new Index Options, as well as close Index Options to
new Purchase Payments and transfers. As such, the limits on Index loss offered under the Contract may change from one Term to the next
if we add an Index Option or discontinue accepting new allocations into an Index Option.
−
If we offer a new Index Option with a Buffer or Floor in
the future, the Buffer or Floor will be no lower than 5% or -25%, respectively.
−
At least one Index Option with a Buffer
no lower than 5% or Floor no lower than -25%,
or an Index Option that provides complete protection from Index losses, will always be available for renewal under the Contract.
At least one Index Option with a Buffer
no lower than 5% or Floor no lower than -25%,
or an Index Option that provides complete protection from Index losses, will always be available for renewal under the Contract.
The current limit on Index loss for an Index Option will
not change for the life of that Index Option. However, we reserve the right to add new Index Options, as well as close Index Options to
new Purchase Payments and transfers. As such, the limits on Index loss offered under the Contract may change from one Term to the next
if we add an Index Option or discontinue accepting new allocations into an Index Option.
Each
Index Option also has an upside feature, either a Trigger Rate, Cap, and/or Participation Rate, used in the calculation of positive Performance
Credits, if any, that may be credited to your investment at the end of a Term. We may limit the amount you can earn on
an Index Option based on the Trigger Rate, Cap or Participation Rate, as applicable.
−
Trigger Rate
– A Trigger Rate represents the positive Performance Credit, if any, that may apply on the Term End Date. The Index Precision Strategy,
Index Dual Precision Strategy, and Index Protection Strategy with Trigger offer Index Options with a Trigger Rate.
○
For the Index Precision Strategy and Index Protection Strategy
with Trigger, the Trigger Rate will apply if the Index Return is positive or zero. For example, if at the end of a Term, the Index Return
is 6% and the Trigger Rate is 3%, we apply a Performance Credit of 3%, meaning your Contract Value allocated to that Index Option will
increase by 3% since the Term Start Date.
○
For the Index Dual Precision Strategy, the Trigger Rate will
apply if the Index Return is positive, zero, or to a limited extent, negative. For example, assume a Trigger Rate of 3% and a Buffer of
10%. If at the end of a Term, the Index Return is positive, zero, or negative but no lower than -10% (i.e., not in excess of the Buffer),
we apply a positive Performance Credit of 3%, meaning your Contract Value allocated to that Index Option will increase by 3% since the
Term Start Date. However, if the negative Index Return were lower than -10% (i.e., in excess of the Buffer), we apply a negative Performance
Credit equal to the negative Index Return plus the Buffer, as previously summarized above.
−
Cap – A Cap represents the maximum positive Performance
Credit, if any, applied on a Term End Date. For example, if at the end of a Term, the Index Return is 12% and the Cap is 10%, we apply
a Performance Credit of 10%, meaning your Contract Value allocated to that Index Option will increase by 10% since the Term Start Date.
The Index Protection Strategy with Cap, Index Guard Strategy, and Index Performance Strategy offer Index Options with a Cap. Index Performance
Strategy multi-year Term Index Options have both a Cap and a Participation Rate (as described below).
−
Participation Rate
– A Participation Rate is the percentage that is multiplied by a positive Index Return in calculating a positive Performance Credit,
if any, subject to any applicable Cap. For example, if at the end of a Term, the Participation Rate is 100%, the Cap is 15%, and the Index
Return is 12% (which is lower than the Cap), we apply a Performance Credit of 12% (i.e.,
100% x 12%). However, if the Index Return were instead 20% (which is higher than the Cap), we would apply the Cap and a Performance Credit
of 15% would be applied. Index Performance Strategy multi-year Term Index Options have both a Participation Rate and a Cap.
−
The Trigger Rate, Cap, and/or Participation Rate for an Index
Option will change from Term to Term, subject to a specified guaranteed minimum that will not change for the life of that Index Option.
Guaranteed minimum Trigger Rates, Caps, and/or Participation Rates vary by Index Option.
−
If we add a new Index Option to the Contract in the future,
the lowest Trigger Rate, Cap, and Participation Rate that we may establish are 0.05%, 0.05%, and 5.00%, respectively. For example, if
the Trigger Rate or Cap for a new Index Option is 0.05% and the Index Return is 10%, a 0.05% Performance Credit would be applied. Similarly,
if the Participation Rate for a new Index Option is 5.00%, the Index Option is uncapped, and the Index Return is 10%, a 0.50% Performance
Credit would be applied.
|
|
FEES,
EXPENSES, AND ADJUSTMENTS |
Prospectus
Location
| ||
|
Are
There
Charges
or
Adjustments
for
Early
Withdrawals?
|
Yes,
your Contract may be subject to charges for early withdrawals. If you withdraw money
within
seven
years after we establish an Annual Contribution Amount, an MVA based on
changes
in interest rates will apply. An MVA may be positive, negative, or equal to zero. The
maximum
negative MVA is -10%
(as a percentage of Contract Value for a full withdrawal, or
as
a percentage of the amount withdrawn for a partial withdrawal). For example, if you take
a
$100,000 withdrawal during the period the MVA applies, you could lose up to $10,000 due
to
a negative MVA. This loss will be greater if there is a negative Daily Adjustment, income
taxes,
or tax penalties.
In
addition, if you take a full or partial withdrawal from an Index Option on a date other than
the
Term End Date, a Daily Adjustment will apply to the Index Option Value available for
withdrawal.
The Daily Adjustment also applies if before the Term End Date you take Income
Payments,
you execute a Performance Lock, you annuitize the Contract, we pay a death
benefit,
or we deduct Contract fees, expenses, or investment advisory fees you authorize
your
Financial Professional’s firm to receive from the Contract. The Daily Adjustment may
be
negative depending on the applicable Crediting Method. You will lose money if the Daily
Adjustment
is negative.
●Index
Dual Precision Strategy, Index Precision Strategy, Index Guard Strategy,
and
Index Performance Strategy. Daily Adjustments
under these Crediting Methods
may
be positive, negative, or equal to zero. A negative Daily Adjustment will result in a
loss,
and could result in a loss beyond the protection of the 10%, 20%, or 30% Buffer;
or
-10% Floor, as applicable. The maximum potential loss from a negative Daily
Adjustment
is: -99% for the Index Dual Precision Strategy, Index Precision Strategy,
and
Index Performance Strategy; and -35% for the Index Guard Strategy. For
example,
if you allocate $100,000 to a 1-year Term Index Option with 10% Buffer and
later
withdraw the entire amount before the Term has ended, you could lose up to
$99,000
of your investment. This loss will be greater if you also are subject to a
negative
MVA, income taxes, and tax penalties.
●Index
Protection Strategy with Trigger and Index Protection Strategy with Cap.
Daily
Adjustments under these Crediting Methods may be positive or equal to zero, but
cannot
be negative. |
Fee
Tables
7.
Expenses and
Adjustments
Appendix
C –
Daily
Adjustment
| ||
|
Are
There
Transaction
Charges?
|
No.
Other than negative MVAs and Daily Adjustments that may apply to withdrawals and
other
transactions under the Contract, there are no other transaction charges. |
Not
Applicable | ||
|
|
FEES,
EXPENSES, AND ADJUSTMENTS |
Prospectus
Location
| ||
|
Are
There
Ongoing
Fees
and
Expenses?
|
Yes,
there are ongoing fees and expenses. The table below describes the fees and
expenses
that you may pay each
year, depending on the options you choose.
Please refer
to
your Contract specifications page for information about the specific fees you will pay
each
year based on the options you have elected.
These ongoing fees and expenses do
not
reflect any investment advisory fees paid to a Financial Professional from your Contract
Value
or other assets of the Owner. If such charges were reflected, these ongoing fees and
expenses
would be higher.
There
is an implicit ongoing fee on Index Options to the extent that your participation
in
Index gains is limited by us through a Cap or Trigger Rate. This
means that your
returns
may be lower than the Index’s returns. In return for accepting this limit on Index
gains,
you will receive some protection from Index losses. This implicit ongoing fee is not
reflected
in the tables below. Additionally,
if we add Index Options with a guaranteed
minimum
Participation Rate less than 100%, the Participation Rate would be an
implicit
ongoing fee and limit Index gains.
|
Fee
Tables
1.
The Contract –
Investment
Advisory
Fees
7.
Expenses and
Adjustments
Appendix
A –
Investment
Options
Available
Under
the
Contract
| ||
|
Annual
Fee |
Minimum
|
Maximum
| ||
|
Base
Contract(1)
|
0.96%
|
0.96%
| ||
|
Investment
Options(2)
(Fund
fees and expenses) |
0.66%
|
0.66%
| ||
|
Optional
Benefits Available for an Additional
Charge(3)
(for
a single optional benefit, if elected) |
0.20%
|
0.20%
| ||
|
|
(1)
Base
Contract fee is comprised of two charges referred to as the “product fee” and the “rider fee for the
Income
Benefit” in the Contract and elsewhere in this prospectus. As a percentage of the Charge Base, plus
an
amount attributable to the contract maintenance charge. |
| ||
|
|
(2)
As a percentage
of the AZL Government Money Market Fund's average daily net assets. |
| ||
|
|
(3)
As
a percentage of the Charge Base. This is the current charge for the Maximum Anniversary Value Death
Benefit.
|
| ||
|
|
Because
your Contract is customizable, the choices you make affect how much you will
pay.
To help you understand the cost of owning your Contract, the following table shows the
lowest
and highest cost you could pay each
year, based on current charges. This estimate
assumes
that you do not take withdrawals from the Contract, which
could add a negative
Daily
Adjustment and/or negative MVA that could substantially increase costs. |
| ||
|
|
Lowest
Annual Cost:
$1,506
|
Highest
Annual Cost:
$1,677
|
| |
|
|
Assumes:
●Investment
of $100,000 in the Variable
Option
(even though you cannot select
the
Variable Option for investment)
●5%
annual appreciation
●0.70%
Income Benefit rider fee
●Traditional
Death Benefit
●No
additional Purchase Payments,
transfers,
or withdrawals
●No
investment advisory fees
●No
Daily Adjustment |
Assumes:
●Investment
of $100,000 in the Variable
Option
(even though you cannot select
the
Variable Option for investment)
●5%
annual appreciation
●0.70%
Income Benefit rider fee
●Maximum
Anniversary Value Death
Benefit
with a 0.20% rider fee
●No
additional Purchase Payments,
transfers,
or withdrawals
●No
investment advisory fees
●No
Daily Adjustment |
| |
Are
There
Charges
or
Adjustments
for
Early
Withdrawals?
Yes,
your Contract may be subject to charges for early withdrawals. If you withdraw money
within
seven
years after we establish an Annual Contribution Amount, an MVA based on
changes
in interest rates will apply. An MVA may be positive, negative, or equal to zero. The
maximum
negative MVA is -10%
(as a percentage of Contract Value for a full withdrawal, or
as
a percentage of the amount withdrawn for a partial withdrawal). For example, if you take
a
$100,000 withdrawal during the period the MVA applies, you could lose up to $10,000 due
to
a negative MVA. This loss will be greater if there is a negative Daily Adjustment, income
taxes,
or tax penalties.
In
addition, if you take a full or partial withdrawal from an Index Option on a date other than
the
Term End Date, a Daily Adjustment will apply to the Index Option Value available for
withdrawal.
The Daily Adjustment also applies if before the Term End Date you take Income
Payments,
you execute a Performance Lock, you annuitize the Contract, we pay a death
benefit,
or we deduct Contract fees, expenses, or investment advisory fees you authorize
your
Financial Professional’s firm to receive from the Contract. The Daily Adjustment may
be
negative depending on the applicable Crediting Method. You will lose money if the Daily
Adjustment
is negative.
●Index
Dual Precision Strategy, Index Precision Strategy, Index Guard Strategy,
and
Index Performance Strategy. Daily Adjustments
under these Crediting Methods
may
be positive, negative, or equal to zero. A negative Daily Adjustment will result in a
loss,
and could result in a loss beyond the protection of the 10%, 20%, or 30% Buffer;
or
-10% Floor, as applicable. The maximum potential loss from a negative Daily
Adjustment
is: -99% for the Index Dual Precision Strategy, Index Precision Strategy,
and
Index Performance Strategy; and -35% for the Index Guard Strategy. For
example,
if you allocate $100,000 to a 1-year Term Index Option with 10% Buffer and
later
withdraw the entire amount before the Term has ended, you could lose up to
$99,000
of your investment. This loss will be greater if you also are subject to a
negative
MVA, income taxes, and tax penalties.
●Index
Protection Strategy with Trigger and Index Protection Strategy with Cap.
Daily
Adjustments under these Crediting Methods may be positive or equal to zero, but
cannot
be negative.
Are
There
Transaction
Charges?
No.
Other than negative MVAs and Daily Adjustments that may apply to withdrawals and
other
transactions under the Contract, there are no other transaction charges.
Not
Applicable
Are
There
Ongoing
Fees
and
Expenses?
Yes,
there are ongoing fees and expenses. The table below describes the fees and
expenses
that you may pay each
year, depending on the options you choose.
Please refer
to
your Contract specifications page for information about the specific fees you will pay
each
year based on the options you have elected.
These ongoing fees and expenses do
not
reflect any investment advisory fees paid to a Financial Professional from your Contract
Value
or other assets of the Owner. If such charges were reflected, these ongoing fees and
expenses
would be higher.
There
is an implicit ongoing fee on Index Options to the extent that your participation
in
Index gains is limited by us through a Cap or Trigger Rate. This
means that your
returns
may be lower than the Index’s returns. In return for accepting this limit on Index
gains,
you will receive some protection from Index losses. This implicit ongoing fee is not
reflected
in the tables below. Additionally,
if we add Index Options with a guaranteed
minimum
Participation Rate less than 100%, the Participation Rate would be an
implicit
ongoing fee and limit Index gains.
Fee
Tables
1.
The Contract –
Investment
Advisory
Fees
7.
Expenses and
Adjustments
Appendix
A –
Investment
Options
Available
Under
the
Contract
Annual
Fee
Minimum
Maximum
Base
Contract(1)
0.96%
0.96%
Investment
Options(2)
(Fund
fees and expenses)
0.66%
0.66%
Optional
Benefits Available for an Additional
Charge(3)
(for
a single optional benefit, if elected)
0.20%
0.20%
(1)
Base
Contract fee is comprised of two charges referred to as the “product fee” and the “rider fee for the
Income
Benefit” in the Contract and elsewhere in this prospectus. As a percentage of the Charge Base, plus
an
amount attributable to the contract maintenance charge.
(2)
As a percentage
of the AZL Government Money Market Fund's average daily net assets.
(3)
As
a percentage of the Charge Base. This is the current charge for the Maximum Anniversary Value Death
Benefit.
Because
your Contract is customizable, the choices you make affect how much you will
pay.
To help you understand the cost of owning your Contract, the following table shows the
lowest
and highest cost you could pay each
year, based on current charges. This estimate
assumes
that you do not take withdrawals from the Contract, which
could add a negative
Daily
Adjustment and/or negative MVA that could substantially increase costs.
Lowest
Annual Cost:
$1,506
Highest
Annual Cost:
$1,677
Assumes:
●Investment
of $100,000 in the Variable
Option
(even though you cannot select
the
Variable Option for investment)
●5%
annual appreciation
●0.70%
Income Benefit rider fee
●Traditional
Death Benefit
●No
additional Purchase Payments,
transfers,
or withdrawals
●No
investment advisory fees
●No
Daily Adjustment
Assumes:
●Investment
of $100,000 in the Variable
Option
(even though you cannot select
the
Variable Option for investment)
●5%
annual appreciation
●0.70%
Income Benefit rider fee
●Maximum
Anniversary Value Death
Benefit
with a 0.20% rider fee
●No
additional Purchase Payments,
transfers,
or withdrawals
●No
investment advisory fees
●No
Daily Adjustment
Base
Contract fee is comprised of two charges referred to as the “product fee” and the “rider fee for the
Income
Benefit” in the Contract and elsewhere in this prospectus. As a percentage of the Charge Base, plus
an
amount attributable to the contract maintenance charge.
As
a percentage of the Charge Base. This is the current charge for the Maximum Anniversary Value Death
Benefit.
Because
your Contract is customizable, the choices you make affect how much you will
pay.
To help you understand the cost of owning your Contract, the following table shows the
lowest
and highest cost you could pay each
year, based on current charges. This estimate
assumes
that you do not take withdrawals from the Contract, which
could add a negative
Daily
Adjustment and/or negative MVA that could substantially increase costs.
Lowest
Annual Cost:
$1,506
Highest
Annual Cost:
$1,677
Assumes:
●Investment
of $100,000 in the Variable
Option
(even though you cannot select
the
Variable Option for investment)
●5%
annual appreciation
●0.70%
Income Benefit rider fee
●Traditional
Death Benefit
●No
additional Purchase Payments,
transfers,
or withdrawals
●No
investment advisory fees
●No
Daily Adjustment
Assumes:
●Investment
of $100,000 in the Variable
Option
(even though you cannot select
the
Variable Option for investment)
●5%
annual appreciation
●0.70%
Income Benefit rider fee
●Maximum
Anniversary Value Death
Benefit
with a 0.20% rider fee
●No
additional Purchase Payments,
transfers,
or withdrawals
●No
investment advisory fees
●No
Daily Adjustment
|
|
RISKS
|
Prospectus
Location
| ||
|
Is
There a Risk
of
Loss from
Poor
Performance?
|
Yes,
you can lose money by investing in the Contract, including loss of principal and
previous
earnings.
The
maximum amount of loss that you could experience from negative Index Return,
after
taking into account the current limits on Index loss provided under the
Contract,
is: -90% with a 10% Buffer; -80% with a 20% Buffer; -70% with a 30% Buffer;
-10%
with the Floor; and 0% with the Index Protection Strategy with Cap and Index
Protection
Strategy with Trigger.
The
limits on Index loss offered under the Contract may change from one Term to the
next
if we add an Index Option or discontinue accepting new allocations into an
Index
Option. However, at least one Index Option with a Buffer no lower than 5% or
Floor
no lower than -25%, or an Index Option that provides complete protection from
Index
losses, will always be available for renewal under the Contract.
|
Principal
Risks of
Investing
In the
Contract
4.
Index Options
6.
Valuing Your
Contract
–
Calculating
Performance
Credits
| ||
|
Is
This a
Short-Term
Investment?
|
• No,
this Contract is not a short-term investment and is not appropriate if you need ready
access
to cash.
• Considering
the benefits of tax deferral, long-term income, and living benefit guarantees,
the
Contract is generally more beneficial to investors with a long investment time horizon.
• Withdrawals
are subject to income taxes, and may also be subject to a 10% additional
federal
tax for amounts withdrawn before age 59 1∕2.
• If,
within seven years after we establish an Annual Contribution Amount, you take a full or
partial
withdrawal or begin Annuity Payments, or we pay a death benefit, an MVA will
apply.
An MVA is an adjustment based on changes in interest rates and may be positive,
negative,
or equal to zero. An MVA will be negative if the corporate bond yield on the date
of
deduction is higher than the corporate bond yield on the date that the Annual
Contribution
Amount was established. If you take a full withdrawal or begin Annuity
Payments,
or if we pay a death benefit, the maximum negative MVA is -10% of Contract
Value.
On a partial withdrawal, we limit the maximum negative MVA to -10% of the
amount
withdrawn.
• Amounts
invested in an Index Option must be held in the Index Option for the full Term
before
they can receive a Performance Credit. We apply a Daily Adjustment if, before the
Term
End Date, you take a full or partial withdrawal, you take Income Payments, you
execute
a Performance Lock, you annuitize the Contract, we pay a death benefit, or we
deduct
Contract fees, expenses, or investment advisory fees that you authorize your
Financial
Professional’s firm to receive from the Contract.
• The
Daily Adjustment may be negative with the Index Dual Precision Strategy, Index
Precision
Strategy, Index Guard Strategy, and Index Performance Strategy. You will lose
money
if the Daily Adjustment is negative.
• Withdrawals
and other deductions from an Index Option prior to a Term End Date will
result
in a proportionate reduction to your Index Option Base. The proportionate reduction
could
be greater than the amount withdrawn or deducted. Reductions to your Index
Option
Base will result in lower Index Option Values for the remainder of the Term and
lower
gains (if any) on the Term End Date.
• On
the Term End Date, you can transfer assets invested in an Index Option by changing
your
allocation instructions. If you do not change your allocation instructions, you will
continue
to be invested in the same Index Option with a new Term Start Date. The new
Term
will be subject to the applicable renewal Trigger Rate, Cap, and/or Participation
Rate.
|
Principal
Risks of
Investing
In the
Contract
4.
Index Options
6.
Valuing Your
Contract
7.
Expenses and
Adjustments
Appendix
C –
Daily
Adjustment | ||
|
|
RISKS
|
Prospectus
Location
| ||
|
What
are the
Risks
Associated
with
the
Investment
Options?
|
• An
investment in the Contract is subject to the risk of poor investment performance and
can
vary depending on the performance of the Variable Option and the Index Options
available
under the Contract.
• The
Variable Option and each Index Option have their own unique risks.
• You
should review the Fund’s prospectus and disclosures, including risk factors, before
making
an investment decision.
•
Caps and Trigger Rates will limit positive Performance Credits (e.g., limited upside). This
may
result in earning less than the Index Return.
– For
example, if at the end of a 1-year Term, the Index Return is 25% and the Cap is
15%,
we apply a Performance Credit of 15%, meaning your Contract Value allocated
to
that Index Option will increase by 15% since the Term Start Date. If at the end of the
Term,
the Index Return is 6% and the Trigger Rate is 3%, we apply a Performance
Credit
of 3%, meaning your Contract Value allocated to that Index Option will increase
by
3% since the Term Start Date.
• The
Buffer or Floor will limit negative Performance Credits (e.g., limited protection in the
case
of Index decline). However,
you bear the risk for all Index losses that exceed
the
Buffer. You also bear the risk for Index losses down to the Floor.
– For
example, if at the end of a Term, the Index Return is -25% and the Buffer is 10%,
we
apply a Performance Credit of -15%, meaning your Contract Value allocated to that
Index
Option will decrease by 15% since the Term Start Date. If the Index Return is
-25%
and the Floor is -10%, we apply a Performance Credit of -10%, meaning your
Contract
Value allocated to that Index Option will decrease by 10% since the Term
Start
Date.
• The
Indexes are price return indexes, not total return indexes. This means that the Index
Options
do not receive any dividends payable on these securities. The Index Options also
do
not directly participate in the returns of the Indexes or the Indexes’ component
securities.
This will reduce the Index Return and may cause the Index to underperform a
direct
investment in the securities composing the Index.
|
Principal
Risks of
Investing
In the
Contract
| ||
|
What
are the
Risks
Related
to
the
Insurance
Company?
|
An
investment in the Contract is subject to the risks related to us. All obligations,
guarantees
or benefits of the Contract, including those relating to the Index Options, are the
obligations
of Allianz Life and are subject to our claims-paying ability and financial strength.
More
information about Allianz Life, including our financial strength ratings, is available
upon
request by visiting https://www.allianzlife.com/about/financial-ratings, or contacting us
at
(800) 624-0197. |
Principal
Risks of
Investing
In the
Contract
| ||
Yes,
there are limits on the Investment Options.
• Certain
Index Options may not be available under your Contract (see Appendix A).
• The
availability of Investment Options may vary depending on the broker-dealer through
which
the Contract is sold (see Appendix H).
• We
can add new Index Options to your Contract in the future.
• You
cannot allocate Purchase Payments to the Variable Option. The sole purpose of the
Variable
Option is to hold Purchase Payments until they are transferred to your selected
Index
Options.
• We
restrict additional Purchase Payments during the Accumulation Phase. Each Index
Year
before the Income Period, you cannot add more than your initial amount (i.e., the
total
of all Purchase Payments received before the first Quarterly Contract Anniversary of
the
first Contract Year) without our prior approval.
• We
do not accept additional Purchase Payments during the Income Period (which is part
of
the Accumulation Phase) or the Annuity Phase.
• We
typically only allow assets to move into the Index Options on the Index Effective Date
and
on subsequent Index Anniversaries as discussed in section 3, Purchasing the
Contract
– Allocation of Purchase Payments and Contract Value Transfers. However, if
you
execute an Early Reallocation, we will move assets into an Index Option on the
Business
Day we receive your Early Reallocation request in Good Order.
• You
can typically transfer Index Option Value only on Term End Dates. However, you can
transfer
assets out of an Index Option before the Term End Date by first executing a
Performance
Lock and then either requesting an Early Reallocation with new allocation
instructions
or changing your allocation instructions before the next Index Anniversary.
For
more information, see section 6, Valuing Your Contract – Performance Locks and
Early
Reallocations.
• We
do not allow assets to move into an established Index Option until the Term End Date.
If
you request to allocate a Purchase Payment into an established Index Option on an
Index
Anniversary that is not a Term End Date, we will allocate those assets to the same
Index
Option with a new Term Start Date.
• We
reserve the right to substitute the Fund in which the Variable Option invests. We also
reserve
the right to close Index Options to new Purchase Payments and transfers, and to
substitute
Indexes either on a Term Start Date or during a Term.
• We
may terminate your ability to make additional Purchase Payments during the
Accumulation
Phase because we reserve the right to decline any or all Purchase
Payments
at any time on a nondiscriminatory basis.
• Caps,
Trigger Rates, and Participation Rates will change from one Term to the next
subject
to their contractual minimum guarantees.
• The
10%, 20%, and 30% Buffers, and -10% Floors for the currently available Index
Options
do not change. However, if we add a new Index Option to your Contract after the
Issue
Date, we establish the Buffer or Floor for it on the date we add the Index Option to
your
Contract. For a new Index Option, the minimum Buffer is 5% and the minimum Floor
is
-25%.
Yes,
there are restrictions on Contract benefits.
• The
availability of Contract benefits may vary depending on the broker-dealer through
which
the Contract is sold (see Appendix H)
• We
do not allow Performance Locks to occur on Term End Dates. We will not execute
your
request for a Performance Lock on Index Protection Strategy with Trigger or Index
Protection
Strategy with Cap Index Options if the Daily Adjustment is zero. This may limit
your
ability to take advantage of the benefits of the Early Reallocation feature. We do not
accept
Early Reallocation requests within 14 calendar days before an Index Anniversary.
You
are limited to twelve Early Reallocation requests each Index Year.
• We
reserve the right to discontinue or modify the Minimum Distribution Program and
Investment
Advisory Fees program.
• Deductions
we make for investment advisory fees reduce your Contract Value (and
therefore
Cash Value) by the amount withdrawn on a dollar for dollar basis. This Contract
Value
reduction also decreases your initial annual maximum Income Payment which is
based
on Contract Value. As Contract Value is one of the components we use to calculate
RMD
payments, these deductions may also reduce your RMD payments. These
deductions
also reduce the following proportionately by the percentage of Contract Value
withdrawn:
Charge Base, Index Option Base, Index Option Value, and Variable Account
Value.
• The
death benefits and Income Benefit are only available during the Accumulation Phase.
Upon
annuitization, these benefits will end.
• The
Income Benefit terms stated in the Income Benefit Supplement may be modified
before
issue. A minimum waiting period applies before Income Payments may be taken
under
the Income Benefit. In addition, even if the waiting period has expired, Income
Payments
cannot begin before age 50. During the Income Period, only the Index Options
with
the Index Protection Strategy with Trigger and Index Protection Strategy with Cap are
available
to you. Withdrawals will reduce the initial annual maximum Income Payment.
Withdrawals
that exceed limits specified by the terms of the Income Benefit (Excess
Withdrawals)
will reduce your future annual maximum Income Payment. These reductions
may
be greater than the value withdrawn and could end the benefit. After the Issue Date
the
Income Benefit may terminate under certain circumstances as stated in section 11,
Income
Benefit.
• The
Traditional Death Benefit may not be modified, but it will terminate if you take
withdrawals
(including Income Payments) that reduce both the Contract Value and
Guaranteed
Death Benefit Value to zero. Withdrawals may reduce the Traditional Death
Benefit’s
Guaranteed Death Benefit Value by more than the value withdrawn and could
end
the Traditional Death Benefit.
• The
optional Maximum Anniversary Value Death Benefit may not be modified.
Withdrawals
(including Income Payments) may reduce the Maximum Anniversary Value
Death
Benefit’s Guaranteed Death Benefit Value by more than the value withdrawn and
will
end the Maximum Anniversary Value Death Benefit if the withdrawals reduce both the
Contract
Value and Guaranteed Death Benefit Value to zero.
• Consult
with a tax professional to determine the tax implications of an investment in and
withdrawals
from or payments received under the Contract.
• If
you purchased the Contract as an individual retirement annuity or through a custodial
individual
retirement account, you do not get any additional tax benefit under the
Contract.
• Generally,
earnings under a Non-Qualified Contract are taxed at ordinary income rates
when
withdrawn, and may also be subject to a 10% additional federal tax for amounts
withdrawn
before age 59 1∕2.
• Generally,
distributions from Qualified Contracts are taxed at ordinary income tax rates
when
withdrawn, and may also be subject to a 10% additional federal tax for amounts
withdrawn
before age 59 1∕2.
We
do not pay sales commissions in connection with sales of the Contracts. Rather, you
pay
an investment advisory fee to your Financial Professional. We do not set your
investment
advisory fee or receive any part of it. However, Financial Professionals and their
managers
may be eligible for benefits from us or our wholly-owned subsidiary distributor,
such
as production incentive bonuses, insurance benefits, and non-cash compensation
items.
We and/or our wholly owned subsidiary distributor may also make marketing support
payments
to certain selling firms for marketing services and costs associated with Contract
sales.
This conflict of interest may influence your Financial Professional to recommend this
Contract
over another investment.
Whether
to exchange your existing Contract for a new contract is a decision that each
investor
should make based on their personal circumstances and financial objectives.
However,
in making this decision you should be aware that some Financial Professionals
may
have a financial incentive to offer you a new contract in place of one you already own.
You
should only exchange your Contract if you determine, after comparing the features,
risks,
and fees of both contracts, including any fees or penalties to terminate your existing
Contract,
that it is better for you to purchase the new contract rather than continue to own
your
existing Contract.
Fee Tables
The following tables
describe the fees, expenses, and adjustments that you will pay when buying, owning, and surrendering or making withdrawals from an Investment
Option or from the Contract. Please refer to your Contract specifications page for information about the specific fees you will pay each
year based on the options you have elected. These tables do not reflect any investment advisory fees you authorize your Financial Professional’s
firm to receive from the Contract. If investment advisory fees were reflected, fees and expenses would be higher.
This Contract has
no transaction expenses that apply at the time you buy the Contract, surrender or make withdrawals from the Contract, or transfer Contract
Value between Investment Options. However, state premium taxes may be deducted.
The tables below
describe the Daily Adjustment and MVA that apply if all or a portion of the Contract Value is removed from an Index Option before the
end of a Term.
Adjustments
|
|
Index
Protection Strategy
with
Trigger
and
Index
Protection Strategy
with
Cap |
Index
Dual Precision Strategy,
Index
Precision Strategy,
and
Index
Performance Strategy |
Index
Guard
Strategy
|
|
Daily
Adjustment Maximum Potential Loss |
0%
|
99%
|
35%
|
|
(as
a percentage of Index Option Value, applies for
distributions
from an Index Option before any Term
End
Date)(1)
|
|
|
|
(1)
This table shows the maximum potential loss due to
the application of the Daily Adjustment (e.g., maximum loss could occur if there is a total distribution within a Term at a time when
the Index price has declined to zero). The Daily Adjustment could result in a loss beyond the protection of the 10%, 20%, or 30% Buffer;
or -10% Floor. The Daily Adjustment applies if, before the Term End Date, you take a full or partial withdrawal, you
take
Income Payments, you execute a Performance Lock, you annuitize the Contract, we pay a death benefit, or we deduct Contract fees, expenses,
or investment advisory fees you authorize your Financial Professional’s firm to receive from the Contract. The actual Daily Adjustment
calculation is determined by a formula described in Appendix C.
|
|
Upon
full or partial withdrawal, Annuity Payments, or death benefit payment |
|
MVA
Maximum Potential Loss(1)
|
10%(3)
|
|
(as
a percentage of each Annual Contribution
Amount)(2)
|
|
(1)
This table shows the maximum potential loss due to
the application of the MVA (e.g., maximum loss could occur if there is a distribution within seven Index Years of the establishment of
an Annual Contribution Amount at a time when the yield on corporate bonds is greater than what they were when the Annual Contribution
Amount was established). The MVA applies if, within seven Index Years of the establishment of an Annual Contribution Amount, you take
a full or partial withdrawal, you take Income Payments, you execute a Performance Lock, you annuitize the Contract, or we pay a death
benefit. We do not apply an MVA to deductions for Contract fees and expenses, or investment advisory fees you authorize your Financial
Professional’s firm to receive from the Contract. See section 7, Expenses and Adjustments – Market Value Adjustment (MVA).
(2)
The Contract provides a free withdrawal privilege before
the Income Period that allows you to withdraw 10% of your total Annual Contribution Amounts annually without incurring an MVA, as discussed
in section 8, Access to Your Money – Free Withdrawal Privilege.
(3)
The maximum total negative MVA is 10% of Contract Value
if you take a full withdrawal, begin Annuity Payments, or if we pay a death benefit. On a partial withdrawal, the maximum total negative
MVA is 10% of the amount withdrawn.
The next table describes
the fees and expenses that you will pay each year during the time that you own the Contract (not including Fund fees and expenses). If
you purchased the optional Maximum Anniversary Value Death Benefit, you pay additional charges, as shown below.
Annual
Contract Expenses
|
Administrative
Expenses (or contract maintenance charge)(1)
(per
year) |
$50
|
|
Base
Contract Expenses(2)
(as
a percentage of the Charge Base) |
0.95%
|
|
Optional
Benefit Expenses – Maximum Anniversary Value Death Benefit
(as
a percentage of the Charge Base) |
0.20%
|
(1)
Referred to as the “contract
maintenance charge” in the Contract and elsewhere in this prospectus. Waived if the Contract Value is at least $100,000. During
the Annuity Phase, we deduct the contract maintenance charge proportionately from each Annuity Payment. See section 7, Expenses and Adjustments
– Contract Maintenance Charge (Administrative Expenses).
(2)
Comprised
of two charges referred to as the “product fee” and the “rider fee for the Income Benefit” in the Contract
and elsewhere in this prospectus. The product fee is 0.25%. The rider fee for the Income Benefit is 0.70%. See section 7, Expenses and
Adjustments – Base Contract Expenses (Product and Rider Fees).
In addition to the
fees described above, we may limit the amount you can earn on the Index Options. This means your returns may be lower than the Index’s
returns. In return for accepting a limit on Index gains, you will receive some protection from Index losses.
The next item shows
the total operating expenses charged by the Fund that you may pay periodically during the time that you own the Contract. Expenses shown
may change over time and may be higher or lower in the future. More information about the Fund, including its annual expenses, may be
found in Appendix A – Investment Options Available Under the Contract.
Annual
Fund Expenses
|
(expenses
that are deducted from Fund assets, including management fees,
distribution
and/or service (12b-1) fees, and other expenses) |
0.66%
|
Example
This Example is
intended to help you compare the cost of investing in the Variable Option with the cost of investing in other annuity contracts that offer
variable options. These costs include transaction expenses, annual Contract expenses, and annual Fund expenses.
The Example assumes
all Contract Value is allocated to the Variable Option, even though you cannot instruct us to allocate Purchase Payments to the Variable
Option. The Example does not reflect the Daily Adjustment or MVA. It
also
does not reflect any investment advisory fees that you authorize your Financial Professional’s firm to receive from the Contract.
If investment advisory fees were reflected, costs would be higher. Your costs could differ from those shown below when you invest in the
Index Options.
The Example assumes
that you invest $100,000 in the Variable Option for the time periods indicated. The Example also assumes that your investment has a 5%
return each year and that you elected the Maximum Anniversary Value Death Benefit for an additional charge. Although your actual
costs may be higher or lower, based on these assumptions, your costs would be:
|
|
1
Year |
3
Years |
5
Years |
10
Years |
|
(1)
If you surrender your Contract (take a full withdrawal) at the end of
the
applicable time period: |
$1,833
|
$5,675
|
$9,763
|
$21,169
|
|
(2)
If you annuitize your Contract at the end of the applicable time
period.
|
N/A*
|
$5,675
|
$9,763
|
$21,169
|
|
(3)
If you do not surrender your Contract. |
$1,833
|
$5,675
|
$9,763
|
$21,169
|
*
The
earliest available Annuity Date is the second Index Anniversary.
The tables below
describe the Daily Adjustment and MVA that apply if all or a portion of the Contract Value is removed from an Index Option before the
end of a Term.
Adjustments
|
|
Index
Protection Strategy
with
Trigger
and
Index
Protection Strategy
with
Cap |
Index
Dual Precision Strategy,
Index
Precision Strategy,
and
Index
Performance Strategy |
Index
Guard
Strategy
|
|
Daily
Adjustment Maximum Potential Loss |
0%
|
99%
|
35%
|
|
(as
a percentage of Index Option Value, applies for
distributions
from an Index Option before any Term
End
Date)(1)
|
|
|
|
(1)
This table shows the maximum potential loss due to
the application of the Daily Adjustment (e.g., maximum loss could occur if there is a total distribution within a Term at a time when
the Index price has declined to zero). The Daily Adjustment could result in a loss beyond the protection of the 10%, 20%, or 30% Buffer;
or -10% Floor. The Daily Adjustment applies if, before the Term End Date, you take a full or partial withdrawal, you
take
Income Payments, you execute a Performance Lock, you annuitize the Contract, we pay a death benefit, or we deduct Contract fees, expenses,
or investment advisory fees you authorize your Financial Professional’s firm to receive from the Contract. The actual Daily Adjustment
calculation is determined by a formula described in Appendix C.
|
|
Upon
full or partial withdrawal, Annuity Payments, or death benefit payment |
|
MVA
Maximum Potential Loss(1)
|
10%(3)
|
|
(as
a percentage of each Annual Contribution
Amount)(2)
|
|
(1)
This table shows the maximum potential loss due to
the application of the MVA (e.g., maximum loss could occur if there is a distribution within seven Index Years of the establishment of
an Annual Contribution Amount at a time when the yield on corporate bonds is greater than what they were when the Annual Contribution
Amount was established). The MVA applies if, within seven Index Years of the establishment of an Annual Contribution Amount, you take
a full or partial withdrawal, you take Income Payments, you execute a Performance Lock, you annuitize the Contract, or we pay a death
benefit. We do not apply an MVA to deductions for Contract fees and expenses, or investment advisory fees you authorize your Financial
Professional’s firm to receive from the Contract. See section 7, Expenses and Adjustments – Market Value Adjustment (MVA).
(2)
The Contract provides a free withdrawal privilege before
the Income Period that allows you to withdraw 10% of your total Annual Contribution Amounts annually without incurring an MVA, as discussed
in section 8, Access to Your Money – Free Withdrawal Privilege.
(3)
The maximum total negative MVA is 10% of Contract Value
if you take a full withdrawal, begin Annuity Payments, or if we pay a death benefit. On a partial withdrawal, the maximum total negative
MVA is 10% of the amount withdrawn.
The next table describes
the fees and expenses that you will pay each year during the time that you own the Contract (not including Fund fees and expenses). If
you purchased the optional Maximum Anniversary Value Death Benefit, you pay additional charges, as shown below.
Annual
Contract Expenses
|
Administrative
Expenses (or contract maintenance charge)(1)
(per
year) |
$50
|
|
Base
Contract Expenses(2)
(as
a percentage of the Charge Base) |
0.95%
|
|
Optional
Benefit Expenses – Maximum Anniversary Value Death Benefit
(as
a percentage of the Charge Base) |
0.20%
|
(1)
Referred to as the “contract
maintenance charge” in the Contract and elsewhere in this prospectus. Waived if the Contract Value is at least $100,000. During
the Annuity Phase, we deduct the contract maintenance charge proportionately from each Annuity Payment. See section 7, Expenses and Adjustments
– Contract Maintenance Charge (Administrative Expenses).
(2)
Comprised
of two charges referred to as the “product fee” and the “rider fee for the Income Benefit” in the Contract
and elsewhere in this prospectus. The product fee is 0.25%. The rider fee for the Income Benefit is 0.70%. See section 7, Expenses and
Adjustments – Base Contract Expenses (Product and Rider Fees).
The next item shows
the total operating expenses charged by the Fund that you may pay periodically during the time that you own the Contract. Expenses shown
may change over time and may be higher or lower in the future. More information about the Fund, including its annual expenses, may be
found in Appendix A – Investment Options Available Under the Contract.
Annual
Fund Expenses
|
(expenses
that are deducted from Fund assets, including management fees,
distribution
and/or service (12b-1) fees, and other expenses) |
0.66%
|
(expenses
that are deducted from Fund assets, including management fees,
distribution
and/or service (12b-1) fees, and other expenses)
(1)
If you surrender your Contract (take a full withdrawal) at the end of
the
applicable time period:
$1,833
$5,675
$9,763
$21,169
(2)
If you annuitize your Contract at the end of the applicable time
period.
N/A*
$5,675
$9,763
$21,169
(3)
If you do not surrender your Contract.
$1,833
$5,675
$9,763
$21,169
Principal Risks of Investing In the Contract
The Contract involves certain risks
that you should understand before investing. You should carefully consider your income needs and risk tolerance to determine whether the
Contract is appropriate for you. The level of risk you bear and your potential investment performance will differ depending on the Index
Options you choose.
Risk
of Loss
Returns on securities and securities
Indexes can vary substantially, which may result in investment losses. The historical performance of the Investment Options does not guarantee
future results. It is impossible to predict whether underlying investment values will fall or rise. Securities markets are influenced
by economic, financial, regulatory, geographic, judicial, political and other complex and interrelated factors. Depending on your individual
circumstances (e.g.,
your selected Index Options and the timing of any Purchase Payments, transfers, or withdrawals), you may experience (perhaps significant)
negative returns under the Contract. You should consult with a Financial Professional.
The Variable Option does not
provide any protection against loss of principal. You
can lose principal and previous earnings for Purchase Payments held in the Variable Option and such losses could be significant.
You should consider whether investing
in an Index Option is consistent with your financial needs. If you allocate Purchase Payments or transfer Contract Value to an Index Option
with the Index Dual Precision Strategy, Index Precision Strategy, Index Guard Strategy, or Index Performance Strategy, negative
Index Returns may cause Performance Credits to be either negative after application of the Buffer, or negative down to the Floor. For
the Index Dual Precision Strategy and Index Performance Strategy, we apply the Buffer for the entire Term length; we do not apply
the Buffer annually on a 3-year or 6-year Term Index Option. Ongoing deductions we make for Contract fees, expenses, and investment
advisory fees that you authorize your Financial Professional’s firm to receive from the Contract could also cause amounts
available for withdrawal to be less than what you invested even if Index performance has been positive. You
can lose principal and previous earnings if you allocate Purchase Payments or transfer Contract Value to the Index Options with the Index
Dual Precision Strategy, Index Precision Strategy, Index Guard Strategy, or Index Performance Strategy, and such losses could
be significant. If you allocate Purchase Payments or transfer Contract Value to the Index Options with the Index Protection Strategy with
Trigger or Index Protection Strategy with Cap you can also lose principal and previous earnings if you do not receive a Performance Credit,
or if the Contract fees, expenses, and investment advisory fees that you authorize your Financial Professional’s firm to receive
from the Contract are greater than the Performance Credit.
The maximum potential
negative Performance Credit for the Index Dual Precision Strategy, Index Precision Strategy, and Index Performance Strategy is based
on the Buffer. If the Buffer is 10%, the maximum negative Performance Credit is -90%; if the Buffer is 20%, the maximum negative Performance
Credit is -80%; and if the Buffer is 30%, the maximum negative Performance Credit is -70%. The maximum potential negative Performance
Credit for the Index Guard Strategy is the -10% Floor. At least one Index Option with a Buffer no lower than 5% or Floor no lower than
-25%, or an Index Option that provides complete protection from Index losses, will always be available for renewal under the Contract.
In addition to
any losses from negative investment performance, you may experience losses under the Contract due to any applicable negative MVAs, other
Contract fees and charges, negative Daily Adjustments, taxes, and tax penalties.
Early
Withdrawal and Liquidity Risk
We designed the Contract to be a
long-term investment that you can use to help build and provide income for retirement. The Contract is not suitable for short-term investment.
Withdrawals under the Contract may be subject to negative MVAs, other Contract fees and charges, negative Daily Adjustments, taxes, and
tax penalties.
If you take a full or partial withdrawal
during the MVA period, we apply an MVA unless the withdrawal is an MVA-Free Withdrawal. We also apply the MVA during the MVA period if
you take Annuity Payments or if we pay a death benefit. While MVA-Free Withdrawals provide some liquidity, they are permitted in only
limited amounts or in special circumstances. If you need to withdraw most or all of your Contract Value in a short period, you will likely
exceed the MVA-Free Withdrawal amounts available to you and we will apply an MVA.
The MVA can be positive or negative
according to the interest rate environment as measured by the corporate bond yields through the Bloomberg US Long Corporate Bond Index.
In periods when bond yields have significantly decreased, the MVA limit (the maximum total positive or negative MVA is either 10% of the
amount withdrawn on a partial withdrawal, or 10% of Contract Value for a full withdrawal, Annuity Payments, or payment of the death benefit)
may reduce the amount you would have received from a positive MVA. In general, as the time remaining in the MVA period drops, a more substantial
bond yield change is required to reach the 10% MVA limit. However, there are also other factors influencing how much bond yields would
have to drop or increase to reach the 10% MVA limit including any gains or losses in the Contract and corporate bond yields at the time
each Annual Contribution Amount begins. For example, assume you purchase a Contract with a single Purchase Payment of $100,000 allocated
to one Index Option, the Issue Date is the Index Effective Date, the initial bond yield is 3%, and you take no partial withdrawals. On
the second Index Anniversary, the Contract Value has decreased to $90,000 and you request a full withdrawal. The maximum negative MVA
of -10% of Contract Value would occur if bond yields increased by 1.96% or more. If instead you wait and take a full withdrawal on the
sixth Index Anniversary when the Contract Value has increased to $120,000, the maximum negative MVA of -10% of Contract Value would occur
if bond yields increased by 14.04% or more.
We calculate the MVA as a percentage
(called the MVA factor) of the amount of Purchase Payment withdrawn from an Annual Contribution Amount, not a percentage of Contract Value.
Consequently, if the Contract Value has declined since the Annual Contribution Amount(s) were established and the MVA is negative, it
is possible that the percentage of Contract Value withdrawn to cover the negative MVA would be greater than if the MVA were deducted as
a percentage of Contract Value. For example, assume you buy the Contract with a single Purchase Payment of $10,000, your Index Effective
Date is the Issue Date, and the yield on the Bloomberg US Long Corporate Bond Index on the Index Effective Date is 2%. On the 5th
Index Anniversary your Contract Value is $8,000 after we deduct Contract fees, expenses, and investment advisory fees that you authorize
your Financial Professional’s firm to receive from the Contract and you request a full withdrawal. If the yield on the Bloomberg
US Long Corporate Bond Index has increased to 3%, the MVA factor is -1.932%. The MVA would be -$193.20 (-1.932% of $10,000). As your Contract
Value is less than $100,000, we will also deduct the $50 contract maintenance charge. This results in you receiving $7,756.80. For purposes
of this example, we have not factored in any final product and rider fees that may apply and be deducted in connection with a full withdrawal.
On a full withdrawal, the free withdrawal
privilege is not available to you, and we apply an MVA against Annual Contribution Amounts that are still within their MVA period, including
amounts previously withdrawn under the free withdrawal privilege. On
a full withdrawal, your total Annual Contribution Amounts may be greater than your Contract Value because the following reduce your Contract
Value, but do not reduce your Annual Contribution Amounts: prior MVA-Free Withdrawals; deductions we make for Contract fees, expenses,
or investment advisory fees you authorize your Financial Professional’s firm to receive from the Contract; and/or poor performance.
The present interest rate environment
is evolving due to a combination of factors, including market conditions (e.g., inflation) and actions by governmental authorities. Future
changes in interest rates, and the potential impact on MVAs, cannot be predicted with certainty. Interest rates may increase, which could
increase the risk of negative MVAs. You should consult with a Financial Professional about how the present interest rate environment may
impact your future decisions related to the Contract. For more information on the MVA, including how we calculate the MVA factor, see
section 7, Expenses and Adjustments – Market Value Adjustment (MVA).
Amounts withdrawn from this Contract
are subject to income taxes and may also be subject to a 10% additional federal tax for amounts withdrawn before age 59 1∕2.
We only apply
Performance Credits to the Index Options once each Term on the Term End Date, rather than daily. In the interim, we calculate Index Option
Values based on the Daily Adjustment. For more information, see “Risks Associated with the Daily Adjustment” later in this
section. The Variable Option is not subject to the Daily Adjustment. Any assets removed from an Index Option during the Term for withdrawals
you take (including Income Payments and other MVA-Free Withdrawals), Annuity Payments, or deductions we make for Contract fees, expenses,
and investment advisory fees that you authorize your Financial Professional’s firm to receive from the Contract, or if we
pay a death benefit, will not be eligible to receive a Performance Credit on the Term End Date. You will receive a Performance Credit
only on any unlocked Index Option Value remaining in an Index Option on the Term End Date.
You can typically transfer Index
Option Value among the Index Options only on Term End Dates. However, you can transfer assets out of an Index Option before the Term End
Date by executing a Performance Lock. Once an Index Option is locked, you can transfer assets out of it on the Index Anniversary that
occurs on or immediately after the Lock Date. For a 3-year or 6-year Term Index Option this means you can transfer out of the locked Index
Option before the Term End Date by executing a Performance Lock on or before the second Index Anniversary of a 3-year Term, or on or before
the fifth Index Anniversary of a 6-year Term. For Contracts issued on or after May 1, 2023, you can also transfer assets out
of any locked Index Option, including 1-year Term Index Options, before the Term End Date by requesting an Early Reallocation. You may
execute twelve Early Reallocations each Index Year, but each request can involve multiple locked Index Options. These restrictions on
transfers may limit your ability to react to changes in market conditions.
Income
Benefit Risks
The Income Benefit is automatically
included in the Contract for an additional rider fee and you cannot remove it.
We generally base Income Payments
on the Lifetime Income Percentage you select and your Contract Value, not
a guaranteed value. Decreases in Contract Value due to
negative Index Option performance during the Accumulation Phase up to and including the Income Benefit Date, deductions for Contract fees
and expenses, and withdrawals, also decrease the Income Payment amount available to you.
If you choose the Level Income payment
option and meet the age requirements stated in section 11, Income Benefit – Calculating Your Income Payments, your initial annual
maximum Income Payment will not be less than the Level Income Guarantee Payment Percentage multiplied by your total Purchase Payments
reduced proportionately for withdrawals you took (including any MVA). However, the Level Income Guarantee Payment Percentage is not available
to you under the Level Income payment option if you do not meet the age requirements stated in section 11, or if you choose the Increasing
Income payment option.
Income Payments made while your Contract
Value is positive are a withdrawal of your own assets and reduce your Contract Value. If your Contract Value remains above zero when the
Income Payments end, you may not realize a benefit from the Income Benefit; the chances of your Contract Value being reduced to zero may
be minimal.
We also base Income Payments on the
Eligible Person(s) that we establish at issue. If you change Owners or Beneficiary(ies), we may remove an Eligible Person or Covered Person
as stated in section 2, which
may cause Income Payments to be unavailable or end prematurely.
We use the age of the Eligible Person(s)
to determine the Income Percentage(s) and Income Percentage Increases. Income Percentage Increases are not available until age 45. This
means if an Eligible Person is younger than age 44 on the Issue Date, you
will not receive an increase to a Lifetime Income Percentage based on that Eligible Person until the Index Anniversary that the Eligible
Person (or younger Eligible Person for joint payments) reaches age 45, and you will pay a rider fee during the period you are not eligible
for an Income Percentage Increase.
The eligibility period to begin Income
Payments is subject to a waiting period and both a minimum and maximum age requirement for the Eligible Person(s). For single Income Payments,
we only allow an Eligible Person who is an Owner to become a Covered Person, and joint Income Payments may not be available if the age
difference between spouses is too great, as stated in section 2, Ownership, Annuitant, Determining Life, Beneficiary, and Payee –
Eligible Person(s) and Covered Person(s). If
you do not begin Income Payments during the eligibility period, the Income Benefit ends and you will have paid for the benefit without
receiving any of its advantages.
In addition, if you have Contract
Value in an Index Option for which the Income Benefit Date is not a Term End Date, we will execute a Performance Lock for that Index Option
if it is not locked and then immediately calculate and begin your Income Payments. If you have Index Options with different Term End Dates,
there may be no date when the Daily Adjustment does not apply. For the Index Protection Strategy with Trigger or Index Protection Strategy
with Cap Index Options, we will execute this Performance Lock even if the Daily Adjustment is zero.
The initial annual
maximum Income Payment available to you must be at least $100. If your Contract Value on the Income Benefit Date is reduced and this $100
minimum cannot be met, the
Income Benefit ends and you will have paid for the benefit without receiving any of its advantages. Income Payments and the Income Benefit
may also end prematurely if you take Excess Withdrawals, or you annuitize the Contract. A full Excess Withdrawal and certain partial Excess
Withdrawals will cause Income Payments to stop and the Contract and
all of its benefits
to end. However, we can convert your Income Payment to
Annuity Payments as described in section 9, The Annuity Phase – When Annuity Payments Begin.
The Income Multiplier Benefit can
provide increased income if you are confined for care or are unable to perform at least two activities of daily living. However, this
benefit has a waiting period and you must meet certain requirements to receive it. If you are unable to meet these requirements the Income
Multiplier Benefit may not be available to you when you need it. If you qualify for the Income Multiplier Benefit, it also may not provide
enough income to pay for the care you require. For joint Covered Persons, if you both qualify for this benefit at the same time you will
get the same payment increase as a single Covered person; we do not apply the increase separately for each Covered Person.
For more information see “How
the Income Benefit Works” and “During the Income Period” in section 11, Income Benefit.
Risk
of Change to the Income Benefit Supplement Prior to the Issue Date
The Income Payment waiting period
and the table showing the Income Percentages and Income Percentage Increases for your Contract are stated in the Income Benefit Supplement
that is in effect on the date you sign your application. The supplement also includes the income multiplier factor and income multiplier
benefit wait period for the Income Multiplier Benefit. Your Financial Professional will give you a copy of the prospectus with the current
Income Benefit supplement when you apply for a Contract. If we do not receive your initial Purchase Payment within 60 calendar days of
the date you sign the application, and the Income Benefit Supplement terms have changed since this date, you will receive the Income Benefit
Supplement terms that are in effect on the Issue Date instead of the terms that were in effect when you applied for the Contract. You
bear the risk that, if there is more than a 60-day delay between the time you apply for the Contract and the Issue Date, the Income Benefit
Supplement terms may change and be less advantageous to you. When we issue the Contract, we send you the current prospectus with the current
Income Benefit Supplement. We cannot change these terms for your Contract once they are established. We publish any changes to these terms
in an amended Income Benefit Supplement at least seven calendar days before they take effect on our website at https://www.allianzlife.com/RILAincomeadvrates.
The amended Income Benefit Supplement is also filed on EDGAR at https://www.sec.gov
under Form N-4 File Numbers 333-264349 and 333-255394. You can contact us to receive the Income Benefit Supplement applicable to your
Contract by calling our Service Center at the toll-free telephone number listed at the back of this prospectus.
You can find historical Income Benefit and
Income Multiplier Benefit Supplement values in Appendix F for benefits issued before May 1, 2026.
Index
Risks
Index Option returns depend, in part,
on the performance of an Index although you are not directly invested in the Index or in the securities tracked by the Index. You will
have no voting rights, no rights to receive cash dividends or other distributions, and no other rights with respect to the companies that
make up the Indexes. Because the S&P 500®
Index, Russell 2000®
Index, Nasdaq-100®
Index, EURO STOXX 50®
and iShares®
MSCI Emerging Markets ETF are each comprised of a collection of equity securities, in each case the value of the component securities
is subject to market risk, or the risk that market fluctuations may cause the value of the component securities to go up or down, sometimes
rapidly and unpredictably. In addition, the value of equity securities may decline for reasons directly related to the issuers of the
securities.
The S&P 500®
Index, Russell 2000®
Index, Nasdaq-100®
Index, and EURO STOXX 50®
are all “price return indexes,” not “total return indexes,” and therefore do not reflect dividends paid on
the securities composing the Index. This will reduce the Index Return and may cause the Index to underperform a direct investment in the
securities composing the Index. For the EURO STOXX 50®,
this Index is a euro “price return index” and Index Returns are determined without any exchange rate adjustment. Because
Index performance for the iShares®
MSCI Emerging Markets ETF is based on the ETF’s closing share price, Index performance is calculated on a “price return”
basis, not a “total return” basis, and therefore does not reflect dividends paid on the securities in which the ETF invests.
In addition, an ETF deducts fees and costs, which reduce Index performance. These factors will reduce the Index Return and may cause the
ETF to underperform a direct investment in the ETF or the securities in which the ETF invests.
In addition to
the foregoing, each Index has its own unique risks, as follows:
●
S&P 500®
Index: This Index is comprised of equity securities issued
by large-capitalization (“large cap”) U.S. companies. In general, large capitalization companies may be unable to respond
quickly to new competitive challenges or changes in their industries, and may not be able to attain the high growth rate of successful
smaller companies.
●
Russell 2000®
Index: This Index is comprised of equity securities of
small-capitalization (“small-cap”) U.S. companies. Generally, the securities of small-cap companies are more volatile and
riskier than the securities of large-cap companies.
●
Nasdaq-100®
Index: This Index is comprised of equity securities of
the largest U.S. and non-U.S. companies listed on the Nasdaq Stock Market, including companies across all major industry groups except
financial companies. In general, large-capitalization companies may be unable to respond quickly to new competitive challenges or changes
in their industries, and may not be able to attain the high growth rate of successful smaller companies. To the extent that the Index
is comprised of securities issued by companies in a particular sector, those securities may not perform as well as the securities of companies
in other sectors or the market as a whole. Also, any securities issued by non-U.S. companies are subject to the risks related to investments
in foreign markets (e.g.,
increased volatility; changing currency exchange rates; and greater political, regulatory, and economic uncertainty).
●
EURO STOXX 50®:
This Index is comprised of the equity securities of large-capitalization companies in the Eurozone. In general, large-capitalization companies
may be unable to respond quickly to new competitive challenges or changes in their industries, and may not be able to attain the high
growth rate of successful smaller companies. Securities issued by non-U.S. companies are subject to the risks related to investments in
foreign markets (e.g.,
increased volatility; changing currency exchange rates; and greater political, regulatory, and economic uncertainty).
●
iShares®
MSCI Emerging Markets ETF: The iShares MSCI Emerging Markets
ETF seeks to track the investment results of an index composed of large- and mid-capitalization emerging market equities. Investments
in emerging market issuers may be subject to a greater risk of loss than investments in issuers located or operating in more developed
markets. Emerging markets may be more likely to experience inflation, social instability, political turmoil or rapid changes in economic
conditions than more developed markets. Companies in many emerging markets are not subject to the same degree of regulatory requirements,
accounting standards or auditor oversight as companies in more developed countries, and as a result, information about the securities
in which the ETF invests may be less reliable or complete. Emerging markets often have less reliable securities valuations and greater
risk associated with custody of securities than developed markets. There may be significant obstacles to obtaining information necessary
for investigations into or litigation against companies and shareholders may have limited legal remedies.
Risks
Associated with the Daily Adjustment
The Daily Adjustment is how we calculate
Index Option Values on Business Days other than the Term Start Date or Term End Date. The
Variable Option is not subject to the Daily Adjustment.
The Daily Adjustment can affect the amounts available for withdrawal, Performance Locks, annuitization, payment of the death benefit,
and the Contract Value used to determine the contract maintenance charge and Charge Base for the product and rider fees. The Daily
Adjustment can be less than the Trigger Rate or Cap even if the current Index return during the Term is greater than the Trigger Rate
or Cap. In addition, even if the Index has performed positively since the beginning of the the Term, the Daily Adjustment may be negative.
However, the Daily Adjustment for the Index Protection Strategy with Trigger and Index Protection Strategy with Cap cannot be negative.
The Daily Adjustment is generally negatively affected by:
●
interest rate decreases,
●
dividend rate increases,
●
poor market performance, and
●
the expected volatility of Index prices. Generally, increases
in the expected volatility of Index prices negatively affect the Index Dual Precision Strategy, Index Precision Strategy, and Index Performance
Strategy 1-year Term Index Options, while decreases in the expected volatility of Index prices negatively affect the Index Guard Strategy.
For the Index Performance Strategy 3-year and 6-year Term Index Options, and Index Protection Strategy with Cap, the impact of changes
in the expected volatility of Index prices is dependent on the market environment and the applicable Caps and Participation Rates. For
the Index Protection Strategy with Trigger, the impact of changes in the expected volatility of Index prices is dependent on the market
environment.
The Daily Adjustment for Index Options
with a Term length of more than 1 year (3-year and 6-year Term Index Options and Early Reallocation to a 1-year Term Index Option) may
be more negatively impacted by changes in the expected volatility of Index prices than 1-year Term Index Options due to the difference
in Term length. Also, the risk of a negative Daily Adjustment is generally greater for Index Options with a Term length of more than 1
year than for 1-year Term
Index Options
due to the Term length. The Index Performance Strategy 3-year and 6-year Term Index Options with a Participation Rate above 100% may also
have larger fluctuations in the Daily Adjustment than Index Options either without a Participation Rate, or with a Participation Rate
equal to 100%. For shorter Term lengths, there is more certainty in both the final Index Values and how Trigger Rates, Caps, Buffers,
and Floors determine Performance Credits. This means there may be less fluctuation in the Daily Adjustment due to changes in Index return
for Index Options with shorter Term lengths.
If amounts are withdrawn or otherwise
removed from an Index Option with the Index Dual Precision Strategy, Index Precision Strategy, Index Guard Strategy, or Index Performance
Strategy before the Term End Date, you
could lose principal and previous earnings due to a negative Daily Adjustment. A negative Daily Adjustment for these Index Options could
result in losses greater than the protection provided by the applicable Buffer or Floor, which apply only on the Term End Date.
The maximum potential loss from a negative
Daily Adjustment is: -99% for the Index Dual Precision Strategy, Index Precision Strategy, and Index Performance Strategy; and -35% for
the Index Guard Strategy. Such
losses will be greater if you take a withdrawal that is subject to a negative MVA, is a deduction of Contract fees or charges, investment
advisory fees that you authorize your Financial Professional’s firm to receive from the Contract, taxes, or tax penalties also
apply.
Risks
Associated with Calculation of Performance Credits
We calculate Performance Credits
each Term on the Term End Date. Because we calculate Index Returns only on a single date in time, you may experience negative or flat
performance even though the Index you selected for a given Crediting Method may have experienced gains through some, or most, of the Term.
If you allocate Purchase Payments or transfer Contract Value to the Index Options with Index Protection Strategy with Trigger or Index
Protection Strategy with Cap, positive returns are limited by the Trigger Rates and Caps. You are not subject, however, to potential negative
Performance Credits for those Index Options. The Trigger Rates on the Index Dual Precision Strategy and Index Precision Strategy
Index Options, and the Caps on the Index Guard Strategy and Index Performance Strategy Index Options also limit positive returns, and
for these Index Options, you may be subject to potential negative Performance Credits. Trigger Rates and Caps could cause performance
to be lower than it would otherwise have been if you invested in a mutual fund or exchange-traded fund designed to track the performance
of the applicable Index.
For the Index Performance Strategy,
we apply the Cap and any Participation Rate for the entire Term length; we do not
apply the Cap and any Participation Rate annually on a
3-year or 6-year Term Index Option. For the Index Dual Precision Strategy, we apply the Trigger Rate for the entire Term length; we do not apply
the Trigger Rate annually on a 3-year or 6-year Term Index Option. See “Risk of Loss” above for information about risks
associated with Buffers and Floors when calculating Performance Credits.
The Index Options do not receive
any dividends payable on these securities. The Index Options also do not directly participate in the returns of the Indexes or the Indexes’
component securities. Index Returns would be higher if they included the dividends from the component securities.
Trigger Rates, Caps, and Participation
Rates may be adjusted on the next Term Start Date and may vary significantly from Term to Term. For more information, see the “Risks
Associated with Changes to Trigger Rates, Caps, and Participation Rates” discussion later in this section.
The Crediting Methods only capture
Index Values on the Term Start Date and Term End Date, so you will bear the risk that the Index Value might be abnormally high on a Term
Start Date or low on a Term End Date, which in either case could negatively impact your Performance Credits at the end of the Term.
Risks
Associated with Performance Locks and Early Reallocations
If a Performance Lock is executed:
●
You will no longer participate in Index performance, positive
or negative, for the remainder of the Term for the locked Index Option. This means that under no circumstances will your Index Option
Value increase during the remainder of the Term for a locked Index Option, and you will begin a new Index Option with a new Term
Start Date on the next Index Anniversary that occurs on or immediately after the Lock Date unless you execute an Early Reallocation (if
available to you). Early Reallocation is not permitted for Contracts issued before May 1, 2023. If you decide to execute an Early
Reallocation, you can execute a Performance Lock and then, at the earliest, execute an Early Reallocation on the same Business Day. When
executing both the Performance Lock and Early Reallocation on the same Business Day, your Lock Date is also the Term Start Date for the
new Index Option.
●
You will not receive a Performance Credit on any locked Index
Option on the Term End Date.
●
We use the Daily Adjustment calculated at the end of the
current
Business Day on the Lock Date to determine your locked Index Option Value. This means that, if you request a Performance Lock, your Index
Option Value will lock at an unknown future value which may be higher or lower than it was at the point in time you requested a Performance
Lock. In addition, if you set a lower target, your Index Option Value may lock at a lower value than the target you set.
●
If a Performance Lock is executed when your Daily Adjustment
has declined, you will lock in any loss. It is possible that you would have realized less of a loss or no loss if the Performance Lock
occurred at a later time, or if the Index Option was not locked.
●
We will not execute your request for a Performance Lock on
the Index Protection Strategy with Trigger or Index Protection Strategy with Cap Index Options if the Daily Adjustment is zero unless
your Contract was issued before May 1, 2023. This may limit your ability to take advantage of the benefits of the Early Reallocation
feature.
●
There are limits on Early Reallocations. We do not accept
Early Reallocation requests within 14 calendar days before an Index Anniversary; and you are limited to twelve Early Reallocation requests
each Index Year, but each request can involve multiple locked Index Options. After you reach the Early Reallocation request limit
in an Index Year, any locked Index Options will remain locked until the next Index Anniversary. These limitations mean you may not be
able to take advantage of any increases to Early Reallocation rates, or any advantageous changes to Index values that may become available
at the optimal time. This may limit your return potential. Early Reallocation is available for amounts allocated to any locked Index Option,
subject to the restrictions described in this prospectus.
●
Early Reallocation Trigger Rates, Caps, and Participation
Rates you receive may be less than the Early Reallocation rates that become available later in the Index Year, or the renewal rates available
on the next Index Anniversary. This may limit your return potential.
|
We
will not provide advice or notify you regarding whether you should execute a Performance Lock or Early
Reallocation
or the optimal time for doing so, if any. We will not warn you if you execute a Performance Lock or
Early
Reallocation at a sub-optimal time. We are not responsible for any losses related to your decision whether or
not
to execute a Performance Lock or Early Reallocation. |
Risks
Associated with Substitution of an Index and Limitation on Further Investments
There is no guarantee that the Indexes
will be available during the entire time that you own your Contract, including the Index we use to calculate the MVA. Once we add an Index
to your Contract, we cannot remove it without simultaneously substituting it. For the Index Options, if we substitute a new Index for
an existing Index, the performance of the new Index may be different and this may affect your ability to receive positive Performance
Credits.
Depending on the constitution of
the substituted Index, the volatility of its investments, and our ability to hedge the Index’s performance, we may determine, in
our discretion, to increase or decrease renewal Trigger Rates, Caps, and Participation Rates associated with the new Index, subject to
their respective minimums. However, we would not implement any change to reflect this difference until the next Term Start Date after
the substitution. The substitution of an Index during a Term may result in an abnormally large change in the Daily Adjustment on the day
we substitute the Index due to changes in Proxy Value inputs (such as volatility, dividend yield, and interest rate). However, you would
only be affected by this change in the Daily Adjustment if a transaction to which the Daily Adjustment applies (such as a withdrawal you
take) occurs on the substitution date.
Risks
Associated with Changes to Trigger Rates, Caps, and Participation Rates
Subject to their respective minimums,
we establish the initial Trigger Rates, Caps, and Participation Rates for a newly issued Contract on the Index Effective Date and they
cannot change until the next Term Start Date. You select the Index Effective Date when you purchase your Contract. It can be any Business
Day from the Issue Date up to and including the first Quarterly Contract Anniversary, but it cannot be the 29th,
30th,
or 31st
of a month.
You should be aware
that, generally, initial Trigger Rates, Caps, and Participation Rates could change every seven calendar days. However, these rates are
guaranteed to be available during the period stated on our website at https://www.allianzlife.com/RILAincomeadvrates
and cannot be superseded until that period ends. If you select an Index Effective Date that is within the guaranteed period for the initial
rates that are available for review on the date you signed your application, you will receive the initial rates that were available on
the date you signed your application. However, if you select an Index Effective Date that is after this guaranteed period, you are subject
to the risk that initial Trigger Rates, Caps, and Participation Rates may change and be less advantageous to you. You are responsible
for reviewing the initial rates before your Index Effective Date to ensure your allocations and the product still meet your needs. Furthermore,
if your Index Effective Date is after the end of the free look period and
you
cancel the Contract, you will receive the Cash Value. On or before the Index Effective Date, the Daily Adjustment and
MVA do not
apply. You may review future rates at least seven calendar days before their effectiveness at https://www.allianzlife.com/RILAincomeadvrates.
Subject to the limitations related to designating the Index Effective Date, you (or your Financial Professional, if authorized) can change
your Index Effective Date at any time before it occurs to be an earlier or later date by submitting a request.
We can change the renewal and Early
Reallocation Trigger Rates, Caps, and Participation Rates for an existing Contract on each new Term Start Date subject to the guaranteed
minimums, in our discretion. You risk the possibility that renewal Trigger Rates, Caps, and Participation Rates will be as low as the
applicable guaranteed minimums.
We will send you a letter at least
30 days before each Index Anniversary. This letter advises you that current Trigger Rates, Caps, and Participation Rates are expiring,
and that renewal rates for the next Term Start Date will be available for your review. The Index Anniversary letter also reminds you of
your opportunity to transfer your Index Option Values on the upcoming Term End Date. On each Term End Date, you have the option of
remaining allocated to your current Index Options at the renewal Trigger Rates, Caps, and Participation Rates that we set on the next
Term Start Date, or transferring to another permitted Index Option. At least seven calendar days before each Index Anniversary, we publish
renewal rates for the next Term Start Date for your review in your account on our website, and on our public website at https://www.allianzlife.com/RILAincomeadvrates.
If you do not review renewal change information when it is published or take no action to transfer to another permitted Index Option,
you will remain allocated to your current Index Options and will automatically become subject to the renewal Trigger Rates, Caps, and
Participation Rates until the next Term End Date.
When your renewal rates change,
if you do not want to remain invested in the same Index Option for a new Term, the only other options available to you are to transfer
Index Option Value between Index Options by changing your allocation instructions, or take a full withdrawal of the Index Option Value
(which may be subject to a negative MVA, is subject to income taxes, and may be subject to tax penalties).
If you execute a Performance Lock,
you may be able to request an Early Reallocation and begin a new Index Option with a new Term Start Date and a new Trigger Rate, Cap,
or Participation Rate before the next Index Anniversary. We can change Early Reallocation Trigger Rates, Caps, and Participation Rates
subject to the guaranteed minimums, in our discretion. We publish Early Reallocation rates at least seven calendar days before the end
of the current Early Reallocation offering period for your review in your account on our website. If you do not execute an Early Reallocation,
you will remain allocated to your current locked Index Options until the Index Anniversary that occurs on or immediately after the Lock
Date.
Initial, renewal, and Early Reallocation
Trigger Rates, Caps, and Participation Rates may vary significantly depending upon a variety of factors, including, but not limited to:
●
Term length,
●
level of downside protection,
●
market volatility,
●
our hedging strategies and investment performance,
●
the availability of hedging instruments,
●
the amount of money available to us through Contract fees
and expenses to purchase hedging instruments,
●
expenses incurred by the Company,
●
your Index Effective Date,
●
the level of interest rates,
●
utilization of Contract benefits by Owners, and
●
our profitability goals.
These factors also impact any new
Buffer or Floor Index Options that become available under the Contract. Due to a combination of factors, including potential changes in
interest rates and other market conditions (e.g. rising inflation), the current economic environment is evolving. The future impact on
initial, renewal, and Early Reallocation Trigger Rates, Caps, and Participation Rates cannot be predicted with certainty. The effect of
a change in interest rates or other market conditions may not be direct or immediate. There may be a lag in changes to Trigger Rates,
Caps, and Participation Rates. Interest rates could increase. In a rising interest rate environment, increases in initial Trigger Rates,
Caps, and Participation Rates, if any, may be substantially slower than increases in interest rates. However, a rising interest rate environment
may have the opposite effect on renewal rates and cause renewal Trigger Rates, Caps, and Participation Rates to decrease.
We manage our
obligation to provide Performance Credits in part by trading call and put options, and other derivatives on the available Indexes. The
costs of the call and put options and other derivatives vary based on market conditions, and we may adjust future renewal and Early Reallocation
Trigger Rates, Caps, and Participation Rates to reflect these cost changes. The primary factor affecting the differences in the initial
Trigger Rates, Caps, and Participation Rates for newly issued Contracts and renewal and Early Reallocation rates for existing Contracts
is the difference in what we can earn from these investments for newly issued Contracts versus what we are earning on the investments
that were made for existing Contracts. In some instances, we may need to reduce initial, renewal, and Early Reallocation Trigger Rates,
Caps, and Participation Rates, or we may need to substitute an Index. You bear the risk that we may reduce Trigger Rates, Caps, and Participation
Rates, which reduces your opportunity to receive positive Performance Credits.
Risks
of Deducting Investment Advisory Fees From the Contract
We designed the Contract to be owned
by individuals (or a trust or other entity acting as an agent for a natural person) who are receiving ongoing investment advice from a
Financial Professional. You can authorize your Financial Professional’s firm to receive investment advisory fees deducted from
your Contract. Deductions we make for investment advisory fees may be subject to a Daily Adjustment (that could be negative), and will
reduce your Contract Value and Cash Value dollar for dollar. We do not consider these deductions to be RMD payments or Income Payments,
and they do not reduce the Maximum Anniversary Value under the Maximum Anniversary Value Death Benefit. However, your initial annual maximum
Income Payment, Income Payment increases under the Level Income payment option, and increases to the Maximum Anniversary Value are based
on Contract Value. So these deductions reduce your initial annual maximum Income Payment, and reduce the likelihood you will receive Income
Payment increases if you select the Level Income payment option, or receive increases to the Maximum Anniversary Value if you select the
Maximum Anniversary Value Death Benefit. Because the death benefit is the greatest of Contract Value, Cash Value, or the Guaranteed Death
Benefit Value, deductions we make for investment advisory fees reduce the death benefit available to your Beneficiaries. As Contract Value
is also one of the components we use to calculate RMD payments, these deductions also reduce RMD payments.
Other
Contract Changes Risk
We reserve the right to modify or
restrict several benefits or features of the Contract. We restrict additional Purchase Payments. Each Index Year during the Accumulation
Phase and before the Income Benefit Date, you cannot add more than your initial amount without our prior approval. Your initial amount
is the total of all Purchase Payments received before the first Quarterly Contract Anniversary of the first Contract Year. We allow you
to add up to the initial amount in the remainder of the first Index Year. In addition to this Purchase Payment restriction, we reserve
the right to decline any or all Purchase Payments at any time on a nondiscriminatory basis. For Contracts issued in certain states, we
reserve the right to hold your initial Purchase Payment in the Variable Option until the free look period ends, and then reallocate your
Contract Value, less fees and expenses, according to your allocation instructions. For further information regarding Purchase Payment
restrictions, see section 3, Purchasing the Contract – Purchase Requirements.
As it relates to the Index Options,
we reserve the right to close Index Options to new Purchase Payments and transfers. However, once an Index Option is added to a Contract,
we cannot remove it, change how it calculates Performance Credits, or change its Buffer or Floor.
We also reserve the right to substitute
the Fund in which the Variable Option invests. We reserve the right to add or eliminate additional variable investment options, subject
to applicable law.
In states that assess a premium tax,
we do not currently deduct it from the Contract, although we reserve the right to do so in the future.
Lastly, we reserve the right to treat
a partial withdrawal that reduces Contract Value below $2,000 as a full withdrawal. If Annuity Payments would be less than $100, we reserve
the right to require you to take a full withdrawal and your Contract will then terminate. However, we do not apply the MVA on this full
withdrawal.
Risks
Associated with Our Financial Strength and Claims-Paying Ability
All payments and financial guarantees
under the Contract are subject to our financial strength and claims-paying ability. We make Income Payments, Annuity Payments, and pay
death benefits from our general account. Our general account assets are subject to claims by our creditors. We apply Performance Credits
from an unregistered, non-unitized, non-insulated separate account (Separate
Account IANA). Like our general account, the assets in
Separate Account
IANA are subject
to our general business operation liabilities and the claims of our creditors. For more information on Separate Account IANA, see The
Insurance Company, Separate Accounts, and General Account – Our Unregistered Separate Account.
Business
and Operational Risks Relevant to the Contract
Business Disruption
and Cybersecurity Risks. Our business relies on technology
systems and networks, including systems and networks managed by third parties, to process, transmit and store information; perform transactions
related to the Contract; and conduct other business activities. Maintaining the integrity of our systems is critical to our business operations
and to the protection of our clients’ personal information. Any cybersecurity breaches or interference that may in the future occur
could have a material adverse impact on our business operations and our financial condition.
Publicly-reported cybersecurity threats
and incidents have dramatically increased in recent years, and financial services companies and their third-party service providers are
increasingly the targets of cyberattacks. We have implemented and maintain security measures designed to protect against breaches of security
and other interference with systems and networks, and require third party vendors to meet certain information security standards; however,
we cannot ensure that our systems and networks will not be subject to breaches or interference, or that we will always be able to readily
detect a cybersecurity incident. Any such event may result in operational disruptions as well as unauthorized access to or the disclosure
or loss of our proprietary information or our clients’ personal information. Any such event may interfere with, impede or cause
delays in our calculation of values, processing of transactions and making of payments under the Contract. Although we maintain cybersecurity
insurance coverage against costs resulting from cybersecurity incidents, it is possible losses will exceed the amount available under
our coverage. We cannot be certain that advances in criminal capabilities, discovery of new vulnerabilities, attempts to exploit vulnerabilities
in our systems, data thefts, physical system or network break-ins or inappropriate access, or other developments will not compromise or
breach the technology or other security measures protecting our networks and systems used in connection with our products and services.
Natural or Man-made
Disasters. The occurrence of natural or man-made disasters
(e.g.,
extreme weather events, acts of terrorism, public health crises, industrial accidents, blackouts, military actions) could adversely affect
our business operations, particularly if those events affect our computer-based data processing, transmission, storage, and retrieval
systems or destroy data. Such disasters may damage our facilities, preventing our employees from performing their roles, otherwise disturbing
our ordinary business operations, and impacting claims processing. We rely on certain third-parties to provide certain services important
to our business operations. While we monitor the business continuity planning of such third-parties, successful implementation and execution
of their business continuity plans are largely outside of our control. Weaknesses or failures within a vendor’s business continuity
plan in light of a natural or man-made disaster could materially disrupt our business operations.
1. The Contract
An annuity is a contract between
you as the Owner, and an insurance company (in this case Allianz Life), where you make payments to us and we invest that money in the
Index Options you select. The Variable Option holds the money you invest before it is transferred to the Index Options. Depending on market
conditions and the returns of your selected Index Options, your Contract may gain or lose value. When you are ready to take money out,
we make payments to you according to your instructions and any restrictions associated with the payment option you select that is described
in this prospectus. Other than to add benefits that are beneficial to you, we do not make any changes to your Contract without your permission
except as may be required by law.
The Contract has an Accumulation
Phase and an Annuity Phase. If you begin taking Income Payments, your Contract will also have an Income Period. The Income Period occurs
during the Accumulation Phase.
The
Accumulation Phase
The Accumulation
Phase is the first phase of your Contract, and it begins
on the Issue Date. During the Accumulation Phase, we invest your money in the Index Options you select and the Variable Option on a tax-deferred
basis. Tax deferral may not be available for certain non-individually owned contracts. Tax deferral means you are not taxed on any earnings
or appreciation on the assets in your Contract until you take money out of your Contract. For more information, see section 13, Taxes.
During the Accumulation Phase, you
can take withdrawals (subject to any MVA). You can also make additional Purchase Payments before the Income Period subject to the
restrictions set out in section 3, Purchasing the Contract – Purchase Requirements. The Contract also offers at issue the optional
Maximum Anniversary Value Death Benefit for an additional rider fee (see section 12) if all Owners and the Annuitant are age 75 or younger
on the Issue Date. The Maximum Anniversary Value Death Benefit can only be added to a Contract at issue. The Maximum Anniversary Value
Death Benefit potentially provides a death benefit greater than the Traditional Death Benefit based on the Maximum Anniversary Value (highest
Contract Value on any Index Anniversary before age 91, increased by the dollar amount of subsequent Purchase Payments, and reduced proportionately
for subsequent withdrawals you take including any MVA).
During the Income
Period we make regular periodic Income Payments based on
the life of the Covered Person(s). During the Income Period we also restrict your selection of Crediting Methods to the Index Protection
Strategy with Trigger or Index Protection Strategy with Cap, and you cannot make additional Purchase Payments. However, unlike the Annuity
Phase, you will have access to your Contract Value and death benefit for a period of time after Income Payments begin. If you do not take
Income Payments your Contract will not have an Income Period. The Income Period ends on the earlier of the last Business Day before the
Annuity Date, or the date the Income Benefit ends. Income Payments can continue for the life of the Covered Person(s) if you do not take
more than your allowed annual maximum payment. See section 11, Income Benefit for more information.
When
the Accumulation Phase Ends
The Accumulation Phase ends upon
the earliest of the following:
●
The Business Day we process your request for a full withdrawal.
●
The Business Day before the Annuity Date.
●
Upon the death of any Owner (or the Annuitant if the Owner
is a non-individual), the Business Day we first receive Valid Claim from any one Beneficiary, unless the surviving spouse/Beneficiary
continues the Contract. If there are multiple Beneficiaries, the remaining Contract Value continues to fluctuate with the performance
of the Investment Options until the complete distribution of the death benefit. A Valid
Claim is the documents we require to be received in Good
Order at our Service Center before we pay any death claim.
The
Annuity Phase
If you request Annuity Payments,
the Accumulation Phase and Income Period (if applicable) of your Contract ends and you enter the Annuity
Phase. During the Annuity Phase, we make regular fixed
periodic Annuity Payments based on a guaranteed period, life, life with a guaranteed period, joint and last survivor, or joint and 2/3
survivor. We send Annuity Payments to the Payee
(the person or entity who receives Annuity Payments during the Annuity Phase). You can choose when Annuity Payments begin, subject to
certain restrictions. We base Annuity Payments on the greater of Contract Value less the final product and rider fees, or Cash Value
and the payout rates for the Annuity Option you select. If the Annuity Date occurs during the Income Period and your Income Payments are
greater than the Annuity Payments as calculated for certain Annuity Options, you can elect to convert Income Payments to Annuity Payments
as described in section 9, The Annuity Phase – When Annuity Payments Begin. Your Annuity Payments do not change unless an Annuitant
dies, or we convert Income Payments made under the Increasing Income payment option to Annuity Payments. The Increasing Income payment
option is discussed in section 11, Income Benefit – Automatic Annual Income Payment Increases. The Annuity Phase ends when we make
the last Annuity Payment under your selected Annuity Option. For more information, see section 9, The Annuity Phase.
When
the Contract Ends
The Contract ends
when:
●
all applicable phases of the Contract (Accumulation Phase,
Income Period and/or Annuity Phase) have ended, and/or
●
if we received a Valid Claim, all applicable death benefit
payments have been made.
For example, if you take a full withdrawal of
the Cash Value, both the Accumulation Phase and the Contract end even though the Income Period and Annuity Phase never began and we did
not make any death benefit payments.
Investment
Advisory Fees
We designed the Contract to be owned
by individuals (or a trust or other entity acting as an agent for a natural person) who are receiving ongoing investment advice from a
Financial Professional. If you want to authorize your Financial Professional’s firm to receive investment advisory fees deducted
from your Contract, you can complete our service form designed specifically for that authorization. Once our Service Center receives this
form in Good Order and we approve it, your Financial Professional’s firm will be able to receive investment advisory fees from
your Contract. Upon receipt and approval of an investment advisory fee request in Good Order from your Financial Professional’s
firm, we deduct these investment advisory fees from the Contract and pay them to your Financial Professional’s firm upon written
request. You can terminate this agreement at any time by providing us written notice. We deduct investment advisory fees that you authorize
your Financial Professional to receive from the Contract proportionately from each Index Option and the AZL Government Money Market Fund.
Contracts issued before May 1, 2023, allowed you to provide us with alternate instructions for deductions of investment advisory fees
as detailed in Appendix G. For these investment advisory fees not
to be treated
as a taxable distribution, and to be exempt from the 10% additional federal tax for amounts withdrawn before age 59 1∕2,
we require that you and your Financial Professional agree to the following:
●
the total amount of investment advisory fees cannot exceed
1.5% of the Contract Value in each Contract Year,
●
that the investment advisory fees compensate the Financial
Professional only for advice they provide to you with respect to this Contract and not for any other services or accounts,
●
this Contract be solely liable for paying these investment
advisory fees directly to your Financial Professional’s firm, and
●
while we are deducting these fees from the Contract, you
agree to not pay investment advisory fees to your Financial Professional or anyone else from any other assets.
If you and your Financial Professional agree to these requirements,
deductions for these investment advisory fees:
●
are not
treated as a taxable distribution,
●
are not
subject to the 10% additional federal tax if you are under age 59 1∕2,
●
are not
subject to an MVA,
●
are not
considered to be an Income Payment, Excess Withdrawal, or RMD payment under our minimum distribution program, and
●
do not
reduce the Annual Contribution Amounts, free withdrawal privilege, total Purchase Payments reduced proportionately for withdrawals you
take (including any MVA) used to determine the minimum initial Income Payment under the Level Income payment option, or your Contract’s
Guaranteed Death Benefit Value.
If you and your
Financial Professional do not agree to these requirements, we will not pay investment advisory fees from this Contract to your Financial
Professional’s firm. You
should consult a tax adviser regarding the tax treatment of the payment of investment advisory fees from your Contract since federal and/or
state taxing authorities could determine that such fees should be treated as taxable distributions.
The maximum investment advisory fee
that we will pay to your Financial Professional’s firm in any Contract Year is 1.5% of Contract Value. Each time we deduct an investment
advisory fee we determine its percentage by dividing the fee amount by the Contract Value determined at the end of the Business Day after
we process all other transactions. We
will not pay any portion of the investment advisory fee that would exceed 1.5% of Contract Value in any Contract Year.
For example, assume your Financial Professional’s
firm requests fee payment twice a year. If the first fee requested is $700 and your Contract Value after processing all other transactions
is $100,000, this fee is 0.7%. This leaves a maximum of 0.8% (1.5% - 0.7%) of the Contract Value available for payment of the second fee.
The amount of Contract Value available
for deduction of investment advisory fees will be affected by the Daily Adjustment (which
can be negative).
Deductions we make for investment
advisory fees reduce your Contract Value (and therefore Cash Value) by the amount withdrawn on a dollar for dollar basis. This Contract
Value reduction also decreases your initial annual maximum Income Payment which is based on Contract Value. As Contract Value is one of
the components we use to calculate RMD payments, these deductions may also reduce your RMD payments. Because
these deductions decrease the Contract Value, they also reduce the likelihood you will receive Income Payment increases under the Level
Income payment option which are based on Contract Value increases, or lock in investment gains to Maximum Anniversary Value under the
Maximum Anniversary Value Death Benefit. In addition, because the death benefit is the greatest of Contract Value, Cash Value, or the
Guaranteed Death Benefit Value, deductions we make for investment advisory fees reduce the death benefit available to your Beneficiaries.
These deductions also reduce the
following proportionately by the percentage of Contract Value withdrawn: Charge Base, Index Option Base, Index Option Value, and Variable
Account Value.
If you do not complete our service
form which authorizes your Financial Professional’s firm to receive investment advisory fees deducted from your Contract, and instead
you take money from the Contract and use it to pay investment advisory fees, we will treat this as a withdrawal. This
withdrawal is subject to income taxes, may also be subject to a 10% additional federal tax for amounts withdrawn before age 59 1∕2,
will be subject to an MVA, and the amount of Contract Value available for withdrawal may be affected by the Daily Adjustment (which
can be negative). This
withdrawal reduces the Contract Value, and the amount available under the free withdrawal privilege by the dollar amount withdrawn. If
taken during the Income Period, we will treat the withdrawal as an Excess Withdrawal if it causes total withdrawals during the Income
Benefit Year to exceed the annual maximum Income Payment. It
may also reduce your Contract’s Guaranteed Death Benefit Value
by more than the amount
withdrawn and these reductions could be
significant.
You should consult a tax adviser regarding the tax treatment of investment advisory fee payments. Please
consult with your Financial Professional to determine the options for paying investment
advisory fees regarding
advice that is provided to you related to this Contract.
Your Financial Professional acts
on your behalf, not ours. We are not party to any agreement between you and your Financial Professional, nor are we responsible for your
Financial Professional’s actions. We do not verify that deductions for investment advisory fees align with the terms of your agreement
with your Financial Professional, but we verify that payments are made in accordance with the authorization service form you submit to
us. We do not set your investment advisory fee or receive any part of it. Any deductions for investment advisory fees you pay is in addition
to this Contract’s fees and expenses.
We do not pay sales commissions in
connection with sales of the Contract. However, Financial Professionals and their managers may be eligible for various benefits such as
production incentive bonuses, insurance benefits, and non-cash compensation items that we may provide jointly with our principal underwriter,
Allianz Life Financial Services, LLC. You should ask your Financial Professional about compensation they receive for this Contract. Allianz
Life is not an investment adviser, and does not provide investment advice in connection with sales of the Contract. We are not a fiduciary
to you, and do not make recommendations or assess suitability.
You can submit a written request
to our Service Center on a form satisfactory to us to allow your Financial Professional to make Index Option transfers and allocation
changes on your behalf. However, we reserve the right to review a Financial Professional’s trading history before allowing him
or her to make transfers. If, in our sole discretion, we believe the Financial Professional’s trading history indicates excessive
trading, we can deny your request. If we approve it, your Financial Professional is subject to the same trading restrictions that apply
to Owners. We can deny or revoke trading authority in our sole discretion.
Investment Advisory
Fee Deduction Example
These calculations show the effects
on the Contract Value, Cash Value, and available Guaranteed Death Benefit Value of authorizing your Financial Professional’s firm
to receive investment advisory fees deducted from your Contract. These deductions immediately reduce the Contract Value and Cash Value
on a dollar for dollar basis, but
they do not reduce the Guaranteed Death Benefit Value if they meet the requirements stated in this section.
The example assumes we deduct the maximum available investment advisory fee of 1.50% of Contract Value once per year on days that are
not Term End Dates and pay it directly to your Financial Professional’s firm. All Contract Value figures reflect the Daily Adjustment.
|
Investment
Advisory Fee
Withdrawal
That Is Not
a
Taxable Distribution |
Contract
Value
|
Cash
Value
|
Guaranteed
Death Benefit
Value
for a Contract with the
Traditional
Death Benefit |
Guaranteed
Death Benefit Value
for
a Contract with the
Maximum
Anniversary Value
Death
Benefit |
|
Prior
to 1st
fee deduction |
$
100,000 |
$
97,000 |
$
90,000 |
$
105,000 |
|
$1,500
fee deduction |
–
$1,500 |
–
$1,500 |
–
$0 |
–
$0 |
|
After
1st
fee deduction |
$
99,300 |
$
96,300 |
$
90,000 |
$
105,000 |
|
|
|
|
|
|
|
Prior
to 2nd
fee deduction |
$
100,500 |
$
97,100 |
$
90,000 |
$
105,000 |
|
$1,507
fee deduction |
–
$1,507 |
–
$1,507 |
–
$0 |
–
$0 |
|
After
fee deduction |
$
98,993 |
$
95,593 |
$
90,000 |
$
105,000 |
|
|
|
|
|
|
|
Prior
to 3rd
fee deduction |
$
97,800 |
$
95,200 |
$
90,000 |
$
105,000 |
|
$1,467
fee deduction |
–
$1,467 |
–
$1,467 |
–
$0 |
–
$0 |
|
After
fee deduction |
$
96,333 |
$
93,733 |
$
90,000 |
$
105,000 |
The death benefit is the greatest
of the Contract Value, Cash Value, or the Guaranteed Death Benefit Value. After we deduct the investment advisory fees the death benefit
would either be the:
●
$99,300 Contract Value under the Traditional Death Benefit,
or the $105,000 Guaranteed Death Benefit Value under the Maximum Anniversary Value Death Benefit after the first fee deduction.
●
$98,993 Contract Value under the Traditional Death Benefit,
or the $105,000 Guaranteed Death Benefit Value under the Maximum Anniversary Value Death Benefit after the second fee deduction.
●
$96,333 Contract Value under the Traditional Death Benefit,
or the $105,000 Guaranteed Death Benefit Value under the Maximum Anniversary Value Death Benefit after the third fee deduction.
Please see section 11, Income Benefit
– Excess Withdrawals for an example showing the impact of not authorizing your Financial Professional’s firm to receive
investment advisory fees deducted from your Contract, and instead taking an Excess Withdrawal of $1,500 from the Contract to pay investment
advisory fees to your Financial Professional.
2. Ownership, Annuitant, Determining Life, Beneficiary, and Payee
Owner
The Owner designated at Contract
issue has all the rights under the Contract. The Owner may be an individual, or a non-individual (such as a trust or other entity acting
as an agent for a natural person). Qualified Contracts and non-individually owned Contracts can only have one Owner. A Qualified
Contract qualifies for special tax treatment under sections
of the Code.
Joint
Owner
A Non-Qualified Contract can be owned
by up to two individual Owners (Joint
Owners). Joint Owners must be spouses within the meaning
of federal tax law. We generally require the signature of both Joint Owners on any forms that are submitted to our Service Center.
Annuitant
The Annuitant is the individual on
whose life we base Annuity Payments. Subject to our approval, you designate an Annuitant when you purchase a Contract. For Qualified Contracts,
before the Annuity Date, the Owner must be the Annuitant unless the Contract is owned by a qualified plan or is part of a custodial arrangement.
You can change the Annuitant on an individually owned Non-Qualified Contract at any time before the Annuity Date. You
cannot change the Annuitant if the Owner is a non-individual.
Subject to our approval, you can add a joint Annuitant on the Annuity Date. For Qualified Contracts, the ability to add a joint Annuitant
is subject to any plan requirements associated with the Contract. For individually owned Contracts, if the Annuitant who is not an Owner
dies before the Annuity Date, the sole Owner (or younger Joint Owner) automatically becomes the new Annuitant, but the Owner can subsequently
name another Annuitant.
Designating different
persons as Owner(s) and Annuitant(s) can have important impacts on whether a death benefit is paid, and on who receives it as indicated
below. For more examples, please see the Appendix A to
the Statement of Additional Information (SAI).
In order to convert Income Payments to Annuity Payments the Covered Person(s) must be named as the Annuitant(s) as discussed in section
9, The Annuity Phase – When Annuity Payments Begin. Designating
different persons as Covered Person(s) and Annuitant(s) will cause the Income Benefit and Income Payments to end
at
the maximum permitted Annuity Date. Use care when designating Owner(s), Covered Person(s) and Annuitant(s), and consult your Financial
Professional if you have questions.
|
UPON
THE DEATH OF A SOLE OWNER | |
|
Action
if the Contract is in the Accumulation Phase |
Action
if the Contract is in the Annuity Phase |
|
• We
pay a death benefit to the Beneficiary unless the
Beneficiary
is the surviving spouse and continues the Contract.
The
Income Benefit and any Income Payments will also end
unless
the Beneficiary is both a surviving spouse and either an
Eligible
Person (if Income Payments have not begun) or a
Covered
Person (if Income Payments have begun).
• If
the deceased Owner was a Determining Life and the
surviving
spouse Beneficiary continues the Contract:
– we
increase the Contract Value to equal the Guaranteed
Death
Benefit Value if greater and available, and the
death
benefit ends,
– the
surviving spouse becomes the new Owner,
– if
Income Payments have not begun the Accumulation
Phase
continues,
– if
Income Payments have begun they can only continue if
the
surviving spouse is a Covered Person; otherwise the
Income
Benefit ends, and
– upon
the surviving spouse’s death, his or her
Beneficiary(ies)
receives the greater of Contract Value or
Cash
Value.
• If
the deceased Owner was not a Determining Life, the
Traditional
Death Benefit or Maximum Anniversary Value Death
Benefit
are not available and the Beneficiary(ies) receives the
greater
of Contract Value or Cash Value. |
• The
Beneficiary becomes the Payee. If we are still required to
make
Annuity Payments under the selected Annuity Option, the
Beneficiary
also becomes the new Owner.
• If
the deceased was not an Annuitant, Annuity Payments to the
Payee
continue. No death benefit is payable.
• If
the deceased was the only surviving Annuitant, Annuity
Payments
end or continue as follows.
– Annuity
Option A or C, payments end when the
guaranteed
period ends.
– Annuity
Option B, F, or G, payments end. If Income
Payments
were converted to Annuity Payments under
Annuity
Option B or F, we will also pay any remaining
value
to the named Beneficiary(ies).
– For
more information on the Annuity Options, please see
section
9.
• If
the deceased was an Annuitant and there is a surviving joint
Annuitant,
Annuity Payments to the Payee continue during the
lifetime
of the surviving joint Annuitant. No death benefit is
payable.
• For
a Qualified Contract, the Annuity Payments generally must
end
no later than the end of the year containing the 10th
anniversary
of the Owner's death. However, in certain
situations,
payments may need to end earlier. |
Determining
Life (Lives)
The Determining Life (Lives) are
the individuals on whose life we base the Guaranteed Death Benefit Value provided by the Traditional Death Benefit or Maximum Anniversary
Value Death Benefit. We establish the Determining Life (Lives) at Contract issue. For an individually owned Contract, the Determining
Life (Lives) are the Owner(s). For a non-individually owned Contract, the Determining Life is the Annuitant. After the Issue Date, the
Determining Life (Lives) only change if:
●
you remove a Joint Owner due to divorce, then we also remove
that person as a Determining Life,
●
you add or change a Joint Owner, then that person will
become a Determining Life if they are the current spouse within the meaning of federal tax law of an existing Owner, or
●
you establish a jointly owned Non-Qualified Contract and
change ownership to a Trust, then we remove the prior Owner who is not the Annuitant as a Determining Life.
Beneficiary
The Beneficiary is the person(s)
or entity you designate to receive any death benefit. You can change the Beneficiary or contingent Beneficiary at any time before your
death unless you name an irrevocable Beneficiary. If a Beneficiary dies before you, or you and a Beneficiary die within 120 hours of each
other, that Beneficiary’s interest in this Contract ends unless your Beneficiary designation specifies otherwise. If there are
no surviving primary Beneficiaries, we pay the death benefit to the contingent Beneficiaries who survive you. If there are no surviving
Beneficiaries or if there is no named Beneficiary, we pay the death benefit to your estate or the Owner if the Owner is a non-individual.
|
● FOR
JOINTLY OWNED CONTRACTS: The sole primary
Beneficiary is the surviving Joint Owner regardless of
any
other named primary Beneficiaries. If both Joint Owners die within 120 hours of each other, we pay the death
benefit
to the named surviving primary Beneficiaries. If there are no named surviving primary Beneficiaries, we pay
the
death benefit to the named surviving contingent Beneficiaries, or equally to the estate of the Joint Owners if there
are
no named surviving contingent Beneficiaries. |
|
● NAMING
AN ESTATE AS A BENEFICIARY: If an estate
is the Beneficiary, the estate must be the sole primary
Beneficiary,
unless the Spouse is the sole primary Beneficiary. If the Spouse is the sole primary Beneficiary, then an
estate
can be a contingent Beneficiary. |
Eligible
Person(s) and Covered Person(s)
We determine Eligible Persons on
the Issue Date based on the Contract’s ownership and tax qualification status. We use Eligible Person(s) to determine the Income
Percentage and Income Percentage Increase, when you will begin receiving Income Percentage Increases, when Income Payments are available
to you, and the payment type (single or joint) available to you.
We base Income Payments on the lives
of the Covered Person(s). We determine the Covered Person(s) on the Income Benefit Date based on the available Eligible Person(s), their
marital status, and the payment type you select. Joint Income Payments are only available if there are two Eligible Persons on the Income
Benefit Date who are also spouses within the meaning of federal tax law and they meet the requirements stated here. Because
Income Payments must begin no later than age 100, and are not available until age 50, joint Income Payments are not available if there
is more than a 50-year age difference between spouses.
Eligible Person and
Covered Person Requirements
For a single, individual Owner:
●
You, the Owner, are an Eligible Person.
●
If you and the sole primary Beneficiary are spouses within
the meaning of federal tax law, the sole primary Beneficiary is also an Eligible Person and you can select joint Income Payments with
both Eligible Persons becoming Covered Persons.
●
If you select single Income Payments only you, the Owner,
can be the Covered Person.
For Joint Owners:
●
Both Joint Owners are Eligible Persons.
●
If you select single Income Payments you can designate either
Eligible Person to be the Covered Person.
●
If you select joint Income Payments you must designate both
Joint Owners to be the Covered Persons.
For Contracts owned by a non-individual:
●
The Annuitant is the Eligible Person.
●
For Non-Qualified Contracts, we only allow one Eligible Person
and joint Income Payments are not available.
●
For Qualified Contracts, if the Owner is a qualified plan
or a custodian and the Annuitant and sole contingent Beneficiary are spouses within the meaning of federal tax law, the sole contingent
Beneficiary is also an Eligible Person. However, joint Income Payments are only available if the qualified plan or custodian is also the
sole primary Beneficiary. This structure allows the surviving non-Annuitant spouse to continue to receive Income Payments, assuming the
surviving non-Annuitant spouse is the beneficiary under the qualified plan or custodial IRA.
●
If you select single Income Payments only the Annuitant can
be the Covered Person.
If an Eligible Person or a Covered
Person is no longer an Owner, Joint Owner, Annuitant, sole primary Beneficiary, or sole contingent Beneficiary as required above due to
death, change in spousal status, an assignment or change of ownership/Beneficiary, we will remove that person from the Contract as an
Eligible Person or Covered Person. If an Eligible Person is removed, you cannot designate that person to be a Covered Person. If a Covered
Person is removed, that person is no longer a Covered Person. If
we remove all Eligible Persons or Covered Persons from the Contract, the Income Benefit ends.
You can only add
or replace an Eligible Person on or before the Income Benefit Date.
If you add or change an Owner, sole primary Beneficiary or sole contingent Beneficiary that person will become an Eligible Person if they
are the current spouse within the meaning of federal tax law of an existing Eligible Person and meet the requirements stated in this section.
If you add or replace an Eligible Person we will recalculate your Lifetime Income Percentages based on the age of
the new Eligible
Person on the Index Effective Date and Index Anniversaries, if applicable, as stated in section 11, Income Benefit – How the Income
Benefit Works. At any given time there cannot be more than two Eligible Persons. After
the Income Benefit Date, you cannot add, remove, or replace a Covered Person even if you add or change an Owner, or Beneficiary.
Change in Spousal Status
of Eligible Persons or Covered Persons
If at any time joint Eligible Persons
or joint Covered Persons are no longer spouses you must send us written notice. If we receive notice on or before the Income Benefit Date,
joint Income Payments will not be available to you unless you remarry and add your new spouse as a Joint Owner or sole primary or contingent
Beneficiary according to the requirements stated in this section. If we receive notice after the Income Benefit Date, we will remove one
former spouse from the Contract as a Covered Person and also as an Owner, Joint Owner, Annuitant and/or Beneficiary.
Upon notification of divorce, we
treat any request to reduce or divide benefits under this Contract as a request for a withdrawal of Contract Value payable to you. However,
for tax purposes this is generally treated as a transfer depending on the terms of the divorce decree. We process the withdrawal and remove
one spouse from the Contract as an Eligible Person or Covered Person, Owner, Annuitant and/or Beneficiary, according to your instructions
or any applicable court order. This withdrawal is subject to any applicable tax or MVA, and may cause Income Payments and the Income Benefit
to end prematurely. However, if you do not notify us of the divorce, the Contract continues and upon the death of an Owner, we pay any
applicable death benefit to the Beneficiary(ies) and the Contract and the Income Benefit both end.
Payee
The Payee is the person or entity
who receives Annuity Payments during the Annuity Phase. The Owner receives tax reporting on those payments. Generally, we require the
Payee to be an Owner. However, we may allow you to name a charitable trust, financial institution, qualified plan, or an individual specified
in a court order as a Payee subject to our approval. For Qualified Contracts owned by a qualified plan, the qualified plan must be the
Payee.
Assignments,
Changes of Ownership and Other Transfers of Contract Rights
You can assign your rights under
this Contract to someone else during the Accumulation Phase. An assignment may be absolute or limited, and includes changes of ownership,
collateral assignments, or any other transfer of specific Contract rights. After an assignment, you may need the consent of the assignee
of record to exercise certain Contract rights depending on the type of assignment and the rights assigned.
The Contract cannot be assigned without
our consent. You must submit your request to assign the Contract in writing to our Service Center. We will not consent if the assignment
would violate or result in noncompliance with any applicable state or federal law or regulation.
We record the assignment as
of the date you signed the request, unless you specify otherwise. We are not responsible for the validity or effect of the assignment.
We are not liable for any actions we take or payments we make before we receive your request in Good Order and record it. Assigning the
Contract does not change, revoke or replace the originally named Annuitant or Beneficiary; if you also want to change the Annuitant or
Beneficiary, you must make a separate request.
|
● An
assignment may be a taxable event. In
addition, there are other restrictions on changing the ownership of a
Qualified
Contract and Qualified Contracts generally cannot be assigned absolutely or on a limited basis. You
should
consult
with your tax adviser before assigning this Contract.
|
|
● An
assignment will only change the Determining Life (Lives) if it involves removing a Joint Owner due to
divorce,
replacing Joint Owners with a Trust, or adding a Joint Owner if that person is a spouse within the
meaning
of federal tax law of the existing Owner. |
3. Purchasing the Contract
Purchase
Requirements
To purchase this Contract, on the
Issue Date, all Owners (or the Annuitant if the Owner is a non-individual) must be:
●
age 80 or younger, or
●
age 75 or younger if you select the Maximum Anniversary Value
Death Benefit.
The Purchase
Payment requirements for this Contract are as follows.
●
The minimum initial Purchase Payment due on the Issue Date
is $5,000.
●
We restrict additional Purchase Payments.
Each Index Year during the Accumulation Phase and before the Income Benefit Date, you cannot add more than your initial amount without
our prior approval. Your initial amount is the total of all Purchase Payments received before the first Quarterly Contract Anniversary
of the first Contract Year. We allow you to add up to the initial amount in the remainder of the first Index Year. The minimum additional
Purchase Payment we will accept is $50.
●
We do not accept additional Purchase Payments on or after
the Income Benefit Date, or on or after the Annuity Date.
●
The maximum total Purchase Payments we accept without our
prior approval is $3 million.
We may, at our sole discretion, waive
the minimum Purchase Payment requirements.
Once we receive your initial Purchase
Payment and all necessary information in Good Order at our Service Center, we issue the Contract within two Business Days. If the Issue
Date is the same as the Index Effective Date, we allocate your initial Purchase Payment to the Index Options. If the Issue Date is not
the Index Effective Date, we hold your initial Purchase Payment in the Variable Option before we transfer it to your selected Index Options.
If you do not give us all the information we need, we contact you or your Financial Professional. If for some reason we are unable to
complete this process within five Business Days, we either send back your Purchase Payment or get your permission to keep it until we
get all the necessary information. If you make additional Purchase Payments, we add this money to your Contract on the Business Day we
receive it in Good Order.
If you submit a Purchase Payment
and/or application to your Financial Professional, we do not begin processing the payment and/or application until we receive it.
We may terminate
your ability to make additional Purchase Payments because we reserve the right to decline any or all Purchase Payments at any time on
a nondiscriminatory basis. This applies to Contracts issued
in all states except as disclosed in Appendix G. If mandated under applicable law, we may be required to reject a Purchase Payment. We
will decline a Purchase Payment we receive on the same Business Day that we receive in Good Order a request for full withdrawal, or Contract
cancellation during the free look period. If
we exercise our right to decline additional Purchase Payments, this may limit your ability to fund your Contract’s guaranteed benefits
such as the Income Benefit, Traditional Death Benefit or Maximum Anniversary Value Death Benefit.
Applications
Sent Electronically
We accept manually signed applications
that are in Good Order and are sent by fax, or email, or uploaded to our website. It is important to verify receipt of any faxed application,
or to receive a confirmation number when using email or the web. We are not liable for applications that we do not receive. A manually
signed application sent by fax, email or over the web is considered the same as an application delivered by mail. Our electronic systems
(fax, email or website) may not always be available; any electronic system can experience outages or slowdowns which may delay application
processing. Although we have taken precautions to help our system handle heavy use, we cannot promise complete reliability. If you experience
problems, please submit your written application by mail to our Service Center. We reserve the right to discontinue or modify our electronic
application policy at any time and for any reason.
Allocation
of Purchase Payments and Contract Value Transfers
The allocation instructions you provide
on your application automatically become your default allocation instructions. We use these allocation instructions for all Purchase Payments
we receive unless you change them. Any change to allocation instructions will replace any existing allocation instructions and will be
used as the basis for transfers between and among the Index Options.
We
only allow Purchase Payments to move into the Index Options on the Index Effective Date and on subsequent Index Anniversaries.
As a result, we hold Purchase Payments in the Variable Option when we receive them on days other than the Index Effective Date or Index
Anniversaries. We then transfer them to the Index Options on the next Index Anniversary according to your allocation instructions. We
apply any Purchase Payments we receive on the Index Effective Date or on an Index Anniversary directly to the Index Options on that day;
these Purchase Payments are not held in the Variable Option.
We
only allow Index Option Value transfers between Index Options on Term End Dates. However, you can transfer between Index Options before
the Term End Date by executing a Performance Lock and an Early Reallocation. For multi-year Term Index Options you can also transfer between
Index Options before the Term End Date by executing a
Performance
Lock before the last year of the Term and changing your allocation instructions before the next Index Anniversary. We do not allow assets
to move into an established Index Option until the Term End Date. If you request to transfer into an established Index Option on a date
that is not a Term End Date, we will transfer those assets into the same Index Option with a new Term Start Date.
You select the Index Effective Date
when you purchase your Contract. It can be any Business Day up to and including the first Quarterly Contract Anniversary, but it cannot
be the 29th,
30th,
or 31st
of a month.
|
On
your application if you select… |
Your
Index Effective Date will be either… |
|
the
earliest Index Effective Date |
• your
Issue Date, or
• the
first Business Day of the next month if the Issue Date is the 29th,
30th,
or 31st
of a
month
|
|
the
deferred Index Effective Date |
• your
first Quarterly Contract Anniversary, or
• the
next Business Day if the first Quarterly Contract Anniversary occurs on a non-Business
Day,
or the first Business Day of the next month if the first Quarterly Contract Anniversary
is
the 29th,
30th,
or 31st
of a month |
You should be aware
that, generally, initial Trigger Rates, Caps, and Participation Rates could change every seven calendar days. However, these rates are
guaranteed to be available during the period stated on our website at https://www.allianzlife.com/RILAincomeadvrates
and cannot be superseded until that period ends. If you select an Index Effective Date that is within the guaranteed period for the initial
rates that are available for review on the date you signed your application, you will receive the initial rates that were available on
the date you signed your application. However, if you select an Index Effective Date that is after this guaranteed period, you are subject
to the risk that initial Trigger Rates, Caps, and Participation Rates may change and be less advantageous to you. Furthermore, if your
Index Effective Date is after the end of the free look period and you cancel your Contract, you will receive the Cash Value. On or before
the Index Effective Date, the Daily Adjustment and
MVA do not
apply. You
may review future rates at least seven calendar days before their effectiveness at https://www.allianzlife.com/RILAincomeadvrates.
Subject to the limitations related to designating the Index Effective Date, you (or your Financial Professional, if authorized) can change
your Index Effective Date at any time before it occurs to be an earlier or later date by submitting a request. However,
your new Index Effective Date cannot be later than the deferred Index Effective Date listed above. We must receive your request in Good
Order at our Service Center before the end of the Business Day on which you want the Index Effective Date to occur. Once your Index Effective
Date occurs, all Index Options for your Contract will have the same Index Anniversary.
You can change your allocation instructions
at any time without fee or penalty. These changes are effective on the Business Day we receive them in Good Order at our Service Center.
We accept changes to allocation instructions from any Owner unless you instruct otherwise. We may allow you to authorize someone else
to change these allocation instructions on your behalf. However, we must receive allocation instruction changes (which will transfer your
Index Option Values) in Good Order at our Service Center before the end of the Business Day on the Term End Date (or the next Business
Day if the Term End Date is a non-Business Day). Changes
to your allocation instructions will transfer existing Index Option Values on the Term End Date.
We notify you at least 30 days in
advance of each Index Anniversary as a reminder that on the upcoming anniversary you may transfer Index Option Value between Index Options.
In order to make a transfer between Index Options, you must provide us with allocation instruction changes in Good Order. On each Term
End Date, if we have not received allocation instruction changes from you, all assets invested continue to be invested in the same Index
Options with new Term Start Dates at the renewal Trigger Rates, Caps, and Participation Rates.
We can add new Crediting Methods,
Terms, and Indexes to your Contract in the future, and you can allocate Purchase Payments or transfer Contract Value to them on the Term
Start Date after we make them available to you. Once we add a Crediting Method to your Contract we cannot remove it, or change how it
calculates Performance Credits. If we add a new Index Option to your Contract, we cannot change its Buffer or Floor after it is established.
For a new Index Option, the minimum Buffer is 5% and the minimum Floor is -25%. However, we can change the renewal and Early Reallocation
Trigger Rates, Caps, and Participation Rates associated with any Index Option on each Term Start Date subject to the guaranteed minimums.
|
● In
order to apply Purchase Payments we receive after
the Index Effective Date to your selected Index Option(s) on
the
next Index Anniversary, we must receive them before
the end of the Business Day on the Index Anniversary (or
before
the end of the prior
Business Day if the anniversary is a non-Business Day).
|
|
● Purchase
Payments we hold in the Variable Option before transferring them to your selected Index Options are
subject
to Contract fees and expenses (e.g. product fee, contract maintenance charge), and market risk and may
lose
value. |
Electronic
Allocation Instructions
We use reasonable procedures to confirm
that electronic allocation instructions given to us are genuine. If we do not use such procedures, we may be liable for any losses due
to unauthorized or fraudulent instructions. We record telephone instructions and log all fax, email and website instructions. We reserve
the right to deny any allocation instruction change, and to discontinue or modify our electronic instruction privileges at any time for
any reason.
Please note that telephone, fax,
email and/or the website may not always be available. Any electronic system, whether it is ours, yours, your service provider’s,
or your Financial Professional’s, can experience outages or slowdowns for a variety of reasons, which may delay or prevent our
processing of your allocation instruction change. Although we have taken precautions to help our systems handle heavy use, we cannot promise
complete reliability. If you are experiencing problems, you should submit your instructions in writing to our Service Center.
By authorizing electronic instructions,
you authorize us to accept and act upon these instructions for your Contract. There are risks associated with electronic communications
that do not occur with a written request. Anyone authorizing or making such requests bears those risks. You should protect your website
password, because the website is available to anyone with your password; we cannot verify that the person providing instructions on the
website is you, or is authorized by you.
Free
Look/Right To Examine Period
If you change your mind about the
Contract, you can cancel it within the free look period stated on the first page of your Contract. In most states, this is ten calendar
days after you receive the Contract. If you cancel your Contract during the free look period, in most states we return your Contract Value
as of the Business Day we receive your cancellation request in Good Order. This may be more or less than your initial Purchase Payment.
In states that require us to return Purchase Payments less withdrawals if you cancel your Contract, we return Contract Value if greater.
IRA Contracts require us to return
Purchase Payments less withdrawals. If you cancel your IRA Contract, we return the greater of Purchase Payments less withdrawals or Contract
Value.
If your cancellation request occurs
after the Index Effective Date, your Contract Value will include the Daily Adjustment, which may be negative for amounts allocated to
the Index Dual Precision Strategy, Index Precision Strategy, Index Guard Strategy, and Index Performance Strategy Index Options.
Some states and certain IRA Contracts
require return of Purchase Payments. For these Contracts, we reserve the right to hold your initial Purchase Payment in the Variable Option
until the free look period ends, and then re-allocate your Contract Value, less fees and expenses, according to your allocation instructions.
If we exercise this right, the Contract Value we use to determine your refund amount on a cancellation request will not include the Daily
Adjustment as the Index Effective Date will not yet have occurred. Currently, we only exercise this right on certain Contracts issued
in California as noted in Appendix G. If we hold your initial Purchase Payment in the Variable Option during the free look period and
the requested Index Effective Date would occur during this time, we change your Index Effective Date to the next Business Day after the
free look period that is not the 29th,
30th,
or 31st
of the month. Then, if you:
●
cancel your Contract during this time, we return the greater
of Purchase Payments less withdrawals and less any investment advisory fees deducted from your Contract if you authorize your Financial
Professional’s firm to receive these fees, or Contract Value. We do not apply an MVA or deduct any other Contract fees or expenses
if you cancel your Contract during the free look period.
●
do not cancel your Contract during this time, we re-allocate
your Contract Value to the Index Options according to your allocation instructions on the Index Effective Date.
In the Contract, the free look provision
is also called the right to examine.
4. Index Options
Overview
of the Index Options
We apply positive, zero, or negative
Performance Credits at the end of a Term to amounts allocated to an Index Option based, in part, on the performance of the applicable
Index. An investment in an Index Option is not an investment in the Index or in any Index fund.
Some Index Options provide complete
protection against negative Index Returns at the end of a Term. Other Index Options provide limited protection against negative Index
Returns at the end of a Term through a Buffer or Floor. Despite the Buffer or Floor, you could lose a significant amount of money if the
Index for such other Index Options declines in value. You may also lose a significant amount of money due to a negative Daily Adjustment
if amounts are removed from such other Index Options prior to the end of a Term.
The Contract currently offers Index
Options with different types of Crediting Methods, including the Index Protection Strategy with Trigger, Index Protection Strategy with
Cap, Index Precision Strategy, Index Dual Precision Strategy, Index Guard Strategy, and Index Performance Strategy. We can add new Index
Options to your Contract in the future. We can change certain features of an Index Option from one Term to the next, including the Index
and the current limit on Index gains (subject to minimum guarantees). We cannot change an existing Index Option’s limit on Index
losses (including a Buffer or Floor) or how it calculates Performance Credits. We reserve the right to close any Index Option to new Purchase
Payments and transfers, but not for renewal upon maturity.
The Contract allows you to transfer
between Index Options on Term End Dates. Additionally, you can transfer between Index Options before the Term End Date by executing a
Performance Lock and an Early Reallocation. For multi-year Term Index Options, you can also transfer between Index Options before the
Term End Date by executing a Performance Lock before the last year of the Term and changing your allocation instructions before the next
Index Anniversary. For more information, see section 3, Purchasing the Contract – Allocation of Purchase Payments and Contract
Value Transfers.
Information regarding the features
of each currently offered Index Option, including (i) the Index’s name, (ii) a brief statement describing the assets that the Index
seeks to track (e.g.,
U.S. large-cap equities), (iii) the Term length, (iv) the Index Option’s Crediting Methodology, (v) the current limit on Index
loss, and (vi) the minimum limit on Index gain, is available in Appendix A – Investment Options Available Under the Contract.
Limits
on Index Losses
Each Index Option offers a certain
level of protection from negative Index Returns, which limits the amount of negative Index Return used in calculating Performance Credits
for an Index Option at the end of a Term.
●
The Index Protection Strategy with Trigger and Index Protection
Strategy with Cap Index Options offer complete (or 100%) protection from negative Index Returns. For example, if at the end of a Term,
the Index Return is -25%, we will apply a 0% Performance Credit to your investment (i.e.,
no loss due to the negative Index Return).
●
Other Index Options include a feature, either a Buffer or
Floor, that provides limited protection from negative Index Returns.
−
A Buffer is the maximum amount of negative Index Return that
we
absorb before applying a negative Performance Credit. For example, if at the end of a Term, the Index Return is -25% and the Buffer is
10%, we apply a Performance Credit of -15%, meaning your Contract Value allocated to that Index Option will decrease by 15% since the
Term Start Date. This reflects the negative Index Return that exceeds the protection of the 10% Buffer. The Index Precision Strategy,
Index Dual Precision Strategy, and Index Performance Strategy offer Index Options with Buffers.
−
A Floor, on the other hand, is the maximum amount of negative
Index Return you
absorb as a negative Performance Credit. We absorb any negative Index Return beyond the Floor. For example, if the Index Return is -25%
and the Floor is -10%, we apply a Performance Credit of -10%, meaning your Contract Value allocated to that Index Option will decrease
by 10% since the Term Start Date. This reflects the negative Index Return down to the -10% Floor. The Index Guard Strategy offers Index
Options with a Floor.
−
We currently offer Index Options with 10%, 20%, and
30% Buffers, and -10% Floors.
The current limit on Index loss for
an Index Option will not change for the life of that Index Option. However, we reserve the right to add new Index Options, as well as
close Index Options to new Purchase Payments and transfers. As such, the limits on Index loss offered under the Contract may change from
one Term to the next if we add an Index Option or
discontinue accepting
new allocations into an Index Option. However,
at least one Index Option with a Buffer no lower than 5% or Floor no lower than -25%,
or an Index Option that provides complete protection from Index losses, will always be available for renewal under the Contract.
Prior to selecting an Index Option,
you should evaluate the protection from negative Index Returns offered by an Index Option. See “Comparing Crediting Methods”
later in this section for additional factors that you should consider when comparing Index Options. Also, see “How We Set Limits
on Index Gains and Losses” below for a description of the factors that we consider when setting rates for the Index Options.
For detailed information on how we
calculate Index Option Values and Performance Credits, see “Determining Index Option Values” and “Calculating Performance
Credits” in section 6, Valuing Your Contract later in this prospectus.
Limits
on Index Gains
Each Index Option also has an upside
feature, either a Trigger Rate, Cap, and/or Participation Rate, used in the calculation of positive Performance Credits, if any,
that may be credited to your investment at the end of a Term. We may limit the amount you can earn on an Index Option based on the Trigger Rate,
Cap, or Participation Rate, as applicable.
●
A Trigger Rate represents the positive Performance Credit,
if any, that may apply on the Term End Date. The Index Precision Strategy, Index Dual Precision Strategy, and Index Protection Strategy
with Trigger offer Index Options with a Trigger Rate.
−
For the Index Precision Strategy and Index Protection Strategy
with Trigger, the Trigger Rate will apply if the Index Return is positive or zero. For example, if at the end of a Term, the Index Return
is 6% and the Trigger Rate is 3%, we apply a Performance Credit of 3%, meaning your Contract Value allocated to that Index Option will
increase by 3% since the Term Start Date.
−
For the Index Dual Precision Strategy, the Trigger Rate will
apply if the Index Return is positive, zero, or to a limited extent, negative. For example, assume a Trigger Rate of 3% and a Buffer of
10%. If at the end of a Term, the Index Return is positive, zero, or negative but no lower than -10% (i.e.,
not in excess of the Buffer), we apply a positive Performance Credit of 3%, meaning your Contract Value allocated to that Index Option
will increase by 3% since the Term Start Date. However, if the negative Index Return were lower than -10% (i.e.,
in excess of the Buffer), we apply a negative Performance Credit equal to the negative Index Return plus the Buffer.
●
A Cap represents the maximum positive Performance Credit,
if any, applied on a Term End Date. For example, if at the end of a Term, the Index Return is 12% and the Cap is 10%, we apply a Performance
Credit of 10%, meaning your Contract Value allocated to that Index Option will increase by 10% since the Term Start Date. The Index Protection
Strategy with Cap, Index Guard Strategy, and Index Performance Strategy offer Index Options with a Cap. Index Performance Strategy multi-year
Term Index Options have both a Cap and a Participation Rate (as described below).
●
A Participation Rate is the percentage that is multiplied
by a positive Index Return in calculating a positive Performance Credit, if any, subject to any applicable Cap. For example, if at the
end of a Term, the Participation Rate is 100%, the Cap is 15%, and the Index Return is 12% (which is lower than the Cap), we apply a Performance
Credit of 12% (i.e.,
100% x 12%). However, if the Index Return were instead 20% (which is higher than the Cap), we would apply the Cap and a Performance Credit
of 15%. Index Performance Strategy multi-year Term Index Options have both a Cap and a Participation Rate.
The
Trigger Rate, Cap, and/or Participation Rate for an Index Option will change from Term to Term, subject to a specified guaranteed
minimum that will not change for the life of that Index Option. Guaranteed minimum Trigger Rates, Caps, and/or Participation Rates vary
by Index Option.
The lowest Trigger Rate,
Cap, and Participation Rate that we may establish if we add a new Index Option to the Contract are 0.05%, 0.05%, and 5.00%, respectively.
The current Trigger Rates, Caps,
and Participation Rates being offered for new Terms of the available Index Options can be located at the following publicly accessible
website: https://www.allianzlife.com/RILAincomeadvrates.
The Trigger Rates, Caps, and Participation Rates posted on that website address are incorporated by reference into this prospectus.
Prior to selecting an Index Option,
you should evaluate the Trigger Rates, Caps, and Participation Rates that we are offering. See “Comparing Crediting Methods”
later in this section for additional factors that you should consider when comparing Index Options. Also, see “How We Set Limits
on Index Gains and Losses” below for a description of the factors that we consider when setting rates for the Index Options.
For detailed
information on how we calculate Index Option Values and Performance Credits, see “Determining Index Option Values” and “Calculating
Performance Credits” in section 6, Valuing Your Contract later in this prospectus.
How
We Set Limits on Index Gains and Losses
We set Trigger Rates, Caps, and Participation
Rates in our discretion, subject to applicable guaranteed minimums. The rates applicable to new terms may differ for initial Terms, renewal
Terms, and Early Reallocations. When setting these limits on Index gains, we consider a variety of factors, including, but not limited
to:
●
Term length,
●
level of downside protection,
●
market volatility,
●
our hedging strategies and investment performance,
●
the availability of hedging instruments,
●
the amount of money available to us through Contract fees
and expenses to purchase hedging instruments,
●
expenses incurred by the Company,
●
your Index Effective Date,
●
the level of interest rates,
●
utilization of Contract benefits by Owners, and
●
our profitability goals.
We also set the limits on Index losses
for new Index Options (e.g.,
Buffers and Floors) in our discretion, but the Buffer or Floor will be no lower than 5% or -25%, respectively. When setting limits on
Index losses, we consider many of the factors listed above, as well as the fact that an Index Option’s limit on Index loss will
not change for the life of the Index Option.
Due to a combination of factors,
including potential changes in interest rates and other market conditions (e.g.
rising inflation), the current economic environment is evolving. The future impact on the rates we declare cannot be predicted with certainty.
The effect of a change in interest rates or other market conditions may not be direct or immediate. There may be a lag in changes to Trigger
Rates, Caps, and Participation Rates. Interest rates could increase. In a rising interest rate environment, increases in initial Trigger
Rates, Caps, and Participation Rates, if any, may be substantially slower than increases in interest rates. However, a rising interest
rate environment may have the opposite effect on renewal rates and cause renewal Trigger Rates, Caps, and Participation Rates to decrease.
We manage our obligation to provide
Performance Credits in part by trading call and put options, and other derivatives on the available Indexes. The costs of the call and
put options and other derivatives vary based on market conditions, and we may adjust future renewal and Early Reallocation Trigger Rates,
Caps, and Participation Rates to reflect these cost changes. The primary factor affecting the differences in the initial Trigger Rates,
Caps, and Participation Rates for newly issued Contracts and renewal and Early Reallocation rates for existing Contracts is the difference
in what we can earn from these investments for newly issued Contracts versus what we are earning on the investments that were made for
existing Contracts. In some instances, we may need to reduce initial, renewal, and Early Reallocation Trigger Rates, Caps, and Participation
Rates, or we may need to substitute an Index. You bear the risk that we may reduce Trigger Rates, Caps, and Participation Rates, which
reduces your opportunity to receive positive Performance Credits.
Terms
We currently offer Index Options
with 1-year, 3-year, and 6-year Terms. Not all Term lengths are available for all types of Crediting Methods. Each Crediting Method offers
1-year Terms. The Index Dual Precision Strategy and Index Performance Strategy also offer 3-year and 6-year Terms.
Prior to selecting an Index Option,
you should evaluate the various Term lengths. You should consider which Term lengths may be appropriate for you based on your liquidity
needs, investment time horizon, and financial goals. Investing in Index Options with shorter Terms will provide more opportunities for
Performance Credits and transferring Contract Value; however, assuming the same Index and limit on Index loss, Index Options with shorter
Terms generally tend to have less potential for Index gains. Conversely, investing in Index Options with longer Terms will provide fewer
opportunities for Performance Credits and transferring Contract Value; however, assuming the same Index and limit on Index loss, Index
Options with longer Terms generally tend to have more potential for gain. Some of the other factors to consider include:
●
How long you intend to hold the Contract.
●
The Daily Adjustment for Index Options with Term lengths
of more than 1-year (including multi-year Terms or extended Term lengths resulting from Early Reallocation) may be more negatively impacted
by changes in the expected volatility of Index prices than 1-year Term Index Options due to the difference in Term length.
●
The risk of a negative Daily Adjustment is generally
greater for Index Options with a Term length of more than 1 year than for 1-year Term Index Options due to the Term length.
●
The Index Performance Strategy 3-year and 6-year Term Index
Options with a Participation Rate above 100% may also have larger fluctuations in the Daily Adjustment than Index Options either without
a Participation Rate, or with a Participation Rate equal to 100%.
●
For shorter Term lengths, there is more certainty in both
the final Index Values and how Trigger Rates, Caps, Buffers, and Floors determine Performance Credits. This means there may be less fluctuation
in the Daily Adjustment due to changes in Index return for Index Options with shorter Term lengths.
Amounts must remain
in an Index Option until the end of its Term to receive a Performance Credit and to avoid a possible negative Daily Adjustment, potential
negative MVA, and any applicable tax consequences. The
Daily Adjustment applies to full or partial withdrawals taken from an Index Option before the end of a Term. The Daily Adjustment also
applies if, before the Term End Date, you take Income Payments, you execute a Performance Lock, you annuitize the Contract, we pay a death
benefit, or we deduct Contract fees, expenses, or investment advisory fees that you authorize your Financial Professional’s firm
to receive from the Contract. A negative MVA applies if, within seven Index Years of the establishment of an Annual Contribution Amount,
you take a full or partial withdrawal, you take Income Payments, you execute a Performance Lock, you annuitize the Contract, or we pay
a death benefit at a time when the yield on corporate bonds is greater than what they were when the Annual Contribution Amount was established.
We do not apply an MVA to deductions for Contract fees and expenses, or investment advisory fees you authorize your Financial Professional’s
firm to receive from the Contract. For more information, see “Daily Adjustment” and “Market Value Adjustment (MVA)”
in section 7, Expenses and Adjustments.
Maturity
We will send you a letter at least
30 days before each Index Anniversary. This letter advises you that current Trigger Rates, Caps, and Participation Rates are expiring,
and that renewal rates for the next Term Start Date will be available for your review. The Index Anniversary letter also reminds you of
your opportunity to transfer your Index Option Values on the upcoming Term End Date. Renewal rates could be higher or lower than
your current Trigger Rates, Caps, and Participation Rates, subject to the guaranteed minimums. On each Term End Date, you have the option
of remaining allocated to your current Index Options at the renewal Trigger Rates, Caps, and Participation Rates that we set on the next
Term Start Date, or transferring to another permitted Index Option.
At least seven calendar days before
each Index Anniversary, we publish renewal rates for the next Term Start Date for your review in your account on our website, and on our
public website at https://www.allianzlife.com/RILAincomeadvrates.
If you do not review renewal rate change information when it is published or take no action to transfer to another permitted Index Option,
you will remain allocated to your current Index Options and will automatically become subject to the renewal Trigger Rates, Caps, and
Participation Rates until the next Term End Date.
For more information regarding your
availability to transfer into new Index Options, see section 3, Purchasing the Contract – Allocation of Purchase Payments and Contract
Value Transfers.
Indexes
The Contract currently offers Index
Options using the following Indexes. For more information on the Indexes, please see Appendix B – Available Indexes. Please note
that Index Values used to calculate Performance Credits are based on the Index’s closing value (for an Index that is a market
index) or closing share price (for an Index that is an ETF).
The S&P 500®
Index, Russell 2000®
Index, Nasdaq-100®
Index, and EURO STOXX 50®
are all “price return indexes,” not “total return indexes,” and therefore do not reflect dividends paid on
the securities composing the Index. This will reduce the Index Return and may cause the Index to underperform a direct investment in the
securities composing the Index. For the EURO STOXX 50®,
this Index is a euro “price return index” and Index Returns are determined without any exchange rate adjustment.
Because Index performance for the
iShares®
MSCI Emerging Markets ETF is based on the ETF’s closing share price, Index performance is calculated on a “price return”
basis, not a “total return” basis, and therefore does not reflect dividends
paid on the securities
in which the ETF invests. In addition, an ETF deducts fees and costs, which reduce Index performance. These factors will reduce the Index
Return and may cause the ETF to underperform a direct investment in the ETF or the securities in which the ETF invests.
S&P 500®
Index. The S&P 500®
Index is comprised of equity securities issued by large-capitalization U.S. companies.
Russell 2000®
Index. The Russell 2000®
Index is comprised of equity securities of small-capitalization U.S. companies.
Nasdaq-100®
Index. The Nasdaq-100®
Index is comprised of equity securities of the largest U.S. and non-U.S. companies listed on The Nasdaq Stock Market, including companies
across all major industry groups except the financial industry.
EURO STOXX 50®.
The EURO STOXX 50®
is comprised of the equity securities of large-capitalization companies in the Eurozone.
iShares®
MSCI Emerging Markets ETF. The iShares®
MSCI Emerging Markets ETF seeks to track the investment results of the MSCI Emerging Markets Index, which is designed to measure equity
market performance in the global emerging markets. The underlying index may include large-and mid-capitalization companies. iShares®
MSCI Emerging Markets ETF is an exchange-traded fund. Additional information about iShares®
MSCI Emerging Markets ETF is available on the SEC’s website at https://www.sec.gov
and copies of that information may be obtained, upon payment of a duplicating fee, by electronic request at the following email address:
publicinfo@sec.gov. Please note that this information is not prepared by us and may be intended for shareholders of the ETF. You will
not be a shareholder of the ETF by investing in an Index Option that is linked to the performance of the ETF. You may also request additional
information about the ETF from our Service Center or your Financial Professional.
Index
Substitutions and Additions
We may substitute a new Index for
an existing Index if:
●
the Index is discontinued,
●
we are unable to use the Index because, for example, changes
to an Index make it impractical or expensive to purchase derivative hedging instruments to hedge the Index, or we are not licensed to
use the Index,
●
the method of calculation of the Index Values changes substantially,
resulting in significantly different Index Values and performance results. This could occur, for example, if an Index altered the types
of securities tracked, or the weighting of different categories of securities, or
●
we determine in our sole discretion that the substitution
is necessary due to unanticipated events outside of our direct control. This might include other events similar to those listed above,
other changes to the Index (such as name or ownership changes) that legally may be considered a substitution, or a breach by the Index
provider of the Index intent or performance expectations.
If we add or substitute an Index,
we first seek any required regulatory approval from each applicable state insurance regulator and then provide you with written notice.
We also provide you with written notice if an Index changes its name. Index substitutions can occur either on a Term Start Date or during
a Term. If we substitute an Index during a Term, we will combine the return of the previously available substituted Index from the Term
Start Date to the substitution date with the return of the new Index from the substitution date to the Term End Date. If we substitute
an Index during a Term:
●
we do not
change the Charge Base we use to calculate the product and rider fees, and
●
the Buffers, Floors, Trigger Rates, Caps, and Participation
Rates for the substituted Index will apply to the new Index. We do not
change the Buffers, Floors, Trigger Rates, Caps, or Participation Rates that were in effect on the Term Start Date.
Similarly, if we substitute an Index
on a Term Start Date, the applicable Buffer, Floor, and minimum Trigger Rate, Cap, or Participation Rate will not change.
Changes to Trigger Rates, Caps, and
Participation Rates associated with the new Index, if any, may occur at the next regularly scheduled Term Start Date, subject to their
respective minimums.
The selection of a substitution Index
is in our discretion; however, it is anticipated that any substitute Index will be substantially similar to the Index it is replacing
and we will substitute any equity Index with a broad-based equity index. In the event a suitable replacement Index is not available, after
seeking any required regulatory approval, we will provide you written notice and information regarding the remaining available Index Options.
We may also close Index Options to
new Purchase Payments and transfers at any time.
Index
Historical Returns
The bar charts shown below provide
each Index’s annual returns for the last 10 calendar years, as well as the Index returns after applying a hypothetical 5% Cap and
a hypothetical 10% Buffer. The charts illustrate the variability of the returns from year to year and show how hypothetical limits on
Index gains and losses may affect these returns. Past performance is not necessarily an indication of future performance.
The performance
below is NOT the performance of any Index Option. Your performance under the Contract will differ, perhaps significantly. The performance
below may reflect a different return calculation, time period, and limit on Index gains and losses than the Index Options, and does not
reflect Contract fees and expenses, including the MVA and Daily Adjustment, which may reduce performance.
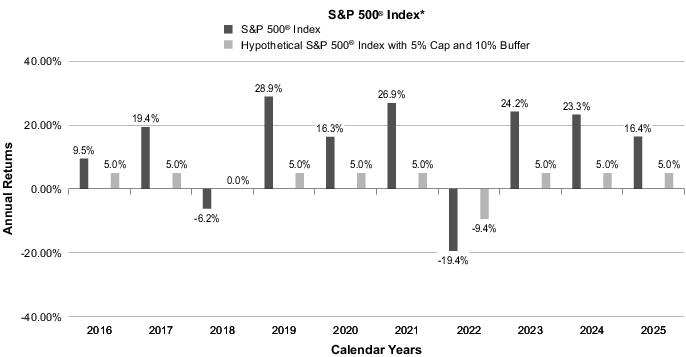
*
This Index is a “price return index,” not a
“total return index,” and therefore does not reflect the dividends paid on the securities composing the Index, which will
reduce the Index Return and may cause the Index to underperform a direct investment in the securities composing the Index.
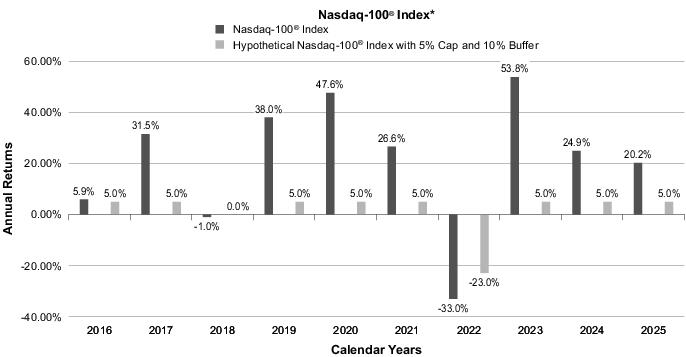
*
This Index is a “price return index,” not a
“total return index,” and therefore does not reflect the dividends paid on the securities composing the Index, which will
reduce the Index Return and may cause the Index to underperform a direct investment in the securities composing the Index.
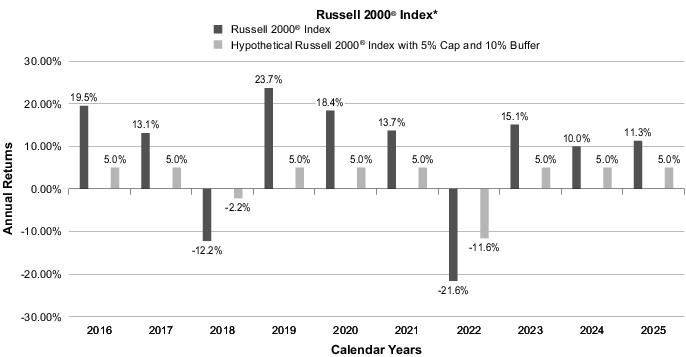
*
This Index is a “price return index,” not a
“total return index,” and therefore does not reflect the dividends paid on the securities composing the Index, which will
reduce the Index Return and may cause the Index to underperform a direct investment in the securities composing the Index.
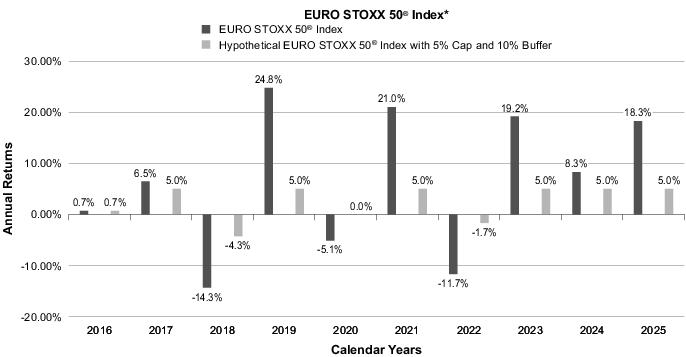
*
This Index is a “price return index,” not a
“total return index,” and therefore does not reflect the dividends paid on the securities composing the Index, which will
reduce the Index Return and may cause the Index to underperform a direct investment in the securities composing the Index. This Index
is a euro “price return index” and Index Returns are determined without any exchange rate adjustment.
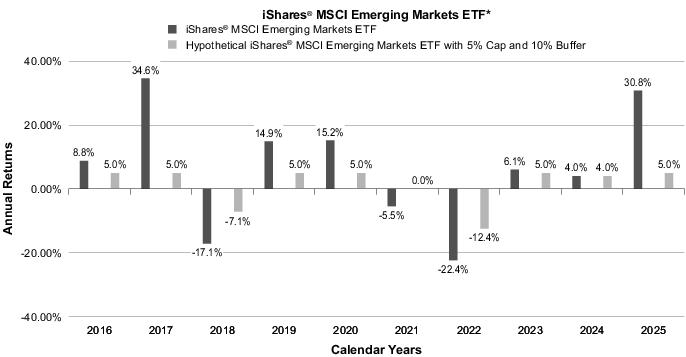
*
This Index is an ETF. Index Values are based on the ETF’s
closing share price. Index performance is calculated on a “price return” basis, not a “total return” basis,
and therefore does not reflect the dividends paid on the securities in which the ETF invests. In addition, an ETF deducts fees and costs,
which reduce Index performance. These factors will reduce the Index Return and may cause the Index to underperform a direct investment
in the ETF or the securities in which the ETF invests.
How
the Crediting Methods Work
The Index
Protection Strategy with Trigger provides a Performance
Credit using the “point-to-point with step-up” method of calculation. You receive a Performance Credit equal to the Trigger
Rate if the Index Value on the Term End Date is equal to or greater than the Index Value on the Term Start Date, regardless of the amount
of actual Index Return. If the current Index Value is less than it was on the Term Start Date, the Performance Credit is zero.
The Index
Protection Strategy with Cap provides a Performance Credit
using the “point-to-point with Cap” method of calculation.
●
If the Index Return is positive, the Performance Credit is
equal to the Index Return up to the Cap.
●
If the Index Value on the Term End Date is equal to or less
than the Index Value on the Term Start Date, the Performance Credit is zero.
The Index
Dual Precision Strategy provides a Performance Credit using
the “point-to-point with step-up” method of calculation.
●
You receive a Performance Credit equal to the Trigger Rate
if the Index Value on the Term End Date is:
−
equal to or greater than the Index Value on the Term Start
Date, regardless of the amount of actual Index Return, or
−
less than the Index Value on the Term Start Date and the
loss is less than or equal to the 10%, 20%, or 30% Buffer.
●
We apply the Trigger Rate for the entire Term length; we
do not apply
the Trigger Rate annually on a 3-year or 6-year Term Index Option.
●
If the Index Return is negative and extends beyond the 10%,
20%, or 30% Buffer, the negative Performance Credit is equal to the negative Index Return plus the 10%, 20%, or 30% Buffer. You participate
in any losses in excess of the 10%, 20%, or 30% Buffer.
The Index
Precision Strategy provides a Performance Credit using
the “point-to-point with step-up” method of calculation.
●
If the Index Value on the Term End Date is equal to or greater
than the Index Value on the Term Start Date, regardless of the amount of actual Index Return, the Performance Credit is equal to the Trigger
Rate.
●
If the Index Return is negative and the loss:
−
is less than or equal to the 10% Buffer, the Performance
Credit is zero. We absorb any loss up to the 10% Buffer.
−
extends beyond the 10% Buffer, the negative Performance Credit
is equal to the negative Index Return plus the 10% Buffer. You participate in any losses in excess of the 10% Buffer.
The Index
Guard Strategy provides a Performance Credit using the
“point-to-point with Cap” method of calculation.
●
If the Index Return is positive, the Performance Credit is
equal to the Index Return up to the Cap.
●
If the Index Value on the Term End Date is equal to the Index
Value on the Term Start Date, the Performance Credit is zero.
●
If the Index Return is negative, the negative Performance
Credit is equal to the negative Index Return down to the -10% Floor. You participate in any losses down to the -10% Floor. We absorb any
negative Index Return beyond the -10% Floor.
The Index
Performance Strategy provides a Performance Credit. The
1-year Term Index Options use the “point-to-point with Cap” method of calculation. The 3-year and 6-year Term Index Options
use the “point-to-point with Cap and enhanced upside” method of calculation.
●
If the Index Return is positive, the Performance Credit is
equal to:
−
the Index Return up to the Cap for a 1-year Term. If the
1-year Term is uncapped, the Performance Credit is equal to the Index Return.
−
the Index Return multiplied by the Participation Rate, up
to the Cap for a 3-year or 6-year Term. If the 3-year or 6-year Term is uncapped, the Performance Credit is equal to the Index
Return multiplied by the Participation Rate. We apply the Participation Rate and Cap for the entire Term length; we do not
apply the Participation Rate and Cap annually on a 3-year or 6-year Term.
●
If the Index Value on the Term End Date is equal to the Index
Value on the Term Start Date, the Performance Credit is zero.
●
If the Index Return is negative and the loss:
−
is less than or equal to the 10%, 20%, or 30% Buffer, the
Performance Credit is zero. We absorb any loss up to the 10%, 20%, or 30% Buffer. We apply the Buffer for the entire Term length; we do
not
apply the Buffer annually on a 3-year or 6-year Term Index Option.
−
extends beyond the 10%, 20%, or 30% Buffer, the negative
Performance Credit is equal to the negative Index Return plus the 10%, 20%, or 30% Buffer. You participate in any losses in excess of
the 10%, 20%, or 30% Buffer.
|
● The
Index Dual Precision Strategy, Index Precision Strategy, Index Guard Strategy, and Index Performance
Strategy
allow negative Performance Credits. As a result, you could lose a significant amount of money in the
form
of negative Performance Credits if an Index declines in value. The
maximum potential negative
Performance
Credit is: -90% with a 10% Buffer; -80% with a 20% Buffer; -70% with a 30% Buffer; and -10%
with
the Floor. |
|
● Because
we calculate Index Returns only on a single date in time, you may experience negative or flat
performance
even though the Index you selected for a given Crediting Method experienced gains through
some,
or most, of the Term. |
|
● If
an Index Performance
Strategy Index Option is “uncapped” for one Term (i.e., we do not declare a Cap for
that
Term) it does not mean that we will not declare a Cap for it on future Term Start Dates.
On the next Term
Start
Date we can declare a Cap for the next Term, or declare it to be uncapped. |
Comparing
Crediting Methods
The Crediting Methods have different
risk and return potentials.
|
What
is the asset protection? | |
|
Index
Protection
Strategy
with Trigger |
• Most
protection.
• If
the Index loses value, the Performance Credit is zero. You do not receive a negative Performance
Credit.
|
|
Index
Protection
Strategy
with Cap |
• Most
protection.
• If
the Index loses value, the Performance Credit is zero. You do not receive a negative Performance
Credit.
|
|
Index
Dual Precision
Strategy
|
• Less
protection than the Index Protection Strategy with Trigger, Index Protection Strategy with Cap,
and
Index Guard Strategy. Protection on the Index Dual Precision Strategy 1-year Term is equal to or
greater
than what is available with the Index Precision Strategy depending on the Index Option. Offers
the
same protection levels as the Index Performance Strategy.
• Buffer
absorbs 10%, 20%, or 30% of loss, but you receive a negative Performance Credit for losses
greater
than the Buffer.
• Potential
for large losses in any Term.
• More
sensitive to large negative market movements because small or moderate negative market
movements
within the applicable 10%, 20%, or 30% Buffer result in a positive Performance Credit. In
a
period of extreme negative market performance, the risk of loss is greater with the Index Dual
Precision
Strategy than with the Index Guard Strategy.
• In
extended periods of moderate to large negative market performance, 3-year and 6-year Terms may
provide
less protection than the 1-year Terms because, in part, the Buffer is applied over a longer
period
of time. |
|
Index
Precision Strategy |
• Less
protection than the Index Protection Strategy with Trigger, Index Protection Strategy with Cap,
and
Index Guard Strategy. Protection may be equal to or less than what is available with the Index
Dual
Precision Strategy and Index Performance Strategy depending on the Index Option.
• Buffer
absorbs 10% of loss, but you receive a negative Performance Credit for losses greater than
10%.
• Potential
for large losses in any Term.
• More
sensitive to large negative market movements because small negative market movements are
absorbed
by the 10% Buffer. In a period of extreme negative market performance, the risk of loss is
greater
with the Index Precision Strategy than with the Index Guard Strategy. |
|
What
is the asset protection? | |
|
Index
Guard Strategy |
• Less
protection than the Index Protection Strategy with Trigger and Index Protection Strategy with
Cap,
but more than Index Dual Precision Strategy, Index Precision Strategy, and Index Performance
Strategy.
• Permits
a negative Performance Credit down to the -10% Floor.
• Protection
from significant losses.
• More
sensitive to smaller negative market movements that persist over time because the -10% Floor
reduces
the impact of large negative market movements.
• In
an extended period of smaller negative market returns, the risk of loss is greater with the Index
Guard
Strategy than with the Index Dual Precision Strategy, Index Precision Strategy, and Index
Performance
Strategy.
• Provides
certainty regarding the maximum loss in any Term. |
|
Index
Performance
Strategy
|
• Less
protection than the Index Protection Strategy with Trigger, Index Protection Strategy with Cap,
and
Index Guard Strategy. 1-year Term Index Options with a 10% Buffer provide the same protection
as
the Index Precision Strategy. The 20% and 30% Buffers provide more protection than what is
available
with the Index Precision Strategy. Offers the same protection levels as the Index Dual
Precision
Strategy.
• Buffer
absorbs 10%, 20%, or 30% of loss depending on the Index Option you select, but you receive
a
negative Performance Credit for losses greater than the Buffer.
• Potential
for large losses in any Term.
• More
sensitive to large negative market movements because small or moderate negative market
movements
are absorbed by the Buffer. In a period of extreme negative market performance, the risk
of
loss is greater with the Index Performance Strategy than with the Index Guard Strategy.
• In
extended periods of moderate to large negative market performance, 3-year and 6-year Terms may
provide
less protection than the 1-year Terms because, in part, the Buffer is applied over a longer
period
of time. |
|
What
is the growth opportunity? | |
|
Index
Protection
Strategy
with Trigger |
• Growth
opportunity limited by the Trigger Rates.
• May
perform best in periods of small positive market movements relative to the other Crediting
Methods,
because such small positive market movements may result in positive Performance Credits
that
are greater than the Index Return while also providing complete protection from any Index losses.
May
have lower return potential compared to other Crediting Methods.
• These
Trigger Rates will generally be less than Caps, and Index Precision Strategy's Trigger Rates.
Growth
opportunity may be more or less than the Index Dual Precision Strategy depending on Trigger
Rates.
|
|
Index
Protection
Strategy
with Cap |
• Growth
opportunity limited by the Caps.
• May
perform best in periods of small positive market movements relative to the other Crediting
Methods,
because such small positive market movements would result in positive Performance
Credits
while also providing complete protection from any Index losses.
• Generally
more growth opportunity than the Index Protection Strategy with Trigger, but less than the
Index
Precision Strategy, Index Guard Strategy, and Index Performance Strategy. Growth opportunity
may
be more or less than the Index Dual Precision Strategy depending on Caps and Trigger Rates.
• Caps
will generally be greater than the Trigger Rates for Index Protection Strategy with Trigger, but
less
than Index Precision Strategy's Trigger Rates, and less than the Caps for the Index Guard
Strategy
and Index Performance Strategy. These Caps may be greater or less than Index Dual
Precision
Strategy's Trigger Rates. |
|
What
is the growth opportunity? | |
|
Index
Dual Precision
Strategy
|
• Growth
opportunity limited by the Trigger Rates. We do not
apply the Trigger Rate annually on 3-year
and
6-year Term Index Options.
• May
perform best in periods of small or moderate negative market movements as it provides a
positive
Performance Credit in these environments while other Crediting Methods do not.
• Generally,
1-year Term Index Options have less growth opportunity than the Index Precision Strategy
and
the 1-year Term Index Options on the Index Performance Strategy.
• Generally,
3-year and 6-year Term Index Options have less growth opportunity than the 3-year and
6-year
Term Index Options on the Index Performance Strategy.
• Growth
opportunity may be more or less than the Index Protection Strategy with Trigger, Index
Protection
Strategy with Cap, and Index Guard Strategy depending on Trigger Rates and Caps. |
|
Index
Precision Strategy |
• Growth
opportunity limited by the Trigger Rates.
• May
perform best in periods of small positive market movements.
• Generally
more growth opportunity than the Index Protection Strategy with Trigger, Index Protection
Strategy
with Cap, and Index Dual Precision Strategy. However, less growth opportunity than the
Index
Dual Precision Strategy during periods of small or moderate negative market movements.
• Growth
opportunity may be more or less than the Index Guard Strategy or Index Performance
Strategy
depending on Trigger Rates and Caps. |
|
Index
Guard Strategy |
• Growth
opportunity limited by the Caps.
• May
perform best in a strong market.
• Growth
opportunity that generally may be matched or exceeded only by the Index Performance
Strategy.
However, growth opportunity may be more or less than the Index Dual Precision Strategy,
Index
Precision Strategy, or Index Performance Strategy depending on Trigger Rates and Caps. |
|
Index
Performance
Strategy
|
• Growth
opportunity limited by the Caps and/or Participation Rates. We do not
apply the Cap annually
on
3-year and 6-year Term Index Options. If
we do not declare a Cap for an Index Option, there is
no
maximum limit on the positive Index Return for that Index Option. In addition, you can
receive
more than the positive Index Return if the Participation Rate applies and is greater
than
its 100% minimum. However, the Participation Rate cannot boost Index Returns beyond a
declared
Cap.
• May
perform best in a strong market.
• Generally,
1-year Term with 10% Buffer Index Options, 3-year Term with 10%, 20%, or 30% Buffer
Index
Options, and 6-year Term with 10%, 20%, or 30% Buffer Index Options have the most growth
opportunity.
• Growth
opportunity for the 1-year Term with 20% or 30% Buffer may be less than the Index Dual
Precision
Strategy 1-year Term, Index Precision Strategy, and Index Guard Strategy depending on
Trigger
Rates and Caps. |
|
What
can change within a Crediting Method? | |
|
Index
Protection
Strategy
with Trigger |
• Renewal
and Early Reallocation Trigger Rates for existing Contracts can change on each Term Start
Date.
– 1-year
Term has a 0.50% minimum Trigger Rate. |
|
Index
Protection
Strategy
with Cap |
• Renewal
and Early Reallocation Caps for existing Contracts can change on each Term Start Date.
– 1-year
Term has a 0.50% minimum Cap. |
|
Index
Dual Precision
Strategy
|
• Renewal
and Early Reallocation Trigger Rates for existing Contracts can change on each Term Start
Date.
– 1-year
Term with 10%, 20%, or 30% Buffer has a 3% minimum Trigger Rate.
– 3-year
Term with 10%, 20%, or 30% Buffer has a 4% minimum Trigger Rate.
– 6-year
Term with 10%, 20%, or 30% Buffer has an 8% minimum Trigger Rate.
• The
10%, 20%, and 30% Buffers for the currently available Index Options cannot change. However, if
we
add a new Index Option to your Contract after the Issue Date, we establish the Buffer for it on the
date
we add the Index Option to your Contract. The minimum Buffer is 5% for a new Index Option. |
|
What
can change within a Crediting Method? | |
|
Index
Precision Strategy |
• Renewal
and Early Reallocation Trigger Rates for existing Contracts can change on each Term Start
Date.
– 1-year
Term has a 3% minimum Trigger Rate.
• The
10% Buffers for the currently available Index Options cannot change. However, if we add a new
Index
Option to your Contract after the Issue Date, we establish the Buffer for it on the date we add
the
Index Option to your Contract. The minimum Buffer is 5% for a new Index Option. |
|
Index
Guard Strategy |
• Renewal
and Early Reallocation Caps for existing Contracts can change on each Term Start Date.
– 1-year
Term has a 3% minimum Cap.
• The
-10% Floors for the currently available Index Options cannot change. However, if we add a new
Index
Option to your Contract after the Issue Date, we establish the Floor for it on the date we add the
Index
Option to your Contract. The minimum Floor is -25% for a new Index Option. |
|
Index
Performance
Strategy
|
• Renewal
and Early Reallocation Caps and/or Participation Rates for existing Contracts can change on
each
Term Start Date.
– 1-year
Term with 10%, 20%, or 30% Buffer has a 3% minimum Cap.
– 3-year
Term with 10%, 20%, or 30% Buffer has a 5% minimum Cap, and 100% minimum
Participation
Rate.
– 6-year
Term with 10%, 20%, or 30% Buffer has a 10% minimum Cap, and 100% minimum
Participation
Rate.
• The
10%, 20%, and 30% Buffers for the currently available Index Options cannot change. However, if
we
add a new Index Option to your Contract after the Issue Date, we establish the Buffer for it on the
date
we add the Index Option to your Contract. The minimum Buffer is 5% for a new Index Option. |
|
• For
any Index Option with the
Index Dual Precision
Strategy, Index Precision Strategy, or Index Performance
Strategy,
you
participate in any negative Index Return in excess of the Buffer,
which reduces your Contract Value.
For
example, for a 10% Buffer we absorb the first -10% of Index Return and you could lose up to 90% of the Index
Option
Value. However, for any Index Option with the Index
Guard Strategy, we
absorb any negative Index Return
in
excess of the -10% Floor, so your maximum loss is limited to -10% of the Index Option Value due to negative
Index
Returns.
|
|
• Trigger
Rates, Caps, and Participation Rates as set by us from time-to-time may vary substantially based on market
conditions.
However,
in extreme market environments, it is possible that all Trigger Rates, Caps, and Participation
Rates
will be reduced to their respective minimums of 0.50%, 3%, 4%, 5%, 8%, 10%, or 100% as stated in the
table above.
|
|
• If
your Contract is within its free look period you may be able to take advantage of any increase in initial Trigger
Rates,
Caps, and/or Participation Rates by cancelling your Contract and purchasing a new Contract. |
|
• If
the initial Trigger Rates, Caps, and/or Participation Rates available on the Index Effective Date are not acceptable
you
have the following options: |
|
– Cancel
your Contract if you are still within the free look period.
|
|
– Request
to extend your Index Effective Date if you have not reached your first Quarterly Contract Anniversary. |
|
– If
the free look period has expired, request a full withdrawal and receive the Cash Value. This withdrawal is subject
to
income taxes, and may also be subject to a 10% additional federal tax for amounts withdrawn before age 59 1∕2. If
this
occurs on or before
the Index Effective Date, the Daily Adjustment and
MVA do not apply.
If this occurs after
the
Index Effective Date, you are
subject to the Daily Adjustment and
MVA. |
|
• Trigger
Rates, Caps, and Participation Rates can be different from Index Option to Index Option. For
example,
Caps
for the Index Performance Strategy 1-year Terms can be different between the S&P 500®
Index and the
Nasdaq-100®
Index; and Caps for the S&P 500®
Index can be different between 1-year, 3-year, and 6-year Terms on
the
Index Performance Strategy, and between the 1-year Terms for the Index Guard Strategy and Index Performance
Strategy.
Initial,
renewal, and Early Reallocation rates may also be different from Contract-to-Contract.
For
example,
assume that on August 3, 2023 we set Caps for the Index Performance Strategy 1-year Term with 10% Buffer
using
the S&P 500®
Index as follows: |
|
– 13%
initial rate and 12% Early Reallocation rate for new Contracts issued in 2023, |
|
– 14%
renewal rate and 14% Early Reallocation rate for existing Contracts issued in 2022, and |
|
– 12%
renewal rate and 13% Early Reallocation rate for existing Contracts issued in 2021. |
We apply positive, zero, or negative
Performance Credits at the end of a Term to amounts allocated to an Index Option based, in part, on the performance of the applicable
Index. An investment in an Index Option is not an investment in the Index or in any Index fund.
Strategy
allow negative Performance Credits. As a result, you could lose a significant amount of money in the
form
of negative Performance Credits if an Index declines in value. The
maximum potential negative
Performance
Credit is: -90% with a 10% Buffer; -80% with a 20% Buffer; -70% with a 30% Buffer; and -10%
with
the Floor.
Limits
on Index Losses
Each Index Option offers a certain
level of protection from negative Index Returns, which limits the amount of negative Index Return used in calculating Performance Credits
for an Index Option at the end of a Term.
●
The Index Protection Strategy with Trigger and Index Protection
Strategy with Cap Index Options offer complete (or 100%) protection from negative Index Returns. For example, if at the end of a Term,
the Index Return is -25%, we will apply a 0% Performance Credit to your investment (i.e.,
no loss due to the negative Index Return).
●
Other Index Options include a feature, either a Buffer or
Floor, that provides limited protection from negative Index Returns.
−
A Buffer is the maximum amount of negative Index Return that
we
absorb before applying a negative Performance Credit. For example, if at the end of a Term, the Index Return is -25% and the Buffer is
10%, we apply a Performance Credit of -15%, meaning your Contract Value allocated to that Index Option will decrease by 15% since the
Term Start Date. This reflects the negative Index Return that exceeds the protection of the 10% Buffer. The Index Precision Strategy,
Index Dual Precision Strategy, and Index Performance Strategy offer Index Options with Buffers.
−
A Floor, on the other hand, is the maximum amount of negative
Index Return you
absorb as a negative Performance Credit. We absorb any negative Index Return beyond the Floor. For example, if the Index Return is -25%
and the Floor is -10%, we apply a Performance Credit of -10%, meaning your Contract Value allocated to that Index Option will decrease
by 10% since the Term Start Date. This reflects the negative Index Return down to the -10% Floor. The Index Guard Strategy offers Index
Options with a Floor.
−
We currently offer Index Options with 10%, 20%, and
30% Buffers, and -10% Floors.
The current limit on Index loss for
an Index Option will not change for the life of that Index Option. However, we reserve the right to add new Index Options, as well as
close Index Options to new Purchase Payments and transfers. As such, the limits on Index loss offered under the Contract may change from
one Term to the next if we add an Index Option or
discontinue accepting
new allocations into an Index Option. However,
at least one Index Option with a Buffer no lower than 5% or Floor no lower than -25%,
or an Index Option that provides complete protection from Index losses, will always be available for renewal under the Contract.
Prior to selecting an Index Option,
you should evaluate the protection from negative Index Returns offered by an Index Option. See “Comparing Crediting Methods”
later in this section for additional factors that you should consider when comparing Index Options. Also, see “How We Set Limits
on Index Gains and Losses” below for a description of the factors that we consider when setting rates for the Index Options.
For detailed information on how we
calculate Index Option Values and Performance Credits, see “Determining Index Option Values” and “Calculating Performance
Credits” in section 6, Valuing Your Contract later in this prospectus.
Limits
on Index Gains
Each Index Option also has an upside
feature, either a Trigger Rate, Cap, and/or Participation Rate, used in the calculation of positive Performance Credits, if any,
that may be credited to your investment at the end of a Term. We may limit the amount you can earn on an Index Option based on the Trigger Rate,
Cap, or Participation Rate, as applicable.
●
A Trigger Rate represents the positive Performance Credit,
if any, that may apply on the Term End Date. The Index Precision Strategy, Index Dual Precision Strategy, and Index Protection Strategy
with Trigger offer Index Options with a Trigger Rate.
−
For the Index Precision Strategy and Index Protection Strategy
with Trigger, the Trigger Rate will apply if the Index Return is positive or zero. For example, if at the end of a Term, the Index Return
is 6% and the Trigger Rate is 3%, we apply a Performance Credit of 3%, meaning your Contract Value allocated to that Index Option will
increase by 3% since the Term Start Date.
−
For the Index Dual Precision Strategy, the Trigger Rate will
apply if the Index Return is positive, zero, or to a limited extent, negative. For example, assume a Trigger Rate of 3% and a Buffer of
10%. If at the end of a Term, the Index Return is positive, zero, or negative but no lower than -10% (i.e.,
not in excess of the Buffer), we apply a positive Performance Credit of 3%, meaning your Contract Value allocated to that Index Option
will increase by 3% since the Term Start Date. However, if the negative Index Return were lower than -10% (i.e.,
in excess of the Buffer), we apply a negative Performance Credit equal to the negative Index Return plus the Buffer.
●
A Cap represents the maximum positive Performance Credit,
if any, applied on a Term End Date. For example, if at the end of a Term, the Index Return is 12% and the Cap is 10%, we apply a Performance
Credit of 10%, meaning your Contract Value allocated to that Index Option will increase by 10% since the Term Start Date. The Index Protection
Strategy with Cap, Index Guard Strategy, and Index Performance Strategy offer Index Options with a Cap. Index Performance Strategy multi-year
Term Index Options have both a Cap and a Participation Rate (as described below).
●
A Participation Rate is the percentage that is multiplied
by a positive Index Return in calculating a positive Performance Credit, if any, subject to any applicable Cap. For example, if at the
end of a Term, the Participation Rate is 100%, the Cap is 15%, and the Index Return is 12% (which is lower than the Cap), we apply a Performance
Credit of 12% (i.e.,
100% x 12%). However, if the Index Return were instead 20% (which is higher than the Cap), we would apply the Cap and a Performance Credit
of 15%. Index Performance Strategy multi-year Term Index Options have both a Cap and a Participation Rate.
The
Trigger Rate, Cap, and/or Participation Rate for an Index Option will change from Term to Term, subject to a specified guaranteed
minimum that will not change for the life of that Index Option. Guaranteed minimum Trigger Rates, Caps, and/or Participation Rates vary
by Index Option
*
This Index is a “price return index,” not a
“total return index,” and therefore does not reflect the dividends paid on the securities composing the Index, which will
reduce the Index Return and may cause the Index to underperform a direct investment in the securities composing the Index.
*
This Index is a “price return index,” not a
“total return index,” and therefore does not reflect the dividends paid on the securities composing the Index, which will
reduce the Index Return and may cause the Index to underperform a direct investment in the securities composing the Index.
*
This Index is a “price return index,” not a
“total return index,” and therefore does not reflect the dividends paid on the securities composing the Index, which will
reduce the Index Return and may cause the Index to underperform a direct investment in the securities composing the Index.
*
This Index is a “price return index,” not a
“total return index,” and therefore does not reflect the dividends paid on the securities composing the Index, which will
reduce the Index Return and may cause the Index to underperform a direct investment in the securities composing the Index. This Index
is a euro “price return index” and Index Returns are determined without any exchange rate adjustment.
*
This Index is an ETF. Index Values are based on the ETF’s
closing share price. Index performance is calculated on a “price return” basis, not a “total return” basis,
and therefore does not reflect the dividends paid on the securities in which the ETF invests. In addition, an ETF deducts fees and costs,
which reduce Index performance. These factors will reduce the Index Return and may cause the Index to underperform a direct investment
in the ETF or the securities in which the ETF invests.
The Daily Adjustment approximates
the Index Option Value that will be available on the Term End Date. It is the estimated present value of the future Performance Credit
that we will apply on the Term End Date. The Daily Adjustment primarily takes into account:
(i)
any Index gains during the Term subject to the applicable
Trigger Rate, Cap, and/or Participation Rate,
(ii)
for the Index Dual Precision Strategy, any Index losses less
than or equal to the 10%, 20%, or 30% Buffer,
(iii)
either any Index losses greater than the 10%, 20%, or 30%
Buffer, or Index losses down to the -10% Floor (not applicable to the Index Protection Strategy with Trigger or Index Protection Strategy
with Cap), and
(iv)
the number of days until the Term End Date.
A withdrawal taken during the Term
may not receive the full benefit of the Buffer or Floor because the Daily Adjustment takes into account what may potentially happen between
the withdrawal date and the Term End Date. All other factors being equal, even if the current Index return during the Term is greater
than the Trigger Rate or Cap, the Daily Adjustment will usually be lower than the Cap or Trigger Rate. For the Index Protection Strategy
with Trigger and Index Precision
Strategy,
even if the current Index return during the Term is greater than or equal to zero, the Daily Adjustment will usually be lower than the
Trigger Rate. For the Index Dual Precision Strategy, even if the Index return during the Term is positive, zero, or negative and
within the applicable Buffer, the Daily Adjustment will usually be lower than the Trigger Rate. This is because there is a possibility
that the Index return could decrease before the Term End Date. Similarly, even though a negative Index return may be within the 10%, 20%,
or 30% Buffer for the Index Dual Precision Strategy, Index Precision Strategy, and Index Performance Strategy, you still may
receive a negative Daily Adjustment because there is a possibility that the Index Return could decrease before the Term End Date. The
Daily Adjustment for Index Options with a Term length of more than 1 year may be more negatively impacted by changes in the expected volatility
of Index prices than 1-year Term Index Options due to the difference in Term length. Also, the risk of a negative Daily
Adjustment is generally greater for Index Options with a Term length of more than 1 year than for 1-year Term Index Options due to
the Term length. The Index Performance Strategy 3-year and 6-year Term Index Options with a Participation Rate above 100% may also have
larger fluctuations in the Daily Adjustment than Index Options either without a Participation Rate, or with a Participation Rate equal
to 100%. Finally, a negative Index return for the Index Guard Strategy may result in you receiving a Daily Adjustment lower than the -10%
Floor, because the Daily Adjustment reflects the present value of the Floor and you will not receive the full benefit of the -10% Floor
until the Term End Date.
A negative Daily Adjustment may cause you to realize loss of principal and previous earnings
10. Benefits Available Under the Contract
The following tables summarize information
about the benefits available under the Contract. The availability of Contract benefits may vary depending on the broker-dealer through
which the Contract is sold. See Appendix H – Financial Intermediary Variations for additional information.
|
Standard
Benefits | |||
|
Name
of
Benefit
|
Purpose
|
Maximum
Fee
|
Brief
Description of Restrictions/Limitations |
|
Free
Withdrawal
Privilege
|
Allows
you to withdraw up to 10% of your total
Annual
Contribution Amounts each Index Year
without
incurring an MVA. |
None
|
• Only
available during the Accumulation
Phase.
• Not
available during the Income Period.
• Not
available upon a full withdrawal.
• Upon
a full withdrawal, an MVA may apply
against
amounts previously withdrawn under
the
free withdrawal privilege.
• Unused
free withdrawal amounts not
available
in future years.
• Program
withdrawals may be subject to
negative
Daily Adjustments.
• Program
withdrawals are subject to income
taxes,
and may also be subject to a 10%
additional
federal tax for amounts withdrawn
before
age 59 1∕2.
|
|
Minimum
Distribution
Program
|
Allows
you to automatically take withdrawals to
satisfy
the required minimum distribution
requirements
(RMD) imposed by the Internal
Revenue
Code. |
None
|
• Only
available during the Accumulation
Phase.
• Only
available to IRA or SEP IRA Contracts.
• Program
withdrawals count against the free
withdrawal
privilege.
• Program
withdrawals may be subject to
negative
Daily Adjustments.
• Program
withdrawals are subject to income
taxes.
• Program
withdrawals may be monthly,
quarterly,
semi-annual or annual, unless you
have
less than $25,000 in Contract Value, in
which
case only annual payments are
available.
• We
reserve the right to discontinue or modify
the
program subject to the requirements of
law.
|
|
Standard
Benefits | |||
|
Name
of
Benefit
|
Purpose
|
Maximum
Fee
|
Brief
Description of Restrictions/Limitations |
|
Investment
Advisory
Fees |
We
designed the Contract for persons who are
receiving
ongoing investment advice from a
Financial
Professional. You can instruct us to
automatically
withdraw investment advisory
fees
from your Contract to pay your Financial
Professional’s
firm. |
None
|
• Only
available during the Accumulation
Phase.
• Investment
advisory fees are in addition to
the
Contract’s fees and expenses.
• Program
withdrawals may be subject to
negative
Daily Adjustments.
• If
you and your Financial Professional do not
agree
to our requirements we will not pay
investment
advisory fees from this Contract
to
your Financial Professional’s firm.
• Our
requirements limit investment advisory
fee
withdrawals to 1.5% of Contract Value
each
Contract Year, require the fees to be
solely
for advisory services provided with
respect
to the Contract, and require the
Contract
to be the sole source of payment.
• Deductions
we make for investment advisory
fees
reduce your Contract Value (and
therefore
Cash Value) dollar for dollar by the
amount
withdrawn. This Contract Value
reduction
also decreases your initial annual
maximum
Income Payment which is based
on
Contract Value. As Contract Value is one
of
the components we use to calculate RMD
payments,
these deductions may also reduce
your
RMD payments. These deductions also
reduce
the following proportionately by the
percentage
of Contract Value withdrawn:
Charge
Base, Index Option Base, Index
Option
Value, and Variable Account Value.
For
more information regarding the impact of
paying
advisory fees with money in the
Contract,
including an example of how
deduction
of investment advisory fees
impacts
the Contract, see section 1, The
Contract
– Investment Advisory Fees. |
|
Standard
Benefits | |||
|
Name
of
Benefit
|
Purpose
|
Maximum
Fee
|
Brief
Description of Restrictions/Limitations |
|
Income
Benefit
|
Guaranteed
lifetime withdrawal benefit
providing
for yearly Income Payments until the
death
of the Covered Person(s) if conditions
are
satisfied.
We
base the initial Income Payment on the
Lifetime
Income Percentage and Contract
Value.
If you choose the Level Income payment
option
and meet the age requirements stated in
section
11, we guarantee your initial annual
maximum
Income Payment will be at least the
Level
Income Guarantee Payment Percentage
multiplied
by your total Purchase Payments
adjusted
for withdrawals.
The
automatic annual payment increase
feature
may increase payments after the
Income
Benefit Date.
If
you elect Level Income, payments increase if
Contract
Value increases from one Income
Benefit
Anniversary to the next and you took
the
maximum permitted payment during the
prior
Income Benefit Year.
Includes
the Income Multiplier Benefit for no
additional
charge that can increase income to
help
pay for needed care.
Section
11 includes examples of the Lifetime
Income
Percentage Calculation, Excess
Withdrawals,
Income Payment increases, and
the
Income Multiplier Benefit. |
0.70%
(as
a
percentage
of
the
Charge
Base)
This
rider fee
is
part of the
Base
Contract
Expenses
in
the
Fee
Tables.
|
• Benefit
cannot be removed from the
Contract.
• See
the Income Benefit Supplement for
current
terms. Please see Appendix F for
historical
information on the terms for
previous
versions of the Income Benefit.
• Benefit
only available during the
Accumulation
Phase.
• Investment
restrictions limit available Index
Options
during Income Period.
• Income
Period cannot begin until after the
waiting
period and reaching age 50. Income
Period
must begin no later than age 100.
• Early
and Excess Withdrawals may
significantly
reduce or end the benefit as
indicated
in section 11.
• A
full Excess Withdrawal and certain
partial
Excess Withdrawals will cause
Income
Payments to stop and the
Contract
and
all of its benefits
to end.
• On
the Income Benefit Date, we execute
Performance
Locks on Index Options for
which
this day is not a Term End Date, and in
such
case the Index Option Value will be
subject
to the Daily Adjustment. We then
reallocate
the total Contract Value, including
amounts
in the Variable Option, into the
Index
Protection Strategy with Trigger and/or
Index
Protection Strategy with Cap Index
Options
according to allocation instructions
you
provide, and begin your Income
Payments.
• Income
Payments are subject to income
taxes,
and may also be subject to a 10%
additional
federal tax for amounts withdrawn
before
age 59 1∕2.
• No
additional Purchase Payments during the
Income
Period.
• No
Income Percentage Increase before age
45.
• Availability
of joint Income Payments is
subject
to age restrictions.
• The
Income Multiplier Benefit is not available
in
all states as indicated in Appendix G.
• Must
establish eligibility to exercise the
Income
Multiplier Benefit (e.g., that you are
confined
for care or unable to perform two
activities
for daily living) and must
re-establish
eligibility each year thereafter.
• Annuitizing
the Contract will end the benefit,
but
you may be able to annuitize your annual
maximum
Income Payment.
• State
variations may apply. |
|
Standard
Benefits | |||
|
Name
of
Benefit
|
Purpose
|
Maximum
Fee
|
Brief
Description of Restrictions/Limitations |
|
Traditional
Death
Benefit |
Provides
a death benefit equal to the greatest
of
the Contract Value, Cash Value, or
Guaranteed
Death Benefit Value. The
Guaranteed
Death Benefit Value is total
Purchase
Payments adjusted for withdrawals.
An
example of the death benefit provided by
the
Traditional Death Benefit is included in
section
12, Death Benefit.
An
example of how deduction of investment
advisory
fees impact the death benefit is
included
in section 1.
The
impact of an Excess Withdrawal on the
death
benefit is included in section 11. |
None
|
• Benefit
only available during the
Accumulation
Phase.
• Withdrawals,
including any negative Daily
Adjustments
and negative MVAs, may
significantly
reduce the benefit as indicated in
the
Investment Advisory Fee Deduction
Example
in section 1, The Contract, and in
the
Excess Withdrawal example in section
11,
Income Benefit.
• Restrictions
on Purchase Payments may limit
the
benefit.
• Annuitizing
the Contract will end the benefit. |
|
Standard
Benefits | |||
|
Name
of
Benefit
|
Purpose
|
Maximum
Fee
|
Brief
Description of Restrictions/Limitations |
|
Performance
Lock
and Early
Reallocations
|
Performance
Lock allows you to capture the
current
Index Option Value during the Term for
an
Index Option. Performance Lock can help
eliminate
doubt about future Index performance
and
possibly limit the impact of negative
performance.
Early Reallocation allows you to
transfer
out of a locked Index Option on days
other
than an Index Anniversary, or a Term End
Date.
A
Performance Lock example is included in
section
6, Valuing Your Contract —
Performance
Locks and Early Reallocations. |
None
|
• Available
during the Accumulation Phase.
Only
available during the Annuity Phase if
you
select Increasing Income and you
annuitize
your annual maximum Income
Payment.
• Performance
Locks must be executed before
the
Term End Date.
• If
a Performance Lock is executed, the
locked
Index Option will no longer participate
in
Index performance (positive or negative)
for
the remainder of the Term, and will not
receive
a Performance Credit on the Term
End
Date.
• You
will not know your locked Index Option
Value
in advance.
• The
locked Index Option Value will reflect a
Daily
Adjustment.
• If
a Performance Lock is executed when the
Daily
Adjustment has declined, it will lock in
any
loss.
• A
Performance Lock can be executed only
once
each Term for each Index Option.
• Cannot
execute a Performance Lock for only
a
portion of the Index Option Value.
• Early
Reallocation requests are not accepted
within
14 calendar days before an Index
Anniversary.
• You
are limited to twelve Early Reallocation
requests
each Index Year.
• Deductions
(e.g. withdrawals, fees) decrease
the
locked Index Option Value.
• Cannot
transfer locked Index Option Value
until
the next Index Anniversary that occurs
on
or immediately after the Lock Date unless
you
execute an Early Reallocation.
• We
will not provide advice or notify you
regarding
whether you should execute a
Performance
Lock or Early Reallocation
or
the optimal time for doing so, if any.
• We
will not warn you if you execute a
Performance
Lock or Early Reallocation at
a
sub-optimal time.
• We
are not responsible for any losses
related
to your decision whether or not to
execute
a Performance Lock or Early
Reallocation.
• Early
Reallocations are not available to
Contracts
issued before May 1, 2023, as
detailed
in Appendix G. |
|
Optional
Benefits | |||
|
Name
of
Benefit
|
Purpose
|
Maximum
Fee
|
Brief
Description of Restrictions/Limitations |
|
Maximum
Anniversary
Value
Death
Benefit
|
Provides
a death benefit equal to the greatest of
the
Contract Value, Cash Value, or Guaranteed
Death
Benefit Value. The Guaranteed Death
Benefit
Value is the Maximum Anniversary Value.
An
example of the death benefit provided by the
Maximum
Anniversary Value Death Benefit, and
calculation
of the Maximum Anniversary Value is
included
in section 12, Death Benefit.
An
example of how deduction of investment
advisory
fees impact the death benefit is
included
in section 1.
The
impact of an Excess Withdrawal on the
death
benefit is included in section 11. |
0.20%
(as
a
percentage
of
the
Charge
Base)
|
• Must
be age 75 or younger to elect.
• Can
only be added to a Contract at issue.
• Replaces
the Traditional Death Benefit if
elected.
• Benefit
cannot be removed from the Contract.
• Only
available during the Accumulation Phase.
• Withdrawals,
including any negative Daily
Adjustment
and negative MVA, may
significantly
reduce the benefit as indicated in
the
Investment Advisory Fee Deduction
Example
in section 1, The Contract, and in the
Excess
Withdrawal example in section 11,
Income
Benefit.
• Withdrawals
reduce the likelihood of receiving
increases
to the Maximum Anniversary Value.
• Investment
restrictions during the Income
Period
may limit the benefit.
• Restrictions
on Purchase Payments may limit
the
benefit.
• Annuitizing
the Contract will end the benefit. |
11. Income Benefit
The Income Benefit is automatically
included in your Contract at issue. It provides guaranteed lifetime Income Payments based on a percentage of your Contract Value. Such
Income Payments can continue up to the point of annuitization. Once the Income Payment waiting period has expired, Income Payments can
begin as early as age 50 or as late as age 100. When
you begin taking Income Payments, you must elect either the Level Income or Increasing Income payment option.
Unlike Annuity Payments, the Income
Benefit allows access to your Contract Value and death benefit for a period of time after Income Payments begin. However, once Income
Payments begin, only the Index Options with the Index Protection Strategy with Trigger and Index Protection Strategy with Cap
are available to you. If you have Contract Value in any of the Index Options with the Index Dual Precision Strategy, Index Precision
Strategy, Index Guard Strategy, or Index Performance Strategy, you must transfer this Contract Value to the Index Options with the Index
Protection Strategy with Trigger or Index Protection Strategy with Cap when you request Income Payments. The Income Benefit has a rider
fee as discussed in the Fee Tables, and section 7, Expenses and Adjustments. The Income Benefit also includes the Income Multiplier Benefit
for no additional charge, which can increase the annual maximum Income Payment after the required wait period to help pay for care if
you should need it.
|
Unless
otherwise stated, the following description of the Income Benefit applies to both the Level Income and Increasing
Income
payment options. |
How
the Income Benefit Works
We designed Income Payments to last
for the lifetime of the Covered Person(s).
Covered Person(s) are based on the Eligible Person(s) and the Income Payment type you select on the Income Benefit Date. We establish
Eligible Person(s)
at issue based on the Contract’s ownership and tax qualification status.
We generally base Income Payments
on the Lifetime Income Percentage and your Contract Value. However, it is possible in periods of extremely low return that the Level Income
Guarantee Payment Percentage could result in a higher initial Income Payment. In those circumstances, we base Income Payments on total
Purchase Payments adjusted for withdrawals instead of Contract Value. We base each Lifetime Income Percentage on its Income
Percentage(s) and Income
Percentage
Increase (the amount that each Lifetime Income Percentage
can increase on each Index Anniversary up to and including the Income Benefit Date). On the Index Effective Date, we establish:
●
An Income Percentage for each payment type using the Eligible
Person’s current age, or younger Eligible Person’s current age for joint payments. This Income Percentage is also the initial
Lifetime Income Percentage for each payment type.
●
An Income Percentage Increase for each Eligible Person based
on their current age (or younger Eligible Person’s current age for joint payments). However, if there are two Eligible Person(s),
the Index Options Statement will not display a single Lifetime Income Percentage for an Eligible Person who is only a Beneficiary, because
only an Eligible Person who is also an Owner (or Annuitant if the Owner is a non-individual) can become a Covered Person if you select
single payments.
During the Accumulation Phase, on
each Index Anniversary on and before the Income Benefit Date, we add an Income Percentage Increase to each Lifetime Income Percentage
once the Eligible Person (or younger Eligible Person for joint payments) reaches age 45. This
means if an Eligible Person is younger than age 44 on the Issue Date:
●
you will not receive an
increase to a Lifetime Income Percentage based on that Eligible Person until the Index Anniversary that the Eligible Person (or younger
Eligible Person for joint payments) reaches age 45, and
●
you will pay a rider fee
during the period you are not eligible for an Income Percentage Increase.
The table showing the Income Percentages
and Income Percentage Increases is stated in the Income Benefit Supplement. Additional Purchase Payments we receive after the Index Effective
Date will adjust each Lifetime Income Percentage on the next Index Anniversary based on:
●
the Income Percentage for the Eligible Person’s current
age, and
●
the Variable Account Value’s percentage of total Contract
Value, and the percentage of the sum of all Index Option Values to total Contract Value.
If we receive additional Purchase
Payments after the Eligible Person reaches age 45, these Purchase Payments will increase the available Income Payment because they increase
the Contract Value, although they actually decrease each Lifetime Income Percentage. Please see the Lifetime Income Percentage Calculation
Example later in this section.
When you are ready to take Income
Payments, you can choose which Lifetime Income Percentage we use to calculate your payment. You will always be able to choose between
Lifetime Income Percentages for the Level Income and Increasing Income payment options. However, once Income Payments begin you cannot
change your payment option.
Level Income
provides an automatic annual increase to your Income Payments if your Contract Value increases from one Income Benefit Anniversary to
the next. If you choose the Level Income
payment option and meet certain age requirements, your
initial Income Payment will not be less than a percentage (Level
Income Guarantee Payment Percentage) of your total Purchase
Payments reduced proportionately for withdrawals you took (including any MVA). All withdrawals you take reduce your total Purchase Payments,
even MVA-Free Withdrawals. However, we do not reduce your total Purchase Payments for deductions we make for Contract fees, expenses,
and investment advisory fees that you authorize your Financial Professional’s firm to receive from the Contract.
Increasing Income
provides Income Payment increases on each Income Benefit Anniversary during the Income Period if your selected Index Option(s) receives
a positive Performance Credit, or you execute a Performance Lock during the prior Income Benefit Year.
If there are two Eligible Person(s)
who both meet the exercise age requirements, you will also be able to choose between Lifetime Income Percentages for single and joint
payments. If both Eligible Persons are also Owners, you will also be able to choose between single Lifetime Income Percentages based on
each Eligible Person. The Lifetime Income Percentages available before the Income Benefit Date are displayed on the Index Options Statement.
During the Income Period this statement will show the annual maximum Income Payment available for the next year. The annual maximum Income
Payment displayed for the Level Income
payment option will reflect the Level Income Guarantee
Payment Percentage if this calculation results in a greater payment and you meet the age requirements stated under “Calculating
Your Income Payments” later in this section.
There
are restrictions on which Eligible Person can become a Covered Person if you select single Income Payments. Joint Income Payments are
not available if the age difference between spouses is more than 50 years (for more information see section 2, Eligible Person(s) and
Covered Person(s)).
Income Payments
are not available until the Index Anniversary that occurs on or after the Income Payment waiting period (which is stated in the Income
Benefit Supplement) expires and the Eligible Person(s) reaches age 50. Income Payments must begin no later than age 100. If
you do not begin Income Payments during the eligibility period, the Income Benefit ends and you will have paid for the benefit without
receiving any of its advantages. In addition, before the Income Period you are paying for a benefit that you are not currently using.
You choose your Income Payment frequency
and amount subject to the annual maximum permitted payment. The payment option (Level Income or Increasing Income) you select determines
how and when your annual maximum Income Payment will increase from one Income Benefit Anniversary to the next as described in “Automatic
Annual Income Payment Increases” later in this section.
We use Contract
Value to calculate your initial annual maximum Income Payment, and any Income Payment increases under the Level Income payment option.
Negative Index Option performance, withdrawals you take, and deductions we make for Contract fees, expenses, and investment advisory fees
you authorize your Financial Professional’s firm to receive from the Contract decrease the Contract Value, which reduces the initial
annual maximum Income Payment available to you, and the likelihood you will receive Income Payment increases if you select the Level Income
payment option. Once established, the annual maximum Income Payment can only decrease if you take an Excess Withdrawal. A
full Excess Withdrawal and certain partial Excess Withdrawals will cause Income Payments to stop and the Contract and
all of its benefits
to end.
The Income Benefit also includes
the Income Multiplier Benefit which, after the required wait period, can increase your income to help pay for care if you should need
it. If you qualify for this benefit, we multiply your annual maximum Income Payment by the income multiplier factor. The income multiplier
factor and income multiplier benefit wait period are stated in the Income Benefit Supplement. The Income Multiplier Benefit is not available
in all states as indicated in Appendix G.
|
● YOU
SHOULD NOT PURCHASE THIS CONTRACT WITHOUT FIRST OBTAINING THE CURRENT
INCOME
BENEFIT SUPPLEMENT.
We publish any changes to the Income Benefit Supplement at least seven
calendar
days before they take effect on our website at https://www.allianzlife.com/RILAincomeadvrates.
|
|
● Please
discuss the Income Benefit’s appropriateness with your Financial Professional and tax adviser. |
During
the Income Period
●
You will receive Income Payments as long as a Covered Person
is alive and continues to meet the requirements stated in section 2. However, Income
Payments and the Income Benefit may end prematurely if you:
−
change the Owner(s) or Beneficiary and all Covered Persons
are removed from the Contract because they no longer meet the requirements stated in section 2,
−
take an Excess Withdrawal that reduces the Contract Value
to $2,000 or less, or
−
annuitize your Contract. However, we
can convert your Income Payment to Annuity Payments as described in section 9, The Annuity Phase – When Annuity Payments Begin.
●
If you begin Income Payments before age
59 1∕2,
the payments may be subject to a 10% additional federal tax.
●
Any part of your annual maximum Income Payment that you do
not withdraw in a given Income Benefit Year remains in your Contract for the remainder of that year, but is not added to the annual maximum
payment available next year.
●
Excess Withdrawals reduce your annual maximum Income Payment
by the percentage of Contract Value withdrawn (including any MVA) on the next Income Benefit Anniversary.
●
You cannot make additional Purchase Payments. If your Contract
includes the Traditional Death Benefit, your Guaranteed Death Benefit Value no longer increases.
●
The Contract Value continues to fluctuate as a result of
Index Option performance. However, only the Index Protection Strategy with Trigger and Index Protection Strategy with Cap are
available to you. This may limit your Contract’s performance potential, and if your Contract includes the Maximum Anniversary Value
Death Benefit, this may also limit your Guaranteed Death Benefit Value.
●
The Contract Value decreases on a dollar for dollar basis
with each Income Payment, Excess Withdrawal, and deductions we make for Contract fees, expenses, and investment advisory fees that
you authorize your Financial Professional’s firm to receive from the Contract. If your Contract includes the Maximum Anniversary
Value Death Benefit, this decrease in Contract Value also reduces the likelihood of locking in investment gains to the Maximum Anniversary
Value.
●
Each Income Payment and any Excess Withdrawal also reduces
your Guaranteed Death Benefit Value and the Charge Base used to calculate product and rider fees by the percentage of Contract Value withdrawn
(including any MVA),
which means these values may be reduced by more than the amount withdrawn.
●
The Income Benefit rider fee continues until the Business
Day the Contract Value reduces to zero, you annuitize the Contract, or the Income Benefit ends.
●
If your Contract also includes the Maximum Anniversary Value
Death Benefit, its rider fee continues as indicated in section 7, Expenses and Adjustments.
●
The free withdrawal privilege is no longer available.
●
If you exercise the Income Multiplier Benefit, we will increase
your annual maximum Income Payment for the remainder of that Income Benefit Year and the next year. To continue receiving this increase
each Income Benefit Year you must reestablish eligibility. Any
increase to your Income Payments as a result of this benefit will more rapidly reduce your Guaranteed Death Benefit Value.
●
If your Contract Value reduces to zero during the Income
Period for any reason other than an Excess Withdrawal or annuitization that does not convert your Income Payments to Annuity Payments,
you will continue to receive your maximum available Income Payment at the previous selected payment frequency until the earlier of the
death of the Owner or last surviving Covered Person. Further, if
you elected Increasing Income, your annual maximum Income
Payment will continue to change based on Index Option performance, including any Performance Locks you execute. If you exercised the Income
Multiplier Benefit, it will end on the Income Benefit Anniversary that occurs on or immediately after your Contract Value reduces to zero.
This means that you will no longer receive the increased annual maximum Income Payment provided by this Benefit; however, you will continue
to receive the maximum available Income Payment, which will be less than the amount you previously received under the Income Multiplier
Benefit.
●
Income Payments made while
Contract Value is greater than zero are payments made from your own money, and the chance of Contract Value being reduced to zero and
receiving lifetime Income Payments from us may be minimal.
An
example of the effect of an Excess Withdrawal on the Guaranteed Death Benefit Value and the annual maximum Income Payment is included
later in this section.
Requesting
Income Payments
You request Income Payments by completing
a payment election form. We must receive your Income Payment election form in Good Order at our Service Center no later than five Business
Days before the Income Benefit Date. Your Income Benefit Date must be on an Index Anniversary. At least one Eligible Person must remain
in the Contract and be alive on the Income Benefit Date in order for Income Payments to begin. Joint payments are only available if there
are two Eligible Persons on the Income Benefit Date. On the Income Benefit Date, we require updated allocation instructions. If you have
Contract Value in an Index Option and the Income Benefit Date is not also a Term End Date, we will execute a Performance Lock for that
Index Option if it is not locked, and in such case the Index Option Value will be subject to the Daily Adjustment. We then reallocate
the total Contract Value, including any amount in the Variable Option, into the Index Protection Strategy with Trigger and/or Index Protection
Strategy with Cap Index Options according to your allocation instructions, and immediately calculate and begin your Income Payments. If
you have Index Options with different Term End Dates, there may be no Income Benefit Date you can select without application of at least
one Daily Adjustment. For the Index Protection Strategy with Trigger or Index Protection Strategy with Cap Index Options, we will execute
this Performance Lock even if the Daily Adjustment is zero.
We will send you a notice letter
at least 30 days before:
●
the Index Anniversary that Income Payments can begin once
the Eligible Person(s) reaches age 50,
●
the last Index Anniversary that joint Income Payments will
be available because the older Eligible Person is reaching age 100 if there are two Eligible Persons, and
●
the last Index Anniversary that Income Payments will be available
because the younger Eligible Person is reaching age 100.
|
● If
Income Payments do not begin by the Index Anniversary upon which the younger Eligible Person reaches
age
100, the Income Benefit ends. |
|
● If
the Income Benefit ends before Income Payments begin, you will have paid for the benefit without receiving
any
of its advantages. |
Calculating
Your Income Payments
The annual maximum Income Payment
is the amount you are entitled to receive each Income Benefit Year. On the Income Benefit Date, if
you select the Level Income payment option and all Covered Persons are age 80 or younger (and were age 75 or younger on the Issue Date)
your initial annual maximum Income Payment is the greater of the following:
●
The Level Income Guarantee Payment Percentage based on the
Covered Person’s current age (or the younger Covered Person’s current age for joint payments) multiplied by total Purchase
Payments reduced for withdrawals you took. Withdrawals reduce total Purchase Payments by the percentage of Contract Value withdrawn (including
any MVA), determined at the end of each Business Day. All
withdrawals you take reduce your total Purchase Payments, even MVA-Free Withdrawals. However, we do not reduce your total Purchase Payments
for deductions we make for Contract fees, expenses, and investment advisory fees that you authorize your Financial Professional’s
firm to receive from the Contract.
●
The Lifetime Income Percentage for the payment type you select
multiplied by the Contract Value determined at the end of the Business Day after we deduct the product fee, rider fee, and contract maintenance
charge and apply any Performance Credits, but before we make any Income Payments or Excess Withdrawals, or we deduct any investment advisory
fees that you authorize your Financial Professional’s firm to receive from the Contract.
If the Covered Persons do not meet
these age requirements (age 80 or younger on the Income Benefit Date, and age 75 or younger on the Issue Date), or
if you select the Increasing Income payment option, we
instead calculate your initial annual maximum Income Payment as stated in the second bullet above (the Lifetime Income Percentage for
the payment type you select multiplied by the Contract Value determined at the end of the Business Day after we deduct the product fee,
rider fee, and contract maintenance charge and apply any Performance Credits, but before we make any Income Payments or deduct Excess
Withdrawals).
|
● If
you have Contract Value in an Index Option for which the Income Benefit Date is not a Term End Date, we
will
execute a Performance Lock for that Index Option if it is not locked and then immediately calculate and
begin
your Income Payments, and in such case the Index Option Value will be subject to the Daily Adjustment.
If
you have Index Options with different Term End Dates, there may be no Income Benefit Date you can select
without
application of at least one Daily Adjustment. This
means you may not receive the full benefit of the
Performance
Credit that you would have received if you had waited until the Term End Date to begin Income
Payments.
|
|
● We
use Contract Value to calculate your initial annual maximum Income Payment, and Income Payment increases
under
the Level Income payment option. Negative Index Option performance, withdrawals you take, and deductions
we
make for Contract fees, expenses, and investment advisory fees that you authorize your Financial Professional’s
firm
to receive from the Contract decrease the Contract Value, which reduces the initial annual maximum Income
Payment
available to you. Negative Index Returns and Performance Credits of zero also reduce the likelihood you
will
receive Income Payment increases. |
Level
Income Guarantee Payment Percentage Table
|
Covered
Person’s age
(or
younger Covered Person’s age for
joint
payments)
on
the Income Benefit Date |
Level
Income Guarantee
Payment
Percentage |
|
50
|
2.23
% |
|
51
|
2.28
% |
|
52
|
2.33
% |
|
53
|
2.39
% |
|
54
|
2.44
% |
|
55
|
2.50
% |
|
56
|
2.57
% |
|
57
|
2.64
% |
|
58
|
2.71
% |
|
59
|
2.78
% |
|
60
|
2.86
% |
|
61
|
2.95
% |
|
62
|
3.04
% |
|
63
|
3.13
% |
|
64
|
3.23
% |
|
65
|
3.34
% |
|
66
|
3.45
% |
|
67
|
3.58
% |
|
68
|
3.71
% |
|
69
|
3.85
% |
|
70
|
4.00
% |
|
71
|
4.17
% |
|
72
|
4.35
% |
|
73
|
4.55
% |
|
74
|
4.77
% |
|
75
|
5.00
% |
|
76
|
5.27
% |
|
77
|
5.56
% |
|
78
|
5.89
% |
|
79
|
6.25
% |
|
80
|
6.67
% |
On the Income Benefit
Date, if your initial annual maximum Income Payment is less than $100, the Income Benefit ends and you will have paid for the benefit
without receiving any of its advantages. For example, assuming
a 4% Lifetime Income Percentage and Contract Value less than $2,500, this would result in an initial annual maximum Income Payment of
less than $100.
You can receive Income Payments monthly,
quarterly, semi-annually, or annually. If the scheduled payment date does not fall on a Business Day, we make the payment on the next
Business Day.
You can change your payment frequency
once each Income Benefit Year while your Contract Value is positive. We must receive your request to change your Income Payment frequency
in Good Order at our Service Center no later than five Business Days before the Income Benefit Anniversary. If the change is available,
we implement it on the Income Benefit Anniversary and it remains in effect until the benefit ends or you request another change. We do
not accept payment frequency changes that would cause us to make payments of $0.01 to $99.99.
The annual maximum Income Payment
is the amount you are entitled to, but you can choose to take less. The annual actual Income Payment is the total amount you choose to
receive each year. Each scheduled Income Payment you receive is equal to the annual actual Income Payment divided by the number of payments
you chose to receive during the Income Benefit Year. Each scheduled Income Payment must either be zero, or $100 or more. For example,
you cannot request a scheduled payment of $50.
Any part of your annual maximum payment
that you do not withdraw in a given Income Benefit Year is not added to the annual maximum payment available next year. However, if your
actual Income Payment is less than your annual maximum payment, you can withdraw the difference and we consider that withdrawal to be
an additional actual Income Payment, and
not an Excess
Withdrawal and not subject to an MVA. We do not consider a withdrawal to be an Excess Withdrawal until you have withdrawn the available
annual maximum Income Payment amount. In addition, once we have paid out your annual maximum Income Payment we will not make any
further scheduled Income Payments for the rest of the Income Benefit Year. For example, assume your annual maximum Income Payment
is $2,000 and you take scheduled semi-annual Income Payments of $500. Within an Income Benefit Year, you can take an additional withdrawal
of up to $1,000 and we consider that to be an additional scheduled Income Payment. If instead you withdraw $1,200 after receiving the
first $500 payment, we consider that withdrawal to be an additional scheduled Income Payment. On the date of the next scheduled Income
Payment we will send you only $300 because that is the amount remaining from your $2,000 annual maximum. If you then took an additional
withdrawal of $200 in that Income Benefit Year, we consider that $200 to be an Excess Withdrawal subject to an MVA.
If you would like to take less than
the maximum available payment, you can change your payment amount once each Income Benefit Year while your Contract Value is positive.
We must receive your request to change your Income Payment amount in Good Order at our Service Center no later than five Business Days
before the Income Benefit Anniversary. If the change is available, we implement it on the Income Benefit Anniversary and it remains in
effect until the Income Benefit ends or you request another change.
If, on a Business Day that we are
deducting an Income Payment, your Contract Value is less than the payment amount, we will add the difference between these amounts to
your Contract Value and then deduct the Income Payment which will reduce your Contract Value to zero. If your Contract Value reduces to
zero during the Income Period for any reason other than an Excess Withdrawal or annuitization that does not convert your Income Payments
to Annuity Payments, you will continue to receive your maximum available Income Payment at the previous selected payment frequency until
the earlier of the death of the Owner or last surviving Covered Person. If
you select Increasing Income, you can continue to receive
payment increases based on Index Option performance. However, if
you select Level Income, your Income Payments will no longer
increase.
We deduct each Income Payment, Excess
Withdrawal, and any additional payment resulting from a required minimum distribution, proportionately from the Index Options to which
you are allocated. While the Contract Value is positive, you can make transfers between the Index Options and execute Performance Locks
and Early Reallocations. If you select
Increasing Income, once the Contract Value reduces to zero,
you can continue to change your Index Option allocations and execute Performance Locks and Early Reallocations as long as the Income Benefit
is in effect. With Increasing Income, we base changes to your annual maximum Income Payment on the proportion of Contract Value in
each Index Option at the end of the last Business Day that your Contract Value is positive. However, you can change the proportion of
each Index Option that we use to calculate these changes after the Contract Value is equal to zero by providing an authorized request
to our Service Center.
|
● For
Qualified Contracts: If we calculate
a required minimum distribution (RMD) based on this Contract, after
making
all Income Payments for the calendar year we determine whether this calendar year’s total RMD has been
satisfied
by these payments and any Excess Withdrawals. If the RMD amount for this Contract has not been satisfied,
we
send you this remaining amount as one RMD payment by the end of the calendar year. We consider this payment
to
be a withdrawal, but it is not an Excess Withdrawal and it is not subject to an MVA. |
|
● For
annuitization: If on the Annuity Date
you are receiving Income Payments and your Contract Value is positive,
we
will convert your Income Payments to Annuity Payments if you take Annuity Payments under Annuity Option B
or
F. If you select any other Annuity Option, we will not convert your Income Payments to Annuity Payments. This
means
that if you annuitize your Contract you may receive less as Annuity Payments than you would have
received
as Income Payments. For more information,
see section 9, The Annuity Phase – When Annuity Payments
Begin.
|
Lifetime
Income Percentage Calculation Example
Assume you are the sole Owner, you
are not married, and your initial Purchase Payment is $20,000. You only select 1-year Term Index Options. You are not married, so you
are also the only Eligible Person. The Income Payment waiting period is three Index Years. On the Index Effective Date you are age 54,
your Income Percentage Increase is 0.25%, and your initial Lifetime Income Percentages are equal to the Income Percentages for single
payments, which are 4.20% for Level Income, and 3.20% for Increasing Income. You take no withdrawals before requesting Income Payments.
On the first
Index Anniversary, we apply your first Income Percentage Increase. Your new Lifetime Income Percentages for single payments are 4.45%
(4.20% + 0.25%) if you elect Level Income and 3.45% (3.20% + 0.25%) if you elect Increasing Income.
Assume you make an additional Purchase
Payment of $2,000 in the fourth Index Year. On the fourth Index Anniversary:
●
you are age 58 and the Income Percentages are 4.60% for Level
Income, and 3.60% for Increasing Income,
●
the Variable Account Value for the additional Purchase Payment
is now $2,002.50, and
●
the Contract Value after application of the additional Purchase
Payment, Performance Credits and before
deducting all Contract fees and expenses is $25,000.
We calculate your new Lifetime Income
Percentages for single payments on the fourth Index Anniversary as follows.
●
Lifetime Income Percentages for the initial Purchase Payment
are now 5.20% (4.20% + (0.25% x 4)) if you elect Level Income and 4.20% (3.20% + (0.25% x 4)) if you elect Increasing Income.
●
Lifetime Income Percentages for the additional Purchase Payment
are 4.60% for Level Income and 3.60% for Increasing Income.
●
The Variable Account Value’s percentage of total Contract
Value is 8.01% ($2,002.50 ÷ $25,000), which means the initial Purchase Payment is 91.99% of total Contract Value (100% - 8.01%).
The final Lifetime Income Percentages
on the fourth Index Anniversary are then:
−
if you elect Level Income: (5.20% x 91.99%) + (4.60% x 8.01%)
= 4.78% + 0.37% = 5.15%
−
if you elect Increasing Income: (4.20% x 91.99%) + (3.60%
x 8.01%) = 3.86% + 0.29% = 4.15%
If you begin Income Payments on the
fourth Index Anniversary, we calculate the annual maximum Income Payment as follows.
|
If
you select Level Income, you receive the greater of…. |
If
you select Increasing Income, you receive… |
|
• Level
Income Guarantee Payment Percentage multiplied by
total
Purchase Payments reduced proportionately for
withdrawals
you took, or: (2.71% x $22,000) = $596.20
• Lifetime
Income Percentage multiplied by the Contract Value,
or:
(5.15% x $25,000) = $1,287.50
|
• Lifetime
Income Percentage multiplied by the Contract Value,
or:
(4.15% x $25,000) = $1,037.50
|
If you select Level
Income, we apply the Level Income Guarantee Payment Percentage
in this calculation because you were 75 or younger when you purchased the Contract and are age 80 or younger on the Income Benefit Date.
On the Income Benefit Date, your Level Income Guarantee Payment Percentage based on your current age of 58 is 2.71%, and your total Purchase
Payments reduced proportionately for withdrawals is $22,000 (your $20,000 initial payment plus the $2,000 we received in the fourth Index
Year). The annual maximum Income Payment calculation and Level Income Guarantee Payment Percentage are discussed in “Calculating
Your Income Payments” next in this section.
If you had not made the additional
Purchase Payment your Lifetime Income Percentages would have been higher (5.20% compared to 5.15% for Level Income, and 4.20% compared
to 4.15% for Increasing Income), but the available annual maximum Income Payment would be lower because the Contract Value would not include
the increase from the additional Purchase Payment. If you had not made the additional Purchase in the fourth Index Year, your Contract
Value would have been $22,997.50 ($25,000 - $2,002.50) and we calculate your annual maximum Income Payment as follows.
|
If
you select Level Income, you receive the greater of…. |
If
you select Increasing Income, you receive… |
|
• Level
Income Guarantee Payment Percentage multiplied by
total
Purchase Payments reduced proportionately for
withdrawals
you took, or: (2.71% x $20,000) = $542.00
• Lifetime
Income Percentage multiplied by the Contract Value,
or:
(5.20% x $22,997.50) = $1,195.87
|
• Lifetime
Income Percentage multiplied by the Contract Value,
or:
(4.20% x $22,997.50) = $965.90
|
Example of when the
Level Income Guarantee Payment Percentage may increase the initial Income Payment
Assume you are the sole Owner, you
are not married, and your initial Purchase Payment is $100,000. You are age 65 on the Index Effective Date and your initial Income Percentage
under Level Income is 5.70% with a 0.40% Income Percentage Increase. You take no withdrawals before requesting Income Payments. You begin
Income Payments on the
fifth Index Anniversary
and select the Level Income payment option.
On the Income Benefit Date you are age 70, your Lifetime Income Percentage is 7.70% and your Level Income Guarantee Payment Percentage
is 4.00%.
|
When
it increases
the initial Income Payment |
When
it does not
increase the initial Income Payment |
|
• Assume
your Contract Value decreases to $50,000 due to
negative
performance. You would receive the greater of:
– Level
Income Guarantee Payment Percentage multiplied
by
total Purchase Payments reduced proportionately for
withdrawals
you took, or: (4.00% x $100,000) = $4,000.00
– Lifetime
Income Percentage multiplied by the Contract
Value,
or: (7.70% x $50,000) = $3,850.00 |
• Assume
your Contract Value decreases to $70,000 due to
negative
performance. You would receive the greater of:
– Level
Income Guarantee Payment Percentage multiplied
by
total Purchase Payments reduced proportionately for
withdrawals
you took, or: (4.00% x $100,000) = $4,000.00
– Lifetime
Income Percentage multiplied by the Contract
Value,
or: (7.70% x $70,000) = $5,390.00
|
Please
note that these examples may differ from your actual results due to rounding.
Excess
Withdrawals
Excess Withdrawals do not include
RMD payments, or deductions we make for Contract fees, expenses, or investment advisory fees you authorize your Financial Professional’s
firm to receive from the Contract. Excess Withdrawals are subject to an MVA. Any partial Excess Withdrawal must be for at least $100,
and, after the partial Excess Withdrawal, the Contract Value must be at least $2,000. If the Contract Value is less than $2,000, you cannot
request a partial Excess Withdrawal, but you can take a full Excess Withdrawal. If a partial Excess Withdrawal reduces the Contract Value
to less than $2,000, we require you to take a full Excess Withdrawal. A
full Excess Withdrawal will cause Income Payments to stop and the Contract and
all of its benefits
to end. We will not provide a warning before you take an Excess Withdrawal, and there will be no opportunity to undo an Excess Withdrawal.
Excess Withdrawals reduce your annual
maximum Income Payment on the next Income Benefit Anniversary after the withdrawal. For each Excess Withdrawal, we reduce your annual
maximum payment by the same percentage that we reduced the Contract Value. If
partial Excess Withdrawals reduce your annual maximum Income Payment to less than $100, we send you the Cash Value, which
will cause Income Payments to stop and the Contract to end.
Excess Withdrawal
Example
These calculations show the effects
of an Excess Withdrawal on the Contract Value, Cash Value, available Guaranteed Death Benefit Value, and Income Payments. Partial Excess
Withdrawals (including any MVA, but not deductions we make for Contract fees, expenses, or investment advisory fees you authorize your
Financial Professional’s firm to receive from the Contract) immediately reduce the Contract Value and Cash Value on a dollar for
dollar basis, and reduce the Guaranteed Death Benefit Value by the percentage of Contract Value withdrawn. Partial Excess Withdrawals
also reduce the annual maximum Income Payment by the percentage of Contract Value withdrawn on the next Income Benefit Anniversary. (The
impact of withdrawals, including Excess Withdrawals, on the Charge Base is included in Appendix D - Annual Contract Fees Calculation Examples.)
The example assumes you do not authorize
your Financial Professional’s firm to receive investment advisory fees deducted from your Contract, and instead take a $1,500 Excess
Withdrawal and use that money to pay investment advisory fees to your Financial Professional when the Contract Value is $100,000, the
Cash Value is $97,000, and the Guaranteed Death Benefit Value under the Traditional Death Benefit is $90,000, or $105,000 under the Maximum
Anniversary Value Death Benefit. It also assumes the $1,500 Excess Withdrawal is subject to an MVA of -$100. Cash Value reflects the MVA
we apply on a full withdrawal. Therefore the Cash Value in this example is only reduced for the $1,500 Excess Withdrawal
because the -$100
MVA is already reflected in the $97,000 Cash Value. All fractional numbers in these examples have been rounded up to the next whole number.
|
Excess
Withdrawal
|
Contract
Value
|
Cash
Value
|
Guaranteed
Death Benefit
Value
for a Contract with the
Traditional
Death Benefit |
Guaranteed
Death Benefit Value
for
a Contract with the
Maximum
Anniversary Value
Death
Benefit |
Next
anniversary’s
annual
maximum
Income
Payment |
|
Prior
to withdrawal |
$
100,000 |
$
97,000 |
$
90,000 |
$
105,000 |
$
4,800 |
|
$1,500
withdrawal
|
–
$1,500 |
–
$1,500 |
–
[($1,500 ÷ 100,000) |
–
[($1,500 ÷ 100,000) |
–
[($1,500 ÷ 100,000) |
|
|
|
|
x
90,000)] = - $1,350 |
x
105,000)] = - $1,575 |
x
4,800)] = - $72 |
|
-$100
MVA |
–
$100 |
|
–
[($100 ÷ 100,000) |
–
[($100 ÷ 100,000) |
–
[($100 ÷ 100,000) |
|
|
|
|
x
90,000)] = - $90 |
x
105,000)] = - $105 |
x
4,800)] = - $5 |
|
|
–
$1,600 |
–
$1,500 |
=
- $1,440 |
=
- $1,680 |
=
- $77 |
|
|
|
|
|
|
|
|
After
withdrawal |
$
98,400 |
$
95,500 |
$
88,560 |
$
103,320 |
$
4,723 |
The death benefit is the greatest
of the Contract Value, Cash Value, or the Guaranteed Death Benefit Value. After the withdrawal and MVA, the death benefit would either
be the $98,400 Contract Value under the Traditional Death Benefit (because it is greater than the Guaranteed Death Benefit Value of $88,560),
or the $103,320 Guaranteed Death Benefit Value under the Maximum Anniversary Value Death Benefit.
Automatic
Annual Income Payment Increases
If you select Level
Income, the annual maximum Income Payment can only decrease
if you take an Excess Withdrawal. However, if you took the maximum permitted payment during the prior Income Benefit Year, we increase
your annual maximum Income Payment if your Contract Value increases from one Income Benefit Anniversary (or the Income Benefit Date if
this is the first Income Benefit Anniversary) to the next. This increase is equal to the percentage of growth between these two Contract
Values. For example, if the Contract Value increased by 1.5%, we also increase your annual maximum Income Payment by 1.5%.
When calculating this payment increase,
we use the Contract Value determined at the end of the Business Day after we apply any Performance Credits (or Daily Adjustment if the
Index Anniversary is not a Term End Date) and we deduct Contract fees, expenses, and investment advisory fees that you authorize
your Financial Professional’s firm to receive from the Contract, but before we make any Income Payments or deduct Excess Withdrawals
taken on this Index Anniversary. If the Income Benefit Date or an Income Benefit Anniversary does not occur on a Business Day, we use
Contract Values from the next Business Day.
Lifetime Income Percentages on the
Income Benefit Date generally will be higher with Level Income, as compared with Increasing Income. However, subsequent payment increases
are less likely with Level Income, as compared with Increasing Income, especially in later Income Benefit Years. This is because only
the Index Protection Strategy with Trigger and Index Protection Strategy with Cap are available once Income Payments are selected, and
those two Crediting Methods may have lower return potential compared to other Crediting Methods. If Index Option performance is less than
the total withdrawals, including Income Payments, Excess Withdrawals and deductions we make for Contract fees, expenses, and investment
advisory fees that you authorize your Financial Professional’s firm to receive from the Contract, taken in an Index Year,
there will be no increase in the annual maximum Income Payment for the Index Year under Level Income.
For example, if you took the maximum
permitted payment during the prior Income Benefit Year and you receive Performance Credits of 2.5% on an Index Anniversary, but the deductions
for Income Payments and Excess Withdrawals taken during the prior Index Year, and deductions we make for Contract fees, expenses, and
investment advisory fees that you authorize your Financial Professional’s firm to receive from the Contract both in the prior
Index Year and on the current Index Anniversary reduce your Contract Value by -6.8% you will not receive a payment increase under Level
Income.
|
If
we increase the Contract Value to equal the death benefit due to a spousal continuation of the Contract during the last
Income
Benefit Year, we also subtract the amount of this increase from the Contract Value on the next Income Benefit
Anniversary
when determining annual payment increases under the Level Income payment option. |
If
you select Increasing Income, the available annual maximum
Income Payments will increase on each Income Benefit Anniversary if your selected Index Option(s) receives a Performance Credit, or if
you executed a Performance Lock on an increased Index Option Value at any time during the prior Income Benefit Year. Any Index Options
that did not receive a Performance Credit and were not locked during the prior Income Benefit Year will not affect the annual maximum
Income Payment on the current Income Benefit Anniversary.
●
If you select multiple Index Options, we take the weighted
average of all Performance Credits, and locked increased Index Option Values based on the percentage of total Index Option Base in each
of your selected Index Options to determine your payment increase as indicated in the example below. When calculating this payment increase,
we use the Index Option Base determined at the end of the Business Day before
we apply any daily transactions (increases for Performance Credits or Daily Adjustments; deductions for Income Payments, Excess Withdrawals,
Contract fees and expenses, or investment advisory fees that you authorize your Financial Professional’s firm to receive from the
Contract; or processing any Early Reallocations or transfers).
−
For Index Options where a Performance Lock was not
executed during the prior Income Benefit Year we use the percentage of total Index Option Base in each of these Index Options on the Income
Benefit Anniversary. If the Income Benefit Anniversary does not occur on a Business Day, we use the Index Option Base from the next Business
Day.
−
For Index Options where a Performance Lock was
executed during the prior Income Benefit Year we use the percentage of Index Option Base in each of these Index Options on the Business
Day the Index Option is reallocated or transferred.
Payment increases can continue even
if your Contract Value reduces to zero, or if you convert Income Payments to Annuity Payments as described in section 9, The Annuity Phase
– When Annuity Payments Begin.
●
If you selected multiple Index Options, we take the weighted
average of all Performance Credits, and locked Daily Adjustments using the percentage of Contract Value in each Index Option either at
the end of the prior Business Day before your Contract Value reduced to zero, or at the end of the Business Day on the Annuity Date if
you convert Income Payments to Annuity Payments.
●
We determine this Contract Value after
we apply any Daily Adjustments (if this day is not
a Term End Date) or Performance Credits (if this day is
a Term End Date), and after
we deduct any Income Payment, Excess Withdrawal, Contract fees and expenses, or investment advisory fees that you authorize your Financial
Professional’s firm to receive from the Contract.
●
You can change the proportions that we use to calculate this
weighted average by submitting an authorized request to our Service Center.
Example of Increasing
Income Payment Increases
Assume your Contract Value is $100,000
and you allocate 20% to the Index Protection Strategy with Trigger using the S&P 500®
Index and 80% to the Index Protection Strategy with the Cap using the EURO STOXX 50®
on the Income Benefit Date.
On the first Income Benefit Anniversary,
the Index Protection Strategy with Trigger Index Option receives a 3.5% Performance Credit and the Index Protection Strategy with the
Cap Index Option receives a 4.2% Performance Credit. On this anniversary, before we apply daily transactions, 20% of your total Index
Option Base is in the Index Protection Strategy with Trigger Index Option, and 80% of your total Index Option Base is in Index Protection
Strategy with the Cap Index Option.
Your annual maximum Income Payment
on the first Income Benefit Anniversary will increase by 4.06% ((3.5% x 20%) + (4.2% x 80%)).
Please see Appendix E for an example
of how we calculate an automatic Income Payment increase if you execute a Performance Lock and Early Reallocation.
Income
Multiplier Benefit
The Income Multiplier Benefit can
increase the annual maximum Income Payment if you:
●
begin confinement after the first Contract Anniversary in
an eligible facility (a hospital, nursing facility, or assisted living facility) for at least 90 days in a 120-day period, or
●
are unable to perform at least two of six activities of daily
living (ADLs) for at least 90 consecutive days. ADLs include bathing, dressing, toileting, continence, eating, and transferring (moving
into or out of a bed, chair, or wheelchair).
We must receive
proof of your staying in an eligible facility or ADL eligibility before we multiply your annual maximum Income Payment by the income multiplier
factor stated in the Income Benefit Supplement. For ADL eligibility we may require, at our expense, an examination or tests by a physician
of our choice. To continue receiving this increase each Income Benefit Year, you must reestablish eligibility.
The Income Multiplier Benefit is
not available before the Income Benefit Date, or before expiration of the income multiplier benefit wait period stated in the Income Benefit
Supplement. In addition, a Covered Person cannot establish eligibility for this benefit more than one Index Year before the Income Benefit
Date. Increased Income Payments based on staying in an eligible facility are not available before the first Contract Anniversary. To qualify
for a payment increase based on performance of ADLs, a Covered Person must have been able to perform each of these six ADLs without substantial
assistance on the Issue Date. If you chose to take less than the annual maximum Income Payment and then qualify for a payment increase
under the Income Multiplier Benefit, we will increase your Income Payments to the available annual maximum before applying the payment
increase.
Example
Assume you elect to receive the maximum
available payment under the Level Income
payment option, your annual maximum Income Payment is $10,000,
the income multiplier factor is 2, and the income multiplier benefit wait period is five Contract Years. After the fifth Contract Anniversary
you suffer an illness and can’t perform two of the six ADLs. At the time of your illness, your annual maximum Income Payment is
still $10,000 and your Contract Value is positive. After we confirm your benefit eligibility with your physician, we increase your annual
maximum Income Payment as follows:
(income multiplier factor) x (annual
maximum Income Payment) = 2 x $10,000 = $20,000
This increase will allow you to receive
up to $20,000 as an Income Payment for this Income Benefit Year, and the next Income Benefit Year. However, in the next Income Benefit
Year your health improves and you are not able to reestablish benefit eligibility for the following Income Benefit Year. So on the second
Income Benefit Anniversary after we increased your payment, we decrease your annual maximum Income Payment as follows:
(annual maximum Income Payment) ÷
(income multiplier factor) = $20,000 ÷ 2 = $10,000
When
the Income Multiplier Benefit Ends
The Income Multiplier
Benefit ends on the earliest of the following.
●
The Annuity Date.
●
The Income Benefit Anniversary that occurs on or immediately
after the date the Contract Value is reduced to zero.
●
The Business Day the Income Benefit ends.
●
The Business Day the Contract ends.
Taxation
of Income Payments
We treat Income Payments as withdrawals
for tax purposes while your Contract Value is positive, and once your Contract Value is reduced to zero we intend to treat Income Payments
as Annuity Payments for tax purposes. For more information, see section 13, Taxes – Taxation of Income Payments.
When
the Income Period Ends
The Income Period ends on the earlier
of the last Business Day before the Annuity Date, or the date the Income Benefit ends. Income Payments can continue for the life of the
Covered Person(s) if you do not take more than your allowed annual maximum payment.
When
the Income Benefit Ends
The Income Benefit
ends on the earliest of the following.
●
The Business Day all Eligible Persons or Covered Persons
are removed from the Contract because they no longer meet the requirements (Owner, Annuitant or sole Beneficiary) stated in section 2.
If this occurs after the Income Benefit Date, Income Payments stop when the last Covered Person is removed from the Contract.
●
The Index Anniversary upon which the younger Eligible Person
reaches age 100 if it occurs before the Income Benefit Date.
●
The Business Day we process your request for a full withdrawal,
other than a full withdrawal caused by an Income Payment.
●
The Income Benefit Date or an Income Benefit Anniversary
if the annual maximum Income Payment is less than $100.
●
Upon the death of an Owner (or Annuitant if the Owner is
a non-individual), the end of the Business Day we first receive a Valid Claim from any one Beneficiary. However, if a federally recognized
spouse is an Eligible Person or Covered Person and continues this Contract, the Income Benefit also continues.
●
During the Accumulation Phase and before the Income Benefit
Date, the Income Benefit ends on the date of death of the last surviving Eligible Person.
●
During the Income Period, the Income Benefit ends on the
date of death of the last surviving Covered Person.
●
The Business Day the Contract ends.
|
If
we receive notice of death of a Covered Person during the Income Period, we will suspend Income Payments and the
Income
Benefit will end as described above. However, if a federally recognized spouse who is also a joint Covered
Person
continues this Contract, we will resume Income Payments and add any Income Payments that we would have
paid
between the time we suspended Income Payments and when they resume future Income Payments. |
12. Death Benefit
“You” in this section
refers to the Owner, or the Annuitant if the Contract is owned by a non-individual.
The Contract provides the Traditional
Death Benefit, the standard death benefit, for no additional charge. If available, you can instead select the optional Maximum Anniversary
Value Death Benefit at Contract issue for an additional rider fee if all Owners and the Annuitant are age 75 or younger. The Maximum Anniversary
Value Death Benefit can only be added to a Contract at issue. The
Maximum Anniversary Value Death Benefit cannot be less than the Traditional Death Benefit, but they may be equal. Please discuss this
benefit’s appropriateness with your Financial Professional.
The death benefit is the greatest of the Contract Value, Cash Value, or Guaranteed Death Benefit Value. The Guaranteed Death Benefit Value
is either total Purchase Payments reduced proportionately for withdrawals you take (including any MVA) if you select the Traditional Death
Benefit, or the Maximum Anniversary Value if you select the Maximum Anniversary Value Death Benefit.
The death benefit
is only available during the Accumulation Phase (and Income Period, if applicable).
If you or the Determining Life (Lives) die during the Accumulation Phase, we process the death benefit using prices determined after we
receive the required information, which is either a Valid Claim or due proof of death as stated here. (For information on due proof of
death see the Glossary – Valid Claim). If we receive this information at or after the end of the current Business Day, we use the
next Business Day’s prices.
If there are multiple Beneficiaries,
each Beneficiary receives the portion of the death benefit he or she is entitled to when we receive his or her Valid Claim. If a Beneficiary
dies before you or the Designated Life, that Beneficiary’s interest in this Contract ends unless your Beneficiary designation specifies
otherwise. If there are no remaining Beneficiaries, or no named Beneficiaries, we pay the death benefit to your estate, or if the Owner
is a non-individual, to the Owner. Unless you instruct us to pay Beneficiaries a specific percentage of the death benefit, each Beneficiary
receives an equal share.
Each Beneficiary’s portion
of the death benefit remains in the Index Options based on the allocation instructions that were in effect on the date of death until
we receive his or her Valid Claim and we either pay the claim or the Beneficiary provides alternate allocation instructions. If there
is Variable Account Value in the Variable Option on the date of death, it remains there until the next Index Anniversary. If an Index
Anniversary occurs before we receive a Valid Claim, we will transfer that Beneficiary’s portion of the Variable Account Value to
the Index Options based on the allocation instructions that were in effect on the date of death.
From the time we determine the death
benefit until we make a complete distribution, any amount in the Investment Options continues to be subject to investment risk that is
borne by the recipient(s). Once we receive notification of death, we may no longer accept or process transfer requests. After we receive
the first Valid Claim from any Beneficiary, we also will not accept additional Purchase Payments or allow any partial or full withdrawals
unless the withdrawal is required to comply with federal tax law.
On the first death of a Determining
Life during the Accumulation Phase, if your selected death benefit is in effect, your Beneficiary(ies) will receive the greatest of the
Contract Value, Cash Value (which on death is the Contract Value after
application of any MVA), or Guaranteed Death Benefit Value. A
positive MVA will increase the death benefit if Cash Value is greater than the Guaranteed Death Benefit Value. However, if the MVA is
negative the death benefit will be the greater of Contract Value (without adjustment for the negative MVA), or the Guaranteed Death Benefit
Value. The
Guaranteed Death
Benefit Value is either total Purchase Payments reduced proportionately for withdrawals you take (including any MVA) if you select the
Traditional Death Benefit, or the Maximum Anniversary Value if you select the Maximum Anniversary Value Death Benefit. For example,
assume total Purchase Payments are $90,000, you take no withdrawals, the highest Contract Value on any Index Anniversary (the Maximum
Anniversary Value) is $105,000, the current Contract Value is $100,000, and the Cash Value is $97,000. The death benefit for the Traditional
Death Benefit is the $100,000 Contract Value, and for the Maximum Anniversary Value Death Benefit it is the $105,000 Maximum Anniversary
Value.
If the date we are determining the
death benefit is not the Term End Date, the Contract Value reflects the Daily Adjustment. Withdrawals you take reduce your Guaranteed
Death Benefit Value by the percentage of Contract Value withdrawn (including any MVA), determined at the end of each Business Day. All
withdrawals you take reduce the Guaranteed Death Benefit Value, Contract Value, and Cash Value, even MVA-Free Withdrawals. However,
we do not reduce the Guaranteed Death Benefit Value for deductions we make for Contract fees, expenses, or investment advisory fees
that you authorize your Financial Professional’s firm to receive from the Contract. These
deductions will, however, decrease the Contract Value and Cash Value by the dollar amount withdrawn and may reduce the likelihood
of receiving increases to the Maximum Anniversary Value. In addition, because the death benefit is the greatest of Contract Value, Cash
Value or the Guaranteed Death Benefit Value, deductions we make for Contract fees, expenses, and authorized investment advisory fees may
reduce the death benefit available to your Beneficiaries.
Examples of the impact of deductions
for investment advisory fees you authorize your Financial Professional’s firm to receive from the Contract on the death benefit
are included in section 1. The impact of an Excess Withdrawal on the death benefit is included in section 11.
Maximum
Anniversary Value
The Maximum Anniversary Value is
initially equal to the Purchase Payment received on the Issue Date. At the end of each Business Day, we adjust the Maximum Anniversary
Value as follows.
●
We increase it by the dollar amount of any additional Purchase
Payments.
●
We reduce it by the percentage of any Contract Value you
withdraw (including any MVA).
If the Index Effective Date occurs
after the Issue Date, the Maximum Anniversary Value on the Index Effective Date is calculated in the same way as on an Index Anniversary.
On each Index Anniversary before
the end date (or on the next Business Day if the Index Anniversary is not on a Business Day) the Maximum Anniversary Value is equal to
the greater of:
●
its current value after processing any additional Purchase
Payments, or withdrawals you take (including any MVA), or
●
the Contract Value determined at the end of the Business
Day after we process all daily transactions including Performance Credits, any additional Purchase Payments, withdrawals you take including
any MVA, and deductions we make for Contract fees, expenses, and investment advisory fees you authorize your Financial Professional’s
firm to receive from the Contract. Contract Value reflects the Daily Adjustment for an Index Option for which this anniversary is not
a Term End Date. Negative
Index Option performance, withdrawals you take, and deductions we make for Contract fees, expenses, and investment advisory fees you authorize
your Financial Professional’s firm to receive from the Contract decrease the Contract Value and may reduce the likelihood of receiving
increases to the Maximum Anniversary Value.
On and after the end date, we no
longer make this comparison and we no longer capture any annual investment gains in the Maximum Anniversary Value.
The end date occurs on the earliest
of:
●
the older Determining Life’s 91st
birthday, or
●
the end of the Business Day we receive the first Valid Claim
from any one Beneficiary.
Example of the Maximum
Anniversary Value
|
|
Contract
Value |
Maximum
Anniversary Value |
|
Issue
Date |
$ 100,000
|
$ 100,000
|
|
1st
Index Anniversary |
$110,000
|
$110,000
|
|
2nd
Index Anniversary |
$95,000
|
$110,000
|
|
3rd
Index Anniversary |
$ 105,000
|
$110,000
|
|
4th
Index Anniversary |
$ 120,000
|
$ 120,000
|
●
On the Issue Date the Maximum Anniversary Value is equal
to the initial Purchase Payment of $100,000.
●
On the 1st
Index Anniversary the Contract Value is greater than the Maximum Anniversary Value, so the Maximum Anniversary Value increases to equal
the Contract Value of $110,000.
●
On the 2nd
and 3rd
Index Anniversaries the Contract Value is less than the Maximum Anniversary Value, so we neither increase nor decrease the Maximum Anniversary
Value. The Maximum Anniversary Value will stay at $110,000 until the Contract Value on an Index Anniversary is greater than this amount
or you make an additional Purchase Payment (either of which will increase the Maximum Anniversary Value), or you take a withdrawal (which
will decrease the Maximum Anniversary Value).
●
On the 4th
Index Anniversary the Contract Value is greater than the Maximum Anniversary Value, so the Maximum Anniversary Value increases to equal
the Contract Value of $120,000.
|
During
the Income Period: |
|
● You
cannot make additional Purchase Payments. If your Contract includes the Traditional Death Benefit this means
the
Guaranteed Death Benefit Value no longer increases. |
|
● Index
Dual Precision Strategy, Index Precision Strategy, Index Performance Strategy, and Index Guard Strategy are
no
longer available. This may limit your Contract’s performance potential and the Guaranteed Death Benefit Value if
your
Contract includes the Maximum Anniversary Value Death Benefit. Income Payments and Excess Withdrawals
also
decrease your Contract Value, which also reduces the likelihood of locking in investment gains to the
Guaranteed
Death Benefit Value if your Contract includes the Maximum Anniversary Value Death Benefit. |
|
● Each
Income Payment and any Excess Withdrawal reduces the Guaranteed Death Benefit Value by the percentage of
Contract
Value withdrawn (including any MVA),
which means this value may be reduced by more than the amount
withdrawn.
Taking
Excess Withdrawals may also cause your selected death benefit to end prematurely. |
What Happens Upon
Death?
If you are the Determining Life,
or if you and the Determining Life (Lives) are different individuals and die within 120 hours of each other, we determine the Guaranteed
Death Benefit Value at the end of the Business Day we receive a Valid Claim. For multiple Beneficiaries, each surviving Beneficiary receives
the greater of their portion of the:
●
Guaranteed Death Benefit Value determined at the end of the
Business Day we receive the first Valid Claim from any one Beneficiary,
●
Contract Value determined at the end of the Business Day
during which we receive his or her Valid Claim, or
●
Cash Value determined at the end of the Business Day during
which we receive his or her Valid Claim.
In this instance, if the Beneficiary:
−
is a surviving spouse and chooses to continue the Contract;
−
selects death benefit payment Option B; or
−
selects death benefit payment Option C and takes payment
over a period not extending beyond the Beneficiary’s life expectancy;
and the Contract Value is less than
the Cash Value or Guaranteed Death Benefit Value, we increase the Contract Value to equal the greatest of these amounts when we receive
a Valid Claim.
If you and the Determining Life (Lives)
are different individuals and do not die within 120 hours of each other, the death benefit is as follows. This
can only occur if you change the Owner after the Issue Date.
●
If a Determining Life dies before you, we
do not pay a death benefit to the Beneficiary(ies), but we may increase the Contract Value if the Traditional Death Benefit or Maximum
Anniversary Value Death Benefit are still in effect. At
the end of the Business Day we receive due proof of a Determining Life’s death, if the Contract Value is less than the Cash Value
or Guaranteed Death Benefit Value, we increase the Contract Value to equal the greatest of these amounts, and
your selected death benefit ends.
●
Upon your death, your Beneficiary(ies) receive the greater
of Contract Value or Cash Value determined at the end of the Business Day during which we receive each Beneficiary’s Valid Claim.
Upon the death of a Determining Life,
if we increase the Contract Value to equal the Guaranteed Death Benefit Value or Cash Value, we allocate this increase to the Variable
Option. On the next Index Anniversary we transfer the Variable Account Value to the Index Options according to the allocation instructions.
The
Traditional Death Benefit and Maximum Anniversary Value Death Benefit end upon the earliest of the following:
●
The Business Day before the Annuity Date.
●
The Business Day that the Guaranteed Death Benefit Value
and Contract Value are both zero.
●
Upon the death of a Determining Life, the end of the Business
Day we receive a Valid Claim from all Beneficiaries if you and the Determining Life are the same individual, or if you and the Determining
Life (Lives) are different individuals and die within 120 hours of each other.
●
Upon the death of a Determining Life, the end of the Business
Day we receive due proof of the Determining Life’s death if you and the Determining Life (Lives) are different individuals and
do not die within 120 hours of each other.
●
Upon the death of an Owner (or Annuitant if the Owner is
a non-individual), the end of the Business Day we receive the first Valid Claim from any one Beneficiary, if the Owner (or Annuitant)
is no longer a Determining Life.
●
The Business Day the Contract ends.
|
We
base the Guaranteed Death Benefit Value on the first death of a Determining Life (or Lives). This means that upon
the
death of an Owner (or Annuitant if the Owner is a non-individual), if
a surviving spouse continues the Contract: |
|
● the
Guaranteed Death Benefit Value is no longer available, and |
|
● if
you selected the Maximum Anniversary Value Death Benefit, we no longer assess its 0.20% rider fee. |
|
Also,
if you and the Determining Life (Lives) are different individuals and you die first, the Guaranteed Death Benefit
Value
is not available to your Beneficiary(ies). |
Death
of the Owner and/or Annuitant
The SAI includes tables that are
intended to help you better understand what happens upon the death of any Owner and/or Annuitant under the different phases of the Contract.
Death
Benefit Payment Options During the Accumulation Phase
Each Beneficiary must select one
of the death benefit payment options listed below.
If a Beneficiary requests a lump
sum payment under Option A, we pay that Beneficiary within seven days of receipt of his or her Valid Claim, unless the suspension of payments
or transfers provision is in effect. Payment of the death benefit may be delayed, pending receipt of any state forms.
Spousal Continuation:
If the Beneficiary is the deceased Owner’s spouse, he or she can choose to continue the Contract with the portion of the death
benefit the spouse is entitled to in his or her own name. For an IRA, Roth IRA, or SEP IRA Contract, spousal continuation can only occur
if the surviving spouse is the Contract’s sole primary Beneficiary. For Qualified Contracts purchased through a qualified plan,
spousal continuation is only available through a direct rollover to an IRA. Spouses
must qualify as such under federal law to continue the Contract.
Individuals who have entered into a registered domestic partnership, civil union, or other similar relationship that is not considered
to be a marriage under state law are also not considered to be married under federal law. An election by the spouse to continue the Contract
must be made on the death claim form before we pay the death benefit. If the deceased Owner was a Determining Life and the surviving spouse
Beneficiary continues the Contract, at the end of the Business Day we receive his or her Valid Claim, if the Contract Value is less than
the Cash Value or Guaranteed Death Benefit Value (if available), we increase the Contract Value to equal the greatest of these amounts,
and your selected death benefit (either the Traditional Death Benefit or the Maximum Anniversary Value Death Benefit) ends. If the surviving
spouse continues the Contract:
●
he or she becomes the new Owner and may exercise all of the
Owner’s rights, including naming a new Beneficiary or Beneficiaries;
●
he or she is subject to any remaining MVA period; and
●
upon the surviving spouse’s death, their Beneficiary(ies)
receive the Contract Value determined at the end of the Business Day during which we receive a Valid Claim from each Beneficiary.
Death
Benefit Payment Options
The following applies to Non-Qualified
Contracts. Different rules may apply to Qualified Contracts. For more information, please see section 13, Taxes – Distributions
Upon the Owner’s Death (or Annuitant’s Death if the Owner is a Non-Individual).
Option A:
Lump sum payment of the death benefit.
Option
B: Payment of the entire death benefit within five years
of the date of any Owner’s death. The Beneficiary can continue to make transfers between Index Options and is subject to the
product fee.
Option C:
If the Beneficiary is an individual, payment of the death benefit as Annuity Payments under Annuity Options A, B, or C. If you take the
death benefit as Annuity Payments, we do not require that the Annuity Date occur on an Index Anniversary. With our written consent other
options may be available for payment over a period not extending beyond the Beneficiary’s life expectancy under which the Beneficiary
can continue to make transfers between Index Options and is subject to the product fee.
Distribution from Non-Qualified Contracts
under Option C must begin within one year of the date of the Owner’s death. Any portion of the death benefit from Non-Qualified
Contracts not applied to Annuity Payments within one year of the date of the Owner’s death must be distributed within five years
of the date of death.
If a Non-Qualified Contract is owned
by a non-individual, then we treat the death of an Annuitant as the death of an Owner for purposes of the Code’s distribution at
death rules, which are set forth in Section 72(s) of the Code.
In all events, notwithstanding any
provision to the contrary in the Contract or this prospectus, a Non-Qualified Contract is interpreted and administered in accordance with
Section 72(s) of the Code.
|
Standard
Benefits | |||
|
Name
of
Benefit
|
Purpose
|
Maximum
Fee
|
Brief
Description of Restrictions/Limitations |
|
Free
Withdrawal
Privilege
|
Allows
you to withdraw up to 10% of your total
Annual
Contribution Amounts each Index Year
without
incurring an MVA. |
None
|
• Only
available during the Accumulation
Phase.
• Not
available during the Income Period.
• Not
available upon a full withdrawal.
• Upon
a full withdrawal, an MVA may apply
against
amounts previously withdrawn under
the
free withdrawal privilege.
• Unused
free withdrawal amounts not
available
in future years.
• Program
withdrawals may be subject to
negative
Daily Adjustments.
• Program
withdrawals are subject to income
taxes,
and may also be subject to a 10%
additional
federal tax for amounts withdrawn
before
age 59 1∕2.
|
|
Minimum
Distribution
Program
|
Allows
you to automatically take withdrawals to
satisfy
the required minimum distribution
requirements
(RMD) imposed by the Internal
Revenue
Code. |
None
|
• Only
available during the Accumulation
Phase.
• Only
available to IRA or SEP IRA Contracts.
• Program
withdrawals count against the free
withdrawal
privilege.
• Program
withdrawals may be subject to
negative
Daily Adjustments.
• Program
withdrawals are subject to income
taxes.
• Program
withdrawals may be monthly,
quarterly,
semi-annual or annual, unless you
have
less than $25,000 in Contract Value, in
which
case only annual payments are
available.
• We
reserve the right to discontinue or modify
the
program subject to the requirements of
law.
|
|
Standard
Benefits | |||
|
Name
of
Benefit
|
Purpose
|
Maximum
Fee
|
Brief
Description of Restrictions/Limitations |
|
Investment
Advisory
Fees |
We
designed the Contract for persons who are
receiving
ongoing investment advice from a
Financial
Professional. You can instruct us to
automatically
withdraw investment advisory
fees
from your Contract to pay your Financial
Professional’s
firm. |
None
|
• Only
available during the Accumulation
Phase.
• Investment
advisory fees are in addition to
the
Contract’s fees and expenses.
• Program
withdrawals may be subject to
negative
Daily Adjustments.
• If
you and your Financial Professional do not
agree
to our requirements we will not pay
investment
advisory fees from this Contract
to
your Financial Professional’s firm.
• Our
requirements limit investment advisory
fee
withdrawals to 1.5% of Contract Value
each
Contract Year, require the fees to be
solely
for advisory services provided with
respect
to the Contract, and require the
Contract
to be the sole source of payment.
• Deductions
we make for investment advisory
fees
reduce your Contract Value (and
therefore
Cash Value) dollar for dollar by the
amount
withdrawn. This Contract Value
reduction
also decreases your initial annual
maximum
Income Payment which is based
on
Contract Value. As Contract Value is one
of
the components we use to calculate RMD
payments,
these deductions may also reduce
your
RMD payments. These deductions also
reduce
the following proportionately by the
percentage
of Contract Value withdrawn:
Charge
Base, Index Option Base, Index
Option
Value, and Variable Account Value.
For
more information regarding the impact of
paying
advisory fees with money in the
Contract,
including an example of how
deduction
of investment advisory fees
impacts
the Contract, see section 1, The
Contract
– Investment Advisory Fees. |
|
Standard
Benefits | |||
|
Name
of
Benefit
|
Purpose
|
Maximum
Fee
|
Brief
Description of Restrictions/Limitations |
|
Income
Benefit
|
Guaranteed
lifetime withdrawal benefit
providing
for yearly Income Payments until the
death
of the Covered Person(s) if conditions
are
satisfied.
We
base the initial Income Payment on the
Lifetime
Income Percentage and Contract
Value.
If you choose the Level Income payment
option
and meet the age requirements stated in
section
11, we guarantee your initial annual
maximum
Income Payment will be at least the
Level
Income Guarantee Payment Percentage
multiplied
by your total Purchase Payments
adjusted
for withdrawals.
The
automatic annual payment increase
feature
may increase payments after the
Income
Benefit Date.
If
you elect Level Income, payments increase if
Contract
Value increases from one Income
Benefit
Anniversary to the next and you took
the
maximum permitted payment during the
prior
Income Benefit Year.
Includes
the Income Multiplier Benefit for no
additional
charge that can increase income to
help
pay for needed care.
Section
11 includes examples of the Lifetime
Income
Percentage Calculation, Excess
Withdrawals,
Income Payment increases, and
the
Income Multiplier Benefit. |
0.70%
(as
a
percentage
of
the
Charge
Base)
This
rider fee
is
part of the
Base
Contract
Expenses
in
the
Fee
Tables.
|
• Benefit
cannot be removed from the
Contract.
• See
the Income Benefit Supplement for
current
terms. Please see Appendix F for
historical
information on the terms for
previous
versions of the Income Benefit.
• Benefit
only available during the
Accumulation
Phase.
• Investment
restrictions limit available Index
Options
during Income Period.
• Income
Period cannot begin until after the
waiting
period and reaching age 50. Income
Period
must begin no later than age 100.
• Early
and Excess Withdrawals may
significantly
reduce or end the benefit as
indicated
in section 11.
• A
full Excess Withdrawal and certain
partial
Excess Withdrawals will cause
Income
Payments to stop and the
Contract
and
all of its benefits
to end.
• On
the Income Benefit Date, we execute
Performance
Locks on Index Options for
which
this day is not a Term End Date, and in
such
case the Index Option Value will be
subject
to the Daily Adjustment. We then
reallocate
the total Contract Value, including
amounts
in the Variable Option, into the
Index
Protection Strategy with Trigger and/or
Index
Protection Strategy with Cap Index
Options
according to allocation instructions
you
provide, and begin your Income
Payments.
• Income
Payments are subject to income
taxes,
and may also be subject to a 10%
additional
federal tax for amounts withdrawn
before
age 59 1∕2.
• No
additional Purchase Payments during the
Income
Period.
• No
Income Percentage Increase before age
45.
• Availability
of joint Income Payments is
subject
to age restrictions.
• The
Income Multiplier Benefit is not available
in
all states as indicated in Appendix G.
• Must
establish eligibility to exercise the
Income
Multiplier Benefit (e.g., that you are
confined
for care or unable to perform two
activities
for daily living) and must
re-establish
eligibility each year thereafter.
• Annuitizing
the Contract will end the benefit,
but
you may be able to annuitize your annual
maximum
Income Payment.
• State
variations may apply. |
|
Standard
Benefits | |||
|
Name
of
Benefit
|
Purpose
|
Maximum
Fee
|
Brief
Description of Restrictions/Limitations |
|
Traditional
Death
Benefit |
Provides
a death benefit equal to the greatest
of
the Contract Value, Cash Value, or
Guaranteed
Death Benefit Value. The
Guaranteed
Death Benefit Value is total
Purchase
Payments adjusted for withdrawals.
An
example of the death benefit provided by
the
Traditional Death Benefit is included in
section
12, Death Benefit.
An
example of how deduction of investment
advisory
fees impact the death benefit is
included
in section 1.
The
impact of an Excess Withdrawal on the
death
benefit is included in section 11. |
None
|
• Benefit
only available during the
Accumulation
Phase.
• Withdrawals,
including any negative Daily
Adjustments
and negative MVAs, may
significantly
reduce the benefit as indicated in
the
Investment Advisory Fee Deduction
Example
in section 1, The Contract, and in
the
Excess Withdrawal example in section
11,
Income Benefit.
• Restrictions
on Purchase Payments may limit
the
benefit.
• Annuitizing
the Contract will end the benefit. |
|
Standard
Benefits | |||
|
Name
of
Benefit
|
Purpose
|
Maximum
Fee
|
Brief
Description of Restrictions/Limitations |
|
Performance
Lock
and Early
Reallocations
|
Performance
Lock allows you to capture the
current
Index Option Value during the Term for
an
Index Option. Performance Lock can help
eliminate
doubt about future Index performance
and
possibly limit the impact of negative
performance.
Early Reallocation allows you to
transfer
out of a locked Index Option on days
other
than an Index Anniversary, or a Term End
Date.
A
Performance Lock example is included in
section
6, Valuing Your Contract —
Performance
Locks and Early Reallocations. |
None
|
• Available
during the Accumulation Phase.
Only
available during the Annuity Phase if
you
select Increasing Income and you
annuitize
your annual maximum Income
Payment.
• Performance
Locks must be executed before
the
Term End Date.
• If
a Performance Lock is executed, the
locked
Index Option will no longer participate
in
Index performance (positive or negative)
for
the remainder of the Term, and will not
receive
a Performance Credit on the Term
End
Date.
• You
will not know your locked Index Option
Value
in advance.
• The
locked Index Option Value will reflect a
Daily
Adjustment.
• If
a Performance Lock is executed when the
Daily
Adjustment has declined, it will lock in
any
loss.
• A
Performance Lock can be executed only
once
each Term for each Index Option.
• Cannot
execute a Performance Lock for only
a
portion of the Index Option Value.
• Early
Reallocation requests are not accepted
within
14 calendar days before an Index
Anniversary.
• You
are limited to twelve Early Reallocation
requests
each Index Year.
• Deductions
(e.g. withdrawals, fees) decrease
the
locked Index Option Value.
• Cannot
transfer locked Index Option Value
until
the next Index Anniversary that occurs
on
or immediately after the Lock Date unless
you
execute an Early Reallocation.
• We
will not provide advice or notify you
regarding
whether you should execute a
Performance
Lock or Early Reallocation
or
the optimal time for doing so, if any.
• We
will not warn you if you execute a
Performance
Lock or Early Reallocation at
a
sub-optimal time.
• We
are not responsible for any losses
related
to your decision whether or not to
execute
a Performance Lock or Early
Reallocation.
• Early
Reallocations are not available to
Contracts
issued before May 1, 2023, as
detailed
in Appendix G. |
|
Optional
Benefits | |||
|
Name
of
Benefit
|
Purpose
|
Maximum
Fee
|
Brief
Description of Restrictions/Limitations |
|
Maximum
Anniversary
Value
Death
Benefit
|
Provides
a death benefit equal to the greatest of
the
Contract Value, Cash Value, or Guaranteed
Death
Benefit Value. The Guaranteed Death
Benefit
Value is the Maximum Anniversary Value.
An
example of the death benefit provided by the
Maximum
Anniversary Value Death Benefit, and
calculation
of the Maximum Anniversary Value is
included
in section 12, Death Benefit.
An
example of how deduction of investment
advisory
fees impact the death benefit is
included
in section 1.
The
impact of an Excess Withdrawal on the
death
benefit is included in section 11. |
0.20%
(as
a
percentage
of
the
Charge
Base)
|
• Must
be age 75 or younger to elect.
• Can
only be added to a Contract at issue.
• Replaces
the Traditional Death Benefit if
elected.
• Benefit
cannot be removed from the Contract.
• Only
available during the Accumulation Phase.
• Withdrawals,
including any negative Daily
Adjustment
and negative MVA, may
significantly
reduce the benefit as indicated in
the
Investment Advisory Fee Deduction
Example
in section 1, The Contract, and in the
Excess
Withdrawal example in section 11,
Income
Benefit.
• Withdrawals
reduce the likelihood of receiving
increases
to the Maximum Anniversary Value.
• Investment
restrictions during the Income
Period
may limit the benefit.
• Restrictions
on Purchase Payments may limit
the
benefit.
• Annuitizing
the Contract will end the benefit. |
Appendix A – Investment Options Available Under the Contract
The availability of Investment Options
may vary depending on the broker-dealer through which the Contract is sold. See Appendix H – Financial Intermediary Variations
for additional information.
Variable
Option
The following includes information
about the Fund available under the Contract. More information about the Fund is available in the Fund’s prospectus, which may be
amended from time to time and can be found online at https://www.allianzlife.com/variableoptions. You can also request this information
at no cost by calling (800) 624-0197, or by sending an email request to prospectus.request@allianzlife.com.
The current expenses and performance
information below reflects fees and expenses of the Fund, but do not reflect the other fees and expenses that your Contract may charge.
Expenses would be higher and performance would be lower if these other charges were included. The Fund’s past performance is not
necessarily an indication of future performance.
|
Investment
Objective |
Fund
and
Adviser/Subadviser
|
Current
Expenses
|
Average
Annual Total Returns
(as
of December 31, 2025) | ||
|
1
Year |
5
Years |
10
Years | |||
|
Current
income consistent with
stability
of principal |
AZL®
Government Money
Market
Fund(1)
Adviser:
Allianz
Investment
Management
LLC
Subadviser:
BlackRock
Advisors,
LLC |
0.65%
|
3.70%
|
2.62%
|
1.57%
|
(1)
The
AZL®
Government Money Market Fund’s annual expenses reflect a temporary fee reduction. Please see the AZL®
Government Money Market Fund’s prospectus for information regarding the expense reimbursement or fee waiver arrangement.
Index
Options
The following is a list of Index
Options currently available under the Contract. We may change certain features of the Index Options listed below (including the Index
and the current limits on Index gains), offer new Index Options, and close Index Options to new Purchase Payments and transfers. We will
provide you with written notice before making any changes other than changes to current limits on Index gains. Information about current
limits on Index gains is available at https://www.allianzlife.com/RILAincomeadvrates. During the Income Phase of the Income Benefit, you
may not be able to invest in certain Index Options, as noted below.
Note: If amounts
are removed from an Index Option before the Term End Date, we will apply a Daily Adjustment. Except for Index Options under the Index
Protection Strategy with Trigger and Index Protection Strategy with Cap, this may result in a significant reduction in your Contract Value
that could exceed any protection from Index loss that would be in place if such amounts were not removed from the Index Option until the
Term End Date. The Index Protection Strategy with Trigger and Index Protection Strategy with Cap are unique in that the Daily Adjustment
for them cannot be negative.
For more information
about the Index Options’ features, see section 4, Index Options, and section 6, Valuing Your Contract. For more information about
Daily Adjustment, see section 7, Expenses and Adjustments – Daily Adjustment.
|
Index
|
Index
Type |
Crediting
Period
(Term
Length)
|
Index
Crediting
Methodology
|
Current
Limit on
Index
Loss
(if
held until
Term
End Date) |
Minimum
Limit on Index Gain
(for
the life of the Index
Option)
|
|
Index
Protection Strategy with Trigger
• During
the Income Period, this is one of the two Crediting Methods available to you. | |||||
|
S&P
500®
Index(1)
|
U.S.
large-cap equities |
1-year
Term |
Point-to-point
with
step-up |
100%
downside
protection
|
0.50%
minimum Trigger Rate |
|
Russell
2000®
Index(1)
|
U.S.
small-cap equities | ||||
|
Nasdaq-100®
Index(1)
|
U.S.
& international
non-financial
large-cap
equities
| ||||
|
EURO
STOXX 50®(1)
|
Eurozone
large-cap equities | ||||
|
iShares®
MSCI Emerging
Markets
ETF(2)
|
International
emerging
markets
equities | ||||
|
Index
Protection Strategy with Cap
• During
the Income Period, this is one of the two Crediting Methods available to you. | |||||
|
S&P
500®
Index(1)
|
U.S.
large-cap equities |
1-year
Term |
Point-to-point
with
Cap |
100%
downside
protection
|
0.50%
minimum Cap |
|
Russell
2000®
Index(1)
|
U.S.
small-cap equities | ||||
|
Nasdaq-100®
Index(1)
|
U.S.
& international
non-financial
large-cap
equities
| ||||
|
EURO
STOXX 50®(1)
|
Eurozone
large-cap equities | ||||
|
iShares®
MSCI Emerging
Markets
ETF(2)
|
International
emerging
markets
equities | ||||
|
Index
Dual Precision Strategy
• For
Contracts issued before November 14, 2023, the Index Dual Precision Strategy is not available.
• For
Contracts issued from November 14, 2023, to April 30, 2024, only the 1-year Term with 10% Buffer is available.
• For
Contracts issued from May 1, 2024, to November 4, 2024, only the 1-year Term with 10%, 20%, and 30% Buffers are available.
• For
Contracts issued from November 5, 2024, to November 3, 2025, all 1-year Term with 10%, 20%, and 30% Buffers are available. Additionally,
only the
3-year
Term with 10% and 20% Buffers, and 6-year Term with 10% and 20% Buffers are available.
• For
Contracts issued since November 4, 2025, all 1-year, 3-year, and 6-year Term Index Options listed below are available. | |||||
|
S&P
500®
Index(1)
|
U.S.
large-cap equities |
1-year
Term |
Point-to-point
with
step-up |
• 10%
Buffer
• 20%
Buffer
• 30%
Buffer
|
3%
minimum Trigger Rate |
|
Russell
2000®
Index(1)
|
U.S.
small-cap equities | ||||
|
Nasdaq-100®
Index(1)
|
U.S.
& international
non-financial
large-cap
equities
| ||||
|
EURO
STOXX 50®(1)
|
Eurozone
large-cap equities | ||||
|
iShares®
MSCI Emerging
Markets
ETF(2)
|
International
emerging
markets
equities | ||||
|
S&P
500®
Index(1)
|
U.S.
large-cap equities |
3-year
Term |
Point-to-point
with
step-up |
• 10%
Buffer
• 20%
Buffer
• 30%
Buffer
|
4%
minimum Trigger Rate |
|
Russell
2000®
Index(1)
|
U.S.
small-cap equities | ||||
|
S&P
500®
Index(1)
|
U.S.
large-cap equities |
6-year
Term |
Point-to-point
with
step-up |
• 10%
Buffer
• 20%
Buffer
• 30%
Buffer
|
8%
minimum Trigger Rate |
|
Russell
2000®
Index(1)
|
U.S.
small-cap equities | ||||
|
Index
|
Index
Type |
Crediting
Period
(Term
Length)
|
Index
Crediting
Methodology
|
Current
Limit on
Index
Loss
(if
held until
Term
End Date) |
Minimum
Limit on Index Gain
(for
the life of the Index
Option)
|
|
Index
Precision Strategy | |||||
|
S&P
500®
Index(1)
|
U.S.
large-cap equities |
1-year
Term |
Point-to-point
with
step-up |
10%
Buffer
|
3%
minimum Trigger Rate |
|
Russell
2000®
Index(1)
|
U.S.
small-cap equities | ||||
|
Nasdaq-100®
Index(1)
|
U.S.
& international
non-financial
large-cap
equities
| ||||
|
EURO
STOXX 50®(1)
|
Eurozone
large-cap equities | ||||
|
iShares®
MSCI Emerging
Markets
ETF(2)
|
International
emerging
markets
equities | ||||
|
Index
Guard Strategy | |||||
|
S&P
500®
Index(1)
|
U.S.
large-cap equities |
1-year
Term |
Point-to-point
with
Cap |
-10%
Floor
|
3%
minimum Cap |
|
Russell
2000®
Index(1)
|
U.S.
small-cap equities | ||||
|
Nasdaq-100®
Index(1)
|
U.S.
& international
non-financial
large-cap
equities
| ||||
|
EURO
STOXX 50®(1)
|
Eurozone
large-cap equities | ||||
|
iShares®
MSCI Emerging
Markets
ETF(2)
|
International
emerging
markets
equities | ||||
|
Index
Performance Strategy
• For
Contracts issued before November 14, 2023, only the 1-year Term with 10% Buffer, 3-year Term with 10% and 20% Buffers, and 6-year Term
with 10%
Buffer
are available.
• For
Contracts issued from November 14, 2023, to November 3, 2025, only the 1-year Term with 10%, 20%, and 30% Buffers, 3-year Term with 10%
and 20%
Buffers,
and 6-year Term with 10% and 20% Buffers are available.
• For
Contracts issued since November 4, 2025, all 1-year, 3-year, and 6-year Term Index Options listed below are available. | |||||
|
S&P
500®
Index(1)
|
U.S.
large-cap equities |
1-year
Term |
Point-to-point
with
Cap |
• 10%
Buffer
• 20%
Buffer
• 30%
Buffer
|
3%
minimum Cap(3)
|
|
Russell
2000®
Index(1)
|
U.S.
small-cap equities | ||||
|
Nasdaq-100®
Index(1)
|
U.S.
& international
non-financial
large-cap
equities
| ||||
|
EURO
STOXX 50®(1)
|
Eurozone
large-cap equities | ||||
|
iShares®
MSCI Emerging
Markets
ETF(2)
|
International
emerging
markets
equities | ||||
|
S&P
500®
Index(1)
|
U.S.
large-cap equities |
3-year
Term |
Point-to-point
with
Cap and
enhanced
upside
|
• 10%
Buffer
• 20%
Buffer
• 30%
Buffer
|
• 5%
minimum Cap(3)
• 100%
minimum Participation
Rate
|
|
Russell
2000®
Index(1)
|
U.S.
small-cap equities | ||||
|
S&P
500®
Index(1)
|
U.S.
large-cap equities |
6-year
Term |
Point-to-point
with
Cap and
enhanced
upside
|
• 10%
Buffer
• 20%
Buffer
• 30%
Buffer
|
• 10%
minimum Cap(3)
• 100%
minimum Participation
Rate
|
|
Russell
2000®
Index(1)
|
U.S.
small-cap equities | ||||
(1)
This Index is a “price return index,”
not a “total return index,” and therefore does not reflect the dividends paid on the securities composing the Index, which
will reduce the Index Return and may cause the Index to underperform a direct investment in the securities composing the Index. For the
EURO STOXX 50®,
this Index is a euro “price return index” and Index Returns are determined without any exchange rate adjustment.
(2)
This Index is an ETF. Index Values are based on the
ETF’s closing share price. Index performance is calculated on a “price return” basis, not a “total return”
basis, and therefore does not reflect the dividends paid on the securities in which the ETF invests. In addition, an ETF deducts fees
and costs, which reduce Index performance. These factors will reduce the Index Return and may cause the Index to underperform a direct
investment in the ETF or the securities in which the ETF invests.
(3)
May be uncapped for a Term.
The
current limit on Index loss for an Index Option will not change for the life of that Index Option. However, we reserve the right to add
new Index Options, as well as close Index Options to new Purchase Payments and transfers. As such, the limits on Index loss offered under
the Contract may change from one Term to the next if we add an Index Option or discontinue accepting new allocations into an Index Option.
If we offer a new
Index Option with a Buffer or Floor in the future, the Buffer or Floor will be no lower than 5% or -25%, respectively. The lowest Trigger
Rate, Cap, and Participation Rate that we may establish if we add a new Index Option to the Contract are 0.05%, 0.05%, and 5.00%, respectively.
At least one Index
Option with a Buffer no lower than 5% or Floor no lower than -25%, or an Index Option that provides complete protection from Index losses,
will always be available for renewal under the Contract.
The following includes information
about the Fund available under the Contract. More information about the Fund is available in the Fund’s prospectus, which may be
amended from time to time and can be found online at https://www.allianzlife.com/variableoptions. You can also request this information
at no cost by calling (800) 624-0197, or by sending an email request to prospectus.request@allianzlife.com.
The current expenses and performance
information below reflects fees and expenses of the Fund, but do not reflect the other fees and expenses that your Contract may charge.
Expenses would be higher and performance would be lower if these other charges were included. The Fund’s past performance is not
necessarily an indication of future performance.
|
Investment
Objective |
Fund
and
Adviser/Subadviser
|
Current
Expenses
|
Average
Annual Total Returns
(as
of December 31, 2025) | ||
|
1
Year |
5
Years |
10
Years | |||
|
Current
income consistent with
stability
of principal |
AZL®
Government Money
Market
Fund(1)
Adviser:
Allianz
Investment
Management
LLC
Subadviser:
BlackRock
Advisors,
LLC |
0.65%
|
3.70%
|
2.62%
|
1.57%
|
Current
income consistent with
stability
of principal
AZL®
Government Money
Market
Fund
Management
LLC
Advisors,
LLC
The following is a list of Index
Options currently available under the Contract. We may change certain features of the Index Options listed below (including the Index
and the current limits on Index gains), offer new Index Options, and close Index Options to new Purchase Payments and transfers. We will
provide you with written notice before making any changes other than changes to current limits on Index gains. Information about current
limits on Index gains is available at https://www.allianzlife.com/RILAincomeadvrates. During the Income Phase of the Income Benefit, you
may not be able to invest in certain Index Options, as noted below.
Note: If amounts
are removed from an Index Option before the Term End Date, we will apply a Daily Adjustment. Except for Index Options under the Index
Protection Strategy with Trigger and Index Protection Strategy with Cap, this may result in a significant reduction in your Contract Value
that could exceed any protection from Index loss that would be in place if such amounts were not removed from the Index Option until the
Term End Date. The Index Protection Strategy with Trigger and Index Protection Strategy with Cap are unique in that the Daily Adjustment
for them cannot be negative.
|
Index
|
Index
Type |
Crediting
Period
(Term
Length)
|
Index
Crediting
Methodology
|
Current
Limit on
Index
Loss
(if
held until
Term
End Date) |
Minimum
Limit on Index Gain
(for
the life of the Index
Option)
|
|
Index
Protection Strategy with Trigger
• During
the Income Period, this is one of the two Crediting Methods available to you. | |||||
|
S&P
500®
Index(1)
|
U.S.
large-cap equities |
1-year
Term |
Point-to-point
with
step-up |
100%
downside
protection
|
0.50%
minimum Trigger Rate |
|
Russell
2000®
Index(1)
|
U.S.
small-cap equities | ||||
|
Nasdaq-100®
Index(1)
|
U.S.
& international
non-financial
large-cap
equities
| ||||
|
EURO
STOXX 50®(1)
|
Eurozone
large-cap equities | ||||
|
iShares®
MSCI Emerging
Markets
ETF(2)
|
International
emerging
markets
equities | ||||
|
Index
Protection Strategy with Cap
• During
the Income Period, this is one of the two Crediting Methods available to you. | |||||
|
S&P
500®
Index(1)
|
U.S.
large-cap equities |
1-year
Term |
Point-to-point
with
Cap |
100%
downside
protection
|
0.50%
minimum Cap |
|
Russell
2000®
Index(1)
|
U.S.
small-cap equities | ||||
|
Nasdaq-100®
Index(1)
|
U.S.
& international
non-financial
large-cap
equities
| ||||
|
EURO
STOXX 50®(1)
|
Eurozone
large-cap equities | ||||
|
iShares®
MSCI Emerging
Markets
ETF(2)
|
International
emerging
markets
equities | ||||
|
Index
Dual Precision Strategy
• For
Contracts issued before November 14, 2023, the Index Dual Precision Strategy is not available.
• For
Contracts issued from November 14, 2023, to April 30, 2024, only the 1-year Term with 10% Buffer is available.
• For
Contracts issued from May 1, 2024, to November 4, 2024, only the 1-year Term with 10%, 20%, and 30% Buffers are available.
• For
Contracts issued from November 5, 2024, to November 3, 2025, all 1-year Term with 10%, 20%, and 30% Buffers are available. Additionally,
only the
3-year
Term with 10% and 20% Buffers, and 6-year Term with 10% and 20% Buffers are available.
• For
Contracts issued since November 4, 2025, all 1-year, 3-year, and 6-year Term Index Options listed below are available. | |||||
|
S&P
500®
Index(1)
|
U.S.
large-cap equities |
1-year
Term |
Point-to-point
with
step-up |
• 10%
Buffer
• 20%
Buffer
• 30%
Buffer
|
3%
minimum Trigger Rate |
|
Russell
2000®
Index(1)
|
U.S.
small-cap equities | ||||
|
Nasdaq-100®
Index(1)
|
U.S.
& international
non-financial
large-cap
equities
| ||||
|
EURO
STOXX 50®(1)
|
Eurozone
large-cap equities | ||||
|
iShares®
MSCI Emerging
Markets
ETF(2)
|
International
emerging
markets
equities | ||||
|
S&P
500®
Index(1)
|
U.S.
large-cap equities |
3-year
Term |
Point-to-point
with
step-up |
• 10%
Buffer
• 20%
Buffer
• 30%
Buffer
|
4%
minimum Trigger Rate |
|
Russell
2000®
Index(1)
|
U.S.
small-cap equities | ||||
|
S&P
500®
Index(1)
|
U.S.
large-cap equities |
6-year
Term |
Point-to-point
with
step-up |
• 10%
Buffer
• 20%
Buffer
• 30%
Buffer
|
8%
minimum Trigger Rate |
|
Russell
2000®
Index(1)
|
U.S.
small-cap equities | ||||
|
Index
|
Index
Type |
Crediting
Period
(Term
Length)
|
Index
Crediting
Methodology
|
Current
Limit on
Index
Loss
(if
held until
Term
End Date) |
Minimum
Limit on Index Gain
(for
the life of the Index
Option)
|
|
Index
Precision Strategy | |||||
|
S&P
500®
Index(1)
|
U.S.
large-cap equities |
1-year
Term |
Point-to-point
with
step-up |
10%
Buffer
|
3%
minimum Trigger Rate |
|
Russell
2000®
Index(1)
|
U.S.
small-cap equities | ||||
|
Nasdaq-100®
Index(1)
|
U.S.
& international
non-financial
large-cap
equities
| ||||
|
EURO
STOXX 50®(1)
|
Eurozone
large-cap equities | ||||
|
iShares®
MSCI Emerging
Markets
ETF(2)
|
International
emerging
markets
equities | ||||
|
Index
Guard Strategy | |||||
|
S&P
500®
Index(1)
|
U.S.
large-cap equities |
1-year
Term |
Point-to-point
with
Cap |
-10%
Floor
|
3%
minimum Cap |
|
Russell
2000®
Index(1)
|
U.S.
small-cap equities | ||||
|
Nasdaq-100®
Index(1)
|
U.S.
& international
non-financial
large-cap
equities
| ||||
|
EURO
STOXX 50®(1)
|
Eurozone
large-cap equities | ||||
|
iShares®
MSCI Emerging
Markets
ETF(2)
|
International
emerging
markets
equities | ||||
|
Index
Performance Strategy
• For
Contracts issued before November 14, 2023, only the 1-year Term with 10% Buffer, 3-year Term with 10% and 20% Buffers, and 6-year Term
with 10%
Buffer
are available.
• For
Contracts issued from November 14, 2023, to November 3, 2025, only the 1-year Term with 10%, 20%, and 30% Buffers, 3-year Term with 10%
and 20%
Buffers,
and 6-year Term with 10% and 20% Buffers are available.
• For
Contracts issued since November 4, 2025, all 1-year, 3-year, and 6-year Term Index Options listed below are available. | |||||
|
S&P
500®
Index(1)
|
U.S.
large-cap equities |
1-year
Term |
Point-to-point
with
Cap |
• 10%
Buffer
• 20%
Buffer
• 30%
Buffer
|
3%
minimum Cap(3)
|
|
Russell
2000®
Index(1)
|
U.S.
small-cap equities | ||||
|
Nasdaq-100®
Index(1)
|
U.S.
& international
non-financial
large-cap
equities
| ||||
|
EURO
STOXX 50®(1)
|
Eurozone
large-cap equities | ||||
|
iShares®
MSCI Emerging
Markets
ETF(2)
|
International
emerging
markets
equities | ||||
|
S&P
500®
Index(1)
|
U.S.
large-cap equities |
3-year
Term |
Point-to-point
with
Cap and
enhanced
upside
|
• 10%
Buffer
• 20%
Buffer
• 30%
Buffer
|
• 5%
minimum Cap(3)
• 100%
minimum Participation
Rate
|
|
Russell
2000®
Index(1)
|
U.S.
small-cap equities | ||||
|
S&P
500®
Index(1)
|
U.S.
large-cap equities |
6-year
Term |
Point-to-point
with
Cap and
enhanced
upside
|
• 10%
Buffer
• 20%
Buffer
• 30%
Buffer
|
• 10%
minimum Cap(3)
• 100%
minimum Participation
Rate
|
|
Russell
2000®
Index(1)
|
U.S.
small-cap equities | ||||
ITEM 31A. INFORMATION ABOUT CONTRACTS WITH INDEX-LINKED OPTIONS AND FIXED OPTIONS SUBJECT TO A CONTRACT ADJUSTMENT
(a) For the calendar year ended December 31, 2025:
| Name of the Contract | Number of Contracts outstanding | Total value attributable to the Index-Linked Option and/or Fixed Option subject to a Contract Adjustment | Number of Contracts sold during the prior calendar year | Gross premiums received during the prior calendar year | Amount of Contract value redeemed during the prior calendar year | Combination Contract (Yes/No) |
| Allianz Index Advantage Income ADV | 1,848 | $553,291,652 | 981 | $204,189,217 | $24,320 | Yes |
Free
Withdrawal
Privilege
Allows
you to withdraw up to 10% of your total
Annual
Contribution Amounts each Index Year
without
incurring an MVA.
• Only
available during the Accumulation
Phase.
• Not
available during the Income Period.
• Not
available upon a full withdrawal.
• Upon
a full withdrawal, an MVA may apply
against
amounts previously withdrawn under
the
free withdrawal privilege.
• Unused
free withdrawal amounts not
available
in future years.
• Program
withdrawals may be subject to
negative
Daily Adjustments.
• Program
withdrawals are subject to income
taxes,
and may also be subject to a 10%
additional
federal tax for amounts withdrawn
before
age 59 1∕2.
Free
Withdrawal
Privilege
Income
Benefit
Guaranteed
lifetime withdrawal benefit
providing
for yearly Income Payments until the
death
of the Covered Person(s) if conditions
are
satisfied.
We
base the initial Income Payment on the
Lifetime
Income Percentage and Contract
Value.
If you choose the Level Income payment
option
and meet the age requirements stated in
section
11, we guarantee your initial annual
maximum
Income Payment will be at least the
Level
Income Guarantee Payment Percentage
multiplied
by your total Purchase Payments
adjusted
for withdrawals.
The
automatic annual payment increase
feature
may increase payments after the
Income
Benefit Date.
If
you elect Level Income, payments increase if
Contract
Value increases from one Income
Benefit
Anniversary to the next and you took
the
maximum permitted payment during the
prior
Income Benefit Year.
Includes
the Income Multiplier Benefit for no
additional
charge that can increase income to
help
pay for needed care.
Section
11 includes examples of the Lifetime
Income
Percentage Calculation, Excess
Withdrawals,
Income Payment increases, and
the
Income Multiplier Benefit.
• Benefit
cannot be removed from the
Contract.
• See
the Income Benefit Supplement for
current
terms. Please see Appendix F for
historical
information on the terms for
previous
versions of the Income Benefit.
• Benefit
only available during the
Accumulation
Phase.
• Investment
restrictions limit available Index
Options
during Income Period.
• Income
Period cannot begin until after the
waiting
period and reaching age 50. Income
Period
must begin no later than age 100.
• Early
and Excess Withdrawals may
significantly
reduce or end the benefit as
indicated
in section 11.
• A
full Excess Withdrawal and certain
partial
Excess Withdrawals will cause
Income
Payments to stop and the
Contract
and
all of its benefits
to end.
• On
the Income Benefit Date, we execute
Performance
Locks on Index Options for
which
this day is not a Term End Date, and in
such
case the Index Option Value will be
subject
to the Daily Adjustment. We then
reallocate
the total Contract Value, including
amounts
in the Variable Option, into the
Index
Protection Strategy with Trigger and/or
Index
Protection Strategy with Cap Index
Options
according to allocation instructions
you
provide, and begin your Income
Payments.
• Income
Payments are subject to income
taxes,
and may also be subject to a 10%
additional
federal tax for amounts withdrawn
before
age 59 1∕2.
• No
additional Purchase Payments during the
Income
Period.
• No
Income Percentage Increase before age
45.
• Availability
of joint Income Payments is
subject
to age restrictions.
• The
Income Multiplier Benefit is not available
in
all states as indicated in Appendix G.
• Must
establish eligibility to exercise the
Income
Multiplier Benefit (e.g., that you are
confined
for care or unable to perform two
activities
for daily living) and must
re-establish
eligibility each year thereafter.
• Annuitizing
the Contract will end the benefit,
but
you may be able to annuitize your annual
maximum
Income Payment.
• State
variations may apply.
Income
Benefit
11. Income Benefit
The Income Benefit is automatically
included in your Contract at issue. It provides guaranteed lifetime Income Payments based on a percentage of your Contract Value. Such
Income Payments can continue up to the point of annuitization. Once the Income Payment waiting period has expired, Income Payments can
begin as early as age 50 or as late as age 100. When
you begin taking Income Payments, you must elect either the Level Income or Increasing Income payment option.
Unlike Annuity Payments, the Income
Benefit allows access to your Contract Value and death benefit for a period of time after Income Payments begin. However, once Income
Payments begin, only the Index Options with the Index Protection Strategy with Trigger and Index Protection Strategy with Cap
are available to you. If you have Contract Value in any of the Index Options with the Index Dual Precision Strategy, Index Precision
Strategy, Index Guard Strategy, or Index Performance Strategy, you must transfer this Contract Value to the Index Options with the Index
Protection Strategy with Trigger or Index Protection Strategy with Cap when you request Income Payments. The Income Benefit has a rider
fee as discussed in the Fee Tables, and section 7, Expenses and Adjustments. The Income Benefit also includes the Income Multiplier Benefit
for no additional charge, which can increase the annual maximum Income Payment after the required wait period to help pay for care if
you should need it.
|
Unless
otherwise stated, the following description of the Income Benefit applies to both the Level Income and Increasing
Income
payment options. |
How
the Income Benefit Works
We designed Income Payments to last
for the lifetime of the Covered Person(s).
Covered Person(s) are based on the Eligible Person(s) and the Income Payment type you select on the Income Benefit Date. We establish
Eligible Person(s)
at issue based on the Contract’s ownership and tax qualification status.
We generally base Income Payments
on the Lifetime Income Percentage and your Contract Value. However, it is possible in periods of extremely low return that the Level Income
Guarantee Payment Percentage could result in a higher initial Income Payment. In those circumstances, we base Income Payments on total
Purchase Payments adjusted for withdrawals instead of Contract Value. We base each Lifetime Income Percentage on its Income
Percentage(s) and Income
Percentage
Increase (the amount that each Lifetime Income Percentage
can increase on each Index Anniversary up to and including the Income Benefit Date). On the Index Effective Date, we establish:
●
An Income Percentage for each payment type using the Eligible
Person’s current age, or younger Eligible Person’s current age for joint payments. This Income Percentage is also the initial
Lifetime Income Percentage for each payment type.
●
An Income Percentage Increase for each Eligible Person based
on their current age (or younger Eligible Person’s current age for joint payments). However, if there are two Eligible Person(s),
the Index Options Statement will not display a single Lifetime Income Percentage for an Eligible Person who is only a Beneficiary, because
only an Eligible Person who is also an Owner (or Annuitant if the Owner is a non-individual) can become a Covered Person if you select
single payments.
During the Accumulation Phase, on
each Index Anniversary on and before the Income Benefit Date, we add an Income Percentage Increase to each Lifetime Income Percentage
once the Eligible Person (or younger Eligible Person for joint payments) reaches age 45. This
means if an Eligible Person is younger than age 44 on the Issue Date:
●
you will not receive an
increase to a Lifetime Income Percentage based on that Eligible Person until the Index Anniversary that the Eligible Person (or younger
Eligible Person for joint payments) reaches age 45, and
●
you will pay a rider fee
during the period you are not eligible for an Income Percentage Increase.
The table showing the Income Percentages
and Income Percentage Increases is stated in the Income Benefit Supplement. Additional Purchase Payments we receive after the Index Effective
Date will adjust each Lifetime Income Percentage on the next Index Anniversary based on:
●
the Income Percentage for the Eligible Person’s current
age, and
●
the Variable Account Value’s percentage of total Contract
Value, and the percentage of the sum of all Index Option Values to total Contract Value.
If we receive additional Purchase
Payments after the Eligible Person reaches age 45, these Purchase Payments will increase the available Income Payment because they increase
the Contract Value, although they actually decrease each Lifetime Income Percentage. Please see the Lifetime Income Percentage Calculation
Example later in this section.
When you are ready to take Income
Payments, you can choose which Lifetime Income Percentage we use to calculate your payment. You will always be able to choose between
Lifetime Income Percentages for the Level Income and Increasing Income payment options. However, once Income Payments begin you cannot
change your payment option.
Level Income
provides an automatic annual increase to your Income Payments if your Contract Value increases from one Income Benefit Anniversary to
the next. If you choose the Level Income
payment option and meet certain age requirements, your
initial Income Payment will not be less than a percentage (Level
Income Guarantee Payment Percentage) of your total Purchase
Payments reduced proportionately for withdrawals you took (including any MVA). All withdrawals you take reduce your total Purchase Payments,
even MVA-Free Withdrawals. However, we do not reduce your total Purchase Payments for deductions we make for Contract fees, expenses,
and investment advisory fees that you authorize your Financial Professional’s firm to receive from the Contract.
Increasing Income
provides Income Payment increases on each Income Benefit Anniversary during the Income Period if your selected Index Option(s) receives
a positive Performance Credit, or you execute a Performance Lock during the prior Income Benefit Year.
If there are two Eligible Person(s)
who both meet the exercise age requirements, you will also be able to choose between Lifetime Income Percentages for single and joint
payments. If both Eligible Persons are also Owners, you will also be able to choose between single Lifetime Income Percentages based on
each Eligible Person. The Lifetime Income Percentages available before the Income Benefit Date are displayed on the Index Options Statement.
During the Income Period this statement will show the annual maximum Income Payment available for the next year. The annual maximum Income
Payment displayed for the Level Income
payment option will reflect the Level Income Guarantee
Payment Percentage if this calculation results in a greater payment and you meet the age requirements stated under “Calculating
Your Income Payments” later in this section.
There
are restrictions on which Eligible Person can become a Covered Person if you select single Income Payments. Joint Income Payments are
not available if the age difference between spouses is more than 50 years (for more information see section 2, Eligible Person(s) and
Covered Person(s)).
Income Payments
are not available until the Index Anniversary that occurs on or after the Income Payment waiting period (which is stated in the Income
Benefit Supplement) expires and the Eligible Person(s) reaches age 50. Income Payments must begin no later than age 100. If
you do not begin Income Payments during the eligibility period, the Income Benefit ends and you will have paid for the benefit without
receiving any of its advantages. In addition, before the Income Period you are paying for a benefit that you are not currently using.
You choose your Income Payment frequency
and amount subject to the annual maximum permitted payment. The payment option (Level Income or Increasing Income) you select determines
how and when your annual maximum Income Payment will increase from one Income Benefit Anniversary to the next as described in “Automatic
Annual Income Payment Increases” later in this section.
We use Contract
Value to calculate your initial annual maximum Income Payment, and any Income Payment increases under the Level Income payment option.
Negative Index Option performance, withdrawals you take, and deductions we make for Contract fees, expenses, and investment advisory fees
you authorize your Financial Professional’s firm to receive from the Contract decrease the Contract Value, which reduces the initial
annual maximum Income Payment available to you, and the likelihood you will receive Income Payment increases if you select the Level Income
payment option. Once established, the annual maximum Income Payment can only decrease if you take an Excess Withdrawal. A
full Excess Withdrawal and certain partial Excess Withdrawals will cause Income Payments to stop and the Contract and
all of its benefits
to end.
The Income Benefit also includes
the Income Multiplier Benefit which, after the required wait period, can increase your income to help pay for care if you should need
it. If you qualify for this benefit, we multiply your annual maximum Income Payment by the income multiplier factor. The income multiplier
factor and income multiplier benefit wait period are stated in the Income Benefit Supplement. The Income Multiplier Benefit is not available
in all states as indicated in Appendix G.
|
● YOU
SHOULD NOT PURCHASE THIS CONTRACT WITHOUT FIRST OBTAINING THE CURRENT
INCOME
BENEFIT SUPPLEMENT.
We publish any changes to the Income Benefit Supplement at least seven
calendar
days before they take effect on our website at https://www.allianzlife.com/RILAincomeadvrates.
|
|
● Please
discuss the Income Benefit’s appropriateness with your Financial Professional and tax adviser. |
During
the Income Period
●
You will receive Income Payments as long as a Covered Person
is alive and continues to meet the requirements stated in section 2. However, Income
Payments and the Income Benefit may end prematurely if you:
−
change the Owner(s) or Beneficiary and all Covered Persons
are removed from the Contract because they no longer meet the requirements stated in section 2,
−
take an Excess Withdrawal that reduces the Contract Value
to $2,000 or less, or
−
annuitize your Contract. However, we
can convert your Income Payment to Annuity Payments as described in section 9, The Annuity Phase – When Annuity Payments Begin.
●
If you begin Income Payments before age
59 1∕2,
the payments may be subject to a 10% additional federal tax.
●
Any part of your annual maximum Income Payment that you do
not withdraw in a given Income Benefit Year remains in your Contract for the remainder of that year, but is not added to the annual maximum
payment available next year.
●
Excess Withdrawals reduce your annual maximum Income Payment
by the percentage of Contract Value withdrawn (including any MVA) on the next Income Benefit Anniversary.
●
You cannot make additional Purchase Payments. If your Contract
includes the Traditional Death Benefit, your Guaranteed Death Benefit Value no longer increases.
●
The Contract Value continues to fluctuate as a result of
Index Option performance. However, only the Index Protection Strategy with Trigger and Index Protection Strategy with Cap are
available to you. This may limit your Contract’s performance potential, and if your Contract includes the Maximum Anniversary Value
Death Benefit, this may also limit your Guaranteed Death Benefit Value.
●
The Contract Value decreases on a dollar for dollar basis
with each Income Payment, Excess Withdrawal, and deductions we make for Contract fees, expenses, and investment advisory fees that
you authorize your Financial Professional’s firm to receive from the Contract. If your Contract includes the Maximum Anniversary
Value Death Benefit, this decrease in Contract Value also reduces the likelihood of locking in investment gains to the Maximum Anniversary
Value.
●
Each Income Payment and any Excess Withdrawal also reduces
your Guaranteed Death Benefit Value and the Charge Base used to calculate product and rider fees by the percentage of Contract Value withdrawn
(including any MVA),
which means these values may be reduced by more than the amount withdrawn.
●
The Income Benefit rider fee continues until the Business
Day the Contract Value reduces to zero, you annuitize the Contract, or the Income Benefit ends.
●
If your Contract also includes the Maximum Anniversary Value
Death Benefit, its rider fee continues as indicated in section 7, Expenses and Adjustments.
●
The free withdrawal privilege is no longer available.
●
If you exercise the Income Multiplier Benefit, we will increase
your annual maximum Income Payment for the remainder of that Income Benefit Year and the next year. To continue receiving this increase
each Income Benefit Year you must reestablish eligibility. Any
increase to your Income Payments as a result of this benefit will more rapidly reduce your Guaranteed Death Benefit Value.
●
If your Contract Value reduces to zero during the Income
Period for any reason other than an Excess Withdrawal or annuitization that does not convert your Income Payments to Annuity Payments,
you will continue to receive your maximum available Income Payment at the previous selected payment frequency until the earlier of the
death of the Owner or last surviving Covered Person. Further, if
you elected Increasing Income, your annual maximum Income
Payment will continue to change based on Index Option performance, including any Performance Locks you execute. If you exercised the Income
Multiplier Benefit, it will end on the Income Benefit Anniversary that occurs on or immediately after your Contract Value reduces to zero.
This means that you will no longer receive the increased annual maximum Income Payment provided by this Benefit; however, you will continue
to receive the maximum available Income Payment, which will be less than the amount you previously received under the Income Multiplier
Benefit.
●
Income Payments made while
Contract Value is greater than zero are payments made from your own money, and the chance of Contract Value being reduced to zero and
receiving lifetime Income Payments from us may be minimal.
An
example of the effect of an Excess Withdrawal on the Guaranteed Death Benefit Value and the annual maximum Income Payment is included
later in this section.
Requesting
Income Payments
You request Income Payments by completing
a payment election form. We must receive your Income Payment election form in Good Order at our Service Center no later than five Business
Days before the Income Benefit Date. Your Income Benefit Date must be on an Index Anniversary. At least one Eligible Person must remain
in the Contract and be alive on the Income Benefit Date in order for Income Payments to begin. Joint payments are only available if there
are two Eligible Persons on the Income Benefit Date. On the Income Benefit Date, we require updated allocation instructions. If you have
Contract Value in an Index Option and the Income Benefit Date is not also a Term End Date, we will execute a Performance Lock for that
Index Option if it is not locked, and in such case the Index Option Value will be subject to the Daily Adjustment. We then reallocate
the total Contract Value, including any amount in the Variable Option, into the Index Protection Strategy with Trigger and/or Index Protection
Strategy with Cap Index Options according to your allocation instructions, and immediately calculate and begin your Income Payments. If
you have Index Options with different Term End Dates, there may be no Income Benefit Date you can select without application of at least
one Daily Adjustment. For the Index Protection Strategy with Trigger or Index Protection Strategy with Cap Index Options, we will execute
this Performance Lock even if the Daily Adjustment is zero.
We will send you a notice letter
at least 30 days before:
●
the Index Anniversary that Income Payments can begin once
the Eligible Person(s) reaches age 50,
●
the last Index Anniversary that joint Income Payments will
be available because the older Eligible Person is reaching age 100 if there are two Eligible Persons, and
●
the last Index Anniversary that Income Payments will be available
because the younger Eligible Person is reaching age 100.
|
● If
Income Payments do not begin by the Index Anniversary upon which the younger Eligible Person reaches
age
100, the Income Benefit ends. |
|
● If
the Income Benefit ends before Income Payments begin, you will have paid for the benefit without receiving
any
of its advantages. |
Calculating
Your Income Payments
The annual maximum Income Payment
is the amount you are entitled to receive each Income Benefit Year. On the Income Benefit Date, if
you select the Level Income payment option and all Covered Persons are age 80 or younger (and were age 75 or younger on the Issue Date)
your initial annual maximum Income Payment is the greater of the following:
●
The Level Income Guarantee Payment Percentage based on the
Covered Person’s current age (or the younger Covered Person’s current age for joint payments) multiplied by total Purchase
Payments reduced for withdrawals you took. Withdrawals reduce total Purchase Payments by the percentage of Contract Value withdrawn (including
any MVA), determined at the end of each Business Day. All
withdrawals you take reduce your total Purchase Payments, even MVA-Free Withdrawals. However, we do not reduce your total Purchase Payments
for deductions we make for Contract fees, expenses, and investment advisory fees that you authorize your Financial Professional’s
firm to receive from the Contract.
●
The Lifetime Income Percentage for the payment type you select
multiplied by the Contract Value determined at the end of the Business Day after we deduct the product fee, rider fee, and contract maintenance
charge and apply any Performance Credits, but before we make any Income Payments or Excess Withdrawals, or we deduct any investment advisory
fees that you authorize your Financial Professional’s firm to receive from the Contract.
If the Covered Persons do not meet
these age requirements (age 80 or younger on the Income Benefit Date, and age 75 or younger on the Issue Date), or
if you select the Increasing Income payment option, we
instead calculate your initial annual maximum Income Payment as stated in the second bullet above (the Lifetime Income Percentage for
the payment type you select multiplied by the Contract Value determined at the end of the Business Day after we deduct the product fee,
rider fee, and contract maintenance charge and apply any Performance Credits, but before we make any Income Payments or deduct Excess
Withdrawals).
|
● If
you have Contract Value in an Index Option for which the Income Benefit Date is not a Term End Date, we
will
execute a Performance Lock for that Index Option if it is not locked and then immediately calculate and
begin
your Income Payments, and in such case the Index Option Value will be subject to the Daily Adjustment.
If
you have Index Options with different Term End Dates, there may be no Income Benefit Date you can select
without
application of at least one Daily Adjustment. This
means you may not receive the full benefit of the
Performance
Credit that you would have received if you had waited until the Term End Date to begin Income
Payments.
|
|
● We
use Contract Value to calculate your initial annual maximum Income Payment, and Income Payment increases
under
the Level Income payment option. Negative Index Option performance, withdrawals you take, and deductions
we
make for Contract fees, expenses, and investment advisory fees that you authorize your Financial Professional’s
firm
to receive from the Contract decrease the Contract Value, which reduces the initial annual maximum Income
Payment
available to you. Negative Index Returns and Performance Credits of zero also reduce the likelihood you
will
receive Income Payment increases. |
Level
Income Guarantee Payment Percentage Table
|
Covered
Person’s age
(or
younger Covered Person’s age for
joint
payments)
on
the Income Benefit Date |
Level
Income Guarantee
Payment
Percentage |
|
50
|
2.23
% |
|
51
|
2.28
% |
|
52
|
2.33
% |
|
53
|
2.39
% |
|
54
|
2.44
% |
|
55
|
2.50
% |
|
56
|
2.57
% |
|
57
|
2.64
% |
|
58
|
2.71
% |
|
59
|
2.78
% |
|
60
|
2.86
% |
|
61
|
2.95
% |
|
62
|
3.04
% |
|
63
|
3.13
% |
|
64
|
3.23
% |
|
65
|
3.34
% |
|
66
|
3.45
% |
|
67
|
3.58
% |
|
68
|
3.71
% |
|
69
|
3.85
% |
|
70
|
4.00
% |
|
71
|
4.17
% |
|
72
|
4.35
% |
|
73
|
4.55
% |
|
74
|
4.77
% |
|
75
|
5.00
% |
|
76
|
5.27
% |
|
77
|
5.56
% |
|
78
|
5.89
% |
|
79
|
6.25
% |
|
80
|
6.67
% |
On the Income Benefit
Date, if your initial annual maximum Income Payment is less than $100, the Income Benefit ends and you will have paid for the benefit
without receiving any of its advantages. For example, assuming
a 4% Lifetime Income Percentage and Contract Value less than $2,500, this would result in an initial annual maximum Income Payment of
less than $100.
You can receive Income Payments monthly,
quarterly, semi-annually, or annually. If the scheduled payment date does not fall on a Business Day, we make the payment on the next
Business Day.
You can change your payment frequency
once each Income Benefit Year while your Contract Value is positive. We must receive your request to change your Income Payment frequency
in Good Order at our Service Center no later than five Business Days before the Income Benefit Anniversary. If the change is available,
we implement it on the Income Benefit Anniversary and it remains in effect until the benefit ends or you request another change. We do
not accept payment frequency changes that would cause us to make payments of $0.01 to $99.99.
The annual maximum Income Payment
is the amount you are entitled to, but you can choose to take less. The annual actual Income Payment is the total amount you choose to
receive each year. Each scheduled Income Payment you receive is equal to the annual actual Income Payment divided by the number of payments
you chose to receive during the Income Benefit Year. Each scheduled Income Payment must either be zero, or $100 or more. For example,
you cannot request a scheduled payment of $50.
Any part of your annual maximum payment
that you do not withdraw in a given Income Benefit Year is not added to the annual maximum payment available next year. However, if your
actual Income Payment is less than your annual maximum payment, you can withdraw the difference and we consider that withdrawal to be
an additional actual Income Payment, and
not an Excess
Withdrawal and not subject to an MVA. We do not consider a withdrawal to be an Excess Withdrawal until you have withdrawn the available
annual maximum Income Payment amount. In addition, once we have paid out your annual maximum Income Payment we will not make any
further scheduled Income Payments for the rest of the Income Benefit Year. For example, assume your annual maximum Income Payment
is $2,000 and you take scheduled semi-annual Income Payments of $500. Within an Income Benefit Year, you can take an additional withdrawal
of up to $1,000 and we consider that to be an additional scheduled Income Payment. If instead you withdraw $1,200 after receiving the
first $500 payment, we consider that withdrawal to be an additional scheduled Income Payment. On the date of the next scheduled Income
Payment we will send you only $300 because that is the amount remaining from your $2,000 annual maximum. If you then took an additional
withdrawal of $200 in that Income Benefit Year, we consider that $200 to be an Excess Withdrawal subject to an MVA.
If you would like to take less than
the maximum available payment, you can change your payment amount once each Income Benefit Year while your Contract Value is positive.
We must receive your request to change your Income Payment amount in Good Order at our Service Center no later than five Business Days
before the Income Benefit Anniversary. If the change is available, we implement it on the Income Benefit Anniversary and it remains in
effect until the Income Benefit ends or you request another change.
If, on a Business Day that we are
deducting an Income Payment, your Contract Value is less than the payment amount, we will add the difference between these amounts to
your Contract Value and then deduct the Income Payment which will reduce your Contract Value to zero. If your Contract Value reduces to
zero during the Income Period for any reason other than an Excess Withdrawal or annuitization that does not convert your Income Payments
to Annuity Payments, you will continue to receive your maximum available Income Payment at the previous selected payment frequency until
the earlier of the death of the Owner or last surviving Covered Person. If
you select Increasing Income, you can continue to receive
payment increases based on Index Option performance. However, if
you select Level Income, your Income Payments will no longer
increase.
We deduct each Income Payment, Excess
Withdrawal, and any additional payment resulting from a required minimum distribution, proportionately from the Index Options to which
you are allocated. While the Contract Value is positive, you can make transfers between the Index Options and execute Performance Locks
and Early Reallocations. If you select
Increasing Income, once the Contract Value reduces to zero,
you can continue to change your Index Option allocations and execute Performance Locks and Early Reallocations as long as the Income Benefit
is in effect. With Increasing Income, we base changes to your annual maximum Income Payment on the proportion of Contract Value in
each Index Option at the end of the last Business Day that your Contract Value is positive. However, you can change the proportion of
each Index Option that we use to calculate these changes after the Contract Value is equal to zero by providing an authorized request
to our Service Center.
|
● For
Qualified Contracts: If we calculate
a required minimum distribution (RMD) based on this Contract, after
making
all Income Payments for the calendar year we determine whether this calendar year’s total RMD has been
satisfied
by these payments and any Excess Withdrawals. If the RMD amount for this Contract has not been satisfied,
we
send you this remaining amount as one RMD payment by the end of the calendar year. We consider this payment
to
be a withdrawal, but it is not an Excess Withdrawal and it is not subject to an MVA. |
|
● For
annuitization: If on the Annuity Date
you are receiving Income Payments and your Contract Value is positive,
we
will convert your Income Payments to Annuity Payments if you take Annuity Payments under Annuity Option B
or
F. If you select any other Annuity Option, we will not convert your Income Payments to Annuity Payments. This
means
that if you annuitize your Contract you may receive less as Annuity Payments than you would have
received
as Income Payments. For more information,
see section 9, The Annuity Phase – When Annuity Payments
Begin.
|
Lifetime
Income Percentage Calculation Example
Assume you are the sole Owner, you
are not married, and your initial Purchase Payment is $20,000. You only select 1-year Term Index Options. You are not married, so you
are also the only Eligible Person. The Income Payment waiting period is three Index Years. On the Index Effective Date you are age 54,
your Income Percentage Increase is 0.25%, and your initial Lifetime Income Percentages are equal to the Income Percentages for single
payments, which are 4.20% for Level Income, and 3.20% for Increasing Income. You take no withdrawals before requesting Income Payments.
On the first
Index Anniversary, we apply your first Income Percentage Increase. Your new Lifetime Income Percentages for single payments are 4.45%
(4.20% + 0.25%) if you elect Level Income and 3.45% (3.20% + 0.25%) if you elect Increasing Income.
Assume you make an additional Purchase
Payment of $2,000 in the fourth Index Year. On the fourth Index Anniversary:
●
you are age 58 and the Income Percentages are 4.60% for Level
Income, and 3.60% for Increasing Income,
●
the Variable Account Value for the additional Purchase Payment
is now $2,002.50, and
●
the Contract Value after application of the additional Purchase
Payment, Performance Credits and before
deducting all Contract fees and expenses is $25,000.
We calculate your new Lifetime Income
Percentages for single payments on the fourth Index Anniversary as follows.
●
Lifetime Income Percentages for the initial Purchase Payment
are now 5.20% (4.20% + (0.25% x 4)) if you elect Level Income and 4.20% (3.20% + (0.25% x 4)) if you elect Increasing Income.
●
Lifetime Income Percentages for the additional Purchase Payment
are 4.60% for Level Income and 3.60% for Increasing Income.
●
The Variable Account Value’s percentage of total Contract
Value is 8.01% ($2,002.50 ÷ $25,000), which means the initial Purchase Payment is 91.99% of total Contract Value (100% - 8.01%).
The final Lifetime Income Percentages
on the fourth Index Anniversary are then:
−
if you elect Level Income: (5.20% x 91.99%) + (4.60% x 8.01%)
= 4.78% + 0.37% = 5.15%
−
if you elect Increasing Income: (4.20% x 91.99%) + (3.60%
x 8.01%) = 3.86% + 0.29% = 4.15%
If you begin Income Payments on the
fourth Index Anniversary, we calculate the annual maximum Income Payment as follows.
|
If
you select Level Income, you receive the greater of…. |
If
you select Increasing Income, you receive… |
|
• Level
Income Guarantee Payment Percentage multiplied by
total
Purchase Payments reduced proportionately for
withdrawals
you took, or: (2.71% x $22,000) = $596.20
• Lifetime
Income Percentage multiplied by the Contract Value,
or:
(5.15% x $25,000) = $1,287.50
|
• Lifetime
Income Percentage multiplied by the Contract Value,
or:
(4.15% x $25,000) = $1,037.50
|
If you select Level
Income, we apply the Level Income Guarantee Payment Percentage
in this calculation because you were 75 or younger when you purchased the Contract and are age 80 or younger on the Income Benefit Date.
On the Income Benefit Date, your Level Income Guarantee Payment Percentage based on your current age of 58 is 2.71%, and your total Purchase
Payments reduced proportionately for withdrawals is $22,000 (your $20,000 initial payment plus the $2,000 we received in the fourth Index
Year). The annual maximum Income Payment calculation and Level Income Guarantee Payment Percentage are discussed in “Calculating
Your Income Payments” next in this section.
If you had not made the additional
Purchase Payment your Lifetime Income Percentages would have been higher (5.20% compared to 5.15% for Level Income, and 4.20% compared
to 4.15% for Increasing Income), but the available annual maximum Income Payment would be lower because the Contract Value would not include
the increase from the additional Purchase Payment. If you had not made the additional Purchase in the fourth Index Year, your Contract
Value would have been $22,997.50 ($25,000 - $2,002.50) and we calculate your annual maximum Income Payment as follows.
|
If
you select Level Income, you receive the greater of…. |
If
you select Increasing Income, you receive… |
|
• Level
Income Guarantee Payment Percentage multiplied by
total
Purchase Payments reduced proportionately for
withdrawals
you took, or: (2.71% x $20,000) = $542.00
• Lifetime
Income Percentage multiplied by the Contract Value,
or:
(5.20% x $22,997.50) = $1,195.87
|
• Lifetime
Income Percentage multiplied by the Contract Value,
or:
(4.20% x $22,997.50) = $965.90
|
Example of when the
Level Income Guarantee Payment Percentage may increase the initial Income Payment
Assume you are the sole Owner, you
are not married, and your initial Purchase Payment is $100,000. You are age 65 on the Index Effective Date and your initial Income Percentage
under Level Income is 5.70% with a 0.40% Income Percentage Increase. You take no withdrawals before requesting Income Payments. You begin
Income Payments on the
fifth Index Anniversary
and select the Level Income payment option.
On the Income Benefit Date you are age 70, your Lifetime Income Percentage is 7.70% and your Level Income Guarantee Payment Percentage
is 4.00%.
|
When
it increases
the initial Income Payment |
When
it does not
increase the initial Income Payment |
|
• Assume
your Contract Value decreases to $50,000 due to
negative
performance. You would receive the greater of:
– Level
Income Guarantee Payment Percentage multiplied
by
total Purchase Payments reduced proportionately for
withdrawals
you took, or: (4.00% x $100,000) = $4,000.00
– Lifetime
Income Percentage multiplied by the Contract
Value,
or: (7.70% x $50,000) = $3,850.00 |
• Assume
your Contract Value decreases to $70,000 due to
negative
performance. You would receive the greater of:
– Level
Income Guarantee Payment Percentage multiplied
by
total Purchase Payments reduced proportionately for
withdrawals
you took, or: (4.00% x $100,000) = $4,000.00
– Lifetime
Income Percentage multiplied by the Contract
Value,
or: (7.70% x $70,000) = $5,390.00
|
Please
note that these examples may differ from your actual results due to rounding.
Excess
Withdrawals
Excess Withdrawals do not include
RMD payments, or deductions we make for Contract fees, expenses, or investment advisory fees you authorize your Financial Professional’s
firm to receive from the Contract. Excess Withdrawals are subject to an MVA. Any partial Excess Withdrawal must be for at least $100,
and, after the partial Excess Withdrawal, the Contract Value must be at least $2,000. If the Contract Value is less than $2,000, you cannot
request a partial Excess Withdrawal, but you can take a full Excess Withdrawal. If a partial Excess Withdrawal reduces the Contract Value
to less than $2,000, we require you to take a full Excess Withdrawal. A
full Excess Withdrawal will cause Income Payments to stop and the Contract and
all of its benefits
to end. We will not provide a warning before you take an Excess Withdrawal, and there will be no opportunity to undo an Excess Withdrawal.
Excess Withdrawals reduce your annual
maximum Income Payment on the next Income Benefit Anniversary after the withdrawal. For each Excess Withdrawal, we reduce your annual
maximum payment by the same percentage that we reduced the Contract Value. If
partial Excess Withdrawals reduce your annual maximum Income Payment to less than $100, we send you the Cash Value, which
will cause Income Payments to stop and the Contract to end.
Excess Withdrawal
Example
These calculations show the effects
of an Excess Withdrawal on the Contract Value, Cash Value, available Guaranteed Death Benefit Value, and Income Payments. Partial Excess
Withdrawals (including any MVA, but not deductions we make for Contract fees, expenses, or investment advisory fees you authorize your
Financial Professional’s firm to receive from the Contract) immediately reduce the Contract Value and Cash Value on a dollar for
dollar basis, and reduce the Guaranteed Death Benefit Value by the percentage of Contract Value withdrawn. Partial Excess Withdrawals
also reduce the annual maximum Income Payment by the percentage of Contract Value withdrawn on the next Income Benefit Anniversary. (The
impact of withdrawals, including Excess Withdrawals, on the Charge Base is included in Appendix D - Annual Contract Fees Calculation Examples.)
The example assumes you do not authorize
your Financial Professional’s firm to receive investment advisory fees deducted from your Contract, and instead take a $1,500 Excess
Withdrawal and use that money to pay investment advisory fees to your Financial Professional when the Contract Value is $100,000, the
Cash Value is $97,000, and the Guaranteed Death Benefit Value under the Traditional Death Benefit is $90,000, or $105,000 under the Maximum
Anniversary Value Death Benefit. It also assumes the $1,500 Excess Withdrawal is subject to an MVA of -$100. Cash Value reflects the MVA
we apply on a full withdrawal. Therefore the Cash Value in this example is only reduced for the $1,500 Excess Withdrawal
because the -$100
MVA is already reflected in the $97,000 Cash Value. All fractional numbers in these examples have been rounded up to the next whole number.
|
Excess
Withdrawal
|
Contract
Value
|
Cash
Value
|
Guaranteed
Death Benefit
Value
for a Contract with the
Traditional
Death Benefit |
Guaranteed
Death Benefit Value
for
a Contract with the
Maximum
Anniversary Value
Death
Benefit |
Next
anniversary’s
annual
maximum
Income
Payment |
|
Prior
to withdrawal |
$
100,000 |
$
97,000 |
$
90,000 |
$
105,000 |
$
4,800 |
|
$1,500
withdrawal
|
–
$1,500 |
–
$1,500 |
–
[($1,500 ÷ 100,000) |
–
[($1,500 ÷ 100,000) |
–
[($1,500 ÷ 100,000) |
|
|
|
|
x
90,000)] = - $1,350 |
x
105,000)] = - $1,575 |
x
4,800)] = - $72 |
|
-$100
MVA |
–
$100 |
|
–
[($100 ÷ 100,000) |
–
[($100 ÷ 100,000) |
–
[($100 ÷ 100,000) |
|
|
|
|
x
90,000)] = - $90 |
x
105,000)] = - $105 |
x
4,800)] = - $5 |
|
|
–
$1,600 |
–
$1,500 |
=
- $1,440 |
=
- $1,680 |
=
- $77 |
|
|
|
|
|
|
|
|
After
withdrawal |
$
98,400 |
$
95,500 |
$
88,560 |
$
103,320 |
$
4,723 |
The death benefit is the greatest
of the Contract Value, Cash Value, or the Guaranteed Death Benefit Value. After the withdrawal and MVA, the death benefit would either
be the $98,400 Contract Value under the Traditional Death Benefit (because it is greater than the Guaranteed Death Benefit Value of $88,560),
or the $103,320 Guaranteed Death Benefit Value under the Maximum Anniversary Value Death Benefit.
Automatic
Annual Income Payment Increases
If you select Level
Income, the annual maximum Income Payment can only decrease
if you take an Excess Withdrawal. However, if you took the maximum permitted payment during the prior Income Benefit Year, we increase
your annual maximum Income Payment if your Contract Value increases from one Income Benefit Anniversary (or the Income Benefit Date if
this is the first Income Benefit Anniversary) to the next. This increase is equal to the percentage of growth between these two Contract
Values. For example, if the Contract Value increased by 1.5%, we also increase your annual maximum Income Payment by 1.5%.
When calculating this payment increase,
we use the Contract Value determined at the end of the Business Day after we apply any Performance Credits (or Daily Adjustment if the
Index Anniversary is not a Term End Date) and we deduct Contract fees, expenses, and investment advisory fees that you authorize
your Financial Professional’s firm to receive from the Contract, but before we make any Income Payments or deduct Excess Withdrawals
taken on this Index Anniversary. If the Income Benefit Date or an Income Benefit Anniversary does not occur on a Business Day, we use
Contract Values from the next Business Day.
Lifetime Income Percentages on the
Income Benefit Date generally will be higher with Level Income, as compared with Increasing Income. However, subsequent payment increases
are less likely with Level Income, as compared with Increasing Income, especially in later Income Benefit Years. This is because only
the Index Protection Strategy with Trigger and Index Protection Strategy with Cap are available once Income Payments are selected, and
those two Crediting Methods may have lower return potential compared to other Crediting Methods. If Index Option performance is less than
the total withdrawals, including Income Payments, Excess Withdrawals and deductions we make for Contract fees, expenses, and investment
advisory fees that you authorize your Financial Professional’s firm to receive from the Contract, taken in an Index Year,
there will be no increase in the annual maximum Income Payment for the Index Year under Level Income.
For example, if you took the maximum
permitted payment during the prior Income Benefit Year and you receive Performance Credits of 2.5% on an Index Anniversary, but the deductions
for Income Payments and Excess Withdrawals taken during the prior Index Year, and deductions we make for Contract fees, expenses, and
investment advisory fees that you authorize your Financial Professional’s firm to receive from the Contract both in the prior
Index Year and on the current Index Anniversary reduce your Contract Value by -6.8% you will not receive a payment increase under Level
Income.
|
If
we increase the Contract Value to equal the death benefit due to a spousal continuation of the Contract during the last
Income
Benefit Year, we also subtract the amount of this increase from the Contract Value on the next Income Benefit
Anniversary
when determining annual payment increases under the Level Income payment option. |
If
you select Increasing Income, the available annual maximum
Income Payments will increase on each Income Benefit Anniversary if your selected Index Option(s) receives a Performance Credit, or if
you executed a Performance Lock on an increased Index Option Value at any time during the prior Income Benefit Year. Any Index Options
that did not receive a Performance Credit and were not locked during the prior Income Benefit Year will not affect the annual maximum
Income Payment on the current Income Benefit Anniversary.
●
If you select multiple Index Options, we take the weighted
average of all Performance Credits, and locked increased Index Option Values based on the percentage of total Index Option Base in each
of your selected Index Options to determine your payment increase as indicated in the example below. When calculating this payment increase,
we use the Index Option Base determined at the end of the Business Day before
we apply any daily transactions (increases for Performance Credits or Daily Adjustments; deductions for Income Payments, Excess Withdrawals,
Contract fees and expenses, or investment advisory fees that you authorize your Financial Professional’s firm to receive from the
Contract; or processing any Early Reallocations or transfers).
−
For Index Options where a Performance Lock was not
executed during the prior Income Benefit Year we use the percentage of total Index Option Base in each of these Index Options on the Income
Benefit Anniversary. If the Income Benefit Anniversary does not occur on a Business Day, we use the Index Option Base from the next Business
Day.
−
For Index Options where a Performance Lock was
executed during the prior Income Benefit Year we use the percentage of Index Option Base in each of these Index Options on the Business
Day the Index Option is reallocated or transferred.
Payment increases can continue even
if your Contract Value reduces to zero, or if you convert Income Payments to Annuity Payments as described in section 9, The Annuity Phase
– When Annuity Payments Begin.
●
If you selected multiple Index Options, we take the weighted
average of all Performance Credits, and locked Daily Adjustments using the percentage of Contract Value in each Index Option either at
the end of the prior Business Day before your Contract Value reduced to zero, or at the end of the Business Day on the Annuity Date if
you convert Income Payments to Annuity Payments.
●
We determine this Contract Value after
we apply any Daily Adjustments (if this day is not
a Term End Date) or Performance Credits (if this day is
a Term End Date), and after
we deduct any Income Payment, Excess Withdrawal, Contract fees and expenses, or investment advisory fees that you authorize your Financial
Professional’s firm to receive from the Contract.
●
You can change the proportions that we use to calculate this
weighted average by submitting an authorized request to our Service Center.
Example of Increasing
Income Payment Increases
Assume your Contract Value is $100,000
and you allocate 20% to the Index Protection Strategy with Trigger using the S&P 500®
Index and 80% to the Index Protection Strategy with the Cap using the EURO STOXX 50®
on the Income Benefit Date.
On the first Income Benefit Anniversary,
the Index Protection Strategy with Trigger Index Option receives a 3.5% Performance Credit and the Index Protection Strategy with the
Cap Index Option receives a 4.2% Performance Credit. On this anniversary, before we apply daily transactions, 20% of your total Index
Option Base is in the Index Protection Strategy with Trigger Index Option, and 80% of your total Index Option Base is in Index Protection
Strategy with the Cap Index Option.
Your annual maximum Income Payment
on the first Income Benefit Anniversary will increase by 4.06% ((3.5% x 20%) + (4.2% x 80%)).
Please see Appendix E for an example
of how we calculate an automatic Income Payment increase if you execute a Performance Lock and Early Reallocation.
Income
Multiplier Benefit
The Income Multiplier Benefit can
increase the annual maximum Income Payment if you:
●
begin confinement after the first Contract Anniversary in
an eligible facility (a hospital, nursing facility, or assisted living facility) for at least 90 days in a 120-day period, or
●
are unable to perform at least two of six activities of daily
living (ADLs) for at least 90 consecutive days. ADLs include bathing, dressing, toileting, continence, eating, and transferring (moving
into or out of a bed, chair, or wheelchair).
We must receive
proof of your staying in an eligible facility or ADL eligibility before we multiply your annual maximum Income Payment by the income multiplier
factor stated in the Income Benefit Supplement. For ADL eligibility we may require, at our expense, an examination or tests by a physician
of our choice. To continue receiving this increase each Income Benefit Year, you must reestablish eligibility.
The Income Multiplier Benefit is
not available before the Income Benefit Date, or before expiration of the income multiplier benefit wait period stated in the Income Benefit
Supplement. In addition, a Covered Person cannot establish eligibility for this benefit more than one Index Year before the Income Benefit
Date. Increased Income Payments based on staying in an eligible facility are not available before the first Contract Anniversary. To qualify
for a payment increase based on performance of ADLs, a Covered Person must have been able to perform each of these six ADLs without substantial
assistance on the Issue Date. If you chose to take less than the annual maximum Income Payment and then qualify for a payment increase
under the Income Multiplier Benefit, we will increase your Income Payments to the available annual maximum before applying the payment
increase.
Example
Assume you elect to receive the maximum
available payment under the Level Income
payment option, your annual maximum Income Payment is $10,000,
the income multiplier factor is 2, and the income multiplier benefit wait period is five Contract Years. After the fifth Contract Anniversary
you suffer an illness and can’t perform two of the six ADLs. At the time of your illness, your annual maximum Income Payment is
still $10,000 and your Contract Value is positive. After we confirm your benefit eligibility with your physician, we increase your annual
maximum Income Payment as follows:
(income multiplier factor) x (annual
maximum Income Payment) = 2 x $10,000 = $20,000
This increase will allow you to receive
up to $20,000 as an Income Payment for this Income Benefit Year, and the next Income Benefit Year. However, in the next Income Benefit
Year your health improves and you are not able to reestablish benefit eligibility for the following Income Benefit Year. So on the second
Income Benefit Anniversary after we increased your payment, we decrease your annual maximum Income Payment as follows:
(annual maximum Income Payment) ÷
(income multiplier factor) = $20,000 ÷ 2 = $10,000
When
the Income Multiplier Benefit Ends
The Income Multiplier
Benefit ends on the earliest of the following.
●
The Annuity Date.
●
The Income Benefit Anniversary that occurs on or immediately
after the date the Contract Value is reduced to zero.
●
The Business Day the Income Benefit ends.
●
The Business Day the Contract ends.
Taxation
of Income Payments
We treat Income Payments as withdrawals
for tax purposes while your Contract Value is positive, and once your Contract Value is reduced to zero we intend to treat Income Payments
as Annuity Payments for tax purposes. For more information, see section 13, Taxes – Taxation of Income Payments.
When
the Income Period Ends
The Income Period ends on the earlier
of the last Business Day before the Annuity Date, or the date the Income Benefit ends. Income Payments can continue for the life of the
Covered Person(s) if you do not take more than your allowed annual maximum payment.
When
the Income Benefit Ends
The Income Benefit
ends on the earliest of the following.
●
The Business Day all Eligible Persons or Covered Persons
are removed from the Contract because they no longer meet the requirements (Owner, Annuitant or sole Beneficiary) stated in section 2.
If this occurs after the Income Benefit Date, Income Payments stop when the last Covered Person is removed from the Contract.
●
The Index Anniversary upon which the younger Eligible Person
reaches age 100 if it occurs before the Income Benefit Date.
●
The Business Day we process your request for a full withdrawal,
other than a full withdrawal caused by an Income Payment.
●
The Income Benefit Date or an Income Benefit Anniversary
if the annual maximum Income Payment is less than $100.
●
Upon the death of an Owner (or Annuitant if the Owner is
a non-individual), the end of the Business Day we first receive a Valid Claim from any one Beneficiary. However, if a federally recognized
spouse is an Eligible Person or Covered Person and continues this Contract, the Income Benefit also continues.
●
During the Accumulation Phase and before the Income Benefit
Date, the Income Benefit ends on the date of death of the last surviving Eligible Person.
●
During the Income Period, the Income Benefit ends on the
date of death of the last surviving Covered Person.
●
The Business Day the Contract ends.
|
If
we receive notice of death of a Covered Person during the Income Period, we will suspend Income Payments and the
Income
Benefit will end as described above. However, if a federally recognized spouse who is also a joint Covered
Person
continues this Contract, we will resume Income Payments and add any Income Payments that we would have
paid
between the time we suspended Income Payments and when they resume future Income Payments. |
Calculating
Your Income Payments
The annual maximum Income Payment
is the amount you are entitled to receive each Income Benefit Year. On the Income Benefit Date, if
you select the Level Income payment option and all Covered Persons are age 80 or younger (and were age 75 or younger on the Issue Date)
your initial annual maximum Income Payment is the greater of the following:
●
The Level Income Guarantee Payment Percentage based on the
Covered Person’s current age (or the younger Covered Person’s current age for joint payments) multiplied by total Purchase
Payments reduced for withdrawals you took. Withdrawals reduce total Purchase Payments by the percentage of Contract Value withdrawn (including
any MVA), determined at the end of each Business Day. All
withdrawals you take reduce your total Purchase Payments, even MVA-Free Withdrawals. However, we do not reduce your total Purchase Payments
for deductions we make for Contract fees, expenses, and investment advisory fees that you authorize your Financial Professional’s
firm to receive from the Contract.
●
The Lifetime Income Percentage for the payment type you select
multiplied by the Contract Value determined at the end of the Business Day after we deduct the product fee, rider fee, and contract maintenance
charge and apply any Performance Credits, but before we make any Income Payments or Excess Withdrawals, or we deduct any investment advisory
fees that you authorize your Financial Professional’s firm to receive from the Contract.
If the Covered Persons do not meet
these age requirements (age 80 or younger on the Income Benefit Date, and age 75 or younger on the Issue Date), or
if you select the Increasing Income payment option, we
instead calculate your initial annual maximum Income Payment as stated in the second bullet above (the Lifetime Income Percentage for
the payment type you select multiplied by the Contract Value determined at the end of the Business Day after we deduct the product fee,
rider fee, and contract maintenance charge and apply any Performance Credits, but before we make any Income Payments or deduct Excess
Withdrawals).
|
● If
you have Contract Value in an Index Option for which the Income Benefit Date is not a Term End Date, we
will
execute a Performance Lock for that Index Option if it is not locked and then immediately calculate and
begin
your Income Payments, and in such case the Index Option Value will be subject to the Daily Adjustment.
If
you have Index Options with different Term End Dates, there may be no Income Benefit Date you can select
without
application of at least one Daily Adjustment. This
means you may not receive the full benefit of the
Performance
Credit that you would have received if you had waited until the Term End Date to begin Income
Payments.
|
|
● We
use Contract Value to calculate your initial annual maximum Income Payment, and Income Payment increases
under
the Level Income payment option. Negative Index Option performance, withdrawals you take, and deductions
we
make for Contract fees, expenses, and investment advisory fees that you authorize your Financial Professional’s
firm
to receive from the Contract decrease the Contract Value, which reduces the initial annual maximum Income
Payment
available to you. Negative Index Returns and Performance Credits of zero also reduce the likelihood you
will
receive Income Payment increases. |
Investment
Advisory
Fees
We
designed the Contract for persons who are
receiving
ongoing investment advice from a
Financial
Professional. You can instruct us to
automatically
withdraw investment advisory
fees
from your Contract to pay your Financial
Professional’s
firm.
• Only
available during the Accumulation
Phase.
• Investment
advisory fees are in addition to
the
Contract’s fees and expenses.
• Program
withdrawals may be subject to
negative
Daily Adjustments.
• If
you and your Financial Professional do not
agree
to our requirements we will not pay
investment
advisory fees from this Contract
to
your Financial Professional’s firm.
• Our
requirements limit investment advisory
fee
withdrawals to 1.5% of Contract Value
each
Contract Year, require the fees to be
solely
for advisory services provided with
respect
to the Contract, and require the
Contract
to be the sole source of payment.
• Deductions
we make for investment advisory
fees
reduce your Contract Value (and
therefore
Cash Value) dollar for dollar by the
amount
withdrawn. This Contract Value
reduction
also decreases your initial annual
maximum
Income Payment which is based
on
Contract Value. As Contract Value is one
of
the components we use to calculate RMD
payments,
these deductions may also reduce
your
RMD payments. These deductions also
reduce
the following proportionately by the
percentage
of Contract Value withdrawn:
Charge
Base, Index Option Base, Index
Option
Value, and Variable Account Value.
For
more information regarding the impact of
paying
advisory fees with money in the
Contract,
including an example of how
deduction
of investment advisory fees
impacts
the Contract, see section 1, The
Contract
– Investment Advisory Fees.
Investment
Advisory
Fees
Maximum
Anniversary
Value
Death
Benefit
Provides
a death benefit equal to the greatest of
the
Contract Value, Cash Value, or Guaranteed
Death
Benefit Value. The Guaranteed Death
Benefit
Value is the Maximum Anniversary Value.
An
example of the death benefit provided by the
Maximum
Anniversary Value Death Benefit, and
calculation
of the Maximum Anniversary Value is
included
in section 12, Death Benefit.
An
example of how deduction of investment
advisory
fees impact the death benefit is
included
in section 1.
The
impact of an Excess Withdrawal on the
death
benefit is included in section 11.
• Must
be age 75 or younger to elect.
• Can
only be added to a Contract at issue.
• Replaces
the Traditional Death Benefit if
elected.
• Benefit
cannot be removed from the Contract.
• Only
available during the Accumulation Phase.
• Withdrawals,
including any negative Daily
Adjustment
and negative MVA, may
significantly
reduce the benefit as indicated in
the
Investment Advisory Fee Deduction
Example
in section 1, The Contract, and in the
Excess
Withdrawal example in section 11,
Income
Benefit.
• Withdrawals
reduce the likelihood of receiving
increases
to the Maximum Anniversary Value.
• Investment
restrictions during the Income
Period
may limit the benefit.
• Restrictions
on Purchase Payments may limit
the
benefit.
• Annuitizing
the Contract will end the benefit.
Maximum
Anniversary
Value
Death
Benefit
Maximum
Anniversary Value
The Maximum Anniversary Value is
initially equal to the Purchase Payment received on the Issue Date. At the end of each Business Day, we adjust the Maximum Anniversary
Value as follows.
●
We increase it by the dollar amount of any additional Purchase
Payments.
●
We reduce it by the percentage of any Contract Value you
withdraw (including any MVA).
If the Index Effective Date occurs
after the Issue Date, the Maximum Anniversary Value on the Index Effective Date is calculated in the same way as on an Index Anniversary.
On each Index Anniversary before
the end date (or on the next Business Day if the Index Anniversary is not on a Business Day) the Maximum Anniversary Value is equal to
the greater of:
●
its current value after processing any additional Purchase
Payments, or withdrawals you take (including any MVA), or
●
the Contract Value determined at the end of the Business
Day after we process all daily transactions including Performance Credits, any additional Purchase Payments, withdrawals you take including
any MVA, and deductions we make for Contract fees, expenses, and investment advisory fees you authorize your Financial Professional’s
firm to receive from the Contract. Contract Value reflects the Daily Adjustment for an Index Option for which this anniversary is not
a Term End Date. Negative
Index Option performance, withdrawals you take, and deductions we make for Contract fees, expenses, and investment advisory fees you authorize
your Financial Professional’s firm to receive from the Contract decrease the Contract Value and may reduce the likelihood of receiving
increases to the Maximum Anniversary Value.
On and after the end date, we no
longer make this comparison and we no longer capture any annual investment gains in the Maximum Anniversary Value.
The end date occurs on the earliest
of:
●
the older Determining Life’s 91st
birthday, or
●
the end of the Business Day we receive the first Valid Claim
from any one Beneficiary.
Example of the Maximum
Anniversary Value
|
|
Contract
Value |
Maximum
Anniversary Value |
|
Issue
Date |
$ 100,000
|
$ 100,000
|
|
1st
Index Anniversary |
$110,000
|
$110,000
|
|
2nd
Index Anniversary |
$95,000
|
$110,000
|
|
3rd
Index Anniversary |
$ 105,000
|
$110,000
|
|
4th
Index Anniversary |
$ 120,000
|
$ 120,000
|
●
On the Issue Date the Maximum Anniversary Value is equal
to the initial Purchase Payment of $100,000.
●
On the 1st
Index Anniversary the Contract Value is greater than the Maximum Anniversary Value, so the Maximum Anniversary Value increases to equal
the Contract Value of $110,000.
●
On the 2nd
and 3rd
Index Anniversaries the Contract Value is less than the Maximum Anniversary Value, so we neither increase nor decrease the Maximum Anniversary
Value. The Maximum Anniversary Value will stay at $110,000 until the Contract Value on an Index Anniversary is greater than this amount
or you make an additional Purchase Payment (either of which will increase the Maximum Anniversary Value), or you take a withdrawal (which
will decrease the Maximum Anniversary Value).
●
On the 4th
Index Anniversary the Contract Value is greater than the Maximum Anniversary Value, so the Maximum Anniversary Value increases to equal
the Contract Value of $120,000.
Minimum
Distribution
Program
Allows
you to automatically take withdrawals to
satisfy
the required minimum distribution
requirements
(RMD) imposed by the Internal
Revenue
Code.
• Only
available during the Accumulation
Phase.
• Only
available to IRA or SEP IRA Contracts.
• Program
withdrawals count against the free
withdrawal
privilege.
• Program
withdrawals may be subject to
negative
Daily Adjustments.
• Program
withdrawals are subject to income
taxes.
• Program
withdrawals may be monthly,
quarterly,
semi-annual or annual, unless you
have
less than $25,000 in Contract Value, in
which
case only annual payments are
available.
• We
reserve the right to discontinue or modify
the
program subject to the requirements of
law.
Minimum
Distribution
Program
Performance
Lock
and Early
Reallocations
Performance
Lock allows you to capture the
current
Index Option Value during the Term for
an
Index Option. Performance Lock can help
eliminate
doubt about future Index performance
and
possibly limit the impact of negative
performance.
Early Reallocation allows you to
transfer
out of a locked Index Option on days
other
than an Index Anniversary, or a Term End
Date.
A
Performance Lock example is included in
section
6, Valuing Your Contract —
Performance
Locks and Early Reallocations.
• Available
during the Accumulation Phase.
Only
available during the Annuity Phase if
you
select Increasing Income and you
annuitize
your annual maximum Income
Payment.
• Performance
Locks must be executed before
the
Term End Date.
• If
a Performance Lock is executed, the
locked
Index Option will no longer participate
in
Index performance (positive or negative)
for
the remainder of the Term, and will not
receive
a Performance Credit on the Term
End
Date.
• You
will not know your locked Index Option
Value
in advance.
• The
locked Index Option Value will reflect a
Daily
Adjustment.
• If
a Performance Lock is executed when the
Daily
Adjustment has declined, it will lock in
any
loss.
• A
Performance Lock can be executed only
once
each Term for each Index Option.
• Cannot
execute a Performance Lock for only
a
portion of the Index Option Value.
• Early
Reallocation requests are not accepted
within
14 calendar days before an Index
Anniversary.
• You
are limited to twelve Early Reallocation
requests
each Index Year.
• Deductions
(e.g. withdrawals, fees) decrease
the
locked Index Option Value.
• Cannot
transfer locked Index Option Value
until
the next Index Anniversary that occurs
on
or immediately after the Lock Date unless
you
execute an Early Reallocation.
• We
will not provide advice or notify you
regarding
whether you should execute a
Performance
Lock or Early Reallocation
or
the optimal time for doing so, if any.
• We
will not warn you if you execute a
Performance
Lock or Early Reallocation at
a
sub-optimal time.
• We
are not responsible for any losses
related
to your decision whether or not to
execute
a Performance Lock or Early
Reallocation.
• Early
Reallocations are not available to
Contracts
issued before May 1, 2023, as
detailed
in Appendix G.
Performance
Lock
and Early
Reallocations
Provides
a death benefit equal to the greatest
of
the Contract Value, Cash Value, or
Guaranteed
Death Benefit Value. The
Guaranteed
Death Benefit Value is total
Purchase
Payments adjusted for withdrawals.
An
example of the death benefit provided by
the
Traditional Death Benefit is included in
section
12, Death Benefit.
An
example of how deduction of investment
advisory
fees impact the death benefit is
included
in section 1.
The
impact of an Excess Withdrawal on the
death
benefit is included in section 11.
• Benefit
only available during the
Accumulation
Phase.
• Withdrawals,
including any negative Daily
Adjustments
and negative MVAs, may
significantly
reduce the benefit as indicated in
the
Investment Advisory Fee Deduction
Example
in section 1, The Contract, and in
the
Excess Withdrawal example in section
11,
Income Benefit.
• Restrictions
on Purchase Payments may limit
the
benefit.
• Annuitizing
the Contract will end the benefit.
Traditional
Death
Benefit
12. Death Benefit
“You” in this section
refers to the Owner, or the Annuitant if the Contract is owned by a non-individual.
The Contract provides the Traditional
Death Benefit, the standard death benefit, for no additional charge. If available, you can instead select the optional Maximum Anniversary
Value Death Benefit at Contract issue for an additional rider fee if all Owners and the Annuitant are age 75 or younger. The Maximum Anniversary
Value Death Benefit can only be added to a Contract at issue. The
Maximum Anniversary Value Death Benefit cannot be less than the Traditional Death Benefit, but they may be equal. Please discuss this
benefit’s appropriateness with your Financial Professional.
The death benefit is the greatest of the Contract Value, Cash Value, or Guaranteed Death Benefit Value. The Guaranteed Death Benefit Value
is either total Purchase Payments reduced proportionately for withdrawals you take (including any MVA) if you select the Traditional Death
Benefit, or the Maximum Anniversary Value if you select the Maximum Anniversary Value Death Benefit.
The death benefit
is only available during the Accumulation Phase (and Income Period, if applicable).
If you or the Determining Life (Lives) die during the Accumulation Phase, we process the death benefit using prices determined after we
receive the required information, which is either a Valid Claim or due proof of death as stated here. (For information on due proof of
death see the Glossary – Valid Claim). If we receive this information at or after the end of the current Business Day, we use the
next Business Day’s prices.
If there are multiple Beneficiaries,
each Beneficiary receives the portion of the death benefit he or she is entitled to when we receive his or her Valid Claim. If a Beneficiary
dies before you or the Designated Life, that Beneficiary’s interest in this Contract ends unless your Beneficiary designation specifies
otherwise. If there are no remaining Beneficiaries, or no named Beneficiaries, we pay the death benefit to your estate, or if the Owner
is a non-individual, to the Owner. Unless you instruct us to pay Beneficiaries a specific percentage of the death benefit, each Beneficiary
receives an equal share.
Each Beneficiary’s portion
of the death benefit remains in the Index Options based on the allocation instructions that were in effect on the date of death until
we receive his or her Valid Claim and we either pay the claim or the Beneficiary provides alternate allocation instructions. If there
is Variable Account Value in the Variable Option on the date of death, it remains there until the next Index Anniversary. If an Index
Anniversary occurs before we receive a Valid Claim, we will transfer that Beneficiary’s portion of the Variable Account Value to
the Index Options based on the allocation instructions that were in effect on the date of death.
From the time we determine the death
benefit until we make a complete distribution, any amount in the Investment Options continues to be subject to investment risk that is
borne by the recipient(s). Once we receive notification of death, we may no longer accept or process transfer requests. After we receive
the first Valid Claim from any Beneficiary, we also will not accept additional Purchase Payments or allow any partial or full withdrawals
unless the withdrawal is required to comply with federal tax law.
On the first death of a Determining
Life during the Accumulation Phase, if your selected death benefit is in effect, your Beneficiary(ies) will receive the greatest of the
Contract Value, Cash Value (which on death is the Contract Value after
application of any MVA), or Guaranteed Death Benefit Value. A
positive MVA will increase the death benefit if Cash Value is greater than the Guaranteed Death Benefit Value. However, if the MVA is
negative the death benefit will be the greater of Contract Value (without adjustment for the negative MVA), or the Guaranteed Death Benefit
Value. The
Guaranteed Death
Benefit Value is either total Purchase Payments reduced proportionately for withdrawals you take (including any MVA) if you select the
Traditional Death Benefit, or the Maximum Anniversary Value if you select the Maximum Anniversary Value Death Benefit. For example,
assume total Purchase Payments are $90,000, you take no withdrawals, the highest Contract Value on any Index Anniversary (the Maximum
Anniversary Value) is $105,000, the current Contract Value is $100,000, and the Cash Value is $97,000. The death benefit for the Traditional
Death Benefit is the $100,000 Contract Value, and for the Maximum Anniversary Value Death Benefit it is the $105,000 Maximum Anniversary
Value.
If the date we are determining the
death benefit is not the Term End Date, the Contract Value reflects the Daily Adjustment. Withdrawals you take reduce your Guaranteed
Death Benefit Value by the percentage of Contract Value withdrawn (including any MVA), determined at the end of each Business Day. All
withdrawals you take reduce the Guaranteed Death Benefit Value, Contract Value, and Cash Value, even MVA-Free Withdrawals. However,
we do not reduce the Guaranteed Death Benefit Value for deductions we make for Contract fees, expenses, or investment advisory fees
that you authorize your Financial Professional’s firm to receive from the Contract. These
deductions will, however, decrease the Contract Value and Cash Value by the dollar amount withdrawn and may reduce the likelihood
of receiving increases to the Maximum Anniversary Value. In addition, because the death benefit is the greatest of Contract Value, Cash
Value or the Guaranteed Death Benefit Value, deductions we make for Contract fees, expenses, and authorized investment advisory fees may
reduce the death benefit available to your Beneficiaries.
Examples of the impact of deductions
for investment advisory fees you authorize your Financial Professional’s firm to receive from the Contract on the death benefit
are included in section 1. The impact of an Excess Withdrawal on the death benefit is included in section 11.
Maximum
Anniversary Value
The Maximum Anniversary Value is
initially equal to the Purchase Payment received on the Issue Date. At the end of each Business Day, we adjust the Maximum Anniversary
Value as follows.
●
We increase it by the dollar amount of any additional Purchase
Payments.
●
We reduce it by the percentage of any Contract Value you
withdraw (including any MVA).
If the Index Effective Date occurs
after the Issue Date, the Maximum Anniversary Value on the Index Effective Date is calculated in the same way as on an Index Anniversary.
On each Index Anniversary before
the end date (or on the next Business Day if the Index Anniversary is not on a Business Day) the Maximum Anniversary Value is equal to
the greater of:
●
its current value after processing any additional Purchase
Payments, or withdrawals you take (including any MVA), or
●
the Contract Value determined at the end of the Business
Day after we process all daily transactions including Performance Credits, any additional Purchase Payments, withdrawals you take including
any MVA, and deductions we make for Contract fees, expenses, and investment advisory fees you authorize your Financial Professional’s
firm to receive from the Contract. Contract Value reflects the Daily Adjustment for an Index Option for which this anniversary is not
a Term End Date. Negative
Index Option performance, withdrawals you take, and deductions we make for Contract fees, expenses, and investment advisory fees you authorize
your Financial Professional’s firm to receive from the Contract decrease the Contract Value and may reduce the likelihood of receiving
increases to the Maximum Anniversary Value.
On and after the end date, we no
longer make this comparison and we no longer capture any annual investment gains in the Maximum Anniversary Value.
The end date occurs on the earliest
of:
●
the older Determining Life’s 91st
birthday, or
●
the end of the Business Day we receive the first Valid Claim
from any one Beneficiary.
Example of the Maximum
Anniversary Value
|
|
Contract
Value |
Maximum
Anniversary Value |
|
Issue
Date |
$ 100,000
|
$ 100,000
|
|
1st
Index Anniversary |
$110,000
|
$110,000
|
|
2nd
Index Anniversary |
$95,000
|
$110,000
|
|
3rd
Index Anniversary |
$ 105,000
|
$110,000
|
|
4th
Index Anniversary |
$ 120,000
|
$ 120,000
|
●
On the Issue Date the Maximum Anniversary Value is equal
to the initial Purchase Payment of $100,000.
●
On the 1st
Index Anniversary the Contract Value is greater than the Maximum Anniversary Value, so the Maximum Anniversary Value increases to equal
the Contract Value of $110,000.
●
On the 2nd
and 3rd
Index Anniversaries the Contract Value is less than the Maximum Anniversary Value, so we neither increase nor decrease the Maximum Anniversary
Value. The Maximum Anniversary Value will stay at $110,000 until the Contract Value on an Index Anniversary is greater than this amount
or you make an additional Purchase Payment (either of which will increase the Maximum Anniversary Value), or you take a withdrawal (which
will decrease the Maximum Anniversary Value).
●
On the 4th
Index Anniversary the Contract Value is greater than the Maximum Anniversary Value, so the Maximum Anniversary Value increases to equal
the Contract Value of $120,000.
|
During
the Income Period: |
|
● You
cannot make additional Purchase Payments. If your Contract includes the Traditional Death Benefit this means
the
Guaranteed Death Benefit Value no longer increases. |
|
● Index
Dual Precision Strategy, Index Precision Strategy, Index Performance Strategy, and Index Guard Strategy are
no
longer available. This may limit your Contract’s performance potential and the Guaranteed Death Benefit Value if
your
Contract includes the Maximum Anniversary Value Death Benefit. Income Payments and Excess Withdrawals
also
decrease your Contract Value, which also reduces the likelihood of locking in investment gains to the
Guaranteed
Death Benefit Value if your Contract includes the Maximum Anniversary Value Death Benefit. |
|
● Each
Income Payment and any Excess Withdrawal reduces the Guaranteed Death Benefit Value by the percentage of
Contract
Value withdrawn (including any MVA),
which means this value may be reduced by more than the amount
withdrawn.
Taking
Excess Withdrawals may also cause your selected death benefit to end prematurely. |
What Happens Upon
Death?
If you are the Determining Life,
or if you and the Determining Life (Lives) are different individuals and die within 120 hours of each other, we determine the Guaranteed
Death Benefit Value at the end of the Business Day we receive a Valid Claim. For multiple Beneficiaries, each surviving Beneficiary receives
the greater of their portion of the:
●
Guaranteed Death Benefit Value determined at the end of the
Business Day we receive the first Valid Claim from any one Beneficiary,
●
Contract Value determined at the end of the Business Day
during which we receive his or her Valid Claim, or
●
Cash Value determined at the end of the Business Day during
which we receive his or her Valid Claim.
In this instance, if the Beneficiary:
−
is a surviving spouse and chooses to continue the Contract;
−
selects death benefit payment Option B; or
−
selects death benefit payment Option C and takes payment
over a period not extending beyond the Beneficiary’s life expectancy;
and the Contract Value is less than
the Cash Value or Guaranteed Death Benefit Value, we increase the Contract Value to equal the greatest of these amounts when we receive
a Valid Claim.
If you and the Determining Life (Lives)
are different individuals and do not die within 120 hours of each other, the death benefit is as follows. This
can only occur if you change the Owner after the Issue Date.
●
If a Determining Life dies before you, we
do not pay a death benefit to the Beneficiary(ies), but we may increase the Contract Value if the Traditional Death Benefit or Maximum
Anniversary Value Death Benefit are still in effect. At
the end of the Business Day we receive due proof of a Determining Life’s death, if the Contract Value is less than the Cash Value
or Guaranteed Death Benefit Value, we increase the Contract Value to equal the greatest of these amounts, and
your selected death benefit ends.
●
Upon your death, your Beneficiary(ies) receive the greater
of Contract Value or Cash Value determined at the end of the Business Day during which we receive each Beneficiary’s Valid Claim.
Upon the death of a Determining Life,
if we increase the Contract Value to equal the Guaranteed Death Benefit Value or Cash Value, we allocate this increase to the Variable
Option. On the next Index Anniversary we transfer the Variable Account Value to the Index Options according to the allocation instructions.
The
Traditional Death Benefit and Maximum Anniversary Value Death Benefit end upon the earliest of the following:
●
The Business Day before the Annuity Date.
●
The Business Day that the Guaranteed Death Benefit Value
and Contract Value are both zero.
●
Upon the death of a Determining Life, the end of the Business
Day we receive a Valid Claim from all Beneficiaries if you and the Determining Life are the same individual, or if you and the Determining
Life (Lives) are different individuals and die within 120 hours of each other.
●
Upon the death of a Determining Life, the end of the Business
Day we receive due proof of the Determining Life’s death if you and the Determining Life (Lives) are different individuals and
do not die within 120 hours of each other.
●
Upon the death of an Owner (or Annuitant if the Owner is
a non-individual), the end of the Business Day we receive the first Valid Claim from any one Beneficiary, if the Owner (or Annuitant)
is no longer a Determining Life.
●
The Business Day the Contract ends.
|
We
base the Guaranteed Death Benefit Value on the first death of a Determining Life (or Lives). This means that upon
the
death of an Owner (or Annuitant if the Owner is a non-individual), if
a surviving spouse continues the Contract: |
|
● the
Guaranteed Death Benefit Value is no longer available, and |
|
● if
you selected the Maximum Anniversary Value Death Benefit, we no longer assess its 0.20% rider fee. |
|
Also,
if you and the Determining Life (Lives) are different individuals and you die first, the Guaranteed Death Benefit
Value
is not available to your Beneficiary(ies). |
Death
of the Owner and/or Annuitant
The SAI includes tables that are
intended to help you better understand what happens upon the death of any Owner and/or Annuitant under the different phases of the Contract.
Death
Benefit Payment Options During the Accumulation Phase
Each Beneficiary must select one
of the death benefit payment options listed below.
If a Beneficiary requests a lump
sum payment under Option A, we pay that Beneficiary within seven days of receipt of his or her Valid Claim, unless the suspension of payments
or transfers provision is in effect. Payment of the death benefit may be delayed, pending receipt of any state forms.
Spousal Continuation:
If the Beneficiary is the deceased Owner’s spouse, he or she can choose to continue the Contract with the portion of the death
benefit the spouse is entitled to in his or her own name. For an IRA, Roth IRA, or SEP IRA Contract, spousal continuation can only occur
if the surviving spouse is the Contract’s sole primary Beneficiary. For Qualified Contracts purchased through a qualified plan,
spousal continuation is only available through a direct rollover to an IRA. Spouses
must qualify as such under federal law to continue the Contract.
Individuals who have entered into a registered domestic partnership, civil union, or other similar relationship that is not considered
to be a marriage under state law are also not considered to be married under federal law. An election by the spouse to continue the Contract
must be made on the death claim form before we pay the death benefit. If the deceased Owner was a Determining Life and the surviving spouse
Beneficiary continues the Contract, at the end of the Business Day we receive his or her Valid Claim, if the Contract Value is less than
the Cash Value or Guaranteed Death Benefit Value (if available), we increase the Contract Value to equal the greatest of these amounts,
and your selected death benefit (either the Traditional Death Benefit or the Maximum Anniversary Value Death Benefit) ends. If the surviving
spouse continues the Contract:
●
he or she becomes the new Owner and may exercise all of the
Owner’s rights, including naming a new Beneficiary or Beneficiaries;
●
he or she is subject to any remaining MVA period; and
●
upon the surviving spouse’s death, their Beneficiary(ies)
receive the Contract Value determined at the end of the Business Day during which we receive a Valid Claim from each Beneficiary.
Death
Benefit Payment Options
The following applies to Non-Qualified
Contracts. Different rules may apply to Qualified Contracts. For more information, please see section 13, Taxes – Distributions
Upon the Owner’s Death (or Annuitant’s Death if the Owner is a Non-Individual).
Option A:
Lump sum payment of the death benefit.
Option
B: Payment of the entire death benefit within five years
of the date of any Owner’s death. The Beneficiary can continue to make transfers between Index Options and is subject to the
product fee.
Option C:
If the Beneficiary is an individual, payment of the death benefit as Annuity Payments under Annuity Options A, B, or C. If you take the
death benefit as Annuity Payments, we do not require that the Annuity Date occur on an Index Anniversary. With our written consent other
options may be available for payment over a period not extending beyond the Beneficiary’s life expectancy under which the Beneficiary
can continue to make transfers between Index Options and is subject to the product fee.
Distribution from Non-Qualified Contracts
under Option C must begin within one year of the date of the Owner’s death. Any portion of the death benefit from Non-Qualified
Contracts not applied to Annuity Payments within one year of the date of the Owner’s death must be distributed within five years
of the date of death.
If a Non-Qualified Contract is owned
by a non-individual, then we treat the death of an Annuitant as the death of an Owner for purposes of the Code’s distribution at
death rules, which are set forth in Section 72(s) of the Code.
In all events, notwithstanding any
provision to the contrary in the Contract or this prospectus, a Non-Qualified Contract is interpreted and administered in accordance with
Section 72(s) of the Code.
iShares®
MSCI Emerging
Markets
ETF
iShares®
MSCI Emerging
Markets
ETF
iShares®
MSCI Emerging
Markets
ETF
iShares®
MSCI Emerging
Markets
ETF
iShares®
MSCI Emerging
Markets
ETF
iShares®
MSCI Emerging
Markets
ETF
Risk
of Loss
Returns on securities and securities
Indexes can vary substantially, which may result in investment losses. The historical performance of the Investment Options does not guarantee
future results. It is impossible to predict whether underlying investment values will fall or rise. Securities markets are influenced
by economic, financial, regulatory, geographic, judicial, political and other complex and interrelated factors. Depending on your individual
circumstances (e.g.,
your selected Index Options and the timing of any Purchase Payments, transfers, or withdrawals), you may experience (perhaps significant)
negative returns under the Contract. You should consult with a Financial Professional.
The Variable Option does not
provide any protection against loss of principal. You
can lose principal and previous earnings for Purchase Payments held in the Variable Option and such losses could be significant.
You should consider whether investing
in an Index Option is consistent with your financial needs. If you allocate Purchase Payments or transfer Contract Value to an Index Option
with the Index Dual Precision Strategy, Index Precision Strategy, Index Guard Strategy, or Index Performance Strategy, negative
Index Returns may cause Performance Credits to be either negative after application of the Buffer, or negative down to the Floor. For
the Index Dual Precision Strategy and Index Performance Strategy, we apply the Buffer for the entire Term length; we do not apply
the Buffer annually on a 3-year or 6-year Term Index Option. Ongoing deductions we make for Contract fees, expenses, and investment
advisory fees that you authorize your Financial Professional’s firm to receive from the Contract could also cause amounts
available for withdrawal to be less than what you invested even if Index performance has been positive. You
can lose principal and previous earnings if you allocate Purchase Payments or transfer Contract Value to the Index Options with the Index
Dual Precision Strategy, Index Precision Strategy, Index Guard Strategy, or Index Performance Strategy, and such losses could
be significant. If you allocate Purchase Payments or transfer Contract Value to the Index Options with the Index Protection Strategy with
Trigger or Index Protection Strategy with Cap you can also lose principal and previous earnings if you do not receive a Performance Credit,
or if the Contract fees, expenses, and investment advisory fees that you authorize your Financial Professional’s firm to receive
from the Contract are greater than the Performance Credit.
The maximum potential
negative Performance Credit for the Index Dual Precision Strategy, Index Precision Strategy, and Index Performance Strategy is based
on the Buffer. If the Buffer is 10%, the maximum negative Performance Credit is -90%; if the Buffer is 20%, the maximum negative Performance
Credit is -80%; and if the Buffer is 30%, the maximum negative Performance Credit is -70%. The maximum potential negative Performance
Credit for the Index Guard Strategy is the -10% Floor. At least one Index Option with a Buffer no lower than 5% or Floor no lower than
-25%, or an Index Option that provides complete protection from Index losses, will always be available for renewal under the Contract.
In addition to
any losses from negative investment performance, you may experience losses under the Contract due to any applicable negative MVAs, other
Contract fees and charges, negative Daily Adjustments, taxes, and tax penalties.
Early
Withdrawal and Liquidity Risk
We designed the Contract to be a
long-term investment that you can use to help build and provide income for retirement. The Contract is not suitable for short-term investment.
Withdrawals under the Contract may be subject to negative MVAs, other Contract fees and charges, negative Daily Adjustments, taxes, and
tax penalties.
If you take a full or partial withdrawal
during the MVA period, we apply an MVA unless the withdrawal is an MVA-Free Withdrawal. We also apply the MVA during the MVA period if
you take Annuity Payments or if we pay a death benefit. While MVA-Free Withdrawals provide some liquidity, they are permitted in only
limited amounts or in special circumstances. If you need to withdraw most or all of your Contract Value in a short period, you will likely
exceed the MVA-Free Withdrawal amounts available to you and we will apply an MVA.
The MVA can be positive or negative
according to the interest rate environment as measured by the corporate bond yields through the Bloomberg US Long Corporate Bond Index.
In periods when bond yields have significantly decreased, the MVA limit (the maximum total positive or negative MVA is either 10% of the
amount withdrawn on a partial withdrawal, or 10% of Contract Value for a full withdrawal, Annuity Payments, or payment of the death benefit)
may reduce the amount you would have received from a positive MVA. In general, as the time remaining in the MVA period drops, a more substantial
bond yield change is required to reach the 10% MVA limit. However, there are also other factors influencing how much bond yields would
have to drop or increase to reach the 10% MVA limit including any gains or losses in the Contract and corporate bond yields at the time
each Annual Contribution Amount begins. For example, assume you purchase a Contract with a single Purchase Payment of $100,000 allocated
to one Index Option, the Issue Date is the Index Effective Date, the initial bond yield is 3%, and you take no partial withdrawals. On
the second Index Anniversary, the Contract Value has decreased to $90,000 and you request a full withdrawal. The maximum negative MVA
of -10% of Contract Value would occur if bond yields increased by 1.96% or more. If instead you wait and take a full withdrawal on the
sixth Index Anniversary when the Contract Value has increased to $120,000, the maximum negative MVA of -10% of Contract Value would occur
if bond yields increased by 14.04% or more.
We calculate the MVA as a percentage
(called the MVA factor) of the amount of Purchase Payment withdrawn from an Annual Contribution Amount, not a percentage of Contract Value.
Consequently, if the Contract Value has declined since the Annual Contribution Amount(s) were established and the MVA is negative, it
is possible that the percentage of Contract Value withdrawn to cover the negative MVA would be greater than if the MVA were deducted as
a percentage of Contract Value. For example, assume you buy the Contract with a single Purchase Payment of $10,000, your Index Effective
Date is the Issue Date, and the yield on the Bloomberg US Long Corporate Bond Index on the Index Effective Date is 2%. On the 5th
Index Anniversary your Contract Value is $8,000 after we deduct Contract fees, expenses, and investment advisory fees that you authorize
your Financial Professional’s firm to receive from the Contract and you request a full withdrawal. If the yield on the Bloomberg
US Long Corporate Bond Index has increased to 3%, the MVA factor is -1.932%. The MVA would be -$193.20 (-1.932% of $10,000). As your Contract
Value is less than $100,000, we will also deduct the $50 contract maintenance charge. This results in you receiving $7,756.80. For purposes
of this example, we have not factored in any final product and rider fees that may apply and be deducted in connection with a full withdrawal.
On a full withdrawal, the free withdrawal
privilege is not available to you, and we apply an MVA against Annual Contribution Amounts that are still within their MVA period, including
amounts previously withdrawn under the free withdrawal privilege. On
a full withdrawal, your total Annual Contribution Amounts may be greater than your Contract Value because the following reduce your Contract
Value, but do not reduce your Annual Contribution Amounts: prior MVA-Free Withdrawals; deductions we make for Contract fees, expenses,
or investment advisory fees you authorize your Financial Professional’s firm to receive from the Contract; and/or poor performance.
The present interest rate environment
is evolving due to a combination of factors, including market conditions (e.g., inflation) and actions by governmental authorities. Future
changes in interest rates, and the potential impact on MVAs, cannot be predicted with certainty. Interest rates may increase, which could
increase the risk of negative MVAs. You should consult with a Financial Professional about how the present interest rate environment may
impact your future decisions related to the Contract. For more information on the MVA, including how we calculate the MVA factor, see
section 7, Expenses and Adjustments – Market Value Adjustment (MVA).
Amounts withdrawn from this Contract
are subject to income taxes and may also be subject to a 10% additional federal tax for amounts withdrawn before age 59 1∕2.
We only apply
Performance Credits to the Index Options once each Term on the Term End Date, rather than daily. In the interim, we calculate Index Option
Values based on the Daily Adjustment. For more information, see “Risks Associated with the Daily Adjustment” later in this
section. The Variable Option is not subject to the Daily Adjustment. Any assets removed from an Index Option during the Term for withdrawals
you take (including Income Payments and other MVA-Free Withdrawals), Annuity Payments, or deductions we make for Contract fees, expenses,
and investment advisory fees that you authorize your Financial Professional’s firm to receive from the Contract, or if we
pay a death benefit, will not be eligible to receive a Performance Credit on the Term End Date. You will receive a Performance Credit
only on any unlocked Index Option Value remaining in an Index Option on the Term End Date.
You can typically transfer Index
Option Value among the Index Options only on Term End Dates. However, you can transfer assets out of an Index Option before the Term End
Date by executing a Performance Lock. Once an Index Option is locked, you can transfer assets out of it on the Index Anniversary that
occurs on or immediately after the Lock Date. For a 3-year or 6-year Term Index Option this means you can transfer out of the locked Index
Option before the Term End Date by executing a Performance Lock on or before the second Index Anniversary of a 3-year Term, or on or before
the fifth Index Anniversary of a 6-year Term. For Contracts issued on or after May 1, 2023, you can also transfer assets out
of any locked Index Option, including 1-year Term Index Options, before the Term End Date by requesting an Early Reallocation. You may
execute twelve Early Reallocations each Index Year, but each request can involve multiple locked Index Options. These restrictions on
transfers may limit your ability to react to changes in market conditions.
Business
and Operational Risks Relevant to the Contract
Business Disruption
and Cybersecurity Risks. Our business relies on technology
systems and networks, including systems and networks managed by third parties, to process, transmit and store information; perform transactions
related to the Contract; and conduct other business activities. Maintaining the integrity of our systems is critical to our business operations
and to the protection of our clients’ personal information. Any cybersecurity breaches or interference that may in the future occur
could have a material adverse impact on our business operations and our financial condition.
Publicly-reported cybersecurity threats
and incidents have dramatically increased in recent years, and financial services companies and their third-party service providers are
increasingly the targets of cyberattacks. We have implemented and maintain security measures designed to protect against breaches of security
and other interference with systems and networks, and require third party vendors to meet certain information security standards; however,
we cannot ensure that our systems and networks will not be subject to breaches or interference, or that we will always be able to readily
detect a cybersecurity incident. Any such event may result in operational disruptions as well as unauthorized access to or the disclosure
or loss of our proprietary information or our clients’ personal information. Any such event may interfere with, impede or cause
delays in our calculation of values, processing of transactions and making of payments under the Contract. Although we maintain cybersecurity
insurance coverage against costs resulting from cybersecurity incidents, it is possible losses will exceed the amount available under
our coverage. We cannot be certain that advances in criminal capabilities, discovery of new vulnerabilities, attempts to exploit vulnerabilities
in our systems, data thefts, physical system or network break-ins or inappropriate access, or other developments will not compromise or
breach the technology or other security measures protecting our networks and systems used in connection with our products and services.
Natural or Man-made
Disasters. The occurrence of natural or man-made disasters
(e.g.,
extreme weather events, acts of terrorism, public health crises, industrial accidents, blackouts, military actions) could adversely affect
our business operations, particularly if those events affect our computer-based data processing, transmission, storage, and retrieval
systems or destroy data. Such disasters may damage our facilities, preventing our employees from performing their roles, otherwise disturbing
our ordinary business operations, and impacting claims processing. We rely on certain third-parties to provide certain services important
to our business operations. While we monitor the business continuity planning of such third-parties, successful implementation and execution
of their business continuity plans are largely outside of our control. Weaknesses or failures within a vendor’s business continuity
plan in light of a natural or man-made disaster could materially disrupt our business operations.
Income
Benefit Risks
The Income Benefit is automatically
included in the Contract for an additional rider fee and you cannot remove it.
We generally base Income Payments
on the Lifetime Income Percentage you select and your Contract Value, not
a guaranteed value. Decreases in Contract Value due to
negative Index Option performance during the Accumulation Phase up to and including the Income Benefit Date, deductions for Contract fees
and expenses, and withdrawals, also decrease the Income Payment amount available to you.
If you choose the Level Income payment
option and meet the age requirements stated in section 11, Income Benefit – Calculating Your Income Payments, your initial annual
maximum Income Payment will not be less than the Level Income Guarantee Payment Percentage multiplied by your total Purchase Payments
reduced proportionately for withdrawals you took (including any MVA). However, the Level Income Guarantee Payment Percentage is not available
to you under the Level Income payment option if you do not meet the age requirements stated in section 11, or if you choose the Increasing
Income payment option.
Income Payments made while your Contract
Value is positive are a withdrawal of your own assets and reduce your Contract Value. If your Contract Value remains above zero when the
Income Payments end, you may not realize a benefit from the Income Benefit; the chances of your Contract Value being reduced to zero may
be minimal.
We also base Income Payments on the
Eligible Person(s) that we establish at issue. If you change Owners or Beneficiary(ies), we may remove an Eligible Person or Covered Person
as stated in section 2, which
may cause Income Payments to be unavailable or end prematurely.
We use the age of the Eligible Person(s)
to determine the Income Percentage(s) and Income Percentage Increases. Income Percentage Increases are not available until age 45. This
means if an Eligible Person is younger than age 44 on the Issue Date, you
will not receive an increase to a Lifetime Income Percentage based on that Eligible Person until the Index Anniversary that the Eligible
Person (or younger Eligible Person for joint payments) reaches age 45, and you will pay a rider fee during the period you are not eligible
for an Income Percentage Increase.
The eligibility period to begin Income
Payments is subject to a waiting period and both a minimum and maximum age requirement for the Eligible Person(s). For single Income Payments,
we only allow an Eligible Person who is an Owner to become a Covered Person, and joint Income Payments may not be available if the age
difference between spouses is too great, as stated in section 2, Ownership, Annuitant, Determining Life, Beneficiary, and Payee –
Eligible Person(s) and Covered Person(s). If
you do not begin Income Payments during the eligibility period, the Income Benefit ends and you will have paid for the benefit without
receiving any of its advantages.
In addition, if you have Contract
Value in an Index Option for which the Income Benefit Date is not a Term End Date, we will execute a Performance Lock for that Index Option
if it is not locked and then immediately calculate and begin your Income Payments. If you have Index Options with different Term End Dates,
there may be no date when the Daily Adjustment does not apply. For the Index Protection Strategy with Trigger or Index Protection Strategy
with Cap Index Options, we will execute this Performance Lock even if the Daily Adjustment is zero.
The initial annual
maximum Income Payment available to you must be at least $100. If your Contract Value on the Income Benefit Date is reduced and this $100
minimum cannot be met, the
Income Benefit ends and you will have paid for the benefit without receiving any of its advantages. Income Payments and the Income Benefit
may also end prematurely if you take Excess Withdrawals, or you annuitize the Contract. A full Excess Withdrawal and certain partial Excess
Withdrawals will cause Income Payments to stop and the Contract and
all of its benefits
to end. However, we can convert your Income Payment to
Annuity Payments as described in section 9, The Annuity Phase – When Annuity Payments Begin.
The Income Multiplier Benefit can
provide increased income if you are confined for care or are unable to perform at least two activities of daily living. However, this
benefit has a waiting period and you must meet certain requirements to receive it. If you are unable to meet these requirements the Income
Multiplier Benefit may not be available to you when you need it. If you qualify for the Income Multiplier Benefit, it also may not provide
enough income to pay for the care you require. For joint Covered Persons, if you both qualify for this benefit at the same time you will
get the same payment increase as a single Covered person; we do not apply the increase separately for each Covered Person.
For more information see “How
the Income Benefit Works” and “During the Income Period” in section 11, Income Benefit.
Index
Risks
Index Option returns depend, in part,
on the performance of an Index although you are not directly invested in the Index or in the securities tracked by the Index. You will
have no voting rights, no rights to receive cash dividends or other distributions, and no other rights with respect to the companies that
make up the Indexes. Because the S&P 500®
Index, Russell 2000®
Index, Nasdaq-100®
Index, EURO STOXX 50®
and iShares®
MSCI Emerging Markets ETF are each comprised of a collection of equity securities, in each case the value of the component securities
is subject to market risk, or the risk that market fluctuations may cause the value of the component securities to go up or down, sometimes
rapidly and unpredictably. In addition, the value of equity securities may decline for reasons directly related to the issuers of the
securities.
The S&P 500®
Index, Russell 2000®
Index, Nasdaq-100®
Index, and EURO STOXX 50®
are all “price return indexes,” not “total return indexes,” and therefore do not reflect dividends paid on
the securities composing the Index. This will reduce the Index Return and may cause the Index to underperform a direct investment in the
securities composing the Index. For the EURO STOXX 50®,
this Index is a euro “price return index” and Index Returns are determined without any exchange rate adjustment. Because
Index performance for the iShares®
MSCI Emerging Markets ETF is based on the ETF’s closing share price, Index performance is calculated on a “price return”
basis, not a “total return” basis, and therefore does not reflect dividends paid on the securities in which the ETF invests.
In addition, an ETF deducts fees and costs, which reduce Index performance. These factors will reduce the Index Return and may cause the
ETF to underperform a direct investment in the ETF or the securities in which the ETF invests.
In addition to
the foregoing, each Index has its own unique risks, as follows:
●
S&P 500®
Index: This Index is comprised of equity securities issued
by large-capitalization (“large cap”) U.S. companies. In general, large capitalization companies may be unable to respond
quickly to new competitive challenges or changes in their industries, and may not be able to attain the high growth rate of successful
smaller companies.
●
Russell 2000®
Index: This Index is comprised of equity securities of
small-capitalization (“small-cap”) U.S. companies. Generally, the securities of small-cap companies are more volatile and
riskier than the securities of large-cap companies.
●
Nasdaq-100®
Index: This Index is comprised of equity securities of
the largest U.S. and non-U.S. companies listed on the Nasdaq Stock Market, including companies across all major industry groups except
financial companies. In general, large-capitalization companies may be unable to respond quickly to new competitive challenges or changes
in their industries, and may not be able to attain the high growth rate of successful smaller companies. To the extent that the Index
is comprised of securities issued by companies in a particular sector, those securities may not perform as well as the securities of companies
in other sectors or the market as a whole. Also, any securities issued by non-U.S. companies are subject to the risks related to investments
in foreign markets (e.g.,
increased volatility; changing currency exchange rates; and greater political, regulatory, and economic uncertainty).
●
EURO STOXX 50®:
This Index is comprised of the equity securities of large-capitalization companies in the Eurozone. In general, large-capitalization companies
may be unable to respond quickly to new competitive challenges or changes in their industries, and may not be able to attain the high
growth rate of successful smaller companies. Securities issued by non-U.S. companies are subject to the risks related to investments in
foreign markets (e.g.,
increased volatility; changing currency exchange rates; and greater political, regulatory, and economic uncertainty).
●
iShares®
MSCI Emerging Markets ETF: The iShares MSCI Emerging Markets
ETF seeks to track the investment results of an index composed of large- and mid-capitalization emerging market equities. Investments
in emerging market issuers may be subject to a greater risk of loss than investments in issuers located or operating in more developed
markets. Emerging markets may be more likely to experience inflation, social instability, political turmoil or rapid changes in economic
conditions than more developed markets. Companies in many emerging markets are not subject to the same degree of regulatory requirements,
accounting standards or auditor oversight as companies in more developed countries, and as a result, information about the securities
in which the ETF invests may be less reliable or complete. Emerging markets often have less reliable securities valuations and greater
risk associated with custody of securities than developed markets. There may be significant obstacles to obtaining information necessary
for investigations into or litigation against companies and shareholders may have limited legal remedies.
Other
Contract Changes Risk
We reserve the right to modify or
restrict several benefits or features of the Contract. We restrict additional Purchase Payments. Each Index Year during the Accumulation
Phase and before the Income Benefit Date, you cannot add more than your initial amount without our prior approval. Your initial amount
is the total of all Purchase Payments received before the first Quarterly Contract Anniversary of the first Contract Year. We allow you
to add up to the initial amount in the remainder of the first Index Year. In addition to this Purchase Payment restriction, we reserve
the right to decline any or all Purchase Payments at any time on a nondiscriminatory basis. For Contracts issued in certain states, we
reserve the right to hold your initial Purchase Payment in the Variable Option until the free look period ends, and then reallocate your
Contract Value, less fees and expenses, according to your allocation instructions. For further information regarding Purchase Payment
restrictions, see section 3, Purchasing the Contract – Purchase Requirements.
As it relates to the Index Options,
we reserve the right to close Index Options to new Purchase Payments and transfers. However, once an Index Option is added to a Contract,
we cannot remove it, change how it calculates Performance Credits, or change its Buffer or Floor.
We also reserve the right to substitute
the Fund in which the Variable Option invests. We reserve the right to add or eliminate additional variable investment options, subject
to applicable law.
In states that assess a premium tax,
we do not currently deduct it from the Contract, although we reserve the right to do so in the future.
Lastly, we reserve the right to treat
a partial withdrawal that reduces Contract Value below $2,000 as a full withdrawal. If Annuity Payments would be less than $100, we reserve
the right to require you to take a full withdrawal and your Contract will then terminate. However, we do not apply the MVA on this full
withdrawal.
Risk
of Change to the Income Benefit Supplement Prior to the Issue Date
The Income Payment waiting period
and the table showing the Income Percentages and Income Percentage Increases for your Contract are stated in the Income Benefit Supplement
that is in effect on the date you sign your application. The supplement also includes the income multiplier factor and income multiplier
benefit wait period for the Income Multiplier Benefit. Your Financial Professional will give you a copy of the prospectus with the current
Income Benefit supplement when you apply for a Contract. If we do not receive your initial Purchase Payment within 60 calendar days of
the date you sign the application, and the Income Benefit Supplement terms have changed since this date, you will receive the Income Benefit
Supplement terms that are in effect on the Issue Date instead of the terms that were in effect when you applied for the Contract. You
bear the risk that, if there is more than a 60-day delay between the time you apply for the Contract and the Issue Date, the Income Benefit
Supplement terms may change and be less advantageous to you. When we issue the Contract, we send you the current prospectus with the current
Income Benefit Supplement. We cannot change these terms for your Contract once they are established. We publish any changes to these terms
in an amended Income Benefit Supplement at least seven calendar days before they take effect on our website at https://www.allianzlife.com/RILAincomeadvrates.
The amended Income Benefit Supplement is also filed on EDGAR at https://www.sec.gov
under Form N-4 File Numbers 333-264349 and 333-255394. You can contact us to receive the Income Benefit Supplement applicable to your
Contract by calling our Service Center at the toll-free telephone number listed at the back of this prospectus.
You can find historical Income Benefit and
Income Multiplier Benefit Supplement values in Appendix F for benefits issued before May 1, 2026.
Risks
Associated with Calculation of Performance Credits
We calculate Performance Credits
each Term on the Term End Date. Because we calculate Index Returns only on a single date in time, you may experience negative or flat
performance even though the Index you selected for a given Crediting Method may have experienced gains through some, or most, of the Term.
If you allocate Purchase Payments or transfer Contract Value to the Index Options with Index Protection Strategy with Trigger or Index
Protection Strategy with Cap, positive returns are limited by the Trigger Rates and Caps. You are not subject, however, to potential negative
Performance Credits for those Index Options. The Trigger Rates on the Index Dual Precision Strategy and Index Precision Strategy
Index Options, and the Caps on the Index Guard Strategy and Index Performance Strategy Index Options also limit positive returns, and
for these Index Options, you may be subject to potential negative Performance Credits. Trigger Rates and Caps could cause performance
to be lower than it would otherwise have been if you invested in a mutual fund or exchange-traded fund designed to track the performance
of the applicable Index.
For the Index Performance Strategy,
we apply the Cap and any Participation Rate for the entire Term length; we do not
apply the Cap and any Participation Rate annually on a
3-year or 6-year Term Index Option. For the Index Dual Precision Strategy, we apply the Trigger Rate for the entire Term length; we do not apply
the Trigger Rate annually on a 3-year or 6-year Term Index Option. See “Risk of Loss” above for information about risks
associated with Buffers and Floors when calculating Performance Credits.
The Index Options do not receive
any dividends payable on these securities. The Index Options also do not directly participate in the returns of the Indexes or the Indexes’
component securities. Index Returns would be higher if they included the dividends from the component securities.
Trigger Rates, Caps, and Participation
Rates may be adjusted on the next Term Start Date and may vary significantly from Term to Term. For more information, see the “Risks
Associated with Changes to Trigger Rates, Caps, and Participation Rates” discussion later in this section.
The Crediting Methods only capture
Index Values on the Term Start Date and Term End Date, so you will bear the risk that the Index Value might be abnormally high on a Term
Start Date or low on a Term End Date, which in either case could negatively impact your Performance Credits at the end of the Term.
Risks
Associated with Changes to Trigger Rates, Caps, and Participation Rates
Subject to their respective minimums,
we establish the initial Trigger Rates, Caps, and Participation Rates for a newly issued Contract on the Index Effective Date and they
cannot change until the next Term Start Date. You select the Index Effective Date when you purchase your Contract. It can be any Business
Day from the Issue Date up to and including the first Quarterly Contract Anniversary, but it cannot be the 29th,
30th,
or 31st
of a month.
You should be aware
that, generally, initial Trigger Rates, Caps, and Participation Rates could change every seven calendar days. However, these rates are
guaranteed to be available during the period stated on our website at https://www.allianzlife.com/RILAincomeadvrates
and cannot be superseded until that period ends. If you select an Index Effective Date that is within the guaranteed period for the initial
rates that are available for review on the date you signed your application, you will receive the initial rates that were available on
the date you signed your application. However, if you select an Index Effective Date that is after this guaranteed period, you are subject
to the risk that initial Trigger Rates, Caps, and Participation Rates may change and be less advantageous to you. You are responsible
for reviewing the initial rates before your Index Effective Date to ensure your allocations and the product still meet your needs. Furthermore,
if your Index Effective Date is after the end of the free look period and
you
cancel the Contract, you will receive the Cash Value. On or before the Index Effective Date, the Daily Adjustment and
MVA do not
apply. You may review future rates at least seven calendar days before their effectiveness at https://www.allianzlife.com/RILAincomeadvrates.
Subject to the limitations related to designating the Index Effective Date, you (or your Financial Professional, if authorized) can change
your Index Effective Date at any time before it occurs to be an earlier or later date by submitting a request.
We can change the renewal and Early
Reallocation Trigger Rates, Caps, and Participation Rates for an existing Contract on each new Term Start Date subject to the guaranteed
minimums, in our discretion. You risk the possibility that renewal Trigger Rates, Caps, and Participation Rates will be as low as the
applicable guaranteed minimums.
We will send you a letter at least
30 days before each Index Anniversary. This letter advises you that current Trigger Rates, Caps, and Participation Rates are expiring,
and that renewal rates for the next Term Start Date will be available for your review. The Index Anniversary letter also reminds you of
your opportunity to transfer your Index Option Values on the upcoming Term End Date. On each Term End Date, you have the option of
remaining allocated to your current Index Options at the renewal Trigger Rates, Caps, and Participation Rates that we set on the next
Term Start Date, or transferring to another permitted Index Option. At least seven calendar days before each Index Anniversary, we publish
renewal rates for the next Term Start Date for your review in your account on our website, and on our public website at https://www.allianzlife.com/RILAincomeadvrates.
If you do not review renewal change information when it is published or take no action to transfer to another permitted Index Option,
you will remain allocated to your current Index Options and will automatically become subject to the renewal Trigger Rates, Caps, and
Participation Rates until the next Term End Date.
When your renewal rates change,
if you do not want to remain invested in the same Index Option for a new Term, the only other options available to you are to transfer
Index Option Value between Index Options by changing your allocation instructions, or take a full withdrawal of the Index Option Value
(which may be subject to a negative MVA, is subject to income taxes, and may be subject to tax penalties).
If you execute a Performance Lock,
you may be able to request an Early Reallocation and begin a new Index Option with a new Term Start Date and a new Trigger Rate, Cap,
or Participation Rate before the next Index Anniversary. We can change Early Reallocation Trigger Rates, Caps, and Participation Rates
subject to the guaranteed minimums, in our discretion. We publish Early Reallocation rates at least seven calendar days before the end
of the current Early Reallocation offering period for your review in your account on our website. If you do not execute an Early Reallocation,
you will remain allocated to your current locked Index Options until the Index Anniversary that occurs on or immediately after the Lock
Date.
Initial, renewal, and Early Reallocation
Trigger Rates, Caps, and Participation Rates may vary significantly depending upon a variety of factors, including, but not limited to:
●
Term length,
●
level of downside protection,
●
market volatility,
●
our hedging strategies and investment performance,
●
the availability of hedging instruments,
●
the amount of money available to us through Contract fees
and expenses to purchase hedging instruments,
●
expenses incurred by the Company,
●
your Index Effective Date,
●
the level of interest rates,
●
utilization of Contract benefits by Owners, and
●
our profitability goals.
These factors also impact any new
Buffer or Floor Index Options that become available under the Contract. Due to a combination of factors, including potential changes in
interest rates and other market conditions (e.g. rising inflation), the current economic environment is evolving. The future impact on
initial, renewal, and Early Reallocation Trigger Rates, Caps, and Participation Rates cannot be predicted with certainty. The effect of
a change in interest rates or other market conditions may not be direct or immediate. There may be a lag in changes to Trigger Rates,
Caps, and Participation Rates. Interest rates could increase. In a rising interest rate environment, increases in initial Trigger Rates,
Caps, and Participation Rates, if any, may be substantially slower than increases in interest rates. However, a rising interest rate environment
may have the opposite effect on renewal rates and cause renewal Trigger Rates, Caps, and Participation Rates to decrease.
We manage our
obligation to provide Performance Credits in part by trading call and put options, and other derivatives on the available Indexes. The
costs of the call and put options and other derivatives vary based on market conditions, and we may adjust future renewal and Early Reallocation
Trigger Rates, Caps, and Participation Rates to reflect these cost changes. The primary factor affecting the differences in the initial
Trigger Rates, Caps, and Participation Rates for newly issued Contracts and renewal and Early Reallocation rates for existing Contracts
is the difference in what we can earn from these investments for newly issued Contracts versus what we are earning on the investments
that were made for existing Contracts. In some instances, we may need to reduce initial, renewal, and Early Reallocation Trigger Rates,
Caps, and Participation Rates, or we may need to substitute an Index. You bear the risk that we may reduce Trigger Rates, Caps, and Participation
Rates, which reduces your opportunity to receive positive Performance Credits.
Risks
Associated with Our Financial Strength and Claims-Paying Ability
All payments and financial guarantees
under the Contract are subject to our financial strength and claims-paying ability. We make Income Payments, Annuity Payments, and pay
death benefits from our general account. Our general account assets are subject to claims by our creditors. We apply Performance Credits
from an unregistered, non-unitized, non-insulated separate account (Separate
Account IANA). Like our general account, the assets in
Separate Account
IANA are subject
to our general business operation liabilities and the claims of our creditors. For more information on Separate Account IANA, see The
Insurance Company, Separate Accounts, and General Account – Our Unregistered Separate Account.
Risks
Associated with Performance Locks and Early Reallocations
If a Performance Lock is executed:
●
You will no longer participate in Index performance, positive
or negative, for the remainder of the Term for the locked Index Option. This means that under no circumstances will your Index Option
Value increase during the remainder of the Term for a locked Index Option, and you will begin a new Index Option with a new Term
Start Date on the next Index Anniversary that occurs on or immediately after the Lock Date unless you execute an Early Reallocation (if
available to you). Early Reallocation is not permitted for Contracts issued before May 1, 2023. If you decide to execute an Early
Reallocation, you can execute a Performance Lock and then, at the earliest, execute an Early Reallocation on the same Business Day. When
executing both the Performance Lock and Early Reallocation on the same Business Day, your Lock Date is also the Term Start Date for the
new Index Option.
●
You will not receive a Performance Credit on any locked Index
Option on the Term End Date.
●
We use the Daily Adjustment calculated at the end of the
current
Business Day on the Lock Date to determine your locked Index Option Value. This means that, if you request a Performance Lock, your Index
Option Value will lock at an unknown future value which may be higher or lower than it was at the point in time you requested a Performance
Lock. In addition, if you set a lower target, your Index Option Value may lock at a lower value than the target you set.
●
If a Performance Lock is executed when your Daily Adjustment
has declined, you will lock in any loss. It is possible that you would have realized less of a loss or no loss if the Performance Lock
occurred at a later time, or if the Index Option was not locked.
●
We will not execute your request for a Performance Lock on
the Index Protection Strategy with Trigger or Index Protection Strategy with Cap Index Options if the Daily Adjustment is zero unless
your Contract was issued before May 1, 2023. This may limit your ability to take advantage of the benefits of the Early Reallocation
feature.
●
There are limits on Early Reallocations. We do not accept
Early Reallocation requests within 14 calendar days before an Index Anniversary; and you are limited to twelve Early Reallocation requests
each Index Year, but each request can involve multiple locked Index Options. After you reach the Early Reallocation request limit
in an Index Year, any locked Index Options will remain locked until the next Index Anniversary. These limitations mean you may not be
able to take advantage of any increases to Early Reallocation rates, or any advantageous changes to Index values that may become available
at the optimal time. This may limit your return potential. Early Reallocation is available for amounts allocated to any locked Index Option,
subject to the restrictions described in this prospectus.
●
Early Reallocation Trigger Rates, Caps, and Participation
Rates you receive may be less than the Early Reallocation rates that become available later in the Index Year, or the renewal rates available
on the next Index Anniversary. This may limit your return potential.
|
We
will not provide advice or notify you regarding whether you should execute a Performance Lock or Early
Reallocation
or the optimal time for doing so, if any. We will not warn you if you execute a Performance Lock or
Early
Reallocation at a sub-optimal time. We are not responsible for any losses related to your decision whether or
not
to execute a Performance Lock or Early Reallocation. |
Risks
Associated with Substitution of an Index and Limitation on Further Investments
There is no guarantee that the Indexes
will be available during the entire time that you own your Contract, including the Index we use to calculate the MVA. Once we add an Index
to your Contract, we cannot remove it without simultaneously substituting it. For the Index Options, if we substitute a new Index for
an existing Index, the performance of the new Index may be different and this may affect your ability to receive positive Performance
Credits.
Depending on the constitution of
the substituted Index, the volatility of its investments, and our ability to hedge the Index’s performance, we may determine, in
our discretion, to increase or decrease renewal Trigger Rates, Caps, and Participation Rates associated with the new Index, subject to
their respective minimums. However, we would not implement any change to reflect this difference until the next Term Start Date after
the substitution. The substitution of an Index during a Term may result in an abnormally large change in the Daily Adjustment on the day
we substitute the Index due to changes in Proxy Value inputs (such as volatility, dividend yield, and interest rate). However, you would
only be affected by this change in the Daily Adjustment if a transaction to which the Daily Adjustment applies (such as a withdrawal you
take) occurs on the substitution date.
Risks
Associated with the Daily Adjustment
The Daily Adjustment is how we calculate
Index Option Values on Business Days other than the Term Start Date or Term End Date. The
Variable Option is not subject to the Daily Adjustment.
The Daily Adjustment can affect the amounts available for withdrawal, Performance Locks, annuitization, payment of the death benefit,
and the Contract Value used to determine the contract maintenance charge and Charge Base for the product and rider fees. The Daily
Adjustment can be less than the Trigger Rate or Cap even if the current Index return during the Term is greater than the Trigger Rate
or Cap. In addition, even if the Index has performed positively since the beginning of the the Term, the Daily Adjustment may be negative.
However, the Daily Adjustment for the Index Protection Strategy with Trigger and Index Protection Strategy with Cap cannot be negative.
The Daily Adjustment is generally negatively affected by:
●
interest rate decreases,
●
dividend rate increases,
●
poor market performance, and
●
the expected volatility of Index prices. Generally, increases
in the expected volatility of Index prices negatively affect the Index Dual Precision Strategy, Index Precision Strategy, and Index Performance
Strategy 1-year Term Index Options, while decreases in the expected volatility of Index prices negatively affect the Index Guard Strategy.
For the Index Performance Strategy 3-year and 6-year Term Index Options, and Index Protection Strategy with Cap, the impact of changes
in the expected volatility of Index prices is dependent on the market environment and the applicable Caps and Participation Rates. For
the Index Protection Strategy with Trigger, the impact of changes in the expected volatility of Index prices is dependent on the market
environment.
The Daily Adjustment for Index Options
with a Term length of more than 1 year (3-year and 6-year Term Index Options and Early Reallocation to a 1-year Term Index Option) may
be more negatively impacted by changes in the expected volatility of Index prices than 1-year Term Index Options due to the difference
in Term length. Also, the risk of a negative Daily Adjustment is generally greater for Index Options with a Term length of more than 1
year than for 1-year Term
Index Options
due to the Term length. The Index Performance Strategy 3-year and 6-year Term Index Options with a Participation Rate above 100% may also
have larger fluctuations in the Daily Adjustment than Index Options either without a Participation Rate, or with a Participation Rate
equal to 100%. For shorter Term lengths, there is more certainty in both the final Index Values and how Trigger Rates, Caps, Buffers,
and Floors determine Performance Credits. This means there may be less fluctuation in the Daily Adjustment due to changes in Index return
for Index Options with shorter Term lengths.
If amounts are withdrawn or otherwise
removed from an Index Option with the Index Dual Precision Strategy, Index Precision Strategy, Index Guard Strategy, or Index Performance
Strategy before the Term End Date, you
could lose principal and previous earnings due to a negative Daily Adjustment. A negative Daily Adjustment for these Index Options could
result in losses greater than the protection provided by the applicable Buffer or Floor, which apply only on the Term End Date.
The maximum potential loss from a negative
Daily Adjustment is: -99% for the Index Dual Precision Strategy, Index Precision Strategy, and Index Performance Strategy; and -35% for
the Index Guard Strategy. Such
losses will be greater if you take a withdrawal that is subject to a negative MVA, is a deduction of Contract fees or charges, investment
advisory fees that you authorize your Financial Professional’s firm to receive from the Contract, taxes, or tax penalties also
apply.
Risks
of Deducting Investment Advisory Fees From the Contract
We designed the Contract to be owned
by individuals (or a trust or other entity acting as an agent for a natural person) who are receiving ongoing investment advice from a
Financial Professional. You can authorize your Financial Professional’s firm to receive investment advisory fees deducted from
your Contract. Deductions we make for investment advisory fees may be subject to a Daily Adjustment (that could be negative), and will
reduce your Contract Value and Cash Value dollar for dollar. We do not consider these deductions to be RMD payments or Income Payments,
and they do not reduce the Maximum Anniversary Value under the Maximum Anniversary Value Death Benefit. However, your initial annual maximum
Income Payment, Income Payment increases under the Level Income payment option, and increases to the Maximum Anniversary Value are based
on Contract Value. So these deductions reduce your initial annual maximum Income Payment, and reduce the likelihood you will receive Income
Payment increases if you select the Level Income payment option, or receive increases to the Maximum Anniversary Value if you select the
Maximum Anniversary Value Death Benefit. Because the death benefit is the greatest of Contract Value, Cash Value, or the Guaranteed Death
Benefit Value, deductions we make for investment advisory fees reduce the death benefit available to your Beneficiaries. As Contract Value
is also one of the components we use to calculate RMD payments, these deductions also reduce RMD payments.
| [1] | Base
Contract fee is comprised of two charges referred to as the “product fee” and the “rider fee for the
Income
Benefit” in the Contract and elsewhere in this prospectus. As a percentage of the Charge Base, plus
an
amount attributable to the contract maintenance charge. |
| [2] | As a percentage of the AZL Government Money Market Fund's average daily net assets. |
| [3] | Referred to as the “contract maintenance charge” in the Contract and elsewhere in this prospectus. Waived if the Contract Value is at least $100,000. During the Annuity Phase, we deduct the contract maintenance charge proportionately from each Annuity Payment. See section 7, Expenses and Adjustments – Contract Maintenance Charge (Administrative Expenses). |