N-4
|
Apr. 22, 2026
USD ($)
yr
|
| Prospectus: |
|
| Document Type |
N-4
|
| Entity Registrant Name |
Metropolitan Life Separate Account E
|
| Entity Central Index Key |
0000744043
|
| Entity Investment Company Type |
N-4
|
| Document Period End Date |
Apr. 22, 2026
|
| Amendment Flag |
false
|
| MetLife Financial Freedom Select e and e Bonus Class |
|
| Item 3. Key Information [Line Items] |
|
| Fees and Expenses [Text Block] |
| |
FEES, EXPENSES AND ADJUSTMENTS |
|
Are there Charges or Adjustments for Early Withdrawals? |
Yes. If You withdraw money from the Contract less than 13 Contract years after You purchased the Contract, You may be assessed a Withdrawal Charge of up to 10% of the amount withdrawn. For example, if You purchase a B Class for $100,000 and surrender your Contract during the first year, You will pay a Withdrawal Charge of up to $10,000. |
Charges – Withdrawal Charges |
Are there Transaction Charges? |
Yes. In addition to Withdrawal Charges, You also may be charged for other transactions, such as transferring Account Value among Divisions or between the Divisions and the Fixed Interest Account. Although we do not currently charge a fee for transfers of Account Value among Divisions or between the Divisions and the Fixed Interest Account, we reserve the right to impose a transfer fee of $25 on transfers in excess of 12 in a Contract Year. Loans will incur a $75 loan initiation fee. The Loan Maintenance Fee is $50.00. Loan fees may be waived or reduced for certain Plans. |
|
Are there Ongoing Fees and Expenses (annual charges)? |
Yes. The table below describes the fees and expenses that You may pay each year, depending on the investment options and optional benefits You choose. Please refer to your Contract specifications page for information about the specific fees You will pay each year based on the options You have elected. |
|
| |
|
|
Base Contract (varies by Contract class) |
|
|
Portfolio fees and expenses |
|
|
Optional benefits available for an additional charge (for a single optional benefit, if elected) |
|
|
| |
(1) As a percentage of your Account Balance in the Separate Account. The Base Contract Fee includes 0.04% for the Annual Contract Fee. The Annual Contract Fee is $30 annually. The Annual Contract Fee may be waived under certain circumstances. For classes B, C, and L this fee is waived if your total purchase payments for the prior 12 months are at least $2,000 on the day the fee is deducted or if your Account Balance is at least $25,000 on the day the fee is deducted and for e and e Bonus classes if your Account Balance is at least $50,000 on the day the fee is deducted. The fee will be deducted on a pro-rata basis (determined based upon the number of complete months that have elapsed since the prior Contract Anniversary) if You take a total withdrawal of your Account Balance. This fee will not be deducted if You are on medical leave approved by your employer or called to active armed service duty at the time the fee is to be deducted and your employer has informed us of your status. During the pay- out phase we reserve the right to deduct this fee. (2) As a percentage of average daily net assets of the Portfolio. (3) For the Enhanced Death Benefit: as a percentage of your Account Balance in the Separate Account. For the GMIB fee: as a percentage of your guaranteed minimum income base. For the LWG fee: as a percentage of your Total Guaranteed Withdrawal Amount. |
|
Because your Contract is customizable, the choices You make affect how much You will pay. To help understand the cost of owning your Contract, the following table shows the lowest and highest cost You could pay each year, based on current charges. This estimate assumes that You do not take withdrawals from the Contract, which could add Withdrawal Charges that substantially increase costs. |
| |
|
|
|
| |
|
Assumes: ●Investment of $100,000 ●5% annual appreciation ●Least expensive combination of Contract classes and Portfolio fees and expenses ●No optional benefits ●No sales charges ●No additional purchase payments, transfers or withdrawals |
Assumes: ●Investment of $100,000 ●5% annual appreciation ●Most expensive combination of Contract classes, optional benefits and Portfolio fees and expenses ●No sales charges ●No additional purchase payments, transfers or withdrawals |
|
| Charges for Early Withdrawals [Text Block] |
Are there Charges or Adjustments for Early Withdrawals? |
Yes. If You withdraw money from the Contract less than 13 Contract years after You purchased the Contract, You may be assessed a Withdrawal Charge of up to 10% of the amount withdrawn. For example, if You purchase a B Class for $100,000 and surrender your Contract during the first year, You will pay a Withdrawal Charge of up to $10,000. |
Charges – Withdrawal Charges |
|
| Surrender Charge Phaseout Period, Years | yr |
13
|
| Surrender Charge (of Amount Surrendered) Maximum [Percent] |
10.00%
|
| Surrender Charge Example Maximum [Dollars] |
$ 10,000
|
| Transaction Charges [Text Block] |
Are there Transaction Charges? |
Yes. In addition to Withdrawal Charges, You also may be charged for other transactions, such as transferring Account Value among Divisions or between the Divisions and the Fixed Interest Account. Although we do not currently charge a fee for transfers of Account Value among Divisions or between the Divisions and the Fixed Interest Account, we reserve the right to impose a transfer fee of $25 on transfers in excess of 12 in a Contract Year. Loans will incur a $75 loan initiation fee. The Loan Maintenance Fee is $50.00. Loan fees may be waived or reduced for certain Plans. |
|
|
| Ongoing Fees and Expenses [Table Text Block] |
Are there Ongoing Fees and Expenses (annual charges)? |
Yes. The table below describes the fees and expenses that You may pay each year, depending on the investment options and optional benefits You choose. Please refer to your Contract specifications page for information about the specific fees You will pay each year based on the options You have elected. |
|
| |
|
|
Base Contract (varies by Contract class) |
|
|
Portfolio fees and expenses |
|
|
Optional benefits available for an additional charge (for a single optional benefit, if elected) |
|
|
| |
(1) As a percentage of your Account Balance in the Separate Account. The Base Contract Fee includes 0.04% for the Annual Contract Fee. The Annual Contract Fee is $30 annually. The Annual Contract Fee may be waived under certain circumstances. For classes B, C, and L this fee is waived if your total purchase payments for the prior 12 months are at least $2,000 on the day the fee is deducted or if your Account Balance is at least $25,000 on the day the fee is deducted and for e and e Bonus classes if your Account Balance is at least $50,000 on the day the fee is deducted. The fee will be deducted on a pro-rata basis (determined based upon the number of complete months that have elapsed since the prior Contract Anniversary) if You take a total withdrawal of your Account Balance. This fee will not be deducted if You are on medical leave approved by your employer or called to active armed service duty at the time the fee is to be deducted and your employer has informed us of your status. During the pay- out phase we reserve the right to deduct this fee. (2) As a percentage of average daily net assets of the Portfolio. (3) For the Enhanced Death Benefit: as a percentage of your Account Balance in the Separate Account. For the GMIB fee: as a percentage of your guaranteed minimum income base. For the LWG fee: as a percentage of your Total Guaranteed Withdrawal Amount. |
|
Because your Contract is customizable, the choices You make affect how much You will pay. To help understand the cost of owning your Contract, the following table shows the lowest and highest cost You could pay each year, based on current charges. This estimate assumes that You do not take withdrawals from the Contract, which could add Withdrawal Charges that substantially increase costs. |
| |
|
|
|
| |
|
Assumes: ●Investment of $100,000 ●5% annual appreciation ●Least expensive combination of Contract classes and Portfolio fees and expenses ●No optional benefits ●No sales charges ●No additional purchase payments, transfers or withdrawals |
Assumes: ●Investment of $100,000 ●5% annual appreciation ●Most expensive combination of Contract classes, optional benefits and Portfolio fees and expenses ●No sales charges ●No additional purchase payments, transfers or withdrawals |
|
| Base Contract (of Other Amount) (N-4) Minimum [Percent] |
0.54%
|
| Base Contract (of Other Amount) (N-4) Maximum [Percent] |
1.49%
|
| Investment Options (of Average Annual Net Assets) Minimum [Percent] |
0.52%
|
| Investment Options (of Average Annual Net Assets) Maximum [Percent] |
1.38%
|
| Optional Benefits Minimum [Percent] |
0.10%
|
| Optional Benefits Maximum [Percent] |
0.95%
|
| Base Contract (N-4) Footnotes [Text Block] |
(1) As a percentage of your Account Balance in the Separate Account. The Base Contract Fee includes 0.04% for the Annual Contract Fee. The Annual Contract Fee is $30 annually. The Annual Contract Fee may be waived under certain circumstances. For classes B, C, and L this fee is waived if your total purchase payments for the prior 12 months are at least $2,000 on the day the fee is deducted or if your Account Balance is at least $25,000 on the day the fee is deducted and for e and e Bonus classes if your Account Balance is at least $50,000 on the day the fee is deducted. The fee will be deducted on a pro-rata basis (determined based upon the number of complete months that have elapsed since the prior Contract Anniversary) if You take a total withdrawal of your Account Balance. This fee will not be deducted if You are on medical leave approved by your employer or called to active armed service duty at the time the fee is to be deducted and your employer has informed us of your status. During the pay-out phase we reserve the right to deduct this fee.
|
| Optional Benefits Footnotes [Text Block] |
(3) For the Enhanced Death Benefit: as a percentage of your Account Balance in the Separate Account. For the GMIB fee: as a percentage of your guaranteed minimum income base. For the LWG fee: as a percentage of your Total Guaranteed Withdrawal Amount.
|
| Investment Options Footnotes [Text Block] |
(2) As a percentage of average daily net assets of the Portfolio.
|
| Lowest and Highest Annual Cost [Table Text Block] |
| |
|
|
|
| |
|
Assumes: ●Investment of $100,000 ●5% annual appreciation ●Least expensive combination of Contract classes and Portfolio fees and expenses ●No optional benefits ●No sales charges ●No additional purchase payments, transfers or withdrawals |
Assumes: ●Investment of $100,000 ●5% annual appreciation ●Most expensive combination of Contract classes, optional benefits and Portfolio fees and expenses ●No sales charges ●No additional purchase payments, transfers or withdrawals |
|
| Lowest Annual Cost [Dollars] |
$ 1,011
|
| Highest Annual Cost [Dollars] |
$ 3,226
|
| Risks [Table Text Block] |
| |
|
|
Is there a Risk of Loss from Poor Performance? |
Yes. You can lose money by investing in the Contract, including loss of principal. |
Principal Risks of Investing in the Contract |
Is this a Short-Term Investment? |
No. This Contract is not a short-term investment and is not appropriate for an investor who needs ready access to cash. ●Withdrawal Charges may apply to withdrawals made less than 13 Contract Years after You purchased the Contract. Withdrawal Charges will reduce the value of your Contract if You withdraw money during that time. ●The benefits of tax deferral and living benefit protections also mean that the Contract is more beneficial to investors with a long time horizon. ●Earnings on your Contract are taxed at ordinary income tax rates when You withdraw them, and You may have to pay a penalty if You take a withdrawal before age 59 1∕2. |
Principal Risks of Investing in the Contract |
What are the Risks Associated with the Investment Options? |
●An investment in the Contract is subject to the risk of poor investment performance and can vary depending on the performance of the investment options available under the Contract (e.g., Portfolios). ●Each investment option (including the Fixed Interest Account investment option) will have its own unique risks. ●You should review these investment options before making an investment decision. ●Subject to certain limitations, if your Account Balance falls below the minimum Account Balance or is not sufficient to pay the Contract charges, we may terminate your Contract. |
Principal Risks of Investing in the Contract |
What are the Risks Related to the Insurance Company? |
An investment in the Contract is subject to the risks related to the Company. Any obligations (including under the Fixed Interest Account), guarantees, or benefits, including any death benefit, are subject to the claims-paying ability of the Company and our long term ability to make such payments, and are not guaranteed by any other party. MetLife is regulated as an insurance company under state law, which generally includes limits on the amount and type of investments in its general account. However, there is no guarantee that we will be able to meet our claims paying obligations; there are risks to purchasing any insurance product. More information about the Company, including its financial strength ratings, is available upon request or by visiting https://www.metlife.com/about-us/ corporate-profile/ratings/. |
Principal Risks of Investing in the Contract |
|
| Investment Restrictions [Text Block] |
Yes. Although we do not currently charge a fee for transfers of Account Value among Divisions or between the Divisions and the Fixed Interest Account, we reserve the right to impose a transfer fee of $25 on transfers in excess of 12 in a Contract Year. The Lifetime Withdrawal Guarantee imposes restrictions and limitations on your choice of Portfolios. These restrictions and requirements are intended to protect the Company and reduce the likelihood that we will have to pay guaranteed benefits under the Lifetime Withdrawal Guarantee out of our own assets. The restrictions and requirements could result in your missing out on some or all positive investment performance by certain of the Portfolios — this means your opportunity for investment gains may be limited.We reserve the right to add, remove or substitute Portfolios.The Company also has policies and procedures that attempt to detect and deter frequent transfers in situations where we determine there is a potential for arbitrage trading, and in those instances, there are additional limits that apply to transfers.
|
| Key Information, Benefit Restrictions [Text Block] |
Yes. Many optional benefits limit or restrict the Portfolios You may select under the Contract. We may change these restrictions in the future.You are required to have a certain Contract Value for some optional benefits. If withdrawals reduce Your Contract below this value, your optional benefits may be reduced or terminated.Withdrawals that exceed limits specified by the terms of an optional benefit may affect the availability of the benefit by reducing the benefit by an amount greater than the value withdrawn, and/or could terminate the benefit.If your annuity was issued in connection with an employer plan, You should check with your employer regarding the availability of riders.
|
| Tax Implications [Text Block] |
You should consult with a tax professional to determine the tax implications of an investment in and purchase payments received under the Contract.●There is no additional tax benefit if You purchase the Contract through a tax-qualified plan or individual retirement account (IRA).●If your Contract was purchased through a tax-qualified plan or IRA, withdrawals will be subject to ordinary income tax. If your Contract is not tax-qualified, earnings on your Contract will be subject to ordinary income tax when You withdraw them. You may also have to pay a penalty if You take a withdrawal before age 59 1∕2.
|
| Investment Professional Compensation [Text Block] |
Your investment professional may receive compensation for selling this Contract to You, both in the form of commissions and because MetLife may share the revenue it earns on this Contract with the professional’s firm. This conflict of interest may influence your investment professional to recommend this Contract over another investment.
|
| Exchanges [Text Block] |
Some investment professionals may have a financial incentive to offer You a new Contract in place of the one You own. You should only exchange your Contract if You determine, after comparing the features, fees, and risks of both contracts, and any fees or penalties to terminate the existing contract, that it is better for You to purchase the new contract rather than continue to own your existing Contract.
|
| Item 4. Fee Table [Line Items] |
|
| Item 4. Fee Table [Text Block] |
FEESThe following tables describe the fees and expenses that You will pay when buying, owning, and surrendering or making withdrawals from the Contract. Please refer to your Contract specifications page for information about the specific fees You will pay each year based on the options You have elected. The first table describes the fees and expenses that You will pay at the time that You buy the Contract, surrender or make withdrawals from the Contract, or transfer Account Value between investment options. State premium taxes may also be deducted.Transaction Fees
| |
|
|
|
|
|
Withdrawal Charge (as a percentage of the amount |
|
|
|
|
|
| |
|
|
|
|
|
| |
|
|
|
|
|
| |
|
|
|
|
| (1)There are times when the Withdrawal Charge does not apply to amounts that are withdrawn from the Deferred Annuity. For example, after the first Contract Year, each year You may withdraw up to 10% of your Account Balance without a Withdrawal Charge. These withdrawals are made on a non-cumulative basis.(2)Although not currently charged, we reserve the right to limit transfers as described later in this Prospectus and we reserve the right to impose a transfer fee. The amount of this fee will be no greater than $25 per transfer on transfers in excess of 12 in a Contract Year.(3)The fee may be waived or reduced for certain Plans.(4)Represents the maximum Withdrawal Charges. For the B Class, other than Connecticut, the maximum Withdrawal Charge is 9%. The B Class in Connecticut has a maximum Withdrawal Charge of 10%. As of January 1, 2024, in New York, the maximum Withdrawal Charge for the L Class is 8% and only the L Class is available for new enrollments in New York.(5)Premium taxes, if applicable, depend on the Contract You purchased and your home state or jurisdiction and range from 0 to 3.50% of Account Value (or, if applicable, purchase payments).The next table describes the fees and expenses that You will pay each year during the time that You own the Contract (not including Portfolio Company fees and expenses). If You choose to purchase an optional benefit, You will pay additional charges, as shown below.Annual Contract Expenses
| |
|
|
|
|
|
Administrative Expenses(1) |
|
|
|
|
|
Base Contract Expenses (as a percentage of your average |
|
|
|
|
|
Optional Annual Step-Up Death Benefit (as a percentage of your average Account Balance) |
|
|
|
|
|
Optional Guaranteed Minimum Income Benefit(4) |
|
|
|
|
|
Optional Lifetime Withdrawal Guarantee Benefit (maximum |
|
|
|
|
|
Annual Loan Maintenance Fee (per loan outstanding)(6) |
|
|
|
|
| (1)The Annual Contract Fee is $30 annually. The Annual Contract Fee may be waived under certain circumstances. For classes B, C, and L this fee is waived if your total purchase payments for the prior 12 months are at least $2,000 on the day the fee is deducted or if your Account Balance is at least $25,000 on the day the fee is deducted and for e and e Bonus classes if your Account Balance is at least $50,000 on the day the fee is deducted. The fee will be deducted on a pro-rata basis (determined based upon the number of complete months that have elapsed since the prior Contract Anniversary) if You take a total withdrawal of your Account Balance. This fee will not be deducted if You are on medical leave approved by your employer or called to active armed service duty at the time the fee is to be deducted and your employer has informed us of your status. During the pay-out phase we reserve the right to deduct this fee.(2)You pay the Base Contract Expenses for your class of the Deferred Annuity during the pay-in phase of your Contract. Charges for optional benefits are those for a Deferred Annuity purchased after April 30, 2009. Different charges may have been in effect for prior time periods. (3)The Base Contract Expenses for the e Bonus Class will be reduced by 0.45% to 0.50% after You have held the Contract for seven years.(4)You may only have one living benefit, the Guaranteed Minimum Income Benefit or the Lifetime Withdrawal Benefit, associated with your Contract at any given time. The charge for the Guaranteed Minimum Income Benefit is a percentage of your guaranteed minimum income base, as defined later in this Prospectus, and is deducted at the end of each Contract Year by withdrawing amounts on a pro-rata basis from your Fixed Interest Account Balance and Your Investment Options (net of any loans). (We take amounts from the Separate Account by canceling, if available, Accumulation Units from your Separate Account Balance.) You do not pay this charge once You are in the pay-out phase of your Contract. Different charges for the Guaranteed Minimum Income Benefit were in effect prior to May 4, 2009.(5)The charge for the Lifetime Withdrawal Guarantee Benefit is a percentage of your Total Guaranteed Withdrawal Amount, as defined later in this Prospectus, and is deducted at the end of each Contract Year by withdrawing amounts on a pro-rata basis from your Fixed Interest Account Balance and Separate Account Balance. (We take amounts from the Separate Account by canceling Accumulation Units from your Separate Account Balance.) You do not pay this charge once You are in the pay-out phase of your Contract or after your rider terminates. If an Automatic Annual Step-Up occurs under a Lifetime Withdrawal Guarantee Benefit, we may increase the Lifetime Withdrawal Guarantee Benefit charge to the current charge, but no more than a maximum of 0.95%. Different charges for the optional Lifetime Withdrawal Guarantee Benefit were in effect prior to May 4, 2009. If, at the time the Contract was issued, the current charge for the benefit was equal to the maximum charge, then the charge for the benefit will not increase upon an Automatic Annual Step-Up.(6)The fee may be waived or reduced for certain Plans. The loan maintenance fee is paid on a quarterly basis at the end of each quarter on a pro-rata basis from the Divisions and the Fixed Interest Account in which You then have a balance.The next table shows the minimum and maximum total operating expenses charged by the Portfolios that You may pay periodically during the time that You own the Contract. Expenses shown may change over time and may be higher or lower in the future. These amounts also include applicable Platform Charges if You choose to invest in certain Portfolios.(1) A complete list of Portfolios available under the Contract, including their annual expenses, may be found in “Appendix A - Investment Options Available Under the Contract” at the back of this Prospectus.Annual Portfolio Company Expenses
| |
|
|
Annual Portfolio Expenses (as a percentage of daily net assets) Expenses that are deducted from Portfolio Company assets, including management fees, distribution and/or service (12b-1) fees, and other expenses |
|
| (1)Investments in the American Funds® Division are subject to a platform charge of 0.25%. We reserve the right to impose an additional platform charge on Divisions that we add to the Contract in the future. The additional amount will not exceed the annual rate of 0.25% of the average Account Balance in any such Divisions.ExamplesThese Examples are intended to help you compare the cost of investing in the Divisions with the cost of investing in other annuity contracts that offer variable options. These costs include Transaction Expenses, Annual Contract Expenses and Annual Portfolio Company Expenses.The Examples assume all Contract Value is allocated to the Divisions. Your costs could differ from those shown below if you invest in the Fixed Interest Account.The Examples assume that you invest $100,000 in the variable options of the Contract for the time periods indicated and that there are no exchanges or other transactions. The Examples also assume that your investment has a 5% return each year. Examples 1 through 5 assume the most expensive combination of Annual Portfolio Company Expenses and optional benefits available for an additional charge. Examples 6 through 10 assume You purchased the Contract with no optional benefits that resulted in the least expensive combination of charges.
|
| Transaction Expenses [Table Text Block] |
Transaction Fees
| |
|
|
|
|
|
Withdrawal Charge (as a percentage of the amount |
|
|
|
|
|
| |
|
|
|
|
|
| |
|
|
|
|
|
| |
|
|
|
|
| (1)There are times when the Withdrawal Charge does not apply to amounts that are withdrawn from the Deferred Annuity. For example, after the first Contract Year, each year You may withdraw up to 10% of your Account Balance without a Withdrawal Charge. These withdrawals are made on a non-cumulative basis.(2)Although not currently charged, we reserve the right to limit transfers as described later in this Prospectus and we reserve the right to impose a transfer fee. The amount of this fee will be no greater than $25 per transfer on transfers in excess of 12 in a Contract Year.(3)The fee may be waived or reduced for certain Plans.(4)Represents the maximum Withdrawal Charges. For the B Class, other than Connecticut, the maximum Withdrawal Charge is 9%. The B Class in Connecticut has a maximum Withdrawal Charge of 10%. As of January 1, 2024, in New York, the maximum Withdrawal Charge for the L Class is 8% and only the L Class is available for new enrollments in New York.(5)Premium taxes, if applicable, depend on the Contract You purchased and your home state or jurisdiction and range from 0 to 3.50% of Account Value (or, if applicable, purchase payments).
|
| Deferred Sales Load, Footnotes [Text Block] |
There are times when the Withdrawal Charge does not apply to amounts that are withdrawn from the Deferred Annuity. For example, after the first Contract Year, each year You may withdraw up to 10% of your Account Balance without a Withdrawal Charge. These withdrawals are made on a non-cumulative basis.
|
| Transfer Fee, Footnotes [Text Block] |
Although not currently charged, we reserve the right to limit transfers as described later in this Prospectus and we reserve the right to impose a transfer fee. The amount of this fee will be no greater than $25 per transfer on transfers in excess of 12 in a Contract Year.
|
| Annual Contract Expenses [Table Text Block] |
Annual Contract Expenses
| |
|
|
|
|
|
Administrative Expenses(1) |
|
|
|
|
|
Base Contract Expenses (as a percentage of your average |
|
|
|
|
|
Optional Annual Step-Up Death Benefit (as a percentage of your average Account Balance) |
|
|
|
|
|
Optional Guaranteed Minimum Income Benefit(4) |
|
|
|
|
|
Optional Lifetime Withdrawal Guarantee Benefit (maximum |
|
|
|
|
|
Annual Loan Maintenance Fee (per loan outstanding)(6) |
|
|
|
|
| (1)The Annual Contract Fee is $30 annually. The Annual Contract Fee may be waived under certain circumstances. For classes B, C, and L this fee is waived if your total purchase payments for the prior 12 months are at least $2,000 on the day the fee is deducted or if your Account Balance is at least $25,000 on the day the fee is deducted and for e and e Bonus classes if your Account Balance is at least $50,000 on the day the fee is deducted. The fee will be deducted on a pro-rata basis (determined based upon the number of complete months that have elapsed since the prior Contract Anniversary) if You take a total withdrawal of your Account Balance. This fee will not be deducted if You are on medical leave approved by your employer or called to active armed service duty at the time the fee is to be deducted and your employer has informed us of your status. During the pay-out phase we reserve the right to deduct this fee.(2)You pay the Base Contract Expenses for your class of the Deferred Annuity during the pay-in phase of your Contract. Charges for optional benefits are those for a Deferred Annuity purchased after April 30, 2009. Different charges may have been in effect for prior time periods. (3)The Base Contract Expenses for the e Bonus Class will be reduced by 0.45% to 0.50% after You have held the Contract for seven years.(4)You may only have one living benefit, the Guaranteed Minimum Income Benefit or the Lifetime Withdrawal Benefit, associated with your Contract at any given time. The charge for the Guaranteed Minimum Income Benefit is a percentage of your guaranteed minimum income base, as defined later in this Prospectus, and is deducted at the end of each Contract Year by withdrawing amounts on a pro-rata basis from your Fixed Interest Account Balance and Your Investment Options (net of any loans). (We take amounts from the Separate Account by canceling, if available, Accumulation Units from your Separate Account Balance.) You do not pay this charge once You are in the pay-out phase of your Contract. Different charges for the Guaranteed Minimum Income Benefit were in effect prior to May 4, 2009.(5)The charge for the Lifetime Withdrawal Guarantee Benefit is a percentage of your Total Guaranteed Withdrawal Amount, as defined later in this Prospectus, and is deducted at the end of each Contract Year by withdrawing amounts on a pro-rata basis from your Fixed Interest Account Balance and Separate Account Balance. (We take amounts from the Separate Account by canceling Accumulation Units from your Separate Account Balance.) You do not pay this charge once You are in the pay-out phase of your Contract or after your rider terminates. If an Automatic Annual Step-Up occurs under a Lifetime Withdrawal Guarantee Benefit, we may increase the Lifetime Withdrawal Guarantee Benefit charge to the current charge, but no more than a maximum of 0.95%. Different charges for the optional Lifetime Withdrawal Guarantee Benefit were in effect prior to May 4, 2009. If, at the time the Contract was issued, the current charge for the benefit was equal to the maximum charge, then the charge for the benefit will not increase upon an Automatic Annual Step-Up.(6)The fee may be waived or reduced for certain Plans. The loan maintenance fee is paid on a quarterly basis at the end of each quarter on a pro-rata basis from the Divisions and the Fixed Interest Account in which You then have a balance.
|
| Base Contract Expense, Footnotes [Text Block] |
The Annual Contract Fee is $30 annually. The Annual Contract Fee may be waived under certain circumstances. For classes B, C, and L this fee is waived if your total purchase payments for the prior 12 months are at least $2,000 on the day the fee is deducted or if your Account Balance is at least $25,000 on the day the fee is deducted and for e and e Bonus classes if your Account Balance is at least $50,000 on the day the fee is deducted. The fee will be deducted on a pro-rata basis (determined based upon the number of complete months that have elapsed since the prior Contract Anniversary) if You take a total withdrawal of your Account Balance. This fee will not be deducted if You are on medical leave approved by your employer or called to active armed service duty at the time the fee is to be deducted and your employer has informed us of your status. During the pay-out phase we reserve the right to deduct this fee.(2)You pay the Base Contract Expenses for your class of the Deferred Annuity during the pay-in phase of your Contract. Charges for optional benefits are those for a Deferred Annuity purchased after April 30, 2009. Different charges may have been in effect for prior time periods. (3)The Base Contract Expenses for the e Bonus Class will be reduced by 0.45% to 0.50% after You have held the Contract for seven years.
|
| Annual Portfolio Company Expenses [Table Text Block] |
| |
|
|
Annual Portfolio Expenses (as a percentage of daily net assets) Expenses that are deducted from Portfolio Company assets, including management fees, distribution and/or service (12b-1) fees, and other expenses |
|
|
|
| Portfolio Company Expenses [Text Block] |
Annual Portfolio Expenses (as a percentage of daily net assets)Expenses that are deducted from Portfolio Company assets, including management fees, distribution and/or service (12b-1) fees, and other expenses
|
| Portfolio Company Expenses Minimum [Percent] |
0.52%
|
| Portfolio Company Expenses Maximum [Percent] |
1.38%
|
| Surrender Example [Table Text Block] |
Example 1 - table 1
| |
|
|
|
|
If You surrender your Contract at the end of the applicable time period |
|
|
|
|
| |
|
|
|
|
| |
|
|
|
| Example 3 - table 1
| |
|
|
|
|
If You surrender your Contract at the end of the applicable time period |
|
|
|
|
| |
|
|
|
|
| |
|
|
|
| Example 5 - table 1
| |
|
|
|
|
If You surrender your Contract at the end of the applicable time period |
|
|
|
|
| |
|
|
|
|
| |
|
|
|
|
|
| Annuitize Example [Table Text Block] |
Example 2
| |
|
|
|
|
If You surrender, annuitize or do not surrender your Contract at the end of the applicable time period |
|
|
|
|
| |
|
|
|
|
| |
|
|
|
| Example 3 - table 2
| |
|
|
|
|
If You annuitize or do not surrender your Contract at the end of the applicable time period |
|
|
|
|
| |
|
|
|
|
| |
|
|
|
| Example 4
| |
|
|
|
|
If You surrender, annuitize or do not surrender your Contract at the end of the applicable time period |
|
|
|
|
| |
|
|
|
|
| |
|
|
|
| Example 5 - table 2
| |
|
|
|
|
If You annuitize or do not surrender your Contract at the end of the applicable time period |
|
|
|
|
| |
|
|
|
|
| |
|
|
|
|
|
| No Surrender Example [Table Text Block] |
Example 1 - table 2
| |
|
|
|
|
If You annuitize or do not surrender your Contract at the end of the applicable time period |
|
|
|
|
| |
|
|
|
|
| |
|
|
|
|
|
| Item 5. Principal Risks [Line Items] |
|
| Item 5. Principal Risks [Table Text Block] |
PRINCIPAL RISKSInvesting in the Contract involves risks. The following are the principal risks of an investment in the Contract. You should carefully consider the below risks in addition to the other information contained in this Prospectus.Market Risk. An investment in the Contract is not a bank deposit and is not guaranteed by the Federal Deposit Insurance Corporation or any other governmental agency. The Contract is subject to market risk (the risk that your investments may decline in value or underperform your expectations). As a result, You can lose money by investing in the Contract, including loss of principal.Early Withdrawal Risk. This Contract is not a short-term investment and is not appropriate for an investor who needs ready access to cash. If You withdraw early, You may have to pay a Withdrawal Charge and/or income taxes, including a tax penalty if You are younger than age 59 1∕2. Withdrawal Charges may apply if You withdraw money from the Contract less than 13 Contract Years after You purchased the Contract. Withdrawal Charges will reduce the value of your Contract if You withdraw money during that time. The benefits of tax deferral and living benefit protections also mean that the Contract is more beneficial to investors with a long time horizon.Risk of Underlying Portfolios. An investment in the Contract is subject to the risk of poor investment performance and can vary depending on the performance of the investment options available under the Contract (e.g., Portfolio Companies). Each investment option (including the Fixed Interest Account investment option) will have its own unique risks. We do not provide any investment advice and do not recommend or endorse any particular Portfolio. You bear the risk of any decline in the Account Balance of your Contract resulting from the performance of the Portfolios You have chosen. You should review these investment options before making an investment decision. Information regarding the Portfolios available under your Contract is available in Appendix A to this Prospectus.Contract Termination Subject to certain limitations, if your Account Balance falls below the minimum Account Balance or is not sufficient to pay the Contract charges, we may terminate your Deferred Annuity.Contract Benefits Risk. Withdrawals that exceed limits specified by the terms of any benefit may affect the availability of the benefit by reducing the benefit by an amount greater than the value withdrawn, and/or could terminate the benefit. In addition, the Lifetime Withdrawal Guarantee imposes restrictions and limitations on your choice of Portfolios. These restrictions and requirements are intended to protect the Company and reduce the likelihood that we will have to pay guaranteed benefits under the Lifetime Withdrawal Guarantee out of our own assets. The restrictions and requirements could result in your missing out on some or all positive investment performance by certain of the Portfolios – this means your opportunity for investment gains may be limited.Insurance Company Risk. An investment in the Contract is subject to the risks related to the Company. Any obligations (including under the Fixed Interest Account), guarantees, or benefits are subject to the financial strength and claims-paying ability of the Company and our long term ability to make such payments, and are not guaranteed by any other party. MetLife is regulated as an insurance company under state law, which generally includes limits on the amount and type of investments in its general account. However, there is no guarantee that we will be able to meet our claims paying obligations; there are risks to purchasing any insurance product.Contract Changes Risk. Subject to applicable law, we have the right to make certain changes to your Contract. Examples of the changes we may make include: (i) operating the Separate Account in any form permitted by law; (ii) taking any action necessary to comply with or obtain and continue any exemptions under the law (including favorable treatment under the Federal income tax laws) including limiting the number, frequency or types of transfers/reallocations permitted; (iii) transferring any assets in a Division to another Division, or to one or more Separate Accounts, or to our general account, or adding, combining or removing Divisions in the Separate Account; (iv) substituting Portfolio shares in any Division, with the shares of another class of Brighthouse Trust I, Brighthouse Trust II, or the shares of another investment company or any other investment permitted by law or closing, adding or removing Portfolios as Investment Division investments as permitted by law; (v) changing the way we assess charges, but without increasing the maximum aggregate amount charged to the Separate Account and any currently available Portfolio in connection with the Contracts; and (vi) making any necessary technical changes in the Contracts in order to conform with any of the above-described actions.Conflicts of Interest. Your investment professional may receive compensation for selling this Contract to You, both in the form of commissions and because MetLife may share the revenue it earns on this Contract with the professional’s firm. This conflict of interest may influence your investment professional to recommend this Contract over another investment. In addition, some investment professionals may have a financial incentive to offer You a new contract in place of the one You own. You should only exchange your Contract if You determine, after comparing the features, fees, and risks of both contracts, that it is better for You to purchase the new contract rather than continue to own your existing Contract.Suitability. An investment in the Contract may not be suitable for all investors. For example, there is no additional tax benefit if You purchase the Contract through a tax-qualified plan or individual retirement account (IRA). Therefore, there should be reasons other than tax deferral for acquiring the Contract. You should consult with a tax or investment professional to determine the tax and other implications of an investment in and purchase payments received under the Contract.Taxation Risk. Although the provisions of the Internal Revenue Code (the “Code”) relevant to the Contract are generally described under “Federal Tax Considerations,” an investor should consult their own tax advisor concerning the effects of federal, state, local and foreign tax law on the Contract. No assurance can be given that, even if the tax provisions currently applicable to the Contract are favorable, the law or regulations or interpretations thereunder will not change and the Contract may be disadvantaged.Cybersecurity. Our business is highly dependent upon the effective operation of our information systems, and those of our service providers, vendors, and other third parties. Cybersecurity breaches of such systems can be intentional or unintentional events, and can occur through unauthorized access to computer systems, networks or devices; infection from computer viruses or other malicious software code; or attacks that shut down, disable, slow or otherwise disrupt operations, business processes or website access or functionality and our disaster recovery systems may be insufficient to safeguard our ability to conduct business. Cybersecurity breaches can interfere with our processing of Contract transactions, including the processing of transfer orders from our website or with the Portfolios; impact our ability to calculate Accumulation Unit Values; cause the release and possible loss or destruction of confidential Contract Owner or business information; impede order processing or cause other operational issues; and result in regulatory enforcement actions or new laws or regulations which could increase our compliance costs. Although we continually make efforts to identify and reduce our exposure to cybersecurity risk, and we require our critical vendors to implement effective cybersecurity and data protection measures, there is no guarantee that we will be able to successfully manage this risk at all times.Bonus Class Risk. Expenses of a class that includes a bonus feature may be higher than expenses of a class of the Contract without the bonus, and the additional amount of the bonus may be more than offset by the additional fees and charges associated with the bonus class, including Withdrawal Charges. Any bonus associated with the class will be retrieved upon exercise of a “Free Look” cancellation. Pandemics and Other Public Health Issues and Other Events. Pandemics and other public health issues or other events, and governmental, business, and consumer reactions to them, may affect economic conditions and may cause a large number of illnesses or deaths. Hurricanes, windstorms, earthquakes, hail, tornadoes, explosions, severe winter weather, fires, floods and mudslides, blackouts and man-made events such as riot, insurrection, terrorist attacks or acts of war may also cause catastrophic losses and increased claims. Any such catastrophes may also result in changes in consumer or business confidence, behavior and investment and business activity, changes to interest rates and other market risk factors, and governmental or other restrictions on economic activity for prolonged periods. Terrorism and Security Risk. The continued threat of terrorism, ongoing or potential military conflict and other actions, and heightened security measures may cause economic uncertainty and result in loss of life, property damage, additional disruptions to commerce and reduced economic activity. The value of MetLife's investment portfolio may be adversely affected by declines in the credit and equity markets and reduced economic activity caused by such threats. Companies in which we maintain investments may suffer losses as a result of financial, commercial or economic disruptions, and such disruptions might affect the ability of those companies to pay interest or principal on their securities or mortgage loans. Terrorist or military actions also could disrupt our operations centers and result in higher than anticipated claims under our insurance policies. Technology Risk. Our business operations rely on functioning and secure information systems, including those of our vendors and other third parties. Technological changes present us with new or intensified challenges, and if we are unable to foresee or adapt to these changes, our business may be adversely affected. Technological changes may affect our business model and how we interact with our customers. The growth and availability of AI technologies, including generative AI, presents significant opportunities but also complex challenges; these include balancing and mitigating potential risks of harm posed by the development or deployment of AI technologies, as well as implementing and maintaining controls reasonably designed to ensure compliance with an increasingly complex AI regulatory landscape, with evolving requirements that may vary across jurisdictions. We may fail to adopt new technologies as effectively or efficiently as others, leading to competitive harm. If we are unable to update our business model to match evolving consumer preferences or the evolving technological landscape, we may be adversely affected.New technologies may impact the configuration of our information systems, and how they connect with those of our vendors, service providers and/or partners. Such technological developments may introduce or uncover information security vulnerabilities, which may result in breaches, increased costs associated with maintaining appropriate data privacy, data protection, and cybersecurity measures, enforcement actions against us by regulators or other outcomes that may adversely impact our operations or business. In addition, any such vulnerability that results in a security breach or failure of our information systems, or those of third parties on which we rely, may result in litigation, regulatory action, negative impacts to our business operations, and reputational harm.
|
| Item 10. Benefits Available [Line Items] |
|
| Benefits Available (N-4) [Text Block] |
BENEFITS AVAILABLE UNDER THE CONTRACTThe following table summarizes information about the benefits available under the Contract:
| |
|
Is Benefit Standard or Optional? |
|
Brief Description of Restrictions/ Limitations |
| |
If You die during the pay-in phase, guarantees that the death benefit will not be less than the greater of (1) your Account Balance less any outstanding loans; or (2) total purchase payment reduced proportionately by the percentage reduction in Account Balance attributable to each partial withdrawal less any outstanding loans (including any applicable Withdrawal Charge). |
|
|
●Withdrawals could significantly reduce the benefit. |
| |
|
Is Benefit Standard or Optional? |
|
Brief Description of Restrictions/ Limitations |
Annual Step-Up Death Benefit |
If You die during the pay-in phase, guarantees that the death benefit will not be less than the greatest of (1) your Account Balance; (2) total purchase payments reduced proportionately for withdrawals and any outstanding loans (including any applicable Withdrawal Charge) or (3) "Highest Anniversary Value" as of each Contract Anniversary prior to your 81st birthday, plus any subsequent purchase payments, reduced for any outstanding loans, and reduced proportionately for withdrawals (including any applicable Withdrawal Charge). |
|
0.10% as a percentage of your average Account Balance |
●Withdrawals could significantly reduce the benefit. ●You may not purchase this benefit if You are 80 years of age or older. ●Available only at issue. |
| |
|
Is Benefit Standard or Optional? |
|
Brief Description of Restrictions/ Limitations |
Guaranteed Minimum Income Benefit |
Designed to guarantee a predictable, minimum level of fixed income payments, regardless of investment performance of your Account Balance during the pay-in phase. |
|
0.70% of your guaranteed minimum income base |
●No longer available for sale. ●You may not have this optional benefit and another optional living benefit (Lifetime Withdrawal Guarantee) in effect at the same time. ●Age restrictions apply. ●May only be exercised after a 10-year waiting period. ●Availability subject to state. ●Cannot be terminated. ●Withdrawals could significantly reduce the benefit. |
| |
|
Is Benefit Standard or Optional? |
|
Brief Description of Restrictions/ Limitations |
Lifetime Withdrawal Guarantee Benefit |
Guaranteed Payments for Life. So long as You make your first withdrawal on or after the date You reach age 59 1∕2, the LWG guarantees that we will make payments to You over your lifetime, even if your Remaining Guaranteed Withdrawal Amount and/or Account Balance decline to zero. |
|
0.95% of your Total Guaranteed Withdrawal Amount |
●No longer available for sale. ●Benefit limits available investment options. (See “Appendix A — Investment Options Available Under the Contract — Investment Allocation Restrictions for Certain Optional Benefits.”) ●Age restrictions apply. ●You may not have this optional benefit and another optional living benefit (Guaranteed Minimum Income Benefit) in effect at the same time. ●In the first 15 Contract Years You may only cancel this benefit every 5 Contract Years. Thereafter You may cancel annually within 30 days following the eligible Contract Anniversary. |
| |
|
Is Benefit Standard or Optional? |
|
Brief Description of Restrictions/ Limitations |
Waiver of Withdrawal Charge for Nursing Home or Hospital Confinement |
Allows you to withdraw money without a Withdrawal Charge in the event of nursing home or hospital confinement, subject to certain conditions. |
|
|
●Only available after the first Contract Year. ●Age restrictions, ownership requirements and doctor certification requirements apply. ●Must be approved in your state. ●You must meet certain length of confinement requirements. |
Waiver of Withdrawal Charge for Terminal Illness |
Allows you to withdraw money without a Withdrawal Charge in the event of a terminal illness, subject to certain conditions. |
|
|
●Only available after the first Contract Year. ●Age restrictions, ownership requirements and doctor certification requirements apply. ●Must be approved in your state. ●Certain requirements relating to the nature of the terminal illness apply. ●You must not have been diagnosed with the terminal illness as of the Contract issue date. |
| |
An amount equal to the interest earned in the Fixed Interest Account is transferred monthly to any one Division based on your selection. |
|
|
●If your Fixed Interest Account Balance at the time of a scheduled transfer is zero, this strategy is automatically discontinued. |
| |
|
Is Benefit Standard or Optional? |
|
Brief Description of Restrictions/ Limitations |
| |
You select a specific asset allocation for your entire Account Balance from among the Divisions and the Fixed Interest Account, if available. Each quarter we transfer amounts among these options to bring the percentage of your Account Balance in each option back to your original allocation. |
|
|
●In the future, we may permit You to allocate less than 100% of your Account Balance to this strategy. |
| |
You may select one of five asset allocation models which are designed to correlate to various risk tolerance levels. Each quarter the percentage in each of the Divisions in which the model invests and any Fixed Interest Account is brought back to the selected model percentage by transferring amounts among the Divisions and any Fixed Interest Account |
|
|
●Benefit limits available investment options. ●The Index Selector is not available with the optional Lifetime Withdrawal Guarantee. |
| |
Transfers a dollar amount of your choice from the Fixed Interest Account to any of the Divisions you choose on a monthly basis. |
|
|
●Minimum periodic transfer of $50 is required. ●Once your Fixed Interest Account Balance is exhausted, the strategy is discontinued. |
| |
|
Is Benefit Standard or Optional? |
|
Brief Description of Restrictions/ Limitations |
Systematic Withdrawal Program |
Automatically withdraws a specific dollar amount or a percentage of your Account Balance of your choice each Contract Year. |
|
|
●Not available under the 457(b) Deferred Annuity issued to tax-exempt organizations. ●Not available in all states. ●Income taxes, tax penalties and Withdrawal Charges may apply to your withdrawals. ●Subject to our required minimums and administrative restrictions. ●Not available to the B and L Classes of the Deferred Annuities until the second Contract Year. ●If You elect to receive payments through this program, You must have no loan outstanding from the Fixed Interest Account and You must either be 59 1∕2 years old or have left your job. Tax law generally prohibits withdrawals from TSA Deferred Annuities before You reach 59 1∕2. ●Not available in conjunction with any automated investment strategy. | *If your annuity was issued in connection with an employer plan, you should check with your employer regarding the availability of benefits.
|
| Benefits Available [Table Text Block] |
| |
|
Is Benefit Standard or Optional? |
|
Brief Description of Restrictions/ Limitations |
| |
If You die during the pay-in phase, guarantees that the death benefit will not be less than the greater of (1) your Account Balance less any outstanding loans; or (2) total purchase payment reduced proportionately by the percentage reduction in Account Balance attributable to each partial withdrawal less any outstanding loans (including any applicable Withdrawal Charge). |
|
|
●Withdrawals could significantly reduce the benefit. |
| |
|
Is Benefit Standard or Optional? |
|
Brief Description of Restrictions/ Limitations |
Annual Step-Up Death Benefit |
If You die during the pay-in phase, guarantees that the death benefit will not be less than the greatest of (1) your Account Balance; (2) total purchase payments reduced proportionately for withdrawals and any outstanding loans (including any applicable Withdrawal Charge) or (3) "Highest Anniversary Value" as of each Contract Anniversary prior to your 81st birthday, plus any subsequent purchase payments, reduced for any outstanding loans, and reduced proportionately for withdrawals (including any applicable Withdrawal Charge). |
|
0.10% as a percentage of your average Account Balance |
●Withdrawals could significantly reduce the benefit. ●You may not purchase this benefit if You are 80 years of age or older. ●Available only at issue. |
| |
|
Is Benefit Standard or Optional? |
|
Brief Description of Restrictions/ Limitations |
Guaranteed Minimum Income Benefit |
Designed to guarantee a predictable, minimum level of fixed income payments, regardless of investment performance of your Account Balance during the pay-in phase. |
|
0.70% of your guaranteed minimum income base |
●No longer available for sale. ●You may not have this optional benefit and another optional living benefit (Lifetime Withdrawal Guarantee) in effect at the same time. ●Age restrictions apply. ●May only be exercised after a 10-year waiting period. ●Availability subject to state. ●Cannot be terminated. ●Withdrawals could significantly reduce the benefit. |
| |
|
Is Benefit Standard or Optional? |
|
Brief Description of Restrictions/ Limitations |
Lifetime Withdrawal Guarantee Benefit |
Guaranteed Payments for Life. So long as You make your first withdrawal on or after the date You reach age 59 1∕2, the LWG guarantees that we will make payments to You over your lifetime, even if your Remaining Guaranteed Withdrawal Amount and/or Account Balance decline to zero. |
|
0.95% of your Total Guaranteed Withdrawal Amount |
●No longer available for sale. ●Benefit limits available investment options. (See “Appendix A — Investment Options Available Under the Contract — Investment Allocation Restrictions for Certain Optional Benefits.”) ●Age restrictions apply. ●You may not have this optional benefit and another optional living benefit (Guaranteed Minimum Income Benefit) in effect at the same time. ●In the first 15 Contract Years You may only cancel this benefit every 5 Contract Years. Thereafter You may cancel annually within 30 days following the eligible Contract Anniversary. |
| |
|
Is Benefit Standard or Optional? |
|
Brief Description of Restrictions/ Limitations |
Waiver of Withdrawal Charge for Nursing Home or Hospital Confinement |
Allows you to withdraw money without a Withdrawal Charge in the event of nursing home or hospital confinement, subject to certain conditions. |
|
|
●Only available after the first Contract Year. ●Age restrictions, ownership requirements and doctor certification requirements apply. ●Must be approved in your state. ●You must meet certain length of confinement requirements. |
Waiver of Withdrawal Charge for Terminal Illness |
Allows you to withdraw money without a Withdrawal Charge in the event of a terminal illness, subject to certain conditions. |
|
|
●Only available after the first Contract Year. ●Age restrictions, ownership requirements and doctor certification requirements apply. ●Must be approved in your state. ●Certain requirements relating to the nature of the terminal illness apply. ●You must not have been diagnosed with the terminal illness as of the Contract issue date. |
| |
An amount equal to the interest earned in the Fixed Interest Account is transferred monthly to any one Division based on your selection. |
|
|
●If your Fixed Interest Account Balance at the time of a scheduled transfer is zero, this strategy is automatically discontinued. |
| |
|
Is Benefit Standard or Optional? |
|
Brief Description of Restrictions/ Limitations |
| |
You select a specific asset allocation for your entire Account Balance from among the Divisions and the Fixed Interest Account, if available. Each quarter we transfer amounts among these options to bring the percentage of your Account Balance in each option back to your original allocation. |
|
|
●In the future, we may permit You to allocate less than 100% of your Account Balance to this strategy. |
| |
You may select one of five asset allocation models which are designed to correlate to various risk tolerance levels. Each quarter the percentage in each of the Divisions in which the model invests and any Fixed Interest Account is brought back to the selected model percentage by transferring amounts among the Divisions and any Fixed Interest Account |
|
|
●Benefit limits available investment options. ●The Index Selector is not available with the optional Lifetime Withdrawal Guarantee. |
| |
Transfers a dollar amount of your choice from the Fixed Interest Account to any of the Divisions you choose on a monthly basis. |
|
|
●Minimum periodic transfer of $50 is required. ●Once your Fixed Interest Account Balance is exhausted, the strategy is discontinued. |
| |
|
Is Benefit Standard or Optional? |
|
Brief Description of Restrictions/ Limitations |
Systematic Withdrawal Program |
Automatically withdraws a specific dollar amount or a percentage of your Account Balance of your choice each Contract Year. |
|
|
●Not available under the 457(b) Deferred Annuity issued to tax-exempt organizations. ●Not available in all states. ●Income taxes, tax penalties and Withdrawal Charges may apply to your withdrawals. ●Subject to our required minimums and administrative restrictions. ●Not available to the B and L Classes of the Deferred Annuities until the second Contract Year. ●If You elect to receive payments through this program, You must have no loan outstanding from the Fixed Interest Account and You must either be 59 1∕2 years old or have left your job. Tax law generally prohibits withdrawals from TSA Deferred Annuities before You reach 59 1∕2. ●Not available in conjunction with any automated investment strategy. |
|
| Item 17. Investment Options [Line Items] |
|
| Investment Options (N-4) [Text Block] |
APPENDIX A — INVESTMENT OPTIONS AVAILABLE UNDER THE CONTRACTThe following is a list of Portfolios currently available. More information about the Portfolios is available in the prospectuses for the Portfolios, which may be amended from time to time and can be found online at https://dfinview.com/metlife/PUFT/MET000211. You can also request this information at no cost by calling (833) 642-1008, by sending an email request to RCG@metlife.com, or through your registered representative. Depending on the optional benefits You choose, You may not be able to invest in certain Portfolio Companies as described below. If your annuity was issued in connection with an employer plan, not all Portfolios are available under all Contracts and You should ask your employer for a list of available Portfolios.The current expenses and performance information below reflects fees and expenses of the Portfolios, but do not reflect the other fees and expenses that your Contract may charge. Expenses would be higher and performance would be lower if these other charges were included. Each Portfolio Company's past performance is not necessarily an indication of future performance.
*The Portfolio is subject to an expense reimbursement or fee waiver arrangement. The annual expenses shown reflect temporary fee reductions.(1)The Portfolio has an additional platform fee of 0.25%. This amount is included in the Mortality and Expense Risk Charge and is not a separate charge.††Effective May 1, 2026, the American Funds Global Small Capitalization Fund changed its name to American Funds SMALLCAP World Fund®.Fixed OptionThe following is information on the Fixed Interest Account currently available under the Contract. You should check with your Employer as to whether the Fixed Interest Account is available under your Contract. We reserve the right to restrict purchase payments and transfers to the Fixed Interest Account when the yield on investments is not expected to support the Minimum Guaranteed Interest Rate. We will provide you with written notice before doing so.
| |
|
Minimum Guaranteed Interest Rate* |
| |
Initial Interest Rate Term: begins on each calendar quarter and will be credited from the date amounts are allocated to the Fixed Interest Account until the last day of the same calendar quarter of the following year. Renewal Rate Term: 12 months. |
| *The Minimum Guaranteed Interest Rate varies by Contract and may be higher than the minimum guaranteed interest rate shown. Check your Contract for the Minimum Guaranteed Interest Rate that applies to your Fixed Interest Account Option.Investment Allocation Restrictions For Certain Optional BenefitsIndex Selector:If You elect the Index Selector You are limited to allocating your purchase payments and Account Balance among the following funding options and the Fixed Interest Account:MetLife Aggregate Bond Index
MetLife Stock Index
MetLife MSCI EAFE Index
MetLife Russell 2000 Index
MetLife Mid Cap Stock IndexLifetime Withdrawal GuaranteeIf You elect the Lifetime Withdrawal Guarantee Optional Benefit, You are limited to allocating your purchase payments and Account Balance among the following funding options and the Fixed Interest Account:Brighthouse Asset Allocation 20
Brighthouse Asset Allocation 40
Brighthouse Asset Allocation 60
Brighthouse Asset Allocation 80
|
| Variable Option [Line Items] |
|
| Prospectuses Available [Text Block] |
The following is a list of Portfolios currently available. More information about the Portfolios is available in the prospectuses for the Portfolios, which may be amended from time to time and can be found online at https://dfinview.com/metlife/PUFT/MET000211. You can also request this information at no cost by calling (833) 642-1008, by sending an email request to RCG@metlife.com, or through your registered representative. Depending on the optional benefits You choose, You may not be able to invest in certain Portfolio Companies as described below. If your annuity was issued in connection with an employer plan, not all Portfolios are available under all Contracts and You should ask your employer for a list of available Portfolios.The current expenses and performance information below reflects fees and expenses of the Portfolios, but do not reflect the other fees and expenses that your Contract may charge. Expenses would be higher and performance would be lower if these other charges were included. Each Portfolio Company's past performance is not necessarily an indication of future performance.
|
| Portfolio Companies [Table Text Block] |
| |
PORTFOLIO AND ADVISER/SUBADVISER |
|
|
CURRENT EXPENSES + PLATFORM CHARGE |
AVERAGE ANNUAL TOTAL RETURNS (as of 12/31/2025) |
| |
|
|
| |
American Funds Growth Fund(1) - Class 2 Capital Research and |
|
|
|
|
|
|
| |
American Funds Growth- Income Fund(1) - Class 2 Capital Research and |
|
|
|
|
|
|
| |
American Funds SMALLCAP World Fund® *(1)†† - Class 2 Capital Research and |
|
|
|
|
|
|
| |
American Funds The Bond Fund of America*(1) - Class 2 Capital Research and |
|
|
|
|
|
|
| |
American Funds® Aggressive Allocation Portfolio - Class C Brighthouse Investment Advisers, LLC |
|
|
|
|
|
|
| |
American Funds® Balanced Allocation Portfolio - Class C Brighthouse Investment Advisers, LLC |
|
|
|
|
|
|
| |
American Funds® Moderate Allocation Portfolio - Class C Brighthouse Investment Advisers, LLC |
|
|
|
|
|
|
| |
PORTFOLIO AND ADVISER/SUBADVISER |
|
|
CURRENT EXPENSES + PLATFORM CHARGE |
AVERAGE ANNUAL TOTAL RETURNS (as of 12/31/2025) |
| |
|
|
| |
BlackRock Bond Income Portfolio* - Class B Brighthouse Investment Advisers, LLC Subadviser: BlackRock Advisors, LLC |
|
|
|
|
|
|
| |
BlackRock Capital Appreciation Portfolio* - Class B Brighthouse Investment Advisers, LLC Subadviser: BlackRock Advisors, LLC |
|
|
|
|
|
|
| |
Brighthouse Asset Allocation 100 Portfolio - Class B Brighthouse Investment Advisers, LLC |
|
|
|
|
|
|
| |
Brighthouse Asset Allocation 20 Portfolio* - Class B Brighthouse Investment Advisers, LLC |
|
|
|
|
|
|
| |
Brighthouse Asset Allocation 40 Portfolio - Class B Brighthouse Investment Advisers, LLC |
|
|
|
|
|
|
| |
Brighthouse Asset Allocation 60 Portfolio - Class B Brighthouse Investment Advisers, LLC |
|
|
|
|
|
|
| |
Brighthouse Asset Allocation 80 Portfolio - Class B Brighthouse Investment Advisers, LLC |
|
|
|
|
|
|
| |
Brighthouse Small Cap Value Portfolio* - Class B Brighthouse Investment Advisers, LLC Subadviser: Allspring Global Investments, LLC |
|
|
|
|
|
|
| |
Brighthouse/Artisan Mid Cap Value Portfolio* - Class B Brighthouse Investment Advisers, LLC Subadviser: Artisan Partners Limited Partnership |
|
|
|
|
|
|
| |
PORTFOLIO AND ADVISER/SUBADVISER |
|
|
CURRENT EXPENSES + PLATFORM CHARGE |
AVERAGE ANNUAL TOTAL RETURNS (as of 12/31/2025) |
| |
|
|
| |
Brighthouse/Franklin Low Duration Total Return Portfolio* - Class B Brighthouse Investment Advisers, LLC Subadviser: Franklin Advisers, Inc. |
|
|
|
|
|
|
| |
Brighthouse/Wellington Balanced Portfolio - Class A Brighthouse Investment Advisers, LLC Subadviser: Wellington Management Company LLP |
|
|
|
|
|
|
| |
Brighthouse/Wellington Core Equity Opportunities Portfolio* - Class B Brighthouse Investment Advisers, LLC Subadviser: Wellington Management Company LLP |
|
|
|
|
|
|
| |
Brighthouse/Wellington Large Cap Research Portfolio* - Class B Brighthouse Investment Advisers, LLC Subadviser: Wellington Management Company LLP |
|
|
|
|
|
|
| |
CBRE Global Real Estate Portfolio* - Class B Brighthouse Investment Advisers, LLC Subadviser: CBRE Investment Management Listed Real Assets LLC |
|
|
|
|
|
|
| |
Freedom 2025 Portfolio - Service Class 2 Fidelity Management & Research Company LLC |
|
|
|
|
|
|
| |
Freedom 2030 Portfolio - Service Class 2 Fidelity Management & Research Company LLC |
|
|
|
|
|
|
| |
Freedom 2035 Portfolio - Service Class 2 Fidelity Management & Research Company LLC |
|
|
|
|
|
|
| |
PORTFOLIO AND ADVISER/SUBADVISER |
|
|
CURRENT EXPENSES + PLATFORM CHARGE |
AVERAGE ANNUAL TOTAL RETURNS (as of 12/31/2025) |
| |
|
|
| |
Freedom 2040 Portfolio - Service Class 2 Fidelity Management & Research Company LLC |
|
|
|
|
|
|
| |
Freedom 2045 Portfolio - Service Class 2 Fidelity Management & Research Company LLC |
|
|
|
|
|
|
| |
Freedom 2050 Portfolio - Service Class 2 Fidelity Management & Research Company LLC |
|
|
|
|
|
|
| |
Freedom 2055 Portfolio - Service Class 2 Fidelity Management & Research Company LLC |
|
|
|
|
|
|
| |
Freedom 2060 Portfolio - Service Class 2 Fidelity Management & Research Company LLC |
|
|
|
|
|
|
| |
Freedom 2065 Portfolio - Service Class 2 Fidelity Management & Research Company LLC |
|
|
|
|
|
|
| |
Freedom 2070 Portfolio - Service Class 2 Fidelity Management & Research Company LLC |
|
|
|
|
|
|
| |
Harris Oakmark International Portfolio* - Class B Brighthouse Investment Advisers, LLC Subadviser: Harris Associates L.P. |
|
|
|
|
|
|
| |
Invesco Global Equity Portfolio* - Class B Brighthouse Investment Advisers, LLC Subadviser: Invesco Advisers, Inc. |
|
|
|
|
|
|
| |
Invesco Small Cap Growth Portfolio* - Class B Brighthouse Investment Advisers, LLC Subadviser: Invesco Advisers, Inc. |
|
|
|
|
|
|
| |
PORTFOLIO AND ADVISER/SUBADVISER |
|
|
CURRENT EXPENSES + PLATFORM CHARGE |
AVERAGE ANNUAL TOTAL RETURNS (as of 12/31/2025) |
| |
|
|
| |
Jennison Growth Portfolio* - Class B Brighthouse Investment Advisers, LLC Subadviser: Jennison Associates LLC |
|
|
|
|
|
|
| |
Loomis Sayles Global Allocation Portfolio* - Class B Brighthouse Investment Advisers, LLC Subadviser: Loomis, Sayles & Company, L.P. |
|
|
|
|
|
|
| |
Loomis Sayles Growth Portfolio* - Class B Brighthouse Investment Advisers, LLC Subadviser: Loomis, Sayles & Company, L.P. |
|
|
|
|
|
|
| |
Loomis Sayles Small Cap Core Portfolio* - Class B Brighthouse Investment Advisers, LLC Subadviser: Loomis, Sayles & Company, L.P. |
|
|
|
|
|
|
| |
Loomis Sayles Small Cap Growth Portfolio* - Class B Brighthouse Investment Advisers, LLC Subadviser: Loomis, Sayles & Company, L.P. |
|
|
|
|
|
|
| |
MetLife Aggregate Bond Index Portfolio* - Class B Brighthouse Investment Advisers, LLC Subadviser: MetLife Investment Management, LLC |
|
|
|
|
|
|
| |
MetLife Mid Cap Stock Index Portfolio - Class B Brighthouse Investment Advisers, LLC Subadviser: MetLife Investment Management, LLC |
|
|
|
|
|
|
| |
PORTFOLIO AND ADVISER/SUBADVISER |
|
|
CURRENT EXPENSES + PLATFORM CHARGE |
AVERAGE ANNUAL TOTAL RETURNS (as of 12/31/2025) |
| |
|
|
| |
MetLife MSCI EAFE® Index Portfolio - Class B Brighthouse Investment Advisers, LLC Subadviser: MetLife Investment Management, LLC |
|
|
|
|
|
|
| |
MetLife Russell 2000® Index Portfolio - Class B Brighthouse Investment Advisers, LLC Subadviser: MetLife Investment Management, LLC |
|
|
|
|
|
|
| |
MetLife Stock Index Portfolio* - Class B Brighthouse Investment Advisers, LLC Subadviser: MetLife Investment Management, LLC |
|
|
|
|
|
|
| |
MFS® Research International Portfolio* - Class B Brighthouse Investment Advisers, LLC Subadviser: Massachusetts Financial Services Company |
|
|
|
|
|
|
| |
MFS® Total Return Portfolio* - Class B Brighthouse Investment Advisers, LLC Subadviser: Massachusetts Financial Services Company |
|
|
|
|
|
|
| |
MFS® Value Portfolio* - Class B Brighthouse Investment Advisers, LLC Subadviser: Massachusetts Financial Services Company |
|
|
|
|
|
|
| |
PORTFOLIO AND ADVISER/SUBADVISER |
|
|
CURRENT EXPENSES + PLATFORM CHARGE |
AVERAGE ANNUAL TOTAL RETURNS (as of 12/31/2025) |
| |
|
|
| |
Morgan Stanley Discovery Portfolio* - Class B Brighthouse Investment Advisers, LLC Subadviser: Morgan Stanley Investment Management Inc. |
|
|
|
|
|
|
| |
Neuberger Berman Genesis Portfolio* - Class B Brighthouse Investment Advisers, LLC Subadviser: Neuberger Berman Investment Advisers LLC |
|
|
|
|
|
|
| |
PIMCO Inflation Protected Bond Portfolio - Class B Brighthouse Investment Advisers, LLC Subadviser: Pacific Investment Management Company LLC |
|
|
|
|
|
|
| |
PIMCO Total Return Portfolio* - Class B Brighthouse Investment Advisers, LLC Subadviser: Pacific Investment Management Company LLC |
|
|
|
|
|
|
| |
State Street Moderate ETF Portfolio - Class B (formerly known as SSGA Growth and Income ETF Portfolio - Class B) Brighthouse Investment Advisers, LLC Subadviser: SSGA Funds Management, Inc. |
|
|
|
|
|
|
| |
State Street Moderately Aggressive ETF Portfolio - Class B (formerly known as SSGA Growth ETF Portfolio - Class B) Brighthouse Investment Advisers, LLC Subadviser: SSGA Funds Management, Inc. |
|
|
|
|
|
|
| |
PORTFOLIO AND ADVISER/SUBADVISER |
|
|
CURRENT EXPENSES + PLATFORM CHARGE |
AVERAGE ANNUAL TOTAL RETURNS (as of 12/31/2025) |
| |
|
|
| |
T. Rowe Price Large Cap Growth Portfolio* - Class B Brighthouse Investment Advisers, LLC Subadviser: T. Rowe Price Associates, Inc. |
|
|
|
|
|
|
| |
T. Rowe Price Mid Cap Growth Portfolio* - Class B Brighthouse Investment Advisers, LLC Subadviser: T. Rowe Price Associates, Inc. is the subadviser T. Rowe Price Investment Management, Inc. is the sub-subadviser |
|
|
|
|
|
|
| |
T. Rowe Price Small Cap Growth Portfolio - Class B Brighthouse Investment Advisers, LLC Subadviser: T. Rowe Price Associates, Inc. |
|
|
|
|
|
|
| |
Victory Sycamore Mid Cap Value Portfolio* - Class B Brighthouse Investment Advisers, LLC Subadviser: Victory Capital Management, Inc. |
|
|
|
|
|
|
| |
Western Asset Management Strategic Bond Opportunities Portfolio* - Class B Brighthouse Investment Advisers, LLC Subadviser: Western Asset Management Company, LLC |
|
|
|
|
|
|
| |
Western Asset Management U.S. Government Portfolio* - Class B Brighthouse Investment Advisers, LLC Subadviser: Western Asset Management Company, LLC |
|
|
|
|
|
|
|
| Temporary Fee Reductions, Current Expenses [Text Block] |
The Portfolio is subject to an expense reimbursement or fee waiver arrangement. The annual expenses shown reflect temporary fee reductions.
|
| Fixed Option [Line Items] |
|
| Fixed Options Available Legend [Text Block] |
Fixed OptionThe following is information on the Fixed Interest Account currently available under the Contract. You should check with your Employer as to whether the Fixed Interest Account is available under your Contract. We reserve the right to restrict purchase payments and transfers to the Fixed Interest Account when the yield on investments is not expected to support the Minimum Guaranteed Interest Rate. We will provide you with written notice before doing so.
| |
|
Minimum Guaranteed Interest Rate* |
| |
Initial Interest Rate Term: begins on each calendar quarter and will be credited from the date amounts are allocated to the Fixed Interest Account until the last day of the same calendar quarter of the following year. Renewal Rate Term: 12 months. |
| *The Minimum Guaranteed Interest Rate varies by Contract and may be higher than the minimum guaranteed interest rate shown. Check your Contract for the Minimum Guaranteed Interest Rate that applies to your Fixed Interest Account Option.
|
| Investment Option Restrictions [Line Items] |
|
| Investment Options Not Always Available for All Benefits [Text Block] |
Investment Allocation Restrictions For Certain Optional BenefitsIndex Selector:If You elect the Index Selector You are limited to allocating your purchase payments and Account Balance among the following funding options and the Fixed Interest Account:MetLife Aggregate Bond Index
MetLife Stock Index
MetLife MSCI EAFE Index
MetLife Russell 2000 Index
MetLife Mid Cap Stock IndexLifetime Withdrawal GuaranteeIf You elect the Lifetime Withdrawal Guarantee Optional Benefit, You are limited to allocating your purchase payments and Account Balance among the following funding options and the Fixed Interest Account:Brighthouse Asset Allocation 20
Brighthouse Asset Allocation 40
Brighthouse Asset Allocation 60
Brighthouse Asset Allocation 80
|
| MetLife Financial Freedom Select e and e Bonus Class | American Funds Growth Fund - Class 2 |
|
| Variable Option [Line Items] |
|
| Portfolio Company Objective [Text Block] |
US Equity
|
| Portfolio Company Name [Text Block] |
American Funds Growth Fund(1) - Class 2
|
| Portfolio Company Adviser [Text Block] |
Capital Research and Management CompanySM
|
| Current Expenses [Percent] |
0.58%
|
| Platform Charge [Percent] |
0.25%
|
| Current Expenses + Platform Charge [Percent] |
0.83%
|
| Average Annual Total Returns, 1 Year [Percent] |
20.24%
|
| Average Annual Total Returns, 5 Years [Percent] |
13.37%
|
| Average Annual Total Returns, 10 Years [Percent] |
17.97%
|
| MetLife Financial Freedom Select e and e Bonus Class | American Funds Growth-Income Fund - Class 2 |
|
| Variable Option [Line Items] |
|
| Portfolio Company Objective [Text Block] |
US Equity
|
| Portfolio Company Name [Text Block] |
American Funds Growth-Income Fund(1) - Class 2
|
| Portfolio Company Adviser [Text Block] |
Capital Research and Management CompanySM
|
| Current Expenses [Percent] |
0.53%
|
| Platform Charge [Percent] |
0.25%
|
| Current Expenses + Platform Charge [Percent] |
0.78%
|
| Average Annual Total Returns, 1 Year [Percent] |
18.06%
|
| Average Annual Total Returns, 5 Years [Percent] |
13.90%
|
| Average Annual Total Returns, 10 Years [Percent] |
13.92%
|
| MetLife Financial Freedom Select e and e Bonus Class | American Funds SMALLCAP World Fund® - Class 2 |
|
| Variable Option [Line Items] |
|
| Portfolio Company Objective [Text Block] |
Global Equity
|
| Portfolio Company Name [Text Block] |
American Funds SMALLCAP World Fund® *(1)†† - Class 2
|
| Portfolio Company Adviser [Text Block] |
Capital Research and Management CompanySM
|
| Current Expenses [Percent] |
0.90%
|
| Platform Charge [Percent] |
0.25%
|
| Current Expenses + Platform Charge [Percent] |
1.15%
|
| Average Annual Total Returns, 1 Year [Percent] |
14.64%
|
| Average Annual Total Returns, 5 Years [Percent] |
0.49%
|
| Average Annual Total Returns, 10 Years [Percent] |
7.23%
|
| MetLife Financial Freedom Select e and e Bonus Class | American Funds The Bond Fund of America - Class 2 |
|
| Variable Option [Line Items] |
|
| Portfolio Company Objective [Text Block] |
US Fixed Income
|
| Portfolio Company Name [Text Block] |
American Funds The Bond Fund of America*(1) - Class 2
|
| Portfolio Company Adviser [Text Block] |
Capital Research and Management CompanySM
|
| Current Expenses [Percent] |
0.47%
|
| Platform Charge [Percent] |
0.25%
|
| Current Expenses + Platform Charge [Percent] |
0.72%
|
| Average Annual Total Returns, 1 Year [Percent] |
7.26%
|
| Average Annual Total Returns, 5 Years [Percent] |
(0.14%)
|
| Average Annual Total Returns, 10 Years [Percent] |
2.36%
|
| MetLife Financial Freedom Select e and e Bonus Class | American Funds Aggressive Allocation Portfolio - Class C |
|
| Variable Option [Line Items] |
|
| Portfolio Company Objective [Text Block] |
Allocation
|
| Portfolio Company Name [Text Block] |
American Funds® Aggressive Allocation Portfolio - Class C
|
| Portfolio Company Adviser [Text Block] |
Brighthouse Investment Advisers, LLC
|
| Current Expenses [Percent] |
0.99%
|
| Current Expenses + Platform Charge [Percent] |
0.99%
|
| Average Annual Total Returns, 1 Year [Percent] |
19.90%
|
| Average Annual Total Returns, 5 Years [Percent] |
9.30%
|
| Average Annual Total Returns, 10 Years [Percent] |
10.88%
|
| MetLife Financial Freedom Select e and e Bonus Class | American Funds Balanced Allocation Portfolio - Class C |
|
| Variable Option [Line Items] |
|
| Portfolio Company Objective [Text Block] |
Allocation
|
| Portfolio Company Name [Text Block] |
American Funds® Balanced Allocation Portfolio - Class C
|
| Portfolio Company Adviser [Text Block] |
Brighthouse Investment Advisers, LLC
|
| Current Expenses [Percent] |
0.96%
|
| Current Expenses + Platform Charge [Percent] |
0.96%
|
| Average Annual Total Returns, 1 Year [Percent] |
17.02%
|
| Average Annual Total Returns, 5 Years [Percent] |
7.26%
|
| Average Annual Total Returns, 10 Years [Percent] |
8.99%
|
| MetLife Financial Freedom Select e and e Bonus Class | American Funds Moderate Allocation Portfolio - Class C |
|
| Variable Option [Line Items] |
|
| Portfolio Company Objective [Text Block] |
Allocation
|
| Portfolio Company Name [Text Block] |
American Funds® Moderate Allocation Portfolio - Class C
|
| Portfolio Company Adviser [Text Block] |
Brighthouse Investment Advisers, LLC
|
| Current Expenses [Percent] |
0.95%
|
| Current Expenses + Platform Charge [Percent] |
0.95%
|
| Average Annual Total Returns, 1 Year [Percent] |
14.46%
|
| Average Annual Total Returns, 5 Years [Percent] |
5.71%
|
| Average Annual Total Returns, 10 Years [Percent] |
7.30%
|
| MetLife Financial Freedom Select e and e Bonus Class | BlackRock Bond Income Portfolio - Class B |
|
| Variable Option [Line Items] |
|
| Portfolio Company Objective [Text Block] |
US Fixed Income
|
| Portfolio Company Name [Text Block] |
BlackRock Bond Income Portfolio* - Class B
|
| Portfolio Company Adviser [Text Block] |
Brighthouse Investment Advisers, LLC
|
| Portfolio Company Subadviser [Text Block] |
BlackRock Advisors, LLC
|
| Current Expenses [Percent] |
0.63%
|
| Current Expenses + Platform Charge [Percent] |
0.63%
|
| Average Annual Total Returns, 1 Year [Percent] |
7.68%
|
| Average Annual Total Returns, 5 Years [Percent] |
(0.42%)
|
| Average Annual Total Returns, 10 Years [Percent] |
2.12%
|
| MetLife Financial Freedom Select e and e Bonus Class | BlackRock Capital Appreciation Portfolio - Class B |
|
| Variable Option [Line Items] |
|
| Portfolio Company Objective [Text Block] |
US Equity
|
| Portfolio Company Name [Text Block] |
BlackRock Capital Appreciation Portfolio* - Class B
|
| Portfolio Company Adviser [Text Block] |
Brighthouse Investment Advisers, LLC
|
| Portfolio Company Subadviser [Text Block] |
BlackRock Advisors, LLC
|
| Current Expenses [Percent] |
0.81%
|
| Current Expenses + Platform Charge [Percent] |
0.81%
|
| Average Annual Total Returns, 1 Year [Percent] |
12.91%
|
| Average Annual Total Returns, 5 Years [Percent] |
10.79%
|
| Average Annual Total Returns, 10 Years [Percent] |
15.51%
|
| MetLife Financial Freedom Select e and e Bonus Class | Brighthouse Asset Allocation 100 Portfolio - Class B |
|
| Variable Option [Line Items] |
|
| Portfolio Company Objective [Text Block] |
Allocation
|
| Portfolio Company Name [Text Block] |
Brighthouse Asset Allocation 100 Portfolio - Class B
|
| Portfolio Company Adviser [Text Block] |
Brighthouse Investment Advisers, LLC
|
| Current Expenses [Percent] |
0.96%
|
| Current Expenses + Platform Charge [Percent] |
0.96%
|
| Average Annual Total Returns, 1 Year [Percent] |
17.06%
|
| Average Annual Total Returns, 5 Years [Percent] |
8.63%
|
| Average Annual Total Returns, 10 Years [Percent] |
10.70%
|
| MetLife Financial Freedom Select e and e Bonus Class | Brighthouse Asset Allocation 20 Portfolio - Class B |
|
| Variable Option [Line Items] |
|
| Portfolio Company Objective [Text Block] |
Allocation
|
| Portfolio Company Name [Text Block] |
Brighthouse Asset Allocation 20 Portfolio* - Class B
|
| Portfolio Company Adviser [Text Block] |
Brighthouse Investment Advisers, LLC
|
| Current Expenses [Percent] |
0.93%
|
| Current Expenses + Platform Charge [Percent] |
0.93%
|
| Average Annual Total Returns, 1 Year [Percent] |
9.25%
|
| Average Annual Total Returns, 5 Years [Percent] |
2.06%
|
| Average Annual Total Returns, 10 Years [Percent] |
3.97%
|
| MetLife Financial Freedom Select e and e Bonus Class | Brighthouse Asset Allocation 40 Portfolio - Class B |
|
| Variable Option [Line Items] |
|
| Portfolio Company Objective [Text Block] |
Allocation
|
| Portfolio Company Name [Text Block] |
Brighthouse Asset Allocation 40 Portfolio - Class B
|
| Portfolio Company Adviser [Text Block] |
Brighthouse Investment Advisers, LLC
|
| Current Expenses [Percent] |
0.91%
|
| Current Expenses + Platform Charge [Percent] |
0.91%
|
| Average Annual Total Returns, 1 Year [Percent] |
11.50%
|
| Average Annual Total Returns, 5 Years [Percent] |
3.84%
|
| Average Annual Total Returns, 10 Years [Percent] |
5.69%
|
| MetLife Financial Freedom Select e and e Bonus Class | Brighthouse Asset Allocation 60 Portfolio - Class B |
|
| Variable Option [Line Items] |
|
| Portfolio Company Objective [Text Block] |
Allocation
|
| Portfolio Company Name [Text Block] |
Brighthouse Asset Allocation 60 Portfolio - Class B
|
| Portfolio Company Adviser [Text Block] |
Brighthouse Investment Advisers, LLC
|
| Current Expenses [Percent] |
0.91%
|
| Current Expenses + Platform Charge [Percent] |
0.91%
|
| Average Annual Total Returns, 1 Year [Percent] |
13.77%
|
| Average Annual Total Returns, 5 Years [Percent] |
5.55%
|
| Average Annual Total Returns, 10 Years [Percent] |
7.47%
|
| MetLife Financial Freedom Select e and e Bonus Class | Brighthouse Asset Allocation 80 Portfolio - Class B |
|
| Variable Option [Line Items] |
|
| Portfolio Company Objective [Text Block] |
Allocation
|
| Portfolio Company Name [Text Block] |
Brighthouse Asset Allocation 80 Portfolio - Class B
|
| Portfolio Company Adviser [Text Block] |
Brighthouse Investment Advisers, LLC
|
| Current Expenses [Percent] |
0.93%
|
| Current Expenses + Platform Charge [Percent] |
0.93%
|
| Average Annual Total Returns, 1 Year [Percent] |
15.63%
|
| Average Annual Total Returns, 5 Years [Percent] |
7.18%
|
| Average Annual Total Returns, 10 Years [Percent] |
9.22%
|
| MetLife Financial Freedom Select e and e Bonus Class | Brighthouse Small Cap Value Portfolio - Class B |
|
| Variable Option [Line Items] |
|
| Portfolio Company Objective [Text Block] |
US Equity
|
| Portfolio Company Name [Text Block] |
Brighthouse Small Cap Value Portfolio* - Class B
|
| Portfolio Company Adviser [Text Block] |
Brighthouse Investment Advisers, LLC
|
| Portfolio Company Subadviser [Text Block] |
Allspring Global Investments, LLC
|
| Current Expenses [Percent] |
1.03%
|
| Current Expenses + Platform Charge [Percent] |
1.03%
|
| Average Annual Total Returns, 1 Year [Percent] |
(3.21%)
|
| Average Annual Total Returns, 5 Years [Percent] |
6.43%
|
| Average Annual Total Returns, 10 Years [Percent] |
8.07%
|
| MetLife Financial Freedom Select e and e Bonus Class | BrighthouseArtisan Mid Cap Value Portfolio - Class B |
|
| Variable Option [Line Items] |
|
| Portfolio Company Objective [Text Block] |
US Equity
|
| Portfolio Company Name [Text Block] |
Brighthouse/Artisan Mid Cap Value Portfolio* - Class B
|
| Portfolio Company Adviser [Text Block] |
Brighthouse Investment Advisers, LLC
|
| Portfolio Company Subadviser [Text Block] |
Artisan Partners Limited Partnership
|
| Current Expenses [Percent] |
1.03%
|
| Current Expenses + Platform Charge [Percent] |
1.03%
|
| Average Annual Total Returns, 1 Year [Percent] |
1.57%
|
| Average Annual Total Returns, 5 Years [Percent] |
6.77%
|
| Average Annual Total Returns, 10 Years [Percent] |
8.05%
|
| MetLife Financial Freedom Select e and e Bonus Class | BrighthouseFranklin Low Duration Total Return Portfolio - Class B |
|
| Variable Option [Line Items] |
|
| Portfolio Company Objective [Text Block] |
US Fixed Income
|
| Portfolio Company Name [Text Block] |
Brighthouse/Franklin Low Duration Total Return Portfolio* - Class B
|
| Portfolio Company Adviser [Text Block] |
Brighthouse Investment Advisers, LLC
|
| Portfolio Company Subadviser [Text Block] |
Franklin Advisers, Inc.
|
| Current Expenses [Percent] |
0.75%
|
| Current Expenses + Platform Charge [Percent] |
0.75%
|
| Average Annual Total Returns, 1 Year [Percent] |
5.25%
|
| Average Annual Total Returns, 5 Years [Percent] |
2.14%
|
| Average Annual Total Returns, 10 Years [Percent] |
2.23%
|
| MetLife Financial Freedom Select e and e Bonus Class | BrighthouseWellington Balanced Portfolio - Class A |
|
| Variable Option [Line Items] |
|
| Portfolio Company Objective [Text Block] |
Allocation
|
| Portfolio Company Name [Text Block] |
Brighthouse/Wellington Balanced Portfolio - Class A
|
| Portfolio Company Adviser [Text Block] |
Brighthouse Investment Advisers, LLC
|
| Portfolio Company Subadviser [Text Block] |
Wellington Management Company LLP
|
| Current Expenses [Percent] |
0.52%
|
| Current Expenses + Platform Charge [Percent] |
0.52%
|
| Average Annual Total Returns, 1 Year [Percent] |
12.67%
|
| Average Annual Total Returns, 5 Years [Percent] |
7.45%
|
| Average Annual Total Returns, 10 Years [Percent] |
9.41%
|
| MetLife Financial Freedom Select e and e Bonus Class | BrighthouseWellington Core Equity Opportunities Portfolio - Class B |
|
| Variable Option [Line Items] |
|
| Portfolio Company Objective [Text Block] |
US Equity
|
| Portfolio Company Name [Text Block] |
Brighthouse/Wellington Core Equity Opportunities Portfolio* - Class B
|
| Portfolio Company Adviser [Text Block] |
Brighthouse Investment Advisers, LLC
|
| Portfolio Company Subadviser [Text Block] |
Wellington Management Company LLP
|
| Current Expenses [Percent] |
0.87%
|
| Current Expenses + Platform Charge [Percent] |
0.87%
|
| Average Annual Total Returns, 1 Year [Percent] |
7.54%
|
| Average Annual Total Returns, 5 Years [Percent] |
8.02%
|
| Average Annual Total Returns, 10 Years [Percent] |
10.45%
|
| MetLife Financial Freedom Select e and e Bonus Class | BrighthouseWellington Large Cap Research Portfolio - Class B |
|
| Variable Option [Line Items] |
|
| Portfolio Company Objective [Text Block] |
US Equity
|
| Portfolio Company Name [Text Block] |
Brighthouse/Wellington Large Cap Research Portfolio* - Class B
|
| Portfolio Company Adviser [Text Block] |
Brighthouse Investment Advisers, LLC
|
| Portfolio Company Subadviser [Text Block] |
Wellington Management Company LLP
|
| Current Expenses [Percent] |
0.79%
|
| Current Expenses + Platform Charge [Percent] |
0.79%
|
| Average Annual Total Returns, 1 Year [Percent] |
15.62%
|
| Average Annual Total Returns, 5 Years [Percent] |
12.01%
|
| Average Annual Total Returns, 10 Years [Percent] |
13.33%
|
| MetLife Financial Freedom Select e and e Bonus Class | CBRE Global Real Estate Portfolio - Class B |
|
| Variable Option [Line Items] |
|
| Portfolio Company Objective [Text Block] |
Sector
|
| Portfolio Company Name [Text Block] |
CBRE Global Real Estate Portfolio* - Class B
|
| Portfolio Company Adviser [Text Block] |
Brighthouse Investment Advisers, LLC
|
| Portfolio Company Subadviser [Text Block] |
CBRE Investment Management Listed Real Assets LLC
|
| Current Expenses [Percent] |
0.91%
|
| Current Expenses + Platform Charge [Percent] |
0.91%
|
| Average Annual Total Returns, 1 Year [Percent] |
6.75%
|
| Average Annual Total Returns, 5 Years [Percent] |
4.03%
|
| Average Annual Total Returns, 10 Years [Percent] |
3.95%
|
| MetLife Financial Freedom Select e and e Bonus Class | Freedom 2025 Portfolio - Service Class 2 |
|
| Variable Option [Line Items] |
|
| Portfolio Company Objective [Text Block] |
Target Date
|
| Portfolio Company Name [Text Block] |
Freedom 2025 Portfolio - Service Class 2
|
| Portfolio Company Adviser [Text Block] |
Fidelity Management & Research Company LLC
|
| Current Expenses [Percent] |
0.71%
|
| Current Expenses + Platform Charge [Percent] |
0.71%
|
| Average Annual Total Returns, 1 Year [Percent] |
14.23%
|
| Average Annual Total Returns, 5 Years [Percent] |
5.25%
|
| Average Annual Total Returns, 10 Years [Percent] |
7.75%
|
| MetLife Financial Freedom Select e and e Bonus Class | Freedom 2030 Portfolio - Service Class 2 |
|
| Variable Option [Line Items] |
|
| Portfolio Company Objective [Text Block] |
Target Date
|
| Portfolio Company Name [Text Block] |
Freedom 2030 Portfolio - Service Class 2
|
| Portfolio Company Adviser [Text Block] |
Fidelity Management & Research Company LLC
|
| Current Expenses [Percent] |
0.74%
|
| Current Expenses + Platform Charge [Percent] |
0.74%
|
| Average Annual Total Returns, 1 Year [Percent] |
15.16%
|
| Average Annual Total Returns, 5 Years [Percent] |
5.98%
|
| Average Annual Total Returns, 10 Years [Percent] |
8.61%
|
| MetLife Financial Freedom Select e and e Bonus Class | Freedom 2035 Portfolio - Service Class 2 |
|
| Variable Option [Line Items] |
|
| Portfolio Company Objective [Text Block] |
Target Date
|
| Portfolio Company Name [Text Block] |
Freedom 2035 Portfolio - Service Class 2
|
| Portfolio Company Adviser [Text Block] |
Fidelity Management & Research Company LLC
|
| Current Expenses [Percent] |
0.78%
|
| Current Expenses + Platform Charge [Percent] |
0.78%
|
| Average Annual Total Returns, 1 Year [Percent] |
16.42%
|
| Average Annual Total Returns, 5 Years [Percent] |
7.28%
|
| Average Annual Total Returns, 10 Years [Percent] |
9.72%
|
| MetLife Financial Freedom Select e and e Bonus Class | Freedom 2040 Portfolio - Service Class 2 |
|
| Variable Option [Line Items] |
|
| Portfolio Company Objective [Text Block] |
Target Date
|
| Portfolio Company Name [Text Block] |
Freedom 2040 Portfolio - Service Class 2
|
| Portfolio Company Adviser [Text Block] |
Fidelity Management & Research Company LLC
|
| Current Expenses [Percent] |
0.82%
|
| Current Expenses + Platform Charge [Percent] |
0.82%
|
| Average Annual Total Returns, 1 Year [Percent] |
18.44%
|
| Average Annual Total Returns, 5 Years [Percent] |
8.73%
|
| Average Annual Total Returns, 10 Years [Percent] |
10.59%
|
| MetLife Financial Freedom Select e and e Bonus Class | Freedom 2045 Portfolio - Service Class 2 |
|
| Variable Option [Line Items] |
|
| Portfolio Company Objective [Text Block] |
Target Date
|
| Portfolio Company Name [Text Block] |
Freedom 2045 Portfolio - Service Class 2
|
| Portfolio Company Adviser [Text Block] |
Fidelity Management & Research Company LLC
|
| Current Expenses [Percent] |
0.85%
|
| Current Expenses + Platform Charge [Percent] |
0.85%
|
| Average Annual Total Returns, 1 Year [Percent] |
19.53%
|
| Average Annual Total Returns, 5 Years [Percent] |
9.16%
|
| Average Annual Total Returns, 10 Years [Percent] |
10.82%
|
| MetLife Financial Freedom Select e and e Bonus Class | Freedom 2050 Portfolio - Service Class 2 |
|
| Variable Option [Line Items] |
|
| Portfolio Company Objective [Text Block] |
Target Date
|
| Portfolio Company Name [Text Block] |
Freedom 2050 Portfolio - Service Class 2
|
| Portfolio Company Adviser [Text Block] |
Fidelity Management & Research Company LLC
|
| Current Expenses [Percent] |
0.85%
|
| Current Expenses + Platform Charge [Percent] |
0.85%
|
| Average Annual Total Returns, 1 Year [Percent] |
19.50%
|
| Average Annual Total Returns, 5 Years [Percent] |
9.15%
|
| Average Annual Total Returns, 10 Years [Percent] |
10.81%
|
| MetLife Financial Freedom Select e and e Bonus Class | Freedom 2055 Portfolio - Service Class 2 |
|
| Variable Option [Line Items] |
|
| Portfolio Company Objective [Text Block] |
Target Date
|
| Portfolio Company Name [Text Block] |
Freedom 2055 Portfolio - Service Class 2
|
| Portfolio Company Adviser [Text Block] |
Fidelity Management & Research Company LLC
|
| Current Expenses [Percent] |
0.85%
|
| Current Expenses + Platform Charge [Percent] |
0.85%
|
| Average Annual Total Returns, 1 Year [Percent] |
19.53%
|
| Average Annual Total Returns, 5 Years [Percent] |
9.16%
|
| MetLife Financial Freedom Select e and e Bonus Class | Freedom 2060 Portfolio - Service Class 2 |
|
| Variable Option [Line Items] |
|
| Portfolio Company Objective [Text Block] |
Target Date
|
| Portfolio Company Name [Text Block] |
Freedom 2060 Portfolio - Service Class 2
|
| Portfolio Company Adviser [Text Block] |
Fidelity Management & Research Company LLC
|
| Current Expenses [Percent] |
0.85%
|
| Current Expenses + Platform Charge [Percent] |
0.85%
|
| Average Annual Total Returns, 1 Year [Percent] |
19.53%
|
| Average Annual Total Returns, 5 Years [Percent] |
9.17%
|
| MetLife Financial Freedom Select e and e Bonus Class | Freedom 2065 Portfolio - Service Class 2 |
|
| Variable Option [Line Items] |
|
| Portfolio Company Objective [Text Block] |
Target Date
|
| Portfolio Company Name [Text Block] |
Freedom 2065 Portfolio - Service Class 2
|
| Portfolio Company Adviser [Text Block] |
Fidelity Management & Research Company LLC
|
| Current Expenses [Percent] |
0.85%
|
| Current Expenses + Platform Charge [Percent] |
0.85%
|
| Average Annual Total Returns, 1 Year [Percent] |
19.52%
|
| Average Annual Total Returns, 5 Years [Percent] |
9.16%
|
| MetLife Financial Freedom Select e and e Bonus Class | Freedom 2070 Portfolio - Service Class 2 |
|
| Variable Option [Line Items] |
|
| Portfolio Company Objective [Text Block] |
Target Date
|
| Portfolio Company Name [Text Block] |
Freedom 2070 Portfolio - Service Class 2
|
| Portfolio Company Adviser [Text Block] |
Fidelity Management & Research Company LLC
|
| Current Expenses [Percent] |
0.85%
|
| Current Expenses + Platform Charge [Percent] |
0.85%
|
| Average Annual Total Returns, 1 Year [Percent] |
19.59%
|
| MetLife Financial Freedom Select e and e Bonus Class | Harris Oakmark International Portfolio - Class B |
|
| Variable Option [Line Items] |
|
| Portfolio Company Objective [Text Block] |
International Equity
|
| Portfolio Company Name [Text Block] |
Harris Oakmark International Portfolio* - Class B
|
| Portfolio Company Adviser [Text Block] |
Brighthouse Investment Advisers, LLC
|
| Portfolio Company Subadviser [Text Block] |
Harris Associates L.P.
|
| Current Expenses [Percent] |
0.97%
|
| Current Expenses + Platform Charge [Percent] |
0.97%
|
| Average Annual Total Returns, 1 Year [Percent] |
32.78%
|
| Average Annual Total Returns, 5 Years [Percent] |
6.46%
|
| Average Annual Total Returns, 10 Years [Percent] |
6.74%
|
| MetLife Financial Freedom Select e and e Bonus Class | Invesco Global Equity Portfolio - Class B |
|
| Variable Option [Line Items] |
|
| Portfolio Company Objective [Text Block] |
Global Equity
|
| Portfolio Company Name [Text Block] |
Invesco Global Equity Portfolio* - Class B
|
| Portfolio Company Adviser [Text Block] |
Brighthouse Investment Advisers, LLC
|
| Portfolio Company Subadviser [Text Block] |
Invesco Advisers, Inc.
|
| Current Expenses [Percent] |
0.83%
|
| Current Expenses + Platform Charge [Percent] |
0.83%
|
| Average Annual Total Returns, 1 Year [Percent] |
15.60%
|
| Average Annual Total Returns, 5 Years [Percent] |
7.30%
|
| Average Annual Total Returns, 10 Years [Percent] |
11.00%
|
| MetLife Financial Freedom Select e and e Bonus Class | Invesco Small Cap Growth Portfolio - Class B |
|
| Variable Option [Line Items] |
|
| Portfolio Company Objective [Text Block] |
US Equity
|
| Portfolio Company Name [Text Block] |
Invesco Small Cap Growth Portfolio* - Class B
|
| Portfolio Company Adviser [Text Block] |
Brighthouse Investment Advisers, LLC
|
| Portfolio Company Subadviser [Text Block] |
Invesco Advisers, Inc.
|
| Current Expenses [Percent] |
0.99%
|
| Current Expenses + Platform Charge [Percent] |
0.99%
|
| Average Annual Total Returns, 1 Year [Percent] |
5.83%
|
| Average Annual Total Returns, 5 Years [Percent] |
(0.91%)
|
| Average Annual Total Returns, 10 Years [Percent] |
9.00%
|
| MetLife Financial Freedom Select e and e Bonus Class | Jennison Growth Portfolio - Class B |
|
| Variable Option [Line Items] |
|
| Portfolio Company Objective [Text Block] |
US Equity
|
| Portfolio Company Name [Text Block] |
Jennison Growth Portfolio* - Class B
|
| Portfolio Company Adviser [Text Block] |
Brighthouse Investment Advisers, LLC
|
| Portfolio Company Subadviser [Text Block] |
Jennison Associates LLC
|
| Current Expenses [Percent] |
0.79%
|
| Current Expenses + Platform Charge [Percent] |
0.79%
|
| Average Annual Total Returns, 1 Year [Percent] |
13.72%
|
| Average Annual Total Returns, 5 Years [Percent] |
10.01%
|
| Average Annual Total Returns, 10 Years [Percent] |
16.41%
|
| MetLife Financial Freedom Select e and e Bonus Class | Loomis Sayles Global Allocation Portfolio - Class B |
|
| Variable Option [Line Items] |
|
| Portfolio Company Objective [Text Block] |
Allocation
|
| Portfolio Company Name [Text Block] |
Loomis Sayles Global Allocation Portfolio* - Class B
|
| Portfolio Company Adviser [Text Block] |
Brighthouse Investment Advisers, LLC
|
| Portfolio Company Subadviser [Text Block] |
Loomis, Sayles & Company, L.P.
|
| Current Expenses [Percent] |
1.04%
|
| Current Expenses + Platform Charge [Percent] |
1.04%
|
| Average Annual Total Returns, 1 Year [Percent] |
12.59%
|
| Average Annual Total Returns, 5 Years [Percent] |
6.25%
|
| Average Annual Total Returns, 10 Years [Percent] |
9.22%
|
| MetLife Financial Freedom Select e and e Bonus Class | Loomis Sayles Growth Portfolio - Class B |
|
| Variable Option [Line Items] |
|
| Portfolio Company Objective [Text Block] |
US Equity
|
| Portfolio Company Name [Text Block] |
Loomis Sayles Growth Portfolio* - Class B
|
| Portfolio Company Adviser [Text Block] |
Brighthouse Investment Advisers, LLC
|
| Portfolio Company Subadviser [Text Block] |
Loomis, Sayles & Company, L.P.
|
| Current Expenses [Percent] |
0.80%
|
| Current Expenses + Platform Charge [Percent] |
0.80%
|
| Average Annual Total Returns, 1 Year [Percent] |
14.90%
|
| Average Annual Total Returns, 5 Years [Percent] |
14.77%
|
| Average Annual Total Returns, 10 Years [Percent] |
13.91%
|
| MetLife Financial Freedom Select e and e Bonus Class | Loomis Sayles Small Cap Core Portfolio - Class B |
|
| Variable Option [Line Items] |
|
| Portfolio Company Objective [Text Block] |
US Equity
|
| Portfolio Company Name [Text Block] |
Loomis Sayles Small Cap Core Portfolio* - Class B
|
| Portfolio Company Adviser [Text Block] |
Brighthouse Investment Advisers, LLC
|
| Portfolio Company Subadviser [Text Block] |
Loomis, Sayles & Company, L.P.
|
| Current Expenses [Percent] |
1.15%
|
| Current Expenses + Platform Charge [Percent] |
1.15%
|
| Average Annual Total Returns, 1 Year [Percent] |
5.02%
|
| Average Annual Total Returns, 5 Years [Percent] |
7.17%
|
| Average Annual Total Returns, 10 Years [Percent] |
9.15%
|
| MetLife Financial Freedom Select e and e Bonus Class | Loomis Sayles Small Cap Growth Portfolio - Class B |
|
| Variable Option [Line Items] |
|
| Portfolio Company Objective [Text Block] |
US Equity
|
| Portfolio Company Name [Text Block] |
Loomis Sayles Small Cap Growth Portfolio* - Class B
|
| Portfolio Company Adviser [Text Block] |
Brighthouse Investment Advisers, LLC
|
| Portfolio Company Subadviser [Text Block] |
Loomis, Sayles & Company, L.P.
|
| Current Expenses [Percent] |
1.14%
|
| Current Expenses + Platform Charge [Percent] |
1.14%
|
| Average Annual Total Returns, 1 Year [Percent] |
3.73%
|
| Average Annual Total Returns, 5 Years [Percent] |
2.28%
|
| Average Annual Total Returns, 10 Years [Percent] |
9.84%
|
| MetLife Financial Freedom Select e and e Bonus Class | MetLife Aggregate Bond Index Portfolio - Class B |
|
| Variable Option [Line Items] |
|
| Portfolio Company Objective [Text Block] |
US Fixed Income
|
| Portfolio Company Name [Text Block] |
MetLife Aggregate Bond Index Portfolio* - Class B
|
| Portfolio Company Adviser [Text Block] |
Brighthouse Investment Advisers, LLC
|
| Portfolio Company Subadviser [Text Block] |
MetLife Investment Management, LLC
|
| Current Expenses [Percent] |
0.51%
|
| Current Expenses + Platform Charge [Percent] |
0.51%
|
| Average Annual Total Returns, 1 Year [Percent] |
6.80%
|
| Average Annual Total Returns, 5 Years [Percent] |
(0.88%)
|
| Average Annual Total Returns, 10 Years [Percent] |
1.51%
|
| MetLife Financial Freedom Select e and e Bonus Class | MetLife Mid Cap Stock Index Portfolio - Class B |
|
| Variable Option [Line Items] |
|
| Portfolio Company Objective [Text Block] |
US Equity
|
| Portfolio Company Name [Text Block] |
MetLife Mid Cap Stock Index Portfolio - Class B
|
| Portfolio Company Adviser [Text Block] |
Brighthouse Investment Advisers, LLC
|
| Portfolio Company Subadviser [Text Block] |
MetLife Investment Management, LLC
|
| Current Expenses [Percent] |
0.55%
|
| Current Expenses + Platform Charge [Percent] |
0.55%
|
| Average Annual Total Returns, 1 Year [Percent] |
6.86%
|
| Average Annual Total Returns, 5 Years [Percent] |
8.54%
|
| Average Annual Total Returns, 10 Years [Percent] |
10.16%
|
| MetLife Financial Freedom Select e and e Bonus Class | MetLife MSCI EAFE Index Portfolio - Class B |
|
| Variable Option [Line Items] |
|
| Portfolio Company Objective [Text Block] |
International Equity
|
| Portfolio Company Name [Text Block] |
MetLife MSCI EAFE® Index Portfolio - Class B
|
| Portfolio Company Adviser [Text Block] |
Brighthouse Investment Advisers, LLC
|
| Portfolio Company Subadviser [Text Block] |
MetLife Investment Management, LLC
|
| Current Expenses [Percent] |
0.62%
|
| Current Expenses + Platform Charge [Percent] |
0.62%
|
| Average Annual Total Returns, 1 Year [Percent] |
30.70%
|
| Average Annual Total Returns, 5 Years [Percent] |
8.35%
|
| Average Annual Total Returns, 10 Years [Percent] |
7.76%
|
| MetLife Financial Freedom Select e and e Bonus Class | MetLife Russell 2000 Index Portfolio - Class B |
|
| Variable Option [Line Items] |
|
| Portfolio Company Objective [Text Block] |
US Equity
|
| Portfolio Company Name [Text Block] |
MetLife Russell 2000® Index Portfolio - Class B
|
| Portfolio Company Adviser [Text Block] |
Brighthouse Investment Advisers, LLC
|
| Portfolio Company Subadviser [Text Block] |
MetLife Investment Management, LLC
|
| Current Expenses [Percent] |
0.55%
|
| Current Expenses + Platform Charge [Percent] |
0.55%
|
| Average Annual Total Returns, 1 Year [Percent] |
12.33%
|
| Average Annual Total Returns, 5 Years [Percent] |
5.71%
|
| Average Annual Total Returns, 10 Years [Percent] |
9.27%
|
| MetLife Financial Freedom Select e and e Bonus Class | MetLife Stock Index Portfolio - Class B |
|
| Variable Option [Line Items] |
|
| Portfolio Company Objective [Text Block] |
US Equity
|
| Portfolio Company Name [Text Block] |
MetLife Stock Index Portfolio* - Class B
|
| Portfolio Company Adviser [Text Block] |
Brighthouse Investment Advisers, LLC
|
| Portfolio Company Subadviser [Text Block] |
MetLife Investment Management, LLC
|
| Current Expenses [Percent] |
0.52%
|
| Current Expenses + Platform Charge [Percent] |
0.52%
|
| Average Annual Total Returns, 1 Year [Percent] |
17.28%
|
| Average Annual Total Returns, 5 Years [Percent] |
13.84%
|
| Average Annual Total Returns, 10 Years [Percent] |
14.24%
|
| MetLife Financial Freedom Select e and e Bonus Class | MFS Research International Portfolio - Class B |
|
| Variable Option [Line Items] |
|
| Portfolio Company Objective [Text Block] |
International Equity
|
| Portfolio Company Name [Text Block] |
MFS® Research International Portfolio* - Class B
|
| Portfolio Company Adviser [Text Block] |
Brighthouse Investment Advisers, LLC
|
| Portfolio Company Subadviser [Text Block] |
Massachusetts Financial Services Company
|
| Current Expenses [Percent] |
0.81%
|
| Current Expenses + Platform Charge [Percent] |
0.81%
|
| Average Annual Total Returns, 1 Year [Percent] |
22.41%
|
| Average Annual Total Returns, 5 Years [Percent] |
5.54%
|
| Average Annual Total Returns, 10 Years [Percent] |
7.57%
|
| MetLife Financial Freedom Select e and e Bonus Class | MFS Total Return Portfolio - Class B |
|
| Variable Option [Line Items] |
|
| Portfolio Company Objective [Text Block] |
Allocation
|
| Portfolio Company Name [Text Block] |
MFS® Total Return Portfolio* - Class B
|
| Portfolio Company Adviser [Text Block] |
Brighthouse Investment Advisers, LLC
|
| Portfolio Company Subadviser [Text Block] |
Massachusetts Financial Services Company
|
| Current Expenses [Percent] |
0.87%
|
| Current Expenses + Platform Charge [Percent] |
0.87%
|
| Average Annual Total Returns, 1 Year [Percent] |
10.83%
|
| Average Annual Total Returns, 5 Years [Percent] |
6.15%
|
| Average Annual Total Returns, 10 Years [Percent] |
7.38%
|
| MetLife Financial Freedom Select e and e Bonus Class | MFS Value Portfolio - Class B |
|
| Variable Option [Line Items] |
|
| Portfolio Company Objective [Text Block] |
US Equity
|
| Portfolio Company Name [Text Block] |
MFS® Value Portfolio* - Class B
|
| Portfolio Company Adviser [Text Block] |
Brighthouse Investment Advisers, LLC
|
| Portfolio Company Subadviser [Text Block] |
Massachusetts Financial Services Company
|
| Current Expenses [Percent] |
0.83%
|
| Current Expenses + Platform Charge [Percent] |
0.83%
|
| Average Annual Total Returns, 1 Year [Percent] |
13.00%
|
| Average Annual Total Returns, 5 Years [Percent] |
9.84%
|
| Average Annual Total Returns, 10 Years [Percent] |
9.99%
|
| MetLife Financial Freedom Select e and e Bonus Class | Morgan Stanley Discovery Portfolio - Class B |
|
| Variable Option [Line Items] |
|
| Portfolio Company Objective [Text Block] |
US Equity
|
| Portfolio Company Name [Text Block] |
Morgan Stanley Discovery Portfolio* - Class B
|
| Portfolio Company Adviser [Text Block] |
Brighthouse Investment Advisers, LLC
|
| Portfolio Company Subadviser [Text Block] |
Morgan Stanley Investment Management Inc.
|
| Current Expenses [Percent] |
0.90%
|
| Current Expenses + Platform Charge [Percent] |
0.90%
|
| Average Annual Total Returns, 1 Year [Percent] |
13.19%
|
| Average Annual Total Returns, 5 Years [Percent] |
(5.83%)
|
| Average Annual Total Returns, 10 Years [Percent] |
14.00%
|
| MetLife Financial Freedom Select e and e Bonus Class | Neuberger Berman Genesis Portfolio - Class B |
|
| Variable Option [Line Items] |
|
| Portfolio Company Objective [Text Block] |
US Equity
|
| Portfolio Company Name [Text Block] |
Neuberger Berman Genesis Portfolio* - Class B
|
| Portfolio Company Adviser [Text Block] |
Brighthouse Investment Advisers, LLC
|
| Portfolio Company Subadviser [Text Block] |
Neuberger Berman Investment Advisers LLC
|
| Current Expenses [Percent] |
1.06%
|
| Current Expenses + Platform Charge [Percent] |
1.06%
|
| Average Annual Total Returns, 1 Year [Percent] |
(4.74%)
|
| Average Annual Total Returns, 5 Years [Percent] |
2.62%
|
| Average Annual Total Returns, 10 Years [Percent] |
8.86%
|
| MetLife Financial Freedom Select e and e Bonus Class | PIMCO Inflation Protected Bond Portfolio - Class B |
|
| Variable Option [Line Items] |
|
| Portfolio Company Objective [Text Block] |
US Fixed Income
|
| Portfolio Company Name [Text Block] |
PIMCO Inflation Protected Bond Portfolio - Class B
|
| Portfolio Company Adviser [Text Block] |
Brighthouse Investment Advisers, LLC
|
| Portfolio Company Subadviser [Text Block] |
Pacific Investment Management Company LLC
|
| Current Expenses [Percent] |
1.38%
|
| Current Expenses + Platform Charge [Percent] |
1.38%
|
| Average Annual Total Returns, 1 Year [Percent] |
7.74%
|
| Average Annual Total Returns, 5 Years [Percent] |
1.15%
|
| Average Annual Total Returns, 10 Years [Percent] |
3.09%
|
| MetLife Financial Freedom Select e and e Bonus Class | PIMCO Total Return Portfolio - Class B |
|
| Variable Option [Line Items] |
|
| Portfolio Company Objective [Text Block] |
US Fixed Income
|
| Portfolio Company Name [Text Block] |
PIMCO Total Return Portfolio* - Class B
|
| Portfolio Company Adviser [Text Block] |
Brighthouse Investment Advisers, LLC
|
| Portfolio Company Subadviser [Text Block] |
Pacific Investment Management Company LLC
|
| Current Expenses [Percent] |
0.83%
|
| Current Expenses + Platform Charge [Percent] |
0.83%
|
| Average Annual Total Returns, 1 Year [Percent] |
8.90%
|
| Average Annual Total Returns, 5 Years [Percent] |
(0.07%)
|
| Average Annual Total Returns, 10 Years [Percent] |
2.30%
|
| MetLife Financial Freedom Select e and e Bonus Class | State Street Moderate ETF Portfolio - Class B |
|
| Variable Option [Line Items] |
|
| Portfolio Company Objective [Text Block] |
Allocation
|
| Portfolio Company Name [Text Block] |
State Street Moderate ETF Portfolio - Class B (formerly known as SSGA Growth and Income ETF Portfolio - Class B)
|
| Portfolio Company Adviser [Text Block] |
Brighthouse Investment Advisers, LLC
|
| Portfolio Company Subadviser [Text Block] |
SSGA Funds Management, Inc.
|
| Current Expenses [Percent] |
0.75%
|
| Current Expenses + Platform Charge [Percent] |
0.75%
|
| Average Annual Total Returns, 1 Year [Percent] |
16.78%
|
| Average Annual Total Returns, 5 Years [Percent] |
7.19%
|
| Average Annual Total Returns, 10 Years [Percent] |
7.85%
|
| MetLife Financial Freedom Select e and e Bonus Class | State Street Moderately Aggressive ETF Portfolio - Class B |
|
| Variable Option [Line Items] |
|
| Portfolio Company Objective [Text Block] |
Allocation
|
| Portfolio Company Name [Text Block] |
State Street Moderately Aggressive ETF Portfolio - Class B (formerly known as SSGA Growth ETF Portfolio - Class B)
|
| Portfolio Company Adviser [Text Block] |
Brighthouse Investment Advisers, LLC
|
| Portfolio Company Subadviser [Text Block] |
SSGA Funds Management, Inc.
|
| Current Expenses [Percent] |
0.78%
|
| Current Expenses + Platform Charge [Percent] |
0.78%
|
| Average Annual Total Returns, 1 Year [Percent] |
19.23%
|
| Average Annual Total Returns, 5 Years [Percent] |
9.01%
|
| Average Annual Total Returns, 10 Years [Percent] |
9.31%
|
| MetLife Financial Freedom Select e and e Bonus Class | T Rowe Price Large Cap Growth Portfolio - Class B |
|
| Variable Option [Line Items] |
|
| Portfolio Company Objective [Text Block] |
US Equity
|
| Portfolio Company Name [Text Block] |
T. Rowe Price Large Cap Growth Portfolio* - Class B
|
| Portfolio Company Adviser [Text Block] |
Brighthouse Investment Advisers, LLC
|
| Portfolio Company Subadviser [Text Block] |
T. Rowe Price Associates, Inc.
|
| Current Expenses [Percent] |
0.81%
|
| Current Expenses + Platform Charge [Percent] |
0.81%
|
| Average Annual Total Returns, 1 Year [Percent] |
15.45%
|
| Average Annual Total Returns, 5 Years [Percent] |
9.37%
|
| Average Annual Total Returns, 10 Years [Percent] |
14.10%
|
| MetLife Financial Freedom Select e and e Bonus Class | T Rowe Price Mid Cap Growth Portfolio - Class B |
|
| Variable Option [Line Items] |
|
| Portfolio Company Objective [Text Block] |
US Equity
|
| Portfolio Company Name [Text Block] |
T. Rowe Price Mid Cap Growth Portfolio* - Class B
|
| Portfolio Company Adviser [Text Block] |
Brighthouse Investment Advisers, LLC
|
| Portfolio Company Subadviser [Text Block] |
T. Rowe Price Associates, Inc. is the subadviserT. Rowe Price Investment Management, Inc. is the sub-subadviser
|
| Current Expenses [Percent] |
0.95%
|
| Current Expenses + Platform Charge [Percent] |
0.95%
|
| Average Annual Total Returns, 1 Year [Percent] |
3.42%
|
| Average Annual Total Returns, 5 Years [Percent] |
3.83%
|
| Average Annual Total Returns, 10 Years [Percent] |
9.77%
|
| MetLife Financial Freedom Select e and e Bonus Class | T Rowe Price Small Cap Growth Portfolio - Class B |
|
| Variable Option [Line Items] |
|
| Portfolio Company Objective [Text Block] |
US Equity
|
| Portfolio Company Name [Text Block] |
T. Rowe Price Small Cap Growth Portfolio - Class B
|
| Portfolio Company Adviser [Text Block] |
Brighthouse Investment Advisers, LLC
|
| Portfolio Company Subadviser [Text Block] |
T. Rowe Price Associates, Inc.
|
| Current Expenses [Percent] |
0.76%
|
| Current Expenses + Platform Charge [Percent] |
0.76%
|
| Average Annual Total Returns, 1 Year [Percent] |
10.00%
|
| Average Annual Total Returns, 5 Years [Percent] |
5.48%
|
| Average Annual Total Returns, 10 Years [Percent] |
10.60%
|
| MetLife Financial Freedom Select e and e Bonus Class | Victory Sycamore Mid Cap Value Portfolio - Class B |
|
| Variable Option [Line Items] |
|
| Portfolio Company Objective [Text Block] |
US Equity
|
| Portfolio Company Name [Text Block] |
Victory Sycamore Mid Cap Value Portfolio* - Class B
|
| Portfolio Company Adviser [Text Block] |
Brighthouse Investment Advisers, LLC
|
| Portfolio Company Subadviser [Text Block] |
Victory Capital Management, Inc.
|
| Current Expenses [Percent] |
0.85%
|
| Current Expenses + Platform Charge [Percent] |
0.85%
|
| Average Annual Total Returns, 1 Year [Percent] |
2.29%
|
| Average Annual Total Returns, 5 Years [Percent] |
9.62%
|
| Average Annual Total Returns, 10 Years [Percent] |
9.58%
|
| MetLife Financial Freedom Select e and e Bonus Class | Western Asset Management Strategic Bond Opportunities Portfolio - Class B |
|
| Variable Option [Line Items] |
|
| Portfolio Company Objective [Text Block] |
US Fixed Income
|
| Portfolio Company Name [Text Block] |
Western Asset Management Strategic Bond Opportunities Portfolio* - Class B
|
| Portfolio Company Adviser [Text Block] |
Brighthouse Investment Advisers, LLC
|
| Portfolio Company Subadviser [Text Block] |
Western Asset Management Company, LLC
|
| Current Expenses [Percent] |
0.82%
|
| Current Expenses + Platform Charge [Percent] |
0.82%
|
| Average Annual Total Returns, 1 Year [Percent] |
8.88%
|
| Average Annual Total Returns, 5 Years [Percent] |
1.17%
|
| Average Annual Total Returns, 10 Years [Percent] |
3.77%
|
| MetLife Financial Freedom Select e and e Bonus Class | Western Asset Management US Government Portfolio - Class B |
|
| Variable Option [Line Items] |
|
| Portfolio Company Objective [Text Block] |
US Fixed Income
|
| Portfolio Company Name [Text Block] |
Western Asset Management U.S. Government Portfolio* - Class B
|
| Portfolio Company Adviser [Text Block] |
Brighthouse Investment Advisers, LLC
|
| Portfolio Company Subadviser [Text Block] |
Western Asset Management Company, LLC
|
| Current Expenses [Percent] |
0.75%
|
| Current Expenses + Platform Charge [Percent] |
0.75%
|
| Average Annual Total Returns, 1 Year [Percent] |
6.81%
|
| Average Annual Total Returns, 5 Years [Percent] |
0.35%
|
| Average Annual Total Returns, 10 Years [Percent] |
1.57%
|
| MetLife Financial Freedom Select e and e Bonus Class | MetLife Aggregate Bond Index Portfolio - Class A |
|
| Investment Option Restrictions [Line Items] |
|
| Investment Option Restricted with Benefit [Flag] |
true
|
| MetLife Financial Freedom Select e and e Bonus Class | MetLife Stock Index Portfolio - Class A |
|
| Investment Option Restrictions [Line Items] |
|
| Investment Option Restricted with Benefit [Flag] |
true
|
| MetLife Financial Freedom Select e and e Bonus Class | MetLife Mid Cap Stock Index Portfolio - Class G |
|
| Investment Option Restrictions [Line Items] |
|
| Investment Option Restricted with Benefit [Flag] |
true
|
| MetLife Financial Freedom Select e and e Bonus Class | Standard Death Benefit [Member] |
|
| Item 10. Benefits Available [Line Items] |
|
| Name of Benefit [Text Block] |
Standard Death Benefit
|
| Purpose of Benefit [Text Block] |
If You die during the pay-in phase, guarantees that the death benefit will not be less than the greater of (1) your Account Balance less any outstanding loans; or (2) total purchase payment reduced proportionately by the percentage reduction in Account Balance attributable to each partial withdrawal less any outstanding loans (including any applicable Withdrawal Charge).
|
| Standard Benefit [Flag] |
true
|
| Standard Benefit Expense (of Benefit Base), Maximum [Percent] |
0.00%
|
| Brief Restrictions / Limitations [Text Block] |
●Withdrawals could significantly reduce the benefit.
|
| Name of Benefit [Text Block] |
Standard Death Benefit
|
| Operation of Benefit [Text Block] |
Death Benefit — GenerallyOne of the insurance guarantees we provide You under your Deferred Annuity is that your Beneficiaries will be protected during the “pay-in” phase against market downturns. You name your Beneficiary(ies).If You intend to purchase the Deferred Annuity for use with a SEP or SIMPLE IRA, please refer to the discussion concerning Qualified Annuity Contracts in the Federal Tax Considerations section of this Prospectus.The standard death benefit is described below. An additional optional death benefit is described in the “Optional Death Benefit” and "Annual Step-Up Death Benefit" sections. Check your Contract and riders for the specific provisions applicable to You. The optional death benefit may not be available in your state (check with your registered representative regarding availability). There is no death benefit after the pay-out phase begins, however, depending on the Pay-Out Option you elect, any remaining guarantee will be paid to your Beneficiary.The death benefit is determined as of the end of the business day on which we receive both due proof of death and an election for the payment method.If we are presented with notification of your death before any requested transaction is completed (including transactions under automated investment strategies, the minimum distribution program and the Systematic Withdrawal Program), we will cancel the request. As described above, the death benefit will be determined when we receive due proof of death and an election for the payment method.Until the Beneficiary (or each Beneficiary if there are multiple Beneficiaries) submits the necessary documentation in Good Order, the Account Balance attributable to his/her portion of the death benefit remains in the Divisions and is subject to investment risk.Where there are multiple Beneficiaries, the death benefit will only be determined as of the time the first Beneficiary submits the necessary documentation in Good Order. If the death benefit payable is an amount that exceeds the Account Balance on the day it is determined, we will apply to the Contract an amount equal to the difference between the death benefit payable and the Account Balance, in accordance with the current allocation of the Account Balance. This death benefit amount remains in the Divisions and/or Fixed Interest Account until each of the other Beneficiaries submits the necessary documentation in Good Order to claim his/her death benefit. Any death benefit amounts held in the Divisions on behalf of the remaining Beneficiaries are subject to investment risk. There is no additional death benefit guarantee.Your Beneficiary has the option to apply the death benefit less any applicable premium and other taxes to a Pay-Out Option offered under your Deferred Annuity. Your Beneficiary may, however, decide to take payment in one sum, including either by check, by placing the amount in an account that earns interest, or by any other method of payment that provides the Beneficiary with immediate and full access to the proceeds or under other settlement options that we may make available. If your contract was issued as an individual flexible contribution deferred variable annuity you may also elect to have surrender proceeds paid into a Total Control Account established for You, subject to our current established administrative procedures and requirements. You should always consult a tax adviser for complete information and advice applicable to your individual situation before having proceeds paid into a Total Control Account.Total Control AccountThe Beneficiary may elect to have the Contract’s death proceeds paid through a settlement option called the Total Control Account, subject to our current established administrative procedures and requirements. The Total Control Account is an interest-bearing account through which the Beneficiary has immediate and full access to the proceeds, with unlimited draft writing privileges. We credit interest to the account at a rate that will not be less than a guaranteed minimum annual effective rate. Assets backing the Total Control Accounts are maintained in our General Account and are subject to the claims of our creditors. We will bear the investment experience of such assets; however, regardless of the investment experience of such assets, the interest credited to the Total Control Account will never fall below the applicable guaranteed minimum annual effective rate. Because we bear the investment experience of the assets backing the Total Control Account, we may receive a profit from these assets. The Total Control Account is not insured by the FDIC or any other governmental agency.
|
| Calculation Method of Benefit [Text Block] |
Standard Death BenefitIf You die during the pay-in phase and You have not chosen the optional death benefit, the death benefit the Beneficiary receives will be equal to the greater of:1.Your Account Balance, less any outstanding loans; or2.Total purchase payments reduced proportionately by the percentage reduction in Account Balance attributable to each partial withdrawal, less any outstanding loans (including any applicable Withdrawal Charge).Example
| |
|
|
|
| |
|
|
|
| |
|
10/1/2020 (First Contract Anniversary) |
|
| |
|
|
$104,000 (= greater of A and B) |
| |
|
10/1/2021 (Second Contract Anniversary) |
|
| |
|
|
$100,000 (= greater of A and D) |
| |
|
|
|
| |
Percentage Reduction in Account Balance |
|
|
| |
Account Balance after Withdrawal |
|
|
| |
Purchase Payments reduced for Withdrawal |
|
|
| |
|
|
$90,000 (= greater of H and I) | Notes to Example:Any Withdrawal Charge withdrawn from the Account Balance is included when determining the percentage of Account Balance withdrawn.Account Balances on 10/1/21 and 10/2/21 are assumed to be equal prior to the withdrawal.There are no loans.
|
| MetLife Financial Freedom Select e and e Bonus Class | Annual Step-Up Death Benefit |
|
| Item 4. Fee Table [Line Items] |
|
| Optional Benefit Expense (of Other Amount), Maximum [Percent] |
0.10%
|
| Item 10. Benefits Available [Line Items] |
|
| Name of Benefit [Text Block] |
Annual Step-Up Death Benefit
|
| Purpose of Benefit [Text Block] |
If You die during the pay-in phase, guarantees that the death benefit will not be less than the greatest of (1) your Account Balance; (2) total purchase payments reduced proportionately for withdrawals and any outstanding loans (including any applicable Withdrawal Charge) or (3) "Highest Anniversary Value" as of each Contract Anniversary prior to your 81st birthday, plus any subsequent purchase payments, reduced for any outstanding loans, and reduced proportionately for withdrawals (including any applicable Withdrawal Charge).
|
| Optional Benefit [Flag] |
true
|
| Optional Benefit Expense (of Other Amount), Maximum [Percent] |
0.10%
|
| Brief Restrictions / Limitations [Text Block] |
●Withdrawals could significantly reduce the benefit.●You may not purchase this benefit if You are 80 years of age or older.●Available only at issue.
|
| Name of Benefit [Text Block] |
Annual Step-Up Death Benefit
|
| Operation of Benefit [Text Block] |
Annual Step-Up Death BenefitThe Annual Step-Up Death Benefit is designed to provide protection against adverse investment experience. In general, it guarantees that the death benefit will not be less than the greatest of (1) your Account Balance; (2) total purchase payments reduced for any outstanding loans and reduced proportionately for withdrawals (including any applicable Withdrawal Charge); or (3) “Highest Anniversary Value” as of each contract anniversary prior to your 81st birthday reduced for any outstanding loans and reduced proportionately for withdrawals and (including any applicable Withdrawal Charge). You may not purchase this benefit if You are 80 years of age or older.You may purchase at application a death benefit that provides that the death benefit amount is equal to the greatest of:1.The Account Balance, less any outstanding loans;2.Total purchase payments reduced proportionately for withdrawals and any outstanding loans (including any applicable Withdrawal Charge); or3.“Highest Anniversary Value” as of each Contract Anniversary, determined as follows:●At issue, the Highest Anniversary Value is your initial purchase payment;●Increase the Highest Anniversary Value by each subsequent purchase payment;●Reduce the Highest Anniversary Value proportionately by the percentage reduction in Account Balance attributable to each subsequent partial withdrawal, less any outstanding loans (including any applicable Withdrawal Charge);●On each Contract Anniversary before your 81st birthday, compare the (1) then Highest Anniversary Value to the (2) current Account Balance and set the Highest Anniversary Value equal to the greater of the two.●After the Contract Anniversary immediately preceding your 81st birthday, adjust the Highest Anniversary Value only to:●Increase the Highest Anniversary Value by each subsequent purchase payment or●Reduce the Highest Anniversary Value proportionately by the percentage reduction in Account Balance attributable to each subsequent partial withdrawal, less any outstanding loans (including any applicable Withdrawal Charge).For purposes of determining the Highest Anniversary Value as of the applicable Contract Anniversary, purchase payments increase the Highest Anniversary Value on a dollar for dollar basis. Partial withdrawals, however, reduce the Highest Anniversary Value proportionately, that is, the percentage reduction is equal to the dollar amount of the withdrawal (plus applicable Withdrawal Charges) divided by the Account Balance immediately before the withdrawal.The Annual Step-Up Death Benefit is available for a charge, in addition to the Standard Death Benefit Separate Account Charge, of 0.10% annually of the average daily value of the amount You have in the Separate Account.
|
| Calculation Method of Benefit [Text Block] |
Example:
| |
|
|
|
| |
|
|
|
| |
|
10/1/2020 (First Contract Anniversary) |
|
| |
Death Benefit (Highest Anniversary Value) |
|
$104,000 (= greater of A and B) |
| |
|
10/1/2021 (Second Contract Anniversary) |
|
| |
Death Benefit (Highest Contract Year Anniversary) |
|
$104,000 (= greater of C and D) |
| |
|
|
|
| |
Percentage Reduction in Account Balance |
|
|
| |
Account Balance after Withdrawal |
|
|
| |
Highest Anniversary Value reduced for Withdrawal |
|
|
| |
|
|
$93,600 (= greater of H and I) | Notes to Example:Any Withdrawal Charge withdrawn from the Account Balance is included when determining the percentage of Account Balance withdrawn.The Account Balances on 10/1/21 and 10/2/21 are assumed to be equal prior to the withdrawal. The purchaser is age 60 at issue.There are no loans.
|
| MetLife Financial Freedom Select e and e Bonus Class | Guaranteed Minimum Income Benefit |
|
| Item 4. Fee Table [Line Items] |
|
| Optional Benefit Expense, Footnotes [Text Block] |
You may only have one living benefit, the Guaranteed Minimum Income Benefit or the Lifetime Withdrawal Benefit, associated with your Contract at any given time. The charge for the Guaranteed Minimum Income Benefit is a percentage of your guaranteed minimum income base, as defined later in this Prospectus, and is deducted at the end of each Contract Year by withdrawing amounts on a pro-rata basis from your Fixed Interest Account Balance and Your Investment Options (net of any loans). (We take amounts from the Separate Account by canceling, if available, Accumulation Units from your Separate Account Balance.) You do not pay this charge once You are in the pay-out phase of your Contract. Different charges for the Guaranteed Minimum Income Benefit were in effect prior to May 4, 2009.
|
| Item 10. Benefits Available [Line Items] |
|
| Name of Benefit [Text Block] |
Guaranteed Minimum Income Benefit
|
| Purpose of Benefit [Text Block] |
Designed to guarantee a predictable, minimum level of fixed income payments, regardless of investment performance of your Account Balance during the pay-in phase.
|
| Optional Benefit [Flag] |
true
|
| Standard Benefit Expense (of Benefit Base), Maximum [Percent] |
0.70%
|
| Optional Benefit Expense, Footnotes [Text Block] |
You may only have one living benefit, the Guaranteed Minimum Income Benefit or the Lifetime Withdrawal Benefit, associated with your Contract at any given time. The charge for the Guaranteed Minimum Income Benefit is a percentage of your guaranteed minimum income base, as defined later in this Prospectus, and is deducted at the end of each Contract Year by withdrawing amounts on a pro-rata basis from your Fixed Interest Account Balance and Your Investment Options (net of any loans). (We take amounts from the Separate Account by canceling, if available, Accumulation Units from your Separate Account Balance.) You do not pay this charge once You are in the pay-out phase of your Contract. Different charges for the Guaranteed Minimum Income Benefit were in effect prior to May 4, 2009.
|
| Brief Restrictions / Limitations [Text Block] |
●No longer available for sale.●You may not have this optional benefit and another optional living benefit (Lifetime Withdrawal Guarantee) in effect at the same time.●Age restrictions apply.●May only be exercised after a 10-year waiting period.●Availability subject to state.●Cannot be terminated.●Withdrawals could significantly reduce the benefit.
|
| Name of Benefit [Text Block] |
Guaranteed Minimum Income Benefit
|
| Operation of Benefit [Text Block] |
Living BenefitsGMIB — (may also be known as the “Predictor” in our sales literature and advertising)As of the close of the Exchange on September, 17, 2018, the GMIB is not available for sale to any new employer sponsored retirement plan or to any new participants under an existing employer sponsored retirement plan.We offered the GMIB that, for an additional charge, offers protection against market risk (the risk that your investments may decline in value or underperform your expectations). Our guaranteed income benefit, called GMIB, is designed to allow You to invest your Account Balance in the market while at the same time assuring a specified guaranteed level of minimum fixed income payments if You elect to receive income payments (“annuitize”). The fixed annuity payment amount is guaranteed regardless of investment performance or the actual Account Balance at the time You elect income payments. Prior to exercising this optional benefit and annuitizing your Contract, You may make withdrawals up to a maximum level and still maintain the optional benefit amount. This optional benefit must be elected at Contract issue.This optional benefit is designed to guarantee a predictable, minimum level of fixed income payments, regardless of investment performance of your Account Balance during the pay-in phase. However, if applying your actual Account Balance at the time You annuitize the Contract to then current annuity purchase rates (outside of the optional benefit) produces higher income payments, You will receive the higher payments, and thus You will have paid for the optional benefit even though it was not used. Also, prior to exercising the optional benefit, You may make specified withdrawals that reduce your income base (as explained below) during the pay-in phase and still leave the optional benefit guarantees intact, provided the conditions of the optional benefit are met. Your registered representative can provide You an illustration of the amounts You would receive, with or without withdrawals, if You exercised the optional benefit.The GMIB was available in all states except New York. In the states of Montana, Utah and West Virginia, the GMIB was only available for elective TSA (non-ERISA) and SEP/SIMPLE Deferred Annuities. In Oregon, the GMIB was only available for TSA ERISA, 403(a) and 457(b) Deferred Annuities.Once elected, the optional benefit cannot be terminated except as discussed below.GMIB and Qualified ContractsThe GMIB may have limited usefulness in connection with a qualified Contract, such as TSA, TSA ERISA, IRA, 403(a), 401(a), 401(k) or 457(b), in circumstances where, due to the 10-year waiting period after purchase, the Contract Owner is unable to exercise the benefit until after the required beginning date of required minimum distributions under the Contract. In such event, required minimum distributions received from the Contract during the 10-year waiting period will have the effect of reducing the income base either on a proportionate or dollar for dollar basis, as the case may be. This may have the effect of reducing or eliminating the value of annuity payments under the GMIB. You should consult your tax adviser prior to electing a GMIB.If You take a full withdrawal of your Account Balance, your Contract is terminated by us due to its small Account Balance and inactivity (see “When We Can Cancel your Deferred Annuity”), your Contract lapses for any reason, or in those instances where your employer has the ability to do so your employer terminates the Contract, and there remains any income base, You forfeit your income base and any further rights to the GMIB.Facts About the Guaranteed Minimum Income BenefitIncome Base and GMIB Income Payments. We calculate an “income base” (as described below) that determines, in part, the minimum amount You receive as an income payment upon exercising the GMIB and annuitizing the Contract. It is important to recognize that this income base is not available for cash withdrawals and does not establish or guarantee your Account Balance or a minimum return for any Division.After a minimum 10-year waiting period, and not more than 30 days after the Contract Anniversary following your 85th birthday, You may exercise the benefit. We then will apply the income base calculated at the time of exercise to the GMIB Annuity Table (as described below) specified in the rider in order to determine your minimum guaranteed lifetime fixed monthly income payments. (Your actual payment may be higher than this minimum if, as discussed above, the base Contract under its terms would provide a higher payment.)If your employer, association or other group Contract holder has instituted loans for its plan or arrangement, You have taken a loan and You have also purchased the GMIB, we will not treat amounts withdrawn from your Account Balance on account of a loan as a withdrawal from the Contract for purposes of determining the income base. In addition, we will not treat the repayment of loan amounts as a purchase payment to the Contract for the purposes of determining the income base.The GMIB Annuity Table. The GMIB Annuity Table is specified in the rider. This table is calculated based on the Annuity 2000 Mortality Table with a 7-year age set back with interest of 2.5% per year. As with other pay-out types, the amount You receive as an income payment also depends on the income type You select, your age, and your sex (where permitted by state law). The annuity rates in the GMIB Annuity Table are conservative and a Withdrawal Charge may be applicable, so the amount of guaranteed minimum lifetime income that the GMIB produces may be less than the amount of annuity income that would be provided by applying your Account Balance on your annuity date to then-current annuity purchase rates.If You exercise the GMIB, your income payments will be the greater of:●the income payment determined by applying the amount of the income base to the GMIB Annuity Table, or●the income payment determined for the same income type in accordance with the base Contract. (See “Pay-Out Options (or Income Options).”)If You choose not to receive income payments as guaranteed under the GMIB, You may elect any of the income options available under the Contract.If the amount of the guaranteed minimum lifetime income that the GMIB produces is less than the amount of annuity income that would be provided by applying your Account Balance on the Annuity Date to the then-current annuity purchase rates, then You would have paid for an optional benefit You did not use.Description of the GMIBIn states where approved, the GMIB was available only up to, but not including, age 76 and You could have only elected the GMIB at the time You purchased the Contract. The GMIB may be exercised after a 10-year waiting period and then only within 30 days following a Contract Anniversary, provided that the exercise must occur no later than the 30-day period following the Contract Anniversary following your 85th birthday.Income BaseThe income base is equal to the greater of (a) or (b) below:(a)Highest Anniversary Value: On the issue date, the “Highest Anniversary Value” is equal to your initial purchase payment. Thereafter, the Highest Anniversary Value will be increased by subsequent purchase payments and reduced proportionately by the percentage reduction in Account Balance attributable to each subsequent withdrawal (including any applicable Withdrawal Charge). On each Contract Anniversary prior to your 81st birthday, the Highest Anniversary Value will be recalculated and set equal to the greater of the Highest Anniversary Value before the recalculation or the Account Balance on the date of the recalculation.The Highest Anniversary Value does not change after the Contract Anniversary immediately preceding your 81st birthday, except that it is increased for each subsequent purchase payment and reduced proportionally by the percentage reduction in Account Balance attributable to each subsequent withdrawal (including any applicable Withdrawal Charge).(b)Annual Increase Amount: On the date we issue your Contract, the “Annual Increase Amount” is equal to your initial purchase payment. Thereafter, the Annual Increase Amount is equal to (i) less (ii), where:(i)is purchase payments accumulated at the Annual Increase Rate of 6% (as defined below); and(ii)is withdrawal adjustments (as defined below) accumulated at the Annual Increase Rate.The Highest Anniversary Value and Annual Increase Amount are calculated independently of each other. When the Highest Anniversary Value is recalculated and set equal to the Account Balance, the Annual Increase Amount is not set equal to the Account Balance.Annual Increase Rate. As noted above we calculate an income base under the GMIB that helps determine the minimum amount You receive as an income payment upon exercising the benefit. One of the factors used in calculating the income base is called the “annual increase rate.” Through the Contract Anniversary immediately prior to your 81st birthday, the Annual Increase Rate is 6%.On the first Contract Anniversary, “at the beginning of the Contract Year” means on the issue date; on a later Contract Anniversary, “at the beginning of the Contract Year” means on the prior Contract Anniversary.During the 30-day period following the Contract Anniversary immediately prior to your 81st birthday, the annual increase rate is 0%.Withdrawal Adjustments. Withdrawal adjustments in a Contract Year are determined according to (a) or (b):(a)The withdrawal adjustment for each withdrawal in a Contract Year is the value of the Annual Increase Amount immediately prior to the withdrawal multiplied by the percentage reduction in Account Balance attributable to the withdrawal (including any applicable Withdrawal Charge); or(b)If total withdrawals in a Contract Year are not greater than the Annual Increase Rate multiplied by the Annual Increase Amount at the beginning of the Contract Year, and if these withdrawals are paid to You, the total withdrawal adjustments for that Contract Year will be set equal to the dollar amount of total withdrawals (including any applicable Withdrawal Charge) in that Contract Year. These withdrawal adjustments will replace the withdrawal adjustments defined in (a) immediately above and be treated as though the corresponding withdrawals occurred at the end of that Contract Year.As described in (a) above, if in any Contract Year You take cumulative withdrawals that exceed the Annual Increase Rate multiplied by the Annual Increase Amount at the beginning of the Contract Year, the Annual Increase Amount will be reduced in the same proportion that the entire withdrawal (including any applicable Withdrawal Charge) reduced the Account Balance. This reduction may be significant, particularly when the Account Balance is lower than the Annual Increase Amount, and could have the effect of reducing or eliminating the value of income payments under the GMIB optional benefit. Limiting your cumulative withdrawals during a Contract Year to not more than the Annual Increase Rate multiplied by the Annual Increase Amount at the beginning of the Contract Year, will result in dollar-for-dollar treatment of the withdrawals as described in (b) immediately above.Partial annuitizations are not permitted. No change in Contract Owner of the Contract or participant is permitted.In determining GMIB income payments, an amount equal to the Withdrawal Charge that would apply upon a complete withdrawal and the amount of any premium taxes and other taxes that may apply will be deducted from the income base. For purposes of calculating the income base, purchase payment credits (i.e., bonus payments) are not included.Exercising the GMIB. The only income types available with the purchase of this benefit are a Lifetime Income Annuity with a 10-Year Guarantee Period or a Lifetime Income Annuity for Two with a 10-Year Guarantee Period. If You decide to receive income payments under a Lifetime Income Annuity with a 10-Year Guarantee Period after age 79, the 10-Year guarantee is reduced as follows:
Lifetime Income Annuity for Two is available if the ages of the joint Annuitants are 10 years apart or less (or as permissible under our then current underwriting requirements, if more favorable).Effect of Outstanding Loans on the GMIB. You may not exercise this benefit if You have an outstanding loan balance. You may exercise this benefit if You repay your outstanding loan balance. If You desire to exercise this benefit and have an outstanding loan balance and repay the loan by making a partial withdrawal, your income base will be reduced to adjust for the repayment of the loan, according to the formula described above.Terminating the GMIB. This benefit will terminate upon the earliest of:1.The 30th day following the Contract Anniversary on or following your 85th birthday;2.The date You make a total withdrawal of your Account Balance (a pro-rata portion of the annual benefit charge for the GMIB will be assessed);3.You elect to receive income payments under the Contract and You do not elect to receive income payments under the GMIB (a pro-rata portion of the annual benefit charge for the GMIB will be assessed);4.On the day there are insufficient amounts to deduct the charge for the GMIB from your Account Balance; or5.If You die.For more information on when we may or may not terminate your Contract, see “When We Can Cancel Your Deferred Annuity”.Charges. The GMIB was available in Deferred Annuities for an additional charge of 0.70% (except for the states of Texas and Virginia for TSA ERISA, 403(a) and 457(b) Deferred Annuities and except for the state of Pennsylvania for TSA, SEP and SIMPLE IRA Deferred Annuities, where the charge is 0.35%) of the income base, deducted at the end of each Contract Year on the Contract Anniversary, by withdrawing amounts on a pro-rata basis from your Fixed Interest Account Balance and Separate Account Balance, net of any outstanding loans. We take amounts from the Separate Account by canceling Accumulation Units from your Separate Account Balance. If You make a total withdrawal of your Account Balance or elect to receive income payments under your Contract, a pro-rata portion of the annual optional benefit charge will be assessed based on the number of months from the last Contract Anniversary to the date of the withdrawal or the beginning of income payments. Prior to May 1, 2009, the charge for the optional GMIB is 0.35% of the income base. (For employer groups with TSA ERISA, 457(b) and 403(a) Deferred Annuities that were established on or before May 1, 2009 which elected at issue to make available the GMIB under their group Contract, participants who submit an application after May 1, 2009, will receive the lower charge of 0.35%.)Graphic. The purpose of the following graphic is to illustrate the operation of the GMIB. The investment results shown are hypothetical and are not representative of past or future performance. Actual investment results may be more or less than those shown and will depend upon a number of factors, including investment allocations and the investment experience of the Divisions chosen. The graphic does not reflect the deduction of fees and charges, Withdrawal Charges or income taxes or penalties.(1)The 6% Annual Increase Amount of the Income BaseDetermining a value upon which future income payments will be basedPrior to annuitization, your Account Balance fluctuates above and below your initial purchase payment depending on the investment performance of the Divisions You selected. Your purchase payments accumulate at the annual increase rate of 6%, through the Contract Anniversary immediately preceding your 81st birthday. Your purchase payments are also adjusted for any withdrawals (including any applicable Withdrawal Charge) made during this period. The line (your purchase payments accumulated at 6% a year adjusted for withdrawals and charges (“the 6% Annual Increase Amount of the Income Base”)) is the value upon which future income payments can be based.
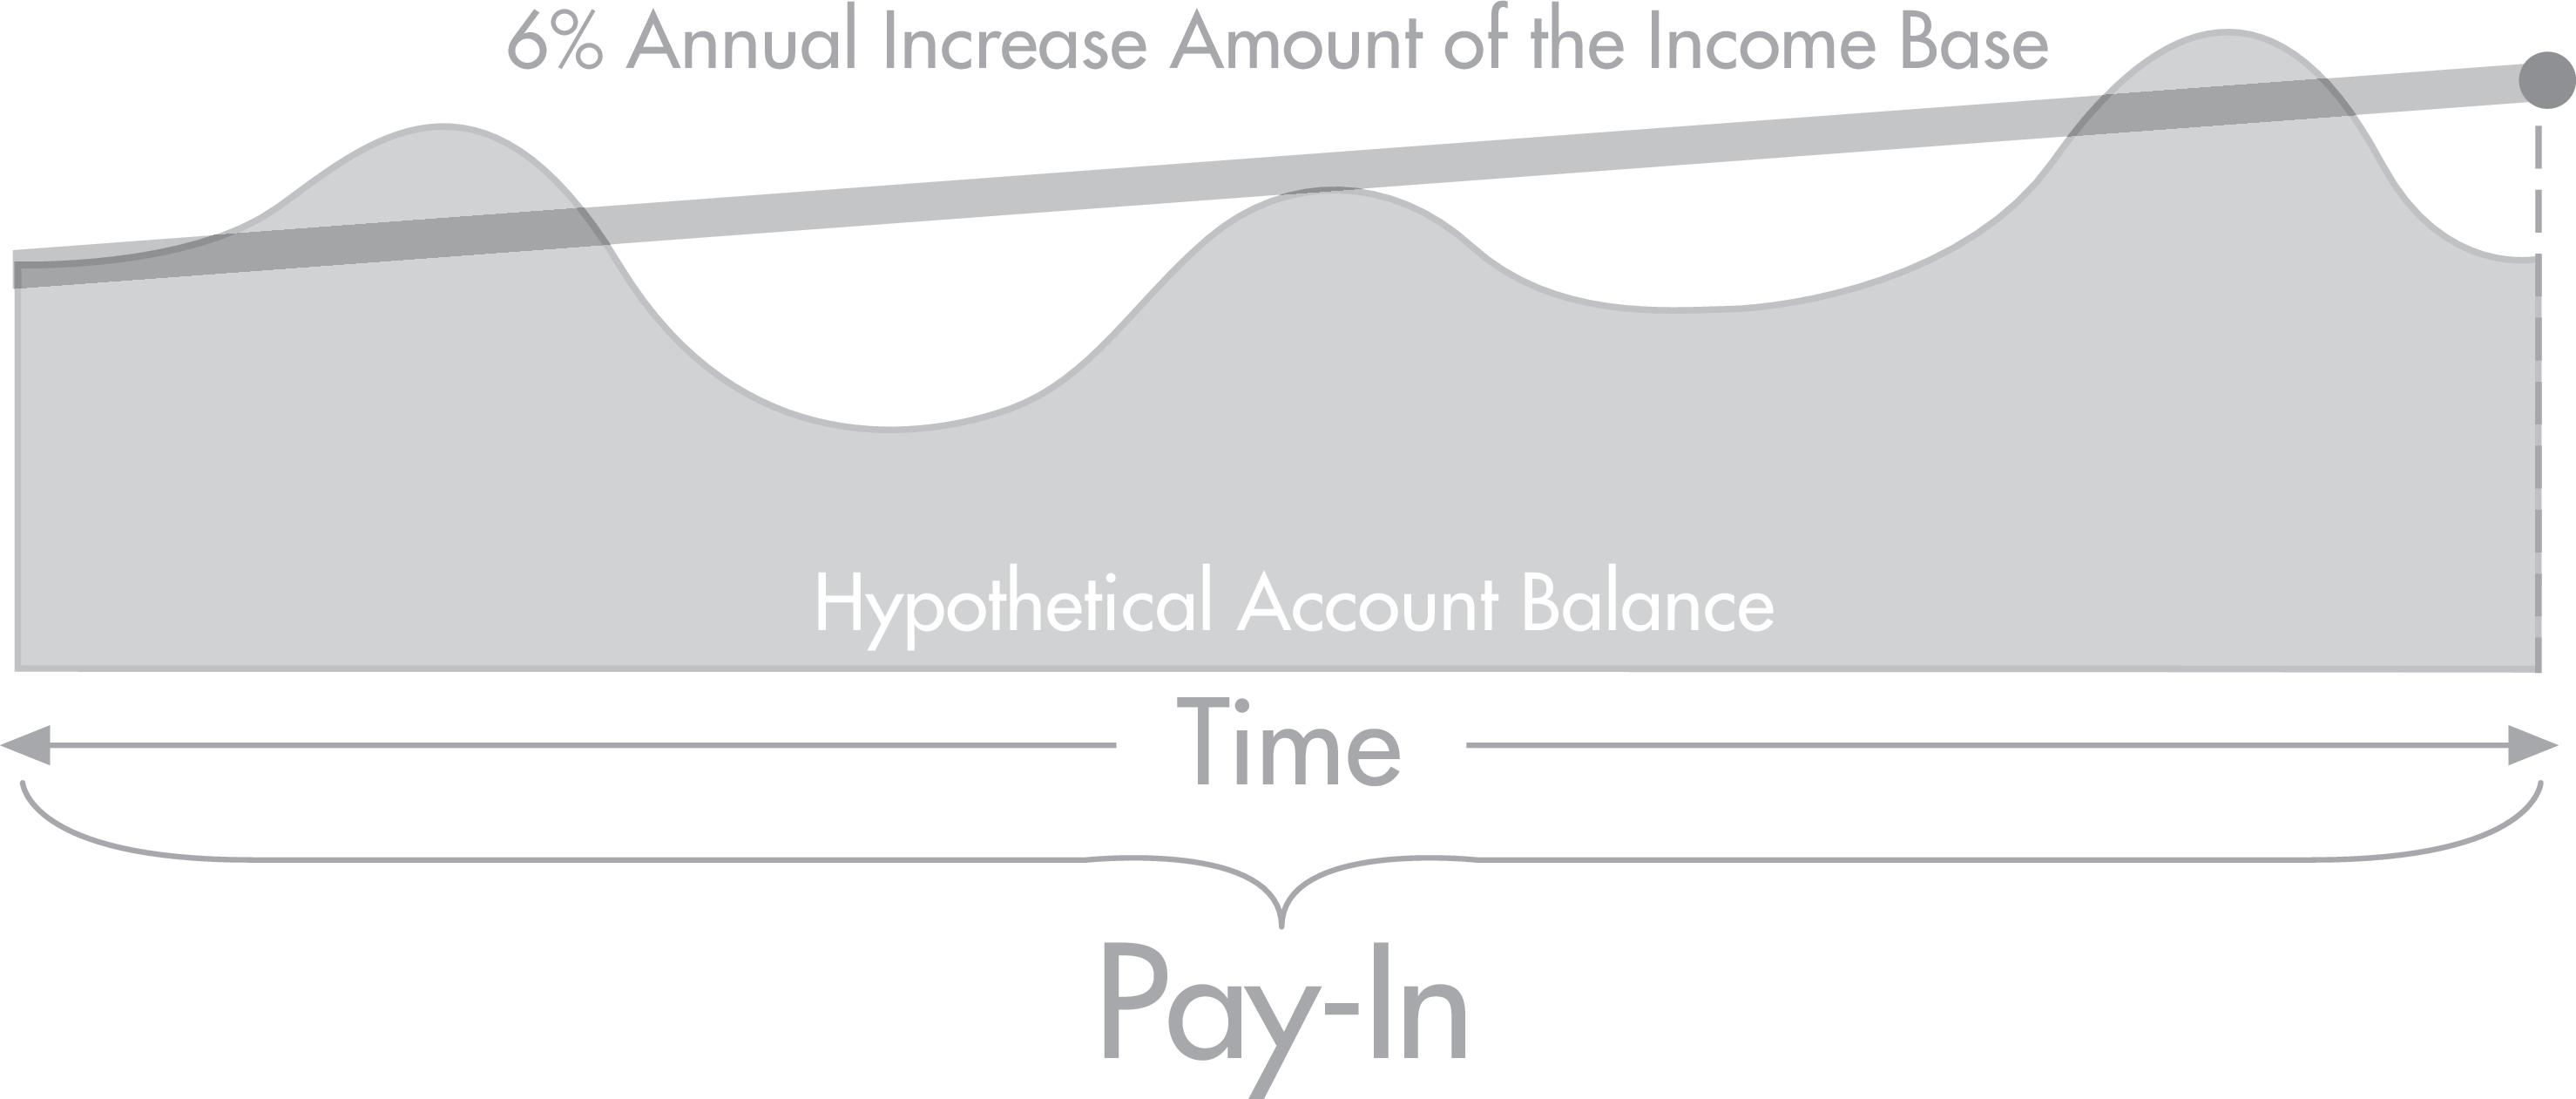 Determining your guaranteed lifetime income streamAssume that You decide to annuitize your Contract and begin taking annuity payments after 30 years. In this example, your 6% Annual Increase Amount of the Income Base is higher than the Highest Anniversary Value and will produce a higher income benefit. Accordingly, the 6% Annual Increase Amount of the Income Base will be applied to the annuity pay-out rates in the GMIB Annuity Table to determine your lifetime annuity payments. The income base is not available for cash withdrawals and is only used for purposes of calculating the GMIB payment and the charge for the benefit.
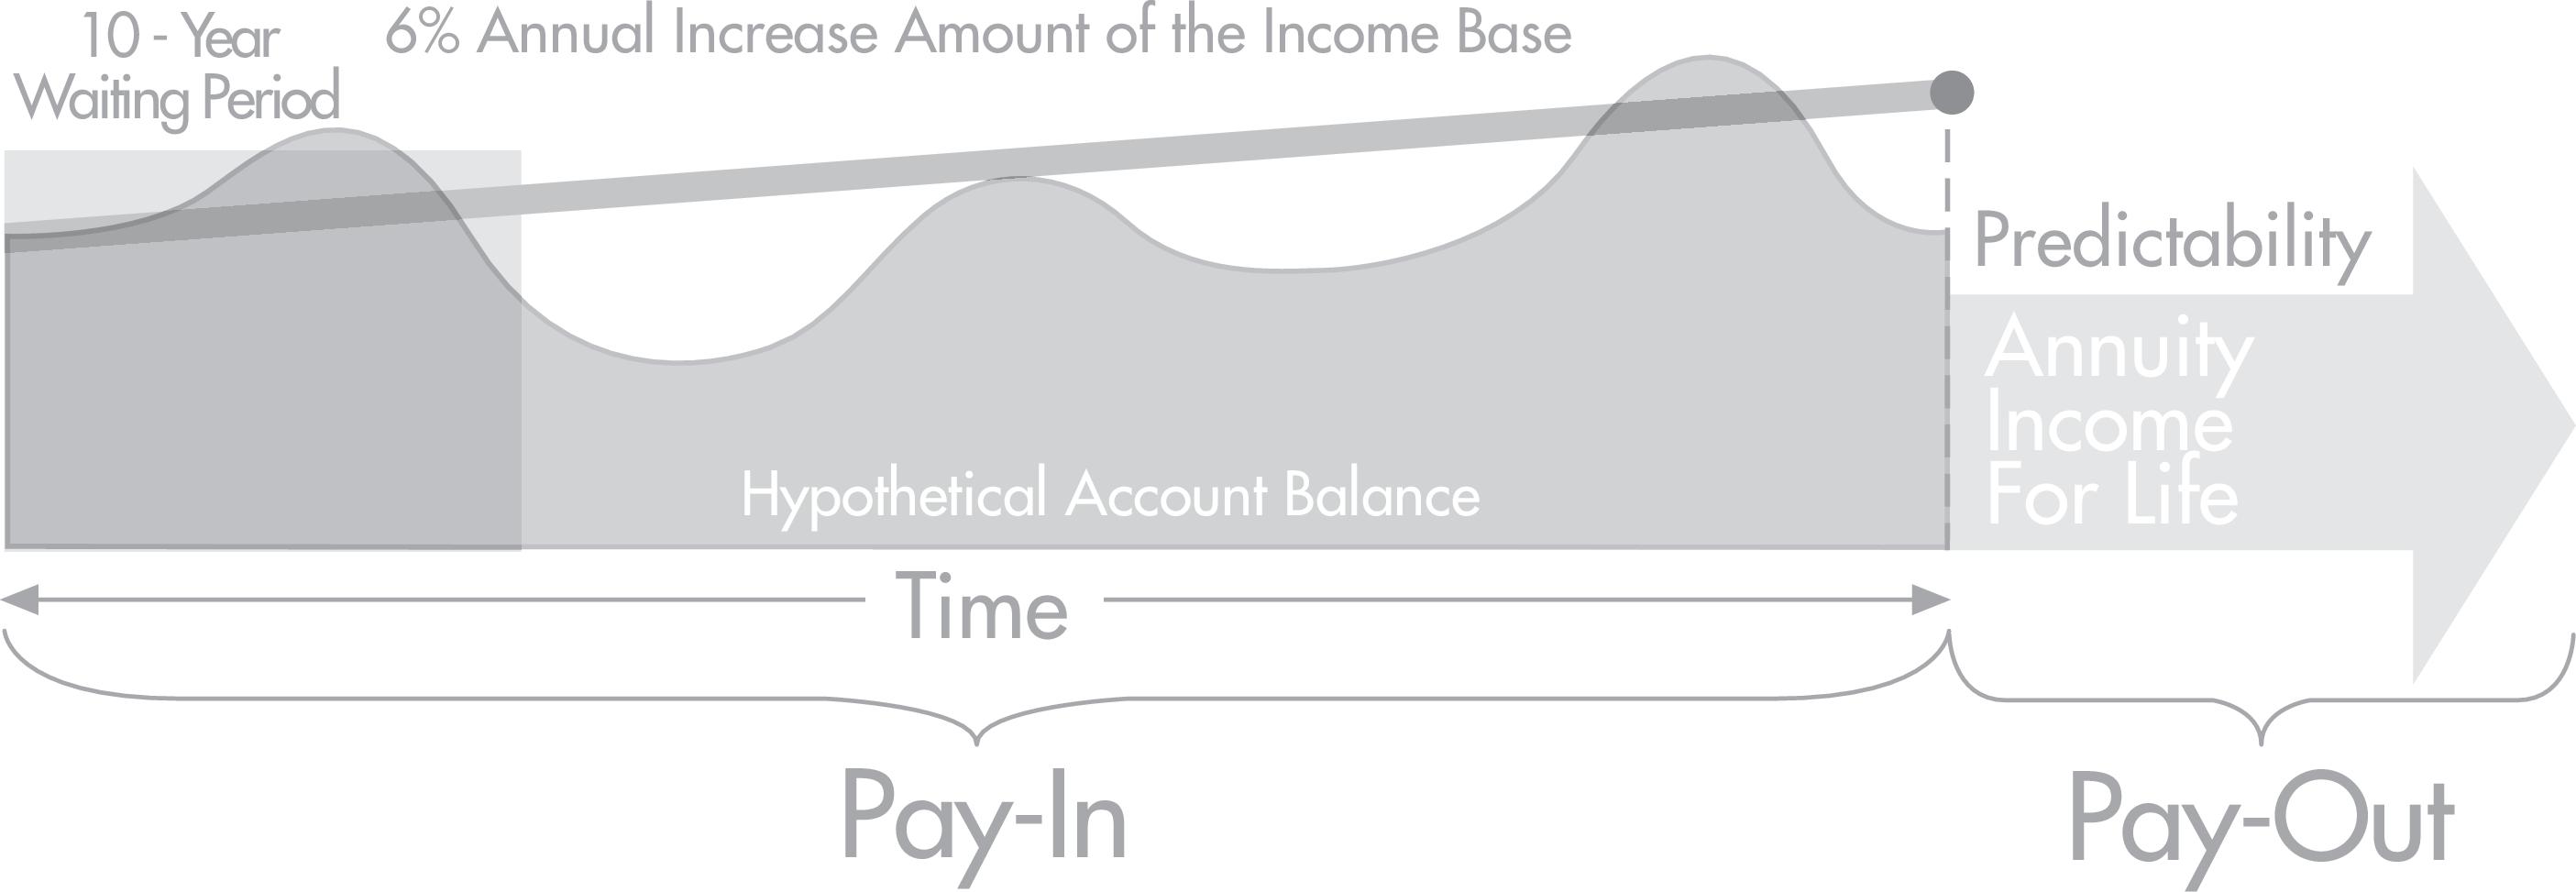 (2)The “Highest Anniversary Value” (“HAV”)Determining a value upon which future income payments will be basedPrior to annuitization, the Highest Anniversary Value at each Contract Anniversary begins to lock in growth. The Highest Anniversary Value is adjusted upward each Contract Anniversary if the Account Balance at that time is greater than the amount of the current Highest Anniversary Value. Upward adjustments will continue until the Contract Anniversary immediately prior to the Contract Owner’s 81st birthday. The Highest Anniversary Value also is adjusted for any withdrawals taken (including any applicable Withdrawal Charge) or any additional payments made. The Highest Anniversary Value line is the value upon which future income payments can be based.
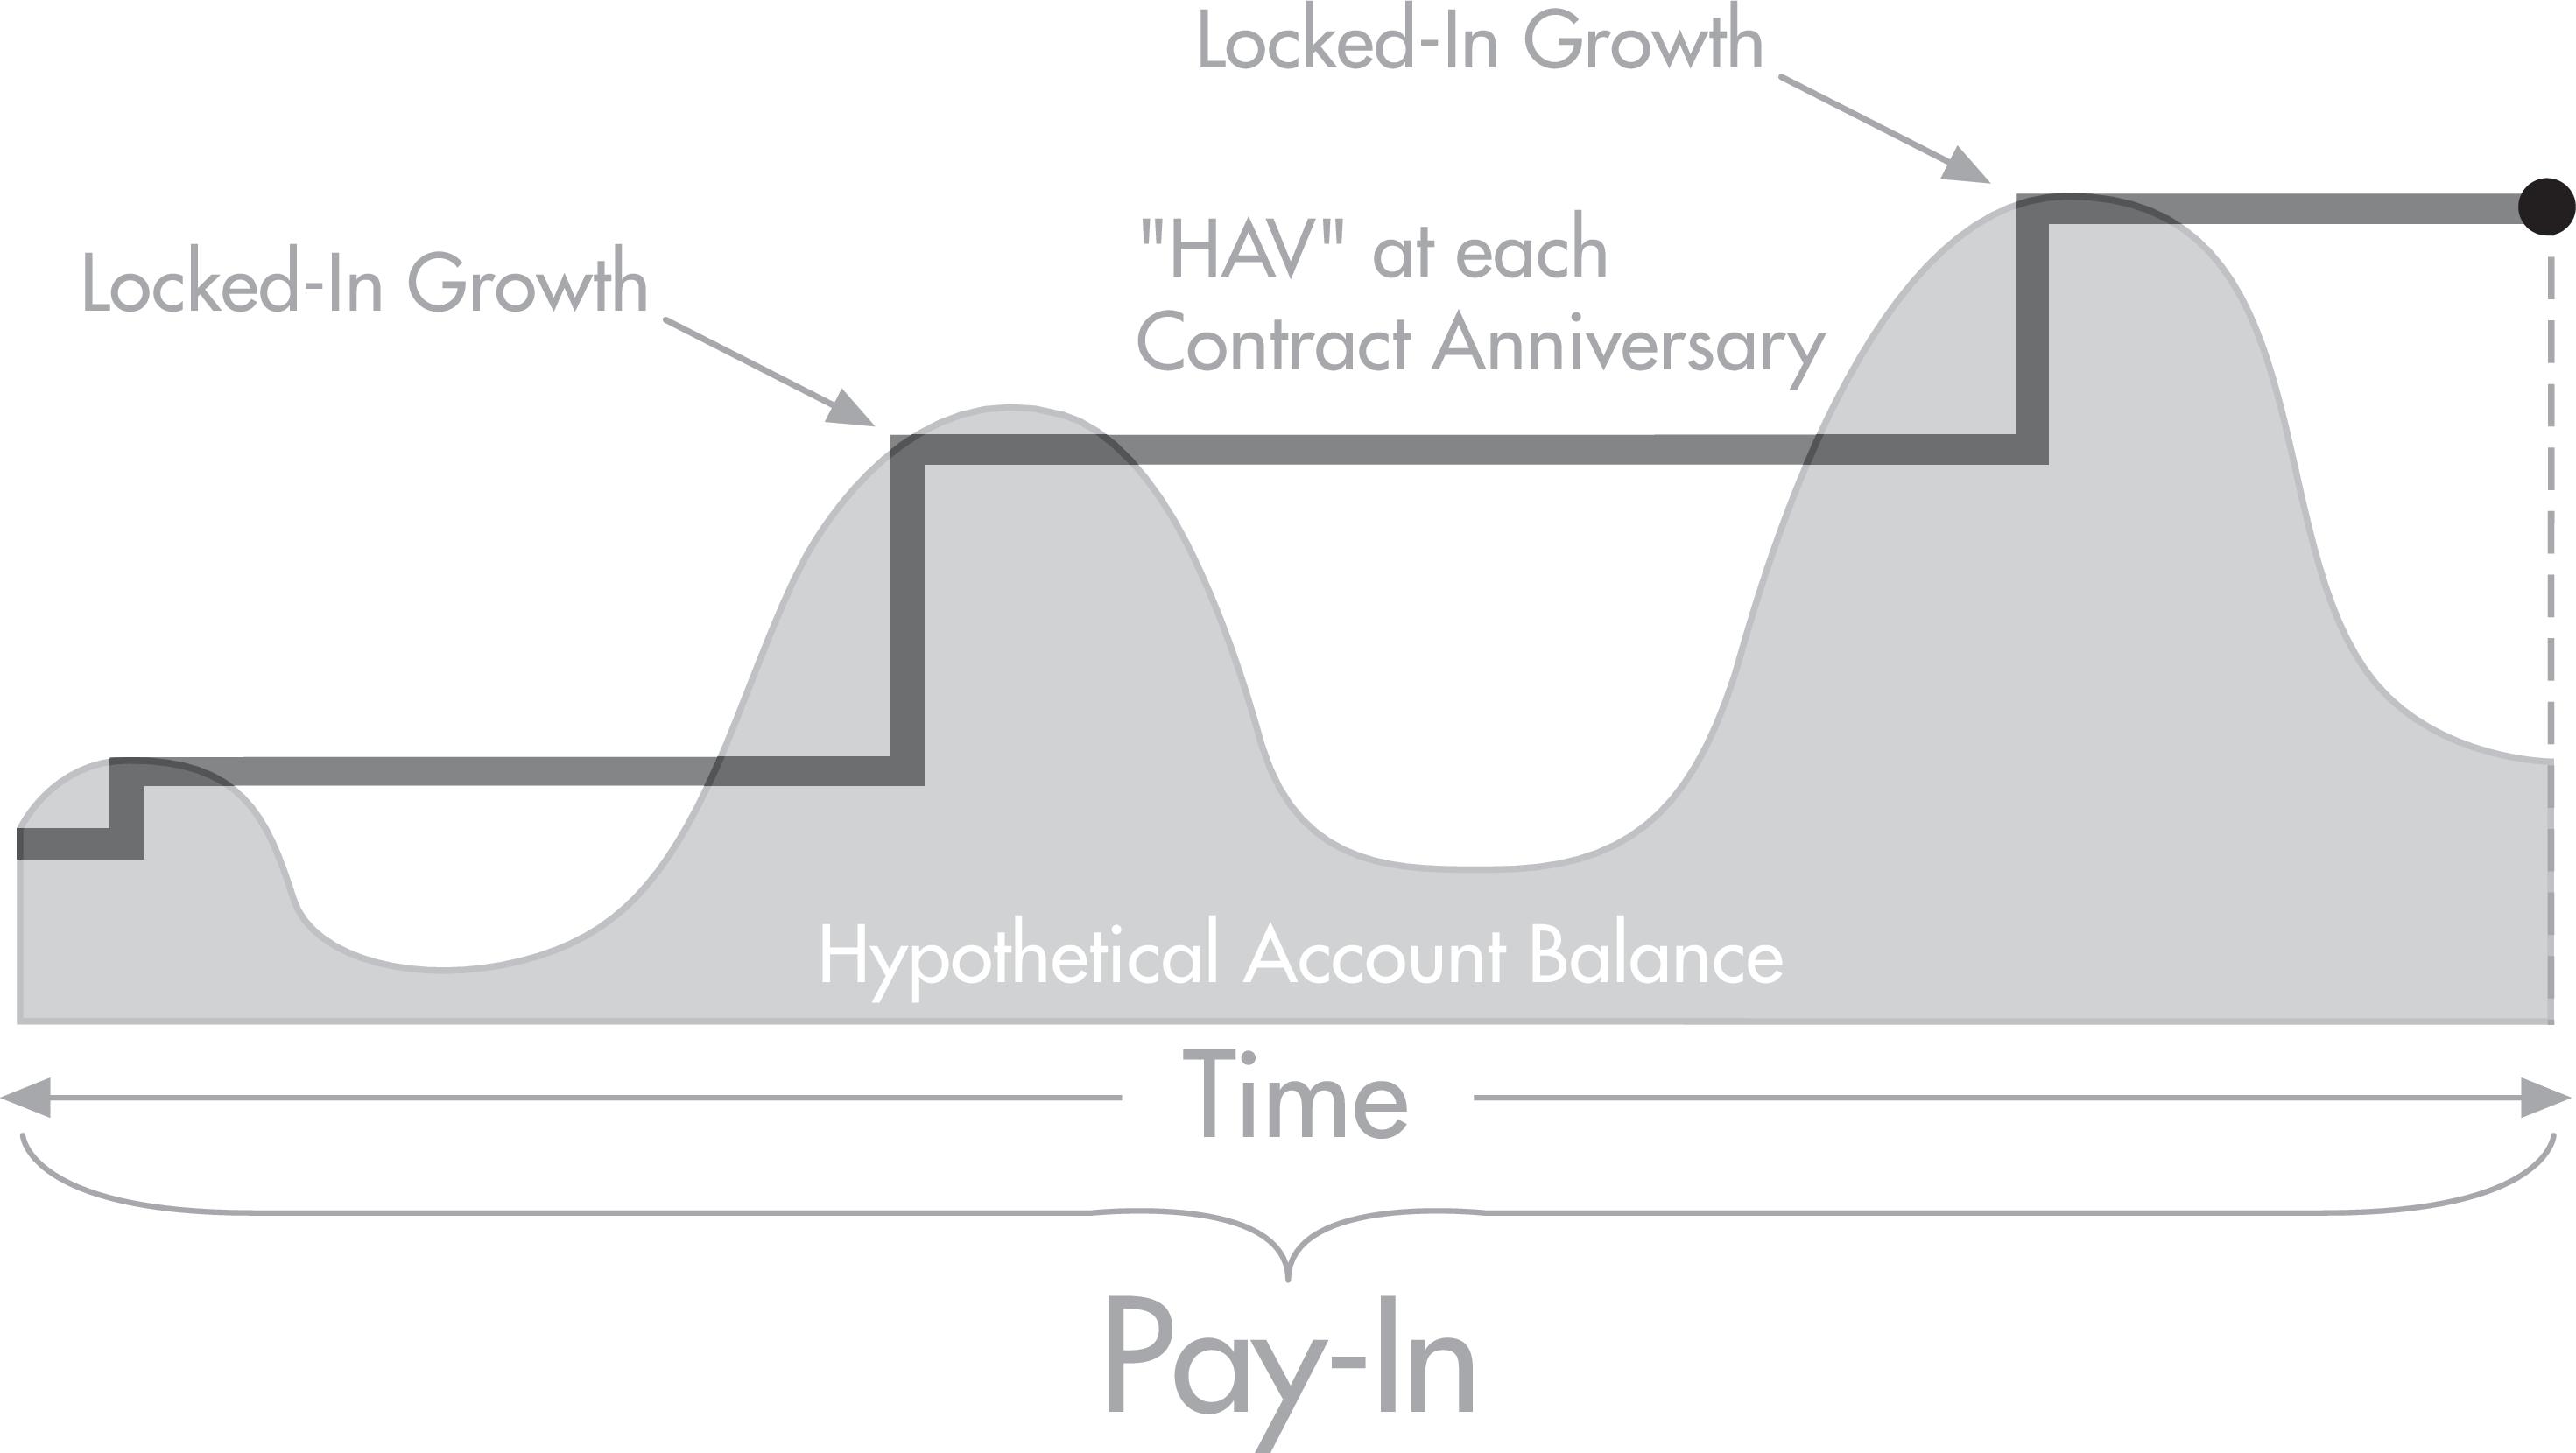 Determining your guaranteed lifetime income streamAssume that You decide to annuitize your Contract and begin taking annuity payments after 20 years. In this example, the Highest Anniversary Value is higher than the Account Balance. Accordingly, the Highest Anniversary Value will be applied to the annuity pay-out rates in the GMIB Annuity Table to determine your lifetime annuity payments. The income base is not available for cash withdrawals and is only used for purposes of calculating the GMIB payment and the charge for the benefit.
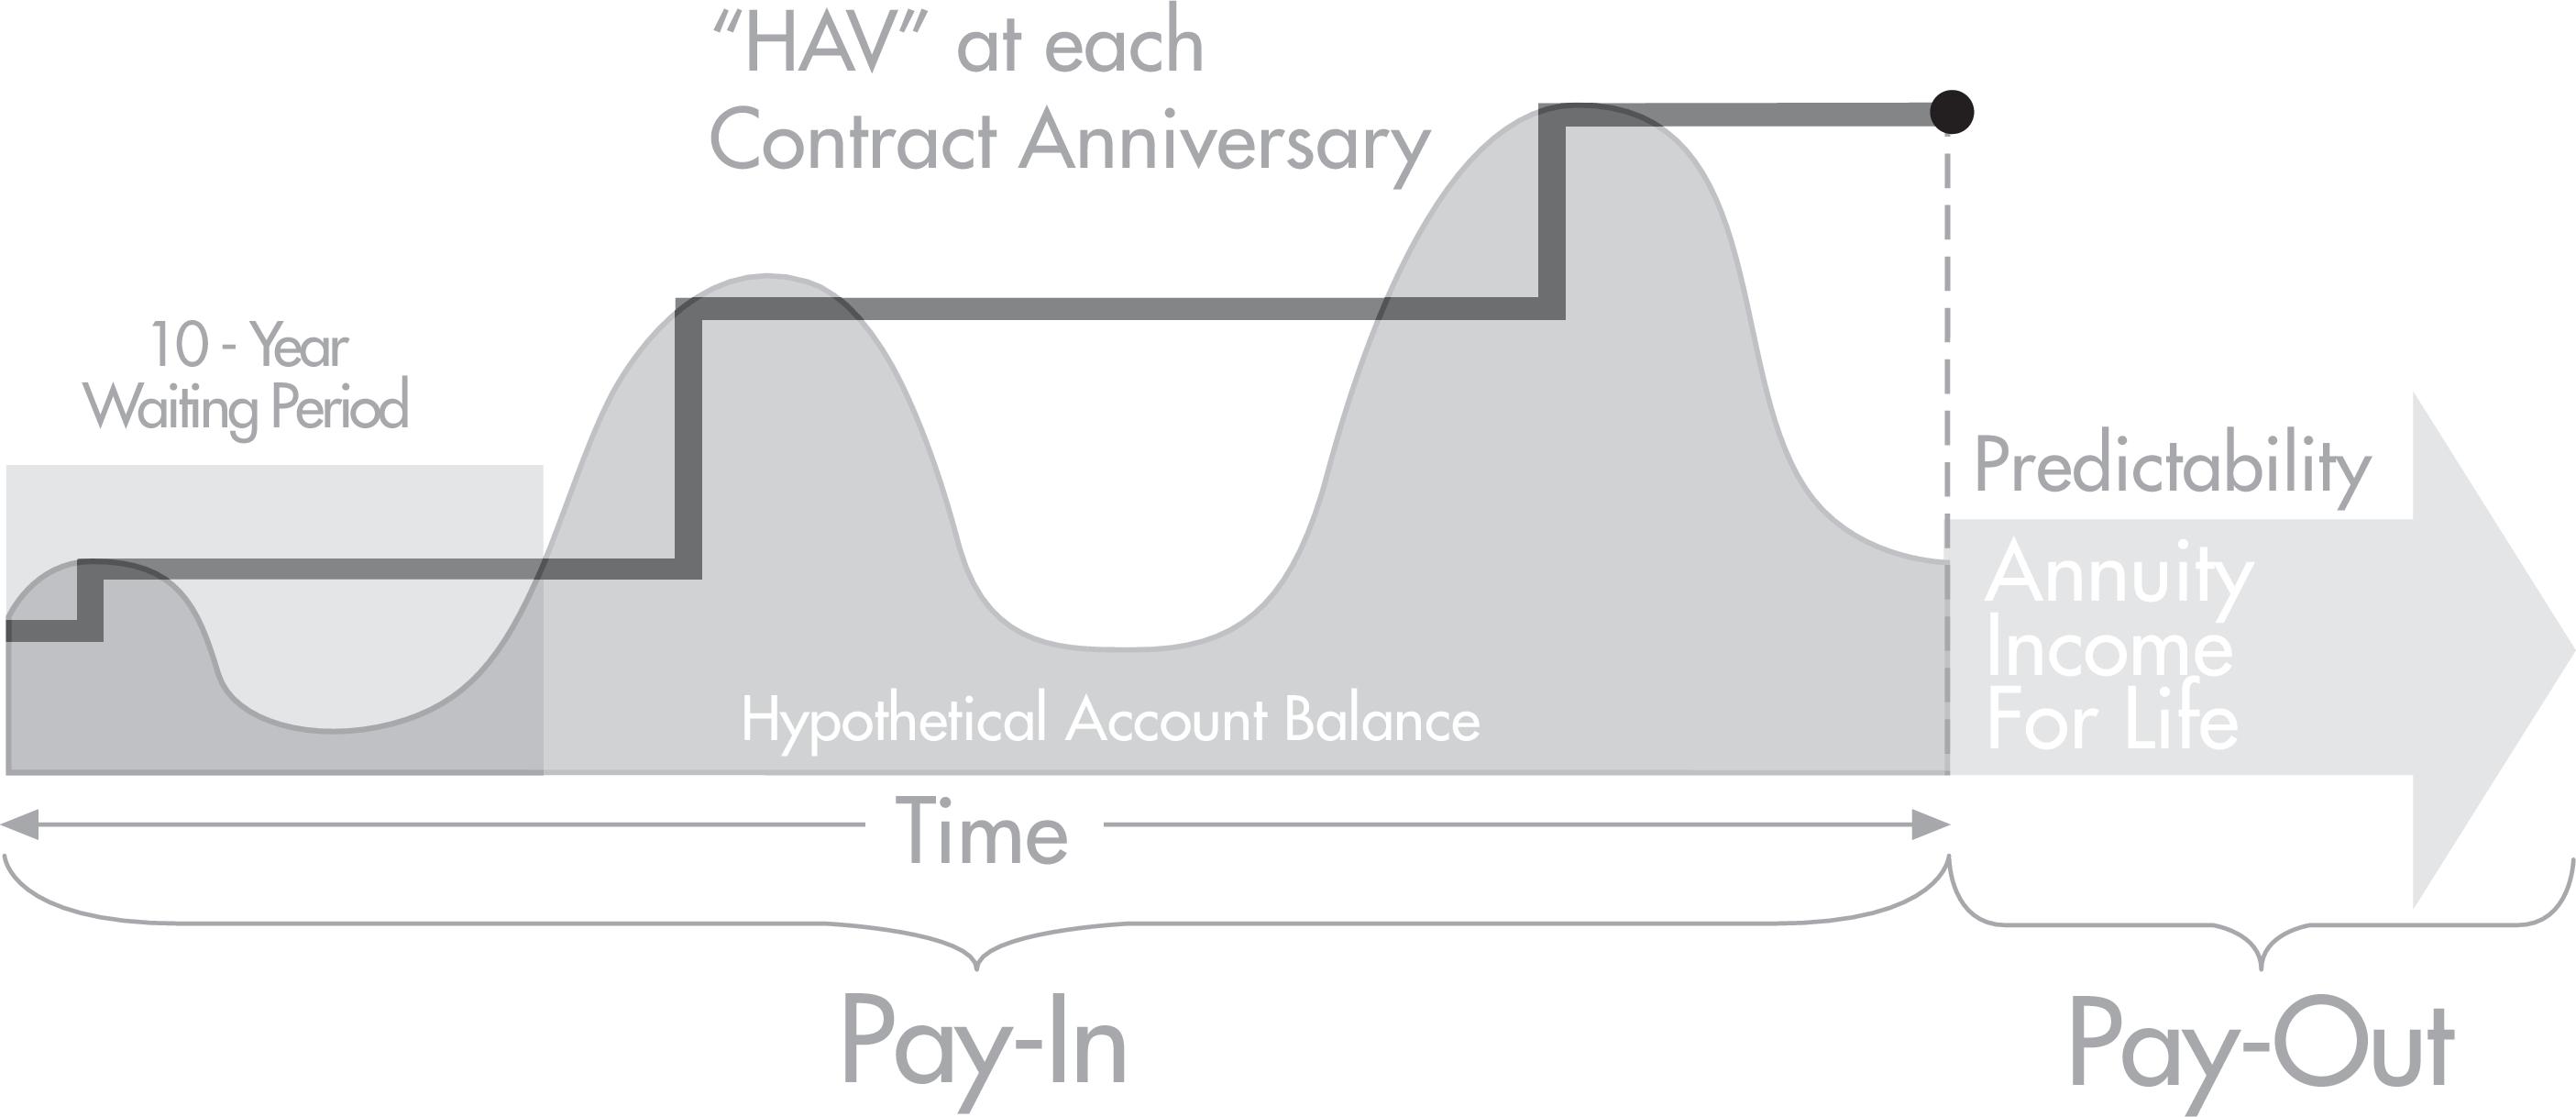 (3)Putting It All TogetherPrior to annuitization, the income base (the 6% Annual Increase Amount of the Income Base and the Highest Anniversary Value) work together to protect your future income. Upon annuitization of the Contract, You will receive income payments for life and the guaranteed minimum income base and the Account Balance will cease to exist. Also, the GMIB may only be exercised no later than the Contract Anniversary on or following the Contract Owner’s 85th birthday, after a 10-year waiting period, and then only within a 30-day period following the Contract Anniversary.
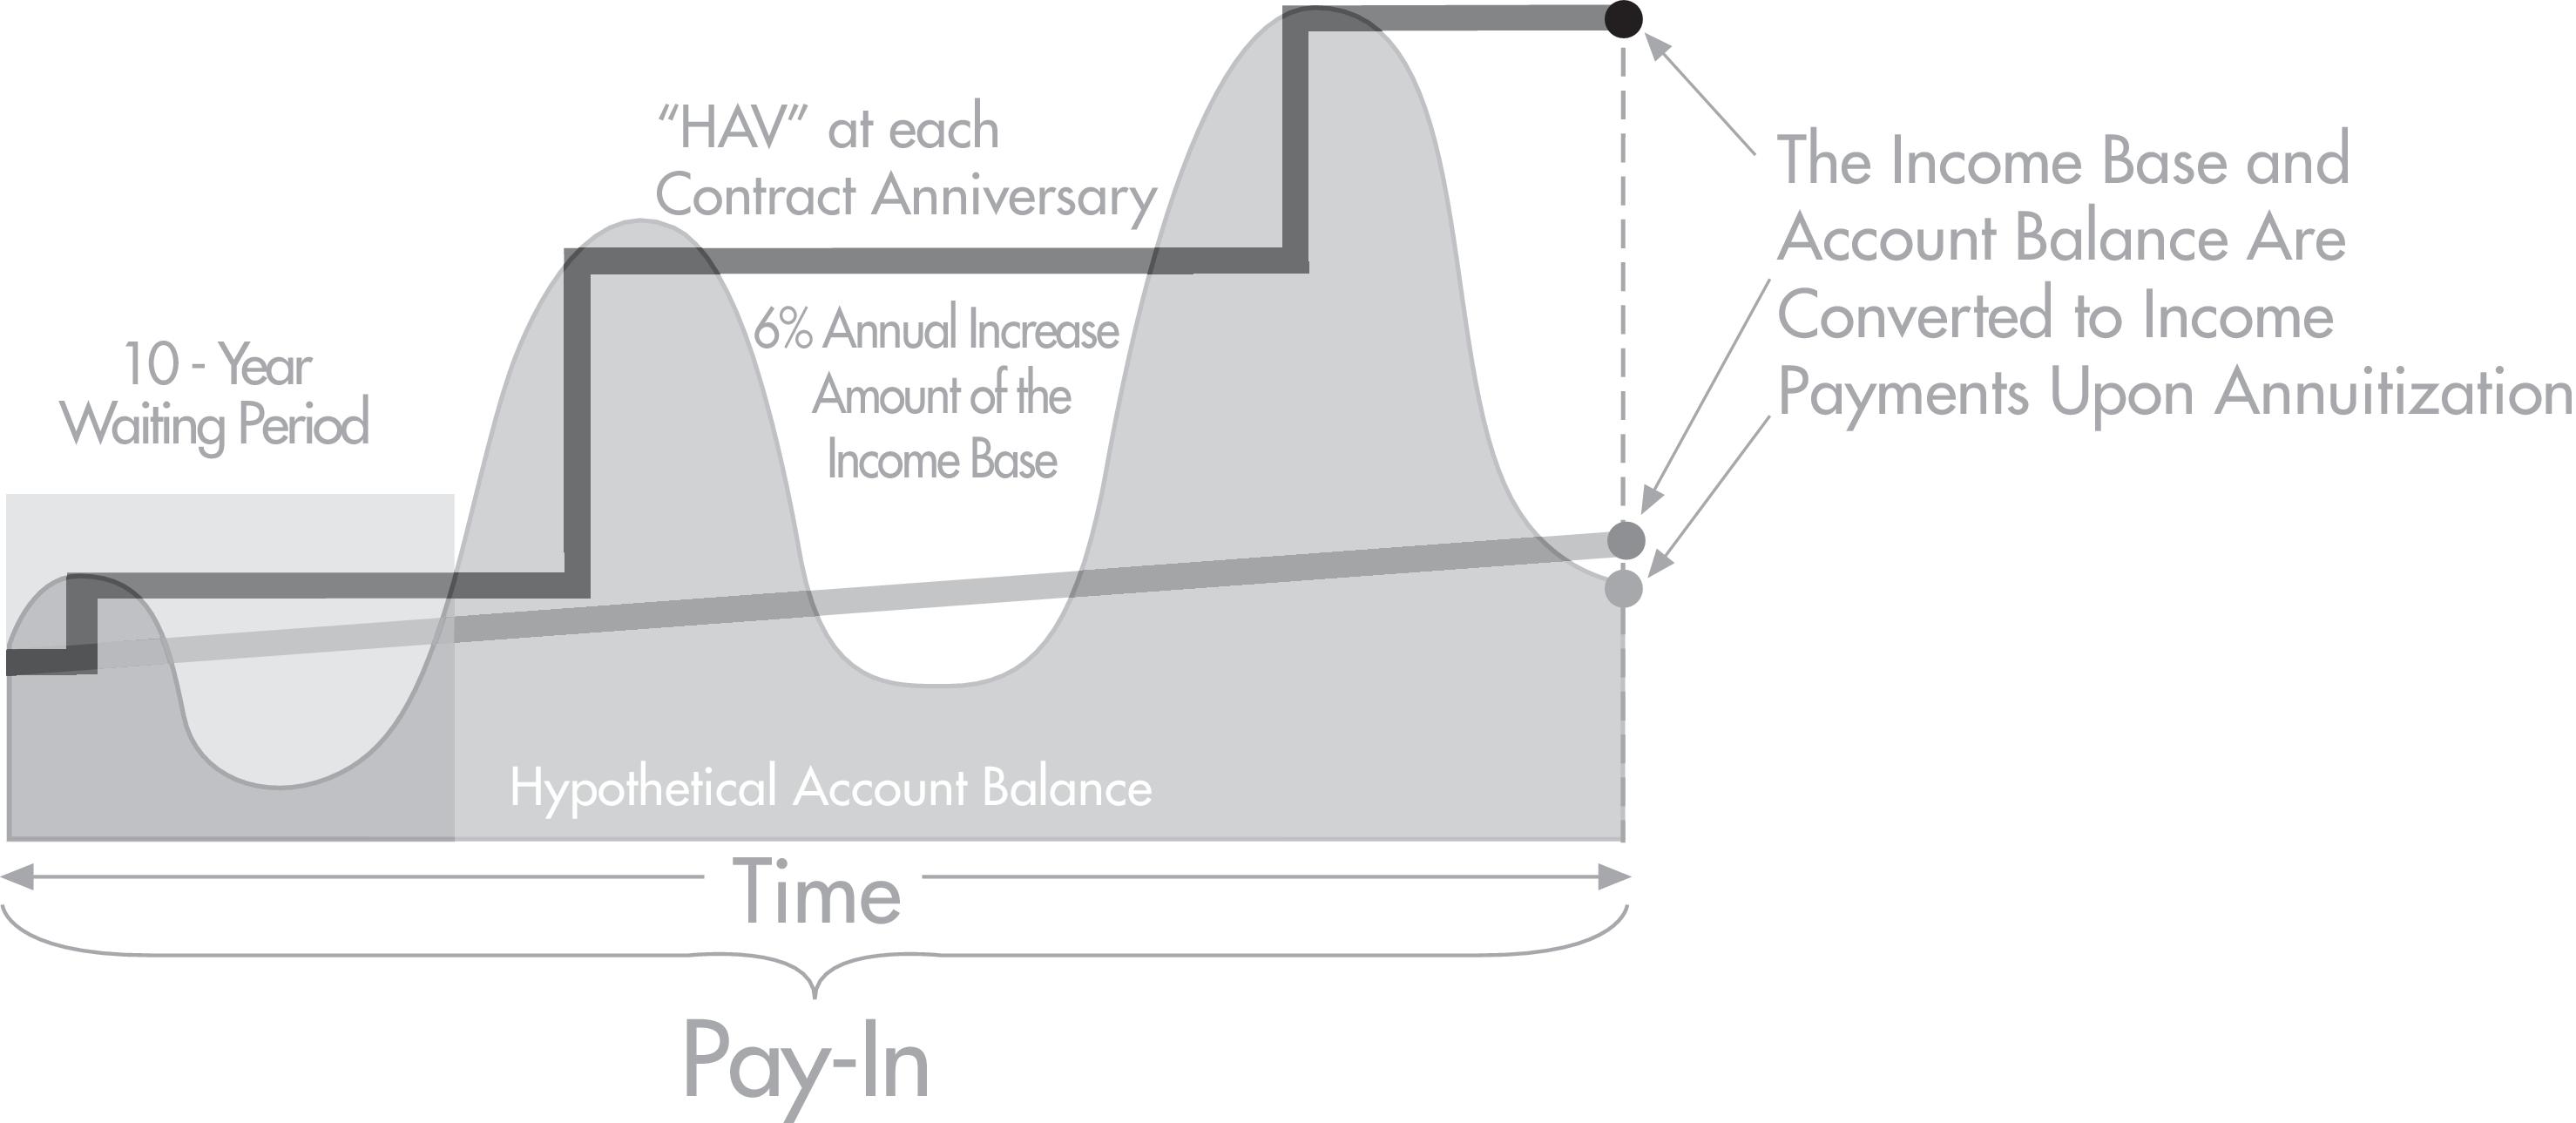 With the GMIB, the income base is applied to special, conservative GMIB annuity purchase factors, which are guaranteed at the time the Contract is issued. However, if then-current annuity purchase factors applied to the Account Balance would produce a greater amount of income, then You will receive the greater amount. In other words, when you annuitize your Contract You will receive whatever amount produces the greatest income payment. Therefore, if your Account Balance would provide greater income than would the amount provided under the GMIB, You will have paid for the GMIB although it was never used. |
| Calculation Method of Benefit [Text Block] |
Example:(This calculation ignores the impact of Highest Anniversary Value which could further increase the guaranteed minimum income base.)Age 55 at issuePurchase Payment = $100,000.No additional purchase payments or partial withdrawals.Guaranteed minimum income base at age 65 = $100,000 × 1.0610 = $179,085 where 10 equals the number of years the purchase payment accumulates for purposes of calculating this benefit.Guaranteed minimum income floor = guaranteed minimum income base applied to the GMIB annuity table.GMIB annuity factor, unisex, age 65 = $4.21 per month per $1,000 applied for lifetime income with 10 years guaranteed.
| |
|
Guaranteed Minimum Income Floor |
| |
|
|
| |
|
|
| |
|
| The above chart ignores the impact of premium taxes and other taxes.
|
| MetLife Financial Freedom Select e and e Bonus Class | Lifetime Withdrawal Guarantee Benefit |
|
| Item 4. Fee Table [Line Items] |
|
| Optional Benefit Expense (of Other Amount), Maximum [Percent] |
0.95%
|
| Optional Benefit Expense, Footnotes [Text Block] |
The charge for the Lifetime Withdrawal Guarantee Benefit is a percentage of your Total Guaranteed Withdrawal Amount, as defined later in this Prospectus, and is deducted at the end of each Contract Year by withdrawing amounts on a pro-rata basis from your Fixed Interest Account Balance and Separate Account Balance. (We take amounts from the Separate Account by canceling Accumulation Units from your Separate Account Balance.) You do not pay this charge once You are in the pay-out phase of your Contract or after your rider terminates. If an Automatic Annual Step-Up occurs under a Lifetime Withdrawal Guarantee Benefit, we may increase the Lifetime Withdrawal Guarantee Benefit charge to the current charge, but no more than a maximum of 0.95%. Different charges for the optional Lifetime Withdrawal Guarantee Benefit were in effect prior to May 4, 2009. If, at the time the Contract was issued, the current charge for the benefit was equal to the maximum charge, then the charge for the benefit will not increase upon an Automatic Annual Step-Up.
|
| Item 10. Benefits Available [Line Items] |
|
| Name of Benefit [Text Block] |
Lifetime Withdrawal Guarantee Benefit
|
| Purpose of Benefit [Text Block] |
Guaranteed Payments for Life. So long as You make your first withdrawal on or after the date You reach age 59 1∕2, the LWG guarantees that we will make payments to You over your lifetime, even if your Remaining Guaranteed Withdrawal Amount and/or Account Balance decline to zero.
|
| Optional Benefit [Flag] |
true
|
| Optional Benefit Expense (of Other Amount), Maximum [Percent] |
0.95%
|
| Optional Benefit Expense, Footnotes [Text Block] |
The charge for the Lifetime Withdrawal Guarantee Benefit is a percentage of your Total Guaranteed Withdrawal Amount, as defined later in this Prospectus, and is deducted at the end of each Contract Year by withdrawing amounts on a pro-rata basis from your Fixed Interest Account Balance and Separate Account Balance. (We take amounts from the Separate Account by canceling Accumulation Units from your Separate Account Balance.) You do not pay this charge once You are in the pay-out phase of your Contract or after your rider terminates. If an Automatic Annual Step-Up occurs under a Lifetime Withdrawal Guarantee Benefit, we may increase the Lifetime Withdrawal Guarantee Benefit charge to the current charge, but no more than a maximum of 0.95%. Different charges for the optional Lifetime Withdrawal Guarantee Benefit were in effect prior to May 4, 2009. If, at the time the Contract was issued, the current charge for the benefit was equal to the maximum charge, then the charge for the benefit will not increase upon an Automatic Annual Step-Up.
|
| Brief Restrictions / Limitations [Text Block] |
●No longer available for sale.●Benefit limits available investment options. (See “Appendix A — Investment Options Available Under the Contract — Investment Allocation Restrictions for Certain Optional Benefits.”)●Age restrictions apply.●You may not have this optional benefit and another optional living benefit (Guaranteed Minimum Income Benefit) in effect at the same time.●In the first 15 Contract Years You may only cancel this benefit every 5 Contract Years. Thereafter You may cancel annually within 30 days following the eligible Contract Anniversary.
|
| Name of Benefit [Text Block] |
Lifetime Withdrawal Guarantee Benefit
|
| Operation of Benefit [Text Block] |
Withdrawal BenefitLWGAs of the close of the Exchange on September, 17, 2018, the LWG is not available for sale to any new employer sponsored retirement plan or to any new participants under an existing employer sponsored retirement plan.In states where approved, we offered the LWG for elective TSA (non-ERISA), SEP and SIMPLE IRA Deferred Annuities. If You elected the LWG, Roth purchase payments may be permitted. The LWG does not establish or guarantee an Account Balance or minimum return for any Division. The Remaining Guaranteed Withdrawal Amount and Total Guaranteed Withdrawal Amount are not available for withdrawal as a lump sum.Withdrawals are subject to applicable Contract Withdrawal Charges unless You take the necessary steps to elect to take your Annual Benefit Payment under a Systematic Withdrawal Program. Ordinary income taxes apply to withdrawals under this benefit and an additional 10% penalty tax may apply if You are under age 59 1∕2. Consult your own tax adviser to determine if an exception to the 10% penalty tax applies. You may not have this benefit and the GMIB in effect at the same time. You should carefully consider if the LWG is best for You. Here are some of the key features of the LWG.●Guaranteed Payments for Life. So long as You make your first withdrawal on or after the date You reach age 59 1∕2, the LWG guarantees that we will make payments to You over your lifetime, even if your Remaining Guaranteed Withdrawal Amount and/or Account Balance decline to zero.●Automatic Annual Step-Ups. The LWG provides automatic step-ups on each Contract Anniversary prior to the Contract Owner’s 86th birthday (and offers the Contract Owner the ability to opt out of the step-ups if the charge for this optional benefit should increase). Each of the Automatic Step-Ups will occur only prior to the Contract Owner’s 86th birthday.●Withdrawal Rates. The LWG uses a 5% withdrawal rate to determine the Annual Benefit Payment.●Cancellation. The LWG provides the ability to cancel the rider every five Contract Years for the first fifteen Contract Years and annually thereafter within 30 days following the eligible Contract Anniversary.●Allocation Restrictions. If You elect the LWG, You are limited to allocating your purchase payments and Account Balance among the Fixed Interest Account, and certain Divisions (as described in “Appendix A — Investment Options Available Under the Contract — Investment Allocation Restrictions for Certain Optional Benefits”).●Tax Treatment. The tax treatment of withdrawals under the LWG is uncertain. It is conceivable that the amount of potential gain could be determined based on the Remaining Guaranteed Withdrawal Amount at the time of the withdrawal, if the Remaining Guaranteed Withdrawal Amount is greater than the Account Balance (prior to Withdrawal Charges, if applicable). This could result in a greater amount of taxable income reported under a withdrawal and conceivably a limited ability to recover any remaining basis if there is a loss on surrender of the Contract. Consult your tax adviser prior to purchase.●Rider Charges. We will continue to assess the LWG rider charge even in the case where your remaining Guaranteed Withdrawal Amount, as described below, equals zero.●Qualified Plans. If your plan determines to terminate the Contract at a time when You have elected LWG, You forfeit any income base and any other rights to the LWG You have accrued under the LWG upon termination of the Contract.In considering whether to have purchased the LWG, You must have considered your desire for protection and the cost of the benefit with the possibility that had You not purchased the benefit, your Account Balance may be higher. In considering the benefit of the lifetime withdrawals, You should consider the impact of inflation. Even relatively low levels of inflation may have significant effect on purchasing power. The Automatic Annual Step-Up, as described below, may provide protection against inflation, if and when there are strong investment returns. As with any guaranteed withdrawal benefit, the LWG, however, does not assure that You will receive strong, let alone any, return on your investments. The LWG must be elected at Contract issue; You must be age 80 or younger at the time of purchase.Total Guaranteed Withdrawal Amount. The Total Guaranteed Withdrawal Amount may be referred to as the “income base” in marketing or other materials. The Total Guaranteed Withdrawal Amount is the minimum amount that You are guaranteed to receive over time while the LWG is in effect. We assess the LWG charge as a percentage of the Total Guaranteed Withdrawal Amount. The initial Total Guaranteed Withdrawal Amount is equal to your initial purchase payment, without taking into account any purchase payment credits (i.e., credit or bonus payments). The Total Guaranteed Withdrawal Amount is increased by each additional purchase payment (up to a maximum benefit amount of $5,000,000). If, however, a withdrawal results in cumulative withdrawals for the current Contract Year that exceed the Annual Benefit Payment, the Total Guaranteed Withdrawal Amount will be reduced by an amount equal to the difference between the Total Guaranteed Withdrawal Amount after the withdrawal and the Account Balance after the withdrawal (if such Account Balance is lower than the Total Guaranteed Withdrawal Amount). This reduction may be significant.Cumulative withdrawals in a given Contract Year will not decrease the Total Guaranteed Withdrawal Amount if such withdrawals do not exceed the Annual Benefit Payment in that Contract Year.Remaining Guaranteed Withdrawal Amount. The remaining Guaranteed Withdrawal Amount is the remaining amount guaranteed to be received over time. The initial remaining Guaranteed Withdrawal Amount is equal to the initial Total Guaranteed Withdrawal Amount. We increase the remaining Guaranteed Withdrawal Amount (up to a maximum amount of $5,000,000) by each additional purchase payment without taking into account any purchase payment credits (i.e., credit or bonus payments). The remaining Guaranteed Withdrawal Amount is also increased by the 5% Compounding Income Amount, as described below. All withdrawals (including applicable Withdrawal Charges) reduce the remaining Guaranteed Withdrawal Amount, not just withdrawals that exceed the Annual Benefit Payment (as with the Total Guaranteed Withdrawal Amount). If the withdrawal exceeds the Annual Benefit Payment, then we will additionally reduce the remaining Guaranteed Withdrawal Amount to equal the difference between the remaining Guaranteed Withdrawal Amount after the withdrawal and the Account Balance after the withdrawal (if lower). This reduction may be significant. The remaining Guaranteed Withdrawal Amount is also used to calculate an alternate death benefit available under the LWG. (See “Additional Information” below.)5% Compounding Income Amount. On each Contract Anniversary until the earlier of: (a) the date of the first withdrawal from the Contract or (b) the 10th Contract Anniversary, the Total Guaranteed Withdrawal Amount and the remaining Guaranteed Withdrawal Amount are increased by an amount equal to 5% multiplied by the Total Guaranteed Withdrawal Amount and the remaining Guaranteed Withdrawal Amount before such increase (up to a maximum benefit amount of $5,000,000). We take the Total Guaranteed Withdrawal Amount and the remaining Guaranteed Withdrawal Amount as of the last day of the Contract Year to determine the amount subject to the increase. The Total Guaranteed Withdrawal Amount and the remaining Guaranteed Withdrawal Amount may also be increased by the Automatic Annual Step-Up, if that would result in a higher Total Guaranteed Withdrawal Amount and remaining Guaranteed Withdrawal Amount.Automatic Annual Step-Up. On each Contract Anniversary prior to the Contract Owner’s 86th birthday, an Automatic Annual Step-Up will occur, provided that the Account Balance exceeds the Total Guaranteed Withdrawal Amount immediately before the Step-Up (and provided that You have not chosen to decline the Step-Up as described below).The Automatic Annual Step-Up will:●reset the Total Guaranteed Withdrawal Amount and the remaining Guaranteed Withdrawal Amount to the Account Balance on the date of the Step-Up, up to a maximum of $5,000,000, regardless of whether or not You have taken any withdrawals;●reset the Annual Benefit Payment equal to 5% of the Total Guaranteed Withdrawal Amount after the Step-Up; and●reset the LWG charge to the then current charge, up to a maximum of 0.95% for the same optional benefit.In the event that the charge applicable to Contract purchases at the time of the Step-Up is higher than your current LWG charge, and we elect to increase the benefit charge in connection with the Step-Up we will notify You in writing a minimum of 30 days in advance of the applicable Contract Anniversary and inform You that You may choose to decline the Automatic Annual Step-Up. If You choose to decline the Automatic Annual Step-Up, You must notify us in accordance with our administrative procedures (currently we require You to submit your request in writing at our Administrative Office no less than seven calendar days prior to the applicable Contract Anniversary).Once You notify us of your decision to decline the Automatic Annual Step-Up, You will no longer be eligible for future Automatic Annual Step-Ups unless You notify us in writing at our Administrative Office that You wish to reinstate the Step-Up. This reinstatement will take effect at the next Contract Anniversary after we receive your request for reinstatement. Please note that the Automatic Annual Step-Up may be of limited benefit if You intend to make purchase payments that would cause your Account Balance to approach $5,000,000 because the Total Guaranteed Withdrawal Amount and remaining Guaranteed Withdrawal Amount cannot exceed $5,000,000.Annual Benefit Payment. The initial Annual Benefit Payment is equal to the initial Total Guaranteed Withdrawal Amount multiplied by the 5% withdrawal rate. The Annual Benefit Payment may be referred to as “annual income amount” in marketing or other materials. If the Total Guaranteed Withdrawal Amount is later recalculated (for example, because of additional purchase payments, the 5% compounding amount, the Automatic Annual Step-Up, or withdrawals greater than the Annual Benefit Payment), the Annual Benefit Payment is reset equal to the new Total Guaranteed Withdrawal Amount multiplied by the 5% withdrawal rate.Important to Note.●If You take your first withdrawal before the date You reach age 59 1∕2, we will continue to pay the Annual Benefit Payment each year until the remaining Guaranteed Withdrawal Amount is depleted, even if your Account Balance declines to zero. This means if your Account Balance is depleted due to withdrawals not greater than the Annual Benefit Payment or the deduction of the benefit charge, and your remaining Guaranteed Withdrawal Amount is greater than zero, we will pay You the remaining Annual Benefit Payment, if any, not yet withdrawn during the Contract Year that the Account Balance was depleted, and beginning in the following Contract Year, we will continue paying the Annual Benefit Payment to You each year until your remaining Guaranteed Withdrawal Amount is depleted. This guarantees that You will receive your purchase payments even if your Account Balance declines to zero due to market performance so long as You do not take withdrawals greater than the Annual Benefit Payment; however, You will not be guaranteed income for the rest of your life.●If You take your first withdrawal on or after the date You reach age 59 1∕2, we will continue to pay the Annual Benefit Payment each year for the rest of your life, even if your remaining Guaranteed Withdrawal Amount and/ or Account Balance declines to zero. This means if your remaining Guaranteed Withdrawal Amount and/or your Account Balance is depleted due to withdrawals not greater than the Annual Benefit Payment or the deduction of the benefit charge, we will pay to You the remaining Annual Benefit Payment, if any, not yet withdrawn during that Contract Year that the Account Balance was depleted, and beginning in the following Contract Year, we will continue paying the Annual Benefit Payment to You each year for the rest of your life. Therefore, You will be guaranteed income for life.You should carefully consider when to begin taking withdrawals if You have elected the LWG Benefit. If You begin withdrawals too soon, your Total Guaranteed Withdrawal Amount and Remaining Guaranteed Withdrawal Amount are no longer increased by the 5% annual compounding increase. On the other hand, if You delay taking withdrawals for too long, You may limit the number of years available for You to take withdrawals in the future (due to life expectancy), and You may be paying for a benefit You are not using.You have the option of receiving withdrawals under the LWG or receiving payments under a Pay-Out Option. You should consult with your registered representative when deciding how to receive income under this Contract. In making this decision, You should consider many factors, including the relative amount of current income provided by the two options, the potential ability to receive higher future payments through potential increases to the value of the LWG, your potential need to make additional withdrawals in the future, and the relative values to You of the death benefits available prior to and after annuitization.At any time during the pay-in phase, You can elect to annuitize under current annuity rates in lieu of continuing the LWG. This may provide higher income amounts and/or different tax treatment than the payments received under the LWG.Effect of Outstanding Loans on the Total Guaranteed Withdrawal Amount and Remaining Guaranteed Withdrawal Amount. If there is an outstanding loan balance (including loans in default which we cannot offset or collect due to tax restrictions), any additional withdrawals will be treated as withdrawals in excess of the Annual Benefit Payment. In that event, the Total Guaranteed Withdrawal Amount will be reduced. The reduction will be equal to the difference between the Total Guaranteed Withdrawal Amount after the withdrawal and the Account Balance after the withdrawal. If the Account Balance after the withdrawal and minus any loan in default is higher than the Total Guaranteed Withdrawal Amount, no reduction will be made.In the event an outstanding loan balance is in default and we can withdraw the defaulted amount from your Account Balance, if the amount of the default does not exceed the Annual Benefit Payment, then the Total Guaranteed Withdrawal Amount will not be decreased. If the amount of the default exceeds the Annual Benefit Payment, the Total Guaranteed Withdrawal Amount will be reduced. The reduction will be equal to the difference between the Total Guaranteed Withdrawal Amount after the withdrawal and the Account Balance after the withdrawal. If the Account Balance after the withdrawal and minus any loan in default is higher than the Total Guaranteed Withdrawal Amount, no reduction will be made.Also, an additional reduction will be made to the Remaining Guaranteed Withdrawal Amount. This additional reduction will be equal to the difference between the Remaining Guaranteed Withdrawal Amount after the withdrawal and the Account Balance after the withdrawal. If the Account Balance after the withdrawal and minus any loan in default is higher than the Remaining Guaranteed Withdrawal Amount, no reduction will be made.Managing Your Withdrawals. It is important that You carefully manage your annual withdrawals. To ensure that You retain the full guarantees of this benefit, your annual withdrawals cannot exceed the Annual Benefit Payment each Contract Year. If a Withdrawal Charge does apply, the charge is not included in the amount withdrawn for the purpose of calculating whether annual withdrawals during a Contract Year exceed the Annual Benefit Payment. If a withdrawal from your Contract does result in annual withdrawals during a Contract Year exceeding the Annual Benefit Payment, the Total Guaranteed Withdrawal Amount will be recalculated and the Annual Benefit Payment will be reduced to the new Total Guaranteed Withdrawal Amount multiplied by the 5% withdrawal rate. In addition, as noted above, if a withdrawal results in cumulative withdrawals for the current Contract Year exceeding the Annual Benefit Payment, the Remaining Guaranteed Withdrawal Amount will also be reduced by an additional amount equal to the difference between the Remaining Guaranteed Withdrawal Amount after the withdrawal and the Account Balance after the withdrawal (if such Account Balance is lower than the Remaining Guaranteed Withdrawal Amount). These reductions in the Total Guaranteed Withdrawal Amount, Annual Benefit Payment, and Remaining Guaranteed Withdrawal Amount may be significant. You are still eligible to receive either lifetime payments or the remainder of the Remaining Guaranteed Withdrawal Amount so long as the withdrawal that exceeded the Annual Benefit Payment did not cause your Account Balance to decline to zero. A withdrawal that results in cumulative withdrawals in the current Contract Year exceeding the Annual Benefit Payment that reduces the Account Balance to zero will terminate the Contract.You can always take annual withdrawals less than the Annual Benefit Payment. However, if You choose to receive only a part of your Annual Benefit Payment in any given Contract Year, your Annual Benefit Payment is not cumulative and your Remaining Guaranteed Withdrawal Amount and Annual Benefit Payment will not increase. For example, since Your Annual Benefit Payment is 5% of your Remaining Guaranteed Withdrawal Amount, You cannot withdraw 3% in one year and then withdraw 7% the next year without exceeding your Annual Benefit Payment in the second year.Systematic Withdrawal Program. If available in your state, You may choose to take your Annual Benefit Payment under the Systematic Withdrawal Program, including the first Contract Year. If You do so, any Withdrawal Charges that would otherwise apply to such withdrawals will be waived. Your Systematic Withdrawal Program withdrawal amount will be adjusted on each Contract Anniversary for any changes in the Annual Benefit Payment as a result of Automatic Annual Step-Up, additional purchase payments or transfers received during the Contract Year. Any withdrawals taken outside of the Systematic Withdrawal Program will cause the Systematic Withdrawal Program to terminate. If the commencement of the Systematic Withdrawal Program does not coincide with a Contract Anniversary, the initial Systematic Withdrawal Program period will be adjusted to end on a Contract Anniversary.Required Minimum Distributions. You may be required to take withdrawals to fulfill minimum distribution requirements. These required distributions may be larger than your Annual Benefit Payment. After the first Contract Year, we will increase your Annual Benefit Payment to equal your required minimum distribution amount for that year, if such amounts are greater than your Annual Benefit Payment. You must be enrolled in the automated required minimum distribution service to qualify for this increase in the Annual Benefit Payment. The frequency of your withdrawals must be annual. The automated required minimum distribution service is based on information relating to this Contract only. To enroll in the automated required minimum distribution service, please contact our Administrative Office.Investment Allocation Restrictions. If You elect the LWG, You are limited to allocating your purchase payments and Account Balance among the Fixed Interest Account and the Divisions listed in “Appendix A — Investment Options Available Under the Contract — Investment Allocation Restrictions for Certain Optional Benefits.”Cancellation. You may elect to cancel the LWG every fifth Contract Anniversary for the first fifteen Contract Years and annually thereafter. We must receive your cancellation request within 30 days following the eligible Contract Anniversary in writing at our Administrative Office. The cancellation will take effect on the day we receive your request. If cancelled, the LWG will terminate, we will no longer deduct the LWG charge, and the allocation restrictions described above will no longer apply. The Contract, however, will continue.Termination. The LWG will terminate upon the earliest of:1.The date of a full withdrawal of the Account Balance (a pro rata portion of the annual charge will be assessed); You are still eligible to receive either the Remaining Guaranteed Withdrawal Amount or lifetime payments provided the withdrawal did not exceed the Annual Benefit Payment and the provisions and conditions of this optional benefit have been met;2.The date the Account Balance is applied to a Pay-Out Option (a pro-rata portion of the annual charge for this rider will be assessed);3.The date there are insufficient funds to deduct the charge from your Account Balance and your Contract is thereby terminated (whatever Account Balance is available to pay the annual charge for the benefit will be applied); You are still eligible to receive either the Remaining Guaranteed Withdrawal Amount or lifetime payments, provided the provisions and conditions of this optional benefit have been met; however, You will have no other benefits under the Contract;4.The date a defaulted loan balance, once offset, causes the Account Balance to reduce to zero;5.The Contract Owner dies;6.There is a change in Contract Owner, for any reason, unless we agree otherwise (a pro-rata portion of the annual charge for this rider will be assessed);7.The Contract is terminated (a pro-rata portion of the annual charge for this rider will be assessed except for termination because of death of the Contract Owner, then no charge will be assessed based on the period from the most recent Contract Anniversary to the date termination takes effect); or8.The effective date of cancellation of this benefit.Additional Information. The LWG may affect the death benefit available under your Contract. If the Contract Owner should die while the LWG is in effect, an alternative death benefit amount will be calculated under the LWG that can be taken in a lump sum. The LWG death benefit amount that may be taken as a lump sum will be equal to total purchase payments less any partial withdrawals and any outstanding loan balance. If this death benefit amount is greater than the death benefit provided by your Contract, and if withdrawals in each Contract Year did not exceed the Annual Benefit Payment, then this death benefit amount will be paid instead of the death benefit provided by the Contract. All other provisions of your Contract’s death benefit will apply.Alternatively, the Beneficiary may elect to receive the Remaining Guaranteed Withdrawal Amount as a death benefit, in which case we will pay the Remaining Guaranteed Withdrawal Amount on a monthly basis (or any mutually agreed upon frequency, but no less frequently than annually) until the Remaining Guaranteed Withdrawal Amount is exhausted. This death benefit will be paid instead of the applicable contractual death benefit (the Standard Death Benefit, the additional death benefit amount calculated under the LWG as described above, or the Annual Step-Up Death Benefit, if that benefit had been purchased by the Contract Owner). Otherwise, the provisions of those contractual death benefits will determine the amount of the death benefit. Except as may be required by the Code, an annual payment will not exceed the Annual Benefit Payment. If your Beneficiary dies while such payments are made, we will continue making the payments to the Beneficiary’s estate unless we have agreed to another payee in writing. Federal income tax law generally requires that such payments be substantially equal and begin over a period no longer than the Beneficiary’s remaining life expectancy with payments beginning no later than the end of the calendar year immediately following the year of your death.We reserve the right to accelerate any payment that is less than $500 or to comply with requirements under the Code (including minimum distribution requirement). If You terminate the LWG because (1) You make a total withdrawal of your Account Balance; (2) your Account Balance is insufficient to pay the LWG charge; or (3) the Contract Owner dies, You may not make additional purchase payments under the Contract.LWG charge. The LWG is available in Deferred Annuities, for an additional charge of 0.95% of the Total Guaranteed Withdrawal Amount, deducted at the end of each Contract Year by withdrawing amounts on a pro-rata basis from your Fixed Interest Account Balance and Separate Account Balance, after applying any 5% Compounding Income Amount and prior to taking into account any Automatic Annual Step-Up occurring on the Contract Anniversary. We take amounts from the Separate Account by canceling Accumulation Units from your Separate Account Balance. If an Automatic Annual Step- Up occurs under a LWG, we may increase the LWG charge to the then current charge for the same optional benefit, but no more than a maximum of 0.95%. If, at the time the Contract was issued, the current charge for the benefit was equal to the maximum charge, then the charge for the benefit will not increase upon an Automatic Annual Step-Up. If the LWG is in effect, the charge will continue even if your Remaining Guaranteed Withdrawal Amount equals zero.
|
| Calculation Method of Benefit [Text Block] |
ExamplesThe purpose of these examples is to illustrate the operation of the LWG. The investment results shown are hypothetical and are not representative of past or future performance. Actual investment results may be more or less than those shown and will depend upon a number of factors, including investment allocations and the investment experience of the Divisions chosen. The examples do not reflect the deduction of fees and charges, Withdrawal Charges and applicable income taxes and penalties. For purposes of the examples, it is assumed that no loans have been taken.A.LWG – The effect of Withdrawals on Your Annual Benefit Payment1.When Withdrawals Do Not Exceed the Annual Benefit PaymentAssume that a Contract had an initial purchase payment of $100,000. The initial Account Balance would be $100,000, the Total Guaranteed Withdrawal Amount would be $100,000, the initial Remaining Guaranteed Withdrawal Amount would be $100,000 and the initial Annual Benefit Payment would be $5,000 ($100,000 × 5%).Assume that $5,000 is withdrawn each year, beginning before the Contract Owner attains age 59 1∕2. The Remaining Guaranteed Withdrawal Amount is reduced by $5,000 each year as withdrawals are taken (the Guaranteed Total Withdrawal Amount is not reduced by these withdrawals). The Annual Benefit Payment of $5,000 is guaranteed to be received until the Remaining Guaranteed Withdrawal Amount is depleted, even if the Account Balance is reduced to zero.
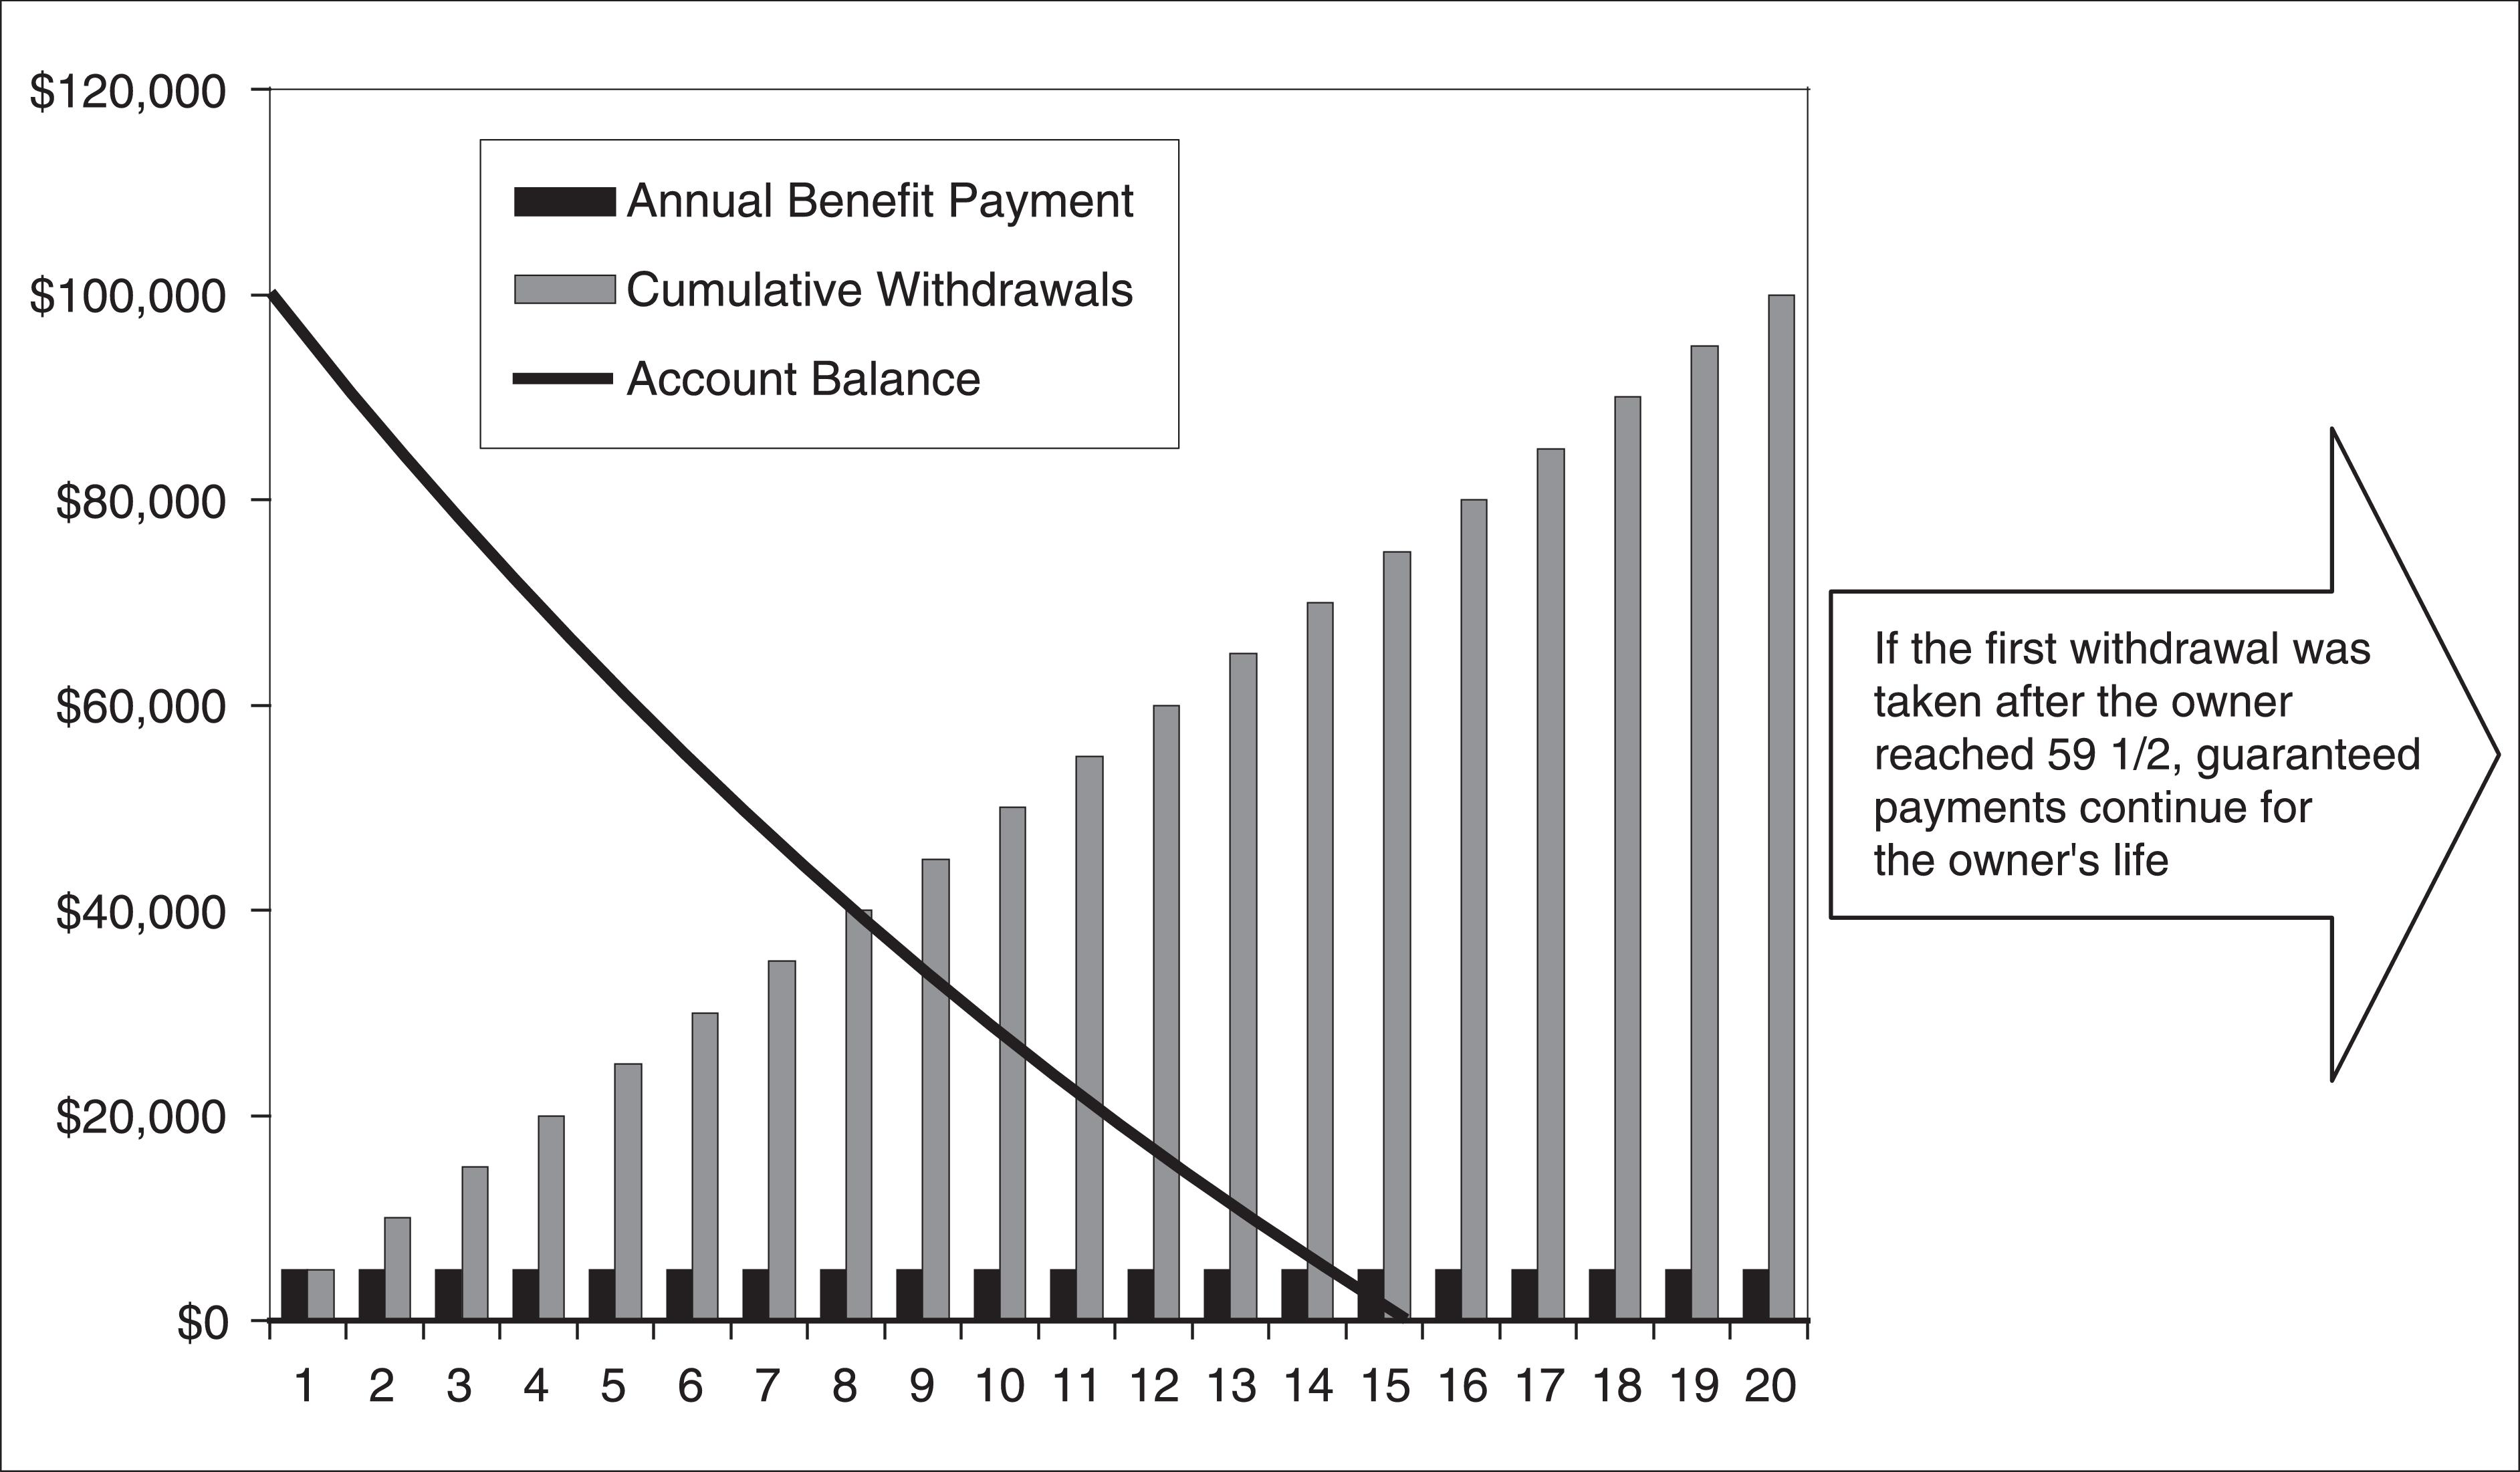 If the first withdrawal is taken after age 59 1∕2, then the Annual Benefit Payment of $5,000 is guaranteed to be received for the Contract Owner’s lifetime, even if the Remaining Guaranteed Withdrawal Amount and the Account Balance are reduced to zero.2.When Withdrawals Do Exceed the Annual Benefit PaymentAssume that a Contract had an initial purchase payment of $100,000. The initial Account Balance would be $100,000, the Total Guaranteed Withdrawal Amount would be $100,000, the initial Remaining Guaranteed Withdrawal Amount would be $100,000 and the initial Annual Benefit Payment would be $5,000 ($100,000 × 5%).Assume that the Remaining Guaranteed Withdrawal Amount is reduced to $95,000 due to a withdrawal of $5,000 in the first year. Assume the Account Balance was further reduced to $75,000 at year two due to poor market performance. If You withdrew $10,000 at this time, your Account Balance would be reduced to $75,000 - $10,000 = $65,000. Your Remaining Guaranteed Withdrawal Amount would be reduced to $95,000 - $10,000 = $85,000. Since the withdrawal of $10,000 exceeded the Annual Benefit Payment of $5,000 and the resulting Remaining Guaranteed Withdrawal Amount would be greater than the resulting Account Balance, there would be an additional reduction to the Remaining Guaranteed Withdrawal Amount. The Remaining Guaranteed Withdrawal Amount after the withdrawal would be set equal to the Account Balance after the withdrawal ($65,000). This new Remaining Guaranteed Withdrawal Amount of $65,000 would now be the amount guaranteed to be available to be withdrawn over time. The Total Guaranteed Withdrawal Amount would also be reduced to $65,000. The Annual Benefit Payment would be set equal to 5% × $65,000 = $3,250.B.LWG — The Effect of Delaying the Exercise of Your LWG on Your Benefit PaymentAssume that a Contract had an initial purchase payment of $100,000. The initial Remaining Guaranteed Withdrawal Amount would be $100,000, the Total Guaranteed Withdrawal Amount would be $100,000, and the Annual Benefit Payment would be $5,000 ($100,000 × 5%).The Total Guaranteed Withdrawal Amount will increase by 5% of the Total Guaranteed Withdrawal Amount until the earlier of the first withdrawal or the 10th Contract Anniversary. The Annual Benefit Payment will be recalculated as 5% of the new Total Guaranteed Withdrawal Amount.If the first withdrawal is taken in the first Contract Year, then there would be no increase. The Total Guaranteed Withdrawal Amount would remain at $100,000 and the Annual Benefit Payment will remain at $5,000 ($100,000 × 5%).If the first withdrawal is taken in the second Contract Year, then the Total Guaranteed Withdrawal Amount would increase to $105,000 ($100,000 × 105%), and the Annual Benefit Payment would increase to $5,250 ($105,000 × 5%).If the first withdrawal is taken in the third Contract Year, then the Total Guaranteed Withdrawal Amount would increase to $110,250 ($105,000 × 105%), and the Annual Benefit Payment would increase to $5,513 ($110,250 × 5%).If the first withdrawal is taken after the 10th Contract Year, then the Total Guaranteed Withdrawal Amount would increase to $162,890 (the initial $100,000, increased by 5% per year, compounded annually for 10 years), and the Annual Benefit Payment would increase to $8,144 ($162,890 × 5%).
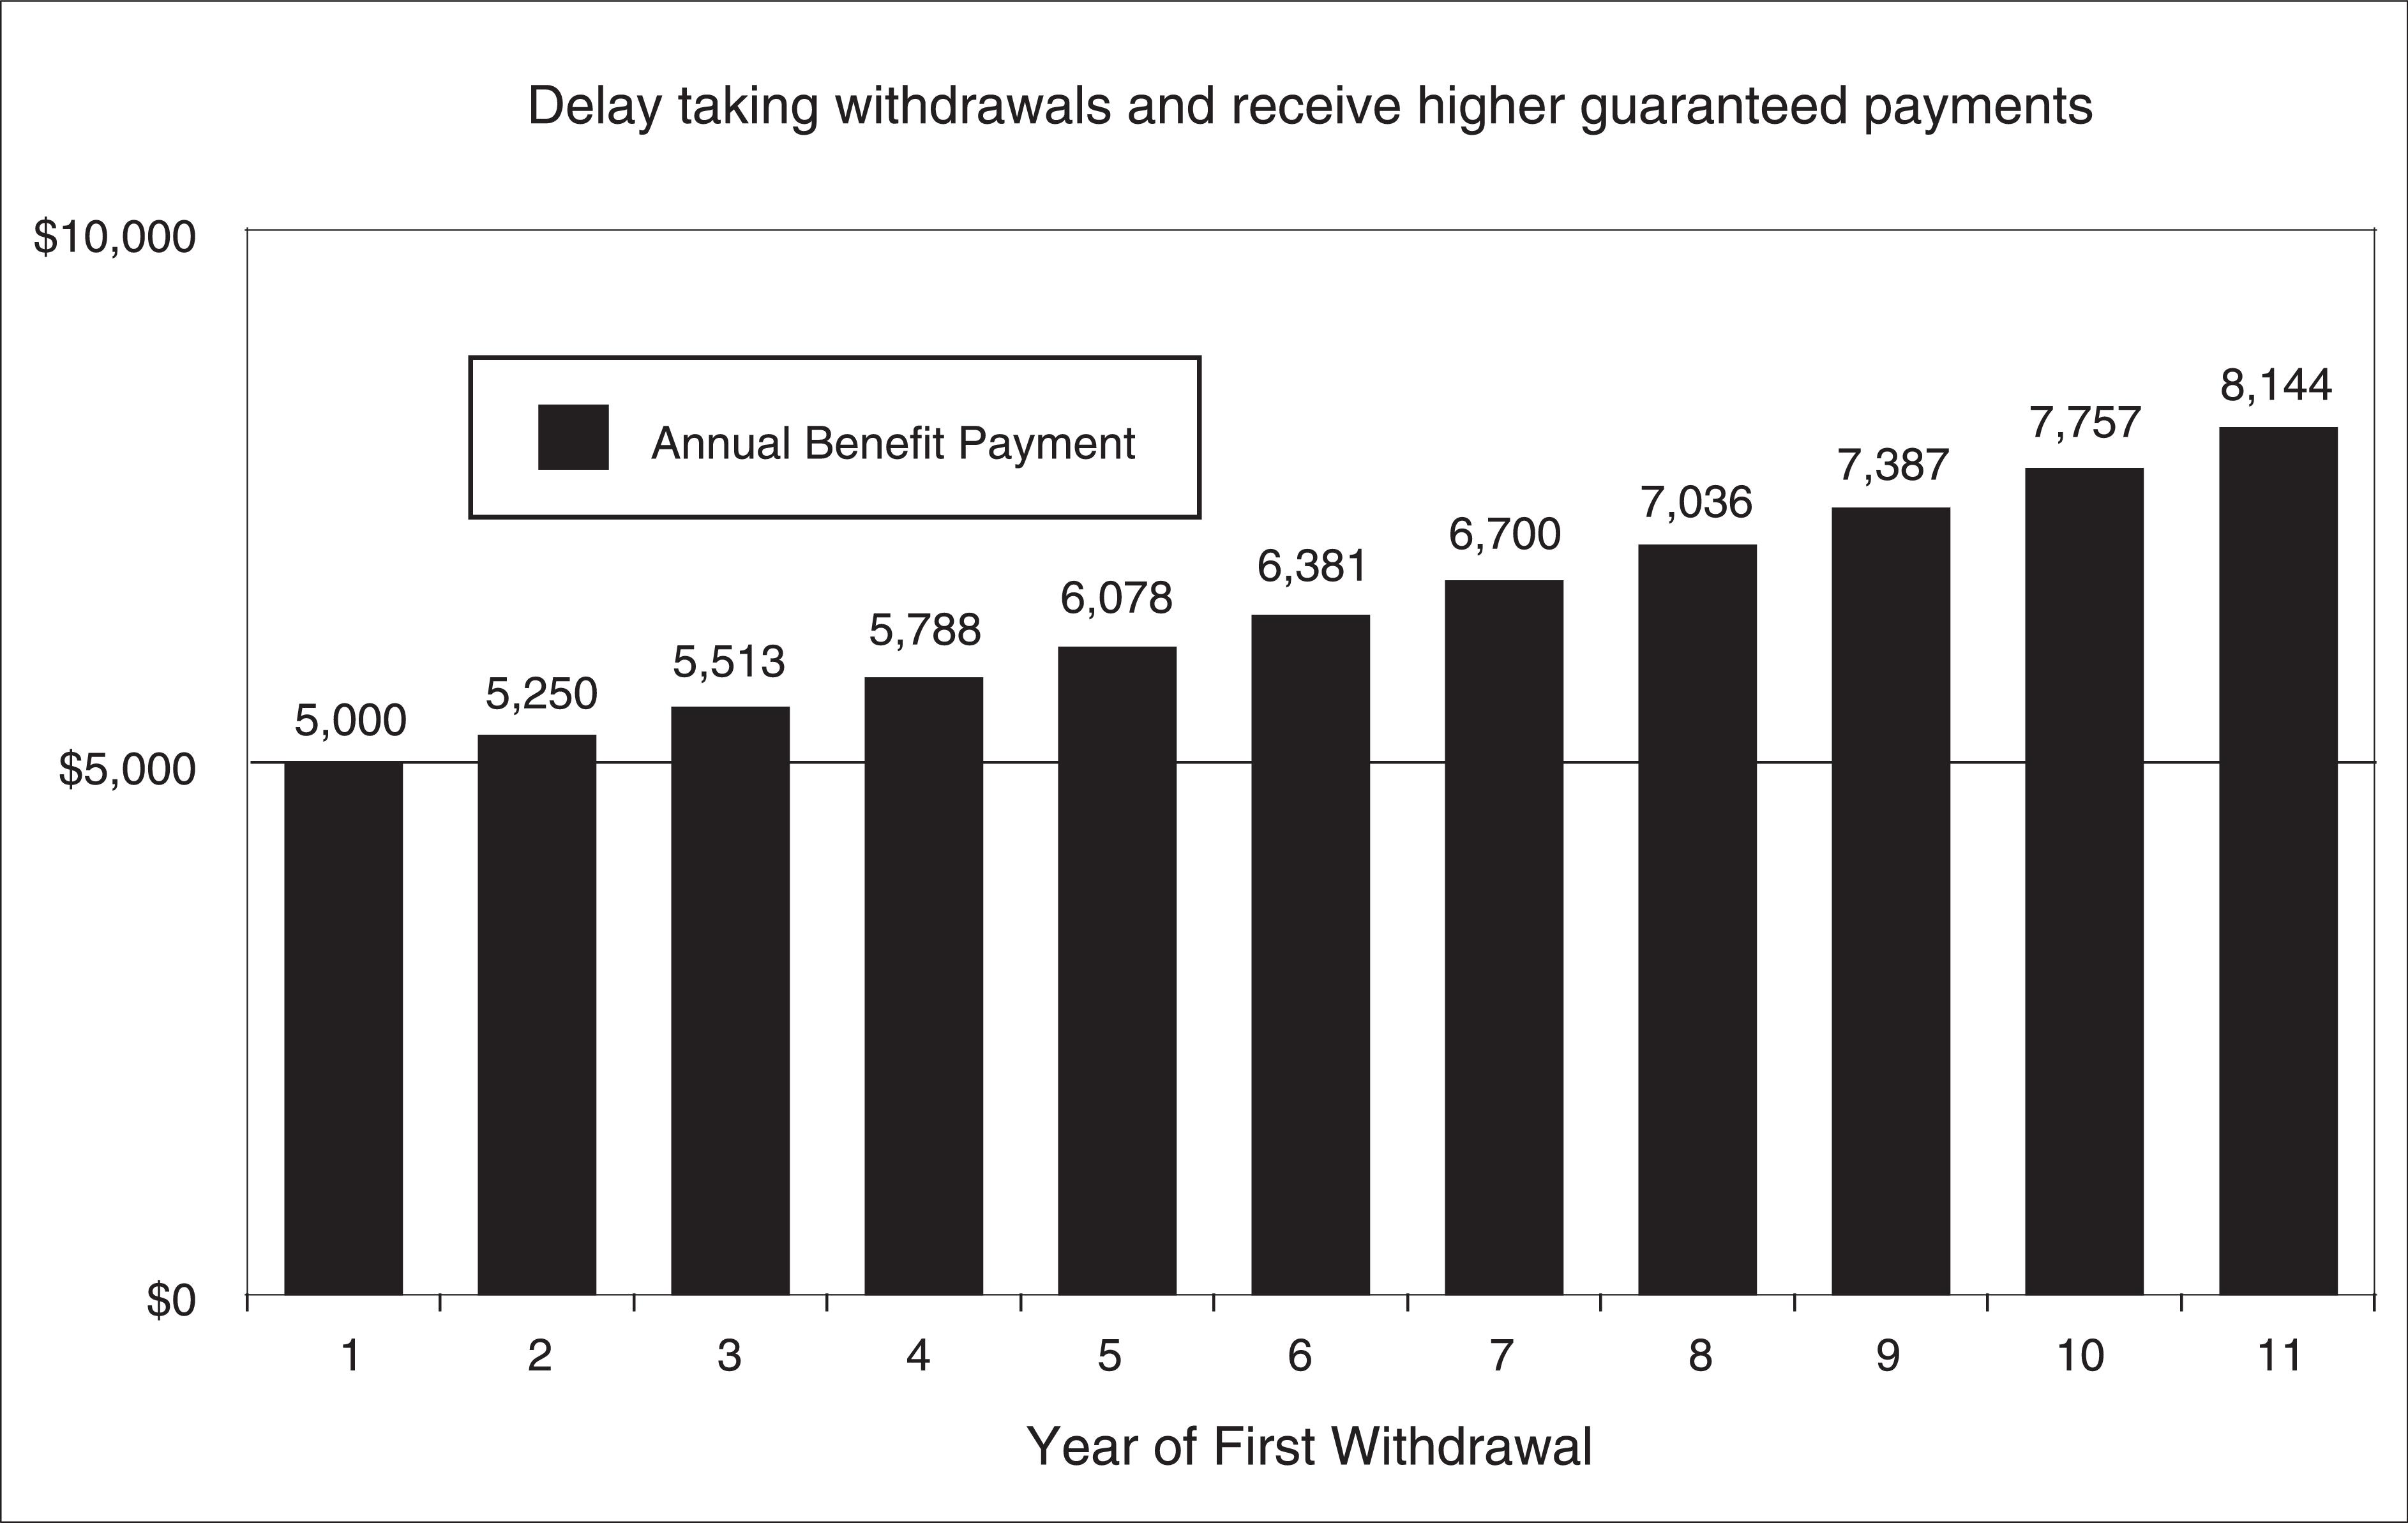 C.LWG — Automatic Annual Step-Ups and 5% Compounding Amount (No withdrawals or loans)Assume that a Contract had an initial purchase payment of $100,000. Assume that no withdrawals or loans are taken.At the first Contract Anniversary, provided that no withdrawals or loans are taken, the Total Guaranteed Withdrawal Amount is increased to $105,000 ($100,000 increased by 5%, compounded annually). Assume the Account Balance has increased to $110,000 at the first Contract Anniversary due to good market performance. The Automatic Annual Step-Up will increase the Total Guaranteed Withdrawal Amount from $105,000 to $110,000 and reset the Annual Benefit Payment to $5,500 ($110,000 × 5%).At the second Contract Anniversary, provided that no withdrawals or loans are taken, the Total Guaranteed Withdrawal Amount is increased to $115,500 ($110,000 increased by 5%, compounded annually). Assume the Account Balance has increased to $120,000 at the second Contract Anniversary due to good market performance. The Automatic Annual Step-Up will increase the Total Guaranteed Withdrawal Amount from $115,500 to $120,000 and reset the Annual Benefit Payment to $6,000 ($120,000 × 5%).Provided that no withdrawals or loans are taken, each year the Total Guaranteed Withdrawal Amount would increase by 5%, compounded annually, from the second Contract Anniversary through the ninth Contract Anniversary, and at that point would be equal to $168,852. Assume that during these Contract Years the Account Balance does not exceed the Total Guaranteed Withdrawal Amount due to poor market performance. Assume the Account Balance at the ninth Contract Anniversary has increased to $180,000 due to good market performance. The Automatic Annual Step-Up will increase the Total Guaranteed Withdrawal Amount from $168,852 to $180,000 and reset the Annual Benefit Payment to $9,000 ($180,000 × 5%).At the 10th Contract Anniversary, provided that no withdrawals or loans are taken, the Total Guaranteed Withdrawal Amount is increased to $189,000 ($180,000 increased by 5%, compounded annually). Assume the Account Balance is less than $189,000. There is no Automatic Annual Step-Up since the Account Balance is below the Total Guaranteed Withdrawal Amount; however, due to the 5% increase in the Total Guaranteed Withdrawal Amount, the Annual Benefit Payment is increased to $9,450 ($189,000 × 5%).LWG — Automatic Annual Step-ups and 5% Compounding Amount (No Withdrawals or Loans)
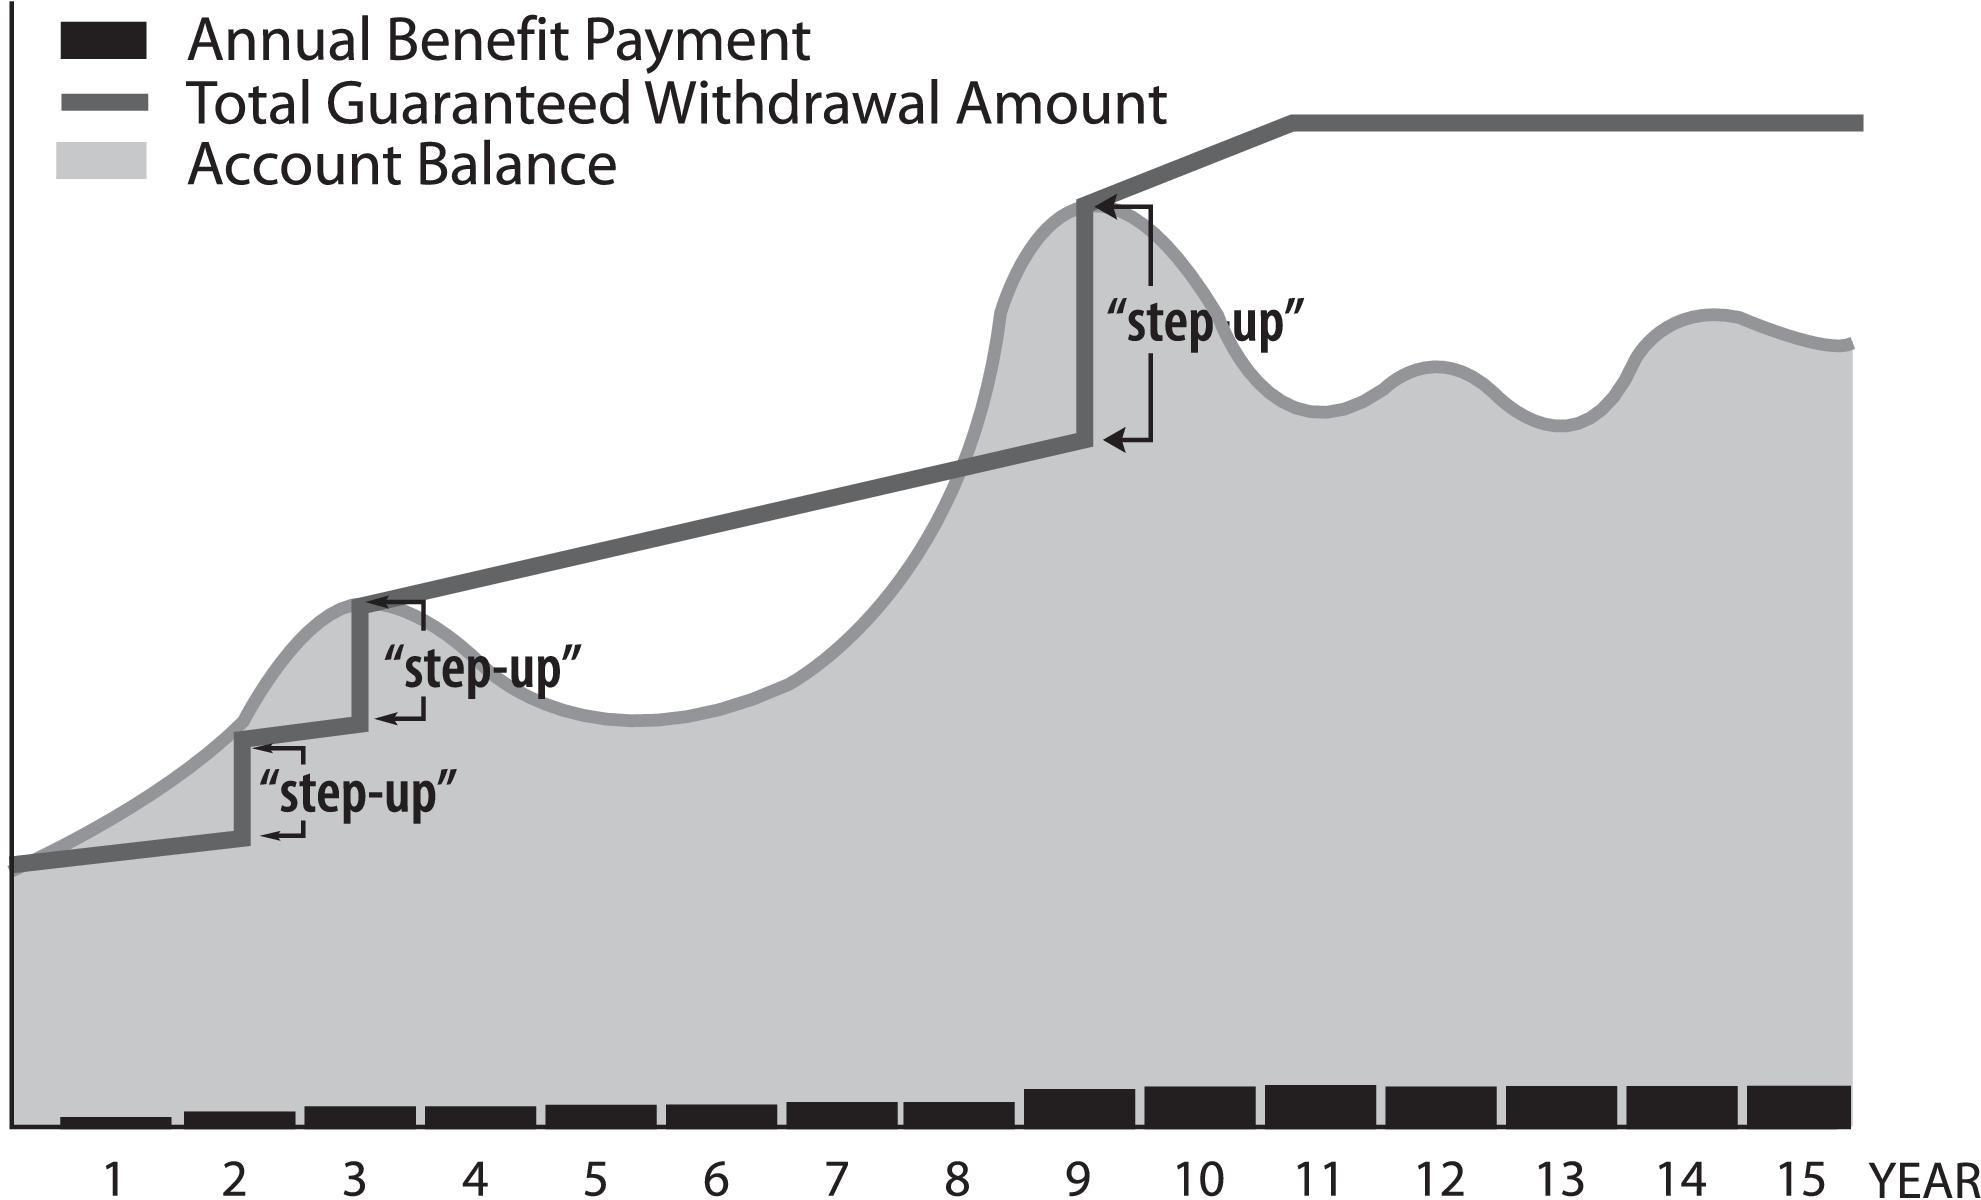
|
| MetLife Financial Freedom Select e and e Bonus Class | Lifetime Withdrawal Guarantee Benefit | Brighthouse Asset Allocation 20 Portfolio - Class B |
|
| Investment Option Restrictions [Line Items] |
|
| Investment Option Available with Benefit [Flag] |
true
|
| MetLife Financial Freedom Select e and e Bonus Class | Lifetime Withdrawal Guarantee Benefit | Brighthouse Asset Allocation 40 Portfolio - Class B |
|
| Investment Option Restrictions [Line Items] |
|
| Investment Option Available with Benefit [Flag] |
true
|
| MetLife Financial Freedom Select e and e Bonus Class | Lifetime Withdrawal Guarantee Benefit | Brighthouse Asset Allocation 60 Portfolio - Class B |
|
| Investment Option Restrictions [Line Items] |
|
| Investment Option Available with Benefit [Flag] |
true
|
| MetLife Financial Freedom Select e and e Bonus Class | Lifetime Withdrawal Guarantee Benefit | Brighthouse Asset Allocation 80 Portfolio - Class B |
|
| Investment Option Restrictions [Line Items] |
|
| Investment Option Available with Benefit [Flag] |
true
|
| MetLife Financial Freedom Select e and e Bonus Class | Waiver of Withdrawal Charge for Nursing Home or Hospital Confinement |
|
| Item 10. Benefits Available [Line Items] |
|
| Name of Benefit [Text Block] |
Waiver of Withdrawal Charge for Nursing Home or Hospital Confinement
|
| Purpose of Benefit [Text Block] |
Allows you to withdraw money without a Withdrawal Charge in the event of nursing home or hospital confinement, subject to certain conditions.
|
| Standard Benefit [Flag] |
true
|
| Standard Benefit Expense (of Benefit Base), Maximum [Percent] |
0.00%
|
| Brief Restrictions / Limitations [Text Block] |
●Only available after the first Contract Year.●Age restrictions, ownership requirements and doctor certification requirements apply.●Must be approved in your state.●You must meet certain length of confinement requirements.
|
| Name of Benefit [Text Block] |
Waiver of Withdrawal Charge for Nursing Home or Hospital Confinement
|
| MetLife Financial Freedom Select e and e Bonus Class | Waiver of Withdrawal Charge for Terminal Illness |
|
| Item 10. Benefits Available [Line Items] |
|
| Name of Benefit [Text Block] |
Waiver of Withdrawal Charge for Terminal Illness
|
| Purpose of Benefit [Text Block] |
Allows you to withdraw money without a Withdrawal Charge in the event of a terminal illness, subject to certain conditions.
|
| Standard Benefit [Flag] |
true
|
| Standard Benefit Expense (of Benefit Base), Maximum [Percent] |
0.00%
|
| Brief Restrictions / Limitations [Text Block] |
●Only available after the first Contract Year.●Age restrictions, ownership requirements and doctor certification requirements apply.●Must be approved in your state.●Certain requirements relating to the nature of the terminal illness apply.●You must not have been diagnosed with the terminal illness as of the Contract issue date.
|
| Name of Benefit [Text Block] |
Waiver of Withdrawal Charge for Terminal Illness
|
| MetLife Financial Freedom Select e and e Bonus Class | The Equity Generator |
|
| Item 10. Benefits Available [Line Items] |
|
| Name of Benefit [Text Block] |
The Equity Generator®
|
| Purpose of Benefit [Text Block] |
An amount equal to the interest earned in the Fixed Interest Account is transferred monthly to any one Division based on your selection.
|
| Standard Benefit [Flag] |
true
|
| Standard Benefit Expense (of Benefit Base), Maximum [Percent] |
0.00%
|
| Brief Restrictions / Limitations [Text Block] |
●If your Fixed Interest Account Balance at the time of a scheduled transfer is zero, this strategy is automatically discontinued.
|
| Name of Benefit [Text Block] |
The Equity Generator®
|
| MetLife Financial Freedom Select e and e Bonus Class | The Rebalancer |
|
| Item 10. Benefits Available [Line Items] |
|
| Name of Benefit [Text Block] |
The Rebalancer®
|
| Purpose of Benefit [Text Block] |
You select a specific asset allocation for your entire Account Balance from among the Divisions and the Fixed Interest Account, if available. Each quarter we transfer amounts among these options to bring the percentage of your Account Balance in each option back to your original allocation.
|
| Standard Benefit [Flag] |
true
|
| Standard Benefit Expense (of Benefit Base), Maximum [Percent] |
0.00%
|
| Brief Restrictions / Limitations [Text Block] |
●In the future, we may permit You to allocate less than 100% of your Account Balance to this strategy.
|
| Name of Benefit [Text Block] |
The Rebalancer®
|
| MetLife Financial Freedom Select e and e Bonus Class | The Index Selector |
|
| Item 10. Benefits Available [Line Items] |
|
| Name of Benefit [Text Block] |
The Index Selector®
|
| Purpose of Benefit [Text Block] |
You may select one of five asset allocation models which are designed to correlate to various risk tolerance levels. Each quarter the percentage in each of the Divisions in which the model invests and any Fixed Interest Account is brought back to the selected model percentage by transferring amounts among the Divisions and any Fixed Interest Account
|
| Standard Benefit [Flag] |
true
|
| Standard Benefit Expense (of Benefit Base), Maximum [Percent] |
0.00%
|
| Brief Restrictions / Limitations [Text Block] |
●Benefit limits available investment options.●The Index Selector is not available with the optional Lifetime Withdrawal Guarantee.
|
| Name of Benefit [Text Block] |
The Index Selector®
|
| MetLife Financial Freedom Select e and e Bonus Class | The Allocator |
|
| Item 10. Benefits Available [Line Items] |
|
| Name of Benefit [Text Block] |
The AllocatorSM
|
| Purpose of Benefit [Text Block] |
Transfers a dollar amount of your choice from the Fixed Interest Account to any of the Divisions you choose on a monthly basis.
|
| Standard Benefit [Flag] |
true
|
| Standard Benefit Expense (of Benefit Base), Maximum [Percent] |
0.00%
|
| Brief Restrictions / Limitations [Text Block] |
●Minimum periodic transfer of $50 is required.●Once your Fixed Interest Account Balance is exhausted, the strategy is discontinued.
|
| Name of Benefit [Text Block] |
The AllocatorSM
|
| MetLife Financial Freedom Select e and e Bonus Class | Systematic Withdrawal Option |
|
| Item 10. Benefits Available [Line Items] |
|
| Name of Benefit [Text Block] |
Systematic Withdrawal Program
|
| Purpose of Benefit [Text Block] |
Automatically withdraws a specific dollar amount or a percentage of your Account Balance of your choice each Contract Year.
|
| Standard Benefit [Flag] |
true
|
| Standard Benefit Expense (of Benefit Base), Maximum [Percent] |
0.00%
|
| Brief Restrictions / Limitations [Text Block] |
●Not available under the 457(b) Deferred Annuity issued to tax-exempt organizations.●Not available in all states.●Income taxes, tax penalties and Withdrawal Charges may apply to your withdrawals.●Subject to our required minimums and administrative restrictions.●Not available to the B and L Classes of the Deferred Annuities until the second Contract Year.●If You elect to receive payments through this program, You must have no loan outstanding from the Fixed Interest Account and You must either be 59 1∕2years old or have left your job. Tax law generally prohibits withdrawals from TSA Deferred Annuities before You reach 59 1∕2.●Not available in conjunction with any automated investment strategy.
|
| Name of Benefit [Text Block] |
Systematic Withdrawal Program
|
| MetLife Financial Freedom Select e and e Bonus Class | Premium Tax |
|
| Item 4. Fee Table [Line Items] |
|
| Other Transaction Fee (of Other Amount), Footnotes [Text Block] |
Premium taxes, if applicable, depend on the Contract You purchased and your home state or jurisdiction and range from 0 to 3.50% of Account Value (or, if applicable, purchase payments).
|
| MetLife Financial Freedom Select e and e Bonus Class | Loans |
|
| Item 4. Fee Table [Line Items] |
|
| Other Transaction Fee (of Other Amount), Footnotes [Text Block] |
The fee may be waived or reduced for certain Plans.
|
| Optional Benefit Expense, Footnotes [Text Block] |
The fee may be waived or reduced for certain Plans. The loan maintenance fee is paid on a quarterly basis at the end of each quarter on a pro-rata basis from the Divisions and the Fixed Interest Account in which You then have a balance.
|
| Item 10. Benefits Available [Line Items] |
|
| Optional Benefit Expense, Footnotes [Text Block] |
The fee may be waived or reduced for certain Plans. The loan maintenance fee is paid on a quarterly basis at the end of each quarter on a pro-rata basis from the Divisions and the Fixed Interest Account in which You then have a balance.
|
| MetLife Financial Freedom Select e and e Bonus Class | Optional Riders |
|
| Item 10. Benefits Available [Line Items] |
|
| Operation of Benefit [Text Block] |
Optional Death BenefitPlease note that the decision to purchase the optional death benefit is made at the time of application and is irrevocable. The optional death benefit is available subject to state approval. Your employer, association or other group Contract holder may limit the availability of any optional benefit. (A loan will decrease the value of any optional benefit purchased with this Contract. See your employer for more information about the availability and features of loans.)
|
| MetLife Financial Freedom Select e and e Bonus Class | Fixed Interest Account |
|
| Fixed Option Details [Line Items] |
|
| Fixed Option Details, Description [Text Block] |
The Fixed Interest AccountThe Deferred Annuities have a fixed interest rate option called the “Fixed Interest Account.” The Fixed Interest Account is not available to all Contract Owners. The Fixed Interest Account is part of our general account and offers an interest rate that is guaranteed by us. The minimum interest rate depends on the date your Contract was issued but will not be less than 3%. The interest rate for each amount allocated to the Fixed Interest Account is set by us in advance on the beginning of each calendar quarter (January 1, April 1, etc.). The declared interest rate in effect when an allocation to the Fixed Interest Account is made will be credited from the date it is received until the last day of the calendar quarter of the following year, at which time a renewal rate will be set. Thereafter, each year a renewal rate will apply to that amount plus the interest previously credited to that amount, as long as the amounts remain in the Fixed Interest Account. The renewal rate will be set by us in advance and will apply for 12 months. Interest will be credited to the Fixed Interest Account on a daily basis. Subject to our transfer rules, You may transfer money into and out of the Fixed Interest Account. For information regarding current interest rates, You may contact our Administrative Office. Information about the Fixed Interest Account, including its name, its term and its minimum guaranteed interest rate is available in Appendix A — Investment Options Available Under the Deferred Annuity — Fixed Option. The current interest rate may vary by Contract class.Because of exemptive and exclusionary provisions, interests in the Fixed Interest Account have not been registered under the Securities Act of 1933 (the “1933 Act”), and neither the Fixed Interest Account nor our general account has been registered as an investment company under the 1940 Act. The Fixed Interest Account and our general account are not subject to the provisions or restrictions of the 1933 Act or the 1940 Act. The Fixed Interest Account is not available with a Deferred Annuity issued in New York State with the optional Guaranteed Minimum Income Benefit. The variable Pay-Out Options under the Deferred Annuities have a fixed payment option called the “Fixed Income Option.” Under the Fixed Income Option, we guarantee the amount of your fixed income payments. These fixed options are not described in this Prospectus although we occasionally refer to them. All guarantees as to purchase payments or Account Balance allocated to the Fixed Interest Account, interest credited to the Fixed Interest Account, and fixed annuity payments are subject to the financial strength and claims-paying ability of Metropolitan Life Insurance Company.
|
| Fixed Option [Line Items] |
|
| Fixed Option Available, Name |
<span style="color:#000000;font-family:Times New Roman;font-size:10pt;margin-left:0.0pt;">Fixed Interest Account</span>
|
| Fixed Option Available, Term |
12 months
|
| Fixed Option Available, Minimum Guaranteed Interest Rate [Percent] |
3.00%
|
| MetLife Financial Freedom Select e and e Bonus Class | Risk of Loss [Member] |
|
| Item 3. Key Information [Line Items] |
|
| Risk [Text Block] |
Yes. You can lose money by investing in the Contract, including loss of principal.
|
| MetLife Financial Freedom Select e and e Bonus Class | Not Short Term Investment Risk [Member] |
|
| Item 3. Key Information [Line Items] |
|
| Risk [Text Block] |
No. This Contract is not a short-term investment and is not appropriate for an investor who needs ready access to cash.●Withdrawal Charges may apply to withdrawals made less than 13 Contract Years after You purchased the Contract. Withdrawal Charges will reduce the value of your Contract if You withdraw money during that time.●The benefits of tax deferral and living benefit protections also mean that the Contract is more beneficial to investors with a long time horizon.●Earnings on your Contract are taxed at ordinary income tax rates when You withdraw them, and You may have to pay a penalty if You take a withdrawal before age 59 1∕2.
|
| MetLife Financial Freedom Select e and e Bonus Class | Market Risk [Member] |
|
| Item 5. Principal Risks [Line Items] |
|
| Principal Risk [Text Block] |
Market Risk. An investment in the Contract is not a bank deposit and is not guaranteed by the Federal Deposit Insurance Corporation or any other governmental agency. The Contract is subject to market risk (the risk that your investments may decline in value or underperform your expectations). As a result, You can lose money by investing in the Contract, including loss of principal.
|
| MetLife Financial Freedom Select e and e Bonus Class | Early Withdrawal Risk [Member] |
|
| Item 5. Principal Risks [Line Items] |
|
| Principal Risk [Text Block] |
Early Withdrawal Risk. This Contract is not a short-term investment and is not appropriate for an investor who needs ready access to cash. If You withdraw early, You may have to pay a Withdrawal Charge and/or income taxes, including a tax penalty if You are younger than age 59 1∕2. Withdrawal Charges may apply if You withdraw money from the Contract less than 13 Contract Years after You purchased the Contract. Withdrawal Charges will reduce the value of your Contract if You withdraw money during that time. The benefits of tax deferral and living benefit protections also mean that the Contract is more beneficial to investors with a long time horizon.
|
| MetLife Financial Freedom Select e and e Bonus Class | Contract Benefits Risk [Member] |
|
| Item 5. Principal Risks [Line Items] |
|
| Principal Risk [Text Block] |
Contract Benefits Risk. Withdrawals that exceed limits specified by the terms of any benefit may affect the availability of the benefit by reducing the benefit by an amount greater than the value withdrawn, and/or could terminate the benefit. In addition, the Lifetime Withdrawal Guarantee imposes restrictions and limitations on your choice of Portfolios. These restrictions and requirements are intended to protect the Company and reduce the likelihood that we will have to pay guaranteed benefits under the Lifetime Withdrawal Guarantee out of our own assets. The restrictions and requirements could result in your missing out on some or all positive investment performance by certain of the Portfolios – this means your opportunity for investment gains may be limited.
|
| MetLife Financial Freedom Select e and e Bonus Class | Insurance Company Risk [Member] |
|
| Item 3. Key Information [Line Items] |
|
| Risk [Text Block] |
An investment in the Contract is subject to the risks related to the Company. Any obligations (including under the Fixed Interest Account), guarantees, or benefits, including any death benefit, are subject to the claims-paying ability of the Company and our long term ability to make such payments, and are not guaranteed by any other party. MetLife is regulated as an insurance company under state law, which generally includes limits on the amount and type of investments in its general account. However, there is no guarantee that we will be able to meet our claims paying obligations; there are risks to purchasing any insurance product. More information about the Company, including its financial strength ratings, is available upon request or by visiting https://www.metlife.com/about-us/corporate-profile/ratings/.
|
| MetLife Financial Freedom Select e and e Bonus Class | Contract Changes Risk [Member] |
|
| Item 5. Principal Risks [Line Items] |
|
| Principal Risk [Text Block] |
Contract Changes Risk. Subject to applicable law, we have the right to make certain changes to your Contract. Examples of the changes we may make include: (i) operating the Separate Account in any form permitted by law; (ii) taking any action necessary to comply with or obtain and continue any exemptions under the law (including favorable treatment under the Federal income tax laws) including limiting the number, frequency or types of transfers/reallocations permitted; (iii) transferring any assets in a Division to another Division, or to one or more Separate Accounts, or to our general account, or adding, combining or removing Divisions in the Separate Account; (iv) substituting Portfolio shares in any Division, with the shares of another class of Brighthouse Trust I, Brighthouse Trust II, or the shares of another investment company or any other investment permitted by law or closing, adding or removing Portfolios as Investment Division investments as permitted by law; (v) changing the way we assess charges, but without increasing the maximum aggregate amount charged to the Separate Account and any currently available Portfolio in connection with the Contracts; and (vi) making any necessary technical changes in the Contracts in order to conform with any of the above-described actions.
|
| MetLife Financial Freedom Select e and e Bonus Class | Risks Associated with Investment Options |
|
| Item 3. Key Information [Line Items] |
|
| Risk [Text Block] |
An investment in the Contract is subject to the risk of poor investment performance and can vary depending on the performance of the investment options available under the Contract (e.g., Portfolios).●Each investment option (including the Fixed Interest Account investment option) will have its own unique risks.●You should review these investment options before making an investment decision.
|
| MetLife Financial Freedom Select e and e Bonus Class | Contract Termination |
|
| Item 3. Key Information [Line Items] |
|
| Risk [Text Block] |
Subject to certain limitations, if your Account Balance falls below the minimum Account Balance or is not sufficient to pay the Contract charges, we may terminate your Contract.
|
| Item 5. Principal Risks [Line Items] |
|
| Principal Risk [Text Block] |
Contract Termination Subject to certain limitations, if your Account Balance falls below the minimum Account Balance or is not sufficient to pay the Contract charges, we may terminate your Deferred Annuity.
|
| MetLife Financial Freedom Select e and e Bonus Class | Risk of Underlying Portfolios |
|
| Item 5. Principal Risks [Line Items] |
|
| Principal Risk [Text Block] |
Risk of Underlying Portfolios. An investment in the Contract is subject to the risk of poor investment performance and can vary depending on the performance of the investment options available under the Contract (e.g., Portfolio Companies). Each investment option (including the Fixed Interest Account investment option) will have its own unique risks. We do not provide any investment advice and do not recommend or endorse any particular Portfolio. You bear the risk of any decline in the Account Balance of your Contract resulting from the performance of the Portfolios You have chosen. You should review these investment options before making an investment decision. Information regarding the Portfolios available under your Contract is available in Appendix A to this Prospectus.
|
| MetLife Financial Freedom Select e and e Bonus Class | Risks Associated with the Company |
|
| Item 5. Principal Risks [Line Items] |
|
| Principal Risk [Text Block] |
Insurance Company Risk. An investment in the Contract is subject to the risks related to the Company. Any obligations (including under the Fixed Interest Account), guarantees, or benefits are subject to the financial strength and claims-paying ability of the Company and our long term ability to make such payments, and are not guaranteed by any other party. MetLife is regulated as an insurance company under state law, which generally includes limits on the amount and type of investments in its general account. However, there is no guarantee that we will be able to meet our claims paying obligations; there are risks to purchasing any insurance product.
|
| MetLife Financial Freedom Select e and e Bonus Class | Conflicts of Interest |
|
| Item 5. Principal Risks [Line Items] |
|
| Principal Risk [Text Block] |
Conflicts of Interest. Your investment professional may receive compensation for selling this Contract to You, both in the form of commissions and because MetLife may share the revenue it earns on this Contract with the professional’s firm. This conflict of interest may influence your investment professional to recommend this Contract over another investment. In addition, some investment professionals may have a financial incentive to offer You a new contract in place of the one You own. You should only exchange your Contract if You determine, after comparing the features, fees, and risks of both contracts, that it is better for You to purchase the new contract rather than continue to own your existing Contract.
|
| MetLife Financial Freedom Select e and e Bonus Class | Suitability |
|
| Item 5. Principal Risks [Line Items] |
|
| Principal Risk [Text Block] |
Suitability. An investment in the Contract may not be suitable for all investors. For example, there is no additional tax benefit if You purchase the Contract through a tax-qualified plan or individual retirement account (IRA). Therefore, there should be reasons other than tax deferral for acquiring the Contract. You should consult with a tax or investment professional to determine the tax and other implications of an investment in and purchase payments received under the Contract.
|
| MetLife Financial Freedom Select e and e Bonus Class | Tax Risks |
|
| Item 5. Principal Risks [Line Items] |
|
| Principal Risk [Text Block] |
Taxation Risk. Although the provisions of the Internal Revenue Code (the “Code”) relevant to the Contract are generally described under “Federal Tax Considerations,” an investor should consult their own tax advisor concerning the effects of federal, state, local and foreign tax law on the Contract. No assurance can be given that, even if the tax provisions currently applicable to the Contract are favorable, the law or regulations or interpretations thereunder will not change and the Contract may be disadvantaged.
|
| MetLife Financial Freedom Select e and e Bonus Class | Cybersecurity |
|
| Item 5. Principal Risks [Line Items] |
|
| Principal Risk [Text Block] |
Cybersecurity. Our business is highly dependent upon the effective operation of our information systems, and those of our service providers, vendors, and other third parties. Cybersecurity breaches of such systems can be intentional or unintentional events, and can occur through unauthorized access to computer systems, networks or devices; infection from computer viruses or other malicious software code; or attacks that shut down, disable, slow or otherwise disrupt operations, business processes or website access or functionality and our disaster recovery systems may be insufficient to safeguard our ability to conduct business. Cybersecurity breaches can interfere with our processing of Contract transactions, including the processing of transfer orders from our website or with the Portfolios; impact our ability to calculate Accumulation Unit Values; cause the release and possible loss or destruction of confidential Contract Owner or business information; impede order processing or cause other operational issues; and result in regulatory enforcement actions or new laws or regulations which could increase our compliance costs. Although we continually make efforts to identify and reduce our exposure to cybersecurity risk, and we require our critical vendors to implement effective cybersecurity and data protection measures, there is no guarantee that we will be able to successfully manage this risk at all times.
|
| MetLife Financial Freedom Select e and e Bonus Class | Bonus Class Risk |
|
| Item 5. Principal Risks [Line Items] |
|
| Principal Risk [Text Block] |
Bonus Class Risk. Expenses of a class that includes a bonus feature may be higher than expenses of a class of the Contract without the bonus, and the additional amount of the bonus may be more than offset by the additional fees and charges associated with the bonus class, including Withdrawal Charges. Any bonus associated with the class will be retrieved upon exercise of a “Free Look” cancellation.
|
| MetLife Financial Freedom Select e and e Bonus Class | Pandemics and Other Public Health Issues and Other Events |
|
| Item 5. Principal Risks [Line Items] |
|
| Principal Risk [Text Block] |
Pandemics and Other Public Health Issues and Other Events. Pandemics and other public health issues or other events, and governmental, business, and consumer reactions to them, may affect economic conditions and may cause a large number of illnesses or deaths. Hurricanes, windstorms, earthquakes, hail, tornadoes, explosions, severe winter weather, fires, floods and mudslides, blackouts and man-made events such as riot, insurrection, terrorist attacks or acts of war may also cause catastrophic losses and increased claims. Any such catastrophes may also result in changes in consumer or business confidence, behavior and investment and business activity, changes to interest rates and other market risk factors, and governmental or other restrictions on economic activity for prolonged periods.
|
| MetLife Financial Freedom Select e and e Bonus Class | Terrorism and Security Risk |
|
| Item 5. Principal Risks [Line Items] |
|
| Principal Risk [Text Block] |
Terrorism and Security Risk. The continued threat of terrorism, ongoing or potential military conflict and other actions, and heightened security measures may cause economic uncertainty and result in loss of life, property damage, additional disruptions to commerce and reduced economic activity. The value of MetLife's investment portfolio may be adversely affected by declines in the credit and equity markets and reduced economic activity caused by such threats. Companies in which we maintain investments may suffer losses as a result of financial, commercial or economic disruptions, and such disruptions might affect the ability of those companies to pay interest or principal on their securities or mortgage loans. Terrorist or military actions also could disrupt our operations centers and result in higher than anticipated claims under our insurance policies.
|
| MetLife Financial Freedom Select e and e Bonus Class | Technology Risk |
|
| Item 5. Principal Risks [Line Items] |
|
| Principal Risk [Text Block] |
Technology Risk. Our business operations rely on functioning and secure information systems, including those of our vendors and other third parties. Technological changes present us with new or intensified challenges, and if we are unable to foresee or adapt to these changes, our business may be adversely affected. Technological changes may affect our business model and how we interact with our customers. The growth and availability of AI technologies, including generative AI, presents significant opportunities but also complex challenges; these include balancing and mitigating potential risks of harm posed by the development or deployment of AI technologies, as well as implementing and maintaining controls reasonably designed to ensure compliance with an increasingly complex AI regulatory landscape, with evolving requirements that may vary across jurisdictions. We may fail to adopt new technologies as effectively or efficiently as others, leading to competitive harm. If we are unable to update our business model to match evolving consumer preferences or the evolving technological landscape, we may be adversely affected.
|
| MetLife Financial Freedom Select e and e Bonus Class | e Class |
|
| Item 4. Fee Table [Line Items] |
|
| Deferred Sales Load (of Amount Surrendered), Maximum [Percent] |
0.00%
|
| Transfer Fee, Maximum [Dollars] |
$ 25
|
| Administrative Expense, Maximum [Dollars] |
$ 30
|
| Base Contract Expense (of Average Account Value), Maximum [Percent] |
0.50%
|
| Surrender Expense, 1 Year, Maximum [Dollars] |
$ 2,960
|
| Surrender Expense, 1 Year, Minimum [Dollars] |
2,100
|
| Surrender Expense, 3 Years, Maximum [Dollars] |
9,088
|
| Surrender Expense, 3 Years, Minimum [Dollars] |
6,484
|
| Surrender Expense, 5 Years, Maximum [Dollars] |
15,591
|
| Surrender Expense, 5 Years, Minimum [Dollars] |
11,214
|
| Surrender Expense, 10 Years, Maximum [Dollars] |
33,647
|
| Surrender Expense, 10 Years, Minimum [Dollars] |
24,743
|
| Annuitized Expense, 1 Year, Maximum [Dollars] |
2,960
|
| Annuitized Expense, 1 Year, Minimum [Dollars] |
2,100
|
| Annuitized Expense, 3 Years, Maximum [Dollars] |
9,088
|
| Annuitized Expense, 3 Years, Minimum [Dollars] |
6,484
|
| Annuitized Expense, 5 Years, Maximum [Dollars] |
15,591
|
| Annuitized Expense, 5 Years, Minimum [Dollars] |
11,214
|
| Annuitized Expense, 10 Years, Maximum [Dollars] |
33,647
|
| Annuitized Expense, 10 Years, Minimum [Dollars] |
24,743
|
| No Surrender Expense, 1 Year, Maximum [Dollars] |
2,960
|
| No Surrender Expense, 1 Year, Minimum [Dollars] |
2,100
|
| No Surrender Expense, 3 Years, Maximum [Dollars] |
9,088
|
| No Surrender Expense, 3 Years, Minimum [Dollars] |
6,484
|
| No Surrender Expense, 5 Years, Maximum [Dollars] |
15,591
|
| No Surrender Expense, 5 Years, Minimum [Dollars] |
11,214
|
| No Surrender Expense, 10 Years, Maximum [Dollars] |
33,647
|
| No Surrender Expense, 10 Years, Minimum [Dollars] |
$ 24,743
|
| MetLife Financial Freedom Select e and e Bonus Class | e Class | Annual Step-Up Death Benefit |
|
| Item 4. Fee Table [Line Items] |
|
| Optional Benefit Expense (of Other Amount), Maximum [Percent] |
0.10%
|
| Item 10. Benefits Available [Line Items] |
|
| Optional Benefit Expense (of Other Amount), Maximum [Percent] |
0.10%
|
| MetLife Financial Freedom Select e and e Bonus Class | e Class | Guaranteed Minimum Income Benefit |
|
| Item 4. Fee Table [Line Items] |
|
| Optional Benefit Expense (of Other Amount), Maximum [Percent] |
0.70%
|
| Item 10. Benefits Available [Line Items] |
|
| Optional Benefit Expense (of Other Amount), Maximum [Percent] |
0.70%
|
| MetLife Financial Freedom Select e and e Bonus Class | e Class | Lifetime Withdrawal Guarantee Benefit |
|
| Item 4. Fee Table [Line Items] |
|
| Optional Benefit Expense (of Other Amount), Maximum [Percent] |
0.95%
|
| Item 10. Benefits Available [Line Items] |
|
| Optional Benefit Expense (of Other Amount), Maximum [Percent] |
0.95%
|
| MetLife Financial Freedom Select e and e Bonus Class | e Class | Premium Tax |
|
| Item 4. Fee Table [Line Items] |
|
| Other Transaction Fee (of Other Amount), Maximum [Percent] |
3.50%
|
| MetLife Financial Freedom Select e and e Bonus Class | e Class | Loans |
|
| Item 4. Fee Table [Line Items] |
|
| Optional Benefit Expense, Maximum [Dollars] |
$ 50
|
| Item 10. Benefits Available [Line Items] |
|
| Optional Benefit Expense, Maximum [Dollars] |
$ 50
|
| MetLife Financial Freedom Select e and e Bonus Class | e Bonus Class |
|
| Item 4. Fee Table [Line Items] |
|
| Deferred Sales Load (of Amount Surrendered), Maximum [Percent] |
3.00%
|
| Transfer Fee, Maximum [Dollars] |
$ 25
|
| Administrative Expense, Maximum [Dollars] |
$ 30
|
| Base Contract Expense (of Average Account Value), Maximum [Percent] |
0.95%
|
| Surrender Expense, 1 Year, Maximum [Dollars] |
$ 6,410
|
| Surrender Expense, 1 Year, Minimum [Dollars] |
5,550
|
| Surrender Expense, 3 Years, Maximum [Dollars] |
13,132
|
| Surrender Expense, 3 Years, Minimum [Dollars] |
10,552
|
| Surrender Expense, 5 Years, Maximum [Dollars] |
20,520
|
| Surrender Expense, 5 Years, Minimum [Dollars] |
16,224
|
| Surrender Expense, 10 Years, Maximum [Dollars] |
36,525
|
| Surrender Expense, 10 Years, Minimum [Dollars] |
27,882
|
| Annuitized Expense, 1 Year, Maximum [Dollars] |
3,410
|
| Annuitized Expense, 1 Year, Minimum [Dollars] |
2,550
|
| Annuitized Expense, 3 Years, Maximum [Dollars] |
10,432
|
| Annuitized Expense, 3 Years, Minimum [Dollars] |
7,852
|
| Annuitized Expense, 5 Years, Maximum [Dollars] |
17,820
|
| Annuitized Expense, 5 Years, Minimum [Dollars] |
13,524
|
| Annuitized Expense, 10 Years, Maximum [Dollars] |
36,525
|
| Annuitized Expense, 10 Years, Minimum [Dollars] |
27,882
|
| No Surrender Expense, 1 Year, Maximum [Dollars] |
3,410
|
| No Surrender Expense, 1 Year, Minimum [Dollars] |
2,550
|
| No Surrender Expense, 3 Years, Maximum [Dollars] |
10,432
|
| No Surrender Expense, 3 Years, Minimum [Dollars] |
7,852
|
| No Surrender Expense, 5 Years, Maximum [Dollars] |
17,820
|
| No Surrender Expense, 5 Years, Minimum [Dollars] |
13,524
|
| No Surrender Expense, 10 Years, Maximum [Dollars] |
36,525
|
| No Surrender Expense, 10 Years, Minimum [Dollars] |
$ 27,882
|
| MetLife Financial Freedom Select e and e Bonus Class | e Bonus Class | Annual Step-Up Death Benefit |
|
| Item 4. Fee Table [Line Items] |
|
| Optional Benefit Expense (of Other Amount), Maximum [Percent] |
0.10%
|
| Item 10. Benefits Available [Line Items] |
|
| Optional Benefit Expense (of Other Amount), Maximum [Percent] |
0.10%
|
| MetLife Financial Freedom Select e and e Bonus Class | e Bonus Class | Guaranteed Minimum Income Benefit |
|
| Item 4. Fee Table [Line Items] |
|
| Optional Benefit Expense (of Other Amount), Maximum [Percent] |
0.70%
|
| Item 10. Benefits Available [Line Items] |
|
| Optional Benefit Expense (of Other Amount), Maximum [Percent] |
0.70%
|
| MetLife Financial Freedom Select e and e Bonus Class | e Bonus Class | Lifetime Withdrawal Guarantee Benefit |
|
| Item 4. Fee Table [Line Items] |
|
| Optional Benefit Expense (of Other Amount), Maximum [Percent] |
0.95%
|
| Item 10. Benefits Available [Line Items] |
|
| Optional Benefit Expense (of Other Amount), Maximum [Percent] |
0.95%
|
| MetLife Financial Freedom Select e and e Bonus Class | e Bonus Class | Premium Tax |
|
| Item 4. Fee Table [Line Items] |
|
| Other Transaction Fee (of Other Amount), Maximum [Percent] |
3.50%
|
| MetLife Financial Freedom Select e and e Bonus Class | e Bonus Class | Loans |
|
| Item 4. Fee Table [Line Items] |
|
| Optional Benefit Expense, Maximum [Dollars] |
$ 50
|
| Item 10. Benefits Available [Line Items] |
|
| Optional Benefit Expense, Maximum [Dollars] |
50
|
| MetLife Financial Freedom Select e and e Bonus Class | C Class |
|
| Item 4. Fee Table [Line Items] |
|
| Surrender Expense, 1 Year, Maximum [Dollars] |
3,910
|
| Surrender Expense, 1 Year, Minimum [Dollars] |
3,050
|
| Surrender Expense, 3 Years, Maximum [Dollars] |
11,912
|
| Surrender Expense, 3 Years, Minimum [Dollars] |
9,358
|
| Surrender Expense, 5 Years, Maximum [Dollars] |
20,248
|
| Surrender Expense, 5 Years, Minimum [Dollars] |
16,040
|
| Surrender Expense, 10 Years, Maximum [Dollars] |
42,646
|
| Surrender Expense, 10 Years, Minimum [Dollars] |
34,536
|
| Annuitized Expense, 1 Year, Maximum [Dollars] |
3,910
|
| Annuitized Expense, 1 Year, Minimum [Dollars] |
3,050
|
| Annuitized Expense, 3 Years, Maximum [Dollars] |
11,912
|
| Annuitized Expense, 3 Years, Minimum [Dollars] |
9,358
|
| Annuitized Expense, 5 Years, Maximum [Dollars] |
20,248
|
| Annuitized Expense, 5 Years, Minimum [Dollars] |
16,040
|
| Annuitized Expense, 10 Years, Maximum [Dollars] |
42,646
|
| Annuitized Expense, 10 Years, Minimum [Dollars] |
34,536
|
| No Surrender Expense, 1 Year, Maximum [Dollars] |
3,910
|
| No Surrender Expense, 1 Year, Minimum [Dollars] |
3,050
|
| No Surrender Expense, 3 Years, Maximum [Dollars] |
11,912
|
| No Surrender Expense, 3 Years, Minimum [Dollars] |
9,358
|
| No Surrender Expense, 5 Years, Maximum [Dollars] |
20,248
|
| No Surrender Expense, 5 Years, Minimum [Dollars] |
16,040
|
| No Surrender Expense, 10 Years, Maximum [Dollars] |
42,646
|
| No Surrender Expense, 10 Years, Minimum [Dollars] |
$ 34,536
|
| MetLife Financial Freedom Select B, L and C Class |
|
| Item 3. Key Information [Line Items] |
|
| Fees and Expenses [Text Block] |
| |
FEES, EXPENSES AND ADJUSTMENTS |
|
Are there Charges or Adjustments for Early Withdrawals? |
Yes. If You withdraw money from the Contract less than 13 Contract years after You purchased the Contract, You may be assessed a Withdrawal Charge of up to 10% of the amount withdrawn. For example, if You purchase a B Class for $100,000 and surrender your Contract during the first year, You will pay a Withdrawal Charge of up to $10,000. |
Charges – Withdrawal Charges |
Are there Transaction Charges? |
Yes. In addition to Withdrawal Charges, You also may be charged for other transactions, such as transferring Account Value among Divisions or between the Divisions and the Fixed Interest Account. Although we do not currently charge a fee for transfers of Account Value among Divisions or between the Divisions and the Fixed Interest Account, we reserve the right to impose a transfer fee of $25 on transfers in excess of 12 in a Contract Year. Loans will incur a $75 loan initiation fee. The Loan Maintenance Fee is $50.00. Loan fees may be waived or reduced for certain Plans. |
|
Are there Ongoing Fees and Expenses (annual charges)? |
Yes. The table below describes the fees and expenses that You may pay each year, depending on the investment options and optional benefits You choose. Please refer to your Contract specifications page for information about the specific fees You will pay each year based on the options You have elected. |
|
| |
|
|
Base Contract (varies by Contract class) |
|
|
Portfolio fees and expenses |
|
|
Optional benefits available for an additional charge (for a single optional benefit, if elected) |
|
|
| |
(1) As a percentage of your Account Balance in the Separate Account. The Base Contract Fee includes 0.04% for the Annual Contract Fee. The Annual Contract Fee is $30 annually. The Annual Contract Fee may be waived under certain circumstances. For classes B, C, and L this fee is waived if your total purchase payments for the prior 12 months are at least $2,000 on the day the fee is deducted or if your Account Balance is at least $25,000 on the day the fee is deducted and for e and e Bonus classes if your Account Balance is at least $50,000 on the day the fee is deducted. The fee will be deducted on a pro-rata basis (determined based upon the number of complete months that have elapsed since the prior Contract Anniversary) if You take a total withdrawal of your Account Balance. This fee will not be deducted if You are on medical leave approved by your employer or called to active armed service duty at the time the fee is to be deducted and your employer has informed us of your status. During the pay- out phase we reserve the right to deduct this fee. (2) As a percentage of average daily net assets of the Portfolio. (3) For the Enhanced Death Benefit: as a percentage of your Account Balance in the Separate Account. For the GMIB fee: as a percentage of your guaranteed minimum income base. For the LWG fee: as a percentage of your Total Guaranteed Withdrawal Amount. |
|
Because your Contract is customizable, the choices You make affect how much You will pay. To help understand the cost of owning your Contract, the following table shows the lowest and highest cost You could pay each year, based on current charges. This estimate assumes that You do not take withdrawals from the Contract, which could add Withdrawal Charges that substantially increase costs. |
| |
|
|
|
| |
|
Assumes: ●Investment of $100,000 ●5% annual appreciation ●Least expensive combination of Contract classes and Portfolio fees and expenses ●No optional benefits ●No sales charges ●No additional purchase payments, transfers or withdrawals |
Assumes: ●Investment of $100,000 ●5% annual appreciation ●Most expensive combination of Contract classes, optional benefits and Portfolio fees and expenses ●No sales charges ●No additional purchase payments, transfers or withdrawals |
|
| Charges for Early Withdrawals [Text Block] |
Are there Charges or Adjustments for Early Withdrawals? |
Yes. If You withdraw money from the Contract less than 13 Contract years after You purchased the Contract, You may be assessed a Withdrawal Charge of up to 10% of the amount withdrawn. For example, if You purchase a B Class for $100,000 and surrender your Contract during the first year, You will pay a Withdrawal Charge of up to $10,000. |
Charges – Withdrawal Charges |
|
| Surrender Charge Phaseout Period, Years | yr |
13
|
| Surrender Charge (of Amount Surrendered) Maximum [Percent] |
10.00%
|
| Surrender Charge Example Maximum [Dollars] |
$ 10,000
|
| Transaction Charges [Text Block] |
Are there Transaction Charges? |
Yes. In addition to Withdrawal Charges, You also may be charged for other transactions, such as transferring Account Value among Divisions or between the Divisions and the Fixed Interest Account. Although we do not currently charge a fee for transfers of Account Value among Divisions or between the Divisions and the Fixed Interest Account, we reserve the right to impose a transfer fee of $25 on transfers in excess of 12 in a Contract Year. Loans will incur a $75 loan initiation fee. The Loan Maintenance Fee is $50.00. Loan fees may be waived or reduced for certain Plans. |
|
|
| Ongoing Fees and Expenses [Table Text Block] |
Are there Ongoing Fees and Expenses (annual charges)? |
Yes. The table below describes the fees and expenses that You may pay each year, depending on the investment options and optional benefits You choose. Please refer to your Contract specifications page for information about the specific fees You will pay each year based on the options You have elected. |
|
| |
|
|
Base Contract (varies by Contract class) |
|
|
Portfolio fees and expenses |
|
|
Optional benefits available for an additional charge (for a single optional benefit, if elected) |
|
|
| |
(1) As a percentage of your Account Balance in the Separate Account. The Base Contract Fee includes 0.04% for the Annual Contract Fee. The Annual Contract Fee is $30 annually. The Annual Contract Fee may be waived under certain circumstances. For classes B, C, and L this fee is waived if your total purchase payments for the prior 12 months are at least $2,000 on the day the fee is deducted or if your Account Balance is at least $25,000 on the day the fee is deducted and for e and e Bonus classes if your Account Balance is at least $50,000 on the day the fee is deducted. The fee will be deducted on a pro-rata basis (determined based upon the number of complete months that have elapsed since the prior Contract Anniversary) if You take a total withdrawal of your Account Balance. This fee will not be deducted if You are on medical leave approved by your employer or called to active armed service duty at the time the fee is to be deducted and your employer has informed us of your status. During the pay- out phase we reserve the right to deduct this fee. (2) As a percentage of average daily net assets of the Portfolio. (3) For the Enhanced Death Benefit: as a percentage of your Account Balance in the Separate Account. For the GMIB fee: as a percentage of your guaranteed minimum income base. For the LWG fee: as a percentage of your Total Guaranteed Withdrawal Amount. |
|
Because your Contract is customizable, the choices You make affect how much You will pay. To help understand the cost of owning your Contract, the following table shows the lowest and highest cost You could pay each year, based on current charges. This estimate assumes that You do not take withdrawals from the Contract, which could add Withdrawal Charges that substantially increase costs. |
| |
|
|
|
| |
|
Assumes: ●Investment of $100,000 ●5% annual appreciation ●Least expensive combination of Contract classes and Portfolio fees and expenses ●No optional benefits ●No sales charges ●No additional purchase payments, transfers or withdrawals |
Assumes: ●Investment of $100,000 ●5% annual appreciation ●Most expensive combination of Contract classes, optional benefits and Portfolio fees and expenses ●No sales charges ●No additional purchase payments, transfers or withdrawals |
|
| Base Contract (of Other Amount) (N-4) Minimum [Percent] |
0.54%
|
| Base Contract (of Other Amount) (N-4) Maximum [Percent] |
1.49%
|
| Investment Options (of Average Annual Net Assets) Minimum [Percent] |
0.52%
|
| Investment Options (of Average Annual Net Assets) Maximum [Percent] |
1.38%
|
| Optional Benefits Minimum [Percent] |
0.10%
|
| Optional Benefits Maximum [Percent] |
0.95%
|
| Base Contract (N-4) Footnotes [Text Block] |
(1) As a percentage of your Account Balance in the Separate Account. The Base Contract Fee includes 0.04% for the Annual Contract Fee. The Annual Contract Fee is $30 annually. The Annual Contract Fee may be waived under certain circumstances. For classes B, C, and L this fee is waived if your total purchase payments for the prior 12 months are at least $2,000 on the day the fee is deducted or if your Account Balance is at least $25,000 on the day the fee is deducted and for e and e Bonus classes if your Account Balance is at least $50,000 on the day the fee is deducted. The fee will be deducted on a pro-rata basis (determined based upon the number of complete months that have elapsed since the prior Contract Anniversary) if You take a total withdrawal of your Account Balance. This fee will not be deducted if You are on medical leave approved by your employer or called to active armed service duty at the time the fee is to be deducted and your employer has informed us of your status. During the pay-out phase we reserve the right to deduct this fee.
|
| Optional Benefits Footnotes [Text Block] |
(3) For the Enhanced Death Benefit: as a percentage of your Account Balance in the Separate Account. For the GMIB fee: as a percentage of your guaranteed minimum income base. For the LWG fee: as a percentage of your Total Guaranteed Withdrawal Amount.
|
| Investment Options Footnotes [Text Block] |
(2) As a percentage of average daily net assets of the Portfolio.
|
| Lowest and Highest Annual Cost [Table Text Block] |
| |
|
|
|
| |
|
Assumes: ●Investment of $100,000 ●5% annual appreciation ●Least expensive combination of Contract classes and Portfolio fees and expenses ●No optional benefits ●No sales charges ●No additional purchase payments, transfers or withdrawals |
Assumes: ●Investment of $100,000 ●5% annual appreciation ●Most expensive combination of Contract classes, optional benefits and Portfolio fees and expenses ●No sales charges ●No additional purchase payments, transfers or withdrawals |
|
| Lowest Annual Cost [Dollars] |
$ 1,011
|
| Highest Annual Cost [Dollars] |
$ 3,226
|
| Risks [Table Text Block] |
| |
|
|
Is there a Risk of Loss from Poor Performance? |
Yes. You can lose money by investing in the Contract, including loss of principal. |
Principal Risks of Investing in the Contract |
Is this a Short-Term Investment? |
No. This Contract is not a short-term investment and is not appropriate for an investor who needs ready access to cash. ●Withdrawal Charges may apply to withdrawals made less than 13 Contract Years after You purchased the Contract. Withdrawal Charges will reduce the value of your Contract if You withdraw money during that time. ●The benefits of tax deferral and living benefit protections also mean that the Contract is more beneficial to investors with a long time horizon. ●Earnings on your Contract are taxed at ordinary income tax rates when You withdraw them, and You may have to pay a penalty if You take a withdrawal before age 59 1∕2. |
Principal Risks of Investing in the Contract |
What are the Risks Associated with the Investment Options? |
●An investment in the Contract is subject to the risk of poor investment performance and can vary depending on the performance of the investment options available under the Contract (e.g., Portfolios). ●Each investment option (including the Fixed Interest Account investment option) will have its own unique risks. ●You should review these investment options before making an investment decision. ●Subject to certain limitations, if your Account Balance falls below the minimum Account Balance or is not sufficient to pay the Contract charges, we may terminate your Contract. |
Principal Risks of Investing in the Contract |
What are the Risks Related to the Insurance Company? |
An investment in the Contract is subject to the risks related to the Company. Any obligations (including under the Fixed Interest Account), guarantees, or benefits, including any death benefit, are subject to the claims-paying ability of the Company and our long term ability to make such payments, and are not guaranteed by any other party. MetLife is regulated as an insurance company under state law, which generally includes limits on the amount and type of investments in its general account. However, there is no guarantee that we will be able to meet our claims paying obligations; there are risks to purchasing any insurance product. More information about the Company, including its financial strength ratings, is available upon request or by visiting https://www.metlife.com/about-us/ corporate-profile/ratings/. |
Principal Risks of Investing in the Contract |
|
| Investment Restrictions [Text Block] |
Yes. Although we do not currently charge a fee for transfers of Account Value among Divisions or between the Divisions and the Fixed Interest Account, we reserve the right to impose a transfer fee of $25 on transfers in excess of 12 in a Contract Year. The Lifetime Withdrawal Guarantee imposes restrictions and limitations on your choice of Portfolios. These restrictions and requirements are intended to protect the Company and reduce the likelihood that we will have to pay guaranteed benefits under the Lifetime Withdrawal Guarantee out of our own assets. The restrictions and requirements could result in your missing out on some or all positive investment performance by certain of the Portfolios — this means your opportunity for investment gains may be limited.We reserve the right to add, remove or substitute Portfolios.The Company also has policies and procedures that attempt to detect and deter frequent transfers in situations where we determine there is a potential for arbitrage trading, and in those instances, there are additional limits that apply to transfers.
|
| Key Information, Benefit Restrictions [Text Block] |
Yes. Many optional benefits limit or restrict the Portfolios You may select under the Contract. We may change these restrictions in the future.You are required to have a certain Contract Value for some optional benefits. If withdrawals reduce Your Contract below this value, your optional benefits may be reduced or terminated.Withdrawals that exceed limits specified by the terms of an optional benefit may affect the availability of the benefit by reducing the benefit by an amount greater than the value withdrawn, and/or could terminate the benefit.If your annuity was issued in connection with an employer plan, You should check with your employer regarding the availability of riders.
|
| Tax Implications [Text Block] |
You should consult with a tax professional to determine the tax implications of an investment in and purchase payments received under the Contract.●There is no additional tax benefit if You purchase the Contract through a tax-qualified plan or individual retirement account (IRA).●If your Contract was purchased through a tax-qualified plan or IRA, withdrawals will be subject to ordinary income tax. If your Contract is not tax-qualified, earnings on your Contract will be subject to ordinary income tax when You withdraw them. You may also have to pay a penalty if You take a withdrawal before age 59 1∕2.
|
| Investment Professional Compensation [Text Block] |
Your investment professional may receive compensation for selling this Contract to You, both in the form of commissions and because MetLife may share the revenue it earns on this Contract with the professional’s firm. This conflict of interest may influence your investment professional to recommend this Contract over another investment.
|
| Exchanges [Text Block] |
Some investment professionals may have a financial incentive to offer You a new Contract in place of the one You own. You should only exchange your Contract if You determine, after comparing the features, fees, and risks of both contracts, and any fees or penalties to terminate the existing contract, that it is better for You to purchase the new contract rather than continue to own your existing Contract.
|
| Item 4. Fee Table [Line Items] |
|
| Item 4. Fee Table [Text Block] |
FEESThe following tables describe the fees and expenses that You will pay when buying, owning, and surrendering or making withdrawals from the Contract. Please refer to your Contract specifications page for information about the specific fees You will pay each year based on the options You have elected. The first table describes the fees and expenses that You will pay at the time that You buy the Contract, surrender or make withdrawals from the Contract, or transfer Account Value between investment options. State premium taxes may also be deducted.Transaction Fees
| |
|
|
|
|
|
Withdrawal Charge (as a percentage of the amount |
|
|
|
|
|
| |
|
|
|
|
|
| |
|
|
|
|
|
| |
|
|
|
|
| (1)There are times when the Withdrawal Charge does not apply to amounts that are withdrawn from the Deferred Annuity. For example, after the first Contract Year, each year You may withdraw up to 10% of your Account Balance without a Withdrawal Charge. These withdrawals are made on a non-cumulative basis.(2)Although not currently charged, we reserve the right to limit transfers as described later in this Prospectus and we reserve the right to impose a transfer fee. The amount of this fee will be no greater than $25 per transfer on transfers in excess of 12 in a Contract Year.(3)The fee may be waived or reduced for certain Plans.(4)Represents the maximum Withdrawal Charges. For the B Class, other than Connecticut, the maximum Withdrawal Charge is 9%. The B Class in Connecticut has a maximum Withdrawal Charge of 10%. As of January 1, 2024, in New York, the maximum Withdrawal Charge for the L Class is 8% and only the L Class is available for new enrollments in New York.(5)Premium taxes, if applicable, depend on the Contract You purchased and your home state or jurisdiction and range from 0 to 3.50% of Account Value (or, if applicable, purchase payments).The next table describes the fees and expenses that You will pay each year during the time that You own the Contract (not including Portfolio Company fees and expenses). If You choose to purchase an optional benefit, You will pay additional charges, as shown below.Annual Contract Expenses
| |
|
|
|
|
|
Administrative Expenses(1) |
|
|
|
|
|
Base Contract Expenses (as a percentage of your average |
|
|
|
|
|
Optional Annual Step-Up Death Benefit (as a percentage of your average Account Balance) |
|
|
|
|
|
Optional Guaranteed Minimum Income Benefit(4) |
|
|
|
|
|
Optional Lifetime Withdrawal Guarantee Benefit (maximum |
|
|
|
|
|
Annual Loan Maintenance Fee (per loan outstanding)(6) |
|
|
|
|
| (1)The Annual Contract Fee is $30 annually. The Annual Contract Fee may be waived under certain circumstances. For classes B, C, and L this fee is waived if your total purchase payments for the prior 12 months are at least $2,000 on the day the fee is deducted or if your Account Balance is at least $25,000 on the day the fee is deducted and for e and e Bonus classes if your Account Balance is at least $50,000 on the day the fee is deducted. The fee will be deducted on a pro-rata basis (determined based upon the number of complete months that have elapsed since the prior Contract Anniversary) if You take a total withdrawal of your Account Balance. This fee will not be deducted if You are on medical leave approved by your employer or called to active armed service duty at the time the fee is to be deducted and your employer has informed us of your status. During the pay-out phase we reserve the right to deduct this fee.(2)You pay the Base Contract Expenses for your class of the Deferred Annuity during the pay-in phase of your Contract. Charges for optional benefits are those for a Deferred Annuity purchased after April 30, 2009. Different charges may have been in effect for prior time periods. (3)The Base Contract Expenses for the e Bonus Class will be reduced by 0.45% to 0.50% after You have held the Contract for seven years.(4)You may only have one living benefit, the Guaranteed Minimum Income Benefit or the Lifetime Withdrawal Benefit, associated with your Contract at any given time. The charge for the Guaranteed Minimum Income Benefit is a percentage of your guaranteed minimum income base, as defined later in this Prospectus, and is deducted at the end of each Contract Year by withdrawing amounts on a pro-rata basis from your Fixed Interest Account Balance and Your Investment Options (net of any loans). (We take amounts from the Separate Account by canceling, if available, Accumulation Units from your Separate Account Balance.) You do not pay this charge once You are in the pay-out phase of your Contract. Different charges for the Guaranteed Minimum Income Benefit were in effect prior to May 4, 2009.(5)The charge for the Lifetime Withdrawal Guarantee Benefit is a percentage of your Total Guaranteed Withdrawal Amount, as defined later in this Prospectus, and is deducted at the end of each Contract Year by withdrawing amounts on a pro-rata basis from your Fixed Interest Account Balance and Separate Account Balance. (We take amounts from the Separate Account by canceling Accumulation Units from your Separate Account Balance.) You do not pay this charge once You are in the pay-out phase of your Contract or after your rider terminates. If an Automatic Annual Step-Up occurs under a Lifetime Withdrawal Guarantee Benefit, we may increase the Lifetime Withdrawal Guarantee Benefit charge to the current charge, but no more than a maximum of 0.95%. Different charges for the optional Lifetime Withdrawal Guarantee Benefit were in effect prior to May 4, 2009. If, at the time the Contract was issued, the current charge for the benefit was equal to the maximum charge, then the charge for the benefit will not increase upon an Automatic Annual Step-Up.(6)The fee may be waived or reduced for certain Plans. The loan maintenance fee is paid on a quarterly basis at the end of each quarter on a pro-rata basis from the Divisions and the Fixed Interest Account in which You then have a balance.The next table shows the minimum and maximum total operating expenses charged by the Portfolios that You may pay periodically during the time that You own the Contract. Expenses shown may change over time and may be higher or lower in the future. These amounts also include applicable Platform Charges if You choose to invest in certain Portfolios.(1) A complete list of Portfolios available under the Contract, including their annual expenses, may be found in “Appendix A - Investment Options Available Under the Contract” at the back of this Prospectus.Annual Portfolio Company Expenses
| |
|
|
Annual Portfolio Expenses (as a percentage of daily net assets) Expenses that are deducted from Portfolio Company assets, including management fees, distribution and/or service (12b-1) fees, and other expenses |
|
| (1)Investments in the American Funds® Division are subject to a platform charge of 0.25%. We reserve the right to impose an additional platform charge on Divisions that we add to the Contract in the future. The additional amount will not exceed the annual rate of 0.25% of the average Account Balance in any such Divisions.ExamplesThese Examples are intended to help you compare the cost of investing in the Divisions with the cost of investing in other annuity contracts that offer variable options. These costs include Transaction Expenses, Annual Contract Expenses and Annual Portfolio Company Expenses.The Examples assume all Contract Value is allocated to the Divisions. Your costs could differ from those shown below if you invest in the Fixed Interest Account.The Examples assume that you invest $100,000 in the variable options of the Contract for the time periods indicated and that there are no exchanges or other transactions. The Examples also assume that your investment has a 5% return each year. Examples 1 through 5 assume the most expensive combination of Annual Portfolio Company Expenses and optional benefits available for an additional charge. Examples 6 through 10 assume You purchased the Contract with no optional benefits that resulted in the least expensive combination of charges.
|
| Transaction Expenses [Table Text Block] |
Transaction Fees
| |
|
|
|
|
|
Withdrawal Charge (as a percentage of the amount |
|
|
|
|
|
| |
|
|
|
|
|
| |
|
|
|
|
|
| |
|
|
|
|
| (1)There are times when the Withdrawal Charge does not apply to amounts that are withdrawn from the Deferred Annuity. For example, after the first Contract Year, each year You may withdraw up to 10% of your Account Balance without a Withdrawal Charge. These withdrawals are made on a non-cumulative basis.(2)Although not currently charged, we reserve the right to limit transfers as described later in this Prospectus and we reserve the right to impose a transfer fee. The amount of this fee will be no greater than $25 per transfer on transfers in excess of 12 in a Contract Year.(3)The fee may be waived or reduced for certain Plans.(4)Represents the maximum Withdrawal Charges. For the B Class, other than Connecticut, the maximum Withdrawal Charge is 9%. The B Class in Connecticut has a maximum Withdrawal Charge of 10%. As of January 1, 2024, in New York, the maximum Withdrawal Charge for the L Class is 8% and only the L Class is available for new enrollments in New York.(5)Premium taxes, if applicable, depend on the Contract You purchased and your home state or jurisdiction and range from 0 to 3.50% of Account Value (or, if applicable, purchase payments).
|
| Deferred Sales Load, Footnotes [Text Block] |
There are times when the Withdrawal Charge does not apply to amounts that are withdrawn from the Deferred Annuity. For example, after the first Contract Year, each year You may withdraw up to 10% of your Account Balance without a Withdrawal Charge. These withdrawals are made on a non-cumulative basis.
|
| Transfer Fee, Footnotes [Text Block] |
Although not currently charged, we reserve the right to limit transfers as described later in this Prospectus and we reserve the right to impose a transfer fee. The amount of this fee will be no greater than $25 per transfer on transfers in excess of 12 in a Contract Year.
|
| Annual Contract Expenses [Table Text Block] |
Annual Contract Expenses
| |
|
|
|
|
|
Administrative Expenses(1) |
|
|
|
|
|
Base Contract Expenses (as a percentage of your average |
|
|
|
|
|
Optional Annual Step-Up Death Benefit (as a percentage of your average Account Balance) |
|
|
|
|
|
Optional Guaranteed Minimum Income Benefit(4) |
|
|
|
|
|
Optional Lifetime Withdrawal Guarantee Benefit (maximum |
|
|
|
|
|
Annual Loan Maintenance Fee (per loan outstanding)(6) |
|
|
|
|
| (1)The Annual Contract Fee is $30 annually. The Annual Contract Fee may be waived under certain circumstances. For classes B, C, and L this fee is waived if your total purchase payments for the prior 12 months are at least $2,000 on the day the fee is deducted or if your Account Balance is at least $25,000 on the day the fee is deducted and for e and e Bonus classes if your Account Balance is at least $50,000 on the day the fee is deducted. The fee will be deducted on a pro-rata basis (determined based upon the number of complete months that have elapsed since the prior Contract Anniversary) if You take a total withdrawal of your Account Balance. This fee will not be deducted if You are on medical leave approved by your employer or called to active armed service duty at the time the fee is to be deducted and your employer has informed us of your status. During the pay-out phase we reserve the right to deduct this fee.(2)You pay the Base Contract Expenses for your class of the Deferred Annuity during the pay-in phase of your Contract. Charges for optional benefits are those for a Deferred Annuity purchased after April 30, 2009. Different charges may have been in effect for prior time periods. (3)The Base Contract Expenses for the e Bonus Class will be reduced by 0.45% to 0.50% after You have held the Contract for seven years.(4)You may only have one living benefit, the Guaranteed Minimum Income Benefit or the Lifetime Withdrawal Benefit, associated with your Contract at any given time. The charge for the Guaranteed Minimum Income Benefit is a percentage of your guaranteed minimum income base, as defined later in this Prospectus, and is deducted at the end of each Contract Year by withdrawing amounts on a pro-rata basis from your Fixed Interest Account Balance and Your Investment Options (net of any loans). (We take amounts from the Separate Account by canceling, if available, Accumulation Units from your Separate Account Balance.) You do not pay this charge once You are in the pay-out phase of your Contract. Different charges for the Guaranteed Minimum Income Benefit were in effect prior to May 4, 2009.(5)The charge for the Lifetime Withdrawal Guarantee Benefit is a percentage of your Total Guaranteed Withdrawal Amount, as defined later in this Prospectus, and is deducted at the end of each Contract Year by withdrawing amounts on a pro-rata basis from your Fixed Interest Account Balance and Separate Account Balance. (We take amounts from the Separate Account by canceling Accumulation Units from your Separate Account Balance.) You do not pay this charge once You are in the pay-out phase of your Contract or after your rider terminates. If an Automatic Annual Step-Up occurs under a Lifetime Withdrawal Guarantee Benefit, we may increase the Lifetime Withdrawal Guarantee Benefit charge to the current charge, but no more than a maximum of 0.95%. Different charges for the optional Lifetime Withdrawal Guarantee Benefit were in effect prior to May 4, 2009. If, at the time the Contract was issued, the current charge for the benefit was equal to the maximum charge, then the charge for the benefit will not increase upon an Automatic Annual Step-Up.(6)The fee may be waived or reduced for certain Plans. The loan maintenance fee is paid on a quarterly basis at the end of each quarter on a pro-rata basis from the Divisions and the Fixed Interest Account in which You then have a balance.
|
| Base Contract Expense, Footnotes [Text Block] |
The Annual Contract Fee is $30 annually. The Annual Contract Fee may be waived under certain circumstances. For classes B, C, and L this fee is waived if your total purchase payments for the prior 12 months are at least $2,000 on the day the fee is deducted or if your Account Balance is at least $25,000 on the day the fee is deducted and for e and e Bonus classes if your Account Balance is at least $50,000 on the day the fee is deducted. The fee will be deducted on a pro-rata basis (determined based upon the number of complete months that have elapsed since the prior Contract Anniversary) if You take a total withdrawal of your Account Balance. This fee will not be deducted if You are on medical leave approved by your employer or called to active armed service duty at the time the fee is to be deducted and your employer has informed us of your status. During the pay-out phase we reserve the right to deduct this fee.(2)You pay the Base Contract Expenses for your class of the Deferred Annuity during the pay-in phase of your Contract. Charges for optional benefits are those for a Deferred Annuity purchased after April 30, 2009. Different charges may have been in effect for prior time periods. (3)The Base Contract Expenses for the e Bonus Class will be reduced by 0.45% to 0.50% after You have held the Contract for seven years.
|
| Annual Portfolio Company Expenses [Table Text Block] |
| |
|
|
Annual Portfolio Expenses (as a percentage of daily net assets) Expenses that are deducted from Portfolio Company assets, including management fees, distribution and/or service (12b-1) fees, and other expenses |
|
|
|
| Portfolio Company Expenses [Text Block] |
Annual Portfolio Expenses (as a percentage of daily net assets)Expenses that are deducted from Portfolio Company assets, including management fees, distribution and/or service (12b-1) fees, and other expenses
|
| Portfolio Company Expenses Minimum [Percent] |
0.52%
|
| Portfolio Company Expenses Maximum [Percent] |
1.38%
|
| Surrender Example [Table Text Block] |
Example 1 - table 1
| |
|
|
|
|
If You surrender your Contract at the end of the applicable time period |
|
|
|
|
| |
|
|
|
|
| |
|
|
|
| Example 3 - table 1
| |
|
|
|
|
If You surrender your Contract at the end of the applicable time period |
|
|
|
|
| |
|
|
|
|
| |
|
|
|
| Example 5 - table 1
| |
|
|
|
|
If You surrender your Contract at the end of the applicable time period |
|
|
|
|
| |
|
|
|
|
| |
|
|
|
|
|
| Annuitize Example [Table Text Block] |
Example 2
| |
|
|
|
|
If You surrender, annuitize or do not surrender your Contract at the end of the applicable time period |
|
|
|
|
| |
|
|
|
|
| |
|
|
|
| Example 3 - table 2
| |
|
|
|
|
If You annuitize or do not surrender your Contract at the end of the applicable time period |
|
|
|
|
| |
|
|
|
|
| |
|
|
|
| Example 4
| |
|
|
|
|
If You surrender, annuitize or do not surrender your Contract at the end of the applicable time period |
|
|
|
|
| |
|
|
|
|
| |
|
|
|
| Example 5 - table 2
| |
|
|
|
|
If You annuitize or do not surrender your Contract at the end of the applicable time period |
|
|
|
|
| |
|
|
|
|
| |
|
|
|
|
|
| No Surrender Example [Table Text Block] |
Example 1 - table 2
| |
|
|
|
|
If You annuitize or do not surrender your Contract at the end of the applicable time period |
|
|
|
|
| |
|
|
|
|
| |
|
|
|
|
|
| Item 5. Principal Risks [Line Items] |
|
| Item 5. Principal Risks [Table Text Block] |
PRINCIPAL RISKSInvesting in the Contract involves risks. The following are the principal risks of an investment in the Contract. You should carefully consider the below risks in addition to the other information contained in this Prospectus.Market Risk. An investment in the Contract is not a bank deposit and is not guaranteed by the Federal Deposit Insurance Corporation or any other governmental agency. The Contract is subject to market risk (the risk that your investments may decline in value or underperform your expectations). As a result, You can lose money by investing in the Contract, including loss of principal.Early Withdrawal Risk. This Contract is not a short-term investment and is not appropriate for an investor who needs ready access to cash. If You withdraw early, You may have to pay a Withdrawal Charge and/or income taxes, including a tax penalty if You are younger than age 59 1∕2. Withdrawal Charges may apply if You withdraw money from the Contract less than 13 Contract Years after You purchased the Contract. Withdrawal Charges will reduce the value of your Contract if You withdraw money during that time. The benefits of tax deferral and living benefit protections also mean that the Contract is more beneficial to investors with a long time horizon.Risk of Underlying Portfolios. An investment in the Contract is subject to the risk of poor investment performance and can vary depending on the performance of the investment options available under the Contract (e.g., Portfolio Companies). Each investment option (including the Fixed Interest Account investment option) will have its own unique risks. We do not provide any investment advice and do not recommend or endorse any particular Portfolio. You bear the risk of any decline in the Account Balance of your Contract resulting from the performance of the Portfolios You have chosen. You should review these investment options before making an investment decision. Information regarding the Portfolios available under your Contract is available in Appendix A to this Prospectus.Contract Termination Subject to certain limitations, if your Account Balance falls below the minimum Account Balance or is not sufficient to pay the Contract charges, we may terminate your Deferred Annuity.Contract Benefits Risk. Withdrawals that exceed limits specified by the terms of any benefit may affect the availability of the benefit by reducing the benefit by an amount greater than the value withdrawn, and/or could terminate the benefit. In addition, the Lifetime Withdrawal Guarantee imposes restrictions and limitations on your choice of Portfolios. These restrictions and requirements are intended to protect the Company and reduce the likelihood that we will have to pay guaranteed benefits under the Lifetime Withdrawal Guarantee out of our own assets. The restrictions and requirements could result in your missing out on some or all positive investment performance by certain of the Portfolios – this means your opportunity for investment gains may be limited.Insurance Company Risk. An investment in the Contract is subject to the risks related to the Company. Any obligations (including under the Fixed Interest Account), guarantees, or benefits are subject to the financial strength and claims-paying ability of the Company and our long term ability to make such payments, and are not guaranteed by any other party. MetLife is regulated as an insurance company under state law, which generally includes limits on the amount and type of investments in its general account. However, there is no guarantee that we will be able to meet our claims paying obligations; there are risks to purchasing any insurance product.Contract Changes Risk. Subject to applicable law, we have the right to make certain changes to your Contract. Examples of the changes we may make include: (i) operating the Separate Account in any form permitted by law; (ii) taking any action necessary to comply with or obtain and continue any exemptions under the law (including favorable treatment under the Federal income tax laws) including limiting the number, frequency or types of transfers/reallocations permitted; (iii) transferring any assets in a Division to another Division, or to one or more Separate Accounts, or to our general account, or adding, combining or removing Divisions in the Separate Account; (iv) substituting Portfolio shares in any Division, with the shares of another class of Brighthouse Trust I, Brighthouse Trust II, or the shares of another investment company or any other investment permitted by law or closing, adding or removing Portfolios as Investment Division investments as permitted by law; (v) changing the way we assess charges, but without increasing the maximum aggregate amount charged to the Separate Account and any currently available Portfolio in connection with the Contracts; and (vi) making any necessary technical changes in the Contracts in order to conform with any of the above-described actions.Conflicts of Interest. Your investment professional may receive compensation for selling this Contract to You, both in the form of commissions and because MetLife may share the revenue it earns on this Contract with the professional’s firm. This conflict of interest may influence your investment professional to recommend this Contract over another investment. In addition, some investment professionals may have a financial incentive to offer You a new contract in place of the one You own. You should only exchange your Contract if You determine, after comparing the features, fees, and risks of both contracts, that it is better for You to purchase the new contract rather than continue to own your existing Contract.Suitability. An investment in the Contract may not be suitable for all investors. For example, there is no additional tax benefit if You purchase the Contract through a tax-qualified plan or individual retirement account (IRA). Therefore, there should be reasons other than tax deferral for acquiring the Contract. You should consult with a tax or investment professional to determine the tax and other implications of an investment in and purchase payments received under the Contract.Taxation Risk. Although the provisions of the Internal Revenue Code (the “Code”) relevant to the Contract are generally described under “Federal Tax Considerations,” an investor should consult their own tax advisor concerning the effects of federal, state, local and foreign tax law on the Contract. No assurance can be given that, even if the tax provisions currently applicable to the Contract are favorable, the law or regulations or interpretations thereunder will not change and the Contract may be disadvantaged.Cybersecurity. Our business is highly dependent upon the effective operation of our information systems, and those of our service providers, vendors, and other third parties. Cybersecurity breaches of such systems can be intentional or unintentional events, and can occur through unauthorized access to computer systems, networks or devices; infection from computer viruses or other malicious software code; or attacks that shut down, disable, slow or otherwise disrupt operations, business processes or website access or functionality and our disaster recovery systems may be insufficient to safeguard our ability to conduct business. Cybersecurity breaches can interfere with our processing of Contract transactions, including the processing of transfer orders from our website or with the Portfolios; impact our ability to calculate Accumulation Unit Values; cause the release and possible loss or destruction of confidential Contract Owner or business information; impede order processing or cause other operational issues; and result in regulatory enforcement actions or new laws or regulations which could increase our compliance costs. Although we continually make efforts to identify and reduce our exposure to cybersecurity risk, and we require our critical vendors to implement effective cybersecurity and data protection measures, there is no guarantee that we will be able to successfully manage this risk at all times.Bonus Class Risk. Expenses of a class that includes a bonus feature may be higher than expenses of a class of the Contract without the bonus, and the additional amount of the bonus may be more than offset by the additional fees and charges associated with the bonus class, including Withdrawal Charges. Any bonus associated with the class will be retrieved upon exercise of a “Free Look” cancellation. Pandemics and Other Public Health Issues and Other Events. Pandemics and other public health issues or other events, and governmental, business, and consumer reactions to them, may affect economic conditions and may cause a large number of illnesses or deaths. Hurricanes, windstorms, earthquakes, hail, tornadoes, explosions, severe winter weather, fires, floods and mudslides, blackouts and man-made events such as riot, insurrection, terrorist attacks or acts of war may also cause catastrophic losses and increased claims. Any such catastrophes may also result in changes in consumer or business confidence, behavior and investment and business activity, changes to interest rates and other market risk factors, and governmental or other restrictions on economic activity for prolonged periods. Terrorism and Security Risk. The continued threat of terrorism, ongoing or potential military conflict and other actions, and heightened security measures may cause economic uncertainty and result in loss of life, property damage, additional disruptions to commerce and reduced economic activity. The value of MetLife's investment portfolio may be adversely affected by declines in the credit and equity markets and reduced economic activity caused by such threats. Companies in which we maintain investments may suffer losses as a result of financial, commercial or economic disruptions, and such disruptions might affect the ability of those companies to pay interest or principal on their securities or mortgage loans. Terrorist or military actions also could disrupt our operations centers and result in higher than anticipated claims under our insurance policies. Technology Risk. Our business operations rely on functioning and secure information systems, including those of our vendors and other third parties. Technological changes present us with new or intensified challenges, and if we are unable to foresee or adapt to these changes, our business may be adversely affected. Technological changes may affect our business model and how we interact with our customers. The growth and availability of AI technologies, including generative AI, presents significant opportunities but also complex challenges; these include balancing and mitigating potential risks of harm posed by the development or deployment of AI technologies, as well as implementing and maintaining controls reasonably designed to ensure compliance with an increasingly complex AI regulatory landscape, with evolving requirements that may vary across jurisdictions. We may fail to adopt new technologies as effectively or efficiently as others, leading to competitive harm. If we are unable to update our business model to match evolving consumer preferences or the evolving technological landscape, we may be adversely affected.New technologies may impact the configuration of our information systems, and how they connect with those of our vendors, service providers and/or partners. Such technological developments may introduce or uncover information security vulnerabilities, which may result in breaches, increased costs associated with maintaining appropriate data privacy, data protection, and cybersecurity measures, enforcement actions against us by regulators or other outcomes that may adversely impact our operations or business. In addition, any such vulnerability that results in a security breach or failure of our information systems, or those of third parties on which we rely, may result in litigation, regulatory action, negative impacts to our business operations, and reputational harm.
|
| Item 10. Benefits Available [Line Items] |
|
| Benefits Available (N-4) [Text Block] |
BENEFITS AVAILABLE UNDER THE CONTRACTThe following table summarizes information about the benefits available under the Contract:
| |
|
Is Benefit Standard or Optional? |
|
Brief Description of Restrictions/ Limitations |
| |
If You die during the pay-in phase, guarantees that the death benefit will not be less than the greater of (1) your Account Balance less any outstanding loans; or (2) total purchase payment reduced proportionately by the percentage reduction in Account Balance attributable to each partial withdrawal less any outstanding loans (including any applicable Withdrawal Charge). |
|
|
●Withdrawals could significantly reduce the benefit. |
| |
|
Is Benefit Standard or Optional? |
|
Brief Description of Restrictions/ Limitations |
Annual Step-Up Death Benefit |
If You die during the pay-in phase, guarantees that the death benefit will not be less than the greatest of (1) your Account Balance; (2) total purchase payments reduced proportionately for withdrawals and any outstanding loans (including any applicable Withdrawal Charge) or (3) "Highest Anniversary Value" as of each Contract Anniversary prior to your 81st birthday, plus any subsequent purchase payments, reduced for any outstanding loans, and reduced proportionately for withdrawals (including any applicable Withdrawal Charge). |
|
0.10% as a percentage of your average Account Balance |
●Withdrawals could significantly reduce the benefit. ●You may not purchase this benefit if You are 80 years of age or older. ●Available only at issue. |
| |
|
Is Benefit Standard or Optional? |
|
Brief Description of Restrictions/ Limitations |
Guaranteed Minimum Income Benefit |
Designed to guarantee a predictable, minimum level of fixed income payments, regardless of investment performance of your Account Balance during the pay-in phase. |
|
0.70% of your guaranteed minimum income base |
●No longer available for sale. ●You may not have this optional benefit and another optional living benefit (Lifetime Withdrawal Guarantee) in effect at the same time. ●Age restrictions apply. ●May only be exercised after a 10-year waiting period. ●Availability subject to state. ●Cannot be terminated. ●Withdrawals could significantly reduce the benefit. |
| |
|
Is Benefit Standard or Optional? |
|
Brief Description of Restrictions/ Limitations |
Lifetime Withdrawal Guarantee Benefit |
Guaranteed Payments for Life. So long as You make your first withdrawal on or after the date You reach age 59 1∕2, the LWG guarantees that we will make payments to You over your lifetime, even if your Remaining Guaranteed Withdrawal Amount and/or Account Balance decline to zero. |
|
0.95% of your Total Guaranteed Withdrawal Amount |
●No longer available for sale. ●Benefit limits available investment options. (See “Appendix A — Investment Options Available Under the Contract — Investment Allocation Restrictions for Certain Optional Benefits.”) ●Age restrictions apply. ●You may not have this optional benefit and another optional living benefit (Guaranteed Minimum Income Benefit) in effect at the same time. ●In the first 15 Contract Years You may only cancel this benefit every 5 Contract Years. Thereafter You may cancel annually within 30 days following the eligible Contract Anniversary. |
| |
|
Is Benefit Standard or Optional? |
|
Brief Description of Restrictions/ Limitations |
Waiver of Withdrawal Charge for Nursing Home or Hospital Confinement |
Allows you to withdraw money without a Withdrawal Charge in the event of nursing home or hospital confinement, subject to certain conditions. |
|
|
●Only available after the first Contract Year. ●Age restrictions, ownership requirements and doctor certification requirements apply. ●Must be approved in your state. ●You must meet certain length of confinement requirements. |
Waiver of Withdrawal Charge for Terminal Illness |
Allows you to withdraw money without a Withdrawal Charge in the event of a terminal illness, subject to certain conditions. |
|
|
●Only available after the first Contract Year. ●Age restrictions, ownership requirements and doctor certification requirements apply. ●Must be approved in your state. ●Certain requirements relating to the nature of the terminal illness apply. ●You must not have been diagnosed with the terminal illness as of the Contract issue date. |
| |
An amount equal to the interest earned in the Fixed Interest Account is transferred monthly to any one Division based on your selection. |
|
|
●If your Fixed Interest Account Balance at the time of a scheduled transfer is zero, this strategy is automatically discontinued. |
| |
|
Is Benefit Standard or Optional? |
|
Brief Description of Restrictions/ Limitations |
| |
You select a specific asset allocation for your entire Account Balance from among the Divisions and the Fixed Interest Account, if available. Each quarter we transfer amounts among these options to bring the percentage of your Account Balance in each option back to your original allocation. |
|
|
●In the future, we may permit You to allocate less than 100% of your Account Balance to this strategy. |
| |
You may select one of five asset allocation models which are designed to correlate to various risk tolerance levels. Each quarter the percentage in each of the Divisions in which the model invests and any Fixed Interest Account is brought back to the selected model percentage by transferring amounts among the Divisions and any Fixed Interest Account |
|
|
●Benefit limits available investment options. ●The Index Selector is not available with the optional Lifetime Withdrawal Guarantee. |
| |
Transfers a dollar amount of your choice from the Fixed Interest Account to any of the Divisions you choose on a monthly basis. |
|
|
●Minimum periodic transfer of $50 is required. ●Once your Fixed Interest Account Balance is exhausted, the strategy is discontinued. |
| |
|
Is Benefit Standard or Optional? |
|
Brief Description of Restrictions/ Limitations |
Systematic Withdrawal Program |
Automatically withdraws a specific dollar amount or a percentage of your Account Balance of your choice each Contract Year. |
|
|
●Not available under the 457(b) Deferred Annuity issued to tax-exempt organizations. ●Not available in all states. ●Income taxes, tax penalties and Withdrawal Charges may apply to your withdrawals. ●Subject to our required minimums and administrative restrictions. ●Not available to the B and L Classes of the Deferred Annuities until the second Contract Year. ●If You elect to receive payments through this program, You must have no loan outstanding from the Fixed Interest Account and You must either be 59 1∕2 years old or have left your job. Tax law generally prohibits withdrawals from TSA Deferred Annuities before You reach 59 1∕2. ●Not available in conjunction with any automated investment strategy. | *If your annuity was issued in connection with an employer plan, you should check with your employer regarding the availability of benefits.
|
| Benefits Available [Table Text Block] |
| |
|
Is Benefit Standard or Optional? |
|
Brief Description of Restrictions/ Limitations |
| |
If You die during the pay-in phase, guarantees that the death benefit will not be less than the greater of (1) your Account Balance less any outstanding loans; or (2) total purchase payment reduced proportionately by the percentage reduction in Account Balance attributable to each partial withdrawal less any outstanding loans (including any applicable Withdrawal Charge). |
|
|
●Withdrawals could significantly reduce the benefit. |
| |
|
Is Benefit Standard or Optional? |
|
Brief Description of Restrictions/ Limitations |
Annual Step-Up Death Benefit |
If You die during the pay-in phase, guarantees that the death benefit will not be less than the greatest of (1) your Account Balance; (2) total purchase payments reduced proportionately for withdrawals and any outstanding loans (including any applicable Withdrawal Charge) or (3) "Highest Anniversary Value" as of each Contract Anniversary prior to your 81st birthday, plus any subsequent purchase payments, reduced for any outstanding loans, and reduced proportionately for withdrawals (including any applicable Withdrawal Charge). |
|
0.10% as a percentage of your average Account Balance |
●Withdrawals could significantly reduce the benefit. ●You may not purchase this benefit if You are 80 years of age or older. ●Available only at issue. |
| |
|
Is Benefit Standard or Optional? |
|
Brief Description of Restrictions/ Limitations |
Guaranteed Minimum Income Benefit |
Designed to guarantee a predictable, minimum level of fixed income payments, regardless of investment performance of your Account Balance during the pay-in phase. |
|
0.70% of your guaranteed minimum income base |
●No longer available for sale. ●You may not have this optional benefit and another optional living benefit (Lifetime Withdrawal Guarantee) in effect at the same time. ●Age restrictions apply. ●May only be exercised after a 10-year waiting period. ●Availability subject to state. ●Cannot be terminated. ●Withdrawals could significantly reduce the benefit. |
| |
|
Is Benefit Standard or Optional? |
|
Brief Description of Restrictions/ Limitations |
Lifetime Withdrawal Guarantee Benefit |
Guaranteed Payments for Life. So long as You make your first withdrawal on or after the date You reach age 59 1∕2, the LWG guarantees that we will make payments to You over your lifetime, even if your Remaining Guaranteed Withdrawal Amount and/or Account Balance decline to zero. |
|
0.95% of your Total Guaranteed Withdrawal Amount |
●No longer available for sale. ●Benefit limits available investment options. (See “Appendix A — Investment Options Available Under the Contract — Investment Allocation Restrictions for Certain Optional Benefits.”) ●Age restrictions apply. ●You may not have this optional benefit and another optional living benefit (Guaranteed Minimum Income Benefit) in effect at the same time. ●In the first 15 Contract Years You may only cancel this benefit every 5 Contract Years. Thereafter You may cancel annually within 30 days following the eligible Contract Anniversary. |
| |
|
Is Benefit Standard or Optional? |
|
Brief Description of Restrictions/ Limitations |
Waiver of Withdrawal Charge for Nursing Home or Hospital Confinement |
Allows you to withdraw money without a Withdrawal Charge in the event of nursing home or hospital confinement, subject to certain conditions. |
|
|
●Only available after the first Contract Year. ●Age restrictions, ownership requirements and doctor certification requirements apply. ●Must be approved in your state. ●You must meet certain length of confinement requirements. |
Waiver of Withdrawal Charge for Terminal Illness |
Allows you to withdraw money without a Withdrawal Charge in the event of a terminal illness, subject to certain conditions. |
|
|
●Only available after the first Contract Year. ●Age restrictions, ownership requirements and doctor certification requirements apply. ●Must be approved in your state. ●Certain requirements relating to the nature of the terminal illness apply. ●You must not have been diagnosed with the terminal illness as of the Contract issue date. |
| |
An amount equal to the interest earned in the Fixed Interest Account is transferred monthly to any one Division based on your selection. |
|
|
●If your Fixed Interest Account Balance at the time of a scheduled transfer is zero, this strategy is automatically discontinued. |
| |
|
Is Benefit Standard or Optional? |
|
Brief Description of Restrictions/ Limitations |
| |
You select a specific asset allocation for your entire Account Balance from among the Divisions and the Fixed Interest Account, if available. Each quarter we transfer amounts among these options to bring the percentage of your Account Balance in each option back to your original allocation. |
|
|
●In the future, we may permit You to allocate less than 100% of your Account Balance to this strategy. |
| |
You may select one of five asset allocation models which are designed to correlate to various risk tolerance levels. Each quarter the percentage in each of the Divisions in which the model invests and any Fixed Interest Account is brought back to the selected model percentage by transferring amounts among the Divisions and any Fixed Interest Account |
|
|
●Benefit limits available investment options. ●The Index Selector is not available with the optional Lifetime Withdrawal Guarantee. |
| |
Transfers a dollar amount of your choice from the Fixed Interest Account to any of the Divisions you choose on a monthly basis. |
|
|
●Minimum periodic transfer of $50 is required. ●Once your Fixed Interest Account Balance is exhausted, the strategy is discontinued. |
| |
|
Is Benefit Standard or Optional? |
|
Brief Description of Restrictions/ Limitations |
Systematic Withdrawal Program |
Automatically withdraws a specific dollar amount or a percentage of your Account Balance of your choice each Contract Year. |
|
|
●Not available under the 457(b) Deferred Annuity issued to tax-exempt organizations. ●Not available in all states. ●Income taxes, tax penalties and Withdrawal Charges may apply to your withdrawals. ●Subject to our required minimums and administrative restrictions. ●Not available to the B and L Classes of the Deferred Annuities until the second Contract Year. ●If You elect to receive payments through this program, You must have no loan outstanding from the Fixed Interest Account and You must either be 59 1∕2 years old or have left your job. Tax law generally prohibits withdrawals from TSA Deferred Annuities before You reach 59 1∕2. ●Not available in conjunction with any automated investment strategy. |
|
| Item 17. Investment Options [Line Items] |
|
| Investment Options (N-4) [Text Block] |
APPENDIX A — INVESTMENT OPTIONS AVAILABLE UNDER THE CONTRACTThe following is a list of Portfolios currently available. More information about the Portfolios is available in the prospectuses for the Portfolios, which may be amended from time to time and can be found online at https://dfinview.com/metlife/PUFT/MET000211. You can also request this information at no cost by calling (833) 642-1008, by sending an email request to RCG@metlife.com, or through your registered representative. Depending on the optional benefits You choose, You may not be able to invest in certain Portfolio Companies as described below. If your annuity was issued in connection with an employer plan, not all Portfolios are available under all Contracts and You should ask your employer for a list of available Portfolios.The current expenses and performance information below reflects fees and expenses of the Portfolios, but do not reflect the other fees and expenses that your Contract may charge. Expenses would be higher and performance would be lower if these other charges were included. Each Portfolio Company's past performance is not necessarily an indication of future performance.
*The Portfolio is subject to an expense reimbursement or fee waiver arrangement. The annual expenses shown reflect temporary fee reductions.(1)The Portfolio has an additional platform fee of 0.25%. This amount is included in the Mortality and Expense Risk Charge and is not a separate charge.††Effective May 1, 2026, the American Funds Global Small Capitalization Fund changed its name to American Funds SMALLCAP World Fund®.Fixed OptionThe following is information on the Fixed Interest Account currently available under the Contract. You should check with your Employer as to whether the Fixed Interest Account is available under your Contract. We reserve the right to restrict purchase payments and transfers to the Fixed Interest Account when the yield on investments is not expected to support the Minimum Guaranteed Interest Rate. We will provide you with written notice before doing so.
| |
|
Minimum Guaranteed Interest Rate* |
| |
Initial Interest Rate Term: begins on each calendar quarter and will be credited from the date amounts are allocated to the Fixed Interest Account until the last day of the same calendar quarter of the following year. Renewal Rate Term: 12 months. |
| *The Minimum Guaranteed Interest Rate varies by Contract and may be higher than the minimum guaranteed interest rate shown. Check your Contract for the Minimum Guaranteed Interest Rate that applies to your Fixed Interest Account Option.Investment Allocation Restrictions For Certain Optional BenefitsIndex Selector:If You elect the Index Selector You are limited to allocating your purchase payments and Account Balance among the following funding options and the Fixed Interest Account:MetLife Aggregate Bond Index
MetLife Stock Index
MetLife MSCI EAFE Index
MetLife Russell 2000 Index
MetLife Mid Cap Stock IndexLifetime Withdrawal GuaranteeIf You elect the Lifetime Withdrawal Guarantee Optional Benefit, You are limited to allocating your purchase payments and Account Balance among the following funding options and the Fixed Interest Account:Brighthouse Asset Allocation 20
Brighthouse Asset Allocation 40
Brighthouse Asset Allocation 60
Brighthouse Asset Allocation 80
|
| Variable Option [Line Items] |
|
| Prospectuses Available [Text Block] |
The following is a list of Portfolios currently available. More information about the Portfolios is available in the prospectuses for the Portfolios, which may be amended from time to time and can be found online at https://dfinview.com/metlife/PUFT/MET000211. You can also request this information at no cost by calling (833) 642-1008, by sending an email request to RCG@metlife.com, or through your registered representative. Depending on the optional benefits You choose, You may not be able to invest in certain Portfolio Companies as described below. If your annuity was issued in connection with an employer plan, not all Portfolios are available under all Contracts and You should ask your employer for a list of available Portfolios.The current expenses and performance information below reflects fees and expenses of the Portfolios, but do not reflect the other fees and expenses that your Contract may charge. Expenses would be higher and performance would be lower if these other charges were included. Each Portfolio Company's past performance is not necessarily an indication of future performance.
|
| Portfolio Companies [Table Text Block] |
| |
PORTFOLIO AND ADVISER/SUBADVISER |
|
|
CURRENT EXPENSES + PLATFORM CHARGE |
AVERAGE ANNUAL TOTAL RETURNS (as of 12/31/2025) |
| |
|
|
| |
American Funds Growth Fund(1) - Class 2 Capital Research and |
|
|
|
|
|
|
| |
American Funds Growth- Income Fund(1) - Class 2 Capital Research and |
|
|
|
|
|
|
| |
American Funds SMALLCAP World Fund® *(1)†† - Class 2 Capital Research and |
|
|
|
|
|
|
| |
American Funds The Bond Fund of America*(1) - Class 2 Capital Research and |
|
|
|
|
|
|
| |
American Funds® Aggressive Allocation Portfolio - Class C Brighthouse Investment Advisers, LLC |
|
|
|
|
|
|
| |
American Funds® Balanced Allocation Portfolio - Class C Brighthouse Investment Advisers, LLC |
|
|
|
|
|
|
| |
American Funds® Moderate Allocation Portfolio - Class C Brighthouse Investment Advisers, LLC |
|
|
|
|
|
|
| |
PORTFOLIO AND ADVISER/SUBADVISER |
|
|
CURRENT EXPENSES + PLATFORM CHARGE |
AVERAGE ANNUAL TOTAL RETURNS (as of 12/31/2025) |
| |
|
|
| |
BlackRock Bond Income Portfolio* - Class B Brighthouse Investment Advisers, LLC Subadviser: BlackRock Advisors, LLC |
|
|
|
|
|
|
| |
BlackRock Capital Appreciation Portfolio* - Class B Brighthouse Investment Advisers, LLC Subadviser: BlackRock Advisors, LLC |
|
|
|
|
|
|
| |
Brighthouse Asset Allocation 100 Portfolio - Class B Brighthouse Investment Advisers, LLC |
|
|
|
|
|
|
| |
Brighthouse Asset Allocation 20 Portfolio* - Class B Brighthouse Investment Advisers, LLC |
|
|
|
|
|
|
| |
Brighthouse Asset Allocation 40 Portfolio - Class B Brighthouse Investment Advisers, LLC |
|
|
|
|
|
|
| |
Brighthouse Asset Allocation 60 Portfolio - Class B Brighthouse Investment Advisers, LLC |
|
|
|
|
|
|
| |
Brighthouse Asset Allocation 80 Portfolio - Class B Brighthouse Investment Advisers, LLC |
|
|
|
|
|
|
| |
Brighthouse Small Cap Value Portfolio* - Class B Brighthouse Investment Advisers, LLC Subadviser: Allspring Global Investments, LLC |
|
|
|
|
|
|
| |
Brighthouse/Artisan Mid Cap Value Portfolio* - Class B Brighthouse Investment Advisers, LLC Subadviser: Artisan Partners Limited Partnership |
|
|
|
|
|
|
| |
PORTFOLIO AND ADVISER/SUBADVISER |
|
|
CURRENT EXPENSES + PLATFORM CHARGE |
AVERAGE ANNUAL TOTAL RETURNS (as of 12/31/2025) |
| |
|
|
| |
Brighthouse/Franklin Low Duration Total Return Portfolio* - Class B Brighthouse Investment Advisers, LLC Subadviser: Franklin Advisers, Inc. |
|
|
|
|
|
|
| |
Brighthouse/Wellington Balanced Portfolio - Class A Brighthouse Investment Advisers, LLC Subadviser: Wellington Management Company LLP |
|
|
|
|
|
|
| |
Brighthouse/Wellington Core Equity Opportunities Portfolio* - Class B Brighthouse Investment Advisers, LLC Subadviser: Wellington Management Company LLP |
|
|
|
|
|
|
| |
Brighthouse/Wellington Large Cap Research Portfolio* - Class B Brighthouse Investment Advisers, LLC Subadviser: Wellington Management Company LLP |
|
|
|
|
|
|
| |
CBRE Global Real Estate Portfolio* - Class B Brighthouse Investment Advisers, LLC Subadviser: CBRE Investment Management Listed Real Assets LLC |
|
|
|
|
|
|
| |
Freedom 2025 Portfolio - Service Class 2 Fidelity Management & Research Company LLC |
|
|
|
|
|
|
| |
Freedom 2030 Portfolio - Service Class 2 Fidelity Management & Research Company LLC |
|
|
|
|
|
|
| |
Freedom 2035 Portfolio - Service Class 2 Fidelity Management & Research Company LLC |
|
|
|
|
|
|
| |
PORTFOLIO AND ADVISER/SUBADVISER |
|
|
CURRENT EXPENSES + PLATFORM CHARGE |
AVERAGE ANNUAL TOTAL RETURNS (as of 12/31/2025) |
| |
|
|
| |
Freedom 2040 Portfolio - Service Class 2 Fidelity Management & Research Company LLC |
|
|
|
|
|
|
| |
Freedom 2045 Portfolio - Service Class 2 Fidelity Management & Research Company LLC |
|
|
|
|
|
|
| |
Freedom 2050 Portfolio - Service Class 2 Fidelity Management & Research Company LLC |
|
|
|
|
|
|
| |
Freedom 2055 Portfolio - Service Class 2 Fidelity Management & Research Company LLC |
|
|
|
|
|
|
| |
Freedom 2060 Portfolio - Service Class 2 Fidelity Management & Research Company LLC |
|
|
|
|
|
|
| |
Freedom 2065 Portfolio - Service Class 2 Fidelity Management & Research Company LLC |
|
|
|
|
|
|
| |
Freedom 2070 Portfolio - Service Class 2 Fidelity Management & Research Company LLC |
|
|
|
|
|
|
| |
Harris Oakmark International Portfolio* - Class B Brighthouse Investment Advisers, LLC Subadviser: Harris Associates L.P. |
|
|
|
|
|
|
| |
Invesco Global Equity Portfolio* - Class B Brighthouse Investment Advisers, LLC Subadviser: Invesco Advisers, Inc. |
|
|
|
|
|
|
| |
Invesco Small Cap Growth Portfolio* - Class B Brighthouse Investment Advisers, LLC Subadviser: Invesco Advisers, Inc. |
|
|
|
|
|
|
| |
PORTFOLIO AND ADVISER/SUBADVISER |
|
|
CURRENT EXPENSES + PLATFORM CHARGE |
AVERAGE ANNUAL TOTAL RETURNS (as of 12/31/2025) |
| |
|
|
| |
Jennison Growth Portfolio* - Class B Brighthouse Investment Advisers, LLC Subadviser: Jennison Associates LLC |
|
|
|
|
|
|
| |
Loomis Sayles Global Allocation Portfolio* - Class B Brighthouse Investment Advisers, LLC Subadviser: Loomis, Sayles & Company, L.P. |
|
|
|
|
|
|
| |
Loomis Sayles Growth Portfolio* - Class B Brighthouse Investment Advisers, LLC Subadviser: Loomis, Sayles & Company, L.P. |
|
|
|
|
|
|
| |
Loomis Sayles Small Cap Core Portfolio* - Class B Brighthouse Investment Advisers, LLC Subadviser: Loomis, Sayles & Company, L.P. |
|
|
|
|
|
|
| |
Loomis Sayles Small Cap Growth Portfolio* - Class B Brighthouse Investment Advisers, LLC Subadviser: Loomis, Sayles & Company, L.P. |
|
|
|
|
|
|
| |
MetLife Aggregate Bond Index Portfolio* - Class B Brighthouse Investment Advisers, LLC Subadviser: MetLife Investment Management, LLC |
|
|
|
|
|
|
| |
MetLife Mid Cap Stock Index Portfolio - Class B Brighthouse Investment Advisers, LLC Subadviser: MetLife Investment Management, LLC |
|
|
|
|
|
|
| |
PORTFOLIO AND ADVISER/SUBADVISER |
|
|
CURRENT EXPENSES + PLATFORM CHARGE |
AVERAGE ANNUAL TOTAL RETURNS (as of 12/31/2025) |
| |
|
|
| |
MetLife MSCI EAFE® Index Portfolio - Class B Brighthouse Investment Advisers, LLC Subadviser: MetLife Investment Management, LLC |
|
|
|
|
|
|
| |
MetLife Russell 2000® Index Portfolio - Class B Brighthouse Investment Advisers, LLC Subadviser: MetLife Investment Management, LLC |
|
|
|
|
|
|
| |
MetLife Stock Index Portfolio* - Class B Brighthouse Investment Advisers, LLC Subadviser: MetLife Investment Management, LLC |
|
|
|
|
|
|
| |
MFS® Research International Portfolio* - Class B Brighthouse Investment Advisers, LLC Subadviser: Massachusetts Financial Services Company |
|
|
|
|
|
|
| |
MFS® Total Return Portfolio* - Class B Brighthouse Investment Advisers, LLC Subadviser: Massachusetts Financial Services Company |
|
|
|
|
|
|
| |
MFS® Value Portfolio* - Class B Brighthouse Investment Advisers, LLC Subadviser: Massachusetts Financial Services Company |
|
|
|
|
|
|
| |
PORTFOLIO AND ADVISER/SUBADVISER |
|
|
CURRENT EXPENSES + PLATFORM CHARGE |
AVERAGE ANNUAL TOTAL RETURNS (as of 12/31/2025) |
| |
|
|
| |
Morgan Stanley Discovery Portfolio* - Class B Brighthouse Investment Advisers, LLC Subadviser: Morgan Stanley Investment Management Inc. |
|
|
|
|
|
|
| |
Neuberger Berman Genesis Portfolio* - Class B Brighthouse Investment Advisers, LLC Subadviser: Neuberger Berman Investment Advisers LLC |
|
|
|
|
|
|
| |
PIMCO Inflation Protected Bond Portfolio - Class B Brighthouse Investment Advisers, LLC Subadviser: Pacific Investment Management Company LLC |
|
|
|
|
|
|
| |
PIMCO Total Return Portfolio* - Class B Brighthouse Investment Advisers, LLC Subadviser: Pacific Investment Management Company LLC |
|
|
|
|
|
|
| |
State Street Moderate ETF Portfolio - Class B (formerly known as SSGA Growth and Income ETF Portfolio - Class B) Brighthouse Investment Advisers, LLC Subadviser: SSGA Funds Management, Inc. |
|
|
|
|
|
|
| |
State Street Moderately Aggressive ETF Portfolio - Class B (formerly known as SSGA Growth ETF Portfolio - Class B) Brighthouse Investment Advisers, LLC Subadviser: SSGA Funds Management, Inc. |
|
|
|
|
|
|
| |
PORTFOLIO AND ADVISER/SUBADVISER |
|
|
CURRENT EXPENSES + PLATFORM CHARGE |
AVERAGE ANNUAL TOTAL RETURNS (as of 12/31/2025) |
| |
|
|
| |
T. Rowe Price Large Cap Growth Portfolio* - Class B Brighthouse Investment Advisers, LLC Subadviser: T. Rowe Price Associates, Inc. |
|
|
|
|
|
|
| |
T. Rowe Price Mid Cap Growth Portfolio* - Class B Brighthouse Investment Advisers, LLC Subadviser: T. Rowe Price Associates, Inc. is the subadviser T. Rowe Price Investment Management, Inc. is the sub-subadviser |
|
|
|
|
|
|
| |
T. Rowe Price Small Cap Growth Portfolio - Class B Brighthouse Investment Advisers, LLC Subadviser: T. Rowe Price Associates, Inc. |
|
|
|
|
|
|
| |
Victory Sycamore Mid Cap Value Portfolio* - Class B Brighthouse Investment Advisers, LLC Subadviser: Victory Capital Management, Inc. |
|
|
|
|
|
|
| |
Western Asset Management Strategic Bond Opportunities Portfolio* - Class B Brighthouse Investment Advisers, LLC Subadviser: Western Asset Management Company, LLC |
|
|
|
|
|
|
| |
Western Asset Management U.S. Government Portfolio* - Class B Brighthouse Investment Advisers, LLC Subadviser: Western Asset Management Company, LLC |
|
|
|
|
|
|
|
| Temporary Fee Reductions, Current Expenses [Text Block] |
The Portfolio is subject to an expense reimbursement or fee waiver arrangement. The annual expenses shown reflect temporary fee reductions.
|
| Fixed Option [Line Items] |
|
| Fixed Options Available Legend [Text Block] |
Fixed OptionThe following is information on the Fixed Interest Account currently available under the Contract. You should check with your Employer as to whether the Fixed Interest Account is available under your Contract. We reserve the right to restrict purchase payments and transfers to the Fixed Interest Account when the yield on investments is not expected to support the Minimum Guaranteed Interest Rate. We will provide you with written notice before doing so.
| |
|
Minimum Guaranteed Interest Rate* |
| |
Initial Interest Rate Term: begins on each calendar quarter and will be credited from the date amounts are allocated to the Fixed Interest Account until the last day of the same calendar quarter of the following year. Renewal Rate Term: 12 months. |
| *The Minimum Guaranteed Interest Rate varies by Contract and may be higher than the minimum guaranteed interest rate shown. Check your Contract for the Minimum Guaranteed Interest Rate that applies to your Fixed Interest Account Option.
|
| Investment Option Restrictions [Line Items] |
|
| Investment Options Not Always Available for All Benefits [Text Block] |
Investment Allocation Restrictions For Certain Optional BenefitsIndex Selector:If You elect the Index Selector You are limited to allocating your purchase payments and Account Balance among the following funding options and the Fixed Interest Account:MetLife Aggregate Bond Index
MetLife Stock Index
MetLife MSCI EAFE Index
MetLife Russell 2000 Index
MetLife Mid Cap Stock IndexLifetime Withdrawal GuaranteeIf You elect the Lifetime Withdrawal Guarantee Optional Benefit, You are limited to allocating your purchase payments and Account Balance among the following funding options and the Fixed Interest Account:Brighthouse Asset Allocation 20
Brighthouse Asset Allocation 40
Brighthouse Asset Allocation 60
Brighthouse Asset Allocation 80
|
| MetLife Financial Freedom Select B, L and C Class | American Funds Growth Fund - Class 2 |
|
| Variable Option [Line Items] |
|
| Portfolio Company Objective [Text Block] |
US Equity
|
| Portfolio Company Name [Text Block] |
American Funds Growth Fund(1) - Class 2
|
| Portfolio Company Adviser [Text Block] |
Capital Research and Management CompanySM
|
| Current Expenses [Percent] |
0.58%
|
| Platform Charge [Percent] |
0.25%
|
| Current Expenses + Platform Charge [Percent] |
0.83%
|
| Average Annual Total Returns, 1 Year [Percent] |
20.24%
|
| Average Annual Total Returns, 5 Years [Percent] |
13.37%
|
| Average Annual Total Returns, 10 Years [Percent] |
17.97%
|
| MetLife Financial Freedom Select B, L and C Class | American Funds Growth-Income Fund - Class 2 |
|
| Variable Option [Line Items] |
|
| Portfolio Company Objective [Text Block] |
US Equity
|
| Portfolio Company Name [Text Block] |
American Funds Growth-Income Fund(1) - Class 2
|
| Portfolio Company Adviser [Text Block] |
Capital Research and Management CompanySM
|
| Current Expenses [Percent] |
0.53%
|
| Platform Charge [Percent] |
0.25%
|
| Current Expenses + Platform Charge [Percent] |
0.78%
|
| Average Annual Total Returns, 1 Year [Percent] |
18.06%
|
| Average Annual Total Returns, 5 Years [Percent] |
13.90%
|
| Average Annual Total Returns, 10 Years [Percent] |
13.92%
|
| MetLife Financial Freedom Select B, L and C Class | American Funds SMALLCAP World Fund® - Class 2 |
|
| Variable Option [Line Items] |
|
| Portfolio Company Objective [Text Block] |
Global Equity
|
| Portfolio Company Name [Text Block] |
American Funds SMALLCAP World Fund® *(1)†† - Class 2
|
| Portfolio Company Adviser [Text Block] |
Capital Research and Management CompanySM
|
| Current Expenses [Percent] |
0.90%
|
| Platform Charge [Percent] |
0.25%
|
| Current Expenses + Platform Charge [Percent] |
1.15%
|
| Average Annual Total Returns, 1 Year [Percent] |
14.64%
|
| Average Annual Total Returns, 5 Years [Percent] |
0.49%
|
| Average Annual Total Returns, 10 Years [Percent] |
7.23%
|
| MetLife Financial Freedom Select B, L and C Class | American Funds The Bond Fund of America - Class 2 |
|
| Variable Option [Line Items] |
|
| Portfolio Company Objective [Text Block] |
US Fixed Income
|
| Portfolio Company Name [Text Block] |
American Funds The Bond Fund of America*(1) - Class 2
|
| Portfolio Company Adviser [Text Block] |
Capital Research and Management CompanySM
|
| Current Expenses [Percent] |
0.47%
|
| Platform Charge [Percent] |
0.25%
|
| Current Expenses + Platform Charge [Percent] |
0.72%
|
| Average Annual Total Returns, 1 Year [Percent] |
7.26%
|
| Average Annual Total Returns, 5 Years [Percent] |
0.14%
|
| Average Annual Total Returns, 10 Years [Percent] |
2.36%
|
| MetLife Financial Freedom Select B, L and C Class | American Funds Aggressive Allocation Portfolio - Class C |
|
| Variable Option [Line Items] |
|
| Portfolio Company Objective [Text Block] |
Allocation
|
| Portfolio Company Name [Text Block] |
American Funds® Aggressive Allocation Portfolio - Class C
|
| Portfolio Company Adviser [Text Block] |
Brighthouse Investment Advisers, LLC
|
| Current Expenses [Percent] |
0.99%
|
| Current Expenses + Platform Charge [Percent] |
0.99%
|
| Average Annual Total Returns, 1 Year [Percent] |
19.90%
|
| Average Annual Total Returns, 5 Years [Percent] |
9.30%
|
| Average Annual Total Returns, 10 Years [Percent] |
10.88%
|
| MetLife Financial Freedom Select B, L and C Class | American Funds Balanced Allocation Portfolio - Class C |
|
| Variable Option [Line Items] |
|
| Portfolio Company Objective [Text Block] |
Allocation
|
| Portfolio Company Name [Text Block] |
American Funds® Balanced Allocation Portfolio - Class C
|
| Portfolio Company Adviser [Text Block] |
Brighthouse Investment Advisers, LLC
|
| Current Expenses [Percent] |
0.96%
|
| Current Expenses + Platform Charge [Percent] |
0.96%
|
| Average Annual Total Returns, 1 Year [Percent] |
17.02%
|
| Average Annual Total Returns, 5 Years [Percent] |
7.26%
|
| Average Annual Total Returns, 10 Years [Percent] |
8.99%
|
| MetLife Financial Freedom Select B, L and C Class | American Funds Moderate Allocation Portfolio - Class C |
|
| Variable Option [Line Items] |
|
| Portfolio Company Objective [Text Block] |
Allocation
|
| Portfolio Company Name [Text Block] |
American Funds® Moderate Allocation Portfolio - Class C
|
| Portfolio Company Adviser [Text Block] |
Brighthouse Investment Advisers, LLC
|
| Current Expenses [Percent] |
0.95%
|
| Current Expenses + Platform Charge [Percent] |
0.95%
|
| Average Annual Total Returns, 1 Year [Percent] |
14.46%
|
| Average Annual Total Returns, 5 Years [Percent] |
5.71%
|
| Average Annual Total Returns, 10 Years [Percent] |
7.30%
|
| MetLife Financial Freedom Select B, L and C Class | BlackRock Bond Income Portfolio - Class B |
|
| Variable Option [Line Items] |
|
| Portfolio Company Objective [Text Block] |
US Fixed Income
|
| Portfolio Company Name [Text Block] |
BlackRock Bond Income Portfolio* - Class B
|
| Portfolio Company Adviser [Text Block] |
Brighthouse Investment Advisers, LLC
|
| Portfolio Company Subadviser [Text Block] |
BlackRock Advisors, LLC
|
| Current Expenses [Percent] |
0.63%
|
| Current Expenses + Platform Charge [Percent] |
0.63%
|
| Average Annual Total Returns, 1 Year [Percent] |
7.68%
|
| Average Annual Total Returns, 5 Years [Percent] |
0.42%
|
| Average Annual Total Returns, 10 Years [Percent] |
2.12%
|
| MetLife Financial Freedom Select B, L and C Class | BlackRock Capital Appreciation Portfolio - Class B |
|
| Variable Option [Line Items] |
|
| Portfolio Company Objective [Text Block] |
US Equity
|
| Portfolio Company Name [Text Block] |
BlackRock Capital Appreciation Portfolio* - Class B
|
| Portfolio Company Adviser [Text Block] |
Brighthouse Investment Advisers, LLC
|
| Portfolio Company Subadviser [Text Block] |
BlackRock Advisors, LLC
|
| Current Expenses [Percent] |
0.81%
|
| Current Expenses + Platform Charge [Percent] |
0.81%
|
| Average Annual Total Returns, 1 Year [Percent] |
12.91%
|
| Average Annual Total Returns, 5 Years [Percent] |
10.79%
|
| Average Annual Total Returns, 10 Years [Percent] |
15.51%
|
| MetLife Financial Freedom Select B, L and C Class | Brighthouse Asset Allocation 100 Portfolio - Class B |
|
| Variable Option [Line Items] |
|
| Portfolio Company Objective [Text Block] |
Allocation
|
| Portfolio Company Name [Text Block] |
Brighthouse Asset Allocation 100 Portfolio - Class B
|
| Portfolio Company Adviser [Text Block] |
Brighthouse Investment Advisers, LLC
|
| Current Expenses [Percent] |
0.96%
|
| Current Expenses + Platform Charge [Percent] |
0.96%
|
| Average Annual Total Returns, 1 Year [Percent] |
17.06%
|
| Average Annual Total Returns, 5 Years [Percent] |
8.63%
|
| Average Annual Total Returns, 10 Years [Percent] |
10.70%
|
| MetLife Financial Freedom Select B, L and C Class | Brighthouse Asset Allocation 20 Portfolio - Class B |
|
| Variable Option [Line Items] |
|
| Portfolio Company Objective [Text Block] |
Allocation
|
| Portfolio Company Name [Text Block] |
Brighthouse Asset Allocation 20 Portfolio* - Class B
|
| Portfolio Company Adviser [Text Block] |
Brighthouse Investment Advisers, LLC
|
| Current Expenses [Percent] |
0.93%
|
| Current Expenses + Platform Charge [Percent] |
0.93%
|
| Average Annual Total Returns, 1 Year [Percent] |
9.25%
|
| Average Annual Total Returns, 5 Years [Percent] |
2.06%
|
| Average Annual Total Returns, 10 Years [Percent] |
3.97%
|
| MetLife Financial Freedom Select B, L and C Class | Brighthouse Asset Allocation 40 Portfolio - Class B |
|
| Variable Option [Line Items] |
|
| Portfolio Company Objective [Text Block] |
Allocation
|
| Portfolio Company Name [Text Block] |
Brighthouse Asset Allocation 40 Portfolio - Class B
|
| Portfolio Company Adviser [Text Block] |
Brighthouse Investment Advisers, LLC
|
| Current Expenses [Percent] |
0.91%
|
| Current Expenses + Platform Charge [Percent] |
0.91%
|
| Average Annual Total Returns, 1 Year [Percent] |
11.50%
|
| Average Annual Total Returns, 5 Years [Percent] |
3.84%
|
| Average Annual Total Returns, 10 Years [Percent] |
5.69%
|
| MetLife Financial Freedom Select B, L and C Class | Brighthouse Asset Allocation 60 Portfolio - Class B |
|
| Variable Option [Line Items] |
|
| Portfolio Company Objective [Text Block] |
Allocation
|
| Portfolio Company Name [Text Block] |
Brighthouse Asset Allocation 60 Portfolio - Class B
|
| Portfolio Company Adviser [Text Block] |
Brighthouse Investment Advisers, LLC
|
| Current Expenses [Percent] |
0.91%
|
| Current Expenses + Platform Charge [Percent] |
0.91%
|
| Average Annual Total Returns, 1 Year [Percent] |
13.77%
|
| Average Annual Total Returns, 5 Years [Percent] |
5.55%
|
| Average Annual Total Returns, 10 Years [Percent] |
7.47%
|
| MetLife Financial Freedom Select B, L and C Class | Brighthouse Asset Allocation 80 Portfolio - Class B |
|
| Variable Option [Line Items] |
|
| Portfolio Company Objective [Text Block] |
Allocation
|
| Portfolio Company Name [Text Block] |
Brighthouse Asset Allocation 80 Portfolio - Class B
|
| Portfolio Company Adviser [Text Block] |
Brighthouse Investment Advisers, LLC
|
| Current Expenses [Percent] |
0.93%
|
| Current Expenses + Platform Charge [Percent] |
0.93%
|
| Average Annual Total Returns, 1 Year [Percent] |
15.63%
|
| Average Annual Total Returns, 5 Years [Percent] |
7.18%
|
| Average Annual Total Returns, 10 Years [Percent] |
9.22%
|
| MetLife Financial Freedom Select B, L and C Class | Brighthouse Small Cap Value Portfolio - Class B |
|
| Variable Option [Line Items] |
|
| Portfolio Company Objective [Text Block] |
US Equity
|
| Portfolio Company Name [Text Block] |
Brighthouse Small Cap Value Portfolio* - Class B
|
| Portfolio Company Adviser [Text Block] |
Brighthouse Investment Advisers, LLC
|
| Portfolio Company Subadviser [Text Block] |
Allspring Global Investments, LLC
|
| Current Expenses [Percent] |
1.03%
|
| Current Expenses + Platform Charge [Percent] |
1.03%
|
| Average Annual Total Returns, 1 Year [Percent] |
3.21%
|
| Average Annual Total Returns, 5 Years [Percent] |
6.43%
|
| Average Annual Total Returns, 10 Years [Percent] |
8.07%
|
| MetLife Financial Freedom Select B, L and C Class | BrighthouseArtisan Mid Cap Value Portfolio - Class B |
|
| Variable Option [Line Items] |
|
| Portfolio Company Objective [Text Block] |
US Equity
|
| Portfolio Company Name [Text Block] |
Brighthouse/Artisan Mid Cap Value Portfolio* - Class B
|
| Portfolio Company Adviser [Text Block] |
Brighthouse Investment Advisers, LLC
|
| Portfolio Company Subadviser [Text Block] |
Artisan Partners Limited Partnership
|
| Current Expenses [Percent] |
1.03%
|
| Current Expenses + Platform Charge [Percent] |
1.03%
|
| Average Annual Total Returns, 1 Year [Percent] |
1.57%
|
| Average Annual Total Returns, 5 Years [Percent] |
6.77%
|
| Average Annual Total Returns, 10 Years [Percent] |
8.05%
|
| MetLife Financial Freedom Select B, L and C Class | BrighthouseFranklin Low Duration Total Return Portfolio - Class B |
|
| Variable Option [Line Items] |
|
| Portfolio Company Objective [Text Block] |
US Fixed Income
|
| Portfolio Company Name [Text Block] |
Brighthouse/Franklin Low Duration Total Return Portfolio* - Class B
|
| Portfolio Company Adviser [Text Block] |
Brighthouse Investment Advisers, LLC
|
| Portfolio Company Subadviser [Text Block] |
Franklin Advisers, Inc.
|
| Current Expenses [Percent] |
0.75%
|
| Current Expenses + Platform Charge [Percent] |
0.75%
|
| Average Annual Total Returns, 1 Year [Percent] |
5.25%
|
| Average Annual Total Returns, 5 Years [Percent] |
2.14%
|
| Average Annual Total Returns, 10 Years [Percent] |
2.23%
|
| MetLife Financial Freedom Select B, L and C Class | BrighthouseWellington Balanced Portfolio - Class A |
|
| Variable Option [Line Items] |
|
| Portfolio Company Objective [Text Block] |
Allocation
|
| Portfolio Company Name [Text Block] |
Brighthouse/Wellington Balanced Portfolio - Class A
|
| Portfolio Company Adviser [Text Block] |
Brighthouse Investment Advisers, LLC
|
| Portfolio Company Subadviser [Text Block] |
Wellington Management Company LLP
|
| Current Expenses [Percent] |
0.52%
|
| Current Expenses + Platform Charge [Percent] |
0.52%
|
| Average Annual Total Returns, 1 Year [Percent] |
12.67%
|
| Average Annual Total Returns, 5 Years [Percent] |
7.45%
|
| Average Annual Total Returns, 10 Years [Percent] |
9.41%
|
| MetLife Financial Freedom Select B, L and C Class | BrighthouseWellington Core Equity Opportunities Portfolio - Class B |
|
| Variable Option [Line Items] |
|
| Portfolio Company Objective [Text Block] |
US Equity
|
| Portfolio Company Name [Text Block] |
Brighthouse/Wellington Core Equity Opportunities Portfolio* - Class B
|
| Portfolio Company Adviser [Text Block] |
Brighthouse Investment Advisers, LLC
|
| Portfolio Company Subadviser [Text Block] |
Wellington Management Company LLP
|
| Current Expenses [Percent] |
0.87%
|
| Current Expenses + Platform Charge [Percent] |
0.87%
|
| Average Annual Total Returns, 1 Year [Percent] |
7.54%
|
| Average Annual Total Returns, 5 Years [Percent] |
8.02%
|
| Average Annual Total Returns, 10 Years [Percent] |
10.45%
|
| MetLife Financial Freedom Select B, L and C Class | BrighthouseWellington Large Cap Research Portfolio - Class B |
|
| Variable Option [Line Items] |
|
| Portfolio Company Objective [Text Block] |
US Equity
|
| Portfolio Company Name [Text Block] |
Brighthouse/Wellington Large Cap Research Portfolio* - Class B
|
| Portfolio Company Adviser [Text Block] |
Brighthouse Investment Advisers, LLC
|
| Portfolio Company Subadviser [Text Block] |
Wellington Management Company LLP
|
| Current Expenses [Percent] |
0.79%
|
| Current Expenses + Platform Charge [Percent] |
0.79%
|
| Average Annual Total Returns, 1 Year [Percent] |
15.62%
|
| Average Annual Total Returns, 5 Years [Percent] |
12.01%
|
| Average Annual Total Returns, 10 Years [Percent] |
13.33%
|
| MetLife Financial Freedom Select B, L and C Class | CBRE Global Real Estate Portfolio - Class B |
|
| Variable Option [Line Items] |
|
| Portfolio Company Objective [Text Block] |
Sector
|
| Portfolio Company Name [Text Block] |
CBRE Global Real Estate Portfolio* - Class B
|
| Portfolio Company Adviser [Text Block] |
Brighthouse Investment Advisers, LLC
|
| Portfolio Company Subadviser [Text Block] |
CBRE Investment Management Listed Real Assets LLC
|
| Current Expenses [Percent] |
0.91%
|
| Current Expenses + Platform Charge [Percent] |
0.91%
|
| Average Annual Total Returns, 1 Year [Percent] |
6.75%
|
| Average Annual Total Returns, 5 Years [Percent] |
4.03%
|
| Average Annual Total Returns, 10 Years [Percent] |
3.95%
|
| MetLife Financial Freedom Select B, L and C Class | Freedom 2025 Portfolio - Service Class 2 |
|
| Variable Option [Line Items] |
|
| Portfolio Company Objective [Text Block] |
Target Date
|
| Portfolio Company Name [Text Block] |
Freedom 2025 Portfolio - Service Class 2
|
| Portfolio Company Adviser [Text Block] |
Fidelity Management & Research Company LLC
|
| Current Expenses [Percent] |
0.71%
|
| Current Expenses + Platform Charge [Percent] |
0.71%
|
| Average Annual Total Returns, 1 Year [Percent] |
14.23%
|
| Average Annual Total Returns, 5 Years [Percent] |
5.25%
|
| Average Annual Total Returns, 10 Years [Percent] |
7.75%
|
| MetLife Financial Freedom Select B, L and C Class | Freedom 2030 Portfolio - Service Class 2 |
|
| Variable Option [Line Items] |
|
| Portfolio Company Objective [Text Block] |
Target Date
|
| Portfolio Company Name [Text Block] |
Freedom 2030 Portfolio - Service Class 2
|
| Portfolio Company Adviser [Text Block] |
Fidelity Management & Research Company LLC
|
| Current Expenses [Percent] |
0.74%
|
| Current Expenses + Platform Charge [Percent] |
0.74%
|
| Average Annual Total Returns, 1 Year [Percent] |
15.16%
|
| Average Annual Total Returns, 5 Years [Percent] |
5.98%
|
| Average Annual Total Returns, 10 Years [Percent] |
8.61%
|
| MetLife Financial Freedom Select B, L and C Class | Freedom 2035 Portfolio - Service Class 2 |
|
| Variable Option [Line Items] |
|
| Portfolio Company Objective [Text Block] |
Target Date
|
| Portfolio Company Name [Text Block] |
Freedom 2035 Portfolio - Service Class 2
|
| Portfolio Company Adviser [Text Block] |
Fidelity Management & Research Company LLC
|
| Current Expenses [Percent] |
0.78%
|
| Current Expenses + Platform Charge [Percent] |
0.78%
|
| Average Annual Total Returns, 1 Year [Percent] |
16.42%
|
| Average Annual Total Returns, 5 Years [Percent] |
7.28%
|
| Average Annual Total Returns, 10 Years [Percent] |
9.72%
|
| MetLife Financial Freedom Select B, L and C Class | Freedom 2040 Portfolio - Service Class 2 |
|
| Variable Option [Line Items] |
|
| Portfolio Company Objective [Text Block] |
Target Date
|
| Portfolio Company Name [Text Block] |
Freedom 2040 Portfolio - Service Class 2
|
| Portfolio Company Adviser [Text Block] |
Fidelity Management & Research Company LLC
|
| Current Expenses [Percent] |
0.82%
|
| Current Expenses + Platform Charge [Percent] |
0.82%
|
| Average Annual Total Returns, 1 Year [Percent] |
18.44%
|
| Average Annual Total Returns, 5 Years [Percent] |
8.73%
|
| Average Annual Total Returns, 10 Years [Percent] |
10.59%
|
| MetLife Financial Freedom Select B, L and C Class | Freedom 2045 Portfolio - Service Class 2 |
|
| Variable Option [Line Items] |
|
| Portfolio Company Objective [Text Block] |
Target Date
|
| Portfolio Company Name [Text Block] |
Freedom 2045 Portfolio - Service Class 2
|
| Portfolio Company Adviser [Text Block] |
Fidelity Management & Research Company LLC
|
| Current Expenses [Percent] |
0.85%
|
| Current Expenses + Platform Charge [Percent] |
0.85%
|
| Average Annual Total Returns, 1 Year [Percent] |
19.53%
|
| Average Annual Total Returns, 5 Years [Percent] |
9.16%
|
| Average Annual Total Returns, 10 Years [Percent] |
10.82%
|
| MetLife Financial Freedom Select B, L and C Class | Freedom 2050 Portfolio - Service Class 2 |
|
| Variable Option [Line Items] |
|
| Portfolio Company Objective [Text Block] |
Target Date
|
| Portfolio Company Name [Text Block] |
Freedom 2050 Portfolio - Service Class 2
|
| Portfolio Company Adviser [Text Block] |
Fidelity Management & Research Company LLC
|
| Current Expenses [Percent] |
0.85%
|
| Current Expenses + Platform Charge [Percent] |
0.85%
|
| Average Annual Total Returns, 1 Year [Percent] |
19.50%
|
| Average Annual Total Returns, 5 Years [Percent] |
9.15%
|
| Average Annual Total Returns, 10 Years [Percent] |
10.81%
|
| MetLife Financial Freedom Select B, L and C Class | Freedom 2055 Portfolio - Service Class 2 |
|
| Variable Option [Line Items] |
|
| Portfolio Company Objective [Text Block] |
Target Date
|
| Portfolio Company Name [Text Block] |
Freedom 2055 Portfolio - Service Class 2
|
| Portfolio Company Adviser [Text Block] |
Fidelity Management & Research Company LLC
|
| Current Expenses [Percent] |
0.85%
|
| Current Expenses + Platform Charge [Percent] |
0.85%
|
| Average Annual Total Returns, 1 Year [Percent] |
19.53%
|
| Average Annual Total Returns, 5 Years [Percent] |
9.16%
|
| MetLife Financial Freedom Select B, L and C Class | Freedom 2060 Portfolio - Service Class 2 |
|
| Variable Option [Line Items] |
|
| Portfolio Company Objective [Text Block] |
Target Date
|
| Portfolio Company Name [Text Block] |
Freedom 2060 Portfolio - Service Class 2
|
| Portfolio Company Adviser [Text Block] |
Fidelity Management & Research Company LLC
|
| Current Expenses [Percent] |
0.85%
|
| Current Expenses + Platform Charge [Percent] |
0.85%
|
| Average Annual Total Returns, 1 Year [Percent] |
19.53%
|
| Average Annual Total Returns, 5 Years [Percent] |
9.17%
|
| MetLife Financial Freedom Select B, L and C Class | Freedom 2065 Portfolio - Service Class 2 |
|
| Variable Option [Line Items] |
|
| Portfolio Company Objective [Text Block] |
Target Date
|
| Portfolio Company Name [Text Block] |
Freedom 2065 Portfolio - Service Class 2
|
| Portfolio Company Adviser [Text Block] |
Fidelity Management & Research Company LLC
|
| Current Expenses [Percent] |
0.85%
|
| Current Expenses + Platform Charge [Percent] |
0.85%
|
| Average Annual Total Returns, 1 Year [Percent] |
19.52%
|
| Average Annual Total Returns, 5 Years [Percent] |
9.16%
|
| MetLife Financial Freedom Select B, L and C Class | Freedom 2070 Portfolio - Service Class 2 |
|
| Variable Option [Line Items] |
|
| Portfolio Company Objective [Text Block] |
Target Date
|
| Portfolio Company Name [Text Block] |
Freedom 2070 Portfolio - Service Class 2
|
| Portfolio Company Adviser [Text Block] |
Fidelity Management & Research Company LLC
|
| Current Expenses [Percent] |
0.85%
|
| Current Expenses + Platform Charge [Percent] |
0.85%
|
| Average Annual Total Returns, 1 Year [Percent] |
19.59%
|
| MetLife Financial Freedom Select B, L and C Class | Harris Oakmark International Portfolio - Class B |
|
| Variable Option [Line Items] |
|
| Portfolio Company Objective [Text Block] |
International Equity
|
| Portfolio Company Name [Text Block] |
Harris Oakmark International Portfolio* - Class B
|
| Portfolio Company Adviser [Text Block] |
Brighthouse Investment Advisers, LLC
|
| Portfolio Company Subadviser [Text Block] |
Harris Associates L.P.
|
| Current Expenses [Percent] |
0.97%
|
| Current Expenses + Platform Charge [Percent] |
0.97%
|
| Average Annual Total Returns, 1 Year [Percent] |
32.78%
|
| Average Annual Total Returns, 5 Years [Percent] |
6.46%
|
| Average Annual Total Returns, 10 Years [Percent] |
6.74%
|
| MetLife Financial Freedom Select B, L and C Class | Invesco Global Equity Portfolio - Class B |
|
| Variable Option [Line Items] |
|
| Portfolio Company Objective [Text Block] |
Global Equity
|
| Portfolio Company Name [Text Block] |
Invesco Global Equity Portfolio* - Class B
|
| Portfolio Company Adviser [Text Block] |
Brighthouse Investment Advisers, LLC
|
| Portfolio Company Subadviser [Text Block] |
Invesco Advisers, Inc.
|
| Current Expenses [Percent] |
0.83%
|
| Current Expenses + Platform Charge [Percent] |
0.83%
|
| Average Annual Total Returns, 1 Year [Percent] |
15.60%
|
| Average Annual Total Returns, 5 Years [Percent] |
7.30%
|
| Average Annual Total Returns, 10 Years [Percent] |
11.00%
|
| MetLife Financial Freedom Select B, L and C Class | Invesco Small Cap Growth Portfolio - Class B |
|
| Variable Option [Line Items] |
|
| Portfolio Company Objective [Text Block] |
US Equity
|
| Portfolio Company Name [Text Block] |
Invesco Small Cap Growth Portfolio* - Class B
|
| Portfolio Company Adviser [Text Block] |
Brighthouse Investment Advisers, LLC
|
| Portfolio Company Subadviser [Text Block] |
Invesco Advisers, Inc.
|
| Current Expenses [Percent] |
0.99%
|
| Current Expenses + Platform Charge [Percent] |
0.99%
|
| Average Annual Total Returns, 1 Year [Percent] |
5.83%
|
| Average Annual Total Returns, 5 Years [Percent] |
0.91%
|
| Average Annual Total Returns, 10 Years [Percent] |
9.00%
|
| MetLife Financial Freedom Select B, L and C Class | Jennison Growth Portfolio - Class B |
|
| Variable Option [Line Items] |
|
| Portfolio Company Objective [Text Block] |
US Equity
|
| Portfolio Company Name [Text Block] |
Jennison Growth Portfolio* - Class B
|
| Portfolio Company Adviser [Text Block] |
Brighthouse Investment Advisers, LLC
|
| Portfolio Company Subadviser [Text Block] |
Jennison Associates LLC
|
| Current Expenses [Percent] |
0.79%
|
| Current Expenses + Platform Charge [Percent] |
0.79%
|
| Average Annual Total Returns, 1 Year [Percent] |
13.72%
|
| Average Annual Total Returns, 5 Years [Percent] |
10.01%
|
| Average Annual Total Returns, 10 Years [Percent] |
16.41%
|
| MetLife Financial Freedom Select B, L and C Class | Loomis Sayles Global Allocation Portfolio - Class B |
|
| Variable Option [Line Items] |
|
| Portfolio Company Objective [Text Block] |
Allocation
|
| Portfolio Company Name [Text Block] |
Loomis Sayles Global Allocation Portfolio* - Class B
|
| Portfolio Company Adviser [Text Block] |
Brighthouse Investment Advisers, LLC
|
| Portfolio Company Subadviser [Text Block] |
Loomis, Sayles & Company, L.P.
|
| Current Expenses [Percent] |
1.04%
|
| Current Expenses + Platform Charge [Percent] |
1.04%
|
| Average Annual Total Returns, 1 Year [Percent] |
12.59%
|
| Average Annual Total Returns, 5 Years [Percent] |
6.25%
|
| Average Annual Total Returns, 10 Years [Percent] |
9.22%
|
| MetLife Financial Freedom Select B, L and C Class | Loomis Sayles Growth Portfolio - Class B |
|
| Variable Option [Line Items] |
|
| Portfolio Company Objective [Text Block] |
US Equity
|
| Portfolio Company Name [Text Block] |
Loomis Sayles Growth Portfolio* - Class B
|
| Portfolio Company Adviser [Text Block] |
Brighthouse Investment Advisers, LLC
|
| Portfolio Company Subadviser [Text Block] |
Loomis, Sayles & Company, L.P.
|
| Current Expenses [Percent] |
0.80%
|
| Current Expenses + Platform Charge [Percent] |
0.80%
|
| Average Annual Total Returns, 1 Year [Percent] |
14.90%
|
| Average Annual Total Returns, 5 Years [Percent] |
14.77%
|
| Average Annual Total Returns, 10 Years [Percent] |
13.91%
|
| MetLife Financial Freedom Select B, L and C Class | Loomis Sayles Small Cap Core Portfolio - Class B |
|
| Variable Option [Line Items] |
|
| Portfolio Company Objective [Text Block] |
US Equity
|
| Portfolio Company Name [Text Block] |
Loomis Sayles Small Cap Core Portfolio* - Class B
|
| Portfolio Company Adviser [Text Block] |
Brighthouse Investment Advisers, LLC
|
| Portfolio Company Subadviser [Text Block] |
Loomis, Sayles & Company, L.P.
|
| Current Expenses [Percent] |
1.15%
|
| Current Expenses + Platform Charge [Percent] |
1.15%
|
| Average Annual Total Returns, 1 Year [Percent] |
5.02%
|
| Average Annual Total Returns, 5 Years [Percent] |
7.17%
|
| Average Annual Total Returns, 10 Years [Percent] |
9.15%
|
| MetLife Financial Freedom Select B, L and C Class | Loomis Sayles Small Cap Growth Portfolio - Class B |
|
| Variable Option [Line Items] |
|
| Portfolio Company Objective [Text Block] |
US Equity
|
| Portfolio Company Name [Text Block] |
Loomis Sayles Small Cap Growth Portfolio* - Class B
|
| Portfolio Company Adviser [Text Block] |
Brighthouse Investment Advisers, LLC
|
| Portfolio Company Subadviser [Text Block] |
Loomis, Sayles & Company, L.P.
|
| Current Expenses [Percent] |
1.14%
|
| Current Expenses + Platform Charge [Percent] |
1.14%
|
| Average Annual Total Returns, 1 Year [Percent] |
3.73%
|
| Average Annual Total Returns, 5 Years [Percent] |
2.28%
|
| Average Annual Total Returns, 10 Years [Percent] |
9.84%
|
| MetLife Financial Freedom Select B, L and C Class | MetLife Aggregate Bond Index Portfolio - Class B |
|
| Variable Option [Line Items] |
|
| Portfolio Company Objective [Text Block] |
US Fixed Income
|
| Portfolio Company Name [Text Block] |
MetLife Aggregate Bond Index Portfolio* - Class B
|
| Portfolio Company Adviser [Text Block] |
Brighthouse Investment Advisers, LLC
|
| Portfolio Company Subadviser [Text Block] |
MetLife Investment Management, LLC
|
| Current Expenses [Percent] |
0.51%
|
| Current Expenses + Platform Charge [Percent] |
0.51%
|
| Average Annual Total Returns, 1 Year [Percent] |
6.80%
|
| Average Annual Total Returns, 5 Years [Percent] |
0.88%
|
| Average Annual Total Returns, 10 Years [Percent] |
1.51%
|
| MetLife Financial Freedom Select B, L and C Class | MetLife Mid Cap Stock Index Portfolio - Class B |
|
| Variable Option [Line Items] |
|
| Portfolio Company Objective [Text Block] |
US Equity
|
| Portfolio Company Name [Text Block] |
MetLife Mid Cap Stock Index Portfolio - Class B
|
| Portfolio Company Adviser [Text Block] |
Brighthouse Investment Advisers, LLC
|
| Portfolio Company Subadviser [Text Block] |
MetLife Investment Management, LLC
|
| Current Expenses [Percent] |
0.55%
|
| Current Expenses + Platform Charge [Percent] |
0.55%
|
| Average Annual Total Returns, 1 Year [Percent] |
6.86%
|
| Average Annual Total Returns, 5 Years [Percent] |
8.54%
|
| Average Annual Total Returns, 10 Years [Percent] |
10.16%
|
| MetLife Financial Freedom Select B, L and C Class | MetLife MSCI EAFE Index Portfolio - Class B |
|
| Variable Option [Line Items] |
|
| Portfolio Company Objective [Text Block] |
International Equity
|
| Portfolio Company Name [Text Block] |
MetLife MSCI EAFE® Index Portfolio - Class B
|
| Portfolio Company Adviser [Text Block] |
Brighthouse Investment Advisers, LLC
|
| Portfolio Company Subadviser [Text Block] |
MetLife Investment Management, LLC
|
| Current Expenses [Percent] |
0.62%
|
| Current Expenses + Platform Charge [Percent] |
0.62%
|
| Average Annual Total Returns, 1 Year [Percent] |
30.70%
|
| Average Annual Total Returns, 5 Years [Percent] |
8.35%
|
| Average Annual Total Returns, 10 Years [Percent] |
7.76%
|
| MetLife Financial Freedom Select B, L and C Class | MetLife Russell 2000 Index Portfolio - Class B |
|
| Variable Option [Line Items] |
|
| Portfolio Company Objective [Text Block] |
US Equity
|
| Portfolio Company Name [Text Block] |
MetLife Russell 2000® Index Portfolio - Class B
|
| Portfolio Company Adviser [Text Block] |
Brighthouse Investment Advisers, LLC
|
| Portfolio Company Subadviser [Text Block] |
MetLife Investment Management, LLC
|
| Current Expenses [Percent] |
0.55%
|
| Current Expenses + Platform Charge [Percent] |
0.55%
|
| Average Annual Total Returns, 1 Year [Percent] |
12.33%
|
| Average Annual Total Returns, 5 Years [Percent] |
5.71%
|
| Average Annual Total Returns, 10 Years [Percent] |
9.27%
|
| MetLife Financial Freedom Select B, L and C Class | MetLife Stock Index Portfolio - Class B |
|
| Variable Option [Line Items] |
|
| Portfolio Company Objective [Text Block] |
US Equity
|
| Portfolio Company Name [Text Block] |
MetLife Stock Index Portfolio* - Class B
|
| Portfolio Company Adviser [Text Block] |
Brighthouse Investment Advisers, LLC
|
| Portfolio Company Subadviser [Text Block] |
MetLife Investment Management, LLC
|
| Current Expenses [Percent] |
0.52%
|
| Current Expenses + Platform Charge [Percent] |
0.52%
|
| Average Annual Total Returns, 1 Year [Percent] |
17.28%
|
| Average Annual Total Returns, 5 Years [Percent] |
13.84%
|
| Average Annual Total Returns, 10 Years [Percent] |
14.24%
|
| MetLife Financial Freedom Select B, L and C Class | MFS Research International Portfolio - Class B |
|
| Variable Option [Line Items] |
|
| Portfolio Company Objective [Text Block] |
International Equity
|
| Portfolio Company Name [Text Block] |
MFS® Research International Portfolio* - Class B
|
| Portfolio Company Adviser [Text Block] |
Brighthouse Investment Advisers, LLC
|
| Portfolio Company Subadviser [Text Block] |
Massachusetts Financial Services Company
|
| Current Expenses [Percent] |
0.81%
|
| Current Expenses + Platform Charge [Percent] |
0.81%
|
| Average Annual Total Returns, 1 Year [Percent] |
22.41%
|
| Average Annual Total Returns, 5 Years [Percent] |
5.54%
|
| Average Annual Total Returns, 10 Years [Percent] |
7.57%
|
| MetLife Financial Freedom Select B, L and C Class | MFS Total Return Portfolio - Class B |
|
| Variable Option [Line Items] |
|
| Portfolio Company Objective [Text Block] |
Allocation
|
| Portfolio Company Name [Text Block] |
MFS® Total Return Portfolio* - Class B
|
| Portfolio Company Adviser [Text Block] |
Brighthouse Investment Advisers, LLC
|
| Portfolio Company Subadviser [Text Block] |
Massachusetts Financial Services Company
|
| Current Expenses [Percent] |
0.87%
|
| Current Expenses + Platform Charge [Percent] |
0.87%
|
| Average Annual Total Returns, 1 Year [Percent] |
10.83%
|
| Average Annual Total Returns, 5 Years [Percent] |
6.15%
|
| Average Annual Total Returns, 10 Years [Percent] |
7.38%
|
| MetLife Financial Freedom Select B, L and C Class | MFS Value Portfolio - Class B |
|
| Variable Option [Line Items] |
|
| Portfolio Company Objective [Text Block] |
US Equity
|
| Portfolio Company Name [Text Block] |
MFS® Value Portfolio* - Class B
|
| Portfolio Company Adviser [Text Block] |
Brighthouse Investment Advisers, LLC
|
| Portfolio Company Subadviser [Text Block] |
Massachusetts Financial Services Company
|
| Current Expenses [Percent] |
0.83%
|
| Current Expenses + Platform Charge [Percent] |
0.83%
|
| Average Annual Total Returns, 1 Year [Percent] |
13.00%
|
| Average Annual Total Returns, 5 Years [Percent] |
9.84%
|
| Average Annual Total Returns, 10 Years [Percent] |
9.99%
|
| MetLife Financial Freedom Select B, L and C Class | Morgan Stanley Discovery Portfolio - Class B |
|
| Variable Option [Line Items] |
|
| Portfolio Company Objective [Text Block] |
US Equity
|
| Portfolio Company Name [Text Block] |
Morgan Stanley Discovery Portfolio* - Class B
|
| Portfolio Company Adviser [Text Block] |
Brighthouse Investment Advisers, LLC
|
| Portfolio Company Subadviser [Text Block] |
Morgan Stanley Investment Management Inc.
|
| Current Expenses [Percent] |
0.90%
|
| Current Expenses + Platform Charge [Percent] |
0.90%
|
| Average Annual Total Returns, 1 Year [Percent] |
13.19%
|
| Average Annual Total Returns, 5 Years [Percent] |
5.83%
|
| Average Annual Total Returns, 10 Years [Percent] |
14.00%
|
| MetLife Financial Freedom Select B, L and C Class | Neuberger Berman Genesis Portfolio - Class B |
|
| Variable Option [Line Items] |
|
| Portfolio Company Objective [Text Block] |
US Equity
|
| Portfolio Company Name [Text Block] |
Neuberger Berman Genesis Portfolio* - Class B
|
| Portfolio Company Adviser [Text Block] |
Brighthouse Investment Advisers, LLC
|
| Portfolio Company Subadviser [Text Block] |
Neuberger Berman Investment Advisers LLC
|
| Current Expenses [Percent] |
1.06%
|
| Current Expenses + Platform Charge [Percent] |
1.06%
|
| Average Annual Total Returns, 1 Year [Percent] |
4.74%
|
| Average Annual Total Returns, 5 Years [Percent] |
2.62%
|
| Average Annual Total Returns, 10 Years [Percent] |
8.86%
|
| MetLife Financial Freedom Select B, L and C Class | PIMCO Inflation Protected Bond Portfolio - Class B |
|
| Variable Option [Line Items] |
|
| Portfolio Company Objective [Text Block] |
US Fixed Income
|
| Portfolio Company Name [Text Block] |
PIMCO Inflation Protected Bond Portfolio - Class B
|
| Portfolio Company Adviser [Text Block] |
Brighthouse Investment Advisers, LLC
|
| Portfolio Company Subadviser [Text Block] |
Pacific Investment Management Company LLC
|
| Current Expenses [Percent] |
1.38%
|
| Current Expenses + Platform Charge [Percent] |
1.38%
|
| Average Annual Total Returns, 1 Year [Percent] |
7.74%
|
| Average Annual Total Returns, 5 Years [Percent] |
1.15%
|
| Average Annual Total Returns, 10 Years [Percent] |
3.09%
|
| MetLife Financial Freedom Select B, L and C Class | PIMCO Total Return Portfolio - Class B |
|
| Variable Option [Line Items] |
|
| Portfolio Company Objective [Text Block] |
US Fixed Income
|
| Portfolio Company Name [Text Block] |
PIMCO Total Return Portfolio* - Class B
|
| Portfolio Company Adviser [Text Block] |
Brighthouse Investment Advisers, LLC
|
| Portfolio Company Subadviser [Text Block] |
Pacific Investment Management Company LLC
|
| Current Expenses [Percent] |
0.83%
|
| Current Expenses + Platform Charge [Percent] |
0.83%
|
| Average Annual Total Returns, 1 Year [Percent] |
8.90%
|
| Average Annual Total Returns, 5 Years [Percent] |
0.07%
|
| Average Annual Total Returns, 10 Years [Percent] |
2.30%
|
| MetLife Financial Freedom Select B, L and C Class | State Street Moderate ETF Portfolio - Class B |
|
| Variable Option [Line Items] |
|
| Portfolio Company Objective [Text Block] |
Allocation
|
| Portfolio Company Name [Text Block] |
State Street Moderate ETF Portfolio - Class B (formerly known as SSGA Growth and Income ETF Portfolio - Class B)
|
| Portfolio Company Adviser [Text Block] |
Brighthouse Investment Advisers, LLC
|
| Portfolio Company Subadviser [Text Block] |
SSGA Funds Management, Inc.
|
| Current Expenses [Percent] |
0.75%
|
| Current Expenses + Platform Charge [Percent] |
0.75%
|
| Average Annual Total Returns, 1 Year [Percent] |
16.78%
|
| Average Annual Total Returns, 5 Years [Percent] |
7.19%
|
| Average Annual Total Returns, 10 Years [Percent] |
7.85%
|
| MetLife Financial Freedom Select B, L and C Class | State Street Moderately Aggressive ETF Portfolio - Class B |
|
| Variable Option [Line Items] |
|
| Portfolio Company Objective [Text Block] |
Allocation
|
| Portfolio Company Name [Text Block] |
State Street Moderately Aggressive ETF Portfolio - Class B (formerly known as SSGA Growth ETF Portfolio - Class B)
|
| Portfolio Company Adviser [Text Block] |
Brighthouse Investment Advisers, LLC
|
| Portfolio Company Subadviser [Text Block] |
SSGA Funds Management, Inc.
|
| Current Expenses [Percent] |
0.78%
|
| Current Expenses + Platform Charge [Percent] |
0.78%
|
| Average Annual Total Returns, 1 Year [Percent] |
19.23%
|
| Average Annual Total Returns, 5 Years [Percent] |
9.01%
|
| Average Annual Total Returns, 10 Years [Percent] |
9.31%
|
| MetLife Financial Freedom Select B, L and C Class | T Rowe Price Large Cap Growth Portfolio - Class B |
|
| Variable Option [Line Items] |
|
| Portfolio Company Objective [Text Block] |
US Equity
|
| Portfolio Company Name [Text Block] |
T. Rowe Price Large Cap Growth Portfolio* - Class B
|
| Portfolio Company Adviser [Text Block] |
Brighthouse Investment Advisers, LLC
|
| Portfolio Company Subadviser [Text Block] |
T. Rowe Price Associates, Inc.
|
| Current Expenses [Percent] |
0.81%
|
| Current Expenses + Platform Charge [Percent] |
0.81%
|
| Average Annual Total Returns, 1 Year [Percent] |
15.45%
|
| Average Annual Total Returns, 5 Years [Percent] |
9.37%
|
| Average Annual Total Returns, 10 Years [Percent] |
14.10%
|
| MetLife Financial Freedom Select B, L and C Class | T Rowe Price Mid Cap Growth Portfolio - Class B |
|
| Variable Option [Line Items] |
|
| Portfolio Company Objective [Text Block] |
US Equity
|
| Portfolio Company Name [Text Block] |
T. Rowe Price Mid Cap Growth Portfolio* - Class B
|
| Portfolio Company Adviser [Text Block] |
Brighthouse Investment Advisers, LLC
|
| Portfolio Company Subadviser [Text Block] |
T. Rowe Price Associates, Inc. is the subadviserT. Rowe Price Investment Management, Inc. is the sub-subadviser
|
| Current Expenses [Percent] |
0.95%
|
| Current Expenses + Platform Charge [Percent] |
0.95%
|
| Average Annual Total Returns, 1 Year [Percent] |
3.42%
|
| Average Annual Total Returns, 5 Years [Percent] |
3.83%
|
| Average Annual Total Returns, 10 Years [Percent] |
9.77%
|
| MetLife Financial Freedom Select B, L and C Class | T Rowe Price Small Cap Growth Portfolio - Class B |
|
| Variable Option [Line Items] |
|
| Portfolio Company Objective [Text Block] |
US Equity
|
| Portfolio Company Name [Text Block] |
T. Rowe Price Small Cap Growth Portfolio - Class B
|
| Portfolio Company Adviser [Text Block] |
Brighthouse Investment Advisers, LLC
|
| Portfolio Company Subadviser [Text Block] |
T. Rowe Price Associates, Inc.
|
| Current Expenses [Percent] |
0.76%
|
| Current Expenses + Platform Charge [Percent] |
0.76%
|
| Average Annual Total Returns, 1 Year [Percent] |
10.00%
|
| Average Annual Total Returns, 5 Years [Percent] |
5.48%
|
| Average Annual Total Returns, 10 Years [Percent] |
10.60%
|
| MetLife Financial Freedom Select B, L and C Class | Victory Sycamore Mid Cap Value Portfolio - Class B |
|
| Variable Option [Line Items] |
|
| Portfolio Company Objective [Text Block] |
US Equity
|
| Portfolio Company Name [Text Block] |
Victory Sycamore Mid Cap Value Portfolio* - Class B
|
| Portfolio Company Adviser [Text Block] |
Brighthouse Investment Advisers, LLC
|
| Portfolio Company Subadviser [Text Block] |
Victory Capital Management, Inc.
|
| Current Expenses [Percent] |
0.85%
|
| Current Expenses + Platform Charge [Percent] |
0.85%
|
| Average Annual Total Returns, 1 Year [Percent] |
2.29%
|
| Average Annual Total Returns, 5 Years [Percent] |
9.62%
|
| Average Annual Total Returns, 10 Years [Percent] |
9.58%
|
| MetLife Financial Freedom Select B, L and C Class | Western Asset Management Strategic Bond Opportunities Portfolio - Class B |
|
| Variable Option [Line Items] |
|
| Portfolio Company Objective [Text Block] |
US Fixed Income
|
| Portfolio Company Name [Text Block] |
Western Asset Management Strategic Bond Opportunities Portfolio* - Class B
|
| Portfolio Company Adviser [Text Block] |
Brighthouse Investment Advisers, LLC
|
| Portfolio Company Subadviser [Text Block] |
Western Asset Management Company, LLC
|
| Current Expenses [Percent] |
0.82%
|
| Current Expenses + Platform Charge [Percent] |
0.82%
|
| Average Annual Total Returns, 1 Year [Percent] |
8.88%
|
| Average Annual Total Returns, 5 Years [Percent] |
1.17%
|
| Average Annual Total Returns, 10 Years [Percent] |
3.77%
|
| MetLife Financial Freedom Select B, L and C Class | Western Asset Management US Government Portfolio - Class B |
|
| Variable Option [Line Items] |
|
| Portfolio Company Objective [Text Block] |
US Fixed Income
|
| Portfolio Company Name [Text Block] |
Western Asset Management U.S. Government Portfolio* - Class B
|
| Portfolio Company Adviser [Text Block] |
Brighthouse Investment Advisers, LLC
|
| Portfolio Company Subadviser [Text Block] |
Western Asset Management Company, LLC
|
| Current Expenses [Percent] |
0.75%
|
| Current Expenses + Platform Charge [Percent] |
0.75%
|
| Average Annual Total Returns, 1 Year [Percent] |
6.81%
|
| Average Annual Total Returns, 5 Years [Percent] |
0.35%
|
| Average Annual Total Returns, 10 Years [Percent] |
1.57%
|
| MetLife Financial Freedom Select B, L and C Class | MetLife Aggregate Bond Index Portfolio - Class A |
|
| Investment Option Restrictions [Line Items] |
|
| Investment Option Restricted with Benefit [Flag] |
true
|
| MetLife Financial Freedom Select B, L and C Class | MetLife Stock Index Portfolio - Class A |
|
| Investment Option Restrictions [Line Items] |
|
| Investment Option Restricted with Benefit [Flag] |
true
|
| MetLife Financial Freedom Select B, L and C Class | MetLife Mid Cap Stock Index Portfolio - Class G |
|
| Investment Option Restrictions [Line Items] |
|
| Investment Option Restricted with Benefit [Flag] |
true
|
| MetLife Financial Freedom Select B, L and C Class | Standard Death Benefit [Member] |
|
| Item 10. Benefits Available [Line Items] |
|
| Name of Benefit [Text Block] |
Standard Death Benefit
|
| Purpose of Benefit [Text Block] |
If You die during the pay-in phase, guarantees that the death benefit will not be less than the greater of (1) your Account Balance less any outstanding loans; or (2) total purchase payment reduced proportionately by the percentage reduction in Account Balance attributable to each partial withdrawal less any outstanding loans (including any applicable Withdrawal Charge).
|
| Standard Benefit [Flag] |
true
|
| Standard Benefit Expense (of Benefit Base), Maximum [Percent] |
0.00%
|
| Brief Restrictions / Limitations [Text Block] |
●Withdrawals could significantly reduce the benefit.
|
| Name of Benefit [Text Block] |
Standard Death Benefit
|
| Operation of Benefit [Text Block] |
Death Benefit — GenerallyOne of the insurance guarantees we provide You under your Deferred Annuity is that your Beneficiaries will be protected during the “pay-in” phase against market downturns. You name your Beneficiary(ies).If You intend to purchase the Deferred Annuity for use with a SEP or SIMPLE IRA, please refer to the discussion concerning Qualified Annuity Contracts in the Federal Tax Considerations section of this Prospectus.The standard death benefit is described below. An additional optional death benefit is described in the “Optional Death Benefit” and "Annual Step-Up Death Benefit" sections. Check your Contract and riders for the specific provisions applicable to You. The optional death benefit may not be available in your state (check with your registered representative regarding availability). There is no death benefit after the pay-out phase begins, however, depending on the Pay-Out Option you elect, any remaining guarantee will be paid to your Beneficiary.The death benefit is determined as of the end of the business day on which we receive both due proof of death and an election for the payment method.If we are presented with notification of your death before any requested transaction is completed (including transactions under automated investment strategies, the minimum distribution program and the Systematic Withdrawal Program), we will cancel the request. As described above, the death benefit will be determined when we receive due proof of death and an election for the payment method.Until the Beneficiary (or each Beneficiary if there are multiple Beneficiaries) submits the necessary documentation in Good Order, the Account Balance attributable to his/her portion of the death benefit remains in the Divisions and is subject to investment risk.Where there are multiple Beneficiaries, the death benefit will only be determined as of the time the first Beneficiary submits the necessary documentation in Good Order. If the death benefit payable is an amount that exceeds the Account Balance on the day it is determined, we will apply to the Contract an amount equal to the difference between the death benefit payable and the Account Balance, in accordance with the current allocation of the Account Balance. This death benefit amount remains in the Divisions and/or Fixed Interest Account until each of the other Beneficiaries submits the necessary documentation in Good Order to claim his/her death benefit. Any death benefit amounts held in the Divisions on behalf of the remaining Beneficiaries are subject to investment risk. There is no additional death benefit guarantee.Your Beneficiary has the option to apply the death benefit less any applicable premium and other taxes to a Pay-Out Option offered under your Deferred Annuity. Your Beneficiary may, however, decide to take payment in one sum, including either by check, by placing the amount in an account that earns interest, or by any other method of payment that provides the Beneficiary with immediate and full access to the proceeds or under other settlement options that we may make available. If your contract was issued as an individual flexible contribution deferred variable annuity you may also elect to have surrender proceeds paid into a Total Control Account established for You, subject to our current established administrative procedures and requirements. You should always consult a tax adviser for complete information and advice applicable to your individual situation before having proceeds paid into a Total Control Account.Total Control AccountThe Beneficiary may elect to have the Contract’s death proceeds paid through a settlement option called the Total Control Account, subject to our current established administrative procedures and requirements. The Total Control Account is an interest-bearing account through which the Beneficiary has immediate and full access to the proceeds, with unlimited draft writing privileges. We credit interest to the account at a rate that will not be less than a guaranteed minimum annual effective rate. Assets backing the Total Control Accounts are maintained in our General Account and are subject to the claims of our creditors. We will bear the investment experience of such assets; however, regardless of the investment experience of such assets, the interest credited to the Total Control Account will never fall below the applicable guaranteed minimum annual effective rate. Because we bear the investment experience of the assets backing the Total Control Account, we may receive a profit from these assets. The Total Control Account is not insured by the FDIC or any other governmental agency.
|
| Calculation Method of Benefit [Text Block] |
Standard Death BenefitIf You die during the pay-in phase and You have not chosen the optional death benefit, the death benefit the Beneficiary receives will be equal to the greater of:1.Your Account Balance, less any outstanding loans; or2.Total purchase payments reduced proportionately by the percentage reduction in Account Balance attributable to each partial withdrawal, less any outstanding loans (including any applicable Withdrawal Charge).Example
| |
|
|
|
| |
|
|
|
| |
|
10/1/2020 (First Contract Anniversary) |
|
| |
|
|
$104,000 (= greater of A and B) |
| |
|
10/1/2021 (Second Contract Anniversary) |
|
| |
|
|
$100,000 (= greater of A and D) |
| |
|
|
|
| |
Percentage Reduction in Account Balance |
|
|
| |
Account Balance after Withdrawal |
|
|
| |
Purchase Payments reduced for Withdrawal |
|
|
| |
|
|
$90,000 (= greater of H and I) | Notes to Example:Any Withdrawal Charge withdrawn from the Account Balance is included when determining the percentage of Account Balance withdrawn.Account Balances on 10/1/21 and 10/2/21 are assumed to be equal prior to the withdrawal.There are no loans.
|
| MetLife Financial Freedom Select B, L and C Class | Annual Step-Up Death Benefit |
|
| Item 4. Fee Table [Line Items] |
|
| Optional Benefit Expense (of Other Amount), Maximum [Percent] |
0.10%
|
| Item 10. Benefits Available [Line Items] |
|
| Name of Benefit [Text Block] |
Annual Step-Up Death Benefit
|
| Purpose of Benefit [Text Block] |
If You die during the pay-in phase, guarantees that the death benefit will not be less than the greatest of (1) your Account Balance; (2) total purchase payments reduced proportionately for withdrawals and any outstanding loans (including any applicable Withdrawal Charge) or (3) "Highest Anniversary Value" as of each Contract Anniversary prior to your 81st birthday, plus any subsequent purchase payments, reduced for any outstanding loans, and reduced proportionately for withdrawals (including any applicable Withdrawal Charge).
|
| Optional Benefit [Flag] |
true
|
| Optional Benefit Expense (of Other Amount), Maximum [Percent] |
0.10%
|
| Brief Restrictions / Limitations [Text Block] |
●Withdrawals could significantly reduce the benefit.●You may not purchase this benefit if You are 80 years of age or older.●Available only at issue.
|
| Name of Benefit [Text Block] |
Annual Step-Up Death Benefit
|
| Operation of Benefit [Text Block] |
Annual Step-Up Death BenefitThe Annual Step-Up Death Benefit is designed to provide protection against adverse investment experience. In general, it guarantees that the death benefit will not be less than the greatest of (1) your Account Balance; (2) total purchase payments reduced for any outstanding loans and reduced proportionately for withdrawals (including any applicable Withdrawal Charge); or (3) “Highest Anniversary Value” as of each contract anniversary prior to your 81st birthday reduced for any outstanding loans and reduced proportionately for withdrawals and (including any applicable Withdrawal Charge). You may not purchase this benefit if You are 80 years of age or older.You may purchase at application a death benefit that provides that the death benefit amount is equal to the greatest of:1.The Account Balance, less any outstanding loans;2.Total purchase payments reduced proportionately for withdrawals and any outstanding loans (including any applicable Withdrawal Charge); or3.“Highest Anniversary Value” as of each Contract Anniversary, determined as follows:●At issue, the Highest Anniversary Value is your initial purchase payment;●Increase the Highest Anniversary Value by each subsequent purchase payment;●Reduce the Highest Anniversary Value proportionately by the percentage reduction in Account Balance attributable to each subsequent partial withdrawal, less any outstanding loans (including any applicable Withdrawal Charge);●On each Contract Anniversary before your 81st birthday, compare the (1) then Highest Anniversary Value to the (2) current Account Balance and set the Highest Anniversary Value equal to the greater of the two.●After the Contract Anniversary immediately preceding your 81st birthday, adjust the Highest Anniversary Value only to:●Increase the Highest Anniversary Value by each subsequent purchase payment or●Reduce the Highest Anniversary Value proportionately by the percentage reduction in Account Balance attributable to each subsequent partial withdrawal, less any outstanding loans (including any applicable Withdrawal Charge).For purposes of determining the Highest Anniversary Value as of the applicable Contract Anniversary, purchase payments increase the Highest Anniversary Value on a dollar for dollar basis. Partial withdrawals, however, reduce the Highest Anniversary Value proportionately, that is, the percentage reduction is equal to the dollar amount of the withdrawal (plus applicable Withdrawal Charges) divided by the Account Balance immediately before the withdrawal.The Annual Step-Up Death Benefit is available for a charge, in addition to the Standard Death Benefit Separate Account Charge, of 0.10% annually of the average daily value of the amount You have in the Separate Account.
|
| Calculation Method of Benefit [Text Block] |
Example:
| |
|
|
|
| |
|
|
|
| |
|
10/1/2020 (First Contract Anniversary) |
|
| |
Death Benefit (Highest Anniversary Value) |
|
$104,000 (= greater of A and B) |
| |
|
10/1/2021 (Second Contract Anniversary) |
|
| |
Death Benefit (Highest Contract Year Anniversary) |
|
$104,000 (= greater of C and D) |
| |
|
|
|
| |
Percentage Reduction in Account Balance |
|
|
| |
Account Balance after Withdrawal |
|
|
| |
Highest Anniversary Value reduced for Withdrawal |
|
|
| |
|
|
$93,600 (= greater of H and I) | Notes to Example:Any Withdrawal Charge withdrawn from the Account Balance is included when determining the percentage of Account Balance withdrawn.The Account Balances on 10/1/21 and 10/2/21 are assumed to be equal prior to the withdrawal. The purchaser is age 60 at issue.There are no loans.
|
| MetLife Financial Freedom Select B, L and C Class | Guaranteed Minimum Income Benefit |
|
| Item 4. Fee Table [Line Items] |
|
| Optional Benefit Expense, Footnotes [Text Block] |
You may only have one living benefit, the Guaranteed Minimum Income Benefit or the Lifetime Withdrawal Benefit, associated with your Contract at any given time. The charge for the Guaranteed Minimum Income Benefit is a percentage of your guaranteed minimum income base, as defined later in this Prospectus, and is deducted at the end of each Contract Year by withdrawing amounts on a pro-rata basis from your Fixed Interest Account Balance and Your Investment Options (net of any loans). (We take amounts from the Separate Account by canceling, if available, Accumulation Units from your Separate Account Balance.) You do not pay this charge once You are in the pay-out phase of your Contract. Different charges for the Guaranteed Minimum Income Benefit were in effect prior to May 4, 2009.
|
| Item 10. Benefits Available [Line Items] |
|
| Name of Benefit [Text Block] |
Guaranteed Minimum Income Benefit
|
| Purpose of Benefit [Text Block] |
Designed to guarantee a predictable, minimum level of fixed income payments, regardless of investment performance of your Account Balance during the pay-in phase.
|
| Optional Benefit [Flag] |
true
|
| Standard Benefit Expense (of Benefit Base), Maximum [Percent] |
0.70%
|
| Optional Benefit Expense, Footnotes [Text Block] |
You may only have one living benefit, the Guaranteed Minimum Income Benefit or the Lifetime Withdrawal Benefit, associated with your Contract at any given time. The charge for the Guaranteed Minimum Income Benefit is a percentage of your guaranteed minimum income base, as defined later in this Prospectus, and is deducted at the end of each Contract Year by withdrawing amounts on a pro-rata basis from your Fixed Interest Account Balance and Your Investment Options (net of any loans). (We take amounts from the Separate Account by canceling, if available, Accumulation Units from your Separate Account Balance.) You do not pay this charge once You are in the pay-out phase of your Contract. Different charges for the Guaranteed Minimum Income Benefit were in effect prior to May 4, 2009.
|
| Brief Restrictions / Limitations [Text Block] |
●No longer available for sale.●You may not have this optional benefit and another optional living benefit (Lifetime Withdrawal Guarantee) in effect at the same time.●Age restrictions apply.●May only be exercised after a 10-year waiting period.●Availability subject to state.●Cannot be terminated.●Withdrawals could significantly reduce the benefit.
|
| Name of Benefit [Text Block] |
Guaranteed Minimum Income Benefit
|
| Operation of Benefit [Text Block] |
Living BenefitsGMIB — (may also be known as the “Predictor” in our sales literature and advertising)As of the close of the Exchange on September, 17, 2018, the GMIB is not available for sale to any new employer sponsored retirement plan or to any new participants under an existing employer sponsored retirement plan.We offered the GMIB that, for an additional charge, offers protection against market risk (the risk that your investments may decline in value or underperform your expectations). Our guaranteed income benefit, called GMIB, is designed to allow You to invest your Account Balance in the market while at the same time assuring a specified guaranteed level of minimum fixed income payments if You elect to receive income payments (“annuitize”). The fixed annuity payment amount is guaranteed regardless of investment performance or the actual Account Balance at the time You elect income payments. Prior to exercising this optional benefit and annuitizing your Contract, You may make withdrawals up to a maximum level and still maintain the optional benefit amount. This optional benefit must be elected at Contract issue.This optional benefit is designed to guarantee a predictable, minimum level of fixed income payments, regardless of investment performance of your Account Balance during the pay-in phase. However, if applying your actual Account Balance at the time You annuitize the Contract to then current annuity purchase rates (outside of the optional benefit) produces higher income payments, You will receive the higher payments, and thus You will have paid for the optional benefit even though it was not used. Also, prior to exercising the optional benefit, You may make specified withdrawals that reduce your income base (as explained below) during the pay-in phase and still leave the optional benefit guarantees intact, provided the conditions of the optional benefit are met. Your registered representative can provide You an illustration of the amounts You would receive, with or without withdrawals, if You exercised the optional benefit.The GMIB was available in all states except New York. In the states of Montana, Utah and West Virginia, the GMIB was only available for elective TSA (non-ERISA) and SEP/SIMPLE Deferred Annuities. In Oregon, the GMIB was only available for TSA ERISA, 403(a) and 457(b) Deferred Annuities.Once elected, the optional benefit cannot be terminated except as discussed below.GMIB and Qualified ContractsThe GMIB may have limited usefulness in connection with a qualified Contract, such as TSA, TSA ERISA, IRA, 403(a), 401(a), 401(k) or 457(b), in circumstances where, due to the 10-year waiting period after purchase, the Contract Owner is unable to exercise the benefit until after the required beginning date of required minimum distributions under the Contract. In such event, required minimum distributions received from the Contract during the 10-year waiting period will have the effect of reducing the income base either on a proportionate or dollar for dollar basis, as the case may be. This may have the effect of reducing or eliminating the value of annuity payments under the GMIB. You should consult your tax adviser prior to electing a GMIB.If You take a full withdrawal of your Account Balance, your Contract is terminated by us due to its small Account Balance and inactivity (see “When We Can Cancel your Deferred Annuity”), your Contract lapses for any reason, or in those instances where your employer has the ability to do so your employer terminates the Contract, and there remains any income base, You forfeit your income base and any further rights to the GMIB.Facts About the Guaranteed Minimum Income BenefitIncome Base and GMIB Income Payments. We calculate an “income base” (as described below) that determines, in part, the minimum amount You receive as an income payment upon exercising the GMIB and annuitizing the Contract. It is important to recognize that this income base is not available for cash withdrawals and does not establish or guarantee your Account Balance or a minimum return for any Division.After a minimum 10-year waiting period, and not more than 30 days after the Contract Anniversary following your 85th birthday, You may exercise the benefit. We then will apply the income base calculated at the time of exercise to the GMIB Annuity Table (as described below) specified in the rider in order to determine your minimum guaranteed lifetime fixed monthly income payments. (Your actual payment may be higher than this minimum if, as discussed above, the base Contract under its terms would provide a higher payment.)If your employer, association or other group Contract holder has instituted loans for its plan or arrangement, You have taken a loan and You have also purchased the GMIB, we will not treat amounts withdrawn from your Account Balance on account of a loan as a withdrawal from the Contract for purposes of determining the income base. In addition, we will not treat the repayment of loan amounts as a purchase payment to the Contract for the purposes of determining the income base.The GMIB Annuity Table. The GMIB Annuity Table is specified in the rider. This table is calculated based on the Annuity 2000 Mortality Table with a 7-year age set back with interest of 2.5% per year. As with other pay-out types, the amount You receive as an income payment also depends on the income type You select, your age, and your sex (where permitted by state law). The annuity rates in the GMIB Annuity Table are conservative and a Withdrawal Charge may be applicable, so the amount of guaranteed minimum lifetime income that the GMIB produces may be less than the amount of annuity income that would be provided by applying your Account Balance on your annuity date to then-current annuity purchase rates.If You exercise the GMIB, your income payments will be the greater of:●the income payment determined by applying the amount of the income base to the GMIB Annuity Table, or●the income payment determined for the same income type in accordance with the base Contract. (See “Pay-Out Options (or Income Options).”)If You choose not to receive income payments as guaranteed under the GMIB, You may elect any of the income options available under the Contract.If the amount of the guaranteed minimum lifetime income that the GMIB produces is less than the amount of annuity income that would be provided by applying your Account Balance on the Annuity Date to the then-current annuity purchase rates, then You would have paid for an optional benefit You did not use.Description of the GMIBIn states where approved, the GMIB was available only up to, but not including, age 76 and You could have only elected the GMIB at the time You purchased the Contract. The GMIB may be exercised after a 10-year waiting period and then only within 30 days following a Contract Anniversary, provided that the exercise must occur no later than the 30-day period following the Contract Anniversary following your 85th birthday.Income BaseThe income base is equal to the greater of (a) or (b) below:(a)Highest Anniversary Value: On the issue date, the “Highest Anniversary Value” is equal to your initial purchase payment. Thereafter, the Highest Anniversary Value will be increased by subsequent purchase payments and reduced proportionately by the percentage reduction in Account Balance attributable to each subsequent withdrawal (including any applicable Withdrawal Charge). On each Contract Anniversary prior to your 81st birthday, the Highest Anniversary Value will be recalculated and set equal to the greater of the Highest Anniversary Value before the recalculation or the Account Balance on the date of the recalculation.The Highest Anniversary Value does not change after the Contract Anniversary immediately preceding your 81st birthday, except that it is increased for each subsequent purchase payment and reduced proportionally by the percentage reduction in Account Balance attributable to each subsequent withdrawal (including any applicable Withdrawal Charge).(b)Annual Increase Amount: On the date we issue your Contract, the “Annual Increase Amount” is equal to your initial purchase payment. Thereafter, the Annual Increase Amount is equal to (i) less (ii), where:(i)is purchase payments accumulated at the Annual Increase Rate of 6% (as defined below); and(ii)is withdrawal adjustments (as defined below) accumulated at the Annual Increase Rate.The Highest Anniversary Value and Annual Increase Amount are calculated independently of each other. When the Highest Anniversary Value is recalculated and set equal to the Account Balance, the Annual Increase Amount is not set equal to the Account Balance.Annual Increase Rate. As noted above we calculate an income base under the GMIB that helps determine the minimum amount You receive as an income payment upon exercising the benefit. One of the factors used in calculating the income base is called the “annual increase rate.” Through the Contract Anniversary immediately prior to your 81st birthday, the Annual Increase Rate is 6%.On the first Contract Anniversary, “at the beginning of the Contract Year” means on the issue date; on a later Contract Anniversary, “at the beginning of the Contract Year” means on the prior Contract Anniversary.During the 30-day period following the Contract Anniversary immediately prior to your 81st birthday, the annual increase rate is 0%.Withdrawal Adjustments. Withdrawal adjustments in a Contract Year are determined according to (a) or (b):(a)The withdrawal adjustment for each withdrawal in a Contract Year is the value of the Annual Increase Amount immediately prior to the withdrawal multiplied by the percentage reduction in Account Balance attributable to the withdrawal (including any applicable Withdrawal Charge); or(b)If total withdrawals in a Contract Year are not greater than the Annual Increase Rate multiplied by the Annual Increase Amount at the beginning of the Contract Year, and if these withdrawals are paid to You, the total withdrawal adjustments for that Contract Year will be set equal to the dollar amount of total withdrawals (including any applicable Withdrawal Charge) in that Contract Year. These withdrawal adjustments will replace the withdrawal adjustments defined in (a) immediately above and be treated as though the corresponding withdrawals occurred at the end of that Contract Year.As described in (a) above, if in any Contract Year You take cumulative withdrawals that exceed the Annual Increase Rate multiplied by the Annual Increase Amount at the beginning of the Contract Year, the Annual Increase Amount will be reduced in the same proportion that the entire withdrawal (including any applicable Withdrawal Charge) reduced the Account Balance. This reduction may be significant, particularly when the Account Balance is lower than the Annual Increase Amount, and could have the effect of reducing or eliminating the value of income payments under the GMIB optional benefit. Limiting your cumulative withdrawals during a Contract Year to not more than the Annual Increase Rate multiplied by the Annual Increase Amount at the beginning of the Contract Year, will result in dollar-for-dollar treatment of the withdrawals as described in (b) immediately above.Partial annuitizations are not permitted. No change in Contract Owner of the Contract or participant is permitted.In determining GMIB income payments, an amount equal to the Withdrawal Charge that would apply upon a complete withdrawal and the amount of any premium taxes and other taxes that may apply will be deducted from the income base. For purposes of calculating the income base, purchase payment credits (i.e., bonus payments) are not included.Exercising the GMIB. The only income types available with the purchase of this benefit are a Lifetime Income Annuity with a 10-Year Guarantee Period or a Lifetime Income Annuity for Two with a 10-Year Guarantee Period. If You decide to receive income payments under a Lifetime Income Annuity with a 10-Year Guarantee Period after age 79, the 10-Year guarantee is reduced as follows:
Lifetime Income Annuity for Two is available if the ages of the joint Annuitants are 10 years apart or less (or as permissible under our then current underwriting requirements, if more favorable).Effect of Outstanding Loans on the GMIB. You may not exercise this benefit if You have an outstanding loan balance. You may exercise this benefit if You repay your outstanding loan balance. If You desire to exercise this benefit and have an outstanding loan balance and repay the loan by making a partial withdrawal, your income base will be reduced to adjust for the repayment of the loan, according to the formula described above.Terminating the GMIB. This benefit will terminate upon the earliest of:1.The 30th day following the Contract Anniversary on or following your 85th birthday;2.The date You make a total withdrawal of your Account Balance (a pro-rata portion of the annual benefit charge for the GMIB will be assessed);3.You elect to receive income payments under the Contract and You do not elect to receive income payments under the GMIB (a pro-rata portion of the annual benefit charge for the GMIB will be assessed);4.On the day there are insufficient amounts to deduct the charge for the GMIB from your Account Balance; or5.If You die.For more information on when we may or may not terminate your Contract, see “When We Can Cancel Your Deferred Annuity”.Charges. The GMIB was available in Deferred Annuities for an additional charge of 0.70% (except for the states of Texas and Virginia for TSA ERISA, 403(a) and 457(b) Deferred Annuities and except for the state of Pennsylvania for TSA, SEP and SIMPLE IRA Deferred Annuities, where the charge is 0.35%) of the income base, deducted at the end of each Contract Year on the Contract Anniversary, by withdrawing amounts on a pro-rata basis from your Fixed Interest Account Balance and Separate Account Balance, net of any outstanding loans. We take amounts from the Separate Account by canceling Accumulation Units from your Separate Account Balance. If You make a total withdrawal of your Account Balance or elect to receive income payments under your Contract, a pro-rata portion of the annual optional benefit charge will be assessed based on the number of months from the last Contract Anniversary to the date of the withdrawal or the beginning of income payments. Prior to May 1, 2009, the charge for the optional GMIB is 0.35% of the income base. (For employer groups with TSA ERISA, 457(b) and 403(a) Deferred Annuities that were established on or before May 1, 2009 which elected at issue to make available the GMIB under their group Contract, participants who submit an application after May 1, 2009, will receive the lower charge of 0.35%.)Graphic. The purpose of the following graphic is to illustrate the operation of the GMIB. The investment results shown are hypothetical and are not representative of past or future performance. Actual investment results may be more or less than those shown and will depend upon a number of factors, including investment allocations and the investment experience of the Divisions chosen. The graphic does not reflect the deduction of fees and charges, Withdrawal Charges or income taxes or penalties.(1)The 6% Annual Increase Amount of the Income BaseDetermining a value upon which future income payments will be basedPrior to annuitization, your Account Balance fluctuates above and below your initial purchase payment depending on the investment performance of the Divisions You selected. Your purchase payments accumulate at the annual increase rate of 6%, through the Contract Anniversary immediately preceding your 81st birthday. Your purchase payments are also adjusted for any withdrawals (including any applicable Withdrawal Charge) made during this period. The line (your purchase payments accumulated at 6% a year adjusted for withdrawals and charges (“the 6% Annual Increase Amount of the Income Base”)) is the value upon which future income payments can be based.
Determining your guaranteed lifetime income streamAssume that You decide to annuitize your Contract and begin taking annuity payments after 30 years. In this example, your 6% Annual Increase Amount of the Income Base is higher than the Highest Anniversary Value and will produce a higher income benefit. Accordingly, the 6% Annual Increase Amount of the Income Base will be applied to the annuity pay-out rates in the GMIB Annuity Table to determine your lifetime annuity payments. The income base is not available for cash withdrawals and is only used for purposes of calculating the GMIB payment and the charge for the benefit.
(2)The “Highest Anniversary Value” (“HAV”)Determining a value upon which future income payments will be basedPrior to annuitization, the Highest Anniversary Value at each Contract Anniversary begins to lock in growth. The Highest Anniversary Value is adjusted upward each Contract Anniversary if the Account Balance at that time is greater than the amount of the current Highest Anniversary Value. Upward adjustments will continue until the Contract Anniversary immediately prior to the Contract Owner’s 81st birthday. The Highest Anniversary Value also is adjusted for any withdrawals taken (including any applicable Withdrawal Charge) or any additional payments made. The Highest Anniversary Value line is the value upon which future income payments can be based.
Determining your guaranteed lifetime income streamAssume that You decide to annuitize your Contract and begin taking annuity payments after 20 years. In this example, the Highest Anniversary Value is higher than the Account Balance. Accordingly, the Highest Anniversary Value will be applied to the annuity pay-out rates in the GMIB Annuity Table to determine your lifetime annuity payments. The income base is not available for cash withdrawals and is only used for purposes of calculating the GMIB payment and the charge for the benefit.
(3)Putting It All TogetherPrior to annuitization, the income base (the 6% Annual Increase Amount of the Income Base and the Highest Anniversary Value) work together to protect your future income. Upon annuitization of the Contract, You will receive income payments for life and the guaranteed minimum income base and the Account Balance will cease to exist. Also, the GMIB may only be exercised no later than the Contract Anniversary on or following the Contract Owner’s 85th birthday, after a 10-year waiting period, and then only within a 30-day period following the Contract Anniversary.
With the GMIB, the income base is applied to special, conservative GMIB annuity purchase factors, which are guaranteed at the time the Contract is issued. However, if then-current annuity purchase factors applied to the Account Balance would produce a greater amount of income, then You will receive the greater amount. In other words, when you annuitize your Contract You will receive whatever amount produces the greatest income payment. Therefore, if your Account Balance would provide greater income than would the amount provided under the GMIB, You will have paid for the GMIB although it was never used.
|
| Calculation Method of Benefit [Text Block] |
Example:(This calculation ignores the impact of Highest Anniversary Value which could further increase the guaranteed minimum income base.)Age 55 at issuePurchase Payment = $100,000.No additional purchase payments or partial withdrawals.Guaranteed minimum income base at age 65 = $100,000 × 1.0610 = $179,085 where 10 equals the number of years the purchase payment accumulates for purposes of calculating this benefit.Guaranteed minimum income floor = guaranteed minimum income base applied to the GMIB annuity table.GMIB annuity factor, unisex, age 65 = $4.21 per month per $1,000 applied for lifetime income with 10 years guaranteed.
| |
|
Guaranteed Minimum Income Floor |
| |
|
|
| |
|
|
| |
|
| The above chart ignores the impact of premium taxes and other taxes.
|
| MetLife Financial Freedom Select B, L and C Class | Lifetime Withdrawal Guarantee Benefit |
|
| Item 4. Fee Table [Line Items] |
|
| Optional Benefit Expense (of Other Amount), Maximum [Percent] |
0.95%
|
| Optional Benefit Expense, Footnotes [Text Block] |
The charge for the Lifetime Withdrawal Guarantee Benefit is a percentage of your Total Guaranteed Withdrawal Amount, as defined later in this Prospectus, and is deducted at the end of each Contract Year by withdrawing amounts on a pro-rata basis from your Fixed Interest Account Balance and Separate Account Balance. (We take amounts from the Separate Account by canceling Accumulation Units from your Separate Account Balance.) You do not pay this charge once You are in the pay-out phase of your Contract or after your rider terminates. If an Automatic Annual Step-Up occurs under a Lifetime Withdrawal Guarantee Benefit, we may increase the Lifetime Withdrawal Guarantee Benefit charge to the current charge, but no more than a maximum of 0.95%. Different charges for the optional Lifetime Withdrawal Guarantee Benefit were in effect prior to May 4, 2009. If, at the time the Contract was issued, the current charge for the benefit was equal to the maximum charge, then the charge for the benefit will not increase upon an Automatic Annual Step-Up.
|
| Item 10. Benefits Available [Line Items] |
|
| Name of Benefit [Text Block] |
Lifetime Withdrawal Guarantee Benefit
|
| Purpose of Benefit [Text Block] |
Guaranteed Payments for Life. So long as You make your first withdrawal on or after the date You reach age 59 1∕2, the LWG guarantees that we will make payments to You over your lifetime, even if your Remaining Guaranteed Withdrawal Amount and/or Account Balance decline to zero.
|
| Optional Benefit [Flag] |
true
|
| Optional Benefit Expense (of Other Amount), Maximum [Percent] |
0.95%
|
| Optional Benefit Expense, Footnotes [Text Block] |
The charge for the Lifetime Withdrawal Guarantee Benefit is a percentage of your Total Guaranteed Withdrawal Amount, as defined later in this Prospectus, and is deducted at the end of each Contract Year by withdrawing amounts on a pro-rata basis from your Fixed Interest Account Balance and Separate Account Balance. (We take amounts from the Separate Account by canceling Accumulation Units from your Separate Account Balance.) You do not pay this charge once You are in the pay-out phase of your Contract or after your rider terminates. If an Automatic Annual Step-Up occurs under a Lifetime Withdrawal Guarantee Benefit, we may increase the Lifetime Withdrawal Guarantee Benefit charge to the current charge, but no more than a maximum of 0.95%. Different charges for the optional Lifetime Withdrawal Guarantee Benefit were in effect prior to May 4, 2009. If, at the time the Contract was issued, the current charge for the benefit was equal to the maximum charge, then the charge for the benefit will not increase upon an Automatic Annual Step-Up.
|
| Brief Restrictions / Limitations [Text Block] |
●No longer available for sale.●Benefit limits available investment options. (See “Appendix A — Investment Options Available Under the Contract — Investment Allocation Restrictions for Certain Optional Benefits.”)●Age restrictions apply.●You may not have this optional benefit and another optional living benefit (Guaranteed Minimum Income Benefit) in effect at the same time.●In the first 15 Contract Years You may only cancel this benefit every 5 Contract Years. Thereafter You may cancel annually within 30 days following the eligible Contract Anniversary.
|
| Name of Benefit [Text Block] |
Lifetime Withdrawal Guarantee Benefit
|
| Operation of Benefit [Text Block] |
Withdrawal BenefitLWGAs of the close of the Exchange on September, 17, 2018, the LWG is not available for sale to any new employer sponsored retirement plan or to any new participants under an existing employer sponsored retirement plan.In states where approved, we offered the LWG for elective TSA (non-ERISA), SEP and SIMPLE IRA Deferred Annuities. If You elected the LWG, Roth purchase payments may be permitted. The LWG does not establish or guarantee an Account Balance or minimum return for any Division. The Remaining Guaranteed Withdrawal Amount and Total Guaranteed Withdrawal Amount are not available for withdrawal as a lump sum.Withdrawals are subject to applicable Contract Withdrawal Charges unless You take the necessary steps to elect to take your Annual Benefit Payment under a Systematic Withdrawal Program. Ordinary income taxes apply to withdrawals under this benefit and an additional 10% penalty tax may apply if You are under age 59 1∕2. Consult your own tax adviser to determine if an exception to the 10% penalty tax applies. You may not have this benefit and the GMIB in effect at the same time. You should carefully consider if the LWG is best for You. Here are some of the key features of the LWG.●Guaranteed Payments for Life. So long as You make your first withdrawal on or after the date You reach age 59 1∕2, the LWG guarantees that we will make payments to You over your lifetime, even if your Remaining Guaranteed Withdrawal Amount and/or Account Balance decline to zero.●Automatic Annual Step-Ups. The LWG provides automatic step-ups on each Contract Anniversary prior to the Contract Owner’s 86th birthday (and offers the Contract Owner the ability to opt out of the step-ups if the charge for this optional benefit should increase). Each of the Automatic Step-Ups will occur only prior to the Contract Owner’s 86th birthday.●Withdrawal Rates. The LWG uses a 5% withdrawal rate to determine the Annual Benefit Payment.●Cancellation. The LWG provides the ability to cancel the rider every five Contract Years for the first fifteen Contract Years and annually thereafter within 30 days following the eligible Contract Anniversary.●Allocation Restrictions. If You elect the LWG, You are limited to allocating your purchase payments and Account Balance among the Fixed Interest Account, and certain Divisions (as described in “Appendix A — Investment Options Available Under the Contract — Investment Allocation Restrictions for Certain Optional Benefits”).●Tax Treatment. The tax treatment of withdrawals under the LWG is uncertain. It is conceivable that the amount of potential gain could be determined based on the Remaining Guaranteed Withdrawal Amount at the time of the withdrawal, if the Remaining Guaranteed Withdrawal Amount is greater than the Account Balance (prior to Withdrawal Charges, if applicable). This could result in a greater amount of taxable income reported under a withdrawal and conceivably a limited ability to recover any remaining basis if there is a loss on surrender of the Contract. Consult your tax adviser prior to purchase.●Rider Charges. We will continue to assess the LWG rider charge even in the case where your remaining Guaranteed Withdrawal Amount, as described below, equals zero.●Qualified Plans. If your plan determines to terminate the Contract at a time when You have elected LWG, You forfeit any income base and any other rights to the LWG You have accrued under the LWG upon termination of the Contract.In considering whether to have purchased the LWG, You must have considered your desire for protection and the cost of the benefit with the possibility that had You not purchased the benefit, your Account Balance may be higher. In considering the benefit of the lifetime withdrawals, You should consider the impact of inflation. Even relatively low levels of inflation may have significant effect on purchasing power. The Automatic Annual Step-Up, as described below, may provide protection against inflation, if and when there are strong investment returns. As with any guaranteed withdrawal benefit, the LWG, however, does not assure that You will receive strong, let alone any, return on your investments. The LWG must be elected at Contract issue; You must be age 80 or younger at the time of purchase.Total Guaranteed Withdrawal Amount. The Total Guaranteed Withdrawal Amount may be referred to as the “income base” in marketing or other materials. The Total Guaranteed Withdrawal Amount is the minimum amount that You are guaranteed to receive over time while the LWG is in effect. We assess the LWG charge as a percentage of the Total Guaranteed Withdrawal Amount. The initial Total Guaranteed Withdrawal Amount is equal to your initial purchase payment, without taking into account any purchase payment credits (i.e., credit or bonus payments). The Total Guaranteed Withdrawal Amount is increased by each additional purchase payment (up to a maximum benefit amount of $5,000,000). If, however, a withdrawal results in cumulative withdrawals for the current Contract Year that exceed the Annual Benefit Payment, the Total Guaranteed Withdrawal Amount will be reduced by an amount equal to the difference between the Total Guaranteed Withdrawal Amount after the withdrawal and the Account Balance after the withdrawal (if such Account Balance is lower than the Total Guaranteed Withdrawal Amount). This reduction may be significant.Cumulative withdrawals in a given Contract Year will not decrease the Total Guaranteed Withdrawal Amount if such withdrawals do not exceed the Annual Benefit Payment in that Contract Year.Remaining Guaranteed Withdrawal Amount. The remaining Guaranteed Withdrawal Amount is the remaining amount guaranteed to be received over time. The initial remaining Guaranteed Withdrawal Amount is equal to the initial Total Guaranteed Withdrawal Amount. We increase the remaining Guaranteed Withdrawal Amount (up to a maximum amount of $5,000,000) by each additional purchase payment without taking into account any purchase payment credits (i.e., credit or bonus payments). The remaining Guaranteed Withdrawal Amount is also increased by the 5% Compounding Income Amount, as described below. All withdrawals (including applicable Withdrawal Charges) reduce the remaining Guaranteed Withdrawal Amount, not just withdrawals that exceed the Annual Benefit Payment (as with the Total Guaranteed Withdrawal Amount). If the withdrawal exceeds the Annual Benefit Payment, then we will additionally reduce the remaining Guaranteed Withdrawal Amount to equal the difference between the remaining Guaranteed Withdrawal Amount after the withdrawal and the Account Balance after the withdrawal (if lower). This reduction may be significant. The remaining Guaranteed Withdrawal Amount is also used to calculate an alternate death benefit available under the LWG. (See “Additional Information” below.)5% Compounding Income Amount. On each Contract Anniversary until the earlier of: (a) the date of the first withdrawal from the Contract or (b) the 10th Contract Anniversary, the Total Guaranteed Withdrawal Amount and the remaining Guaranteed Withdrawal Amount are increased by an amount equal to 5% multiplied by the Total Guaranteed Withdrawal Amount and the remaining Guaranteed Withdrawal Amount before such increase (up to a maximum benefit amount of $5,000,000). We take the Total Guaranteed Withdrawal Amount and the remaining Guaranteed Withdrawal Amount as of the last day of the Contract Year to determine the amount subject to the increase. The Total Guaranteed Withdrawal Amount and the remaining Guaranteed Withdrawal Amount may also be increased by the Automatic Annual Step-Up, if that would result in a higher Total Guaranteed Withdrawal Amount and remaining Guaranteed Withdrawal Amount.Automatic Annual Step-Up. On each Contract Anniversary prior to the Contract Owner’s 86th birthday, an Automatic Annual Step-Up will occur, provided that the Account Balance exceeds the Total Guaranteed Withdrawal Amount immediately before the Step-Up (and provided that You have not chosen to decline the Step-Up as described below).The Automatic Annual Step-Up will:●reset the Total Guaranteed Withdrawal Amount and the remaining Guaranteed Withdrawal Amount to the Account Balance on the date of the Step-Up, up to a maximum of $5,000,000, regardless of whether or not You have taken any withdrawals;●reset the Annual Benefit Payment equal to 5% of the Total Guaranteed Withdrawal Amount after the Step-Up; and●reset the LWG charge to the then current charge, up to a maximum of 0.95% for the same optional benefit.In the event that the charge applicable to Contract purchases at the time of the Step-Up is higher than your current LWG charge, and we elect to increase the benefit charge in connection with the Step-Up we will notify You in writing a minimum of 30 days in advance of the applicable Contract Anniversary and inform You that You may choose to decline the Automatic Annual Step-Up. If You choose to decline the Automatic Annual Step-Up, You must notify us in accordance with our administrative procedures (currently we require You to submit your request in writing at our Administrative Office no less than seven calendar days prior to the applicable Contract Anniversary).Once You notify us of your decision to decline the Automatic Annual Step-Up, You will no longer be eligible for future Automatic Annual Step-Ups unless You notify us in writing at our Administrative Office that You wish to reinstate the Step-Up. This reinstatement will take effect at the next Contract Anniversary after we receive your request for reinstatement. Please note that the Automatic Annual Step-Up may be of limited benefit if You intend to make purchase payments that would cause your Account Balance to approach $5,000,000 because the Total Guaranteed Withdrawal Amount and remaining Guaranteed Withdrawal Amount cannot exceed $5,000,000.Annual Benefit Payment. The initial Annual Benefit Payment is equal to the initial Total Guaranteed Withdrawal Amount multiplied by the 5% withdrawal rate. The Annual Benefit Payment may be referred to as “annual income amount” in marketing or other materials. If the Total Guaranteed Withdrawal Amount is later recalculated (for example, because of additional purchase payments, the 5% compounding amount, the Automatic Annual Step-Up, or withdrawals greater than the Annual Benefit Payment), the Annual Benefit Payment is reset equal to the new Total Guaranteed Withdrawal Amount multiplied by the 5% withdrawal rate.Important to Note.●If You take your first withdrawal before the date You reach age 59 1∕2, we will continue to pay the Annual Benefit Payment each year until the remaining Guaranteed Withdrawal Amount is depleted, even if your Account Balance declines to zero. This means if your Account Balance is depleted due to withdrawals not greater than the Annual Benefit Payment or the deduction of the benefit charge, and your remaining Guaranteed Withdrawal Amount is greater than zero, we will pay You the remaining Annual Benefit Payment, if any, not yet withdrawn during the Contract Year that the Account Balance was depleted, and beginning in the following Contract Year, we will continue paying the Annual Benefit Payment to You each year until your remaining Guaranteed Withdrawal Amount is depleted. This guarantees that You will receive your purchase payments even if your Account Balance declines to zero due to market performance so long as You do not take withdrawals greater than the Annual Benefit Payment; however, You will not be guaranteed income for the rest of your life.●If You take your first withdrawal on or after the date You reach age 59 1∕2, we will continue to pay the Annual Benefit Payment each year for the rest of your life, even if your remaining Guaranteed Withdrawal Amount and/ or Account Balance declines to zero. This means if your remaining Guaranteed Withdrawal Amount and/or your Account Balance is depleted due to withdrawals not greater than the Annual Benefit Payment or the deduction of the benefit charge, we will pay to You the remaining Annual Benefit Payment, if any, not yet withdrawn during that Contract Year that the Account Balance was depleted, and beginning in the following Contract Year, we will continue paying the Annual Benefit Payment to You each year for the rest of your life. Therefore, You will be guaranteed income for life.You should carefully consider when to begin taking withdrawals if You have elected the LWG Benefit. If You begin withdrawals too soon, your Total Guaranteed Withdrawal Amount and Remaining Guaranteed Withdrawal Amount are no longer increased by the 5% annual compounding increase. On the other hand, if You delay taking withdrawals for too long, You may limit the number of years available for You to take withdrawals in the future (due to life expectancy), and You may be paying for a benefit You are not using.You have the option of receiving withdrawals under the LWG or receiving payments under a Pay-Out Option. You should consult with your registered representative when deciding how to receive income under this Contract. In making this decision, You should consider many factors, including the relative amount of current income provided by the two options, the potential ability to receive higher future payments through potential increases to the value of the LWG, your potential need to make additional withdrawals in the future, and the relative values to You of the death benefits available prior to and after annuitization.At any time during the pay-in phase, You can elect to annuitize under current annuity rates in lieu of continuing the LWG. This may provide higher income amounts and/or different tax treatment than the payments received under the LWG.Effect of Outstanding Loans on the Total Guaranteed Withdrawal Amount and Remaining Guaranteed Withdrawal Amount. If there is an outstanding loan balance (including loans in default which we cannot offset or collect due to tax restrictions), any additional withdrawals will be treated as withdrawals in excess of the Annual Benefit Payment. In that event, the Total Guaranteed Withdrawal Amount will be reduced. The reduction will be equal to the difference between the Total Guaranteed Withdrawal Amount after the withdrawal and the Account Balance after the withdrawal. If the Account Balance after the withdrawal and minus any loan in default is higher than the Total Guaranteed Withdrawal Amount, no reduction will be made.In the event an outstanding loan balance is in default and we can withdraw the defaulted amount from your Account Balance, if the amount of the default does not exceed the Annual Benefit Payment, then the Total Guaranteed Withdrawal Amount will not be decreased. If the amount of the default exceeds the Annual Benefit Payment, the Total Guaranteed Withdrawal Amount will be reduced. The reduction will be equal to the difference between the Total Guaranteed Withdrawal Amount after the withdrawal and the Account Balance after the withdrawal. If the Account Balance after the withdrawal and minus any loan in default is higher than the Total Guaranteed Withdrawal Amount, no reduction will be made.Also, an additional reduction will be made to the Remaining Guaranteed Withdrawal Amount. This additional reduction will be equal to the difference between the Remaining Guaranteed Withdrawal Amount after the withdrawal and the Account Balance after the withdrawal. If the Account Balance after the withdrawal and minus any loan in default is higher than the Remaining Guaranteed Withdrawal Amount, no reduction will be made.Managing Your Withdrawals. It is important that You carefully manage your annual withdrawals. To ensure that You retain the full guarantees of this benefit, your annual withdrawals cannot exceed the Annual Benefit Payment each Contract Year. If a Withdrawal Charge does apply, the charge is not included in the amount withdrawn for the purpose of calculating whether annual withdrawals during a Contract Year exceed the Annual Benefit Payment. If a withdrawal from your Contract does result in annual withdrawals during a Contract Year exceeding the Annual Benefit Payment, the Total Guaranteed Withdrawal Amount will be recalculated and the Annual Benefit Payment will be reduced to the new Total Guaranteed Withdrawal Amount multiplied by the 5% withdrawal rate. In addition, as noted above, if a withdrawal results in cumulative withdrawals for the current Contract Year exceeding the Annual Benefit Payment, the Remaining Guaranteed Withdrawal Amount will also be reduced by an additional amount equal to the difference between the Remaining Guaranteed Withdrawal Amount after the withdrawal and the Account Balance after the withdrawal (if such Account Balance is lower than the Remaining Guaranteed Withdrawal Amount). These reductions in the Total Guaranteed Withdrawal Amount, Annual Benefit Payment, and Remaining Guaranteed Withdrawal Amount may be significant. You are still eligible to receive either lifetime payments or the remainder of the Remaining Guaranteed Withdrawal Amount so long as the withdrawal that exceeded the Annual Benefit Payment did not cause your Account Balance to decline to zero. A withdrawal that results in cumulative withdrawals in the current Contract Year exceeding the Annual Benefit Payment that reduces the Account Balance to zero will terminate the Contract.You can always take annual withdrawals less than the Annual Benefit Payment. However, if You choose to receive only a part of your Annual Benefit Payment in any given Contract Year, your Annual Benefit Payment is not cumulative and your Remaining Guaranteed Withdrawal Amount and Annual Benefit Payment will not increase. For example, since Your Annual Benefit Payment is 5% of your Remaining Guaranteed Withdrawal Amount, You cannot withdraw 3% in one year and then withdraw 7% the next year without exceeding your Annual Benefit Payment in the second year.Systematic Withdrawal Program. If available in your state, You may choose to take your Annual Benefit Payment under the Systematic Withdrawal Program, including the first Contract Year. If You do so, any Withdrawal Charges that would otherwise apply to such withdrawals will be waived. Your Systematic Withdrawal Program withdrawal amount will be adjusted on each Contract Anniversary for any changes in the Annual Benefit Payment as a result of Automatic Annual Step-Up, additional purchase payments or transfers received during the Contract Year. Any withdrawals taken outside of the Systematic Withdrawal Program will cause the Systematic Withdrawal Program to terminate. If the commencement of the Systematic Withdrawal Program does not coincide with a Contract Anniversary, the initial Systematic Withdrawal Program period will be adjusted to end on a Contract Anniversary.Required Minimum Distributions. You may be required to take withdrawals to fulfill minimum distribution requirements. These required distributions may be larger than your Annual Benefit Payment. After the first Contract Year, we will increase your Annual Benefit Payment to equal your required minimum distribution amount for that year, if such amounts are greater than your Annual Benefit Payment. You must be enrolled in the automated required minimum distribution service to qualify for this increase in the Annual Benefit Payment. The frequency of your withdrawals must be annual. The automated required minimum distribution service is based on information relating to this Contract only. To enroll in the automated required minimum distribution service, please contact our Administrative Office.Investment Allocation Restrictions. If You elect the LWG, You are limited to allocating your purchase payments and Account Balance among the Fixed Interest Account and the Divisions listed in “Appendix A — Investment Options Available Under the Contract — Investment Allocation Restrictions for Certain Optional Benefits.”Cancellation. You may elect to cancel the LWG every fifth Contract Anniversary for the first fifteen Contract Years and annually thereafter. We must receive your cancellation request within 30 days following the eligible Contract Anniversary in writing at our Administrative Office. The cancellation will take effect on the day we receive your request. If cancelled, the LWG will terminate, we will no longer deduct the LWG charge, and the allocation restrictions described above will no longer apply. The Contract, however, will continue.Termination. The LWG will terminate upon the earliest of:1.The date of a full withdrawal of the Account Balance (a pro rata portion of the annual charge will be assessed); You are still eligible to receive either the Remaining Guaranteed Withdrawal Amount or lifetime payments provided the withdrawal did not exceed the Annual Benefit Payment and the provisions and conditions of this optional benefit have been met;2.The date the Account Balance is applied to a Pay-Out Option (a pro-rata portion of the annual charge for this rider will be assessed);3.The date there are insufficient funds to deduct the charge from your Account Balance and your Contract is thereby terminated (whatever Account Balance is available to pay the annual charge for the benefit will be applied); You are still eligible to receive either the Remaining Guaranteed Withdrawal Amount or lifetime payments, provided the provisions and conditions of this optional benefit have been met; however, You will have no other benefits under the Contract;4.The date a defaulted loan balance, once offset, causes the Account Balance to reduce to zero;5.The Contract Owner dies;6.There is a change in Contract Owner, for any reason, unless we agree otherwise (a pro-rata portion of the annual charge for this rider will be assessed);7.The Contract is terminated (a pro-rata portion of the annual charge for this rider will be assessed except for termination because of death of the Contract Owner, then no charge will be assessed based on the period from the most recent Contract Anniversary to the date termination takes effect); or8.The effective date of cancellation of this benefit.Additional Information. The LWG may affect the death benefit available under your Contract. If the Contract Owner should die while the LWG is in effect, an alternative death benefit amount will be calculated under the LWG that can be taken in a lump sum. The LWG death benefit amount that may be taken as a lump sum will be equal to total purchase payments less any partial withdrawals and any outstanding loan balance. If this death benefit amount is greater than the death benefit provided by your Contract, and if withdrawals in each Contract Year did not exceed the Annual Benefit Payment, then this death benefit amount will be paid instead of the death benefit provided by the Contract. All other provisions of your Contract’s death benefit will apply.Alternatively, the Beneficiary may elect to receive the Remaining Guaranteed Withdrawal Amount as a death benefit, in which case we will pay the Remaining Guaranteed Withdrawal Amount on a monthly basis (or any mutually agreed upon frequency, but no less frequently than annually) until the Remaining Guaranteed Withdrawal Amount is exhausted. This death benefit will be paid instead of the applicable contractual death benefit (the Standard Death Benefit, the additional death benefit amount calculated under the LWG as described above, or the Annual Step-Up Death Benefit, if that benefit had been purchased by the Contract Owner). Otherwise, the provisions of those contractual death benefits will determine the amount of the death benefit. Except as may be required by the Code, an annual payment will not exceed the Annual Benefit Payment. If your Beneficiary dies while such payments are made, we will continue making the payments to the Beneficiary’s estate unless we have agreed to another payee in writing. Federal income tax law generally requires that such payments be substantially equal and begin over a period no longer than the Beneficiary’s remaining life expectancy with payments beginning no later than the end of the calendar year immediately following the year of your death.We reserve the right to accelerate any payment that is less than $500 or to comply with requirements under the Code (including minimum distribution requirement). If You terminate the LWG because (1) You make a total withdrawal of your Account Balance; (2) your Account Balance is insufficient to pay the LWG charge; or (3) the Contract Owner dies, You may not make additional purchase payments under the Contract.LWG charge. The LWG is available in Deferred Annuities, for an additional charge of 0.95% of the Total Guaranteed Withdrawal Amount, deducted at the end of each Contract Year by withdrawing amounts on a pro-rata basis from your Fixed Interest Account Balance and Separate Account Balance, after applying any 5% Compounding Income Amount and prior to taking into account any Automatic Annual Step-Up occurring on the Contract Anniversary. We take amounts from the Separate Account by canceling Accumulation Units from your Separate Account Balance. If an Automatic Annual Step- Up occurs under a LWG, we may increase the LWG charge to the then current charge for the same optional benefit, but no more than a maximum of 0.95%. If, at the time the Contract was issued, the current charge for the benefit was equal to the maximum charge, then the charge for the benefit will not increase upon an Automatic Annual Step-Up. If the LWG is in effect, the charge will continue even if your Remaining Guaranteed Withdrawal Amount equals zero.
|
| Calculation Method of Benefit [Text Block] |
ExamplesThe purpose of these examples is to illustrate the operation of the LWG. The investment results shown are hypothetical and are not representative of past or future performance. Actual investment results may be more or less than those shown and will depend upon a number of factors, including investment allocations and the investment experience of the Divisions chosen. The examples do not reflect the deduction of fees and charges, Withdrawal Charges and applicable income taxes and penalties. For purposes of the examples, it is assumed that no loans have been taken.A.LWG – The effect of Withdrawals on Your Annual Benefit Payment1.When Withdrawals Do Not Exceed the Annual Benefit PaymentAssume that a Contract had an initial purchase payment of $100,000. The initial Account Balance would be $100,000, the Total Guaranteed Withdrawal Amount would be $100,000, the initial Remaining Guaranteed Withdrawal Amount would be $100,000 and the initial Annual Benefit Payment would be $5,000 ($100,000 × 5%).Assume that $5,000 is withdrawn each year, beginning before the Contract Owner attains age 59 1∕2. The Remaining Guaranteed Withdrawal Amount is reduced by $5,000 each year as withdrawals are taken (the Guaranteed Total Withdrawal Amount is not reduced by these withdrawals). The Annual Benefit Payment of $5,000 is guaranteed to be received until the Remaining Guaranteed Withdrawal Amount is depleted, even if the Account Balance is reduced to zero.
If the first withdrawal is taken after age 59 1∕2, then the Annual Benefit Payment of $5,000 is guaranteed to be received for the Contract Owner’s lifetime, even if the Remaining Guaranteed Withdrawal Amount and the Account Balance are reduced to zero.2.When Withdrawals Do Exceed the Annual Benefit PaymentAssume that a Contract had an initial purchase payment of $100,000. The initial Account Balance would be $100,000, the Total Guaranteed Withdrawal Amount would be $100,000, the initial Remaining Guaranteed Withdrawal Amount would be $100,000 and the initial Annual Benefit Payment would be $5,000 ($100,000 × 5%).Assume that the Remaining Guaranteed Withdrawal Amount is reduced to $95,000 due to a withdrawal of $5,000 in the first year. Assume the Account Balance was further reduced to $75,000 at year two due to poor market performance. If You withdrew $10,000 at this time, your Account Balance would be reduced to $75,000 - $10,000 = $65,000. Your Remaining Guaranteed Withdrawal Amount would be reduced to $95,000 - $10,000 = $85,000. Since the withdrawal of $10,000 exceeded the Annual Benefit Payment of $5,000 and the resulting Remaining Guaranteed Withdrawal Amount would be greater than the resulting Account Balance, there would be an additional reduction to the Remaining Guaranteed Withdrawal Amount. The Remaining Guaranteed Withdrawal Amount after the withdrawal would be set equal to the Account Balance after the withdrawal ($65,000). This new Remaining Guaranteed Withdrawal Amount of $65,000 would now be the amount guaranteed to be available to be withdrawn over time. The Total Guaranteed Withdrawal Amount would also be reduced to $65,000. The Annual Benefit Payment would be set equal to 5% × $65,000 = $3,250.B.LWG — The Effect of Delaying the Exercise of Your LWG on Your Benefit PaymentAssume that a Contract had an initial purchase payment of $100,000. The initial Remaining Guaranteed Withdrawal Amount would be $100,000, the Total Guaranteed Withdrawal Amount would be $100,000, and the Annual Benefit Payment would be $5,000 ($100,000 × 5%).The Total Guaranteed Withdrawal Amount will increase by 5% of the Total Guaranteed Withdrawal Amount until the earlier of the first withdrawal or the 10th Contract Anniversary. The Annual Benefit Payment will be recalculated as 5% of the new Total Guaranteed Withdrawal Amount.If the first withdrawal is taken in the first Contract Year, then there would be no increase. The Total Guaranteed Withdrawal Amount would remain at $100,000 and the Annual Benefit Payment will remain at $5,000 ($100,000 × 5%).If the first withdrawal is taken in the second Contract Year, then the Total Guaranteed Withdrawal Amount would increase to $105,000 ($100,000 × 105%), and the Annual Benefit Payment would increase to $5,250 ($105,000 × 5%).If the first withdrawal is taken in the third Contract Year, then the Total Guaranteed Withdrawal Amount would increase to $110,250 ($105,000 × 105%), and the Annual Benefit Payment would increase to $5,513 ($110,250 × 5%).If the first withdrawal is taken after the 10th Contract Year, then the Total Guaranteed Withdrawal Amount would increase to $162,890 (the initial $100,000, increased by 5% per year, compounded annually for 10 years), and the Annual Benefit Payment would increase to $8,144 ($162,890 × 5%).
C.LWG — Automatic Annual Step-Ups and 5% Compounding Amount (No withdrawals or loans)Assume that a Contract had an initial purchase payment of $100,000. Assume that no withdrawals or loans are taken.At the first Contract Anniversary, provided that no withdrawals or loans are taken, the Total Guaranteed Withdrawal Amount is increased to $105,000 ($100,000 increased by 5%, compounded annually). Assume the Account Balance has increased to $110,000 at the first Contract Anniversary due to good market performance. The Automatic Annual Step-Up will increase the Total Guaranteed Withdrawal Amount from $105,000 to $110,000 and reset the Annual Benefit Payment to $5,500 ($110,000 × 5%).At the second Contract Anniversary, provided that no withdrawals or loans are taken, the Total Guaranteed Withdrawal Amount is increased to $115,500 ($110,000 increased by 5%, compounded annually). Assume the Account Balance has increased to $120,000 at the second Contract Anniversary due to good market performance. The Automatic Annual Step-Up will increase the Total Guaranteed Withdrawal Amount from $115,500 to $120,000 and reset the Annual Benefit Payment to $6,000 ($120,000 × 5%).Provided that no withdrawals or loans are taken, each year the Total Guaranteed Withdrawal Amount would increase by 5%, compounded annually, from the second Contract Anniversary through the ninth Contract Anniversary, and at that point would be equal to $168,852. Assume that during these Contract Years the Account Balance does not exceed the Total Guaranteed Withdrawal Amount due to poor market performance. Assume the Account Balance at the ninth Contract Anniversary has increased to $180,000 due to good market performance. The Automatic Annual Step-Up will increase the Total Guaranteed Withdrawal Amount from $168,852 to $180,000 and reset the Annual Benefit Payment to $9,000 ($180,000 × 5%).At the 10th Contract Anniversary, provided that no withdrawals or loans are taken, the Total Guaranteed Withdrawal Amount is increased to $189,000 ($180,000 increased by 5%, compounded annually). Assume the Account Balance is less than $189,000. There is no Automatic Annual Step-Up since the Account Balance is below the Total Guaranteed Withdrawal Amount; however, due to the 5% increase in the Total Guaranteed Withdrawal Amount, the Annual Benefit Payment is increased to $9,450 ($189,000 × 5%).LWG — Automatic Annual Step-ups and 5% Compounding Amount (No Withdrawals or Loans)
|
| MetLife Financial Freedom Select B, L and C Class | Lifetime Withdrawal Guarantee Benefit | Brighthouse Asset Allocation 20 Portfolio - Class B |
|
| Investment Option Restrictions [Line Items] |
|
| Investment Option Available with Benefit [Flag] |
true
|
| MetLife Financial Freedom Select B, L and C Class | Lifetime Withdrawal Guarantee Benefit | Brighthouse Asset Allocation 40 Portfolio - Class B |
|
| Investment Option Restrictions [Line Items] |
|
| Investment Option Available with Benefit [Flag] |
true
|
| MetLife Financial Freedom Select B, L and C Class | Lifetime Withdrawal Guarantee Benefit | Brighthouse Asset Allocation 60 Portfolio - Class B |
|
| Investment Option Restrictions [Line Items] |
|
| Investment Option Available with Benefit [Flag] |
true
|
| MetLife Financial Freedom Select B, L and C Class | Lifetime Withdrawal Guarantee Benefit | Brighthouse Asset Allocation 80 Portfolio - Class B |
|
| Investment Option Restrictions [Line Items] |
|
| Investment Option Available with Benefit [Flag] |
true
|
| MetLife Financial Freedom Select B, L and C Class | Waiver of Withdrawal Charge for Nursing Home or Hospital Confinement |
|
| Item 10. Benefits Available [Line Items] |
|
| Name of Benefit [Text Block] |
Waiver of Withdrawal Charge for Nursing Home or Hospital Confinement
|
| Purpose of Benefit [Text Block] |
Allows you to withdraw money without a Withdrawal Charge in the event of nursing home or hospital confinement, subject to certain conditions.
|
| Standard Benefit [Flag] |
true
|
| Standard Benefit Expense (of Benefit Base), Maximum [Percent] |
0.00%
|
| Brief Restrictions / Limitations [Text Block] |
●Only available after the first Contract Year.●Age restrictions, ownership requirements and doctor certification requirements apply.●Must be approved in your state.●You must meet certain length of confinement requirements.
|
| Name of Benefit [Text Block] |
Waiver of Withdrawal Charge for Nursing Home or Hospital Confinement
|
| MetLife Financial Freedom Select B, L and C Class | Waiver of Withdrawal Charge for Terminal Illness |
|
| Item 10. Benefits Available [Line Items] |
|
| Name of Benefit [Text Block] |
Waiver of Withdrawal Charge for Terminal Illness
|
| Purpose of Benefit [Text Block] |
Allows you to withdraw money without a Withdrawal Charge in the event of a terminal illness, subject to certain conditions.
|
| Standard Benefit [Flag] |
true
|
| Standard Benefit Expense (of Benefit Base), Maximum [Percent] |
0.00%
|
| Brief Restrictions / Limitations [Text Block] |
●Only available after the first Contract Year.●Age restrictions, ownership requirements and doctor certification requirements apply.●Must be approved in your state.●Certain requirements relating to the nature of the terminal illness apply.●You must not have been diagnosed with the terminal illness as of the Contract issue date.
|
| Name of Benefit [Text Block] |
Waiver of Withdrawal Charge for Terminal Illness
|
| MetLife Financial Freedom Select B, L and C Class | The Equity Generator |
|
| Item 10. Benefits Available [Line Items] |
|
| Name of Benefit [Text Block] |
The Equity Generator®
|
| Purpose of Benefit [Text Block] |
An amount equal to the interest earned in the Fixed Interest Account is transferred monthly to any one Division based on your selection.
|
| Standard Benefit [Flag] |
true
|
| Standard Benefit Expense (of Benefit Base), Maximum [Percent] |
0.00%
|
| Brief Restrictions / Limitations [Text Block] |
●If your Fixed Interest Account Balance at the time of a scheduled transfer is zero, this strategy is automatically discontinued.
|
| Name of Benefit [Text Block] |
The Equity Generator®
|
| MetLife Financial Freedom Select B, L and C Class | The Rebalancer |
|
| Item 10. Benefits Available [Line Items] |
|
| Name of Benefit [Text Block] |
The Rebalancer®
|
| Purpose of Benefit [Text Block] |
You select a specific asset allocation for your entire Account Balance from among the Divisions and the Fixed Interest Account, if available. Each quarter we transfer amounts among these options to bring the percentage of your Account Balance in each option back to your original allocation.
|
| Standard Benefit [Flag] |
true
|
| Standard Benefit Expense (of Benefit Base), Maximum [Percent] |
0.00%
|
| Brief Restrictions / Limitations [Text Block] |
●In the future, we may permit You to allocate less than 100% of your Account Balance to this strategy.
|
| Name of Benefit [Text Block] |
The Rebalancer®
|
| MetLife Financial Freedom Select B, L and C Class | The Index Selector |
|
| Item 10. Benefits Available [Line Items] |
|
| Name of Benefit [Text Block] |
The Index Selector®
|
| Purpose of Benefit [Text Block] |
You may select one of five asset allocation models which are designed to correlate to various risk tolerance levels. Each quarter the percentage in each of the Divisions in which the model invests and any Fixed Interest Account is brought back to the selected model percentage by transferring amounts among the Divisions and any Fixed Interest Account
|
| Standard Benefit [Flag] |
true
|
| Standard Benefit Expense (of Benefit Base), Maximum [Percent] |
0.00%
|
| Brief Restrictions / Limitations [Text Block] |
●Benefit limits available investment options.●The Index Selector is not available with the optional Lifetime Withdrawal Guarantee.
|
| Name of Benefit [Text Block] |
The Index Selector®
|
| MetLife Financial Freedom Select B, L and C Class | The Allocator |
|
| Item 10. Benefits Available [Line Items] |
|
| Name of Benefit [Text Block] |
The AllocatorSM
|
| Purpose of Benefit [Text Block] |
Transfers a dollar amount of your choice from the Fixed Interest Account to any of the Divisions you choose on a monthly basis.
|
| Standard Benefit [Flag] |
true
|
| Standard Benefit Expense (of Benefit Base), Maximum [Percent] |
0.00%
|
| Brief Restrictions / Limitations [Text Block] |
●Minimum periodic transfer of $50 is required.●Once your Fixed Interest Account Balance is exhausted, the strategy is discontinued.
|
| Name of Benefit [Text Block] |
The AllocatorSM
|
| MetLife Financial Freedom Select B, L and C Class | Systematic Withdrawal Option |
|
| Item 10. Benefits Available [Line Items] |
|
| Name of Benefit [Text Block] |
Systematic Withdrawal Program
|
| Purpose of Benefit [Text Block] |
Automatically withdraws a specific dollar amount or a percentage of your Account Balance of your choice each Contract Year.
|
| Standard Benefit [Flag] |
true
|
| Standard Benefit Expense (of Benefit Base), Maximum [Percent] |
0.00%
|
| Brief Restrictions / Limitations [Text Block] |
●Not available under the 457(b) Deferred Annuity issued to tax-exempt organizations.●Not available in all states.●Income taxes, tax penalties and Withdrawal Charges may apply to your withdrawals.●Subject to our required minimums and administrative restrictions.●Not available to the B and L Classes of the Deferred Annuities until the second Contract Year.●If You elect to receive payments through this program, You must have no loan outstanding from the Fixed Interest Account and You must either be 59 1∕2years old or have left your job. Tax law generally prohibits withdrawals from TSA Deferred Annuities before You reach 59 1∕2.●Not available in conjunction with any automated investment strategy.
|
| Name of Benefit [Text Block] |
Systematic Withdrawal Program
|
| MetLife Financial Freedom Select B, L and C Class | Premium Tax |
|
| Item 4. Fee Table [Line Items] |
|
| Other Transaction Fee (of Other Amount), Footnotes [Text Block] |
Premium taxes, if applicable, depend on the Contract You purchased and your home state or jurisdiction and range from 0 to 3.50% of Account Value (or, if applicable, purchase payments).
|
| MetLife Financial Freedom Select B, L and C Class | Loans |
|
| Item 4. Fee Table [Line Items] |
|
| Other Transaction Fee (of Other Amount), Footnotes [Text Block] |
The fee may be waived or reduced for certain Plans.
|
| Optional Benefit Expense, Footnotes [Text Block] |
The fee may be waived or reduced for certain Plans. The loan maintenance fee is paid on a quarterly basis at the end of each quarter on a pro-rata basis from the Divisions and the Fixed Interest Account in which You then have a balance.
|
| Item 10. Benefits Available [Line Items] |
|
| Optional Benefit Expense, Footnotes [Text Block] |
The fee may be waived or reduced for certain Plans. The loan maintenance fee is paid on a quarterly basis at the end of each quarter on a pro-rata basis from the Divisions and the Fixed Interest Account in which You then have a balance.
|
| MetLife Financial Freedom Select B, L and C Class | Optional Riders |
|
| Item 10. Benefits Available [Line Items] |
|
| Operation of Benefit [Text Block] |
Optional Death BenefitPlease note that the decision to purchase the optional death benefit is made at the time of application and is irrevocable. The optional death benefit is available subject to state approval. Your employer, association or other group Contract holder may limit the availability of any optional benefit. (A loan will decrease the value of any optional benefit purchased with this Contract. See your employer for more information about the availability and features of loans.)
|
| MetLife Financial Freedom Select B, L and C Class | Fixed Interest Account |
|
| Fixed Option Details [Line Items] |
|
| Fixed Option Details, Description [Text Block] |
The Fixed Interest AccountThe Deferred Annuities have a fixed interest rate option called the “Fixed Interest Account.” The Fixed Interest Account is not available to all Contract Owners. The Fixed Interest Account is part of our general account and offers an interest rate that is guaranteed by us. The minimum interest rate depends on the date your Contract was issued but will not be less than 3%. The interest rate for each amount allocated to the Fixed Interest Account is set by us in advance on the beginning of each calendar quarter (January 1, April 1, etc.). The declared interest rate in effect when an allocation to the Fixed Interest Account is made will be credited from the date it is received until the last day of the calendar quarter of the following year, at which time a renewal rate will be set. Thereafter, each year a renewal rate will apply to that amount plus the interest previously credited to that amount, as long as the amounts remain in the Fixed Interest Account. The renewal rate will be set by us in advance and will apply for 12 months. Interest will be credited to the Fixed Interest Account on a daily basis. Subject to our transfer rules, You may transfer money into and out of the Fixed Interest Account. For information regarding current interest rates, You may contact our Administrative Office. Information about the Fixed Interest Account, including its name, its term and its minimum guaranteed interest rate is available in Appendix A — Investment Options Available Under the Deferred Annuity — Fixed Option. The current interest rate may vary by Contract class.Because of exemptive and exclusionary provisions, interests in the Fixed Interest Account have not been registered under the Securities Act of 1933 (the “1933 Act”), and neither the Fixed Interest Account nor our general account has been registered as an investment company under the 1940 Act. The Fixed Interest Account and our general account are not subject to the provisions or restrictions of the 1933 Act or the 1940 Act. The Fixed Interest Account is not available with a Deferred Annuity issued in New York State with the optional Guaranteed Minimum Income Benefit. The variable Pay-Out Options under the Deferred Annuities have a fixed payment option called the “Fixed Income Option.” Under the Fixed Income Option, we guarantee the amount of your fixed income payments. These fixed options are not described in this Prospectus although we occasionally refer to them. All guarantees as to purchase payments or Account Balance allocated to the Fixed Interest Account, interest credited to the Fixed Interest Account, and fixed annuity payments are subject to the financial strength and claims-paying ability of Metropolitan Life Insurance Company.
|
| Fixed Option [Line Items] |
|
| Fixed Option Available, Name |
<span style="color:#000000;font-family:Times New Roman;font-size:10pt;margin-left:0.0pt;">Fixed Interest Account</span>
|
| Fixed Option Available, Term |
12 months
|
| Fixed Option Available, Minimum Guaranteed Interest Rate [Percent] |
3.00%
|
| MetLife Financial Freedom Select B, L and C Class | Risk of Loss [Member] |
|
| Item 3. Key Information [Line Items] |
|
| Risk [Text Block] |
Yes. You can lose money by investing in the Contract, including loss of principal.
|
| MetLife Financial Freedom Select B, L and C Class | Not Short Term Investment Risk [Member] |
|
| Item 3. Key Information [Line Items] |
|
| Risk [Text Block] |
No. This Contract is not a short-term investment and is not appropriate for an investor who needs ready access to cash.●Withdrawal Charges may apply to withdrawals made less than 13 Contract Years after You purchased the Contract. Withdrawal Charges will reduce the value of your Contract if You withdraw money during that time.●The benefits of tax deferral and living benefit protections also mean that the Contract is more beneficial to investors with a long time horizon.●Earnings on your Contract are taxed at ordinary income tax rates when You withdraw them, and You may have to pay a penalty if You take a withdrawal before age 59 1∕2.
|
| MetLife Financial Freedom Select B, L and C Class | Market Risk [Member] |
|
| Item 5. Principal Risks [Line Items] |
|
| Principal Risk [Text Block] |
Market Risk. An investment in the Contract is not a bank deposit and is not guaranteed by the Federal Deposit Insurance Corporation or any other governmental agency. The Contract is subject to market risk (the risk that your investments may decline in value or underperform your expectations). As a result, You can lose money by investing in the Contract, including loss of principal.
|
| MetLife Financial Freedom Select B, L and C Class | Early Withdrawal Risk [Member] |
|
| Item 5. Principal Risks [Line Items] |
|
| Principal Risk [Text Block] |
Early Withdrawal Risk. This Contract is not a short-term investment and is not appropriate for an investor who needs ready access to cash. If You withdraw early, You may have to pay a Withdrawal Charge and/or income taxes, including a tax penalty if You are younger than age 59 1∕2. Withdrawal Charges may apply if You withdraw money from the Contract less than 13 Contract Years after You purchased the Contract. Withdrawal Charges will reduce the value of your Contract if You withdraw money during that time. The benefits of tax deferral and living benefit protections also mean that the Contract is more beneficial to investors with a long time horizon.
|
| MetLife Financial Freedom Select B, L and C Class | Contract Benefits Risk [Member] |
|
| Item 5. Principal Risks [Line Items] |
|
| Principal Risk [Text Block] |
Contract Benefits Risk. Withdrawals that exceed limits specified by the terms of any benefit may affect the availability of the benefit by reducing the benefit by an amount greater than the value withdrawn, and/or could terminate the benefit. In addition, the Lifetime Withdrawal Guarantee imposes restrictions and limitations on your choice of Portfolios. These restrictions and requirements are intended to protect the Company and reduce the likelihood that we will have to pay guaranteed benefits under the Lifetime Withdrawal Guarantee out of our own assets. The restrictions and requirements could result in your missing out on some or all positive investment performance by certain of the Portfolios – this means your opportunity for investment gains may be limited.
|
| MetLife Financial Freedom Select B, L and C Class | Insurance Company Risk [Member] |
|
| Item 3. Key Information [Line Items] |
|
| Risk [Text Block] |
An investment in the Contract is subject to the risks related to the Company. Any obligations (including under the Fixed Interest Account), guarantees, or benefits, including any death benefit, are subject to the claims-paying ability of the Company and our long term ability to make such payments, and are not guaranteed by any other party. MetLife is regulated as an insurance company under state law, which generally includes limits on the amount and type of investments in its general account. However, there is no guarantee that we will be able to meet our claims paying obligations; there are risks to purchasing any insurance product. More information about the Company, including its financial strength ratings, is available upon request or by visiting https://www.metlife.com/about-us/corporate-profile/ratings/.
|
| MetLife Financial Freedom Select B, L and C Class | Contract Changes Risk [Member] |
|
| Item 5. Principal Risks [Line Items] |
|
| Principal Risk [Text Block] |
Contract Changes Risk. Subject to applicable law, we have the right to make certain changes to your Contract. Examples of the changes we may make include: (i) operating the Separate Account in any form permitted by law; (ii) taking any action necessary to comply with or obtain and continue any exemptions under the law (including favorable treatment under the Federal income tax laws) including limiting the number, frequency or types of transfers/reallocations permitted; (iii) transferring any assets in a Division to another Division, or to one or more Separate Accounts, or to our general account, or adding, combining or removing Divisions in the Separate Account; (iv) substituting Portfolio shares in any Division, with the shares of another class of Brighthouse Trust I, Brighthouse Trust II, or the shares of another investment company or any other investment permitted by law or closing, adding or removing Portfolios as Investment Division investments as permitted by law; (v) changing the way we assess charges, but without increasing the maximum aggregate amount charged to the Separate Account and any currently available Portfolio in connection with the Contracts; and (vi) making any necessary technical changes in the Contracts in order to conform with any of the above-described actions.
|
| MetLife Financial Freedom Select B, L and C Class | Risks Associated with Investment Options |
|
| Item 3. Key Information [Line Items] |
|
| Risk [Text Block] |
An investment in the Contract is subject to the risk of poor investment performance and can vary depending on the performance of the investment options available under the Contract (e.g., Portfolios).●Each investment option (including the Fixed Interest Account investment option) will have its own unique risks.●You should review these investment options before making an investment decision.
|
| MetLife Financial Freedom Select B, L and C Class | Contract Termination |
|
| Item 3. Key Information [Line Items] |
|
| Risk [Text Block] |
Subject to certain limitations, if your Account Balance falls below the minimum Account Balance or is not sufficient to pay the Contract charges, we may terminate your Contract.
|
| Item 5. Principal Risks [Line Items] |
|
| Principal Risk [Text Block] |
Contract Termination Subject to certain limitations, if your Account Balance falls below the minimum Account Balance or is not sufficient to pay the Contract charges, we may terminate your Deferred Annuity.
|
| MetLife Financial Freedom Select B, L and C Class | Risk of Underlying Portfolios |
|
| Item 5. Principal Risks [Line Items] |
|
| Principal Risk [Text Block] |
Risk of Underlying Portfolios. An investment in the Contract is subject to the risk of poor investment performance and can vary depending on the performance of the investment options available under the Contract (e.g., Portfolio Companies). Each investment option (including the Fixed Interest Account investment option) will have its own unique risks. We do not provide any investment advice and do not recommend or endorse any particular Portfolio. You bear the risk of any decline in the Account Balance of your Contract resulting from the performance of the Portfolios You have chosen. You should review these investment options before making an investment decision. Information regarding the Portfolios available under your Contract is available in Appendix A to this Prospectus.
|
| MetLife Financial Freedom Select B, L and C Class | Risks Associated with the Company |
|
| Item 5. Principal Risks [Line Items] |
|
| Principal Risk [Text Block] |
Insurance Company Risk. An investment in the Contract is subject to the risks related to the Company. Any obligations (including under the Fixed Interest Account), guarantees, or benefits are subject to the financial strength and claims-paying ability of the Company and our long term ability to make such payments, and are not guaranteed by any other party. MetLife is regulated as an insurance company under state law, which generally includes limits on the amount and type of investments in its general account. However, there is no guarantee that we will be able to meet our claims paying obligations; there are risks to purchasing any insurance product.
|
| MetLife Financial Freedom Select B, L and C Class | Conflicts of Interest |
|
| Item 5. Principal Risks [Line Items] |
|
| Principal Risk [Text Block] |
Conflicts of Interest. Your investment professional may receive compensation for selling this Contract to You, both in the form of commissions and because MetLife may share the revenue it earns on this Contract with the professional’s firm. This conflict of interest may influence your investment professional to recommend this Contract over another investment. In addition, some investment professionals may have a financial incentive to offer You a new contract in place of the one You own. You should only exchange your Contract if You determine, after comparing the features, fees, and risks of both contracts, that it is better for You to purchase the new contract rather than continue to own your existing Contract.
|
| MetLife Financial Freedom Select B, L and C Class | Suitability |
|
| Item 5. Principal Risks [Line Items] |
|
| Principal Risk [Text Block] |
Suitability. An investment in the Contract may not be suitable for all investors. For example, there is no additional tax benefit if You purchase the Contract through a tax-qualified plan or individual retirement account (IRA). Therefore, there should be reasons other than tax deferral for acquiring the Contract. You should consult with a tax or investment professional to determine the tax and other implications of an investment in and purchase payments received under the Contract.
|
| MetLife Financial Freedom Select B, L and C Class | Tax Risks |
|
| Item 5. Principal Risks [Line Items] |
|
| Principal Risk [Text Block] |
Taxation Risk. Although the provisions of the Internal Revenue Code (the “Code”) relevant to the Contract are generally described under “Federal Tax Considerations,” an investor should consult their own tax advisor concerning the effects of federal, state, local and foreign tax law on the Contract. No assurance can be given that, even if the tax provisions currently applicable to the Contract are favorable, the law or regulations or interpretations thereunder will not change and the Contract may be disadvantaged.
|
| MetLife Financial Freedom Select B, L and C Class | Cybersecurity |
|
| Item 5. Principal Risks [Line Items] |
|
| Principal Risk [Text Block] |
Cybersecurity. Our business is highly dependent upon the effective operation of our information systems, and those of our service providers, vendors, and other third parties. Cybersecurity breaches of such systems can be intentional or unintentional events, and can occur through unauthorized access to computer systems, networks or devices; infection from computer viruses or other malicious software code; or attacks that shut down, disable, slow or otherwise disrupt operations, business processes or website access or functionality and our disaster recovery systems may be insufficient to safeguard our ability to conduct business. Cybersecurity breaches can interfere with our processing of Contract transactions, including the processing of transfer orders from our website or with the Portfolios; impact our ability to calculate Accumulation Unit Values; cause the release and possible loss or destruction of confidential Contract Owner or business information; impede order processing or cause other operational issues; and result in regulatory enforcement actions or new laws or regulations which could increase our compliance costs. Although we continually make efforts to identify and reduce our exposure to cybersecurity risk, and we require our critical vendors to implement effective cybersecurity and data protection measures, there is no guarantee that we will be able to successfully manage this risk at all times.
|
| MetLife Financial Freedom Select B, L and C Class | Bonus Class Risk |
|
| Item 5. Principal Risks [Line Items] |
|
| Principal Risk [Text Block] |
Bonus Class Risk. Expenses of a class that includes a bonus feature may be higher than expenses of a class of the Contract without the bonus, and the additional amount of the bonus may be more than offset by the additional fees and charges associated with the bonus class, including Withdrawal Charges. Any bonus associated with the class will be retrieved upon exercise of a “Free Look” cancellation.
|
| MetLife Financial Freedom Select B, L and C Class | Pandemics and Other Public Health Issues and Other Events |
|
| Item 5. Principal Risks [Line Items] |
|
| Principal Risk [Text Block] |
Pandemics and Other Public Health Issues and Other Events. Pandemics and other public health issues or other events, and governmental, business, and consumer reactions to them, may affect economic conditions and may cause a large number of illnesses or deaths. Hurricanes, windstorms, earthquakes, hail, tornadoes, explosions, severe winter weather, fires, floods and mudslides, blackouts and man-made events such as riot, insurrection, terrorist attacks or acts of war may also cause catastrophic losses and increased claims. Any such catastrophes may also result in changes in consumer or business confidence, behavior and investment and business activity, changes to interest rates and other market risk factors, and governmental or other restrictions on economic activity for prolonged periods.
|
| MetLife Financial Freedom Select B, L and C Class | Terrorism and Security Risk |
|
| Item 5. Principal Risks [Line Items] |
|
| Principal Risk [Text Block] |
Terrorism and Security Risk. The continued threat of terrorism, ongoing or potential military conflict and other actions, and heightened security measures may cause economic uncertainty and result in loss of life, property damage, additional disruptions to commerce and reduced economic activity. The value of MetLife's investment portfolio may be adversely affected by declines in the credit and equity markets and reduced economic activity caused by such threats. Companies in which we maintain investments may suffer losses as a result of financial, commercial or economic disruptions, and such disruptions might affect the ability of those companies to pay interest or principal on their securities or mortgage loans. Terrorist or military actions also could disrupt our operations centers and result in higher than anticipated claims under our insurance policies.
|
| MetLife Financial Freedom Select B, L and C Class | Technology Risk |
|
| Item 5. Principal Risks [Line Items] |
|
| Principal Risk [Text Block] |
Technology Risk. Our business operations rely on functioning and secure information systems, including those of our vendors and other third parties. Technological changes present us with new or intensified challenges, and if we are unable to foresee or adapt to these changes, our business may be adversely affected. Technological changes may affect our business model and how we interact with our customers. The growth and availability of AI technologies, including generative AI, presents significant opportunities but also complex challenges; these include balancing and mitigating potential risks of harm posed by the development or deployment of AI technologies, as well as implementing and maintaining controls reasonably designed to ensure compliance with an increasingly complex AI regulatory landscape, with evolving requirements that may vary across jurisdictions. We may fail to adopt new technologies as effectively or efficiently as others, leading to competitive harm. If we are unable to update our business model to match evolving consumer preferences or the evolving technological landscape, we may be adversely affected.
|
| MetLife Financial Freedom Select B, L and C Class | e Class | Loans |
|
| Item 4. Fee Table [Line Items] |
|
| Other Transaction Fee, Current [Dollars] |
$ 75
|
| MetLife Financial Freedom Select B, L and C Class | e Bonus Class | Loans |
|
| Item 4. Fee Table [Line Items] |
|
| Other Transaction Fee, Current [Dollars] |
$ 75
|
| MetLife Financial Freedom Select B, L and C Class | C Class |
|
| Item 4. Fee Table [Line Items] |
|
| Deferred Sales Load (of Amount Surrendered), Maximum [Percent] |
0.00%
|
| Transfer Fee, Maximum [Dollars] |
$ 25
|
| Administrative Expense, Maximum [Dollars] |
$ 30
|
| Base Contract Expense (of Average Account Value), Maximum [Percent] |
1.45%
|
| Surrender Expense, 1 Year, Maximum [Dollars] |
$ 3,910
|
| Surrender Expense, 1 Year, Minimum [Dollars] |
3,050
|
| Surrender Expense, 3 Years, Maximum [Dollars] |
11,912
|
| Surrender Expense, 3 Years, Minimum [Dollars] |
9,358
|
| Surrender Expense, 5 Years, Maximum [Dollars] |
20,248
|
| Surrender Expense, 5 Years, Minimum [Dollars] |
16,040
|
| Surrender Expense, 10 Years, Maximum [Dollars] |
42,646
|
| Surrender Expense, 10 Years, Minimum [Dollars] |
34,536
|
| Annuitized Expense, 1 Year, Maximum [Dollars] |
3,910
|
| Annuitized Expense, 1 Year, Minimum [Dollars] |
3,050
|
| Annuitized Expense, 3 Years, Maximum [Dollars] |
11,912
|
| Annuitized Expense, 3 Years, Minimum [Dollars] |
9,358
|
| Annuitized Expense, 5 Years, Maximum [Dollars] |
20,248
|
| Annuitized Expense, 5 Years, Minimum [Dollars] |
16,040
|
| Annuitized Expense, 10 Years, Maximum [Dollars] |
42,646
|
| Annuitized Expense, 10 Years, Minimum [Dollars] |
34,536
|
| No Surrender Expense, 1 Year, Maximum [Dollars] |
3,910
|
| No Surrender Expense, 1 Year, Minimum [Dollars] |
3,050
|
| No Surrender Expense, 3 Years, Maximum [Dollars] |
11,912
|
| No Surrender Expense, 3 Years, Minimum [Dollars] |
9,358
|
| No Surrender Expense, 5 Years, Maximum [Dollars] |
20,248
|
| No Surrender Expense, 5 Years, Minimum [Dollars] |
16,040
|
| No Surrender Expense, 10 Years, Maximum [Dollars] |
42,646
|
| No Surrender Expense, 10 Years, Minimum [Dollars] |
$ 34,536
|
| MetLife Financial Freedom Select B, L and C Class | C Class | Annual Step-Up Death Benefit |
|
| Item 4. Fee Table [Line Items] |
|
| Optional Benefit Expense (of Other Amount), Maximum [Percent] |
0.10%
|
| Item 10. Benefits Available [Line Items] |
|
| Optional Benefit Expense (of Other Amount), Maximum [Percent] |
0.10%
|
| MetLife Financial Freedom Select B, L and C Class | C Class | Guaranteed Minimum Income Benefit |
|
| Item 4. Fee Table [Line Items] |
|
| Optional Benefit Expense (of Other Amount), Maximum [Percent] |
0.70%
|
| Item 10. Benefits Available [Line Items] |
|
| Optional Benefit Expense (of Other Amount), Maximum [Percent] |
0.70%
|
| MetLife Financial Freedom Select B, L and C Class | C Class | Lifetime Withdrawal Guarantee Benefit |
|
| Item 4. Fee Table [Line Items] |
|
| Optional Benefit Expense (of Other Amount), Maximum [Percent] |
0.95%
|
| Item 10. Benefits Available [Line Items] |
|
| Optional Benefit Expense (of Other Amount), Maximum [Percent] |
0.95%
|
| MetLife Financial Freedom Select B, L and C Class | C Class | Premium Tax |
|
| Item 4. Fee Table [Line Items] |
|
| Other Transaction Fee (of Other Amount), Maximum [Percent] |
3.50%
|
| MetLife Financial Freedom Select B, L and C Class | C Class | Loans |
|
| Item 4. Fee Table [Line Items] |
|
| Other Transaction Fee, Current [Dollars] |
$ 75
|
| Optional Benefit Expense, Maximum [Dollars] |
50
|
| Item 10. Benefits Available [Line Items] |
|
| Optional Benefit Expense, Maximum [Dollars] |
$ 50
|
| MetLife Financial Freedom Select B, L and C Class | B Class |
|
| Item 4. Fee Table [Line Items] |
|
| Deferred Sales Load (of Amount Surrendered), Maximum [Percent] |
10.00%
|
| Transfer Fee, Maximum [Dollars] |
$ 25
|
| Administrative Expense, Maximum [Dollars] |
$ 30
|
| Base Contract Expense (of Average Account Value), Maximum [Percent] |
1.15%
|
| Surrender Expense, 1 Year, Maximum [Dollars] |
$ 12,610
|
| Surrender Expense, 1 Year, Minimum [Dollars] |
11,750
|
| Surrender Expense, 3 Years, Maximum [Dollars] |
19,126
|
| Surrender Expense, 3 Years, Minimum [Dollars] |
16,556
|
| Surrender Expense, 5 Years, Maximum [Dollars] |
25,997
|
| Surrender Expense, 5 Years, Minimum [Dollars] |
21,736
|
| Surrender Expense, 10 Years, Maximum [Dollars] |
42,595
|
| Surrender Expense, 10 Years, Minimum [Dollars] |
34,241
|
| Annuitized Expense, 1 Year, Maximum [Dollars] |
3,610
|
| Annuitized Expense, 1 Year, Minimum [Dollars] |
2,750
|
| Annuitized Expense, 3 Years, Maximum [Dollars] |
11,026
|
| Annuitized Expense, 3 Years, Minimum [Dollars] |
8,456
|
| Annuitized Expense, 5 Years, Maximum [Dollars] |
18,797
|
| Annuitized Expense, 5 Years, Minimum [Dollars] |
14,536
|
| Annuitized Expense, 10 Years, Maximum [Dollars] |
39,895
|
| Annuitized Expense, 10 Years, Minimum [Dollars] |
31,541
|
| No Surrender Expense, 1 Year, Maximum [Dollars] |
3,610
|
| No Surrender Expense, 1 Year, Minimum [Dollars] |
2,750
|
| No Surrender Expense, 3 Years, Maximum [Dollars] |
11,026
|
| No Surrender Expense, 3 Years, Minimum [Dollars] |
8,456
|
| No Surrender Expense, 5 Years, Maximum [Dollars] |
18,797
|
| No Surrender Expense, 5 Years, Minimum [Dollars] |
14,536
|
| No Surrender Expense, 10 Years, Maximum [Dollars] |
39,895
|
| No Surrender Expense, 10 Years, Minimum [Dollars] |
$ 31,541
|
| MetLife Financial Freedom Select B, L and C Class | B Class | Annual Step-Up Death Benefit |
|
| Item 4. Fee Table [Line Items] |
|
| Optional Benefit Expense (of Other Amount), Maximum [Percent] |
0.10%
|
| Item 10. Benefits Available [Line Items] |
|
| Optional Benefit Expense (of Other Amount), Maximum [Percent] |
0.10%
|
| MetLife Financial Freedom Select B, L and C Class | B Class | Guaranteed Minimum Income Benefit |
|
| Item 4. Fee Table [Line Items] |
|
| Optional Benefit Expense (of Other Amount), Maximum [Percent] |
0.70%
|
| Item 10. Benefits Available [Line Items] |
|
| Optional Benefit Expense (of Other Amount), Maximum [Percent] |
0.70%
|
| MetLife Financial Freedom Select B, L and C Class | B Class | Lifetime Withdrawal Guarantee Benefit |
|
| Item 4. Fee Table [Line Items] |
|
| Optional Benefit Expense (of Other Amount), Maximum [Percent] |
0.95%
|
| Item 10. Benefits Available [Line Items] |
|
| Optional Benefit Expense (of Other Amount), Maximum [Percent] |
0.95%
|
| MetLife Financial Freedom Select B, L and C Class | B Class | Premium Tax |
|
| Item 4. Fee Table [Line Items] |
|
| Other Transaction Fee (of Other Amount), Maximum [Percent] |
3.50%
|
| MetLife Financial Freedom Select B, L and C Class | B Class | Loans |
|
| Item 4. Fee Table [Line Items] |
|
| Other Transaction Fee, Current [Dollars] |
$ 75
|
| Optional Benefit Expense, Maximum [Dollars] |
50
|
| Item 10. Benefits Available [Line Items] |
|
| Optional Benefit Expense, Maximum [Dollars] |
$ 50
|
| MetLife Financial Freedom Select B, L and C Class | L Class |
|
| Item 4. Fee Table [Line Items] |
|
| Deferred Sales Load (of Amount Surrendered), Maximum [Percent] |
9.00%
|
| Transfer Fee, Maximum [Dollars] |
$ 25
|
| Administrative Expense, Maximum [Dollars] |
$ 30
|
| Base Contract Expense (of Average Account Value), Maximum [Percent] |
1.30%
|
| Surrender Expense, 1 Year, Maximum [Dollars] |
$ 12,760
|
| Surrender Expense, 1 Year, Minimum [Dollars] |
11,900
|
| Surrender Expense, 3 Years, Maximum [Dollars] |
17,770
|
| Surrender Expense, 3 Years, Minimum [Dollars] |
15,208
|
| Surrender Expense, 5 Years, Maximum [Dollars] |
24,025
|
| Surrender Expense, 5 Years, Minimum [Dollars] |
19,790
|
| Surrender Expense, 10 Years, Maximum [Dollars] |
41,281
|
| Surrender Expense, 10 Years, Minimum [Dollars] |
33,050
|
| Annuitized Expense, 1 Year, Maximum [Dollars] |
3,760
|
| Annuitized Expense, 1 Year, Minimum [Dollars] |
2,900
|
| Annuitized Expense, 3 Years, Maximum [Dollars] |
11,470
|
| Annuitized Expense, 3 Years, Minimum [Dollars] |
8,908
|
| Annuitized Expense, 5 Years, Maximum [Dollars] |
19,525
|
| Annuitized Expense, 5 Years, Minimum [Dollars] |
15,290
|
| Annuitized Expense, 10 Years, Maximum [Dollars] |
41,281
|
| Annuitized Expense, 10 Years, Minimum [Dollars] |
33,050
|
| No Surrender Expense, 1 Year, Maximum [Dollars] |
3,760
|
| No Surrender Expense, 1 Year, Minimum [Dollars] |
2,900
|
| No Surrender Expense, 3 Years, Maximum [Dollars] |
11,470
|
| No Surrender Expense, 3 Years, Minimum [Dollars] |
8,908
|
| No Surrender Expense, 5 Years, Maximum [Dollars] |
19,525
|
| No Surrender Expense, 5 Years, Minimum [Dollars] |
15,290
|
| No Surrender Expense, 10 Years, Maximum [Dollars] |
41,281
|
| No Surrender Expense, 10 Years, Minimum [Dollars] |
$ 33,050
|
| MetLife Financial Freedom Select B, L and C Class | L Class | Annual Step-Up Death Benefit |
|
| Item 4. Fee Table [Line Items] |
|
| Optional Benefit Expense (of Other Amount), Maximum [Percent] |
0.10%
|
| Item 10. Benefits Available [Line Items] |
|
| Optional Benefit Expense (of Other Amount), Maximum [Percent] |
0.10%
|
| MetLife Financial Freedom Select B, L and C Class | L Class | Guaranteed Minimum Income Benefit |
|
| Item 4. Fee Table [Line Items] |
|
| Optional Benefit Expense (of Other Amount), Maximum [Percent] |
0.70%
|
| Item 10. Benefits Available [Line Items] |
|
| Optional Benefit Expense (of Other Amount), Maximum [Percent] |
0.70%
|
| MetLife Financial Freedom Select B, L and C Class | L Class | Lifetime Withdrawal Guarantee Benefit |
|
| Item 4. Fee Table [Line Items] |
|
| Optional Benefit Expense (of Other Amount), Maximum [Percent] |
0.95%
|
| Item 10. Benefits Available [Line Items] |
|
| Optional Benefit Expense (of Other Amount), Maximum [Percent] |
0.95%
|
| MetLife Financial Freedom Select B, L and C Class | L Class | Premium Tax |
|
| Item 4. Fee Table [Line Items] |
|
| Other Transaction Fee (of Other Amount), Maximum [Percent] |
3.50%
|
| MetLife Financial Freedom Select B, L and C Class | L Class | Loans |
|
| Item 4. Fee Table [Line Items] |
|
| Other Transaction Fee, Current [Dollars] |
$ 75
|
| Optional Benefit Expense, Maximum [Dollars] |
50
|
| Item 10. Benefits Available [Line Items] |
|
| Optional Benefit Expense, Maximum [Dollars] |
$ 50
|