N-4
May 01, 2026
USD ($)
yr
Contract
Dec. 31, 2025
Dec. 31, 2024
Dec. 31, 2023
Dec. 31, 2022
Dec. 31, 2021
Dec. 31, 2020
Dec. 31, 2019
Dec. 31, 2018
Dec. 31, 2017
Dec. 31, 2016
You could lose as much as 60% (for Segments
with a -40% Segment Buffer) to 90% (for Segments
with a -10% Segment Buffer) to 100% (for Growth
Multiplier Segments with a 0% Segment Buffer) of your
principal and previously credited interest due to negative index performance at Segment maturity, depending on the Segment Buffer applicable to the Segment in which you invest. The cumulative loss over the life of the contract could be much greater.
There is a risk of a substantial loss of your principal and previously credited
-25%
and the Segment Buffer is -10%,
we will credit -15%
(the amount that exceeds the Segment Buffer) on the Segment Maturity Date, assuming there are no fees or charges assessed, meaning your Segment Investment will decrease by 15%. We may change the Indices and/or Segment Options in the future, but we will always offer a Segment
Contract Adjustments
We use the Segment Interim Values for your Segments of the SIO if you remove any amount from a Segment on any date prior to the Segment Maturity Date. This amount may be less than the amount invested and may be less than the amount you would receive had you held the investment until maturity and, as a result, the amount paid upon death, surrender or free look prior to the Segment Maturity Date may also be less. You could lose a significant amount of money due to the use of the Segment Interim Values.
The Segment Interim Value will generally be negatively affected by increases in the expected volatility of index prices, interest rate increases, and by poor market performance. All other factors being equal, the Segment Interim Value would generally be lower the earlier a withdrawal, transfer or surrender is made during a Segment. Also, for all contracts using a Performance Cap Rate limiting factor, participation in upside performance for early withdrawals is
pro-rated
based on the period those amounts were invested in a Segment. This means you participate to a lesser extent in upside performance the earlier you take a withdrawal, transfer or surrender. A partial withdrawal or transfer out of a Segment will reduce the Segment Investment and such reduction may be greater than the dollar amount of the withdrawal or transfer. These withdrawals may also be subject to withdrawal charges, taxes, and possible tax consequences. FEES, EXPENSES AND ADJUSTMENTS | ||
Are There Charges or Adjustments for Early Withdrawals? |
Yes. Withdrawal Charges Each series of the contract provides for different withdrawal charge periods and percentages. Investment Edge ® ® Investment Edge ® Select Investment Edge ® ADV Segment Interim Value There is a Segment Interim Value adjustment for amounts removed from a Segment of the SIO before Segment maturity and because the end-of-term downside protection provided by a Segment Buffer does not apply to the Segment Interim Value, it is theoretically possible that you could lose up to 100% of your investment and previously credited interest in certain extreme scenarios even for Segments with a Segment Buffer. For example, if you allocate $100,000 to a 5-year Segment and later withdraw the entire amount before the 5 years have ended, you could lose up to $100,000 of your investment. This loss may be greater if you also have to pay a withdrawal charge under an Investment Edge® ® ® For additional information about charges and adjustments for surrenders and early withdrawals see “Withdrawal charge” and “Adjustments with respect to early distributions from Segments” in “Charges, expenses, and adjustments” in the Prospectus. | |
Are There Transaction Charges? |
Yes. For additional information about transaction charges see “Charges that the Company deducts” in “Charges, expenses, and adjustments” in the Prospectus. | |
Are There Ongoing Fees and Expenses? |
Yes. The table below describes the fees and expenses that you may pay each year , ® There is an implicit ongoing fee associated with Segments because the amount you can earn on a Segment is limited by us by the Segment’s Performance Cap Rate. The Performance Cap Rate may cause your returns under the Segment to be lower than the Index’s returns. In return for accepting this limit on Index gains, you receive some protection from Index losses through the Segment Buffer. The implicit ongoing fee from the Performance Cap Rate is not reflected in the tables below. |
Annual Fee |
Minimum |
Maximum | ||
Base Contract (varies by contract series) (1) |
0.00% |
1.25% | ||
Portfolio Company fees and expenses (2) |
0.54% |
3.48% | ||
Optional benefits available for an additional charge (for a single optional benefit, if elected) (3) |
0.30% |
0.50% | ||
(1) Expressed as an annual percent of daily net assets in the variable investment options and as a percentage of the rate of return for Segments in the SIO. (2) Expressed as an annual percentage of daily net assets in the Portfolio. This range is for the year ended December 31, 2025 and could change from year to year. (3) Expressed as an annual percentage of the applicable benefit base. | ||
Because your contract is customizable, the choices you make affect how much you will pay. To help you understand the cost of owning your contract, the following table shows the lowest and highest cost you could pay each year, which could add withdrawal charges and negative Segment Interim Value adjustments that substantially increase costs. |
Lowest Annual Cost $527 |
Highest Annual Cost $4,148 | |
Assumes: • Investment of $100,000 • 5% annual appreciation • Least expensive combination of contract series and Portfolio fees and expenses • No optional benefits • No sales charges or advisory fees • No additional contributions, transfers or withdrawals • No contract adjustments |
Assumes: • Investment of $100,000 • 5% annual appreciation • Most expensive combination of contract series (Investment Edge ® • No sales charges or advisory fees • No additional contributions, transfers or withdrawals • No contract adjustments | |
| For additional information about ongoing fees and expenses see “Fee Table” in the Prospectus. | ||
Yes.
Withdrawal Charges
Each series of the contract provides for different withdrawal charge periods and percentages.
Investment Edge
®
®
Investment Edge
®
Select
Investment Edge
®
ADV
Segment Interim Value
There is a Segment Interim Value adjustment for amounts removed from a Segment of the SIO before Segment maturity and because the end-of-term downside protection provided by a Segment Buffer does not apply to the Segment Interim Value, it is theoretically possible that you could lose up to 100% of your investment and previously credited interest in certain extreme scenarios even for Segments with a Segment Buffer. For example, if you allocate $100,000 to a contract, and/or if you have to pay taxes or tax penalties. Prior to the Segment Maturity Date, the following transactions trigger the Segment Interim Value calculation: (1) the receipt of an in good order death claim by your beneficiary; (2) a withdrawal (including a systematic withdrawal, a required minimum distribution, a withdrawal to pay advisory fees under an Investment Edge ADV contract and a free withdrawal under an Investment Edge Select contract); (3) a transfer; (4) if you surrender or annuitize your contract; or (5) if you cancel your contract and return it to us for a refund within your state’s “free look” period.
5-year
Segment and later withdraw the entire amount before the 5 years have ended, you could lose up to $100,000 of your investment. This loss may be greater if you also have to pay a withdrawal charge under an Investment Edge®
®
®
For additional information about charges and adjustments for surrenders and early withdrawals see “Withdrawal charge” and “Adjustments with respect to early distributions from Segments” in “Charges, expenses, and adjustments” in the Prospectus.
5-year
Segment and later withdraw the entire amount before the 5 years have ended, you could lose up to $100,000 of your investment. This loss may be greater if you also have to pay a withdrawal charge under an Investment Edge®
Yes.
For additional information about transaction charges see “Charges that the Company deducts” in “Charges, expenses, and adjustments” in the Prospectus.
Are There Ongoing Fees and Expenses? |
Yes. The table below describes the fees and expenses that you may pay each year , ® There is an implicit ongoing fee associated with Segments because the amount you can earn on a Segment is limited by us by the Segment’s Performance Cap Rate. The Performance Cap Rate may cause your returns under the Segment to be lower than the Index’s returns. In return for accepting this limit on Index gains, you receive some protection from Index losses through the Segment Buffer. The implicit ongoing fee from the Performance Cap Rate is not reflected in the tables below. |
Annual Fee |
Minimum |
Maximum | ||
Base Contract (varies by contract series) (1) |
0.00% |
1.25% | ||
Portfolio Company fees and expenses (2) |
0.54% |
3.48% | ||
Optional benefits available for an additional charge (for a single optional benefit, if elected) (3) |
0.30% |
0.50% | ||
(1) Expressed as an annual percent of daily net assets in the variable investment options and as a percentage of the rate of return for Segments in the SIO. (2) Expressed as an annual percentage of daily net assets in the Portfolio. This range is for the year ended December 31, 2025 and could change from year to year. (3) Expressed as an annual percentage of the applicable benefit base. | ||
Expressed as an annual percent of daily net assets in the variable investment options and as a percentage of the rate of return for Segments in the SIO.
Expressed as an annual percentage of the applicable benefit base.
Expressed as an annual percentage of daily net assets in the Portfolio. This range is for the year ended December 31, 2025 and could change from year to year.
Because your contract is customizable, the choices you make affect how much you will pay. To help you understand the cost of owning your contract, the following table shows the lowest and highest cost you could pay each year, which could add withdrawal charges and negative Segment Interim Value adjustments that substantially increase costs. |
Lowest Annual Cost $527 |
Highest Annual Cost $4,148 | |
Assumes: • Investment of $100,000 • 5% annual appreciation • Least expensive combination of contract series and Portfolio fees and expenses • No optional benefits • No sales charges or advisory fees • No additional contributions, transfers or withdrawals • No contract adjustments |
Assumes: • Investment of $100,000 • 5% annual appreciation • Most expensive combination of contract series (Investment Edge ® • No sales charges or advisory fees • No additional contributions, transfers or withdrawals • No contract adjustments | |
| For additional information about ongoing fees and expenses see “Fee Table” in the Prospectus. | ||
Assumes:
•
Investment of $100,000
•
5% annual appreciation
•
Least expensive combination of contract series and Portfolio fees and expenses
•
No optional benefits
•
No sales charges or advisory fees
•
No additional contributions, transfers or withdrawals
•
No contract adjustments
Assumes:
•
Investment of $100,000
•
5% annual appreciation
•
Most expensive combination of contract series (Investment Edge Select), optional benefits (Return of Premium death benefit) and Portfolio fees and expenses
®
•
No sales charges or advisory fees
•
No additional contributions, transfers or withdrawals
•
No contract adjustments
RISKS | ||
Is There a Risk of Loss from Poor Performance? |
Yes. The return on the Segments of the SIO may be negative and there is a risk of substantial loss of your principal and previously credited interest due to negative index performance because you agree to absorb all losses to the extent they exceed the Segment Buffer. You could lose as much as 60% (for Segments with a - 40 % Segment Buffer) to 90% (for Segments with a -10% Segment Buffer) to 100% (for Growth Multiplier Segments with a 0 % Segment Buffer) of your principal and previously credited interest due to negative index performance on the Segment Maturity Date. We may change the Indices and/or Segment Options in the future, but we will always offer a Segment Option with a Segment Buffer that protects the first 10% of loss.For additional information about the risk of loss see “Principal risks of investing in the contract” in the Prospectus. | |
Is this a Short-Term Investment? |
No. Contract value in a Segment will be reallocated at Segment Maturity according to your instructions. If you have not provided us with maturity instructions for a maturing Segment, the Segment Maturity Value will be transferred to the Segment Type Holding Account for the same Segment Type as the maturing Segment. Your Segment Maturity Value would then be transferred from that Segment Type Holding Account into the next Segment of that Segment Type on the Segment Start Date. If the |
next Segment to be created would not meet the Segment Maturity Date Requirement or the Segment Type has been terminated, we will instead transfer your Segment Maturity Value to the EQ/Money Market variable investment option. If you are impacted by these delays, you may transfer your Segment Maturity Value into another Segment Type Holding Account or into any other investment options available under your contract at any time before the next month’s Segment Start Date. For additional information about the investment profile of the contract see “Fee Table” in the Prospectus. | ||
What Are the Risks Associated with the Investment Options? |
An investment in the contract is subject to the risk of poor investment performance and can vary depending on the performance of the variable investment options (e.g., the Portfolios) and the SIO (e.g., the reference Indices). Each investment option available under the contract has its own unique risks. You should review the Portfolios and the Segments of the SIO available under the contract before making an investment decision. The Performance Cap Rate of a Segment may limit your participation in positive returns on the Segment Maturity Date. For example, if the Index return is 12% and the Performance Cap Rate is 4%, we will credit 4% in interest on the Segment Maturity Date, assuming there are no fees or charges assessed, meaning your Segment Investment will increase by 4%. The Performance Cap Rate may cause your returns under the Segment to be lower than the Index’s returns. The Segment Buffer of a Segment provides some protection against negative returns on the Segment Maturity Date. The Segment Buffer is the maximum amount of negative interest we will assume and we will credit any negative interest in excess of the Segment Buffer, which means you bear all loss that exceeds the Segment Buffer. For example, if the Index return is -25% and the Segment Buffer is -10%, we will credit -15% (the amount that exceeds the Segment Buffer) on the Segment Maturity Date, assuming there are no fees or charges assessed, meaning your Segment Investment will decrease by 15%.All of the Indices we currently offer are “price return” indices, not “total return” indices, and therefore the performance of any Index does not reflect dividends paid on the securities included in the Index. This reduces the Index return, and the Index will underperform a direct investment in the securities composing the Index. For additional information about the risks associated with investment options see ”Structured Investment Option”, “Variable investment options” and “Portfolios of the Trusts” in “Purchasing the contract”, as well as, “Principal risks of investing in the contract” and Appendix “Investment Options available under the contract” in the Prospectus. | |
What Are the Risks Related to the Insurance Company? |
An investment in the contract is subject to the risks related to the Company. The Company is solely responsible to the contract owner for the contract’s account value. The general obligations, including the SIO and the death benefits, under the contract are supported by our general account and are subject to our claims-paying ability. An owner should look solely to our financial strength for our claims-paying ability. More information about the Company, including our financial strength ratings, may be obtained at https://equitable.com/about-us/financial-strength-ratings. For additional information about insurance company risks see “About the general account” in “More information” in the Prospectus. |
Contract value in a Segment will be reallocated at Segment Maturity according to your instructions. If you have not provided us with maturity instructions for a maturing Segment, the Segment Maturity Value will be transferred to the Segment Type Holding Account for the same Segment Type as the maturing Segment. Your Segment Maturity Value would then be transferred from that Segment Type
Holding Account into the next Segment of that Segment Type on the Segment Start Date. If the
next Segment to be created would not meet the Segment Maturity Date Requirement or the Segment Type has been terminated, we will instead transfer your Segment Maturity Value to the EQ/Money Market variable investment option.
The Performance Cap Rate may cause your returns under the Segment to be lower than the Index’s returns.
-25%
and the Segment Buffer is -10%,
we will credit -15%
(the amount that exceeds the Segment Buffer) on the Segment Maturity Date, assuming there are no fees or charges assessed
Yes.
You will not be permitted to invest in a Segment if the Segment Maturity Date is later than your contract maturity date. The maximum current number of active variable investment options (including variable investment options with an allocation on file), Segments, and funded holding accounts that may be active in your contract at any time is 88.
We reserve the right to offer any or all Segment Types more or less frequently or to stop offering any or all of them temporarily for some or all contracts. If we stop offering these options, you will be limited to investing in the other investment options described in this Prospectus.
We may offer new Segment Types in the future, and we may change the features of a Segment Type between Segments, including the Index, the Segment Buffer, and the Performance Cap Rate (subject to the minimum rates disclosed herein).
We have the right to substitute an alternative Index prior to the Segment Maturity Date if the publication of one or more Indices is discontinued, or if we no longer have a license agreement with the publishers of the Index, or at our sole discretion we determine that our use of such Indices should be discontinued because hedging instruments become difficult to acquire or the cost of hedging becomes excessive, or if the calculation of one or more of the Indices is substantially changed. In addition, we reserve the right to use any or all reasonable methods to end any outstanding Segments that use such Indices. We also have the right to add additional Indices under the contract at any time.
We can refuse to accept any application or contribution from you at any time, including after you purchase the contract. We reserve the right to discontinue the acceptance of, and/or place additional limitations on, contributions into certain investment options, including any or all of the Segments comprising the Structured Investment Option. If we exercise this right, your ability to invest in your contract, increase your account value and, consequently, increase your death or living benefits under the contract, if elected, will be limited. However, subject to any limitations under your variable annuity contract, you could continue to invest in your contract through other available investment options.
Currently, we do not charge for transfers among investment options under the contract. However, we reserve the right to charge for any transfers in excess of 12 per contract year. We will provide you with advance notice if we decide to assess the transfer charge, which will never exceed $35 per transfer.
For additional information about restrictions on the investment options, see “Transfer charge” in “Charges, expenses, and adjustments”, “The Separate Account” in “More Information”, and “Portfolios of the Trusts” and “Structured Investment Option” in “Purchasing the contract” in the Prospectus.
Yes.
If you elect the Return of Premium death benefit you generally cannot make additional contributions to your contract once you reach age 76.
Withdrawals, including withdrawals to pay advisory fees, that exceed limits specified by the terms of an optional benefit may affect the availability of the benefit by reducing the benefit by an amount greater than the value withdrawn, and/or could terminate the benefit.
If you purchase an Investment Edge ADV contract and you elect to pay the advisory fee from your account value, then this deduction will be treated as a withdrawal and will reduce the standard death benefit, the Return of Premium death benefit, and payments under the Income Edge payment program, and may also be subject to federal and state income taxes and a 10% federal penalty tax. See “Fee based programs” in “Purchasing the contract” in the Prospectus.
®
For additional information about the optional benefits see “How you can purchase and contribute to your contract” in “Purchasing the contract” and “Benefits available under the contract” in the Prospectus.
You should consult with a tax professional to determine the tax implications of an investment in, and payments received under, the contract. There is no additional tax benefit to you if the contract is purchased through a tax-qualified plan or individual retirement account (IRA). Withdrawals will be subject to ordinary income tax and may be subject to tax penalties. Generally, you are not taxed until you make a withdrawal from the contract.
For additional information about tax implications see “Tax information” in the Prospectus.
Some financial professionals may receive compensation for selling the contract to you, both in the form of commissions or in the form of contribution-based compensation. Financial professionals may also receive additional compensation for enhanced marketing opportunities and other services (commonly referred to as “marketing allowances”). This conflict of interest may influence the financial professional to recommend this contract over another investment.
For additional information about compensation to financial professionals see “Distribution of the contracts” in “More information” in the Prospectus.
Some financial professionals may have a financial incentive to offer a new contract in place of the one you already own. You should only exchange your contract if you determine, after comparing the features, fees, and risks of both contracts, as well as any fees or penalties to terminate your existing contract, that it is preferable to purchase the new contract rather than continue to own your existing contract.
For additional information about exchanges see “Charge for third-party transfer or exchange” in “Charges, expenses, and adjustments” in the Prospectus.
Fee Table
The following tables describe the fees, expenses, and adjustments that you will pay when buying, owning, surrendering or making withdrawals from an investment option or from the contract.
Please refer to your contract specifications page for information about the specific fees you will pay each year based on the options you have elected.
The fees and expenses do not reflect any advisory fees paid to a financial intermediary from the contract or other assets of the owner and if such charges were reflected such fees and expenses would be higher.
The first table describes fees and expenses that you will pay at the time that you buy the contract, surrender the contract or if you make certain withdrawals from an investment option or from the contract, transfer account value between investment options, or request special services. Charges designed to approximate certain taxes that may be imposed on us, such as premium taxes in your state, may also apply.
Transaction Expenses | ||||||||
Investment Edge ® |
Investment Edge ® Select |
Investment Edge ® ADV | ||||
| Sales Load Imposed on Purchases (as a percentage of purchase payments) | None | None | None | |||
| Withdrawal Charge (as a percentage of contributions withdrawn) | 6.00% (1) |
None | None | |||
| Transfer Fee (2) |
$35 | $35 | $35 | |||
| Third Party Transfer or Exchange Fee (3) |
$125 | $125 | $125 | |||
| Special Service Charges (4) |
$90 | $90 | $90 |
(1) |
For Investment Edge ® |
Charge as a % of contribution for each year following contribution | ||||||||||||
1 |
2 |
3 |
4 |
5 |
6+ | |||||||
| Investment Edge ® |
6% | 6% | 5% | 4% | 3% | 0% | ||||||
| (2) | Currently, we do not charge for transfers among investment options under the contract. However, we reserve the right to charge for transfers in excess of 12 transfers per contract year. We will charge no more than $35 for each transfer at the time each transfer is processed. See “Transfer charge” under “Charges that the Company deducts” in “Charges, expenses, and adjustments”. |
| (3) | Currently, we do not charge for third party transfers or exchanges. However, we reserve the right to discontinue this waiver at any time, with or without notice. The maximum third party transfer or exchange fee is $125. The current charge (which, as described above is waived) is $65. This charge will never exceed 2% of the amount disbursed or transferred. These charges may increase over time to cover our administrative costs. We may discontinue these services at any time. |
| (4) | Special service charges include (1) express mail charge; (2) wire transfer charge; (3) duplicate contract charge; (4) check preparation charge (the sum of this charge will never exceed 2% of the amount distributed); and (5) Duplicate Annual and/or Quarterly Statement of Account or Annual Payout Statement Charge. The current maximum charge for each service is $90. These charges may increase over time to cover our administrative costs. We may discontinue these services at any time. |
The
next
table
describes
the adjustments, in addition to any transaction expenses, that apply if all or a portion of the account value is removed from an investment option or from the contract before the expiration of a specified period.
Adjustments |
||||||
Investment Edge ® |
Investment Edge ® Select |
Investment Edge ® ADV | ||||
SIO Segment Maximum Potential Loss Due to Segment Interim Value adjustment (as a percentage of account value invested in the Segment on the Segment Start Date) (1) |
100% |
100% |
100% | |||
| (1) | The actual amount of the Segment Interim Value calculation is determined by a formula that depends on, among other things, the Segment Option, Segment Buffer and how the Index has performed since the Segment Start Date. The maximum loss would occur if there is a total distribution for a Growth Multiplier Segment at a time when the Index price has declined to zero. If you surrender or cancel your variable annuity contract, die, transfer or make a withdrawal from a Segment before the Segment Maturity Date, the Segment Buffer, if any, will not necessarily apply to the extent it would on the Segment Maturity Date, and any upside performance may be limited to a percentage lower than the Performance Cap Rate. See “Structured Investment Option” for more information. |
The next table describes the fees and expenses that you will pay
each year
during the time that you own the contract (not including Portfolio fees and expenses). If you choose to purchase an optional benefit, you will pay additional charges, as shown below.
Annual Contract Expenses | ||||||
Investment Edge ® |
Investment Edge ® Select |
Investment Edge ® ADV | ||||
| Contract Maintenance Fee (1) |
$50 (1) |
$50 (1) |
None | |||
| Base Contract Expenses (as a percentage of daily net assets in the variable investment options and as a percentage of the rate of return for Segments of the SIO) (2) |
1.00% | 1.25% | None | |||
Optional Benefits Expenses (as a percentage of the benefit base)(3)(4) |
||||||
| Return of Premium death benefit charge | 0.50% (5) |
0.50% (5) |
0.50% (5) | |||
| (1) | Beginning with your first contract date anniversary, we will deduct this charge on any contract date anniversary on which your account value is less than $50,000. If the contract is surrendered or annuitized or a death benefit is paid on any date other than the contract date anniversary, we will deduct a pro rata portion of the charge for that year. Otherwise, we will deduct the full charge. This charge will no longer apply to NQ contracts following election of an Income Edge payment program, even if your account value falls below $50,000. |
| (2) | The Contract Fee percentage reduces the Segment Rate of Return. If the contract is surrendered or annuitized, a withdrawal or transfer out is taken, or a death benefit is paid, on any date other than the Segment Maturity Date, we will deduct a pro rata portion of the charge from each Segment as part of the Segment Interim Value calculation. |
| (3) | The benefit base is equal to your initial contribution to the contract less any withdrawals you made from the contract. |
| (4) | If on any date other than the contract date anniversary your contract is surrendered or annuitized, an Income Edge payment program is elected and become effective, a death benefit is paid, or the Return of Premium death benefit is otherwise terminated, we will deduct a pro rata portion of the charge from your account value. |
| (5) | The current charge is 0.30%. |
In addition to the fees described above, we limit the amount you can earn on the Segments. This means your returns may be lower than the Index’s returns. In return for accepting this limit on Index gains, you will receive some protection from Index losses.
The next item shows the minimum and maximum total operating expenses charged by the underlying Portfolios that you may pay periodically during the time that you own the contract. Expenses shown may change over time and may be higher or lower in the future. A complete list of Portfolios available under the contract, including their annual expenses, may be found at the back of this document. See Appendix “Investment Options available under the contract.”
Annual Portfolio Expenses |
||||
Minimum |
Maximum | |||
Annual Portfolio Expenses prior to Expense Limitation Arrangement (expenses that are deducted from Portfolio assets including management fees, 12b-1 fees, service fees, and other expenses) (1) |
0.54% |
3.48% | ||
Annual Portfolio Expenses after Expense Limitation Arrangement (expenses that are deducted from Portfolio assets including management fees, 12b-1 fees, service fees, and other expenses) (1) |
0.53% |
3.29% | ||
(1) |
“Annual Portfolio Expenses” are based, in part, on estimated amounts of such expenses. The expenses listed are for the year ended December 31, 2025. Pursuant to a contract, Equitable Investment Management Group, LLC has agreed to make payments or waive its management, administrative and other fees to limit the expenses of certain affiliated Portfolios through April 30, 2027 (“Expense Limitation Arrangement”) (unless the Trust’s Board of Trustees consents to an earlier revision or termination of this agreement). The Expense Limitation Arrangement may be terminated by Equitable Investment Management Group, LLC at any time after April 30, 2027. The Expense Limitation Arrangement does not apply to unaffiliated Portfolios. |
Examples
These Examples are intended to help you compare the cost of investing in the variable investment options with the cost of investing in other annuity contracts that offer variable investment options. These costs include transaction expenses, annual contract expenses, and annual Portfolio expenses.
These Examples assume all account value is allocated to the variable investment options. The Examples do not reflect the Segment Interim Value adjustment for the Segments of the SIO. Your costs could differ from those shown below if you invest in the Segments.
These Examples do not reflect any advisory fees paid to a financial intermediary from the contract or other assets of the owner and if such charges were reflected the costs would be higher.
These Examples assume that you invest $100,000 in the variable investment options for the time periods indicated. The Examples also assume that your investment has a 5% return each year and assume the most expensive combination of annual Portfolio expenses and benefits available for an additional charge (the Return of Premium death benefit (at its maximum charge)).
Although your actual costs may be higher or lower, based on these assumptions, your cost would be:
If you surrender your contract or annuitize (under a non-life option) at the end of the applicable time period |
If you do not surrender your contract |
|||||||||||||||||||||||||||||||
1 year |
3 years |
5 years |
10 years |
1 year |
3 years |
5 years |
10 years |
|||||||||||||||||||||||||
InvestmentEdge ® |
$ |
11,205 |
$ |
20,585 |
$ |
28,925 |
$ |
51,606 |
$ |
5,205 |
$ |
15,585 |
$ |
25,925 |
$ |
51,606 |
||||||||||||||||
InvestmentEdge ® |
$ |
5,467 |
$ |
16,330 |
$ |
27,101 |
$ |
53,622 |
$ |
5,467 |
$ |
16,330 |
$ |
27,101 |
$ |
53,622 |
||||||||||||||||
InvestmentEdge ® |
$ |
4,161 |
$ |
12,587 |
$ |
21,156 |
$ |
43,214 |
$ |
4,161 |
$ |
12,587 |
$ |
21,156 |
$ |
43,214 |
||||||||||||||||
The first table describes fees and expenses that you will pay at the time that you buy the contract, surrender the contract or if you make certain withdrawals from an investment option or from the contract, transfer account value between investment options, or request special services. Charges designed to approximate certain taxes that may be imposed on us, such as premium taxes in your state, may also apply.
Transaction Expenses | ||||||||
Investment Edge ® |
Investment Edge ® Select |
Investment Edge ® ADV | ||||
| Sales Load Imposed on Purchases (as a percentage of purchase payments) | None | None | None | |||
| Withdrawal Charge (as a percentage of contributions withdrawn) | 6.00% (1) |
None | None | |||
| Transfer Fee (2) |
$35 | $35 | $35 | |||
| Third Party Transfer or Exchange Fee (3) |
$125 | $125 | $125 | |||
| Special Service Charges (4) |
$90 | $90 | $90 |
(1) |
For Investment Edge ® |
Charge as a % of contribution for each year following contribution | ||||||||||||
1 |
2 |
3 |
4 |
5 |
6+ | |||||||
| Investment Edge ® |
6% | 6% | 5% | 4% | 3% | 0% | ||||||
| (2) | Currently, we do not charge for transfers among investment options under the contract. However, we reserve the right to charge for transfers in excess of 12 transfers per contract year. We will charge no more than $35 for each transfer at the time each transfer is processed. See “Transfer charge” under “Charges that the Company deducts” in “Charges, expenses, and adjustments”. |
| (3) | Currently, we do not charge for third party transfers or exchanges. However, we reserve the right to discontinue this waiver at any time, with or without notice. The maximum third party transfer or exchange fee is $125. The current charge (which, as described above is waived) is $65. This charge will never exceed 2% of the amount disbursed or transferred. These charges may increase over time to cover our administrative costs. We may discontinue these services at any time. |
| (4) | Special service charges include (1) express mail charge; (2) wire transfer charge; (3) duplicate contract charge; (4) check preparation charge (the sum of this charge will never exceed 2% of the amount distributed); and (5) Duplicate Annual and/or Quarterly Statement of Account or Annual Payout Statement Charge. The current maximum charge for each service is $90. These charges may increase over time to cover our administrative costs. We may discontinue these services at any time. |
®
The next table describes the fees and expenses that you will pay
each year
during the time that you own the contract (not including Portfolio fees and expenses). If you choose to purchase an optional benefit, you will pay additional charges, as shown below.
Annual Contract Expenses | ||||||
Investment Edge ® |
Investment Edge ® Select |
Investment Edge ® ADV | ||||
| Contract Maintenance Fee (1) |
$50 (1) |
$50 (1) |
None | |||
| Base Contract Expenses (as a percentage of daily net assets in the variable investment options and as a percentage of the rate of return for Segments of the SIO) (2) |
1.00% | 1.25% | None | |||
Optional Benefits Expenses (as a percentage of the benefit base)(3)(4) |
||||||
| Return of Premium death benefit charge | 0.50% (5) |
0.50% (5) |
0.50% (5) | |||
| (1) | Beginning with your first contract date anniversary, we will deduct this charge on any contract date anniversary on which your account value is less than $50,000. If the contract is surrendered or annuitized or a death benefit is paid on any date other than the contract date anniversary, we will deduct a pro rata portion of the charge for that year. Otherwise, we will deduct the full charge. This charge will no longer apply to NQ contracts following election of an Income Edge payment program, even if your account value falls below $50,000. |
| (2) | The Contract Fee percentage reduces the Segment Rate of Return. If the contract is surrendered or annuitized, a withdrawal or transfer out is taken, or a death benefit is paid, on any date other than the Segment Maturity Date, we will deduct a pro rata portion of the charge from each Segment as part of the Segment Interim Value calculation. |
| (3) | The benefit base is equal to your initial contribution to the contract less any withdrawals you made from the contract. |
| (4) | If on any date other than the contract date anniversary your contract is surrendered or annuitized, an Income Edge payment program is elected and become effective, a death benefit is paid, or the Return of Premium death benefit is otherwise terminated, we will deduct a pro rata portion of the charge from your account value. |
| (5) | The current charge is 0.30%. |
The next item shows the minimum and maximum total operating expenses charged by the underlying Portfolios that you may pay periodically during the time that you own the contract. Expenses shown may change over time and may be higher or lower in the future. A complete list of Portfolios available under the contract, including their annual expenses, may be found at the back of this document. See Appendix “Investment Options available under the contract.”
Annual Portfolio Expenses |
||||
Minimum |
Maximum | |||
Annual Portfolio Expenses prior to Expense Limitation Arrangement (expenses that are deducted from Portfolio assets including management fees, 12b-1 fees, service fees, and other expenses) (1) |
0.54% |
3.48% | ||
Annual Portfolio Expenses after Expense Limitation Arrangement (expenses that are deducted from Portfolio assets including management fees, 12b-1 fees, service fees, and other expenses) (1) |
0.53% |
3.29% | ||
(1) |
“Annual Portfolio Expenses” are based, in part, on estimated amounts of such expenses. The expenses listed are for the year ended December 31, 2025. Pursuant to a contract, Equitable Investment Management Group, LLC has agreed to make payments or waive its management, administrative and other fees to limit the expenses of certain affiliated Portfolios through April 30, 2027 (“Expense Limitation Arrangement”) (unless the Trust’s Board of Trustees consents to an earlier revision or termination of this agreement). The Expense Limitation Arrangement may be terminated by Equitable Investment Management Group, LLC at any time after April 30, 2027. The Expense Limitation Arrangement does not apply to unaffiliated Portfolios. |
Examples
These Examples are intended to help you compare the cost of investing in the variable investment options with the cost of investing in other annuity contracts that offer variable investment options. These costs include transaction expenses, annual contract expenses, and annual Portfolio expenses.
These Examples assume all account value is allocated to the variable investment options. The Examples do not reflect the Segment Interim Value adjustment for the Segments of the SIO. Your costs could differ from those shown below if you invest in the Segments.
These Examples do not reflect any advisory fees paid to a financial intermediary from the contract or other assets of the owner and if such charges were reflected the costs would be higher.
These Examples assume that you invest $100,000 in the variable investment options for the time periods indicated. The Examples also assume that your investment has a 5% return each year and assume the most expensive combination of annual Portfolio expenses and benefits available for an additional charge (the Return of Premium death benefit (at its maximum charge)).
Although your actual costs may be higher or lower, based on these assumptions, your cost would be:
If you surrender your contract or annuitize (under a non-life option) at the end of the applicable time period |
If you do not surrender your contract |
|||||||||||||||||||||||||||||||
1 year |
3 years |
5 years |
10 years |
1 year |
3 years |
5 years |
10 years |
|||||||||||||||||||||||||
InvestmentEdge ® |
$ |
11,205 |
$ |
20,585 |
$ |
28,925 |
$ |
51,606 |
$ |
5,205 |
$ |
15,585 |
$ |
25,925 |
$ |
51,606 |
||||||||||||||||
InvestmentEdge ® |
$ |
5,467 |
$ |
16,330 |
$ |
27,101 |
$ |
53,622 |
$ |
5,467 |
$ |
16,330 |
$ |
27,101 |
$ |
53,622 |
||||||||||||||||
InvestmentEdge ® |
$ |
4,161 |
$ |
12,587 |
$ |
21,156 |
$ |
43,214 |
$ |
4,161 |
$ |
12,587 |
$ |
21,156 |
$ |
43,214 |
||||||||||||||||
3.
This section discusses certain risks associated with purchasing a contract. The level of risk you bear and your potential investment performance will differ depending on the investments you choose.
Variable Investment Options
| • | The value of your variable investment options will fluctuate and you could lose some or all of your account value. |
• |
The level of risk you bear and your potential investment performance will differ depending on the investments you choose. |
Structured Investment Option
An investor is not invested in the Index or in the securities tracked by the Index.
Limiting Negative Returns (Segment Risk of Loss)
| • | There is a risk of a substantial loss of your principal and previously credited interest despite limits on negative index returns because you agree to absorb all losses from the portion of any negative Index Performance Rate that exceeds the Segment Buffer on the Segment Maturity Date. Some Segments have a 0% Segment Buffer which provides no protection and, therefore, you could lose as much as 100% of your principal and previously credited interest due to negative index performance on the Segment Maturity Date in those Segments. The highest level of protection provided by a single Segment Investment Option is the -40% Segment Buffer (only available on certain Segments) and the lowest level of protection is the -10% Segment Buffer. You could lose as much as 60% (for Segments with a -40% Segment Buffer) to 90% (for Segments with a -10% Segment Buffer) of your principal and previously credited interest due to negative index performance on the Segment Maturity Date. |
We may change the Indices and/or Segment Options in the future, but we will always offer a Segment Option with a Segment Buffer that protects the first 10% of loss.
| — | For example, the -10% Segment Buffer protects your Segment Investment against the first 10% of loss. If the Index Performance Rate declines by more than the Segment Buffer, you will lose an amount equal to 1% of your Segment Investment for every 1% that the Index Performance Rate declines below the Segment Buffer. This means that you could lose up to 60% of your principal and previously credited interest with a -40% Segment Buffer, up to 80% of your principal and previously credited interest with a -20% Segment Buffer, up to 85% of your principal and previously credited interest with a -15% Segment Buffer, up to 90% of your principal and previously credited interest with a -10% Segment Buffer, and up to 100% of your principal and previously |
| credited interest with a 0% Segment Buffer. Each time you roll over your Segment Maturity Value into a new Segment you are subject to the same risk of loss as described above. |
Limiting Positive Returns (Performance Cap Rates)
| • | The Performance Cap Rate is a rate of return from the Segment Start Date to the Segment Maturity Date, and not an annual rate of return, even if the Segment Duration is longer than one year. |
| • | Your Segment Rate of Return for any Segment with a positive Index Performance Rate is limited by its Performance Cap Rate, if applicable, which could cause your Segment Rate of Return to be lower than it would otherwise be if you invested in a mutual fund designed to track the performance of the applicable Index. |
| • | The Performance Cap Rate, if applicable, may limit your participation in any increases in the underlying Index associated with a Segment. |
| • | Each contract series may have different Performance Cap Rates. |
| • | The Performance Cap Rate for the same Segment may vary between owners but will not be less than the minimum Performance Cap Rate. |
| • | If you elect a Cap Rate Hold, the Performance Cap Rates applicable to your Segments may be lower or higher than the Performance Cap Rates otherwise applicable for the same Segments on that Segment Start Date. This means you would receive lower Performance Cap Rates for your Segments than an owner investing in those same Segments who did not elect a Cap Rate Hold. See “Structured Investment Option — Segment Performance Cap Rate Hold” in “Purchasing the contract” for more information. |
| • | Other Segments will generally have lower Performance Cap Rates than Standard Segments with the same Index, Segment Duration and Segment Buffer. |
| • | Segment Types with greater protection tend to have lower Performance Cap Rates than other similar Segment Types that use the same Index and duration but provide less protection. |
Risks Related to Withdrawals (Segment Interim Value)
• |
There is a risk of loss of principal and previously credited interest in (1) taking a withdrawal (including a systematic withdrawal and/or required minimum distribution); (2) transferring account value to a different investment option; (3) deducting account value to pay fees, including advisory fees; (4) surrendering or annuitizing your contract; (5) payment of a death claim; and (6) canceling your contract and returning it to us for a refund within your state’s |
“free look” period prior to a Segment Maturity Date due to charges and Segment Interim Value adjustments imposed on those distributions, and this may occur even if index performance has been positive. |
| • | The method we use in calculating your Segment Interim Value may result in an amount lower than your Segment Investment, even if the corresponding Index has experienced positive investment performance since the Segment Start Date. Also, this amount may be less than the amount you would receive had you held the investment until the Segment Maturity Date. Because the end-of-term downside protection provided by a Segment Buffer does not apply to the Segment Interim Value, it is theoretically possible that you could lose up to 100% of your investment and previously credited interest in certain extreme scenarios even for Segments with a Segment Buffer. ® contract, or if you have to pay taxes or tax penalties. See “Withdrawals and surrenders” below. |
| — | If you take a withdrawal, including required minimum distributions, and there is insufficient value in the variable investment options, the Segment Type Holding Accounts and the dollar cost averaging account, we will withdraw amounts from any active Segments in your contract. Amounts withdrawn from active Segments will be valued using the formula for calculating the Segment Interim Value and will reduce your Segment Investment. |
| — | If you die, annuitize, cancel or surrender your contract before the Segment Maturity Date, we will pay the Segment Interim Value. |
| — | Any calculation of the Segment Interim Value will generally be affected by changes in both the volatility and level of the relevant Index, as well as interest rates. The calculation of the Segment Interim Value is linked to various factors, including the value of hypothetical fixed instruments and derivatives as described in “Adjustments with respect to early distributions from Segments” in “Charges, expenses, and adjustments” in this Prospectus. The Segment Interim Value will generally be negatively affected by increases in the expected volatility of index prices, interest rate increases, and by poor market performance. Prior to the Segment Maturity Date, for all contracts using a Performance Cap Rate limiting factor, you will not receive the full potential of the Performance Cap since the participation in upside performance for early withdrawals is pro-rated based on the period those amounts were invested in a Segment. Generally, you will not receive the full protection of the Segment Buffer prior to the Segment Maturity Date because the Segment Interim Value only reflects a portion of the downside protection expected to be provided on the Segment Maturity Date. As a Segment moves closer to the Segment Maturity Date, the Segment Interim Value would generally reflect higher realized gains of the Index |
| performance or, in the case of negative performance, increased downside Segment Buffer protection. All other factors being equal, the Segment Interim Value would generally be lower the earlier a withdrawal or surrender is made during a Segment. This means you participate to a lesser extent in upside performance and downside protection the earlier you take a withdrawal. |
| — | The Company’s decision to use investment rates, which are generally higher than swap rates, to calculate the Fair Value of Hypothetical Fixed Instruments component of the Segment Interim Value will result in a lower value for that component relative to using swap rates to calculate that component and, all other things being equal, will result in a lower recalculated Segment Investment if a partial withdrawal is taken from a Segment or a lower withdrawal amount if a full withdrawal is taken from a Segment. |
Risks Related to Segments, Segment Returns, and Segment Type Holding Accounts
| • | We may, in our sole discretion, not offer certain Segments on one or more Segment Start Dates. |
• |
We may not offer new Segments of any Segment Type, so certain Segments may not be available for you to transfer your Segment Maturity Value into. |
| • | On the Segment Maturity Date, the value of your maturing Segments will be reallocated according to your instructions on file, assuming that all participation requirements for those allocations are met. If you have not provided us with maturity instructions for a maturing Segment, then by default the Segment Maturity Value will be transferred to the same Segment Type as the maturing Segment. Our current Performance Cap Rates will apply to the new Segment, which may be lower than the Performance Cap Rate of the maturing Segment. If you decide to remove the amounts that were transferred to the new Segment before the new Segment’s Segment Maturity Date, the transaction will trigger the Segment Interim Value and may be subject to withdrawal charges, taxes and tax penalties. |
| • | If the next Segment to be created in the Segment Type would have a Segment Maturity Date that is later than your contract maturity date or if that Segment Type has been terminated, we will instead transfer your Segment Maturity Value to the EQ/Money Market variable investment option. The amounts transferred to the EQ/Money Market variable investment option may earn a return that is less than the return that could be earned in a different investment option. |
| • | The amounts held in a Segment Type Holding Account may earn a return that is less than the return you might have earned if those amounts were held in another investment option. |
| • | For Growth Multiplier Segments, there is a risk of substantial loss of your principal because you agree to |
absorb all losses from any negative Index Performance Rate. This means that you could lose up to 100% of your principal and previously credited interest. Each time you roll over your Segment Maturity Value into a new Growth Multiplier Segment you are subject to the same risk of loss. Unlike other Segments, Growth Multiplier Segments do not have any protection against negative index performance because the Segment Buffer is zero. |
| • | Growth Multiplier Segments will have uncapped performance, but your Segment Rate of Return will be lower than the performance of the securities comprising the index because the index does not include in its return calculation dividends paid on the securities. |
| • | The Multiplier Rate for Growth Multiplier Segments can fluctuate on Segment Start Dates. |
| • | Because of the way Segment Rate of Return is calculated for Step Up Segments, when the Index Performance Rate is near zero, a very small difference in the Index of Performance Rate on the Segment Maturity Date can result in a very different Segment Rate of Return. For example, if the Performance Cap Rate is 8.00% and the Index Performance Rate is 0.00% on the Segment Maturity Date, the Segment Rate of Return would be 8.00%. However, if the Index Performance Rate had instead been -0.01% on the Segment Maturity Date the Segment Rate of Return would be 0.00%. |
| • | Because of the way Segment Rate of Return is calculated for Dual Direction Segments: |
| — | When the Index Performance Rate is near the Segment Buffer, a very small difference in the Index Performance Rate on the Segment Maturity Date can result in a very different Segment Rate of Return. For example, for a Dual Direction Segment with a -15% Segment Buffer, if the Index Performance Rate is -15.00% on the Segment Maturity Date the Segment Rate of Return is 15.00%, the absolute value of the negative performance, whereas, if the Index Performance Rate is -15.01% on the Segment Maturity Date the Segment Rate of Return is -0.01%. |
| — | The Segment Rate of Return may be greater for negative Index Performance Rates than for the corresponding positive Index Performance Rates. For example, for a Dual Direction Segment with a -15% Segment Buffer, which credits the absolute value to the Segment Buffer, and a Performance Cap Rate of 10%, if the Index Performance Rate is -14% on the Segment Maturity Date the Segment Rate of Return is 14% whereas, if the Index Performance Rate is 14% on the Segment Maturity Date the Segment Rate of Return is 10%. |
| • | Because of the way Segment Rate of Return is calculated for Dual Step Up Segments, when the Index Performance Rate is near the Segment Buffer, a very small difference in the Index of Performance Rate on the Segment Maturity Date can result in a very different Segment Rate of Return. For example, for a Dual Step Up Segment with a -10% Segment Buffer, if the Index |
Performance Rate is -10.00% on the Segment Maturity Date the Segment Rate of Return is 10.00% whereas, if the Index Performance Rate is -10.01% on the Segment Maturity Date the Segment Rate of Return is -0.01%. |
| • | Your Segment Maturity Value is subject to application of the Performance Cap Rate for positive and flat Index Performance Rates and the Segment Buffer for negative Index Performance Rates. For all Segments, your Segment Maturity Value is not affected by the price of the Index on any date between the Segment Start Date and the Segment Maturity Date. |
| • | In the highly unlikely event we were forced to stop offering new Segments, contract owners would be limited to transferring or contributing to the other investment options. You could choose to surrender your contract, but you may be subject to withdrawal charges, taxes, and tax penalties, and if you purchase another retirement vehicle, it may have different features, fees, and risks than your annuity contract. If you are buying the annuity contract for the Structured Investment Option, you should speak to your financial adviser as to whether this product is suitable for you. |
Risks Related to Indices
| • | The Segments track the performance of an Index. By investing in the Structured Investment Option, you are not actually invested in an Index or any underlying securities tracked by the Index. However, the Segments are indirectly exposed to the investment risks associated with the Indices they track. Because the Indices are composed of other securities, they are subject to market risk and issuer risk. |
| • | As an investor in the Segment, you will not have voting rights or rights to receive cash dividends or other distributions or other rights that holders of the shares of the funds or holders of securities comprising the indices would have. |
| • | Price return indices only consider price changes and do not account for dividends or other distributions paid out by the underlying securities, which can significantly contribute to long-term returns. |
| • | Market Risk. |
| • | Large Cap Risk. |
| • | Small Cap Risk. |
They may also be more volatile and less liquid than more established large-capitalization companies. The Russell 2000 ® Price Return Index is comprised of small-cap companies. |
| • | Foreign Securities Risk. |
| — | Foreign markets may be less liquid, more volatile and subject to less government supervision than domestic markets. Differences between U.S. and foreign legal, political and economic systems, regulatory regimes and market practices also may impact security values. There are greater risks involved with investments linked to emerging market countries and/or their securities markets. Investments in these countries and/or markets may present market, credit, currency, liquidity, legal, political, technical and other risks different from, or greater than, the risks of investing in developed countries. For this purpose, China may be viewed as an emerging market and there may also be significant risks related to investments in China. |
| — | Indices with exposure to non-U.S. companies and securities, especially in emerging and frontier markets, also include the following risks: the potential for errors in Index data, Index computation, and/or Index construction if information on non-U.S. companies is unreliable or outdated, or if less information about the non-U.S. companies is publicly available due to differences in regulatory, accounting, auditing, and financial recordkeeping standards; the potential significance of such errors on the Index’s performance; limitations on the Company’s ability to oversee the Index provider’s due diligence process over Index data prior to its use in Index computation, construction, and/or rebalancing; and the rights and remedies associated with investments that track an Index comprised of foreign securities may be different from investments that track an Index of domestic securities. The MSCI Emerging Markets Price Return Index is exposed to emerging markets. |
| • | Past performance of an Index is not an indication of its future performance. |
| • | We have the right to substitute an alternative index prior to Segment Maturity if the publication of one or more Indices is discontinued, or if we no longer have a license agreement with the publishers of the Index, or at our sole discretion we determine that our use of such Indices should be discontinued because hedging instruments become difficult to acquire or the cost of hedging becomes excessive, or if the calculation of one |
or more of the Indices is substantially changed. The a lte rnative index may not be desirable to you. If we substitute an index for an existing Segment, we would not change the Segment Buffer or Performance Cap Rate. We would attempt to choose a substitute index that has a similar investment objective and risk profile to the replaced Index. The alternative index would be used to calculate performance from the Segment Start Date to the Segment Maturity Date. In addition, we reserve the right to use any or all reasonable methods to end any outstanding Segments that use such Indices. If a similar index cannot be found, we will end the affected Segments prematurely by applying the Segment Performance Cap Rate and Segment Buffer to the actual gains or losses on the original Index as of the date of termination which could result in a loss or less gain than if the Segment had continued to the Segment Maturity Date. |
• |
If the value for the underlying Index of a Segment is not published by the Index because of an emergency close on the Segment Maturity Date, we will not be able to calculate the Segment Maturity Value, and we will keep your account value in the Segment. Once the underlying Index publishes this value and we have calculated the Segment Maturity Value, we will allocate your Segment Maturity Value in accordance with your instructions. There is no way for us to predict how long it may take the underlying Index to publish the value. There is a risk that waiting for the value could result in a loss or less gain than if the Segment had ended on the original Segment Maturity Date. |
Withdrawals and Surrenders
| • | Withdrawals and surrenders for Investment Edge ® contracts may be subject to withdrawal charges. |
| • | Withdrawals will reduce your account value and death benefit and the amount of the reduction in the death benefit may be greater than the dollar amount of the withdrawal. |
| • | If you take a withdrawal or surrender from a Segment prior to Segment maturity you may receive less than the amount invested and less than the amount you would receive had you held the investment until Segment maturity. See “Segment Interim Value” above. |
| • | If your account value falls below the applicable minimum account size as a result of a withdrawal, the contract will terminate. |
| • | If you take a withdrawal or surrender your Investment Edge ® contract, any applicable withdrawal charge is calculated as a percentage of contributions, not account value. It is possible that the percentage of account value withdrawn could exceed the applicable withdrawal charge percentage. For example, assume you make a onetime contribution of $1,000 at contract issue. If your account value is $800 in contract year 3 and you surrender your contract, a withdrawal charge percentage |
of 5% is applied. The withdrawal charge would be $50 (5% of the $1,000 contribution). This is a 6.25% reduction of your account value, which results in a cash value of $750 paid to you. |
| • | We may apply fees if you access your account value during the accumulation period or surrender your contract. For example, in addition to possible tax consequences, you may incur fees for accessing your account value such as a withdrawal charge, transfer fee, third party transfer or exchange fee and/or a charge for any optional benefits. |
| • | Withdrawals may be subject to income taxes and tax penalties. The minimum partial withdrawal amount is $300. Withdrawals will reduce your account value and optional benefit bases and the amount of the reduction may be greater than the dollar amount of the withdrawal. Certain withdrawals may also terminate your contract. |
Investment Edge
®
ADV Contracts Investment Edge
®
ADV contracts are only available through advisors who charge an advisory fee for their services, and this fee is in addition to contract fees and expenses. If you elect to pay the advisory fee from your account value (using either the Advisory Fee Service or by taking withdrawals), then these deductions will reduce the account value, reduce the death benefit, and payments under an Income Edge payment program, will not receive index interest, and could reduce the Segment Investment by more than the amount of the deductions, and, over time, could result in a significant loss of principal and previously credited interest. NOTE: If you do not elect the Advisory Fee Service, withdrawals to pay advisory fees also may be subject to federal and state income taxes and a 10% federal penalty tax. You should consider using a source other than the account value under the contract to pay advisory fees, if possible, to avoid these potential consequences, but if you do use your account value, you should use the Advisory Authorization Form.Return of Premium Death Benefit
• |
Please note that withdrawals under the contract, including systematic withdrawals, required minimum distributions, and withdrawals to pay advisory fees under an Investment Edge ® ADV contract, could reduce the Return of Premium death benefit by substantially more than the amount of the withdrawal. |
| • | You cannot terminate the Return of Premium death benefit once you elect it. This means that you cannot avoid paying the charge for the Return of Premium death benefit even if you no longer want or need the protection offered by the Return of Premium death benefit. This also means you cannot avoid paying the charge when the account value is higher than your Return of Premium benefit base. |
Contract Changes Risk
| • | We reserve the right to stop accepting any application or contribution from you at any time, including after you purchase the contract. We reserve the right to discontinue the acceptance of, and/or place additional |
limitations on, contributions into certain investment options, including any of the Segments of the SIO. If we exercise this right, your ability to invest in your contract, increase your account value and, consequently, increase your death benefit will be limited. |
• |
We may, at any time, exercise our rights to limit or terminate your contributions, allocations and transfers to any of the investment options and to limit the number of investment options which you may select. Such rights include, among others, removing or substituting the Portfolios, combining any two or more investment options and transferring account value from any investment option to another investment option. |
• |
We reserve the right to offer any or all Segments more or less frequently or to stop offering any of them (except we will always offer a Segment Option with a Segment Buffer that protects the first 10% of loss) or to suspend offering any or all of them temporarily for some or all contracts. If we stop offering these options, you will be limited to investing in only one Segment Option and in the variable investment options, which are not tied to the performance of an index. |
| • | We may offer new Segment Types in the future, and we may change the features of a Segment Type between Segments, including the Index, the Segment Buffer, and the Performance Cap Rate (subject to the minimum rates disclosed herein). |
Insurance Company Risk
No company other than us has any legal responsibility to pay amounts that we owe under the contract including amounts allocated to the Structured Investment Option. The general obligations and any guaranteed benefits under the contract are supported by our general account and are subject to our claims-paying ability. You should look solely to our financial strength for our claims-paying ability.
Possible adverse tax consequences
The tax considerations associated with the contract vary and can be complicated. The applicable tax rules can differ, depending on the type of contract, whether NQ, traditional IRA, Roth IRA or QP. The tax consequences discussed in this Prospectus are general in nature and describe only federal income tax law (not state, local, foreign or other federal tax laws). Moreover, the tax aspects that apply to a particular person’s contract may vary depending on the facts applicable to that person. Tax rules may change without notice. We cannot predict whether, when, or how these rules could change. Any change could affect contracts purchased before the change. Congress may also consider further proposals to comprehensively reform or overhaul the United States tax and retirement systems, which if enacted, could affect the tax benefits of a contract. We cannot predict what, if any, legislation will actually be proposed or enacted. Before making contributions to your contract or taking other action related to your contract, you should consult with a tax professional to determine the tax implications of an investment in, and payments received under, the contract.
Withdrawals are generally subject to income tax and may be subject to tax penalties if taken before age 59
1
⁄2
. Not a short-term investment
The contract is not a short-term investment and is not appropriate for an investor who needs ready access to cash because the contract is designed to provide for the accumulation of retirement savings and income on a long-term basis. As such, you should not use the contract as a short-term investment or savings vehicle and you should consider whether investing in the contract is consistent with the purpose for which the investment is being considered.
Risk of loss
All investments have risks to some degree and it is possible that you could lose money by investing in the contract. An investment in the contract is not a deposit with a bank and is not insured or guaranteed by the Federal Deposit Insurance Corporation or any other government agency.
Availability by financial intermediary
Some financial intermediaries (e.g., selling broker-dealer firms) may not offer and/or may limit the offering of certain investment options, contract benefits, and other contract features based on issue age or other criteria established by the selling broker-dealer. For example, your financial professional may not recommend a particular investment option or contract benefit to you that is described in this Prospectus. Before you purchase the contract, you should discuss with your financial professional any limitations, restrictions, or other variations related to the investment options, contract benefits or other contract features available to you through your financial professional. If a particular feature that interests you is not recommended through your broker-dealer, you may want to contact us to explore its availability.
Business disruption, cybersecurity, and artificial intelligence (“AI”) technologies risks
We rely heavily on technology, including interconnected computer systems and data storage networks and digital communications, to conduct our business. Because our business is highly dependent upon the effective operation of our computer systems and those of our service providers and other business partners, our business is vulnerable to disruptions from utility outages, and susceptible to operational and information security risks resulting from information systems failure (e.g., hardware and software malfunctions), and cyberattacks. Cyberattacks may be systemic (e.g., affecting the internet, cloud services, or other infrastructure) or targeted (e.g., failures in or breach of our systems or those of third parties on whom we rely, including ransomware and malware attacks). Cybersecurity risks include, among other things, the loss, theft, misuse, corruption and destruction of data maintained online or digitally, interference with or denial of service, attacks on our websites (or the websites of third parties on whom we rely), other operational disruption and unauthorized release, use or abuse of confidential customer information. The risk of cyberattacks may be higher during periods of geopolitical turmoil. Due to the increasing sophistication of cyberattacks, a cybersecurity breach could occur and persist for an extended period of time without detection. Systems failures and cyberattacks, as well as, any other catastrophic event, including natural and manmade disasters, public health
emergencies, pandemic diseases, terrorist attacks, floods or severe storms affecting us, any third-party administrator, the underlying funds, intermediaries and other affiliated or third-party service providers may adversely affect us, our business operations and your account value and interfere with our ability to process contract transactions and calculate account values. Systems failures and cyberattacks may also interfere with our processing of contract transactions, including the processing of orders from our website or with the underlying funds, impact our ability to calculate account values and unit values and/or the underlying funds to be unable to calculate share values, cause the release or possible destruction of confidential customer and/or business information, impede order processing or cause other operational issues, subject us and/or our service providers and intermediaries to regulatory fines, litigation and financial losses and/or cause reputational damage. Cybersecurity risks may also impact the issuers of securities in which the underlying funds invest, which may cause the underlying funds to lose value. The preventative actions we take to reduce the frequency and severity of cybersecurity incidents and protect our computer systems may be insufficient to prevent a cybersecurity breach from impacting our operations of your contract value. There can be no assurance that we or the underlying funds or our service providers and intermediaries will be able to avoid cybersecurity breaches affecting your contract.
The development and deployment of AI tools and technologies, including generative AI, and its use and anticipated use by us or by third parties on whom we rely, may increase our existing operational risks or create new operational risks that we are not currently anticipating. AI and generative AI may be misused by us or by third parties upon which we rely, and that risk is increased by the relative newness of the technology, the speed at which it is being adopted, and the uncertain and evolving policy and regulatory landscape governing its use. Such misuse could expose us to legal or regulatory risk. Because the generative AI technology is so new, many of the potential risks of generative AI are currently unknowable.
In addition, we are also exposed to risks related to natural and man-made disasters, including, but not limited to the occurrence of any storms, fires, floods, earthquakes, public health crises, malicious acts, and terrorist acts or any other event, which could adversely affect our ability to conduct business. A natural or man-made disaster, including a pandemic such as COVID-19, could result in our workforce, and/or employees of service providers and/or third-party administrators, being compromised and unable or unwilling to fully perform their responsibilities, which could likewise result in interruptions in our service. This could interfere with our processing of contract transactions, including processing orders from owners and orders with the underlying funds, impact our ability to calculate contract value, or have other adverse impacts on our operations. These events may also negatively affect our service providers and intermediaries, the underlying funds and issuers of securities in which the underlying funds invest, which may cause the funds underlying your contract to lose value. There can be no assurance that we or the underlying funds or our service providers and intermediaries will be able to avoid negative impacts associated with natural and man-made disasters.
no
protection and, therefore, you could lose as much as 100% of your principal and previously credited interest due to negative index performance on the Segment Maturity Date in those Segments. The highest level of protection provided by a single Segment Investment Option is the -40% Segment Buffer (only available on certain Segments) and the lowest level of protection is the -10% Segment Buffer. You could lose as much as 60% (for Segments with a -40% Segment Buffer) to 90% (for Segments with a -10% Segment Buffer) of your principal and previously credited interest due to negative index performance on the Segment Maturity Date.
Structured Investment Option
The Structured Investment Option consists of a number of Segment Types, each of which provides a rate of return tied to the performance of a specified Index from the Segment Start Date to the Segment Maturity Date. You generally have the opportunity to invest in any of the Segment Types described below, subject to the requirements, limitations and procedures disclosed in this section. You participate in the performance of an Index by investing in the corresponding Segment. Investments in Segments are not investments in underlying mutual funds; Segments are not “index funds.”
Segment Types
Information regarding the features of each of the currently available Segment Types, including the Index name and type, the Segment Duration, the Segment Rate of Return calculation method, the current Segment Buffer, and the minimum Performance Cap Rate for the life of the Segment Type, is available in an appendix to the Prospectus. See Appendix “Investment Options available under the contract.” We are not obligated to offer any one particular Segment Type. Also, we are not obligated to offer any Segment Types. Each investment in a Segment Type that starts on a particular Segment Start Date is referred to as a Segment.
A Segment Type refers to a Segment Option that has the same Index, Segment Duration, and Segment Buffer. Each Segment Type has a corresponding Segment Type Holding Account. Please refer to the “Definitions of key terms” for a discussion of these terms.
We reserve the right to offer any or all Segment Types more or less frequently or to stop offering any or all of them or to suspend offering any or all of them temporarily for some or all contracts. Please see “Suspension, termination and changes to Segment Types” later in this section. All Segment Types may not be available in all states. We may also add Segment Types in the future.
The maximum current number of active variable investment options (including variable investment options with an allocation on file), Segments, and funded holding accounts that may be active in your contract at any time is 88.
Segment Start Date
Each Segment will have a Segment Start Date. Segments generally start on the first or third Thursday of each month. However, the Segment Start Date may sometimes be a different day under certain circumstances. Please see “Setting the Segment Maturity Date and Segment Start Date”. Also, we may offer Segments more or less frequently and on different days for some or all contracts.
Segment Type Holding Accounts
Any contribution or transfer designated for a Segment Type will be allocated to the corresponding Segment Type Holding Account until the Segment Start Date. The Segment Type Holding Accounts are part of the EQ/Money Market variable investment option but we do not apply a Contract Fee to amounts in a Segment Type Holding Account. You
must transfer or contribute to the Segment Type Holding Account for the corresponding Segment Type if you want to invest in a Segment; you cannot transfer or contribute directly to a Segment.
You can transfer amounts from a Segment Type Holding Account into any available variable investment options, or another Segment Type Holding Account at any time up to the close of business on the last business day before the Segment Start Date.
Please refer to the “How to reach us” section in this Prospectus for more information regarding contacting us and communicating your instructions. We also have specific forms that we recommend you use for electing the Structured Investment Option and any Structured Investment Option transactions.
Segment Participation Requirements
Provided that all participation requirements are met, all amounts allocated to a Segment Type that are in the associated Segment Type Holding Account as of the close of business on the business day preceding the Segment Start Date, plus any earnings on those amounts, will be transferred into the new Segment on the Segment Start Date. However, amounts transferred into the Segment Type Holding Account on the Segment Start Date itself will not be included in any new Segment created that day. These amounts will remain in the Segment Type Holding Account until they are transferred out or the next Segment Start Date on which the participation requirements are met for the amounts to be transferred into a new Segment.
The participation requirements are as follows: (1) Segment is available and (2) Segment Maturity Date Requirement is met. If these requirements are met, your account value in the Segment Type Holding Account will be transferred into a new Segment. This amount is your initial Segment Investment.
(1) Segment is available.
The Segment must actually be created on the Segment Start Date as scheduled. We may suspend or terminate any Segment Type, at our sole discretion, at any time. If we terminate a Segment Type, no new Segments of that Segment Type will be created, and the amount that would have been transferred to the Segment will be transferred to the EQ/Money Market variable investment option instead. If we suspend a Segment Type, no new Segments of that Segment Type will be created until the suspension ends, and the amount that would have been transferred to the Segment will remain in the Segment Type Holding Account.
(2) Segment Maturity Date Requirement is met.
The Segment Maturity Date must occur on or before the contract maturity date. If the Segment Maturity Date is after the contract maturity date, your account value in the Segment Type Holding Account will be transferred to the EQ/Money Market variable investment option.
Segment Duration
We currently offer Segment Types with a duration of 1 or 5 years. Amounts removed from a Segment prior to the Segment Maturity Date (i) will not receive the full potential of
the Performance Cap since the participation in upside performance for early withdrawals is pro-rated based on the period those amounts were invested in a Segment for all contracts using a Performance Cap Rate limiting factor; (ii) will not receive the full protection of the Segment Buffer because the Segment Interim Value only reflects a portion of the downside protection expected to be provided on the Segment Maturity Date; and (iii) could reduce the Segment Investment (which we use to calculate the Segment Maturity Value on the Segment Maturity Date as described in “Segment Maturity Value”) by more than the amount withdrawn due to the Segment Interim Value. Amounts must remain in the Segment for the full Segment Duration to be credited with full interest, to receive the full protection of the Segment Buffer, and to avoid a possible negative Segment Interim Value adjustment in addition to potential withdrawal charges, taxes and tax penalties. See “Segment Interim Value” below and “Adjustments with respect to early distributions from Segments” in “Charges, expenses, and adjustments” for more information.
Before selecting a Segment for investment, you should consider whether you are likely to make a withdrawal or transfer from the Segment or surrender or annuitize your contract prior to the end of the 1 or 5 year Segment Duration. You should also consider whether you want your returns to be linked to the applicable Index for the Segment Duration and whether the Segment Buffer and Performance Cap Rate are consistent with your investment goals and risk tolerance for the 1 or 5 year period.
Segment Maturity Date
Your Segment Maturity Date is the Segment Business Day on which a Segment ends. You will receive advance notice of maturing Segments in which you are currently invested in your quarterly statement. You will generally also receive a second advance notice of maturing Segments in which you are currently invested. The additional notice is available by mail or electronically and is generally provided at least 30 days before a Segment Maturity Date. You can instruct us to stop delivering this second notice to you at any time. We reserve the right to discontinue this second notice at any time.
Setting the Segment Maturity Date and Segment Start Date
There will generally be two or more Segment Maturity Dates and Segment Start Dates each month that the contract is outstanding. The Segment Maturity Date for Segments maturing and the Segment Start Date for new corresponding Segments will generally be scheduled to occur on consecutive business days that are also Segment Business Days.
If a Segment Maturity Date falls on a holiday, the Segment Maturity Date will generally be the preceding Segment Business Day. If a Segment Start Date falls on a holiday, the Segment Start Date will generally be the preceding Segment Business Day unless that preceding Segment Business Day is not in the same month. In these instances, no Segment will begin until the next scheduled Segment Start Date. Please see Appendix “Segment Maturity Date and Segment Start Date Examples” for a demonstration of the effects that scheduled holidays can have on the Segment Maturity Date and the Segment Start Date.
Segment Maturity Instructions.
You may specify maturity instructions that tell us how to allocate the Segment Maturity Value among the investment options and you can change these instructions at any time. You may tell us either to follow your instructions on file for new contributions, to withdraw all or part of your Segment Maturity Value, or to transfer your Segment Maturity Value to the next available Segment of the same Segment Type, provided the participation requirements are met. While you may specify or change your maturity instructions for maturing Segments at any time until the close of business on the Segment Maturity Date, we recommend submitting new or revised instructions at least five business days prior to the Segment Maturity Date.
As stated above, you may elect to have maturing Segments invested according to your instructions on file, and those instructions may include allocations to different Segment Types, or you may elect to transfer your Segment Maturity Value to the next available Segment of the same Segment Type in which you are currently invested. If you take either of these steps, then the designated portion of your Segment Maturity Value will be transferred to the corresponding Segment Type Holding Account, as of the close of business on the Segment Maturity Date. Assuming that all participation requirements are met, the designated amounts will be treated like any other amounts in a Segment Type Holding Account. On the next Segment Start Date, the designated amounts in the Segment Type Holding Account will be transferred into the corresponding Segment. Typically, this means the designated amounts would be held in a Segment Type Holding Account for at least one business day.
If you have not provided us with maturity instructions for a maturing Segment, then by default the Segment Maturity Value will be transferred to the Segment Type Holding Account for the same Segment Type as the maturing Segment. Your Segment Maturity Value would then be transferred from that Segment Type Holding Account into the next Segment of that Segment Type on the Segment Start Date except that if the next Segment to be created in the Segment Type would not meet the Segment Maturity Date Requirement or that Segment Type has been terminated, we will instead transfer your Segment Maturity Value to the EQ/ Money Market variable investment option.
If you are impacted by these delays, you may transfer your Segment Maturity Value into another Segment Type Holding Account or any other investment option at any time before the next Segment Start Date.
Segment Maturity Value
We calculate your Segment Maturity Value on the Segment Maturity Date using your Segment Investment and the Segment Rate of Return.
Your Segment Maturity Value for all Segments is calculated as follows:
We multiply your Segment Investment by your Segment Rate of Return to get your Segment Return Amount. Your Segment Maturity Value is equal to your Segment Investment plus your Segment Return Amount. Your Segment Return Amount may be negative, in which case your Segment Maturity Value will be less than your Segment Investment. Please note that
(1) the Contract Fee reduces the Segment Rate of Return and (2) the Segment Investment and resulting Segment Return Amount will have been reduced by any optional Return of Premium death benefit charge if those charges were deducted from the Segment on any contract date anniversary during the Segment.
Segment Interim Value
The total amount earned on an investment in a Segment of the SIO is only applied at Segment maturity. If any amount leaves a Segment on any date prior to the Segment Maturity Date, we calculate the Segment Interim Value of the Segment as described in “Charges, expenses, and adjustments.” Prior to the Segment Maturity Date, the following transactions trigger the Segment Interim Value calculation: (1) the receipt of an in good order death claim by your beneficiary; (2) a withdrawal (including a systematic withdrawal, a required minimum distribution, a withdrawal to pay advisory fees under an Investment Edge ADV contract and a free withdrawal under an Investment Edge Select contract); (3) a transfer; (4) if you surrender or annuitize your contract; or (5) if you cancel your contract and return it to us for a refund within your state’s “free look” period.
®
®
If you make one of these transactions, because the end-of-term downside protection provided by a Segment Buffer does not apply to the Segment Interim Value, it is theoretically possible that you could lose up to 100% of your investment and previously credited interest in certain extreme scenarios even for Segments with a Segment Buffer.
We deduct a pro rata portion of the Contract Fee from the Segment Interim Value as part of the calculation.
Segment Rate of Return
The Segment Rate of Return is calculated using the Segment Buffer or Performance Cap Rate as described below for each Segment Type. See Appendix “Segment Maturity Value Calculation Examples” for numerical examples of each calculation method.
Standard Segments.
For Standard Segments, the Segment Rate of Return is equal to the Index Performance Rate (the percentage change in the value of the related Index from the Segment Start Date to the Segment Maturity Date), subject to the Performance Cap Rate and Segment Buffer minus the Contract Fee, as follows:
If the Index Performance Rate: |
Your Segment Rate of Return will be: | |
| exceeds the Performance Cap Rate | equal to the Performance Cap Rate minus the Contract Fee | |
| is positive but less than or equal to the Performance Cap Rate | equal to the Index Performance Rate minus the Contract Fee | |
| is flat or negative by a percentage equal to or less than the Segment Buffer | equal to 0% minus the Contract Fee | |
| is negative by a percentage greater than the Segment Buffer | negative, equal to the extent of the percentage exceeding the Segment Buffer minus the Contract Fee |
These values are based on the value of the relevant Index on the Segment Start Date and the Segment Maturity Date. Any fluctuations in the value of the Index between those dates is ignored in calculating the Segment Rate of Return.
Please see Appendix “Investment Options available under the contract” for a list of the current Standard Segment Types.
Standard Segment example
year/-10%
Segment Type, a Segment could be established as S&P 500 Price Return Index/1 year/-10%
with a 11% Performance Cap Rate. This means that you will participate in the performance of the S&P 500 Price Return Index for one year starting from the Segment Start Date. The following examples assume no withdrawals. If the Index performs positively during this period, your Segment Rate of Return could be as much as 11% minus the applicable Contract Fee for that Segment Duration. If the Index performs negatively during this period, at maturity you will be protected from the first 10% of the Index’s decline minus the applicable Contract Fee. If the Index performance is between -10%
and 0%, your Segment Maturity Value on the Segment Maturity Date will be equal to your Segment Investment minus the applicable Contract Fee. See Appendix “Segment Maturity Value Calculation Examples” for examples showing the Segment Maturity Value calculation. Step Up Segments.
For Step Up Segments, the Segment Rate of Return is equal to:
| • | the Performance Cap Rate if the Index Performance Rate (the percentage change in the value of the related Index from the Segment Start Date to the Segment Maturity Date) is greater than or equal to zero minus the Contract Fee or |
| • | the Index Performance Rate if the Index Performance Rate is negative, subject to the Segment Buffer minus the Contract Fee, as follows: |
If the Index Performance Rate: |
Your Segment Rate of Return will be: | |
| is greater than or equal to zero | equal to the Performance Cap Rate minus the Contract Fee | |
| is negative by a percentage equal to or less than the Segment Buffer | equal to 0% minus the Contract Fee | |
| is negative by a percentage greater than the Segment Buffer | negative, equal to the extent of the percentage exceeding the Segment Buffer minus the Contract Fee |
These values are based on the value of the relevant Index on the Segment Start Date and the Segment Maturity Date. Any fluctuations in the value of the Index between those dates is ignored in calculating the Segment Rate of Return.
Please note:
Performance Rate on the Segment Maturity Date can result in a very different Segment Rate of Return. For example, if the Performance Cap Rate is 8.00% and the Index Performance Rate is 0.00% on the Segment Maturity Date, the Segment Rate of Return would be 8.00% less the amount of the Contract Fee whereas, if the Index Performance Rate is
-0.01%
on the Segment Maturity Date the Segment Rate of Return is 0.00% less the amount of the Contract Fee. Please see Appendix “Investment Options available under the contract” for a list of the current Step Up Segment Types.
Step Up Segment example
year/-10%
Segment Type, a Segment could be established as S&P 500 Price Return Index Step Up/1 year/-10%
with an 8% Performance Cap Rate. This means that you will participate in the performance of the S&P 500 Price Return Index for one year starting from the Segment Start Date. The following examples assume no withdrawals. If the Index performs positively or equal to zero during this period, your Segment Rate of Return would be 8% minus the applicable Contract Fee for that Segment Duration. If the Index performs negatively during this period, at maturity you will be protected from the first 10% of the Index’s decline minus the applicable Contract Fee. If the Index performance is between -10%
and 0%, your Segment Maturity Value on the Segment Maturity Date will be equal to your Segment Investment minus the applicable Contract Fee. See Appendix “Segment Maturity Value Calculation Examples” for examples showing the Segment Maturity Value calculation. Step Up Segments will generally have lower Performance Cap Rates than Standard Segments with the same Index, Segment Duration and Segment Buffer. This is because the Segment Rate of Return for Step Up Segments is equal to the Performance Cap Rate for certain lower returns.
Dual Direction Segments.
For Dual Direction Segments, the Segment Rate of Return is equal to the Index Performance Rate subject to the Performance Cap Rate for positive and flat Index Performance Rates and the absolute value of negative Index Performance Rates unless the Index Performance Rate is less than the Segment Buffer in which case it is equal to the Index Performance Rate subject to the Segment Buffer, minus the Contract Fee, as follows:
If the Index Performance Rate: |
Your Segment Rate of Return will be: | |
| is greater than the Performance Cap Rate | equal to the Performance Cap Rate minus the Contract Fee | |
| is between the Performance Cap Rate and Segment Buffer (or equal to either) | equal to the absolute value of the Index Performance Rate minus the Contract Fee | |
| is negative by a percentage greater than the Segment Buffer | negative, equal to the extent of the percentage exceeding the Segment Buffer minus the Contract Fee |
Please note:
| • | Because of the way the Segment Rate of Return is calculated for Dual Direction Segments, when the Index Performance Rate is near the Segment Buffer, a very small difference in the Index Performance Rate on the Segment Maturity Date can result in a very different Segment Rate of Return. For example, for a 1-year Dual Direction Segment with a -10% Segment Buffer, if the Index Performance Rate is -10.00% on the Segment Maturity Date the Segment Rate of Return is 10.00% whereas, if the Index Performance Rate is -10.01% on the Segment Maturity Date the Segment Rate of Return is -0.01%. |
| • | Because of the way the Segment Rate of Return is calculated for Dual Direction Segments, in certain situations the Segment Rate of Return may be greater for negative Index Performance Rates than for the corresponding positive Index Performance Rates. For example, for a 1-year Dual Direction Segment with a Performance Cap Rate of 7% and a -10% Segment Buffer, if the Index Performance Rate is -9% on the Segment Maturity Date the Segment Rate of Return is 9% whereas, if the Index Performance Rate is 9% on the Segment Maturity Date the Segment Rate of Return is 7%. |
Please see Appendix “Investment Options available under the contract” for a list of the current Dual Direction Segment Types.
Dual Direction Segment example:
Please note:
Dual Direction Segments will generally have lower Performance Cap Rates than Standard Segments with the same Index, Segment Duration and Segment Buffer. This is because the Segment Rate of Return for Dual Direction Segments is equal to the absolute value of the Index Performance Rate for certain negative returns. Please note that the Performance Cap Rate and Segment Rate of Return for Dual Direction 5-year Segments are cumulative rates of return over the 5-year period from the Segment Start Date to the Segment Maturity Date. They are NOT annual rates, even if the Segment Duration is longer than one year.
Dual Step Up Segments.
For Dual Step Up Segments, the Segment Rate of Return is equal to the Performance Cap Rate unless the Index Performance Rate is less than the Segment Buffer in which case it is equal to the Index Performance Rate subject to the Segment Buffer, minus the Contract Fee, as follows:
If the Index Performance Rate: |
Your Segment Rate of Return will be: | |
| is greater than or equal to the Segment Buffer | equal to the Performance Cap Rate minus the Contract Fee | |
| is negative by a percentage greater than the Segment Buffer | negative, equal to the extent of the percentage exceeding the Segment Buffer minus the Contract Fee |
These values are based on the value of the relevant Index on the Segment Start Date and the Segment Maturity Date. Any fluctuations in the value of the Index between those dates is ignored in calculating the Segment Rate of Return.
Please note:
-10%
and the Index Performance Rate is -10.00%
on the Segment Maturity Date, the Segment Rate of Return would be 10.00% whereas, if the Index Performance Rate is -10.01%
on the Segment Maturity Date the Segment Rate of Return is -0.01%.
Please see Appendix “Investment Options available under the contract” for a list of the current Dual Step Up Segment Types.
Dual Step Up Segment example:
year/-10%
Segment Type, a Segment could be established as S&P 500 Price Return Index Dual Step Up/1 year/-10%
with a 10% Performance Cap Rate. This means that you will participate in the performance of the S&P 500 Price Return Index for one year starting from the Segment Start Date. The following examples assume no withdrawals. If the Index performs equal to or better than the Segment Buffer, your Segment Rate of Return will be 10% for that Segment Duration. This means if the Index performs negatively down to and including -10%, then your Segment Rate of Return will be 10%. If the Index performs more negatively than the Segment Buffer, your Segment Rate of Return will be negative equal to the percentage loss in the Index which exceeds the Segment Buffer. The Contract Fee will reduce your Segment Rate of Return. See Appendix “Segment Maturity Value Calculation Examples” for examples showing the Segment Maturity Value calculation.
Dual Step Up Segments will generally have lower Performance Cap Rates than Standard Segments with the same Index, Segment Duration and Segment Buffer. This is because the Segment Rate of Return for Dual Step Up Segments is equal to the Performance Cap Rate for certain lower and negative returns.
Growth Multiplier Segments.
For Growth Multiplier Segments, the Segment Rate of Return is equal to:
| • | the Index Performance Rate increased by the applicable Multiplier Rate if the Index Performance Rate is positive or |
| • | the Index Performance Rate if the Index Performance Rate is flat or negative, |
minus the Contract Fee, as follows:
If the Index Performance Rate: |
Your Segment Rate of Return will be: | |
| is positive | the Index Performance Rate multiplied by the applicable Multiplier Rate minus the Contract Fee | |
| is flat or negative | equal to the Index Performance Rate minus the Contract Fee |
These values are based on the value of the relevant Index on the Segment Start Date and the Segment Maturity Date. Any fluctuations in the value of the Index between those dates is ignored in calculating the Segment Rate of Return.
Please see Appendix “Investment Options available under the contract” for a list of the current Growth Multiplier Segment Types.
Growth Multiplier Segment example
:
The Multiplier Rate applicable to each Growth Multiplier Segment, including the applicable Multiplier Rate for Segments
selected on your application may vary and will be preannounced at least one week before the Segment Start Date and can be found at www.equitable.com/ie21-rates-prospectus. The Multiplier Rate for the same Segment may be higher or lower for owners who elect that Segment during their first Contract Year than for owners who are in their second or later Contract Year. The Multiplier Rate is used to increase positive Index Performance Rates as part of the Segment Rate of Return calculation. The Multiplier Rate is only used to calculate the Segment Rate of Return. The Multiplier Rate is not an annual rate of return even if the Segment Duration is longer than one year. The Multiplier Rate will never be less than 105%. We will not open a Segment with a Multiplier Rate below the minimum and the Multiplier Rate will not change during the Segment Duration.
Growth Multiplier Segments do not have a Performance Cap Rate and, therefore, are always uncapped. . Accordingly, your Segment Rate of Return will equal any negative Index Performance Rate on a Segment Maturity Date and, therefore, your Segment Maturity Value will decline by the entire amount of the negative index performance.
The Segment Buffer is zero for Growth Multiplier Segments
Please note:
| • | Growth Multiplier Segments do not have a Performance Cap Rate (e.g., they are always uncapped). |
| • | Growth Multiplier Segments do not have any protection against negative Index performance because the Segment Buffer is zero. With a 0% Segment Buffer there is no protection from negative index performance and you could lose up to 100% of principal and previously credited interest. |
The Indices are described in more detail below, under the header “Indices.”
Performance Cap Rate
The Performance Cap Rate is generally the highest Index Performance Rate that can be used to calculate the Segment Rate of Return on the Segment Maturity Date. The Performance Cap Rate, if applicable, may limit your participation in any increases in the underlying Index associated with a Segment. For example, if the Index return is 12% and the Performance Cap Rate is 4%, we will credit 4% in interest on the Segment Maturity Date assuming there are no fees or charges assessed, meaning your Segment Investment will increase by 4%.
Our minimum Performance Cap Rate is 2%. We guarantee that for the life of your contract we will not open a Segment with a Performance Cap Rate below the applicable minimum Performance Cap Rate. In some cases, we may decide not to declare a Performance Cap Rate for a Segment, in which case there is no maximum Segment Rate of Return for that Segment. When this happens, the Segment is referred to as uncapped. Growth Multiplier Segments do not have a Performance Cap Rate.
The current Performance Cap Rates for each Segment Type, including the applicable Performance Cap Rates for Segments
selected on your application, are announced at least one week before the Segment Start Date and are incorporated into this Prospectus by reference from www.equitable.com/ie21-rates-prospectus. The Performance Cap Rate for each Segment will not change throughout the Segment Duration. The Performance Cap Rate for the same Segment may vary between owners but will never be less than the applicable minimum Performance Cap Rate. Since Performance Cap Rates are announced online at least one week before the Segment Start Date, you should consider any differences in the Performance Cap Rates when deciding which contract series to purchase.
Please note that the Performance Cap Rate and Segment Rate of Return are cumulative rates of return from the Segment Start Date to the Segment Maturity Date, NOT annual rates, even if the Segment Duration is longer than one year.
The Performance Cap Rate is set at our sole discretion. In determining the current Performance Cap Rate for a Segment Type, we consider, among other factors, the Segment Rate of Return calculation method, the cost of hedging instruments, the rates offered by our competitors, the rates of other Segments, and the current market environment. In general, the Performance Cap Rates will be lower for Segment Types that offer greater protection from negative returns or additional enhancements to positive returns. Before selecting a Segment for investment, you should consider whether the current Performance Cap Rate is acceptable to you in return for the protection from negative returns or enhancements to positive returns that may be applied at the end of the Segment Duration for that Segment Type.
Segment Performance Cap Rate Hold
The Cap Rate Hold is not currently available.
Segment Buffer
The SIO provides some protection against negative returns on the Segment Maturity Date through the use of a Segment Buffer,
except Growth Multiplier Segments which do not have a Segment Buffer. The extent of the downside protection provided by the Segment Buffer varies by Segment, ranging from the first 10% to 40% of loss. There is a
risk of a substantial loss of your principal and previously credited interest because you agree to absorb
all losses to the extent they exceed the applicable Segment Buffer on the Segment Maturity Date.
The Segment Buffer for each Segment will not change throughout the Segment Duration. See Appendix “Investment Options available under the contract” for the current Segment Buffer for each Segment Type.
We may change the Indices and/or Segment Options in the future, but we will always offer a Segment Option with a Segment Buffer that protects the first 10% of loss.
The Segment Buffer is set at our sole discretion. In determining the current Segment Buffer for a Segment Type, we consider, among other factors, the Segment Rate of Return calculation method, the cost of hedging instruments, the range of Performance Cap Rates that may be offered with the Segment Buffer, protection levels offered by our competitors, and the current market environment. Before selecting a Segment for investment, you should consider whether the Segment Buffer is consistent with your risk tolerance and investment goals for the Segment Duration of the Segment Type.
On a Segment Maturity Date, the highest level of protection provided by a Segment Buffer is the -40% Segment Buffer and lowest level of protection provided by a Segment Buffer is the -10% Segment Buffer.
Indices
Each Segment Type references an Index that determines the performance of its associated Segments. We currently offer Segment Types based on the performance of securities indices. Throughout this Prospectus, we refer to these indices using the term “Index” or, collectively, “Indices.” Not all Indices may be available under your contract.
Securities Indices.
The following securities Indices are currently available:
S&P 500 Price Return Index.
MSCI Emerging Markets Price Return Index
market country indices: Brazil, Chile, China, Colombia, Czech Republic, Egypt, Hungary, India, Indonesia, Korea, Malaysia, Mexico, Morocco, Peru, Philippines, Poland, Russia, South Africa, Taiwan, Thailand, and Turkey. The MSCI Emerging Markets Price Return Index does not include dividends declared by any of the companies included in this Index, which will reduce Index performance. Additional information about the Index may be found in Appendix “Index Publishers”. If you would like to request additional information about the Index, contact the customer service group or your financial professional.
NASDAQ-100 Price Return Index
Russell 2000
®
Price Return Index.
®
®
small-cap
segment of the U.S. equity universe. The Russell 2000®
®
2000 Price Return Index does not include dividends declared by any of the companies included in this Index, which will reduce Index performance. Additional information about the Index may be found in Appendix “Index Publishers”. If you would like to request additional information about the Index, contact the customer service group or your financial professional.
®
MSCI EAFE Price Return Index
The bar charts shown below provide each Index’s annual returns for the last 10 calendar years (or for the life of the Index if less than 10 years), as well as the Index returns after applying a hypothetical 5% Performance Cap Rate and a hypothetical -10% Segment Buffer. The chart illustrates the variability of the returns from year to year and shows how hypothetical limits on Index gains and losses may affect these returns. Past performance is not necessarily an indication of future performance.
The performance below is NOT the performance of any Segment of the SIO. Your performance under the contract will differ, perhaps significantly. The performance below may reflect a different return calculation, time period, and limit on Index gains and losses than the Segments of the SIO, and does not reflect contract fees and charges, including withdrawal charges and negative Segment Interim Value adjustments, which reduce performance. The performance does not reflect any advisory fees paid to a financial intermediary from the contract or other assets of the owner and if such charges were reflected such performance would be lower.
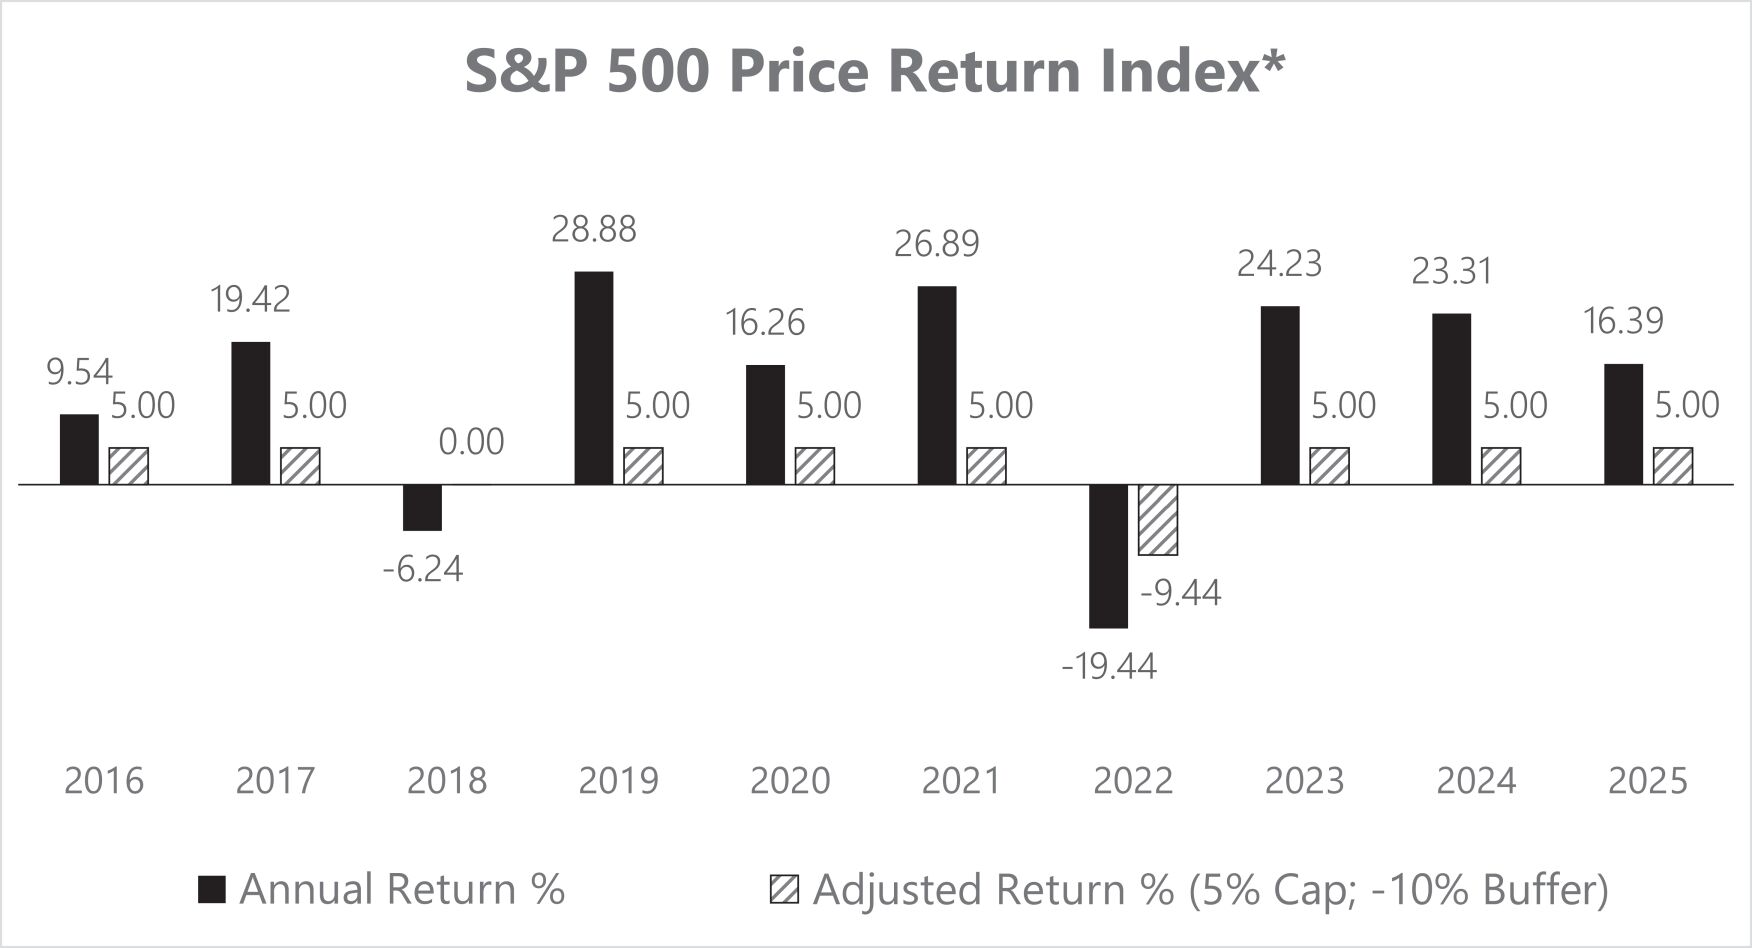
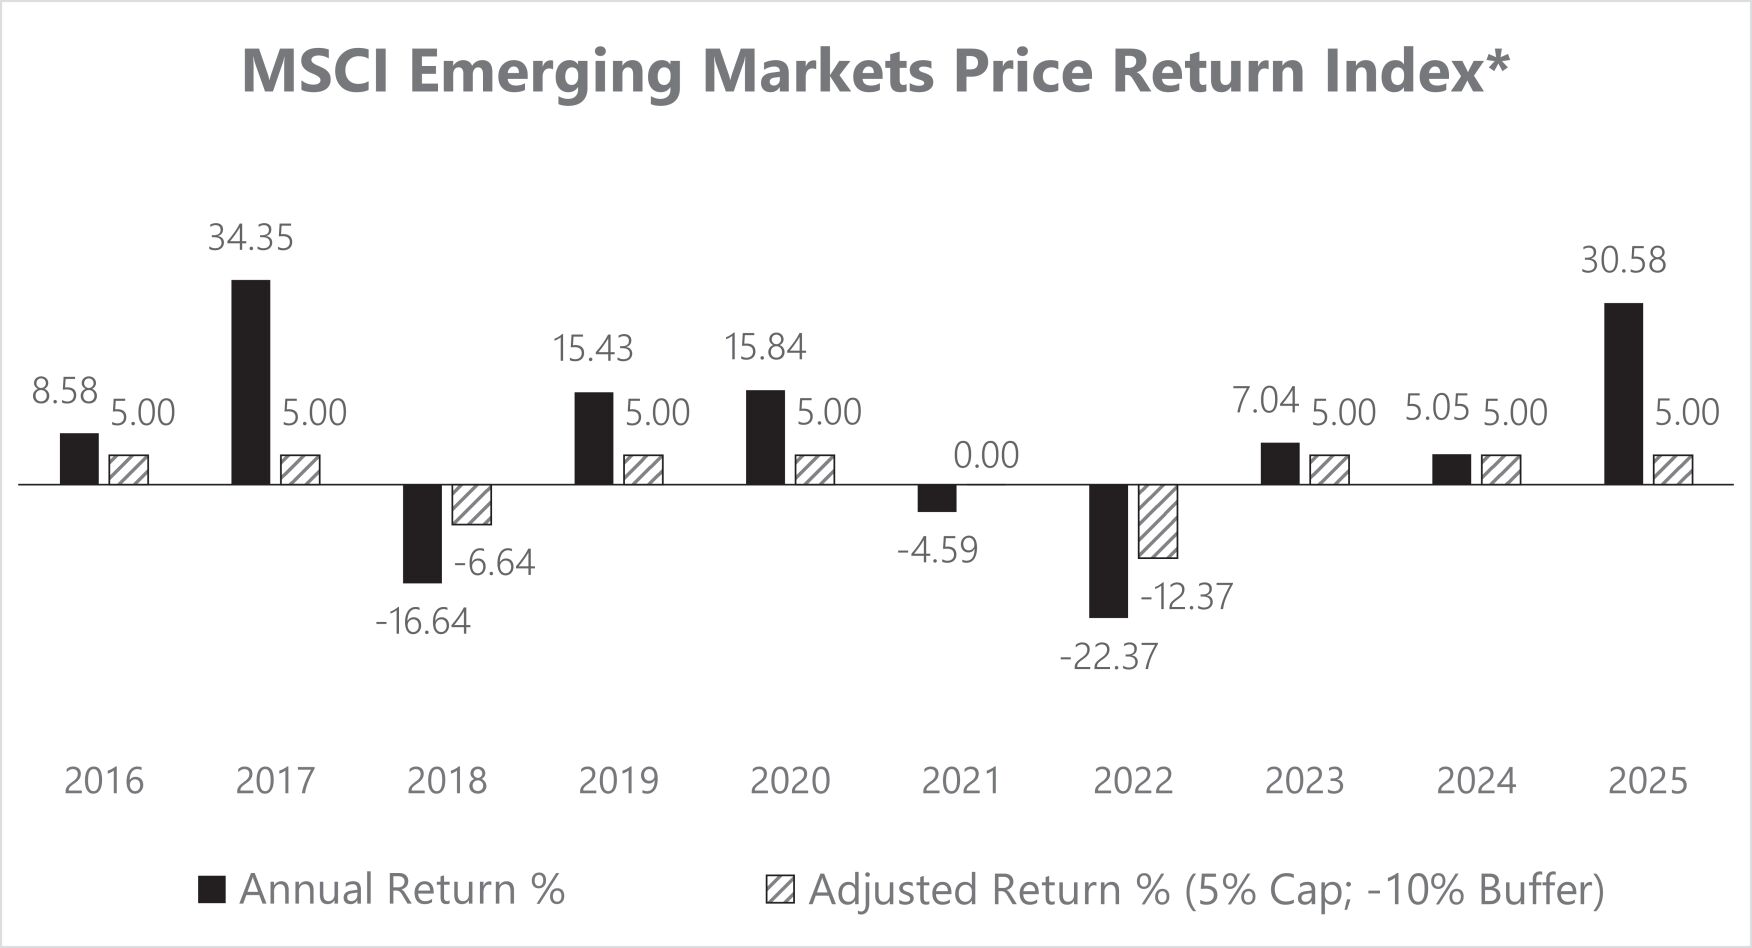
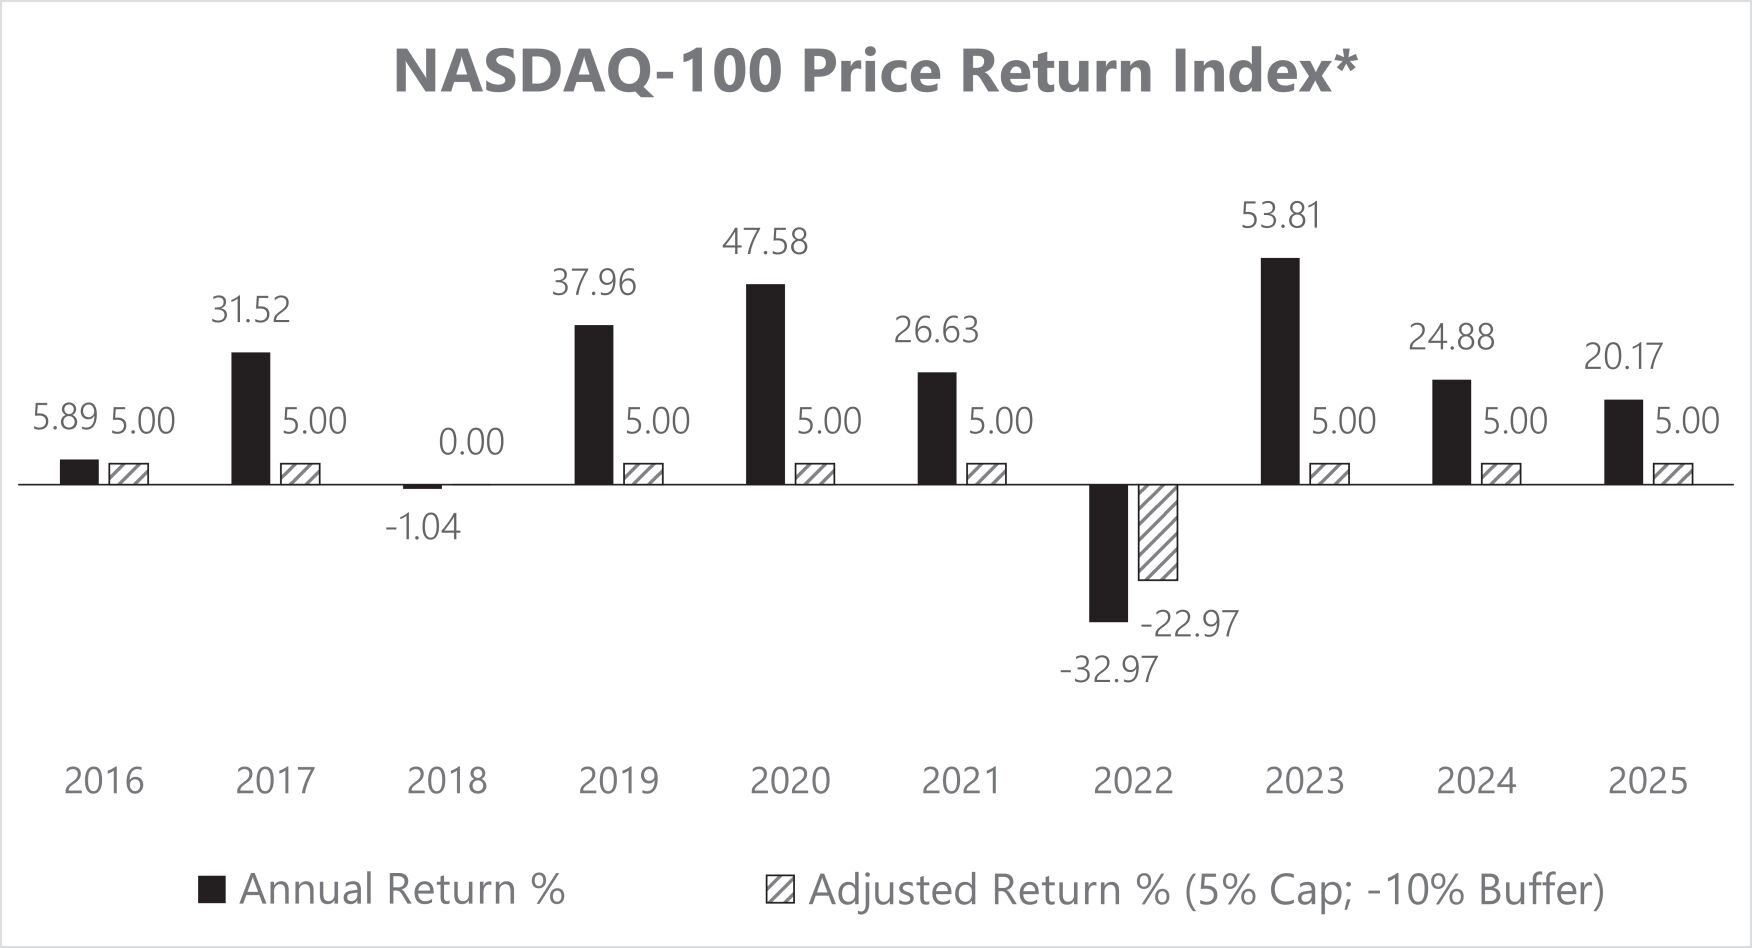
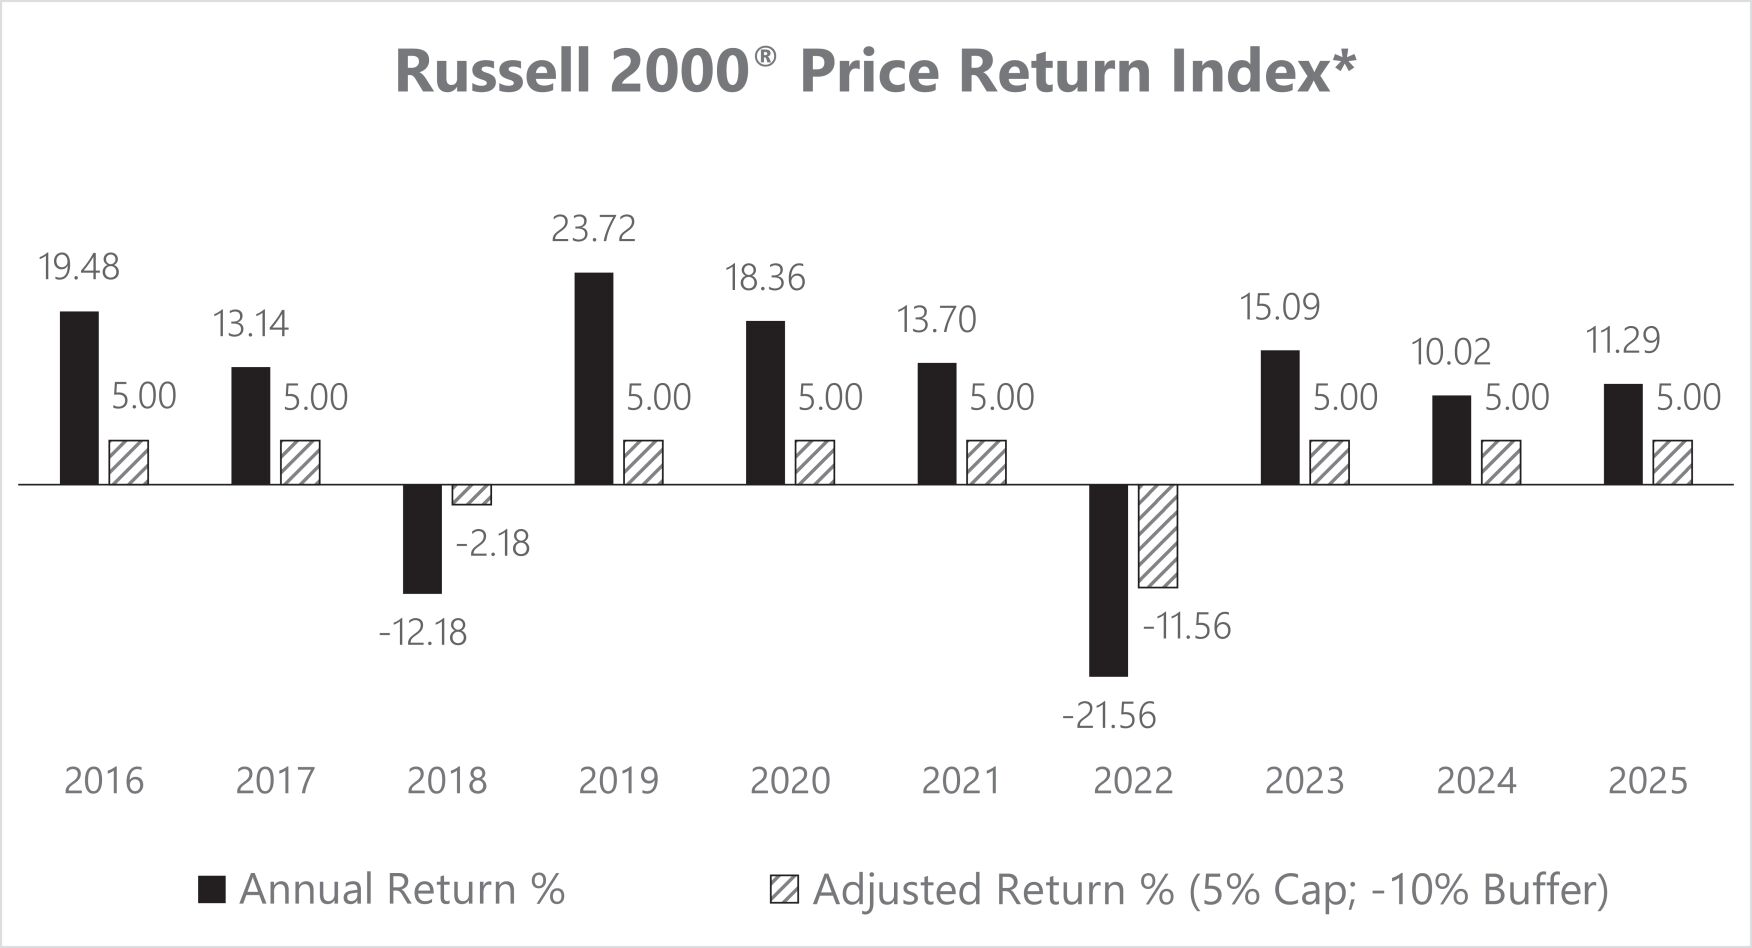
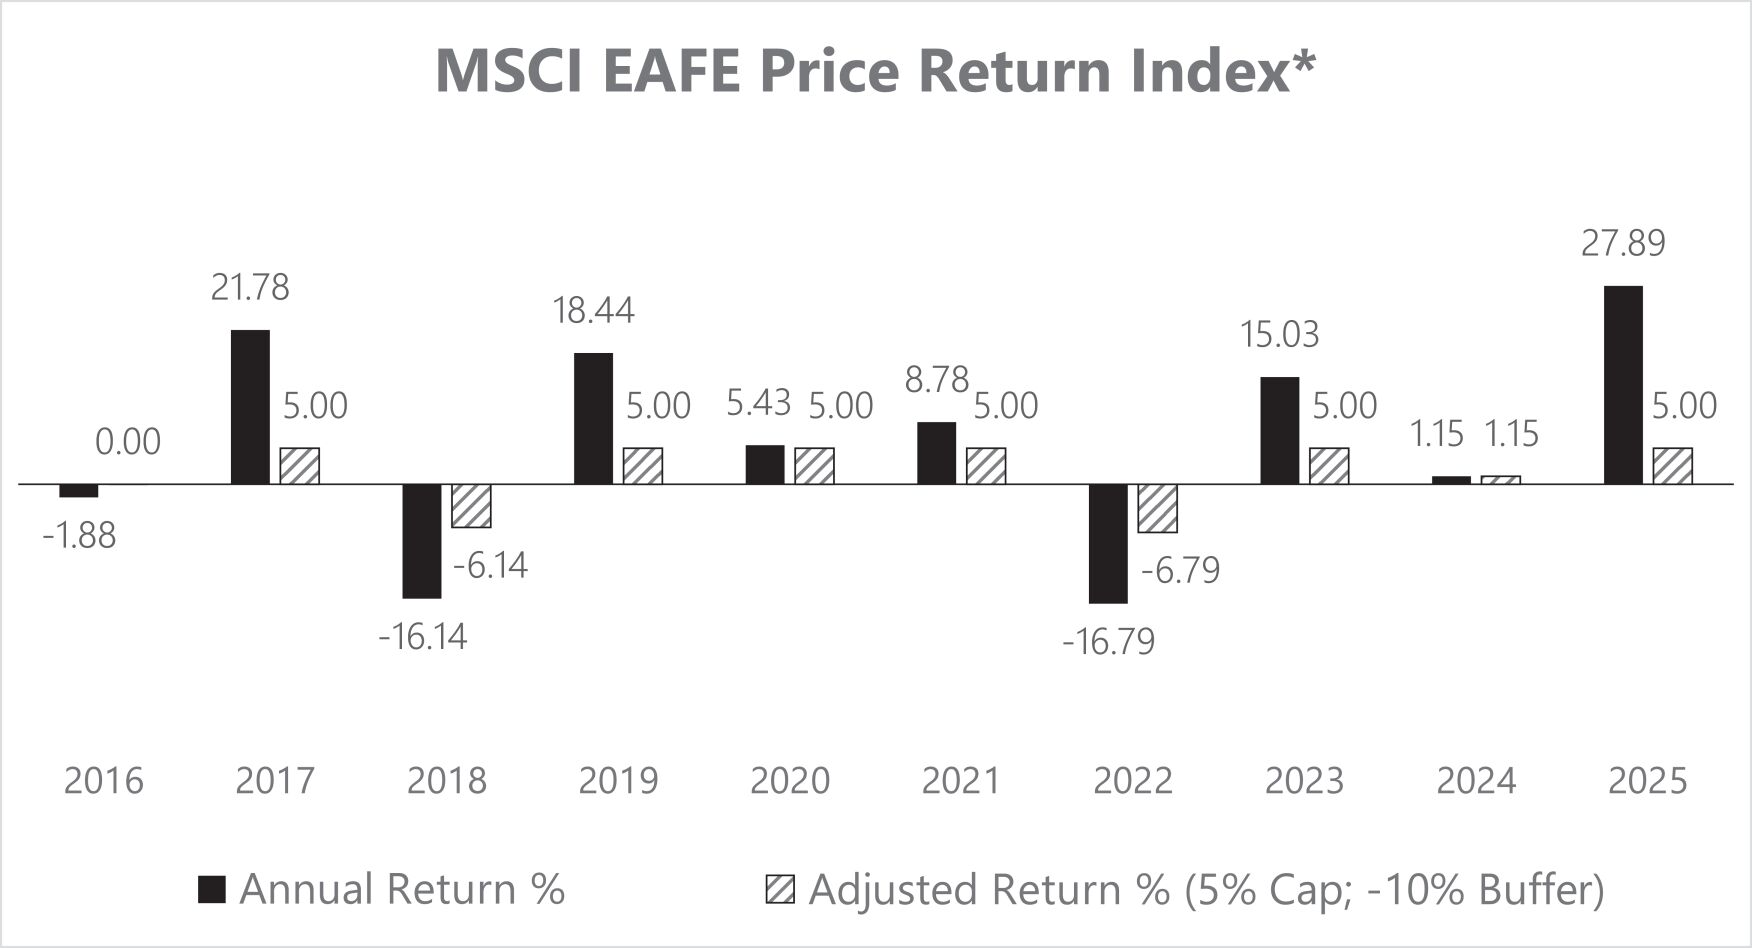
| * | The Index is a “price return” index, not a “total return” index, and therefore the performance of the Index does not reflect dividends declared by any of the companies included in the Index, reducing the Index return. As a result, the Index will underperform a direct investment in the securities composing the Index. |
Effect of an emergency close.
Segments are scheduled to mature and start on Segment Business Days. The Segment Maturity Date for Segments maturing and the Segment Start Date for new corresponding Segments starting will generally occur on consecutive business days that are also Segment Business Days. It is possible that an Index could be affected by an emergency close on a Segment Business Day, thereby affecting the Index’s ability to publish a price and our ability to mature or start Segments based on the affected Index. Emergency closes can have two consequences.
1. |
If the NYSE experiences an emergency close and Indices cannot publish prices, we will delay the maturity or start of all Segments for all Indices. |
2. |
If any Index not on the NYSE experiences an emergency close, we will delay the maturity and start of the Segments using the affected Index and mature or start Segments for all unaffected Indices. |
The emergency closure of an can have a different effect if it occurs on a Segment Maturity Date rather than a Segment Start Date. We do not currently offer any such Index, but may in the future.
Index not on the NYSE
| • | If an emergency close occurs on a scheduled Segment Maturity Date, |
• |
If an emergency close occurs on an Index not on the NYSE on a scheduled Segment Start Date, |
Maturity Values designated for Segment Types that utilize an affected Index would not be allocated to Segments and would remain in the corresponding Segment Type Holding Account. |
If the conditions that cause an emergency close persist, we will use reasonable efforts to calculate the Segment Maturity Value of any affected Segments. If the affected Index cannot be priced within eight days, we will contact a calculating agency, normally a bank we have a contractual relationship with, which will determine a price to reflect a reasonable estimate of the Index level.
Suspension, Termination and Changes to Segment Types and Indices
We may decide at any time until the close of business on each Segment Start Date whether to offer any or all of the Segment Types described in this Prospectus on a Segment Start Date for a particular Segment. We may suspend a Segment Type for a week, month or a period of several months, or we may terminate a Segment Type entirely.
If a Segment Type is suspended, your account value will remain in the Segment Type Holding Account until a Segment of that Segment Type is offered or you transfer out of the Segment Type Holding Account. We will provide you with written confirmation when money is not transferred from a Segment Type Holding Account into a segment due to the suspension of a Segment Type.
If a Segment Type is terminated, your account value in the corresponding Segment Type Holding Account will be defaulted into the EQ/Money Market variable investment option on the date that would have been the Segment Start Date.
We have the right to substitute an alternative index prior to Segment maturity if the publication of one or more Indices is
discontinued, or if we no longer have a license agreement with the publishers of the Index, or at our sole discretion we determine that our use of such Indices should be discontinued because hedging instruments become difficult to acquire or the cost of hedging becomes excessive, or if the calculation of one or more of the Indices is substantially changed. We would attempt to choose a substitute index that has a similar investment objective and risk profile to the replaced index. For example, if the Russell 2000
®
Index were not available, we might use the NASDAQ Composite Index. We also have the right to add additional Indices under the contract at any time. We would provide notice about the use of additional Indices before they are available for use with a Segment or alternative Indices, as soon as practicable, after the Indices are no longer being used. If an alternative index is used, its performance could impact the Index Performance Rate, Segment Rate of Return, Segment Maturity Value, and Segment Interim Value because it would be used to calculate the performance from the Segment Start Date to the Segment Maturity Date. An alternative index would not change the Segment Buffer or Performance Cap Rate for an existing Segment.
In addition, we reserve the right to use any or all reasonable methods to end any outstanding Segments that use such Indices. If a similar index cannot be found, we will end the affected Segments prematurely by applying the Segment Performance Cap Rate and Segment Buffer to the actual gains or losses on the original Index as of the date of termination.
We reserve the right to offer any or all Segment Types more or less frequently than we have been or to stop offering any or all of them or to suspend offering any or all of them temporarily for some or all contracts. If we stop offering or suspend certain Segment Types, each existing Segment of those Segment Types will remain invested until its respective Segment Maturity Date.
In the highly unlikely event we were forced to stop offering new Segments, contract owners would be limited to transferring or contributing to the other investment options described in the variable annuity contract prospectus. You could choose to surrender your contract, but you may be subject to the Segment Interim Value calculation, withdrawal charges, taxes, and tax penalties, and if you
purchase another retirement vehicle, it may have different features, fees, and risks than your annuity contract. If you are buying the annuity contract for the
Structured Investment Option, you should speak to your financial adviser as to whether this product is suitable for you.
Allocating your contributions
Your initial contribution and any subsequent contributions will be allocated according to the investment allocations on file. If you would like your subsequent contributions to be allocated differently, you must submit (either in writing or electronically, depending on the form being used) new allocation instructions on a form that we provide. The maximum number
of investment options that may be listed in your allocation instructions on file or for rebalancing (whether scheduled/recurring or one time) is 100.
Transfers.
Generally, you may transfer your account value among the investment options. We may, at any time, exercise our right to terminate transfers to any of the investment options, to add variable investment options, and to limit the number of investment options which you may elect.
Transfer requests do not change the allocation instructions on file for any future contribution or scheduled/recurring rebalancing. This means that upon the next scheduled/recurring rebalancing, we will transfer amounts among your investment options pursuant to the allocation instructions previously on file for your account. For more information about transferring your account value, please see “Transferring your money among investment options”.
You may also provide instructions for a one-time rebalancing of your account.
Allocation instruction changes.
You may change your instructions for allocations of future contributions. Please note that an allocation change for future contributions will not automatically change the scheduled/recurring rebalancing instructions on file for your account.
Your responsibility for allocation decisions
The contract is between you and the Company. The contract is not an investment advisory account, and the Company is not providing any investment advice or managing the allocations under your contract. In the absence of a specific written arrangement to the contrary, you, as the owner of the contract, have the sole authority to make investment allocations and other decisions under the contract. Your Equitable Advisors financial professional is acting as a broker-dealer registered representative, and is not authorized to act as an investment advisor or to manage the allocations under your contract. Certain Equitable Advisors financial professionals who are registered as investment advisory representatives (IARs) of Equitable Advisors may enter into a separate agreement with you to provide investment advice for a fee regarding the management of your Series ADV contract. That arrangement will be governed by a separate investment advisory contract, and different terms and conditions will apply (as set forth in that separate investment advisory contract and related disclosures, such as pertinent Forms ADV Part 2A). If your financial professional is a registered representative with a broker-dealer other than Equitable Advisors, you should speak with him/her regarding any different arrangements that may apply, particularly with regard to any fee-based arrangement you may have in connection with your Series ADV contract.
Breakpoint Credit
You may be eligible for an annual reduction in the Contract fee of up to 0.15% of your account value. This reduction is not available with the Investment Edge ADV series contract. This credit, which we refer to as the Breakpoint Credit
®
(“BPC”) is calculated quarterly and credited to your account annually as follows:
| • | On each Valuation Date, if your account value is at least equal to a BPC Threshold, we will calculate a credit equal to 0.025% or 0.0375% of your account value on that Valuation Date depending on which BPC Threshold your account meets. We will then credit your account with the aggregate BPC on the Crediting Date. “Valuation Date”, “BPC Threshold” and “Crediting Date” are defined below. |
| • | There are four Valuation Dates each year: (a) Three “quarterversaries”, which are the dates that occur every three months on the same calendar day as your Contract Date, but excluding your contract date anniversary) and (b) your contract date anniversary. If a quarterversary falls on a non-business day, the Valuation Date for that quarterversary will be the next business day. If your Contract Date falls after the 28th of a month, the Valuation Date for each quarterversary will be the first business day of the following month. If your contract date anniversary occurs on a day other than a business day, the Valuation Date will be the business day immediately preceding your Contract date anniversary. |
| • | There are two BPC Thresholds. The first BPC Threshold is (a) on a quarterversary Valuation Date, $500,000, without deduction of any fees for the Return of Premium death benefit (if elected) and without including any accrued BPCs from prior quarterversaries; and (b) on the contract date anniversary Valuation Date, $500,000, after deduction of all fees and charges. The second BPC Threshold is (a) on a quarterversary Valuation date, $1,000,000, without the deduction of any fees for the Return of Premium death benefit (if elected) and without including any BPCs from prior quarterversaries; and (b) on the contract date anniversary Valuation Date, $1,000,000, after deduction of all fees and charges. |
| • | The Crediting Date is the date on which we credit your account with the BPC, and is the Valuation Date associated with your contract date anniversary. |
| • | If during a contract year your account value meets a BPC Threshold on one or more, but not all, Valuation Dates, you will be credited with the aggregate accrued BPC for the Valuation Dates on which your account value did meet the BPC Threshold. For example, if your account value satisfied the BPC Threshold on the first and third quarterversaries, but not on the second quarterversary or your contract date anniversary, your account will be credited on the Crediting Date with the aggregate BPC calculated for your first and third quarterversaries. |
| • | On the Crediting Date, any BPC attributable to the variable investment options will be credited to your current variable investment options pro rata. If you have set up a dollar cost averaging program, the BPC will be credited according to your allocation instructions for the dollar cost averaging program. Any BPC attributable to the |
Structured Investment Option will be credited to the EQ/Money Market variable investment option. |
| • | Account value in the Segment Type Holding Accounts and Segments (using the Segment Interim Value) will be included in determining whether you meet the BPC Thresholds and in calculating the amount, if any, of the Breakpoint credit. On the Crediting Date, the BPC attributable to the SIO will be credited to the EQ/Money Market variable investment option. |
| • | The BPC is not a contribution for purposes of the rules governing contributions to your contract. |
| • | Upon your death, or if you surrender or annuitize your contract, we will credit your account with a prorated amount of any accrued BPC. |
| • | If you elect an Income Edge payment program, you will continue to be eligible for the BPC in accordance with the rules above. Valuation Dates for quarterversaries will be determined based on your Income Edge Anniversary Date and your account will be credited with the BPC on your Income Edge Anniversary Date. Any BPC amounts that had accrued prior to your Income Edge payment program election will be credited on your Income Edge Effective Date. |
| • | Investment Edge ® |
Examples: BPC Calculations
Valuation Date |
Account Value |
Eligible for BPC? |
BPC Amount | |||
| First Quarterversary | $480,000 | No | $0 | |||
| Second Quarterversary | $530,000 | Yes | $132.50 ($530,000 * 0.025%) | |||
| Third Quarterversary | $520,000 | Yes | $130.00 ($520,000 * 0.025%) | |||
| Contract date anniversary | $550,000 | Yes | $137.50 ($550,000 * 0.025%) |
The BPC that will be credited on the Crediting Date is $400.
Valuation Date |
Account Value |
Eligible for BPC? |
BPC Amount | |||
| First Quarterversary | $900,000 | Yes | $225.00 ($900,000 * 0.025%) | |||
| Second Quarterversary | $850,000 | Yes | $212.50 ($850,000 * 0.025%) | |||
| Third Quarterversary | $1,100,000 | Yes | $412.50 ($1,100,000 * 0.0375%) | |||
| Contract date anniversary | $1,050,000 | Yes | $393.75 ($1,050,000 * 0.0375%) |
The BPC that will be credited on the Crediting Date is $1,244.
Inherited IRA beneficiary continuation contract
The Inherited IRA beneficiary continuation contract is intended to provide options to beneficiaries in
complying with federal income tax rules. There are a number of limitations on who can purchase the contract, how the contract is purchased, and the features that are available under the contract. A prospective purchaser should seek tax advice before making a decision to purchase the contract.
We offer the Inherited IRA beneficiary continuation contract to eligible beneficiaries under individual retirement arrangements (traditional or Roth) where the original individual retirement account or annuity was not issued by the Company. The beneficiary may want to change the investments of the “original IRA” inherited from the
now-deceased
IRA owner, but must take post-death required minimum distribution (“RMD”) payments from an IRA that was inherited. The Inherited IRA beneficiary continuation contract has provisions intended to meet post-death RMD rules, which are similar to those of the Beneficiary continuation option (“BCO”) restricted to eligible beneficiaries of contracts issued by the Company. See “Beneficiary continuation option for traditional IRA and Roth IRA contracts only” under “Beneficiary continuation option” in “Benefits available under the contract”. Further, since the Inherited IRA beneficiary continuation contract is intended to replace the investment originally selected by the now-deceased
IRA owner, a prospective purchaser should carefully consider the features and investments available under the Inherited IRA beneficiary continuation contract, and the limitations and costs under the contract in comparison with the existing arrangement before making any purchase decision. Finally, the contract may not be available in all states. Please speak with your financial professional for further information. Who can purchase an Inherited IRA beneficiary continuation contract
The Inherited IRA beneficiary continuation contract is offered only to beneficiaries of contracts not issued by us as follows:
| • | beneficiaries of IRAs who are individuals (“IRA beneficiaries”); and |
| • | eligible non-spousal individual beneficiaries of deceased plan participants in qualified plans, 403(b) plans and governmental employer 457(b) plans (“Non-spousal Applicable Plan beneficiaries”). The purpose is to enable such beneficiaries to elect certain post-death RMD payment choices available to them under federal income tax rules, which may not be offered under the Applicable Plan. |
Certain trusts with only individual beneficiaries are treated as individuals and are eligible to purchase the Inherited IRA beneficiary continuation contract if such trust is either an IRA beneficiary or a
Non-spousal
Applicable Plan beneficiary. How an Inherited IRA beneficiary continuation contract is purchased
IRA Beneficiary.
A traditional Inherited IRA beneficiary continuation contract can only be purchased by a direct transfer of the beneficiary’s interest under the deceased owner’s original traditional IRA. An Inherited Roth IRA
beneficiary continuation contract can only be purchased by a direct transfer of the beneficiary’s interest under the deceased owner’s original Roth IRA. In this discussion, “you” refers to the owner of the Inherited IRA beneficiary continuation contract. The owner of the Inherited IRA beneficiary continuation contract owns the contract in his/her capacity as beneficiary of the original traditional or Roth IRA, and not in his/her own right. For this reason, the contract must also contain the name of the deceased owner.
Non-spousal
Applicable Plan Beneficiary. In the case of a
non-spousal
beneficiary under a deceased plan participant’s Applicable Plan, the Inherited IRA can only be purchased by a direct rollover of the death benefit under the Applicable Plan. In this discussion, “you” refers to the owner of the Inherited IRA beneficiary continuation contract. The owner of the Inherited IRA beneficiary continuation contract owns the contract in his/her capacity as beneficiary of the deceased plan participant, and not in his/her own right. For this reason, the contract must also contain the name of the deceased plan participant. In this discussion, references to “deceased owner” include “deceased plan participant”; references to “original IRA” include “the deceased plan participant’s interest or benefit under the Applicable Plan”, and references to “individual beneficiary of a traditional IRA” include “individual non-spousal
beneficiary under an Applicable Plan.” Limitations on certain features under the Inherited IRA beneficiary continuation contract
When the Inherited IRA beneficiary continuation contract is owned by an IRA beneficiary:
| • | The Inherited IRA beneficiary continuation contract can be purchased even though you have already begun taking post-death RMD payments of your interest as a beneficiary from the deceased owner’s original IRA. You should discuss with your own tax adviser when payments must begin or must be made. |
| • | The initial contribution must be a direct transfer from the deceased owner’s original IRA and is subject to minimum contribution amounts. See Appendix “Rules regarding contributions to your contract” for more information. |
| • | Subsequent contributions of at least $1,000 are permitted but must be direct transfers of your interest as a beneficiary from another IRA with a financial institution other than the Company, where the deceased owner is the same as under the original IRA contract. |
| • | If the deceased owner died on or before December 31, 2019 or you are an “eligible designated beneficiary” (as defined later in this Prospectus) electing to stretch out your payments over your life expectancy, the Inherited IRA contract is designed to pay you at least annually (but you can elect to receive payments monthly or quarterly). Payments are generally made over your life expectancy determined in the calendar year after the deceased owner’s death and determined on a term certain basis. If |
you maintain another IRA of the same type (traditional or Roth) of the same deceased owner and you are also taking distributions over your life from that inherited IRA, you may qualify to take an amount from that other inherited IRA which would otherwise satisfy the amount required to be distributed from our Inherited IRA contract. If you choose not to take a payment from your Inherited IRA contract in any year, you must notify us in writing before we make the payment from the Inherited IRA contract, and we will not make any future payment unless you request in writing a reasonable time before we make such payment. If you choose to take a required payment from another inherited IRA, you are responsible for calculating the appropriate amount and reporting it on your income tax return. Please feel free to speak with your financial professional, or call our processing office, if you have any questions. |
| • | If you are not an eligible designated beneficiary and the deceased owner died after December 31, 2019, the Inherited IRA contract is required to have all amounts within the contract withdrawn within ten years of the deceased owner’s death, in accordance with federal law. In this case, the Inherited IRA contract can only be purchased if you have at least 8 years remaining on the 10 year post-death payment period. |
When the Inherited IRA beneficiary continuation contract is owned by a
Non-spousal
Applicable Plan beneficiary: | • | The initial contribution must be a direct rollover from the deceased plan participant’s Applicable Plan and is subject to minimum contribution amounts. See Appendix “Rules regarding contributions to your contract” for more information. |
| • | There are no subsequent contributions. |
| • | If the deceased participant died on or before December 31, 2019 or you are an “eligible designated beneficiary” (as defined later in this Prospectus) electing to stretch out your payments over your life expectancy, you must receive payments at least annually (but can elect to receive payments monthly or quarterly). Payments are made over your life expectancy determined in the calendar year after the deceased owner’s death and determined on a term certain basis. Shorter payment periods are not permitted. |
| • | If you are not an eligible designated beneficiary and the deceased participant died after December 31, 2019, the Inherited IRA contract is required to have all amounts within the contract withdrawn within ten years of the deceased owner’s death, in accordance with federal law. In this case, the Inherited IRA contract can only be purchased if you have at least 8 years remaining on the 10 year post-death payment period. |
Features of the Inherited IRA beneficiary continuation contract which apply to either type of owner:
| • | The beneficiary of the original IRA (or the Non-spousal Applicable Plan beneficiary) will be the annuitant under |
the Inherited IRA beneficiary continuation contract. In the case where the beneficiary is a “see-through trust,” the oldest beneficiary of the trust will be the annuitant. |
| • | An inherited IRA beneficiary continuation contract is not available for owners over age 75. |
| • | You may make transfers among the investment options. In addition, you may participate in the dollar cost averaging program. |
| • | You may choose at any time to withdraw all or a portion of the account value. Any partial withdrawal must be at least $300. Withdrawal charges will apply as described in “Charges, expenses, and adjustments”. |
| • | If you die, we will pay to a beneficiary that you choose the account value. |
| • | Upon your death, your beneficiary has the following options: (1) if you were an EDB or the deceased owner (or deceased participant) died on or before December 31, 2019, your beneficiary must withdraw any remaining amount within ten years of your death; or (2) if you were not an EDB, the beneficiary must withdraw any remaining amount within 10 years of the deceased owner’s (or deceased participant’s) death. |
| • | For beneficiaries who are required to take the entire interest within 10 years, we offer our post-death automatic RMD option to help the beneficiary meet the RMD requirements if the deceased owner died on or after the Required Beginning Date. We calculate post-death RMD payments using the beneficiary’s life expectancy determined in accordance with IRS tables. Instead of electing our post-death automatic RMD option, you may choose to calculate the required amount yourself and request partial withdrawals. Regardless of whether you elect this option, any remaining amounts will be distributed to you by the end of the 10th calendar year following the year of the owner’s death. It is your responsibility to ensure that you comply with RMD rules under federal tax law. |
Inherited NQ beneficiary payout contract
The Inherited NQ beneficiary payout contract (“Inherited NQ”) is intended to provide options to individuals who are beneficiaries under nonqualified deferred annuity contracts issued by other insurance companies. Qualifying individuals direct the issuing insurance company to exchange their interest in the original contract’s death benefit with an Inherited NQ contract, which is intended to comply with federal income tax rules governing payments following the death of the holder of a contract, while providing the Inherited NQ contract owner with continuing access to the Inherited NQ contract’s account value as scheduled payments are made.
There are a number of limitations on who can purchase an Inherited NQ contract, how the contract is purchased, and the features that are available under
the contract. There is a short timeframe for purchasing an Inherited NQ contract and providing the Company with all of the necessary information to make payments. Also, whether an Inherited NQ contract can be issued and the form of payout under the contract is dependent in part on the agreement and cooperation of the insurance company that issued the original nonqualified deferred annuity contract. Before making a decision to purchase an Inherited NQ contract, a prospective purchaser should seek tax advice and review the issuing insurance company’s requirements applicable to an exchange.
An Inherited NQ contract is issued as an Investment Edge, Investment Edge Select or Investment Edge ADV contract. The Inherited NQ contract provides a non-life contingent, variable annuity payout for the purpose of distributing to a beneficiary certain payments required after the death of a “holder” (typically, the owner) of a nonqualified deferred annuity contract. We offer the Inherited NQ contract to an individual who is a beneficiary upon the death of the owner under an original nonqualified deferred annuity contract not issued by the Company (“source contract”). We offer two payout options under the Inherited NQ contract, “Income Edge Beneficiary Advantage” and “Beneficiary NQ Stretch,” both of which are described below.
®
®
®
The beneficiary under the source contract may want to change the investments of the inherited source contract while still taking the payments required with respect to the death of the owner of the source contract. The beneficiary may also want continuing access to the Inherited NQ contract’s account value as scheduled payments are made, and may also wish to elect the contract’s Income Edge Beneficiary Advantage option.
Since an Inherited NQ contract is intended to replace the investments originally selected by the now-deceased owner of the source contract, a prospective purchaser should carefully consider the investments and features available under the Inherited NQ contract (such as the choice between the Beneficiary NQ Stretch and Income Edge Beneficiary Advantage payout methods), and the limitations and costs under the Inherited NQ contract as compared to the available investments and features under the source contract before making any purchase decision.
Since, as discussed below, the Inherited NQ contract can only be purchased through a Section 1035 exchange, a prospective purchaser should also confirm with the insurance company that issued the source contract the requirements for exchanging the death benefit under the source contract with an Inherited NQ contract. Finally, the Inherited NQ contract may not be available in all states. Please speak with your financial professional for further information.
Who can purchase an Inherited NQ contract
The Inherited NQ contract is offered only to individuals who are death beneficiaries under nonqualified deferred annuity contracts not issued by us. The Inherited NQ contract is not available to non-natural persons or purchasers over the age of 75. Joint owners or annuitants are not permitted.
The owner of the Inherited NQ contract owns the contract in his/her capacity as beneficiary of the deceased owner of the source contract. For this reason, the Inherited NQ contract must also contain the name of the deceased owner.
When can an Inherited NQ contract be purchased
An Inherited NQ contract can only be purchased after the death of the owner of the source contract and (1) before the first anniversary of the owner’s death if payments have not started under the source contract or (2) before the anniversary of the last payment date under the source contract if payments have started under the source contract (the “Required Inherited NQ Payment Starting Date”).
An individual may not purchase an Inherited NQ contract if he/she has less than 10 years life expectancy remaining.
How an Inherited NQ contract is purchased
An Inherited NQ contract can only be purchased through a Section 1035 exchange of the beneficiary’s interest after the death of the owner under the source contract. If the source contract is owned by a non-natural owner, the deceased individual whose death triggers the requirement to make post-death payments from or with respect to the proceeds of the source contract must have been the primary annuitant deemed to be the “holder” or owner of the source contract under federal income tax rules.
The source contract must be a nonqualified deferred annuity contract, and cannot be a life insurance contract.
An individual must apply the entire value of his/her beneficiary share in the source contract to the Inherited NQ contract; we do not accept partial exchanges. The individual need not be the only beneficiary under the source contract. If the individual is one of several beneficiaries, we will accept an exchange into the Inherited NQ contact as long as the beneficiary’s entire share under the source contract is exchanged.
Similarly, if the individual is a beneficiary under more than one source contract owned by the same deceased owner, the individual may direct each insurance company issuing each such source contract to make a Section 1035 exchange into the Inherited NQ contract. Each of the multiple Section 1035 exchanges must meet the requirements described in this section, and must include a contribution of at least $1,000.
No contributions will be accepted after we begin scheduled payments under the Inherited NQ contracts. See the description under “Income Edge Beneficiary Advantage” for the requirements regarding provision of cost basis information.
We must receive all contributions and the information we require from the insurance company (or companies) that issued the source contract(s) in sufficient time for us to begin making scheduled payments under the Inherited NQ contract. If payments have not started under the source contract, this must be no later than 12 months after the date of death of the deceased owner of the source contract. This deadline is generally 9 months after the date of
death of the deceased owner of the source contract. If payments have already started under the source contract, we must receive all contributions and information no later than 12 months before the anniversary of the last payment date (if there are multiple source contracts that have started payments, we must receive all contributions and information no later than 12 months before the earliest anniversary of the contracts’ last payment date). The deadline is generally 3 months before the anniversary of the last payment date. No additional contributions are allowed once we have begun making payments.
If the insurance company that issued the source contract does not provide us with a 1035 exchange contribution and the information we need in a timely manner, we may not be able to issue the Inherited NQ contract or honor an election for Income Edge Beneficiary Advantage. See “Payment options under an Inherited NQ contract”.
Payment options under an Inherited NQ contract
There are two payment options under the Inherited NQ contract, “Income Edge Beneficiary Advantage” and “Beneficiary NQ Stretch.” We describe these options and the conditions and limitations that apply to each option later in this section.
Regardless of payment option, there are some features, conditions and limitations that are common to both options:
| • | The Inherited NQ contract is intended only for beneficiaries under source contracts who plan to take payments from the Inherited NQ contract at least annually over a period measured by their life expectancy. We call these “scheduled payments.” These scheduled payments must begin no later than the Required Inherited NQ Payment Starting Date. Beneficiaries who do not want to take scheduled payments at least annually and want to wait up to five years after the death of the owner of the source contract to withdraw the entire amount of their interest in the source contract should not purchase an Inherited NQ contract. Because of the Inherited NQ contract’s focus on scheduled payments, certain features more suitable to long-term accumulation vehicles are not available under the Inherited NQ contract. |
| • | We have no minimum age requirement for issuing an Inherited NQ contract, but we will not issue an Inherited NQ contract to an individual over age 75. |
| • | The Inherited NQ contract owner must receive scheduled payments at least annually (but can elect to receive scheduled payments monthly or quarterly). The Inherited NQ contract owner can choose a date to start scheduled payments earlier than the Required Inherited NQ Payment Starting Date, as long as we have the Section 1035 exchange contribution(s) and information we need to start scheduled payments on the earlier date. |
| • | The amount of the first scheduled payment is determined by dividing the account value as of the date payments begin by the owner’s life expectancy. Each subsequent annual scheduled payment is determined by dividing the remaining annuity account value as of |
the anniversary date by the initial life expectancy, reduced by 1 for each subsequent year. |
For example, if on the date of the first scheduled payment your account value is $100,000 and your life expectancy is 20 years, the amount of the first scheduled payment will be $5,000. If on the date of the second scheduled payment your account value is $99,750, the amount of the second scheduled payment will be $5,200 ($99,750 divided by 19).
| • | Payment amounts are taken on a pro rata basis from your variable investment options. |
| • | The Inherited NQ contract owner may make transfers among the variable investment options. |
| • | Once scheduled payments begin, they cannot be stopped until the account value falls to zero. |
| • | No form of annuity benefit other than scheduled payments as described in this section is available under the Inherited NQ contract. |
| • | An Inherited NQ contract owner may choose to withdraw all or a portion of his/her account value at any time. Any partial withdrawal must be at least $300. Unlike Income Edge Beneficiary Advantage scheduled payments, no portion of such withdrawals will represent a return of cost basis in the contract, and thus will not affect the Tax-Free Amount applicable to subsequent Income Edge Beneficiary Advantage scheduled payments. Withdrawal charges will apply, as described in “Charges, expenses, and adjustments”. |
| • | Change of ownership of an Inherited NQ contract is not permitted. |
| • | The Return of Premium death benefit is not available under an Inherited NQ contract. |
| • | At the death of the Inherited NQ contract owner, we will continue scheduled payments to a successor beneficiary/owner chosen by the Inherited NQ contract owner. The successor beneficiary/owner has the same rights as the Inherited NQ contract owner to take partial withdrawals in addition to scheduled payments and to fully surrender (redeem) the Inherited NQ contract. If there is more than one individual or entity chosen by the Inherited NQ contract owner to be successor beneficiary/owner, we will make payments in equal shares unless the Inherited NQ contract owner instructed us in writing to pay one or more successor beneficiary/owner differently. |
Income Edge Beneficiary Advantage
Under the Income Edge Beneficiary Advantage payment option for an Inherited NQ contract (“Income Edge BA”), we take into account the “cost basis” in calculating and reporting income amounts with respect to scheduled payments. A portion of each scheduled payment is a return of the cost basis in the contract and thus excludable from taxes. The “cost basis” in an Inherited NQ contract with Income Edge
BA is the amount of investment in the source contract carried over from the source contract to the Inherited NQ contract (as reported to us in the context of the Section 1035 exchange by the insurance company which issued the source contract), plus or minus any subsequent adjustments.
The payment period for scheduled payments is initially based on the age of the Inherited NQ contract owner, using an IRS table for post-death payments and rounding down to the nearest whole number. The Inherited NQ contract owner may select a shorter payment period, which will generally result in larger payments.
The conditions applicable to an Income Edge BA election are as follows:
| • | Income Edge BA must be elected on our form. |
| • | The account value of the Inherited NQ contract must be at least $35,000. |
| • | The account value of the Inherited NQ contract must be greater than the cost basis reported to us in the context of the Section 1035 exchange by the insurance company which issued the source contract. |
| • | We must have received all Section 1035 exchange contributions from each source contract at least three months prior to the Required Inherited NQ Payment Starting Date. |
| • | We must have all cost basis information, in good order, from the insurance company which issued the source contract, at least three months prior to the Required Inherited NQ Payment Starting Date for an Income Edge BA election to be effective. If we do not receive complete cost basis information in this timeframe, your Income BA election will not take effect and your contract will default to the Beneficiary NQ Stretch payment option. If there are multiple source contracts for the same deceased owner, as long as we have cost basis information in good order for any source contract, we will use that amount as the cost basis. |
| • | We may impose a charge approximating premium tax in certain states. |
| • | If an Inherited NQ contract owner elects Income Edge BA, and we cannot honor or implement that election because of a failure to meet any of the conditions for Income Edge BA noted above, we will begin scheduled payments under the Beneficiary NQ Stretch payment option for the Inherited NQ contract no later than the Required Inherited NQ Payment Starting Date. |
| • | Return of Premium death benefit is not available with Income Edge. |
Income Edge BA payment may not be available in all states. We also offer a version of Income Edge Beneficiary Advantage as a death benefit option for a beneficiary under an NQ Investment Edge contract where the contract owner dies before an annuity option under the contract has been elected. See “Benefits available under the contract”.
®
We believe, based on our review and interpretation of applicable federal tax law, that the Income Edge BA payout methodology constitutes a series of “substantially equal periodic payments” over a “period not extending beyond the life expectancy” of a beneficiary within the applicable requirements of 72(s) of the Code and therefore complies with current federal tax law requirements applicable to post-death payouts from variable annuity contracts. See “Income Edge payment program” under “Tax Information”.
Beneficiary NQ Stretch
Under the Beneficiary NQ Stretch payment option for the Inherited NQ contract, we do not report all scheduled payments as being a partial return of cost basis. Instead, we report scheduled payments as taxable to the extent that there is income in the contract.
Beneficiary NQ Stretch must be elected on our form. However, for an Inherited NQ contract owner who elected Income Edge BA, Beneficiary NQ Stretch will apply by default if one or more of the conditions for honoring or implementing an Income Edge BA election could not be met before the Required Inherited NQ Payment Starting Date.
The payment period is based on the age of the Inherited NQ contract owner, using an IRS table for post-death payments and rounding down to the nearest whole number. A shorter payment period may not be elected under Beneficiary NQ Stretch.
Based on our interpretation of the requirements of Section 72(s) of the Code, we believe that the Beneficiary NQ Stretch payout methodology complies with current federal tax law requirements applicable to post-death payouts from variable annuity contracts.
Your right to cancel within a certain number of days
If for any reason you are not satisfied with your contract, you may return it to us for a refund. To exercise this cancellation right you must mail the contract, with a signed letter of instruction electing this right, to our processing office within 10 days after you receive it. If state law requires, this “free look” period may be longer. Other state variations may apply. Please contact your financial professional and/or see Appendix “State contract availability and/or variations of certain features and benefits” to find out what applies in your state.
Generally, your refund will equal your account value under the contract on the day we receive notification to cancel the contract and will reflect any investment gain or loss in the variable investment options (less the daily charges we deduct), through the date we receive your contract. Some states, however, require that we refund the full amount of your contribution. In addition, in some states, the amount of your refund (either your account value or the full amount of your contributions), and the length of your “free look” period, depend on whether you purchased the contract as a replacement. For any IRA contract returned to us within seven days after you receive it, we are required to refund the
full amount of your contribution. When required by applicable law to return the full amount of your contribution, we will return the greater of your contribution or your contract’s cash value.
Please note that if you are invested in Segments of SIO when you free look your contract, the Segment Interim Value will apply.
We may require that you wait six months before you may apply for a contract with us again if:
| • | you cancel your contract during the free look period; or |
| • | you change your mind before you receive your contract whethe r we have received your contribution or not. |
Please see “Tax information” for possible consequences of cancelling your contract.
If you fully convert an existing traditional IRA contract to a Roth IRA contract, you may cancel your Roth IRA contract and return to a traditional IRA contract. Our processing office, or your financial professional, can provide you with the cancellation instructions.
In addition to the cancellation right described above, you have the right to surrender your contract, rather than cancel it. Please see “Surrendering your contract to receive its cash value”. Surrendering your contract may yield results different than canceling your contract, including a greater potential for taxable income. In some cases, your cash value upon surrender may be greater than your contributions to the contract. Please see “Tax information”.
The SIO provides some protection against negative returns on the Segment Maturity Date through the use of a Segment Buffer,
except Growth Multiplier Segments which do not have a Segment Buffer.
There is a
risk of a substantial loss of your principal and previously credited interest because you agree to absorb
The performance below is NOT the performance of any Segment of the SIO. Your performance under the contract will differ, perhaps significantly. The performance below may reflect a different return calculation, time period, and limit on Index gains and losses than the Segments of the SIO, and does not reflect contract fees and charges, including withdrawal charges and negative Segment Interim Value adjustments, which reduce performance. The performance does not reflect any advisory fees paid to a financial intermediary from the contract or other assets of the owner and if such charges were reflected such performance would be lower.
| * | The Index is a “price return” index, not a “total return” index, and therefore the performance of the Index does not reflect dividends declared by any of the companies included in the Index, reducing the Index return. As a result, the Index will underperform a direct investment in the securities composing the Index. |
Segment Types
Information regarding the features of each of the currently available Segment Types, including the Index name and type, the Segment Duration, the Segment Rate of Return calculation method, the current Segment Buffer, and the minimum Performance Cap Rate for the life of the Segment Type, is available in an appendix to the Prospectus. See Appendix “Investment Options available under the contract.” We are not obligated to offer any one particular Segment Type. Also, we are not obligated to offer any Segment Types. Each investment in a Segment Type that starts on a particular Segment Start Date is referred to as a Segment.
A Segment Type refers to a Segment Option that has the same Index, Segment Duration, and Segment Buffer. Each Segment Type has a corresponding Segment Type Holding Account. Please refer to the “Definitions of key terms” for a discussion of these terms.
We reserve the right to offer any or all Segment Types more or less frequently or to stop offering any or all of them or to suspend offering any or all of them temporarily for some or all contracts. Please see “Suspension, termination and changes to Segment Types” later in this section. All Segment Types may not be available in all states. We may also add Segment Types in the future.
The maximum current number of active variable investment options (including variable investment options with an allocation on file), Segments, and funded holding accounts that may be active in your contract at any time is 88.
Segment Start Date
Each Segment will have a Segment Start Date. Segments generally start on the first or third Thursday of each month. However, the Segment Start Date may sometimes be a different day under certain circumstances. Please see “Setting the Segment Maturity Date and Segment Start Date”. Also, we may offer Segments more or less frequently and on different days for some or all contracts.
Segment Type Holding Accounts
Any contribution or transfer designated for a Segment Type will be allocated to the corresponding Segment Type Holding Account until the Segment Start Date. The Segment Type Holding Accounts are part of the EQ/Money Market variable investment option but we do not apply a Contract Fee to amounts in a Segment Type Holding Account. You
must transfer or contribute to the Segment Type Holding Account for the corresponding Segment Type if you want to invest in a Segment; you cannot transfer or contribute directly to a Segment.
You can transfer amounts from a Segment Type Holding Account into any available variable investment options, or another Segment Type Holding Account at any time up to the close of business on the last business day before the Segment Start Date.
Please refer to the “How to reach us” section in this Prospectus for more information regarding contacting us and communicating your instructions. We also have specific forms that we recommend you use for electing the Structured Investment Option and any Structured Investment Option transactions.
Segment Participation Requirements
Provided that all participation requirements are met, all amounts allocated to a Segment Type that are in the associated Segment Type Holding Account as of the close of business on the business day preceding the Segment Start Date, plus any earnings on those amounts, will be transferred into the new Segment on the Segment Start Date. However, amounts transferred into the Segment Type Holding Account on the Segment Start Date itself will not be included in any new Segment created that day. These amounts will remain in the Segment Type Holding Account until they are transferred out or the next Segment Start Date on which the participation requirements are met for the amounts to be transferred into a new Segment.
The participation requirements are as follows: (1) Segment is available and (2) Segment Maturity Date Requirement is met. If these requirements are met, your account value in the Segment Type Holding Account will be transferred into a new Segment. This amount is your initial Segment Investment.
(1) Segment is available.
The Segment must actually be created on the Segment Start Date as scheduled. We may suspend or terminate any Segment Type, at our sole discretion, at any time. If we terminate a Segment Type, no new Segments of that Segment Type will be created, and the amount that would have been transferred to the Segment will be transferred to the EQ/Money Market variable investment option instead. If we suspend a Segment Type, no new Segments of that Segment Type will be created until the suspension ends, and the amount that would have been transferred to the Segment will remain in the Segment Type Holding Account.
(2) Segment Maturity Date Requirement is met.
The Segment Maturity Date must occur on or before the contract maturity date. If the Segment Maturity Date is after the contract maturity date, your account value in the Segment Type Holding Account will be transferred to the EQ/Money Market variable investment option.
Segment Duration
We currently offer Segment Types with a duration of 1 or 5 years. Amounts removed from a Segment prior to the Segment Maturity Date (i) will not receive the full potential of
the Performance Cap since the participation in upside performance for early withdrawals is pro-rated based on the period those amounts were invested in a Segment for all contracts using a Performance Cap Rate limiting factor; (ii) will not receive the full protection of the Segment Buffer because the Segment Interim Value only reflects a portion of the downside protection expected to be provided on the Segment Maturity Date; and (iii) could reduce the Segment Investment (which we use to calculate the Segment Maturity Value on the Segment Maturity Date as described in “Segment Maturity Value”) by more than the amount withdrawn due to the Segment Interim Value. Amounts must remain in the Segment for the full Segment Duration to be credited with full interest, to receive the full protection of the Segment Buffer, and to avoid a possible negative Segment Interim Value adjustment in addition to potential withdrawal charges, taxes and tax penalties. See “Segment Interim Value” below and “Adjustments with respect to early distributions from Segments” in “Charges, expenses, and adjustments” for more information.
Before selecting a Segment for investment, you should consider whether you are likely to make a withdrawal or transfer from the Segment or surrender or annuitize your contract prior to the end of the 1 or 5 year Segment Duration. You should also consider whether you want your returns to be linked to the applicable Index for the Segment Duration and whether the Segment Buffer and Performance Cap Rate are consistent with your investment goals and risk tolerance for the 1 or 5 year period.
Segment Maturity Date
Your Segment Maturity Date is the Segment Business Day on which a Segment ends. You will receive advance notice of maturing Segments in which you are currently invested in your quarterly statement. You will generally also receive a second advance notice of maturing Segments in which you are currently invested. The additional notice is available by mail or electronically and is generally provided at least 30 days before a Segment Maturity Date. You can instruct us to stop delivering this second notice to you at any time. We reserve the right to discontinue this second notice at any time.
Setting the Segment Maturity Date and Segment Start Date
There will generally be two or more Segment Maturity Dates and Segment Start Dates each month that the contract is outstanding. The Segment Maturity Date for Segments maturing and the Segment Start Date for new corresponding Segments will generally be scheduled to occur on consecutive business days that are also Segment Business Days.
If a Segment Maturity Date falls on a holiday, the Segment Maturity Date will generally be the preceding Segment Business Day. If a Segment Start Date falls on a holiday, the Segment Start Date will generally be the preceding Segment Business Day unless that preceding Segment Business Day is not in the same month. In these instances, no Segment will begin until the next scheduled Segment Start Date. Please see Appendix “Segment Maturity Date and Segment Start Date Examples” for a demonstration of the effects that scheduled holidays can have on the Segment Maturity Date and the Segment Start Date.
Segment Maturity Instructions.
You may specify maturity instructions that tell us how to allocate the Segment Maturity Value among the investment options and you can change these instructions at any time. You may tell us either to follow your instructions on file for new contributions, to withdraw all or part of your Segment Maturity Value, or to transfer your Segment Maturity Value to the next available Segment of the same Segment Type, provided the participation requirements are met. While you may specify or change your maturity instructions for maturing Segments at any time until the close of business on the Segment Maturity Date, we recommend submitting new or revised instructions at least five business days prior to the Segment Maturity Date.
As stated above, you may elect to have maturing Segments invested according to your instructions on file, and those instructions may include allocations to different Segment Types, or you may elect to transfer your Segment Maturity Value to the next available Segment of the same Segment Type in which you are currently invested. If you take either of these steps, then the designated portion of your Segment Maturity Value will be transferred to the corresponding Segment Type Holding Account, as of the close of business on the Segment Maturity Date. Assuming that all participation requirements are met, the designated amounts will be treated like any other amounts in a Segment Type Holding Account. On the next Segment Start Date, the designated amounts in the Segment Type Holding Account will be transferred into the corresponding Segment. Typically, this means the designated amounts would be held in a Segment Type Holding Account for at least one business day.
If you have not provided us with maturity instructions for a maturing Segment, then by default the Segment Maturity Value will be transferred to the Segment Type Holding Account for the same Segment Type as the maturing Segment. Your Segment Maturity Value would then be transferred from that Segment Type Holding Account into the next Segment of that Segment Type on the Segment Start Date except that if the next Segment to be created in the Segment Type would not meet the Segment Maturity Date Requirement or that Segment Type has been terminated, we will instead transfer your Segment Maturity Value to the EQ/ Money Market variable investment option.
If you are impacted by these delays, you may transfer your Segment Maturity Value into another Segment Type Holding Account or any other investment option at any time before the next Segment Start Date.
Segment Maturity Value
We calculate your Segment Maturity Value on the Segment Maturity Date using your Segment Investment and the Segment Rate of Return.
Your Segment Maturity Value for all Segments is calculated as follows:
We multiply your Segment Investment by your Segment Rate of Return to get your Segment Return Amount. Your Segment Maturity Value is equal to your Segment Investment plus your Segment Return Amount. Your Segment Return Amount may be negative, in which case your Segment Maturity Value will be less than your Segment Investment. Please note that
(1) the Contract Fee reduces the Segment Rate of Return and (2) the Segment Investment and resulting Segment Return Amount will have been reduced by any optional Return of Premium death benefit charge if those charges were deducted from the Segment on any contract date anniversary during the Segment.
Segment Interim Value
The total amount earned on an investment in a Segment of the SIO is only applied at Segment maturity. If any amount leaves a Segment on any date prior to the Segment Maturity Date, we calculate the Segment Interim Value of the Segment as described in “Charges, expenses, and adjustments.” Prior to the Segment Maturity Date, the following transactions trigger the Segment Interim Value calculation: (1) the receipt of an in good order death claim by your beneficiary; (2) a withdrawal (including a systematic withdrawal, a required minimum distribution, a withdrawal to pay advisory fees under an Investment Edge ADV contract and a free withdrawal under an Investment Edge Select contract); (3) a transfer; (4) if you surrender or annuitize your contract; or (5) if you cancel your contract and return it to us for a refund within your state’s “free look” period.
®
®
If you make one of these transactions, because the end-of-term downside protection provided by a Segment Buffer does not apply to the Segment Interim Value, it is theoretically possible that you could lose up to 100% of your investment and previously credited interest in certain extreme scenarios even for Segments with a Segment Buffer.
We deduct a pro rata portion of the Contract Fee from the Segment Interim Value as part of the calculation.
Segment Rate of Return
The Segment Rate of Return is calculated using the Segment Buffer or Performance Cap Rate as described below for each Segment Type. See Appendix “Segment Maturity Value Calculation Examples” for numerical examples of each calculation method.
Standard Segments.
For Standard Segments, the Segment Rate of Return is equal to the Index Performance Rate (the percentage change in the value of the related Index from the Segment Start Date to the Segment Maturity Date), subject to the Performance Cap Rate and Segment Buffer minus the Contract Fee, as follows:
If the Index Performance Rate: |
Your Segment Rate of Return will be: | |
| exceeds the Performance Cap Rate | equal to the Performance Cap Rate minus the Contract Fee | |
| is positive but less than or equal to the Performance Cap Rate | equal to the Index Performance Rate minus the Contract Fee | |
| is flat or negative by a percentage equal to or less than the Segment Buffer | equal to 0% minus the Contract Fee | |
| is negative by a percentage greater than the Segment Buffer | negative, equal to the extent of the percentage exceeding the Segment Buffer minus the Contract Fee |
These values are based on the value of the relevant Index on the Segment Start Date and the Segment Maturity Date. Any fluctuations in the value of the Index between those dates is ignored in calculating the Segment Rate of Return.
Please see Appendix “Investment Options available under the contract” for a list of the current Standard Segment Types.
Standard Segment example
year/-10%
Segment Type, a Segment could be established as S&P 500 Price Return Index/1 year/-10%
with a 11% Performance Cap Rate. This means that you will participate in the performance of the S&P 500 Price Return Index for one year starting from the Segment Start Date. The following examples assume no withdrawals. If the Index performs positively during this period, your Segment Rate of Return could be as much as 11% minus the applicable Contract Fee for that Segment Duration. If the Index performs negatively during this period, at maturity you will be protected from the first 10% of the Index’s decline minus the applicable Contract Fee. If the Index performance is between -10%
and 0%, your Segment Maturity Value on the Segment Maturity Date will be equal to your Segment Investment minus the applicable Contract Fee. See Appendix “Segment Maturity Value Calculation Examples” for examples showing the Segment Maturity Value calculation. Step Up Segments.
For Step Up Segments, the Segment Rate of Return is equal to:
| • | the Performance Cap Rate if the Index Performance Rate (the percentage change in the value of the related Index from the Segment Start Date to the Segment Maturity Date) is greater than or equal to zero minus the Contract Fee or |
| • | the Index Performance Rate if the Index Performance Rate is negative, subject to the Segment Buffer minus the Contract Fee, as follows: |
If the Index Performance Rate: |
Your Segment Rate of Return will be: | |
| is greater than or equal to zero | equal to the Performance Cap Rate minus the Contract Fee | |
| is negative by a percentage equal to or less than the Segment Buffer | equal to 0% minus the Contract Fee | |
| is negative by a percentage greater than the Segment Buffer | negative, equal to the extent of the percentage exceeding the Segment Buffer minus the Contract Fee |
These values are based on the value of the relevant Index on the Segment Start Date and the Segment Maturity Date. Any fluctuations in the value of the Index between those dates is ignored in calculating the Segment Rate of Return.
Please note:
Performance Rate on the Segment Maturity Date can result in a very different Segment Rate of Return. For example, if the Performance Cap Rate is 8.00% and the Index Performance Rate is 0.00% on the Segment Maturity Date, the Segment Rate of Return would be 8.00% less the amount of the Contract Fee whereas, if the Index Performance Rate is
-0.01%
on the Segment Maturity Date the Segment Rate of Return is 0.00% less the amount of the Contract Fee. Please see Appendix “Investment Options available under the contract” for a list of the current Step Up Segment Types.
Step Up Segment example
year/-10%
Segment Type, a Segment could be established as S&P 500 Price Return Index Step Up/1 year/-10%
with an 8% Performance Cap Rate. This means that you will participate in the performance of the S&P 500 Price Return Index for one year starting from the Segment Start Date. The following examples assume no withdrawals. If the Index performs positively or equal to zero during this period, your Segment Rate of Return would be 8% minus the applicable Contract Fee for that Segment Duration. If the Index performs negatively during this period, at maturity you will be protected from the first 10% of the Index’s decline minus the applicable Contract Fee. If the Index performance is between -10%
and 0%, your Segment Maturity Value on the Segment Maturity Date will be equal to your Segment Investment minus the applicable Contract Fee. See Appendix “Segment Maturity Value Calculation Examples” for examples showing the Segment Maturity Value calculation. Step Up Segments will generally have lower Performance Cap Rates than Standard Segments with the same Index, Segment Duration and Segment Buffer. This is because the Segment Rate of Return for Step Up Segments is equal to the Performance Cap Rate for certain lower returns.
Dual Direction Segments.
For Dual Direction Segments, the Segment Rate of Return is equal to the Index Performance Rate subject to the Performance Cap Rate for positive and flat Index Performance Rates and the absolute value of negative Index Performance Rates unless the Index Performance Rate is less than the Segment Buffer in which case it is equal to the Index Performance Rate subject to the Segment Buffer, minus the Contract Fee, as follows:
If the Index Performance Rate: |
Your Segment Rate of Return will be: | |
| is greater than the Performance Cap Rate | equal to the Performance Cap Rate minus the Contract Fee | |
| is between the Performance Cap Rate and Segment Buffer (or equal to either) | equal to the absolute value of the Index Performance Rate minus the Contract Fee | |
| is negative by a percentage greater than the Segment Buffer | negative, equal to the extent of the percentage exceeding the Segment Buffer minus the Contract Fee |
Please note:
| • | Because of the way the Segment Rate of Return is calculated for Dual Direction Segments, when the Index Performance Rate is near the Segment Buffer, a very small difference in the Index Performance Rate on the Segment Maturity Date can result in a very different Segment Rate of Return. For example, for a 1-year Dual Direction Segment with a -10% Segment Buffer, if the Index Performance Rate is -10.00% on the Segment Maturity Date the Segment Rate of Return is 10.00% whereas, if the Index Performance Rate is -10.01% on the Segment Maturity Date the Segment Rate of Return is -0.01%. |
| • | Because of the way the Segment Rate of Return is calculated for Dual Direction Segments, in certain situations the Segment Rate of Return may be greater for negative Index Performance Rates than for the corresponding positive Index Performance Rates. For example, for a 1-year Dual Direction Segment with a Performance Cap Rate of 7% and a -10% Segment Buffer, if the Index Performance Rate is -9% on the Segment Maturity Date the Segment Rate of Return is 9% whereas, if the Index Performance Rate is 9% on the Segment Maturity Date the Segment Rate of Return is 7%. |
Please see Appendix “Investment Options available under the contract” for a list of the current Dual Direction Segment Types.
Dual Direction Segment example:
Please note:
Dual Direction Segments will generally have lower Performance Cap Rates than Standard Segments with the same Index, Segment Duration and Segment Buffer. This is because the Segment Rate of Return for Dual Direction Segments is equal to the absolute value of the Index Performance Rate for certain negative returns. Please note that the Performance Cap Rate and Segment Rate of Return for Dual Direction 5-year Segments are cumulative rates of return over the 5-year period from the Segment Start Date to the Segment Maturity Date. They are NOT annual rates, even if the Segment Duration is longer than one year.
Dual Step Up Segments.
For Dual Step Up Segments, the Segment Rate of Return is equal to the Performance Cap Rate unless the Index Performance Rate is less than the Segment Buffer in which case it is equal to the Index Performance Rate subject to the Segment Buffer, minus the Contract Fee, as follows:
If the Index Performance Rate: |
Your Segment Rate of Return will be: | |
| is greater than or equal to the Segment Buffer | equal to the Performance Cap Rate minus the Contract Fee | |
| is negative by a percentage greater than the Segment Buffer | negative, equal to the extent of the percentage exceeding the Segment Buffer minus the Contract Fee |
These values are based on the value of the relevant Index on the Segment Start Date and the Segment Maturity Date. Any fluctuations in the value of the Index between those dates is ignored in calculating the Segment Rate of Return.
Please note:
-10%
and the Index Performance Rate is -10.00%
on the Segment Maturity Date, the Segment Rate of Return would be 10.00% whereas, if the Index Performance Rate is -10.01%
on the Segment Maturity Date the Segment Rate of Return is -0.01%.
Please see Appendix “Investment Options available under the contract” for a list of the current Dual Step Up Segment Types.
Dual Step Up Segment example:
year/-10%
Segment Type, a Segment could be established as S&P 500 Price Return Index Dual Step Up/1 year/-10%
with a 10% Performance Cap Rate. This means that you will participate in the performance of the S&P 500 Price Return Index for one year starting from the Segment Start Date. The following examples assume no withdrawals. If the Index performs equal to or better than the Segment Buffer, your Segment Rate of Return will be 10% for that Segment Duration. This means if the Index performs negatively down to and including -10%, then your Segment Rate of Return will be 10%. If the Index performs more negatively than the Segment Buffer, your Segment Rate of Return will be negative equal to the percentage loss in the Index which exceeds the Segment Buffer. The Contract Fee will reduce your Segment Rate of Return. See Appendix “Segment Maturity Value Calculation Examples” for examples showing the Segment Maturity Value calculation.
Dual Step Up Segments will generally have lower Performance Cap Rates than Standard Segments with the same Index, Segment Duration and Segment Buffer. This is because the Segment Rate of Return for Dual Step Up Segments is equal to the Performance Cap Rate for certain lower and negative returns.
Growth Multiplier Segments.
For Growth Multiplier Segments, the Segment Rate of Return is equal to:
| • | the Index Performance Rate increased by the applicable Multiplier Rate if the Index Performance Rate is positive or |
| • | the Index Performance Rate if the Index Performance Rate is flat or negative, |
minus the Contract Fee, as follows:
If the Index Performance Rate: |
Your Segment Rate of Return will be: | |
| is positive | the Index Performance Rate multiplied by the applicable Multiplier Rate minus the Contract Fee | |
| is flat or negative | equal to the Index Performance Rate minus the Contract Fee |
These values are based on the value of the relevant Index on the Segment Start Date and the Segment Maturity Date. Any fluctuations in the value of the Index between those dates is ignored in calculating the Segment Rate of Return.
Please see Appendix “Investment Options available under the contract” for a list of the current Growth Multiplier Segment Types.
Growth Multiplier Segment example
:
The Multiplier Rate applicable to each Growth Multiplier Segment, including the applicable Multiplier Rate for Segments
selected on your application may vary and will be preannounced at least one week before the Segment Start Date and can be found at www.equitable.com/ie21-rates-prospectus. The Multiplier Rate for the same Segment may be higher or lower for owners who elect that Segment during their first Contract Year than for owners who are in their second or later Contract Year. The Multiplier Rate is used to increase positive Index Performance Rates as part of the Segment Rate of Return calculation. The Multiplier Rate is only used to calculate the Segment Rate of Return. The Multiplier Rate is not an annual rate of return even if the Segment Duration is longer than one year. The Multiplier Rate will never be less than 105%. We will not open a Segment with a Multiplier Rate below the minimum and the Multiplier Rate will not change during the Segment Duration.
Growth Multiplier Segments do not have a Performance Cap Rate and, therefore, are always uncapped. . Accordingly, your Segment Rate of Return will equal any negative Index Performance Rate on a Segment Maturity Date and, therefore, your Segment Maturity Value will decline by the entire amount of the negative index performance.
The Segment Buffer is zero for Growth Multiplier Segments
Please note:
| • | Growth Multiplier Segments do not have a Performance Cap Rate (e.g., they are always uncapped). |
| • | Growth Multiplier Segments do not have any protection against negative Index performance because the Segment Buffer is zero. With a 0% Segment Buffer there is no protection from negative index performance and you could lose up to 100% of principal and previously credited interest. |
The Indices are described in more detail below, under the header “Indices.”
Performance Cap Rate
The Performance Cap Rate is generally the highest Index Performance Rate that can be used to calculate the Segment Rate of Return on the Segment Maturity Date. The Performance Cap Rate, if applicable, may limit your participation in any increases in the underlying Index associated with a Segment. For example, if the Index return is 12% and the Performance Cap Rate is 4%, we will credit 4% in interest on the Segment Maturity Date assuming there are no fees or charges assessed, meaning your Segment Investment will increase by 4%.
Our minimum Performance Cap Rate is 2%. We guarantee that for the life of your contract we will not open a Segment with a Performance Cap Rate below the applicable minimum Performance Cap Rate. In some cases, we may decide not to declare a Performance Cap Rate for a Segment, in which case there is no maximum Segment Rate of Return for that Segment. When this happens, the Segment is referred to as uncapped. Growth Multiplier Segments do not have a Performance Cap Rate.
The current Performance Cap Rates for each Segment Type, including the applicable Performance Cap Rates for Segments
selected on your application, are announced at least one week before the Segment Start Date and are incorporated into this Prospectus by reference from www.equitable.com/ie21-rates-prospectus. The Performance Cap Rate for each Segment will not change throughout the Segment Duration. The Performance Cap Rate for the same Segment may vary between owners but will never be less than the applicable minimum Performance Cap Rate. Since Performance Cap Rates are announced online at least one week before the Segment Start Date, you should consider any differences in the Performance Cap Rates when deciding which contract series to purchase.
Please note that the Performance Cap Rate and Segment Rate of Return are cumulative rates of return from the Segment Start Date to the Segment Maturity Date, NOT annual rates, even if the Segment Duration is longer than one year.
The Performance Cap Rate is set at our sole discretion. In determining the current Performance Cap Rate for a Segment Type, we consider, among other factors, the Segment Rate of Return calculation method, the cost of hedging instruments, the rates offered by our competitors, the rates of other Segments, and the current market environment. In general, the Performance Cap Rates will be lower for Segment Types that offer greater protection from negative returns or additional enhancements to positive returns. Before selecting a Segment for investment, you should consider whether the current Performance Cap Rate is acceptable to you in return for the protection from negative returns or enhancements to positive returns that may be applied at the end of the Segment Duration for that Segment Type.
Segment Performance Cap Rate Hold
The Cap Rate Hold is not currently available.
Segment Buffer
The SIO provides some protection against negative returns on the Segment Maturity Date through the use of a Segment Buffer,
except Growth Multiplier Segments which do not have a Segment Buffer. The extent of the downside protection provided by the Segment Buffer varies by Segment, ranging from the first 10% to 40% of loss. There is a
risk of a substantial loss of your principal and previously credited interest because you agree to absorb
all losses to the extent they exceed the applicable Segment Buffer on the Segment Maturity Date.
The Segment Buffer for each Segment will not change throughout the Segment Duration. See Appendix “Investment Options available under the contract” for the current Segment Buffer for each Segment Type.
We may change the Indices and/or Segment Options in the future, but we will always offer a Segment Option with a Segment Buffer that protects the first 10% of loss.
The Segment Buffer is set at our sole discretion. In determining the current Segment Buffer for a Segment Type, we consider, among other factors, the Segment Rate of Return calculation method, the cost of hedging instruments, the range of Performance Cap Rates that may be offered with the Segment Buffer, protection levels offered by our competitors, and the current market environment. Before selecting a Segment for investment, you should consider whether the Segment Buffer is consistent with your risk tolerance and investment goals for the Segment Duration of the Segment Type.
On a Segment Maturity Date, the highest level of protection provided by a Segment Buffer is the -40% Segment Buffer and lowest level of protection provided by a Segment Buffer is the -10% Segment Buffer.
Indices
Each Segment Type references an Index that determines the performance of its associated Segments. We currently offer Segment Types based on the performance of securities indices. Throughout this Prospectus, we refer to these indices using the term “Index” or, collectively, “Indices.” Not all Indices may be available under your contract.
Securities Indices.
The following securities Indices are currently available:
S&P 500 Price Return Index.
MSCI Emerging Markets Price Return Index
market country indices: Brazil, Chile, China, Colombia, Czech Republic, Egypt, Hungary, India, Indonesia, Korea, Malaysia, Mexico, Morocco, Peru, Philippines, Poland, Russia, South Africa, Taiwan, Thailand, and Turkey. The MSCI Emerging Markets Price Return Index does not include dividends declared by any of the companies included in this Index, which will reduce Index performance. Additional information about the Index may be found in Appendix “Index Publishers”. If you would like to request additional information about the Index, contact the customer service group or your financial professional.
NASDAQ-100 Price Return Index
Russell 2000
®
Price Return Index.
®
®
small-cap
segment of the U.S. equity universe. The Russell 2000®
®
2000 Price Return Index does not include dividends declared by any of the companies included in this Index, which will reduce Index performance. Additional information about the Index may be found in Appendix “Index Publishers”. If you would like to request additional information about the Index, contact the customer service group or your financial professional.
®
MSCI EAFE Price Return Index
The bar charts shown below provide each Index’s annual returns for the last 10 calendar years (or for the life of the Index if less than 10 years), as well as the Index returns after applying a hypothetical 5% Performance Cap Rate and a hypothetical -10% Segment Buffer. The chart illustrates the variability of the returns from year to year and shows how hypothetical limits on Index gains and losses may affect these returns. Past performance is not necessarily an indication of future performance.
7.
Charges that the Company deducts
We deduct the following charges each day from the net assets of each variable investment option. These charges are reflected in the unit values of each variable investment option:
| • | An operations charge |
| • | An administrative charge |
| • | A distribution charge |
The sum of the annual rate of the operations, administrative and distribution charges is also referred to as the Contract Fee. While we do not deduct the Contract Fee from the Segment Type Holding Accounts, we do deduct a Contract Fee from each Segment based on the total number of days in the Segment Duration. The charge is equal to an annual rate of 1.00% (and a daily rate of 0.002740%) for Investment Edge contracts, an annual rate of 1.25% (and a daily rate of 0.003425%) for Investment Edge Select contracts, and no charge for Investment Edge ADV contracts for each Segment for the Segment Duration and is deducted when calculating the Segment Rate of Return on the Segment Maturity Date. Since the Contract Fee is based on the total number of days in the Segment Duration, the total cumulative Contract Fee for a 5-year Segment is approximately 5% for Investment Edge contracts and approximately 6.25% for Investment Edge Select contracts. A pro rata portion of this charge is deducted as part of the Segment Interim Value calculation if a partial withdrawal or transfer is taken from a Segment on a date other than the Segment Maturity Date or if the contract is surrendered, annuitized or a death benefit paid on a date other than the Segment Maturity Date. The Segment Investment is also reduced. We apply the Segment Interim Value adjustment if you surrender or cancel your contract, die or make a transfer or withdrawal from a Segment before the Segment Maturity Date which could result in a loss of up to 100% of the Segment Investment.
®
®
®
®
®
We may also deduct the following charges from your account value. If we deduct these charges from your variable investment options we reduce the number of units credited to your contract:
| • | On each contract date anniversary (or, for NQ contracts where an Income Edge payment program has been elected, the Income Edge Anniversary Date) — the Contract Maintenance Fee, if applicable. |
| • | At the time you make certain withdrawals or surrender your contract — a withdrawal charge (if applicable). |
| • | At the time annuity payments are to begin including, for NQ contracts, Income Edge payment program scheduled payments — charges designed to approximate certain taxes that may be imposed on us, such as premium taxes in your state. |
| • | At the time you request a transfer in excess of 12 transfers in a contract year — a transfer charge (currently, there is no charge). |
| • | Charge for third-party transfer or exchange. |
| • | Special services charges (if applicable). |
| • | Duplicate Annual and/or Quarterly Statement of Account or Annual Payout Statement charge (if applicable). |
More information about these charges appears below. We will not increase these charges for the life of your contract, except as noted.
The charges under the contracts are designed to cover, in the aggregate, our direct and indirect costs of selling, administering and providing benefits under the contracts. They are also designed, in the aggregate, to compensate us for the risks of loss we assume pursuant to the contracts. If, as we expect, the charges that we collect from the contracts exceed our total costs in connection with the contracts, we will earn a profit. Otherwise, we will incur a loss.
The rates of certain of our charges have been set with reference to estimates of the amount of specific types of expenses or risks that we will incur. In most cases, this Prospectus identifies such expenses or risks in the name of the charge; however, the fact that any charge bears the name of, or is designed primarily to defray, a particular expense or risk does not mean that the amount we collect from that charge will never be more than the amount of such expense or risk. Nor does it mean that we may not also be compensated for such expense or risk out of any other charges we are permitted to deduct by the terms of the contracts.
To help with your retirement planning, we may offer other annuities with different charges, benefits, and features. Please contact your financial professional for more information.
Base Contract expenses
Operations charge.
We deduct a daily charge from the net assets in each variable investment option to compensate us for operations expenses, a portion of which compensates us for mortality and expense risks. Below is the daily charge shown as an annual rate of the net assets in each variable investment option for each contract in the Investment Edge series:
®
Investment Edge ® |
0.60% | |
Investment Edge ® |
0.75% | |
Investment Edge ® |
no charge | |
The mortality risk we assume is the risk that annuitants as a group will live for a longer time than our actuarial tables predict. If that happens, we would be paying more in annuity
income than we planned. We also assume a risk that the mortality assumptions reflected in our guaranteed annuity payment tables, shown in each contract, will differ from actual mortality experience. The expense risk we assume is the risk that it will cost us more to issue and administer the contracts than we expect.
Administrative charge.
We deduct a daily charge from the net assets in each variable investment option. The charge, together with the Contract Maintenance Fee described below, is to compensate us for administrative expenses under the contracts. Below is the daily charge shown as an annual rate of the net assets in each variable investment option:
Investment Edge ® |
0.30% | |
Investment Edge ® |
0.30% | |
Investment Edge ® |
no charge | |
Distribution charge.
We deduct a daily charge from the net assets in each variable investment option to compensate us for a portion of our sales expenses under the contracts. Below is the daily charge shown as an annual rate of the net assets in each variable investment option:
Investment Edge ® |
0.10% | |
Investment Edge ® |
0.20% | |
Investment Edge ® |
no charge | |
Account value charges
Contract Maintenance Fee
. We will deduct a $50 dollar charge on any contract date anniversary on which your account value is less than $50,000. This charge will no longer apply to NQ contracts following Income Edge election, even if your account value falls below $50,000. This charge is intended to compensate us for the cost of providing administrative services in connection with your contract.
We will deduct this charge from your value in the variable investment options on a pro rata basis on the last day of each contract year. If those amounts are insufficient, we will deduct all or a portion of the charge (as applicable) from amounts in the dollar cost averaging program (if any). If there is insufficient value or no value in the dollar cost averaging program to deduct the contract maintenance fee, then any remaining portion of the fee or the total fee will be deducted from the Segment Type Holding Accounts, and if there is insufficient value or no value in the holding accounts, any remaining portion of the fee will be deducted pro rata from the Segments.
If the contract is surrendered or annuitized or a death benefit is paid on any date other than the contract date anniversary, we will deduct a pro rata portion of the charge for that year.
If your account value is insufficient to pay this charge, your contract will terminate without value.
Transfer charge
Currently, we do not charge for transfers among investment options under the contract. In addition we reserve the right, at any time but always with prior notice, to charge for any
transfers in excess of 12 per contract year (or, for NQ contracts where an Income Edge payment program has been elected, per Annual Payout Period).
In the event that such a charge is imposed, it will be subject to the following:
| • | We reserve the right to waive such charge for transfers requested electronically. |
| • | The charge will never exceed $35 and will be assessed at the time that the transfer is processed. |
| • | For the purposes of this charge, all transfers made on the same business day as to a particular contract will be considered one transfer. |
| • | Any transfer charge will be deducted from the investment option(s) from which the transfer was made. |
| • | No charge will be imposed for transfers made in connection with the dollar cost averaging program. |
Special services charges
We deduct a charge for providing the special services described below. These charges compensate us for the expense of processing each special service. For certain services, we will deduct from your account value any withdrawal charge that applies and the charge for the special service. Please note that we may discontinue some or all of these services without notice.
Wire transfer charge.
We charge $90 for outgoing wire transfers. Unless you specify otherwise, this charge will be deducted from the amount you request.
Express mail charge.
We charge $35 for sending you a check by express mail delivery. This charge will be deducted from the amount you request.
Duplicate contract charge.
We charge $35 for providing a copy of your contract. The charge for this service can be paid (i) using a credit card acceptable to us, (ii) by sending a check to our processing office, or (iii) by any other means we make available to you.
Check preparation charge.
The standard form of payment for all withdrawals is direct deposit. If direct deposit instructions are not provided, payment will be made by check. Currently, we do not charge for check preparation, however, we reserve the right to impose a charge, which would be deducted from the amount you request following imposition of such a charge. We reserve the right to charge a maximum of $85.
Charge for third-party transfer or exchange
Currently, we are waiving the $65 charge for each third-party transfer or exchange; this waiver may be discontinued at any time, with or without notice. Absent this waiver, we deduct a charge for direct rollovers or direct transfers of amounts from your contract to a third party, such as in the case of a transfer for an IRA contract, or if you request that your contract be exchanged for a contract issued by another insurance company. This charge will be deducted from the amount
trustee-to-trustee
you request. We reserve the right to increase this charge to a maximum of $125. Please see Appendix “State contract availability and/or variations of certain features and benefits” for variations in your state.
Duplicate Annual and/or Quarterly Statement of Account or Annual Payout Statement charge.
Currently, we do not charge for providing a duplicate copy of your Annual or Quarterly Statement of Account or Annual Payout Statement. However, we reserve the right to impose such a charge, regardless of whether you are enrolled in electronic delivery or whether the request is for an electronic or hard copy duplicate of the applicable document. Any such charge would be deducted from your account value in the variable investment options at the time of the request on a pro rata basis.
Withdrawal charge
(for Investment Edge
®
contracts only) A withdrawal charge applies in three circumstances: (1) if you make one or more withdrawals during a contract year that, in total, exceed the 10% free withdrawal amount, described below, (2) if you surrender your contract to receive its cash value or (3) if you annuitize your contract and elect a non-life contingent annuity option. For more information about the withdrawal charge if you select an annuity payout option, see “Your annuity payout options — The amount applied to purchase an annuity payout option” in “Accessing your money”.
The withdrawal charge equals a percentage of the contributions withdrawn even if the account value is less than total net contributions.
The percentage of the withdrawal charge that applies to each contribution depends on how long each contribution has been invested in the contract. We determine the withdrawal charge separately for each contribution according to the following table:
Withdrawal charge as a % of contribution for each year following the contribution |
||||||||||||||||||||||||
1 |
2 |
3 |
4 |
5 |
6+ |
|||||||||||||||||||
Investment Edge ® |
6% | 6% | 5% | 4% | 3% | 0% | (1) | |||||||||||||||||
| (1) | Charge does not apply in the 6th and subsequent years following contribution. |
For purposes of calculating the withdrawal charge, we treat the contract year in which we receive a contribution as “year 1,” and the withdrawal charge is reduced or expires on each applicable contract date anniversary. Amounts withdrawn that are not subject to the withdrawal charge are not considered withdrawals of any contribution. We also treat contributions that have been invested the longest as being withdrawn first. We treat contributions as withdrawn before earnings for purposes of calculating the withdrawal charge. However, federal income tax rules treat earnings under your contract as withdrawn first. See “Tax information”.
Please see Appendix “State contract availability and/or variations of certain features and benefits” for possible withdrawal charge schedule variations in your state.
In order to give you the exact dollar amount of the withdrawal you request, we deduct the amount of the withdrawal and the withdrawal charge from your account value. Any amount deducted to pay withdrawal charges is also subject to that same withdrawal charge percentage. We deduct the charge in proportion to the amount of the withdrawal subtracted from each investment option. The withdrawal charge helps cover our sales expenses.
We offer two versions of the contract that do not include a withdrawal charge.
The withdrawal charge does not apply in the circumstances described below.
10% free withdrawal amount.
Each contract year you can withdraw up to 10% of your account value without paying a withdrawal charge. The 10% free withdrawal amount is determined using your account value at the beginning of each contract year. For NQ contracts, following election of an Income Edge payment program, the amount is determined using your account value at the beginning of each Annual Payout Period. In the first contract year, the 10% free withdrawal amount is determined using all contributions received in the first 90 days of the contract year. Additional contributions during the contract year do not increase your 10% free withdrawal amount. The 10% free withdrawal amount does not apply if you surrender your contract except where required by law.
Substantially equal withdrawals
.
®
Income Edge.
Payments made under any form of Income Edge payment program that we offer are not subject to withdrawal charges.
Disability, terminal illness, or confinement to nursing home.
There are specific circumstances (described below) under which the withdrawal charge will not apply. At any time after the first contract date anniversary, you may submit a claim to have the withdrawal charge waived if you
(1)
meet certain requirements. You are not eligible to make a claim prior to your first contract date anniversary. Also, your claim must be on the specific form we provide for this purpose.
The withdrawal charge does not apply if:
| (i) | We receive proof satisfactory to us (including certification by a licensed physician) that an owner (or older joint owner, if applicable) is unable to perform three of the following “activities of daily living”: |
| — | “Bathing” means washing oneself by sponge bath; or in either a tub or shower, including the task of getting into or out of the tub or shower. |
(1) |
When used in this section, “you” means (a) for single owner contracts, the owner; (b) for jointly owned contracts, the older owner; (c) for contracts with non-natural owner(s) and a single annuitant, the annuitant; and (d) for contracts with non-natural owner(s) and joint annuitants, the older annuitant. |
| — | “Continence” means the ability to maintain control of bowel and bladder function; or, when unable to maintain control of bowel or bladder function, the ability to perform associated personal hygiene (including caring for catheter or colostomy bag). |
| — | “Dressing” means putting on and taking off all items of clothing and any necessary braces, fasteners or artificial limbs. |
| — | “Eating” means feeding oneself by food into the body from a receptacle (such as a plate, cup or table) or by a feeding tube or intravenously. |
| — | “Toileting” means getting to and from the toilet, getting on and off the toilet, and performing associated personal hygiene. |
| — | “Transferring” means moving into or out of a bed, chair or wheelchair. |
(ii) |
We receive proof satisfactory to us (including certification by a licensed physician) that an owner’s (or older joint owner’s, if applicable) life expectancy is six months or less. |
| (iii) | An owner (or older joint owner, if applicable) has been confined to a nursing home for more than 90 days (or such other period, as required in your state) as verified by a licensed physician. A nursing home for this purpose means one that is (a) approved by Medicare as a provider of skilled nursing care service, or (b) licensed as a skilled nursing home by the state or territory in which it is located (it must be within the United States, Puerto Rico, or U.S. Virgin Islands) and meets all of the following: |
| — | its main function is to provide skilled, intermediate, or custodial nursing care; |
| — | it provides continuous room and board to three or more persons; |
| — | it is supervised by a registered nurse or licensed practical nurse; |
| — | it keeps daily medical records of each patient; |
| — | it controls and records all medications dispensed; and |
| — | its primary service is other than to provide housing for residents. |
Some states may not permit us to waive the withdrawal charge in the above circumstances, or may limit the circumstances for which the withdrawal charge may be waived. Your financial professional can provide more information or you may contact our processing office.
Charges for state premium and other applicable taxes
We deduct a charge designed to approximate certain taxes that may be imposed on us, such as premium taxes in your state. Generally, we deduct the charge from the amount applied to provide an annuity payout option. For NQ contracts, we also deduct this charge from your account value
as of the date that you elect an Income Edge payment program. The current tax charge that might be imposed varies by jurisdiction and ranges from 0% to 3.5%.
Please call our processing office for more information.
Fee-based expenses (Investment Edge
®
ADV contracts only)
The fees and expenses of a fee-based program are separate from and in addition to the fees and expenses of the contract. Please consult with your program sponsor for more details about your fee-based program. You should consider maintaining sufficient assets outside of this contract in order to pay advisory or custodial account expenses. Withdrawals from your Investment Edge ADV contract to pay those expenses will be treated like any other withdrawal.
®
Return of Premium death benefit charge
If you elect the Return of Premium death benefit, we will deduct a charge annually from each of your investment options on each contract date anniversary for which it is in effect. The charge is currently equal to 0.30% of the Return of Premium benefit base as of the day the charge is deducted. The maximum charge is 0.50%. For example, if the Return of Premium benefit base is $100,000 on the contract date anniversary, $300 ($100,000 * 0.30%) will be deducted from the account value. See “Return of Premium death benefit” in “Contract benefits and features” for more information about this benefit base. If on any date other than the contract date anniversary your contract is surrendered or annuitized, an Income Edge payment program is elected and becomes effective, a death benefit is paid, or the Return of Premium death benefit is otherwise terminated, we will deduct a pro rata portion of the charge from your account value calculated from the beginning of the contract year to the date of termination, death or annuitization. The Return of Premium death benefit charge is to compensate us for providing a death benefit at least equal to adjusted contributions.
This fee is deducted from the account value in the variable investment options on a pro rata basis on the contract date anniversary. If there is insufficient value or no value in the variable investment options, any remaining portion of the charge or the total charge will be deducted from amounts in the dollar cost averaging program. If there is insufficient value or no value in the dollar cost averaging program to deduct the charge, then any remaining portion of the charge or the total charge will be deducted from the Segment Type Holding Accounts, and if there is insufficient value or no value in the holding accounts, any remaining portion of the charge will be deducted pro rata from the Segments. If any portion of this charge is deducted from one or more Segments the Segment Interim Value adjustment will apply and, over time, could result in a significant loss of principal and previously credited interest.
We reserve the right to increase (up to the maximum charge) or decrease the fees for the Return of Premium death benefit at any time beginning in the 3rd contract year. While any new fee will not generally be deducted until the
next contract date anniversary, it will be effective from the beginning of the contract year in which the fee change occurred. You have a right to terminate the Return of Premium death benefit upon notification of a fee increase. Once terminated, the Return of Premium death benefit cannot be re-elected. You may only terminate the Return of Premium death benefit from the fee change notification date to the business day before the fee change effective date. We will provide you a minimum of 30 days notice before a fee change will apply. The fee change notification date is the date the fee increase is declared and notification is sent to the contract owners. The fee change effective date is the date on which the new fee becomes effective and the new fee will be charged on a contract on the contract date anniversary that falls on or after this date. We may notify owners of a change in the fee during the first two contract years, but such change will not be effective any earlier than the first business day following the second contract date anniversary.
Please note that because the Return of Premium death benefit charge is based on the Return of Premium death benefit base rather than current account value, there is a risk that the deduction of this charge could cause the contract to terminate, particularly if the account value is low in comparison to the Return of Premium death benefit base.
Adjustments
Adjustments with respect to early distributions from Segments
We calculate the Segment Interim Value when any amount leaves a Segment whether a partial withdrawal or a full contract surrender, or upon death or cancellation or annuitization of the contract, from a Segment prior to the Segment Maturity Date. Prior to the Segment Maturity Date, the following transactions trigger the Segment Interim Value Calculation: (1) the receipt of an in good order death claim by your beneficiary; (2) a withdrawal (including a systematic withdrawal, a required minimum distribution, a withdrawal to pay advisory fees under an Investment Edge ADV contract and a free withdrawal under an Investment Edge contract); (3) a transfer; (4) if you surrender or annuitize your contract; or (5) if you cancel your contract and return it to us for a refund within your state’s “free look” period.
®
®
If you make one of these transactions, because the end-of-term downside protection provided by a Segment Buffer does not apply to the Segment Interim Value, it is theoretically possible that you could lose up to 100% of your investment and previously credited interest in certain extreme scenarios even for Segments with a Segment Buffer.
The Segment Interim Value is calculated based on a formula that provides a treatment for an early distribution that is designed to be consistent with how distributions at the end of a Segment are treated. The formula is designed to measure the fair value of your Segment Investment on the particular interim date, and is based on the downside protection provided by the Segment Buffer, the limit on participation in investment gain provided by the Performance Cap
Rate, and an adjustment for the effect of a withdrawal prior to the Segment Maturity Date. You should note that even if a corresponding Index has experienced positive growth, the calculation of your Segment Interim Value may result in an amount lower than your Segment Investment.
The Segment Interim Value will generally be negatively affected by increases in the expected volatility of index prices, interest rate increases, and by poor market performance. All other factors being equal, the Segment Interim Value would be lower the earlier a withdrawal or surrender is made during a Segment. Also, for all contracts using a Performance Cap Rate limiting factor, participation in upside performance for early withdrawals is pro-rated based on the period those amounts were invested in a Segment. This means you participate to a lesser extent in upside performance the earlier you take a withdrawal.
Withdrawals from a Segment prior to your Segment Maturity Date reduce the Segment Investment on a pro rata basis by the same proportion that the Segment Interim Value is reduced on the date of the withdrawal. We use the Segment Investment to determine your Segment Maturity Value.
The formula we use, in part, derives the fair value of hypothetical investments in fixed instruments and derivatives. These values provide us with protection from the risk that we will have to pay out account value related to a Segment prior to the Segment Maturity Date. The formula also includes an adjustment relating to the Cap Calculation Factor. This is a positive adjustment of the percentage of the estimated expenses corresponding to the portion of the Segment Duration that has not elapsed. Additional information about Segment Interim Values, including the actual calculation formula and examples illustrating the operation of the Segment Interim Value adjustment, is located in the SAI.
You can obtain the current Segment Interim Values for the Segments in which you are invested by calling 1-877-899-3743. The Segment Interim Value of a Segment can fluctuate daily, and the current value quoted to you may differ from the actual Segment Interim Value calculated at the time you make a transaction that triggers the Segment Interim Value calculation.
Charges that the Trusts deduct
The Trusts deduct charges for the following types of fees and expenses:
| • | Management fees. |
| • | 12b-1 fees. |
| • | Operating expenses, such as trustees’ fees, independent public accounting firms’ fees, legal counsel fees, administrative service fees, custodian fees and liability insurance. |
| • | Investment-related expenses, such as brokerage commissions. |
These charges are reflected in the daily share price of each Portfolio. Since shares of each Trust are purchased at their net asset value, these fees and expenses are, in effect, passed on to the variable investment options and are reflected in their unit values. Certain Portfolios available under the contract in turn invest in shares of other Portfolios of the Trusts and/or shares of unaffiliated portfolios (collectively, the “underlying Portfolios”). The underlying Portfolios each have their own fees and expenses, including management fees, operating expenses, and investment related expenses such as brokerage commissions. For more information about these charges, please refer to the prospectuses for the Trusts.
Other distribution arrangements
We may reduce or eliminate charges when sales are made in a manner that results in savings of sales and administrative expenses, such as sales through persons who are compensated by clients for recommending investments and who receive no commission or reduced commissions in connection with the sale of the contracts. We will not permit a reduction or elimination of charges where it would be unfairly discriminatory.
2.
Summary of Benefits
The following tables summarize important information about the benefits available under the contract.
Death Benefits
These death benefits are available during the accumulation phase:
Name of Benefit |
Purpose |
Standard/ Optional |
Annual Fee |
Brief Description of Restrictions/ Limitations | ||||||
Max |
Current | |||||||||
| Standard Death Benefit | Guarantees beneficiaries will receive a benefit equal to your account value. | Standard | No Additional Charge |
• Available only at contract purchase | ||||||
| Return of Premium Death Benefit | Guarantees beneficiaries will receive a benefit at least equal to your contributions less adjusted withdrawals. | Optional | 0.50% (1) |
0.30% (1) |
• Available only at contract purchase • Available only to contract holder age 75 or younger • Withdrawals, including the withdrawal of advisory fees, could significantly reduce or terminate the benefit • Generally no contributions once reach age 76 • If elected, you will not get the Standard Death Benefit | |||||
| (1) | Expressed as an annual percentage of the benefit base. |
Other Benefits
These other benefits are available during the accumulation phase:
Name of Benefit |
Purpose |
Standard/ Optional |
Annual Fee |
Brief Description of Restrictions/Limitations | ||||||
Max |
Current | |||||||||
Rebalancing |
Periodically rebalance to your desired asset mix. | Optional | No Charge | • Must rebalance 100% of account value | ||||||
| Dollar Cost Averaging | Transfer account value to selected investment options on a regular basis to potentially reduce the impact of market volatility. | Optional | No Charge | • $5,000 minimum to begin program | ||||||
| Income Edge Payment Program (1) |
Pay out entire account value via scheduled payments over a set period of time, with a portion of each payment being a return of your cost basis in the contract and thus excludable from taxes. | Optional | No Charge | • Not available with Return of Premium Death Benefit • NQ contracts only • Age and account value requirements may apply • Adverse tax consequences if surrender contract after payments start • Withdrawals, including payment of advisor fees, could significantly reduce or terminate the benefit | ||||||
| (1) | The Income Edge payment program versions are not available for contracts with applications signed on or after August 19, 2024. |
There are no restrictions on which investment options you can invest in for the death benefits. The Segments and variable investment options may be conservative in nature and you may receive a higher rate of return from other investment options. If you are seeking more aggressive investment options the allowable investments may not be appropriate for you.
Return of Premium death benefit
At issue, you may elect the optional Return of Premium death benefit if you are age 75 or younger on the Contract Date. The Return of Premium death benefit is equal to the greater of (a) your Return of Premium death benefit base on the date of death and (b) your account value on the date of claim. The current charge for this benefit is 0.30%.
I
f you elect the Return of Premium death benefit you may not make additional contributions to your contract once you reach age 76.
The Return of Premium death benefit base is not an account value or cash value. On the contract issue date it is equal to your initial contribution. Thereafter, it is equal to:
| • | your initial contribution and any subsequent contributions to your contract, less |
| • | a deduction that reflects any withdrawals you make (including any applicable withdrawal charges). The way we calculate this deduction is described in “Pro rata treatment of withdrawals”. |
The benefit base is calculated on the contract date and on each contract date anniversary, and it is recalculated if there is a withdrawal.
The date of claim is the date on which we receive satisfactory proof of the owner’s (or older joint owner’s, if applicable) death, and any required instructions for the method of payment, forms necessary to effect payment and any other information we may require.
For purposes of calculating your Return of Premium death benefit, any accrued but unpaid Breakpoint Credit amount will be added to your account value and any accrued but unpaid Return of Premium death benefit charge will be deducted from your account value.
Pro rata treatment of withdrawals
value. Accordingly, your Return of Premium death benefit base and therefore the death benefit is reduced by 12.5% to $87,500 (12.5% of $100,000 is $12,500, and $100,000 minus $12,500 is $87,500).
Please note: A withdrawal (including withdrawals to pay advisory fees) will reduce your Return of Premium death benefit, and the reduction may be substantially more than the amount of the withdrawal.
Amounts withdrawn from any Segment before the Segment Maturity Date to pay the death
benefit will reflect the Segment Interim Value calculation. For more information, see “Adjustments with respect to early distributions from Segments” in “Charges, expenses, and adjustments” in this Prospectus.
If you have an Investment Edge ADV contract, please note that withdrawals to pay advisory fees reduce your death benefit and any Income Edge program payments on a pro rata basis, which means it could reduce the benefit base significantly and by substantially more than the actual amount of the deduction. For example, assume your starting account value is $100,000 (all invested in variable investment options) and that you decide to withdraw your advisory fee of 1.50% annual rate at the end of each quarter. Assuming a growth rate of 5% annually (net of all other fees and charges), if you withdraw the advisory fees from your Investment Edge ADV contract, by the end of one year you will withdraw $1,546.50 to pay your adviser, your account value will be $103,425.00 and the Return of Premium death benefit base will be $98,500. Had you chosen not to take advisory fees from your contract, your account value at the end of the year and, therefore, your death benefit amount at that time, would have been $105,000. Over ten years, assuming a constant net growth rate of 5%, the account value and death benefit amount would be lower by $22,848.43 and the Return of Premium death benefit base would be $85,973.04, due to the withdrawals to pay the advisory fee. You should consider whether it is in your best interest to take withdrawals from your contract to pay advisory fees or pay them from another source.
®
®
If you have a Series ADV contract, please discuss deducting advisory fees from your contract with your financial professional before making an election.
You may not terminate the Return of Premium death benefit once elected, except if a fee increase is declared. When a fee increase is declared the Return of Premium death benefit rider can be dropped at any time from the fee change notification date until the date before the fee change effective date. We will drop the rider as of the day we receive the election form in good order and a pro rata fee will be applied through that date. Once you terminate the Return of Premium death benefit, you may not reelect it. The Return of Premium death benefit is not available for election after issue. For NQ contracts, if you elect an Income Edge payment program, the Return of Premium death benefit will be automatically terminated on your Income Edge Effective Date.
The charge for the Return of Premium death benefit is a percentage of the Return of Premium benefit base, calculated and deducted from the Account value on each contract date anniversary. Please refer to “Return of Premium death benefit charge” in “Charges, expenses, and adjustments” for information about how we calculate the charge for this guaranteed benefit and, if your account value is low, the risk that this charge could cause your contract and the guaranteed benefit to terminate.
The Return of Premium death benefit is not available for election by Inherited NQ contract holders.
Effect of your death on the Structured Investment Option
Once we have received notice of your death and until the death benefit is processed, we will not make any transfers from the Segment Type Holding Account to a Segment. Amounts in the Segment Type Holding Account will be defaulted into the EQ/Money Market variable investment option. If Segments mature, the Segment Maturity Value will be transferred to the EQ/Money Market variable investment option.
If the contract has active Segments at the time an account value death benefit is paid, we will use the Segment Interim Value calculation to determine the value in the active Segments which could result in a substantial loss of up to 60% to 100% of your principal and previously credited interest in those Segments.
Payment of Death Benefit
Your beneficiary and payment of benefit
You designate your beneficiary when you apply for your contract. You may change your beneficiary at any time during your lifetime and while the contract is in force. A beneficiary change will be effective as of the date the written request is executed, whether or not you are living on the date the change is received in our processing office. We are not responsible for any beneficiary change request that we do not receive. We are not liable for any payments we make or actions we take before we receive the change. We will send you a written confirmation when we receive your request.
Under jointly owned contracts, the surviving owner is considered the beneficiary, and will take the place of any other beneficiary. Under a contract with a
non-natural
owner that has joint annuitants, who continue to be spouses at the time of death, the surviving annuitant is considered the beneficiary, and will take the place of any other beneficiary. In a QP contract, the beneficiary must be the plan trust. Where an NQ contract is owned for the benefit of a minor pursuant to the Uniform Gifts to Minors Act or the Uniform Transfers to Minors Act, the beneficiary must be the estate of the minor. Where an IRA contract is owned in a custodial individual retirement account, the custodian must be the beneficiary. For NQ contracts where an Income Edge payment program has been elected with the Joint Election payment method, the joint owner, successor owner, or joint annuitant, as applicable, supersedes any inconsistent beneficiary designations. This means that a previous beneficiary designation may be invalidated. The death benefit is equal to your account value (the standard death benefit) or, if elected, the Return of Premium death benefit. We determine the amount of the death benefit as of the date we receive satisfactory proof of the owner’s or older joint owner’s, if applicable, death, any required instructions for the method of payment, forms necessary to effect payment and any other information we may require (“date of claim”). Payment of the death benefit terminates the contract.
If there are multiple beneficiaries, any accrued Breakpoint Credit, the Contract Maintenance Fee (if applicable) and, if the Return of Premium death benefit was in effect at the time of your death, any accrued Return of Premium death benefit charge will be applied pro rata to each beneficiary’s portion of the death benefit payment.
When we use the terms
owner
and
joint
owner
, we intend these to be references to
annuitant
and
joint annuitant
, respectively, if the contract has a
non-natural
owner. If the contract is jointly owned or is issued to a non-natural
owner, the death benefit is payable upon the death of the older joint owner or older joint annuitant, as applicable. Subject to applicable laws and regulations, you may impose restrictions on the timing and manner of the payment of the death benefit to your beneficiary. For example, your beneficiary designation may specify the form of death benefit payout (such as a life annuity), provided the payout you elect is one that we offer both at the time of designation and when the death benefit is payable. In general, the beneficiary will have no right to change the election. However, you should be aware that (i) in accordance with current federal income tax rules, we apply a predetermined death benefit annuity payout election only if payment of the death benefit amount begins within one year following the date of death (the “1-year rule”), which payment may not occur if the beneficiary has failed to provide all required information before the end of that period, (ii) we will not apply the predetermined death benefit payout election if doing so would violate any federal income tax rules or any other applicable law, and (iii) a beneficiary or a successor owner who continues the contract under one of the continuation options described below will have the right to change your annuity payout election.
In general, if the annuitant dies, the owner (or older joint owner, if applicable) will become the annuitant, and the death benefit is not payable. If the contract had joint annuitants, it will become a single annuitant contract.
Equitable Access Account
If the beneficiary is a natural person (i.e., not an entity such as a corporation or a trust) and so elects, death benefit proceeds can be paid through the “Equitable Access Account,” which is a draft account that works in certain respects like an interest-bearing checking account. In that case, we will send the beneficiary a draftbook, and the beneficiary will have immediate access to the proceeds by writing a draft for all or part of the amount of the death benefit proceeds. The Company will retain the funds until a draft is presented for payment. Interest on the Equitable Access
Account is earned from the date we establish the account until the account is closed by your beneficiary or by us if the account balance falls below the minimum balance requirement, which is currently $1,000. The Equitable Access Account is part of the Company’s general account and is subject to the claims of our creditors. We will receive any investment earnings during the period such amounts remain in the general account. The Equitable Access Account is not a bank account or a checking account and it is not insured by the FDIC. Funds held by insurance companies in the general account are guaranteed by the respective state guaranty association.
Effect of the owner’s death
In general, if the owner dies while the contract is in force, the contract terminates and the applicable death benefit is paid. If the contract is jointly owned, the death benefit is payable upon the death of the older owner. See “Special Rules for NQ contracts when Income Edge or Income Edge Early Retirement Option is in effect” for more information regarding special rules applicable to such contracts.
There are various circumstances, however, in which the contract can be continued by a successor owner or under a Beneficiary continuation option. For NQ contracts with spouses who are joint owners, the surviving spouse will automatically be able to continue the contract under the “Spousal continuation” feature or under our Beneficiary continuation option, as discussed below. For NQ contracts with
non-spousal
joint owners, the joint owner will be able to continue the contract as a successor owner subject to the limitations discussed below under “Non-spousal joint owner contract continuation.” If you are the sole owner of an NQ contract and your spouse is the sole primary beneficiary, your surviving spouse may have the option to:
| • | take the death benefit proceeds in a lump sum; |
| • | continue the contract as a successor owner under “Spousal continuation” or under our Beneficiary continuation option; |
| • | elect Income Edge Beneficiary Advantage, as discussed below; or |
| • | for traditional and Roth IRA contracts, roll the death benefit proceeds over into another similar arrangement. |
If your surviving spouse rolls over the death benefit proceeds into a contract issued by us, the amount of the death benefit will be calculated as of the date we receive all requirements necessary to issue your spouse’s new contract. Any death proceeds will remain invested in this contract until your spouse’s new contract is issued. The amount of the death benefit will be calculated to equal the account value as of the date your spouse’s new contract is issued. This means that the death benefit proceeds could vary up or down, based on investment performance, until your spouse’s new contract is issued.
Non-spousal single owner contract continuation
For single owner contracts, if the beneficiary is not the surviving spouse, federal income tax rules generally require payments of amounts under the contract to be made within five years of an owner’s death (the
“5-year
rule”). In certain cases, an individual beneficiary may opt to receive payments over his/her life (or over a period not in excess of his/her life expectancy) if payments commence within one year of the owner’s death, continue the contract under the Beneficiary Continuation option or elect Income Edge Beneficiary Advantage. If the Return of Premium death benefit if any, was greater than the account value on the date of claim, then we will reset the account value to equal the Return of Premium death benefit. If the contract continues, withdrawal charges, if applicable under your contract, will no longer apply, the Return of Premium death benefit (and associated charge) is terminated and no additional contributions will be permitted. Any such election must be made in accordance with our rules at the time of death. Non-spousal
joint owner contract continuation Upon the death of either owner, the surviving joint owner becomes the sole owner.
Any death benefit (if the older owner dies first) or cash value (if the younger owner dies first) must generally be fully paid to the surviving joint owner within five years. The surviving owner may instead elect to receive a life annuity, provided payments begin within one year of the deceased owner’s death. If the life annuity is elected, the terms of the supplemental contract supersede the terms of the contract.
If the older owner dies first, the surviving owner can elect to (1) take the death benefit as a lump sum payment; (2) annuitize within one year; (3) continue the contract for up to five years; (4) continue the contract under the Beneficiary continuation option; or (5) elect Income Edge Beneficiary Advantage. If the Return of Premium death benefit, if any, was greater than the account value on the date of claim, then we will reset the account value to equal the Return of Premium death benefit. If the contract continues, withdrawal charges, if applicable under your contract, will no longer apply, the Return of Premium death benefit (and associated charge) is terminated and no additional contributions will be permitted.
If the younger owner dies first, the surviving owner can elect to (1) take the death benefit as a lump sum payment; (2) annuitize within one year; (3) continue the contract for up to five years; (4) continue the contract under the Beneficiary continuation option; or (5) elect Income Edge Beneficiary Advantage. If the contract continues (other than under the Beneficiary continuation option or through an election of Income Edge Beneficiary Advantage), withdrawal charges, if applicable under your contract, will continue to apply and no additional contributions will be permitted. The Return of Premium death benefit, if any, will remain in effect based on the older owner’s age, and becomes payable to the beneficiary if the older owner dies within five years. Charges for the Return of Premium death benefit will continue to apply. If
Income Edge Beneficiary Advantage is elected, the Return of Premium death benefit, if any, will be terminated on the Income Edge Effective Date, and any Return of Premium death benefit charge will be deducted on that date.
Spousal continuation
If you are the contract owner and your spouse is the sole primary beneficiary or you jointly own the contract with your younger spouse, or if the contract owner is a
non-natural
person and you and your younger spouse are joint annuitants, your spouse may elect to continue the contract as successor owner upon your death. Spousal beneficiaries (who are not also joint owners) must be 95 or younger as of the date of the deceased spouse’s death in order to continue the contract under Spousal continuation. The determination of spousal status is made under applicable state law. However, in the event of a conflict between federal and state law, we follow federal rules. In addition, where such a contract is owned by a Living Trust, as defined in the contract, and at the time of the annuitant’s death the annuitant’s spouse is the sole beneficiary of the Living Trust, the Trustee, as owner of the contract, may request that the spouse be substituted as annuitant as of the date of the annuitant’s death. No further change of annuitant will be permitted.
For jointly owned NQ contracts where an Income Edge payment program has not been elected or, if elected, payments have not yet begun, if the spouse dies first no death benefit is paid, and the contract continues as follows:
younger
| • | If the deceased spouse was the annuitant, the surviving spouse becomes the annuitant. If the deceased spouse was a joint annuitant, the contract will become a single annuitant contract. |
| • | If the annuitant was neither the deceased or the surviving spouse, the surviving spouse can elect to become the annuitant and supersede the named annuitant. Alternatively, the surviving spouse can allow the named annuitant to remain on the contract and instead become the annuitant upon the death of the named annuitant. |
| • | The withdrawal charge schedule, if applicable, remains in effect. |
| • | The Return of Premium death benefit, if any, will remain in effect based on the older spouse’s age, and charges for the Return of Premium death benefit will continue to apply. |
| • | An Income Edge payment program may be elected at any time so long as the eligibility rules for the feature are satisfied. |
For jointly owned NQ contracts where an Income Edge payment program has not been elected or, if elected, payments have not yet begun, if the spouse dies first, the surviving owner can (1) take the death benefit as a lump sum payment; (2) annuitize within one year; (3) continue the contract under the Spousal continuation
older
option; (4) continue the contract under the Beneficiary continuation option; or (5) elect Income Edge Beneficiary Advantage. If the Return of Premium death benefit, if any, was greater than the account value on the date of claim, then we will reset the account value to equal the Return of Premium death benefit.
If the contract continues under the Spousal continuation option:
| • | The surviving spouse becomes the sole owner. If the deceased spouse was the annuitant, the surviving spouse becomes the annuitant. |
| • | If the surviving spouse is age 86 or older, election of an Income Edge payment program is not available. A surviving spouse aged 86 or older who wishes to elect Income Edge should consider electing Income Edge Beneficiary Advantage instead of Spousal continuation. |
| • | If the deceased spouse was a joint annuitant, the contract will become a single annuitant contract. If the annuitant was neither the deceased or the surviving spouse, the surviving spouse can elect to become the annuitant and supersede the named annuitant. Alternatively, the surviving spouse can allow the named annuitant to remain on the contract and instead become the annuitant upon the death of the named annuitant. |
| • | The Return of Premium death benefit, if any, will remain in effect if on the date of the older spouse’s death the surviving spouse is 95 or younger. For details of how we calculate charges for the Return of Premium death benefit under joint owner Spousal continuation, see “Return of Premium death benefit charge” in “Charges, expenses, and adjustments”. |
| • | Withdrawal charges, if applicable under the contract, will no longer apply to the account value on the date of the older spouse’s death, but they will apply to the amount of any subsequent contributions by the surviving spouse. |
For single owner NQ contracts with a where Income Edge or Income Edge Early Retirement Option has not been elected or, if elected, payments have not yet begun, the sole spousal beneficiary can (1) take the death benefit as a lump sum payment within five years of the deceased owner’s death; (2) annuitize within one year; (3) continue the contract under the Spousal continuation (if eligible per the age restriction); (4) continue the contract under the Beneficiary continuation option; or (5) elect Income Edge Beneficiary Advantage. If the Return of Premium death benefit, if any, was greater than the account value on the date of claim, then we will reset the account value to equal the Return of Premium death benefit.
sole spousal beneficiary
If the contract continues under the Spousal continuation option:
| • | The sole spousal beneficiary becomes the sole owner. If the deceased owner was also the annuitant, the sole spousal beneficiary becomes the annuitant. |
| • | If the deceased owner was a joint annuitant, the contract will become a single annuitant contract. If the deceased owner was not the annuitant, the sole spousal beneficiary can elect to become the annuitant and supersede the named annuitant. Alternatively, the sole spousal beneficiary can allow the named annuitant to remain on the contract and instead become the annuitant upon the death of the named annuitant. |
| • | A sole spousal beneficiary who is age 85 or younger can elect Income Edge Beneficiary Advantage at any time prior to age 86, rather than having to make such election within 9 months of the date of death. For information about Income Edge Beneficiary Advantage, see “Income Edge Beneficiary Advantage for NQ contracts only”. |
| • | The Return of Premium death benefit, if any, will remain in effect if on the date of the deceased owner’s death the sole spousal beneficiary is 75 or younger. For details of how we calculate charges for the Return of Premium death benefit under Spousal continuation, see “Return of Premium death benefit charge” in “Charges, expenses, and adjustments”. |
| • | Withdrawal charges, if applicable under the contract, will no longer apply to the account value as of the date of the deceased spouse’s death, but they will apply to the amount of any subsequent contributions by the sole spousal beneficiary. |
Non-natural owner with spousal joint annuitants
.
| • | If the younger spouse dies first, no death benefit is payable. The contract, including the Return of Premium death benefit (if elected), continues unchanged and withdrawal charges (if applicable) will continue to apply. |
| • | If the older spouse dies first, the surviving younger spouse can (1) take the death benefit as a lump sum payment; (2) annuitize within one year; (3) continue the contract under the Spousal continuation option; (4) continue the contract under the Beneficiary continuation option; or (5) elect Income Edge Beneficiary Advantage. If the Return of Premium death benefit, if any, was greater than the account value on the date of claim, then we will reset the account value to equal the Return of Premium death benefit. If the contract continues under the Spousal continuation option, the Return of Premium death benefit, if any, will remain in effect if on the date of the older spouse’s death the surviving spouse is 95 or younger. For details of how we calculate charges for the Return of Premium death benefit under Spousal continuation, see “Return of Premium death benefit charge” in “Charges and expenses”. If Income Edge Beneficiary Advantage is elected, the Return of Premium death benefit, if any, will be terminated on the Income Edge Effective Date, and any Return of Premium death benefit charge will be deducted on that date. |
Where an IRA contract is owned in a custodial individual retirement account, and your spouse is the sole beneficiary of the account, the custodian may request that the spouse be substituted as annuitant after your death.
If you divorce, Spousal continuation does not apply.
Beneficiary continuation option
We make this option available to beneficiaries under traditional IRA, Roth IRA and NQ contracts. For NQ contracts, where Income Edge or Income Edge Early Retirement Option has not been elected or, if elected, payments have not yet begun, this feature permits a designated individual, on the contract owner’s death, to either:
| • | maintain a contract with the deceased contract owner’s name on it and receive distributions under the contract; or |
| • | elect Income Edge Beneficiary Advantage, |
instead of receiving the death benefit in a single sum. Each of these options is described below.
For traditional and Roth IRAs, depending on the beneficiary, this option may be restricted for deaths after December 31, 2019, due to the changes made by the Setting Every Community Up for Retirement Enhancement Act (“SECURE Act”) enacted at the end of 2019. Please speak with your financial professional for further information.
Where an IRA contract is owned in a custodial individual retirement account, the custodian may reinvest the death benefit in an individual retirement annuity contract, using the account beneficiary as the annuitant. Depending on the beneficiary, this option may be restricted for deaths after December 31, 2019, due to the changes made by the SECURE Act. Please speak with your financial professional for further information.
Beneficiary continuation option for traditional IRA and Roth IRA contracts only.
The Beneficiary continuation option must be elected by September 30th of the year following the calendar year of your death and before any other inconsistent election is made. Beneficiaries who do not make a timely election will not be eligible for this option.
For deaths after December 31, 2019, only specified individuals who are “eligible designated beneficiaries” or “EDBs” may stretch post-death payments over the beneficiary’s life expectancy. See “required minimum distributions after your death” under “Tax Information.” Individual beneficiaries who do not have EDB status (including beneficiaries named by the original beneficiary to receive any remaining interest after the death of the original beneficiary) must take out any remaining interest in the IRA or plan within 10 years of the applicable death.
Under the Beneficiary continuation option for IRA and Roth IRA contracts:
| • | The contract continues with your name on it for the benefit of your beneficiary. |
| • | The beneficiary replaces the deceased owner as annuitant. |
| • | This feature is only available if the beneficiary is an individual. Certain trusts with only individual beneficiaries will be treated as individuals for this purpose. |
| • | If there is more than one beneficiary, each beneficiary’s share will be separately accounted for. It will be distributed over the beneficiary’s own life expectancy, if payments over life expectancy are chosen. |
| • | The minimum amount that is required in order to elect the beneficiary continuation option is $5,000 for each beneficiary. |
| • | The beneficiary may make transfers among the investment options but no additional contributions will be permitted. |
| • | The beneficiary may choose at any time to withdraw all or a portion of the account value and no withdrawal charges, if any, will apply. |
| • | Any partial withdrawal must be at least $300. |
| • | Your beneficiary will have the right to name a beneficiary to receive any remaining interest in the contract. |
| • | Upon the death of your beneficiary, the following distribution rules will apply to the subsequent beneficiary named by your beneficiary: (1) if your beneficiary is an EDB or you died on or before December 31, 2019, the subsequent beneficiary must withdraw any remaining amount within ten years of your beneficiary’s death; or (2) if your beneficiary is not an EDB, the subsequent beneficiary must withdraw any remaining amount within 10 years of your death. The option elected will be processed when we receive satisfactory proof of death, any required instructions for the method of payment and any required information and forms necessary to effect payment. |
| • | For beneficiaries who are required to take the entire interest within 10 years, we offer our post-death automatic RMD option to help the beneficiary meet the RMD requirements if the deceased owner died on or after the Required Beginning Date. We calculate post-death RMD payments using the beneficiary’s life expectancy determined in accordance with IRS tables. Instead of electing our post-death automatic RMD option, your beneficiary may choose to calculate the required amount themselves and request partial withdrawals. Regardless of whether your beneficiary elects this option, any remaining amounts will be distributed to your beneficiary by the end of the 10th calendar year following the year of your death. It is the beneficiary’s responsibility to ensure compliance with the post-death RMD rules under federal tax law. |
Beneficiary continuation option for NQ contracts only.
This feature, also known as Inherited annuity, may only be elected when the NQ contract owner has not elected Income Edge or Income Edge Early Retirement Option and dies before the
annuity maturity date, whether or not the owner and the annuitant are the same person. In addition, this feature may be available following election of Income Edge or Income Edge Early Retirement Option if the NQ contract owner dies before the first Income Edge or Income Edge Early Retirement Option scheduled payment is made. For purposes of this discussion, “beneficiary” refers to the successor owner. This feature must be elected within 9 months following the date of your death and before any other inconsistent election is made. Beneficiaries who do not make a timely election will not be eligible for this option.
If you are interested in electing an Income Edge payment program, please see “Income Edge Beneficiary Advantage for NQ contracts only”.
Generally, payments will be made once a year to the beneficiary over the beneficiary’s life expectancy, determined on a term certain basis and in the year payments start. These payments must begin no later than one year after the date of your death and are referred to as “scheduled payments.” The beneficiary may choose the
“5-year
rule” instead of scheduled payments over life expectancy. If the beneficiary chooses the 5-year
rule, there will be no scheduled payments. Under the 5-year
rule, the beneficiary may take withdrawals as desired, but the entire account value must be fully withdrawn by the fifth anniversary of your death. Under the Beneficiary continuation option for NQ contracts:
| • | This feature is only available if the beneficiary is an individual. It is not available for any entity such as a trust, even if all of the beneficiaries of the trust are individuals. |
| • | The beneficiary automatically replaces the existing annuitant. |
| • | The contract continues with your name on it for the benefit of your beneficiary. |
| • | If there is more than one beneficiary, each beneficiary’s share will be separately accounted for. It will be distributed over the respective beneficiary’s own life expectancy, if scheduled payments are chosen. |
| • | The minimum amount that is required in order to elect the Beneficiary continuation option is $5,000 for each beneficiary. |
| • | The beneficiary may make transfers among the investment options but no additional contributions will be permitted. |
| • | If the beneficiary chooses the “5-year rule,” withdrawals may be made at any time. If the beneficiary instead chooses scheduled payments, the beneficiary may take withdrawals, in addition to scheduled payments, at any time. |
| • | Any partial withdrawals must be at least $300. |
| • | Your beneficiary will have the right to name a beneficiary to receive any remaining interest in the contract on the beneficiary’s death. |
| • | Upon the death of your beneficiary, the beneficiary he or she has named has the option to either continue taking scheduled payments based on the remaining life expectancy of the deceased beneficiary (if scheduled payments were chosen) or to receive any remaining interest in the contract in a lump sum. We will pay any remaining interest in the contract in a lump sum if your beneficiary elects the 5-year rule. The option elected will be processed when we receive satisfactory proof of death, any required instructions for the method of payment and any required information and forms necessary to effect payment. |
| • | All payments are taxable to the extent there are gains remaining in the contract. |
If the deceased is the owner or the older joint owner:
| • | No withdrawal charges, if applicable, will apply to any withdrawals by the beneficiary. |
If the deceased is the younger
non-spousal
joint owner: | • | The contract’s withdrawal charge schedule, if applicable, will continue to be applied to any withdrawal or surrender other than scheduled payments; the contract’s free withdrawal amount will continue to apply to withdrawals but does not apply to surrenders. |
| • | We do not impose a withdrawal charge on scheduled payments except if, when added to any withdrawals previously taken in the same contract year, including for this purpose a contract surrender, the total amount of withdrawals and scheduled payments exceed the 10% free withdrawal amount. See the “Withdrawal charges” in “Charges, expenses, and adjustments” in this Prospectus. |
A surviving spouse should speak to his or her tax professional about whether Spousal continuation or the Beneficiary continuation option is appropriate for him or her. Factors to consider include but are not limited to the surviving spouse’s age, and any need for immediate income.
Income Edge Beneficiary Advantage for NQ contracts only.
The Income Edge Beneficiary Advantage payment option is a form of Income Edge payment program available under NQ contracts in the circumstances described below. We also offer a version of Income Edge Beneficiary Advantage under the Inherited NQ contract, which is a contract we offer to individual beneficiaries under nonqualified deferred annuity contracts issued by other insurance companies for the purpose of making post-death payments on the death of the holder. See “Inherited NQ beneficiary payout contract” in “Purchasing the contract”.
Under the Income Edge Beneficiary Advantage death benefit option for the Investment Edge NQ contract (“Income Edge BA”), we take into account the cost basis in calculating and reporting income amounts for “scheduled payments” (as described below) we make to your beneficiary. A portion of each scheduled payment is a return of the cost basis in the contract and thus excludable from taxes.
®
The conditions for electing Income Edge BA are as follows:
| • | The deceased NQ contract owner cannot have previously elected Income Edge, Income Edge Early Retirement Option, or any other annuity payout option. However, Income Edge BA may be available following election of Income Edge or Income Edge Early Retirement Option if the NQ contract owner dies before the first scheduled payment is made under Income Edge or Income Edge Early Retirement Option. |
| • | Income Edge BA is available only to beneficiaries who are individuals. This option is available whether or not the owner and the annuitant are the same person. For example, if an Investment Edge ® |
| • | Income Edge BA is intended only for beneficiaries who plan to take payments at least annually over a period measured by their life expectancy. We call these “scheduled payments.” Scheduled payments must begin no later than the Required Inherited NQ Payment Starting Date. Beneficiaries who do not want to take scheduled payments at least annually and prefer to wait up to five years after your death to withdraw the entire amount of their death benefit should instead consider the Beneficiary continuation option for NQ contracts as discussed in this section. |
| • | Income Edge BA must be elected within 9 months following the date of your death and before any other inconsistent election is made. Beneficiaries who do not make a timely election will not be eligible for this option. |
| • | There are no minimum age restrictions for a beneficiary’s election of Income Edge BA. A surviving spouse must be age 85 or younger under a single life contract, or 95 or younger under a joint life contract, to elect Income Edge BA. |
| • | The account value from the Investment Edge ® |
| • | If your Investment Edge ® |
If there are multiple beneficiaries under an Investment Edge NQ contract, the account value is split among the beneficiaries in accordance with your instructions, and we treat the separate shares of each beneficiary as a separate contract for the purpose of determining whether Income Edge BA is available.
®
We do not need to receive Income Edge BA elections from all eligible beneficiaries before we commence payments. Each eligible beneficiary can submit his/her own election. If the conditions for Income Edge BA are met, we will establish a supplementary payout contract for that beneficiary based on his/her own life expectancy. The supplementary payout contract will be issued in the beneficiary’s name with your name on it to reflect the status of the supplementary contract as a beneficiary payout contract. We will also allocate the cost basis of your Investment Edge contract to the supplementary payout contracts in proportion to each beneficiary’s share of the account value of your Investment Edge contract.
®
®
We may impose a charge approximating premium tax in certain states on the election of Income Edge BA.
If the conditions for electing Income Edge BA are met:
| • | Payment period ® ® ® |
| • | Your beneficiary must receive scheduled payments at least annually, but can elect to receive scheduled payments monthly or quarterly. |
| • | We will make the first scheduled payment no later than the Required Inherited NQ Payment Starting Date. Your beneficiary can choose a date to start scheduled payments earlier than the Required Inherited NQ Payment Starting Date, as long as we have all information we need to start scheduled payments on the earlier date. |
| • | The amount of the first scheduled payment is determined by dividing the account value as of the date payments start by the payment period as determined above. Each subsequent annual scheduled payment is determined by dividing the remaining account value as of the contract date anniversary by the initial payment period reduced by 1 for each subsequent year. |
| • | Payment amounts are taken on a pro rata basis from your variable investment options. |
| • | Your beneficiary may make transfers among the variable investment options. |
| • | Once scheduled payments begin, they cannot be stopped until the account value falls to zero. |
| • | No other form of payout or annuity benefit is available after Income Edge BA is elected. |
| • | Partial withdrawals |
| • | Change of ownership of the supplementary contract is not permitted after Income Edge BA is elected. |
| • | At the death of a beneficiary who has elected Income Edge BA, the Spousal continuation and beneficiary continuation options are not available. We will continue scheduled payments to a successor beneficiary chosen by your beneficiary. The successor beneficiary has the same rights as your beneficiary to take partial withdrawals in addition to scheduled payments and to fully surrender (redeem) the contract. If there is more than one individual or entity chosen by your beneficiary to be a successor beneficiary, we will make payments in equal shares unless your beneficiary had instructed us in writing to pay one or more successor beneficiaries in a different manner. |
How the Structured Investment Option affects the Beneficiary continuation option
Under the Beneficiary continuation option, if you have any account value in a Segment or Segment Type Holding Account:
| • | The transfer restrictions on amounts in Segments prior to election of the beneficiary continuation option remain in place. The Segment Maturity Value may be reinvested in other investment options. However, if the beneficiary has chosen the “5-year rule” (for NQ contracts) or is subject to the “10-year rule” (for IRA contracts), amounts may not be invested in Segments with Segment Maturity Dates later than December 31st of the calendar year which contains the fifth (for NQ contracts) or tenth (for IRA contracts) anniversary of your death. |
| • | If there is more than one beneficiary, then as of the date we receive satisfactory proof of death, any required instructions, information and forms necessary to effect the beneficiary continuation option feature for the first beneficiary, all Segments will continue for each beneficiary. |
An eligible beneficiary who chooses to receive annual payments over his life expectancy should consult his tax adviser about selecting Segments that provide sufficient liquidity to satisfy the payout requirements under this option.
For more information, please see the “Beneficiary continuation option” and “Required minimum distributions” in this Prospectus.
Special Rules for NQ Contracts when Income Edge or Income Edge Early Retirement Option is in effect
For NQ contracts where Income Edge or Income Edge Early Retirement Option has been elected prior to the owner’s death, the following rules apply upon the death of the owner:
| • | Any successor owner or joint annuitant named in connection with the election of Income Edge will supersede any inconsistent designated beneficiary. |
| • | If the owner dies after the first scheduled payment under Income Edge or Income Edge Early Retirement Option is made, scheduled payments will continue and will be made to the beneficiary on the same schedule as they would otherwise have been made. |
| • | The beneficiary (including a joint owner, successor owner, or joint annuitant, as applicable) may instead surrender the contract and take a lump sum payment of the account value. |
| • | For contracts with named or designated multiple beneficiaries, each beneficiary must choose, as to their share of the proceeds of the contract, whether to (i) continue receiving scheduled payments; or (ii) surrender the contract and take a lump sum payment. Each beneficiary will be able to claim their proportionate share of the Tax-Free Amount remaining at the time that all required paperwork for their election is received in good order. |
Scheduled payments under Income Edge or Income Edge Early Retirement Option will continue to be made to the deceased owner until all required paperwork from the beneficiary is received in good order. In the case of multiple beneficiaries, scheduled payments to the deceased owner will continue and be adjusted accordingly until all required paperwork has been received in good order from each beneficiary. Until claimed by the appropriate beneficiary, contract proceeds will remain invested as they were at the time of the owner’s death, and will thus be subject to market performance during that time.
Other Benefits
Dollar cost averaging
We offer a dollar cost averaging program via scheduled transfers from the EQ/Money Market investment option to the other available investment options. The program allows you to gradually allocate amounts to available investment options by periodically transferring approximately the same dollar amount to the variable investment options you select. Regular allocations to the variable investment options will cause you to purchase more units if the unit value is low and fewer units if the unit value is high. Therefore, you may get a lower average cost per unit over the long term. This plan of investing, however, does not guarantee that you will earn a profit or be protected against losses. We may, at any time,
exercise our right to terminate transfers to any of the investment options, to add investment options, and to limit the number of investment options which you may elect. For NQ contracts, existing dollar cost averaging programs will continue after the election of an Income Edge payment program.
You may dollar cost average from the EQ/Money Market investment option, subject to the following:
| • | Initial contributions to the program must be at least $5,000 (i.e., your value in the EQ/Money Market variable investment option must be at least $5,000 when you begin the program). |
| • | Contributions into the program may be new contributions, or you may transfer amounts allocated to other variable investment options to initiate the program. You can make additional contributions to a program after a program has started. |
| • | You may choose either a 3 month, 6 month, or 12 month time period for participation in the dollar cost averaging program; however, you may only have one time period in effect at any time and once you select a time period, you may not change it and subsequent contributions or transfers into the program will not extend the duration of an existing program. |
| • | Currently, your account value may only be transferred from the program into the variable investment options on a monthly basis. We may offer these programs in the future with transfers on a different basis. |
| • | For the program, you may select different variable investment options than those in your allocation instructions on file, except that you may not do so on your initial application for the contract. |
| • | If the value in the EQ/Money Market variable investment option is less than or equal to the scheduled transfer amount, the entire amount in the account will be transferred and the program will terminate. |
| • | You can enroll in a dollar cost averaging program on your contract application or at any time after your contract has been issued. A program will become effective on the date we receive your first contribution directing us to allocate funds to the EQ/Money Market variable investment option. The date we receive your initial contribution will also be the date of the first transfer to the other variable investment options or the Segment Type Holding Account(s) if you are allocating to Segments in accordance with your allocation instructions for the program. Each subsequent transfer date for the time period selected will be one month from the date of the previous transfer. If a transfer date falls on a non-business day, the transfer will be made on the next business day. We will transfer all amounts by the end of the chosen time period for your program. |
For example, assume you enroll in a 3-month dollar cost averaging program. On the date we receive your initial
contribution (say, $60,000) to the program, your program becomes effective and the first transfer of $20,000 is made immediately in accordance with your program’s allocation instructions. The second transfer of $20,000 will be made one month after your first contribution and the third and final transfer of $20,000 will be made two months after your first contribution.
| • | If you enroll in a dollar cost averaging program and the transfer date is the 29th, 30th or 31st day of the month, for any subsequent month in your program with less than 29, 30 or 31 days respectively, the transfer will take place on the first business day of the following month and continue on the first of every month. |
| • | If you request to transfer 100% out of your program, your program will terminate. A manual transfer of 100% of the amount out of the EQ/Money Market will terminate the DCA program. A partial transfer is allowed and will not terminate the DCA. |
| • | The scheduled/recurring rebalancing program is available while the dollar cost averaging program is in effect, and for NQ contracts, remains available after election of an Income Edge payment program. However, rebalancing is not available for amounts allocated to a Segment Type Holding Account or to any Segment. |
| • | If you make subsequent contributions into an existing DCA account with allocation instructions that differ from those on file, we will update the current instructions for the remainder of the program and they will become the new instructions on file. |
| • | You may cancel your participation in the program at any time by notifying us in writing. If you terminate your program, we will allocate any remaining amounts in your program pursuant to your program allocations instructions on file. |
We do not deduct a transfer charge for any transfer made in connection with our dollar cost averaging program. Note that participation in the dollar cost averaging program is not cancelled by your request for a one-time rebalancing of your account. The dollar cost averaging program is not available in all states. See Appendix “State contract availability and/or variations of certain features and benefits” for more information on state availability.
Rebalancing your account value
Our rebalancing program offers two options — scheduled/recurring rebalancing and one-time rebalancing — that you can use to automatically reallocate your account value among the variable investment options.
To enroll in the scheduled/recurring rebalancing program, you must notify us in writing by completing our investment option selection form, telling us:
| (a) | in whole percentages only, the percentage you want invested in each investment option, and |
| (b) | how often you want the rebalancing to occur (quarterly, semiannually, or annually). |
While your scheduled/recurring rebalancing program is in effect, we will transfer amounts among each variable investment option, so that the percentage of your account value that you specify is invested in each option at the end of each rebalancing date. Your entire account value must be included in the scheduled/recurring rebalancing program. Currently, we permit rebalancing of up to 100 investment options.
Rebalancing does not assure a profit or protect against loss. You should periodically review your allocation percentages as your needs change. You may want to discuss the rebalancing program with your financial professional before electing the program.
You may elect or terminate the scheduled/recurring rebalancing program at any time. You may also change your allocations under the scheduled/recurring program at any time. Once enrolled in the scheduled/recurring rebalancing program, it will remain in effect until you instruct us in writing to terminate the program. Requesting an investment option transfer while enrolled in our scheduled/recurring rebalancing program will not automatically change your allocation instructions for rebalancing your account value. This means that upon the next scheduled rebalancing, we will transfer amounts among your investment options pursuant to the allocation instructions previously on file for your scheduled/recurring program. Changes to your allocation instructions for the scheduled/recurring rebalancing program (or termination of your enrollment in the program) may be requested through the Equitable Client portal; otherwise, they must be made in writing and sent to our processing office. The scheduled/recurring rebalancing program is available while the dollar cost averaging program is in effect, and for NQ contracts, remains available after election of an Income Edge payment program.
Income Edge Payment Program
(NQ contracts only)
The Income Edge Payment Program versions (Income Edge, Income Edge Early Retirement Option, and Income Edge Beneficiary Advantage) are not available for contracts with applications signed on or after August 19, 2024.
An Income Edge payment program, when elected, will pay out your entire account value via scheduled payments over a set period of time, with a portion of each payment being a return of your cost basis in the contract and thus excludable from taxes (the “Tax-Free Amount”).
(1)
Unlike traditional forms of annuitization, an Income Edge payment program allows for a form of annuity payout that provides continuing access to your contract’s account value by allowing you to take partial withdrawals or surrender your contract during the payout period. We offer several Income Edge payment program versions, each of which is described in detail in this Prospectus:
| • | Income Edge — the standard form of Income Edge payment program, described immediately below. |
| (1) | Unlike systematic withdrawals and 72(q) exception withdrawals, these payments cannot be stopped once they begin. |
| • | Income Edge Early Retirement Option — available for election by contract holders under the age of 59½. See “Income Edge Early Retirement Option”. |
| • | Income Edge Beneficiary Advantage — available for election: |
| — | by Investment Edge ® |
| — | as one of two payout options under an Inherited NQ contract, as described in “Inherited NQ beneficiary payout contract” in the “Purchasing the contract” section. |
When used in this Prospectus, “Income Edge Payment Program” refers generally to all forms of Income Edge payment programs, unless we indicate otherwise.
Income Edge
In order to elect the standard form of Income Edge, at the time of election your account value must be (i) at least $35,000 and (ii) more than your cost basis in the contract. In addition, there are certain age requirements for electing this feature, which are described below, and in some states there may be other limitations regarding election of Income Edge. Please see Appendix “State contract availability and/or variations of certain features and benefits” for more information. You also cannot elect Income Edge while you are receiving systematic withdrawals or “substantially equal withdrawals”, until the mandatory period has elapsed. See “Substantially equal withdrawals”. For contracts purchased through a Section 1035 exchange, Income Edge cannot be elected unless all expected contributions have been received; in addition, you will be responsible for ensuring that the cost basis information for all contracts being exchanged into the Investment Edge contract has been reported to us by the original insurance companies. Finally, for contracts with a non-natural owner, Income Edge may only be elected where the contract is owned by a trust or other entity as an agent or nominee for an individual.
®
Maximum payment period.
In order to elect the Single Election method, the Applicable Individual must be at least age 59
1
⁄2
but not older than age 85 at the time that Income Edge is elected. Note that for jointly owned contracts where the Single Election method is chosen, the owner who is not chosen as the Applicable Individual need not satisfy this age requirement. In order to elect the Joint Election method, both persons who are eligible to be designated as the Applicable Individual must be at least age 591
⁄2
but not older than age 85 at the time that Income Edge is elected. In order to elect the Joint Election method for contracts with either (i) an individual owner or (ii) a non-natural owner with a single annuitant, the individual added to the contract as either a successor owner or joint annuitant for purposes of electing the Joint Election method must meet the age requirements set forth above. In addition, please note that adding a successor owner or joint annuitant to the contract in connection with making the election may change your beneficiary designation. See “Your beneficiary and payment of death benefit” in “Benefits available under the contract” in this Prospectus. If the Single Election method is chosen, the maximum period over which you will receive payments (and recover your cost basis in the contract) is determined by the following formula: Age 95 minus the age of the Applicable Individual at the time that Income Edge is elected. If the Joint Election method is chosen, that period is determined by the following formula: Age 100 minus the age of the Applicable Individual at the time that Income Edge is elected. Under either method, a shorter period than that calculated by the applicable formula can be chosen; however, for Investment Edge Select and Investment Edge ADV contracts, that period cannot be shorter than 10 years and for Investment Edge contracts, that period cannot be shorter than 15 years. Please see the following table for examples of the payment period calculation.
®
®
®
Chosen Payment Period Method |
Age of Applicable Individual at time of Election |
Maximum Payment Period |
Shorter Payment Period Available? | |||
| Single Election | 63 | 32 years | Yes (at least 10 years or 15 years, depending on contract version) | |||
| Single Election | 81 | 14 years | Yes for Investment Edge ® ® ® | |||
| Joint Election | 63 | 37 years | Yes (at least 10 or 15 years depending on contract version) | |||
| Joint Election | 81 | 19 years | Yes (at least 10 or 15 years depending on contract version) |
The amount of the payments we will make is redetermined on an annual basis, meaning that the amount of your payments may vary each year of the payment period (called an Annual Payout Period). In contrast, the amount of each payment that is considered to be the return of a portion of your cost basis in the contract is determined at the time that you elect Income Edge and does not change during the payment period.
Your Income Edge payment program becomes effective on the Income Edge Effective Date, which is the date by which we have received your election to begin Income Edge payments along with all required information, exchanges and cost basis.
You may choose to receive monthly, quarterly, or annual payments (“payment modes”) during each Annual Payout Period over the payment period. A change in your chosen payment frequency is not permitted. You may request to have your payments made on any day of the month, subject to the following restrictions:
| • | you must select a date that is no more than one payment mode away from the date on which you elect Income Edge; and |
| • | you cannot select the 29th, 30th, or 31st. |
If you do not select a date, we will make the payments on the same day of the month as the day we receive your request to elect Income Edge, subject to the restrictions listed above.
For the first Annual Payout Period, the total amount of payments for that year is calculated by dividing your account value at the time that you elect Income Edge by the payment period selected.
(1)
For each subsequent Annual Payout Period the total amount of payments for that year is calculated by dividing your account value on the last day of the preceding Annual Payout Period by the remaining number of years in the payment period as of the first day of the current Annual Payout Period. If not sooner, your account value will always equal zero by the end of the payment period selected. Note that we reserve the right to change the manner in which Income Edge scheduled payments are calculated, but such a change will not affect any payments made pursuant to an Income Edge election that preceded the effective date of the change. Please see below for an example of the payment amount calculation. In addition, see Appendix “Income Edge scheduled payment amount expressed as a Percentage of Account Value” for a demonstration of the payment amount calculation as a percentage of account value.
Example
Income Edge is elected on 6/15/2026 with the Single Life election method by an 80 year old contract holder whose account value is $150,000 at the time of election. The contract owner has chosen to receive quarterly payments over the maximum payment period.
(1) |
Note that during the first Annual Payout Period your monthly or quarterly payments must be at least $250. |
Annual Payout Period Year |
Account Value for Payment Calculation |
Remaining number of years in Payment Period |
Total Payments for Annual Payout Period | |||
1 |
$150,000 (as of 6/15/26) |
15 |
$10,000 (in quarterly payments of $2,500) | |||
2 |
$155,000 (as of 6/14/27) |
14 |
$11,071.43 (in quarterly payments of $2,767.86) | |||
3 |
$140,000 (as of 6/14/28) |
13 |
$10,769.23 (in quarterly payments of $2,692.31) | |||
15 |
$12,000 (as of 6/14/40) |
1 (Annual Payout Period Year 15) |
$12,000 (in quarterly payments of $3,000) |
Note, however, that if your account value is less than or equal to the amount of any Income Edge scheduled payment on the date that such payment is due, the entire amount of your account value will be paid and your contract will terminate. In addition, if your account value is greater than the amount of the last Income Edge scheduled payment on the date that such payment is due, the last Income Edge scheduled payment will be equal to your entire account value.
For Investment Edge contracts, Income Edge scheduled payments are not subject to withdrawal charges and they will not reduce the contribution amounts in the contract that are subject to withdrawal charges. However, such payments will reduce the 10% free withdrawal amount. If your contract terminates for any reason prior to the end of Income Edge scheduled payments, no further Income Edge scheduled payments will be made.
®
A portion of each Income Edge scheduled payment represents a return of your cost basis in the contract, and is called the Tax-Free Amount. The Tax-Free Amount for each Annual Payout Period is calculated at the time that you elect Income Edge and does not change once it is calculated. It is calculated by dividing the remaining cost basis in the contract at the time that Income Edge is elected by the number of years in the payment period selected at the time of election. That number is then divided by the number of Income Edge scheduled payments in each Annual Payout Period to determine the Tax-Free Amount that applies to each Income Edge scheduled payment.
For example, if the remaining cost basis in the contract at the time that Income Edge is elected is $100,000, and the payment period chosen at election is 10 years, then the Tax-Free Amount for each Annual Payout Period is $10,000. And if that contract owner had selected quarterly payments, then $2,500 (1/4th of $10,000) would be the amount of each Income Edge scheduled payment that would represent a return of cost basis in the contract.
Your actual cost basis in the contract is reduced by the Tax-Free Amount upon receipt of each Income Edge scheduled payment. Income Edge is designed to deplete your entire cost basis in the contract by the end of the payment period selected. Special rules may apply if you have purchased more than one nonqualified annuity contract from the Company in the same calendar year. Please see “Tax Information” for more information.
All options selected as part of electing Income Edge (e.g., Joint Election, payment period) are final, although you may cancel your election if your request to do so is received prior to the date on which your first Income Edge scheduled payment is made.
Once Income Edge scheduled payments begin, they cannot be stopped, although the contract can be fully redeemed (surrendered) for the then-current account value net of withdrawal charges, if applicable. In addition, upon election of Income Edge the following limitations on your contract apply:
| • | Additional contributions — including Section 1035 exchanges — to your contract are not permitted. |
| • | Contract ownership cannot be changed, and no rights under the contract may be assigned. |
| • | Any systematic withdrawal option or 72(q) substantially equal withdrawal option that is in effect will end. |
| • | You may not select any of the other annuity payout options available under your contract, and the maturity date is no longer applicable. |
| • | If you have elected the Joint Election payment method, the joint owner, successor owner, or joint annuitant, as applicable, supersedes all inconsistent beneficiary designations. |
| • | Any existing instructions that you specified regarding the manner in which the death benefit should be paid out will no longer be in effect. |
| • | The beneficiary continuation option, Spousal continuation option, and other annuity options are not available to beneficiaries. |
| • | The Return of Premium death benefit, if elected, will be terminated on the Income Edge Effective Date. A pro rata charge for the Return of Premium death benefit will be deducted on that date. |
In addition, we may impose a premium tax charge on contracts issued in certain states upon election of Income Edge. If such a charge is applicable, it will be taken out of your account value on the date that you elect Income Edge on a pro rata basis prior to calculating the Income Edge scheduled payment(s) due during the first Annual Payout Period.
See “Special Rules for NQ contracts when Income Edge or Income Edge Early Retirement Option is in effect” in “Benefits available under the contract” for more information on rules that apply upon the death of the owner.
Partial Withdrawals.
withdrawal charges, if applicable. Note that unlike Income Edge scheduled payments, no portion of such withdrawals will represent a return of your cost basis in the contract, and thus will not affect the Tax-Free Amount applicable to subsequent Income Edge scheduled payments. In addition, the withdrawal charge schedule remains unchanged upon election of Income Edge, and any withdrawal charge waivers that were in effect at the time that Income Edge was elected will continue to be in effect in accordance with their terms. If you have an Investment Edge ADV contract, please note that withdrawals to pay advisory fees reduce your Income Edge program payments on a pro rata basis which means your payments could be reduced by more than the amount of the withdrawal.
®
Income Edge Early Retirement Option
Income Edge Early Retirement Option (“Income Edge ERO”) is a version of Income Edge available for election by Investment Edge NQ contract owners aged between 10 and 59½. To elect Income Edge ERO, your account value must be (i) at least $50,000 and (ii) more than your cost basis in the contract. Like the “substantially equal withdrawals” option discussed in this section, Income Edge ERO is intended to meet the “substantially equal periodic payments” exception provided under Section 72(q) of the Internal Revenue Code that otherwise applies a 10% additional federal income tax penalty to distributions taken before age 59½. Unlike the “substantially equal withdrawals” option:
®
| • | Income Edge ERO will pay out your entire account value via scheduled payments over a set period of time, with a portion of each payment representing a return of your cost basis in the contract. |
| • | Income Edge ERO scheduled payments cannot be stopped once they begin, and annuitization options under the contract are no longer available. |
The features of Income Edge discussed immediately above also apply to Income Edge ERO, subject to these distinctions:
| • | We will continue to make payments under Income Edge ERO even after you are age 59½ until all payments are made under the contract, unless you request to surrender (redeem) your contract. Depending both on your age and the length of time you have been receiving payments under Income Edge ERO, we may have to report such redemption as being subject to a federal tax penalty. |
| • | Income Edge ERO is only available for election by individual contract owners. Income Edge ERO cannot be elected under a jointly owned contract or by non-natural owners. |
| • | Payment period. |
determine your life expectancy by referring to an IRS table used for determining “substantially equal periodic payments” and round down to the nearest whole number. Unlike Income Edge, you cannot select a payment period that is shorter than the life expectancy period we determine. |
The amount of the first scheduled payment is determined by dividing the account value as of the date payments start by your life expectancy as determined above. Each subsequent annual scheduled payment is determined by dividing the remaining account value as of the anniversary date by the initial life expectancy, reduced by 1 for each subsequent year.
| • | Partial withdrawals. if you take partial withdrawals or fully surrender (redeem) your contract (i) prior to age 59½ or (ii) after age 59 1 ⁄2 but prior to having received five full years of IncomeEdge ERO scheduled payments, there may be adverse tax consequences. ® |
If you are under age 59½, you should carefully consider whether to elect Income Edge ERO or instead wait until you are older than age 59½ and elect Income Edge. As discussed above, Income Edge ERO has certain limitations that do not apply to Income Edge, and even though there are no contractual restrictions on your ability to take withdrawals that are in addition to your scheduled payments, or to fully redeem your contract, adverse tax consequences may apply if you are under age 59½ and/or have not received five full years of scheduled Income Edge ERO payments.
Income Edge Beneficiary Advantage
The Income Edge Beneficiary Advantage (“Income Edge BA”) payment option is a form of Income Edge payment program available under NQ contracts (a) to Investment Edge contract beneficiaries as a death benefit option; and (b) as one of two payout options for beneficiaries under an Inherited NQ contract.
®
Features of the version of Income Edge BA available for election by an Investment Edge contract beneficiary include the following:
®
| • | We will determine a payment period at the time that scheduled payments begin. The payment period is based |
on your beneficiary’s age, using an IRS table for post-death payments and rounding down to the nearest whole number. Before scheduled payments start, your beneficiary may choose a shorter payment period than the one we determine, but a payment period must be at least 15 years (for beneficiaries of Investment Edge ® ® ® |
| • | Your beneficiary may choose at any time to withdraw all or a portion of the account value. Any partial withdrawal must be at least $300. Unlike Income Edge BA scheduled payments, no portion of such withdrawals will represent a return of cost basis in the contract, and thus will not affect the Tax-Free Amount applicable to subsequent Income Edge BA scheduled payments. Withdrawal charges will apply. |
This version of Income Edge BA is described in more detail in “Income Edge Beneficiary Advantage for NQ contracts only” in the “Benefits available under the contract” section of the Prospectus.
Features of the version of Income Edge BA available for election by beneficiaries under an Inherited NQ contract include the following:
| • | We will determine a payment period at the time that scheduled payments are due to begin. The payment period is based on the Inherited NQ contract owner’s life expectancy. The Inherited NQ contract owner may select a shorter payment period, which will generally result in larger payments. |
| • | The Inherited NQ contract owner may choose at any time to withdraw all or a portion of the account value. Any partial withdrawal must be at least $300. Unlike Income Edge BA scheduled payments, no portion of such withdrawals will represent a return of cost basis in the contract, and thus will not affect the Tax-Free Amount applicable to subsequent Income Edge BA scheduled payments. Withdrawal charges will apply. |
This version of Income Edge BA is described in more detail in “Inherited NQ beneficiary payout contract” in the “Purchasing the contract” section of the Prospectus.
Summary of Benefits
The following tables summarize important information about the benefits available under the contract.
Death Benefits
These death benefits are available during the accumulation phase:
Name of Benefit |
Purpose |
Standard/ Optional |
Annual Fee |
Brief Description of Restrictions/ Limitations | ||||||
Max |
Current | |||||||||
| Standard Death Benefit | Guarantees beneficiaries will receive a benefit equal to your account value. | Standard | No Additional Charge |
• Available only at contract purchase | ||||||
| Return of Premium Death Benefit | Guarantees beneficiaries will receive a benefit at least equal to your contributions less adjusted withdrawals. | Optional | 0.50% (1) |
0.30% (1) |
• Available only at contract purchase • Available only to contract holder age 75 or younger • Withdrawals, including the withdrawal of advisory fees, could significantly reduce or terminate the benefit • Generally no contributions once reach age 76 • If elected, you will not get the Standard Death Benefit | |||||
| (1) | Expressed as an annual percentage of the benefit base. |
Other Benefits
These other benefits are available during the accumulation phase:
Name of Benefit |
Purpose |
Standard/ Optional |
Annual Fee |
Brief Description of Restrictions/Limitations | ||||||
Max |
Current | |||||||||
Rebalancing |
Periodically rebalance to your desired asset mix. | Optional | No Charge | • Must rebalance 100% of account value | ||||||
| Dollar Cost Averaging | Transfer account value to selected investment options on a regular basis to potentially reduce the impact of market volatility. | Optional | No Charge | • $5,000 minimum to begin program | ||||||
| Income Edge Payment Program (1) |
Pay out entire account value via scheduled payments over a set period of time, with a portion of each payment being a return of your cost basis in the contract and thus excludable from taxes. | Optional | No Charge | • Not available with Return of Premium Death Benefit • NQ contracts only • Age and account value requirements may apply • Adverse tax consequences if surrender contract after payments start • Withdrawals, including payment of advisor fees, could significantly reduce or terminate the benefit | ||||||
| (1) | The Income Edge payment program versions are not available for contracts with applications signed on or after August 19, 2024. |
| (3) | The benefit base is equal to your initial contribution to the contract less any withdrawals you made from the contract. |
| (4) | If on any date other than the contract date anniversary your contract is surrendered or annuitized, an Income Edge payment program is elected and become effective, a death benefit is paid, or the Return of Premium death benefit is otherwise terminated, we will deduct a pro rata portion of the charge from your account value. |
| (5) | The current charge is 0.30%. |
Appendix: Investment Options available under the contract
Variable Investment Options
The following is a list of Portfolio Companies available under the contract. More information about the Portfolio Companies is available in the prospectuses for the Portfolio Companies, which may be amended from time to time and can be found online at www.equitable.com/ICSR#EQH161810. You can request this information at no cost by calling 1-877-522-5035 or by sending an email request to EquitableFunds@dfinsolutions.com.
The current expenses and performance information below reflects fee and expenses of the Portfolios, but do not reflect the other fees and expenses that your Contract may charge. Expenses would be higher and performance would be lower if these other charges were included. Each Portfolio’s past performance is not necessarily an indication of future performance.
Affiliated Portfolio Companies:
TYPE |
Portfolio Company — Investment Adviser; Sub-Adviser(s), as applicable |
Current Expenses |
Average Annual Total Returns (as of 12/31/2025) |
|||||||||||||||
1 year |
5 year |
10 year |
||||||||||||||||
| Specialty | 1290 VT Convertible Securities — Equitable Investment Management Group, LLC (“EIMG”); SSGA Funds Management, Inc. |
0.90% |
^ |
15.79% |
2.91% |
8.89% |
||||||||||||
| Fixed Income | 1290 VT DoubleLine Opportunistic Bond — EIMG; DoubleLine Capital LP |
0.91% |
^ |
7.25% |
0.27% |
2.12% |
||||||||||||
| Equity | 1290 VT Equity Income — EIMG; Barrow, Hanley, Mewhinney & Strauss, LLC d/b/a Barrow Hanley Global Investors |
0.95% |
^ |
13.04% |
11.25% |
8.85% |
||||||||||||
| Specialty | 1290 VT GAMCO Mergers & Acquisitions — EIMG; GAMCO Asset Management, Inc. |
1.29% |
^ |
15.91% |
7.70% |
5.38% |
||||||||||||
| Equity | 1290 VT GAMCO Small Company Value — EIMG; GAMCO Asset Management, Inc. |
1.05% |
12.82% |
11.24% |
10.77% |
|||||||||||||
| Fixed Income | 1290 VT High Yield Bond — EIMG; AXA Investment Managers US Inc., Post Advisory Group, LLC |
1.02% |
^ |
7.54% |
3.92% |
5.41% |
||||||||||||
| Equity | 1290 VT Micro Cap — EIMG; BlackRock Investment Management, LLC, Lord, Abbett & Co. LLC |
1.15% |
^ |
16.42% |
4.31% |
12.26% |
||||||||||||
| Specialty | 1290 VT Multi-Alternative Strategies — EIMG | 1.53% |
^ |
13.40% |
3.50% |
— |
||||||||||||
| Specialty | 1290 VT Natural Resources — EIMG; AllianceBernstein L.P. |
0.90% |
^ |
28.04% |
16.06% |
9.42% |
||||||||||||
| Specialty | 1290 VT Real Estate — EIMG; AllianceBernstein L.P. |
0.90% |
^ |
9.67% |
2.69% |
3.28% |
||||||||||||
| Equity | 1290 VT Small Cap Value — EIMG; BlackRock Investment Management, LLC, Horizon Kinetics Asset Management LLC |
1.23% |
^ |
6.11% |
13.44% |
11.19% |
||||||||||||
| Equity | 1290 VT SmartBeta Equity ESG — EIMG; AXA Investment Managers US Inc. |
1.10% |
13.95% |
10.21% |
10.74% |
|||||||||||||
| Equity | 1290 VT Socially Responsible — EIMG; BlackRock Investment Management, LLC |
0.90% |
17.23% |
13.04% |
13.83% |
|||||||||||||
| Equity | EQ/500 Managed Volatility† — EIMG; AllianceBernstein L.P., BlackRock Investment Management, LLC |
0.80% |
13.33% |
12.43% |
13.15% |
|||||||||||||
| Asset Allocation | EQ/AB Dynamic Moderate Growth Δ — EIMG ; AllianceBernstein L.P. |
1.13% |
13.46% |
6.31% |
6.12% |
|||||||||||||
| Fixed Income | EQ/AB Short Duration Government Bond — EIMG; AllianceBernstein L.P. |
0.77% |
^ |
4.17% |
2.11% |
1.56% |
||||||||||||
| Equity | EQ/AB Small Cap Growth — EIMG; AllianceBernstein L.P. |
0.92% |
9.21% |
3.43% |
10.10% |
|||||||||||||
| Asset Allocation | EQ/Aggressive Allocation† — EIMG | 1.15% |
12.97% |
7.79% |
9.47% |
|||||||||||||
| Asset Allocation | EQ/All Asset Growth Allocation — EIMG | 1.25% |
^ |
17.18% |
7.12% |
8.28% |
||||||||||||
| Equity | EQ/American Century Mid Cap Value — EIMG; American Century Investment Management, Inc. |
1.00% |
^ |
8.72% |
8.64% |
— |
||||||||||||
| Asset Allocation | EQ/American Century Moderate Growth Allocation Δ — EIMG ; American Century Investment Management, Inc. |
1.15% |
^ |
12.37% |
5.35% |
— |
||||||||||||
| Equity | EQ/ClearBridge Large Cap Growth ESG — EIMG; ClearBridge Investments, LLC |
1.00% |
^ |
7.69% |
10.47% |
13.63% |
||||||||||||
| Equity | EQ/ClearBridge Select Equity Managed Volatility† — EIMG; BlackRock Investment Management, LLC, ClearBridge Investments, LLC |
1.06% |
^ |
7.66% |
8.42% |
12.21% |
||||||||||||
| Equity | EQ/Common Stock Index — EIMG; AllianceBernstein L.P. |
0.67% |
^ |
16.28% |
12.50% |
13.55% |
||||||||||||
| Asset Allocation | EQ/Conservative Allocation† — EIMG | 1.00% |
^ |
7.48% |
1.74% |
3.11% |
||||||||||||
| Asset Allocation | EQ/Conservative Growth Strategy † (2) — EIMG |
0.97% |
9.32% |
3.76% |
5.10% |
|||||||||||||
TYPE |
Portfolio Company — Investment Adviser; Sub-Adviser(s), as applicable |
Current Expenses |
Average Annual Total Returns (as of 12/31/2025) |
|||||||||||||||
1 year |
5 year |
10 year |
||||||||||||||||
| Fixed Income | EQ/Core Bond Index (1) — EIMG ; SSGA Funds Management, Inc. |
0.62% |
^ |
6.43% |
0.35% |
1.70% |
||||||||||||
| Fixed Income | EQ/Core Plus Bond — EIMG; Brandywine Global Investment Management, LLC, Loomis, Sayles & Company, L.P. |
0.93% |
^ |
8.58% |
-0.68% |
2.17% |
||||||||||||
| Equity | EQ/Emerging Markets Equity PLUS — EIMG; AllianceBernstein L.P., EARNEST Partners, LLC |
1.20% |
^ |
33.46% |
4.64% |
7.73% |
||||||||||||
| Equity | EQ/Equity 500 Index — EIMG; AllianceBernstein L.P. |
0.53% |
^ |
17.23% |
13.79% |
14.15% |
||||||||||||
| Equity | EQ/Fidelity Institutional AM ® Large Cap — EIMG ; FIAM LLC |
0.87% |
^ |
18.34% |
13.86% |
— |
||||||||||||
| Equity | EQ/Franklin Rising Dividends — EIMG; Franklin Advisers, Inc. |
0.87% |
^ |
11.84% |
9.50% |
— |
||||||||||||
| Asset Allocation | EQ/Goldman Sachs Growth Allocation Δ — EIMG ; Goldman Sachs Asset Management L.P. |
1.15% |
^ |
12.09% |
7.29% |
— |
||||||||||||
| Equity | EQ/Goldman Sachs Mid Cap Value — EIMG; Goldman Sachs Asset Management L.P. |
1.09% |
^ |
9.22% |
9.66% |
— |
||||||||||||
| Asset Allocation | EQ/Goldman Sachs Moderate Growth Allocation Δ — EIMG ; Goldman Sachs Asset Management L.P. |
1.15% |
^ |
10.02% |
5.02% |
5.76% |
||||||||||||
| Fixed Income | EQ/Intermediate Corporate Bond — EIMG; AllianceBernstein L.P. |
0.64% |
^ |
9.06% |
— |
— |
||||||||||||
| Fixed Income | EQ/Intermediate Government Bond ( 1) — EIMG ; SSGA Funds Management, Inc. |
0.62% |
^ |
5.54% |
0.30% |
1.15% |
||||||||||||
| Equity | EQ/International Equity Index — EIMG; AllianceBernstein L.P. |
0.72% |
^ |
31.46% |
9.91% |
8.07% |
||||||||||||
| Equity | EQ/Invesco Comstock — EIMG; Invesco Advisers, Inc. |
1.00% |
^ |
16.93% |
14.99% |
11.71% |
||||||||||||
| Equity | EQ/Invesco Global — EIMG; Invesco Advisers, Inc. |
1.10% |
^ |
15.40% |
6.95% |
10.59% |
||||||||||||
| Specialty | EQ/Invesco Global Real Assets — EIMG; Invesco Advisers, Inc. |
1.16% |
15.93% |
7.11% |
— |
|||||||||||||
| Equity | EQ/Janus Enterprise — EIMG; Janus Henderson Investors US LLC |
1.04% |
8.05% |
7.06% |
10.61% |
|||||||||||||
| Asset Allocation | EQ/JPMorgan Growth Allocation Δ — EIMG ; J.P. Morgan Investment Management Inc. |
1.15% |
^ |
10.81% |
6.54% |
— |
||||||||||||
| Equity | EQ/JPMorgan Growth Stock — EIMG; J.P. Morgan Investment Management Inc. |
0.96% |
^ |
14.76% |
9.43% |
14.08% |
||||||||||||
| Asset Allocation | EQ/JPMorgan Hedged Equity and Premium Income ∞ Δ — EIMG |
1.15% |
^ |
12.41% |
4.65% |
— |
||||||||||||
| Equity | EQ/JPMorgan Value Opportunities — EIMG; J.P. Morgan Investment Management Inc. |
0.95% |
15.40% |
12.77% |
12.08% |
|||||||||||||
| Equity | EQ/Large Cap Growth Index — EIMG; AllianceBernstein L.P. |
0.71% |
17.74% |
14.51% |
17.26% |
|||||||||||||
| Equity | EQ/Large Cap Value Index — EIMG; AllianceBernstein L.P. |
0.74% |
15.04% |
10.52% |
9.77% |
|||||||||||||
| Equity | EQ/Lazard Emerging Markets Equity — EIMG; Lazard Asset Management LLC |
1.35% |
^ |
42.06% |
10.84% |
— |
||||||||||||
| Fixed Income | EQ/Long-Term Bond — EIMG; AllianceBernstein L.P. |
0.64% |
^ |
5.85% |
— |
— |
||||||||||||
| Equity | EQ/Loomis Sayles Growth — EIMG; Loomis, Sayles & Company, L.P. |
1.03% |
^ |
13.08% |
12.72% |
15.87% |
||||||||||||
| Equity | EQ/MFS International Growth — EIMG; Massachusetts Financial Services Company d/b/a MFS Investment Management |
1.10% |
^ |
20.90% |
6.90% |
9.61% |
||||||||||||
| Equity | EQ/MFS International Intrinsic Value — EIMG; Massachusetts Financial Services Company d/b/a MFS Investment Management |
1.15% |
^ |
32.95% |
6.99% |
— |
||||||||||||
| Specialty | EQ/MFS Technology — EIMG; Massachusetts Financial Services Company d/b/a MFS Investment Management |
1.10% |
16.24% |
12.06% |
— |
|||||||||||||
| Specialty | EQ/MFS Utilities Series — EIMG; Massachusetts Financial Services Company d/b/a MFS Investment Management |
1.05% |
^ |
14.65% |
7.33% |
— |
||||||||||||
| Equity | EQ/Mid Cap Index — EIMG; AllianceBernstein L.P. |
0.64% |
^ |
6.80% |
8.42% |
9.99% |
||||||||||||
| Asset Allocation | EQ/Moderate Allocation† — EIMG | 1.08% |
10.25% |
4.14% |
5.78% |
|||||||||||||
| Asset Allocation | EQ/Moderate-Plus Allocation† — EIMG | 1.11% |
11.50% |
5.88% |
7.67% |
|||||||||||||
| Cash/Cash Equivalent | EQ/Money Market* — EIMG; Dreyfus, a division of Mellon Investments Corporation |
0.67% |
3.66% |
2.79% |
1.73% |
|||||||||||||
| Fixed Income | EQ/PIMCO Global Real Return — EIMG; Pacific Investment Management Company LLC |
2.74% |
^ |
5.52% |
-0.90% |
2.48% |
||||||||||||
| Fixed Income | EQ/PIMCO Total Return ESG — EIMG; Pacific Investment Management Company LLC |
0.75% |
^ |
8.70% |
-0.14% |
— |
||||||||||||
| Fixed Income | EQ/PIMCO Ultra Short Bond — EIMG; Pacific Investment Management Company LLC |
0.80% |
^ |
4.47% |
2.93% |
2.32% |
||||||||||||
| Equity | EQ/Small Company Index — EIMG; AllianceBernstein L.P. |
0.63% |
12.57% |
6.16% |
9.44% |
|||||||||||||
| Specialty | EQ/T. Rowe Price Health Sciences — EIMG; T. Rowe Price Associates, Inc. |
1.20% |
^ |
19.21% |
3.62% |
— |
||||||||||||
| Equity | EQ/Value Equity — EIMG; Aristotle Capital Management, LLC |
0.91% |
11.01% |
8.65% |
8.47% |
|||||||||||||
| Specialty | EQ/Wellington Energy — EIMG; Wellington Management Company LLP |
1.19% |
^ |
12.17% |
17.90% |
— |
||||||||||||
TYPE |
Portfolio Company — Investment Adviser; Sub-Adviser(s), as applicable |
Current Expenses |
Average Annual Total Returns (as of 12/31/2025) |
|||||||||||||||
1 year |
5 year |
10 year |
||||||||||||||||
| Asset Allocation | Equitable Conservative Growth MF/ETF Portfolio — EIMG | 1.10% |
^ |
12.03% |
4.95% |
6.85% |
||||||||||||
| Asset Allocation | Equitable Growth MF/ETF — EIMG | 1.15% |
^ |
14.37% |
— |
— |
||||||||||||
| Asset Allocation | Equitable Moderate Growth MF/ETF — EIMG | 1.10% |
^ |
13.43% |
— |
— |
||||||||||||
| Specialty | Multimanager Technology — EIMG; AllianceBernstein L.P., FIAM LLC, Wellington Management Company LLP |
1.23% |
^ |
25.87% |
12.46% |
19.41% |
||||||||||||
^ |
This Portfolio’s annual expenses reflect temporary fee reductions. |
Δ |
Certain other affiliated Portfolios, as well as unaffiliated Portfolios, may utilize volatility management techniques (including Fund of Fund Portfolios that invest in other Portfolios that utilize volatility management techniques) that differ from the EQ volatility management strategy. Affiliated Portfolios that utilize these volatility management techniques are identified in the chart by a “∆”. Any such unaffiliated Portfolio is not identified in the chart. See “Portfolios of the Trusts” for more information regarding volatility management. |
† |
EQ Managed Volatility Portfolios that include the EQ volatility management strategy as part of their investment objective and/or principal investment strategy, and the EQ/affiliated Fund of Fund Portfolios that invest in Portfolios that use the EQ volatility management strategy, are identified in the chart by a “†“. See “Portfolios of the Trusts” for more information regarding volatility management. |
* |
The Portfolio operates as a “government money market fund.” The Portfolio will invest at least 99.5% of its total assets in U.S. government securities, cash, and/or repurchase agreements that are fully collateralized by U.S. government securities or cash. |
∞ |
“ J.P. Morgan” and “JPMorgan” are registered trademarks of J.P. Morgan Chase Bank, NA (“JPMC”) and have been licensed for use by Equitable Investment Management Group, LLC. EQ/JPMorgan Hedged Equity and Premium Income Portfolio is not sponsored, endorsed, or promoted by JPMC and JPMC makes no representation regarding the advisability of investing in EQ/JPMorgan Hedged Equity and Premium Income Portfolio. |
(1) |
Effective on or about June 29, 2026, and subject to shareholder approval, SSGA Funds Management, Inc. will be replaced as a sub-adviser to the Portfolio (or an allocated portion thereof) with AllianceBernstein L.P. |
(2) |
This investment option is only available if you purchased your contract before approximately November 13, 2023. |
Unaffiliated Portfolio Companies:
TYPE |
Portfolio Company — Investment Adviser; Sub-Adviser(s), as applicable |
Current Expenses |
Average Annual Total Returns (as of 12/31/2025) |
|||||||||||||||
1 year |
5 year |
10 year |
||||||||||||||||
| Equity | AB VPS Discovery Value Portfolio — AllianceBernstein L.P. | 1.07% |
2.64% |
8.48% |
8.27% |
|||||||||||||
| Asset Allocation | American Funds Insurance Series ® Asset Allocation Fund — Capital Research and Management Company |
0.79% |
15.59% |
8.70% |
9.50% |
|||||||||||||
| Equity | American Funds Insurance Series ® Global Growth Fund — Capital Research and Management Company |
0.90% |
^ |
21.34% |
7.97% |
11.89% |
||||||||||||
| Equity | American Funds Insurance Series ® Global Small Capitalization Fund — Capital Research and Management Company |
1.15% |
^ |
14.33% |
0.23% |
6.96% |
||||||||||||
| Equity | American Funds Insurance Series ® New World Fund ® — Capital Research and Management Company |
1.07% |
^ |
27.93% |
5.06% |
8.98% |
||||||||||||
| Asset Allocation | BlackRock Global Allocation V.I. Fund — BlackRock Advisors, LLC; BlackRock International Limited, BlackRock (Singapore) Limited |
1.01% |
^ |
19.51% |
5.51% |
7.33% |
||||||||||||
| Specialty | Eaton Vance VT Floating-Rate Income Fund — Eaton Vance Management | 1.19% |
3.94% |
4.64% |
4.43% |
|||||||||||||
| Equity | Fidelity ® VIP Mid Cap Portfolio — Fidelity Management and Research Company (FMR) |
0.80% |
11.49% |
9.83% |
10.31% |
|||||||||||||
| Fixed Income | Fidelity ® VIP Strategic Income Portfolio — Fidelity Management and Research Company (FMR) |
0.88% |
8.58% |
2.79% |
4.40% |
|||||||||||||
| Asset Allocation | Franklin Allocation VIP Fund (1) — Franklin Advisers, Inc. |
0.82% |
^ |
12.60% |
5.73% |
7.32% |
||||||||||||
| Asset Allocation | Franklin Income VIP Fund — Franklin Advisers, Inc. | 0.72% |
12.56% |
7.66% |
7.30% |
|||||||||||||
| Asset Allocation | Invesco V.I. Balanced-Risk Allocation Fund — Invesco Advisers, Inc. | 1.13% |
^ |
8.69% |
2.27% |
4.91% |
||||||||||||
| Specialty | Invesco V.I. Health Care Fund — Invesco Advisers, Inc. | 1.24% |
15.08% |
3.54% |
6.31% |
|||||||||||||
| Asset Allocation | Janus Henderson Balanced Portfolio — Janus Henderson Investors US LLC | 0.87% |
14.82% |
8.21% |
9.86% |
|||||||||||||
| Fixed Income | Janus Henderson Flexible Bond Portfolio — Janus Henderson Investors US LLC | 0.82% |
^ |
7.22% |
-0.47% |
2.07% |
||||||||||||
| Fixed Income | Lord Abbett Bond Debenture Portfolio (VC) — Lord, Abbett & Co. LLC | 0.98% |
8.33% |
2.10% |
4.72% |
|||||||||||||
| Specialty | PIMCO CommodityRealReturn ® Strategy Portfolio — Pacific Investment Management Company LLC |
3.29% |
^ |
18.85% |
10.44% |
6.42% |
||||||||||||
| Specialty | PIMCO Emerging Markets Bond Portfolio — Pacific Investment Management Company LLC | 1.27% |
14.86% |
2.34% |
4.96% |
|||||||||||||
TYPE |
Portfolio Company — Investment Adviser; Sub-Adviser(s), as applicable |
Current Expenses |
Average Annual Total Returns (as of 12/31/2025) |
|||||||||||||||
1 year |
5 year |
10 year |
||||||||||||||||
| Fixed Income | PIMCO Global Bond Opportunities Portfolio (Unhedged) — Pacific Investment Management Company LLC | 1.15% |
12.87% |
0.14% |
2.46% |
|||||||||||||
| Asset Allocation | PIMCO Global Managed Asset Allocation Portfolio — Pacific Investment Management Company LLC | 1.31% |
^ |
21.77% |
6.94% |
7.88% |
||||||||||||
| Fixed Income | PIMCO Income Portfolio — Pacific Investment Management Company LLC | 1.02% |
10.08% |
3.31% |
— |
|||||||||||||
| Equity | Putnam VT U.S. Research Fund — Putnam Investment Management, LLC; Franklin Advisers, Inc., Franklin Templeton Investment Management Limited, The Putnam Advisory Company, LLC |
0.93% |
17.88% |
14.52% |
15.07% |
|||||||||||||
| Equity | T. Rowe Price Equity Income Portfolio - II — T. Rowe Price Associates, Inc. | 0.99% |
14.07% |
10.89% |
10.24% |
|||||||||||||
| Fixed Income | Templeton Global Bond VIP Fund — Franklin Advisers, Inc. | 0.75% |
^ |
15.73% |
-0.96% |
-0.15% |
||||||||||||
^ |
This Portfolio’s annual expenses reflect temporary fee reductions. |
(1) |
This investment option is only available if you purchased your contract before approximately November 13, 2023. |
Index-Linked Options
The following is a list of Segments of the SIO currently available under the contract. We may change the features of the Segments listed below (including the Index and the current limits on Index gains and losses), offer new Segments, and terminate existing Segments. We will provide you with written notice before making any changes other than changes to current limits on Index gains. Information about current limits on index gains is available at www.equitable.com/ie21-rates-prospectus. See “Structured Investment Option” in “Purchasing the contract” for additional information about the Indices, the Segment Rate of Return calculation methods, and the operation of the Segment Buffer and Performance Cap Rate.
Note: If amounts are removed from a Segment before the Segment Maturity Date, we will apply a Segment Interim Value adjustment. This may result in a significant reduction in your account value that could exceed any protection from Index loss that would be in place if you held the option until the Segment Maturity Date. See “Adjustments with respect to early distributions from Segments” in “Charges, expenses, and adjustments” for more information about Segment Interim Value.
Index |
Type of Index |
Segment Duration |
Segment Rate of Return Calculation Method |
Current Limit on Index Loss if held until Segment Maturity Date (Segment Buffer) |
Minimum Limit on Index Gain for the life of the Segment (Performance Cap Rate) | |||||
S&P 500 Price Return Index* |
Market Index | 5 year 1 year |
Standard | -10%; -15%; -20% -10%; -15%; -20%; -40% |
10% 2% | |||||
Russell 2000 ® |
Market Index | 5 year 1 year |
Standard | -10%; -15%; -20% -10%; -15%; -20%; -40% |
10% 2% | |||||
MSCI EAFE Price Return Index* |
Market Index | 5 year 1 year |
Standard | -10%; -15%; -20% -10%; -15%; -20%; -40% |
10% 2% | |||||
NASDAQ-100 Price Return Index* |
Market Index | 5 year 1 year |
Standard | -10%; -15%; -20% -10%; -15%; -20%; -40% |
10% 2% | |||||
MSCI Emerging Markets Price Return Index* |
Market Index | 1 year | Standard | -10%; -15%; -20%; -40% |
2% | |||||
S&P 500 Price Return Index* |
Market Index | 5 year 1 year |
Step Up | -10% -10%; -15% |
10% 2% | |||||
Russell 2000 ® |
Market Index | 5 year 1 year |
Step Up | -10% -10%; -15% |
10% 2% | |||||
MSCI EAFE Price Return Index* |
Market Index | 5 year 1 year |
Step Up | -10% -10%; -15% |
10% 2% | |||||
NASDAQ-100 Price Return Index* |
Market Index | 5 year 1 year |
Step Up | -10% -10%; -15% |
10% 2% | |||||
S&P 500 Price Return Index* |
Market Index | 5 year 1 year |
Dual Direction | -10%; -15%; -20% -10%; -15%; -20% |
10% 2% | |||||
Russell 2000 ® |
Market Index | 5 year 1 year |
Dual Direction | -10%; -15%; -20% -10%; -15%; -20% |
10% 2% | |||||
MSCI EAFE Price Return Index* |
Market Index | 5 year 1 year |
Dual Direction | -10%; -15%; -20% -10%; -15%; -20% |
10% 2% | |||||
NASDAQ-100 Price Return Index* |
Market Index | 5 year 1 year |
Dual Direction | -10%; -15%; -20% -10%; -15%; -20% |
10% 2% | |||||
S&P 500 Price Return Index* |
Market Index | 1 year | Dual Step Up | -10%; -15%; -20% |
2% | |||||
Russell 2000 ® |
Market Index | 1 year | Dual Step Up | -10%; -15%; -20% |
2% | |||||
MSCI EAFE Price Return Index* |
Market Index | 1 year | Dual Step Up | -10%; -15%; -20% |
2% | |||||
NASDAQ-100 Price Return Index* |
Market Index | 1 year | Dual Step Up | -10%; -15%; -20% |
2% | |||||
S&P 500 Price Return Index* |
Market Index | 5 year 1 year |
Growth Multiplier | 0% 0% |
Not applicable 1 |
| * | The Index is a “price return” index, not a “total return” index, and therefore the performance of the Index does not reflect dividends declared by any of the companies included in the Index, reducing the Index return. As a result, the Index will underperform a direct investment in the securities composing the Index. |
1 |
Minimum multiplier rate is 105% |
We may change the Indices and/or Segment Options, but we will always offer a Segment Option with a Segment Buffer that protects the first 10% of loss. Our minimum Performance Cap Rate for 5 year Segment Types is 10% (2% for 1 year Segments). We will not open a Segment with a Performance Cap Rate (if applicable) below the applicable minimum rate.
*Seung Hee (“Stella”) Lee |
Assistant Secretary | |
*Christine Medy |
Assistant Secretary | |
* Principal Business Address: |
||
1345 Avenue of the Americas |
||
NY, NY 10105 |
||
(c) |
||
Name of Principal Underwriter |
Net Underwriting Discounts |
Compensation onRedemption |
Brokerage Commission |
Other Compensation | ||||
Equitable Advisors, LLC |
N/A | $0 | $0 | $0 | ||||
Equitable Distributors, LLC |
N/A | $0 | $0 | $0 |
ITEM 31A. INFORMATION ABOUT CONTRACTS WITH INDEX-LINKED
OPTIONS
AND FIXED OPTIONS SUBJECT TO A CONTRACT A
DJUSTMENT (a)
Name of the Contract |
Number of Contracts Outstanding |
Total value attributable to the Index- Linked Option and/or Fixed Option subject to a Contract Adjustment |
Number of Contracts sold during the prior calendar year |
Gross premiums received during the prior calendar year |
Amount of Contract value redeemed during the prior calendar year |
Combination Contract (Yes/No) | ||||||
Investment Edge ® 21.0 |
20,978 | $3,410,304,263 | 7,598 | $1,656,865,541 | $160,957,778 | Yes |
(b) See exhibit (27)(r) - Historical Current Limits on Index Gains
SSGA Funds Management, Inc.
DoubleLine Capital LP
Barrow, Hanley, Mewhinney & Strauss, LLC d/b/a Barrow Hanley Global Investors
GAMCO Asset Management, Inc.
GAMCO Asset Management, Inc.
AXA Investment Managers US Inc., Post Advisory Group, LLC
BlackRock Investment Management, LLC, Lord, Abbett & Co. LLC
AllianceBernstein L.P.
AllianceBernstein L.P.
BlackRock Investment Management, LLC, Horizon Kinetics Asset Management LLC
AXA Investment Managers US Inc.
BlackRock Investment Management, LLC
AllianceBernstein L.P., BlackRock Investment Management, LLC
EQ/AB Dynamic Moderate Growth
EIMG
AllianceBernstein L.P.
AllianceBernstein L.P.
AllianceBernstein L.P.
American Century Investment Management, Inc.
EQ/American Century Moderate Growth Allocation
EIMG
American Century Investment Management, Inc.
ClearBridge Investments, LLC
BlackRock Investment Management, LLC, ClearBridge Investments, LLC
AllianceBernstein L.P.
EQ/Conservative Growth Strategy
EIMG
EQ/Core Bond Index
EIMG
SSGA Funds Management, Inc.
Brandywine Global Investment Management, LLC, Loomis, Sayles & Company, L.P.
AllianceBernstein L.P., EARNEST Partners, LLC
AllianceBernstein L.P.
EQ/Fidelity Institutional AM
®
Large Cap
EIMG
FIAM LLC
Franklin Advisers, Inc.
EQ/Goldman Sachs Growth Allocation
EIMG
Goldman Sachs Asset Management L.P.
Goldman Sachs Asset Management L.P.
EQ/Goldman Sachs Moderate Growth Allocation
EIMG
Goldman Sachs Asset Management L.P.
AllianceBernstein L.P.
EQ/Intermediate Government Bond
EIMG
SSGA Funds Management, Inc.
AllianceBernstein L.P.
Invesco Advisers, Inc.
Invesco Advisers, Inc.
Invesco Advisers, Inc.
Janus Henderson Investors US LLC
EQ/JPMorgan Growth Allocation
EIMG
J.P. Morgan Investment Management Inc.
J.P. Morgan Investment Management Inc.
EQ/JPMorgan Hedged Equity and Premium Income
∞
EIMG
J.P. Morgan Investment Management Inc.
AllianceBernstein L.P.
AllianceBernstein L.P.
Lazard Asset Management LLC
AllianceBernstein L.P.
Loomis, Sayles & Company, L.P.
Massachusetts Financial Services Company d/b/a MFS Investment Management
Massachusetts Financial Services Company d/b/a MFS Investment Management
Massachusetts Financial Services Company d/b/a MFS Investment Management
Massachusetts Financial Services Company d/b/a MFS Investment Management
AllianceBernstein L.P.
Dreyfus, a division of Mellon Investments Corporation
Pacific Investment Management Company LLC
Pacific Investment Management Company LLC
Pacific Investment Management Company LLC
AllianceBernstein L.P.
T. Rowe Price Associates, Inc.
Aristotle Capital Management, LLC
Wellington Management Company LLP
AllianceBernstein L.P., FIAM LLC, Wellington Management Company LLP
American Funds Insurance Series
®
Asset Allocation Fund
Capital Research and Management Company
American Funds Insurance Series
®
Global Growth Fund
Capital Research and Management Company
American Funds Insurance Series
®
Global Small Capitalization Fund
Capital Research and Management Company
American Funds Insurance Series
®
New World Fund
®
Capital Research and Management Company
BlackRock International Limited, BlackRock (Singapore) Limited
Fidelity
®
VIP Mid Cap Portfolio
Fidelity Management and Research Company (FMR)
Fidelity
®
VIP Strategic Income Portfolio
Fidelity Management and Research Company (FMR)
Franklin Allocation VIP Fund
Franklin Advisers, Inc.
PIMCO CommodityRealReturn
®
Strategy Portfolio
Pacific Investment Management Company LLC
Franklin Advisers, Inc., Franklin Templeton Investment Management Limited, The Putnam Advisory Company, LLC
•
Available only at contract purchase
•
Available only to contract holder age 75 or younger
•
Withdrawals, including the withdrawal of advisory fees, could significantly reduce or terminate the benefit
•
Generally no contributions once reach age 76
•
If elected, you will not get the Standard Death Benefit
•
Not available with Return of Premium Death Benefit
•
NQ contracts only
•
Age and account value requirements may apply
•
Adverse tax consequences if surrender contract after payments start
•
Withdrawals, including payment of advisor fees, could significantly reduce or terminate the benefit
Yes.
The return on the Segments of the SIO may be negative and there is a risk of substantial loss of your principal and previously credited interest due to negative index performance because you agree to absorb all losses to the extent they exceed the Segment Buffer.
You could lose as much as 60% (for Segments with a -
40
% Segment Buffer) to 90% (for Segments with a -10% Segment Buffer) to 100% (for Growth Multiplier Segments with a 0
% Segment Buffer) of your principal and previously credited interest due to negative index performance on the Segment Maturity Date. We may change the Indices and/or Segment Options in the future, but we will always offer a Segment Option with a Segment Buffer that protects the first 10% of loss.For additional information about the risk of loss see “Principal risks of investing in the contract” in the Prospectus.
Risk of loss
All investments have risks to some degree and it is possible that you could lose money by investing in the contract. An investment in the contract is not a deposit with a bank and is not insured or guaranteed by the Federal Deposit Insurance Corporation or any other government agency.
No.
Contract value in a Segment will be reallocated at Segment Maturity according to your instructions. If you have not provided us with maturity instructions for a maturing Segment, the Segment Maturity Value will be transferred to the Segment Type Holding Account for the same Segment Type as the maturing Segment. Your Segment Maturity Value would then be transferred from that Segment Type
Holding Account into the next Segment of that Segment Type on the Segment Start Date. If the
next Segment to be created would not meet the Segment Maturity Date Requirement or the Segment Type has been terminated, we will instead transfer your Segment Maturity Value to the EQ/Money Market variable investment option. If you are impacted by these delays, you may transfer your Segment Maturity Value into another Segment Type Holding Account or into any other investment options available under your contract at any time before the next month’s Segment Start Date. For additional information about the investment profile of the contract see “Fee Table” in the Prospectus.
Not a short-term investment
The contract is not a short-term investment and is not appropriate for an investor who needs ready access to cash because the contract is designed to provide for the accumulation of retirement savings and income on a long-term basis. As such, you should not use the contract as a short-term investment or savings vehicle and you should consider whether investing in the contract is consistent with the purpose for which the investment is being considered.
An investment in the contract is subject to the risk of poor investment performance and can vary depending on the performance of the variable investment options (e.g., the Portfolios) and the SIO (e.g., the reference Indices). Each investment option available under the contract has its own unique risks. You should review the Portfolios and the Segments of the SIO available under the contract before making an investment decision.
The Performance Cap Rate of a Segment may limit your participation in positive returns on the Segment Maturity Date. For example, if the Index return is 12% and the Performance Cap Rate is 4%, we will credit 4% in interest on the Segment Maturity Date, assuming there are no fees or charges assessed, meaning your Segment Investment will increase by 4%.
The Performance Cap Rate may cause your returns under the Segment to be lower than the Index’s returns.
The Segment Buffer of a Segment provides some protection against negative returns on the Segment Maturity Date. The Segment Buffer is the maximum amount of negative interest we will assume and we will credit any negative interest in excess of the Segment Buffer, which means you bear all loss that exceeds the Segment Buffer. For example, if the Index return is
-25%
and the Segment Buffer is -10%,
we will credit -15%
(the amount that exceeds the Segment Buffer) on the Segment Maturity Date, assuming there are no fees or charges assessed, meaning your Segment Investment will decrease by 15%.All of the Indices we currently offer are “price return” indices, not “total return” indices, and therefore the performance of any Index does not reflect dividends paid on the securities included in the Index. This reduces the Index return, and the Index will underperform a direct investment in the securities composing the Index.
For additional information about the risks associated with investment options see ”Structured Investment Option”, “Variable investment options” and “Portfolios of the Trusts” in “Purchasing the contract”, as well as, “Principal risks of investing in the contract” and Appendix “Investment Options available under the contract” in the Prospectus.
An investment in the contract is subject to the risks related to the Company. The Company is solely responsible to the contract owner for the contract’s account value. The general obligations, including the SIO and the death benefits, under the contract are supported by our general account and are subject to our claims-paying ability. An owner should look solely to our financial strength for our claims-paying ability. More information about the Company, including our financial strength ratings, may be obtained at https://equitable.com/about-us/financial-strength-ratings.
For additional information about insurance company risks see “About the general account” in “More information” in the Prospectus.
Insurance Company Risk
No company other than us has any legal responsibility to pay amounts that we owe under the contract including amounts allocated to the Structured Investment Option. The general obligations and any guaranteed benefits under the contract are supported by our general account and are subject to our claims-paying ability. You should look solely to our financial strength for our claims-paying ability.
Contract Changes Risk
| • | We reserve the right to stop accepting any application or contribution from you at any time, including after you purchase the contract. We reserve the right to discontinue the acceptance of, and/or place additional |
limitations on, contributions into certain investment options, including any of the Segments of the SIO. If we exercise this right, your ability to invest in your contract, increase your account value and, consequently, increase your death benefit will be limited. |
• |
We may, at any time, exercise our rights to limit or terminate your contributions, allocations and transfers to any of the investment options and to limit the number of investment options which you may select. Such rights include, among others, removing or substituting the Portfolios, combining any two or more investment options and transferring account value from any investment option to another investment option. |
• |
We reserve the right to offer any or all Segments more or less frequently or to stop offering any of them (except we will always offer a Segment Option with a Segment Buffer that protects the first 10% of loss) or to suspend offering any or all of them temporarily for some or all contracts. If we stop offering these options, you will be limited to investing in only one Segment Option and in the variable investment options, which are not tied to the performance of an index. |
| • | We may offer new Segment Types in the future, and we may change the features of a Segment Type between Segments, including the Index, the Segment Buffer, and the Performance Cap Rate (subject to the minimum rates disclosed herein). |
Variable Investment Options
| • | The value of your variable investment options will fluctuate and you could lose some or all of your account value. |
• |
The level of risk you bear and your potential investment performance will differ depending on the investments you choose. |
Structured Investment Option
An investor is not invested in the Index or in the securities tracked by the Index.
Limiting Negative Returns (Segment Risk of Loss)
| • | There is a risk of a substantial loss of your principal and previously credited interest despite limits on negative index returns because you agree to absorb all losses from the portion of any negative Index Performance Rate that exceeds the Segment Buffer on the Segment Maturity Date. Some Segments have a 0% Segment Buffer which provides no protection and, therefore, you could lose as much as 100% of your principal and previously credited interest due to negative index performance on the Segment Maturity Date in those Segments. The highest level of protection provided by a single Segment Investment Option is the -40% Segment Buffer (only available on certain Segments) and the lowest level of protection is the -10% Segment Buffer. You could lose as much as 60% (for Segments with a -40% Segment Buffer) to 90% (for Segments with a -10% Segment Buffer) of your principal and previously credited interest due to negative index performance on the Segment Maturity Date. |
We may change the Indices and/or Segment Options in the future, but we will always offer a Segment Option with a Segment Buffer that protects the first 10% of loss.
| — | For example, the -10% Segment Buffer protects your Segment Investment against the first 10% of loss. If the Index Performance Rate declines by more than the Segment Buffer, you will lose an amount equal to 1% of your Segment Investment for every 1% that the Index Performance Rate declines below the Segment Buffer. This means that you could lose up to 60% of your principal and previously credited interest with a -40% Segment Buffer, up to 80% of your principal and previously credited interest with a -20% Segment Buffer, up to 85% of your principal and previously credited interest with a -15% Segment Buffer, up to 90% of your principal and previously credited interest with a -10% Segment Buffer, and up to 100% of your principal and previously |
| credited interest with a 0% Segment Buffer. Each time you roll over your Segment Maturity Value into a new Segment you are subject to the same risk of loss as described above. |
Limiting Positive Returns (Performance Cap Rates)
| • | The Performance Cap Rate is a rate of return from the Segment Start Date to the Segment Maturity Date, and not an annual rate of return, even if the Segment Duration is longer than one year. |
| • | Your Segment Rate of Return for any Segment with a positive Index Performance Rate is limited by its Performance Cap Rate, if applicable, which could cause your Segment Rate of Return to be lower than it would otherwise be if you invested in a mutual fund designed to track the performance of the applicable Index. |
| • | The Performance Cap Rate, if applicable, may limit your participation in any increases in the underlying Index associated with a Segment. |
| • | Each contract series may have different Performance Cap Rates. |
| • | The Performance Cap Rate for the same Segment may vary between owners but will not be less than the minimum Performance Cap Rate. |
| • | If you elect a Cap Rate Hold, the Performance Cap Rates applicable to your Segments may be lower or higher than the Performance Cap Rates otherwise applicable for the same Segments on that Segment Start Date. This means you would receive lower Performance Cap Rates for your Segments than an owner investing in those same Segments who did not elect a Cap Rate Hold. See “Structured Investment Option — Segment Performance Cap Rate Hold” in “Purchasing the contract” for more information. |
| • | Other Segments will generally have lower Performance Cap Rates than Standard Segments with the same Index, Segment Duration and Segment Buffer. |
| • | Segment Types with greater protection tend to have lower Performance Cap Rates than other similar Segment Types that use the same Index and duration but provide less protection. |
Risks Related to Withdrawals (Segment Interim Value)
• |
There is a risk of loss of principal and previously credited interest in (1) taking a withdrawal (including a systematic withdrawal and/or required minimum distribution); (2) transferring account value to a different investment option; (3) deducting account value to pay fees, including advisory fees; (4) surrendering or annuitizing your contract; (5) payment of a death claim; and (6) canceling your contract and returning it to us for a refund within your state’s |
“free look” period prior to a Segment Maturity Date due to charges and Segment Interim Value adjustments imposed on those distributions, and this may occur even if index performance has been positive. |
| • | The method we use in calculating your Segment Interim Value may result in an amount lower than your Segment Investment, even if the corresponding Index has experienced positive investment performance since the Segment Start Date. Also, this amount may be less than the amount you would receive had you held the investment until the Segment Maturity Date. Because the end-of-term downside protection provided by a Segment Buffer does not apply to the Segment Interim Value, it is theoretically possible that you could lose up to 100% of your investment and previously credited interest in certain extreme scenarios even for Segments with a Segment Buffer. ® contract, or if you have to pay taxes or tax penalties. See “Withdrawals and surrenders” below. |
| — | If you take a withdrawal, including required minimum distributions, and there is insufficient value in the variable investment options, the Segment Type Holding Accounts and the dollar cost averaging account, we will withdraw amounts from any active Segments in your contract. Amounts withdrawn from active Segments will be valued using the formula for calculating the Segment Interim Value and will reduce your Segment Investment. |
| — | If you die, annuitize, cancel or surrender your contract before the Segment Maturity Date, we will pay the Segment Interim Value. |
| — | Any calculation of the Segment Interim Value will generally be affected by changes in both the volatility and level of the relevant Index, as well as interest rates. The calculation of the Segment Interim Value is linked to various factors, including the value of hypothetical fixed instruments and derivatives as described in “Adjustments with respect to early distributions from Segments” in “Charges, expenses, and adjustments” in this Prospectus. The Segment Interim Value will generally be negatively affected by increases in the expected volatility of index prices, interest rate increases, and by poor market performance. Prior to the Segment Maturity Date, for all contracts using a Performance Cap Rate limiting factor, you will not receive the full potential of the Performance Cap since the participation in upside performance for early withdrawals is pro-rated based on the period those amounts were invested in a Segment. Generally, you will not receive the full protection of the Segment Buffer prior to the Segment Maturity Date because the Segment Interim Value only reflects a portion of the downside protection expected to be provided on the Segment Maturity Date. As a Segment moves closer to the Segment Maturity Date, the Segment Interim Value would generally reflect higher realized gains of the Index |
| performance or, in the case of negative performance, increased downside Segment Buffer protection. All other factors being equal, the Segment Interim Value would generally be lower the earlier a withdrawal or surrender is made during a Segment. This means you participate to a lesser extent in upside performance and downside protection the earlier you take a withdrawal. |
| — | The Company’s decision to use investment rates, which are generally higher than swap rates, to calculate the Fair Value of Hypothetical Fixed Instruments component of the Segment Interim Value will result in a lower value for that component relative to using swap rates to calculate that component and, all other things being equal, will result in a lower recalculated Segment Investment if a partial withdrawal is taken from a Segment or a lower withdrawal amount if a full withdrawal is taken from a Segment. |
Risks Related to Segments, Segment Returns, and Segment Type Holding Accounts
| • | We may, in our sole discretion, not offer certain Segments on one or more Segment Start Dates. |
• |
We may not offer new Segments of any Segment Type, so certain Segments may not be available for you to transfer your Segment Maturity Value into. |
| • | On the Segment Maturity Date, the value of your maturing Segments will be reallocated according to your instructions on file, assuming that all participation requirements for those allocations are met. If you have not provided us with maturity instructions for a maturing Segment, then by default the Segment Maturity Value will be transferred to the same Segment Type as the maturing Segment. Our current Performance Cap Rates will apply to the new Segment, which may be lower than the Performance Cap Rate of the maturing Segment. If you decide to remove the amounts that were transferred to the new Segment before the new Segment’s Segment Maturity Date, the transaction will trigger the Segment Interim Value and may be subject to withdrawal charges, taxes and tax penalties. |
| • | If the next Segment to be created in the Segment Type would have a Segment Maturity Date that is later than your contract maturity date or if that Segment Type has been terminated, we will instead transfer your Segment Maturity Value to the EQ/Money Market variable investment option. The amounts transferred to the EQ/Money Market variable investment option may earn a return that is less than the return that could be earned in a different investment option. |
| • | The amounts held in a Segment Type Holding Account may earn a return that is less than the return you might have earned if those amounts were held in another investment option. |
| • | For Growth Multiplier Segments, there is a risk of substantial loss of your principal because you agree to |
absorb all losses from any negative Index Performance Rate. This means that you could lose up to 100% of your principal and previously credited interest. Each time you roll over your Segment Maturity Value into a new Growth Multiplier Segment you are subject to the same risk of loss. Unlike other Segments, Growth Multiplier Segments do not have any protection against negative index performance because the Segment Buffer is zero. |
| • | Growth Multiplier Segments will have uncapped performance, but your Segment Rate of Return will be lower than the performance of the securities comprising the index because the index does not include in its return calculation dividends paid on the securities. |
| • | The Multiplier Rate for Growth Multiplier Segments can fluctuate on Segment Start Dates. |
| • | Because of the way Segment Rate of Return is calculated for Step Up Segments, when the Index Performance Rate is near zero, a very small difference in the Index of Performance Rate on the Segment Maturity Date can result in a very different Segment Rate of Return. For example, if the Performance Cap Rate is 8.00% and the Index Performance Rate is 0.00% on the Segment Maturity Date, the Segment Rate of Return would be 8.00%. However, if the Index Performance Rate had instead been -0.01% on the Segment Maturity Date the Segment Rate of Return would be 0.00%. |
| • | Because of the way Segment Rate of Return is calculated for Dual Direction Segments: |
| — | When the Index Performance Rate is near the Segment Buffer, a very small difference in the Index Performance Rate on the Segment Maturity Date can result in a very different Segment Rate of Return. For example, for a Dual Direction Segment with a -15% Segment Buffer, if the Index Performance Rate is -15.00% on the Segment Maturity Date the Segment Rate of Return is 15.00%, the absolute value of the negative performance, whereas, if the Index Performance Rate is -15.01% on the Segment Maturity Date the Segment Rate of Return is -0.01%. |
| — | The Segment Rate of Return may be greater for negative Index Performance Rates than for the corresponding positive Index Performance Rates. For example, for a Dual Direction Segment with a -15% Segment Buffer, which credits the absolute value to the Segment Buffer, and a Performance Cap Rate of 10%, if the Index Performance Rate is -14% on the Segment Maturity Date the Segment Rate of Return is 14% whereas, if the Index Performance Rate is 14% on the Segment Maturity Date the Segment Rate of Return is 10%. |
| • | Because of the way Segment Rate of Return is calculated for Dual Step Up Segments, when the Index Performance Rate is near the Segment Buffer, a very small difference in the Index of Performance Rate on the Segment Maturity Date can result in a very different Segment Rate of Return. For example, for a Dual Step Up Segment with a -10% Segment Buffer, if the Index |
Performance Rate is -10.00% on the Segment Maturity Date the Segment Rate of Return is 10.00% whereas, if the Index Performance Rate is -10.01% on the Segment Maturity Date the Segment Rate of Return is -0.01%. |
| • | Your Segment Maturity Value is subject to application of the Performance Cap Rate for positive and flat Index Performance Rates and the Segment Buffer for negative Index Performance Rates. For all Segments, your Segment Maturity Value is not affected by the price of the Index on any date between the Segment Start Date and the Segment Maturity Date. |
| • | In the highly unlikely event we were forced to stop offering new Segments, contract owners would be limited to transferring or contributing to the other investment options. You could choose to surrender your contract, but you may be subject to withdrawal charges, taxes, and tax penalties, and if you purchase another retirement vehicle, it may have different features, fees, and risks than your annuity contract. If you are buying the annuity contract for the Structured Investment Option, you should speak to your financial adviser as to whether this product is suitable for you. |
Risks Related to Indices
| • | The Segments track the performance of an Index. By investing in the Structured Investment Option, you are not actually invested in an Index or any underlying securities tracked by the Index. However, the Segments are indirectly exposed to the investment risks associated with the Indices they track. Because the Indices are composed of other securities, they are subject to market risk and issuer risk. |
| • | As an investor in the Segment, you will not have voting rights or rights to receive cash dividends or other distributions or other rights that holders of the shares of the funds or holders of securities comprising the indices would have. |
| • | Price return indices only consider price changes and do not account for dividends or other distributions paid out by the underlying securities, which can significantly contribute to long-term returns. |
| • | Market Risk. |
| • | Large Cap Risk. |
| • | Small Cap Risk. |
They may also be more volatile and less liquid than more established large-capitalization companies. The Russell 2000 ® Price Return Index is comprised of small-cap companies. |
| • | Foreign Securities Risk. |
| — | Foreign markets may be less liquid, more volatile and subject to less government supervision than domestic markets. Differences between U.S. and foreign legal, political and economic systems, regulatory regimes and market practices also may impact security values. There are greater risks involved with investments linked to emerging market countries and/or their securities markets. Investments in these countries and/or markets may present market, credit, currency, liquidity, legal, political, technical and other risks different from, or greater than, the risks of investing in developed countries. For this purpose, China may be viewed as an emerging market and there may also be significant risks related to investments in China. |
| — | Indices with exposure to non-U.S. companies and securities, especially in emerging and frontier markets, also include the following risks: the potential for errors in Index data, Index computation, and/or Index construction if information on non-U.S. companies is unreliable or outdated, or if less information about the non-U.S. companies is publicly available due to differences in regulatory, accounting, auditing, and financial recordkeeping standards; the potential significance of such errors on the Index’s performance; limitations on the Company’s ability to oversee the Index provider’s due diligence process over Index data prior to its use in Index computation, construction, and/or rebalancing; and the rights and remedies associated with investments that track an Index comprised of foreign securities may be different from investments that track an Index of domestic securities. The MSCI Emerging Markets Price Return Index is exposed to emerging markets. |
| • | Past performance of an Index is not an indication of its future performance. |
| • | We have the right to substitute an alternative index prior to Segment Maturity if the publication of one or more Indices is discontinued, or if we no longer have a license agreement with the publishers of the Index, or at our sole discretion we determine that our use of such Indices should be discontinued because hedging instruments become difficult to acquire or the cost of hedging becomes excessive, or if the calculation of one |
or more of the Indices is substantially changed. The a lte rnative index may not be desirable to you. If we substitute an index for an existing Segment, we would not change the Segment Buffer or Performance Cap Rate. We would attempt to choose a substitute index that has a similar investment objective and risk profile to the replaced Index. The alternative index would be used to calculate performance from the Segment Start Date to the Segment Maturity Date. In addition, we reserve the right to use any or all reasonable methods to end any outstanding Segments that use such Indices. If a similar index cannot be found, we will end the affected Segments prematurely by applying the Segment Performance Cap Rate and Segment Buffer to the actual gains or losses on the original Index as of the date of termination which could result in a loss or less gain than if the Segment had continued to the Segment Maturity Date. |
• |
If the value for the underlying Index of a Segment is not published by the Index because of an emergency close on the Segment Maturity Date, we will not be able to calculate the Segment Maturity Value, and we will keep your account value in the Segment. Once the underlying Index publishes this value and we have calculated the Segment Maturity Value, we will allocate your Segment Maturity Value in accordance with your instructions. There is no way for us to predict how long it may take the underlying Index to publish the value. There is a risk that waiting for the value could result in a loss or less gain than if the Segment had ended on the original Segment Maturity Date. |
Withdrawals and Surrenders
| • | Withdrawals and surrenders for Investment Edge ® contracts may be subject to withdrawal charges. |
| • | Withdrawals will reduce your account value and death benefit and the amount of the reduction in the death benefit may be greater than the dollar amount of the withdrawal. |
| • | If you take a withdrawal or surrender from a Segment prior to Segment maturity you may receive less than the amount invested and less than the amount you would receive had you held the investment until Segment maturity. See “Segment Interim Value” above. |
| • | If your account value falls below the applicable minimum account size as a result of a withdrawal, the contract will terminate. |
| • | If you take a withdrawal or surrender your Investment Edge ® contract, any applicable withdrawal charge is calculated as a percentage of contributions, not account value. It is possible that the percentage of account value withdrawn could exceed the applicable withdrawal charge percentage. For example, assume you make a onetime contribution of $1,000 at contract issue. If your account value is $800 in contract year 3 and you surrender your contract, a withdrawal charge percentage |
of 5% is applied. The withdrawal charge would be $50 (5% of the $1,000 contribution). This is a 6.25% reduction of your account value, which results in a cash value of $750 paid to you. |
| • | We may apply fees if you access your account value during the accumulation period or surrender your contract. For example, in addition to possible tax consequences, you may incur fees for accessing your account value such as a withdrawal charge, transfer fee, third party transfer or exchange fee and/or a charge for any optional benefits. |
| • | Withdrawals may be subject to income taxes and tax penalties. The minimum partial withdrawal amount is $300. Withdrawals will reduce your account value and optional benefit bases and the amount of the reduction may be greater than the dollar amount of the withdrawal. Certain withdrawals may also terminate your contract. |
Investment Edge
®
ADV Contracts Investment Edge
®
ADV contracts are only available through advisors who charge an advisory fee for their services, and this fee is in addition to contract fees and expenses. If you elect to pay the advisory fee from your account value (using either the Advisory Fee Service or by taking withdrawals), then these deductions will reduce the account value, reduce the death benefit, and payments under an Income Edge payment program, will not receive index interest, and could reduce the Segment Investment by more than the amount of the deductions, and, over time, could result in a significant loss of principal and previously credited interest. NOTE: If you do not elect the Advisory Fee Service, withdrawals to pay advisory fees also may be subject to federal and state income taxes and a 10% federal penalty tax. You should consider using a source other than the account value under the contract to pay advisory fees, if possible, to avoid these potential consequences, but if you do use your account value, you should use the Advisory Authorization Form.Return of Premium Death Benefit
• |
Please note that withdrawals under the contract, including systematic withdrawals, required minimum distributions, and withdrawals to pay advisory fees under an Investment Edge ® ADV contract, could reduce the Return of Premium death benefit by substantially more than the amount of the withdrawal. |
| • | You cannot terminate the Return of Premium death benefit once you elect it. This means that you cannot avoid paying the charge for the Return of Premium death benefit even if you no longer want or need the protection offered by the Return of Premium death benefit. This also means you cannot avoid paying the charge when the account value is higher than your Return of Premium benefit base. |
Possible adverse tax consequences
The tax considerations associated with the contract vary and can be complicated. The applicable tax rules can differ, depending on the type of contract, whether NQ, traditional IRA, Roth IRA or QP. The tax consequences discussed in this Prospectus are general in nature and describe only federal income tax law (not state, local, foreign or other federal tax laws). Moreover, the tax aspects that apply to a particular person’s contract may vary depending on the facts applicable to that person. Tax rules may change without notice. We cannot predict whether, when, or how these rules could change. Any change could affect contracts purchased before the change. Congress may also consider further proposals to comprehensively reform or overhaul the United States tax and retirement systems, which if enacted, could affect the tax benefits of a contract. We cannot predict what, if any, legislation will actually be proposed or enacted. Before making contributions to your contract or taking other action related to your contract, you should consult with a tax professional to determine the tax implications of an investment in, and payments received under, the contract.
Withdrawals are generally subject to income tax and may be subject to tax penalties if taken before age 59
1
⁄2
. Availability by financial intermediary
Some financial intermediaries (e.g., selling broker-dealer firms) may not offer and/or may limit the offering of certain investment options, contract benefits, and other contract features based on issue age or other criteria established by the selling broker-dealer. For example, your financial professional may not recommend a particular investment option or contract benefit to you that is described in this Prospectus. Before you purchase the contract, you should discuss with your financial professional any limitations, restrictions, or other variations related to the investment options, contract benefits or other contract features available to you through your financial professional. If a particular feature that interests you is not recommended through your broker-dealer, you may want to contact us to explore its availability.
Business disruption, cybersecurity, and artificial intelligence (“AI”) technologies risks
We rely heavily on technology, including interconnected computer systems and data storage networks and digital communications, to conduct our business. Because our business is highly dependent upon the effective operation of our computer systems and those of our service providers and other business partners, our business is vulnerable to disruptions from utility outages, and susceptible to operational and information security risks resulting from information systems failure (e.g., hardware and software malfunctions), and cyberattacks. Cyberattacks may be systemic (e.g., affecting the internet, cloud services, or other infrastructure) or targeted (e.g., failures in or breach of our systems or those of third parties on whom we rely, including ransomware and malware attacks). Cybersecurity risks include, among other things, the loss, theft, misuse, corruption and destruction of data maintained online or digitally, interference with or denial of service, attacks on our websites (or the websites of third parties on whom we rely), other operational disruption and unauthorized release, use or abuse of confidential customer information. The risk of cyberattacks may be higher during periods of geopolitical turmoil. Due to the increasing sophistication of cyberattacks, a cybersecurity breach could occur and persist for an extended period of time without detection. Systems failures and cyberattacks, as well as, any other catastrophic event, including natural and manmade disasters, public health
emergencies, pandemic diseases, terrorist attacks, floods or severe storms affecting us, any third-party administrator, the underlying funds, intermediaries and other affiliated or third-party service providers may adversely affect us, our business operations and your account value and interfere with our ability to process contract transactions and calculate account values. Systems failures and cyberattacks may also interfere with our processing of contract transactions, including the processing of orders from our website or with the underlying funds, impact our ability to calculate account values and unit values and/or the underlying funds to be unable to calculate share values, cause the release or possible destruction of confidential customer and/or business information, impede order processing or cause other operational issues, subject us and/or our service providers and intermediaries to regulatory fines, litigation and financial losses and/or cause reputational damage. Cybersecurity risks may also impact the issuers of securities in which the underlying funds invest, which may cause the underlying funds to lose value. The preventative actions we take to reduce the frequency and severity of cybersecurity incidents and protect our computer systems may be insufficient to prevent a cybersecurity breach from impacting our operations of your contract value. There can be no assurance that we or the underlying funds or our service providers and intermediaries will be able to avoid cybersecurity breaches affecting your contract.
The development and deployment of AI tools and technologies, including generative AI, and its use and anticipated use by us or by third parties on whom we rely, may increase our existing operational risks or create new operational risks that we are not currently anticipating. AI and generative AI may be misused by us or by third parties upon which we rely, and that risk is increased by the relative newness of the technology, the speed at which it is being adopted, and the uncertain and evolving policy and regulatory landscape governing its use. Such misuse could expose us to legal or regulatory risk. Because the generative AI technology is so new, many of the potential risks of generative AI are currently unknowable.
In addition, we are also exposed to risks related to natural and man-made disasters, including, but not limited to the occurrence of any storms, fires, floods, earthquakes, public health crises, malicious acts, and terrorist acts or any other event, which could adversely affect our ability to conduct business. A natural or man-made disaster, including a pandemic such as COVID-19, could result in our workforce, and/or employees of service providers and/or third-party administrators, being compromised and unable or unwilling to fully perform their responsibilities, which could likewise result in interruptions in our service. This could interfere with our processing of contract transactions, including processing orders from owners and orders with the underlying funds, impact our ability to calculate contract value, or have other adverse impacts on our operations. These events may also negatively affect our service providers and intermediaries, the underlying funds and issuers of securities in which the underlying funds invest, which may cause the funds underlying your contract to lose value. There can be no assurance that we or the underlying funds or our service providers and intermediaries will be able to avoid negative impacts associated with natural and man-made disasters.
S&P 500 Price Return Index.
MSCI Emerging Markets Price Return Index
NASDAQ-100 Price Return Index
Russell 2000
®
Price Return Index.
®
®
small-cap
segment of the U.S. equity universe. The Russell 2000®
®
®
®
MSCI EAFE Price Return Index
The bar charts shown below provide each Index’s annual returns for the last 10 calendar years (or for the life of the Index if less than 10 years), as well as the Index returns after applying a hypothetical 5% Performance Cap Rate and a hypothetical -10% Segment Buffer. The chart illustrates the variability of the returns from year to year and shows how hypothetical limits on Index gains and losses may affect these returns. Past performance is not necessarily an indication of future performance.
| [1] | Expressed as an annual percent of daily net assets in the variable investment options and as a percentage of the rate of return for Segments in the SIO. |
| [2] | Expressed as an annual percentage of daily net assets in the Portfolio. This range is for the year ended December 31, 2025 and could change from year to year. |
| [3] | Expressed as an annual percentage of the applicable benefit base. |
| [4] | This Portfolio’s annual expenses reflect temporary fee reductions. |
| [5] | EQ Managed Volatility Portfolios that include the EQ volatility management strategy as part of their investment objective and/or principal investment strategy, and the EQ/affiliated Fund of Fund Portfolios that invest in Portfolios that use the EQ volatility management strategy, are identified in the chart by a “†“. See “Portfolios of the Trusts” for more information regarding volatility management. |
| [6] | Certain other affiliated Portfolios, as well as unaffiliated Portfolios, may utilize volatility management techniques (including Fund of Fund Portfolios that invest in other Portfolios that utilize volatility management techniques) that differ from the EQ volatility management strategy. Affiliated Portfolios that utilize these volatility management techniques are identified in the chart by a “∆”. Any such unaffiliated Portfolio is not identified in the chart. See “Portfolios of the Trusts” for more information regarding volatility management. |
| [7] | This investment option is only available if you purchased your contract before approximately November 13, 2023. |
| [8] | “J.P. Morgan” and “JPMorgan” are registered trademarks of J.P. Morgan Chase Bank, NA (“JPMC”) and have been licensed for use by Equitable Investment Management Group, LLC. EQ/JPMorgan Hedged Equity and Premium Income Portfolio is not sponsored, endorsed, or promoted by JPMC and JPMC makes no representation regarding the advisability of investing in EQ/JPMorgan Hedged Equity and Premium Income Portfolio. |
| [9] | The Portfolio operates as a “government money market fund.” The Portfolio will invest at least 99.5% of its total assets in U.S. government securities, cash, and/or repurchase agreements that are fully collateralized by U.S. government securities or cash. |
| [10] | “Annual Portfolio Expenses” are based, in part, on estimated amounts of such expenses. The expenses listed are for the year ended December 31, 2025. Pursuant to a contract, Equitable Investment Management Group, LLC has agreed to make payments or waive its management, administrative and other fees to limit the expenses of certain affiliated Portfolios through April 30, 2027 (“Expense Limitation Arrangement”) (unless the Trust’s Board of Trustees consents to an earlier revision or termination of this agreement). The Expense Limitation Arrangement may be terminated by Equitable Investment Management Group, LLC at any time after April 30, 2027. The Expense Limitation Arrangement does not apply to unaffiliated Portfolios. |
| [11] | Expressed as an annual percentage of the benefit base. |
| [12] | The Index is a “price return” index, not a “total return” index, and therefore the performance of the Index does not reflect dividends declared by any of the companies included in the Index, reducing the Index return. As a result, the Index will underperform a direct investment in the securities composing the Index. |
| [13] | For Investment Edge® only, the charge percentage we use is determined by the number of years since receipt of the contribution to which the charge relates if you make a withdrawal, surrender your contract to receive its cash value, or, if offered, surrender your contract to apply your cash value to a non-life contingent annuity payment option. |
| [14] | Currently, we do not charge for third party transfers or exchanges. However, we reserve the right to discontinue this waiver at any time, with or without notice. The maximum third party transfer or exchange fee is $125. The current charge (which, as described above is waived) is $65. This charge will never exceed 2% of the amount disbursed or transferred. These charges may increase over time to cover our administrative costs. We may discontinue these services at any time. |
| [15] | The actual amount of the Segment Interim Value calculation is determined by a formula that depends on, among other things, the Segment Option, Segment Buffer and how the Index has performed since the Segment Start Date. The maximum loss would occur if there is a total distribution for a Growth Multiplier Segment at a time when the Index price has declined to zero. If you surrender or cancel your variable annuity contract, die, transfer or make a withdrawal from a Segment before the Segment Maturity Date, the Segment Buffer, if any, will not necessarily apply to the extent it would on the Segment Maturity Date, and any upside performance may be limited to a percentage lower than the Performance Cap Rate. See “Structured Investment Option” for more information. |
| [16] | Beginning with your first contract date anniversary, we will deduct this charge on any contract date anniversary on which your account value is less than $50,000. If the contract is surrendered or annuitized or a death benefit is paid on any date other than the contract date anniversary, we will deduct a pro rata portion of the charge for that year. Otherwise, we will deduct the full charge. This charge will no longer apply to NQ contracts following election of an Income Edge payment program, even if your account value falls below $50,000. |
| [17] | The Contract Fee percentage reduces the Segment Rate of Return. If the contract is surrendered or annuitized, a withdrawal or transfer out is taken, or a death benefit is paid, on any date other than the Segment Maturity Date, we will deduct a pro rata portion of the charge from each Segment as part of the Segment Interim Value calculation. |
| [18] | If on any date other than the contract date anniversary your contract is surrendered or annuitized, an Income Edge payment program is elected and become effective, a death benefit is paid, or the Return of Premium death benefit is otherwise terminated, we will deduct a pro rata portion of the charge from your account value. |
| [19] | The benefit base is equal to your initial contribution to the contract less any withdrawals you made from the contract. |
| [20] | The current charge is 0.30%. |
| [21] | Currently, we do not charge for transfers among investment options under the contract. However, we reserve the right to charge for transfers in excess of 12 transfers per contract year. We will charge no more than $35 for each transfer at the time each transfer is processed. See “Transfer charge” under “Charges that the Company deducts” in “Charges, expenses, and adjustments”. |
| [22] | Special service charges include (1) express mail charge; (2) wire transfer charge; (3) duplicate contract charge; (4) check preparation charge (the sum of this charge will never exceed 2% of the amount distributed); and (5) Duplicate Annual and/or Quarterly Statement of Account or Annual Payout Statement Charge. The current maximum charge for each service is $90. These charges may increase over time to cover our administrative costs. We may discontinue these services at any time. |