AMERICAN FIDELITY ASSURANCE COMPANY (A Stock Company) 2000 N. Classen Boulevard Oklahoma City, Oklahoma American Fidelity Assurance
Company (the Company) will pay each Participant under this Contract the benefits to which he becomes entitled under the Contract subject to all of its terms. The Contract is issued in consideration of: (1) the application, which is attached;
and (2) any payment which the Employer may make to the Company. President Secretary IN WITNESS WHEREOF, the American Fidelity Assurance Company has caused this Contract to be executed at its Home Office in Oklahoma City, Oklahoma. GROUP
DEFERRED VARIABLE ANNUITY Master Contract Individual Allocation Separate Account Non-Participating ALL PAYMENTS AND VALUES PROVIDED BY THIS CONTRACT ARE BASED ON INVESTMENT EXPERIENCE OF A SEPARATE ACCOUNT.
THE VALUES ARE VARIABLE AND ARE NOT GUARANTEED AS TO FIXED DOLLAR AMOUNT.
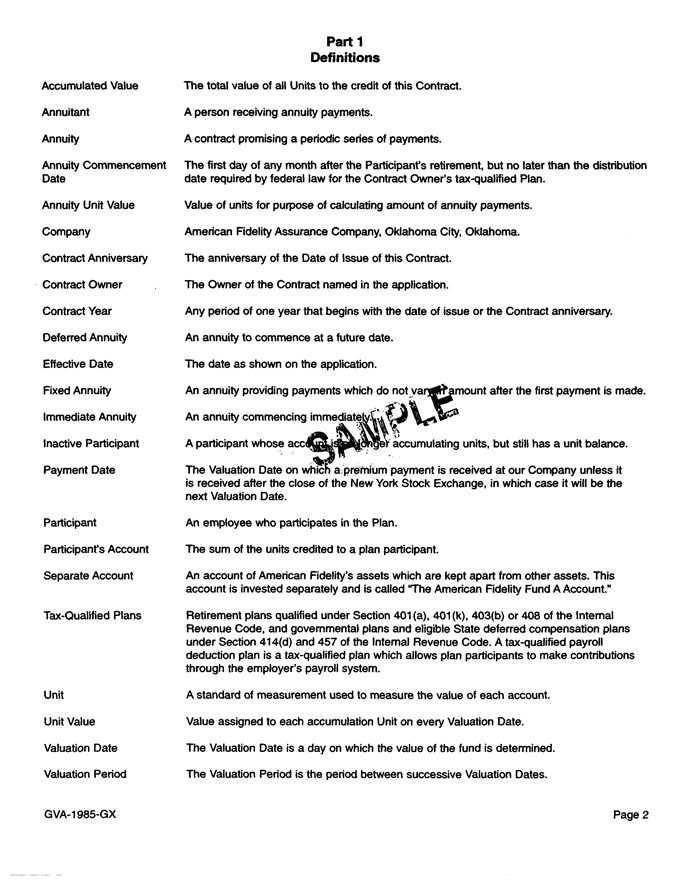
Part1 Definitions Accumulated Value The total value of all Units to the credit of this Contract. Annuitant A person receiving annuity
payments. Annuity A contract promising a periodic series of payments. Annuity Commencement The first day of any month after the Participant’s retirement, but no later than the distribution Date date required by federal law for the Contract
Owner’s tax-qualified Plan. Annuity Unit Value Value of units for purpose of calculating amount of annuity payments. Company American Fidelity Assurance Company, Oklahoma City, Oklahoma. Contract Anniversary The anniversary of the Date of
Issue of this Contract. Contract Owner . The Owner of the Contract named in the application. Contract Year Any period of one year that begins with the date of issue or the Contract anniversary. Deferred Annuity An annuity to commence at a future
date. Effective Date The date as shown on the application. Fixed Annuity An annuity providing payments which do not yan^^amount after the first payment is made. Immediate Annuity An annuity commencing immediate|y£a Inactive
Participant A participant whose acc^^LdM^d^eF accumulating units, but still has a unit balance. Payment Date The Valuation Date on whrcE a premium payment is received at our Company unless it is received after the close of the
New York Stock Exchange, in which case it will be the next Valuation Date. Participant An employee who participates in the Plan. Participant’s Account The sum of the units credited to a plan participant. Separate Account An account of American
Fidelity’s assets which are kept apart from other assets. This account is invested separately and is called “The American Fidelity Fund A Account.” Tax-Qualified Plans Retirement plans qualified under Section 401 (a), 401 (k),
403(b) or 408 of the Internal Revenue Code, and governmental plans and eligible State deferred compensation plans under Section 414(d) and 457 of the Internal Revenue Code. A tax-qualified payroll deduction plan is a tax-qualified plan which allows
plan participants to make contributions through the employer’s payroll system. Unit A standard of measurement used to measure the value of each account. Unit Value Value assigned to each accumulation Unit on every Valuation Date. Valuation
Date The Valuation Date is a day on which the value of the fund is determined. Valuation Period The Valuation Period is the period between successive Valuation Dates. GVA-1985-GX Page 2
ii
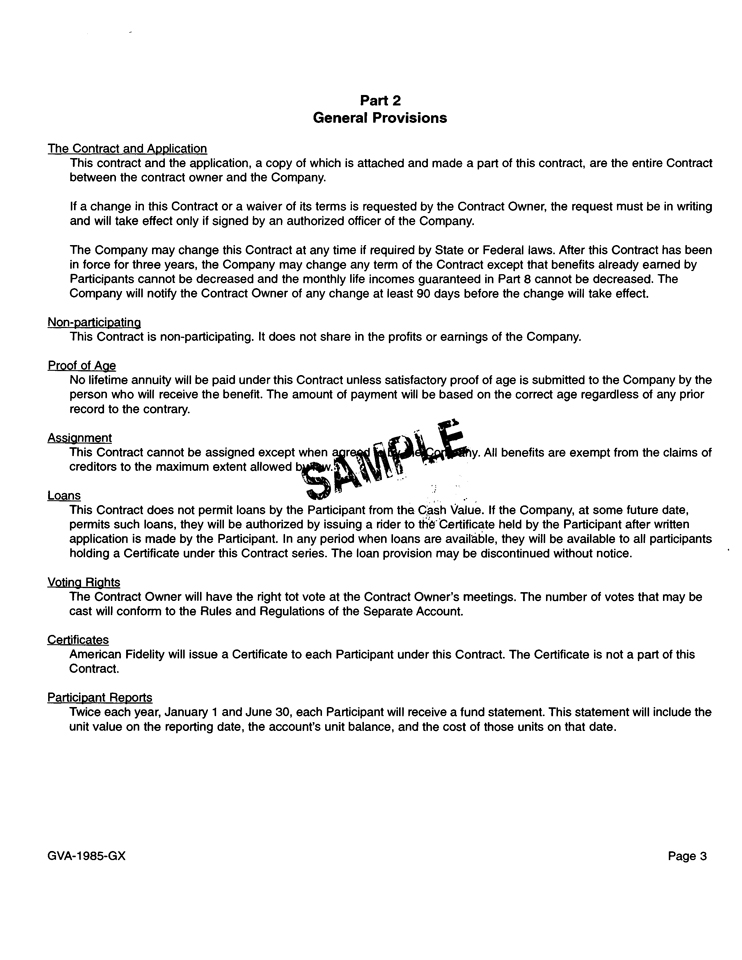
Part 2 General Provisions The Contract and Application This contract and the application, a copy of which is attached and made a part of
this contract, are the entire Contract between the contract owner and the Company. If a change in this Contract or a waiver of its terms is requested by the Contract Owner, the request must be in writing and will take effect only if signed by an
authorized officer of the Company. The Company may change this Contract at any time if required by State or Federal laws. After this Contract has been in force for three years, the Company may change any term of the Contract except that benefits
already earned by Participants cannot be decreased and the monthly life incomes guaranteed in Part 8 cannot be decreased. The Company will notify the Contract Owner of any change at least 90 days before the change will take effect. Non-participating
This Contract is non-participating. It does not share in the profits or earnings of the Company. Proof of Age No lifetime annuity will be paid under this Contract unless satisfactory proof of age is submitted to the Company by the person who will
receive the benefit. The amount of payment will be based on the correct age regardless of any prior record to the contrary. Assignment This Contract cannot be assigned except when agreed WEMRe. All benefits are exempt from the claims of creditors to
the maximum extent allowed Loans w “ This Contract does not permit loans by the Participant from the Cash Value. If the Company, at some future date, permits such loans, they will be authorized by issuing a rider to this Certificate held by
the Participant after written application is made by the Participant. In any period when loans are available, they will be available to all participants holding a Certificate under this Contract series. The loan provision may be discontinued without
notice. ‘ Voting Rights The Contract Owner will have the right tot vote at the Contract Owner’s meetings. The number of votes that may be cast will conform to the Rules and Regulations of the Separate Account. Certificates American
Fidelity will issue a Certificate to each Participant under this Contract. The Certificate is not a part of this Contract. Participant Reports Twice each year, January 1 and June 30, each Participant will receive a fund statement. This statement
will include the unit value on the reporting date, the account’s unit balance, and the cost of those units on that date. GVA-1985-GX Page 3
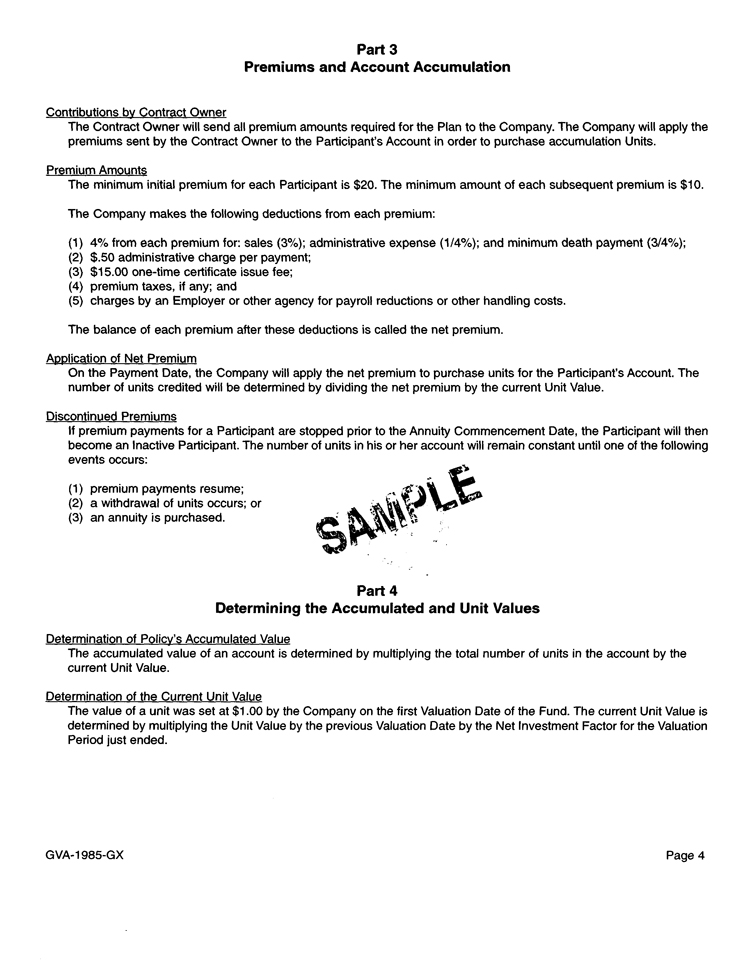
Part3 Premiums and Account Accumulation Contributions by Contract Owner The Contract Owner will send all premium amounts required for
the Plan to the Company. The Company will apply the premiums sent by the Contract Owner to the Participant’s Account in order to purchase accumulation Units. Premium Amounts The minimum initial premium for each Participant is $20. The minimum
amount of each subsequent premium is $10. The Company makes the following deductions from each premium: (1) 4% from each premium for: sales (3%); administrative expense (1/4%); and minimum death payment (3/4%); (2) $.50 administrative charge per
payment; (3) $15.00 one-time certificate issue fee; (4) premium taxes, if any; and (5) charges by an Employer or other agency for payroll reductions or other handling costs. The balance of each
premium after these deductions is called the net premium. Application of Net Premium On the Payment Date, the Company will apply the net premium to purchase units for the Participant’s Account. The number of units credited will be determined
by dividing the net premium by the current Unit Value. Discontinued Premiums If premium payments for a Participant are stopped prior to the Annuity Commencement Date, the Participant will then become an Inactive Participant. The number of units in
his or her account will remain constant until one of the following events occurs: (1) premium payments resume; (2) a withdrawal of units occurs; or (3) an annuity is purchased. Part 4 Determining the Accumulated and Unit Values
Determination of Policy’s Accumulated Value The accumulated value of an account is determined by multiplying the total number of units in the account by the current Unit Value. Determination of the Current Unit Value The value of a unit was
set at $1.00 by the Company on the first Valuation Date of the Fund. The current Unit Value is determined by multiplying the Unit Value by the previous Valuation Date by the Net Investment Factor for the Valuation Period just ended.
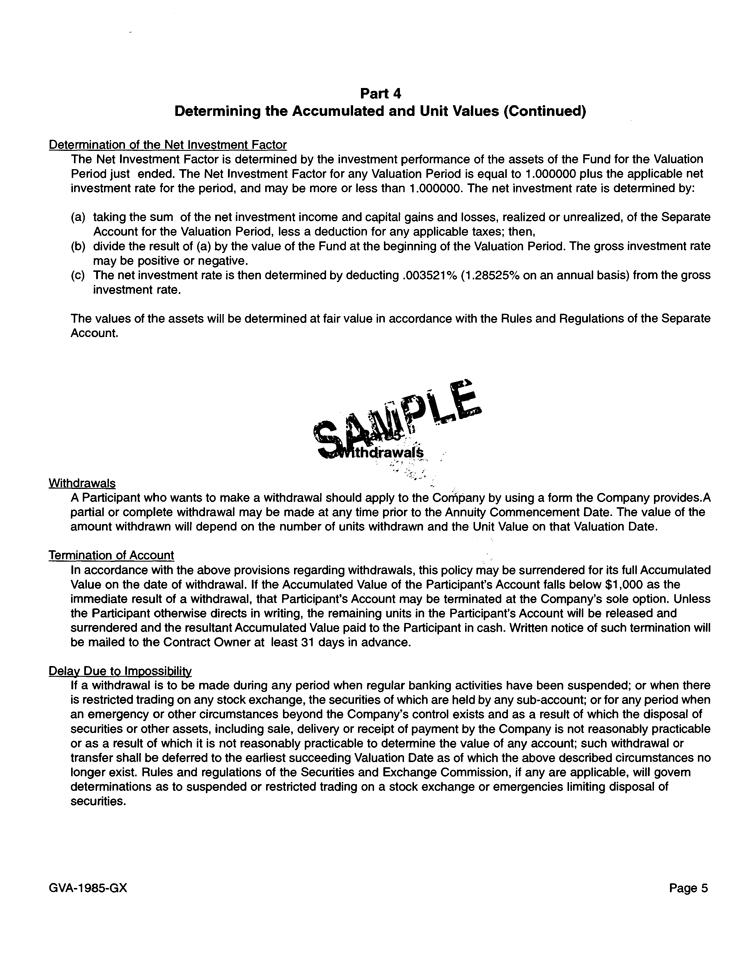
Part 4 Determining the Accumulated and Unit Values (Continued) Determination of the Net Investment Factor The Net Investment Factor is
determined by the investment performance of the assets of the Fund for the Valuation Period just ended. The Net Investment Factor for any Valuation Period is equal to 1.000000 plus the applicable net investment rate for the period, and may be more
or less than 1.000000. The net investment rate is determined by: (a) taking the sum of the net investment income and capital gains and losses, realized or unrealized, of the Separate Account for the Valuation Period, less a deduction for any
applicable taxes; then, (b) divide the result of (a) by the value of the Fund at the beginning of the Valuation Period. The gross investment rate may be positive or negative. (c) The net investment rate is then determined by deducting
.003521% (1.28525% on an annual basis) from the gross investment rate. The values of the assets will be determined at fair value in accordance with the Rules and Regulations of the Separate Account. Withdrawals “ A Participant who wants to
make a withdrawal should apply to the Conipany by using a form the Company provides.A partial or complete withdrawal may be made at any time prior to the Annuity Commencement Date. The value of the amount withdrawn will depend on the number of units
withdrawn and the Unit Value on that Valuation Date. Termination of Account In accordance with the above provisions regarding withdrawals, this policy may be surrendered for its full Accumulated Value on the date of withdrawal. If the Accumulated
Value of the Participant’s Account falls below $1,000 as the immediate result of a withdrawal, that Participant’s Account may be terminated at the Company’s sole option. Unless the Participant otherwise directs in writing, the
remaining units in the Participant’s Account will be released and surrendered and the resultant Accumulated Value paid to the Participant in cash. Written notice of such termination will be mailed to the Contract Owner at least 31 days in
advance. Delay Due to Impossibility If a withdrawal is to be made during any period when regular banking activities have been suspended; or when there is restricted trading on any stock exchange, the securities of which are held by any sub-account; or for any period when an emergency or other circumstances beyond the Company’s control exists and as a result of which the disposal of securities or other assets, including sale, delivery or
receipt of payment by the Company is not reasonably practicable or as a result of which it is not reasonably practicable to determine the value of any account; such withdrawal or transfer shall be deferred to the earliest succeeding Valuation Date
as of which the above described circumstances no longer exist. Rules and regulations of the Securities and Exchange Commission, if any are applicable, will govern determinations as to suspended or restricted trading on a stock exchange or
emergencies limiting disposal of securities. GVA-1985-GX
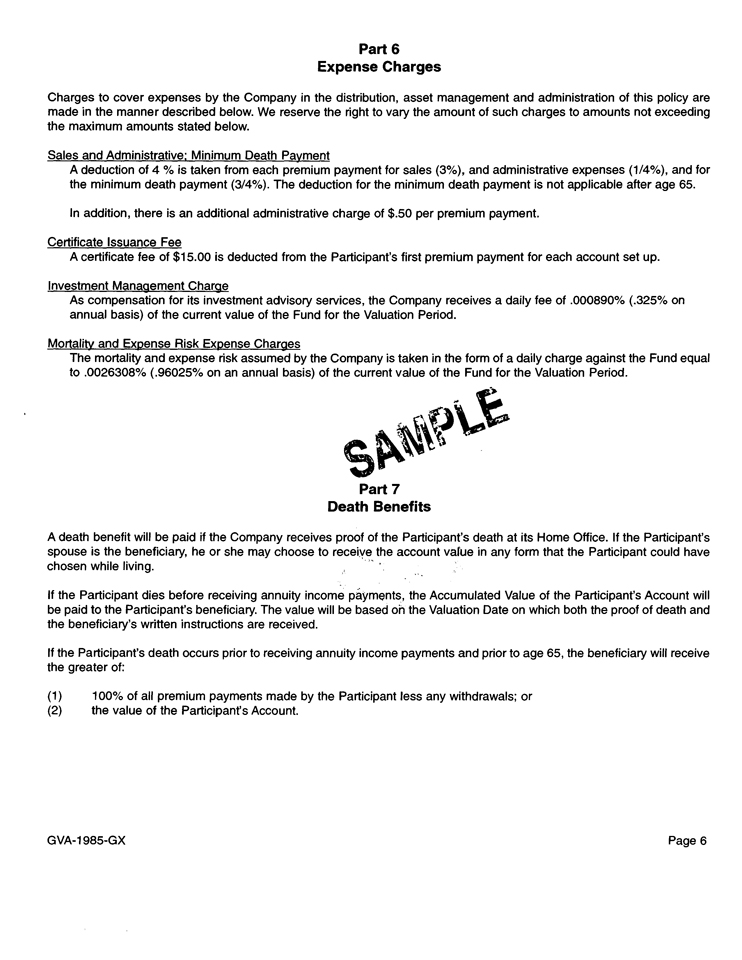
Part 6 Expense Charges Charges to cover expenses by the Company in the distribution, asset management and administration of this policy
are made in the manner described below. We reserve the right to vary the amount of such charges to amounts not exceeding the maximum amounts stated below. Sales and Administrative: Minimum Death Payment A deduction of 4 % is taken from each
premium payment for sales (3%), and administrative expenses (1/4%), and for the minimum death payment (3/4%). The deduction for the minimum death payment is not applicable after age 65. In addition, there is an additional administrative charge of
$.50 per premium payment. Certificate Issuance Fee A certificate fee of $15.00 is deducted from the Participant’s first premium payment for each account set up. Investment Management Charge As compensation for its investment advisory services,
the Company receives a daily fee of .000890% (.325% on annual basis) of the current value of the Fund for the Valuation Period. Mortality and Expense Risk Expense Charges The mortality and expense risk assumed by the Company is taken in the form of
a daily charge against the Fund equal to .0026308% (.96025% on an annual basis) of the current value of the Fund for the Valuation Period. Part 7 Death Benefits A death benefit will be paid if the Company receives proof of the Participant’s
death at its Home Office. If the Participant’s spouse is the beneficiary, he or she may choose to receive the account value in any form that the Participant could have chosen while living. If the Participant dies before receiving annuity
income payments, the Accumulated Value of the Participant’s Account will be paid to the Participant’s beneficiary. The value will be based oh the Valuation Date on which both the proof of death and the beneficiary’s written
instructions are received. If the Participant’s death occurs prior to receiving annuity income payments and prior to age 65, the beneficiary will receive the greater of: (1) 100% of all premium payments made by the Participant less any
withdrawals: or (2) the value of the Participant’s Account.
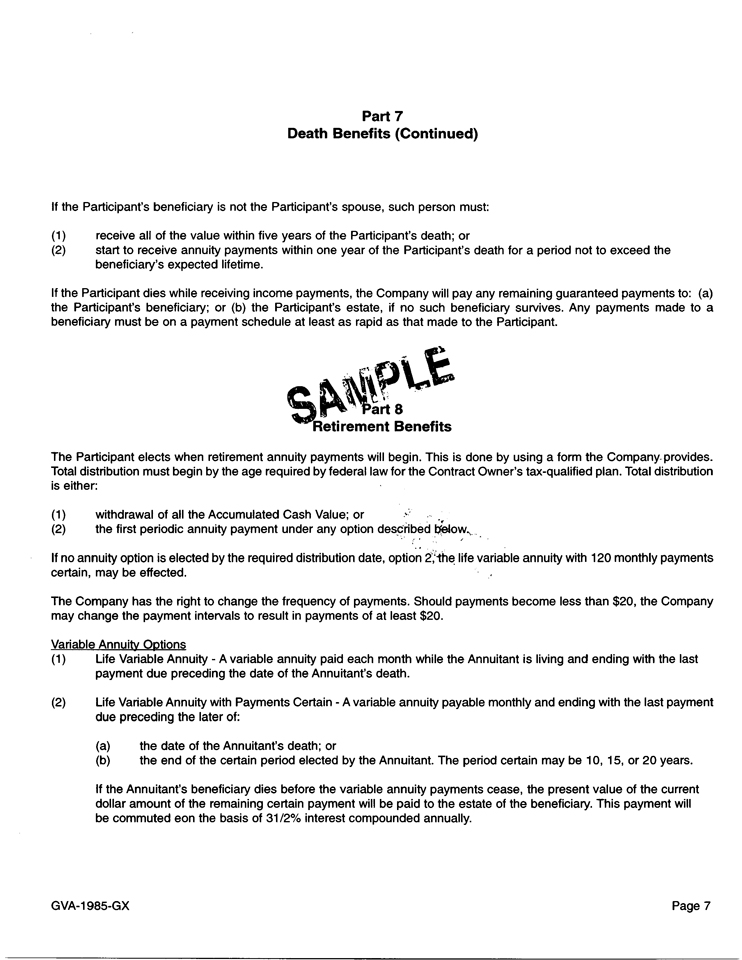
Part 7 Death Benefits (Continued) If the Participant’s beneficiary is not the Participant’s spouse, such person must:
(1) receive all of the value within five years of the Participant’s death; or (2) start to receive annuity payments within one year of the Participant’s death for a period not to exceed the beneficiary’s expected
lifetime. If the Participant dies while receiving income payments, the Company will pay any remaining guaranteed payments to: (a) the Participant’s beneficiary; or (b) the Participant’s estate, if no such beneficiary survives.
Any payments made to a beneficiary must be on a payment schedule at least as rapid as that made to the Participant. The Participant elects when retirement annuity payments will begin. This is done by using a form the Company provides. Total
distribution must begin by the age required by federal law for the Contract Owner’s tax-qualified plan. Total distribution is either: (1) withdrawal of all the Accumulated Cash Value; or
(2) the first periodic annuity payment under any option described below. If no annuity option is elected by the required distribution date, option 2,the life variable annuity with 120 monthly payments certain, may be effected. The Company has
the right to change the frequency of payments. Should payments become less than $20, the Company may change the payment intervals to result in payments of at least $20. Variable Annuity Potions (1) Life Variable Annuity—A variable annuity
paid each month while the Annuitant is living and ending with the last payment due preceding the date of the Annuitant’s death. (2) Life Variable Annuity with Payments Certain—A variable annuity payable monthly and ending with the
last payment due preceding the later of: (a) the date of the Annuitant’s death; or (b) the end of the certain period elected by the Annuitant. The period certain may be 10, 15, or 20 years. If the Annuitant’s beneficiary dies
before the variable annuity payments cease, the present value of the current dollar amount of the remaining certain payment will be paid to the estate of the beneficiary. This payment will be commuted eon the basis of 31/2% interest compounded
annually. GVA-1985-GX
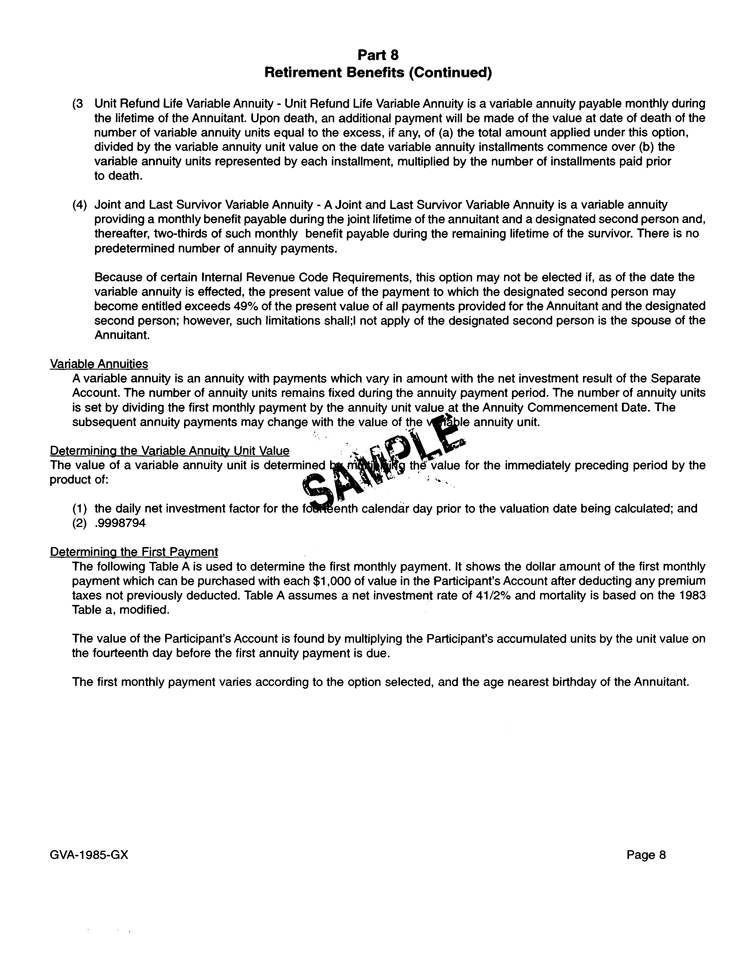
Part 8 Retirement Benefits (Continued) (3 Unit Refund Life Variable Annuity—Unit Refund Life Variable Annuity is a variable
annuity payable monthly during the lifetime of the Annuitant. Upon death, an additional payment will be made of the value at date of death of the number of variable annuity units equal to the excess, if any, of (a) the total amount applied
under this option, divided by the variable annuity unit value on the date variable annuity installments commence over (b) the variable annuity units represented by each installment, multiplied by the number of installments paid prior to death.
(4) Joint and Last Survivor Variable Annuity—A Joint and Last Survivor Variable Annuity is a variable annuity providing a monthly benefit payable during the joint lifetime of the annuitant and a designated second person and, thereafter, two-thirds of such monthly benefit payable during the remaining lifetime of the survivor. There is no predetermined number of annuity payments. Because of certain Internal Revenue Code Requirements, this option may
not be elected if, as of the date the variable annuity is effected, the present value of the payment to which the designated second person may become entitled exceeds 49% of the present value of all payments provided for the Annuitant and the
designated second person; however, such limitations shall;l not apply of the designated second person is the spouse of the Annuitant. Variable Annuities A variable annuity is an annuity with payments which vary in amount with the net investment
result of the Separate Account. The number of annuity units remains fixed during the annuity payment period. The number of annuity units is set by dividing the first monthly payment by the annuity unit value at the Annuity Commencement Date. The
subsequent annuity payments may change with the value of the annuity unit.
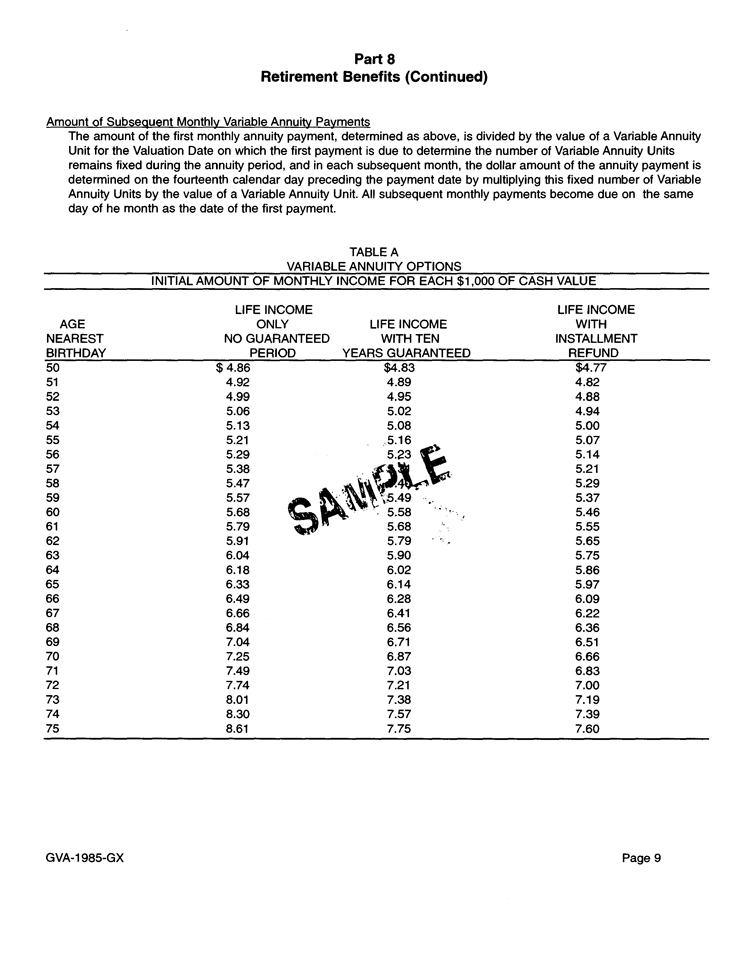
Part 8 Retirement Benefits (Continued) Amount of Subsequent Monthly Variable Annuity Payments The amount of the first monthly annuity
payment, determined as above, is divided by the value of a Variable Annuity Unit for the Valuation Date on which the first payment is due to determine the number of Variable Annuity Units remains fixed during the annuity period, and in each
subsequent month, the dollar amount of the annuity payment is determined on the fourteenth calendar day preceding the payment date by multiplying this fixed number of Variable Annuity Units by the value of a Variable Annuity Unit. All subsequent
monthly payments become due on the same day of he month as the date of the first payment. TABLE A VARIABLE ANNUITY OPTIONS INITIAL AMOUNT OF MONTHLY INCOME FOR EACH $1,000 OF CASH VALUE AGE NEAREST BIRTHDAY LIFE INCOME ONLY NO GUARANTEED PERIOD LIFE
INCOME WITH TEN YEARS GUARANTEED LIFE INCOME WITH INSTALLMENT REFUND 50 $4.86 $4.83 $4.77 51 4.92 4.89 4.82 52 4.99 4.95 4.88 53 5.06 5.02 4.94 54 5.13 5.08 5.00 55 5.21 5.16 5.07 56 5.29 5.23 5.14 57 5.38 5.21 58 5.47 5.29 59 5 57 5.49 5.37 60 5.68
5.58 5.46 61 5.79 5.68 5.55 62 5.91 5.79 5.65 63 6.04 5.90 5.75 64 6.18 6.02 5.86 65 6.33 6.14 5.97 66 6.49 6.28 6.09 67 6.66 6.41 6.22 68 6.84 6.56 6.36 69 7.04 6.71 6.51 70 7.25 6.87 6.66 71 7.49 7.03 6.83 72 7.74 7.21 7.00 73 8.01 7.38 7.19 74
8.30 7.57 7.39 75 8.61 7.75 7.60 Part 8 Retirement Benefits (Continued) Fixed Annuity Options A Participant also has the option to elect forms of fixed annuities with essentially the same characteristics as Annuity Options (1) through (4)
described in this Part. Table B applies to Fixed Annuity Options and is based on the 1983 Table a, modified, with interest at the rate of 4% per year. TABLE B VARIABLE ANNUITY OPTIONSMONTHLY INCOME PER $1,000 OF CASH VALUE
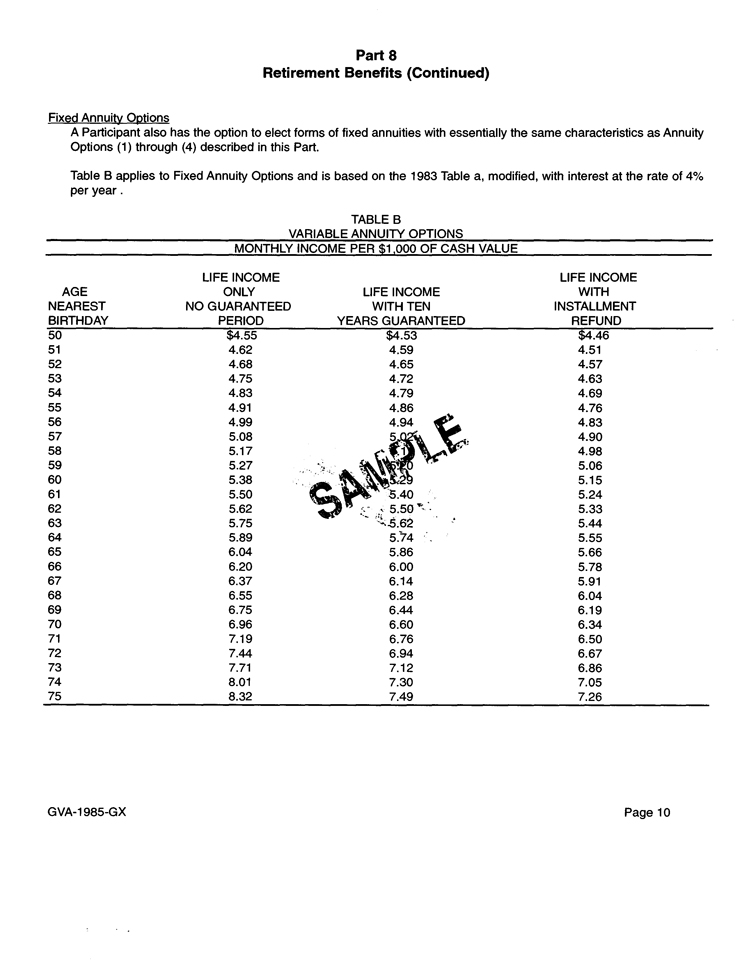
AGE NEAREST BIRTHDAY LIFE INCOME ONLY NO GUARANTEED PERIOD LIFE INCOME WITH TEN YEARS GUARANTEED LIFE INCOME WITH INSTALLMENT REFUND 50
$4.55 $4.53 $4.46 51 4.62 4.59 4.51 52 4.68 4.65 4.57 53 4.75 4.72 4.63 54 4.83 4.79 4.69 55 4.91 4.86 4.76 56 4.99 494 4.83 57 5.08 4.90 58 5.17 4.98 59 5.27 5.06 60 5.38 5.15 61 5.50 5.40 5.24 62 5.62 5.50 5.33 63 5.75 5.62 5.44 64 5.89 5.74 5.55
65 6.04 5.86 5.66 66 6.20 6.00 5.78 67 6.37 6.14 5.91 68 6.55 6.28 6.04 69 6.75 6.44 6.19 70 6.96 6.60 6.34 71 7.19 6.76 6.50 72 7.44 6.94 6.67 73 7.71 7.12 6.86 74 8.01 7.30 7.05 75 8.32 7.49 7.26
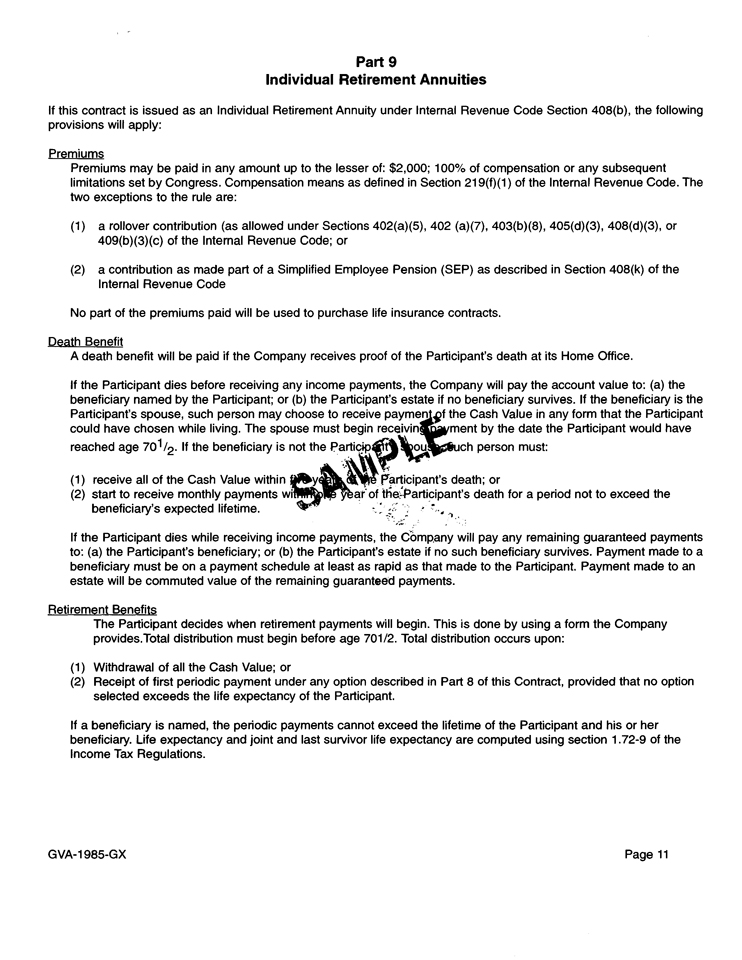
Part 9 Individual Retirement Annuities If this contract is issued as an Individual Retirement Annuity under Internal Revenue Code
Section 408(b), the following provisions will apply: Premiums Premiums may be paid in any amount up to the lesser of: $2,000; 100% of compensation or any subsequent limitations set by Congress. Compensation means as defined in
Section 219(f)(1) of the Internal Revenue Code. The two exceptions to the rule are: (1) a rollover contribution (as allowed under Sections 402(a)(5), 402 (a)(7), 403(b)(8), 405(d)(3), 408(d)(3), or 409(b)(3)(c) of the Internal Revenue
Code; or (2) a contribution as made part of a Simplified Employee Pension (SEP) as described in Section 408(k) of the Internal Revenue Code No part of the premiums paid will be used to purchase life insurance contracts. Death Benefit A
death benefit will be paid if the Company receives proof of the Participant’s death at its Home Office. If the Participant dies before receiving any income payments, the Company will pay the account value to: (a) the beneficiary named by
the Participant; or (b) the Participant’s estate if no beneficiary survives. If the beneficiary is the Participant’s spouse, such person may choose to receive payment of the Cash Value in any form that the Participant could have
chosen while living. The spouse must begin receiving payment by the date the Participant would have reached age 70 . If the beneficiary is not the Participate Such person must: If the Participant dies while receiving income payments, the Company
will pay any remaining guaranteed payments to: (a) the Participant’s beneficiary; or (b) the Participant’s estate if no such beneficiary survives. Payment made to a beneficiary must be on a payment schedule at least as rapid as
that made to the Participant. Payment made to an estate will be commuted value of the remaining guaranteed payments. Retirement Benefits The Participant decides when retirement payments will begin. This is done by using a form the Company
provides.Total distribution must begin before age 701/2. Total distribution occurs upon: (1) Withdrawal of all the Cash Value; or (2) Receipt of first periodic payment under any option described in Part 8 of this Contract, provided that no
option selected exceeds the life expectancy of the Participant. If a beneficiary is named, the periodic payments cannot exceed the lifetime of the Participant and his or her beneficiary. Life expectancy and joint and last survivor life expectancy
are computed using section 1.72-9 of the Income Tax Regulations. GVA-1985-GX
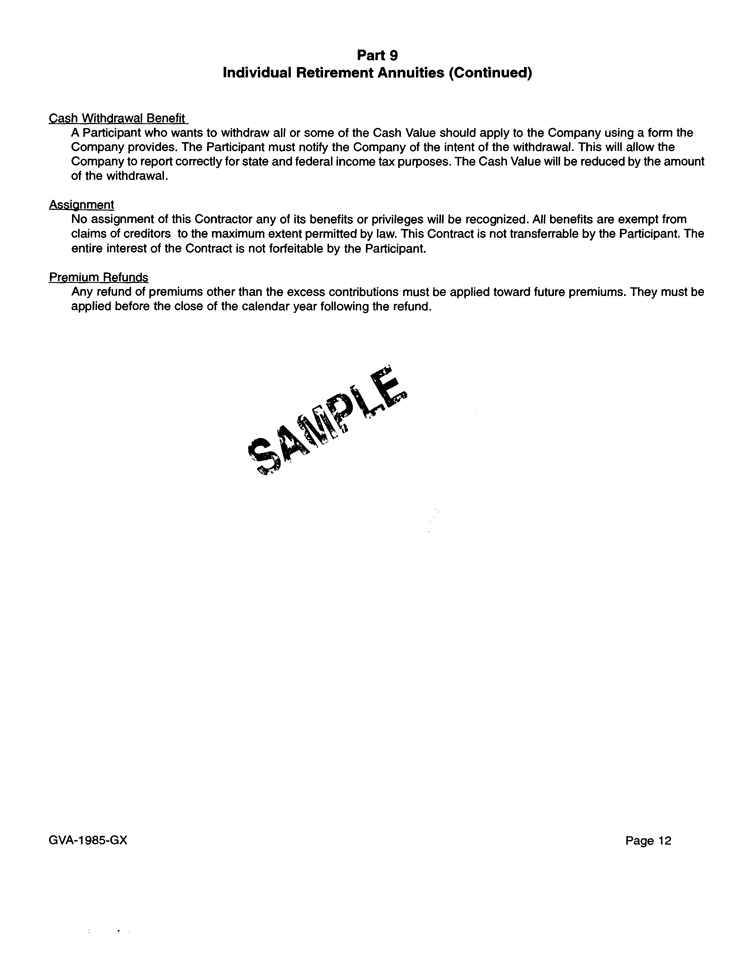
Part 9 Individual Retirement Annuities (Continued) Cash Withdrawal Benefit A Participant who wants to withdraw all or some of the Cash
Value should apply to the Company using a form the Company provides. The Participant must notify the Company of the intent of the withdrawal. This will allow the Company to report correctly for state and federal income tax purposes. The Cash Value
will be reduced by the amount of the withdrawal. Assignment No assignment of this Contractor any of its benefits or privileges will be recognized. All benefits are exempt from claims of creditors to the maximum extent permitted by law. This Contract
is not transferrable by the Participant. The entire interest of the Contract is not forfeitable by the Participant. Premium Refunds Any refund of premiums other than the excess contributions must be applied toward future premiums. They must be
applied before the close of the calendar year following the refund. (1) receive all of the Cash Value within Participant’s death; or (2) start to receive monthly payments year of the Participant’s death for a period not
to exceed the beneficiary’s expected lifetime Page 11