Exhibit 99.1
NOTICE OF SPECIAL MEETING
and
MANAGEMENT INFORMATION CIRCULAR
of
Gold Basin Resources Corporation
for the
SPECIAL MEETING OF SHAREHOLDERS
to be held June 4, 2026
in connection with a proposed
PLAN OF ARRANGEMENT
involving
CANEX METALS INC.,
GOLD BASIN RESOURCES CORPORATION
and the
SHAREHOLDERS OF GOLD BASIN RESOURCES CORPORATION
May 14, 2026
| TAKE ACTION AND VOTE TODAY
These materials are important and require your immediate attention. If you are in doubt as to how to make such decisions, please contact your financial, legal, tax or other professional advisors. No securities regulatory authority in Canada, the United States or elsewhere has expressed an opinion about, or passed upon the fairness or merits of, the transactions described in this document, the securities being offered pursuant to such transactions or the adequacy of the information contained in this document and it is an offense to claim otherwise. Shareholders that require further assistance may contact Gold Basin’s proxy solicitation agent, Laurel Hill Advisory Group, by calling 1-877-452-7184 (North America Toll-Free) or 416-304-0211 (outside of North America), by texting “INFO” to either number, or by emailing assistance@laurelhill.com. |
GOLD BASIN RESOURCES CORPORATION
1200 Waterfront Centre, 200 Burrard Street
Vancouver, British Columbia, Canada, V7X 1T2
Telephone: 403-233-2636
NOTICE OF SPECIAL MEETING OF
THE SHAREHOLDERS OF GOLD BASIN RESOURCES CORPORATION
NOTICE IS HEREBY GIVEN that a special meeting (the “Meeting”) of the holders (the “Shareholders”) of common shares (the “Shares”) of Gold Basin Resources Corporation (“Gold Basin”) will be held at 1200 Waterfront Centre, 200 Burrard St., Vancouver, British Columbia on June 4, 2026, at 10:00 a.m. (Vancouver time), for the following purposes:
| 1. | to consider and, if thought advisable, to pass, with or without variation, a special resolution (the “Arrangement Resolution”), the full text of which is set forth in Appendix A to the accompanying management information circular dated May 14, 2026 (the “Circular”), authorizing and approving a plan of arrangement (the “Plan of Arrangement”) pursuant to section 288 of the Business Corporations Act (British Columbia) (the “BCBCA”) involving CANEX Metals Inc., Gold Basin and the Shareholders; and |
| 2. | to transact such further and other business as may properly be brought before the Meeting or any adjournment or postponement thereof. |
The Circular includes more detailed information relating to the matters to be considered at the Meeting.
The record date for determining the Shareholders entitled to receive notice of and vote at the Meeting is the close of business on May 5, 2026 (the “Record Date”).
Shareholders will be able to attend the Meeting in person. Registered Shareholders and duly appointed proxyholders will be able to attend, participate and vote at the Meeting. Non-registered (beneficial) Shareholders who have not appointed themselves as proxyholder will be able to attend the Meeting as guests, however, they will not be able to participate or vote at the Meeting.
Forms of proxy must be returned to TSX Trust Company, Gold Basin’s transfer agent, prior to 10:00 a.m. (Vancouver time) on June 2, 2026, or at least 48 hours (excluding Saturdays, Sundays and holidays) before any adjournment or postponement of the Meeting. The time limit for deposit of proxies may be waived or extended by the chair of the Meeting at their discretion, without notice.
If you are a beneficial Shareholder and have received these materials through your broker or through another intermediary, please complete and return the voting instruction form provided to you by your broker or other intermediary in accordance with the instructions provided therein.
If appointing a person, other than the management nominees identified on the form of proxy or voting instruction form, to represent you at the Meeting, you must follow the instructions in the Circular or on the form of proxy or voting instruction form to appoint such proxyholder by such proxy deadline. Once appointed, registering the proxyholder before such proxy deadline is an additional step in order for the proxyholder to participate in the Meeting. Additional information on how to attend and participate at the Meeting can be found in the accompanying Circular. Shareholders who are planning to return the form of proxy or a voting instruction form are encouraged to review the Circular carefully before submitting the form of proxy or voting instruction form.
- 2 -
Pursuant to an interim order made by the Supreme Court of British Columbia (the “Court”) pursuant to section 291 of the BCBCA (the “Interim Order”), each registered Shareholder as of the Record Date will be granted the right to dissent in respect of the Arrangement Resolution. To exercise such dissent right: (a) a written notice of dissent to the Arrangement Resolution must be received by Gold Basin c/o Fasken Martineau DuMoulin LLP, 550 Burrard Street, Suite 2900, Vancouver, British Columbia, V6C 0A3 (Attention: Mark Pontin) by 5:00 p.m. (Vancouver time) on June 2, 2026, or two business days prior to any adjournment or postponement of the Meeting; (b) the Shareholder must not have voted in favour of the Arrangement Resolution; and (c) the Shareholder must have otherwise complied with the provisions of sections 237 to 247 of the BCBCA, as modified and supplemented by the Plan of Arrangement, the Interim Order and a final order made by the Court (the “Final Order”) approving the arrangement (if applicable). The right to dissent is described in the Circular and the text of each of the Plan of Arrangement, the proposed form of Interim Order and sections 237 to 247 of the BCBCA, which are set forth in Appendices B, G and J, respectively, to the Circular.
Persons who are beneficial holders of Shares registered in the name of a broker, custodian, nominee or other intermediary who wish to dissent in respect of the Arrangement Resolution should be aware that only registered Shareholders as of the Record Date are entitled to dissent. Accordingly, a beneficial Shareholder desiring to exercise this right of dissent must make arrangements for the registered Shareholder which holds shares as nominee for such beneficial Shareholder to dissent on their behalf.
Failure to strictly comply with the requirements set forth in sections 237 to 247 of the BCBCA, as modified and supplemented by the Plan of Arrangement, the Interim Order and the Final Order (if applicable), may result in the loss of any right of dissent with respect to the Arrangement Resolution.
Your vote is very important, regardless of the number of shares that you own. Whether or not you expect to attend the Meeting, we encourage you to vote using the form of proxy or voting instruction form, as applicable, as promptly as possible to ensure that your vote will be counted at the Meeting.
If you have any questions or require assistance in completing your form of proxy or voting information form, please contact our proxy solicitation agent, Laurel Hill Advisory Group, by calling 1-877-452-7184 (North America Toll-Free) or 416-304-0211 (outside of North America), by texting “INFO” to either number, or by emailing assistance@laurelhill.com.
| THE BOARD OF DIRECTORS UNANIMOUSLY RECOMMENDS THAT SHAREHOLDERS VOTE FOR THE ARRANGEMENT RESOLUTION. |
DATED at Vancouver, British Columbia, this 14th day of May, 2026.
| By Order of the Board of Directors | |
| (signed) “Jordan Ross” | |
| Jordan Ross | |
| Director |
Table of Contents
| GLOSSARY OF TERMS | 1 | |
| GENERAL PROXY INFORMATION | 10 | |
| Introduction | 10 | |
| Information For United States Shareholders | 10 | |
| Currency Exchange Rates | 12 | |
| Cautionary Statement Regarding Forward-Looking Information | 13 | |
| SUMMARY | 18 | |
| The Meeting | 18 | |
| Parties to the Arrangement | 18 | |
| The Arrangement | 19 | |
| Background to the Arrangement | 20 | |
| Reasons for the Arrangement | 20 | |
| Fairness Opinion | 22 | |
| Recommendation of the Special Committee | 23 | |
| Recommendation of the Board | 23 | |
| Lock-Up Agreements | 23 | |
| Description of the Arrangement | 24 | |
| Court Approval | 25 | |
| Procedure for Exchange of Shares for CANEX Shares | 25 | |
| Dissent Rights with Respect to the Arrangement | 26 | |
| Income Tax Considerations | 26 | |
| Risk Factors | 26 | |
| GENERAL PROXY MATTERS | 27 | |
| Solicitation of Proxies | 27 | |
| Voting Procedures | 27 | |
| Appointment and Revocation of Proxies | 27 | |
| Revoking a Proxy | 28 | |
| Voting of Shares Represented by Management Proxies | 28 | |
| Advice to Beneficial Holders of Shares | 29 | |
| Voting Securities of Gold Basin and Principal Holders Thereof | 30 | |
| THE ARRANGEMENT | 31 | |
| Background to the Arrangement | 31 | |
| Reasons for the Arrangement | 34 | |
| Fairness Opinion | 37 | |
| Recommendation of the Special Committee | 37 | |
| Recommendation of the Board | 38 | |
| Lock-Up Agreements | 38 |
- ii -
| Description of the Arrangement | 38 | |
| Shareholder Approval | 39 | |
| Court Approval | 40 | |
| Regulatory Matters | 40 | |
| Procedure for Exchange of Shares for CANEX Shares | 41 | |
| Withholding Rights | 42 | |
| THE ARRANGEMENT AGREEMENT | 42 | |
| Effective Date and Conditions of Arrangement | 43 | |
| Representations and Warranties | 43 | |
| Conditions to the Arrangement Becoming Effective | 43 | |
| Covenants | 45 | |
| Non-Solicitation Covenant and Acquisition Proposal | 48 | |
| SECURITIES LAW CONSIDERATIONS | 52 | |
| Interests of Certain Persons and Companies in the Arrangement | 52 | |
| MI 61-101 | 53 | |
| United States Securities Law Considerations | 55 | |
| Dissent Rights Under the Arrangement | 56 | |
| Information Concerning CANEX | 59 | |
| Information Concerning Gold Basin | 60 | |
| Information Concerning the Resulting Issuer Following Completion of the Arrangement | 60 | |
| INCOME TAX CONSIDERATIONS | 60 | |
| Certain Canadian Federal Income Tax Considerations | 60 | |
| RISK FACTORS | 66 | |
| The Arrangement May Not Be Completed | 67 | |
| The Arrangement Agreement Limits Gold Basin’s Ability to Pursue Alternatives to the Arrangement | 67 | |
| Possible Failure to Realize Anticipated Benefits of the Arrangement | 67 | |
| Risks Related to the Businesses of CANEX and Gold Basin | 68 | |
| Gold Basin is Subject to Covenants in Respect of the Operation of their Business | 68 | |
| Restrictions on Dividends | 68 | |
| Diversion of Management’s Attention and Resources | 68 | |
| Dissent Rights | 68 | |
| The CANEX Shares Issued in Connection with the Arrangement May Have a Market Value Different Than Expected | 68 | |
| CANEX May Not Realize the Benefits of its Growth Projects | 69 | |
| CANEX Will Be Subject to Significant Capital Requirements Associated with its Expanded Portfolio of Development Projects | 69 | |
| Directors and Officers of Gold Basin May Have Interests in the Arrangement That are Different From Those of the Shareholders | 69 | |
| Following the Arrangement the Trading Price of CANEX May be Volatile | 69 | |
| Fluctuation in Mineral Prices | 70 |
- iii -
| Exploration, Development and Operating Risks | 70 | |
| Gold Basin Expects to Incur Costs Associated with the Arrangement | 70 | |
| AUDITORS, TRANSFER AGENTS AND REGISTRARS | 70 | |
| Auditors | 70 | |
| Transfer Agents, Registrars or Other Agents | 71 | |
| OTHER MATTERS | 71 | |
| Other Business | 71 | |
| Other Material Facts | 71 | |
| ADDITIONAL INFORMATION | 71 | |
| DIRECTORS’ APPROVAL | 72 | |
| CONSENT OF STIFEL NICOLAUS CANADA INC. | 73 |
| Appendix A | Arrangement Resolution |
| Appendix B | Plan of Arrangement |
| Appendix C | Information Concerning Gold Basin Resources Corporation |
| Appendix D | Information Concerning Canex Metals Inc. |
| Appendix E | Information Concerning the Resulting Issuer |
| Appendix F | Fairness Opinion |
| Appendix G | Interim Order |
| Appendix H | Notice of Hearing of Petition |
| Appendix I | Petition |
| Appendix J | BCBCA Dissent Provisions |
| Appendix K | Cease Trade Order and Partial Revocation Order |
| Appendix L | Gold Basin unaudited consolidated financial statements of for the years ended December 31, 2025 and 2024 |
| Appendix M | CANEX audited consolidated financial statements for the years ended September 30, 2024 and 2025 and management’s Discussion and Analysis in respect thereof |
| Appendix N | CANEX unaudited condensed interim consolidated financial statements for the three months ended December 31, 2025 and management’s Discussion and Analysis in respect thereof |
| Appendix O | Pro Forma Consolidated Financial Statements |
GLOSSARY OF TERMS
The following is a glossary of certain terms used in this Circular including Appendices C, D and E. Terms and abbreviations used in the other Appendices to this Circular are defined separately and the terms and abbreviations defined below are not used therein, except where otherwise indicated.
“Acquisition Proposal” means, other than the transactions contemplated by the Arrangement Agreement, any offer, proposal, expression of interest or inquiry, or public announcement of an intention (orally or in writing) from any person (other than CANEX or any of its subsidiaries) after the date of the Arrangement Agreement (including, for greater certainty, amendments or variations after the date of the Arrangement Agreement to any offer, proposal, expression of interest or inquiry that was made before the date of the Arrangement Agreement), relating to:
| (a) | any joint venture, earn in right, royalty grant, lease, license, acquisition, sale, disposition or transfer, direct or indirect, in a single transaction or a series of related transactions, of: |
| (i) | the assets of Gold Basin or any of its subsidiaries that, individually or in the aggregate, constitute 20% or more of the fair market value of the consolidated assets of Gold Basin and its subsidiaries, taken as a whole, or contribute 20% or more of the consolidated revenue of Gold Basin; or |
| (ii) | 20% or more of the issued and outstanding voting or equity securities (and/or securities convertible into, or exchangeable or exercisable for voting or equity securities) of Gold Basin or any of its subsidiaries; |
| (b) | any take over bid, tender offer, exchange offer, treasury issuance or other transaction that, if consummated, would result in such person beneficially owning, directly or indirectly, 20% or more of any class of the issued and outstanding voting or equity securities (and/or securities convertible into, or exchangeable or exercisable for voting or equity securities) of Gold Basin or any of its subsidiaries; |
| (c) | a plan of arrangement, merger, amalgamation, consolidation, share exchange, share issuance, business combination, reorganization, recapitalization, liquidation, dissolution, share reclassification or other similar transaction involving Gold Basin or any of its subsidiaries; or |
| (d) | any other transaction or series of transactions, the consummation of which could reasonably be expected to impede, interfere with, prevent or delay the transactions contemplated by the Arrangement Agreement or the Arrangement or which could reasonably be expected to materially reduce the benefits to CANEX under the Arrangement Agreement or the Arrangement; |
“affiliate” has the meaning ascribed to such term in NI 45-106;
“allowable capital loss” has the meaning ascribed to such term in the section titled “Income Tax Considerations – Certain Canadian Federal Income Tax Considerations – Holders Resident in Canada”;
“Arrangement” means the arrangement proposed pursuant to Division 5 of Part 9 of the BCBCA with respect to, inter alia, Gold Basin, the Shareholders and CANEX on the terms and subject to the conditions set out in the Plan of Arrangement, subject to any amendments or variations thereto made in accordance with the Plan of Arrangement or made at the direction of the Court in the Interim Order or the Final Order with the consent of Gold Basin and CANEX, each acting reasonably;
“Arrangement Agreement” means the arrangement agreement dated May 11, 2026 between Gold Basin and CANEX (including the schedules attached thereto), as the same may be amended, supplemented or otherwise modified from time to time in accordance with the terms thereof;
- 2 -
“Arrangement Notice Shares” has the meaning ascribed to such term in the section titled “Securities Law Considerations – Dissent Rights Under the Arrangement”;
“Arrangement Resolution” means the special resolution of the Shareholders approving the Arrangement, in the form set out in Appendix A;
“BCBCA” means the Business Corporations Act (British Columbia) including all regulations made thereunder, as promulgated or amended from time to time;
“Board” means the board of directors of Gold Basin as the same is constituted from time to time;
“Board Recommendation” means the unanimous recommendation of the Board to the Shareholders to vote in favour of the Arrangement Resolution after consultation with Stifel Nicolaus and legal advisors, and following the recommendation from the Special Committee, that the Plan of Arrangement is fair to the Shareholders and is in the best interests of Gold Basin;
“Broadridge” means Broadridge Financial Solutions, Inc.;
“business day” means any day of the year, other than a Saturday, Sunday or any day on which major banks are closed for business in the City of Vancouver, British Columbia, Canada;
“CANEX” means CANEX Metals Inc., a corporation existing under the Business Corporations Act (Alberta);
“CANEX Shareholders” means, at any time, the holders of CANEX Shares;
“CANEX Shares” means the common shares of CANEX, as currently constituted;
“Cease Trade Order” means the cease trade order dated May 6, 2025 issued by the British Columbia Securities Commission against the Shares;
“Change in Recommendation” means the circumstances where the Board (1) fails to provide the Board Recommendation, (2) withdraws, withholds, amends, modifies or qualifies, or proposes publicly to withdraw, withhold, amend, modify or qualify the Board Recommendation, (3) approves, accepts, endorses, or recommends or proposes publicly to approve, accept, endorse or recommend, any Acquisition Proposal, or (4) fails to reaffirm the Board Recommendation within the later of: (y) five (5) business days (and in any case prior to the Meeting) after having been requested in writing by CANEX to do so; and (z) if such request is made during a Response Period, within five (5) business days of the end of the Response Period (and in any case prior to the Meeting) (it being understood that the taking of a neutral position or no position with respect to a publicly announced Acquisition Proposal beyond the foregoing period (or beyond the time of the Meeting, if sooner) shall be considered a failure of the Board to reaffirm its recommendation within the requisite time period);
“CIM Standards” has the meaning ascribed to such term in the section titled “General Proxy Information – Information for United States Shareholders”;
“Circular” means this management information circular;
“CIRO” means the Canadian Investment Regulatory Organization;
“Consideration Shares” means the CANEX Shares to be issued to the Former Shareholders pursuant to the Arrangement;
“Convention” means the Convention Between Canada and the United States of America with Respect to Taxes on Income and on Capital, signed September 26, 1980, as amended;
“Court” means the Supreme Court of British Columbia;
- 3 -
“CRA” means the Canada Revenue Agency;
“Depositary” has the meaning ascribed to such term in the section titled “Summary – Procedure for Exchange of Shares for CANEX Shares”;
“Discovery Group” has the meaning ascribed to such term in the section titled “The Arrangement – Background to the Arrangement”;
“Dissent Rights” means the rights of dissent granted in favour of Registered Shareholders as of the Record Date in respect of the Arrangement, as described in the Plan of Arrangement;
“Dissenting Non-Resident Holder” has the meaning ascribed to such term in the section titled “Income Tax Considerations – Certain Canadian Federal Income Tax Considerations – Holders Not Resident in Canada”;
“Dissenting Resident Holder” has the meaning ascribed to such term in the section titled “Income Tax Considerations – Certain Canadian Federal Income Tax Considerations – Holders Resident in Canada”;
“Dissenting Shareholder” means a Registered Shareholder as of the Record Date who has duly and validly exercised the Dissent Rights in respect of the Arrangement Resolution in strict compliance with the Dissent Rights and who has not withdrawn or been deemed to have withdrawn such exercise of Dissent Rights;
“DRS Advice” has the meaning ascribed to such term in the section titled “Summary – Procedure for Exchange of Shares for CANEX Shares”;
“Effective Date” means the date that is two (2) business days after the last of the conditions to completion of the Arrangement as set forth in Article 5 to the Arrangement Agreement have been satisfied or waived (other than those conditions which cannot, by their terms, be satisfied until the Effective Date, but subject to satisfaction or waiver of such conditions as of the Effective Date) or such earlier or later date as is agreed to in writing by Gold Basin and CANEX;
“Effective Time” means the beginning of the day (Vancouver time) on the Effective Date or such other time as Gold Basin and CANEX may agree upon in writing;
“Fairness Opinion” means the fairness opinion of Stifel Nicolaus attached to this Circular as Appendix F;
“Final Order” means the final order of the Court approving the Arrangement under Section 291(4) of the BCBCA, and setting forth any necessary language for reliance upon the exemption from registration under Section 3(a)(10) of the U.S. Securities Act with respect to the Consideration Shares issued pursuant to the Arrangement, in form and substance acceptable to Gold Basin and CANEX, each acting reasonably, after a hearing upon the procedural and substantive fairness of the terms and conditions of the Arrangement, as such order may be affirmed, amended, modified, supplemented or varied by the Court (with the consent of both Gold Basin and CANEX, each acting reasonably) at any time prior to the Effective Date or, if appealed, as affirmed or amended (provided that any such amendment is acceptable to both Gold Basin and CANEX, each acting reasonably) on appeal unless such appeal is withdrawn, abandoned or denied;
“Former Shareholder” means the holders of Shares immediately prior to the Effective Time, other than any Dissenting Shareholder properly exercising Dissent Rights, CANEX or any other affiliate of CANEX;
“forward-looking information” has the meaning ascribed to such term in the section titled “General Proxy Information – Cautionary Statement Regarding Forward-Looking Information”;
“Gold Basin” means Gold Basin Resources Corporation, a corporation existing under the BCBCA;
- 4 -
“Gold Basin Project” has the meaning ascribed to such term in the section titled “Securities Law Considerations – Information Concerning Gold Basin”;
“Gold Range Project” has the meaning ascribed to such term in the section titled “Securities Law Considerations – Information Concerning CANEX”;
“Governmental Authority” means any foreign or domestic multinational, federal, provincial, territorial, state, regional, municipal, local or other government or governmental body and any division, agent, official, agency, bureau, commission, board or authority of any government, governmental body, governmental or public department, central bank, foreign investment authority, quasi governmental or private body (including the TSXV or any other stock exchange) exercising any statutory, regulatory, expropriation, environmental or taxing authority under the authority of any of the foregoing and any domestic, foreign or international judicial, quasi judicial or administrative court, tribunal, commission, board, panel or arbitrator acting under the authority of any of the foregoing;
“Halt” means the temporary halt in the trading of Shares ordered by CIRO on May 7, 2025;
“Helix” has the meaning ascribed to such term in the section titled “The Arrangement – Background to the Arrangement”;
“Holder” has the meaning ascribed to such term in the section titled “Income Tax Considerations – Certain Canadian Federal Income Tax Considerations”;
“IFRS” means International Financial Reporting Standards, which are issued by the International Accounting Standards Board, as adopted in Canada;
“Interim Order” means an interim order of the Court concerning the Arrangement pursuant to section 291(2) of the BCBCA, providing for, among other things, the calling and holding of the Meeting, as such order may be amended, affirmed, modified, supplemented or varied by the Court with the consent of Gold Basin and CANEX, each acting reasonably, a copy of the proposed form of which is attached to this Circular as Appendix G;
“Intermediary” has the meaning ascribed to such term in the section titled “General Proxy Matters – Advice to Beneficial Holders of Shares”;
“IRS” means the U.S. Internal Revenue Service;
“June 6 EOI” has the meaning ascribed to such term in the section titled “The Arrangement – Background to the Arrangement”;
“June 9 Press Release” has the meaning ascribed to such term in the section titled “The Arrangement – Background to the Arrangement”;
“Laurel Hill” means Laurel Hill Advisory Group;
“Law” or “Laws” means all laws, statutes, codes, ordinances (including zoning), decrees, rules, regulations, bylaws, notices, judicial, arbitral, administrative, ministerial, departmental or regulatory judgments, injunctions, Orders, decisions, settlements, writs, assessments, arbitration awards, rulings, determinations or awards, decrees or other requirements of any Governmental Authority having the force of law and any legal requirements arising under the common law or principles of law or equity and the term “applicable” with respect to such Laws and, in the context that refers to any person, means such Laws as are applicable at the relevant time or times to such person or its business, undertaking, property or securities and emanate from a Governmental Authority having jurisdiction over such person or its business, undertaking, property or securities;
“Letter of Transmittal” means the letter of transmittal enclosed with the Meeting Materials sent to Registered Shareholders;
- 5 -
“liens” means any hypothecs, mortgages, pledges, assignments, liens, charges, security interests, encumbrances and adverse rights or claims, whether contingent or absolute, and any agreement, option, right or privilege (whether by Law, contract or otherwise) capable of becoming any of the foregoing;
“Lock-Up Agreements” means the voting and support agreements dated May 7, 2026, between CANEX, on the one hand, and each of the senior officers and directors of Gold Basin who did not tender their Shares to the Offer, on the other hand, entered into as a condition precedent in favour of CANEX;
“Locked-up Shareholders” means each of the senior officers and directors of Gold Basin who have entered into Lock-Up Agreements;
“Louise Project” has the meaning ascribed to such term in the section titled “Securities Law Considerations – Information Concerning CANEX”;
“Mayfair” has the meaning ascribed to such term in the section titled “The Arrangement – Background to the Arrangement”;
“Mayfair Offer” has the meaning ascribed to such term in the section titled “The Arrangement – Background to the Arrangement”;
“Meeting” has the meaning ascribed to such term in the section titled “General Proxy Information – Introduction”;
“Meeting Materials” means, collectively, the Notice of Meeting and this Circular;
“MI 61-101” means Multilateral Instrument 61-101 — Protection of Minority Security Holders in Special Transactions of the Canadian Securities Administrators;
“MLI” has the meaning ascribed to such term in the section titled “Income Tax Considerations – Certain Canadian Federal Income Tax Considerations – Holders Not Resident in Canada”;
“NI 43-101” means National Instrument 43-101 — Standards of Disclosure for Mineral Projects of the Canadian Securities Administrators;
“NI 45-106” means National Instrument 45-106 — Prospectus Exemptions of the Canadian Securities Administrators;
“NI 51-102” means National Instrument 51-102 — Continuous Disclosure Obligations of the Canadian Securities Administrators;
“NI 54-101” means National Instrument 54-101 — Communication with Beneficial Owners of Securities of a Reporting Issuer of the Canadian Securities Administrators;
“Non-Registered Shareholder” has the meaning ascribed to such term in the section titled “General Proxy Matters – Advice to Beneficial Holders of Shares”;
“Non-Resident Holder” has the meaning ascribed to such term in the section titled “Income Tax Considerations – Certain Canadian Federal Income Tax Considerations – Holders Not Resident in Canada”;
“Notice of Dissent” has the meaning ascribed to such term in the section titled “Securities Law Considerations – Dissent Rights Under the Arrangement”;
“Notice of Meeting” means the notice of meeting of Gold Basin dated May 14, 2026 regarding the Meeting;
“Offer” has the meaning ascribed to such term in the section titled “The Arrangement – Background to the Arrangement”;
“Option Plan” means the stock option plan for directors, officers, employees and consultants of Gold Basin;
- 6 -
“Options” means options granted by Gold Basin to purchase Shares pursuant to the Option Plan;
“Outside Date” means the date by which the transactions contemplated by the Arrangement Agreement are to be completed, failing which the Arrangement Agreement may be terminated by either Gold Basin or CANEX, which date shall be June 10, 2026 or such later date as the Parties may agree;
“Partial Revocation Order” has the meaning ascribed to such term in the section titled “The Arrangement – Background to the Arrangement”;
“Parties” means CANEX and Gold Basin, and “Party” means any one of them, as applicable;
“Petition” means the Petition for the Final Order attached as Appendix I;
“Plan of Arrangement” means the plan of arrangement, substantially in the form of Appendix B, as amended, modified or supplemented from time to time in accordance with the Plan of Arrangement or at the direction of the Court in the Interim Order or Final Order, with the consent of Gold Basin and CANEX, each acting reasonably;
“Pro Forma Consolidated Financial Statements” means, collectively, (i) an unaudited pro forma consolidated statement of financial position of CANEX as at December 31, 2025, which gives effect to the Arrangement as if the transaction had closed on December 31, 2025; and (ii) unaudited pro forma consolidated statements of loss of CANEX for the three months ended December 31, 2025, which give effect to the Arrangement as if the Arrangement had closed on October 1, 2025;
“Proposed Amendments” has the meaning ascribed to such term in the section titled “Income Tax Considerations – Certain Canadian Federal Income Tax Considerations”;
“Proposed Offer” has the meaning ascribed to such term in the section titled “The Arrangement – Background to the Arrangement”;
“Proxy” has the meaning ascribed to such term in the section titled “General Proxy Matters – Appointment and Revocation of Proxies”;
“Record Date” has the meaning ascribed to such term in the section titled “General Proxy Matters – Voting Securities of Gold Basin and Principal Holders Thereof”;
“Registered Plans” has the meaning ascribed to such term in the section titled “Income Tax Considerations – Certain Canadian Federal Income Tax Considerations – Holders Resident in Canada – Eligibility for Investment”;
“Registered Shareholder” means a Shareholder who has their Shares registered in the name of the Shareholder;
“Regulation S” means Regulation S under the U.S. Securities Act;
“Representative” means the officers, directors, employees, financial advisors, legal counsel, accountants and other agents and representatives of a Party;
“Resident Holder” has the meaning ascribed to such term in the section titled “Income Tax Considerations – Certain Canadian Federal Income Tax Considerations – Holders Resident in Canada”;
“Response” has the meaning ascribed to such term in the section titled “Summary – Court Approval”;
“Response Period” has the meaning ascribed to such term in the section titled “The Arrangement Agreement – Non-Solicitation Covenant and Acquisition Proposal”;
“Resulting Issuer” means CANEX following completion of the Arrangement;
“Resulting Issuer Shares” means common shares of the Resulting Issuer;
- 7 -
“Rule 144” means Rule 144 under the U.S. Securities Act;
“SEC” means the United States Securities and Exchange Commission;
“Section 3(a)(10) Exemption” means the exemption from the registration requirements of the U.S. Securities Act provided by section 3(a)(10) thereof;
“SEDAR+” means the System for Electronic Document Analysis and Retrieval +;
“Share Consideration” means, in respect of each Share, 0.592 of a CANEX Share;
“Shareholder Approval” (i) 662/3% of the votes cast on the Arrangement Resolution by the Shareholders present in person or represented by proxy at the Meeting voting together as a single class; and (ii) if required under applicable Law, a simple majority of the votes cast by the Shareholders on the Arrangement Resolution excluding the votes for Shares held or controlled by “related parties” and “interested parties” as defined under MI 61-101; provided that, pursuant to section 8.2 of MI 61-101, the securities acquired by CANEX under the Offer may be voted in favor of the Arrangement Resolution;
“Shareholders” means, at any time, the holders of Shares;
“Shares” means the common shares of Gold Basin, as currently constituted;
“Shell Company” has the meaning ascribed to such term in the section titled “Securities Law Considerations – United States Securities Law Considerations”;
“Special Committee” means the special committee of the Board as the same is constituted from time to time;
“Stifel Nicolaus” means Stifel Nicolaus Canada Inc.;
“Superior Proposal” means any unsolicited, bona fide written Acquisition Proposal from a person or persons who is or are, as at the date of the Arrangement Agreement, a party that deals at arm’s length with Gold Basin, that is made after the date of the Arrangement Agreement (and is not obtained in violation of the Arrangement Agreement or any agreement between the person making such Acquisition Proposal and Gold Basin) that:
| (a) | is reasonably likely to be consummated without undue delay, taking into account all financial, legal, regulatory and other aspects of such Acquisition Proposal and the person or persons making such Acquisition Proposal; |
| (b) | is not subject to any financing condition and in respect of which the funds or other consideration necessary to complete the Acquisition Proposal, in the opinion of the Board, acting in good faith, after receiving the advice of its outside legal advisors and Stifel Nicolaus, are committed or will be immediately available to fund completion of the Acquisition Proposal at the time and upon the satisfaction of all conditions set out therein; |
| (c) | is not subject to any due diligence, access or investigation condition; |
| (d) | complies with securities Laws; |
| (e) | did not result from a breach of the Arrangement Agreement; and |
| (f) | in respect of which the Board determines, in its good faith judgment, after receiving the advice of its outside legal counsel and financial advisors, that: |
| (i) | failure to recommend such Acquisition Proposal to the Shareholders would be inconsistent with its fiduciary duties under applicable Laws, and |
- 8 -
| (ii) | having regard to all of its terms and conditions, including the certainty, timing and conditionality of completion, such Acquisition Proposal would, if consummated in accordance with its terms (and without assuming away any risk of non-completion), result in a transaction more favourable to Shareholders from a financial point of view than the Arrangement (after taking into account any change to the Arrangement proposed by CANEX pursuant to the terms of the Arrangement Agreement); |
for greater certainty, an Acquisition Proposal shall not constitute a Superior Proposal unless it is an Acquisition Proposal to acquire (A) all of the outstanding Shares (other than Shares beneficially owned by the person making such proposal) or (B) all or substantially all of the assets of Gold Basin and its subsidiaries, taken as a whole, and, if it relates to an acquisition of Shares, is made to all Shareholders on the same terms and conditions;
“Take-Over Bid Circular” has the meaning ascribed to such term in the section titled “The Arrangement – Background to the Arrangement”;
“Tax Act” means the Income Tax Act (Canada) and the regulations promulgated thereunder, as amended;
“taxable capital gain” has the meaning ascribed to such term in the section titled “Income Tax Considerations – Certain Canadian Federal Income Tax Considerations – Holders Resident in Canada”;
“Taxes” means:
| (a) | all taxes, imposts, levies, withholdings, duties, fees, premiums, assessments and other charges of any kind, however denominated, in each case imposed or levied by any Governmental Authority, including any interest, penalties or other additions that may become payable in respect thereof, whether disputed or not and whether assessed or unassessed, which taxes shall include, without limiting the generality of the foregoing, all income or profits taxes (including, but not limited to, federal, provincial, state and local income taxes), capital taxes, payroll and employee withholding taxes, employment insurance, social insurance taxes (including Canada Pension Plan or other government pension plan premiums or contributions), sales and use taxes, goods and services tax, harmonized sales tax, ad valorem taxes, excise taxes, franchise taxes, gross receipts taxes, business license taxes, occupation taxes, real and personal property taxes, stamp taxes, environmental taxes, transfer taxes, workers’ compensation premiums or charges, pension assessments and other governmental charges of a similar nature to any of the foregoing, whether disputed or not; and |
| (b) | any liability for the payment of any amount described in clause (a) of this definition as a result of being a member of an affiliated, consolidated, combined or unitary group for any period, as a result of any tax sharing or tax allocation agreement, arrangement or understanding, or as a result of being liable for another person’s taxes by contract or otherwise, |
and “Tax” has a corresponding meaning;
“Term Loan” means a term loan from CANEX to Gold Basin on substantially the terms and conditions in the term sheet set out in Schedule C to the Arrangement Agreement;
“Termination Fee” has the meaning ascribed to such term in the section titled “The Arrangement Agreement - Non-Solicitation Covenant and Acquisition Proposal”;
“TFSA”, “FHSA”, “RDSP”, “RESP”, “RRIF” and “RRSP” have the meanings ascribed to such terms in the section titled “Income Tax Considerations – Certain Canadian Federal Income Tax Considerations – Holders Resident in Canada”;
“TSX Trust Company” means TSX Trust Company, in its capacity as transfer agent of Gold Basin;
“TSXV” means the TSX Venture Exchange;
- 9 -
“U.S. Exchange Act” means the United States Securities Exchange Act of 1934, as amended, and the rules and regulations promulgated thereunder;
“U.S. Securities Act” means the United States Securities Act of 1933, as amended, and the rules and regulations promulgated thereunder;
“U.S. Tax Code” means the United States Internal Revenue Code of 1986, as amended;
“United States GAAP” has the meaning ascribed to such term in the in the section “General Proxy Information – Information for United States Shareholders”;
“United States” or “U.S.” means the United States of America, its territories and possessions, any State of the United States and the District of Columbia;
“VWAP” has the meaning ascribed to such term in the section titled “The Arrangement – Background to the Arrangement”; and
“White Hills Project” has the meaning ascribed to such term in the section titled “The Arrangement – Background to the Arrangement”.
Unless the context otherwise requires, words importing the singular include the plural and vice versa, words importing any gender include all genders and words importing persons include firms and corporations and vice versa.
- 10 -
MANAGEMENT INFORMATION CIRCULAR
GENERAL PROXY INFORMATION
Introduction
This Circular is furnished in connection with the solicitation of proxies by the management of Gold Basin Resources Corporation (“Gold Basin”) for use at the special meeting of Shareholders to be held at 1200 Waterfront Centre, 200 Burrard St., Vancouver, British Columbia on June 4, 2026, at 10:00 a.m. (Vancouver time) (the “Meeting”), respectively, and at any adjournment(s) or postponement(s) thereof.
This Circular does not constitute an offer to sell or a solicitation of an offer to purchase any securities or the solicitation of a proxy by any person in any jurisdiction in which such an offer or solicitation is not authorized or in which the person making such offer or solicitation is not qualified to do so or to any person to whom it is unlawful to make such an offer or solicitation of an offer or a proxy solicitation. Neither the delivery of this Circular nor any distribution of the securities referred to in this Circular will, under any circumstances, create an implication that there has been no change in the information set forth herein since the date at which such information is given in this Circular.
The information concerning CANEX contained in this Circular has been provided by CANEX. Although Gold Basin has no knowledge that would indicate that any of such information is untrue or incomplete, Gold Basin does not assume any responsibility for the accuracy or completeness of such information or the failure by Gold Basin to disclose events that may have occurred or may affect the completeness or accuracy of such information but that are unknown to Gold Basin.
The Plan of Arrangement is attached to this Circular as Appendix B. You are urged to carefully read the full text of the Arrangement Agreement and the Plan of Arrangement. All summaries of, and references to, the Arrangement Agreement, the Arrangement and the Plan of Arrangement in this Circular are qualified in their entirety by reference to the complete text of the Arrangement Agreement and the Plan of Arrangement. A copy of the Arrangement Agreement may be found under Gold Basin’s profile on SEDAR+ at www.sedarplus.ca.
Information contained in this Circular is given as of May 14, 2026 except where otherwise noted and except that information in documents incorporated by reference is given as of the dates noted therein.
Information contained in this Circular should not be construed as legal, tax or financial advice and Shareholders are urged to consult their own professional advisors in connection therewith.
No broker, dealer, salesperson or other person has been authorized to give any information or make any representation in connection with the Arrangement and the issuance of CANEX Shares in connection with the Arrangement, or other matters to be considered at the Meeting, other than those contained in this Circular, and if given or made, any such information or representation must not be relied upon as having been authorized.
Information For United States Shareholders
THE CONSIDERATION SHARES ISSUABLE TO SHAREHOLDERS HAS NOT BEEN APPROVED OR DISAPPROVED BY THE SEC OR THE SECURITIES REGULATORY AUTHORITY OF ANY STATE OF THE UNITED STATES, NOR HAS THE SEC OR THE SECURITIES REGULATORY AUTHORITY OF ANY STATE OF THE UNITED STATES PASSED ON THE ADEQUACY OR ACCURACY OF THIS CIRCULAR OR THE FAIRNESS OR MERITS OF THE PLAN OF ARRANGEMENT. ANY REPRESENTATION TO THE CONTRARY IS A CRIMINAL OFFENCE.
The issuance of the Consideration Shares to Shareholders in exchange for their Shares has not been and will not be registered under the U.S. Securities Act, or any U.S. state securities Laws, and will be issued to Shareholders in reliance upon the Section 3(a)(10) Exemption. The Section 3(a)(10) Exemption exempts the issuance of any securities issued in exchange for one or more bona fide outstanding securities from the general requirement of registration where the terms and conditions of the issuance and exchange of such securities have been determined by a court of competent jurisdiction, expressly authorized by Law to grant such approval, to be substantively and procedurally fair to the recipients of the securities, after a hearing upon the fairness of the terms and conditions of such issuance and exchange at which all persons to whom it is proposed to issue the securities have the right to appear and receive timely and adequate notice thereof.
- 11 -
The solicitation of proxies for the Meeting by means of this Circular is not subject to the requirements of section 14(a) of the U.S. Exchange Act. The proxy solicitation rules do not apply to solicitations made by a “foreign private issuer” (as such term is defined in Rule 3b-4 under the U.S. Exchange Act). Accordingly, the solicitations contemplated in this Circular are being made in the United States in accordance with Canadian corporate Laws and Canadian securities Laws, and this Circular has been prepared solely in accordance with disclosure requirements applicable in Canada. CANEX Shareholders and Shareholders in the United States should be aware that such requirements are different from those of the United States applicable to registration statements under the U.S. Securities Act and proxy statements under the U.S. Exchange Act.
The Consideration Shares issued to Shareholders in the United States pursuant to the Arrangement will not be registered under the U.S. Securities Act, but will be freely tradable under the U.S. Securities Act, except by persons who are “affiliates” (as defined in Rule 144) of CANEX after the completion of the Arrangement or who were affiliates of CANEX within 90 days prior to the completion of the Arrangement. The Consideration Shares issued to Shareholders who are such affiliates (or former affiliates) will be subject to certain restrictions on resale imposed by the U.S. Securities Act. See “Securities Law Considerations – United States Securities Law Considerations”.
Information concerning the properties and operations of each of CANEX and Gold Basin have been prepared in accordance with the requirements of Canadian securities Laws, which differ from the requirements of United States securities Laws. Mineral reserve and mineral resource estimates, as applicable, included or incorporated by reference in this Circular have been prepared in accordance with NI 43-101 and the Canadian Institute of Mining, Metallurgy and Petroleum definitions and classification system (the “CIM Standards”). NI 43-101 is a rule developed by the Canadian Securities Administrators which establishes standards for all public disclosure an issuer makes of scientific and technical information concerning mineral projects. Canadian standards, including NI 43-101, differ significantly from the current requirements of the SEC, and mineral reserve and mineral resource information contained or incorporated by reference in this Circular may not be comparable to similar information disclosed by United States companies.
Information concerning descriptions of mineralization and resources contained herein may not be comparable to information made public by U.S. companies which have historically been subject to the reporting and disclosure requirements of the SEC under the SEC’s Industry Guide 7. For example, this Circular uses the terms “measured”, “indicated” and “inferred” mineral resources. Gold Basin advises U.S. investors that while these terms are recognized and required by Canadian Securities Administrators and have more recently been recognized by the SEC in subpart 1300 of Regulation S-K (which is in the process of being implemented and will replace the SEC’s Industry Guide 7), they are not recognized by SEC Industry Guide 7. Furthermore, while subpart 1300 of Regulation S-K represents a substantial convergence of United States and Canadian mandated reporting for public mining companies, the two regimes are not the same.
Prior to the adoption of subpart 1300 of Regulation S-K, the SEC did not recognize the reporting of mineral deposits which do not meet the SEC Industry Guide 7 definition of “reserve”. The estimation of “measured” and “inferred” mineral resources involves greater uncertainty as to their existence and economic feasibility than the estimation of proven and probable reserves. The estimation of “inferred” resources involves far greater uncertainty as to their existence and economic viability than the estimation of other categories of resources. It cannot be assumed that all or any part of a “measured”, “inferred” or “indicated” mineral resource will ever be upgraded to a higher category or converted into a mineral “reserve”, as defined by the SEC. Under Canadian rules, estimates of “inferred mineral resources” may not form the basis of feasibility studies, pre-feasibility studies or other economic studies, except in prescribed cases, such as in a preliminary economic assessment under certain circumstances. SEC Industry Guide 7 currently only permits issuers to report mineralization that does not constitute “reserves” as in-place tonnage and grade without reference to unit measures. Under SEC Industry Guide 7, mineralization may not be classified as a “reserve” unless the determination has been made that the mineralization could be economically and legally produced or extracted at the time the reserve determination is made. U.S. investors are cautioned not to assume that any part or all of a “measured”, “indicated” or “inferred” mineral resource exists or is economically or legally mineable. Mineral resources that are not mineral reserves do not have demonstrated economic viability. The estimate of mineral resources may be materially affected by environmental, permitting, legal, title, taxation, socio-political, marketing, or other relevant issues. The quantity and grade of reported inferred resources in this estimation are uncertain in nature and there has been insufficient exploration to define these inferred resources as an indicated or measured mineral resource and it is uncertain if further exploration will result in upgrading them to an indicated or measured mineral resource category. Inferred mineral resources are considered too speculative geologically to have the economic considerations applied to enable them to be categorized as mineral reserves. The mineral resources in this Circular were reported using CIM Standards.
- 12 -
The financial statements and other financial information of Gold Basin included or incorporated by reference in this Circular are subject to Canadian auditing and auditor independence standards, which differ from United States generally accepted accounting principles (“United States GAAP”) and United States auditing and auditor independence standards in certain material respects and thus are not directly comparable to financial statements of United States companies which are prepared in accordance with United States GAAP and that are subject to United States auditing and auditor independence standards. This Circular does not include an explanation of the principal differences between, or any reconciliation of, IFRS and United States GAAP. Investors should consult with their own professional advisors for an understanding of the differences between IFRS and United States GAAP, and of how those differences might affect the financial information presented herein.
Shareholders subject to United States federal taxation should be aware that the Arrangement and the ownership and disposition of CANEX Shares may have material tax consequences in the United States, including, without limitation, the possibility that the Arrangement is a taxable transaction, in whole or in part, for United States federal income tax purposes. Shareholders should consult their own tax advisors to determine the particular tax consequences to them of participating in the Arrangement and the ownership and disposition of CANEX Shares acquired pursuant to the Arrangement.
The enforcement by CANEX Shareholders and Shareholders of civil liabilities under United States federal and state securities Laws may be affected adversely by the fact that CANEX and Gold Basin are organized under the Laws of Alberta and British Columbia, Canada, respectively, being a jurisdictions outside the United States, that some or all of the officers and directors of CANEX and Gold Basin, respectively, are residents of countries other than the United States, that some or all of the experts named in this Circular are residents of countries other than the United States and that all or a substantial portion of the assets of CANEX, Gold Basin and such persons are located outside the United States. As a result, it may be difficult or impossible for CANEX Shareholders and Shareholders in the United States to effect service of process within the United States upon CANEX, Gold Basin, their respective directors or officers or such experts, or to realize, against them, upon judgments of courts of the United States predicated upon civil liabilities under the federal securities Laws of the United States or “blue sky” Laws of any state within the United States. In addition, CANEX Shareholders and Shareholders in the United States should not assume that the courts of Canada: (a) would enforce judgments of United States courts obtained in actions against such persons predicated upon civil liabilities under the federal securities Laws of the United States or “blue sky” Laws of any state within the United States; or (b) would enforce, in original actions, liabilities against such persons predicated upon civil liabilities under the federal securities Laws of the United States or “blue sky” Laws of any state within the United States.
Currency Exchange Rates
The following table sets forth the high and low daily average exchange rates for one U.S. dollar expressed in Canadian dollars for each period indicated, the average of the daily average exchange rates for each period indicated and the daily average exchange rate at the end of each such period, based upon the daily average exchange rates provided by the Bank of Canada:
Three Months ended March 31 | Year ended December 31 | |||||||||||||||||||
| 2026 | 2025 | 2025 | 2024 | 2023 | ||||||||||||||||
| (C$) | (C$) | (C$) | (C$) | (C$) | ||||||||||||||||
| High | $ | 1.3939 | $ | 1.4603 | $ | 1.4603 | $ | 1.4416 | $ | 1.3875 | ||||||||||
| Low | $ | 1.3515 | $ | 1.4166 | $ | 1.3558 | $ | 1.3316 | $ | 1.3128 | ||||||||||
| Average rate for period | $ | 1.3717 | $ | 1.4353 | $ | 1.3978 | $ | 1.3698 | $ | 1.3497 | ||||||||||
| Rate at end of period | $ | 1.3939 | $ | 1.4376 | $ | 1.3706 | $ | 1.4389 | $ | 1.3226 | ||||||||||
- 13 -
Cautionary Statement Regarding Forward-Looking Information
This Circular (including the Appendices hereto) contains certain statements or disclosures that may constitute forward-looking information or forward-looking statements within the meaning of applicable securities Laws (“forward-looking information”). All statements and disclosures, other than those of historical fact, which address activities, events, outcomes, results or developments that management of CANEX or Gold Basin, as applicable, anticipates or expects may or will occur in the future (in whole or in part) should be considered forward-looking information. In some cases, forward-looking information can be identified by terms such as “anticipate”, “believe”, “contemplate”, “continue”, “could”, “enable”, “expect”, “forecast”, “future”, “may”, “plan”, “potential”, “will” or other comparable terminology.
Various assumptions or factors are typically applied in drawing conclusions or making the forecasts or projections set out in forward-looking information. Those assumptions and factors are based on information currently available to Gold Basin, including information obtained from third-party industry analysts and other third-party sources. In some instances, material assumptions and factors are presented or discussed elsewhere in this Circular (including the Appendices hereto) in connection with the statements or disclosure containing the forward-looking information. You are cautioned that the following list of material factors and assumptions is not exhaustive. The factors and assumptions include, but are not limited to:
| · | the approval of the Arrangement by the Court and Shareholders; |
| · | the approval of the issuance of CANEX Shares; |
| · | the timely receipt of all required regulatory approvals, including conditional approval of the TSXV with respect to listing the Consideration Shares and making the Term Loan; |
| · | satisfaction of the other closing conditions in all material respects in accordance with the Arrangement Agreement; |
| · | no unforeseen changes in the legislative and operating framework for the business of CANEX or Gold Basin, as applicable; |
| · | no significant adverse changes in economic conditions; |
| · | no significant adverse changes in commodity prices; |
| · | a stable competitive environment; |
| · | the ability to obtain equipment, services, supplies and personnel in a timely manner to carry out development activities; |
| · | the impact of increasing competition; |
| · | the continued availability of adequate debt and equity financing and cash flow from operations to fund planned expenditures; |
| · | the ability to obtain financing on acceptable terms; and |
- 14 -
| · | no significant event occurring outside the ordinary course of business such as a natural disaster or other calamity. |
In particular, this Circular (including the Appendices hereto) and the documents incorporated by reference herein contain forward-looking information and statements, including forward-looking information and statements pertaining to the following:
| · | the Interim Order; |
| · | the Meeting; |
| · | the reasons for, and the perceived benefits of, the Arrangement and possible synergies resulting from the Arrangement; |
| · | the structure, steps, timing and effects of the Arrangement; |
| · | the timing of the Final Order and the Effective Date of the Arrangement; |
| · | the satisfaction of conditions for listing of CANEX Shares to be issued in connection with the Arrangement following the Effective Time on the TSXV and the timing thereof; |
| · | the anticipated number of CANEX Shares to be issued in connection with the Arrangement; |
| · | the value and nature of the CANEX Shares issued to Shareholders pursuant to the Arrangement; |
| · | the availability of the Section 3(a)(10) Exemption for the issuance of the Consideration Shares; |
| · | the delisting of the Shares; |
| · | sources of income; |
| · | objectives, business plans and strategies; |
| · | financial conditions; |
| · | industry conditions; |
| · | future capital expenditures (including general and administrative expenses), including the timing, amount and nature thereof and sources of financing thereof; |
| · | pro forma information, including the Pro Forma Consolidated Financial Statements; |
| · | Gold Basin’s ability to continue as a going concern; |
| · | potential impairment of the Gold Basin Project; |
| · | the composition of the board of directors and management of the Resulting Issuer following the completion of the Arrangement; |
| · | other trends of the capital markets; |
| · | projection of market prices and costs; |
| · | supply and demand for gold and commodity prices; |
| · | treatment under governmental regulatory regimes and Tax Laws; |
| · | realization of the anticipated benefits of acquisitions and dispositions; |
| · | movements in currency exchange rates; |
- 15 -
| · | anticipated income Taxes; |
| · | plans and objectives of CANEX and Gold Basin management for future operations; |
| · | quantity of the existing mineral reserves and resources of CANEX and Gold Basin, if any; |
| · | fluctuating mineral prices; |
| · | expectations regarding the ability to raise capital and to add to reserves through acquisitions, exploration, development and divestiture of assets; |
| · | the exercise of Dissent Rights by Shareholders with regard to the Arrangement; |
| · | forecast business results; |
| · | anticipated tax treatment of the Arrangement on Shareholders; |
| · | anticipated financial and operational performance; |
| · | statements made in, and based upon, the Fairness Opinion; and |
| · | insiders and control persons of the Resulting Issuer. |
The forward-looking information in statements or disclosures in this Circular (including the Appendices hereto) and the documents incorporated by reference is based (in whole or in part) upon factors which may cause actual results, performance or achievements of CANEX or Gold Basin, as applicable, to differ materially from those contemplated (whether expressly or by implication) in the forward-looking information. Those factors are based on information currently available to CANEX and Gold Basin, as applicable, including information obtained from third-party industry analysts and other third-party sources. Actual results or outcomes may differ materially from those predicted by such statements or disclosures. While CANEX and Gold Basin do not know what impact any of those differences may have, their business, results of operations, financial condition and credit stability may be materially adversely affected. Factors that could cause actual results or outcomes to differ materially from the results expressed or implied by forward-looking information include, among other things:
| · | failure to complete the Arrangement in all material respects in accordance with the Arrangement Agreement or at all; |
| · | inability to obtain required consents, permits or approvals, including the Final Order, Shareholder Approval and conditional approval of the TSXV with respect to listing the Consideration Shares and the Term Loan; |
| · | sufficient liquidity for future operations; |
| · | cost of capital risk to carry out operations; |
| · | increased competition and the lack of availability of qualified personnel or management; |
| · | loss of key personnel; |
| · | uncertainty of government policy changes; |
| · | the risk of carrying out operations with minimal environmental impact; |
| · | operational hazards and availability of insurance; |
| · | industry conditions, including changes in Laws and regulations, including the adoption of new environmental Laws and regulations and changes in how they are interpreted and enforced; |
| · | general economic, market and business conditions; |
- 16 -
| · | competitive action by other companies; |
| · | the ability of suppliers to meet commitments; |
| · | stock market volatility; |
| · | creditworthiness of counterparties; |
| · | currency fluctuations, gold price volatility and fluctuations in the spot and forward price of gold or certain other commodities (such as silver), and the availability and increased costs associated with mining inputs and labour; |
| · | the focus of management’s time and attention on the Arrangement may detract from other aspects of the respective businesses of CANEX and Gold Basin; |
| · | the anticipated benefits and value creation from the Arrangement may not be realized, or may not be realized in the expected timeframes; |
| · | the businesses of CANEX and Gold Basin may not be successfully integrated following completion of the Arrangement; |
| · | increased costs, delays, suspensions and technical challenges associated with the construction of capital projects; |
| · | risk of loss due to acts of war, terrorism, sabotage and civil disturbances; |
| · | increased costs and physical risks, including extreme weather events and resource shortages, related to climate change; and |
| · | discrepancies between actual and estimated production for both CANEX and Gold Basin. |
The forward-looking information contained in this Circular (including the Appendices hereto) and the documents incorporated by reference herein are made as of the date of such documents. Gold Basin is not obligated to update or revise any forward-looking information, whether as a result of new information, future events or otherwise, except as required by applicable Laws. Because of the risks, uncertainties and assumptions contained herein, investors should not place undue reliance on forward-looking information. The foregoing statements expressly qualify any forward-looking information contained herein.
The reader is further cautioned that the preparation of financial statements in accordance with IFRS requires management to make certain judgments and estimates that affect the reported amounts of assets, liabilities, revenues and expenses. These estimates may change and such changes may be material, having either a negative or positive effect on net earnings as further information becomes available, and as the economic environment changes.
Shareholders are cautioned that these factors and risks are difficult to predict and that the assumptions used in the preparation of such information, although considered reasonably accurate at the time of preparation, may prove to be incorrect. Accordingly, Shareholders are cautioned that the actual results achieved will vary from the information provided herein and the variations may be material. Gold Basin cautions you that the above list of factors is not exhaustive. Consequently, there is no representation by Gold Basin that actual results achieved will be the same in whole or in part as those set out in the forward-looking information. Other factors which could cause actual results, performance or achievements of CANEX or Gold Basin to differ materially from those contemplated (whether expressly or by implication) in the forward-looking information are disclosed under “Risk Factors”.
Accounting Principles
The unaudited pro forma consolidated financial information of CANEX following the Arrangement as at December 31, 2025 and for the three months ended December 31, 2025 (the “Pro Forma Financial Statements”), are presented in Canadian dollars and are attached as Appendix O to this Circular.
- 17 -
The Pro Forma Financial Statements consist of: (i) an unaudited pro forma consolidated statement of financial position as at December 31, 2025, which gives effect to the Arrangement as if the transaction had closed on December 31, 2025; and (ii) unaudited pro forma consolidated statements of loss for the three months ended December 31, 2025, which give effect to the Arrangement as if the Arrangement had closed on October 1, 2025.
The Pro Forma Financial Statements are based on the respective historical consolidated financial statements of CANEX and Gold Basin. The Pro Forma Financial Statements should be read together with: (a) the unaudited condensed interim consolidated financial statements of CANEX for the three months ended December 31, 2025 which are attached as Appendix N to this Circular; and (b) the unaudited consolidated financial statements of Gold Basin for the years ended December 31, 2025 and 2024, which are attached as Appendix L to this Circular. The Pro Forma Financial Statements and adjustments, including the allocation of the purchase price, are based upon preliminary estimates of fair values of assets acquired and liabilities assumed, current available information and certain assumptions that CANEX believes are reasonable in the circumstances, as described in the notes to the Pro Forma Financial Statements.
Gold Basin has made a dual application pursuant to National Policy 11-203 – Process for Exemptive Relief Applications in Multiple Jurisdictions and Multilateral Instrument 11-102 – Passport System pursuant to Section 13.1 of NI 51-102 to securities regulatory authorities in British Columbia, Alberta and Ontario for exemptive relief from the requirement to include, among other things, certain financial statements, including audited financial statements for the for the years ended December 31, 2025 and 2024, in this Circular as prescribed by Item 14.2 of Form 51-102F5 in respect of this Circular (the “Exemptive Relief”). As of the date hereof, the Exemptive Relief has not been granted and there is no assurance that it will be granted. Under the Arrangement Agreement it is a condition to holding the Meeting and to completing the Arrangement that the Exemptive Relief is granted.
Although unaudited consolidated financial statements of Gold Basin for the years ended December 31, 2025 and 2024 have been prepared and are attached as Appendix L to this Circular, these statements are the responsibility of the Gold Basin’s management and have not been audited or reviewed on behalf of the shareholders by the independent external auditors of Gold Basin. To date, Gold Basin has been unable to provide audited consolidated financial statements for the years ended December 31, 2025 and 2024 and management’s discussion and analysis thereof, because:
| • | there have been significant changes in Gold Basin’s management and personnel responsible for accounting and financial reporting; |
| • | certain accounting records of Gold Basin may have been reconstructed after the fact; |
| • | there are unresolved questions regarding the nature, authorization, and supporting documentation of certain transactions and payments of Gold Basin; |
| • | there is uncertainty regarding the terms, substance, and related-party nature of certain financing arrangements and agreements of Gold Basin; and |
| • | there are limitations in the availability of supporting documentation and cooperation from certain persons previously involved with Gold Basin. |
Circumstances of this nature would generally be expected to create significant challenges in completing an audit in accordance with Canadian Auditing Standards. Such circumstances may increase audit risk, require substantially expanded audit procedures, and result in increased time and cost associated with the auditor’s engagement.
In addition, where there are concerns regarding the completeness of accounting records, authorization of transactions, related-party relationships, or the reliability of supporting documentation, auditors would typically be required to exercise heightened professional skepticism and perform extensive additional procedures to obtain sufficient appropriate audit evidence.
- 18 -
SUMMARY
This summary is qualified in its entirety by the more detailed information appearing elsewhere in the accompanying Notice of Meeting and this Circular, including the Appendices hereto. Capitalized terms used in this summary and not otherwise defined herein have the meanings set forth under “Glossary of Terms”.
The Meeting
The Meeting will be held at 1200 Waterfront Centre, 200 Burrard St., Vancouver, British Columbia on June 4, 2026, at 10:00 a.m. (Vancouver time), for the purposes set forth in the accompanying Notice of Meeting. The business of the Meeting will be to consider and vote upon, among other things, the Arrangement Resolution and to transact such further and other business as may properly be brought before the Meeting. See “The Arrangement”.
Parties to the Arrangement
CANEX
CANEX is a junior mineral exploration company focused on advancing the 100% owned Gold Range Project in Mohave County, Arizona and the Louise Project in British Columbia. Since inception, the efforts of CANEX have been devoted to the acquisition, exploration, and development of mineral properties. CANEX exists under the Business Corporations Act (Alberta) and its head and registered office is located at Suite 1620, 734 – 7th Avenue SW, Calgary, Alberta T2P 3P8, Canada. CANEX Shares trade on the TSXV under the symbol “CANX” and are quoted on the OTC Market under the symbol “NOMNF”. For further information regarding CANEX, refer to CANEX’s filings with the applicable securities regulatory authorities in Canada which may be obtained through SEDAR+ at www.sedarplus.ca. For further information concerning the business and operations of CANEX, see Appendix D.
Gold Basin
Gold Basin is a mineral exploration company focused on advancing its district-scale Gold Basin Project in Mohave County, Arizona. Gold Basin’s exploration efforts are focused on delineating and expanding near-surface oxide gold deposits. Gold Basin was incorporated under the BCBCA and its registered and head office located at 1200 Waterfront Centre, 200 Burrard Street, Vancouver, British Columbia, Canada. Prior to the Halt in trading ordered by CIRO on May 7, 2025, the Shares traded on the TSXV under the symbol “GXX”. The Shares also are quoted on the OTC Market under the symbol “GXXFF”. For further information regarding Gold Basin, refer to Gold Basin’s filings with the applicable securities regulatory authorities in Canada which may be obtained through SEDAR+ at www.sedarplus.ca. Information in Gold Basin’s publicly filed documents may be out of date, inaccurate or incomplete and may not be reflective of the current condition, including financial condition, of Gold Basin. See Appendix K of the Circular, “Cease Trade Order and Partial Revocation Order”.
Gold Basin has not filed continuous disclosure documents publicly since December 2, 2024, including its annual audited financial statements and annual management’s discussion and analysis for the year ended December 31, 2024, its certifications of annual filings for the year ended December 31, 2024, its unaudited interim financial statements and interim management’s discussion and analysis for the periods ended March 31, 2025, June 30, 2025, and September 30, 2025, its certifications of interim filings for the periods ended March 31, 2025, June 30, 2025 and September 30, 2025, and its notice, information circular and proxy materials for its 2025 annual general meeting. Accordingly, information in Gold Basin’s publicly filed documents may be out of date, inaccurate or incomplete and may not be reflective of the current condition, including financial condition, of Gold Basin. See Appendix K of the Circular, “Cease Trade Order and Partial Revocation Order”.
For further information concerning the business and operations of Gold Basin, see Appendix C of the Circular, “Information Concerning Gold Basin Resources Corporation”.
- 19 -
Resulting Issuer
As a result of the Arrangement, Gold Basin will be a wholly-owned subsidiary of CANEX. For further information concerning the business and operations of CANEX following completion of the Arrangement, see Appendix E.
Pro Forma Consolidated Financial Statements
See Appendix O for the Pro Forma Consolidated Financial Statements.
The Arrangement
The following is a summary only and reference should be made to the full text of the Arrangement Agreement which may be found under Gold Basin’s profile on SEDAR+ at www.sedarplus.ca, and the Plan of Arrangement attached as Appendix B.
The purpose of the Arrangement is to effect the combination of the businesses of CANEX and Gold Basin through the acquisition by CANEX of all of the issued and outstanding Shares, other than the Shares already owned or controlled by CANEX, or any other affiliate of CANEX.
If approved, the Arrangement will become effective at the Effective Time, which is expected to be at the beginning of the day (Vancouver time) on the Effective Date or such other time as Gold Basin and CANEX may agree upon in writing. At the Effective Time, the following shall occur or be deemed to occur sequentially in the following order:
| 1. | each Share issued and outstanding held by a Dissenting Shareholder shall be and shall be deemed to be transferred by the holder thereof, free and clear of all liens, to Gold Basin for cancellation and Gold Basin (with Gold Basin funds not directly or indirectly provided by CANEX or any affiliate of CANEX) shall thereupon be obliged to pay the amount therefor determined and payable in accordance with the Arrangement Agreement, and such Dissenting Shareholder shall cease to have any rights as a Shareholder other than the right to be paid the amount for such Dissenting Shareholder’s Shares determined in accordance with the Arrangement Agreement and the name of such holder shall be removed from the central securities register of Gold Basin as a Shareholder; |
| 2. | each Share held by a Former Shareholder shall be transferred by the holder thereof to CANEX in exchange for 0.592 of a CANEX Share in accordance with the terms and conditions set forth in the take over bid offer and circular of CANEX dated August 28, 2025, as amended by the notice of variation, change and extension dated December 12, 2025, the notice of variation, change and extension dated January 9, 2026, the notice of variation, change and extension dated January 19, 2026, and the notice of variation, change and extension dated January 30, 2026 and subject to the Arrangement Agreement, and upon such exchange: |
| i. | the Former Shareholders shall cease to be holders of Shares and to have any rights as holders of such Share other than the right to be paid the Share Consideration in accordance with the Plan of Arrangement; |
| ii. | the names of the Former Shareholders shall be removed from the register of Shareholders and added to the register of holders of CANEX Shares; |
| iii. | CANEX shall become the holder of the Shares so exchanged and shall be added to the register of Shareholders as the registered holder of such Shares; |
| 3. | Gold Basin will file an election with the CRA to cease to be a public corporation for the purposes of the Tax Act; and |
| 4. | the exchanges, transfers and cancellations provided under the Arrangement Agreement will be deemed to occur on the Effective Date, notwithstanding that certain of the procedures related thereto are not completed until after the Effective Date. |
- 20 -
See “The Arrangement – Description of the Arrangement”.
Background to the Arrangement
The execution of the Arrangement Agreement was the result of arm’s length negotiations among representatives and legal and financial advisors of CANEX and Gold Basin. This Circular contains a summary of the material events, including the meetings, negotiations, discussions and actions between the Parties and their representatives that preceded the execution and public announcement of the Arrangement Agreement.
See “The Arrangement – Background to the Arrangement”.
Reasons for the Arrangement
In reaching a conclusion that the Arrangement is in the best interest of Gold Basin, and in making their recommendations to the Shareholders, the Board and the Special Committee considered and relied upon a number of factors, including:
| (a) | Significant Upfront Premium to Shareholders. The consideration offered under the Arrangement represents a 242.0% premium to the last trading price of the Shares prior to the Cease Trade Order, based on the closing price of the CANEX Shares as of May 8, 2026. |
| (e) | Consolidation of Gold Districts and Near-Term Exploration and Expansion. The Arrangement will consolidate an advanced oxide gold exploration camp in Mohave County, Arizona hosting multiple zones of gold mineralization with strong drill results across an eight kilometre by eight kilometre area, opening up potential near-term exploration on favourable targets. |
| (f) | G&A Cost Savings. The complementary assets of Gold Basin and CANEX are expected to create synergies for the Resulting Issuer, including general and administrative cost savings to the Resulting Issuer of approximately $250,000 per year. These savings will be realized from a reduction of duplicate management roles and administrative expenses, and are expected to be fully realized in 2027. |
| (g) | Diversification. Completing the Arrangement will provide Shareholders not only with exposure to a consolidated gold district in Mohave County, Arizona, but also to the Resulting Issuer’s Louise Project in British Columbia. On July 31, 2025, CANEX announced results from an induced polarization geophysical survey which identified a new and previously unknown chargeability target two kilometres west of the historic Louise Project deposit and a steeply dipping zone of high chargeability below and to the north of the historic Louise Project deposit. |
| (h) | Focused, Professional and Cost-Effective Management Team. The Arrangement places the consolidated district under CANEX’s highly focused, professional and cost-effective management team, which will provide strong operational and governance oversight. |
| (i) | Experienced Board of Directors. Following the Arrangement, the Resulting Issuer’s board of directors will be led by experienced industry professionals, comprised of members of the current board of directors of CANEX. |
| (j) | Liquidity. The Arrangement will provide Shareholders with a more liquid investment. Trading in the Shares is restricted. On May 6, 2025, the British Columbia Securities Commission imposed the Cease Trade Order against the Shares. The next day, CIRO imposed the Halt in trading of the Shares on the TSXV. The CANEX Shares trade on the TSXV under the symbol “CANX” and are quoted on the OTC Market under the symbol “NOMNF”. CANEX has applied to list the CANEX Shares issuable pursuant to the Arrangement for trading on the TSXV. As of the date hereof, the TSXV has not conditionally approved the listing and there is no assurance that it will do so. Such listing will be subject to CANEX fulfilling all of the requirements of the TSXV, which cannot be guaranteed. There is no expectation that the Cease Trade Order will be rescinded if the Arrangement were not to proceed and Gold Basin were to continue in the status quo. |
- 21 -
| (k) | Enhanced Financial Capacity. CANEX has demonstrated an ability to raise capital and has strong support from a number of high profile industry professionals. With an enhanced capital markets profile, the Resulting Issuer is expected have even better access to lower-cost capital and an increased capability to advance its exploration properties. |
| (l) | Going Concern. In the absence of the Arrangement, there is considerable risk that Gold Basin will not have the ability to continue as a going concern and realize its assets and discharge its liabilities in the normal course of business. Gold Basin’s financial situation has significantly deteriorated since its last filed audited financial statements. As at May 14, 2026, Gold Basin has asserted liabilities of approximately $2,123,183 (of which $691,724 is purportedly owed to former management and directors, their related parties and their counsel), no cash or marketable securities and no revenue. Gold Basin’s ability to raise equity financing is restricted by the Cease Trade Order. |
| (m) | Potential Impairment of Gold Basin Project. Gold Basin’s former board and management may have potentially impaired Gold Basin’s ownership interest in its sole mineral asset, the Gold Basin Project in Mohave County, Arizona, through purported agreements, abandonment or encumbrances involving related parties or parties controlled by former directors and officers of Gold Basin for no or inadequate consideration. Although Gold Basin is taking steps to address these potential impairments and has reserved all rights against the former directors of Gold Basin, any impairment to Gold Basin’s ownership interest in the Gold Basin Project could have a material adverse impact on Gold Basin’s financial condition and operations. See “Recent Developments - Helix”, “Recent Developments - Settlement Agreement with Charrua Capital LLC” and “Exploration Projects – Gold Basin Project – Property Acquisition” in Appendix C. |
| (n) | Superior Proposals. Subject to compliance with the Arrangement Agreement, Gold Basin is permitted to furnish information and take certain other actions in respect of an unsolicited Acquisition Proposal that could reasonably be expected to lead to a Superior Proposal. The ability to terminate the Arrangement Agreement in specified circumstances and to accept a Superior Proposal, on payment of the Termination Fee of $211,777, which is subject to a right to match, provides further assurance to the Board that Gold Basin will have a reasonable opportunity to consider a potential superior unsolicited alternative transaction if one is subsequently proposed. See “The Arrangement Agreement – Non-Solicitation Covenant and Acquisition Proposal”. |
| (o) | Support of Shareholders. Certain Shareholders, including all of the directors and officers of Gold Basin who did not tender their Shares to the Offer, have entered into Lock-Up Agreements pursuant to which, and subject to the terms thereof, each has agreed to vote their Shares in favour of the Arrangement Resolution, representing in the aggregate approximately 0.64% of the issued and outstanding Shares. |
| (b) | Fairness Opinion. Stifel Nicolaus provided the Fairness Opinion to the Special Committee to the effect that, as at May 11, 2026, and subject to the assumptions, limitations and qualifications set out in the Fairness Opinion, the consideration to be received by the Shareholders pursuant to the Arrangement is fair, from a financial point of view, to the Shareholders (other than CANEX). See “The Arrangement – Fairness Opinion”. |
| (p) | Court Approval. The procedures by which the Arrangement is to be approved, including the requirement for approval by the Court after a hearing at which the fairness of the Arrangement to Shareholders will be considered. |
| (q) | Availability of Dissent Rights. The availability of Dissent Rights to Registered Shareholders as of the Record Date with respect to the Arrangement. |
- 22 -
| (r) | Review by Special Committee. In the judgment of the Special Committee relying on financial, legal and other advisors and discussions with management and their review of the Fairness Opinion, the Consideration Shares to be received by the Shareholders (other than CANEX and its affiliates) is fair, from a financial point of view, to the Shareholders (other than CANEX and its affiliates). |
| (s) | Transaction Certainty. The completion of the Arrangement is subject to a limited number of conditions, which the Special Committee, after consultation with independent legal and other advisors, considers likely to be satisfied. |
| (t) | 100% Acquisition of Shares. The Arrangement is for 100% of the Shares and, under the Plan of Arrangement, all Shareholders are treated identically (other than CANEX and its affiliates). |
| (u) | Canadian Tax Deferral. A Shareholder who is a Holder should generally be able to exchange Shares for the Consideration Shares under the Arrangement on a fully tax-deferred basis for Canadian income tax purposes. |
See Appendix E for further information concerning the Resulting Issuer.
The Board and the Special Committee also considered a number of potential issues regarding potentially negative factors and risks resulting from the Arrangement, including:
| (a) | The risks to Gold Basin if the Arrangement is not completed, including the costs to Gold Basin in resources and management attention in pursuing the Arrangement and the restrictions on the conduct of business prior to the completion of the Arrangement, including the ability to raise new funding. |
| (b) | The Arrangement Agreement’s restrictions on Gold Basin soliciting third parties to make an Acquisition Proposal prior to completion of the Arrangement and the specific requirements regarding what constitutes a Superior Proposal. |
| (c) | The Termination Fee of $211,777 payable to CANEX in certain circumstances, including if Gold Basin enters into an agreement with a third party to acquire Gold Basin that constitutes a Superior Proposal. |
| (d) | The right of CANEX to terminate the Arrangement Agreement under certain limited circumstances. |
| (e) | The potential risk of not obtaining certain consents from third parties required to complete the Arrangement, including from the Court, Shareholders, securities regulators and the TSXV. |
| (f) | The potential negative effect on Gold Basin’s relationship with its stakeholders, including suppliers and employees. |
| (g) | The dilution of Shareholders’ interest in Gold Basin business upon becoming shareholders of the Resulting Issuer. |
The Board’s and the Special Committee’s reasons for recommending the Arrangement include certain assumptions relating to forward-looking information, and such information and assumptions are subject to various risks. See “Risk Factors”.
See “The Arrangement – Reasons for the Arrangement”.
Fairness Opinion
In determining to recommend the approval of the Arrangement to the Board, the Special Committee considered, among other things, the Fairness Opinion delivered by Stifel Nicolaus.
- 23 -
Stifel Nicolaus provided the Fairness Opinion to the Special Committee to the effect that, as at May 11, 2026, and subject to the assumptions, limitations and qualifications set out in the Fairness Opinion, the consideration to be received by the Shareholders pursuant to the Arrangement is fair, from a financial point of view, to the Shareholders (other than CANEX). See “The Arrangement – Fairness Opinion”.
The summary of the Fairness Opinion in this Circular is qualified in its entirety by reference to the full text of the Fairness Opinion attached to this Circular as Appendix F. The full text of the Fairness Opinion sets out the assumptions made, procedures followed, information reviewed, matters considered and limitations and qualifications on the review undertaken by Stifel Nicolaus in connection with the Fairness Opinion. The Special Committee and the Board urge Shareholders to read the Fairness Opinion carefully and in its entirety. The Fairness Opinion has been prepared and provided solely for the use of the Special Committee and for inclusion in the Circular relating to the Arrangement and may not be used or relied upon by any person other than the Special Committee without Stifel Nicolaus’ express prior written consent. The Fairness Opinion does not address the relative merits of the Arrangement as compared to any other strategic alternative that may be available to Gold Basin. The Fairness Opinion is not a recommendation as to how any Shareholder should vote with respect to the Arrangement or any other matter.
See “The Arrangement – Fairness Opinion” and Appendix F to this Circular.
Recommendation of the Special Committee
The Special Committee composed of Jordan Ross, an independent director of Gold Basin (as defined in MI 61-101), was formed to, among other things, examine and review the merits of a possible transaction involving CANEX and Gold Basin and to consider other available strategic alternatives in conjunction with management and Gold Basin’s professional advisors and to make recommendations to the Board with respect to any such proposed transactions.
After careful consideration, including a thorough review of the Arrangement Agreement, the Fairness Opinion, as well as a thorough review of other materials and information, including matters discussed in this Circular, and taking into account the best interests of Gold Basin and in consultation with its legal advisors, the Special Committee unanimously recommended to the Board that the Board determine that the Share Consideration to be received by the Shareholders (other than CANEX and its affiliates) is fair, from a financial point of view, to the Shareholders (other than CANEX and its affiliates), that the Arrangement is in the best interests of Gold Basin, that the Arrangement Agreement and the Plan of Arrangement contemplated therein be unanimously approved, that Gold Basin enter into the Arrangement Agreement and for the Board to take all reasonable action to facilitate the Arrangement, and that the Board unanimously recommend that the Shareholders approve the Arrangement and vote in favour of the resolution approving the Arrangement.
See “The Arrangement – Recommendation of the Special Committee” and “The Arrangement – Reasons for the Arrangement”.
Recommendation of the Board
After careful consideration, including a thorough review of the Arrangement Agreement, the Fairness Opinion, as well as a thorough review of other matters, including those discussed in this Circular, and on the unanimous recommendation of the Special Committee, the Board unanimously determined that the acquisition to be effected by way of the Plan of Arrangement is in the best interests of Gold Basin, that the Consideration Shares to be received by the Shareholders (other than CANEX and its affiliates) pursuant to the Arrangement is fair, from a financial point of view, to the Shareholders (other than CANEX and its affiliates) and has unanimously approved the transactions contemplated by the Arrangement Agreement. Accordingly, the Board has unanimously approved the Arrangement and recommends that the Shareholders vote FOR the Arrangement Resolution.
See “The Arrangement – Recommendation of the Board” and “The Arrangement – Reasons for the Arrangement”.
Lock-Up Agreements
CANEX has entered into Lock-Up Agreements with the Locked-up Shareholders, pursuant to which the Locked-up Shareholders have agreed, subject to the terms and conditions of the Lock-Up Agreements, to vote their Shares in favour of the Arrangement Resolution approving the Arrangement. The Locked-up Shareholders collectively beneficially own or exercise control or direction over 866,667 Shares, representing approximately 0.64% of the outstanding Shares.
- 24 -
The obligations of a Locked-up Shareholder under their respective Lock-Up Agreements may be terminated at any time upon the written agreement of CANEX, Gold Basin and such Locked-up Shareholder, and will be terminated if the Arrangement Agreement is terminated in accordance with its terms.
Furthermore, CANEX is obligated under the Arrangement Agreement to vote its Shares in favour of the Arrangement Resolution to approve the Arrangement. CANEX beneficially owns or exercises control or direction over 70,088,199 Shares, representing approximately 51.86% of the outstanding Shares.
See “The Arrangement – Lock-Up Agreements”.
Description of the Arrangement
If approved, the Arrangement will become effective at the Effective Time, which is expected to be at the beginning of the day (Vancouver time) on the Effective Date or such other time as Gold Basin and CANEX may agree upon in writing. At the Effective Time, the following shall occur or be deemed to occur sequentially in the following order:
| 1. | each Share issued and outstanding held by a Dissenting Shareholder shall be and shall be deemed to be transferred by the holder thereof, free and clear of all liens, to Gold Basin for cancellation and Gold Basin (with Gold Basin funds not directly or indirectly provided by CANEX or any affiliate of CANEX) shall thereupon be obliged to pay the amount therefor determined and payable in accordance with the Arrangement Agreement, and such Dissenting Shareholder shall cease to have any rights as a Shareholder other than the right to be paid the amount for such Dissenting Shareholder’s Shares determined in accordance with the Arrangement Agreement and the name of such holder shall be removed from the central securities register of Gold Basin as a Shareholder; |
| 2. | each Share held by a Former Shareholder shall be transferred by the holder thereof to CANEX in exchange for 0.592 of a CANEX Share in accordance with the terms and conditions set forth in the take over bid offer and circular of CANEX dated August 28, 2025, as amended by the notice of variation, change and extension dated December 12, 2025, the notice of variation, change and extension dated January 9, 2026, the notice of variation, change and extension dated January 19, 2026, and the notice of variation, change and extension dated January 30, 2026 and subject to the Arrangement Agreement, and upon such exchange: |
| i. | the Former Shareholders shall cease to be holders of Shares and to have any rights as holders of such Shares other than the right to be paid the Share Consideration in accordance with the Plan of Arrangement; |
| ii. | the names of the Former Shareholders shall be removed from the register of Shareholders and added to the register of holders of CANEX Shares; |
| iii. | CANEX shall become the holder of the Shares so exchanged and shall be added to the register of Shareholders as the registered holder of such Shares; |
| 3. | Gold Basin will file an election with the CRA to cease to be a public corporation for the purposes of the Tax Act; and |
| 4. | the exchanges, transfers and cancellations provided under the Arrangement Agreement will be deemed to occur on the Effective Date, notwithstanding that certain of the procedures related thereto are not completed until after the Effective Date. |
No fractional CANEX Shares will be issued to the Former Shareholders. The number of CANEX Shares to be issued to the Former Shareholders will be rounded down to the nearest whole number of CANEX Shares in accordance with the BCBCA (with no compensation in lieu of such fractional share) in the event that a Former Shareholder is entitled to a fractional share.
- 25 -
See the “The Arrangement – Description of the Arrangement” and the Plan of Arrangement attached as Appendix B for additional information.
At the Meeting, Shareholders will be asked to consider and, if thought advisable, to pass, with or without variation, the Arrangement Resolution authorizing and approving the Arrangement, the full text of which is set out in Appendix A.
See “The Arrangement – Shareholder Approval”.
Court Approval
The BCBCA requires that the Court approve the Arrangement.
On or about May 14, 2026 Gold Basin applied for the Interim Order providing for the calling and holding of the Meeting and other procedural matters and filed a Notice of Hearing of Petition for the Final Order to approve the Arrangement. Copies of the proposed form of Interim Order and the Notice of Hearing of Petition are attached as Appendices G and H, respectively, to this Circular.
The Court hearing in respect of the Final Order is expected to take place at 9:45 a.m. (Vancouver time) on June 8, 2026, or as soon thereafter as counsel for Gold Basin may be heard, at the courthouse, 800 Smithe Street, Vancouver, British Columbia, subject to the Shareholder Approval. At the hearing, the Court will consider, among other things, the fairness of the terms and conditions of the Arrangement and the rights and interests of every person affected. The Court may approve the Arrangement in any manner the Court may direct, subject to compliance with such terms and conditions, if any, as the Court deems fit.
Under the terms of the Interim Order, each Shareholder and holder of Options will have the right to appear before the Court and make submissions at the application for the Final Order. Any person desiring to appear at the hearing of the application for the Final Order is required to indicate their intention to appear by filing with the Court and serving Gold Basin at the address set out below, on or before 4:00 p.m. (Vancouver time) on June 4, 2026, a Response to Petition (“Response”), including their address for service, together with all materials on which they intend to rely at the application. The Response and supporting materials must be delivered, within the time specified, to Gold Basin at the following address:
Fasken Martineau DuMoulin LLP
550 Burrard Street, Suite 2900
Vancouver, British Columbia V6C 0A3
Attention: Mark Pontin
The Final Order, if granted, will constitute a basis for the Section 3(a)(10) Exemption with respect to CANEX Shares to be issued to Shareholders pursuant to the Arrangement. Prior to the hearing on the Final Order, the Court has been or will be informed of this effect of the Final Order.
The Petition is attached as Appendix I. See “The Arrangement – Court Approval”.
Procedure for Exchange of Shares for CANEX Shares
For each Registered Shareholder, accompanying this Circular is a Letter of Transmittal.
In order for a Registered Shareholder to receive the Consideration Shares following the Effective Time for each Share held by such Registered Shareholder, such Registered Shareholder must, among other things, deposit the certificate(s) or Direct Registration System advice (“DRS Advice”) representing their Shares with TSX Trust Company (in its capacity as depositary pursuant to the Arrangement) (the “Depositary”). The Letter of Transmittal, duly completed and signed, together with all other documents and instruments referred to in the Letter of Transmittal or requested by the Depositary, must accompany all certificates or DRS Advices for Shares deposited in exchange for Consideration Shares pursuant to the Arrangement.
- 26 -
Notwithstanding the foregoing, CANEX shall have full discretion to determine whether any Letter of Transmittal and any accompanying certificates or DRS Advices representing Shares are complete and proper and CANEX shall have the absolute right to determine whether to accept or reject any or all Letters of Transmittal not complete or in proper form. Delivery to an address other than to the specified address in the Letter of Transmittal does not constitute delivery for the purpose of receiving Consideration Shares.
Any Non-Registered Shareholder whose Shares are registered in the name of a broker, investment dealer, bank, trust corporation, trustee or other nominee should contact that nominee for assistance in depositing such Shares and should follow the instructions of such nominee in order to deposit such Shares with the Depositary. Delivery to an address other than to the specified address in the Letter of Transmittal does not constitute delivery for the purpose of receiving Consideration Shares.
See “The Arrangement – Procedure for Exchange of Shares for CANEX Shares”.
Dissent Rights with Respect to the Arrangement
Registered Shareholders as of the Record Date have Dissent Rights with respect to the Arrangement. Any Registered Shareholders as of the Record Date who dissent from the Arrangement Resolution in accordance with sections 237 to 247 of the BCBCA, as amended by the Plan of Arrangement, the Interim Order and the Final Order (if applicable), will be entitled to be paid by Gold Basin the fair value of the Shares held by such Shareholders determined as at the point in time immediately before the Arrangement Resolution is approved by the Shareholders. The Dissent Rights with respect to the Arrangement must be strictly complied with in order for Registered Shareholders to receive cash representing the fair value of Shares held.
To exercise the Dissent Rights with respect to the Arrangement Resolution, a written notice of dissent to the Arrangement Resolution must be received by Gold Basin at Fasken Martineau DuMoulin LLP, 550 Burrard Street, Suite 2900, Vancouver, British Columbia, V6C 0A3 (Attention: Mark Pontin) not later than 5:00 p.m. (Vancouver time) on June 2, 2026, or the business day that is two business days prior to the Meeting.
The right to dissent is described in this Circular and the text of each of the Plan of Arrangement, the proposed form of Interim Order and sections 237 to 247 of the BCBCA, being set forth in Appendices B, G and J, respectively, to this Circular. See “Securities Law Considerations – Dissent Rights Under the Arrangement”.
Income Tax Considerations
Shareholders should consult their own tax advisors about the applicable Canadian or United States federal and provincial and local tax consequences of the Arrangement and the ownership and disposition of CANEX Shares acquired pursuant to the Arrangement.
For a summary of certain material Canadian income tax consequences of the Arrangement, see “Income Tax Considerations – Certain Canadian Federal Income Tax Considerations”. Such summary is not intended to be legal or tax advice to any particular Shareholder.
Risk Factors
Shareholders who vote in favour of the Arrangement Resolution will be voting in favour of combining the businesses of CANEX and Gold Basin, and to invest in CANEX Shares. There are certain risk factors associated with the Arrangement and investment in CANEX Shares, which should be carefully considered by Shareholders, including the fact that the Arrangement may not be completed if, among other things, the Arrangement Resolution is not approved at the Meeting or if any other conditions precedent to the completion of the Arrangement are not satisfied or waived, as applicable. Readers are cautioned that such risk factors are not exhaustive.
See “Risk Factors”.
- 27 -
GENERAL PROXY MATTERS
Solicitation of Proxies
This Circular is provided in connection with the solicitation of proxies by the management of Gold Basin for use at the Meeting to be held at 1200 Waterfront Centre, 200 Burrard St., Vancouver, British Columbia on June 4, 2026, at 10:00 a.m. (Vancouver time) for the purposes set forth in the accompanying Notice of Meeting. While it is expected that the solicitation will be made primarily by mail, proxies may be solicited personally or by telephone by directors, officers and employees of Gold Basin (who will not be specifically remunerated therefor). Gold Basin has retained Laurel Hill to assist it in its solicitation of proxies from Shareholders and provide additional services including but not limited to strategic shareholder communications and recommending corporate governance best practices. Gold Basin has agreed to pay Laurel Hill an aggregate fee of $36,750, plus reasonable out-of-pocket expenses, for these services. All costs of the solicitation for the Meeting will be borne by Gold Basin.
Shareholders consist of registered (or direct) shareholders and non-registered (or indirect or beneficial) shareholders. You are a Registered Shareholder if your name appears on a physical share certificate or DRS Advice issued by Gold Basin’s transfer agent, TSX Trust Company. You are a Non-Registered Shareholder if you hold Shares through an Intermediary, such as a bank, trust company, securities dealer, broker or other nominee or a clearing agency. Most of the Shareholders are Non-Registered Shareholders.
If you owned Shares (either directly or through an Intermediary) as of the Record Date, you are entitled to have your vote counted at the Meeting. The instructions provided below set forth the different procedures to be followed to ensure you are represented at the Meeting whether you are a registered or non-registered (beneficial) holder of Shares. If your Shares are held in more than one form, you should sign and submit all forms of proxy and voting instruction forms received in accordance with the instructions provided.
The information set forth below generally applies to Registered Shareholders. If you are a beneficial holder of Shares (i.e., your Shares are held through an Intermediary, such as a bank, trust company, securities dealer, broker or other nominee or a clearing agency), see “General Proxy Matters – Advice to Beneficial Holders of Shares”.
Voting Procedures
Registered Shareholders and duly appointed proxyholders may attend the Meeting and vote their Shares. Registered Shareholders and duly appointed proxyholders can participate in the Meeting in person.
Voting at the Meeting will only be available for Registered Shareholders and duly appointed proxyholders who have properly registered.
Shareholders who wish to appoint a third-party proxyholder, who is not the management designated proxyholder, to represent them at the Meeting, including Non-Registered Shareholders who wish to appoint themselves or another third party as proxyholder to attend, participate or vote at the Meeting, MUST submit their duly completed proxy or voting instruction form. See “Advice to Beneficial Holders of Shares” below for further details.
Non-Registered Shareholders who have not duly appointed themselves as proxyholder will be able to attend the Meeting as guests, but will not be able to participate or vote at the Meeting.
Appointment and Revocation of Proxies
Registered Shareholders who cannot attend the Meeting in-person may vote by proxy either by mail, personal delivery or fax. Proxies must be completed in accordance with the instructions provided on the form of proxy enclosed with respect to the Meeting (the “Proxy”) and must be received by Gold Basin’s transfer agent, TSX Trust Company, by 10:00 a.m. (Vancouver time) on June 2, 2026, or not less than 48 hours before the commencement of any adjournment or postponement of the Meeting. Registered Shareholders must return the properly completed Proxy to TSX Trust Company as follows:
| (a) | By mail or personal delivery to TSX Trust Company, Suite 301 - 100 Adelaide Street West, Toronto, Ontario, Canada, M5H 4H1; or |
- 28 -
| (b) | By fax to TSX Trust Company at 1-416-595-9593. |
The chair of the Meeting will have the discretion to accept or reject Proxies deposited in any other manner.
To be valid, the Proxy must be executed by a Registered Shareholder or a Registered Shareholder’s attorney duly authorized in writing or, if the Registered Shareholder is a body corporate, by a duly authorized officer or attorney. If the form of Proxy is executed by an attorney for an individual Registered Shareholder or by an officer or attorney of a Registered Shareholder that is a company or association, documentation evidencing the power to execute the Proxy may be required with signing capacity stated. If not dated, the Proxy will be deemed to have been dated the date that it is mailed to Shareholders.
Management of Gold Basin has designated Shane Ebert and Barbara O’Neill as proxyholders to attend the Meeting and act for those Shareholders at the Meeting who have not specified a particular proxyholder. You have the right to appoint a person other than the designated proxyholders, who need not be a Shareholder, to be your proxyholder if you choose. If you are returning your Proxy to TSX Trust Company, such right may be exercised by inserting such person’s name in the blank space provided in the form of proxy and striking out the names of the designated proxyholders. If you appoint a proxyholder other than the designated proxyholders, that proxyholder must attend the Meeting and vote at the Meeting for your vote to be counted.
A Registered Shareholder executing the Proxy may indicate the manner in which the appointee is to vote with respect to any specific item by checking the appropriate space. The persons named in the enclosed form of proxy will vote the Shares in respect of which they are appointed by proxy on any ballot that may be called for in accordance with the instructions thereon. In the absence of such instructions, such Shares will be voted in favour of each of the matters referred to herein by the persons named in the enclosed form of proxy.
Revoking a Proxy
A Proxy given pursuant to this solicitation may be revoked at any time prior to its use.
If you are a Registered Shareholder and have given a Proxy, you may revoke it as to any matter on which a vote has not already been cast pursuant to the authority conferred by the Proxy. Proxies may be revoked by depositing a written instrument giving notice of revocation at the office of TSX Trust Company, set out above, or at the registered office of Gold Basin, c/o Fasken Martineau DuMoulin LLP, 550 Burrard Street, Suite 2900, Vancouver, British Columbia, V6C 0A3 (Attention: Mark Pontin), on or before the last business day preceding the day of the Meeting at which such Proxy is to be used. The written notice of revocation must be executed by you or by an officer (if the Registered Shareholder is a corporation or association) or attorney upon presentation of your written authorization.
Proxies may also be revoked by: (a) executing another form of proxy bearing a later date and depositing the same at the offices of TSX Trust Company, prior to the deadline for depositing Proxies set out above; or (b) by attending the Meeting and voting your Shares. A Proxy may also be revoked by any other method permitted by applicable Law.
Only Registered Shareholders have the right to revoke a Proxy in this manner. Non-Registered Shareholders that wish to revoke their voting instructions must, in sufficient time in advance of the Meeting, contact their Intermediary to arrange a revocation.
Voting of Shares Represented by Management Proxies
On any matter to be acted upon or any ballot that may be called for at the Meeting, the Shares represented by each properly executed Proxy in favour of the persons designated in the enclosed Proxy received by Gold Basin will be voted for or against in accordance with the specifications given by the Registered Shareholder. In the absence of such specifications in an enclosed Proxy where the Registered Shareholder has appointed the persons whose names have been pre-printed in the enclosed Proxy as the Shareholder’s nominee at the Meeting, the Shares represented by such Proxies will be voted FOR each of the matters specified in this Circular, including the Arrangement Resolution.
- 29 -
The enclosed Proxy confers discretionary authority upon the persons named therein with respect to amendments to or variations of matters identified in the Notice of Meeting and with respect to other matters, if any, which may properly come before the Meeting. At the date of this Circular, the management of Gold Basin knows of no such amendments, variations or other matters to come before the Meeting. However, where a Registered Shareholder has appointed the persons whose names have been pre-printed in the enclosed Proxy as the Registered Shareholder’s nominee at the Meeting, if any amendments or variations to matters identified in the Notice of Meeting or other matters which are not now known to management of Gold Basin should properly come before the Meeting, the enclosed Proxy may be voted on such matters in accordance with the best judgment of the person voting the Proxy.
Advice to Beneficial Holders of Shares
Registered Shareholders or the persons they validly appoint as their proxies are permitted to vote at the Meeting. However, in many cases, Shares beneficially owned by a person (a “Non-Registered Shareholder”) are registered either: (i) in the name of an intermediary (including banks, trust companies, securities dealers or brokers and trustees or administrators of self-administered RRSPs, RRIFs, RESPs and similar plans) that the Non-Registered Shareholder deals with in respect of the Shares (an “Intermediary”), or (ii) in the name of a clearing agency (such as CDS Clearing and Depository Services Inc.) of which the Intermediary is a participant, and therefore are not a Registered Shareholder. Only Registered Shareholders or duly appointed proxyholders are permitted to vote at the Meeting. Without specific instructions, Intermediaries are prohibited from voting securities for their clients.
Gold Basin will have caused its agent to deliver copies of the Meeting Materials to the clearing agencies and Intermediaries for onward distribution to Non-Registered Shareholders.
Non-Registered Shareholders who do not hold their Shares in their own name should also instruct their broker or other Intermediary to complete the Letter of Transmittal with respect to such holders’ Shares and to deliver such Letter of Transmittal to TSX Trust Company, as depositary, in order to receive the Consideration Shares pursuant to the Arrangement.
Intermediaries are required to forward the Meeting Materials to Non-Registered Shareholders unless a Non-Registered Shareholder has waived their right to receive them. Intermediaries often use service companies, such as Broadridge, to forward the Meeting Materials to Non-Registered Shareholders. Applicable regulatory policy requires Intermediaries to seek voting instructions from Non-Registered Shareholders in advance of shareholder meetings. Every Intermediary has its own mailing procedures and provides its own return instructions, which should be carefully followed by Non-Registered Shareholders in order to ensure that their Shares are voted at the Meeting or any adjournment or postponement thereof. Often, the voting instruction form supplied to a Non-Registered Shareholder by its Intermediary is identical to the form of proxy provided to Registered Shareholders; however, its purpose is limited to instructing the Registered Shareholder on how to vote on behalf of the Non-Registered Shareholder. Generally, those Non-Registered Shareholders who have not waived the right to receive Meeting Materials will either:
| (a) | be given a Proxy which has already been signed by the Intermediary (typically by a facsimile stamped signature), which is restricted as to the number of Shares beneficially owned by the Non-Registered Shareholder, but which is otherwise uncompleted. This Proxy need not be signed by the Non-Registered Shareholder. In this case, the Non-Registered Shareholder who wishes to submit a Proxy should properly complete the Proxy and deposit it with TSX Trust Company in the manner set out above in this Circular, with respect to the Shares beneficially owned by such Non-Registered Shareholder; or |
| (b) | more typically, be given a voting information form which is not signed by the Intermediary and which, when properly completed and signed by the Non-Registered Shareholder and returned to the Intermediary or its service company, will constitute voting instructions which the Intermediary must follow. Typically, the voting information form will consist of a one page pre-printed form. The purpose of this procedure is to permit the Non-Registered Shareholder to direct the voting of the Shares beneficially owned by such Non-Registered Shareholder. |
- 30 -
The majority of Intermediaries now delegate responsibility for obtaining instructions from clients to Broadridge. Broadridge typically mails a scannable voting instruction form in lieu of the form of proxy. If you are a Non-Registered Shareholder (holding your Shares through a bank, broker, trust company, or custodian) and have received a scannable voting instruction form from Broadridge, you are requested to complete and return the voting instruction form to Broadridge by mail or facsimile or your Intermediary as instructed on the voting instruction form. Alternatively, Non-Registered Shareholders can call the toll-free telephone number printed on their voting instruction form or go to www.proxyvote.com and enter their 16 digit control number to deliver their voting instructions. Broadridge tabulates the results of all instructions received and provides appropriate instructions respecting the voting of Shares to be represented at the Meeting or any adjournment or postponement thereof.
If a Non-Registered Shareholder wishes to attend the Meeting and vote in-person (or have another person attend in-person and vote on behalf of the Non-Registered Shareholder), the Non-Registered Shareholder should insert the Non-Registered Shareholder’s name (or the name of the person the Non-Registered Shareholder wants to attend and vote on the Non-Registered Shareholder’s behalf) in the space provided for that purpose on the request for voting instructions form and return it to the Non-Registered Shareholder’s Intermediary or send the Intermediary another written request that the Non-Registered Shareholder or its nominee be appointed as proxyholder. The Intermediary is required under NI 54-101 to arrange, without expense to the Non-Registered Shareholder, to appoint the Non-Registered Shareholder or its nominee as proxyholder in respect of the Non-Registered Shareholder’s Shares. Under NI 54-101, unless corporate Law does not allow it, if the Intermediary makes an appointment in this manner, the Non-Registered Shareholder or its nominee, as applicable, must be given authority to attend, vote and otherwise act for and on behalf of the Intermediary (who is the registered shareholder) in respect of all matters that come before the meeting and any adjournment or postponement of the meeting. An Intermediary who receives such instructions at least one business day before the deadline for submission of proxies is required to deposit the proxy within that deadline, in order to appoint the Non-Registered Shareholder or its nominee as proxyholder. If a Non-Registered Shareholder requests that the Intermediary appoint the Non-Registered Shareholder or its nominee as proxyholder, the Non-Registered Shareholder or its appointed nominee, as applicable, will need to attend the meeting in-person in order for the Non-Registered Shareholder’s vote to be counted.
Gold Basin may utilize the Broadridge QuickVote™ service to assist Non-Registered Shareholders that are “non-objecting beneficial owners” with voting their Shares over the telephone.
If you have questions, you may contact Gold Basin’s proxy solicitation agent, Laurel Hill, by calling 1-877-452-7184 (North America Toll-Free) or 416-304-0211 (outside of North America), by texting “INFO” to either number, or by emailing assistance@laurelhill.com.
Voting Securities of Gold Basin and Principal Holders Thereof
The Board has fixed the close of business on May 5, 2026 as the record date (the “Record Date”), being the date for the determination of the registered holders of Shares entitled to receive notice of, and vote at, the Meeting. All such holders of record of Shares on the Record Date are entitled either to attend the Meeting and vote the Shares held by them or, provided a completed and executed Proxy shall have been delivered to TSX Trust Company, within the time specified in the attached Notice of Meeting, to attend by Proxy and to vote the Shares held by them.
At the Meeting, Shareholders will be asked to consider and, if thought advisable, to pass, with or without variation, the Arrangement Resolution authorizing the Arrangement, the full text of which is set out in Appendix A. In order to become effective, the Arrangement Resolution must be approved by an affirmative vote of: (i) 662/3% of the votes cast on the Arrangement Resolution by the Shareholders present in person or represented by proxy at the Meeting voting together as a single class; and (ii) if required under applicable Law, a simple majority of the votes cast by the Shareholders on the Arrangement Resolution excluding the votes for Shares held or controlled by “related parties” and “interested parties” as defined under MI 61-101; provided that, pursuant to section 8.2 of MI 61-101, the securities acquired by CANEX under the Offer may be voted in favor of the Arrangement Resolution.
- 31 -
The authorized share capital of Gold Basin consists of an unlimited number of Shares without par value. As at the Record Date, there were 135,130,486 Shares issued and outstanding. Each Share entitles the holder thereof to one vote on all matters to be acted upon at the Meeting.
Business may be transacted at the Meeting if two persons who are, or who represent by proxy, shareholders who, in the aggregate, hold at least one-twentieth of the issued shares entitled to be voted at the meeting are present.
To the knowledge of the directors and executive officers of Gold Basin, as at the date hereof, the following are the only persons or companies that beneficially own or exercise control or direction over, directly or indirectly, 10% or more of the voting rights attached to all of the issued and outstanding Shares:
| Name of Shareholder | Number and Percentage of Shares | |
| CANEX Metals Inc. | 70,088,199 (51.86%) |
THE ARRANGEMENT
As at the date hereof, there are 135,130,486 Shares issued and outstanding, of which 70,088,199 Shares are held by CANEX. Based on the respective share values at the date of announcement of the Arrangement, Shareholders (other than CANEX and its affiliates, but including Shareholders which tendered to the Offer) are expected to own approximately 32.3% of the post-Arrangement Resulting Issuer Shares on a diluted in-the-money basis (assuming no Dissent Rights are exercised). The Arrangement will be implemented by way of a court-approved plan of arrangement under the BCBCA pursuant to the terms of the Arrangement Agreement, the Interim Order and the Final Order.
Background to the Arrangement
The following is a summary of the material events, discussions and actions leading up to the Arrangement.
CANEX has had discussions with Gold Basin regarding potential merger opportunities and the relative valuation of the companies since 2022. During 2023 and 2024, various meetings were held between CANEX’s and Gold Basin’s management and board members regarding the potential consolidation of the Gold Basin exploration district in Mohave County, Arizona by merging the Gold Basin Project and the Gold Range Project. While a number of Gold Basin’s then directors, including Jim Paterson, John Robins and Darren Klinck, were supportive of merging the district, Gold Basin’s Australia-based management were mostly opposed, but at times would express interest – especially when Gold Basin was financially constrained.
In September 2023, Gold Basin sent an informal merger ratio proposal by email to CANEX, suggesting an exchange ratio of 1.0 Share for 3.75 CANEX Shares which represented a zero (0%) percent premium transaction. CANEX did not find the valuation acceptable and the discussion did not advance.
During 2023, the valuations discussed were based on the then market capitalization of Gold Basin, and a higher valuation was supported by Gold Basin’s larger market capitalization. From September 2023 to November 2024, the market price of the Shares on the TSXV declined by approximately 80%, and Gold Basin’s interim financial statements for the period ended September 30, 2024 revealed a substantial reduction of Gold Basin’s cash, a large increase in debt (which includes an unsecured loan in the aggregate principal amount of US$500,000 to Gold Basin from Charrua Capital LLC, bearing interest at a rate of 15% per annum), and increased risk of insolvency. As a result, the subsequent merger discussions focused on a valuation of Gold Basin being roughly equal to CANEX.
On November 28, 2024, CANEX delivered a non-binding expression of interest directly to the Board and management proposing to merge either the Gold Basin Project or Gold Basin into CANEX. CANEX proposed a cash and stock transaction with an effective merger ratio of 52.4% CANEX: 47.6% Gold Basin, with CANEX paying $1,000,000 of Gold Basin’s debt, representing a 60% premium to the November 27, 2024 closing price of the Shares on the TSXV and a 25% premium to the 30-day volume weighted average market price (“VWAP”) of the Shares on the TSXV ending November 27, 2024. Gold Basin rejected the proposal.
- 32 -
On February 20, 2025, Mayfair Acquisition Corp. (“Mayfair”), a reporting issuer in British Columbia and Ontario and whose shares are listed on the TSXV, made a formal proposal to CANEX’s and Gold Basin’s boards of directors for a shareholder approved business combination of the three entities.
Subsequently, on March 20, 2025, Mayfair issued a press release announcing its intention to make a take-over bid to acquire all of the issued and outstanding shares of both Gold Basin and CANEX in exchange for common shares of Mayfair (the “Mayfair Offer”). The Mayfair Offer proposed to merge CANEX and Gold Basin on an equal valuation basis (50% CANEX: 50% Gold Basin).
The Mayfair Offer was being made with the assistance of, and facilitated by, an alliance of mineral exploration and development companies, including Aquitaine Metals Corp., CopperEx Resources Corp., Defense Metals Corp., K2 Gold Corp., Kodiak Copper Corp., Prospector Metals Corp. and ValOre Metals Corp (collectively, the “Discovery Group”). Representatives of the Discovery Group, including Jim Paterson, John Robins and Darren Klinck, were former directors of Gold Basin. The Mayfair Offer was also supported by Shareholders, who together held significant shareholdings in Gold Basin.
On March 28, 2025, eight days following the public announcement of the Mayfair Offer, Helix Resources Limited (“Helix”), an Australian Securities Exchange listed company, announced in a press release that it had entered into conditional binding letter agreements with Centric Minerals Management (USA) Inc. and White Hills Exploration LLC to acquire the White Hills Project (as defined below), which directly adjoins Gold Basin’s Gold Basin Project in Mohave County, Arizona. Centric Minerals Management (USA) Inc. and White Hills Exploration LLC were the 100% registered and beneficial holder of the White Hills farm-in agreement and the associated private mineral claims and leases (the “White Hills Project”). The beneficial owners of the vendors of the White Hills Project were Charles Straw, who was the President, interim Chief Executive Officer and a director of Gold Basin, and Calvin Heron. Helix’s press release discloses that the vendors will receive AUD$200,000 in cash and AUD$1.3 million in Helix shares in connection with these agreements.
On April 28, 2025, one month following the public announcement of the Mayfair Offer, Gold Basin announced that it had executed a binding farm-in agreement with Helix whereby Helix has the right to earn a minority interest in the Gold Basin Project.
On May 1, 2025, Mayfair announced that it was “assessing its alternatives including litigation and regulatory complaints” due to the current regulatory issues facing Gold Basin, as well as certain transactions involving Gold Basin and its current and former senior management which Mayfair questioned as involving “apparent self-dealing and conflicts of interest”.
On May 6, 2025, the regulator of the British Columbia Securities Commission issued the Cease Trade Order in response to Gold Basin’s failure to file its annual audited financial statements and annual management’s discussion and analysis for the period ended December 31, 2024 and its certifications of annual filings for the year ended December 31, 2024. The next day, CIRO imposed the Halt in trading of the Shares on the TSXV.
Notwithstanding the foregoing, CANEX remained of the view that a combination of its and Gold Basin’s mining projects in the Gold Basin exploration district in Mohave County, Arizona is strategically compelling and would benefit the CANEX Shareholders and the Shareholders, and stakeholders of both CANEX and Gold Basin.
Accordingly, CANEX delivered a non-binding expression of interest to Gold Basin on June 6, 2025, after the close of North American markets (the “June 6 EOI”) with respect to a proposed acquisition by CANEX of all of the Shares in exchange for CANEX Shares in an all-share transaction. The June 6 EOI valued Gold Basin and CANEX equally based on the 30-day VWAP as of the date of the Cease Trade Order and would have resulted in CANEX issuing 122,414,332 CANEX Shares at an exchange rate of 0.871 of a CANEX Share for each one Share. The June 6 EOI valued Gold Basin at $5.52 million implying a roughly 12% premium to the 30-day VWAP of the Shares prior to the imposition of the Cease Trade Order, based on the closing price of the CANEX Shares on June 5, 2025. The transactions contemplated by the June 6 EOI were explicitly subject to the revocation of the Cease Trade Order.
The June 6 EOI remained open for acceptance until 5:00 pm (Toronto time) on June 8, 2025. Gold Basin did not respond to the June 6 EOI.
- 33 -
CANEX announced, in a press release issued on June 9, 2025 (the “June 9 Press Release”), its intention to make a formal offer to acquire all of the Shares in an all-share transaction by way of a take-over bid under the Securities Act (British Columbia) and National Instrument 62-104 – Take-Over Bids and Issuer Bids.
Similar to the June 6 EOI, the proposed offer in the June 9 Press Release (the “Proposed Offer”) valued Gold Basin and CANEX equally based on the 30-day VWAP of the CANEX Shares and the Shares as at the date of the Cease Trade Order and would result in CANEX issuing 122,414,332 CANEX Shares at an exchange rate of 0.871 of a CANEX Share for each one Share. The Proposed Offer valued Gold Basin at $8.57 million based on the CANEX Shares’ closing price on June 6, 2025, implying a roughly 41% premium to the closing price of the Shares on the TSXV prior to the Cease Trade Order. Based on the 30-day VWAP of the CANEX Shares as of June 6, 2025 and the 30-day VWAP of the Shares prior to the Cease Trade Order, the Proposed Offer implied a roughly 21% premium.
The share exchange ratio of 0.871 of a CANEX Share for each Share was estimated inclusive of further dilution to the CANEX Shares and market capitalization appreciation from the subsequently completed $1 million non-brokered private placement by CANEX in June 2025, which resulted in CANEX issuing approximately 18,000,000 CANEX Shares at $0.055 per CANEX Share as announced in the June 9 Press Release.
CANEX initially intended to formally commence the Proposed Offer on or around July 9, 2025 as disclosed in the June 9 Press Release; however, the initial targeted timeline was delayed due to: (i) CANEX’s desire to first receive an order from the British Columbia Securities Commission partially revoking the Cease Trade Order in respect of the Proposed Offer and certain related transactions (the “Partial Revocation Order”) prior to launching the Proposed Offer to ensure compliance with applicable securities laws and the Cease Trade Order, which Partial Revocation Order was issued to CANEX on August 18, 2025, a copy of which is set forth in Appendix K to this Circular; and (ii) the failure of Gold Basin to provide its shareholders list as required by applicable securities laws and the BCBCA.
New high priority geophysical targets from an induced polarization (IP) geophysical survey recently completed over the Louise Project as disclosed in CANEX’s news release dated July 31, 2025 contributed to strong market performance by the CANEX Shares in early August 2025. As a result thereof, CANEX amended its previously announced share exchange ratio and, on August 28, 2025, commenced an offer to purchase all of the Shares on the basis of 0.592 of a CANEX Share for each Share (the “Offer”). The share exchange ratio of 0.592 of a CANEX Share for each Share was estimated inclusive of further dilution to the CANEX Shares from CANEX’s acquisition of three mining claims at the Louise Project and the issuance of a total of 400,000 CANEX Shares as a result thereof.
The Offer represented a $1.16 million increase in consideration to the Shareholders compared to the Proposed Offer value, with a lower exchange ratio reflecting the strong market performance of the CANEX Shares between the date of the Proposed Offer and the Offer, as well as significant increase in CANEX’s market capitalization. The Offer represented a 24.2% premium to the 30-day volume weighted average price of the Shares prior to the Cease Trade Order, based on the 30-day volume weighted average price of the CANEX Shares as of August 27.
On August 21, 2025, Mayfair announced that it would no longer be pursuing the Mayfair Offer but that the representatives of the Discovery Group who were supporting the Mayfair Offer, being Jim Paterson, John Robins and Darren Klinck, would support the Offer.
On August 28, 2025, CANEX commenced the Offer and filed the offer and accompanying take-over bid circular of CANEX dated August 28, 2025, as amended by the notice of variation, change and extension dated December 12, 2025, the notice of variation, change and extension dated January 9, 2026, the notice of variation, change and extension dated January 19, 2026, and the notice of variation, change and extension dated January 30, 2026 (the “Take-Over Bid Circular”).
On February 10, 2026, CANEX completed the Offer. CANEX took up a total of 70,088,199 Shares, representing 51.86% of the issued and outstanding Shares, and issued 41,492,194 CANEX Shares to the Shareholders.
On February 11, 2026, the Supreme Court of British Columbia ordered that an annual general meeting of the shareholders of Gold Basin be held on March 16, 2026 and that CANEX could send notice and conduct the meeting in the same manner as a general meeting called by the directors of Gold Basin. At the meeting on March 16, 2026, Shane Ebert, Mark Ernst, Jim Paterson, John Robins, and Jordan Ross were elected to the board of directors of Gold Basin, constituting a new board of directors and entirely replacing the previous board. The directors of Gold Basin appointed Shane Ebert as President and Chief Executive Officer, Jean-Pierre Jutras as Vice President, Chantelle Collins as Chief Financial Officer, and Barbara O’Neill as Corporate Secretary of Gold Basin.
- 34 -
On March 29, 2026, CANEX delivered a non-binding express of interest with respect to an offer to acquire the remaining Shares not currently held by CANEX for the purpose of Gold Basin becoming, directly or indirectly, a wholly-owned subsidiary of CANEX.
On April 2, 2026, the Special Committee was formed, with Jordan Ross as its chair and the Special Committee retained Fasken as its independent legal counsel.
Between April 2, 2026 and April 6, 2026, Gold Basin and its counsel reviewed and negotiated with CANEX and its counsel the non-binding expression of interest and related exclusivity agreement and confidentiality agreement
On April 6, 2026, CANEX and Gold Basin signed the non-binding expression of interest and related exclusivity agreement and confidentiality agreement.
On April 15, 2026, the Special Committee engaged Stifel as its financial advisor and to prepare the Fairness Opinion.
Between April 6, 2026 and May 11, 2026, CANEX and its legal counsel, on one hand, and Gold Basin and its legal counsel, on the other hand, negotiated the Term Loan and Arrangement Agreement with the Arrangement Agreement being finalized and executed on May 11, 2026.
On May 11, 2026, Stifel provided the Fairness Opinion to the Special Committee and the Board. The Board unanimously determined (with interested directors declaring their interest and abstaining from voting) after consideration of, among other factors, the Fairness Opinion, that the Arrangement was fair to the Shareholders (other than CANEX and its affiliates) and that the Arrangement is in the best interests of Gold Basin and approved the Arrangement Agreement.
Reasons for the Arrangement
In reaching a conclusion that the Arrangement is in the best interest of Gold Basin, and in making their recommendations to the Shareholders, the Board and the Special Committee considered and relied upon a number of factors, including:
| (a) | Significant Upfront Premium to Shareholders. The consideration offered under the Arrangement represents a 242.0% premium to the last trading price of the Shares prior to the Cease Trade Order, based on the closing price of the CANEX Shares as of May 8, 2026. |
| (v) | Consolidation of Gold Districts and Near-Term Exploration and Expansion. The Arrangement will consolidate an advanced oxide gold exploration camp in Mohave County, Arizona hosting multiple zones of gold mineralization with strong drill results across an eight kilometre by eight kilometre area, opening up potential near-term exploration on favourable targets. |
| (w) | G&A Cost Savings. The complementary assets of Gold Basin and CANEX are expected to create synergies for the Resulting Issuer, including general and administrative cost savings to the Resulting Issuer of approximately $250,000 per year. These savings will be realized from a reduction of duplicate management roles and administrative expenses, and are expected to be fully realized in 2027. |
| (x) | Diversification. Completing the Arrangement will provide Shareholders not only with exposure to a consolidated gold district in Mohave County, Arizona, but also to the Resulting Issuer’s Louise Project in British Columbia. On July 31, 2025, CANEX announced results from an induced polarization geophysical survey which identified a new and previously unknown chargeability target two kilometres west of the historic Louise Project deposit and a steeply dipping zone of high chargeability below and to the north of the historic Louise Project deposit. |
- 35 -
| (y) | Focused, Professional and Cost-Effective Management Team. The Arrangement places the consolidated district under CANEX’s highly focused, professional and cost-effective management team, which will provide strong operational and governance oversight. |
| (z) | Experienced Board of Directors. Following the Arrangement, the Resulting Issuer’s board of directors will be led by experienced industry professionals, comprised of members of the current board of directors of CANEX. |
| (aa) | Liquidity. The Arrangement will provide Shareholders with a more liquid investment. Trading in the Shares is restricted. On May 6, 2025, the British Columbia Securities Commission imposed the Cease Trade Order against the Shares. The next day, CIRO imposed the Halt in trading of the Shares on the TSXV. The CANEX Shares trade on the TSXV under the symbol “CANX” and are quoted on the OTC Market under the symbol “NOMNF”. CANEX has applied to list the CANEX Shares issuable pursuant to the Arrangement for trading on the TSXV. As of the date hereof, the TSXV has not conditionally approved the listing and there is no assurance that it will do so. Such listing will be subject to CANEX fulfilling all of the requirements of the TSXV, which cannot be guaranteed. There is no expectation that the Cease Trade Order will be rescinded if the Arrangement were not to proceed and Gold Basin were to continue in the status quo. |
| (bb) | Enhanced Financial Capacity. CANEX has demonstrated an ability to raise capital and has strong support from a number of high profile industry professionals. With an enhanced capital markets profile, the Resulting Issuer is expected have even better access to lower-cost capital and an increased capability to advance its exploration properties. |
| (cc) | Going Concern. In the absence of the Arrangement, there is considerable risk that Gold Basin will not have the ability to continue as a going concern and realize its assets and discharge its liabilities in the normal course of business. Gold Basin’s financial situation has significantly deteriorated since its last filed audited financial statements. As at May 14, 2026, Gold Basin has asserted liabilities of approximately $2,123,183 (of which $691,724 is purportedly owed to former management and directors, their related parties and their counsel), no cash or marketable securities and no revenue. Gold Basin’s ability to raise equity financing is restricted by the Cease Trade Order. |
| (dd) | Potential Impairment of Gold Basin Project. Gold Basin’s former board and management may have potentially impaired Gold Basin’s ownership interest in its sole mineral asset, the Gold Basin Project in Mohave County, Arizona, through purported agreements, abandonment or encumbrances involving related parties or parties controlled by former directors and officers of Gold Basin for no or inadequate consideration. Although Gold Basin is taking steps to address these potential impairments and has reserved all rights against the former directors of Gold Basin, any impairment to Gold Basin’s ownership interest in the Gold Basin Project could have a material adverse impact on Gold Basin’s financial condition and operations. See “Recent Developments - Helix”, “Recent Developments - Settlement Agreement with Charrua Capital LLC” and “Exploration Projects – Gold Basin Project – Property Acquisition” in Appendix C. |
| (ee) | Superior Proposals. Subject to compliance with the Arrangement Agreement, Gold Basin is permitted to furnish information and take certain other actions in respect of an unsolicited Acquisition Proposal that could reasonably be expected to lead to a Superior Proposal. The ability to terminate the Arrangement Agreement in specified circumstances and to accept a Superior Proposal, on payment of the Termination Fee of $211,777, which is subject to a right to match, provides further assurance to the Board that Gold Basin will have a reasonable opportunity to consider a potential superior unsolicited alternative transaction if one is subsequently proposed. See “The Arrangement Agreement – Non-Solicitation Covenant and Acquisition Proposal”. |
| (ff) | Support of Shareholders. Certain Shareholders, including all of the directors and officers of Gold Basin who did not tender their Shares to the Offer, have entered into Lock-Up Agreements pursuant to which, and subject to the terms thereof, each has agreed to vote their Shares in favour of the Arrangement Resolution, representing in the aggregate approximately 0.64% of the issued and outstanding Shares. |
- 36 -
| (b) | Fairness Opinion. Stifel Nicolaus provided the Fairness Opinion to the Special Committee to the effect that, as at May 11, 2026, and subject to the assumptions, limitations and qualifications set out in the Fairness Opinion, the consideration to be received by the Shareholders pursuant to the Arrangement is fair, from a financial point of view, to the Shareholders (other than CANEX). See “The Arrangement – Fairness Opinion”. |
| (gg) | Court Approval. The procedures by which the Arrangement is to be approved, including the requirement for approval by the Court after a hearing at which the fairness of the Arrangement to Shareholders will be considered. |
| (hh) | Availability of Dissent Rights. The availability of Dissent Rights to Registered Shareholders as of the Record Date with respect to the Arrangement. |
| (ii) | Review by Special Committee. In the judgment of the Special Committee relying on financial, legal and other advisors and discussions with management and their review of the Fairness Opinion, the Consideration Shares to be received by the Shareholders (other than CANEX and its affiliates) is fair, from a financial point of view, to the Shareholders (other than CANEX and its affiliates). |
| (jj) | Transaction Certainty. The completion of the Arrangement is subject to a limited number of conditions, which the Special Committee, after consultation with independent legal and other advisors, considers likely to be satisfied. |
| (kk) | 100% Acquisition of Shares. The Arrangement is for 100% of the Shares and, under the Plan of Arrangement, all Shareholders are treated identically (other than CANEX and its affiliates). |
| (ll) | Canadian Tax Deferral. A Shareholder who is a Holder should generally be able to exchange Shares for the Consideration Shares under the Arrangement on a fully tax-deferred basis for Canadian income tax purposes. |
The Board and the Special Committee also considered a number of potential issues regarding potentially negative factors and risks resulting from the Arrangement, including:
| (a) | The risks to Gold Basin if the Arrangement is not completed, including the costs to Gold Basin in resources and management attention in pursuing the Arrangement and the restrictions on the conduct of business prior to the completion of the Arrangement, including the ability to raise new funding. |
| (b) | The Arrangement Agreement’s restrictions on Gold Basin soliciting third parties to make an Acquisition Proposal prior to completion of the Arrangement and the specific requirements regarding what constitutes a Superior Proposal. |
| (c) | The Termination Fee of $211,777 payable to CANEX in certain circumstances, including if Gold Basin enters into an agreement with a third party to acquire Gold Basin that constitutes a Superior Proposal. |
| (d) | The right of CANEX to terminate the Arrangement Agreement under certain limited circumstances. |
| (e) | The potential risk of not obtaining certain consents from third parties required to complete the Arrangement, including from the Court, Shareholders, securities regulators and the TSXV. |
| (f) | The potential negative effect on Gold Basin’s relationship with its stakeholders, including suppliers and employees. |
| (g) | The dilution of Shareholders’ interest in Gold Basin business upon becoming shareholders of the Resulting Issuer. |
- 37 -
The Board’s and the Special Committee’s reasons for recommending the Arrangement include certain assumptions relating to forward-looking information, and such information and assumptions are subject to various risks. See “Risk Factors”.
The foregoing summary of the information and factors considered by the Board and the Special Committee is not intended to be exhaustive. In view of the variety of factors and the amount of information considered in connection with its evaluation of the Arrangement, the Board and the Special Committee did not find it practical to, and did not, quantify or otherwise attempt to assign any relative weight to each specific factor considered in reaching its conclusion and recommendation. The Board’s and the Special Committee’s recommendation was made after considering all of the above-noted factors and in light of the Board’s and the Special Committee’s knowledge of the business, financial condition and prospects of Gold Basin, and was also based on the advice of legal advisors to the Board and the Special Committee. In addition, individual members of the Board and the Special Committee may have assigned different weights to different factors.
Fairness Opinion
In determining to recommend the approval of the Arrangement to the Board, the Special Committee considered, among other things, the Fairness Opinion prepared by Stifel Nicolaus.
Stifel Nicolaus provided the Fairness Opinion to the Special Committee to the effect that, as at May 11, 2026, and subject to the assumptions, limitations and qualifications set out in the Fairness Opinion, the consideration to be received by the Shareholders pursuant to the Arrangement is fair, from a financial point of view, to the Shareholders (other than CANEX). See “The Arrangement – Fairness Opinion”.
The summary of the Fairness Opinion in this Circular is qualified in its entirety by reference to the full text of the Fairness Opinion attached to this Circular as Appendix F. The full text of the Fairness Opinion sets out the assumptions made, procedures followed, information reviewed, matters considered and limitations and qualifications on the review undertaken by Stifel Nicolaus in connection with the Fairness Opinion. The Special Committee and the Board urge Shareholders to read the Fairness Opinion carefully and in its entirety. The Fairness Opinion has been prepared and provided solely for the use of the Special Committee and for inclusion in the Circular relating to the Arrangement and may not be used or relied upon by any person other than the Special Committee without Stifel Nicolaus’ express prior written consent. The Fairness Opinion does not address the relative merits of the Arrangement as compared to any other strategic alternative that may be available to Gold Basin. The Fairness Opinion is not a recommendation as to how any Shareholder should vote with respect to the Arrangement or any other matter.
Recommendation of the Special Committee
The Special Committee composed of Jordan Ross, an independent director of Gold Basin (as defined in MI 61-101), was formed to, among other things, examine and review the merits of a possible transaction involving CANEX and Gold Basin and to consider other available strategic alternatives in conjunction with management and Gold Basin’s professional advisors and make recommendations to the Board with respect to any such proposed transactions.
After careful consideration, including a thorough review of the Arrangement Agreement, the Fairness Opinion, as well as a thorough review of other materials and information, including matters discussed in this Circular, and taking into account the best interests of Gold Basin and in consultation with its legal advisors, the Special Committee unanimously recommended to the Board that the Board determine that the Share Consideration to be received by the Shareholders (other than CANEX and its affiliates) is fair, from a financial point of view, to the Shareholders (other than CANEX and its affiliates), that the Arrangement is in the best interests of Gold Basin, that the Arrangement Agreement and the Plan of Arrangement contemplated therein be unanimously approved, that Gold Basin enter into the Arrangement Agreement and for the Board to take all reasonable action to facilitate the Arrangement, and that the Board unanimously recommend that the Shareholders approve the Arrangement and vote in favour of the resolution approving the Arrangement.
- 38 -
Recommendation of the Board
After careful consideration, including a thorough review of the Arrangement Agreement, the Fairness Opinion, as well as a thorough review of other matters, including those discussed in this Circular, and on the unanimous recommendation of the Special Committee, the Board unanimously determined that the acquisition to be effected by way of the Plan of Arrangement is in the best interests of Gold Basin, that the Consideration Shares to be received by the Shareholders (other than CANEX and its affiliates) pursuant to the Arrangement is fair, from a financial point of view, to the Shareholders (other than CANEX and its affiliates) and has unanimously approved the transactions contemplated by the Arrangement Agreement. Accordingly, the Board has unanimously approved the Arrangement and recommends that the Shareholders vote FOR the Arrangement Resolution.
Lock-Up Agreements
CANEX has entered into Lock-Up Agreements with the Locked-up Shareholders, pursuant to which the Locked-up Shareholders have agreed, subject to the terms and conditions of the Lock-Up Agreements, to vote their Shares in favour of the Arrangement Resolution approving the Arrangement. The Locked-up Shareholders collectively beneficially own or exercise control or direction over 866,667 Shares, representing approximately 0.64% of the outstanding Shares.
The obligations of a Locked-up Shareholder under their respective Lock-Up Agreements may be terminated at any time upon the written agreement of CANEX, Gold Basin and such Locked-up Shareholder, and will be terminated if the Arrangement Agreement is terminated in accordance with its terms.
Furthermore, CANEX is obligated under the Arrangement Agreement to vote its Shares in favour of the Arrangement Resolution to approve the Arrangement. CANEX beneficially owns or exercises control or direction over 70,088,199 Shares, representing approximately 51.86% of the outstanding Shares.
The description of the Lock-Up Agreements, both above and elsewhere in this Circular, is a summary only, is not exhaustive and is qualified in its entirety by reference to the terms of the Lock-Up Agreements, which are incorporated by reference herein and may be found under Gold Basin’s profile on SEDAR+ at www.sedarplus.ca.
Description of the Arrangement
The following description of the Arrangement is qualified in its entirety by reference to the full text of the Plan of Arrangement, which is attached as Appendix B of this Circular.
The reason for the Arrangement is to effect the acquisition by CANEX of all of the issued and outstanding Shares, other than the Shares already owned or controlled by CANEX, or any other affiliate of CANEX. Pursuant to the Arrangement Agreement, CANEX and Gold Basin have agreed to complete the Arrangement pursuant to which, among other things, CANEX will acquire all of the issued and outstanding Shares that it does not already own.
If approved, the Arrangement will become effective at the Effective Time, which is expected to be at the beginning of the day (Vancouver time) on the Effective Date or such other time as Gold Basin and CANEX may agree upon in writing. At the Effective Time, the following shall occur or be deemed to occur sequentially in the following order:
| 1. | each Share issued and outstanding held by a Dissenting Shareholder shall be and shall be deemed to be transferred by the holder thereof, free and clear of all liens, to Gold Basin for cancellation and Gold Basin (with Gold Basin funds not directly or indirectly provided by CANEX or any affiliate of CANEX) shall thereupon be obliged to pay the amount therefor determined and payable in accordance with the Arrangement Agreement, and such Dissenting Shareholder shall cease to have any rights as a Shareholder other than the right to be paid the amount for such Dissenting Shareholder’s Shares determined in accordance with the Arrangement Agreement and the name of such holder shall be removed from the central securities register of Gold Basin as a Shareholder; |
- 39 -
| 2. | each Share held by a Former Shareholder shall be transferred by the holder thereof to CANEX in exchange for 0.592 of a CANEX Share in accordance with the terms and conditions set forth in the take over bid offer and circular of CANEX dated August 28, 2025, as amended by the notice of variation, change and extension dated December 12, 2025, the notice of variation, change and extension dated January 9, 2026, the notice of variation, change and extension dated January 19, 2026, and the notice of variation, change and extension dated January 30, 2026 and subject to the Arrangement Agreement, and upon such exchange: |
| i. | the Former Shareholders shall cease to be holders of Shares and to have any rights as holders of such Shares other than the right to be paid the Share Consideration in accordance with the Plan of Arrangement; |
| ii. | the names of the Former Shareholders shall be removed from the register of Shareholders and added to the register of holders of CANEX Shares; |
| iii. | CANEX shall become the holder of the Shares so exchanged and shall be added to the register of Shareholders as the registered holder of such Shares; |
| 3. | Gold Basin will file an election with the CRA to cease to be a public corporation for the purposes of the Tax Act; and |
| 4. | the exchanges, transfers and cancellations provided under the Arrangement Agreement will be deemed to occur on the Effective Date, notwithstanding that certain of the procedures related thereto are not completed until after the Effective Date. |
If any Former Shareholder fails to deliver to the Depositary the certificates, documents or instruments required to be delivered to the Depositary under the Arrangement Agreement in order for such Former Shareholder to receive the Share Consideration which such former holder is entitled to receive pursuant to the Arrangement Agreement, on or before the sixth anniversary of the Effective Date, on the sixth anniversary of the Effective Date (i) such former holder will be deemed to have donated and forfeited to CANEX or its successor any Share Consideration held by the Depositary in trust for such former holder to which such former holder is entitled and (ii) any certificate representing Shares formerly held by such former holder will cease to represent a claim of any nature whatsoever and will be deemed to have been surrendered to CANEX and will be cancelled. Neither Gold Basin nor CANEX, or any of their respective successors, will be liable to any person in respect of any Share Consideration (including any consideration previously held by the Depositary in trust for any such former holder) which is forfeited to Gold Basin or CANEX or delivered to any public official pursuant to any applicable abandoned property, escheat or similar law.
No fractional CANEX Shares will be issued to the Former Shareholders. The number of CANEX Shares to be issued to the Former Shareholders will be rounded down to the nearest whole number of CANEX Shares in accordance with the BCBCA (with no compensation in lieu of such fractional share) in the event that a Former Shareholder is entitled to a fractional share.
See the Plan of Arrangement attached as Appendix B for additional information.
Shareholder Approval
Shareholder Approval
At the Meeting, Shareholders will be asked to consider and, if thought advisable, to pass, with or without variation, the Arrangement Resolution authorizing and approving the Arrangement, the full text of which is set out in Appendix A. In order to become effective, the Arrangement Resolution must be approved by an affirmative vote of: (i) 662/3% of the votes cast on the Arrangement Resolution by the Shareholders present in person or represented by proxy at the Meeting voting together as a single class; and (ii) if required under applicable Law, a simple majority of the votes cast by the Shareholders on the Arrangement Resolution excluding the votes for Shares held or controlled by “related parties” and “interested parties” as defined under MI 61-101; provided that, pursuant to section 8.2 of MI 61-101, the securities acquired by CANEX under the Offer may be voted in favor of the Arrangement Resolution.
- 40 -
The Board unanimously recommends that Shareholders vote FOR the Arrangement Resolution. It is the intention of the persons named in the instrument of proxy enclosed with the Meeting Materials, if not expressly directed to the contrary in such instrument of proxy, to vote such proxy FOR the Arrangement Resolution.
Court Approval
The BCBCA requires that the Court approve the Arrangement.
On or about May 14, 2026 Gold Basin applied for the Interim Order providing for the calling and holding of the Meeting and other procedural matters and filed a Notice of Hearing of Petition for the Final Order to approve the Arrangement. Copies of the proposed form of Interim Order and the Notice of Hearing of Petition are attached as Appendices G and H, respectively, to this Circular.
The Court hearing in respect of the Final Order is expected to take place at 9:45 a.m. (Vancouver time) on June 8, 2026, or as soon thereafter as counsel for Gold Basin may be heard, at the courthouse, 800 Smithe Street, Vancouver, British Columbia, subject to the Shareholder Approval. At the hearing, the Court will consider, among other things, the fairness of the terms and conditions of the Arrangement and the rights and interests of every person affected. The Court may approve the Arrangement in any manner the Court may direct, subject to compliance with such terms and conditions, if any, as the Court deems fit.
The Section 3(a)(10) Exemption provides an exemption from the registration requirements of the U.S. Securities Act for securities issued in exchange for one or more outstanding securities where the terms and conditions of the issuance and exchange of such securities have been approved by a court authorized to grant such approval after a hearing upon the fairness of the terms and conditions of the issuance and exchange at which all persons to whom the securities will be issued have the right to appear and have received timely and adequate notice thereof. Pursuant to the BCBCA, the Court is authorized to conduct a hearing at which the fairness of the terms and conditions of the Arrangement will be considered.
Under the terms of the Interim Order, each Shareholder and holder of Options will have the right to appear before the Court and make submissions at the application for the Final Order. Any person desiring to appear at the hearing of the application for the Final Order is required to indicate their intention to appear by filing with the Court and serving Gold Basin at the address set out below, on or before 4:00 p.m. (Vancouver time) on June 4, 2026, a Response, including their address for service, together with all materials on which they intend to rely at the application. The Response and supporting materials must be delivered, within the time specified, to Gold Basin at the following address:
Fasken Martineau DuMoulin LLP
550 Burrard Street, Suite 2900
Vancouver, British Columbia V6C 0A3
Attention: Mark Pontin
Subject to the Court ordering otherwise, only those persons who file a Response in compliance with the Interim Order will be provided with notice of the materials to be filed with the Court and the opportunity to make submissions in support or opposition of the Final Order. In the event that the hearing is postponed, adjourned or rescheduled, then subject to further order of the Court only those persons having previously served a Response in compliance with the Interim Order will be given notice of the postponement, adjournment or rescheduled date. A copy of the Petition is attached as Appendix I to this Circular.
The Final Order, if granted, will constitute a basis for the Section 3(a)(10) Exemption with respect to the CANEX Shares to be issued to Shareholders pursuant to the Arrangement. Prior to the hearing on the Final Order, the Court has been or will be informed of this effect of the Final Order.
- 41 -
Regulatory Matters
It is a condition to the completion of the Arrangement that:
| 1. | the TSXV will have conditionally approved the listing and posting for trading on the TSXV of the CANEX Shares to be issued to Shareholders as Share Consideration pursuant to the Plan of Arrangement, subject only to satisfaction of customary conditions of the TSXV; |
| 2. | the Parties will have used commercially reasonable efforts to obtain conditional approval from the TSXV for the Term Loan; and |
| 3. | securities regulatory authorities in British Columbia, Alberta and Ontario grant the Exemptive Relief to Gold Basin from the requirement to include, among other things, certain financial statements, including audited financial statements for the for the years ended December 31, 2025 and 2024, in this Circular as prescribed by Item 14.2 of Form 51-102F5 in respect of this Circular. |
CANEX has applied to list the CANEX Shares issuable pursuant to the Arrangement for trading on the TSXV. As of the date hereof, the TSXV has not conditionally approved the listing and there is no assurance that it will do so. Such listing will be subject to CANEX fulfilling all of the requirements of the TSXV, which cannot be guaranteed.
Each of Gold Basin and CANEX have applied for approval from the TSXV for the Term Loan. As of the date hereof, the TSXV has not approved the Term Loan and there is no assurance that it will do so. Such approval will be subject to Gold Basin and CANEX fulfilling all of the requirements of the TSXV, which cannot be guaranteed.
Gold Basin has made a dual application pursuant to National Policy 11-203 – Process for Exemptive Relief Applications in Multiple Jurisdictions and Multilateral Instrument 11-102 – Passport System for the Exemptive Relief As of the date hereof, the Exemptive Relief has not been granted and there is no assurance that it will be granted. Under the Arrangement Agreement it is a condition to holding the Meeting and to completing the Arrangement that the Exemptive Relief is granted.
Procedure for Exchange of Shares for CANEX Shares
For each Registered Shareholder, accompanying this Circular is a Letter of Transmittal. Gold Basin has enclosed an envelope with the Meeting Materials in order to assist Shareholders with returning Letters of Transmittal and related documents to the Depositary.
In order for a Registered Shareholder to receive the Consideration Shares following the Effective Time for each Share held by such Registered Shareholder, such Registered Shareholder must, among other things, deposit the certificate(s) or DRS Advice representing their Shares with the Depositary. The Letter of Transmittal, duly completed and signed, together with all other documents and instruments referred to in the Letter of Transmittal or requested by the Depositary, must accompany all certificates or DRS Advices for Shares deposited in exchange for Consideration Shares pursuant to the Arrangement.
The Letter of Transmittal contains procedural information relating to the Arrangement and should be reviewed carefully. In all cases, issuance of the Consideration Shares for Shares will be made only after timely receipt by the Depositary of a duly completed and signed Letter of Transmittal, together with certificates representing such Shares or applicable DRS Advices and such other documents and instruments referred to in the Letter of Transmittal or as the Depositary may require from time to time. The Depositary will issue the Consideration Shares a Registered Shareholder is entitled to receive in accordance with the instructions in the Letter of Transmittal. CANEX reserves the right, if it so elects in its absolute discretion, to instruct the Depositary to waive any irregularity contained in any Letter of Transmittal received by the Depositary. As soon as practicable following the later of the Effective Date and the deposit of the Shares, including delivery of the Letter of Transmittal, certificates and other corresponding documents required from the Shareholder, the Depositary shall forward the Consideration Shares payable to the applicable Shareholder in accordance with the Plan of Arrangement and the instructions in the Letter of Transmittal.
Any Non-Registered Shareholder whose Shares are registered in the name of a broker, investment dealer, bank, trust corporation, trustee or other nominee should contact that nominee for assistance in depositing such Shares and should follow the instructions of such nominee in order to deposit such Shares with the Depositary.
- 42 -
The method used to deliver a Letter of Transmittal and any accompanying certificates and other relevant documents, if any, is at the option and risk of the relevant Shareholder. Delivery will be deemed effective only when such documents are actually received by the Depositary at the address set out in the Letter of Transmittal. Gold Basin recommends that the necessary documentation be hand delivered to the Depositary and a receipt obtained; otherwise, the use of registered mail with return receipt requested, properly insured, is recommended.
Under no circumstances will interest on the Consideration Shares to be issued in connection with the Arrangement accrue or be paid by CANEX, Gold Basin or the Depositary to persons delivering a Letter of Transmittal in connection with the Arrangement, regardless of any delay in making such payment.
Certificates representing CANEX Shares will be forwarded by first class mail to the addresses supplied in the Letter of Transmittal, if any, or to the address of the Registered Shareholder as last shown on record with Gold Basin, or held at a Depositary office set out in the Letter of Transmittal for pick-up. Delivery of such certificates representing CANEX Shares in accordance with a Shareholder’s instructions in the Letter of Transmittal will be deemed to constitute receipt by such Shareholder.
In the event any certificate which immediately prior to the Effective Time represented one or more outstanding Shares that were transferred or surrendered pursuant to the Plan of Arrangement shall have been lost, stolen or destroyed, then the Letter of Transmittal should be completed as fully as possible and forwarded, together with a letter describing the loss, to the Depositary. Upon making of an affidavit of that fact that such certificate has been lost, stolen or destroyed by the Registered Shareholder of such Shares and the receipt by the Depositary of a Letter of Transmittal and any other documents the Depositary requires, the Depositary will issue in exchange for such lost, stolen or destroyed certificate, the Consideration Shares which such Registered Shareholder is entitled to receive pursuant to the Plan of Arrangement. When authorizing such payment in relation to any lost, stolen or destroyed certificate, the Registered Shareholder to whom the payment is made will, as a condition precedent to the delivery of such Consideration Shares, be required to give a bond satisfactory to CANEX and the Depositary, in such sum as CANEX and the Depositary may direct or otherwise indemnify CANEX and the Depositary in a manner satisfactory to CANEX and the Depositary against any claim that may be made against CANEX and the Depositary with respect to the certificate alleged to have been lost, stolen or destroyed.
Withholding Rights
Pursuant to the terms of the Plan of Arrangement, Gold Basin, CANEX and the Depositary will be entitled to deduct and withhold from any consideration otherwise payable to any Shareholder or Former Shareholder under the Plan of Arrangement (including any payment to Dissenting Shareholders) such amounts as Gold Basin, CANEX or the Depositary is required to deduct and withhold with respect to such payment under the Tax Act, the U.S. Tax Code, and the rules and regulations promulgated thereunder, or any provision of any provincial, state, local or foreign tax law as counsel may advise is required to be so deducted and withheld by Gold Basin, CANEX or the Depositary, as the case may be. For the purposes of the Plan of Arrangement, all such withheld amounts shall be treated as having been paid to the person in respect of which such deduction and withholding was made on account of the obligation to make payment to such person under the Plan of Arrangement, provided that such deducted or withheld amounts are actually remitted to the appropriate governmental entity by or on behalf of Gold Basin, CANEX or the Depositary, as the case may be. To the extent necessary, such deductions and withholdings may be effected by selling any CANEX Shares to which any such person may otherwise be entitled under the Plan of Arrangement on behalf of such person to satisfy such person’s tax liability, and any amount remaining following the sale, deduction and remittance shall be paid to the person entitled thereto as soon as reasonably practicable.
THE ARRANGEMENT AGREEMENT
The description of the Arrangement Agreement, both below and elsewhere in this Circular, is a summary only, is not exhaustive and is qualified in its entirety by reference to the terms of the Arrangement Agreement, which is incorporated by reference herein and may be found under each of CANEX and Gold Basin’s profiles on SEDAR+ at www.sedarplus.ca.
- 43 -
Effective Date and Conditions of Arrangement
If the Arrangement Resolution is passed, the Final Order of the Court is obtained approving the Arrangement and all other conditions to the Arrangement Agreement are satisfied or waived, the Arrangement will become effective at the Effective Time, which is expected to be at the beginning of the day (Vancouver time) on the Effective Date or such other time as Gold Basin and CANEX may agree upon in writing.
Representations and Warranties
The Arrangement Agreement contains representations and warranties made by each Party to the other Party. Those representations and warranties were made solely for purposes of the Arrangement Agreement and may be subject to important qualifications, limitations and exceptions agreed to by the Parties in connection with negotiating its terms and as set out in certain disclosure delivered in connection with the Arrangement Agreement. In particular, some of the representations and warranties are subject to a contractual standard of materiality or material adverse effect that is different from that generally applicable to public disclosure, or are used for the purpose of allocating risk between the Parties to the Arrangement Agreement. For the foregoing reasons, you should not rely on the representations and warranties contained in the Arrangement Agreement as statements of factual information at the time they were made or otherwise.
The representations and warranties provided by Gold Basin in favour of CANEX relate to, among other things, the Board recommendation, the Fairness Opinion, organization and qualification and authority relative to the Arrangement Agreement.
The representations and warranties provided by CANEX in favour of Gold Basin relate to, among other things, organization and qualification, authority relative to the Arrangement Agreement, government approvals, absence of certain violations, capitalization, financial statements, internal controls, auditors, undisclosed liabilities, reporting status and securities Laws, CANEX’s filings, material changes, compliance with laws, bankruptcy and insolvency, Taxes, mineral properties, mineral reserves and resources; permits, material contracts, litigation, listing of CANEX’s Shares issuable as Share Consideration on the TSXV, Investment Canada Act (Canada) and brokers.
Conditions to the Arrangement Becoming Effective
In order for the Arrangement to become effective, certain conditions must have been satisfied or waived which conditions are summarized below.
Mutual Conditions Precedent
The obligations of CANEX and Gold Basin to complete the Arrangement will be subject to the fulfillment of, among others, the following conditions precedent, which may only be waived with the mutual consent of each of the Parties:
| 1. | the Arrangement Resolution shall have been approved by the Shareholders at the Meeting in accordance with the Interim Order and applicable Laws; |
| 2. | each of the Interim Order and the Final Order shall each have been obtained in form and substance satisfactory to each of Gold Basin and CANEX, each acting reasonably, and shall not have been set aside or modified in a manner unacceptable to either Gold Basin or CANEX, each acting reasonably, on appeal or otherwise; |
| 3. | no Law shall be in effect that makes the consummation of the Arrangement illegal or otherwise prohibits or enjoins Gold Basin or CANEX from consummating the Arrangement; |
| 4. | there shall not be in force any order or decree restraining or enjoining or materially modifying or imposing material conditions on the consummation of the transaction contemplated under the Arrangement Agreement or under the Plan of Arrangement, and there shall be no proceeding, whether of a judicial or administrative nature or otherwise brought by a Governmental Authority, that relates to or results from the transactions contemplated under the Arrangement Agreement that would, if successful, result in an order or ruling that would preclude completion of, or materially modify or impose material conditions on, the transaction contemplated under the Arrangement Agreement or under the Plan of Arrangement in accordance with the terms and conditions of the Arrangement Agreement or the Plan of Arrangement; |
- 44 -
| 5. | conditional approval shall have been obtained for the listing and posting for trading on the TSXV of the CANEX Shares to be issued to Shareholders as Share Consideration pursuant to the Plan of Arrangement, subject only to satisfaction of customary conditions of the TSXV; |
| 6. | the Consideration Shares to be issued pursuant to the Arrangement shall be exempt from the registration requirements of the U.S. Securities Act pursuant to the Section 3(a)(10) Exemption thereof and pursuant to exemptions from applicable securities laws of any state of the United States, provided, however, that Gold Basin shall be not entitled to the benefit of exemption from the registration requirements, and shall be deemed to have waived such condition in the event that Gold Basin fails to advise the Court prior to the hearing in respect of the Interim Order that CANEX intends to rely on the Section 3(a)(10) Exemption of the U.S. Securities Act based on the Court’s approval of the Arrangement and comply with the requirements set forth in the Arrangement Agreement and the Final Order shall reflect such reliance; and |
| 7. | the Exemptive Relief is obtained. |
CANEX Conditions Precedent
The obligations of CANEX to complete the transactions contemplated by the Arrangement Agreement shall also be subject to the fulfillment of each of the following conditions precedent (each of which is for the exclusive benefit of CANEX and may only be waived by CANEX in its sole discretion):
| 1. | Gold Basin shall have fulfilled or complied in all material respects with each of the covenants of Gold Basin contained in the Arrangement Agreement to be fulfilled or complied with by it on or prior to the Effective Time; |
| 2. | there shall be no action or proceeding pending or threatened by any person (other than CANEX) in any jurisdiction that is reasonably likely to: |
| (a) | cease trade, enjoin, prohibit, or impose any limitations, damages or conditions on, CANEX’s ability to acquire, hold, or exercise full rights of ownership over, any Shares, including the right to vote Shares; or |
| (b) | prohibit or restrict the Arrangement, or the ownership or operation by CANEX of the business or assets of CANEX, Gold Basin or any of its subsidiaries, or compel CANEX to dispose of or hold separate any material portion of the business or assets of CANEX, Gold Basin or any of its subsidiaries as a result of the Arrangement; |
| 3. | the representations and warranties of Gold Basin set forth in the Arrangement Agreement shall be true and correct in all respects as of the date of the Arrangement Agreement and the Effective Time as though made at and as of the Effective Time (except for representations and warranties made as of a specified date, the accuracy of which shall be determined as of that specified date), in each case without regard to any materiality qualifications contained in the Arrangement Agreement, except where the failure or failures of all such representations and warranties to be so true and correct in all respects would not reasonably be expected to impede, interfere with, prevent or delay the transactions contemplated by the Arrangement Agreement or the Arrangement or which could reasonably be expected to materially reduce the benefits to CANEX under the Arrangement Agreement or the Arrangement; and |
| 4. | Dissent Rights shall have not been exercised with respect to more than 10% of the issued and outstanding Shares. |
- 45 -
Gold Basin Conditions Precedent
The obligations of Gold Basin to complete the transactions contemplated by the Arrangement Agreement shall also be subject to the fulfilment of the following conditions precedent (which are for the exclusive benefit of Gold Basin and may only be waived by Gold Basin in its sole discretion):
| 1. | CANEX shall have fulfilled or complied in all material respects with each of the covenants of CANEX contained in the Arrangement Agreement to be fulfilled or complied with by it on or prior to the Effective Time; |
| 2. | the representations and warranties of CANEX set forth in the Arrangement Agreement shall be true and correct in all respects as of the date of the Arrangement Agreement and as of the Effective Time as though made at and as of the Effective Time (except for representations and warranties made as of a specified date, the accuracy of which shall be determined as of that specified date), in each case without regard to any materiality or material adverse affect qualifications contained in the Arrangement Agreement, except where the failure or failures of all such representations and warranties to be so true and correct in all respects would not reasonably be expected to result in, individually or in the aggregate, a material adverse affect as set out in the Arrangement Agreement; and |
| 3. | subject to the terms and conditions of the Term Loan, CANEX shall have advanced to Gold Basin the full amount of any advance of the Term Loan requested by Gold Basin. |
Covenants
Covenants of CANEX
CANEX has made certain covenants to Gold Basin, including that CANEX shall:
| 1. | conduct its business in the ordinary course; |
| 2. | not, directly or indirectly, |
| (a) | amend CANEX’s constating documents or the constating documents (including any joint venture or similar agreement in respect thereof) of any of its subsidiaries; |
| (b) | split, consolidate, redeem, purchase or otherwise acquire any of the outstanding shares or other securities of CANEX or any of its subsidiaries; |
| (c) | amend the terms of any of the securities of CANEX or any of its subsidiaries; |
| (d) | adopt a plan of liquidation or resolutions providing for the liquidation, dissolution, merger, consolidation or reorganization of CANEX or any of its subsidiaries; |
| (e) | complete any reorganization of the corporate structure, business, operations or assets of CANEX or any of its subsidiaries; |
| (f) | sell, assign, transfer, pledge, lease, dispose of or encumber any material assets of CANEX and its subsidiaries (taken as a whole); or |
| (g) | authorize, agree, resolve, commit or propose any of the foregoing, or enter into, modify or terminate any contract, agreement, plan, commitment or arrangement with respect to any of the foregoing; |
| 3. | reserve and keep available a sufficient number of authorized but unissued CANEX Shares to satisfy its obligations to issue Consideration Shares pursuant to the Arrangement. |
- 46 -
Covenants of Gold Basin
Gold Basin has made certain covenants to CANEX, including that Gold Basin shall:
| 1. | conduct its business in the ordinary course; |
| 2. | not, and shall not permit any of its subsidiaries to, directly or indirectly: |
| (a) | amend Gold Basin’s constating documents or the constating documents (including any joint venture or similar agreement in respect thereof) of any of its subsidiaries; |
| (b) | declare, set aside or pay any dividend or other distribution or payment in cash, shares or property other than distributions and dividends paid solely to Gold Basin or to a direct or indirect wholly-owned subsidiary of Gold Basin; |
| (c) | issue, grant, sell or pledge or agree to issue, grant, sell or pledge any shares or securities of Gold Basin or any of its subsidiaries, or securities convertible into or exchangeable or exercisable for, or otherwise evidencing a right to acquire, shares or securities of Gold Basin or any of its subsidiaries; |
| (d) | split, consolidate, redeem, purchase or otherwise acquire any of the outstanding shares or other securities of Gold Basin or any of its subsidiaries; |
| (e) | amend the terms of any of the securities of Gold Basin or any of its subsidiaries; |
| (f) | adopt a plan of liquidation or resolutions providing for the liquidation, dissolution, merger, consolidation or reorganization of Gold Basin or any of its subsidiaries; |
| (g) | complete any reorganization of the corporate structure, business, operations or assets of Gold Basin or any of its subsidiaries; |
| (h) | sell, assign, transfer, pledge, lease, dispose of or encumber any material assets of Gold Basin and its subsidiaries (taken as a whole); |
| (i) | acquire (by merger, amalgamation, consolidation or acquisition of shares or assets) any material asset or property or any corporation, partnership or other business organization or division thereof, or make any material investment either by the purchase of securities, contributions of capital (other than to wholly-owned subsidiaries) or property transfer, or purchase of any property or assets of any other person (other than a wholly-owned subsidiary); |
| (j) | settle any material litigation or claims; |
| (k) | waive, release, grant or transfer any rights of material value; |
| (l) | make any changes in financial accounting methods, principles, policies or practices, except as required, in each case, by IFRS or by applicable Law; |
| (m) | enter into, adopt, terminate, repudiate, amend, or fail to perform, any contract with a value individually exceeding $100,000 except in the ordinary course of business, and in all cases not exceeding a term of one year, or waive, release or relinquish, or authorize or propose to do so, any contractual right in any such contract; |
| (n) | incur any indebtedness for borrowed money for capital expenditures other than in connection with capital expenditure plans disclosed to CANEX; |
- 47 -
| (o) | settle, pay, compromise, discharge or satisfy any claims, liabilities or obligations (including any regulatory investigation) with a value individually exceeding $100,000 or in the aggregate exceeding $500,000; |
| (p) | grant any general salary increases, award or pay any bonus, or issue, adopt, award or grant any employee incentive awards or any securities or other instruments or equity based compensation providing similar benefits; |
| (q) | hire or agree to hire any new employees; |
| (r) | enter into, terminate or modify any contract with any employees or directors or consultants or enter into any contract with any consultants that are not terminable without payment or penalty with 30 days or less notice or in accordance with applicable Laws; or |
| (s) | authorize, agree, resolve, commit or propose any of the foregoing, or enter into, modify or terminate any contract, agreement, plan, commitment or arrangement with respect to any of the foregoing; |
| 3. | notify CANEX in writing of: |
| (a) | any material change (actual, anticipated, contemplated or, to the knowledge of Gold Basin, threatened, financial or otherwise) in the business, operations, results of operations, properties, assets, liabilities (whether absolute, accrued, contingent or otherwise), or financial condition of Gold Basin or any of its subsidiaries; or |
| (b) | any notice or other communication from any Governmental Authority in connection with the Arrangement Agreement. |
Mutual Covenants
Each Party has also made certain covenants to the other Party to take or cause to be taken all actions and to do or cause to be done all things necessary, proper or advisable under Law to consummate the Arrangement as soon as practicable, including:
| 1. | using commercially reasonable efforts to defend all lawsuits or other legal, regulatory or other proceedings to which it is a party challenging or affecting the Arrangement Agreement or the consummation of the transactions contemplated by the Arrangement Agreement; |
| 2. | effecting all necessary registrations, filings and submissions of information required by Governmental Authorities; |
| 3. | carrying out the terms of the Interim Order and the Final Order applicable to it and complying promptly with all requirements imposed by Law on it or its subsidiaries with respect to the Arrangement Agreement or the Arrangement; |
| 4. | using, to the extent necessary to permit implementation of the Arrangement, commercially reasonable efforts to have lifted or rescinded any injunction or restraining order or other order relating to it, which may adversely affect the ability of the Parties to consummate the transactions contemplated by the Arrangement Agreement; |
| 5. | using commercially reasonable efforts to obtain conditional approval for the listing on the TSXV of the Consideration Shares; |
| 6. | not taking any action, or refraining from taking any commercially reasonable action, or permitting any action to be taken or not taken, which is inconsistent with the Arrangement Agreement or which would reasonably be expected to prevent, delay or otherwise impede the consummation of the Arrangement; |
- 48 -
| 7. | taking all such actions as are within its power to control, and using commercially reasonable efforts to cause other actions to be taken which are not within its power to control, to complete the transactions contemplated by the Arrangement Agreement; and |
| 8. | use commercially reasonable efforts to obtain conditional approval from the TSXV for the Term Loan and upon receipt of such conditional approval, enter into a loan agreement in respect of the Term Loan as soon as practicable following the execution of the Arrangement Agreement. |
Non-Solicitation Covenant and Acquisition Proposal
Gold Basin has covenanted to CANEX that it shall not, directly or indirectly, through any person, and shall cause its subsidiaries not to:
| 1. | solicit, assist, initiate, encourage or otherwise facilitate any inquiries or proposals, whether publicly or otherwise, regarding an Acquisition Proposal, or take any action that could reasonably be expected to lead to an Acquisition Proposal, provided that, for greater certainty, Gold Basin may advise any person making an unsolicited Acquisition Proposal that such Acquisition Proposal does not constitute a Superior Proposal when the Board has so determined; |
| 2. | enter into, continue or participate in any discussions or negotiations with any person regarding an Acquisition Proposal or that could reasonably be expected to lead to an Acquisition Proposal; |
| 3. | approve or recommend, or propose publicly to approve or recommend, any Acquisition Proposal (it being understood that publicly taking no position or a neutral position with respect to a publicly announced, or otherwise publicly disclosed Acquisition Proposal for a period of ten (10) days shall not be considered to be a breach of this covenant); |
| 4. | make or propose publicly to make a Change in Recommendation; or |
| 5. | accept or enter into any agreement, understanding or arrangement in respect of an Acquisition Proposal (other than a confidentiality agreement permitted by the provisions of the Arrangement Agreement). |
Gold Basin has covenanted to CANEX that it shall, and shall cause its subsidiaries and its Representatives to, immediately terminate any existing discussions or negotiations with any parties (other than CANEX) with respect to any offer, proposal, expression of interest or inquiry that constitutes an Acquisition Proposal and shall provide written confirmation to CANEX of such termination. Gold Basin shall, as soon as possible, to the extent it is entitled to do so, request the return or destruction of all information provided to any third party which to Gold Basin’s actual knowledge has entered into a confidentiality agreement with Gold Basin or its subsidiaries relating to a potential Acquisition Proposal. Gold Basin has represented and warranted to CANEX that to the best of its knowledge neither it nor any of its subsidiaries has waived any provision of any existing confidentiality agreement relating to a potential Acquisition Proposal or any standstill agreement to which it is a party. Gold Basin has agreed, except as permitted by the provisions of the Arrangement Agreement, that it shall not waive any provision of any existing confidentiality agreement relating to a potential Acquisition Proposal or any standstill agreement to which it is a party (it being acknowledged and agreed that the automatic termination or release of any standstill provisions of any such agreement as the result of the entering into or announcement of the Arrangement Agreement pursuant to the terms of any such agreement, shall not be a breach of this covenant).
- 49 -
Notwithstanding the foregoing and any other provision of the Arrangement Agreement or any other agreement between Gold Basin and CANEX, if at any time following the date of the Arrangement Agreement and prior to the Meeting, provided that Gold Basin is in compliance in all material respects with all of its obligations under the Arrangement Agreement, the Board receives a written Acquisition Proposal that was not solicited after entering into the Arrangement Agreement in breach of the provisions of the Arrangement Agreement, the Board may (directly or through its advisors or Representatives):
| 1. | contact the person making such Acquisition Proposal and its Representatives to clarify the terms and conditions of such Acquisition Proposal and the likelihood of consummation so as to determine whether such proposal is, or could reasonably be expected to lead to, a Superior Proposal; and |
| 2. | if, in the opinion of the Board, acting in good faith and after receiving advice from its outside financial advisor and outside legal counsel, the Acquisition Proposal is, or could reasonably be expected to be, a Superior Proposal, and that failure to furnish information with respect to Gold Basin and its subsidiaries to the person making such Acquisition Proposal or participate in discussions with such person would be inconsistent with its fiduciary duties under applicable Law, Gold Basin may, provided it has first complied with the provisions of the Arrangement Agreement and provided CANEX with a copy of any confidentiality and standstill agreement to be entered into with the person making such Acquisition Proposal: |
| (a) | furnish information with respect to Gold Basin and its subsidiaries to the person making such Acquisition Proposal and its Representatives; and/or |
| (b) | consider such Acquisition Proposal and/or, participate and/or engage in discussions with the person making such Acquisition Proposal and its representatives; |
provided that Gold Basin shall not, and shall not allow its Representatives to, disclose any non-public information with respect to Gold Basin to such person without entering into a confidentiality and standstill agreement having confidentiality and standstill terms no more favourable to such person than the equivalent terms of the confidentiality agreement between the Parties dated April 2, 2026, and provided that CANEX is promptly provided with a list and copies of all information provided to such person not previously provided to CANEX and is promptly provided with access to information similar to that which was provided to such person.
Gold Basin shall promptly (and in any event within 24 hours) notify CANEX of (i) any oral or written Acquisition Proposal or offer, proposal, expression of interest or inquiry that is reasonably expected to lead to an Acquisition Proposal, in each case received after the date hereof and prior to the Meeting, of which any of its directors or officers are or become aware, (ii) any material amendments to an Acquisition Proposal, (iii) any request for non-public information relating to Gold Basin or any of its subsidiaries in connection with an Acquisition Proposal or which request is reasonably expected to lead to an Acquisition Proposal, and (iv) any request for access to the properties, books or records of Gold Basin or any of its subsidiaries by any person that informs Gold Basin or such subsidiary that it is considering making, or has made, an Acquisition Proposal. Any such notice shall include, the identity of the person making the Acquisition Proposal or offer, proposal, expression of interest or inquiry and a description of the material terms and conditions of any such Acquisition Proposal or amendment or offer, proposal, expression of interest or inquiry (and copies of all written documents, correspondence or other material received in respect thereof). Gold Basin shall keep CANEX promptly and reasonably informed (to the extent permitted by the confidentiality agreement contemplated in the Arrangement Agreement) of discussions with respect to such Acquisition Proposal or offer, proposal, expression of interest or inquiry or any material changes, modifications or amendments thereto.
Subject to the provisions of the Arrangement Agreement, at any time following the date of the Arrangement Agreement and prior to the Meeting, if the Board receives an Acquisition Proposal which the Board determines in good faith constitutes a Superior Proposal, the Board may enter into a definitive agreement with respect to such Superior Proposal, provided:
| 1. | the person making such Superior Proposal is not restricted from making an Acquisition Proposal pursuant to an existing standstill, confidentiality, non-disclosure, business purpose, use or similar restriction (other than a confidentiality and standstill agreement permitted pursuant to the terms of the Arrangement Agreement); and |
| 2. | Gold Basin has been, and continues to be, in compliance with its obligations under the Arrangement Agreement in all material respects. |
- 50 -
Right to Match
Gold Basin has covenanted that it will not accept, approve, recommend or enter into any agreement, understanding or arrangement in respect of a Superior Proposal (other than a confidentiality and standstill agreement permitted by the non-solicitation provisions of the Arrangement Agreement) unless:
| 1. | an Acquisition Proposal has been made that the Board determines in good faith constitutes a Superior Proposal; |
| 2. | Gold Basin has complied in all material respects with its obligations under the non-solicitation provisions of the Arrangement Agreement and the other provisions of the additional agreements article of the Arrangement Agreement and has provided CANEX with all material information relating to the Superior Proposal, including a copy of the Superior Proposal (and, if the consideration proposed under the Superior Proposal includes non-cash consideration (other than publicly traded securities listed on a major stock exchange), a written notice from the Board setting out the value in financial terms that the Board, in consultation with Stifel Nicolaus, determined in good faith should be ascribed to such non-cash consideration), promptly and in any event within 24 hours of the Board’s determination; |
| 3. | a period (the “Response Period”) of five (5) business days shall have elapsed from the date on which CANEX received written notice from the Board that the Board determined, subject only to compliance with the right to match provisions of the Arrangement Agreement, to accept, approve, recommend or enter into a binding agreement to proceed with the Superior Proposal; |
| 4. | if CANEX has proposed to amend the terms of the Arrangement Agreement in accordance with the Arrangement Agreement, the Board shall have determined, in good faith and with the advice of outside legal and financial advisors, that the Acquisition Proposal continues to constitute a Superior Proposal after taking into account such amendments; |
| 5. | Gold Basin shall have terminated, or shall concurrently terminate, the Arrangement Agreement in accordance with the applicable provisions of the Arrangement Agreement; and |
| 6. | Gold Basin has previously, or concurrently will have, paid to CANEX (or as CANEX may direct by notice in writing) the Termination Fee. |
During the Response Period, CANEX will have the right, but not the obligation, to offer to amend the terms of the Arrangement Agreement. The Board will, in good faith and with the advice of outside legal and financial advisors, review any such written proposal by CANEX to amend the terms of the Arrangement Agreement, including an increase in, or modification of, the consideration to be received by Shareholders, to determine whether the Acquisition Proposal to which CANEX is responding would constitute a Superior Proposal when assessed against the Arrangement as it is proposed by CANEX to be amended. If the Board does not so determine, the Board will promptly reaffirm its recommendation of the transactions contemplated under the Arrangement Agreement in the same manner as described in the Arrangement Agreement by the prompt issuance of a press release to that effect and shall enter into an amended agreement with CANEX reflecting the Arrangement as proposed by CANEX. If the Board does so determine, Gold Basin may after the end of the Response Period approve, recommend, accept or enter into an agreement, understanding or arrangement to proceed with the Superior Proposal, provided that the Response Period has fully expired and all procedural steps have been completed.
Termination Fee
If the Arrangement Agreement is terminated because (i) the Effective Time does not occur on or before the Outside Date; (ii) the Arrangement Resolution fails to receive the requisite vote for approval from Shareholders at the Meeting (including any adjournment or postponement thereof) in accordance with the Interim Order; (iii) Gold Basin breaches any representation or warranty or fails to perform any covenant or agreement on the part of Gold Basin which causes the mutual conditions precedent or the additional conditions precedent to the obligations of CANEX pursuant to the Arrangement Agreement not to be satisfied by the Outside Date; (iv) breach by Gold Basin of the non-solicitation provisions of the Arrangement Agreement, but only if prior to the termination of the Arrangement Agreement, an Acquisition Proposal shall have been made to Shareholders or any person (other than CANEX or any of its affiliates) shall have publicly announced an intention to make an Acquisition Proposal, and such Acquisition Proposal is consummated or effected within twelve (12) months of such termination or within twelve (12) months of such termination, Gold Basin or one or more of its subsidiaries enters into a binding written agreement in respect of, or the Board approves or recommends, a transaction contemplated above and that transaction is subsequently consummated at any time thereafter, provided that for purposes of the above, the references in the definition of “Acquisition Proposal” to “20%” shall be deemed to be references to “50%”; or (v) CANEX terminates the Arrangement Agreement because Gold Basin enters into an agreement, understanding or arrangement to effect an Acquisition Proposal that is a Superior Proposal or makes a Change in Recommendation, then Gold Basin shall pay, or cause to be paid, to CANEX the amount of $211,777 (the “Termination Fee”).
- 51 -
Termination
Subject to payment of the Termination Fee where applicable, the Arrangement Agreement may be terminated at any time prior to the Effective Time:
| 1. | by mutual written agreement of Gold Basin and CANEX; |
| 2. | by either Gold Basin or CANEX, if: |
| (a) | the Effective Time shall not have occurred on or before the Outside Date, except that the right to terminate the Arrangement Agreement shall not be available to any Party whose failure to fulfill any of its obligations or breach of any of its representations and warranties under the Arrangement Agreement has been the cause of, or resulted in, the failure of the Effective Time to occur by such Outside Date; |
| (b) | after the date of the Arrangement Agreement, there shall be enacted or made any applicable Law that makes consummation of the Arrangement illegal or otherwise prohibited or enjoins Gold Basin or CANEX from consummating the Arrangement and such applicable Law or enjoinment shall have become final and non appealable, except that the right to terminate the Arrangement Agreement shall not be available to any Party unless such Party has used commercially reasonable efforts to, as applicable, appeal or overturn or otherwise have such applicable Law lifted or rendered non applicable in respect of the Arrangement; or |
| (c) | the Arrangement Resolution shall have failed to receive the requisite vote for approval from Shareholders at the Meeting (including any adjournment or postponement thereof) in accordance with the Interim Order, provided that a Party may not terminate this if the failure to receive the approval from Shareholders has been caused by, or is a result of, a breach by such Party of any of its representations or warranties or the failure of such Party to perform any of its covenants or agreements under the Arrangement Agreement; |
| 3. | by CANEX, if: |
| (a) | the Board (i) fails to provide the Board Recommendation, (ii) withdraws, withholds, amends, modifies or qualifies, or proposes publicly to withdraw, withhold, amend, modify or qualify the Board Recommendation, (iii) approves, accepts, endorses, or recommends or proposes publicly to approve, accept, endorse or recommend, any Acquisition Proposal, or (iv) fails to reaffirm the Board Recommendation within the later of: (y) five (5) business days (and in any case prior to the Meeting) after having been requested in writing by CANEX to do so; and (z) if such request is made during a Response Period, within five (5) business days of the end of the Response Period (and in any case prior to the Meeting) (it being understood that the taking of a neutral position or no position with respect to a publicly announced Acquisition Proposal beyond the foregoing period (or beyond the time of the Meeting, if sooner) shall be considered a failure of the Board to reaffirm its recommendation within the requisite time period); |
- 52 -
| (b) | any of the mutual conditions precedent or the additional conditions precedent to the obligations of CANEX pursuant to the Arrangement Agreement are not satisfied, and such condition is incapable of being satisfied by the Outside Date; provided that CANEX is not then in breach of the Arrangement Agreement so as to cause any of the mutual conditions precedent or the additional conditions precedent to the obligations of Gold Basin pursuant to the Arrangement Agreement not to be satisfied; |
| (c) | without limiting the above, Gold Basin is in breach or in default in any material respect of the non-solicitation provisions of the Arrangement Agreement; or |
| (d) | the Meeting has not occurred on or before June 4, 2026; provided that the right to terminate the Arrangement Agreement shall not be available to CANEX if the failure by CANEX to fulfil any obligation hereunder is the cause of, or results in, the failure of the Meeting to occur on or before such date; |
| 4. | by Gold Basin, if: |
| (a) | the Board authorizes Gold Basin subject to complying with the terms of the Arrangement Agreement, to enter into a binding written agreement relating to a Superior Proposal; provided that concurrent with such termination, Gold Basin pays, or causes to be paid, the Termination Fee; or |
| (b) | any of the conditions set forth in the mutual conditions precedent or the additional conditions precedent to the obligations of Gold Basin pursuant to the Arrangement Agreement are not satisfied, and such condition is incapable of being satisfied by the Outside Date; provided that Gold Basin is not then in breach of the Arrangement Agreement so as to cause any of the mutual conditions precedent or additional conditions precedent to the obligations of CANEX pursuant to the Arrangement Agreement not to be satisfied. |
SECURITIES LAW CONSIDERATIONS
Interests of Certain Persons and Companies in the Arrangement
The directors and executive officers and other related parties of Gold Basin may have interests in the Arrangement that are, or may be, different from, or in addition to, the interests of other Shareholders. These interests include those described herein. The Board was aware of these interests and considered them, among other matters, when recommending approval of the Arrangement by Shareholders.
Gold Basin
All benefits received, or to be received, by directors or executive officers of Gold Basin as a result of the Arrangement are, and will be, solely in connection with their services as directors or employees of Gold Basin or as Shareholders, other than Dr. Shane Ebert, President, Chief Executive Officer and a director of CANEX, Jean Pierre Jutras, Vice President and a director of CANEX, Chantelle Collins, Chief Financial Officer of CANEX and Barbara O’Neill, Corporate Secretary of CANEX, and who have also received, or will also receive, certain benefits solely in connection with their services as directors and officers of CANEX, as more particularly described in this Circular. No benefit has been, or will be, conferred for the purpose of increasing the value of consideration payable to any such person for their Shares, nor is it, or will it be, conditional on the person supporting the Arrangement.
All of the Shares held by the directors and executive officers of Gold Basin will be treated in the same fashion under the Arrangement as Shares held by any other Shareholder.
Consideration
The following table sets out the names, positions and security holdings of the directors and executive officers of Gold Basin owning, or exercising control or direction over, Shares and Options. Where known after reasonable inquiry, such security holdings include any such securities held by the respective associates or affiliates of such directors and executive officers of Gold Basin as of such date and the consideration to be received for such Shares and Options pursuant to the Arrangement.
- 53 -
| Name and Position | Shares | Consideration Shares |
| John Robins, Director | 666, 667 | 394,666 |
| James Paterson, Director | 200,000 | 118,400 |
| Mark Ernst, Director | Nil | Nil |
| Jordan Ross, Director | Nil | Nil |
| Dr. Shane
Ebert, President, Chief Executive Officer and Director(1) |
Nil | Nil |
| Jean Pierre Jutras, Vice President(2) | Nil | Nil |
| Chantelle Collins, Chief Financial Officer(3) | Nil | Nil |
| Barbara O’Neill, Corporate Secretary(4) | Nil | Nil |
Notes:
| 1. | Dr. Shane Ebert is also the President, Chief Executive Officer and a director of CANEX. |
| 2. | Jean Pierre Jutras is also the Vice President and a director of CANEX. |
| 3. | Chantelle Collins is also the Chief Financial Officer of CANEX. |
| 4. | Barbara O’Neill is also the Corporate Secretary of CANEX. |
MI 61-101
Gold Basin is required to comply with MI 61-101. MI 61-101 is intended to regulate certain transactions to ensure equality of treatment among securityholders, generally requiring enhanced disclosure, approval by a majority of securityholders excluding interested or related parties, independent valuations and, in certain instances, approval and oversight of the transaction by a special committee of independent directors. The protections of MI 61-101 generally apply to “business combinations” that terminate the interests of securityholders without their consent and related party transactions.
Business Combination
If the Arrangement constitutes a “business combination” of Gold Basin, MI 61-101 requires that the Arrangement Resolution be approved by a majority of the minority of Shareholders.
A “business combination” includes, for an issuer, a transaction (including an arrangement) as a consequence of which the interest of a holder of an equity security of the issuer may be terminated without the holder’s consent, and where a person who is a “related party”, as defined in MI 61-101, of the issuer at the time the transaction is agreed to (a) would, as a consequence of the transaction, directly or indirectly acquire the issuer or the business of the issuer, or combine with the issuer, through an amalgamation, arrangement or otherwise, whether alone or with joint actors, or (b) is entitled to receive, directly or indirectly, as a consequence of the transaction, a “collateral benefit”, as defined in MI 61-101.
Accordingly, the Arrangement is considered a “business combination” under MI 61-101 because CANEX, which is a “related party” of Gold Basin by virtue of being a “control person” of Gold Basin, and beneficially owns, or has control or direction of, over 10% of the outstanding Shares, would acquire Gold Basin as a consequence of the Arrangement.
In addition, the Arrangement may be considered a “business combination” under MI 61-101 because, as described under the heading “Securities Law Considerations – Interests of Certain Persons and Companies in the Arrangement”, the payments to and benefits to be received by certain senior officers and directors of Gold Basin may be considered a “collateral benefit” for the purposes of MI 61-101.
- 54 -
For the purposes of MI 61-101, directors, senior officers and other related parties of Gold Basin, which include the directors and senior officers of CANEX, which is a “control person” of Gold Basin, receive a “collateral benefit” if they are entitled to receive, subject to certain exceptions, directly or indirectly, as a consequence of the Arrangement, any benefit, including an increase in salary, a lump sum payment, a payment for surrendering securities, or other enhancement in benefits related to past or future services as an employee, director or consultant of Gold Basin, or of another person, regardless of the existence of any offsetting costs to the related party or whether the benefit is provided, or agreed to, by CANEX or Gold Basin, as applicable, or another party to the Arrangement. Among other things, a “collateral benefit” does not include a payment of the Consideration Shares that is identical in amount and form to the entitlement of the general body of Shareholders in Canada.
Minority Approval
In determining minority approval for a business combination, Gold Basin is required to exclude the votes attached to Shares that, to the knowledge of Gold Basin and its directors and officers after reasonable inquiry, are beneficially owned or over which control or direction is exercised by all “interested parties” and their “related parties” and “joint actors” all as defined in MI 61-101. For the purposes of MI 61-101, “interested parties” includes any “related parties” of the issuer (including any directors or senior officers of Gold Basin and any directors or senior officers of any “control person” of Gold Basin, including CANEX) if the related party would, as a consequence of the transaction, (a) directly or indirectly acquire the issuer or the business of the issuer, or combine with the issuer, through an amalgamation, arrangement or otherwise, whether alone or with joint actors, or (b) receive a collateral benefit.
Following disclosure by each of the directors and executive officers of Gold Basin to the Board of the number of Shares held by them and any benefits or payments that they expect to receive pursuant to the Arrangement, the Board has determined that none of the directors and executive officers of Gold Basin is receiving a “collateral benefit” for the purposes of MI 61-101. See “Securities Law Considerations – Interests of Certain Persons and Companies in the Arrangement”.
As CANEX is a “related party” of Gold Basin by virtue of being a “control person” of Gold Basin and beneficially owns, or has control or direction of, over 10% of the outstanding Shares and will acquire Gold Basin as a consequence of the Arrangement, CANEX is considered an “interested party” to Gold Basin for the purposes of the Arrangement. MI 61-101 also provides that CANEX may treat the Shares acquired under the Offer as “minority” shares and to vote them, or to consider them voted, in favour of such business combination if, among other things: (a) the business combination is completed no later than 120 days after the date of expiry of the Offer; (b) the consideration per security in the business combination is at least equal in value to and in the same form as the consideration that the tendering security holders were entitled to receive in the Offer; and (c) the Shareholder who tendered such Shares under the Offer was not (i) a “joint actor” (within the meaning of MI 61-101) with CANEX in respect of the Offer; (ii) a direct or indirect party to any “connected transaction” (within the meaning of MI 61-101) to the Offer; or (iii) entitled to receive, directly or indirectly, in connection with the Offer, a “collateral benefit” (within the meaning of MI 61-101) or consideration per Share that is not identical in amount and form to the entitlement of the general body of holders in Canada of the Shares.
As a result, for the purposes of determining minority approval in accordance with MI 61-101, Shares held by each of the directors and executive officers of Gold Basin will be excluded from the vote at the Meeting to the extent that such directors and officers are receiving a “collateral benefit” for the purposes of MI 61-101. As at the date hereof, no Shares held, directly or indirectly, by any “interested parties” will be excluded.
As a result of the foregoing, the Arrangement is a “business combination” of Gold Basin for the purposes of MI 61-101 and the minority approval requirements of MI 61-101 will apply in connection with the approval of the Arrangement by the Shareholders. In addition to obtaining approval of the Arrangement Resolution by an affirmative vote of at least 662/3% of the votes cast on the Arrangement Resolution by the Shareholders present in-person or by proxy at the Meeting, if required under applicable Law, approval will also be sought from a simple majority of the votes cast by Shareholders on the Arrangement Resolution excluding the votes for Shares held or controlled by “related parties” and “interested parties” as defined under MI 61-101; provided that, pursuant to section 8.2 of MI 61-101, the securities acquired by CANEX under the Offer may be voted in favor of the Arrangement Resolution.
- 55 -
Formal Valuation
MI 61-101 also provides that, unless an exemption is available, an issuer proposing to carry out a “business combination” is required to obtain a formal valuation of the “affected securities” (in this case, being the Shares) and any non-cash consideration being offered to, or to be received by, the holders of the “affected securities” (in this case, being the Consideration Shares) from a qualified independent valuator where an “interested party” (in the case of the Arrangement) would, as a consequence of the transaction, directly or indirectly acquire the issuer or the business of the issuer, whether alone or with joint actors.
As discussed previously, CANEX is an “interested party” and would acquire Gold Basin as a consequence of the Arrangement. However, Gold Basin is relying on an exemption from the formal valuation requirements under Section 4.4(1)(a) of MI 61-101, as Gold Basin is not a CSE senior tier issuer and no securities of Gold Basin are listed or quoted on the Toronto Stock Exchange, Cboe Canada Inc., the New York Stock Exchange, the American Stock Exchange, the NASDAQ Stock Market, or a stock exchange outside of Canada and the United States other than the Alternative Investment Market of the London Stock Exchange or the AQSE Growth Market operated by Aquis Stock Exchange Limited.
Prior Valuations
To the knowledge of Gold Basin, other than the Fairness Opinion, after reasonable inquiry, there has been no prior valuation of Gold Basin, the Shares or its material assets in the 24 months prior to the date of this Circular.
United States Securities Law Considerations
The following discussion is only a general overview of certain requirements of the United States federal securities Laws that may be applicable to the Consideration Shares issuable upon completion of the Arrangement. All holders of such securities are urged to consult with their own counsel to ensure compliance with applicable U.S. federal and state securities Laws.
Further information applicable to U.S. securityholders is disclosed under the heading “General Proxy Information – Information for United States Shareholders”.
The following discussion does not address the Canadian securities Laws that will apply to the issue of Consideration Shares, or the resale of any such securities, within Canada by Shareholders in the United States. Shareholders in the United States reselling any such securities in Canada must comply with Canadian securities Laws, as outlined elsewhere in this Circular.
The issuance of the Consideration Shares to Shareholders in exchange for their Shares, pursuant to the Arrangement, has not been and will not be registered under the U.S. Securities Act or applicable U.S. state securities Laws, and such securities will be issued to Shareholders in certain states in reliance upon the Section 3(a)(10) Exemption and exemptions from most applicable U.S. state securities Laws. The Section 3(a)(10) Exemption exempts the issuance of securities issued in exchange for one or more bona fide outstanding securities from the general requirement of registration under the U.S. Securities Act where the terms and conditions of the issuance and exchange of such securities have been determined to be substantively and procedurally fair to the persons to whom the securities will be issued by a court of competent jurisdiction, expressly authorized by Law to grant such approval, after a hearing upon the fairness of the terms and conditions of the issuance and exchange at which all persons to whom the securities will be issued have the right to appear and receive timely and adequate notice thereof. Pursuant to the BCBCA, the Court is authorized to conduct a hearing at which the fairness of the terms and conditions of the Arrangement will be considered. All Shareholders are entitled to appear and be heard at this hearing, provided that they satisfy the applicable conditions set forth in the Interim Order. The Court is expected to grant the Interim Order on or about May 14, 2026 and, subject to the approval of the Arrangement by Shareholders, a hearing on the Arrangement will be held on or about June 8, 2026 by the Court. Accordingly, the Final Order, if granted, will constitute a basis for the Section 3(a)(10) Exemption from the registration requirement of the U.S. Securities Act. See “The Arrangement – Court Approval”. The issuance of the Consideration Shares to Shareholders in exchange for Shares, pursuant to the Arrangement, is expected to be exempt from registration under the U.S. Securities Act pursuant to the Section 3(a)(10) Exemption.
- 56 -
The Consideration Shares to be received by Shareholders upon completion of the Arrangement may be resold without restriction under the U.S. Securities Act, except by persons who are “affiliates” (as defined in Rule 144) of CANEX after the Effective Date or who have been affiliates of CANEX within 90 days before the Effective Date. Persons who may be deemed to be affiliates of an issuer generally include individuals or entities that control, are controlled by, or are under common control with, the issuer, whether through the ownership of voting securities, by contract or otherwise, and generally include executive officers and directors of the issuer as well as principal shareholders of the issuer. Consideration Shares received by such affiliates or former affiliates of CANEX will be subject to certain restrictions on resale imposed by the U.S. Securities Act, such that they may not resell such securities in the absence of registration under the U.S. Securities Act or an exemption from such registration, if available, such as the exemptions contained in Rule 144 or Rule 904 of Regulation S.
In general, pursuant to Rule 144, such affiliates or former affiliates will be entitled to sell, during any three-month period, the Consideration Shares that they receive pursuant to the Arrangement, provided that the number of such securities sold does not exceed the greater of one percent of the then outstanding securities of such class or, if such securities are listed on a United States securities exchange and/or reported through the automated quotation system of a U.S. registered securities association, the average weekly trading volume of such securities during the four calendar week period preceding the date of sale, subject to specified restrictions on manner of sale requirements, aggregation rules, notice filing requirements and the availability of current public information about the issuer required under Rule 144. Such affiliates will continue to be subject to the resale restrictions described in this paragraph for so long as they continue to be affiliates of CANEX. Unless certain conditions are satisfied, Rule 144 is not available for resales of securities of any issuer (each, a “Shell Company”) that has ever had (i) no or nominal operations and (ii) no or nominal assets other than cash and cash equivalents. If CANEX were ever to be deemed to be, or to have at any time previously been, a Shell Company, Rule 144 may be unavailable for resales of CANEX Shares unless and until CANEX has satisfied the applicable conditions.
In general, under Regulation S, persons who are affiliates or former affiliates of CANEX solely by virtue of their status as an officer or director of CANEX may sell the Consideration Shares outside the United States in an “offshore transaction” (which would include a sale through the TSXV, if applicable) if neither the seller nor any person acting on its behalf engages in “directed selling efforts” in the United States and no selling commission, fee or other remuneration is paid in connection with such sale other than a usual and customary broker’s commission. For purposes of Regulation S, “directed selling efforts” means “any activity undertaken for the purpose of, or that could reasonably be expected to have the effect of, conditioning the market in the United States for any of the securities being offered” in the sale transaction. Certain additional restrictions are applicable to a holder of Consideration Shares who is an “affiliate” (as defined in Rule 144) of CANEX after the Arrangement other than by virtue of their status as an officer or director of CANEX.
Dissent Rights Under the Arrangement
Registered Shareholders who wish to dissent with respect to the Arrangement Resolution should take note that strict compliance with the dissent procedures is required.
The following description of the dissent procedures is not a comprehensive statement of the procedures to be followed by a Dissenting Shareholder who seeks payment of the fair value of its Shares, as applicable, and is qualified in its entirety by the reference to the Plan of Arrangement, the full text of the proposed form of Interim Order and Part 8, Division 2 of the BCBCA, which are attached to this Circular as Appendices B, G and J, respectively. A Dissenting Shareholder who intends to exercise the Dissent Rights should carefully consider and comply with the provisions of sections 237 to 247 of the BCBCA, as modified by the Interim Order and the Plan of Arrangement, and seek independent legal advice. Failure to comply strictly with the provisions of the BCBCA, as modified by the Interim Order and the Plan of Arrangement, and to adhere to the procedures established therein, may result in the loss of all rights thereunder.
- 57 -
The Court hearing the application for the Final Order has the discretion to alter the Dissent Rights with respect to the Arrangement described herein based on the evidence presented at such hearing.
Each Registered Shareholder as of the Record Date may exercise Dissent Rights in connection with the Arrangement pursuant to and in the manner set forth in Division 2 of Part 8 of the BCBCA, as modified by the Plan of Arrangement, the Interim Order and the Final Order (if applicable). Each Dissenting Shareholder who duly exercises its Dissent Rights in accordance with the Plan of Arrangement, shall be deemed to have transferred all Shares held by such Dissenting Shareholder and in respect of which Dissent Rights have been validly exercised, to Gold Basin, free and clear of all liens, and if such Dissenting Shareholder:
| (a) | is ultimately entitled to be paid fair value for its Shares in respect of which they exercised Dissent Rights, which fair value shall be the fair value of such shares immediately before the passing by the Shareholders of the Arrangement Resolution, such Dissenting Shareholder shall be paid an amount equal to such fair value by Gold Basin and will be deemed to have irrevocably transferred such Shares in consideration for such fair value; and |
| (b) | is ultimately not entitled, for any reason, to be paid fair value for such Shares, such Dissenting Shareholder shall be deemed to have participated in the Arrangement, as of the Effective Time, on the same basis as a non-dissenting holder of Shares and shall be entitled to receive only the consideration contemplated by the Plan of Arrangement that such Dissenting Shareholder would have received pursuant to the Arrangement if such Dissenting Shareholder had not exercised its Dissent Rights, |
but in no case shall Gold Basin or any other person be required to recognize holders of Shares who purport to exercise Dissent Rights as holders of Shares after the time that is immediately prior to the Effective Time, and the names of such holders of Shares who exercise Dissent Rights shall be deleted from the central securities register as holders Shares at the Effective Time.
Non-Registered Shareholders as of the Record Date who wish to dissent with respect to their Shares should be aware that only Registered Shareholders are entitled to dissent with respect to them. A Registered Shareholder such as an Intermediary who holds Shares as nominee for Non-Registered Shareholders some of whom wish to dissent, must exercise Dissent Rights with respect to the Arrangement on behalf of such Non-Registered Shareholders with respect to the Shares held for such Non-Registered Shareholders. In such case, the Notice of Dissent (as defined below) should set forth the number of Shares it covers.
Pursuant to section 238 of the BCBCA, the Interim Order and the Plan of Arrangement, every Registered Shareholder as of the Record Date who dissents from the Arrangement Resolution in compliance with sections 237 to 247 of the BCBCA will be entitled to be paid by Gold Basin the fair value of the Shares held by such Dissenting Shareholder determined as of the close of business on the business day immediately preceding the date on which the Arrangement Resolution was adopted.
A Dissenting Shareholder must dissent with respect to all Shares in which the holder owns a beneficial interest. A Registered Shareholder who wishes to dissent to the Arrangement Resolution must deliver written notice of dissent (a “Notice of Dissent”) to Gold Basin at Fasken Martineau DuMoulin LLP, 550 Burrard Street, Suite 2900, Vancouver, British Columbia, V6C 0A3 (Attention: Mark Pontin) by 5:00 p.m. (Vancouver time) on June 2, 2026, or two business days prior to any adjournment or postponement of the Meeting, and such Notice of Dissent must strictly comply with the requirements of section 242 of the BCBCA.
Any failure by a Registered Shareholder to fully comply may result in the loss of that holder’s Dissent Rights with respect to the Arrangement. Non-Registered Shareholders who wish to exercise such Dissent Rights must arrange for the Registered Shareholder holding their Shares to deliver the Notice of Dissent.
The delivery of a Notice of Dissent does not deprive a Dissenting Shareholder of the right to vote at the Meeting on the Arrangement Resolution; however, a Dissenting Shareholder is not entitled to exercise the Dissent Rights with respect to the Arrangement with respect to any of their Shares if the Dissenting Shareholder votes in favour of the Arrangement Resolution. A vote against the Arrangement Resolution, whether in-person or by proxy, does not constitute a Notice of Dissent.
- 58 -
A Dissenting Shareholder must prepare a separate Notice of Dissent for themselves, if dissenting on their own behalf, and for each other person who beneficially owns Shares registered in the Dissenting Shareholder’s name and on whose behalf the Dissenting Shareholder is dissenting, and must dissent with respect to all of the Shares registered in their name beneficially owned by the Non-Registered Shareholder on whose behalf they are dissenting. The Notice of Dissent must set out the number of Shares in respect of which the Notice of Dissent is to be sent (the “Arrangement Notice Shares”) and: (a) if such Shares constitute all of the Shares of which the Dissenting Shareholder is the registered and beneficial owner and that holder owns no other Shares as beneficial owner, a statement to that effect; (b) if such Shares constitute all of the Shares of which the Dissenting Shareholder is both the registered and beneficial owner but the Dissenting Shareholder owns additional Shares beneficially, a statement to that effect and the names of the Registered Shareholders, the number of Shares held by such registered owners and a statement that written Notice of Dissents are being or have been sent with respect to such other Shares; or (c) if the Dissent Rights with respect to the Arrangement are being exercised by a registered owner on behalf of a Non-Registered Shareholder who is not the dissenting shareholder, a statement to that effect and the name of the Non-Registered Shareholder and a statement that the registered owner is dissenting with respect to all Shares of the Non-Registered Shareholder registered in such registered owner’s name.
If the Arrangement Resolution is approved by the Shareholders as required at the Meeting, and if Gold Basin notifies the Dissenting Shareholders of its intention to act upon the Arrangement Resolution, the Dissenting Shareholder is then required within one month after Gold Basin gives such notice, to send to Gold Basin the certificates representing the Arrangement Notice Shares and a written statement that requires Gold Basin to purchase all of the Arrangement Notice Shares. If the Dissent Rights with respect to the Arrangement are being exercised by the Dissenting Shareholder on behalf of a Non-Registered Shareholder who is not the Dissenting Shareholder, a statement signed by such Non-Registered Shareholder is required which sets out whether the Non-Registered Shareholder is the beneficial owner of other Shares and if so, (i) the names of the Registered Shareholders of such Shares; (ii) the number of such Shares; and (iii) that dissent is being exercised in respect of all of such Shares. Upon delivery of these documents, the Dissenting Shareholder is deemed to have sold the Shares and Gold Basin is deemed to have purchased them as of the Effective Time.
The Dissenting Shareholder and Gold Basin may agree on the payout value of the Arrangement Notice Shares; otherwise, either party may apply to the Court to determine the fair value of the Arrangement Notice Shares or apply for an order that value be established by arbitration or by reference to the registrar or a referee of the Court. After a determination of the payout value of the Arrangement Notice Shares, Gold Basin must then promptly pay that amount to the Dissenting Shareholder.
A Dissenting Shareholder loses their Dissent Rights with respect to the Arrangement if, before full payment is made for the Arrangement Notice Shares, Gold Basin abandons the corporate action that has given rise to such Dissent Rights (namely, the Arrangement), a court permanently enjoins the action, or the Dissenting Shareholder withdraws the Notice of Dissent with Gold Basin’s consent. When any one of these events occur, Gold Basin must return the share certificates to the Dissenting Shareholder and the Dissenting Shareholder regains the ability to vote and exercise shareholder rights.
The discussion above is only a summary of the Dissent Rights with respect to the Arrangement, which are technical and complex. A Shareholder who intends to exercise such Dissent Rights should carefully consider and comply with the provisions of sections 237 to 247 of the BCBCA as modified by the Interim Order, the Final Order and the Plan of Arrangement. Non-Registered Shareholders who wish to dissent should be aware that only a Registered Shareholder is entitled to dissent.
Gold Basin suggests that any Shareholder wishing to avail themselves of the Dissent Rights with respect to the Arrangement seek their own legal advice, as failure to comply strictly with the applicable provisions of the BCBCA and the Interim Order, Final Order and Plan of Arrangement may prejudice the availability of such Dissent Rights. Dissenting Shareholders should note that the exercise of Dissent Rights with respect to the Arrangement can be a complex, time-consuming and expensive process.
- 59 -
If a Dissenting Shareholder fails to strictly comply with the requirements of the Dissent Rights with respect to the Arrangement, it will lose such Dissent Rights, Gold Basin will return to the Dissenting Shareholder the certificate(s) representing the Arrangement Notice Shares that were delivered to Gold Basin, if any, and if the Arrangement is completed, that Dissenting Shareholder will be deemed to have participated in the Arrangement on the same terms as a non-dissenting Shareholder.
If, as of the Effective Date, the aggregate number of Shares in respect of which Shareholders have duly and validly exercised Dissent Rights, or have instituted proceedings to exercise Dissent Rights in connection with the Arrangement, exceeds 10% of the Shares then outstanding, CANEX is entitled, in its discretion, not to complete the Arrangement. See “The Arrangement Agreement — Conditions to the Arrangement Becoming Effective – CANEX Conditions Precedent”.
Information Concerning CANEX
CANEX is a junior mineral exploration company focused on advancing the 100% owned Gold Range Project in Mohave County, Arizona (the “Gold Range Project”) and the Louise Copper-Gold Porphyry Project in British Columbia (the “Louise Project”). Since inception, the efforts of CANEX have been devoted to the acquisition, exploration, and development of mineral properties.
CANEX’s principal asset is the 100% owned Gold Range Project, located in northern Arizona, in Mohave County. The project has yielded several near-surface, bulk-tonnage gold discoveries across a four kilometre gold-mineralized trend. The Gold Range Project represents an early-stage gold exploration opportunity with the potential for resource expansion through further drilling and exploration. In addition to the Gold Range Project, CANEX is advancing the Louise Project in British Columbia which contains a large historic copper-gold resource. The Louise Project has seen limited deep or lateral exploration, providing near-term, low-cost discovery potential for copper and gold mineralization. CANEX has recently completed a large scale and deep looking induced polarization geophysical survey at the Louise Project. The survey has identified two new high priority chargeability targets that have never been identified nor drill tested previously. One, the west Louise Project target, is located two kilometres west of the historic Louise Project deposit and contains similar chargeability and resistivity values as known mineralization. The second, the Louise Project deep target, is a high chargeability zone located immediately north and below the historic Louise Project deposit. This target has potential to host the main body or roots of the faulted Louise Project system and identifying this target was a key objective of the survey.
CANEX is led by an experienced management team with a track record of multiple porphyry and bulk-tonnage discoveries across North America. CANEX is supported by a significant shareholder, Altius Minerals Corporation (Toronto Stock Exchange: ALS), which has invested in CANEX as a strategic sponsor.
CANEX was originally incorporated under the laws of the Province of Quebec on March 15, 1971, and was continued under the Business Corporations Act (Alberta) on July 14, 2011. On April 3, 2017, CANEX amended its articles to change its name from “Northern Abitibi Mining Corp.” to “CANEX Metals Inc.”. CANEX’s 100% owned subsidiary, Canexco Inc., was incorporated on June 5, 2019, in Arizona, to conduct CANEX’s exploration and development business in the United States.
CANEX’s head and registered office is located at Suite 1620, 734 – 7th Avenue SW, Calgary, Alberta T2P 3P8, Canada.
The CANEX Shares trade on the TSXV under the symbol “CANX” and are quoted on the OTC Market under the symbol “NOMNF”.
The following documents of CANEX, filed with securities commissions or similar regulatory authorities in British Columbia, Alberta and Ontario, are attached to this Circular:
| (i) | audited annual consolidated financial statements for the years ended September 30, 2025 and 2024, together with the notes thereto and the independent auditor’s report thereon and management’s discussion and analysis in respect thereof at Appendix M; and |
- 60 -
| (ii) | unaudited interim condensed consolidated financial statements for the three months ended December 31, 2025 and 2024 and management’s discussion and analysis in respect thereof at Appendix N. |
For further information concerning the business and operations of CANEX, see Appendix D. CANEX’s filings with the applicable securities regulatory authorities in Canada may be obtained through SEDAR+ at www.sedarplus.ca.
Information Concerning Gold Basin
Gold Basin was incorporated on November 24, 2017 under the laws of the Province of British Columbia, and is a mineral exploration company engaged in the acquisition, exploration and development of mineral properties in North America.
Gold Basin’s principal asset is the “Gold Basin Project”, a 42 km² district-scale gold exploration property located in Mohave County, Arizona. The Gold Basin Project is accessible year-round via a 1.5-hour drive southeast of Las Vegas on U.S. Highway I-93. High-voltage power lines originating from the Hoover Dam crosscut the southern portion of the project area, providing access to infrastructure.
The registered and head office is located at 1200 Waterfront Centre, 200 Burrard Street, Vancouver, British Columbia, Canada.
Prior to a Halt in trading ordered by CIRO on May 7, 2025, the Shares traded on the TSXV under the symbol “GXX”. The Shares also are quoted on the OTC Market under the symbol “GXXFF”.
For further information concerning the business and operations of Gold Basin, see Appendix C. Gold Basin’s filings with the applicable securities regulatory authorities in Canada may be obtained through SEDAR+ at www.sedarplus.ca. Information in Gold Basin’s publicly filed documents may be out of date, inaccurate or incomplete and may not be reflective of the current condition, including financial condition, of Gold Basin. See Appendix K of the Circular, “Cease Trade Order and Partial Revocation Order”.
Information Concerning the Resulting Issuer Following Completion of the Arrangement
As a result of the Arrangement, Gold Basin will be a wholly-owned subsidiary of CANEX. For further information concerning the business and operations of the Resulting Issuer following completion of the Arrangement, see Appendix E.
Pro Forma Consolidated Financial Statements
See Appendix O for the Pro Forma Consolidated Financial Statements.
INCOME TAX CONSIDERATIONS
Certain Canadian Federal Income Tax Considerations
The following summary describes, as of the date hereof, the principal Canadian federal income tax considerations under the Tax Act of the Arrangement generally applicable to a beneficial owner of Shares who, at all relevant times, for purposes of the Tax Act: (i) deals at arm’s length with Gold Basin and CANEX; (ii) is not affiliated with Gold Basin or CANEX; and (iii) holds its Shares, and will hold the CANEX Shares received upon the Arrangement, as capital property (a “Holder”).
Shares will generally be considered to be capital property to a Holder unless such Shares are held by the Holder in the course of carrying on a business of buying and selling securities or were acquired in one or more transactions considered to be an adventure or concern in the nature of trade.
- 61 -
This summary is not applicable to a Holder: (i) that is a “specified financial institution” for the purposes of the Tax Act; (ii) that is a “financial institution” for the purposes of the mark-to-market rules in the Tax Act; (iii) whose interest in which is a “tax shelter investment” for the purposes of the Tax Act; (iv) who makes or has made a functional currency reporting election for the purposes of the Tax Act; (v) that is a foreign affiliate, as defined in the Tax Act, of a taxpayer resident in Canada; (vi) that has entered into or will enter into a “derivative forward agreement” or a “synthetic disposition arrangement”, each as defined in the Tax Act, in respect of the Shares or CANEX Shares; (vii) who acquired or will acquire Shares under an employee stock option plan or other equity-based employment compensation arrangement; (viii) that receives or will receive dividends on the Shares or CANEX Shares under or as part of a “dividend rental arrangement”, as defined in the Tax Act; or (ix) that is exempt from Tax under the Tax Act. In addition, this summary does not address the tax considerations to holders of the Options. Such holders should consult their own tax advisors to determine the tax consequences to them of the Arrangement.
This summary does not address the possible application of the “foreign affiliate dumping” rules that may be applicable to a Holder that is a corporation resident in Canada (for the purposes of the Tax Act) and is or becomes, or does not deal at arm’s length with a corporation resident in Canada (for the purposes of the Tax Act) that is or becomes, as part of a transaction or event or series of transactions or events that includes the Arrangement, controlled by a non-resident person, or a group of non-resident persons not dealing with each other at arm’s length (for purposes of the Tax Act), for purposes of the rules in section 212.3 of the Tax Act. Such Holders should consult their own tax advisors with respect to the tax consequences to them of the Arrangement.
This summary is based on the current provisions of the Tax Act, and on counsel’s understanding of the current administrative policies and assessing practices of the CRA published in writing prior to the date hereof. This summary takes into account all specific proposals to amend the Tax Act publicly announced by or on behalf of the Minister of Finance (Canada) prior to the date hereof (the “Proposed Amendments”) and assumes that all Proposed Amendments will be enacted in the form proposed. However, no assurances can be given that the Proposed Amendments will be enacted as proposed, or at all. Except for the Proposed Amendments, this summary does not otherwise take into account or anticipate any changes in Law or administrative policy or assessing practice of the CRA whether by legislative, regulatory, administrative or judicial action, nor does it take into account tax legislation or considerations of any province, territory or foreign jurisdiction, which may differ from those discussed herein.
This summary is of a general nature only and is not, and is not intended to be, nor should it be construed to be, legal or tax advice or representations to any particular Holder, and no representations with respect to the income tax consequences to any Holder are made. This summary is not exhaustive of all Canadian federal income tax considerations. Accordingly, Holders should consult their own tax advisors for advice with respect to the tax consequences of the transactions described in this Circular, having regard to their own particular circumstances.
Currency Conversion
Subject to certain exceptions not discussed herein, for purposes of the Tax Act, all amounts (including amounts related to the acquisition, holding or disposition of Shares or CANEX Shares, such as dividends, adjusted cost base and proceeds of disposition) must be expressed in Canadian dollars, and amounts denominated in a currency other than the Canadian dollar generally must be converted into Canadian dollars using the applicable rate of exchange (for purposes of the Tax Act) quoted by the Bank of Canada on the date such amounts arose, or such other rate of exchange as is acceptable to the Minister of National Revenue (Canada).
Holders Resident in Canada
This portion of the summary is generally applicable to a Holder who, at all relevant times, for purposes of the application of the Tax Act and any applicable income tax treaty or convention, is, or is deemed to be, resident in Canada (a “Resident Holder”). Certain Resident Holders whose Shares or CANEX Shares might not otherwise qualify as capital property may, in certain circumstances, be entitled to have such shares, and every other “Canadian security” (as defined in the Tax Act) owned by them in the taxation year and any subsequent taxation year deemed to be capital property by making an irrevocable election in accordance with subsection 39(4) of the Tax Act. Resident Holders considering making such an election should consult their own tax advisors for advice as to whether the election is available or advisable in their own particular circumstances.
- 62 -
Exchange of Shares for CANEX Shares
A Resident Holder of Shares who, under the Arrangement, receives CANEX Shares in consideration for the Resident Holder’s Shares will be deemed to have disposed of the Resident Holder’s Shares for proceeds of disposition equal to the Resident Holder’s adjusted cost base of those shares immediately before the Effective Time under section 85.1 of the Tax Act and consequently will not realize a gain (or loss), unless such Resident Holder chooses to include any portion of the gain (or loss), otherwise determined, in computing their income for the taxation year which includes the Arrangement. A Resident Holder will be deemed to have acquired the CANEX Shares at an aggregate cost equal to the proceeds of disposition of the Resident Holder’s Shares. If the Resident Holder owns any other CANEX Shares at the Effective Time, the cost of each CANEX Share owned by the Resident Holder immediately after the Effective Time will be determined by averaging the cost of the CANEX Shares acquired on the Arrangement with the adjusted cost base of those other CANEX Shares.
If a Resident Holder chooses to treat the exchange of Shares for CANEX Shares as a taxable transaction by including any portion of the gain (or loss), otherwise determined, in computing their income, the Resident Holder will realize a capital gain (or capital loss) equal to the amount by which the proceeds of disposition of the Shares received by the Resident Holder, being the fair market value of the CANEX Shares received therefor, are greater (or less) than the total of the Resident Holder’s adjusted cost base of the Shares immediately before the exchange and any reasonable costs of disposition. In this event, the cost to the Resident Holder of the CANEX Shares received will be equal to the fair market value of such CANEX Shares determined at the Effective Time. The cost of the CANEX Shares so acquired will be averaged with the adjusted cost base of any other CANEX Shares held by the Resident Holder as capital property immediately before the acquisition for the purpose of determining the adjusted cost base of each CANEX Share held by the Resident Holder. See “Certain Canadian Federal Income Tax Considerations – Holders Residents in Canada – Taxation of Capital Gains and Capital Losses” for further details.
Dissenting Resident Holders
A Resident Holder who validly exercises Dissent Rights in respect of the Arrangement (a “Dissenting Resident Holder”) will be deemed to have transferred such Dissenting Resident Holder’s Shares to Gold Basin, and will be entitled to receive a payment from Gold Basin of an amount equal to the fair value of such Dissenting Resident Holder’s Shares. A Dissenting Resident Holder will be deemed to have received a taxable dividend equal to the amount, if any, by which such payment (other than any portion of the payment that is interest, if any, awarded by the Court) exceeds the “paid-up capital” (computed for the purposes of the Tax Act) of the Dissenting Resident Holder’s Shares immediately before their surrender to Gold Basin pursuant to the Arrangement. In the case of a Dissenting Resident Holder that is a corporation, in some circumstances, the amount of such deemed dividend may be treated as proceeds of disposition and not a dividend. The tax consequences described below under the heading “Holders Resident in Canada – Dividends on CANEX Shares” will generally apply with respect to any dividend deemed to be paid by Gold Basin to a Dissenting Resident Holder.
In addition, the Dissenting Resident Holder will be considered to have disposed of such Shares for proceeds of disposition equal to the amount paid to such Dissenting Resident Holder (other than any portion of the payment that is interest, if any, awarded by the Court), less the amount of any dividend deemed to be paid by Gold Basin on the surrender of such Shares as described above. The Dissenting Resident Holder will, in general, realize a capital gain (or a capital loss) equal to the amount by which such proceeds of disposition, net of any reasonable costs of disposition, exceed (or are exceeded by) the adjusted cost base to such Dissenting Resident Holder of the Shares immediately before their surrender to Gold Basin pursuant to the Arrangement. See “Holders Resident in Canada – Taxation of Capital Gains and Capital Losses” below for a general discussion of the treatment of capital gains and losses under the Tax Act.
Any interest awarded by the Court to a Dissenting Resident Holder will be included in such Dissenting Resident Holder’s income for the purposes of the Tax Act.
A Dissenting Resident Holder that is throughout the relevant taxation year a “Canadian-controlled private corporation” (as defined in the Tax Act) or at any time in the relevant taxation year a “substantive CCPC” (as defined in the Tax Act) may be liable to pay an additional tax (refundable in certain circumstances) on its “aggregate investment income” (as defined in the Tax Act), including amounts in respect of taxable capital gains, taxable dividends and interest.
- 63 -
Resident Holders who are contemplating exercising their Dissent Rights should consult their own tax advisors with respect to the tax consequences of exercising their Dissent Rights.
Dividends on CANEX Shares
A Resident Holder who is an individual will be required to include in income any dividends received or deemed to be received on the Resident Holder’s CANEX Shares. In the case of a Resident Holder who is an individual (other than certain trusts), such dividends will be subject to the gross-up and dividend tax credit rules normally applicable under the Tax Act to taxable dividends received from taxable Canadian corporations, including the enhanced gross-up and dividend tax credit rules applicable to any dividends designated by CANEX as “eligible dividends”, as defined in the Tax Act. There may be limitations on the ability of CANEX to designate dividends as eligible dividends.
A Resident Holder that is a corporation will be required to include in income any dividends received or deemed to be received on the Resident Holder’s CANEX Shares in computing its income for tax purposes, but generally will be entitled to deduct an equivalent amount in computing taxable income. In certain circumstances, subsection 55(2) of the Tax Act will treat a taxable dividend received or deemed to be received by a Resident Holder that is a corporation as proceeds of a disposition or a capital gain and not as a dividend. Resident Holders that are corporations should consult their own tax advisors having regard to their own circumstances.
A “private corporation” or a “subject corporation” (each as defined in the Tax Act) may be liable under Part IV of the Tax Act to pay a tax (refundable in certain circumstances) on any dividend that it receives or is deemed to receive on CANEX Shares to the extent that the dividend is deductible in computing CANEX’s taxable income.
Taxable dividends received by an individual or a trust, other than certain specified trusts, may give rise to minimum tax as calculated under the detailed rules set out in the Tax Act.
Disposing of CANEX Shares
Generally on a disposition or deemed disposition of a CANEX Share (other than a tax-deferred transaction or a disposition to CANEX that is not a sale in the open market in the manner in which shares would normally be purchased by any member of the public in the open market, subject to certain detailed exceptions in the Tax Act), a Resident Holder will realize a capital gain (or a capital loss) equal to the amount, if any, by which the proceeds of disposition of the CANEX Share, net of any reasonable costs of disposition, exceed (or are exceeded by) the adjusted cost base to the Resident Holder of the CANEX Share immediately before the disposition or deemed disposition. For a description of the tax treatment of capital gains and capital losses, see “Holders Resident in Canada – Taxation of Capital Gains and Capital Losses” below.
Taxation of Capital Gains and Capital Losses
Generally, one-half of any capital gain (a “taxable capital gain”) realized by a Resident Holder in a taxation year must be included in the Resident Holder’s income for the year, and one-half of any capital loss (an “allowable capital loss”) realized by a Resident Holder in a taxation year must be deducted from taxable capital gains realized by the Resident Holder in that year (subject to and in accordance with rules contained in the Tax Act). Allowable capital losses for a taxation year in excess of taxable capital gains for that year generally may be carried back and deducted in any of the three preceding taxation years or carried forward and deducted in any subsequent taxation year against net taxable capital gains realized in such years, to the extent and under the circumstances described in the Tax Act.
A Resident Holder that is throughout the relevant taxation year a “Canadian-controlled private corporation” (as defined in the Tax Act) or at any time in the relevant taxation year a “substantive CCPC” (as defined in the Tax Act) may be liable to pay an additional tax (refundable in certain circumstances) on its “aggregate investment income” (as defined in the Tax Act), including amounts in respect of taxable capital gains.
The amount of any capital loss realized by a Resident Holder that is a corporation on the disposition or deemed disposition of a CANEX Share may be reduced by the amount of certain dividends previously received (or deemed to be received) by the Resident Holder on such share (or, in certain circumstances, another share where the share has been acquired in exchange for such other share) to the extent and under circumstances prescribed by the Tax Act. Similar rules may apply where a Resident Holder that is a corporation is a member of a partnership or a beneficiary of a trust that owns a CANEX Share or where a trust or partnership of which a Resident Holder that is a corporation is a beneficiary or a member is itself a member of a partnership or a beneficiary of a trust that owns a CANEX Share. Resident Holders to whom these rules may be relevant should consult their own tax advisors.
- 64 -
Capital gains realized by an individual or trust, other than certain specified trusts, may give rise to a liability for minimum tax as calculated under the detailed rules set out in the Tax Act.
Eligibility for Investment
Based on the current provisions of the Tax Act as of the date hereof, the CANEX Shares issued pursuant to the Arrangement would be, if issued on the date hereof, “qualified investments” under the Tax Act for trusts governed by a registered retirement savings plan (“RRSP”), a registered retirement income fund (“RRIF”), a registered education savings plan (“RESP”), a registered disability savings plan (“RDSP”), a tax-free savings account (“TFSA”), a first home savings account (a “FHSA” and, together with a RRSP, a RRIF, a RESP, a RDSP and a TFSA, “Registered Plans”) or a deferred profit sharing plan (each as defined in the Tax Act), at any particular time, provided that, at that time, the CANEX Shares are listed on a “designated stock exchange” for purposes of the Tax Act (which currently includes the TSXV).
Notwithstanding the foregoing, if the CANEX shares are a “prohibited investment” for a Registered Plan (as defined in the Tax Act), the holder, subscriber or annuitant of the particular Registered Plan, as the case may be, will be subject to a penalty tax as set out in the Tax Act. The CANEX Shares will generally not be a “prohibited investment” for Registered Plans provided that (i) such holder, subscriber or annuitant, as applicable, deals at arm’s length with CANEX for purposes of the Tax Act and does not have a “significant interest” (within the meaning of the prohibited investment rules in the Tax Act) in CANEX, or (ii) the CANEX Shares are “excluded property” for a Registered Plan within the meaning of the prohibited investment rules in the Tax Act. A holder, subscriber or annuitant of a Registered Plan, as the case may be, should consult its own tax advisor in this regard.
Holders Not Resident in Canada
This portion of the summary is generally applicable to a Holder who, at all relevant times, for the purposes of the application of the Tax Act and any applicable tax treaty or convention, is not, and is not deemed to be, resident in Canada and does not use or hold, and is not deemed to use or hold, the Shares or CANEX Shares in a business carried on in Canada (a “Non-Resident Holder”). Special rules, which are not discussed in this summary, may apply to certain holders that are insurers carrying on an insurance business in Canada and elsewhere or an “authorized foreign bank” (as defined in the Tax Act).
Exchange of Shares for CANEX Shares
A Non-Resident Holder will not be subject to tax under the Tax Act on any capital gain realized on a disposition or deemed disposition of a Share pursuant to the Arrangement, unless the Share is: (i) “taxable Canadian property” of the Non-Resident Holder at the time of disposition or deemed disposition for purposes of the Tax Act; and (ii) not “treaty-protected property” (as defined in the Tax Act) of the Non-Resident Holder at the time of disposition or deemed disposition. Provided that at the time of disposition or deemed disposition the Shares are listed on a “designated stock exchange” for purposes of the Tax Act (which currently includes the TSXV), the Shares will not be “taxable Canadian property” of a Non-Resident Holder at that time, unless at any time during the 60-month period immediately preceding that time the following two conditions are met concurrently: (i) one or any combination of (a) the Non-Resident Holder, (b) persons with whom the Non-Resident Holder does not deal at arm’s length for purposes of the Tax Act, and (c) partnerships in which the Non-Resident Holder or a person described in (b) holds a membership interest directly or indirectly through one or more partnerships, owned 25% or more of the issued shares of any class or series of the capital stock of Gold Basin; and (ii) more than 50% of the fair market value of the Shares was derived directly or indirectly from one or any combination of real or immovable property situated in Canada, “Canadian resource property” (as defined in the Tax Act), “timber resource property” (as defined in the Tax Act), and options in respect of, or interests in, or for civil law rights in, any such property (whether or not such property exists). Notwithstanding the foregoing, the Shares may be deemed to be “taxable Canadian property” in certain circumstances as set in the Tax Act.
- 65 -
In the event that the Shares constitute or are deemed to constitute taxable Canadian property to any Non-Resident Holder, such Non-Resident Holder may be entitled to relief under the provisions of an applicable income tax treaty or convention if the Shares are “treaty-protected property” to the Non-Resident Holder. Shares owned by a Non-Resident Holder will generally be treaty-protected property if the gain from the disposition of such shares would, because of an applicable income tax treaty or convention between Canada and the country in which the Non-Resident Holder is resident, be exempt from tax under Part I of the Tax Act.
If the Shares are considered to be taxable Canadian property, but not treaty-protected property to the Non-Resident Holder at the time of disposition (including as a result of the application of the MLI (as defined below)), such Non-Resident Holder will generally be subject to the same income tax considerations as those discussed above with respect to Resident Holders under “Holders Resident in Canada – Exchange of Shares for CANEX Shares” and “Certain Canadian Federal Income Tax Considerations – Residents of Canada – Taxation of Capital Gains and Capital Losses”, including the potential for the deferral of any capital gain or loss that would otherwise be realized on the disposition of Shares in exchange for CANEX Shares under the provisions of section 85.1 of the Tax Act. In addition, if section 85.1 of the Tax Act applies, CANEX Shares acquired by the Non-Resident Holder in exchange for Shares that were taxable Canadian property of the Non-Resident Holder will be deemed to be, at any time that is within 60 months after such exchange, taxable Canadian property of the Non-Resident Holder.
Non-Resident Holders whose Shares are, or may be, taxable Canadian property should consult their own tax advisors for advice regarding their particular circumstances, including whether their Shares constitute treaty-protected property, and any resulting Canadian tax reporting obligations.
Dissenting Non-Resident Holders
A Non-Resident Holder who validly exercises Dissent Rights in respect of the Arrangement (a “Dissenting Non-Resident Holder”) will be deemed to have transferred such Dissenting Non-Resident Holder’s Shares to Gold Basin, and will be entitled to receive a payment from Gold Basin of an amount equal to the fair value of such Dissenting Non-Resident Holder’s Shares. A Dissenting Non-Resident Holder will be deemed to receive a taxable dividend equal to the amount, if any, by which such payment (other than any portion of the payment that is interest, if any, awarded by the Court) exceeds the “paid-up capital” (computed for the purposes of the Tax Act) of the Dissenting Non-Resident Holder’s Shares immediately before their surrender to Gold Basin pursuant to the Arrangement. Any such dividend will be subject to Canadian withholding tax under the Tax Act at a rate of 25% of the gross amount of the dividend, unless the rate of withholding is reduced under the provisions of an applicable income tax treaty or convention.
A Dissenting Non-Resident Holder of Shares will also be considered to have disposed of such Shares for proceeds of disposition equal to the amount paid to such Dissenting Non-Resident Holder less an amount in respect of interest, if any, awarded by the Court and the amount of any deemed dividend. A Dissenting Non-Resident Holder will generally not be subject to income tax under the Tax Act in respect of any capital gain realized on a disposition of Shares pursuant to the exercise of the Dissenting Non-Resident Holder’s Dissent Rights unless such Shares constitute, or are deemed to constitute, “taxable Canadian property” of the Dissenting Non-Resident Holder and the Dissenting Non-Resident Holder is not entitled to relief under an applicable income tax treaty or convention. See the discussion below under the heading “Disposing of CANEX Shares” for more detail.
Any interest paid or credited to a Dissenting Non-Resident Holder will generally not be subject to Canadian withholding tax under the Tax Act provided such interest is not “participating debt interest” (as defined in the Tax Act).
Non-Resident Holders who are contemplating exercising their Dissent Rights should consult their own tax advisors with respect to the tax consequences of exercising their Dissent Rights.
Dividends on CANEX Shares
Dividends paid or credited, or deemed to be paid or credited, on a Non-Resident Holder’s CANEX Shares will generally be subject to Canadian withholding tax under the Tax Act at a rate of 25% of the gross amount of the dividend, unless the rate of withholding is reduced under the provisions of an applicable income tax treaty or convention. For example, under the Convention, a Non-Resident Holder who is resident in the U.S. for purposes of the Convention and who is entitled to the benefits of such treaty will generally be subject to Canadian withholding tax at a rate of 15% of the amount of such dividends (or 5% of the amount of such dividends if such Non-Resident Holder is a company that holds at least 10% of the voting stock of CANEX).
- 66 -
The Multilateral Convention to Implement Tax Treaty Related Measures to Prevent Base Erosion and Profit Shifting (the “MLI”), of which Canada is a signatory, affects many of Canada’s bilateral tax treaties (but not the Convention), including the ability to claim benefits thereunder. Non-Resident Holders should consult their own tax advisors in this regard.
Disposing of CANEX Shares
A Non-Resident Holder will not be subject to tax under the Tax Act on any capital gain realized on a disposition or deemed disposition of a CANEX Share acquired pursuant to the Arrangement, unless the CANEX Share is: (i) “taxable Canadian property” of the Non-Resident Holder at the time of disposition or deemed disposition for purposes of the Tax Act; and (ii) not “treaty-protected property” (as defined in the Tax Act) of the Non-Resident Holder at the time of disposition or deemed disposition.
In circumstances where a CANEX Share is, or is deemed to be, taxable Canadian property of the Non-Resident Holder, any capital gain that would be realized on the disposition of such security that is not exempt from tax under the Tax Act pursuant to an applicable income tax treaty or convention (including as a result of the application of the MLI) will generally be subject to the same Canadian income tax consequences discussed above for a Resident Holder in “Certain Canadian Federal Income Tax Considerations – Residents of Canada – Taxation of Capital Gains and Capital Losses”. Such Non-Resident Holders should consult their tax advisors about their particular circumstances.
Provided that at the time of disposition or deemed disposition the CANEX Shares are listed on a designated stock exchange for purposes of the Tax Act (which currently includes the TSXV), the CANEX Shares will not be “taxable Canadian property” of a Non-Resident Holder at that time, unless at any time during the 60-month period immediately preceding that time the following two conditions are met concurrently: (i) one or any combination of (a) the Non-Resident Holder, (b) persons with whom the Non-Resident Holder does not deal at arm’s length for purposes of the Tax Act, and (c) partnerships in which the Non-Resident Holder or a person described in (b) holds a membership interest directly or indirectly through one or more partnerships, owned 25% or more of the issued shares of any class or series of the capital stock of CANEX; and (ii) more than 50% of the fair market value of the CANEX Shares was derived directly or indirectly from one or any combination of real or immovable property situated in Canada, “Canadian resource property” (as defined in the Tax Act), “timber resource property” (as defined in the Tax Act), and options in respect of, or interests in, or for civil law rights in, any such property (whether or not such property exists). Notwithstanding the foregoing, the CANEX Shares may be deemed to be “taxable Canadian property” in certain circumstances set out in the Tax Act.
Non-Resident Holders who dispose of CANEX Shares that may constitute “taxable Canadian property” should consult their own tax advisors with respect to the tax consequences of the disposition having regard to their particular circumstances.
RISK FACTORS
Shareholders who vote in favour of the Arrangement Resolution will be voting in favour of combining the businesses of CANEX and Gold Basin, and to invest in CANEX Shares. There are certain risk factors associated with the Arrangement, an investment in CANEX Shares which should be carefully considered by the Shareholders, including the fact that the Arrangement may not be completed, if among other things, the Arrangement Resolution is not approved at the Meeting or if any other conditions precedent to the completion of the Arrangement are not satisfied or waived, as applicable. Readers are cautioned that such risk factors are not exhaustive. These risk factors should be considered in conjunction with the other information included in this Circular, Appendices C, D and E, and documents filed by Gold Basin and CANEX pursuant to applicable Laws from time to time.
- 67 -
The Arrangement May Not Be Completed
Each of the Parties has the right to terminate the Arrangement Agreement in certain circumstances. Accordingly, there is no certainty, nor can the Parties provide any assurance, that the Arrangement Agreement will not be terminated before the completion of the Arrangement.
In addition, the completion of the Arrangement is subject to a number of conditions precedent, certain of which are outside the control of the Parties, including obtaining approval of Shareholders of the Arrangement Resolution, conditional approval of the TSXV of the listing of the CANEX Shares to be issued to Shareholders as Share Consideration, conditional approval from the TSXV for the Term Loan, approval of the Arrangement by the TSXV, and approval of the Court. There is no certainty, nor can the Parties provide any assurance, that these conditions will be satisfied or, if satisfied, when they will be satisfied.
There are a number of material risks to which Gold Basin is subject relating to the Arrangement not being completed, including the following:
| (a) | if the Arrangement is not completed, the market price of Shares may be adversely affected; and |
| (b) | if the Arrangement Agreement is terminated and the Board decides to seek another sale, there can be no assurance that it will be able to find a party willing to pay an equivalent or more attractive price than the price to be paid pursuant to the Arrangement and, under certain circumstances, Gold Basin may be required to pay the Termination Fee to CANEX. |
The Arrangement Agreement Limits Gold Basin’s Ability to Pursue Alternatives to the Arrangement
Under the Arrangement Agreement, Gold Basin is restricted, subject to limited exceptions, from pursuing or entering into alternative transactions in lieu of the Arrangement. In general, unless and until the Arrangement Agreement is terminated, Gold Basin is restricted from soliciting alternative Acquisition Proposals and providing information to or engaging in discussions with third parties, except in the limited circumstances as provided in the Arrangement Agreement. The Board is limited in its ability to change its recommendation with respect to the Arrangement-related proposals. Gold Basin has the right to terminate the Arrangement Agreement and enter into an agreement with respect to a Superior Proposal only if specified conditions have been satisfied, including compliance with the non-solicitation provisions of the Arrangement Agreement, the expiration of certain right to match periods that may give CANEX an opportunity to amend the Arrangement Agreement so the Superior Proposal is no longer a Superior Proposal and the payment of the required Termination Fee. These provisions could discourage a third party that may have an interest in acquiring all or a significant part of Gold Basin from considering or proposing such an acquisition, even if such third party were prepared to pay consideration with a higher per share cash or market value than the consideration proposed to be received or realized in the Arrangement, or might result in a potential acquirer proposing to pay a lower price than it would otherwise have proposed to pay because of the added expense of the Termination Fee that may become payable.
Possible Failure to Realize Anticipated Benefits of the Arrangement
The ability to realize the benefits of the Arrangement will depend in part on successfully consolidating functions and integrating operations, procedures and personnel in a timely and efficient manner, as well as on CANEX’s ability to realize the anticipated growth opportunities and synergies from integrating Gold Basin’s business following completion of the Arrangement. This integration will require the dedication of management effort, time and resources which may divert management’s focus and resources from other strategic opportunities available to CANEX following completion of the Arrangement, and from operational matters during this process. The integration process may result in the loss of key employees or directors and the disruption of ongoing business and employee relationships that may adversely affect the ability of CANEX to achieve the anticipated benefits of the Arrangement as well as any anticipated benefits from possible future acquisitions.
- 68 -
Risks Related to the Businesses of CANEX and Gold Basin
Each of the businesses of CANEX and Gold Basin are subject to significant risks. See the risk factors set out in Appendices C, D and E. While each of CANEX and Gold Basin have completed due diligence investigations, including reviewing technical, environmental, legal, tax, accounting, financial and other matters, on the other Party, certain risks either may not have been uncovered or are not known at this time. Such risks may have an adverse impact on CANEX and the combined assets of CANEX and Gold Basin following the Arrangement and may have a negative impact on the value of the CANEX Shares.
Gold Basin is Subject to Covenants in Respect of the Operation of their Business
Pursuant to the Arrangement Agreement, Gold Basin has agreed to certain interim operating covenants intended to ensure that that Gold Basin carries on its business in the ordinary course, except as required or expressly authorized by the Arrangement Agreement. These operating covenants cover a broad range of activities and business practices. Consequently, it is possible that a business opportunity will arise that is out of the ordinary course and that Gold Basin will not be able to pursue or undertake the opportunity, or be impeded from doing so, due to its covenants in the Arrangement Agreement.
Restrictions on Dividends
Any future payments of dividends by CANEX will be dependent upon the financial requirements of CANEX to finance future growth, the financial condition of CANEX, and other factors which the board of directors of CANEX may consider appropriate in the circumstance. In any event, CANEX is not expected to adopt a dividend or distribution policy at this time nor is it expected to pay a dividend.
Diversion of Management’s Attention and Resources
In pursuing the Arrangement, Gold Basin will incur costs associated with the Arrangement whether or not it is completed including the diversion of their respective management’s attention away from conducting their respective business in the ordinary course and the potential impact on their current business relationships.
Dissent Rights
Registered Shareholders as of the Record Date have the right to exercise certain dissent and appraisal rights and demand payment of the fair value of their Shares in cash in connection with the Arrangement in accordance with the BCBCA, as modified and supplemented by the Plan of Arrangement, the Interim Order and the Final Order (if applicable). If there are a significant number of Dissenting Shareholders, a substantial cash payment may be required to be made to such Shareholders that could have an adverse effect on CANEX’s financial condition and cash resources if the Arrangement is completed. If, as of the Effective Date, the aggregate number of Shares in respect of which Shareholders have duly and validly exercised Dissent Rights, or have instituted proceedings to exercise Dissent Rights, exceeds 10% of the Shares then outstanding, CANEX is entitled, in its discretion, not to complete the Arrangement. See “Securities Law Considerations – Dissent Rights Under the Arrangement”.
The CANEX Shares Issued in Connection with the Arrangement May Have a Market Value Different Than Expected
Pursuant to the Arrangement, each Shareholder will be entitled to receive 0.592 of one CANEX Share for each Share held, subject to adjustment for fractional shares. Because the Share Consideration under the Arrangement will not be adjusted to reflect any changes in the market value of CANEX Shares or the Shares, the market values of the CANEX Shares and the Shares at the Effective Time may vary significantly from the values at the date of this Circular and at the Effective Time. If the market price of CANEX Shares declines, the value of the consideration received by Shareholders will decline as well. Variations may occur as a result of changes in, or market perceptions of changes in, the business, operations or prospects of CANEX, market assessments of the likelihood the Arrangement will be consummated, regulatory considerations, adverse political developments, general market and economic conditions, changes in the prices of gold and other factors over which Gold Basin has no control.
- 69 -
CANEX May Not Realize the Benefits of its Growth Projects
As part of its strategy, following the completion of the Arrangement, CANEX will continue existing efforts and initiate new efforts to develop new projects and may have a larger number of such projects as a result of the Arrangement, including the assets and projects of Gold Basin. A number of risks and uncertainties are associated with the development of these types of projects, including political, regulatory, design, construction, labour, operating, technical, and technological risks, uncertainties relating to capital and other costs, and financing risks. The failure to develop one or more of these initiatives successfully could have an adverse effect on CANEX’s financial position and results of operations.
CANEX Will Be Subject to Significant Capital Requirements Associated with its Expanded Portfolio of Development Projects
Following completion of the Arrangement, CANEX must be able to utilize available financing sources to finance its growth and sustain capital requirements. CANEX could be required to raise significant additional capital through equity financings in the capital markets or to incur significant borrowings through debt financings to meet its capital requirements. If these financings are required, CANEX’s cost of raising capital in the future may be adversely affected. In addition, if CANEX is required to make significant interest and principal payments resulting from a debt financing, CANEX’s financial condition and ability to raise additional funds may be adversely impacted. Any significant delay in completing its development projects or the incurring of capital costs that are significantly higher than estimated could have a significant adverse effect on CANEX’s results of operations and financial condition. If additional capital is raised by the issuance of CANEX Shares following completion of the Arrangement, Shareholders may suffer dilution.
Directors and Officers of Gold Basin May Have Interests in the Arrangement That are Different From Those of the Shareholders
Shareholders should be aware that directors and officers of Gold Basin may have interests in the Arrangement that are, or may be, different from, or in addition to, the interests of other Shareholders. See “Securities Law Considerations – Interests of Certain Persons and Companies in the Arrangement”.
Following the Arrangement the Trading Price of CANEX May be Volatile
The trading prices of CANEX Shares and the Shares have been and may continue to be subject to and, following completion of the Arrangement, may be subject to, material fluctuations and may increase or decrease in response to a number of events and factors. The CANEX Shares may be subject to, material fluctuations and may increase or decrease in response to a number of events and factors, including:
| · | changes in the market price of the commodities that CANEX and Gold Basin sell and purchase; |
| · | current events affecting the economic situation in Canada and internationally; |
| · | trends in gold mining and mining, in general; |
| · | regulatory or government actions; |
| · | changes in financial estimates and recommendations by securities analysts; |
| · | acquisitions and financings; |
| · | the economics of current and future projects of CANEX or Gold Basin; |
| · | quarterly variations in operating results; and |
| · | the operating and share price performance of other companies, including those that investors may deem comparable. |
- 70 -
Following completion of the Arrangement, existing CANEX Shareholders will continue to have the ability to significantly influence certain corporate actions of CANEX. Immediately following the completion of the Arrangement, based on the respective share values at the date of announcement of the Arrangement, CANEX Shareholders are expected to own approximately 67.7% and Shareholders (other than CANEX and its affiliates, but including Shareholders which tendered to the Offer) are expected to own approximately 32.3% of the post-Arrangement CANEX Shares on a diluted in-the-money basis (assuming no Dissent Rights are exercised). Existing CANEX Shareholders will be in a position to exercise significant influence over all matters requiring shareholder approval, including the election of directors, determination of significant corporate actions, amendments to CANEX’s articles of incorporation and the approval of any business combinations, mergers or takeover attempts, in a manner that could conflict with the interests of other shareholders. Although there are no agreements or understandings between the CANEX Shareholders of which Gold Basin is aware as to voting, if they voted in concert they would exert significant influence over CANEX.
Fluctuation in Mineral Prices
The economics of mineral exploration are affected by many factors beyond CANEX’s control, including commodity prices, the cost of operations, variations in the grade of minerals explored and fluctuations in the market price of minerals. Depending on the price of minerals CANEX may determine that it is impractical to continue a mineral exploration operation. Mineral prices are prone to fluctuations and the marketability of minerals is affected by government regulation relating to price, royalties, allowable production and the importing and exporting of minerals, the effect of which cannot be accurately predicted. There is no assurance that a profitable market will exist for the sale of any minerals found on CANEX’s properties.
Exploration, Development and Operating Risks
CANEX is in the process of exploring its properties and has not yet determined whether its properties contain economically recoverable reserves and, therefore, does not generate any revenues from production. The recovery of expenditures on mineral properties and the related deferred exploration expenditures are dependent on the existence of economically recoverable mineralization, the ability of CANEX to obtain financing necessary to complete the exploration and development of its properties, and upon future profitable production, or alternatively, on the sufficiency of proceeds from disposition. Mineral exploration is highly speculative in nature, involves many risks and frequently is non-productive. There is no assurance that exploration efforts will be successful.
Gold Basin Expects to Incur Costs Associated with the Arrangement
Gold Basin will incur direct transaction costs in connection with the Arrangement. While such costs were anticipated, actual direct transaction costs incurred in connection with the Arrangement may be higher than expected. Moreover, certain of Gold Basin’s costs related to the Arrangement, including legal, certain financial advisory services, accounting, printing and mailing costs, must be paid even if the Arrangement is not completed. CANEX is liable for its own costs incurred in connection with the Arrangement except, in certain circumstances in which the Arrangement is not completed, Gold Basin may be required to pay CANEX the Termination Fee. See “The Arrangement Agreement – Non-Solicitation Covenant and Acquisition Proposal”.
AUDITORS, TRANSFER AGENTS AND REGISTRARS
Auditors
Gold Basin’s auditors are Manning Elliot LLP, having an address at 1700-1030 West Georgia St., Vancouver, British Columbia, V6E 2Y3, Canada. Manning Elliott LLP was appointed as Gold Basin’s auditor on March 16, 2026.
- 71 -
Transfer Agents, Registrars or Other Agents
The transfer agent and registrar for Gold Basin is TSX Trust Company, having an address at 733 Seymour Street, Suite 2310, Vancouver, British Columbia, V6B 0S6, Canada.
OTHER MATTERS
Other Business
The management of Gold Basin knows of no amendment, variation or other matter to come before the Meeting other than the matters referred to in the Notice of Meeting. However, if any other matter properly comes before the Meeting, the accompanying applicable proxy will be voted on such matter in accordance with the best judgment of the person voting the proxy.
Other Material Facts
There are no other material facts relating to the Arrangement not disclosed elsewhere in this Circular.
ADDITIONAL INFORMATION
Additional information relating to CANEX is available on SEDAR+ at www.sedarplus.ca. Financial information is provided in CANEX’s consolidated financial statements and management’s discussion and analysis for its most recently completed financial year, which are filed on SEDAR+ at www.sedarplus.ca.
For further information concerning the business and operations of Gold Basin, see Appendix C. Gold Basin’s filings with the applicable securities regulatory authorities in Canada may be obtained through SEDAR+ at www.sedarplus.ca. Information in Gold Basin’s publicly filed documents may be out of date, inaccurate or incomplete and may not be reflective of the current condition, including financial condition, of Gold Basin. See Appendix K of the Circular, “Cease Trade Order and Partial Revocation Order”.
- 72 -
DIRECTORS’ APPROVAL
The contents and the sending of the Notice of Meeting and this Circular have been approved by the Board.
DATED: May 14, 2026
ON BEHALF OF THE BOARD OF DIRECTORS OF GOLD BASIN RESOURCES CORPORATION
| (signed) “Jordan Ross” |
Jordan Ross
Director
- 73 -
CONSENT OF STIFEL NICOLAUS CANADA INC.
To: Gold Basin Resources Corporation (“Gold Basin”)
We refer to the fairness opinion of our firm dated May 11, 2026 (the “Opinion”), which we prepared for the special committee established by the board of directors of Gold Basin (the “Gold Basin Special Committee”) in connection with a plan of arrangement under the Business Corporations Act (British Columbia) involving Gold Basin and CANEX Metals Inc. (the “Arrangement”). We refer also to the management information circular of Gold Basin dated May 14, 2026 (the “Circular”) relating to the special meeting of shareholders of Gold Basin to approve, among other things, the Arrangement.
We hereby consent to the filing of the Opinion with the applicable securities regulatory authorities, the reference to our firm name and the Opinion in the Circular, the inclusion of a summary of the Opinion in the Circular and the inclusion of the full text of the Opinion in the Circular. In providing such consent, we do not intend that any person, other than the Gold Basin Special Committee and the board of directors of Gold Basin, shall be entitled to rely upon such Opinion.
Stifel Nicolaus Canada Inc.
Toronto, Ontario, Canada
May 11, 2026
Appendix A
Arrangement Resolution
[See attached]
The text of the Arrangement Resolution which the Shareholders will be asked to pass at the Meeting is as follows:
“BE IT RESOLVED THAT:
The arrangement (the “Arrangement”) under Section 288 of the Business Corporations Act (British Columbia) (the “BCBCA”) involving Gold Basin Resources Corporation (“Gold Basin”), its shareholders and CANEX Metals Inc. (“CANEX”), as set out in the Plan of Arrangement and as described in the management information circular (the “Circular”) of Gold Basin dated as of May 14, 2026 accompanying the notice of special meeting (as the Arrangement may be amended, modified or supplemented in accordance with the arrangement agreement dated May 11, 2026 (the “Arrangement Agreement”) between Gold Basin and CANEX), is hereby authorized, approved and adopted.
| 1. | The plan of arrangement of Gold Basin setting out the terms of the Arrangement (as it has been or may be amended, modified or supplemented in accordance with the Arrangement Agreement and its terms (the “Plan of Arrangement”)), the full text of which is set out in an appendix to the Circular (as the Plan of Arrangement may be, or may have been, modified or amended in accordance with its terms or the terms of the Arrangement Agreement), is hereby authorized, approved and adopted. |
| 2. | The Arrangement Agreement, the actions of the directors of Gold Basin in approving the Arrangement and the actions of the directors or officers of Gold Basin in executing and delivering the Arrangement Agreement and any amendments thereto are hereby ratified, confirmed and approved. |
| 3. | Notwithstanding that this special resolution has been passed (and the Arrangement adopted) by the shareholders of Gold Basin or that the Arrangement has been approved by the Supreme Court of British Columbia, the directors of Gold Basin are hereby authorized and empowered, without notice to or approval of the holders of common shares of Gold Basin, (a) to amend, modify or supplement the Arrangement Agreement or the Plan of Arrangement to the extent permitted by the Arrangement Agreement and the Plan of Arrangement, and (b) subject to the terms of the Arrangement Agreement, not to proceed with the Arrangement. |
| 4. | Any director or officer of Gold Basin is hereby authorized and directed for and on behalf of Gold Basin to execute, whether under seal of Gold Basin or otherwise, and to deliver such records, documents and information as are necessary or desirable to the Registrar of Companies under the BCBCA in accordance with the Arrangement Agreement for filing. |
| 5. | Any one or more officers or directors of Gold Basin is hereby authorized and directed for and on behalf of and in the name of Gold Basin to execute or cause to be executed and to deliver or cause to be delivered, whether under the seal of Gold Basin or not, all such agreements, forms, waivers, notices, certificates, confirmations and such other documents and instruments and to perform or cause to be performed all such other acts and things as such person determines may be necessary or desirable or useful to give full effect to the foregoing resolutions and the matters authorized thereby, such determination to be conclusively evidenced by the execution and delivery of such document or instrument or the doing of any such act or thing.” |
Appendix B
Plan of Arrangement
[See attached]
PLAN
OF ARRANGEMENT UNDER DIVISION 5 OF PART 9
OF THE BUSINESS CORPORATIONS ACT (BRITISH COLUMBIA)
Article 1
Interpretation
| 1.1 | Definitions |
In this Plan of Arrangement, unless there is something in the subject matter or context inconsistent therewith, the following terms shall have the respective meanings set out below and grammatical variations of those terms shall have corresponding meanings:
| (a) | “Arrangement” means the arrangement under the provisions of Section 288 of the BCBCA, on the terms and conditions set out in this Plan of Arrangement, subject to any amendments or variations thereto made in accordance with the Arrangement Agreement or Article 6 of this Plan of Arrangement or made at the direction of the Court in the Final Order with the consent of the Company and the Purchaser, each acting reasonably; |
| (b) | “Arrangement Agreement” means the agreement made as of May 11, 2026 between the Company and the Purchaser (including the Schedules attached thereto), as the same may be amended, supplemented or restated or otherwise modified from time to time in accordance with the terms thereof; |
| (c) | “Arrangement Resolution” means the special resolution to be considered and, if thought fit, passed by the Company Shareholders at the Company Meeting to approve the Arrangement, to be substantially in the form and content attached as Schedule B to the Arrangement Agreement; |
| (d) | “BCBCA” means the Business Corporations Act (British Columbia) including all regulations made thereunder, as promulgated or amended from time to time; |
| (e) | “Business Day” means a day other than a Saturday, a Sunday or any other day on which commercial banking institutions in Vancouver, British Columbia are authorized or required by applicable Law to be closed; |
| (f) | “Company” means Gold Basin Resources Corporation, a corporation incorporated under the laws of the Province of British Columbia; |
| (g) | “Company Meeting” means the special meeting of the Company Shareholders, including any adjournment or postponement thereof, to be called and held in accordance with the Interim Order for the purpose of considering and, if thought fit, approving the Arrangement Resolution; |
| (h) | “Company Shareholder” means a holder of one or more Company Shares; |
| (i) | “Company Shares” means the common shares without par value in the capital of the Company; |
B-1
| (j) | “Company Share Letter of Transmittal” means the letter of transmittal to be delivered by the Company to the Company Shareholders providing for the delivery of Company Shares to the Depositary; |
| (k) | “Consideration Shares” means the Purchaser Shares to be issued pursuant to the Arrangement; |
| (l) | “Court” means the Supreme Court of British Columbia; |
| (m) | “CRA” means the Canada Revenue Agency; |
| (n) | “Depositary” means Computershare Investor Services Inc., or any other trust company, bank or financial institution agreed to in writing by each of the Parties for the purpose of, among other things, exchanging certificates or DRS Advices representing Company Shares for the Share Consideration in connection with the Arrangement; |
| (o) | “Dissent Rights” has the meaning ascribed thereto in Section 4.1; |
| (p) | “Dissenting Shares” means the Company Shares held by Dissenting Shareholders in respect of which such Dissenting Shareholders have given Notice of Dissent; |
| (q) | “Dissenting Shareholder” means a registered holder of Company Shares as of the record date of the Company Meeting who has duly and validly exercised the Dissent Rights in respect of the Arrangement Resolution in strict compliance with the Dissent Rights and who has not withdrawn or been deemed to have withdrawn such exercise of Dissent Rights; |
| (r) | “DRS Advice” means Direct Registration System advice; |
| (s) | “Effective Date” means the date that is two (2) Business Days after the last of the conditions to completion of the Arrangement as set forth in Article 5 to the Arrangement Agreement have been satisfied or waived (other than those conditions which cannot, by their terms, be satisfied until the Effective Date, but subject to satisfaction or waiver of such conditions as of the Effective Date) or such earlier or later date as is agreed to in writing by the Company and the Purchaser; |
| (t) | “Effective Time” means the beginning of the day (Vancouver time) on the Effective Date or such other time as the Company and the Purchaser may agree upon in writing; |
| (u) | “Final Order” means the final order of the Court approving the Arrangement under Section 291(4) of the BCBCA, and setting forth any necessary language for reliance upon the exemption from registration under Section 3(a)(10) of the U.S. Securities Act with respect to the Consideration Shares issued pursuant to the Arrangement, in form and substance acceptable to the Company and the Purchaser, each acting reasonably, after a hearing upon the procedural and substantive fairness of the terms and conditions of the Arrangement, as such order may be affirmed, amended, modified, supplemented or varied by the Court (with the consent of both the Company and the Purchaser, each acting reasonably) at any time prior to the Effective Date or, if appealed, as affirmed or amended (provided that any such amendment is acceptable to both the Company and the Purchaser, each acting reasonably) on appeal unless such appeal is withdrawn, abandoned or denied; |
B-2
| (v) | “Former Company Shareholders” means the holders of Company Shares immediately prior to the Effective Time, other than any Dissenting Shareholder properly exercising Dissent Rights, the Purchaser or any other affiliate of the Purchaser; |
| (w) | “Governmental Authority” means any foreign or domestic multinational, federal, provincial, territorial, state, regional, municipal, local or other government or governmental body and any division, agent, official, agency, bureau, commission, board or authority of any government, governmental body, governmental or public department, central bank, foreign investment authority, quasi-governmental or private body (including the TSXV or any other stock exchange) exercising any statutory, regulatory, expropriation, environmental or taxing authority under the authority of any of the foregoing and any domestic, foreign or international judicial, quasi-judicial or administrative court, tribunal, commission, board, panel or arbitrator acting under the authority of any of the foregoing; |
| (x) | “holder”, when used with reference to any securities of the Company, means the holder of such securities shown from time to time in the central securities register maintained by or on behalf of the Company in respect of such securities; |
| (y) | “Interim Order” means the interim order of the Court to be issued following the application therefor submitted to the Court as contemplated by Section 2.2(a) of the Arrangement Agreement, after being informed of the intention to rely upon the exemption from registration under Section 3(a)(10) of the U.S. Securities Act with respect to the Consideration Shares issued pursuant to the Arrangement, in form and substance acceptable to the Company and the Purchaser, each acting reasonably, providing for, among other things, the calling and holding of the Company Meeting, as such order may be affirmed, amended, modified, supplemented or varied by the Court with the consent of both the Company and the Purchaser, each acting reasonably; |
| (z) | “Liens” means any mortgage, hypothec, prior claim, lien, pledge, assignment for security, security interest, option, right of first offer or first refusal or other charge or encumbrance of any kind and adverse claim; |
| (aa) | “Notice of Dissent” means a notice of dissent duly and validly given by a registered holder of Company Shares as of the record date of the Company Meeting exercising Dissent Rights as contemplated in the Interim Order and as described in Article 4; |
| (bb) | “Plan of Arrangement” means this plan of arrangement, as amended, modified or supplemented from time to time in accordance with the terms hereof or at the direction of the Court in the Final Order, with the consent of the Company and the Purchaser, each acting reasonably; |
B-3
| (cc) | “Purchaser” means CANEX Metals Inc.; |
| (dd) | “Purchaser Shares” means common shares in the capital of the Purchaser; |
| (ee) | “Registrar” means the person appointed as the Registrar of Companies under section 400 of the BCBCA; |
| (ff) | “Share Consideration” means, in respect of each Company Share, 0.592 of a Purchaser Share; |
| (gg) | “Tax Act” means the Income Tax Act (Canada) including all regulations thereunder; |
| (hh) | “U.S. Securities Act” means the United States Securities Act of 1933, as amended and the rules and regulations promulgated by the U.S. Securities and Exchange Commission thereunder; and |
| (ii) | “U.S. Tax Code” means the United States Internal Revenue Code of 1986, as amended. |
Any capitalized terms used but not defined herein shall have the meaning ascribed to such terms in the Arrangement Agreement. In addition, words and phrases used herein and defined in the BCBCA and not otherwise defined herein or in the Arrangement Agreement shall have the same meaning herein as in the BCBCA unless the context otherwise requires.
| 1.2 | Interpretation Not Affected by Headings, etc. |
The division of this Plan of Arrangement into Articles, Sections, paragraphs and other portions and the insertion of headings are for convenience of reference only and shall not affect the construction or interpretation hereof. Unless otherwise indicated, all references to an “Article”, “Section” or “paragraph” followed by a number and/or a letter refer to the specified Article, Section or paragraph of this Plan of Arrangement.
| 1.3 | Number |
In this Plan of Arrangement, unless the context otherwise requires, words used herein importing the singular include the plural and vice versa.
| 1.4 | Date of Any Action |
In the event that any date on which any action is required to be taken hereunder by any of the Parties is not a Business Day, such action shall be required to be taken on the next succeeding day which is a Business Day.
B-4
| 1.5 | Time |
Time shall be of the essence in every matter or action contemplated hereunder. All times expressed herein or in any letter of transmittal contemplated herein are local time (Vancouver, British Columbia) unless otherwise stipulated herein or therein.
| 1.6 | Currency |
Unless otherwise stated, all references in this Plan of Arrangement to sums of money are expressed in lawful money of Canada.
Article 2
EFFECT OF THE ARRANGEMENT
| 2.1 | Arrangement Agreement |
This Plan of Arrangement is made pursuant to, and in accordance with the provisions of, and forms a part of the Arrangement Agreement.
| 2.2 | Binding Effect |
This Plan of Arrangement will become effective at the Effective Time and shall be binding upon the Purchaser, the Company, and the Company Shareholders.
Article 3
ARRANGEMENT
| 3.1 | The Arrangement |
Commencing at the Effective Time, each of the events set out below shall occur and be deemed to occur in the following sequence, in each case without any further authorization, act or formality of or by the Company, the Purchaser or any other person except as otherwise expressly provided herein:
| (a) | each Company Share issued and outstanding held by a Dissenting Shareholder shall be and shall deemed to be transferred by the holder thereof, free and clear of all Liens, to the Company for cancellation and the Company (with Company funds not directly or indirectly provided by the Purchaser or any affiliate of the Purchaser) shall thereupon be obliged to pay the amount therefor determined and payable in accordance with Article 4 hereof, and such Dissenting Shareholder shall cease to have any rights as a Company Shareholder other than the right to be paid the amount for such Dissenting Shareholder’s Company Shares determined in accordance with Article 4 and the name of such holder shall be removed from the central securities register of the Company as a holder of Company Shares; |
B-5
| (b) | each Company Share held by a Former Company Shareholder shall be transferred by the holder thereof to the Purchaser in exchange for 0.592 of a Purchaser Share in accordance with the terms and conditions set forth in the take-over bid offer and circular of the Purchaser dated August 28, 2025, as amended by the notice of variation, change and extension dated December 12, 2025, the notice of variation, change and extension dated January 9, 2026, the notice of variation, change and extension dated January 19, 2026, and the notice of variation, change and extension dated January 30, 2026 and subject to section 3.3 and Article 5 hereof, and upon such exchange: |
| (i) | the Former Company Shareholders shall cease to be holders of Company Shares and to have any rights as holders of such Company Share other than the right to be paid the Share Consideration in accordance with this Plan of Arrangement; |
| (ii) | the names of the holders of such Company Shares shall be removed from the register of Company Shareholders and added to the register of holders of Purchaser Shares; |
| (iii) | the Purchaser shall become the holder of the Company Shares so exchanged and shall be added to the register of the Company Shareholders as the registered holder of such Company Shares; |
| (c) | the Company will file an election with the CRA to cease to be a public corporation for the purposes of the Tax Act; and |
| (d) | the exchanges, transfers and cancellations provided for in this Section 3.1 will be deemed to occur on the Effective Date, notwithstanding that certain of the procedures related thereto are not completed until after the Effective Date. |
| 3.2 | Post Effective Time Procedures |
| (a) | Following the receipt of the Final Order and prior to the Effective Date, the Purchaser shall deliver electronically to the Depositary for transmittal, or arrange to be delivered to the Depositary the certificates or DRS Advices, representing the Purchaser Shares required to be issued to Former Company Shareholders, in accordance with the provisions of Section 3.1 hereof, and any such certificates or DRS Advices shall be held by the Depositary as agent and nominee for such Former Company Shareholders for distribution to such Former Company Shareholders in accordance with the provisions of Article 5 hereof. |
| (b) | Subject to the provisions of Article 5 hereof, and upon return of a properly completed Company Share Letter of Transmittal by a registered Former Company Shareholder together with certificates or DRS Advices representing Company Shares and such other documents as the Depositary may require, Former Company Shareholders shall be entitled to receive electronically, or by delivery of the certificates or DRS Advices representing, the Purchaser Shares to which they are entitled pursuant to Section 3.1 hereof. |
B-6
| 3.3 | No Fractional Purchaser Shares |
In no event shall any holder of Company Shares be entitled to a fractional Purchaser Share. Where the aggregate number of Purchaser Shares to be issued to an Company Shareholder as consideration under or as a result of this Arrangement would result in a fraction of a Purchaser Share being issuable, the number of Purchaser Shares to be received by such Company Shareholder shall be rounded down to the nearest whole Purchaser Share and no Former Company Shareholder will be entitled to any compensation in respect of a fractional Purchaser Share.
| 3.4 | U.S. Securities Law Exemption |
Notwithstanding any provision herein to the contrary, the Purchaser and the Company agree that the Plan of Arrangement will be carried out with the intention that all Consideration Shares issued and exchanged on completion of the Plan of Arrangement to the Company Shareholders will be issued by the Purchaser in reliance on the exemption from the registration requirements of the U.S. Securities Act, as amended, as provided by Section 3(a)(10) thereof and applicable securities laws of any state of the United States, and pursuant to the terms, conditions and procedures set forth in the Arrangement Agreement.
Article 4
DISSENT RIGHTS
| 4.1 | Rights of Dissent |
Pursuant to the Interim Order, each registered Company Shareholder as of the record date of the Company Meeting may exercise rights of dissent (“Dissent Rights”) under Section 238 of the BCBCA and in the manner set forth in Sections 242 to 247 of the BCBCA, all as modified by this Article 4 as the same may be modified by the Interim Order or the Final Order in respect of the Arrangement, provided that the written objection to the Arrangement Resolution contemplated by Section 242 of the BCBCA must be sent to and received by the Company not later than 5:00 p.m. on the Business Day that is two Business Days before the Company Meeting. Company Shareholders who duly exercise such rights of dissent and who:
| (a) | are ultimately determined to be entitled to be paid fair value from the Company (with Company funds not directly or indirectly provided by the Purchaser or any affiliate of the Purchaser), for the Dissenting Shares in respect of which they have exercised Dissent Rights, notwithstanding anything to the contrary contained in Section 245 of the BCBCA, will be deemed to have irrevocably transferred such Dissenting Shares to the Company for cancellation pursuant to Section 3.1(a) in consideration of such fair value; or |
| (b) | are ultimately not entitled, for any reason, to be paid fair value for the Dissenting Shares in respect of which they have exercised Dissent Rights, will be deemed to have participated in the Arrangement on the same basis as a Company Shareholder who has not exercised Dissent Rights, as at and from the time specified in Section 3.1(a), and be entitled to receive only the consideration set forth in Section 3.1(a), |
B-7
but in no case will the Company or the Purchaser or any other person be required to recognize such holders as holders of Company Shares after the completion of the steps set forth in Section 3.1(a), and each Dissenting Shareholder will cease to be entitled to the rights of a Company Shareholder in respect of the Company Shares in relation to which such Dissenting Shareholder has exercised Dissent Rights and the central securities register of the Company will be amended to reflect that such former holder is no longer the holder of such Company Shares as and from the completion of the steps in Section 3.1(a).
In addition to any other restrictions set forth in the BCBCA, Company Shareholders who vote in favour of the Arrangement Resolution shall not be entitled to exercise Dissent Rights.
Article 5
CERTIFICATES AND PAYMENTS
| 5.1 | Payment of Share Consideration |
| (a) | As soon as practicable following the later of the Effective Date and the surrender to the Depositary for cancellation of a certificate or DRS Advice that immediately prior to the Effective Time represented outstanding Company Shares that were transferred under Section 3.1, together with a duly completed Company Share Letter of Transmittal and such additional documents and instruments as the Depositary may reasonably require and such other documents and instruments as would have been required to effect such transfer under the BCBCA and the articles of the Company after giving effect to Section 3.1 the former holder of such Company Shares shall be entitled to receive in exchange therefor, and the Depositary shall deliver electronically to such holder following the Effective Time, or make available for pick up at its offices during normal business hours a certificate or DRS Advice representing, the Purchaser Shares that such holder is entitled to receive in accordance with Section 3.1 hereof, less any amounts withheld pursuant to Section 5.4. |
| (b) | Subject to Section 5.3, each certificate and DRS Advice which immediately prior to the Effective Time represented Company Shares held by Former Company Shareholders will be deemed after the Effective Time and until surrendered for cancellation as contemplated by Section 5.1(a) hereof, to represent only the right to receive from the Depositary upon such surrender, electronic delivery of, or a certificate or DRS Advice representing, the Purchaser Shares that the holder of such certificate is entitled to receive in accordance with Section 3.1 hereof or, in the case of Dissenting Shareholders, to be paid the fair value for the Company Shares in accordance with Article 4, in each case, less any amounts withheld pursuant to Section 5.4. |
B-8
| (c) | The Company and the Purchaser will cause the Depositary, as soon as a Former Company Shareholder becomes entitled to the Share Consideration in accordance with Section 3.1, to: |
| (i) | forward or cause to be forwarded by first class mail (postage paid) to such former holder at the address specified in the Company Share Letter of Transmittal; |
| (ii) | if requested by such former holder in the Company Share Letter of Transmittal make available at the offices of the Depositary specified in the Company Share Letter of Transmittal; or |
| (iii) | if the Company Share Letter of Transmittal neither specifies an address as described in Section 5.1(c)(i) nor contains a request as described in Section 5.1(c)(ii) forward or cause to be forwarded by first class mail (postage paid) to such former holder at the address of such former holder as shown on the applicable securities register maintained by or on behalf of the Company immediately prior to the Effective Time; |
a certificate or DRS Advice representing, or deliver electronically, the Share Consideration to such Former Company Shareholder in accordance with the provisions hereof.
| (d) | No holder of Company Shares shall be entitled to receive any consideration or entitlement with respect to such Company Shares, other than any consideration or entitlement to which such holder is entitled to receive in accordance with Section 3.1, this Section 5.1 and the other terms of this Plan of Arrangement and, for greater certainty, no such holder with be entitled to receive any interest, dividends, premium or other payment in connection therewith, other than any declared but unpaid dividends. |
| 5.2 | Loss of Certificates |
In the event any certificate which immediately prior to the Effective Time represented any outstanding Company Shares that were acquired by the Purchaser or the Company pursuant to Section 3.1 has been lost, stolen or destroyed, upon the making of an affidavit of that fact by the former holder of such Company Shares, the Depositary will deliver to such person or make available for pick up at its offices in exchange for such lost, stolen or destroyed certificate, a certificate or DRS Advice representing the Purchaser Shares to which the former holder of such Company Shares is entitled to receive pursuant to Section 3.1 hereof in accordance with such holder’s Company Share Letter of Transmittal. When authorizing such payment in relation to any lost, stolen or destroyed certificate, the former holder of such Company Shares will, as a condition precedent to the delivery of such Share Consideration, give a bond satisfactory to the Company, the Purchaser and the Depositary in such sum as the Purchaser may direct or otherwise indemnify the Company and the Purchaser in a manner satisfactory to the Company and the Purchaser against any claim that may be made against the Company or the Purchaser with respect to the certificate alleged to have been lost, stolen or destroyed.
B-9
| 5.3 | Extinction of Rights |
If any Former Company Shareholder fails to deliver to the Depositary the certificates, documents or instruments required to be delivered to the Depositary under Section 5.1 or Section 5.2 in order for such Former Company Shareholder to receive the Share Consideration which such former holder is entitled to receive pursuant to Section 3.1, on or before the sixth anniversary of the Effective Date, on the sixth anniversary of the Effective Date (i) such former holder will be deemed to have donated and forfeited to the Purchaser or its successor any Share Consideration held by the Depositary in trust for such former holder to which such former holder is entitled and (ii) any certificate representing Company Shares formerly held by such former holder will cease to represent a claim of any nature whatsoever and will be deemed to have been surrendered to the Purchaser and will be cancelled. Neither the Company nor the Purchaser, or any of their respective successors, will be liable to any person in respect of any Share Consideration (including any consideration previously held by the Depositary in trust for any such former holder) which is forfeited to the Company or the Purchaser or delivered to any public official pursuant to any applicable abandoned property, escheat or similar law.
| 5.4 | Withholding Rights |
The Company, the Purchaser and the Depositary will be entitled to deduct and withhold from any consideration otherwise payable to any Company Shareholder or Former Company Shareholder under this Plan of Arrangement (including any payment to Dissenting Shareholders) such amounts as the Company, the Purchaser or the Depositary is required to deduct and withhold with respect to such payment under the Tax Act, the U.S. Tax Code, and the rules and regulations promulgated thereunder, or any provision of any provincial, state, local or foreign tax law as counsel may advise is required to be so deducted and withheld by the Company, the Purchaser or the Depositary, as the case may be. For the purposes hereof, all such withheld amounts shall be treated as having been paid to the person in respect of which such deduction and withholding was made on account of the obligation to make payment to such person hereunder, provided that such deducted or withheld amounts are actually remitted to the appropriate Governmental Authority by or on behalf of the Company, the Purchaser or the Depositary, as the case may be. To the extent necessary, such deductions and withholdings may be effected by selling any Purchaser Shares to which any such person may otherwise be entitled under the Plan of Arrangement, and any amount remaining following the sale, deduction and remittance shall be paid to the person entitled thereto as soon as reasonably practicable.
| 5.5 | No Liens |
Any exchange or transfer of securities pursuant to this Plan of Arrangement shall be free and clear of any Liens or other claims of third parties of any kind.
| 5.6 | Paramountcy |
From and after the Effective Time: (a) this Plan of Arrangement shall take precedence and priority over any and all Company Shares issued prior to the Effective Time, (b) the rights and obligations of the Company Shareholders, the Company, the Purchaser, the Depositary and any transfer agent or other depositary therefor in relation thereto, shall be solely as provided for in this Plan of Arrangement, and (c) all actions, causes of action, claims or proceedings (actual or contingent and whether or not previously asserted) based on or in any way relating to any Company Shares shall be deemed to have been settled, compromised, released and determined without liability except as set forth in this Plan of Arrangement.
B-10
Article 6
AMENDMENTS
| 6.1 | Amendments to Plan of Arrangement |
| (a) | The Company reserves the right to amend, modify or supplement this Plan of Arrangement at any time and from time to time prior to the Effective Time, provided that each such amendment, modification or supplement must be (i) set out in writing, (ii) approved by the Purchaser, (iii) filed with the Court and, if made following the Company Meeting, approved by the Court and (iv) communicated to or approved by the Company Shareholders if and as required by the Court. |
| (b) | Any amendment, modification or supplement to this Plan of Arrangement may be proposed by the Company at any time prior to the Company Meeting (provided that the Purchaser has consented thereto) with or without any other prior notice or communication and, if so proposed and accepted by the persons voting at the Company Meeting (other than as may be required under the Interim Order), will become part of this Plan of Arrangement for all purposes. |
| (c) | Any amendment, modification or supplement to this Plan of Arrangement that is approved or directed by the Court following the Company Meeting will be effective only if such amendment, modification or supplement (i) is consented to by each of the Company and the Purchaser and (ii) if required by the Court or applicable Law, is consented to by Company Shareholders voting in the manner directed by the Court. |
| (d) | Any amendment, modification or supplement to this Plan of Arrangement may be made following the Effective Date unilaterally by the Purchaser provided that it concerns a matter which, in the reasonable opinion of the Purchaser, is of an administrative nature required to better give effect to the implementation of this Plan of Arrangement and is not adverse to the financial or economic interests of any Former Company Shareholder. |
Article 7
FURTHER ASSURANCES
Notwithstanding that the transactions and events set out herein will occur and be deemed to occur in the order set out in this Plan of Arrangement without any further act or formality, each of the Company and the Purchaser will make, do and execute, or cause to be made, done and executed, any such further acts, deeds, agreements, transfers, assurances, instruments or documents as may reasonably be required by any of them in order to further document or evidence any of the transactions or events set out herein.
B-11
Appendix C
Information Concerning Gold Basin Resources Corporation
[See attached]
NOTICE TO READER
The following information provided by Gold Basin is presented on a pre-Arrangement basis (except where otherwise indicated) and reflects the current business, financial and share capital position of Gold Basin.
Unless the context indicates otherwise, capitalized terms which are used in this Appendix C and not otherwise defined in this Appendix C have the meanings given to such terms under the heading “Glossary of Terms” in the Circular.
FORWARD-LOOKING INFORMATION
Certain statements contained in this Appendix C constitute forward-looking statements and forward-looking information (collectively referred to as “forward-looking information”) within the meaning of applicable securities laws. Such forward-looking information relates to future events or Gold Basin’s future performance. See “General Proxy Information – Cautionary Statement Regarding Forward-Looking Information” in the Circular. Readers should also carefully consider the matters and cautionary statements discussed under the heading “Risk Factors” in the Circular, and under the heading “Risk Factors” in this Appendix C.
GOLD BASIN RESOURCES CORPORATION
Gold Basin was incorporated on November 24, 2017 under the laws of the Province of British Columbia, and is a mineral exploration company engaged in the acquisition, exploration and development of mineral properties in North America.
Gold Basin’s principal asset is the “Gold Basin Project” (or the “Project”), a district-scale gold exploration property located in Mohave County, Arizona. The Gold Basin Project is accessible year-round via a 1.5-hour drive southeast of Las Vegas on U.S. Highway I-93. High-voltage power lines originating from the Hoover Dam crosscut the southern portion of the project area, providing access to infrastructure.
The registered and head office is located at 1200 Waterfront Centre, 200 Burrard Street, Vancouver, British Columbia, Canada.
Prior to a Halt in trading ordered by CIRO on May 7, 2025, the Shares traded on the TSXV under the symbol “GXX”. The Shares also are quoted on the OTC Market under the symbol “GXXFF”.
For further information regarding Gold Basin, refer to Gold Basin’s filings with the applicable securities regulatory authorities in Canada which may be obtained through SEDAR+ at www.sedarplus.com.
Intercorporate Relationships
Gold Basin owns all of the issued and outstanding shares of Gold Basin Resources (Arizona), Inc., and Gold Basin Resources (Australia) Pty. Ltd.
Recent Developments
The Take Over Bid
On June 9, 2025, CANEX announced its intention to make a formal all-share takeover bid to acquire all outstanding shares of Gold Basin. The closing price of the Shares on the TSXV on May 6, 2025, the last trading day prior to the Cease Trade Order, was $0.045. The closing price of the CANEX Shares on the TSXV on August 27, 2025, the last trading day prior to the date of the Offer, was $0.075.
C-2
The Offer was completed on February 10, 2026, resulting in CANEX acquiring 70,088,199 Shares, approximately 51.86% of the issued and outstanding Shares.
Helix
On April 29, 2025, Gold Basin’s prior board of directors announced a conditional letter agreement with Helix for Helix to earn-in up to a 40% interest in the Gold Basin Project. On October 28, 2025, certain shareholders of Gold Basin launched a petition before the Court to set aside the agreement on the basis that one or more former directors had a material undisclosed interest in Helix and that the agreement was not fair or reasonable to Gold Basin. On March 16, 2026, on which date Gold Basin’s entire board of directors was replaced by a unanimous vote of shareholders at a court-ordered annual general meeting, Helix announced that it had executed a formal joint venture agreement to earn-in up to a 40% interest in the Gold Basin Project. On March 19, 2026, the new board of directors of Gold Basin announced that the formal joint venture agreement was in violation of a restraining order issued by the Court on February 2, 2026, that it intended to withdraw Gold Basin’s objection to the Court’s jurisdiction and to support the shareholders’ petition to set aside the agreement with Helix, and that it had reserved all rights against the former directors of Gold Basin.
Termination of Charles Straw
On March 16, 2026, Gold Basin terminated Charles Straw for cause as its President and Interim Chief Executive Officer for serious misconduct, breach of his duties and obligations, conflicts of interest and repeated lack of judgment, care and diligence causing financial loss to Gold Basin. Based on Gold Basin’s investigation to date it is aware of Mr. Straw’s: conversion for personal use and loss of Gold Basin’s funds; misappropriation of corporate opportunities; causing Gold Basin to enter into transactions with parties in which Mr. Straw or his associates had a personal interest on financial and commercial terms which were neither fair nor reasonable to Gold Basin; and causing Gold Basin to breach its obligations under Canadian securities laws, the BCBCA, stock exchange requirements and a restraining order of the British Columbia Supreme Court.
On March 17, 2026, in response to notice of his termination, Mr. Straw indicated in writing that, among other things, in 2024 he was the victim of wire fraud relating to a business email compromise. What is not explained by Mr. Straw is why he wired large sums of money from Gold Basin’s corporate bank account to a private account he controlled before he “fell victim” to wire fraud. The board of directors of Gold Basin have not been provided with any information or documents that could explain the reason for the diversion of corporate funds to Mr. Straw’s private account.
Gold Basin has reserved all of its rights against Mr. Straw and intends to take such steps or initiate such proceedings as may be available and appropriate to recover from him the losses Gold Basin alleges it has suffered, and may continue to suffer, and recover the gains Gold Basin alleges Mr. Straw may have benefited from, due to his misconduct.
Settlement Agreement with Charrua Capital LLC
On May 5, 2026, Gold Basin announced that it reached a settlement agreement with Charrua Capital LLC (“Charrua”) in respect of the disputed enforceability of an unsecured loan agreement dated August 21, 2024 between Gold Basin and Charrua, which was purportedly amended on January 19, 2025 to place security against Gold Basin’s 100%-owned private minerals parcels in Mohave County, Arizona (the “Loan Agreement”). The Loan Agreement bore a principal amount of US$500,000, initial interest rate of 15%, high fees and costs, and restrictions on Gold Basin’s use of funds. Under the settlement agreement, Gold Basin agreed to pay Charrua US$217,367.40 upon, among other things, the release and discharge of any and all security interests and claims against Gold Basin and its assets.
C-3
The Arrangement
On May 11, 2026, Gold Basin entered into the Arrangement Agreement with CANEX, pursuant to which CANEX proposed to acquire all of the outstanding Shares not currently owned by CANEX by way of a plan of arrangement under the BCBCA. For a full description of the Arrangement and the Arrangement Agreement, see “The Arrangement” and “The Arrangement Agreement” in the Circular. Also see Appendix A and Appendix B to the Circular.
EXPLORATION PROJECTS
Gold Basin has exploration assets in Arizona, U.S., which are described in more detail below.
Gold Basin Project
Property Description
The Gold Basin Project is located approximately 70 miles southeast of Las Vegas, Nevada, and 50 miles northwest of Kingman, Arizona, in the Gold Basin mining district of Mohave County, Arizona, U.S., and is accessible via Interstate Highway 93 from either Las Vegas or Kingman. The approximate geographic center of the Gold Basin Project area is located at 35˚48’N latitude and 114˚14’W longitude (N3,963,278m, E748,824m; WGS84, UTM Zone 11S). The Project area is comprised of five split estate mineral rights (2,389 acres) and 332 unpatented federal mining claims (6,845 acres), which together total approximately 7,669 acres (roughly 12 mi2) of land surface. In July 2021, Gold Basin completed the purchase of surface rights associated with the Gold Basin Project, totaling approximately 160 acres in the Gold Basin Mining District, Mohave County, Arizona.
Property Acquisition
Gold Basin entered into two assignment and assumption agreements dated June 16, 2020 with Centric Minerals Corporation (“Centric”), an arm’s length private British Columbia corporation, whereby Centric assigned to Gold Basin all of its rights under two letter agreements with third party vendors that were at arm’s length to Gold Basin. Gold Basin was assigned the right to acquire an approximate aggregate 75% interest in and to the Gold Basin Project (the “Assignment”) in consideration for 8,000,000 Shares, and subsequently Gold Basin negotiated the acquisition of a 100% interest in the Project.
Following the Assignment, Gold Basin entered into a relinquishment of rights and release deed, and a relinquishment of rights agreement and termination, whereby certain third parties with existing rights to the Project (the “Vendors”) agreed to relinquish all of their right, title and interest in the Project (the “Relinquishment”) in favour of the underlying owner of the Project, Aurum Exploration Inc. (“Aurum”), effective September 3, 2020. As consideration for the Relinquishment, Gold Basin made a cash payment of AUD$1,000,000 and issued an aggregate of 10,000,001 Shares, valued at $4,625,000, to the Vendors.
Gold Basin acquired its 100% interest in the Project through its wholly-owned subsidiary Gold Basin Resources (Arizona), Inc., (“Gold Basin (US)”) pursuant to a purchase and sale agreement made as of September 3, 2020 (the “Purchase Agreement”) among Gold Basin, Gold Basin (US), and Aurum (the “Property Acquisition”). All of Aurum’s right, title and interest in the 290 unpatented federal mining claims which comprise the bulk of the Project area was transferred to Gold Basin (US) by Quitclaim Deed on September 14, 2020. Pursuant to the Purchase Agreement, Gold Basin issued an aggregate of 15,000,000 Shares to Aurum’s nominees with the value of $6,000,000. The closing of the Property Acquisition took place on September 18, 2020.
C-4
The 290 unpatented federal mining claims are also subject to a 1% Gross Returns Royalty (the “Centric Royalty”) held by Centric Minerals Management Pty Ltd (“Centric (AUS)”) pursuant to a gross returns royalty agreement dated as of January 1, 2020 between Aurum and Centric (AUS) (the “Centric Royalty Agreement”). The Centric Royalty Agreement was assigned to Gold Basin (US) by Aurum pursuant to an assignment and assumption agreement made effective as of September 14, 2020 among Aurum, Gold Basin (US) and Centric (AUS), whereby Aurum assigned all of its right, title, benefit and interest in the Centric Royalty Agreement to Gold Basin (US) and Gold Basin (US) assumed all of Aurum’s obligations thereunder, including the payment of the Centric Royalty thereunder.
Four of the five split estate mineral rights are subject to a perpetual production royalty held by Newmont Corporation of 3.5% gross returns from the sale or other disposition of all metals and minerals produced from those portions of the Project area previously owned by Santa Fe Pacific Railroad Company pursuant to the terms of an option agreement entered into by Santa Fe Pacific Railroad Company and Aurumbank Incorporated as of February 9, 2004.
Gold Basin has filed a National Instrument 43-101 Standards of Disclosure for Mineral Projects (“NI 43-101”) Technical Report entitled “National Instrument 43-101 Technical Report, Geology and Exploration at the Gold Basin Project, Mohave County, Arizona, USA”, dated February 25, 2021 with an effective date of February 5, 2021 (the “Technical Report”). The Technical Report was prepared by Hard Rock Consulting LLC, and can be viewed on Gold Basin’s profile on the SEDAR+ website at www.sedarplus.ca.
A large portion of the technical information included below is sourced from the Technical Report. As the information is necessarily summarized, readers are encouraged to review the Technical Report in its entirety, including all qualifications and assumptions. The Technical Report is intended to be read as a whole, and sections should not be read or relied upon out of context. For the purposes of the following summary, capitalized terms not defined herein have the meanings given to them in the Technical Report.
On May 10, 2022, Gold Basin signed an option agreement (the “Option Agreement”) to acquire 100% interest in forty (40) unpatented mining claims located between the Cyclopic and Stealth deposits, consolidating the entire Gold Basin project area. Under the terms of the Option Agreement, Gold Basin can acquire a 100% interest in the claims by paying US$750,000 in varying annual payment installments over a period of up to 9 years. The first-year payment amount is US$25,000, with increasing annual payments totaling US$350,000 by Year 7. Gold Basin, at its sole discretion, is able to exercise the option at any time during the option period.
Upon the execution of the Option Agreement, the current owners will receive a Net Profits Interest Royalty of 3.5%, which will be paid on profits from production on the claims. Gold Basin has the right within 10 years of the grant to purchase back 1.5% of the royalty by paying $3,000,000 to the royalty holders. The total claim area under Gold Basin’s control will increase to 40 km2 upon grant of these claims. The status of this option agreement remains uncertain. Gold Basin’s former management purportedly failed to make an option payment and new management is working to bring the agreement into compliance.
On March 16, 2026, Helix announced that it had executed a formal joint venture agreement to earn-in up to a 40% interest in the Gold Basin Project. On March 19, 2026, the new board of Gold Basin announced that the formal joint venture agreement was in violation of a restraining order issued by the Court on February 2, 2026 and that it intended to support a shareholders’ petition to set aside the agreement with Helix.
C-5
Accessibility
The Gold Basin Project is readily accessible from both Las Vegas, Nevada and Kingman, Arizona via Interstate Highway 93 to Pierce Ferry Road. The primary Project access road, BLM Road 9748, extends to the west from Pierce Ferry Road immediately past mile marker 17 (northeast of Highway 93). BLM Road 9748 is a well-used but largely unimproved gravel road that turns into BLM Road 9761 within about a mile of the Project area. Local access throughout the Project area, including to old workings and drill pads, is provided by an assortment of secondary gravel roads and jeep trails, most of which are suitable for two- wheel drive vehicles.
Exploration work can be carried out year-round, though local flooding during heavy rains in the late summer months can occasionally limit access to and throughout the Project site for short periods of time.
Geology and Mineralization
Bedrock in the Project area is primarily comprised of Precambrian gneiss and rapakivi-like granite, and a Cretaceous two-mica granite. The Precambrian and Cretaceous rocks are both cut by the Cyclopic detachment fault, the southernmost extension of the regional South Virgin-White River detachment. The Cyclopic detachment consists of at least two low-angle normal faults that strike northwest and dip generally less than 20° southwest. The fault contains Precambrian crystalline rocks in both its hanging wall and footwall and locally cuts the Cretaceous two-mica granite.
The Cyclopic detachment fault is the most dominant structural feature in the Gold Basin district, and it is presently thought to be the primary district-scale control over gold mineralization. Gold grade and distribution at the Gold Basin Project are primarily controlled by structure, specifically the series of near- horizontal detachment fault planes cutting the Precambrian gneissic basement. Gold mineralization is the result of a low sulphidation and shallow epithermal depositional system and localized within brecciated, gouged, and shattered zones which range in thickness from 1m to 30m.
Exploration Status
In May 2022, Gold Basin executed an Option Agreement to consolidate its ground position at the Gold Basin oxide gold project in north-west Arizona.
| · | Option Agreement signed to acquire 100% interest in forty (40) unpatented mining claims located between the Cyclopic and Stealth deposits, consolidating the entire Gold Basin project area. |
| · | New ground has excellent potential to host extensions of both the Cyclopic and Stealth mineralisation. |
| · | Historical drilling on the option claims has previously intercepted gold mineralisation, notably at the Red Cloud deposit, which lies to the south-east of the Stealth Deposit on the same north-west structure. |
| · | Gold Basin has also staked 74 new claims adjacent to its existing land package to secure exploration targets identified by geophysical survey data. |
C-6
| · | Total claim area under Gold Basin’s control will increase to 40 km2 upon grant of these claims. |
Gold Basin undertook a drilling program at the Stealth deposit, the results were (announced June 1, 2022). The drilling continued to intersect thick gold intersections showing a consistent broad zone of higher-grade (>1.0g/t) gold mineralisation along the 350 m of strike length drilled to date. The deposit remained open in all directions.
The results included the following intersections:
| · | 80.6 m (True Width) @ 1.0 g/t Au from 22.9 m in hole ST22-009 |
| · | 70.1 m @ 1.0 g/t Au from 13.7 m in hole ST22-013 |
| · | 32 m @ 1.3 g/t Au from 42.7 m in hole ST22-017 |
| · | 47.2 m @ 1.0 g/t Au from surface in hole ST22-021 |
| · | 29.0 m (True Width) @ 1.4 g/t Au from 45.7 m in hole ST22-023 |
The drilling completed at the Stealth oxide gold deposit focused on confirming historical drilling intercepts and testing both lateral and depth extensions of the known gold mineralisation. Results have exceeded all expectations, with multiple broad intersections of gold mineralisation in 23 of the 25 holes drilled.
These intersections include 17 with a grade over 1 g/t Au and an average thickness of 38 m; in addition to these, multiple significant intersections of mineralisation greater than 0.5 g/t Au also contributed to delineate a deep mineralised zone that extends almost from surface along the 350m strike length drilled.
The 2022 drill program at Stealth has tested a relatively small area (350 m x 150 m) of the mapped Stealth Fault that is over 8 km in strike length and remains largely undrilled for most of this extent.
The total metres drilled at both the Cyclopic and Stealth deposits at Gold Basin during 2022 campaign was 11,799 m in 109 holes with 3,714 m drilled at Stealth.
In January 2023, Gold Basin commenced a 5,004.8 metre (in 41 holes) reverse-circulation (“RC”) drill program with a focus of potential resource delineation at the Stealth, Red Cloud and PLM targets, as detailed in Gold Basin’s News Release, released on January 17, 2023. Results of the first 29 of 41 holes were released in on March 22, 2023, and the final 12 holes were released on April 27, 2023. Highlights include:
| · | 57.9 m @ 1.82 g/t Au from 4.6m in hole CM23-022, incl. 15.2 m @ 4.12 g/t Au from 10.7 m |
| · | 42.7 m @ 2.44 g/t Au from surface in hole CM23-029, incl. 18.3 m @ 5.53 g/t Au from 2.13 m |
| · | 53.3 m @ 1.37 g/t Au from surface in hole CM23-018, incl. 22.9 m @ 2.44 g/t Au from 9.1 m |
| · | 50.3 m @ 1.35 g/t Au from surface in hole CM23-025, incl. 19.8 m @ 2.55 g/t Au from 16.8 m |
C-7
| · | 47.2 m @ 1.07 g/t Au from surface in hole CM23-015, incl. 18.2 m @ 1.41 g/t Au from 29.0 m |
| · | 24.4 m @ 2.22 g/t Au from surface in hole CM23-002, incl. 7.6m @ 4.33 g/t Au from 16.8 m |
A follow-up 2,224-metre (in 18 RC holes) drill program was conducted in April and May 2023, with a focus on testing the Gap Zone between Red Cloud and Stealth, the southeast strike of Red Cloud, and select reconnaissance targets distal to the main deposit areas. Assay results for the first 11 holes were released on July 26, 2023, with 6 of these holes returning near-surface intervals of oxide gold mineralization, hosted dominantly from surface to 60 metres vertical depth. Drillhole CM23-057, located in the central portion of the Gap Zone between Stealth and Red Cloud, returned a shallow oxide gold intercept comparable in thickness, grade and gram*metre to that of the neighbouring deposits (60.96 m @ 0.46 g/t Au from 32.00 m, incl. 28.86 m @ 0.74 g/t Au from 33.53 m), suggesting the presence of a 1.5-km-long gold system, spanning the Stealth-Red Cloud trend.
Regional reconnaissance drillhole CM23-047, located 1.7 km along strike (to the southeast) from Red Cloud, returned a significant result from a regional prospectivity point of view. The hole cut 30 metres of strongly oxidized detachment fault zone (Fe-oxide rich polylithic breccia, gouge, oxidized quartz fragments) which returned locally anomalous gold, including 3.04 m @ 0.13 g/t Au from 67.06 m. This indicates that the gold-bearing detachment fault that hosts both Stealth and Red Cloud is intact and auriferous at least 1.7 km southeast of and along strike from Red Cloud. The extension to the trend represents a high-priority drill target for Q3/Q4 2023.
The final 7 RC drill holes were released on September 28, 2023, with significant results coming from the Gap Zone in between Stealth and Red Cloud. Exploration holes drilled by Gold Basin in this program intersected near-surface gold in 4 of 6 holes drilled along the main Gap Zone trend over a strike length of approximately 250 metres, demonstrating continuity of mineralization between the Red Cloud and Stealth deposits. Additional holes are under preparation in the Gap Zone to determine deposit geometry.
In March 2023, Gold Basin engaged Eagle Mapping Services Ltd. to conduct a property-wide LiDAR survey to assist in future NI 43-101 resource estimation, and property-wide exploration initiatives. Preliminary interpretations have identified over 230 sites of small-scale historical mining, including small shafts, adits, and pits, with the vast majority of these sites having no record of drilling or modern-day exploration. In particular, a ~2 km by 2 km area (the “AOI”) to the E and NE of the Cyclopic Deposit hosts a notable density of these showings (~125), none of which have been drilled.
As a first phase in assessing the gold potential of the LiDAR-derived AOI, Gold Basin collected 530 soil samples along a grid with northeast-southwest orientated lines running northeast from Cyclopic (assays for 179 of 530 soils received and released on July 18, 2023, and remaining 351 soil assays were released on October 11, 2023). In addition, 110 regional rock samples were collected while prospecting at undrilled sites of small-scale historical mining (all 110 rock samples reported released July 18, 2023). Soil and rock assays defined multiple kilometre-scale gold trends, including 3.25-km-long and 1.7-km-long trends north of the Cyclopic oxide gold deposit, and a 1.0-km-long trend located 2.3 km southeast of and along strike from Cyclopic. Significant undrilled gold anomalies were also returned at this historical “Golden Chalice” and “Ring Bear” mines, and both of these anomalies remain open to the east and west, respectively. Of the 110 rocks samples collected, 28 returned assays of ≥1 g/t Au, 11 returned assays of >5 g/t Au, and 6 returned assays of >10 g/t Au, including: 12.40, 12.55, 15.70, 17.95, 29.00 and 35.50 g/t Au, and visible gold (in-situ and subcrop) was discovered and sampled at 7 separate locations, all of which are undrilled, and spaced approximately 1 to 2 km apart.
C-8
Gold Basin bolstered its technical team in July 2023 with the addition of Senior Geologist, Kevin Rafferty, to spearhead geological and structural mapping, target generation, and regional generative work. Mr. Rafferty has over a decade of experience in classical field geology and extensive knowledge of the North American Cordillera. His technical expertise includes geological mapping, structural geology, stratigraphy, clastic sedimentation, and regional target generation. Before joining Gold Basin, Kevin spent four years advancing both brownfield and greenfield exploration projects in North and South America with SSR Mining Inc. Mr. Rafferty graduated with a B.Sc. in Geology from Weber State University and is a current graduate student (M.Sc.) in Geology at the University of Nevada, Las Vegas.
A detailed geological and structural mapping (1:5000 scale) campaign was commenced by Mr. Rafferty in September 2023, with an initial focus on the roughly 2 km x 2 km area of soil sampling to the east and northeast of the Cyclopic deposit. The ultimate goal of Mr. Rafferty’s mapping is drill target generation, and bettering Gold Basin’s understanding of the geological genesis of gold-mineralization at Gold Basin to aid in regional interpretations and exploration tactics. Synthesis and compilation is on-going. Mapping (1:5000 scale) has also commenced along the Stealth-Gap-Red Cloud trend, as well as the geological exposures to the east of this trend.
Geophysical Targets
As announced on November 1, 2022 Gold Basin reported a summary of an extensive review of multiple sets of geophysical data collected by Gold Basin over the previous 18 months, interpreting Airborne/UAV Magnetic, Radiometric and Induced Polarisation and Electrical Resistivity (“IP/ER”) surveys on its Gold Basin Property.
Geophysical targeting is dependent on geological deposit models and the conceptual models that were used for this are:
| 1. | Epithermal Au along the Detachment Faults and Normal Faults |
| 2. | Porphyry Cu-Au style at depth (>200m) |
| 3. | Iron oxide gold (IOG) deposits, like the Cyclopic and Stealth Au Mineralisation |
The geophysical target information was taken from three individual reports and were described in detail for two areas of the Gold Basin property:
Cyclopic-Stealth Targets and the Senator-Owens targets.
Within the Cyclopic and Stealth area, the most detailed geophysics was acquired including an IP/Resistivity survey. As a result, this target area has the most targets. The summary report combines and redefines the major geophysical targets within the following areas of the Gold Basin licences:
| · | Target Area 1 – East Cyclopic |
| · | Target Area 2 – SE Extension of the Cyclopic Fault |
| · | Target Area 3 – Stealth Cyclopic DTF |
| · | Target Area 4 – West Cyclopic |
| · | Target Area 5 – Senator and Owen |
C-9
As a result of the geophysical review Gold Basin has, in addition to obvious strike extensional targets resulting from the Stealth drilling program results but multiple new targets including previously unknown areas of potential mineralisation.
Metallurgical Test Work
On September 8th 2022, Gold Basin reported on its column leach Metallurgical Test work conducted by Kappes Cassiday & Associates (KCA) in Reno, Nevada between December 2021 and May 2022 on diamond core samples from the Cyclopic area of its 100%-owned Gold Basin project in Mohave County, Northern Arizona, USA.
In summary the results:
| · | Gold extractions up to 80% (after 67-72 days of leach) on Cyclopic diamond core composite samples |
| · | Gold extractions between 50 and 70% after 7 days in leach |
| · | Agglomeration and compaction tests showed all agglomerated samples passed percolation tests up to 100 metres dump height (KCA standard height recommendation is 40 metres) |
| · | Gold Basin mineralisation extremely low in preg-robbing soluates and less than 0.61% total carbon in the material |
| · | Low reagent consumption in leach |
All results indicate Gold Basin mineralisation is a rapid leaching material with low preg-robbing characteristics that when agglomerated passes industry criteria for flow rates for dump heights up to 100 metres.
The initial set of metallurgical test work results demonstrate strong recoveries that are indicative of a broad range of heap-leach projects in the SW USA. In consultation with KCA, Gold Basin expects future optimisation test work to begin evaluating coarser crush opportunities. The results are an excellent start and confirm there are no metallurgical barriers to a heap-leach gold extraction operation at Gold Basin.
2023 Ground Water Supply Evaluation and Water Rights and Engineering Study
Gold Basin engaged Mongomery & Associates (“M&A”) and Westland Resources Ltd. (“Westland”) in Q2/Q3 2023 to conduct a ground water supply evaluation (M&A) and water rights and engineering (Westland) study using a base-case open pit heap leach mining scenario of 100,000 oz Au per year for a mine life of 10 years. The estimated water requirement to support this scale of operation was ascertained from a 2012 United States Geological Survey (“USGS”) paper1 titled, “Estimated Water Requirements for Gold Heap-Leach Operations”.
M&A has completed their portion of the study, and the available well and aquifer data available for the Hualapi Valley (immediately to the east of Gold Basin) indicates that there is sufficient aquifer capacity to support the base case mining scenario. In addition, the recent Irrigation Non-Expansion Area (“INA”) applied to the Hualapi Valley has no impact on the drilling of wellfields and use of aquifer water for mining. In fact, the INA serves to benefit water availability for mining applications because it limits water resource use for agricultural purposes.
| 1 | USGS paper citation: Bleiwas, D.I., 2012, Estimated water requirements for gold heap-leach operations: U.S. Geological Survey Open-File Report 2012–1085, 15 p., http://pubs.usgs.gov/of/2012/1085 |
C-10
Westland’s portion of the study (water rights and engineering) has commenced, with initial findings summarized as follows. Westland met with Arizona Department of Water Resources (“ADWR”) and discussed the feasibility of utilizing ground water out of the Hualapai Valley INA, and ADWR confirmed to Westland that groundwater use for mining is not restricted by the INA and new wells can be drilled for mining. Westland water rights expert reviewed the project area and limitations surrounding the site and concluded that we should have no issues pulling the expected volume of water out of the Hualapai Basin. The engineering facet of Westland’s study has been paused, with the intention of recommencing after Gold Basin’s next capital raise.
Quality Control and Quality Assurance
Gold Basin initiated RC drilling on the Gold Basin Project on November 14, 2020, and as of August 29, 2024 had drilled approximately 9,537m in 103 holes, with hole depths ranging from 67m to 110m. All holes are vertical and are being drilled with dry air (no injected water or other fluid) using a centre-return hammer.
Samples are collected every 5 feet (1.52m) and are reduced on-site using a triple-tier Gilson splitter, producing a 2kg - 3kg assay sample and a 3kg - 5kg twin sample that can be used for met testing or re- assay work. Coarse blank material, standard reference pulps, and split duplicates are inserted into the sample stream on a 1-in-20 sample basis such that each 23-sample group contains one blank, one duplicate, and one reference pulp. Three standard reference pulps at three different gold grades (0.154 ppm, 0.778ppm, and 2.58ppm) are being used. One 1.52m drill interval in every four intervals is weighed in order to monitor recovery.
Assay samples are placed in shipping sacks, together with the field inserts, upon completion of each hole. After four holes are completed, all assay samples are transported in their respective shipping sacks to the FedEx Freight centre in Kingman, Arizona by a site geologist, and the samples are sent via FedEx to American Assay Lab (“AAL”) in Reno, Nevada. Prior to shipping, all assay samples are maintained under the direct control and supervision of the on-site geological staff.
Upon arrival in Reno, Nevada at AAL, the samples are prepared using AAL code PV03 procedure (pulverize 0.3kg split to 85% passing 75 micron) and fire-assayed for gold using AAL code FA-PB30-ICP procedure (30gm fire with ICP-OES finish). AAL also inserts its own certified reference materials plus blanks and duplicates.
DESCRIPTION OF CAPITAL STRUCTURE
The authorized capital of Gold Basin consists of an unlimited number of Shares without par value, each Share carrying the right to one vote. As at the date of this Circular, there were 135,130,486 Shares issued and outstanding.
PRIOR SALES
Gold Basin has not filed continuous disclosure documents publicly since December 2, 2024, including its annual audited financial statements and annual management’s discussion and analysis for the year ended December 31, 2024, its certifications of annual filings for the year ended December 31, 2024, its unaudited interim financial statements and interim management’s discussion and analysis for the periods ended March 31, 2025, June 30, 2025, and September 30, 2025, its certifications of interim filings for the periods ended March 31, 2025, June 30, 2025 and September 30, 2025, and its notice, information circular and proxy materials for its 2025 annual general meeting. Accordingly, information in Gold Basin’s publicly filed documents may be out of date, inaccurate or incomplete and may not be reflective of the current condition, including financial condition, of Gold Basin.
C-11
On May 6, 2025, the regulator of the British Columbia Securities Commission (the “Commission”) issued a Cease Trade Order against the Shares in response to Gold Basin’s failure to file its annual audited financial statements and annual management’s discussion and analysis for the period ended December 31, 2024 and its certifications of annual filings for the year ended December 31, 2024. The next day, CIRO imposed a Halt in trading of the Shares on the TSXV.
CANEX applied to the Commission for the Partial Revocation Order to permit the Offer.
The Partial Revocation Order was issued by the Commission on August 18, 2025. The Partial Revocation Order was set to expire on January 31, 2026, however, upon CANEX completing the Offer prior to January 31, 2026, the Partial Revocation Order will expire now on April 30, 2026.
The Partial Revocation Order was issued by the Commission to solely to allow the CANEX to proceed with the Offer and the securities of Gold Basin remain subject to the Cease Trade Order until a full revocation order is granted by the Commission. Shareholders should refer to Appendix K to this Circular which contains the Cease Trade Order and the Partial Revocation Order.
PREVIOUS DISTRIBUTIONS
Except as disclosed below, no Shares were distributed during the five years preceding the date of this Circular:
| Date of Issuance | Nature of Distribution | Number of Shares Issued | Price Per Share | Aggregate Proceeds | ||||||||||
| August 12, 2024 | Assignment and Assumption Agreement(1) | 5,000,000 | $ | 0.095 | $ | 475,000.00 | ||||||||
| March 5, 2024 | Private Placement(3) | 5,500,000 | $0.10 per Unit | $ | 550,000 | |||||||||
| March 1, 2024 | Private Placement(2) | 9,720,303 | $0.10 per Unit | $ | 972,030 | |||||||||
| September 7, 2023 | Private Placement | 6,422,335 | $ | 0.15 | $ | 963,350.25 | ||||||||
| March 3, 2023 | Private Placement | 2,340,002 | $ | 0.15 | $ | 351,000.30 | ||||||||
| February 17, 2023 | Private Placement | 14,676,735 | $ | 0.15 | $ | 2,201,510.25 | ||||||||
Notes:
| 1. | Shares were issued pursuant to the terms of an assignment and assumption agreement between Gold Basin and 1470906 B.C. Ltd. (the “Assignor”) whereby the Assignor assigned all of its right, title and interest under a letter of intent to Gold Basin in consideration for the delivery of an aggregate of 5,000,000 Shares at the Market Price (as defined in the policies of the TSXV) on May 6, 2024. |
| 2. | On March 1, 2024, Gold Basin announced that it had closed the first tranche of its previously announced non-brokered private placement (the “Financing”) for aggregate gross proceeds of $972,030 through the issuance of 9,720,303 units (each, a “Unit”) at a subscription price of $0.10 per Unit. Each Unit consisted of one common share in the capital of Gold Basin and one-half of one transferable common share purchase warrant (each whole warrant, a “Warrant”), with each Warrant entitling the holder thereof to purchase one Share at an exercise price of $0.15 per Share for a period of one year from the closing of the Financing. In connection with the closing of the first tranche of the Financing, Gold Basin paid cash finder’s fees and issued non-transferable finder’s warrants to Canaccord Genuity Corp. (as to $1,500 cash and 10,000 finder’s warrants) and Brava Capital Pty Ltd. (as to AUD $60,000 and 400,000 finder’s warrants) in connection with the introduction by the finders to Gold Basin of eligible investors in the Financing. The finder’s warrants entitle the holder thereof to purchase one Share at an exercise price of $0.15 per Share for a period of one year from the closing of the Financing. |
C-12
| 3. | On March 5, 2024, Gold Basin announced that it had closed the second and final tranche of the Financing through the issuance of 5,500,000 Units for gross proceeds of approximately $550,000. The Financing was oversubscribed, and Gold Basin issued an aggregate of 15,220,303 Units for aggregate gross proceeds of $1,522,030. In connection with the closing of the second tranche of the Financing, Gold Basin paid cash finder’s fees and issued non-transferable finder’s warrants to Leede Jones Gable Inc. (as to $3,000 cash and 30,000 finder’s warrants). |
Warrants
During the year ended December 31, 2025, there were warrants issued.
On March 1, 2024, 4,860,151 Warrants were issued with an exercise price of $0.15 and expiry of March 1, 2025, as part of the first tranche of the Financing. The fair value of the warrants was recorded as $141,193 in contributed surplus, which was calculated using the Black-Scholes option pricing model assuming an expected life of 12 months, a risk-free interest rate of 4.06%, an expected dividend rate of 0%, a price on grant date of $0.10 and an expected annual volatility of 104%.
On March 1, 2024, 410,000 finder’s warrants were issued with an exercise price of $0.15 and expiry of March 1, 2025, as part of the first tranche of the Financing. The fair value of the warrants was recorded as $11,906 in contributed surplus, which was calculated using the Black-Scholes option pricing model assuming an expected life of 12 months, a risk-free interest rate of 4.06%, an expected dividend rate of 0%, a price on grant date of $0.10 and an expected annual volatility of 104%.
On March 5, 2024, 2,750,000 Warrants were issued with an exercise price of $0.15 and expiry of March 5, 2025, as part of the second tranche of the Financing. The fair value of the warrants were recorded as $80,068 in contributed surplus, which was calculated using the Black-Scholes option pricing model assuming an expected life of 12 months, a risk-free interest rate of 4.04%, an expected dividend rate of 0%, a price on grant date of $0.10 and an expected annual volatility of 104%.
Stock Options
During the year ended December 31, 2025, 7,100,00 options were cancelled upon the resignation of the optionees. On January 22, 2024, 400,000 stock options with an exercise price of $0.10 expired.
On March 9, 2024, 600,000 stock options with an exercise price of $0.35 expired.
On May 6, 2024, 10,300,000 options with an exercise price of $0.075 were granted to various officers and consultants of Gold Basin, 9,900,000 of such options vested on grant and 400,000 of such options vest quarterly over 12 months. All such options expire on May 6, 2027.
TRADING IN SECURITIES
The Shares traded on the TSXV under the symbol “GXX”. The Shares also are quoted on the OTC Market under the symbol “GXXFF”.
As a result of the Cease Trade Order, no securities of Gold Basin have been traded on the TSXV since May 6, 2025.
The closing price of the Shares on the TSXV on May 6, 2025, the last trading day on which the Shares traded on the TSXV prior to the Cease Trade Order, was $0.045.
C-13
The following table sets forth the high and low trading prices per outstanding Share and the trading volumes for the Shares on the OTC Market for the 6-month period prior to the date hereof, as reported by the OTC Market. All share prices are shown in Canadian dollars.
| Period | High (C$) | Low (C$) | Aggregate Volume | |||||||||
| May 1 – May 8, 2026 | - | - | - | |||||||||
| April 2026 | - | - | - | |||||||||
| March 2026 | - | - | - | |||||||||
| February 2026 | $ | 0.0794 | $ | 0.0794 | 100 | |||||||
| January 2026 | $ | 0.0389 | $ | 0.0102 | 12,565 | |||||||
| December 2025 | $ | 0.0710 | $ | 0.0100 | 28,000 | |||||||
| November 2025 | $ | 0.1250 | $ | 0.1000 | 15,938 | |||||||
The closing price of the Shares on the OTC Market on May 8, 2025, the last trading day prior to Gold Basin announcing the Arrangement, was $0.045.
OWNERSHIP OF SECURITIES
The following table sets forth the number of securities beneficially owned or controlled, directly or indirectly by each of the directors and executive officers of Gold Basin and, to the knowledge of the directors and executive officers of Gold Basin, any of their respective associates or affiliates, any other insiders of Gold Basin or their respective associates or affiliates or any person acting jointly or in concert with Gold Basin as of the date hereof:
| Name and Position | Type of Security |
Number of Securities |
| John Robins, Director | Shares | 666,667 |
| Options | Nil | |
| James Paterson, Director | Shares | 200,000 |
| Options | Nil | |
| Mark Ernst, Director | Shares | Nil |
| Jordan Ross, Director | Shares | Nil |
| Shane Ebert, President, Chief Executive Officer and Director(1) | Shares | Nil |
| Jean Pierre Jutras, Vice President(2) | Shares | Nil |
| Chantelle Collins, Chief Financial Officer(3) | Shares | Nil |
| Barbara O’Neill, Corporate Secretary(4) | Shares | Nil |
| CANEX, Insider | Shares | 70,088,199 |
C-14
Notes:
| 1. | Dr. Shane Ebert is also the President, Chief Executive Officer and a director of CANEX. |
| 2. | Mr. Jean Pierre Jutras is also the Vice-President and a director of CANEX |
| 3. | Ms. Chantelle Collins is also the Chief Financial Officer of CANEX. |
| 4. | Ms. Barbara O’Neill is also the Corporate Secretary of CANEX |
AUDITORS, TRANSFER AGENTS AND REGISTRARS
Auditors
Gold Basin’s auditors are Manning Elliot LLP, having an address at 1700-1030 West Georgia St., Vancouver, British Columbia, V6E 2Y3, Canada.
Transfer Agents, Registrars or Other Agents
The transfer agent and registrar for Gold Basin is TSX Trust Company, having an address at 733 Seymour Street, Suite 2310, Vancouver, British Columbia, V6B 0S6, Canada.
RISK FACTORS
An investment in the securities of Gold Basin is subject to certain risks. Readers should carefully consider the risk factors described below, as well as the risk factors set forth elsewhere in this Circular. If any of the identified risks were to materialize, Gold Basin’s business, financial position, results and/or future operations may be materially affected.
The risk factors that are identified in this Circular are not exhaustive and other factors may impact Gold Basin in the future that are currently not foreseen by management of Gold Basin that may present additional risks in the future.
Going Concern
In the absence of the Arrangement, there is considerable risk that Gold Basin will not have the ability to continue as a going concern and realize its assets and discharge its liabilities in the normal course of business. Gold Basin’s financial situation has significantly deteriorated since its last filed audited financial statements. As at May 11, 2026, Gold Basin has asserted liabilities of approximately $2,123,183 (of which $691,724 is purportedly owed to former management and directors, their related parties and their counsel), no cash or marketable securities and no revenue. Gold Basin’s ability to raise equity financing is restricted by the Cease Trade Order.
Gold Basin does not presently have sufficient financial resources, has no source of operating cash flow and has no assurance that additional funding will be available to it for an application to lift the Cease Trade Order, to fund its ongoing compliance with securities Laws, to fund further exploration and development of its projects or to fulfill its obligations under any applicable agreements. There can be no assurance that it will be able to obtain adequate financing in the future or that the terms of such financing will be favorable. Failure to obtain such additional financing could result in delay or indefinite postponement of further exploration and development of its projects with the possible loss of such properties. Failure to raise the required funds could result in Gold Basin losing, or being required to dispose of, its interest in its properties.
C-15
If Gold Basin is unable to continue as a going concern it may be forced to seek relief under applicable bankruptcy and insolvency Laws. If Gold Basin seeks relief under applicable bankruptcy and insolvency Laws, its business and operations will be subject to certain risks, including but not limited to, the following:
| · | an insolvency filing by or against Gold Basin will adversely affect its business prospects, including its ability to continue to obtain and maintain the contracts necessary to further exploration and development of its projects or to fulfill its obligations under any applicable agreements; |
| · | there can be no assurance as to Gold Basin’s ability to maintain or obtain sufficient financing sources for operations or to fund any reorganization plan and meet future obligations; |
| · | there can be no assurance that Gold Basin will be able to successfully develop, prosecute, confirm and consummate one or more plans of reorganization that are acceptable to the applicable courts and its creditors, equity holders and other parties in interest; and |
| · | the value of the Shares could be reduced to zero as result of an insolvency filing. |
In the event that Gold Basin successfully applies for the Cease Trade Order to be lifted, Gold Basin may need to continue its reliance on the sale of securities for future financing. Gold Basin may issue securities on less than favorable terms to raise sufficient capital to fund its business plan. Any transaction involving the issuance of equity securities or securities convertible into Shares would result in dilution, that is possibly substantial, to present and prospective holders of Shares.
Unaudited Financial Statements
Although unaudited consolidated financial statements of Gold Basin for the years ended December 31, 2025 and 2024 have been prepared and are attached as Appendix L to the Circular, these statements are the responsibility of Gold Basin’s management and have not been audited or reviewed on behalf of the shareholders by the independent external auditors of Gold Basin. To date, Gold Basin has been unable to provide audited consolidated financial statements for the years ended December 31, 2025 and 2024 and management’s discussion and analysis thereof, because:
| · | there have been significant changes in Gold Basin’s management and personnel responsible for accounting and financial reporting; |
| · | certain accounting records of Gold Basin may have been reconstructed after the fact; |
| · | there are unresolved questions regarding the nature, authorization, and supporting documentation of certain transactions and payments of Gold Basin; |
| · | there is uncertainty regarding the terms, substance, and related-party nature of certain financing arrangements and agreements of Gold Basin; and |
| · | there are limitations in the availability of supporting documentation and cooperation from certain persons previously involved with Gold Basin. |
Circumstances of this nature would generally be expected to create significant challenges in completing an audit in accordance with IFRS. Such circumstances may increase audit risk, require substantially expanded audit procedures, and result in increased time and cost associated with the auditor’s engagement.
C-16
In addition, where there are concerns regarding the completeness of accounting records, authorization of transactions, related-party relationships, or the reliability of supporting documentation, auditors would typically be required to exercise heightened professional skepticism and perform extensive additional procedures to obtain sufficient appropriate audit evidence.
Potential Impairment of Gold Basin Project
Gold Basin’s former board and management may have potentially impaired Gold Basin’s ownership interest in its sole mineral asset, the Gold Basin Project in Mohave County, Arizona, through purported agreements, abandonment or encumbrances involving related parties or parties controlled by former directors and officers of Gold Basin for no or inadequate consideration. See “Recent Developments - Helix”, “Recent Developments - Settlement Agreement with Charrua Capital LLC” and “Exploration Projects – Gold Basin Project – Property Acquisition” in this Appendix C. Although Gold Basin is taking steps to address these potential impairments and has reserved all rights against the former directors of Gold Basin, any impairment to Gold Basin’s ownership interest in the Gold Basin Project could have a material adverse impact on Gold Basin’s financial condition and operations.
Resource Industry is Intensely Competitive
Gold Basin’s business is the acquisition, exploration and development of resource properties. The resource industry is intensely competitive, and Gold Basin will compete with other companies that have far greater resources.
Resource Exploration and Development is Generally a Speculative Business
Resource exploration and development is a speculative business and involves a high degree of risk, including, among other things, unprofitable efforts resulting both from the failure to discover mineral deposits and from finding mineral deposits which, though present, are insufficient in size and grade at the then prevailing market conditions to return a profit from production. The marketability of natural resources which may be acquired or discovered by Gold Basin will be affected by numerous factors beyond the control of Gold Basin. These factors include market fluctuations, the proximity and capacity of natural resource markets, government regulations, including regulations relating to prices, taxes, royalties, land use, importing and exporting of minerals and environmental protection. The exact effect of these factors cannot be accurately predicted, but the combination of these factors may result in Gold Basin not receiving an adequate return on invested capital.
Fluctuation of Prices
Even if commercial quantities of resource deposits are discovered by Gold Basin, there is no guarantee that a profitable market will exist for the sale of the product produced. Factors beyond the control of Gold Basin may affect the marketability of any substances discovered. Commodity prices have experienced significant movement over short periods of time and are affected by numerous factors beyond the control of Gold Basin, including international economic and political trends, expectations of inflation, currency exchange fluctuations, interest rates and global or regional consumption patterns, speculative activities and increased production due to improved exploration and production methods. The supply of commodities is affected by various factors, including political events, economic conditions and production costs in major producing regions. There can be no assurance that the price of any commodities will be such that any of the properties in which Gold Basin has, or has the right to acquire, an interest may be mined at a profit.
C-17
Permits and Licenses
The operations of Gold Basin will require consents, approvals, licenses and/or permits from various Governmental Authorities. There can be no assurance that Gold Basin will be able to obtain all necessary consents, approvals, licenses and permits that may be required to carry out exploration, development and production operations at its projects.
No Assurance of Profitability
Gold Basin has no history of earnings and due to the nature of its business there can be no assurance that Gold Basin will ever be profitable. Gold Basin has not paid dividends on its shares since incorporation and does not anticipate doing so in the foreseeable future. The only present source of funds available to Gold Basin is from the sale of its Shares or, possibly, from the sale or optioning of a portion of its interest in its resource properties. Even if the results of exploration are encouraging, Gold Basin may not have sufficient funds to conduct the further exploration that may be necessary to determine whether a commercial deposit exists. While Gold Basin may generate additional working capital through further equity offerings or through the sale or possible syndication of its properties, there can be no assurance that any such funds will be available on favorable terms, or at all. At present, it is impossible to determine what amounts of additional funds, if any, may be required. Failure to raise such additional capital could put the continued viability of Gold Basin at risk.
Uninsured or Uninsurable Risks
Gold Basin may become subject to liability for pollution or hazards against which it cannot insure or against which it may elect not to insure where premium costs are disproportionate to Gold Basin’s perception of the relevant risks. The payment of such insurance premiums and of such liabilities would reduce the funds available for exploration and production activities.
Government Regulations and Political Climate
Mineral exploration on Gold Basin’s properties is affected to varying degrees by: (i) government regulations relating to such matters as environmental protection, health, safety and labour; (ii) mining law reform; (iii) tax laws; (iv) restrictions on production, price controls, and tax increases; (v) maintenance of claims; (vi) tenure; and (vii) expropriation of property through nationalization, requisition or confiscation. Any mineral exploration activities conducted by Gold Basin, including commencement of production, require permits from Governmental Authorities and such operations are and will be governed by laws and regulations governing prospecting, mining, production, exports, taxes, labour standards, occupational health, waste disposal, toxic substances, land use, environmental protection, mine safety and other matters.
Companies engaged in the development and operation of mines and related facilities generally experience increased costs, and delays in development and/or production and other schedules as a result of the need to comply with applicable laws, regulations and permits. All permits required for the conduct of exploration, development and mining operations, including the construction of mining facilities, may not be obtainable by Gold Basin on reasonable terms, which would have an adverse effect on any mining project Gold Basin might undertake. Additionally, failure to comply with applicable laws, regulations and permitting requirements may result in enforcement actions thereunder, including orders issued by regulatory or judicial authorities causing operations to cease or be curtailed, and may include corrective measures requiring capital expenditures, installation of additional equipment, or remedial actions. Parties engaged in mining exploration, development or operations may be required to compensate those suffering loss or damage by reason of the mining activities and may have civil or criminal fines or penalties imposed for violations of applicable laws or regulations.
C-18
To the best of Gold Basin’s knowledge, Gold Basin is and will continue to operate in compliance with applicable legal and environmental regulations and social requirements. However, amendments to current governmental laws and regulations affecting mining companies, or the more stringent application thereof, or shifts in political conditions or attitudes could adversely affect Gold Basin’s operations including the potential to curtail or cease exploration programs or to preclude entirely the economic viability of a mineral property. The extent of future changes to governmental laws and regulations cannot be predicted or quantified, but it should be assumed that such laws and regulations will become more stringent in the future. Generally, new laws and regulations will result in increased compliance costs, including costs and time and effort for obtaining permits, and increased delays or fines resulting from loss of permits or failure to comply with the new requirements.
General Economic Conditions
The recent unprecedented events in global financial markets have had a profound impact on the global economy. Many industries, including the gold and base metal mining industry, are impacted by these market conditions. Some of the key impacts of the recent financial market turmoil include contraction in credit markets resulting in a widening of credit risk, devaluations and high volatility in global equity, commodity, foreign exchange and precious metal markets, and a lack of market liquidity. A continued or worsened slowdown in the financial markets or other economic conditions, including but not limited to, consumer spending, employment rates, business conditions, inflation, fuel and energy costs, consumer debt levels, lack of available credit, the state of the financial markets, interest rates, and tax rates may adversely affect Gold Basin’s growth and profitability.
Specifically:
| · | global credit or liquidity crisis could impact the cost and availability of financing and Gold Basin’s overall liquidity; |
| · | the volatility of commodity prices may impact Gold Basin’s future revenues, profits and cash flow; |
| · | volatile energy prices, commodity and consumables prices and currency exchange rates impact potential production costs; and |
| · | the devaluation and volatility of global stock markets impacts the valuation of the Shares, which may impact Gold Basin’s ability to raise funds through the issuance of Shares. |
These factors could have a material adverse effect on Gold Basin’s financial condition and results of operations.
Exploration and Mining Risks
Fires, power outages, labor disruptions, flooding, explosions, cave-ins, landslides and the inability to obtain suitable or adequate machinery, equipment or labor are other risks involved in the operation of mines and the conduct of exploration programs. Substantial expenditures are required to establish reserves through drilling, to develop metallurgical processes, to develop the mining and processing facilities and infrastructure at any site chosen for mining. Although substantial benefits may be derived from the discovery of a major mineralized deposit, no assurance can be given that minerals will be discovered in sufficient quantities to justify commercial operations or that funds required for development can be obtained on a timely basis. The economics of developing mineral properties is affected by many factors including the cost of operations, variations of the grade of ore mined, fluctuations in the price of gold or other minerals produced, costs of processing equipment and such other factors as government regulations, including regulations relating to royalties, allowable production, importing and exporting of minerals and environmental protection. In addition, the grade of mineralization ultimately mined may differ from that indicated by drilling results and such differences could be material. Short term factors, such as the need for orderly development of ore bodies or the processing of new or different grades, may have an adverse effect on mining operations and on the results of operations. There can be no assurance that minerals recovered in small scale laboratory tests will be duplicated in large scale tests under on-site conditions or in production scale operations. Material changes in geological resources, grades, stripping ratios or recovery rates may affect the economic viability of projects.
C-19
No Known Mineral Reserves
Gold Basin’s mineral properties are in the exploration stage and it is without known mineral reserves. Although Gold Basin may discover mineral reserves through its exploration programs, commercial production may not be warranted due to insufficient quantities or unfavourable economic conditions.
In the event a mineral reserve is discovered, substantial expenditures are required to develop the mineral reserve for production including facilities for mining, processing, infrastructure and transportation. The marketability of any minerals discovered may be affected by numerous factors which are beyond Gold Basin’s control and which cannot be accurately predicted, such as global economic conditions, mineral markets and mineral pricing, global smelting and refining availability, and such other factors as government regulations, including regulations relating to royalties, allowable production, importing and exporting of minerals, and environmental protection. Depending on the price of minerals produced, Gold Basin may determine that it is not warranted to commence or continue commercial production.
Environmental Matters
Existing and possible future environmental legislation, regulations and actions could cause significant expense, capital expenditures, restrictions and delays in the activities of Gold Basin, the extent of which cannot be predicted and which may well be beyond the capacity of Gold Basin to fund. Gold Basin’s right to exploit any resource property is and will continue to be subject to various reporting requirements and to obtaining certain government approvals and there can be no assurance that such approvals, including environment approvals, will be obtained without inordinate delay or at all.
There are numerous historic excavations, prospect pits, and shafts within the Gold Basin Project area, as well as a number of associated waste rock dumps, access roads, and tailings dumps. It is uncertain at present if the historic workings pose a potential environmental liability to the Gold Basin Project, nor if or to what extent Gold Basin might be responsible for their reclamation.
Increased Costs
Management anticipates that costs at Gold Basin’s projects will frequently be subject to variation from one year to the next due to a number of factors, such as the results of ongoing exploration activities (positive or negative), changes in the nature of mineralization encountered, and revisions to exploration programs, if any, in response to the foregoing. In addition, exploration program costs are affected by the price of commodities such as fuel, rubber and electricity and the availability (or otherwise) of consultants and drilling contractors. Increases in the prices of such commodities or a scarcity of consultants or drilling contractors could render the costs of exploration programs to increase significantly over those budgeted. A material increase in costs for any significant exploration programs could have a significant effect on Gold Basin’s operating funds and ability to continue its planned exploration programs.
C-20
Dependence Upon Others and Key Personnel
The success of Gold Basin’s operations will depend upon numerous factors, many of which are beyond Gold Basin’s control, including (i) the ability to design and carry out appropriate exploration programs on its resource properties; (ii) the ability to produce resources from any resource deposits that may be located; (iii) the ability to attract and retain additional key personnel in exploration, marketing, mine development and finance; and (iv) the ability and the operating resources to develop and maintain the properties held by Gold Basin. These and other factors will require the use of outside suppliers as well as the talents and efforts of Gold Basin and its consultants and employees. There can be no assurance of success with any or all of these factors on which Gold Basin’s operations will depend, or that Gold Basin will be successful in finding and retaining the necessary employees, personnel and/or consultants in order to be able to successfully carry out such activities.
Conflicts of Interest
Certain directors of Gold Basin also serve as directors and/or officers of other companies involved in other business ventures. Consequently, there exists the possibility for such directors to be in a position of conflict. Any decision made by such directors involving Gold Basin will be made in accordance with their duties and obligations to deal fairly and in good faith with Gold Basin and such other companies. In addition, such directors will declare, and refrain from voting on, any matter in which such directors may have a conflict of interest.
Cyber Security Risk
Cyber security risk is the risk of negative impact on the operations and financial affairs of Gold Basin due to cyber-attacks, destruction or corruption of data, and breaches of its electronic systems. Management believes that it has taken reasonable and adequate steps to mitigate the risk of potential damage to Gold Basin from such risks. Gold Basin also relies on third-party service providers for the storage and processing of various data. A cyber security incident against Gold Basin or its contractors and service providers could result in the loss of business sensitive, confidential or personal information as well as violation of privacy and security laws, litigation and regulatory enforcement and costs. Gold Basin has not experienced any material losses relating to cyber-attacks or other information security breaches, however there can be no assurance that it will not incur such losses in the future.
Price Fluctuations and Share Price Volatility
In recent years, the securities markets in the United States and Canada have experienced a high level of price and volume volatility, and the market price of securities of many companies, particularly those considered exploration stage companies, have experienced wide fluctuations in price which have not necessarily been related to the operating performance, underlying asset values or prospects of such companies. There can be no assurance that continual and extreme fluctuations in price will not occur.
Surface Rights and Access
Although Gold Basin acquires the rights to some or all of the resources in the ground subject to the tenures that it acquires, or has a right to acquire, in most cases it does not thereby acquire any rights to, or ownership of, the surface to the areas covered by its resource tenures. In such cases, applicable laws usually provide for rights of access to the surface for the purpose of carrying on exploration activities, however, the enforcement of such rights can be costly and time consuming. In areas where there are no existing surface rights holders, this does not usually cause a problem, as there are no impediments to surface access. However, in areas where there are local populations or landowners, it is necessary, as a practical matter, to negotiate surface access. There can be no guarantee that, despite having the right at law to access the surface and carry on exploration activities, Gold Basin will be able to negotiate a satisfactory agreement with any such existing landowners/occupiers for such access, and therefore it may be unable to carry out exploration activities. In addition, in circumstances where such access is denied, or no agreement can be reached, Gold Basin may need to rely on the assistance of local officials or the courts in such jurisdiction.
C-21
Title
Although Gold Basin has taken steps to verify the title to the resource properties in which it has an interest in accordance with industry standards for the current stage of exploration of such properties, these procedures do not guarantee title. Title to resource properties may be subject to unregistered prior agreements or transfers and may also be affected by undetected defects or the rights of indigenous peoples.
PREVIOUS PURCHASES AND SALES BY GOLD BASIN
No Shares have been purchased or sold by Gold Basin during the 12-month period prior to the date hereof.
COMMITMENTS TO ACQUIRE GOLD BASIN SHARES
Except as otherwise described in this Circular, none of Gold Basin or its directors and executive officers or, to the knowledge of the directors and executive officers of Gold Basin, any of their respective associates or affiliates, any other insiders of Gold Basin or their respective associates or affiliates or any person acting jointly or in concert with Gold Basin has made any agreement, commitment or understanding to acquire securities of Gold Basin.
BENEFITS FROM THE ARRANGEMENT
Except as otherwise described in this Circular, none of Gold Basin or its directors and executive officers or, to the knowledge of the directors and executive officers of Gold Basin, any of their respective associates or affiliates, any other insiders of the Gold Basin, or their respective associates or affiliates or any person acting jointly or in concert with Gold Basin will receive any direct or indirect benefits from the Arrangement.
DIVIDEND POLICY
Gold Basin has not declared or paid any dividends on the Shares during the two years preceding the date of this Circular. Gold Basin does not currently have a dividend or distribution policy in place. Except as otherwise disclosed in this Circular or pursuant to the policies of the stock exchange on which the Shares are listed from time to time and the BCBCA, there are no restrictions on Gold Basin that would prevent it from paying a dividend or distribution.
INTEREST OF INFORMED PERSONS IN MATERIAL TRANSACTIONS
Other than as set forth under “Securities Law Considerations – Interests of Certain Persons and Companies in the Arrangement” and “General Proxy Matters – Voting Securities of Gold Basin and Principal Holders Thereof” in the Circular or elsewhere in this Circular, there were no material interests, direct or indirect, of Gold Basin’s directors or executive officers, or any director or executive officer of a subsidiary of Gold Basin or any person who beneficially owns, or controls or directs, directly or indirectly, more than 10% of the outstanding Shares, or any associate or affiliate of such persons, in any transaction since the commencement of Gold Basin’ last completed financial year or in any proposed transaction which has materially affected, or would materially affect, Gold Basin or any of its subsidiaries.
C-22
EXPENSES OF GOLD BASIN
The aggregate fees and expenses expected to be incurred by Gold Basin in connection with the Arrangement are estimated to be approximately $700,000, including legal, financial advisory, accounting, filing and printing costs, the costs of preparing and mailing this Circular and fees in respect of the Fairness Opinion.
MATERIAL CHANGE IN THE AFFAIRS OF GOLD BASIN
Except as described in this Circular, the directors and executive officers of Gold Basin are not aware of any plans or proposals for material changes in the affairs of the Gold Basin.
INTEREST OF EXPERTS
Richard A. Schwering, P.G., SME-RM, Jennifer J. Brown, P.G., Jeffery W. Choquette, P.E. are named as having prepared or certified the Technical Report. As at the date hereof, to the best knowledge of Gold Basin: such persons collectively held less than one percent of the securities of Gold Basin when they prepared or certified a report valuation, statement or opinion, as applicable, referred to above and as at the date hereof; and they did not receive any direct or indirect interest in any securities of Gold Basin or of any associate or affiliate of Gold Basin in connection with the preparation or certification of such report, valuation, statement or opinion, as applicable. As at the date hereof, none of the aforementioned persons is or is currently expected to be elected, appointed or employed as a director, officer or employee of Gold Basin or of any associate or affiliate of Gold Basin.
SCIENTIFIC AND TECHNICAL INFORMATION
Dr. Shane Ebert, P.Geo, is the “Qualified Person” under NI 43-101 for Gold Basin and has approved the technical and scientific disclosure of Gold Basin contained in this Circular.
ADDITIONAL INFORMATION
Additional information relating to Gold Basin is available on SEDAR+ at www.sedarplus.ca.
C-23
Appendix D
Information Concerning Canex Metals Inc.
[See attached]
NOTICE TO READER
The following information provided by CANEX is presented on a pre-Arrangement basis (except where otherwise indicated) and reflects the current business, financial and share capital position of CANEX.
Unless the context indicates otherwise, capitalized terms which are used in this Appendix D and not otherwise defined in this Appendix D have the meanings given to such terms under the heading “Glossary of Terms” in the Circular.
FORWARD-LOOKING INFORMATION
Certain statements contained in this Appendix D constitute forward-looking statements and forward-looking information (collectively referred to as “forward-looking information”) within the meaning of applicable securities laws. Such forward-looking information relates to future events or CANEX’s future performance. See “General Proxy Information – Cautionary Statement Regarding Forward-Looking Information” in the Circular. Readers should also carefully consider the matters and cautionary statements discussed under the heading “Risk Factors” in the Circular, and under the heading “Risk Factors” in this Appendix D.
CANEX METALS INC.
CANEX was originally incorporated under the laws of the Province of Quebec on March 15, 1971, and was continued under the Business Corporations Act (Alberta) on July 14, 2011. On April 3, 2017, CANEX amended its articles to change its name from “Northern Abitibi Mining Corp.” to “CANEX Metals Inc.”.
CANEX’s 100% owned subsidiary, Canexco Inc. (“Canexco”), was incorporated on June 5, 2019, in Arizona, to conduct CANEX’s exploration and development business in the United States.
CANEX’s head and registered office is located at Suite 1620, 734 – 7th Avenue SW, Calgary, Alberta T2P 3P8, Canada.
CANEX Shares trade on the TSXV under the symbol “CANX” and are quoted on the OTC Market under the symbol “NOMNF”.
Business of CANEX
CANEX is a junior mineral exploration company focused on advancing the 100% owned Gold Range Project and the Louise Project. Since inception, the efforts of CANEX have been devoted to the acquisition, exploration, and development of mineral properties.
CANEX’s principal asset is the 100% owned Gold Range Project, located in northern Arizona, in Mohave County, within an area that has seen historic lode and placer gold production but limited modern gold exploration. Over the past five years, CANEX has been advancing its Gold Range Project, making new gold discoveries and drill-defining gold zones along a 4 kilometer mineralized trend that continues onto Gold Basin’s claims and is the longest defined gold trend in the district, extending at least 6.5 kilometres across both properties. CANEX commissioned an independent third party evaluation of the Gold Range Project which was published on October 27, 2025. The report provides a review of the Gold Range Project, highlighting the history, geology and exploration results completed to the date of the report. The independent qualified author concludes that “The Gold Range Project presents a compelling exploration opportunity within a well understood geological framework and deposit model. The evidence supports a structurally controlled, multi-episodic mineralizing system with the potential to host both high-grade vein-hosted and bulk-tonnage oxide gold resources. Continued exploration is warranted and should focus on expanding known zones, drill testing structural intersections and alteration halos and advancing regional targeting within the broader Gold Basin District”. The report is available on the CANEX website at www.canexmetals.ca and under CANEX’s profile on SEDAR+ at www.sedarplus.ca. CANEX has acquired a controlling interest in Gold Basin, a company with a large and advanced gold project directly adjacent to the Gold Range Project.
-2-
In addition to the Gold Range Project, CANEX is advancing the Louise Project in British Columbia which contains a large historic copper-gold resource. The Louise Project offers a low-risk, high value opportunity with untested discovery potential that can be advanced as market conditions allow. CANEX has completed a large scale and deep looking induced polarization geophysical survey at the Louise Project, which has identified two new high priority chargeability targets that have never been identified nor drill tested previously. One, the west Louise Project target, is located two kilometres west of the historic Louise Project deposit and contains similar chargeability and resistivity values as known mineralization. The second, the Louise Project deep target, is a high chargeability zone located immediately north and below the historic Louise Project deposit. This target has potential to host the main body or roots of the faulted Louise Project system and identifying this target was a key objective of the survey.
CANEX is led by an experienced management team which has made three notable porphyry and bulk-tonnage discoveries in North America. CANEX is supported by a significant shareholder, Altius Minerals Corporation (Toronto Stock Exchange: ALS), which has invested in CANEX as a strategic sponsor.
Specialized Skill and Knowledge
Exploration at the Gold Range Project requires specialized experience exploring for metamorphic and intrusive rock hosted mesothermal gold deposits and understanding primary structural controls on mineralization. The CANEX geologic team has extensive experience exploring and researching these types of deposits throughout North and South America. The Louise Project hosts a copper-gold porphyry system, a style of deposit the CANEX team understands well. The CANEX team discovered and delineated a large porphyry copper deposit in Northern Mexico while with Tyler Resources Inc., and has worked on numerous large porphyry deposits since, including involvement in a subsequent porphyry discovery.
Competitive Conditions
Shane Ebert, the President and CEO of CANEX, completed a PhD in geology studying a large gold system in Nevada and subsequently spent over 10 years exploring across the western United States and Northern Mexico. Jean Pierre Jutras, the Vice President of CANEX, also has extensive experience operating in the United States. The core geologic team at CANEX is well positioned and well qualified to manage and operate effective exploration in Arizona. The CANEX team has several decades of experience overseeing large exploration programs in western Canada and is well positioned and qualified to advance the Louise Project.
Cyclical Nature of Operations
Mineral exploration in British Columbia can be more challenging in winter due to snow conditions, and although drilling can occur in the winter, exploration program can be seasonal. In Arizona exploration can typically be conducted year-round.
-3-
Environmental Protection
Environmental protection requirements are a key consideration for all responsibly managed modern exploration programs, in all jurisdictions. The capital requirements for environmental protections are built into all exploration programs as a requirement of operating and, as a result of this exploration philosophy, no unforeseen future financial liabilities are anticipated.
Employees
CANEX does not operate with employees. All officers and consultants to the company are independent third party contractors.
Authorized and Outstanding Share Capital
The authorized share capital of CANEX consists of an unlimited number of CANEX Shares without par value.
As at December 31, 2025, there were 166,950,482 CANEX Shares. To the knowledge of the board of directors of CANEX and executive officers of CANEX, no person beneficially owns, or exercises control or direction over, securities carrying 10% or more of the voting rights attached to any class of voting securities of CANEX.
The holders of CANEX Shares are entitled to notice of, to attend and to one vote per CANEX Share held at any meeting of the CANEX Shareholders. The holders of CANEX Shares are entitled to receive dividends as and when declared by the board of directors of CANEX. The holders of CANEX Shares are entitled in the event of any liquidation, dissolution or winding-up of CANEX, whether voluntary or involuntary, or any other distribution of the assets of CANEX among the holders of CANEX Shares for the purpose of winding-up its affairs in such assets of CANEX as are available for distribution.
Consolidated Capitalization
The following table sets forth the consolidated capitalization of CANEX based on its unaudited consolidated financial statements as at December 31, 2025: (a) on an actual basis; and (b) as adjusted to take into account the acquisition by CANEX of all outstanding Shares under the Arrangement. The financial information set out below should be read in conjunction with CANEX’s unaudited interim consolidated financial statements for the three month period ended December 31, 2025. Other than as set forth below, there have been no material changes to CANEX’s share and loan capital since December 31, 2025.
| December 31, 2025 | ||||||||
| Proforma Consolidated Capitalization as at period ended (unaudited) | Actual | As adjusted | ||||||
| Debt | - | 3,257,998 | ||||||
| Share capital | 26,121,922 | 50,276,526 | ||||||
| Reserves | 2,503,770 | 2,503,770 | ||||||
| Deficit | (18,577,082 | ) | (18,773,161 | ) | ||||
| Total Equity | 10,048,610 | 34,007,135 | ||||||
| Proforma Consolidated Capitalization | 10,048,610 | 37,265,133 | ||||||
-4-
Price Range and Trading Volume
CANEX Shares are listed and traded under the symbol “CANX” on the TSXV and quoted on the OTC Market under the symbol “NOMNF”.
The following table sets forth, for the periods indicated, the high and low trading prices (based on intra-day prices) in Canadian dollars and trading volumes of CANEX Shares on the TSXV:
| Price Range | |||||||||||||
| Period | High (CAD$) | Low (CAD$) | Volume | ||||||||||
| May 2025 | 0.050 | 0.040 | 972,365 | ||||||||||
| June 2025 | 0.080 | 0.050 | 1,766,856 | ||||||||||
| July 2025 | 0.120 | 0.065 | 3,331,997 | ||||||||||
| August 2025 | 0.095 | 0.070 | 1,061,526 | ||||||||||
| September 2025 | 0.175 | 0.095 | 6,677,294 | ||||||||||
| October 2025 | 0.165 | 0.100 | 2,174,073 | ||||||||||
| November 2025 | 0.145 | 0.090 | 6,922,853 | ||||||||||
| December 2025 | 0.230 | 0.115 | 4,082,611 | ||||||||||
| January 2026 | 0.330 | 0.215 | 5,496,203 | ||||||||||
| February 2026 | 0.330 | 0.240 | 5,101,156 | ||||||||||
| March 2026 026 | 0.265 | 0.215 | 3,064,397 | ||||||||||
| April 2026 | 0.260 | 0.210 | 3,328,190 | ||||||||||
| May 1 – 8, 2026 | 0.260 | 0.215 | 947,271 | ||||||||||
The following table sets forth, for the periods indicated, the high and low trading prices (based on intra-day prices) in U.S. dollars and trading volumes of CANEX Shares on the OTC Market:
| Price Range | |||||||||||||
| Period | High (U.S.$) | Low (U.S.$) | Volume | ||||||||||
| May 2025 | 0.040 | 0.0041 | 197,720 | ||||||||||
| June 2025 | 0.120 | 0.0369 | 322,180 | ||||||||||
| July 2025 | 0.060 | 0.045 | 140,700 | ||||||||||
| August 2025 | 0.060 | 0.050 | 128,168 | ||||||||||
| September 2025 | 0.110 | 0.054 | 102,600 | ||||||||||
| October 2025 | 0.110 | 0.044 | 52,217 | ||||||||||
| November 2025 | 0.090 | 0.048 | 521,404 | ||||||||||
| December 2025 | 0.1766 | 0.0772 | 460,449 | ||||||||||
| January 2026 | 0.350 | 0.164 | 451,249 | ||||||||||
| February 2026 | 0.260 | 0.180 | 646,273 | ||||||||||
| March 2026 | 0.250 | 0.151 | 258,684 | ||||||||||
| April 2026 | 0.245 | 0.1504 | 288,481 | ||||||||||
| May 1 – 8, 2026 | 0.22 | 0.1604 | 70,402 | ||||||||||
The closing prices of CANEX Shares on the TSXV and the OTC Market on May 8, 2026 was $0.255 and US$0.1877, respectively.
-5-
Prior Sales
The following table summarizes the issuances of CANEX Shares and securities convertible into CANEX Shares in the 12-month period prior to the date hereof. Other than as summarized in the below table, CANEX has not issued any CANEX Shares or securities convertible into CANEX Shares in the above-mentioned period of time:
| Date | Type of Security Issued | Number of Securities Issued | Issuance/Exercise Price per Security ($) | ||||||||
| June 26, 2025 | CANEX Shares | 23,636,380 | 0.055 | ||||||||
| August 18, 2025 | CANEX Shares | 400,000 | 0.070 | ||||||||
| December 23, 2025 | CANEX Shares | 20,000,000 | 0.150 | ||||||||
| January 30, 2026 | CANEX Shares | 41,154,418 | 0.302 | ||||||||
| February 10, 2026 | CANEX Shares | 337,776 | 0.302 | ||||||||
| February 19, 2026 | CANEX Shares | 185,186 | 0.270 | ||||||||
| April 8, 2026 | CANEX Shares | 150,000 | 0.060 | ||||||||
| April 15, 2026 | CANEX Shares | 150,000 | 0.060 | ||||||||
Escrowed Securities
CANEX does not have any escrowed securities.
Principal Holders of CANEX Shares
To the knowledge of the directors and senior officers of CANEX, as of May 11, 2026, no one beneficially owns, directly or indirectly, or exercises control or direction over more than ten percent (10%) of the votes attached to the securities of CANEX.
To the knowledge of the directors and senior officers of CANEX, none of the CANEX Shares are held, or are to be held following closing of the Arrangement, subject to any voting trust or other similar agreement.
General Development of the Business of CANEX
Two-Year History
The following is a summary of the significant disclosures affecting the development of CANEX’s business over the last two years and to date in this current fiscal, summarized by fiscal period.
| (i) | Fiscal year ended September 30, 2024 |
On November 29, 2023, CANEX announced it had completed the purchase of the Excelsior Mine Property located adjacent to CANEX’s other Gold Range Project properties.
On March 5, 2024, CANEX announced it had entered into an option agreement to acquire a 100% interest in the Louise Project in British Columbia from prospector Bernie Kreft. The option involved staged payments totaling $775,000 in shares or cash over five years, with no required exploration expenditures. Kreft retained a 2.5% net smelter royalty, of which CANEX could repurchase 1% for $1.5 million. The Louise Project featured a large, road-accessible historic resource with significant exploration potential, including untested depth extensions and modern geophysical survey opportunities.
-6-
On March 12, 2024, CANEX announced that it had received an amended exploration permit for its Gold Range Project, allowing construction of 34 additional drill pads, particularly around the new WestGold gold discovery. The permit, accepted by the U.S. Bureau of Land Management, was contingent on a reclamation bond increase of U.S.$6,060. A surface exploration program was set to begin in March, aimed at refining drill targets at WestGold, evaluating other areas including the Eldorado zone, and assessing recently acquired infrastructure at the Excelsior Mine Property.
On April 9, 2024, CANEX announced it had received TSXV approval for the option agreement that allowed it to acquire a 100% interest in the Louise Project.
On July 3, 2024, CANEX announced the results of a March surface exploration program at its Gold Range Project, highlighting the discovery of three new mineralized zones with high-grade gold values. Key findings included 19.4 g/t gold over three metres from chip sampling in an untested eastern zone, 11.2 g/t from a grab sample north of the Excelsior deposit, and 5.05 g/t from a newly discovered quartz vein zone in the west-central area. At the WestGold zone, the project’s largest exploration target to date, mapping expanded the target area to 800 by 400 metres. Sampling confirmed bulk tonnage potential with grades up to 6.67 g/t in veins and up to 0.97 g/t over two metres in mineralized halos.
On September 24, 2024, CANEX announced the advancement of drill data compilation at its Louise Project. Historic drilling had outlined a near-surface mineralized zone measuring approximately 1,000 metres by 400 metres and extending to a depth of 300 metres, with notable results including 158 metres grading 0.41% copper and 0.40 g/t gold. CANEX believed deeper copper-gold targets might have existed and proposed a deep induced polarization (IP) geophysical survey covering up to 1,000 metres depth and 6–7 kilometres of strike length to assess district-scale potential. The compiled drill data supported significant lateral and vertical exploration potential beyond the known mineralized zone.
| (ii) | Fiscal year ended September 30, 2025 |
On November 25, 2024, CANEX closed a non-brokered private placement, completing a total raise of $437,000. It consisted of CANEX Shares priced at $0.045 and flow-through CANEX Shares priced at $0.06, with proceeds intended to fund exploration at the Louise Project and support work at the Gold Range Project. Flow-through share proceeds qualified as critical mineral flow-through mining expenditures under the Tax Act and were to be used before December 2025. Additionally, CANEX granted 5,200,000 incentive stock options to directors, officers, and consultants, exercisable at $0.05 per share over five years.
On December 10, 2024, CANEX announced it had received an exploration permit from the British Columbia Ministry of Energy, Mines and Low Carbon Innovation to conduct up to 56 line-kilometres of ground-based induced polarization geophysical surveying at the Louise Project. The survey was fully funded, a contractor was selected, and it was planned to commence in spring 2025 when snow conditions permitted. CANEX had secured support and collaboration agreements with local First Nation groups for early-stage exploration.
On March 21, 2025, Mayfair announced its intention to make an unsolicited all-share offer to acquire all outstanding shares of CANEX and Gold Basin, with the goal of consolidating their Arizona gold assets under a company sponsored by the Discovery Group.
On May 8, 2025, Mayfair continued discussions with CANEX regarding its previously announced unsolicited all-share proposal to acquire CANEX and Gold Basin and supported the concept of consolidating the two companies’ Arizona gold assets, viewing a merger as a strong opportunity to unlock value for shareholders. Meanwhile, CANEX announced it would commence a fully funded, district-scale, deep-looking induced polarization survey at its Louise Project around May 15, 2025, aimed at identifying new copper-gold targets to expand the project’s historic resource.
-7-
On June 9, 2025, CANEX announced its intention to make a formal all-share takeover bid to acquire all outstanding shares of Gold Basin. The proposed offer valued Gold Basin at approximately $8.57 million, representing a 41% premium to Gold Basin’s last trading price before the Cease Trade Order was issued on May 6, 2025, and a 21% premium based on 30-day volume-weighted averages.
On June 26, 2025, CANEX closed a non-brokered private placement of 23,636,380 CANEX Shares issued at a price of $0.055 per CANEX Share for gross proceeds of $1,300,000.90.
On July 31, 2025, CANEX announced results from an induced polarization geophysical survey completed over the Louise Project in British Columbia. A new and previously unknown chargeability target has been identified two kilometres west of the historic Louise deposit and has been named the west Louise Project target. In addition, a steeply dipping zone of high chargeability has been identified below and to the north of the historic Louise Project deposit and has been termed the Louise Project deep target. The Louise Project deep target is interpreted to have potential to host the mineralized roots of the historic Louise Project system and shows continuity to roughly 1,000 metres below surface, the limit of the geophysical survey. Neither the west Louise Project nor Louise Project deep targets have been drill-tested previously.
On August 18, 2025, CANEX received an order from the British Columbia Securities Commission dated August 18, 2025, partially revoking the failure-to-file cease trade order issued against Gold Basin on May 6, 2025. The Partial Revocation Order permitted CANEX to proceed with making an offer to acquire all of the issued and outstanding Shares by way of the Offer.
On August 28, 2025, CANEX formally commenced the Offer. The Offer provided Shareholders with 0.592 of a CANEX Share in exchange for each Share held by such Shareholders.
| (iii) | Subsequent Events Since September 30, 2025 |
On October 27, 2025, CANEX filed an independent technical report titled “Geology and Exploration Review at the Gold Basin Project, Mohave County, Arizona, USA” on the Gold Range Project, with an effective date of September 1, 2025.
On December 23, 2025, CANEX closed a non-brokered private placement of 20,000,000 CANEX Shares for gross proceeds of $3,000,000. Mr. Eric Fier was the lead investor in the financing, and strategic investor, Mr. Michael Gentile, reinforced his strong support for CANEX and also participated in the financing alongside the CANEX management and board.
On February 10, 2026, CANEX completed the Offer. CANEX took up a total of 70,088,199 Shares, representing 51.86% of the issued and outstanding Shares, and issued 41,492,194 CANEX Shares to the Shareholders.
On February 11, 2026, the Supreme Court of British Columbia ordered that an annual general meeting of the shareholders of Gold Basin be held on March 16, 2026 and that CANEX could send notice and conduct the meeting in the same manner as a general meeting called by the directors of Gold Basin. At the meeting on March 16, 2026, Shane Ebert, Mark Ernst, Jim Paterson, John Robins, and Jordan Ross were elected to the board of directors of Gold Basin, constituting a new board of directors and entirely replacing the previous board. The directors of Gold Basin have appointed Shane Ebert as President and Chief Executive Officer, Jean-Pierre Jutras as Vice President, Chantelle Collins as Chief Financial Officer, and Barbara O’Neill as Corporate Secretary of Gold Basin.
-8-
CANEX’s Mineral Properties
Gold Range Project, Arizona, USA
| (a) | Technical Report |
On October 27, 2025, CANEX filed an independent technical report titled “Geology and Exploration Review at the Gold Basin Project, Mohave County, Arizona, USA” on the Gold Range Project, prepared by Burgex Mining Consultants (“Burgex”) and endorsed by Mark W. Travis, and with a report date of August 26, 2025 and an effective date of September 1, 2025 (the “Technical Report”).
Detailed disclosure in the Technical Report is hereby incorporated by reference herein, and can be accessed on CANEX’s website at www.canexmetals.ca and under CANEX’s profile on SEDAR+ at sedarplus.ca.
| (b) | Project Description, Location and Access |
The Gold Range Project is comprised of 261 unpatented lode claims located on federal land administered by the U.S. Bureau of Land Management and three patented mining claims. The claims are located within a historic mining district that has seen widespread small scale lode and placer gold production. CANEX is the first company to consolidate the district sufficiently to allow modern systematic exploration over a large mineralized system. CANEX is focused on identifying zones within this large system that have the potential to host large near surface oxide gold deposits.
On June 11, 2019, CANEX’s subsidiary Canexco entered into an option agreement to acquire a 100% interest in three unpatented lode claims, totaling 61.98 acres, from Jason Gieske. The purchase agreement required Canexco to make option payments and minimum exploration expenditures. On June 11, 2023, the Company completed its payment and expenditure obligations and earned 100% of the Gieske claims, with Gieske retaining a 2% Net Smelter Royalty(“NSR”). 1 % of the NSR can be extinguished by paying Gieske U.S.$500,000 and the remaining 1% for U.S.$1,000,000.
In a separate transaction, Canexco signed a letter of intent on January 12, 2021, granting them the right to earn up to a 90% interest in the adjacent Excelsior Mine property from Silmar of Arizona, LLC (“Silmar”). On November 29, 2023, CANEX finalized the staged earn-in by issuing 8,694,170 CANEX Shares valued at $0.035 each (for a total consideration of $304,295) and making a cash payment of U.S.$120,000. Under the terms of this agreement, Silmar retains a 1.5% NSR. CANEX also secured a right of first refusal should Silmar choose to sell the royalty.
CANEX expanded its land position further in February 2020 by entering into an agreement with Onyx Exploration Inc. (“Onyx”) to acquire the Never Get Left Claim, a single lode mineral claim comprising approximately 20.99 acres. This claim is located adjacent to the Project’s Pit Zone target. The final acquisition occurred in February 2024 upon payment of US$30,000. Onyx retains a 2% NSR on the claim, which may be bought out for U.S.$1,000,000. Additionally, CANEX is obligated to pay Onyx 10% of any profits derived from the processing and recovery of metals from existing leach pad materials located on the claim.
A formal review of mineral title is beyond the scope of the Technical Report. However, a review of the U.S. Bureau of Land Management’s Mineral & Land Records System on July 30, 2025 indicates that the owner of the unpatented mining claims is Canexco and all claims are listed as “Active”. To keep the unpatented mining claims active and in good standing, Canexco must pay an annual maintenance fee of U.S.$200 per claim to the Bureau of Land Management on or before September 1 each year.
-9-
| (c) | History |
Gold was first discovered in the Gold Basin district in the early 1870s, with initial production from quartz vein systems at the El Dorado, Cyclopic, O.K., and Excelsior mines. By 1882, the El Dorado Mine had produced about 26,000 tons of ore. Supporting infrastructure developed quickly, with stamp mills constructed in the early 1880s and a cyanide mill operating at Cyclopic by 1905, later upgraded to a 125- ton/day facility in 1933.
A second mining boom occurred in the 1930s, driven by the Great Depression, expanding operations at Cyclopic and nearby prospects such as Harmoncia, San Juan, and Gold Hill. Activity ceased in 1942 due to World War II restrictions. Between 1901 and 1942, the Gold Basin and adjacent Lost Basin districts produced approximately 13,508 oz of gold and 6,857 oz of silver, with 98% of the value from gold— about $359,000 at historical prices.
In the Lost Basin district, the King Tut Placers (discovered in 1931) were the most significant placer gold source, with an estimated 90,000 tons of indicated reserves. Active mining through 1933 produced 117 ounces of gold in the final four months of that year alone.
Minor activity persisted into the mid-1960s, including small-scale heap-leach testing at Cyclopic, but large-scale mining did not resume. Renewed exploration in the 1980s - most notably the Cambior Roadrunner Project (1989) - identified potential disseminated gold mineralization in mylonitic leucogranite and pegmatite zones, though no commercial-scale production followed.
There has been no systematic modern exploration or land consolidation across the Gold Range Property prior to CANEX initiating exploration in 2019, and very little documentation of past programs has been found. In 1983 Santa Fe Minerals (now Newmont) conducted limited surface evaluations on multiple parcels of private land across the district where they held mineral rights. In 1989, ECM conducted limited scale reconnaissance exploration in the area, staking 76 claims and conducting surface sampling. No historic data has been found to document historic drilling or advanced exploration on the Gold Range property.
| (d) | Geological Setting, Mineralization and Deposit Types |
The Gold Range district contains Precambrian metamorphic rocks that have been intruded by Cretaceous granites and modified by Laramide to Tertiary age compression and extension. Most mineralized veins are mesothermal in nature and contain trace to a few percent sulfides consisting of galena, chalcopyrite, pyrite, sphalerite, and traces of native gold.
-10-
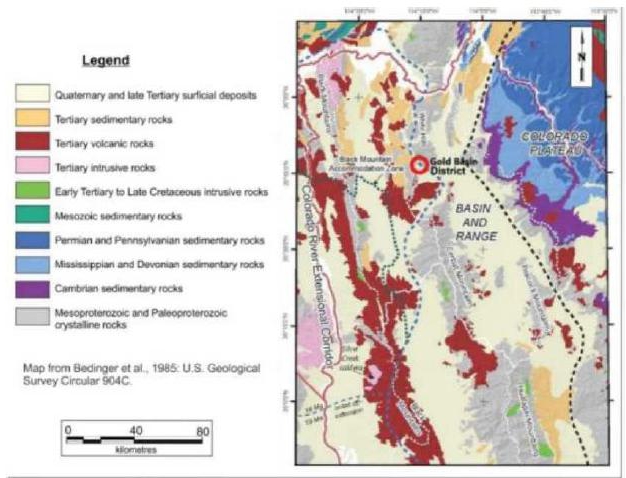
Simplified regional geologic selling of the Gold Basin District
Figure 1. General Geologic Setting
The regional stratigraphy comprises Precambrian metamorphic and intrusive rocks, Late Cretaceous granites, and Miocene to Quaternary volcanic and sedimentary units, with local basin fill sequences reaching thicknesses over 3,000 meters. Tertiary extension resulted in prominent low-angle detachment faults, including the Salt Spring Fault of the South Virgin–White Hills Detachment System, although these structures appear to play a secondary role in mineralization at Gold Range.
Local Geology and Stratigraphy
The Project area is underlain by Proterozoic biotite-rich quartzofeldspathic gneiss, amphibolite, pelitic schist, and quartz-muscovite schist, interpreted as metaturbidites and metavolcanic rocks derived from a deep-marine, arc-related depositional setting. These basement units have been intruded by several plutonic suites:
| · | Gneissic granodiorite (1.7–1.8 Ga) – forms the core host unit for many mineralized zones. |
| · | Porphyritic monzogranite (~1.65 Ga) – regionally extensive and weakly foliated. |
| · | Leucocratic granites and pegmatites – conformable and crosscutting bodies, commonly altered and mineralized. |
| · | Late Cretaceous two-mica granites (~72 Ma) – undeformed, peraluminous granites spatially associated with gold-bearing episyenites and altered dikes. |
-11-
Miocene volcanic rocks of the Mount Davis Volcanics (14.7–10 Ma), including rhyodacitic tuffs, basaltic andesite, and alkali basalts, unconformably overlie the basement. These are locally interbedded with coarse fanglomerates and basin-fill sediments. Overlying Pliocene to Quaternary units (e.g., Hualapai Limestone and Bullhead Alluvium) reflect fluvial incision and reworking by the ancestral Colorado River system.
Rock exposure on the property is dominated by Proterozoic metamorphic basement rocks. On the property the units are simplified into the following:
| · | Mixed gneiss package which includes quartzo-feldspathic gneiss, muscovite biotiteschist, and intermixed mafic and felsic units consisting of both para and orthogneiss. Lenses and zone of amphibolite also occur in this package; |
| · | Megacrystic granite gneiss intrudes the mixed gneiss package and contains large feldspar phenocrysts to 5 centimeters in matrix of quartz-feldspar-biotite-hornblende; |
| · | Granodiorite gneiss is an equigranular medium to coarse grained meta-intrusive composed of feldspar-biotite-quartz and covers much of the central and southern part of the property; |
| · | Granite gneiss is a fine to medium grained quartz-feldspar rich unit and is only differentiated from the mixed gneiss package where it forms large bodies. |
Cretaceous granite is a distinct post metamorphic rock that occurs as small plugs and dikes throughout the property. The unit contains feldspar-quartz-biotite-muscovite and includes pegmatite dikes with the same composition. The youngest intrusive rocks found on the property are biotite rich lamprophyre dikes that are interpreted to be Tertiary in age and postdate gold mineralization.
-12-
The Project Geology is summarized in the map below.
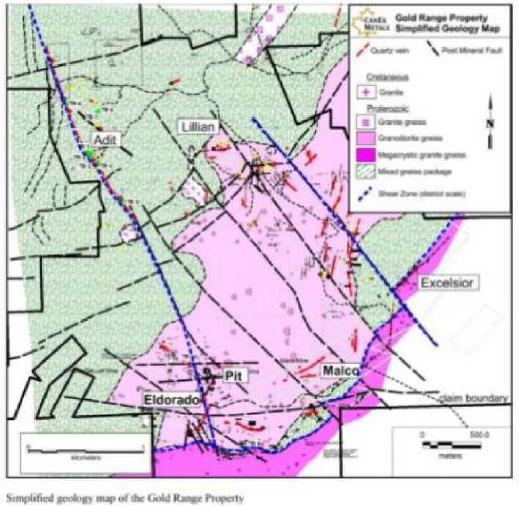
Figure 2. Simplified Geology Map
Structural Geology
The Gold Range occupies a structurally complex zone at the intersection of multiple tectonic fabrics. These include:
| · | Proterozoic ductile shear zones and gneissic foliations; |
| · | Laramide and mid-Tertiary high-angle brittle faults; and |
| · | Low-angle extensional faults such as the Cyclopic and Salt Spring Faults. |
The primary gold controls are steeply dipping fault and shear zones, many of which trend NE–SW and NW–SE. Key structures include:
| · | Gold Basin Shear Fault (E–W trending) – connects known mineralized areas from Bug through Cyclopic NW and the Excelsior corridor. |
| · | Stealth Fault (NW trending) – hosts gold at Stealth, Red Cloud, and potentially the PLM Mine. |
-13-
| · | Cyclopic Fault (NW trending) – bounds the resource area and correlates with gold-bearing zones at Cyclopic NW. |
| · | A north–south reverse fault along the eastern margin of the property, interpreted as having uplifted blocks and localized mineralization. |
These structures acted as long-lived conduits for fluid migration, and their intersections with low-angle faults or compositional contrasts creating localized dilation zones favorable for gold precipitation.
Mineralization and Alteration
Gold mineralization at Gold Range is interpreted as a mesothermal to shallow orogenic gold system, likely emplaced during multiple structural events and overprinted in places by low-sulfidation epithermal processes in near-surface zones.
Mineralization occurs as:
| · | Quartz-fissure veins and sheeted vein arrays in high-angle structures. |
| · | Disseminated gold within altered gneiss, granodiorite, and paragneiss. |
| · | Gold-bearing pegmatites and episyenite dikes. |
| · | Stockwork zones and breccia bodies localized along structural intersections. |
Characteristic alteration includes:
| · | Hematitic clays, silica replacement, and carbonate flooding. |
| · | Sericite, chlorite, and Fe–Mn carbonates. |
| · | Oxidation halos with limonite, jarosite, and minor supergene enrichment. |
| · | Trace to minor sulfides, primarily pyrite with galena, sphalerite, and chalcopyrite. |
Gold is commonly associated with quartz-carbonate vein systems that display open-space filling, brecciation, and minor sulfide mineralization. These zones are often bounded by broader envelopes of hydrothermal alteration, some of which host oxide gold.
Notable mineralized zones include Excelsior, Eldorado, Malco, Central, and Shaft, with true mineralized thicknesses ranging from a few meters up to over 25 meters. These zones remain open along strike and at depth.
The Gold Range South Target hosts the most intense alteration and geochemical anomalies, interpreted as a bulk-tonnage, low-grade oxide gold system. In contrast, the Gold Range North Target includes high-grade fissure veins, altered pegmatites, and potential disseminated gold in pendant bodies of paragneiss.
-14-
| (e) | Exploration |
CANEX first became interested in the Gold Range Property in 2019, following the discovery of a quartz vein containing abundant visible gold by a local prospector in an area termed the Discovery Zone. Subsequent mapping and soil and rock sampling identified a 1000-metre-long linear trend of historic workings and exposed quartz veins centered around the Adit zone.
Additional programs of surface sampling, mapping, trenching, airborne magnetic and lidar surveying, along with reverse circulation drilling, have resulted in further expansion of the claim holdings and the recognition of a 4-kilometre-long mineralized corridor stretching from the Eldorado to Excelsior to WestGold Zones.
The Gold Range Project is in the early stages of systematic exploration yet benefits from a well-defined geological and structural framework that supports a focussed exploration strategy. Gold mineralization is structurally controlled, multi-episodic, and hosted in both high-grade vein systems and broader disseminated zones within altered metamorphic and intrusive rocks.
To the date of the Technical Report, CANEX has executed an exploration program that is well aligned with the interpreted deposit model. Field activities have targeted known and inferred structural corridors, including high-angle shear zones and their intersections with low-angle fault systems features identified as critical fluid conduits and traps during mineralizing events. The program emphasizes surface mapping, geochemical sampling, and reverse circulation drilling, designed to test both near-surface oxide zones and deeper primary mineralization.
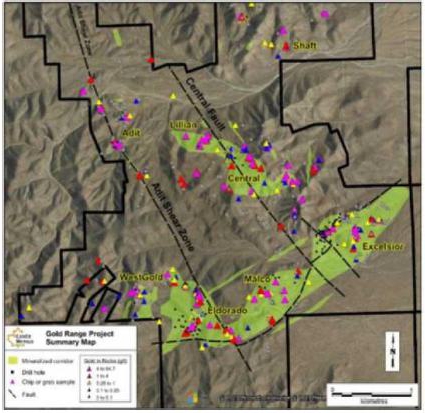
Figure 3. General Project Geology
-15-
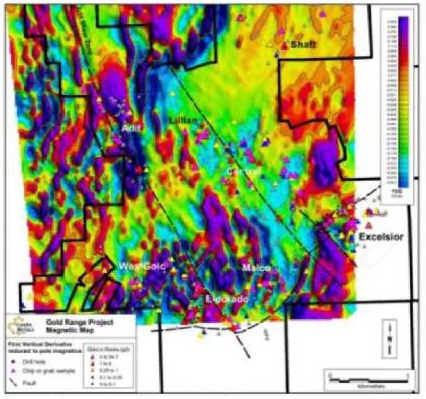
Figure 4. First Vertical Derivative Magnetics
Burgex has reviewed the exploration data and protocols and finds them appropriate for a project at this stage of development. The quantity and quality of lithological logging, drill collar surveying, and downhole data collection are consistent with standard industry practices and suitable for a structurally complex, early-stage gold system.
Quality assurance and quality control (QA/QC) procedures implemented by CANEX are judged to be effective and compliant with industry norms. Analytical work has been carried out by reputable, accredited laboratories that are widely used across the industry. Burgex is not aware of any sampling, drilling, or recovery factors that would materially affect the reliability of the results to the date of the Technical Report.
In Burgex’s opinion, the drilling, logging, sampling, and QA/QC procedures employed on the Gold Range Project meet accepted industry standards for early-stage gold exploration. The current approach is consistent with the evolving understanding of the structural and lithologic controls on mineralization and supports further staged exploration focused on delineating both high-grade and bulk-tonnage gold targets.
| (f) | Drilling |
The drilling program at the Gold Range Project consisted of 138 reverse circulation (RC) drill holes, completed between August 25, 2020, and April 24, 2023. These holes collectively account for a total of 15,411.77 meters drilled (50,563.55 ft), with an average hole depth of approximately 111.7 meters (366.4 ft). The drilling was carried out by two contractors: Drillrite and Boart Longyear. A broad range of exploration zones was targeted, including key areas such as Mid Pit, Top Pit, NW Pit, Eldorado Vein (East and West), Excelsior, Malco Mine, Contact Zone, and Central Zone, among others. This program reflects a comprehensive effort to evaluate the structural and lithologic controls on gold mineralization across multiple prospective zones within the Gold Range project area. Each drilling target is discussed below.
-16-
Excelsior Zone - The Excelsior Mine saw small scale underground production from 1900 to 1906, with levels to a depth of 30 meters below surface and over a length of about 152 meters. A small open pit was excavated aroundthe1970’s or1980’s with material processed through a small ball mill that remains on site. The zone contains a 0.5- to 1-meter-wide northeast striking, roughly 45 degrees northwest dipping high grade quartz vein and fault gouge zone that separates mixed gneiss to the northwest from megacrystic granite gneiss to the southeast. The Excelsior quartz vein and gouge zone occurs along a district scale shear zone that has been mapped for several kilometers. Thin quartz and locally quartz-iron-carbonate veinlets host low grade gold mineralization in the hanging wall and locally in the footwall of the fault. Multiple mineralized zones parallel to the Excelsior have been identified immediately east of the zone and show potential for additional near surface gold mineralization.
Eldorado Zone - The potential for bulk tonnage mineralization at the Eldorado Zone was first recognized by CANEX during a 2020 reverse circulation drilling program. The Eldorado Zone contained a few historic workings along a narrow high grade quartz vein, but had no evidence of modern exploration despite its location immediately south-southwest of the Pit Zone which contains a small high grade open pit and heap leach gold operation that operated in the 1980’s.
Mineralization at Eldorado is hosted within a variably foliated meta-quartz-diorite to granodiorite unit labelled “granodiorite gneiss” on the property geology map but locally referred to as “meta-diorite”. This unit hosts many of the gold zones in the southern part of the claim block including Eldorado, Pit Zone, and Malco, and is interpreted to be a good host rock amenable to fracturing based on its massive and relatively brittle nature. Mineralization at Eldorado is interpreted to occur in one or more flat lying zones and has been traced over an area roughly 100 meters by 200 meters, which occurs within a larger area 300 by 400 meters where gold has been intercepted in drilling and remains poorly defined. The Eldorado Zone appears to be fault bounded on some sides. Additional low grade mineralized areas have been identified adjacent to Eldorado but remain poorly defined. Reverse circulation drill holes GR20-08 and 09 are interpreted to have ended in a post metamorphic cretaceous granite that is blind to surface and locally contains anomalous gold values.
Shaft Zone - The Shaft Zone is located in the northeast part of the property off of the main gold trends. Hole GR22-110 intersected 1.1 g/t gold over 27.4 meters from 33.54 meters downhole, including 1.7 g/t over 15.24 meters. An exposed historic shaft at the zone exposes a northeast trending shear zone and quartz vein system with a near vertical dip. The zone extends under cover to the southwest, and 200 meters southwest of hole GR22-110 is a small zone of historic placer mining.
WestGold - The WestGold mineralized zone contains mineralized quartz veins occurring along a flat dipping shear zone that is surrounded by a wider halo of irregular quartz veins and veinlets suggesting a possible bulk tonnage oxide gold target. WestGold is located 450 meters west of known mineralization at Eldorado, extending the known strike length of the main mineralized trend on the property to 4 kilometers from the previously outlined 3.5 kilometers.
The WestGold target is a topographic high interpreted to contain remnants of a mostly eroded flat dipping fault structure (the “WestGold Structure”) hosting discontinuous veins, lenses, pods, and shoots of high-grade gold-quartz mineralization. A similar flat structure occurs at the Eldorado and Pit zones at lower relative elevation. Steeply dipping mineralized quartz veins occur within and around the WestGold Structure and Eldorado and Pits zones, potentially acting as feeders, and complicating structural interpretation. Surface sampling and 2023 drilling indicate the WestGold Structure contains a halo of disseminated gold mineralization (35m grading 0.7 g/t Au encountered in hole GR23-120) at potential economic grade which is currently the main target of interest for CANEX.
-17-
| (g) | Sampling, Analysis and Data Verification |
The QA/QC (Quality Assurance/Quality Control) protocol for the Gold Range drilling program includes the use of certified reference materials to ensure analytical accuracy and reliability of the assay data. Specifically, the standards sourced from Canadian Resource Labs were utilized for calibration and performance monitoring. These standards were regularly inserted into the assay stream to monitor accuracy and precision, highlighting a disciplined approach to analytical quality control.
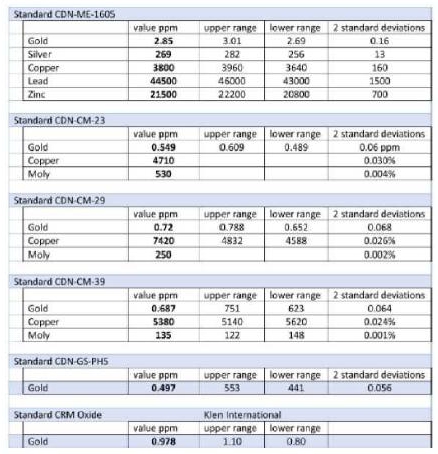
Figure 5. Standards
Standard CDN-CN-23, Standard CDN-CN-29, Standard CDN-CN-39, & Standard CN-23 were used in the assay drill database, but reference data was not provided. Sampling intervals were well-controlled, with an average length of 1.37 meters, and ranging from 0.61 to 3.05 meters—indicative of standard RC sampling procedures aligned with early exploration best practices.
The Gold Range drill database includes a total of 11,024 assay records, demonstrating the scope and scale of geochemical sampling undertaken during the exploration program. Each record corresponds to a downhole sample interval and includes both elemental assay results and supporting metadata. The elemental analyses cover over 35 elements, with a focus on gold (reported in both parts per billion and grams per tonne), silver, and a range of key pathfinder and base metals including arsenic, copper, lead, zinc, molybdenum, and sulfur. This multi-element dataset allows for comprehensive geochemical characterization, aiding in the identification of mineralized zones, alteration halos, and lithologic variations.
-18-
In addition to the assay values, each record is accompanied by contextual metadata such as drill hole ID, depth intervals (measured in both feet and meters), sample numbers, descriptions of lithology or mineralization, and comments from drill logs. The data also includes references to the laboratory, year of analysis, and the specific assay certificate under which each sample was processed. Over 100 unique assay certificates are logged in the database, including identifiers like “5DER20-002,” “5DER21-011,” and “REN22000244_4.” These certificates trace the analytical work back to laboratory-issued QA documents, ensuring transparency and accountability.
Altogether, the structure and content of the assay data reflect a disciplined, QA/QC-integrated exploration workflow.
| (h) | Mineral Processing and Metallurgical Testing |
The CN Soluble Au dataset contains 318 valid samples comparing fire assay (“FA”) gold grades with cyanide-soluble gold values. Overall, the fire assay gold values average 605 ppb Au, while the cyanide-soluble values average slightly lower at 512 ppb Au, reflecting that most but not all gold is recoverable by cyanidation. The calculated average cyanide-soluble recovery is ~79%, with most samples falling between 65% and 94%. Recoveries are highly variable, ranging from as low as ~12% to above 140%, the latter likely due to analytical or sampling variability. Median recovery is approximately 82%, suggesting that in typical cases, the majority of contained gold is readily leachable. These results indicate that a substantial portion of gold in the tested intervals is cyanide soluble, though certain samples demonstrate partial or anomalously high recoveries, warranting further validation and potentially composite testing for more consistent characterization.
The metallurgical testing program conducted by SGS Canada evaluated eight reverse circulation drill samples through bottle roll cyanidation tests. The samples, with head gold grades ranging from 0.2 g/t to 2.9 g/t Au, demonstrated excellent metallurgical response. Gold recoveries were consistently high, ranging between 94% and 99%, with low residue grades of 0.01 to 0.06 g/t Au, confirming that all material tested is free milling and non-refractory.
Leach kinetics were rapid, with over 70% extraction achieved within the first six hours and more than 91% recovered after 24 hours, ultimately reaching maximum recoveries by 48 hours. Reagent consumption was modest, with cyanide usage of 0.24–0.32 kg/t and lime addition of 0.7–1.5 kg/t, and no further additions were required after initial dosing.
-19-
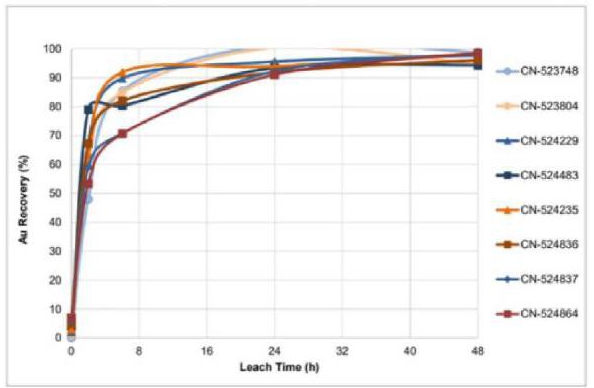
Figure 6. Bottle roll leach kinetics
All tests were carried out at a grind size of approximately P80 60 µm, which contributed to the high extraction rates. The results suggest that the Gold Range samples are highly amenable to conventional mill cyanidation, with an average calculated head grade of 1.2 g/t Au and an average residual gold grade of 0.03 g/t Au in the leached tails.
Based on these findings, further work is recommended, including complete chemical characterization, Bond Work Index determination, and the creation of composite samples to better simulate future processing scenarios. Additional test work should also examine the potential to optimize operating conditions by evaluating coarser grind sizes, lower cyanide concentrations and pH levels, and shorter leach durations of potentially 24 hours instead of 48.
These next steps will provide valuable input for advancing toward a preliminary economic assessment of the project. Together, the two datasets demonstrate a consistent picture. The CN-soluble assays highlight that most gold is amenable to cyanidation, while the bottle roll tests confirm this under process- simulated conditions with far less variability. The relatively lower and more scattered recoveries in the CN-soluble dataset reflect the limitations of the quick-test method, whereas the bottle roll tests validate that under controlled leach conditions, recoveries are consistently high, and the material behaves as free milling. In essence, CN-soluble assays provide a first-pass geochemical proxy, while bottle roll tests provide metallurgical confirmation of leachability and processing potential.
Louise Project, British Columbia
| (a) | Introduction |
On March 5, 2024, CANEX announced that it had signed an option agreement to acquire a 100% interest in the Louise Project located in west central British Columbia. The agreement was signed on March 1, 2024, and received TSXV approval on April 9, 2024.
-20-
Historic drilling has identified a mineralized zone that is 1000 metres long by 400 metres wide and currently extends to a depth of approximately 300 metres. Past work largely focused in and around the original surface discovery area and only extends to about 300 metres deep, with some drill holes ending in mineralization. Data suggests potential for a copper and gold target below and lateral to the existing resource.
An induced polarization geophysical survey conducted at the Louise Project in May 2025 has identified two new high priority targets that have not been drill tested previously. The West Louise target has been identified two kilometres west of the historic Louise Cu-Au porphyry deposit and has a geophysical expression similar to known mineralization and extends over an area 600 metres wide by 800 metres long by up to 500 metres vertically and remains open along strike. A second new target, termed the Louise Deep target, occurs below and immediately north of the historic Louise deposit and spans an area up to 700 metres wide and extends to 1000 metres below surface, remaining open at depth. CANEX intends to drill test both of the new targets at the Louise Project during 2026 upon receipt of required exploration permits.
| (b) | Project Description, Location and Access |
The Louise Project is road-accessible and located approximately 35 kilometres west of Smithers, in west central British Columbia. The property benefits from significant logging road infrastructure with the McDonell-Louise Forest Service Road transecting the property The project hosts a copper-gold-molybdenum deposit, previously drill-defined over an area 1,000 metres long by 400 metres wide and to a depth of approximately 300 metres.
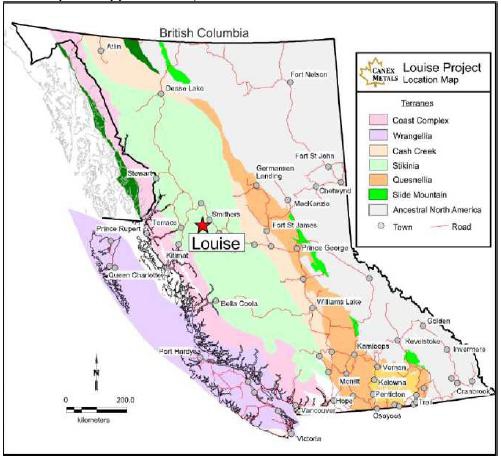
Figure 1. Location of the Louise Project
-21-
On March 5, 2024, CANEX announced that it had signed an option agreement to acquire a 100% interest in the Louise Project located in west central British Columbia from the claim owner Berni Kreft. The agreement was signed on March 1, 2024, and received TSXV approval on April 9, 2024. The total cost to exercise the option is $775,000 with $740,000 of the total commitment still outstanding per the payment schedule. The vendor retains a 2.5% NSR, of which CANEX has the right to repurchase 40% (1% of 2.5%) for $1,500,000. CANEX also holds a right of first refusal on the royalty. Two milestone bonuses of $50,000 each, payable in cash or shares, will be due upon drilling more than 4,250 metres of core and publishing a resource estimate containing over 1.5 million ounces of gold.
The Louise Project is comprised of nine mineral claims with a total area of 5456.04 ha. In British Columbia mineral claims require qualifying exploration expenditures (assessment work) or cash payments to remain valid, and exploration expenditures must be supported and documented in an assessment report. One of the Louise Project claims has a good to date of January 5, 2027, four of the Louise Project claims have good to dates of January 15, 2031 and four of the Louise Project claims have good to dates of January 15, 2032.
Louise Claim Data
| Tenure Number | Owner | Issue date | Good to date | Area (ha) |
| 1111361 | Berni Kreft | Feb 19, 2024 | Jan 15 2031 | 1656.75 |
| 1111363 | Berni Kreft | Feb 19, 2024 | Jan 15 2031 | 987.29 |
| 1111370 | Berni Kreft | Feb 19, 2024 | Jan 15, 2032 | 111.72 |
| 1111369 | Berni Kreft | Feb 19, 2024 | Jan 15, 2032 | 260.68 |
| 1111367 | Berni Kreft | Feb 19, 2024 | Jan 15 2031 | 651.99 |
| 1111365 | Berni Kreft | Feb 19, 2024 | Jan 15 2031 | 1694.5 |
| 1109801 | CANEX | Apr 17, 2024 | Jan 15 2032 | 18.62 |
| 1123232 | CANEX | Feb 19, 2024 | Jan 15 2032 | 37.24 |
| 1123668 | CANEX | May 28, 2025 | Jan 15 2032 | 37.25 |
On December 10, 2024, CANEX received a notice of work exploration permit allowing up to 56 line-kilometres of induced polarization geophysical surveying. The induced polarization survey recently completed at the project was conducted under this permit. Additional permitting will be required for advanced exploration such as drill test of any targets identified. CANEX has signed a Communication and Engagement Agreement with one local First Nation group and received a letter of support from another. Engagement with local stakeholders has been positive, and CANEX is committed to ongoing collaboration throughout early-stage exploration.
| (c) | History |
| · | The Louise Copper Gold Porphyry district has seen multiple exploration efforts from the 1960’s to present following the discovery of porphyry copper style mineralization in outcrop. A summary of these efforts is highlighted below. |
| · | In 1968, Mastodon-Highland Bell Mines discovered anomalous copper values from outcrop and silt sampling and followed up with geological mapping, soil sampling, IP geophysical surveying, and trenching, and defined a 245 by 490 metre area of low-grade copper-molybdenite mineralization called Main Zone. |
-22-
| · | In 1969, Canadian Superior Exploration conducted soil sampling and in 1970 conducted IP surveying and drilled 17 holes totaling 2,021 metres of drilling. |
| · | In 1976, Granby Mining Corporation conducted soil sampling. |
| · | In 1979, Bethlehem Copper Corporation completed soil sampling, IP geophysical surveying and resampling of select sections of core to assess gold potential, with values to 150 ppb Au obtained. |
| · | In 1980, Noranda Exploration Company completed an airborne VLF-EM and magnetometer survey and in 1983 conducted geological mapping and rock sampling. |
| · | In 1987, Lacana Mining Corp. conducted a program of re-logging and resampling drill core from the 1970 program by Canadian Superior as well as prospecting. |
| · | In 1988 and 1989, Corona Corporation conducted mapping and petrography, silt-soil-rock sampling, backhoe trenching, VLF-EM surveying and five NQ-sized holes totalling 916 meters. |
| · | In 1992, Equity Silver Mines Limited conducted a 13-hole, 2651.6-meter drill program at the Main Zone that identified a tabular body between 40 and 80 metres thick, approximately 850 metres long, dipping 20 degrees north and plunging shallowly to the west, with the deposit remaining open down dip and to the west. Analytical results average approximately 0.3% copper and 0.31 grams per tonne of gold for this zone. |
| · | In 1995, Global Mineral and Chemical Ltd. conducted rock and soil sampling and IP surveying, and in 1996 completed five diamond drill holes totaling 1,128 metres within Main Zone. In 1998, Global drilled five holes targeting the eastern IP geophysical anomaly underlying Louise Lake. |
| · | In 2005, North American Gem 2005 conducted property wide prospecting and drilled seven holes for 2,412.3 metres of diamond drilling targeting the Main Zone. They identified that the Main zone is truncated at depth by a flat lying fault called the “Terminator” fault and speculated the offset portion of a yet undiscovered basal mineralized zone could exist nearby. The alteration and presence of copper sulphosalts is indicative of the top of a porphyry system. If so, the uniformity of mineralogy combined with a porphyry target’s tendency to increase in grade as the core is approached suggests that any basal zone occurring beneath the Terminator could be very large and economically significant, possibly dwarfing Main Zone itself. |
| · | North American Gem conducted additional drilling programs from 2006 to 2008. |
| · | In 2019, 79 Resources Ltd. Conducted reconnaissance prospecting and sampling in areas peripheral to the Main Zone. |
| (d) | Geological Setting, Mineralization and Deposit Types |
-23-
Regional Geology
The Louise property is located within the Stikine Terrane of the Intermontane Tectonic Belt. The Stikine terrane is a Devonian to Jurassic island arc volcanic and sedimentary assemblage. It was accreted to the western margin of North America during the Middle Jurassic along with the Quesnel and Cache Creek terranes. Four main intrusive events are recognized in the region, Late Triassic Topley Suite, Early Jurassic Kleanza Suite, Late Cretaceous Bulkley Suite, and the Eocene aged Nanika and Babine Suites. To the date of the Technical Report, the post-accretion Late Cretaceous and Eocene intrusive suites have proven most prospective for mineralization. Porphyry copper targets such as the past producing Huckelberry Mine and precious metals enriched epithermal targets such as the large Blackwater-Davidson deposit are related to Late Cretaceous Bulkley Suite magmatism while targets related to Eocene aged intrusive activity include numerous porphyry copper deposits and past producers in the Babine Porphyry Belt, as well as epithermal style small showings and anomalies hosted by Ootsa Lake Group volcanics.
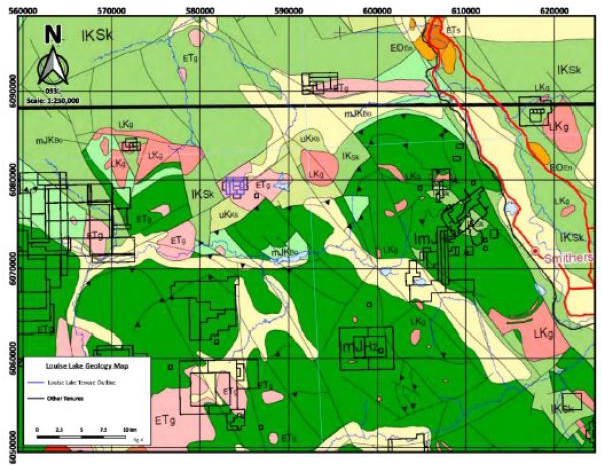
Figure 2. Regional Geology Map
-24-
Local Geology
The core area of the Louise Copper Gold Porphyry property occurs along the east-northeast trending arc-transverse regional-scale Coal Creek lineament, comprising at least two parallel fault zones about 300 m apart. This fault zone forms the contact between lower Cretaceous Skeena Group clastic sediments and intercalated volcanics to the northwest, and lower to middle Jurassic Hazelton Group volcanics and sediments to the southeast.
Skeena Group stratigraphy consists largely of polymictic conglomerate and sandstone, with lesser argillite and siltstone, intercalated with units of volcanic ash tuff, lapilli tuff and agglomerate. In 2004, interpretation by Schulze suggests these belong to the Kitsuns Creek Formation. Hazelton Group stratigraphy consists largely of andesitic to basaltic flows, feldspar porphyritic flows including tuff to agglomerate units, lesser rhyolitic flows, and abundant conglomerate which is coarser grained than Kitsuns Creek conglomerate.
-25-
The proximal area north of the Coal Creek lineament is underlain by roughly east-west striking andesite flows and tuff to fragmental units. These are intercalated with sedimentary horizons comprised largely of conglomerate to sandstone, with lesser greywacke and siltstone, locally laminated. Volcanic units occur primarily in the mineralized “Main Zone” area, where they have been intruded by several east-west trending, moderately north-dipping slabs of feldspar porphyritic monzonite. Feldspar porphyritic andesite flow units also occur southwest of the Main Zone but north of the Coal Creek lineament.
Sedimentary horizons underlie areas to the north and east of the Main Zone. In 2005, mapping and drill log analysis revealed a larger quartz monzonitic stock west of the Main Zone, with an appendage extending eastwards south of the Main Zone. A small unit of moderately limonitic and argillically altered quartz-feldspar porphyritic monzonite occurs towards the Coal Creek lineament. Another feldspar porphyritic monzonite stock occurs northeast of the Main Zone. This stock has undergone moderate argillic and silica alteration, and hosts up to 12% disseminated pyrite. The dimensions of the western and northern stocks remain undetermined.
Figure 3. . Louise Property Geology Map
Mineralization
The Main Zone, the major mineralized deposit on the property, is a tabular deposit dipping from 30o to 40o to the north and has been traced along strike for about 1,000 metres. Block modeling in 2006 by SRK Consulting (Canada) Inc. (“SRK”) indicates the deposit has a footprint in plan view of almost 500 metres and extends to a depth of almost 300 metres. Block modeling revealed central portions have lower copper-equivalent grades than western and eastern portions, although a lower density of drilling may negatively influence grades during block modeling. The deposit occurs within a series of several tabular units of feldspar porphyritic monzonite separated by conglomerate and lesser sedimentary units in central areas, and andesite fragmental units in northern and western areas.
-26-
Mineralization in the Main Zone area consists of fine-grained disseminated and vein-controlled sulphides, consisting of an almost even mixture of chalcopyrite and enargite, a copper-arsenic sulphide. These occur within a broad area of strong pyritization, with up to 10% disseminated, fracture and vein-controlled pyrite.
Most of the Main Zone is marked by moderate to strong silicification and sericitic alteration, and moderate argillic alteration. Several pulses of vein stockwork emplacement have occurred, with quartz-pyrite veins crosscut by later nearly massive pyrite veins. Mineralogy consists of an assemblage atypical to most British Columbia porphyry deposits, although enargite is a common constituent of porphyry-copper systems elsewhere, including the Chuquicamata deposit in Chile. Chalcopyrite-enargite occurs as fine-grained disseminated, fracture and lesser vein-controlled grains locally comprising up to 4% of the rock mass. Copper-gold ratios show a strong correlation, with an approximate deposit-wide average ratio of 1% Cu: 1 g/t Au. Molybdenum values show a larger variation; molybdenum-bearing quartz stringers occur on surface near Hole LL-04-06 and in basal portions of the western part of the Main Zone. Silver values reported from drill core analysis are generally less than 2.0 g/t; rare high values to 81.5 g/t/ 2.0m likely indicate vein or fault intercepts.
Interpretation of 2004 through 2006 results with past drilling results indicate the Main Zone is bounded by a basal flat-lying fault at depths of 250m to 270m, called the “Terminator” with a minimal displacement of several hundred metres. North-dipping mineralized zones are truncated by this flat-lying fault, forming a wedge-shaped northern terminus. High grade mineralization is abruptly “terminated” by the Terminator; with weakly anomalous to background values returned from underlying stratigraphy. Lower grade mineralization, comprising the North Horizon, overlies eastern and central portions of the Main Zone, and is also truncated by the Terminator.
Feldspar-porphyritic monzonite units are most abundant in central and eastern portions of the Main Zone, where they host much of the mineralization. In western areas, the primary host for mineralization is andesite tuff to fragmental rocks, with minor host conglomerate and sandstone. The highest copper and gold grades occur in these areas, returning values to 0.592% copper with 0.586 g/t gold across 35.7 metres, and locally exceeding 0.800% copper and 0.800 g/t gold, from DDH LL-05-02. Hole LL-06-09, collared nearby, returned 0.362% copper, 0.017% molybdenum and 0.257 g/t gold across 66.1 metres. The highest molybdenum grades also occur here, to 349 ppm (0.035%) Mo across the same 35.7-metre interval in DDH LL-05-02. Nearly massive molybdenum and minor massive enargite +/- chalcopyrite veins to 0.5 cm in width occur.
Deposit Type
The Main Zone is classed as a “calc-alkaline suite” porphyry system and the primary exploration model is of porphyry-style mineralization. In porphyry systems, through the region satellite occurrences of base metal silver veining and “Bonanza-style” gold veins and epithermal gold +/- silver deposits are also viable targets.
The porphyry deposit type consists of bulk-tonnage-style copper-molybdenum-gold mineralization related to a feldspar porphyritic intrusive stock. Core areas consist of intrusive hosted disseminated copper sulfides, largely chalcopyrite and bornite, commonly with accessory molybdenum and gold. Mineralization is spatially associated with the core intrusion but not necessarily confined to it. Stocks are typified by concentric zones of potassic, phyllic (sericitic) and propylitic alteration, commonly with argillic (clay) alteration and overlying zones of advanced argillic alteration where mineralization can transition to high sulfidation style epithermal mineralization. Some secondary (supergene) mineralization commonly occurs near-surface, marked by oxidation of sulphide minerals and enrichment of economic minerals.
-27-
Mineralization at Louise occurs primarily as an almost even distribution of chalcopyrite and enargite/ tennantite group minerals. This indicates the deposit may represent a high level porphyry system occurring at or just below the transition from high sulfidation epithermal style mineralization and copper-gold porphyry style mineralization.
| (e) | Exploration |
In 2024, CANEX compiled historic exploration data into digital databases and is using this relatively high-quality historic data to plan and advance exploration at the property. The database includes drilling, historic geophysical data, and surface geochemical sampling. The compilation includes 2515 soils collected by previous operators between 1969 and 2019 and 486 historic silt samples. The main Louise Project Cu-Au-Mo historic estimate area stands out well in in the copper in soil data, forming an anomaly containing 50 to 2500 ppm copper over an area 1000 metres by 450 metres. A narrow zone of elevated copper in soils extends to the southwest and northeast along the “Coal Creek Fault”. The inferred down ice glacial direction is also to the southwest. The main Louise Project soil anomaly appears to be cut off by the Coal Creek Fault. The historic Canadian Superior Exploration induced polarization geophysical survey has a chargeability high that also appears to be offset by the Coal Creek Fault by approximately 900 meters with apparent left lateral displacement. This data suggests the Coal Creek Fault had post mineral displacement and offsets the Louise Project system.
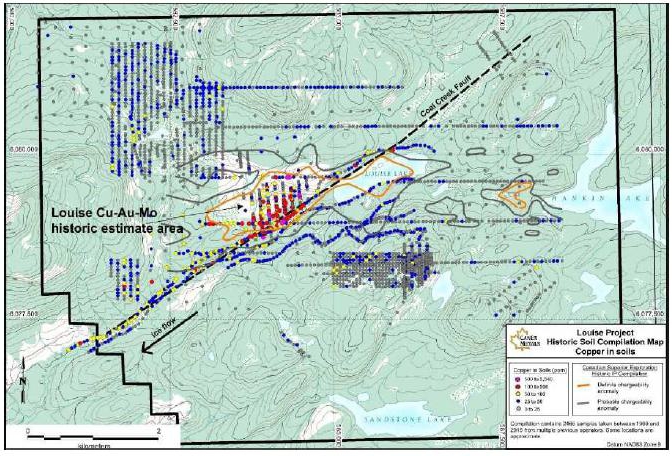
Figure 4. Louise Project historic copper in soil compilation map.
-28-
The area immediately southwest of the Louise Project Cu-Au-Mo historic estimate area contains the only significant zone of elevated copper in values and this area requires further evaluation. This area also occurs down ice from the main Louise deposit. No other coherent copper in soil anomalies are evident in the historic data.
The historic IP data has an overall east-west trend with a strong coherent anomaly over the known deposit that remains open to the west, and a weaker patchy expression to the east.
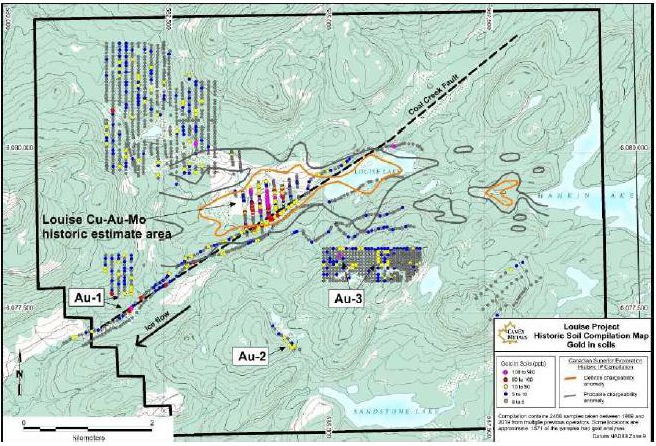
Figure 5. Louise Project historic gold in soil compilation map.
The main Louise Project Cu-Au-Mo historic estimate area stands out well in the historic gold in soil data similar to the copper in soil expression. Gold in soils over the Louise deposit are generally in the 10 to 200 ppb range and show good continuity over a 750 by 450 metre area. The gold in soil anomaly appears to be bounded on the east side by the Coal Creek Fault.
The compiled soil and silt data highlight multiple areas outside the main Louise deposit area that warrant further evaluation and exploration. None of the targets show the size, continuity, or intensity of the main Louise deposit, however, if any of the zones contain significant glacial cover or occur at deep levels a subdued geochemical response would be expected. The main target of interest to CANEX is porphyry-related Cu-Au (Mo-As) mineralization similar to the Louise deposit. It is acknowledged that some of these targets could represent zones of distal Au-As or base metal-Ag mineralization that are common around porphyry systems in the region, and these are a secondary target.
-28-
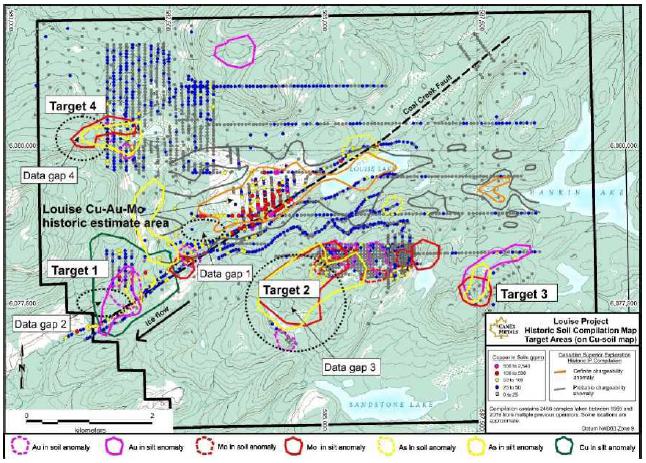
Figure 6. Louise Project surface geochemical compilation map on Cu-in-soil background showing main surface geochemical exploration targets and priority target areas with gaps in surface geochemical data.
Four main geochemical targets are shown on the Louise Historic Compilation Map. Target 1 is southwest of the main Louise deposit and “down ice” and some mechanical dispersion is likely. The area is over 1km by 1km in scale with variably overlapping Cu-Au-As in soil anomalies and Cu-Au in silt anomalies. A larger As-in-silt anomaly is immediately adjacent to the north-northeast. The area occurs along the projected southwest trend of the historic IP chargeability anomaly. The overlap of multiple soil and silt anomalies and the projected trend of known chargeability toward this area make this a compelling target worthy of additional work. Some fill in surface geochemical work is warranted to address a gap in surface data and new IP survey coverage over this area could be a cost-effective next step to potentially identity sulfides within the zone.
Target 2 is south-southeast of the main Louise deposit and contains partially overlapping Au-Mo-As in soil anomalies and Mo-As in silt anomalies. The anomalies are not particularly strong and are somewhat erratic, and data over the zone is lacking (data gap 3 on Figure 6). Four or five systematic soil line across the zone where data is lacking would be a good next step for evaluating the potential of the area.
Target 3 is east of the main Louise deposit and is highlighted by single strong Au and Mo in silt sample near the top of a pronounced topographic high with several consecutive Au and Mo in silt samples downstream along the same creek. Arsenic in silt is elevated in the same samples. Soil sampling on the northeast side of the topographic high do not show any compelling soil anomalies, however, a few soil lines traversing the main topographic high would help assess the potential of the zone and identify next steps.
-29-
Target 4 is located west of the main Louise deposit. It contains discontinuous Cu-Mo-As in soil anomalies over a 1000 by 600 metre area, with overlapping Au-As in silt anomalies. The target occurs within a topographic low and is likely to have significant glacial cover resulting in a subdued geochemical expression. An IP line extending to cover the topographic low in the general area would help evaluate the sulfide potential of the zone and the potential for covered mineralization.
CANEX Exploration
In late 2024, CANEX collected 80 soil samples at Louise to fill some geochemical data gaps in the historic surveys. Soil samples were collected using soil augers with locations identified by hand held GPS and sample sites marked with flagging. About 0.5 kg of material was collected for each soil sample from the B horizon and placed into a numbered 10 cm × 15 cm Kraft paper bag. Soil samples were shipped to ALS in Kamloops for analyses where the samples were dried and sieved with the -80 mesh fraction analyzed by ALS sample code AuME-TL43 (25g sample dissolved by aqua regia digestion and analyzed by ICP-MS).
The location of the 2024 soil samples and copper results are shown on the map below. Copper, gold, and arsenic in soil data all help expand the historic soil anomaly associated with the Louise deposit to the southwest, with anomalous values becoming patchy toward the southwest, likely reflecting increased glacial cover and or erratic down ice mechanical dispersion. Copper in soil values range from 5 to 245 ppm, molybdenum in soil values range from 0.5 to 6.1 ppm, gold in soil values range from 0 to 0.145 ppm, and arsenic in soil values range from 10 to 182 ppm.
-30-
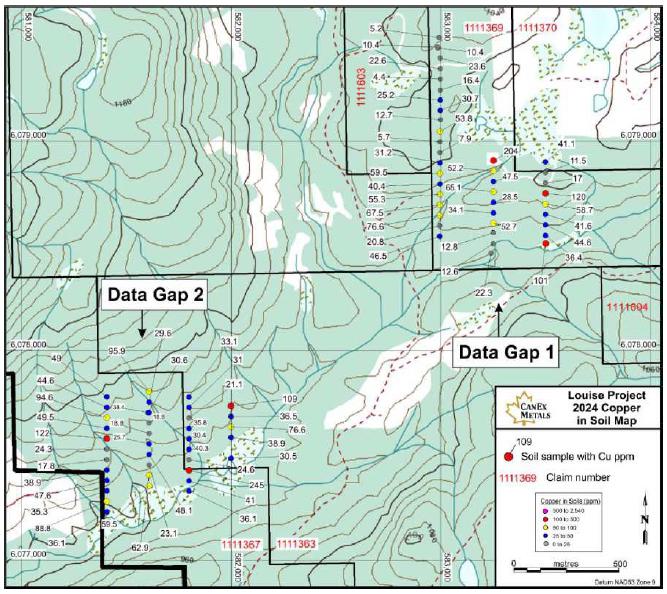
Figure 7. Copper in soil Map for 2024 soil samples
taken by CANEX at the
Louise Property
In May 2025, CANEX commissioned an Alpha IPTM wireless time domain distributed IP technology geophysical survey from contractor Simcoe Geoscience. The planned survey consisted of nine north-south oriented lines, each four kilometres long, and spaced 400 metres apart. The survey was designed to provide data up to 1000 metres depth. The survey was started in mid May and completed in June 2025. Results from the survey are pending.
| (f) | Drilling |
Multiple drill programs have been conducted at Louise since 1969, as summarized in the History section above. CANEX has not conducted any drilling at the Louise Project but has compiled all available historic drill data. In total the historic drill database consists of 94 diamond core holes, drilled by five different exploration companies.
-31-
Historic drill hole highlights
| Hole | From (m) | To (m) | Interval (m) | Cu (%) |
Au (g/t) |
Mo (%) | Ag (g/t) |
| LL04-03 | 49.5 | 253.5 | 204.0 | 0.37 | 0.35 | 0.012 | 1.2 |
| including | 53.5 | 211.5 | 158.0 | 0.41 | 0.40 | 0.014 | 1.3 |
| LL05-04 | 103.0 | 295.1 | 192.1 | 0.27 | 0.26 | 0.011 | 1.0 |
| LL05-05 | 140.8 | 311.3 | 170.5 | 0.25 | 0.25 | 0.011 | 0.9 |
| LL04-03 | 53.5 | 211.5 | 158.0 | 0.41 | 0.40 | 0.014 | 1.3 |
| LL04-02 | 147.0 | 297.0 | 150.0 | 0.34 | 0.34 | 0.018 | 1.1 |
| including | 188.9 | 293.0 | 104.1 | 0.42 | 0.41 | 0.019 | 1.4 |
| LL06-10 | 208.8 | 289.0 | 80.2 | 0.40 | 0.41 | 0.005 | 1.5 |
| LL05-02 | 221.6 | 300.3 | 78.7 | 0.45 | 0.44 | 0.037 | 1.2 |
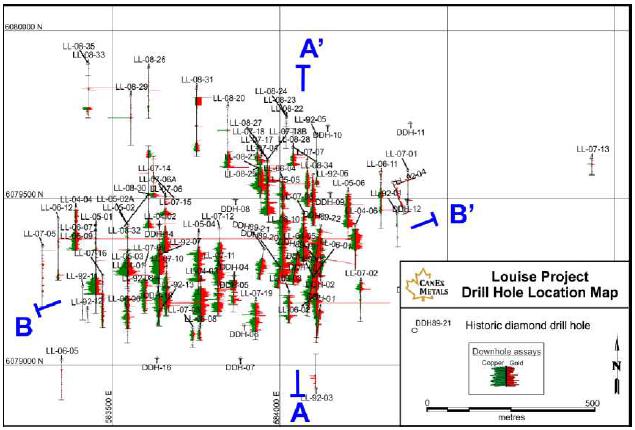
Figure 8. Historic drill hole compilation map, Louise Project
-32-
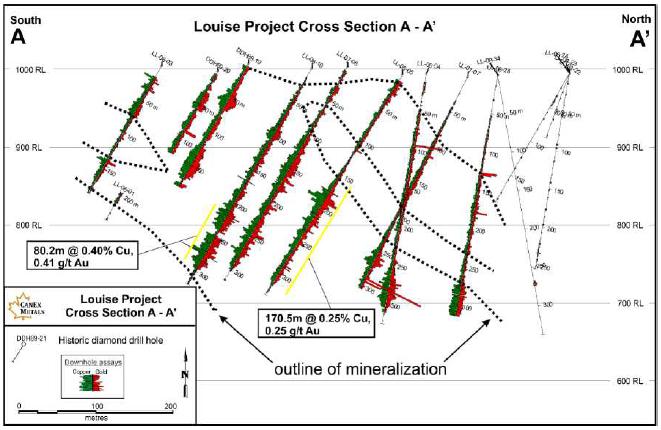
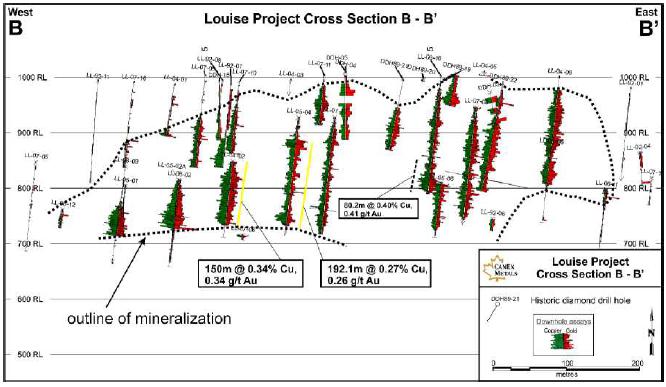
Figure 9. Top: North-south cross section A – A’ showing historic drilling through the Louise deposit. Bottom: Roughly east-west cross section B – B’ showing historic drilling through the Louise deposit
-33-
Cross sections through the deposit in roughly north-south and east-west orientations are shown above. The data show a strong and continuously mineralized zone that extends from surface to around 300 metres depth. The mineralized zone consists of volcanic and sedimentary rock hosted mineralization along with mineralized intrusive dikes. A central controlling porphyry intrusion has not been identified and remains a key exploration target at Louise. A flat dipping fault truncates mineralization at depth in multiple holes and a better understanding of the structural setting will be important for district scale targeting.
| (g) | Sampling, Analysis and Data Verification |
The historic drill hole and surface geochemical data for the Louise Project has been assembled from multiple sources including assessment reports, technical reports issued to former project operators, and from a former project manager. Drill logs and assay certificates have been obtained for most, but not all, of the historic drilling and surface sampling. Historic sampling and quality control measures have been reviewed and found to be consistent with acceptable industry standards. CANEX considers the assembled Louise drill hole and surface geochemical data bases to be complete and accurate and suitable for exploration targeting purposes. Additional due diligence, quality control sampling, and evaluation of historic drill holes would be required prior to CANEX utilizing historic drill data in a current mineral resource estimate.
| (h) | Mineral Processing and Metallurgical Testing |
In 2006 North American Gem Inc used G & T Metallurgical Services of Kamloops, British Columbia, to conduct preliminary metallurgical analysis. A 164-kg bulk sample of re-split core from the Main Zone was use to make a composite sample and perform a series of rougher floatation and one cleaner floatation test. The composite averaged about 0.3 percent copper by weight, which was distributed almost evenly between chalcopyrite and enargite/tennantite (arsenic-copper sulfosalt minerals).
A single locked cycle test using a primary grind size of 100μm and a regrind of 26μm, resulted in copper recovery of about 85 percent into a concentrate assaying about 29 percent by weight copper. The copper concentrate also contained payable levels of gold and silver and contained 11% arsenic. Follow up investigation regarding industry standard techniques for treating high arsenic concentrate or smelters that specialize in high arsenic concentrates was recommended.
| (i) | Mineral Resource and Mineral Reserve Estimates |
The Louise Project contains historic estimates conducted in 2006 and 2007 by SRK for North American Gem Inc. CANEX is not relying on these historic estimates but is using them as a positive exploration guide demonstrating that a strong porphyry system occurs at the project and gives insight into the character and controls on mineralization. The historic estimate contains a large amount of high-quality surface and drill hole exploration data that will aid immensely in the understanding of the system and the targeting of new zones.
-34-
Louise Project 2007 Historic Estimate Summary
| Contained Metals | ||||||||
| Historic Estimate Category | M Tonnes | CuEq%2 | Cu% | Au g/t | Mo% | Ag g/t | Cu lbs | Au oz |
| indicated | 26 | 0.36 | 0.231 | 0.22 | 0.008 | 1.01 | 132,409,743 | 183,902 |
| inferred | 125 | 0.38 | 0.239 | 0.23 | 0.009 | 0.99 | 658,631,546 | 924,333 |
This historic estimate for the Louise Project is historic in nature, was not issued to CANEX Metals, and has not been verified by CANEX or a qualified person for CANEX. A qualified person has not done sufficient work to classify the historic estimate as current mineral resources or mineral reserves and additional data verification is required to upgrade or verify the historic estimate as current mineral resources or mineral reserves. The resource estimate was done to CIM standards but CANEX is not treating it as a current mineral resource estimate. It is considered relevant as a guide for future exploration and is included for reference purposes only. The initial historic estimate was reported in a technical report dated July 2006 and titled “Independent Technical Report and Resource Estimate for the Louise Lake Property, Omineca Mining Division, British Columbia.” The historic estimate was updated in 2007 incorporating an additional 13 holes drilled in 2007. The 2006 technical report utilized 59 drill holes with resource estimation carried out by ordinary kriging using Gemcom software. A 0.15% copper equivalent cut off was used assuming metal prices of (U.S.) $1.20lb/Cu, $450/oz/Au, $8/lb/Mo, and $7/ozAg, with no provision for recoveries. The historic estimate is not constrained by a conceptual open pit.
| (j) | Mining Operations |
There have been no historical economic studies done for the Louise Project and no mining operations have been considered.
| (k) | Processing and Recovery Operations |
There have been no historical economic studies done for the Louise Project and no advanced processing or recovery operations have been considered.
| (l) | Infrastructure, Permitting and Compliance Activities |
There have been no historical economic studies done for the Louise Project and no infrastructure, permitting, or compliance activities have been conducted.
| (m) | Capital and Operating Costs |
There have been no historical economic studies done for the Louise Project and there are no estimates of capital or operating costs.
-35-
| (n) | Exploration, Development, and Production |
CANEX commissioned a district-scale IP survey at the Louise Project which was completed in June 2025. The IP survey was designed to evaluate the potential for undiscovered porphyry-style copper-gold mineralization at depth and laterally from the known zone. The survey covered about six kilometres of strike length along 9 geophysical lines, and reached depths of up to 1,000 metres. The survey has identified two new high priority chargeability targets that have never been identified nor drill tested previously. One, the West Louise Target is located two kilometres west of the historic Louise deposit and contains similar chargeability and resistivity values as known mineralization. The second, the Louise Deep Target, is a high chargeability zone located immediately north and below the historic Louise deposit. This target has potential to host the main body or roots of the faulted Louise system and identifying this target was a key objective of the survey. CANEX remains committed to working closely with local First Nations throughout early-stage development activities.
The map below shows a prominent zone of high chargeability that extends across the survey area in an east-west orientation and remains open to the east and west.
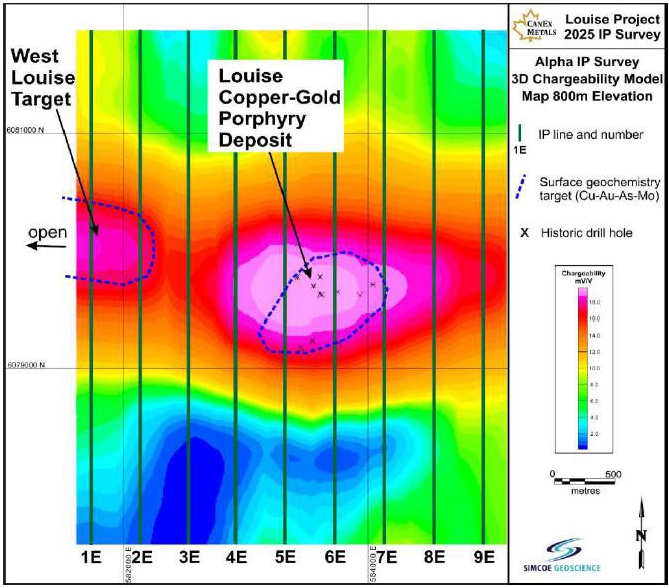
Figure 10. Map of the Louise Project showing the 3D chargeability model at 800m elevation and the location of the 9 geophysical lines recently completed. Surface geochemistry anomaly outlines are shown as blue dashed lines
-36-
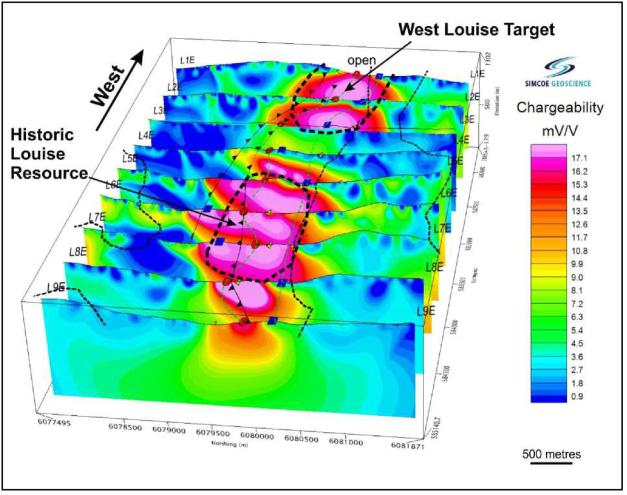
Figure 11. 2D stacked sections showing chargeability highlighting the historic Louise resource area and the new West Louise Target that remains open to the west. Top down view looking toward the west
The figure above shows a series of stacked cross sections and highlights the high chargeability zone associated with the historic Louise resource and the high chargeability feature at the West Louise Target which remains open to the west. Mineralization at the Louise deposit typically has chargeability values ranging from 16 to 22 mV/V and resistivity values ranging from 190 to <50 Ohm-m (moderate to strong conductor).
The figures below show geophysical cross sections 1E and 2E, respectively, highlighting the high chargeability feature associated with the West Louise Target which has chargeability values ranging from 15 to >20 mV/v and resistivity values ranging from 150 to 50 Ohm-m. The West Louise Target extends over an area 600 metres wide by 400 to 500 metres deep and is at least 800 meters long and remains open along strike to the west. The anomaly comes to surface on line 1E and starts around 150m below surface on line 2E. On lines 1E and 2E the extent of moderate level chargeability values expand at depth, possibly suggesting the West Louise Target could represent the upper levels of a large sulfide alteration system. The West Louise Target has the same geophysical chargeability and resistivity expression as Louise copper-gold mineralization and has never been explored or drill tested previously. The zone is a high priority target that warrants immediate field follow up, drill permitting, and drill testing.
-37-
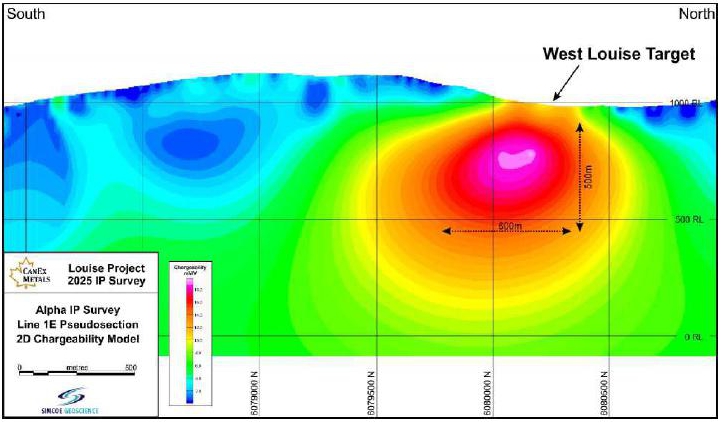
Figure 12. Pseudosection through the 2D chargeability model showing Line 1E and highlighting the West Louise Target. See map above for section location
-38-
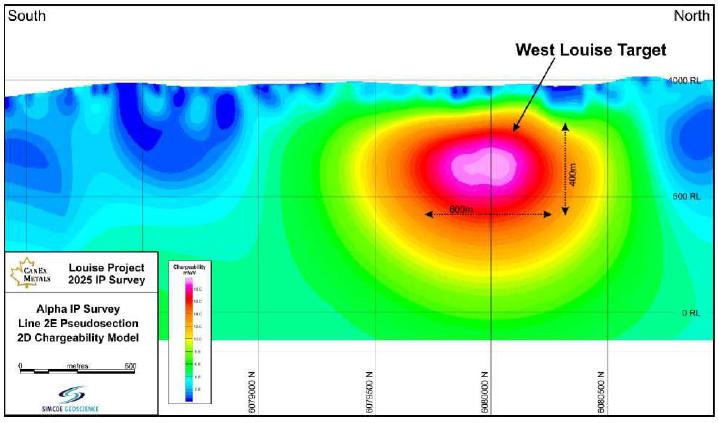
Figure 13. Pseudosection through the 2D chargeability model showing Line 2E and highlighting the West Louise Target. See map above for section location
The figure below shows geophysical cross section 6E along with drilling and copper and gold values downhole, the interpreted flat dipping Terminator Fault, and the interpreted Louise Deep Target. The Louise Deep Target directly underlies the north edge of a large near-surface chargeability zone and is 700 to 900 metres wide and extends vertically for at least 750 metres to the limit of the geophysical survey. This target could be the conceptual “main body” of the Louise Porphyry that is partially offset from the historic resource along the Terminator Fault. Identifying this target was a key objective of the survey and this remains a high priority target for permitting and drill testing.
-39-
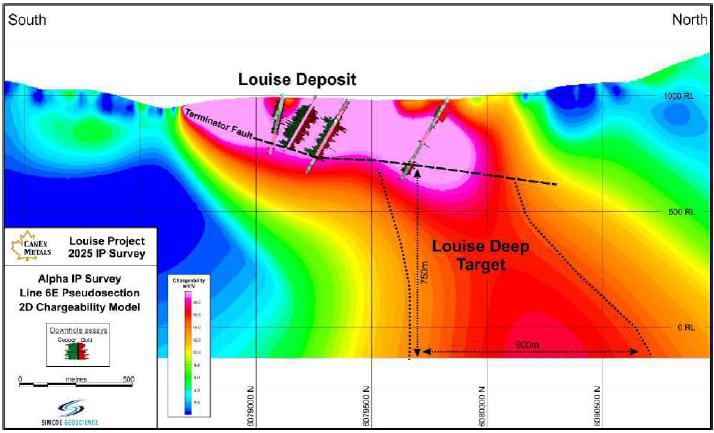
Figure 14. Pseudosection through the 2D chargeability model showing Line 6E and highlighting copper-gold mineralization at the Louise deposit, the Terminator Fault, and the Louise Deep Target
Selected Financial Information of CANEX
Annual Information
The following selected financial data for CANEX is based upon, and should be read in conjunction with, the more detailed financial information appearing in its audited consolidated financial statements for the years ended September 30, 2024 and 2025, together with the auditor’s report thereon and the notes thereto and management’s discussion and analysis in respect thereof contained in Appendix M to this Circular.
| Summary Financial Data Year ended September 30, | ||||||||
| Consolidated Statements of Loss and Comprehensive Loss | 2025 | 2024 | ||||||
| Revenue | - | - | ||||||
| Expenditures | 496,817 | 279,148 | ||||||
| Net loss and comprehensive loss | (496,817 | ) | (279,148 | ) | ||||
| Basic and diluted loss per share | 0.00 | 0.00 | ||||||
| Weighted average shares outstanding | 127,743,757 | 112,895,636 | ||||||
Quarterly Information
The following selected financial data for CANEX is based upon, and should be read in conjunction with, the more-detailed financial information appearing in its unaudited condensed interim consolidated financial statements for the three months ended December 31, 2025, and the notes thereto and management’s discussion and analysis in respect thereof contained in Appendix N to this Circular.
-40-
| Condensed Interim Consolidated Statements of Loss and Comprehensive Loss | Summary Financial Data Three-months ended December 31, 2025 | |||
| Revenue | - | |||
| Expenditures | 230,845 | |||
| Net loss and comprehensive loss | (230,845 | ) | ||
| Basic and diluted loss per share | 0.00 | |||
| Weighted average shares outstanding | 148,689,612 | |||
| Consolidated Statements of Financial Position as at Period Ended | December 31, 2025 | |||
| Total assets | 10,357,050 | |||
| Share capital | 26,121,922 | |||
| Total equity | 10,048,610 | |||
Dividend Policy
CANEX has not declared or paid any dividends on CANEX Shares since its incorporation. Any decision to pay dividends on CANEX Shares will be made by the board of directors of CANEX on the basis of the corporation’s earnings, financial requirements and other conditions existing at such future time.
Directors and Officers
The name, municipality of residence, position held with CANEX and principal occupation during the last five years of each of the directors and senior officers of CANEX are as follows:
| Name and Municipality of Residence |
Position and Date | Principal Occupation During Last Five Years |
| Dr. Shane Ebert, Ph.D., P.Geo.(1) British Columbia, Canada | President and Director since March 13, 2003 | Self-employed Professional Geologist. President of Vector Resources Inc. and consulting geologist 1999 to present. Director of Jade Leader Corp. since 2001. President and Director of Surge Copper Corp. from December 2011 to March 2015 and April 2011 to present, respectively. Vice-President Exploration of Surge Copper from March 2015 to present. |
-41-
| Name and Municipality of Residence |
Position and Date | Principal Occupation During Last Five Years |
| Chantelle Collins, CPA, CGA British Columbia, Canada | Chief Financial Officer since September 23, 2019 | Ms. Collins holds a Bachelor’s degree in Accounting and is a member of the Chartered Professional Accountants Association of BC (CPA, CGA). Ms. Collins has over 18 years’ experience working in the public sector and is well versed in the financial reporting requirements of public companies and currently serves as an officer for three other public companies. |
|
Barbara O’Neill Alberta, Canada |
Corporate Secretary since March 18, 1993 | Ms. O’Neill has been the Corporate Secretary for a number of TSX and TSXV corporations primarily in the mining industry, both nationally and internationally, for the last 35 years. She has extensive experience in public offerings, public listings and exchange matters, share and asset acquisitions and dispositions, restructurings, securities regulatory requirements for public issuers and other related business transactions. She is currently Corporate Secretary of three public companies. |
| Jean Pierre Jutras, P.Geo. Alberta, Canada | Director and Vice-President since October 4, 2000 | Self-employed Professional Geologist from 1996 to date. Vice President and Director of Jade Leader Corp. since 2000 and President from March 2014 to date. |
-42-
| Name and Municipality of Residence |
Position and Date | Principal Occupation During Last Five Years |
|
Gregory Hanks(1) British Columbia, Canada |
Director since September 19, 2019 | Self-employed consultant from 2017 to present. Mr. Hanks holds a B.Comm (Honors) with a major in Finance. He has held a number of management and senior management roles throughout his more than 25 years in the financial services industry and has extensive experience in commercial and industrial lending. He is a past director of Freegold Ventures Limited. |
| Lesley Hayes, MBA(1) Alberta, Canada | Director since December 6, 1996 | Self-employed consultant from 2002 to present. Ms. Hayes is CCO of Hesse Partners and CEO of NoDrama Media, training CEOs and Presidents with Young President’s Organization and Entrepreneurs Organization in the U.S., Canada and internationally. |
|
Blair Schultz(1) Ontario, Canada |
Director since May 1, 2022 |
Mr. Schultz brings over 25 years of experience in financial, operational, project finance and capital markets experience. He held the position of Interim CEO for both 1911 Gold Corp. (TSXV:AUMB) from June 2018 to January 2019 and Eastmain Resources Inc. (TSXV:ER) from December 2019 to October 2020. Since 2014, Mr. Schultz has consulted for and merchant banked a number of mining and resources projects through Schultz Capital, his family office. |
(1) Member of the Audit Committee.
-43-
Corporate Cease Trade Orders or Bankruptcies
Other than as disclosed below, to the knowledge of CANEX, no director or executive officer is, or has been within the 10 years to the date of this Circular, a director or officer of any corporation, including CANEX, that, while such person was acting in that capacity:
| (a) | was subject to a cease trade or similar order or an order that denied the relevant company access to any exemption under securities legislation, for a period of more than 30 consecutive days, that was issued while that person was acting in that capacity; |
| (b) | was subject to a cease trade or similar order or an order that denied the relevant company access to any exemption under securities legislation, for a period of more than 30 consecutive days, that was issued after the proposed director ceased to act in that capacity, and which resulted from an event that occurred while that person was acting in that capacity; or |
| (c) | while that person was acting in that capacity, or within a year of that person ceasing to act in that capacity, became bankrupt, made a proposal under any legislation relating to bankruptcy or insolvency or was subject to or instituted any proceedings, arrangement or compromise with creditors or had a receiver, receiver manager or trustee appointed to hold its assets. |
Ms. Hayes was a director and officer (CEO) of Crailar Technology Inc. (“Crailar”) who on November 9, 2015 obtained a court order from the Supreme Court of British Columbia pursuant to the Companies’ Creditor Arrangement Act (“CCAA”). The stay expired on May 31, 2016. The company petitioned under Chapter 15 of the US Bankruptcy Code in the District of South Carolina on December 21, 2015, and received recognition that the CCAA was the main proceeding. Crailar was further assigned into bankruptcy on July 5, 2016. The Bowra Group Inc. of Vancouver, British Columbia was appointed trustee in bankruptcy.
Individual Bankruptcies
No director or executive officer of CANEX is or has, within the 10 years prior to the date hereof, become bankrupt, made a proposal under any legislation relating to bankruptcy or insolvency, or become subject to or instituted any proceedings, arrangement or compromise with creditors or had a receiver, receiver manager or trustee appointed to hold the assets of that individual.
Penalties or Sanctions
Other than as disclosed below, no director or executive officer of CANEX has been subject to any penalties or sanctions imposed by a court relating to securities legislation or by a securities regulatory authority or has entered into a settlement agreement with a securities regulatory authority.
Ms. O’Neill was Assistant Corporate Secretary in 1990, when GR Capital, a wholly owned subsidiary of Golden Rule Resources Ltd., acquired additional shares of Waddy Lake Resources Inc. in the open market. In the absence of a formal takeover bid, the interest was in excess of that allowed by security regulations. A settlement agreement dated July 9, 1991 with the Alberta Securities Commission, allowed GR Capital to dispose of a sufficient number of shares in the open market to bring them below 10%.
Conflicts of Interest
The directors and executive officers of CANEX may, from time to time, be involved with the business and operations of other issuers, in which case a conflict of interest may arise between their duties as officers and directors of CANEX and as officers and/or directors of such other companies. Such conflicts must be disclosed in accordance with, and are subject to such procedures and remedies, as applicable, under the Business Corporations Act (Alberta).
-44-
Executive Compensation
Compensation of Directors
CANEX compensated outside directors with a fee of $500 per meeting attended. For the financial year ended September 30, 2025, a total of $5,500 was paid in director fees. CANEX will reimburse its directors for any expenses incurred in connection with their services as directors, however, there were no expenses incurred during the year ended September 30, 2025. From time-to-time directors receive grants of stock options under CANEX’s stock option plan, as amended from time to time (the “CANEX Option Plan”).
The following table summarizes all amounts of compensation provided to the directors, in their capacities as directors, during the financial year ended September 30, 2025.
| Name | Fees Earned ($) | ShareBased Awards ($) | OptionBased Awards ($) | Non-Equity Incentive Plan Compensation ($) | Pension Value ($) | All Other Compensation ($) | Total Compensation ($) | |||||||||||||||||
| Lesley Hayes Director | $ | 1,500 | Nil | Nil | Nil | Nil | Nil | $ | 1,500 | |||||||||||||||
| Jean Pierre Jutras(1) Director and Vice President | Nil | Nil | Nil | Nil | Nil | $ | 12,771 | $ | 12,771 | |||||||||||||||
| Shane Ebert (2) President and Director | Nil | Nil | Nil | Nil | Nil | Nil | Nil | |||||||||||||||||
| Gregory Hanks Director | $ | 2,000 | Nil | Nil | Nil | Nil | Nil | $ | 2,000 | |||||||||||||||
| Blair Schultz Director | $ | 2,000 | Nil | Nil | Nil | Nil | Nil | $ | 2,000 | |||||||||||||||
Note:
| (1) | Geological consulting services were provided by Mr. Jutras through 635280 Alberta Ltd. totaling $12,771 but not in his capacity as a director. | |
| (2) | For a description of all compensation paid to Dr. Ebert, for the year ending September 30, 2024 in his capacity as a Named Executive Officer (as defined below) of CANEX, please refer to the section herein entitled “Compensation of Executive Officers”. |
| (a) | Outstanding Share-Based Awards and Option-Based Awards |
No share-based (as opposed to option-based) awards have ever been granted to the directors. No stock options granted to the directors have been repriced or cancelled during the year ended September 30, 2025. During the year ended September 30, 2025, no options were exercised. A total of 2,300,000 options at $0.05 per share and an expiry date of November 25, 2029 were granted.
-45-
Details of options awarded to directors, who were not Named Executive Officers (as defined below), that were outstanding as at September 30, 2025 are set forth in the following table:
| Option-Based Awards | Share-Based Awards | |||||||||||||||
| Name and Principal Position |
Number of securities underlying unexercised options (#) |
Option Exercise Price ($)(1) |
Option Expiration Date | Value of unexercised in-the-money options ($) |
Number of Shares or Units of Shares that have not Vested (#) |
Market or Payout Value of Share-Based Awards that have not Vested ($) | ||||||||||
| Lesley Hayes Director |
500,000 100,000 |
$ $ |
0.05 0.18 |
November 25, 2029 May 1, 2027 |
$ | 57,500 Nil |
Nil Nil |
Nil Nil | ||||||||
| Jean Pierre Jutras Director and Vice President |
800,000 137,500 |
$ $ |
0.05 0.18 |
November 25, 2029 May 1, 2027 |
$ | 92,000 Nil |
Nil Nil |
Nil Nil | ||||||||
| Gregory Hanks Director |
500,000 100,000 |
$ $ |
0.05 0.18 |
November 25, 2029 May 1, 2027 |
$ | 57,500 Nil |
Nil Nil |
Nil Nil | ||||||||
| Blair Schultz Director |
500,000 600,000 |
$ $ |
0.05 0.18 |
November 25, 2029 May 1, 2027 |
$ | 57,500 Nil |
Nil Nil |
Nil Nil | ||||||||
Note:
| (1) | Value of in-the-money options is calculated as the difference between the closing price of the CANEX Shares on the TSXV on September 30, 2025, which closing price was $0.165 and the exercise prices of the options multiplied by the number of CANEX Shares underlying the options |
| (b) | Incentive Awards – Value Vested or Earned During the Year |
The following table summarizes the value of options on the vesting date held by directors who were not Named Executive Officers (as defined below) that vested during the financial year ended September 30, 2025:
| Name and Principal Position | Option-Based Awards – Value Vested During the Year ($)(1) | Share-Based Awards – Value Vested During the Year ($) | Non-Equity Incentive Plan Compensation – Value Earned During the Year ($) | |||
| Lesley Hayes Director | Nil | Nil | Nil | |||
| Jean Pierre Jutras | Nil | Nil | Nil | |||
| Gregory Hanks Director | Nil | Nil | Nil | |||
| Blair Schultz Director | Nil | Nil | Nil |
-46-
Note:
(1) Calculated as the difference between the market price of CANEX Shares underlying the options on the vesting date and the exercise price of the options.
Compensation of Executive Officers
The named executive officers of CANEX for the year ended September 30, 2025 were Dr. Shane Ebert, President and Ms. Chantelle Collins, Chief Financial Officer (collectively, the “Named Executive Officers”). Dr. Ebert billed on an hourly or per diem basis individually or through his controlled company for consulting services in the aggregate amount of $103,919 for fiscal 2025. Ms. Collins billed on an hourly or per diem basis individually or through her controlled company for consulting services in the aggregate amount of $2,200 for fiscal 2025. Other than as described above there were no other Named Executive Officers for the year ending on September 30, 2025, as no other employees earned in excess of $150,000 in fiscal 2025. The Named Executive Officers are also eligible to participate in the CANEX Option Plan.
| (a) | Summary Compensation Table |
The following table sets forth information concerning the total compensation paid during the years ended September 30, 2023, 2024 and 2025 to the Named Executive Officers.
| Annual Compensation | Non-Equity Incentive Plan Compensation ($) | |||||||||||||||||||||||||||||
| Name and Principal Position | Fiscal Year Ended Sept. 30 | Salary ($) | Share- Based Awards ($) | Option- Based Awards ($) | Annual Incentive Plans | Long-Term Incentive Plans | Pension Value ($) | All Other Compensation ($) | Total Compensation ($) | |||||||||||||||||||||
| Shane Ebert, President and Director | 2025 | Nil | Nil | $ | 40,962 | (2) | Nil | Nil | Nil | $ | 103,919 | (1) | $ | 144,881 | ||||||||||||||||
| 2024 | Nil | Nil | Nil | Nil | Nil | Nil | $ | 43,377 | (1) | $ | 43,377 | |||||||||||||||||||
| 2023 | Nil | Nil | Nil | Nil | Nil | Nil | $ | 112,175 | (1) | $ | 112,175 | |||||||||||||||||||
| Chantelle Collins, CFO | 2025 | Nil | Nil | $ | 16,385 | (2) | Nil | Nil | Nil | $ | 2,200 | (1) | $ | 18,585 | ||||||||||||||||
| 2024 | Nil | Nil | Nil | Nil | Nil | Nil | $ | 1,980 | (1) | $ | 1,980 | |||||||||||||||||||
| 2023 | Nil | Nil | Nil | Nil | Nil | Nil | $ | 1,950 | (1) | $ | 1,950 | |||||||||||||||||||
| Note: |
| (1) | Represent amounts paid to the individual or his/her controlled corporation for consulting services billed on an hourly or per diem basis. |
| (2) | The options were valued using the Black-Scholes option pricing model assuming a 5-year term, volatility of 151.03%, a risk free discount rate of 3.18% and a dividend rate of 0%. |
| (b) | Outstanding Share-Based Awards and Option-Based Awards |
No share-based (as opposed to option-based) awards have been granted to the Named Executive Officers during the year ended September 30, 2025. No options were granted or repriced during the year ended September 30, 2025 to the Named Executive Officers. A total of 1,400,000 options at $0.05 per share and an expiry date of November 25, 2029 were granted to Named Executive Officers.
-47-
Details of options awarded to Named Executive Officers that were outstanding as at September 30, 2025, are set forth in the following table:
| Option-Based Awards | Share-Based Awards | |||||||||||||||||||||||
| Name and Principal Position | Number of (#) | Option Price | Option Expiration Date | Value of ($) | Number of (#) | Market or Payout Value of Share-Based Awards that have not Vested ($) | ||||||||||||||||||
| Shane Ebert | 1,000,000 | $ | 0.05 | Nov 25, 2029 | $ | 115,000 | Nil | Nil | ||||||||||||||||
| President and Director | 200,000 | $ | 0.18 | May 1, 2027 | Nil | Nil | Nil | |||||||||||||||||
| Chantelle Collins | 400,000 | $ | 0.05 | Nov 25, 2029 | $ | 46,000 | Nil | Nil | ||||||||||||||||
| CFO | 75,000 | $ | 0.18 | May 1, 2027 | Nil | Nil | Nil | |||||||||||||||||
| Note: |
| (1) | Value of in-the-money options is calculated as the difference between the closing price of the CANEX Shares on the TSXV on September 30, 2025, which closing price was $0.165 and the exercise prices of the options multiplied by the number of CANEX Shares underlying the options. |
| (c) | Incentive Awards – Value Vested or Earned During the Year |
The following table summarizes the value of options held by Named Executive Officers that vested during the year ended September 30, 2025.
| Name and Principal Position | Option-Based Awards – Value ($) | Share-Based Awards – Value ($) | Non-Equity Incentive Plan ($) | |||
| Shane Ebert, President and Director | Nil | Nil | Nil | |||
| Chantelle Collins, CFO | Nil | Nil | Nil |
| Note: |
| (1) | Calculated as the difference between the market price of the CANEX Shares underlying the options on the vesting date and the exercise price of the options. |
| (d) | Pension Plan Benefits |
CANEX does not have any defined benefit or defined contribution pension plans in place which provide for payments or benefits at, following, or in connection with retirement.
-48-
Termination of Employment, Change in Responsibilities and Employment Contracts
Remuneration for the corporate administrative and geological services of Shane Ebert (President) were billed or accrued through his controlled company, Vector Resources Inc., at a rate of $700 per diem or at the rate of $87.50 per hour for the fiscal year ended September 30, 2025. The consulting agreement with Shane Ebert includes a change of control provision that allows for the greater of a one-time payment of $50,000 or the average of the consultant’s invoicing for a six-month period based on 3 years trailing salary and contains a non-competition clause. CANEX can give Mr. Ebert a two-month notice of termination but there are no requirements for any payment to Mr. Ebert during that period.
Jean Pierre Jutras, Vice-President, provided corporate and administration and geological services through his controlled company, 635280 Alberta Ltd. at the rate of $700 per diem or at the rate of $87.50 per hour for the fiscal year ended September 30, 2025. The consulting agreement with Jean Pierre Jutras includes a change of control provision that allows for the greater of a one-time payment of $35,000 or the average of the consultant’s invoicing for a six-month period based on 3 years trailing salary. CANEX can give Mr. Jutras a one month notice of termination but there are no requirements for any payment to Mr. Jutras during that period.
Chantelle Collins, CFO, charged consulting fees of $110 per hour for the fiscal year ended September 30, 2025. The consulting agreement with Chantelle Collins includes a change of control provision that allows for the greater of a one-time payment of $25,000 or the average of the consultants invoicing for a six-month period based on 3 years trailing salary. CANEX can give Ms. Collins a one-month notice of termination but there are no requirements for any payment to Ms. Collins during that period.
Barbara O’Neill, Corporate Secretary, charged consulting fees of $60 per hour for the fiscal year ended September 30, 2025. The consulting agreement with Barbara O’Neill includes a change of control provision that allows for the greater of a one-time payment of $35,000 or the average of the consultants invoicing for a 6 month period based on 3 years trailing salary. CANEX can give Ms. O’Neill a one month notice of termination but there are no requirements for any payment to Ms. O’Neill during that period.
Indebtedness of Directors and Executive Officers
None of the directors and officers of CANEX or any associate of any director, officer is or has been indebted to CANEX at any time at any time since the beginning of the last completed financial year of CANEX.
Risk Factors
CANEX is subject to exploration, development, and operating risks due the highly speculative nature of its ongoing property exploration and the uncertainty of economically recoverable reserves.
CANEX is in the process of exploring its properties and has not yet determined whether its properties contain economically recoverable reserves and, therefore, does not generate any revenues from production. The recovery of expenditures on mineral properties and the related deferred exploration expenditures are dependent on the existence of economically recoverable mineralization, the ability of CANEX to obtain financing necessary to complete the exploration and development of its properties, and upon future profitable production, or alternatively, on the sufficiency of proceeds from disposition. Mineral exploration is highly speculative in nature, involves many risks and frequently is non-productive. There is no assurance that exploration efforts will be successful.
CANEX requires substantial capital and faces liquidity challenges due to its current and planned mining operations.
-49-
Substantial additional funds for the establishment of CANEX’s current and planned mining operations will be required. No assurances can be given that CANEX will be able to raise the additional funding that may be required for such activities, should such funding not be fully generated from operations. Mineral prices, environmental rehabilitation or restitution, revenues, taxes, transportation costs, capital expenditures and operating expenses and geological results are all factors which will have an impact on the amount of additional capital that may be required. To meet such funding requirements, CANEX may be required to undertake additional equity financing, which would be dilutive to shareholders. Debt financing, if available, may also involve restrictions on financing and operating activities. There is no assurance that additional financing will be available on terms acceptable to CANEX or at all. If CANEX is unable to obtain additional financing as needed, it may be required to reduce the scope of its operation and pursue only those projects that can be funded through cash flows generated from its existing operations, if any.
Fluctuating mineral prices affect the economics of CANEX’s exploration activities, making future profitability uncertain.
The economics of mineral exploration are affected by many factors beyond CANEX’s control, including commodity prices, the cost of operations, variations in the grade of minerals explored and fluctuations in the market price of minerals. Depending on the price of minerals, CANEX may determine that it is impractical to continue a mineral exploration operation. Mineral prices are prone to fluctuations and the marketability of minerals is affected by government regulation relating to price, royalties, allowable production and the importing and exporting of minerals, the effect of which cannot be accurately predicted. There is no assurance that a profitable market will exist for the sale of any minerals found on CANEX’s properties.
CANEX is subject to regulatory, permit, and license requirements, and failure to obtain necessary documentation and approval may have an adverse impact on CANEX.
The current or future operations of CANEX require permits from various Governmental Authorities, and such operations are and will be governed by laws and regulations concerning exploration, development, production, taxes, labour standards, occupational health, waste disposal, toxic substances, land use, environmental and species protection, site safety, aboriginal consultation and other matters. Companies engaged in the exploration and development of mineral properties generally experience increased costs and delays in development and other schedules as a result of the need to comply with applicable Laws, regulations and permits. There can be no assurance that all permits which CANEX may require for facilities and the conduct of exploration and development operations on its properties will be obtainable on reasonable terms, or that such laws and regulation will not have an adverse effect on any exploration or development project which CANEX might undertake.
Failure to comply with applicable Laws, regulations and permitting requirements may result in enforcement actions, including orders issued by regulatory or judicial authorities causing operations to cease or be curtailed and may include corrective measures requiring capital expenditures, installation of additional equipment or remedial actions. Parties engaged in exploration and development operations may be required to compensate those suffering loss or damage by reason of the exploration and development activities and may have civil or criminal fines or penalties imposed upon them for violation of applicable Laws or regulations. Amendments to current laws, regulations and permits governing operations and activities of mineral companies, or more stringent implementation thereof, could have a material adverse impact on CANEX and cause increases in capital expenditures or exploration and development costs, or require abandonment or delays in the development of new or existing properties.
CANEX’s limited financial resources may require the issuance of additional equity, which would result in a dilution to CANEX Shareholders.
-50-
CANEX has limited financial resources, no operations, and no revenues. If CANEX’s exploration program on a property is successful, additional funds will be required for the purposes of further exploration and development. There can be no assurance that CANEX will be able to obtain adequate financing in the future or that such financing will be available on favorable terms or at all. It is likely such additional capital will be raised through the issuance of additional equity which will result in dilution to CANEX Shareholders.
CANEX faces challenges securing and maintaining title to its mineral properties, with potential disputes and risks involved.
Acquisition of title to mineral properties is a very detailed and time-consuming process. Title to, and the area of, mineral properties may be disputed. CANEX cannot give an assurance that title to its properties will not be challenged or impugned. Mineral properties sometimes contain claims or transfer histories that examiners cannot verify. A successful claim that the optionors or CANEX, as the case may be does not have title to its properties could cause CANEX to lose any rights to explore, develop and mine any minerals on its properties without compensation for its prior expenditures relating to its properties.
CANEX faces significant competition in the mineral exploration and development industry, impacting its ability to acquire resources and talent.
The mineral exploration and development industry is highly competitive. CANEX will have to compete with other mining companies, many of which have greater financial, technical and other resources than CANEX, for, among other things, the acquisition of mineral claims, leases and other mineral interests as well as for the recruitment and retention of qualified employees and other personnel. Failure to compete successfully against other mining companies could have a material adverse effect on CANEX and its prospects.
CANEX’s success is heavily dependent on its management and key personnel, with challenges attracting and retaining talent in a competitive space.
The success of CANEX will be largely dependent upon the performance of its directors and officers and the ability to attract and retain key personnel. The loss of the services of these persons may have a material adverse effect on CANEX’s business and prospects. CANEX will compete with numerous other companies for the recruitment and retention of qualified employees and contractors. There is no assurance that CANEX can maintain the service of its directors and officers or other qualified personnel required to operate its business. Failure to do so could have a material adverse effect on CANEX and its prospects.
Evolving environmental obstacles and various levels of governmental regulatory requirements pose a significant risk to CANEX’s exploration and appraisal programs.
CANEX’s exploration and appraisal programs will, in general, be subject to approval by regulatory bodies. Additionally, all phases of the mining business present environmental risks and hazards and are subject to environmental regulation pursuant to a variety of international conventions and provincial and municipal Laws and regulations. Environmental legislation provides for, among other things, restrictions and prohibitions on spills, releases or emissions of various substances produced in association with mining operations. The legislation also requires that wells and facility sites be operated, maintained, abandoned and reclaimed to the satisfaction of applicable regulatory authorities. Compliance with such legislation can require significant expenditures and a breach may result in the imposition of fines and penalties, some of which may be material. Environmental legislation is evolving in a manner expected to result in stricter standards and enforcement, larger fines and liability and potentially increase capital expenditures and operating costs.
-51-
CANEX may encounter conflicts of interest stemming from the various external business engagements of its directors and officers, which would require a resolution in accordance with the applicable Laws.
Certain of the directors and officers of CANEX are engaged in, and will continue to engage in, other business activities on their own behalf and on behalf of other companies and, as a result of these and other activities, such directors and officers of CANEX may become subject to conflicts of interest. Canadian corporate Laws provide that in the event that a director has an interest in a contract or proposed contract or agreement, the director shall disclose his interest in such contact or agreement and shall refrain from voting on any matter in respect of such contract or agreement unless otherwise provided under those laws. To the extent that conflicts of interest arise, such conflicts will be resolved in accordance with the provisions of the applicable Canadian corporate Laws.
CANEX is subject to certain uninsurable risks in its exploration and product operations, potentially impacting its financial performance and share value.
Exploration, development, and production operations on mineral properties involve numerous risks, including unexpected or unusual geological operating conditions, rock bursts, cave-ins, fires, floods, earthquakes and other environmental occurrences, any of which could result in damage to, or destruction of mines and other producing facilities, damage to life or property, environmental damage and possible legal liability. Although precautions to minimize risk will be taken, operations are subject hazards that may result in environmental pollution and consequent liability that could have a material adverse impact on the business, operations and financial performance of CANEX. It is not always possible to obtain insurance against all such risks and CANEX may decide not to insure against certain risks as a result of high premiums or other reasons. Should such liabilities arise, they could have an adverse impact on CANEX’s results of operations and financial condition and could cause a decline in the value of CANEX Shares.
CANEX may be subject to various civil or other legal proceedings.
CANEX and/or its directors may be subject to a variety of civil or other legal proceedings, with or without merit.
Legal Proceedings and Regulatory Actions
In the ordinary course of business, CANEX may become involved in various legal, administrative, regulatory and other proceedings, actions, claims and inquiries relating to its business. CANEX is not aware of any actual or pending legal proceedings material to CANEX to which CANEX is or was a party to, or that any of its property is or was the subject of, since the beginning of CANEX’s most recently completed financial year. In addition, CANEX is not currently aware of any such legal proceedings being contemplated.
To the best of CANEX’s knowledge, following due enquiry there have been no penalties or sanctions imposed against CANEX by a court relating to federal, state, provincial and territorial securities legislation or by a securities regulatory authority within the three years immediately preceding the date of the Circular, nor have there been any other penalties or sanctions imposed by a court or regulatory body against CANEX and it has not entered into any settlement agreements before a court relating to provincial and territorial securities legislation or with a securities regulatory authority.
Interest of Management and Others in Material Transactions
None of the directors or executive officers of CANEX, or principal shareholders of CANEX, or associates or affiliates of any of these persons, has any material interest, direct or indirect, in any transaction within the three years before the date of the Circular or in any proposed transaction which, in either case, has materially affected or would materially affect CANEX.
-52-
Auditors, Transfer Agent and Registrars
The auditor of CANEX is BDO Canada LLP, located at 903 – 8th Avenue SW, Suite 620, Calgary, Alberta T2P 0P7. Computershare Trust Company of Canada, at its principal office in Calgary, Alberta, is the registrar and transfer agent for CANEX Shares.
For further information regarding CANEX, refer to CANEX’s filings with the applicable securities regulatory authorities in Canada which may be obtained through SEDAR+ at www.sedarplus.ca.
Material Contracts
On May 7, 2026, CANEX entered into the Lock-Up Agreements. Additional information regarding the Lock-Up Agreements can be found in the Circular under the section titled “The Arrangement – Lock-Up Agreements”.
CANEX entered into lock-up agreements between August 2025 and October 2025 with certain shareholders of Gold Basin, who own, collectively, over 30% of the outstanding Shares. Pursuant to the lock-up agreements, such shareholders agreed, among other things, to deposit their Shares, including Shares acquired upon exercise of Convertible Securities (as defined in the Take-Over Bid Circular), under the Offer and, subject to certain limited exceptions, not to withdraw such Shares.
Copies of the lock-up agreements are available under CANEX’s profile on SEDAR+ at www.sedarplus.ca.
Scientific and Technical Information
Certain scientific and technical information contained in this Circular and the documents incorporated by reference are derived from, and in some instances are an extract from, the Technical Report.
Each co-author of the Technical Report listed in the section entitled “Experts” of this Appendix is a “qualified person” as defined in NI 43-101 (“QP”) and has reviewed, approved and verified certain scientific and technical information in this prospectus that is derived from the Technical Report.
Reference should be made to the full text of the Technical Report which have been filed with certain Canadian securities regulatory authorities pursuant to NI 43-101 and is available for review under CANEX profile on SEDAR at www.sedarplus.ca and on EDGAR at www.sec.gov. Alternatively, copies of the Technical Report may be inspected during normal business hours at CANEX’s head office.
Experts
The scientific and technical information contained in this Circular relating to CANEX has been reviewed and approved by Shane W. Ebert P. Geo., President and a director of CANEX and a qualified person as such term is defined under National Instrument 43-101 Standards of Disclosure for Mineral Project.
-53-
Shane Ebert has verified the data disclosed, including sampling and analytical data. The CANEX related data has been verified by direct field oversight on sampling, quality control measures, and handling of assays received from the assay lab. Select Gold Basin related data has been checked within available databases assembled by other and in public disclosure. Other qualified persons have been relied on for the quality and accuracy of Gold Basin data, and checks of assay results from laboratories or quality control measures have not been conducted by Dr. Shane Ebert.
CANEX’s auditors are BDO Canada LLP, located at 903 – 8th Avenue SW, Suite 620, Calgary AB T2P 0P7, Canada. BDO Canada LLP has advised that they are independent with respect to CANEX within the meaning of the Rules of Professional Conduct of the Chartered Professional Accountants of Alberta.
As of the date hereof, to the knowledge of CANEX, each of the persons identified as experts above (including, in case of partnerships, partners and associates, as a group) each beneficially owned, directly or indirectly, less than 1% of the outstanding CANEX Shares, other than Shane Ebert, who owns 2,722,067 CANEX Shares representing approximately 1.3% of the issued and outstanding CANEX Shares. None of the aforementioned firms or persons, nor any directors, officers or employees of such firms, are currently expected to be elected, appointed or employed as a director, officer or employee of CANEX or of any associate or affiliate of the Company other than Shane Ebert, CANEX’s President, CEO and a director.
Other Material Facts
Other than as set out elsewhere in this Circular, there are no other material facts about CANEX or its securities which are necessary in order for this Circular to contain full, true and plain disclosure of all material facts relating to CANEX and its respective securities.
Additional Information
Additional information relating to CANEX is available on SEDAR+ at www.sedarplus.ca.
-54-
Appendix E
Information Concerning the Resulting Issuer
[See attached]
Notice to Reader
The following information is on a post-Arrangement basis and contains significant amounts of forward-looking information. Readers are cautioned that actual results may vary. See “General Proxy Information – Cautionary Statement Regarding Forward-Looking Information”.
Unless the context indicates otherwise, capitalized terms which are used in this Appendix C and not otherwise defined in this Appendix C have the meanings given to such terms under the heading “Glossary of Terms” in the Circular.
Corporate Summary
At the Effective Time, CANEX will own all of the issued and outstanding Shares.
The Resulting Issuer will continue to be a publicly traded company focused on acquisition, exploration, and development of mineral properties, including the material mineral projects and other mineral properties of Gold Basin and CANEX, as set out in Appendix C and Appendix D of this Circular. The Resulting Issuer will operate and manage the business of Gold Basin, in addition to the business currently carried on by CANEX, and will generally be subject to the same risks applicable to Gold Basin and CANEX, all as further described in this Circular. The Resulting Issuer’s existing policies and procedures, including those related to executive compensation and corporate governance, are not expected to change as a result of the completion of the Arrangement. See Appendix C and D of this Circular for business, financial and share capital information relating to Gold Basin and CANEX, respectively.
As a result of the Arrangement, Gold Basin will be a wholly-owned subsidiary of the Resulting Issuer. The Resulting Issuer will be a reporting issuer in each of the provinces of Alberta, British Columbia, Ontario and Québec.
Directors and Executive Officers
It is anticipated that the current directors and executive officers of CANEX will continue in their positions for the Resulting Issuer following completion of the Arrangement.
Pro Forma Consolidated Financial Information
The following selected unaudited pro forma consolidated financial information of the Resulting Issuer has been derived from the Pro Forma Consolidated Financial Statements. The Pro Forma Consolidated Financial Statements are presented in Canadian dollars and are attached as Appendix O to this Circular.
The Pro Forma Financial Statements consist of: (i) an unaudited pro forma consolidated statement of financial position of CANEX as at December 31, 2025, which gives effect to the Arrangement as if the transaction had closed on December 31, 2025; and (ii) unaudited pro forma consolidated statements of loss of CANEX for the three months ended December 31, 2025, which give effect to the Arrangement as if the Arrangement had closed on October 1, 2025.
The Pro Forma Financial Statements are based on the respective historical consolidated financial statements of CANEX and Gold Basin. The Pro Forma Financial Statements should be read together with: (a) the unaudited condensed interim consolidated financial statements of CANEX for the three months ended December 31, 2025 which are attached as Appendix N to this Circular; and (b) the unaudited consolidated financial statements of Gold Basin for the years ended December 31, 2025 and 2024, which are attached as Appendix L to this Circular. The Pro Forma Financial Statements and adjustments, including the allocation of the purchase price, are based upon preliminary estimates of fair values of assets acquired and liabilities assumed, current available information and certain assumptions that CANEX believes are reasonable in the circumstances, as described in the notes to the Pro Forma Financial Statements.
E-2
Gold Basin has made a dual application to securities regulatory authorities in British Columbia, Alberta and Ontario for Exemptive Relief from the requirement to include, among other things, certain financial statements, including audited financial statements for the for the years ended December 31, 2025 and 2024, in this Circular. As of the date hereof, the Exemptive Relief has not been granted and there is no assurance that it will be granted. Under the Arrangement Agreement it is a condition to holding the Meeting and to completing the Arrangement that the Exemptive Relief is granted.
Although unaudited consolidated financial statements of Gold Basin for the years ended December 31, 2025 and 2024 have been prepared and are attached as Appendix L to this Circular, these statements are the responsibility of Gold Basin’s management and have not been audited or reviewed on behalf of the shareholders by the independent external auditors of Gold Basin. To date, Gold Basin has been unable to provide audited consolidated financial statements for the years ended December 31, 2025 and 2024 and management’s discussion and analysis thereof, because:
| · | there have been significant changes in Gold Basin’s management and personnel responsible for accounting and financial reporting; |
| · | certain accounting records of Gold Basin may have been reconstructed after the fact; |
| · | there are unresolved questions regarding the nature, authorization, and supporting documentation of certain transactions and payments of Gold Basin; |
| · | there is uncertainty regarding the terms, substance, and related-party nature of certain financing arrangements and agreements of Gold Basin; and |
| · | there are limitations in the availability of supporting documentation and cooperation from certain persons previously involved with Gold Basin. |
Circumstances of this nature would generally be expected to create significant challenges in completing an audit in accordance with Canadian Auditing Standards. Such circumstances may increase audit risk, require substantially expanded audit procedures, and result in increased time and cost associated with the auditor’s engagement.
In addition, where there are concerns regarding the completeness of accounting records, authorization of transactions, related-party relationships, or the reliability of supporting documentation, auditors would typically be required to exercise heightened professional skepticism and perform extensive additional procedures to obtain sufficient appropriate audit evidence.
Adjustments have been made to prepare the Pro Forma Consolidated Financial Statements, which adjustments are based on certain assumptions. Both the adjustments and the assumptions made in respect thereof are described in the notes to the Pro Forma Consolidated Financial Statements.
The following selected unaudited pro forma financial information and the unaudited pro forma consolidated financial statements are presented for illustrative purposes only and are not intended to reflect: (i) the operating or financial results that would have occurred had the Arrangement actually occurred at the times contemplated by the notes to the Pro Forma Consolidated Financial Statements; or (ii) of the results expected in future periods.
E-3
See the Pro Forma Consolidated Financial Statements set forth in Appendix O to this Circular.
Selected Pro Forma Consolidated Statement of Financial Position (Unaudited: expressed in CAD)
| As at December 31, 2025 | ||||
| Cash | 3,161,674 | |||
| Accounts receivable | 175,715 | |||
| Prepaid expenses and deposits | 68,524 | |||
| Exploration and evaluation asset advances and deposits | 52,164 | |||
| Exploration and evaluation assets | 33,942,776 | |||
| Total assets | 37,400,853 | |||
| Accounts payable and accrued liabilities | 2,955,729 | |||
| Loan payable | 302,269 | |||
| Decommissioning obligation | 52,545 | |||
| Total liabilities | 3,310,543 | |||
| Total equity | 34,090,310 | |||
| Total revenue | 0 | |||
| Total expenses | 380,728 | |||
| Other (income) and expense | (3,429 | ) | ||
| Net loss and comprehensive loss for the period | 377,299 | |||
| Basic and diluted loss per share | 0.00 | |||
Selected Pro Forma Consolidated Statement of Comprehensive Loss (Unaudited; expressed in CAD)
| Three Months Ended December 31, 2025 | ||||
| Total revenue | - | |||
| Total expenses | 380,728 | |||
| Other (income) and expense | (3,429 | ) | ||
| Net loss and comprehensive loss for the period | 377,299 | |||
| Basic and diluted loss per share | 0.00 | |||
E-4
Pro Forma Consolidated Capitalization
See “Consolidated Capitalization” in Appendix D to this Circular.
Principal Holders of the Resulting Issuer Shares
Except as otherwise disclosed in this Circular, as of the date of this Circular, to the knowledge of CANEX and Gold Basin, CANEX and Gold Basin expect that no new insider will be created by virtue of such person holding at least 10% of the Resulting Issuer Shares and no new control person of the Resulting Issuer will be created as a result of the issuance of the Share Consideration.
Description of the Resulting Issuer Share Structure
The authorized share structure of the Resulting Issuer following completion of the Arrangement will continue to be as described in Appendix D and the rights and restrictions of shares of the Resulting Issuer will remain unchanged.
Resulting Issuer Share Capital
The issued share capital of the Resulting Issuer will change as a result of the consummation of the Arrangement, to reflect the issuance of the Consideration Shares. At the Effective Time, CANEX expects to issue 38,505,033 Resulting Issuer Shares, which would result in 247,432,895 Resulting Issuer Shares issued and outstanding.
Dividends
Any decision to pay dividends on Resulting Issuer Shares will be made by the board of directors of the Resulting Issuer on the basis of the corporation’s earnings, financial requirements and other conditions existing at such future time.
Auditors, Registrar of the Resulting Issuer
BDO Canada LLP, the auditors for CANEX, will be the continuing auditors for the Resulting Issuer following completion of the Arrangement.
Following the completion of the Arrangement, the transfer agent and registrar of the Resulting Issuer is expected to be Computershare Trust Company of Canada, at its principal office in Calgary, Alberta.
Appendix F
Fairness Opinion
[See attached]
 |
Stifel Nicolaus Canada
Inc. 161 Bay Street, Suite 3800 Toronto, ON M5J 2S1 Tel: (416) 367-8600 |
May 11, 2026
The Special Committee of the Board of Directors
Gold Basin Resources Corporation
Suite 3200, 733 Seymour St.
Vancouver, B.C. V6B 0S6
Canada
To the Special Committee of the Board of Directors:
Stifel Nicolaus Canada Inc. (“Stifel”, “we”, “us” or “our”) understands that Gold Basin Resources Corporation (“Gold Basin” or the “Company”) and CANEX Metals Inc. (“CANEX” or the “Acquiror”) propose to enter into an arrangement agreement to be dated on or about May 11, 2026 (the “Arrangement Agreement”) pursuant to which, among other things, the Acquirer will acquire all of the outstanding common shares of the Company (the “Shares”), by way of a plan of arrangement under the Business Corporations Act (British Columbia) (the “Arrangement”). Under the terms of the Arrangement, at closing, holders of the issued and outstanding common shares of Gold Basin (the “Gold Basin Shareholders”) will receive 0.5920 common shares of the Acquiror (each, an “Acquiror Share”) per Share (the “Consideration”).
We understand that Acquiror has also agreed to provide the Company with a C$900,000 secured bridge loan (the “Bridge Loan”) to service aged payables, day to day working capital and general corporate expenditures and direct advances paid by CANEX to third party suppliers, service providers and creditors of Gold Basin, and expenses in connection with a proposed Arrangement. The Bridge Loan will have an interest rate of 5% per annum plus the Royal Bank of Canada Prime Rate and a term to maturity of six months. Stifel has not assessed whether the existence of the Bridge Loan may have influenced the conduct or recommendations of the Company’s management in connection with the Arrangement.
The terms and conditions of the Arrangement will be summarized in the Company’s management information circular (the “Circular”) to be mailed to the Gold Basin Shareholders in connection with a special meeting of Gold Basin Shareholders to be held to consider and, if deemed advisable, approve the Arrangement.
Engagement of Stifel
The Company initially contacted Stifel on April 7, 2026 regarding a potential advisory assignment. Stifel was formally engaged by the Company pursuant to an agreement dated April 15, 2026, (the “Engagement Letter”) to act as financial advisor in connection with the Arrangement, including by preparing and delivering an opinion (the “Opinion”) to the special committee appointed by the board of directors of the Company (the “Special Committee”) as to the fairness from a financial point of view of the Consideration to be received by the Gold Basin Shareholders, other than the Acquiror, pursuant to the Arrangement.
The Engagement Letter provides for the payment by the Company of a fixed fee for our delivery of the Opinion, which amount is payable to us regardless of the conclusion reached by us in this Opinion and whether or not the Arrangement or any other transaction is completed. In addition, Stifel is not receiving, and will not receive, any success fee or other compensation contingent upon the consummation of the Arrangement or the achievement of any particular outcome. Stifel will be reimbursed for its reasonable out-of pocket expenses and indemnified by the Company in certain circumstances.
Stifel has been advised by the Special Committee that the Arrangement is exempt from any requirement to obtain a formal valuation under MI 61-101 and, as such, Stifel has not been asked to prepare and has not prepared a formal valuation (as defined in MI 61-101) of any of the securities or assets of the Company and this Opinion should not be construed as such. Stifel has relied, without independent investigation or verification, on the advice of the Company and its legal advisors regarding the applicability of MI 61-101 to the Arrangement, including the availability of any exemptions thereunder, and Stifel has not independently evaluated or determined the applicability of MI 61-101 or any other applicable securities laws to the Arrangement or any related transaction, nor does Stifel express any opinion with respect thereto.
Relationship with Interested Parties
Neither Stifel, nor any of its affiliates is an insider, associate or affiliate (as those terms are defined in the Securities Act (British Columbia)) of the Company, the Acquiror or any of their respective associates or affiliates (collectively, the “Interested Parties”). Neither Stifel nor any of its affiliates has been engaged to provide any financial advisory services, nor has Stifel or any of its affiliates participated in any financing, involving the Interested Parties within the past two years, other than acting as financial advisor to the Special Committee pursuant to the Engagement Letter.
Other than as set forth above, there are no understandings, agreements or commitments between Stifel and the Interested Parties with respect to any future business dealings. Stifel may, in the future, in the ordinary course of its business, perform financial advisory or investment banking services for the Interested Parties.
Stifel acts as a trader and dealer, both as principal and agent, in major financial markets and, as such, may have had and may in the future have positions in the securities of the Company or the Acquiror and, from time to time, may have executed or may execute transactions for such companies and clients from whom it received or may receive compensation. Stifel, its affiliates and certain of their respective employees may in the ordinary course of business hold long or short positions in, or actively trade, securities of the Company or the Acquiror, and may have provided or may in the future provide investment banking, research, trading, lending or other financial services to the Company, the Acquiror or their respective affiliates, for which Stifel may receive customary compensation. Stifel, as an investment dealer, conducts research on securities and may, in the ordinary course of its business, provide research reports and investment advice to its clients on investment matters, including with respect to the Company or the Acquiror.
Credentials of Stifel
Stifel is a leading independent Canadian investment dealer focused on investment banking and institutional equities for corporate clients and institutional investors. As part of our investment banking activities, Stifel is regularly engaged in the valuation of securities in connection with mergers and acquisitions, public offerings and private placements of listed and unlisted securities and regularly engages in market making, underwriting and secondary trading of securities in connection with a variety of transactions. Stifel is not in the business of providing auditing services and is not controlled by a financial institution. Stifel is a brand name of Stifel Nicolaus Canada Inc. The Opinion is the opinion of Stifel, and the form and content herein has been reviewed and approved for release by a group of professionals of Stifel, each of whom is experienced in merger, acquisition, divestiture, valuation and fairness opinion matters.
Scope of Review
In connection with rendering our Opinion, we have reviewed and relied upon, among other things, the following:
| a) | a draft of the Arrangement Agreement; |
| b) | a draft of the Plan of Arrangement; |
| c) | a draft of the Bridge Loan Agreement; |
| d) | publicly available documents regarding the Company, including annual and quarterly reports, financial statements, management’s discussion and analysis, annual information forms, management circulars, NI 43-101 technical reports, and other filings deemed relevant; |
| e) | publicly available documents regarding the Acquiror, including annual and quarterly reports, financial statements, management’s discussion and analysis, annual information forms, management circulars, NI 43-101 technical reports, and other filings deemed relevant; |
| f) | certain internal management budgets, analysis and financial models prepared by or on behalf of the management of the Company that were provided to us in the course of our engagement; |
| g) | access to certain other non-public information prepared and provided to us by the Company, primarily financial in nature, concerning the Company’s and the Acquiror’s business, assets, liabilities and prospects; |
| h) | trading statistics and selected financial information of the Company, the Acquiror and other selected public companies, to the extent deemed relevant by us, in the exercise of our professional judgment; |
| i) | public information with respect to selected precedent transactions considered by us to be relevant, in the exercise of our professional judgment; |
| j) | consultation with Fasken Martineau DuMoulin LLP, legal advisors to the Company; |
| k) | such other information, discussions and analyses as Stifel considered, in the exercise of our professional judgment, necessary or appropriate in the circumstances; and |
| l) | a certificate addressed to Stifel, from senior officers of the Company regarding the completeness and accuracy of the information upon which this Opinion is based. |
Stifel has not, to the best of its knowledge, been denied access by the Company to any information under the control of the Company that has been requested by Stifel.
In rendering the Opinion, Stifel also considered certain qualitative factors relating to the Company, the Arrangement and the surrounding circumstances.
Prior Valuations
Senior Officers of the Company have represented to Stifel that, to the best of their knowledge, there have been no prior valuations (as defined for the purposes of MI 61-101) of the Company or any of its material assets or subsidiaries prepared within the past twenty-four (24) months.
Assumptions and Limitations
The Opinion is subject to the assumptions, qualifications and limitations set out below and elsewhere in this letter. The assumptions stated in this section are not intended to be exhaustive, and additional assumptions may be stated or implicit in other sections of this letter.
Stifel Nicolaus Canada Inc. has relied upon the completeness, accuracy and fair presentation of all financial and other information, data, advice, opinions and representations obtained by us from public sources, or provided to us by the Company, its subsidiaries or their respective directors, officers, associates, affiliates, consultants, advisors and representatives (collectively, the “Information”). We have assumed that the Information did not omit to state any material fact or any fact necessary to be stated to make the Information not misleading and that the Company has not filed any confidential material report which, as of the date hereof, remains confidential. Our Opinion is conditional upon such completeness, accuracy and fair presentation of the Information. We have not been requested to nor, subject to the exercise of professional judgment, have we attempted to verify independently the completeness, accuracy or fair presentation of the Information.
Senior officers of the Company have represented to Stifel in a certificate delivered as of the date hereof, among other things, that (i) the Information provided orally by, or in the presence of, an officer or employee of the Company or in writing by the Company or any of its subsidiaries, associates or affiliates or their respective representatives, was, at the date the Information was provided to Stifel, and is at the date hereof complete, true and correct in all material respects, and did not and does not contain any untrue statement of a material fact in respect of the Company, its subsidiaries or the Arrangement and did not and does not omit to state a material fact in respect of the Company, its subsidiaries or the Arrangement necessary to make the Information or any statement contained therein not misleading in light of the circumstances under which the Information was provided or any such statement was made; and that (ii) since the dates on which the Information was provided to Stifel, except as disclosed to Stifel, there has been no material change, financial or otherwise, in the financial condition, assets, liabilities (contingent or otherwise), business, operations or prospects of the Company or any of its subsidiaries and no material change has occurred or is planned to occur in the Information or any part thereof which would have or which would render any portion of the Information untrue or misleading in any material respect.
With respect to any forecasts, projections, estimates and/or budgets provided by the Company or, in the case of the Acquiror forecast, reviewed by the Company and used in its analyses, Stifel notes that projecting future results of any company is inherently subject to uncertainty. Stifel has assumed, however, that such forecasts, projections, estimates and/or budgets were prepared or reviewed using the assumptions identified therein and that such assumptions in the opinion of the Company, are (or were at the time) reasonable in the circumstances. Stifel has relied upon forecasts, projections, estimates and budgets provided by the Company, each assumed to be reasonably prepared, reflecting the best currently available assumptions, estimates and judgments of the Company management considering the Company’s business, plans, financial condition and prospects, and are not, in the reasonable belief of the Company’s management, misleading in any material respect. In respect of the Acquiror, Stifel has relied upon forecasts, projections, estimates, and budgets provided by the Acquiror and reviewed by the Company, each assumed to be reasonably prepared, reflecting the best currently available assumptions, estimates and judgements of the Company management considering the financial and other information and data, advice, opinions, representations and other material provided to the Company by Acquiror with respect to the Acquiror’s business, plans, financial condition and prospects. Stifel has assumed that there are no independent valuations or appraisals or material non-independent appraisals or valuations relating to the Company, the Acquiror, or any of their respective subsidiaries or any of their respective material assets or liabilities that have been prepared in two years preceding the date hereof and which have not been provided to Stifel.
Stifel has assumed that, in all respects material to its analysis, the Arrangement Agreement executed by the parties will be in substantially the form and substance of the draft provided to us, the representations and warranties of the parties to the Arrangement Agreement contained therein are complete, true and correct in all material respects, such parties will each perform all of the respective covenants and agreements to be performed by them under the Arrangement Agreement, and all conditions to the obligations of such parties as specified in the Arrangement Agreement will be satisfied or waived. Stifel has also assumed that there are no agreements, undertakings, commitments or understandings (written or oral, formal or informal), relating to the Arrangement, except as have been disclosed to Stifel. Stifel has also assumed that all material approvals and consents required in connection with the consummation of the Arrangement will be obtained and, that in connection with any necessary approvals and consents, no limitations, restrictions or conditions will be imposed that would have an adverse effect on the Company or the Acquiror.
Stifel has assumed that the replacement of the board of directors of the Company on March 16, 2026, and all related corporate actions (including the court-ordered annual general meeting, reinstatement of the transfer agent, and termination of the former President and Interim Chief Executive Officer), were validly and effectively carried out in accordance with applicable law and court orders.
The analysis performed by Stifel is not reliant upon, and does not assume or depend in any respect on, the issuance, approval, or denial of any governmental, regulatory, or other permits, licenses, or authorizations relating to Gold Basin’s projects. Stifel has assumed that the Arrangement will not impair the solvency of the Company or the Acquiror or otherwise give rise to any claims under applicable insolvency or creditors’ rights laws.
Stifel has not undertaken any independent investigation into the financial condition, solvency or viability of the Company or CANEX, including in light of any liquidity constraints, regulatory restrictions (including the cease trade order affecting the Company), governance matters or litigation, and has relied solely on the Information provided.
Stifel has not independently verified or assessed the impact of such matters on the Company’s value or prospects.
Stifel expresses no opinion as to the fair value of any securities or assets of the Company or the Acquiror for the purposes of any dissent, appraisal or similar proceeding, or as to the price at which any securities may trade or otherwise be transferable at any time.
Stifel expresses no view as to whether the Arrangement will be consummated or as to the timing thereof.
This Opinion does not address the relative merits of the Arrangement as compared to other business strategies or transactions that might be available with respect to the Company or the Company’s underlying business decision to effect the Arrangement or any other term or aspect of the Arrangement or the Arrangement Agreement or any other agreement entered into or amended in connection with the Arrangement. Stifel was not requested to solicit, initiate or evaluate alternative transactions or other strategic alternatives that may have been available to the Company, nor did Stifel undertake any process to do so.
Stifel did not meet with the auditors of the Company or the Acquiror and has assumed the accuracy, completeness and fair presentation of, and has relied upon, without independent verification, the financial statements of the Company and the Acquiror and any reports of the auditors thereon. Stifel has assumed that all financial information provided to it was prepared on a basis consistent in all material respects with the accounting policies applied in the Company’s most recent audited consolidated financial statements and does not contain any untrue statement of material fact or omit to state any material fact. We are not legal, tax or accounting experts and we express no opinion concerning any legal, tax or accounting matters concerning the Arrangement and have relied upon, without independent verification, the assessment by the Company and the Acquiror and their legal and tax advisors with respect to such matters. We express no opinion as to the value at which the Acquiror Shares may trade following completion of the Arrangement.
Stifel expressly disclaims any duty of care or liability to any person other than the Special Committee (including, without limitation, the Gold Basin Shareholders, creditors, or regulators), whether in contract, tort (including negligence), or otherwise, in connection with this Opinion. In no event shall Stifel be liable for any indirect, consequential, special or punitive damages, or loss of profits, even if advised of the possibility thereof.
Stifel is not acting as an expert for purposes of any applicable securities, corporate or other law, and this Opinion should not be construed as an expert report or opinion for any such purpose. Stifel is not a “qualified person” as defined under National Instrument 43-101 - Standards of Disclosure for Mineral Projects (“NI 43-101”) and has not independently verified any technical, geological or mineral resource information, including any estimates of mineral reserves or resources. Stifel was not engaged to review the quality, quantity or mining economics of the mineral reserves and resources of any of the assets included in the Arrangement from a technical, engineering or geological standpoint and, accordingly, expresses no view thereof.
Stifel has not been requested to, and does not, express any opinion as to the solvency, financial viability or fair value of the Company or the Acquiror under any applicable insolvency, bankruptcy, fraudulent conveyance, transfer or preference laws, or similar laws affecting creditors’ rights, and no such opinion is expressed.
The preparation of a fairness opinion is a complex process and is not necessarily capable of being partially analyzed or summarized. Any attempt to do so could lead to undue emphasis on any particular factor or analysis. Stifel believes that its analyses must be considered as a whole and that selecting portions of the analyses or the factors considered by it, without considering all factors and analyses together, could create an incomplete view of the process underlying the Opinion. The Opinion should be read in its entirety.
This Opinion is rendered as at the date hereof and on the basis of securities markets, economic and general business and financial conditions prevailing as at the date hereof and the conditions and prospects, financial and otherwise, of the Company and the Acquiror as they are reflected in the Information and as they were represented to us in our discussions with the management and directors of the Company. Certain financial analyses and market data reviewed by Stifel reflected market conditions and trading information as of May 8, 2026.
In our analyses and in connection with the preparation of our Opinion, we made numerous assumptions with respect to industry performance, general business, market and economic conditions and other matters, many of which are beyond the control of Stifel and any party involved in the Arrangement. While, in the professional opinion of Stifel, the assumptions used in preparing the Opinion are reasonable in the current circumstances, some or all of these assumptions may prove to be incorrect. Stifel disclaims any undertaking or obligation to advise any person of any change in any fact or matter affecting the Opinion which may come or be brought to the attention of Stifel after the date hereof. Stifel assumes no obligation to update, revise or reaffirm the Opinion. Without limiting the foregoing, in the event that there is any material change in any fact or matter affecting the Opinion after the date hereof, Stifel reserves the right to change, modify or withdraw the Opinion.
This Opinion is addressed to and is for the sole use and benefit of the Special Committee and may not be referred to, summarized, circulated, publicized or reproduced or disclosed to or used or relied upon by any other party or for any other purpose without the express written consent of Stifel, other than in the Circular in its entirety and a summary thereof (in a form acceptable to us, acting reasonably). This Opinion does not create any fiduciary duty or other legal relationship between Stifel and the Gold Basin Shareholders or any other person, and no Gold Basin Shareholder or any other person is entitled to rely on this Opinion in making any investment or voting decision. This Opinion is not to be construed or used as a recommendation to Gold Basin Shareholders to vote in favour or against the Arrangement. The Opinion does not address the individual circumstances of any particular Gold Basin Shareholder, including tax consequences, and each Gold Basin Shareholder should make its own determination regarding the Arrangement based on its own circumstances and independent advice.
This Opinion has been prepared in accordance with the disclosure standards for formal valuations and fairness opinions of the Canadian Investment Regulatory Organization (“CIRO”), but CIRO has not been involved in the preparation or review of this Opinion.
All dollar amounts herein are expressed in Canadian dollars, unless stated otherwise. Certain figures have been rounded for presentation purposes.
Description of Gold Basin
Gold Basin is a Canadian exploration company focused on advancing its 100% owned Gold Basin property located in Arizona, USA. Gold Basin is an oxide gold project in the Walker Lane Trend, which is one of the most productive gold belts in the United States. Its shares were previously listed and posted for trading on the TSX Venture Exchange under the trading symbol “GXX”. A cease trade order was issued by the British Columbia Securities Commission on May 6, 2025, against Gold Basin for failing to file certain outstanding continuous disclosure documents prescribed by applicable securities laws. Stifel has assumed that the cease trade order does not impair the completeness or accuracy of the Information provided directly by the Company to Stifel, and that all information that would otherwise have been publicly filed during the period of the cease trade order has been provided to Stifel in its entirety.
Stifel has been advised that, prior to the Arrangement, the Company has experienced certain regulatory, financial, operational and governance challenges, including the cease trade order described above, which formed part of the overall context in which the Arrangement and the Consideration were evaluated.
Description of CANEX
CANEX is a Canadian exploration company focused on advancing its 100% owned Gold Range property located in Arizona, USA. It also has option agreements to earn 100% ownership in the Louise and Gibson properties, both in British Columbia, Canada. CANEX has a market capitalization of approximately C$55 million and enterprise value of approximately C$51 million. Its shares are listed and posted for trading on the TSX Venture Exchange under the trading symbol “CANX”.
Approach to Fairness
In support of the Opinion, Stifel has performed a variety of financial and comparative analyses based on the methodologies and assumptions that Stifel considered appropriate in the circumstances for the purposes of providing its Opinion. Stifel has not attributed any particular weight to any specific analysis or factor, but rather has made qualitative judgments based on its experience in rendering such opinions and on the circumstances and Information as a whole. No single analysis or factor was determinative and Stifel applied its professional judgment in evaluating the relative significance of the analyses and factors considered in the aggregate. Stifel believes that its analyses must be considered as a whole and that selecting portions of the analyses or the factors considered by it, without considering all factors and analyses together, could create a misleading view of the process underlying the Opinion.
In rendering the Opinion, Stifel also considered certain qualitative factors relating to the Company, the Acquiror, the Arrangement and the surrounding circumstances, including regulatory, financial, operational and market considerations, as part of its overall evaluation of the Consideration, although no particular weight was attributed to any specific qualitative factor.
As part of the financial and comparative analyses and investigations carried out in the preparation of the Opinion, Stifel reviewed and considered the items outlined under “Scope of Review”. In the context of the Opinion, Stifel has considered, among other things, the following matters, among others:
Hectare Analysis
Gold Basin Hectares
Gold Basin owns the Gold Basin property which contains the following hectares (the “Gold Basin Hectares”) as per public disclosure:
| Property | Hectares | ||
| Gold Basin | 4,200 |
CANEX Hectares
CANEX 100% owns or has option agreements in place to own 100% of the properties below which contain the following hectares (the “CANEX Hectares”) as per public disclosure:
| Property | Hectares | ||
| Gold Range | 1,650 | ||
| Louise | 5,363 | ||
| Gibson | 887 |
Consideration Analysis
In evaluating the Acquiror Shares to be issued as the Consideration, Stifel compared the value range of Acquiror Shares with their current trading price per share.
Stifel reviewed publicly traded precious metals exploration stage companies and compared those companies to CANEX on several bases, including jurisdiction and stage of development. Stifel primarily analyzed the multiple of enterprise value to hectares based on public disclosure. Stifel considered the following publicly traded companies for the purposes of the comparable trading analysis (the “CANEX Comparable Companies”):
| Arizona Gold and Silver Inc. | Almadex Minerals Ltd. | American Pacific Mining Corp. |
| Eminent Gold Corp. | Headwater Gold Inc. | North Peak Resources Ltd. |
| Phenom Resources Corp. | Riley Gold Corp. | Ridgeline Minerals Corp. |
| Sierra Nevada Gold Inc. |
Stifel calculated the range and median of multiples observed below:
| Low | High | Average | Median | |||||||||||||
| EV / Hectare | $ | 1,310 | $ | 66,111 | $ | 13,894 | $ | 6,820 | ||||||||
Stifel selected the representative multiple range described below:
| Representative Range | |||
| EV / Hectare | $3,151 - $12,311 |
Stifel calculated the range and median of multiples observed and selected a representative multiple range which was then applied to the Company’s respective values to calculate an implied range of share prices for the Company summarized in the table below:
| Representative Range | Reference Range (C$) | |||||||||||||||
| Method | Low | High | Low | High | ||||||||||||
| EV / Hectare | $ | 3,151 | $ | 12,311 | $ | 0.133 | $ | 0.466 | ||||||||
No company utilized in the comparable trading analysis is identical to the Acquiror. Accordingly, an analysis of the results of the foregoing necessarily involves complex considerations and judgements concerning the differences between the Acquiror and the companies to which it is being compared as well as other factors that could affect trading values.
In evaluating the Consideration, Stifel has made no downward adjustment to reflect the liquidity of the Acquiror Shares or the effect of the Arrangement on the Acquiror Shares or their marketability.
Stifel has not evaluated the liquidity, trading depth or marketability of the Acquiror Shares, or the ability of shareholders to sell such shares in the market at prevailing prices and expresses no view as to the price or timing at which such shares may be sold. Stifel notes that the trading price and liquidity of the Acquiror Shares may be subject to volatility and may not be indicative of the price at which such shares could be sold in the market in significant volumes. The Consideration consists of common shares of the Acquiror, the value of which will fluctuate based on market conditions; Stifel has not assumed any specific level of liquidity or trading price at which such shares may be sold and has not considered the impact of any potential market dislocation or trading constraints on the ability of shareholders to realize value.
The Acquiror Shares closed at C$0.255 on May 8, 2026.
Comparable Trading Analysis
Stifel reviewed publicly traded precious metals exploration stage companies and compared those companies to Gold Basin on several bases, including jurisdiction and stage of development. Stifel primarily analyzed the multiple of enterprise value to hectares based on public disclosure. Stifel considered the following publicly traded companies for the purposes of the comparable trading analysis (the “Gold Basin Comparable Companies”):
| Arizona Gold and Silver Inc. | Almadex Minerals Ltd. | American Pacific Mining Corp. |
| Eminent Gold Corp. | Headwater Gold Inc. | North Peak Resources Ltd. |
| Phenom Resources Corp. | Riley Gold Corp. | Ridgeline Minerals Corp. |
| Sierra Nevada Gold Inc. |
Stifel calculated the range and median of multiples observed below:
| Low | High | Average | Median | |||||||||||||
| EV / Hectare | $ | 1,310 | $ | 66,111 | $ | 13,894 | $ | 6,820 | ||||||||
Stifel selected the representative multiple range described below:
| Representative Range | |||
| EV / Hectare | $3,151 - $12,311 |
Stifel calculated the range and median of multiples observed and selected a representative multiple range which was then applied to the Company’s respective values to calculate an implied range of share prices for the Company summarized in the table below:
| Representative Range | Reference Range (C$) | |||||||||||||||
| Method | Low | High | Low | High | ||||||||||||
| EV / Hectare | $ | 3,151 | $ | 12,311 | $ | 0.096 | $ | 0.381 | ||||||||
No company utilized in the comparable trading analysis is identical to the Company. Accordingly, an analysis of the results of the foregoing necessarily involves complex considerations and judgements concerning the differences between the Company and the companies to which it is being compared as well as other factors that could affect trading values.
In evaluating the Shares, Stifel has made no downward adjustment to reflect the prolonged trading halt of the Shares resulting from the cease trade order. The Shares last closed at C$0.045 on May 6, 2025.
Precedent Transaction Analysis
Stifel reviewed the purchase prices and premium paid in selected precedent transactions that Stifel, based on its experience in the mining industry, considered relevant.
Stifel primarily analyzed (i) the premium paid by the purchaser relative to the most recent share price of the target company (the “Premium to Close”), and (ii) the premium paid by the purchaser relative to the 20-day volume weighted average trading price of the target company (the “Premium to 20-day”). Stifel analyzed these premiums for select transactions since 2014 in which the target companies were pre-production companies.
| Date | Buyer | Target |
| 20-Oct-25 | IAMGOLD Corporation | Mines D’Or Orbec Inc. |
| 19-Oct-25 | IAMGOLD Corporation | Northern Superior Resources Inc. |
| 14-Oct-25 | McEwen Mining Inc. | Canadian Gold Corp. |
| 1-Oct-25 | Gold X2 Mining Inc. | Kesselrun Resources Ltd. |
| 16-Jul-25 | AngloGold Ashanti plc | Augusta Gold Corp. |
| 7-Apr-25 | Wesdome Gold Mines Ltd. | Angus Gold Inc. |
| 28-Oct-24 | Minera Alamos Inc. | Sabre Gold Mines Corp. |
| 2-May-24 | Contango Ore Inc. | HighGold Mining Inc. |
| 5-Dec-23 | IAMGOLD Corporation | Vanstar Mining Resources Inc. |
| 28-Feb-23 | Alamos Gold Inc. | Manitou Gold Inc. |
| 27-Feb-23 | i-80 Gold Corp. | Paycore Minerals Inc. |
| 11-Mar-22 | MAG Silver Corp. | Gatling Exploration Inc. |
| 16-Jan-26 | Mansa Resources Limited | Pasofino Gold Limited |
| 18-Aug-25 | Tombador Iron Limited | GoviEx Uranium Inc. |
| 11-Sep-17 | GFG Resources Inc. | Rapier Gold Inc. |
| 29-Sep-17 | Endeavour Mining plc | Avnel Gold Mining Limited |
| 4-Sep-16 | Endeavour Mining plc | True Gold Mining Inc. |
| 15-Oct15 | Alamos Gold Inc. | Carlisle Goldfields Limited |
| 28-Sep-15 | Starcore International Mines Ltd. | Cortez Gold Corp. |
| 7-Sep-14 | Scorpio Mining Corporation | U.S. Silver & Gold Inc. |
| 8-Sep-14 | Agnico Eagle Mines Limited | Cayden Resources Inc. |
| 1-Sep-14 | Orosur Mining Inc. | Waymar Resources Ltd. |
Stifel calculated the range and median of premiums observed below:
| Low | High | Average | Median | |||||||||||||
| Premium to Close | 4 | % | 116 | % | 52 | % | 47 | % | ||||||||
| Premium to 20-day | (8 | )% | 156 | % | 60 | % | 48 | % | ||||||||
Stifel selected the representative premium range described below:
| Representative Range | |||
| Premium to Close | 27% - 77% | ||
| Premium to 20-day | 33% - 84% |
Stifel calculated the range and median of premiums observed and selected a representative premium range which was then applied to the Company’s respective values to calculate an implied range of share prices for the Company summarized in the table below:
| Representative Range | Reference Range (C$) | |||||||||||||||
| Method | Low | High | Low | High | ||||||||||||
| Premium to Close | 27 | % | 77 | % | $ | 0.057 | $ | 0.080 | ||||||||
| Premium to 20-day | 33 | % | 84 | % | $ | 0.049 | $ | 0.068 | ||||||||
No company or transaction utilized in the precedent transactions analysis is identical to the Company, its assets or the Arrangement. Accordingly, an analysis of the results of the foregoing necessarily involves complex considerations and judgements concerning the differences between the Company, the Acquiror and the Arrangement and the companies and transactions to which they are being compared as well as other factors that could affect transaction values.
In evaluating the Shares, Stifel has made no downward adjustment to reflect the prolonged trading halt of the Shares resulting from the cease trade order. The Shares last closed at C$0.045 on May 6, 2025.
Other Factors Considered
Although not forming part of our financial analysis, Stifel considered a number of other factors deemed relevant in arriving at the Opinion, including the following:
| · | the historical trading prices of the Shares on the TSX-V during the 52-week period ended May 6, 2025, which indicate a 52-week intraday low to high per share price range for the Shares of C$0.02 to C$0.10; |
| · | the premiums implied by the Consideration relative to the closing price and the 20-day volume weighted average trading price of the Shares on the TSX-V as at May 6, 2025, which were approximately 235% and 306% respectively; |
| · | illustrative implied premium scenarios represented by the Consideration based on projections of the Company’s trading performance had the Shares continued to trade post cease trade order in line with the relevant peer group, commodities and mining indices; |
| · | the immediate liquidity afforded to minority shareholders by the Arrangement; and |
| · | Other quantitative and qualitative factors deemed relevant. |
Opinion
Based upon and subject to the foregoing, and such other matters as we considered relevant, it is our opinion, as of the date hereof, that the Consideration to be received by the Gold Basin Shareholders pursuant to the Arrangement is fair, from a financial point of view, to the Gold Basin Shareholders (other than the Acquiror).
Yours very truly,
Appendix G
Interim Order
[See attached]
| NO. | |
| VANCOUVER REGISTRY |
IN THE SUPREME COURT OF BRITISH COLUMBIA
GOLD BASIN RESOURCES CORPORATION
PETITIONER
RE: IN THE MATTER OF SECTION 288 OF THE BUSINESS
CORPORATIONS ACT, S.B.C. 2002, C.57
AND:
IN THE MATTER OF A PROPOSED ARRANGEMENT
INVOLVING GOLD BASIN RESOURCES CORPORATION,
CANEX METALS INC. AND THE SHAREHOLDERS OF
GOLD BASIN RESOURCES CORPORATION
ORDER MADE AFTER APPLICATION
| ) | ) | ||
| ) | ) | ||
| BEFORE ) | ASSOCIATE JUSTICE | ) | May 14, 2026 |
| ) | ) | ||
| ) | ) |
ON THE APPLICATION of the Petitioner, Gold Basin Resources Corporation (the “Petitioner” or “Gold Basin”), pursuant to sections 186 and 288-297 of the Business Corporations Act, S.B.C. 2002, c. 57, as amended (the “BCBCA”), for an Interim Order for directions in seeking approval of a plan of arrangement under Division 5 of Part 9 of the BCBCA (the “Plan of Arrangement”), coming on for hearing at the Law Courts, 800 Smithe Street, Vancouver, British Columbia on May 14, 2026, AND ON HEARING Mark Pontin, counsel for the Petitioner, AND UPON READING the Petition and other materials filed herein AND UPON being advised that it is the intention of Gold Basin to rely upon Section 3(a)(10), of the United States Securities Act of 1933, as amended (the “1933 Act” ) as a basis for an exemption from the registration requirements of the 1933 Act with respect to the exchange of common shares of Gold Basin under the proposed Plan of Arrangement based on the Court’s approval of the Arrangement (as defined below) and determination that the Arrangement is substantively and procedurally fair to the Shareholders (as defined below);
- 2 -
THIS COURT ORDERS that:
DEFINITIONS
| 1. | As used in this order made after application (the “Interim Order”), unless otherwise defined, defined terms have the respective meanings set out in the draft Notice of Special Meeting and Management Information Circular of Gold Basin (the “Circular”) relating to the special meeting of the Shareholders of Gold Basin attached as Exhibit “B” to the Affidavit of [●], sworn May [●], 2026 (the “Gold Basin Affidavit”). |
MEETING
| 2. | Pursuant to sections 289 and 291 of the BCBCA, Gold Basin is authorized and directed to call, a meeting (the “Gold Basin Meeting”) of the holders (the “Shareholders”) of the issued and outstanding common shares (the “Shares”), to be held at 1200 Waterfront Centre, 200 Burrard St., Vancouver, British Columbia on June 4, 2026, at 10:00 a.m. (Vancouver time), subject to any adjournment or adjournments thereof: |
| (a) | to consider and, if thought fit, pass, with or without amendment, the Arrangement Resolution (in the form attached as Appendix A to the Circular which is attached as Exhibit “B” to the Affidavit of [●]) authorizing and approving the Plan of Arrangement pursuant to section 288 of the BCBCA involving CANEX, Gold Basin and the Shareholders; and |
| (a) | to transact such further or other business as may properly come before the Gold Basin Meeting and any adjournment or postponement thereof. |
| 3. | The Gold Basin Meeting shall be called, held and conducted in accordance with the BCBCA, applicable securities legislation, the Circular, and the articles of Gold Basin (the “Articles”), subject to the terms of this Interim Order, and any further order of this Court, and the rulings and directions of the Chair of the Gold Basin Meeting, such rulings and directions not to be inconsistent with this Interim Order and to the extent of any inconsistency or discrepancy between this Interim Order and the terms of any instrument creating or governing or collateral to the Shares, or the Articles, this Interim Order shall govern. |
| 4. | The chair of the Gold Basin Meeting (the “Chair”) shall be the chair of the Board or such other person authorized in accordance with the Articles. The Chair is at liberty to call on the assistance of legal counsel to Gold Basin at any time and from time to time as the Chair of the Gold Basin Meeting may deem necessary or appropriate. |
- 3 -
ADJOURNMENT
| 5. | Notwithstanding the provisions of the BCBCA and the Articles, Gold Basin, if it deems advisable, is specifically authorized to adjourn or postpone the Gold Basin Meeting on one or more occasions without the necessity of first convening the Gold Basin Meeting or first obtaining any vote of the Shareholders respecting the adjournment or postponement and without the need for approval of the Court. Notice of any such adjournments or postponements shall be given by press release, news release, newspaper advertisement, or by notice sent to the Shareholders by the methods specified in paragraph 10 of this Interim Order, as determined to be the most appropriate method of communication by the Board. |
| 6. | The Record Date (as defined in paragraph 8 below) shall not change in respect of adjournments or postponements of the Gold Basin Meeting. |
AMENDMENTS
| 7. | Prior to the Gold Basin Meeting but not later than the Effective Time, CANEX and Gold Basin are authorized to make amendments to the Plan of Arrangement in accordance with the terms of the Arrangement Agreement without any additional notice to the Shareholders or further order of this Court, and the Plan of Arrangement as so amended shall be the Plan of Arrangement submitted to the Gold Basin Meeting and the subject of the Arrangement. |
RECORD DATE
| 8. | The record date for the determination of the registered holders of Shares entitled to receive notice of, and vote at, the Gold Basin Meeting is May 5, 2026 (the “Record Date”). Only Shareholders whose names were entered in the register of Gold Basin at the close of business on the Record Date will be entitled to receive notice of and to vote at the Gold Basin Meeting in respect of the Arrangement. |
NOTICE OF MEETING
| 9. | The Circular is hereby deemed to represent sufficient and adequate disclosure, including for the purpose of section 290(1)(a) of the BCBCA, and Gold Basin shall not be required to send to the Shareholders any other or additional statement pursuant to section 290(1)(a) of the BCBCA. |
| 10. | The Circular, which includes an explanation of the effect of the Arrangement, the Arrangement Resolution, the Plan of Arrangement, copies of the Interim Order, Notice of Hearing of Petition and the Petition, which includes the form of Final Order, the form of proxy for Shareholders and a voting instruction form for beneficial Shareholders (collectively referred to as the “Meeting Materials”) in substantially the same form as contained in Exhibits “B” and “C” to the Affidavit of [●], with such deletions, amendments or additions thereto as may be necessary or desirable, provided that such amendments are not inconsistent with the terms of this Interim Order, shall, if applicable, be sent to: |
| (a) | registered Shareholders as they appear on the central securities register of Gold Basin as at the Record Date at least 21 days prior to the date of the Gold Basin Meeting, excluding the date of mailing, delivery or transmittal and the date of the Gold Basin Meeting, by one or more of the following methods: |
| (i) | by prepaid regular mail addressed to the Shareholders at their address as it appears on the central securities register of Gold Basin as at the Record Date; or |
- 4 -
| (ii) | by email or facsimile transmission to any Shareholders who identifies themselves to the satisfaction of Gold Basin, acting through its representatives, who requests such email or facsimile transmission; and |
| (b) | in the case of non-registered Shareholders, by providing copies of the relevant portions of the Meeting Materials to intermediaries and registered nominees for sending to beneficial owners at least 21 days prior to the date of the Gold Basin Meeting; and |
| (c) | the directors and auditors of Gold Basin by electronic mail or by prepaid regular mail, at least 21 days prior to the date of the Gold Basin Meeting, excluding the date of mailing or transmittal and the date of the Gold Basin Meeting; |
substantial compliance with this paragraph shall constitute good and sufficient notice of the Gold Basin Meeting and these proceedings, and no notice shall be required to be given to any other party. Gold Basin is at liberty to give notice of the Gold Basin Meeting and these proceedings to persons outside the jurisdiction of this Honourable Court in the manner specified herein.
| 11. | Accidental failure of or omission by Gold Basin to give notice to any one or more Shareholders, or any other Person set out in paragraph 10, or the non-receipt of such notice by one or more Shareholders, or any other Person set out in paragraph 10, or any failure or omission to give such notice as a result of events beyond the reasonable control of Gold Basin, shall not constitute a breach of this Interim Order or a defect in the calling of the Gold Basin Meeting, and shall not invalidate any resolution passed or proceeding taken at the Gold Basin Meeting, but if any such failure or omission is brought to the attention of Gold Basin then it shall use reasonable commercial efforts to rectify it by the method and in the time most reasonably practicable in the circumstances. |
| 12. | Provided that notice of the Gold Basin Meeting and the provision of the Meeting Materials to the Shareholders take place in substantial compliance with this Interim Order, the requirement of section 290(1)(b) of the BCBCA to include certain disclosure in any advertisement of the Gold Basin Meeting is waived. |
DEEMED RECEIPT OF NOTICE
| 13. | The Meeting Materials shall be deemed, for the purposes of this Interim Order, to have been served upon and received: |
| (a) | in the case of mailing, the day, Saturdays, Sundays and holidays excepted, following the date of mailing; |
| (b) | in the case of any means of transmitted, recorded or electronic communication, when dispatched or delivered for dispatch; |
| (c) | in the case of non-registered Shareholders, three days after delivery thereof to intermediaries and registered nominees; and |
- 5 -
| (d) | in the case of advertisement, at the time of publication of the advertisement. |
UPDATING MEETING MATERIALS
| 14. | Notice of any amendments, updates or supplement to any of the information provided in the Meeting Materials may be communicated to the Shareholders by press release, news release, newspaper advertisement or by notice sent to the Shareholders by the means set forth in paragraph 10 herein, as determined to be the most appropriate method of communication by the Board. |
QUORUM AND VOTING
| 15. | The votes taken at the Gold Basin Meeting required to pass the Arrangement Resolution shall be: (i) 662/3% of the votes cast on the Arrangement Resolution by the Shareholders present in person or represented by proxy at the Gold Basin Meeting voting together as a single class; and (ii) if required under applicable Law, a simple majority of the votes cast by the Shareholders on the Arrangement Resolution excluding the votes for Shares held or controlled by “related parties” and “interested parties” as defined under MI 61-101; provided that, pursuant to section 8.2 of MI 61-101, the securities acquired by CANEX under the Offer may be voted in favor of the Arrangement Resolution (collectively, the “Requisite Gold Basin Shareholder Approval”). |
| 16. | Provided the conditions precedent to the Arrangement as described in the Circular have been satisfied or waived in accordance with the Arrangement Agreement, as applicable, the Requisite Gold Basin Shareholder Approval shall be sufficient to authorize and direct Gold Basin to do all such acts and things as may be necessary or desirable to give effect to the Plan of Arrangement on a basis consistent with what is provided for in the Circular, in accordance with the Plan of Arrangement, without the necessity of any further approval by the Shareholders, subject only to final approval by this Honourable Court. |
| 17. | The quorum required at the Gold Basin Meeting shall be the quorum required by the Articles, being two persons who are, or who represent by proxy, shareholders who, in the aggregate, hold at least one-twentieth of the issued Shares entitled to be voted at the Gold Basin Meeting. |
| 18. | For the purpose of counting votes respecting the Arrangement Resolution, any spoiled votes, illegible votes, defective votes and abstentions shall be deemed to be votes not cast and the Shares represented by such spoiled votes, illegible votes, defective votes or abstentions shall not be counted in determining the number of Shares represented at the Gold Basin Meeting. Proxies that are properly signed and dated but which do not contain voting instructions shall be voted in favour of the Arrangement Resolution. |
| 19. | A representative of Gold Basin who attends the Gold Basin Meeting shall file in due course with the Court an affidavit verifying the actions taken and the decisions reached by the Shareholders at the Gold Basin Meeting with respect to the Plan of Arrangement. |
- 6 -
PERMITTED ATTENDEES
| 20. | The only persons entitled to attend the Gold Basin Meeting shall be the Shareholders, as of the Record Date or their respective proxyholders, Gold Basin’s directors, officers, auditors and advisors, the scrutineers, and any other persons admitted on the invitation of the Board or on the invitation of the Chair, and the only persons entitled to be represented and to vote at the Gold Basin Meeting shall be the Shareholders as at the close of business (Vancouver Time) on the Record Date, or their respective proxyholders. |
SCRUTINEERS
| 21. | A representative of Gold Basin’s registrar and transfer agent (or any agent thereof), is authorized to act as scrutineer for the Gold Basin Meeting. |
SOLICITATION OF PROXIES
| 22. | Gold Basin is authorized to use the form of proxy in connection with the Gold Basin Meeting in substantially the same form as attached as Exhibit “C” to the Gold Basin Affidavit and the voting methods as set out in the Meeting Materials, and Gold Basin may in its discretion waive generally the time limits for deposit of proxies by Shareholders if Gold Basin deems it reasonable to do so. Gold Basin is authorized, at its expense, to solicit proxies, directly and through its officers, directors and employees, and through such agents or representatives as it may retain for that purpose, and by mail or such other forms of personal or electronic communication as may be determined. |
| 23. | The procedure for the use of proxies at the Gold Basin Meeting, including the time limit for place of deposit, the voting methods and revocation of proxy, shall be as set out in the Meeting Materials. Gold Basin may in its discretion waive the time limits for the deposit of proxies by Shareholders if Gold Basin deems it advisable to do so, such waiver to be endorsed on the proxy by the initials of the Chair of the Gold Basin Meeting. |
DISSENT RIGHTS
| 24. | Each of the registered Shareholders as of the Record Date, shall have the right to dissent (a “Dissenting Shareholder”) in respect of the Arrangement Resolution in accordance with sections 237 to 247 of the BCBCA, as varied by the Plan of Arrangement, this Interim Order and the Final Order (the “Dissent Rights”). |
| 25. | In order for a registered Shareholder to exercise his, her or its Dissent Rights: |
| (a) | notwithstanding section 242(1)(a) of the BCBCA, a Dissenting Shareholder shall deliver a written notice to Gold Basin, c/o Fasken Martineau DuMoulin LLP, at 2900 - 550 Burrard St. Vancouver, BC V6C 0A3, Canada, to the attention of Mark Pontin, by 5:00 pm, Vancouver time, on June 2, 2026 or the business day that is two business days before the Gold Basin Meeting or any date to which the Gold Basin Meeting may be postponed or adjourned. |
| (b) | a Dissenting Shareholder must dissent with respect to dissent with respect to all Shares in which the holder owns a beneficial interest; and |
- 7 -
| (c) | any such exercise of the Dissent Rights must otherwise comply with the requirements of sections 237–247 of the BCBCA, as modified by the Plan of Arrangement and this Interim Order. |
| 26. | Notice to the Shareholders of their Dissent Rights with respect to the Arrangement Resolution and their right to receive, subject to the provisions of the BCBCA and the Plan of Arrangement, the fair value of their Shares shall be given by including information with respect to this right in the Circular to be sent to the Shareholders in accordance with the Interim Order. |
| 27. | None of the Shareholders who vote or have instructed a proxyholder to vote the Shares in favour of the Arrangement Resolution shall be entitled to exercise their Dissent Rights. |
| 28. | Subject to this Interim Order and further order of this Court, the rights available to the Shareholders under the BCBCA and the Plan of Arrangement to dissent from the Arrangement will constitute full and sufficient Dissent Rights for the Shareholders with respect to the Arrangement. |
APPLICATION FOR FINAL ORDER
| 29. | Upon the approval, with or without variation by the Shareholders, of the Arrangement, in the manner set forth in this Interim Order, Gold Basin may apply to this Court for, inter alia, an Order that: |
| (a) | the Arrangement, and its terms and conditions, be approved; |
| (b) | the Arrangement be implemented in the manner and sequence set forth in the Plan of Arrangement, and pursuant to sections 291, 292 and 296 of the BCBCA, the Arrangement will take effect as of the Effective Time (as defined in the Plan of Arrangement); |
| (c) | declares that the terms and conditions of the Arrangement, including the exchange of shares to be effected by completion of the Arrangement, are procedurally and substantively fair and reasonable to the Shareholders; |
| (d) | the Arrangement shall be binding on CANEX, Gold Basin and the Shareholders upon the taking effect of the Arrangement pursuant to section 297 of the BCBCA; and |
| (e) | Gold Basin shall be entitled to seek the advice and direction of this Court as to the implementation of this Order or to apply for such further Order or Orders as may be appropriate (collectively, the “Final Order”). |
| 30. | Gold Basin is at liberty to proceed with the hearing of the Final Order on June 8, 2026 at 9:45 a.m. (Vancouver Time) at the Courthouse at 800 Smithe Street, Vancouver, British Columbia or as soon thereafter as the hearing of the Final Order can be heard or at such other date and time as Gold Basin may determine or this Court may direct. |
- 8 -
| 31. | Any Shareholder desiring to support or oppose the application has the right to appear (either in person or by counsel) and make submissions at the hearing of the application for the Final Order, subject to filing a Response to Petition and delivering a copy of the filed Response to Petition together with a copy of any additional affidavits or other materials on which the person intends to rely at the hearing for the Final Order on or before 4:00 p.m. (Vancouver Time) on June 4, 2026, to the solicitors for the Petitioner at: |
FASKEN MARTINEAU DuMOULIN LLP
Suite 2900, 550 Burrard Street
Vancouver, BC V6C 0A3
Attention: Mark Pontin
| 32. | Sending the Petition and this Interim Order, attached to the Circular in accordance with paragraph 10 of this Interim Order, shall constitute good and sufficient service of the within proceedings and no other form of service need be made and no other material need be served on such persons in respect of these proceedings and service of the affidavits, including the Gold Basin Affidavit, is dispensed with. Gold Basin shall be at liberty to give notice of this Petition to persons outside the jurisdiction of this Court in the manner specified herein. |
| 33. | In the event the hearing for the Final Order is adjourned, only those persons who have filed and delivered a Response to Petition in accordance with this Interim Order need be provided notice of materials filed in this proceeding and the adjourned hearing date. |
VARIANCE
| 34. | Gold Basin shall be entitled, at any time, to apply to vary this Interim Order and apply for such other orders and direction from the Court as may be appropriate. |
| 35. | Supreme Court Civil Rules 8-1 and 16-1(3) will not apply to any further applications in respect of this proceeding, including the application for the Final Order and any application to vary this Interim Order. |
THE FOLLOWING PARTIES APPROVE THE FORM OF THIS ORDER AND CONSENT TO EACH OF THE ORDERS, IF ANY, THAT ARE INDICATED ABOVE AS BEING BY CONSENT:
- 9 -
| Signature of | ||
| x Lawyer for the Petitioner, Gold Basin Resources Corporation | ||
| MARK PONTIN | ||
| BY THE COURT | ||
| REGISTRAR |
No. ___________
Vancouver Registry
IN THE SUPREME COURT OF BRITISH COLUMBIA
GOLD BASIN RESOURCES CORPORATION
PETITIONER
RE: IN THE MATTER OF SECTION 288 OF THE
BUSINESS CORPORATIONS ACT, S.B.C. 2002, C. 57
ORDER MADE AFTER APPLICATION
FASKEN MARTINEAU DuMOULIN LLP
Barristers and Solicitors
550 Burrard Street, Suite 2900
Vancouver, BC, V6C 0A3
+1 604 631 3131
Counsel: Mark Pontin
Appendix H
Notice of Hearing of Petition
[See attached]
No. S-257170
Vancouver Registry
IN THE SUPREME COURT OF BRITISH COLUMBIA
GOLD BASIN RESOURCES CORPORATION
PETITIONER
RE: IN THE MATTER OF SECTION 288 OF THE BUSINESS
CORPORATIONS ACT, S.B.C. 2002, C.57
AND:
IN THE MATTER OF A PROPOSED ARRANGEMENT
INVOLVING GOLD BASIN RESOURCES CORPORATION,
CANEX METALS INC. AND THE SHAREHOLDERS OF
GOLD BASIN RESOURCES CORPORATION
NOTICE OF HEARING
| To: | Without Notice |
TAKE NOTICE that the Petition of Gold Basin Resources Corporation dated May 12, 2026 will be heard at the courthouse at 800 Smithe Street, Vancouver B.C on June 8, 2026 at 9:45 a.m.
| 1. | Date of hearing |
| x | The Petition is unopposed, by consent or without notice. |
| 2. | Duration of hearing |
| x | The parties have been unable to agree as to how long the hearing will take and |
| (a) | the time estimate of the Petitioner’s is 20 minutes, and |
| (b) | the Petition Respondent’s have not given a time estimate. |
| 3. | Jurisdiction |
| ¨ | This matter is within the jurisdiction of an Associate Judge. |
| x | This matter is not within the jurisdiction of an Associate Judge. |
| Dated: | June 8, 2026 | ||
| Signature of ¨ Petitioner x Lawyer for Petitioner, Gold Basin Resources Corporation | |||
| Mark Pontin |
The Solicitors for the Petitioner are Fasken Martineau DuMoulin LLP, whose office address and address for delivery is 550 Burrard Street, Suite 2900, Vancouver, BC V6C 0A3 Telephone: +1 604 631 3131 Facsimile: +1 604 631 3232 E-mail: mpontin@fasken.com (Reference: Mark Pontin)
Appendix I
Petition
[See attached]
| No. | |
| Vancouver Registry |
IN THE SUPREME COURT OF BRITISH COLUMBIA
GOLD BASIN RESOURCES CORPORATION
PETITIONER
RE: IN THE MATTER OF SECTION 288 OF THE BUSINESS
CORPORATIONS ACT, S.B.C. 2002, C.57
AND:
IN THE MATTER OF A PROPOSED ARRANGEMENT
INVOLVING GOLD BASIN RESOURCES CORPORATION,
CANEX METALS INC. AND THE SHAREHOLDERS OF
GOLD BASIN RESOURCES CORPORATION
Re: Gold Basin Resources Corporation
PETITION TO THE COURT
WITHOUT NOTICE
The address of the registry is: 800 Smithe Street Vancouver, B.C.
The petitioner estimates that the hearing of the petition will take 20 minutes.
| ¨ | This matter is an application for judicial review. |
| x | This matter is not an application for judicial review. |
This proceeding is brought for the relief set out in Part 1 below, by
| ¨ | the person(s) named as petitioner(s) in the style of proceedings above |
| x | Gold Basin Resources Corporation (the petitioner) |
| If you intend to respond to this Petition, you or your lawyer must |
| (a) | file a Response to Petition in Form 67 in the above-named registry of this Court within the time for Response to Petition described below, and |
| (b) | serve on the Petitioner |
| (i) | 2 copies of the filed Response to Petition, and |
| (ii) | 2 copies of each filed Affidavit on which you intend to rely at the hearing. |
- 2 -
Orders, including orders granting the relief claimed, may be made against you, without any further notice to you, if you fail to file the Response to Petition within the time for response.
Time for Response to Petition
A Response to Petition must be filed and served on the petitioner
| (a) | if you were served with the petition anywhere in Canada, within 21 days after that service, |
| (b) | if you were served with the petition anywhere in the United States of America, within 35 days after that service, |
| (c) | if you were served with the petition anywhere else, within 49 days after that service, or |
| (d) | if the time for response has been set by Order of the Court, within that time. |
| (1) | The ADDRESS FOR DELIVERY is: |
Fasken Martineau DuMoulin LLP 2900 - 550 Burrard Street Vancouver, B.C. V6C 0A3
Fax number for delivery is: n/a E-mail address for service is: n/a | |
| (2) | The name and office address of the Petitioner’s Solicitor is: |
Mark Pontin Fasken Martineau DuMoulin LLP 2900 - 550 Burrard Street Vancouver, B.C. V6C 0A3 Telephone: 604 631 3131. (Reference: 346669.00001/15283) |
CLAIM OF THE PETITIONER
Part 1:ORDERS SOUGHT
1. An order (the “Interim Order”) pursuant to sections 186 and 288-297 of the Business Corporations Act, S.B.C., 2002, c. 57 (the “BCBCA”) and Rules 2-1, 4-4, 4-5 and 16-1 of the Supreme Court Civil Rules, in the form attached as Appendix “A” providing directions for, inter alia:
| (a) | the convening and conduct by the Petitioner, Gold Basin Resources Corporation (the “Petitioner” or “Gold Basin”), of a special meeting (the “Gold Basin Meeting”) of the holders (the “Shareholders”) of the issued and outstanding common shares (the “Shares”), to be held at 1200 Waterfront Centre, 200 Burrard St., Vancouver, British Columbia on June 4, 2026, at 10:00 a.m. (Vancouver time), subject to any adjournment or adjournments thereof, to (i) consider and, if thought fit, pass, with or without amendment, the Arrangement Resolution authorizing and approving the Plan of Arrangement pursuant to section 288 of the BCBCA involving CANEX Metals Inc. (“CANEX”), Gold Basin and the Shareholders and (ii) transact such further and other business as may properly be brought before the Gold Basin Meeting or any adjournment or postponement thereof; |
- 3 -
| (b) | the giving of notice of the Gold Basin Meeting and the provision of materials regarding the Arrangement to the Shareholders. |
| 2. | An order (the “Final Order”) pursuant to sections 288-297 of the BCBCA, Rules 2-1, 16-1, 4-4 and 4-5 of the Supreme Court Civil Rules, and the inherent jurisdiction of the Court that, inter alia: |
| (a) | the Arrangement, and its terms and conditions, be approved; |
| (b) | the Arrangement be implemented in the manner and sequence set forth in the Plan of Arrangement, and pursuant to sections 291, 292 and 296 of the BCBCA, the Arrangement will take effect as of the Effective Time (as defined in the Plan of Arrangement); |
| (c) | a declaration that the terms and conditions of the Arrangement, including the exchange of shares to be effected by completion of the Arrangement, are fair and reasonable; and |
| (d) | that the Arrangement shall be binding on CANEX, the Petitioner and the Shareholders upon taking effect pursuant to section 297 of the BCBCA; and |
| 3. | Such further and other relief as counsel may advise and this Honourable Court may deem just. |
Part 2: FACTUAL BASIS
DEFINITIONS
| 4. | As used in this Petition, unless otherwise defined, terms beginning with capital letters have the respective meaning set out in the Notice of Special Meeting and Management Information Circular of Gold Basin (the “Circular”) attached as Exhibit “B” to the Affidavit of Chantelle Collins, sworn May 12, 2026. |
- 4 -
THE PARTIES
Gold Basin Resources Corporation
| 5. | Gold Basin is a mineral exploration company focused on advancing its district-scale Gold Basin Project in Mohave County, Arizona. Gold Basin’s exploration efforts are focused on delineating and expanding near- surface oxide gold deposits. Gold Basin was incorporated under the BCBCA and its registered and head office located at 1200 Waterfront Centre, 200 Burrard Street, Vancouver, British Columbia, Canada. Prior to the Halt in trading ordered by CIRO on May 7, 2025, the Shares traded on the TSX Venture Exchange (the “TSXV”) under the symbol “GXX”. The Shares also are quoted on the OTC Market under the symbol “GXXFF”. |
CANEX Metals Inc.
| 6. | CANEX is a junior mineral exploration company focused on advancing the 100% owned Gold Range Project in Mohave County, Arizona and the Louise Project in British Columbia. Since inception, the efforts of CANEX have been devoted to the acquisition, exploration, and development of mineral properties. CANEX exists under the Business Corporations Act (Alberta) and its head and registered office is located at Suite 1620, 734 – 7th Avenue SW, Calgary, Alberta T2P 3P8, Canada. The common shares of CANEX (the “CANEX Shares”) trade on the TSXV under the symbol “CANX” and are quoted on the OTC Market under the symbol “NOMNF”. |
OVERVIEW OF THE ARRANGEMENT
| 7. | Gold Basin proposes, in accordance with sections 186, 289 and 291 of the BCBCA and the Interim Order, to call, hold and conduct the Gold Basin Meeting. |
| 8. | At the Gold Basin Meeting, the Shareholders shall, among other things: |
| (a) | consider and, if thought fit, pass, with or without amendment, the Arrangement Resolution (in the form attached as Appendix A to the Circular which is attached as Exhibit “B” to the Affidavit of Chantelle Collins) authorizing and approving the Plan of Arrangement pursuant to section 288 of the BCBCA involving CANEX, Gold Basin and the Shareholders; and |
| (b) | transact such further or other business as may properly come before the Gold Basin Meeting and any adjournment or postponement thereof. |
| 9. | The purpose of the Arrangement is to effect the combination of the businesses of CANEX and Gold Basin through the acquisition by CANEX of all of the issued and outstanding Shares, other than the Shares already owned or controlled by CANEX or an affiliate of CANEX. |
- 5 -
| 10. | If approved, the Arrangement will become effective at the Effective Time, which is expected to be at the beginning of the day (Vancouver time) on the Effective Date or such other time as Gold Basin and CANEX may agree upon in writing. At the Effective Time, the following shall occur or be deemed to occur sequentially in the following order: |
| (a) | each Share issued and outstanding held by a Dissenting Shareholder as of the Record Date shall be and shall be deemed to be transferred by the holder thereof, free and clear of all liens, to Gold Basin for cancellation and Gold Basin (with Gold Basin funds not directly or indirectly provided by CANEX or any affiliate of CANEX) shall thereupon be obliged to pay the amount therefor determined and payable in accordance with the Arrangement Agreement between CANEX and Gold Basin dated May 11, 2026 (the “Arrangement Agreement”), and such Dissenting Shareholder shall cease to have any rights as a Shareholder other than the right to be paid the amount for such Dissenting Shareholder’s Shares determined in accordance with the Arrangement Agreement and the name of such holder shall be removed from the central securities register of Gold Basin as a Shareholder; |
| (b) | each Share held by a Former Shareholder shall be transferred by the holder thereof to CANEX in exchange for 0.592 of a CANEX Share in accordance with the terms and conditions set forth in the take over bid offer and circular of CANEX dated August 28, 2025, as amended by the notice of variation, change and extension dated December 12, 2025, the notice of variation, change and extension dated January 9, 2026, the notice of variation, change and extension dated January 19, 2026, and the notice of variation, change and extension dated January 30, 2026 and subject to the Arrangement Agreement, and upon such exchange: |
| (i) | the Former Shareholders shall cease to be holders of Shares and to have any rights as holders of such Share other than the right to be paid the Share Consideration in accordance with the Plan of Arrangement; |
| (ii) | the names of the Former Shareholders shall be removed from the register of Shareholders and added to the register of holders of CANEX Shares; |
| (iii) | CANEX shall become the holder of the Shares so exchanged and shall be added to the register of Shareholders as the registered holder of such Shares; |
| (c) | Gold Basin will file an election with the CRA to cease to be a public corporation for the purposes of the Tax Act; and |
| (d) | the exchanges, transfers and cancellations provided under the Arrangement Agreement will be deemed to occur on the Effective Date, notwithstanding that certain of the procedures related thereto are not completed until after the Effective Date. |
BACKGROUND AND FAIRNESS OF THE ARRANGEMENT
| 11. | The execution of the Arrangement Agreement was the result of arm’s length negotiations among representatives and legal and financial advisors of CANEX and Gold Basin. |
- 6 -
| 12. | CANEX has had discussions with Gold Basin regarding potential merger opportunities and the relative valuation of the companies since 2022. During 2023 and 2024, various meetings were held between CANEX’s and Gold Basin’s board of directors (the “Board”) and management regarding the potential consolidation of the Gold Basin exploration district. While a number of Gold Basin’s then directors were supportive of merging the district, Gold Basin’s Australia-based management were mostly opposed, but at times would express interest, especially when Gold Basin was financially constrained. In September 2023, Gold Basin proposed a merger at a 1:3.75 exchange ratio, which represented a zero percent premium and was CANEX rejected as undervaluing CANEX. Discussions did not progress. |
| 13. | From September 2023 to November 2024, the market price of the Shares on the TSXV declined by approximately 80%, and Gold Basin’s interim financial statements for the period ended September 30, 2024 revealed a substantial reduction in cash and material increase in debt. On November 28, 2024, CANEX submitted a non-binding proposal to merge, offering a cash-and-share transaction, with an effective merger ratio of 52.4% CANEX: 47.6% Gold Basin, with CANEX paying $1,000,000 of Gold Basin’s debt, representing a 60% premium to the November 27, 2024 closing price of the Shares and a 25% premium to the 30-day volume weighted average market price of the Shares. Gold Basin rejected this proposal. |
| 14. | On February 20, 2025, Mayfair Acquisition Corp. (“Mayfair”) proposed and, on March 20, 2025 publicly announced, a three-way business combination and take-over bid for CANEX and Gold Basin on an equal valuation basis (the “Mayfair Offer”). The Mayfair Offer was supported by significant Shareholders and an alliance of mineral exploration and development companies, including Aquitaine Metals Corp., CopperEx Resources Corp., Defense Metals Corp., K2 Gold Corp., Kodiak Copper Corp., Prospector Metals Corp. and ValOre Metals Corp (collectively, the “Discovery Group”). |
| 15. | On March 28, 2025, Helix Resources Limited (“Helix”) announced agreements to acquire the White Hills Project, adjacent to the Gold Basin Project, from entities beneficially owned by Charles Straw, then President, interim Chief Executive Officer and a director of Gold Basin, and Calvin Heron, for A$200,000 in cash and A$1.3 million in common shares of Helix. On April 28, 2025, Gold Basin entered into a binding farm-in agreement with Helix granting Helix the right to earn a minority interest in the Gold Basin Project. |
| 16. | On May 1, 2025, Mayfair announced that it was “assessing its alternatives including litigation and regulatory complaints” due to the current regulatory issues facing Gold Basin, as well as certain transactions involving Gold Basin and its current and former senior management which Mayfair questioned as involving “apparent self-dealing and conflicts of interest”. |
| 17. | On May 6, 2025, the British Columbia Securities Commission issued a cease trade order against Gold Basin for failure to file required continuous disclosure (the “Cease Trade Order”), and trading was halted the following day. |
- 7 -
| 18. | On June 9, 2025, CANEX announced its intention to proceed with a formal take-over bid on similar terms, with a 0.871 exchange ratio (the “Proposed Offer”). The Proposed Offer valued Gold Basin at $8,570,000 based on the closing price of the CANEX Shares on June 6, 2025, implying a roughly 41% premium to the closing price of the Shares on the TSXV prior to the Cease Trade Order. Based on the 30-day volume weight average market price of the CANEX Shares as of June 6, 2025 and the 30-day volume weighted average market price of the Shares prior to the Cease Trade Order, the Proposed Offer implied a roughly 21% premium. |
| 19. | Following improved CANEX market performance, CANEX commenced a formal offer on August 28, 2025 (the “Offer”) at a revised 0.592 exchange ratio, representing a 24.2% premium to the 30-day volume weighted average price of the Shares prior to the Cease Trade Order, based on the 30-day volume weighted average price of the CANEX Shares as of August 27. On August 21, 2025, Mayfair announced that it would no longer pursue the Mayfair Offer and that representatives of the Discovery Group who were supporting the Mayfair Offer would support the Offer. |
| 20. | On February 10, 2026, CANEX completed the Offer. CANEX took up a total of 70,088,199 Shares, representing 51.86% of the issued and outstanding Shares, and issued 41,492,194 CANEX Shares to the Shareholders. On March 16, 2026, following a court-ordered meeting, a new board and management team of Gold Basin were appointed, replacing the prior board. |
| 21. | On March 29, 2026, CANEX submitted a further non-binding proposal to acquire the remaining Shares and complete the acquisition of Gold Basin. |
| 22. | On April 2, 2026, the Special Committee of Gold Basin was formed, with Jordan Ross as its chair and the Special Committee retained Fasken as independent legal counsel to the Special Committee. |
| 23. | Between April 2, 206 and April 6, 2026, Gold Basin and its counsel reviewed and negotiated with CANEX and its counsel he non-binding express of interest and related exclusivity agreement and confidentiality agreement |
| 24. | On April 6, 2026 CANEX and Gold Basin signed the non-binding express of interest and related exclusivity agreement and confidentiality agreement. |
| 25. | On April 15, 2026, the Special Committee engaged Stifel as its financial advisor and to prepare the Fairness Opinion. |
| 26. | Between April 6, 2026 and May 11, 2026 CANEX and its legal counsel, on the one hand and Gold Basin and its legal counsel, on the other hand, negotiated the Term Loan and Arrangement Agreement with the Arrangement Agreement being finalized and executed on May 11, 2026. |
| 27. | On May 11, 2026, Stifel provided the Fairness Opinion to the Special Committee and the Board and the Board unanimously determined (with interested directors declaring their interest and abstaining from voting) after consideration of, among other factors, the Fairness Opinion, that the Arrangement was fair to Company Shareholders (other than CANEX and its affiliates) and that the Arrangements is in the best interests of Gold Basin and approved the Arrangement Agreement. |
- 8 -
Recommendation of the Special Committee and the Board
| 28. | The Special Committee composed of Jordan Ross, an independent director of Gold Basin (as defined in MI 61-101), was formed to, among other things, examine and review the merits of a possible transaction involving CANEX and Gold Basin and to consider other available strategic alternatives in conjunction with management and Gold Basin’s professional advisors and make recommendations to the Board with respect to any such proposed transactions. |
| 29. | After careful consideration, including a thorough review of the Arrangement Agreement, the Fairness Opinion, as well as a thorough review of other materials and information, including matters discussed in the Circular, and taking into account the best interests of Gold Basin and in consultation with its legal advisors, the Special Committee unanimously recommended to the Board that the Board determine that the Share Consideration to be received by the Shareholders (other than CANEX and its affiliates) is fair, from a financial point of view, to the Shareholders (other than CANEX and its affiliates), that the Arrangement is in the best interests of Gold Basin, that the Arrangement Agreement and the Plan of Arrangement contemplated therein be unanimously approved, that Gold Basin enter into the Arrangement Agreement and for the Board to take all reasonable action to facilitate the Arrangement, and that the Board unanimously recommend that the Shareholders approve the Arrangement and vote in favour of the resolution approving the Arrangement. |
| 30. | After careful consideration, including a thorough review of the Arrangement Agreement, the Fairness Opinion, as well as a thorough review of other matters, including those discussed in the Circular, and on the unanimous recommendation of the Special Committee, the Board unanimously determined that the acquisition to be effected by way of the Plan of Arrangement is in the best interests of Gold Basin, that the Consideration Shares to be received by the Shareholders (other than CANEX and its affiliates) pursuant to the Arrangement is fair, from a financial point of view, to the Shareholders (other than CANEX and its affiliates) and has unanimously approved the transactions contemplated by the Arrangement Agreement. |
| 31. | In reaching a conclusion that the Arrangement is in the best interest of Gold Basin, and in making their recommendations to the Shareholders, the Board and the Special Committee considered and relied upon a number of factors, including: |
| (a) | Significant Upfront Premium to Shareholders. The consideration offered under the Arrangement represents a 242.0% premium to the last trading price of the Shares prior to the Cease Trade Order, based on the closing price of the CANEX Shares as of May 8, 2026. |
| (b) | Consolidation of Gold Districts and Near-Term Exploration and Expansion. The Arrangement will consolidate an advanced oxide gold exploration camp in Mohave County, Arizona hosting multiple zones of gold mineralization with strong drill results across an eight kilometre by eight kilometre area, opening up potential near-term exploration on favourable targets. |
- 9 -
| (c) | G&A Cost Savings. The complementary assets of Gold Basin and CANEX are expected to create synergies for the Resulting Issuer, including general and administrative cost savings to the Resulting Issuer of approximately $250,000 per year. These savings will be realized from a reduction of duplicate management roles and administrative expenses, and are expected to be fully realized in 2027. |
| (d) | Diversification. Completing the Arrangement will provide Shareholders not only with exposure to a consolidated gold district in Mohave County, Arizona, but also to the Resulting Issuer’s Louise Project in British Columbia. On July 31, 2025, CANEX announced results from an induced polarization geophysical survey which identified a new and previously unknown chargeability target two kilometres west of the historic Louise Project deposit and a steeply dipping zone of high chargeability below and to the north of the historic Louise Project deposit. |
| (e) | Focused, Professional and Cost-Effective Management Team. The Arrangement places the consolidated district under CANEX’s highly focused, professional and cost-effective management team, which will provide strong operational and governance oversight. |
| (f) | Experienced Board of Directors. Following the Arrangement, the Resulting Issuer’s board of directors will be led by experienced industry professionals, comprised of members of the current board of directors of CANEX. |
| (g) | Liquidity. The Arrangement will provide Shareholders with a more liquid investment. Trading in the Shares is restricted. On May 6, 2025, the British Columbia Securities Commission imposed the Cease Trade Order against the Shares. The next day, CIRO imposed the Halt in trading of the Shares on the TSXV. The CANEX Shares trade on the TSXV under the symbol “CANX” and are quoted on the OTC Market under the symbol “NOMNF”. CANEX has applied to list the CANEX Shares issuable pursuant to the Arrangement for trading on the TSXV. As of the date hereof, the TSXV has not conditionally approved the listing and there is no assurance that it will do so. Such listing will be subject to CANEX fulfilling all of the requirements of the TSXV, which cannot be guaranteed. There is no expectation that the Cease Trade Order will be rescinded if the Arrangement were not to proceed and Gold Basin were to continue in the status quo. |
| (h) | Enhanced Financial Capacity. CANEX has demonstrated an ability to raise capital and has strong support from a number of high profile industry professionals. With an enhanced capital markets profile, the Resulting Issuer is expected have even better access to lower-cost capital and an increased capability to advance its exploration properties. |
- 10 -
| (i) | Going Concern. In the absence of the Arrangement, there is considerable risk that Gold Basin will not have the ability to continue as a going concern and realize its assets and discharge its liabilities in the normal course of business. Gold Basin’s financial situation has significantly deteriorated since its last filed audited financial statements. As at May 14, 2026, Gold Basin has asserted liabilities of approximately $2,123,183 (of which $691,724 is purportedly owed to former management and directors, their related parties and their counsel), no cash or marketable securities and no revenue. Gold Basin’s ability to raise equity financing is restricted by the Cease Trade Order. |
| (j) | Potential Impairment of Gold Basin Project. Gold Basin’s former board and management may have potentially impaired Gold Basin’s ownership interest in its sole mineral asset, the Gold Basin Project in Mohave County, Arizona, through purported agreements, abandonment or encumbrances involving related parties or parties controlled by former directors and officers of Gold Basin for no or inadequate consideration. Although Gold Basin is taking steps to address these potential impairments and has reserved all rights against the former directors of Gold Basin, any impairment to Gold Basin’s ownership interest in the Gold Basin Project could have a material adverse impact on Gold Basin’s financial condition and operations. |
| (k) | Superior Proposals. Subject to compliance with the Arrangement Agreement, Gold Basin is permitted to furnish information and take certain other actions in respect of an unsolicited Acquisition Proposal that could reasonably be expected to lead to a Superior Proposal. The ability to terminate the Arrangement Agreement in specified circumstances and to accept a Superior Proposal, on payment of the Termination Fee of $211,777, which is subject to a right to match, provides further assurance to the Board that Gold Basin will have a reasonable opportunity to consider a potential superior unsolicited alternative transaction if one is subsequently proposed. |
| (l) | Support of Shareholders. Certain Shareholders, including all of the directors and officers of Gold Basin who did not tender their Shares to the Offer, have entered into Lock-Up Agreements pursuant to which, and subject to the terms thereof, each has agreed to vote their Shares in favour of the Arrangement Resolution, representing in the aggregate approximately 0.64% of the issued and outstanding Shares. |
| (m) | Fairness Opinion. Stifel Nicolaus provided the Fairness Opinion to the Special Committee to the effect that, as at May 11, 2026, and subject to the assumptions, limitations and qualifications set out in the Fairness Opinion, the consideration to be received by the Shareholders pursuant to the Arrangement is fair, from a financial point of view, to the Shareholders (other than CANEX). |
| (n) | Court Approval. The procedures by which the Arrangement is to be approved, including the requirement for approval by the Court after a hearing at which the fairness of the Arrangement to Shareholders will be considered. |
| (o) | Availability of Dissent Rights. The availability of Dissent Rights to Registered Shareholders as of the Record Date with respect to the Arrangement. |
- 11 -
| (p) | Review by Special Committee. In the judgment of the Special Committee relying on financial, legal and other advisors and discussions with management and their review of the Fairness Opinion, the Consideration Shares to be received by the Shareholders (other than CANEX and its affiliates) is fair, from a financial point of view, to the Shareholders (other than CANEX and its affiliates). |
| (q) | Transaction Certainty. The completion of the Arrangement is subject to a limited number of conditions, which the Special Committee, after consultation with independent legal and other advisors, considers likely to be satisfied. |
| (r) | 100% Acquisition of Shares. The Arrangement is for 100% of the Shares and, under the Plan of Arrangement, all Shareholders are treated identically (other than CANEX and its affiliates). |
| (s) | Canadian Tax Deferral. A Shareholder who is a Holder should generally be able to exchange Shares for the Consideration Shares under the Arrangement on a fully tax-deferred basis for Canadian income tax purposes. |
| 32. | The Board and the Special Committee also considered a number of potential issues regarding potentially negative factors and risks resulting from the Arrangement, including: |
| (a) | The risks to Gold Basin if the Arrangement is not completed, including the costs to Gold Basin in resources and management attention in pursuing the Arrangement and the restrictions on the conduct of business prior to the completion of the Arrangement, including the ability to raise new funding. |
| (b) | The Arrangement Agreement’s restrictions on Gold Basin soliciting third parties to make an Acquisition Proposal prior to completion of the Arrangement and the specific requirements regarding what constitutes a Superior Proposal. |
| (c) | The Termination Fee of $211,777 payable to CANEX in certain circumstances, including if Gold Basin enters into an agreement with a third party to acquire Gold Basin that constitutes a Superior Proposal. |
| (d) | The right of CANEX to terminate the Arrangement Agreement under certain limited circumstances. |
| (e) | The potential risk of not obtaining certain consents from third parties required to complete the Arrangement, including from the Court, Shareholders, securities regulatory authorities and the TSXV. |
| (f) | The potential negative effect on Gold Basin’s relationship with its stakeholders, including suppliers and employees. |
| (g) | The dilution of Shareholders’ interest in Gold Basin business upon becoming shareholders of the Resulting Issuer. |
- 12 -
THE MEETING AND APPROVALS
| 33. | The Board resolved that the record date for determining the Shareholders entitled to receive notice of, attend and vote at the Gold Basin Meeting be fixed at May 5, 2026 (the “Record Date”). |
| 34. | In connection with the Gold Basin Meeting, Gold Basin intends to send to each of the Shareholders the following materials and documentation substantially in the form attached as Exhibit “B” and “C” to the Affidavit of Chantelle Collins, sworn May 12, 2026: |
| (a) | Gold Basin Notice of Special Meeting and accompanying Circular that includes, among other things: |
| (i) | the full text of Division 2 of Part 8 of the BCBCA setting out the dissent provisions of the BCBCA; |
| (ii) | the Arrangement Resolution; |
| (iii) | the Plan of Arrangement; |
| (iv) | a copy of the Interim Order; |
| (v) | a copy of the Notice of Hearing of Petition; and |
| (vi) | a copy of the Petition, which includes the form of Final Order; |
| (b) | The form of proxy for registered Shareholders; and |
| (c) | The voting instruction form for beneficial Shareholders. | |
| (hereinafter, collectively referred to as the “Meeting Materials”) |
| 35. | It is proposed that the Meeting Materials may contain such amendments thereto as the Petitioner may deem necessary or desirable, provided such amendments are not inconsistent with the terms of the Interim Order. |
| 36. | It is proposed that the Meeting Materials will be delivered as follows: |
| (a) | to registered Shareholders by pre-paid ordinary mail to their registered addresses as they appear on the records of Gold Basin at the close of business on May 5, 2026, or by email or facsimile transmission to any Shareholders who identifies themselves to the satisfaction of Gold Basin, acting through its representatives, who requests such email or facsimile transmission; and |
| (b) | to non-registered Shareholders, by providing copies of the relevant portions of the Meeting Materials to intermediaries and registered nominees for sending to the beneficial owners. |
- 13 -
QUORUM AND VOTING
| 37. | At the Gold Basin Meeting, the Shareholders will be asked to consider and, if thought advisable, to pass, with or without variation, the Arrangement Resolution authorizing the Arrangement. |
| 38. | In order to become effective, the Arrangement Resolution must be approved by an affirmative vote of: (i) 662/3% of the votes cast on the Arrangement Resolution by the Shareholders present in person or represented by proxy at the Gold Basin Meeting voting together as a single class; and (ii) if required under applicable Law, a simple majority of the votes cast by the Shareholders on the Arrangement Resolution excluding the votes for Shares held or controlled by “related parties” and “interested parties” as defined under MI 61-101; provided that, pursuant to section 8.2 of MI 61-101, the securities acquired by CANEX under the Offer may be voted in favor of the Arrangement Resolution (the “Requisite Approval”). |
| 39. | As set out in the articles of Gold Basin, a quorum for the transaction of business at the Gold Basin Meeting is two persons who are, or who represent by proxy, shareholders who, in the aggregate, hold at least one-twentieth of the issued Shares entitled to be voted at the Gold Basin Meeting. |
DISSENT RIGHTS
| 40. | Each of the registered Shareholders shall have the right to dissent in respect of the Arrangement Resolution in accordance with the provisions of Sections 237-247 of the BCBCA, as varied by the Plan of Arrangement, the Interim Order or the Final Order. |
NO CREDITOR IMPACT
| 41. | The Arrangement does not contemplate a compromise of any debt or any debt instruments of Gold Basin and no creditor of Gold Basin will be materially negatively affected by the Arrangement. |
U.S. SECURITIES LAW EXEMPTION
| 42. | Section 3(a)(10) of the United States Securities Act of 1933 (the “1933 Act”) provides an exemption from the registration requirements of the 1933 Act for the issue of securities in exchange for other outstanding securities where the terms and conditions of the issue and exchange are approved by a court of competent jurisdiction after a hearing upon the fairness of such terms and conditions at which all persons to whom it is proposed to issue such securities shall have the right to appear. |
| 43. | In order to ensure securities issued or made issuable to the Shareholders pursuant to the Arrangement will be exempt from the registration requirements of the 1933 Act pursuant to Section 3(a)(10) of the 1933 Act, it is necessary that: |
| (a) | the Arrangement is subject to the approval of the Court; |
| (b) | the Court is advised of the intention of the parties to rely upon Section 3(a)(10) of the 1933 Act prior to the hearing at which the Final Order will be sought; |
- 14 -
| (c) | all Shareholders are given adequate notice advising them of their rights to attend the hearing of the Court to approve the Arrangement and are provided with sufficient information necessary for them to exercise that right; |
| (d) | the Court is required to satisfy itself as to the fairness of the Arrangement to the Shareholders; |
| (e) | the Shareholders that will be issued shares have been advised that such securities have not been registered under the 1933 Act and will be issued in reliance on Section 3(a)(10) of the 1933 Act and exemptions under applicable state securities laws; and |
| (f) | the Final Order of the Court will expressly state that the Arrangement is approved by the Court as being fair to the Shareholders. |
| 44. | Since the completion of the Arrangement involves issuances of shares to Shareholders in the United States, the Petitioner hereby gives notice to the Court of its intention to rely on Section 3(a)(10) of the 1933 Act in completing the Arrangement. |
Part 3: LEGAL BASIS
| 45. | Pursuant to Sections 288-291 of the BCBCA, the Arrangement requires the approval of this Honourable Court to proceed. |
| 46. | Section 291 of the BCBCA contemplates plan of arrangement approval under the BCBCA as a three-step process: |
| (a) | the first step is an application for the Interim Order for directions for calling a shareholders’ meeting to consider and vote on the arrangement, and the first application proceeds ex parte because of the administrative burden of serving the Shareholders; |
| (b) | the second step is the Gold Basin Meeting, where the Arrangement is voted upon, and must be approved by the Requisite Approval; and |
| (c) | the third step is the application for final Court approval of the Arrangement. |
| 47. | The final Court approval should be granted as: |
| (a) | the statutory provisions will have been complied with, as amended by the terms of the Arrangement and the Interim Order; |
| (b) | the vote of the Shareholders will be bona fide; and |
| (c) | the Arrangement is fair and reasonable. |
Part 2: MATERIAL TO BE RELIED ON
| 48. | Affidavit #1 of Chantelle Collins; and |
- 15 -
| 49. | Such further materials to be advised by counsel. |
| Dated: | May 12, 2026 | ||
| Lawyer for Petitioner | |||
| Mark Pontin |
| To be completed by the court only: | ||
| Order made | ||
| ¨ | in the terms requested in paragraphs ________ of Part 1 of this Petition | |
| ¨ | with the following variations and additional terms: | |
| ________ | ||
| Date: | ||
| Signature of ¨ Judge ¨ Associate Judge | ||
Appendix J
BCBCA Dissent Provisions
Pursuant to the Interim Order, Registered Shareholders will have the right to dissent in respect of the Arrangement. Such right of dissent is described in this Circular. The full text of Division 2 (Dissent Proceedings) of Part 8 (Proceedings) of the BCBCA is set forth below.
DIVISION 2 OF PART 8 OF THE BUSINESS CORPORATIONS ACT (BRITISH COLUMBIA)
Definitions and application
237 (1) In this Division:
“dissenter” means a shareholder who, being entitled to do so, sends written notice of dissent when and as required by section 242;
“notice shares” means, in relation to a notice of dissent, the shares in respect of which dissent is being exercised under the notice of dissent;
“payout value” means,
| (a) | in the case of a dissent in respect of a resolution, the fair value that the notice shares had immediately before the passing of the resolution, |
| (b) | in the case of a dissent in respect of an arrangement approved by a court order made under section 291 (2) (c) that permits dissent, the fair value that the notice shares had immediately before the passing of the resolution adopting the arrangement, |
| (c) | in the case of a dissent in respect of a matter approved or authorized by any other court order that permits dissent, the fair value that the notice shares had at the time specified by the court order, or |
| (d) | in the case of a dissent in respect of a community contribution company, the value of the notice shares set out in the regulations, |
excluding any appreciation or depreciation in anticipation of the corporate action approved or authorized by the resolution or court order unless exclusion would be inequitable.
(2) This Division applies to any right of dissent exercisable by a shareholder except to the extent that
| (a) | the court orders otherwise, or |
| (b) | in the case of a right of dissent authorized by a resolution referred to in section 238 (1) (g), the court orders otherwise or the resolution provides otherwise. |
Right to dissent
238 (1) A shareholder of a company, whether or not the shareholder’s shares carry the right to vote, is entitled to dissent as follows:
| (a) | under section 260, in respect of a resolution to alter the articles |
| (i) | to alter restrictions on the powers of Gold Basin or on the business Gold Basin is permitted to carry on, |
| (ii) | without limiting subparagraph (i), in the case of a community contribution company, to alter any of Gold Basin’s community purposes within the meaning of section 51.91; or |
| (iii) | without limiting subparagraph (i), in the case of a benefit company, to alter Gold Basin’s benefit provision; |
| (b) | under section 272, in respect of a resolution to adopt an amalgamation agreement; |
| (c) | under section 287, in respect of a resolution to approve an amalgamation under Division 4 of Part 9; |
| (d) | in respect of a resolution to approve an arrangement, the terms of which arrangement permit dissent; |
| (e) | under section 301 (5), in respect of a resolution to authorize or ratify the sale, lease or other disposition of all or substantially all of Gold Basin’s undertaking; |
| (f) | under section 309, in respect of a resolution to authorize the continuation of Gold Basin into a jurisdiction other than British Columbia; |
| (g) | in respect of any other resolution, if dissent is authorized by the resolution; |
| (h) | in respect of any court order that permits dissent. |
(1.1) A shareholder of a company, whether or not the shareholder’s shares carry the right to vote, is entitled to dissent under section 51.995 (5) in respect of a resolution to alter its notice of articles to include or to delete the benefit statement.
(2) A shareholder wishing to dissent must
| (a) | prepare a separate notice of dissent under section 242 for |
| (i) | the shareholder, if the shareholder is dissenting on the shareholder’s own behalf, and |
| (ii) | each other person who beneficially owns shares registered in the shareholder’s name and on whose behalf the shareholder is dissenting, |
| (b) | identify in each notice of dissent, in accordance with section 242 (4), the person on whose behalf dissent is being exercised in that notice of dissent, and |
| (c) | dissent with respect to all of the shares, registered in the shareholder’s name, of which the person identified under paragraph (b) of this subsection is the beneficial owner. |
(3) Without limiting subsection (2), a person who wishes to have dissent exercised with respect to shares of which the person is the beneficial owner must
| (a) | dissent with respect to all of the shares, if any, of which the person is both the registered owner and the beneficial owner, and |
| (b) | cause each shareholder who is a registered owner of any other shares of which the person is the beneficial owner to dissent with respect to all of those shares. |
Waiver of right to dissent
239 (1) A shareholder may not waive generally a right to dissent but may, in writing, waive the right to dissent with respect to a particular corporate action.
(2) A shareholder wishing to waive a right of dissent with respect to a particular corporate action must
| (a) | provide to Gold Basin a separate waiver for |
| (i) | the shareholder, if the shareholder is providing a waiver on the shareholder’s own behalf, and |
| (ii) | each other person who beneficially owns shares registered in the shareholder’s name and on whose behalf the shareholder is providing a waiver, and |
| (b) | identify in each waiver the person on whose behalf the waiver is made. |
(3) If a shareholder waives a right of dissent with respect to a particular corporate action and indicates in the waiver that the right to dissent is being waived on the shareholder’s own behalf, the shareholder’s right to dissent with respect to the particular corporate action terminates in respect of the shares of which the shareholder is both the registered owner and the beneficial owner, and this Division ceases to apply to
| (a) | the shareholder in respect of the shares of which the shareholder is both the registered owner and the beneficial owner, and |
| (b) | any other shareholders, who are registered owners of shares beneficially owned by the first mentioned shareholder, in respect of the shares that are beneficially owned by the first mentioned shareholder. |
(4) If a shareholder waives a right of dissent with respect to a particular corporate action and indicates in the waiver that the right to dissent is being waived on behalf of a specified person who beneficially owns shares registered in the name of the shareholder, the right of shareholders who are registered owners of shares beneficially owned by that specified person to dissent on behalf of that specified person with respect to the particular corporate action terminates and this Division ceases to apply to those shareholders in respect of the shares that are beneficially owned by that specified person.
Notice of resolution
240 (1) If a resolution in respect of which a shareholder is entitled to dissent is to be considered at a meeting of shareholders, Gold Basin must, at least the prescribed number of days before the date of the proposed meeting, send to each of its shareholders, whether or not their shares carry the right to vote,
| (a) | a copy of the proposed resolution, and |
| (b) | a notice of the meeting that specifies the date of the meeting, and contains a statement advising of the right to send a notice of dissent. |
(2) If a resolution in respect of which a shareholder is entitled to dissent is to be passed as a consent resolution of shareholders or as a resolution of directors and the earliest date on which that resolution can be passed is specified in the resolution or in the statement referred to in paragraph (b), Gold Basin may, at least 21 days before that specified date, send to each of its shareholders, whether or not their shares carry the right to vote,
| (a) | a copy of the proposed resolution, and |
| (b) | a statement advising of the right to send a notice of dissent. |
(3) If a resolution in respect of which a shareholder is entitled to dissent was or is to be passed as a resolution of shareholders without Gold Basin complying with subsection (1) or (2), or was or is to be passed as a directors’ resolution without Gold Basin complying with subsection (2), Gold Basin must, before or within 14 days after the passing of the resolution, send to each of its shareholders who has not, on behalf of every person who beneficially owns shares registered in the name of the shareholder, consented to the resolution or voted in favour of the resolution, whether or not their shares carry the right to vote,
| (a) | a copy of the resolution, |
| (b) | a statement advising of the right to send a notice of dissent, and |
| (c) | if the resolution has passed, notification of that fact and the date on which it was passed. |
(4) Nothing in subsection (1), (2) or (3) gives a shareholder a right to vote in a meeting at which, or on a resolution on which, the shareholder would not otherwise be entitled to vote.
Notice of court orders
241 If a court order provides for a right of dissent, Gold Basin must, not later than 14 days after the date on which Gold Basin receives a copy of the entered order, send to each shareholder who is entitled to exercise that right of dissent
| (a) | a copy of the entered order, and |
| (b) | a statement advising of the right to send a notice of dissent. |
Notice of dissent
242 (1) A shareholder intending to dissent in respect of a resolution referred to in section 238 (1) (a), (b), (c), (d), (e) or (f) or (1.1) must,
| (a) | if Gold Basin has complied with section 240 (1) or (2), send written notice of dissent to Gold Basin at least 2 days before the date on which the resolution is to be passed or can be passed, as the case may be, |
| (b) | if Gold Basin has complied with section 240 (3), send written notice of dissent to Gold Basin not more than 14 days after receiving the records referred to in that section, or |
| (c) | if Gold Basin has not complied with section 240 (1), (2) or (3), send written notice of dissent to Gold Basin not more than 14 days after the later of |
| (i) | the date on which the shareholder learns that the resolution was passed, and |
| (ii) | the date on which the shareholder learns that the shareholder is entitled to dissent. |
(2) A shareholder intending to dissent in respect of a resolution referred to in section 238 (1) (g) must send written notice of dissent to Gold Basin
| (a) | on or before the date specified by the resolution or in the statement referred to in section 240 (2) (b) or (3) (b) as the last date by which notice of dissent must be sent, or |
| (b) | if the resolution or statement does not specify a date, in accordance with subsection (1) of this section. |
(3) A shareholder intending to dissent under section 238 (1) (h) in respect of a court order that permits dissent must send written notice of dissent to Gold Basin
| (a) | within the number of days, specified by the court order, after the shareholder receives the records referred to in section 241, or |
| (b) | if the court order does not specify the number of days referred to in paragraph (a) of this subsection, within 14 days after the shareholder receives the records referred to in section 241. |
(4) A notice of dissent sent under this section must set out the number, and the class and series, if applicable, of the notice shares, and must set out whichever of the following is applicable:
| (a) | if the notice shares constitute all of the shares of which the shareholder is both the registered owner and beneficial owner and the shareholder owns no other shares of Gold Basin as beneficial owner, a statement to that effect; |
| (b) | if the notice shares constitute all of the shares of which the shareholder is both the registered owner and beneficial owner but the shareholder owns other shares of Gold Basin as beneficial owner, a statement to that effect and |
| (i) | the names of the registered owners of those other shares, |
| (ii) | the number, and the class and series, if applicable, of those other shares that are held by each of those registered owners, and |
| (iii) | a statement that notices of dissent are being, or have been, sent in respect of all of those other shares; |
| (c) | if dissent is being exercised by the shareholder on behalf of a beneficial owner who is not the dissenting shareholder, a statement to that effect and |
| (i) | the name and address of the beneficial owner, and |
| (ii) | a statement that the shareholder is dissenting in relation to all of the shares beneficially owned by the beneficial owner that are registered in the shareholder’s name. |
(5) The right of a shareholder to dissent on behalf of a beneficial owner of shares, including the shareholder, terminates and this Division ceases to apply to the shareholder in respect of that beneficial owner if subsections (1) to (4) of this section, as those subsections pertain to that beneficial owner, are not complied with.
Notice of intention to proceed
243 (1) A company that receives a notice of dissent under section 242 from a dissenter must,
| (a) | if Gold Basin intends to act on the authority of the resolution or court order in respect of which the notice of dissent was sent, send a notice to the dissenter promptly after the later of |
| (i) | the date on which Gold Basin forms the intention to proceed, and |
| (ii) | the date on which the notice of dissent was received, or |
| (b) | if Gold Basin has acted on the authority of that resolution or court order, promptly send a notice to the dissenter. |
(2) A notice sent under subsection (1) (a) or (b) of this section must
| (a) | be dated not earlier than the date on which the notice is sent, |
| (b) | state that Gold Basin intends to act, or has acted, as the case may be, on the authority of the resolution or court order, and |
| (c) | advise the dissenter of the manner in which dissent is to be completed under section 244. |
Completion of dissent
244 (1) A dissenter who receives a notice under section 243 must, if the dissenter wishes to proceed with the dissent, send to Gold Basin or its transfer agent for the notice shares, within one month after the date of the notice,
| (a) | a written statement that the dissenter requires Gold Basin to purchase all of the notice shares, |
| (b) | the certificates, if any, representing the notice shares, and |
| (c) | if section 242 (4) (c) applies, a written statement that complies with subsection (2) of this section. |
(2) The written statement referred to in subsection (1) (c) must
| (a) | be signed by the beneficial owner on whose behalf dissent is being exercised, and |
| (b) | set out whether or not the beneficial owner is the beneficial owner of other shares of Gold Basin and, if so, set out |
| (i) | the names of the registered owners of those other shares, |
| (ii) | the number, and the class and series, if applicable, of those other shares that are held by each of those registered owners, and |
| (iii) | that dissent is being exercised in respect of all of those other shares. |
(3) After the dissenter has complied with subsection (1),
| (a) | the dissenter is deemed to have sold to Gold Basin the notice shares, and |
| (b) | Gold Basin is deemed to have purchased those shares, and must comply with section 245, whether or not it is authorized to do so by, and despite any restriction in, its memorandum or articles. |
(4) Unless the court orders otherwise, if the dissenter fails to comply with subsection (1) of this section in relation to notice shares, the right of the dissenter to dissent with respect to those notice shares terminates and this Division, other than section 247, ceases to apply to the dissenter with respect to those notice shares.
(5) Unless the court orders otherwise, if a person on whose behalf dissent is being exercised in relation to a particular corporate action fails to ensure that every shareholder who is a registered owner of any of the shares beneficially owned by that person complies with subsection (1) of this section, the right of shareholders who are registered owners of shares beneficially owned by that person to dissent on behalf of that person with respect to that corporate action terminates and this Division, other than section 247, ceases to apply to those shareholders in respect of the shares that are beneficially owned by that person.
(6) A dissenter who has complied with subsection (1) of this section may not vote, or exercise or assert any rights of a shareholder, in respect of the notice shares, other than under this Division.
Payment for notice shares
245 (1) A company and a dissenter who has complied with section 244 (1) may agree on the amount of the payout value of the notice shares and, in that event, Gold Basin must
| (a) | promptly pay that amount to the dissenter, or |
| (b) | if subsection (5) of this section applies, promptly send a notice to the dissenter that Gold Basin is unable lawfully to pay dissenters for their shares. |
(2) A dissenter who has not entered into an agreement with Gold Basin under subsection (1) or Gold Basin may apply to the court and the court may
| (a) | determine the payout value of the notice shares of those dissenters who have not entered into an agreement with Gold Basin under subsection (1), or order that the payout value of those notice shares be established by arbitration or by reference to the registrar, or a referee, of the court, |
| (b) | join in the application each dissenter, other than a dissenter who has entered into an agreement with Gold Basin under subsection (1), who has complied with section 244 (1), and |
| (c) | make consequential orders and give directions it considers appropriate. |
(3) Promptly after a determination of the payout value for notice shares has been made under subsection (2) (a) of this section, Gold Basin must
| (a) | pay to each dissenter who has complied with section 244 (1) in relation to those notice shares, other than a dissenter who has entered into an agreement with Gold Basin under subsection (1) of this section, the payout value applicable to that dissenter’s notice shares, or |
| (b) | if subsection (5) applies, promptly send a notice to the dissenter that Gold Basin is unable lawfully to pay dissenters for their shares. |
(4) If a dissenter receives a notice under subsection (1) (b) or (3) (b),
| (a) | the dissenter may, within 30 days after receipt, withdraw the dissenter’s notice of dissent, in which case Gold Basin is deemed to consent to the withdrawal and this Division, other than section 247, ceases to apply to the dissenter with respect to the notice shares, or |
| (b) | if the dissenter does not withdraw the notice of dissent in accordance with paragraph (a) of this subsection, the dissenter retains a status as a claimant against Gold Basin, to be paid as soon as Gold Basin is lawfully able to do so or, in a liquidation, to be ranked subordinate to the rights of creditors of Gold Basin but in priority to its shareholders. |
(5) A company must not make a payment to a dissenter under this section if there are reasonable grounds for believing that
| (a) | Gold Basin is insolvent, or |
| (b) | the payment would render Gold Basin insolvent. |
Loss of right to dissent
246 The right of a dissenter to dissent with respect to notice shares terminates and this Division, other than section 247, ceases to apply to the dissenter with respect to those notice shares, if, before payment is made to the dissenter of the full amount of money to which the dissenter is entitled under section 245 in relation to those notice shares, any of the following events occur:
| (a) | the corporate action approved or authorized, or to be approved or authorized, by the resolution or court order in respect of which the notice of dissent was sent is abandoned; |
| (b) | the resolution in respect of which the notice of dissent was sent does not pass; |
| (c) | the resolution in respect of which the notice of dissent was sent is revoked before the corporate action approved or authorized by that resolution is taken; |
| (d) | the notice of dissent was sent in respect of a resolution adopting an amalgamation agreement and the amalgamation is abandoned or, by the terms of the agreement, will not proceed; |
| (e) | the arrangement in respect of which the notice of dissent was sent is abandoned or by its terms will not proceed; |
| (f) | a court permanently enjoins or sets aside the corporate action approved or authorized by the resolution or court order in respect of which the notice of dissent was sent; |
| (g) | with respect to the notice shares, the dissenter consents to, or votes in favour of, the resolution in respect of which the notice of dissent was sent; |
| (h) | the notice of dissent is withdrawn with the written consent of Gold Basin; |
| (i) | the court determines that the dissenter is not entitled to dissent under this Division or that the dissenter is not entitled to dissent with respect to the notice shares under this Division. |
Shareholders entitled to return of shares and rights
247 If, under section 244 (4) or (5), 245 (4) (a) or 246, this Division, other than this section, ceases to apply to a dissenter with respect to notice shares,
| (a) | Gold Basin must return to the dissenter each of the applicable share certificates, if any, sent under section 244 (1) (b) or, if those share certificates are unavailable, replacements for those share certificates, |
| (b) | the dissenter regains any ability lost under section 244 (6) to vote, or exercise or assert any rights of a shareholder, in respect of the notice shares, and |
| (c) | the dissenter must return any money that Gold Basin paid to the dissenter in respect of the notice shares under, or in purported compliance with, this Division. |
Appendix K
Cease Trade Order and Partial Revocation Order
[See attached]

Citation: 2025 BCSECCOM 212
Cease Trade Order
4 Touchdowns Capital Inc.
ASEP Medical Holdings Inc.
Battery Mineral Resources Corp.
Beta Energy Corp.
BioNeutra Global Corporation
Cannibble Foodtech Ltd.
Eon Lithium Corp.
EvokAI Creative Labs Inc.
Evome Medical Technologies Inc.
Geologica Resource Corp
Gold Basin Resources Corporation
Goldex Resources Corporation
Highbank Resources Ltd.
Ibero Mining Corp.
Icarus Capital Corp.
International Bethlehem Mining Corp.
New Zealand Energy Corp.
(each referred to separately as the Issuer)
Under the securities legislation of British Columbia (Legislation)
Background
| 1 | This is the order of the regulator of the British Columbia Securities Commission (the Decision Maker). |
| 2 | The Issuer has not filed the following periodic disclosure required by the Legislation: |
| 1. | annual audited financial statements for the year ended December 31, 2024, |
| 2. | annual management’s discussion and analysis for the year ended December 31, 2024, and |
| 3. | certification of annual filings for the year ended December 31, 2024. |
| 3 | As a result of this order, if the Issuer is a reporting issuer in a jurisdiction in which Multilateral Instrument 11-103 Failure-to-File Cease Trade Orders in Multiple Jurisdictions applies, a person or company must not trade in or purchase a security of the Issuer in that jurisdiction, except in accordance with the conditions that are contained in this order, if any, for so long as this order remains in effect. |
| 4 | Further, this order takes automatic effect in each jurisdiction of Canada that has a statutory reciprocal order provision, subject to the terms of the local securities legislation. |
Interpretation
| 5 | Terms defined in the Legislation, National Instrument 14-101 Definitions and National Policy |
11-207 Failure-to-File Cease Trade Orders and Revocations in Multiple Jurisdictions have the same meaning if used in this order, unless otherwise defined.
Order
| 6 | The Decision Maker is satisfied that the decision concerning the cease trade meets the test set out in the Legislation to make this decision. |
| 7 | It is ordered under the Legislation that trading cease in respect of each security of the Issuer. |
| 8 | Despite this order, a beneficial securityholder of the Issuer who is not, and was not at the date of this order, an insider or control person of the Issuer, may sell securities of the Issuer acquired before the date of this order if both of the following apply: |
| 1. | the sale is made through a “foreign organized regulated market”, as defined in section 1.1 of the Universal Market Integrity Rules of the Investment Industry Regulatory Organization of Canada; and |
| 2. | the sale is made through an investment dealer registered in a jurisdiction of Canada in accordance with applicable securities legislation. |
| 9 | May 6, 2025 |
Michael Moretto, CPA, CA, CPA (Illinois)
Deputy Director, Corporate Disclosure

Citation: 2025 BCSECCOM 374
Partial Revocation Order
Gold Basin Resources Corporation
Under the securities legislation of British Columbia (the Legislation)
Background
| 1 | Gold Basin Resources Corporation (the Issuer) is subject to a failure-to-file cease trade order (the FFCTO) issued by the British Columbia Securities Commission (the Principal Regulator) on May 6, 2025. |
| 2 | CANEX Metals Inc. (the Filer) has applied to the Principal Regulator for a partial revocation of the FFCTO to permit an offer the Filer proposes to make to acquire all of the issued and outstanding common shares of the Issuer (the Common Shares) by way of a take-over bid under the Legislation, including the following steps associated with the take-over bid: |
| (a) | the Filer preparing, filing and sending to the holders of the Common Shares an offer and bid circular in the form of Form 62-104F1 Take-over Bid Circular (the TOB Circular), |
| (b) | the Filer entering into lock-up agreements in respect of the take-over bid with certain holders of Common Shares, |
| (c) | the Filer taking up and paying for deposited Common Shares pursuant to the take-over bid, |
| (d) | the Filer, or an affiliate or associate of the Filer, acquiring the Common Shares not deposited under the take-over bid by way of a compulsory acquisition pursuant to section 300 of the Business Corporations Act (British Columbia) (a Compulsory Acquisition), and |
| (e) | the Filer, or an affiliate or associate of the Filer, acquiring any Common Shares not deposited under the take-over bid pursuant to applicable corporate law (a Second Step Transaction) | |
| (collectively, the Bid). |
Interpretation
| 3 | Terms defined in National Instrument 14-101 Definitions, National Policy 11-207 Failure-to-File Cease Trade Orders and Revocations in Multiple Jurisdictions and National Instrument 62-104 Take-Over Bids and Issuer Bids (NI 62-104) have the same meaning if used in this order, unless otherwise defined. |
Representations
| 4 | This decision is based on the following facts represented by the Filer: |
The Issuer
| 1. | The Issuer was incorporated under the laws of British Columbia on November 24, 2017. |
| 2. | The Issuer’s head office is currently located in Vancouver, British Columbia. |
| 3. | The Issuer is authorized to issue an unlimited number of Common Shares without par value. As at December 2, 2024, the date the Issuer’s most recently filed financial statements for the interim period ended September 30, 2024 were filed on SEDAR+, the Issuer disclosed having 130,130,486 Common Shares issued and outstanding. |
| 4. | The Issuer is currently a reporting issuer in Alberta, British Columbia and Ontario. |
| 5. | The Common Shares are listed on the TSX Venture Exchange (TSXV) and quoted on the OTC Pink Current Market in the United States; trading of the Common Shares has been halted on the TSXV as a result of the FFCTO. |
| 6. | The Issuer’s stated principal business activities are the acquisition and exploration of mineral properties. The Issuer has reported owning an interest in a single exploration property, the Gold Basin project in Mojave County, Arizona (the Gold Basin Project). |
| 7. | The FFCTO was issued by the Principal Regulator due to the failure of the Issuer to file the following continuous disclosure documents: |
| (a) | annual audited financial statements for the year ended December 31, 2024, |
| (b) | management’s discussion and analysis for the year ended December 31, 2024, and |
| (c) | certification of annual filings for the year ended December 31, 2024. |
The Filer
| 8. | The Filer was incorporated under the laws of Quebec on March 15, 1971 and was continued under the laws of Alberta on July 14, 2011. |
| 9. | The Filer’s head office is currently located in Calgary, Alberta. |
| 10. | The Filer is authorized to issue an unlimited number of common shares (the Filer Shares) without par value. As at March 31, 2025, there were 122,914,102 Filer Shares issued and outstanding. |
| 11. | The Filer is currently a reporting issuer in Alberta, British Columbia, Ontario and Quebec. |
| 12. | The Filer Shares are listed on the TSXV. |
| 13. | The Filer is not in default of securities legislation in any jurisdiction of Canada. |
| 14. | The Filer is a gold-focused mineral exploration and development company that owns, among other projects, a 100% interest in the Gold Range property in Mojave County, Arizona (the Gold Range Project). The Gold Basin Project and the Gold Range Project are adjacent to one another. |
The Bid
| 15. | On June 6, 2025, the Filer submitted an expression of interest to the Issuer with respect to a proposed acquisition by the Filer of all of the Common Shares of the Issuer in exchange for Filer Shares. The Filer received no response on the proposal. |
| 16. | Given its inability to reach an agreement with the Issuer, the Filer announced in a press release issued on June 9, 2025 (the June 9 Press Release) its intention to make a formal offer by way of the Bid to acquire all of the Common Shares in an all-share transaction. |
| 17. | The June 9 Press Release disclosed that the Bid will be conditional upon receiving a partial revocation of the FFCTO to permit the completion of the Bid. The June 9 Press Release also disclosed that the Filer would make an application to the Principal Regulator for partial revocation of the FFCTO to permit the Bid and that there was no assurance that the application would be granted. |
| 18. | The Filer will include in the TOB Circular: |
| (a) | a copy of the FFCTO imposed on the Issuer, |
| (b) | a copy of this partial revocation order, and |
| (c) | disclosure that states that this partial revocation order was issued solely to allow the Filer to proceed with the Bid and that the securities of the Issuer will remain subject to the FFCTO until a full revocation order is granted. |
| 19. | Following the issuance of this order, the Filer will issue and file a news release announcing the order and its intention to proceed with the Bid. |
Order
| 5 | The Principal Regulator is satisfied that a partial revocation order of the FFCTO meets the test set out in the Legislation for the Principal Regulator to make the decision. |
| 6 | The decision of the Principal Regulator under the Legislation is that the FFCTO is partially revoked as it applies to the Issuer solely to permit the Bid. |
| 7 | This order expires on January 31, 2026; provided, however, that if more than 50% of the outstanding Common Shares have been tendered to the Bid and taken up and paid for by the Filer on or prior to January 31, 2026, this order will expire on April 30, 2026 in respect of a Compulsory Acquisition or Second Step Transaction undertaken by the Filer to facilitate the acquisition by the Filer of 100% of the issued and outstanding Common Shares. |
| 8 | August 18, 2025 | |
| /s/ Peter J. Brady | ||
| Peter J. Brady | ||
| Executive Director | ||
To:
Gold Basin Resources Corporation
880 – 320 Granville Street
Vancouver BC V6C 1S9
Email: info@goldbasincorp.com / Charles@centricminerals.com
Borden Ladner Gervais
Fred Pletcher
Waterfront Centre
1200 – 200 Burrard Street
Vancouver BC V7X 1T2
Email: fpletcher@blg.com
Stock Transfer Department
TSX Trust Company
2310 – 733 Seymour Street
Vancouver BC V6B 0S6
Email: tsxtix@tm.com
Appendix L
Gold Basin unaudited consolidated financial statements of for the years ended December 31, 2025 and 2024
[See attached]
GOLD BASIN RESOURCES CORPORATION
CONSOLIDATED FINANCIAL STATEMENTS
FOR THE YEARS ENDED DECEMBER 31, 2025 AND 2024
(Expressed in Canadian Dollars)
(Unaudited)
|
GOLD BASIN RESOURCES CORPORATION
CONSOLIDATED STATEMENTS OF FINANCIAL POSITION
(Expressed in Canadian dollars)
(Unaudited)
| December 31, | December 31, | ||||||||||
| Note | 2025 | 2024 | |||||||||
| ASSETS | |||||||||||
| CURRENT | |||||||||||
| Cash | $ | 11,653 | $ | 18,328 | |||||||
| GST receivable | 135,611 | 131,956 | |||||||||
| Due from related parties | 9 | 101,251 | 98,614 | ||||||||
| 248,515 | 248,898 | ||||||||||
| EXPLORATION AND EVALUATION ASSETS | 5 | 20,509,029 | 20,956,011 | ||||||||
| TOTAL ASSETS | $ | 20,757,544 | $ | 21,204,909 | |||||||
| LIABILITIES | |||||||||||
| CURRENT | |||||||||||
| Accounts payable and accrued liabilities | 9 | $ | 1,463,734 | $ | 1,234,337 | ||||||
| Loan payable | 6 | 302,269 | 282,759 | ||||||||
| - | |||||||||||
| TOTAL LIABILITIES | 1,766,003 | 1,517,096 | |||||||||
| EQUITY | |||||||||||
| Share Capital | 7 | 26,978,176 | 26,978,176 | ||||||||
| Contributed Surplus | 7 | 3,813,572 | 3,813,572 | ||||||||
| Share Applications | - | - | |||||||||
| Accumulated other comprehensive income | 91,033 | (33,569 | ) | ||||||||
| Deficit | (11,891,240 | ) | (11,070,366 | ) | |||||||
| TOTAL EQUITY | 18,991,541 | 19,687,813 | |||||||||
| TOTAL LIABILITIES AND SHAREHOLDERS’ EQUITY | $ | 20,757,544 | $ | 21,204,909 | |||||||
NATURE OF BUSINESS AND CONTINUING OPERATIONS (Note 1)
SUBSEQUENT EVENTS (Note 11)
Approved and authorized for issue on behalf of the Board on May 11, 2026.
| “Jordan Ross” | Director | “Shane Ebert” | Director |
The accompanying notes are an integral part of these condensed consolidated financial statements.
- 1 -
GOLD BASIN RESOURCES CORPORATION
CONSOLIDATED STATEMENTS OF LOSS AND COMPREHENSIVE LOSS
(Expressed in Canadian dollars)
(Unaudited)
| Year ended | Year ended | ||||||||||
| December 31, | December 31, | ||||||||||
| Note | 2025 | 2024 | |||||||||
| EXPENSES | |||||||||||
| Advertising and promotion | $ | 400 | $ | 44,780 | |||||||
| Consulting | 38,358 | 44,358 | |||||||||
| Foreign exchange | 25,480 | 115,974 | |||||||||
| Interest and accretion | 6 | 24,498 | 23,688 | ||||||||
| Management fees | 9 | 121,750 | 498,461 | ||||||||
| Office and administrative | 11,867 | 45,682 | |||||||||
| Professional fees | 9 | 123,521 | 627,167 | ||||||||
| Rent | 9 | - | 8,133 | ||||||||
| Share-based payments | 7,9 | - | 678,292 | ||||||||
| Travel | - | 4,229 | |||||||||
| Impairment of Exploration and Evaluation assets | 475,000 | ||||||||||
| Total expenses | 820,874 | 2,090,764 | |||||||||
| NET LOSS | $ | 820,874 | $ | 2,090,764 | |||||||
| OTHER ITEMS | |||||||||||
| Foreign currency translation | 124,602 | 25,112 | |||||||||
| TOTAL COMPREHENSIVE LOSS | $ | 945,476 | $ | 2,115,876 | |||||||
| LOSS PER SHARE – Basic and diluted | (0.010 | ) | (0.020 | ) | |||||||
| WEIGHTED AVERAGE NUMBER OF COMMON SHARES OUTSTANDING | 135,130,486 | 129,836,690 | |||||||||
The accompanying notes are an integral part of these consolidated financial statements
- 2 -
GOLD BASIN RESOURCES CORPORATION
CONSOLIDATED STATEMENTS OF CHANGES IN EQUITY
(Expressed in Canadian dollars)
(Unaudited)
| Accumulated | ||||||||||||||||||||||||||||
| Common Shares | Share | Other | ||||||||||||||||||||||||||
| Number of | subscriptions | Contributed | Comprehensive | |||||||||||||||||||||||||
| Shares | Amount | Advanced | Surplus | Income | Deficit | Total | ||||||||||||||||||||||
| Balance, December 31, 2023 | 114,910,183 | 25,192,663 | - | 2,980,433 | (8,457 | ) | (8,979,602 | ) | 19,185,037 | |||||||||||||||||||
| Shares issued for cash | 15,220,303 | 1,522,030 | 1,522,030 | |||||||||||||||||||||||||
| Shares issued for property payments | 5,000,000 | 475,000 | 475,000 | |||||||||||||||||||||||||
| Share issuance costs - finders' fees | (56,670 | ) | (56,670 | ) | ||||||||||||||||||||||||
| Share issuance costs - finders' warrants | (12,780 | ) | 12,780 | - | ||||||||||||||||||||||||
| Warrants reserve | (142,067 | ) | 142,067 | - | ||||||||||||||||||||||||
| Share-based payments | 678,292 | 678,292 | ||||||||||||||||||||||||||
| Foreign currency translation | (25,112 | ) | (25,112 | ) | ||||||||||||||||||||||||
| Net loss for the year | (2,090,764 | ) | (2,090,764 | ) | ||||||||||||||||||||||||
| Balance, December 31, 2024 | 135,130,486 | 26,978,176 | - | 3,813,572 | (33,569 | ) | (11,070,366 | ) | 19,687,813 | |||||||||||||||||||
| Shares issued for cash | - | |||||||||||||||||||||||||||
| Share issuance costs - finders' fees | - | |||||||||||||||||||||||||||
| Share issuance costs - finders' warrants | - | |||||||||||||||||||||||||||
| Warrants reserve | - | |||||||||||||||||||||||||||
| Share-based payments | - | |||||||||||||||||||||||||||
| Foreign currency translation | 124,602 | 124,602 | ||||||||||||||||||||||||||
| Net loss for the year | (820,874 | ) | (820,874 | ) | ||||||||||||||||||||||||
| - | ||||||||||||||||||||||||||||
| Balance, December 31, 2025 | 135,130,486 | $ | 26,978,176 | $ | - | $ | 3,813,572 | $ | 91,033 | $ | (11,891,240 | ) | $ | 18,991,541 | ||||||||||||||
The accompanying notes are an integral part of these consolidated financial statements
- 3 -
GOLD BASIN RESOURCES CORPORATION
CONSOLIDATED STATEMENTS OF CASH FLOWS
(Expressed in Canadian dollars)
(Unaudited)
| Year ended | Year ended | |||||
| December 31, 2025 | December 31, 2024 | |||||
| $ | $ | |||||
| CASH PROVIDED BY (USED IN): | ||||||
| OPERATING ACTIVITIES | ||||||
| Net loss for the year | (820,874 | ) | (2,090,764 | ) | ||
| Item not involving cash: | ||||||
| Foreign exchange gain | (8,227 | ) | 115,974 | |||
| Share-based payments | 475,000 | 678,292 | ||||
| Write-off of exploration and evalutaion assets | ||||||
| Equipment Depreciation | ||||||
| Interest and accretion expense | 19,510 | 23,688 | ||||
| Loss on disposal of asset | ||||||
| Investment in subsidiary | ||||||
| Changes in non-cash working capital balances: | ||||||
| Accounts receivable | (3,655 | ) | (28,328 | ) | ||
| Prepaid expenses | - | |||||
| Accounts payable and accrued liabilities | 229,398 | 767,814 | ||||
| Cash used in operating activities | (108,848 | ) | (533,324 | ) | ||
| INVESTING ACTIVITIES | ||||||
| Exploration and evaluation asset | (28,019 | ) | (1,470,519 | ) | ||
| Cash used in investing activities | (28,019 | ) | (1,470,519 | ) | ||
| FINANCING ACTIVITIES | ||||||
| Issuance of common shares, net of issuance costs | 1,465,360 | |||||
| Issuance of common shares for exploration assets | 475,000 | |||||
| Advances to related parties | (2,637 | ) | (98,614 | ) | ||
| Proceeds from loan | 259,071 | |||||
| Cash provided by financing activities | (2,637 | ) | 2,100,817 | |||
| CHANGE IN CASH | (139,504 | ) | 96,974 | |||
| EFFECT OF FOREIGN EXCHANGE RATE CHANGES | 132,829 | (141,087 | ) | |||
| CASH, BEGINNING OF YEAR | 18,327 | 62,440 | ||||
| CASH, END OF YEAR | 11,652 | 18,327 |
The accompanying notes are an integral part of these consolidated financial statements.
- 4 -
GOLD BASIN RESOURCES CORPORATION
NOTES TO THE CONSOLIDATED FINANCIAL STATEMENTS
FOR THE YEARS ENDED DECEMBER 31, 2025 AND DECEMBER 31, 2024
(Expressed in Canadian dollars)
(Unaudited)
| 1. | NATURE OF BUSINESS AND CONTINUING OPERATIONS |
Gold Basin Resources Corporation (“the Company”) was incorporated on November 24, 2017 under the laws of British Columbia. The address of the Company’s corporate office and its principal place of business is 1020 – 800 West Pender Street, Vancouver, British Columbia, Canada. The Company’s common shares trade on the TSXV under the symbol "GXX" and are listed on the OTCQB Venture Market under the symbol "GXX".
The Company’s principal business activities include the acquisition and exploration of mineral property assets. As at December 31, 2025, the Company had not yet determined whether the Company’s mineral property assets contain ore reserves that are economically recoverable. The recoverability of amount shown for exploration and evaluation assets is dependent upon the discovery of economically recoverable reserves, confirmation of the Company’s interest in the underlying mineral claims, the ability of the Company to obtain the necessary financing to complete the development of and the future profitable production from the property or realizing proceeds from its disposition. The outcome of these matters cannot be predicted at this time and the uncertainties cast significant doubt upon the Company’s ability to continue as a going concern.
The Company had a working capital deficit of $1,517,488 (2024 - $1,268,198), and a deficit of $11,891,240 (2024 – $11,070,366) as at December 31, 2025, which has been funded by the issuance of equity. The Company’s ability to continue its operations and to realize its assets at their carrying values is dependent upon obtaining additional financing and generating revenues sufficient to cover its operating costs. These conditions indicate the existence of a material uncertainty that may cast significant doubt upon the Company’s ability to continue as a going concern.
These condensed consolidated financial statements do not give effect to any adjustments which would be necessary should the Company be unable to continue as a going concern and therefore be required to realize its assets and discharge its liabilities in other than the normal course of business and at amounts different from those reflected in these condensed consolidated financial statements.
| 2. | BASIS OF CONSOLIDATION |
The consolidated financial statements include the accounts of the Company and its wholly-owned subsidiaries. All significant intercompany balances, transactions and any unrealized gains and losses arising from intercompany transactions, have been eliminated. The Company’s subsidiaries are presented in the table below.
| Entity | Country of Incorporation | Effective Economic Interest | ||||
| Gold Basin Resources (Arizona), Inc. | USA | 100 | % | |||
| (“Gold Basin Arizona”) | ||||||
| Gold Basin Resources (Australia) Pty Ltd | Australia | 100 | % | |||
| (“Gold Basin Australia”) | ||||||
- 5 -
GOLD BASIN RESOURCES CORPORATION
NOTES TO THE CONSOLIDATED FINANCIAL STATEMENTS
FOR THE YEARS ENDED DECEMBER 31, 2025 AND DECEMBER 31, 2024
(Expressed in Canadian dollars)
(Unaudited)
| 3. | MATERIAL ACCOUNTING POLICY INFORMATION |
| a) | Statement of compliance |
These condensed consolidated financial statements have been prepared in accordance with IFRS Accounting Standards (“IFRS”) issued by the IASB.
These condensed consolidated financial statements were authorized for issue in accordance with a resolution from the Board of Directors on May 11, 2026.
| a) | Basis of presentation |
The condensed consolidated financial statements have been prepared on the historical cost basis, with the exception of financial instruments which are measured at fair value, as explained in the accounting policies set out below. In addition, these condensed consolidated financial statements have been prepared using the accrual basis of accounting, except for cash flow information.
These condensed consolidated financial statements are presented in Canadian dollars, which is the Company’s functional currency. The functional currency of Gold Basin Arizona is the U.S. dollar and the functional currency of Gold Basin Australia is the Australian dollar. The assets and liabilities of Gold Basin Arizona and Gold Basin Australia are translated into Canadian dollars at the rate of exchange prevailing at the reporting date and their income and expense items are translated at the spot exchange rate for the period. Exchange differences arising on the translation are recognized in other comprehensive income.
The accounting policies set out below have been applied consistently to all periods presented in these consolidated financial statements.
| b) | Cash and cash equivalents |
Cash in the condensed consolidated statements of financial position is comprised of cash in banks and cash held in trust.
| c) | Exploration and evaluation assets |
All costs related to the acquisition, exploration and development of mineral properties are capitalized. Upon commencement of commercial production, the related accumulated costs are amortized against projected income using the units-of-production method over estimated recoverable reserves.
Management annually assesses carrying values of non-producing properties and properties for which events and circumstances may indicate possible impairment. Impairment of a property is generally considered to have occurred if the property has been abandoned, there are unfavourable changes in the property economics, there are restrictions on development, or when there has been an undue delay in development, which exceeds three years. In the event that estimated discounted cash flows expected from its use or eventual disposition is determined by management to be insufficient to recover the carrying value of the property, the carrying value is written-down to the estimated recoverable amount.
The recoverability of mineral properties and exploration and development costs is dependent on the existence of economically recoverable reserves, the ability to obtain the necessary financing to complete the development of the reserves, and the profitability of future operations. The Company has not yet determined whether or not any of its future mineral properties contain economically recoverable reserves. Amounts capitalized to mineral properties as exploration and development costs do not necessarily reflect present or future values. When options are granted on mineral properties or properties are sold, proceeds are credited to the cost of the property. If no future capital expenditure is required and proceeds exceed costs, the excess proceeds are reported as a gain.
- 6 -
GOLD BASIN RESOURCES CORPORATION
NOTES TO THE CONSOLIDATED FINANCIAL STATEMENTS
FOR THE YEARS ENDED DECEMBER 31, 2025 AND DECEMBER 31, 2024
(Expressed in Canadian dollars)
(Unaudited)
| 3. | MATERIAL ACCOUNTING POLICY INFORMATION (continued) |
| d) | Share-based payments |
Share-based payments to employees and others providing similar services are measured at the estimated fair value of the instruments issued on the grant date and amortized over the vesting periods. Share-based payments to non-employees are measured at the fair value of the goods or services received or the fair value of the equity instruments issued if it is determined the fair value of the goods or services cannot be reliably measured, and are recorded at the date the goods or services are received. The amount recognized as an expense is adjusted to reflect the number of awards expected to vest. The offset to the recorded cost is to equity settled share-based payments reserve.
Consideration received on the exercise of stock options is recorded as share capital and the related equity settled share-based payments reserve is transferred to share capital. Charges for options that are forfeited before vesting are reversed from equity settled share-based payment reserve.
Share-based compensation expense relating to deferred share units is accrued over the vesting period of the units based on the quoted market price. As these awards can be settled in cash, the expense and liability are adjusted each reporting period for changes in the underlying share price.
| e) | Foreign currency |
Transactions and balances in currencies other than the Canadian dollar, the currency of the primary economic environment in which the Company operates (the “functional currency”), are translated into the functional currency using the exchange rates prevailing at the dates of the transactions. Foreign exchange gains and losses resulting from the settlement of such transactions and from the translation of monetary assets and liabilities denominated in foreign currencies at exchange prevailing on the statement of financial position date are recognized in the statement of comprehensive loss.
| f) | Decommissioning, restoration and similar liabilities |
An obligation to incur restoration, rehabilitation and environmental costs arises when environmental disturbance is caused by the exploration or development of a mineral property interest. Such costs arising from the decommissioning of plant and other site preparation work, discounted to their net present value, are provided for and capitalized at the start of each project to the carrying amount of the asset, along with a corresponding liability as soon as the obligation to incur such costs arises. The timing of the actual rehabilitation expenditure is dependent on a number of factors such as the life and nature of the asset, the operating license conditions and, when applicable, the environment in which the mine operates.
Discount rates using a pre-tax rate that reflects the time value of money are used to calculate the net present value. These costs are charged against profit or loss over the economic life of the related asset, through amortization using either the units-of-production or the straight-line method. The corresponding liability is progressively increased as the effect of discounting unwinds creating an expense recognized in profit or loss.
Decommissioning costs are also adjusted for changes in estimates. Those adjustments are accounted for as a change in the corresponding capitalized cost, except where a reduction in costs is greater than the unamortized capitalized cost of the related assets, in which case the capitalized cost is reduced to nil and the remaining adjustment is recognized in profit or loss.
The operations of the Company have been, and may in the future be, affected from time to time in varying degree by changes in environmental regulations, including those for site restoration costs. Both the likelihood of new regulations and their overall effect upon the Company are not predictable.
- 7 -
GOLD BASIN RESOURCES CORPORATION
NOTES TO THE CONSOLIDATED FINANCIAL STATEMENTS
FOR THE YEARS ENDED DECEMBER 31, 2025 AND DECEMBER 31, 2024
(Expressed in Canadian dollars)
(Unaudited)
| 3. | MATERIAL ACCOUNTING POLICY INFORMATION (continued) |
| f) | Decommissioning, restoration and similar liabilities (continued) |
The Company has no material restoration, rehabilitation and environmental obligations as the disturbance to date is immaterial.
| g) | Loss per share |
The Company presents basic and diluted loss per share data for its common shares, calculated by dividing the loss attributable to common shareholders of the Company by the weighted average number of common shares outstanding during the period. Diluted loss per share does not adjust the loss attributable to common shareholders or the weighted average number of common shares outstanding when the effect is anti-dilutive.
| h) | Income taxes |
Current tax is the expected tax payable or receivable on the taxable income or loss for the year, using tax rates enacted or substantively enacted at the balance sheet date, and includes any adjustments to tax payable or receivable in respect of previous years.
Deferred income taxes are recorded using the liability method whereby deferred tax is recognized in respect of temporary differences between the carrying amounts of assets and liabilities for financial reporting purposes and the amounts used for taxation purpose.
Deferred tax is measured at the tax rates that are expected to be applied to temporary differences when they reverse, based on the laws that have been enacted or substantively enacted by the statement of financial position date. Deferred tax is not recognized for temporary differences which arise on the initial recognition of assets or liabilities in a transaction that is not a business combination and that affects neither accounting, nor taxable profit or loss.
A deferred tax asset is recognized for unused tax losses, tax credits and deductible temporary differences, to the extent that it is probable that future taxable profits will be available against which they can be utilized. Deferred tax assets are reviewed at each reporting date and are reduced to the extent that it is no longer probable that the related tax benefit will be realized.
| i) | Financial instruments |
On initial recognition financial assets are classified as measured at:
| i. | Amortized cost; |
| ii. | Fair value through other comprehensive income (“FVOCI”); and |
| iii. | Fair value through profit and loss (“FVTPL”). |
Financial assets are not reclassified subsequent to their initial recognition unless the Company changes its business model for managing financial assets in which case all affected financial assets are reclassified on the first day of the first reporting period following the change in the business model.
At initial recognition, the Company measures a financial asset at its fair value plus, in the case of a financial asset not at FVTPL, transaction costs that are directly attributable to the acquisition of the financial asset. Transaction costs of financial assets carried at FVTPL are expensed in profit or loss. Financial assets are considered in their entirety when determining whether their cash flows are solely payment of principal and interest.
- 8 -
GOLD BASIN RESOURCES CORPORATION
NOTES TO THE CONSOLIDATED FINANCIAL STATEMENTS
FOR THE YEARS ENDED DECEMBER 31, 2025 AND DECEMBER 31, 2024
(Expressed in Canadian dollars)
(Unaudited)
| 3. | MATERIAL ACCOUNTING POLICY INFORMATION (continued) |
| i) | Financial instruments (continued) |
Subsequent measurement of financial assets depends on their classification:
i. Amortized cost
Assets that are held for collection of contractual cash flows where those cash flows represent solely payments of principal and interest are measured at amortized cost. A gain or loss on a debt investment that is subsequently measured at amortized cost is recognized in profit or loss when the asset is derecognized or impaired. Interest income from these financial assets is included as finance income using the effective interest rate method.
The Company classifies its amounts receivable at amortized cost.
ii. FVOCI
Assets that are held for collection of contractual cash flows and for selling the financial assets, where the assets’ cash flows represent solely payments of principal and interest, are measured at FVOCI. Movements in the carrying amount are taken through OCI, except for the recognition of impairment gains and losses, interest revenue, and foreign exchange gains and losses which are recognized in profit or loss. When the financial asset is derecognized, the cumulative gain or loss previously recognized in OCI is reclassified from equity to profit or loss and recognized in other gains (losses). Interest income from these financial assets is included as finance income using the effective interest rate method.
The Company does not have any assets classified at FVOCI.
iii. FVTPL
Assets that do not meet the criteria for amortized cost or FVOCI are measured at FVTPL. A gain or loss on an investment that is subsequently measured at FVTPL is recognized in profit or loss and presented net as revenue in the Statement of Loss and Comprehensive Loss in the period in which it arises.
The Company’s cash is classified at FVTPL.
Financial Liabilities and Equity
Debt and equity instruments are classified as either financial liabilities or as equity in accordance with the substance of the contractual arrangement. An equity instrument is any contract that evidences a residual interest in the assets of an entity after deducting all of its liabilities. Equity instruments issued by the group entities are recorded at the proceeds received, net of direct issue costs.
Financial liabilities are classified as measured at (i) FVTPL; or (ii) amortized cost.
A financial liability is classified as at FVTPL if it is classified as held-for-trading or is designated as such on initial recognition. Directly attributable transaction costs are recognized in profit or loss as incurred. The amount of change in the fair value that is attributable to changes in the credit risk of the liability is presented in OCI and the remaining amount of the change in the fair value is presented in profit or loss.
The Company does not classify any financial liabilities at FVTPL.
- 9 -
GOLD BASIN RESOURCES CORPORATION
NOTES TO THE CONSOLIDATED FINANCIAL STATEMENTS
FOR THE YEARS ENDED DECEMBER 31, 2025 AND DECEMBER 31, 2024
(Expressed in Canadian dollars)
(Unaudited)
| 3. | MATERIAL ACCOUNTING POLICY INFORMATION (continued) |
| i) | Financial instruments (continued) |
Other non-derivative financial liabilities are initially measured at fair value less any directly attributable transaction costs. Subsequent to initial recognition, these liabilities are measured at amortized cost using the effective interest method.
The Company classifies its accounts payable and lease liability at amortized cost.
A financial liability is derecognized when the contractual obligation under the liability is discharged, cancelled or expires or its terms are modified and the cash flows of the modified liability are substantially different, in which case a new financial liability based on the modified terms is recognized at fair value.
| j) | Share issuance costs |
Professional, consulting, regulatory and other costs directly attributable to financing transactions are recorded as deferred financing costs until the financing transactions are completed, if the completion of the transaction is considered likely; otherwise they are expensed as incurred. Share issue costs are charged to share capital when the related shares are issued. Deferred financing costs related to financing transactions that are not completed are expensed.
| k) | Accounting standards amendments issued and adoption of new accounting standards |
The Company has adopted new standards and amendments for the first time, which became effective for annual periods starting on or after January 1, 2023.
Amendment to IAS 1 – Disclosure of Accounting Policies.
Issued by the IASB in February 2021, these amendments provide clarity on implementing the materiality concept in disclosing accounting policies. The key changes introduced are:
| · | The requirement for entities to disclose their material accounting policies, shifting the focus from significant accounting policies. |
| · | A clarification that accounting policies concerning transactions, events, or conditions that are immaterial do not require disclosure. |
| · | An explanation that not every accounting policy related to material transactions, events, or conditions is necessarily material itself. |
The Company has reviewed its previously reported significant accounting policies and now regards them as material accounting policies. Additionally, certain accounting policies previously reported and now deemed immaterial by the Company have been omitted from the financial statements.
Amendment to IAS 8 – Defining Accounting Estimates
In February 2021, the IASB updated IAS 8 to include a specific definition of ‘accounting estimates’. The amendment elucidates the differences between adjustments in accounting estimates and alterations in accounting policies, as well as error rectifications. They further detail the methods and inputs entities should employ to formulate accounting estimates. The Company has not had any changes in accounting policies or changes in accounting estimates during the year ended December 31, 2025.
Apart from these, the Company has not implemented any other standards, interpretations, or amendments that have been published but are not yet in effect.
- 10 -
GOLD BASIN RESOURCES CORPORATION
NOTES TO THE CONSOLIDATED FINANCIAL STATEMENTS
FOR THE YEARS ENDED DECEMBER 31, 2025 AND DECEMBER 31, 2024
(Expressed in Canadian dollars)
(Unaudited)
| 4. | SIGNIFICANT ACCOUNTING ESTIMATES AND JUDGMENTS |
The preparation of these consolidated financial statements requires management to make certain estimates, judgments and assumptions that affect the reported amounts of assets and liabilities at the date of the consolidated financial statements and reported amounts of expenses during the reporting period. Actual outcomes could differ from these estimates. These consolidated financial statements include estimates which, by their nature, are uncertain. The impacts of such estimates are pervasive throughout the consolidated financial statements, and may require accounting adjustments based on future occurrences. Revisions to accounting estimates are recognized in the period in which the estimate is revised and future periods if the revision affects both current and future periods. These estimates are based on historical experience, current and future economic conditions and other factors, including expectations of future events that are believed to be reasonable under the circumstances.
Significant assumptions about the future and other sources of estimation uncertainty that management has made at the financial position reporting date, that could result in a material adjustment to the carrying amounts of assets and liabilities, in the event that actual results differ from assumptions made, relate to, but are not limited to, the following:
Significant accounting estimates
| i. | the measurement of deferred income tax assets and liabilities; and |
| ii. | the inputs used in accounting for share-based payments. |
Significant accounting judgments
| i. | the determination of categories of financial assets and financial liabilities; |
| ii. | the evaluation of the Company’s ability to continue as a going concern; and |
| iii. | the assessment of indications of impairment of the mineral property and related determination of the net realizable value and write-down of the mineral property where applicable. |
| 5. | EXPLORATION AND EVALUATION ASSETS |
| Acquisition Costs | Exploration Costs | Total | ||||||||||
| $ | $ | $ | ||||||||||
| Balance, December 31, 2023 | 13,005,417 | 6,480,075 | 19,485,492 | |||||||||
| Additions | 516,043 | 1,057,750 | 1,573,793 | |||||||||
| Balance, December 31, 2024 | 13,521,460 | 7,537,825 | 21,059,285 | |||||||||
| Additions | - | 28018 | 28,018 | |||||||||
| Impairments | (475,000 | ) | - | (475,000 | ) | |||||||
| Balance, December 31, 2025 | 13,046,460 | 7,565,843 | 20,612,303 | |||||||||
- 11 -
GOLD BASIN RESOURCES CORPORATION
NOTES TO THE CONSOLIDATED FINANCIAL STATEMENTS
FOR THE YEARS ENDED DECEMBER 31, 2025 AND DECEMBER 31, 2024
(Expressed in Canadian dollars)
(Unaudited)
| 5. | EXPLORATION AND EVALUATION ASSETS (continued) |
Gold Basin Property
The Company entered into two assignment and assumption agreements dated June 16, 2020 with Centric Minerals Corporation ("Centric"), an arm's length private British Columbia corporation, whereby Centric assigned to the Company all of its rights under two letter agreements with third party vendors that were at arm's length to the Company. The Company was assigned the right to acquire an approximate aggregate 75% interest in and to the Gold Basin Project (the "Assignment"), located approximately 70 miles southeast of Las Vegas, Nevada, and 50 miles northwest of Kingman, Arizona, in the Gold Basin mining district of Mohave County, Arizona, U.S.A in consideration for 8,000,000 common shares in its capital, and subsequently the Company negotiated the acquisition of a 100% interest in the Project.
Following the Assignment, the Company entered into a relinquishment of rights and release deed, and a relinquishment of rights agreement and termination, whereby certain third parties with existing rights to the Project (the "Vendors") agreed to relinquish all of their right, title and interest in the Project (the "Relinquishment") in favour of the underlying owner of the Project, Aurum Exploration Inc. ("Aurum"), effective September 3, 2020. As consideration for the Relinquishment, the Company made a cash payment of AU$1,000,000 and issued an aggregate of 10,000,001 common shares in its capital, valued at $2,000,000, to the Vendors.
The Company acquired its 100% interest in the Project through its wholly-owned subsidiary Gold Basin Arizona pursuant to a purchase and sale agreement made as of September 3, 2020 (the "Purchase Agreement") among the Company, Gold Basin Arizona, and Aurum (the "Property Acquisition"). All of Aurum's right, title and interest in the 290 unpatented federal mining claims which comprise the bulk of the Project area was transferred to Gold Basin Arizona by Quitclaim Deed on September 14, 2020. Pursuant to the Purchase Agreement, the Company issued an aggregate of 15,000,000 common shares in its capital to Aurum's nominees with the value of $3,000,000. The closing of the Property Acquisition took place on September 18, 2020.
The 290 unpatented federal mining claims are also subject to a 1% Gross Returns Royalty (the "Centric Royalty") held by Centric Minerals Management Pty Ltd ("Centric (AUS)") pursuant to a gross returns royalty agreement dated as of January 1, 2020 between Aurum and Centric (AUS) (the "Centric Royalty Agreement"). The Centric Royalty Agreement was assigned to Gold Basin Arizona by Aurum pursuant to an assignment and assumption agreement made effective as of September 14, 2020 among Aurum, Gold Basin Arizona and Centric (AUS), whereby Aurum assigned all of its right, title, benefit and interest in the Centric Royalty Agreement to Gold Basin Arizona and Gold Basin Arizona assumed all of Aurum's obligations thereunder, including the payment of the Centric Royalty thereunder.
The split estate mineral rights are subject to a perpetual production royalty held by Newmont Corporation of 3.5% gross returns from the sale or other disposition of all metals and minerals produced from those portions of the Project area previously owned by Sante Fe Pacific Railroad Company pursuant to the terms of an option agreement entered into by Sante Fe Pacific Railroad Company and Aurumbank Incorporated as of February 9, 2004.
As at December 31, 2022, the Company has earned a 100% right and title in the Project through its wholly-owned subsidiary Gold Basin Arizona, subject to the abovementioned royalties.
On May 10, 2022 the Company executed an Option Agreement to acquire 100% interest in forty (40) unpatented mining claims located between the Cyclopic and Stealth deposits, consolidating the entire Gold Basin project area.
- 12 -
GOLD BASIN RESOURCES CORPORATION
NOTES TO THE CONSOLIDATED FINANCIAL STATEMENTS
FOR THE YEARS ENDED DECEMBER 31, 2025 AND DECEMBER 31, 2024
(Expressed in Canadian dollars)
(Unaudited)
| 5. | EXPLORATION AND EVALUATION ASSETS (continued) |
Under the Option Agreement the Company shall:
| (a) | pay the Optionor an additional $745,000 as follows: |
| (i) | $20,000 on or before the first anniversary of the Effective Date (paid); |
| (ii) | an additional $30,000 on or before the second anniversary of the Effective Date (paid); |
| (iii) | an additional $35,000 on or before the third anniversary of the Effective Date (unpaid); |
| (iv) | an additional $40,000 on or before the fourth anniversary of the Effective Date (unpaid); |
| (v) | an additional $60,000 on or before the fifth anniversary of the Effective Date (unpaid); |
| (vi) | an additional $80,000 on or before the sixth anniversary of the Effective Date (unpaid); |
| (vii) | an additional $80,000 on or before the seventh anniversary of the Effective Date (unpaid); and | |
| (viii) | an additional $400,000 on or before the ninth anniversary of the Effective Date (unpaid). |
| (b) | On completion of Option Payments, the Company will grant a Royalty in the Property equal to three and a half (3.5%) percent of Net Profit Interest received from production on the Property. |
On May 3, 2024 The Company entered into a property option agreement with Iconic Minerals Ltd. ("Iconic") and a wholly owned subsidiary of Iconic for the exclusive option to acquire an undivided 50% right, title and interest in and to the unpatented mineral claims comprising the New Pass Property. 5,000,000 common shares each with a deemed value of $0.095 were issued pursuant to the agreement which was terminated prior to September 30, 2025, and the $475,000 was impaired.
| 6. | LOAN PAYABLE |
On August 21, 2024, the Company executed an unsecured loan arangement for upto USD $500,000 from Charrua Capital, LLC. The loan called for a maturity date of August 21, 2025 and bore a stated interest rate of 15% per annum. The lender failed to fund the originally contemplated amount and accordingly the loan was recorded at its actual obligation amount. Subsequent to the period end, on May 05, 2026 the loan was settled in full for USD $217,367. Accrued financing charges of $14,214 (2024 - $4,469) were recorded in the year.
| 7. | SHARE CAPITAL |
| a) | Authorized: |
The Company is authorized to issue an unlimited number of common shares without par value.
| b) | Issued and Outstanding as at December 31, 2025: 135,130,486 (2024 – 135,130,486) common shares. |
During the year ended December 31, 2025, there were no share capital transactions.
- 13 -
GOLD BASIN RESOURCES CORPORATION
NOTES TO THE CONSOLIDATED FINANCIAL STATEMENTS
FOR THE YEARS ENDED DECEMBER 31, 2025 AND DECEMBER 31, 2024
(Expressed in Canadian dollars)
(Unaudited)
| 7. | SHARE CAPITAL (continued) |
During the year ended December 31, 2024, the Company had the following share capital transactions:
| (i) | On March 1, 2024, the Company announced that it has closed the first tranche of its previously announced non-brokered private placement (the "Financing") for aggregate gross proceeds of $972,030 through the issuance of 9,720,303 units (each, a "Unit") at a subscription price of $0.10 per Unit. Each Unit consisted of one common share in the capital of the Company (each, a "Share") and one-half of one transferable common share purchase warrant (each whole warrant, a "Warrant"), with each Warrant entitling the holder thereof to purchase one Share at an exercise price of $0.15 per Share for a period of one year from the closing of the Financing. In connection with the closing of the first tranche of the Financing, the Company paid cash finder's fees and issued non-transferable finder's warrants to Canaccord Genuity Corp. (as to $1,500 cash and 10,000 finder's warrants) and Brava Capital Pty Ltd. (as to AUD $60,000 and 400,000 finder's warrants) in connection with the introduction by the finders to the Company of eligible investors in the Financing. The finder's warrants entitle the holder thereof to purchase one Share at an exercise price of $0.15 per Share for a period of one year from the closing of the Financing. |
| (ii) | On March 5, 2024, the Company announced that it has closed the second and final tranche of the Financing through the issuance of 5,500,000 Units for gross proceeds of approximately $550,000. The Financing was oversubscribed, and the Company issued an aggregate of 15,220,303 Units for aggregate gross proceeds of $1,522,030. In connection with the closing of the second tranche of the Financing, the Company paid cash finder's fees and issued non-transferable finder's warrants to Leede Jones Gable Inc. (as to $3,000 cash and 30,000 finder's warrants). |
| d) | Warrants |
During the year ended December 31, 2025, there were warrants issued.
On March 1, 2024, 4,860,151 Warrants were issued with an exercise price of $0.15 and expiry of March 1, 2025, as part of the first tranche of the Financing. The fair value of the warrants were recorded as $141,193 in contributed surplus, which was calculated using the Black-Scholes option pricing model assuming an expected life of 12 months, a risk-free interest rate of 4.06%, an expected dividend rate of 0%, a price on grant date of $0.10 and an expected annual volatility of 104%.
On March 1, 2024, 410,000 finder’s warrants were issued with an exercise price of $0.15 and expiry of March 1, 2025, as part of the first tranche of the Financing. The fair value of the warrants were recorded as $11,906 in contributed surplus, which was calculated using the Black-Scholes option pricing model assuming an expected life of 12 months, a risk-free interest rate of 4.06%, an expected dividend rate of 0%, a price on grant date of $0.10 and an expected annual volatility of 104%.
On March 5, 2024, 2,750,000 Warrants were issued with an exercise price of $0.15 and expiry of March 5, 2025, as part of the second tranche of the Financing. The fair value of the warrants were recorded as $80,068 in contributed surplus, which was calculated using the Black-Scholes option pricing model assuming an expected life of 12 months, a risk-free interest rate of 4.04%, an expected dividend rate of 0%, a price on grant date of $0.10 and an expected annual volatility of 104%.
- 14 -
GOLD BASIN RESOURCES CORPORATION
NOTES TO THE CONSOLIDATED FINANCIAL STATEMENTS
FOR THE YEARS ENDED DECEMBER 31, 2025 AND DECEMBER 31, 2024
(Expressed in Canadian dollars)
(Unaudited)
| 7. | SHARE CAPITAL (continued) |
On March 5, 2024, 30,000 finder’s warrants were issued with an exercise price of $0.15 and expiry of March 5, 2025, as part of the second tranche of the Financing. The fair value of the warrants were recorded as $874 in contributed surplus, which was calculated using the Black-Scholes option pricing model assuming an expected life of 12 months, a risk-free interest rate of 4.04%, an expected dividend rate of 0%, a price on grant date of $0.10 and an expected annual volatility of 104%.
A continuity of the warrants outstanding as at December 31, 2025 is as follows:
| Number of Warrants | Weighted average exercise price | |||||||
| Balance, December 31, 2023 and 2024 | 8,050,151 | $ | 0.15 | |||||
| Expired | (8,050,151 | ) | $ | 0.15 | ||||
| Balance, December 31, 2025 | - | - | ||||||
As at December 31, 2025, the Company had no warrants outstanding – all warrants expired as follows:
| Number
of warrants | Exercise price | Weighted
average years outstanding | Expiry date | ||||||||||
| 5,270,151 | $ | 0.15 | - | March 1, 2025 | |||||||||
| 2,780,000 | $ | 0.15 | - | March 5, 2025 | |||||||||
| e) | Stock options |
The Company has a Stock Option Plan (‘Plan’) for directors, officers, employees and consultants of the Company. The Company may grant options to individuals, options are exercisable over periods of up to ten years, as determined by the Board of Directors of the Company, to buy shares of the Company at the fair market value on the date the option is granted. The maximum number of shares which may be issuable under the Plan cannot exceed 10% of the total number of issued and outstanding shares on a non-diluted basis.
A continuity of the stock options outstanding as at December 31, is as follows:
| Number of Stock options | Weighted average exercise price | |||||||
| Balance, December 31, 2023 | 3,700,000 | $ | 0.30 | |||||
| Granted | 10,300,000 | $ | 0.075 | |||||
| Expired | (1,000,000 | ) | $ | 0.30 | ||||
| Balance, December 31, 2024 | 13,000,000 | $ | 0.075 | |||||
| Granted | - | - | ||||||
| Cancelled | (7,100,000 | ) | $ | 0.075 | ||||
| Expired | - | - | ||||||
| Balance, December 31, 2025 | 5,900,000 | $ | 0.075 | |||||
- 15 -
GOLD BASIN RESOURCES CORPORATION
NOTES TO THE CONSOLIDATED FINANCIAL STATEMENTS
FOR THE YEARS ENDED DECEMBER 31, 2025 AND DECEMBER 31, 2024
(Expressed in Canadian dollars)
(Unaudited)
| 7. | SHARE CAPITAL (continued) |
During the year ended December 31, 2025, 7,100,00 option were cancelled upon the resignation of the optionees. On January 22, 2024, 400,000 stock options with an exercise price of $0.10 that expired.
On March 9, 2024, 600,000 stock options with an exercise price of $0.35 that expired.
On May 06, 2024, 10,300,000 options with an exercise price of $0.075 were granted to various officers and consultants of the Company, 9,900,000 vested on grant and 400,000 of which vest over quarterly over 12 months and all expire on May 06, 2027.
The fair value of the stock options granted in the year ended December 31, 2025 was $NIL (2024 - $678,292), which was calculated using the Black-Scholes pricing model. During the year ended December 31, 2025, the Company recognized share-based compensation of $NIL (2024 - $678,292). The weighted average inputs used in the Black-Scholes calculation for the options are as follows:
| 2025 | 2024 | |||||||
| Share price | - | $ | 0.075 | |||||
| Risk-free dividend rate | - | 4.18 | ||||||
| Expected life | - | 3 Years | ||||||
| Dividend rate | - | - | ||||||
| Annualized volatility | - | 231 | % | |||||
As at December 31, 2025 the Company had the following outstanding stock options:
| Number
of options | Exercise price | Weighted
average years outstanding | Expiry date | ||||||||||
| 2,700,000 | $ | 0.20 | 0.20 | March 15, 2026 | |||||||||
| 10,300,000 | $ | 0.075 | 1.35 | May 6, 2027 | |||||||||
| 13,000,000 | |||||||||||||
8. MANAGEMENT OF CAPITAL
The Company’s objectives when managing capital are to safeguard the Company’s ability to continue as a going concern in order to pursue the sourcing and exploration of its resource property. The Company does not have any externally imposed capital requirements to which it is subject.
The Company considers the aggregate of its share capital, contributed surplus and deficit as capital. The Company manages the capital structure and makes adjustments to it in light of changes in economic conditions and the risk characteristics of the underlying assets. To maintain or adjust the capital structure, the Company may attempt to issue new shares or dispose of assets or adjust the amount of cash.
- 16 -
GOLD BASIN RESOURCES CORPORATION
NOTES TO THE CONSOLIDATED FINANCIAL STATEMENTS
FOR THE YEARS ENDED DECEMBER 31, 2025 AND DECEMBER 31, 2024
(Expressed in Canadian dollars)
(Unaudited)
9. RELATED PARTY BALANCES AND TRANSACTIONS
Parties are considered to be related if one party has the ability, directly or indirectly, to control the other party or exercise significant influence over the other party in making financial and operating decisions. Related parties may be individuals or corporate entities and include officers and directors. A transaction is considered to be a related party transaction when there is a transfer of resources or obligations between related parties.
The Company had incurred the following key management personnel cost from related parties:
| Twelve months | Twelve months | |||||||
| ended December | ended December | |||||||
| 31, 2025 | 31, 2024 | |||||||
| $ | $ | |||||||
| Chief Executive Officer fees | 162,139 | 179,552 | ||||||
| Chief Financial Officer fees | 99,242 | 120,825 | ||||||
| Management fees | 77,153 | 297,980 | ||||||
| Professional fees | 55,779 | 403,421 | ||||||
During the year ended December 31, 2025, the Company paid the directors of the Company total fees of $58,309 (2024 - $736,323) for management services. At December 31, 2025, there was $NIL (2024 - $87,202) in accounts payable owing to certain directors and $104,204 (2024 - $Nil) owing to an officer of the Company. At December 31, 2025, there was $101,251 (2024 - $nil) receivable from a director of the Company, with no specific terms of repayment.
10. FINANCIAL INSTRUMENTS AND FINANCIAL RISK
Financial risk management objectives and policies
The Company’s financial instruments include cash and accounts payable. The risks associated with these financial instruments and the policies on how to mitigate these risks are set out below.
The fair value of the Company’s financial instruments approximates their carrying value as at December 31, 2025 because of the demand nature or short-term maturity of these instruments.
Management manages and monitors these exposures to ensure appropriate measures are implemented on a timely and effective manner.
(i) Currency risk
The Company is not exposed to significant foreign currency risk on fluctuations related to cash and accounts payable that are denominated in AUD and USD dollars. The Company has not entered into any foreign currency contracts to mitigate this risk.
(ii) Interest rate risk
The Company is exposed to interest rate risk on the variable rate of interest earned on bank deposits. The fair value interest rate risk on bank deposits is insignificant as the deposits are short-term. The Company has not entered into any derivative instruments to manage interest rate fluctuations.
- 17 -
GOLD BASIN RESOURCES CORPORATION
NOTES TO THE CONSOLIDATED FINANCIAL STATEMENTS
FOR THE YEARS ENDED DECEMBER 31, 2025 AND DECEMBER 31, 2024
(Expressed in Canadian dollars)
(Unaudited)
10. FINANCIAL INSTRUMENTS AND FINANCIAL RISK (continued)
(iii) Credit risk
Credit risk is the risk of loss associated with the counterparty’s inability to fulfill its payment obligations. Financial instruments that potentially subject the Company to concentrations of credit risks consist principally of cash. To minimize the credit risk, the Company places these instruments with a high quality financial institution.
(iv) Liquidity risk
In the management of liquidity risk of the Company, the Company maintains a balance between continuity of funding and the flexibility through the use of borrowings. Management closely monitors the liquidity position and expects to have adequate sources of funding to finance the Company’s projects and operations.
11. INCOME TAXES
The Company has losses carried forward approximately $8,521,000 available to reduce income taxes in future years which begin to expire in 2038.
The Company has not recognized any deferred income tax assets. The Company recognizes deferred income tax assets based on the extent to which it is probable that sufficient taxable income will be realized during the carry forward periods to utilize all deferred tax assets.
The following table reconciles the amount of income tax recoverable on application of the statutory Canadian federal and provincial income tax rates:
| 2025 | 2024 | |||||||
| Effective tax rate | 27 | % | 27 | % | ||||
| $ | $ | |||||||
| Income tax recovery at statutory rate | (158,068 | ) | (497,350 | ) | ||||
| Effect of income taxes of: | - | 420,604 | ||||||
| Permanent differences and other | ||||||||
| Change in deferred tax assets not recognized | 158,068 | 76,743 | ||||||
| Deferred income tax recovery | - | - | ||||||
The temporary differences that give rise to significant portions of the deferred tax assets not recognized are presented below:
| 2025 | 2024 | |||||||
| $ | $ | |||||||
| Non-capital loss carry forwards | 2,458,939 | 2,300,871 | ||||||
| Equipment | - | - | ||||||
| Share issuance costs | - | 93,300 | ||||||
| Exploration and evaluation assets | - | 47,100 | ||||||
| Deferred tax assets not recognized | (2,458,939 | ) | (2,441,271 | ) | ||||
| - | - | |||||||
- 18 -
GOLD BASIN RESOURCES CORPORATION
NOTES TO THE CONSOLIDATED FINANCIAL STATEMENTS
FOR THE YEARS ENDED DECEMBER 31, 2025 AND DECEMBER 31, 2024
(Expressed in Canadian dollars)
(Unaudited)
12. COMMITTMENTS
On November 19, 2024, the Company received notice that it had been named as a defendant in a lawsuit commenced in the Superior Court of Arizona in Maricopa County by Harris Exploration Drilling & Associates in respect of a claim for outstanding payments of USD $285,193.
13. SUBSEQUENT EVENTS
On March 19, 2026 the Company responded to the March 16, 2026 announcement by Helix Resources Limited ("Helix") that it has executed a formal joint venture agreement to earn-in up to a 40% interest in the Company's 42 square kilometre Gold Basin project in Mohave County Arizona.
Helix's announcement was made just prior to the replacement of the Company's entire board of directors by a unanimous vote of shareholders at a court-ordered annual general meeting held on March 16, 2026.
Any such agreement would be in violation of a restraining order issued by the Supreme Court of British Columbia on February 11, 2026.
A previous conditional letter agreement between Helix and Gold Basin announced on April 29, 2025 is subject to a petition (the "Petition") before the Court dated October 28, 2025, launched by Gold Basin shareholders, to set aside the agreement on the basis of one or more former directors of Gold Basin having a material undisclosed interest in Helix and the agreement not being fair or reasonable to Gold Basin.
On May 05, 2026 the Company reached a settlement agreement with Charrua Capital LLC in respect of the disputed enforceability of the unsecured loan agreement dated Aug. 21, 2024, between Gold Basin and Charrua. The loan agreement bore a principal amount of $500,000 (USD), initial interest rate of 15 per cent, high fees and costs, and restrictions on Gold Basin's use of funds.
Under the settlement agreement, Gold Basin has agreed to pay Charrua $217,367.40 (USD) upon, among other things, the release and discharge of any and all security interests, and claims against Gold Basin and its assets.
On May 05, 2026 Gold Basin commenced a legal challenging a purported joint venture between Gold Basin and Helix Resources Ltd. (the invalid Helix joint venture) announced by Helix in its ASX (Australian Securities Exchange) announcement on April 29, 2026. Gold Basin’s position is that the invalid agreement has no standing. Accordingly, it is the Company's opinion that Helix has no interest or rights in the Gold Basin property.
The status of an option agreement executed on May 10, 2022 to acquire a 100% interest in forty (40) unpatented mining claims remains uncertain. Gold Basin’s former board and management purportedly failed to make an option payment and new management is working to bring the agreement into compliance.
- 19 -
Appendix M
CANEX audited consolidated financial statements for the years ended September 30, 2024 and 2025 and management’s Discussion and Analysis in respect thereof
[See attached]
CANEX Metals Inc.
Consolidated Financial Statements
(Expressed in Canadian Dollars)
September 30, 2025 and 2024
| Contents | Page |
| Auditor's Report | 2 |
| Consolidated Statements of Financial Position | 6 |
| Consolidated Statements of Loss and Comprehensive Loss | 7 |
| Consolidated Statements of Cash Flows | 8 |
| Consolidated Statement of Changes in Equity | 9 |
| Notes to the Consolidated Financial Statements | 10 |
1
|
Tel: 403 266 5608 | BDO Canada LLP |
| Fax: 403 233 7833 | 903 - 8th Avenue SW, Suite 620 | |
| www.bdo.ca | Calgary AB T2P 0P7 | |
| Canada |
Independent Auditor’s Report
To the Shareholders of CANEX Metals Inc.:
Opinion
We have audited the consolidated financial statements of CANEX Metals Inc. and its subsidiaries (the Group), which comprise the consolidated statement of financial position as at September 30, 2025 and 2024, and the consolidated statements of loss and comprehensive loss, changes in equity and cash flows for the years then ended, and notes to the consolidated financial statements, including material accounting policy information.
In our opinion, the accompanying consolidated financial statements present fairly, in all material respects, the consolidated financial position of the Group as at September 30, 2025 and 2024, and its consolidated financial performance and its consolidated cash flows for the years then ended in accordance with International Financial Reporting Standards and International Accounting Standards as issued by the International Accounting Standards Board (IASB) and Interpretations (collectively IFRS Accounting Standards).
Basis for Opinion
We conducted our audit in accordance with Canadian generally accepted auditing standards. Our responsibilities under those standards are further described in the Auditor’s Responsibilities for the Audit of the Consolidated Financial Statements section of our report. We are independent of the Group in accordance with the ethical requirements that are relevant to our audit of the consolidated financial statements in Canada, and we have fulfilled our other ethical responsibilities in accordance with these requirements. We believe that the audit evidence we have obtained is sufficient and appropriate to provide a basis for our opinion.
Material Uncertainty Related to Going Concern
We draw attention to Note 1 in the consolidated financial statements, which indicates that the Group incurred a net loss of $496,817 during the year ended September 30, 2025 and, as of that date, the Entity has a deficit of $18,346,237 and a working capital surplus of $506,487. As stated in Note 1, these events or conditions, along with other matters as set forth in Note 1, indicate that a material uncertainty exists that may cast significant doubt on the Group's ability to continue as a going concern. Our opinion is not modified in respect of this matter.
Key Audit Matters
Key audit matters are those matters that, in our professional judgment, were of most significance in our audit of the consolidated financial statements of the current period. These matters were addressed in the context of our audit of the consolidated financial statements as a whole, and in forming our opinion thereon, and we do not provide a separate opinion on these matters. In addition to the matter described in the Material Uncertainty Related to Going Concern section, we have determined the matter described below to be the key audit matter to be communicated in our report.
Impairment of Exploration and Evaluation Assets
Description of the key audit matter
Exploration and Evaluation Assets is carried at $6,296,930. Management is required to assess whether any facts and circumstances suggest that the carrying amount may exceed the recoverable amount at the end of each reporting period. If facts and circumstances were identified then an impairment test is required. The assessment of any facts and circumstances requires high levels of judgement and as such are significant to the audit. See Note 3e), 4a) and 8 to the consolidated financial statements.
BDO Canada LLP, a Canadian limited liability partnership, is a member of BDO International Limited, a UK company limited by guarantee, and forms part of the International BDO network of independent member firms.
How the key audit matter was addressed in the audit
Our approach in addressing this matter included the following procedures, among others:
| · | Evaluated management’s assessment of whether facts and circumstances of impairment existed and obtained evidence regarding management’s conclusion including reviewing historical data, historical expenditures, budgets and press releases. |
| · | Verified ownership and claim standing through review of public records, and claim renewal documentation and evidence of claim payments made. |
| · | Obtained evidence to evaluate the completeness and accuracy of the information presented by management through review of press releases, examination of external invoices, and disclosures in Management Discussion and Analysis. |
| · | Reviewing the adequacy of the disclosures in the consolidated financial statements, including disclosures related to significant judgments and estimates. |
Other Information
Management is responsible for the other information. The other information comprises:
The information, other than the consolidated financial statements and our auditor’s report thereon, included in the Mangement Discussion and Analysis for the year ended September 30, 2025.
Our opinion on the consolidated financial statements does not cover the other information and we do not express any form of assurance conclusion thereon.
In connection with our audit of the consolidated financial statements, our responsibility is to read the other information identified above and, in doing so, consider whether the other information is materially inconsistent with the consolidated financial statements or our knowledge obtained in the audit, or otherwise appears to be materially misstated.
We obtained the Management Discussion and Analysis prior to the date of this auditor’s report. If, based on the work we have performed on this other information, we conclude that there is a material misstatement of this other information, we are required to report that fact in this auditor’s report. We have nothing to report in this regard.
Responsibilities of Management and Those Charged with Governance for the Consolidated Financial Statements
Management is responsible for the preparation and fair presentation of the consolidated financial statements in accordance with IFRS Accounting Standards, and for such internal control as management determines is necessary to enable the preparation of consolidated financial statements that are free from material misstatement, whether due to fraud or error.
In preparing the consolidated financial statements, management is responsible for assessing the Group’s ability to continue as a going concern, disclosing, as applicable, matters related to going concern and using the going concern basis of accounting unless management either intends to liquidate the Group or to cease operations, or has no realistic alternative but to do so.
Those charged with governance are responsible for overseeing the Group’s financial reporting process.
Auditor’s Responsibilities for the Audit of the Consolidated Financial Statements
Our objectives are to obtain reasonable assurance about whether the consolidated financial statements as a whole are free from material misstatement, whether due to fraud or error, and to issue an auditor’s report that includes our opinion. Reasonable assurance is a high level of assurance, but is not a guarantee that an audit conducted in accordance with Canadian generally accepted auditing standards will always detect a material misstatement when it exists. Misstatements can arise from fraud or error and are considered material if, individually or in the aggregate, they could reasonably be expected to influence the economic decisions of users taken on the basis of these consolidated financial statements.
As part of an audit in accordance with Canadian generally accepted auditing standards, we exercise professional judgment and maintain professional skepticism throughout the audit. We also:
| · | Identify and assess the risks of material misstatement of the consolidated financial statements, whether due to fraud or error, design and perform audit procedures responsive to those risks, and obtain audit evidence that is sufficient and appropriate to provide a basis for our opinion. The risk of not detecting a material misstatement resulting from fraud is higher than for one resulting from error, as fraud may involve collusion, forgery, intentional omissions, misrepresentations, or the override of internal control. |
| · | Obtain an understanding of internal control relevant to the audit in order to design audit procedures that are appropriate in the circumstances, but not for the purpose of expressing an opinion on the effectiveness of the Group’s internal control. |
| · | Evaluate the appropriateness of accounting policies used and the reasonableness of accounting estimates and related disclosures made by management. |
| · | Conclude on the appropriateness of management’s use of the going concern basis of accounting and, based on the audit evidence obtained, whether a material uncertainty exists related to events or conditions that may cast significant doubt on the Group’s ability to continue as a going concern. If we conclude that a material uncertainty exists, we are required to draw attention in our auditor’s report to the related disclosures in the consolidated financial statements or, if such disclosures are inadequate, to modify our opinion. Our conclusions are based on the audit evidence obtained up to the date of our auditor’s report. However, future events or conditions may cause the Group to cease to continue as a going concern. |
| · | Evaluate the overall presentation, structure and content of the consolidated financial statements, including the disclosures, and whether the consolidated financial statements represent the underlying transactions and events in a manner that achieves fair presentation. |
| · | Plan and perform the group audit to obtain sufficient appropriate audit evidence regarding the financial information of the entities or business units within the Group as a basis for forming an opinion on the group financial statements. We are responsible for the direction, supervision and review of the audit work performed for purposes of the group audit. We remain solely responsible for our audit opinion. |
We communicate with those charged with governance regarding, among other matters, the planned scope and timing of the audit and significant audit findings, including any significant deficiencies in internal control that we identify during our audit.
We also provide those charged with governance with a statement that we have complied with relevant ethical requirements regarding independence, and to communicate with them all relationships and other matters that may reasonably be thought to bear on our independence, and where applicable, related safeguards.
From the matters communicated with those charged with governance, we determine those matters that were of most significance in the audit of the consolidated financial statements of the current period and are therefore the key audit matters. We describe these matters in our auditor's report unless law or regulation precludes public disclosure about the matter or when, in extremely rare circumstances, we determine that a matter should not be communicated in our report because the adverse consequences of doing so would reasonably be expected to outweigh the public interest benefits of such communication.
The engagement partner on the audit resulting in this independent auditor’s report is Jeannette Toner.
Chartered Professional Accountants
Calgary, Alberta
December 19, 2025
CANEX Metals Inc.
Consolidated Statements of Financial Position
(Expressed in Canadian Dollars)
As at September 30
| 2025 | 2024 | |||||||
| ASSETS | ||||||||
| Current Assets | ||||||||
| Cash (Note 5) | $ | 663,907 | $ | 158,093 | ||||
| Accounts receivable (Note 6) | 35,548 | 2,116 | ||||||
| Prepaid expenses | 74,241 | 12,786 | ||||||
| Short-term investments (Note 7) | - | 31,035 | ||||||
| $ | 773,696 | $ | 204,030 | |||||
| Non-current Assets | ||||||||
| Mineral property advances and deposits (Note 8) | $ | 526,479 | $ | 51,164 | ||||
| Exploration and evaluation assets (Note 8) | 6,296,930 | 5,713,501 | ||||||
| $ | 6,823,409 | $ | 5,764,665 | |||||
| TOTAL ASSETS | $ | 7,597,105 | $ | 5,968,695 | ||||
| EQUITY AND LIABILITIES | ||||||||
| Current Liabilities | ||||||||
| Accounts payable and accrued liabilities (Note 9) | 267,209 | 46,116 | ||||||
Non-current Liabilities | ||||||||
| Decommissioning obligation (Note 10) | 52,558 | 50,031 | ||||||
| TOTAL LIABILITIES | $ | 319,767 | $ | 96,147 | ||||
| EQUITY | ||||||||
| Share capital (Note 11) | 23,139,647 | 21,450,899 | ||||||
| Reserves | 2,483,928 | 2,271,069 | ||||||
| Deficit | (18,346,237 | ) | (17,849,420 | ) | ||||
| TOTAL EQUITY | 7,277,338 | 5,872,548 | ||||||
| TOTAL EQUITY AND LIABILITIES | $ | 7,597,105 | $ | 5,968,695 | ||||
Nature of operations and continuance of operations (Note 1)
Subsequent events (Note 23)
Approved by the Board
“Shane Ebert” Director
“Jean-Pierre Jutras” Director
See accompanying notes to consolidated financial statements.
6
CANEX Metals Inc.
Consolidated Statements of Loss and Comprehensive Loss
(Expressed in Canadian Dollars)
For the years ended September 30
| 2025 | 2024 | |||||||
| Expenses | ||||||||
| General and administrative (Note 13) | $ | (505,969 | ) | $ | (198,063 | ) | ||
| Reporting to shareholders | (13,835 | ) | (20,825 | ) | ||||
| Professional fees | (60,375 | ) | (48,689 | ) | ||||
| Stock exchange and transfer agent fees | (12,614 | ) | (18,304 | ) | ||||
| Property fees and taxes | - | (2,094 | ) | |||||
| Accretion | (4,734 | ) | (2,131 | ) | ||||
| Operating loss | (597,527 | ) | (290,106 | ) | ||||
| Interest and other | 5,037 | 9,821 | ||||||
| Realization of flow through premium (Note 16) | 75,500 | |||||||
| Gain (loss) from short-term investments | 20,173 | 1,137 | ||||||
| 100,710 | 10,958 | |||||||
| Net loss and comprehensive loss for the year | $ | (496,817 | ) | $ | (279,148 | ) | ||
| Basic and diluted loss per share (Note 15) | $ | (0.00 | ) | $ | (0.00 | ) | ||
| Weighted average shares outstanding - basic and diluted (Note 15) | 127,743,757 | 112,895,636 | ||||||
See accompanying notes to the consolidated financial statements.
7
CANEX Metals Inc.
Consolidated Statements of Cash Flows
(Expressed in Canadian Dollars)
For the years ended September 30
| 2025 | 2024 | |||||||
| Increase in cash and cash equivalents | ||||||||
| Operating activities | ||||||||
| Cash paid to suppliers and contractors (Note 19) | $ | (252,237 | ) | $ | (251,900 | ) | ||
| Cash used in operating activities | (252,237 | ) | (251,900 | ) | ||||
| Investing activities | ||||||||
| Interest and other items (expended) received | 5,033 | 9,819 | ||||||
| Cash received on sale of short-term investments | 51,208 | 59,944 | ||||||
| Cash expended on exploration and evaluation assets (Note 19) | (537,124 | ) | (344,230 | ) | ||||
| Cash expended on mineral property advances and deposits | (475,315 | ) | (8,198 | ) | ||||
| Cash used by investing activities | (956,198 | ) | (282,665 | ) | ||||
| Financing activities | ||||||||
| Share capital and warrant issue proceeds | 1,737,004 | - | ||||||
| Cash share issuance and transaction costs | (22,755 | ) | (3,254 | ) | ||||
| Cash provided by financing activities | 1,714,249 | (3,254 | ) | |||||
| Increase in cash and cash equivalents | 505,814 | (537,819 | ) | |||||
| Cash, beginning of period | 158,093 | 695,912 | ||||||
| Cash, end of period | $ | 663,907 | $ | 158,093 | ||||
See accompanying notes to the consolidated financial statements.
8
CANEX Metals Inc.
Consolidated Statement of Changes in Equity
(Expressed in Canadian Dollars)
As at September 30
| Common share capital | Equity settled share based payments | Other Reserves* | Total Reserves | Deficit | Total | |||||||||||||||||||
| $ | $ | $ | $ | $ | $ | |||||||||||||||||||
| Balance, September 30, 2023 | 21,135,858 | 345,879 | 1,914,896 | 2,260,775 | (17,570,272 | ) | 5,826,361 | |||||||||||||||||
| Net and comprehensive loss for the year | - | - | - | - | (279,148 | ) | (279,148 | ) | ||||||||||||||||
| Share issuance – Property November 2023 | 304,296 | - | - | - | - | 304,296 | ||||||||||||||||||
| Share issuance – Property April 2024 | 14,000 | - | - | - | - | 14,000 | ||||||||||||||||||
| Options cancelled – November 2023 | - | (16,583 | ) | 16,583 | - | - | - | |||||||||||||||||
| Options issued – July 2023 | - | 10,294 | - | 10,294 | - | 10,294 | ||||||||||||||||||
| Options expiry – July 2024 | - | (124,301 | ) | 124,301 | - | - | - | |||||||||||||||||
| Share issuance costs | (3,255 | ) | - | - | - | - | (3,255 | ) | ||||||||||||||||
| Balance, September 30, 2024 | 21,450,899 | 215,289 | 2,055,780 | 2,271,069 | (17,849,420 | ) | 5,872,548 | |||||||||||||||||
| Net and comprehensive loss for the year | - | - | - | - | (496,817 | ) | (496,817 | ) | ||||||||||||||||
| Share issuance – November 2024 | 135,000 | - | - | - | - | 135,000 | ||||||||||||||||||
| Flow through Share issuance – November 2024 | 302,002 | - | - | - | - | 302,002 | ||||||||||||||||||
| Flow through Share Premium | (75,500 | ) | - | - | - | - | (75,500 | ) | ||||||||||||||||
| Share issuance – Property February 2025 | 20,000 | - | - | - | - | 20,000 | ||||||||||||||||||
| Share issuance – June 2025 | 1,300,001 | - | - | - | - | 1,300,001 | ||||||||||||||||||
| Share issuance – Property July 2025 | 30,000 | - | - | - | - | 30,000 | ||||||||||||||||||
| Options issued – July 2023 | - | 161,159 | - | 161,159 | - | 161,159 | ||||||||||||||||||
| Options issued – July 2025 | - | 51,700 | - | 51,700 | - | 51,700 | ||||||||||||||||||
| Options expiry – October 2024 | - | (37,417 | ) | 37,417 | - | - | - | |||||||||||||||||
| Share issuance costs | (22,755 | ) | - | - | - | - | (22,755 | ) | ||||||||||||||||
| Balance, September 30, 2025 | 23,139,647 | 390,731 | 2,093,197 | 2,483,928 | (18,346,237 | ) | 7,277,338 | |||||||||||||||||
*Other reserves is comprised of the aggregate of options and warrants that expired or were fully vested and forfeited without exercise. These values were relieved from common share capital, share based payment reserve and warrants reserve respectively upon the expiry of the equity instrument.
See accompanying notes to the consolidated financial statements
9
CANEX Metals Inc.
Notes to the Consolidated Financial Statements
(Expressed in Canadian Dollars)
For the year ended September 30, 2025
| 1. | Nature of operations and continuance of operations |
CANEX Metals Inc. ("CANEX" or the "Company") is engaged in the business of mineral exploration and development in Canada. The Company was originally incorporated under the laws of the Province of Quebec, Canada and has been continued under the Alberta Business Corporations Act, Canada. The address of its primary office is Suite 1620, 734-7th Avenue SW, Calgary, Alberta, Canada, T2P 3P8. The Company's common shares are listed on the TSX Venture Exchange under the trading symbol CANX.
Since inception, the efforts of the Company have been devoted to the acquisition, exploration and development of mineral properties. To date the Company has not received any revenue from mining operations and has not determined whether its mineral exploration properties contain ore reserves that are economically recoverable.
The Company incurred a net loss of $496,817 during the year ended September 30, 2025. The Company has a deficit of $18,346,237 at September 30, 2025 and a working capital surplus of $506,487. Any increase in expenditures over budget, exploration programs, and new property acquisitions will require additional financing. There can be no assurance that the Company will be successful in obtaining financing. These material uncertainties cast significant doubt on the Company’s ability to continue as a going concern. These financial statements do not include any adjustments which could be significant should the Company be unable to continue as a going concern.
| 2. | Basis of presentation |
a) Basis of presentation
These Consolidated Financial Statements have been prepared in accordance with International Financial Reporting Standards as issued by the International Accounting Standards Board (“IASB") and interpretations (collectively “IFRS Accounting Standards”) , effective for the periods ended September 30, 2025 and 2024, using the material accounting policies outlined in Note 3. The Consolidated Financial Statements were authorized for issue by the board of directors on December 19, 2025.
These Consolidated Financial Statements have been prepared on a historical cost basis except for certain financial instruments described in Note 12 and decommissioning obligation described in Note 10. In addition, these statements have been prepared using the accrual basis of accounting except for cash flow information.
The presentation and functional currency of the Company is the Canadian dollar.
b) Principles of consolidation
These Consolidated Financial Statements include the accounts of the Company and its wholly-owned US subsidiary, Canexco Inc. (“Canexco”). Canexco was incorporated by the Company on June 5, 2019 in Arizona, USA, to conduct its exploration and development business in the USA, (refer to Note 8 - “Exploration and evaluation assets” for more information). All intercompany transactions and balances have been eliminated on consolidation. Subsidiaries are those entities that the Company controls through its power to govern the financial and operating policies of the subsidiary. Subsidiaries are fully consolidated from the date control is obtained and are de-consolidated from the date control ceases.
10
CANEX Metals Inc.
Notes to the Consolidated Financial Statements
(Expressed in Canadian Dollars)
For the year ended September 30, 2025
| 3. | Material accounting polices |
a) New accounting pronouncements
Future standards not yet adopted include IFRS 18 - Presentation and Disclosure in Financial Statements (IFRS 18). IFRS 18 will replace IAS 1, Presentation of Financial Statements which aims to improve how companies communicate in their financial statements, with a focus on information about financial performance in the statement of profit or loss, in particular additional defined subtotals, disclosures about management-defined performance measures and new principles for aggregation and disaggregation of information. IFRS 18 is accompanied by limited amendments to the requirements in IAS 7 Statement of Cash Flows. IFRS 18 is effective from January 1, 2027. Companies are permitted to apply the new standard before that date. The Company is not yet able to determine the impact to the Consolidated Financial Statements from the adoption of this standard.
Certain pronouncements were issued by the IASB but are not yet effective as at September 30, 2025. The Company intends to adopt these standards when they become effective but does not expect these amendments to have a material effect on its Consolidated Financial Statements.
b) Financial Instruments
The Company's financial instruments consist of the following:
| Financial Assets | Classification | |
| Cash | Financial asset measured at amortized cost | |
| Accounts receivable | Financial asset measured at amortized cost | |
| Short-term investments | Financial asset measured at fair value | |
| Financial Liabilities | Classification | |
| Accounts payable and accrued liabilities | Financial liabilities measured at amortized cost |
The Company records financial assets initially at fair value and subsequently measures these financial assets at either amortized cost or fair value on the basis of both the Company's business model for managing the financial assets and the contractual cash flow characteristics of the financial asset. A financial asset is measured at amortized cost if both of the following conditions are met:
| I. | the asset is held within a business model whose objective is to hold assets in order to collect contractual cash flows; and |
| II. | the contractual terms of the financial asset give rise on specified dates to cash flows that are solely payments of principal and interest on the principal amount outstanding. |
If the financial asset is not measured at amortized cost as per the above, the financial asset is measured at fair value.
Financial assets measured at fair value
Financial assets measured at fair value are carried at fair value at each period end, with the related gains and losses recognized in profit or loss. The sale of equity investments is accounted for using trade date accounting.
11
CANEX Metals Inc.
Notes to the Consolidated Financial Statements
(Expressed in Canadian Dollars)
For the year ended September 30, 2025
| 3. | Material accounting polices |
b) Financial Instruments (continued)
Financial assets measured at amortized cost
Financial assets measured at amortized cost are recorded at fair value upon initial recognition, plus any applicable transaction costs that are directly attributable to the acquisition of the financial asset, and subsequently carried at amortized cost, using the effective interest method. A gain or loss on a financial asset that is measured at amortized cost is recognized in profit or loss when the financial asset is derecognized, impaired, or reclassified.
Financial liabilities measured at amortized cost
Financial liabilities measured at amortized cost are recorded at fair value upon initial recognition, less any applicable transaction costs that are directly attributable to the acquisition of the financial liability, and are subsequently measured at amortized cost using the effective interest method. A gain or loss on a financial liability that is measured at amortized cost is recognized in profit or loss when the financial liability is derecognized.
Impairment of financial assets
The Company recognizes a loss allowance for expected credit losses on financial assets that are measured at amortized cost using the “simplified method”. At each reporting date, the Company measures the loss allowance for the financial asset at an amount equal to the lifetime expected credit losses if the credit risk on the financial asset has increased significantly since initial recognition. If at the reporting date, the financial asset has not increased significantly since initial recognition, the Company measures the loss allowance for the financial asset at an amount equal to the twelve month expected credit losses. The Company shall recognize in the Consolidated Statements of Loss and Comprehensive Loss as an impairment gain or loss, the amount of expected credit losses that is required to adjust the loss allowance at the reporting date to the amount that is required to be recognized.
The carrying amount of financial assets is reduced by any impairment loss directly except in the case of accounts receivable, where the carrying amount is reduced through the use of an allowance account. When an account receivable is considered uncollectible, it is written-off against the allowance account. Subsequent recoveries of accounts receivable previously written off are credited against the allowance account. Changes in the carrying amount of the allowance account are recognized in earnings.
If, in a subsequent period, the amount of the impairment loss decreases for financial assets except accounts receivable, and the decrease can be related objectively to an event occurring after the impairment was recognized, the reversal is recognized in profit or loss and is limited to the carrying amount that would have been determined had no impairment loss been recognized in prior years.
Cash
Cash includes cash held in Canadian dollar and US dollar current accounts, highly liquid Canadian dollar denominated investments in bankers’ acceptances or term deposits, with terms to maturity of 90 days or less when acquired and cash held in short-term investment accounts. The counter-parties are financial institutions.
c) Provisions
Provisions are recognized when the Company has a present obligation, whether legal or constructive, as a result of a past event for which it is probable that an outflow of resources embodying economic benefits will be required to settle the obligation and a reliable estimate can be made of the amount of the obligation. Provisions are measured at the present value of the expenditures expected to be required to settle the obligation discounted using the pre-tax, risk-free rate, updated at each reporting date.
12
CANEX Metals Inc.
Notes to the Consolidated Financial Statements
(Expressed in Canadian Dollars)
For the year ended September 30, 2025
| 3. | Material accounting polices (continued) |
d) Decommissioning obligation
Decommissioning obligation includes obligations related to future removal of property and equipment, and site restoration costs. A liability, for the fair value of environmental and site restoration obligations, is recorded in accordance with the broader policy described in "c) Provisions" above. Provisions for restoration costs do not include any additional obligations that are expected to arise from future disturbance. The amortization or unwinding of the discount applied in establishing the net present value of provisions is charged to earnings in a systematic manner. Other movements in the provision, including those from new disturbance, updated cost estimates, changes to the lives of operations and revisions to discount rates are capitalized to exploration and evaluation assets. The amounts included in capitalized costs are depleted using the unit-of-production method at such point that the mineral property achieves commercial production, or the costs will be written-off at such time that management considers that the value of the related property has been impaired.
e) Exploration and evaluation assets
The Company is in the exploration stage with respect to its investment in mineral properties. The Company capitalizes costs directly related to the acquisition, exploration and evaluation of mineral properties. Such costs include, but are not restricted to, geological, geophysical, drilling, trenching and sampling costs including the support costs and supplies required in relation thereto. These assets are recorded at cost as adjusted for impairments in value. Impairment is assessed when facts and circumstances suggest that the carrying amount of the asset may exceed its recoverable amount. In assessing impairment, exploration and evaluation assets are grouped into Cash Generating Units ("CGU's"), on the basis of areas of interest. Management groups mineral claims that are contiguous and specific to an area that encompasses the same prospective minerals, into one area of interest and assigns a name to this mineral property. Each named mineral property is considered an area of interest and a CGU.
Exploration and evaluation assets are reviewed for impairment if there is an indication that the carrying amount may not be recoverable. When a review for impairment is conducted, the recoverable amount is assessed by reference to the higher of "value in use" (being the net present value of expected future cash flows of the relevant cash generating unit ("CGU"), or "fair value less costs to sell”. Where there is no binding sale agreement or active market, fair value less costs to sell is based on the best information available to reflect the amount the Company could receive for the assets in an arm's length transaction.
The discount rate applied in calculating net present value of expected future cash flows, is based upon pre-tax discount rates that reflect current market assessments of the time value of money and the risks associated with the relevant cash flows, to the extent that such risks are not reflected in the forecasted cash flows.
If the carrying amount of the asset exceeds its recoverable amount, the asset impairment loss is charged to earnings and reduces the carrying amount of the asset. A previously recognized impairment loss is reversed if the recoverable amount increases as a result of a reversal of the conditions that originally precipitated the impairment. This reversal is recognized in profit or loss and is limited to the carrying amount that would have been determined, net of depreciation, had no impairment loss been recognized in prior years.
An impairment loss may be reversed in a situation where there is a change in the circumstances that had initially dictated that an impairment had occurred. An example of such a situation might include, but not be limited to, the re-commencement of exploration activity on a mineral property due to a significant change in commodity prices.
13
CANEX Metals Inc.
Notes to the Consolidated Financial Statements
(Expressed in Canadian Dollars)
For the year ended September 30, 2025
3. Material accounting polices
e) Exploration and evaluation assets (continued)
Although not an exhaustive list, one or more of the following facts and circumstances indicate that a specific CGU should be tested for impairment:
| · | The period for which the entity has the right to explore in the specific area has expired during the financial statement period or will expire in the near future and is not expected to be renewed. |
| · | Substantive expenditure on further exploration for, and evaluation of, mineral resources in the specific area is neither budgeted nor planned. |
| · | Exploration for and evaluation of mineral resources in the specific area has not led to the discovery of commercially viable quantities of mineral resources and the entity has decided to discontinue such activities in the specific area. |
| · | Sufficient data exists to indicate that, although a development in the specific area is likely to proceed, the carrying amount of the exploration and evaluation asset is unlikely to be recovered in full from successful development or sale. |
Where the Company’s exploration commitments for a CGU are performed under option agreements with a third party, the proceeds of any option payments under such agreements are applied to the CGU to the extent of costs incurred. The excess, if any, is credited to operations. Option payments made by the Company are recorded as exploration and evaluation assets. Options are exercisable entirely at the discretion of the optionee and accordingly, are recorded as exploration and evaluation assets or recoveries when the payments are made or received. The proceeds on the sale of exploration and evaluation assets are applied to the area of interest to the extent of costs incurred and the excess, if any, is credited to operations. In some circumstances option payments received by or made by the Company are made in whole or in part through the issuance of common shares. The value of these share-based payments is calculated using the closing price of the shares on the date of issue as determined by the public exchange upon which they are listed as this is the most readily determinable value. When the Company enters the development stage for a CGU, the exploration and evaluation costs are transferred into mine development costs and all subsequent expenditures on the construction, installation or completion of infrastructure net of incidental revenue, is capitalized. Upon commencement of commercial production, all mine development assets for the relevant CGU are transferred to producing mine assets at which point the costs will commence being charged to earnings on a unit-of-production basis.
f) Share capital
Equity instruments are contracts that give a residual interest in the net assets of the Company. Financial instruments issued by the Company are classified as equity only to the extent that they do not meet the definition of a financial liability or financial asset. The Company’s common shares and share warrants are classified as equity instruments. Incremental costs attributable to the issue of new shares or options are shown in equity as a deduction from the proceeds.
The Company has adopted a residual value method with respect the measurement of shares and warrants issued as private placement units. The residual value method first allocates value to the most easily measurable component based on fair value and then the residual value if any, to the less easily measurable component.
g) Share-based payment transactions
The fair value of stock options granted to employees is recognized as an expense over the vesting period with a corresponding increase in the equity-settled share based payment reserve in equity. Employees, for the purpose of this calculation, also include individuals who provide services similar to those performed by a direct employee, including directors and consultants of the Company. The fair value of the options granted is measured using the Black-Scholes Option Pricing Model taking into account the terms and conditions upon which the options were granted. Consideration received on the exercise of stock options is recorded as share capital and
14
CANEX Metals Inc.
Notes to the Consolidated Financial Statements
(Expressed in Canadian Dollars)
For the year ended September 30, 2025
| 3. | Material accounting polices |
g) Share-based payment transactions (continued)
the related equity-settled share based payment amount is transferred to share capital. If options expire or are cancelled without being exercised, the associated value is transferred from equity-settled share based payment reserve to other reserves.
h) Loss per share
Basic loss per common share is computed by dividing the net earnings loss attributable to common shareholders by the weighted average number of common shares outstanding for the period. Diluted per share amounts reflect the potential dilution that could occur if securities or other contracts to issue common shares were exercised or converted to common shares. Only “in-the-money” dilutive instruments impact the dilution calculations and potentially dilutive instruments shall only be treated as dilutive when their conversion increases loss per share. Refer to Note 11 for a summary of options and warrants outstanding that could potentially dilute basic earnings per share in the future, but were excluded from the calculation in the periods disclosed because their effect was anti-dilutive. Refer to Note 15 for calculations of loss per share.
i) Income taxes
Income tax on net earnings or loss for the periods presented is comprised of current and deferred tax as applicable. Income tax pertaining to earnings or loss is recognized in earnings or loss; income taxes pertaining to items recognized directly in equity is recorded through equity. Current tax is the tax expected to be payable on the taxable income for the year calculated using rates that have been enacted or substantively enacted by the balance sheet date. It includes adjustments for tax expected to be payable or recoverable in respect of previous periods.
Deferred tax is provided for temporary differences between the carrying amounts of assets and liabilities for financial reporting purposes and the amounts used for taxation purposes. The amount of deferred tax provided is based on the expected manner of realization or settlement of the carrying amount of assets and liabilities, using tax rates enacted or substantively enacted at the statement of financial position date. Deferred tax assets are only recognized to the extent that it is probable that the deductible temporary differences will reverse in the foreseeable future and future taxable profit will be available against which the temporary difference can be utilized.
4. Critical accounting judgments and estimates
The preparation of financial statements requires management to make certain estimates, judgments and assumptions that affect the reported amounts of assets, liabilities and disclosure of contingent assets and liabilities at the date of the financial statements and the reported amounts of revenues and expenses during the reporting period. Actual outcomes could differ from these estimates. Circumstances and changes in assumptions could arise over the years that would require material revisions to these estimates. These financial statements include estimates that, by their nature, are uncertain. The impacts of such estimates are pervasive throughout the financial statements and may require accounting adjustments based on future occurrences. Adjustments resulting from revisions to accounting estimates are recognized in the period in which the estimate is revised, and future periods if the revision affects both current and future periods. These estimates are based on historical experience, current and future economic conditions and other factors, including expectation of future events that are believed to be reasonable under the circumstances.
| a) | Exploration and evaluation assets |
The carrying values of exploration and evaluation assets and property and equipment that are included in the Consolidated Statements of Financial Position, include the assumptions that are incorporated into the impairment assessments, and the amount of depreciation and/or impairments that are included in the Consolidated Statements of Loss and Comprehensive Loss.
15
CANEX Metals Inc.
Notes to the Consolidated Financial Statements
(Expressed in Canadian Dollars)
For the year ended September 30, 2025
| 4. | Critical accounting judgments and estimates |
| a) | Exploration and evaluation assets (continued) |
In assessing whether an impairment loss should be recorded on exploration and evaluation assets, management considers the four factors outlined in Note 3 e) to the Consolidated Financial Statements. A number of assumptions are required in making valuation assessments including, mineral prices, continued exploration activity in the surrounding areas increasing the likelihood of being able to option out the property, and the availability of future financing to further develop the property failing the optioning out of the property. As the properties of the Company are at the exploration and evaluation level, they are not yet at the stage where there are assessments of possible or probable reserves. Consequently any estimates of value of the properties may require judgements and estimates. There is a risk that: 1) the properties could have little or no value if exploration activities on the property and in the surrounding areas cease, 2) prices will not be high enough to make extraction, regardless of quantities, economical or, 3) the Company will be unable to acquire future financing to enable exploration before the claims expire.
| b) | Decommissioning obligations |
The amount of decommissioning obligations and the inputs used in determining the net present value of the liabilities for decommissioning obligations included in the Consolidated Statements of Financial Position are estimated and incorporate assumptions made by management of interest rates and future inflation rates.
| c) | Share-based compensation |
The value of share-based compensation expense in the Consolidated Statements of Loss and Comprehensive Loss included in the Consolidated Statements of Financial Position, are valued using valuation models and incorporate assumptions made by management of stock volatility, interest rates and exercise periods.
| d) | Functional currency |
Management has assessed the functional currency to be the Canadian dollar when recording the transactions of its wholly owned subsidiary. In accordance with IAS 21, a number of factors are considered in determining the functional currency of an entity. When indicators are mixed and the functional currency is not obvious, management uses its judgment to determine the functional currency that most faithfully represents the economic effects of the underlying transactions, events and conditions.
| 5. | Cash |
Cash is comprised of:
| Sept 30, 2025 | Sept 30, 2024 | |||||||
| Current bank accounts | $ | 656,442 | $ | 156,488 | ||||
| Cash held in foreign currencies | 7,465 | 1,605 | ||||||
| $ | 663,907 | $ | 158,093 | |||||
16
CANEX Metals Inc.
Notes to the Consolidated Financial Statements
(Expressed in Canadian Dollars)
For the year ended September 30, 2025
| 6. | Accounts receivable |
| Sept 30, 2025 | Sept 30, 2024 | |||||||
| Due from related parties | $ | - | $ | 121 | ||||
| Sales tax receivables | 35,548 | 1,995 | ||||||
| $ | 35,548 | $ | 2,116 | |||||
| 7. | Short-term investments |
| Homeland Nickel Inc. | Number of shares | Carrying Value | ||||||
| Balance at September 30, 2023 | 1,633,500 | $ | 89,842 | |||||
| Cost base of shares sold | (599,000 | ) | (54,160 | ) | ||||
| Valuation adjustment - loss | - | (4,647 | ) | |||||
| Balance at September 30, 2024 | 1,034,500 | $ | 31,035 | |||||
| Cost base of shares sold | (1,034,500 | ) | (93,536 | ) | ||||
| Valuation adjustment - recovery | - | 62,501 | ||||||
| Balance at September 30, 2025 | - | $ | - | |||||
On March 18, 2025, the Company sold the remaining 1,034,500 shares for net proceeds of $51,208 and a net gain on sale of $20,173.
On December 1, 2023 the Company sold 599,000 shares for net proceeds of $59,944 resulting in a net gain on sale of $1,137. The common shares of Homeland Nickel Inc. (formerly Spruce Ridge Resources Ltd.), held at September 30, 2024, were valued at fair value, based on the period-end trading price.
| 8. | Exploration and evaluation assets |
Mineral properties are recognized in these financial statements in accordance with the accounting policies outlined in Note 3 (e) “Exploration and evaluation assets”. Accordingly, their carrying values represent costs incurred to date, net of recoveries, abandonments and impairments. The recoverability of these amounts is dependent upon the existence of economically recoverable mineral reserves; the acquisition and maintenance of appropriate permits, licenses and rights; the ability of the Company to obtain necessary financing to complete the development of properties where necessary, and upon future profitable operations; or alternatively, upon the Company’s ability to recover its costs through a disposition of its interests in its mineral exploration properties.
Louise Cu-Au Porphyry Project, British Columbia, Canada
On March 1, 2024, the Company entered into an option agreement to acquire nine mineral claims totalling 5,362.95 hectares located in the Omineca Mining Division, British Columbia. Under the terms of the option agreement, the Company will either pay an aggregate of $775,000 in common shares of CANEX or make cash payments. Future remaining commitments are scheduled as follows:
| Due Date | Value of underlying Common Shares | |||
| March 1, 2026 | $ | 50,000 | ||
| March 1, 2027 | $ | 90,000 | ||
| March 1, 2028 | $ | 200,000 | ||
| March 1, 2029 | $ | 400,000 | ||
| Total future commitment | $ | 740,000 | ||
17
CANEX Metals Inc.
Notes to the Consolidated Financial Statements
(Expressed in Canadian Dollars)
For the year ended September 30, 2025
| 8. | Exploration and evaluation assets |
Louise Cu-Au Porphyry Project, British Columbia, Canada (continued)
On April 8, 2024, the first option payment was made by issuing 200,000 common shares of the Company at a price of $0.07 per share.
On February 25, 2025, the second option payment was made by issuing 500,000 common shares of the Company at a price of $0.04 per share and a cash payment of $3,500.
The Vendor retains a 2.5% NSR (net smelter royalty) with Canex having the right to buy back 40% of the NSR (1% of the 2.5% NSR) for $1,500,000. A milestone bonus of $50,000 in shares or cash will also be payable if CANEX drills over 4250 metres of core, and a second milestone bonus of $50,000 in shares or cash will be payable if CANEX publishes a resource estimate with greater than 1.5 million contained ounces of gold.
On July 29, 2025, the Company acquired a 100% interest in three small claims located internal to the Louise Cu-Au Porphyry Project (Louise) by issuing 400,000 common shares to the Vendor. The shares are subject to a hold period of four months and a day from the date of regulatory approval. The Vendor retains a net smelter royalty of 1% which can be purchased by the Company at any time for $500,000.
On September 25, 2025 applications for 2 new mining claims totaling 3350 hectares were approved, brining the total claim size at Louise to 8806.1 hectares.
The gross costs and impairments recorded to the Louise property at September 30, 2025, are $466,261 and $nil respectively (September 30, 2024 - $28,594 and $nil).
Gold Range Property, Arizona, USA
On June 11, 2019, the Company’s wholly owned subsidiary, Canexco Inc., entered into an arm’s length Option Agreement to acquire a 100% interest in the Gold Range Property, Arizona, USA from a Prospector, the “Optionor”. On June 11, 2023, the Company completed its payment and expenditure obligations and the 100% earn in was completed. The Optionor will retain a 2% NSR, half of which can be bought back by the Company for US$500,000 and the remaining half for US$1,000,000. The Gold Range Property is located in Mohave County, Arizona, USA.
On February 24, 2020, the Company’s wholly owned subsidiary, Canexco Inc., entered into an arm’s length Option Agreement to acquire a 100% interest in the Never Get Left Claim from Onyx Exploration Inc., the “Optionor”. Under the terms of the agreement, the Company was committed to option payments totaling US$90,000 over four years. On February 24, 2024, the Company made the final payment of $49,314 (US$30,000), extinguishing its payment obligations, and the 100% earn in was complete. The Optionor will retain a 2% NSR, half of which can be bought back by the Company for US$500,000; the remaining half for US$500,000. Additionally, the Company must pay 10% of any profits realized from the processing and recovery of metals from the existing leach pad materials located within the Optionor’s claim.
On January 12, 2021, the Company, and its wholly owned subsidiary, Canexco Inc., signed a letter of intent allowing the Company to earn into the Excelsior Mine Property located adjacent to the Company’s other Gold Range properties. On November 29, 2023, 8,694,170 common shares, valued at $0.035 per share (total value - $304,295 were issued plus US$120,000 cash (CAD$166,058) and the 100% earn in was completed. The Optionor will continue to hold a 1.5% NSR as outlined in the original agreement and the Company will retain a right of first refusal (ROFR), should this royalty ever be offered for sale. In addition, until August 31, 2030, should the Company be subject to any event that would impact the creditors rights that is not cured in 30 days, it will deliver the mine property back to the Vendor under the reversion clause of the agreement.
18
CANEX Metals Inc.
Notes to the Consolidated Financial Statements
(Expressed in Canadian Dollars)
For the year ended September 30, 2025
| 8. | Exploration and evaluation assets |
Gold Range Property, Arizona, USA (continued)
On June 9, 2025, the Company announced its intention to make a formal offer to acquire all of the issued and outstanding shares of Gold Basin Resources Corporation (Gold Basin) in a share for share exchange transaction. The assets of Gold Basin are directly adjacent to the existing Gold Range property, and the acquisition would consolidate a large oxide gold camp in northern Arizona. The transaction has not closed as of the date of these Consolidated Financial Statements.
As of September 30, 2025, the Company holds 261 lode mining claims and 2 patented claims (approximately 1650 hectares) in respect of the Gold Range Property, including acquisitions via the option agreements noted above as well as staking. The gross costs and impairments recorded to the Gold Range Property at September 30, 2025, are $5,830,669 and $nil respectively (September 30, 2024 - $5,684,907 and $nil).
Gibson Prospect, British Columbia
On May 17, 2017, the Company had signed a purchase agreement to acquire a 100% interest in the Gibson property from Altius Resources Inc. ("Altius"). Gibson is 887 Ha in size and located in central British Columbia, approximately 95 kilometres northwest of Fort St. James. The Company also assumed the obligations of an underlying option agreement with Steven Scott. The gross costs and impairments recorded to the Gibson Prospect as at September 30, 2025, and September 30, 2024 are $473,527 and $473,527 respectively.
During the year ended September 30, 2021, the Company determined that further exploration on this property would no longer be a priority unless a third-party partner could be found to further advance the exploration program; however, the Company continues to hold claims which expire in January 2029. Accordingly, the Company recorded an impairment of the full amount of exploration expenditures to September 30, 2021. In August 2024, the Company received a further extension to meet its minimum exploration expenditures of $500,000 to December 31, 2025. All other terms of the option agreement remain unchanged.
As at September 30, 2025, under the terms of the Agreement, the Company is committed to the following share issuances and minimum exploration expenditures:
| Altius | ||||||||
| Share issues | Minimum Exploration Expenditures* | |||||||
| Expenditure commitment, on or before December 31, 2025 | - | $ | 500,000 | |||||
| Following the completion of the Expenditure Commitment | 1,240,000 | - | ||||||
| Total remaining commitment | 1,240,000 | $ | 500,000 | |||||
| * - as at September 30, 2025, the Company has incurred exploration expenditures of $293,500 | ||||||||
In addition, Altius will retain a right to purchase an underlying 1.5% NSR and preferential rights on any future royalties or streams granted on the Property. If the Company achieves measured and indicated mineral resources in excess of 1 million gold equivalent ounces, a Milestone Payment of 1,275,000 shares will be issued to Altius. Altius will have a pro rata right to participate in future equity financings of the Company for two years.
Pursuant to the Underlying Agreement, Steven Scott is also entitled to the additional milestone bonuses of 1) $25,000 in cash or securities upon a Bankable Feasibility Study; and 2) $50,000 in cash or securities upon Commercial Production.
19
CANEX Metals Inc.
Notes to the Consolidated Financial Statements
(Expressed in Canadian Dollars)
For the year ended September 30, 2025
| 8. | Exploration and evaluation assets (continued) |
Summary exploration and evaluation expenditures:
A summary of exploration and evaluation expenditures by category for the years ended September 30, 2025 and 2025 is as follows:
| Arizona USA | BC Canada | Total | ||||||||||
| Year ended September 30, 2025 | Gold Range Property | Louise Property | ||||||||||
| Exploration expenditures: | ||||||||||||
| Balance, September 30, 2024 | $ | 4,321,817 | $ | 5,860 | $ | 4,327,677 | ||||||
| Geological consulting | 9,402 | 49,309 | 58,711 | |||||||||
| Travel | 2,321 | 8,459 | 10,780 | |||||||||
| Field Costs | 20,821 | 6,707 | 27,528 | |||||||||
| Survey | - | 301,510 | 301,510 | |||||||||
| Analysis and other | 40,964 | 4,300 | 45,264 | |||||||||
| Decommissioning | (2,208 | ) | - | (2,208 | ) | |||||||
| Balance, September 30, 2025 | $ | 4,393,117 | $ | 376,145 | $ | 4,769,262 | ||||||
| Property acquisition costs: | ||||||||||||
| Balance, September 30, 2024 | $ | 1,363,090 | $ | 22,734 | $ | 1,385,824 | ||||||
| Acquisition costs incurred | 74,462 | 67,382 | 141,844 | |||||||||
| Balance, September 30, 2025 | $ | 1,437,552 | $ | 90,116 | $ | 1,527,668 | ||||||
| Total Exploration and evaluation assets, September 30, 2025 | $ | 5,830,669 | $ | 466,261 | $ | 6,296,930 | ||||||
| Arizona USA | BC Canada | Total | ||||||||||
| Year ended September 30, 2024 | Gold Range Property | Louise Property | ||||||||||
| Exploration expenditures: | ||||||||||||
| Balance, September 30, 2023 | $ | 4,274,794 | $ | - | $ | 4,274,794 | ||||||
| Geological consulting | 14,025 | 5,162 | 19,187 | |||||||||
| Travel | 5,885 | 698 | 6,583 | |||||||||
| Field Costs | 308 | - | 308 | |||||||||
| Analysis and other | 17,285 | - | 17,285 | |||||||||
| Decommissioning | 9,520 | - | 9,520 | |||||||||
| Balance, September 30, 2024 | $ | 4,321,817 | $ | 5,860 | $ | 4,327,677 | ||||||
| Property acquisition costs: | ||||||||||||
| Balance, September 30, 2023 | $ | 778,791 | $ | - | $ | 778,791 | ||||||
| Acquisition costs incurred | 584,299 | 22,734 | 607,033 | |||||||||
| Balance, September 30, 2024 | $ | 1,363,090 | $ | 22,734 | $ | 1,385,824 | ||||||
| Total Exploration and evaluation assets, September 30, 2024 | $ | 5,684,907 | $ | 28,594 | $ | 5,713,501 | ||||||
20
CANEX Metals Inc.
Notes to the Consolidated Financial Statements
(Expressed in Canadian Dollars)
For the year ended September 30, 2025
| 8. | Exploration and evaluation assets (continued) |
Mineral property advances and deposits
| Sept 30, 2025 | Sept 30, 2024 | |||||||
| Gibson exploration deposit | $ | 10,000 | $ | 10,000 | ||||
| Louise exploration deposit | 1,000 | - | ||||||
| Gold Range exploration deposit | 41,164 | 41,164 | ||||||
| Pre-takeover bid expenditures | 474,315 | - | ||||||
| $ | 526,479 | $ | 51,164 | |||||
Costs that relate directly to the acquisition of mineral interests are recorded as advances until such time as the transaction is completed. At that time, they will either be capitalized as part of the exploration asset acquired or expensed for the period if the acquisition is unsuccessful. Professional fees for legal , advisory, geological consulting and accounting are included in this category. Also, from time to time the Company is required to pay a deposit or bond to a government agency prior to their commencing exploration work on the mineral interest. The advances are held until reclamation work is complete and the Company makes application to have the deposit or bond returned.
| 9. | Accounts payable and accrued liabilities |
| Sept 30, 2025 | Sept 30, 2024 | |||||||
| Trade payables | $ | 202,248 | $ | - | ||||
| Due to related parties | 18,173 | 5,211 | ||||||
| Accrued liabilities | 46,800 | 40,900 | ||||||
| Commodity taxes payable | (12 | ) | 5 | |||||
| $ | 267,209 | $ | 46,116 | |||||
| 10. | Decommissioning obligation |
Changes in the decommissioning obligation:
| Sept 30, 2025 | Sept 30, 2024 | |||||||
| Balance, beginning of year | $ | 50,031 | $ | 38,380 | ||||
| Accretion | 4,734 | 2,131 | ||||||
| Change in estimates | (2,207 | ) | 9,520 | |||||
| Expenditures | - | - | ||||||
| Balance, end of year | $ | 52,558 | $ | 50,031 | ||||
The provision noted above represents estimated costs to restore the Company's mineral property which includes the cost of filling trenches and revegetation as applicable. Management believes that there are no other significant legal and constructive obligations as at the respective year end dates for current and future decommissioning obligations. The year end present value of the decommissioning obligation was determined using a risk-free rate of 2.47% (September 30, 2024 – 3.99%). The estimated total undiscounted amount, using an inflation rate of 2.50% (September 30, 2024 – 2.50%) for the year ended September 30, 2025 is $53,594 (2024 - $53,415). The timing of future decommissioning costs is uncertain, as the costs will not be incurred until the Company gives up its legal right to explore the property or the current land use permits expire, at which time the reclamation has to have been completed.
| 11. | Share capital and stock options |
| a) | Authorized |
Unlimited number of common shares without par value.
21
CANEX Metals Inc.
Notes to the Consolidated Financial Statements
(Expressed in Canadian Dollars)
For the year ended September 30, 2025
| 11. | Share capital and stock options (continued) |
| b) | Issued and outstanding common share capital |
| Shares | $ Value | |||||||
| Balance, as at September 30, 2024 | 114,380,737 | 21,450,899 | ||||||
| Common shares – November 2024 | 3,000,000 | 135,000 | ||||||
| Flow through shares – November 2024 | 5,033,365 | 226,502 | ||||||
| Shares issued for property – February 2025 | 500,000 | 20,000 | ||||||
| Common shares – June 2025 | 23,636,380 | 1,300,001 | ||||||
| Shares issued for property – August 2025 | 400,000 | 30,000 | ||||||
| Share issuance costs | - | (22,755 | ) | |||||
| Balance, as at September 30, 2025 | 146,950,482 | 23,139,647 | ||||||
| Shares | $ Value | |||||||
| Balance, as at September 30, 2023 | 105,486,567 | 21,135,858 | ||||||
| Shares issued for property – November 2023 | 8,694,170 | 304,296 | ||||||
| Shares issued for property – April 2024 | 200,000 | 14,000 | ||||||
| Share issuance costs | - | (3,255 | ) | |||||
| Balance, as at September 30, 2024 | 114,380,737 | 21,450,899 | ||||||
2025
Subsequent to the date of these Consolidated Financial Statements the Company announced a private placement issue of 20,000,000 common shares at a price of $0.15 per share for gross proceeds of $3,000,000. See Note 23 – Subsequent Event for more detail.
On August 19, 2025 the Company received regulatory approval to issue 400,000 common shares in exchange for three additional mining claims internal to the Louise Cu-Au Porphyry Project. The transaction was valued at the closing CANEX share price on the date of issue.
On June 26, 2025, the Company announced the closing of a non-brokered private placement of 23,636,380 common shares for gross proceeds of $1,300,001. The shares were issued at $0.055 per share and are subject to a hold period of four months plus one day from the date of closing. No commissions were paid on the transaction and insiders purchased a total of 1,139,054 common shares.
On February 25, 2025, the Company issued 500,000 common shares in accordance with the Louise option agreement and were valued at the closing CANEX share price on the date of issue.
During November 2024, the Company announced an equity financing for cash that closed in two tranches, November 14 and November 25, 2024. The non-brokered private placement consisted of 3,000,000 common shares and 5,033,365 flow through common shares for gross proceeds of $437,002. Common shares were offered at $0.045 per share and the flow through common shares were offered at $0.06 per share. The tax benefit of the flow through common shares, renounced to shareholders, was determined to be $75,500 and recorded as a current liability which was amortized through earnings as the critical mineral flow through mining expenditures are incurred. More details on the transaction are included in Note 16 – “Flow through shares”, to these Consolidated Financial Statements.
2024
On April 8, 2024, 200,000 common shares were issued in accordance with the Louise option agreement and were valued at the closing CANEX share price on the date of issue.
On November 29, 2023, 8,694,170 common shares were issued in accordance with the Excelsior Mine Property amended option agreement and were valued at the closing CANEX share price on the date of issue.
22
CANEX Metals Inc.
Notes to the Consolidated Financial Statements
(Expressed in Canadian Dollars)
For the year ended September 30, 2025
| 11. | Share capital and stock options (continued) |
c) Stock options outstanding
| Number of options | Exercise | |||||||||||
| Expiry | Sept 30, 2025 | Sept 30, 2024 | Price | |||||||||
| October 4, 2024 | - | 710,000 | $ | 0.055 | ||||||||
| May 1, 2027 | 1,462,500 | 1,462,500 | $ | 0.18 | ||||||||
| July 11, 2026 | 400,000 | 400,000 | $ | 0.06 | ||||||||
| November 25, 2029 | 5,200,000 | - | $ | 0.05 | ||||||||
| July 14, 2030 | 700,000 | - | $ | 0.08 | ||||||||
| 7,762,500 | 2,572,500 | |||||||||||
The Company has implemented a 10% Rolling Stock Option Plan whereby 10% of the issued shares will be reserved for issuance under the stock based compensation plan ("the Plan"). Under the Plan, the options that have been granted expire at the earlier of five years from the grant date, the date at which the Directors determine, or 60 days from the date on which the optionee ceases to be a director, officer, employee or consultant. The exercise price of the options granted under the Plan will not be less than that from time to time permitted under the rules of the stock exchange or exchanges on which the shares are then listed, which price reflects trading values at that time.
d) Stock option transactions
| Number of options | Weighted average exercise price | |||||||
| Balance, September 30, 2024 | 2,572,500 | $ | 0.13 | |||||
| Expired October 2024 | (710,000 | ) | $ | 0.055 | ||||
| Issued November 2024 | 5,200,000 | $ | 0.05 | |||||
| Issued July 2025 | 700,000 | $ | 0.08 | |||||
| Balance, September 30, 2025 | 7,762,500 | $ | 0.08 | |||||
| Number of options | Weighted average exercise price | |||||||
| Balance, September 30, 2023 | 5,410,000 | $ | 0.12 | |||||
| Cancelled | (262,500 | ) | (0.13 | ) | ||||
| Expired | (2,575,000 | ) | $ | (0.11 | ) | |||
| Balance, September 30, 2024 | 2,572,500 | $ | 0.13 | |||||
On November 25, 2024, 5,200,000 options were issued at $0.05 per share to existing directors, officers and consultants. One third of the options vested immediately and the remaining two thirds vest evenly over the next two years. If not exercised, the options will expire 5 years from date of grant.
On July 14, 2025, 700,000 options were issued at $0.08 per share to a consultant providing services to the Company. The options vest immediately and if not exercised will expire 5 years from the date of grant.
e) Warrant transactions and warrants outstanding
On May 27, 2024, the remaining 9,615,458 warrants outstanding with an exercise price of $0.18 per share expired without exercise.
23
CANEX Metals Inc.
Notes to the Consolidated Financial Statements
(Expressed in Canadian Dollars)
For the year ended September 30, 2025
| 12. | Financial instruments |
Financial instruments recorded at fair value are classified using a fair value hierarchy that prioritizes the inputs to fair value measurements. The three levels of fair value are summarized below:
| · | Level 1 - Unadjusted quoted prices in active markets for identical assets or liabilities; |
| · | Level 2 - Inputs other than quoted prices that are observable for assets or liabilities either directly, (i.e. prices), or indirectly, (i.e. derived from prices); and |
| · | Level 3 - Inputs that are not based on observable market data. |
Level 1 has been utilized to value common shares included in short-term investments.
The following summarizes the categories of the various financial instruments:
| Sept 30, 2025 | Sept 30, 2024 | |||||||
| Carrying Value | ||||||||
| Financial Assets | ||||||||
| Financial assets measured at fair value: | ||||||||
| Short-term investments | $ | - | $ | 31,035 | ||||
| Financial assets measured at amortized cost: | ||||||||
| Cash | 663,907 | 158,093 | ||||||
| Accounts receivable | - | 121 | ||||||
| $ | 663,907 | $ | 158,214 | |||||
Financial Liabilities
| Sept 30, 2025 | Sept 30, 2024 | |||||||
| Carrying Value | ||||||||
| Financial liabilities measured at amortized cost: | ||||||||
| Accounts payable and accrued liabilities | $ | 267,217 | $ | 46,111 | ||||
The above noted financial instruments are exclusive of any sales tax.
The carrying value of financial assets and liabilities measured at amortized cost approximates fair value due to the short-term nature of the instruments. Unless otherwise noted, it is management’s opinion that the Company is not exposed to significant interest or credit risks arising from these financial instruments.
The Company undertakes transactions denominated in US currency through its exploration in the US; consequently, it is exposed to exchange rate fluctuations. The Company will acquire US funds from time to time to settle US$ denominated liabilities. At September 30, 2025, the Company had US$5,358 (CAD$7,465) (2024 - US$1,189 (CAD$1,605)) in a US denominated bank account. The effect of a foreign currency increase or decrease of 10% on this cash holding would result in an increase or decrease of $747 (2024 - $161).
24
CANEX Metals Inc.
Notes to the Consolidated Financial Statements
(Expressed in Canadian Dollars)
For the year ended September 30, 2025
| 13. | General and administrative |
| Sept 30, 2025 | Sept 30, 2024 | |||||||
| Administrative consulting fees | $ | 184,189 | $ | 95,286 | ||||
| Share-based compensation (Note 14) | 212,860 | 10,294 | ||||||
| Occupancy costs | 23,106 | 22,686 | ||||||
| Office, secretarial, supplies and other | 58,261 | 45,301 | ||||||
| Insurance | 13,679 | 15,091 | ||||||
| Directors' fees | 5,500 | 6,000 | ||||||
| Computer network and website maintenance | 3,189 | 2,411 | ||||||
| Travel and promotion | 5,185 | 994 | ||||||
| $ | 505,969 | $ | 198,063 | |||||
| 14. | Share-based payment transactions |
On November 25, 2024, the Company issued 5,200,000 options that may be exercised at $0.05 per share to November 25, 2029. The options vest one third on issue, one third on the first anniversary date and the remainder on the second anniversary date. Stock based compensation is recognized each quarter based upon the portion that vests during the period. Vested options were valued at $71,000 and the remainder at $142,000 using the Black-Scholes Options Pricing model assuming a 5-year term, volatility of 151.03%, a risk free discount rate of 3.18% and a dividend rate of 0%, on the grant date.
On July 14, 2025, the Company issued 700,000 options that may be exercised at $0.08 per share to July 14, 2030. The options were issued to a consultant for completed and future work and vest immediately. Stock based compensation of $51,700 was recognized on issue using the Black-Scholes Options Pricing model assuming a 5-year term, volatility of 155.20%, a risk free discount rate of 3.04% and a dividend rate of 0%, on the grant date.
During the year ended September 30, 2024, the Company did not issue any options, but recognized stock based compensation related to options that were issued in July of 2023 that were fully vested.
| 15. | Loss per share |
Basic loss per share is calculated using the weighted average number of common shares outstanding during the period. Diluted loss per share is computed using the treasury stock method. Stock options and warrants outstanding are not included in the computation of diluted loss per share if their inclusion would be anti-dilutive.
The following adjustments were made in arriving at diluted weighted average number of common shares for the years ended September 30:
| Weighted average number of common shares: | Sept 30, 2025 | Sept 30, 2024 | ||||||
| Basic and Diluted | 127,743,757 | 112,895,636 | ||||||
| Loss per share | ||||||||
| Basic and diluted | $ | (0.00 | ) | $ | (0.00 | ) | ||
25
CANEX Metals Inc.
Notes to the Consolidated Financial Statements
(Expressed in Canadian Dollars)
For the year ended September 30, 2025
| 16. | Flow through shares |
Flow through common shares require the Company to spend an amount equivalent to the proceeds of the issued flow-through common shares on Canadian qualifying exploration expenditures. The Company may be required to indemnify the holders of such shares for any tax and other costs payable by them in the event the Company has not made the required exploration expenditures. During November 2024, the Company received $302,002 from the issuance of flow-through shares, of which $75,500 was attributed to a premium over the fair value of the shares issued and recorded as a liability for accounting purposes. At September 30, 2025, the Company has fulfilled all obligations associated with the flow through issue and recognized the full value of the flow through liability through earnings. Funds raised in connection with the flow-through shares were spent on qualified mineral exploration that met the definition of Canadian Exploration Expenditures as defined in the Canadian Income Tax Act. The tax benefit of the expenditures was renounced in favor of investors subscribing for flow through shares and the amounts are not available to the Company for income tax purposes.
| 17. | Income tax information |
Rate reconciliation:
The combined provision for taxes in the Consolidated Statement of Loss and Comprehensive Loss reflects an effective tax rate which differs from the expected statutory rate as follows:
| Sept 30, 2025 | Sept 30, 2024 | |||||||
| Income (loss) before income taxes | $ | (496,817 | ) | $ | (279,148 | ) | ||
| Computed expected expense (recovery) based on a combined rate of 23.00% (2024 – 23.00%) | (114,268 | ) | (64,204 | ) | ||||
| Change resulting from: | ||||||||
| True up of opening balance | 6,752 | (26,753 | ) | |||||
| Differential tax rate of foreign jurisdiction | (3,898 | ) | (4,776 | ) | ||||
| Non-deductible (taxable) items and other | (12,924 | ) | (11,353 | ) | ||||
| Unrecognized deferred tax asset | 124,338 | 107,086 | ||||||
| Income tax expense | $ | - | $ | - | ||||
The combined statutory rate is 23.00% for 2025 (2024 – 23.00%). The deferred combined statutory rate is expected to be 23.00% for 2025 and subsequent years (2024 – 23.00%).
Temporary differences and tax loss not recognized for accounting purposes:
| Sept 30, 2025 | Sept 30, 2024 | |||||||
| Non-capital loss carry-forwards | $ | 4,574,541 | $ | 4,375,714 | ||||
| Capital loss carry-forwards | 1,007,367 | 986,203 | ||||||
| Share issuance costs | 26,947 | 20,658 | ||||||
| US net operating loss | 4,488,625 | 4,154,541 | ||||||
| Mineral properties | 1,088,965 | 1,672,153 | ||||||
| Short-term investments | - | 41,667 | ||||||
| Interest | 571,245 | 393,044 | ||||||
| Total | $ | 11,757,690 | $ | 11,643,980 | ||||
26
CANEX Metals Inc.
Notes to the Consolidated Financial Statements
(Expressed in Canadian Dollars)
For the year ended September 30, 2025
| 17. | Income tax information (continued) |
As future taxable profits of the Company are uncertain, no deferred tax asset has been recognized. As at September 30, 2025, the Company had unused non-capital loss carry forwards of approximately $4.6 million that expire between the years 2026 and 2045. Capital loss carry-forwards may be carried forward indefinitely. The Company has unused US net operating loss carry forwards of approximately $4.5 million that may be carried forward indefinitely.
| 18. | Related party balances and transactions and key management remuneration |
The Company is considered a related party to Jade Leader Corp. ("Jade Leader") because of its common directors, officers and key management personnel that have some direct financial interest in both the Company and Jade Leader. In addition, related parties include members of the board of directors, officers and their close family members. Vector Resources Inc., a company controlled by Shane Ebert, President and director of CANEX Metals; and 635280 Alberta Ltd., a company controlled by Jean Pierre Jutras, an officer and director of CANEX Metals are also considered related parties.
The Company incurred the following amounts charged to (by) related parties:
| Sept 30, 2025 | Sept 30, 2024 | |||||||||
| Key management remuneration | ||||||||||
| President and director | a | $ | (103,919 | ) | $ | (43,377 | ) | |||
| Corporate secretary | b | (54,030 | ) | (37,380 | ) | |||||
| Chief Financial Officer | c | (2,200 | ) | (1,980 | ) | |||||
| Directors’ fees | d | (5,500 | ) | (6,000 | ) | |||||
| Total Management remuneration | $ | (165,649 | ) | $ | (88,737 | ) | ||||
| Sept 30, 2025 | Sept 30, 2024 | |||||||||
| Other related party transactions | ||||||||||
| Jade Leader | ||||||||||
| Office rent and operating costs paid | $ | (23,106 | ) | $ | (23,343 | ) | ||||
| General and administrative and secretarial costs paid | $ | (5,032 | ) | $ | (5,350 | ) | ||||
| General and administrative and secretarial cost recovery | $ | 663 | $ | 435 | ||||||
| 635280 Alberta Ltd. | ||||||||||
| Geological consulting services | e | $ | (12,771 | ) | $ | (1,356 | ) | |||
The following amounts were due to or receivable from related parties at the respective year ends:
| Balances Receivable (Payable) | Sept 30, 2025 | Sept 30, 2024 | ||||||||
| Consulting fees: | ||||||||||
| President and director | a | $ | (6,615 | ) | $ | (3,309 | ) | |||
| Chief Financial Officer | c | $ | (2,310 | ) | $ | - | ||||
| 635280 Alberta Ltd. | e | $ | (1,240 | ) | - | |||||
| Office rent and operating costs | ||||||||||
| Jade Leader | $ | - | $ | 121 | ||||||
| General and administrative and other: | ||||||||||
| Directors Fees | d | $ | (500 | ) | $ | - | ||||
| Jade Leader | $ | (998 | ) | $ | (1,539 | ) | ||||
| Corporate secretary | b | $ | (5,985 | ) | $ | - | ||||
| President and director | a | $ | (525 | ) | $ | (363 | ) | |||
27
CANEX Metals Inc.
Notes to the Consolidated Financial Statements
(Expressed in Canadian Dollars)
For the year ended September 30, 2025
| 18. | Related party balances and transactions and key management remuneration (continued) |
Management compensation payable to "key management personnel" during the years ended September 30, 2025 and 2024 is reflected in the table above and consists of consulting fees paid to the President, the CFO, fees for the Corporate Secretary and directors' fees. Officers and directors are also compensated through the granting of options from time-to-time. During the year ended September 30, 2025, 4.2 million options at $0.05 were issued to related parties. During 2024, the Company did not grant any stock options to related parties. There were no other benefits granted to officers, directors and consultants during the years ended September 30, 2025 and 2024. Key management personnel are defined as those persons having authority and responsibility for planning, directing and controlling the activities of the entity, directly or indirectly, including any director of the Company.
| a) | The President and director of the Company billed for consulting services that were either expensed or, when his services related directly to mineral property exploration, capitalized to exploration and evaluation assets (Note 8). During the year ended September 30, 2025, $56,875 (2024 - $26,950) was expensed through administrative expenses, $47,044 (2024 - $15,427) was capitalized to exploration and evaluation assets. |
| b) | The Corporate Secretary provides services to the Company on a contract basis. |
| c) | The Chief Financial Officer provides services to the Company on a contract basis. |
| d) | The Company pays directors who are not officers, $500 for attendance at board meetings. There are three directors who are not officers and the amounts above reflect directors’ fees paid/payable for meetings attended during the above-noted periods. |
| e) | During the years ended September 30, 2025 and 2024, geological consulting services were provided by 635280 Alberta Ltd. |
Related party receivables pertain to billings plus applicable sales taxes for which payment has not been received and related party payables reflect billings plus applicable sales taxes that were not yet paid by the Company at the respective period ends. Related party transactions were measured at the amounts agreed to by the transacting parties.
| 19. | Supplemental disclosure statement of cash flows |
Reconciliation of cash used in operating activities to operating loss for the years ended:
| Sept 30, 2025 | Sept 30, 2024 | |||||||
| Loss and comprehensive loss | $ | (496,817 | ) | $ | (279,148 | ) | ||
| Stock-based compensation | 212,860 | 10,294 | ||||||
| Accretion | 4,734 | 2,131 | ||||||
| Interest and other items | (5,037 | ) | (9,820 | ) | ||||
| (Gain) loss on short-term investments | (20,173 | ) | (1,137 | ) | ||||
| Realization of flow through premium | (75,500 | ) | - | |||||
| Changes in assets and liabilities pertaining to operations: | ||||||||
| Accounts receivable | (33,432 | ) | 2,532 | |||||
| Prepaid expenses | (61,454 | ) | 23,321 | |||||
| Accounts payable and accrued liabilities | 222,582 | (73 | ) | |||||
| Cash paid to suppliers and contractors | $ | (252,237 | ) | $ | (251,900 | ) | ||
28
CANEX Metals Inc.
Notes to the Consolidated Financial Statements
(Expressed in Canadian Dollars)
For the year ended September 30, 2025
| 19. | Supplemental disclosure statement of cash flows (continued) |
Reconciliation of cash expended on exploration and evaluation assets for the years ended:
| Sept 30, 2025 | Sept 30, 2024 | |||||||
| Change in exploration and evaluation assets | $ | (583,428 | ) | $ | (659,916 | ) | ||
| Property acquisition – Share issuance | 50,000 | 318,296 | ||||||
| Provision for decommissioning | (2,207 | ) | 9,520 | |||||
| Accounts receivable | - | 1,549 | ||||||
| Accounts payable and accrued liabilities | (1,489 | ) | (13,679 | ) | ||||
| Cash expended on exploration and evaluation assets | $ | (537,124 | ) | $ | (344,230 | ) | ||
Interest and taxes
No cash was expended on interest or taxes during the years ended September 30, 2025 and September 30, 2024.
Non-cash transactions
During the year ended September 30, 2025, the company issued 500,000 common shares valued at $20,000 pursuant to an option agreement on the Louise Cu-Au Porphyry Project. In addition, 400,000 shares were issued to acquire additional claims within the Louise property. These shares were valued at $30,000. All shares issued for property are valued based on the closing price on the date of issue.
During the year ended September 30, 2024, the Company issued 8,694,170 common shares valued at $304,296 pursuant to an option agreement on the Gold Range Property. In addition, 200,000 common shares valued at $14,000 were issued pursuant to an option agreement on the Louise property.
During 2025, the Company granted 5,900,000 (2024-nil) stock options to directors and consultants and recorded a non-cash charge for vested stock based payments of $212,860 (2024-$10,294) which is included in general and administrative expenses (Note 13). Refer to Note 14 – “Share-based payment transactions” for further information.
| 20. | Segment disclosures |
During the years ended September 30, 2025 and September 30, 2024, the Company was only engaged in mineral exploration and all exploration activities were undertaken in Canada and/or the United States. Activities undertaken in both countries were similar in nature. As at September 30, 2025, the value of non-current assets associated with United States operations is $5,871,833 (2024 - $5,726,071) including mineral property advances and deposits of $41,164 (2024 - $41,164) and exploration and evaluation assets of $5,830,669 (2024 - $5,684,907). All remaining non-current assets are associated with Canadian operations. Consequently, segmented information is not presented in these financial statements. Refer to Note 8 – “Exploration and evaluation assets” for details of the carrying amounts of these assets at the respective period ends.
29
CANEX Metals Inc.
Notes to the Consolidated Financial Statements
(Expressed in Canadian Dollars)
For the year ended September 30, 2025
| 21. | Capital |
The Company’s objective when managing capital is to continue as a going concern so that it can provide value to shareholders by acquiring and conducting exploration on mineral exploration properties with the ultimate objective of finding commercial quantities of base and/or precious metals. Capital is defined as capital stock, warrants, contributed surplus and deficit. The Company has traditionally financed through equity issues rather than debt and does not anticipate using debt to finance its continuing grass roots exploration. Should the Company evolve to the point where it is developing or operating a mine, debt options will be investigated.The Company will raise equity as cash flow requirements dictate and will attempt, when able, to time financings with more favorable market conditions. The Company can scale back exploration, and to a certain extent, discretionary administrative costs during tighter equity markets. The Company invests capital that is surplus to its immediate operational needs in short-term, liquid and highly-rated financial instruments such as Bankers’ Acceptances and Term Deposits until such time as it required to pay operating expenses and mineral property costs, including option payments (Note 8). The Company objective is to manage its capital to safeguard its cash and its ability to continue as a going concern, and to utilize as much of its available capital.
| 22. | Financial risk management |
a) Credit risk
Credit risk is the risk of financial loss to the Company if counterparties to a financial instrument fail to meet their contractual obligations. The Company’s financial instruments that could be subject to credit risk consist of receivables, excluding sales tax. The Company has had a history of prompt receipt of its receivables and considers credit risk to be low on these instruments as at September 30, 2025 and September 30, 2024.
b) Liquidity risk
Liquidity risk is the risk that the Company will not be able to meet its financial obligations as they come due. The Company’s approach to managing liquidity risk is the utilization of budgets, to attempt to maintain sufficient liquidity in order to meet operational and exploration requirements as well as property acquisition commitments. The Company raises capital through equity issues and its ability to do so is dependent on a number of factors including market acceptance, stock price and exploration results. The Company is continually investigating financing options. The continuing operations of the Company are dependent upon its ability to obtain adequate financing or to commence profitable operations in the future. During the year ended September 30, 2025, the Company issued 31,669,745 common shares for cash proceeds, before issue costs, of $1,737,004. Increases in activity levels, new property acquisitions and any level of exploration on its mineral properties may require additional financing. There can be no assurance that the Company will be successful in obtaining financing. Refer to Note 1 - "Nature of operations and continuance of operations".
The Company’s significant remaining contractual maturities for financial liabilities as at September 30, 2025 and 2024 are as follows:
| · | Accounts payable and accrued liabilities are due within one year. |
| c) | Interest rate risk |
The Company has no debt facilities and has minimal amounts of interest income, it is not exposed to significant interest rate risk at this time. All market risk is associated with the Company's investments in common shares, which are recorded at fair value at the respective period ends with the resultant gains or losses recorded in earnings.
30
CANEX Metals Inc.
Notes to the Consolidated Financial Statements
(Expressed in Canadian Dollars)
For the year ended September 30, 2025
| 22. | Financial risk management (continued) |
| d) | Foreign exchange risk |
The Company undertakes transactions denominated in US currency; consequently, it is exposed to exchange rate fluctuations. Refer to Note 12 – “Financial instruments” for the foreign exchange risk associated with the foreign denominated cash balances held.
| 23. | Subsequent event |
Subsequent to the date of these Consolidated Financial Statements the Company announced a non-brokered private placement offering up to 20,000,000 common shares at $0.15 per share for total potential proceeds of $3,000,000. Under the terms of the offering, once closed, the shares will be subject to a four month hold period and are subject to TSX Venture Exchange approval. The transaction is expected to close prior to January 9, 2026.
31
CANEX Metals Inc.
MANAGEMENT’S DISCUSSION AND ANALYSIS
FOR THE YEAR ENDED SEPTEMBER 30, 2025
The following management discussion and analysis (MD&A) is management’s assessment of the results and financial condition of CANEX Metals Inc. (“CANEX” or “the Company”) for the three months and year ended September 30, 2025. The information included in this MD&A, with an effective date of December 19, 2025, should be read in conjunction with the Consolidated Financial Statements as at and for year ended September 30, 2025, and related notes thereto. CANEX Metal’s common shares trade on the TSX Venture Exchange under the symbol “CANX”. The Company’s most recent filings are available on the System for Electronic Document Analysis and Retrieval (“SEDAR+”) and can be accessed at www.sedarplus.ca.
The Company’s Consolidated Financial Statements have been prepared in accordance with International Financial Reporting Standards and International Accounting Standards as issued by the International Accounting Standards Board (IASB) and Interpretations (collectively IFRS Accounting Standards) as at and for year ended September 30, 2025. The Company has consistently applied the same accounting policies throughout all periods presented. The Company’s accounting policies are provided in Note 3 “Material accounting policies” to the annual audited Consolidated Financial Statements at September 30, 2025. All dollar amounts are in Canadian dollars, unless otherwise noted.
The “Qualified Person” under the guidelines of National Instrument 43-101 of the Canadian Securities Administrators (“NI 43-101”) for CANEX Metals’ exploration projects in the following MD&A is Dr. Shane Ebert, P. Geo., a Professional Geologist, registered in the Province of British Columbia and the President and Director of CANEX Metals. The scientific and technical information concerning such properties contained herein has been reviewed by Dr. Ebert.
Statements and/or financial forecasts that are unaudited and not historical, including without limitation, exploration budgets, data regarding potential mineralization, exploration results and future plans and objectives, are to be regarded as forward-looking statements that are subject to risks and uncertainties that can cause actual results to differ materially from those anticipated. Such risks and uncertainties include risks related to the Company’s business including but not limited to general market and economic conditions, limited operating history, continued industry and public acceptance, regulatory compliance, potential liability claims, additional capital requirements and uncertainty of obtaining additional financing and dependence on key personnel. Actual exploration and administrative expenditures can differ from budget due to unforeseen circumstances, changes in the marketplace that will cause suppliers’ prices to change, and additional findings that will dictate that the exploration plan be altered to result in more or less work.
All forward-looking information is stated as of the effective date of this document and is subject to change after this date. There can be no assurance that forward-looking information will prove to be accurate and future events and actual results could differ materially from those anticipated.
1. Principal Business of the Company
CANEX Metals, including its wholly owned subsidiary, Canexco Inc. (“Canexco”), is engaged exclusively in the business of mineral exploration and development and, as the Company has no mining operations and no earnings there from, it is considered to be in the exploration stage. The recoverability of the amounts comprising exploration and evaluation assets is dependent upon the existence of economically recoverable mineral reserves; the acquisition and maintenance of appropriate permits, licenses and rights; the ability of the Company to obtain financing to complete the development of the mineral properties where necessary and upon future profitable production; or, alternatively, upon the Company’s ability to recover its costs through a disposition of its interests. The Company’s philosophy is to acquire projects at the grass roots level and advance them to a point where partners can be brought in to further the properties to the stage where a mine is commercially feasible, or the property can be sold outright.
The Company has no operating income and no earnings; exploration and operating activities are financed by the sale of common shares. None of the Company’s mineral properties are in production. Consequently, the Company’s net income is a limited indicator of its performance and potential.
| 1 |
CANEX Metals Inc.
MANAGEMENT’S DISCUSSION AND ANALYSIS
FOR THE YEAR ENDED SEPTEMBER 30, 2025
2. Highlights
· On December 10, 2025, The Company announced a non-brokered private placement and the extension of the offer to Gold Basin Resources Corporation (Gold Basin) shareholders. Under the terms of the financing CANEX will issue up to 20,000,000 common shares at $0.15 per share for total gross proceeds of $3,000,000. The offering, once closed, will result in a new insider acquiring 9.9% of the Company. Proceeds will be used to advance the district consolidation opportunity, for exploration at the Company’s Gold Range and Louise projects and for general working capital. It is subject to TSXV approval and is expected to close on or before January 9, 2026.
· In conjunction with the Company’s response to Gold Basin directors’ circular, on October 27, 2025, CANEX published an independent technical report for the Gold Range Project. The report is posted on the Company’s website and under the Company’s profile on SEDAR+. Interested parties should read the report in its entirety. The independent qualified author concludes that “The Gold Range project presents a compelling exploration opportunity within a well understood geological framework and deposit model. The evidence supports a structurally controlled, multi-episodic mineralizing system with the potential to host both high-grade vein-hosted and bulk-tonnage oxide gold resources. Continued exploration is warranted and should focus on expanding known zones drill testing structural intersections and alteration halos and advancing regional targeting within the broader Gold Basin District”.
· On August 28, 2025, the Company formally commenced its offer to acquire all of the issued and outstanding common shares of Gold Basin by way of a take-over bid. The offer is open for acceptance until December 12, 2025, unless it is extended, accelerated or withdrawn. The offer provides Gold Basin shareholders with 0.592 of a common share in the capital of CANEX in exchange for each Gold Basin share.
· On July 31, 2025, the Company announced that based on the geophysical survey recently completed over the Louise Copper-Gold Porphyry Project (Louise Project or Louise) in BC, two new previously unknown high chargeability targets have been identified west and below the historic Louise Project deposit. The Company continues to study the results and will determine next steps to advance this discovery.
· To consolidate the Company’s land position for the Louise Project on June 12, 2025, CANEX applied to stake 4.8 kilometers of additional strike length along the western projection of the geophysical trend. On July 29, 2025, the Company entered into a claim purchase agreement on three claims that sit internal to the Louise claim block for total consideration of 400,000 CANEX shares. The Vendor retains a 1% net smelter return royalty which can be bought back by CANEX for $500,000. In addition, on July 30, 2025, CANEX applied to stake 2.5 kilometres of additional strike length along the eastern projection of the geophysical trend.
· On June 26, 2025, the Company closed a non-brokered private placement for 23,636,380 common shares at $0.055 per share for gross proceeds of $1,300.001. No commissions were paid, and the shares are subject to a four month hold period. Insiders purchased a total of 1,139,054 shares in connection with the private placement. Proceeds will be used to advance the consolidation process at the Gold Range property, exploration at Gold Range and Louise Projects and for general working capital.
· On June 9, 2025, the Company announced its intention to make a formal offer to acquire all of the issued and outstanding shares of Gold Basin Resources Corporation (Gold Basin) in exchange for shares in CANEX. The transaction is notionally valued at $5.52 million and is subject to obtaining necessary regulatory approvals. Gold Basin holds assets that are directly adjacent to and on trend with the CANEX Gold Range Property.
| 2 |
CANEX Metals Inc.
MANAGEMENT’S DISCUSSION AND ANALYSIS
FOR THE YEAR ENDED SEPTEMBER 30, 2025
· On February 25, 2025, the Company the Company made the second, in a series of required annual option payments for the Louise Cu-Au porphyry deposit in British Columbia by issuing 500,000 common shares of the company at a notional price of $0.05 per share and cash of $3,500. The project is road accessible, contains an historic copper-gold-molybdenum resource and has only been explored to shallow depths. There are no expenditure commitments allowing CANEX to advance the project as market conditions allow. Total option payments of $35,000 in shares or cash have been made and the remaining $740,000, are scheduled over the next 4 years. A milestone bonus of $50,000 in shares or cash will also be payable if CANEX drills over 4250 metres of core, and a second milestone bonus of $50,000 in shares or cash will be payable if CANEX publishes a resource estimate with greater than 1.5 million contained ounces of gold. The vendor will retain a 2.5% net smelter royalty (NSR), with CANEX having the right to buy back 40% of the NSR for $1,500,000 and a right of first refusal on any sale of the royalty.
· On November 14, 2024, CANEX closed the first tranche of an equity financing and on November 25th closed the second and final tranche to complete the oversubscribed transaction. In total the Company issued 3,000,000 common shares at $0.045 per share. In addition, 5,033,365 flow-through common shares (FT shares) were issued at $0.06 per share. Gross proceeds of $437,002 were used to advance the Louise Cu-Au porphyry in British Columbia and the Gold Range oxide gold project in northern Arizona.
· On September 24, 2024, the Company presented the drill data compilation results from the Louise Cu-Au porphyry project in British Columbia. The Louise Project hosts a copper-gold deposit that has been drill defined over an area 1000 meters long by 400 meters wide and to approximately 300 meters depth. Strong grades occur in the system highlighted by hole LL04-03 which returned 158 metres grading 0.41% copper and 0.40 g/t gold. CANEX is planning to conduct a modern deep looking induced polarization (IP) survey to explore the district across 6 to 7 kilometres of strike length and to depths up to 1000 metres to fully assess the district potential surrounding the known historic resource.
| 3. | Mineral Properties |
Gold Range Property, Arizona, USA
The Gold Range Property is in Northern Arizona within an area that has seen historic lode and placer gold production but limited modern gold exploration. CANEX first became interested in the Gold Range property in 2019, following the discovery of a quartz vein containing abundant visible gold by a local prospector in an area termed the Discovery Zone. Subsequent mapping and soil and rock sampling identified a 1000-metre-long linear trend of historic workings and exposed quartz veins centered around the Adit zone. Additional programs of surface sampling, mapping, trenching, airborne magnetic and lidar surveying, along with reverse circulation drilling have resulted in further expansion of the claim holdings and the recognition of a 4-kilometre-long mineralized corridor stretching from the Eldorado to Excelsior to WestGold Zones.
As of September 30, 2025, the Gold Range Property consists of 261 lode mining claims and 2 patented claims and is approximately 1650 hectares in size. The Company has drilled 15,412 metres in 138 holes and defined bulk tonnage oxide mineralization at the Excelsior, Eldorado, Malco, Central, and WestGold Zones. The oxide gold zones extend to surface and positive bottle roll metallurgical test work suggests mineralization is amenable to low cost heap leach extraction.
| 3 |
CANEX Metals Inc.
MANAGEMENT’S DISCUSSION AND ANALYSIS
FOR THE YEAR ENDED SEPTEMBER 30, 2025
On June 9, 2025, the Company announced its intention to make a takeover bid to acquire all of the outstanding shares of Gold Basin Resources in exchange for shares in CANEX. On August 19, 2025, CANEX received partial revocation of the cease trade order imposed on Gold Basin by the British Columbia Securities Commission allowing CANEX to proceed with making the bid and on August 28, 2025, CANEX filed the Offer and Take-over Bid Circular for Gold Basin and formally commenced the take-over bid. The offer provides Gold Basin shareholders with 0.592 of a common share in the capital of CANEX in exchange for each Gold Basin share held by such shareholders and is open for acceptance until December 12, 2025. The proposed combination of the two companies would consolidate a large oxide gold camp in Northern Arizona. Over the past five years CANEX has been advancing its Gold Range property, making new gold discoveries and drill defining gold zones along a 4.0 kilometer mineralized trend that continues onto Gold Basin’s claims and is the longest defined gold trend in the district, extending at least 6.5 kilometres across both properties. To support the take-over offer, CANEX commissioned an independent third party evaluation of the Gold Range project which was published on October 27, 2025. The report provides a review of this project, highlighting the history, geology and exploration results completed to date. The independent qualified author concludes that “The Gold Range project presents a compelling exploration opportunity within a well understood geological framework and deposit model. The evidence supports a structurally controlled, multi-episodic mineralizing system with the potential to host both high-grade vein-hosted and bulk-tonnage oxide gold resources. Continued exploration is warranted and should focus on expanding known zones drill testing structural intersections and alteration halos and advancing regional targeting within the broader Gold Basin District”. The report is available on the CANEX website at www.canexmetals.ca and under the Company’s profile on SEDAR+ at sedarplus.ca.
During 2024 the Company successfully obtained a permit amendment to allow for drill testing of the new WestGold discovery, and the permits allows for an additional 34 pads located across the property. In March 2024 CANEX completed a field program focusing on refining drill targets in the WestGold area.
Highlights from the March 2024 surface exploration project at the Gold Range Project in Arizona include collecting 151 surface rock and soil samples, detailed mapping at the significantly expanded WestGold target and three new zones have been identified where assays from all three zones have returned high-grade gold mineralization. Areas of particular interest include:
· Surface chip sampling in the eastern part of the Gold Range property returned 19.4 g/t gold over 3 metres in a zone that has never been drill tested.
· A new zone of high-grade mineralization was identified 300 metres north of the Excelsior deposit, in the east-central part of the property, returning 11.2 g/t gold from a grab sample.
· A new zone of quartz veining and gold mineralization was discovered in the west-central part of the Gold Range property with a grab sample from a poorly exposed area returning 5.05 g/t gold.
· Grab samples of quartz veins in the WestGold area have returned grades up to 6.67 g/t gold and mineralized halos surrounding larger quartz veins have returned 0.97 g/t over 2 metres and 0.66 g/t gold over 3 metres in chip samples, confirming the presence of bulk tonnage targets at the zone.
Mapping has expanded the exploration target at WestGold to an area 800 metres by 400 metres and WestGold in now the largest exploration target on the Gold Range property. The zone is fully permitted, and drill testing can commence as markets strengthen.
On February 24, 2024, the Company completed an option agreement and acquired 100% ownership in the Never Get Left Prospect claim by making the final option payment of $US30,000 ($CAD40,581). Under the terms of the agreement the optionor will retain a 2% NSR. Canexco can purchase half (1%) of the NSR for $US500,000 and the remaining half (1%) for an additional $US500,000.
Prior period drilling highlights from across the Gold Range Property include:
Hole GR21-57: 1.0 g/t gold over 59.45 metres (Excelsior)
Hole GR21-37: 1.6 g/t gold over 35.1 metres (Excelsior)
Hole GR21-46: 2.2 g/t gold over 18.3 metres (Excelsior)
| 4 |
CANEX Metals Inc.
MANAGEMENT’S DISCUSSION AND ANALYSIS
FOR THE YEAR ENDED SEPTEMBER 30, 2025
Hole GR22-82: 9.7 g/t gold over 1.5 metres (Excelsior)
Hole GR22-90: 1.2 g/t gold over 12.19 metres (Excelsior)
Hole GR23-131: 4.1 g/t gold over 6.1 metres (Excelsior)
Hole GR22-97: 1.4 g/t gold over 6.1 metres (East of Excelsior)
Hole Gr23-127: 2.3 g/t gold over 3.1 metres (East of Excelsior)
Hole GR22-91: 0.6 g/t gold over 27.44 metres (Central)
Hole GR22-110: 1.1 g/t gold over 27.4 metres (Shaft)
Hole GR21-25: 1.3 g/t gold over 21.3 metres (Eldorado)
Hole GR20-4: 10 g/t gold over 1.5 metres (Eldorado)
Hole GR23-118: 0.2 g/t gold over 54.9 metres (WestGold)
Hole GR23-120: 0.7 g/t gold over 35 metres (WestGold)
During 2023 the Company completed surface exploration programs at Gold Range, a LiDar and air photo survey, and drill tested three new target areas defined previously, including WestGold, the zones parallel to Excelsior, and the new Shaft discovery. The WestGold target contains the largest and highest-grade gold in soil anomaly defined on the Gold Range property to date and the Company’s drill test of that target has resulted in a new and potentially very significant gold discovery that continues to be an important focus for the Company.
On November 29, 2023, the Company and its 100% owned Arizona subsidiary Canexco Inc. announced the completion of the Excelsior Mine Property 100% purchase as defined in the Amended Excelsior Mine Property Option Agreement. Under the amended agreement CANEX earned a 100% interest in the Excelsior Mine Property in exchange for issuing 8,694,170 CANEX shares and paying US$120,000 (CAD$166,058) in cash. The Vendors will retain a 1.5% NSR and CANEX retains a right of first refusal on the sale of the royalty. In addition, until August 31, 2030, should the Company be subject to any event that would impact the creditors rights that is not cured in 30 days, they will deliver the mine property back to the Vendor under the reversion clause of the agreement. The Excelsior Mine Property consists of 11 lode mining claims and 2 patented mining claims covering 3 past producing historic gold mines located within the Company’s larger Gold Range Project in Arizona. CANEX has drilled 72 holes into the main Excelsior deposit, defining a moderately dipping gold mineralized zone up to 400 meters long by 20 to 60 metres wide, that has been traced at least 100 metres down dip.
Operational highlights for the last eight quarters:
| o | The Company released an independent technical report commissioned to review the Company’s Gold Range project and the broader Gold Basin District. Report indicates further exploration is warranted. – October 2025 | |
| o | The Company files offer and takeover bid circular for Gold Basin and formally commences takeover bid – August 2025 | |
| o | CANEX receives partial revocation of cease trade order imposed on Gold Basin by the British Columbia Securities Commission allowing CANEX to proceed with making a takeover bid of Gold Basin – August 2025 | |
| o | The Company announces intention to make a takeover bid to acquire all of the outstanding shares of Gold Basin Resources – June 2025 | |
| o | Field mapping and soil sampling identified 3 new zones in WestGold– March 2024 | |
| o | The Company acquires 100% ownership in the Never Get Left Claim – February 2024 | |
| o | Amended exploration permit received – March 2024 | |
| o | The Company acquired 100% ownership in Excelsior property – November 2023 |
The gross costs and impairments recorded for the Gold Range Property at September 30, 2025, are $5,830,669 and $nil, respectively (September 30, 2024 - $5,684,907 and $nil).
| 5 |
CANEX Metals Inc.
MANAGEMENT’S DISCUSSION AND ANALYSIS
FOR THE YEAR ENDED SEPTEMBER 30, 2025
Louise Cu-Au Porphyry Project, British Columbia
In March 2024, the Company entered into an option agreement, with no spending requirements, to earn a 100% interest in the Louise Project subject to certain scheduled option payments. The project offers a low-risk, high value opportunity with untested discovery potential that can be advanced as market conditions allow. The property is located approximately 35 kilometres west of Smithers, in west central British Columbia, It is road accessible and previous drilling has returned strong copper and gold trades including 0.41% copper and 0.40 g/t gold over 158 metres and several holes indicating increasing grades with depth.
During 2024, in conjunction with signing the agreement, CANEX advanced $8,733 to the optionor to stake certain claims that are contained within the 5,362.94 hectare optioned property and subject to the terms of the agreement. Remaining obligations under the option agreement are discussed below in Section 7 a), Contractual Obligations.
The Company assembled and analyzed the historic data for the Louise Project and announced the results of this work on September 24, 2024. Highlights included:
· Historic drilling has identified a mineralized zone that is 1000 metres long by 400 metres wide and currently extends to a depth of approximately 300 metres.
· Strong copper and gold grades occur in the system highlighted by hole LL04-03 which returned an interval of 158 metres grading 0.41% copper and 0.40 g/t gold starting at 53.5 metres downhole.
· Past work largely focused in and around the original surface discovery area and only extends to about 300 metres deep, with some drill holes ending in mineralization.
· Data suggests potential for a copper and gold target below and lateral to the existing resource.
See the press release dated September 24, 2024, for further technical details and mapping of this prospect.
To better understand the district scale potential of this porphyry system, CANEX proposed a deep looking induced polarization (IP) survey that can potentially look up to 1000 metres deep and extend that survey across 6 to 7 kilometres of strike length.
During November 2024, CANEX closed, in two tranches, a non-brokered financing, as discussed in 2) Highlights, 4) Operating results and 5) Liquidity and Capital Resources, to fund this project. FT share proceeds of $302,002 were used for general exploration expenditures at the Louise Project which constituted Canadian Exploration Expenses within the meaning of subsection 66.1(6) of the Income Tax Act (Canada) (the “Tax Act”), that qualify as “critical mineral flow through mining expenditures” within the meaning of the Tax Act. At September 30, 2025, the Company has incurred the required $302,002 of qualifying expenditures through a geophysical survey and there are no remaining commitments under the Tax Act.
On December 10th, 2024, CANEX announced receipt of an exploration permit for the Louise Cu-Au porphyry project in British Columbia allowing the Company to conduct surface geophysical surveying over the target area.
During May and June 2025, Simcoe Geoscience conducted a geophysical survey at the Louise Project using their Alpha IPTM wireless time domain distributed induced polarization technology. A total of 36.9 line kilometres on nine lines were surveyed; each line was 4100 metres long and spaced 400 metres apart. The survey used a 100-metre dipole spacing with a dipole-pole-dipole (reverse & forward) configuration enabling double data density to be acquired providing high definition and resolution.
A new and previously unknown chargeability target has been identified two kilometres west of the historic Louise deposit and has been named the West Louise Target. In addition, a steeply dipping zone of high chargeability has been identified below and to the north of the historic Louise deposit and has been termed the Louise Deep Target. The Louise Deep Target is interpreted to have potential to host the mineralized roots of the historic Louise system and shows continuity to roughly 1000 metres below surface, the limit of the geophysical survey. Neither the West Louise nor Louise Deep targets have been drill-tested previously.
| 6 |
CANEX Metals Inc.
MANAGEMENT’S DISCUSSION AND ANALYSIS
FOR THE YEAR ENDED SEPTEMBER 30, 2025
Highlights:
· The West Louise Target is located two kilometres west of the historic Louise resource and correlates with a low-level surface Cu-Mo-Au-As geochemical anomaly in a flat area covered by glacial till.
· The West Louise Target is defined by chargeability values from 15 to >20 mV/V over an area 600 metres wide by 400 to 500 metres deep and extending at least 800 meters along strike, with the anomaly remaining open to the west. The anomaly comes to surface on line 1E and starts around 150m below surface on line 2E.
· The West Louise Target contains similar chargeability and resistivity values as the historic Louise deposit and has never been identified or drill tested previously. The target could represent a new porphyry centre with potential to host copper-gold mineralization similar to that at the Louise deposit.
· The Louise Deep Target contains a sub vertical zone of high chargeability located below and immediately north of the Louise deposit. This target is 700 metres wide and extends to 1000 metres below surface, the depth limit of the geophysical survey. This target could be the conceptual “main body” of the Louise Project that is partially offset from the resource area along the Terminator Fault. Identifying this target was a key objective of the survey.
· CANEX has purchased three small claims located internal to the Louise claim block by issuing 400,000 shares to the vendor. In addition, CANEX has staked a further 4.8 kilometres of strike length along the western projection and 2.5 kilometres of strike length along the eastern projection of the geophysical trend.
The gross costs and impairments recorded for the Louise Project at September 30, 2025, are $466,261 and $nil, respectively. (September 30, 2024 - $28,594 and $nil).
Gibson Prospect, British Columbia
In 2017 the Company entered into an option agreement with owner Altius Resource Inc. (“Altius”) to acquire a 100% interest in the Gibson property located in central British Columbia, approximately 95 kilometres northwest of Fort St. James. The Company conducted surface mapping and sampling, trenching, and drilled 10 holes into the Gibson property in 2017 and 2018. This work resulted in strong precious metal results including:
Hole G18-01: 0.81 g/t gold and 40 g/t silver over 31.5 metres from 33.5 metres depth Trench 1: 1.6 g/t gold and 175 g/t silver over 12.0 metres
Hole G18-01: 3.7 g/t gold and 321 g/t silver over 2.5 metres from 54 metres depth
Hole G18-01: 11.9 g/t gold and 301 g/t silver over 1.0 metres from 64 metres depth
Hole G18-03: 2.7 g/t gold and 872g/t silver over 0.5 metres from 19 metres depth
The Company has identified promising precious metal potential at Gibson and the mineralized zone remains open in all directions under shallow cover.
During the year ended September 30, 2021, the Company determined that further exploration on this property, would no longer be a priority unless a third-party partner could be found to further advance the exploration program; however, the Company continues to hold claims which expire in January 2029. Accordingly, the Company recorded an impairment of the full amount of exploration expenditures to September 30, 2021. In August 2024, the Company received a further extension to meet its minimum exploration expenditures to December 31, 2025. All other terms of the option agreement remain unchanged. For more information, refer to Section 7 b), Contractual Obligations below.
| 7 |
CANEX Metals Inc.
MANAGEMENT’S DISCUSSION AND ANALYSIS
FOR THE YEAR ENDED SEPTEMBER 30, 2025
4. Operating results
A summarized statement of operations appears below to assist in the discussion that follows:
| Three months ended, | Year ended, | |||||||||||||||
| September 30 | September 30 | |||||||||||||||
| 2025 | 2024 | 2025 | 2024 | |||||||||||||
| General and administrative | $ | 170,841 | $ | 31,280 | $ | 505,969 | $ | 198,063 | ||||||||
| Reporting to shareholders | 7,179 | 13,927 | 13,835 | 20,825 | ||||||||||||
| Professional fees | 50,545 | 40,900 | 60,375 | 48,689 | ||||||||||||
| Stock exchange and transfer agent fees | 3,398 | 4,217 | 12,614 | 18,304 | ||||||||||||
| Accretion | 2,041 | 2,131 | 4,734 | 2,131 | ||||||||||||
| Property fees and taxes | - | - | - | 2,094 | ||||||||||||
| Interest and other (income) | (2,769 | ) | (1,763 | ) | (5,037 | ) | (9,821 | ) | ||||||||
| Realization of flow through premium | - | - | (75,500 | ) | - | |||||||||||
| Gain (loss) on short-term investments | - | 10,345 | (20,173 | ) | (1,137 | ) | ||||||||||
| Net and comprehensive loss | $ | 231,233 | $ | 101,037 | $ | 496,817 | $ | 279,148 | ||||||||
The most significant changes in expenditure follow:
· Variances in general and administrative expenditures and professional fees are examined in further detail in the chart below.
· Reporting to shareholders’ expenditures during the three months and year ended September 30, 2025, and 2024, include fees for filing the annual audited financial statements, costs of the annual general meeting (AGM) as well as the annual fees paid to the TSX. The decrease for three months ended and year ended September 30, 2025, relates to the timing of the AGM. The most recent was held in October 2025 and the costs incurred subsequent to year end.
· Professional fees and period over period variances are explained in the chart below.
· Stock exchange and transfer agent fees relate to the Company’s equity and the fees charged to maintain the company’s shareholder list and fees paid to the TSXV. The amount is influenced by the value of the equity, number of transactions and number of shares outstanding as well as activity in the company that requires exchange approval. Costs incurred during three months and year ended September 30, 2024, were higher than current periods as additional costs were incurred for filing fees on the acquisition of the Louise Project.
· Accretion, when material is recorded on a quarterly basis. Changes in interest rates, inflation or the magnitude of anticipated future reclamation costs will influence the recording of the estimated expense.
· Property fees and taxes are regulatory taxes and maintenance fees incurred on mineral properties that may not be recoverable in the future and are therefore expensed as incurred. During the year ended September 30, 2024, the amounts were paid to various US jurisdictions for permit amendments to allow for additional drilling at the new WestGold discovery; no expenditures were incurred during the current comparative periods.
· Interest and other income include interest earned from a high interest savings account and foreign exchange gains and losses incurred on US$ denominated transactions. The variance between the current and comparative periods relates to higher and lower bank balances and higher and lower interest rates during the comparative periods.
· Realization of flow through premium liability relates to the tax benefit renounced to shareholders on the issuance of flow-through common shares (FT shares). During the year ended September 30, 2025, the Company issued FT shares and determined the premium to market on the issue to be $75,500. This amount was recorded as a liability until such time as the qualifying expenditures were made on the Louise project. The amount is amortized to earnings in proportion to the qualifying exploration expenditures made during the period. At September 30, 2025, $302,002 in critical mineral flow through mining expenditures within the meaning of the Income Tax Act (Canada) were made and $75,500 of the liability was recognized in earnings as all obligations were satisfied under the arrangement. There were no FT shares issued nor outstanding during the comparative period ended September 30, 2024.
| 8 |
CANEX Metals Inc.
MANAGEMENT’S DISCUSSION AND ANALYSIS
FOR THE YEAR ENDED SEPTEMBER 30, 2025
· During the year ended September 30, 2025, the Company sold the remaining 1,034,500 shares of Homeland Nickel Inc. at an average price of $0.05 per share and net proceeds of $51,208. The recognized gain on sale is the sum of the proceeds less the cost base of the shares of $93,536 plus the reversal of the previously recognized valuation adjustment of $62,501, for a total net gain of $20,173. For the same period ended 2024, the Company recorded a realized net gain of $5,784 (proceeds of $59,944) on the sale of a portion of the investment and an unrealized gain of $5,698 based upon the mark to market valuation of the remaining short-term investments.
General and administrative expenses
| Three months ended, | Year ended, | |||||||||||||||
| September 30 | September 30 | |||||||||||||||
| 2025 | 2024 | 2025 | 2024 | |||||||||||||
| Administrative consulting fees | $ | 55,325 | $ | 9,118 | $ | 184,189 | $ | 95,286 | ||||||||
| Stock-based compensation | 78,544 | 93 | 212,860 | 10,294 | ||||||||||||
| Occupancy costs | 6,092 | 5,671 | 23,106 | 22,686 | ||||||||||||
| Office, secretarial and supplies | 21,026 | 10,884 | 58,261 | 45,301 | ||||||||||||
| Travel and promotion | 4,110 | - | 5,185 | 994 | ||||||||||||
| Insurance | 3,343 | 3,458 | 13,679 | 15,091 | ||||||||||||
| Directors’ fees | 1,500 | 1,500 | 5,500 | 6,000 | ||||||||||||
| Network and website | 901 | 556 | 3,189 | 2,411 | ||||||||||||
| Total professional fees | $ | 170,841 | $ | 31,280 | $ | 505,969 | $ | 198,063 | ||||||||
· Administrative consulting fees, which consist of fees for the controller, geological consulting, and services provided by other consultants, have significantly increased for the three months and year ended September 30, 2025, compared to September 30, 2024. The Company is actively exploring the Louise Project and working on the expansion of the Gold Range Project through a takeover bid. The President and a geological consultant have increased their billable time during the fiscal year to evaluate and make recommendations for exploiting these opportunities.
· Stock-based compensation relates to the recognition of the value, vesting over time, of certain options issued during the period and any issued in prior periods. During the year ended September 30, 2025, the Company granted, pursuant to its stock option plan, a total of 5,200,000 incentive stock options to existing directors, officers, and consultants of the Company. The options are exercisable at a price of $0.05 per share for five years, with a portion vesting immediately and the remaining vesting over a two year period. These incentive options replace 3,285,000 options that expired during 2024. The options were valued, on the grant date, November 25, 2024, at $231,600, using the Black-Scholes Options Pricing model assuming a 5-year term, volatility of 245.35%, a risk-free discount rate of 3.18% and a dividend rate of 0%. During comparative period 2024, the expense relates only to the trailing cost of options issued in fiscal 2023.
· Occupancy costs are slightly higher, period over period, due to an increase in the base rate that came into effect on September 1, 2025, in conjunction with the renewal of the rental agreement for a further 12 month period. Base rent has increased by $243 to $2,228 per month, a 12% increase over the previous term.
· Office and secretarial fees, which relate primarily to contract administrative services and office supplies, have increased for the three month and year ended September 30, 2025, consistent with more activity in the Company during this period compared to the prior period. Issuing and tracking flow through shares and the takeover offer for Gold Basis were the transactions that contributed significantly to the increase.
· Travel and promotion costs have also increase in the three months and year ended September 30, 2025 relating to corporate travel associated with the continuing exploration activities at the Louise Project in BC.
· The Company pays directors who are not officers of the Company $500 for meeting attendance. There are currently three directors who are not officers and the amounts above reflect the directors’ fees paid or payable for meetings attended during the above-noted periods.
| 9 |
CANEX Metals Inc.
MANAGEMENT’S DISCUSSION AND ANALYSIS
FOR THE YEAR ENDED SEPTEMBER 30, 2025
Professional fees
The following summarizes the components of professional fees included in the statement of net and comprehensive loss:
| Three months ended, | Year ended, | |||||||||||||||
| September 30 | September 30 | |||||||||||||||
| 2025 | 2024 | 2025 | 2024 | |||||||||||||
| Audit and accounting | $ | 50,545 | $ | 40,900 | $ | 53,837 | $ | 44,209 | ||||||||
| Legal and filing fees | - | - | 6,538 | 4,480 | ||||||||||||
| Total professional fees | $ | 50,545 | $ | 40,900 | $ | 60,375 | $ | 48,689 | ||||||||
· Accounting fees were higher in the three months and year ended September 30, 2025 due to additional work required to include the financial statements in the Gold Basin offering document along with annual increases in year-end audit fees.
· Legal fees relate to fees charged for filing news releases and general corporate matters and are higher during 2025 compared to 2024 due to the increased activity in the Company and the need to obtain associated legal advice.
5. Liquidity and Capital Resources
The Company’s working capital position at September 30, 2025, was $453,929 (September 30, 2024 - $157,914), an improvement of $296,015. Significant changes to working capital are discussed below:
· The Company used $252,237 to cover the cost of operations during the year ended September 30, 2025, compared to $251,900 for the comparative period 2024. The variances are consistent with the factors described in Section 4) Operating results.
· During the year ended September 30, 2025, the Company disposed of its remaining 1,034,500 Homeland Nickel Inc. common shares for net cash proceeds of $51,208 During the comparative period ended September 30, 2024, the Company disposed of 599,000 Homeland Nickel Inc. (formerly Spruce Ridge Resources Ltd.) common shares for net cash proceeds of $59,944.
· During the year ended September 30, 2025, the Company invested $537,124 of cash in exploration and evaluation activities. Of this, $387,667 was spent on the Louise Project for surveying, geological consulting and analysis, option payments and mineral property lease renewal. At the Gold Range Property in Arizona, $143,556 was spent related to geological consulting, travel costs and mineral property lease renewal. Changes in working capital for the period make up the difference. During the year ended September 30, 2024, the Company invested $344,230 of cash in exploration and evaluation activities. Of this, $14,594 was spent on claim staking and preliminary property analysis for the newly acquired Louise Project. The remainder, $329,636 related to exploration and acquisition at the Gold Range Property, Arizona, USA and changes in working capital for the period. See Note 8 - “Exploration and evaluation assets” of the Consolidated Financial Statements at September 30, 2025, which accompany this document and Section 3) “Mineral properties” for more information.
· The Company used $475,315 to increase the amount of funds held in mineral property advances and deposits. $474,317 of the total relates to the upfront costs associated with the announced takeover bid of Gold Basin and once the outcome is determined the costs will be capitalized upon success or expensed to the period. In addition, the Company was required to make a deposit of $1,000 with the Government of BC, in conjunction with approval to undertake exploration activities on the Louise Project. During the comparative period 2024, an additional reclamation deposit of $8,198 ($US 6,060) was required upon approval of the expansion of the gold Range Property Exploration Permit.
· During the year ended September 30, 2025, the Company received $1,737,004 as proceeds on several non-brokered private placement share issuances and incurred $22,755 in share issuance costs. Share issue costs incurred in the year ended September 30, 2024, relate to the issuance of common shares in exchange for property. Subsequent to the year ended September 30, 2025, the Company announced a further financing as discussed below in Section 6. Financing.
| 10 |
CANEX Metals Inc.
MANAGEMENT’S DISCUSSION AND ANALYSIS
FOR THE YEAR ENDED SEPTEMBER 30, 2025
The Company is continually investigating financing options. The continuing operations of the Company are dependent upon its ability to obtain adequate financing or to commence profitable operations in the future. The Company feels that it has sufficient working capital to finance general and administration, other operating expenses, and current activities at the properties for approximately the next full year. However, increases in activity levels, new property acquisitions, and any additional exploration on its mineral properties will require additional financing. There can be no assurance that the Company will be successful in obtaining financing. Refer to Note 1 “Nature of operations and continuance of operations” to the audited Consolidated Financial Statements at September 30, 2025, that accompany this document.
6. Financing
2025
Subsequent to September 30, 2025, the Company announced a non-brokered private placement and the extension of the offer to Gold Basin shareholders. Under the terms of the financing CANEX will issue up to 20,000,000 common shares at $0.15 per share for total gross proceeds of $3,000,000. The offering, once closed, will result in a new insider acquiring 9.9% of the Company. Proceeds will be used to advance the district consolidation opportunity, for exploration at the Company’s Gold Range and Louise projects and for general working capital. It is subject to TSXV approval and is expected to close on or before January 9, 2026.
On June 26, 2025, the Company closed a non-brokered private placement for 23,636,380 common shares at $0.055 per share for gross proceeds of $1,300,001. No commissions were paid, and the shares are subject to a four month hold period. Insiders purchased a total of 1,139,054 shares in connection with the private placement.
On February 25, 2025, the Company issued 500,000 common shares under the terms of the option agreement governing the Louise Project. The shares were valued at $0.04 per share, the closing trading price on the date of issue, a book value of $20,000. Further information on this agreement is contained in Section 7, Contractual Obligations.
During October 2024, the Company announced an equity financing for cash that closed in two tranches, November 14 and November 25, 2024. The non-brokered private placement consisted of 3,000,000 common shares and 5,033,365 flow through common shares for gross proceeds of $437,002. Common shares were offered at $0.045 per share and the flow through common shares were offered at $0.06 per share. The tax benefit of the flow through common shares, renounced to shareholders, was determined to be $75,500 and recorded as a current liability which was amortized through earnings as the critical mineral flow through mining expenditures were incurred. At September 30, 2025, no further obligation remains related to these flow through shares.
2024
On April 8, 2024, the Company issued 200,000 common shares under the terms of the option agreement governing the Louise Project. The shares were valued at $0.07 per share, the closing trading price on the date of issue, a book value of $14,000. Further information on this agreement is contained in Section 7, Contractual Obligations.
On November 27, 2023, the Company issued 8,694,170 common shares valued at $304,295 pursuant to a purchase agreement on the Gold Range property. The common share issuance price used to value the transaction was the closing trading price on the date of issue.
7. Contractual Obligations
a) On March 5, 2024, the Company announced it had signed an Option Agreement to acquire a 100% interest in the Louise Project located in west central British Columbia. The agreement was signed on March 1, 2024, and received Exchange approval on April 9, 2024.
| 11 |
CANEX Metals Inc.
MANAGEMENT’S DISCUSSION AND ANALYSIS
FOR THE YEAR ENDED SEPTEMBER 30, 2025
The commitments are as follows:
| Shares or Cash | ||||
| Upon regulatory approval | $ | 10,000 | ||
| March 1, 2025 | $ | 25,000 | ||
| March 1, 2026 | $ | 50,000 | ||
| March 1, 2027 | $ | 90,000 | ||
| March 1, 2028 | $ | 200,000 | ||
| March 1, 2029 | $ | 400,000 | ||
| Total commitment | $ | 775,000 | ||
| Payments made in shares or cash | $ | (35,000 | ) | |
| Total remaining commitment | $ | 740,000 | ||
On February 25, 2025, the second option payment of $25,000 for the Louise Project was made by issuing 500,000 common shares of the Company and making a cash payment of $3,500. Under the terms of the Option agreement dated March 1, 2024, the number of shares issued was calculated using the volume-weighted average (“VWAP”) trading price on the exchange for the 30 trading days ending five trading days prior to the issuance of shares. As the VWAP fell below $0.05 per share, the difference in value between the calculation and $0.05 per share was paid in cash. On April 9, 2024, the Company made the first option payment of $10,000 by issuing 200,000 shares at a notional price of $0.05 per share. The transaction was valued at $14,000 based upon the closing trading price of the shares on the payment date. In addition, there is a milestone bonus in shares or cash if CANEX drills over 4250 metres of core, and a second milestone bonus of $50,000 in shares or cash if CANEX publishes a resource estimate with greater than 1.5 million contained ounces of gold. The Optionor will retain a NSR of 2.5% of which 1% can be purchased by CANEX for $1.5 million.
On July 29, 2025, the Company acquired a 100% interest in three small claims located internal to the Louise Cu-Au Porphyry Project by issuing 400,000 common shares to the Vendor. The shares are subject to a hold period of four months and a day from the date of regulatory approval. The Vendor retains a net smelter royalty of 1% which can be purchased by the Company at any time for $500,000.
b) On April 4, 2017, the Company announced it had signed a Letter of intent to acquire a 100% interest in the Gibson property from Altius Resources Inc. (“Altius”). Gibson is 887 Ha in size and located in central British Columbia. The purchase agreement was executed on May 12, 2017, and received Exchange approval on May 17, 2017.
| The remaining commitments of the agreement are as follows: |
| Altius | ||||||||
| Minimum | ||||||||
| Exploration | ||||||||
| Share issues | Expenditures* | |||||||
| ($) | ||||||||
| Expenditure commitment, on or before December 31, 2025 | - | 500,000 | ||||||
| Following the completion of the Expenditure Commitment | 1,240,000 | - | ||||||
| Total remaining commitment | 1,240,000 | 500,000 | ||||||
* as at June 30, 2025, the Company has incurred exploration expenditures of $293,500
In addition, Altius will retain a right to purchase an underlying 1.5% NSR and preferential rights on any future royalties or streams granted on the Property. If the Company achieves measured and indicated mineral resources in excess of 1 million gold equivalent ounces, a Milestone Payment of 1,275,000 shares will be issued to Altius. Altius will have a pro rata right to participate in future equity financings of the Company for two years.
Pursuant to the Underlying Agreement, Steven Scott is also entitled to the additional milestone bonuses of 1) $25,000 in cash or securities upon a Bankable Feasibility Study; and 2) $50,000 in cash or securities upon Commercial Production. The agreement has been amended to allow the Company to meet minimum exploration expenditures by December 31, 2025. All other terms of the agreement remain unchanged.
| 12 |
CANEX Metals Inc.
MANAGEMENT’S DISCUSSION AND ANALYSIS
FOR THE YEAR ENDED SEPTEMBER 30, 2025
c) Other commitments remaining on 100% owned property are as follows:
| Optionor | Property | Commitment | Buy-out | |||
| Gieske | Gold Range Property | 2% NSR | $500k first 1%, $1M 2nd 1% | |||
| Onyx | Never Get Left Claim | 2% NSR | $500k first 1%, $1.5M 2nd 1% | |||
| Silmar of Arizona | Excelsior Claim | 1.5% NSR | Right of First Refusal on Sale |
In addition to the above, CANEX has committed to a reversion agreement to August 30, 2030, on the Excelsior Claim, whereby the Company, if subject to any event that would impact the optionors rights, if not cured in 30 days, would deliver the property back to the Optionor.
| 8. | Exploration Expenditures |
Refer to “Exploration and evaluation assets,” Note 8 to the Consolidated Financial Statements dated September 30, 2025.
| 9. | Off-Balance Sheet Transactions |
There are no off-balance sheet transactions to report.
| 10. | Selected Quarterly Financial Information |
The following selected financial data has been extracted from the unaudited interim consolidated financial statements for the fiscal periods indicated and should be read in conjunction with those unaudited financial statements.
| Sept 30 | June 30 | Mar 31 | Dec 31 | Sep 30 | Jun 30 | Mar 31 | Dec 31 | |||||||||||||||||
| 2025 | 2025 | 2025 | 2024 | 2024 | 2024 | 2024 | 2023 | |||||||||||||||||
| (Q4 2025) | (Q3 2025) | (Q2 2025) | (Q1 2025) | (Q4 2024) | (Q3 2024) | (Q2 2024) | (Q1 2024) | |||||||||||||||||
| Three months ended | $ | $ | $ | $ | $ | $ | $ | $ | ||||||||||||||||
| Loss before impairment of exploration and evaluation assets | (234,012 | ) | (124,787 | ) | (60,394 | ) | (178,334 | ) | (92,456 | ) | (45,782 | ) | (63,929 | ) | (87,939 | ) | ||||||||
| Impairment of exploration and evaluation assets | - | - | - | - | - | - | - | - | ||||||||||||||||
| Operating loss | (234,012 | ) | (124,787 | ) | (60,394 | ) | (178,334 | ) | (92,456 | ) | (45,782 | ) | (63,929 | ) | (87,939 | ) | ||||||||
| Interest and other income | 2,778 | 500 | 637 | 1,124 | 1,764 | 2,281 | 2,307 | 3,468 | ||||||||||||||||
| Gain (loss) on short-term investments | - | - | 30,518 | (10,347 | ) | (10,345 | ) | (15,517 | ) | (31,035 | ) | 58,034 | ||||||||||||
| Realization of flow through premium liability | - | 69,290 | 2,330 | 3,880 | - | - | - | - | ||||||||||||||||
| Comprehensive profit (loss) | (231,234 | ) | (54,997 | ) | (26,909 | ) | (183,677 | ) | (101,037 | ) | (59,018 | ) | (92,657 | ) | (26,437 | ) | ||||||||
| Basic and diluted earnings (loss) per share | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
Generally, the most significant influence on the variability of profit or loss is the amount of stock-based compensation, the amount of exploration and evaluation asset impairments or recoveries, and gains or losses on short-term investments. Options issued during Q1 2025 and Q4 2025 negatively impacted earnings for the quarter without impacting cashflow. Impacting Q4 and Q3 2025, in part due to successful financing efforts, the Company has undertaken two significant projects to advance the Louise Project and Gold Range properties. The result is an increase in general and administrative expenses related to consulting fees for the President, outside geological support and corporate secretarial services as well as increases in audit and accounting fees.
| 13 |
CANEX Metals Inc.
MANAGEMENT’S DISCUSSION AND ANALYSIS
FOR THE YEAR ENDED SEPTEMBER 30, 2025
The timing of the impairments and gains on sale of the Company’s exploration and evaluation assets cannot be predicted in advance and will vary from one reporting period to the next. As a result, there may be dramatic changes in the financial results and balance sheet position reported by the Company on a period-by-period basis.
Interest and other reflect foreign exchange gains and losses incurred on a US dollar denominated bank account held by the Company to conduct its business in the United States as well as interest earned on bank balances during the period.
Occasionally the Company receives common shares in publicly traded Companies as partial consideration for the sale of mineral property interests. The sale of Homeland Nickel Inc common shares during Q2 2025 and Q1 2024 positively impacted earnings in those periods when the sale proceeds net of the cost of the shares and the reversal of prior period valuation losses resulted in a gain on the sale of these securities.
The Company’s improved working capital position is the result of the equity issues in Q1 2025 and Q3 2025.
Flow through share commitments were fully funded, as well as all other activities currently underway.
| 11. | Directors and Officers |
| Shane Ebert | Director and President | Gregory Hanks | Director |
| Jean Pierre Jutras | Director and Vice-President | Lesley Hayes | Director |
| Barbara O’Neill | Corporate Secretary | Blair Schultz | Director |
| Chantelle Collins | Chief Financial Officer |
| 12. | Related Party Transactions and Key Management Remuneration |
Related party transactions for the year ended September 30, 2025, and 2024, are disclosed and explained in Note 18 to the Consolidated Financial Statements dated September 30, 2025, that accompany this MD&A.
| 13. | Share Capital and Equity Reserves |
Refer to Note 11 in the Consolidated Financial Statements dated September 30, 2025, as well as the Consolidated Statement of Changes in Equity that accompany this MD&A for common share capital and stock option transactions for year ended September 30, 2024, and balances as at that date.
On July 29, 2025, the Company issued 400,000 common shares at $0.075 per share to acquire a 100% interest in three small claims located internal to the Louise Cu-Au Porphyry Project.
On July 14, 2025, 700,000 options were issued at $0.08 per share to a consultant providing services to the Company. The options vest immediately and if not exercised will expire 5 years from the date of grant.
On June 26, 2025, the Company closed a non-brokered private placement for 23,636,380 common shares at $0.055 per share for gross proceeds of $1,300,001. No commissions were paid, and the shares are subject to a four month hold period. Insiders purchased a total of 1,139,054 shares in connection with the private placement.
On February 25, 2025, the Company issued 500,000 common shares at $0.04 per share in partial settlement of an obligation contained within the Louise Project option agreement, further details in Section 7, Contractual Obligations.
| 14 |
CANEX Metals Inc.
MANAGEMENT’S DISCUSSION AND ANALYSIS
FOR THE YEAR ENDED SEPTEMBER 30, 2025
On November 14, 2024, CANEX closed the first tranche of an equity financing and on November 25th announced the closing of the second and final tranche to complete the oversubscribed transaction. In total the Company issued 3,000,000 common shares at $0.045 per share. In addition, 5,033,365 flow-through common shares (FT shares) were issued at $0.06 per share. Gross proceeds of $437,002 will be used to advance the Louise Cu-Au porphyry in British Columbia and the Gold Range oxide gold project in northern Arizona. Related parties comprised of officers and directors acquired 111,108 common shares and 583,335 FT shares.
On November 25, 2024, the Company granted, pursuant to its stock option plan, a total of 5,200,000 incentive stock options to existing directors, officers, and consultants of the Company. The options are exercisable at a price of $0.05 per share for five years, with a portion vesting immediately and the remaining vesting over a two year period. These incentive options replace 3,285,000 options that expired during 2024.
| 14. | Financial Instruments |
The carrying value of the Company’s financial instruments, consisting of cash and cash equivalents, accounts receivable (net of sales tax) and accounts payable and accrued liabilities approximate their fair value due to the short-term nature of the instruments.
It is management’s opinion that the Company is not exposed to significant interest or credit risks arising from these financial instruments. The carrying value of financial assets and liabilities measured at amortized cost approximates fair value due to the short-term nature of the instruments.
The Company undertakes transactions denominated in US currency through its exploration in the US; consequently, it is exposed to exchange rate fluctuations. The Company will acquire US funds from time to time to settle US$ denominated liabilities. On September 30, 2025, the Company had US$5,358 (CAD$7,465) in a US denominated bank account (September 30, 2024 - US$1,189, (CAD$1,605)) The effect of a foreign currency increase or decrease of 10% on this cash holding would result in an increase or decrease of $747 (2024 - $161).
| 15. | Financial risk management |
a) Credit risk
Credit risk is the risk of financial loss to the Company if counterparties to a financial instrument fail to meet their contractual obligations. The Company’s financial instruments that could be subject to credit risk consist of receivables. The Company has had a history of prompt receipt of their receivables and considers credit risk to be low on these instruments as at September 30, 2025 and 2024.
b) Liquidity risk
Liquidity risk is the risk that the Company will not be able to meet its financial obligations as they are due. The Company’s approach to managing liquidity risk is the utilization of budgets, to attempt to maintain sufficient liquidity in order to meet operational and exploration requirements, as well as property acquisition commitments. The Company raises capital through equity issues and its ability to do so is dependent on a number of factors including market acceptance, stock price and exploration results. The Company is continually investigating financing options. The Company feels that it has sufficient working capital to finance general and administrative, other operating expenses and current property activities for approximately the full year, assuming similar activity levels to the previous year. Additional financing will be required to fund new property acquisitions and future exploration programs. There can be no assurance that the Company will be successful in obtaining financing. These material uncertainties cast significant doubt on the Company’s ability to continue as a going concern. The audited consolidated financial statements do not include any adjustments which could be significant should the Company be unable to continue as a going concern.
| 15 |
CANEX Metals Inc.
MANAGEMENT’S DISCUSSION AND ANALYSIS
FOR THE YEAR ENDED SEPTEMBER 30, 2025
c) Market risk
The Company’s equity investments are subject to market price risk. These investments were received as partial proceeds for the sale of mineral property interests. The Company does not invest excess cash in equity investments. The investments in common shares and warrants are recorded at fair value at the respective period ends with the resultant gains or losses recorded in earnings. The price or value of these investments can vary from period to period. During the year ended September 30, 2025, the Company sold all the remaining equity investments and no longer has any exposure to this risk.
The Company has not yet developed producing mineral interests; it is not exposed to commodity price risk associated with developed properties at this time.
d) Interest rate risk
The Company has no debt facilities and has minimal amounts of interest income; it is not exposed to significant interest rate risk at this time.
| e) | Foreign exchange risk |
The Company undertakes transactions denominated in US currency; consequently, it is exposed to exchange rate fluctuations. The Company has disclosed US$ commitments pertaining to royalty rights in Section 7- Contractual obligation. Refer to Section 14 - Financial instruments for the foreign exchange risk associated with the foreign denominated cash balances held in US$ at September 30, 2025 and 2024.
| 16. | Subsequent Events |
Subsequent to September 30, 2025, the Company announced a non-brokered private placement and the extension of the offer to Gold Basin shareholders. Under the terms of the financing CANEX will issue up to 20,000,000 common shares at $0.15 per share for total gross proceeds of $3,000,000. The offering, once closed, will result in a new insider acquiring 9.9% of the Company. Proceeds will be used to advance the district consolidation opportunity, for exploration at the Company’s Gold Range and Louise projects and for general working capital. It is subject to TSXV approval and is expected to close on or before January 9, 2026.
| 17. | Outlook |
The Company’s primary objective is to discover mineral resources in economic quantities capable of supporting an operating mine. Should the Company discover such a promising property, it would likely attempt to ally with a more senior mining company that might option-in on the property or purchase the property outright, as the Company does not have expertise in operating a mine.
As discussed above the Company made a takeover offer for Gold Basin Resources (“Gold Basin”) (TSX.V:GXX) in an all share transaction. The Board of Directors and management of CANEX are highly supportive of the concept of consolidating the CANEX and Gold Basin properties and view a merger of the large gold system that spans both Company’s properties an excellent opportunity to unlock value for both CANEX and Gold Basin shareholders.
At the Gold Range property, the WestGold target contains the largest and highest-grade gold in soil anomaly defined to date and the Company’s drill test of that target has resulted in a new and potentially very significant gold discovery that will be an important focus for the Company moving forward. Although there are opportunities to further explore the Gold Range Property in Arizona, USA, the Company only has sufficient working capital to conduct measured low-cost surface exploration programs, such as those undertaken in March 2024 at WestGold, without the need for additional financing. Near and midterm objectives will include low-cost advancement of surface targets in preparation for drill testing to be conducted once market conditions allow further financing opportunities.
At the Louise Project, the Company has completed a modern deep looking induced polarization (IP) survey to explore the district across 6 to 7 kilometres of strike length and to depths up to 1000 metres to fully assess the district potential surrounding the known historic resource. Based on the results of this survey two new previously unknown high chargeability targets have been identified west and below the historic Louise Project deposit. The Company completed a surface exploration program consisting of mapping, prospecting, and surface sampling. The Company will now focus on permitting to allow drill testing of the two new high priority chargeability targets.
| 16 |
CANEX Metals Inc.
MANAGEMENT’S DISCUSSION AND ANALYSIS
FOR THE YEAR ENDED SEPTEMBER 30, 2025
With respect to the Gibson Prospect, to date the Company has expended $293,500 on exploration activities. Due to limited resources, including manpower, the Company has focussed its attention on exploration activities on the Gold Range property and the Louise Project as discussed above. The Company continues to hold core claims which expire January 2029, keeping possibilities open for the Company to find a third-party partner to further the exploration program.
The Company continues to actively search for new early-stage exploration opportunities and avenues for growth in stable jurisdictions within North America. The Company has not entered into any business combination, acquisition, or similar agreements except as noted above.
| 18. | Risks |
The business and operations of the Company are subject to numerous risks, many of which are beyond the Company’s control. The Company considers the risks set out below to be some of the most significant to potential investors in the Company, but not all of the risks associated with an investment in securities of the Company. If any of these risks materialize into actual events or circumstances or other possible additional risks and uncertainties of which the Company is currently unaware or which it considers to be material in relation to the Company’s business actually occur, the Company’s assets, liabilities, financial condition, results of operation (including future results of operations), business and business prospects, are likely to be materially and adversely affected. In such circumstances, the price of the Company’s securities could decline and investors may lose all or part of their investment.
The Company is a natural resource company engaged in the acquisition, exploration and development of mineral properties. Given the nature of the mining business, the limited extent of the Company’s assets and the present stage of exploration, the following risk factors, among others, should be considered:
· Exploration, development, and operating risks
The Company is in the process of exploring its properties and has not yet determined whether its properties contain economically recoverable reserves and, therefore, does not generate any revenues from production. The recovery of expenditures on mineral properties and the related deferred exploration expenditures are dependent on the existence of economically recoverable mineralization, the ability of the Company to obtain financing necessary to complete the exploration and development of its properties, and upon future profitable production, or alternatively, on the sufficiency of proceeds from disposition. Mineral exploration is highly speculative in nature, involves many risks and frequently is non-productive. There is no assurance that exploration efforts will be successful.
· Substantial capital requirements and liquidity
Substantial additional funds for the establishment of the Company’s current and planned mining operations will be required. No assurances can be given that the Company will be able to raise the additional funding that may be required for such activities, should such funding not be fully generated from operations. Mineral prices, environmental rehabilitation or restitution, revenues, taxes, transportation costs, capital expenditures and operating expenses and geological results are all factors which will have an impact on the amount of additional capital that may be required. To meet such funding requirements, the Company may be required to undertake additional equity financing, which would be dilutive to shareholders. Debt financing, if available, may also involve restrictions on financing and operating activities. There is no assurance that additional financing will be available on terms acceptable to the Company or at all. If the Company is unable to obtain additional financing as needed, it may be required to reduce the scope of its operation and pursue only those projects that can be funded through cash flows generated from its existing operations, if any.
| 17 |
CANEX Metals Inc.
MANAGEMENT’S DISCUSSION AND ANALYSIS
FOR THE YEAR ENDED SEPTEMBER 30, 2025
· Fluctuating mineral prices
The economics of mineral exploration are affected by many factors beyond the Company’s control, including commodity prices, the cost of operations, variations in the grade of minerals explored and fluctuations in the market price of minerals. Depending on the price of minerals, the Company may determine that it is impractical to continue a mineral exploration operation. Mineral prices are prone to fluctuations and the marketability of minerals is affected by government regulation relating to price, royalties, allowable production and the importing and exporting of minerals, the effect of which cannot be accurately predicted. There is no assurance that a profitable market will exist for the sale of any minerals found on the Company’s properties.
· Regulatory, permit and license requirements
The current or future operations of the Company require permits from various governmental authorities, and such operations are and will be governed by laws and regulations concerning exploration, development, production, taxes, labour standards, occupational health, waste disposal, toxic substances, land use, environmental protection, site safety and other matters. Companies engaged in the exploration and development of mineral properties generally experience increased costs and delays in development and other schedules as a result of the need to comply with applicable laws, regulations and permits. There can be no assurance that all permits which the Company may require for facilities and the conduct of exploration and development operations on the Properties will be obtainable on reasonable terms, or that such laws and regulation will not have an adverse effect on any exploration or development project which the Company might undertake.
Failure to comply with applicable laws, regulations and permitting requirements may result in enforcement actions, including orders issued by regulatory or judicial authorities causing operations to cease or be curtailed and may include corrective measures requiring capital expenditures, installation of additional equipment or remedial actions. Parties engaged in exploration and development operations may be required to compensate those suffering loss or damage by reason of the exploration and development activities and may have civil or criminal fines or penalties imposed upon them for violation of applicable laws or regulations. Amendments to current laws, regulations and permits governing operations and activities of mineral companies, or more stringent implementation thereof, could have a material adverse impact on the Company and cause increases in capital expenditures or exploration and development costs, or require abandonment or delays in the development of new or existing properties.
· Financing risks and dilution to shareholders
The Company has limited financial resources, no operations, and no revenues. If the Company’s exploration program on its properties is successful, additional funds will be required for the purposes of further exploration and development. There can be no assurance that the Company will be able to obtain adequate financing in the future or that such financing will be available on favorable terms or at all. It is likely such additional capital will be raised through the issuance of additional equity which will result in dilution to the Company’s shareholders.
· Title to properties
Acquisition of title to mineral properties is a very detailed and time-consuming process. Title to, and the area of, mineral properties may be disputed. The Company cannot give an assurance that title to its properties will not be challenged or impugned. Mineral properties sometimes contain claims or transfer histories that examiners cannot verify. A successful claim that the Optionors or the Company, as the case may be does not have title to its properties could cause the Company to lose any rights to explore, develop and mine any minerals on its properties without compensation for its prior expenditures relating to its properties.
· Competition
The mineral exploration and development industry is highly competitive. The Company will have to compete with other mining companies, many of which have greater financial, technical and other resources than the Company, for, among other things, the acquisition of mineral claims, leases and other mineral interest as well as for the recruitment and retention of qualified employees and other personnel. Failure to compete successfully against other mining companies could have a material adverse effect on the Company and its prospects.
| 18 |
CANEX Metals Inc.
MANAGEMENT’S DISCUSSION AND ANALYSIS
FOR THE YEAR ENDED SEPTEMBER 30, 2025
· Reliance on management and dependence on key personnel
The success of the Company will be largely dependent upon the performance of its directors and officers and the ability to attract and retain key personnel. The loss of the services of these persons may have a material adverse effect on the Company’s business and prospects. The Company will compete with numerous other companies for the recruitment and retention of qualified employees and contractors. There is no assurance that the Company can maintain the service of its directors and officers or other qualified personnel required to operate its business. Failure to do so could have a material adverse effect on the Company and its prospects.
· Environmental risks
The Company’s exploration and appraisal programs will, in general, be subject to approval by regulatory bodies. Additionally, all phases of the mining business present environmental risks and hazards and are subject to environmental regulation pursuant to a variety of international conventions and provincial and municipal laws and regulations. Environmental legislation provides for, among other things, restrictions and prohibitions on spills, releases or emissions of various substances produced in association with mining operations. The legislation also requires that wells and facility sites be operated, maintained, abandoned and reclaimed to the satisfaction of applicable regulatory authorities. Compliance with such legislation can require significant expenditures and a breach may result in the imposition of fines and penalties, some of which may be material. Environmental legislation is evolving in a manner expected to result in stricter standards and enforcement, larger fines and liability and potentially increase capital expenditures and operating costs.
· Conflicts of interest
Certain of the Directors and Officers of the Company are engaged in, and will continue to engage in, other business activities on their own behalf and on behalf of other companies and, as a result of these and other activities, such Directors and Officers of the Company may become subject to conflicts of interest. Canadian corporate laws provide that in the event that a Director has an interest in a contract or proposed contract or agreement, the director shall disclose his interest in such contact or agreement and shall refrain from voting on any matter in respect of such contract or agreement unless otherwise provided under those laws. To the extent that conflicts of interest arise, such conflicts will be resolved in accordance with the provisions of the applicable Canadian corporate laws.
· Uninsurable risks
Exploration, development, and production operations on mineral properties involve numerous risks, including unexpected or unusual geological operating conditions, rock bursts, cave-ins, fires, floods, earthquakes and other environmental occurrences, any of which could result in damage to, or destruction of mines and other producing facilities, damage to life or property, environmental damage and possible legal liability. Although precautions to minimize risk will be taken, operations are subject hazards that may result in environmental pollution and consequent liability that could have a material adverse impact on the business, operations and financial performance of the Company. It is not always possible to obtain insurance against all such risks and the Company may decide not to insure against certain risks as a result of high premiums or other reasons. Should such liabilities arise, they could have an adverse impact on the Company’s results of operations and financial condition and could cause a decline in the value of the Company’s shares.
· Litigation
The Company and/or its directors may be subject to a variety of civil or other legal proceedings, with or without merit.
| 19 |
CANEX Metals Inc.
MANAGEMENT’S DISCUSSION AND ANALYSIS
FOR THE YEAR ENDED SEPTEMBER 30, 2025
| 18. | Critical Accounting Estimates |
The most significant accounting estimate for the Company relates to the carrying value of its exploration and evaluation assets. Exploration and evaluation assets consist of the capitalized costs of exploration and mining concessions. Acquisition and leasehold costs and exploration costs are capitalized and deferred until such time as the property is put into production or the properties are disposed of either through sale or abandonment. The estimated values of exploration and evaluation assets are evaluated by management on a regular basis to determine whether facts and circumstances suggest that the carrying amount of the asset may exceed its recoverable amount. Reference is made to project economics, including the timing of the exploration and/or development work, the work programs and exploration results experienced by the Company and others, financing, the extent to which optionees have committed, or are expected to commit to, exploration on the property and the imminent expiry of the right to explore, among other factors. When it becomes apparent that the carrying value of a specific property will not be realized, an impairment provision is made for the estimated decline in value.
The Company’s estimate for decommissioning obligations is based on existing laws, contracts and other policies. The value of the obligation is based on estimated future costs for abandonments and reclamations which require certain assumptions to be made. By their nature, these estimates are subject to measurement uncertainty.
Another significant accounting estimate relates to valuing stock-based compensation. The Company uses the Black-Scholes Option Pricing Model. Option pricing models require the input of highly subjective assumptions including the expected price volatility. Changes in the subjective input assumptions can materially affect the fair value estimate, and therefore the existing models do not necessarily provide a reliable single measure of the fair value of the Company’s stock options granted and vested during the year.
The Company estimates the fair value of its short-term equity investments at the end of each period as they are carried at fair value in the Balance Sheet. The Company uses the closing price of the common shares on the period-end date. The price at which these instruments can ultimately be sold will vary from these estimates due to the timing of their sale, the volume of trading in the securities at any given time and changes in the market over time, among other factors.
| 19. | New Accounting Policies |
The Company did not adopt any new accounting policies during the year ended September 30, 2025.
Future standards not yet adopted include the Presentation and Disclosure in Financial Statements (IFRS 18). IFRS 18 will replace IAS 1, Presentation of Financial Statements which aims to improve how companies communicate in their financial statements, with a focus on information about financial performance in the statement of profit or loss, in particular additional defined subtotals, disclosures about management-defined performance measures and new principles for aggregation and disaggregation of information. IFRS 18 is accompanied by limited amendments to the requirements in IAS 7 Statement of Cash Flows. IFRS 18 is effective from January 1, 2027. Companies are permitted to adopt IFRS 18 before that date. The Company is not yet able to determine the impact to the consolidated financial statements from the adoption of this standard.
Certain pronouncements were issued by the IASB but are not yet effective at September 30, 2025. The Company intends to adopt these standards when they become effective but does not expect these amendments to have a material effect on its consolidated financial statements.
| 20. | Other |
Additional information relating to the Company may be found on SEDAR+ at www.sedarplus.ca
| 20 |
Appendix N
CANEX
unaudited condensed interim consolidated financial statements for
the three months ended December 31, 2025 and management’s Discussion and
Analysis in respect thereof
[See attached]
CANEX Metals Inc.
Condensed Interim Consolidated Financial Statements
(Expressed in Canadian Dollars)
For the three months ended December 31, 2025
(Unaudited)
CANEX Metals Inc.
Condensed Interim Consolidated Statements of Financial Position
(Expressed in Canadian Dollars)
(Unaudited - Prepared by Management)
| December 31,
2025 |
September 30, 2025 |
|||||||
| ASSETS | ||||||||
| Current Assets | ||||||||
| Cash (Note 5) | $ | 3,161,674 | $ | 663,907 | ||||
| Accounts receivable (Note 6) | 40,104 | 35,548 | ||||||
| Prepaid expenses | 68,524 | 74,241 | ||||||
| 3,270,302 | 773,696 | |||||||
| Non-current Assets | ||||||||
| Exploration and evaluation asset advances and deposits (Note 8) | 797,060 | 526,479 | ||||||
| Exploration and evaluation assets (Note 8) | 6,289,688 | 6,296,930 | ||||||
| 7,086,748 | 6,823,409 | |||||||
| TOTAL ASSETS | $ | 10,357,050 | $ | 7,597,105 | ||||
| EQUITY AND LIABILITIES | ||||||||
| Current Liabilities | ||||||||
| Accounts payable and accrued liabilities (Note 9) | $ | 255,895 | $ | 267,209 | ||||
| Non-current Liabilities | ||||||||
| Decommissioning obligation (Note 10) | 52,545 | 52,558 | ||||||
| TOTAL LIABILITIES | 308,440 | 319,767 | ||||||
| EQUITY | ||||||||
| Share capital (Note 11) | 26,121,922 | 23,139,647 | ||||||
| Reserves | 2,503,770 | 2,483,928 | ||||||
| Deficit | (18,577,082 | ) | (18,346,237 | ) | ||||
| TOTAL EQUITY | 10,048,610 | 7,277,338 | ||||||
| TOTAL EQUITY AND LIABILITIES | $ | 10,357,050 | $ | 7,597,105 | ||||
Nature and continuance of operations (Note 1)
Subsequent events (Note 19)
Approved by the Board
| “Shane Ebert” | ||
| Director | ||
| Shane Ebert | ||
| “Jean Pierre Jutras” | ||
| Director | ||
| Jean Pierre Jutras | ||
See accompanying notes to the financial statements.
CANEX Metals Inc.
Condensed Interim Consolidated Statements of Loss and
Comprehensive Loss
(Expressed in Canadian Dollars)
For the three months ended December 31
(Unaudited - Prepared by Management)
| 2025 | 2024 | |||||||
| Expenses | ||||||||
| General and administrative (Note 14) | $ | 215,862 | $ | 165,093 | ||||
| Reporting to shareholders | 12,728 | 4,806 | ||||||
| Professional fees | 4,841 | 4,413 | ||||||
| Stock exchange and transfer agent fees | 4,824 | 2,881 | ||||||
| Accretion | 214 | 1,141 | ||||||
| 238,469 | 178,334 | |||||||
| Operating loss | (238,469 | ) | (178,334 | ) | ||||
| Interest and other | 7,624 | 1,122 | ||||||
| Realization of flow through premium liability | - | 3,880 | ||||||
| Loss from investments (Note 7) | - | (10,345 | ) | |||||
| 7,624 | (5,343 | ) | ||||||
| Net loss and comprehensive loss for the period | $ | (230,845 | ) | $ | (183,677 | ) | ||
| Basic and diluted loss per share | $ | (0.00 | ) | $ | (0.00 | ) | ||
| Weighted average shares outstanding – basic and diluted | 148,689,612 | 117,524,228 | ||||||
Nature and continuance of operations (Note 1)
See accompanying notes to the financial statements.
CANEX Metals Inc.
Condensed Interim Consolidated Statements of Cash Flows
(Expressed in Canadian Dollars)
For the three months ended December 31
(Unaudited - Prepared by Management)
| 2025 | 2024 | |||||||
| Increase (decrease) in cash | ||||||||
| Operating activities | ||||||||
| Cash paid to suppliers and contractors | $ | (228,214 | ) | $ | (102,111 | ) | ||
| Cash used in operating activities (Note 17) | (228,214 | ) | (102,111 | ) | ||||
| Investing activities | ||||||||
| Interest and foreign exchange | (1,906 | ) | 1,124 | |||||
| Cash received on sale of equipment | 54,194 | - | ||||||
| Cash expended on costs of equipment sale | (44,666 | ) | - | |||||
| Cash expended on exploration advances and deposits | (270,581 | ) | (1,000 | ) | ||||
| Cash expended on exploration and evaluation asset additions, net (Note 17) | 6,664 | (36,953 | ) | |||||
| Cash used in investing activities | (256,295 | ) | (36,829 | ) | ||||
| Financing activities | ||||||||
| Share capital issuance proceeds | 3,000,000 | 437,002 | ||||||
| Cash share issuance and transaction costs | (17,724 | ) | (9,236 | ) | ||||
| Cash provided by financing activities | 2,982,276 | 427,766 | ||||||
| Increase in cash | 2,497,767 | 288,826 | ||||||
| Beginning of period | 663,907 | 158,093 | ||||||
| End of period | $ | 3,161,674 | $ | 446,919 | ||||
See accompanying notes to the financial statements
CANEX Metals Inc.
Condensed Interim Consolidated Statement of Changes in Equity
(Expressed in Canadian Dollars)
(Unaudited - Prepared by Management)
| Common share capital | Equity- settled share based payment | Other Reserves* | Total Reserves | Deficit | Total | |||||||||||||||||||
| $ | $ | $ | $ | $ | $ | |||||||||||||||||||
| Balance, September 30, 2024 | 21,450,899 | 215,289 | 2,055,780 | 2,271,069 | (17,849,420 | ) | 5,872,548 | |||||||||||||||||
| Net and comprehensive loss for the period | - | - | - | - | (183,677 | ) | (183,677 | ) | ||||||||||||||||
| Common share issuance – November 2024 | 135,000 | - | - | - | - | 135,000 | ||||||||||||||||||
| Flow through share issuance – November 2024 | 302,002 | - | - | - | - | 302,002 | ||||||||||||||||||
| Flow through share premium (Note 12) | (75,500 | ) | - | - | - | - | (75,500 | ) | ||||||||||||||||
| Share issuance costs | (9,236 | ) | - | - | - | - | (9,236 | ) | ||||||||||||||||
| Options expired | - | (37,417 | ) | 37,417 | - | - | - | |||||||||||||||||
| Options issued – November 2024 | - | 88,621 | - | 88,621 | - | 88,621 | ||||||||||||||||||
| Balance, December 31, 2024 | 21,803,165 | 266,493 | 2,093,197 | 2,359,690 | (18,033,097 | ) | 6,129,758 | |||||||||||||||||
| Net and comprehensive loss for the period | - | - | - | - | (313,140 | ) | (313,140 | ) | ||||||||||||||||
| Share issuance – Property February 2025 | 20,000 | - | - | - | - | 20,000 | ||||||||||||||||||
| Share issuance – June 2025 | 1,300,001 | - | - | - | - | 1,300,001 | ||||||||||||||||||
| Share issuance – Property July 2025 | 30,000 | - | - | - | - | 30,000 | ||||||||||||||||||
| Share issuance costs | (13,519 | ) | - | - | - | - | (13,519 | ) | ||||||||||||||||
| Options issued – November 2024 | - | 72,538 | - | 72,538 | - | 72,538 | ||||||||||||||||||
| Options issued – July 2025 | - | 51,700 | - | 51,700 | - | 51,700 | ||||||||||||||||||
| Balance, September 30, 2025 | 23,139,647 | 390,731 | 2,093,197 | 2,483,928 | (18,346,237 | ) | 7,277,338 | |||||||||||||||||
| Net and comprehensive loss for the period | - | - | - | - | (230,845 | ) | (230,845 | ) | ||||||||||||||||
| Common share issuance – December 2025 | 3,000,000 | - | - | - | - | 3,000,000 | ||||||||||||||||||
| Share issuance costs | (17,725 | ) | - | - | - | - | (17,725 | ) | ||||||||||||||||
| Options issued – November 2024 | - | 19,842 | - | 19,842 | - | 19,842 | ||||||||||||||||||
| Balance, December 31, 2025 | 26,121,922 | 410,573 | 2,093,197 | 2,503,770 | (18,577,082 | ) | 10,048,610 | |||||||||||||||||
*Other Reserves, is comprised of the aggregate of options and warrants that expired or were forfeited without exercise. These values were relieved from Common share capital, Equity-settled share based payment reserve and Warrants reserve respectively upon the expiry of the equity instrument.
See accompanying notes to the financial statements
CANEX Metals Inc.
Notes to the Condensed Interim Consolidated Financial Statements
(Expressed in Canadian Dollars)
Three months ended December 31, 2025
(Unaudited - Prepared by Management)
| 1. | Nature and continuance of operations |
CANEX Metals Inc. (“CANEX“ or “the Company”) is engaged in the business of mineral exploration and development in Canada. The Company was originally incorporated under the laws of the Province of Quebec, Canada and has been continued under the Alberta Business Corporations Act, Canada. The address of its primary office is Suite 1620, 734 – 7th Avenue SW, Calgary, Alberta, Canada, T2P 3P8. The Company’s common shares are listed on the TSX Venture Exchange under the symbol CANX.
Since inception, the efforts of the Company have been devoted to the acquisition, exploration, and development of mineral properties. To date the Company has not received any revenue from mining operations and has not determined whether mineral properties contain ore reserves that are economically recoverable.
The Company incurred a net loss of $230,845 during the three-month period ended December 31, 2025. The Company has a deficit of $18,577,082 at December 31, 2025. The Company’s ability to continue to explore and develop its mineral properties and to continue as a going concern is dependent upon its ability to raise additional equity financing. There is no assurance that the Company will be successful in achieving profitable operations given its early-stage exploration and no assurance that it will obtain financing. These uncertainties cast significant doubt on the Company’s ability to continue as a going concern. These financial statements do not include any adjustments which could be significant should the Company be unable to continue as a going concern.
| 2. | Basis of presentation |
| a) | Basis of presentation |
These unaudited condensed interim consolidated financial statements are unaudited and have been prepared in accordance with International Accounting Standard (“IAS”) 34 “Interim Financial Reporting”, using accounting policies consistent with IFRS Accounting Standards as issued by the International Accounting Standards Board (IASB).
These unaudited condensed interim consolidated financial statements have been prepared on a historical cost basis except for decommissioning obligations and financial instruments. In addition, these statements have been prepared using the accrual basis of accounting except for cash flow information.
| b) | Principles of consolidation |
These consolidated financial statements include the accounts of the Company and its wholly owned US subsidiary, Canexco Inc. (“Canexco”). Canexco was incorporated by the Company on June 5, 2019, in Arizona, USA, to conduct its exploration and development business in the USA. All intercompany transactions and balances have been eliminated on consolidation. Subsidiaries are those entities that the Company controls through its power to govern the financial and operating policies of the subsidiary. Subsidiaries are fully consolidated from the date control is obtained and are de-consolidated from the date control ceases.
| 3. | Material accounting policies and future standards not yet adopted |
The financial framework and material accounting policies applied in the preparation of these unaudited condensed interim consolidated financial statements are consistent with those as disclosed in its most recently completed audited annual consolidated financial statements for the year ended September 30, 2025. CANEX did not adopt any new accounting policies during the three months ended December 31, 2025.
Future standards not yet adopted include the Presentation and disclosure in Financial Statements (IFRS 18). IFRS 18 will replace IAS 1, Presentation of Financial Statements which aims to improve how companies communicate in their financial statements, with a focus on information about financial performance in the statement of profit or loss, in particular additional defined subtotals, disclosures about management-defined performance measures and new principles for aggregation and disaggregation of information. IFRS 18 is
CANEX Metals Inc.
Notes to the Condensed Interim Consolidated Financial Statements
(Expressed in Canadian Dollars)
Three months ended December 31, 2025
(Unaudited - Prepared by Management)
| 3. | Material accounting policies and future standards not yet adopted (continued) |
accompanied by limited amendments to the requirements in IAS 7 Statement of Cash Flows. IFRS 18 is effective from January 1, 2027. Companies are permitted to apply IFRS 18 before that date. The Company is not yet able to determine the impact to the consolidated financial statements from the adoption of this standard.
Certain pronouncements were issued by the IASB but are not yet effective as at December 31, 2025. The Company intends to adopt these standards when they become effective but does not expect these amendments to have a material effect on its consolidated financial statements.
| 4. | Significant accounting judgments and estimates |
The preparation of financial statements requires management to make certain estimates, judgments and assumptions that affect the reported amounts of assets, liabilities and disclosure of contingent assets and liabilities at the date of the financial statements and the reported amounts of revenues and expenses during the reporting period. Actual outcomes could differ from these estimates. Circumstances could arise over the years that would require material revisions to these estimates. Changes in assumptions could have a material effect on the fair value of estimates.
These financial statements include estimates that, by their nature, are uncertain. The impacts of such estimates are pervasive throughout the financial statements and may require accounting adjustments based on future occurrences. Adjustments resulting from revisions to accounting estimates are recognized in the period in which the estimate is revised, and future periods if the revision affects both current and future periods. These estimates are based on historical experience, current and future economic conditions, and other factors, including expectation of future events that are believed to be reasonable under the circumstances.
Critical estimates include:
| a) | The carrying values of exploration and evaluation assets that are included in the statement of financial position, including the assumptions that are incorporated into the impairment assessments, and the amount of impairments that are included in the statement of loss and comprehensive loss |
| b) | The estimate of the amount of decommissioning obligation and the inputs used in determining the net present value of the liabilities for decommissioning obligations included in the statement of financial position. |
| c) | The estimated fair value of share purchase options and broker warrants requires determining the most appropriate model as well as the applicable inputs. |
| d) | Judgment is required in determining whether or not deferred tax assets are recognized on the statement of financial position. |
| e) | Management’s assessment of the Company’s ability to continue as a going concern involves making judgements as to whether suitable conditions and events exist to support the Company’s future operations and is reassessed at each reporting period. |
| 5. | Cash |
Cash is comprised of:
| Dec 31, 2025 | Sept 30, 2025 | |||||||
| Current bank accounts | $ | 3,124,958 | $ | 656,442 | ||||
| Cash held in foreign currencies | 36,716 | 7,465 | ||||||
| $ | 3,161,674 | $ | 663,907 | |||||
CANEX Metals Inc.
Notes to the Condensed Interim Consolidated Financial Statements
(Expressed in Canadian Dollars)
Three months ended December 31, 2025
(Unaudited - Prepared by Management)
| 6. | Accounts receivable |
| Dec 31, 2025 | Sept 30, 2025 | |||||||
| Due from related parties | $ | 40 | $ | - | ||||
| Sales tax receivables | 40,064 | 35,548 | ||||||
| $ | 40,104 | $ | 35,548 | |||||
| 7. | Short-term investments |
At period end December 31, 2025, the Company did not hold any short term investments.
At period end December 31, 2024, the Company held 1,034,500 shares of Homeland Nickle Inc. with a cost base of $0.0904 per share.
On March 18, 2025, the Company sold the remaining 1,034,500 shares for net proceeds of $51,208.
| 8. | Exploration and evaluation assets |
Mineral properties are recognized in these financial statements in accordance with the accounting policies outlined in Note 3 (e) “Exploration and evaluation assets” of the annual audited financial statements for the year ended September 30, 2025. Accordingly, their carrying values represent costs incurred to date, net of recoveries, abandonments, and impairments. The recoverability of these amounts is dependent upon the existence of economically recoverable mineral reserves; the acquisition and maintenance of appropriate permits, licenses, and rights; the ability of the Company to obtain necessary financing to complete the development of properties where necessary, and upon future profitable operations; or alternatively, upon the Company’s ability to recover its costs through a disposition of its interests in its mineral exploration properties.
Louise Cu-Au Porphyry Project, British Columbia, Canada
On March 1, 2024, the Company entered into an option agreement to acquire six mineral claims totalling 5,362.95 hectares located in the Omineca Mining Division, British Columbia. Under the terms of the option agreement, the Company will either pay an aggregate of $775,000 in common shares of CANEX or make cash payments.
Future remaining commitments are scheduled as follows:
| Due Date | Value of
underlying Common Shares | |||
| March 1, 2026 | $ | 50,000 | ||
| March 1, 2027 | $ | 90,000 | ||
| March 1, 2028 | $ | 200,000 | ||
| March 1, 2029 | $ | 400,000 | ||
| Total future commitment | $ | 740,000 | ||
On April 8, 2024, the first option payment was made by issuing 200,000 common shares of the Company at a price of $0.07 per share.
On February 25, 2025, the second option payment was made by issuing 500,000 common shares of the Company at a price of $0.04 per share and a cash payment of $3,500.
Subsequent to the date of these condensed interim consolidated financial statements the Company made the third option payment as defined in the terms of the agreement. Further details of the transaction are contained below in Note 19 – Subsequent events.
The Vendor retains a 2.5% NSR (net smelter royalty) with CANEX having the right to buy back 40% of the NSR (1% of the 2.5% NSR) for $1,500,000. A milestone bonus of $50,000 in shares or cash will also be payable if
CANEX Metals Inc.
Notes to the Condensed Interim Consolidated Financial Statements
(Expressed in Canadian Dollars)
Three months ended December 31, 2025
(Unaudited - Prepared by Management)
| 8. | Exploration and evaluation assets |
Louise Cu-Au Porphyry Project, British Columbia, Canada (continued)
CANEX drills over 4250 metres of core, and a second milestone bonus of $50,000 in shares or cash will be payable if CANEX publishes a resource estimate with greater than 1.5 million contained ounces of gold.
On July 29, 2025, the Company acquired a 100% interest in three small claims located internal to the Louise Cu-Au Porphyry Project (Louise) by issuing 400,000 common shares to the Vendor. The shares are subject to a hold period of four months and a day from the date of regulatory approval. The Vendor retains a net smelter royalty of 1% which can be purchased by the Company at any time for $500,000.
On September 25, 2025, applications for 2 new mining claims totaling 3350 hectares were approved, bringing the total claim size at Louise to 8806.1 hectares.
The gross costs and impairments recorded to the Louise property at December 31, 2025, are $477,345 and $nil respectively (September 30, 2025 - $466,261 and $nil).
Gold Range Property, Arizona, USA
On June 11, 2019, the Company’s wholly owned subsidiary, Canexco Inc., entered into an arm’s length Option Agreement to acquire a 100% interest in the Gold Range Property, Arizona, USA from a Prospector, the “Optionor”. On June 11, 2023, the Company completed its payment and expenditure obligations and the 100% earn in was completed. The Optionor will retain a 2% NSR, half of which can be bought back by the Company for US$500,000 and the remaining half for US$1,000,000. The Gold Range Property is located in Mohave County, Arizona, USA.
On February 24, 2020, the Company’s wholly owned subsidiary, Canexco Inc., entered into an arm’s length Option Agreement to acquire a 100% interest in the Never Get Left Claim from Onyx Exploration Inc., the “Optionor”. Under the terms of the agreement, the Company was committed to option payments totaling US$90,000 over four years. On February 24, 2024, the Company made the final payment of $49,314 (US$30,000), extinguishing its payment obligations, and the 100% earn in was complete. The Optionor will retain a 2% NSR, half of which can be bought back by the Company for US$500,000; the remaining half for US$500,000. Additionally, the Company must pay 10% of any profits realized from the processing and recovery of metals from the existing leach pad materials located within the Optionor’s claim.
On January 12, 2021, the Company, and its wholly owned subsidiary, Canexco Inc., signed a letter of intent allowing the Company to earn into the Excelsior Mine Property located adjacent to the Company’s other Gold Range properties. On November 29, 2023, 8,694,170 common shares, valued at $0.035 per share (total value - $304,295 were issued plus US$120,000 cash (CAD$166,058) and the 100% earn in was completed. The Optionor will continue to hold a 1.5% NSR as outlined in the original agreement and the Company will retain a right of first refusal (ROFR), should this royalty ever be offered for sale. In addition, until August 31, 2030, should the Company be subject to any event that would impact the creditors rights that is not cured in 30 days, it will deliver the mine property back to the Vendor under the reversion clause of the agreement.
On June 9, 2025, the Company announced its intention to make a formal offer to acquire all of the issued and outstanding shares of Gold Basin Resources Corporation (Gold Basin) in a share for share exchange
transaction. The assets of Gold Basin are directly adjacent to the existing Gold Range property, and the acquisition would consolidate a large oxide gold camp in northern Arizona. Subsequent to the date of these condensed interim consolidated financial statements, the Company announced that sufficient shares had been deposited under the offer and the process for take-up and payment has been initiated. Further details of the transaction are contained below in Note 19 – Subsequent events.
CANEX Metals Inc.
Notes to the Condensed Interim Consolidated Financial Statements
(Expressed in Canadian Dollars)
Three months ended December 31, 2025
(Unaudited - Prepared by Management)
| 8. | Exploration and evaluation assets |
Gold Range Property, Arizona, USA (continued)
As of December 31, 2025, the Company holds 261 lode mining claims and 2 patented claims (approximately 1650 hectares) in respect of the Gold Range Property, including acquisitions via the option agreements noted
above as well as staking. The gross costs and impairments recorded to the Gold Range Property at December 31, 2025, are $5,812,343 and $nil respectively (September 30, 2025 - $5,830,669 and $nil).
Gibson Prospect, British Columbia
On May 17, 2017, the Company had signed a purchase agreement and received exchange approval to acquire a 100% interest in the Gibson property from Altius Resources Inc. ("Altius"). Gibson is 887 Ha in size and located in central British Columbia, approximately 95 kilometres northwest of Fort St. James. The Company also assumed the obligations of an underlying option agreement with Steven Scott. The gross costs and impairments recorded to the Gibson Prospect as at December 31, and September 30, 2025, are $473,527 and $473,527 respectively.
During the year ended September 30, 2021, the Company determined that further exploration on this property would no longer be a priority unless a third-party partner could be found to further advance the exploration program; however, the Company continues to hold claims which expire in January 2029. Accordingly, the Company recorded an impairment of the full amount of exploration expenditures to September 30, 2021. In December 2025, the Company received a further extension to meet its minimum exploration expenditures of $500,000 to December 31, 2026. All other terms of the option agreement remain unchanged.
As at December 31, 2025, under the terms of the Agreement, the Company is committed to the following share issuances and minimum exploration expenditures:
| Altius | ||||||||
| Share issues | Minimum Exploration Expenditures* | |||||||
| ($) | ||||||||
| Expenditure commitment, on or before December 31, 2026 | - | 500,000 | ||||||
| Following the completion of the Expenditure Commitment | 1,240,000 | - | ||||||
| Total remaining commitment | 1,240,000 | 500,000 | ||||||
| *as at December 31, 2025, the Company has incurred exploration expenditures of $293,500 | ||||||||
In addition, Altius will retain a right to purchase an underlying 1.5% NSR and preferential rights on any future royalties or streams granted on the Property. If the Company achieves measured and indicated mineral resources in excess of 1 million gold equivalent ounces, a Milestone Payment of 1,275,000 shares will be issued to Altius. Altius will have a pro rata right to participate in future equity financings of the Company for two years.
Pursuant to the Underlying Agreement, Steven Scott is also entitled to the additional milestone bonuses of 1) $25,000 in cash or securities upon a Bankable Feasibility Study; and 2) $50,000 in cash or securities upon Commercial Production.
CANEX Metals Inc.
Notes to the Condensed Interim Consolidated Financial Statements
(Expressed in Canadian Dollars)
Three months ended December 31, 2025
(Unaudited - Prepared by Management)
| 8. | Exploration and evaluation assets (continued) |
Summary exploration and evaluation expenditures
A summary of exploration and evaluation expenditures by category for the three month period ended December 31, 2025, and year ended September 30, 2025, appear below:
| Arizona USA | BC Canada | Total | ||||||||||
| Three months ended December 31, 2025 | Gold Range Property | Louise Property | ||||||||||
| Exploration expenditures: | ||||||||||||
| Balance, September 30, 2025 | $ | 4,393,117 | $ | 376,145 | $ | 4,769,262 | ||||||
| Geological consulting | - | 4,375 | 4,375 | |||||||||
| Field Costs, net | (18,380 | ) | 4,002 | (14,378 | ) | |||||||
| Analysis and other | - | 2,335 | 2,335 | |||||||||
| Decommissioning | (226 | ) | - | (226 | ) | |||||||
| Balance, December 31, 2025 | $ | 4,374,511 | 386,857 | 4,761,368 | ||||||||
| Property acquisition costs: | ||||||||||||
| Balance, September 30, 2025 | $ | 1,437,552 | 90,116 | 1,527,668 | ||||||||
| Acquisition costs incurred | 280 | 372 | 652 | |||||||||
| Balance, December 31, 2025 | $ | 1,437,832 | 90,488 | 1,528,320 | ||||||||
| Total Exploration and evaluation assets, December 31, 2025 | $ | 5,812,343 | 477,345 | 6,289,688 | ||||||||
| Arizona USA | BC Canada | Total | ||||||||||
| Year ended September 30, 2025 | Gold Range Property | Louise Property | ||||||||||
| Exploration expenditures: | ||||||||||||
| Balance, September 30, 2024 | $ | 4,321,817 | $ | 5,860 | $ | 4,327,677 | ||||||
| Geological consulting | 9,402 | 49,309 | 58,711 | |||||||||
| Travel | 2,321 | 8,459 | 10,780 | |||||||||
| Field Costs | 20,821 | 6,707 | 27,528 | |||||||||
| Survey | - | 301,510 | 301,510 | |||||||||
| Analysis and other | 40,964 | 4,300 | 45,264 | |||||||||
| Decommissioning | (2,208 | ) | - | (2,208 | ) | |||||||
| Balance, September 30, 2025 | $ | 4,393,117 | $ | 376,145 | $ | 4,769,262 | ||||||
| Property acquisition costs: | ||||||||||||
| Balance, September 30, 2024 | $ | 1,363,090 | $ | 22,734 | $ | 1,385,824 | ||||||
| Acquisition costs incurred | 74,462 | 67,382 | 141,844 | |||||||||
| Balance, September 30, 2025 | $ | 1,437,552 | $ | 90,116 | $ | 1,527,668 | ||||||
| Total Exploration and evaluation assets, September 30, 2025 | $ | 5,830,669 | $ | 466,261 | $ | 6,296,930 | ||||||
CANEX Metals Inc.
Notes to the Condensed Interim Consolidated Financial Statements
(Expressed in Canadian Dollars)
Three months ended December 31, 2025
(Unaudited - Prepared by Management)
| 8. | Exploration and evaluation assets (continued) |
Mineral property advances and deposits
| Dec 31, 2025 | Sept 30, 2025 | |||||||
| Gibson exploration deposit | $ | 10,000 | $ | 10,000 | ||||
| Louise exploration deposit | 1,000 | 1,000 | ||||||
| Gold Range exploration deposit | 41,164 | 41,164 | ||||||
| Pre-takeover bid expenditures | 744,896 | 474,315 | ||||||
| $ | 797,060 | $ | 526,479 | |||||
Costs that relate directly to the acquisition of mineral interests are recorded as advances until such time as the transaction is completed. At that time, they will either be capitalized as part of the exploration asset acquired or expensed for the period if the acquisition is unsuccessful. Professional fees for legal , advisory, geological consulting and accounting are included in this category. Also, from time to time the Company is required to pay a deposit or bond to a government agency prior to their commencing exploration work on the mineral interest. The advances are held until reclamation work is complete and the Company makes application to have the deposit or bond returned.
| 9. | Accounts payable and accrued liabilities |
| December 31,
2025 | September 30,
2025 | |||||||
| Trade payables | $ | 221,212 | $ | 202,248 | ||||
| Due to related parties | 31,564 | 18,173 | ||||||
| Accrued liabilities | 3,116 | 46,800 | ||||||
| Commodity taxes payable | 3 | (12 | ) | |||||
| $ | 255,895 | $ | 267,209 | |||||
| 10. | Decommissioning obligation |
Changes in the decommissioning obligation:
| December 31, 2025 | September 30, 2025 | |||||||
| Balance, beginning of period | $ | 52,558 | $ | 50,031 | ||||
| Accretion | 214 | 4,734 | ||||||
| Change in assumptions | (227 | ) | (2,207 | ) | ||||
| Expenditures | - | - | ||||||
| $ | 52,545 | $ | 52,558 | |||||
The above noted provision represents estimated costs to restore the Company's mineral property which includes the cost of filling trenches and revegetation as applicable. Management believes that there are no other significant legal obligations as at the respective period end dates for current and future decommissioning obligations. The period end present value of the decommissioning obligation was determined using a risk-free rate of 2.58% (September 30, 2025 – 2.47%). The estimated total undiscounted amount, using an inflation rate of 2.5% (September 30, 2025 – 2.5%) for the three-month period ended December 31, 2025, is $52,547(September 30, 2025 - $53,594). The timing of future decommissioning costs is uncertain, as the costs will not be incurred until the Company gives up its legal right to explore the property or the current land use permits expire, at which time the reclamation must have been completed.
CANEX Metals Inc.
Notes to the Condensed Interim Consolidated Financial Statements
(Expressed in Canadian Dollars)
Three months ended December 31, 2025
(Unaudited - Prepared by Management)
| 11. | Share capital and stock options |
| a) | Authorized |
Unlimited number of common shares without par value
| b) | Issued and outstanding common share capital |
| Shares | Value $ | ||||||||
| Balance, as at September 30, 2025 | 146,950,482 | 23,139,647 | |||||||
| Common shares – December 2025 | 20,000,000 | 3,000,000 | |||||||
| Share issuance costs | - | (17,725 | ) | ||||||
| Balance, as at December 31, 2025 | 166,950,482 | 26,121,922 | |||||||
| Shares | Value $ | ||||||||
| Balance, as at September 30, 2024 | 114,380,737 | 21,450,899 | |||||||
| Common shares – November 2024 | 3,000,000 | 135,000 | |||||||
| Flow through shares – November 2024 | 5,033,365 | 226,502 | |||||||
| Shares issued for property – February 2025 | 500,000 | 20,000 | |||||||
| Common shares – June 2025 | 23,636,380 | 1,300,001 | |||||||
| Shares issued for property – August 2025 | 400,000 | 30,000 | |||||||
| Share issuance costs | - | (22,755 | ) | ||||||
| Balance, as at September 30, 2025 | 146,950,482 | 23,139,647 | |||||||
Three month period ended December 31, 2025
On December 23, 2025, the Company announced the closing of a non-brokered private placement of 20,000,000 common shares for gross proceeds of $3,000,000. The shares were issued at $0.15 per share and are subject to a hold period of four months plus one day from the date of closing. No commissions were paid on the transaction and insiders purchased a total of 670,147 common shares.
Year ended September 30, 2025
On August 19, 2025, the Company received regulatory approval to issue 400,000 common shares in exchange for three additional mining claims internal to the Louise Cu-Au Porphyry Project. The transaction was valued at the closing CANEX share price on the date of issue.
On June 26, 2025, the Company announced the closing of a non-brokered private placement of 23,636,380 common shares for gross proceeds of $1,300,001. The shares were issued at $0.055 per share and are subject to a hold period of four months plus one day from the date of closing. No commissions were paid on the transaction, and insiders purchased a total of 1,139,054 common shares.
On February 25, 2025, the Company issued 500,000 common shares in accordance with the Louise option agreement and were valued at the closing CANEX share price on the date of issue.
During November 2024, the Company announced an equity financing for cash that closed in two tranches, November 14 and November 25, 2024. The non-brokered private placement consisted of 3,000,000 common shares and 5,033,365 flow through common shares for gross proceeds of $437,002. Common shares were offered at $0.045 per share and the flow through common shares were offered at $0.06 per share. The tax benefit of the flow through common shares, renounced to shareholders, was determined to be $75,500 and recorded as a current liability which was amortized through earnings as the critical mineral flow through mining expenditures were incurred.
During the period subsequent to the date of these financial statements there were no shares issued, and none cancelled and returned to treasury.
CANEX Metals Inc.
Notes to the Condensed Interim Consolidated Financial Statements
(Expressed in Canadian Dollars)
Three months ended December 31, 2025
(Unaudited - Prepared by Management)
| 11. | Share capital and stock options (continued) |
| c) | Stock options outstanding |
| Number of options | Exercise | |||||||||||
| Expiry | Dec 31, 2025 | Sept 30, 2025 | Price | |||||||||
| May 1, 2027 | 1,462,500 | 1,462,500 | $ | 0.18 | ||||||||
| July 11, 2026 | 400,000 | 400,000 | $ | 0.06 | ||||||||
| November 25, 2029 | 5,200,000 | 5,200,000 | $ | 0.05 | ||||||||
| July 14, 2030 | 700,000 | 700,000 | $ | 0.08 | ||||||||
| 7,762,500 | 7,762,500 | |||||||||||
The Company has implemented a 10% Rolling Stock Option Plan whereby 10% of the issued shares will be reserved for issuance under the stock based compensation plan ("the Plan"). Under the Plan, the options that have been granted expire at the earlier of five years from the grant date, the date at which the Directors determine, or 60 days from the date on which the optionee ceases to be a director, officer, employee or consultant. The exercise price of the options granted under the Plan will not be less than that from time to time permitted under the rules of the stock exchange or exchanges on which the shares are then listed, which price reflects trading values at that time.
| d) | Stock option transactions |
Three month period ended December 31, 2025
| Number
of options | Weighted
average exercise price | |||||||
| Balance, September 30, 2025 | 7,762,500 | $ | 0.08 | |||||
| Expired | - | - | ||||||
| Issued | - | - | ||||||
| Balance, December 31, 2025 | 7,762,500 | $ | 0.08 | |||||
Year ended September 30, 2025
| Number
of options | Weighted
average exercise price | ||||||||
| Balance, September 30, 2024 | 2,572,500 | $ | 0.13 | ||||||
| Expired | (710,000 | ) | $ | (0.06 | ) | ||||
| Issued November 2024 | 5,200,000 | $ | 0.05 | ||||||
| Issued July 2025 | 700,000 | $ | 0.08 | ||||||
| Balance, September 30, 2025 | 7,762,500 | $ | 0.08 | ||||||
During the period subsequent to the date of these financial statements, no stock options were issued nor expired and none were exercised.
| 12. | Flow through shares |
Flow through common shares require the Company to spend an amount equivalent to the proceeds of the issued flow-through common shares on Canadian qualifying exploration expenditures. The Company may be required to indemnify the holders of such shares for any tax and other costs payable by them in the event the Company has not made the required exploration expenditures. During the three months ended December 31, 2024, the
CANEX Metals Inc.
Notes to the Condensed Interim Consolidated Financial Statements
(Expressed in Canadian Dollars)
Three months ended December 31, 2025
(Unaudited - Prepared by Management)
| 12. | Flow through shares (continued) |
Company received $302,002 from the issue of flow-through shares, of which $75,500 was attributed to a premium over the fair value of the shares issued and recorded as a liability for accounting purposes. Of this premium, $3,880 was subsequently recognized in income as the related expenditures were incurred, and $71,620 remained outstanding at December 31, 2024. By year ended, September 30, 2025, all qualifying expenditures had been made and no further obligation remains under the terms of the flow through agreement. Funds raised in connection with the flow-through shares must be spent on qualified mineral exploration and are restricted to Canadian Exploration Expenditures as defined in the Canadian Income Tax Act. The expenditures are renounced in favor of investors subscribing for flow through shares and the amounts are not available to the Company for income tax purposes.
| 13. | Financial instruments |
The following summarizes the categories of the various financial instruments:
| December 31, 2025 | September 30, 2025 | |||||||
| Carrying Value | ||||||||
| Financial Assets | ||||||||
| Financial asset measured at amortized cost: | ||||||||
| Cash | $ | 3,161,674 | $ | 663,907 | ||||
| Accounts receivable | 40 | - | ||||||
| $ | 3,161,714 | $ | 663,907 | |||||
| Financial Liabilities | ||||||||
| Financial liabilities measured at amortized cost: | ||||||||
| Accounts payable and accrued liabilities | $ | 255,888 | $ | 267,217 | ||||
The above noted financial instruments are exclusive of any sales tax. The carrying value of financial assets and liabilities measured at amortized cost approximates fair value due to the short-term nature of the instruments. Unless otherwise noted, it is management’s opinion that the Company is not exposed to significant interest or credit risks arising from these financial instruments.
The Company undertakes transactions denominated in US currency through its exploration in the US; consequently, it is exposed to exchange rate fluctuations. The Company will acquire US funds from time to time to settle US$ denominated liabilities. At December 31, 2025, the Company had US$26,789, (CAD$36,716) in a US denominated bank account (September 30, 2025 - US$5,358, (CAD$7,465)). The effect of a foreign currency increase or decrease of 10% on this cash holding would result in an increase or decrease of $3,672 (September 30, 2025 - $747).
CANEX Metals Inc.
Notes to the Condensed Interim Consolidated Financial Statements
(Expressed in Canadian Dollars)
Three months ended December 31, 2025
(Unaudited - Prepared by Management)
| 14. | General and administrative |
| December 31, | December 31, | |||||||
| 2025 | 2024 | |||||||
| Administrative consulting fees | $ | 154,450 | $ | 51,888 | ||||
| Stock-based compensation (Note 15) | 19,841 | 88,621 | ||||||
| Occupancy costs | 6,366 | 5,671 | ||||||
| Office, secretarial, supplies and other | 18,996 | 13,605 | ||||||
| Travel and promotion | 10,650 | 219 | ||||||
| Insurance | 3,343 | 3,458 | ||||||
| Directors' fees | 1,500 | 1,000 | ||||||
| Computer network and website maintenance | 716 | 631 | ||||||
| $ | 215,862 | $ | 165,093 | |||||
| 15. | Stock-based payment transactions |
During the three month period ended December 31, 2025, the Company did not issue any options, but recognized stock-based compensation related to options that were issued in November 2024, that will continue to vest over the following 12 months.
During the three month period ended December 31, 2024, the Company issued 5,200,000 options that may be exercised at $0.05 per share to November 25, 2029. The options vest one third on issue, one third on the first anniversary date and the remainder on the second anniversary date. Stock based compensation is recognized each quarter based upon the portion that vests during the period. Vested options were valued at $71,000 and the remainder at $142,000 using the Black-Scholes Options Pricing model assuming a 5-year term, volatility of 151.03%, a risk free discount rate of 3.18% and a dividend rate of 0%, on the grant date, November 25, 2024.
Subsequent to the three month period ended December 31, 2025, the Company issued 1,000,000 options that vest immediately and may be exercised at $0.225 over the next 5 years. Further details of the issuance can be found in Note 19 – Subsequent events to these condensed interim consolidated financial statements.
| 16. | Related party balances and transactions and key management remuneration |
The Company is considered a related party to Jade Leader Corp. (“Jade Leader”) by virtue of common officers and directors. In addition, related parties include members of the Board of directors, officers and their close family members. Vector Resources Inc., a company controlled by Shane Ebert, President, and director of CANEX; 635280 Alberta Ltd., a company controlled by Jean Pierre Jutras, an officer and director of CANEX are also considered related parties. The Company incurred the following amounts charged to (by) related parties:
| Three months ended: | December 31,
2025 | December 31,
2024 | ||||||
| Key management remuneration: | ||||||||
| President and director | a | $ | (33,950 | ) | $ | (25,807 | ) | |
| Corporate secretary | b | (16,530 | ) | (16,305 | ) | |||
| Directors’ fees | d | (1,500 | ) | (1,000 | ) | |||
| $ | (51,980 | ) | $ | (43,112 | ) | |||
CANEX Metals Inc.
Notes to the Condensed Interim Consolidated Financial Statements
(Expressed in Canadian Dollars)
Three months ended December 31, 2025
(Unaudited - Prepared by Management)
| 16. | Related party balances and transactions and key management remuneration (continued) |
| Three months ended: | December 31, 2025 | December 31, 2024 | ||||||
| Other related party transactions: | ||||||||
| Jade Leader | ||||||||
| Office rent and operating costs paid | e | $ | (6,684 | ) | $ | (5,671 | ) | |
| General, administrative and secretarial costs paid | e | $ | (1,941 | ) | $ | (1,711 | ) | |
| 635280 Alberta Ltd. | ||||||||
| Geological consulting services | f | $ | (1,925 | ) | $ | (613 | ) | |
The following amounts were receivable from or due to related parties at the respective period ends:
| Balances Receivable (Payable) | December 31, 2025 | September 30,
2025 | ||||||
| Consulting fees: | ||||||||
| President and director | a | $ | (12,863 | ) | $ | (6,615 | ) | |
| Chief Financial Officer | c | $ | - | $ | (2,310 | ) | ||
| 635280 Alberta Ltd. | f | $ | (689 | ) | $ | (1,240 | ) | |
| Office rent and operating costs: | ||||||||
| Jade Leader | e | $ | - | $ | - | |||
| General and administrative and secretarial costs: | ||||||||
| Directors Fees | d | $ | (1,500 | ) | $ | (500 | ) | |
| Jade Leader | e | $ | (1,946 | ) | $ | (998 | ) | |
| Corporate secretary | b | $ | (7,702 | ) | $ | (5,985 | ) | |
| President and director | a | $ | (6,825 | ) | $ | (525 | ) | |
Management compensation payable to “key management personnel” during the respective three-month periods is reflected in the table above and consists of consulting fees paid to the President, and the Corporate Secretary and directors’ fees. Officers and directors are also compensated through the granting of options. More detail on options granted during the current and prior period is contained in Note 15 – Stock-based payment transactions.
| a) | The President and director of the Company billed for consulting services that were either expensed or, when his services related directly to mineral property exploration, capitalized to exploration and evaluation assets.For three months ended December 31, 2025, $29,575 (2024 - $8,575) was expensed as consulting fees and the remainder, $4,375 (2024 - $17,232) was capitalized. |
| b) | The Corporate Secretary provides services to the Company on a contract basis. |
| c) | The Chief financial officer provides services to the Company on a contract basis. |
| d) | The Company pays directors who are not officers of the Company $500 for meeting attendance in person or by telephone. As at December 31, 2025, there are three directors who are not officers and the amounts above reflect directors’ fees paid or payable for meetings attended during the above-noted periods. |
| e) | Jade Leader incurred certain administrative expenses on the Company’s behalf that are subsequently billed to the Company on a quarterly basis. Further, the Company incurred certain administrative costs on behalf of Jade Leader that are billed on a quarterly basis. The Company has leased office space from Jade Leader since April 1, 2015. Jade Leader and the Company share two common officers and two common directors. |
| f) | During the three-month period ended December 31, 2025 and 2024, geological consulting services were provided by 635280 Alberta Ltd. |
Related party transactions were measured at the amounts agreed to by the transacting parties.
CANEX Metals Inc.
Notes to the Condensed Interim Consolidated Financial Statements
(Expressed in Canadian Dollars)
Three months ended December 31, 2025
(Unaudited - Prepared by Management)
| 17. | Supplemental disclosure statement of cash flows |
Reconciliation of cash used in operating activities to operating loss:
| Three months ended December 31, | 2025 | 2024 | ||||||
| Operating loss | $ | (238,469 | ) | $ | (178,334 | ) | ||
| Stock based compensation | 19,841 | 88,621 | ||||||
| Accretion | 214 | 1,141 | ||||||
| Changes in assets and liabilities pertaining to operations: | ||||||||
| Accounts receivable | (4,555 | ) | (3,934 | ) | ||||
| Prepaid expenses | 5,718 | 2,813 | ||||||
| Accounts payable and accrued liabilities | (10,963 | ) | (12,418 | ) | ||||
| Cash used in operating activities | $ | (228,214 | ) | $ | (102,111 | ) | ||
Reconciliation of cash expended on exploration and evaluation assets:
| Three months ended December 31, | 2025 | 2024 | ||||||
| Change in exploration assets | $ | 7,241 | $ | (33,560 | ) | |||
| Decommissioning asset | (227 | ) | (8,950 | ) | ||||
| Changes in assets and liabilities pertaining to exploration and evaluation assets: | ||||||||
| Accounts receivable | - | (2,126 | ) | |||||
| Accounts payable and accrued liabilities | (350 | ) | 7,683 | |||||
| Cash expended on exploration and evaluation assets | $ | 6,664 | $ | (36,953 | ) | |||
| 18. | Segment disclosures |
During the three-month periods ended December 31, 2025, and December 31, 2024, and the year ended September 30, 2025, the Company was only engaged in mineral exploration, and all exploration activities were undertaken in Canada and/or the United States. Activities undertaken in both countries were similar in nature. As at December 31, 2025, the value of non-current assets associated with United States operations is $5,853,507 (September 30, 2025 - $5,871,833) including exploration and evaluation asset advances and deposits of $41,164 (September 30, 2025 - $41,164) and exploration and evaluation assets of $5,812,343 (September 30, 2025 - $5,830,669). All remaining non-current assets are associated with Canadian operations. Consequently, segmented information is not presented in these financial statements. Refer to Note 8 – “Exploration and evaluation assets” for details of the carrying amounts of these assets at the respective period ends.
| 19. | Subsequent events |
On January 10, 2026, the Company issued 1,000,000 options that may be exercised at $0.225 per share to January 10, 2031. The options vest immediately and were valued at $206,200 using the Black-Scholes Options Pricing model assuming a 5-year term, volatility of 151.63%, a risk free discount rate of 2.92% and a dividend rate of 0%.
On January 30, 2026, the Company issued 41,154,418 common shares at $0.302 and on February 10, 2026, 337,776 common shares at $0.295 in exchange for Gold Basin Resources Corporation (Gold Basin) shares deposited under the CANEX offer and the Company now owns 51.87% of Gold Basin; a controlling interest. The
CANEX Metals Inc.
Notes to the Condensed Interim Consolidated Financial Statements
(Expressed in Canadian Dollars)
Three months ended December 31, 2025
(Unaudited - Prepared by Management)
| 19. | Subsequent events (continued) |
number of CANEX common shares issued was determined by the offering agreement whereby Gold Basin shareholders received 0.592 CANEX shares for every Gold Basin share tendered to the arrangement. The transaction was valued at $12,528,278, based upon the closing price of the CANEX shares on the date of issue.
CANEX intends to call a special meeting of Gold Basin Shareholders for the purpose of, among other things, seeking shareholder approval for a subsequent acquisition transaction, under similar terms and conditions, to complete the privatization of Gold Basin and acquire the remaining 48.13% of Gold Basin common shares.
On May 1, 2026, CANEX advanced sufficient funds and jointly, with Gold Basin, entered into a settlement agreement with Charrua Capital LLC whereby Gold Basin would pay $217,367.40 in full and final settlement of all obligations under a disputed loan agreement that was undertaken by the former officers of Gold Basin on August 21, 2024, for unsecured principle of $500,000 USD, bearing interest at 15% per annum.
On February 19, 2026, the Company made the third required option payment on the Louise Property of $50,000 by issuing 185,186 shares at a notional price of $0.27 per share. In March 2024, the Company entered into an option agreement to acquire the Louise Cu-Au Porphyry Project in British Columbia, Canada for total consideration of $775,000 in common shares of CANEX or cash. To date, $85,000 of the total commitment has been retired by issuing common shares of the Company under the terms of the option agreement.
CANEX Metals Inc.
MANAGEMENT'S DISCUSSION AND ANALYSIS
FOR THE THREE MONTHS ENDED DECEMBER 31, 2025
The following management discussion and analysis (MD&A) is management's assessment of the results and financial condition of CANEX Metals Inc. ("CANEX" or "the Company") for the three months ended December 31, 2025. The information included in this MD&A, with an effective date of May 14, 2026, should be read in conjunction with the condensed interim consolidated financial statements as at and for three months ended December 31, 2025, and related notes thereto. CANEX Metal's common shares trade on the TSX Venture Exchange under the symbol "CANX". The Company's most recent filings are available on the System for Electronic Document Analysis and Retrieval ("SEDAR+") and can be accessed at www.sedarplus.ca.
The Company's consolidated financial statements have been prepared in accordance with International Financial Reporting Standards and International Accounting Standards as issued by the International Accounting Standards Board (IASB) and Interpretations (collectively IFRS Accounting Standards) as at and for the three months ended December 31, 2025. The Company has consistently applied the same accounting policies throughout all periods presented. The Company's accounting policies are provided in Note 3 "Material accounting policies" to the annual audited consolidated financial statements at September 30, 2025. All dollar amounts are in Canadian dollars, unless otherwise noted.
The "Qualified Person" under the guidelines of National Instrument 43-101 of the Canadian Securities Administrators ("NI 43-101") for CANEX Metals' exploration projects in the following MD&A is Dr. Shane Ebert, P. Geo., a Professional Geologist, registered in the Province of British Columbia and the President and Director of CANEX Metals. The scientific and technical information concerning such properties contained herein has been reviewed by Dr. Ebert.
Statements and/or financial forecasts that are unaudited and not historical, including without limitation, exploration budgets, data regarding potential mineralization, exploration results and future plans and objectives, are to be regarded as forward-looking statements that are subject to risks and uncertainties that can cause actual results to differ materially from those anticipated. Such risks and uncertainties include risks related to the Company’s business including but not limited to general market and economic conditions, limited operating history, continued industry and public acceptance, regulatory compliance, potential liability claims, additional capital requirements and uncertainty of obtaining additional financing and dependence on key personnel. Actual exploration and administrative expenditures can differ from budget due to unforeseen circumstances, changes in the marketplace that will cause suppliers’ prices to change, and additional findings that will dictate that the exploration plan be altered to result in more or less work.
All forward-looking information is stated as of the effective date of this document and is subject to change after this date. There can be no assurance that forward-looking information will prove to be accurate and future events and actual results could differ materially from those anticipated.
| 1. | Principal Business of the Company |
CANEX Metals, including its wholly owned subsidiary, Canexco Inc. (“Canexco”), is engaged exclusively in the business of mineral exploration and development and, as the Company has no mining operations and no earnings there from, it is considered to be in the exploration stage. The recoverability of the amounts comprising exploration and evaluation assets is dependent upon the existence of economically recoverable mineral reserves; the acquisition and maintenance of appropriate permits, licenses and rights; the ability of the Company to obtain financing to complete the development of the mineral properties where necessary and upon future profitable production; or, alternatively, upon the Company’s ability to recover its costs through a disposition of its interests. The Company’s philosophy is to acquire projects at the grass roots level and advance them to a point where partners can be brought in to further the properties to the stage where a mine is commercially feasible, or the property can be sold outright.
1
CANEX Metals Inc.
MANAGEMENT'S DISCUSSION AND ANALYSIS
FOR THE THREE MONTHS ENDED DECEMBER 31, 2025
| 2. | Highlights |
The Company has no operating income and no earnings; exploration and operating activities are financed by the sale of common shares. None of the Company’s mineral properties are in production. Consequently, the Company’s net income is a limited indicator of its performance and potential.
| · | On May 6, 2026, CANEX was pleased to report that Gold Basin Resources Corporation (“Gold Basin”) announced a settlement agreement with Charrua Capital LLC (“Charrua”) in respect of the disputed enforceability of the unsecured loan agreement dated August 21, 2024, between Gold Basin and Charrua. The loan agreement bore a principal amount of $500,000, an initial interest rate of 15% and included high fees and costs and restrictions on Gold Basin’s use of funds. Under the terms of the settlement agreement, Gold Basin has agreed to pay Charrua US$217,367.40 upon, among other things, the release and discharge of any and all security interest and claims against Gold Basin and its assets. |
| · | On May 5, 2026, Canex reported that Gold Basin was pleased to announce that the purported joint venture between Gold Basin and Helix Resources Limited (“Helix”), previously announced by Helix in its ASX Announcement on April 29, 2026, is not valid and has no standing. Accordingly, Gold Basin and its controlling shareholder, CANEX , have the stated opinion that Helix has no interest or rights in the Gold Basin Property |
| · | On February 12, 2026, the Company announced that the Supreme Court of British Columbia ordered that the annual general meeting of the shareholders of Gold Basis Resources Corporation be Fheld on March 16, 2026, where CANEX will nominate a slate of highly qualified and experienced directors to the board of Gold Basin, and whose election is assured by CANEX’s majority position. |
| · | On January 29, 2026, CANEX announced that it had satisfied the statutory minimum tender requirements for its offer to acquire all of the issued and outstanding common shares of Gold Basinand is proceeding to take-up and pay for shares tendered under the offer. Following the take up CANEX will become the controlling shareholder of Gold Basin and will address and rectify regulatory deficiencies, install a new board of directors, settle debts and lawsuits, and work to facilitate a Subsequent Acquisition Transaction (as defined in the Original Offer and Circular) and then work to unlock the potential of the consolidated Arizona district. |
| · | On December 23, 2025, The Company announced the closing of a non-brokered common share private placement . Under the terms of the financing CANEX issued 20,000,000 common shares at $0.15 per share for total gross proceeds of $3,000,000. The offering, resulted in a new insider, Eric Fier, acquiring 10% of the Company. Proceeds will be used to advance the district consolidation opportunity, for exploration at the Company’s Gold Range and Louise projects and for general working capital. |
| · | On February 19, 2026, the Company made the third in a series of required annual option payments for the Louise Cu-Au porphyry deposit in British Columbia by issuing 185,186 common shares of the company at a notional price of $0.27 for total consideration of $50,000. To date $85,000 of the total $775,000 acquisition obligation has been retired. |
| · | In conjunction with the Company’s response to Gold Basin directors’ circular, on October 27, 2025, CANEX published an independent technical report for the Gold Range Project. The report is posted on the Company’s website and under the Company’s profile on SEDAR+. Interested parties should read the report in its entirety. The independent qualified author concludes that “The Gold Range project presents a compelling exploration opportunity within a well understood geological framework and deposit model. The evidence supports a structurally controlled, multi-episodic mineralizing system with the potential to host both high-grade vein-hosted and bulk-tonnage oxide gold resources. Continued exploration is warranted and should focus on expanding known zones drill testing structural intersections and alteration halos and advancing regional targeting within the broader Gold Basin District”. |
2
CANEX Metals Inc.
MANAGEMENT'S DISCUSSION AND ANALYSIS
FOR THE THREE MONTHS ENDED DECEMBER 31, 2025
| · | On August 28, 2025, the Company formally commenced its offer to acquire all of the issued and outstanding common shares of Gold Basin by way of a take-over bid. The offer was originally open for acceptance until December 12, 2025, but has been extended several times to accommodate Gold Basin shareholders who experienced difficulties in the tender process as Gold Basin has no transfer agent. The offer provided Gold Basin shareholders with 0.592 of a common share in the capital of CANEX in exchange for each Gold Basin share. |
| · | On July 31, 2025, the Company announced that based on the geophysical survey recently completed over the Louise Copper-Gold Porphyry Project (Louise Project or Louise) in BC, two new previously unknown high chargeability targets have been identified west and below the historic Louise Project deposit. The Company continues to study the results and will determine next steps to advance this discovery. |
| · | To consolidate the Company’s land position for the Louise Project on June 12, 2025, CANEX applied to stake 4.8 kilometers of additional strike length along the western projection of the geophysical trend. On July 29, 2025, the Company entered into a claim purchase agreement on three claims that sit internal to the Louise claim block for total consideration of 400,000 CANEX shares. The Vendor retains a 1% net smelter return royalty which can be bought back by CANEX for $500,000. In addition, on July 30, 2025, CANEX applied to stake 2.5 kilometres of additional strike length along the eastern projection of the geophysical trend. |
| · | On June 26, 2025, the Company closed a non-brokered private placement for 23,636,380 common shares at $0.055 per share for gross proceeds of $1,300,001. No commissions were paid, and the shares are subject to a four month hold period. Insiders purchased a total of 1,139,054 shares in connection with the private placement. Proceeds will be used to advance the consolidation process at the Gold Range property, exploration at Gold Range and Louise Projects and for general working capital. |
| · | On June 9, 2025, the Company announced its intention to make a formal offer to acquire all of the issued and outstanding shares of Gold Basin Resources Corporation (Gold Basin) in exchange for shares in CANEX. The transaction is notionally valued at $5.52 million and is subject to obtaining necessary regulatory approvals. Gold Basin holds assets that are directly adjacent to and on trend with the CANEX Gold Range Property. |
| 3. | Mineral Properties |
Gold Range Property, Arizona, USA
The Gold Range Property is in Northern Arizona within an area that has seen historic lode and placer gold production but limited modern gold exploration. CANEX first became interested in the Gold Range property in 2019, following the discovery of a quartz vein containing abundant visible gold by a local prospector in an area termed the Discovery Zone. Subsequent mapping and soil and rock sampling identified a 1000-metre-long linear trend of historic workings and exposed quartz veins centered around the Adit zone. Additional programs of surface sampling, mapping, trenching, airborne magnetic and lidar surveying, along with reverse circulation drilling have resulted in further expansion of the claim holdings and the recognition of a 4-kilometre-long mineralized corridor stretching from the Eldorado to Excelsior to WestGold Zones.
As of December 31, 2025, the Gold Range Property consists of 261 lode mining claims and 2 patented claims and is approximately 1650 hectares in size. The Company has drilled 15,412 metres in 138 holes and defined bulk tonnage oxide mineralization at the Excelsior, Eldorado, Malco, Central, and WestGold Zones. The oxide gold zones extend to surface and positive bottle roll metallurgical test work suggests mineralization is amenable to low cost heap leach extraction.
3
CANEX Metals Inc.
MANAGEMENT'S DISCUSSION AND ANALYSIS
FOR THE THREE MONTHS ENDED DECEMBER 31, 2025
On June 9, 2025, the Company announced its intention to make a takeover bid to acquire all of the outstanding shares of Gold Basin in exchange for shares in CANEX. On August 19, 2025, CANEX received partial revocation of the cease trade order imposed on Gold Basin by the British Columbia Securities Commission allowing CANEX to proceed with making the bid and on August 28, 2025, CANEX filed the Offer and Take-over Bid Circular for Gold Basin and formally commenced the take-over bid. The offer provides Gold Basin shareholders with 0.592 of a common share in the capital of CANEX in exchange for each Gold Basin share held by such shareholders and was open for acceptance until December 12, 2025. Several extensions were announced to allow Gold Basin shareholders who had difficulty with the process due to the lack of a Gold Basin transfer agent to tender to the offer. On January 29, 2026, CANEX announced that it had satisfied the statutory minimum tender requirement for its offer to acquire all of the issued and outstanding common shares of Gold Basin, had waived all remaining conditions to the offer, and was proceeding to take-up and pay for the tendered shares. Following the share take-up CANEX will become the controlling shareholder of Gold Basin and will take the required steps needed to complete consolidation and begin work to unlock the potential of the oxide-gold district in northern Arizona. The proposed combination of the two companies would consolidate a large oxide gold camp in Northern Arizona.
Over the past five years CANEX has been advancing its Gold Range property, making new gold discoveries and drill defining gold zones along a 4.0 kilometer mineralized trend that continues onto Gold Basin’s claims and is the longest defined gold trend in the district, extending at least 6.5 kilometres across both properties. To support the takeover offer, CANEX commissioned an independent third party evaluation of the Gold Range project which was published on October 27, 2025. The report provides a review of this project, highlighting the history, geology and exploration results completed to date. The independent qualified author concludes that “The Gold Range project presents a compelling exploration opportunity within a well understood geological framework and deposit model. The evidence supports a structurally controlled, multi-episodic mineralizing system with the potential to host both high-grade vein-hosted and bulk-tonnage oxide gold resources. Continued exploration is warranted and should focus on expanding known zones drill testing structural intersections and alteration halos and advancing regional targeting within the broader Gold Basin District”. The report is available on the CANEX website at www.canexmetals.ca and under the Company’s profile on SEDAR+ at sedarplus.ca.
During 2024 the Company successfully obtained a permit amendment to allow for drill testing of the new WestGold discovery, and the permits allows for an additional 34 pads located across the property. In March 2024 CANEX completed a field program focusing on refining drill targets in the WestGold area.
Highlights from the March 2024 surface exploration project at the Gold Range Project in Arizona include collecting 151 surface rock and soil samples, detailed mapping at the significantly expanded WestGold target and three new zones have been identified where assays from all three zones have returned high-grade gold mineralization. Areas of particular interest include:
· Surface chip sampling in the eastern part of the Gold Range property returned 19.4 g/t gold over 3 metres in a zone that has never been drill tested.
· A new zone of high-grade mineralization was identified 300 metres north of the Excelsior deposit, in the east-central part of the property, returning 11.2 g/t gold from a grab sample.
· A new zone of quartz veining and gold mineralization was discovered in the west-central part of the Gold Range property with a grab sample from a poorly exposed area returning 5.05 g/t gold.
· Grab samples of quartz veins in the WestGold area have returned grades up to 6.67 g/t gold and mineralized halos surrounding larger quartz veins have returned 0.97 g/t over 2 metres and 0.66 g/t gold over 3 metres in chip samples, confirming the presence of bulk tonnage targets at the zone.
Mapping has expanded the exploration target at WestGold to an area 800 metres by 400 metres and WestGold in now the largest exploration target on the Gold Range property. The zone is fully permitted, and drill testing can commence as markets strengthen.
4
CANEX Metals Inc.
MANAGEMENT'S DISCUSSION AND ANALYSIS
FOR THE THREE MONTHS ENDED DECEMBER 31, 2025
On February 24, 2024, the Company completed an option agreement and acquired 100% ownership in the Never Get Left Prospect claim by making the final option payment of $US30,000 ($CAD40,581). Under the terms of the agreement the optionor will retain a 2% NSR. Canexco can purchase half (1%) of the NSR for $US500,000 and the remaining half (1%) for an additional $US500,000.
Prior period drilling highlights from across the Gold Range Property include:
Hole GR21-57: 1.0 g/t gold over 59.45 metres (Excelsior)
Hole GR21-37: 1.6 g/t gold over 35.1 metres (Excelsior)
Hole GR21-46: 2.2 g/t gold over 18.3 metres (Excelsior)
Hole GR22-82: 9.7 g/t gold over 1.5 metres (Excelsior)
Hole GR22-90: 1.2 g/t gold over 12.19 metres (Excelsior)
Hole GR23-131: 4.1 g/t gold over 6.1 metres (Excelsior)
Hole GR22-97: 1.4 g/t gold over 6.1 metres (East of Excelsior)
Hole Gr23-127: 2.3 g/t gold over 3.1 metres (East of Excelsior)
Hole GR22-91: 0.6 g/t gold over 27.44 metres (Central)
Hole GR22-110: 1.1 g/t gold over 27.4 metres (Shaft)
Hole GR21-25: 1.3 g/t gold over 21.3 metres (Eldorado)
Hole GR20-4: 10 g/t gold over 1.5 metres (Eldorado)
Hole GR23-118: 0.2 g/t gold over 54.9 metres (WestGold)
Hole GR23-120: 0.7 g/t gold over 35 metres (WestGold)
During 2023 the Company completed surface exploration programs at Gold Range, a LiDar and air photo survey, and drill tested three new target areas defined previously, including WestGold, the zones parallel to Excelsior, and the new Shaft discovery. The WestGold target contains the largest and highest-grade gold in soil anomaly defined on the Gold Range property to date and the Company’s drill test of that target has resulted in a new and potentially very significant gold discovery that continues to be an important focus for the Company.
On November 29, 2023, the Company and its 100% owned Arizona subsidiary Canexco Inc. announced the completion of the Excelsior Mine Property 100% purchase as defined in the Amended Excelsior Mine Property Option Agreement. Under the amended agreement CANEX earned a 100% interest in the Excelsior Mine Property in exchange for issuing 8,694,170 CANEX shares and paying US$120,000 (CAD$166,058) in cash. The Vendors will retain a 1.5% NSR and CANEX retains a right of first refusal on the sale of the royalty. In addition, until August 31, 2030, should the Company be subject to any event that would impact the creditors rights that is not cured in 30 days, they will deliver the mine property back to the Vendor under the reversion clause of the agreement. The Excelsior Mine Property consists of 11 lode mining claims and 2 patented mining claims covering 3 past producing historic gold mines located within the Company’s larger Gold Range Project in Arizona. CANEX has drilled 72 holes into the main Excelsior deposit, defining a moderately dipping gold mineralized zone up to 400 meters long by 20 to 60 metres wide, that has been traced at least 100 metres down dip.
Operational highlights for the last eight quarters:
| o | CANEX achieves the statutory minimum tender requirement for its offer for Gold Basin and begins the process to take-up shares tendered to the offer – January 2026 |
| o | The Company released an independent technical report commissioned to review the Company’s Gold Range project and the broader Gold Basin District. Report indicates further exploration is warranted – October 2025 |
| o | The Company files offer and takeover bid circular for Gold Basin and formally commences takeover bid – August 2025 |
| o | CANEX receives partial revocation of cease trade order imposed on Gold Basin by the British Columbia Securities Commission allowing CANEX to proceed with making a takeover bid of Gold Basin – August 2025 |
| o | The Company announces intention to make a takeover bid to acquire all of the outstanding shares of Gold Basin Resources – June 2025 |
| o | Field mapping and soil sampling identified 3 new zones in WestGold– March 2024 |
5
CANEX Metals Inc.
MANAGEMENT'S DISCUSSION AND ANALYSIS
FOR THE THREE MONTHS ENDED DECEMBER 31, 2025
| o | The Company acquires 100% ownership in the Never Get Left Claim – February 2024 |
| o | Amended exploration permit received – March 2024 |
The gross costs and impairments recorded for the Gold Range Property at December 31, 2025, are $5,812,343 and $nil, respectively (September 30, 2025 - $5,830,669 and $nil).
Louise Cu-Au Porphyry Project, British Columbia
In March 2024, the Company entered into an option agreement, with no spending requirements, to earn a 100% interest in the Louise Project subject to certain scheduled option payments. The project offers a low-risk, high value opportunity with untested discovery potential that can be advanced as market conditions allow. The property is located approximately 35 kilometres west of Smithers, in west central British Columbia, it is road accessible and previous drilling has returned strong copper and gold trades including 0.41% copper and 0.40 g/t gold over 158 metres and several holes indicating increasing grades with depth.
During 2024, in conjunction with signing the agreement, CANEX advanced $8,733 to the optionor to stake certain claims that are contained within the 5,362.94 hectare optioned property and subject to the terms of the agreement. Remaining obligations under the option agreement are discussed below in Section 7 a), Contractual Obligations.
The Company assembled and analyzed the historic data for the Louise Project and announced the results of this work on September 24, 2024. Highlights included:
| · | Historic drilling has identified a mineralized zone that is 1000 metres long by 400 metres wide and currently extends to a depth of approximately 300 metres. |
| · | Strong copper and gold grades occur in the system highlighted by hole LL04-03 which returned an interval of 158 metres grading 0.41% copper and 0.40 g/t gold starting at 53.5 metres downhole. |
| · | Past work largely focused in and around the original surface discovery area and only extends to about 300 metres deep, with some drill holes ending in mineralization. |
| · | Data suggests potential for a copper and gold target below and lateral to the existing resource. |
To better understand the district scale potential of this porphyry system, CANEX proposed a deep looking induced polarization (IP) survey that can potentially look up to 1000 metres deep and extend that survey across 6 to 7 kilometres of strike length.
During November 2024, CANEX closed, in two tranches, a non-brokered financing, as discussed in 2) Highlights, 4) Operating results and 5) Liquidity and Capital Resources, to fund this project. FT share proceeds of $302,002 were used for general exploration expenditures at the Louise Project which constituted Canadian Exploration Expenses within the meaning of subsection 66.1(6) of the Income Tax Act (Canada) (the “Tax Act”), that qualify as “critical mineral flow through mining expenditures” within the meaning of the Tax Act. During year ended September 30, 2025, the Company incurred the required $302,002 of qualifying expenditures through a geophysical survey and there are no remaining commitments under the Tax Act.
On December 10th, 2024, CANEX announced receipt of an exploration permit for the Louise Cu-Au porphyry project in British Columbia allowing the Company to conduct surface geophysical surveying over the target area.
During May and June 2025, Simcoe Geoscience conducted a geophysical survey at the Louise Project using their Alpha IPTM wireless time domain distributed induced polarization technology. A total of 36.9 line kilometres on nine lines were surveyed; each line was 4100 metres long and spaced 400 metres apart. The survey used a 100-metre dipole spacing with a dipole-pole-dipole (reverse & forward) configuration enabling double data density to be acquired providing high definition and resolution.
6
CANEX Metals Inc.
MANAGEMENT'S DISCUSSION AND ANALYSIS
FOR THE THREE MONTHS ENDED DECEMBER 31, 2025
A new and previously unknown chargeability target has been identified two kilometres west of the historic Louise deposit and has been named the West Louise Target. In addition, a steeply dipping zone of high chargeability has been identified below and to the north of the historic Louise deposit and has been termed the Louise Deep Target. The Louise Deep Target is interpreted to have potential to host the mineralized roots of the historic Louise system and shows continuity to roughly 1000 metres below surface, the limit of the geophysical survey. Neither the West Louise nor Louise Deep targets have been drill-tested previously.
Highlights:
| · | The West Louise Target is located two kilometres west of the historic Louise resource and correlates with a low-level surface Cu-Mo-Au-As geochemical anomaly in a flat area covered by glacial till. |
| · | The West Louise Target is defined by chargeability values from 15 to >20 mV/V over an area 600 metres wide by 400 to 500 metres deep and extending at least 800 meters along strike, with the anomaly remaining open to the west. The anomaly comes to surface on line 1E and starts around 150m below surface on line 2E. |
| · | The West Louise Target contains similar chargeability and resistivity values as the historic Louise deposit and has never been identified or drill tested previously. The target could represent a new porphyry centre with potential to host copper-gold mineralization similar to that at the Louise deposit. |
| · | The Louise Deep Target contains a sub vertical zone of high chargeability located below and immediately north of the Louise deposit. This target is 700 metres wide and extends to 1000 metres below surface, the depth limit of the geophysical survey. This target could be the conceptual “main body” of the Louise Project that is partially offset from the resource area along the Terminator Fault. Identifying this target was a key objective of the survey. |
| · | CANEX has purchased three small claims located internal to the Louise claim block by issuing 400,000 shares to the vendor. In addition, CANEX has staked a further 4.8 kilometres of strike length along the western projection and 2.5 kilometres of strike length along the eastern projection of the geophysical trend. |
The gross costs and impairments recorded for the Louise Project at December 31, 2025, are $477,345 and $nil, respectively. (September 30, 2025 - $466,261 and $nil).
Gibson Prospect, British Columbia
In 2017 the Company entered into an option agreement with owner Altius Resource Inc. (“Altius”) to acquire a 100% interest in the Gibson property located in central British Columbia, approximately 95 kilometres northwest of Fort St. James. The Company conducted surface mapping and sampling, trenching, and drilled 10 holes into the Gibson property in 2017 and 2018.
This work resulted in strong precious metal results including:
Hole G18-01: 0.81 g/t gold and 40 g/t silver over 31.5 metres from 33.5 metres depth
Trench 1: 1.6 g/t gold and 175 g/t silver over 12.0 metres
Hole G18-01: 3.7 g/t gold and 321 g/t silver over 2.5 metres from 54 metres depth
Hole G18-01: 11.9 g/t gold and 301 g/t silver over 1.0 metres from 64 metres depth
Hole G18-03: 2.7 g/t gold and 872g/t silver over 0.5 metres from 19 metres depth
The Company has identified promising precious metal potential at Gibson and the mineralized zone remains open in all directions under shallow cover.
During the year ended September 30, 2021, the Company determined that further exploration on this property, would no longer be a priority unless a third-party partner could be found to further advance the exploration program; however, the Company continues to hold claims which expire in January 2029. Accordingly, the Company recorded an impairment of the full amount of exploration expenditures to September 30, 2021. In August 2024, the Company received a further extension to meet its minimum exploration expenditures to December 31, 2026. All other terms of the option agreement remain unchanged. For more information, refer to Section 7 b), Contractual Obligations below.
7
CANEX Metals Inc.
MANAGEMENT'S DISCUSSION AND ANALYSIS
FOR THE THREE MONTHS ENDED DECEMBER 31, 2025
| 4. | Operating results |
A summarized statement of operations appears below to assist in the discussion that follows:
| Three months ended, December 31 | 2025 | 2024 | ||||||
| General and administrative | $ | 215,862 | $ | 165,093 | ||||
| Reporting to shareholders | 12,728 | 4,806 | ||||||
| Professional fees | 4,841 | 4,413 | ||||||
| Stock exchange and transfer agent fees | 4,824 | 2,881 | ||||||
| Accretion | 214 | 1,141 | ||||||
| Interest and other (income) | (7,624 | ) | (1,124 | ) | ||||
| Realization of flow through premium liability | - | (3,880 | ) | |||||
| (Gain) loss on short-term investments | - | 10,347 | ||||||
| Net and comprehensive loss | $ | 230,845 | $ | 183,677 | ||||
The most significant changes in expenditure follow:
| · | Variances in general and administrative expenditures and professional fees are examined in further detail in the chart below. |
| · | Reporting to shareholders’ expenditures during the three months ended December 31, 2025, and 2024, include fees for filing the annual audited financial statements. The increase for three months ended December 31, 2025, relates to the timing of the AGM. The most recent was held in the current quarter October 30, 2025, and the previous year was held in the fourth quarter of 2025. |
| · | Stock exchange and transfer agent fees relate to the Company’s equity and the fees charged to maintain the company’s shareholder list and fees paid to the TSXV. The amount is influenced by the value of the equity, number of transactions and number of shares outstanding as well as activity in the company that requires exchange approval. Costs incurred during three months ended December 31, 2025, were higher than the comparative period in 2024 as additional costs were incurred for filing fees on the equity issue that closed in the current quarter. |
| · | Accretion, when material is recorded on a quarterly basis. Changes in interest rates, inflation or the magnitude of anticipated future reclamation costs will influence the recording of the estimated expense. |
| · | Interest and other income include interest earned from a high interest savings account and foreign exchange gains and losses incurred on US$ denominated transactions. The variance between the current and comparative periods relates to higher and lower bank balances and higher and lower interest rates during the comparative periods as well as a gain of $9.5k on the sale of equipment that is no longer required for use at the Gold Range Property in Arizona. |
| · | Realization of flow through premium liability relates to the tax benefit renounced to shareholders on the issuance of flow-through common shares (FT shares). During the year ended September 30, 2025, the Company issued FT shares and determined the premium to market on the issue to be $75,500. This amount was recorded as a liability until such time as the qualifying expenditures were made on the Louise project. The amount is amortized to earnings in proportion to the qualifying exploration expenditures made during the period. At December 31, 2025, all obligations had been previously satisfied and fully amortized. At December 31, 2024, $15,530 in critical mineral flow through mining expenditures within the meaning of the Income Tax Act (Canada) were made and $3,880 of the liability was recognized in earnings. |
| · | Prior to three months ended December 31, 2025, the remaining shares in Homeland Nickel Inc were sold and no short term investments remain. During the three months ended December 31, 2024, the Company recognized an unrealized loss of $10,345 on the mark to market valuation of then outstanding, short-term investments. |
8
CANEX Metals Inc.
MANAGEMENT'S DISCUSSION AND ANALYSIS
FOR THE THREE MONTHS ENDED DECEMBER 31, 2025
General and administrative expenses
| Three months ended December 31, | 2025 | 2024 | ||||||
| Administrative consulting fees | $ | 154,450 | $ | 51,888 | ||||
| Share based compensation | 19,841 | 88,621 | ||||||
| Occupancy costs | 6,366 | 5,671 | ||||||
| Office, secretarial and supplies | 18,996 | 13,605 | ||||||
| Travel and promotion | 10,650 | 219 | ||||||
| Insurance | 3,343 | 3,458 | ||||||
| Directors’ fees | 1,500 | 1,000 | ||||||
| Computer network and website maintenance | 716 | 631 | ||||||
| Total | $ | 215,862 | $ | 165,093 | ||||
| · | Administrative consulting fees, which consist of fees for the controller, geological consulting, and services provided by other consultants, have significantly increased for the three months ended December 31, 2025, compared to December 31, 2024. The Company is actively advancing the Louise Project and working on the expansion of the Gold Range Project through a takeover bid. The President and a geological consultant have increased their billable time during the three months ended December 31, 2025, to evaluate and make recommendations for exploiting these opportunities. |
| · | Stock-based compensation relates to the recognition of the value, vesting over time, of certain options issued during the period and any issued in prior periods. During the three months ended December 31, 2025, the Company did not issue any options and the amount above relates to options issued in prior periods that vest over time. During the three months ended December 31, 2024, the Company granted, pursuant to its stock option plan, a total of 5,200,000 incentive stock options to existing directors, officers, and consultants of the Company. The options are exercisable at a price of $0.05 per share for five years, with a portion vesting immediately and the remaining vesting over a two year period. These incentive options replace 3,285,000 options that expired during 2024. Vested options were valued at $71,000 and the remainder at $142,000 using the Black-Scholes Options Pricing model assuming a 5-year term, volatility of 151.03%, a risk free discount rate of 3.18% and a dividend rate of 0%. |
| · | Occupancy costs are slightly higher, period over period, due to an increase in the base rate that came into effect on September 1, 2025, in conjunction with the renewal of the rental agreement for a further 12 month period. Base rent has increased by $243 to $2,228 per month, a 12% increase over the previous term. |
| · | Office and secretarial fees, which relate primarily to contract administrative services and office supplies, have increased for the three month period ended December 31, 2025, consistent with more activity in the Company during this period compared to the prior period. Issuing shares and advancing the takeover offer for Gold Basis were activities that contributed significantly to the increase. |
| · | Travel and promotion costs have also increase in the three months ended December 31, 2025, relating to corporate travel associated with promoting the equity issue during the period and advancing the takeover offer for Gold Basin. |
| · | The Company pays directors who are not officers of the Company $500 for meeting attendance. There are currently three directors who are not officers and the amounts above reflect the directors’ fees paid or payable for meetings attended during the above-noted periods. |
Professional fees
| Three months ended December 31, | 2025 | 2024 | ||||||
| Audit and accounting | $ | 3,381 | $ | 3,292 | ||||
| Legal and filing fees | 1,460 | 1,121 | ||||||
| Total professional fees | $ | 4,841 | $ | 4,413 | ||||
9
CANEX Metals Inc.
MANAGEMENT'S DISCUSSION AND ANALYSIS
FOR THE THREE MONTHS ENDED DECEMBER 31, 2025
The following summarizes the components of professional fees included in the statement of net and comprehensive loss:
| · | Accounting fees incurred during the current and comparative three months ended December 31, 2025, include costs associated with the annual filing of the US tax returns for Canexco. |
| · | Legal fees relate to fees charged for filing news releases and general corporate matters and are higher during 2025 compared to 2024 due to the increased activity in the Company and the need to obtain associated legal advice. |
| 5. | Liquidity and Capital Resources |
The Company’s working capital position at December 31, 2025, was $3,014,407 (September 30, 2025 - $506,487), an improvement of $2,507,920. Significant changes to working capital are discussed below:
| · | The Company used $228,214 to cover the cost of operations during the three months ended December 31, 2025, compared to $102,111 for the comparative period 2024. The variances are consistent with the factors described in Section 4) Operating results. |
| · | During the three months ended December 31, 2025, the Company invested $263,917 of cash in exploration and evaluation activities. Of this, $270,581 related to the costs associated with the takeover bid of Gold Basin. The remainder relates to the sale of superfluous equipment at the Gold Range, Excelsior Mine Property, geological consulting at the Louise Project and changes in working capital. During the three months ended December 31, 2024, the Company invested $37,953 of cash in exploration and evaluation activities. Of this, $28,130 was spent on the Louise project for geological consulting and analysis as well as First Nations consultation. $8,823 related to exploration and acquisition at the Gold Range Property, Arizona, USA, $1,000 was a deposit required by the Government of BC in conjunction with approval to undertake exploration activities on the Louise project and changes in working capital for the period. See Note 8 - "Exploration and evaluation assets" of the condensed interim consolidated financial statements at December 31, 2025, which accompany this document and Section 3) “Mineral properties” for more information. |
| · | During the three months ended December 31, 2025, the Company received $3,000,000 as proceeds on a non-brokered private placement share issuance and incurred $17,724 in share issuance costs. During the three months ended December 31, 2024, the Company received $437,002 as proceeds on a non-brokered private placement share issuance and incurred $9,236 in share issuance costs. |
The Company is continually investigating financing options. The continuing operations of the Company are dependent upon its ability to obtain adequate financing or to commence profitable operations in the future. The Company feels that it has sufficient working capital to finance general and administration, other operating expenses, and current activities at the properties for approximately the next full year. However, increases in activity levels, new property acquisitions, and any additional exploration on its mineral properties will require additional financing. There can be no assurance that the Company will be successful in obtaining financing. Refer to Note 1 "Nature of operations and continuance of operations" to the condensed interim consolidated financial statements at December 31, 2025, that accompany this document.
| 6. | Financing |
Three months ended December 31, 2025
On December 23, 2025, the Company announced the closing of a non-brokered private placement of 20,000,000 common shares for gross proceeds of $3,000,000. The shares were issued at $0.15 per share and are subject to a hold period of four months plus one day from the date of closing. No commissions were paid on the transaction, and insiders purchased a total of 670,147 common shares.
10
CANEX Metals Inc.
MANAGEMENT'S DISCUSSION AND ANALYSIS
FOR THE THREE MONTHS ENDED DECEMBER 31, 2025
Three months ended December 31, 2024
During October 2024, the Company announced an equity financing for cash that closed in two tranches, November 14 and November 25, 2024. The non-brokered private placement consisted of 3,000,000 common shares and 5,033,365 flow through common shares for gross proceeds of $437,002. Common shares were offered at $0.045 per share and the flow through common shares were offered at $0.06 per share. The tax benefit of the flow through common shares, renounced to shareholders, was determined to be $75,500 and recorded as a current liability which was amortized through earnings as the critical mineral flow through mining expenditures were incurred.
| 7. | Contractual Obligations |
a) On March 5, 2024, the Company announced it had signed an Option Agreement to acquire a 100% interest in the Louise Project located in west central British Columbia. The agreement was signed on March 1, 2024, and received Exchange approval on April 9, 2024.
The remaining commitments are as follows:
| Shares or Cash | ||||
| Upon regulatory approval | $ | 10,000 | ||
| March 1, 2025 | $ | 25,000 | ||
| March 1, 2026 | $ | 50,000 | ||
| March 1, 2027 | $ | 90,000 | ||
| March 1, 2028 | $ | 200,000 | ||
| March 1, 2029 | $ | 400,000 | ||
| Total commitment | $ | 775,000 | ||
| Payments made in shares or cash | $ | (85,000 | ) | |
| Total remaining commitment | $ | 690,000 | ||
On February 19, 2026, the third option payment of $50,000 for the Louise Project was made by issuing 185,186 common shares of the Company at a notional price of $0.27 per common share. Under the terms of the Option agreement dated March 1, 2024, the number of shares issued was calculated using the volume-weighted average (“VWAP”) trading price on the exchange for the 30 trading days ending five trading days prior to the issuance of shares. As the VWAP fell below $0.05 per share, the difference in value between the calculation and $0.05 per share was paid in cash. On February 25, 2025, the second option payment of $25,000 for the Louise Project was made by issuing 500,000 common shares of the Company and making a cash payment of $3,500. On April 9, 2024, the Company made the first option payment of $10,000 by issuing 200,000 shares at a notional price of $0.05 per share. The transaction was valued at $14,000 based upon the closing trading price of the shares on the payment date. In addition, there is a milestone bonus in shares or cash if CANEX drills over 4250 metres of core, and a second milestone bonus of $50,000 in shares or cash if CANEX publishes a resource estimate with greater than 1.5 million contained ounces of gold. The Optionor will retain a NSR of 2.5% of which 1% can be purchased by CANEX for $1.5 million.
On July 29, 2025, the Company acquired a 100% interest in three small claims located internal to the Louise Cu-Au Porphyry Project by issuing 400,000 common shares to the Vendor. The shares are subject to a hold period of four months and a day from the date of regulatory approval. The Vendor retains a net smelter royalty of 1% which can be purchased by the Company at any time for $500,000.
b) On April 4, 2017, the Company announced it had signed a Letter of intent to acquire a 100% interest in the Gibson property from Altius Resources Inc. ("Altius"). Gibson is 887 Ha in size and located in central British Columbia. The purchase agreement was executed on May 12, 2017, and received Exchange approval on May 17, 2017.
11
CANEX Metals Inc.
MANAGEMENT'S DISCUSSION AND ANALYSIS
FOR THE THREE MONTHS ENDED DECEMBER 31, 2025
The remaining commitments of the agreement are as follows:
| Altius | ||||||||
| Share issues | Minimum Exploration Expenditures* | |||||||
| ($) | ||||||||
| Expenditure commitment, on or before December 31, 2025 | - | 500,000 | ||||||
| Following the completion of the Expenditure Commitment | 1,240,000 | - | ||||||
| Total remaining commitment | 1,240,000 | 500,000 | ||||||
* as at December 31, 2025, the Company has incurred exploration expenditures of $293,500
In addition, Altius will retain a right to purchase an underlying 1.5% NSR and preferential rights on any future royalties or streams granted on the Property. If the Company achieves measured and indicated mineral resources in excess of 1 million gold equivalent ounces, a Milestone Payment of 1,275,000 shares will be issued to Altius. Altius will have a pro rata right to participate in future equity financings of the Company for two years.
Pursuant to the Underlying Agreement, Steven Scott is also entitled to the additional milestone bonuses of 1) $25,000 in cash or securities upon a Bankable Feasibility Study; and 2) $50,000 in cash or securities upon Commercial Production. The agreement has been amended to allow the Company to meet minimum exploration expenditures by December 31, 2026. All other terms of the agreement remain unchanged.
| c) | Other commitments remaining on 100% owned property are as follows: |
| Optionor | Property | Commitment | Buy-out |
| Gieske | Gold Range Property | 2% NSR | $500k first 1%, $1M 2nd 1% |
| Onyx | Never Get Left Claim | 2% NSR | $500k first 1%, $500k 2nd 1% |
| Silmar of Arizona | Excelsior Claim | 1.5% NSR | Right of First Refusal on Sale |
In addition to the above, CANEX has committed to a reversion agreement to August 30, 2030, on the Excelsior Claim, whereby the Company, if subject to any event that would impact the optionors rights, if not cured in 30 days, would deliver the property back to the Optionor.
| 8. | Exploration Expenditures |
Refer to “Exploration and evaluation assets,” Note 8 to the condensed interim consolidated financial statements as at December 31, 2025.
| 9. | Off-Balance Sheet Transactions |
There are no off-balance sheet transactions to report.
12
CANEX Metals Inc.
MANAGEMENT'S DISCUSSION AND ANALYSIS
FOR THE THREE MONTHS ENDED DECEMBER 31, 2025
| 10. | Selected Quarterly Financial Information |
The following selected financial data has been extracted from the unaudited interim consolidated financial statements for the fiscal periods indicated and should be read in conjunction with those unaudited financial statements.
| Three months ended | Dec
31 2025 (Q1 2026) |
Sept
30 2025 (Q4 2025) |
June 30
2025 (Q3 2025) |
Mar
31 2025 (Q2 2025) |
Dec
31 2024 (Q1 2025) |
Sep
30 2024 (Q4 2024) |
Jun
30 2024 (Q3 2024) |
Mar
31 2024 (Q2 2024) |
||||||||||||||||
| $ | $ | $ | $ | $ | $ | $ | $ | |||||||||||||||||
| Loss before impairment of exploration and evaluation assets | (238,469 | ) | (234,012 | ) | (124,787 | ) | (60,394 | ) | (178,334 | ) | (92,456 | ) | (45,782 | ) | (63,929 | ) | ||||||||
| Impairment of exploration and evaluation assets | - | - | - | - | - | - | - | - | ||||||||||||||||
| Operating loss | (238,469 | ) | (234,012 | ) | (124,787 | ) | (60,394 | ) | (178,334 | ) | (92,456 | ) | (45,782 | ) | (63,929 | ) | ||||||||
| Interest and other income | 7,624 | 2,778 | 500 | 637 | 1,124 | 1,764 | 2,281 | 2,307 | ||||||||||||||||
| Gain (loss) on short-term investments | - | - | - | 30,518 | (10,347 | ) | (10,345 | ) | (15,517 | ) | (31,035 | ) | ||||||||||||
| Realization of flow through premium liability | - | - | 69,290 | 2,330 | 3,880 | - | - | - | ||||||||||||||||
| Comprehensive profit (loss) | (230,845 | ) | (231,234 | ) | (54,997 | ) | (26,909 | ) | (183,677 | ) | (101,037 | ) | (59,018 | ) | (92,657 | ) | ||||||||
| Basic and diluted earnings (loss) per share | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
Generally, the most significant influence on the variability of profit or loss is the amount of stock-based compensation, the amount of exploration and evaluation asset impairments or recoveries, and gains or losses on short-term investments. Options issued during Q1 2025 and Q4 2025 negatively impacted earnings for the quarter without impacting cashflow. Impacting the current quarter, Q1 2026, as well as Q4 and Q3 2025, the Company has undertaken two significant projects to advance the Louise Project and Gold Range properties. The result is an increase in general and administrative expenses related to consulting fees for the President, outside geological support and corporate secretarial services as well as increases in audit and accounting fees.
The timing of the impairments and gains on sale of the Company’s exploration and evaluation assets cannot be predicted in advance and will vary from one reporting period to the next. As a result, there may be dramatic changes in the financial results and balance sheet position reported by the Company on a period-by-period basis.
Interest and other reflect foreign exchange gains and losses incurred on a US dollar denominated bank account held by the Company to conduct its business in the United States as well as interest earned on bank balances during the period.
Occasionally the Company receives common shares in publicly traded Companies as partial consideration for the sale of mineral property interests. The sale of Homeland Nickel Inc common shares during Q2 2025 positively impacted earnings in that periods when the sale proceeds net of the cost of the shares and the reversal of prior period valuation losses resulted in a gain on the sale of these securities.
The Company’s improved working capital position is the result of the equity issues in Q1 2026, Q3 2025 and Q1 2025.
| 11. | Directors and Officers |
| Shane Ebert | Director and President | Gregory Hanks | Director | |||||
| Jean Pierre Jutras | Director and Vice-President | Lesley Hayes | Director | |||||
| Barbara O’Neill | Corporate Secretary | Blair Schultz | Director | |||||
| Chantelle Collins | Chief Financial Officer |
13
CANEX Metals Inc.
MANAGEMENT'S DISCUSSION AND ANALYSIS
FOR THE THREE MONTHS ENDED DECEMBER 31, 2025
| 12. | Related Party Transactions and Key Management Remuneration |
Related party transactions for the three months ended December 31, 2025, and 2024, are disclosed and explained in Note 16 to the condensed interim consolidated financial statements as at December 31, 2025, that accompany this MD&A.
| 13. | Share Capital and Equity Reserves |
Refer to Note 11 in the consolidated financial statements dated December 31, 2025, as well as the condensed interim consolidated statement of changes in equity that accompany this MD&A for common share capital and stock option transactions for the three months ended December 31, 2025, and balances as at that date.
On December 23, 2025, the Company announced the closing of a non-brokered private placement of 20,000,000 common shares for gross proceeds of $3,000,000. The shares were issued at $0.15 per share and are subject to a hold period of four months plus one day from the date of closing.
| 14. | Financial Instruments |
The carrying value of the Company's financial instruments, consisting of cash and cash equivalents, accounts receivable (net of sales tax) and accounts payable and accrued liabilities approximate their fair value due to the short-term nature of the instruments.
It is management's opinion that the Company is not exposed to significant interest or credit risks arising from these financial instruments. The carrying value of financial assets and liabilities measured at amortized cost approximates fair value due to the short-term nature of the instruments.
The Company undertakes transactions denominated in US currency through its exploration in the US; consequently, it is exposed to exchange rate fluctuations. The Company will acquire US funds from time to time to settle US$ denominated liabilities. At December 31, 2025, the Company had US$26,789, (CAD$36,716) in a US denominated bank account (September 30, 2025 - US$5,358, (CAD$7,465)). The effect of a foreign currency increase or decrease of 10% on this cash holding would result in an increase or decrease of $3,672 (September 30, 2025 - $747).
| 15. | Financial risk management |
a) Credit risk
Credit risk is the risk of financial loss to the Company if counterparties to a financial instrument fail to meet their contractual obligations. The Company’s financial instruments that could be subject to credit risk consist of receivables. The Company has had a history of prompt receipt of their receivables and considers credit risk to be low on these instruments as at December 31, 2025, and 2024.
b) Liquidity risk
Liquidity risk is the risk that the Company will not be able to meet its financial obligations as they are due. The Company’s approach to managing liquidity risk is the utilization of budgets, to attempt to maintain sufficient liquidity in order to meet operational and exploration requirements, as well as property acquisition commitments. The Company raises capital through equity issues and its ability to do so is dependent on a number of factors including market acceptance, stock price and exploration results. The Company is continually investigating financing options. The Company feels that it has sufficient working capital to finance general and administrative, other operating expenses and current property activities for approximately the full year, assuming similar activity levels to the previous year. Additional financing will be required to fund new property acquisitions and future exploration programs. There can be no assurance that the Company will be successful in obtaining financing. These material uncertainties cast significant doubt on the Company’s ability to continue as a going concern. The consolidated financial statements do not include any adjustments which could be significant should the Company be unable to continue as a going concern.
14
CANEX Metals Inc.
MANAGEMENT'S DISCUSSION AND ANALYSIS
FOR THE THREE MONTHS ENDED DECEMBER 31, 2025
c) Market risk
The Company's equity investments are subject to market price risk. These investments were received as partial proceeds for the sale of mineral property interests. The Company does not invest excess cash in equity investments. The investments in common shares and warrants are recorded at fair value at the respective period ends with the resultant gains or losses recorded in earnings. The price or value of these investments can vary from period to period. During the year ended September 30, 2025, the Company sold all the remaining equity investments and no longer has any exposure to this risk.
The Company has not yet developed producing mineral interests; it is not exposed to commodity price risk associated with developed properties at this time.
| d) | Interest rate risk |
The Company has no debt facilities and has minimal amounts of interest income; it is not exposed to significant interest rate risk at this time.
| e) | Foreign exchange risk |
The Company undertakes transactions denominated in US currency; consequently, it is exposed to exchange rate fluctuations. The Company has disclosed US$ commitments pertaining to royalty rights in Section 7- Contractual Obligation. Refer to Section 14 - Financial Instruments for the foreign exchange risk associated with the foreign denominated cash balances held in US$ at December 31, 2025, and 2024.
| 16. | Subsequent Events |
On January 10, 2026, the Company issued 1,000,000 options that may be exercised at $0.225 per share to January 10, 2031. The options vest immediately and were valued at $206,200 using the Black-Scholes Options Pricing model assuming a 5-year term, volatility of 151.63%, a risk free discount rate of 2.92% and a dividend rate of 0%.
On January 30, 2026, the Company issued 41,154,418 common shares at $0.302 and on February 10, 2026, 337,776 common shares at $0.295 in exchange for Gold Basin Resources Corporation (Gold Basin) shares deposited under the CANEX offer and the Company now owns 51.87% of Gold Basin; a controlling interest. The number of CANEX common shares issued was determined by the offering agreement whereby Gold Basin shareholders received 0.592 CANEX shares for every Gold Basin share tendered to the arrangement. The transaction was valued at $12,528,278, based upon the closing price of the CANEX shares on the date of issue.
On March 16, 2026, Gold Basin held an annual general meeting of shareholders where CANEX nominated and elected a slate of highly qualified and experienced directors to the board of Gold Basin
CANEX intends to call a special meeting of Gold Basin Shareholders for the purpose of, among other things, seeking shareholder approval for a subsequent acquisition transaction, under similar terms and conditions, to complete the privatization of Gold Basin and acquire the remaining 48.13% of Gold Basin common shares.
On May 1, 2026, Gold Basin entered into a settlement agreement with Charrua Capital LLC whereby Gold Basin would pay $217,367.40 in full and final settlement of all obligations under a disputed loan agreement that was undertaken by the former officers of Gold Basin on August 21, 2024, for unsecured principle of $500,000 USD, bearing interest at 15% per annum.
On February 19, 2026, the Company made the third required option payment on the Louise Property of $50,000 by issuing 185,186 shares at a notional price of $0.27 per share. In March 2024, the Company entered into an option agreement to acquire the Louise Cu-Au Porphyry Project in British Columbia, Canada for total consideration of $775,000 in common shares of CANEX or cash. To date, $85,000 of the total commitment has been retired by issuing common shares of the Company under the terms of the option agreement.
15
CANEX Metals Inc.
MANAGEMENT'S DISCUSSION AND ANALYSIS
FOR THE THREE MONTHS ENDED DECEMBER 31, 2025
| 17. | Outlook |
The Company’s primary objective is to discover mineral resources in economic quantities capable of supporting an operating mine. Should the Company discover such a promising property, it would likely attempt to ally with a more senior mining company that might option-in on the property or purchase the property outright, as the Company does not have expertise in operating a mine.
Canex Metals successfully prevailed in its proxy contest for Gold Basin, securing shareholder support to advance its strategic vision for the district. Over the coming months and potentially several quarters, Canex intends to transition board leadership, align governance, and formally advance the combination of the two companies into a single, unified entity. The objective is to consolidate the neighboring assets, streamline development strategy, and unlock the combined value of the properties to establish a scalable Northern Arizona oxide gold camp.
At the Gold Range property, the WestGold target contains the largest and highest-grade gold in soil anomaly defined to date and the Company’s drill test of that target has resulted in a new and potentially very significant gold discovery that will be an important focus for the Company moving forward. Upon the conclusion of the Gold Basin acquisition, CANEX will look to announce detailed exploration, and if required, funding plans, to aggressively explore the consolidated Arizona district.
At the Louise Project, the Company has completed a modern deep looking induced polarization (IP) survey to explore the district across 6 to 7 kilometres of strike length and to depths up to 1000 metres to fully assess the district potential surrounding the known historic resource. Based on the results of this survey two new previously unknown high chargeability targets have been identified west and below the historic Louise Project deposit. The Company completed a surface exploration program consisting of mapping, prospecting, and surface sampling. The Company is now focusing on permitting to allow drill testing of the two new high priority chargeability targets. Once drill permits are received the Company will announce plans to fund and drill test both priority targets at Louise.
With respect to the Gibson Prospect, to date the Company has expended $293,500 on exploration activities. Due to limited resources, including manpower, the Company has focussed its attention on exploration activities on the Gold Range property and the Louise Project as discussed above. The Company continues to hold core claims which expire January 2029, keeping possibilities open for the Company to find a third-party partner to further the exploration program.
The Company continues to actively search for new early-stage exploration opportunities and avenues for growth in stable jurisdictions within North America. The Company has not entered into any business combination, acquisition, or similar agreements except as noted above.
| 18. | Risks |
The business and operations of the Company are subject to numerous risks, many of which are beyond the Company's control. The Company considers the risks set out below to be some of the most significant to potential investors in the Company, but not all of the risks associated with an investment in securities of the Company. If any of these risks materialize into actual events or circumstances or other possible additional risks and uncertainties of which the Company is currently unaware or which it considers to be material in relation to the Company's business actually occur, the Company's assets, liabilities, financial condition, results of operation (including future results of operations), business and business prospects, are likely to be materially and adversely affected. In such circumstances, the price of the Company's securities could decline and investors may lose all or part of their investment.
16
CANEX Metals Inc.
MANAGEMENT'S DISCUSSION AND ANALYSIS
FOR THE THREE MONTHS ENDED DECEMBER 31, 2025
The Company is a natural resource company engaged in the acquisition, exploration and development of mineral properties. Given the nature of the mining business, the limited extent of the Company's assets and the present stage of exploration, the following risk factors, among others, should be considered:
| · | Exploration, development, and operating risks |
The Company is in the process of exploring its properties and has not yet determined whether its properties contain economically recoverable reserves and, therefore, does not generate any revenues from production. The recovery of expenditures on mineral properties and the related deferred exploration expenditures are dependent on the existence of economically recoverable mineralization, the ability of the Company to obtain financing necessary to complete the exploration and development of its properties, and upon future profitable production, or alternatively, on the sufficiency of proceeds from disposition. Mineral exploration is highly speculative in nature, involves many risks and frequently is non-productive. There is no assurance that exploration efforts will be successful.
| · | Substantial capital requirements and liquidity |
Substantial additional funds for the establishment of the Company's current and planned mining operations will be required. No assurances can be given that the Company will be able to raise the additional funding that may be required for such activities, should such funding not be fully generated from operations. Mineral prices, environmental rehabilitation or restitution, revenues, taxes, transportation costs, capital expenditures and operating expenses and geological results are all factors which will have an impact on the amount of additional capital that may be required. To meet such funding requirements, the Company may be required to undertake additional equity financing, which would be dilutive to shareholders. Debt financing, if available, may also involve restrictions on financing and operating activities. There is no assurance that additional financing will be available on terms acceptable to the Company or at all. If the Company is unable to obtain additional financing as needed, it may be required to reduce the scope of its operation and pursue only those projects that can be funded through cash flows generated from its existing operations, if any.
| · | Fluctuating mineral prices |
The economics of mineral exploration are affected by many factors beyond the Company's control, including commodity prices, the cost of operations, variations in the grade of minerals explored and fluctuations in the market price of minerals. Depending on the price of minerals, the Company may determine that it is impractical to continue a mineral exploration operation. Mineral prices are prone to fluctuations and the marketability of minerals is affected by government regulation relating to price, royalties, allowable production and the importing and exporting of minerals, the effect of which cannot be accurately predicted. There is no assurance that a profitable market will exist for the sale of any minerals found on the Company's properties.
| · | Regulatory, permit and license requirements |
The current or future operations of the Company require permits from various governmental authorities, and such operations are and will be governed by laws and regulations concerning exploration, development, production, taxes, labour standards, occupational health, waste disposal, toxic substances, land use, environmental protection, site safety and other matters. Companies engaged in the exploration and development of mineral properties generally experience increased costs and delays in development and other schedules as a result of the need to comply with applicable laws, regulations and permits. There can be no assurance that all permits which the Company may require for facilities and the conduct of exploration and development operations on the Properties will be obtainable on reasonable terms, or that such laws and regulation will not have an adverse effect on any exploration or development project which the Company might undertake.
Failure to comply with applicable laws, regulations and permitting requirements may result in enforcement actions, including orders issued by regulatory or judicial authorities causing operations to cease or be curtailed and may include corrective measures requiring capital expenditures, installation of additional equipment or remedial actions. Parties engaged in exploration and development operations may be required to compensate those suffering loss or damage by reason of the exploration and development activities and may have civil or criminal fines or penalties imposed upon them for violation of applicable laws or regulations. Amendments to current laws, regulations and permits governing operations and activities of mineral companies, or more stringent implementation thereof, could have a material adverse impact on the Company and cause increases in capital expenditures or exploration and development costs, or require abandonment or delays in the development of new or existing properties.
17
CANEX Metals Inc.
MANAGEMENT'S DISCUSSION AND ANALYSIS
FOR THE THREE MONTHS ENDED DECEMBER 31, 2025
| · | Financing risks and dilution to shareholders |
The Company has limited financial resources, no operations, and no revenues. If the Company's exploration program on its properties is successful, additional funds will be required for the purposes of further exploration and development. There can be no assurance that the Company will be able to obtain adequate financing in the future or that such financing will be available on favorable terms or at all. It is likely such additional capital will be raised through the issuance of additional equity which will result in dilution to the Company's shareholders.
| · | Title to properties |
Acquisition of title to mineral properties is a very detailed and time-consuming process. Title to, and the area of, mineral properties may be disputed. The Company cannot give an assurance that title to its properties will not be challenged or impugned. Mineral properties sometimes contain claims or transfer histories that examiners cannot verify. A successful claim that the Optionors or the Company, as the case may be does not have title to its properties could cause the Company to lose any rights to explore, develop and mine any minerals on its properties without compensation for its prior expenditures relating to its properties.
| · | Competition |
The mineral exploration and development industry is highly competitive. The Company will have to compete with other mining companies, many of which have greater financial, technical and other resources than the Company, for, among other things, the acquisition of mineral claims, leases and other mineral interest as well as for the recruitment and retention of qualified employees and other personnel. Failure to compete successfully against other mining companies could have a material adverse effect on the Company and its prospects.
| · | Reliance on management and dependence on key personnel |
The success of the Company will be largely dependent upon the performance of its directors and officers and the ability to attract and retain key personnel. The loss of the services of these persons may have a material adverse effect on the Company's business and prospects. The Company will compete with numerous other companies for the recruitment and retention of qualified employees and contractors. There is no assurance that the Company can maintain the service of its directors and officers or other qualified personnel required to operate its business. Failure to do so could have a material adverse effect on the Company and its prospects.
| · | Environmental risks |
The Company's exploration and appraisal programs will, in general, be subject to approval by regulatory bodies. Additionally, all phases of the mining business present environmental risks and hazards and are subject to environmental regulation pursuant to a variety of international conventions and provincial and municipal laws and regulations. Environmental legislation provides for, among other things, restrictions and prohibitions on spills, releases or emissions of various substances produced in association with mining operations. The legislation also requires that wells and facility sites be operated, maintained, abandoned and reclaimed to the satisfaction of applicable regulatory authorities. Compliance with such legislation can require significant expenditures and a breach may result in the imposition of fines and penalties, some of which may be material. Environmental legislation is evolving in a manner expected to result in stricter standards and enforcement, larger fines and liability and potentially increase capital expenditures and operating costs.
18
CANEX Metals Inc.
MANAGEMENT'S DISCUSSION AND ANALYSIS
FOR THE THREE MONTHS ENDED DECEMBER 31, 2025
| · | Conflicts of interest |
Certain of the Directors and Officers of the Company are engaged in, and will continue to engage in, other business activities on their own behalf and on behalf of other companies and, as a result of these and other activities, such Directors and Officers of the Company may become subject to conflicts of interest. Canadian corporate laws provide that in the event that a Director has an interest in a contract or proposed contract or agreement, the director shall disclose his interest in such contact or agreement and shall refrain from voting on any matter in respect of such contract or agreement unless otherwise provided under those laws. To the extent that conflicts of interest arise, such conflicts will be resolved in accordance with the provisions of the applicable Canadian corporate laws.
| · | Uninsurable risks |
Exploration, development, and production operations on mineral properties involve numerous risks, including unexpected or unusual geological operating conditions, rock bursts, cave-ins, fires, floods, earthquakes and other environmental occurrences, any of which could result in damage to, or destruction of mines and other producing facilities, damage to life or property, environmental damage and possible legal liability. Although precautions to minimize risk will be taken, operations are subject to hazards that may result in environmental pollution and consequent liability that could have a material adverse impact on the business, operations and financial performance of the Company. It is not always possible to obtain insurance against all such risks and the Company may decide not to insure against certain risks as a result of high premiums or other reasons. Should such liabilities arise, they could have an adverse impact on the Company's results of operations and financial condition and could cause a decline in the value of the Company's shares.
| · | Litigation |
The Company and/or its directors may be subject to a variety of civil or other legal proceedings, with or without merit.
18. Critical Accounting Estimates
The most significant accounting estimate for the Company relates to the carrying value of its exploration and evaluation assets. Exploration and evaluation assets consist of the capitalized costs of exploration and mining concessions. Acquisition and leasehold costs and exploration costs are capitalized and deferred until such time as the property is put into production or the properties are disposed of either through sale or abandonment. The estimated values of exploration and evaluation assets are evaluated by management on a regular basis to determine whether facts and circumstances suggest that the carrying amount of the asset may exceed its recoverable amount. Reference is made to project economics, including the timing of the exploration and/or development work, the work programs and exploration results experienced by the Company and others, financing, the extent to which optionees have committed, or are expected to commit to, exploration on the property and the imminent expiry of the right to explore, among other factors. When it becomes apparent that the carrying value of a specific property will not be realized, an impairment provision is made for the estimated decline in value.
The Company’s estimate for decommissioning obligations is based on existing laws, contracts and other policies. The value of the obligation is based on estimated future costs for abandonments and reclamations which require certain assumptions to be made. By their nature, these estimates are subject to measurement uncertainty.
Another significant accounting estimate relates to valuing stock-based compensation. The Company uses the Black-Scholes Option Pricing Model. Option pricing models require the input of highly subjective assumptions including the expected price volatility. Changes in the subjective input assumptions can materially affect the fair value estimate, and therefore the existing models do not necessarily provide a reliable single measure of the fair value of the Company’s stock options granted and vested during the year.
The Company estimates the fair value of its short-term equity investments at the end of each period as they are carried at fair value in the Balance Sheet. The Company uses the closing price of the common shares on the period-end date. The price at which these instruments can ultimately be sold will vary from these estimates due to the timing of their sale, the volume of trading in the securities at any given time and changes in the market over time, among other factors.
19
CANEX Metals Inc.
MANAGEMENT'S DISCUSSION AND ANALYSIS
FOR THE THREE MONTHS ENDED DECEMBER 31, 2025
19. New Accounting Policies
The Company did not adopt any new accounting policies during the three months ended December 31, 2025.
Future standards not yet adopted include the Presentation and Disclosure in Financial Statements (IFRS 18). IFRS 18 will replace IAS 1, Presentation of Financial Statements which aims to improve how companies communicate in their financial statements, with a focus on information about financial performance in the statement of profit or loss, in particular additional defined subtotals, disclosures about management-defined performance measures and new principles for aggregation and disaggregation of information. IFRS 18 is accompanied by limited amendments to the requirements in IAS 7 Statement of Cash Flows. IFRS 18 is effective from January 1, 2027. Companies are permitted to adopt IFRS 18 before that date. The Company is not yet able to determine the impact to the consolidated financial statements from the adoption of this standard.
Certain pronouncements were issued by the IASB but are not yet effective at December 31, 2025. The Company intends to adopt these standards when they become effective but does not expect these amendments to have a material effect on its consolidated financial statements.
20. Other
Additional information relating to the Company may be found on SEDAR+ at www.sedarplus.ca
20
Appendix O
Pro Forma Consolidated Financial Statements
[See attached]
UNAUDITED PRO FORMA CONDENSED CONSOLIDATED FINANCIAL STATEMENTS OF
CANEX METALS INC.
(in Canadian Dollars)
Reflecting the Arrangement with:
Gold Basin Resources Corporation
CANEX METALS INC.
PRO FORMA CONDENSED CONSOLIDATED STATEMENT OF FINANCIAL POSITION
December 31, 2025
(Unaudited)
| CANEX Metals Inc. | Gold Basin Resources Corporation | Note | Pro forma adjustments | Pro forma CANEX Metals Inc. | ||||||||||||||
| $ | $ | $ | $ | |||||||||||||||
| ASSETS | ||||||||||||||||||
| Current assets | ||||||||||||||||||
| Cash | 3,161,674 | 11,653 | 4(ii) | (11,653 | ) | 3,161,674 | ||||||||||||
| Accounts receivable | 40,104 | 135,611 | 4(ii) | (49,625 | ) | 126,090 | ||||||||||||
| Prepaid expenses and deposits | 68,524 | - | - | 68,524 | ||||||||||||||
| Due from related parties | - | 101,251 | 4(ii) | (101,251 | ) | - | ||||||||||||
| 3.270,302 | 248,515 | (162,529 | ) | 3,356,288 | ||||||||||||||
| Non-current assets | ||||||||||||||||||
| Exploration and evaluation asset advances and deposits | 797,060 | - | 4(iii) | (744,896 | ) | 52,164 | ||||||||||||
| Exploration and evaluation assets | 6,289,688 | 20,509,029 | 4(vi) | 7,110,509 | 33,909,226 | |||||||||||||
| 7,086,748 | 20,509,029 | 6,365,613 | 33,961,390 | |||||||||||||||
| TOTAL ASSETS | 10,357,050 | 20,757,544 | 6,203,084 | 37,317,678 | ||||||||||||||
| EQUITY AND LIABILITIES | ||||||||||||||||||
| Current liabilities | ||||||||||||||||||
| Accounts payable and accrued liabilities | 255,895 | 1,463,734 | 4(iv) | 1,236,100 | 2,955,729 | |||||||||||||
| Loan payable | - | 302,269 | - | 302,269 | ||||||||||||||
| Non-current liabilities | ||||||||||||||||||
| Decommissioning obligation | 52,545 | - | - | 52,545 | ||||||||||||||
| TOTAL LIABILITIES | 308,440 | 1,766,003 | 1,236,100 | 3,310,543 | ||||||||||||||
| EQUITY | ||||||||||||||||||
| Share Capital | 26,121,922 | 26,978,176 | 4(v) | (26,978,176 | ) | |||||||||||||
| 3 | 12,528,278 | |||||||||||||||||
| 3 | 11,626,326 | 50,276,526 | ||||||||||||||||
| Reserves | 2,503,770 | 3,813,572 | 4(v) | (3,813,572 | ) | 2,503,770 | ||||||||||||
| Accumulated other comprehensive income | - | 91,033 | 4(v) | (91,033 | ) | - | ||||||||||||
| Deficit | (18,577,082 | ) | (11,891,240 | ) | 4(v) | 11,695,161 | (18,773,161 | ) | ||||||||||
| TOTAL EQUITY | 10,048,610 | 18,991,541 | 4,966,984 | 34,007,135 | ||||||||||||||
| TOTAL EQUITY AND LIABILITIES | 10,357,050 | 20,757,544 | 6,203,084 | 37,317,678 | ||||||||||||||
The accompanying notes are an integral part of these pro forma condensed consolidated financial statements.
CANEX METALS INC.
PRO FORMA CONDENSED CONSOLIDATED STATEMENT OF COMPREHENSIVE LOSS
FOR THREE MONTH PERIOD ENDED DECEMBER 31, 2025
(Unaudited)
| CANEX Metals Inc. | Gold Basin Resources Corporation | Note | Pro forma adjustments | Pro forma CANEX Metals Inc. | ||||||||||||||
| $ | $ | $ | $ | |||||||||||||||
| Expenses | ||||||||||||||||||
| General and administration | 215,862 | 29,355 | - | 245,217 | ||||||||||||||
| Reporting to shareholders | 12,728 | - | - | 12,728 | ||||||||||||||
| Professional fees | 4,841 | - | - | 4,841 | ||||||||||||||
| Stock exchange and transfer agent fees | 4,824 | - | - | 4,824 | ||||||||||||||
| Accretion | 214 | - | - | 214 | ||||||||||||||
| Impairment | - | - | 4(ii) | 162,529 | 162,529 | |||||||||||||
| Operating loss | 238,469 | 29,355 | 162,529 | 430,353 | ||||||||||||||
| Interest and other | (10,223 | ) | 3,554 | - | (6,669 | ) | ||||||||||||
| oreign exchange | 2,599 | 641 | - | 3,240 | ||||||||||||||
| Net loss and comprehensive loss for the period | 230,845 | 33,550 | 162,529 | 426,924 | ||||||||||||||
| Basic and diluted loss per share | (0.00 | ) | (0.00 | ) | (0.00 | ) | (0.00 | ) | ||||||||||
| Weighted average shares outstanding – basic and diluted | 148,689,612 | 135,130,486 | 5 | (55,133,258) | 228,686,840 | |||||||||||||
The accompanying notes are an integral part of these pro forma condensed consolidated financial statements.
CANEX METALS INC.
NOTES TO THE PRO FORMA CONDENSED CONSOLIDATED INTERIM FINANCIAL STATEMENTS
THREE MONTHS ENDED DECEMBER 31, 2025
(Unaudited)
| 1. | BASIS OF PRESENTATION |
The unaudited pro forma condensed consolidated statement of financial position of CANEX Metals Inc. (“CANEX”) at December 31, 2025 (the “Pro Forma Consolidated Financial Statements”) have been prepared by management of CANEX for illustrative purposes only, based on financial statements prepared in accordance with IFRS. The unaudited pro forma condensed consolidated statement of financial position at December 31, 2025, shows the effect of the Arrangement (as defined and described in Note 3), whereby each share of Gold Basin Resources Corporation (“Gold Basin”) would be exchanged for 0.592 of a CANEX share as if the Arrangement had occurred on December 31, 2025. The unaudited pro forma condensed consolidated statement of comprehensive loss shows the effect of the Arrangement as if it had occurred on October 1, 2025.
These Pro Forma Consolidated Financial Statements should be read in conjunction with the historical audited financial statements and notes thereto of CANEX as at and for the year ended September 30, 2025 and the unaudited condensed interim financial statements of CANEX as at and for the three-month period ended December 31, 2025, and with the unaudited consolidated financial statements and notes thereto of Gold Basin as at and for the year ended December 31, 2025 and 2024as derived from its internal records. Gold Basin has not prepared interim financial statements for the three months ended December 31, 2025. Accordingly, the expenses included in the pro forma condensed consolidated interim statement of comprehensive loss for that period are based on management-prepared financial information and estimates that have not been audited or reviewed. Such amounts may differ from those that would have been determined had interim financial statements been prepared for Gold Basin in accordance with IFRS."
It is management’s opinion that these Pro Forma Consolidated Financial Statements include all adjustments necessary for fair presentation, in all material respects, of the Arrangement described in Note 3, in accordance with IFRS. The Pro Forma Consolidated Financial Statements are not intended to be indicative of the results or financial condition that would have been achieved if the transaction had been completed on the dates or for the periods presented, nor do they purport to project the results of operations or the financial position of the consolidated entity for any future period or as of any future date. The Pro Forma Consolidated Financial Statements do not reflect any special items such as integration costs or operating synergies that may be incurred as a result of the Arrangement. The Pro Forma Consolidated Financial Statements and the pro forma adjustments and allocation of the purchase price are based upon currently available information. Actual adjustments may differ from the pro forma adjustments and these differences could be material. The final purchase price allocation will be completed as of the date of the completion of the Arrangement. Accordingly, the final allocation will impact the actual consolidated financial statements of CANEX, but such impact, which could be material, cannot be estimated in preparing these Pro Forma Consolidated Financial Statements. Gold Basin will become the wholly owned subsidiary of CANEX Metals Inc. Upon completion of the Arrangement Gold Basin’s shareholders will hold approximately 32.4% of the shares of CANEX on an outstanding common shares basis.
| 2. | SIGNIFICANT ACCOUNTING POLICES |
The accounting policies used in preparing the Pro Forma Consolidated Financial Statements are in accordance with International Financial Reporting Standards (IFRS) and are set out in Note 4 of CANEX’s audited financial statements for the year ended September 30, 2025. Management believes that the accounting policies of CANEX and Gold Basin are consistent in all material respects.
| 3. | ACQUISITION OF GOLD BASIN RESOURCES CORPORATION |
On February 10, 2026, CANEX announced that a total of 70,088,199 common shares of Gold Basin representing 51.87% of the issued and outstanding common shares have been validly deposited under CANEX’s offer to purchase all of the Gold Basin . CANEX issued 41,492,194 common shares to the shareholders of Gold Basin who validly deposited their common shares to the Bid.
On March 16, 2026, Gold Basin held an AGM, Shane Ebert, Mark Ernst, Jim Paterson, John Robins, and Jordan Ross have been elected to the board of directors of Gold Basin, constituting a new board of directors and replacing the previous board. Shareholders of Gold Basin also approved fixing the number of directors at five, and the appointment of Manning Elliott LLP as auditors of Gold Basin. The directors of Gold Basin have appointed Shane Ebert as President and Chief Executive Officer, Jean-Pierre Jutras as Vice President, Chantelle Collins as Chief Financial Officer, and Barbara O’Neill as Corporate Secretary of Gold Basin. Jim Paterson, John Robins, and Mark Ernst have been named to the audit committee of the board of directors of Gold Basin. Jordan Ross has been appointed lead independent director.
CANEX METALS INC.
NOTES TO THE PRO FORMA CONDENSED CONSOLIDATED INTERIM FINANCIAL STATEMENTS
THREE MONTHS ENDED DECEMBER 31, 2025
(Unaudited)
| 3. | ACQUISITION OF GOLD BASIN RESOURCES CORPORATION (continued) |
Accounting for the Arrangement
As per the Arrangement, Gold Basin will become a wholly owned subsidiary of CANEX. Using the equity method CANEX will record the purchase consideration as an Investment in the subsidiary, with all intercompany accounts and transactions eliminated upon consolidation. Upon consolidation, until such time as CANEX is able to acquire 100% of Gold Basin shares, Non-controlling interest will be recorded as a component of equity to represent the portion of Gold Basin that is still owned by the legacy shareholders. The estimated total purchase price for the Arrangement is $26,135,600. The value of CANEX shares used to calculate the estimated total purchase price is based on the weighted average TSXV closing prices on the dates the shares tendered under the original offering document were taken up and paid for by issuing CANEX common shares. On January 30, 2026 CANEX issued 41,154,418 common shares and on February 10, 2026 issued a further 337,776 valued at the weighted average closing price on the date of issue of $0.302 per CANEX share and representing 51.87% of the issued and outstanding shares of Gold Basin. The remaining 48.13% of Gold Basin shares were valued applying this same weighted average price. The actual valuation date of the CANEX share for the purpose of calculating the final 48.13% of purchase consideration will be on the applicable dates when the Gold Basin shares are exchanged for CANEX common shares.
The final purchase price and final values of the assets and liabilities will be determined as of the date that 100% of the shares are acquired and may differ from the amounts disclosed below in the assumed pro forma purchase price allocation because of changes in book values of the assets and liabilities to the date of transaction. The transaction is expected to be accounted for as an asset acquisition under IFRS. The final allocation of the purchase price will likely result in different adjustments than those presented in these Pro Forma Consolidated Financial Statements. The preliminary purchase price allocation is subject to change and is summarized as follows:
| Fair value of 41,492,194 CANEX common shares issued for Gold Basin shares | $ | 12,528,278 | ||
| Proforma value of 38,505,034 CANEX common shares to be issued for Gold Basin shares | 11,626,326 | |||
| Acquisition costs incurred | 1,980,996 | |||
| Purchase consideration | $ | 26,135,600 |
| 4. | EFFECT OF TRANSACTION ON PRO FORMA CONSOLIDATED FINANCIAL STATEMENTS |
The Pro Forma Consolidated Financial Statements incorporate the following unaudited pro forma adjustments and assumptions:
| (i) | The elimination of inter-company balances and transactions. |
| (ii) | This pro forma adjustment results from an inability to confirm bank balances and determine the collectability of receivables from parties related to Gold Basin. Due to the adversarial nature of the transaction, CANEX is not certain that these amounts will ever be recovered and will write them off as an expense of the period once the transaction is completed. |
| (iii) | This pro forma adjustment reflects the reclassification of acquisition costs of $744,896 previously deferred until CANEX obtained a controlling interest in Gold Basin. Once CANEX acquired 51.87% of Gold Basin equity these costs were reclassified as a component of the purchase price. |
| (iv) | This pro forma adjustment relates to the accrual for future acquisition costs that are expected to be incurred to acquire the remaining 48.13% of Gold Basin shares. The estimated costs to complete the Arrangement (including estimated legal, financial advisory, accounting, meeting related and regulatory fees) are $1,236,100. The offset to the payable accrued is as a component of the purchase price. |
| (v) | Consolidation entry. Gold Basin’s equity balances are being eliminated and adjusted to the consolidated deficit |
CANEX METALS INC.
NOTES TO THE PRO FORMA CONDENSED CONSOLIDATED INTERIM FINANCIAL STATEMENTS
THREE MONTHS ENDED DECEMBER 31, 2025
(Unaudited)
| 4. | EFFECT OF TRANSACTION ON PRO FORMA CONSOLIDATED FINANCIAL STATEMENTS (continued) |
| (vi) | Provisional allocation of excess consideration to exploration and evaluation costs, reconciled as follows: |
| Aggregate fair value of consideration issued | $ | 26,135,600 | ||
| Less: net book value of Gold Basin identifiable assets acquired* | 1,483,938 | |||
| Allocation of excess to exploration and evaluation assets | $ | 27,619,538 | ||
| Less: Gold Basin exploration and evaluation assets, at cost | (20,509,029 | ) | ||
| Fair value allocated to exploration and evaluation assets | $ | 7,110,509 | ||
| Costs applicable to exploration and evaluation assets | ||||
| CANEX | 6,289,688 | |||
| Gold Basin | 20,509,029 | |||
| Exploration and evaluation assets, pro forma | $ | 33,909,226 |
*Exclusive of exploration and evaluation assets.
| 5. | CANEX SHARES OUTSTANDING AND LOSS PER SHARE |
The pro forma total number of shares outstanding at December 31, 2025, is as follows:,
| Number of outstanding shares of CANEX at December 31, 2025, | 148,689,612 | |||
| Issued to acquire 51.87% of Gold Basin shares subsequent to December 31, 2025, | 41,492,192 | |||
| Proforma to acquire remaining 48.13% of Gold Basin subsequent to December 31, 2025, | 38,505,034 | |||
| Pro forma number of outstanding shares of CANEX at December 31, 2025, | 228,686,840 |
The average number of common shares used in the computation of pro forma basic and diluted loss per share has been determined as:
| Three-months ended December 31, 2025 | ||||
| Basic and diluted | ||||
| Weighted average number of shares of CANEX outstanding for the period | 148,689,612 | |||
| Issued to acquire 51.87% Gold Basin | 41,492,194 | |||
| To be issued to acquire remaining 48.13% of Gold Basin | 38,505,034 | |||
| Pro forma weighted average number of shares of CANEX | 228,686,840 | |||
The diluted pro forma weighted average number of shares is the same as the basic pro forma weighted average number of shares due to the anti-dilutive effect of the outstanding stock options.
QUESTIONS MAY BE DIRECTED TO THE PROXY SOLICITATION AGENT
LAUREL HILL ADVISORY GROUP
North America Toll Free: 1-877-452-7184
Outside North America: 416-304-0211
Text Message: Text “INFO” to 416-304-0211 or 1-877-452-7184
Email: assistance@laurelhill.com